
SYF 8-K
Synchrony Financial (SYF)
8-K
2022-01-28
For: 2022-01-28
View Original
Added on
July 04, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d)
OF THE SECURITIES EXCHANGE ACT OF 1934
Date of Report
(Date of earliest event reported)
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) | ||||||||||||
| (Address of principal executive offices) | (Zip Code) | ||||||||||
(203 ) 585-2400
(Registrant’s telephone number, including area code)
N/A
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities Registered Pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
| Emerging growth company | |||||||||||
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
Item 2.02 Results of Operations and Financial Condition.
On January 28, 2022 , Synchrony Financial (the “Company”) issued a press release setting forth the Company’s fourth quarter 2021 earnings. A copy of the Company’s press release is being furnished as Exhibit 99.1 and hereby incorporated by reference. The information furnished pursuant to this Item 2.02, including Exhibits, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934 (the “Exchange Act”) or otherwise subject to the liabilities under that Section and shall not be deemed to be incorporated by reference into any filing of the Company under the Securities Act of 1933 or the Exchange Act.
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits
The following exhibits are being furnished as part of this report:
| Number | Description | |||||||
| 99.1 | Press release, dated January 28, 2022, issued by Synchrony Financial | |||||||
| 99.2 | Financial Data Supplement of the Company for the quarter ended December 31, 2021 | |||||||
| 99.3 | Financial Results Presentation of the Company for the quarter ended December 31, 2021 | |||||||
| 99.4 | Explanation of Non-GAAP Measures | |||||||
| 104 | The cover page from this Current Report on Form 8-K, formatted in Inline XBRL | |||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
SYNCHRONY FINANCIAL | ||||||||||||||||||||
| Date: January 28, 2022 | By: | /s/ Jonathan Mothner | ||||||||||||||||||
Name: | Jonathan Mothner | |||||||||||||||||||
Title: | Executive Vice President, General Counsel and Secretary | |||||||||||||||||||
EXHIBIT INDEX
| Number | Description | |||||||
| 104 | The cover page from this Current Report on Form 8-K, formatted in Inline XBRL | |||||||
Exhibit 99.1
For Immediate Release Synchrony Financial (NYSE: SYF) January 28, 2022 |  | |||||||
FOURTH QUARTER 2021 RESULTS AND KEY METRICS
3.4% Return on Assets | 15.6% CET1 Ratio | $1.1B Capital Returned | CEO COMMENTARY | |||||||||||||||||||||||||||||
“Synchrony’s strong fourth quarter performance reflected broad-based growth across our business as the compelling value of our products resonated with the heightened demand from a strong consumer,” said Brian Doubles, Synchrony’s President and Chief Executive Officer. “We closed the year with strong new account originations, and record purchase volume and net earnings – a testament to our high level of execution across our key strategic priorities. During the year, we grew our existing partner programs and added new partners. We also continued to diversify our products and expand our distribution channels. Synchrony also continued to prioritize innovation through further investment in our digital products and capabilities – all with a focus on delivering best-in-class omnichannel experiences for our partners and customers. “As we continue to execute on these and the many opportunities ahead, we are well-positioned to reach and serve even more partners and customers and, in so doing, drive sustainable growth, attractive returns and considerable capital for our stakeholders over the long-term.” | ||||||||||||||||||||||||||||||||
$85.1B Loans includes Loan Receivables of $80.7B and loans HFS of $4.4B | ||||||||||||||||||||||||||||||||
 | Net Earnings of $813 Million or $1.48 Per Diluted Share, including a post-tax benefit of $0.14 per diluted share due to reserve reductions related to held for sale portfolios | |||||||||||||||||||||||||||||||
 | Record Purchase Volume | |||||||||||||||||||||||||||||||
 | Broad-based loan growth across all sales platforms | |||||||||||||||||||||||||||||||
STAMFORD, Conn. – Synchrony Financial (NYSE: SYF) today announced fourth quarter 2021 net earnings of $813 million, or $1.48 per diluted share, compared to $738 million, or $1.24 per diluted share in the fourth quarter 2020. Fourth quarter 2021 net earnings included a $74 million post-tax benefit, or $0.14 per diluted share, due to reserve reductions related to held for sale portfolios. | ||||||||||||||||||||||||||||||||
| KEY OPERATING & FINANCIAL METRICS* | ||||||||||||||||||||||||||||||||
| PURCHASE VOLUME AND CREDIT TRENDS REFLECT CONSUMER STRENGTH, DRIVING CONTINUED STRONG PERFORMANCE | ||||||||||||||||||||||||||||||||
•Purchase volume increased 18% to $47.1 billion •Loans of $85.1 billion, including $80.7 billion of loan receivables and $4.4 billion of loan receivables held for sale, increased 4% •Average active accounts increased 5% to 69.4 million •New accounts increased 20% to 7.3 million •Net interest margin increased 113 basis points to 15.77% •Efficiency ratio increased 4.0 percentage points to 41.1% •Return on assets increased 0.3 percentage points to 3.4% •Return on equity decreased 0.6 percentage points to 23.0% | ||||||||||||||||||||||||||||||||
| CFO COMMENTARY | BUSINESS AND FINANCIAL RESULTS FOR THE FOURTH QUARTER OF 2021* | |||||||||||||||||||||||||
“Our fourth quarter financial results reflect the core strengths of our differentiated business model: our diversified partner portfolio; our scalable technology platform, which enables efficient and swift partner integrations and seamless omnichannel capabilities; our deep industry expertise and advanced analytics, and our digitally-enabled product suite, the combination of which powers compelling value and best-in-class experiences for our customers and partners,” said Brian Wenzel, Synchrony’s Executive Vice President and Chief Financial Officer. “By leveraging these core strengths, Synchrony delivered a third consecutive quarter of double-digit purchase volume growth across four of our five platforms, as well as record purchase volume for the business. We did so while maintaining market-leading risk-adjusted returns and cost discipline and, in turn, produced record return on assets for the full year. “Synchrony is emerging from the pandemic with strong momentum, as the operating environment continues to normalize and we further advance our core differentiators, we remain confident in our ability to achieve the long-term operating metrics we laid out at Investor Day to drive considerable value for all our stakeholders.” | ||||||||||||||||||||||||||
| BUSINESS HIGHLIGHTS | ||||||||||||||||||||||||||
| CONTINUED TO RENEW KEY PARTNERSHIPS AND EXPAND NETWORK AND INNOVATIVE CAPABILITIES | ||||||||||||||||||||||||||
•Renewed seven programs including American Signature Furniture, City Furniture, and Husqvarna •Broadened CareCredit network and card utility via a new partnership with Thrive Pet Healthcare •Invested in Skipify to expand innovative product offerings through additional distribution channels | ||||||||||||||||||||||||||
| FINANCIAL HIGHLIGHTS | ||||||||||||||||||||||||||
| EARNINGS GROWTH DRIVEN BY BROAD BASED STRENGTH ACROSS THE BUSINESS | ||||||||||||||||||||||||||
•Interest and fees on loans increased 2% to $4 billion, mainly due to growth in average loan receivables, partially offset by lower yield. •Net interest income increased $171 million, or 5%, to $3.8 billion. •Retailer share arrangements increased $220 million, or 21%, to $1.3 billion, mainly driven by lower provision for credit losses and continued strong program performance. •Provision for credit losses decreased $189 million, or 25%, to $561 million, driven by lower net charge-offs and lower reserve charge including amounts attributable to held for sale portfolios. •Other income increased $85 million, or 104%, to $167 million, primarily driven by gain in a venture investment. •Other expense increased $122 million, or 12%, to $1.1 billion, primarily driven by asset impairments, certain incremental marketing investments, and higher employee costs. •Net earnings increased to $813 million, including a $74 million post-tax benefit, or $0.14 per diluted share, due to reserve reductions related to the held for sale portfolios. | ||||||||||||||||||||||||||
| CREDIT QUALITY | ||||||||||||||||||||||||||
| CREDIT PERFORMANCE CONTINUED TO BE DRIVEN BY A STRONG CONSUMER | ||||||||||||||||||||||||||
•Loans 30+ days past due as a percentage of total period-end loan receivables were 2.62% compared to 3.07% last year, reflecting a decline of 45 basis points. Excluding the impact of the held for sale portfolios from both periods, the year over year decline was approximately 60 basis points. •Net charge-offs as a percentage of total average loan receivables were 2.37% compared to 3.16% last year. •The allowance for credit losses as a percentage of total period-end loan receivables was 10.76%. | ||||||||||||||||||||||||||
| SALES PLATFORM HIGHLIGHTS | |||||||||||||||||||||||
| DIVERSITY ACROSS OUR PLATFORMS CONTINUES TO PROVIDE RESILIENCE | |||||||||||||||||||||||
•Home & Auto** purchase volume increased 13%, reflecting continued strength. Period-end loan receivables increased 3% and interest and fees on loans were flat compared to the prior year. Average active accounts increased 1%. •Digital purchase volume increased 22% and period-end loan receivables increased 6%, reflecting strength in digital-based partners due to the shift in consumer behavior. Interest and fees on loans increased 5%, driven primarily by loan receivables growth, while average active accounts increased 9%. •Diversified & Value purchase volume increased 26%. Period-end loan receivables increased 2% reflecting above average seasonal purchase volume, partially offset by higher payment rates. Interest and fees on loans decreased 1%, driven primarily by lower yields, and average active accounts increased 9%. •Health & Wellness purchase volume increased 14% and period-end loan receivables increased 7%, reflecting broad based growth across all markets. Interest and fees on loans increased 2%, driven primarily by loan receivables growth, and average active accounts increased 3%. •Lifestyle purchase volume increased 6% reflecting broad-based growth across the platform, but impacted by the comparison to last year’s strong power sports growth. Period-end loan receivables increased 7%, reflecting continued strength in power sports and music. Interest and fees on loans increased 4%, driven primarily by loan receivables growth, and average active accounts were relatively flat. | |||||||||||||||||||||||
| BALANCE SHEET, LIQUIDITY & CAPITAL | |||||||||||||||||||||||
| FUNDING, CAPITAL & LIQUIDITY REMAIN ROBUST | |||||||||||||||||||||||
•Loans of $85.1 billion, including $80.7 billion of loan receivables and $4.4 billion of loan receivables held for sale, increased 4%; purchase volume increased 18% and average active accounts increased 5%. •Loan receivables held for sale includes the current quarter reclassification of $0.5 billion of loan receivables associated with the BP portfolio. •Deposits decreased $0.5 billion, or 1%, to $62.3 billion and comprised 81% of funding. •Total liquidity (liquid assets and undrawn credit facilities) of $15.7 billion, or 16.4% of total assets. •Total capital returned of $1.1 billion, reflecting $982 million of share repurchases and $120 million of common stock dividends. •As of December 31, 2021, the Company had $1.2 billion remaining of its share repurchase authorization. •The Company has elected to defer the regulatory capital effects of CECL for two years; the estimated Common Equity Tier 1 ratio was 15.6% compared to 15.9%, and the estimated Tier 1 Capital ratio was 16.5% compared to 16.8%, reflecting our strong capital generation capabilities. | |||||||||||||||||||||||
*All comparisons are for the fourth quarter of 2021 compared to the fourth quarter of 2020, unless otherwise noted. | |||||||||||||||||||||||
** All metrics discussed above for the Home & Auto sales platform exclude amounts related to the BP portfolio. See the detailed financial tables for additional information. | |||||||||||||||||||||||
| CORRESPONDING FINANCIAL TABLES AND INFORMATION | |||||||||||||||||||||||
No representation is made that the information in this news release is complete. Investors are encouraged to review the foregoing summary and discussion of Synchrony Financial's earnings and financial condition in conjunction with the detailed financial tables and information that follow and the Company’s Annual Report on Form 10-K for the fiscal year ended December 31, 2020, as filed February 11, 2021, and the Company’s forthcoming Annual Report on Form 10-K for the year ended December 31, 2021. The detailed financial tables and other information are also available on the Investor Relations page of the Company’s website at www.investors.synchronyfinancial.com. This information is also furnished in a Current Report on Form 8-K filed with the SEC today. | |||||||||||||||||||||||
CONFERENCE CALL AND WEBCAST | ||||||||||||||
On Friday, January 28, 2022, at 8:00 a.m. Eastern Time, Brian Doubles, President and Chief Executive Officer, and Brian Wenzel Sr., Executive Vice President and Chief Financial Officer, will host a conference call to review the financial results and outlook for certain business drivers. The conference call can be accessed via an audio webcast through the Investor Relations page on the Synchrony Financial corporate website, www.investors.synchronyfinancial.com, under Events and Presentations. A replay will also be available on the website. | ||||||||||||||
ABOUT SYNCHRONY FINANCIAL
Synchrony (NYSE: SYF) is a premier consumer financial services company. We deliver a wide range of specialized financing programs, as well as innovative consumer banking products, across key industries including digital, retail, home, auto, travel, health and pet. Synchrony enables our partners to grow sales and loyalty with consumers. We are one of the largest issuers of private label credit cards in the United States; we also offer co-branded products, installment loans and consumer financing products for small- and medium-sized businesses, as well as healthcare providers.
Synchrony is changing what’s possible through our digital capabilities, deep industry expertise, actionable data insights, frictionless customer experience and customized financing solutions.
For more information, visit www.synchrony.com and Twitter: @Synchrony.
| Investor Relations | Media Relations | ||||
| Kathryn Miller | Sue Bishop | ||||
| (203) 585-6291 | (203) 585-2802 | ||||
CAUTIONARY STATEMENT REGARDING FORWARD-LOOKING STATEMENTS
This news release contains certain forward-looking statements as defined in Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, which are subject to the "safe harbor" created by those sections. Forward-looking statements may be identified by words such as "expects," "intends," "anticipates," "plans," "believes," "seeks," "targets," "outlook," "estimates," "will," "should," "may" or words of similar meaning, but these words are not the exclusive means of identifying forward-looking statements. Forward-looking statements are based on management's current expectations and assumptions, and are subject to inherent uncertainties, risks and changes in circumstances that are difficult to predict. As a result, actual results could differ materially from those indicated in these forward-looking statements. Factors that could cause actual results to differ materially include global political, economic, business, competitive, market, regulatory and other factors and risks, such as: the impact of macroeconomic conditions and whether industry trends we have identified develop as anticipated, including the future impacts of the novel coronavirus disease (“COVID-19”) outbreak and measures taken in response thereto for which future developments are highly uncertain and difficult to predict; retaining existing partners and attracting new partners, concentration of our revenue in a small number of partners, and promotion and support of our products by our partners; cyber-attacks or other security breaches; disruptions in the operations of our and our outsourced partners' computer systems and data centers; the financial performance of our partners; the sufficiency of our allowance for credit losses and the accuracy of the assumptions or estimates used in preparing our financial statements, including those related to the CECL accounting guidance; higher borrowing costs and adverse financial market conditions impacting our funding and liquidity, and any reduction in our credit ratings; our ability to grow our deposits in the future; damage to our reputation; our ability to securitize our loan receivables, occurrence of an early amortization of our securitization facilities, loss of the right to service or subservice our securitized loan receivables, and lower payment rates on our securitized loan receivables; changes in market interest rates and the impact of any margin compression; effectiveness of our risk management processes and procedures, reliance on models which may be inaccurate or misinterpreted, our ability to manage our credit risk; our ability to offset increases in our costs in retailer share arrangements; competition in the consumer finance industry; our concentration in the U.S. consumer credit market; our ability to successfully develop and commercialize new or enhanced products and services; our ability to realize the value of acquisitions and strategic investments; reductions in interchange fees; fraudulent activity; failure of third parties to provide various services that are important to our operations; international risks and compliance and regulatory risks and costs associated with international operations; alleged infringement of intellectual property rights of others and our ability to protect our intellectual property; litigation and regulatory actions; our ability to attract, retain and motivate key officers and employees; tax legislation initiatives or challenges to our tax positions and/or interpretations, and state sales tax rules and regulations; regulation, supervision, examination and enforcement of our business by governmental authorities, the impact of the Dodd-Frank Wall Street Reform and Consumer Protection Act and other legislative and regulatory developments and the impact of the Consumer Financial Protection Bureau’s regulation of our business; impact of capital adequacy rules and liquidity requirements; restrictions that limit our ability to pay dividends and repurchase our common stock, and restrictions that limit the Synchrony Bank’s ability to pay dividends to us; regulations relating to privacy, information security and data protection; use of third-party vendors and ongoing third-party business relationships; and failure to comply with anti-money laundering and anti-terrorism financing laws.
CAUTIONARY STATEMENT REGARDING FORWARD-LOOKING STATEMENTS
For the reasons described above, we caution you against relying on any forward-looking statements, which should also be read in conjunction with the other cautionary statements that are included elsewhere in this news release and in our public filings, including under the heading "Risk Factors" in the Company's Annual Report on Form 10-K for the fiscal year ended December 31, 2020, as filed on February 11, 2021. You should not consider any list of such factors to be an exhaustive statement of all the risks, uncertainties, or potentially inaccurate assumptions that could cause our current expectations or beliefs to change. Further, any forward-looking statement speaks only as of the date on which it is made, and we undertake no obligation to update or revise any forward-looking statement to reflect events or circumstances after the date on which the statement is made or to reflect the occurrence of unanticipated events, except as otherwise may be required by law.
NON-GAAP MEASURES
The information provided herein includes measures we refer to as "tangible common equity", and certain “CECL fully phased-in" capital measures, which are not prepared in accordance with U.S. generally accepted accounting principles ("GAAP"). For a reconciliation of these non-GAAP measures to the most directly comparable GAAP measures, please see the detailed financial tables and information that follow. For a statement regarding the usefulness of these measures to investors, please see the Company's Current Report on Form 8-K filed with the SEC today.
Exhibit 99.2
| SYNCHRONY FINANCIAL | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FINANCIAL SUMMARY | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (unaudited, in millions, except per share statistics) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | Twelve Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Dec 31, 2021 | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | 4Q'21 vs. 4Q'20 | Dec 31, 2021 | Dec 31, 2020 | YTD'21 vs. YTD'20 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| EARNINGS | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 3,830 | $ | 3,658 | $ | 3,312 | $ | 3,439 | $ | 3,659 | $ | 171 | 4.7 | % | $ | 14,239 | $ | 14,402 | $ | (163) | (1.1) | % | |||||||||||||||||||||||||||||||||||||
| Retailer share arrangements | (1,267) | (1,266) | (1,006) | (989) | (1,047) | (220) | 21.0 | % | (4,528) | (3,645) | (883) | 24.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 561 | 25 | (194) | 334 | 750 | (189) | (25.2) | % | 726 | 5,310 | (4,584) | (86.3) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income, after retailer share arrangements and provision for credit losses | 2,002 | 2,367 | 2,500 | 2,116 | 1,862 | 140 | 7.5 | % | 8,985 | 5,447 | 3,538 | 65.0 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Other income | 167 | 94 | 89 | 131 | 82 | 85 | 103.7 | % | 481 | 405 | 76 | 18.8 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Other expense | 1,122 | 961 | 948 | 932 | 1,000 | 122 | 12.2 | % | 3,963 | 4,055 | (92) | (2.3) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Earnings before provision for income taxes | 1,047 | 1,500 | 1,641 | 1,315 | 944 | 103 | 10.9 | % | 5,503 | 1,797 | 3,706 | 206.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Provision for income taxes | 234 | 359 | 399 | 290 | 206 | 28 | 13.6 | % | 1,282 | 412 | 870 | 211.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Net earnings | $ | 813 | $ | 1,141 | $ | 1,242 | $ | 1,025 | $ | 738 | $ | 75 | 10.2 | % | $ | 4,221 | $ | 1,385 | $ | 2,836 | 204.8 | % | |||||||||||||||||||||||||||||||||||||
| Net earnings available to common stockholders | $ | 803 | $ | 1,130 | $ | 1,232 | $ | 1,014 | $ | 728 | $ | 75 | 10.3 | % | $ | 4,179 | $ | 1,343 | $ | 2,836 | 211.2 | % | |||||||||||||||||||||||||||||||||||||
| COMMON SHARE STATISTICS | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Basic EPS | $ | 1.49 | $ | 2.02 | $ | 2.13 | $ | 1.74 | $ | 1.25 | $ | 0.24 | 19.2 | % | $ | 7.40 | $ | 2.28 | $ | 5.12 | 224.6 | % | |||||||||||||||||||||||||||||||||||||
| Diluted EPS | $ | 1.48 | $ | 2.00 | $ | 2.12 | $ | 1.73 | $ | 1.24 | $ | 0.24 | 19.4 | % | $ | 7.34 | $ | 2.27 | $ | 5.07 | 223.3 | % | |||||||||||||||||||||||||||||||||||||
| Dividend declared per share | $ | 0.22 | $ | 0.22 | $ | 0.22 | $ | 0.22 | $ | 0.22 | $ | — | — | % | $ | 0.88 | $ | 0.88 | $ | — | — | % | |||||||||||||||||||||||||||||||||||||
| Common stock price | $ | 46.39 | $ | 48.88 | $ | 48.52 | $ | 40.66 | $ | 34.71 | $ | 11.68 | 33.7 | % | $ | 46.39 | $ | 34.71 | $ | 11.68 | 33.7 | % | |||||||||||||||||||||||||||||||||||||
| Book value per share | $ | 24.53 | $ | 24.13 | $ | 23.48 | $ | 21.86 | $ | 20.49 | $ | 4.04 | 19.7 | % | $ | 24.53 | $ | 20.49 | $ | 4.04 | 19.7 | % | |||||||||||||||||||||||||||||||||||||
Tangible common equity per share(1) | $ | 20.21 | $ | 20.12 | $ | 19.64 | $ | 17.95 | $ | 16.72 | $ | 3.49 | 20.9 | % | $ | 20.21 | $ | 16.72 | $ | 3.49 | 20.9 | % | |||||||||||||||||||||||||||||||||||||
| Beginning common shares outstanding | 547.2 | 573.4 | 581.1 | 584.0 | 583.8 | (36.6) | (6.3) | % | 584.0 | 615.9 | (31.9) | (5.2) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Issuance of common shares | — | — | — | — | — | — | — | % | — | — | — | — | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Stock-based compensation | 0.1 | 0.5 | 1.0 | 2.2 | 0.2 | (0.1) | (50.0) | % | 3.8 | 1.7 | 2.1 | 123.5 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Shares repurchased | (20.5) | (26.7) | (8.7) | (5.1) | — | (20.5) | NM | (61.0) | (33.6) | (27.4) | 81.5 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Ending common shares outstanding | 526.8 | 547.2 | 573.4 | 581.1 | 584.0 | (57.2) | (9.8) | % | 526.8 | 584.0 | (57.2) | (9.8) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Weighted average common shares outstanding | 537.8 | 560.6 | 577.2 | 583.3 | 583.9 | (46.1) | (7.9) | % | 564.6 | 589.0 | (24.4) | (4.1) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Weighted average common shares outstanding (fully diluted) | 543.0 | 565.6 | 581.7 | 587.5 | 586.6 | (43.6) | (7.4) | % | 569.3 | 590.8 | (21.5) | (3.6) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| (1) Tangible Common Equity ("TCE") is a non-GAAP measure. For corresponding reconciliation of TCE to a GAAP financial measure, see Reconciliation of Non-GAAP Measures and Calculations of Regulatory Measures. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
1
| SYNCHRONY FINANCIAL | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| SELECTED METRICS | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (unaudited, $ in millions) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | Twelve Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Dec 31, 2021 | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | 4Q'21 vs. 4Q'20 | Dec 31, 2021 | Dec 31, 2020 | YTD'21 vs. YTD'20 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| PERFORMANCE METRICS | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Return on assets(1) | 3.4 | % | 4.9 | % | 5.3 | % | 4.3 | % | 3.1 | % | 0.3 | % | 4.5 | % | 1.4 | % | 3.1 | % | |||||||||||||||||||||||||||||||||||||||||
Return on equity(2) | 23.0 | % | 32.1 | % | 36.5 | % | 31.8 | % | 23.6 | % | (0.6) | % | 30.8 | % | 11.2 | % | 19.6 | % | |||||||||||||||||||||||||||||||||||||||||
Return on tangible common equity(3) | 28.7 | % | 40.1 | % | 46.3 | % | 40.8 | % | 30.4 | % | (1.7) | % | 38.8 | % | 14.4 | % | 24.4 | % | |||||||||||||||||||||||||||||||||||||||||
Net interest margin(4) | 15.77 | % | 15.45 | % | 13.78 | % | 13.98 | % | 14.64 | % | 1.13 | % | 14.74 | % | 14.29 | % | 0.45 | % | |||||||||||||||||||||||||||||||||||||||||
Efficiency ratio(5) | 41.1 | % | 38.7 | % | 39.6 | % | 36.1 | % | 37.1 | % | 4.0 | % | 38.9 | % | 36.3 | % | 2.6 | % | |||||||||||||||||||||||||||||||||||||||||
| Other expense as a % of average loan receivables, including held for sale | 5.44 | % | 4.84 | % | 4.95 | % | 4.82 | % | 5.01 | % | 0.43 | % | 5.02 | % | 5.06 | % | (0.04) | % | |||||||||||||||||||||||||||||||||||||||||
| Effective income tax rate | 22.3 | % | 23.9 | % | 24.3 | % | 22.1 | % | 21.8 | % | 0.5 | % | 23.3 | % | 22.9 | % | 0.4 | % | |||||||||||||||||||||||||||||||||||||||||
| CREDIT QUALITY METRICS | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net charge-offs as a % of average loan receivables, including held for sale | 2.37 | % | 2.18 | % | 3.57 | % | 3.62 | % | 3.16 | % | (0.79) | % | 2.92 | % | 4.58 | % | (1.66) | % | |||||||||||||||||||||||||||||||||||||||||
30+ days past due as a % of period-end loan receivables(6) | 2.62 | % | 2.42 | % | 2.11 | % | 2.83 | % | 3.07 | % | (0.45) | % | 2.62 | % | 3.07 | % | (0.45) | % | |||||||||||||||||||||||||||||||||||||||||
90+ days past due as a % of period-end loan receivables(6) | 1.17 | % | 1.05 | % | 1.00 | % | 1.52 | % | 1.40 | % | (0.23) | % | 1.17 | % | 1.40 | % | (0.23) | % | |||||||||||||||||||||||||||||||||||||||||
| Net charge-offs | $ | 489 | $ | 432 | $ | 684 | $ | 699 | $ | 631 | $ | (142) | (22.5) | % | $ | 2,304 | $ | 3,668 | $ | (1,364) | (37.2) | % | |||||||||||||||||||||||||||||||||||||
Loan receivables delinquent over 30 days(6) | $ | 2,114 | $ | 1,850 | $ | 1,653 | $ | 2,175 | $ | 2,514 | $ | (400) | (15.9) | % | $ | 2,114 | $ | 2,514 | $ | (400) | (15.9) | % | |||||||||||||||||||||||||||||||||||||
Loan receivables delinquent over 90 days(6) | $ | 942 | $ | 804 | $ | 784 | $ | 1,170 | $ | 1,143 | $ | (201) | (17.6) | % | $ | 942 | $ | 1,143 | $ | (201) | (17.6) | % | |||||||||||||||||||||||||||||||||||||
| Allowance for credit losses (period-end) | $ | 8,688 | $ | 8,616 | $ | 9,023 | $ | 9,901 | $ | 10,265 | $ | (1,577) | (15.4) | % | $ | 8,688 | $ | 10,265 | $ | (1,577) | (15.4) | % | |||||||||||||||||||||||||||||||||||||
Allowance coverage ratio(7) | 10.76 | % | 11.28 | % | 11.51 | % | 12.88 | % | 12.54 | % | (1.78) | % | 10.76 | % | 12.54 | % | (1.78) | % | |||||||||||||||||||||||||||||||||||||||||
| BUSINESS METRICS | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Purchase volume(8)(9) | $ | 47,072 | $ | 41,912 | $ | 42,121 | $ | 34,749 | $ | 39,874 | $ | 7,198 | 18.1 | % | $ | 165,854 | $ | 139,084 | $ | 26,770 | 19.2 | % | |||||||||||||||||||||||||||||||||||||
| Period-end loan receivables | $ | 80,740 | $ | 76,388 | $ | 78,374 | $ | 76,858 | $ | 81,867 | $ | (1,127) | (1.4) | % | $ | 80,740 | $ | 81,867 | $ | (1,127) | (1.4) | % | |||||||||||||||||||||||||||||||||||||
| Credit cards | $ | 76,628 | $ | 72,289 | $ | 74,429 | $ | 73,244 | $ | 78,455 | $ | (1,827) | (2.3) | % | $ | 76,628 | $ | 78,455 | $ | (1,827) | (2.3) | % | |||||||||||||||||||||||||||||||||||||
| Consumer installment loans | $ | 2,675 | $ | 2,614 | $ | 2,507 | $ | 2,319 | $ | 2,125 | $ | 550 | 25.9 | % | $ | 2,675 | $ | 2,125 | $ | 550 | 25.9 | % | |||||||||||||||||||||||||||||||||||||
| Commercial credit products | $ | 1,372 | $ | 1,401 | $ | 1,379 | $ | 1,248 | $ | 1,250 | $ | 122 | 9.8 | % | $ | 1,372 | $ | 1,250 | $ | 122 | 9.8 | % | |||||||||||||||||||||||||||||||||||||
| Other | $ | 65 | $ | 84 | $ | 59 | $ | 47 | $ | 37 | $ | 28 | 75.7 | % | $ | 65 | $ | 37 | $ | 28 | 75.7 | % | |||||||||||||||||||||||||||||||||||||
| Average loan receivables, including held for sale | $ | 81,784 | $ | 78,714 | $ | 76,821 | $ | 78,358 | $ | 79,452 | $ | 2,332 | 2.9 | % | $ | 78,928 | $ | 80,138 | $ | (1,210) | (1.5) | % | |||||||||||||||||||||||||||||||||||||
Period-end active accounts (in thousands)(9)(10) | 72,420 | 67,245 | 66,892 | 65,219 | 68,540 | 3,880 | 5.7 | % | 72,420 | 68,540 | 3,880 | 5.7 | % | ||||||||||||||||||||||||||||||||||||||||||||||
Average active accounts (in thousands)(9)(10) | 69,397 | 67,189 | 65,810 | 66,280 | 66,261 | 3,136 | 4.7 | % | 67,334 | 67,131 | 203 | 0.3 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| LIQUIDITY | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Liquid assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash and equivalents | $ | 8,337 | $ | 9,806 | $ | 11,117 | $ | 16,620 | $ | 11,524 | $ | (3,187) | (27.7) | % | $ | 8,337 | $ | 11,524 | $ | (3,187) | (27.7) | % | |||||||||||||||||||||||||||||||||||||
| Total liquid assets | $ | 12,989 | $ | 14,664 | $ | 16,297 | $ | 22,636 | $ | 18,321 | $ | (5,332) | (29.1) | % | $ | 12,989 | $ | 18,321 | $ | (5,332) | (29.1) | % | |||||||||||||||||||||||||||||||||||||
| Undrawn credit facilities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Undrawn credit facilities | $ | 2,700 | $ | 3,700 | $ | 4,900 | $ | 5,400 | $ | 5,400 | $ | (2,700) | (50.0) | % | $ | 2,700 | $ | 5,400 | $ | (2,700) | (50.0) | % | |||||||||||||||||||||||||||||||||||||
| Total liquid assets and undrawn credit facilities | $ | 15,689 | $ | 18,364 | $ | 21,197 | $ | 28,036 | $ | 23,721 | $ | (8,032) | (33.9) | % | $ | 15,689 | $ | 23,721 | $ | (8,032) | (33.9) | % | |||||||||||||||||||||||||||||||||||||
| Liquid assets % of total assets | 13.57 | % | 15.95 | % | 17.71 | % | 23.62 | % | 19.09 | % | (5.52) | % | 13.57 | % | 19.09 | % | (5.52) | % | |||||||||||||||||||||||||||||||||||||||||
| Liquid assets including undrawn credit facilities % of total assets | 16.39 | % | 19.97 | % | 23.04 | % | 29.25 | % | 24.72 | % | (8.33) | % | 16.39 | % | 24.72 | % | (8.33) | % | |||||||||||||||||||||||||||||||||||||||||
| (1) Return on assets represents net earnings as a percentage of average total assets. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (2) Return on equity represents net earnings as a percentage of average total equity. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (3) Return on tangible common equity represents net earnings available to common stockholders as a percentage of average tangible common equity. Tangible common equity ("TCE") is a non-GAAP measure. For corresponding reconciliation of TCE to a GAAP financial measure, see Reconciliation of Non-GAAP Measures and Calculations of Regulatory Measures. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (4) Net interest margin represents net interest income divided by average interest-earning assets. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (5) Efficiency ratio represents (i) other expense, divided by (ii) net interest income, plus other income, less retailer share arrangements. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (6) Based on customer statement-end balances extrapolated to the respective period-end date. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (7) Allowance coverage ratio represents allowance for credit losses divided by total period-end loan receivables. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (8) Purchase volume, or net credit sales, represents the aggregate amount of charges incurred on credit cards or other credit product accounts less returns during the period. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (9) Includes activity and accounts associated with loan receivables held for sale. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (10) Active accounts represent credit card or installment loan accounts on which there has been a purchase, payment or outstanding balance in the current month. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
2
| SYNCHRONY FINANCIAL | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| STATEMENTS OF EARNINGS | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (unaudited, $ in millions) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | Twelve Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Dec 31, 2021 | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | 4Q'21 vs. 4Q'20 | Dec 31, 2021 | Dec 31, 2020 | YTD'21 vs. YTD'20 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 4,042 | $ | 3,887 | $ | 3,567 | $ | 3,732 | $ | 3,981 | $ | 61 | 1.5 | % | $ | 15,228 | $ | 15,950 | $ | (722) | (4.5) | % | |||||||||||||||||||||||||||||||||||||
| Interest on cash and debt securities | 11 | 11 | 11 | 10 | 12 | (1) | (8.3) | % | 43 | 117 | (74) | (63.2) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Total interest income | 4,053 | 3,898 | 3,578 | 3,742 | 3,993 | 60 | 1.5 | % | 15,271 | 16,067 | (796) | (5.0) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Interest expense: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest on deposits | 119 | 131 | 146 | 170 | 200 | (81) | (40.5) | % | 566 | 1,094 | (528) | (48.3) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Interest on borrowings of consolidated securitization entities | 33 | 41 | 44 | 51 | 52 | (19) | (36.5) | % | 169 | 237 | (68) | (28.7) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Interest on senior unsecured notes | 71 | 68 | 76 | 82 | 82 | (11) | (13.4) | % | 297 | 334 | (37) | (11.1) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Total interest expense | 223 | 240 | 266 | 303 | 334 | (111) | (33.2) | % | 1,032 | 1,665 | (633) | (38.0) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | 3,830 | 3,658 | 3,312 | 3,439 | 3,659 | 171 | 4.7 | % | 14,239 | 14,402 | (163) | (1.1) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Retailer share arrangements | (1,267) | (1,266) | (1,006) | (989) | (1,047) | (220) | 21.0 | % | (4,528) | (3,645) | (883) | 24.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 561 | 25 | (194) | 334 | 750 | (189) | (25.2) | % | 726 | 5,310 | (4,584) | (86.3) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income, after retailer share arrangements and provision for credit losses | 2,002 | 2,367 | 2,500 | 2,116 | 1,862 | 140 | 7.5 | % | 8,985 | 5,447 | 3,538 | 65.0 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Other income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interchange revenue | 254 | 232 | 223 | 171 | 185 | 69 | 37.3 | % | 880 | 652 | 228 | 35.0 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Debt cancellation fees | 79 | 70 | 66 | 69 | 72 | 7 | 9.7 | % | 284 | 278 | 6 | 2.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Loyalty programs | (310) | (256) | (247) | (179) | (202) | (108) | 53.5 | % | (992) | (649) | (343) | 52.9 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Other | 144 | 48 | 47 | 70 | 27 | 117 | NM | 309 | 124 | 185 | 149.2 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Total other income | 167 | 94 | 89 | 131 | 82 | 85 | 103.7 | % | 481 | 405 | 76 | 18.8 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Other expense: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Employee costs | 409 | 369 | 359 | 364 | 347 | 62 | 17.9 | % | 1,501 | 1,380 | 121 | 8.8 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Professional fees | 207 | 196 | 189 | 190 | 186 | 21 | 11.3 | % | 782 | 759 | 23 | 3.0 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Marketing and business development | 167 | 110 | 114 | 95 | 139 | 28 | 20.1 | % | 486 | 448 | 38 | 8.5 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Information processing | 143 | 139 | 137 | 131 | 128 | 15 | 11.7 | % | 550 | 492 | 58 | 11.8 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Other | 196 | 147 | 149 | 152 | 200 | (4) | (2.0) | % | 644 | 976 | (332) | (34.0) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Total other expense | 1,122 | 961 | 948 | 932 | 1,000 | 122 | 12.2 | % | 3,963 | 4,055 | (92) | (2.3) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Earnings before provision for income taxes | 1,047 | 1,500 | 1,641 | 1,315 | 944 | 103 | 10.9 | % | 5,503 | 1,797 | 3,706 | 206.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Provision for income taxes | 234 | 359 | 399 | 290 | 206 | 28 | 13.6 | % | 1,282 | 412 | 870 | 211.2 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Net earnings | $ | 813 | $ | 1,141 | $ | 1,242 | $ | 1,025 | $ | 738 | $ | 75 | 10.2 | % | $ | 4,221 | $ | 1,385 | $ | 2,836 | 204.8 | % | |||||||||||||||||||||||||||||||||||||
| Net earnings available to common stockholders | $ | 803 | $ | 1,130 | $ | 1,232 | $ | 1,014 | $ | 728 | $ | 75 | 10.3 | % | $ | 4,179 | $ | 1,343 | $ | 2,836 | 211.2 | % | |||||||||||||||||||||||||||||||||||||
3
| SYNCHRONY FINANCIAL | ||||||||||||||||||||||||||||||||||||||
| STATEMENTS OF FINANCIAL POSITION | ||||||||||||||||||||||||||||||||||||||
| (unaudited, $ in millions) | ||||||||||||||||||||||||||||||||||||||
| Quarter Ended | ||||||||||||||||||||||||||||||||||||||
| Dec 31, 2021 | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | Dec 31, 2021 vs. Dec 31, 2020 | |||||||||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||||||||
| Cash and equivalents | $ | 8,337 | $ | 9,806 | $ | 11,117 | $ | 16,620 | $ | 11,524 | $ | (3,187) | (27.7) | % | ||||||||||||||||||||||||
| Debt securities | 5,283 | 5,444 | 5,728 | 6,550 | 7,469 | (2,186) | (29.3) | % | ||||||||||||||||||||||||||||||
| Loan receivables: | ||||||||||||||||||||||||||||||||||||||
| Unsecuritized loans held for investment | 60,211 | 56,745 | 55,994 | 53,823 | 56,472 | 3,739 | 6.6 | % | ||||||||||||||||||||||||||||||
| Restricted loans of consolidated securitization entities | 20,529 | 19,643 | 22,380 | 23,035 | 25,395 | (4,866) | (19.2) | % | ||||||||||||||||||||||||||||||
| Total loan receivables | 80,740 | 76,388 | 78,374 | 76,858 | 81,867 | (1,127) | (1.4) | % | ||||||||||||||||||||||||||||||
| Less: Allowance for credit losses | (8,688) | (8,616) | (9,023) | (9,901) | (10,265) | 1,577 | (15.4) | % | ||||||||||||||||||||||||||||||
| Loan receivables, net | 72,052 | 67,772 | 69,351 | 66,957 | 71,602 | 450 | 0.6 | % | ||||||||||||||||||||||||||||||
| Loan receivables held for sale | 4,361 | 3,450 | — | 23 | 5 | 4,356 | NM | |||||||||||||||||||||||||||||||
| Goodwill | 1,105 | 1,105 | 1,105 | 1,104 | 1,078 | 27 | 2.5 | % | ||||||||||||||||||||||||||||||
| Intangible assets, net | 1,168 | 1,090 | 1,098 | 1,169 | 1,125 | 43 | 3.8 | % | ||||||||||||||||||||||||||||||
| Other assets | 3,442 | 3,270 | 3,618 | 3,431 | 3,145 | 297 | 9.4 | % | ||||||||||||||||||||||||||||||
| Total assets | $ | 95,748 | $ | 91,937 | $ | 92,017 | $ | 95,854 | $ | 95,948 | $ | (200) | (0.2) | % | ||||||||||||||||||||||||
| Liabilities and Equity | ||||||||||||||||||||||||||||||||||||||
| Deposits: | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposit accounts | $ | 61,911 | $ | 59,998 | $ | 59,500 | $ | 62,419 | $ | 62,469 | $ | (558) | (0.9) | % | ||||||||||||||||||||||||
| Non-interest-bearing deposit accounts | 359 | 355 | 341 | 342 | 313 | 46 | 14.7 | % | ||||||||||||||||||||||||||||||
| Total deposits | 62,270 | 60,353 | 59,841 | 62,761 | 62,782 | (512) | (0.8) | % | ||||||||||||||||||||||||||||||
| Borrowings: | ||||||||||||||||||||||||||||||||||||||
| Borrowings of consolidated securitization entities | 7,288 | 6,288 | 6,987 | 7,193 | 7,810 | (522) | (6.7) | % | ||||||||||||||||||||||||||||||
| Senior unsecured notes | 7,219 | 6,472 | 6,470 | 7,967 | 7,965 | (746) | (9.4) | % | ||||||||||||||||||||||||||||||
| Total borrowings | 14,507 | 12,760 | 13,457 | 15,160 | 15,775 | (1,268) | (8.0) | % | ||||||||||||||||||||||||||||||
| Accrued expenses and other liabilities | 5,316 | 4,888 | 4,522 | 4,494 | 4,690 | 626 | 13.3 | % | ||||||||||||||||||||||||||||||
| Total liabilities | 82,093 | 78,001 | 77,820 | 82,415 | 83,247 | (1,154) | (1.4) | % | ||||||||||||||||||||||||||||||
| Equity: | ||||||||||||||||||||||||||||||||||||||
| Preferred stock | 734 | 734 | 734 | 734 | 734 | — | — | % | ||||||||||||||||||||||||||||||
| Common stock | 1 | 1 | 1 | 1 | 1 | — | — | % | ||||||||||||||||||||||||||||||
| Additional paid-in capital | 9,669 | 9,649 | 9,620 | 9,592 | 9,570 | 99 | 1.0 | % | ||||||||||||||||||||||||||||||
| Retained earnings | 14,245 | 13,562 | 12,560 | 11,470 | 10,621 | 3,624 | 34.1 | % | ||||||||||||||||||||||||||||||
| Accumulated other comprehensive income (loss) | (69) | (64) | (56) | (56) | (51) | (18) | 35.3 | % | ||||||||||||||||||||||||||||||
| Treasury stock | (10,925) | (9,946) | (8,662) | (8,302) | (8,174) | (2,751) | 33.7 | % | ||||||||||||||||||||||||||||||
| Total equity | 13,655 | 13,936 | 14,197 | 13,439 | 12,701 | 954 | 7.5 | % | ||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 95,748 | $ | 91,937 | $ | 92,017 | $ | 95,854 | $ | 95,948 | $ | (200) | (0.2) | % | ||||||||||||||||||||||||
4
| SYNCHRONY FINANCIAL | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| AVERAGE BALANCES, NET INTEREST INCOME AND NET INTEREST MARGIN | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (unaudited, $ in millions) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Dec 31, 2021 | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest | Average | Interest | Average | Interest | Average | Interest | Average | Interest | Average | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average | Income/ | Yield/ | Average | Income/ | Yield/ | Average | Income/ | Yield/ | Average | Income/ | Yield/ | Average | Income/ | Yield/ | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Balance | Expense | Rate | Balance | Expense | Rate | Balance | Expense | Rate | Balance | Expense | Rate | Balance | Expense | Rate | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning cash and equivalents | $ | 9,024 | $ | 4 | 0.18 | % | $ | 9,559 | $ | 3 | 0.12 | % | $ | 13,584 | $ | 4 | 0.12 | % | $ | 14,610 | $ | 4 | 0.11 | % | $ | 11,244 | $ | 4 | 0.14 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Securities available for sale | 5,517 | 7 | 0.50 | % | 5,638 | 8 | 0.56 | % | 5,988 | 7 | 0.47 | % | 6,772 | 6 | 0.36 | % | 8,706 | 8 | 0.37 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loan receivables, including held for sale: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Credit cards | 77,642 | 3,946 | 20.16 | % | 74,686 | 3,793 | 20.15 | % | 72,989 | 3,484 | 19.15 | % | 74,865 | 3,657 | 19.81 | % | 76,039 | 3,908 | 20.45 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Consumer installment loans | 2,641 | 65 | 9.76 | % | 2,555 | 64 | 9.94 | % | 2,417 | 59 | 9.79 | % | 2,219 | 53 | 9.69 | % | 2,057 | 50 | 9.67 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial credit products | 1,434 | 30 | 8.30 | % | 1,407 | 29 | 8.18 | % | 1,363 | 23 | 6.77 | % | 1,231 | 21 | 6.92 | % | 1,293 | 23 | 7.08 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other | 67 | 1 | NM | 66 | 1 | NM | 52 | 1 | NM | 43 | 1 | NM | 63 | — | — | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total loan receivables, including held for sale | 81,784 | 4,042 | 19.61 | % | 78,714 | 3,887 | 19.59 | % | 76,821 | 3,567 | 18.62 | % | 78,358 | 3,732 | 19.32 | % | 79,452 | 3,981 | 19.93 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 96,325 | 4,053 | 16.69 | % | 93,911 | 3,898 | 16.47 | % | 96,393 | 3,578 | 14.89 | % | 99,740 | 3,742 | 15.22 | % | 99,402 | 3,993 | 15.98 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest-earning assets: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 1,606 | 1,588 | 1,559 | 1,635 | 1,525 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Allowance for credit losses | (8,648) | (8,956) | (9,801) | (10,225) | (10,190) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other assets | 5,424 | 5,405 | 5,238 | 5,305 | 5,228 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total non-interest-earning assets | (1,618) | (1,963) | (3,004) | (3,285) | (3,437) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 94,707 | $ | 91,948 | $ | 93,389 | $ | 96,455 | $ | 95,965 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposit accounts | $ | 61,090 | $ | 119 | 0.77 | % | $ | 59,275 | $ | 131 | 0.88 | % | $ | 60,761 | $ | 146 | 0.96 | % | $ | 62,724 | $ | 170 | 1.10 | % | $ | 62,800 | $ | 200 | 1.27 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Borrowings of consolidated securitization entities | 7,105 | 33 | 1.84 | % | 7,051 | 41 | 2.31 | % | 7,149 | 44 | 2.47 | % | 7,694 | 51 | 2.69 | % | 7,809 | 52 | 2.65 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Senior unsecured notes | 6,999 | 71 | 4.02 | % | 6,471 | 68 | 4.17 | % | 7,276 | 76 | 4.19 | % | 7,965 | 82 | 4.18 | % | 7,963 | 82 | 4.10 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 75,194 | 223 | 1.18 | % | 72,797 | 240 | 1.31 | % | 75,186 | 266 | 1.42 | % | 78,383 | 303 | 1.57 | % | 78,572 | 334 | 1.69 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest-bearing liabilities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest-bearing deposit accounts | 343 | 358 | 349 | 346 | 308 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 5,137 | 4,676 | 4,199 | 4,655 | 4,663 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total non-interest-bearing liabilities | 5,480 | 5,034 | 4,548 | 5,001 | 4,971 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities | 80,674 | 77,831 | 79,734 | 83,384 | 83,543 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total equity | 14,033 | 14,117 | 13,655 | 13,071 | 12,422 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 94,707 | $ | 91,948 | $ | 93,389 | $ | 96,455 | $ | 95,965 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 3,830 | $ | 3,658 | $ | 3,312 | $ | 3,439 | $ | 3,659 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Interest rate spread(1) | 15.51 | % | 15.16 | % | 13.47 | % | 13.65 | % | 14.29 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Net interest margin(2) | 15.77 | % | 15.45 | % | 13.78 | % | 13.98 | % | 14.64 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (1) Interest rate spread represents the difference between the yield on total interest-earning assets and the rate on total interest-bearing liabilities. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (2) Net interest margin represents net interest income divided by average interest-earning assets. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
5
| SYNCHRONY FINANCIAL | |||||||||||||||||||||||||||||||||||
| AVERAGE BALANCES, NET INTEREST INCOME AND NET INTEREST MARGIN | |||||||||||||||||||||||||||||||||||
| (unaudited, $ in millions) | |||||||||||||||||||||||||||||||||||
| Twelve Months Ended Dec 31, 2021 | Twelve Months Ended Dec 31, 2020 | ||||||||||||||||||||||||||||||||||
| Interest | Average | Interest | Average | ||||||||||||||||||||||||||||||||
| Average | Income/ | Yield/ | Average | Income/ | Yield/ | ||||||||||||||||||||||||||||||
| Balance | Expense | Rate | Balance | Expense | Rate | ||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||
| Interest-earning assets: | |||||||||||||||||||||||||||||||||||
| Interest-earning cash and equivalents | $ | 11,673 | $ | 15 | 0.13 | % | $ | 13,301 | $ | 53 | 0.40 | % | |||||||||||||||||||||||
| Securities available for sale | 5,975 | 28 | 0.47 | % | 7,367 | 64 | 0.87 | % | |||||||||||||||||||||||||||
| Loan receivables, including held for sale: | |||||||||||||||||||||||||||||||||||
| Credit cards | 75,052 | 14,880 | 19.83 | % | 77,115 | 15,672 | 20.32 | % | |||||||||||||||||||||||||||
| Consumer installment loans | 2,460 | 241 | 9.80 | % | 1,733 | 168 | 9.69 | % | |||||||||||||||||||||||||||
| Commercial credit products | 1,359 | 103 | 7.58 | % | 1,231 | 108 | 8.77 | % | |||||||||||||||||||||||||||
| Other | 57 | 4 | 7.02 | % | 59 | 2 | 3.39 | % | |||||||||||||||||||||||||||
| Total loan receivables, including held for sale | 78,928 | 15,228 | 19.29 | % | 80,138 | 15,950 | 19.90 | % | |||||||||||||||||||||||||||
| Total interest-earning assets | 96,576 | 15,271 | 15.81 | % | 100,806 | 16,067 | 15.94 | % | |||||||||||||||||||||||||||
| Non-interest-earning assets: | |||||||||||||||||||||||||||||||||||
| Cash and due from banks | 1,597 | 1,488 | |||||||||||||||||||||||||||||||||
| Allowance for loan losses | (9,402) | (9,488) | |||||||||||||||||||||||||||||||||
| Other assets | 5,343 | 4,932 | |||||||||||||||||||||||||||||||||
| Total non-interest-earning assets | (2,462) | (3,068) | |||||||||||||||||||||||||||||||||
| Total assets | $ | 94,114 | $ | 97,738 | |||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||
| Interest-bearing deposit accounts | $ | 60,953 | $ | 566 | 0.93 | % | $ | 63,755 | $ | 1,094 | 1.72 | % | |||||||||||||||||||||||
| Borrowings of consolidated securitization entities | 7,248 | 169 | 2.33 | % | 8,675 | 237 | 2.73 | % | |||||||||||||||||||||||||||
| Senior unsecured notes | 7,173 | 297 | 4.14 | % | 8,171 | 334 | 4.09 | % | |||||||||||||||||||||||||||
| Total interest-bearing liabilities | 75,374 | 1,032 | 1.37 | % | 80,601 | 1,665 | 2.07 | % | |||||||||||||||||||||||||||
| Non-interest-bearing liabilities | |||||||||||||||||||||||||||||||||||
| Non-interest-bearing deposit accounts | 349 | 306 | |||||||||||||||||||||||||||||||||
| Other liabilities | 4,668 | 4,498 | |||||||||||||||||||||||||||||||||
| Total non-interest-bearing liabilities | 5,017 | 4,804 | |||||||||||||||||||||||||||||||||
| Total liabilities | 80,391 | 85,405 | |||||||||||||||||||||||||||||||||
| Equity | |||||||||||||||||||||||||||||||||||
| Total equity | 13,723 | 12,333 | |||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 94,114 | $ | 97,738 | |||||||||||||||||||||||||||||||
| Net interest income | $ | 14,239 | $ | 14,402 | |||||||||||||||||||||||||||||||
Interest rate spread(1) | 14.44 | % | 13.87 | % | |||||||||||||||||||||||||||||||
Net interest margin(2) | 14.74 | % | 14.29 | % | |||||||||||||||||||||||||||||||
| (1) Interest rate spread represents the difference between the yield on total interest-earning assets and the rate on total interest-bearing liabilities. | |||||||||||||||||||||||||||||||||||
| (2) Net interest margin represents net interest income divided by average interest-earning assets. | |||||||||||||||||||||||||||||||||||
6
| SYNCHRONY FINANCIAL | ||||||||||||||||||||||||||||||||||||||
| BALANCE SHEET STATISTICS | ||||||||||||||||||||||||||||||||||||||
| (unaudited, $ in millions, except per share statistics) | ||||||||||||||||||||||||||||||||||||||
| Quarter Ended | ||||||||||||||||||||||||||||||||||||||
| Dec 31, 2021 | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | Dec 31, 2021 vs. Dec 31, 2020 | |||||||||||||||||||||||||||||||||
| BALANCE SHEET STATISTICS | ||||||||||||||||||||||||||||||||||||||
| Total common equity | $ | 12,921 | $ | 13,202 | $ | 13,463 | $ | 12,705 | $ | 11,967 | $ | 954 | 8.0 | % | ||||||||||||||||||||||||
| Total common equity as a % of total assets | 13.49 | % | 14.36 | % | 14.63 | % | 13.25 | % | 12.47 | % | 1.02 | % | ||||||||||||||||||||||||||
| Tangible assets | $ | 93,475 | $ | 89,742 | $ | 89,814 | $ | 93,581 | $ | 93,745 | $ | (270) | (0.3) | % | ||||||||||||||||||||||||
Tangible common equity(1) | $ | 10,648 | $ | 11,007 | $ | 11,260 | $ | 10,432 | $ | 9,764 | $ | 884 | 9.1 | % | ||||||||||||||||||||||||
Tangible common equity as a % of tangible assets(1) | 11.39 | % | 12.27 | % | 12.54 | % | 11.15 | % | 10.42 | % | 0.97 | % | ||||||||||||||||||||||||||
Tangible common equity per share(1) | $ | 20.21 | $ | 20.12 | $ | 19.64 | $ | 17.95 | $ | 16.72 | $ | 3.49 | 20.9 | % | ||||||||||||||||||||||||
REGULATORY CAPITAL RATIOS(2)(3) | ||||||||||||||||||||||||||||||||||||||
| Basel III - CECL Transition | ||||||||||||||||||||||||||||||||||||||
Total risk-based capital ratio(4) | 17.8 | % | 19.3 | % | 20.1 | % | 19.7 | % | 18.1 | % | ||||||||||||||||||||||||||||
Tier 1 risk-based capital ratio(5) | 16.5 | % | 18.0 | % | 18.7 | % | 18.3 | % | 16.8 | % | ||||||||||||||||||||||||||||
Tier 1 leverage ratio(6) | 14.7 | % | 15.5 | % | 15.6 | % | 14.5 | % | 14.0 | % | ||||||||||||||||||||||||||||
| Common equity Tier 1 capital ratio | 15.6 | % | 17.1 | % | 17.8 | % | 17.4 | % | 15.9 | % | ||||||||||||||||||||||||||||
| (1) Tangible common equity ("TCE") is a non-GAAP measure. We believe TCE is a more meaningful measure of the net asset value of the Company to investors. For corresponding reconciliation of TCE to a GAAP financial measure, see Reconciliation of Non-GAAP Measures and Calculations of Regulatory Measures. | ||||||||||||||||||||||||||||||||||||||
| (2) Regulatory capital ratios at December 31, 2021 are preliminary and therefore subject to change. | ||||||||||||||||||||||||||||||||||||||
| (3) Capital ratios starting March 31, 2020 reflect election to delay for two years an estimate of CECL’s effect on regulatory capital in accordance with the interim final rule issued by U.S. banking agencies in March 2020. | ||||||||||||||||||||||||||||||||||||||
| (4) Total risk-based capital ratio is the ratio of total risk-based capital divided by risk-weighted assets. | ||||||||||||||||||||||||||||||||||||||
| (5) Tier 1 risk-based capital ratio is the ratio of Tier 1 capital divided by risk-weighted assets. | ||||||||||||||||||||||||||||||||||||||
| (6) Tier 1 leverage ratio is the ratio of Tier 1 capital divided by total average assets, after certain adjustments. Tier 1 leverage ratios are based upon the use of daily averages for all periods presented. | ||||||||||||||||||||||||||||||||||||||
7
| SYNCHRONY FINANCIAL | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| PLATFORM RESULTS | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (unaudited, unrounded, $ in millions) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Quarter Ended | Twelve Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Dec 31, 2021 | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | 4Q'21 vs. 4Q'20 | Dec 31, 2021 | Dec 31, 2020 | YTD'21 vs. YTD'20 | |||||||||||||||||||||||||||||||||||||||||||||||||||
HOME & AUTO(6) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Purchase volume(1) | $ | 10,919 | $ | 11,069 | $ | 11,523 | $ | 9,337 | $ | 9,698 | $ | 1,221 | 12.6 | % | $ | 42,848 | $ | 37,422 | $ | 5,426 | 14.5 | % | |||||||||||||||||||||||||||||||||||||
| Period-end loan receivables | $ | 26,781 | $ | 26,210 | $ | 25,588 | $ | 24,942 | $ | 25,935 | $ | 846 | 3.3 | % | $ | 26,781 | $ | 25,935 | $ | 846 | 3.3 | % | |||||||||||||||||||||||||||||||||||||
| Average loan receivables, including held for sale | $ | 26,455 | $ | 25,800 | $ | 25,111 | $ | 25,273 | $ | 25,678 | $ | 777 | 3.0 | % | $ | 25,663 | $ | 25,663 | $ | — | — | % | |||||||||||||||||||||||||||||||||||||
Average active accounts (in thousands)(3) | 17,655 | 17,516 | 17,307 | 17,149 | 17,437 | 218 | 1.3 | % | 17,414 | 17,578 | (164) | (0.9) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 1,126 | $ | 1,092 | $ | 993 | $ | 1,036 | $ | 1,121 | $ | 5 | 0.4 | % | $ | 4,247 | $ | 4,402 | $ | (155) | (3.5) | % | |||||||||||||||||||||||||||||||||||||
| Other income | $ | 18 | $ | 18 | $ | 16 | $ | 17 | $ | 15 | $ | 3 | 20.0 | % | $ | 69 | $ | 60 | $ | 9 | 15.0 | % | |||||||||||||||||||||||||||||||||||||
| DIGITAL | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Purchase volume(1) | $ | 13,451 | $ | 10,980 | $ | 10,930 | $ | 9,340 | $ | 11,005 | $ | 2,446 | 22.2 | % | $ | 44,701 | $ | 35,876 | $ | 8,825 | 24.6 | % | |||||||||||||||||||||||||||||||||||||
| Period-end loan receivables | $ | 21,751 | $ | 19,636 | $ | 19,233 | $ | 18,907 | $ | 20,427 | $ | 1,324 | 6.5 | % | $ | 21,751 | $ | 20,427 | $ | 1,324 | 6.5 | % | |||||||||||||||||||||||||||||||||||||
| Average loan receivables, including held for sale | $ | 20,388 | $ | 19,286 | $ | 18,783 | $ | 19,437 | $ | 19,392 | $ | 996 | 5.1 | % | $ | 19,475 | $ | 19,253 | $ | 222 | 1.2 | % | |||||||||||||||||||||||||||||||||||||
Average active accounts (in thousands)(3) | 18,375 | 17,655 | 17,258 | 17,318 | 16,898 | 1,477 | 8.7 | % | 17,685 | 16,593 | 1,092 | 6.6 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 1,025 | $ | 973 | $ | 891 | $ | 903 | $ | 976 | $ | 49 | 5.0 | % | $ | 3,792 | $ | 3,801 | $ | (9) | (0.2) | % | |||||||||||||||||||||||||||||||||||||
| Other income | $ | (28) | $ | (19) | $ | (28) | $ | (12) | $ | (26) | $ | (2) | 7.7 | % | $ | (87) | $ | (54) | $ | (33) | 61.1 | % | |||||||||||||||||||||||||||||||||||||
| DIVERSIFIED & VALUE | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Purchase volume(1) | $ | 14,154 | $ | 12,006 | $ | 11,618 | $ | 9,220 | $ | 11,267 | $ | 2,887 | 25.6 | % | $ | 46,998 | $ | 37,985 | $ | 9,013 | 23.7 | % | |||||||||||||||||||||||||||||||||||||
| Period-end loan receivables | $ | 16,075 | $ | 14,415 | $ | 14,357 | $ | 14,217 | $ | 15,761 | $ | 314 | 2.0 | % | $ | 16,075 | $ | 15,761 | $ | 314 | 2.0 | % | |||||||||||||||||||||||||||||||||||||
| Average loan receivables, including held for sale | $ | 14,999 | $ | 14,328 | $ | 14,101 | $ | 14,574 | $ | 15,024 | $ | (25) | (0.2) | % | $ | 14,501 | $ | 15,724 | $ | (1,223) | (7.8) | % | |||||||||||||||||||||||||||||||||||||
Average active accounts (in thousands)(3) | 18,829 | 17,903 | 17,301 | 17,457 | 17,324 | 1,505 | 8.7 | % | 17,953 | 17,987 | (34) | (0.2) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 817 | $ | 780 | $ | 729 | $ | 789 | $ | 822 | $ | (5) | (0.6) | % | $ | 3,115 | $ | 3,528 | $ | (413) | (11.7) | % | |||||||||||||||||||||||||||||||||||||
| Other income | $ | (23) | $ | (8) | $ | (2) | $ | 5 | $ | 20 | $ | (43) | (215.0) | % | $ | (28) | $ | 90 | $ | (118) | (131.1) | % | |||||||||||||||||||||||||||||||||||||
| HEALTH & WELLNESS | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Purchase volume(1) | $ | 3,055 | $ | 3,024 | $ | 2,988 | $ | 2,648 | $ | 2,676 | $ | 379 | 14.2 | % | $ | 11,715 | $ | 10,025 | $ | 1,690 | 16.9 | % | |||||||||||||||||||||||||||||||||||||
| Period-end loan receivables | $ | 10,244 | $ | 9,879 | $ | 9,515 | $ | 9,317 | $ | 9,580 | $ | 664 | 6.9 | % | $ | 10,244 | $ | 9,580 | $ | 664 | 6.9 | % | |||||||||||||||||||||||||||||||||||||
| Average loan receivables, including held for sale | $ | 10,057 | $ | 9,654 | $ | 9,334 | $ | 9,442 | $ | 9,476 | $ | 581 | 6.1 | % | $ | 9,623 | $ | 9,591 | $ | 32 | 0.3 | % | |||||||||||||||||||||||||||||||||||||
Average active accounts (in thousands)(3) | 5,922 | 5,707 | 5,585 | 5,706 | 5,724 | 198 | 3.5 | % | 5,739 | 5,952 | (213) | (3.6) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 603 | $ | 587 | $ | 523 | $ | 558 | $ | 589 | $ | 14 | 2.4 | % | $ | 2,271 | $ | 2,273 | $ | (2) | (0.1) | % | |||||||||||||||||||||||||||||||||||||
| Other income | $ | 42 | $ | 41 | $ | 36 | $ | 40 | $ | 27 | $ | 15 | 55.6 | % | $ | 159 | $ | 107 | $ | 52 | 48.6 | % | |||||||||||||||||||||||||||||||||||||
| LIFESTYLE | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Purchase volume(1) | $ | 1,462 | $ | 1,298 | $ | 1,405 | $ | 1,154 | $ | 1,383 | $ | 79 | 5.7 | % | $ | 5,319 | $ | 4,933 | $ | 386 | 7.8 | % | |||||||||||||||||||||||||||||||||||||
| Period-end loan receivables | $ | 5,479 | $ | 5,234 | $ | 5,158 | $ | 4,988 | $ | 5,098 | $ | 381 | 7.5 | % | $ | 5,479 | $ | 5,098 | $ | 381 | 7.5 | % | |||||||||||||||||||||||||||||||||||||
| Average loan receivables, including held for sale | $ | 5,297 | $ | 5,185 | $ | 5,050 | $ | 5,003 | $ | 4,920 | $ | 377 | 7.7 | % | $ | 5,135 | $ | 4,727 | $ | 408 | 8.6 | % | |||||||||||||||||||||||||||||||||||||
Average active accounts (in thousands)(3) | 2,548 | 2,465 | 2,442 | 2,573 | 2,536 | 12 | 0.5 | % | 2,515 | 2,568 | (53) | (2.1) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 194 | $ | 187 | $ | 182 | $ | 181 | $ | 187 | $ | 7 | 3.7 | % | $ | 744 | $ | 734 | $ | 10 | 1.4 | % | |||||||||||||||||||||||||||||||||||||
| Other income | $ | 6 | $ | 6 | $ | 6 | $ | 5 | $ | 6 | $ | — | — | % | $ | 23 | $ | 20 | $ | 3 | 15.0 | % | |||||||||||||||||||||||||||||||||||||
CORP, OTHER(4)(6) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Purchase volume(1)(2) | $ | 4,031 | $ | 3,535 | $ | 3,657 | $ | 3,050 | $ | 3,845 | $ | 186 | 4.8 | % | $ | 14,273 | $ | 12,843 | $ | 1,430 | 11.1 | % | |||||||||||||||||||||||||||||||||||||
Period-end loan receivables(5) | $ | 410 | $ | 1,014 | $ | 4,523 | $ | 4,487 | $ | 5,066 | $ | (4,656) | (91.9) | % | $ | 410 | $ | 5,066 | $ | (4,656) | (91.9) | % | |||||||||||||||||||||||||||||||||||||
| Average loan receivables, including held for sale | $ | 4,588 | $ | 4,461 | $ | 4,442 | $ | 4,629 | $ | 4,962 | $ | (374) | (7.5) | % | $ | 4,531 | $ | 5,180 | $ | (649) | (12.5) | % | |||||||||||||||||||||||||||||||||||||
Average active accounts (in thousands)(2)(3) | 6,068 | 5,943 | 5,917 | 6,077 | 6,342 | (274) | (4.3) | % | 6,028 | 6,453 | (425) | (6.6) | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 277 | $ | 268 | $ | 249 | $ | 265 | $ | 286 | $ | (9) | (3.1) | % | $ | 1,059 | $ | 1,212 | $ | (153) | (12.6) | % | |||||||||||||||||||||||||||||||||||||
| Other income | $ | 152 | $ | 56 | $ | 61 | $ | 76 | $ | 40 | $ | 112 | 280.0 | % | $ | 345 | $ | 182 | $ | 163 | 89.6 | % | |||||||||||||||||||||||||||||||||||||
| TOTAL SYF | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Purchase volume(1)(2) | $ | 47,072 | $ | 41,912 | $ | 42,121 | $ | 34,749 | $ | 39,874 | $ | 7,198 | 18.1 | % | $ | 165,854 | $ | 139,084 | $ | 26,770 | 19.2 | % | |||||||||||||||||||||||||||||||||||||
Period-end loan receivables(5) | $ | 80,740 | $ | 76,388 | $ | 78,374 | $ | 76,858 | $ | 81,867 | $ | (1,127) | (1.4) | % | $ | 80,740 | $ | 81,867 | $ | (1,127) | (1.4) | % | |||||||||||||||||||||||||||||||||||||
| Average loan receivables, including held for sale | $ | 81,784 | $ | 78,714 | $ | 76,821 | $ | 78,358 | $ | 79,452 | $ | 2,332 | 2.9 | % | $ | 78,928 | $ | 80,138 | $ | (1,210) | (1.5) | % | |||||||||||||||||||||||||||||||||||||
Average active accounts (in thousands)(2)(3) | 69,397 | 67,189 | 65,810 | 66,280 | 66,261 | 3,136 | 4.7 | % | 67,334 | 67,131 | 203 | 0.3 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 4,042 | $ | 3,887 | $ | 3,567 | $ | 3,732 | $ | 3,981 | $ | 61 | 1.5 | % | $ | 15,228 | $ | 15,950 | $ | (722) | (4.5) | % | |||||||||||||||||||||||||||||||||||||
| Other income | $ | 167 | $ | 94 | $ | 89 | $ | 131 | $ | 82 | $ | 85 | 103.7 | % | $ | 481 | $ | 405 | $ | 76 | 18.8 | % | |||||||||||||||||||||||||||||||||||||
| (1) Purchase volume, or net credit sales, represents the aggregate amount of charges incurred on credit cards or other credit product accounts less returns during the period. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (2) Includes activity and balances associated with loan receivables held for sale. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (3) Active accounts represent credit card or installment loan accounts on which there has been a purchase, payment or outstanding balance in the current month. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (4) Includes activity and balances associated with our program agreement with Gap Inc. and BP except where noted, which are both scheduled to expire in 2Q 2022. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (5) Reflects the reclassification of $3.5 billion and $0.5 billion to loan receivables held for sale in 3Q 2021 and 4Q 2021, respectively. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (6) In December 2021, we entered into an agreement to sell $0.5 billion of loan receivables associated with our program agreement with BP. In connection with this agreement, revenue activities for the BP portfolio are no longer managed within our Home & Auto sales platform. All metrics for the BP portfolio previously reported within our Home & Auto sales platform, are now reported within our Corp, Other information. We have recast all prior-period reported metrics for our Home & Auto sales platform and Corp, Other to conform to the current-period presentation. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
8
| SYNCHRONY FINANCIAL | |||||||||||||||||||||||||||||
RECONCILIATION OF NON-GAAP MEASURES AND CALCULATIONS OF REGULATORY MEASURES(1) | |||||||||||||||||||||||||||||
| (unaudited, $ in millions, except per share statistics) | |||||||||||||||||||||||||||||
| Quarter Ended | |||||||||||||||||||||||||||||
| Dec 31, 2021 | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | |||||||||||||||||||||||||
COMMON EQUITY AND REGULATORY CAPITAL MEASURES(2) | |||||||||||||||||||||||||||||
| GAAP Total equity | $ | 13,655 | $ | 13,936 | $ | 14,197 | $ | 13,439 | $ | 12,701 | |||||||||||||||||||
| Less: Preferred stock | (734) | (734) | (734) | (734) | (734) | ||||||||||||||||||||||||
| Less: Goodwill | (1,105) | (1,105) | (1,105) | (1,104) | (1,078) | ||||||||||||||||||||||||
| Less: Intangible assets, net | (1,168) | (1,090) | (1,098) | (1,169) | (1,125) | ||||||||||||||||||||||||
| Tangible common equity | $ | 10,648 | $ | 11,007 | $ | 11,260 | $ | 10,432 | $ | 9,764 | |||||||||||||||||||
| Add: CECL transition amount | 2,292 | 2,274 | 2,376 | 2,595 | 2,686 | ||||||||||||||||||||||||
| Adjustments for certain deferred tax liabilities and certain items in accumulated comprehensive income (loss) | 329 | 299 | 301 | 354 | 341 | ||||||||||||||||||||||||
| Common equity Tier 1 | $ | 13,269 | $ | 13,580 | $ | 13,937 | $ | 13,381 | $ | 12,791 | |||||||||||||||||||
| Preferred stock | 734 | 734 | 734 | 734 | 734 | ||||||||||||||||||||||||
| Tier 1 capital | $ | 14,003 | $ | 14,314 | $ | 14,671 | $ | 14,115 | $ | 13,525 | |||||||||||||||||||
| Add: Allowance for credit losses includible in risk-based capital | 1,119 | 1,052 | 1,039 | 1,031 | 1,079 | ||||||||||||||||||||||||
| Total Risk-based capital | $ | 15,122 | $ | 15,366 | $ | 15,710 | $ | 15,146 | $ | 14,604 | |||||||||||||||||||
ASSET MEASURES(2) | |||||||||||||||||||||||||||||
| Total average assets | $ | 94,707 | $ | 91,948 | $ | 93,389 | $ | 96,455 | $ | 95,965 | |||||||||||||||||||
| Adjustments for: | |||||||||||||||||||||||||||||
| Add: CECL transition amount | 2,292 | 2,274 | 2,376 | 2,595 | 2,686 | ||||||||||||||||||||||||
| Disallowed goodwill and other disallowed intangible assets (net of related deferred tax liabilities) and other | (1,999) | (1,960) | (1,965) | (1,987) | (1,924) | ||||||||||||||||||||||||
| Total assets for leverage purposes | $ | 95,000 | $ | 92,262 | $ | 93,800 | $ | 97,063 | $ | 96,727 | |||||||||||||||||||
| Risk-weighted assets | $ | 84,950 | $ | 79,597 | $ | 78,281 | $ | 76,965 | $ | 80,561 | |||||||||||||||||||
| CECL FULLY PHASED-IN CAPITAL MEASURES | |||||||||||||||||||||||||||||
| Tier 1 capital | $ | 14,003 | $ | 14,314 | $ | 14,671 | $ | 14,115 | $ | 13,525 | |||||||||||||||||||
| Less: CECL transition adjustment | (2,292) | (2,274) | (2,376) | (2,595) | (2,686) | ||||||||||||||||||||||||
| Tier 1 capital (CECL fully phased-in) | $ | 11,711 | $ | 12,040 | $ | 12,295 | $ | 11,520 | $ | 10,839 | |||||||||||||||||||
| Add: Allowance for credit losses | 8,688 | 8,616 | 9,023 | 9,901 | 10,265 | ||||||||||||||||||||||||
| Tier 1 capital (CECL fully phased-in) + Reserves for credit losses | $ | 20,399 | $ | 20,656 | $ | 21,318 | $ | 21,421 | $ | 21,104 | |||||||||||||||||||
| Risk-weighted assets | $ | 84,950 | $ | 79,597 | $ | 78,281 | $ | 76,965 | $ | 80,561 | |||||||||||||||||||
| Less: CECL transition adjustment | (1,353) | (2,065) | (2,166) | (2,386) | (2,477) | ||||||||||||||||||||||||
| Risk-weighted assets (CECL fully phased-in) | $ | 83,597 | $ | 77,532 | $ | 76,115 | $ | 74,579 | $ | 78,084 | |||||||||||||||||||
| TANGIBLE COMMON EQUITY PER SHARE | |||||||||||||||||||||||||||||
| GAAP book value per share | $ | 24.53 | $ | 24.13 | $ | 23.48 | $ | 21.86 | $ | 20.49 | |||||||||||||||||||
| Less: Goodwill | (2.10) | (2.02) | (1.93) | (1.90) | (1.85) | ||||||||||||||||||||||||
| Less: Intangible assets, net | (2.22) | (1.99) | (1.91) | (2.01) | (1.92) | ||||||||||||||||||||||||
| Tangible common equity per share | $ | 20.21 | $ | 20.12 | $ | 19.64 | $ | 17.95 | $ | 16.72 | |||||||||||||||||||
| (1) Regulatory measures at December 31, 2021 are presented on an estimated basis. | |||||||||||||||||||||||||||||
| (2) Capital ratios starting March 31, 2020 reflect election to delay for two years an estimate of CECL’s effect on regulatory capital in accordance with the interim final rule issued by U.S. banking agencies in March 2020. | |||||||||||||||||||||||||||||
9
4Q'21 FINANCIAL RESULTS January 28th, 2021 Exhibit 99.3
2 Cautionary Statement Regarding Forward-Looking Statements The following slides are part of a presentation by Synchrony Financial in connection with reporting quarterly financial results. No representation is made that the information in these slides is complete. For additional information, see the earnings release and financial supplement included as exhibits to our Current Report on Form 8-K filed today and available on our website (www.synchronyfinancial.com) and the SEC's website (www.sec.gov). All references to net earnings and net income are intended to have the same meaning. All comparisons are for the fourth quarter of 2021 compared to the fourth quarter of 2020, unless otherwise noted. This presentation contains certain forward-looking statements as defined in Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, which are subject to the "safe harbor" created by those sections. Forward-looking statements may be identified by words such as "expects," "intends," "anticipates," "plans," "believes," "seeks," "targets," "outlook," "estimates," "will," "should," "may" or words of similar meaning, but these words are not the exclusive means of identifying forward-looking statements. Forward- looking statements are based on management's current expectations and assumptions, and are subject to inherent uncertainties, risks and changes in circumstances that are difficult to predict. As a result, actual results could differ materially from those indicated in these forward-looking statements. Factors that could cause actual results to differ materially include global political, economic, business, competitive, market, regulatory and other factors and risks, such as: the impact of macroeconomic conditions and whether industry trends we have identified develop as anticipated, including the future impacts of the novel coronavirus disease (“COVID-19”) outbreak and measures taken in response thereto for which future developments are highly uncertain and difficult to predict; retaining existing partners and attracting new partners, concentration of our revenue in a small number of partners, and promotion and support of our products by our partners; cyber-attacks or other security breaches; disruptions in the operations of our and our outsourced partners' computer systems and data centers; the financial performance of our partners; the sufficiency of our allowance for credit losses and the accuracy of the assumptions or estimates used in preparing our financial statements, including those related to the CECL accounting guidance; higher borrowing costs and adverse financial market conditions impacting our funding and liquidity, and any reduction in our credit ratings; our ability to grow our deposits in the future; damage to our reputation; our ability to securitize our loan receivables, occurrence of an early amortization of our securitization facilities, loss of the right to service or sub-service our securitized loan receivables, and lower payment rates on our securitized loan receivables; changes in market interest rates and the impact of any margin compression; effectiveness of our risk management processes and procedures, reliance on models which may be inaccurate or misinterpreted, our ability to manage our credit risk; our ability to offset increases in our costs in retailer share arrangements; competition in the consumer finance industry; our concentration in the U.S. consumer credit market; our ability to successfully develop and commercialize new or enhanced products and services; our ability to realize the value of acquisitions and strategic investments; reductions in interchange fees; fraudulent activity; failure of third-parties to provide various services that are important to our operations; international risks and compliance and regulatory risks and costs associated with international operations; alleged infringement of intellectual property rights of others and our ability to protect our intellectual property; litigation and regulatory actions; our ability to attract, retain and motivate key officers and employees; tax legislation initiatives or challenges to our tax positions and/or interpretations, and state sales tax rules and regulations; regulation, supervision, examination and enforcement of our business by governmental authorities, the impact of the Dodd-Frank Wall Street Reform and Consumer Protection Act (the “Dodd-Frank Act”) and other legislative and regulatory developments and the impact of the Consumer Financial Protection Bureau’s (the “CFPB”) regulation of our business; impact of capital adequacy rules and liquidity requirements; restrictions that limit our ability to pay dividends and repurchase our common stock, and restrictions that limit the Bank’s ability to pay dividends to us; regulations relating to privacy, information security and data protection; use of third-party vendors and ongoing third-party business relationships; and failure to comply with anti-money laundering and anti-terrorism financing laws. For the reasons described above, we caution you against relying on any forward-looking statements, which should also be read in conjunction with the other cautionary statements that are included elsewhere in this presentation and in our public filings, including under the heading “Risk Factors Relating to Our Business” and “Risk Factors Relating to Regulation” in the Company's Annual Report on Form 10-K for the fiscal year ended December 31, 2020, as filed on February 11, 2021. You should not consider any list of such factors to be an exhaustive statement of all the risks, uncertainties, or potentially inaccurate assumptions that could cause our current expectations or beliefs to change. Further, any forward-looking statement speaks only as of the date on which it is made, and we undertake no obligation to update or revise any forward-looking statement to reflect events or circumstances after the date on which the statement is made or to reflect the occurrence of unanticipated events, except as otherwise may be required by law. Disclaimers
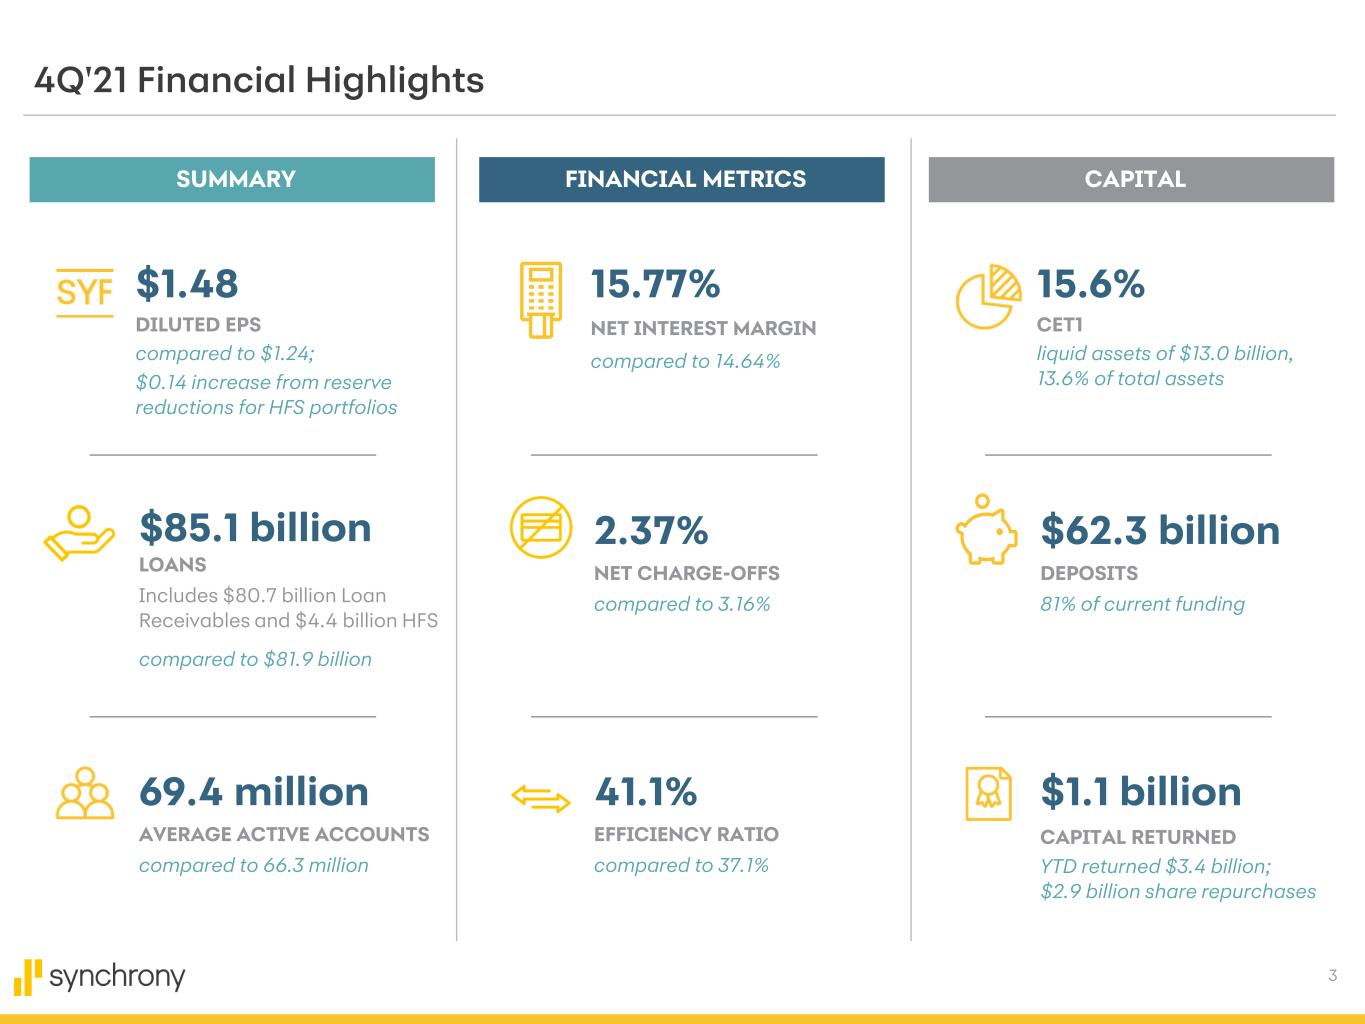
3 $1.48 DILUTED EPS compared to $1.24; $0.14 increase from reserve reductions for HFS portfolios 15.77% NET INTEREST MARGIN compared to 14.64% 15.6% CET1 liquid assets of $13.0 billion, 13.6% of total assets SUMMARY FINANCIAL METRICS CAPITAL 4Q'21 Financial Highlights $85.1 billion LOANS Includes $80.7 billion Loan Receivables and $4.4 billion HFS compared to $81.9 billion $62.3 billion DEPOSITS 81% of current funding 2.37% NET CHARGE-OFFS compared to 3.16% 69.4 million AVERAGE ACTIVE ACCOUNTS compared to 66.3 million $1.1 billion CAPITAL RETURNED YTD returned $3.4 billion; $2.9 billion share repurchases 41.1% EFFICIENCY RATIO compared to 37.1%
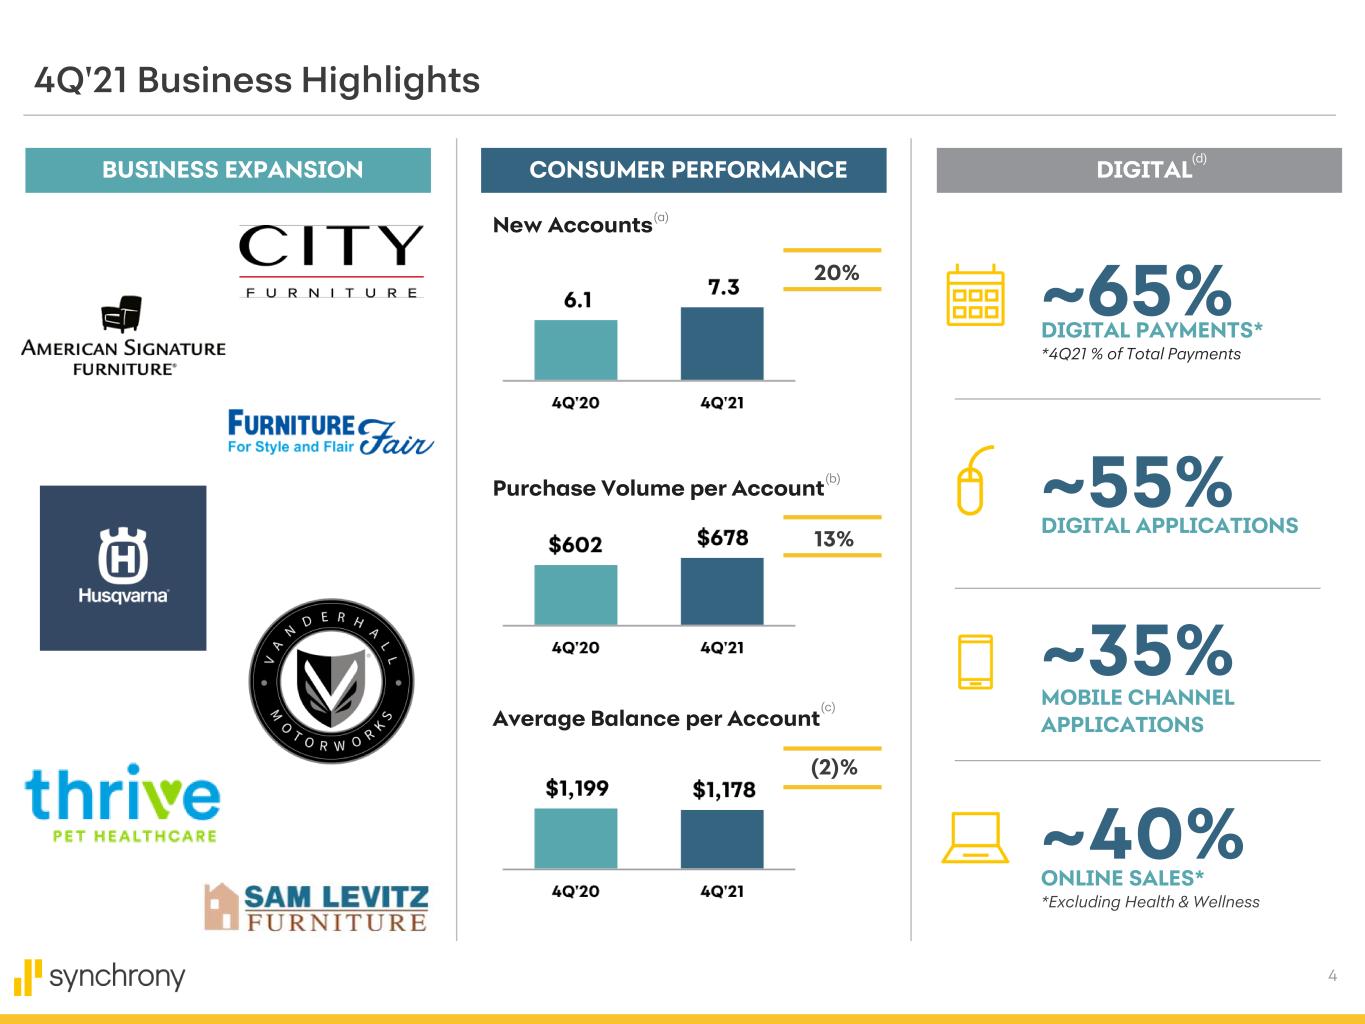
4 ~65% 4Q'21 Business Highlights BUSINESS EXPANSION CONSUMER PERFORMANCE DIGITAL 20% 13% (2)% New Accounts Purchase Volume per Account Average Balance per Account (a) (b) (c) ~40% ONLINE SALES* *Excluding Health & Wellness DIGITAL APPLICATIONS ~35% MOBILE CHANNEL APPLICATIONS DIGITAL PAYMENTS* *4Q21 % of Total Payments ~55% (d)
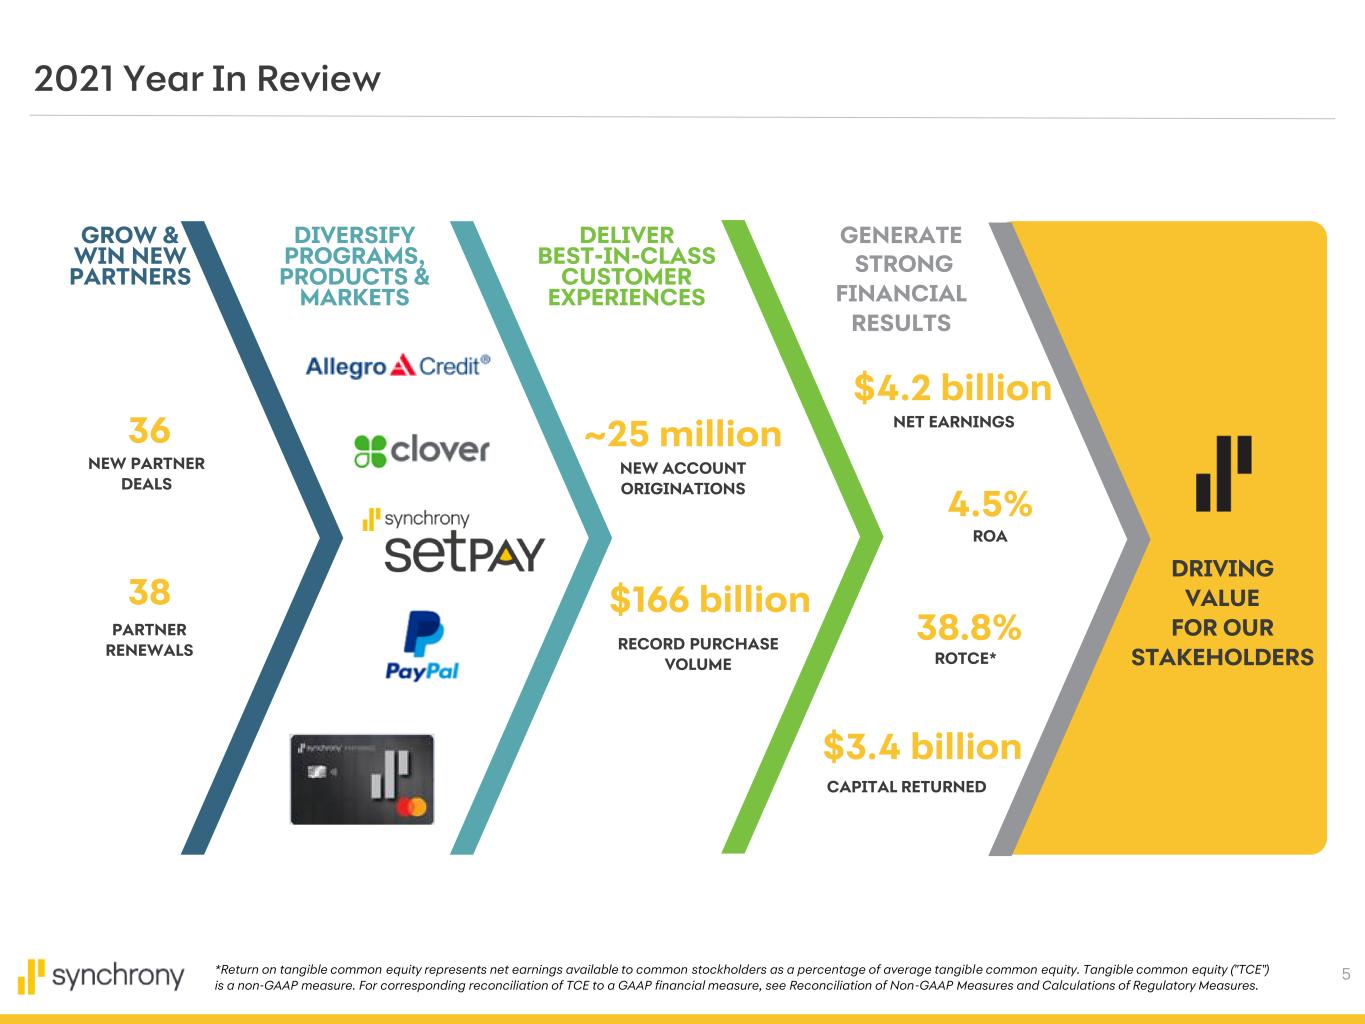
5 GENERATE STRONG FINANCIAL RESULTS DIVERSIFY PROGRAMS, PRODUCTS & MARKETS GROW & WIN NEW PARTNERS DELIVER BEST-IN-CLASS CUSTOMER EXPERIENCES 36 NEW PARTNER DEALS ~25 million NEW ACCOUNT ORIGINATIONS 2021 Year In Review 38 PARTNER RENEWALS 38.8% ROTCE* 4.5% ROA $4.2 billion NET EARNINGS $166 billion RECORD PURCHASE VOLUME $3.4 billion CAPITAL RETURNED DRIVING VALUE FOR OUR STAKEHOLDERS *Return on tangible common equity represents net earnings available to common stockholders as a percentage of average tangible common equity. Tangible common equity ("TCE") is a non-GAAP measure. For corresponding reconciliation of TCE to a GAAP financial measure, see Reconciliation of Non-GAAP Measures and Calculations of Regulatory Measures.
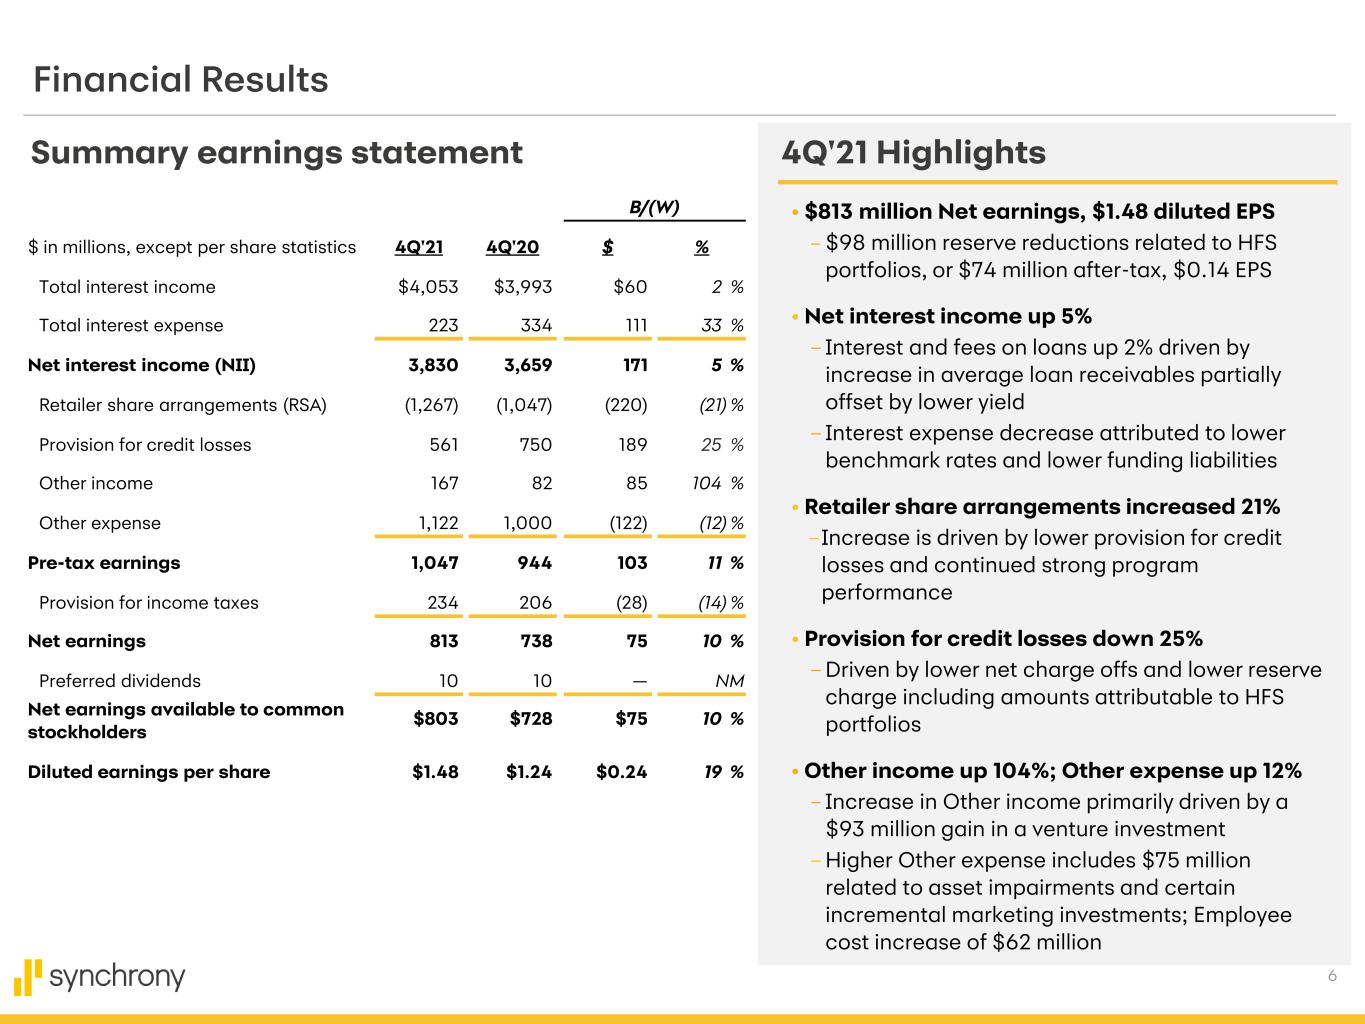
6 B/(W) $ in millions, except per share statistics 4Q'21 4Q'20 $ % Total interest income $4,053 $3,993 $60 2 % Total interest expense 223 334 111 33 % Net interest income (NII) 3,830 3,659 171 5 % Retailer share arrangements (RSA) (1,267) (1,047) (220) (21) % Provision for credit losses 561 750 189 25 % Other income 167 82 85 104 % Other expense 1,122 1,000 (122) (12) % Pre-tax earnings 1,047 944 103 11 % Provision for income taxes 234 206 (28) (14) % Net earnings 813 738 75 10 % Preferred dividends 10 10 — NM Net earnings available to common stockholders $803 $728 $75 10 % Diluted earnings per share $1.48 $1.24 $0.24 19 % Financial Results 4Q'21 HighlightsSummary earnings statement • $813 million Net earnings, $1.48 diluted EPS – $98 million reserve reductions related to HFS portfolios, or $74 million after-tax, $0.14 EPS • Net interest income up 5% – Interest and fees on loans up 2% driven by increase in average loan receivables partially offset by lower yield – Interest expense decrease attributed to lower benchmark rates and lower funding liabilities • Retailer share arrangements increased 21% –Increase is driven by lower provision for credit losses and continued strong program performance • Provision for credit losses down 25% – Driven by lower net charge offs and lower reserve charge including amounts attributable to HFS portfolios • Other income up 104%; Other expense up 12% – Increase in Other income primarily driven by a $93 million gain in a venture investment – Higher Other expense includes $75 million related to asset impairments and certain incremental marketing investments; Employee cost increase of $62 million
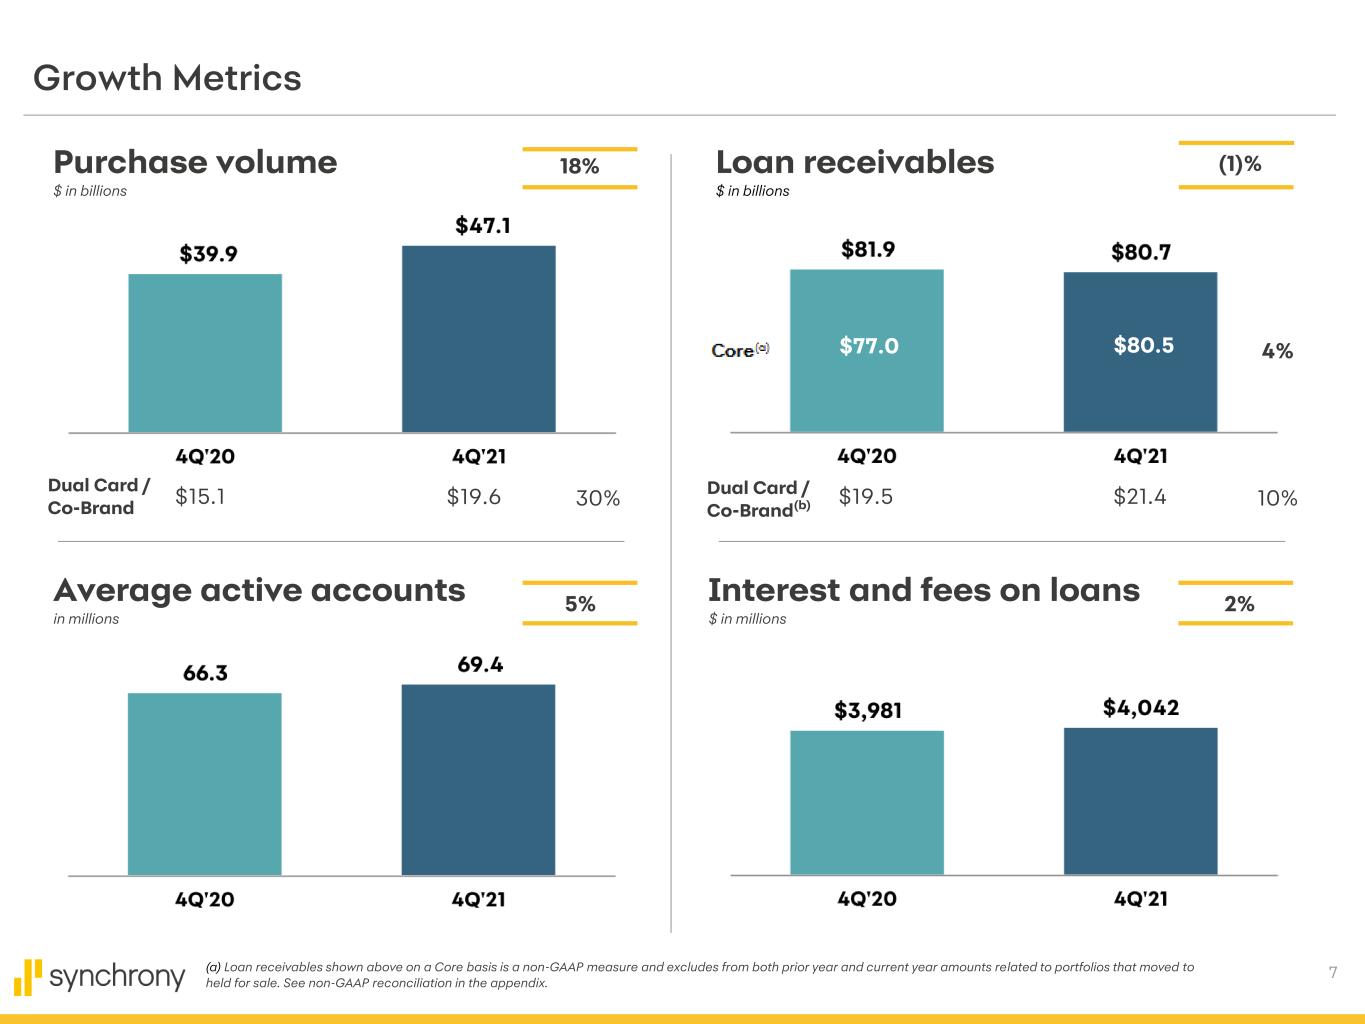
7 $44.0 Dual Card / Co-Brand Growth Metrics 59.4 62.1 $74.5 $76.3 $3,586 $3,641 $33.5 $39.0 4% 18% 5% 2% (1)%Purchase volume $ in billions Loan receivables $ in billions Average active accounts in millions Interest and fees on loans $ in millions $15.1 30%$19.6 10%$19.5 $21.4 $77.0 $80.5 (a) Loan receivables shown above on a Core basis is a non-GAAP measure and excludes from both prior year and current year amounts related to portfolios that moved to held for sale. See non-GAAP reconciliation in the appendix. Dual Card / Co-Brand(b)
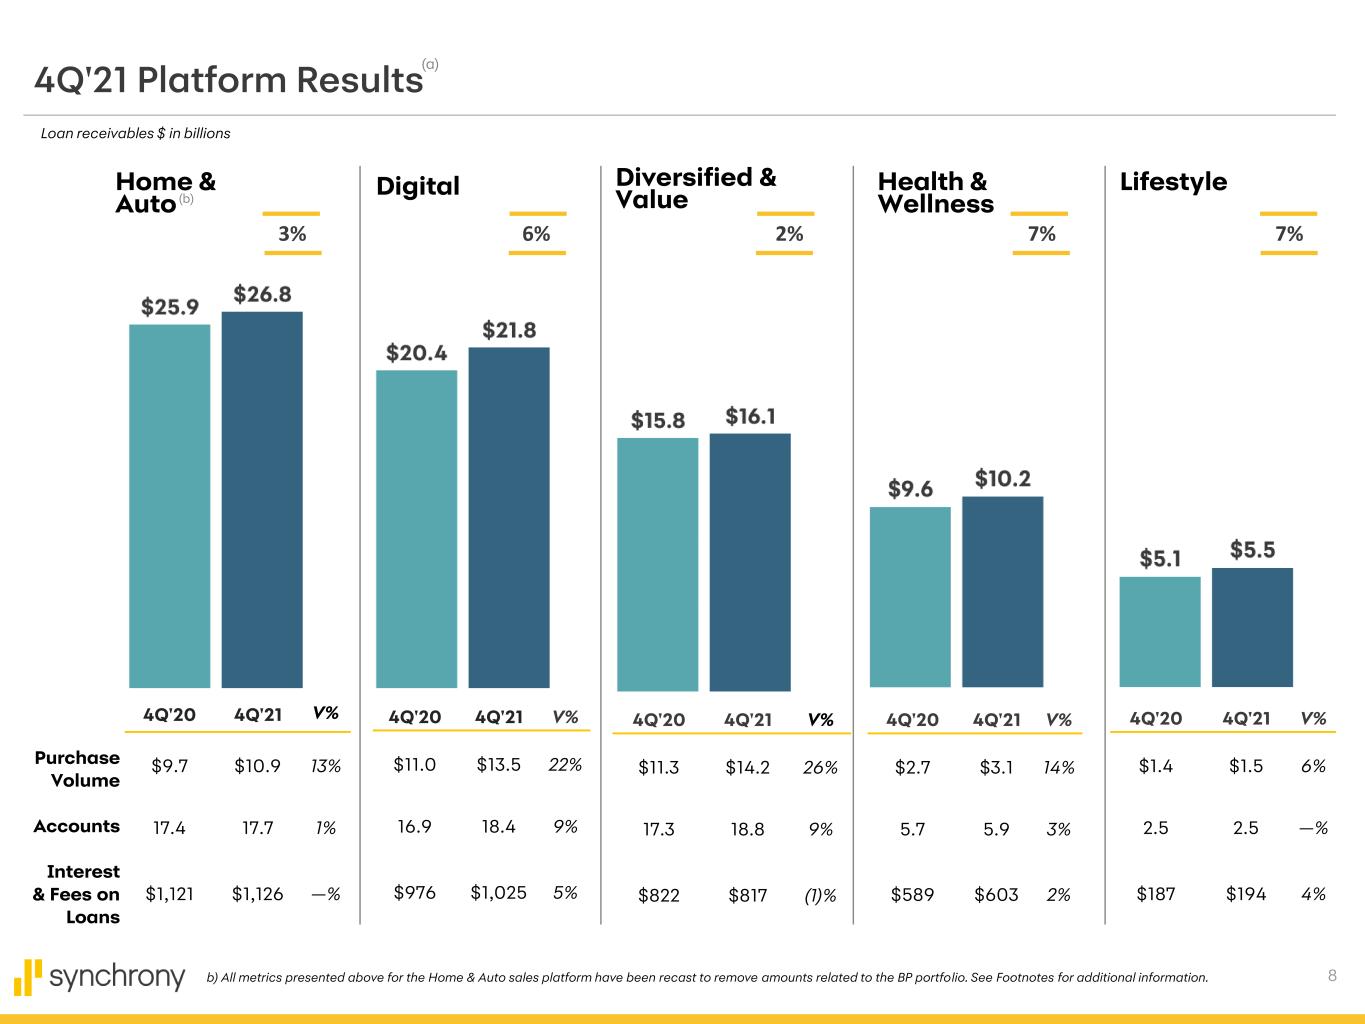
8 Home & Auto 4Q'21 Platform Results Digital Diversified & Value Health & Wellness Lifestyle 3% 2% 7% 7%6% 4Q'20 4Q'21 V% $9.7 $10.9 13% 17.4 17.7 1% $1,121 $1,126 —% 4Q'20 4Q'21 V% $11.0 $13.5 22% 16.9 18.4 9% $976 $1,025 5% 4Q'20 4Q'21 V% $11.3 $14.2 26% 17.3 18.8 9% $822 $817 (1)% 4Q'20 4Q'21 V% $2.7 $3.1 14% 5.7 5.9 3% $589 $603 2% 4Q'20 4Q'21 V% $1.4 $1.5 6% 2.5 2.5 —% $187 $194 4% Loan receivables $ in billions (a) Purchase Volume Accounts Interest & Fees on Loans b) All metrics presented above for the Home & Auto sales platform have been recast to remove amounts related to the BP portfolio. See Footnotes for additional information. (b)
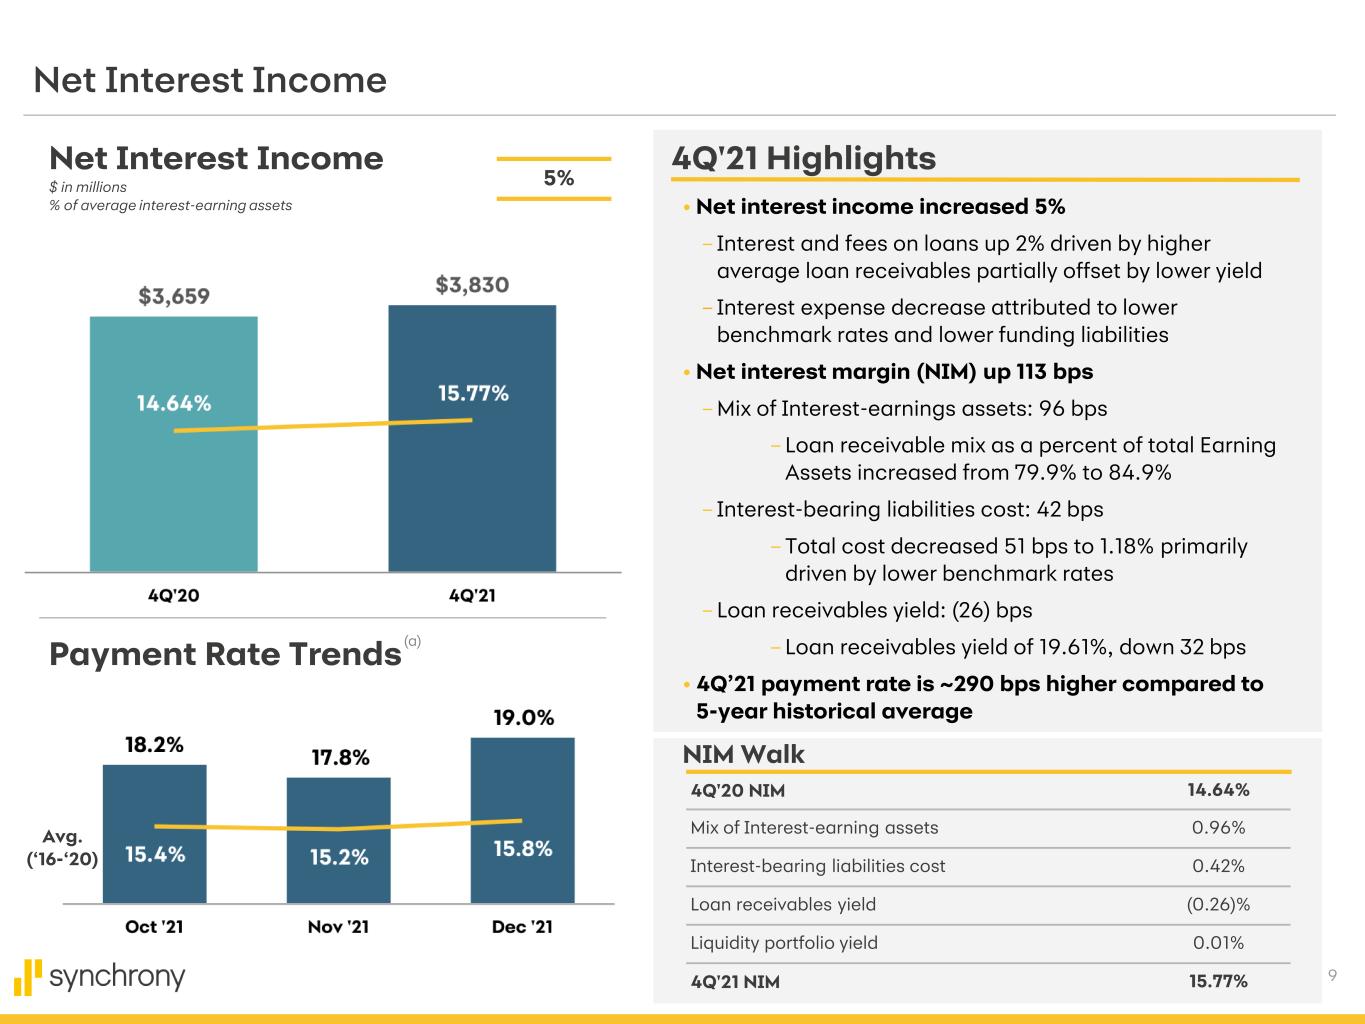
9 Net Interest Income Net Interest Income $ in millions % of average interest-earning assets • Net interest income increased 5% – Interest and fees on loans up 2% driven by higher average loan receivables partially offset by lower yield – Interest expense decrease attributed to lower benchmark rates and lower funding liabilities • Net interest margin (NIM) up 113 bps – Mix of Interest-earnings assets: 96 bps – Loan receivable mix as a percent of total Earning Assets increased from 79.9% to 84.9% – Interest-bearing liabilities cost: 42 bps – Total cost decreased 51 bps to 1.18% primarily driven by lower benchmark rates – Loan receivables yield: (26) bps – Loan receivables yield of 19.61%, down 32 bps • 4Q’21 payment rate is ~290 bps higher compared to 5-year historical average 4Q'21 Highlights 4Q'20 NIM 14.64% Mix of Interest-earning assets 0.96% Interest-bearing liabilities cost 0.42% Loan receivables yield (0.26)% Liquidity portfolio yield 0.01% 4Q'21 NIM 15.77% NIM Walk Payment Rate Trends (a) 5% Avg. (‘16-‘20)
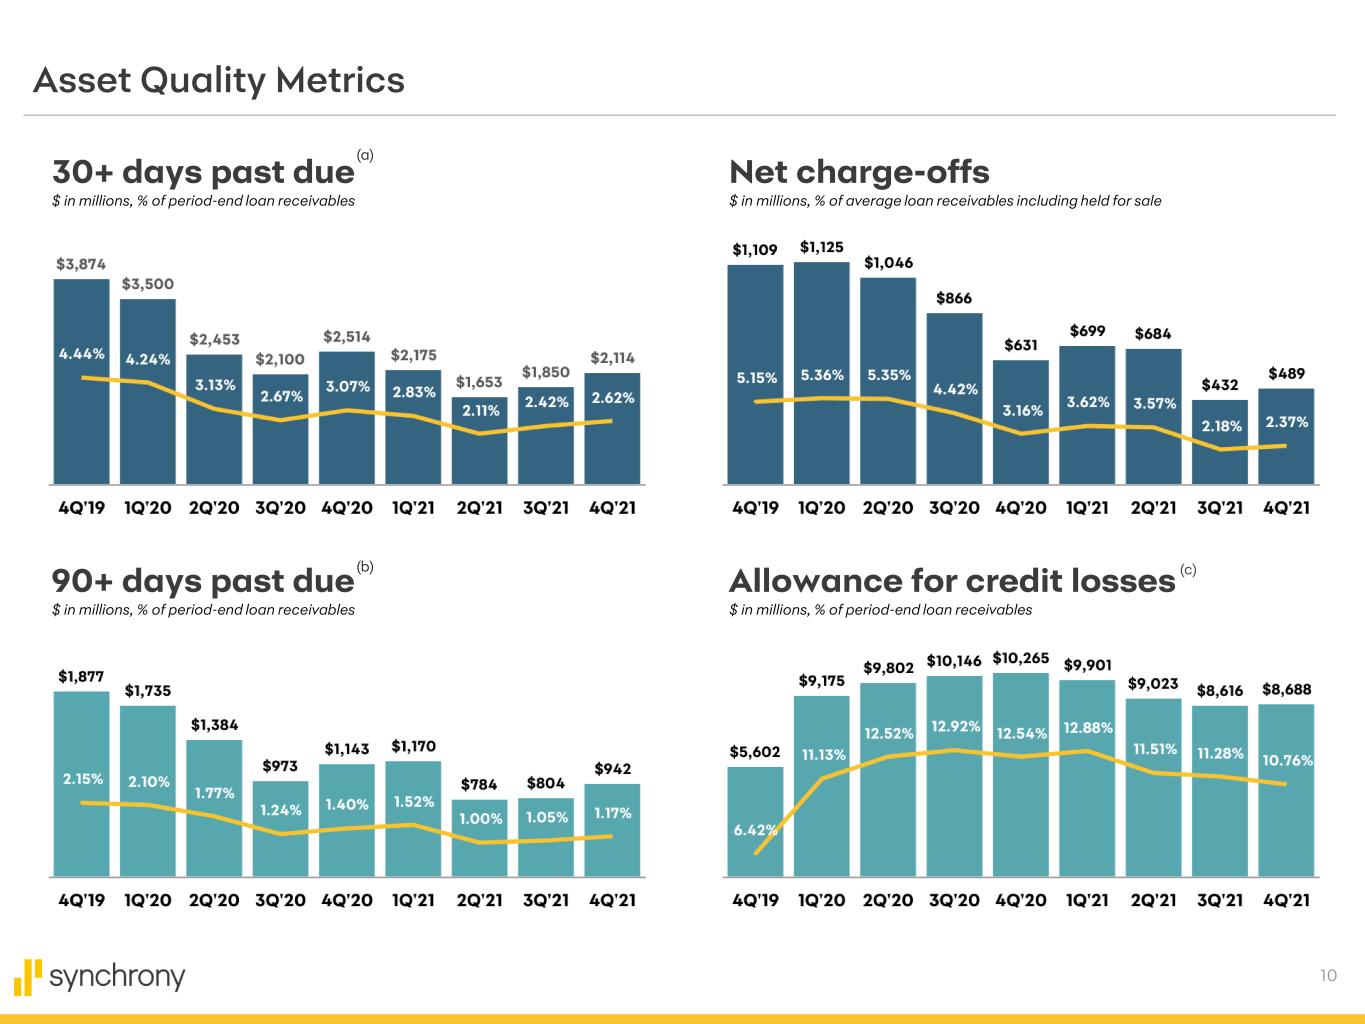
10 Asset Quality Metrics Allowance for credit losses $ in millions, % of period-end loan receivables Net charge-offs $ in millions, % of average loan receivables including held for sale 30+ days past due $ in millions, % of period-end loan receivables 90+ days past due $ in millions, % of period-end loan receivables (c) (a) (b)
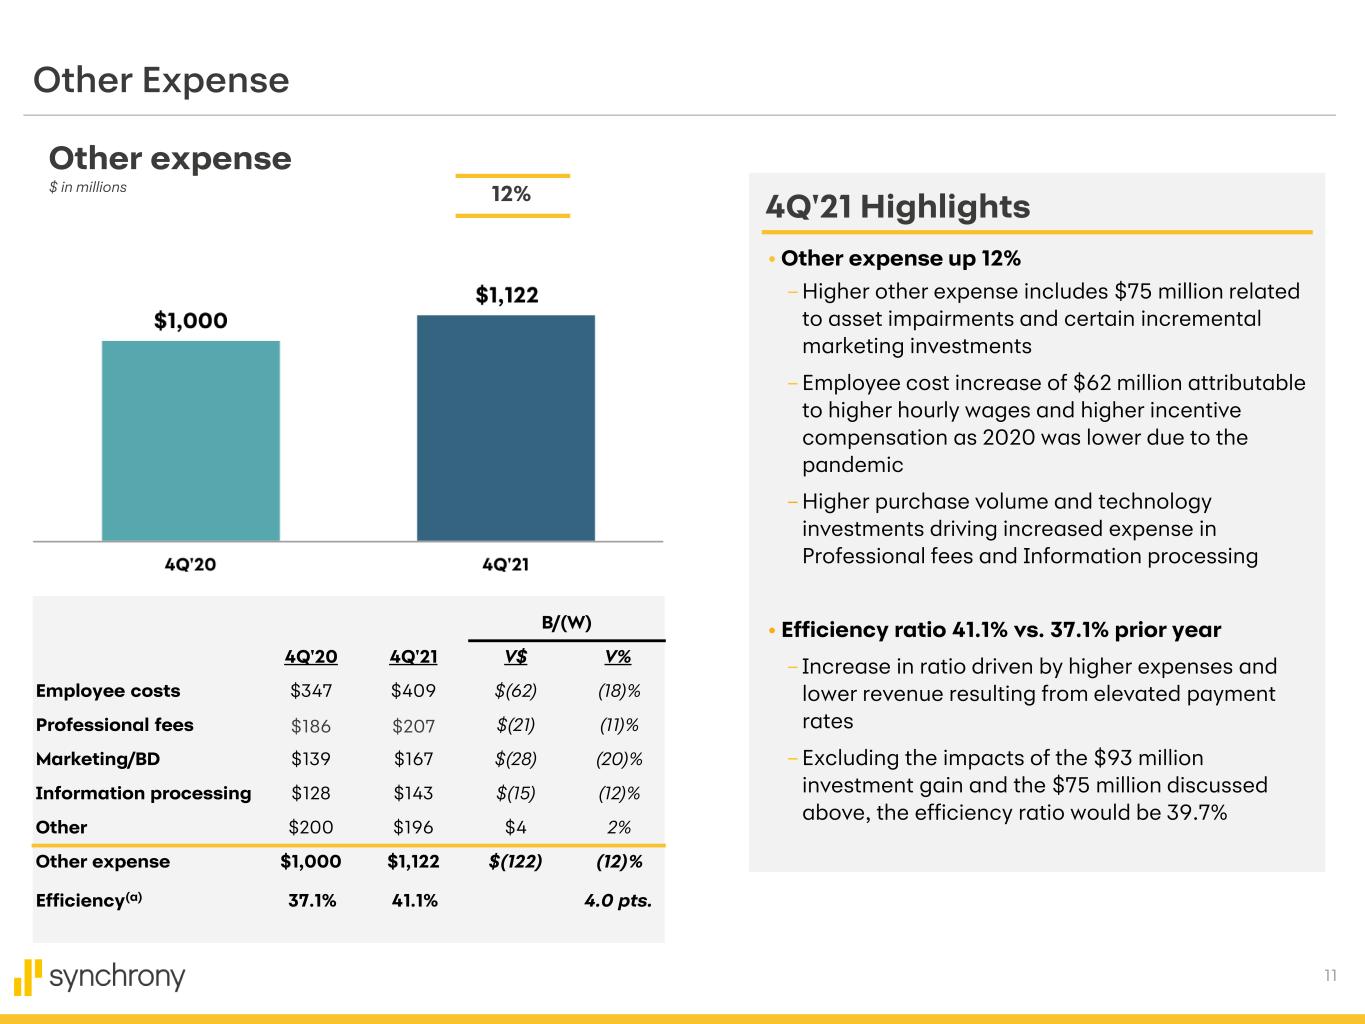
11 B/(W) 4Q'20 4Q'21 V$ V% Employee costs $347 $409 $(62) (18)% Professional fees $186 $207 $(21) (11)% Marketing/BD $139 $167 $(28) (20)% Information processing $128 $143 $(15) (12)% Other $200 $196 $4 2% Other expense $1,000 $1,122 $(122) (12)% Efficiency(a) 37.1% 41.1% 4.0 pts. Other Expense Other expense $ in millions 4Q'21 Highlights12% • Other expense up 12% – Higher other expense includes $75 million related to asset impairments and certain incremental marketing investments – Employee cost increase of $62 million attributable to higher hourly wages and higher incentive compensation as 2020 was lower due to the pandemic – Higher purchase volume and technology investments driving increased expense in Professional fees and Information processing • Efficiency ratio 41.1% vs. 37.1% prior year – Increase in ratio driven by higher expenses and lower revenue resulting from elevated payment rates – Excluding the impacts of the $93 million investment gain and the $75 million discussed above, the efficiency ratio would be 39.7%
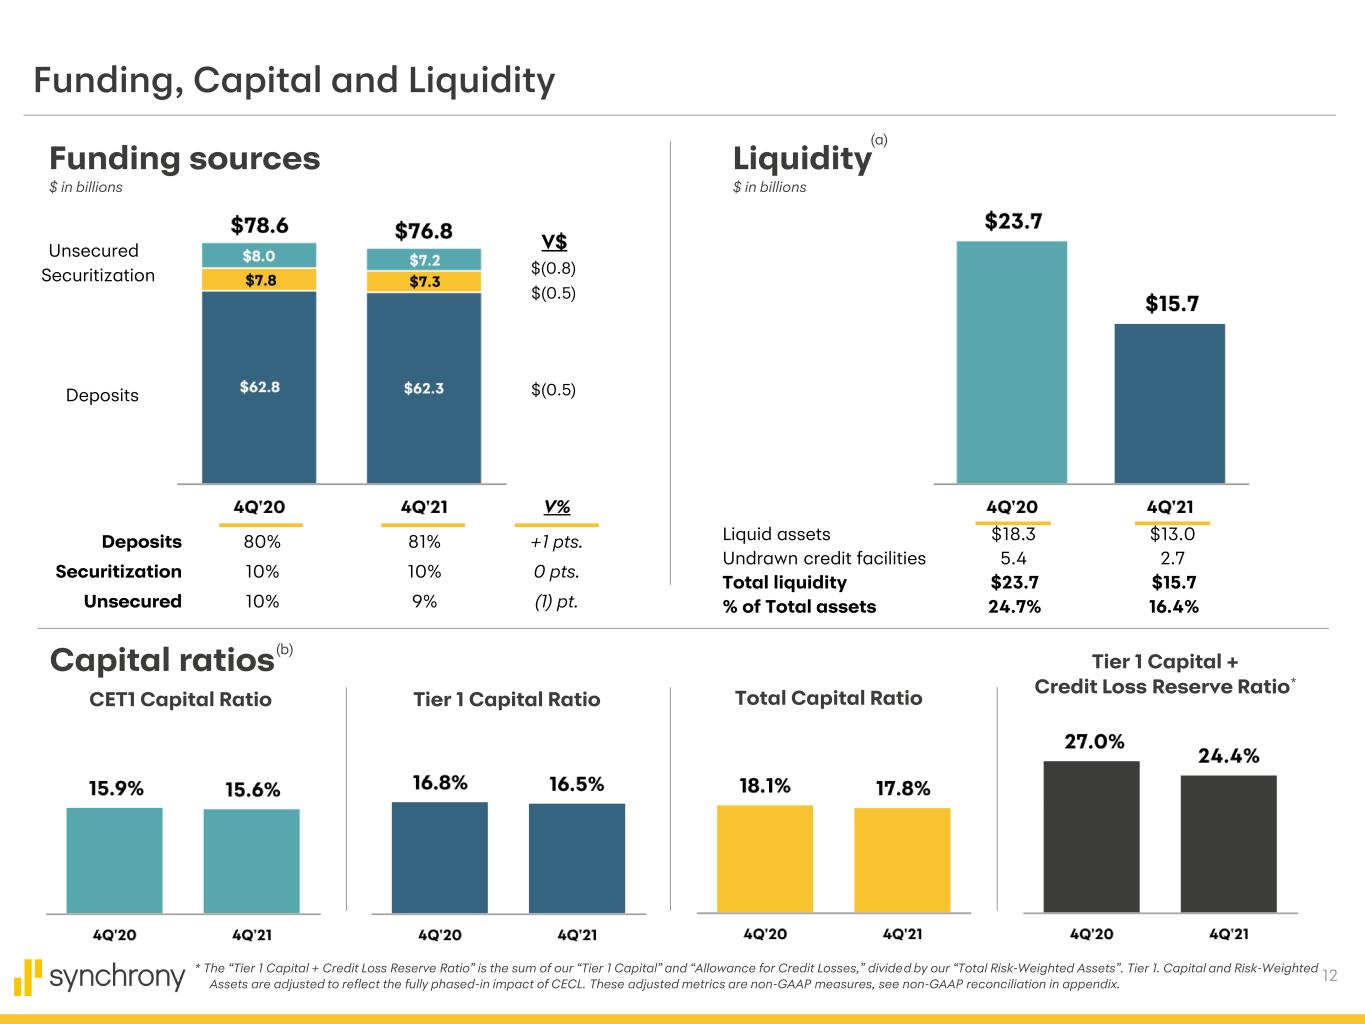
12 Tier 1 Capital + Credit Loss Reserve Ratio* Capital ratios Funding, Capital and Liquidity Funding sources $ in billions V$ $(0.8) $(0.5) $(0.5) V% Liquidity $ in billions CET1 Capital Ratio Tier 1 Capital Ratio Total Capital Ratio * The “Tier 1 Capital + Credit Loss Reserve Ratio” is the sum of our “Tier 1 Capital” and “Allowance for Credit Losses,” divided by our “Total Risk-Weighted Assets”. Tier 1. Capital and Risk-Weighted Assets are adjusted to reflect the fully phased-in impact of CECL. These adjusted metrics are non-GAAP measures, see non-GAAP reconciliation in appendix. Unsecured Securitization Deposits Deposits 80% 81% +1 pts. Securitization 10% 10% 0 pts. Unsecured 10% 9% (1) pt. Liquid assets $18.3 $13.0 Undrawn credit facilities 5.4 2.7 Total liquidity $23.7 $15.7 % of Total assets 24.7% 16.4% (a) (b)
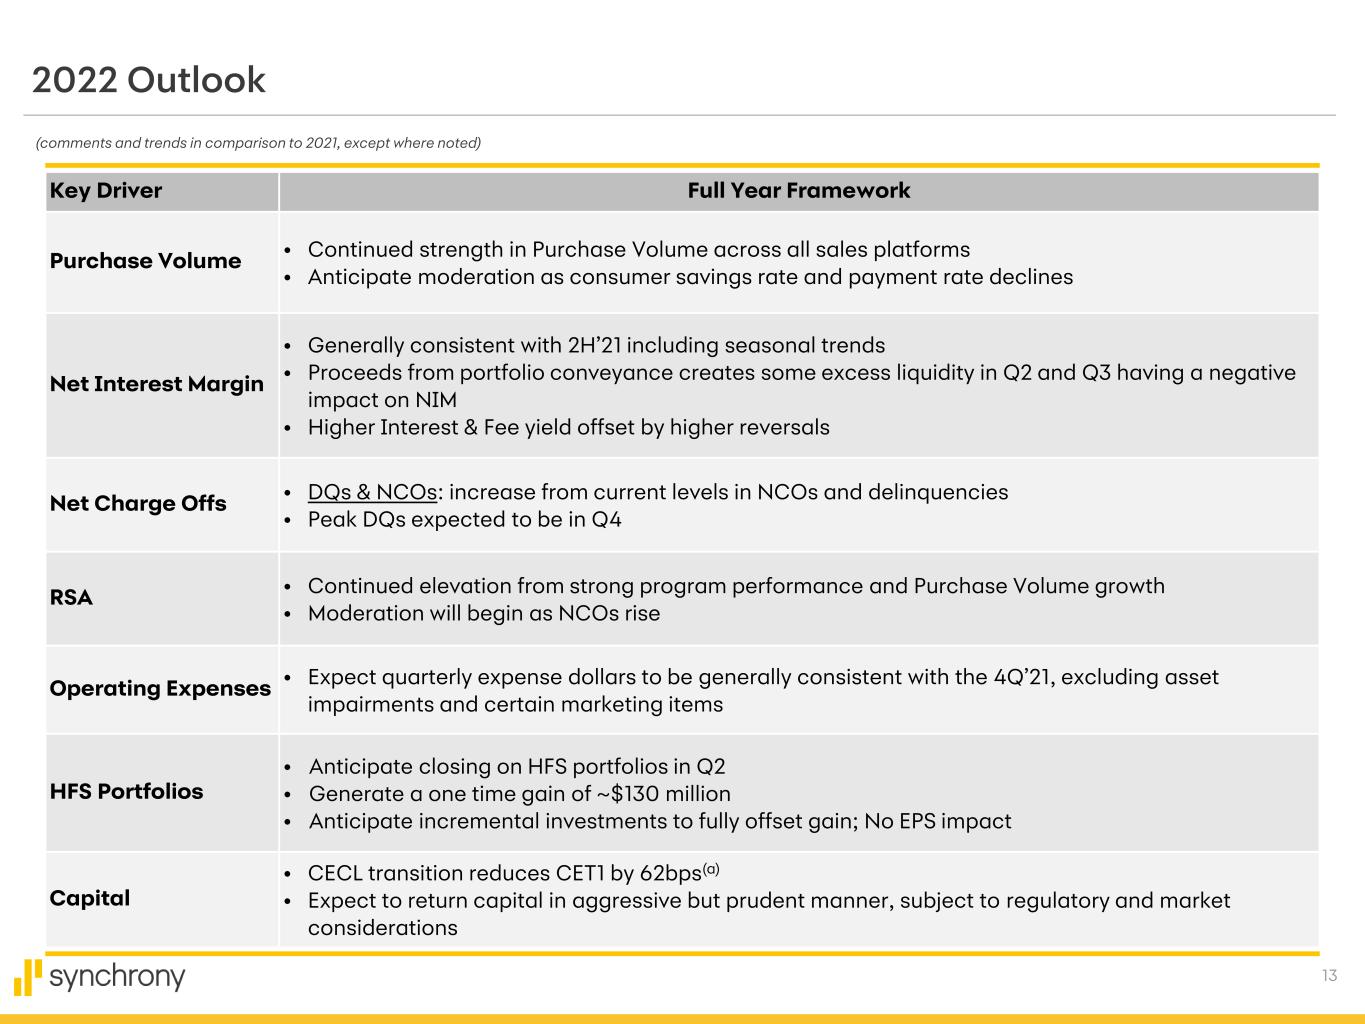
13 2022 Outlook Key Driver Full Year Framework Purchase Volume • Continued strength in Purchase Volume across all sales platforms • Anticipate moderation as consumer savings rate and payment rate declines Net Interest Margin • Generally consistent with 2H’21 including seasonal trends • Proceeds from portfolio conveyance creates some excess liquidity in Q2 and Q3 having a negative impact on NIM • Higher Interest & Fee yield offset by higher reversals Net Charge Offs • DQs & NCOs: increase from current levels in NCOs and delinquencies • Peak DQs expected to be in Q4 RSA • Continued elevation from strong program performance and Purchase Volume growth • Moderation will begin as NCOs rise Operating Expenses • Expect quarterly expense dollars to be generally consistent with the 4Q’21, excluding asset impairments and certain marketing items HFS Portfolios • Anticipate closing on HFS portfolios in Q2 • Generate a one time gain of ~$130 million • Anticipate incremental investments to fully offset gain; No EPS impact Capital • CECL transition reduces CET1 by 62bps(a) • Expect to return capital in aggressive but prudent manner, subject to regulatory and market considerations (comments and trends in comparison to 2021, except where noted)
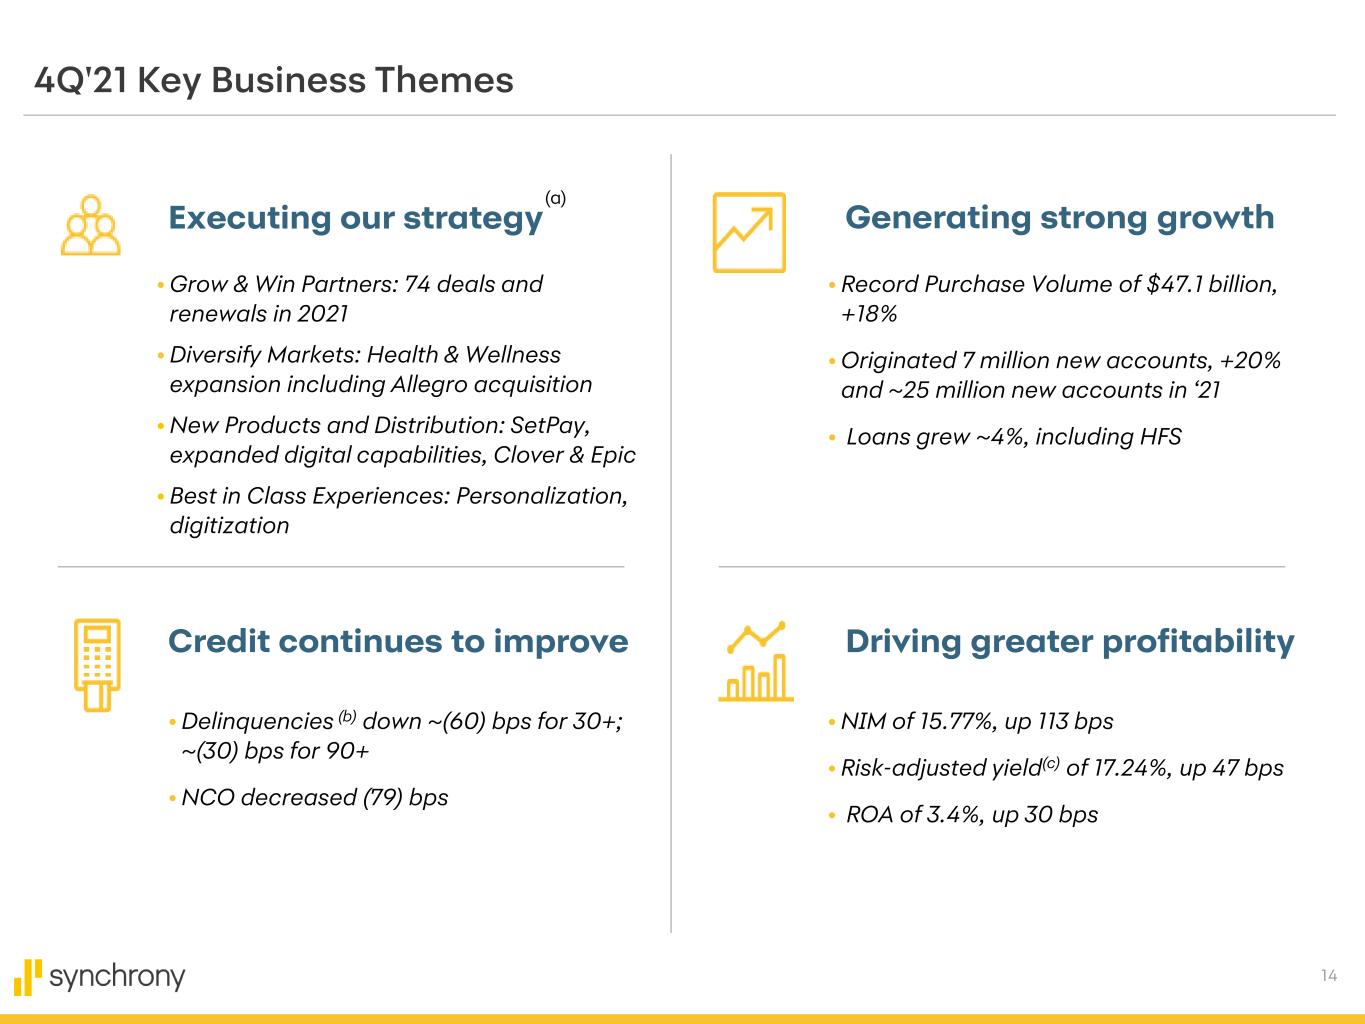
14 4Q'21 Key Business Themes Executing our strategy Generating strong growth Driving greater profitabilityCredit continues to improve • Grow & Win Partners: 74 deals and renewals in 2021 • Diversify Markets: Health & Wellness expansion including Allegro acquisition • New Products and Distribution: SetPay, expanded digital capabilities, Clover & Epic • Best in Class Experiences: Personalization, digitization • Record Purchase Volume of $47.1 billion, +18% • Originated 7 million new accounts, +20% and ~25 million new accounts in ‘21 • Loans grew ~4%, including HFS • Delinquencies (b) down ~(60) bps for 30+; ~(30) bps for 90+ • NCO decreased (79) bps • NIM of 15.77%, up 113 bps • Risk-adjusted yield(c) of 17.24%, up 47 bps • ROA of 3.4%, up 30 bps (a)
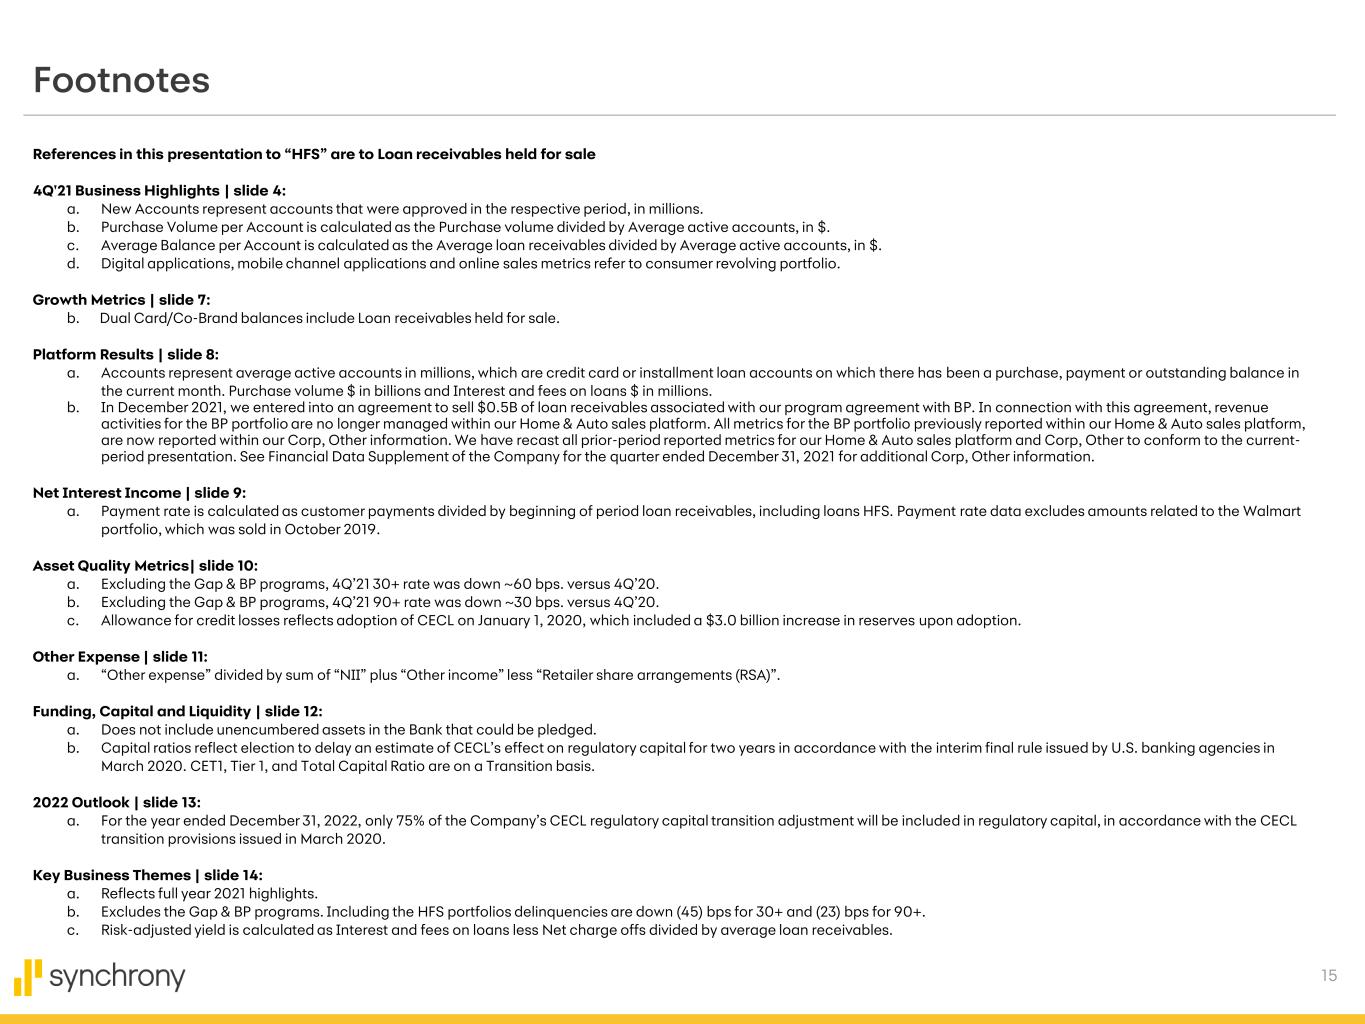
15 Footnotes References in this presentation to “HFS” are to Loan receivables held for sale 4Q'21 Business Highlights | slide 4: a. New Accounts represent accounts that were approved in the respective period, in millions. b. Purchase Volume per Account is calculated as the Purchase volume divided by Average active accounts, in $. c. Average Balance per Account is calculated as the Average loan receivables divided by Average active accounts, in $. d. Digital applications, mobile channel applications and online sales metrics refer to consumer revolving portfolio. Growth Metrics | slide 7: b. Dual Card/Co-Brand balances include Loan receivables held for sale. Platform Results | slide 8: a. Accounts represent average active accounts in millions, which are credit card or installment loan accounts on which there has been a purchase, payment or outstanding balance in the current month. Purchase volume $ in billions and Interest and fees on loans $ in millions. b. In December 2021, we entered into an agreement to sell $0.5B of loan receivables associated with our program agreement with BP. In connection with this agreement, revenue activities for the BP portfolio are no longer managed within our Home & Auto sales platform. All metrics for the BP portfolio previously reported within our Home & Auto sales platform, are now reported within our Corp, Other information. We have recast all prior-period reported metrics for our Home & Auto sales platform and Corp, Other to conform to the current- period presentation. See Financial Data Supplement of the Company for the quarter ended December 31, 2021 for additional Corp, Other information. Net Interest Income | slide 9: a. Payment rate is calculated as customer payments divided by beginning of period loan receivables, including loans HFS. Payment rate data excludes amounts related to the Walmart portfolio, which was sold in October 2019. Asset Quality Metrics| slide 10: a. Excluding the Gap & BP programs, 4Q’21 30+ rate was down ~60 bps. versus 4Q’20. b. Excluding the Gap & BP programs, 4Q’21 90+ rate was down ~30 bps. versus 4Q’20. c. Allowance for credit losses reflects adoption of CECL on January 1, 2020, which included a $3.0 billion increase in reserves upon adoption. Other Expense | slide 11: a. “Other expense” divided by sum of “NII” plus “Other income” less “Retailer share arrangements (RSA)”. Funding, Capital and Liquidity | slide 12: a. Does not include unencumbered assets in the Bank that could be pledged. b. Capital ratios reflect election to delay an estimate of CECL’s effect on regulatory capital for two years in accordance with the interim final rule issued by U.S. banking agencies in March 2020. CET1, Tier 1, and Total Capital Ratio are on a Transition basis. 2022 Outlook | slide 13: a. For the year ended December 31, 2022, only 75% of the Company’s CECL regulatory capital transition adjustment will be included in regulatory capital, in accordance with the CECL transition provisions issued in March 2020. Key Business Themes | slide 14: a. Reflects full year 2021 highlights. b. Excludes the Gap & BP programs. Including the HFS portfolios delinquencies are down (45) bps for 30+ and (23) bps for 90+. c. Risk-adjusted yield is calculated as Interest and fees on loans less Net charge offs divided by average loan receivables.
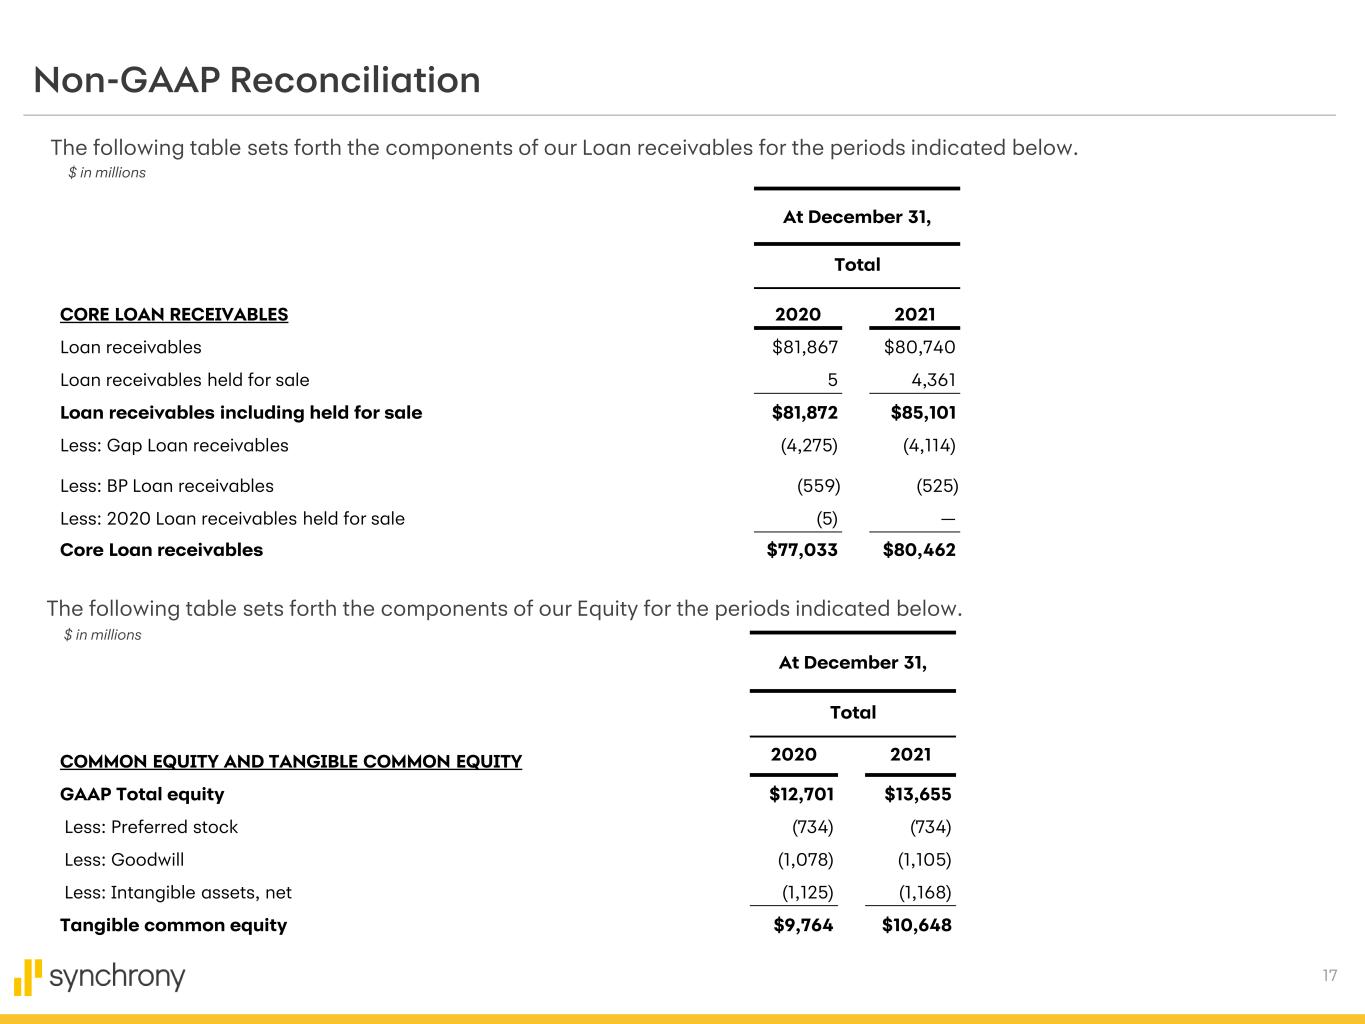
17 Non-GAAP Reconciliation The following table sets forth the components of our Loan receivables for the periods indicated below. $ in millions At December 31, Total CORE LOAN RECEIVABLES 2020 2021 Loan receivables $81,867 $80,740 Loan receivables held for sale 5 4,361 Loan receivables including held for sale $81,872 $85,101 Less: Gap Loan receivables (4,275) (4,114) Less: BP Loan receivables (559) (525) Less: 2020 Loan receivables held for sale (5) — Core Loan receivables $77,033 $80,462 At December 31, Total COMMON EQUITY AND TANGIBLE COMMON EQUITY 2020 2021 GAAP Total equity $12,701 $13,655 Less: Preferred stock (734) (734) Less: Goodwill (1,078) (1,105) Less: Intangible assets, net (1,125) (1,168) Tangible common equity $9,764 $10,648 The following table sets forth the components of our Equity for the periods indicated below. $ in millions
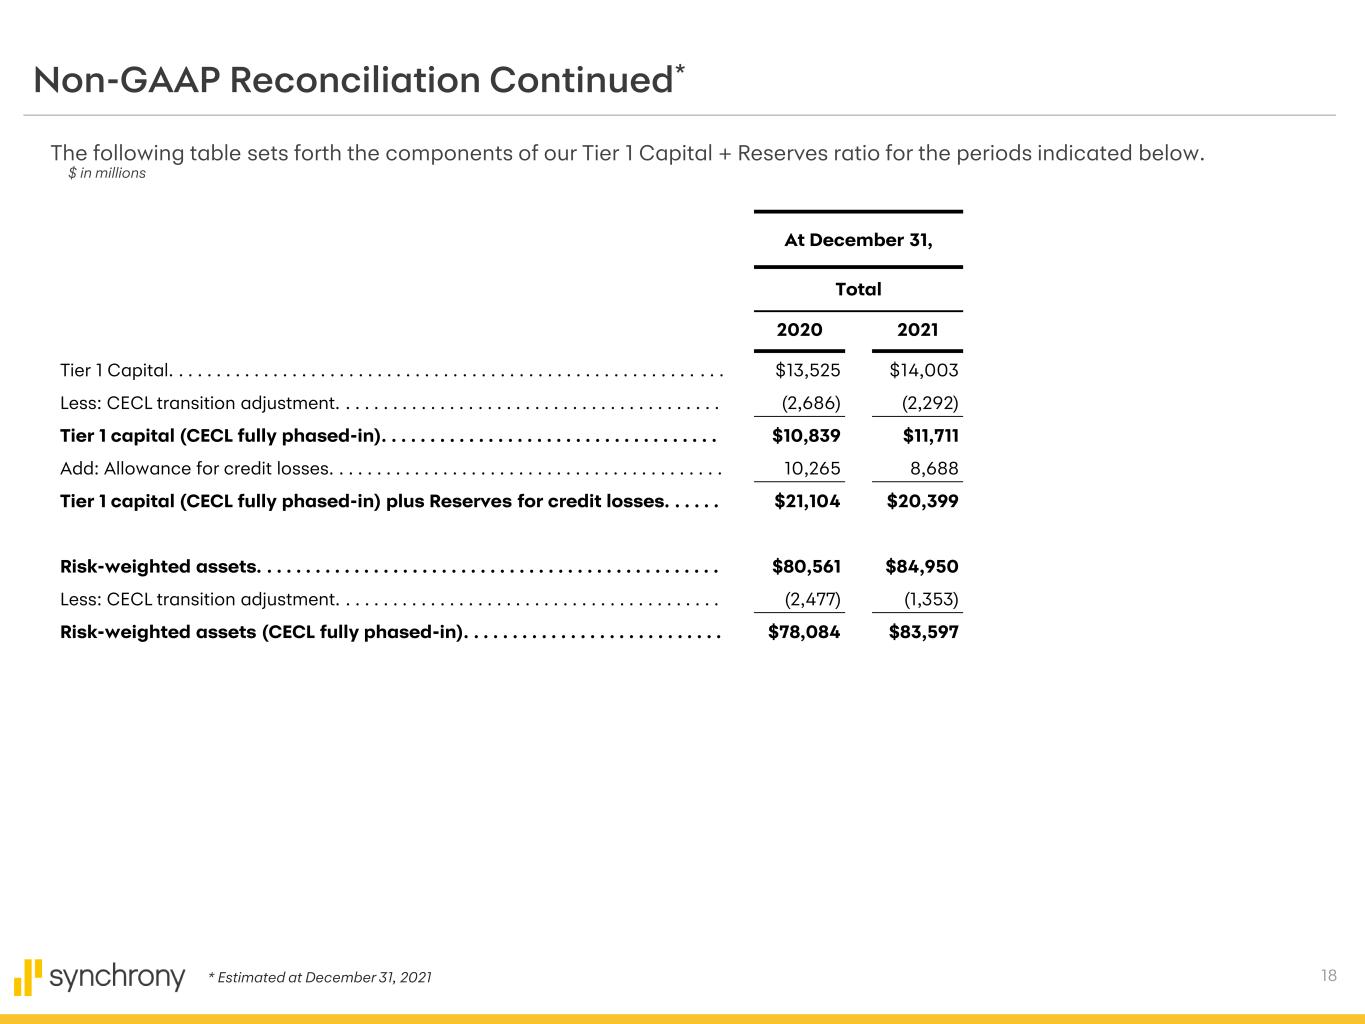
18 Non-GAAP Reconciliation Continued* The following table sets forth the components of our Tier 1 Capital + Reserves ratio for the periods indicated below. $ in millions At December 31, Total 2020 2021 Tier 1 Capital. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . $13,525 $14,003 Less: CECL transition adjustment. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . (2,686) (2,292) Tier 1 capital (CECL fully phased-in). . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . $10,839 $11,711 Add: Allowance for credit losses. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . 10,265 8,688 Tier 1 capital (CECL fully phased-in) plus Reserves for credit losses. . . . . . $21,104 $20,399 Risk-weighted assets. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . $80,561 $84,950 Less: CECL transition adjustment. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . (2,477) (1,353) Risk-weighted assets (CECL fully phased-in). . . . . . . . . . . . . . . . . . . . . . . . . . . $78,084 $83,597 * Estimated at December 31, 2021
Exhibit 99.4
Explanation of Non-GAAP Measures
The information provided in this Form 8-K and exhibits includes measures which are not prepared in accordance with U.S. generally accepted accounting principles ("GAAP").
We present certain information on our loan receivables that have been adjusted to exclude amounts related to held for sale portfolios, which we refer to as "Core" financial measures, in this Form 8-K and exhibits. These Core financial measures are not measures presented in accordance with GAAP. Given the planned sale of the Gap Inc. and BP portfolios which are expected to be completed in the second quarter of 2022, we believe the presentation of certain Core financial measures is a more meaningful measure to investors of the Company's ongoing credit programs. The reconciliation of these Core financial measures to the comparable GAAP component is included in Exhibit 99.3.
In addition, we also present certain capital measures in this Form 8-K and exhibits. Our “fully-phased Tier 1 Capital and Credit Loss Reserve Ratio” is not required by regulators to be disclosed, and therefore is considered a non-GAAP measure. We believe this ratio is a useful measure to investors as it provides a meaningful measure of what the Company’s total loss absorption capacity would be if the transitional rules currently in effect, which permit the temporary deferral of the regulatory capital effects of CECL, were no longer available for us to apply.
We also present a measure we refer to as “tangible common equity” in this Form 8-K and exhibits. Tangible common equity itself is not a measure presented in accordance with GAAP. We believe tangible common equity is a more meaningful measure to investors of the net asset value of the Company.
The reconciliations of these capital and equity related non-GAAP measures to the applicable comparable GAAP financial measures are included in the detailed financial tables included in Exhibit 99.2.