
TCBI 8-K
Texas Capital Bancshares Inc/Tx (TCBI)
8-K
2025-01-23
For: 2025-01-23
View Original
Added on
July 04, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d)
of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): January 23, 2025
TEXAS CAPITAL BANCSHARES, INC.
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (I.R.S. Employer Identification Number) | ||||||
(Address of principal executive offices)
(Zip Code)
Registrant’s telephone number, including area code: (214) 932-6600
N/A
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition.
On January 23, 2025, Texas Capital Bancshares, Inc. (the “Company”) issued a press release and made available presentation slides regarding its operating and financial results for its fiscal quarter and year ended March 31, 2024. A copy of the press release is attached hereto as Exhibit 99.1. A copy of the presentation is attached hereto as Exhibit 99.2.
The information in Item 2.02 of this report (including Exhibits 99.1 and 99.2) shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liability of that section, nor shall such information be deemed incorporated by reference in any filing under the Securities Act of 1933, as amended, or the Exchange Act of 1934, as amended, except as expressly set forth by specific reference in such a filing.
Item 8.01. Other Events.
Announcement of Share Repurchase Program
On January 22, 2025, the Company’s board of directors authorized a new share repurchase program under which the Company may repurchase up to $200.0 million in shares of its outstanding common stock through January 31, 2026. Any repurchases under the repurchase program will be made in accordance with applicable securities laws from time to time in open market or private transactions. The extent to which the Company repurchases shares, and the timing of such repurchases, will be at management’s discretion and will depend upon a variety of factors, including market conditions, our capital position and amount of retained earnings, regulatory requirements and other considerations. Remaining repurchase authorization under the January 17, 2024 share repurchase program was terminated upon authorization of this new program.
Item 9.01. Financial Statements and Exhibits.
(d) Exhibits
99.1 Press Release, dated January 23, 2025 announcing Texas Capital Bancshares, Inc.'s operating and financial results for its fiscal quarter and year ended December 31, 2024
99.2 Presentation dated January 23, 2025 discussing Texas Capital Bancshares, Inc.’s operating and financial results for its fiscal quarter and year ended December 31, 2024
104 Cover Page Interactive Data File (embedded within the Inline XBRL document)
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Date: | January 23, 2025 | TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||
| By: | /s/ J. Matthew Scurlock | ||||||||||||||||
| J. Matthew Scurlock Chief Financial Officer | |||||||||||||||||
Exhibit 99.1

| INVESTOR CONTACT | ||||||||
| Jocelyn Kukulka, 469.399.8544 | ||||||||
| [email protected] | ||||||||
| MEDIA CONTACT | ||||||||
| Julia Monter, 469.399.8425 | ||||||||
| [email protected] | ||||||||
TEXAS CAPITAL BANCSHARES, INC. ANNOUNCES FOURTH QUARTER AND FULL YEAR 2024 RESULTS
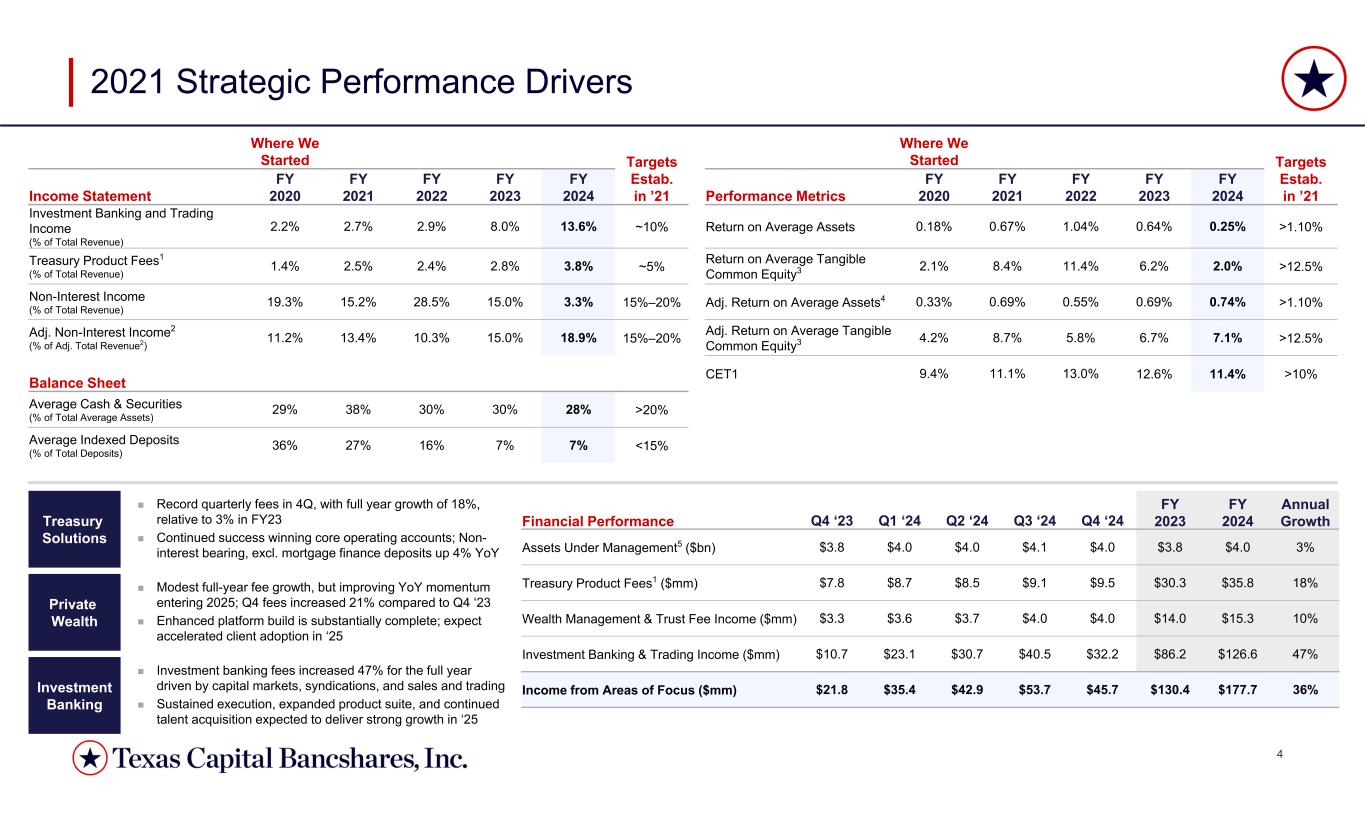
Income in fee areas of focus(1) increased 38% year-over-year
Strong balance sheet growth with total deposits increasing 13% and total loans growing 10% year-over-year
Book Value and Tangible Book Value(2) per share both increased 8% year-over-year, reaching record levels
Capital ratios continue to be strong, including 11.4% CET1 and 15.4% Total Capital
DALLAS - January 23, 2025 - Texas Capital Bancshares, Inc. (NASDAQ: TCBI), the parent company of Texas Capital Bank, announced operating results for the fourth quarter and full year of 2024.
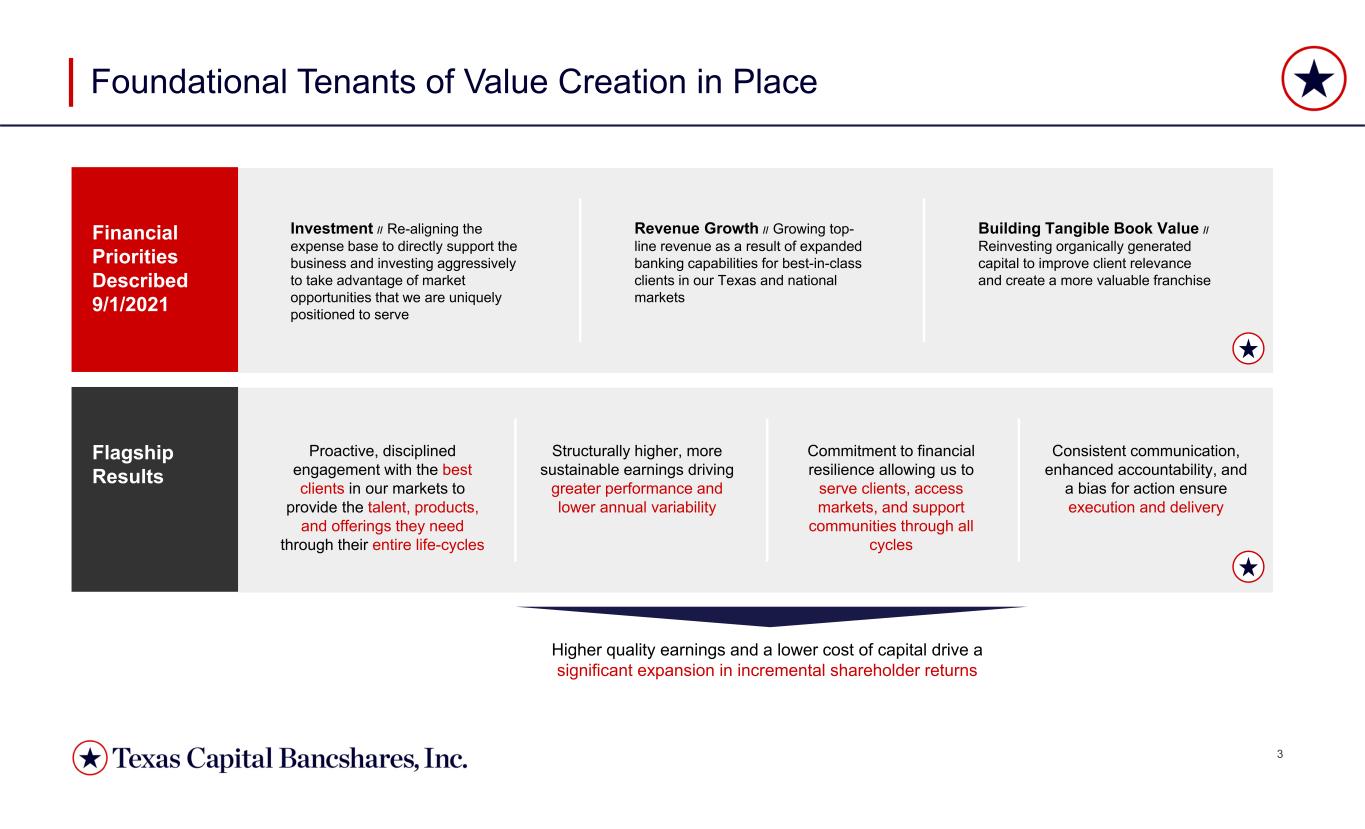
“For the past four years, our team steadily pursued the strategy we laid out in 2021, positioning Texas Capital to serve the best clients in all our markets,” said Rob C. Holmes, President and CEO. “Given full year 2024 financial results, the successful execution of significant strategic milestones and the realization of client adoption trends, the firm has proven that it is poised to deliver in 2025.”
| 4th Quarter | 3rd Quarter | 4th Quarter | Full Year | Full Year | |||||||||||||||||||||||||
| (dollars in thousands except per share data) | 2024 | 2024 | 2023 | 2024 | 2023 | ||||||||||||||||||||||||
| OPERATING RESULTS | |||||||||||||||||||||||||||||
| Net income/(loss) | $ | 71,023 | $ | (61,319) | $ | 20,150 | $ | 77,508 | $ | 189,141 | |||||||||||||||||||
| Net income/(loss) available to common stockholders | $ | 66,711 | $ | (65,632) | $ | 15,838 | $ | 60,258 | $ | 171,891 | |||||||||||||||||||
Pre-provision net revenue(4) | $ | 111,522 | $ | (69,993) | $ | 44,465 | $ | 174,061 | $ | 318,595 | |||||||||||||||||||
| Diluted earnings/(loss) per common share | $ | 1.43 | $ | (1.41) | $ | 0.33 | $ | 1.28 | $ | 3.54 | |||||||||||||||||||
| Diluted common shares | 46,770,961 | 46,608,742 | 48,097,517 | 46,989,204 | 48,610,206 | ||||||||||||||||||||||||
| Return on average assets | 0.88 | % | (0.78) | % | 0.27 | % | 0.25 | % | 0.64 | % | |||||||||||||||||||
| Return on average common equity | 8.50 | % | (8.87) | % | 2.25 | % | 2.04 | % | 6.15 | % | |||||||||||||||||||
OPERATING RESULTS, ADJUSTED(3) | |||||||||||||||||||||||||||||
| Net income/(loss) | $ | 71,023 | $ | 78,654 | $ | 35,403 | $ | 225,595 | $ | 204,394 | |||||||||||||||||||
| Net income/(loss) available to common stockholders | $ | 66,711 | $ | 74,341 | $ | 31,091 | $ | 208,345 | $ | 187,144 | |||||||||||||||||||
Pre-provision net revenue(4) | $ | 111,522 | $ | 114,860 | $ | 64,351 | $ | 369,394 | $ | 338,481 | |||||||||||||||||||
| Diluted earnings/(loss) per common share | $ | 1.43 | $ | 1.59 | $ | 0.65 | $ | 4.43 | $ | 3.85 | |||||||||||||||||||
| Diluted common shares | 46,770,961 | 46,608,742 | 48,097,517 | 46,989,204 | 48,610,206 | ||||||||||||||||||||||||
| Return on average assets | 0.88 | % | 1.00 | % | 0.47 | % | 0.74 | % | 0.69 | % | |||||||||||||||||||
| Return on average common equity | 8.50 | % | 10.04 | % | 4.41 | % | 7.05 | % | 6.70 | % | |||||||||||||||||||
| BALANCE SHEET | |||||||||||||||||||||||||||||
| Loans held for investment | $ | 17,234,492 | $ | 16,764,512 | $ | 16,362,230 | |||||||||||||||||||||||
| Loans held for investment, mortgage finance | 5,215,574 | 5,529,659 | 3,978,328 | ||||||||||||||||||||||||||
| Total loans held for investment | 22,450,066 | 22,294,171 | 20,340,558 | ||||||||||||||||||||||||||
| Loans held for sale | — | 9,022 | 44,105 | ||||||||||||||||||||||||||
| Total assets | 30,731,883 | 31,629,299 | 28,356,266 | ||||||||||||||||||||||||||
| Non-interest bearing deposits | 7,485,428 | 9,070,804 | 7,328,276 | ||||||||||||||||||||||||||
| Total deposits | 25,238,599 | 25,865,255 | 22,371,839 | ||||||||||||||||||||||||||
| Stockholders’ equity | 3,367,936 | 3,354,044 | 3,199,142 | ||||||||||||||||||||||||||
(1) Fee areas of focus include service charges on deposit accounts, wealth management and trust fee income, investment banking and advisory fees and trading income.
(2) Stockholders’ equity excluding preferred stock, less goodwill and intangibles, divided by shares outstanding at period end.
(3) These adjusted measures are non-GAAP measures. Please refer to “GAAP to Non-GAAP Reconciliations” for the computations of these adjusted measures and the reconciliation of these non-GAAP measures to the most directly comparable GAAP measure.
(4) Net interest income plus non-interest income, less non-interest expense.
FOURTH QUARTER 2024 COMPARED TO THIRD QUARTER 2024
For the fourth quarter of 2024, net income available to common stockholders was $66.7 million, or $1.43 net income per diluted share, compared to net loss available to common stockholders of $65.6 million, or $1.41 net loss per diluted share, for the third quarter of 2024.
Provision for credit losses for the fourth quarter of 2024 was $18.0 million, compared to $10.0 million for the third quarter of 2024. The $18.0 million provision for credit losses recorded in the fourth quarter of 2024 resulted primarily from growth in total loans held for investment (“LHI”) and $12.1 million in net charge-offs.
Net interest income was $229.6 million for the fourth quarter of 2024, compared to $240.1 million for the third quarter of 2024, as a decrease in yields on average earning assets and an increase in average interest bearing deposits were partially offset by an increase in average total LHI and a decrease in funding costs. Net interest margin for the fourth quarter of 2024 was 2.93%, a decrease of 23 basis points from the third quarter of 2024, reflecting the impact of decreases in interest rates during the fourth quarter of 2024. LHI, excluding mortgage finance, yields decreased 44 basis points from the third quarter of 2024 and LHI, mortgage finance, yields decreased 47 basis points from the third quarter of 2024. Total cost of deposits was 2.81% for the fourth quarter of 2024, a 13 basis point decrease from the third quarter of 2024.
Non-interest income for the fourth quarter of 2024 increased $168.8 million compared to the third quarter of 2024 primarily due to the inclusion of a $179.6 million loss on sale of available-for-sale debt securities recognized during the third quarter of 2024, partially offset by decreases in investment banking and advisory fees and other non-interest income.
Non-interest expense for the fourth quarter of 2024 decreased $23.2 million, or 12%, compared to the third quarter of 2024, primarily due to a decrease in salaries and benefits resulting from restructuring expenses recognized in the third quarter of 2024, as well as reductions in headcount and adjustments to compensation accruals.
FOURTH QUARTER 2024 COMPARED TO FOURTH QUARTER 2023
Net income available to common stockholders was $66.7 million, or $1.43 per diluted share, for the fourth quarter of 2024, compared to net income available to common stockholders of $15.8 million, or $0.33 per diluted share, for the fourth quarter of 2023.
The fourth quarter of 2024 included a $18.0 million provision for credit losses, reflecting growth in total LHI and $12.1 million in net charge-offs, compared to a $19.0 million provision for credit losses for the fourth quarter of 2023.
Net interest income increased to $229.6 million for the fourth quarter of 2024, compared to $214.7 million for the fourth quarter of 2023, primarily due to an increase in average total LHI and a decrease in funding costs, partially offset by an increase in average interest bearing liabilities. Net interest margin was unchanged at 2.93% for the fourth quarter of 2024, as compared to the fourth quarter of 2023. LHI, excluding mortgage finance, yields decreased 32 basis points compared to the fourth quarter of 2023 and LHI, mortgage finance yields increased 34 basis points from the fourth quarter of 2023. Total cost of deposits decreased 1 basis point compared to the fourth quarter of 2023.
Non-interest income for the fourth quarter of 2024 increased $22.9 million compared to the fourth quarter of 2023 primarily due to an increase in investment banking and advisory fees.
Non-interest expense for the fourth quarter of 2024 decreased $29.2 million, or 15%, compared to the fourth quarter of 2023, primarily due to decreases in salaries and benefits, primarily from lower headcount, and Federal Deposit Insurance Corporation (“FDIC”) expense. The fourth quarter of 2023 included $19.9 million in FDIC special assessment expense.
CREDIT QUALITY
Net charge-offs of $12.1 million were recorded during the fourth quarter of 2024, compared to net charge-offs of $6.1 million and $13.8 million during the third quarter of 2024 and the fourth quarter of 2023, respectively. Criticized loans totaled $714.0 million at December 31, 2024, compared to $897.7 million at September 30, 2024 and $738.2 million at December 31, 2023. Non-accrual LHI totaled $111.2 million at December 31, 2024, compared to $89.0 million at September 30, 2024 and $81.4 million at December 31, 2023. The ratio of non-accrual LHI to total LHI for the fourth quarter of 2024 was 0.50%, compared to 0.40% for the third quarter of 2024 and 0.40% for the fourth quarter of 2023. The ratio of total allowance for credit losses to total LHI was 1.45% at December 31, 2024, compared to 1.43% and 1.46% at September 30, 2024 and December 31, 2023, respectively.
REGULATORY RATIOS AND CAPITAL
All regulatory ratios continue to be in excess of “well capitalized” requirements as of December 31, 2024. CET1, tier 1 capital, total capital and leverage ratios were 11.4%, 12.8%, 15.4% and 11.3%, respectively, at December 31, 2024, compared to 11.2%, 12.6%, 15.2% and 11.4%, respectively, at September 30, 2024 and 12.6%, 14.2%, 17.1% and 12.2%, respectively, at December 31, 2023. At December 31, 2024, our ratio of tangible common equity to total tangible assets was 10.0%, compared to 9.7% at September 30, 2024 and 10.2% at December 31, 2023.
On January 22, 2025, the Company’s board of directors authorized a new share repurchase program under which the Company may repurchase up to $200.0 million in shares of its outstanding common stock through January 31, 2026. Remaining repurchase authorization under the January 17, 2024 share repurchase program was terminated upon authorization of this new program.
2
About Texas Capital Bancshares, Inc.
Texas Capital Bancshares, Inc. (NASDAQ: TCBI), a member of the Russell 2000® Index and the S&P MidCap 400®, the parent company of Texas Capital Bank d/b/a Texas Capital, is a full-service financial services firm that delivers customized solutions to businesses, entrepreneurs and individual customers. Founded in 1998, the institution is headquartered in Dallas with offices in Austin, Houston, San Antonio, and Fort Worth, and has built a network of clients across the country. With the ability to service clients through their entire lifecycles, Texas Capital has established commercial banking, consumer banking, investment banking and wealth management capabilities.
Forward Looking Statements
This communication contains “forward-looking statements” within the meaning of and pursuant to the Private Securities Litigation Reform Act of 1995 regarding, among other things, TCBI’s financial condition, results of operations, business plans and future performance. These statements are not historical in nature and may often be identified by the use of words such as “believes,” “projects,” “expects,” “may,” “estimates,” “should,” “plans,” “targets,” “intends” “could,” “would,” “anticipates,” “potential,” “confident,” “optimistic” or the negative thereof, or other variations thereon, or comparable terminology, or by discussions of strategy, objectives, estimates, trends, guidance, expectations and future plans.
Because forward-looking statements relate to future results and occurrences, they are subject to inherent and various uncertainties, risks, and changes in circumstances that are difficult to predict, may change over time, are based on management’s expectations and assumptions at the time the statements are made and are not guarantees of future results. Numerous risks and other factors, many of which are beyond management’s control, could cause actual results to differ materially from future results expressed or implied by such forward-looking statements. While there can be no assurance that any list of risks is complete, important risks and other factors that could cause actual results to differ materially from those contemplated by forward-looking statements include, but are not limited to: economic or business conditions in Texas, the United States or globally that impact TCBI or its customers; negative credit quality developments arising from the foregoing or other factors; increased or expanded competition from banks and other financial service providers in TCBI’s markets; TCBI’s ability to effectively manage its liquidity and maintain adequate regulatory capital to support its businesses; TCBI’s ability to pursue and execute upon growth plans, whether as a function of capital, liquidity or other limitations; TCBI’s ability to successfully execute its business strategy, including its strategic plan and developing and executing new lines of business and new products and services and potential strategic acquisitions; the extensive regulations to which TCBI is subject and its ability to comply with applicable governmental regulations, including legislative and regulatory changes; TCBI’s ability to effectively manage information technology systems, including third party vendors, cyber or data privacy incidents or other failures, disruptions or security breaches; TCBI’s ability to use technology to provide products and services to its customers; risks related to the development and use of artificial intelligence; changes in interest rates, including the impact of interest rates on TCBI’s securities portfolio and funding costs, as well as related balance sheet implications stemming from the fair value of our assets and liabilities; the effectiveness of TCBI’s risk management processes strategies and monitoring; fluctuations in commercial and residential real estate values, especially as they relate to the value of collateral supporting TCBI’s loans; the failure to identify, attract and retain key personnel and other employees; adverse developments in the banking industry and the potential impact of such developments on customer confidence, liquidity and regulatory responses to these developments, including in the context of regulatory examinations and related findings and actions; negative press and social media attention with respect to the banking industry or TCBI, in particular; claims, litigation or regulatory investigations and actions that TCBI may become subject to; severe weather, natural disasters, climate change, acts of war, terrorism, global conflict (including those already reported by the media, as well as others that may arise), or other external events, as well as related legislative and regulatory initiatives; and the risks and factors more fully described in TCBI’s most recent Annual Report on Form 10-K, Quarterly Reports on Form 10-Q and other documents and filings with the SEC. The information contained in this communication speaks only as of its date. Except to the extent required by applicable law or regulation, we disclaim any obligation to update such factors or to publicly announce the results of any revisions to any of the forward-looking statements included herein to reflect future events or developments.
3
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||||
| SELECTED FINANCIAL HIGHLIGHTS (UNAUDITED) | |||||||||||||||||
| (dollars in thousands except per share data) | |||||||||||||||||
| 4th Quarter | 3rd Quarter | 2nd Quarter | 1st Quarter | 4th Quarter | |||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2023 | |||||||||||||
| CONSOLIDATED STATEMENTS OF INCOME | |||||||||||||||||
| Interest income | $ | 437,571 | $ | 452,533 | $ | 422,068 | $ | 417,378 | $ | 417,072 | |||||||
| Interest expense | 207,964 | 212,431 | 205,486 | 202,369 | 202,355 | ||||||||||||
| Net interest income | 229,607 | 240,102 | 216,582 | 215,009 | 214,717 | ||||||||||||
| Provision for credit losses | 18,000 | 10,000 | 20,000 | 19,000 | 19,000 | ||||||||||||
| Net interest income after provision for credit losses | 211,607 | 230,102 | 196,582 | 196,009 | 195,717 | ||||||||||||
| Non-interest income | 54,074 | (114,771) | 50,424 | 41,319 | 31,133 | ||||||||||||
| Non-interest expense | 172,159 | 195,324 | 188,409 | 202,393 | 201,385 | ||||||||||||
| Income/(loss) before income taxes | 93,522 | (79,993) | 58,597 | 34,935 | 25,465 | ||||||||||||
| Income tax expense/(benefit) | 22,499 | (18,674) | 16,935 | 8,793 | 5,315 | ||||||||||||
| Net income/(loss) | 71,023 | (61,319) | 41,662 | 26,142 | 20,150 | ||||||||||||
| Preferred stock dividends | 4,312 | 4,313 | 4,312 | 4,313 | 4,312 | ||||||||||||
| Net income/(loss) available to common stockholders | $ | 66,711 | $ | (65,632) | $ | 37,350 | $ | 21,829 | $ | 15,838 | |||||||
| Diluted earnings/(loss) per common share | $ | 1.43 | $ | (1.41) | $ | 0.80 | $ | 0.46 | $ | 0.33 | |||||||
| Diluted common shares | 46,770,961 | 46,608,742 | 46,872,498 | 47,711,192 | 48,097,517 | ||||||||||||
| CONSOLIDATED BALANCE SHEET DATA | |||||||||||||||||
| Total assets | $ | 30,731,883 | $ | 31,629,299 | $ | 29,854,994 | $ | 29,180,585 | $ | 28,356,266 | |||||||
| Loans held for investment | 17,234,492 | 16,764,512 | 16,700,569 | 16,677,691 | 16,362,230 | ||||||||||||
| Loans held for investment, mortgage finance | 5,215,574 | 5,529,659 | 5,078,161 | 4,153,313 | 3,978,328 | ||||||||||||
| Loans held for sale | — | 9,022 | 36,785 | 37,750 | 44,105 | ||||||||||||
| Interest bearing cash and cash equivalents | 3,012,307 | 3,894,537 | 2,691,352 | 3,148,157 | 3,042,357 | ||||||||||||
| Investment securities | 4,396,115 | 4,405,520 | 4,388,976 | 4,414,280 | 4,143,194 | ||||||||||||
| Non-interest bearing deposits | 7,485,428 | 9,070,804 | 7,987,715 | 8,478,215 | 7,328,276 | ||||||||||||
| Total deposits | 25,238,599 | 25,865,255 | 23,818,327 | 23,954,037 | 22,371,839 | ||||||||||||
| Short-term borrowings | 885,000 | 1,035,000 | 1,675,000 | 750,000 | 1,500,000 | ||||||||||||
| Long-term debt | 660,346 | 660,172 | 659,997 | 859,823 | 859,147 | ||||||||||||
| Stockholders’ equity | 3,367,936 | 3,354,044 | 3,175,601 | 3,170,662 | 3,199,142 | ||||||||||||
| End of period shares outstanding | 46,233,812 | 46,207,757 | 46,188,078 | 46,986,275 | 47,237,912 | ||||||||||||
| Book value per share | $ | 66.36 | $ | 66.09 | $ | 62.26 | $ | 61.10 | $ | 61.37 | |||||||
Tangible book value per share(1) | $ | 66.32 | $ | 66.06 | $ | 62.23 | $ | 61.06 | $ | 61.34 | |||||||
| SELECTED FINANCIAL RATIOS | |||||||||||||||||
| Net interest margin | 2.93 | % | 3.16 | % | 3.01 | % | 3.03 | % | 2.93 | % | |||||||
| Return on average assets | 0.88 | % | (0.78) | % | 0.56 | % | 0.36 | % | 0.27 | % | |||||||
Return on average assets, adjusted(4) | 0.88 | % | 1.00 | % | 0.57 | % | 0.47 | % | 0.47 | % | |||||||
| Return on average common equity | 8.50 | % | (8.87) | % | 5.26 | % | 3.03 | % | 2.25 | % | |||||||
Return on average common equity, adjusted(4) | 8.50 | % | 10.04 | % | 5.31 | % | 4.11 | % | 4.41 | % | |||||||
Efficiency ratio(2) | 60.7 | % | 155.8 | % | 70.6 | % | 79.0 | % | 81.9 | % | |||||||
Efficiency ratio, adjusted(2)(4) | 60.7 | % | 62.3 | % | 70.4 | % | 75.1 | % | 73.8 | % | |||||||
| Non-interest income to average earning assets | 0.69 | % | (1.52) | % | 0.71 | % | 0.59 | % | 0.43 | % | |||||||
Non-interest income to average earning assets, adjusted(4) | 0.69 | % | 0.86 | % | 0.71 | % | 0.59 | % | 0.43 | % | |||||||
| Non-interest expense to average earning assets | 2.21 | % | 2.59 | % | 2.65 | % | 2.89 | % | 2.79 | % | |||||||
Non-interest expense to average earning assets, adjusted(4) | 2.21 | % | 2.52 | % | 2.65 | % | 2.74 | % | 2.52 | % | |||||||
| Common equity to total assets | 10.0 | % | 9.7 | % | 9.6 | % | 9.8 | % | 10.2 | % | |||||||
Tangible common equity to total tangible assets(3) | 10.0 | % | 9.7 | % | 9.6 | % | 9.8 | % | 10.2 | % | |||||||
| Common Equity Tier 1 | 11.4 | % | 11.2 | % | 11.6 | % | 12.4 | % | 12.6 | % | |||||||
| Tier 1 capital | 12.8 | % | 12.6 | % | 13.1 | % | 13.9 | % | 14.2 | % | |||||||
| Total capital | 15.4 | % | 15.2 | % | 15.7 | % | 16.6 | % | 17.1 | % | |||||||
| Leverage | 11.3 | % | 11.4 | % | 12.2 | % | 12.4 | % | 12.2 | % | |||||||
(1) Stockholders’ equity excluding preferred stock, less goodwill and intangibles, divided by shares outstanding at period end.
(2) Non-interest expense divided by the sum of net interest income and non-interest income.
(3) Stockholders’ equity excluding preferred stock, less goodwill and intangibles, divided by total assets, less goodwill and intangibles.
(4) These adjusted measures are non-GAAP measures. Please refer to “GAAP to Non-GAAP Reconciliations” for the computations of these adjusted measures and the reconciliation of these non-GAAP measures to the most directly comparable GAAP measure.
4
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||
| CONSOLIDATED BALANCE SHEETS (UNAUDITED) | |||||||||||
| (dollars in thousands) | |||||||||||
| December 31, 2024 | December 31, 2023 | % Change | |||||||||
| Assets | |||||||||||
| Cash and due from banks | $ | 176,501 | $ | 200,493 | (12) | % | |||||
| Interest bearing cash and cash equivalents | 3,012,307 | 3,042,357 | (1) | % | |||||||
| Available-for-sale debt securities | 3,524,686 | 3,225,892 | 9 | % | |||||||
| Held-to-maturity debt securities | 796,168 | 865,477 | (8) | % | |||||||
| Equity securities | 75,261 | 51,825 | 45 | % | |||||||
| Investment securities | 4,396,115 | 4,143,194 | 6 | % | |||||||
| Loans held for sale | — | 44,105 | (100) | % | |||||||
| Loans held for investment, mortgage finance | 5,215,574 | 3,978,328 | 31 | % | |||||||
| Loans held for investment | 17,234,492 | 16,362,230 | 5 | % | |||||||
| Less: Allowance for credit losses on loans | 271,709 | 249,973 | 9 | % | |||||||
| Loans held for investment, net | 22,178,357 | 20,090,585 | 10 | % | |||||||
| Premises and equipment, net | 85,443 | 32,366 | 164 | % | |||||||
| Accrued interest receivable and other assets | 881,664 | 801,670 | 10 | % | |||||||
| Goodwill and intangibles, net | 1,496 | 1,496 | — | % | |||||||
| Total assets | $ | 30,731,883 | $ | 28,356,266 | 8 | % | |||||
| Liabilities and Stockholders’ Equity | |||||||||||
| Liabilities: | |||||||||||
| Non-interest bearing deposits | $ | 7,485,428 | $ | 7,328,276 | 2 | % | |||||
| Interest bearing deposits | 17,753,171 | 15,043,563 | 18 | % | |||||||
| Total deposits | 25,238,599 | 22,371,839 | 13 | % | |||||||
| Accrued interest payable | 23,680 | 33,234 | (29) | % | |||||||
| Other liabilities | 556,322 | 392,904 | 42 | % | |||||||
| Short-term borrowings | 885,000 | 1,500,000 | (41) | % | |||||||
| Long-term debt | 660,346 | 859,147 | (23) | % | |||||||
| Total liabilities | 27,363,947 | 25,157,124 | 9 | % | |||||||
| Stockholders’ equity: | |||||||||||
| Preferred stock, $.01 par value, $1,000 liquidation value: | |||||||||||
| Authorized shares - 10,000,000 | |||||||||||
Issued shares - 300,000 shares issued at December 31, 2024 and 2023 | 300,000 | 300,000 | — | % | |||||||
| Common stock, $.01 par value: | |||||||||||
| Authorized shares - 100,000,000 | |||||||||||
Issued shares - 51,520,315 and 51,142,979 at December 31, 2024 and 2023, respectively | 515 | 511 | 1 | % | |||||||
| Additional paid-in capital | 1,056,719 | 1,045,576 | 1 | % | |||||||
| Retained earnings | 2,495,651 | 2,435,393 | 2 | % | |||||||
Treasury stock - 5,286,503 and 3,905,067 shares at cost at December 31, 2024 and 2023, respectively | (301,842) | (220,334) | 37 | % | |||||||
| Accumulated other comprehensive loss, net of taxes | (183,107) | (362,004) | (49) | % | |||||||
| Total stockholders’ equity | 3,367,936 | 3,199,142 | 5 | % | |||||||
| Total liabilities and stockholders’ equity | $ | 30,731,883 | $ | 28,356,266 | 8 | % | |||||
5
| TEXAS CAPITAL BANCSHARES, INC. | ||||||||||||||
| CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED) | ||||||||||||||
| (dollars in thousands except per share data) | ||||||||||||||
| Three Months Ended December 31, | Year Ended December 31, | |||||||||||||
| 2024 | 2023 | 2024 | 2023 | |||||||||||
| Interest income | ||||||||||||||
| Interest and fees on loans | $ | 340,388 | $ | 325,210 | $ | 1,377,925 | $ | 1,300,653 | ||||||
| Investment securities | 44,102 | 28,454 | 148,219 | 108,294 | ||||||||||
| Interest bearing cash and cash equivalents | 53,081 | 63,408 | 203,406 | 220,976 | ||||||||||
| Total interest income | 437,571 | 417,072 | 1,729,550 | 1,629,923 | ||||||||||
| Interest expense | ||||||||||||||
| Deposits | 189,061 | 170,173 | 736,196 | 587,775 | ||||||||||
| Short-term borrowings | 10,678 | 18,069 | 49,994 | 70,642 | ||||||||||
| Long-term debt | 8,225 | 14,113 | 42,060 | 57,383 | ||||||||||
| Total interest expense | 207,964 | 202,355 | 828,250 | 715,800 | ||||||||||
| Net interest income | 229,607 | 214,717 | 901,300 | 914,123 | ||||||||||
| Provision for credit losses | 18,000 | 19,000 | 67,000 | 72,000 | ||||||||||
| Net interest income after provision for credit losses | 211,607 | 195,717 | 834,300 | 842,123 | ||||||||||
| Non-interest income | ||||||||||||||
| Service charges on deposit accounts | 6,989 | 5,397 | 25,546 | 20,874 | ||||||||||
| Wealth management and trust fee income | 4,009 | 3,302 | 15,315 | 13,955 | ||||||||||
| Brokered loan fees | 2,519 | 2,076 | 8,961 | 8,918 | ||||||||||
| Investment banking and advisory fees | 26,740 | 6,906 | 104,965 | 63,670 | ||||||||||
| Trading income | 5,487 | 3,819 | 21,635 | 22,512 | ||||||||||
Available-for-sale debt securities gains/(losses), net | — | — | (179,581) | 489 | ||||||||||
| Other | 8,330 | 9,633 | 34,205 | 31,001 | ||||||||||
| Total non-interest income | 54,074 | 31,133 | 31,046 | 161,419 | ||||||||||
| Non-interest expense | ||||||||||||||
| Salaries and benefits | 97,873 | 107,970 | 466,578 | 459,700 | ||||||||||
| Occupancy expense | 11,926 | 9,483 | 45,266 | 38,494 | ||||||||||
| Marketing | 4,454 | 5,686 | 22,349 | 25,854 | ||||||||||
| Legal and professional | 15,180 | 17,127 | 53,783 | 64,924 | ||||||||||
| Communications and technology | 24,007 | 23,607 | 93,085 | 81,262 | ||||||||||
| Federal Deposit Insurance Corporation insurance assessment | 4,454 | 25,143 | 23,351 | 36,775 | ||||||||||
| Other | 14,265 | 12,369 | 53,873 | 49,938 | ||||||||||
| Total non-interest expense | 172,159 | 201,385 | 758,285 | 756,947 | ||||||||||
| Income before income taxes | 93,522 | 25,465 | 107,061 | 246,595 | ||||||||||
| Income tax expense | 22,499 | 5,315 | 29,553 | 57,454 | ||||||||||
| Net income | 71,023 | 20,150 | 77,508 | 189,141 | ||||||||||
| Preferred stock dividends | 4,312 | 4,312 | 17,250 | 17,250 | ||||||||||
| Net income available to common stockholders | $ | 66,711 | $ | 15,838 | $ | 60,258 | $ | 171,891 | ||||||
| Basic earnings per common share | $ | 1.44 | $ | 0.33 | $ | 1.29 | $ | 3.58 | ||||||
| Diluted earnings per common share | $ | 1.43 | $ | 0.33 | $ | 1.28 | $ | 3.54 | ||||||
6
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||||
| SUMMARY OF CREDIT LOSS EXPERIENCE | |||||||||||||||||
| (dollars in thousands) | |||||||||||||||||
| 4th Quarter | 3rd Quarter | 2nd Quarter | 1st Quarter | 4th Quarter | |||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2023 | |||||||||||||
| Allowance for credit losses on loans: | |||||||||||||||||
| Beginning balance | $ | 273,143 | $ | 267,297 | $ | 263,962 | $ | 249,973 | $ | 244,902 | |||||||
| Allowance established for acquired purchase credit deterioration loans | — | 2,579 | — | — | — | ||||||||||||
| Loans charged-off: | |||||||||||||||||
| Commercial | 14,100 | 6,120 | 9,997 | 7,544 | 8,356 | ||||||||||||
| Commercial real estate | 2,566 | 262 | 2,111 | 3,325 | 5,500 | ||||||||||||
| Consumer | — | 30 | — | — | — | ||||||||||||
| Total charge-offs | 16,666 | 6,412 | 12,108 | 10,869 | 13,856 | ||||||||||||
| Recoveries: | |||||||||||||||||
| Commercial | 4,562 | 329 | 153 | 105 | 15 | ||||||||||||
| Commercial real estate | 18 | — | — | — | 4 | ||||||||||||
| Consumer | 15 | — | — | — | — | ||||||||||||
| Total recoveries | 4,595 | 329 | 153 | 105 | 19 | ||||||||||||
| Net charge-offs | 12,071 | 6,083 | 11,955 | 10,764 | 13,837 | ||||||||||||
| Provision for credit losses on loans | 10,637 | 9,350 | 15,290 | 24,753 | 18,908 | ||||||||||||
| Ending balance | $ | 271,709 | $ | 273,143 | $ | 267,297 | $ | 263,962 | $ | 249,973 | |||||||
| Allowance for off-balance sheet credit losses: | |||||||||||||||||
| Beginning balance | $ | 45,969 | $ | 45,319 | $ | 40,609 | $ | 46,362 | $ | 46,270 | |||||||
| Provision for off-balance sheet credit losses | 7,363 | 650 | 4,710 | (5,753) | 92 | ||||||||||||
| Ending balance | $ | 53,332 | $ | 45,969 | $ | 45,319 | $ | 40,609 | $ | 46,362 | |||||||
| Total allowance for credit losses | $ | 325,041 | $ | 319,112 | $ | 312,616 | $ | 304,571 | $ | 296,335 | |||||||
| Total provision for credit losses | $ | 18,000 | $ | 10,000 | $ | 20,000 | $ | 19,000 | $ | 19,000 | |||||||
| Allowance for credit losses on loans to total loans held for investment | 1.21 | % | 1.23 | % | 1.23 | % | 1.27 | % | 1.23 | % | |||||||
| Allowance for credit losses on loans to average total loans held for investment | 1.22 | % | 1.24 | % | 1.27 | % | 1.32 | % | 1.24 | % | |||||||
Net charge-offs to average total loans held for investment(1) | 0.22 | % | 0.11 | % | 0.23 | % | 0.22 | % | 0.27 | % | |||||||
Net charge-offs to average total loans held for investment for last 12 months(1) | 0.19 | % | 0.20 | % | 0.22 | % | 0.20 | % | 0.25 | % | |||||||
Total provision for credit losses to average total loans held for investment(1) | 0.32 | % | 0.18 | % | 0.38 | % | 0.38 | % | 0.37 | % | |||||||
Total allowance for credit losses to total loans held for investment | 1.45 | % | 1.43 | % | 1.44 | % | 1.46 | % | 1.46 | % | |||||||
(1)Interim period ratios are annualized.
7
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||||
| SUMMARY OF NON-PERFORMING ASSETS AND PAST DUE LOANS | |||||||||||||||||
| (dollars in thousands) | |||||||||||||||||
| 4th Quarter | 3rd Quarter | 2nd Quarter | 1st Quarter | 4th Quarter | |||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2023 | |||||||||||||
| Non-accrual loans held for investment | $ | 111,165 | $ | 88,960 | $ | 85,021 | $ | 92,849 | $ | 81,398 | |||||||
| Non-accrual loans held for sale(1) | — | — | — | 9,250 | — | ||||||||||||
| Other real estate owned | — | — | — | — | — | ||||||||||||
| Total non-performing assets | $ | 111,165 | $ | 88,960 | $ | 85,021 | $ | 102,099 | $ | 81,398 | |||||||
| Non-accrual loans held for investment to total loans held for investment | 0.50 | % | 0.40 | % | 0.39 | % | 0.45 | % | 0.40 | % | |||||||
| Total non-performing assets to total assets | 0.36 | % | 0.28 | % | 0.28 | % | 0.35 | % | 0.29 | % | |||||||
| Allowance for credit losses on loans to non-accrual loans held for investment | 2.4x | 3.1x | 3.1x | 2.8x | 3.1x | ||||||||||||
| Total allowance for credit losses to non-accrual loans held for investment | 2.9x | 3.6x | 3.7x | 3.3x | 3.6x | ||||||||||||
Loans held for investment past due 90 days and still accruing | $ | 4,265 | $ | 5,281 | $ | 286 | $ | 3,674 | $ | 19,523 | |||||||
| Loans held for investment past due 90 days to total loans held for investment | 0.02 | % | 0.02 | % | — | % | 0.02 | % | 0.10 | % | |||||||
Loans held for sale past due 90 days and still accruing | $ | — | $ | — | $ | 64 | $ | 147 | $ | — | |||||||
(1) First quarter 2024 includes one non-accrual loan previously reported in loans held for investment that was transferred at fair value to held for sale as of March 31, 2024.
8
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||||
| CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED) | |||||||||||||||||
| (dollars in thousands) | |||||||||||||||||
| 4th Quarter | 3rd Quarter | 2nd Quarter | 1st Quarter | 4th Quarter | |||||||||||||
| 2024 | 2024 | 2024 | 2024 | 2023 | |||||||||||||
| Interest income | |||||||||||||||||
| Interest and fees on loans | $ | 340,388 | $ | 361,407 | $ | 345,251 | $ | 330,879 | $ | 325,210 | |||||||
| Investment securities | 44,102 | 38,389 | 33,584 | 32,144 | 28,454 | ||||||||||||
| Interest bearing deposits in other banks | 53,081 | 52,737 | 43,233 | 54,355 | 63,408 | ||||||||||||
| Total interest income | 437,571 | 452,533 | 422,068 | 417,378 | 417,072 | ||||||||||||
| Interest expense | |||||||||||||||||
| Deposits | 189,061 | 190,255 | 181,280 | 175,600 | 170,173 | ||||||||||||
| Short-term borrowings | 10,678 | 13,784 | 12,749 | 12,783 | 18,069 | ||||||||||||
| Long-term debt | 8,225 | 8,392 | 11,457 | 13,986 | 14,113 | ||||||||||||
| Total interest expense | 207,964 | 212,431 | 205,486 | 202,369 | 202,355 | ||||||||||||
| Net interest income | 229,607 | 240,102 | 216,582 | 215,009 | 214,717 | ||||||||||||
| Provision for credit losses | 18,000 | 10,000 | 20,000 | 19,000 | 19,000 | ||||||||||||
| Net interest income after provision for credit losses | 211,607 | 230,102 | 196,582 | 196,009 | 195,717 | ||||||||||||
| Non-interest income | |||||||||||||||||
| Service charges on deposit accounts | 6,989 | 6,307 | 5,911 | 6,339 | 5,397 | ||||||||||||
| Wealth management and trust fee income | 4,009 | 4,040 | 3,699 | 3,567 | 3,302 | ||||||||||||
| Brokered loan fees | 2,519 | 2,400 | 2,131 | 1,911 | 2,076 | ||||||||||||
| Investment banking and advisory fees | 26,740 | 34,753 | 25,048 | 18,424 | 6,906 | ||||||||||||
| Trading income | 5,487 | 5,786 | 5,650 | 4,712 | 3,819 | ||||||||||||
| Available-for-sale debt securities losses, net | — | (179,581) | — | — | — | ||||||||||||
| Other | 8,330 | 11,524 | 7,985 | 6,366 | 9,633 | ||||||||||||
| Total non-interest income | 54,074 | (114,771) | 50,424 | 41,319 | 31,133 | ||||||||||||
| Non-interest expense | |||||||||||||||||
| Salaries and benefits | 97,873 | 121,138 | 118,840 | 128,727 | 107,970 | ||||||||||||
| Occupancy expense | 11,926 | 12,937 | 10,666 | 9,737 | 9,483 | ||||||||||||
| Marketing | 4,454 | 5,863 | 5,996 | 6,036 | 5,686 | ||||||||||||
| Legal and professional | 15,180 | 11,135 | 11,273 | 16,195 | 17,127 | ||||||||||||
| Communications and technology | 24,007 | 25,951 | 22,013 | 21,114 | 23,607 | ||||||||||||
| Federal Deposit Insurance Corporation insurance assessment | 4,454 | 4,906 | 5,570 | 8,421 | 25,143 | ||||||||||||
| Other | 14,265 | 13,394 | 14,051 | 12,163 | 12,369 | ||||||||||||
| Total non-interest expense | 172,159 | 195,324 | 188,409 | 202,393 | 201,385 | ||||||||||||
| Income/(loss) before income taxes | 93,522 | (79,993) | 58,597 | 34,935 | 25,465 | ||||||||||||
| Income tax expense/(benefit) | 22,499 | (18,674) | 16,935 | 8,793 | 5,315 | ||||||||||||
| Net income/(loss) | 71,023 | (61,319) | 41,662 | 26,142 | 20,150 | ||||||||||||
| Preferred stock dividends | 4,312 | 4,313 | 4,312 | 4,313 | 4,312 | ||||||||||||
| Net income/(loss) available to common shareholders | $ | 66,711 | $ | (65,632) | $ | 37,350 | $ | 21,829 | $ | 15,838 | |||||||
9
| TEXAS CAPITAL BANCSHARES, INC. | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
TAXABLE EQUIVALENT NET INTEREST INCOME ANALYSIS (UNAUDITED)(1) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 4th Quarter 2024 | 3rd Quarter 2024 | 2nd Quarter 2024 | 1st Quarter 2024 | 4th Quarter 2023 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Balance | Income/ Expense | Yield/ Rate | Average Balance | Income/ Expense | Yield/ Rate | Average Balance | Income/ Expense | Yield/ Rate | Average Balance | Income/ Expense | Yield/ Rate | Average Balance | Income/ Expense | Yield/ Rate | |||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Investment securities(2) | $ | 4,504,101 | $ | 44,102 | 3.79 | % | $ | 4,314,834 | $ | 38,389 | 3.34 | % | $ | 4,427,023 | $ | 33,584 | 2.80 | % | $ | 4,299,368 | $ | 32,144 | 2.77 | % | $ | 4,078,975 | $ | 28,454 | 2.48 | % | |||||||||||||||||||||||||||||
| Interest bearing cash and cash equivalents | 4,472,772 | 53,081 | 4.72 | % | 3,958,843 | 52,737 | 5.30 | % | 3,273,069 | 43,233 | 5.31 | % | 4,051,627 | 54,355 | 5.40 | % | 4,637,374 | 63,408 | 5.42 | % | |||||||||||||||||||||||||||||||||||||||
| Loans held for sale | — | — | — | % | 23,793 | 565 | 9.44 | % | 28,768 | 683 | 9.55 | % | 51,164 | 1,184 | 9.31 | % | 29,071 | 672 | 9.17 | % | |||||||||||||||||||||||||||||||||||||||
Loans held for investment, mortgage finance(4) | 5,409,980 | 50,685 | 3.73 | % | 5,152,317 | 54,371 | 4.20 | % | 4,357,288 | 42,722 | 3.94 | % | 3,517,707 | 31,455 | 3.60 | % | 3,946,280 | 33,709 | 3.39 | % | |||||||||||||||||||||||||||||||||||||||
Loans held for investment(3)(4) | 16,919,925 | 289,916 | 6.82 | % | 16,792,446 | 306,541 | 7.26 | % | 16,750,788 | 301,910 | 7.25 | % | 16,522,089 | 298,306 | 7.26 | % | 16,164,233 | 290,897 | 7.14 | % | |||||||||||||||||||||||||||||||||||||||
Less: Allowance for credit losses on loans | 272,975 | — | — | 266,915 | — | — | 263,145 | — | — | 249,936 | — | — | 244,287 | — | — | ||||||||||||||||||||||||||||||||||||||||||||
| Loans held for investment, net | 22,056,930 | 340,601 | 6.14 | % | 21,677,848 | 360,912 | 6.62 | % | 20,844,931 | 344,632 | 6.65 | % | 19,789,860 | 329,761 | 6.70 | % | 19,866,226 | 324,606 | 6.48 | % | |||||||||||||||||||||||||||||||||||||||
| Total earning assets | 31,033,803 | 437,784 | 5.59 | % | 29,975,318 | 452,603 | 5.96 | % | 28,573,791 | 422,132 | 5.86 | % | 28,192,019 | 417,444 | 5.88 | % | 28,611,646 | 417,140 | 5.69 | % | |||||||||||||||||||||||||||||||||||||||
| Cash and other assets | 1,178,284 | 1,239,855 | 1,177,061 | 1,058,463 | 1,120,354 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 32,212,087 | $ | 31,215,173 | $ | 29,750,852 | $ | 29,250,482 | $ | 29,732,000 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities and Stockholders’ Equity | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Transaction deposits | $ | 2,141,739 | $ | 15,403 | 2.86 | % | $ | 1,988,688 | $ | 15,972 | 3.20 | % | $ | 2,061,622 | $ | 16,982 | 3.31 | % | $ | 2,006,493 | $ | 16,858 | 3.38 | % | $ | 1,972,324 | $ | 15,613 | 3.14 | % | |||||||||||||||||||||||||||||
| Savings deposits | 12,932,458 | 144,393 | 4.44 | % | 12,240,616 | 147,770 | 4.80 | % | 11,981,668 | 143,173 | 4.81 | % | 11,409,677 | 136,790 | 4.82 | % | 11,043,155 | 132,801 | 4.77 | % | |||||||||||||||||||||||||||||||||||||||
| Time deposits | 2,331,009 | 29,265 | 4.99 | % | 2,070,537 | 26,513 | 5.09 | % | 1,658,899 | 21,125 | 5.12 | % | 1,719,325 | 21,952 | 5.14 | % | 1,716,812 | 21,759 | 5.03 | % | |||||||||||||||||||||||||||||||||||||||
| Total interest bearing deposits | 17,405,206 | 189,061 | 4.32 | % | 16,299,841 | 190,255 | 4.64 | % | 15,702,189 | 181,280 | 4.64 | % | 15,135,495 | 175,600 | 4.67 | % | 14,732,291 | 170,173 | 4.58 | % | |||||||||||||||||||||||||||||||||||||||
| Short-term borrowings | 883,326 | 10,678 | 4.81 | % | 1,012,608 | 13,784 | 5.42 | % | 927,253 | 12,749 | 5.53 | % | 912,088 | 12,783 | 5.64 | % | 1,257,609 | 18,069 | 5.70 | % | |||||||||||||||||||||||||||||||||||||||
| Long-term debt | 660,270 | 8,225 | 4.96 | % | 660,098 | 8,392 | 5.06 | % | 778,401 | 11,457 | 5.92 | % | 859,509 | 13,986 | 6.54 | % | 858,858 | 14,113 | 6.52 | % | |||||||||||||||||||||||||||||||||||||||
| Total interest bearing liabilities | 18,948,802 | 207,964 | 4.37 | % | 17,972,547 | 212,431 | 4.70 | % | 17,407,843 | 205,486 | 4.75 | % | 16,907,092 | 202,369 | 4.81 | % | 16,848,758 | 202,355 | 4.76 | % | |||||||||||||||||||||||||||||||||||||||
| Non-interest bearing deposits | 9,319,711 | 9,439,020 | 8,647,594 | 8,637,775 | 9,247,491 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 522,641 | 558,368 | 537,754 | 509,286 | 541,162 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Stockholders’ equity | 3,420,933 | 3,245,238 | 3,157,661 | 3,196,329 | 3,094,589 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 32,212,087 | $ | 31,215,173 | $ | 29,750,852 | $ | 29,250,482 | $ | 29,732,000 | |||||||||||||||||||||||||||||||||||||||||||||||||
Net interest income | $ | 229,820 | $ | 240,172 | $ | 216,646 | $ | 215,075 | $ | 214,785 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin | 2.93 | % | 3.16 | % | 3.01 | % | 3.03 | % | 2.93 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
(1) Taxable equivalent rates used where applicable.
(2) Yields on investment securities are calculated using available-for-sale securities at amortized cost.
(3) Average balances include non-accrual loans.
(4) In the first quarter of 2024, enhancements were made to our methodology for applying relationship pricing credits to mortgage client loans. To conform to the current period presentation, certain prior period interest income amounts have been reclassified from loans held for investment, mortgage finance to loans held for investment and related yields have been adjusted accordingly.
10
GAAP TO NON-GAAP RECONCILIATIONS
The following items are non-GAAP financial measures: adjusted net income, adjusted net income available to common stockholders, adjusted pre-provision net revenue (“PPNR”), adjusted diluted earnings/(loss) per common share, adjusted return on average assets, adjusted return on average common equity, adjusted efficiency ratio, adjusted non-interest income to average earning assets and adjusted non-interest expense to average earning assets. These are not measures recognized under GAAP and therefore are considered non-GAAP financial measures. The table below provides a reconciliation of these non-GAAP financial measures to the most comparable GAAP measures.
These non-GAAP financial measures are adjusted for certain items, listed below, that management believes are non-operating in nature and not representative of its actual operating performance. Management believes that these non-GAAP financial measures provide meaningful additional information about Texas Capital Bancshares, Inc. to assist management and investors in evaluating operating results, financial strength, business performance and capital position. Non-GAAP financial measures have inherent limitations, are not required to be uniformly applied and are not audited. As such, these non-GAAP financial measures should not be considered in isolation or as a substitute for analyses of operating results or capital position as reported under GAAP.
| Reconciliation of Non-GAAP Financial Measures | |||||||||||||||||||||||
| (dollars in thousands except per share data) | 4th Quarter 2024 | 3rd Quarter 2024 | 2nd Quarter 2024 | 1st Quarter 2024 | 4th Quarter 2023 | Full Year 2024 | Full Year 2023 | ||||||||||||||||
| Net interest income | $ | 229,607 | $ | 240,102 | $ | 216,582 | $ | 215,009 | $ | 214,717 | $ | 901,300 | $ | 914,123 | |||||||||
| Non-interest income | 54,074 | (114,771) | 50,424 | 41,319 | 31,133 | 31,046 | 161,419 | ||||||||||||||||
| Available-for-sale debt securities losses, net | — | 179,581 | — | — | — | 179,581 | — | ||||||||||||||||
| Non-interest income, adjusted | 54,074 | 64,810 | 50,424 | 41,319 | 31,133 | 210,627 | 161,419 | ||||||||||||||||
| Non-interest expense | 172,159 | 195,324 | 188,409 | 202,393 | 201,385 | 758,285 | 756,947 | ||||||||||||||||
| FDIC special assessment | — | 651 | (462) | (3,000) | (19,886) | (2,811) | (19,886) | ||||||||||||||||
| Restructuring expenses | — | (5,923) | — | (2,018) | — | (7,941) | — | ||||||||||||||||
| Legal Settlement | — | — | — | (5,000) | — | (5,000) | — | ||||||||||||||||
| Non-interest expense, adjusted | 172,159 | 190,052 | 187,947 | 192,375 | 181,499 | 742,533 | 737,061 | ||||||||||||||||
| Provision for credit losses | 18,000 | 10,000 | 20,000 | 19,000 | 19,000 | 67,000 | 72,000 | ||||||||||||||||
| Income tax expense/(benefit) | 22,499 | (18,674) | 16,935 | 8,793 | 5,315 | 29,553 | 57,454 | ||||||||||||||||
| Tax effect of adjustments | — | 44,880 | 104 | 2,262 | 4,633 | 47,246 | 4,633 | ||||||||||||||||
| Income tax expense/(benefit), adjusted | 22,499 | 26,206 | 17,039 | 11,055 | 9,948 | 76,799 | 62,087 | ||||||||||||||||
Net income/(loss)(1) | $ | 71,023 | $ | (61,319) | $ | 41,662 | $ | 26,142 | $ | 20,150 | $ | 77,508 | $ | 189,141 | |||||||||
Net income/(loss), adjusted(1) | $ | 71,023 | $ | 78,654 | $ | 42,020 | $ | 33,898 | $ | 35,403 | $ | 225,595 | $ | 204,394 | |||||||||
| Preferred stock dividends | 4,312 | 4,313 | 4,312 | 4,313 | 4,312 | 17,250 | 17,250 | ||||||||||||||||
Net income/(loss) to common stockholders(2) | $ | 66,711 | $ | (65,632) | $ | 37,350 | $ | 21,829 | $ | 15,838 | $ | 60,258 | $ | 171,891 | |||||||||
Net income/(loss) to common stockholders, adjusted(2) | $ | 66,711 | $ | 74,341 | $ | 37,708 | $ | 29,585 | $ | 31,091 | $ | 208,345 | $ | 187,144 | |||||||||
PPNR(3) | $ | 111,522 | $ | (69,993) | $ | 78,597 | $ | 53,935 | $ | 44,465 | $ | 174,061 | $ | 318,595 | |||||||||
PPNR(3), adjusted | $ | 111,522 | $ | 114,860 | $ | 79,059 | $ | 63,953 | $ | 64,351 | $ | 369,394 | $ | 338,481 | |||||||||
| Weighted average common shares outstanding, diluted | 46,770,961 | 46,608,742 | 46,872,498 | 47,711,192 | 48,097,517 | 46,989,204 | 48,610,206 | ||||||||||||||||
| Diluted earnings/(loss) per common share | $ | 1.43 | $ | (1.41) | $ | 0.80 | $ | 0.46 | $ | 0.33 | $ | 1.28 | $ | 3.54 | |||||||||
| Diluted earnings/(loss) per common share, adjusted | $ | 1.43 | $ | 1.59 | $ | 0.80 | $ | 0.62 | $ | 0.65 | $ | 4.43 | $ | 3.85 | |||||||||
| Average total assets | $ | 32,212,087 | $ | 31,215,173 | $ | 29,750,852 | $ | 29,250,482 | $ | 29,732,000 | $ | 30,613,195 | $ | 29,537,344 | |||||||||
| Return on average assets | 0.88 | % | (0.78) | % | 0.56 | % | 0.36 | % | 0.27 | % | 0.25 | % | 0.64 | % | |||||||||
| Return on average assets, adjusted | 0.88 | % | 1.00 | % | 0.57 | % | 0.47 | % | 0.47 | % | 0.74 | % | 0.69 | % | |||||||||
Average common equity | $ | 3,120,933 | $ | 2,945,238 | $ | 2,857,661 | $ | 2,896,329 | $ | 2,794,589 | $ | 2,955,467 | $ | 2,794,964 | |||||||||
| Return on average common equity | 8.50 | % | (8.87) | % | 5.26 | % | 3.03 | % | 2.25 | % | 2.04 | % | 6.15 | % | |||||||||
| Return on average common equity, adjusted | 8.50 | % | 10.04 | % | 5.31 | % | 4.11 | % | 4.41 | % | 7.05 | % | 6.70 | % | |||||||||
Efficiency ratio(4) | 60.7 | % | 155.8 | % | 70.6 | % | 79.0 | % | 81.9 | % | 81.3 | % | 70.4 | % | |||||||||
Efficiency ratio, adjusted(4) | 60.7 | % | 62.3 | % | 70.4 | % | 75.1 | % | 73.8 | % | 66.8 | % | 68.5 | % | |||||||||
| Average earning assets | $ | 31,033,803 | $ | 29,975,318 | $ | 28,573,791 | $ | 28,192,019 | $ | 28,611,646 | $ | 29,449,530 | $ | 28,457,737 | |||||||||
| Non-interest income to average earning assets | 0.69 | % | (1.52) | % | 0.71 | % | 0.59 | % | 0.43 | % | 0.11 | % | 0.57 | % | |||||||||
| Non-interest income to average earning assets, adjusted | 0.69 | % | 0.86 | % | 0.71 | % | 0.59 | % | 0.43 | % | 0.72 | % | 0.57 | % | |||||||||
| Non-interest expense to average earning assets | 2.21 | % | 2.59 | % | 2.65 | % | 2.89 | % | 2.79 | % | 2.57 | % | 2.66 | % | |||||||||
| Non-interest expense to average earning assets, adjusted | 2.21 | % | 2.52 | % | 2.65 | % | 2.74 | % | 2.52 | % | 2.52 | % | 2.59 | % | |||||||||
(1) Net interest income plus non-interest income, less non-interest expense, provision for credit losses and income tax expense/(benefit). On an adjusted basis, net interest income plus non-interest income, adjusted, less non-interest expense, adjusted, provision for credit losses and income tax expense/(benefit), adjusted.
(2) Net income/(loss), less preferred stock dividends. On an adjusted basis, net income/(loss), adjusted, less preferred stock dividends.
(3) Net interest income plus non-interest income, less non-interest expense. On an adjusted basis, net interest income plus non-interest income, adjusted, less non-interest expense, adjusted.
(4) Non-interest expense divided by the sum of net interest income and non-interest income. On an adjusted basis, non-interest expense, adjusted, divided by the sum of net interest income and non-interest income, adjusted.
11
© 2025 Texas Capital Bank Member FDIC January 23, 2025 Q4-2024 Earnings
2 Forward-Looking Statements This communication contains “forward-looking statements” within the meaning of and pursuant to the Private Securities Litigation Reform Act of 1995 regarding, among other things, TCBI’s financial condition, results of operations, business plans and future performance. These statements are not historical in nature and may often be identified by the use of words such as “believes,” “projects,” “expects,” “may,” “estimates,” “should,” “plans,” “targets,” “intends” “could,” “would,” “anticipates,” “potential,” “confident,” “optimistic” or the negative thereof, or other variations thereon, or comparable terminology, or by discussions of strategy, objectives, estimates, trends, guidance, expectations and future plans. Because forward-looking statements relate to future results and occurrences, they are subject to inherent and various uncertainties, risks, and changes in circumstances that are difficult to predict, may change over time, are based on management’s expectations and assumptions at the time the statements are made and are not guarantees of future results. Numerous risks and other factors, many of which are beyond management’s control, could cause actual results to differ materially from future results expressed or implied by such forward-looking statements. While there can be no assurance that any list of risks is complete, important risks and other factors that could cause actual results to differ materially from those contemplated by forward- looking statements include, but are not limited to: economic or business conditions in Texas, the United States or globally that impact TCBI or its customers; negative credit quality developments arising from the foregoing or other factors; increased or expanded competition from banks and other financial service providers in TCBI’s markets; TCBI’s ability to effectively manage its liquidity and maintain adequate regulatory capital to support its businesses; TCBI’s ability to pursue and execute upon growth plans, whether as a function of capital, liquidity or other limitations; TCBI’s ability to successfully execute its business strategy, including its strategic plan and developing and executing new lines of business and new products and services and potential strategic acquisitions; the extensive regulations to which TCBI is subject and its ability to comply with applicable governmental regulations, including legislative and regulatory changes; TCBI’s ability to effectively manage information technology systems, including third party vendors, cyber or data privacy incidents or other failures, disruptions or security breaches; TCBI’s ability to use technology to provide products and services to its customers; risks related to the development and use of artificial intelligence; changes in interest rates, including the impact of interest rates on TCBI’s securities portfolio and funding costs, as well as related balance sheet implications stemming from the fair value of our assets and liabilities; the effectiveness of TCBI’s risk management processes strategies and monitoring; fluctuations in commercial and residential real estate values, especially as they relate to the value of collateral supporting TCBI’s loans; the failure to identify, attract and retain key personnel and other employees; adverse developments in the banking industry and the potential impact of such developments on customer confidence, liquidity and regulatory responses to these developments, including in the context of regulatory examinations and related findings and actions; negative press and social media attention with respect to the banking industry or TCBI, in particular; claims, litigation or regulatory investigations and actions that TCBI may become subject to; severe weather, natural disasters, climate change, acts of war, terrorism, global conflict (including those already reported by the media, as well as others that may arise), or other external events, as well as related legislative and regulatory initiatives; and the risks and factors more fully described in TCBI’s most recent Annual Report on Form 10-K, Quarterly Reports on Form 10-Q and other documents and filings with the SEC. The information contained in this communication speaks only as of its date. Except to the extent required by applicable law or regulation, we disclaim any obligation to update such factors or to publicly announce the results of any revisions to any of the forward-looking statements included herein to reflect future events or developments.
3 Foundational Tenants of Value Creation in Place Financial Priorities Described 9/1/2021 Building Tangible Book Value // Reinvesting organically generated capital to improve client relevance and create a more valuable franchise Investment // Re-aligning the expense base to directly support the business and investing aggressively to take advantage of market opportunities that we are uniquely positioned to serve Revenue Growth // Growing top- line revenue as a result of expanded banking capabilities for best-in-class clients in our Texas and national markets Flagship Results Proactive, disciplined engagement with the best clients in our markets to provide the talent, products, and offerings they need through their entire life-cycles Structurally higher, more sustainable earnings driving greater performance and lower annual variability Consistent communication, enhanced accountability, and a bias for action ensure execution and delivery Commitment to financial resilience allowing us to serve clients, access markets, and support communities through all cycles Higher quality earnings and a lower cost of capital drive a significant expansion in incremental shareholder returns
4 Targets Estab. in ’21 Where We StartedTargets Estab. in ’21 Where We Started FY 2024 FY 2023 FY 2022 FY 2021 FY 2020Performance Metrics FY 2024 FY 2023 FY 2022 FY 2021 FY 2020Income Statement >1.10%0.25%0.64%1.04%0.67%0.18%Return on Average Assets~10%13.6%8.0%2.9%2.7%2.2% Investment Banking and Trading Income (% of Total Revenue) >12.5%2.0% 6.2%11.4%8.4%2.1%Return on Average Tangible Common Equity3~5%3.8%2.8%2.4%2.5%1.4%Treasury Product Fees1 (% of Total Revenue) >1.10%0.74%0.69%0.55%0.69%0.33%Adj. Return on Average Assets415%–20% 3.3%15.0%28.5%15.2%19.3%Non-Interest Income (% of Total Revenue) >12.5%7.1%6.7%5.8%8.7%4.2%Adj. Return on Average Tangible Common Equity315%–20%18.9%15.0%10.3%13.4%11.2%Adj. Non-Interest Income2 (% of Adj. Total Revenue2) >10%11.4%12.6%13.0%11.1%9.4%CET1Balance Sheet >20%28%30%30%38%29%Average Cash & Securities (% of Total Average Assets) <15%7%7%16%27%36%Average Indexed Deposits (% of Total Deposits) 2021 Strategic Performance Drivers Treasury Solutions Private Wealth Investment Banking Annual Growth FY 2024 FY 2023Q4 ‘24Q3 ‘24Q2 ‘24Q1 ‘24Q4 ‘23Financial Performance 3%$4.0$3.8 $4.0$4.1$4.0$4.0$3.8Assets Under Management5 ($bn) 18%$35.8 $30.3 $9.5 $9.1 $8.5 $8.7 $7.8 Treasury Product Fees1 ($mm) 10%$15.3 $14.0 $4.0 $4.0 $3.7 $3.6 $3.3 Wealth Management & Trust Fee Income ($mm) 47%$126.6 $86.2 $32.2 $40.5 $30.7 $23.1 $10.7 Investment Banking & Trading Income ($mm) 36%$177.7 $130.4 $45.7 $53.7 $42.9 $35.4 $21.8 Income from Areas of Focus ($mm) Record quarterly fees in 4Q, with full year growth of 18%, relative to 3% in FY23 Continued success winning core operating accounts; Non- interest bearing, excl. mortgage finance deposits up 4% YoY Investment banking fees increased 47% for the full year driven by capital markets, syndications, and sales and trading Sustained execution, expanded product suite, and continued talent acquisition expected to deliver strong growth in ‘25 Modest full-year fee growth, but improving YoY momentum entering 2025; Q4 fees increased 21% compared to Q4 ‘23 Enhanced platform build is substantially complete; expect accelerated client adoption in ‘25
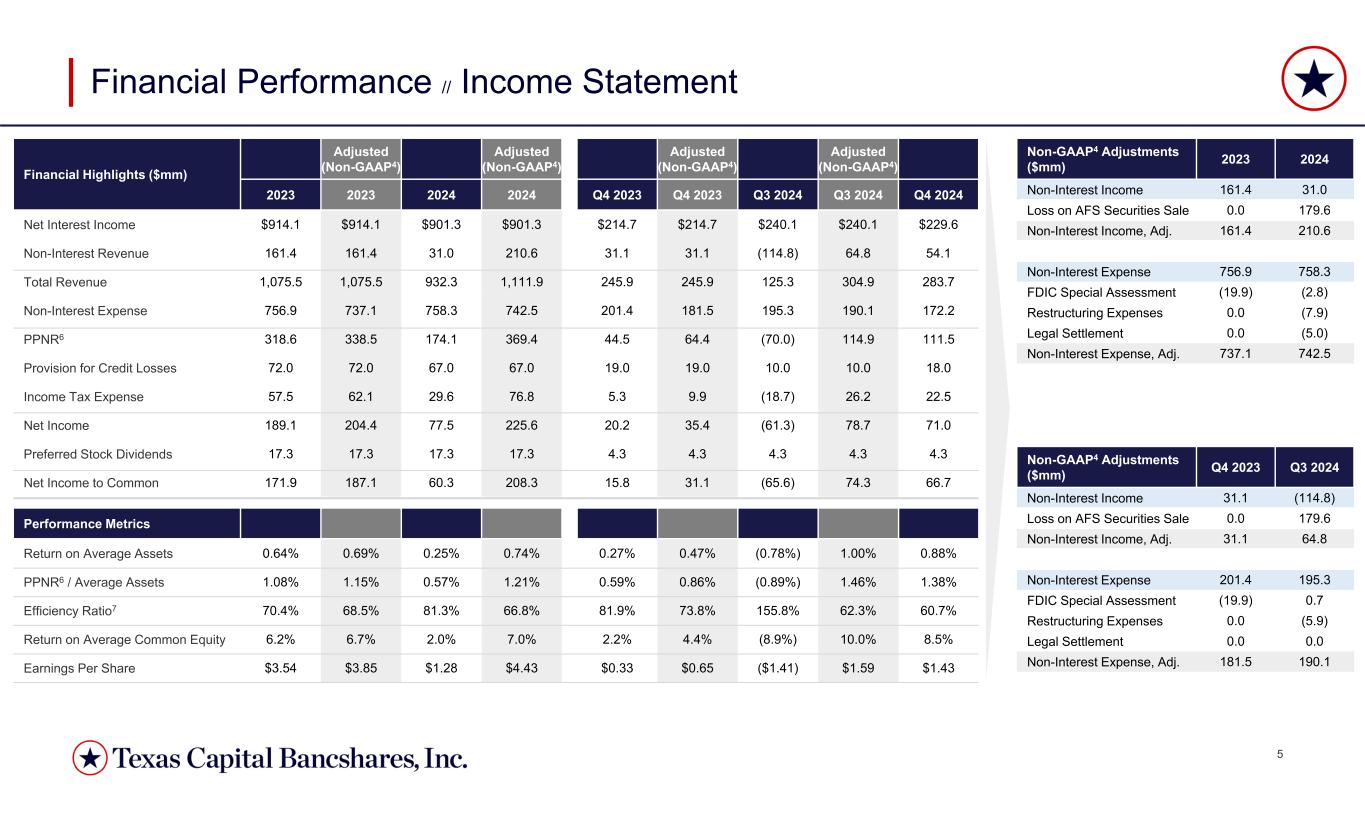
5 Financial Performance // Income Statement Adjusted (Non-GAAP4) Adjusted (Non-GAAP4) Adjusted (Non-GAAP4) Adjusted (Non-GAAP4)Financial Highlights ($mm) Q4 2024Q3 2024Q3 2024Q4 2023Q4 20232024202420232023 $229.6 $240.1 $240.1 $214.7 $214.7 $901.3 $901.3 $914.1$914.1Net Interest Income 54.1 64.8 (114.8)31.1 31.1 210.6 31.0 161.4161.4Non-Interest Revenue 283.7 304.9 125.3 245.9 245.9 1,111.9 932.3 1,075.51,075.5Total Revenue 172.2 190.1 195.3 181.5 201.4 742.5 758.3 737.1756.9Non-Interest Expense 111.5 114.9 (70.0)64.4 44.5 369.4 174.1 338.5318.6PPNR6 18.0 10.0 10.0 19.0 19.0 67.0 67.0 72.072.0Provision for Credit Losses 22.5 26.2 (18.7)9.9 5.3 76.8 29.6 62.157.5Income Tax Expense 71.0 78.7 (61.3)35.4 20.2 225.6 77.5 204.4189.1Net Income 4.3 4.3 4.3 4.3 4.3 17.3 17.3 17.317.3Preferred Stock Dividends 66.7 74.3 (65.6)31.1 15.8 208.3 60.3 187.1171.9Net Income to Common Performance Metrics 0.88% 1.00% (0.78%)0.47% 0.27% 0.74% 0.25% 0.69%0.64%Return on Average Assets 1.38% 1.46% (0.89%)0.86% 0.59% 1.21% 0.57% 1.15%1.08%PPNR6 / Average Assets 60.7% 62.3% 155.8% 73.8% 81.9% 66.8% 81.3% 68.5%70.4%Efficiency Ratio7 8.5% 10.0% (8.9%)4.4% 2.2% 7.0% 2.0% 6.7%6.2%Return on Average Common Equity $1.43 $1.59 ($1.41)$0.65 $0.33 $4.43 $1.28 $3.85$3.54Earnings Per Share Q3 2024Q4 2023Non-GAAP4 Adjustments ($mm) (114.8)31.1Non-Interest Income 179.60.0Loss on AFS Securities Sale 64.8 31.1Non-Interest Income, Adj. 195.3201.4Non-Interest Expense 0.7(19.9)FDIC Special Assessment (5.9)0.0Restructuring Expenses 0.00.0Legal Settlement 190.1181.5Non-Interest Expense, Adj. 20242023Non-GAAP4 Adjustments ($mm) 31.0161.4Non-Interest Income 179.60.0Loss on AFS Securities Sale 210.6161.4Non-Interest Income, Adj. 758.3756.9Non-Interest Expense (2.8)(19.9)FDIC Special Assessment (7.9)0.0Restructuring Expenses (5.0)0.0Legal Settlement 742.5737.1Non-Interest Expense, Adj.
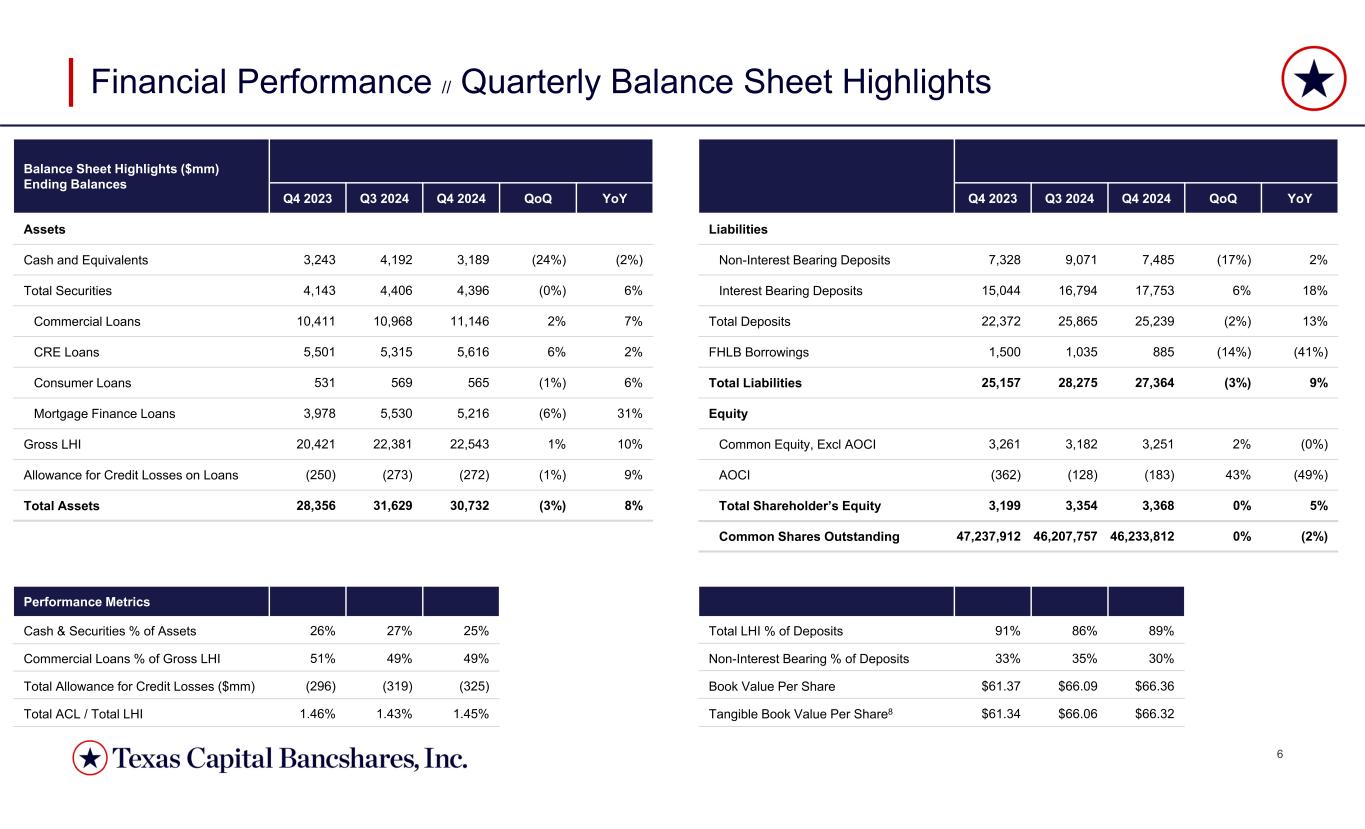
6 Balance Sheet Highlights ($mm) Ending Balances YoYQoQQ4 2024Q3 2024Q4 2023 Assets (2%)(24%)3,189 4,192 3,243 Cash and Equivalents 6% (0%)4,396 4,406 4,143 Total Securities 7% 2% 11,146 10,968 10,411 Commercial Loans 2% 6% 5,616 5,315 5,501 CRE Loans 6% (1%)565 569 531 Consumer Loans 31% (6%)5,216 5,530 3,978 Mortgage Finance Loans 10% 1% 22,543 22,381 20,421 Gross LHI 9% (1%)(272)(273)(250)Allowance for Credit Losses on Loans 8% (3%)30,732 31,629 28,356 Total Assets Financial Performance // Quarterly Balance Sheet Highlights Performance Metrics 25% 27% 26% Cash & Securities % of Assets 49% 49% 51% Commercial Loans % of Gross LHI (325)(319)(296)Total Allowance for Credit Losses ($mm) 1.45% 1.43% 1.46% Total ACL / Total LHI YoYQoQQ4 2024Q3 2024Q4 2023 Liabilities 2% (17%)7,485 9,071 7,328 Non-Interest Bearing Deposits 18% 6% 17,753 16,794 15,044 Interest Bearing Deposits 13% (2%)25,239 25,865 22,372 Total Deposits (41%)(14%)885 1,035 1,500 FHLB Borrowings 9% (3%)27,364 28,275 25,157 Total Liabilities Equity (0%)2% 3,251 3,182 3,261 Common Equity, Excl AOCI (49%)43% (183)(128)(362)AOCI 5% 0% 3,368 3,354 3,199 Total Shareholder’s Equity (2%)0% 46,233,812 46,207,757 47,237,912 Common Shares Outstanding 89% 86% 91% Total LHI % of Deposits 30% 35% 33% Non-Interest Bearing % of Deposits $66.36 $66.09 $61.37 Book Value Per Share $66.32 $66.06 $61.34 Tangible Book Value Per Share8
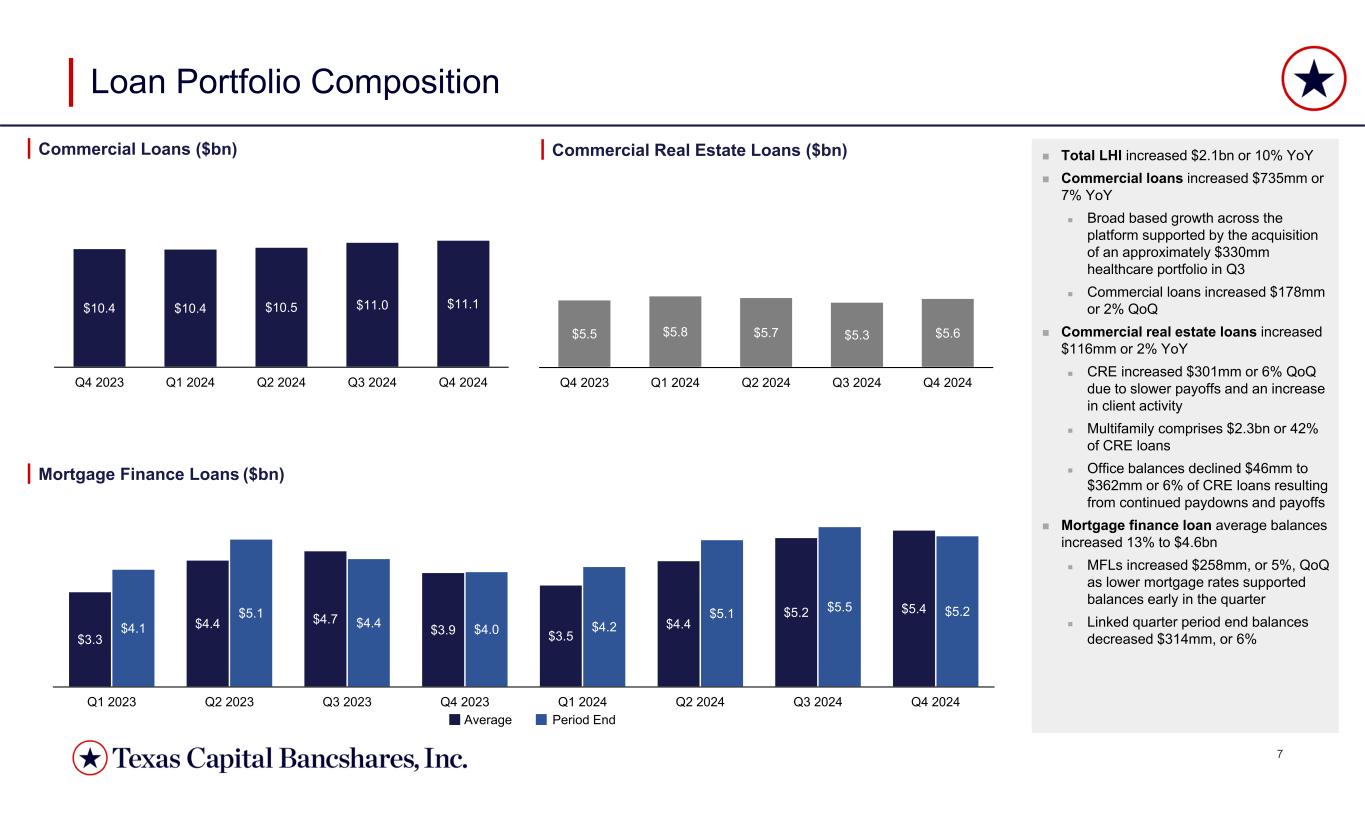
7 $3.3 $4.4 $4.7 $3.9 $3.5 $4.4 $5.2 $5.4 $4.1 $5.1 $4.4 $4.0 $4.2 $5.1 $5.5 $5.2 Q1 2023 Q2 2023 Q3 2023 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 $5.5 $5.8 $5.7 $5.3 $5.6 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 $10.4 $10.4 $10.5 $11.0 $11.1 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Total LHI increased $2.1bn or 10% YoY Commercial loans increased $735mm or 7% YoY Broad based growth across the platform supported by the acquisition of an approximately $330mm healthcare portfolio in Q3 Commercial loans increased $178mm or 2% QoQ Commercial real estate loans increased $116mm or 2% YoY CRE increased $301mm or 6% QoQ due to slower payoffs and an increase in client activity Multifamily comprises $2.3bn or 42% of CRE loans Office balances declined $46mm to $362mm or 6% of CRE loans resulting from continued paydowns and payoffs Mortgage finance loan average balances increased 13% to $4.6bn MFLs increased $258mm, or 5%, QoQ as lower mortgage rates supported balances early in the quarter Linked quarter period end balances decreased $314mm, or 6% Loan Portfolio Composition Mortgage Finance Loans ($bn) Average Period End Commercial Loans ($bn) Commercial Real Estate Loans ($bn)
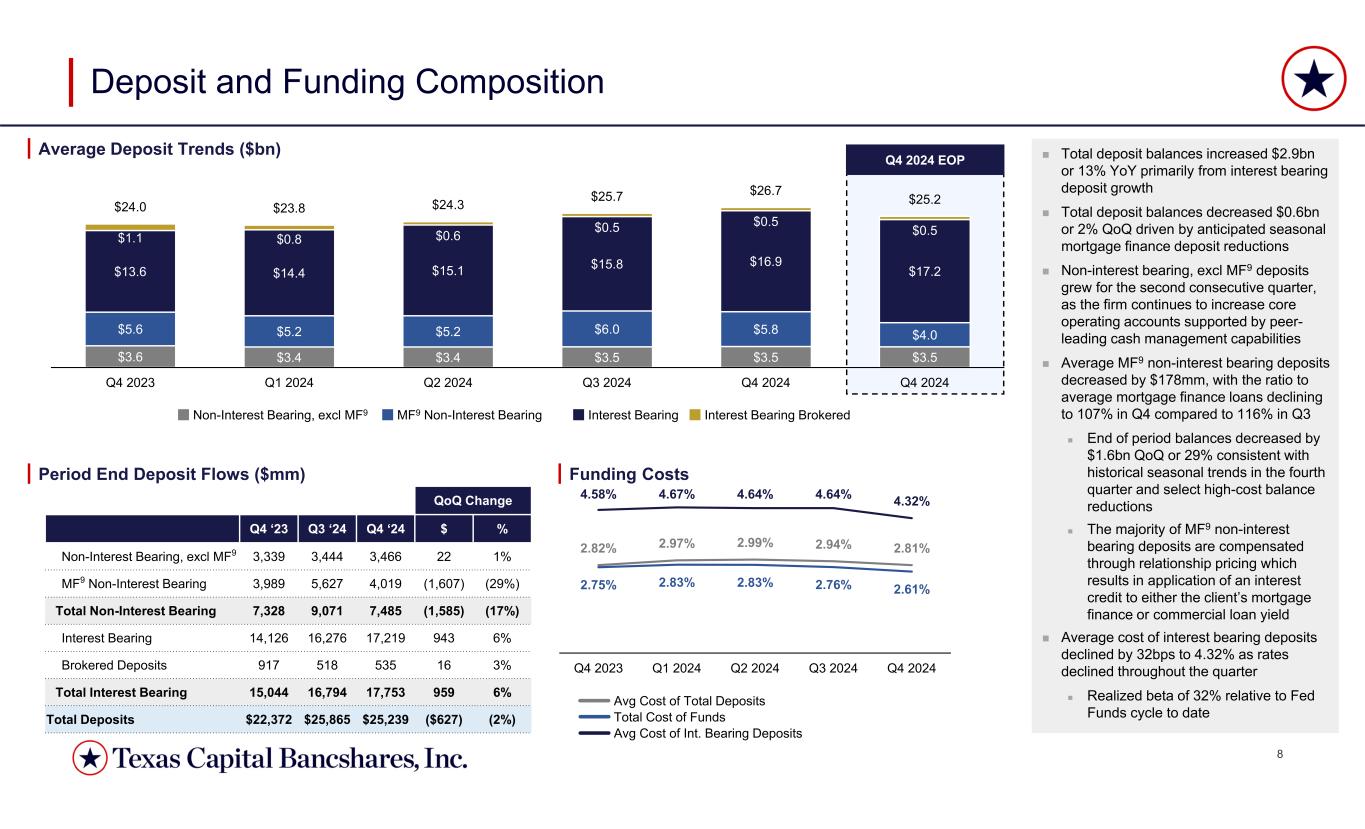
8 2.82% 2.97% 2.99% 2.94% 2.81% 2.75% 2.83% 2.83% 2.76% 2.61% 4.58% 4.67% 4.64% 4.64% 4.32% Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 $3.6 $3.4 $3.4 $3.5 $3.5 $3.5 $5.6 $5.2 $5.2 $6.0 $5.8 $4.0 $13.6 $14.4 $15.1 $15.8 $16.9 $17.2 $1.1 $0.8 $0.6 $0.5 $0.5 $0.5 $24.0 $23.8 $24.3 $25.7 $26.7 $25.2 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q4 2024 Q4 2024 EOP Deposit and Funding Composition Total deposit balances increased $2.9bn or 13% YoY primarily from interest bearing deposit growth Total deposit balances decreased $0.6bn or 2% QoQ driven by anticipated seasonal mortgage finance deposit reductions Non-interest bearing, excl MF9 deposits grew for the second consecutive quarter, as the firm continues to increase core operating accounts supported by peer- leading cash management capabilities Average MF9 non-interest bearing deposits decreased by $178mm, with the ratio to average mortgage finance loans declining to 107% in Q4 compared to 116% in Q3 End of period balances decreased by $1.6bn QoQ or 29% consistent with historical seasonal trends in the fourth quarter and select high-cost balance reductions The majority of MF9 non-interest bearing deposits are compensated through relationship pricing which results in application of an interest credit to either the client’s mortgage finance or commercial loan yield Average cost of interest bearing deposits declined by 32bps to 4.32% as rates declined throughout the quarter Realized beta of 32% relative to Fed Funds cycle to date Average Deposit Trends ($bn) Period End Deposit Flows ($mm) Funding Costs Non-Interest Bearing, excl MF9 MF9 Non-Interest Bearing Interest Bearing Interest Bearing Brokered QoQ Change %$Q4 ‘24Q3 ‘24Q4 ‘23 1% 22 3,466 3,444 3,339 Non-Interest Bearing, excl MF9 (29%)(1,607)4,019 5,627 3,989 MF9 Non-Interest Bearing (17%)(1,585)7,485 9,071 7,328 Total Non-Interest Bearing 6% 943 17,219 16,276 14,126 Interest Bearing 3% 16 535 518 917 Brokered Deposits 6% 959 17,753 16,794 15,044 Total Interest Bearing (2%)($627)$25,239 $25,865 $22,372 Total Deposits Total Cost of Funds Avg Cost of Int. Bearing Deposits Avg Cost of Total Deposits
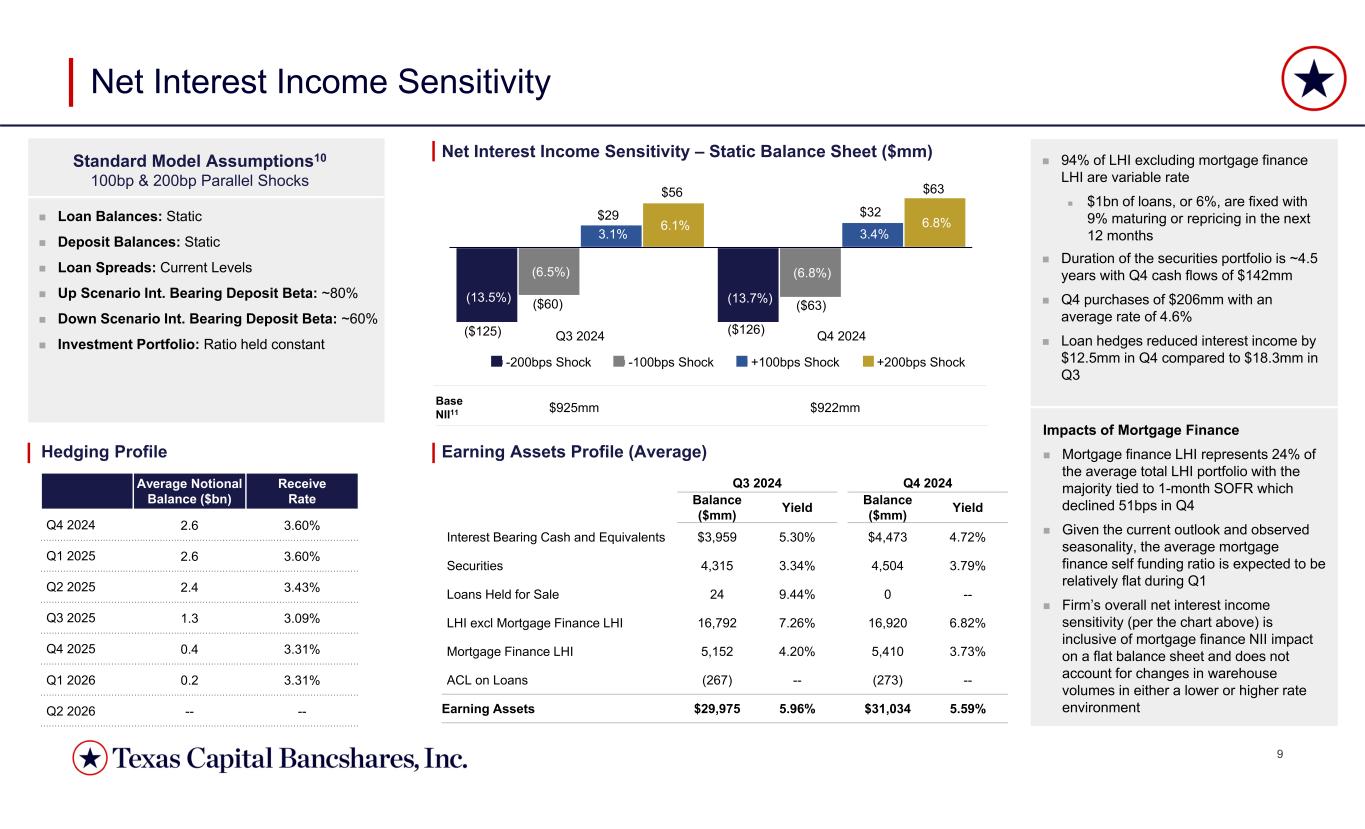
9 (13.5%) (13.7%) (6.5%) (6.8%) 3.1% 3.4% 6.1% 6.8% (10.0%) (8.0%) (6.0%) (4.0%) (2.0%) 0.0% 2.0% 4.0% 6.0% 8.0% 10.0% Q3 2024 Q4 2024 -200bps Shock -100bps Shock +100bps Shock +200bps Shock Net Interest Income Sensitivity Standard Model Assumptions10 100bp & 200bp Parallel Shocks Loan Balances: Static Deposit Balances: Static Loan Spreads: Current Levels Up Scenario Int. Bearing Deposit Beta: ~80% Down Scenario Int. Bearing Deposit Beta: ~60% Investment Portfolio: Ratio held constant Hedging Profile Net Interest Income Sensitivity – Static Balance Sheet ($mm) $922mm$925mmBase NII11 Earning Assets Profile (Average) Q4 2024Q3 2024 YieldBalance ($mm)YieldBalance ($mm) 4.72% $4,473 5.30% $3,959 Interest Bearing Cash and Equivalents 3.79% 4,504 3.34% 4,315 Securities --0 9.44% 24 Loans Held for Sale 6.82% 16,920 7.26% 16,792 LHI excl Mortgage Finance LHI 3.73% 5,410 4.20% 5,152 Mortgage Finance LHI --(273)--(267)ACL on Loans 5.59% $31,034 5.96% $29,975 Earning Assets 94% of LHI excluding mortgage finance LHI are variable rate $1bn of loans, or 6%, are fixed with 9% maturing or repricing in the next 12 months Duration of the securities portfolio is ~4.5 years with Q4 cash flows of $142mm Q4 purchases of $206mm with an average rate of 4.6% Loan hedges reduced interest income by $12.5mm in Q4 compared to $18.3mm in Q3 Impacts of Mortgage Finance Mortgage finance LHI represents 24% of the average total LHI portfolio with the majority tied to 1-month SOFR which declined 51bps in Q4 Given the current outlook and observed seasonality, the average mortgage finance self funding ratio is expected to be relatively flat during Q1 Firm’s overall net interest income sensitivity (per the chart above) is inclusive of mortgage finance NII impact on a flat balance sheet and does not account for changes in warehouse volumes in either a lower or higher rate environment $56 $29 ($60) ($125) $63 $32 ($63) ($126) Receive Rate Average Notional Balance ($bn) 3.60%2.6 Q4 2024 3.60%2.6 Q1 2025 3.43%2.4 Q2 2025 3.09%1.3 Q3 2025 3.31%0.4 Q4 2025 3.31%0.2 Q1 2026 ----Q2 2026
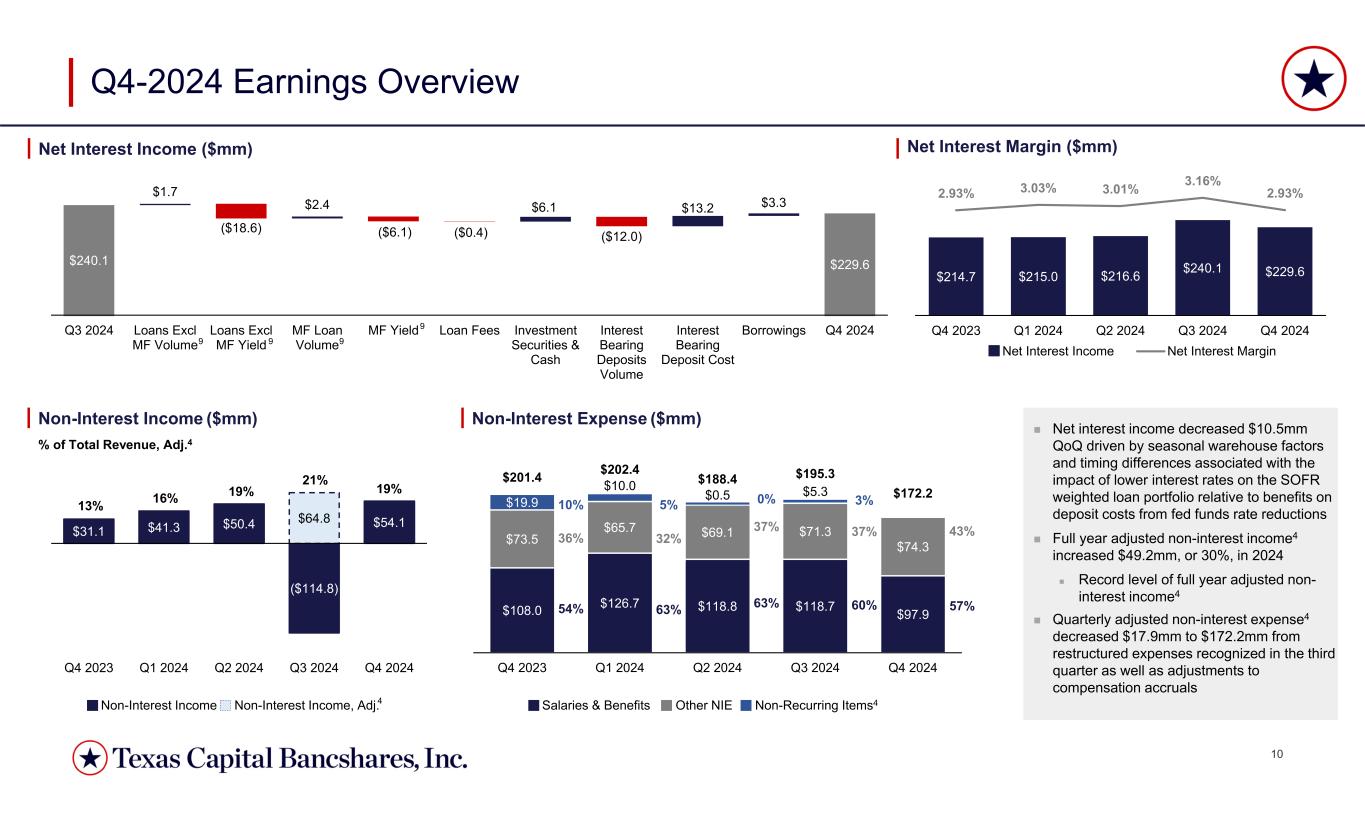
10 $108.0 $126.7 $118.8 $118.7 $97.9 $73.5 $65.7 $69.1 $71.3 $74.3 $19.9 $10.0 $0.5 $5.3 $201.4 $202.4 $188.4 $195.3 $172.2 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 $240.1 $1.7 ($18.6) $2.4 ($6.1) ($0.4) $6.1 ($12.0) $13.2 $3.3 $229.6 Q3 2024 Loans Excl MF Volume Loans Excl MF Yield MF Loan Volume MF Yield Loan Fees Investment Securities & Cash Interest Bearing Deposits Volume Interest Bearing Deposit Cost Borrowings Q4 2024 $214.7 $215.0 $216.6 $240.1 $229.6 2.93% 3.03% 3.01% 3.16% 2.93% Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Net Interest Income Net Interest Margin $31.1 $41.3 $50.4 ($114.8) $54.1 $64.8 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 3% 36% 54% 63% 63% 60% Q4-2024 Earnings Overview Net Interest Margin ($mm)Net Interest Income ($mm) Non-Interest Income ($mm) Non-Interest Expense ($mm) Salaries & Benefits Non-Recurring Items4Other NIE 57% Net interest income decreased $10.5mm QoQ driven by seasonal warehouse factors and timing differences associated with the impact of lower interest rates on the SOFR weighted loan portfolio relative to benefits on deposit costs from fed funds rate reductions Full year adjusted non-interest income4 increased $49.2mm, or 30%, in 2024 Record level of full year adjusted non- interest income4 Quarterly adjusted non-interest expense4 decreased $17.9mm to $172.2mm from restructured expenses recognized in the third quarter as well as adjustments to compensation accruals 9 9 9 9 43%37% % of Total Revenue, Adj.4 13% 16% 19% 21% 19% Non-Interest Income Non-Interest Income, Adj.4 10% 32% 5% 0% 37%
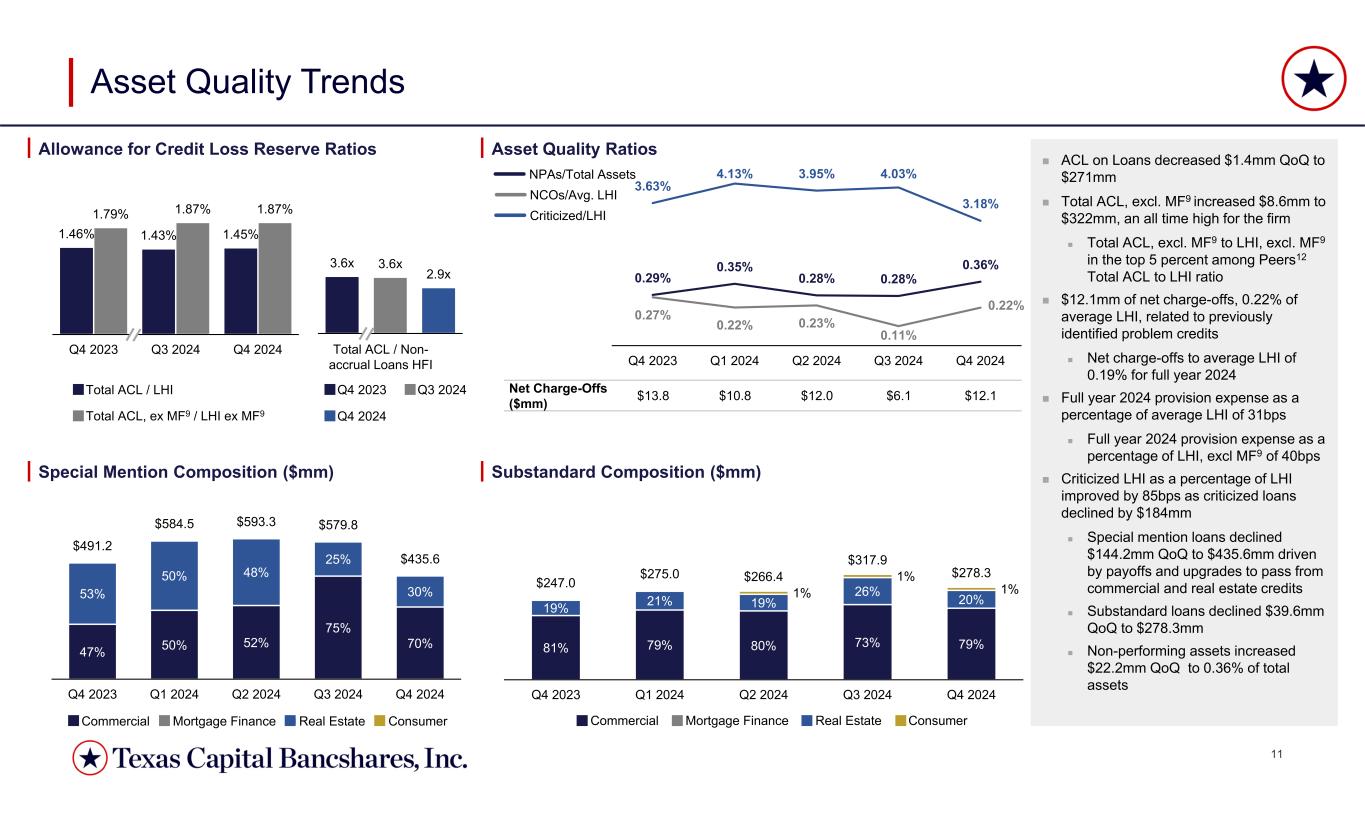
11 47% 50% 52% 75% 70% 53% 50% 48% 25% 30% $491.2 $584.5 $593.3 $579.8 $435.6 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Commercial Mortgage Finance Real Estate Consumer 81% 79% 80% 73% 79% 19% 21% 19% 26% 20% 1% 1% 1% $247.0 $275.0 $266.4 $317.9 $278.3 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Commercial Mortgage Finance Real Estate Consumer 0.29% 0.35% 0.28% 0.28% 0.36% 0.27% 0.22% 0.23% 0.11% 0.22% 3.63% 4.13% 3.95% 4.03% 3.18% Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 3.6x 3.6x 2.9x 1.46% 1.43% 1.45% 1.79% 1.87% 1.87% Q4 2023 Q3 2024 Q4 2024 Q4 2023 Q3 2024 Q4 2024Total ACL, ex MF9 / LHI ex MF9 Total ACL / LHI Asset Quality Trends Allowance for Credit Loss Reserve Ratios Asset Quality Ratios Special Mention Composition ($mm) Substandard Composition ($mm) $12.1 $6.1 $12.0 $10.8 $13.8 Net Charge-Offs ($mm) NPAs/Total Assets Criticized/LHI NCOs/Avg. LHI Total ACL / Non- accrual Loans HFI ACL on Loans decreased $1.4mm QoQ to $271mm Total ACL, excl. MF9 increased $8.6mm to $322mm, an all time high for the firm Total ACL, excl. MF9 to LHI, excl. MF9 in the top 5 percent among Peers12 Total ACL to LHI ratio $12.1mm of net charge-offs, 0.22% of average LHI, related to previously identified problem credits Net charge-offs to average LHI of 0.19% for full year 2024 Full year 2024 provision expense as a percentage of average LHI of 31bps Full year 2024 provision expense as a percentage of LHI, excl MF9 of 40bps Criticized LHI as a percentage of LHI improved by 85bps as criticized loans declined by $184mm Special mention loans declined $144.2mm QoQ to $435.6mm driven by payoffs and upgrades to pass from commercial and real estate credits Substandard loans declined $39.6mm QoQ to $278.3mm Non-performing assets increased $22.2mm QoQ to 0.36% of total assets
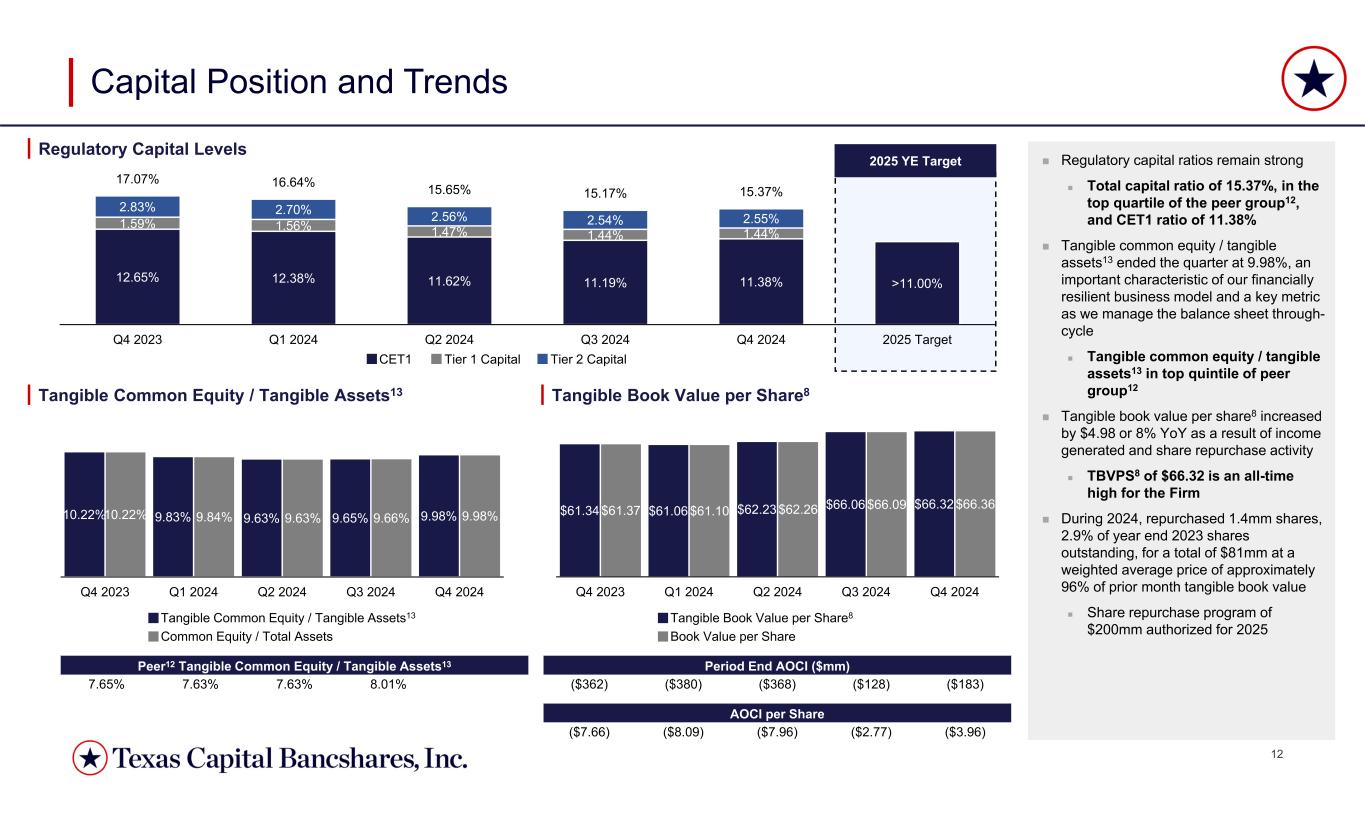
12 12.65% 12.38% 11.62% 11.19% 11.38% >11.00% 1.59% 1.56% 1.47% 1.44% 1.44% 2.83% 2.70% 2.56% 2.54% 2.55% 17.07% 16.64% 15.65% 15.17% 15.37% Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 2025 Target $61.34 $61.06 $62.23 $66.06 $66.32 $61.37 $61.10 $62.26 $66.09 $66.36 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 10.22% 9.83% 9.63% 9.65% 9.98% 10.22% 9.84% 9.63% 9.66% 9.98% Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 2025 YE Target Capital Position and Trends Regulatory capital ratios remain strong Total capital ratio of 15.37%, in the top quartile of the peer group12, and CET1 ratio of 11.38% Tangible common equity / tangible assets13 ended the quarter at 9.98%, an important characteristic of our financially resilient business model and a key metric as we manage the balance sheet through- cycle Tangible common equity / tangible assets13 in top quintile of peer group12 Tangible book value per share8 increased by $4.98 or 8% YoY as a result of income generated and share repurchase activity TBVPS8 of $66.32 is an all-time high for the Firm During 2024, repurchased 1.4mm shares, 2.9% of year end 2023 shares outstanding, for a total of $81mm at a weighted average price of approximately 96% of prior month tangible book value Share repurchase program of $200mm authorized for 2025 Regulatory Capital Levels Tangible Common Equity / Tangible Assets13 Tangible Book Value per Share8 Period End AOCI ($mm) ($183)($128)($368)($380)($362) AOCI per Share ($3.96)($2.77)($7.96)($8.09)($7.66) Tangible Common Equity / Tangible Assets13 Common Equity / Total Assets Peer12 Tangible Common Equity / Tangible Assets13 8.01%7.63%7.63%7.65% Tangible Book Value per Share8 Book Value per Share CET1 Tier 2 CapitalTier 1 Capital
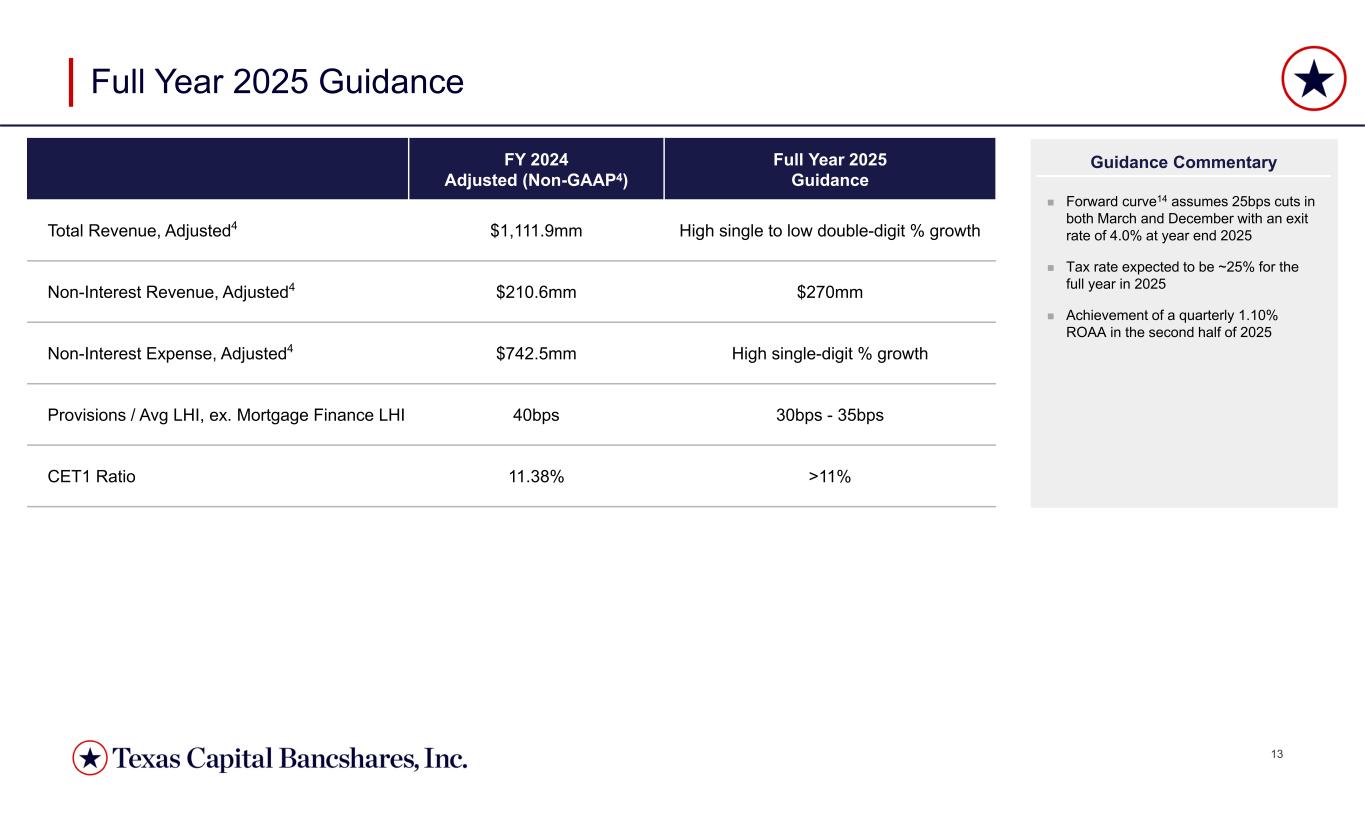
13 Full Year 2025 Guidance FY 2024 Adjusted (Non-GAAP4) High single to low double-digit % growth$1,111.9mmTotal Revenue, Adjusted4 $270mm$210.6mmNon-Interest Revenue, Adjusted4 High single-digit % growth$742.5mmNon-Interest Expense, Adjusted4 30bps - 35bps40bpsProvisions / Avg LHI, ex. Mortgage Finance LHI >11%11.38%CET1 Ratio Full Year 2025 Guidance Forward curve14 assumes 25bps cuts in both March and December with an exit rate of 4.0% at year end 2025 Tax rate expected to be ~25% for the full year in 2025 Achievement of a quarterly 1.10% ROAA in the second half of 2025 Guidance Commentary
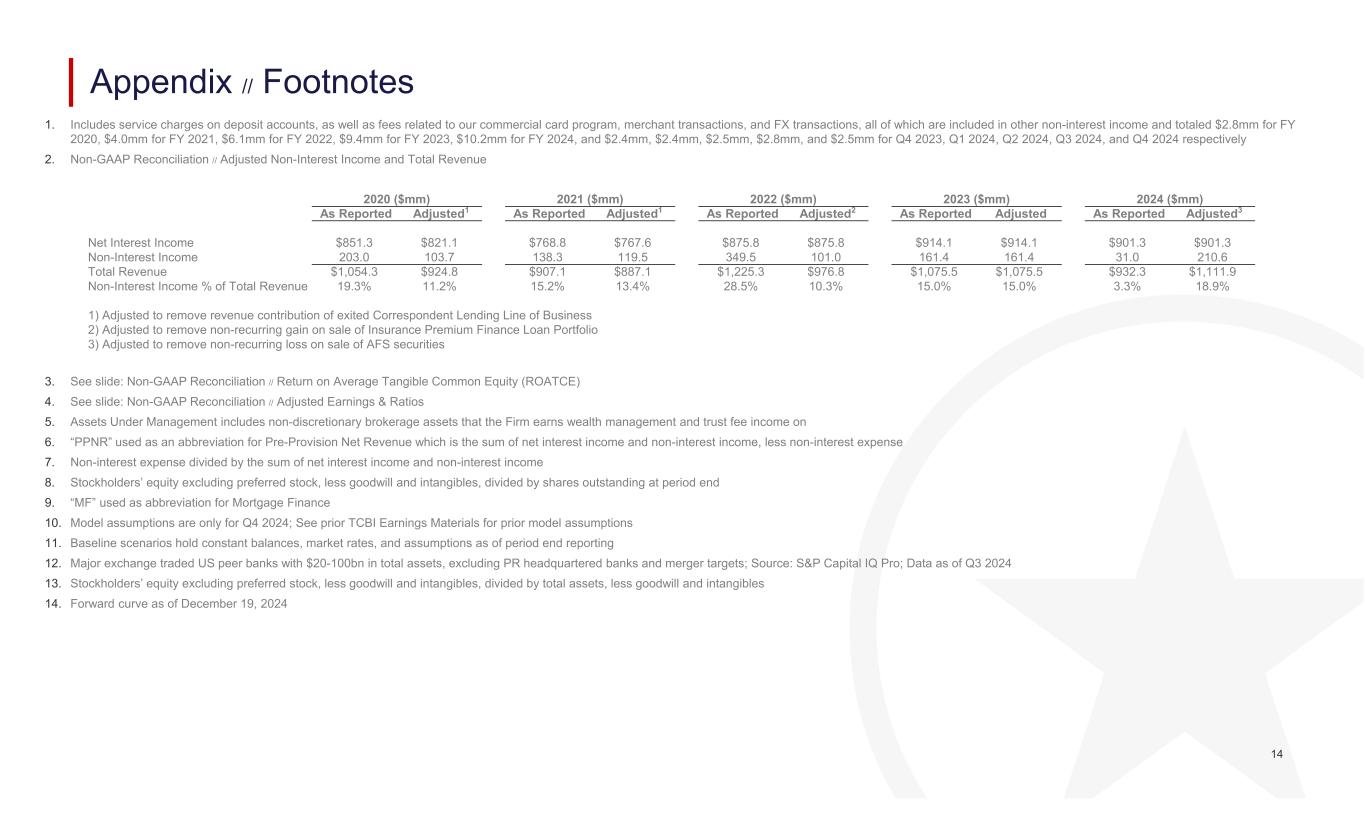
14 1. Includes service charges on deposit accounts, as well as fees related to our commercial card program, merchant transactions, and FX transactions, all of which are included in other non-interest income and totaled $2.8mm for FY 2020, $4.0mm for FY 2021, $6.1mm for FY 2022, $9.4mm for FY 2023, $10.2mm for FY 2024, and $2.4mm, $2.4mm, $2.5mm, $2.8mm, and $2.5mm for Q4 2023, Q1 2024, Q2 2024, Q3 2024, and Q4 2024 respectively 2. Non-GAAP Reconciliation // Adjusted Non-Interest Income and Total Revenue 3. See slide: Non-GAAP Reconciliation // Return on Average Tangible Common Equity (ROATCE) 4. See slide: Non-GAAP Reconciliation // Adjusted Earnings & Ratios 5. Assets Under Management includes non-discretionary brokerage assets that the Firm earns wealth management and trust fee income on 6. “PPNR” used as an abbreviation for Pre-Provision Net Revenue which is the sum of net interest income and non-interest income, less non-interest expense 7. Non-interest expense divided by the sum of net interest income and non-interest income 8. Stockholders’ equity excluding preferred stock, less goodwill and intangibles, divided by shares outstanding at period end 9. “MF” used as abbreviation for Mortgage Finance 10. Model assumptions are only for Q4 2024; See prior TCBI Earnings Materials for prior model assumptions 11. Baseline scenarios hold constant balances, market rates, and assumptions as of period end reporting 12. Major exchange traded US peer banks with $20-100bn in total assets, excluding PR headquartered banks and merger targets; Source: S&P Capital IQ Pro; Data as of Q3 2024 13. Stockholders’ equity excluding preferred stock, less goodwill and intangibles, divided by total assets, less goodwill and intangibles 14. Forward curve as of December 19, 2024 2024 ($mm)2023 ($mm)2022 ($mm)2021 ($mm)2020 ($mm) Adjusted3As Reported Adjusted As Reported Adjusted2As Reported Adjusted1As Reported Adjusted1As Reported $901.3 $901.3 $914.1 $914.1 $875.8 $875.8 $767.6 $768.8 $821.1 $851.3 Net Interest Income 210.6 31.0 161.4 161.4 101.0 349.5 119.5 138.3 103.7 203.0 Non-Interest Income $1,111.9 $932.3 $1,075.5 $1,075.5 $976.8 $1,225.3 $887.1 $907.1 $924.8 $1,054.3 Total Revenue 18.9%3.3%15.0%15.0%10.3%28.5%13.4%15.2%11.2%19.3%Non-Interest Income % of Total Revenue 1) Adjusted to remove revenue contribution of exited Correspondent Lending Line of Business 2) Adjusted to remove non-recurring gain on sale of Insurance Premium Finance Loan Portfolio 3) Adjusted to remove non-recurring loss on sale of AFS securities Appendix // Footnotes
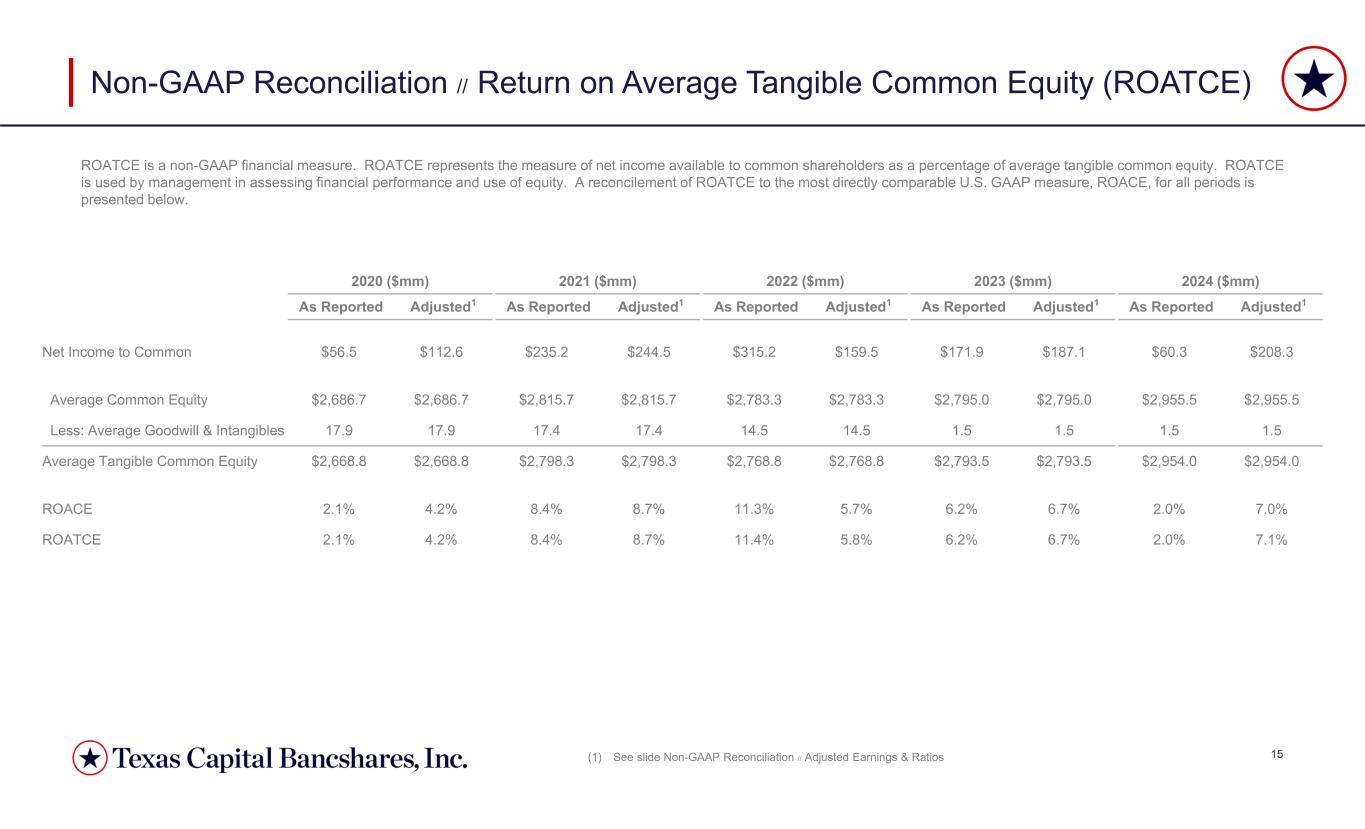
15 2024 ($mm)2023 ($mm)2022 ($mm)2021 ($mm)2020 ($mm) Adjusted1As Reported Adjusted1As Reported Adjusted1As Reported Adjusted1As Reported Adjusted1As Reported $208.3 $60.3 $187.1$171.9$159.5$315.2$244.5$235.2$112.6$56.5Net Income to Common $2,955.5 $2,955.5 $2,795.0$2,795.0$2,783.3$2,783.3$2,815.7$2,815.7$2,686.7$2,686.7Average Common Equity 1.5 1.5 1.51.514.514.517.417.417.917.9Less: Average Goodwill & Intangibles $2,954.0 $2,954.0 $2,793.5$2,793.5$2,768.8$2,768.8$2,798.3$2,798.3$2,668.8$2,668.8Average Tangible Common Equity 7.0%2.0%6.7%6.2%5.7%11.3%8.7%8.4%4.2%2.1%ROACE 7.1%2.0%6.7%6.2%5.8%11.4%8.7%8.4%4.2%2.1%ROATCE Non-GAAP Reconciliation // Return on Average Tangible Common Equity (ROATCE) ROATCE is a non-GAAP financial measure. ROATCE represents the measure of net income available to common shareholders as a percentage of average tangible common equity. ROATCE is used by management in assessing financial performance and use of equity. A reconcilement of ROATCE to the most directly comparable U.S. GAAP measure, ROACE, for all periods is presented below. (1) See slide Non-GAAP Reconciliation // Adjusted Earnings & Ratios
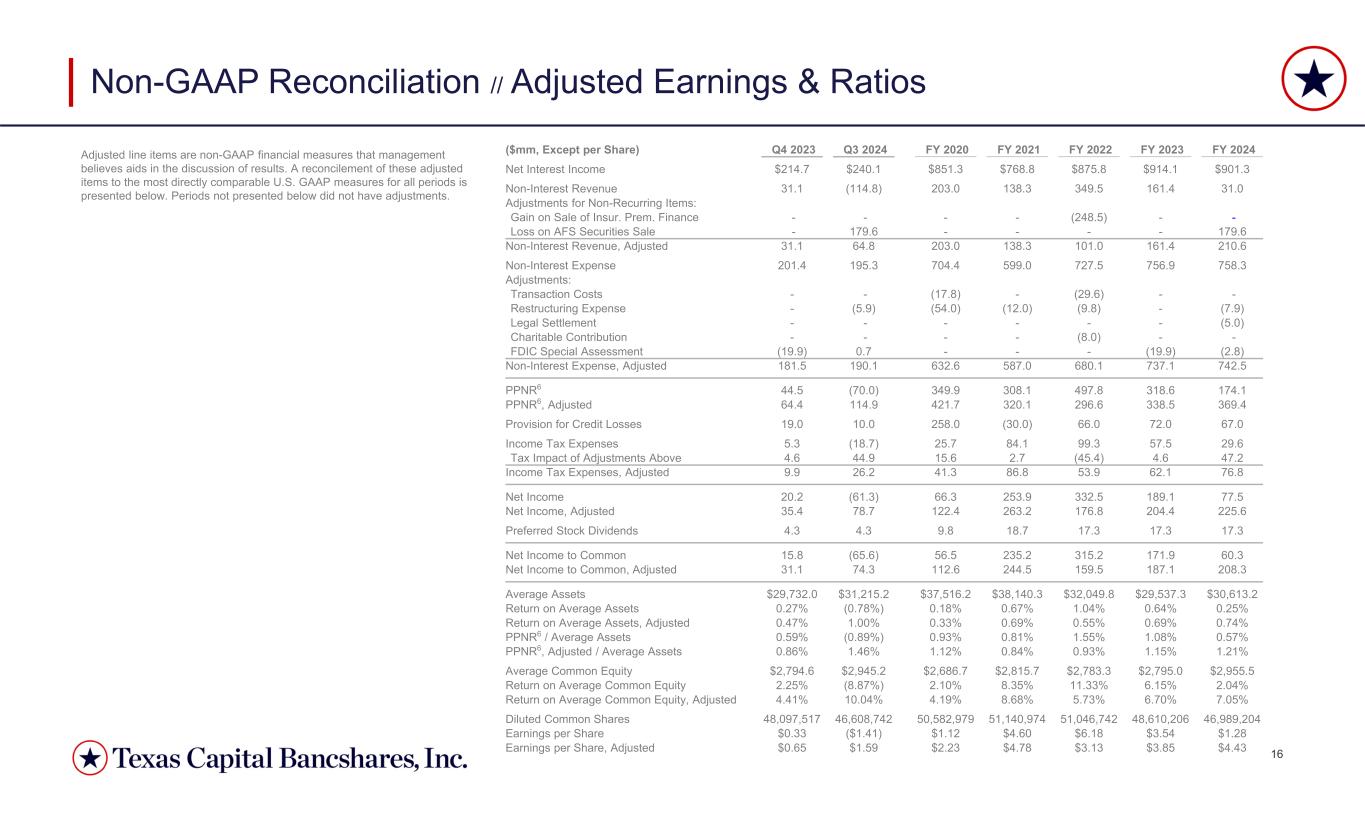
16 FY 2024 FY 2023 FY 2022 FY 2021 FY 2020 Q3 2024 Q4 2023 ($mm, Except per Share) $901.3 $914.1 $875.8 $768.8 $851.3 $240.1 $214.7 Net Interest Income 31.0 161.4 349.5 138.3 203.0 (114.8)31.1 Non-Interest Revenue Adjustments for Non-Recurring Items: --(248.5)----Gain on Sale of Insur. Prem. Finance 179.6 ----179.6-Loss on AFS Securities Sale 210.6 161.4 101.0 138.3 203.064.8 31.1 Non-Interest Revenue, Adjusted 758.3 756.9 727.5 599.0 704.4 195.3 201.4Non-Interest Expense Adjustments: --(29.6)-(17.8)--Transaction Costs (7.9)-(9.8)(12.0)(54.0)(5.9)-Restructuring Expense (5.0)------Legal Settlement --(8.0)----Charitable Contribution (2.8)(19.9)---0.7 (19.9)FDIC Special Assessment 742.5 737.1 680.1 587.0 632.6 190.1 181.5 Non-Interest Expense, Adjusted 174.1 318.6 497.8 308.1 349.9 (70.0)44.5 PPNR6 369.4 338.5 296.6 320.1 421.7 114.9 64.4 PPNR6, Adjusted 67.0 72.0 66.0 (30.0)258.0 10.0 19.0 Provision for Credit Losses 29.6 57.5 99.3 84.1 25.7 (18.7)5.3 Income Tax Expenses 47.2 4.6 (45.4)2.7 15.6 44.9 4.6 Tax Impact of Adjustments Above 76.8 62.1 53.9 86.8 41.3 26.2 9.9 Income Tax Expenses, Adjusted 77.5 189.1 332.5 253.9 66.3 (61.3)20.2 Net Income 225.6 204.4 176.8 263.2 122.4 78.7 35.4 Net Income, Adjusted 17.3 17.3 17.3 18.7 9.8 4.3 4.3 Preferred Stock Dividends 60.3 171.9 315.2 235.2 56.5 (65.6)15.8 Net Income to Common 208.3 187.1 159.5 244.5 112.6 74.3 31.1 Net Income to Common, Adjusted $30,613.2 $29,537.3 $32,049.8 $38,140.3 $37,516.2 $31,215.2 $29,732.0 Average Assets 0.25% 0.64%1.04%0.67%0.18%(0.78%)0.27% Return on Average Assets 0.74% 0.69%0.55%0.69%0.33%1.00% 0.47% Return on Average Assets, Adjusted 0.57% 1.08%1.55%0.81%0.93%(0.89%)0.59% PPNR6 / Average Assets 1.21% 1.15%0.93%0.84%1.12%1.46% 0.86% PPNR6, Adjusted / Average Assets $2,955.5 $2,795.0 $2,783.3 $2,815.7 $2,686.7 $2,945.2 $2,794.6 Average Common Equity 2.04% 6.15%11.33%8.35%2.10%(8.87%)2.25% Return on Average Common Equity 7.05% 6.70%5.73%8.68%4.19%10.04% 4.41% Return on Average Common Equity, Adjusted 46,989,204 48,610,206 51,046,742 51,140,974 50,582,979 46,608,742 48,097,517 Diluted Common Shares $1.28 $3.54 $6.18 $4.60 $1.12 ($1.41)$0.33 Earnings per Share $4.43 $3.85 $3.13 $4.78 $2.23 $1.59 $0.65 Earnings per Share, Adjusted Non-GAAP Reconciliation // Adjusted Earnings & Ratios Adjusted line items are non-GAAP financial measures that management believes aids in the discussion of results. A reconcilement of these adjusted items to the most directly comparable U.S. GAAP measures for all periods is presented below. Periods not presented below did not have adjustments.