
ABCB 8-K
Ameris Bancorp (ABCB)
8-K
2025-07-28
For: 2025-07-28
View Original
Added on
April 12, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
| Date of report (Date of earliest event reported): | |||||
| (Exact Name of Registrant as Specified in Charter) | ||
| (State or Other Jurisdiction of Incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||
| (Address of Principal Executive Offices) | (Zip Code) | |||||||
| Registrant’s telephone number, including area code: | ||||||||
(Former Name or Former Address, if Changed Since Last Report) | ||
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
Securities registered pursuant to Section 12(b) of the Act:
Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
Item 2.02 Results of Operations and Financial Condition.
On July 28, 2025, Ameris Bancorp (the “Company”) issued a press release announcing its unaudited financial results for the quarter ended June 30, 2025. A copy of that press release is attached to this Current Report on Form 8-K (this “Report”) as Exhibit 99.1.
The information contained in this Item 2.02 and in Exhibit 99.1 attached to this Report is being furnished and shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of such section. Furthermore, such information shall not be deemed to be incorporated by reference into any registration statement or other document filed pursuant to the Securities Act of 1933, as amended.
Item 7.01 Regulation FD Disclosure.
A copy of the investor presentation material that the Company will present regarding its earnings during the teleconference beginning at 9:00 a.m. Eastern time on July 29, 2025 is attached to this Report as Exhibit 99.2. The investor presentation material is also available on the “Investor Relations” page of the Company’s website (http://www.amerisbank.com).
The information contained in this Item 7.01 and in Exhibit 99.2 attached to this Report is being furnished and shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of such section. Furthermore, such information shall not be deemed to be incorporated by reference into any registration statement or other document filed pursuant to the Securities Act of 1933, as amended.
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits.
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | ||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the registrant has duly caused this report to be signed on its behalf by the undersigned, hereunto duly authorized.
AMERIS BANCORP
| By: | /s/ Nicole S. Stokes | ||||
| Nicole S. Stokes | |||||
| Chief Financial Officer | |||||
Date: July 28, 2025
News Release
AMERIS BANCORP ANNOUNCES SECOND QUARTER 2025 FINANCIAL RESULTS
Highlights of Ameris’s results for the second quarter of 2025 include the following:
•Net income of $109.8 million, or $1.60 per diluted share
•Return on average assets of 1.65%
•Return on average tangible common equity(1) of 15.82%
•Tangible book value(1) growth of $1.54 per share, or 15.5% annualized, to $41.32 at June 30, 2025
•TCE ratio(1) increased to 11.09%, compared with 9.72% one year ago
•Net interest margin (TE) expansion of 4bps to 3.77% for the second quarter of 2025
•Efficiency ratio improved to 51.63%
•Growth in total revenue of $14.9 million, or 20.9% annualized, from first quarter of 2025
•Growth in average earning assets of $564.3 million, or 9.3% annualized
•Loan growth of $334.9 million, or 6.5% annualized
•Continued growth in noninterest-bearing deposits, now representing 31.0% of total deposits
•Annualized net charge-offs improved to 0.14% of average total loans
ATLANTA, GA, July 28, 2025 - Ameris Bancorp (NYSE: ABCB) (the “Company”) today reported net income of $109.8 million, or $1.60 per diluted share, for the quarter ended June 30, 2025, compared with $90.8 million, or $1.32 per diluted share, for the quarter ended June 30, 2024.
For the year-to-date period ending June 30, 2025, the Company reported net income of $197.8 million, or $2.87 per diluted share, compared with $165.1 million, or $2.39 per diluted share, for the same period in 2024.
Commenting on the Company’s results, Palmer Proctor, the Company’s Chief Executive Officer, said, “Our second quarter results underscore the strength, consistency, and long-term value of the Ameris franchise. We delivered above-peer profitability, with a return on assets of 1.65% and a return on tangible common equity of 15.82%. Tangible book value per share - one of our long-standing strategic priorities - grew at a 15.5% annualized rate to surpass $41. Other key performance indicators, including our net interest margin, allowance coverage ratio, and efficiency ratio, remain among the best in the industry. Backed by a strong balance sheet and a proven ability to execute, we are well positioned to capitalize on growth opportunities across our Southeast footprint and drive continued success through the remainder of 2025 and beyond.”
Net Interest Income and Net Interest Margin
Net interest income on a tax-equivalent basis (TE) grew to $232.7 million in the second quarter of 2025, an increase of $10.0 million, or 4.5%, from last quarter and an increase of $19.9 million, or 9.3%, compared with the second quarter of 2024. The Company's average earning assets increased during the quarter by $564.3 million, or 9.3% annualized, due to a $308.0 million increase in average portfolio loans outstanding, a $165.2 million increase in average loans held for sale during the quarter and a $119.3 million increase in the average balance of investment securities.
The Company's net interest margin expanded to 3.77% for the second quarter of 2025, a four basis point increase from 3.73% reported for the first quarter of 2025 and a 19 basis point improvement from the 3.58% reported for the second quarter of 2024.
Yields on earning assets increased three basis points during the quarter to 5.64%, compared with 5.61% in the first quarter of 2025. This increase is primarily related to a 17 basis point increase in yield on taxable securities and a three basis point increase in yield on portfolio loans during the second quarter of 2025.
The Company’s total cost of funds was stable at 2.06% in the second quarter of 2025, when compared with the first quarter of 2025, and improved 42 basis points compared with the second quarter of 2024. Deposit costs decreased three basis points during the second quarter of 2025 to 1.95%, compared with 1.98% in the first quarter of 2025. Costs of interest-bearing deposits during the quarter were 2.83%, unchanged from the first quarter of 2025.
Noninterest Income
Noninterest income increased $4.9 million, or 7.6%, in the second quarter of 2025 to $68.9 million, compared with $64.0 million for the first quarter of 2025. The increase was primarily driven by mortgage banking activity, which increased $4.0 million, or 11.3%, to $39.2 million in the second quarter of 2025, compared with $35.3 million for the first quarter of 2025. Total production in the retail mortgage division increased $334.9 million, or 35.9%, to $1.27 billion in the second quarter of 2025, compared with $933.0 million for the first quarter of 2025. The retail mortgage open pipeline was $719.1 million at the end of the second quarter of 2025, compared with $771.6 million for the first quarter of 2025. Gain on sale spreads increased to 2.22% in the second quarter of 2025 from 2.17% for the first quarter of 2025. Other noninterest income increased $678,000, or 8.7%, in the second quarter of 2025 to $8.5 million, compared with $7.8 million for the first quarter of 2025.
Noninterest Expense
Noninterest expense increased $4.3 million, or 2.8%, to $155.3 million during the second quarter of 2025, compared with $151.0 million for the first quarter of 2025. Salaries and employee benefits increased $2.7 million, or 3.1%, during the second quarter of 2025 primarily due to variable compensation related to mortgage production and annual merit increases, partially offset by seasonal declines in payroll taxes. Advertising and marketing expenses increased $862,000 resulting from targeted ad campaigns during the quarter. Management continues to focus on operating efficiency, and the efficiency ratio improved to 51.63% in the second quarter of 2025, compared with 52.83% in the first quarter of 2025 and 51.68% in the second quarter of 2024.
Income Tax Expense
The Company's effective tax rate for the second quarter of 2025 was 23.0%, compared with 22.1% for the first quarter of 2025. The increased rate resulted primarily from a reduction in excess benefits from the vesting of equity compensation awards and the impact of enacted state tax changes during the second quarter.
Balance Sheet Trends
Total assets at June 30, 2025 were $26.68 billion, compared with $26.51 billion at March 31, 2025 and $26.26 billion at December 31, 2024. During the second quarter of 2025, loans, net of unearned income, increased by $334.9 million, or 6.5% annualized, to end at $21.04 billion at June 30, 2025, compared with $20.71 billion at March 31, 2025 and $20.74 billion at December 31, 2024. Loans held for sale increased to $544.1 million at June 30, 2025 from $528.6 million at December 31, 2024. Debt securities available-for-sale amounted to $1.87 billion, compared with $1.94 billion at March 31, 2025 and $1.67 billion at December 31, 2024.
At June 30, 2025, total deposits amounted to $21.93 billion, compared with $21.72 billion at December 31, 2024. During the second quarter of 2025, deposits grew $20.3 million, with noninterest-bearing accounts increasing $55.7 million, brokered CDs increasing $81.8 million and interest-bearing demand accounts increasing $13.0 million, with such increases offset by decreases in retail CDs of $77.4 million, money market accounts of $38.6 million and savings accounts of $14.2 million. Noninterest-bearing accounts as a percentage of total deposits increased, such that at June 30, 2025, noninterest-bearing deposit accounts represented $6.80 billion, or 31.0% of total deposits, compared with $6.50 billion, or 29.9% of total deposits, at December 31, 2024.
Shareholders’ equity at June 30, 2025 totaled $3.92 billion, an increase of $166.2 million, or 4.4%, from December 31, 2024. The increase in shareholders’ equity was primarily the result of earnings of $197.8 million during the first six months of 2025 and an improvement in other comprehensive loss of $23.2 million resulting from changes in interest rates on the Company's investment portfolio, partially offset by dividends declared and share repurchases. Tangible book value per share(1) increased $2.73 per share, or 14.3% annualized, during the first six months of 2025 to $41.32 at June 30, 2025. Tangible common equity as a percentage of tangible assets was 11.09% at June 30, 2025, compared with 10.59% at the end of 2024. The Company repurchased 212,472 shares in the quarter ending June 30, 2025.
Subordinated Debt
In July 2025, the Company notified holders of its 5.875% Fixed-To-Floating Rate Subordinated Notes due 2030 that it would be redeeming the notes in full at the September 1, 2025 interest payment date. These notes, which currently total $74 million outstanding, bear interest at 8.22% and will be redeemed at par.
Credit Quality
During the second quarter of 2025, the Company recorded a provision for credit losses of $2.8 million, compared with a provision of $21.9 million in the first quarter of 2025. The allowance for credit losses on loans was 1.62% of loans at June 30, 2025, compared with 1.63% at the end of 2024. Nonperforming assets as a percentage of total assets decreased eight basis points to 0.36% during the quarter. Approximately $11.7 million, or 12.1%, of the nonperforming assets at June 30, 2025 were GNMA-guaranteed mortgage loans, which have minimal loss exposure. Excluding these government-guaranteed loans, nonperforming assets as a percentage of total assets decreased six basis points to 0.32% at June 30, 2025, compared with 0.38% at the end of the first quarter of 2025. The net charge-off ratio was 14 basis points for the second quarter of 2025, compared with 18 basis points in the first quarter of 2025.
Conference Call
The Company will host a teleconference at 9:00 a.m. Eastern time on Tuesday, July 29, 2025, to discuss the Company's results and answer appropriate questions. The conference call can be accessed by dialing 1-844-481-2939. The conference call ID is Ameris Bancorp. A replay of the call will be available beginning one hour after the end of the conference call until August 5, 2025. To listen to the replay, dial 1-877-344-7529. The conference replay access code is 6141708. The financial information discussed will be available on the Investor Relations page of the Ameris Bank website at ir.amerisbank.com. Participants also may listen to a live webcast of the presentation by visiting the link on the Investor Relations page of the Ameris Bank website.
About Ameris Bancorp
Ameris Bancorp is the parent of Ameris Bank, a state-chartered bank headquartered in Atlanta, Georgia. Ameris operates financial centers in five southeastern states and also serves consumer and business customers nationwide through select lending channels. Ameris manages $26.7 billion in assets as of June 30, 2025, and provides a full range of traditional banking and lending products, treasury and cash management, insurance premium financing, and mortgage and refinancing services. Learn more about Ameris at www.amerisbank.com.
(1) Considered non-GAAP financial measure - See reconciliation of GAAP to non-GAAP financial measures in tables 9A - 9D.
This news release contains certain performance measures determined by methods other than in accordance with accounting principles generally accepted in the United States of America (“GAAP”). The Company’s management uses these non-GAAP financial measures in its analysis of the Company’s performance. These measures are useful when evaluating the underlying performance and efficiency of the Company’s operations and balance sheet. The Company’s management believes that these non-GAAP financial measures provide a greater understanding of ongoing operations, enhance comparability of results with prior periods and demonstrate the effects of significant gains and charges in the current period. The Company’s management believes that investors may use these non-GAAP financial measures to evaluate the Company’s financial performance without the impact of unusual items that may obscure trends in the Company’s underlying performance. These disclosures should not be viewed as a substitute for financial measures determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP financial measures that may be presented by other companies.
This news release contains forward-looking statements, as defined by federal securities laws, including, among other forward-looking statements, certain plans, expectations and goals. Words such as “may,” “believe,” “expect,” “anticipate,” “intend,” “will,” “should,” “plan,” “estimate,” “predict,” “continue” and “potential” or the negative of these terms or other comparable terminology, as well as similar expressions, are meant to identify forward-looking statements. The forward-looking statements in this news release are based on current expectations and are provided to assist in the understanding of potential future performance. Such forward-looking statements involve numerous assumptions, risks and uncertainties that may cause actual results to differ materially from those expressed or implied in any such statements, including, without limitation, the following: general competitive, economic, unemployment, political and market conditions and fluctuations, including real estate market conditions, and the effects of such conditions and fluctuations on the creditworthiness and payment behavior of borrowers, collateral values, asset recovery values and the value of investment securities; movements in interest rates and their impacts on
net interest margin, investment security valuations and other performance measures; expectations on credit quality and performance; legislative and regulatory changes; changes in U.S. government trade, monetary and fiscal policies, including tariffs; competitive pressures on product pricing and services; fraud, theft or other misconduct impacting our customers or operations; cybersecurity risks, including data breaches, malware, ransomware and account takeover; the success and timing of our business strategies and plans; our outlook and long-term goals for future growth; and natural disasters, geopolitical events, acts of war or terrorism or other hostilities, public health crises and other catastrophic events beyond our control. For a discussion of some of the other risks and other factors that may cause such forward-looking statements to differ materially from actual results, please refer to the Company’s filings with the Securities and Exchange Commission, including the Company’s Annual Report on Form 10-K for the year ended December 31, 2024 and the Company's subsequently filed periodic reports and other filings. Forward-looking statements speak only as of the date they are made, and the Company undertakes no obligation to update or revise forward-looking statements.
For more information, contact:
Brady Gailey
Executive Director of Corporate Development
(404) 240-1517
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Financial Highlights | Table 1 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| EARNINGS | |||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 109,834 | $ | 87,935 | $ | 94,376 | $ | 99,212 | $ | 90,785 | $ | 197,769 | $ | 165,097 | |||||||||||||||||||||||||||
Adjusted net income(1) | $ | 109,444 | $ | 88,044 | $ | 95,078 | $ | 95,187 | $ | 80,763 | $ | 197,488 | $ | 156,375 | |||||||||||||||||||||||||||
| COMMON SHARE DATA | |||||||||||||||||||||||||||||||||||||||||
| Earnings per share available to common shareholders | |||||||||||||||||||||||||||||||||||||||||
| Basic | $ | 1.60 | $ | 1.28 | $ | 1.37 | $ | 1.44 | $ | 1.32 | $ | 2.88 | $ | 2.40 | |||||||||||||||||||||||||||
| Diluted | $ | 1.60 | $ | 1.27 | $ | 1.37 | $ | 1.44 | $ | 1.32 | $ | 2.87 | $ | 2.39 | |||||||||||||||||||||||||||
Adjusted diluted EPS(1) | $ | 1.59 | $ | 1.28 | $ | 1.38 | $ | 1.38 | $ | 1.17 | $ | 2.87 | $ | 2.27 | |||||||||||||||||||||||||||
| Cash dividends per share | $ | 0.20 | $ | 0.20 | $ | 0.15 | $ | 0.15 | $ | 0.15 | $ | 0.40 | $ | 0.30 | |||||||||||||||||||||||||||
| Book value per share (period end) | $ | 57.02 | $ | 55.49 | $ | 54.32 | $ | 53.30 | $ | 51.64 | $ | 57.02 | $ | 51.64 | |||||||||||||||||||||||||||
Tangible book value per share (period end)(1) | $ | 41.32 | $ | 39.78 | $ | 38.59 | $ | 37.51 | $ | 35.79 | $ | 41.32 | $ | 35.79 | |||||||||||||||||||||||||||
| Weighted average number of shares | |||||||||||||||||||||||||||||||||||||||||
| Basic | 68,594,608 | 68,785,458 | 68,799,464 | 68,798,093 | 68,824,150 | 68,689,506 | 68,818,618 | ||||||||||||||||||||||||||||||||||
| Diluted | 68,796,577 | 69,030,331 | 69,128,946 | 69,066,298 | 69,013,834 | 68,912,750 | 69,010,010 | ||||||||||||||||||||||||||||||||||
| Period end number of shares | 68,711,043 | 68,910,924 | 69,068,609 | 69,067,019 | 69,066,573 | 68,711,043 | 69,066,573 | ||||||||||||||||||||||||||||||||||
| Market data | |||||||||||||||||||||||||||||||||||||||||
| High intraday price | $ | 65.43 | $ | 68.85 | $ | 74.56 | $ | 65.40 | $ | 51.18 | $ | 68.85 | $ | 53.99 | |||||||||||||||||||||||||||
| Low intraday price | $ | 48.27 | $ | 55.32 | $ | 59.12 | $ | 48.21 | $ | 44.23 | $ | 48.27 | $ | 44.00 | |||||||||||||||||||||||||||
| Period end closing price | $ | 64.70 | $ | 57.57 | $ | 62.57 | $ | 62.39 | $ | 50.35 | $ | 64.70 | $ | 50.35 | |||||||||||||||||||||||||||
| Average daily volume | 416,355 | 430,737 | 384,406 | 379,896 | 301,784 | 423,428 | 353,985 | ||||||||||||||||||||||||||||||||||
| PERFORMANCE RATIOS | |||||||||||||||||||||||||||||||||||||||||
| Return on average assets | 1.65 | % | 1.36 | % | 1.42 | % | 1.49 | % | 1.41 | % | 1.51 | % | 1.30 | % | |||||||||||||||||||||||||||
Adjusted return on average assets(1) | 1.64 | % | 1.36 | % | 1.43 | % | 1.43 | % | 1.25 | % | 1.50 | % | 1.23 | % | |||||||||||||||||||||||||||
| Return on average common equity | 11.40 | % | 9.39 | % | 10.09 | % | 10.91 | % | 10.34 | % | 10.41 | % | 9.49 | % | |||||||||||||||||||||||||||
Adjusted return on average tangible common equity(1) | 15.76 | % | 13.16 | % | 14.37 | % | 14.99 | % | 13.35 | % | 14.48 | % | 13.12 | % | |||||||||||||||||||||||||||
| Earning asset yield (TE) | 5.64 | % | 5.61 | % | 5.67 | % | 5.81 | % | 5.86 | % | 5.63 | % | 5.79 | % | |||||||||||||||||||||||||||
| Total cost of funds | 2.06 | % | 2.06 | % | 2.22 | % | 2.50 | % | 2.48 | % | 2.06 | % | 2.44 | % | |||||||||||||||||||||||||||
| Net interest margin (TE) | 3.77 | % | 3.73 | % | 3.64 | % | 3.51 | % | 3.58 | % | 3.75 | % | 3.54 | % | |||||||||||||||||||||||||||
| Efficiency ratio | 51.63 | % | 52.83 | % | 52.26 | % | 53.49 | % | 51.68 | % | 52.22 | % | 53.54 | % | |||||||||||||||||||||||||||
Adjusted efficiency ratio (TE)(1) | 51.58 | % | 52.62 | % | 51.82 | % | 54.25 | % | 55.00 | % | 52.09 | % | 54.79 | % | |||||||||||||||||||||||||||
| CAPITAL ADEQUACY (period end) | |||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity to assets | 14.68 | % | 14.42 | % | 14.28 | % | 13.94 | % | 13.45 | % | 14.68 | % | 13.45 | % | |||||||||||||||||||||||||||
Tangible common equity to tangible assets(1) | 11.09 | % | 10.78 | % | 10.59 | % | 10.24 | % | 9.72 | % | 11.09 | % | 9.72 | % | |||||||||||||||||||||||||||
| OTHER DATA (period end) | |||||||||||||||||||||||||||||||||||||||||
| Full time equivalent employees | |||||||||||||||||||||||||||||||||||||||||
| Banking Division | 2,036 | 2,045 | 2,021 | 2,056 | 2,073 | 2,036 | 2,073 | ||||||||||||||||||||||||||||||||||
| Retail Mortgage Division | 550 | 577 | 585 | 592 | 595 | 550 | 595 | ||||||||||||||||||||||||||||||||||
| Warehouse Lending Division | 8 | 7 | 8 | 9 | 9 | 8 | 9 | ||||||||||||||||||||||||||||||||||
| Premium Finance Division | 78 | 81 | 77 | 76 | 74 | 78 | 74 | ||||||||||||||||||||||||||||||||||
| Total Ameris Bancorp FTE headcount | 2,672 | 2,710 | 2,691 | 2,733 | 2,751 | 2,672 | 2,751 | ||||||||||||||||||||||||||||||||||
| Branch locations | 164 | 164 | 164 | 164 | 164 | 164 | 164 | ||||||||||||||||||||||||||||||||||
| Deposits per branch location | $ | 133,736 | $ | 133,612 | $ | 132,454 | $ | 133,410 | $ | 130,757 | $ | 133,736 | $ | 130,757 | |||||||||||||||||||||||||||
(1)Considered non-GAAP financial measure - See reconciliation of GAAP to non-GAAP financial measures in tables 9A - 9D | |||||||||||||||||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Income Statement | Table 2 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| Interest income | |||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 315,893 | $ | 304,168 | $ | 318,843 | $ | 325,622 | $ | 317,664 | $ | 620,061 | $ | 621,057 | |||||||||||||||||||||||||||
| Interest on taxable securities | 20,696 | 18,492 | 15,923 | 15,555 | 16,948 | 39,188 | 30,040 | ||||||||||||||||||||||||||||||||||
| Interest on nontaxable securities | 334 | 329 | 337 | 336 | 335 | 663 | 665 | ||||||||||||||||||||||||||||||||||
| Interest on deposits in other banks | 10,715 | 10,789 | 11,260 | 13,633 | 12,376 | 21,504 | 25,013 | ||||||||||||||||||||||||||||||||||
| Total interest income | 347,638 | 333,778 | 346,363 | 355,146 | 347,323 | 681,416 | 676,775 | ||||||||||||||||||||||||||||||||||
| Interest expense | |||||||||||||||||||||||||||||||||||||||||
| Interest on deposits | 106,796 | 105,215 | 115,556 | 129,698 | 121,245 | 212,011 | 239,419 | ||||||||||||||||||||||||||||||||||
| Interest on other borrowings | 9,029 | 6,724 | 8,986 | 11,388 | 14,157 | 15,753 | 24,047 | ||||||||||||||||||||||||||||||||||
| Total interest expense | 115,825 | 111,939 | 124,542 | 141,086 | 135,402 | 227,764 | 263,466 | ||||||||||||||||||||||||||||||||||
| Net interest income | 231,813 | 221,839 | 221,821 | 214,060 | 211,921 | 453,652 | 413,309 | ||||||||||||||||||||||||||||||||||
| Provision for loan losses | 3,110 | 16,519 | 12,657 | 6,313 | 25,348 | 19,629 | 50,871 | ||||||||||||||||||||||||||||||||||
| Provision for unfunded commitments | (335) | 5,373 | 148 | (204) | (6,570) | 5,038 | (10,992) | ||||||||||||||||||||||||||||||||||
| Provision for other credit losses | (3) | — | 3 | (2) | (5) | (3) | (1) | ||||||||||||||||||||||||||||||||||
| Provision for credit losses | 2,772 | 21,892 | 12,808 | 6,107 | 18,773 | 24,664 | 39,878 | ||||||||||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 229,041 | 199,947 | 209,013 | 207,953 | 193,148 | 428,988 | 373,431 | ||||||||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||
| Service charges on deposit accounts | 13,493 | 13,133 | 13,544 | 12,918 | 12,672 | 26,626 | 24,431 | ||||||||||||||||||||||||||||||||||
| Mortgage banking activity | 39,221 | 35,254 | 36,699 | 37,947 | 46,399 | 74,475 | 85,829 | ||||||||||||||||||||||||||||||||||
| Other service charges, commissions and fees | 1,158 | 1,109 | 1,182 | 1,163 | 1,211 | 2,267 | 2,413 | ||||||||||||||||||||||||||||||||||
| Gain (loss) on securities | — | 40 | (16) | (8) | 12,335 | 40 | 12,328 | ||||||||||||||||||||||||||||||||||
| Equipment finance activity | 6,572 | 6,698 | 5,947 | 5,398 | 4,983 | 13,270 | 10,319 | ||||||||||||||||||||||||||||||||||
| Other noninterest income | 8,467 | 7,789 | 11,603 | 12,291 | 11,111 | 16,256 | 19,269 | ||||||||||||||||||||||||||||||||||
| Total noninterest income | 68,911 | 64,023 | 68,959 | 69,709 | 88,711 | 132,934 | 154,589 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 89,308 | 86,615 | 87,810 | 88,700 | 88,201 | 175,923 | 171,131 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment | 11,401 | 10,677 | 11,624 | 11,716 | 12,559 | 22,078 | 25,444 | ||||||||||||||||||||||||||||||||||
| Data processing and communications expenses | 15,366 | 14,855 | 14,631 | 15,221 | 15,193 | 30,221 | 29,847 | ||||||||||||||||||||||||||||||||||
Credit resolution-related expenses(1) | 657 | 765 | 1,271 | (110) | 840 | 1,422 | 1,326 | ||||||||||||||||||||||||||||||||||
| Advertising and marketing | 3,745 | 2,883 | 2,730 | 3,959 | 3,456 | 6,628 | 5,923 | ||||||||||||||||||||||||||||||||||
| Amortization of intangible assets | 4,076 | 4,103 | 4,180 | 4,180 | 4,407 | 8,179 | 8,829 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 30,707 | 31,136 | 29,703 | 28,111 | 30,701 | 61,843 | 61,568 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 155,260 | 151,034 | 151,949 | 151,777 | 155,357 | 306,294 | 304,068 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 142,692 | 112,936 | 126,023 | 125,885 | 126,502 | 255,628 | 223,952 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 32,858 | 25,001 | 31,647 | 26,673 | 35,717 | 57,859 | 58,855 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 109,834 | $ | 87,935 | $ | 94,376 | $ | 99,212 | $ | 90,785 | $ | 197,769 | $ | 165,097 | |||||||||||||||||||||||||||
| Diluted earnings per common share | $ | 1.60 | $ | 1.27 | $ | 1.37 | $ | 1.44 | $ | 1.32 | $ | 2.87 | $ | 2.39 | |||||||||||||||||||||||||||
| (1) Includes expenses associated with problem loans and OREO, as well as OREO losses and writedowns. | |||||||||||||||||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||
| Period End Balance Sheet | Table 3 | ||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | |||||||||||||||||||||||||
| (dollars in thousands) | 2025 | 2025 | 2024 | 2024 | 2024 | ||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Cash and due from banks | $ | 249,676 | $ | 253,289 | $ | 244,980 | $ | 231,515 | $ | 257,297 | |||||||||||||||||||
| Interest-bearing deposits in banks | 920,594 | 1,039,111 | 975,397 | 1,127,641 | 1,104,897 | ||||||||||||||||||||||||
| Debt securities available-for-sale, at fair value | 1,871,298 | 1,943,011 | 1,671,260 | 1,441,552 | 1,531,047 | ||||||||||||||||||||||||
| Debt securities held-to-maturity, at amortized cost | 176,487 | 173,757 | 164,677 | 161,220 | 148,538 | ||||||||||||||||||||||||
| Other investments | 69,910 | 65,630 | 66,298 | 63,899 | 96,613 | ||||||||||||||||||||||||
| Loans held for sale | 544,091 | 545,388 | 528,599 | 553,379 | 570,180 | ||||||||||||||||||||||||
| Loans, net of unearned income | 21,041,497 | 20,706,644 | 20,739,906 | 20,964,981 | 20,992,603 | ||||||||||||||||||||||||
| Allowance for credit losses | (341,567) | (345,555) | (338,084) | (334,457) | (336,218) | ||||||||||||||||||||||||
| Loans, net | 20,699,930 | 20,361,089 | 20,401,822 | 20,630,524 | 20,656,385 | ||||||||||||||||||||||||
| Other real estate owned | 1,825 | 863 | 2,433 | 9,482 | 2,213 | ||||||||||||||||||||||||
| Premises and equipment, net | 211,434 | 207,895 | 209,460 | 210,931 | 213,255 | ||||||||||||||||||||||||
| Goodwill | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | ||||||||||||||||||||||||
| Other intangible assets, net | 62,582 | 66,658 | 70,761 | 74,941 | 79,120 | ||||||||||||||||||||||||
| Cash value of bank owned life insurance | 414,381 | 410,890 | 408,574 | 460,699 | 376,458 | ||||||||||||||||||||||||
| Other assets | 442,299 | 431,713 | 502,143 | 418,353 | 469,079 | ||||||||||||||||||||||||
| Total assets | $ | 26,680,153 | $ | 26,514,940 | $ | 26,262,050 | $ | 26,399,782 | $ | 26,520,728 | |||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||
| Noninterest-bearing | $ | 6,800,519 | $ | 6,744,781 | $ | 6,498,293 | $ | 6,670,320 | $ | 6,649,220 | |||||||||||||||||||
| Interest-bearing | 15,132,156 | 15,167,628 | 15,224,155 | 15,208,945 | 14,794,923 | ||||||||||||||||||||||||
| Total deposits | 21,932,675 | 21,912,409 | 21,722,448 | 21,879,265 | 21,444,143 | ||||||||||||||||||||||||
| Other borrowings | 376,700 | 276,744 | 291,788 | 346,446 | 946,413 | ||||||||||||||||||||||||
| Subordinated deferrable interest debentures | 133,306 | 132,807 | 132,309 | 131,811 | 131,312 | ||||||||||||||||||||||||
| Other liabilities | 319,794 | 369,178 | 363,983 | 360,892 | 432,246 | ||||||||||||||||||||||||
| Total liabilities | 22,762,475 | 22,691,138 | 22,510,528 | 22,718,414 | 22,954,114 | ||||||||||||||||||||||||
| Shareholders' Equity | |||||||||||||||||||||||||||||
| Preferred stock | — | — | — | — | — | ||||||||||||||||||||||||
| Common stock | 72,897 | 72,885 | 72,699 | 72,698 | 72,697 | ||||||||||||||||||||||||
| Capital stock | 1,964,896 | 1,961,732 | 1,958,642 | 1,954,532 | 1,950,846 | ||||||||||||||||||||||||
| Retained earnings | 2,023,493 | 1,927,489 | 1,853,428 | 1,772,989 | 1,684,218 | ||||||||||||||||||||||||
| Accumulated other comprehensive loss, net of tax | (6,886) | (14,430) | (30,119) | (15,724) | (38,020) | ||||||||||||||||||||||||
| Treasury stock | (136,722) | (123,874) | (103,128) | (103,127) | (103,127) | ||||||||||||||||||||||||
| Total shareholders' equity | 3,917,678 | 3,823,802 | 3,751,522 | 3,681,368 | 3,566,614 | ||||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 26,680,153 | $ | 26,514,940 | $ | 26,262,050 | $ | 26,399,782 | $ | 26,520,728 | |||||||||||||||||||
| Other Data | |||||||||||||||||||||||||||||
| Earning assets | $ | 24,623,877 | $ | 24,473,541 | $ | 24,146,137 | $ | 24,312,672 | $ | 24,443,878 | |||||||||||||||||||
| Intangible assets | 1,078,228 | 1,082,304 | 1,086,407 | 1,090,587 | 1,094,766 | ||||||||||||||||||||||||
| Interest-bearing liabilities | 15,642,162 | 15,577,179 | 15,648,252 | 15,687,202 | 15,872,648 | ||||||||||||||||||||||||
| Average assets | 26,757,322 | 26,229,423 | 26,444,894 | 26,442,984 | 25,954,808 | ||||||||||||||||||||||||
| Average common shareholders' equity | 3,865,031 | 3,798,149 | 3,719,888 | 3,618,052 | 3,530,869 | ||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Asset Quality Information | Table 4 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| Allowance for Credit Losses | |||||||||||||||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 381,507 | $ | 368,663 | $ | 364,885 | $ | 366,852 | $ | 357,232 | $ | 368,663 | $ | 348,727 | |||||||||||||||||||||||||||
| Provision for loan losses | 3,110 | 16,519 | 12,657 | 6,313 | 25,348 | 19,629 | 50,871 | ||||||||||||||||||||||||||||||||||
| Provision for unfunded commitments | (335) | 5,373 | 148 | (204) | (6,570) | 5,038 | (10,992) | ||||||||||||||||||||||||||||||||||
| Provision for other credit losses | (3) | — | 3 | (2) | (5) | (3) | (1) | ||||||||||||||||||||||||||||||||||
| Provision for credit losses | 2,772 | 21,892 | 12,808 | 6,107 | 18,773 | 24,664 | 39,878 | ||||||||||||||||||||||||||||||||||
| Charge-offs | 14,227 | 15,383 | 17,460 | 15,352 | 16,845 | 29,610 | 35,302 | ||||||||||||||||||||||||||||||||||
| Recoveries | 7,129 | 6,335 | 8,430 | 7,278 | 7,692 | 13,464 | 13,549 | ||||||||||||||||||||||||||||||||||
| Net charge-offs (recoveries) | 7,098 | 9,048 | 9,030 | 8,074 | 9,153 | 16,146 | 21,753 | ||||||||||||||||||||||||||||||||||
| Ending balance | $ | 377,181 | $ | 381,507 | $ | 368,663 | $ | 364,885 | $ | 366,852 | $ | 377,181 | $ | 366,852 | |||||||||||||||||||||||||||
| Allowance for loan losses | $ | 341,567 | $ | 345,555 | $ | 338,084 | $ | 334,457 | $ | 336,218 | $ | 341,567 | $ | 336,218 | |||||||||||||||||||||||||||
| Allowance for unfunded commitments | 35,548 | 35,883 | 30,510 | 30,362 | 30,566 | 35,548 | 30,566 | ||||||||||||||||||||||||||||||||||
| Allowance for other credit losses | 66 | 69 | 69 | 66 | 68 | 66 | 68 | ||||||||||||||||||||||||||||||||||
| Total allowance for credit losses | $ | 377,181 | $ | 381,507 | $ | 368,663 | $ | 364,885 | $ | 366,852 | $ | 377,181 | $ | 366,852 | |||||||||||||||||||||||||||
| Non-Performing Assets | |||||||||||||||||||||||||||||||||||||||||
| Nonaccrual portfolio loans | $ | 75,286 | $ | 86,229 | $ | 90,206 | $ | 87,339 | $ | 85,878 | $ | 75,286 | $ | 85,878 | |||||||||||||||||||||||||||
| Other real estate owned | 1,825 | 863 | 2,433 | 9,482 | 2,213 | 1,825 | 2,213 | ||||||||||||||||||||||||||||||||||
| Repossessed assets | 2 | — | 9 | 19 | 22 | 2 | 22 | ||||||||||||||||||||||||||||||||||
| Accruing loans delinquent 90 days or more | 8,415 | 14,930 | 17,733 | 12,234 | 15,909 | 8,415 | 15,909 | ||||||||||||||||||||||||||||||||||
| Non-performing portfolio assets | $ | 85,528 | $ | 102,022 | $ | 110,381 | $ | 109,074 | $ | 104,022 | $ | 85,528 | $ | 104,022 | |||||||||||||||||||||||||||
| Serviced GNMA-guaranteed mortgage nonaccrual loans | 11,733 | 13,441 | 12,012 | 8,168 | 93,520 | 11,733 | 93,520 | ||||||||||||||||||||||||||||||||||
| Total non-performing assets | $ | 97,261 | $ | 115,463 | $ | 122,393 | $ | 117,242 | $ | 197,542 | $ | 97,261 | $ | 197,542 | |||||||||||||||||||||||||||
| Asset Quality Ratios | |||||||||||||||||||||||||||||||||||||||||
| Non-performing portfolio assets as a percent of total assets | 0.32 | % | 0.38 | % | 0.42 | % | 0.41 | % | 0.39 | % | 0.32 | % | 0.39 | % | |||||||||||||||||||||||||||
| Total non-performing assets as a percent of total assets | 0.36 | % | 0.44 | % | 0.47 | % | 0.44 | % | 0.74 | % | 0.36 | % | 0.74 | % | |||||||||||||||||||||||||||
| Net charge-offs as a percent of average loans (annualized) | 0.14 | % | 0.18 | % | 0.17 | % | 0.15 | % | 0.18 | % | 0.16 | % | 0.21 | % | |||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||
| Loan Information | Table 5 | ||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | |||||||||||||||||||||||||
| (dollars in thousands) | 2025 | 2025 | 2024 | 2024 | 2024 | ||||||||||||||||||||||||
| Loans by Type | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 3,184,211 | $ | 3,075,971 | $ | 2,953,135 | $ | 2,949,957 | $ | 2,860,973 | |||||||||||||||||||
| Consumer | 209,990 | 213,902 | 221,735 | 221,201 | 234,122 | ||||||||||||||||||||||||
| Mortgage warehouse | 1,092,475 | 891,412 | 965,053 | 985,910 | 1,070,921 | ||||||||||||||||||||||||
| Municipal | 436,759 | 429,227 | 441,408 | 449,561 | 454,967 | ||||||||||||||||||||||||
| Premium Finance | 1,294,293 | 1,176,309 | 1,155,614 | 1,246,452 | 1,151,261 | ||||||||||||||||||||||||
| Real estate - construction and development | 1,485,842 | 1,842,431 | 1,998,506 | 2,232,114 | 2,336,987 | ||||||||||||||||||||||||
| Real estate - commercial and farmland | 8,877,750 | 8,574,626 | 8,445,958 | 8,249,981 | 8,103,634 | ||||||||||||||||||||||||
| Real estate - residential | 4,460,177 | 4,502,766 | 4,558,497 | 4,629,805 | 4,779,738 | ||||||||||||||||||||||||
| Total loans | $ | 21,041,497 | $ | 20,706,644 | $ | 20,739,906 | $ | 20,964,981 | $ | 20,992,603 | |||||||||||||||||||
| Loans by Risk Grade | |||||||||||||||||||||||||||||
| Pass | $ | 20,820,888 | $ | 20,468,496 | $ | 20,457,340 | $ | 20,676,342 | $ | 20,623,416 | |||||||||||||||||||
| Other assets especially mentioned | 66,677 | 73,783 | 110,936 | 124,479 | 115,477 | ||||||||||||||||||||||||
| Substandard | 153,932 | 164,365 | 171,630 | 164,160 | 253,710 | ||||||||||||||||||||||||
| Total loans | $ | 21,041,497 | $ | 20,706,644 | $ | 20,739,906 | $ | 20,964,981 | $ | 20,992,603 | |||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Average Balances | Table 6 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| Earning Assets | |||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in banks | $ | 951,851 | $ | 980,164 | $ | 899,162 | $ | 997,308 | $ | 899,866 | $ | 965,930 | $ | 911,855 | |||||||||||||||||||||||||||
| Debt securities - taxable | 2,117,596 | 1,998,226 | 1,761,984 | 1,733,418 | 1,663,841 | 2,058,241 | 1,631,773 | ||||||||||||||||||||||||||||||||||
| Debt securities - nontaxable | 41,299 | 41,391 | 41,494 | 41,496 | 41,396 | 41,344 | 41,341 | ||||||||||||||||||||||||||||||||||
| Loans held for sale | 730,770 | 565,531 | 795,904 | 575,461 | 491,000 | 648,607 | 407,175 | ||||||||||||||||||||||||||||||||||
| Loans | 20,928,825 | 20,620,777 | 20,868,216 | 21,023,629 | 20,820,361 | 20,775,652 | 20,570,520 | ||||||||||||||||||||||||||||||||||
| Total Earning Assets | $ | 24,770,341 | $ | 24,206,089 | $ | 24,366,760 | $ | 24,371,312 | $ | 23,916,464 | $ | 24,489,774 | $ | 23,562,664 | |||||||||||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | $ | 6,766,557 | $ | 6,522,784 | $ | 6,684,851 | $ | 6,622,952 | $ | 6,558,427 | $ | 6,645,340 | $ | 6,480,864 | |||||||||||||||||||||||||||
| NOW accounts | 3,939,802 | 3,988,458 | 3,888,404 | 3,753,528 | 3,824,538 | 3,963,995 | 3,827,257 | ||||||||||||||||||||||||||||||||||
| MMDA | 6,918,382 | 6,911,554 | 6,864,265 | 6,508,770 | 6,251,719 | 6,914,988 | 6,102,054 | ||||||||||||||||||||||||||||||||||
| Savings accounts | 766,331 | 767,148 | 761,980 | 765,909 | 781,588 | 766,738 | 788,738 | ||||||||||||||||||||||||||||||||||
| Retail CDs | 2,393,402 | 2,436,974 | 2,474,804 | 2,478,875 | 2,430,416 | 2,415,067 | 2,404,547 | ||||||||||||||||||||||||||||||||||
| Brokered CDs | 1,145,043 | 962,768 | 1,057,808 | 1,493,352 | 1,167,174 | 1,054,409 | 1,274,278 | ||||||||||||||||||||||||||||||||||
| Total Deposits | 21,929,517 | 21,589,686 | 21,732,112 | 21,623,386 | 21,013,862 | 21,760,537 | 20,877,738 | ||||||||||||||||||||||||||||||||||
| Non-Deposit Funding | |||||||||||||||||||||||||||||||||||||||||
| Federal funds purchased and securities sold under agreements to repurchase | — | — | — | — | 1 | — | — | ||||||||||||||||||||||||||||||||||
| FHLB advances | 326,054 | 149,537 | 215,116 | 358,332 | 548,251 | 238,283 | 383,920 | ||||||||||||||||||||||||||||||||||
| Other borrowings | 193,492 | 193,494 | 279,961 | 298,073 | 307,449 | 193,493 | 307,829 | ||||||||||||||||||||||||||||||||||
| Subordinated deferrable interest debentures | 133,043 | 132,544 | 132,048 | 131,547 | 131,050 | 132,795 | 130,801 | ||||||||||||||||||||||||||||||||||
| Total Non-Deposit Funding | 652,589 | 475,575 | 627,125 | 787,952 | 986,751 | 564,571 | 822,550 | ||||||||||||||||||||||||||||||||||
| Total Funding | $ | 22,582,106 | $ | 22,065,261 | $ | 22,359,237 | $ | 22,411,338 | $ | 22,000,613 | $ | 22,325,108 | $ | 21,700,288 | |||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Interest Income and Interest Expense (TE) | Table 7 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| Interest Income | |||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in banks | $ | 10,715 | $ | 10,789 | $ | 11,260 | $ | 13,633 | $ | 12,376 | $ | 21,504 | $ | 25,013 | |||||||||||||||||||||||||||
| Debt securities - taxable | 20,696 | 18,492 | 15,923 | 15,555 | 16,948 | 39,188 | 30,040 | ||||||||||||||||||||||||||||||||||
| Debt securities - nontaxable (TE) | 423 | 416 | 427 | 426 | 423 | 839 | 841 | ||||||||||||||||||||||||||||||||||
| Loans held for sale | 11,578 | 9,045 | 11,853 | 9,142 | 8,189 | 20,623 | 13,537 | ||||||||||||||||||||||||||||||||||
| Loans (TE) | 305,154 | 295,964 | 307,852 | 317,358 | 310,347 | 601,118 | 609,254 | ||||||||||||||||||||||||||||||||||
| Total Earning Assets | $ | 348,566 | $ | 334,706 | $ | 347,315 | $ | 356,114 | $ | 348,283 | $ | 683,272 | $ | 678,685 | |||||||||||||||||||||||||||
| Interest Expense | |||||||||||||||||||||||||||||||||||||||||
| Interest-Bearing Deposits | |||||||||||||||||||||||||||||||||||||||||
| NOW accounts | $ | 18,144 | $ | 18,306 | $ | 19,099 | $ | 20,535 | $ | 21,020 | $ | 36,450 | $ | 41,594 | |||||||||||||||||||||||||||
| MMDA | 53,469 | 52,261 | 57,160 | 61,620 | 58,332 | 105,730 | 112,285 | ||||||||||||||||||||||||||||||||||
| Savings accounts | 826 | 830 | 850 | 960 | 984 | 1,656 | 1,970 | ||||||||||||||||||||||||||||||||||
| Retail CDs | 21,852 | 23,245 | 25,610 | 26,775 | 25,711 | 45,097 | 50,287 | ||||||||||||||||||||||||||||||||||
| Brokered CDs | 12,505 | 10,573 | 12,837 | 19,808 | 15,198 | 23,078 | 33,283 | ||||||||||||||||||||||||||||||||||
| Total Interest-Bearing Deposits | 106,796 | 105,215 | 115,556 | 129,698 | 121,245 | 212,011 | 239,419 | ||||||||||||||||||||||||||||||||||
| Non-Deposit Funding | |||||||||||||||||||||||||||||||||||||||||
| FHLB advances | 3,508 | 1,362 | 2,393 | 4,443 | 7,167 | 4,870 | 9,745 | ||||||||||||||||||||||||||||||||||
| Other borrowings | 2,499 | 2,350 | 3,346 | 3,514 | 3,574 | 4,849 | 7,453 | ||||||||||||||||||||||||||||||||||
| Subordinated deferrable interest debentures | 3,022 | 3,012 | 3,247 | 3,431 | 3,416 | 6,034 | 6,849 | ||||||||||||||||||||||||||||||||||
| Total Non-Deposit Funding | 9,029 | 6,724 | 8,986 | 11,388 | 14,157 | 15,753 | 24,047 | ||||||||||||||||||||||||||||||||||
| Total Interest-Bearing Funding | $ | 115,825 | $ | 111,939 | $ | 124,542 | $ | 141,086 | $ | 135,402 | $ | 227,764 | $ | 263,466 | |||||||||||||||||||||||||||
| Net Interest Income (TE) | $ | 232,741 | $ | 222,767 | $ | 222,773 | $ | 215,028 | $ | 212,881 | $ | 455,508 | $ | 415,219 | |||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
Yields(1) | Table 8 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | |||||||||||||||||||||||||||||||||||
| Earning Assets | |||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in banks | 4.52 | % | 4.46 | % | 4.98 | % | 5.44 | % | 5.53 | % | 4.49 | % | 5.52 | % | |||||||||||||||||||||||||||
| Debt securities - taxable | 3.92 | % | 3.75 | % | 3.60 | % | 3.57 | % | 4.10 | % | 3.84 | % | 3.70 | % | |||||||||||||||||||||||||||
| Debt securities - nontaxable (TE) | 4.11 | % | 4.08 | % | 4.09 | % | 4.08 | % | 4.11 | % | 4.09 | % | 4.09 | % | |||||||||||||||||||||||||||
| Loans held for sale | 6.35 | % | 6.49 | % | 5.92 | % | 6.32 | % | 6.71 | % | 6.41 | % | 6.69 | % | |||||||||||||||||||||||||||
| Loans (TE) | 5.85 | % | 5.82 | % | 5.87 | % | 6.01 | % | 6.00 | % | 5.83 | % | 5.96 | % | |||||||||||||||||||||||||||
| Total Earning Assets | 5.64 | % | 5.61 | % | 5.67 | % | 5.81 | % | 5.86 | % | 5.63 | % | 5.79 | % | |||||||||||||||||||||||||||
| Interest-Bearing Deposits | |||||||||||||||||||||||||||||||||||||||||
| NOW accounts | 1.85 | % | 1.86 | % | 1.95 | % | 2.18 | % | 2.21 | % | 1.85 | % | 2.19 | % | |||||||||||||||||||||||||||
| MMDA | 3.10 | % | 3.07 | % | 3.31 | % | 3.77 | % | 3.75 | % | 3.08 | % | 3.70 | % | |||||||||||||||||||||||||||
| Savings accounts | 0.43 | % | 0.44 | % | 0.44 | % | 0.50 | % | 0.51 | % | 0.44 | % | 0.50 | % | |||||||||||||||||||||||||||
| Retail CDs | 3.66 | % | 3.87 | % | 4.12 | % | 4.30 | % | 4.25 | % | 3.77 | % | 4.21 | % | |||||||||||||||||||||||||||
| Brokered CDs | 4.38 | % | 4.45 | % | 4.83 | % | 5.28 | % | 5.24 | % | 4.41 | % | 5.25 | % | |||||||||||||||||||||||||||
| Total Interest-Bearing Deposits | 2.83 | % | 2.83 | % | 3.06 | % | 3.44 | % | 3.37 | % | 2.83 | % | 3.34 | % | |||||||||||||||||||||||||||
| Non-Deposit Funding | |||||||||||||||||||||||||||||||||||||||||
| Federal funds purchased and securities sold under agreements to repurchase | — | % | — | % | — | % | — | % | — | % | — | % | — | % | |||||||||||||||||||||||||||
| FHLB advances | 4.32 | % | 3.69 | % | 4.43 | % | 4.93 | % | 5.26 | % | 4.12 | % | 5.10 | % | |||||||||||||||||||||||||||
| Other borrowings | 5.18 | % | 4.93 | % | 4.75 | % | 4.69 | % | 4.68 | % | 5.05 | % | 4.87 | % | |||||||||||||||||||||||||||
| Subordinated deferrable interest debentures | 9.11 | % | 9.22 | % | 9.78 | % | 10.38 | % | 10.48 | % | 9.16 | % | 10.53 | % | |||||||||||||||||||||||||||
| Total Non-Deposit Funding | 5.55 | % | 5.73 | % | 5.70 | % | 5.75 | % | 5.77 | % | 5.63 | % | 5.88 | % | |||||||||||||||||||||||||||
Total Interest-Bearing Liabilities | 2.94 | % | 2.92 | % | 3.16 | % | 3.55 | % | 3.53 | % | 2.93 | % | 3.48 | % | |||||||||||||||||||||||||||
| Net Interest Spread | 2.70 | % | 2.69 | % | 2.51 | % | 2.26 | % | 2.33 | % | 2.70 | % | 2.31 | % | |||||||||||||||||||||||||||
Net Interest Margin(2) | 3.77 | % | 3.73 | % | 3.64 | % | 3.51 | % | 3.58 | % | 3.75 | % | 3.54 | % | |||||||||||||||||||||||||||
Total Cost of Funds(3) | 2.06 | % | 2.06 | % | 2.22 | % | 2.50 | % | 2.48 | % | 2.06 | % | 2.44 | % | |||||||||||||||||||||||||||
| (1) Interest and average rates are calculated on a tax-equivalent basis using an effective tax rate of 21%. | |||||||||||||||||||||||||||||||||||||||||
| (2) Rate calculated based on average earning assets. | |||||||||||||||||||||||||||||||||||||||||
| (3) Rate calculated based on total average funding including noninterest-bearing deposits. | |||||||||||||||||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Non-GAAP Reconciliations | |||||||||||||||||||||||||||||||||||||||||
| Adjusted Net Income | Table 9A | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $ | 109,834 | $ | 87,935 | $ | 94,376 | $ | 99,212 | $ | 90,785 | $ | 197,769 | $ | 165,097 | |||||||||||||||||||||||||||
| Adjustment items: | |||||||||||||||||||||||||||||||||||||||||
| Gain on sale of MSR | (356) | 14 | (536) | (5,245) | (4,713) | (342) | (4,713) | ||||||||||||||||||||||||||||||||||
| Gain on conversion of Visa Class B-1 stock | — | — | — | — | (12,554) | — | (12,554) | ||||||||||||||||||||||||||||||||||
| Gain on BOLI proceeds | — | (11) | — | — | (466) | (11) | (1,464) | ||||||||||||||||||||||||||||||||||
| FDIC special assessment | (138) | 138 | (559) | — | (895) | — | 2,014 | ||||||||||||||||||||||||||||||||||
| Natural disaster expenses | — | — | 400 | 150 | — | — | — | ||||||||||||||||||||||||||||||||||
| Loss on disposition of bank premises | — | — | 1,203 | — | — | — | — | ||||||||||||||||||||||||||||||||||
Tax effect of adjustment items (Note 1) | 104 | (32) | (107) | 1,070 | 3,814 | 72 | 3,203 | ||||||||||||||||||||||||||||||||||
| After tax adjustment items | (390) | 109 | 401 | (4,025) | (14,814) | (281) | (13,514) | ||||||||||||||||||||||||||||||||||
| Tax expense attributable to BOLI restructuring | — | — | 301 | — | 4,792 | — | 4,792 | ||||||||||||||||||||||||||||||||||
| Adjusted net income | $ | 109,444 | $ | 88,044 | $ | 95,078 | $ | 95,187 | $ | 80,763 | $ | 197,488 | $ | 156,375 | |||||||||||||||||||||||||||
| Weighted average number of shares - diluted | 68,796,577 | 69,030,331 | 69,128,946 | 69,066,298 | 69,013,834 | 68,912,750 | 69,010,010 | ||||||||||||||||||||||||||||||||||
| Net income per diluted share | $ | 1.60 | $ | 1.27 | $ | 1.37 | $ | 1.44 | $ | 1.32 | $ | 2.87 | $ | 2.39 | |||||||||||||||||||||||||||
| Adjusted net income per diluted share | $ | 1.59 | $ | 1.28 | $ | 1.38 | $ | 1.38 | $ | 1.17 | $ | 2.87 | $ | 2.27 | |||||||||||||||||||||||||||
| Average assets | $ | 26,757,322 | $ | 26,229,423 | $ | 26,444,894 | $ | 26,442,984 | $ | 25,954,808 | $ | 26,494,831 | $ | 25,624,948 | |||||||||||||||||||||||||||
| Return on average assets | 1.65 | % | 1.36 | % | 1.42 | % | 1.49 | % | 1.41 | % | 1.51 | % | 1.30 | % | |||||||||||||||||||||||||||
| Adjusted return on average assets | 1.64 | % | 1.36 | % | 1.43 | % | 1.43 | % | 1.25 | % | 1.50 | % | 1.23 | % | |||||||||||||||||||||||||||
| Average common equity | $ | 3,865,031 | $ | 3,798,149 | $ | 3,719,888 | $ | 3,618,052 | $ | 3,530,869 | $ | 3,831,775 | $ | 3,496,870 | |||||||||||||||||||||||||||
| Average tangible common equity | $ | 2,784,819 | $ | 2,713,847 | $ | 2,631,452 | $ | 2,525,421 | $ | 2,433,958 | $ | 2,749,529 | $ | 2,397,751 | |||||||||||||||||||||||||||
| Return on average common equity | 11.40 | % | 9.39 | % | 10.09 | % | 10.91 | % | 10.34 | % | 10.41 | % | 9.49 | % | |||||||||||||||||||||||||||
| Return on average tangible common equity | 15.82 | % | 13.14 | % | 14.27 | % | 15.63 | % | 15.00 | % | 14.50 | % | 13.85 | % | |||||||||||||||||||||||||||
| Adjusted return on average tangible common equity | 15.76 | % | 13.16 | % | 14.37 | % | 14.99 | % | 13.35 | % | 14.48 | % | 13.12 | % | |||||||||||||||||||||||||||
| Note 1: Tax effect is calculated utilizing a 21% rate for taxable adjustments. Gain on BOLI proceeds is non-taxable and no tax effect is included. | |||||||||||||||||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Non-GAAP Reconciliations (continued) | |||||||||||||||||||||||||||||||||||||||||
| Adjusted Efficiency Ratio (TE) | Table 9B | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| Adjusted Noninterest Expense | |||||||||||||||||||||||||||||||||||||||||
| Total noninterest expense | $ | 155,260 | $ | 151,034 | $ | 151,949 | $ | 151,777 | $ | 155,357 | $ | 306,294 | $ | 304,068 | |||||||||||||||||||||||||||
| Adjustment items: | |||||||||||||||||||||||||||||||||||||||||
| FDIC special assessment | 138 | (138) | 559 | — | 895 | — | (2,014) | ||||||||||||||||||||||||||||||||||
| Natural disaster expenses | — | — | (400) | (150) | — | — | — | ||||||||||||||||||||||||||||||||||
| Loss on disposition of bank premises | — | — | (1,203) | — | — | — | — | ||||||||||||||||||||||||||||||||||
| Adjusted noninterest expense | $ | 155,398 | $ | 150,896 | $ | 150,905 | $ | 151,627 | $ | 156,252 | $ | 306,294 | $ | 302,054 | |||||||||||||||||||||||||||
| Total Revenue | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 231,813 | $ | 221,839 | $ | 221,821 | $ | 214,060 | $ | 211,921 | $ | 453,652 | $ | 413,309 | |||||||||||||||||||||||||||
| Noninterest income | 68,911 | 64,023 | 68,959 | 69,709 | 88,711 | 132,934 | 154,589 | ||||||||||||||||||||||||||||||||||
| Total revenue | $ | 300,724 | $ | 285,862 | $ | 290,780 | $ | 283,769 | $ | 300,632 | $ | 586,586 | $ | 567,898 | |||||||||||||||||||||||||||
| Adjusted Total Revenue | |||||||||||||||||||||||||||||||||||||||||
| Net interest income (TE) | $ | 232,741 | $ | 222,767 | $ | 222,773 | $ | 215,028 | $ | 212,881 | $ | 455,508 | $ | 415,219 | |||||||||||||||||||||||||||
| Noninterest income | 68,911 | 64,023 | 68,959 | 69,709 | 88,711 | 132,934 | 154,589 | ||||||||||||||||||||||||||||||||||
| Total revenue (TE) | 301,652 | 286,790 | 291,732 | 284,737 | 301,592 | 588,442 | 569,808 | ||||||||||||||||||||||||||||||||||
| Adjustment items: | |||||||||||||||||||||||||||||||||||||||||
| (Gain) loss on securities | — | (40) | 16 | 8 | (12,335) | (40) | (12,328) | ||||||||||||||||||||||||||||||||||
| Gain on sale of MSR | (356) | 14 | (536) | (5,245) | (4,713) | (342) | (4,713) | ||||||||||||||||||||||||||||||||||
| Gain on BOLI proceeds | — | (11) | — | — | (466) | (11) | (1,464) | ||||||||||||||||||||||||||||||||||
| Adjusted total revenue (TE) | $ | 301,296 | $ | 286,753 | $ | 291,212 | $ | 279,500 | $ | 284,078 | $ | 588,049 | $ | 551,303 | |||||||||||||||||||||||||||
| Efficiency ratio | 51.63 | % | 52.83 | % | 52.26 | % | 53.49 | % | 51.68 | % | 52.22 | % | 53.54 | % | |||||||||||||||||||||||||||
| Adjusted efficiency ratio (TE) | 51.58 | % | 52.62 | % | 51.82 | % | 54.25 | % | 55.00 | % | 52.09 | % | 54.79 | % | |||||||||||||||||||||||||||
| Tangible Book Value Per Share | Table 9C | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| Total shareholders' equity | $ | 3,917,678 | $ | 3,823,802 | $ | 3,751,522 | $ | 3,681,368 | $ | 3,566,614 | $ | 3,917,678 | $ | 3,566,614 | |||||||||||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||||||||||||||
| Goodwill | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | ||||||||||||||||||||||||||||||||||
| Other intangibles, net | 62,582 | 66,658 | 70,761 | 74,941 | 79,120 | 62,582 | 79,120 | ||||||||||||||||||||||||||||||||||
| Total tangible shareholders' equity | $ | 2,839,450 | $ | 2,741,498 | $ | 2,665,115 | $ | 2,590,781 | $ | 2,471,848 | $ | 2,839,450 | $ | 2,471,848 | |||||||||||||||||||||||||||
| Period end number of shares | 68,711,043 | 68,910,924 | 69,068,609 | 69,067,019 | 69,066,573 | 68,711,043 | 69,066,573 | ||||||||||||||||||||||||||||||||||
| Book value per share (period end) | $ | 57.02 | $ | 55.49 | $ | 54.32 | $ | 53.30 | $ | 51.64 | $ | 57.02 | $ | 51.64 | |||||||||||||||||||||||||||
| Tangible book value per share (period end) | $ | 41.32 | $ | 39.78 | $ | 38.59 | $ | 37.51 | $ | 35.79 | $ | 41.32 | $ | 35.79 | |||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||
| Non-GAAP Reconciliations (continued) | |||||||||||||||||||||||||||||
| Tangible Common Equity to Tangible Assets | Table 9D | ||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | |||||||||||||||||||||||||
| (dollars in thousands except per share data) | 2025 | 2025 | 2024 | 2024 | 2024 | ||||||||||||||||||||||||
| Total shareholders' equity | $ | 3,917,678 | $ | 3,823,802 | $ | 3,751,522 | $ | 3,681,368 | $ | 3,566,614 | |||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||
| Goodwill | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | ||||||||||||||||||||||||
| Other intangibles, net | 62,582 | 66,658 | 70,761 | 74,941 | 79,120 | ||||||||||||||||||||||||
| Total tangible shareholders' equity | $ | 2,839,450 | $ | 2,741,498 | $ | 2,665,115 | $ | 2,590,781 | $ | 2,471,848 | |||||||||||||||||||
| Total assets | $ | 26,680,153 | $ | 26,514,940 | $ | 26,262,050 | $ | 26,399,782 | $ | 26,520,728 | |||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||
| Goodwill | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | ||||||||||||||||||||||||
| Other intangibles, net | 62,582 | 66,658 | 70,761 | 74,941 | 79,120 | ||||||||||||||||||||||||
| Total tangible assets | $ | 25,601,925 | $ | 25,432,636 | $ | 25,175,643 | $ | 25,309,195 | $ | 25,425,962 | |||||||||||||||||||
| Equity to Assets | 14.68 | % | 14.42 | % | 14.28 | % | 13.94 | % | 13.45 | % | |||||||||||||||||||
| Tangible Common Equity to Tangible Assets | 11.09 | % | 10.78 | % | 10.59 | % | 10.24 | % | 9.72 | % | |||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Segment Reporting | Table 10 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| Retail Mortgage Division | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 22,031 | $ | 21,844 | $ | 23,714 | $ | 23,553 | $ | 23,742 | $ | 43,875 | $ | 47,029 | |||||||||||||||||||||||||||
| Provision for credit losses | 1,010 | 5,191 | (2,503) | 254 | (2,882) | 6,201 | (550) | ||||||||||||||||||||||||||||||||||
| Noninterest income | 37,726 | 34,729 | 36,623 | 41,498 | 50,145 | 72,455 | 88,910 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 24,358 | 20,995 | 22,876 | 23,233 | 25,254 | 45,353 | 46,327 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment expenses | 811 | 829 | 951 | 957 | 1,008 | 1,640 | 2,057 | ||||||||||||||||||||||||||||||||||
| Data processing and telecommunications expenses | 1,391 | 1,297 | 1,222 | 1,184 | 1,276 | 2,688 | 2,642 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 12,496 | 11,963 | 12,118 | 12,164 | 13,397 | 24,459 | 25,927 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 39,056 | 35,084 | 37,167 | 37,538 | 40,935 | 74,140 | 76,953 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 19,691 | 16,298 | 25,673 | 27,259 | 35,834 | 35,989 | 59,536 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 4,135 | 3,423 | 5,391 | 5,724 | 7,525 | 7,558 | 12,503 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 15,556 | $ | 12,875 | $ | 20,282 | $ | 21,535 | $ | 28,309 | $ | 28,431 | $ | 47,033 | |||||||||||||||||||||||||||
| Warehouse Lending Division | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 7,091 | $ | 5,902 | $ | 6,640 | $ | 7,812 | $ | 6,292 | $ | 12,993 | $ | 12,320 | |||||||||||||||||||||||||||
| Provision for credit losses | 369 | (175) | (59) | (170) | 359 | 194 | 504 | ||||||||||||||||||||||||||||||||||
| Noninterest income | 1,893 | 554 | 676 | 1,765 | 1,028 | 2,447 | 1,768 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 618 | 552 | 583 | 621 | 1,124 | 1,170 | 2,012 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment expenses | 7 | 7 | 6 | 6 | 7 | 14 | 14 | ||||||||||||||||||||||||||||||||||
| Data processing and telecommunications expenses | 59 | 38 | 44 | 32 | 59 | 97 | 84 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 96 | 270 | 224 | 217 | 298 | 366 | 535 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 780 | 867 | 857 | 876 | 1,488 | 1,647 | 2,645 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 7,835 | 5,764 | 6,518 | 8,871 | 5,473 | 13,599 | 10,939 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 1,646 | 1,210 | 1,369 | 1,863 | 1,149 | 2,856 | 2,297 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 6,189 | $ | 4,554 | $ | 5,149 | $ | 7,008 | $ | 4,324 | $ | 10,743 | $ | 8,642 | |||||||||||||||||||||||||||
| Premium Finance Division | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 11,190 | $ | 9,880 | $ | 10,390 | $ | 10,060 | $ | 8,350 | $ | 21,070 | $ | 15,955 | |||||||||||||||||||||||||||
| Provision for credit losses | 716 | 456 | 517 | 457 | 408 | 1,172 | (91) | ||||||||||||||||||||||||||||||||||
| Noninterest income | 17 | 16 | 13 | 11 | 11 | 33 | 21 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 2,331 | 2,352 | 2,029 | 2,212 | 1,900 | 4,683 | 3,953 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment expenses | 36 | 37 | 51 | 28 | 70 | 73 | 146 | ||||||||||||||||||||||||||||||||||
| Data processing and telecommunications expenses | 91 | 129 | 106 | 83 | 102 | 220 | 181 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 1,115 | 969 | 1,173 | 1,140 | 1,095 | 2,084 | 2,123 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 3,573 | 3,487 | 3,359 | 3,463 | 3,167 | 7,060 | 6,403 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 6,918 | 5,953 | 6,527 | 6,151 | 4,786 | 12,871 | 9,664 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 1,410 | 1,214 | 1,334 | 1,254 | 953 | 2,624 | 1,937 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 5,508 | $ | 4,739 | $ | 5,193 | $ | 4,897 | $ | 3,833 | $ | 10,247 | $ | 7,727 | |||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Segment Reporting (continued) | Table 10 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| Banking Division | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 191,501 | $ | 184,213 | $ | 181,077 | $ | 172,635 | $ | 173,537 | $ | 375,714 | $ | 338,005 | |||||||||||||||||||||||||||
| Provision for credit losses | 677 | 16,420 | 14,853 | 5,566 | 20,888 | 17,097 | 40,015 | ||||||||||||||||||||||||||||||||||
| Noninterest income | 29,275 | 28,724 | 31,647 | 26,435 | 37,527 | 57,999 | 63,890 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 62,001 | 62,716 | 62,322 | 62,634 | 59,923 | 124,717 | 118,839 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment expenses | 10,547 | 9,804 | 10,616 | 10,725 | 11,474 | 20,351 | 23,227 | ||||||||||||||||||||||||||||||||||
| Data processing and telecommunications expenses | 13,825 | 13,391 | 13,259 | 13,922 | 13,756 | 27,216 | 26,940 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 25,478 | 25,685 | 24,369 | 22,619 | 24,614 | 51,163 | 49,061 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 111,851 | 111,596 | 110,566 | 109,900 | 109,767 | 223,447 | 218,067 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 108,248 | 84,921 | 87,305 | 83,604 | 80,409 | 193,169 | 143,813 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 25,667 | 19,154 | 23,553 | 17,832 | 26,090 | 44,821 | 42,118 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 82,581 | $ | 65,767 | $ | 63,752 | $ | 65,772 | $ | 54,319 | $ | 148,348 | $ | 101,695 | |||||||||||||||||||||||||||
| Total Consolidated | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 231,813 | $ | 221,839 | $ | 221,821 | $ | 214,060 | $ | 211,921 | $ | 453,652 | $ | 413,309 | |||||||||||||||||||||||||||
| Provision for credit losses | 2,772 | 21,892 | 12,808 | 6,107 | 18,773 | 24,664 | 39,878 | ||||||||||||||||||||||||||||||||||
| Noninterest income | 68,911 | 64,023 | 68,959 | 69,709 | 88,711 | 132,934 | 154,589 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 89,308 | 86,615 | 87,810 | 88,700 | 88,201 | 175,923 | 171,131 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment expenses | 11,401 | 10,677 | 11,624 | 11,716 | 12,559 | 22,078 | 25,444 | ||||||||||||||||||||||||||||||||||
| Data processing and telecommunications expenses | 15,366 | 14,855 | 14,631 | 15,221 | 15,193 | 30,221 | 29,847 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 39,185 | 38,887 | 37,884 | 36,140 | 39,404 | 78,072 | 77,646 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 155,260 | 151,034 | 151,949 | 151,777 | 155,357 | 306,294 | 304,068 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 142,692 | 112,936 | 126,023 | 125,885 | 126,502 | 255,628 | 223,952 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 32,858 | 25,001 | 31,647 | 26,673 | 35,717 | 57,859 | 58,855 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 109,834 | $ | 87,935 | $ | 94,376 | $ | 99,212 | $ | 90,785 | $ | 197,769 | $ | 165,097 | |||||||||||||||||||||||||||

2nd Quarter 2025 Results Investor Presentation
Cautionary Statements 1 This presentation contains forward-looking statements, as defined by federal securities laws, including, among other forward- looking statements, certain plans, expectations and goals. Words such as “may,” “believe,” “expect,” “anticipate,” “intend,” “will,” “should,” “plan,” “estimate,” “predict,” “continue” and “potential” or the negative of these terms or other comparable terminology, as well as similar expressions, are meant to identify forward-looking statements. The forward-looking statements in this presentation are based on current expectations and are provided to assist in the understanding of potential future performance. Such forward- looking statements involve numerous assumptions, risks and uncertainties that may cause actual results to differ materially from those expressed or implied in any such statements, including, without limitation, the following: general competitive, economic, unemployment, political and market conditions and fluctuations, including real estate market conditions, and the effects of such conditions and fluctuations on the creditworthiness and payment behaviors of borrowers, collateral values, asset recovery values and the value of investment securities; movements in interest rates and their impacts on net interest margin, investment security valuations and other performance measures; expectations on credit quality and performance; legislative and regulatory changes; changes in U.S. government trade, monetary and fiscal policies, including tariffs; competitive pressures on product pricing and services; fraud, theft or other misconduct impacting our customers or operations; cybersecurity risks, including data breaches, malware, ransomware and account takeovers; the success and timing of our business strategies and plans; our outlook and long- term goals for future growth; and natural disasters, geopolitical events, acts of war or terrorism or other hostilities, public health crises and other catastrophic events beyond our control. For a discussion of some of the other risks and other factors that may cause such forward-looking statements to differ materially from actual results, please refer to the Company’s filings with the Securities and Exchange Commission, including the Company’s Annual Report on Form 10-K for the year ended December 31, 2024 and the Company’s subsequently filed periodic reports and other filings. Forward-looking statements speak only as of the date they are made, and the Company undertakes no obligation to update or revise forward-looking statements.
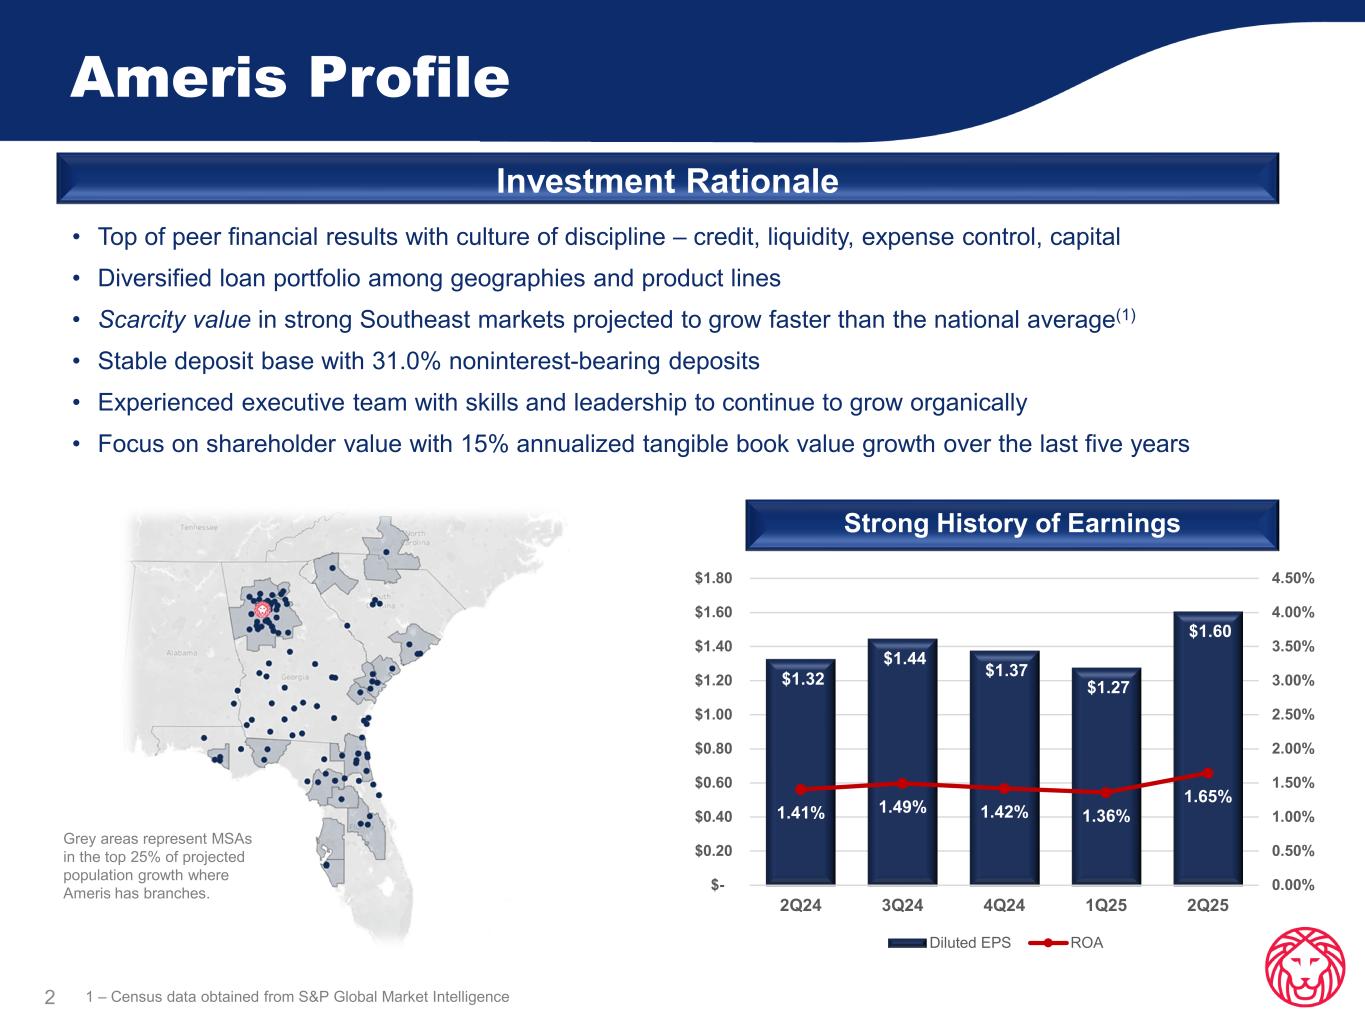
Ameris Profile Investment Rationale • Top of peer financial results with culture of discipline – credit, liquidity, expense control, capital • Diversified loan portfolio among geographies and product lines • Scarcity value in strong Southeast markets projected to grow faster than the national average(1) • Stable deposit base with 31.0% noninterest-bearing deposits • Experienced executive team with skills and leadership to continue to grow organically • Focus on shareholder value with 15% annualized tangible book value growth over the last five years Strong History of Earnings 2 1 – Census data obtained from S&P Global Market Intelligence $1.32 $1.44 $1.37 $1.27 $1.60 1.41% 1.49% 1.42% 1.36% 1.65% 0.00% 0.50% 1.00% 1.50% 2.00% 2.50% 3.00% 3.50% 4.00% 4.50% $- $0.20 $0.40 $0.60 $0.80 $1.00 $1.20 $1.40 $1.60 $1.80 2Q24 3Q24 4Q24 1Q25 2Q25 Diluted EPS ROA Grey areas represent MSAs in the top 25% of projected population growth where Ameris has branches.

51.6% Efficiency Ratio 1.7x National Growth Markets(3) 1.62% Allowance for Credit Losses 13.0% CET1 Ratio(2) 15% 5-yr TBV(1) CAGR 15.8% ROTCE(1) 23% Fees to Revenue Disciplined and Focused Mgmt Team 11.1% TCE/TA Ratio(1) 31.0% NIB Deposits 3.77% Net Interest Margin 1.65% ROA 1 – Considered Non-GAAP measures – See reconciliation of GAAP to Non-GAAP measures in Appendix 2 – Regulatory capital ratios are estimated for most recent period end 3 – Ameris Southeast Markets projected to grow approximately 1.7x the national average over the next five years per census data obtained from S&P Global Market Intelligence3 Why Ameris? Leading Industry Performance
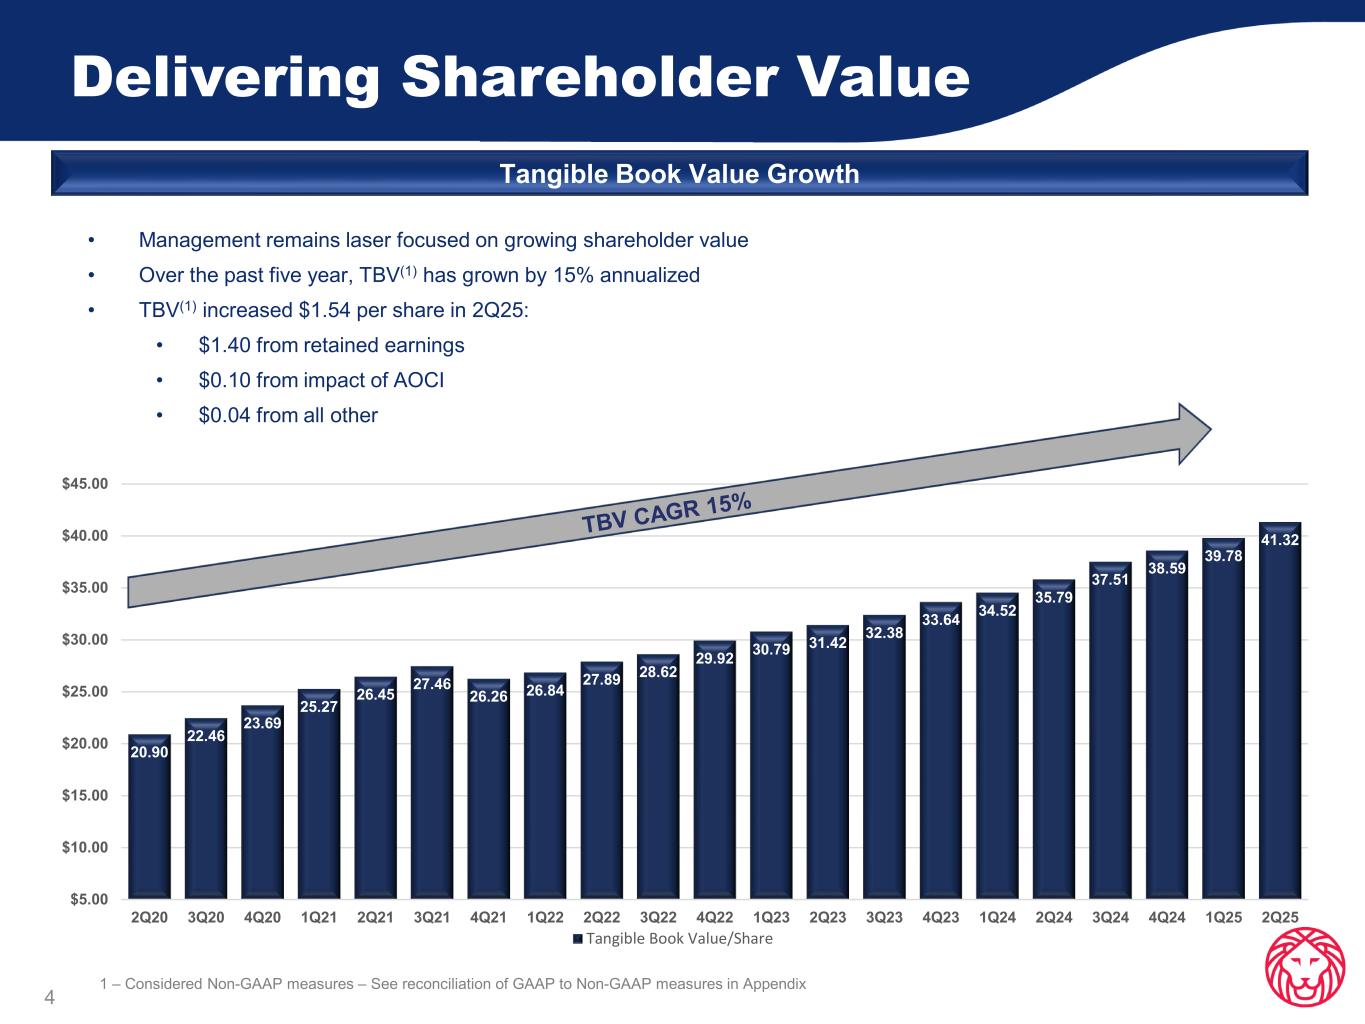
20.90 22.46 23.69 25.27 26.45 27.46 26.26 26.84 27.89 28.62 29.92 30.79 31.42 32.38 33.64 34.52 35.79 37.51 38.59 39.78 41.32 $5.00 $10.00 $15.00 $20.00 $25.00 $30.00 $35.00 $40.00 $45.00 2Q20 3Q20 4Q20 1Q21 2Q21 3Q21 4Q21 1Q22 2Q22 3Q22 4Q22 1Q23 2Q23 3Q23 4Q23 1Q24 2Q24 3Q24 4Q24 1Q25 2Q25 Tangible Book Value/Share Delivering Shareholder Value Tangible Book Value Growth 4 • Management remains laser focused on growing shareholder value • Over the past five year, TBV(1) has grown by 15% annualized • TBV(1) increased $1.54 per share in 2Q25: • $1.40 from retained earnings • $0.10 from impact of AOCI • $0.04 from all other 1 – Considered Non-GAAP measures – See reconciliation of GAAP to Non-GAAP measures in Appendix
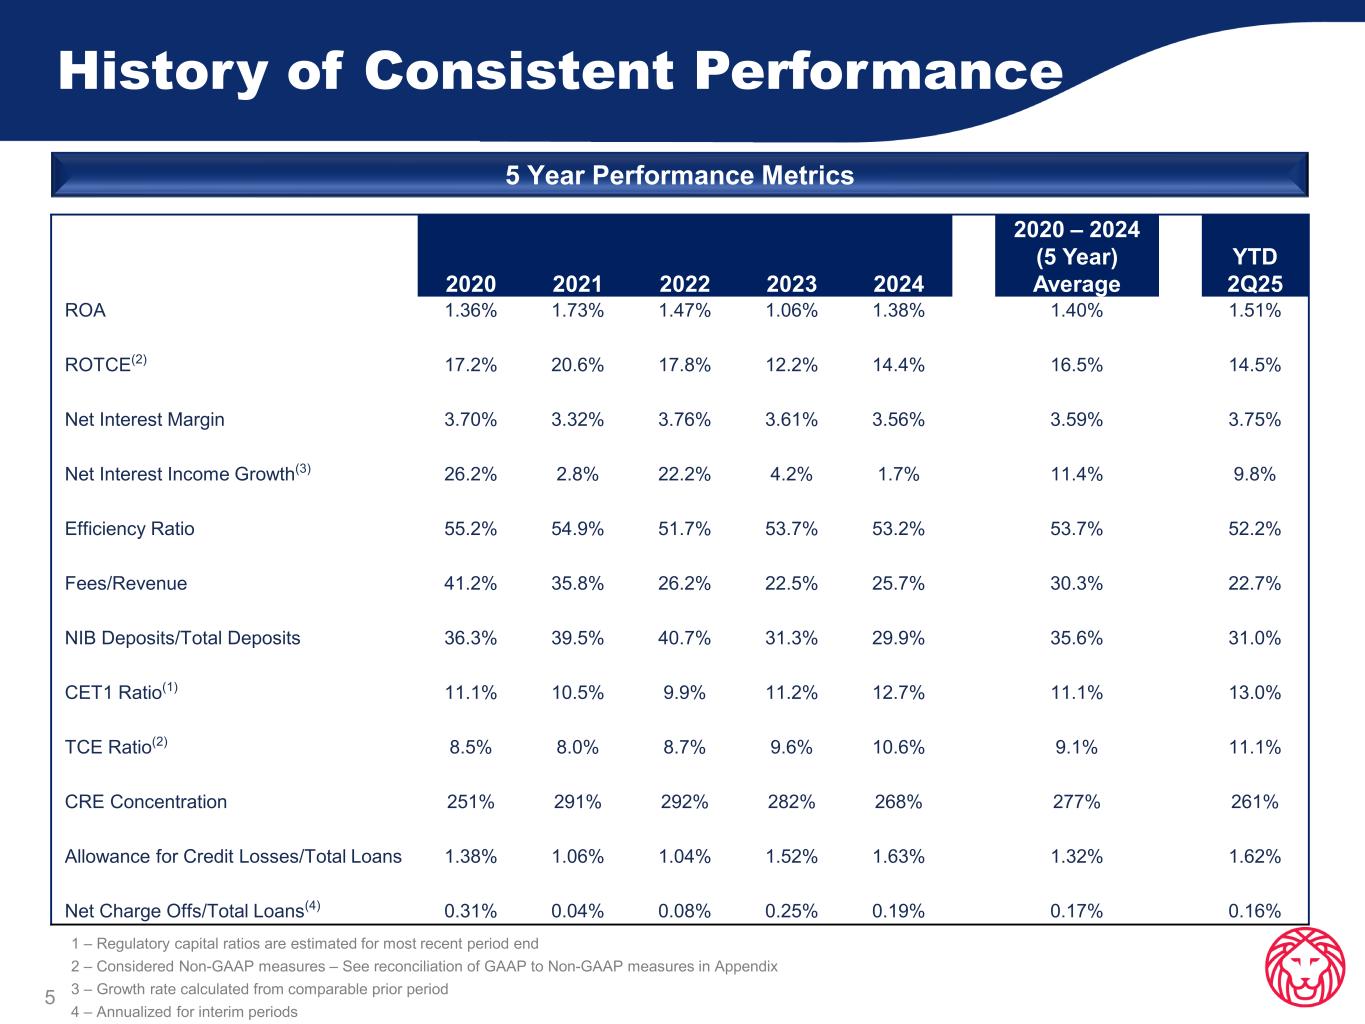
1 – Regulatory capital ratios are estimated for most recent period end 2 – Considered Non-GAAP measures – See reconciliation of GAAP to Non-GAAP measures in Appendix 3 – Growth rate calculated from comparable prior period 4 – Annualized for interim periods 5 History of Consistent Performance 2020 2021 2022 2023 2024 2020 – 2024 (5 Year) Average YTD 2Q25 ROA 1.36% 1.73% 1.47% 1.06% 1.38% 1.40% 1.51% ROTCE(2) 17.2% 20.6% 17.8% 12.2% 14.4% 16.5% 14.5% Net Interest Margin 3.70% 3.32% 3.76% 3.61% 3.56% 3.59% 3.75% Net Interest Income Growth(3) 26.2% 2.8% 22.2% 4.2% 1.7% 11.4% 9.8% Efficiency Ratio 55.2% 54.9% 51.7% 53.7% 53.2% 53.7% 52.2% Fees/Revenue 41.2% 35.8% 26.2% 22.5% 25.7% 30.3% 22.7% NIB Deposits/Total Deposits 36.3% 39.5% 40.7% 31.3% 29.9% 35.6% 31.0% CET1 Ratio(1) 11.1% 10.5% 9.9% 11.2% 12.7% 11.1% 13.0% TCE Ratio(2) 8.5% 8.0% 8.7% 9.6% 10.6% 9.1% 11.1% CRE Concentration 251% 291% 292% 282% 268% 277% 261% Allowance for Credit Losses/Total Loans 1.38% 1.06% 1.04% 1.52% 1.63% 1.32% 1.62% Net Charge Offs/Total Loans(4) 0.31% 0.04% 0.08% 0.25% 0.19% 0.17% 0.16% 5 Year Performance Metrics
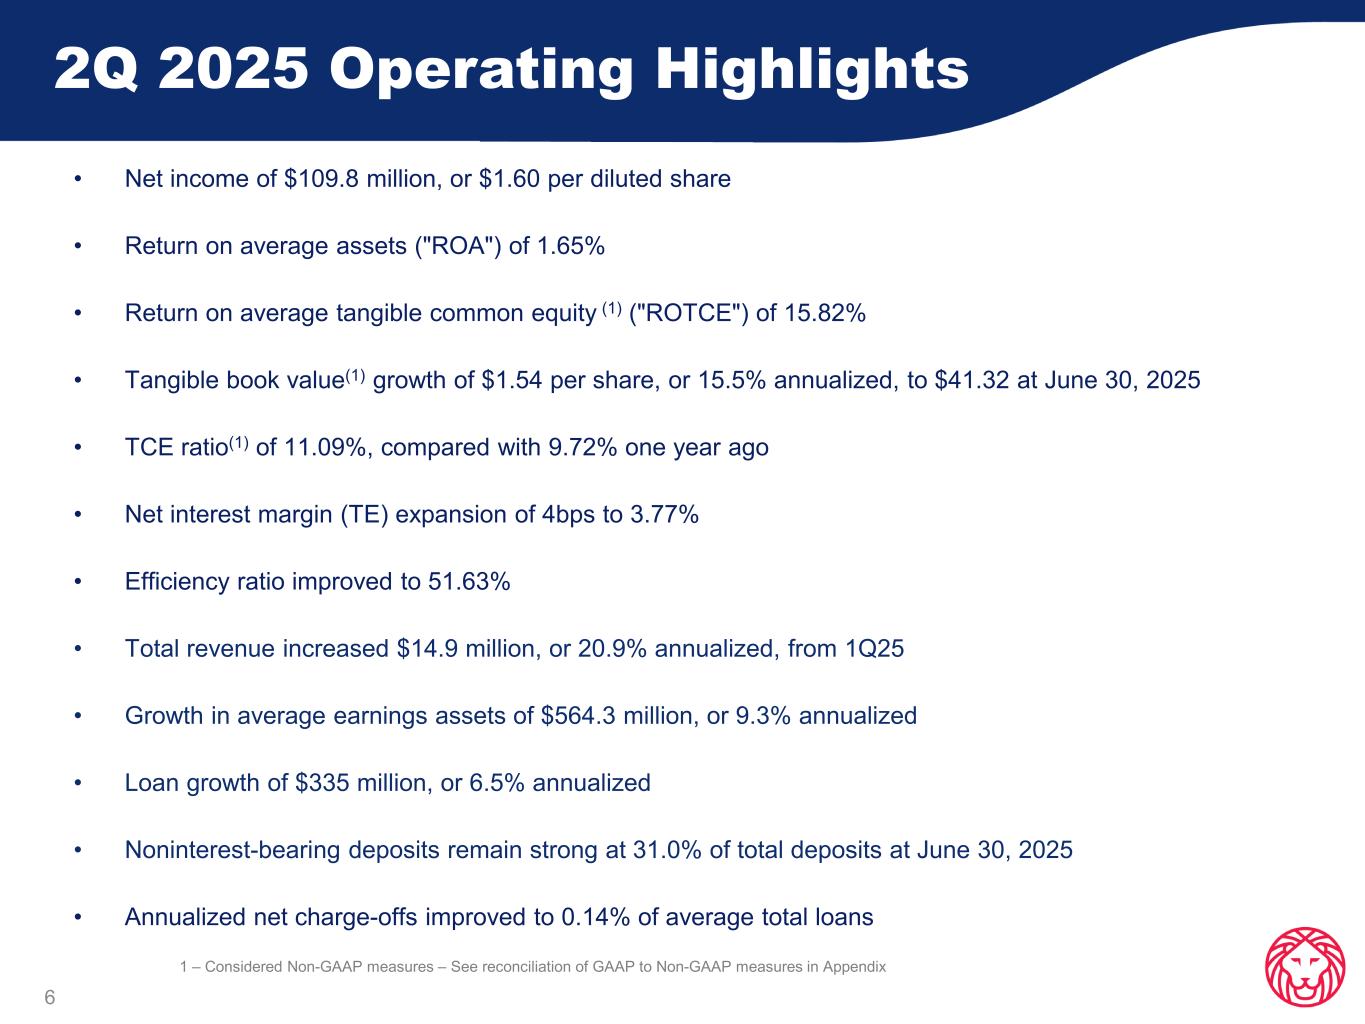
2Q 2025 Operating Highlights 6 • Net income of $109.8 million, or $1.60 per diluted share • Return on average assets ("ROA") of 1.65% • Return on average tangible common equity (1) ("ROTCE") of 15.82% • Tangible book value(1) growth of $1.54 per share, or 15.5% annualized, to $41.32 at June 30, 2025 • TCE ratio(1) of 11.09%, compared with 9.72% one year ago • Net interest margin (TE) expansion of 4bps to 3.77% • Efficiency ratio improved to 51.63% • Total revenue increased $14.9 million, or 20.9% annualized, from 1Q25 • Growth in average earnings assets of $564.3 million, or 9.3% annualized • Loan growth of $335 million, or 6.5% annualized • Noninterest-bearing deposits remain strong at 31.0% of total deposits at June 30, 2025 • Annualized net charge-offs improved to 0.14% of average total loans 1 – Considered Non-GAAP measures – See reconciliation of GAAP to Non-GAAP measures in Appendix

2Q 2025 Financial Highlights 7 1 – Considered Non-GAAP measures – See reconciliation of GAAP to Non-GAAP measures in Appendix (dollars in thousands, except per share data) 2Q25 1Q25 Change 2Q24 Change 2025 2024 Change Net Income $109,834 $ 87,935 25% $ 90,785 21% $ 197,769 $ 165,097 20% Adjusted Net Income(1) $109,444 $ 88,044 24% $ 80,763 36% $ 197,488 $ 156,375 26% Net Income Per Diluted Share $ 1.60 $ 1.27 26% $ 1.32 21% $ 2.87 $ 2.39 20% Adjusted Net Income Per Share(1) $ 1.59 $ 1.28 24% $ 1.17 36% $ 2.87 $ 2.27 26% Return on Assets 1.65% 1.36% 21% 1.41% 17% 1.51% 1.30% 16% Adjusted Return on Assets(1) 1.64% 1.36% 21% 1.25% 31% 1.50% 1.23% 22% Return on Equity 11.40% 9.39% 21% 10.34% 10% 10.41% 9.49% 10% Return on TCE(1) 15.82% 13.14% 20% 15.00% 5% 14.50% 13.85% 5% Adjusted Return on TCE(1) 15.76% 13.16% 20% 13.35% 18% 14.48% 13.12% 10% Efficiency Ratio 51.63% 52.83% -2% 51.68% 0% 52.22% 53.54% -2% Adjusted Efficiency Ratio(1) 51.58% 52.62% -2% 55.00% -6% 52.09% 54.79% -5% Net Interest Margin 3.77% 3.73% 1% 3.58% 5% 3.75% 3.54% 6% Quarter to Date Results Year To Date Results

Strong Net Interest Margin 8 • Net interest margin improved 4bps to 3.77% in the second quarter of 2025 • Net interest income (TE) grew by $10.0 million in 2Q25 • Interest income (TE) increased $13.9 million • Interest expense increased $3.9 million • Average earning assets increased 9.3% annualized Spread Income and Margin Interest Rate Sensitivity • Asset sensitivity continues near neutrality in preparation for further potential FOMC rate changes: • -0.7% asset sensitivity in -100bps • -0.4% asset sensitivity in -50bps • +0.4% asset sensitivity in +50bps • +0.8% asset sensitivity in +100bps • Approximately $11.5 billion of total loans reprice within one year through either maturities or floating rate indices $212.9 $215.0 $222.8 $222.8 $232.7 3.58% 3.51% 3.64% 3.73% 3.77% 3.00% 3.50% 4.00% 4.50% $190.0 $200.0 $210.0 $220.0 $230.0 $240.0 2Q24 3Q24 4Q24 1Q25 2Q25 Net Interest Income (TE) (in millions) NIM
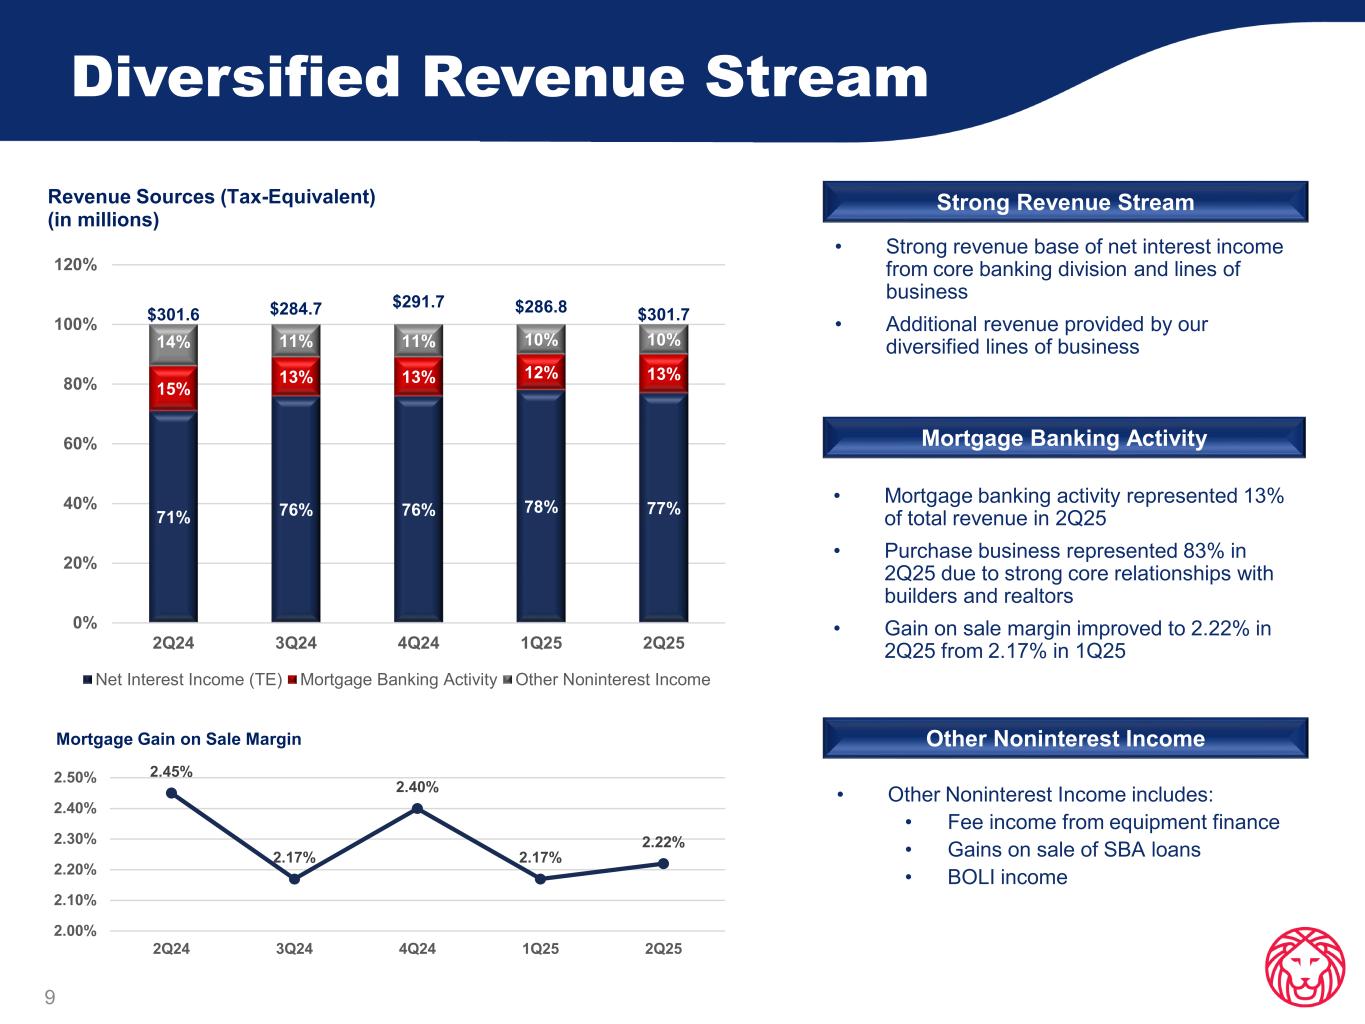
Diversified Revenue Stream 9 • Strong revenue base of net interest income from core banking division and lines of business • Additional revenue provided by our diversified lines of business Mortgage Banking Activity • Mortgage banking activity represented 13% of total revenue in 2Q25 • Purchase business represented 83% in 2Q25 due to strong core relationships with builders and realtors • Gain on sale margin improved to 2.22% in 2Q25 from 2.17% in 1Q25 Other Noninterest Income • Other Noninterest Income includes: • Fee income from equipment finance • Gains on sale of SBA loans • BOLI income Strong Revenue Stream 2.45% 2.17% 2.40% 2.17% 2.22% 2.00% 2.10% 2.20% 2.30% 2.40% 2.50% 2Q24 3Q24 4Q24 1Q25 2Q25 Mortgage Gain on Sale Margin 71% 76% 76% 78% 77% 15% 13% 13% 12% 13% 14% 11% 11% 10% 10% $301.6 $284.7 $291.7 $286.8 $301.7 0% 20% 40% 60% 80% 100% 120% 2Q24 3Q24 4Q24 1Q25 2Q25 Revenue Sources (Tax-Equivalent) (in millions) Net Interest Income (TE) Mortgage Banking Activity Other Noninterest Income

Disciplined Expense Control Noninterest Expense and Efficiency Ratio Expense Highlights 10 • Management continues to deliver high performing operating efficiency • Efficiency ratio of 51.63% in 2Q25 • 120bps improvement compared with 52.83% in 1Q25 • 5bps improvement compared with 51.68% in 2Q24 • Total expenses increased $4.2 million in 2Q25 compared with 1Q25: • Increase of approximately $2.7 million of salaries and employee benefits primarily due to variable mortgage incentives tied to production • Occupancy and equipment costs increased approximately $700,000, and advertising and marketing expenses increased approximately $900,000 $109.8 $109.9 $110.6 $111.6 $111.9 $45.6 $41.9 $41.4 $39.4 $43.4 20.0 40.0 60.0 80.0 100.0 120.0 140.0 160.0 180.0 2Q24 3Q24 4Q24 1Q25 2Q25 Noninterest Expense (in millions) Banking LOBs 51.68% 53.49% 52.26% 52.83% 51.63% 40.00% 45.00% 50.00% 55.00% 60.00% 65.00% 2Q24 3Q24 4Q24 1Q25 2Q25 Efficiency Ratio

Strong Core Deposit Base 11 Deposits by Product Type Deposit Type Balance (in 000s) % of Total Count Average per account NIB $ 6,800,519 31.0% 311,427 $ 21,837 NOW 4,038,284 18.4% 42,435 95,164 MMDA 6,847,686 31.2% 32,984 207,606 Savings 760,093 3.5% 63,629 11,946 CD 3,486,093 15.9% 38,966 89,465 Total $ 21,932,675 100% 489,441 $ 44,812 • Total deposits increased $20.3 million, or 0.4% annualized, during 2Q25: • Seasonal outflows of public funds totaled $77.1 million • Brokered CDs increased $81.8 million, and represent only 5% of total deposits • Remaining (non-brokered, non-public fund) deposits increased $15.6 million • Noninterest-bearing deposits remained strong at 31.0% of total deposits, an increase from 30.8% at March 31, 2025 2Q25 Highlights Consumer 35% Commercial 45% Public 15% Brokered 5% 2Q25 Deposits by Customer
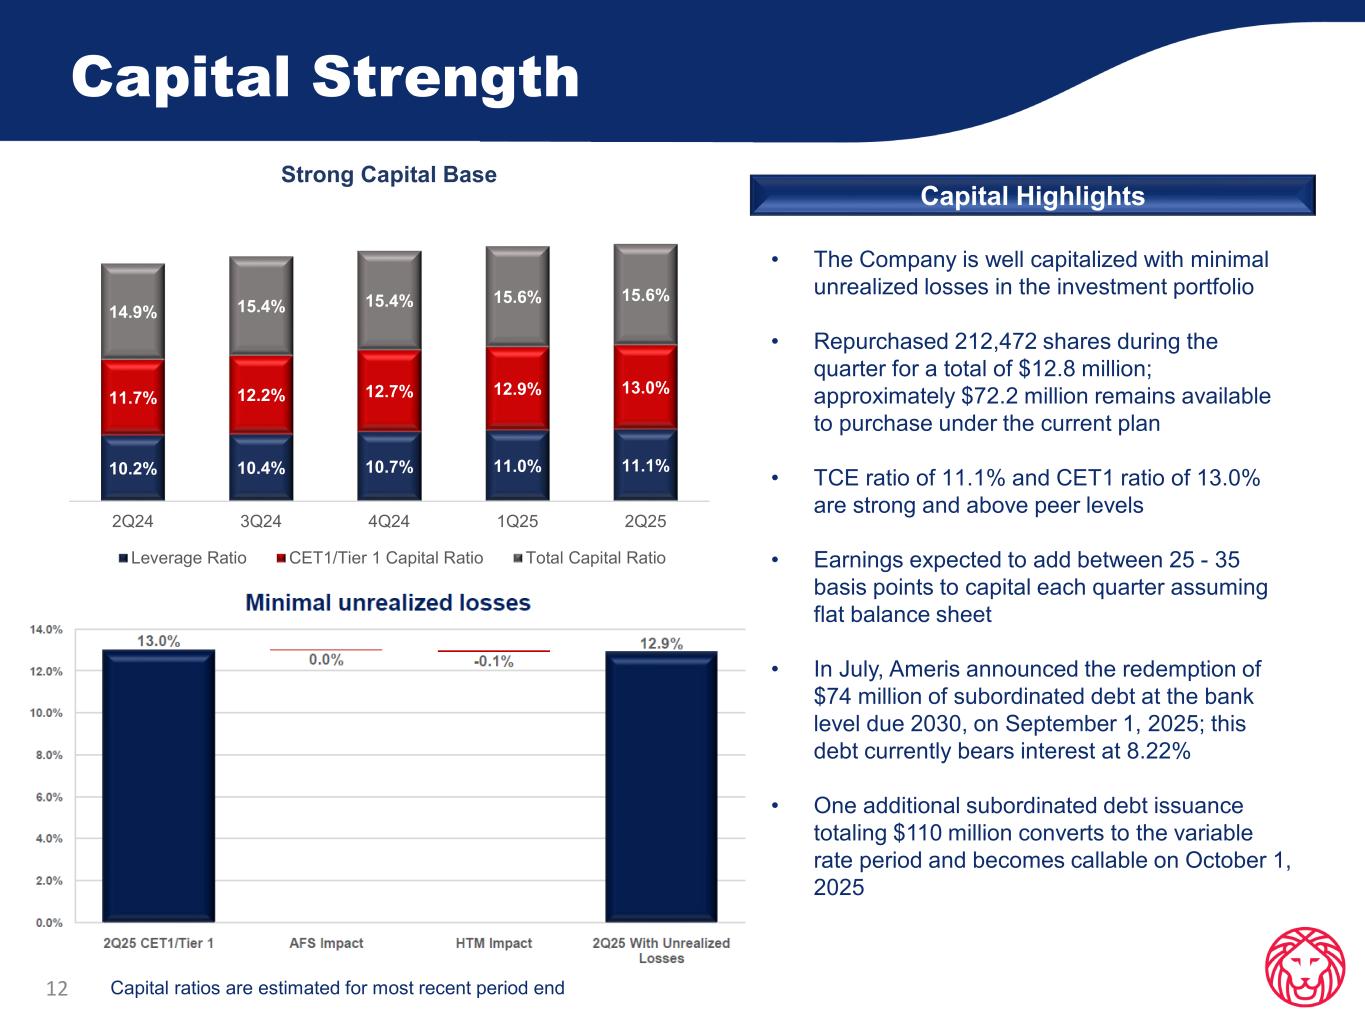
Capital Strength 12 Capital Highlights • The Company is well capitalized with minimal unrealized losses in the investment portfolio • Repurchased 212,472 shares during the quarter for a total of $12.8 million; approximately $72.2 million remains available to purchase under the current plan • TCE ratio of 11.1% and CET1 ratio of 13.0% are strong and above peer levels • Earnings expected to add between 25 - 35 basis points to capital each quarter assuming flat balance sheet • In July, Ameris announced the redemption of $74 million of subordinated debt at the bank level due 2030, on September 1, 2025; this debt currently bears interest at 8.22% • One additional subordinated debt issuance totaling $110 million converts to the variable rate period and becomes callable on October 1, 2025 Capital ratios are estimated for most recent period end 10.2% 10.4% 10.7% 11.0% 11.1% 11.7% 12.2% 12.7% 12.9% 13.0% 14.9% 15.4% 15.4% 15.6% 15.6% 2Q24 3Q24 4Q24 1Q25 2Q25 Strong Capital Base Leverage Ratio CET1/Tier 1 Capital Ratio Total Capital Ratio
Loan Diversification and Credit Quality
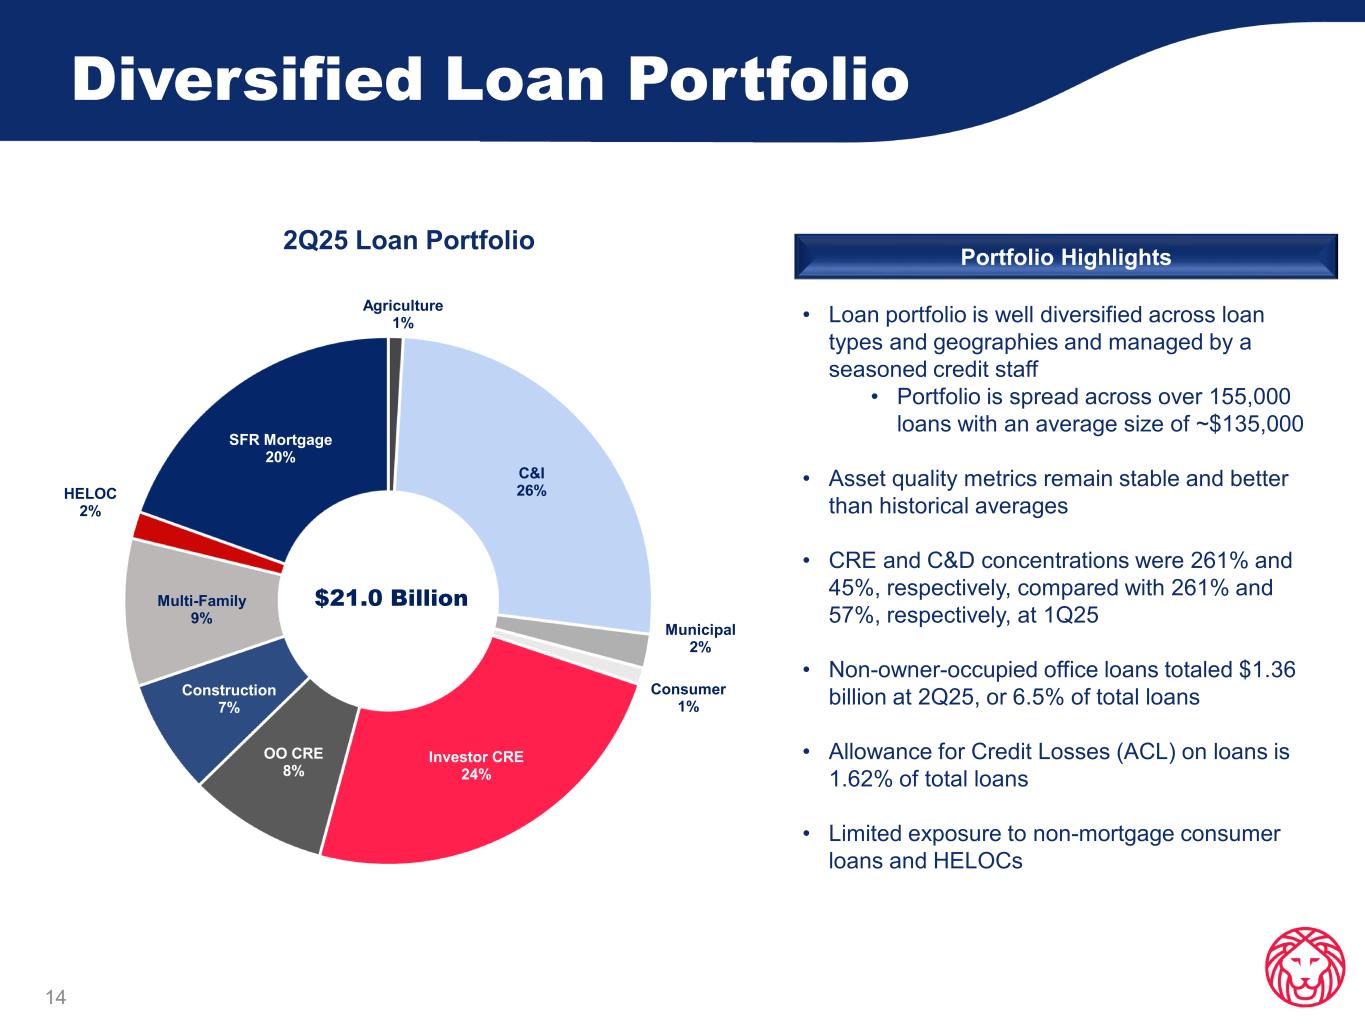
Diversified Loan Portfolio 2Q25 Loan Portfolio 14 • Loan portfolio is well diversified across loan types and geographies and managed by a seasoned credit staff • Portfolio is spread across over 155,000 loans with an average size of ~$135,000 • Asset quality metrics remain stable and better than historical averages • CRE and C&D concentrations were 261% and 45%, respectively, compared with 261% and 57%, respectively, at 1Q25 • Non-owner-occupied office loans totaled $1.36 billion at 2Q25, or 6.5% of total loans • Allowance for Credit Losses (ACL) on loans is 1.62% of total loans • Limited exposure to non-mortgage consumer loans and HELOCs Portfolio Highlights Agriculture 1% C&I 26% Municipal 2% Consumer 1% Investor CRE 24% OO CRE 8% Construction 7% Multi-Family 9% HELOC 2% SFR Mortgage 20% $21.0 Billion

Loan Balance Changes 2Q25 Loan Balance Changes 15 • Loan balances increased $335 million, or 6.5% annualized, during 2Q25 • Increases in C&I were largely attributable to fundings of mortgage warehouse lines and premium finance loans • Decline in construction is the result of multi-family projects moving to term financing in 2Q25 • 2Q25 exhibited the highest production levels since 2022 • 28.5% increase from 1Q25 • 15.7% increase from 2Q24 (in millions) (1) C&I includes premium finance, mortgage warehouse, traditional C&I, CSVLI, and equipment finance $415 $271 $111 $13 $(42) $(76) $(357) $(400) $(300) $(200) $(100) $- $100 $200 $300 $400 $500 C&I (1) Multi-Family Investor CRE Other RE - RES OO CRE Construction
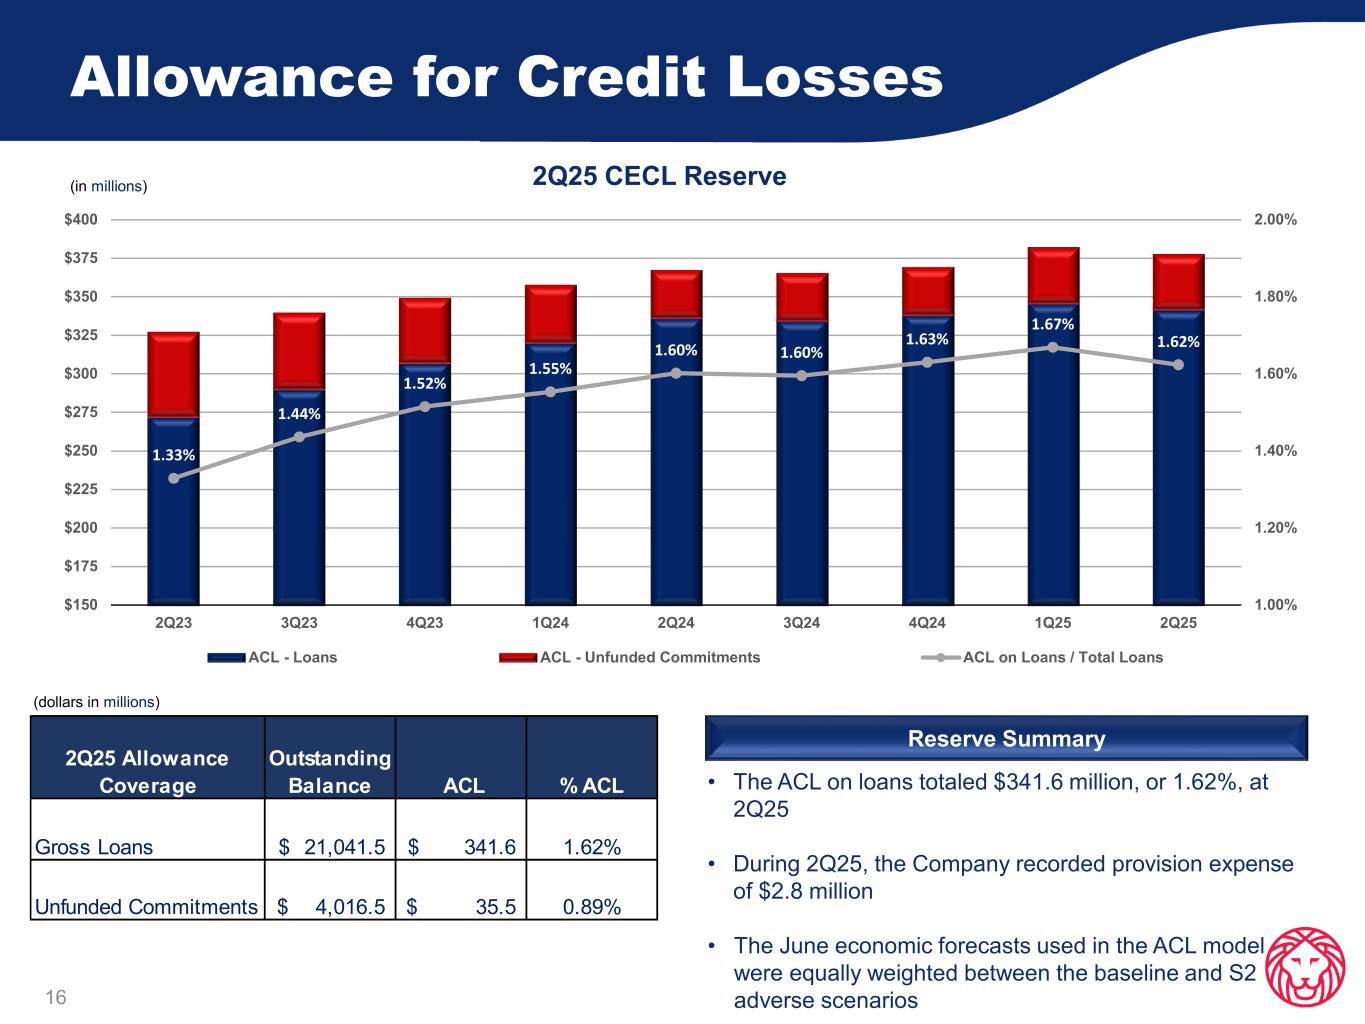
Allowance for Credit Losses 16 • The ACL on loans totaled $341.6 million, or 1.62%, at 2Q25 • During 2Q25, the Company recorded provision expense of $2.8 million • The June economic forecasts used in the ACL model were equally weighted between the baseline and S2 adverse scenarios 2Q25 CECL Reserve Reserve Summary (in millions) 2Q25 Allowance Coverage Outstanding Balance ACL % ACL Gross Loans 21,041.5$ 341.6$ 1.62% Unfunded Commitments 4,016.5$ 35.5$ 0.89% (dollars in millions) 1.33% 1.44% 1.52% 1.55% 1.60% 1.60% 1.63% 1.67% 1.62% 1.00% 1.20% 1.40% 1.60% 1.80% 2.00% $150 $175 $200 $225 $250 $275 $300 $325 $350 $375 $400 2Q23 3Q23 4Q23 1Q24 2Q24 3Q24 4Q24 1Q25 2Q25 ACL - Loans ACL - Unfunded Commitments ACL on Loans / Total Loans
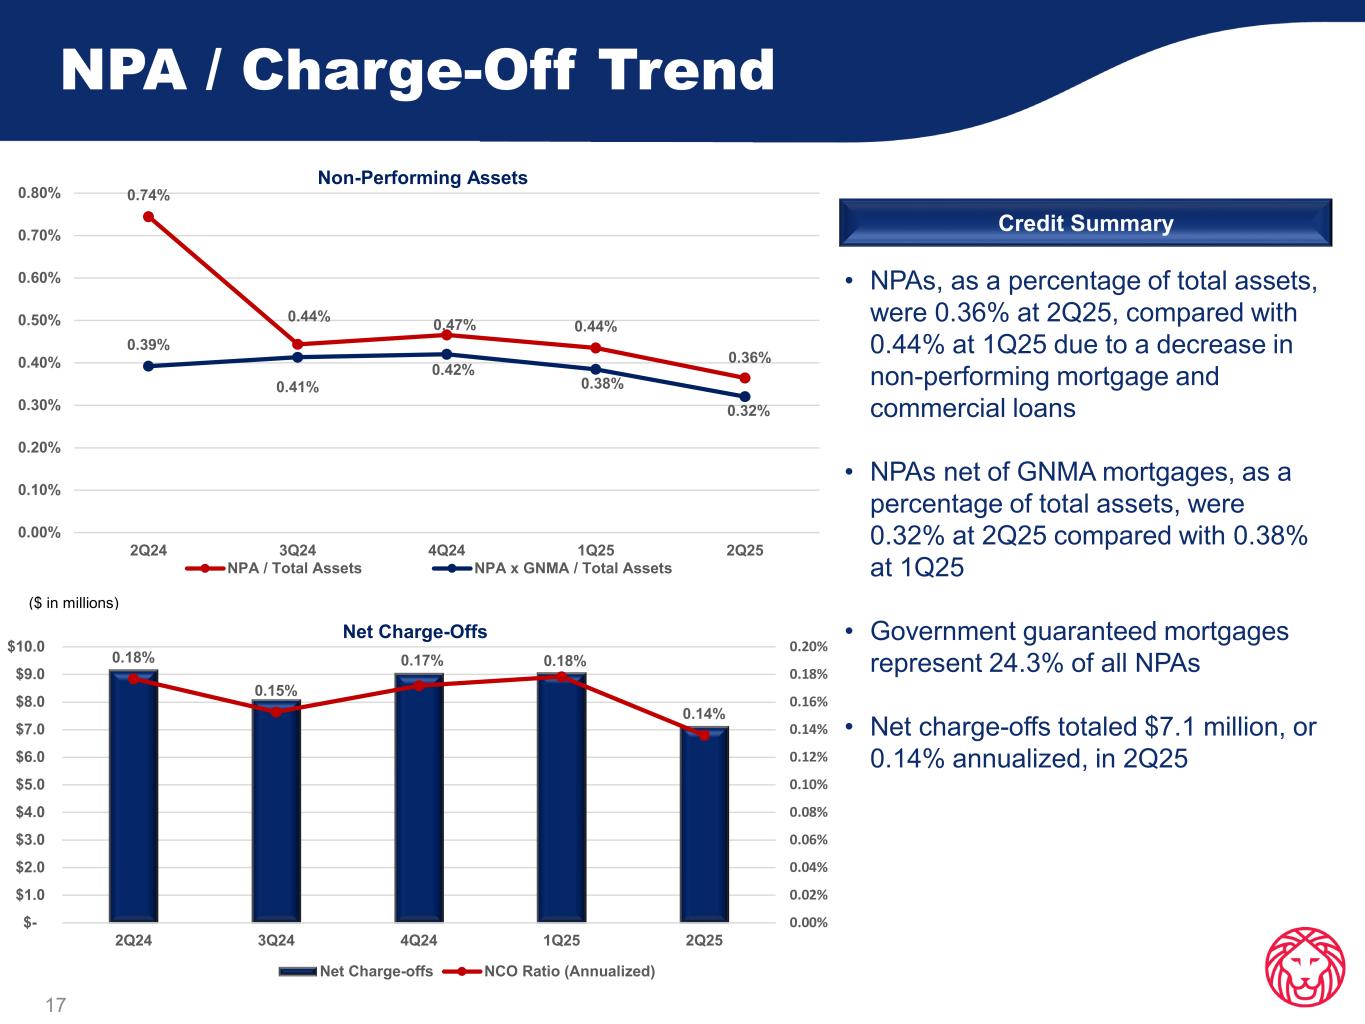
NPA / Charge-Off Trend 17 • NPAs, as a percentage of total assets, were 0.36% at 2Q25, compared with 0.44% at 1Q25 due to a decrease in non-performing mortgage and commercial loans • NPAs net of GNMA mortgages, as a percentage of total assets, were 0.32% at 2Q25 compared with 0.38% at 1Q25 • Government guaranteed mortgages represent 24.3% of all NPAs • Net charge-offs totaled $7.1 million, or 0.14% annualized, in 2Q25 Credit Summary ($ in millions) 0.74% 0.44% 0.47% 0.44% 0.36% 0.39% 0.41% 0.42% 0.38% 0.32% 0.00% 0.10% 0.20% 0.30% 0.40% 0.50% 0.60% 0.70% 0.80% 2Q24 3Q24 4Q24 1Q25 2Q25 Non-Performing Assets NPA / Total Assets NPA x GNMA / Total Assets 0.18% 0.15% 0.17% 0.18% 0.14% 0.00% 0.02% 0.04% 0.06% 0.08% 0.10% 0.12% 0.14% 0.16% 0.18% 0.20% $- $1.0 $2.0 $3.0 $4.0 $5.0 $6.0 $7.0 $8.0 $9.0 $10.0 2Q24 3Q24 4Q24 1Q25 2Q25 Net Charge-Offs Net Charge-offs NCO Ratio (Annualized)

Problem Loan Trends 18 • Total criticized loans (including special mention), excluding GNMA- guaranteed mortgage loans, decreased $15.8 million, or 7.0%, in 2Q25 • Classified loans, excluding GNMA-guaranteed mortgage loans, decreased $8.7 million, or 5.8%, in 2Q25 • Nonperforming loans, excluding GNMA-guaranteed mortgage loans, decreased $17.5 million, or 17.3%, in 2Q25 • The largest component of classified and nonperforming loans at 2Q25 was residential mortgages including government guaranteed Highlights (in millions) Note: Criticized, Classified and Nonperforming loan totals exclude GNMA-guaranteed loans. Ratios expressed as a percentage of total loans net of GNMA-backed mortgage loans. 1.31% 1.34% 1.30% 1.09% 0.99% 0.76% 0.74% 0.77% 0.73% 0.68% 0.48% 0.47% 0.52% 0.49% 0.40% $0 $50 $100 $150 $200 $250 $300 $350 2Q24 3Q24 4Q24 1Q25 2Q25 Criticized Loans Classified Loans Nonperforming Loans % Criticized ACL Coverage 164% Classified ACL Coverage 240% NPL ACL Coverage 408%

Term Investor CRE • Past dues for investor CRE loans were 0.05% and NPLs 0.06% at 2Q25 • Investor CRE portfolio is well diversified with over 80% of CRE loans located in MSAs in the Bank’s footprint, which exhibit population growth forecasts exceeding the national average 19 Highlights (1) Results based on stabilized term loans, or 62% of total Investor CRE loans Investor CRE Multi-Family $1,938 Office $1,287 Retail - Anchored $1,197 Retail - Non Anchored $925 Warehouse / Industrial $837 Hotel $406 All Other CRE $555 Investor CRE by Property Type GA $2,479 FL $2,491 SC $871 NC $560 All Other $745 Investor CRE by Property Location Outstanding $6.97 B Unfunded $0.18 B Total Committed Exposure $7.15 B Average Loan Size $3.96 M Allowance Coverage 1.51% PD Ratio 0.05% NPL Ratio 0.06% Criticized Ratio 0.96% Criticized ACL Coverage 157% Average LTV (1) 58% Average DSC (1) 1.61
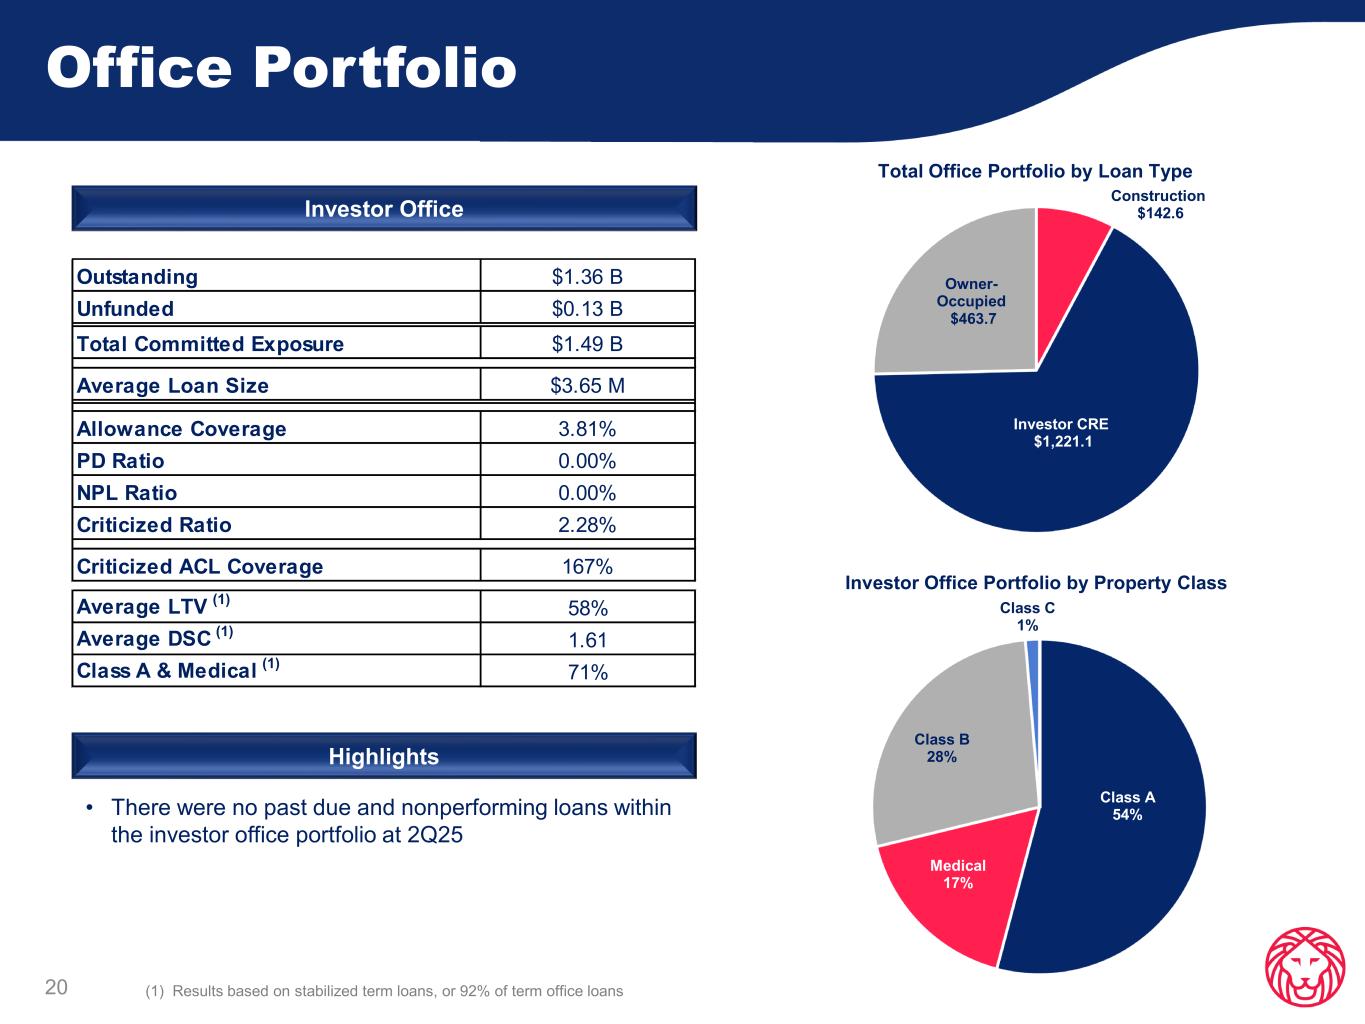
Office Portfolio • There were no past due and nonperforming loans within the investor office portfolio at 2Q25 20 Highlights (1) Results based on stabilized term loans, or 92% of term office loans Investor Office Construction $142.6 Investor CRE $1,221.1 Owner- Occupied $463.7 Total Office Portfolio by Loan Type Class A 54% Medical 17% Class B 28% Class C 1% Investor Office Portfolio by Property Class Outstanding $1.36 B Unfunded $0.13 B Total Committed Exposure $1.49 B Average Loan Size $3.65 M Allowance Coverage 3.81% PD Ratio 0.00% NPL Ratio 0.00% Criticized Ratio 2.28% Criticized ACL Coverage 167% Average LTV (1) 58% Average DSC (1) 1.61 Class A & Medical (1) 71%

Appendix

22 Reconciliation of GAAP to Non-GAAP Measures (dollars in thousands) 2Q25 1Q25 2Q24 2025 2024 Net Income $ 109,834 $ 87,935 $ 90,785 $ 197,769 $ 165,097 Adjustment items Gain on sale of MSR (356) 14 (4,713) (342) (4,713) Gain on conversion of Visa Class B-1 stock - - (12,554) - (12,554) Gain on BOLI proceeds - (11) (466) (11) (1,464) FDIC special assessment (138) 138 (895) - 2,014 Tax effect of adjustment items 104 (32) 3,814 72 3,203 After tax adjustment items (390) 109 (14,814) (281) (13,514) Tax expense attributable to BOLI restructuring - - 4,792 - 4,792 Adjusted Net Income $ 109,444 $ 88,044 $ 80,763 $ 197,488 $ 156,375 Weighted average number of shares - diluted 68,796,577 69,030,331 69,013,834 68,912,750 69,010,010 Net income per diluted share $ 1.60 $ 1.27 $ 1.32 $ 2.87 $ 2.39 Adjusted net income per diluted share $ 1.59 $ 1.28 $ 1.17 $ 2.87 $ 2.27 Average assets 26,757,322 26,229,423 25,954,808 26,494,831 25,624,948 Return on average assets 1.65% 1.36% 1.41% 1.51% 1.30% Adjusted return on average assets 1.64% 1.36% 1.25% 1.50% 1.23% Average common equity 3,865,031 3,798,149 3,530,869 3,831,775 3,496,870 Average tangible common equity 2,784,819 2,713,847 2,433,958 2,749,529 2,397,751 Return on average common equity 11.40% 9.39% 10.34% 10.41% 9.49% Return on average tangible common equity 15.82% 13.14% 15.00% 14.50% 13.85% Adjusted return on average tangible common equity 15.76% 13.16% 13.35% 14.48% 13.12% Quarter to Date Year to Date
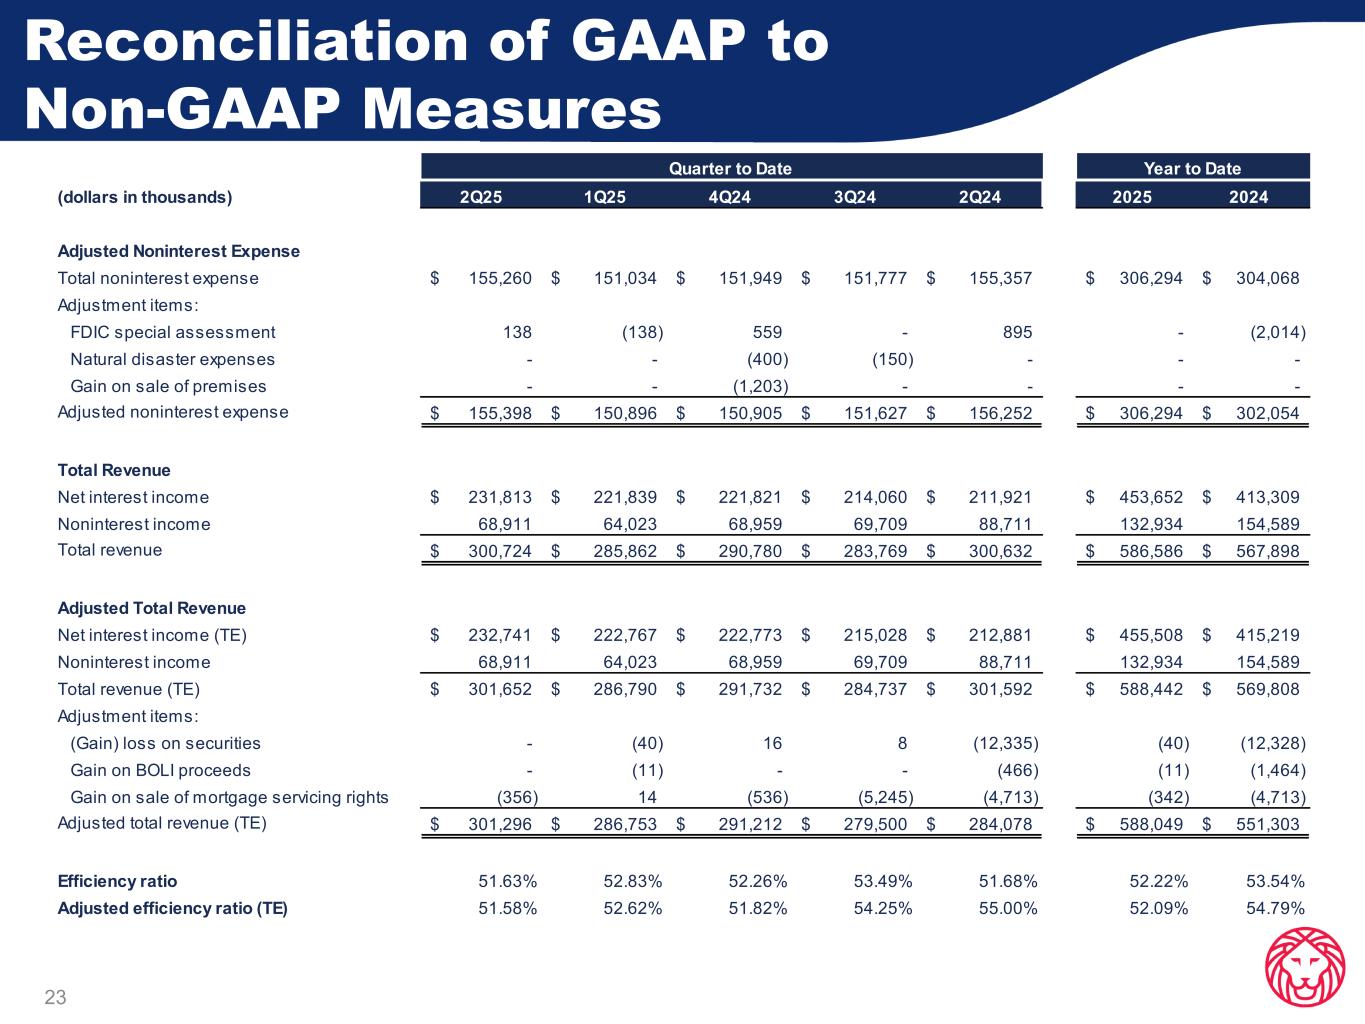
23 Reconciliation of GAAP to Non-GAAP Measures (dollars in thousands) 2Q25 1Q25 4Q24 3Q24 2Q24 2025 2024 Adjusted Noninterest Expense Total noninterest expense 155,260$ 151,034$ 151,949$ 151,777$ 155,357$ 306,294$ 304,068$ Adjustment items: FDIC special assessment 138 (138) 559 - 895 - (2,014) Natural disaster expenses - - (400) (150) - - - Gain on sale of premises - - (1,203) - - - - Adjusted noninterest expense 155,398$ 150,896$ 150,905$ 151,627$ 156,252$ 306,294$ 302,054$ Total Revenue Net interest income 231,813$ 221,839$ 221,821$ 214,060$ 211,921$ 453,652$ 413,309$ Noninterest income 68,911 64,023 68,959 69,709 88,711 132,934 154,589 Total revenue 300,724$ 285,862$ 290,780$ 283,769$ 300,632$ 586,586$ 567,898$ Adjusted Total Revenue Net interest income (TE) 232,741$ 222,767$ 222,773$ 215,028$ 212,881$ 455,508$ 415,219$ Noninterest income 68,911 64,023 68,959 69,709 88,711 132,934 154,589 Total revenue (TE) 301,652$ 286,790$ 291,732$ 284,737$ 301,592$ 588,442$ 569,808$ Adjustment items: (Gain) loss on securities - (40) 16 8 (12,335) (40) (12,328) Gain on BOLI proceeds - (11) - - (466) (11) (1,464) Gain on sale of mortgage servicing rights (356) 14 (536) (5,245) (4,713) (342) (4,713) Adjusted total revenue (TE) 301,296$ 286,753$ 291,212$ 279,500$ 284,078$ 588,049$ 551,303$ Efficiency ratio 51.63% 52.83% 52.26% 53.49% 51.68% 52.22% 53.54% Adjusted efficiency ratio (TE) 51.58% 52.62% 51.82% 54.25% 55.00% 52.09% 54.79% Year to DateQuarter to Date
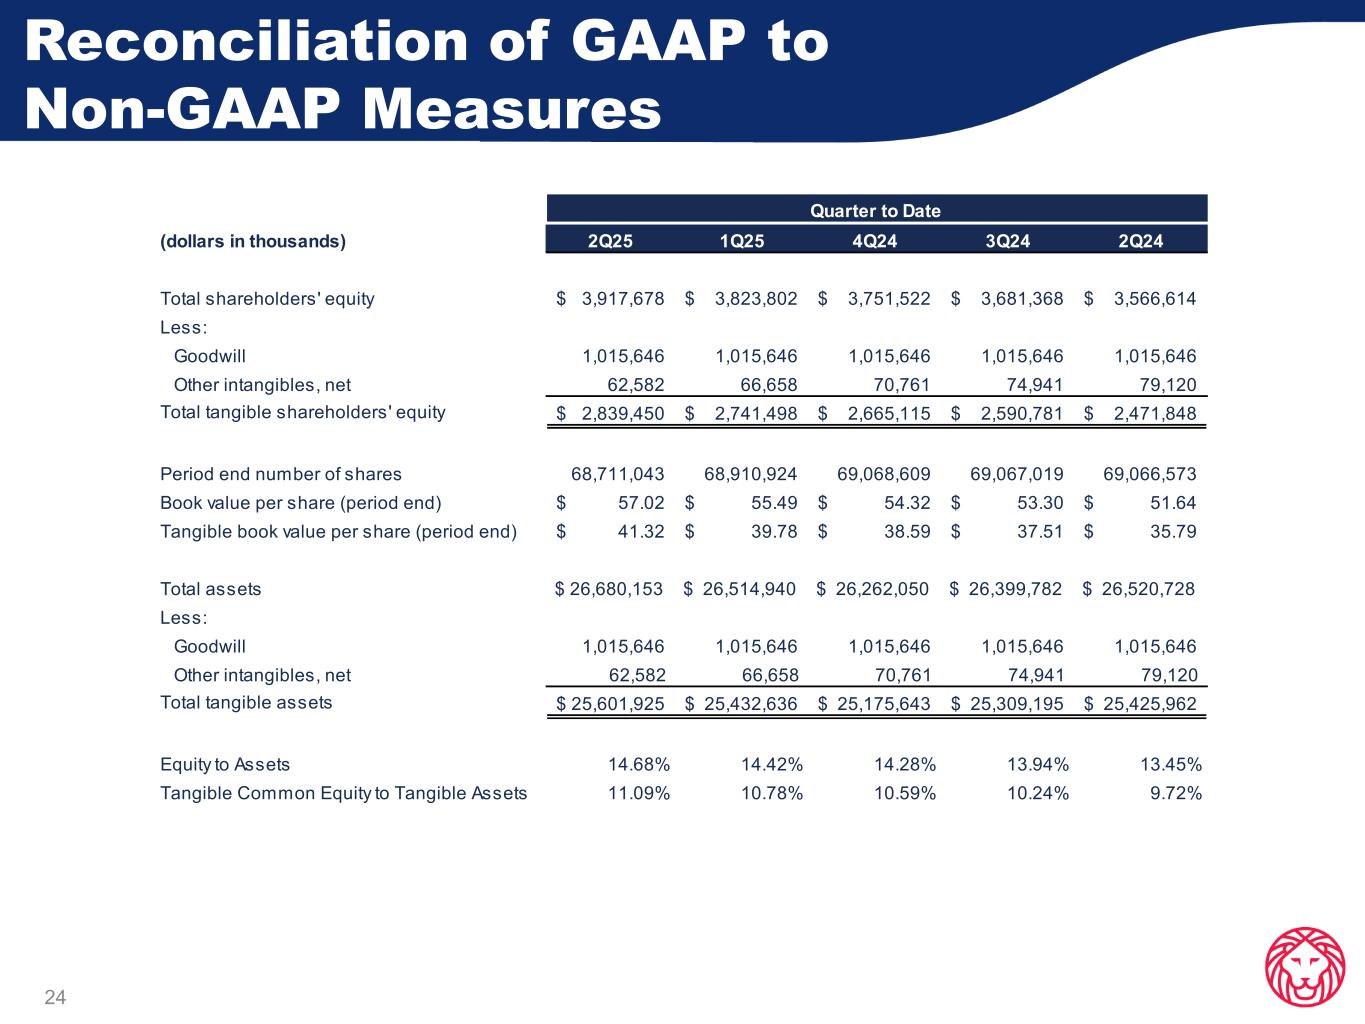
24 Reconciliation of GAAP to Non-GAAP Measures (dollars in thousands) 2Q25 1Q25 4Q24 3Q24 2Q24 Total shareholders' equity 3,917,678$ 3,823,802$ 3,751,522$ 3,681,368$ 3,566,614$ Less: Goodwill 1,015,646 1,015,646 1,015,646 1,015,646 1,015,646 Other intangibles, net 62,582 66,658 70,761 74,941 79,120 Total tangible shareholders' equity 2,839,450$ 2,741,498$ 2,665,115$ 2,590,781$ 2,471,848$ Period end number of shares 68,711,043 68,910,924 69,068,609 69,067,019 69,066,573 Book value per share (period end) 57.02$ 55.49$ 54.32$ 53.30$ 51.64$ Tangible book value per share (period end) 41.32$ 39.78$ 38.59$ 37.51$ 35.79$ Total assets $ 26,680,153 $ 26,514,940 $ 26,262,050 $ 26,399,782 $ 26,520,728 Less: Goodwill 1,015,646 1,015,646 1,015,646 1,015,646 1,015,646 Other intangibles, net 62,582 66,658 70,761 74,941 79,120 Total tangible assets 25,601,925$ 25,432,636$ 25,175,643$ 25,309,195$ 25,425,962$ Equity to Assets 14.68% 14.42% 14.28% 13.94% 13.45% Tangible Common Equity to Tangible Assets 11.09% 10.78% 10.59% 10.24% 9.72% Quarter to Date
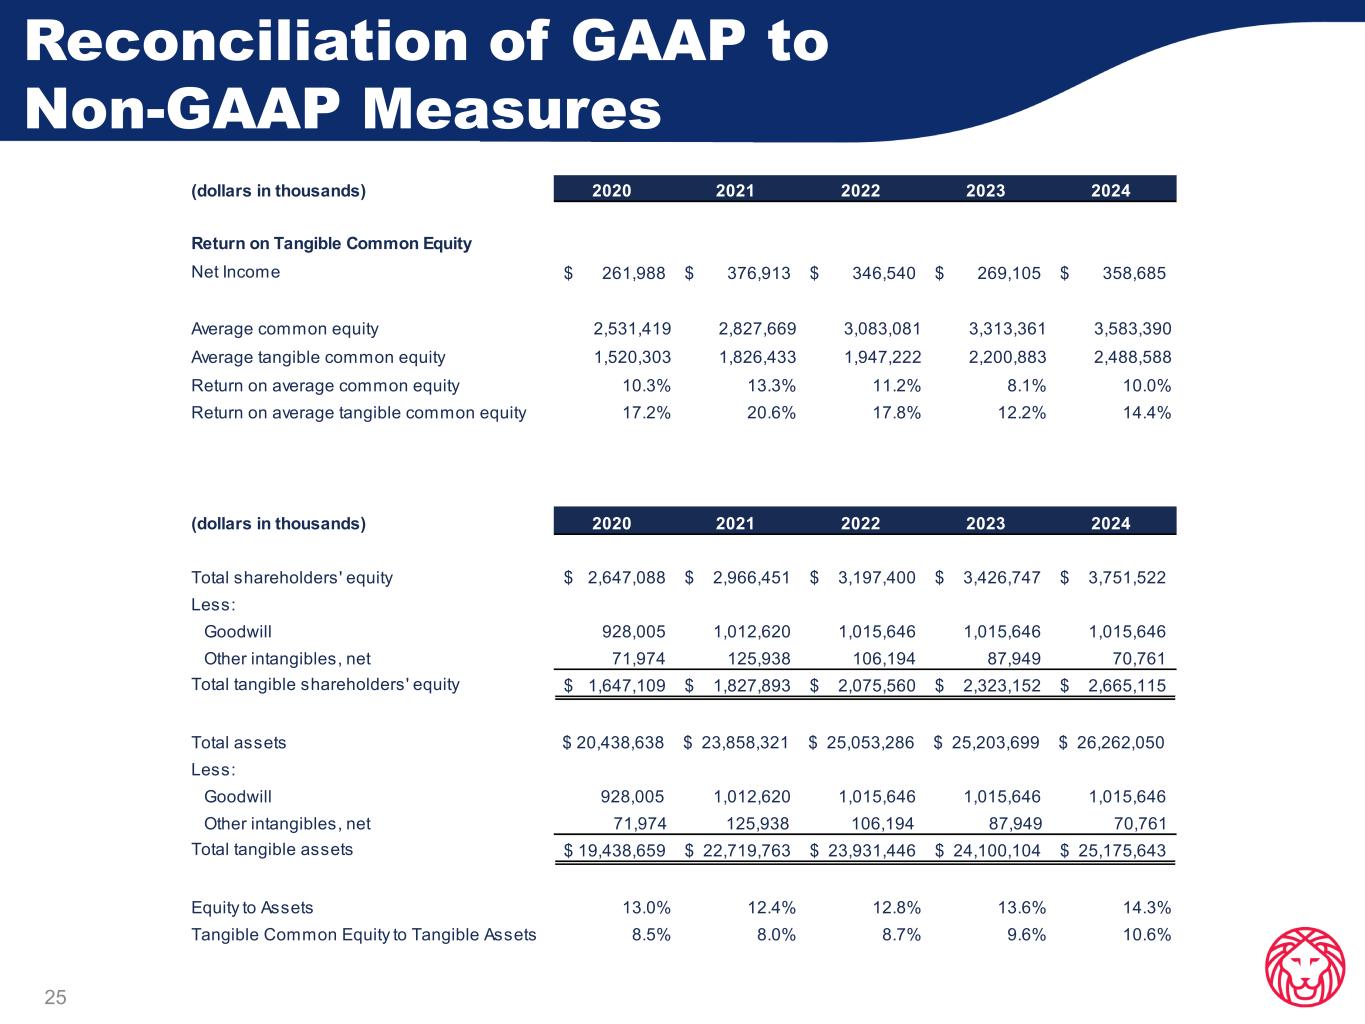
25 Reconciliation of GAAP to Non-GAAP Measures (dollars in thousands) 2020 2021 2022 2023 2024 Return on Tangible Common Equity Net Income 261,988$ 376,913$ 346,540$ 269,105$ 358,685$ Average common equity 2,531,419 2,827,669 3,083,081 3,313,361 3,583,390 Average tangible common equity 1,520,303 1,826,433 1,947,222 2,200,883 2,488,588 Return on average common equity 10.3% 13.3% 11.2% 8.1% 10.0% Return on average tangible common equity 17.2% 20.6% 17.8% 12.2% 14.4% (dollars in thousands) 2020 2021 2022 2023 2024 Total shareholders' equity 2,647,088$ 2,966,451$ 3,197,400$ 3,426,747$ 3,751,522$ Less: Goodwill 928,005 1,012,620 1,015,646 1,015,646 1,015,646 Other intangibles, net 71,974 125,938 106,194 87,949 70,761 Total tangible shareholders' equity 1,647,109$ 1,827,893$ 2,075,560$ 2,323,152$ 2,665,115$ Total assets $ 20,438,638 $ 23,858,321 $ 25,053,286 $ 25,203,699 $ 26,262,050 Less: Goodwill 928,005 1,012,620 1,015,646 1,015,646 1,015,646 Other intangibles, net 71,974 125,938 106,194 87,949 70,761 Total tangible assets 19,438,659$ 22,719,763$ 23,931,446$ 24,100,104$ 25,175,643$ Equity to Assets 13.0% 12.4% 12.8% 13.6% 14.3% Tangible Common Equity to Tangible Assets 8.5% 8.0% 8.7% 9.6% 10.6%
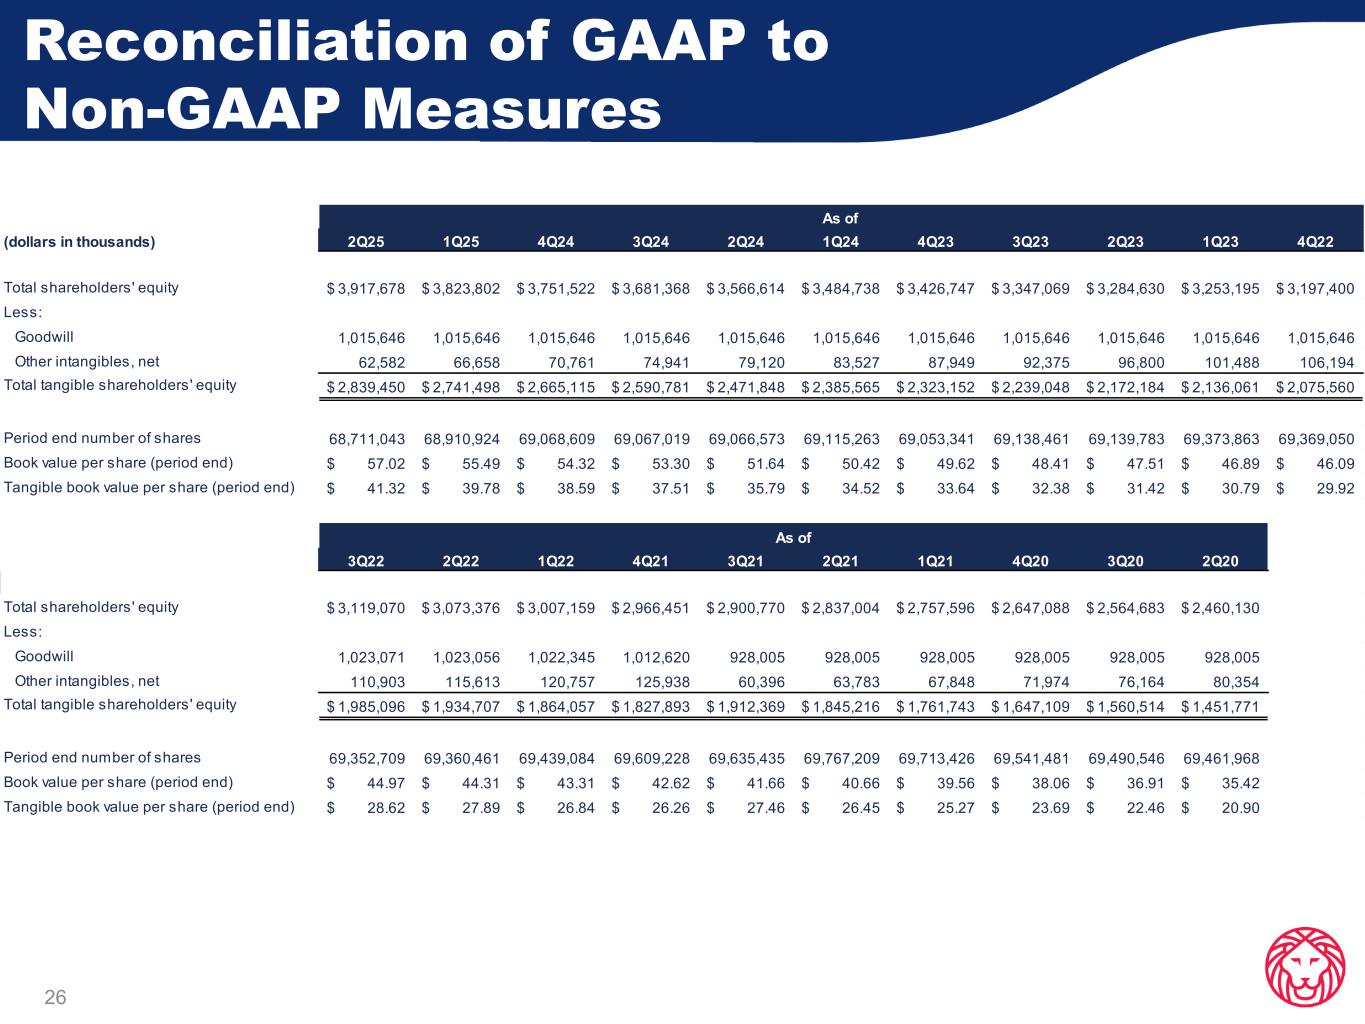
26 Reconciliation of GAAP to Non-GAAP Measures (dollars in thousands) 2Q25 1Q25 4Q24 3Q24 2Q24 1Q24 4Q23 3Q23 2Q23 1Q23 4Q22 Total shareholders' equity 3,917,678$ 3,823,802$ 3,751,522$ 3,681,368$ 3,566,614$ 3,484,738$ 3,426,747$ 3,347,069$ 3,284,630$ 3,253,195$ 3,197,400$ Less: Goodwill 1,015,646 1,015,646 1,015,646 1,015,646 1,015,646 1,015,646 1,015,646 1,015,646 1,015,646 1,015,646 1,015,646 Other intangibles, net 62,582 66,658 70,761 74,941 79,120 83,527 87,949 92,375 96,800 101,488 106,194 Total tangible shareholders' equity 2,839,450$ 2,741,498$ 2,665,115$ 2,590,781$ 2,471,848$ 2,385,565$ 2,323,152$ 2,239,048$ 2,172,184$ 2,136,061$ 2,075,560$ Period end number of shares 68,711,043 68,910,924 69,068,609 69,067,019 69,066,573 69,115,263 69,053,341 69,138,461 69,139,783 69,373,863 69,369,050 Book value per share (period end) 57.02$ 55.49$ 54.32$ 53.30$ 51.64$ 50.42$ 49.62$ 48.41$ 47.51$ 46.89$ 46.09$ Tangible book value per share (period end) 41.32$ 39.78$ 38.59$ 37.51$ 35.79$ 34.52$ 33.64$ 32.38$ 31.42$ 30.79$ 29.92$ 3Q22 2Q22 1Q22 4Q21 3Q21 2Q21 1Q21 4Q20 3Q20 2Q20 Total shareholders' equity 3,119,070$ 3,073,376$ 3,007,159$ 2,966,451$ 2,900,770$ 2,837,004$ 2,757,596$ 2,647,088$ 2,564,683$ 2,460,130$ Less: Goodwill 1,023,071 1,023,056 1,022,345 1,012,620 928,005 928,005 928,005 928,005 928,005 928,005 Other intangibles, net 110,903 115,613 120,757 125,938 60,396 63,783 67,848 71,974 76,164 80,354 Total tangible shareholders' equity 1,985,096$ 1,934,707$ 1,864,057$ 1,827,893$ 1,912,369$ 1,845,216$ 1,761,743$ 1,647,109$ 1,560,514$ 1,451,771$ Period end number of shares 69,352,709 69,360,461 69,439,084 69,609,228 69,635,435 69,767,209 69,713,426 69,541,481 69,490,546 69,461,968 Book value per share (period end) 44.97$ 44.31$ 43.31$ 42.62$ 41.66$ 40.66$ 39.56$ 38.06$ 36.91$ 35.42$ Tangible book value per share (period end) 28.62$ 27.89$ 26.84$ 26.26$ 27.46$ 26.45$ 25.27$ 23.69$ 22.46$ 20.90$ As of As of