
ABCB 8-K
Ameris Bancorp (ABCB)
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
|
Date of report (Date of earliest event reported): |
|
|
|
||
|
(Exact Name of Registrant as Specified in Charter)
|
||
|
|
|
|
|
(State or Other Jurisdiction of Incorporation) |
(Commission File Number) |
(IRS Employer Identification No.) |
|
|
|
|
(Address of Principal Executive Offices) |
(Zip Code)
|
|
Registrant’s telephone number, including area code: |
( |
|
|
|
(Former Name or Former Address, if Changed Since Last Report) |
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
Securities registered pursuant to Section 12(b) of the Act:
|
Title of each class |
Trading Symbol(s) |
Name of each exchange on which registered |
|
|
|
|
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition.
On April 23, 2020, Ameris Bancorp (the “Company”) issued a press release announcing its unaudited financial results for the quarter ended March 31, 2020. A copy of that press release is attached to this Current Report on Form 8-K (this “Report”) as Exhibit 99.1.
The information contained in this Item 2.02 and in Exhibit 99.1 attached to this Report is being furnished and shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of such section. Furthermore, such information shall not be deemed to be incorporated by reference into any registration statement or other document filed pursuant to the Securities Act of 1933, as amended.
Item 7.01 Regulation FD Disclosure.
A copy of the investor presentation material that the Company will present regarding its earnings during the teleconference beginning at 9:00 a.m. Eastern time on April 24, 2020 is attached to this Report as Exhibit 99.2. The investor presentation material is also available on the “Investor Relations” page of the Company’s website (http://www.amerisbank.com).
The information contained in this Item 7.01 and in Exhibit 99.2 attached to this Report is being furnished and shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of such section. Furthermore, such information shall not be deemed to be incorporated by reference into any registration statement or other document filed pursuant to the Securities Act of 1933, as amended.
Item 9.01 Financial Statements and Exhibits.
(d)Exhibits.
|
99.1 |
|
|
|
99.2 |
|
|
|
104 |
|
Cover Page Interactive Data File (embedded within the Inline XBRL document) |
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the registrant has duly caused this report to be signed on its behalf by the undersigned, hereunto duly authorized.
AMERIS BANCORP
|
By: |
/s/ Nicole S. Stokes |
|
|
Nicole S. Stokes |
|
|
Executive Vice President and Chief Financial Officer |
Date: April 23, 2020
Ameris Bancorp Announces Financial Results For First Quarter 2020
ATLANTA, April 23, 2020 /PRNewswire/ -- Ameris Bancorp (Nasdaq: ABCB) (the "Company") today reported net income of $19.3 million, or $0.28 per diluted share, for the quarter ended March 31, 2020, compared with $39.9 million, or $0.84 per diluted share, for the quarter ended March 31, 2019. The decline in net income is attributable to a $37.6 million increase in provision for loan loss expense and a $22.2 million servicing asset write-down in the first quarter of 2020. The Company reported adjusted net income of $39.2 million, or $0.56 per diluted share, for the quarter ended March 31, 2020, compared with $42.6 million, or $0.90 per diluted share, for the same period in 2019. Adjusted net income excludes after-tax merger and conversion charges, servicing right valuation adjustments, restructuring charges related to previously announced branch consolidations, certain legal expenses, loss on sale of bank premises and expenses related to natural disasters and the COVID-19 pandemic, but does not exclude the increased provision for credit losses.
Commenting on the Company's results, Palmer Proctor, the Company's Chief Executive Officer, said, "While this has certainly been a historically unprecedented quarter, I am proud that our company could absorb over $41 million of provision for credit loss expense and a $22 million write-down of our servicing assets and still produce net income of over $19 million. Our current allowance for loan loss ended the quarter at over $149 million, up from $38 million at year end, and our capital levels remain strong. We have committed bankers who continue to serve our customers and our communities through the COVID-19 pandemic and have been successful in lending $685 million under the Paycheck Protection Program ("PPP") in April. We are prepared to face the challenges of today's environment and we remain confident in our position for the future in these uncertain times."
On January 1, 2020, the Company adopted ASC 326, which provides for an expected credit loss model, referred to as the "Current Expected Credit Loss" ("CECL") model. The adoption of this standard resulted in the opening balances of the allowance for credit losses increasing $91.4 million and shareholders' equity decreasing $56.7 million. In addition, the Company recorded $41.0 million of provision for credit loss expense in the first quarter of 2020, of which $37.0 million was expense for loan credit losses and $4.0 million was for an increase in unfunded commitment reserve. Net charge-offs for the first quarter of 2020 were $4.4 million. As a result of these items, at March 31, 2020, the allowance for loan loss was $149.5 million, and the total allowance for credit losses was $167.3 million, compared with $38.2 million and $39.3 million, respectively, at December 31, 2019.
Significant items from the Company's results for the first quarter of 2020 include the following:
- Net income of $19.3 million, after pre-tax provision for credit losses of $41.0 million and servicing asset write-downs of $22.2 million
- Growth in adjusted total revenue of $12.9 million, or 6.1% when compared with the fourth quarter of 2019
- Adjusted efficiency ratio of 59.87%, compared with 55.61%, in the fourth quarter of 2019
- Adjusted return on average assets of 0.87%, compared with 1.47% in the fourth quarter of 2019
- Net interest margin of 3.70%, compared with 3.86% in the fourth quarter of 2019
- Improvement in deposit mix such that noninterest bearing deposits represent 30.53% of total deposits, up from 29.94% at December 31, 2019 and 28.09% a year ago
- Annualized net charge-offs of 0.14% of average total loans
- Non-performing assets of 0.61% of total assets, compared with 0.56% at the end of 2019
Following is a summary of the adjustments between reported net income and adjusted net income:
Adjusted Net Income Reconciliation |
|
|
| ||||
|
| Three Months Ended | ||||||
|
| March 31, | ||||||
(dollars in thousands, except per share data) | 2020 |
| 2019 | ||||
Net income available to common shareholders | $ | 19,322 |
|
| $ | 39,905 |
|
|
|
|
|
| ||||
Adjustment items: |
|
|
| ||||
Merger and conversion charges | 540 |
|
| 2,057 |
| ||
Restructuring charges | — |
|
| 245 |
| ||
Servicing right impairment | 22,165 |
|
| — |
| ||
Natural disaster and pandemic charges | 548 |
|
| (89) |
| ||
Expenses related to SEC and DOJ investigation | 1,443 |
|
| — |
| ||
Loss on sale of premises | 470 |
|
| 919 |
| ||
Tax effect of adjustment items | (5,283) |
|
| (450) |
| ||
After-tax adjustment items | 19,883 |
|
| 2,682 |
| ||
|
|
|
|
| ||||
Adjusted net income | $ | 39,205 |
|
| $ | 42,587 |
|
|
|
|
|
| ||||
Reported net income per diluted share | $ | 0.28 |
|
| $ | 0.84 |
|
Adjusted net income per diluted share | $ | 0.56 |
|
| $ | 0.90 |
|
|
|
|
|
| ||||
Reported return on average assets | 0.43 | % |
| 1.42 | % | ||
Adjusted return on average assets | 0.87 | % |
| 1.51 | % | ||
|
|
|
|
| ||||
Reported return on average common equity | 3.16 | % |
| 10.95 | % | ||
Adjusted return on average tangible common equity | 10.98 | % |
| 18.82 | % | ||
Net Interest Income and Net Interest Margin
Net interest income on a tax-equivalent basis for the first quarter of 2020 totaled $149.0 million, compared with $156.5 million for the fourth quarter of 2019 and $100.5 million for the first quarter of 2019. The Company's net interest margin was 3.70% for the first quarter of 2020, down from 3.86% reported for the fourth quarter of 2019 and 3.95% reported for the first quarter of 2019. The decrease in net interest margin in the current quarter is primarily attributable to decreases in accretion income and the yield on loans as market interest rates declined, partially offset by a decrease in the cost of interest-bearing liabilities. Accretion income for the first quarter of 2020 decreased to $6.6 million, compared with $9.7 million for the fourth quarter of 2019, and increased from $2.9 million for the first quarter of 2019. The decrease in accretion income in the
first quarter is primarily attributable to the successful resolution of an acquired non-performing loan during the fourth quarter of 2019 that had a substantial discount and stabilization in the level of payoffs of acquired loans.
Yields on all loans decreased to 5.02% during the first quarter of 2020, compared with 5.28% for the fourth quarter of 2019 and 5.37% reported for the first quarter of 2019. Loan production in the banking division during the first quarter of 2020 totaled $918.4 million, with weighted average yields of 4.55%, compared with $1.1 billion and 4.70%, respectively, in the fourth quarter of 2019 and $613.5 million and 5.78%, respectively, in the first quarter of 2019. Loan production in the lines of business (including retail mortgage, warehouse lending, SBA and premium finance) amounted to an additional $3.9 billion during the first quarter of 2020, with weighted average yields of 4.15%, compared with $4.1 billion and 4.29%, respectively, during the fourth quarter of 2019 and $1.9 billion and 5.47%, respectively, during the first quarter of 2019.
Interest expense during the first quarter of 2020 decreased to $34.8 million, compared with $38.7 million in the fourth quarter of 2019, and increased from $25.5 million in the first quarter of 2019. The Company's total cost of funds moved nine basis points lower to 0.91% in the first quarter of 2020 as compared with the fourth quarter of 2019. Deposit costs also decreased nine basis points during the first quarter of 2020 to 0.71%, compared with 0.80% in the fourth quarter of 2019. Costs of interest-bearing deposits decreased during the quarter from 1.13% in the fourth quarter of 2019 to 1.01% in the first quarter of 2020.
Noninterest Income
Noninterest income decreased $734,000, or 1.3%, in the first quarter of 2020 to $54.4 million, compared with $55.1 million for the fourth quarter of 2019, primarily as a result of decreased service charge revenue. Service charge revenue decreased $1.7 million, or 12.7%, to $11.8 million in the first quarter of 2020, compared with $13.6 million for the fourth quarter of 2019. This decrease was primarily attributable to a decline in interchange income of $626,000 and a decrease of $634,000 in NSF income resulting from a decrease in volume and a slight increase in waivers.
Mortgage banking activity increased $2.2 million, or 6.5%, to $35.3 million in the first quarter of 2020, compared with $33.2 million for the fourth quarter of 2019. This increase was a result of expansion in our gain on sale spread. Gain on sale spreads increased to 2.88% in the first quarter of 2020 from 2.60% for the fourth quarter of 2019. Total production in the retail mortgage division decreased to $1.36 billion in the first quarter of 2020, compared with $1.57 billion for the fourth quarter of 2019. Mortgage banking activity was negatively impacted during the first quarter of 2020 by a $20.9 million servicing right impairment, compared with an impairment of $104,000 for the fourth quarter of 2019. The retail mortgage open pipeline finished the first quarter of 2020 at $2.43 billion, compared with $1.16 billion at December 31, 2019.
Other noninterest income decreased $1.2 million, or 16.6%, in the first quarter of 2020 to $6.1 million, compared with $7.3 million for the fourth quarter of 2019, primarily as a result of an unfavorable fair value adjustment on our SBA servicing rights of $1.3 million for the first quarter of 2020.
Noninterest Expense
Noninterest expense increased $15.5 million, or 12.6%, to $138.1 million during the first quarter of 2020, compared with $122.6 million for the fourth quarter of 2019. During the first quarter of 2020, the Company recorded $3.0 million of charges to earnings, related to the previously announced SEC/DOJ investigations, merger and conversion charges, natural disaster and pandemic charges and loss on sale of premises, compared with $4.3 million in charges in the fourth quarter of 2019 that were related principally to merger and conversion charges and loss on sale of premises. Excluding these charges, adjusted expenses increased approximately $16.8 million, or 14.2%, to $135.1 million in the first quarter of 2020, from $118.3 million in the fourth quarter of 2019. The majority of this increase is attributable to variable expenses related to increased mortgage production and
seasonal increase in payroll tax expense, as well as increases in credit resolution-related expenses, professional fees and FDIC insurance. The Company continues to focus on its operating efficiency ratio. The Company's adjusted efficiency ratio increased from 55.61% in the fourth quarter of 2019 to 59.87% in the first quarter of 2020.
Income Tax Expense
The Company's effective tax rate for the first quarter of 2020 was 16.8%, compared with 25.5% in the fourth quarter of 2019. The decreased rate for the first quarter of 2020 was primarily a result of loss carrybacks allowed as a result of the recently enacted CARES Act. The elevated rate for the fourth quarter of 2019 resulted from a return to provision adjustment occurring when the Company filed its 2018 income tax returns during the fourth quarter of 2019 and additional tax expense in connection with merger-related compensation and acquired BOLI.
Balance Sheet Trends
Total assets at March 31, 2020 were $18.2 billion, which is essentially unchanged from December 31, 2019. Total loans, including loans held for sale, were $14.49 billion at March 31, 2020, compared with $14.48 billion at December 31, 2019. Total loans held for investment were $13.09 billion at March 31, 2020, compared with $12.82 billion at December 31, 2019. Loans held for investment increased $275.6 million, or 8.6% annualized, compared with December 31, 2019. Loan production in the banking division during the first quarter of 2020 was down 16% from the fourth quarter of 2019, but was 50% higher than the first quarter of 2019.
At March 31, 2020, total deposits amounted to $13.84 billion, or 89.2% of total funding, compared with $14.03 billion and 90.1%, respectively, at December 31, 2019. At March 31, 2020, noninterest-bearing deposit accounts were $4.23 billion, or 30.5% of total deposits, compared with $4.20 billion, or 29.9% of total deposits, at December 31, 2019. Non-rate sensitive deposits (including non-interest bearing, NOW and savings) totaled $7.14 billion at March 31, 2020, compared with $7.21 billion at December 31, 2019. These funds represented 51.6% of the Company's total deposits at March 31, 2020, compared with 51.4% at the end of 2019.
Shareholders' equity at March 31, 2020 totaled $2.44 billion, a decrease of $32.4 million, or 1.3%, from December 31, 2019. The decrease in shareholders' equity was primarily the result of the CECL adoption impact of $56.7 million and dividends declared, partially offset by earnings of $19.3 million during the first quarter of 2020. Tangible book value per share was $20.44 at March 31, 2020, compared with $20.81 at December 31, 2019. Tangible common equity as a percentage of tangible assets was 8.25% at March 31, 2020, compared with 8.40% at the end of the 2019.
Credit Quality
Credit quality remains strong in the Company. During the first quarter of 2020, the Company recorded provision for credit losses of $41.0 million, compared with $5.7 million in the fourth quarter of 2019. This increase in provision was primarily attributable to declines in forecasted economic conditions, particularly levels of unemployment and GDP, compared with conditions at the adoption of CECL. The Company has been prudently working with borrowers to support their credit needs during the challenging economic conditions and monitoring the level of modifications on a daily basis. Certain loans modified in response to the COVID-19 pandemic were downgraded to risk grade 5 out of an abundance of caution. Nonperforming assets as a percentage of total assets increased by five basis points to 0.61% during the quarter. The increase in nonperforming assets is primarily a
result of the migration of a small number of credits to nonaccrual and OREO and an increase in accruing loans delinquent 90 days or more in our premium finance division. The net charge-off ratio was 14 basis points for the first quarter of 2020, compared with nine basis points in the fourth quarter of 2019 and 17 basis points in the first quarter of 2019.
Conference Call
The Company will host a teleconference at 9:00 a.m. Eastern time Friday, April 24, 2020, to discuss the Company's results and answer appropriate questions. The conference call can be accessed by dialing 1-877-504-1190 (or 1-855-669-9657 for participants in Canada and 1-412-902-6630 for other international participants). The conference ID name is Ameris Bancorp ABCB. A replay of the call will be available one hour after the end of the conference call until May 8, 2020. To listen to the replay, dial 1-877-344-7529 (or 1-855-669-9658 for participants in Canada and 1-412-317-0088 for other international participants). The conference replay access code is 10142204. The conference call replay and the financial information discussed will also be available on the Investor Relations page of the Ameris Bank website at ir.amerisbank.com.
About Ameris Bancorp
Ameris Bancorp is a bank holding company headquartered in Atlanta, Georgia. The Company's banking subsidiary, Ameris Bank, had 170 locations in Georgia, Florida, South Carolina and Alabama at the end of the most recent quarter.
This news release contains certain performance measures determined by methods other than in accordance with accounting principles generally accepted in the United States of America ("GAAP"). The Company's management uses these non-GAAP measures in its analysis of the Company's performance. These measures are useful when evaluating the underlying performance and efficiency of the Company's operations and balance sheet. The Company's management believes that these non-GAAP measures provide a greater understanding of ongoing operations, enhance comparability of results with prior periods and demonstrate the effects of significant gains and charges in the current period. The Company's management believes that investors may use these non-GAAP financial measures to evaluate the Company's financial performance without the impact of unusual items that may obscure trends in the Company's underlying performance. These disclosures should not be viewed as a substitute for financial measures determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies.
This news release contains forward-looking statements, as defined by federal securities laws, including, among other forward-looking statements, certain plans, expectations and goals. Words such as "may," "believe," "expect," "anticipate," "intend," "will," "should," "plan," "estimate," "predict," "continue" and "potential" or the negative of these terms or other comparable terminology, as well as similar expressions, are meant to identify forward-looking statements. The forward-looking statements in this news release are based on current expectations and are provided to assist in the understanding of potential future performance. Such forward-looking statements involve numerous assumptions, risks and uncertainties that may cause actual results to differ materially from those expressed or implied in any such statements, including, without limitation, the following: general competitive, economic, political and market conditions and fluctuations; movements in interest rates and our expectations regarding net interest margin; expectations on credit quality and performance; legislative and regulatory changes; the impact of the COVID-19 pandemic on the general economy, our customers and the allowance for loan losses; the benefits that may be realized by our customers from government assistance programs and regulatory actions related to the COVID-19 pandemic; competitive pressures on product pricing and services; the cost savings and any revenue synergies expected to result from acquisition transactions, which may not be fully realized within the expected timeframes if at all; the success and timing of other business strategies; our outlook and long-term goals for future growth; and natural disasters, geopolitical events, public health crises and other catastrophic events beyond our control. For a discussion of some of the other risks and other factors that may cause such forward-looking statements to differ materially from actual results, please refer to the Company's filings with the Securities and Exchange Commission, including the Company's Annual Report on Form 10-K for the year ended December 31, 2019, as amended, and its subsequently filed periodic reports and other filings. Forward-looking statements speak only as of the date they are made, and the Company undertakes no obligation to update or revise forward-looking statements.
AMERIS BANCORP AND SUBSIDIARIES | ||||||||||||||||||||||||||||||||||||
FINANCIAL TABLES | ||||||||||||||||||||||||||||||||||||
|
| ||||||||||||||||||||||||||||||||||||
Financial Highlights | Table 1 | |||||||||||||||||||||||||||||||||||
|
| Three Months Ended | |||||||||||||||||||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | |||||||||||||||||||||||||||
(dollars in thousands except per share data) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | |||||||||||||||||||||||||||
EARNINGS |
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
Net income | $ | 19,322 |
|
| $ | 61,248 |
|
| $ | 21,384 |
|
| $ | 38,904 |
|
| $ | 39,905 |
| |||||||||||||||||
Adjusted net income | $ | 39,205 |
|
| $ | 66,608 |
|
| $ | 68,539 |
|
| $ | 45,210 |
|
| $ | 42,587 |
| |||||||||||||||||
|
|
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
COMMON SHARE DATA |
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
Earnings per share available to common shareholders |
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
Basic | $ | 0.28 |
|
| $ | 0.88 |
|
| $ | 0.31 |
|
| $ | 0.82 |
|
| $ | 0.84 |
| |||||||||||||||||
Diluted | $ | 0.28 |
|
| $ | 0.88 |
|
| $ | 0.31 |
|
| $ | 0.82 |
|
| $ | 0.84 |
| |||||||||||||||||
Adjusted diluted EPS | $ | 0.56 |
|
| $ | 0.96 |
|
| $ | 0.98 |
|
| $ | 0.96 |
|
| $ | 0.90 |
| |||||||||||||||||
Cash dividends per share | $ | 0.15 |
|
| $ | 0.15 |
|
| $ | 0.15 |
|
| $ | 0.10 |
|
| $ | 0.10 |
| |||||||||||||||||
Book value per share (period end) | $ | 35.10 |
|
| $ | 35.53 |
|
| $ | 34.78 |
|
| $ | 32.52 |
|
| $ | 31.43 |
| |||||||||||||||||
Tangible book value per share (period end) | $ | 20.44 |
|
| $ | 20.81 |
|
| $ | 20.29 |
|
| $ | 20.81 |
|
| $ | 19.73 |
| |||||||||||||||||
Weighted average number of shares |
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
Basic | 69,247,661 |
|
| 69,429,193 |
|
| 69,372,125 |
|
| 47,310,561 |
|
| 47,366,296 |
| ||||||||||||||||||||||
Diluted | 69,502,022 |
|
| 69,683,999 |
|
| 69,600,499 |
|
| 47,337,809 |
|
| 47,456,314 |
| ||||||||||||||||||||||
Period end number of shares | 69,441,274 |
|
| 69,503,833 |
|
| 69,593,833 |
|
| 47,261,584 |
|
| 47,585,309 |
| ||||||||||||||||||||||
Market data |
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
High intraday price | $ | 43.79 |
|
| $ | 44.90 |
|
| $ | 40.65 |
|
| $ | 39.60 |
|
| $ | 42.01 |
| |||||||||||||||||
Low intraday price | $ | 17.89 |
|
| $ | 38.34 |
|
| $ | 33.71 |
|
| $ | 33.57 |
|
| $ | 31.27 |
| |||||||||||||||||
Period end closing price | $ | 23.76 |
|
| $ | 42.54 |
|
| $ | 40.24 |
|
| $ | 39.19 |
|
| $ | 34.35 |
| |||||||||||||||||
Average daily volume | 461,692 |
|
| 353,783 |
|
| 461,289 |
|
| 352,684 |
|
| 387,800 |
| ||||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
PERFORMANCE RATIOS |
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
Return on average assets | 0.43 | % |
| 1.35 | % |
| 0.49 | % |
| 1.34 | % |
| 1.42 | % | ||||||||||||||||||||||
Adjusted return on average assets | 0.87 | % |
| 1.47 | % |
| 1.57 | % |
| 1.56 | % |
| 1.51 | % | ||||||||||||||||||||||
Return on average common equity | 3.16 | % |
| 9.97 | % |
| 3.49 | % |
| 10.27 | % |
| 10.95 | % | ||||||||||||||||||||||
Adjusted return on average tangible common equity | 10.98 | % |
| 18.45 | % |
| 18.95 | % |
| 18.79 | % |
| 18.82 | % | ||||||||||||||||||||||
Earning asset yield (TE) | 4.56 | % |
| 4.82 | % |
| 4.86 | % |
| 4.95 | % |
| 4.95 | % | ||||||||||||||||||||||
Total cost of funds | 0.91 | % |
| 1.00 | % |
| 1.07 | % |
| 1.10 | % |
| 1.05 | % | ||||||||||||||||||||||
Net interest margin (TE) | 3.70 | % |
| 3.86 | % |
| 3.84 | % |
| 3.91 | % |
| 3.95 | % | ||||||||||||||||||||||
Noninterest income excluding securities transactions, as a percent of total revenue (TE) | 22.83 | % |
| 22.02 | % |
| 28.89 | % |
| 21.27 | % |
| 19.59 | % | ||||||||||||||||||||||
Efficiency ratio | 68.23 | % |
| 58.24 | % |
| 85.35 | % |
| 59.36 | % |
| 57.95 | % | ||||||||||||||||||||||
Adjusted efficiency ratio (TE) | 59.87 | % |
| 55.61 | % |
| 57.25 | % |
| 53.77 | % |
| 55.12 | % | ||||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
CAPITAL ADEQUACY (period end) |
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
Shareholders' equity to assets | 13.37 | % |
| 13.54 | % |
| 13.63 | % |
| 12.93 | % |
| 12.83 | % | ||||||||||||||||||||||
Tangible common equity to tangible assets | 8.25 | % |
| 8.40 | % |
| 8.43 | % |
| 8.68 | % |
| 8.46 | % | ||||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
EQUITY TO ASSETS RECONCILIATION |
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
Tangible common equity to tangible assets | 8.25 | % |
| 8.40 | % |
| 8.43 | % |
| 8.68 | % |
| 8.46 | % | ||||||||||||||||||||||
Effect of goodwill and other intangibles | 5.12 | % |
| 5.14 | % |
| 5.20 | % |
| 4.25 | % |
| 4.37 | % | ||||||||||||||||||||||
Equity to assets (GAAP) | 13.37 | % |
| 13.54 | % |
| 13.63 | % |
| 12.93 | % |
| 12.83 | % | ||||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
OTHER DATA (period end) |
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
Full time equivalent employees |
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
Banking Division | 1,865 |
|
| 1,913 |
|
| 2,001 |
|
| 1,336 |
|
| 1,343 |
| ||||||||||||||||||||||
Retail Mortgage Division | 689 |
|
| 690 |
|
| 785 |
|
| 348 |
|
| 328 |
| ||||||||||||||||||||||
Warehouse Lending Division | 9 |
|
| 9 |
|
| 9 |
|
| 10 |
|
| 9 |
| ||||||||||||||||||||||
SBA Division | 44 |
|
| 42 |
|
| 45 |
|
| 21 |
|
| 22 |
| ||||||||||||||||||||||
Premium Finance Division | 72 |
|
| 68 |
|
| 66 |
|
| 62 |
|
| 64 |
| ||||||||||||||||||||||
Total Ameris Bancorp FTE headcount | 2,679 |
|
| 2,722 |
|
| 2,906 |
|
| 1,777 |
|
| 1,766 |
| ||||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
| |||||||||||||||||||||||||||
Assets per Banking Division FTE | $ | 9,772 |
|
| $ | 9,536 |
|
| $ | 8,878 |
|
| $ | 8,889 |
|
| $ | 8,679 |
| |||||||||||||||||
Branch locations | 170 |
|
| 170 |
|
| 172 |
|
| 114 |
|
| 114 |
| ||||||||||||||||||||||
Deposits per branch location | $ | 81,439 |
|
| $ | 82,512 |
|
| $ | 79,416 |
|
| $ | 84,056 |
|
| $ | 85,973 |
| |||||||||||||||||
AMERIS BANCORP AND SUBSIDIARIES |
| |||||||||||||||||||||||||||||||||||
FINANCIAL TABLES |
| |||||||||||||||||||||||||||||||||||
|
|
| |||||||||||||||||||||||||||||||||||
Income Statement | Table 2 |
| ||||||||||||||||||||||||||||||||||
|
| Three Months Ended |
| ||||||||||||||||||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar |
| ||||||||||||||||||||||||||
(dollars in thousands except per share data) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 |
| ||||||||||||||||||||||||||
Interest income |
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
Interest and fees on loans | $ | 171,242 |
|
| $ | 182,391 |
|
| $ | 175,046 |
|
| $ | 117,010 |
|
| $ | 112,401 |
|
| ||||||||||||||||
Interest on taxable securities | 10,082 |
|
| 10,358 |
|
| 11,354 |
|
| 9,383 |
|
| 9,043 |
|
| |||||||||||||||||||||
Interest on nontaxable securities | 157 |
|
| 167 |
|
| 168 |
|
| 102 |
|
| 156 |
|
| |||||||||||||||||||||
Interest on deposits in other banks | 1,211 |
|
| 1,091 |
|
| 1,622 |
|
| 2,276 |
|
| 3,150 |
|
| |||||||||||||||||||||
Interest on federal funds sold | 76 |
|
| 69 |
|
| 171 |
|
| 257 |
|
| 179 |
|
| |||||||||||||||||||||
Total interest income | 182,768 |
|
| 194,076 |
|
| 188,361 |
|
| 129,028 |
|
| 124,929 |
|
| |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
Interest expense |
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
Interest on deposits | 24,102 |
|
| 27,970 |
|
| 29,425 |
|
| 23,454 |
|
| 21,684 |
|
| |||||||||||||||||||||
Interest on other borrowings | 10,721 |
|
| 10,755 |
|
| 10,167 |
|
| 3,923 |
|
| 3,850 |
|
| |||||||||||||||||||||
Total interest expense | 34,823 |
|
| 38,725 |
|
| 39,592 |
|
| 27,377 |
|
| 25,534 |
|
| |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
Net interest income | 147,945 |
|
| 155,351 |
|
| 148,769 |
|
| 101,651 |
|
| 99,395 |
|
| |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
Provision for loan losses | 37,047 |
|
| 5,693 |
|
| 5,989 |
|
| 4,668 |
|
| 3,408 |
|
| |||||||||||||||||||||
Provision for unfunded commitments | 4,000 |
|
| — |
|
| — |
|
| — |
|
| — |
|
| |||||||||||||||||||||
Provision for credit losses | 41,047 |
|
| 5,693 |
|
| 5,989 |
|
| 4,668 |
|
| 3,408 |
|
| |||||||||||||||||||||
Net interest income after provision for credit losses | 106,898 |
|
| 149,658 |
|
| 142,780 |
|
| 96,983 |
|
| 95,987 |
|
| |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
Noninterest income |
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
Service charges on deposits accounts | 11,844 |
|
| 13,567 |
|
| 13,411 |
|
| 12,168 |
|
| 11,646 |
|
| |||||||||||||||||||||
Mortgage banking activity | 35,333 |
|
| 33,168 |
|
| 53,041 |
|
| 18,523 |
|
| 14,677 |
|
| |||||||||||||||||||||
Other service charges, commissions and fees | 1,128 |
|
| 1,085 |
|
| 1,236 |
|
| 803 |
|
| 789 |
|
| |||||||||||||||||||||
Gain (loss) on securities | (9) |
|
| (1) |
|
| 4 |
|
| 69 |
|
| 66 |
|
| |||||||||||||||||||||
Other noninterest income | 6,083 |
|
| 7,294 |
|
| 9,301 |
|
| 3,673 |
|
| 3,593 |
|
| |||||||||||||||||||||
Total noninterest income | 54,379 |
|
| 55,113 |
|
| 76,993 |
|
| 35,236 |
|
| 30,771 |
|
| |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
Noninterest expense |
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
Salaries and employee benefits | 75,946 |
|
| 69,642 |
|
| 77,633 |
|
| 38,331 |
|
| 38,332 |
|
| |||||||||||||||||||||
Occupancy and equipment expenses | 12,028 |
|
| 11,919 |
|
| 12,639 |
|
| 7,834 |
|
| 8,204 |
|
| |||||||||||||||||||||
Data processing and telecommunications expenses | 11,954 |
|
| 11,362 |
|
| 10,372 |
|
| 8,388 |
|
| 8,391 |
|
| |||||||||||||||||||||
Credit resolution related expenses(1) | 2,198 |
|
| 1,098 |
|
| 1,094 |
|
| 979 |
|
| 911 |
|
| |||||||||||||||||||||
Advertising and marketing expenses | 2,358 |
|
| 2,250 |
|
| 1,949 |
|
| 1,987 |
|
| 1,741 |
|
| |||||||||||||||||||||
Amortization of intangible assets | 5,631 |
|
| 5,741 |
|
| 5,719 |
|
| 3,121 |
|
| 3,132 |
|
| |||||||||||||||||||||
Merger and conversion charges | 540 |
|
| 2,415 |
|
| 65,158 |
|
| 3,475 |
|
| 2,057 |
|
| |||||||||||||||||||||
Other noninterest expenses | 27,398 |
|
| 18,137 |
|
| 18,133 |
|
| 17,136 |
|
| 12,657 |
|
| |||||||||||||||||||||
Total noninterest expense | 138,053 |
|
| 122,564 |
|
| 192,697 |
|
| 81,251 |
|
| 75,425 |
|
| |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
Income before income tax expense | 23,224 |
|
| 82,207 |
|
| 27,076 |
|
| 50,968 |
|
| 51,333 |
|
| |||||||||||||||||||||
Income tax expense | 3,902 |
|
| 20,959 |
|
| 5,692 |
|
| 12,064 |
|
| 11,428 |
|
| |||||||||||||||||||||
Net income (loss) | $ | 19,322 |
|
| $ | 61,248 |
|
| $ | 21,384 |
|
| $ | 38,904 |
|
| $ | 39,905 |
|
| ||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
Diluted earnings per common share | $ | 0.28 |
|
| $ | 0.88 |
|
| $ | 0.31 |
|
| $ | 0.82 |
|
| $ | 0.84 |
|
| ||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||||||||||||||||||
(1) Includes expenses associated with problem loans and OREO, as well as OREO losses and writedowns. |
| |||||||||||||||||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||
FINANCIAL TABLES | |||||||||||||||||||
|
| |||||||||||||||||||
Period End Balance Sheet | Table 3 | ||||||||||||||||||
|
| Three Months Ended | ||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | ||||||||||
(dollars in thousands) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | ||||||||||
Assets |
|
|
|
|
|
|
|
|
| ||||||||||
Cash and due from banks | $ | 255,312 |
|
| $ | 246,234 |
|
| $ | 193,976 |
|
| $ | 151,186 |
|
| $ | 144,801 |
|
Federal funds sold and interest-bearing deposits in banks | 396,844 |
|
| 375,615 |
|
| 285,713 |
|
| 186,969 |
|
| 712,199 |
| |||||
Time deposits in other banks | 249 |
|
| 249 |
|
| 499 |
|
| 748 |
|
| 7,371 |
| |||||
Investment securities available for sale, at fair value | 1,353,040 |
|
| 1,403,403 |
|
| 1,491,207 |
|
| 1,273,244 |
|
| 1,234,435 |
| |||||
Other investments | 81,754 |
|
| 66,919 |
|
| 66,921 |
|
| 32,481 |
|
| 15,157 |
| |||||
Loans held for sale, at fair value | 1,398,229 |
|
| 1,656,711 |
|
| 1,187,551 |
|
| 261,073 |
|
| 112,070 |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Loans, net of unearned income | 13,094,106 |
|
| 12,818,476 |
|
| 12,826,284 |
|
| 9,049,870 |
|
| 8,482,339 |
| |||||
Allowance for loan losses | (149,524) |
|
| (38,189) |
|
| (35,530) |
|
| (31,793) |
|
| (28,659) |
| |||||
Loans, net | 12,944,582 |
|
| 12,780,287 |
|
| 12,790,754 |
|
| 9,018,077 |
|
| 8,453,680 |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Other real estate owned | 21,027 |
|
| 19,500 |
|
| 20,710 |
|
| 14,675 |
|
| 16,871 |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Premises and equipment, net | 231,347 |
|
| 233,102 |
|
| 239,428 |
|
| 141,378 |
|
| 141,698 |
| |||||
Goodwill | 931,947 |
|
| 931,637 |
|
| 911,488 |
|
| 501,140 |
|
| 501,308 |
| |||||
Other intangible assets, net | 85,955 |
|
| 91,586 |
|
| 97,328 |
|
| 52,437 |
|
| 55,557 |
| |||||
Cash value of bank owned life insurance | 176,239 |
|
| 175,270 |
|
| 174,442 |
|
| 105,064 |
|
| 104,597 |
| |||||
Deferred income taxes, net | 24,196 |
|
| 2,180 |
|
| 22,111 |
|
| 30,812 |
|
| 33,295 |
| |||||
Other assets | 323,827 |
|
| 259,886 |
|
| 282,149 |
|
| 120,052 |
|
| 123,236 |
| |||||
Total assets | $ | 18,224,548 |
|
| $ | 18,242,579 |
|
| $ | 17,764,277 |
|
| $ | 11,889,336 |
|
| $ | 11,656,275 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Liabilities |
|
|
|
|
|
|
|
|
| ||||||||||
Deposits |
|
|
|
|
|
|
|
|
| ||||||||||
Noninterest-bearing | $ | 4,226,253 |
|
| $ | 4,199,448 |
|
| $ | 4,077,856 |
|
| $ | 2,771,443 |
|
| $ | 2,753,173 |
|
Interest-bearing | 9,618,365 |
|
| 9,827,625 |
|
| 9,581,738 |
|
| 6,810,927 |
|
| 7,047,702 |
| |||||
Total deposits | 13,844,618 |
|
| 14,027,073 |
|
| 13,659,594 |
|
| 9,582,370 |
|
| 9,800,875 |
| |||||
Federal funds purchased and securities sold under agreements to repurchase | 15,160 |
|
| 20,635 |
|
| 17,744 |
|
| 3,307 |
|
| 4,259 |
| |||||
Other borrowings | 1,543,371 |
|
| 1,398,709 |
|
| 1,351,172 |
|
| 564,636 |
|
| 151,454 |
| |||||
Subordinated deferrable interest debentures | 122,890 |
|
| 127,560 |
|
| 127,075 |
|
| 89,871 |
|
| 89,529 |
| |||||
FDIC loss-share payable, net | 18,111 |
|
| 19,642 |
|
| 19,490 |
|
| 20,596 |
|
| 18,834 |
| |||||
Other liabilities | 243,248 |
|
| 179,378 |
|
| 168,479 |
|
| 91,435 |
|
| 95,740 |
| |||||
Total liabilities | 15,787,398 |
|
| 15,772,997 |
|
| 15,343,554 |
|
| 10,352,215 |
|
| 10,160,691 |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Shareholders' Equity |
|
|
|
|
|
|
|
|
| ||||||||||
Preferred stock | — |
|
| — |
|
| — |
|
| — |
|
| — |
| |||||
Common stock | 71,652 |
|
| 71,500 |
|
| 71,447 |
|
| 49,099 |
|
| 49,126 |
| |||||
Capital stock | 1,908,721 |
|
| 1,907,108 |
|
| 1,904,789 |
|
| 1,053,500 |
|
| 1,053,190 |
| |||||
Retained earnings | 460,153 |
|
| 507,950 |
|
| 457,127 |
|
| 446,182 |
|
| 412,005 |
| |||||
Accumulated other comprehensive income (loss), net of tax | 39,551 |
|
| 17,995 |
|
| 15,482 |
|
| 16,462 |
|
| (1,178) |
| |||||
Treasury stock | (42,927) |
|
| (34,971) |
|
| (28,122) |
|
| (28,122) |
|
| (17,559) |
| |||||
Total shareholders' equity | 2,437,150 |
|
| 2,469,582 |
|
| 2,420,723 |
|
| 1,537,121 |
|
| 1,495,584 |
| |||||
Total liabilities and shareholders' equity | $ | 18,224,548 |
|
| $ | 18,242,579 |
|
| $ | 17,764,277 |
|
| $ | 11,889,336 |
|
| $ | 11,656,275 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Other Data |
|
|
|
|
|
|
|
|
| ||||||||||
Earning assets | $ | 16,324,222 |
|
| $ | 16,321,373 |
|
| $ | 15,858,175 |
|
| $ | 10,804,385 |
|
| $ | 10,563,571 |
|
Intangible assets | 1,017,902 |
|
| 1,023,223 |
|
| 1,008,816 |
|
| 553,577 |
|
| 556,865 |
| |||||
Interest-bearing liabilities | 11,299,786 |
|
| 11,374,529 |
|
| 11,077,729 |
|
| 7,468,741 |
|
| 7,292,944 |
| |||||
Average assets | 18,056,445 |
|
| 17,998,494 |
|
| 17,340,387 |
|
| 11,625,344 |
|
| 11,423,677 |
| |||||
Average common shareholders' equity | 2,456,617 |
|
| 2,437,272 |
|
| 2,432,182 |
|
| 1,519,598 |
|
| 1,478,462 |
| |||||
AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||
FINANCIAL TABLES | |||||||||||||||||||
|
| |||||||||||||||||||
Asset Quality Information | Table 4 | ||||||||||||||||||
|
| Three Months Ended | ||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | ||||||||||
(dollars in thousands) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | ||||||||||
Allowance for Credit Losses |
|
|
|
|
|
|
|
|
| ||||||||||
Balance at beginning of period | $ | 39,266 |
|
| $ | 36,607 |
|
| $ | 31,793 |
|
| $ | 28,659 |
|
| $ | 28,819 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
CECL adoption impact on allowance for loan losses | 78,660 |
|
| — |
|
| — |
|
| — |
|
| — |
| |||||
CECL adoption impact on allowance for unfunded commitments | 12,714 |
|
| — |
|
| — |
|
| — |
|
| — |
| |||||
Total CECL adoption impact | 91,374 |
|
| — |
|
| — |
|
| — |
|
| — |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Acquisition accounting impact | — |
|
| — |
|
| 1,077 |
|
| — |
|
| — |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Provision for loan losses | 37,047 |
|
| 5,693 |
|
| 5,989 |
|
| 4,668 |
|
| 3,408 |
| |||||
Provision for unfunded commitments | 4,000 |
|
| — |
|
| — |
|
| — |
|
| — |
| |||||
Provision for credit losses | 41,047 |
|
| 5,693 |
|
| 5,989 |
|
| 4,668 |
|
| 3,408 |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Charge-offs | 6,717 |
|
| 5,664 |
|
| 5,249 |
|
| 3,496 |
|
| 5,379 |
| |||||
Recoveries | 2,345 |
|
| 2,630 |
|
| 2,997 |
|
| 1,962 |
|
| 1,811 |
| |||||
Net charge-offs | 4,372 |
|
| 3,034 |
|
| 2,252 |
|
| 1,534 |
|
| 3,568 |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Ending balance | $ | 167,315 |
|
| $ | 39,266 |
|
| $ | 36,607 |
|
| $ | 31,793 |
|
| $ | 28,659 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Allowance for loan losses | $ | 149,524 |
|
| $ | 38,189 |
|
| $ | 35,530 |
|
| $ | 31,793 |
|
| $ | 28,659 |
|
Allowance for unfunded commitments | 17,791 |
|
| 1,077 |
|
| 1,077 |
|
| — |
|
| — |
| |||||
Total allowance for credit losses | $ | 167,315 |
|
| $ | 39,266 |
|
| $ | 36,607 |
|
| $ | 31,793 |
|
| $ | 28,659 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Net Charge-off Information |
|
|
|
|
|
|
|
|
| ||||||||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Charge-offs |
|
|
|
|
|
|
|
|
| ||||||||||
Commercial, financial and agricultural | $ | 3,316 |
|
| $ | 2,713 |
|
| $ | 1,757 |
|
| $ | 1,337 |
|
| $ | 2,004 |
|
Real estate - construction and development | — |
|
| 145 |
|
| — |
|
| 244 |
|
| 25 |
| |||||
Real estate - commercial and farmland | 927 |
|
| 181 |
|
| 1,318 |
|
| 589 |
|
| 1,254 |
| |||||
Real estate - residential | 100 |
|
| 100 |
|
| 37 |
|
| 155 |
|
| 199 |
| |||||
Consumer installment | 2,374 |
|
| 2,525 |
|
| 2,210 |
|
| 1,171 |
|
| 1,897 |
| |||||
Total charge-offs | 6,717 |
|
| 5,664 |
|
| 5,322 |
|
| 3,496 |
|
| 5,379 |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Recoveries |
|
|
|
|
|
|
|
|
| ||||||||||
Commercial, financial and agricultural | 1,046 |
|
| 1,293 |
|
| 1,036 |
|
| 1,032 |
|
| 1,233 |
| |||||
Real estate - construction and development | 342 |
|
| 429 |
|
| 930 |
|
| 269 |
|
| 117 |
| |||||
Real estate - commercial and farmland | 85 |
|
| 140 |
|
| 74 |
|
| 78 |
|
| 39 |
| |||||
Real estate - residential | 207 |
|
| 67 |
|
| 169 |
|
| 294 |
|
| 207 |
| |||||
Consumer installment | 665 |
|
| 701 |
|
| 861 |
|
| 289 |
|
| 215 |
| |||||
Total recoveries | 2,345 |
|
| 2,630 |
|
| 3,070 |
|
| 1,962 |
|
| 1,811 |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Net charge-offs | $ | 4,372 |
|
| $ | 3,034 |
|
| $ | 2,252 |
|
| $ | 1,534 |
|
| $ | 3,568 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Non-Performing Assets |
|
|
|
|
|
|
|
|
| ||||||||||
Nonaccrual loans | $ | 77,866 |
|
| $ | 75,124 |
|
| $ | 100,501 |
|
| $ | 41,479 |
|
| $ | 41,879 |
|
Other real estate owned | 21,027 |
|
| 19,500 |
|
| 20,710 |
|
| 14,675 |
|
| 16,871 |
| |||||
Repossessed assets | 783 |
|
| 939 |
|
| 1,258 |
|
| — |
|
| — |
| |||||
Accruing loans delinquent 90 days or more | 11,969 |
|
| 5,754 |
|
| 6,325 |
|
| 4,613 |
|
| 3,676 |
| |||||
Total non-performing assets | $ | 111,645 |
|
| $ | 101,317 |
|
| $ | 128,794 |
|
| $ | 60,767 |
|
| $ | 62,426 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Asset Quality Ratios |
|
|
|
|
|
|
|
|
| ||||||||||
Non-performing assets as a percent of total assets | 0.61 | % |
| 0.56 | % |
| 0.73 | % |
| 0.51 | % |
| 0.54 | % | |||||
Net charge-offs as a percent of average loans (annualized) | 0.14 | % |
| 0.09 | % |
| 0.07 | % |
| 0.07 | % |
| 0.17 | % | |||||
AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||
FINANCIAL TABLES | |||||||||||||||||||
|
| |||||||||||||||||||
Loan Information | Table 5 | ||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | ||||||||||
(dollars in thousands) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | ||||||||||
Loans by Type |
|
|
|
|
|
|
|
|
| ||||||||||
Commercial, financial and agricultural | $ | 2,246,927 |
|
| $ | 2,030,711 |
|
| $ | 2,166,592 |
|
| $ | 1,900,811 |
|
| $ | 1,710,879 |
|
Real estate - construction and development | 1,628,367 |
|
| 1,549,061 |
|
| 1,468,695 |
|
| 1,103,550 |
|
| 915,976 |
| |||||
Real estate - commercial and farmland | 4,516,451 |
|
| 4,353,039 |
|
| 4,209,912 |
|
| 3,182,213 |
|
| 3,175,452 |
| |||||
Real estate - residential | 3,252,090 |
|
| 3,334,831 |
|
| 3,380,356 |
|
| 2,389,101 |
|
| 2,216,927 |
| |||||
Consumer installment | 1,450,271 |
|
| 1,550,834 |
|
| 1,600,729 |
|
| 474,195 |
|
| 463,105 |
| |||||
Total loans | $ | 13,094,106 |
|
| $ | 12,818,476 |
|
| $ | 12,826,284 |
|
| $ | 9,049,870 |
|
| $ | 8,482,339 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Troubled Debt Restructurings |
|
|
|
|
|
|
|
|
| ||||||||||
Accruing troubled debt restructurings |
|
|
|
|
|
|
|
|
| ||||||||||
Commercial, financial and agricultural | $ | 798 |
|
| $ | 672 |
|
| $ | 680 |
|
| $ | 331 |
|
| $ | 147 |
|
Real estate - construction and development | 925 |
|
| 936 |
|
| 947 |
|
| 1,124 |
|
| 1,153 |
| |||||
Real estate - commercial and farmland | 5,587 |
|
| 6,732 |
|
| 8,617 |
|
| 8,793 |
|
| 9,058 |
| |||||
Real estate - residential | 29,021 |
|
| 21,261 |
|
| 21,472 |
|
| 21,124 |
|
| 20,537 |
| |||||
Consumer installment | 4 |
|
| 8 |
|
| 9 |
|
| 10 |
|
| 11 |
| |||||
Total accruing troubled debt restructurings | $ | 36,335 |
|
| $ | 29,609 |
|
| $ | 31,725 |
|
| $ | 31,382 |
|
| $ | 30,906 |
|
Nonaccrual troubled debt restructurings |
|
|
|
|
|
|
|
|
| ||||||||||
Commercial, financial and agricultural | $ | 335 |
|
| $ | 335 |
|
| $ | 144 |
|
| $ | 162 |
|
| $ | 167 |
|
Real estate - construction and development | 289 |
|
| 253 |
|
| 258 |
|
| 265 |
|
| 270 |
| |||||
Real estate - commercial and farmland | 2,415 |
|
| 2,071 |
|
| 1,958 |
|
| 2,109 |
|
| 2,027 |
| |||||
Real estate - residential | 3,992 |
|
| 2,857 |
|
| 2,103 |
|
| 1,760 |
|
| 1,749 |
| |||||
Consumer installment | 105 |
|
| 107 |
|
| 120 |
|
| 123 |
|
| 113 |
| |||||
Total nonaccrual troubled debt restructurings | $ | 7,136 |
|
| $ | 5,623 |
|
| $ | 4,583 |
|
| $ | 4,419 |
|
| $ | 4,326 |
|
Total troubled debt restructurings | $ | 43,471 |
|
| $ | 35,232 |
|
| $ | 36,308 |
|
| $ | 35,801 |
|
| $ | 35,232 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Loans by Risk Grade |
|
|
|
|
|
|
|
|
| ||||||||||
Grade 1 - Prime credit | $ | 774,956 |
|
| $ | 587,877 |
|
| $ | 613,281 |
|
| $ | 622,034 |
|
| $ | 621,328 |
|
Grade 2 - Strong credit | 785,770 |
|
| 840,372 |
|
| 856,618 |
|
| 811,690 |
|
| 672,526 |
| |||||
Grade 3 - Good credit | 5,772,834 |
|
| 6,034,398 |
|
| 6,086,576 |
|
| 3,829,422 |
|
| 3,303,143 |
| |||||
Grade 4 - Satisfactory credit | 4,353,733 |
|
| 4,884,541 |
|
| 4,746,020 |
|
| 3,401,265 |
|
| 3,517,166 |
| |||||
Grade 5 - Fair credit | 1,131,128 |
|
| 233,020 |
|
| 252,424 |
|
| 211,229 |
|
| 178,176 |
| |||||
Grade 6 - Other assets especially mentioned | 106,885 |
|
| 86,412 |
|
| 114,235 |
|
| 64,075 |
|
| 71,548 |
| |||||
Grade 7 - Substandard | 168,561 |
|
| 151,846 |
|
| 157,114 |
|
| 110,152 |
|
| 118,446 |
| |||||
Grade 8 - Doubtful | 239 |
|
| 8 |
|
| 14 |
|
| — |
|
| — |
| |||||
Grade 9 - Loss | — |
|
| 2 |
|
| 2 |
|
| 3 |
|
| 6 |
| |||||
Total loans | $ | 13,094,106 |
|
| $ | 12,818,476 |
|
| $ | 12,826,284 |
|
| $ | 9,049,870 |
|
| $ | 8,482,339 |
|
AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||
FINANCIAL TABLES | |||||||||||||||||||
|
| |||||||||||||||||||
Average Balances | Table 6 | ||||||||||||||||||
|
| Three Months Ended | ||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | ||||||||||
(dollars in thousands) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | ||||||||||
Earning Assets |
|
|
|
|
|
|
|
|
| ||||||||||
Federal funds sold | $ | 27,380 |
|
| $ | 23,104 |
|
| $ | 28,459 |
|
| $ | 41,683 |
|
| $ | 31,291 |
|
Interest-bearing deposits in banks | 419,260 |
|
| 304,427 |
|
| 324,127 |
|
| 341,937 |
|
| 467,379 |
| |||||
Time deposits in other banks | 249 |
|
| 401 |
|
| 548 |
|
| 3,792 |
|
| 10,221 |
| |||||
Investment securities - taxable | 1,359,651 |
|
| 1,426,062 |
|
| 1,514,534 |
|
| 1,233,297 |
|
| 1,186,896 |
| |||||
Investment securities - nontaxable | 22,839 |
|
| 23,580 |
|
| 23,759 |
|
| 15,288 |
|
| 24,136 |
| |||||
Other investments | 73,972 |
|
| 64,852 |
|
| 53,712 |
|
| 15,830 |
|
| 14,532 |
| |||||
Loans held for sale | 1,587,131 |
|
| 1,537,648 |
|
| 856,572 |
|
| 154,707 |
|
| 101,521 |
| |||||
Loans | 12,712,997 |
|
| 12,697,912 |
|
| 12,677,063 |
|
| 8,740,561 |
|
| 8,483,978 |
| |||||
Total Earning Assets | $ | 16,203,479 |
|
| $ | 16,077,986 |
|
| $ | 15,478,774 |
|
| $ | 10,547,095 |
|
| $ | 10,319,954 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Deposits |
|
|
|
|
|
|
|
|
| ||||||||||
Noninterest-bearing deposits | $ | 4,080,920 |
|
| $ | 4,124,872 |
|
| $ | 4,040,592 |
|
| $ | 2,723,843 |
|
| $ | 2,545,043 |
|
NOW accounts | 2,287,947 |
|
| 2,204,666 |
|
| 2,049,175 |
|
| 1,506,721 |
|
| 1,553,988 |
| |||||
MMDA | 4,004,644 |
|
| 3,953,717 |
|
| 3,815,185 |
|
| 2,655,108 |
|
| 2,677,015 |
| |||||
Savings accounts | 643,422 |
|
| 649,118 |
|
| 661,555 |
|
| 405,506 |
|
| 399,089 |
| |||||
Retail CDs | 2,624,209 |
|
| 2,721,829 |
|
| 2,804,243 |
|
| 1,962,422 |
|
| 1,892,138 |
| |||||
Brokered CDs | 61,190 |
|
| 249,644 |
|
| 150,176 |
|
| 486,292 |
|
| 510,301 |
| |||||
Total Deposits | 13,702,332 |
|
| 13,903,846 |
|
| 13,520,926 |
|
| 9,739,892 |
|
| 9,577,574 |
| |||||
Non-Deposit Funding |
|
|
|
|
|
|
|
|
| ||||||||||
Federal funds purchased and securities sold under agreements to repurchase | 15,637 |
|
| 17,088 |
|
| 19,914 |
|
| 3,213 |
|
| 15,879 |
| |||||
FHLB advances | 1,267,303 |
|
| 1,080,516 |
|
| 810,384 |
|
| 22,390 |
|
| 6,257 |
| |||||
Other borrowings | 269,454 |
|
| 234,001 |
|
| 220,918 |
|
| 145,453 |
|
| 145,473 |
| |||||
Subordinated deferrable interest debentures | 127,731 |
|
| 127,292 |
|
| 133,519 |
|
| 89,686 |
|
| 89,343 |
| |||||
Total Non-Deposit Funding | 1,680,125 |
|
| 1,458,897 |
|
| 1,184,735 |
|
| 260,742 |
|
| 256,952 |
| |||||
Total Funding | $ | 15,382,457 |
|
| $ | 15,362,743 |
|
| $ | 14,705,661 |
|
| $ | 10,000,634 |
|
| $ | 9,834,526 |
|
AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||
FINANCIAL TABLES | |||||||||||||||||||
|
| |||||||||||||||||||
Interest Income and Interest Expense (TE) | Table 7 | ||||||||||||||||||
|
| Three Months Ended | ||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | ||||||||||
(dollars in thousands) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | ||||||||||
Interest Income |
|
|
|
|
|
|
|
|
| ||||||||||
Federal funds sold | $ | 76 |
|
| $ | 69 |
|
| $ | 171 |
|
| $ | 257 |
|
| $ | 179 |
|
Interest-bearing deposits in banks | 1,210 |
|
| 1,089 |
|
| 1,620 |
|
| 2,260 |
|
| 3,099 |
| |||||
Time deposits in other banks | 1 |
|
| 2 |
|
| 2 |
|
| 16 |
|
| 51 |
| |||||
Investment securities - taxable | 10,082 |
|
| 10,358 |
|
| 11,354 |
|
| 9,383 |
|
| 9,043 |
| |||||
Investment securities - nontaxable (TE) | 199 |
|
| 212 |
|
| 213 |
|
| 129 |
|
| 197 |
| |||||
Loans held for sale | 13,637 |
|
| 14,330 |
|
| 7,889 |
|
| 1,632 |
|
| 1,152 |
| |||||
Loans (TE) | 158,636 |
|
| 169,119 |
|
| 168,239 |
|
| 116,413 |
|
| 112,266 |
| |||||
Total Earning Assets | $ | 183,841 |
|
| $ | 195,179 |
|
| $ | 189,488 |
|
| $ | 130,090 |
|
| $ | 125,987 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Accretion income (included above) | $ | 6,562 |
|
| $ | 9,727 |
|
| $ | 4,222 |
|
| $ | 3,103 |
|
| $ | 2,883 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Interest Expense |
|
|
|
|
|
|
|
|
| ||||||||||
Interest-Bearing Deposits |
|
|
|
|
|
|
|
|
| ||||||||||
NOW accounts | $ | 2,774 |
|
| $ | 2,728 |
|
| $ | 2,843 |
|
| $ | 2,260 |
|
| $ | 2,109 |
|
MMDA | 9,748 |
|
| 11,311 |
|
| 12,593 |
|
| 9,488 |
|
| 9,047 |
| |||||
Savings accounts | 210 |
|
| 233 |
|
| 274 |
|
| 85 |
|
| 77 |
| |||||
Retail CDs | 11,064 |
|
| 12,220 |
|
| 12,905 |
|
| 8,585 |
|
| 7,330 |
| |||||
Brokered CDs | 306 |
|
| 1,478 |
|
| 810 |
|
| 3,036 |
|
| 3,121 |
| |||||
Total Interest-Bearing Deposits | 24,102 |
|
| 27,970 |
|
| 29,425 |
|
| 23,454 |
|
| 21,684 |
| |||||
Non-Deposit Funding |
|
|
|
|
|
|
|
|
| ||||||||||
Federal funds purchased and securities sold under agreements to repurchase | 40 |
|
| 41 |
|
| 32 |
|
| 2 |
|
| 11 |
| |||||
FHLB advances | 5,109 |
|
| 5,241 |
|
| 4,618 |
|
| 141 |
|
| 44 |
| |||||
Other borrowings | 3,511 |
|
| 3,358 |
|
| 3,332 |
|
| 2,210 |
|
| 2,227 |
| |||||
Subordinated deferrable interest debentures | 2,061 |
|
| 2,115 |
|
| 2,185 |
|
| 1,570 |
|
| 1,568 |
| |||||
Total Non-Deposit Funding | 10,721 |
|
| 10,755 |
|
| 10,167 |
|
| 3,923 |
|
| 3,850 |
| |||||
Total Interest-Bearing Funding | $ | 34,823 |
|
| $ | 38,725 |
|
| $ | 39,592 |
|
| $ | 27,377 |
|
| $ | 25,534 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Net Interest Income (TE) | $ | 149,018 |
|
| $ | 156,454 |
|
| $ | 149,896 |
|
| $ | 102,713 |
|
| $ | 100,453 |
|
AMERIS BANCORP AND SUBSIDIARIES | ||||||||||||||
FINANCIAL TABLES | ||||||||||||||
|
| ||||||||||||||
Yields(1) | Table 8 | |||||||||||||
|
| Three Months Ended | |||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | |||||
|
| 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | |||||
Earning Assets |
|
|
|
|
|
|
|
|
| |||||
Federal funds sold | 1.12 | % |
| 1.18 | % |
| 2.38 | % |
| 2.47 | % |
| 2.32 | % |
Interest-bearing deposits in banks | 1.16 | % |
| 1.42 | % |
| 1.98 | % |
| 2.65 | % |
| 2.69 | % |
Time deposits in other banks | 1.62 | % |
| 1.98 | % |
| 1.45 | % |
| 1.69 | % |
| 2.02 | % |
Investment securities - taxable | 2.98 | % |
| 2.88 | % |
| 2.97 | % |
| 3.05 | % |
| 3.09 | % |
Investment securities - nontaxable (TE) | 3.50 | % |
| 3.57 | % |
| 3.56 | % |
| 3.38 | % |
| 3.31 | % |
Loans held for sale | 3.46 | % |
| 3.70 | % |
| 3.65 | % |
| 4.23 | % |
| 4.60 | % |
Loans (TE) | 5.02 | % |
| 5.28 | % |
| 5.16 | % |
| 5.32 | % |
| 5.37 | % |
Total Earning Assets | 4.56 | % |
| 4.82 | % |
| 4.86 | % |
| 4.95 | % |
| 4.95 | % |
|
|
|
|
|
|
|
|
|
|
| |||||
Interest-Bearing Deposits |
|
|
|
|
|
|
|
|
| |||||
NOW accounts | 0.49 | % |
| 0.49 | % |
| 0.55 | % |
| 0.60 | % |
| 0.55 | % |
MMDA | 0.98 | % |
| 1.14 | % |
| 1.31 | % |
| 1.43 | % |
| 1.37 | % |
Savings accounts | 0.13 | % |
| 0.14 | % |
| 0.16 | % |
| 0.08 | % |
| 0.08 | % |
Retail CDs | 1.70 | % |
| 1.78 | % |
| 1.83 | % |
| 1.75 | % |
| 1.57 | % |
Brokered CDs | 2.01 | % |
| 2.35 | % |
| 2.14 | % |
| 2.50 | % |
| 2.48 | % |
Total Interest-Bearing Deposits | 1.01 | % |
| 1.13 | % |
| 1.23 | % |
| 1.34 | % |
| 1.25 | % |
Non-Deposit Funding |
|
|
|
|
|
|
|
|
| |||||
Federal funds purchased and securities sold under agreements to repurchase | 1.03 | % |
| 0.95 | % |
| 0.64 | % |
| 0.25 | % |
| 0.28 | % |
FHLB advances | 1.62 | % |
| 1.92 | % |
| 2.26 | % |
| 2.53 | % |
| 2.85 | % |
Other borrowings | 5.24 | % |
| 5.69 | % |
| 5.98 | % |
| 6.09 | % |
| 6.21 | % |
Subordinated deferrable interest debentures | 6.49 | % |
| 6.59 | % |
| 6.49 | % |
| 7.02 | % |
| 7.12 | % |
Total Non-Deposit Funding | 2.57 | % |
| 2.92 | % |
| 3.40 | % |
| 6.03 | % |
| 6.08 | % |
Total Interest-Bearing Liabilities | 1.24 | % |
| 1.37 | % |
| 1.47 | % |
| 1.51 | % |
| 1.42 | % |
|
|
|
|
|
|
|
|
|
|
| |||||
Net Interest Spread | 3.32 | % |
| 3.45 | % |
| 3.39 | % |
| 3.44 | % |
| 3.53 | % |
|
|
|
|
|
|
|
|
|
|
| |||||
Net Interest Margin(2) | 3.70 | % |
| 3.86 | % |
| 3.84 | % |
| 3.91 | % |
| 3.95 | % |
|
|
|
|
|
|
|
|
|
|
| |||||
Total Cost of Funds(3) | 0.91 | % |
| 1.00 | % |
| 1.07 | % |
| 1.10 | % |
| 1.05 | % |
(1) Interest and average rates are calculated on a tax-equivalent basis using an effective tax rate of 21%. | ||||||||||||||
(2) Rate calculated based on average earning assets. | ||||||||||||||
(3) Rate calculated based on total average funding including noninterest-bearing deposits. | ||||||||||||||
AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||
FINANCIAL TABLES | |||||||||||||||||||
|
| |||||||||||||||||||
Non-GAAP Reconciliations | |||||||||||||||||||
|
| |||||||||||||||||||
Adjusted Net Income | Table 9A | ||||||||||||||||||
|
| Three Months Ended | ||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | ||||||||||
(dollars in thousands except per share data) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | ||||||||||
Net income available to common shareholders | $ | 19,322 |
|
| $ | 61,248 |
|
| $ | 21,384 |
|
| $ | 38,904 |
|
| $ | 39,905 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Adjustment items: |
|
|
|
|
|
|
|
|
| ||||||||||
Merger and conversion charges | 540 |
|
| 2,415 |
|
| 65,158 |
|
| 3,475 |
|
| 2,057 |
| |||||
Restructuring charges | — |
|
| — |
|
| — |
|
| — |
|
| 245 |
| |||||
Servicing right impairment (recovery) | 22,165 |
|
| 366 |
|
| (1,319) |
|
| 1,460 |
|
| — |
| |||||
Gain on BOLI proceeds | — |
|
| 752 |
|
| (4,335) |
|
| — |
|
| — |
| |||||
Expenses related to SEC/DOJ Investigation | 1,443 |
|
| 463 |
|
| — |
|
| — |
|
| — |
| |||||
Natural disaster and pandemic charges | 548 |
|
| — |
|
| — |
|
| 50 |
|
| (89) |
| |||||
Loss on sale of premises | 470 |
|
| 1,413 |
|
| 889 |
|
| 2,800 |
|
| 919 |
| |||||
Tax effect of adjustment items (Note 1) | (5,283) |
|
| (898) |
|
| (13,238) |
|
| (1,479) |
|
| (450) |
| |||||
After tax adjustment items | 19,883 |
|
| 4,511 |
|
| 47,155 |
|
| 6,306 |
|
| 2,682 |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Tax expense attributable to acquisition related compensation and acquired BOLI | — |
|
| 849 |
|
| — |
|
| — |
|
| — |
| |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Adjusted net income | $ | 39,205 |
|
| $ | 66,608 |
|
| $ | 68,539 |
|
| $ | 45,210 |
|
| $ | 42,587 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Weighted average number of shares - diluted | 69,502,022 |
|
| 69,683,999 |
|
| 69,600,499 |
|
| 47,337,809 |
|
| 47,456,314 |
| |||||
Net income per diluted share | $ | 0.28 |
|
| $ | 0.88 |
|
| $ | 0.31 |
|
| $ | 0.82 |
|
| $ | 0.84 |
|
Adjusted net income per diluted share | $ | 0.56 |
|
| $ | 0.96 |
|
| $ | 0.98 |
|
| $ | 0.96 |
|
| $ | 0.90 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Average assets | $ | 18,056,445 |
|
| $ | 17,998,494 |
|
| $ | 17,340,387 |
|
| $ | 11,625,344 |
|
| $ | 11,423,677 |
|
Return on average assets | 0.43 | % |
| 1.35 | % |
| 0.49 | % |
| 1.34 | % |
| 1.42 | % | |||||
Adjusted return on average assets | 0.87 | % |
| 1.47 | % |
| 1.57 | % |
| 1.56 | % |
| 1.51 | % | |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Average common equity | $ | 2,456,617 |
|
| $ | 2,437,272 |
|
| $ | 2,432,182 |
|
| $ | 1,519,598 |
|
| $ | 1,478,462 |
|
Average tangible common equity | $ | 1,436,108 |
|
| $ | 1,432,081 |
|
| $ | 1,434,829 |
|
| $ | 964,841 |
|
| $ | 917,876 |
|
Return on average common equity | 3.16 | % |
| 9.97 | % |
| 3.49 | % |
| 10.27 | % |
| 10.95 | % | |||||
Adjusted return on average tangible common equity | 10.98 | % |
| 18.45 | % |
| 18.95 | % |
| 18.79 | % |
| 18.82 | % | |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Note 1: A portion of the merger and conversion charges for all periods are nondeductible for tax purposes. | |||||||||||||||||||
AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||
FINANCIAL TABLES | |||||||||||||||||||
|
| |||||||||||||||||||
Non-GAAP Reconciliations (continued) | |||||||||||||||||||
|
| |||||||||||||||||||
Adjusted Efficiency Ratio (TE) | Table 9B | ||||||||||||||||||
|
| Three Months Ended | ||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | ||||||||||
(dollars in thousands) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | ||||||||||
Adjusted Noninterest Expense |
|
|
|
|
|
|
|
|
| ||||||||||
Total noninterest expense | $ | 138,053 |
|
| $ | 122,564 |
|
| $ | 192,697 |
|
| $ | 81,251 |
|
| $ | 75,425 |
|
Adjustment items: |
|
|
|
|
|
|
|
|
| ||||||||||
Merger and conversion charges | (540) |
|
| (2,415) |
|
| (65,158) |
|
| (3,475) |
|
| (2,057) |
| |||||
Restructuring charges | — |
|
| — |
|
| — |
|
| — |
|
| (245) |
| |||||
Expenses related to SEC/DOJ Investigation | (1,443) |
|
| (463) |
|
| — |
|
| — |
|
| — |
| |||||
Natural disaster and pandemic charges | (548) |
|
| — |
|
| — |
|
| (50) |
|
| 89 |
| |||||
Loss on sale of premises | (470) |
|
| (1,413) |
|
| (889) |
|
| (2,800) |
|
| (919) |
| |||||
Adjusted noninterest expense | $ | 135,052 |
|
| $ | 118,273 |
|
| $ | 126,650 |
|
| $ | 74,926 |
|
| $ | 72,293 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Total Revenue |
|
|
|
|
|
|
|
|
| ||||||||||
Net interest income | $ | 147,945 |
|
| $ | 155,351 |
|
| $ | 148,769 |
|
| $ | 101,651 |
|
| $ | 99,395 |
|
Noninterest income | 54,379 |
|
| 55,113 |
|
| 76,993 |
|
| 35,236 |
|
| 30,771 |
| |||||
Total revenue | $ | 202,324 |
|
| $ | 210,464 |
|
| $ | 225,762 |
|
| $ | 136,887 |
|
| $ | 130,166 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Adjusted Total Revenue |
|
|
|
|
|
|
|
|
| ||||||||||
Net interest income (TE) | $ | 149,018 |
|
| $ | 156,454 |
|
| $ | 149,896 |
|
| $ | 102,713 |
|
| $ | 100,453 |
|
Noninterest income | 54,379 |
|
| 55,113 |
|
| 76,993 |
|
| 35,236 |
|
| 30,771 |
| |||||
Total revenue (TE) | 203,397 |
|
| 211,567 |
|
| 226,889 |
|
| 137,949 |
|
| 131,224 |
| |||||
Adjustment items: |
|
|
|
|
|
|
|
|
| ||||||||||
(Gain) loss on securities | 9 |
|
| (1) |
|
| (4) |
|
| (69) |
|
| (66) |
| |||||
Loss (gain) on BOLI proceeds | — |
|
| 752 |
|
| (4,335) |
|
| — |
|
| — |
| |||||
Servicing right impairment (recovery) | 22,165 |
|
| 366 |
|
| (1,319) |
|
| 1,460 |
|
| — |
| |||||
Adjusted total revenue (TE) | $ | 225,571 |
|
| $ | 212,684 |
|
| $ | 221,231 |
|
| $ | 139,340 |
|
| $ | 131,158 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Efficiency ratio | 68.23 | % |
| 58.24 | % |
| 85.35 | % |
| 59.36 | % |
| 57.95 | % | |||||
Adjusted efficiency ratio (TE) | 59.87 | % |
| 55.61 | % |
| 57.25 | % |
| 53.77 | % |
| 55.12 | % | |||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Tangible Book Value Per Share | Table 9C | ||||||||||||||||||
|
| Three Months Ended | ||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | ||||||||||
(dollars in thousands except per share data) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | ||||||||||
Total shareholders' equity | $ | 2,437,150 |
|
| $ | 2,469,582 |
|
| $ | 2,420,723 |
|
| $ | 1,537,121 |
|
| $ | 1,495,584 |
|
Less: |
|
|
|
|
|
|
|
|
| ||||||||||
Goodwill | 931,947 |
|
| 931,637 |
|
| 911,488 |
|
| 501,140 |
|
| 501,308 |
| |||||
Other intangibles, net | 85,955 |
|
| 91,586 |
|
| 97,328 |
|
| 52,437 |
|
| 55,557 |
| |||||
Total tangible shareholders' equity | $ | 1,419,248 |
|
| $ | 1,446,359 |
|
| $ | 1,411,907 |
|
| $ | 983,544 |
|
| $ | 938,719 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Period end number of shares | 69,441,274 |
|
| 69,503,833 |
|
| 69,593,833 |
|
| 47,261,584 |
|
| 47,585,309 |
| |||||
Book value per share (period end) | $ | 35.10 |
|
| $ | 35.53 |
|
| $ | 34.78 |
|
| $ | 32.52 |
|
| $ | 31.43 |
|
Tangible book value per share (period end) | $ | 20.44 |
|
| $ | 20.81 |
|
| $ | 20.29 |
|
| $ | 20.81 |
|
| $ | 19.73 |
|
AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||
FINANCIAL TABLES | |||||||||||||||||||
|
| |||||||||||||||||||
Segment Reporting | Table 10 | ||||||||||||||||||
|
| Three Months Ended | ||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | ||||||||||
(dollars in thousands) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | ||||||||||
Banking Division |
|
|
|
|
|
|
|
|
| ||||||||||
Net interest income | $ | 118,375 |
|
| $ | 124,957 |
|
| $ | 124,262 |
|
| $ | 84,755 |
|
| $ | 85,039 |
|
Provision for loan losses | 35,997 |
|
| 4,741 |
|
| 3,549 |
|
| 2,306 |
|
| 2,058 |
| |||||
Noninterest income | 17,773 |
|
| 18,632 |
|
| 21,173 |
|
| 14,830 |
|
| 14,370 |
| |||||
Noninterest expense |
|
|
|
|
|
|
|
|
| ||||||||||
Salaries and employee benefits | 41,621 |
|
| 38,180 |
|
| 39,794 |
|
| 24,228 |
|
| 27,932 |
| |||||
Occupancy and equipment expenses | 10,347 |
|
| 10,216 |
|
| 10,750 |
|
| 7,034 |
|
| 7,281 |
| |||||
Data processing and telecommunications expenses | 10,797 |
|
| 10,156 |
|
| 9,551 |
|
| 7,635 |
|
| 7,592 |
| |||||
Other noninterest expenses | 30,645 |
|
| 23,176 |
|
| 87,059 |
|
| 22,728 |
|
| 16,956 |
| |||||
Total noninterest expense | 93,410 |
|
| 81,728 |
|
| 147,154 |
|
| 61,625 |
|
| 59,761 |
| |||||
Income before income tax expense | 6,741 |
|
| 57,120 |
|
| (5,268) |
|
| 35,654 |
|
| 37,590 |
| |||||
Income tax expense (benefit) | 275 |
|
| 15,412 |
|
| (1,269) |
|
| 8,691 |
|
| 8,775 |
| |||||
Net income (loss) | $ | 6,466 |
|
| $ | 41,708 |
|
| $ | (3,999) |
|
| $ | 26,963 |
|
| $ | 28,815 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Retail Mortgage Division |
|
|
|
|
|
|
|
|
| ||||||||||
Net interest income | $ | 17,756 |
|
| $ | 18,223 |
|
| $ | 13,009 |
|
| $ | 7,567 |
|
| $ | 5,753 |
|
Provision for loan losses | 1,997 |
|
| 1,237 |
|
| 1,490 |
|
| 609 |
|
| 136 |
| |||||
Noninterest income | 34,369 |
|
| 33,335 |
|
| 52,493 |
|
| 18,070 |
|
| 14,290 |
| |||||
Noninterest expense |
|
|
|
|
|
|
|
|
| ||||||||||
Salaries and employee benefits | 31,097 |
|
| 28,233 |
|
| 34,144 |
|
| 11,886 |
|
| 8,207 |
| |||||
Occupancy and equipment expenses | 1,504 |
|
| 1,544 |
|
| 1,686 |
|
| 670 |
|
| 766 |
| |||||
Data processing and telecommunications expenses | 986 |
|
| 1,034 |
|
| 660 |
|
| 394 |
|
| 330 |
| |||||
Other noninterest expenses | 5,875 |
|
| 4,553 |
|
| 3,484 |
|
| 2,385 |
|
| 2,114 |
| |||||
Total noninterest expense | 39,462 |
|
| 35,364 |
|
| 39,974 |
|
| 15,335 |
|
| 11,417 |
| |||||
Income before income tax expense | 10,666 |
|
| 14,957 |
|
| 24,038 |
|
| 9,693 |
|
| 8,490 |
| |||||
Income tax expense | 2,408 |
|
| 3,371 |
|
| 5,048 |
|
| 2,170 |
|
| 1,613 |
| |||||
Net income | $ | 8,258 |
|
| $ | 11,586 |
|
| $ | 18,990 |
|
| $ | 7,523 |
|
| $ | 6,877 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Warehouse Lending Division |
|
|
|
|
|
|
|
|
| ||||||||||
Net interest income | $ | 3,302 |
|
| $ | 3,771 |
|
| $ | 3,169 |
|
| $ | 2,987 |
|
| $ | 2,690 |
|
Provision for loan losses | (9) |
|
| 67 |
|
| — |
|
| — |
|
| — |
| |||||
Noninterest income | 960 |
|
| 610 |
|
| 560 |
|
| 450 |
|
| 379 |
| |||||
Noninterest expense |
|
|
|
|
|
|
|
|
| ||||||||||
Salaries and employee benefits | 210 |
|
| 325 |
|
| 286 |
|
| 162 |
|
| 161 |
| |||||
Occupancy and equipment expenses | 1 |
|
| 1 |
|
| 2 |
|
| 1 |
|
| 1 |
| |||||
Data processing and telecommunications expenses | 41 |
|
| 47 |
|
| 41 |
|
| 38 |
|
| 30 |
| |||||
Other noninterest expenses | 34 |
|
| 53 |
|
| 27 |
|
| 75 |
|
| 68 |
| |||||
Total noninterest expense | 286 |
|
| 426 |
|
| 356 |
|
| 276 |
|
| 260 |
| |||||
Income before income tax expense | 3,985 |
|
| 3,888 |
|
| 3,373 |
|
| 3,161 |
|
| 2,809 |
| |||||
Income tax expense | 837 |
|
| 816 |
|
| 708 |
|
| 664 |
|
| 590 |
| |||||
Net income | $ | 3,148 |
|
| $ | 3,072 |
|
| $ | 2,665 |
|
| $ | 2,497 |
|
| $ | 2,219 |
|
AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||
FINANCIAL TABLES | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Segment Reporting (continued) | Table 10 | ||||||||||||||||||
|
| Three Months Ended | ||||||||||||||||||
|
| Mar |
| Dec |
| Sep |
| Jun |
| Mar | ||||||||||
(dollars in thousands) | 2020 |
| 2019 |
| 2019 |
| 2019 |
| 2019 | ||||||||||
SBA Division |
|
|
|
|
|
|
|
|
| ||||||||||
Net interest income | $ | 2,181 |
|
| $ | 2,190 |
|
| $ | 2,573 |
|
| $ | 1,182 |
|
| $ | 1,086 |
|
Provision for loan losses | (903) |
|
| 150 |
|
| (15) |
|
| 178 |
|
| 231 |
| |||||
Noninterest income | 1,277 |
|
| 2,536 |
|
| 2,766 |
|
| 1,883 |
|
| 1,730 |
| |||||
Noninterest expense |
|
|
|
|
|
|
|
|
| ||||||||||
Salaries and employee benefits | 1,476 |
|
| 1,336 |
|
| 1,985 |
|
| 735 |
|
| 727 |
| |||||
Occupancy and equipment expenses | 97 |
|
| 79 |
|
| 66 |
|
| 65 |
|
| 59 |
| |||||
Data processing and telecommunications expenses | 13 |
|
| 5 |
|
| 22 |
|
| 3 |
|
| 2 |
| |||||
Other noninterest expenses | 515 |
|
| 402 |
|
| 503 |
|
| 359 |
|
| 387 |
| |||||
Total noninterest expense | 2,101 |
|
| 1,822 |
|
| 2,576 |
|
| 1,162 |
|
| 1,175 |
| |||||
Income before income tax expense | 2,260 |
|
| 2,754 |
|
| 2,778 |
|
| 1,725 |
|
| 1,410 |
| |||||
Income tax expense | 475 |
|
| 578 |
|
| 584 |
|
| 362 |
|
| 296 |
| |||||
Net income | $ | 1,785 |
|
| $ | 2,176 |
|
| $ | 2,194 |
|
| $ | 1,363 |
|
| $ | 1,114 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Premium Finance Division |
|
|
|
|
|
|
|
|
| ||||||||||
Net interest income | $ | 6,331 |
|
| $ | 6,210 |
|
| $ | 5,756 |
|
| $ | 5,160 |
|
| $ | 4,827 |
|
Provision for loan losses | 3,965 |
|
| (502) |
|
| 965 |
|
| 1,575 |
|
| 983 |
| |||||
Noninterest income | — |
|
| — |
|
| 1 |
|
| 3 |
|
| 2 |
| |||||
Noninterest expense |
|
|
|
|
|
|
|
|
| ||||||||||
Salaries and employee benefits | 1,542 |
|
| 1,568 |
|
| 1,424 |
|
| 1,320 |
|
| 1,305 |
| |||||
Occupancy and equipment expenses | 79 |
|
| 79 |
|
| 135 |
|
| 64 |
|
| 97 |
| |||||
Data processing and telecommunications expenses | 117 |
|
| 120 |
|
| 98 |
|
| 318 |
|
| 437 |
| |||||
Other noninterest expenses | 1,056 |
|
| 1,457 |
|
| 980 |
|
| 1,151 |
|
| 973 |
| |||||
Total noninterest expense | 2,794 |
|
| 3,224 |
|
| 2,637 |
|
| 2,853 |
|
| 2,812 |
| |||||
(Loss) income before income tax expense | (428) |
|
| 3,488 |
|
| 2,155 |
|
| 735 |
|
| 1,034 |
| |||||
Income tax expense (benefit) | (93) |
|
| 782 |
|
| 621 |
|
| 177 |
|
| 154 |
| |||||
Net (loss) income | $ | (335) |
|
| $ | 2,706 |
|
| $ | 1,534 |
|
| $ | 558 |
|
| $ | 880 |
|
|
|
|
|
|
|
|
|
|
|
| ||||||||||
Total Consolidated |
|
|
|
|
|
|
|
|
| ||||||||||
Net interest income | $ | 147,945 |
|
| $ | 155,351 |
|
| $ | 148,769 |
|
| $ | 101,651 |
|
| $ | 99,395 |
|
Provision for loan losses | 41,047 |
|
| 5,693 |
|
| 5,989 |
|
| 4,668 |
|
| 3,408 |
| |||||
Noninterest income | 54,379 |
|
| 55,113 |
|
| 76,993 |
|
| 35,236 |
|
| 30,771 |
| |||||
Noninterest expense |
|
|
|
|
|
|
|
|
| ||||||||||
Salaries and employee benefits | 75,946 |
|
| 69,642 |
|
| 77,633 |
|
| 38,331 |
|
| 38,332 |
| |||||
Occupancy and equipment expenses | 12,028 |
|
| 11,919 |
|
| 12,639 |
|
| 7,834 |
|
| 8,204 |
| |||||
Data processing and telecommunications expenses | 11,954 |
|
| 11,362 |
|
| 10,372 |
|
| 8,388 |
|
| 8,391 |
| |||||
Other noninterest expenses | 38,125 |
|
| 29,641 |
|
| 92,053 |
|
| 26,698 |
|
| 20,498 |
| |||||
Total noninterest expense | 138,053 |
|
| 122,564 |
|
| 192,697 |
|
| 81,251 |
|
| 75,425 |
| |||||
Income before income tax expense | 23,224 |
|
| 82,207 |
|
| 27,076 |
|
| 50,968 |
|
| 51,333 |
| |||||
Income tax expense | 3,902 |
|
| 20,959 |
|
| 5,692 |
|
| 12,064 |
|
| 11,428 |
| |||||
Net income | $ | 19,322 |
|
| $ | 61,248 |
|
| $ | 21,384 |
|
| $ | 38,904 |
|
| $ | 39,905 |
|

CONTACT: Nicole S. Stokes, Executive Vice President and CFO, (404) 240-1514
1st Quarter 2020 Results Investor Presentation Exhibit 99.2
Cautionary Statements This presentation contains forward-looking statements, as defined by federal securities laws, including, among other forward-looking statements, certain plans, expectations and goals. Words such as “may,” “believe,” “expect,” “anticipate,” “intend,” “will,” “should,” “plan,” “estimate,” “predict,” “continue” and “potential” or the negative of these terms or other comparable terminology, as well as similar expressions, are meant to identify forward-looking statements. The forward-looking statements in this presentation are based on current expectations and are provided to assist in the understanding of potential future performance. Such forward-looking statements involve numerous assumptions, risks and uncertainties that may cause actual results to differ materially from those expressed or implied in any such statements, including, without limitation, the following: general competitive, economic, political and market conditions and fluctuations; movements in interest rates and our expectations regarding net interest margin; expectations on credit quality and performance; legislative and regulatory changes; the impact of the COVID-19 pandemic on the general economy, our customers and the allowance for loan losses; the benefits that may be realized by our customers from government assistance programs and regulatory actions related to the COVID-19 pandemic; competitive pressures on product pricing and services; the cost savings and any revenue synergies expected to result from acquisition transactions, which may not be fully realized within the expected timeframes if at all; the success and timing of other business strategies; our outlook and long-term goals for future growth; and natural disasters, geopolitical events, public health crises and other catastrophic events beyond our control. For a discussion of some of the other risks and other factors that may cause such forward-looking statements to differ materially from actual results, please refer to the Company’s filings with the Securities and Exchange Commission, including the Company’s Annual Report on Form 10-K for the year ended December 31, 2019 and its subsequently filed periodic reports and other filings. Forward-looking statements speak only as of the date they are made, and the Company undertakes no obligation to update or revise forward-looking statements.
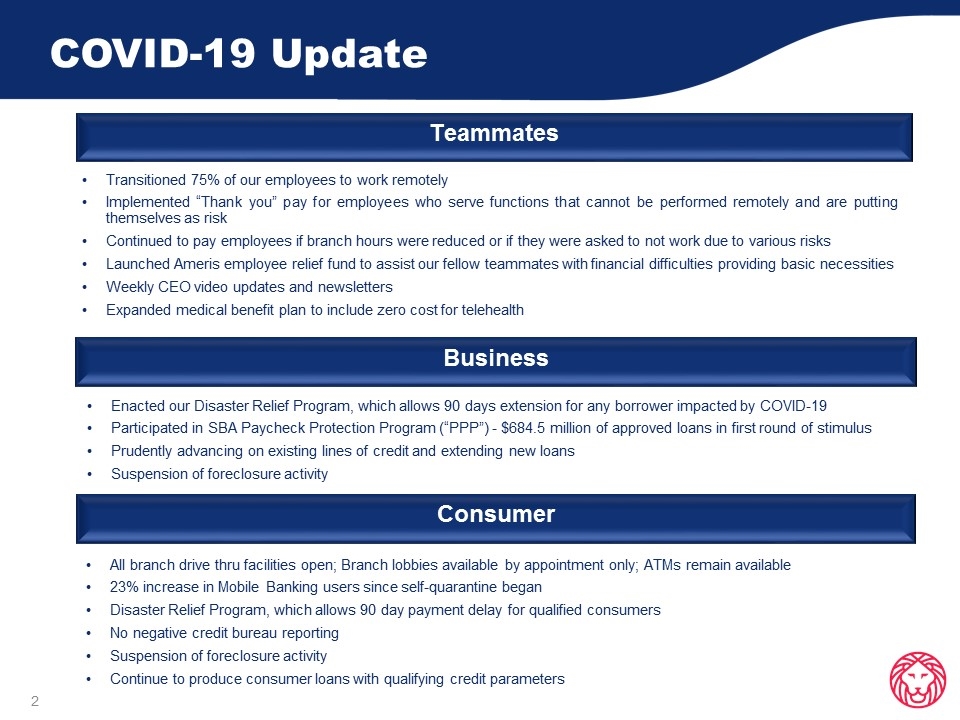
COVID-19 Update Business Enacted our Disaster Relief Program, which allows 90 days extension for any borrower impacted by COVID-19 Participated in SBA Paycheck Protection Program (“PPP”) - $684.5 million of approved loans in first round of stimulus Prudently advancing on existing lines of credit and extending new loans Suspension of foreclosure activity Consumer All branch drive thru facilities open; Branch lobbies available by appointment only; ATMs remain available 23% increase in Mobile Banking users since self-quarantine began Disaster Relief Program, which allows 90 day payment delay for qualified consumers No negative credit bureau reporting Suspension of foreclosure activity Continue to produce consumer loans with qualifying credit parameters Teammates Transitioned 75% of our employees to work remotely Implemented “Thank you” pay for employees who serve functions that cannot be performed remotely and are putting themselves as risk Continued to pay employees if branch hours were reduced or if they were asked to not work due to various risks Launched Ameris employee relief fund to assist our fellow teammates with financial difficulties providing basic necessities Weekly CEO video updates and newsletters Expanded medical benefit plan to include zero cost for telehealth
Risk Management Operating Strength Diversification Entered pandemic in position of strength and forward momentum: Well capitalized Strong liquidity and continued funding opportunities Premier Southeastern markets Historically top quartile return on assets (>1.50% ROA for 2019) Disciplined rate cuts on funding side while growing core deposits Culture of Discipline Geographic Diversification Balance Sheet Diversification: CRE concentrations are moderate and forecast to decline Diversified loan portfolio across geography and product lines No credit exposure to energy – closest energy exposure is $169.1 million of loans to convenience store operators
1st Quarter 2020 Financial Results
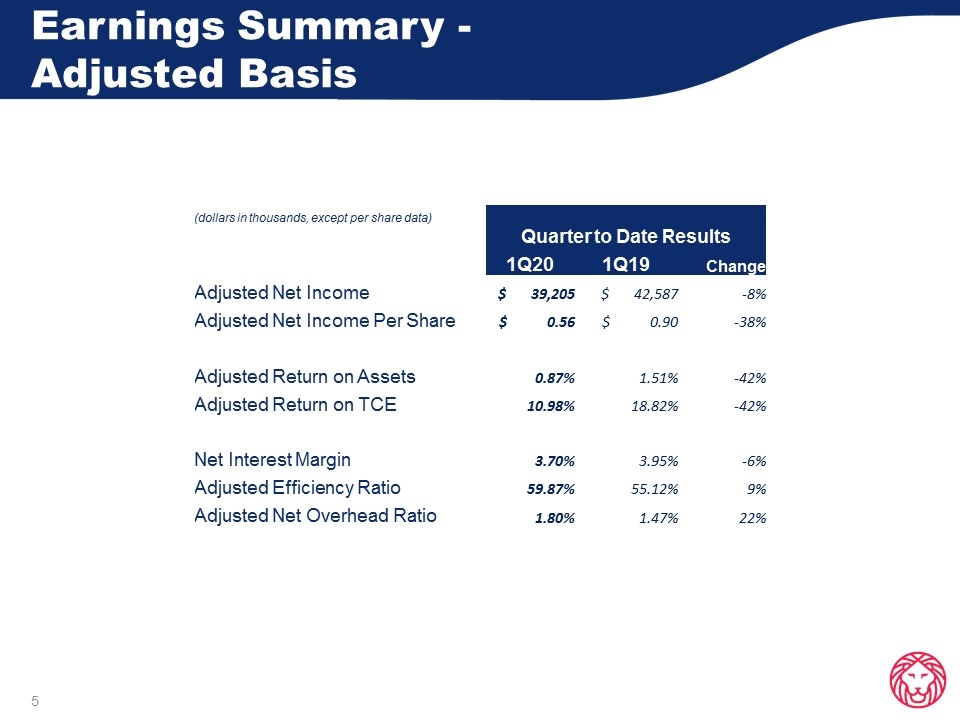
Earnings Summary - Adjusted Basis (dollars in thousands, except per share data) Quarter to Date Results 1Q20 1Q19 Change Adjusted Net Income $ 39,205 $ 42,587 -8% Adjusted Net Income Per Share $ 0.56 $ 0.90 -38% Adjusted Return on Assets 0.87% 1.51% -42% Adjusted Return on TCE 10.98% 18.82% -42% Net Interest Margin 3.70% 3.95% -6% Adjusted Efficiency Ratio 59.87% 55.12% 9% Adjusted Net Overhead Ratio 1.80% 1.47% 22%
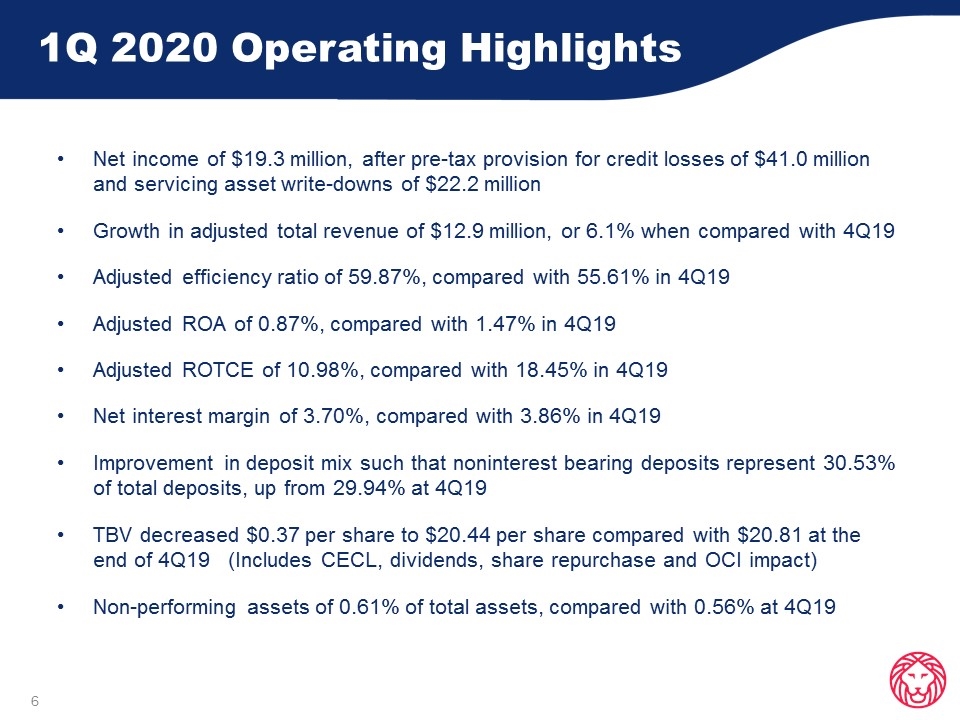
1Q 2020 Operating Highlights Net income of $19.3 million, after pre-tax provision for credit losses of $41.0 million and servicing asset write-downs of $22.2 million Growth in adjusted total revenue of $12.9 million, or 6.1% when compared with 4Q19 Adjusted efficiency ratio of 59.87%, compared with 55.61% in 4Q19 Adjusted ROA of 0.87%, compared with 1.47% in 4Q19 Adjusted ROTCE of 10.98%, compared with 18.45% in 4Q19 Net interest margin of 3.70%, compared with 3.86% in 4Q19 Improvement in deposit mix such that noninterest bearing deposits represent 30.53% of total deposits, up from 29.94% at 4Q19 TBV decreased $0.37 per share to $20.44 per share compared with $20.81 at the end of 4Q19 (Includes CECL, dividends, share repurchase and OCI impact) Non-performing assets of 0.61% of total assets, compared with 0.56% at 4Q19
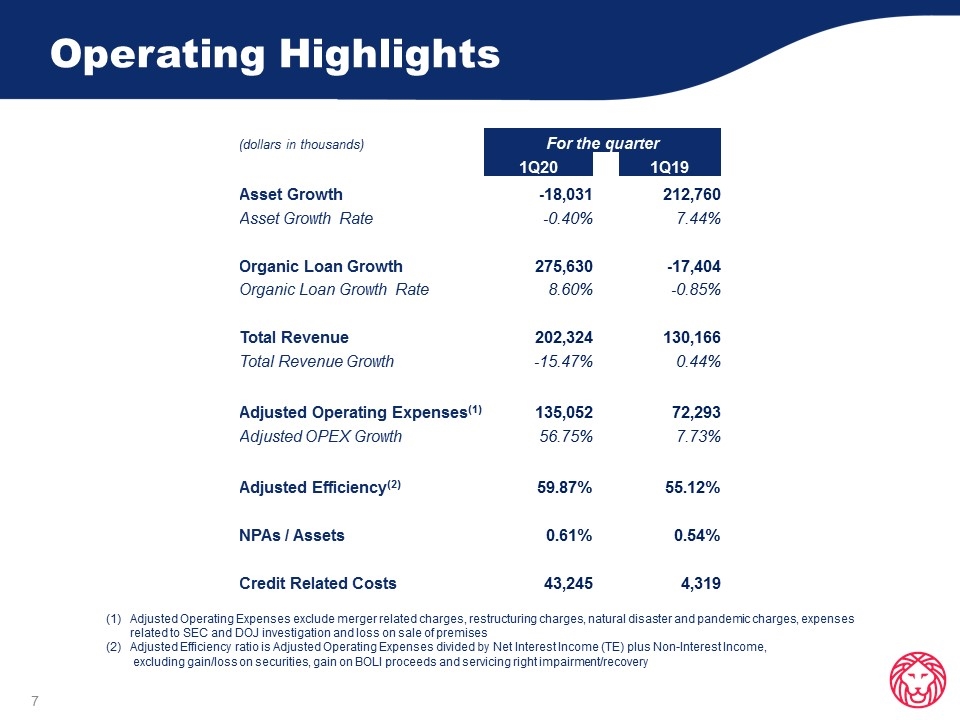
Operating Highlights (dollars in thousands) For the quarter 1Q20 1Q19 Asset Growth -18,031 212,760 Asset Growth Rate -0.40% 7.44% Organic Loan Growth 275,630 -17,404 Organic Loan Growth Rate 8.60% -0.85% Total Revenue 202,324 130,166 Total Revenue Growth -15.47% 0.44% Adjusted Operating Expenses(1) 135,052 72,293 Adjusted OPEX Growth 56.75% 7.73% Adjusted Efficiency(2) 59.87% 55.12% NPAs / Assets 0.61% 0.54% Credit Related Costs 43,245 4,319 Adjusted Operating Expenses exclude merger related charges, restructuring charges, natural disaster and pandemic charges, expenses related to SEC and DOJ investigation and loss on sale of premises Adjusted Efficiency ratio is Adjusted Operating Expenses divided by Net Interest Income (TE) plus Non-Interest Income, excluding gain/loss on securities, gain on BOLI proceeds and servicing right impairment/recovery
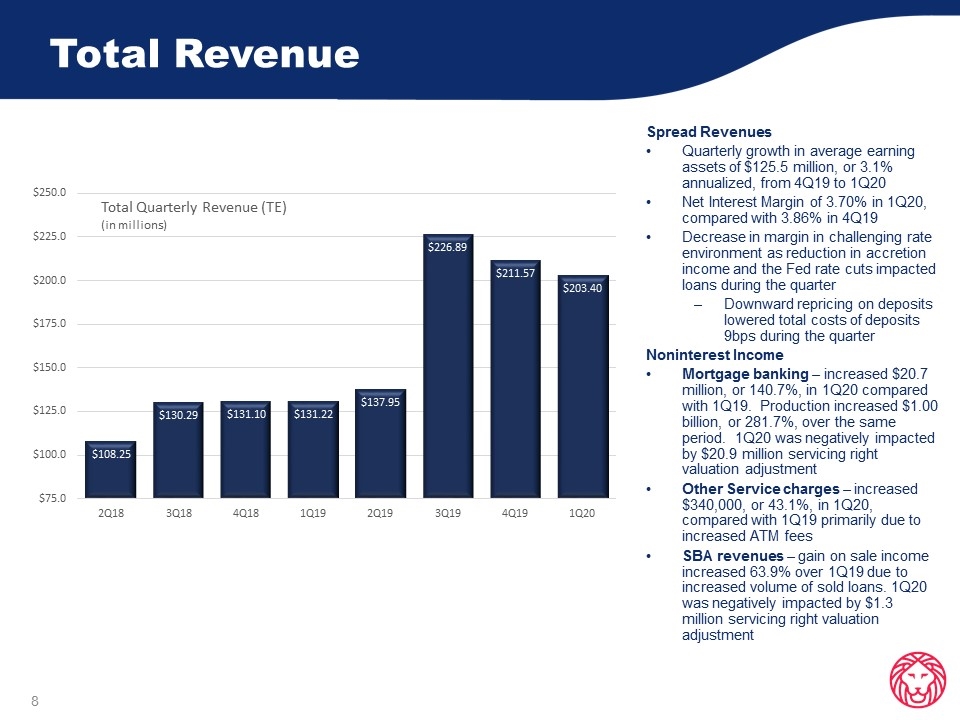
Total Revenue Spread Revenues Quarterly growth in average earning assets of $125.5 million, or 3.1% annualized, from 4Q19 to 1Q20 Net Interest Margin of 3.70% in 1Q20, compared with 3.86% in 4Q19 Decrease in margin in challenging rate environment as reduction in accretion income and the Fed rate cuts impacted loans during the quarter Downward repricing on deposits lowered total costs of deposits 9bps during the quarter Noninterest Income Mortgage banking – increased $20.7 million, or 140.7%, in 1Q20 compared with 1Q19. Production increased $1.00 billion, or 281.7%, over the same period. 1Q20 was negatively impacted by $20.9 million servicing right valuation adjustment Other Service charges – increased $340,000, or 43.1%, in 1Q20, compared with 1Q19 primarily due to increased ATM fees SBA revenues – gain on sale income increased 63.9% over 1Q19 due to increased volume of sold loans. 1Q20 was negatively impacted by $1.3 million servicing right valuation adjustment
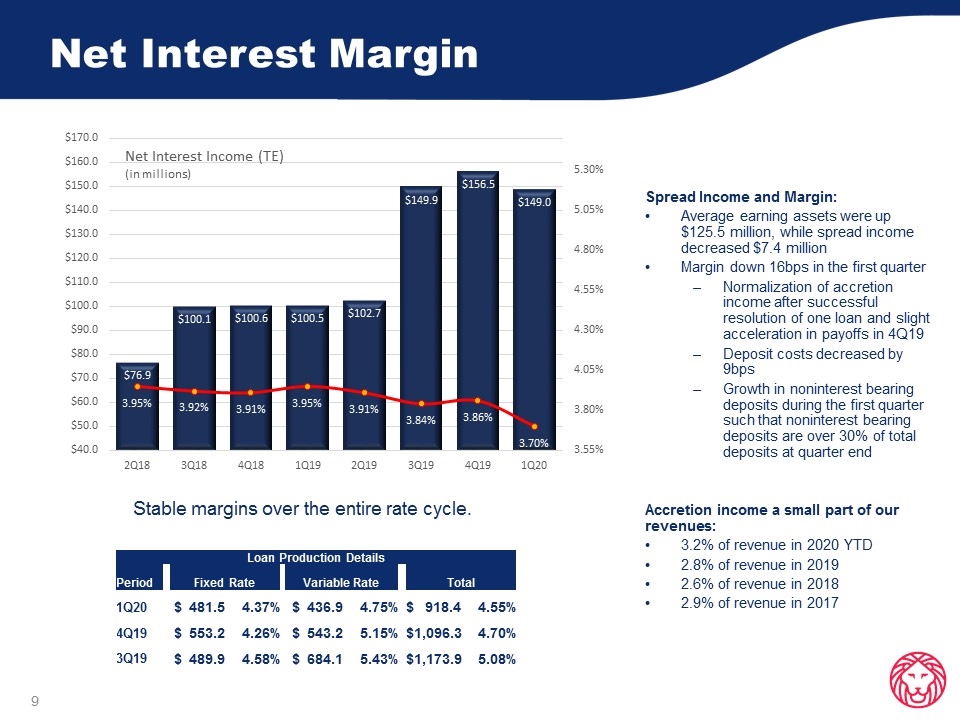
Net Interest Margin Stable margins over the entire rate cycle. Loan Production Details Period Fixed Rate Variable Rate Total 1Q20 $ 481.5 4.37% $ 436.9 4.75% $ 918.4 4.55% 4Q19 $ 553.2 4.26% $ 543.2 5.15% $1,096.3 4.70% 3Q19 $ 489.9 4.58% $ 684.1 5.43% $1,173.9 5.08% Spread Income and Margin: Average earning assets were up $125.5 million, while spread income decreased $7.4 million Margin down 16bps in the first quarter Normalization of accretion income after successful resolution of one loan and slight acceleration in payoffs in 4Q19 Deposit costs decreased by 9bps Growth in noninterest bearing deposits during the first quarter such that noninterest bearing deposits are over 30% of total deposits at quarter end Accretion income a small part of our revenues: 3.2% of revenue in 2020 YTD 2.8% of revenue in 2019 2.6% of revenue in 2018 2.9% of revenue in 2017
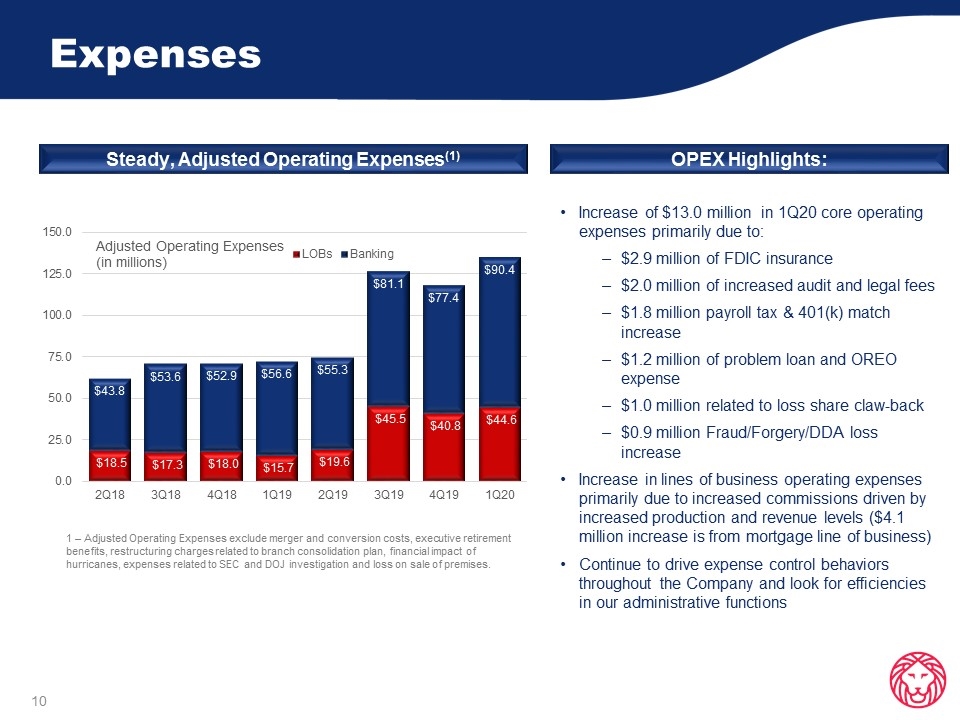
Expenses Steady, Adjusted Operating Expenses(1) OPEX Highlights: 1 – Adjusted Operating Expenses exclude merger and conversion costs, executive retirement benefits, restructuring charges related to branch consolidation plan, financial impact of hurricanes, expenses related to SEC and DOJ investigation and loss on sale of premises. Increase of $13.0 million in 1Q20 core operating expenses primarily due to: $2.9 million of FDIC insurance $2.0 million of increased audit and legal fees $1.8 million payroll tax & 401(k) match increase $1.2 million of problem loan and OREO expense $1.0 million related to loss share claw-back $0.9 million Fraud/Forgery/DDA loss increase Increase in lines of business operating expenses primarily due to increased commissions driven by increased production and revenue levels ($4.1 million increase is from mortgage line of business) Continue to drive expense control behaviors throughout the Company and look for efficiencies in our administrative functions
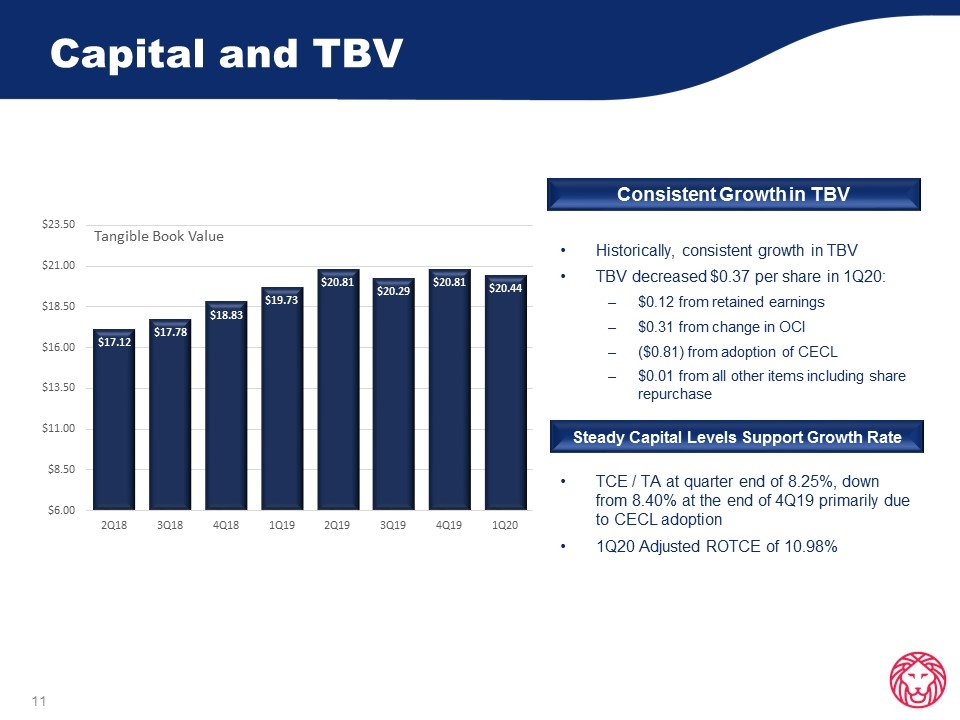
Capital and TBV Consistent Growth in TBV Steady Capital Levels Support Growth Rate Historically, consistent growth in TBV TBV decreased $0.37 per share in 1Q20: $0.12 from retained earnings $0.31 from change in OCI ($0.81) from adoption of CECL $0.01 from all other items including share repurchase TCE / TA at quarter end of 8.25%, down from 8.40% at the end of 4Q19 primarily due to CECL adoption 1Q20 Adjusted ROTCE of 10.98%
Credit Quality and Loan Diversification
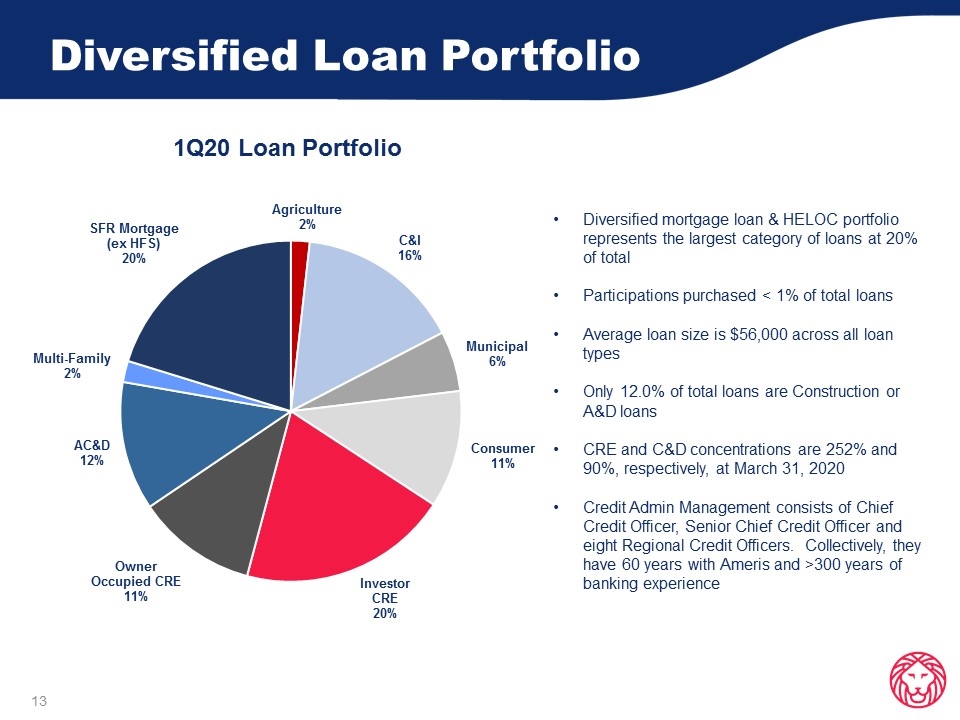
Diversified Loan Portfolio 1Q20 Loan Portfolio Diversified mortgage loan & HELOC portfolio represents the largest category of loans at 20% of total Participations purchased < 1% of total loans Average loan size is $56,000 across all loan types Only 12.0% of total loans are Construction or A&D loans CRE and C&D concentrations are 252% and 90%, respectively, at March 31, 2020 Credit Admin Management consists of Chief Credit Officer, Senior Chief Credit Officer and eight Regional Credit Officers. Collectively, they have 60 years with Ameris and >300 years of banking experience
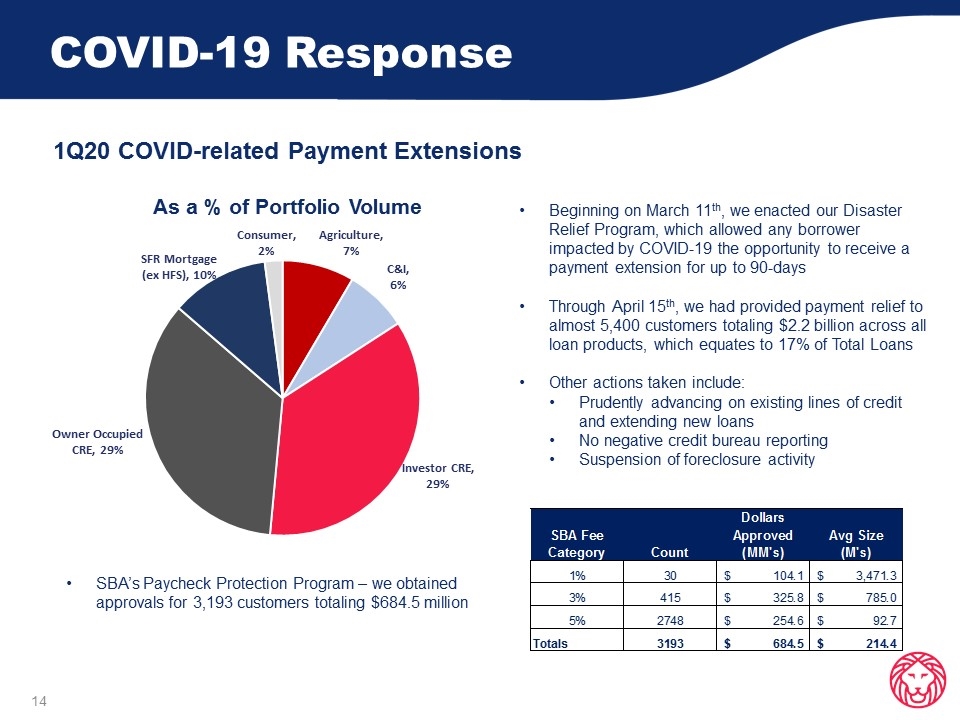
COVID-19 Response 1Q20 COVID-related Payment Extensions As a % of Portfolio Volume Beginning on March 11th, we enacted our Disaster Relief Program, which allowed any borrower impacted by COVID-19 the opportunity to receive a payment extension for up to 90-days Through April 15th, we had provided payment relief to almost 5,400 customers totaling $2.2 billion across all loan products, which equates to 17% of Total Loans Other actions taken include: Prudently advancing on existing lines of credit and extending new loans No negative credit bureau reporting Suspension of foreclosure activity SBA’s Paycheck Protection Program – we obtained approvals for 3,193 customers totaling $684.5 million SBA Fee Category Count Dollars Approved (MM's) Avg Size (M's) 0.01 30 $104.1 $3,471.3 0.03 415 $325.8 $785 0.05 2748 $254.6 $92.7 Totals 3193 $684.5 $214.4
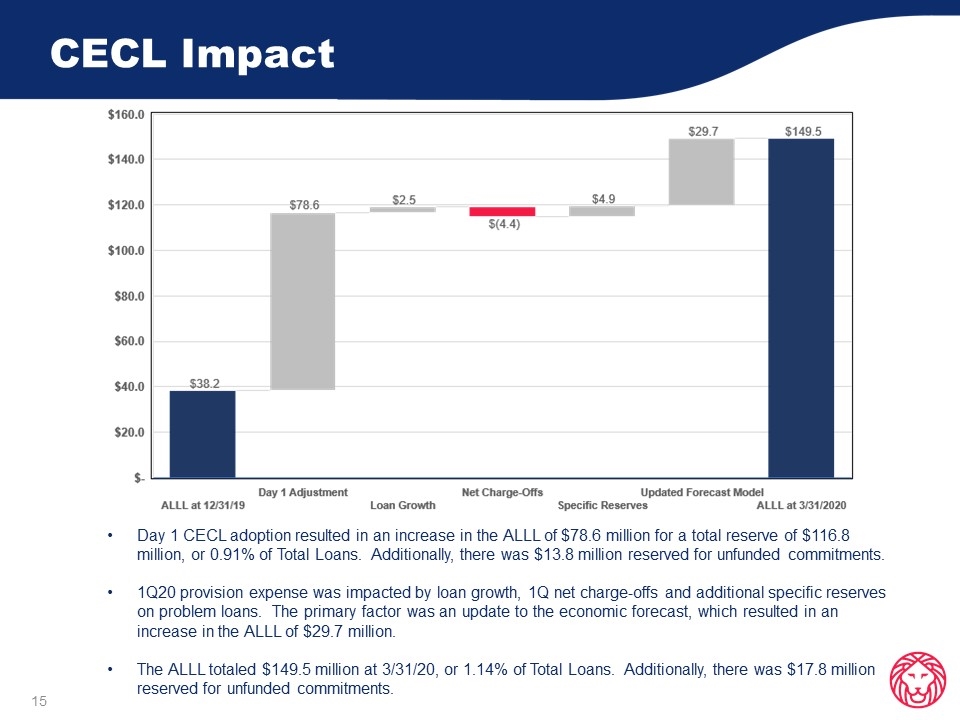
CECL Impact Day 1 CECL adoption resulted in an increase in the ALLL of $78.6 million for a total reserve of $116.8 million, or 0.91% of Total Loans. Additionally, there was $13.8 million reserved for unfunded commitments. 1Q20 provision expense was impacted by loan growth, 1Q net charge-offs and additional specific reserves on problem loans. The primary factor was an update to the economic forecast, which resulted in an increase in the ALLL of $29.7 million. The ALLL totaled $149.5 million at 3/31/20, or 1.14% of Total Loans. Additionally, there was $17.8 million reserved for unfunded commitments.
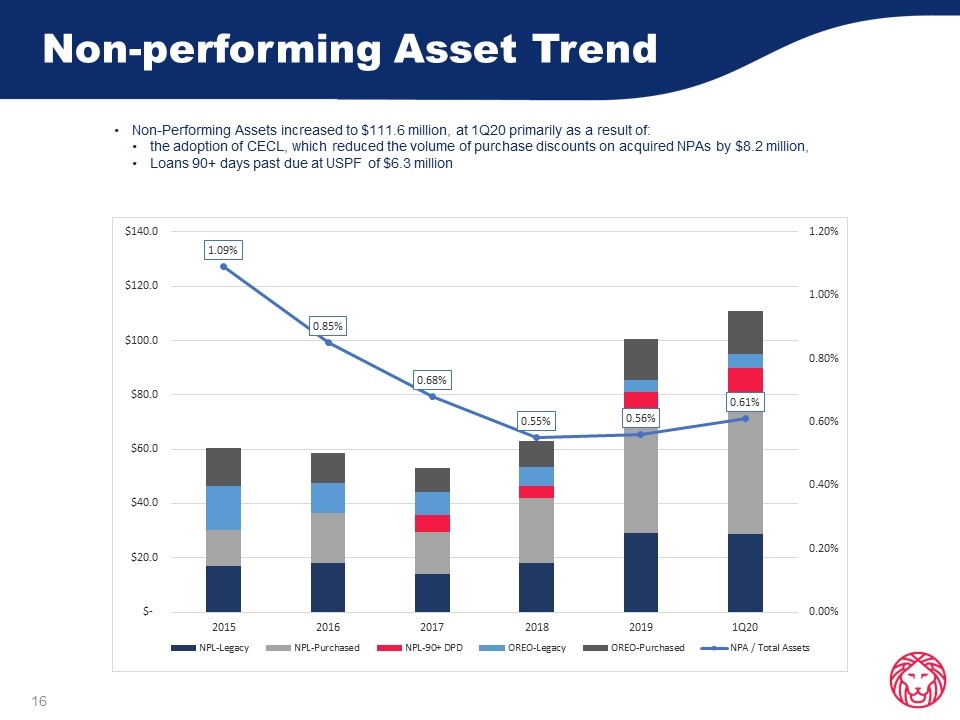
Non-performing Asset Trend Non-Performing Assets increased to $111.6 million, at 1Q20 primarily as a result of: the adoption of CECL, which reduced the volume of purchase discounts on acquired NPAs by $8.2 million, Loans 90+ days past due at USPF of $6.3 million
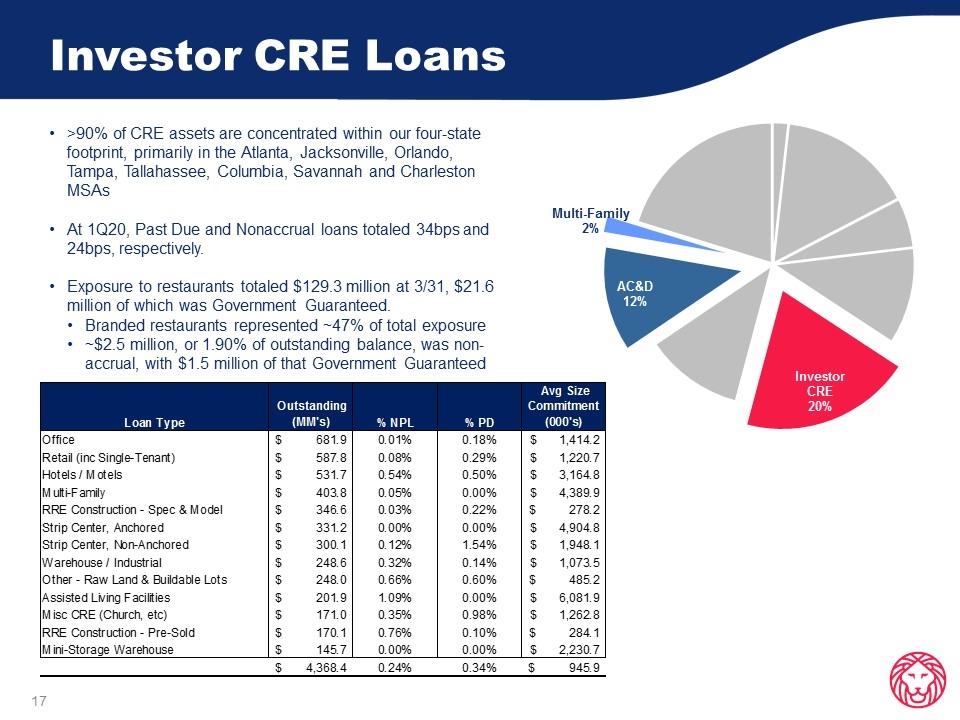
Investor CRE Loans >90% of CRE assets are concentrated within our four-state footprint, primarily in the Atlanta, Jacksonville, Orlando, Tampa, Tallahassee, Columbia, Savannah and Charleston MSAs At 1Q20, Past Due and Nonaccrual loans totaled 34bps and 24bps, respectively. Exposure to restaurants totaled $129.3 million at 3/31, $21.6 million of which was Government Guaranteed. Branded restaurants represented ~47% of total exposure ~$2.5 million, or 1.90% of outstanding balance, was non-accrual, with $1.5 million of that Government Guaranteed
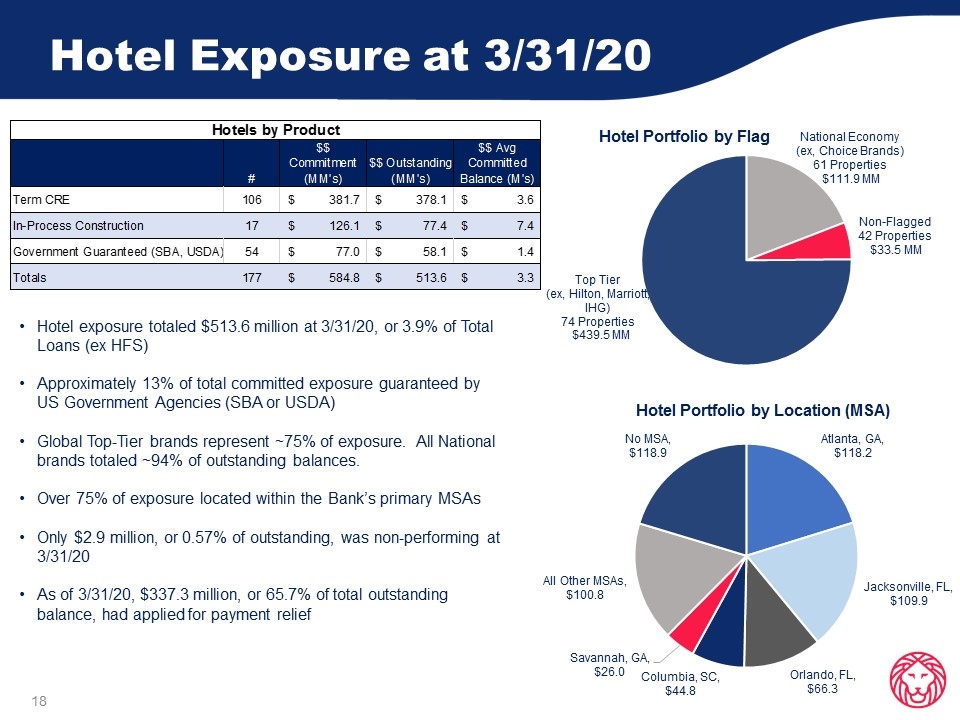
Hotel Exposure at 3/31/20 Hotel exposure totaled $513.6 million at 3/31/20, or 3.9% of Total Loans (ex HFS) Approximately 13% of total committed exposure guaranteed by US Government Agencies (SBA or USDA) Global Top-Tier brands represent ~75% of exposure. All National brands totaled ~94% of outstanding balances. Over 75% of exposure located within the Bank’s primary MSAs Only $2.9 million, or 0.57% of outstanding, was non-performing at 3/31/20 As of 3/31/20, $337.3 million, or 65.7% of total outstanding balance, had applied for payment relief Hotels by Product # $$ Commitment (MM's) $$ Outstanding (MM's) $$ Avg Committed Balance (M's) Term CRE 106 $381.7 $378.1 $3.6 In-Process Construction 17 $126.1 $77.400000000000006 $7.4 Government Guaranteed (SBA, USDA) 54 $77 $58.1 $1.4 Totals 177 $584.79999999999995 $513.6 $3.3 Hotel Portfolio by Brands # Net FMV TCE Avg FMV Avg TCE National Economy 61 $108.8 $111.9 $1.8 $1.8 Non-Flagged 42 $33.6 $33.5 $0.8 $0.8 Top Tier 74 $371.2 $439.5 $5 $5.9 Grand Total 177 $513.6 $584.9 $2.9 $3.3 MSA # Net FMV TCE Avg FMV Avg TCE Atlanta, GA 21 $104 $118.2 $4.9000000000000004 $5.6 Jacksonville, FL 19 $85.6 $109.9 $4.5 $5.8 Orlando, FL 15 $62.8 $66.3 $4.2 $4.4000000000000004 Columbia, SC 4 $44.8 $44.8 $11.2 $11.2 Savannah, GA 19 $24.5 $26 $1.3 $1.4 All Other MSAs 26 $93.4 $100.8 $50.9 $56.5 No MSA 73 $98.6 $118.9 $1.4 $1.6 Grand Total 177 $513.70000000000005 $584.90000000000009 $2.9 $3.3
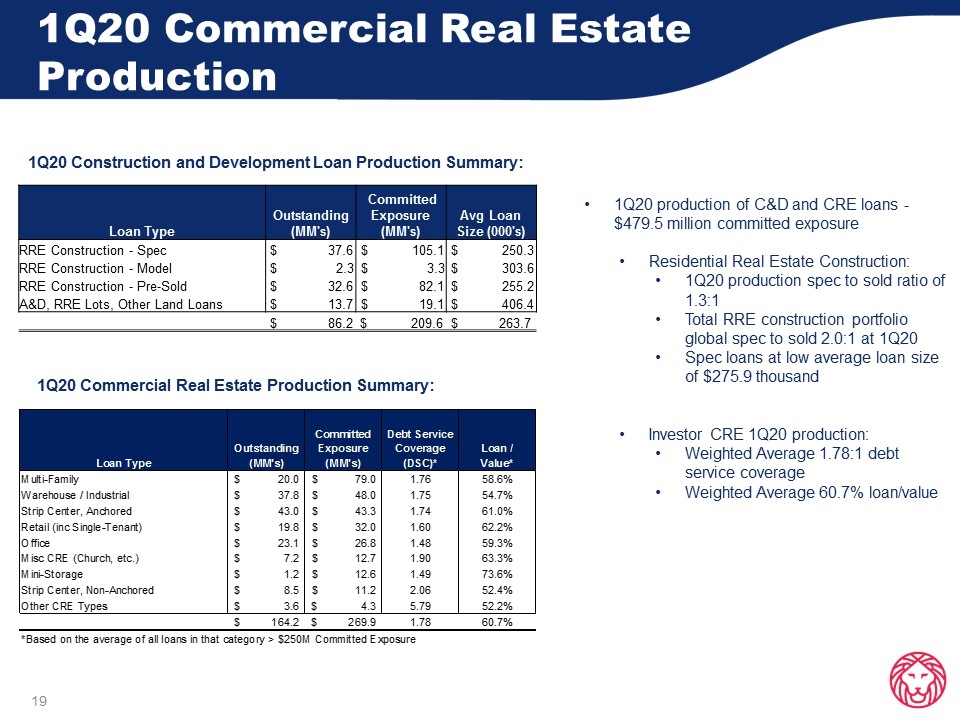
1Q20 Commercial Real Estate Production 1Q20 Commercial Real Estate Production Summary: 1Q20 Construction and Development Loan Production Summary: Loan Type Outstanding (MM's) Committed Exposure (MM's) Avg Loan Size (000's) RRE Construction - Spec $ 37.6 $ 105.1 $ 250.3 RRE Construction - Model $ 2.3 $ 3.3 $ 303.6 RRE Construction - Pre-Sold $ 32.6 $ 82.1 $ 255.2 A&D, RRE Lots, Other Land Loans $ 13.7 $ 19.1 $ 406.4 $ 86.2 $ 209.6 $ 263.7 1Q20 production of C&D and CRE loans - $479.5 million committed exposure Residential Real Estate Construction: 1Q20 production spec to sold ratio of 1.3:1 Total RRE construction portfolio global spec to sold 2.0:1 at 1Q20 Spec loans at low average loan size of $275.9 thousand Investor CRE 1Q20 production: Weighted Average 1.78:1 debt service coverage Weighted Average 60.7% loan/value
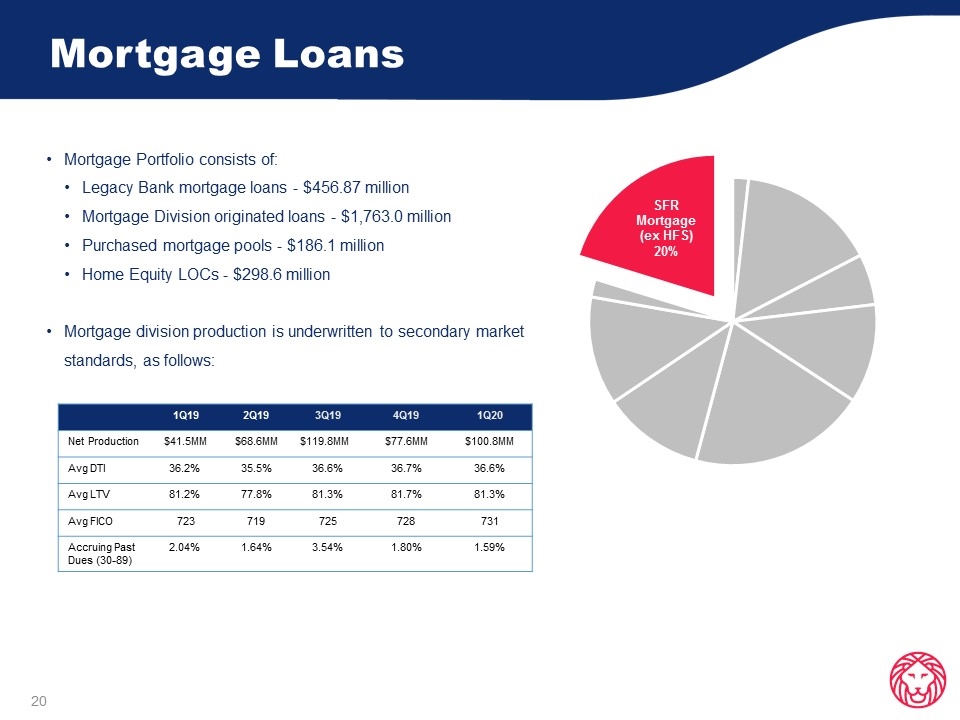
Mortgage Loans SFR Mortgage (ex HFS) 21.0% Mortgage Portfolio consists of: Legacy Bank mortgage loans - $456.87 million Mortgage Division originated loans - $1,763.0 million Purchased mortgage pools - $186.1 million Home Equity LOCs - $298.6 million Mortgage division production is underwritten to secondary market standards, as follows: 1Q19 2Q19 3Q19 4Q19 1Q20 Net Production $41.5MM $68.6MM $119.8MM $77.6MM $100.8MM Avg DTI 36.2% 35.5% 36.6% 36.7% 36.6% Avg LTV 81.2% 77.8% 81.3% 81.7% 81.3% Avg FICO 723 719 725 728 731 Accruing Past Dues (30-89) 2.04% 1.64% 3.54% 1.80% 1.59%
Ameris Bancorp Press Release & Financial Highlights March 31, 2020