
ALLY 8-K
Ally Financial Inc. (ALLY)
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM
CURRENT REPORT
Pursuant to Section 13 or 15(d)
of the Securities Exchange Act of 1934
Commission file number:
(Exact name of registrant as specified in its charter)
(State or other jurisdiction of incorporation or organization) |
(I.R.S. Employer Identification No.) |
(Address of principal executive offices)
(Zip Code)
(
(Registrant’s telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
| |
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) |
| |
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) |
| |
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) |
| |
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) |
Securities registered pursuant to Section 12(b) of the Act (all listed on the
Title of each class |
Trading symbols | |
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
| Item 2.02 | Results of Operation and Financial Condition. |
On April 20, 2020, Ally Financial Inc. issued a press release announcing preliminary operating results for the first quarter ended March 31, 2020. The press release is attached hereto and incorporated by reference as Exhibit 99.1. Charts furnished to securities analysts are attached hereto and incorporated by reference as Exhibit 99.2. In addition, supplemental financial data furnished to securities analysts is attached hereto and incorporated by reference as Exhibit 99.3.
| Item 9.01 | Financial Statements and Exhibits. |
| Exhibit |
Description | |||
| 99.1 |
||||
| 99.2 |
||||
| 99.3 |
Supplemental Financial Data Furnished to Securities Analysts | |||
| 104 |
The cover page from this Current Report on Form 8-K, formatted in Inline XBRL | |||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| ALLY FINANCIAL INC. | ||||
| (Registrant) | ||||
| Dated: April 20, 2020 |
/s/ David J. DeBrunner | |||
| David J. DeBrunner | ||||
| Vice President, Chief Accounting Officer | ||||
| and Controller |
Exhibit 99.1

News release: IMMEDIATE RELEASE
Ally Financial Reports First Quarter 2020 Financial Results
Net Loss of $(319) million, $(0.85) EPS, $(0.44) Adjusted EPS1
| First Quarter Results | ||||
| PRE-TAX LOSS | RETURN ON EQUITY | COMMON SHAREHOLDER EQUITY | ||||||||||
| $(411) million | (9.1)% | $36.23/share | ||||||||||
| CORE PRE-TAX LOSS1 $(217) million |
CORE ROTCE1 (5.4)% |
ADJUSTED TANGIBLE BOOK VALUE1 $32.80/share | ||||||||||
| TOTAL DEPOSITS | TOTAL LIQUIDITY | COMMON EQUITY TIER 1 RATIO | ||||||||||
| $122.3 billion | $30.1 billion | 9.3% |
| NOTABLE QUARTERLY ITEMS | • Total Net Revenue of $1.41 billion, down 12% YoY; Adjusted Total Net Revenue1 of $1.61 billion, up 5% YoY
• Total Net Revenue includes mark-to-market on equity portfolio of $185 million
• Results include $903 million provision expense | Reserve increase reflects forecasted macroeconomic changes associated with the Coronavirus Disease 2019 (COVID-19) pandemic
• Implemented current expected credit losses (CECL) framework
• Consumer auto originations of $9.1 billion, sourced from 3.0 million applications
• 1Q2020 Estimated Retail Auto Originated Yield1 of 7.25% | Retail auto net charge-off rate of 1.44%, up 12 bps YoY
• Insurance written premiums of $317 million, up 4% YoY – highest first quarter result
• Total deposits of $122.3 billion, up $9.0 billion YoY
• Retail deposits of $106.1 billion, up $2.3 billion QoQ and up 11% YoY
• Total retail deposit customers of 2.04 million, up 71 thousand QoQ and up 15% YoY
• Ally Home® direct-to-consumer mortgage originations of $0.7 billion
• Ally Invest self-directed net funded accounts up 17% YoY to 373 thousand – retained $0.7 billion of Ally deposit transfers to brokers
• Ally Lending gross originations of $70 million, up 5% QoQ
• Corporate Finance held-for-investment loan portfolio of $6.5 billion, up 31% YoY – $0.6 billion revolver draw activity in March
• Suspended share repurchases through the end of the second quarter and submitted Capital Plan to FRB in April
• Cardworks integration planning underway – filed application for regulatory approval |
|
Ally Chief Executive Officer Jeffrey Brown commented on the quarter:
“The emergence of the COVID-19 pandemic and its impact on the global economy has resulted in heightened uncertainty and challenges for consumers and businesses around the world. Against this difficult backdrop, I am proud of how the Ally team has resolutely focused on our customers while embracing our core values.
“As this public health crisis unfolded, we took decisive and comprehensive actions to support our people, customers and communities. In addition to rapidly mobilizing 99% of our company with work-from-home capabilities and a $1,200 financial assistance payment for employees earning less than $100,000, we materially expanded health and family care benefits to ensure our employees were safe and optimally positioned to focus on our customers.
“In mid-March, we led the industry by introducing comprehensive relief programs providing financial support to our consumer and commercial customers. These programs are directly aimed at providing increased flexibility during uncertain times. The deferment plans, fee suspensions, and robust outreach to our customers have been met with resoundingly positive feedback, reinforcing our view that these actions will strengthen long-term relationships and mitigate loss performance in the future.
“In response to the developing situation, we suspended our share repurchase program through June 30th and demonstrated funding access through a $750 million unsecured debt transaction in early April, further benefitting our capital and liquidity position. We continue to serve as a source of strength for our customers. Our ‘Do It Right’ culture, innovative spirit, deep industry experience and market leading platforms will allow Ally to navigate the challenges ahead, and I remain confident that we will leverage these qualities to emerge even stronger.
“We are prepared for a difficult period and recessionary conditions. Our provision for loan losses reflects the tough environment ahead. However, our company, like our great nation, has proven to rise even when conditions are dark – I am a firm believer Ally will emerge even stronger post this environment and continue demonstrating our solid operational performance across our businesses.”
|
| 1 | The following are non-GAAP financial measures which Ally believes are important to the reader of the Consolidated Financial Statements, but which are supplemental to and not a substitute for GAAP measures: Adjusted Earnings per Share (Adjusted EPS), Adjusted Total Net Revenue, Core Pre-Tax Income / (Loss), Core Net Income / (Loss) Attributable to Common Shareholders, Core OID, Core Return on Tangible Common Equity (Core ROTCE), Estimated Retail Auto Originated Yield, Tangible Common Equity, Net Financing Revenue (excluding Core OID) and Adjusted Tangible Book Value per Share (Adjusted TBVPS). These measures are used by management and we believe are useful to investors in assessing the company’s operating performance and capital. Refer to the Definitions of Non-GAAP Financial Measures and Other Key Terms, and Reconciliation to GAAP later in this press release. |

| Discussion of First Quarter Results | ||||
|
Net loss attributable to common shareholders was $319 million in the quarter, compared to net income attributable to common shareholders of $374 million in the first quarter of 2019, driven by higher provision for loan losses due to reserve build driven by forecasted macroeconomic changes associated with the COVID-19 pandemic as well as the decline in the fair value of equity securities given the overall decline in equity markets in March.
Net financing revenue improved to $1.15 billion, up $14 million from the same period a year ago, driven by higher retail auto portfolio yield and balance as well as liability mix shift, partially offset by lower commercial auto balance and portfolio yield. Net financing revenue was $10 million lower quarter-over-quarter, largely due to lower retail auto portfolio yield.
Other revenue decreased $200 million year-over-year, primarily due to a $185 million decline in the fair value of equity securities in the quarter compared to a $70 million increase in the fair value of equity securities in the prior-year quarter. Other revenue, excluding the change in fair value of equity securitiesA, increased $55 million year-over-year, driven primarily by higher realized investment gains.
Net interest margin (“NIM”) of 2.66%, including Core OIDB of 2 bps, decreased 1 bp year-over-year. Excluding Core OIDB, NIM was 2.68%, down 1 bp versus the prior-year period, and up 2 bps versus the prior quarter.
Provision for loan losses increased $621 million year-over-year to $903 million due to reserve build, primarily driven by forecasted macroeconomic changes associated with the COVID-19 pandemic.
Noninterest expense increased $90 million year-over-year, primarily driven by technology spend supporting business initiatives, higher insurance expenses directly linked to higher earned premiums and the addition of Ally Lending in the fourth quarter of 2019. | ||||
| A | Adjusted other revenue is a non-GAAP financial measure. Effective 1/1/2018, ASU 2016-01 requires change in the fair value of equity securities to be recognized in current period net income as compared to prior periods in which such adjustments were recognized through other comprehensive income, a component of equity. |
| B | Represents a non-GAAP financial measure. Refer to definitions of Non-GAAP Financial Measures and Other Key Terms later in this press release. |
| First Quarter Financial Results | ||||
| Increase/(Decrease) vs. | ||||||||||||||||||||
| ($ millions except per share data) | 1Q 20 | 4Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||
| Net Financing Revenue (excluding Core OID)1 |
$ | 1,154 | $ | 1,164 | $ | 1,139 | $ | (10) | $ | 16 | ||||||||||
| Core OID |
(8) | (8) | (7) | (0) | (2) | |||||||||||||||
| (a) Net Financing Revenue (as reported) |
1,146 | 1,156 | 1,132 | (10) | 14 | |||||||||||||||
| Other Revenue (excluding Change in Fair Value of Equity Securities)2 |
451 | 458 | 396 | (7) | 55 | |||||||||||||||
| Change in Fair Value of Equity Securities2 |
(185) | 29 | 70 | (214) | (255) | |||||||||||||||
| (b) Other Revenue (as reported) |
266 | 487 | 466 | (221) | (200) | |||||||||||||||
| (c) Provision for Loan Losses |
903 | 276 | 282 | 627 | 621 | |||||||||||||||
| (d) Noninterest Expense |
920 | 880 | 830 | 40 | 90 | |||||||||||||||
| Pre-Tax (Loss) / Income from Continuing Operations (a+b-c-d) |
$ | (411) | $ | 487 | $ | 486 | $ | (898) | $ | (897) | ||||||||||
| Income Tax (Benefit) Expense |
(92) | 106 | 111 | (198) | (203) | |||||||||||||||
| (Loss) / Income from Discontinued Operations, Net of Tax |
- | (3) | (1) | 3 | 1 | |||||||||||||||
| Net (Loss) Income |
$ | (319) | $ | 378 | $ | 374 | $ | (697) | $ | (693) | ||||||||||
| 1Q 20 | 4Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | ||||||||||||||||
| GAAP EPS (diluted)3 |
$ | (0.85) | $ | 0.99 | $ | 0.92 | ($ | 1.83) | $ | (1.77) | ||||||||||
| Discontinued Operations, Net of Tax |
- | 0.01 | 0.00 | (0.01) | (0.00) | |||||||||||||||
| Core OID, Net of Tax |
0.02 | 0.02 | 0.01 | 0.00 | 0.00 | |||||||||||||||
| Change in Fair Value of Equity Securities, Net of Tax |
0.39 | (0.06) | (0.14) | 0.45 | 0.53 | |||||||||||||||
| Adjusted EPS4 |
$ | (0.44) | $ | 0.95 | $ | 0.80 | $ | (1.39) | $ | (1.24) | ||||||||||
| Core ROTCE4 |
-5.4% | 11.2% | 10.9% |
|
|
|
|
|
| |||||||||||
| Adjusted Efficiency Ratio4 |
52.3% | 49.4% | 48.9% |
|
|
|
|
|
| |||||||||||
| Effective Tax Rate |
22.5% | 21.7% | 22.8% |
|
|
|
|
|
| |||||||||||
| (1) | Represents a non-GAAP financial measure. Adjusted for Core OID. Refer to the Definitions of Non-GAAP Financial Measures and Other Key Terms and Reconciliation to GAAP later in this press release. |
| (2) | Represents a non-GAAP financial measure. Adjusted for change in the fair value of equity securities due to the implementation of ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity. |
| (3) | Due to the antidilutive effect of the net loss from continuing operations for the three months ended March 31, 2020, basic weighted-average common shares outstanding were used to calculate basic and diluted earnings per share |
| (4) | Represents a non-GAAP financial measure. Refer to the Definitions of Non-GAAP Financial Measures and Other Key Terms and Reconciliation to GAAP later in this press release. |
2
| Pre-Tax (Loss) / Income by Segment | ||||
| Increase/(Decrease) vs. | ||||||||||||||||||||
| ($ millions) | 1Q 20 | 4Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||
| Automotive Finance |
$ | (173 | ) | $ | 401 | $ | 329 | $ | (574 | ) | $ | (502 | ) | |||||||
| Insurance |
(105 | ) | 114 | 145 | (219 | ) | (250 | ) | ||||||||||||
| Dealer Financial Services |
$ | (278 | ) | $ | 515 | $ | 474 | $ | (793) | $ | (752 | ) | ||||||||
| Corporate Finance |
(68 | ) | 50 | 13 | (118 | ) | (81 | ) | ||||||||||||
| Mortgage Finance |
12 | 2 | 13 | 10 | (1 | ) | ||||||||||||||
| Corporate and Other |
(77 | ) | (80 | ) | (14 | ) | 3 | (63 | ) | |||||||||||
| Pre-Tax (Loss) Income from Continuing Operations |
$ | (411 | ) | $ | 487 | $ | 486 | $ | (898 | ) | $ | (897 | ) | |||||||
| Core OID1 |
8 | 8 | 7 | 0 | 2 | |||||||||||||||
| Change in Fair Value of Equity Securities2 |
185 | (29 | ) | (70 | ) | 214 | 255 | |||||||||||||
| Core Pre-Tax (Loss) Income3 |
$ | (217 | ) | $ | 466 | $ | 423 | $ | (683 | ) | $ | (640 | ) | |||||||
| (1) | Core OID for all periods shown is applied to the pre-tax income of the Corporate and Other segment. Refer to the Definitions of Non-GAAP Financial Measures and Other Key Terms and Reconciliation to GAAP later in this press release. |
| (2) | Change in fair value of equity securities impacts the Insurance and Corporate Finance segments. Reflects equity fair value adjustments related to ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity. |
| (3) | Core pre-tax income is a non-GAAP financial measure that adjusts pre-tax income from continuing operations for Core OID and equity fair value adjustments related to ASU 2016-01. Management believes core pre-tax income can help the reader better understand the operating performance of the core businesses and their ability to generate earnings. Refer to the Definitions of Non-GAAP Financial Measures and Other Key Terms later in this press release. |
| Discussion of Segment Results | ||||
|
Auto Finance Pre-tax loss of $173 million was down $502 million year-over-year, primarily due to higher provision for loan losses associated with reserve build given COVID-19 forecasted macroeconomic changes.
Net financing revenue of $1.04 billion was $60 million higher year-over-year due to higher retail auto yields and higher retail auto balances. Retail auto portfolio yield increased 7 bps year-over-year to 6.54%. Ally’s conversion to a new consumer servicing and accounting platform resulted in a $28 million negative impact to net financing revenue in the first quarter, the majority of which will be re-timed over the remaining life of the loans.
Provision for loan losses increased $504 million year-over-year due to reserve build primarily driven by COVID-19 forecasted macroeconomic changes.
Consumer auto originations decreased to $9.1 billion from $9.2 billion in the prior year period, and included $5.0 billion of used retail volume, or 55% of total originations, $2.9 billion of new retail volume, and $1.2 billion of leases. Estimated retail auto originated yieldC of 7.25% was down 30 bps year-over-year despite significant decreases in benchmarks.
End-of-period auto earning assets decreased $2.6 billion year-over-year from $115.6 billion to $112.9 billion. End-of-period consumer auto earning assets were up $1.7 billion year-over-year driven by growth in the retail auto portfolio. End-of-period commercial earning assets of $31.4 billion were $4.3 billion lower year-over-year, primarily due to lower OEM inventory levels.
Insurance Pre-tax loss of $105 million was down $250 million year-over-year, primarily due to a $182 million decline in the fair value of equity securitiesE in the quarter compared to a $65 million increase in the fair value of equity securitiesE in the prior year quarter. Core pre-tax incomeD decreased $3 million year-over-year to $77 million as higher loss expense, mostly associated with higher weather losses, offset higher earned premiums and higher realized investment gains.
Written premiums were up $12 million year-over-year at $317 million, reflecting higher vehicle service contract rates and growth in diversified channels.
Total investment income was $12 million higher year-over-year at $54 million, excluding a $182 million decrease in the fair value of equity securities during the quarterE, driven by higher realized investment gains. |
CRepresents a non-GAAP financial measure. Refer to the Definitions of Non-GAAP Financial Measures and Other Key Terms and Reconciliation to GAAP later in this press release.
DRepresents a non-GAAP financial measure. Excludes equity fair value adjustments related to ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity. Refer to the definitions of Non-GAAP Financial Measures and Other Key Terms and Reconciliation to GAAP later in this press release.
EASU 2016-01 requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity.
3
| Corporate Finance Pre-tax loss of $68 million in the quarter, down $81 million year-over-year, primarily due to higher provision for loan losses associated with forecasted COVID-19 macroeconomic impacts.
Net financing revenue increased $14 million year-over-year to $68 million, driven by higher portfolio balances. Total net revenue, excluding the decline in the fair value of equity securitiesF, increased $24 million to $85 million, driven by higher portfolio balances and higher syndication fee income.
The held-for-investment loan portfolio increased 31% year-over-year from $5.0 billion to $6.5 billion. Draw-down activity on revolving credit lines totaled $0.6 billion in March, significantly slowing in April.
Provision for loan losses increased to $114 million, up $91 million year-over-year, primarily driven by COVID-19 forecasted macroeconomic impacts.
Mortgage Finance Pre-tax income was $12 million in the quarter, down $1 million year-over-year, as higher other revenue, lower provision for loan losses and lower noninterest expense was offset by lower net financing revenue.
Net financing revenue was down $12 million year-over-year to $38 million reflecting faster prepayments and higher premium amortization. Other revenue increased $8 million year-over-year to $10 million primarily driven by fee income given higher held-for-sale direct-to-consumer origination volume.
Noninterest expense decreased $2 million year-over-year to $35 million.
Direct-to-consumer originations totaled $0.7 billion in the quarter, up $0.4 billion year-over-year, with 51% of first quarter origination volume from existing Ally Bank customers. |
| Capital, Liquidity & Deposits | ||||
| Capital Ally paid a $0.19 per share quarterly common dividend and completed $104 million of share repurchases in the first quarter, including shares withheld to cover income taxes owed by participants related to share-based incentive plans. On March 17th, Ally announced that it was suspending share repurchases through the second quarter of 2020 in support of the Federal Reserve’s effort to mitigate the impact of the COVID-19 pandemic on the U.S. economy and the financial system. Ally’s Board of Directors approved a $0.19 per share common dividend for the second quarter of 2020.
Preliminary Basel III Transition Common Equity Tier 1 (CET1) capital ratio decreased from 9.5% to 9.3% quarter-over-quarter primarily due to the net loss realized in the quarter. Ally elected to delay the estimated impact of CECL on regulatory capital for a two-year period per the interim final rule issued by U.S. banking agencies in March 2020.
Liquidity & Funding Consolidated cash and cash equivalents totaled $5.7 billion at quarter-end, up $2.5 billion relative to the end of the fourth quarter. Total liquidityG was $30.1 billion at quarter-end. |
|
At quarter-end, 93% of Ally’s total assets were funded at Ally Bank, up from 89% a year ago.
Deposits represented 75% of Ally’s funding portfolio at quarter-end, excluding Core OID balanceH, increasing from 70% a year ago.
Deposits Retail deposits increased to $106.1 billion at quarter-end, up $10.6 billion year-over-year and up $2.3 billion for the quarter. Total deposits increased to $122.3 billion at quarter-end, up $9.0 billion year-over-year.
The average retail portfolio deposit rate was 1.88% for the quarter, down 26 bps year-over-year and down 14 bps quarter-over-quarter.
Ally’s retail deposit customer base grew 15% year-over-year, totaling 2.04 million customers at quarter-end, while adding 71 thousand customers during the quarter, representing the second highest customer growth level during a first quarter. Average customer balance ended the quarter at $52 thousand. Millennials continue to comprise the largest generation segment of new customers, accounting for 59% of new customers in the first quarter.
Ally launched a ‘Smart Savings Tool’ to help customers save more, exceeding expectations with approximately 24% of new customers using the tool during the quarter. |
FASU 2016-01 requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity.
G Total liquidity includes cash & cash equivalents, highly liquid securities and current committed unused borrowing capacity. See page 18 of the Financial Supplement for more details.
H Represents a non-GAAP financial measure. Refer to the definitions of Non-GAAP Financial Measures and Other Key Terms and Reconciliation to GAAP later in this press release.
4
| Definitions of Non-GAAP Financial Measures and Other Key Terms | ||||
Ally believes the non-GAAP financial measures defined here are important to the reader of the Consolidated Financial Statements, but these are supplemental to and not a substitute for GAAP measures.
Adjusted Earnings per Share (Adjusted EPS) is a non-GAAP financial measure that adjusts GAAP EPS for revenue and expense items that are typically strategic in nature or that management otherwise does not view as reflecting the operating performance of the company. Management believes Adjusted EPS can help the reader better understand the operating performance of the core businesses and their ability to generate earnings. In the numerator of Adjusted EPS, GAAP net income attributable to common shareholders is adjusted for the following items: (1) excludes discontinued operations, net of tax, as Ally is primarily a domestic company and sales of international businesses and other discontinued operations in the past have significantly impacted GAAP EPS, (2) adds back the tax-effected non-cash Core OID, and (3) excludes equity fair value adjustments (net of tax) related to ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity.
Adjusted Efficiency Ratio is a non-GAAP financial measure that management believes is helpful to readers in comparing the efficiency of its core banking and lending businesses with those of its peers. In the numerator of Adjusted Efficiency Ratio, total noninterest expense is adjusted for Insurance segment expense and rep and warrant expense. In the denominator, total net revenue is adjusted for Insurance segment revenue and Core OID. See Reconciliation to GAAP on page 7 for calculation methodology and details.
Adjusted Tangible Book Value per Share (Adjusted TBVPS) is a non-GAAP financial measure that reflects the book value of equity attributable to shareholders even if Core OID balance were accelerated immediately through the financial statements. As a result, management believes Adjusted TBVPS provides the reader with an assessment of value that is more conservative than GAAP common shareholder’s equity per share. Adjusted TBVPS generally adjusts common equity for: (1) goodwill and identifiable intangibles, net of deferred tax liabilities (DTLs) and (2) tax-effected Core OID balance to reduce tangible common equity in the event the corresponding discounted bonds are redeemed/tendered. In December 2017, tax-effected Core OID balance was adjusted from a statutory U.S. federal tax rate of 35% to 21% (“rate”) as a result of changes to U.S. tax law. The adjustment conservatively increased the tax-effected Core OID balance and consequently reduced Adjusted TBVPS as any acceleration of the non-cash charge in the future periods would flow through the financial statements at a 21% rate versus a previously modeled 35% rate. See Reconciliation to GAAP on page 7 for calculation methodology and details.
Core Net (Loss) / Income Attributable to Common Shareholders is a non-GAAP financial measure that serves as the numerator in the calculations of Adjusted EPS and Core ROTCE and that, like those measures, is believed by management to help the reader better understand the operating performance of the core businesses and their ability to generate earnings. Core net income attributable to common shareholders adjusts GAAP net income attributable to common shareholders for discontinued operations net of tax, tax-effected Core OID expense, significant discrete tax items, and tax-effected changes in equity investments measured at fair value. See Reconciliation to GAAP on page 6 for calculation methodology and details.
Core Original Issue Discount (Core OID) Amortization Expense is a non-GAAP financial measure for OID, primarily related to bond exchange OID which excludes international operations and future issuances. See page 7 for calculation methodology and details.
Core Outstanding Original Issue Discount Balance (Core OID balance) is a non-GAAP financial measure for outstanding OID, primarily related to bond exchange OID which excludes international operations and future issuances. See page 7 for calculation methodology and details.
Core Pre-tax (Loss)/ Income is a non-GAAP financial measure that adjusts pre-tax income from continuing operations by excluding (1) Core OID, and (2) equity fair value adjustments related to ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity. Management believes core pre-tax income can help the reader better understand the operating performance of the core businesses and their ability to generate earnings. See the Pre-Tax (Loss) / Income by Segment Table on page 3 for calculation methodology and details.
Core Return on Tangible Common Equity (Core ROTCE) is a non-GAAP financial measure that management believes is helpful for readers to better understand the ongoing ability of the company to generate returns on its equity base that supports core operations. For purposes of this calculation, tangible common equity is adjusted for Core OID balance and net DTA. Ally’s core net income attributable to common shareholders for purposes of calculating Core ROTCE is based on the actual effective tax rate for the period adjusted for significant discrete tax items including tax reserve releases, which aligns with the methodology used in calculating adjusted earnings per share.
| (1) | In the numerator of Core ROTCE, GAAP net income attributable to common shareholders is adjusted for discontinued operations net of tax, tax-effected Core OID, fair value adjustments (net of tax) related to ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity, and significant discrete tax items. |
| (2) | In the denominator, GAAP shareholder’s equity is adjusted for goodwill and identifiable intangibles net of DTL, Core OID balance, and net DTA. |
Corporate and Other primarily consists of activity related to centralized corporate treasury activities such as management of the cash and corporate investment securities and loan portfolios, short- and long-term debt, retail and brokered deposit liabilities, derivative instruments, the amortization of the discount associated with new debt issuances and bond exchanges, and the residual impacts of our corporate FTP and treasury ALM activities. Corporate and Other also includes certain equity investments, the management of our legacy mortgage portfolio, and reclassifications and eliminations between the reportable operating segments. Subsequent to June 1, 2016, the revenue and expense activity associated with Ally Invest was included within the Corporate and Other segment. Subsequent to October 1, 2019, the revenue and expense activity associated with Health Credit Services (rebranded Ally Lending) was included within the Corporate and Other segment.
Estimated impact of CECL on regulatory capital per interim final rule issued by U.S. banking agencies - In December 2018, the FRB and other U.S. banking agencies approved a final rule to address the impact of CECL on regulatory capital by allowing BHCs and banks, including Ally, the option to phase in the day-one impact of CECL over a three-year period. In March 2020, the FRB and other U.S. banking agencies issued an interim final rule that became effective on March 31, 2020, and provides an alternative option for banks to temporarily delay the impacts of CECL, relative to the incurred loss methodology for estimating the allowance for loan losses, on regulatory capital. For regulatory capital purposes, these rules permitted us to delay recognizing the estimated impact of CECL on regulatory capital until after a two-year deferral period, which for us extends through December 31, 2021. Beginning on January 1, 2022, we will be required to phase in 25% of the previously deferred estimated capital impact of CECL, with an additional 25% to be phased in at the beginning of each subsequent year until fully phased in by the first quarter of 2025. Under these rules, firms that adopt CECL and elect the five-year transition will calculate the estimated impact of CECL on regulatory capital as the day-one impact of adoption plus 25% of the subsequent change in allowance during the two-year deferral period, which according to the interim final rule approximates the impact of CECL relative to an incurred loss model. We adopted this transition option during the first quarter of 2020, and plan to phase in the regulatory capital impacts of CECL based on this five-year transition period.
5
Estimated Retail Auto Originated Yield is a forward-looking non-GAAP financial measure determined by calculating the estimated average annualized yield for loans originated during the period. At this time there currently is no comparable GAAP financial measure for Estimated Retail Auto Originated Yield and therefore this forecasted estimate of yield at the time of origination cannot be quantitatively reconciled to comparable GAAP information.
Net Financing Revenue (excluding OID) excludes Core OID.
Net Charge-Off Ratios are calculated as annualized net charge-offs divided by average outstanding finance receivables and loans excluding loans measured at fair value and loans held-for-sale.
Tangible Common Equity is a non-GAAP financial measure that is defined as common stockholders’ equity less goodwill and identifiable intangible assets, net of deferred tax liabilities. Ally considers various measures when evaluating capital adequacy, including tangible common equity. Ally believes that tangible common equity is important because we believe readers may assess our capital adequacy using this measure. Additionally, presentation of this measure allows readers to compare certain aspects of our capital adequacy on the same basis to other companies in the industry. For purposes of calculating Core return on tangible common equity (Core ROTCE), tangible common equity is further adjusted for Core OID balance and net deferred tax asset. See page 6 for calculation methodology & details.
| Reconciliation to GAAP | ||||
| Adjusted Earnings per Share |
||||||||||||||
| Numerator ($ millions) | 1Q 20 | 4Q 19 | 1Q 19 | |||||||||||
| GAAP Net (Loss) Income Attributable to Common Shareholders |
$ (319 | ) | $ | 378 | $ | 374 | ||||||||
| Discontinued Operations, Net of Tax |
- | 3 | 1 | |||||||||||
| Core OID |
8 | 8 | 7 | |||||||||||
| Change in Fair Value of Equity Securities |
185 | (29 | ) | (70 | ) | |||||||||
| Tax on: Core OID & Change in Fair Value of Equity Securities (21% starting 1Q18) |
(41 | ) | 4 | 13 | ||||||||||
| Core Net (Loss) Income Attributable to Common Shareholders |
[a] |
$ | (166 | ) | $ | 364 | $ | 325 | ||||||
| Denominator |
||||||||||||||
| Weighted-Average Common Shares Outstanding - (Diluted, thousands) |
[b] |
375,723 | 383,391 | 405,959 | ||||||||||
| Adjusted EPS |
[a] ÷ [b] |
$ | (0.44 | ) | $ | 0.95 | $ | 0.80 | ||||||
| Core Return on Tangible Common Equity (ROTCE) | ||||||||||||||
| Numerator ($ millions) | 1Q 20 | 4Q 19 | 1Q 19 | |||||||||||
| GAAP Net (Loss) Income Attributable to Common Shareholders |
$ | (319 | ) | $ | 378 | $ | 374 | |||||||
| Discontinued Operations, Net of Tax |
- | 3 | 1 | |||||||||||
| Core OID |
8 | 8 | 7 | |||||||||||
| Change in Fair Value of Equity Securities |
185 | (29 | ) | (70 | ) | |||||||||
| Tax on: Core OID & Change in Fair Value of Equity Securities (21% starting 1Q18) |
(41 | ) | 4 | 13 | ||||||||||
| Core Net (Loss) Income Attributable to Common Shareholders |
[a] |
$ | (166 | ) | $ | 364 | $ | 325 | ||||||
| Denominator (2-period average, $ billions) |
||||||||||||||
| GAAP Shareholder’s Equity |
$ | 14.0 | $ | 14.4 | $ | 13.5 | ||||||||
| Goodwill & Identifiable Intangibles, Net of Deferred Tax Liabilities (DTLs) |
(0.4 | ) | (0.4 | ) | (0.3 | ) | ||||||||
| Tangible Common Equity |
$ | 13.5 | $ | 14.1 | $ | 13.2 | ||||||||
| Core OID Balance |
(1.1 | ) | (1.1 | ) | (1.1 | ) | ||||||||
| Net Deferred Tax Asset (DTA) |
(0.1 | ) | (0.0 | ) | (0.2 | ) | ||||||||
| Normalized Common Equity | [b] | $ | 12.3 | $ | 13.0 | $ | 11.9 | |||||||
| Core Return on Tangible Common Equity |
[a] ÷ [b] |
-5.4 | % | 11.2 | % | 10.9 | % | |||||||
6
| Adjusted Tangible Book Value per Share |
||||||||||||||
| Numerator ($ billions) | 1Q 20 | 4Q 19 | 1Q 19 | |||||||||||
| GAAP Common Shareholder’s Equity |
$ | 13.5 | $ | 14.4 | $ | 13.7 | ||||||||
| Goodwill and Identifiable Intangible Assets, Net of DTLs |
(0.4 | ) | (0.5 | ) | (0.3 | ) | ||||||||
| Tangible Common Equity |
13.1 | 14.0 | 13.4 | |||||||||||
| Tax-effected Core OID Balance (21% starting in 4Q17) |
(0.8 | ) | (0.8 | ) | (0.9 | ) | ||||||||
| Adjusted Tangible Book Value |
[a] |
$ | 12.2 | $ | 13.1 | $ | 12.6 | |||||||
| Denominator |
||||||||||||||
| Issued Shares Outstanding (period-end, thousands) | [b] | 373,155 | 374,332 | 399,761 | ||||||||||
| Metric |
||||||||||||||
| GAAP Common Shareholder’s Equity per Share |
$ | 36.2 | $ | 38.5 | $ | 34.3 | ||||||||
| Goodwill and Identifiable Intangible Assets, Net of DTLs per Share |
(1.2 | ) | (1.2 | ) | (0.7 | ) | ||||||||
| Tangible Common Equity per Share |
$ | 35.0 | $ | 37.3 | $ | 33.6 | ||||||||
| Tax-effected Core OID Balance (21% starting in 4Q17) per Share |
(2.2 | ) | (2.2 | ) | (2.1 | ) | ||||||||
| Adjusted Tangible Book Value per Share |
[a] ÷ [b] |
$ | 32.8 | $ | 35.1 | $ | 31.4 | |||||||
| Adjusted Efficiency Ratio |
| |||||||||||||
| Numerator ($ millions) | 1Q 20 | 4Q 19 | 1Q 19 | |||||||||||
| GAAP Noninterest Expense |
$ | 920 | $ | 880 | $ | 830 | ||||||||
| Rep and Warrant Expense |
- | - | - | |||||||||||
| Insurance Expense |
(256 | ) | (238 | ) | (227 | ) | ||||||||
| Adjusted Noninterest Expense for Adjusted Efficiency Ratio |
[a] |
$ | 664 | $ | 642 | $ | 603 | |||||||
| Denominator ($ millions) | ||||||||||||||
| Total Net Revenue |
$ | 1,412 | $ | 1,643 | $ | 1,598 | ||||||||
| Core OID |
8 | 8 | 7 | |||||||||||
| Insurance Revenue |
(151 | ) | (352 | ) | (372 | ) | ||||||||
| Adjusted Net Revenue for Adjusted Efficiency Ratio |
[b] |
$ | 1,269 | $ | 1,299 | $ | 1,233 | |||||||
| Adjusted Efficiency Ratio |
[a] ÷ [b] |
52.3 | % | 49.4 | % | 48.9 | % | |||||||
| Original Issue Discount Amortization Expense ($ millions) | 1Q 20 | 4Q 19 | 1Q 19 | |||||||||||
| Core Original Issue Discount (Core OID) Amortization Expense (excl. accelerated OID) |
$ | 8 | $ | 8 | $ | 7 | ||||||||
| Other OID |
3 | 3 | 3 | |||||||||||
| GAAP Original Issue Discount Amortization Expense |
$ | 11 | $ | 11 | $ | 10 | ||||||||
| Outstanding Original Issue Discount Balance ($ millions) | 1Q 20 | 4Q 19 | 1Q 19 | |||||||||||
| Core Outstanding Original Issue Discount Balance (Core OID Balance) |
$ | (1,055 | ) | $ | (1,063 | ) | $ | (1,085 | ) | |||||
| Other Outstanding OID Balance |
(34 | ) | (37 | ) | (39 | ) | ||||||||
| GAAP Outstanding Original Issue Discount Balance |
$ | (1,089 | ) | $ | (1,100 | ) | $ | (1,125 | ) | |||||
7
| Net Financing Revenue (ex. Core OID) | ||||||||||||||||
| ($ millions) | 1Q 20 | 4Q 19 | 1Q 19 | |||||||||||||
| GAAP Net Financing Revenue |
$ | 1,146 | $ | 1,156 | $ | 1,132 | ||||||||||
| Core OID |
8 | 8 | 7 | |||||||||||||
| Net Financing Revenue (ex. Core OID) |
[a] | $ | 1,154 | $ | 1,164 | $ | 1,139 | |||||||||
| Adjusted Other Revenue | ||||||||||||||||
| ($ millions) | 1Q 20 | 4Q 19 | 1Q 19 | |||||||||||||
| GAAP Other Revenue |
$ | 266 | $ | 487 | $ | 466 | ||||||||||
| Change in Fair Value of Equity Securities |
185 | (29) | (70) | |||||||||||||
| Adjusted Other Revenue |
[b] | $ | 451 | $ | 458 | $ | 396 | |||||||||
| Adjusted Total Net Revenue | ||||||||||||||||
| ($ millions) | 1Q 20 | 4Q 19 | 1Q 19 | |||||||||||||
| Adjusted Total Net Revenue |
[a] + [b] | $ | 1,606 | $ | 1,662 | $ | 1,535 | |||||||||
| Insurance Non-GAAP Walk to Core Pre-Tax Income |
| |||||||||||||||||||||||||||||||
| 1Q 2020 | 1Q 2019 | |||||||||||||||||||||||||||||||
| ($ millions)
Insurance |
GAAP | Core OID | |
Change in the fair value of equity securities |
|
Non-GAAP1 | GAAP | Core OID | |
Change in the fair value of equity securities |
|
Non-GAAP1 | ||||||||||||||||||||
| Premiums, Service Revenue Earned and Other |
$ | 279 | $ | - | $ | - | $ | 279 | $ | 265 | $ | - | $ | - | $ | 265 | ||||||||||||||||
| Losses and Loss Adjustment Expenses |
74 | - | - | 74 | 59 | - | - | 59 | ||||||||||||||||||||||||
| Acquisition and Underwriting Expenses |
182 | - | - | 182 | 168 | - | - | 168 | ||||||||||||||||||||||||
| Investment Income and Other |
(128 | ) | - | 182 | 54 | 107 | - | (65 | ) | 42 | ||||||||||||||||||||||
| Pre-Tax (Loss) Income from Continuing Operations |
$ | (105 | ) | $ | - | $ | 182 | $ | 77 | $ | 145 | $ | - | $ | (65 | ) | $ | 80 | ||||||||||||||
1 Non-GAAP line items walk to Core Pre-Tax Income, a non-GAAP financial measure that adjusts Pre-Tax Income.
8
| Additional Financial Information | ||||
For additional financial information, the first quarter 2020 earnings presentation and financial supplement are available in the Events & Presentations section of Ally’s Investor Relations Website at http://www.ally.com/about/investor/events-presentations/.
About Ally Financial Inc.
Ally Financial Inc. (NYSE: ALLY) is a leading digital financial-services company with $182.5 billion in assets as of March 31, 2020. As a customer-centric company with passionate customer service and innovative financial solutions, we are relentlessly focused on “Doing it Right” and being a trusted financial-services provider to our consumer, commercial, and corporate customers. We are one of the largest full-service automotive-finance operations in the country and offer a wide range of financial services and insurance products to automotive dealerships and consumers. Our award-winning online bank (Ally Bank, Member FDIC and Equal Housing Lender) offers mortgage lending, personal lending, and a variety of deposit and other banking products, including savings, money-market, and checking accounts, certificates of deposit (CDs), and individual retirement accounts (IRAs). Additionally, we offer securities-brokerage and investment-advisory services through Ally Invest. Our robust corporate finance business offers capital for equity sponsors and middle-market companies.
For more information and disclosures about Ally, visit https://www.ally.com/#disclosures.
Forward-Looking Statements
This earnings release and related communications should be read in conjunction with the financial statements, notes, and other information contained in our Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q, and Current Reports on Form 8-K. This information is preliminary and based on company and third-party data available at the time of the release or related communication.
This earnings release and related communications contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements can be identified by the fact that they do not relate strictly to historical or current facts—such as statements about the outlook for various financial and operating metrics and statements about future capital allocation and actions. Forward-looking statements often use words such as “believe,” “expect,” “anticipate,” “intend,” “pursue,” “seek,” “continue,” “estimate,” “project,” “outlook,” “forecast,” “potential,” “target,” “objective,” “trend,” “plan,” “goal,” “initiative,” “priorities,” or other words of comparable meaning or future-tense or conditional verbs such as “may,” “will,” “should,” “would,” or “could.” Forward-looking statements convey our expectations, intentions, or forecasts about future events, circumstances, or results. All forward-looking statements, by their nature, are subject to assumptions, risks, and uncertainties, which may change over time and many of which are beyond our control. You should not rely on any forward-looking statement as a prediction or guarantee about the future.
Actual future objectives, strategies, plans, prospects, performance, conditions, or results may differ materially from those set forth in any forward-looking statement. Some of the factors that may cause actual results or other future events or circumstances to differ from those in forward-looking statements are described in our Annual Report on Form 10-K for the year ended December 31, 2019, our subsequent Quarterly Reports on Form 10-Q or Current Reports on Form 8-K, or other applicable documents that are filed or furnished with the U.S. Securities and Exchange Commission (collectively, our “SEC filings”). Any forward-looking statement made by us or on our behalf speaks only as of the date that it was made. We do not undertake to update any forward-looking statement to reflect the impact of events, circumstances, or results that arise after the date that the statement was made, except as required by applicable securities laws. You, however, should consult further disclosures (including disclosures of a forward-looking nature) that we may make in any subsequent SEC filings.
This earnings release and related communications contain specifically identified non-GAAP financial measures, which supplement the results that are reported according to generally accepted accounting principles (“GAAP”). These non-GAAP financial measures may be useful to investors but should not be viewed in isolation from, or as a substitute for, GAAP results. Differences between non-GAAP financial measures and comparable GAAP financial measures are reconciled in the release.
Unless the context otherwise requires, the following definitions apply. The term “loans” means the following consumer and commercial products associated with our direct and indirect financing activities: loans, retail installment sales contracts, lines of credit, and other financing products excluding operating leases. The term “operating leases” means consumer- and commercial-vehicle lease agreements where Ally is the lessor and the lessee is generally not obligated to acquire ownership of the vehicle at lease-end or compensate Ally for the vehicle’s residual value. The terms “lend,” “finance,” and “originate” mean our direct extension or origination of loans, our purchase or acquisition of loans, or our purchase of operating leases as applicable. The term “consumer” means all consumer products associated with our loan and operating-lease activities and all commercial retail installment sales contracts. The term “commercial” means all commercial products associated with our loan activities, other than commercial retail installment sales contracts.
| Contacts: | ||
| Daniel Eller | Rebecca Anderson | |
| Ally Investor Relations | Ally Communications (Media) | |
| 704-444-5216 | 980-312-8681 | |
| [email protected] | [email protected] |
9
Ally Financial Inc. 1Q 2020 Earnings Review April 20, 2020 Contact Ally Investor Relations at (866) 710-4623 or [email protected] Exhibit 99.2
Forward-Looking Statements and Additional Information This presentation and related communications should be read in conjunction with the financial statements, notes, and other information contained in our Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q, and Current Reports on Form 8-K. This information is preliminary and based on company and third-party data available at the time of the presentation or related communication. This presentation and related communications contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements can be identified by the fact that they do not relate strictly to historical or current facts—such as statements about future effects of COVID-19, the outlook for financial and operating metrics, and future capital allocation and actions. Forward-looking statements often use words such as “believe,” “expect,” “anticipate,” “intend,” “pursue,” “seek,” “continue,” “estimate,” “project,” “outlook,” “forecast,” “potential,” “target,” “objective,” “trend,” “plan,” “goal,” “initiative,” “priorities,” or other words of comparable meaning or future-tense or conditional verbs such as “may,” “will,” “should,” “would,” or “could.” Forward-looking statements convey our expectations, intentions, or forecasts about future events, circumstances, or results. All forward-looking statements, by their nature, are subject to assumptions, risks, and uncertainties, which may change over time and many of which are beyond our control. You should not rely on any forward-looking statement as a prediction or guarantee about the future. Actual future objectives, strategies, plans, prospects, performance, conditions, or results may differ materially from those set forth in any forward-looking statement. Some of the factors that may cause actual results or other future events or circumstances to differ from those in forward-looking statements are described in our Annual Report on Form 10-K for the year ended December 31, 2019, our subsequent Quarterly Reports on Form 10-Q or Current Reports on Form 8-K, or other applicable documents that are filed or furnished with the U.S. Securities and Exchange Commission (collectively, our “SEC filings”). Any forward-looking statement made by us or on our behalf speaks only as of the date that it was made. We do not undertake to update any forward-looking statement to reflect the impact of events, circumstances, or results that arise after the date that the statement was made, except as required by applicable securities laws. You, however, should consult further disclosures (including disclosures of a forward-looking nature) that we may make in any subsequent SEC filings. This presentation and related communications contain specifically identified non-GAAP financial measures, which supplement the results that are reported according to U.S. generally accepted accounting principles (“GAAP”). These non-GAAP financial measures may be useful to investors but should not be viewed in isolation from, or as a substitute for, GAAP results. Differences between non-GAAP financial measures and comparable GAAP financial measures are reconciled in the presentation. Unless the context otherwise requires, the following definitions apply. The term “loans” means the following consumer and commercial products associated with our direct and indirect financing activities: loans, retail installment sales contracts, lines of credit, and other financing products excluding operating leases. The term “operating leases” means consumer- and commercial-vehicle lease agreements where Ally is the lessor and the lessee is generally not obligated to acquire ownership of the vehicle at lease-end or compensate Ally for the vehicle’s residual value. The terms “lend,” “finance,” and “originate” mean our direct extension or origination of loans, our purchase or acquisition of loans, or our purchase of operating leases, as applicable. The term “consumer” means all consumer products associated with our loan and operating-lease activities and all commercial retail installment sales contracts. The term “commercial” means all commercial products associated with our loan activities, other than commercial retail installment sales contracts.
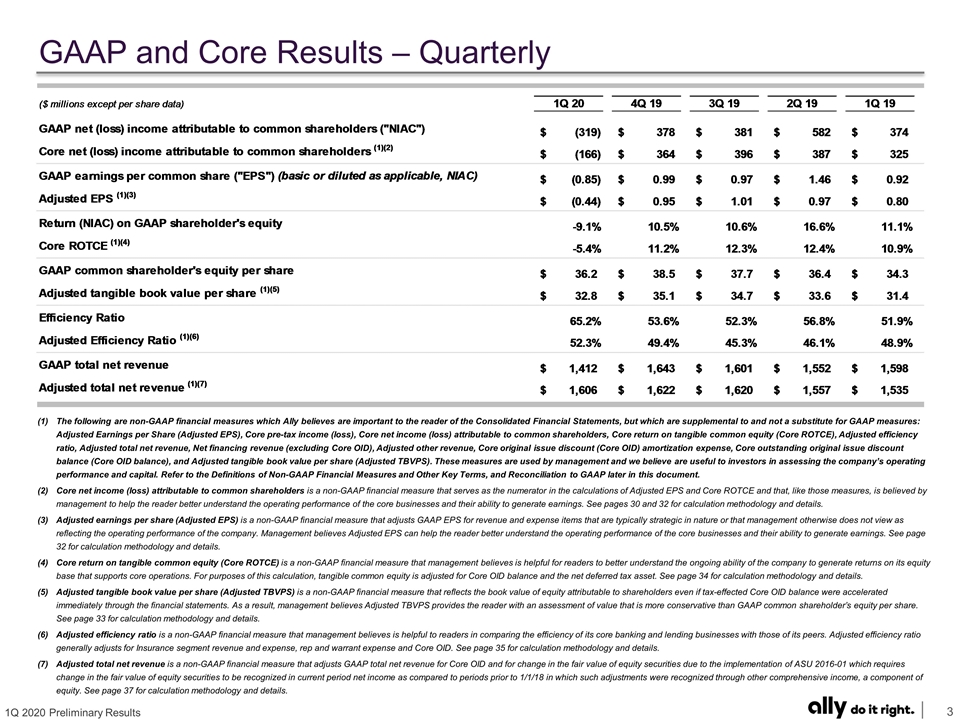
GAAP and Core Results – Quarterly The following are non-GAAP financial measures which Ally believes are important to the reader of the Consolidated Financial Statements, but which are supplemental to and not a substitute for GAAP measures: Adjusted Earnings per Share (Adjusted EPS), Core pre-tax income (loss), Core net income (loss) attributable to common shareholders, Core return on tangible common equity (Core ROTCE), Adjusted efficiency ratio, Adjusted total net revenue, Net financing revenue (excluding Core OID), Adjusted other revenue, Core original issue discount (Core OID) amortization expense, Core outstanding original issue discount balance (Core OID balance), and Adjusted tangible book value per share (Adjusted TBVPS). These measures are used by management and we believe are useful to investors in assessing the company’s operating performance and capital. Refer to the Definitions of Non-GAAP Financial Measures and Other Key Terms, and Reconciliation to GAAP later in this document. Core net income (loss) attributable to common shareholders is a non-GAAP financial measure that serves as the numerator in the calculations of Adjusted EPS and Core ROTCE and that, like those measures, is believed by management to help the reader better understand the operating performance of the core businesses and their ability to generate earnings. See pages 30 and 32 for calculation methodology and details. Adjusted earnings per share (Adjusted EPS) is a non-GAAP financial measure that adjusts GAAP EPS for revenue and expense items that are typically strategic in nature or that management otherwise does not view as reflecting the operating performance of the company. Management believes Adjusted EPS can help the reader better understand the operating performance of the core businesses and their ability to generate earnings. See page 32 for calculation methodology and details. Core return on tangible common equity (Core ROTCE) is a non-GAAP financial measure that management believes is helpful for readers to better understand the ongoing ability of the company to generate returns on its equity base that supports core operations. For purposes of this calculation, tangible common equity is adjusted for Core OID balance and the net deferred tax asset. See page 34 for calculation methodology and details. Adjusted tangible book value per share (Adjusted TBVPS) is a non-GAAP financial measure that reflects the book value of equity attributable to shareholders even if tax-effected Core OID balance were accelerated immediately through the financial statements. As a result, management believes Adjusted TBVPS provides the reader with an assessment of value that is more conservative than GAAP common shareholder’s equity per share. See page 33 for calculation methodology and details. Adjusted efficiency ratio is a non-GAAP financial measure that management believes is helpful to readers in comparing the efficiency of its core banking and lending businesses with those of its peers. Adjusted efficiency ratio generally adjusts for Insurance segment revenue and expense, rep and warrant expense and Core OID. See page 35 for calculation methodology and details. Adjusted total net revenue is a non-GAAP financial measure that adjusts GAAP total net revenue for Core OID and for change in the fair value of equity securities due to the implementation of ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/18 in which such adjustments were recognized through other comprehensive income, a component of equity. See page 37 for calculation methodology and details.
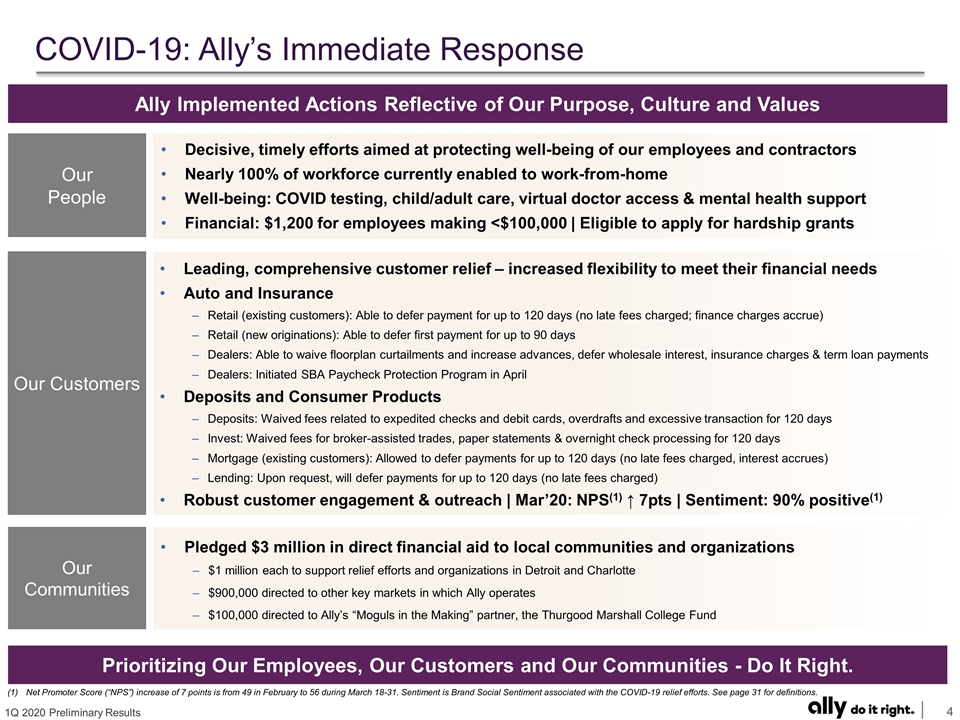
Leading, comprehensive customer relief – increased flexibility to meet their financial needs Auto and Insurance Retail (existing customers): Able to defer payment for up to 120 days (no late fees charged; finance charges accrue) Retail (new originations): Able to defer first payment for up to 90 days Dealers: Able to waive floorplan curtailments and increase advances, defer wholesale interest, insurance charges & term loan payments Dealers: Initiated SBA Paycheck Protection Program in April Deposits and Consumer Products Deposits: Waived fees related to expedited checks and debit cards, overdrafts and excessive transaction for 120 days Invest: Waived fees for broker-assisted trades, paper statements & overnight check processing for 120 days Mortgage (existing customers): Allowed to defer payments for up to 120 days (no late fees charged, interest accrues) Lending: Upon request, will defer payments for up to 120 days (no late fees charged) Robust customer engagement & outreach | Mar’20: NPS(1) ↑ 7pts | Sentiment: 90% positive(1) COVID-19: Ally’s Immediate Response Decisive, timely efforts aimed at protecting well-being of our employees and contractors Nearly 100% of workforce currently enabled to work-from-home Well-being: COVID testing, child/adult care, virtual doctor access & mental health support Financial: $1,200 for employees making <$100,000 | Eligible to apply for hardship grants Our People Our Customers Our Communities Pledged $3 million in direct financial aid to local communities and organizations $1 million each to support relief efforts and organizations in Detroit and Charlotte $900,000 directed to other key markets in which Ally operates $100,000 directed to Ally’s “Moguls in the Making” partner, the Thurgood Marshall College Fund Ally Implemented Actions Reflective of Our Purpose, Culture and Values Prioritizing Our Employees, Our Customers and Our Communities - Do It Right. Net Promoter Score (“NPS”) increase of 7 points is from 49 in February to 56 during March 18-31. Sentiment is Brand Social Sentiment associated with the COVID-19 relief efforts. See page 31 for definitions.
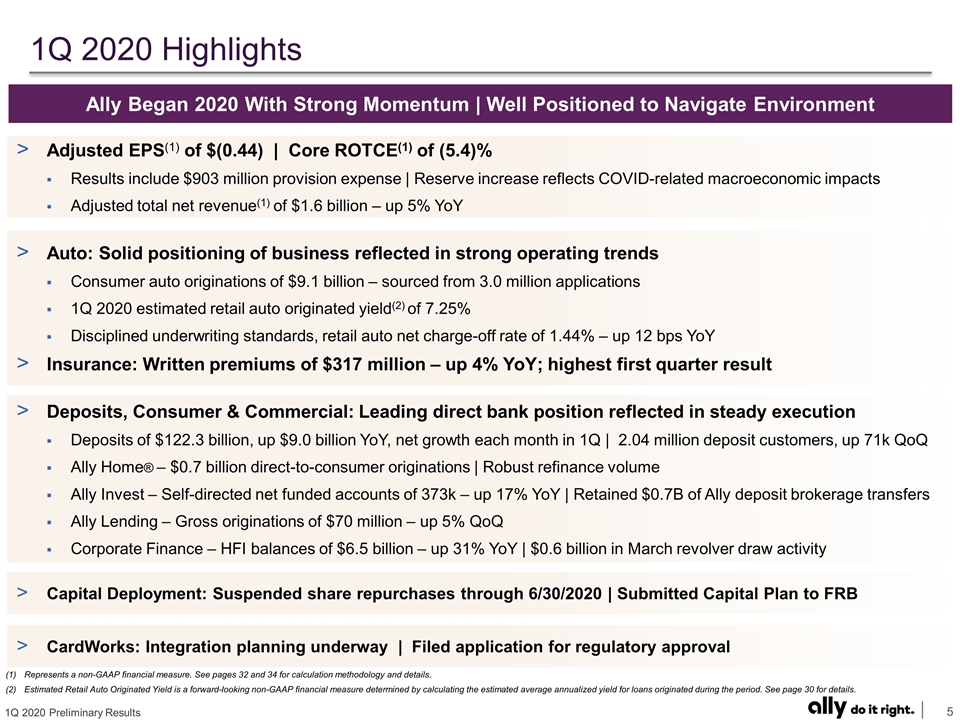
1Q 2020 Highlights Adjusted EPS(1) of $(0.44) | Core ROTCE(1) of (5.4)% Results include $903 million provision expense | Reserve increase reflects COVID-related macroeconomic impacts Adjusted total net revenue(1) of $1.6 billion – up 5% YoY Auto: Solid positioning of business reflected in strong operating trends Consumer auto originations of $9.1 billion – sourced from 3.0 million applications 1Q 2020 estimated retail auto originated yield(2) of 7.25% Disciplined underwriting standards, retail auto net charge-off rate of 1.44% – up 12 bps YoY Insurance: Written premiums of $317 million – up 4% YoY; highest first quarter result Deposits, Consumer & Commercial: Leading direct bank position reflected in steady execution Deposits of $122.3 billion, up $9.0 billion YoY, net growth each month in 1Q | 2.04 million deposit customers, up 71k QoQ Ally Home® – $0.7 billion direct-to-consumer originations | Robust refinance volume Ally Invest – Self-directed net funded accounts of 373k – up 17% YoY | Retained $0.7B of Ally deposit brokerage transfers Ally Lending – Gross originations of $70 million – up 5% QoQ Corporate Finance – HFI balances of $6.5 billion – up 31% YoY | $0.6 billion in March revolver draw activity Ally Began 2020 With Strong Momentum | Well Positioned to Navigate Environment Represents a non-GAAP financial measure. See pages 32 and 34 for calculation methodology and details. Estimated Retail Auto Originated Yield is a forward-looking non-GAAP financial measure determined by calculating the estimated average annualized yield for loans originated during the period. See page 30 for details. Capital Deployment: Suspended share repurchases through 6/30/2020 | Submitted Capital Plan to FRB CardWorks: Integration planning underway | Filed application for regulatory approval
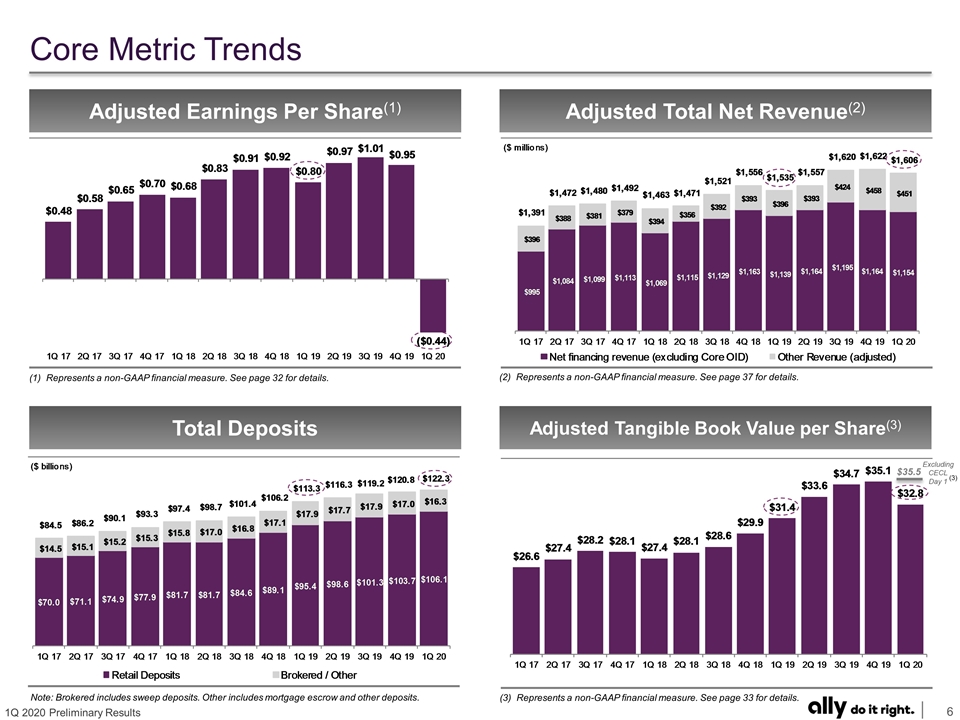
Adjusted Earnings Per Share(1) Adjusted Total Net Revenue(2) Total Deposits Adjusted Tangible Book Value per Share(3) Core Metric Trends (2) Represents a non-GAAP financial measure. See page 37 for details. (1) Represents a non-GAAP financial measure. See page 32 for details. (3) Represents a non-GAAP financial measure. See page 33 for details. Note: Brokered includes sweep deposits. Other includes mortgage escrow and other deposits. $35.5 Excluding CECL Day 1 (3)
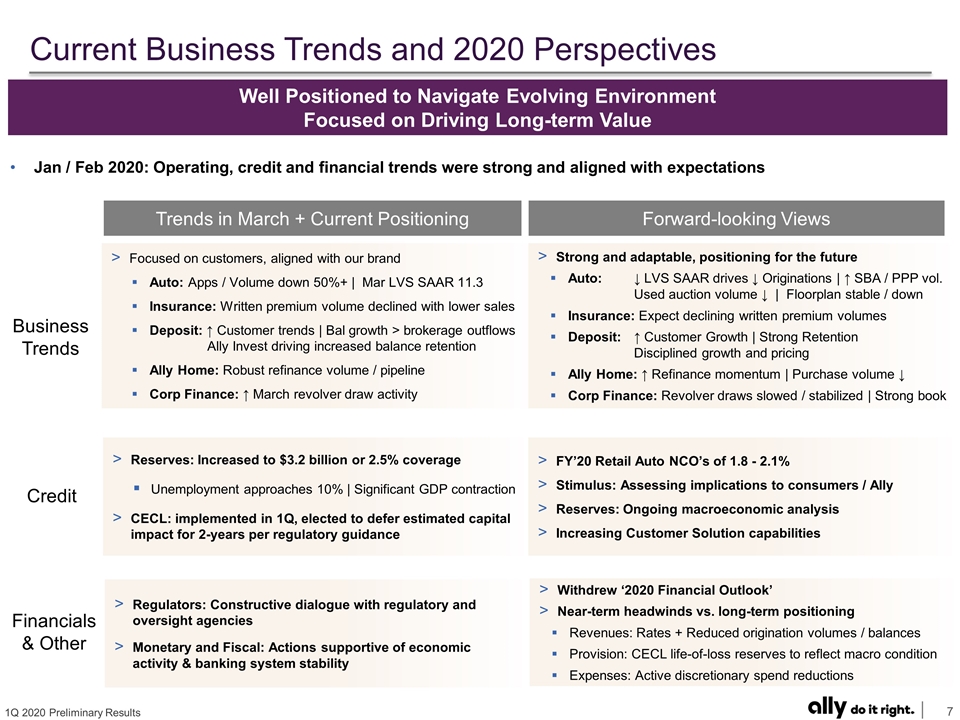
Current Business Trends and 2020 Perspectives Focused on customers, aligned with our brand Auto: Apps / Volume down 50%+ | Mar LVS SAAR 11.3 Insurance: Written premium volume declined with lower sales Deposit: ↑ Customer trends | Bal growth > brokerage outflows Ally Invest driving increased balance retention Ally Home: Robust refinance volume / pipeline Corp Finance: ↑ March revolver draw activity Business Trends Credit Financials & Other Reserves: Increased to $3.2 billion or 2.5% coverage Unemployment approaches 10% | Significant GDP contraction CECL: implemented in 1Q, elected to defer estimated capital impact for 2-years per regulatory guidance Well Positioned to Navigate Evolving Environment Focused on Driving Long-term Value Trends in March + Current Positioning Forward-looking Views Strong and adaptable, positioning for the future Auto: ↓ LVS SAAR drives ↓ Originations | ↑ SBA / PPP vol. Used auction volume ↓ | Floorplan stable / down Insurance: Expect declining written premium volumes Deposit: ↑ Customer Growth | Strong Retention Disciplined growth and pricing Ally Home: ↑ Refinance momentum | Purchase volume ↓ Corp Finance: Revolver draws slowed / stabilized | Strong book FY’20 Retail Auto NCO’s of 1.8 - 2.1% Stimulus: Assessing implications to consumers / Ally Reserves: Ongoing macroeconomic analysis Increasing Customer Solution capabilities Regulators: Constructive dialogue with regulatory and oversight agencies Monetary and Fiscal: Actions supportive of economic activity & banking system stability Withdrew ‘2020 Financial Outlook’ Near-term headwinds vs. long-term positioning Revenues: Rates + Reduced origination volumes / balances Provision: CECL life-of-loss reserves to reflect macro condition Expenses: Active discretionary spend reductions Jan / Feb 2020: Operating, credit and financial trends were strong and aligned with expectations
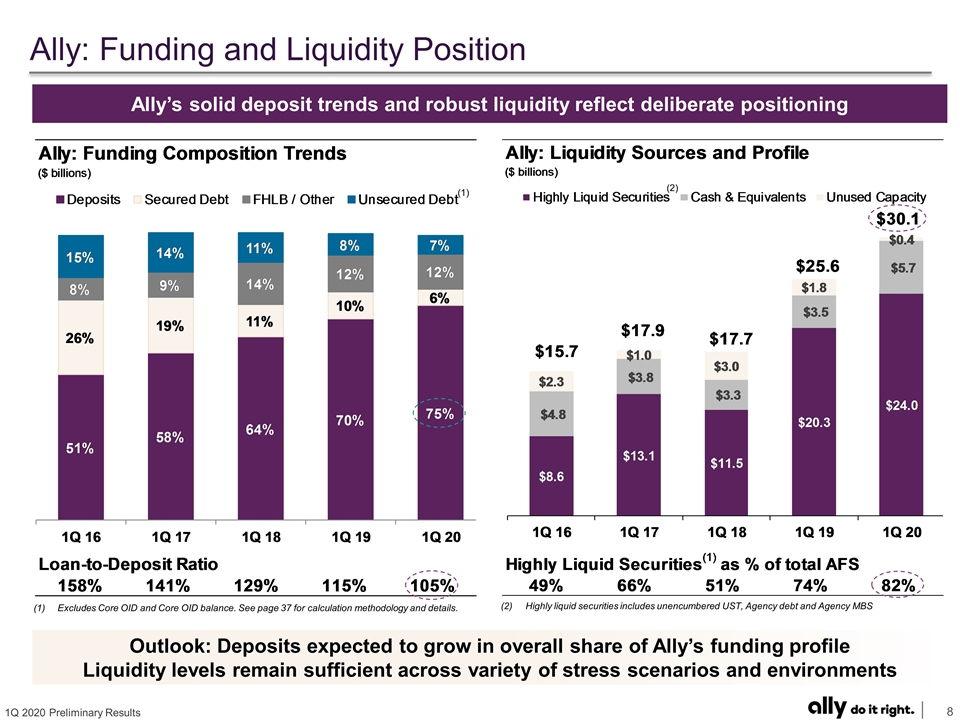
Ally: Funding and Liquidity Position Outlook: Deposits expected to grow in overall share of Ally’s funding profile Liquidity levels remain sufficient across variety of stress scenarios and environments Ally’s solid deposit trends and robust liquidity reflect deliberate positioning (2) Highly liquid securities includes unencumbered UST, Agency debt and Agency MBS (2) Excludes Core OID and Core OID balance. See page 37 for calculation methodology and details. (1)
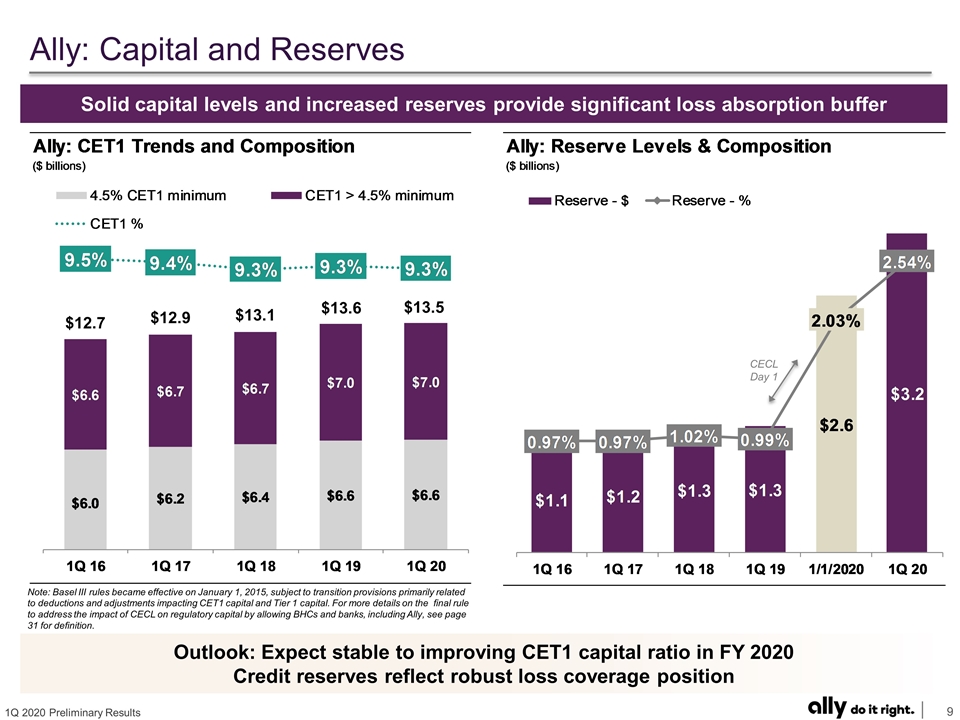
Ally: Capital and Reserves Solid capital levels and increased reserves provide significant loss absorption buffer $12.7 $12.9 $13.1 $13.6 $13.5 Outlook: Expect stable to improving CET1 capital ratio in FY 2020 Credit reserves reflect robust loss coverage position CECL Day 1 Note: Basel III rules became effective on January 1, 2015, subject to transition provisions primarily related to deductions and adjustments impacting CET1 capital and Tier 1 capital. For more details on the final rule to address the impact of CECL on regulatory capital by allowing BHCs and banks, including Ally, see page 31 for definition.
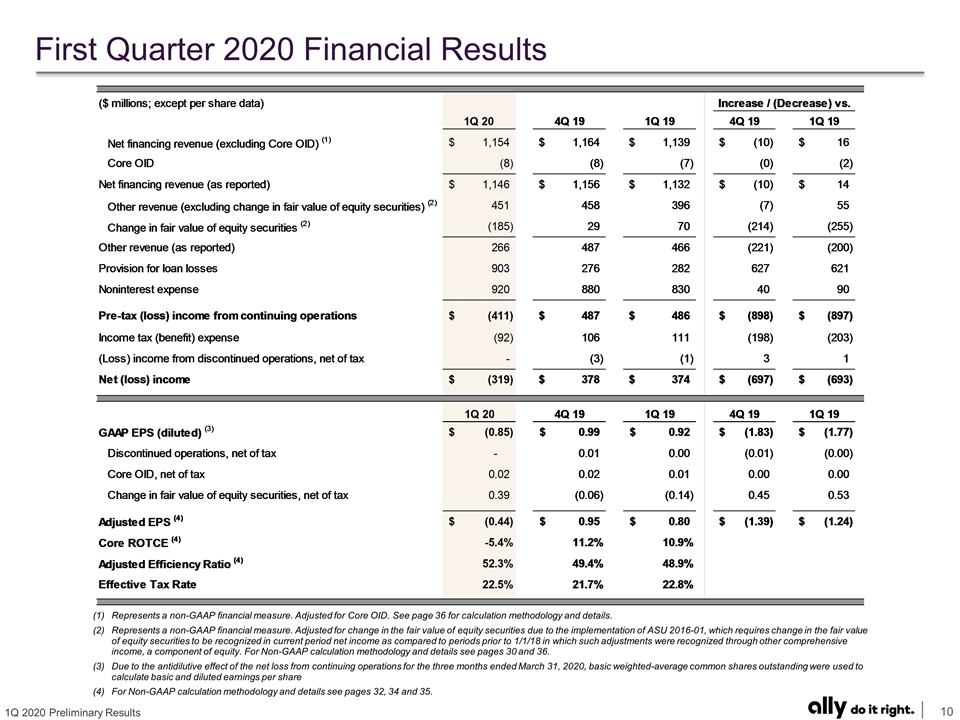
First Quarter 2020 Financial Results Represents a non-GAAP financial measure. Adjusted for Core OID. See page 36 for calculation methodology and details. Represents a non-GAAP financial measure. Adjusted for change in the fair value of equity securities due to the implementation of ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/18 in which such adjustments were recognized through other comprehensive income, a component of equity. For Non-GAAP calculation methodology and details see pages 30 and 36. Due to the antidilutive effect of the net loss from continuing operations for the three months ended March 31, 2020, basic weighted-average common shares outstanding were used to calculate basic and diluted earnings per share For Non-GAAP calculation methodology and details see pages 32, 34 and 35.
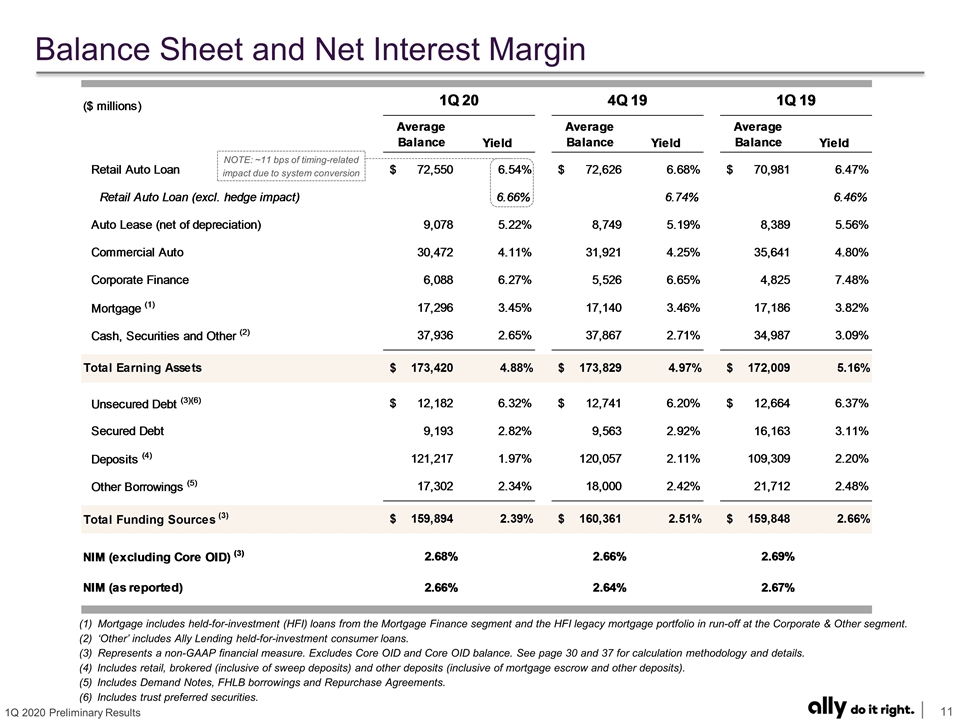
Balance Sheet and Net Interest Margin Mortgage includes held-for-investment (HFI) loans from the Mortgage Finance segment and the HFI legacy mortgage portfolio in run-off at the Corporate & Other segment. ‘Other’ includes Ally Lending held-for-investment consumer loans. Represents a non-GAAP financial measure. Excludes Core OID and Core OID balance. See page 30 and 37 for calculation methodology and details. Includes retail, brokered (inclusive of sweep deposits) and other deposits (inclusive of mortgage escrow and other deposits). Includes Demand Notes, FHLB borrowings and Repurchase Agreements. Includes trust preferred securities. NOTE: ~11 bps of timing-related impact due to system conversion
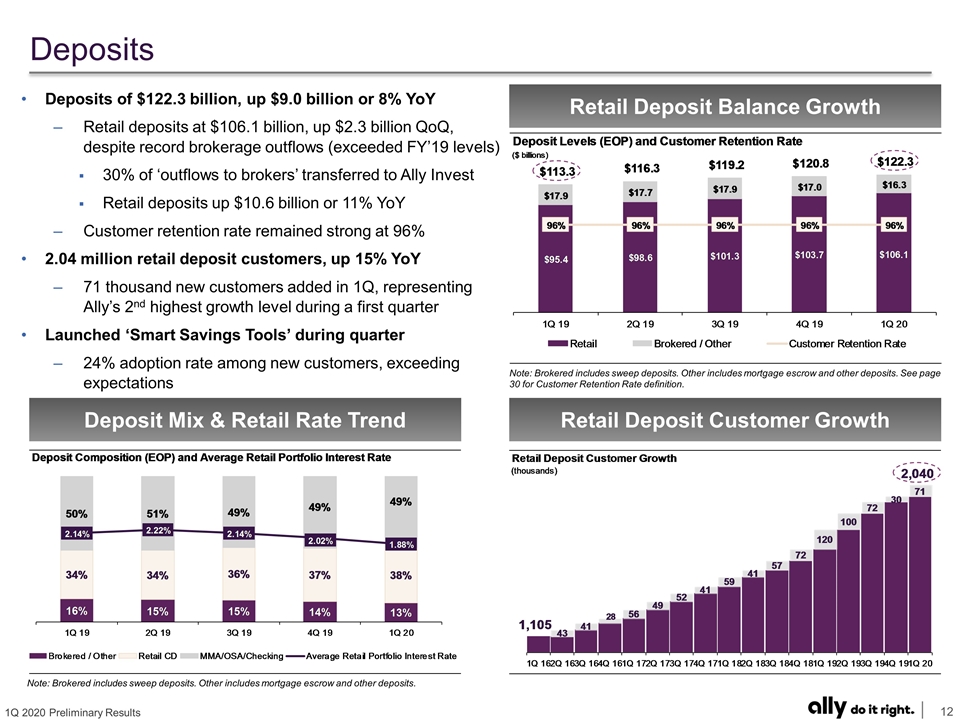
Retail Deposit Balance Growth Deposit Mix & Retail Rate Trend Retail Deposit Customer Growth Deposits Note: Brokered includes sweep deposits. Other includes mortgage escrow and other deposits. See page 30 for Customer Retention Rate definition. Deposits of $122.3 billion, up $9.0 billion or 8% YoY Retail deposits at $106.1 billion, up $2.3 billion QoQ, despite record brokerage outflows (exceeded FY’19 levels) 30% of ‘outflows to brokers’ transferred to Ally Invest Retail deposits up $10.6 billion or 11% YoY Customer retention rate remained strong at 96% 2.04 million retail deposit customers, up 15% YoY 71 thousand new customers added in 1Q, representing Ally’s 2nd highest growth level during a first quarter Launched ‘Smart Savings Tools’ during quarter 24% adoption rate among new customers, exceeding expectations Note: Brokered includes sweep deposits. Other includes mortgage escrow and other deposits.
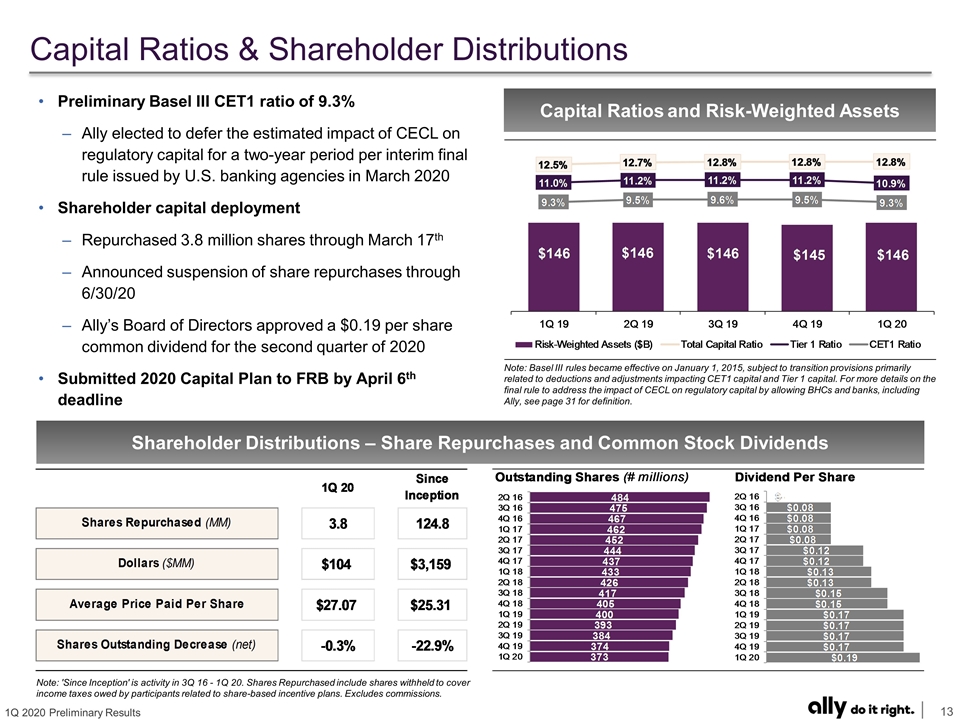
Capital Ratios and Risk-Weighted Assets Capital Ratios & Shareholder Distributions Preliminary Basel III CET1 ratio of 9.3% Ally elected to defer the estimated impact of CECL on regulatory capital for a two-year period per interim final rule issued by U.S. banking agencies in March 2020 Shareholder capital deployment Repurchased 3.8 million shares through March 17th Announced suspension of share repurchases through 6/30/20 Ally’s Board of Directors approved a $0.19 per share common dividend for the second quarter of 2020 Submitted 2020 Capital Plan to FRB by April 6th deadline Note: Basel III rules became effective on January 1, 2015, subject to transition provisions primarily related to deductions and adjustments impacting CET1 capital and Tier 1 capital. For more details on the final rule to address the impact of CECL on regulatory capital by allowing BHCs and banks, including Ally, see page 31 for definition. Note: 'Since Inception' is activity in 3Q 16 - 1Q 20. Shares Repurchased include shares withheld to cover income taxes owed by participants related to share-based incentive plans. Excludes commissions. Shareholder Distributions – Share Repurchases and Common Stock Dividends
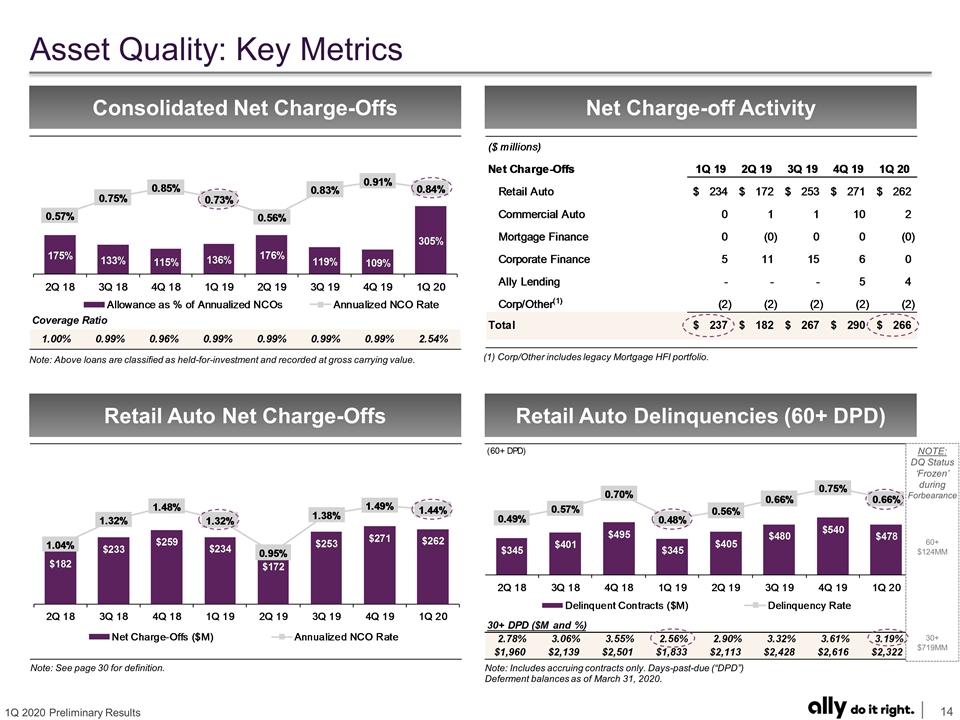
NOTE: DQ Status ‘Frozen’ during Forbearance Consolidated Net Charge-Offs Net Charge-off Activity Retail Auto Net Charge-Offs Retail Auto Delinquencies (60+ DPD) Asset Quality: Key Metrics Note: Above loans are classified as held-for-investment and recorded at gross carrying value. Note: Includes accruing contracts only. Days-past-due (“DPD”) Deferment balances as of March 31, 2020. (1) Corp/Other includes legacy Mortgage HFI portfolio. Note: See page 30 for definition. 60+ $124MM 30+ $719MM
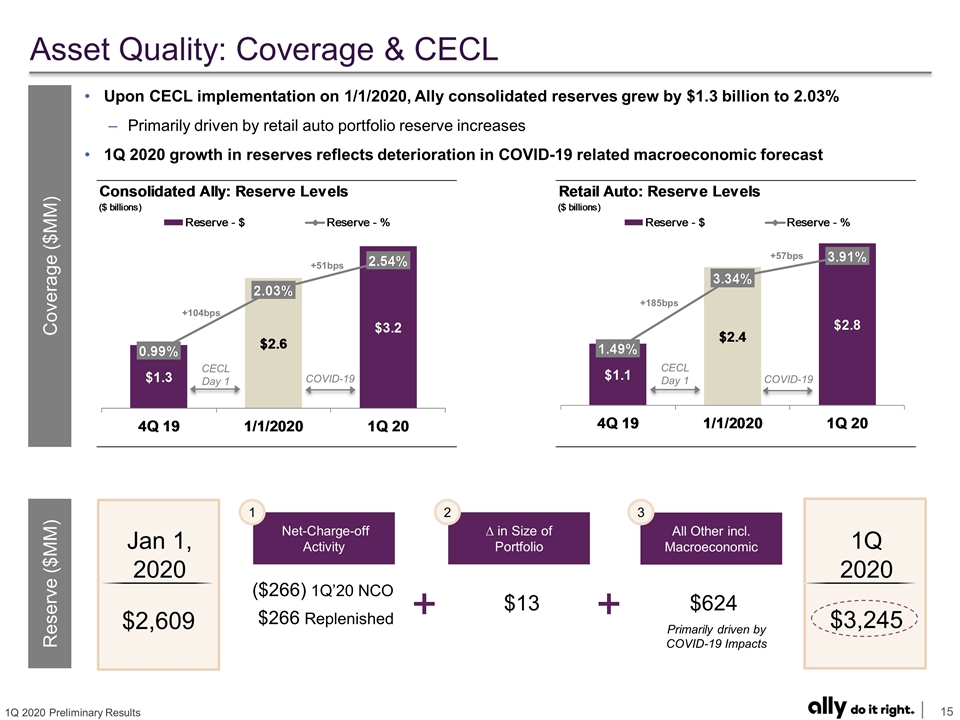
Asset Quality: Coverage & CECL Coverage ($MM) Reserve ($MM) Net-Charge-off Activity 1 ∆ in Size of Portfolio 2 All Other incl. Macroeconomic 3 Jan 1, 2020 $2,609 ($266) 1Q’20 NCO 1Q 2020 $3,245 $13 $624 Upon CECL implementation on 1/1/2020, Ally consolidated reserves grew by $1.3 billion to 2.03% Primarily driven by retail auto portfolio reserve increases 1Q 2020 growth in reserves reflects deterioration in COVID-19 related macroeconomic forecast $266 Replenished CECL Day 1 COVID-19 CECL Day 1 COVID-19 Primarily driven by COVID-19 Impacts +51bps +104bps +185bps +57bps
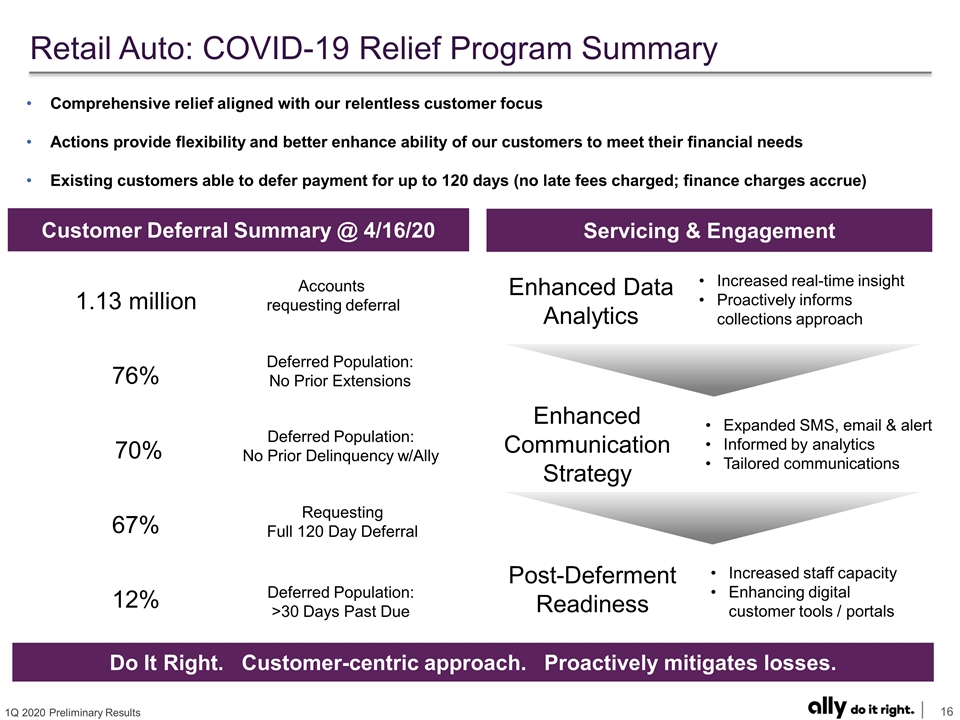
Retail Auto: COVID-19 Relief Program Summary Comprehensive relief aligned with our relentless customer focus Actions provide flexibility and better enhance ability of our customers to meet their financial needs Existing customers able to defer payment for up to 120 days (no late fees charged; finance charges accrue) Customer Deferral Summary @ 4/16/20 1.13 million Accounts requesting deferral 67% Requesting Full 120 Day Deferral 12% Deferred Population: >30 Days Past Due 76% Deferred Population: No Prior Extensions 70% Deferred Population: No Prior Delinquency w/Ally Servicing & Engagement Enhanced Data Analytics Increased real-time insight Proactively informs collections approach Enhanced Communication Strategy Expanded SMS, email & alert Informed by analytics Tailored communications Post-Deferment Readiness Increased staff capacity Enhancing digital customer tools / portals Do It Right. Customer-centric approach. Proactively mitigates losses.
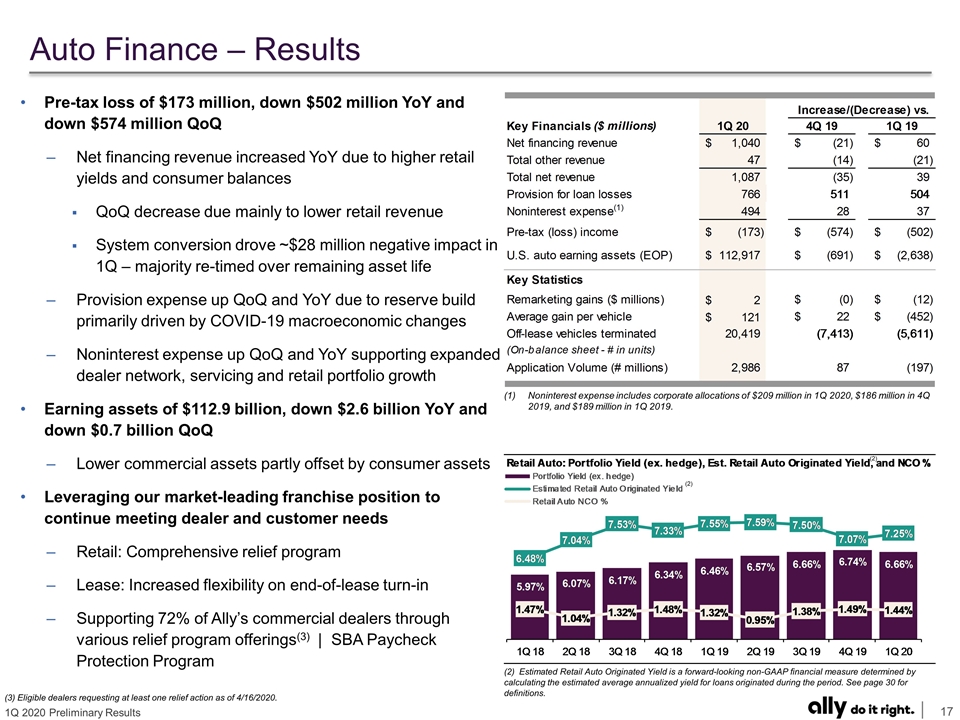
Auto Finance – Results Noninterest expense includes corporate allocations of $209 million in 1Q 2020, $186 million in 4Q 2019, and $189 million in 1Q 2019. Pre-tax loss of $173 million, down $502 million YoY and down $574 million QoQ Net financing revenue increased YoY due to higher retail yields and consumer balances QoQ decrease due mainly to lower retail revenue System conversion drove ~$28 million negative impact in 1Q – majority re-timed over remaining asset life Provision expense up QoQ and YoY due to reserve build primarily driven by COVID-19 macroeconomic changes Noninterest expense up QoQ and YoY supporting expanded dealer network, servicing and retail portfolio growth Earning assets of $112.9 billion, down $2.6 billion YoY and down $0.7 billion QoQ Lower commercial assets partly offset by consumer assets Leveraging our market-leading franchise position to continue meeting dealer and customer needs Retail: Comprehensive relief program Lease: Increased flexibility on end-of-lease turn-in Supporting 72% of Ally’s commercial dealers through various relief program offerings(3) | SBA Paycheck Protection Program (2) Estimated Retail Auto Originated Yield is a forward-looking non-GAAP financial measure determined by calculating the estimated average annualized yield for loans originated during the period. See page 30 for definitions. (2) (2) (3) Eligible dealers requesting at least one relief action as of 4/16/2020.
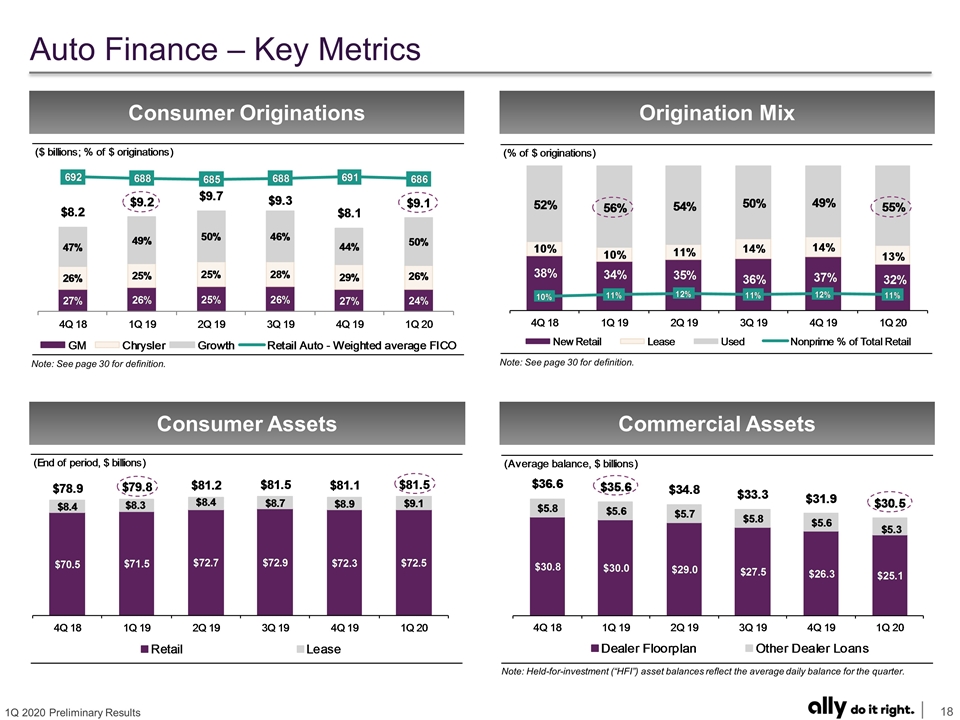
Consumer Originations Origination Mix Consumer Assets Commercial Assets Auto Finance – Key Metrics Note: Held-for-investment (“HFI”) asset balances reflect the average daily balance for the quarter. Note: See page 30 for definition. Note: See page 30 for definition.
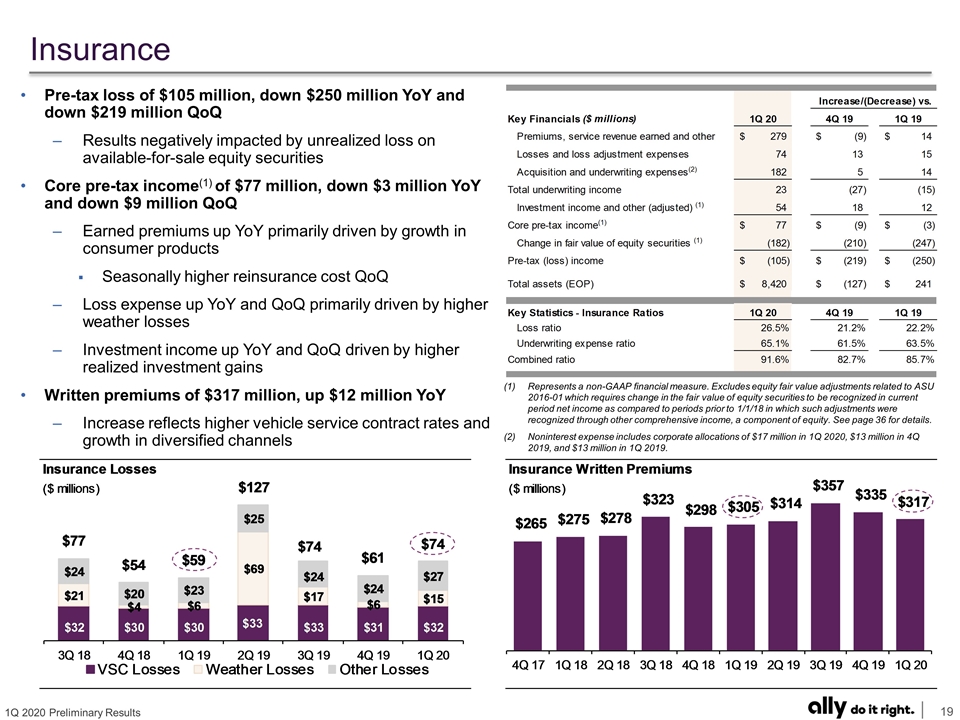
Insurance Represents a non-GAAP financial measure. Excludes equity fair value adjustments related to ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/18 in which such adjustments were recognized through other comprehensive income, a component of equity. See page 36 for details. Noninterest expense includes corporate allocations of $17 million in 1Q 2020, $13 million in 4Q 2019, and $13 million in 1Q 2019. Pre-tax loss of $105 million, down $250 million YoY and down $219 million QoQ Results negatively impacted by unrealized loss on available-for-sale equity securities Core pre-tax income(1) of $77 million, down $3 million YoY and down $9 million QoQ Earned premiums up YoY primarily driven by growth in consumer products Seasonally higher reinsurance cost QoQ Loss expense up YoY and QoQ primarily driven by higher weather losses Investment income up YoY and QoQ driven by higher realized investment gains Written premiums of $317 million, up $12 million YoY Increase reflects higher vehicle service contract rates and growth in diversified channels
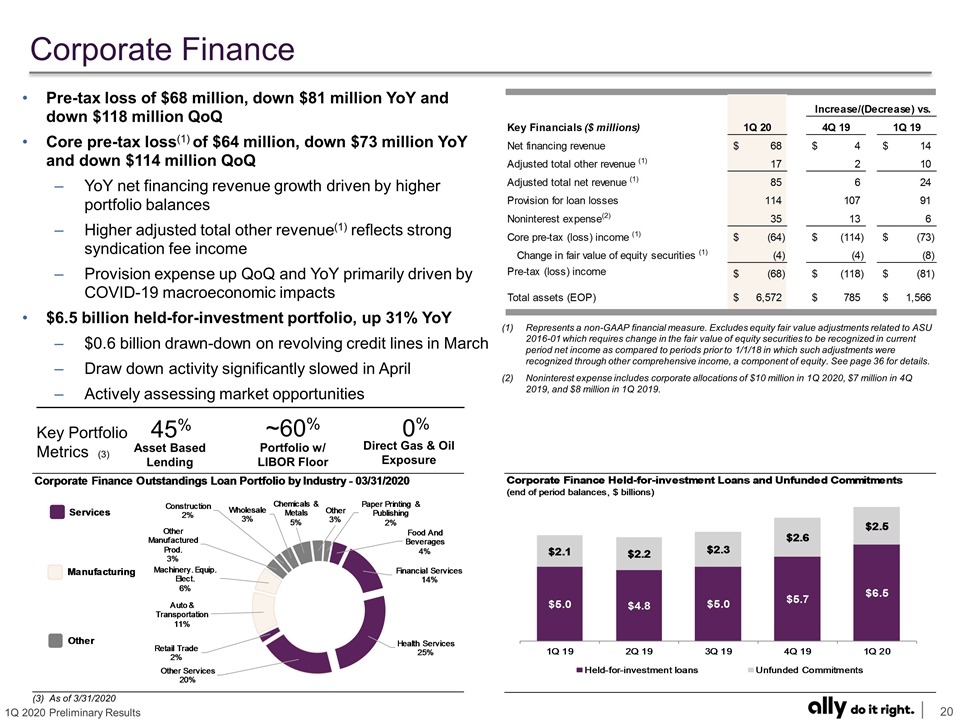
Corporate Finance Represents a non-GAAP financial measure. Excludes equity fair value adjustments related to ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/18 in which such adjustments were recognized through other comprehensive income, a component of equity. See page 36 for details. Noninterest expense includes corporate allocations of $10 million in 1Q 2020, $7 million in 4Q 2019, and $8 million in 1Q 2019. Pre-tax loss of $68 million, down $81 million YoY and down $118 million QoQ Core pre-tax loss(1) of $64 million, down $73 million YoY and down $114 million QoQ YoY net financing revenue growth driven by higher portfolio balances Higher adjusted total other revenue(1) reflects strong syndication fee income Provision expense up QoQ and YoY primarily driven by COVID-19 macroeconomic impacts $6.5 billion held-for-investment portfolio, up 31% YoY $0.6 billion drawn-down on revolving credit lines in March Draw down activity significantly slowed in April Actively assessing market opportunities Asset Based Lending 45% ~60% 0% Portfolio w/ LIBOR Floor Direct Gas & Oil Exposure Key Portfolio Metrics (3) (3) As of 3/31/2020
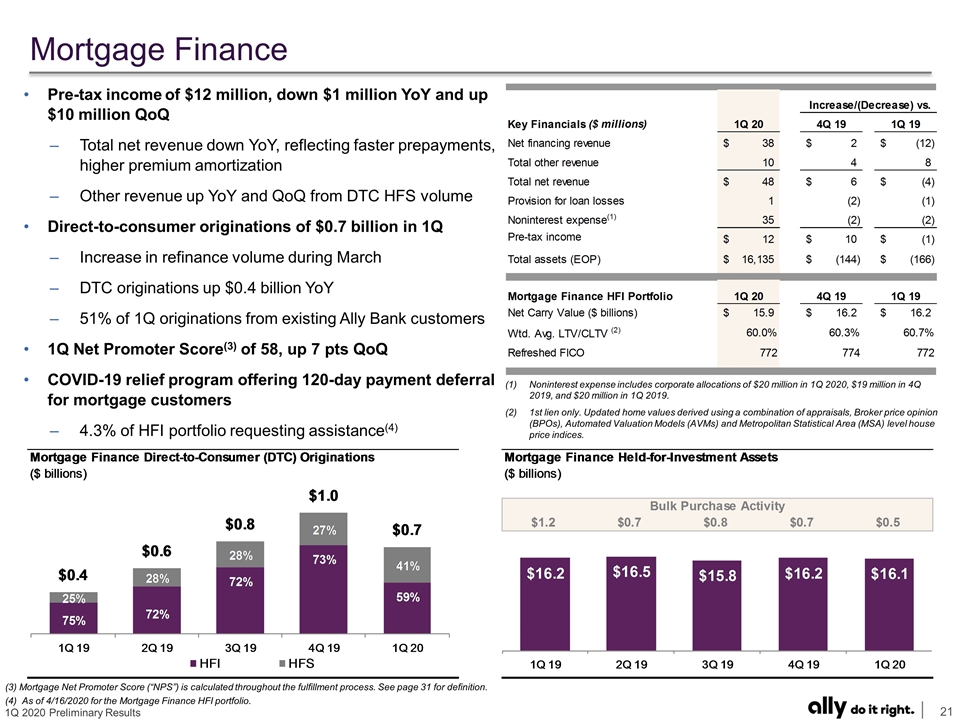
Mortgage Finance Noninterest expense includes corporate allocations of $20 million in 1Q 2020, $19 million in 4Q 2019, and $20 million in 1Q 2019. 1st lien only. Updated home values derived using a combination of appraisals, Broker price opinion (BPOs), Automated Valuation Models (AVMs) and Metropolitan Statistical Area (MSA) level house price indices. Pre-tax income of $12 million, down $1 million YoY and up $10 million QoQ Total net revenue down YoY, reflecting faster prepayments, higher premium amortization Other revenue up YoY and QoQ from DTC HFS volume Direct-to-consumer originations of $0.7 billion in 1Q Increase in refinance volume during March DTC originations up $0.4 billion YoY 51% of 1Q originations from existing Ally Bank customers 1Q Net Promoter Score(3) of 58, up 7 pts QoQ COVID-19 relief program offering 120-day payment deferral for mortgage customers 4.3% of HFI portfolio requesting assistance(4) (3) Mortgage Net Promoter Score (“NPS”) is calculated throughout the fulfillment process. See page 31 for definition. (4) As of 4/16/2020 for the Mortgage Finance HFI portfolio.
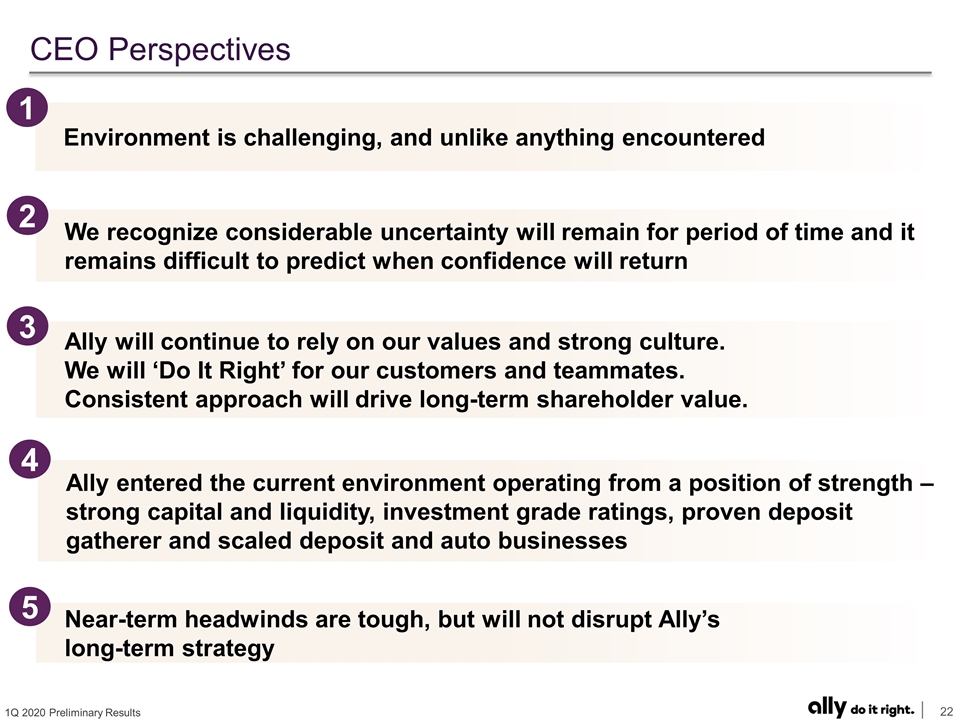
Near-term headwinds are tough, but will not disrupt Ally’s long-term strategy We recognize considerable uncertainty will remain for period of time and it remains difficult to predict when confidence will return Environment is challenging, and unlike anything encountered CEO Perspectives 1 Ally entered the current environment operating from a position of strength – strong capital and liquidity, investment grade ratings, proven deposit gatherer and scaled deposit and auto businesses 2 4 5 Ally will continue to rely on our values and strong culture. We will ‘Do It Right’ for our customers and teammates. Consistent approach will drive long-term shareholder value. 3
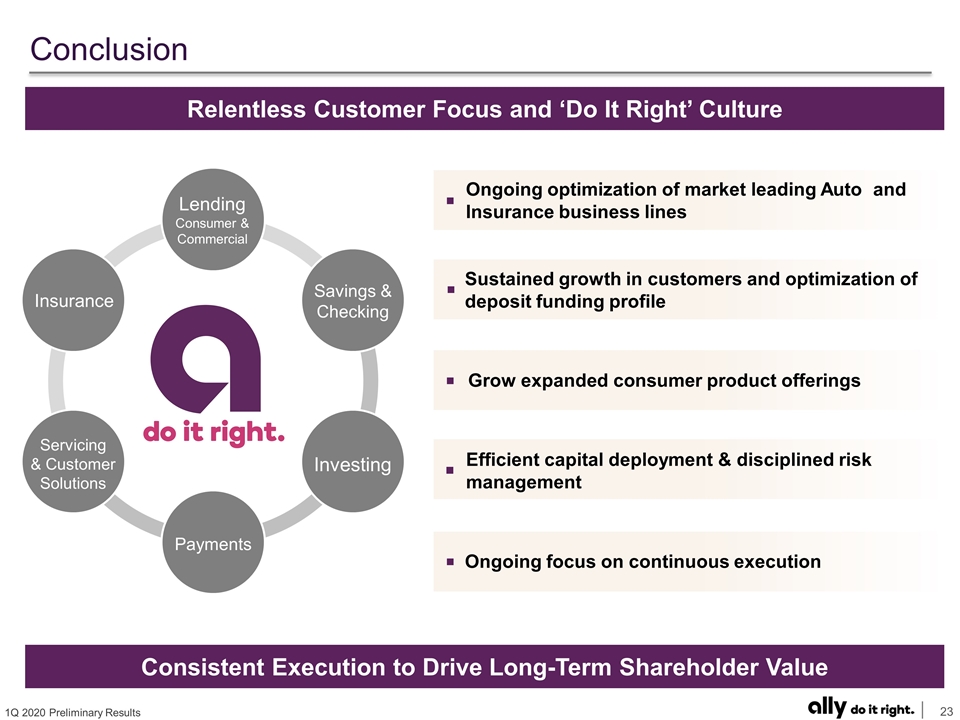
Conclusion Relentless Customer Focus and ‘Do It Right’ Culture Consistent Execution to Drive Long-Term Shareholder Value Ongoing optimization of market leading Auto and Insurance business lines Sustained growth in customers and optimization of deposit funding profile Grow expanded consumer product offerings Efficient capital deployment & disciplined risk management Ongoing focus on continuous execution Servicing & Customer Solutions Payments Investing Savings & Checking Lending Consumer & Commercial Insurance
Supplemental
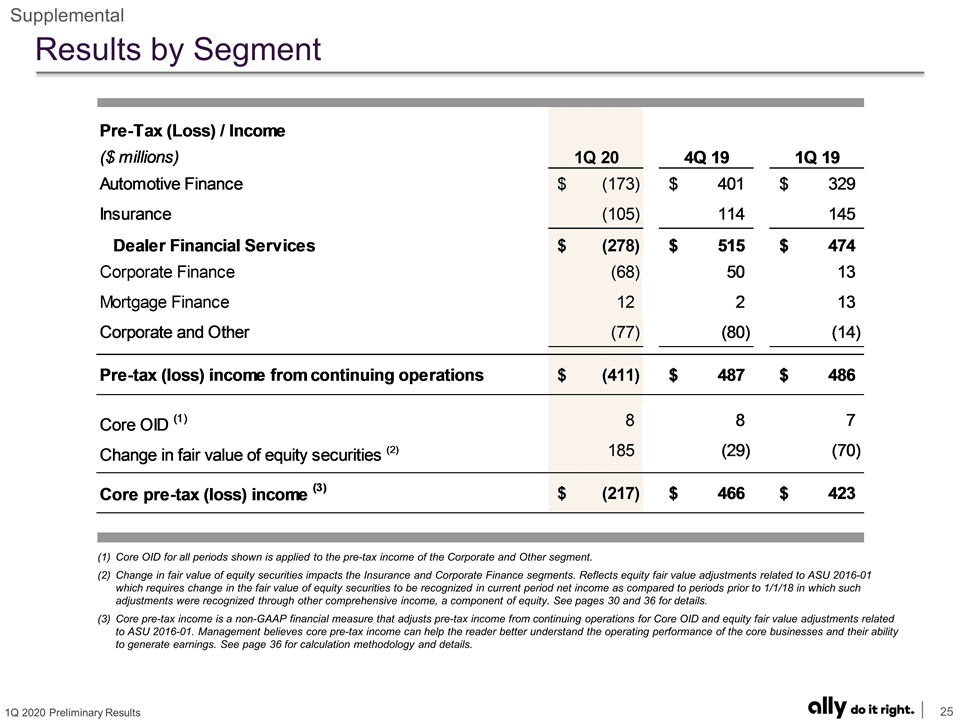
Results by Segment Core OID for all periods shown is applied to the pre-tax income of the Corporate and Other segment. Change in fair value of equity securities impacts the Insurance and Corporate Finance segments. Reflects equity fair value adjustments related to ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/18 in which such adjustments were recognized through other comprehensive income, a component of equity. See pages 30 and 36 for details. Core pre-tax income is a non-GAAP financial measure that adjusts pre-tax income from continuing operations for Core OID and equity fair value adjustments related to ASU 2016-01. Management believes core pre-tax income can help the reader better understand the operating performance of the core businesses and their ability to generate earnings. See page 36 for calculation methodology and details. Supplemental
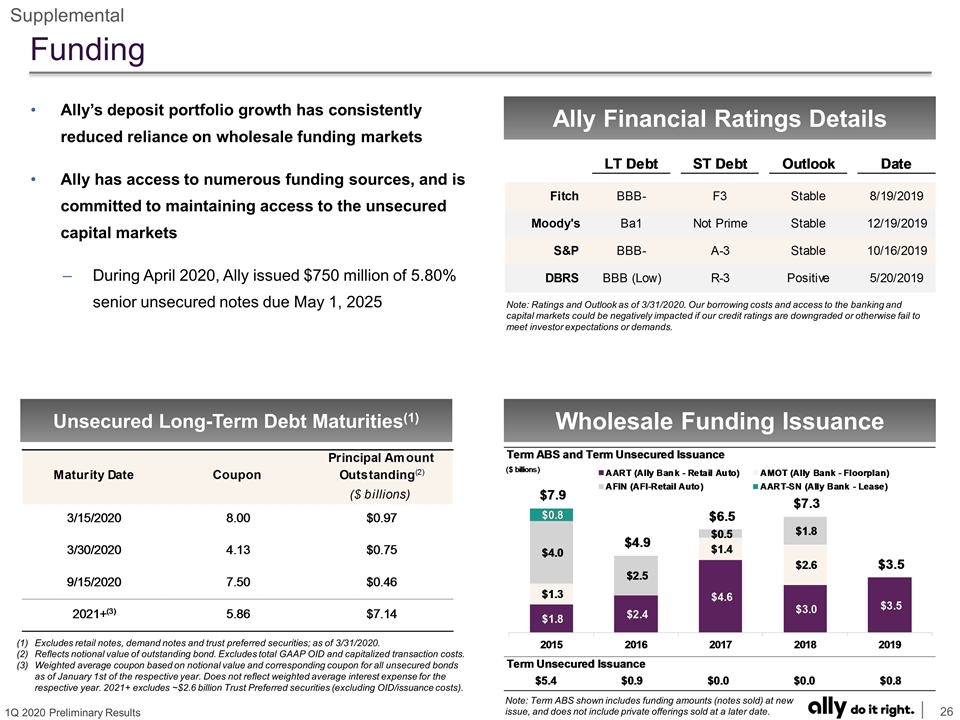
Unsecured Long-Term Debt Maturities(1) Funding Ally’s deposit portfolio growth has consistently reduced reliance on wholesale funding markets Ally has access to numerous funding sources, and is committed to maintaining access to the unsecured capital markets During April 2020, Ally issued $750 million of 5.80% senior unsecured notes due May 1, 2025 Supplemental Excludes retail notes, demand notes and trust preferred securities; as of 3/31/2020. Reflects notional value of outstanding bond. Excludes total GAAP OID and capitalized transaction costs. Weighted average coupon based on notional value and corresponding coupon for all unsecured bonds as of January 1st of the respective year. Does not reflect weighted average interest expense for the respective year. 2021+ excludes ~$2.6 billion Trust Preferred securities (excluding OID/issuance costs). Wholesale Funding Issuance Ally Financial Ratings Details Note: Ratings and Outlook as of 3/31/2020. Our borrowing costs and access to the banking and capital markets could be negatively impacted if our credit ratings are downgraded or otherwise fail to meet investor expectations or demands. Note: Term ABS shown includes funding amounts (notes sold) at new issue, and does not include private offerings sold at a later date.
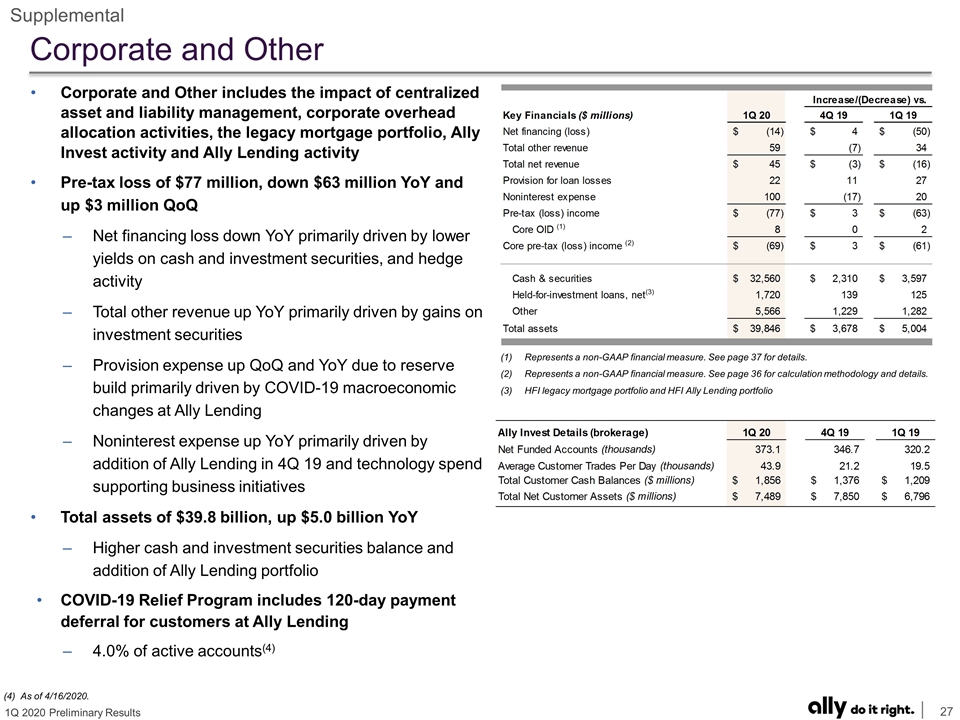
Corporate and Other Represents a non-GAAP financial measure. See page 37 for details. Represents a non-GAAP financial measure. See page 36 for calculation methodology and details. HFI legacy mortgage portfolio and HFI Ally Lending portfolio Corporate and Other includes the impact of centralized asset and liability management, corporate overhead allocation activities, the legacy mortgage portfolio, Ally Invest activity and Ally Lending activity Pre-tax loss of $77 million, down $63 million YoY and up $3 million QoQ Net financing loss down YoY primarily driven by lower yields on cash and investment securities, and hedge activity Total other revenue up YoY primarily driven by gains on investment securities Provision expense up QoQ and YoY due to reserve build primarily driven by COVID-19 macroeconomic changes at Ally Lending Noninterest expense up YoY primarily driven by addition of Ally Lending in 4Q 19 and technology spend supporting business initiatives Total assets of $39.8 billion, up $5.0 billion YoY Higher cash and investment securities balance and addition of Ally Lending portfolio COVID-19 Relief Program includes 120-day payment deferral for customers at Ally Lending 4.0% of active accounts(4) Supplemental (4) As of 4/16/2020.
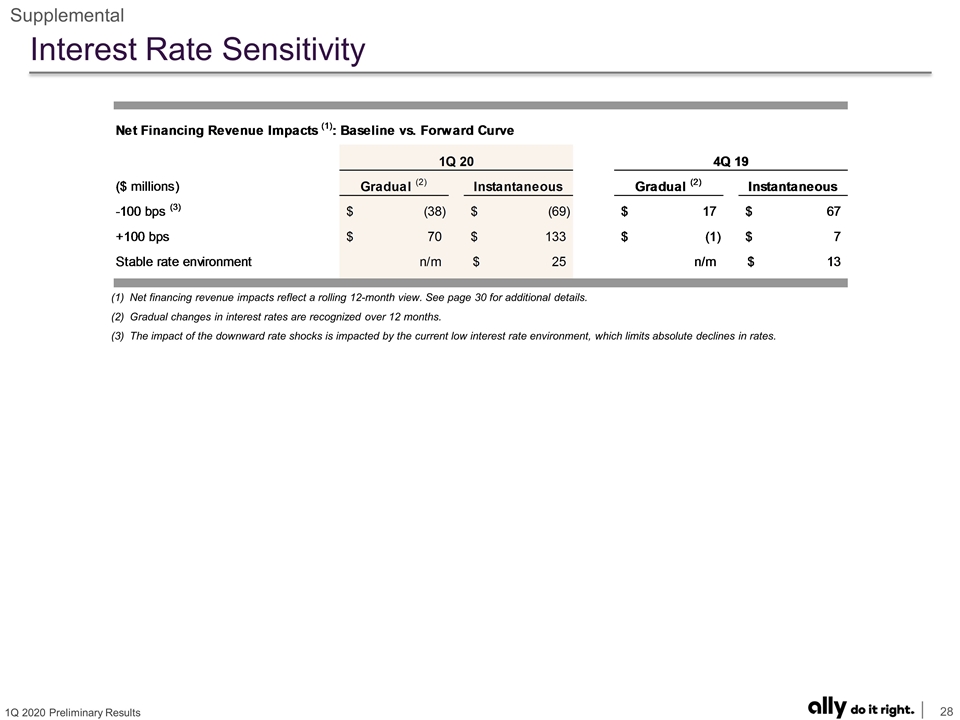
Interest Rate Sensitivity Supplemental Net financing revenue impacts reflect a rolling 12-month view. See page 30 for additional details. Gradual changes in interest rates are recognized over 12 months. The impact of the downward rate shocks is impacted by the current low interest rate environment, which limits absolute declines in rates.
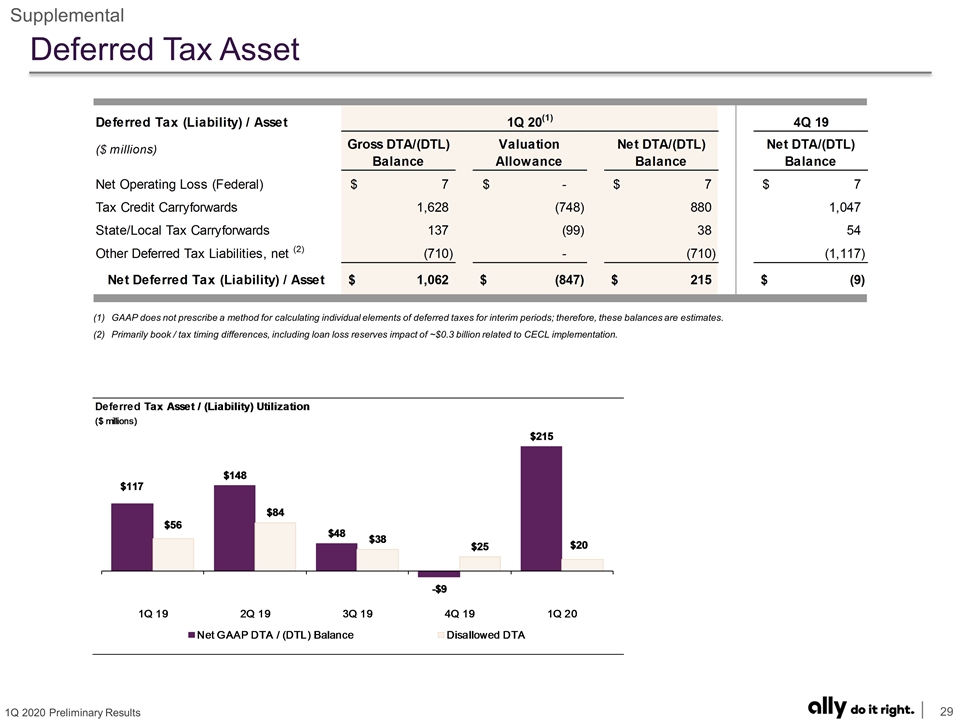
GAAP does not prescribe a method for calculating individual elements of deferred taxes for interim periods; therefore, these balances are estimates. Primarily book / tax timing differences, including loan loss reserves impact of ~$0.3 billion related to CECL implementation. Deferred Tax Asset Supplemental
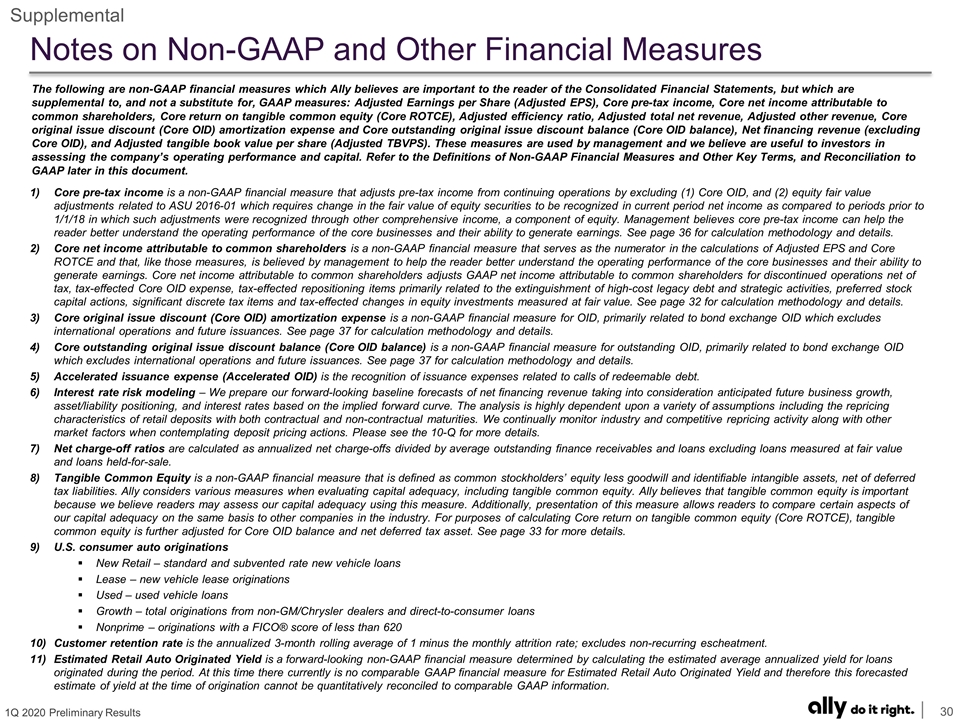
Notes on Non-GAAP and Other Financial Measures Supplemental Core pre-tax income is a non-GAAP financial measure that adjusts pre-tax income from continuing operations by excluding (1) Core OID, and (2) equity fair value adjustments related to ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/18 in which such adjustments were recognized through other comprehensive income, a component of equity. Management believes core pre-tax income can help the reader better understand the operating performance of the core businesses and their ability to generate earnings. See page 36 for calculation methodology and details. Core net income attributable to common shareholders is a non-GAAP financial measure that serves as the numerator in the calculations of Adjusted EPS and Core ROTCE and that, like those measures, is believed by management to help the reader better understand the operating performance of the core businesses and their ability to generate earnings. Core net income attributable to common shareholders adjusts GAAP net income attributable to common shareholders for discontinued operations net of tax, tax-effected Core OID expense, tax-effected repositioning items primarily related to the extinguishment of high-cost legacy debt and strategic activities, preferred stock capital actions, significant discrete tax items and tax-effected changes in equity investments measured at fair value. See page 32 for calculation methodology and details. Core original issue discount (Core OID) amortization expense is a non-GAAP financial measure for OID, primarily related to bond exchange OID which excludes international operations and future issuances. See page 37 for calculation methodology and details. Core outstanding original issue discount balance (Core OID balance) is a non-GAAP financial measure for outstanding OID, primarily related to bond exchange OID which excludes international operations and future issuances. See page 37 for calculation methodology and details. Accelerated issuance expense (Accelerated OID) is the recognition of issuance expenses related to calls of redeemable debt. Interest rate risk modeling – We prepare our forward-looking baseline forecasts of net financing revenue taking into consideration anticipated future business growth, asset/liability positioning, and interest rates based on the implied forward curve. The analysis is highly dependent upon a variety of assumptions including the repricing characteristics of retail deposits with both contractual and non-contractual maturities. We continually monitor industry and competitive repricing activity along with other market factors when contemplating deposit pricing actions. Please see the 10-Q for more details. Net charge-off ratios are calculated as annualized net charge-offs divided by average outstanding finance receivables and loans excluding loans measured at fair value and loans held-for-sale. Tangible Common Equity is a non-GAAP financial measure that is defined as common stockholders’ equity less goodwill and identifiable intangible assets, net of deferred tax liabilities. Ally considers various measures when evaluating capital adequacy, including tangible common equity. Ally believes that tangible common equity is important because we believe readers may assess our capital adequacy using this measure. Additionally, presentation of this measure allows readers to compare certain aspects of our capital adequacy on the same basis to other companies in the industry. For purposes of calculating Core return on tangible common equity (Core ROTCE), tangible common equity is further adjusted for Core OID balance and net deferred tax asset. See page 33 for more details. U.S. consumer auto originations New Retail – standard and subvented rate new vehicle loans Lease – new vehicle lease originations Used – used vehicle loans Growth – total originations from non-GM/Chrysler dealers and direct-to-consumer loans Nonprime – originations with a FICO® score of less than 620 Customer retention rate is the annualized 3-month rolling average of 1 minus the monthly attrition rate; excludes non-recurring escheatment. Estimated Retail Auto Originated Yield is a forward-looking non-GAAP financial measure determined by calculating the estimated average annualized yield for loans originated during the period. At this time there currently is no comparable GAAP financial measure for Estimated Retail Auto Originated Yield and therefore this forecasted estimate of yield at the time of origination cannot be quantitatively reconciled to comparable GAAP information. The following are non-GAAP financial measures which Ally believes are important to the reader of the Consolidated Financial Statements, but which are supplemental to, and not a substitute for, GAAP measures: Adjusted Earnings per Share (Adjusted EPS), Core pre-tax income, Core net income attributable to common shareholders, Core return on tangible common equity (Core ROTCE), Adjusted efficiency ratio, Adjusted total net revenue, Adjusted other revenue, Core original issue discount (Core OID) amortization expense and Core outstanding original issue discount balance (Core OID balance), Net financing revenue (excluding Core OID), and Adjusted tangible book value per share (Adjusted TBVPS). These measures are used by management and we believe are useful to investors in assessing the company’s operating performance and capital. Refer to the Definitions of Non-GAAP Financial Measures and Other Key Terms, and Reconciliation to GAAP later in this document.
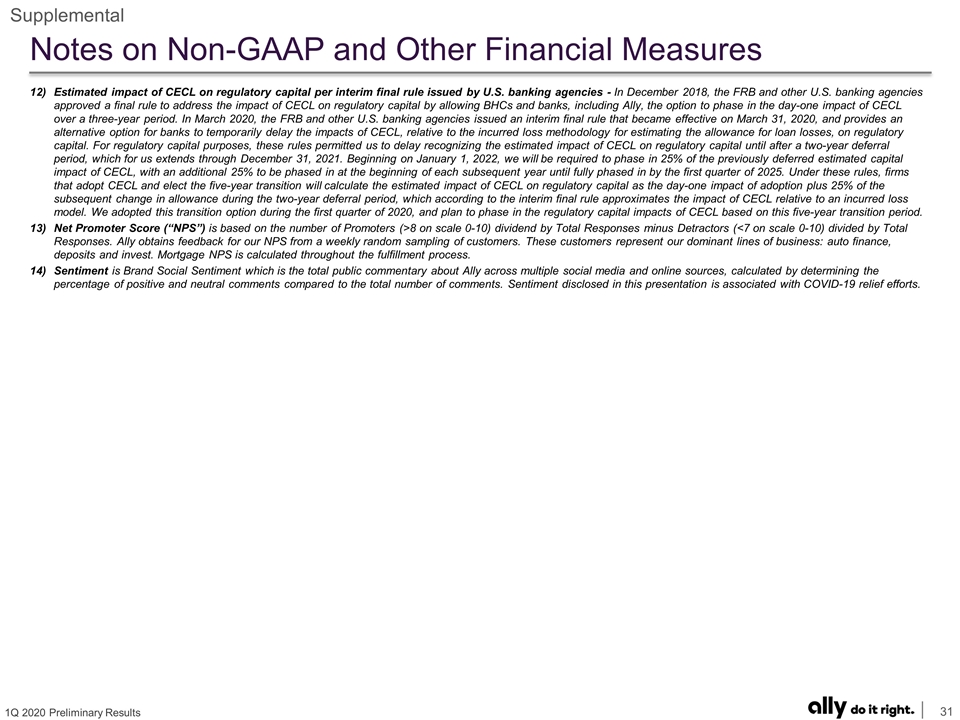
Notes on Non-GAAP and Other Financial Measures Supplemental Estimated impact of CECL on regulatory capital per interim final rule issued by U.S. banking agencies - In December 2018, the FRB and other U.S. banking agencies approved a final rule to address the impact of CECL on regulatory capital by allowing BHCs and banks, including Ally, the option to phase in the day-one impact of CECL over a three-year period. In March 2020, the FRB and other U.S. banking agencies issued an interim final rule that became effective on March 31, 2020, and provides an alternative option for banks to temporarily delay the impacts of CECL, relative to the incurred loss methodology for estimating the allowance for loan losses, on regulatory capital. For regulatory capital purposes, these rules permitted us to delay recognizing the estimated impact of CECL on regulatory capital until after a two-year deferral period, which for us extends through December 31, 2021. Beginning on January 1, 2022, we will be required to phase in 25% of the previously deferred estimated capital impact of CECL, with an additional 25% to be phased in at the beginning of each subsequent year until fully phased in by the first quarter of 2025. Under these rules, firms that adopt CECL and elect the five-year transition will calculate the estimated impact of CECL on regulatory capital as the day-one impact of adoption plus 25% of the subsequent change in allowance during the two-year deferral period, which according to the interim final rule approximates the impact of CECL relative to an incurred loss model. We adopted this transition option during the first quarter of 2020, and plan to phase in the regulatory capital impacts of CECL based on this five-year transition period. Net Promoter Score (“NPS”) is based on the number of Promoters (>8 on scale 0-10) dividend by Total Responses minus Detractors (<7 on scale 0-10) divided by Total Responses. Ally obtains feedback for our NPS from a weekly random sampling of customers. These customers represent our dominant lines of business: auto finance, deposits and invest. Mortgage NPS is calculated throughout the fulfillment process. Sentiment is Brand Social Sentiment which is the total public commentary about Ally across multiple social media and online sources, calculated by determining the percentage of positive and neutral comments compared to the total number of comments. Sentiment disclosed in this presentation is associated with COVID-19 relief efforts.
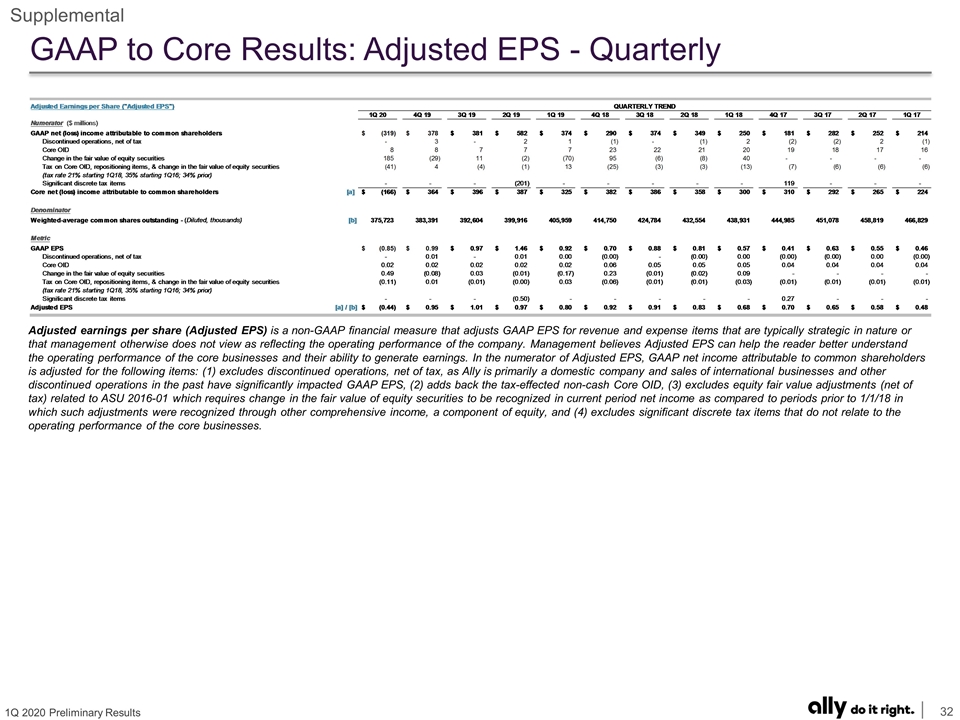
GAAP to Core Results: Adjusted EPS - Quarterly Supplemental Adjusted earnings per share (Adjusted EPS) is a non-GAAP financial measure that adjusts GAAP EPS for revenue and expense items that are typically strategic in nature or that management otherwise does not view as reflecting the operating performance of the company. Management believes Adjusted EPS can help the reader better understand the operating performance of the core businesses and their ability to generate earnings. In the numerator of Adjusted EPS, GAAP net income attributable to common shareholders is adjusted for the following items: (1) excludes discontinued operations, net of tax, as Ally is primarily a domestic company and sales of international businesses and other discontinued operations in the past have significantly impacted GAAP EPS, (2) adds back the tax-effected non-cash Core OID, (3) excludes equity fair value adjustments (net of tax) related to ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/18 in which such adjustments were recognized through other comprehensive income, a component of equity, and (4) excludes significant discrete tax items that do not relate to the operating performance of the core businesses.
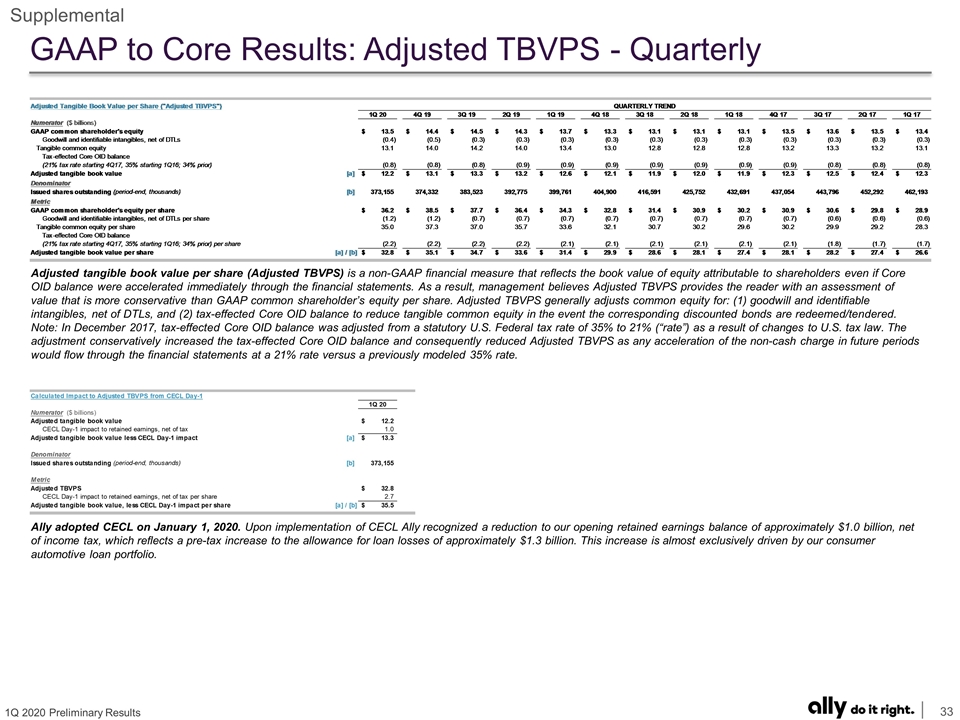
GAAP to Core Results: Adjusted TBVPS - Quarterly Supplemental Adjusted tangible book value per share (Adjusted TBVPS) is a non-GAAP financial measure that reflects the book value of equity attributable to shareholders even if Core OID balance were accelerated immediately through the financial statements. As a result, management believes Adjusted TBVPS provides the reader with an assessment of value that is more conservative than GAAP common shareholder’s equity per share. Adjusted TBVPS generally adjusts common equity for: (1) goodwill and identifiable intangibles, net of DTLs, and (2) tax-effected Core OID balance to reduce tangible common equity in the event the corresponding discounted bonds are redeemed/tendered. Note: In December 2017, tax-effected Core OID balance was adjusted from a statutory U.S. Federal tax rate of 35% to 21% (“rate”) as a result of changes to U.S. tax law. The adjustment conservatively increased the tax-effected Core OID balance and consequently reduced Adjusted TBVPS as any acceleration of the non-cash charge in future periods would flow through the financial statements at a 21% rate versus a previously modeled 35% rate. Ally adopted CECL on January 1, 2020. Upon implementation of CECL Ally recognized a reduction to our opening retained earnings balance of approximately $1.0 billion, net of income tax, which reflects a pre-tax increase to the allowance for loan losses of approximately $1.3 billion. This increase is almost exclusively driven by our consumer automotive loan portfolio.
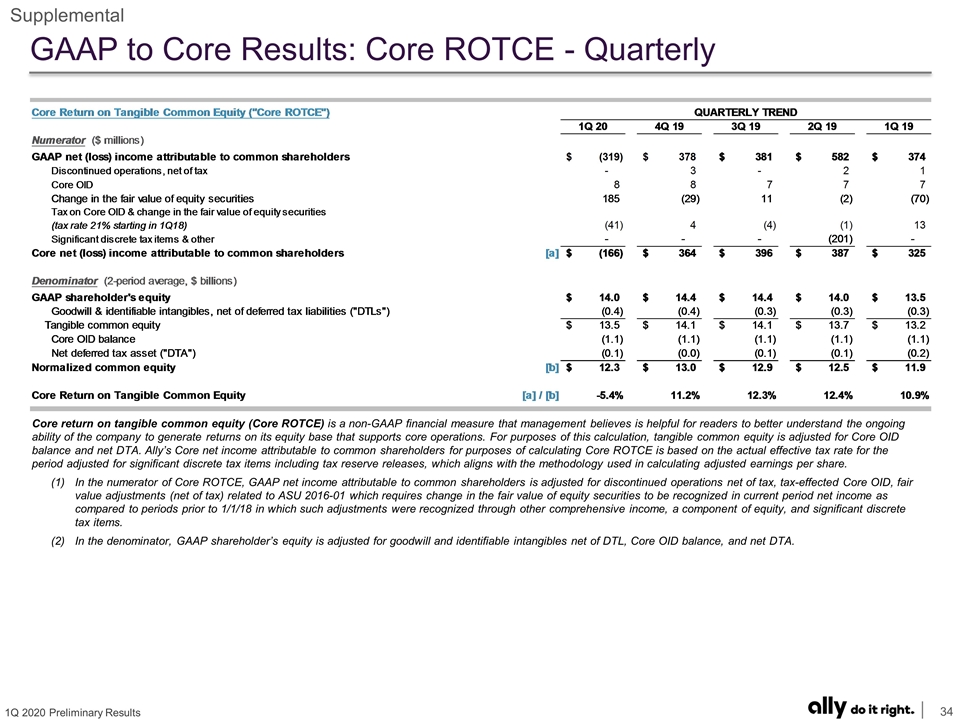
GAAP to Core Results: Core ROTCE - Quarterly Supplemental Core return on tangible common equity (Core ROTCE) is a non-GAAP financial measure that management believes is helpful for readers to better understand the ongoing ability of the company to generate returns on its equity base that supports core operations. For purposes of this calculation, tangible common equity is adjusted for Core OID balance and net DTA. Ally’s Core net income attributable to common shareholders for purposes of calculating Core ROTCE is based on the actual effective tax rate for the period adjusted for significant discrete tax items including tax reserve releases, which aligns with the methodology used in calculating adjusted earnings per share. In the numerator of Core ROTCE, GAAP net income attributable to common shareholders is adjusted for discontinued operations net of tax, tax-effected Core OID, fair value adjustments (net of tax) related to ASU 2016-01 which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/18 in which such adjustments were recognized through other comprehensive income, a component of equity, and significant discrete tax items. In the denominator, GAAP shareholder’s equity is adjusted for goodwill and identifiable intangibles net of DTL, Core OID balance, and net DTA.
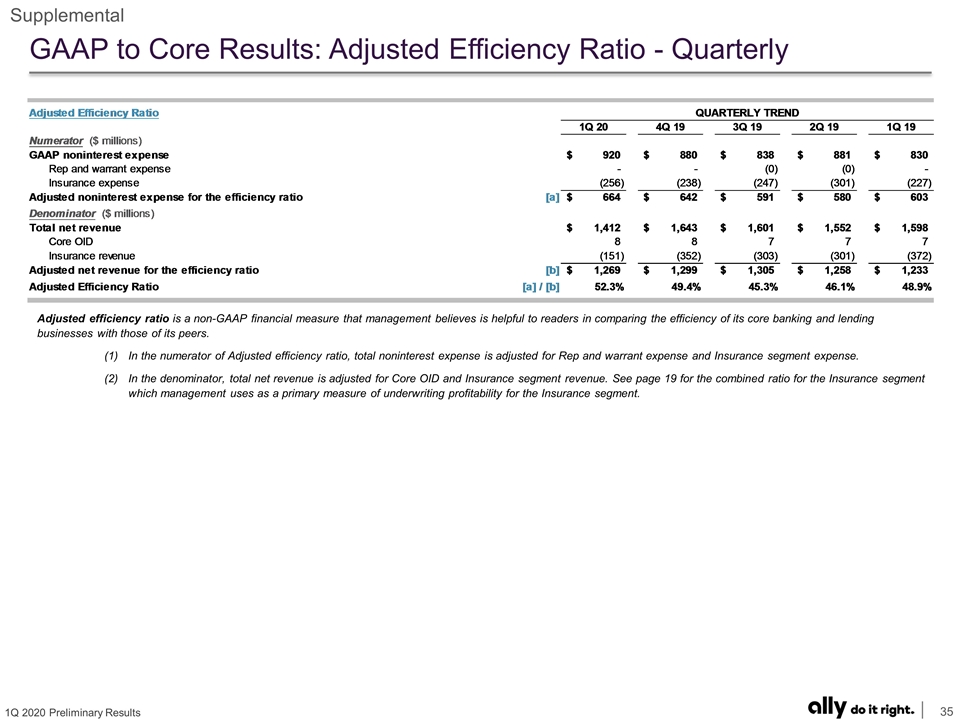
GAAP to Core Results: Adjusted Efficiency Ratio - Quarterly Supplemental Adjusted efficiency ratio is a non-GAAP financial measure that management believes is helpful to readers in comparing the efficiency of its core banking and lending businesses with those of its peers. In the numerator of Adjusted efficiency ratio, total noninterest expense is adjusted for Rep and warrant expense and Insurance segment expense. In the denominator, total net revenue is adjusted for Core OID and Insurance segment revenue. See page 19 for the combined ratio for the Insurance segment which management uses as a primary measure of underwriting profitability for the Insurance segment.
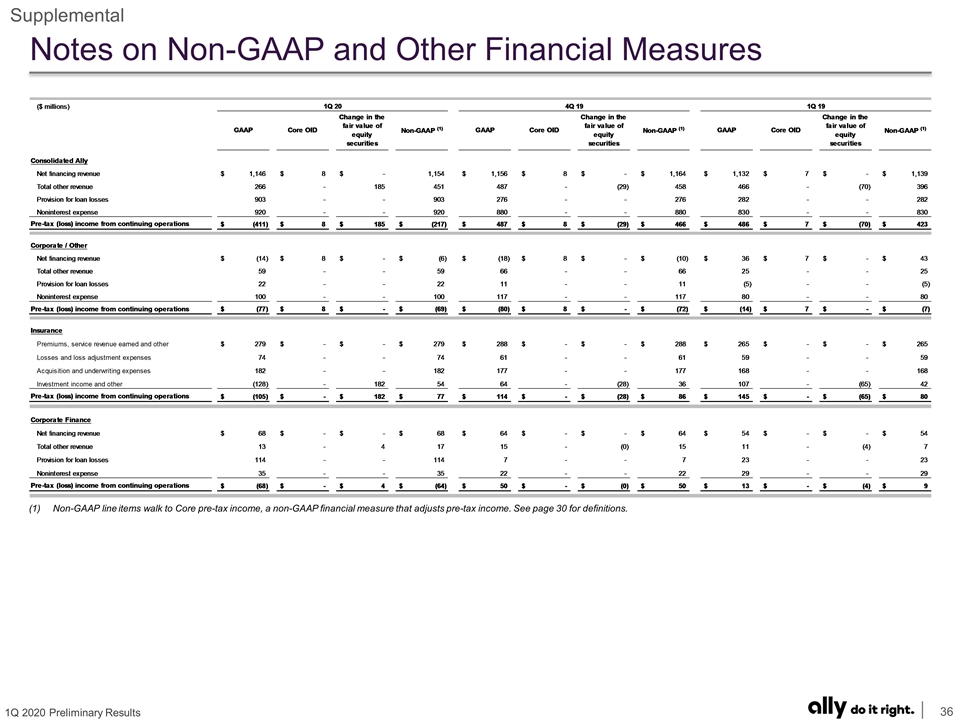
Notes on Non-GAAP and Other Financial Measures Supplemental Non-GAAP line items walk to Core pre-tax income, a non-GAAP financial measure that adjusts pre-tax income. See page 30 for definitions.
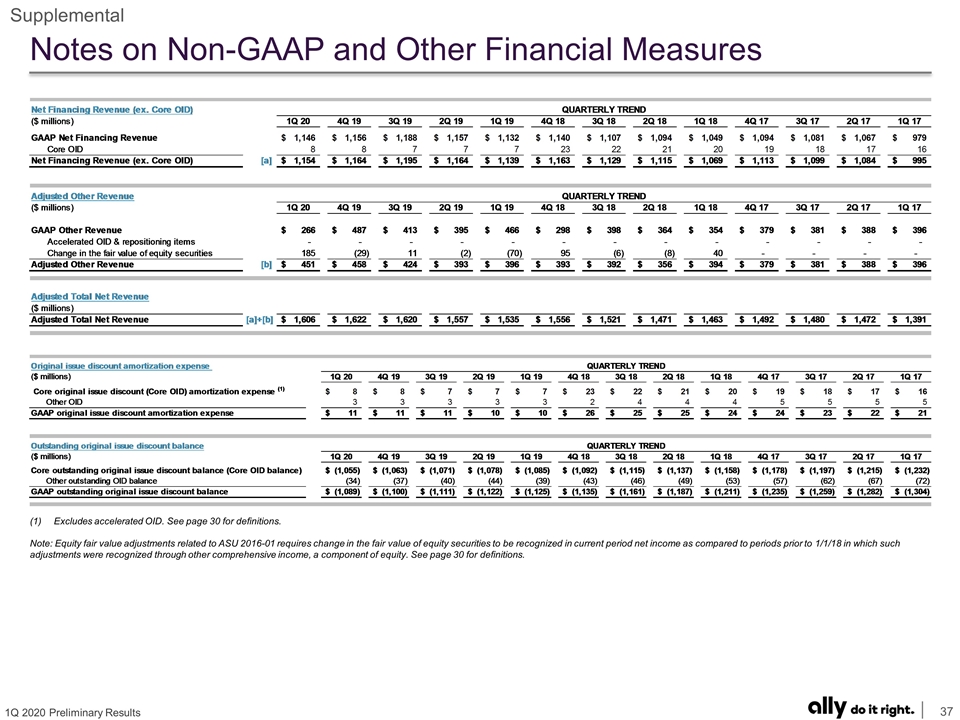
Notes on Non-GAAP and Other Financial Measures Supplemental Excludes accelerated OID. See page 30 for definitions. Note: Equity fair value adjustments related to ASU 2016-01 requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/18 in which such adjustments were recognized through other comprehensive income, a component of equity. See page 30 for definitions.
Exhibit 99.3
FIRST QUARTER 2020
FINANCIAL SUPPLEMENT
| ALLY FINANCIAL INC. FORWARD-LOOKING STATEMENTS AND ADDITIONAL INFORMATION |

|
This document and related communications should be read in conjunction with the financial statements, notes, and other information contained in our Annual Reports on Form 10-K, Quarterly Reports on Form 10-Q, and Current Reports on Form 8-K. This information is preliminary and based on company and third-party data available at the time of the presentation or related communication.
This document and related communications contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements can be identified by the fact that they do not relate strictly to historical or current facts—such as statements about future effects of COVID-19, the outlook for financial and operating metrics, and future capital allocation and actions. Forward-looking statements often use words such as “believe,” “expect,” “anticipate,” “intend,” “pursue,” “seek,” “continue,” “estimate,” “project,” “outlook,” “forecast,” “potential,” “target,” “objective,” “trend,” “plan,” “goal,” “initiative,” “priorities,” or other words of comparable meaning or future-tense or conditional verbs such as “may,” “will,” “should,” “would,” or “could.” Forward-looking statements convey our expectations, intentions, or forecasts about future events, circumstances, or results. All forward-looking statements, by their nature, are subject to assumptions, risks, and uncertainties, which may change over time and many of which are beyond our control. You should not rely on any forward-looking statement as a prediction or guarantee about the future. Actual future objectives, strategies, plans, prospects, performance, conditions, or results may differ materially from those set forth in any forward-looking statement. Some of the factors that may cause actual results or other future events or circumstances to differ from those in forward-looking statements are described in our Annual Report on Form 10-K for the year ended December 31, 2019, our subsequent Quarterly Reports on Form 10-Q or Current Reports on Form 8-K, or other applicable documents that are filed or furnished with the U.S. Securities and Exchange Commission (collectively, our “SEC filings”). Any forward-looking statement made by us or on our behalf speaks only as of the date that it was made. We do not undertake to update any forward-looking statement to reflect the impact of events, circumstances, or results that arise after the date that the statement was made, except as required by applicable securities laws. You, however, should consult further disclosures (including disclosures of a forward-looking nature) that we may make in any subsequent SEC filings.
This document and related communications contain specifically identified non-GAAP financial measures, which supplement the results that are reported according to U.S. generally accepted accounting principles (“GAAP”). These non-GAAP financial measures may be useful to investors but should not be viewed in isolation from, or as a substitute for, GAAP results. Differences between non-GAAP financial measures and comparable GAAP financial measures are reconciled in the presentation.
Unless the context otherwise requires, the following definitions apply. The term “loans” means the following consumer and commercial products associated with our direct and indirect financing activities: loans, retail installment sales contracts, lines of credit, and other financing products excluding operating leases. The term “operating leases” means consumer- and commercial-vehicle lease agreements where Ally is the lessor and the lessee is generally not obligated to acquire ownership of the vehicle at lease-end or compensate Ally for the vehicle’s residual value. The terms “lend,” “finance,” and “originate” mean our direct extension or origination of loans, our purchase or acquisition of loans, or our purchase of operating leases, as applicable. The term “consumer” means all consumer products associated with our loan and operating-lease activities and all commercial retail installment sales contracts. The term “commercial” means all commercial products associated with our loan activities, other than commercial retail installment sales contracts.
| 1Q 2020 Preliminary Results | 2 |
| ALLY FINANCIAL INC. TABLE OF CONTENTS |
|
| Page(s) | ||||
| Consolidated Results |
||||
| Consolidated Financial Highlights |
4 | |||
| Consolidated Income Statement |
5 | |||
| Consolidated Period-End Balance Sheet |
6 | |||
| Consolidated Average Balance Sheet |
7 | |||
| Segment Detail |
||||
| Segment Highlights |
8 | |||
| Automotive Finance |
9-10 | |||
| Insurance |
11 | |||
| Mortgage Finance |
12 | |||
| Corporate Finance |
13 | |||
| Corporate and Other |
14 | |||
| Credit Related Information |
15-16 | |||
| Supplemental Detail |
||||
| Capital |
17 | |||
| Liquidity |
18 | |||
| Net Interest Margin and Deposits |
19 | |||
| Ally Bank Consumer Mortgage HFI Portfolios |
20 | |||
| Earnings Per Share Related Information |
21 | |||
| Adjusted Tangible Book Value Per Share Related Information |
22 | |||
| Core ROTCE Related Information |
23 | |||
| Adjusted Efficiency Ratio Related Information |
24 | |||
| 1Q 2020 Preliminary Results | 3 |
| ALLY FINANCIAL INC. CONSOLIDATED FINANCIAL HIGHLIGHTS |
|
($ in millions, shares in thousands)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Selected Income Statement Data |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Net financing revenue (ex. Core OID) (1) |
$ | 1,154 | $ | 1,164 | $ | 1,195 | $ | 1,164 | $ | 1,139 | $ | (10 | ) | $ | 16 | |||||||||||||
| Core OID |
(8 | ) | (8 | ) | (7 | ) | (7 | ) | (7 | ) | (0 | ) | (2 | ) | ||||||||||||||
| Net financing revenue (as reported) |
1,146 | 1,156 | 1,188 | 1,157 | 1,132 | (10 | ) | 14 | ||||||||||||||||||||
| Other revenue (ex. change in the fair value of equity securities) (2) |
451 | 458 | 424 | 393 | 396 | (7 | ) | 55 | ||||||||||||||||||||
| Change in the fair value of equity securities (3) |
(185 | ) | 29 | (11 | ) | 2 | 70 | (214 | ) | (255 | ) | |||||||||||||||||
| Other revenue (as reported) |
266 | 487 | 413 | 395 | 466 | (221 | ) | (200 | ) | |||||||||||||||||||
| Provision for loan losses |
903 | 276 | 263 | 177 | 282 | 627 | 621 | |||||||||||||||||||||
| Total noninterest expense (4) |
920 | 880 | 838 | 881 | 830 | 40 | 90 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Pre-tax (loss) income from continuing operations |
(411 | ) | 487 | 500 | 494 | 486 | (898 | ) | (897 | ) | ||||||||||||||||||
| Income tax (benefit) expense |
(92 | ) | 106 | 119 | (90 | ) | 111 | (198 | ) | (203 | ) | |||||||||||||||||
| (Loss) / income from discontinued operations, net of tax |
- | (3 | ) | - | (2 | ) | (1 | ) | 3 | 1 | ||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net (loss) income attributable to common shareholders |
$ | (319 | ) | $ | 378 | $ | 381 | $ | 582 | $ | 374 | $ | (697) | $ | (693 | ) | ||||||||||||
| Selected Balance Sheet Data (Period-End) |
||||||||||||||||||||||||||||
| Total assets |
$ | 182,527 | $ | 180,644 | $ | 181,485 | $ | 180,448 | $ | 180,117 | $ | 1,883 | $ | 2,410 | ||||||||||||||
| Consumer loans |
90,066 | 89,924 | 90,081 | 90,698 | 89,211 | 142 | 855 | |||||||||||||||||||||
| Commercial loans |
38,073 | 38,307 | 38,528 | 38,512 | 40,844 | (234 | ) | (2,771 | ) | |||||||||||||||||||
| Allowance for loan losses |
(3,245 | ) | (1,263 | ) | (1,277 | ) | (1,282 | ) | (1,288 | ) | (1,982 | ) | (1,957 | ) | ||||||||||||||
| Deposits |
122,324 | 120,752 | 119,230 | 116,325 | 113,299 | 1,572 | 9,025 | |||||||||||||||||||||
| Total equity |
13,519 | 14,416 | 14,450 | 14,316 | 13,699 | (897 | ) | (180 | ) | |||||||||||||||||||
| Common Share Count |
||||||||||||||||||||||||||||
| Weighted average basic (5) |
375,723 | 380,793 | 390,205 | 398,100 | 404,129 | (5,070 | ) | (28,406 | ) | |||||||||||||||||||
| Weighted average diluted (5) |
375,723 | 383,391 | 392,604 | 399,916 | 405,959 | (7,668 | ) | (30,236 | ) | |||||||||||||||||||
| Issued shares outstanding (period-end) |
373,155 | 374,332 | 383,523 | 392,775 | 399,761 | (1,177 | ) | (26,606 | ) | |||||||||||||||||||
| Per Common Share Data |
||||||||||||||||||||||||||||
| Earnings per share (basic) (5) |
$ | (0.85 | ) | $ | 0.99 | $ | 0.98 | $ | 1.46 | $ | 0.93 | $ | (1.84) | $ | (1.77 | ) | ||||||||||||
| Earnings per share (diluted) (5) |
(0.85 | ) | 0.99 | 0.97 | 1.46 | 0.92 | (1.83 | ) | (1.77 | ) | ||||||||||||||||||
| Adjusted earnings per share (6) |
(0.44 | ) | 0.95 | 1.01 | 0.97 | 0.80 | (1.39 | ) | (1.24 | ) | ||||||||||||||||||
| Book value per share |
36.2 | 38.5 | 37.7 | 36.4 | 34.3 | (2.3 | ) | 2.0 | ||||||||||||||||||||
| Tangible book value per share (7) |
35.0 | 37.3 | 37.0 | 35.7 | 33.6 | (2.3 | ) | 1.5 | ||||||||||||||||||||
| Adjusted tangible book value per share (7) |
32.8 | 35.1 | 34.7 | 33.6 | 31.4 | (2.3 | ) | 1.4 | ||||||||||||||||||||
| Select Financial Ratios |
||||||||||||||||||||||||||||
| Net interest margin (as reported) |
2.66% | 2.64% | 2.70% | 2.66% | 2.67% | |||||||||||||||||||||||
| Net interest margin (ex. Core OID) (8) |
2.68% | 2.66% | 2.72% | 2.67% | 2.69% | |||||||||||||||||||||||
| Cost of funds |
2.43% | 2.55% | 2.66% | 2.74% | 2.70% | |||||||||||||||||||||||
| Cost of funds (ex. Core OID) (8) |
2.39% | 2.51% | 2.62% | 2.70% | 2.66% | |||||||||||||||||||||||
| Efficiency Ratio (9) |
65.2% | 53.6% | 52.3% | 56.8% | 51.9% | |||||||||||||||||||||||
| Adjusted efficiency ratio (8)(9) |
52.3% | 49.4% | 45.3% | 46.1% | 48.9% | |||||||||||||||||||||||
| Return on average assets (10) |
-0.7% | 0.8% | 0.8% | 1.3% | 0.8% | |||||||||||||||||||||||
| Return on average total equity (10) |
-9.1% | 10.5% | 10.6% | 16.6% | 11.1% | |||||||||||||||||||||||
| Return on average tangible common equity (10) |
-9.4% | 10.7% | 10.8% | 17.0% | 11.3% | |||||||||||||||||||||||
| Core ROTCE (11) |
-5.4% | 11.2% | 12.3% | 12.4% | 10.9% | |||||||||||||||||||||||
| Capital Ratios (12) |
||||||||||||||||||||||||||||
| Common Equity Tier 1 (CET1) capital ratio |
9.3% | 9.5% | 9.6% | 9.5% | 9.3% | |||||||||||||||||||||||
| Tier 1 capital ratio |
10.9% | 11.2% | 11.2% | 11.2% | 11.0% | |||||||||||||||||||||||
| Total capital ratio |
12.8% | 12.8% | 12.8% | 12.7% | 12.5% | |||||||||||||||||||||||
| Tier 1 leverage ratio |
8.9% | 9.1% | 9.1% | 9.0% | 9.0% | |||||||||||||||||||||||
(1) Represents a non-GAAP financial measure. Excludes Core OID. For more details refer to page 21.
(2) Represents a non-GAAP financial measure. Adjusted for change in the fair value of equity securities due to the implementation of ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity. For Non-GAAP calculation methodology and details see page 21.
(3) Change in fair value of equity securities impacts the Insurance and Corporate Finance segments. Excludes equity fair value adjustments related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity.
(4) Including but not limited to employee related expenses, commissions and provision for losses and loss adjustment expense related to the insurance business, information technology expenses, servicing expenses, facilities expenses, marketing expenses, and other professional and legal expenses.
(5) Due to antidilutive effect of the net loss from pre-tax loss from continuing operations attributable to common shareholders for the first quarter 2020, basic weighted average common shares outstanding were used to calculate diluted earnings per share.
(6) Represents a non-GAAP financial measure. For more details refer to page 21.
(7) Represents a non-GAAP financial measure. For more details refer to page 22.
(8) Represents a non-GAAP financial measure. Excludes Core OID. For more details refer to page 21.
(9) Represents a non-GAAP financial measure. For more details refer to page 24.
(10) Return metrics are annualized.
(11) Return metrics are annualized. Represents a non-GAAP financial measure. For more details refer to page 23.
(12) Basel III rules became effective on January 1, 2015, subject to transition provisions primarily related to deductions and adjustments impacting CET1 capital and Tier 1 capital. For more details on the final rule to address the impact of CECL on regulatory capital by allowing BHCs and banks, including Ally.
| 1Q 2020 Preliminary Results | 4 |
| ALLY FINANCIAL INC. CONSOLIDATED INCOME STATEMENT |
|
($ in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| 1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | ||||||||||||||||||||||
| Financing revenue and other interest income |
||||||||||||||||||||||||||||
| Interest and fees on finance receivables and loans |
$ | 1,742 | $ | 1,811 | $ | 1,859 | $ | 1,860 | $ | 1,807 | $ | (69 | ) | $ | (65 | ) | ||||||||||||
| Interest on loans held-for-sale |
2 | 4 | 8 | 3 | 2 | (2 | ) | - | ||||||||||||||||||||
| Total interest and dividends on investment securities |
213 | 217 | 221 | 227 | 222 | (4 | ) | (9 | ) | |||||||||||||||||||
| Interest-bearing cash |
14 | 15 | 19 | 21 | 23 | (1 | ) | (9 | ) | |||||||||||||||||||
| Other earning assets |
13 | 17 | 16 | 17 | 18 | (4 | ) | (5 | ) | |||||||||||||||||||
| Operating leases |
367 | 378 | 368 | 363 | 361 | (11 | ) | 6 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total financing revenue and other interest income |
2,351 | 2,442 | 2,491 | 2,491 | 2,433 | (91 | ) | (82 | ) | |||||||||||||||||||
| Interest expense |
||||||||||||||||||||||||||||
| Interest on deposits |
592 | 637 | 658 | 651 | 592 | (45 | ) | - | ||||||||||||||||||||
| Interest on short-term borrowings |
17 | 21 | 33 | 37 | 44 | (4 | ) | (27 | ) | |||||||||||||||||||
| Interest on long-term debt |
348 | 366 | 378 | 407 | 419 | (18 | ) | (71 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total interest expense |
957 | 1,024 | 1,069 | 1,095 | 1,055 | (67 | ) | (98 | ) | |||||||||||||||||||
| Depreciation expense on operating lease assets |
248 | 262 | 234 | 239 | 246 | (14 | ) | 2 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net financing revenue (as reported) |
$ | 1,146 | $ | 1,156 | $ | 1,188 | $ | 1,157 | $ | 1,132 | $ | (10 | ) | $ | 14 | |||||||||||||
| Other revenue |
||||||||||||||||||||||||||||
| Servicing fees |
3 | 3 | 4 | 5 | 6 | (0 | ) | (3 | ) | |||||||||||||||||||
| Insurance premiums and service revenue earned |
277 | 285 | 280 | 261 | 261 | (8 | ) | 16 | ||||||||||||||||||||
| Gain on mortgage and automotive loans, net |
(12 | ) | 6 | 10 | 2 | 10 | (18 | ) | (22 | ) | ||||||||||||||||||
| Other (loss) / gain on investments, net |
(79 | ) | 69 | 27 | 39 | 108 | (148 | ) | (187 | ) | ||||||||||||||||||
| Other income, net of losses |
77 | 125 | 92 | 88 | 81 | (48 | ) | (5 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total other revenue |
266 | 487 | 413 | 395 | 466 | (221 | ) | (200 | ) | |||||||||||||||||||
| Total net revenue |
1,412 | 1,643 | 1,601 | 1,552 | 1,598 | (231 | ) | (186 | ) | |||||||||||||||||||
| Provision for loan losses |
903 | 276 | 263 | 177 | 282 | 627 | 621 | |||||||||||||||||||||
| Noninterest expense |
||||||||||||||||||||||||||||
| Compensation and benefits expense |
360 | 312 | 296 | 296 | 318 | 48 | 42 | |||||||||||||||||||||
| Insurance losses and loss adjustment expenses |
74 | 61 | 74 | 127 | 59 | 13 | 15 | |||||||||||||||||||||
| Other operating expenses |
486 | 507 | 468 | 458 | 453 | (21 | ) | 33 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total noninterest expense |
920 | 880 | 838 | 881 | 830 | 40 | 90 | |||||||||||||||||||||
| Pre-tax (loss) income from continuing operations |
$ | (411 | ) | $ | 487 | $ | 500 | $ | 494 | $ | 486 | $ | (898 | ) | $ | (897 | ) | |||||||||||
| Income tax (benefit) expense from continuing operations |
(92 | ) | 106 | 119 | (90 | ) | 111 | (198 | ) | (203 | ) | |||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net (loss) income from continuing operations |
(319 | ) | 381 | 381 | 584 | 375 | (700 | ) | (694 | ) | ||||||||||||||||||
| Income / (Loss) from discontinued operations, net of tax |
- | (3 | ) | - | (2 | ) | (1 | ) | 3 | 1 | ||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net (loss) income |
$ | (319 | ) | $ | 378 | $ | 381 | $ | 582 | $ | 374 | $ | (697 | ) | $ | (693 | ) | |||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Core Pre-Tax Income Walk |
||||||||||||||||||||||||||||
| Net financing revenue (ex. Core OID) (1) |
$ | 1,154 | $ | 1,164 | $ | 1,195 | $ | 1,164 | $ | 1,139 | $ | (10 | ) | $ | 16 | |||||||||||||
| Adjusted other revenue (2) |
451 | 458 | 424 | 393 | 396 | (7 | ) | 55 | ||||||||||||||||||||
| Provision for loan losses |
903 | 276 | 263 | 177 | 282 | 627 | 621 | |||||||||||||||||||||
| Noninterest expense |
920 | 880 | 838 | 881 | 830 | 40 | 90 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Core pre-tax (loss) income (3) |
$ | (217 | ) | $ | 466 | $ | 519 | $ | 499 | $ | 423 | $ | (683 | ) | $ | (640 | ) | |||||||||||
| Core OID |
(8 | ) | (8 | ) | (7 | ) | (7 | ) | (7 | ) | (0 | ) | (2 | ) | ||||||||||||||
| Change in the fair value of equity securities (4) |
(185 | ) | 29 | (11 | ) | 2 | 70 | (214 | ) | (255 | ) | |||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Pre-tax (loss) income from continuing operations |
$ | (411 | ) | $ | 487 | $ | 500 | $ | 494 | $ | 486 | $ | (898 | ) | $ | (897 | ) | |||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
(1) Represents a non-GAAP financial measure. Excludes Core OID. For more details refer to page 21.
(2) Represents a non-GAAP financial measure. Excludes equity fair value adjustments related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity. For more details refer to page 21.
(3) Core pre-tax income is a non-GAAP financial measure that adjusts pre-tax income from continuing operations by excluding (1) Core OID and (2) equity fair value adjustments related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity. Management believes core pre-tax income can help the reader better understand the operating performance of the core businesses and their ability to generate earnings.
(4) Change in fair value of equity securities impacts the Insurance and Corporate Finance segments. Excludes equity fair value adjustments related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity.
| 1Q 2020 Preliminary Results | 5 |
| ALLY FINANCIAL INC. CONSOLIDATED PERIOD-END BALANCE SHEET |
|
($in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| 1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | ||||||||||||||||||||||
| Assets |
||||||||||||||||||||||||||||
| Cash and cash equivalents |
||||||||||||||||||||||||||||
| Noninterest-bearing |
$ | 453 | $ | 619 | $ | 723 | $ | 659 | $ | 946 | $ | (166 | ) | $ | (493 | ) | ||||||||||||
| Interest-bearing |
5,708 | 2,936 | 2,894 | 2,904 | 3,011 | 2,772 | 2,697 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total cash and cash equivalents |
6,161 | 3,555 | 3,617 | 3,563 | 3,957 | 2,606 | 2,204 | |||||||||||||||||||||
| Investment securities (1) |
31,619 | 32,468 | 32,572 | 31,740 | 30,553 | (849 | ) | 1,066 | ||||||||||||||||||||
| Loans held-for-sale, net |
235 | 158 | 1,000 | 275 | 107 | 77 | 128 | |||||||||||||||||||||
| Finance receivables and loans |
128,139 | 128,231 | 128,609 | 129,210 | 130,055 | (92 | ) | (1,916 | ) | |||||||||||||||||||
| Allowance for loan losses |
(3,245 | ) | (1,263 | ) | (1,277 | ) | (1,282 | ) | (1,288 | ) | (1,982 | ) | (1,957 | ) | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total finance receivables and loans, net |
124,894 | 126,968 | 127,332 | 127,928 | 128,767 | (2,074 | ) | (3,873 | ) | |||||||||||||||||||
| Investment in operating leases, net |
9,064 | 8,864 | 8,653 | 8,407 | 8,339 | 200 | 725 | |||||||||||||||||||||
| Premiums receivables and other insurance assets |
2,576 | 2,558 | 2,521 | 2,460 | 2,401 | 18 | 175 | |||||||||||||||||||||
| Other assets |
7,978 | 6,073 | 5,790 | 6,075 | 5,993 | 1,905 | 1,985 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total assets |
$ | 182,527 | $ | 180,644 | $ | 181,485 | $ | 180,448 | $ | 180,117 | $ | 1,883 | $ | 2,410 | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Liabilities |
||||||||||||||||||||||||||||
| Deposit liabilities |
||||||||||||||||||||||||||||
| Noninterest-bearing |
$ | 139 | $ | 119 | $ | 156 | $ | 162 | $ | 141 | $ | 20 | $ | (2 | ) | |||||||||||||
| Interest-bearing |
122,185 | 120,633 | 119,074 | 116,163 | 113,158 | 1,552 | 9,027 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total deposit liabilities |
122,324 | 120,752 | 119,230 | 116,325 | 113,299 | 1,572 | 9,025 | |||||||||||||||||||||
| Short-term borrowings |
9,493 | 5,531 | 5,335 | 6,519 | 6,115 | 3,962 | 3,378 | |||||||||||||||||||||
| Long-term debt |
31,066 | 34,027 | 35,730 | 37,466 | 41,490 | (2,961 | ) | (10,424 | ) | |||||||||||||||||||
| Interest payable |
710 | 641 | 894 | 744 | 696 | 69 | 14 | |||||||||||||||||||||
| Unearned insurance premiums and service revenue |
3,305 | 3,305 | 3,246 | 3,171 | 3,096 | - | 209 | |||||||||||||||||||||
| Accrued expense and other liabilities |
2,110 | 1,972 | 2,600 | 1,907 | 1,722 | 138 | 388 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total liabilities |
$ | 169,008 | $ | 166,228 | $ | 167,035 | $ | 166,132 | $ | 166,418 | $ | 2,780 | $ | 2,590 | ||||||||||||||
| Equity |
||||||||||||||||||||||||||||
| Common stock and paid-in capital (2) |
$ | 18,278 | $ | 18,350 | $ | 18,628 | $ | 18,914 | $ | 19,119 | $ | (72 | ) | $ | (841 | ) | ||||||||||||
| Accumulated deficit |
(5,465 | ) | (4,057 | ) | (4,368 | ) | (4,682 | ) | (5,195 | ) | (1,408 | ) | (270 | ) | ||||||||||||||
| Accumulated other comprehensive income / (loss) |
706 | 123 | 190 | 84 | (225 | ) | 583 | 931 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total equity |
13,519 | 14,416 | 14,450 | 14,316 | 13,699 | (897 | ) | (180 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total liabilities and equity |
$ | 182,527 | $ | 180,644 | $ | 181,485 | $ | 180,448 | $ | 180,117 | $ | 1,883 | $ | 2,410 | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
(1) Includes held-to-maturity securities.
(2) Includes Treasury stock.
| 1Q 2020 Preliminary Results | 6 |
| ALLY FINANCIAL INC. CONSOLIDATED AVERAGE BALANCE SHEET (1) |
|
($in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| 1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | ||||||||||||||||||||||
| Assets |
||||||||||||||||||||||||||||
| Interest-bearing cash and cash equivalents |
$ | 4,853 | $ | 3,811 | $ | 3,539 | $ | 3,713 | $ | 4,212 | $ | 1,042 | $ | 641 | ||||||||||||||
| Investment securities and other earning assets |
32,694 | 33,680 | 32,708 | 32,446 | 30,555 | (986 | ) | 2,139 | ||||||||||||||||||||
| Loans held-for-sale, net |
150 | 405 | 745 | 191 | 190 | (255 | ) | (40 | ) | |||||||||||||||||||
| Total finance receivables and loans, net (2) |
126,646 | 127,184 | 128,799 | 129,950 | 128,663 | (538 | ) | (2,017 | ) | |||||||||||||||||||
| Investment in operating leases, net |
9,078 | 8,749 | 8,525 | 8,370 | 8,389 | 329 | 689 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total interest earning assets |
173,420 | 173,829 | 174,316 | 174,670 | 172,009 | (409 | ) | 1,411 | ||||||||||||||||||||
| Noninterest-bearing cash and cash equivalents |
418 | 297 | 391 | 544 | 445 | 121 | (27 | ) | ||||||||||||||||||||
| Other assets |
7,583 | 7,232 | 7,012 | 6,722 | 6,558 | 351 | 1,025 | |||||||||||||||||||||
| Allowance for loan losses |
(2,629 | ) | (1,277 | ) | (1,287 | ) | (1,284 | ) | (1,248 | ) | (1,352 | ) | (1,381 | ) | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total assets |
$ | 178,792 | $ | 180,081 | $ | 180,432 | $ | 180,652 | $ | 177,764 | $ | (1,289 | ) | $ | 1,028 | |||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Liabilities |
||||||||||||||||||||||||||||
| Interest-bearing deposit liabilities |
||||||||||||||||||||||||||||
| Retail deposit liabilities |
$ | 104,483 | $ | 102,362 | $ | 99,874 | $ | 96,855 | $ | 91,881 | $ | 2,121 | $ | 12,602 | ||||||||||||||
| Other interest-bearing deposit liabilities (3) |
16,593 | 17,553 | 17,615 | 17,402 | 17,291 | (960 | ) | (698 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total Interest-bearing deposit liabilities |
121,076 | 119,915 | 117,489 | 114,257 | 109,172 | 1,161 | 11,904 | |||||||||||||||||||||
| Short-term borrowings |
4,496 | 4,283 | 5,550 | 5,887 | 7,054 | 213 | (2,558 | ) | ||||||||||||||||||||
| Long-term debt (4) |
33,122 | 34,954 | 36,395 | 40,222 | 42,396 | (1,832 | ) | (9,274 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total interest-bearing liabilities (4) |
158,694 | 159,152 | 159,434 | 160,366 | 158,622 | (458 | ) | 72 | ||||||||||||||||||||
| Noninterest-bearing deposit liabilities |
141 | 142 | 149 | 135 | 137 | (1 | ) | 4 | ||||||||||||||||||||
| Other liabilities |
6,137 | 6,352 | 6,468 | 6,357 | 5,660 | (215 | ) | 477 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total liabilities |
$ | 164,972 | $ | 165,646 | $ | 166,051 | $ | 166,858 | $ | 164,419 | $ | (674 | ) | $ | 553 | |||||||||||||
| Equity |
||||||||||||||||||||||||||||
| Total equity |
$ | 13,820 | $ | 14,435 | $ | 14,381 | $ | 13,794 | $ | 13,345 | $ | (615 | ) | $ | 475 | |||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total liabilities and equity |
$ | 178,792 | $ | 180,081 | $ | 180,432 | $ | 180,652 | $ | 177,764 | $ | (1,289 | ) | $ | 1,028 | |||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
(1) Average balances are calculated using a combination of monthly and daily average methodologies.
(2) Nonperforming finance receivables and loans are included in the average balances net of unearned income, unamortized premiums and discounts, and deferred fees and costs.
(3) Includes brokered (inclusive of sweep deposits) and other deposits (inclusive of mortgage escrow, and other deposits).
(4) Includes average Core OID balance of $1,059 million in 1Q 20, $1,067 million in 4Q 19, $1,075 million in 3Q 19, $1,082 million in 2Q 19, and $1,089 million in 1Q 19.
| 1Q 2020 Preliminary Results | 7 |
| ALLY FINANCIAL INC. SEGMENT HIGHLIGHTS |
|
($ in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| 1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | ||||||||||||||||||||||
| Pre-tax Income / (Loss) |
||||||||||||||||||||||||||||
| Automotive Finance |
$ | (173 | ) | $ | 401 | $ | 429 | $ | 459 | $ | 329 | $ | (574 | ) | $ | (502 | ) | |||||||||||
| Insurance |
(105 | ) | 114 | 56 | - | 145 | (219 | ) | (250 | ) | ||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Dealer Financial Services |
(278 | ) | 515 | 485 | 459 | 474 | (793 | ) | (752 | ) | ||||||||||||||||||
| Corporate Finance |
(68 | ) | 50 | 44 | 46 | 13 | (118 | ) | (81 | ) | ||||||||||||||||||
| Mortgage Finance |
12 | 2 | 11 | 14 | 13 | 10 | (1 | ) | ||||||||||||||||||||
| Corporate and Other (1) |
(77 | ) | (80 | ) | (40 | ) | (25 | ) | (14 | ) | 3 | (63 | ) | |||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Pre-tax (loss) income from continuing operations |
$ | (411 | ) | $ | 487 | $ | 500 | $ | 494 | $ | 486 | $ | (898 | ) | $ | (897 | ) | |||||||||||
| Core OID (2) |
8 | 8 | 7 | 7 | 7 | 0 | 2 | |||||||||||||||||||||
| Change in the fair value of equity securities (3) |
185 | (29 | ) | 11 | (2 | ) | (70 | ) | 214 | 255 | ||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Core pre-tax (loss) income (4) |
$ | (217 | ) | $ | 466 | $ | 519 | $ | 499 | $ | 423 | $ | (683 | ) | $ | (640 | ) | |||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
(1) Corporate and Other includes the impact of centralized asset and liability management, corporate overhead allocation activities, the legacy mortgage portfolio, Ally Invest activity, and Ally Lending activity.
(2) Core OID for all periods shown are applied to the pre-tax income of the Corporate and Other segment.
(3) Change in fair value of equity securities impacts the Insurance and Corporate Finance segments. Excludes equity fair value adjustments related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity.
(4) Core pre-tax income is a non-GAAP financial measure that adjusts pre-tax income from continuing operations by excluding (1) Core OID and (2) equity fair value adjustments related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity. Management believes core pre-tax income can help the reader better understand the operating performance of the core businesses and their ability to generate earnings.
| 1Q 2020 Preliminary Results | 8 |
| ALLY FINANCIAL INC. AUTOMOTIVE FINANCE - CONDENSED FINANCIAL STATEMENTS |
|
($ in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Income Statement |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Net financing revenue |
||||||||||||||||||||||||||||
| Consumer |
$ | 1,202 | $ | 1,234 | $ | 1,227 | $ | 1,184 | $ | 1,130 | $ | (32 | ) | $ | 72 | |||||||||||||
| Commercial |
307 | 342 | 385 | 412 | 422 | (35 | ) | (115 | ) | |||||||||||||||||||
| Loans held for sale |
- | (1 | ) | - | - | 1 | 1 | (1 | ) | |||||||||||||||||||
| Operating leases |
367 | 378 | 368 | 363 | 361 | (11 | ) | 6 | ||||||||||||||||||||
| Other interest income |
1 | 1 | 3 | 3 | 1 | - | - | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total financing revenue and other interest income |
1,877 | 1,954 | 1,983 | 1,962 | 1,915 | (77 | ) | (38 | ) | |||||||||||||||||||
| Interest expense |
589 | 631 | 671 | 701 | 689 | (42 | ) | (100 | ) | |||||||||||||||||||
| Depreciation expense on operating lease assets: |
||||||||||||||||||||||||||||
| Depreciation expense on operating lease assets (ex. remarketing) |
251 | 265 | 262 | 261 | 262 | (15 | ) | (11 | ) | |||||||||||||||||||
| Remarketing gains |
2 | 3 | 28 | 23 | 15 | (0 | ) | (13 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total depreciation expense on operating lease assets |
248 | 262 | 234 | 239 | 246 | (14 | ) | 2 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net financing revenue |
1,040 | 1,061 | 1,078 | 1,022 | 980 | (21 | ) | 60 | ||||||||||||||||||||
| Other revenue |
||||||||||||||||||||||||||||
| Servicing fees |
1 | 2 | 3 | 4 | 5 | (1 | ) | (4 | ) | |||||||||||||||||||
| Gain/(loss) on automotive loans, net |
- | - | - | - | 8 | - | (8 | ) | ||||||||||||||||||||
| Other income |
46 | 58 | 57 | 57 | 56 | (13 | ) | (10 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total other revenue |
47 | 61 | 59 | 61 | 68 | (14 | ) | (21 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total net revenue |
1,087 | 1,122 | 1,137 | 1,083 | 1,048 | (35 | ) | 39 | ||||||||||||||||||||
| Provision for loan losses |
766 | 255 | 265 | 180 | 262 | 511 | 504 | |||||||||||||||||||||
| Noninterest expense |
||||||||||||||||||||||||||||
| Compensation and benefits |
148 | 133 | 128 | 127 | 136 | 15 | 12 | |||||||||||||||||||||
| Other operating expenses |
346 | 333 | 315 | 317 | 321 | 13 | 25 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total noninterest expense |
494 | 466 | 443 | 444 | 457 | 28 | 37 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Pre-tax (loss) income |
$ | (173 | ) | $ | 401 | $ | 429 | $ | 459 | $ | 329 | $ | (574 | ) | $ | (502 | ) | |||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Memo: Net lease revenue |
||||||||||||||||||||||||||||
| Operating lease revenue |
$ | 367 | $ | 378 | $ | 368 | $ | 363 | $ | 361 | $ | (11 | ) | $ | 6 | |||||||||||||
| Depreciation expense on operating lease assets (ex. remarketing) |
251 | 265 | 262 | 261 | 262 | (15 | ) | (11 | ) | |||||||||||||||||||
| Remarketing gains (losses), net of repo valuation |
2 | 3 | 28 | 23 | 15 | (0 | ) | (13 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total depreciation expense on operating lease assets |
248 | 262 | 234 | 239 | 246 | (14 | ) | 2 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net lease revenue |
$ | 119 | $ | 116 | $ | 134 | $ | 124 | $ | 115 | $ | 3 | $ | 4 | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Balance Sheet (Period-End) |
||||||||||||||||||||||||||||
| Cash, trading and investment securities |
$ | 23 | $ | 23 | $ | 23 | $ | 23 | $ | 23 | $ | - | $ | - | ||||||||||||||
| Consumer loans |
72,463 | 72,254 | 72,894 | 72,746 | 71,490 | 209 | 973 | |||||||||||||||||||||
| Commercial loans |
31,390 | 32,490 | 33,330 | 33,575 | 35,726 | (1,100 | ) | (4,336 | ) | |||||||||||||||||||
| Allowance for loan losses |
(2,968 | ) | (1,130 | ) | (1,156 | ) | (1,146 | ) | (1,138 | ) | (1,838 | ) | (1,830 | ) | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total finance receivables and loans, net |
100,885 | 103,614 | 105,068 | 105,175 | 106,078 | (2,729 | ) | (5,193 | ) | |||||||||||||||||||
| Investment in operating leases, net |
9,064 | 8,864 | 8,653 | 8,407 | 8,339 | 200 | 725 | |||||||||||||||||||||
| Other assets |
1,582 | 1,362 | 1,352 | 1,350 | 1,349 | 220 | 233 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total assets |
$ | 111,554 | $ | 113,863 | $ | 115,096 | $ | 114,955 | $ | 115,789 | $ | (2,309 | ) | $ | (4,235 | ) | ||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| 1Q 2020 Preliminary Results | 9 |
| ALLY FINANCIAL INC. AUTOMOTIVE FINANCE - KEY STATISTICS |
|
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| 1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | ||||||||||||||||||||||
| U.S. Consumer Originations (1) ($ in billions) |
||||||||||||||||||||||||||||
| Retail standard - new vehicle GM |
$ | 1.0 | $ | 1.2 | $ | 1.3 | $ | 1.2 | $ | 1.0 | $ | (0.2 | ) | $ | (0.0 | ) | ||||||||||||
| Retail standard - new vehicle Chrysler |
0.8 | 0.8 | 0.9 | 0.9 | 0.8 | (0.0 | ) | (0.0 | ) | |||||||||||||||||||
| Retail standard - new vehicle Growth |
1.1 | 1.0 | 1.2 | 1.3 | 1.2 | 0.1 | (0.1 | ) | ||||||||||||||||||||
| Used vehicle |
5.0 | 3.9 | 4.6 | 5.3 | 5.2 | 1.0 | (0.2 | ) | ||||||||||||||||||||
| Lease |
1.2 | 1.2 | 1.3 | 1.1 | 0.9 | 0.0 | 0.3 | |||||||||||||||||||||
| Retail subvented |
0.0 | 0.0 | 0.1 | 0.1 | 0.1 | (0.0 | ) | (0.0 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total originations |
$ | 9.1 | $ | 8.1 | $ | 9.3 | $ | 9.7 | $ | 9.2 | $ | 0.9 | $ | (0.1 | ) | |||||||||||||
| U.S. Consumer Originations - FICO Score |
||||||||||||||||||||||||||||
| Super Prime (740+) |
$ | 2.1 | $ | 2.1 | $ | 2.2 | $ | 2.2 | $ | 2.1 | $ | 0.0 | $ | (0.0 | ) | |||||||||||||
| Prime (660-739) |
3.4 | 2.9 | 3.4 | 3.6 | 3.3 | 0.4 | 0.0 | |||||||||||||||||||||
| Prime/Near (620-659) |
1.9 | 1.6 | 2.0 | 2.1 | 2.1 | 0.3 | (0.1 | ) | ||||||||||||||||||||
| Non Prime (540-619) |
0.9 | 0.8 | 0.9 | 1.0 | 0.9 | 0.1 | 0.1 | |||||||||||||||||||||
| Sub Prime (0-539) |
0.1 | 0.1 | 0.1 | 0.1 | 0.1 | 0.0 | (0.0 | ) | ||||||||||||||||||||
| Commercial Services Group (2) |
0.6 | 0.7 | 0.7 | 0.7 | 0.7 | (0.0 | ) | (0.0 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total originations |
$ | 9.1 | $ | 8.1 | $ | 9.3 | $ | 9.7 | $ | 9.2 | $ | 0.9 | $ | (0.1 | ) | |||||||||||||
| U.S. Market |
||||||||||||||||||||||||||||
| Light vehicle sales (SAAR - units in millions) |
15.0 | 16.7 | 17.0 | 17.0 | 16.9 | (1.7 | ) | (1.9 | ) | |||||||||||||||||||
| Light vehicle sales (NSA - units in millions) |
3.5 | 4.3 | 4.3 | 4.4 | 4.0 | (0.8 | ) | (0.5 | ) | |||||||||||||||||||
| GM market share |
17.7% | 17.3% | 17.2% | 16.9% | 16.6% | |||||||||||||||||||||||
| Chrysler market share |
12.8% | 12.7% | 13.1% | 13.5% | 12.4% | |||||||||||||||||||||||
| Ally U.S. Consumer Penetration |
||||||||||||||||||||||||||||
| GM |
6.2% | 5.6% | 5.7% | 5.6% | 5.7% | |||||||||||||||||||||||
| Chrysler |
13.2% | 12.5% | 12.1% | 11.1% | 12.1% | |||||||||||||||||||||||
| Ally U.S. Commercial Outstandings EOP ($ in billions) |
||||||||||||||||||||||||||||
| Floorplan outstandings |
$ | 26.1 | $ | 27.0 | $ | 27.7 | $ | 27.9 | $ | 30.1 | $ | (0.9 | ) | $ | (4.0 | ) | ||||||||||||
| Dealer loans and other |
5.3 | 5.5 | 5.6 | 5.6 | 5.7 | (0.2 | ) | (0.3 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total Commercial outstandings |
$ | 31.4 | $ | 32.5 | $ | 33.3 | $ | 33.6 | $ | 35.7 | $ | (1.1 | ) | $ | (4.3 | ) | ||||||||||||
| U.S. Off-Lease Remarketing |
||||||||||||||||||||||||||||
| Off-lease vehicles terminated - on-balance sheet (# in units) |
20,419 | 27,832 | 29,985 | 29,267 | 26,030 | (7,413 | ) | (5,611 | ) | |||||||||||||||||||
| Average gain / (loss) per vehicle |
$ | 121 | $ | 99 | $ | 944 | $ | 776 | $ | 573 | $ | 22 | $ | (452 | ) | |||||||||||||
| Total gain / (loss) ($ in millions) |
$ | 2 | $ | 3 | $ | 28 | $ | 23 | $ | 15 | $ | (0 | ) | $ | (12 | ) | ||||||||||||
(1) Some standard rate loan originations contain manufacturer sponsored cash back rebate incentives. Some lease originations contain rate subvention. While Ally may jointly develop marketing programs for these originations, Ally does not have exclusive rights to such originations under operating agreements with manufacturers.
(2) Commercial Services Group (CSG) are business customers. Average annualized credit losses of 40-45 bps on CSG loans from 2016 through 1Q20
| 1Q 2020 Preliminary Results | 10 |
| ALLY FINANCIAL INC. INSURANCE - CONDENSED FINANCIAL STATEMENTS AND KEY STATISTICS |
|
($ in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Income Statement (GAAP View) |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Net financing revenue |
||||||||||||||||||||||||||||
| Interest and dividends on investment securities |
$ | 29 | $ | 29 | $ | 28 | $ | 29 | $ | 27 | $ | - | $ | 2 | ||||||||||||||
| Interest bearing cash |
5 | 5 | 6 | 5 | 4 | - | 1 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total financing revenue and other interest revenue |
34 | 34 | 34 | 34 | 31 | - | 3 | |||||||||||||||||||||
| Interest expense |
20 | 21 | 20 | 19 | 19 | (1 | ) | 1 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net financing revenue |
14 | 13 | 14 | 15 | 12 | 1 | 2 | |||||||||||||||||||||
| Other revenue |
||||||||||||||||||||||||||||
| Insurance premiums and service revenue earned |
277 | 285 | 280 | 261 | 261 | (8 | ) | 16 | ||||||||||||||||||||
| Other (loss) / gain on investments, net |
(142 | ) | 51 | 6 | 23 | 95 | (193 | ) | (237 | ) | ||||||||||||||||||
| Other income, net of losses |
2 | 3 | 3 | 2 | 4 | (1 | ) | (2 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total other revenue |
137 | 339 | 289 | 286 | 360 | (202 | ) | (223 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total net revenue |
151 | 352 | 303 | 301 | 372 | (201 | ) | (221 | ) | |||||||||||||||||||
| Noninterest expense |
||||||||||||||||||||||||||||
| Compensation and benefits expense |
21 | 20 | 19 | 20 | 21 | 1 | - | |||||||||||||||||||||
| Insurance losses and loss adjustment expenses |
74 | 61 | 74 | 127 | 59 | 13 | 15 | |||||||||||||||||||||
| Other operating expenses |
161 | 157 | 154 | 154 | 147 | 4 | 14 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total noninterest expense |
256 | 238 | 247 | 301 | 227 | 18 | 29 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Pre-tax (loss) income |
$ | (105 | ) | $ | 114 | $ | 56 | $ | - | $ | 145 | $ | (219 | ) | $ | (250 | ) | |||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Memo: Income Statement (Managerial View) |
||||||||||||||||||||||||||||
| Insurance premiums and other income |
||||||||||||||||||||||||||||
| Insurance premiums and service revenue earned |
$ | 277 | $ | 285 | $ | 280 | $ | 261 | $ | 261 | $ | (8 | ) | $ | 16 | |||||||||||||
| Investment income (adjusted) (1) |
54 | 36 | 30 | 34 | 42 | 18 | 12 | |||||||||||||||||||||
| Other income |
2 | 3 | 3 | 2 | 4 | (1 | ) | (2 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total insurance premiums and other income |
333 | 324 | 313 | 297 | 307 | 9 | 26 | |||||||||||||||||||||
| Expense |
||||||||||||||||||||||||||||
| Insurance losses and loss adjustment expenses |
74 | 61 | 74 | 127 | 59 | 13 | 15 | |||||||||||||||||||||
| Acquisition and underwriting expenses |
||||||||||||||||||||||||||||
| Compensation and benefit expense |
21 | 20 | 19 | 20 | 21 | 1 | - | |||||||||||||||||||||
| Insurance commission expense |
126 | 123 | 120 | 117 | 114 | 3 | 12 | |||||||||||||||||||||
| Other expense |
35 | 34 | 34 | 37 | 33 | 1 | 2 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total acquisition and underwriting expense |
182 | 177 | 173 | 174 | 168 | 5 | 14 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total expense |
256 | 238 | 247 | 301 | 227 | 18 | 29 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Core pre-tax income / (loss) (1) |
77 | 86 | 66 | (4 | ) | 80 | (9 | ) | (3 | ) | ||||||||||||||||||
| Change in the fair value of equity securities (1) |
(182 | ) | 28 | (10 | ) | 4 | 65 | (210 | ) | (247 | ) | |||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| (Loss) / income before income tax expense |
$ | (105 | ) | $ | 114 | $ | 56 | $ | - | $ | 145 | $ | (219 | ) | $ | (250 | ) | |||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Balance Sheet (Period-End) |
||||||||||||||||||||||||||||
| Cash, trading and investment securities |
$ | 5,193 | $ | 5,742 | $ | 5,713 | $ | 5,538 | $ | 5,512 | $ | (549 | ) | $ | (319 | ) | ||||||||||||
| Premiums receivable and other insurance assets |
2,594 | 2,576 | 2,539 | 2,478 | 2,420 | 18 | 174 | |||||||||||||||||||||
| Other assets |
633 | 229 | 226 | 225 | 247 | 404 | 386 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total assets |
$ | 8,420 | $ | 8,547 | $ | 8,478 | $ | 8,241 | $ | 8,179 | $ | (127 | ) | $ | 241 | |||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Key Statistics |
||||||||||||||||||||||||||||
| Total written premiums and revenue (2) |
$ | 317 | $ | 335 | $ | 357 | $ | 314 | $ | 305 | $ | (18 | ) | $ | 12 | |||||||||||||
| Loss ratio (3) |
26.5% | 21.2% | 26.1% | 48.5% | 22.2% | |||||||||||||||||||||||
| Underwriting expense ratio (4) |
65.1% | 61.5% | 61.4% | 65.9% | 63.5% | |||||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||||||||||||||
| Combined ratio |
91.6% | 82.7% | 87.5% | 114.4% | 85.7% | |||||||||||||||||||||||
(1) Represents a non-GAAP financial measure. Excludes equity fair value adjustments related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity.
(2) Written premiums are net of ceded premium for reinsurance.
(3) Loss Ratio is calculated as Insurance losses and loss adjustment expenses divided by Insurance premiums and service revenue earned and Other Income, net of losses.
(4) Underwriting Expense Ratio is calculated as Compensation and benefits expense and Other operating expenses divided by Insurance premiums and service revenue earned and Other Income, net of losses.
| 1Q 2020 Preliminary Results | 11 |
| ALLY FINANCIAL INC. MORTGAGE FINANCE - CONDENSED FINANCIAL STATEMENTS |
|
($ in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Income Statement |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Net financing revenue |
||||||||||||||||||||||||||||
| Total financing revenue and other interest income |
$ | 138 | $ | 137 | $ | 144 | $ | 150 | $ | 146 | $ | 1 | $ | (8 | ) | |||||||||||||
| Interest expense |
100 | 101 | 105 | 104 | 96 | (1 | ) | 4 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net financing revenue |
38 | 36 | 39 | 46 | 50 | 2 | (12 | ) | ||||||||||||||||||||
| Gain on mortgage loans, net |
9 | 6 | 10 | 2 | 2 | 3 | 7 | |||||||||||||||||||||
| Other income, net of losses |
1 | - | - | 2 | - | 1 | 1 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total other revenue |
10 | 6 | 10 | 4 | 2 | 4 | 8 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total net revenue |
48 | 42 | 49 | 50 | 52 | 6 | (4 | ) | ||||||||||||||||||||
| Provision for loan losses |
1 | 3 | - | - | 2 | (2 | ) | (1 | ) | |||||||||||||||||||
| Noninterest expense |
||||||||||||||||||||||||||||
| Compensation and benefits expense |
6 | 7 | 7 | 9 | 8 | (1 | ) | (2 | ) | |||||||||||||||||||
| Other operating expense |
29 | 30 | 31 | 27 | 29 | (1 | ) | - | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total noninterest expense |
35 | 37 | 38 | 36 | 37 | (2 | ) | (2 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Pre-tax income |
$ | 12 | $ | 2 | $ | 11 | $ | 14 | $ | 13 | $ | 10 | $ | (1 | ) | |||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Balance Sheet (Period-End) |
||||||||||||||||||||||||||||
| Finance receivables and loans, net: |
||||||||||||||||||||||||||||
| Consumer loans |
$ | 15,949 | $ | 16,181 | $ | 15,782 | $ | 16,485 | $ | 16,225 | $ | (232 | ) | $ | (276 | ) | ||||||||||||
| Allowance for loan losses |
(18 | ) | (19 | ) | (17 | ) | (18 | ) | (18 | ) | 1 | - | ||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total finance receivables and loans, net |
15,931 | 16,162 | 15,765 | 16,467 | 16,207 | (231 | ) | (276 | ) | |||||||||||||||||||
| Other assets |
204 | 117 | 818 | 117 | 94 | 87 | 110 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total assets |
$ | 16,135 | $ | 16,279 | $ | 16,583 | $ | 16,584 | $ | 16,301 | $ | (144 | ) | $ | (166 | ) | ||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| 1Q 2020 Preliminary Results | 12 |
| ALLY FINANCIAL INC. CORPORATE FINANCE - CONDENSED FINANCIAL STATEMENTS |
|
($ in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Income Statement |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Net financing revenue |
||||||||||||||||||||||||||||
| Total financing revenue and other interest income |
$ | 95 | $ | 93 | $ | 93 | $ | 97 | $ | 90 | $ | 2 | $ | 5 | ||||||||||||||
| Interest expense |
27 | 29 | 33 | 36 | 36 | (2 | ) | (9 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net financing revenue |
68 | 64 | 60 | 61 | 54 | 4 | 14 | |||||||||||||||||||||
| Total other revenue (adjusted) (1) |
17 | 15 | 10 | 12 | 7 | 2 | 10 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total net revenue |
85 | 79 | 70 | 73 | 61 | 6 | 24 | |||||||||||||||||||||
| Provision for loan losses |
114 | 7 | 3 | 3 | 23 | 107 | 91 | |||||||||||||||||||||
| Noninterest expense |
||||||||||||||||||||||||||||
| Compensation and benefits expense |
21 | 13 | 13 | 13 | 19 | 8 | 2 | |||||||||||||||||||||
| Other operating expense |
14 | 9 | 9 | 9 | 10 | 5 | 4 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total noninterest expense |
35 | 22 | 22 | 22 | 29 | 13 | 6 | |||||||||||||||||||||
| Core pre-tax income (1) |
(64 | ) | 50 | 45 | 48 | 9 | (114 | ) | (73 | ) | ||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Change in the fair value of equity securities (2) |
(4 | ) | 0 | (1 | ) | (2 | ) | 4 | (4 | ) | (8 | ) | ||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Pre-tax (loss) income |
$ | (68 | ) | $ | 50 | $ | 44 | $ | 46 | $ | 13 | $ | (118 | ) | $ | (81 | ) | |||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Balance Sheet (Period-End) |
||||||||||||||||||||||||||||
| Cash, trading and investment securities |
$ | 4 | $ | 8 | $ | 8 | $ | 9 | $ | 12 | $ | (4 | ) | $ | (8 | ) | ||||||||||||
| Loans held for sale |
133 | 100 | 240 | 195 | 24 | 33 | 109 | |||||||||||||||||||||
| Commercial loans |
6,549 | 5,688 | 5,033 | 4,795 | 5,001 | 861 | 1,548 | |||||||||||||||||||||
| Allowance for loan losses |
(191 | ) | (77 | ) | (75 | ) | (87 | ) | (96 | ) | (114 | ) | (95 | ) | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total finance receivables and loans, net |
6,358 | 5,611 | 4,958 | 4,708 | 4,905 | 747 | 1,453 | |||||||||||||||||||||
| Other assets |
77 | 68 | 69 | 68 | 65 | 9 | 12 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total assets |
$ | 6,572 | $ | 5,787 | $ | 5,275 | $ | 4,980 | $ | 5,006 | $ | 785 | $ | 1,566 | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
(1) Represents a non-GAAP financial measure. Excludes equity fair value adjustments related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity. See page 21 for more details.
(2) Excludes equity fair value adjustments related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity.
| 1Q 2020 Preliminary Results | 13 |
| ALLY FINANCIAL INC. CORPORATE AND OTHER - CONDENSED FINANCIAL STATEMENTS |
|
($ in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Income Statement |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Net financing revenue |
||||||||||||||||||||||||||||
| Total financing revenue and other interest income |
$ | 207 | $ | 224 | $ | 237 | $ | 248 | $ | 251 | $ | (17 | ) | $ | (44 | ) | ||||||||||||
| Interest expense |
||||||||||||||||||||||||||||
| Core original issue discount amortization |
8 | 8 | 7 | 7 | 7 | 0 | 2 | |||||||||||||||||||||
| Other interest expense |
213 | 234 | 233 | 228 | 208 | (21 | ) | 4 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total interest expense |
221 | 242 | 240 | 235 | 215 | (21 | ) | 6 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net financing (loss) / revenue |
(14 | ) | (18 | ) | (3 | ) | 13 | 36 | 4 | (50 | ) | |||||||||||||||||
| Other revenue |
||||||||||||||||||||||||||||
| Other gain on investments, net |
67 | 18 | 22 | 14 | 9 | 49 | 58 | |||||||||||||||||||||
| Other income, net of losses (1) |
(8 | ) | 48 | 24 | 20 | 16 | (56 | ) | (24 | ) | ||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total other revenue |
59 | 66 | 46 | 34 | 25 | (7 | ) | 34 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total net revenue |
45 | 48 | 43 | 47 | 61 | (3 | ) | (16 | ) | |||||||||||||||||||
| Provision for loan losses |
22 | 11 | (5 | ) | (6 | ) | (5 | ) | 11 | 27 | ||||||||||||||||||
| Noninterest expense |
||||||||||||||||||||||||||||
| Compensation and benefits expense |
164 | 139 | 129 | 127 | 134 | 25 | 30 | |||||||||||||||||||||
| Other operating expense (2) |
(64 | ) | (22 | ) | (41 | ) | (49 | ) | (54 | ) | (42 | ) | (10 | ) | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total noninterest expense |
100 | 117 | 88 | 78 | 80 | (17 | ) | 20 | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Pre-tax (loss) income |
$ | (77 | ) | $ | (80 | ) | $ | (40 | ) | $ | (25 | ) | $ | (14 | ) | $ | 3 | $ | (63 | ) | ||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Balance Sheet (Period-End) |
||||||||||||||||||||||||||||
| Cash, trading and investment securities |
$ | 32,560 | $ | 30,250 | $ | 30,445 | $ | 29,733 | $ | 28,963 | $ | 2,310 | $ | 3,597 | ||||||||||||||
| Loans held-for-sale |
34 | 30 | 67 | 58 | 50 | 4 | (16 | ) | ||||||||||||||||||||
| Consumer loans |
1,654 | 1,489 | 1,405 | 1,467 | 1,496 | 165 | 158 | |||||||||||||||||||||
| Commercial loans (3) |
134 | 129 | 165 | 142 | 135 | 5 | (1 | ) | ||||||||||||||||||||
| Allowance for loan losses |
(68 | ) | (37 | ) | (29 | ) | (31 | ) | (36 | ) | (31 | ) | (32 | ) | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total finance receivables and loans, net |
1,720 | 1,581 | 1,541 | 1,578 | 1,595 | 139 | 125 | |||||||||||||||||||||
| Other assets |
5,532 | 4,307 | 4,000 | 4,319 | 4,234 | 1,225 | 1,298 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total assets |
$ | 39,846 | $ | 36,168 | $ | 36,053 | $ | 35,688 | $ | 34,842 | $ | 3,678 | $ | 5,004 | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Core OID Amortization Schedule (4) |
2020 | 2021 | 2022 | 2023 | 2024 & After | |||||||||||||||||||||||
| Remaining Core OID amortization expense |
$ | 27 | $ | 41 | $ | 47 | $ | 54 | Avg = $52/yr | |||||||||||||||||||
(1) Includes the impact of centralized asset and liability management, corporate overhead allocation activities, the legacy mortgage portfolio, Ally Invest activity, and Ally Lending activity.
(2) Other operating expenses includes corporate overhead allocated to the other business segments. Amounts of corporate overhead allocated were $256 million for 1Q20, $225 million for 4Q19, $225 million for 3Q19, $219 million for 2Q19 and $229 million for 1Q19. The receiving business segment records the allocation of corporate overhead expense within other operating expenses.
(3) Includes intercompany.
(4) Represents a non-GAAP financial measure. For more details refer to page 21.
| 1Q 2020 Preliminary Results | 14 |
| ALLY FINANCIAL INC. CREDIT RELATED INFORMATION |
|
($ in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Asset Quality - Consolidated (1) |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Ending loan balance |
$ | 128,129 | $ | 128,220 | $ | 128,609 | $ | 129,210 | $ | 130,055 | $ | (91 | ) | $ | (1,926 | ) | ||||||||||||
| 30+ Accruing DPD |
$ | 2,622 | $ | 2,709 | $ | 2,561 | $ | 2,227 | $ | 1,920 | $ | (87 | ) | $ | 702 | |||||||||||||
| 30+ Accruing DPD % |
2.05% | 2.11% | 1.99% | 1.72% | 1.48% | |||||||||||||||||||||||
| Non-performing loans (NPLs) |
$ | 1,458 | $ | 1,036 | $ | 929 | $ | 903 | $ | 987 | $ | 422 | $ | 471 | ||||||||||||||
| Net charge-offs (NCOs) |
$ | 266 | $ | 290 | $ | 267 | $ | 182 | $ | 237 | $ | (24 | ) | $ | 29 | |||||||||||||
| Net charge-off rate (2) |
0.84% | 0.91% | 0.83% | 0.56% | 0.73% | |||||||||||||||||||||||
| Provision for loan losses |
$ | 903 | $ | 276 | $ | 263 | $ | 177 | $ | 282 | $ | 627 | $ | 621 | ||||||||||||||
| Allowance for loan losses (ALLL) |
$ | 3,245 | $ | 1,263 | $ | 1,277 | $ | 1,282 | $ | 1,288 | $ | 1,982 | $ | 1,957 | ||||||||||||||
| ALLL as % of Loans (3) (4) |
2.54% | 0.99% | 0.99% | 0.99% | 0.99% | |||||||||||||||||||||||
| ALLL as % of NPLs (3) |
223% | 122% | 137% | 142% | 130% | |||||||||||||||||||||||
| ALLL as % of NCOs (3) |
305% | 109% | 119% | 176% | 136% | |||||||||||||||||||||||
| US Auto Delinquencies - HFI Retail Contract $‘s (5) |
||||||||||||||||||||||||||||
| Delinquent contract $ |
$ | 2,528 | $ | 2,616 | $ | 2,428 | $ | 2,113 | $ | 1,833 | $ | (88 | ) | $ | 695 | |||||||||||||
| % of retail contract $ outstanding |
3.47% | 3.61% | 3.32% | 2.90% | 2.56% | |||||||||||||||||||||||
| U.S. Auto Annualized Net Charge-Offs - HFI Retail Contract $‘s |
||||||||||||||||||||||||||||
| Net charge-offs |
$ | 262 | $ | 271 | $ | 253 | $ | 172 | $ | 234 | $ | (9 | ) | $ | 28 | |||||||||||||
| % of avg. HFI assets (2) |
1.44% | 1.49% | 1.38% | 0.95% | 1.32% | |||||||||||||||||||||||
| U.S. Auto Annualized Net Charge-Offs - HFI Commercial Contract $‘s |
||||||||||||||||||||||||||||
| Net charge-offs |
$ | 2 | $ | 10 | $ | 1 | $ | 1 | $ | 0 | $ | (8 | ) | $ | 2 | |||||||||||||
| % of avg. HFI assets (2) |
0.03% | 0.12% | 0.02% | 0.01% | 0.00% | |||||||||||||||||||||||
(1) Loans within this table are classified as held-for-investment recorded at amortized cost as these loans are included in our allowance for loan losses.
(2) Net charge-off ratios are calculated as annualized net charge-offs divided by average outstanding finance recievables and loans excluding loans measured at fair value, conditional repurchase loans and loans held-for-sale during the year for each loan category.
(3) ALLL coverage ratios are based on the allowance for loan losses related to loans held-for-investment excluding those loans held at fair value as a percentage of the unpaid principal balance, net of premiums and discounts.
(4) Excludes $370 million of fair value adjustment for loans in hedge accounting relationships in 1Q20, $135 million in 4Q19, $176 million in 3Q19, $153 million in 2Q19 and $63 million in 1Q19.
(5) Dollar amount of accruing contracts greater than 30 days past due
| 1Q 2020 Preliminary Results | 15 |
| ALLY FINANCIAL INC. CREDIT RELATED INFORMATION, CONTINUED |
|
($ in millions)
CONTINUING OPERATIONS
| Automotive Finance (1) |
QUARTERLY TRENDS | CHANGE VS. | ||||||||||||||||||||||||||
| Consumer | 1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Allowance for loan losses |
$ | 2,833 | $ | 1,075 | $ | 1,090 | $ | 1,078 | $ | 1,070 | $ | 1,758 | $ | 1,763 | ||||||||||||||
| Total consumer loans (2) |
$ | 72,832 | $ | 72,390 | $ | 73,071 | $ | 72,898 | $ | 71,553 | $ | 442 | $ | 1,279 | ||||||||||||||
| Coverage ratio (3) |
3.91% | 1.49% | 1.50% | 1.48% | 1.50% | |||||||||||||||||||||||
| Commercial |
||||||||||||||||||||||||||||
| Allowance for loan losses |
$ | 135 | $ | 55 | $ | 66 | $ | 68 | $ | 68 | $ | 80 | $ | 67 | ||||||||||||||
| Total commercial loans |
$ | 31,390 | $ | 32,490 | $ | 33,330 | $ | 33,575 | $ | 35,708 | $ | (1,100 | ) | $ | (4,318 | ) | ||||||||||||
| Coverage ratio |
0.43% | 0.17% | 0.20% | 0.20% | 0.19% | |||||||||||||||||||||||
| Mortgage (1) |
||||||||||||||||||||||||||||
| Consumer |
||||||||||||||||||||||||||||
| Mortgage Finance |
||||||||||||||||||||||||||||
| Allowance for loan losses |
$ | 18 | $ | 19 | $ | 17 | $ | 18 | $ | 18 | $ | (1 | ) | $ | - | |||||||||||||
| Total consumer loans |
$ | 15,949 | $ | 16,181 | $ | 15,782 | $ | 16,485 | $ | 16,225 | $ | (232 | ) | $ | (276 | ) | ||||||||||||
| Coverage ratio |
0.11% | 0.12% | 0.11% | 0.11% | 0.11% | |||||||||||||||||||||||
| Mortgage - Legacy |
||||||||||||||||||||||||||||
| Allowance for loan losses |
$ | 21 | $ | 27 | $ | 27 | $ | 31 | $ | 34 | $ | (6 | ) | $ | (13 | ) | ||||||||||||
| Total consumer loans |
$ | 1,061 | $ | 1,141 | $ | 1,228 | $ | 1,315 | $ | 1,433 | $ | (80 | ) | $ | (372 | ) | ||||||||||||
| Coverage ratio |
1.99% | 2.35% | 2.23% | 2.35% | 2.36% | |||||||||||||||||||||||
| Total Mortgage |
||||||||||||||||||||||||||||
| Allowance for loan losses |
$ | 39 | $ | 46 | $ | 44 | $ | 49 | $ | 52 | $ | (7 | ) | $ | (13 | ) | ||||||||||||
| Total consumer loans |
$ | 17,010 | $ | 17,322 | $ | 17,010 | $ | 17,800 | $ | 17,658 | $ | (312 | ) | $ | (648 | ) | ||||||||||||
| Coverage ratio |
0.23% | 0.27% | 0.26% | 0.27% | 0.29% | |||||||||||||||||||||||
| Consumer Other (1)(4) |
||||||||||||||||||||||||||||
| Allowance for loan losses |
$ | 45 | $ | 9 | $ | 36 | $ | 45 | ||||||||||||||||||||
| Total consumer loans |
$ | 214 | $ | 201 | $ | 13 | $ | 214 | ||||||||||||||||||||
| Coverage ratio |
21.23% | 4.65% | ||||||||||||||||||||||||||
| Corporate Finance (1) |
||||||||||||||||||||||||||||
| Allowance for loan losses |
$ | 191 | $ | 77 | $ | 75 | $ | 87 | $ | 96 | $ | 114 | $ | 95 | ||||||||||||||
| Total commercial loans |
$ | 6,549 | $ | 5,688 | $ | 5,033 | $ | 4,795 | $ | 5,001 | $ | 861 | $ | 1,548 | ||||||||||||||
| Coverage ratio |
2.92% | 1.35% | 1.50% | 1.81% | 1.91% | |||||||||||||||||||||||
| Corporate and Other (1) |
||||||||||||||||||||||||||||
| Allowance for loan losses |
$ | 2 | $ | 1 | $ | 2 | $ | 0 | $ | 2 | $ | 1 | $ | - | ||||||||||||||
| Total commercial loans |
$ | 134 | $ | 129 | $ | 165 | $ | 142 | $ | 135 | $ | 5 | $ | (1 | ) | |||||||||||||
| Coverage ratio |
1.36% | 0.69% | 0.93% | 0.34% | 1.31% | |||||||||||||||||||||||
(1) ALLL coverage ratios are based on the domestic allowance as a percentage of finance receivables and loans reported at their gross carrying value, which includes the principal amount outstanding, net of unearned income, unamortized deferred fees reduced by costs on originated loans, unamortized premiums and discounts on purchased loans, unamortized basis adjustments arising from the designation of finance receivables and loans as the hedged item in qualifying fair value hedge relationships, and cumulative principal charge-offs. Excludes loans held at fair value.
(2) Includes $370 million of fair value adjustment for loans in hedge accounting relationships in 1Q20, $135 million in 4Q19, $176 million in 3Q19, $153 million in 2Q19 and $63 million in 1Q19.
(3) Excludes $370 million of fair value adjustment for loans in hedge accounting relationships in 1Q20, $135 million in 4Q19, $176 million in 3Q19, $153 million in 2Q19 and $63 million in 1Q19.
(4) Represents Health Credit Services (HCS) which Ally acquired in 4Q19 (now Ally Lending).
| 1Q 2020 Preliminary Results | 16 |
| ALLY FINANCIAL INC. CAPITAL |
|
($ in billions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Basel III Transition | ||||||||||||||||||||||||||||
| Capital (1) |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Risk-weighted assets |
$ | 146.0 | $ | 145.1 | $ | 146.1 | $ | 145.9 | $ | 145.9 | $ | 0.9 | $ | 0.1 | ||||||||||||||
| Common Equity Tier 1 (CET1) capital ratio |
9.3% | 9.5% | 9.6% | 9.5% | 9.3% | |||||||||||||||||||||||
| Tier 1 capital ratio |
10.9% | 11.2% | 11.2% | 11.2% | 11.0% | |||||||||||||||||||||||
| Total capital ratio |
12.8% | 12.8% | 12.8% | 12.7% | 12.5% | |||||||||||||||||||||||
| Tangible common equity / Tangible assets (2)(3) |
7.2% | 7.8% | 7.8% | 7.8% | 7.5% | |||||||||||||||||||||||
| Tangible common equity / Risk-weighted assets (2) |
9.0% | 9.6% | 9.7% | 9.6% | 9.2% | |||||||||||||||||||||||
| Shareholders’ equity |
$ | 13.5 | $ | 14.4 | $ | 14.5 | $ | 14.3 | $ | 13.7 | $ | (0.9 | ) | $ | (0.2 | ) | ||||||||||||
| add: CECL phase-in adjustment |
1.2 | |||||||||||||||||||||||||||
| less: Disallowed DTA |
- | - | - | (0.1 | ) | (0.1 | ) | - | 0.1 | |||||||||||||||||||
| Certain AOCI items and other adjustments |
(1.1 | ) | (0.6 | ) | (0.5 | ) | (0.3 | ) | - | (0.5 | ) | (1.1 | ) | |||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Common Equity Tier 1 capital |
$ | 13.5 | $ | 13.8 | $ | 14.0 | $ | 13.9 | $ | 13.6 | $ | (0.3 | ) | $ | (0.1 | ) | ||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Common Equity Tier 1 capital |
$ | 13.5 | $ | 13.8 | $ | 14.0 | $ | 13.9 | $ | 13.6 | $ | (0.3 | ) | $ | (0.1 | ) | ||||||||||||
| add: Trust preferred securities |
2.5 | 2.5 | 2.5 | 2.5 | 2.5 | - | - | |||||||||||||||||||||
| less: Other adjustments |
(0.1 | ) | (0.1 | ) | (0.1 | ) | (0.1 | ) | (0.1 | ) | - | - | ||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Tier 1 capital |
$ | 16.0 | $ | 16.3 | $ | 16.4 | $ | 16.3 | $ | 16.0 | $ | (0.3 | ) | $ | - | |||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Tier 1 capital |
$ | 16.0 | $ | 16.3 | $ | 16.4 | $ | 16.3 | $ | 16.0 | $ | (0.3 | ) | $ | - | |||||||||||||
| add: Qualifying subordinated debt |
1.0 | 1.0 | 1.0 | 1.0 | 1.0 | - | - | |||||||||||||||||||||
| Allowance for loan and lease losses includible in Tier 2 capital and other adjustments |
1.7 | 1.2 | 1.2 | 1.2 | 1.2 | 0.5 | 0.5 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total capital |
$ | 18.6 | $ | 18.5 | $ | 18.6 | $ | 18.6 | $ | 18.3 | $ | 0.1 | $ | 0.3 | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total shareholders’ equity |
$ | 13.5 | $ | 14.4 | $ | 14.5 | $ | 14.3 | $ | 13.7 | $ | (0.9 | ) | $ | (0.2 | ) | ||||||||||||
| Goodwill and intangible assets, net of deferred tax liabilities |
(0.4 | ) | (0.5 | ) | (0.3 | ) | (0.3 | ) | (0.3 | ) | 0.1 | (0.1 | ) | |||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Tangible common equity (2) |
$ | 13.1 | $ | 14.0 | $ | 14.2 | $ | 14.0 | $ | 13.4 | $ | (0.9 | ) | $ | (0.3 | ) | ||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total assets |
$ | 182.5 | $ | 180.6 | $ | 181.5 | $ | 180.4 | $ | 180.1 | $ | 1.9 | $ | 2.4 | ||||||||||||||
| less: Goodwill and intangible assets, net of deferred tax liabilities |
(0.4 | ) | (0.5 | ) | (0.3 | ) | (0.3 | ) | (0.3 | ) | 0.1 | (0.1 | ) | |||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Tangible assets (3) |
$ | 182.1 | $ | 180.2 | $ | 181.2 | $ | 180.2 | $ | 179.8 | $ | 1.9 | $ | 2.3 | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Denominator for Common equity tier 1 ratio |
||||||||||||||||||||||||||||
| Risk-weighted assets (transition) |
$ | 146.0 | $ | 145.1 | $ | 146.1 | $ | 145.9 | $ | 145.9 | ||||||||||||||||||
| Metric |
||||||||||||||||||||||||||||
| Common equity tier 1 ratio (transition) |
9.3% | 9.5% | 9.6% | 9.5% | 9.3% | |||||||||||||||||||||||
Note: Numbers may not foot due to rounding
(1) Basel III rules became effective on January 1, 2015, subject to transition provisions primarily related to deductions and adjustments impacting CET1 capital and Tier 1 capital
(2) Represents a non-GAAP financial measure. Tangible Common Equity is a non-GAAP financial measure that is defined as common stockholders’ equity less goodwill and identifiable intangible assets, net of deferred tax liabilities. Ally considers various measures when evaluating capital adequacy, including tangible common equity. Ally believes that tangible common equity is important because we believe readers may assess our capital adequacy using this measure. Additionally, presentation of this measure allows readers to compare certain aspects of our capital adequacy on the same basis to other companies in the industry. For purposes of calculating Core return on tangible common equity (Core ROTCE), tangible common equity is further adjusted for tax-effected Core OID balance and net deferred tax asset.
(3) Represents a non-GAAP financial measure. Ally defines tangible assets as total assets less goodwill and intangible assets, net of deferred tax liabilities.
In December 2018, the FRB and other U.S. banking agencies approved a final rule to address the impact of CECL on regulatory capital by allowing BHCs and banks, including Ally, the option to phase in the day-one impact of CECL over a three-year period. In March 2020, the FRB and other U.S. banking agencies issued an interim final rule that became effective on March 31, 2020, and provides an alternative option for banks to temporarily delay the impacts of CECL, relative to the incurred loss methodology for estimating the allowance for loan losses, on regulatory capital. For regulatory capital purposes, these rules permitted us to delay recognizing the estimated impact of CECL on regulatory capital until after a two-year deferral period, which for us extends through December 31, 2021. Beginning on January 1, 2022, we will be required to phase in 25% of the previously deferred estimated capital impact of CECL, with an additional 25% to be phased in at the beginning of each subsequent year until fully phased in by the first quarter of 2025. Under these rules, firms that adopt CECL and elect the five-year transition will calculate the estimated impact of CECL on regulatory capital as the day-one impact of adoption plus 25% of the subsequent change in allowance during the two-year deferral period, which according to the interim final rule approximates the impact of CECL relative to an incurred loss model. We adopted this transition option during the first quarter of 2020, and plan to phase in the regulatory capital impacts of CECL based on this five-year transition period.
| 1Q 2020 Preliminary Results | 17 |
| ALLY FINANCIAL INC. LIQUIDITY |
|
($ in billions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Consolidated Available Liquidity |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Cash and cash equivalents (1) |
$ | 5.7 | $ | 3.1 | $ | 3.2 | $ | 3.2 | $ | 3.5 | $ | 2.5 | $ | 2.2 | ||||||||||||||
| Highly liquid securities (2) |
24.0 | 24.7 | 23.5 | 21.5 | 20.3 | (0.7 | ) | 3.7 | ||||||||||||||||||||
| Current committed unused capacity |
0.4 | 2.1 | 2.0 | 1.6 | 1.8 | (1.7 | ) | (1.5 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total current available liquidity |
$ | 30.1 | $ | 29.9 | $ | 28.6 | $ | 26.3 | $ | 25.6 | $ | 0.2 | $ | 4.4 | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Unsecured Long-Term Debt Maturity Profile |
2020 | 2021 | 2022 | 2023 | 2024 | 2025 & After | ||||||||||||||||||||||
| Consolidated remaining maturities |
$ | 0.5 | $ | 0.7 | $ | 1.1 | $ | 0.0 | $ | 1.5 | $ | 6.9 | ||||||||||||||||
(1) May include the restricted cash accumulation for retained notes maturing within the following 30 days and returned to Ally on the distribution date
(2) Includes unencumbered UST, Agency debt and Agency MBS
| 1Q 2020 Preliminary Results | 18 |
| ALLY FINANCIAL INC. NET INTEREST MARGIN AND DEPOSITS |
|
($ in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Average Balance Details |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Retail Auto Loans |
$ | 72,550 | $ | 72,626 | $ | 73,162 | $ | 72,274 | $ | 70,981 | $ | (76 | ) | $ | 1,569 | |||||||||||||
| Auto Lease (net of dep) |
9,078 | 8,749 | 8,525 | 8,370 | 8,389 | 329 | 689 | |||||||||||||||||||||
| Commercial Auto |
30,472 | 31,921 | 33,273 | 34,757 | 35,641 | (1,449 | ) | (5,169 | ) | |||||||||||||||||||
| Corporate Finance |
6,088 | 5,526 | 5,166 | 5,080 | 4,825 | 562 | 1,263 | |||||||||||||||||||||
| Mortgage |
17,296 | 17,140 | 17,723 | 17,841 | 17,186 | 156 | 110 | |||||||||||||||||||||
| Cash, Securities and Other(1) |
37,936 | 37,867 | 36,467 | 36,348 | 34,987 | 69 | 2,949 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total Earning Assets |
$ | 173,420 | $ | 173,829 | $ | 174,316 | $ | 174,670 | $ | 172,009 | $ | (409 | ) | $ | 1,411 | |||||||||||||
| Interest Revenue |
2,103 | 2,180 | 2,257 | 2,252 | 2,187 | (77 | ) | (84 | ) | |||||||||||||||||||
| Unsecured Debt (ex. Core OID balance) (2)(5) |
$ | 12,182 | $ | 12,741 | $ | 13,164 | $ | 12,749 | $ | 12,664 | $ | (558 | ) | $ | (482 | ) | ||||||||||||
| Secured Debt |
9,193 | 9,563 | 9,860 | 13,722 | 16,163 | (370 | ) | (6,970 | ) | |||||||||||||||||||
| Deposits (3) |
121,217 | 120,057 | 117,638 | 114,392 | 109,309 | 1,160 | 11,908 | |||||||||||||||||||||
| Other Borrowings (4) |
17,302 | 18,000 | 19,996 | 20,720 | 21,712 | (698 | ) | (4,410 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total Funding Sources (ex. Core OID balance) (2) |
$ | 159,894 | $ | 160,361 | $ | 160,658 | $ | 161,583 | $ | 159,848 | $ | (467 | ) | $ | 47 | |||||||||||||
| Interest Expense (ex. Core OID) (2) |
949 | 1,016 | 1,062 | 1,088 | 1,048 | (67 | ) | (99 | ) | |||||||||||||||||||
| Net Financing Revenue (ex. Core OID) (2) |
$ | 1,154 | $ | 1,164 | $ | 1,195 | $ | 1,164 | $ | 1,139 | $ | (10 | ) | $ | 16 | |||||||||||||
| Net Interest Margin (yield details) |
||||||||||||||||||||||||||||
| Retail Auto Loan |
6.54% | 6.68% | 6.66% | 6.58% | 6.47% | -0.14% | 0.07% | |||||||||||||||||||||
| memo: retail auto hedge impact |
-0.12% | -0.07% | 0.01% | 0.02% | 0.01% | -0.05% | -0.13% | |||||||||||||||||||||
| Auto Lease (net of dep) |
5.22% | 5.19% | 6.24% | 5.94% | 5.56% | 0.03% | -0.34% | |||||||||||||||||||||
| Commercial Auto |
4.11% | 4.25% | 4.59% | 4.75% | 4.80% | -0.14% | -0.69% | |||||||||||||||||||||
| Corporate Finance |
6.27% | 6.65% | 7.14% | 7.66% | 7.48% | -0.38% | -1.21% | |||||||||||||||||||||
| Mortgage |
3.45% | 3.46% | 3.51% | 3.71% | 3.82% | -0.01% | -0.37% | |||||||||||||||||||||
| Cash, Securities and Other(1) |
2.65% | 2.71% | 2.82% | 2.96% | 3.09% | -0.06% | -0.44% | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total Earning Assets |
4.88% | 4.97% | 5.14% | 5.17% | 5.16% | -0.09% | -0.28% | |||||||||||||||||||||
| Unsecured Debt (ex. Core OID & Core OID balance) (2)(5) |
6.32% | 6.20% | 6.15% | 6.32% | 6.37% | 0.12% | -0.05% | |||||||||||||||||||||
| Secured Debt |
2.82% | 2.92% | 3.02% | 3.16% | 3.11% | -0.10% | -0.29% | |||||||||||||||||||||
| Deposits (3) |
1.97% | 2.11% | 2.22% | 2.29% | 2.20% | -0.14% | -0.23% | |||||||||||||||||||||
| Other Borrowings (4) |
2.34% | 2.42% | 2.48% | 2.48% | 2.48% | -0.08% | -0.14% | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total Funding Sources (ex. Core OID & Core OID balance) (2) |
2.39% | 2.51% | 2.62% | 2.70% | 2.66% | -0.12% | -0.27% | |||||||||||||||||||||
| NIM (as reported) |
2.66% | 2.64% | 2.70% | 2.66% | 2.67% | 0.02% | -0.01% | |||||||||||||||||||||
| NIM (ex. Core OID & Core OID balance) (2) |
2.68% | 2.66% | 2.72% | 2.67% | 2.69% | 0.02% | -0.01% | |||||||||||||||||||||
| Ally Bank Deposits |
||||||||||||||||||||||||||||
| Key Deposit Statistics |
||||||||||||||||||||||||||||
| Average retail CD maturity (months) |
19.9 | 20.1 | 20.3 | 20.6 | 20.9 | (0.2 | ) | (1.0 | ) | |||||||||||||||||||
| Average retail deposit rate |
1.88% | 2.02% | 2.14% | 2.22% | 2.14% | |||||||||||||||||||||||
| End of Period Deposit Levels |
||||||||||||||||||||||||||||
| Retail |
$ | 106,068 | $ | 103,734 | $ | 101,295 | $ | 98,600 | $ | 95,423 | $ | 2,335 | $ | 10,645 | ||||||||||||||
| Brokered & other(3) |
16,256 | 17,018 | 17,935 | 17,725 | 17,876 | (763 | ) | (1,620 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Total deposits |
$ | 122,324 | $ | 120,752 | $ | 119,230 | $ | 116,325 | $ | 113,299 | $ | 1,572 | $ | 9,025 | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Deposit Mix |
||||||||||||||||||||||||||||
| Retail CD |
38% | 37% | 36% | 34% | 34% | |||||||||||||||||||||||
| MMA/OSA/Checking |
49% | 49% | 49% | 51% | 50% | |||||||||||||||||||||||
| Brokered(3) |
13% | 14% | 15% | 15% | 16% | |||||||||||||||||||||||
(1) ‘Other’ includes held-for-investment consumer loans associated with Health Credit Services (HCS), now Ally Lending.
(2) Represents a non-GAAP financial measure. Excludes Core OID from interest expense and Core OID balance from Unsecured Debt.
(3) Includes retail, brokered, and other deposits. Brokered includes sweep deposits. Other includes mortgage escrow and other deposits.
(4) Includes Demand Notes, FHLB Borrowings and Repurchase Agreements.
(5) Includes trust preferred securities.
| 1Q 2020 Preliminary Results | 19 |
| ALLY FINANCIAL INC. ALLY BANK CONSUMER MORTGAGE HFI PORTFOLIOS (PERIOD-END) |
|
($ in billions)
| HISTORICAL QUARTERLY TRENDS | ||||||||||||||||||||
| Mortgage Finance HFI Portfolio |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | |||||||||||||||
| Loan Value |
||||||||||||||||||||
| Gross carry value |
$ | 15.9 | $ | 16.2 | $ | 15.8 | $ | 16.5 | $ | 16.2 | ||||||||||
| Net carry value |
$ | 15.9 | $ | 16.2 | $ | 15.8 | $ | 16.5 | $ | 16.2 | ||||||||||
| Estimated Pool Characteristics |
||||||||||||||||||||
| % Second lien |
0.0% | 0.0% | 0.0% | 0.0% | 0.0% | |||||||||||||||
| % Interest only |
0.0% | 0.0% | 0.0% | 0.1% | 0.1% | |||||||||||||||
| % 30+ Day delinquent |
0.5% | 0.5% | 0.8% | 0.6% | 0.4% | |||||||||||||||
| % Low/No documentation |
0.2% | 0.1% | 0.1% | 0.1% | 0.0% | |||||||||||||||
| % Non-primary residence |
4.5% | 4.5% | 4.5% | 4.7% | 4.6% | |||||||||||||||
| Refreshed FICO |
772 | 774 | 774 | 774 | 772 | |||||||||||||||
| Wtd. Avg. LTV/CLTV (1) |
60.0% | 60.3% | 60.7% | 60.6% | 60.7% | |||||||||||||||
| Corporate Other Legacy Mortgage HFI Portfolio |
||||||||||||||||||||
| Loan Value |
||||||||||||||||||||
| Gross carry value |
$ | 1.1 | $ | 1.1 | $ | 1.2 | $ | 1.3 | $ | 1.4 | ||||||||||
| Net carry value |
$ | 1.0 | $ | 1.1 | $ | 1.2 | $ | 1.3 | $ | 1.4 | ||||||||||
| Estimated Pool Characteristics |
||||||||||||||||||||
| % Second lien |
13.6% | 13.9% | 14.0% | 15.2% | 15.6% | |||||||||||||||
| % Interest only |
0.1% | 0.1% | 0.1% | 0.2% | 0.3% | |||||||||||||||
| % 30+ Day delinquent |
5.1% | 5.4% | 5.2% | 5.7% | 5.4% | |||||||||||||||
| % Low/No documentation |
23.1% | 23.5% | 23.2% | 23.2% | 23.2% | |||||||||||||||
| % Non-primary residence |
7.1% | 7.2% | 7.1% | 7.4% | 7.5% | |||||||||||||||
| Refreshed FICO |
729 | 730 | 731 | 731 | 729 | |||||||||||||||
| Wtd. Avg. LTV/CLTV (1) |
63.0% | 63.8% | 64.5% | 65.4% | 65.9% | |||||||||||||||
(1) First lien only. Updated home values derived using a combination of appraisals, Broker Price opinion (BPOs), Automated valuation models (AVMs) and Metropolitan statistical area (MSA) level house price indices.
| 1Q 2020 Preliminary Results | 20 |
| ALLY FINANCIAL INC. EARNINGS PER SHARE RELATED INFORMATION |
|
($ in millions, shares in thousands)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Earnings Per Share Data |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| GAAP net (loss) income attributable to common shareholders |
$ | (319 | ) | $ | 378 | $ | 381 | $ | 582 | $ | 374 | $ | (697 | ) | $ | (693 | ) | |||||||||||
| Weighted-average common shares outstanding - basic (1) |
375,723 | 380,793 | 390,205 | 398,100 | 404,129 | (5,070 | ) | (28,406 | ) | |||||||||||||||||||
| Weighted-average common shares outstanding - diluted (1) |
375,723 | 383,391 | 392,604 | 399,916 | 405,959 | (7,668 | ) | (30,236 | ) | |||||||||||||||||||
| Issued shares outstanding (period-end) |
373,155 | 374,332 | 383,523 | 392,775 | 399,761 | (1,177 | ) | (26,606 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net (loss) income per share - basic (1) |
$ | (0.85 | ) | $ | 0.99 | $ | 0.98 | $ | 1.46 | $ | 0.93 | $ | (1.84 | ) | $ | (1.77 | ) | |||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net (loss) income per share - diluted (1) |
$ | (0.85 | ) | $ | 0.99 | $ | 0.97 | $ | 1.46 | $ | 0.92 | $ | (1.83 | ) | $ | (1.77 | ) | |||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Adjusted Earnings per Share (“Adjusted EPS”) |
||||||||||||||||||||||||||||
| Numerator |
||||||||||||||||||||||||||||
| GAAP net (loss) income attributable to common shareholders |
$ | (319 | ) | $ | 378 | $ | 381 | $ | 582 | $ | 374 | $ | (697 | ) | $ | (693 | ) | |||||||||||
| Discontinued operations, net of tax |
- | 3 | - | 2 | 1 | (3 | ) | (1 | ) | |||||||||||||||||||
| Core OID |
8 | 8 | 7 | 7 | 7 | 0 | 2 | |||||||||||||||||||||
| Change in the fair value of equity securities (2) |
185 | (29 | ) | 11 | (2 | ) | (70 | ) | 214 | 255 | ||||||||||||||||||
| Core OID & change in the fair value of equity securities tax (tax rate 21% starting 1Q18) (2) |
(41 | ) | 4 | (4 | ) | (1 | ) | 13 | (45 | ) | (54 | ) | ||||||||||||||||
| Significant discrete tax items |
- | - | - | (201 | ) | - | - | - | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Core net income attributable to common shareholders (3) |
$ | (166 | ) | $ | 364 | $ | 396 | $ | 387 | $ | 325 | $ | (530 | ) | $ | (491 | ) | |||||||||||
| Denominator |
||||||||||||||||||||||||||||
| Weighted-average common shares outstanding - diluted (1) |
375,723 | 383,391 | 392,604 | 399,916 | 405,959 | (7,668 | ) | (30,236 | ) | |||||||||||||||||||
| Adjusted EPS (4) |
$ | (0.44 | ) | $ | 0.95 | $ | 1.01 | $ | 0.97 | $ | 0.80 | $ | (1.39 | ) | $ | (1.24 | ) | |||||||||||
| Memo |
||||||||||||||||||||||||||||
| Original Issue Discount Amortization Expense |
||||||||||||||||||||||||||||
| Core original issue discount (Core OID) amortization expense (5) |
$ | 8 | $ | 8 | $ | 7 | $ | 7 | $ | 7 | $ | 0 | $ | 2 | ||||||||||||||
| Other OID |
3 | 3 | 3 | 3 | 3 | (0 | ) | (0 | ) | |||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| GAAP original issue discount amortization expense |
$ | 11 | $ | 11 | $ | 11 | $ | 10 | $ | 10 | $ | 0 | $ | 1 | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Outstanding Original Issue Discount Balance |
||||||||||||||||||||||||||||
| Core outstanding original issue discount balance (Core OID balance) (6) |
$ | (1,055 | ) | $ | (1,063 | ) | $ | (1,071 | ) | $ | (1,078 | ) | $ | (1,085 | ) | $ | 8 | $ | 31 | |||||||||
| Other outstanding OID balance |
(34 | ) | (37 | ) | (40 | ) | (44 | ) | (39 | ) | 3 | 5 | ||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| GAAP outstanding original issue discount balance |
$ | (1,089 | ) | $ | (1,100 | ) | $ | (1,111 | ) | $ | (1,122 | ) | $ | (1,125 | ) | $ | 11 | $ | 36 | |||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Adjusted Other Revenue |
||||||||||||||||||||||||||||
| GAAP Other Revenue |
$ | 266 | $ | 487 | $ | 413 | $ | 395 | $ | 466 | $ | (221 | ) | $ | (200 | ) | ||||||||||||
| Change in the fair value of equity securities (2) |
185 | (29 | ) | 11 | (2 | ) | (70 | ) | 214 | 255 | ||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Adjusted Other Revenue |
$ | 451 | $ | 458 | $ | 424 | $ | 393 | $ | 396 | $ | (7 | ) | $ | 55 | |||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net Financing Revenue (ex. Core OID) |
||||||||||||||||||||||||||||
| GAAP net financing revenue |
$ | 1,146 | $ | 1,156 | $ | 1,188 | $ | 1,157 | $ | 1,132 | $ | (10 | ) | $ | 14 | |||||||||||||
| Core OID |
8 | 8 | 7 | 7 | 7 | 0 | 2 | |||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Net Financing Revenue (ex. Core OID) |
$ | 1,154 | $ | 1,164 | $ | 1,195 | $ | 1,164 | $ | 1,139 | $ | (10 | ) | $ | 16 | |||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
(1) Due to antidilutive effect of the net loss from pre-tax loss from continuing operations attributable to common shareholders for the first quarter 2020, basic weighted average common shares outstanding were used to calculate diluted earnings per share.
(2) Change in fair value of equity securities impacts the Insurance and Corporate Finance segments. Excludes equity fair value adjustments related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity.
(3) Core net income attributable to common shareholders is a non-GAAP financial measure that serves as the numerator in the calculations of Adjusted EPS and Core ROTCE and that, like those measures, is believed by management to help the reader better understand the operating performance of the core businesses and their ability to generate earnings. Core net income attributable to common shareholders adjusts GAAP net income attributable to common shareholders for discontinued operations net of tax, tax-effected Core OID expense, significant discrete tax items and tax-effected changes in equity investments measured at fair value.
(4) Adjusted earnings per share (Adjusted EPS) is a non-GAAP financial measure that adjusts GAAP EPS for revenue and expense items that are typically strategic in nature or that management otherwise does not view as reflecting the operating performance of the company. Management believes Adjusted EPS can help the reader better understand the operating performance of the core businesses and their ability to generate earnings. In the numerator of Adjusted EPS, GAAP net income attributable to common shareholders is adjusted for the following items: (1) excludes discontinued operations, net of tax, as Ally is primarily a domestic company and sales of international businesses and other discontinued operations in the past have significantly impacted GAAP EPS, (2) adds back the tax-effected non-cash Core OID, (3) excludes equity fair value adjustments (net of tax) related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity that do not reflect the operating performance of the core businesses, and (4) excludes significant discrete tax items that do not relate to the operating performance of the core businesses.
(5) Core original issue discount (Core OID) amortization expense is a non-GAAP financial measure for OID, primarily related to bond exchange OID which excludes international operations and future issuances.
(6) Core outstanding original issue discount balance (Core OID balance) is a non-GAAP financial measure for outstanding OID, primarily related to bond exchange OID which excludes international operations and future issuances.
| 1Q 2020 Preliminary Results | 21 |
| ALLY FINANCIAL INC. ADJUSTED TANGIBLE BOOK VALUE PER SHARE RELATED INFORMATION |
|
($ in billions, shares in thousands)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Adjusted Tangible Book Value Per Share (“Adjusted TBVPS”) Information |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Numerator |
||||||||||||||||||||||||||||
| GAAP Common shareholder’s equity |
$ | 13.5 | $ | 14.4 | $ | 14.5 | $ | 14.3 | $ | 13.7 | $ | (0.9 | ) | $ | (0.2 | ) | ||||||||||||
| Goodwill and identifiable intangibles, net of DTLs |
(0.4 | ) | (0.5 | ) | (0.3 | ) | (0.3 | ) | (0.3 | ) | 0.0 | (0.2 | ) | |||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Tangible common equity |
13.1 | 14.0 | 14.2 | 14.0 | 13.4 | (0.9 | ) | (0.3 | ) | |||||||||||||||||||
| Tax-effected Core OID balance (21% tax rate starting 4Q17) |
(0.8 | ) | (0.8 | ) | (0.8 | ) | (0.9 | ) | (0.9 | ) | 0.0 | 0.0 | ||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Adjusted tangible book value (1) |
$ | 12.2 | $ | 13.1 | $ | 13.3 | $ | 13.2 | $ | 12.6 | $ | (0.9 | ) | $ | (0.3 | ) | ||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Denominator |
||||||||||||||||||||||||||||
| Issued shares outstanding (period-end, thousands) |
373,155 | 374,332 | 383,523 | 392,775 | 399,761 | (1,177 | ) | (26,606 | ) | |||||||||||||||||||
| GAAP Common shareholder’s equity per share |
$ | 36.2 | $ | 38.5 | $ | 37.7 | $ | 36.4 | $ | 34.3 | $ | (2.3 | ) | $ | 2.0 | |||||||||||||
| Goodwill and identifiable intangibles, net of DTLs per share |
(1.2 | ) | (1.2 | ) | (0.7 | ) | (0.7 | ) | (0.7 | ) | 0.0 | (0.5 | ) | |||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Tangible common equity per share |
35.0 | 37.3 | 37.0 | 35.7 | 33.6 | (2.3 | ) | 1.5 | ||||||||||||||||||||
| Tax-effected Core OID (21% tax rate starting 4Q17) per share |
(2.2 | ) | (2.2 | ) | (2.2 | ) | (2.2 | ) | (2.1 | ) | 0.0 | (0.1 | ) | |||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Adjusted tangible book value per share (1) |
$ | 32.8 | $ | 35.1 | $ | 34.7 | $ | 33.6 | $ | 31.4 | $ | (2.3 | ) | $ | 1.4 | |||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
(1) Adjusted tangible book value per share (Adjusted TBVPS) is a non-GAAP financial measure that reflects the book value of equity attributable to shareholders even if Core OID balance were accelerated immediately through the financial statements. As a result, management believes Adjusted TBVPS provides the reader with an assessment of value that is more conservative than GAAP common shareholder’s equity per share. Adjusted TBVPS generally adjusts common equity for (1) goodwill and identifiable intangibles, net of DTLs, and (2) tax-effected Core OID balance to reduce tangible common equity in the event the corresponding discounted bonds are redeemed/tendered.
| 1Q 2020 Preliminary Results | 22 |
| ALLY FINANCIAL INC. CORE ROTCE RELATED INFORMATION |
|
($ in millions) unless noted otherwise
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Core Return on Tangible Common Equity (“Core ROTCE”) |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Numerator |
||||||||||||||||||||||||||||
| GAAP net (loss) income attributable to common shareholders |
$ | (319 | ) | $ | 378 | $ | 381 | $ | 582 | $ | 374 | $ | (697 | ) | $ | (693 | ) | |||||||||||
| Discontinued operations, net of tax |
- | 3 | - | 2 | 1 | (3 | ) | (1 | ) | |||||||||||||||||||
| Core OID |
8 | 8 | 7 | 7 | 7 | 0 | 2 | |||||||||||||||||||||
| Change in the fair value of equity securities (1) |
185 | (29 | ) | 11 | (2 | ) | (70 | ) | 214 | 255 | ||||||||||||||||||
| Core OID & change in the fair value of equity securities tax (tax rate 21% starting 1Q18) (1) |
(41 | ) | 4 | (4 | ) | (1 | ) | 13 | (45 | ) | (54 | ) | ||||||||||||||||
| Significant discrete tax items |
- | - | - | (201 | ) | - | - | - | ||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Core net (loss) income attributable to common shareholders (2) |
$ | (166 | ) | $ | 364 | $ | 396 | $ | 387 | $ | 325 | $ | (530 | ) | $ | (491 | ) | |||||||||||
| Denominator (2-period average, $ billions) |
||||||||||||||||||||||||||||
| GAAP shareholder’s equity |
$ | 14.0 | $ | 14.4 | $ | 14.4 | $ | 14.0 | $ | 13.5 | $ | (0.5 | ) | $ | 0.5 | |||||||||||||
| Goodwill & identifiable intangibles, net of deferred tax liabilities (“DTLs”) |
(0.4 | ) | (0.4 | ) | (0.3 | ) | (0.3 | ) | (0.3 | ) | (0.1 | ) | (0.2 | ) | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Tangible common equity |
$ | 13.5 | $ | 14.1 | $ | 14.1 | $ | 13.7 | $ | 13.2 | $ | (0.5 | ) | $ | 0.3 | |||||||||||||
| Core OID balance |
(1.1 | ) | (1.1 | ) | (1.1 | ) | (1.1 | ) | (1.1 | ) | 0.0 | 0.0 | ||||||||||||||||
| Net deferred tax asset (“DTA”) |
(0.1 | ) | (0.0 | ) | (0.1 | ) | (0.1 | ) | (0.2 | ) | (0.1 | ) | 0.1 | |||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Normalized common equity (3) |
$ | 12.3 | $ | 13.0 | $ | 12.9 | $ | 12.5 | $ | 11.9 | $ | (0.6 | ) | $ | 0.5 | |||||||||||||
| Core Return on Tangible Common Equity (4) |
-5.4% | 11.2% | 12.3% | 12.4% | 10.9% | |||||||||||||||||||||||
(1) Change in fair value of equity securities impacts the Insurance and Corporate Finance segments. Excludes equity fair value adjustments related to ASU 2016-01, which requires change in the fair value of equity securities to be recognized in current period net income as compared to periods prior to 1/1/2018 in which such adjustments were recognized through other comprehensive income, a component of equity.
(2) Core net income attributable to common shareholders is a non-GAAP financial measure that serves as the numerator in the calculations of Adjusted EPS and Core ROTCE and that, like those measures, is believed by management to help the reader better understand the operating performance of the core businesses and their ability to generate earnings. Core net income attributable to common shareholders adjusts GAAP net income attributable to common shareholders for discontinued operations net of tax, tax-effected Core OID expense, significant discrete tax items and tax-effected changes in equity investments measured at fair value.
(3) Normalized common equity is a non-GAAP measure calculated using 2 period average
(4) Core return on tangible common equity (Core ROTCE) is a non-GAAP financial measure that management believes is helpful for readers to better understand the ongoing ability of the company to generate returns on its equity base that supports core operations. For purposes of this calculation, tangible common equity is adjusted for Core OID balance and net DTA. Ally’s Core net income attributable to common shareholders for purposes of calculating Core ROTCE is based on the actual effective tax rate for the period adjusted for significant discrete tax items including tax reserve releases, which aligns with the methodology used in calculating adjusted earnings per share.
| 1. | In the numerator of Core ROTCE, GAAP net income attributable to common shareholders is adjusted for discontinued operations net of tax, tax-effected Core OID, fair value adjustments (net of tax) related to ASU 2016-01, effective 1/1/2018, which requires change in the fair value of equity securities to be recognized in current period net income as compared to prior periods in which such adjustments were recognized through other comprehensive income, a component of equity, and significant discrete tax items that do not relate to the operating performance of the core businesses. |
| 2. | In the denominator, GAAP shareholder’s equity is adjusted for goodwill and identifiable intangibles net of DTL, Core OID balance, and net DTA. |
| 1Q 2020 Preliminary Results | 23 |
| ALLY FINANCIAL INC. ADJUSTED EFFICIENCY RATIO RELATED INFORMATION |
|
($ in millions)
| QUARTERLY TRENDS | CHANGE VS. | |||||||||||||||||||||||||||
| Adjusted Efficiency Ratio Calculation |
1Q 20 | 4Q 19 | 3Q 19 | 2Q 19 | 1Q 19 | 4Q 19 | 1Q 19 | |||||||||||||||||||||
| Numerator |
||||||||||||||||||||||||||||
| GAAP noninterest expense |
$ | 920 | $ | 880 | $ | 838 | $ | 881 | $ | 830 | $ | 40 | $ | 90 | ||||||||||||||
| Rep and warrant expense |
- | - | (0 | ) | (0 | ) | - | - | - | |||||||||||||||||||
| Insurance expense |
(256 | ) | (238 | ) | (247 | ) | (301 | ) | (227 | ) | (18 | ) | (29 | ) | ||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Adjusted noninterest expense for the Adjusted Efficiency Ratio |
$ | 664 | $ | 642 | $ | 591 | $ | 580 | $ | 603 | $ | 22 | $ | 61 | ||||||||||||||
| Denominator |
||||||||||||||||||||||||||||
| Total net revenue |
$ | 1,412 | $ | 1,643 | $ | 1,601 | $ | 1,552 | $ | 1,598 | $ | (231 | ) | $ | (186 | ) | ||||||||||||
| Core OID |
8 | 8 | 7 | 7 | 7 | 0 | 2 | |||||||||||||||||||||
| Insurance revenue |
(151 | ) | (352 | ) | (303 | ) | (301 | ) | (372 | ) | 201 | 221 | ||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
| ||||||||
| Adjusted net revenue for the Adjusted Efficiency Ratio |
$ | 1,269 | $ | 1,299 | $ | 1,305 | $ | 1,258 | $ | 1,233 | $ | (30 | ) | $ | 37 | |||||||||||||
| Adjusted Efficiency Ratio (1) |
52.3% | 49.4% | 45.3% | 46.1% | 48.9% | |||||||||||||||||||||||
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
|
||||||||||||||
(1) Adjusted efficiency ratio is a non-GAAP financial measure that management believes is helpful to readers in comparing the efficiency of its core banking and lending businesses with those of its peers. In the numerator of Adjusted efficiency ratio, total noninterest expense is adjusted for Insurance segment expense and Rep and warrant expense. In the denominator, total net revenue is adjusted for Insurance segment revenue and Core OID. See page 11 for the combined ratio for the Insurance segment which management uses as a primary measure of underwriting profitability for the Insurance business.
| 1Q 2020 Preliminary Results | 24 |