AMTB 8-K
Amerant Bancorp Inc. (AMTB)
8-K
2021-04-28
For: 2021-04-28
View Original
Added on
April 08, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported): April 28, 2021
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation | (Commission file number) | (IRS Employer Identification Number) | ||||||||||||
(Address of principal executive offices)
(305 ) 460-8728
(Registrant's telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbols | Name of exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (17 CFR§230.405) or Rule 12b-2 of the Securities Exchange Act of 1934 (17 CFR §240.12b-2).
| Emerging growth company | ||||||||
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition
On April 28, 2021, Amerant Bancorp Inc. (the "Company") issued a press release to report the Company’s financial results for the fiscal quarter ended March 31, 2021. The release is attached as Exhibit 99.1 to this Current Report on Form 8-K and incorporated by reference to this Item 2.02.
In accordance with General Instruction B.2. of Form 8-K, the information in this Item 2.02 of this Current Report on Form 8-K, including Exhibit 99.1 attached hereto, is being “furnished” and shall not be deemed “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of that section, nor shall it be deemed incorporated by reference in any filing under the Securities Act of 1933, as amended, or the Securities Exchange Act of 1934, as amended, except as shall be expressly set forth by specific reference in such filing.
Item 7.01 Regulation FD Disclosure
On April 29, 2021, the Company will hold a live audio webcast to discuss its financial results for the fiscal quarter ended March 31, 2021. In connection with the webcast, the Company is furnishing to the U.S. Securities and Exchange Commission the earnings slide presentation attached as Exhibit 99.2 to this Current Report on Form 8-K and incorporated by reference to this Item 7.01.
In accordance with General Instruction B.2 of Form 8-K, the information in this Item 7.01 of this Current Report on Form 8-K, including Exhibit 99.2 attached hereto, is being “furnished” and shall not be deemed “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of that section, nor shall it be deemed incorporated by reference in any filing under the Securities Act of 1933, as amended, or the Securities Exchange Act of 1934, as amended, except as shall be expressly set forth by specific reference in such a filing.
Item 9.01 Financial Statements and Exhibits
| Number | Exhibit | ||||
| 99.1 | |||||
| 99.2 | |||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | ||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Date: April 28, 2021 | Amerant Bancorp Inc. | |||||||||||||
| By: | /s/ Julio V. Pena | |||||||||||||
| Name: Julio V. Pena | ||||||||||||||
| Title: SVP, Securities Counsel and Assistant Corporate Secretary | ||||||||||||||
CONTACTS: | ||||||||
Investors | ||||||||
| Laura Rossi | ||||||||
(305) 460-8728 | ||||||||
| Media | ||||||||
| Silvia M. Larrieu | ||||||||
(305) 441-8414 | ||||||||
AMERANT REPORTS FIRST QUARTER 2021 NET INCOME OF $14.5 MILLION, DILUTED EARNINGS PER SHARE OF $0.38
Originated $81.5 million in Paycheck Protection Program (“PPP”) loans;
Reached $2 billion in Assets Under Management (“AUM”)
CORAL GABLES, FLORIDA, April 28, 2021. Amerant Bancorp Inc. (NASDAQ: AMTB and AMTBB) (the “Company” or “Amerant”) today reported net income of $14.5 million in the first quarter of 2021, or $0.38 per diluted share, compared to $8.5 million, or $0.20 per diluted share, in the fourth quarter of 2020 and $3.4 million, or $0.08 per diluted share, in the first quarter of 2020. Pre-provision net revenue (“PPNR”) (non-GAAP) was $18.1 million in the first quarter of 2021, an increase from $8.5 million in the fourth quarter of 2020, and a decrease from $26.3 million in the first quarter of 2020.
Annualized return on assets (“ROA”) and return on equity (“ROE”) were 0.76% and 7.47%, respectively, in the first quarter of 2021, compared to 0.42% and 4.09%, respectively, in the fourth quarter of 2020, and 0.17% and 1.61%, respectively, in the first quarter of 2020.
“We are pleased to report improved results in the first quarter of 2021, compared with the prior quarter,” stated Jerry Plush, vice chairman and chief executive officer. “These positive results were driven primarily from higher non-interest income and lower expenses. Additionally, based on the adequacy of the loan loss allowance, there was no provision for loan losses this quarter. As we look forward for the balance of the year, we will be focused on core deposit growth, building brand awareness, rationalizing our business lines and geographies, driving cost efficiencies across the business and optimizing our capital, with a clear goal to continue on the path toward improved performance.”
Summary Results
The summary results of the first quarter ended March 31, 2021 were as follows:
•Net income of $14.5 million in the first quarter of 2021, up 70.7% from $8.5 million in the fourth quarter of 2020 and up 327.5% from $3.4 million in the first quarter of 2020.
1
•Net Interest Income (“NII”) was $47.6 million, down 2.2% from $48.7 million in the fourth quarter of 2020, and down 3.4% from $49.2 million in the first quarter of 2020. Net interest margin (“NIM”) was 2.66% in the first quarter of 2021, up 5 basis points from 2.61% in the fourth quarter of 2020 and up 1 basis point from 2.65% in the first quarter of 2020.
•No provision for loan losses was recorded during the first quarter of 2021 or the fourth quarter of 2020, as compared to a $22.0 million provision recorded in the first quarter of 2020. The ratio of allowance for loan losses (“ALL”) to total loans was 1.93% as of March 31, 2021, up from 1.90% as of December 31, 2020 and up from 1.29% as of March 31, 2020. The Company had no net charge offs in the first quarter of 2021. The ratio of net charge-offs to average total loans in the fourth and first quarter of 2020 was 0.40% and 0.09%, respectively.
•Noninterest income was $14.2 million in the first quarter of 2021, up 23.0% from $11.5 million in the fourth quarter of 2020, and down 35.4% from $21.9 million in the first quarter of 2020.
•Noninterest expense was $43.6 million, down 15.5% from $51.6 million in the fourth quarter of 2020, and down 2.8% from $44.9 million in the first quarter of 2020. Adjusted noninterest expense (non-GAAP) was $43.4 million in the first quarter of 2021, up 0.4% from $43.2 million in the fourth quarter of 2020, and down 2.5% from $44.5 million in the first quarter of 2020.
•The efficiency ratio was 70.7% in the first quarter of 2021, compared to 85.8% in the fourth quarter of 2020, and 63.1% for the first quarter of 2020.
•Total loans were $5.8 billion at March 31, 2021, down $87.5 million, or 1.5%, compared to December 31, 2020. Total deposits were $5.7 billion at March 31, 2021, down $53.6 million, or 0.9%, compared to December 31, 2020.
•Stockholders’ book value per common share remained at $20.70 at March 31, 2021, compared to December 31, 2020. Tangible book value per common share (“TBV”) remained flat at $20.13 as of March 31, 2021, compared to December 31, 2020.
2
Credit Quality
The ALL was $110.9 million as of the close of the first quarter of 2021, unchanged from the close of the fourth quarter of 2020. The ALL was $72.9 million at the close of the first quarter of 2020. The Company recorded no provision for loan losses in the first quarter 2021, compared to a $22.0 million provision for loan losses in the first quarter of 2020. As in the fourth quarter of 2020, the absence of expense for loan losses during the first quarter of 2021 was primarily due to the decrease in reserves associated with the COVID-19 pandemic, as a result of improving economic conditions, and lower loan portfolio volumes, offset by downgrades primarily in certain commercial, owner-occupied and residential loans during the period. The ALL associated with the pandemic decreased to $10.5 million as of March 31, 2021 from $14.8 million at the end of the fourth quarter of 2020, and from $19.8 million in the first quarter of 2020 at the onset of the pandemic.
Classified loans totaled $91.3 million at the end of the first quarter of 2021 compared to $88.5 million and $36.4 million in the fourth quarter of 2020 and first quarter of 2020, respectively. These loans increased $2.8 million, or 3.2%, compared to the fourth quarter of 2020, and $55.0 million, or 151.2%, compared to the first quarter of 2020. The quarter-over-quarter increases were primarily driven by the downgrade of four commercial loans totaling $3.2 million, two single-family loans totaling $1.2 million, and one Commercial Real Estate (“CRE”) loan totaling $0.7 million. These increases were partially offset by loan paydowns and payoffs during the first quarter of 2021. The year-over-year increases were primarily due to specific loan downgrades disclosed in previous quarters. These loans included the $39.8 million Coffee Trader loan relationship (out of which $19.3 million were charged-off in September 2020, and $0.9 million was collected as partial payment), as well as downgrades of (i) a $13.1 million loan to a food wholesaler with exposure to the cruise industry, (ii) two CRE multifamily loans totaling $9.9 million, (iii) one CRE retail loan totaling $6.2 million and (iv) six single family loans totaling $6.0 million.
Special mention loans as of March 31, 2021 totaled $109.6 million, a decrease of $9.2 million, or 7.8%, from $118.8 million as of December 31, 2020. This decrease was primarily due to paydowns and payoffs of approximately $10.2 million and the downgrade of one commercial loan totaling $1.6 million to substandard, partially offset by the downgrade of one $2.8 million commercial loan relationship to special mention. First quarter special mention loans increased $89.9 million, or 458.2%, compared to the first quarter of 2020, due to downgrades disclosed in previous quarters, primarily two CRE retail loans totaling $40.4 million, two commercial loans totaling $36.9 million and two owner occupied loans totaling $14.7 million; and offset primarily by the payoff of one construction loan totaling $9.9 million. All special mention loans remain current.
Non-performing assets totaled $89.9 million at the end of the first quarter of 2021, an increase of $1.8 million or 2.0%, quarter-over-quarter, and $56.5 million, or 169.0%, year-over-year due to the increase in classified loans described above. The ratio of non-performing assets to total assets was 116 basis points, up 3 basis points from the fourth quarter of 2020 and up 75 basis points from the first quarter of 2020.
3
As of March 31, 2021, $62.1 million, or 1.1% of total loans, were still under applicable deferral and/or forbearance periods, an increase from $43.4 million, or 0.7% of total loans, at the end of fourth quarter 2020, and significantly down from $1.1 billion, or 19.3% of total loans, at the beginning of the loan mitigation programs established in April 2020 in response to the pandemic. The quarter-over-quarter increase was primarily due to new modifications granted to two CRE retail loans in New York totaling $37.1 million and one multifamily loan in New York totaling $2.4 million, partially offset by $20.7 million in loans that resumed regular payments after deferral and/or forbearance periods ended.
Additionally, 99.5% of the loans under deferral and/or forbearance are secured by real estate collateral with average Loan to Value (“LTV”) of 68.2%. All loans that have moved out of forbearance status have resumed regular payments. The Company continues to closely monitor the performance of the remaining loans in deferral and/or forbearance periods under the terms of the temporary relief granted.
Loans and Deposits
Total loans as of March 31, 2021 were $5.8 billion, down $87.5 million, or 1.5%, compared to December 31, 2020.
Loan prepayments increased during the first quarter of 2021, primarily across Amerant’s commercial and industrial (“C&I”) portfolio, while loan production across all segments continued to be challenged, despite early signs of recovery in economic activity. Prepayments received during the first quarter were approximately $220 million, including $111.3 million related to PPP loans. During the first quarter of 2021, Amerant continued purchasing higher yielding consumer loans, as planned. Consumer loans, including $61.7 million of high-yield indirect consumer loans purchased during the most recent quarter, increased $31.7 million, or 12.8%, quarter-over-quarter.
During the first quarter of 2021, a third round of Paycheck Protection Program (“PPP”) loans provided additional stimulus relief to small businesses and underserved individuals who are self-employed or independent contractors. Amerant continues to focus on providing funding to customers and communities by actively participating in the PPP and related government sponsored programs. The Company originated $81.5 million in PPP loans under this new program during the first quarter of 2021 and processed $178.6 million of forgiveness applications for PPP loans granted under previous funding rounds, in line with program guidelines. PPP loan forgiveness is provided for under the CARES Act and consists of full payment by the Small Business Administration of the unpaid principal balance and accrued interest after loan forgiveness to eligible borrowers has been approved. As of March 31, 2021, total PPP loans outstanding were $164.8 million, or 2.9% of total loans, compared to $198.5 million, or 3.4% of total loans as of December 31, 2020. The Company estimates as of March 31, 2021, there were $173.2 million of deposits related to the PPP compared to $95.4 million as of December 31, 2020.
Total deposits as of March 31, 2021 totaled $5.7 billion, down $53.6 million, or 0.9%, compared to December 31, 2020. Domestic deposits totaled $3.2 billion, down $27.4 million, or 0.9%, compared to December 31, 2020, while foreign deposits totaled $2.5 billion, down $26.2 million, or 1.0%, compared to December 31, 2020.
4
The quarter-over-quarter decline in deposits was primarily attributable to a $159.6 million, or 10.3%, reduction in customer CDs compared to the prior quarter, as the Company continued to aggressively lower CD rates and focus on increasing core deposits and emphasizing multi-product relationships versus single product higher-cost CDs. This decline in CDs includes a $48.1 million, or 24.2%, reduction in online CD balances. During the first quarter of 2021 brokered deposits also decreased $81.9 million, or 12.9%, as the Company continued to focus on reduced reliance on this source of funding. The decreases in total customer CDs and brokered deposits were partially offset by an increase of $188.0 million, or 5.3%, in customer transaction accounts, inclusive of PPP deposits.
Net Interest Income and Net Interest Margin
First quarter 2021 NII was $47.6 million, down $1.1 million, or 2.2%, from $48.7 million in the fourth quarter of 2020 and down $1.7 million, or 3.4%, from $49.2 million in the first quarter of 2020. The quarter-over-quarter decrease was primarily driven by lower average loan volumes due to higher prepayment activity and lower loan production as the economy slowly recovers from the COVID-19 pandemic. Also contributing to the decrease were lower average balances on available for sale securities due to prepayments and sale of securities in the first quarter. Lower overall deposit costs and declines in average balances on customer CDs partially offset this decrease.
The year-over-year decline was primarily driven by significantly lower market rates across all interest earning assets. Additionally, the company completed its offering of $60.0 million of 5.75% senior notes in June 2020 contributing to the decline in NII during the period. These decreases were partially offset by lower costs across all deposit types as well as lower average balances on customer and brokered time deposits. Lower cost and average balances on FHLB advances and other borrowings also helped to offset the year-over-year NII decline.
During the first quarter of 2021, Amerant continued to focus on offsetting ongoing NIM pressure by (i) strategically repricing customer time and relationship money market deposits at lower rates; (ii) implementing floor rates in the loan portfolio; and (iii) evaluating additional interest-earning opportunities in higher-yielding lending programs.
As of March 31, 2021, Amerant had $460.2 million of time deposits maturing in the second quarter of 2021. This is expected to decrease the average cost of CDs by approximately 40bps and the overall cost of deposits by 10bps.
Noninterest income
In the first quarter of 2021, noninterest income was $14.2 million, up 23.0% from $11.5 million in the fourth quarter of 2020. The increase was primarily driven by the absence of the loss on the sale of the Beacon operations center recorded in the fourth quarter of 2020, higher net gains on securities, and increased fees from brokerage and advisory activities. In the first quarter of 2021, Amerant realized a total net gain on securities of $2.6 million as the Company continued to manage its investment securities portfolio to hedge against the declining NII. The quarter-over-quarter increase in noninterest income was partially offset by the absence of loan
5
fees in connection with the Main Street Lending Program, decreased derivative income, and lower wire transfer fees during the first quarter of 2021.
Noninterest income decreased $7.7 million, or 35.4%, from $21.9 million in the same first quarter of 2020. The year-over-year decrease in noninterest income was primarily driven by a $7.0 million decrease in net gains on securities as well as lower derivative income in the current period compared to the first quarter of 2020. The year-over-year decrease in noninterest income was partially offset by increased brokerage, advisory and fiduciary fees due to higher volume of customer trading activity following increased market volatility and advisory services executed during the first quarter of 2021.
The Company’s assets under management and custody (“AUM”) totaled $2.02 billion as of March 31, 2021, increasing $46.5 million, or 2.4%, from $1.97 billion as of December 31, 2020, and $446.5 million, or 28.4%, from $1.57 billion as of March 31, 2020 primarily driven by increased market value in AUM. From these increases in AUM net new assets represent $4.1 million, or 0.2%, compared to the fourth quarter of 2020 and $88.6 million, or 5.6%, compared to the first quarter of 2020, as a result of the Company’s client-focused and relationship-centric strategy. Amerant remains focused on growing AUM, both domestically and internationally, in an effort to further build the franchise and strengthen the Company’s fee-driven business.
Noninterest expense
First quarter of 2021 noninterest expense was $43.6 million, down $8.0 million, or 15.5%, from $51.6 million in the fourth quarter of 2020. The decrease was primarily driven by lower salaries and employee benefits expenses as a result of severance expenses in connection with voluntary and involuntary separation plans implemented in the fourth quarter of 2020 as part of the Company's transformation and efficiency improvement efforts. Also there were lower depreciation and amortization, and occupancy and equipment expenses as a result of the branch closures implemented during the same period, in addition to other lower operating expenses. The absence of severance expenses in connection with the aforementioned separation plans also contributed to the quarter-over-quarter decrease in noninterest expense. This decrease was partially offset by higher bonus compensation, as the company adjusted its variable compensation program at expected performance levels after having curtailed during 2020 in response to the pandemic, and adopted a new long-term equity incentive compensation program. Additionally there were higher consulting fees, primarily in connection with the Company’s compensation program and renegotiation of certain vendor contracts, as well as increased telecommunications and data processing expenses during the period.
Noninterest expense for the first quarter of 2021, decreased $1.2 million, or 2.8% compared to $44.9 million in the first quarter of 2020 primarily driven by lower salaries and employee benefits costs following the Company’s ongoing transformation and efficiency improvement efforts. Higher professional and other services fees, occupancy and equipment costs, as well as FDIC assessments and insurance expenses in the first quarter of 2021 partially offset this year-over-year decrease. Also contributing to the offset were higher expenses in connection with variable and long-term equity incentive compensation programs during the first quarter of 2021, as referenced above.
Adjusted noninterest expense (non-GAAP) was $43.4 million in the first quarter of 2021, up $0.2 million, or 0.4%, from $43.2 million in the fourth quarter of 2020, and down $1.1 million,
6
or 2.5%, from $44.5 million in the first quarter of 2020. Restructuring expenses totaled $0.2 million in the first quarter of 2021, down $8.2 million, or 97.1%, compared to the fourth quarter of 2020 and down $0.1 million, or 32.2%, compared to first quarter of 2020, due to lower severance and digital transformation expenses.
Amerant remains dedicated to finding new ways to increase efficiencies across the Company while simultaneously providing an enhanced banking experience for customers. As part of these continued efforts, Amerant completed the full rollout of nCino for Commercial use in the most recent quarter, a significant milestone in the Company's digital transformation. Amerant expects to complete the rollout of nCino for Retail use in the second half of 2021.
The efficiency ratio was 70.7% in the first quarter of 2021, compared to 85.8% during the fourth quarter of 2020, and 63.1% for the first quarter of 2020. The quarter-over-quarter decrease in the efficiency ratio was driven from the fourth quarter of 2020 including severance expenses incurred in connection with the voluntary and the involuntary severance plans previously referenced above. The year-over-year increase was primarily attributable to lower total revenue primarily as a result of lower gains on sale of securities during the first quarter of 2021 compared to the first quarter last year.
Capital Resources and Liquidity
The Company’s capital continues to be strong and well in excess of the minimum regulatory requirements to be considered “well-capitalized” at March 31, 2021.
Stockholders’ equity totaled $785.0 million as of March 31, 2021, up $1.6 million, or 0.2%, from $783.4 million as of December 31, 2020. This sequential increase in stockholder’s equity was primarily driven by the increase in net income in the first quarter of 2021, partially offset by lower valuation of the Company’s debt securities available for sale as a result of market increases in long-term yield curves. Book value per common share remained flat at $20.70 at March 31, 2021 and December 31, 2020. TBV remained flat at $20.13 at March 31, 2021 and December 31, 2020.
At the end of the fourth quarter of 2020, the Company completed a modified Dutch auction tender offer for its shares of Class B common stock and accepted for purchase 4,249,785 shares of such stock. These shares represented approximately 32% of the shares of Class B common stock outstanding as of November 12, 2020. The tender offer contributed 3 cents to EPS, or 10%, in the first quarter of 2021.
On March 10, 2021, the Company announced the Board’s authorization to purchase up to $40 million of its shares of Class B common stock. Repurchases of shares of Class B common stock will depend upon market conditions, regulatory requirements, other corporate liquidity requirements and priorities and other factors as may be considered in the Company’s sole discretion. While shares of Class B common stock currently trade at a discount to TBV, buybacks of such shares would be accretive to both TBV and earnings per share.
Amerant’s liquidity position continues to be strong and includes cash and cash equivalents of $233.5 million at the close of the first quarter of 2021, compared to $214.4 million as of December 31, 2020. Additionally, as of March 31, 2021, the Company had $1.3 billion in borrowing capacity with the FHLB.
7
Mr. Plush noted “Following the successful completion of the tender offer for our Class B shares in the fourth quarter of 2020, this quarter we launched our first Class B share repurchase program for the repurchase of up to $40 million of our Class B shares. We have repurchased approximately $4 million since March 11, 2021 through April 27, 2021, demonstrating our commitment to optimal use of capital”.
First Quarter 2021 Earnings Conference Call
As previously announced, the Company will hold an earnings conference call on Thursday, April 29th, 2021 at 9:00 a.m. (Eastern Time) to discuss its first quarter 2021 results. The conference call and presentation materials can be accessed via webcast by logging on from the Investor Relations section of the company’s website at https://investor.amerantbank.com. The online replay will remain available for approximately one month following the call through the above link.
About Amerant Bancorp Inc.
The Company is a bank holding company headquartered in Coral Gables, Florida since 1979. The Company operates through its subsidiaries, Amerant Bank, N.A. (the “Bank”), Amerant Investments, Inc., Elant Bank and Trust Ltd., and Amerant Mortgage, LLC. The Company provides individuals and businesses in the U.S., as well as select international clients, with deposit, credit and wealth management services. The Bank, which has operated for over 40 years, is the second largest community bank headquartered in Florida. The Bank operates 25 banking centers – 18 in South Florida and 7 in the Houston, Texas area, as well as a commercial real estate loan production office in New York City.
nCino® is a registered trademark of nCino, Inc. used in accordance with contractual terms.
Visit our investor relations page at https://investor.amerantbank.com for additional information.
Cautionary Notice Regarding Forward-Looking Statements
This press release contains “forward-looking statements” within the meaning of the Securities Act of 1933 and the Securities Exchange Act of 1934, including statements with respect to our objectives, expectations and intentions and other statements that are not historical facts. All statements other than statements of historical fact are statements that could be forward-looking statements. You can identify these forward-looking statements through our use of words such as “may,” “will,” “anticipate,” “assume,” “should,” “indicate,” “would,” “believe,” “contemplate,” “expect,” “estimate,” “continue,” “plan,” “point to,” “project,” “could,” “intend,” “target,” “goals,” “outlooks,” “modeled,” “dedicated,” “create,” and other similar words and expressions of the future.
8
Forward-looking statements, including those as to our beliefs, plans, objectives, goals, expectations, anticipations, estimates and intentions, involve known and unknown risks, uncertainties and other factors, which may be beyond our control, and which may cause the Company’s actual results, performance, achievements, or financial condition to be materially different from future results, performance, achievements, or financial condition expressed or implied by such forward-looking statements. You should not rely on any forward-looking statements as predictions of future events. You should not expect us to update any forward-looking statements, except as required by law. All written or oral forward-looking statements attributable to us are expressly qualified in their entirety by this cautionary notice, together with those risks and uncertainties described in “Risk factors” in our annual report on Form 10-K for the fiscal year ended December 31, 2020 and in our other filings with the U.S. Securities and Exchange Commission (the “SEC”), which are available at the SEC’s website www.sec.gov.
Interim Financial Information
Unaudited financial information as of and for interim periods, including as of and for the three months ended March 31, 2021 and 2020, may not reflect our results of operations for our fiscal year ending, or financial condition as of December 31, 2021, or any other period of time or date.
Non-GAAP Financial Measures
The Company supplements its financial results that are determined in accordance with accounting principles generally accepted in the United States of America (“GAAP”) with non-GAAP financial measures, such as “pre-provision net revenue (PPNR)”, “adjusted noninterest income”, “adjusted noninterest expense”, “adjusted net income (loss)”, “adjusted net income (loss) per share (basic and diluted)”, “adjusted return on assets (ROA)”, “adjusted return on equity (ROE)”, and other ratios. This supplemental information is not required by, or are not presented in accordance with GAAP. The Company refers to these financial measures and ratios as “non-GAAP financial measures” and they should not be considered in isolation or as a substitute for the GAAP measures presented herein.
We use certain non-GAAP financial measures, including those mentioned above, both to explain our results to shareholders and the investment community and in the internal evaluation and management of our businesses. Our management believes that these non-GAAP financial measures and the information they provide are useful to investors since these measures permit investors to view our performance using the same tools that our management uses to evaluate our past performance and prospects for future performance, especially in light of the additional costs we have incurred in connection with the Company’s restructuring activities that began in 2018 and continued into 2021 and the one-time loss on the sale of the Beacon operations center in the fourth quarter of 2020. While we believe that these non-GAAP financial measures are useful in evaluating our performance, this information should be considered as supplemental and not as a substitute for or superior to the related financial information prepared in accordance with GAAP. Additionally, these non-GAAP financial measures may differ from similar measures presented by other companies.
Exhibit 2 reconciles these non-GAAP financial measures to reported results.
9
Exhibit 1- Selected Financial Information
The following table sets forth selected financial information derived from our unaudited and audited consolidated financial statements.
(in thousands) | March 31, 2021 | December 31, 2020 | September 30, 2020 | June 30, 2020 | March 31, 2020 | ||||||||||||||||||||||||
| Consolidated Balance Sheets | |||||||||||||||||||||||||||||
| Total assets | $ | 7,751,098 | $ | 7,770,893 | $ | 7,977,047 | $ | 8,130,723 | $ | 8,098,810 | |||||||||||||||||||
| Total investments | 1,375,292 | 1,372,567 | 1,468,796 | 1,674,811 | 1,769,987 | ||||||||||||||||||||||||
| Total gross loans (1) | 5,754,838 | 5,842,337 | 5,924,617 | 5,872,271 | 5,668,327 | ||||||||||||||||||||||||
| Allowance for loan losses | 110,940 | 110,902 | 116,819 | 119,652 | 72,948 | ||||||||||||||||||||||||
| Total deposits | 5,678,079 | 5,731,643 | 5,877,546 | 6,024,702 | 5,842,212 | ||||||||||||||||||||||||
| Advances from the FHLB and other borrowings | 1,050,000 | 1,050,000 | 1,050,000 | 1,050,000 | 1,265,000 | ||||||||||||||||||||||||
| Senior notes (2) | 58,656 | 58,577 | 58,498 | 58,419 | — | ||||||||||||||||||||||||
| Junior subordinated debentures (3) | 64,178 | 64,178 | 64,178 | 64,178 | 64,178 | ||||||||||||||||||||||||
| Stockholders' equity (4) | 785,014 | 783,421 | 829,533 | 830,198 | 841,117 | ||||||||||||||||||||||||
Assets under management and custody (5) | 2,018,870 | 1,972,321 | 1,762,803 | 1,715,804 | 1,572,322 | ||||||||||||||||||||||||
Three Months Ended | |||||||||||||||||||||||||||||
(in thousands, except percentages and per share amounts) | March 31, 2021 | December 31, 2020 | September 30, 2020 | June 30, 2020 | March 31, 2020 | ||||||||||||||||||||||||
Consolidated Results of Operations | |||||||||||||||||||||||||||||
| Net interest income | $ | 47,569 | $ | 48,652 | $ | 45,348 | $ | 46,323 | $ | 49,229 | |||||||||||||||||||
| Provision for loan losses | — | — | 18,000 | 48,620 | 22,000 | ||||||||||||||||||||||||
| Noninterest income | 14,163 | 11,515 | 20,292 | 19,753 | 21,910 | ||||||||||||||||||||||||
| Noninterest expense | 43,625 | 51,629 | 45,500 | 36,740 | 44,867 | ||||||||||||||||||||||||
| Net income (loss) | 14,459 | 8,473 | 1,702 | (15,279) | 3,382 | ||||||||||||||||||||||||
| Effective income tax rate | 20.15 | % | 0.76 | % | 20.47 | % | 20.77 | % | 20.83 | % | |||||||||||||||||||
Common Share Data | |||||||||||||||||||||||||||||
| Stockholders' book value per common share | $ | 20.70 | $ | 20.70 | $ | 19.68 | $ | 19.69 | $ | 19.95 | |||||||||||||||||||
| Tangible stockholders' equity (book value) per common share (6) | $ | 20.13 | $ | 20.13 | $ | 19.17 | $ | 19.18 | $ | 19.43 | |||||||||||||||||||
| Basic earnings (loss) per common share | $ | 0.38 | $ | 0.21 | $ | 0.04 | $ | (0.37) | $ | 0.08 | |||||||||||||||||||
| Diluted earnings (loss) per common share (7) | $ | 0.38 | $ | 0.20 | $ | 0.04 | $ | (0.37) | $ | 0.08 | |||||||||||||||||||
| Basic weighted average shares outstanding | 37,618 | 41,326 | 41,722 | 41,720 | 42,185 | ||||||||||||||||||||||||
| Diluted weighted average shares outstanding (7) | 37,846 | 41,688 | 42,065 | 41,720 | 42,533 | ||||||||||||||||||||||||
10
| Three Months Ended | |||||||||||||||||||||||||||||
| March 31, 2021 | December 31, 2020 | September 30, 2020 | June 30, 2020 | March 31, 2020 | |||||||||||||||||||||||||
| Other Financial and Operating Data (8) | |||||||||||||||||||||||||||||
| Profitability Indicators (%) | |||||||||||||||||||||||||||||
| Net interest income / Average total interest earning assets (NIM) (9) | 2.66 | % | 2.61 | % | 2.39 | % | 2.44 | % | 2.65 | % | |||||||||||||||||||
| Net income (loss) / Average total assets (ROA) (10) | 0.76 | % | 0.42 | % | 0.08 | % | (0.75) | % | 0.17 | % | |||||||||||||||||||
| Net income (loss) / Average stockholders' equity (ROE) (11) | 7.47 | % | 4.09 | % | 0.81 | % | (7.21) | % | 1.61 | % | |||||||||||||||||||
| Noninterest income / Total revenue (12) | 22.94% | 19.14% | 30.91% | 29.89% | 30.80% | ||||||||||||||||||||||||
| Capital Indicators (%) | |||||||||||||||||||||||||||||
| Total capital ratio (13) | 14.12 | % | 13.96 | % | 14.56 | % | 14.34 | % | 14.54 | % | |||||||||||||||||||
| Tier 1 capital ratio (14) | 12.87 | % | 12.71 | % | 13.30 | % | 13.08 | % | 13.38 | % | |||||||||||||||||||
| Tier 1 leverage ratio (15) | 10.54 | % | 10.11 | % | 10.52 | % | 10.39 | % | 10.82 | % | |||||||||||||||||||
| Common equity tier 1 capital ratio (CET1) (16) | 11.90 | % | 11.73 | % | 12.34 | % | 12.13 | % | 12.42 | % | |||||||||||||||||||
| Tangible common equity ratio (17) | 9.88 | % | 9.83 | % | 10.16 | % | 9.97 | % | 10.14 | % | |||||||||||||||||||
| Asset Quality Indicators (%) | |||||||||||||||||||||||||||||
| Non-performing assets / Total assets (18) | 1.16 | % | 1.13 | % | 1.08 | % | 0.95 | % | 0.41 | % | |||||||||||||||||||
| Non-performing loans / Total loans (1) (19) | 1.56 | % | 1.50 | % | 1.46 | % | 1.32 | % | 0.59 | % | |||||||||||||||||||
| Allowance for loan losses / Total non-performing loans | 123.92 | % | 126.46 | % | 135.09 | % | 154.87 | % | 218.49 | % | |||||||||||||||||||
| Allowance for loan losses / Total loans (1) | 1.93 | % | 1.90 | % | 1.97 | % | 2.04 | % | 1.29 | % | |||||||||||||||||||
| Net charge-offs / Average total loans (20) | — | % | 0.40 | % | 1.41 | % | 0.13 | % | 0.09 | % | |||||||||||||||||||
| Efficiency Indicators (% except FTE) | |||||||||||||||||||||||||||||
| Noninterest expense / Average total assets | 2.28 | % | 2.59 | % | 2.24 | % | 1.81 | % | 2.27 | % | |||||||||||||||||||
| Salaries and employee benefits / Average total assets | 1.38 | % | 1.62 | % | 1.39 | % | 1.06 | % | 1.48 | % | |||||||||||||||||||
| Other operating expenses/ Average total assets (21) | 0.90 | % | 0.97 | % | 0.85 | % | 0.75 | % | 0.79 | % | |||||||||||||||||||
| Efficiency ratio (22) | 70.67 | % | 85.81 | % | 69.32 | % | 55.60 | % | 63.07 | % | |||||||||||||||||||
| Full-Time-Equivalent Employees (FTEs) | 731 | 713 | 807 | 825 | 825 | ||||||||||||||||||||||||
11
| Three Months Ended | |||||||||||||||||||||||||||||
(in thousands, except percentages and per share amounts) | March 31, 2021 | December 31, 2020 | September 30, 2020 | June 30, 2020 | March 31, 2020 | ||||||||||||||||||||||||
| Adjusted Selected Consolidated Results of Operations and Other Data (6) | |||||||||||||||||||||||||||||
| Pre-provision net revenue | 18,107 | 8,538 | 20,140 | 29,336 | 26,272 | ||||||||||||||||||||||||
| Adjusted noninterest income | $ | 14,163 | $ | 13,244 | $ | 20,292 | $ | 19,753 | $ | 21,910 | |||||||||||||||||||
| Adjusted noninterest expense | 43,385 | 43,222 | 43,654 | 35,422 | 44,513 | ||||||||||||||||||||||||
| Adjusted net income (loss) | 14,651 | 11,112 | 3,163 | (14,234) | 3,662 | ||||||||||||||||||||||||
| Adjusted basic earnings (loss) per common share | 0.39 | 0.27 | 0.08 | (0.34) | 0.09 | ||||||||||||||||||||||||
| Adjusted earnings (loss) per diluted common share (7) | 0.39 | 0.27 | 0.08 | (0.34) | 0.09 | ||||||||||||||||||||||||
| Adjusted net income (loss) / Average total assets (Adjusted ROA) (10) | 0.77 | % | 0.56 | % | 0.16 | % | (0.70) | % | 0.19 | % | |||||||||||||||||||
| Adjusted net income (loss) / Average stockholders' equity (Adjusted ROE) (11) | 7.57 | % | 5.36 | % | 1.51 | % | (6.72) | % | 1.74 | % | |||||||||||||||||||
__________________
(1) Total gross loans are net of unamortized deferred loan origination fees and costs. At March 31, 2021, total loans include $1.0 million in loans held for sale. There were no loans held for sale at any of the other dates presented.
(2) During the second quarter of 2020, the Company completed a $60 million offering of Senior Notes with a coupon rate of 5.75%. Senior Notes are presented net of direct issuance cost which is deferred and amortized over 5 years.
(3) During the three months ended March 31, 2020, the Company redeemed $26.8 million of its 8.90% trust preferred securities. The Company simultaneously redeemed the junior subordinated debentures associated with these trust preferred securities.
(4) On March 10, 2021, the Company’s Board of Directors approved a stock repurchase program which provides for the potential repurchase of up to $40 million of shares of the Company’s Class B common stock (the “2021 Stock Repurchase Program”). In the first quarter of 2021, the Company repurchased an aggregate of 116,037 shares of Class B common stock at a weighted average price per share of $15.98 under the 2021 Stock Repurchase Program. In the fourth quarter of 2020, the Company completed a modified “Dutch auction” tender offer to purchase, for cash, up to $50.0 million of shares of its Class B common stock, and accepted to purchase 4,249,785 shares of Class B common stock in the tender offer at a price of $12.55 per share. The purchase price for this transaction was approximately $54.1 million, including $0.8 million in related fees and other expenses. During the first quarter of 2020, the Company repurchased an aggregate of 932,459 shares of its Class B common stock in two privately negotiated transactions for $16.00 per share. The aggregate purchase price for these transactions was approximately $15.2 million, including $0.3 million in broker fees and other expenses.
(5) Assets held for clients in an agency or fiduciary capacity which are not assets of the Company and therefore are not included in the consolidated financial statements.
(6) This presentation contains adjusted financial information determined by methods other than GAAP. This adjusted financial information is reconciled to GAAP in Exhibit 2 - Non-GAAP Financial Measures Reconciliation.
(7) Potential dilutive instruments consisted of unvested shares of restricted stock and restricted stock units. For the three months ended June 30, 2020, potential dilutive instruments were not included in the diluted earnings per share computation because the Company reported a net loss and their inclusion would have an antidilutive effect. For all other periods presented, potential dilutive instruments were included in the diluted earnings per share computation because, when the unamortized deferred compensation cost related to these shares was divided by the average market price per share in those periods, fewer shares would have been purchased than restricted shares assumed issued. Therefore, in those periods, such awards resulted in higher diluted weighted average shares outstanding than basic weighted average shares outstanding, and had a dilutive effect in per share earnings.
(8) Operating data for the periods presented have been annualized.
(9) NIM is defined as NII divided by average interest-earning assets, which are loans, securities, deposits with banks and other financial assets which yield interest or similar income.
(10)Calculated based upon the average daily balance of total assets.
(11) Calculated based upon the average daily balance of stockholders’ equity.
(12) Total revenue is the result of net interest income before provision for loan losses plus noninterest income.
12
(13) Total stockholders’ equity divided by total risk-weighted assets, calculated according to the standardized regulatory capital ratio calculations.
(14) Tier 1 capital divided by total risk-weighted assets. Tier 1 capital is composed of Common Equity Tier 1 (CET1) capital plus outstanding qualifying trust preferred securities of $62.3 million at March 31, 2021, December 31, 2020, September 30, 2020, June 30, 2020 and March 31, 2020. See footnote 3 for more information about trust preferred securities redemption transactions in the first quarter of 2020.
(15) Tier 1 capital divided by quarter to date average assets.
(16)CET1 capital divided by total risk-weighted assets.
(17) Tangible common equity is calculated as the ratio of common equity less goodwill and other intangibles divided by total assets less goodwill and other intangible assets. Other intangibles assets are included in other assets in the Company’s consolidated balance sheets.
(18)Non-performing assets include all accruing loans past due by 90 days or more, all nonaccrual loans, restructured loans that are considered “troubled debt restructurings” or “TDRs”, and OREO properties acquired through or in lieu of foreclosure.
(19)Non-performing loans include all accruing loans past due by 90 days or more, all nonaccrual loans and restructured loans that are considered TDRs.
(20)Calculated based upon the average daily balance of outstanding loan principal balance net of unamortized deferred loan origination fees and costs, excluding the allowance for loan losses. During the first quarter of 2021, there were zero net charge offs. During the third quarter of 2020, the Company charged off $19.3 million against the allowance for loan losses as result of the deterioration of one commercial loan relationship.
(21)Other operating expenses is the result of total noninterest expense less salary and employee benefits.
(22)Efficiency ratio is the result of noninterest expense divided by the sum of noninterest income and NII.
13
Exhibit 2- Non-GAAP Financial Measures Reconciliation
The following table sets forth selected financial information derived from the Company’s interim unaudited and annual audited consolidated financial statements, adjusted for certain costs incurred by the Company in the periods presented related to tax deductible restructuring costs and the after-tax loss of $0.7 million on the sale of the Beacons operations center in the fourth quarter of 2020.The Company believes these adjusted numbers are useful to understand the Company’s performance absent these transactions and events.
| Three Months Ended, | |||||||||||||||||
(in thousands) | March 31, 2021 | December 31, 2020 | September 30, 2020 | June 30, 2020 | March 31, 2020 | ||||||||||||
| Total noninterest income | $ | 14,163 | $ | 11,515 | $ | 20,292 | $ | 19,753 | $ | 21,910 | |||||||
Plus: loss on sale of the Beacon operations center (1) | — | 1,729 | — | — | — | ||||||||||||
| Adjusted noninterest income | $ | 14,163 | $ | 13,244 | $ | 20,292 | $ | 19,753 | $ | 21,910 | |||||||
| Total noninterest expenses | $ | 43,625 | $ | 51,629 | $ | 45,500 | $ | 36,740 | $ | 44,867 | |||||||
| Less: restructuring costs (2): | |||||||||||||||||
| Staff reduction costs (3) | 6 | 5,345 | 646 | 360 | 54 | ||||||||||||
| Digital transformation expenses | 234 | 658 | 1,200 | 958 | 300 | ||||||||||||
| Branch closure expenses | — | 2,404 | — | — | — | ||||||||||||
| Total restructuring costs | $ | 240 | $ | 8,407 | $ | 1,846 | $ | 1,318 | $ | 354 | |||||||
| Adjusted noninterest expenses | $ | 43,385 | $ | 43,222 | $ | 43,654 | $ | 35,422 | $ | 44,513 | |||||||
| Net income (loss) | $ | 14,459 | $ | 8,473 | $ | 1,702 | $ | (15,279) | $ | 3,382 | |||||||
| Plus after-tax restructuring costs: | |||||||||||||||||
| Restructuring costs before income tax effect | 240 | 8,407 | 1,846 | 1,318 | 354 | ||||||||||||
| Income tax effect | (48) | (6,455) | (385) | (273) | (74) | ||||||||||||
| Total after-tax restructuring costs | 192 | 1,952 | 1,461 | 1,045 | 280 | ||||||||||||
Less after-tax loss on sale of the Beacon operations center: | |||||||||||||||||
| Loss on sale of the Beacon Operations Center before income tax effect | — | 1,729 | — | — | — | ||||||||||||
| Income tax effect | — | (1,042) | — | — | — | ||||||||||||
| Total after-tax loss on sale of Beacon Operations Center | — | 687 | — | — | — | ||||||||||||
| Adjusted net income (loss) | $ | 14,651 | $ | 11,112 | $ | 3,163 | $ | (14,234) | $ | 3,662 | |||||||
14
| Three Months Ended, | |||||||||||||||||
(in thousands, except percentages and per share amounts) | March 31, 2021 | December 31, 2020 | September 30, 2020 | June 30, 2020 | March 31, 2020 | ||||||||||||
| Net income (loss) | $ | 14,459 | $ | 8,473 | $ | 1,702 | $ | (15,279) | $ | 3,382 | |||||||
| Plus: provision for loan losses | — | — | 18,000 | 48,620 | 22,000 | ||||||||||||
| Plus: provision for income tax expense (benefit) | 3,648 | 65 | 438 | (4,005) | 890 | ||||||||||||
| Pre-provision net revenue | $ | 18,107 | $ | 8,538 | $ | 20,140 | $ | 29,336 | $ | 26,272 | |||||||
| Basic earnings (loss) per share | $ | 0.38 | $ | 0.21 | $ | 0.04 | $ | (0.37) | $ | 0.08 | |||||||
| Plus: after tax impact of restructuring costs | 0.01 | 0.04 | 0.04 | 0.03 | 0.01 | ||||||||||||
| Plus: after tax loss on sale of the Beacon Operations Center | — | 0.02 | — | — | — | ||||||||||||
| Total adjusted basic earnings (loss) per common share | $ | 0.39 | $ | 0.27 | $ | 0.08 | $ | (0.34) | $ | 0.09 | |||||||
| Diluted earnings (loss) per share (4) | $ | 0.38 | $ | 0.20 | $ | 0.04 | $ | (0.37) | $ | 0.08 | |||||||
| Plus: after tax impact of restructuring costs | 0.01 | 0.05 | 0.04 | 0.03 | 0.01 | ||||||||||||
| Plus: after tax loss on sale of the Beacon Operations Center | — | 0.02 | — | — | — | ||||||||||||
| Total adjusted diluted earnings (loss) per common share | $ | 0.39 | $ | 0.27 | $ | 0.08 | $ | (0.34) | $ | 0.09 | |||||||
| Net income (loss) / Average total assets (ROA) | 0.76 | % | 0.42 | % | 0.08 | % | (0.75) | % | 0.17 | % | |||||||
| Plus: after tax impact of restructuring costs | 0.01 | % | 0.11 | % | 0.08 | % | 0.05 | % | 0.02 | % | |||||||
| Plus: after tax loss on sale of the Beacon Operations Center | — | % | 0.03 | % | — | % | — | % | — | % | |||||||
| Adjusted net income (loss) / Average total assets (Adjusted ROA) | 0.77 | % | 0.56 | % | 0.16 | % | (0.70) | % | 0.19 | % | |||||||
| Net income (loss) / Average stockholders' equity (ROE) | 7.47 | % | 4.09 | % | 0.81 | % | (7.21) | % | 1.61 | % | |||||||
| Plus: after tax impact of restructuring costs | 0.10 | % | 0.94 | % | 0.70 | % | 0.49 | % | 0.13 | % | |||||||
| Plus: after tax loss on sale of the Beacon Operations Center | — | % | 0.33 | % | — | % | — | % | — | % | |||||||
| Adjusted net income (loss) / Average stockholders' equity (Adjusted ROE) | 7.57 | % | 5.36 | % | 1.51 | % | (6.72) | % | 1.74 | % | |||||||
| Stockholders' equity | $ | 785,014 | $ | 783,421 | $ | 829,533 | $ | 830,198 | $ | 841,117 | |||||||
| Less: goodwill and other intangibles | (21,515) | (21,561) | (21,607) | (21,653) | (21,698) | ||||||||||||
| Tangible common stockholders' equity | $ | 763,499 | $ | 761,860 | $ | 807,926 | $ | 808,545 | $ | 819,419 | |||||||
| Total assets | 7,751,098 | 7,770,893 | 7,977,047 | 8,130,723 | 8,098,810 | ||||||||||||
| Less: goodwill and other intangibles | (21,515) | (21,561) | (21,607) | (21,653) | (21,698) | ||||||||||||
| Tangible assets | $ | 7,729,583 | $ | 7,749,332 | $ | 7,955,440 | $ | 8,109,070 | $ | 8,077,112 | |||||||
| Common shares outstanding | 37,922 | 37,843 | 42,147 | 42,159 | 42,166 | ||||||||||||
| Tangible common equity ratio | 9.88 | % | 9.83 | % | 10.16 | % | 9.97 | % | 10.14 | % | |||||||
| Stockholders' book value per common share | $ | 20.70 | $ | 20.70 | $ | 19.68 | $ | 19.69 | $ | 19.95 | |||||||
| Tangible stockholders' book value per common share | $ | 20.13 | $ | 20.13 | $ | 19.17 | $ | 19.18 | $ | 19.43 | |||||||
15
____________
(1) The Company leased-back the property for a 2-year term.
(2) Expenses incurred for actions designed to implement the Company’s strategy as a new independent company. These actions include, but are not limited to reductions in workforce, streamlining operational processes, rolling out the Amerant brand, implementation of new technology system applications, enhanced sales tools and training, expanded product offerings and improved customer analytics to identify opportunities.
(3) On October 9, 2020, the Board of Directors of the Company adopted a voluntary early retirement plan for certain eligible long-term employees and an involuntary severance plan for certain other positions consistent with the Company’s effort to streamline operations and better align its operating structure with its business activities. 31 employees elected to participate in the voluntary plan, all of whom retired on or before December 31, 2020. The involuntary plan impacted 31 employees most of whom no longer worked for the Company and/or its subsidiaries by December 31, 2020. On December 28, 2020, the Company determined the termination costs and annual savings related to the voluntary and involuntary plans. The Company incurred approximately $3.5 million and $1.8 million in one-time termination costs in the fourth quarter of 2020 in connection with the voluntary and involuntary plans, respectively, the majority of which will be paid over time in the form of installment payments until December 2021. The Company estimates that the voluntary and involuntary plans will yield estimated annual savings of approximately $4.2 million and $5.5 million, respectively, for combined estimated annual savings of approximately $9.7 million beginning in 2021.
(4) Potential dilutive instruments consisted of unvested shares of restricted stock and restricted stock units. For the three months ended of June 30, 2020, potential dilutive instruments were not included in the diluted earnings per share computation because the Company reported a net loss and their inclusion would have an antidilutive effect. For all other periods presented, potential dilutive instruments were included in the diluted earnings per share computation because, when the unamortized deferred compensation cost related to these shares was divided by the average market price per share in those periods, fewer shares would have been purchased than restricted shares assumed issued. Therefore, in those periods, such awards resulted in higher diluted weighted average shares outstanding than basic weighted average shares outstanding, and had a dilutive effect in per share earnings.
16
Exhibit 3 - Average Balance Sheet, Interest and Yield/Rate Analysis
The following tables present average balance sheet information, interest income, interest expense and the corresponding average yields earned and rates paid for the periods presented. The average balances for loans include both performing and nonperforming balances. Interest income on loans includes the effects of discount accretion and the amortization of non-refundable loan origination fees, net of direct loan origination costs, accounted for as yield adjustments. Average balances represent the daily average balances for the periods presented.
| Three Months Ended | |||||||||||||||||||||||||||||||||||
| March 31, 2021 | December 31, 2020 | March 31, 2020 | |||||||||||||||||||||||||||||||||
| (in thousands, except percentages) | Average Balances | Income/ Expense | Yield/ Rates | Average Balances | Income/ Expense | Yield/ Rates | Average Balances | Income/ Expense | Yield/ Rates | ||||||||||||||||||||||||||
| Interest-earning assets: | |||||||||||||||||||||||||||||||||||
| Loan portfolio, net (1) | $ | 5,678,547 | $ | 52,771 | 3.77 | % | $ | 5,809,246 | $ | 54,891 | 3.76 | % | $ | 5,573,627 | $ | 59,788 | 4.31 | % | |||||||||||||||||
| Debt securities available for sale (2) | 1,207,764 | 6,495 | 2.18 | % | 1,274,493 | 7,126 | 2.22 | % | 1,549,502 | 9,497 | 2.47 | % | |||||||||||||||||||||||
| Debt securities held to maturity (3) | 67,729 | 302 | 1.81 | % | 60,084 | 311 | 2.06 | % | 72,472 | 400 | 2.22 | % | |||||||||||||||||||||||
| Debt securities held for trading | 104 | 1 | 3.90 | % | — | — | — | % | — | — | — | % | |||||||||||||||||||||||
| Equity securities with readily determinable fair value not held for trading | 24,225 | 84 | 1.41 | % | 24,354 | 96 | 1.57 | % | 24,052 | 131 | 2.19 | % | |||||||||||||||||||||||
| Federal Reserve Bank and FHLB stock | 63,781 | 625 | 3.97 | % | 65,426 | 677 | 4.12 | % | 71,192 | 1,037 | 5.86 | % | |||||||||||||||||||||||
| Deposits with banks | 205,355 | 51 | 0.10 | % | 195,347 | 54 | 0.11 | % | 171,848 | 462 | 1.08 | % | |||||||||||||||||||||||
| Total interest-earning assets | 7,247,505 | 60,329 | 3.38 | % | 7,428,950 | 63,155 | 3.38 | % | 7,462,693 | 71,315 | 3.84 | % | |||||||||||||||||||||||
| Total non-interest-earning assets less allowance for loan losses | 498,754 | 516,346 | 488,651 | ||||||||||||||||||||||||||||||||
| Total assets | $ | 7,746,259 | $ | 7,945,296 | $ | 7,951,344 | |||||||||||||||||||||||||||||
17
| Three Months Ended | |||||||||||||||||||||||||||||||||||
| March 31, 2021 | December 31, 2020 | March 31, 2020 | |||||||||||||||||||||||||||||||||
| (in thousands, except percentages) | Average Balances | Income/ Expense | Yield/ Rates | Average Balances | Income/ Expense | Yield/ Rates | Average Balances | Income/ Expense | Yield/ Rates | ||||||||||||||||||||||||||
| Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||
| Checking and saving accounts - | |||||||||||||||||||||||||||||||||||
| Interest bearing DDA | $ | 1,258,301 | $ | 113 | 0.04 | % | $ | 1,218,536 | $ | 103 | 0.03 | % | $ | 1,071,558 | $ | 135 | 0.05 | % | |||||||||||||||||
| Money market | 1,236,026 | 966 | 0.32 | % | 1,257,239 | 1,001 | 0.32 | % | 1,136,501 | 3,249 | 1.15 | % | |||||||||||||||||||||||
| Savings | 318,800 | 14 | 0.02 | % | 322,077 | 14 | 0.02 | % | 322,682 | 17 | 0.02 | % | |||||||||||||||||||||||
| Total checking and saving accounts | 2,813,127 | 1,093 | 0.16 | % | 2,797,852 | 1,118 | 0.16 | % | 2,530,741 | 3,401 | 0.54 | % | |||||||||||||||||||||||
| Time deposits | 1,956,559 | 7,360 | 1.53 | % | 2,131,085 | 9,001 | 1.68 | % | 2,461,073 | 13,484 | 2.20 | % | |||||||||||||||||||||||
| Total deposits | 4,769,686 | 8,453 | 0.72 | % | 4,928,937 | 10,119 | 0.82 | % | 4,991,814 | 16,885 | 1.36 | % | |||||||||||||||||||||||
| Securities sold under agreements to repurchase | — | — | — | % | 533 | 1 | 0.75 | % | — | — | — | % | |||||||||||||||||||||||
| Advances from the FHLB and other borrowings (4) | 1,050,000 | 2,758 | 1.07 | % | 1,060,217 | 2,826 | 1.06 | % | 1,195,714 | 4,412 | 1.48 | % | |||||||||||||||||||||||
| Senior notes | 58,618 | 942 | 6.52 | % | 58,539 | 942 | 6.40 | % | — | — | — | % | |||||||||||||||||||||||
| Junior subordinated debentures | 64,178 | 607 | 3.84 | % | 64,178 | 615 | 3.81 | % | 73,123 | 789 | 4.34 | % | |||||||||||||||||||||||
| Total interest-bearing liabilities | 5,942,482 | 12,760 | 0.87 | % | 6,112,404 | 14,503 | 0.94 | % | 6,260,651 | 22,086 | 1.42 | % | |||||||||||||||||||||||
| Non-interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||
| Non-interest bearing demand deposits | 925,266 | 902,799 | 757,599 | ||||||||||||||||||||||||||||||||
| Accounts payable, accrued liabilities and other liabilities | 93,450 | 105,160 | 88,894 | ||||||||||||||||||||||||||||||||
| Total non-interest-bearing liabilities | 1,018,716 | 1,007,959 | 846,493 | ||||||||||||||||||||||||||||||||
| Total liabilities | 6,961,198 | 7,120,363 | 7,107,144 | ||||||||||||||||||||||||||||||||
| Stockholders’ equity | 785,061 | 824,933 | 844,200 | ||||||||||||||||||||||||||||||||
| Total liabilities and stockholders' equity | $ | 7,746,259 | $ | 7,945,296 | $ | 7,951,344 | |||||||||||||||||||||||||||||
| Excess of average interest-earning assets over average interest-bearing liabilities | $ | 1,305,023 | $ | 1,316,546 | $ | 1,202,042 | |||||||||||||||||||||||||||||
| Net interest income | $ | 47,569 | $ | 48,652 | $ | 49,229 | |||||||||||||||||||||||||||||
| Net interest rate spread | 2.51 | % | 2.44 | % | 2.42 | % | |||||||||||||||||||||||||||||
| Net interest margin (5) | 2.66 | % | 2.61 | % | 2.65 | % | |||||||||||||||||||||||||||||
| Cost of total deposits (6) | 0.60 | % | 0.69 | % | 1.18 | % | |||||||||||||||||||||||||||||
| Ratio of average interest-earning assets to average interest-bearing liabilities | 121.96 | % | 121.54 | % | 119.20 | % | |||||||||||||||||||||||||||||
| Average non-performing loans/ Average total loans | 1.54 | % | 1.55 | % | 0.58 | % | |||||||||||||||||||||||||||||
_______________
(1) Average non-performing loans of $89.2 million, $91.7 million and $32.8 million for the three months ended March 31, 2021, December 31, 2020 and March 31, 2020, respectively, are included in the average loan portfolio, net. Interest income that would have been recognized on these non-performing loans totaled $0.8 million, $0.7 million and $0.4 million, in the three months ended March 31, 2021, December 31, 2020 and March 31, 2020, respectively.
(2) Includes nontaxable securities with average balances of $54.7 million, $75.8 million and $49.4 million for the three months ended March 31, 2021, December 31, 2020 and March 31, 2020, respectively. The tax equivalent yield for these nontaxable securities was 3.80%, 0.37% and 3.88% for the three months ended March 31, 2021, December 31, 2020 and March 31, 2020, respectively. In 2021 and 2020, the tax equivalent yields were calculated by assuming a 21% tax rate and dividing the actual yield by 0.79.
(3) Includes nontaxable securities with average balances of $56.6 million, $60.1 million and $72.5 million for the three months ended March 31, 2021, December 31, 2020 and March 31, 2020, respectively. The tax equivalent yield for these nontaxable securities was 2.40%, 2.61% and 2.81% for the three months ended March 31, 2021, December 31, 2020 and March 31, 2020, respectively. In 2021 and 2020, the tax equivalent yields were calculated assuming a 21% tax rate and dividing the actual yield by 0.79.
(4) The terms of the FHLB advance agreements require the Bank to maintain certain investment securities or loans as collateral for these advances.
(5) NIM is defined as net interest income divided by average interest-earning assets, which are loans, securities, deposits with banks and other financial assets which yield interest or similar income.
(6) Calculated based upon the average balance of total noninterest bearing and interest bearing deposits.
18
Exhibit 4 - Noninterest Income
This table shows the amounts of each of the categories of noninterest income for the periods presented.
| Three Months Ended | ||||||||||||||||||||||||||
| March 31, 2021 | December 31, 2020 | March 31, 2020 | ||||||||||||||||||||||||
| (in thousands, except percentages) | Amount | % | Amount | % | Amount | % | ||||||||||||||||||||
| Deposits and service fees | $ | 4,106 | 29.0 | % | $ | 4,173 | 36.2 | % | $ | 4,290 | 19.6 | % | ||||||||||||||
| Brokerage, advisory and fiduciary activities | 4,603 | 32.5 | % | 4,219 | 36.6 | % | 4,133 | 18.9 | % | |||||||||||||||||
Change in cash surrender value of bank owned life insurance (“BOLI”)(1) | 1,356 | 9.6 | % | 1,417 | 12.3 | % | 1,414 | 6.5 | % | |||||||||||||||||
| Cards and trade finance servicing fees | 339 | 2.4 | % | 333 | 2.9 | % | 395 | 1.8 | % | |||||||||||||||||
| Loss on early extinguishment of FHLB advances, net | — | — | % | — | — | % | (7) | — | % | |||||||||||||||||
| Data processing and fees for other services | — | — | % | — | — | % | — | — | % | |||||||||||||||||
Securities gains, net (2) | 2,582 | 18.2 | % | 1,033 | 9.0 | % | 9,620 | 43.9 | % | |||||||||||||||||
Other noninterest income (3) | 1,177 | 8.3 | % | 340 | 3.0 | % | 2,065 | 9.3 | % | |||||||||||||||||
| Total noninterest income | $ | 14,163 | 100.0 | % | $ | 11,515 | 100.0 | % | $ | 21,910 | 100.0 | % | ||||||||||||||
__________________
(1) Changes in cash surrender value of BOLI are not taxable.
(2) Includes net gain on sale of securities of $2.9 million, $1.1 million and $9.2 million during the three months ended March 31, 2021, December 31, 2020 and March 31, 2020, respectively, and unrealized losses of $0.4 million and $0.1 million during the three months ended March 31, 2021 and December 31, 2020, respectively, and unrealized gain of $0.4 million in the three months ended March 31, 2020, related to the change in market value of mutual funds.
(3) Includes a loss of $1.7 million on the sale of the Beacon operations center in the fourth quarter of 2020, rental income, income from derivative and foreign currency exchange transactions with customers, and valuation income on the investment balances held in the non-qualified deferred compensation plan.
19
Exhibit 5 - Noninterest Expense
This table shows the amounts of each of the categories of noninterest expense for the periods presented.
| Three Months Ended | ||||||||||||||||||||||||||
| March 31, 2021 | December 31, 2020 | March 31, 2020 | ||||||||||||||||||||||||
| (in thousands, except percentages) | Amount | % | Amount | % | Amount | % | ||||||||||||||||||||
Salaries and employee benefits (1) | $ | 26,427 | 60.6 | % | $ | 32,305 | 62.6 | % | $ | 29,326 | 65.4 | % | ||||||||||||||
Occupancy and equipment (2) | 4,488 | 10.3 | % | 5,320 | 10.3 | % | 3,803 | 8.5 | % | |||||||||||||||||
Professional and other services fees (3) | 3,784 | 8.7 | % | 3,137 | 6.1 | % | 2,954 | 6.6 | % | |||||||||||||||||
| Telecommunications and data processing | 3,727 | 8.5 | % | 3,082 | 6.0 | % | 3,464 | 7.7 | % | |||||||||||||||||
Depreciation and amortization (4) | 1,786 | 4.1 | % | 3,473 | 6.7 | % | 1,959 | 4.4 | % | |||||||||||||||||
| FDIC assessments and insurance | 1,755 | 4.0 | % | 1,885 | 3.7 | % | 1,118 | 2.5 | % | |||||||||||||||||
Other operating expenses (5) | 1,658 | 3.8 | % | 2,427 | 4.6 | % | 2,243 | 4.9 | % | |||||||||||||||||
| Total noninterest expense | $ | 43,625 | 100.0 | % | $ | 51,629 | 100.0 | % | $ | 44,867 | 100.0 | % | ||||||||||||||
___________
(1) Includes $0.5 million in connection with a Long Term Incentive Compensation Program adopted in the first quarter of 2021. Includes $5.3 million in staff reduction costs in the fourth quarter of 2020, primarily related to the voluntary and involuntary plans approved in October 2020.
(2) Includes an additional expense of $1.1 million for the remaining lease obligation in connection with the closure of two of our branches in the fourth quarter of 2020.
(3) Other services fees include expenses on derivative contracts.
(4) Includes a charge of $1.3 million for the accelerated amortization of leasehold improvements in connection with the closure of one of our branches in the fourth quarter of 2020.
(5) Includes advertising, marketing, charitable contributions, community engagement, postage and courier expenses, provisions for possible losses on contingent loans, and debits which mirror the valuation income on the investment balances held in the non-qualified deferred compensation plan in order to adjust the liability to participants of the deferred compensation plan.
20
Exhibit 6 - Consolidated Balance Sheets
| (in thousands, except share data) | March 31, 2021 | December 31, 2020 | September 30, 2020 | June 30, 2020 | March 31, 2020 | ||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Cash and due from banks | $ | 37,744 | $ | 30,179 | $ | 34,091 | $ | 35,651 | $ | 22,303 | |||||||||||||||||||
| Interest earning deposits with banks | 195,755 | 184,207 | 193,069 | 181,698 | 248,750 | ||||||||||||||||||||||||
| Cash and cash equivalents | 233,499 | 214,386 | 227,160 | 217,349 | 271,053 | ||||||||||||||||||||||||
| Securities | |||||||||||||||||||||||||||||
| Debt securities available for sale | 1,190,201 | 1,225,083 | 1,317,724 | 1,519,784 | 1,601,303 | ||||||||||||||||||||||||
| Debt securities held to maturity | 104,657 | 58,127 | 61,676 | 65,616 | 70,336 | ||||||||||||||||||||||||
| Equity securities with readily determinable fair value not held for trading | 23,965 | 24,342 | 24,381 | 24,425 | 24,225 | ||||||||||||||||||||||||
| Federal Reserve Bank and Federal Home Loan Bank stock | 56,469 | 65,015 | 65,015 | 64,986 | 74,123 | ||||||||||||||||||||||||
| Securities | 1,375,292 | 1,372,567 | 1,468,796 | 1,674,811 | 1,769,987 | ||||||||||||||||||||||||
| Loans held for sale | 1,044 | — | — | — | — | ||||||||||||||||||||||||
| Loans held for investment, gross | 5,753,794 | 5,842,337 | 5,924,617 | 5,872,271 | 5,668,327 | ||||||||||||||||||||||||
| Less: Allowance for loan losses | 110,940 | 110,902 | 116,819 | 119,652 | 72,948 | ||||||||||||||||||||||||
| Loans held for investment, net | 5,642,854 | 5,731,435 | 5,807,798 | 5,752,619 | 5,595,379 | ||||||||||||||||||||||||
| Bank owned life insurance | 218,903 | 217,547 | 216,130 | 214,693 | 213,266 | ||||||||||||||||||||||||
| Premises and equipment, net | 109,071 | 109,990 | 126,895 | 128,327 | 128,232 | ||||||||||||||||||||||||
| Deferred tax assets, net | 15,607 | 11,691 | 16,206 | 15,647 | 4,933 | ||||||||||||||||||||||||
| Goodwill | 19,506 | 19,506 | 19,506 | 19,506 | 19,506 | ||||||||||||||||||||||||
| Accrued interest receivable and other assets (1) | 135,322 | 93,771 | 94,556 | 107,771 | 96,454 | ||||||||||||||||||||||||
| Total assets | $ | 7,751,098 | $ | 7,770,893 | $ | 7,977,047 | $ | 8,130,723 | $ | 8,098,810 | |||||||||||||||||||
| Liabilities and Stockholders' Equity | |||||||||||||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||
| Demand | |||||||||||||||||||||||||||||
| Noninterest bearing | $ | 977,595 | $ | 872,151 | $ | 916,889 | $ | 956,351 | $ | 779,842 | |||||||||||||||||||
| Interest bearing | 1,324,127 | 1,230,054 | 1,210,639 | 1,186,613 | 1,088,033 | ||||||||||||||||||||||||
| Savings and money market | 1,494,227 | 1,587,876 | 1,496,119 | 1,447,661 | 1,432,891 | ||||||||||||||||||||||||
| Time | 1,882,130 | 2,041,562 | 2,253,899 | 2,434,077 | 2,541,446 | ||||||||||||||||||||||||
| Total deposits | 5,678,079 | 5,731,643 | 5,877,546 | 6,024,702 | 5,842,212 | ||||||||||||||||||||||||
| Advances from the Federal Home Loan Bank and other borrowings | 1,050,000 | 1,050,000 | 1,050,000 | 1,050,000 | 1,265,000 | ||||||||||||||||||||||||
| Senior notes | 58,656 | 58,577 | 58,498 | 58,419 | — | ||||||||||||||||||||||||
| Junior subordinated debentures held by trust subsidiaries | 64,178 | 64,178 | 64,178 | 64,178 | 64,178 | ||||||||||||||||||||||||
| Accounts payable, accrued liabilities and other liabilities (1) | 115,171 | 83,074 | 97,292 | 103,226 | 86,303 | ||||||||||||||||||||||||
| Total liabilities | 6,966,084 | 6,987,472 | 7,147,514 | 7,300,525 | 7,257,693 | ||||||||||||||||||||||||
| Stockholders’ equity | |||||||||||||||||||||||||||||
| Class A common stock | 2,904 | 2,882 | 2,886 | 2,887 | 2,888 | ||||||||||||||||||||||||
| Class B common stock | 892 | 904 | 1,329 | 1,329 | 1,329 | ||||||||||||||||||||||||
| Additional paid in capital | 304,448 | 305,569 | 359,553 | 359,028 | 358,277 | ||||||||||||||||||||||||
| Retained earnings | 456,861 | 442,402 | 433,929 | 432,227 | 447,506 | ||||||||||||||||||||||||
| Accumulated other comprehensive income | 19,909 | 31,664 | 31,836 | 34,727 | 31,117 | ||||||||||||||||||||||||
| Total stockholders' equity | 785,014 | 783,421 | 829,533 | 830,198 | 841,117 | ||||||||||||||||||||||||
| Total liabilities and stockholders' equity | $ | 7,751,098 | $ | 7,770,893 | $ | 7,977,047 | $ | 8,130,723 | $ | 8,098,810 | |||||||||||||||||||
__________
(1) Includes the effect of adopting ASU 2016-02 (Leases) in the first quarter of 2021.
21
Exhibit 7 - Loans
Loans by Type
The loan portfolio consists of the following loan classes:
| (in thousands) | March 31, 2021 | December 31, 2020 | September 30, 2020 | June 30, 2020 | March 31, 2020 | ||||||||||||||||||||||||
| Real estate loans | |||||||||||||||||||||||||||||
| Commercial real estate | |||||||||||||||||||||||||||||
| Non-owner occupied | $ | 1,713,967 | $ | 1,749,839 | $ | 1,797,230 | $ | 1,841,075 | $ | 1,875,293 | |||||||||||||||||||
| Multi-family residential | 722,783 | 737,696 | 853,159 | 823,450 | 834,016 | ||||||||||||||||||||||||
| Land development and construction loans | 351,502 | 349,800 | 335,184 | 284,766 | 225,179 | ||||||||||||||||||||||||
| 2,788,252 | 2,837,335 | 2,985,573 | 2,949,291 | 2,934,488 | |||||||||||||||||||||||||
| Single-family residential | 625,298 | 639,569 | 597,280 | 589,713 | 569,340 | ||||||||||||||||||||||||
| Owner occupied | 940,126 | 947,127 | 937,946 | 938,511 | 923,260 | ||||||||||||||||||||||||
| 4,353,676 | 4,424,031 | 4,520,799 | 4,477,515 | 4,427,088 | |||||||||||||||||||||||||
| Commercial loans | 1,104,594 | 1,154,550 | 1,197,156 | 1,247,455 | 1,084,751 | ||||||||||||||||||||||||
| Loans to financial institutions and acceptances | 16,658 | 16,636 | 16,623 | 16,597 | 16,576 | ||||||||||||||||||||||||
| Consumer loans and overdrafts | 278,866 | 247,120 | 190,039 | 130,704 | 139,912 | ||||||||||||||||||||||||
| Total loans | $ | 5,753,794 | $ | 5,842,337 | $ | 5,924,617 | $ | 5,872,271 | $ | 5,668,327 | |||||||||||||||||||
22
Non-Performing Assets
This table shows a summary of our non-performing assets by loan class, which includes non-performing loans and other real estate owned, or OREO, at the dates presented. Non-performing loans consist of (i) nonaccrual loans; (ii) accruing loans 90 days or more contractually past due as to interest or principal; and (iii) restructured loans that are considered TDRs.
| (in thousands) | March 31, 2021 | December 31, 2020 | September 30, 2020 | June 30, 2020 | March 31, 2020 | ||||||||||||||||||||||||
Non-Accrual Loans(1) | |||||||||||||||||||||||||||||
| Real Estate Loans | |||||||||||||||||||||||||||||
| Commercial real estate (CRE) | |||||||||||||||||||||||||||||
| Non-owner occupied | $ | 8,515 | $ | 8,219 | $ | 8,289 | $ | 8,426 | $ | 1,936 | |||||||||||||||||||
| Multi-family residential | 11,369 | 11,340 | 1,484 | — | — | ||||||||||||||||||||||||
| 19,884 | 19,559 | 9,773 | 8,426 | 1,936 | |||||||||||||||||||||||||
| Single-family residential | 10,814 | 10,667 | 11,071 | 7,975 | 7,077 | ||||||||||||||||||||||||
| Owner occupied | 12,527 | 12,815 | 14,539 | 11,828 | 13,897 | ||||||||||||||||||||||||
| 43,225 | 43,041 | 35,383 | 28,229 | 22,910 | |||||||||||||||||||||||||
Commercial loans (2) | 45,282 | 44,205 | 50,991 | 48,961 | 9,993 | ||||||||||||||||||||||||
| Consumer loans and overdrafts | 270 | 233 | 104 | 70 | 467 | ||||||||||||||||||||||||
| Total Non-Accrual Loans | $ | 88,777 | $ | 87,479 | $ | 86,478 | $ | 77,260 | $ | 33,370 | |||||||||||||||||||
Past Due Accruing Loans(3) | |||||||||||||||||||||||||||||
| Real Estate Loans | |||||||||||||||||||||||||||||
| Commercial real estate (CRE) | |||||||||||||||||||||||||||||
| Non-owner occupied | $ | 743 | $ | — | $ | — | $ | — | $ | — | |||||||||||||||||||
| Single-family residential | — | — | 1 | — | 5 | ||||||||||||||||||||||||
| Owner occupied | — | 220 | — | — | — | ||||||||||||||||||||||||
| Consumer loans and overdrafts | 3 | 1 | 1 | — | 12 | ||||||||||||||||||||||||
| Total Past Due Accruing Loans | 746 | 221 | 2 | — | 17 | ||||||||||||||||||||||||
| Total Non-Performing Loans | 89,523 | 87,700 | 86,480 | 77,260 | 33,387 | ||||||||||||||||||||||||
| Other Real Estate Owned | 400 | 427 | 42 | 42 | 42 | ||||||||||||||||||||||||
| Total Non-Performing Assets | $ | 89,923 | $ | 88,127 | $ | 86,522 | $ | 77,302 | $ | 33,429 | |||||||||||||||||||
__________________
(1) Includes loan modifications that met the definition of TDRs which may be performing in accordance with their modified loan terms. As of March 31, 2021, December 31, 2020, September 30, 2020, June 30, 2020 and March 31, 2020, non-performing TDRs include $9.8 million, $8.4 million, $9.0 million, $9.3 million and $9.7 million, respectively, in a multiple loan relationship to a South Florida borrower.
(2) As of March 31, 2021, December 31, 2020, September 30, 2020 and June 30, 2020, includes $19.6 million, $19.6 million, $19.6 million, and $39.8 million, respectively, in a commercial relationship placed in nonaccrual status during the second quarter of 2020. During the third quarter of 2020, the Company charged off $19.3 million against the allowance for loan losses as result of the deterioration of this commercial relationship.
(3) Loans past due 90 days or more but still accruing.
23
Loans by Credit Quality Indicators
This tables shows the Company’s loans by credit quality indicators. We have no purchased credit-impaired loans.
| March 31, 2021 | December 31, 2020 (3) | March 31, 2020 | ||||||||||||||||||||||||||||||||||||||||||
| (in thousands) | Special Mention | Substandard | Doubtful | Total (1) | Special Mention | Substandard | Doubtful | Total (1) | Special Mention | Substandard | Doubtful | Total (1) | ||||||||||||||||||||||||||||||||
| Real Estate Loans | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial Real Estate (CRE) | ||||||||||||||||||||||||||||||||||||||||||||
| Non-owner occupied | $ | 45,206 | $ | 5,684 | $ | 3,576 | $ | 54,466 | $ | 46,872 | $ | 4,994 | $ | 3,969 | $ | 55,835 | $ | — | $ | 757 | $ | 1,936 | $ | 2,693 | ||||||||||||||||||||
| Multi-family residential | — | 11,369 | — | 11,369 | — | 11,340 | — | 11,340 | — | — | — | — | ||||||||||||||||||||||||||||||||
| Land development and construction loans | — | — | — | — | 7,164 | — | — | 7,164 | 9,852 | — | — | 9,852 | ||||||||||||||||||||||||||||||||
| 45,206 | 17,053 | 3,576 | 65,835 | 54,036 | 16,334 | 3,969 | 74,339 | 9,852 | 757 | 1,936 | 12,545 | |||||||||||||||||||||||||||||||||
| Single-family residential | — | 10,814 | — | 10,814 | — | 10,667 | — | 10,667 | — | 7,082 | — | 7,082 | ||||||||||||||||||||||||||||||||
| Owner occupied | 21,045 | 12,627 | — | 33,672 | 22,343 | 12,917 | — | 35,260 | 7,190 | 14,005 | — | 21,195 | ||||||||||||||||||||||||||||||||
| 66,251 | 40,494 | 3,576 | 110,321 | 76,379 | 39,918 | 3,969 | 120,266 | 17,042 | 21,844 | 1,936 | 40,822 | |||||||||||||||||||||||||||||||||
| Commercial loans (2) | 43,313 | 21,045 | 25,917 | 90,275 | 42,434 | 21,152 | 23,256 | 86,842 | 2,587 | 9,459 | 2,643 | 14,689 | ||||||||||||||||||||||||||||||||
| Consumer loans and overdrafts | — | 298 | — | 298 | — | 238 | — | 238 | — | 41 | 434 | 475 | ||||||||||||||||||||||||||||||||
| $ | 109,564 | $ | 61,837 | $ | 29,493 | $ | 200,894 | $ | 118,813 | $ | 61,308 | $ | 27,225 | $ | 207,346 | $ | 19,629 | $ | 31,344 | $ | 5,013 | $ | 55,986 | |||||||||||||||||||||
__________
(1) There were no loans categorized as “Loss” as of the dates presented.
(2) As of March 31,2021 and December 31, 2020, include $19.6 million in a commercial relationship placed in nonaccrual status and downgraded during the second quarter of 2020. As of March 31, 2021 and December 31, 2020, Substandard loans include $7.3 million, and doubtful loans include $12.3 million, related to this commercial relationship. During the third quarter of 2020, the Company charged off $19.3 million against the allowance for loan losses as result of the deterioration of this commercial relationship.
(3) Balances have been updated from the balances reported in the Company’s press release, dated January 29, 2021, relating to its financial results for the fourth quarter and year ended December 31, 2020. This was due to downgrades resulting from ongoing reviews that took place during the preparation of the Company’s Form 10-K for the year ended December 31, 2020.
Exhibit 8 - Deposits by Country of Domicile
This tables shows the Company’s deposits by country of domicile of the depositor as of the dates presented.
| (in thousands) | March 31, 2021 | December 31, 2020 | September 30, 2020 | June 30, 2020 | March 31, 2020 | ||||||||||||||||||||||||
| Domestic | $ | 3,175,522 | $ | 3,202,936 | $ | 3,310,343 | $ | 3,432,971 | $ | 3,253,972 | |||||||||||||||||||
| Foreign: | |||||||||||||||||||||||||||||
| Venezuela | 2,088,519 | 2,119,412 | 2,169,621 | 2,202,340 | 2,224,353 | ||||||||||||||||||||||||
| Others | 414,038 | 409,295 | 397,582 | 389,391 | 363,887 | ||||||||||||||||||||||||
| Total foreign | 2,502,557 | 2,528,707 | 2,567,203 | 2,591,731 | 2,588,240 | ||||||||||||||||||||||||
| Total deposits | $ | 5,678,079 | $ | 5,731,643 | $ | 5,877,546 | $ | 6,024,702 | $ | 5,842,212 | |||||||||||||||||||
24
Earnings Call April 29, 2021 First Quarter 2021 Financial Review
2 Forward-Looking Statements This presentation contains “forward-looking statements” within the meaning of the Securities Act of 1933 and the Securities Exchange Act of 1934, including, statements with respect to our objectives, expectations and intentions and other statements that are not historical facts. All statements other than statements of historical fact are statements that could be forward-looking statements. You can identify these forward-looking statements through our use of words such as “may,” “will,” “anticipate,” “assume,” “should,” “indicate,” “would,” “believe,” “contemplate,” “expect,” “estimate,” “continue,” “plan,” “point to,” “project,” “could,” “intend,” “target,” “goals,” “outlooks,” “modeled,” "create" and other similar words and expressions of the future. Forward-looking statements, including those as to our beliefs, plans, objectives, goals, expectations, anticipations, estimates and intentions, involve known and unknown risks, uncertainties and other factors, which may be beyond our control, and which may cause the Company’s actual results, performance, achievements, or financial condition to be materially different from future results, performance, achievements, or financial condition expressed or implied by such forward-looking statements. You should not rely on any forward-looking statements as predictions of future events. You should not expect us to update any forward-looking statements. All written or oral forward-looking statements attributable to us are expressly qualified in their entirety by this cautionary notice, together with those risks and uncertainties described in “Risk factors” in our annual report on Form 10-K for the fiscal year ended December 31, 2020, and in our other filings with the U.S. Securities and Exchange Commission (the “SEC”), which are available at the SEC’s website www.sec.gov. Interim Financial Information Unaudited financial information as of and for interim periods, including as of and for the three month periods ended March 31, 2021 and 2020, may not reflect our results of operations for our fiscal year ending, or financial condition as of December 31, 2021, or any other period of time or date. Non-GAAP Financial Measures The Company supplements its financial results that are determined in accordance with accounting principles generally accepted in the United States of America (“GAAP”) with non- GAAP financial measures, such as “pre-provision net revenue (PPNR)”, “adjusted noninterest income”, “adjusted noninterest expense”, “adjusted net income (loss)”, “adjusted net income (loss) per share (basic and diluted)”, “adjusted return on assets (ROA)”, “adjusted return on equity (ROE)”, and other ratios. This supplemental information is not required by, or are not presented in accordance with, U.S. generally accepted accounting principles (“GAAP”). The Company refers to these financial measures and ratios as “non-GAAP financial measures” and they should not be considered in isolation or as a substitute for the GAAP measures presented herein. We use certain non-GAAP financial measures, including those mentioned above, both to explain our results to shareholders and the investment community and in the internal evaluation and management of our businesses. Our management believes that these non-GAAP financial measures and the information they provide are useful to investors since these measures permit investors to view our performance using the same tools that our management uses to evaluate our past performance and prospects for future performance, especially in light of the additional costs we have incurred in connection with the Company’s restructuring activities that began in 2018 and continued into 2021 and the one-time loss on sale of the Beacon operations center in the fourth quarter of 2020. While we believe that these non-GAAP financial measures are useful in evaluating our performance, this information should be considered as supplemental and not as a substitute for or superior to the related financial information prepared in accordance with GAAP. Additionally, these non-GAAP financial measures may differ from similar measures presented by other companies. Important Notices and Disclaimers
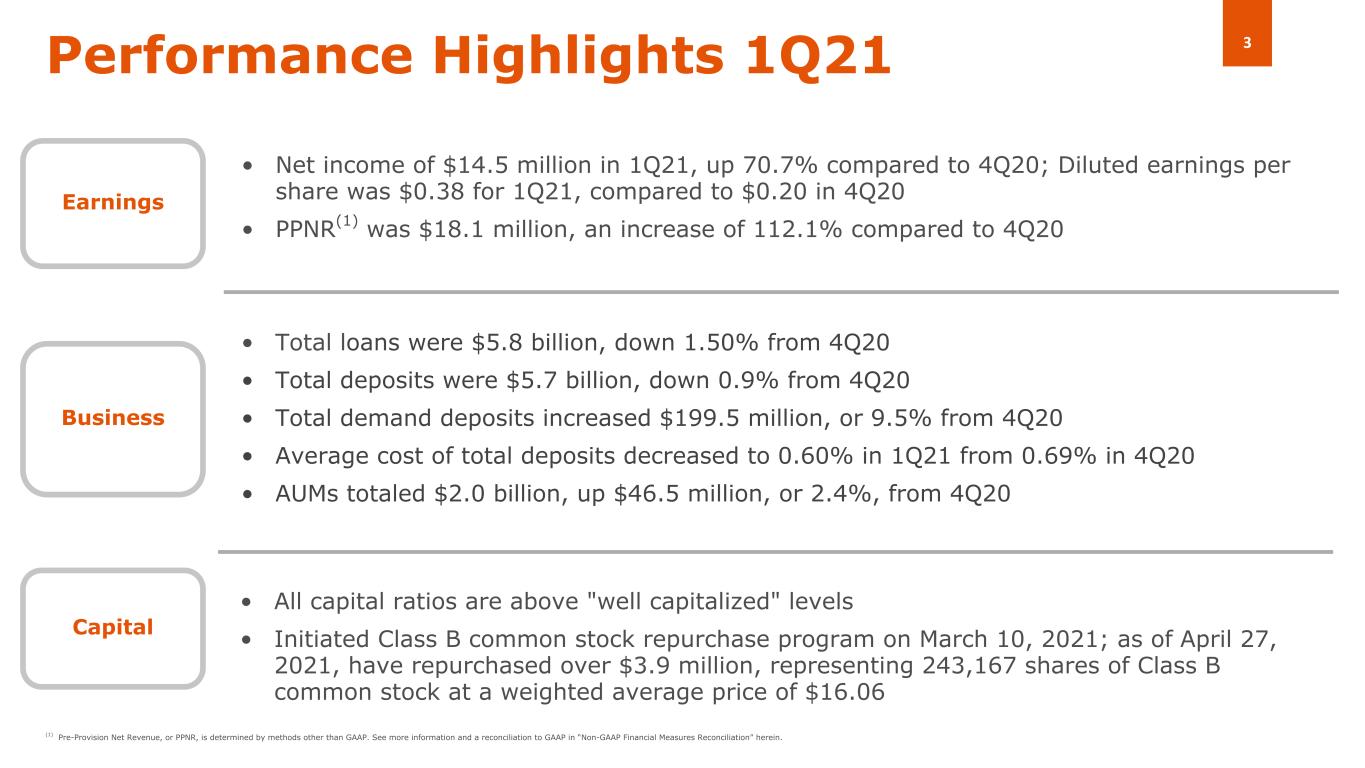
3 • All capital ratios are above "well capitalized" levels • Initiated Class B common stock repurchase program on March 10, 2021; as of April 27, 2021, have repurchased over $3.9 million, representing 243,167 shares of Class B common stock at a weighted average price of $16.06 Performance Highlights 1Q21 Capital Business • Net income of $14.5 million in 1Q21, up 70.7% compared to 4Q20; Diluted earnings per share was $0.38 for 1Q21, compared to $0.20 in 4Q20 • PPNR(1) was $18.1 million, an increase of 112.1% compared to 4Q20 • Total loans were $5.8 billion, down 1.50% from 4Q20 • Total deposits were $5.7 billion, down 0.9% from 4Q20 • Total demand deposits increased $199.5 million, or 9.5% from 4Q20 • Average cost of total deposits decreased to 0.60% in 1Q21 from 0.69% in 4Q20 • AUMs totaled $2.0 billion, up $46.5 million, or 2.4%, from 4Q20 Earnings (1) Pre-Provision Net Revenue, or PPNR, is determined by methods other than GAAP. See more information and a reconciliation to GAAP in “Non-GAAP Financial Measures Reconciliation” herein.
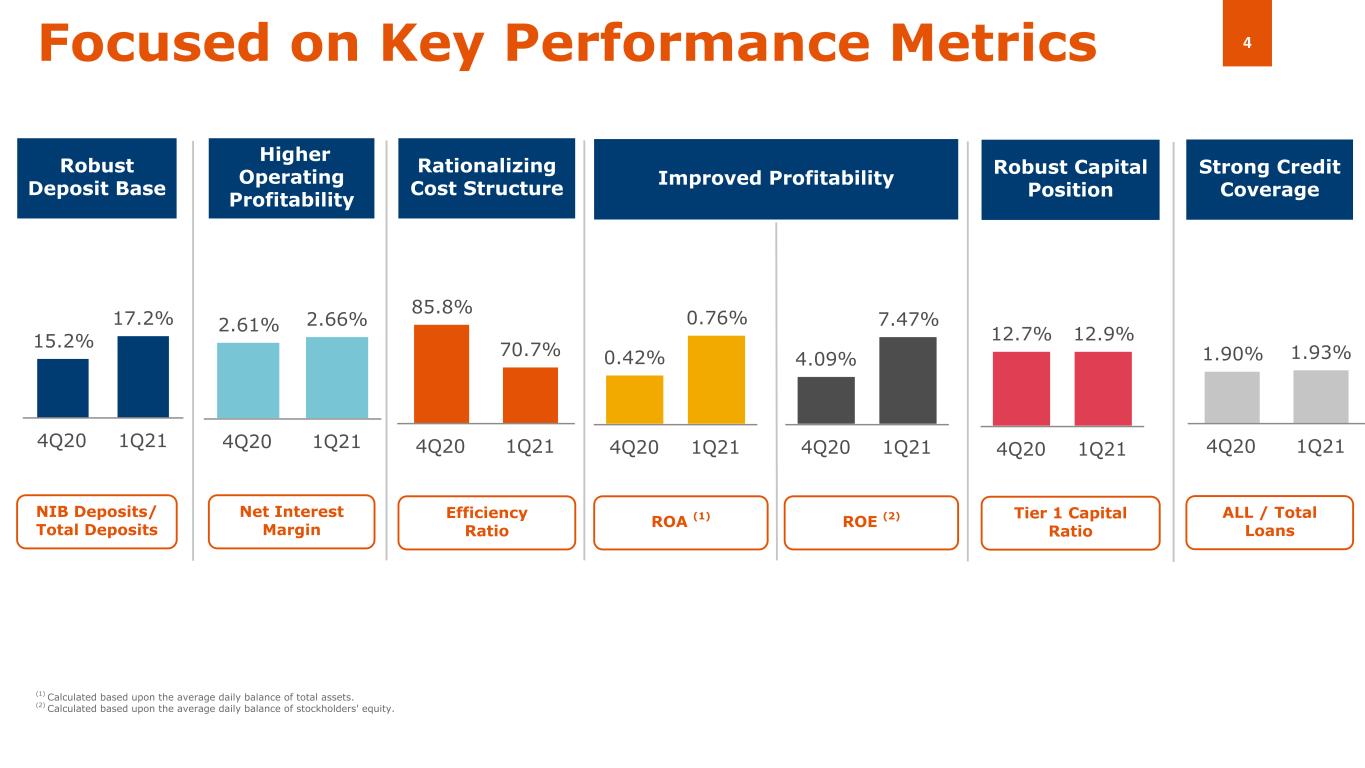
4 85.8% 70.7% 4Q20 1Q21 15.2% 17.2% 4Q20 1Q21 12.7% 12.9% 4Q20 1Q21 2.61% 2.66% 4Q20 1Q21 Focused on Key Performance Metrics Robust Deposit Base Robust Capital Position Higher Operating Profitability Rationalizing Cost Structure (1) Calculated based upon the average daily balance of total assets. (2) Calculated based upon the average daily balance of stockholders' equity. 1.90% 1.93% 4Q20 1Q21 Strong Credit Coverage 0.42% 0.76% 4Q20 1Q21 Improved Profitability 4.09% 7.47% 4Q20 1Q21 NIB Deposits/ Total Deposits Tier 1 Capital Ratio Net Interest Margin Efficiency Ratio ALL / Total LoansROA (1) ROE (2)
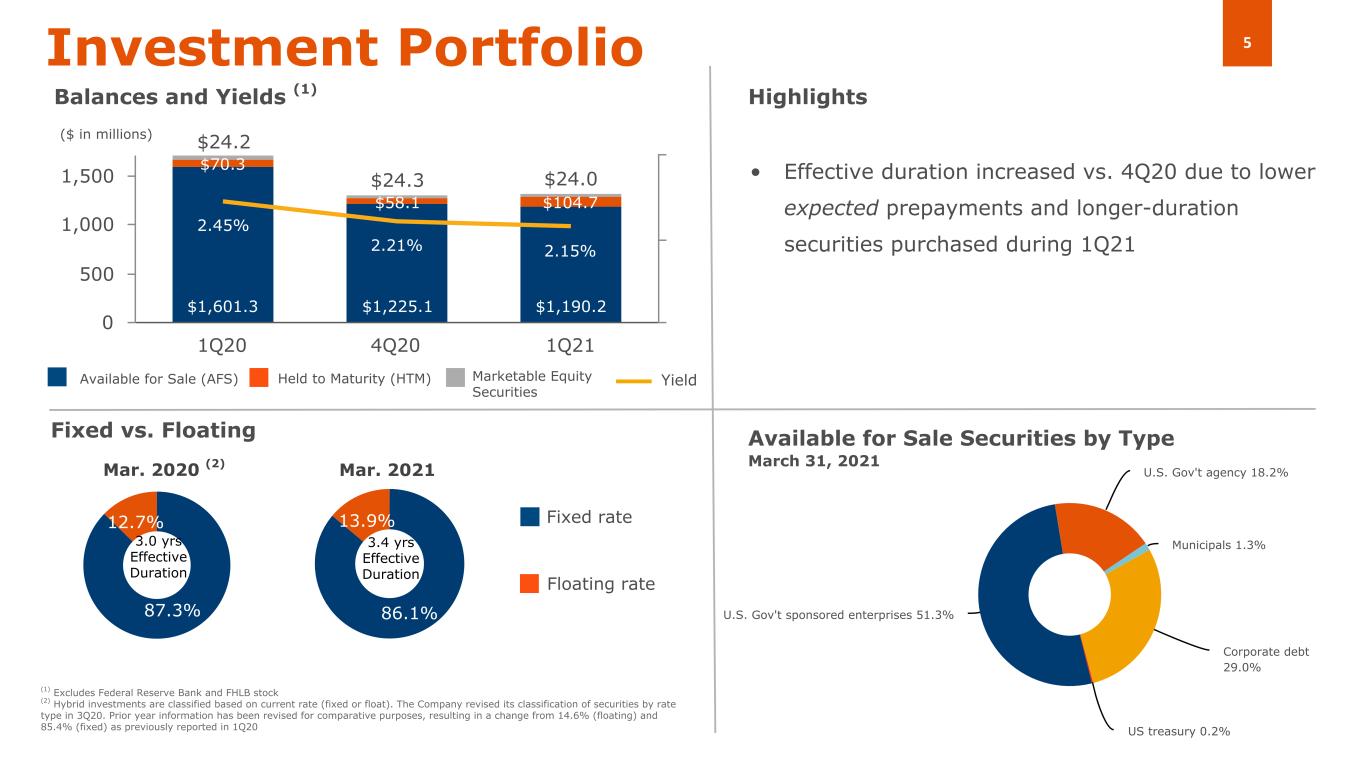
5 86.1% 13.9% U.S. Gov't sponsored enterprises 51.3% U.S. Gov't agency 18.2% Municipals 1.3% Corporate debt 29.0% US treasury 0.2% $1,601.3 $1,225.1 $1,190.2 $70.3 $58.1 $104.7 $24.2 $24.3 $24.0 2.45% 2.21% 2.15% 1Q20 4Q20 1Q21 0 500 1,000 1,500 87.3% 12.7% • Effective duration increased vs. 4Q20 due to lower expected prepayments and longer-duration securities purchased during 1Q21 Investment Portfolio Balances and Yields (1) Available for Sale (AFS) Held to Maturity (HTM) Highlights Fixed vs. Floating Mar. 2020 (2) Mar. 2021 Floating rate Fixed rate Available for Sale Securities by Type March 31, 2021 3.0 yrs Effective Duration ($ in millions) Marketable Equity Securities (1) Excludes Federal Reserve Bank and FHLB stock (2) Hybrid investments are classified based on current rate (fixed or float). The Company revised its classification of securities by rate type in 3Q20. Prior year information has been revised for comparative purposes, resulting in a change from 14.6% (floating) and 85.4% (fixed) as previously reported in 1Q20 Yield 3.4 yrs Effective Duration
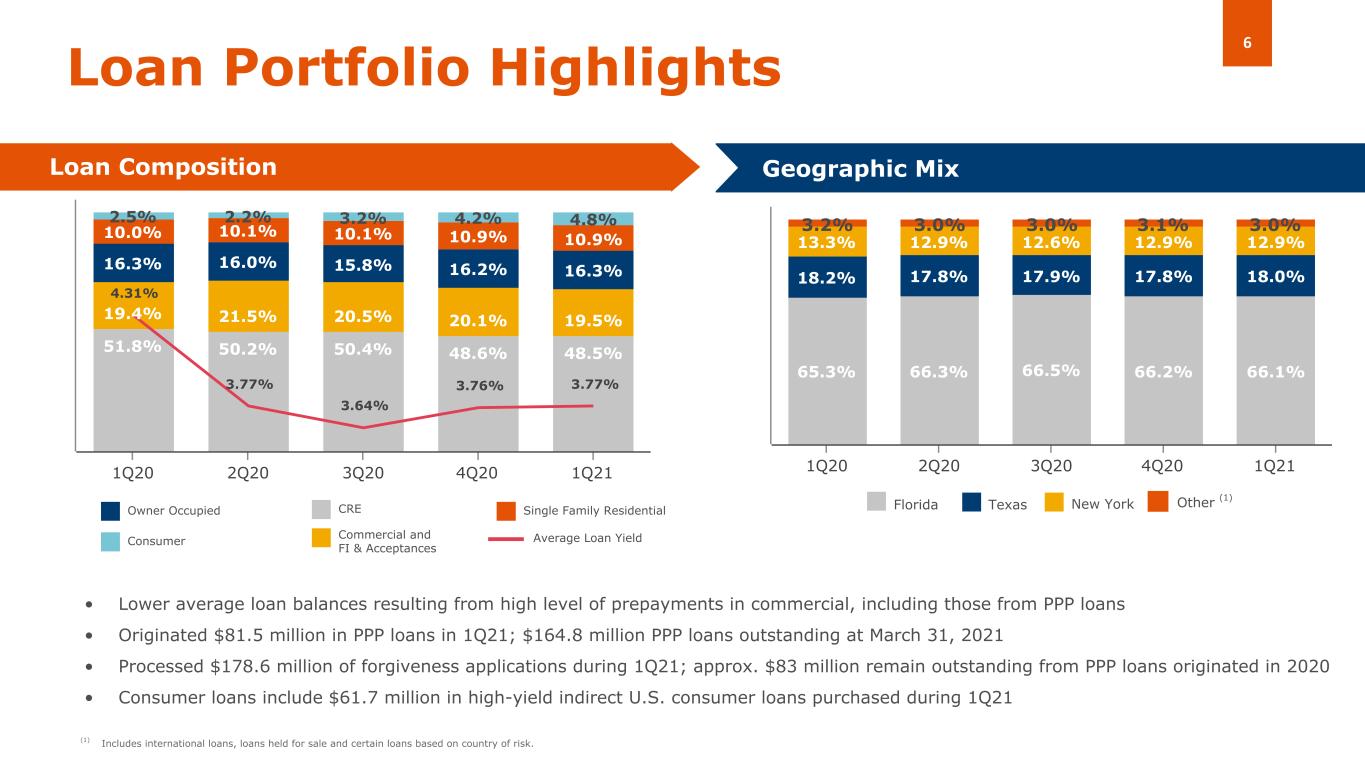
6 51.8% 50.2% 50.4% 48.6% 48.5% 19.4% 21.5% 20.5% 20.1% 19.5% 16.3% 16.0% 15.8% 16.2% 16.3% 10.0% 10.1% 10.1% 10.9% 10.9% 2.5% 2.2% 3.2% 4.2% 4.8% 4.31% 3.77% 3.64% 3.76% 3.77% 1Q20 2Q20 3Q20 4Q20 1Q21 65.3% 66.3% 66.5% 66.2% 66.1% 18.2% 17.8% 17.9% 17.8% 18.0% 13.3% 12.9% 12.6% 12.9% 12.9% 3.2% 3.0% 3.0% 3.1% 3.0% 1Q20 2Q20 3Q20 4Q20 1Q21 Consumer CRE Commercial and FI & Acceptances Owner Occupied Single Family Residential Loan Portfolio Highlights Loan Composition Geographic Mix (Domestic) • Lower average loan balances resulting from high level of prepayments in commercial, including those from PPP loans • Originated $81.5 million in PPP loans in 1Q21; $164.8 million PPP loans outstanding at March 31, 2021 • Processed $178.6 million of forgiveness applications during 1Q21; approx. $83 million remain outstanding from PPP loans originated in 2020 • Consumer loans include $61.7 million in high-yield indirect U.S. consumer loans purchased during 1Q21 Florida Texas New York Average Loan Yield Other (1) (1) Includes international loans, loans held for sale and certain loans based on country of risk.
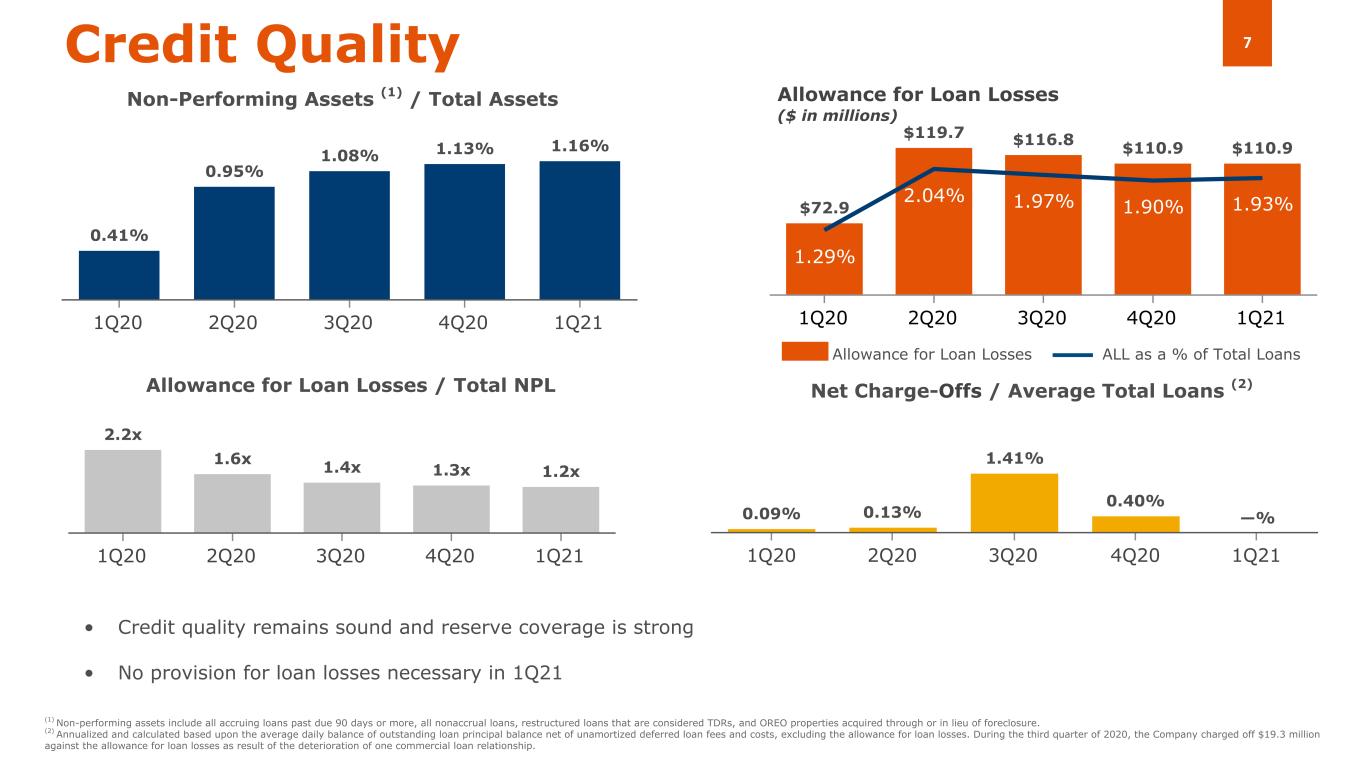
7 $72.9 $119.7 $116.8 $110.9 $110.9 1.29% 2.04% 1.97% 1.90% 1.93% 1Q20 2Q20 3Q20 4Q20 1Q21 0.09% 0.13% 1.41% 0.40% —% 1Q20 2Q20 3Q20 4Q20 1Q21 • Credit quality remains sound and reserve coverage is strong • No provision for loan losses necessary in 1Q21 Net Charge-Offs / Average Total Loans (2) Credit Quality Allowance for Loan Losses ($ in millions) Non-Performing Assets (1) / Total Assets Allowance for Loan Losses / Total NPL Allowance for Loan Losses ALL as a % of Total Loans (1) Non-performing assets include all accruing loans past due 90 days or more, all nonaccrual loans, restructured loans that are considered TDRs, and OREO properties acquired through or in lieu of foreclosure. (2) Annualized and calculated based upon the average daily balance of outstanding loan principal balance net of unamortized deferred loan fees and costs, excluding the allowance for loan losses. During the third quarter of 2020, the Company charged off $19.3 million against the allowance for loan losses as result of the deterioration of one commercial loan relationship. 0.41% 0.95% 1.08% 1.13% 1.16% 1Q20 2Q20 3Q20 4Q20 1Q21 2.2x 1.6x 1.4x 1.3x 1.2x 1Q20 2Q20 3Q20 4Q20 1Q21
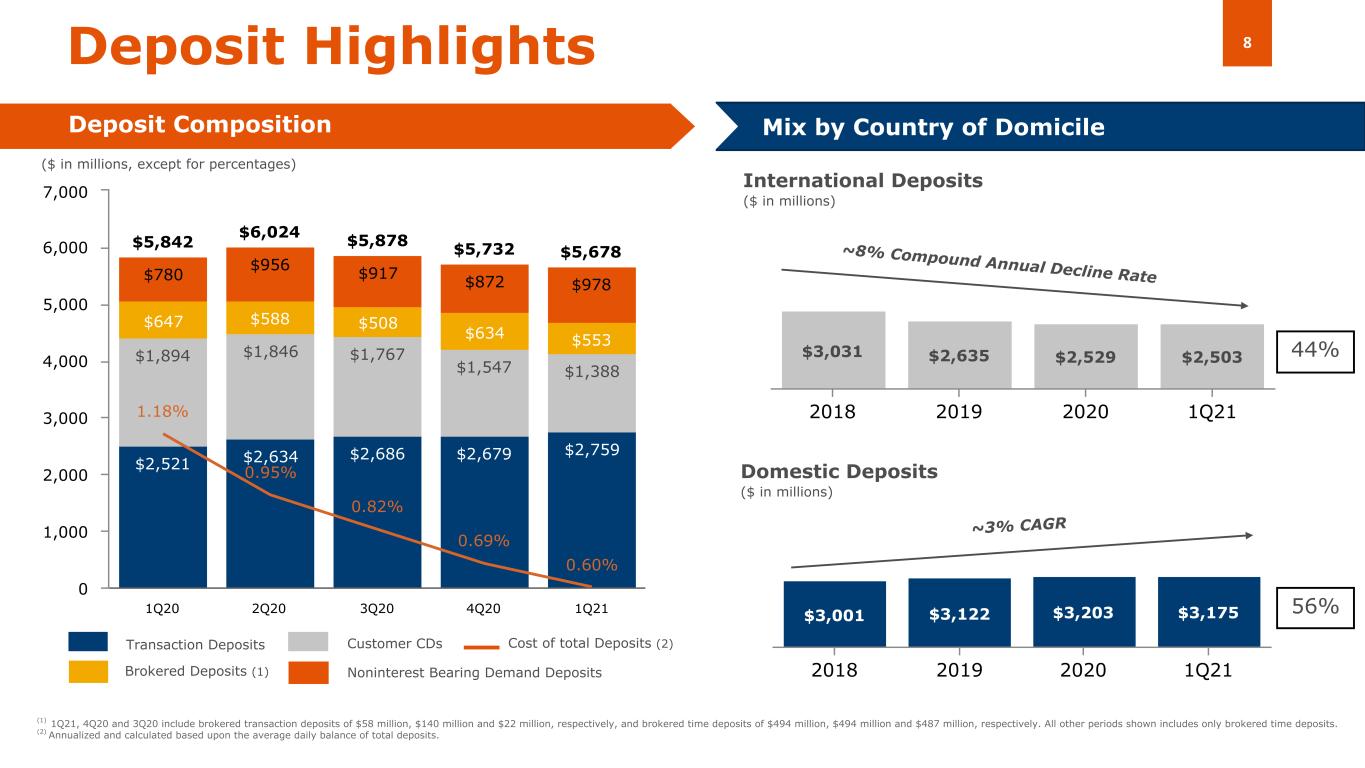
8 $5,842 $6,024 $5,878 $5,732 $5,678 $2,521 $2,634 $2,686 $2,679 $2,759 $1,894 $1,846 $1,767 $1,547 $1,388 $647 $588 $508 $634 $553 $780 $956 $917 $872 $978 1.18% 0.95% 0.82% 0.69% 0.60% 1Q20 2Q20 3Q20 4Q20 1Q21 0 1,000 2,000 3,000 4,000 5,000 6,000 7,000 $3,031 $2,635 $2,529 $2,503 2018 2019 2020 1Q21 $3,001 $3,122 $3,203 $3,175 2018 2019 2020 1Q21 ~3% CAGR Domestic Deposits ($ in millions) ~8% Compound Annual Decline Rate Deposit Highlights Deposit Composition 56% International Deposits ($ in millions) Mix by Country of Domicile Transaction Deposits Customer CDs Brokered Deposits (1) Cost of total Deposits (2) ($ in millions, except for percentages) 44% (1) 1Q21, 4Q20 and 3Q20 include brokered transaction deposits of $58 million, $140 million and $22 million, respectively, and brokered time deposits of $494 million, $494 million and $487 million, respectively. All other periods shown includes only brokered time deposits. (2) Annualized and calculated based upon the average daily balance of total deposits. Noninterest Bearing Demand Deposits
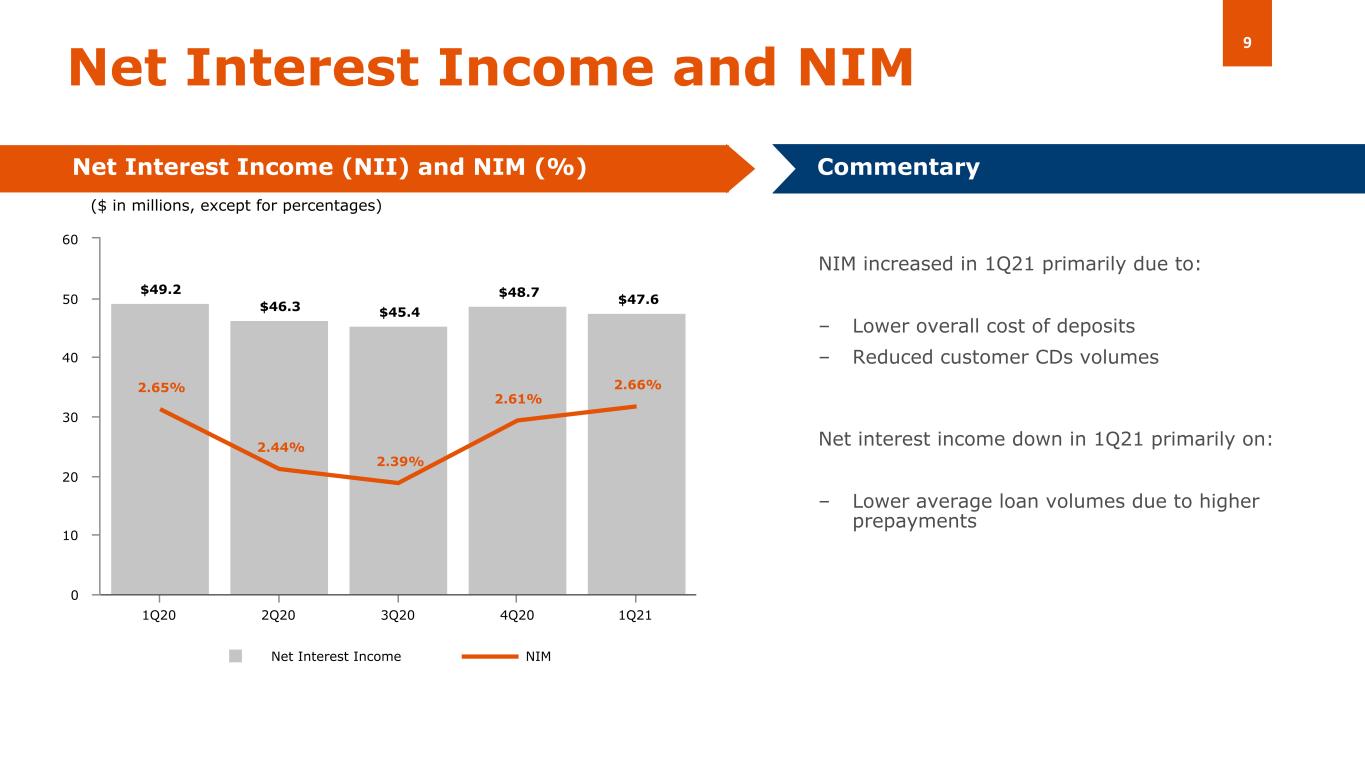
9 $49.2 $46.3 $45.4 $48.7 $47.6 2.65% 2.44% 2.39% 2.61% 2.66% Net Interest Income NIM 1Q20 2Q20 3Q20 4Q20 1Q21 0 10 20 30 40 50 60 NIM increased in 1Q21 primarily due to: – Lower overall cost of deposits – Reduced customer CDs volumes Net interest income down in 1Q21 primarily on: – Lower average loan volumes due to higher prepayments Net Interest Income and NIM Net Interest Income (NII) and NIM (%) Commentary ($ in millions, except for percentages)
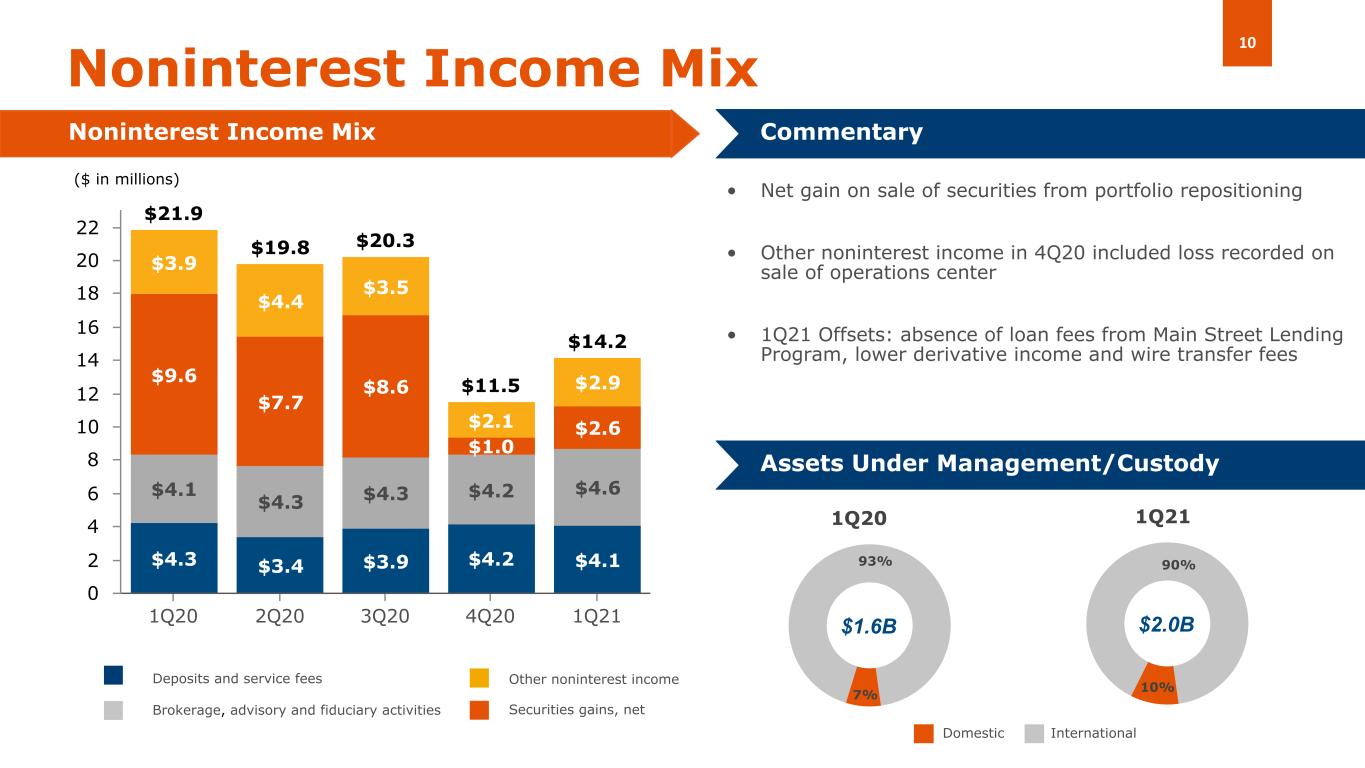
10 $21.9 $19.8 $20.3 $11.5 $14.2 $4.3 $3.4 $3.9 $4.2 $4.1 $4.1 $4.3 $4.3 $4.2 $4.6 $9.6 $7.7 $8.6 $1.0 $2.6 $3.9 $4.4 $3.5 $2.1 $2.9 1Q20 2Q20 3Q20 4Q20 1Q21 0 2 4 6 8 10 12 14 16 18 20 22 7% 93% 10% 90% Noninterest Income Mix Noninterest Income Mix Commentary • Net gain on sale of securities from portfolio repositioning • Other noninterest income in 4Q20 included loss recorded on sale of operations center • 1Q21 Offsets: absence of loan fees from Main Street Lending Program, lower derivative income and wire transfer fees Assets Under Management/Custody Deposits and service fees Brokerage, advisory and fiduciary activities Other noninterest income $2.0B Domestic International 1Q211Q20 $1.6B ($ in millions) Securities gains, net
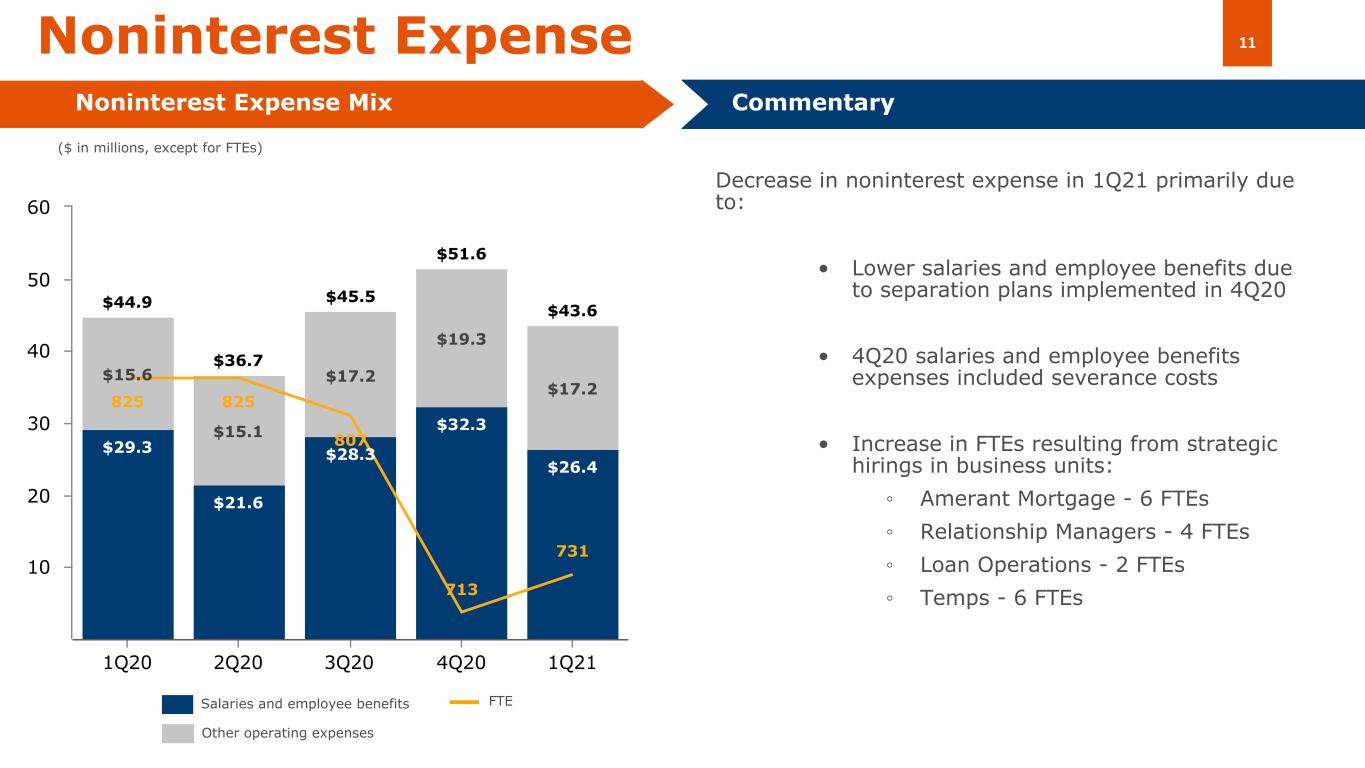
11 Decrease in noninterest expense in 1Q21 primarily due to: • Lower salaries and employee benefits due to separation plans implemented in 4Q20 • 4Q20 salaries and employee benefits expenses included severance costs • Increase in FTEs resulting from strategic hirings in business units: ◦ Amerant Mortgage - 6 FTEs ◦ Relationship Managers - 4 FTEs ◦ Loan Operations - 2 FTEs ◦ Temps - 6 FTEs $44.9 $36.7 $45.5 $51.6 $43.6 $29.3 $21.6 $28.3 $32.3 $26.4 $15.6 $15.1 $17.2 $19.3 $17.2 825 825 807 713 731 1Q20 2Q20 3Q20 4Q20 1Q21 10 20 30 40 50 60 Noninterest Expense Noninterest Expense Mix Commentary Other operating expenses Salaries and employee benefits FTE ($ in millions, except for FTEs)
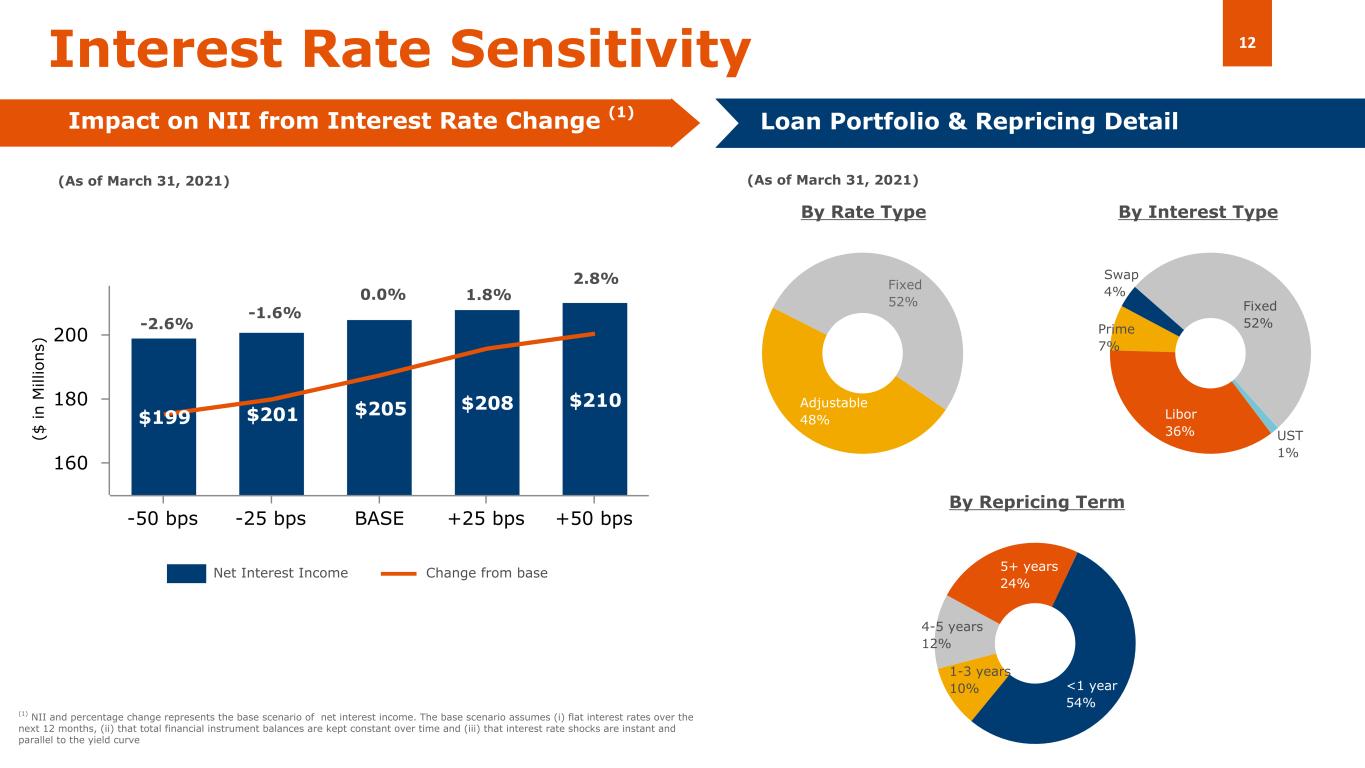
12 $199 $201 $205 $208 $210 -50 bps -25 bps BASE +25 bps +50 bps 160 180 200 (As of March 31, 2021) Fixed 52% Adjustable 48% Interest Rate Sensitivity By Interest TypeBy Rate Type By Repricing Term (1) NII and percentage change represents the base scenario of net interest income. The base scenario assumes (i) flat interest rates over the next 12 months, (ii) that total financial instrument balances are kept constant over time and (iii) that interest rate shocks are instant and parallel to the yield curve Loan Portfolio & Repricing Detail Impact on NII from Interest Rate Change (1) Net Interest Income Change from base <1 year 54% 1-3 years 10% 4-5 years 12% 5+ years 24% -2.6% -1.6% 0.0% 2.8% 1.8% ($ i n M ill io n s) (As of March 31, 2021) Swap 4% Fixed 52% UST 1% Libor 36% Prime 7%
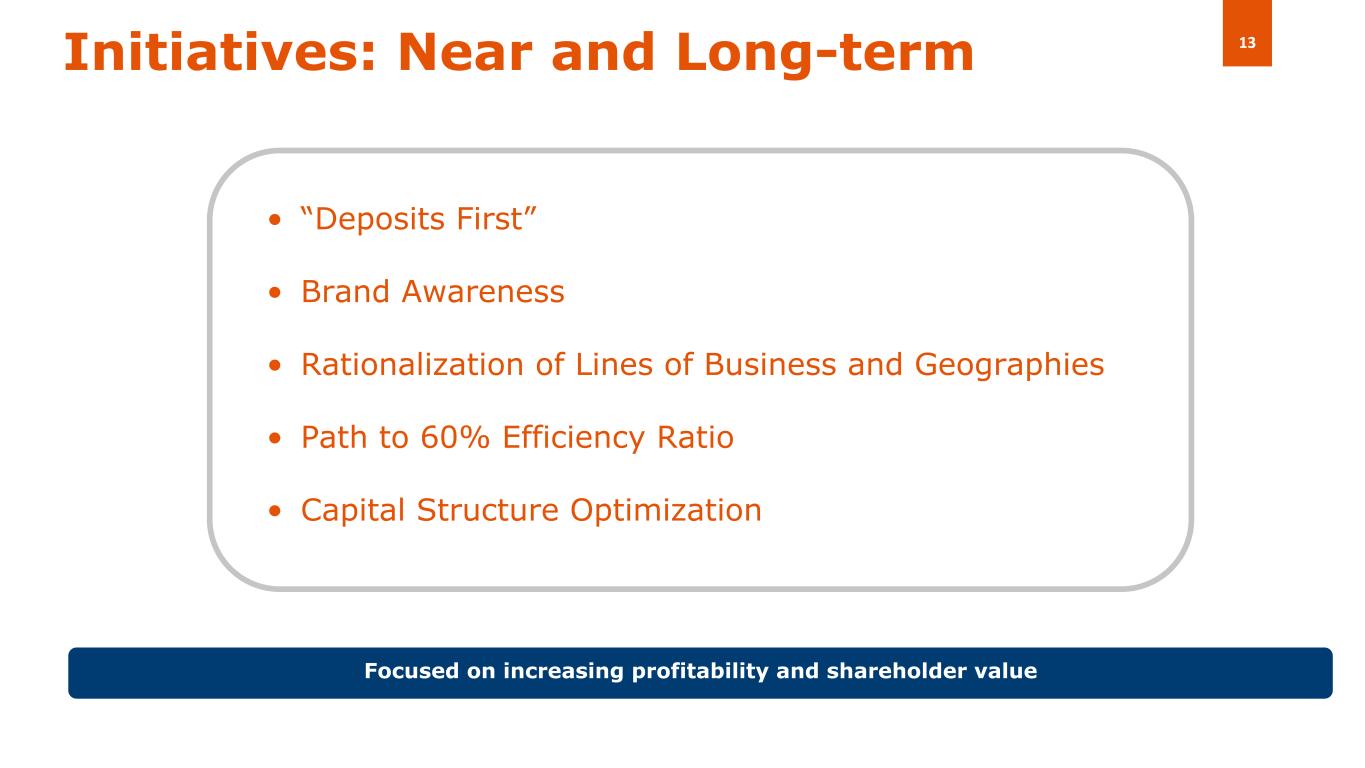
13Initiatives: Near and Long-term • “Deposits First” • Brand Awareness • Rationalization of Lines of Business and Geographies • Path to 60% Efficiency Ratio • Capital Structure Optimization Focused on increasing profitability and shareholder value
Supplemental Loan Portfolio Information
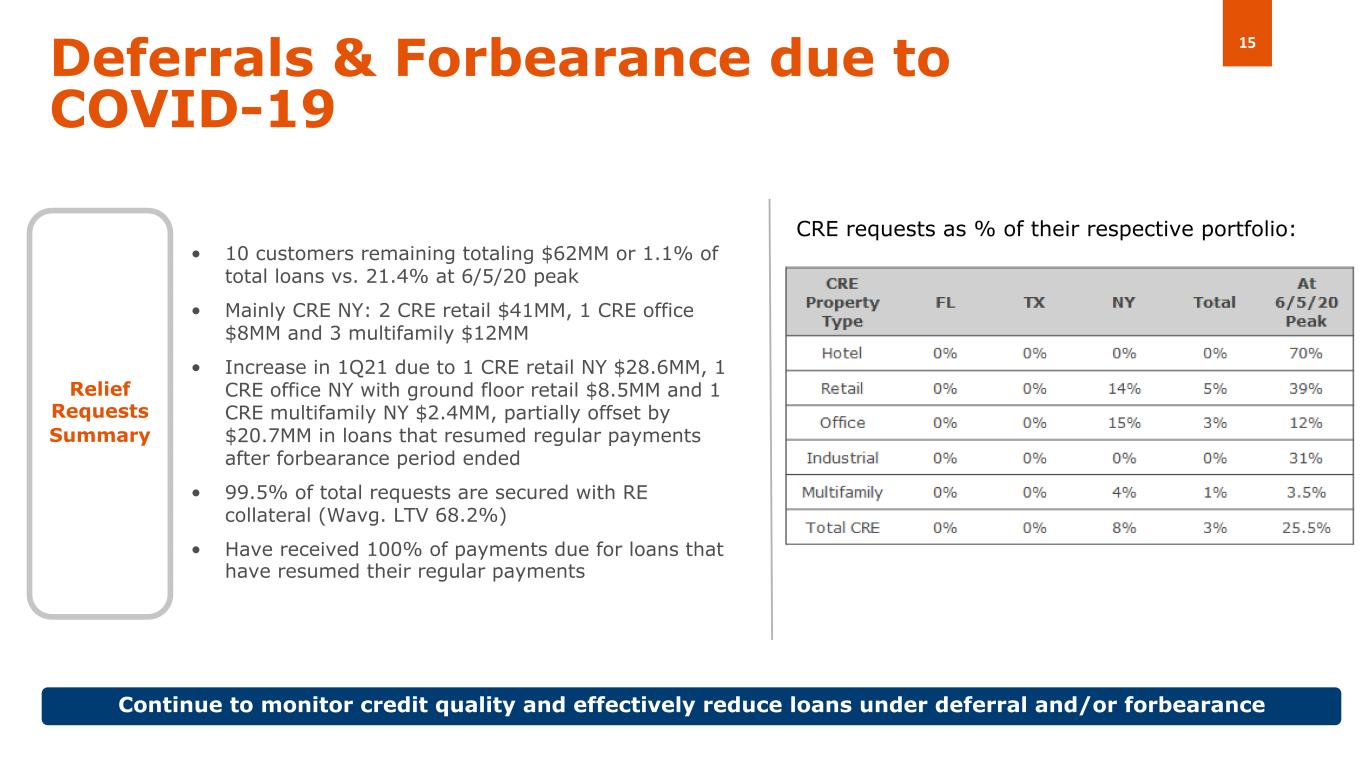
15Deferrals & Forbearance due to COVID-19 • 10 customers remaining totaling $62MM or 1.1% of total loans vs. 21.4% at 6/5/20 peak • Mainly CRE NY: 2 CRE retail $41MM, 1 CRE office $8MM and 3 multifamily $12MM • Increase in 1Q21 due to 1 CRE retail NY $28.6MM, 1 CRE office NY with ground floor retail $8.5MM and 1 CRE multifamily NY $2.4MM, partially offset by $20.7MM in loans that resumed regular payments after forbearance period ended • 99.5% of total requests are secured with RE collateral (Wavg. LTV 68.2%) • Have received 100% of payments due for loans that have resumed their regular payments Relief Requests Summary Continue to monitor credit quality and effectively reduce loans under deferral and/or forbearance CRE requests as % of their respective portfolio:
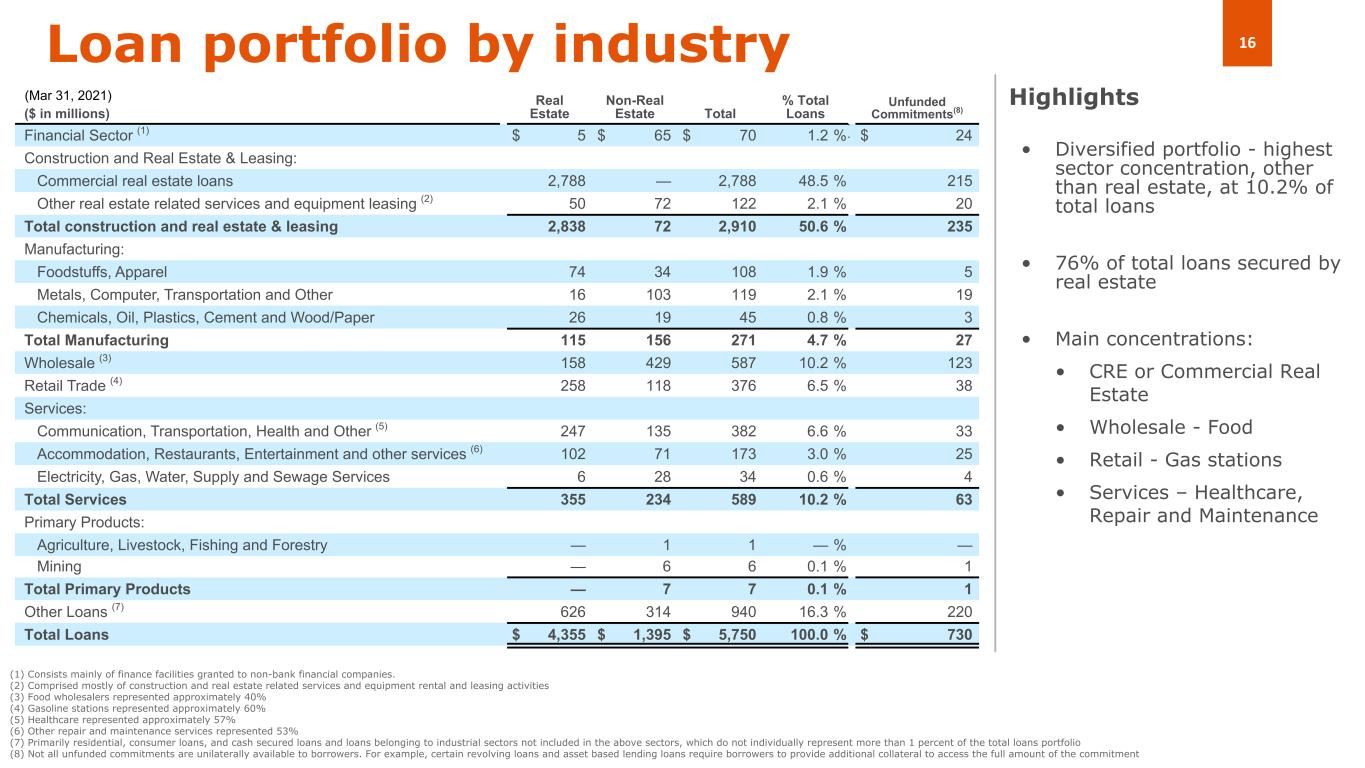
16Loan portfolio by industry • Diversified portfolio - highest sector concentration, other than real estate, at 10.2% of total loans • 76% of total loans secured by real estate • Main concentrations: • CRE or Commercial Real Estate • Wholesale - Food • Retail - Gas stations • Services – Healthcare, Repair and Maintenance Highlights (1) Consists mainly of finance facilities granted to non-bank financial companies. (2) Comprised mostly of construction and real estate related services and equipment rental and leasing activities (3) Food wholesalers represented approximately 40% (4) Gasoline stations represented approximately 60% (5) Healthcare represented approximately 57% (6) Other repair and maintenance services represented 53% (7) Primarily residential, consumer loans, and cash secured loans and loans belonging to industrial sectors not included in the above sectors, which do not individually represent more than 1 percent of the total loans portfolio (8) Not all unfunded commitments are unilaterally available to borrowers. For example, certain revolving loans and asset based lending loans require borrowers to provide additional collateral to access the full amount of the commitment ($ in millions) Real Estate Non-Real Estate Total % Total Loans Unfunded Commitments(8) Financial Sector (1) $ 5 $ 65 $ 70 1.2 % 2 4 $ 24 Construction and Real Estate & Leasing: Commercial real estate loans 2,788 — 2,788 48.5 % 215 Other real estate related services and equipment leasing (2) 50 72 122 2.1 % 20 Total construction and real estate & leasing 2,838 72 2,910 50.6 % 235 Manufacturing: Foodstuffs, Apparel 74 34 108 1.9 % 5 Metals, Computer, Transportation and Other 16 103 119 2.1 % 19 Chemicals, Oil, Plastics, Cement and Wood/Paper 26 19 45 0.8 % 3 Total Manufacturing 115 156 271 4.7 % 27 Wholesale (3) 158 429 587 10.2 % 123 Retail Trade (4) 258 118 376 6.5 % 38 Services: Communication, Transportation, Health and Other (5) 247 135 382 6.6 % 33 Accommodation, Restaurants, Entertainment and other services (6) 102 71 173 3.0 % 25 Electricity, Gas, Water, Supply and Sewage Services 6 28 34 0.6 % 4 Total Services 355 234 589 10.2 % 63 Primary Products: Agriculture, Livestock, Fishing and Forestry — 1 1 — % — Mining — 6 6 0.1 % 1 Total Primary Products — 7 7 0.1 % 1 Other Loans (7) 626 314 940 16.3 % 220 Total Loans $ 4,355 $ 1,395 $ 5,750 100.0 % $ 730 (Mar 31, 2021)
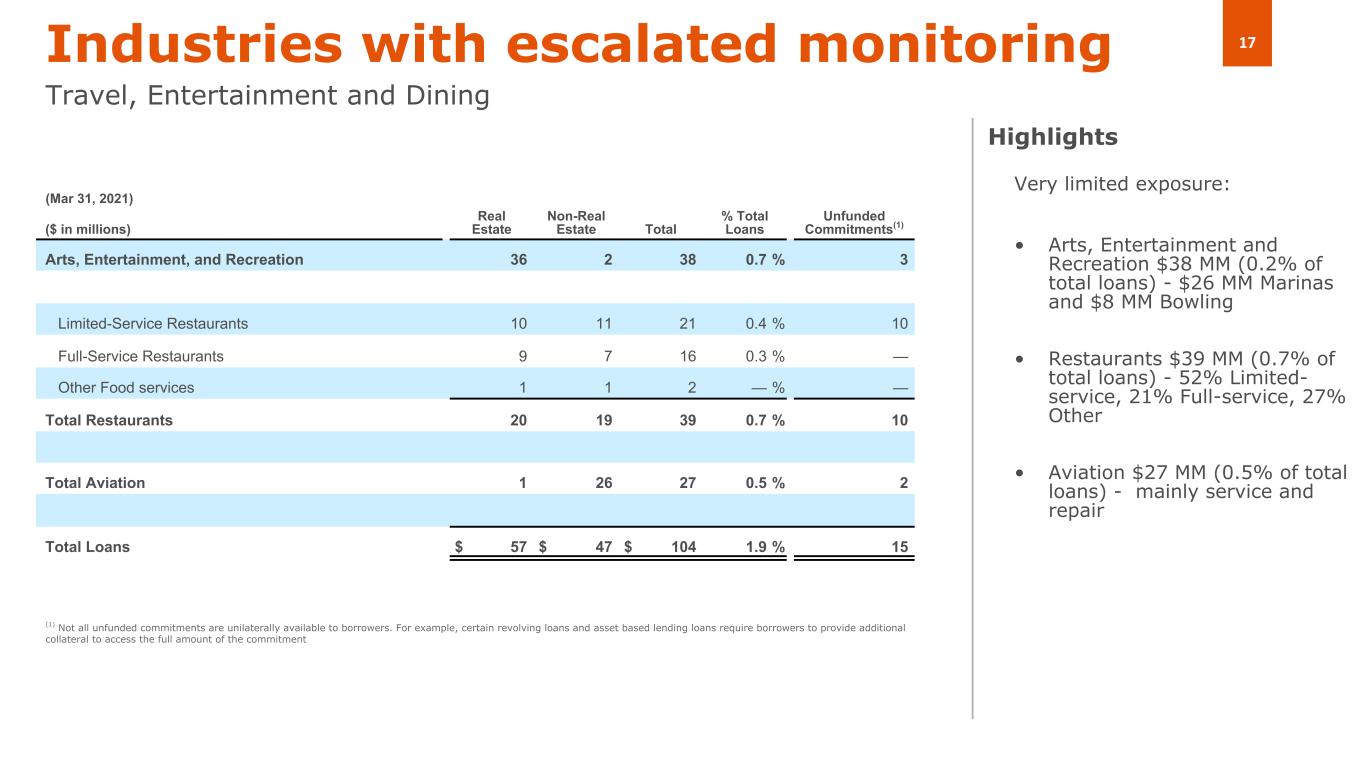
17Industries with escalated monitoring Travel, Entertainment and Dining Very limited exposure: • Arts, Entertainment and Recreation $38 MM (0.2% of total loans) - $26 MM Marinas and $8 MM Bowling • Restaurants $39 MM (0.7% of total loans) - 52% Limited- service, 21% Full-service, 27% Other • Aviation $27 MM (0.5% of total loans) - mainly service and repair Highlights (1) Not all unfunded commitments are unilaterally available to borrowers. For example, certain revolving loans and asset based lending loans require borrowers to provide additional collateral to access the full amount of the commitment ($ in millions) Real Estate Non-Real Estate Total % Total Loans Unfunded Commitments(1) Arts, Entertainment, and Recreation 36 2 38 0.7 % 3 Limited-Service Restaurants 10 11 21 0.4 % 10 Full-Service Restaurants 9 7 16 0.3 % — Other Food services 1 1 2 — % — Total Restaurants 20 19 39 0.7 % 10 Total Aviation 1 26 27 0.5 % 2 Total Loans $ 57 $ 47 $ 104 1.9 % 15 (Mar 31, 2021)
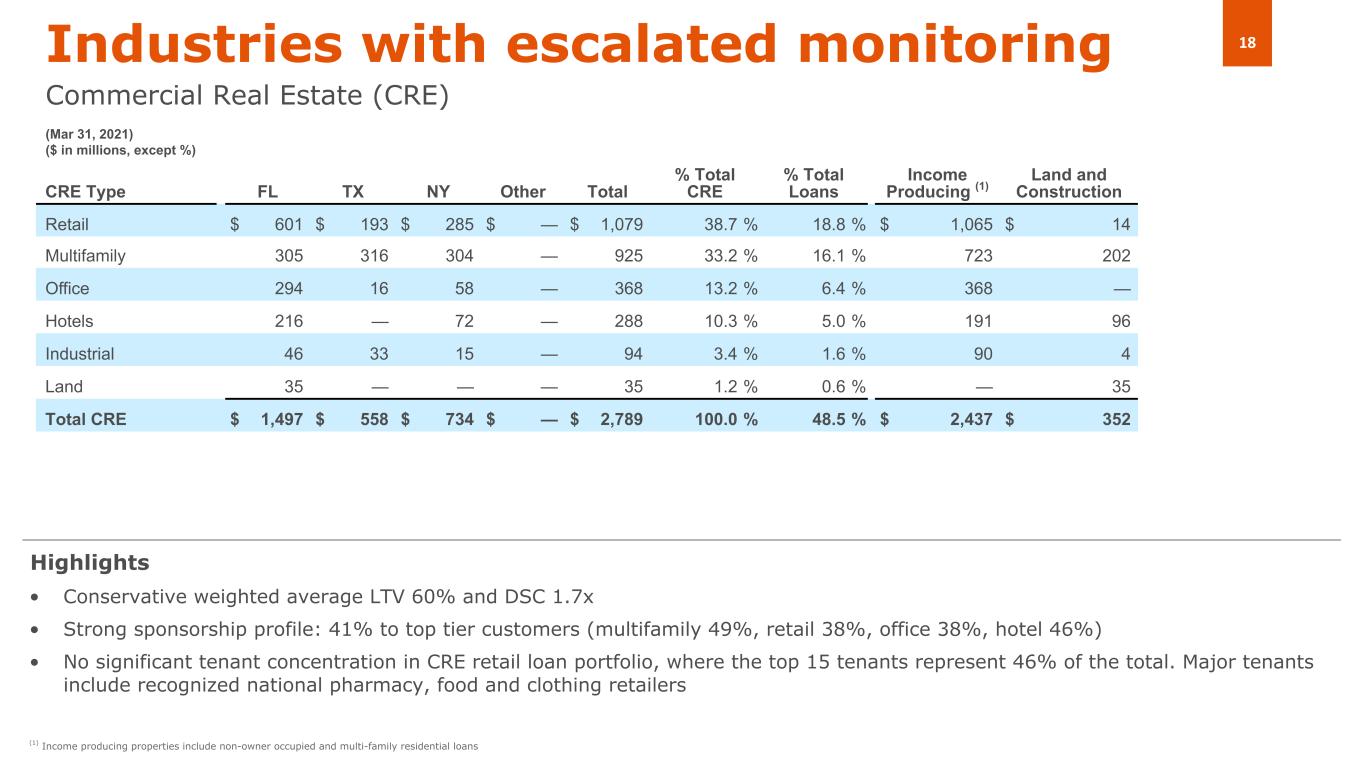
18Industries with escalated monitoring Commercial Real Estate (CRE) CRE Type FL TX NY Other Total % Total CRE % Total Loans Income Producing (1) Land and Construction Retail $ 601 $ 193 $ 285 $ — $ 1,079 38.7 % 18.8 % $ 1,065 $ 14 Multifamily 305 316 304 — 925 33.2 % 16.1 % 723 202 Office 294 16 58 — 368 13.2 % 6.4 % 368 — Hotels 216 — 72 — 288 10.3 % 5.0 % 191 96 Industrial 46 33 15 — 94 3.4 % 1.6 % 90 4 Land 35 — — — 35 1.2 % 0.6 % — 35 Total CRE $ 1,497 $ 558 $ 734 $ — $ 2,789 100.0 % 48.5 % $ 2,437 $ 352 • Conservative weighted average LTV 60% and DSC 1.7x • Strong sponsorship profile: 41% to top tier customers (multifamily 49%, retail 38%, office 38%, hotel 46%) • No significant tenant concentration in CRE retail loan portfolio, where the top 15 tenants represent 46% of the total. Major tenants include recognized national pharmacy, food and clothing retailers (1) Income producing properties include non-owner occupied and multi-family residential loans Highlights (Mar 31, 2021) ($ in millions, except %)
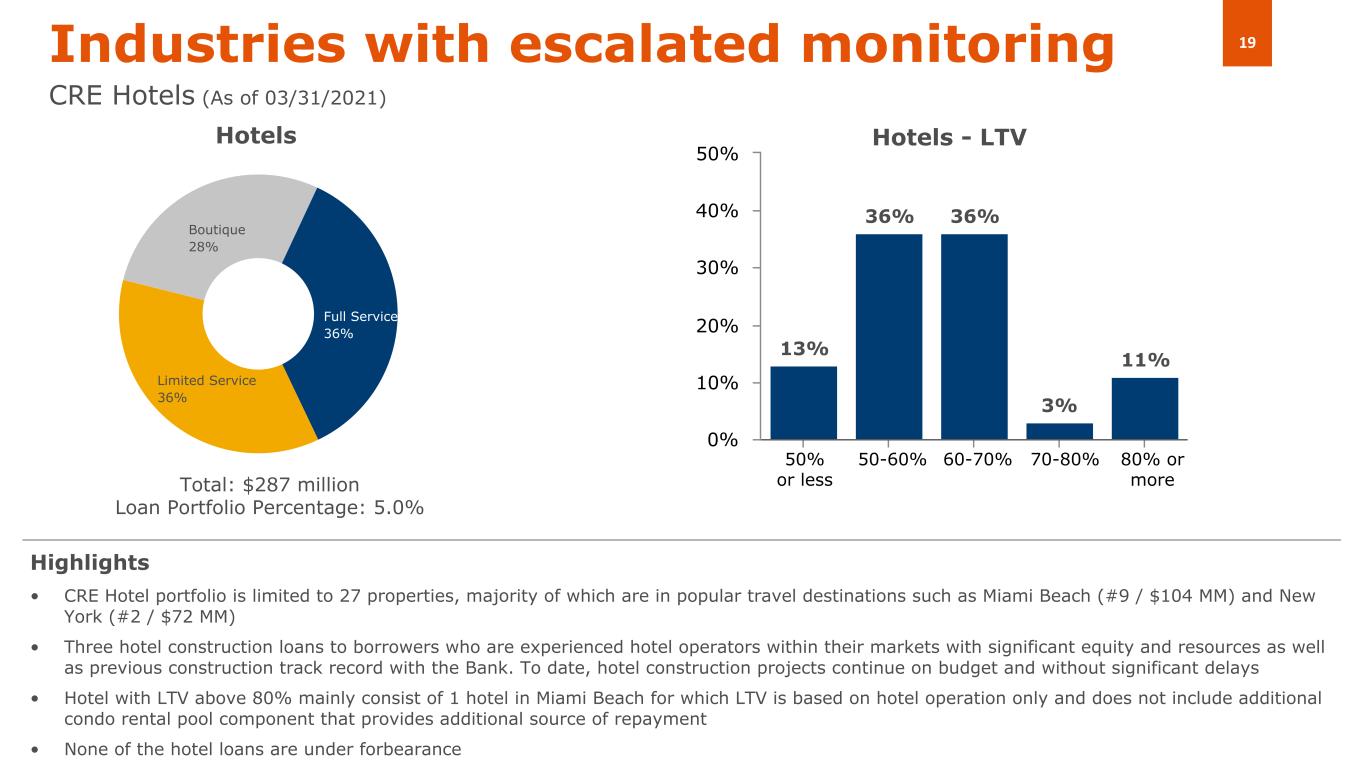
19Industries with escalated monitoring CRE Hotels (As of 03/31/2021) • CRE Hotel portfolio is limited to 27 properties, majority of which are in popular travel destinations such as Miami Beach (#9 / $104 MM) and New York (#2 / $72 MM) • Three hotel construction loans to borrowers who are experienced hotel operators within their markets with significant equity and resources as well as previous construction track record with the Bank. To date, hotel construction projects continue on budget and without significant delays • Hotel with LTV above 80% mainly consist of 1 hotel in Miami Beach for which LTV is based on hotel operation only and does not include additional condo rental pool component that provides additional source of repayment • None of the hotel loans are under forbearance Highlights Full Service 36% Limited Service 36% Boutique 28% Hotels 13% 36% 36% 3% 11% 0% 10% 20% 30% 40% 50% 50% or less 50-60% 60-70% 70-80% 80% or more Hotels - LTV Total: $287 million Loan Portfolio Percentage: 5.0%
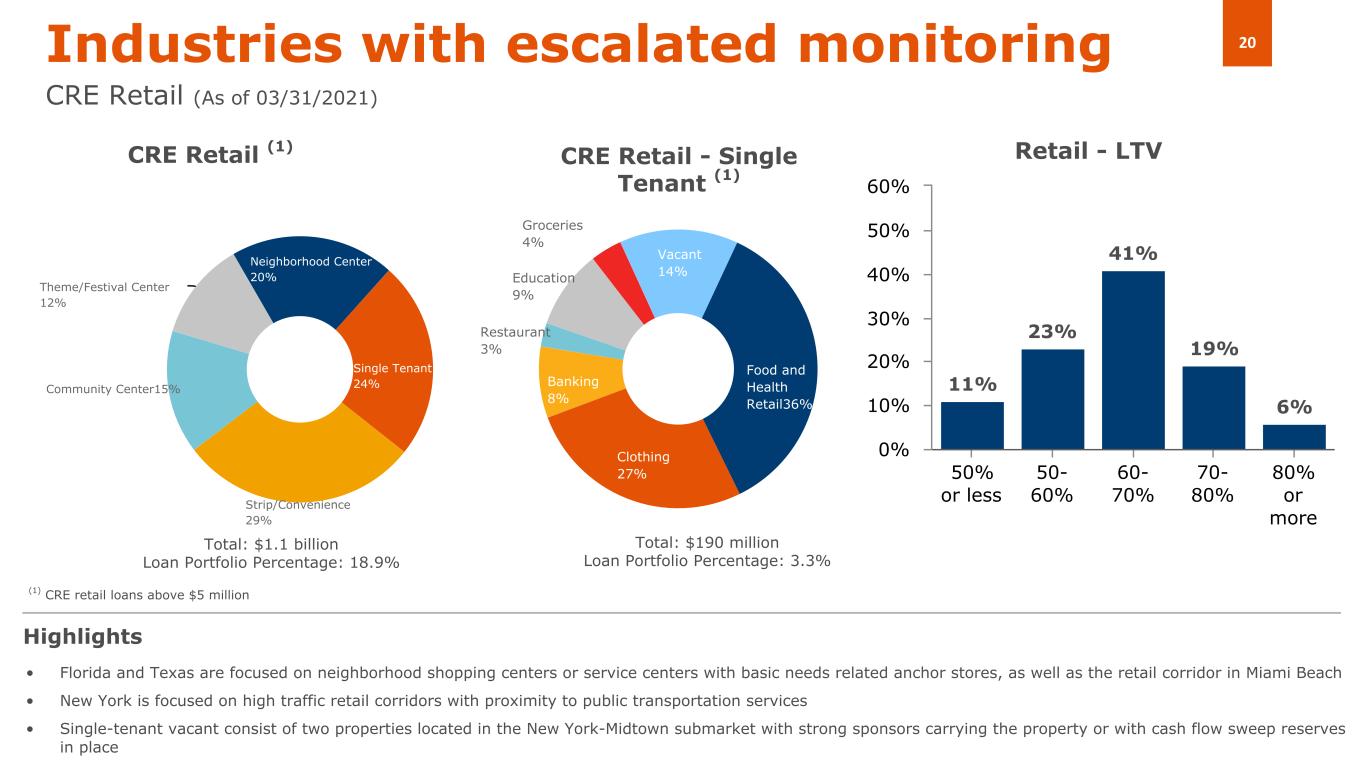
20 11% 23% 41% 19% 6% 50% or less 50- 60% 60- 70% 70- 80% 80% or more 0% 10% 20% 30% 40% 50% 60% Industries with escalated monitoring CRE Retail (As of 03/31/2021) • Florida and Texas are focused on neighborhood shopping centers or service centers with basic needs related anchor stores, as well as the retail corridor in Miami Beach • New York is focused on high traffic retail corridors with proximity to public transportation services • Single-tenant vacant consist of two properties located in the New York-Midtown submarket with strong sponsors carrying the property or with cash flow sweep reserves in place Highlights CRE Retail (1) Retail - LTV Food and Health Retail36% Clothing 27% Banking 8% Restaurant 3% Education 9% Groceries 4% Vacant 14% CRE Retail - Single Tenant (1) (1) CRE retail loans above $5 million Total: $1.1 billion Loan Portfolio Percentage: 18.9% Total: $190 million Loan Portfolio Percentage: 3.3% Neighborhood Center 20% Single Tenant 24% Strip/Convenience 29% Community Center15% Theme/Festival Center 12%
Appendices
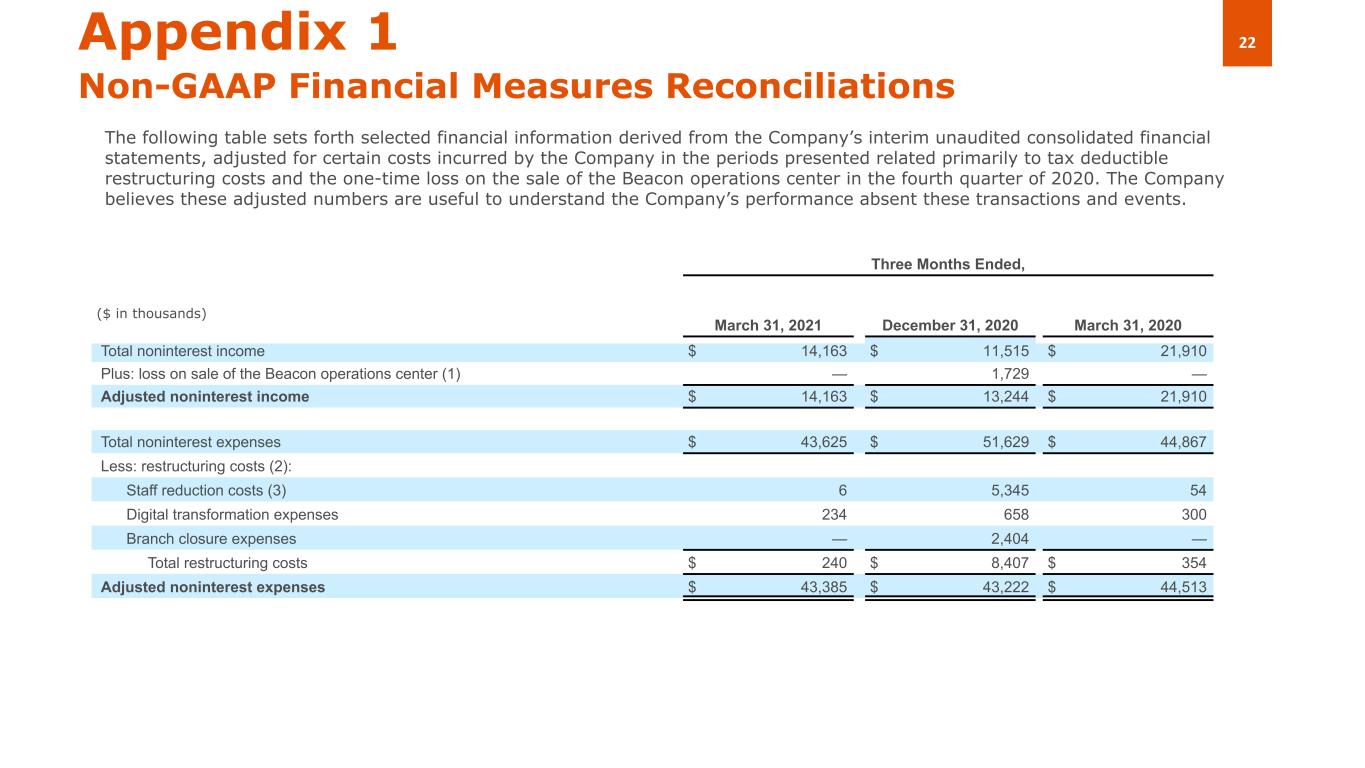
22Appendix 1 Non-GAAP Financial Measures Reconciliations The following table sets forth selected financial information derived from the Company’s interim unaudited consolidated financial statements, adjusted for certain costs incurred by the Company in the periods presented related primarily to tax deductible restructuring costs and the one-time loss on the sale of the Beacon operations center in the fourth quarter of 2020. The Company believes these adjusted numbers are useful to understand the Company’s performance absent these transactions and events. Three Months Ended, ($ in thousands) March 31, 2021 December 31, 2020 March 31, 2020 Total noninterest income $ 14,163 $ 11,515 $ 21,910 Plus: loss on sale of the Beacon operations center (1) — 1,729 — Adjusted noninterest income $ 14,163 $ 13,244 $ 21,910 Total noninterest expenses $ 43,625 $ 51,629 $ 44,867 Less: restructuring costs (2): Staff reduction costs (3) 6 5,345 54 Digital transformation expenses 234 658 300 Branch closure expenses — 2,404 — Total restructuring costs $ 240 $ 8,407 $ 354 Adjusted noninterest expenses $ 43,385 $ 43,222 $ 44,513
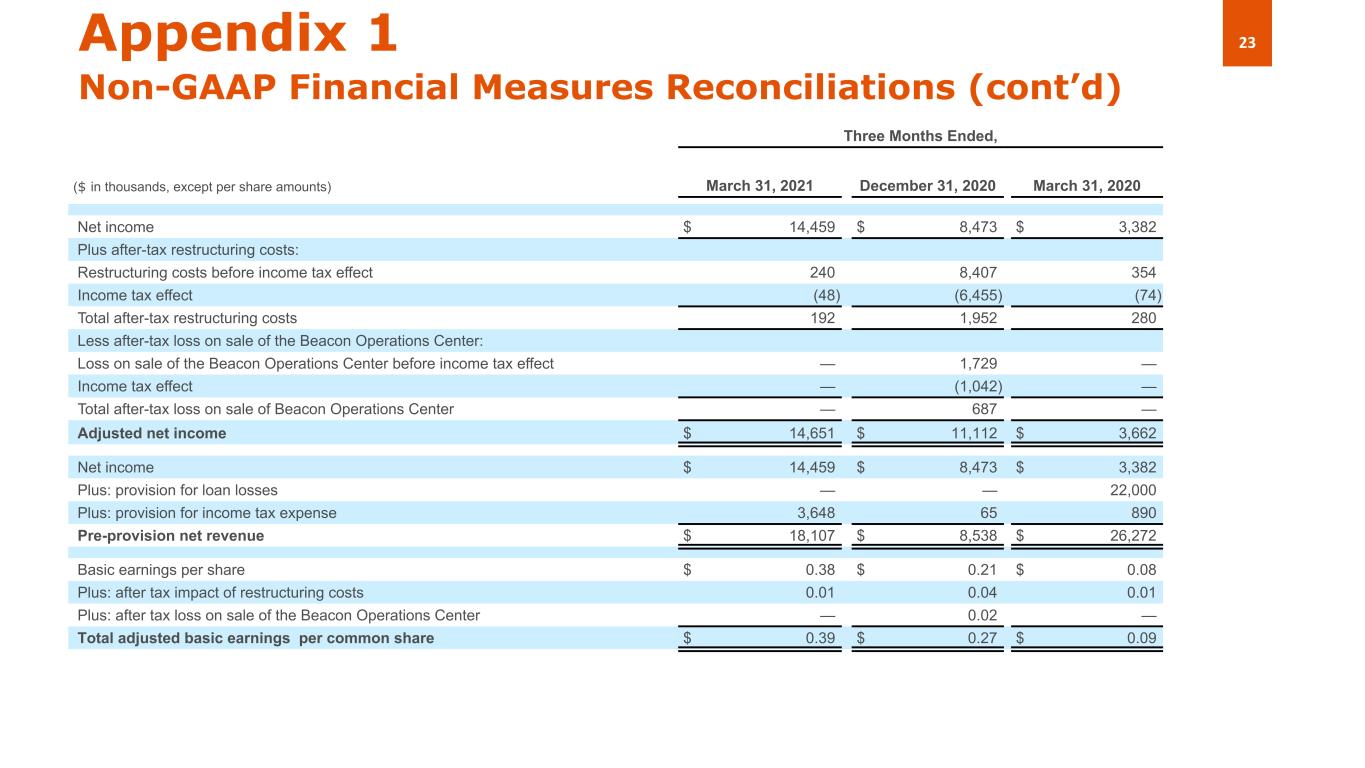
23Appendix 1 Non-GAAP Financial Measures Reconciliations (cont’d) Three Months Ended, ($ in thousands, except per share amounts) March 31, 2021 December 31, 2020 March 31, 2020 Net income $ 14,459 $ 8,473 $ 3,382 Plus after-tax restructuring costs: Restructuring costs before income tax effect 240 8,407 354 Income tax effect (48) (6,455) (74) Total after-tax restructuring costs 192 1,952 280 Less after-tax loss on sale of the Beacon Operations Center: Loss on sale of the Beacon Operations Center before income tax effect — 1,729 — Income tax effect — (1,042) — Total after-tax loss on sale of Beacon Operations Center — 687 — Adjusted net income $ 14,651 $ 11,112 $ 3,662 Net income $ 14,459 $ 8,473 $ 3,382 Plus: provision for loan losses — — 22,000 Plus: provision for income tax expense 3,648 65 890 Pre-provision net revenue $ 18,107 $ 8,538 $ 26,272 Basic earnings per share $ 0.38 $ 0.21 $ 0.08 Plus: after tax impact of restructuring costs 0.01 0.04 0.01 Plus: after tax loss on sale of the Beacon Operations Center — 0.02 — Total adjusted basic earnings per common share $ 0.39 $ 0.27 $ 0.09
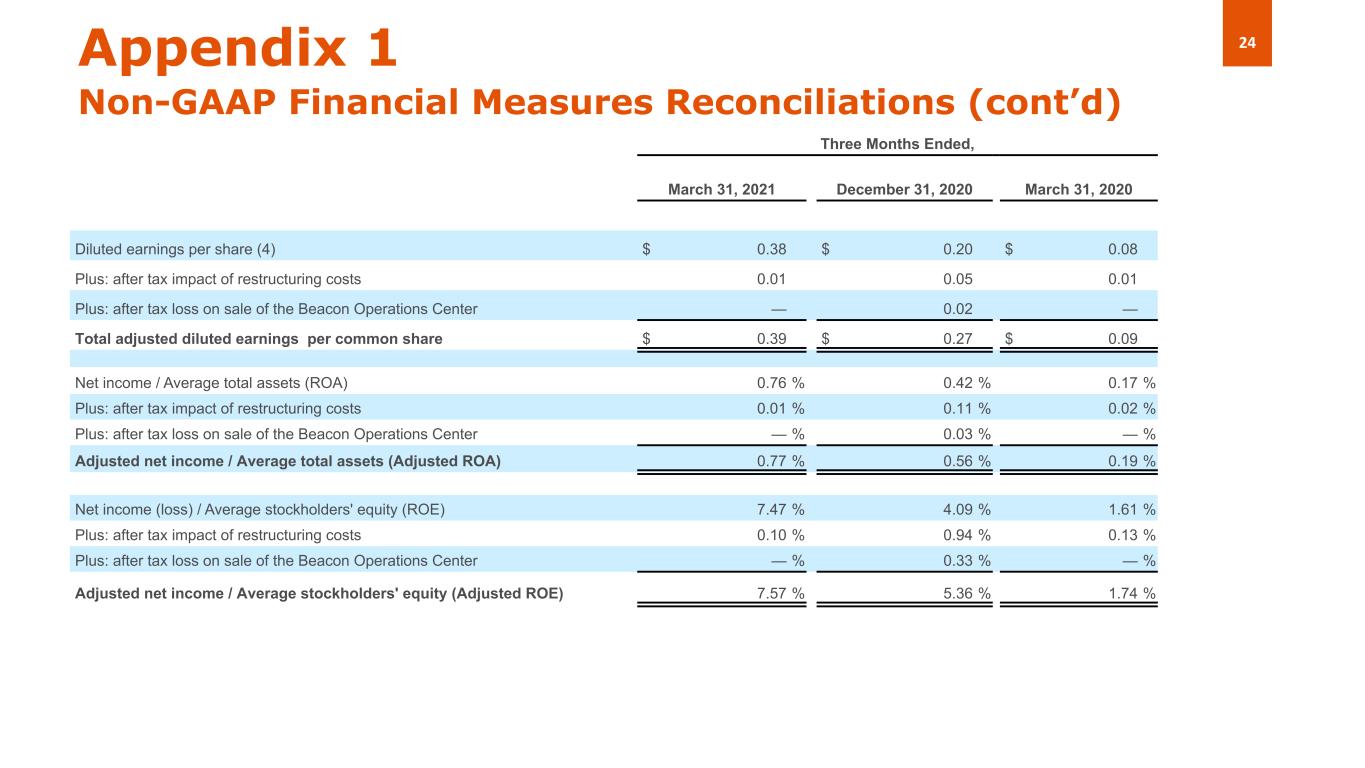
24Appendix 1 Non-GAAP Financial Measures Reconciliations (cont’d) Three Months Ended, March 31, 2021 December 31, 2020 March 31, 2020 Diluted earnings per share (4) $ 0.38 $ 0.20 $ 0.08 Plus: after tax impact of restructuring costs 0.01 0.05 0.01 Plus: after tax loss on sale of the Beacon Operations Center — 0.02 — Total adjusted diluted earnings per common share $ 0.39 $ 0.27 $ 0.09 Net income / Average total assets (ROA) 0.76 % 0.42 % 0.17 % Plus: after tax impact of restructuring costs 0.01 % 0.11 % 0.02 % Plus: after tax loss on sale of the Beacon Operations Center — % 0.03 % — % Adjusted net income / Average total assets (Adjusted ROA) 0.77 % 0.56 % 0.19 % Net income (loss) / Average stockholders' equity (ROE) 7.47 % 4.09 % 1.61 % Plus: after tax impact of restructuring costs 0.10 % 0.94 % 0.13 % Plus: after tax loss on sale of the Beacon Operations Center — % 0.33 % — % Adjusted net income / Average stockholders' equity (Adjusted ROE) 7.57 % 5.36 % 1.74 %
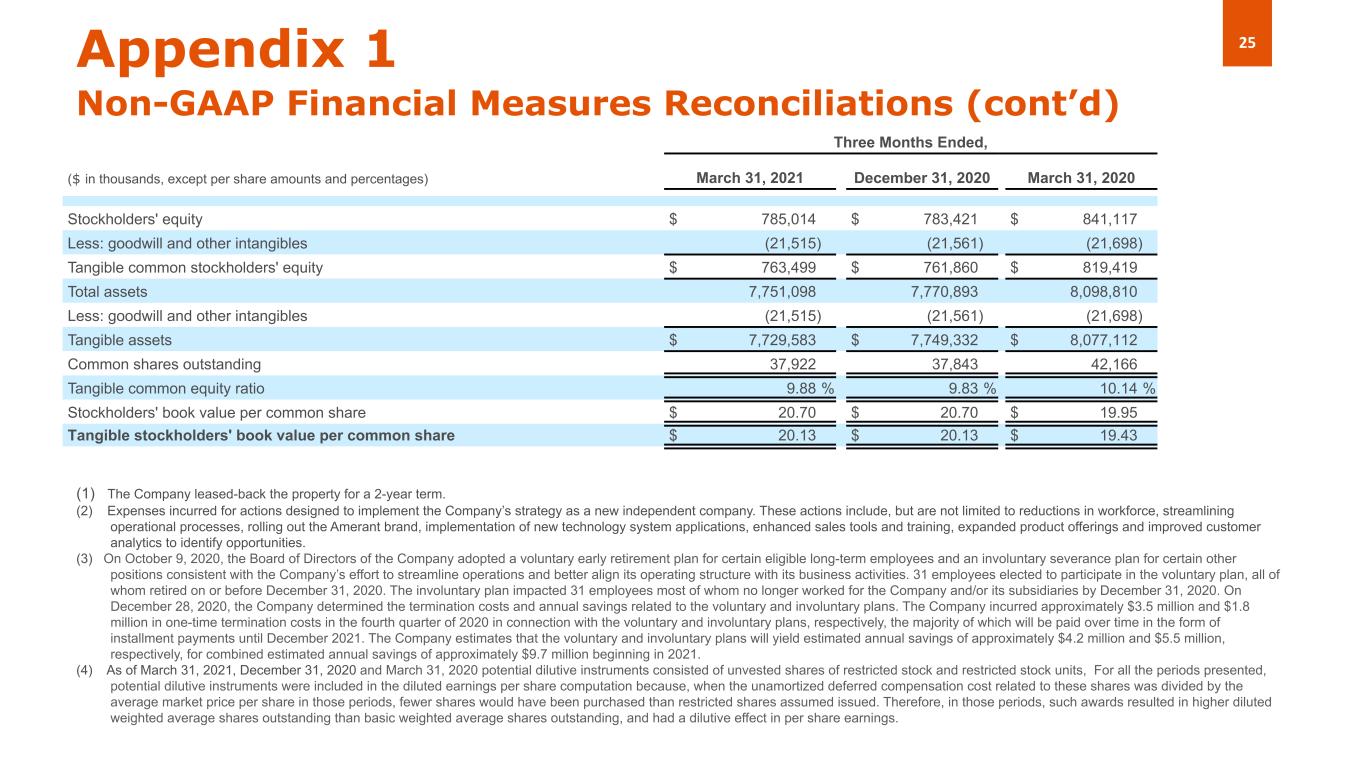
25Appendix 1 Non-GAAP Financial Measures Reconciliations (cont’d) Three Months Ended, ($ in thousands, except per share amounts and percentages) March 31, 2021 December 31, 2020 March 31, 2020 Stockholders' equity $ 785,014 $ 783,421 $ 841,117 Less: goodwill and other intangibles (21,515) (21,561) (21,698) Tangible common stockholders' equity $ 763,499 $ 761,860 $ 819,419 Total assets 7,751,098 7,770,893 8,098,810 Less: goodwill and other intangibles (21,515) (21,561) (21,698) Tangible assets $ 7,729,583 $ 7,749,332 $ 8,077,112 Common shares outstanding 37,922 37,843 42,166 Tangible common equity ratio 9.88 % 9.83 % 10.14 % Stockholders' book value per common share $ 20.70 $ 20.70 $ 19.95 Tangible stockholders' book value per common share $ 20.13 $ 20.13 $ 19.43 (1) The Company leased-back the property for a 2-year term. (2) Expenses incurred for actions designed to implement the Company’s strategy as a new independent company. These actions include, but are not limited to reductions in workforce, streamlining operational processes, rolling out the Amerant brand, implementation of new technology system applications, enhanced sales tools and training, expanded product offerings and improved customer analytics to identify opportunities. (3) On October 9, 2020, the Board of Directors of the Company adopted a voluntary early retirement plan for certain eligible long-term employees and an involuntary severance plan for certain other positions consistent with the Company’s effort to streamline operations and better align its operating structure with its business activities. 31 employees elected to participate in the voluntary plan, all of whom retired on or before December 31, 2020. The involuntary plan impacted 31 employees most of whom no longer worked for the Company and/or its subsidiaries by December 31, 2020. On December 28, 2020, the Company determined the termination costs and annual savings related to the voluntary and involuntary plans. The Company incurred approximately $3.5 million and $1.8 million in one-time termination costs in the fourth quarter of 2020 in connection with the voluntary and involuntary plans, respectively, the majority of which will be paid over time in the form of installment payments until December 2021. The Company estimates that the voluntary and involuntary plans will yield estimated annual savings of approximately $4.2 million and $5.5 million, respectively, for combined estimated annual savings of approximately $9.7 million beginning in 2021. (4) As of March 31, 2021, December 31, 2020 and March 31, 2020 potential dilutive instruments consisted of unvested shares of restricted stock and restricted stock units, For all the periods presented, potential dilutive instruments were included in the diluted earnings per share computation because, when the unamortized deferred compensation cost related to these shares was divided by the average market price per share in those periods, fewer shares would have been purchased than restricted shares assumed issued. Therefore, in those periods, such awards resulted in higher diluted weighted average shares outstanding than basic weighted average shares outstanding, and had a dilutive effect in per share earnings.