
BAC 8-K
Bank Of America Corp /De/ (BAC)
8-K
2024-04-16
For: 2024-04-16
View Original
Added on
April 05, 2026
As filed with the Securities and Exchange Commission on April 16, 2024
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported):
(Exact name of registrant as specified in its charter)
| (State or Other Jurisdiction of Incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||||||||
(Address of principal executive offices)
(704 ) 386-5681
(Registrant’s telephone number, including area code)
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
| Bank of America Corporation Floating Rate Non-Cumulative | ||||||||
| Preferred Stock, Series 1 | ||||||||
| Bank of America Corporation Floating Rate Non-Cumulative | ||||||||
| Preferred Stock, Series 2 | ||||||||
| Bank of America Corporation Floating Rate Non-Cumulative | ||||||||
| Preferred Stock, Series 4 | ||||||||
| Bank of America Corporation Floating Rate Non-Cumulative | ||||||||
| Preferred Stock, Series 5 | ||||||||
| November 28, 2031 of BofA Finance LLC (and the guarantee of the | ||||||||
| Registrant with respect thereto) | ||||||||
| Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (17 CFR 230.405) or Rule 12b-2 of the Securities Exchange Act of 1934 (17 CFR 240.12b-2). | |||||
| Emerging growth company | |||||
| If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. | ☐ | ||||
ITEM 2.02. RESULTS OF OPERATIONS AND FINANCIAL CONDITION.
On April 16, 2024 , Bank of America Corporation (the “Corporation”) announced financial results for the first quarter ended March 31, 2024, reporting first quarter net income of $6.7 billion, or $0.76 per diluted share. A copy of the press release announcing the Corporation’s results for the first quarter ended March 31, 2024 (the “Press Release”) is attached hereto as Exhibit 99.1 and is incorporated by reference in this Item 2.02. The Press Release is available on the Corporation’s website.
The information provided in Item 2.02 of this report, including Exhibit 99.1, shall be deemed to be “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended.
ITEM 7.01. REGULATION FD DISCLOSURE.
On April 16, 2024 , the Corporation will hold an investor conference call and webcast to discuss financial results for the first quarter ended March 31, 2024, including the Press Release and other matters relating to the Corporation.
The Corporation has also made available on its website presentation materials containing certain historical and forward-looking information relating to the Corporation (the “Presentation Materials”) and materials that contain additional information about the Corporation’s financial results for the first quarter ended March 31, 2024 (the “Supplemental Information”). The Presentation Materials and the Supplemental Information are furnished herewith as Exhibit 99.2 and Exhibit 99.3, respectively, and are incorporated by reference in this Item 7.01. All information in Exhibits 99.2 and 99.3 is presented as of the particular date or dates referenced therein, and the Corporation does not undertake any obligation to, and disclaims any duty to, update any of the information provided.
The information provided in Item 7.01 of this report, including Exhibits 99.2 and 99.3, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, nor shall the information or Exhibits 99.2 or 99.3 be deemed incorporated by reference in any filings under the Securities Act of 1933, as amended.
ITEM 9.01. FINANCIAL STATEMENTS AND EXHIBITS.
(d) Exhibits.
Exhibit 99.1 is filed herewith. Exhibits 99.2 and 99.3 are furnished herewith.
| EXHIBIT NO. | DESCRIPTION OF EXHIBIT | |||||||
| 104 | Cover Page Interactive Data File (embedded in the cover page formatted in Inline XBRL) | |||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the Corporation has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| BANK OF AMERICA CORPORATION | ||||||||
| By: | /s/ Rudolf A. Bless | |||||||
| Rudolf A. Bless | ||||||||
| Chief Accounting Officer | ||||||||
Dated: April 16, 2024
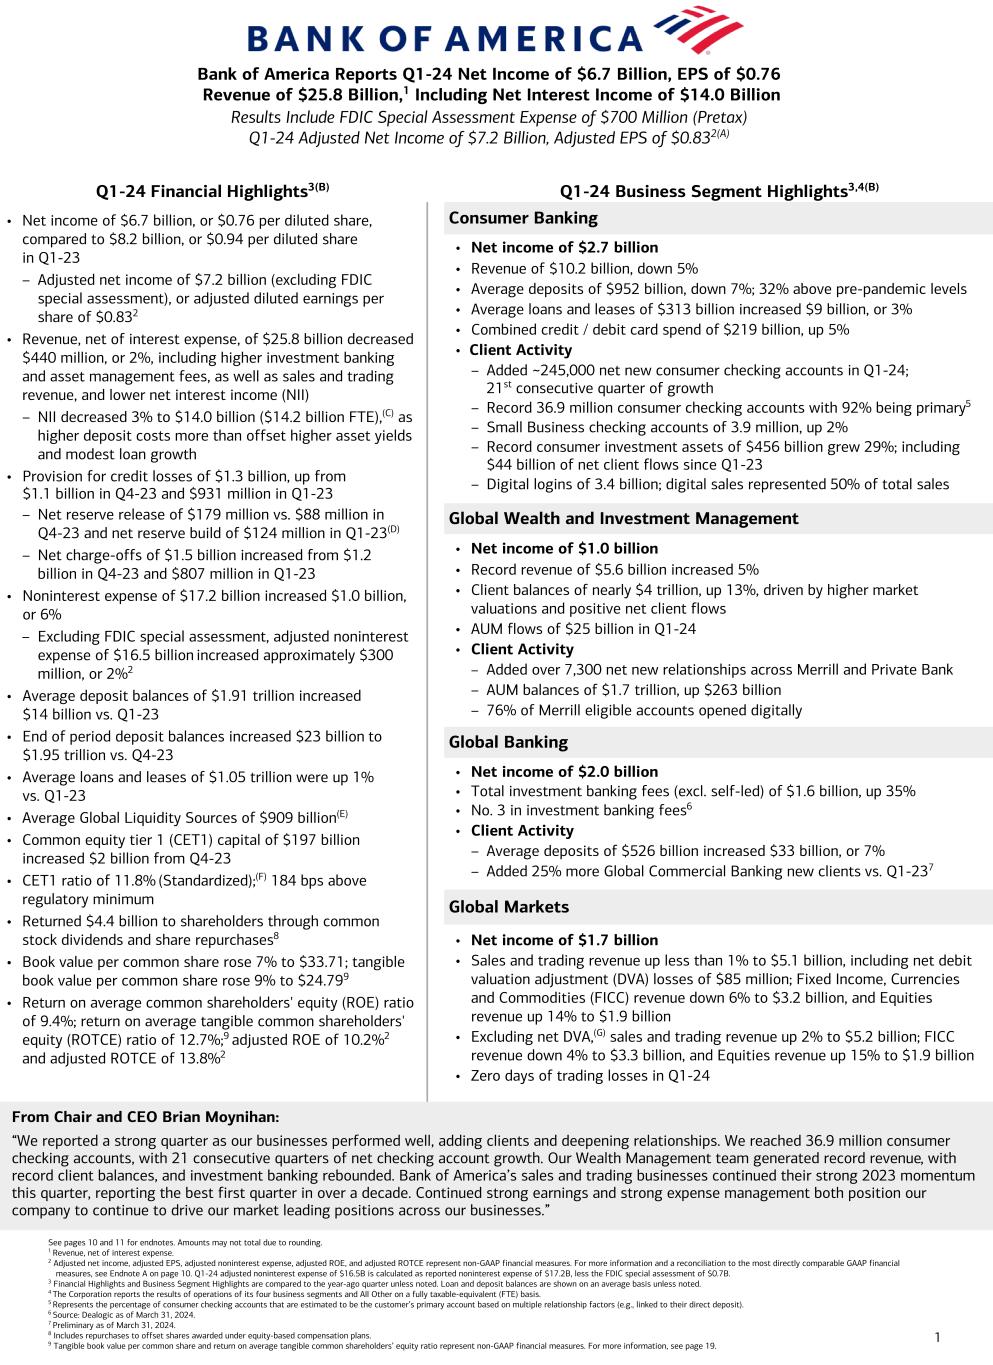
1 Q1-24 Financial Highlights3(B) Q1-24 Business Segment Highlights3,4(B) Consumer Banking Global Wealth and Investment Management Global Banking Global Markets See pages 10 and 11 for endnotes. Amounts may not total due to rounding. 1 Revenue, net of interest expense. 2 Adjusted net income, adjusted EPS, adjusted noninterest expense, adjusted ROE, and adjusted ROTCE represent non-GAAP financial measures. For more information and a reconciliation to the most directly comparable GAAP financial measures, see Endnote A on page 10. Q1-24 adjusted noninterest expense of $16.5B is calculated as reported noninterest expense of $17.2B, less the FDIC special assessment of $0.7B. 3 Financial Highlights and Business Segment Highlights are compared to the year-ago quarter unless noted. Loan and deposit balances are shown on an average basis unless noted. 4 The Corporation reports the results of operations of its four business segments and All Other on a fully taxable-equivalent (FTE) basis. 5 Represents the percentage of consumer checking accounts that are estimated to be the customer’s primary account based on multiple relationship factors (e.g., linked to their direct deposit). 6 Source: Dealogic as of March 31, 2024. 7 Preliminary as of March 31, 2024. 8 Includes repurchases to offset shares awarded under equity-based compensation plans. 9 Tangible book value per common share and return on average tangible common shareholders’ equity ratio represent non-GAAP financial measures. For more information, see page 19. • Net income of $6.7 billion, or $0.76 per diluted share, compared to $8.2 billion, or $0.94 per diluted share in Q1-23 – Adjusted net income of $7.2 billion (excluding FDIC special assessment), or adjusted diluted earnings per share of $0.832 • Revenue, net of interest expense, of $25.8 billion decreased $440 million, or 2%, including higher investment banking and asset management fees, as well as sales and trading revenue, and lower net interest income (NII) – NII decreased 3% to $14.0 billion ($14.2 billion FTE),(C) as higher deposit costs more than offset higher asset yields and modest loan growth • Provision for credit losses of $1.3 billion, up from $1.1 billion in Q4-23 and $931 million in Q1-23 – Net reserve release of $179 million vs. $88 million in Q4-23 and net reserve build of $124 million in Q1-23(D) – Net charge-offs of $1.5 billion increased from $1.2 billion in Q4-23 and $807 million in Q1-23 • Noninterest expense of $17.2 billion increased $1.0 billion, or 6% – Excluding FDIC special assessment, adjusted noninterest expense of $16.5 billion increased approximately $300 million, or 2%2 • Average deposit balances of $1.91 trillion increased $14 billion vs. Q1-23 • End of period deposit balances increased $23 billion to $1.95 trillion vs. Q4-23 • Average loans and leases of $1.05 trillion were up 1% vs. Q1-23 • Average Global Liquidity Sources of $909 billion(E) • Common equity tier 1 (CET1) capital of $197 billion increased $2 billion from Q4-23 • CET1 ratio of 11.8% (Standardized);(F) 184 bps above regulatory minimum • Returned $4.4 billion to shareholders through common stock dividends and share repurchases8 • Book value per common share rose 7% to $33.71; tangible book value per common share rose 9% to $24.799 • Return on average common shareholders' equity (ROE) ratio of 9.4%; return on average tangible common shareholders' equity (ROTCE) ratio of 12.7%;9 adjusted ROE of 10.2%2 and adjusted ROTCE of 13.8%2 • Net income of $1.7 billion • Sales and trading revenue up less than 1% to $5.1 billion, including net debit valuation adjustment (DVA) losses of $85 million; Fixed Income, Currencies and Commodities (FICC) revenue down 6% to $3.2 billion, and Equities revenue up 14% to $1.9 billion • Excluding net DVA,(G) sales and trading revenue up 2% to $5.2 billion; FICC revenue down 4% to $3.3 billion, and Equities revenue up 15% to $1.9 billion • Zero days of trading losses in Q1-24 From Chair and CEO Brian Moynihan: “We reported a strong quarter as our businesses performed well, adding clients and deepening relationships. We reached 36.9 million consumer checking accounts, with 21 consecutive quarters of net checking account growth. Our Wealth Management team generated record revenue, with record client balances, and investment banking rebounded. Bank of America’s sales and trading businesses continued their strong 2023 momentum this quarter, reporting the best first quarter in over a decade. Continued strong earnings and strong expense management both position our company to continue to drive our market leading positions across our businesses.” • Net income of $1.0 billion • Record revenue of $5.6 billion increased 5% • Client balances of nearly $4 trillion, up 13%, driven by higher market valuations and positive net client flows • AUM flows of $25 billion in Q1-24 • Client Activity – Added over 7,300 net new relationships across Merrill and Private Bank – AUM balances of $1.7 trillion, up $263 billion – 76% of Merrill eligible accounts opened digitally • Net income of $2.0 billion • Total investment banking fees (excl. self-led) of $1.6 billion, up 35% • No. 3 in investment banking fees6 • Client Activity – Average deposits of $526 billion increased $33 billion, or 7% – Added 25% more Global Commercial Banking new clients vs. Q1-237 • Net income of $2.7 billion • Revenue of $10.2 billion, down 5% • Average deposits of $952 billion, down 7%; 32% above pre-pandemic levels • Average loans and leases of $313 billion increased $9 billion, or 3% • Combined credit / debit card spend of $219 billion, up 5% • Client Activity – Added ~245,000 net new consumer checking accounts in Q1-24; 21st consecutive quarter of growth – Record 36.9 million consumer checking accounts with 92% being primary5 – Small Business checking accounts of 3.9 million, up 2% – Record consumer investment assets of $456 billion grew 29%; including $44 billion of net client flows since Q1-23 – Digital logins of 3.4 billion; digital sales represented 50% of total sales Bank of America Reports Q1-24 Net Income of $6.7 Billion, EPS of $0.76 Revenue of $25.8 Billion,1 Including Net Interest Income of $14.0 Billion Results Include FDIC Special Assessment Expense of $700 Million (Pretax) Q1-24 Adjusted Net Income of $7.2 Billion, Adjusted EPS of $0.832(A)
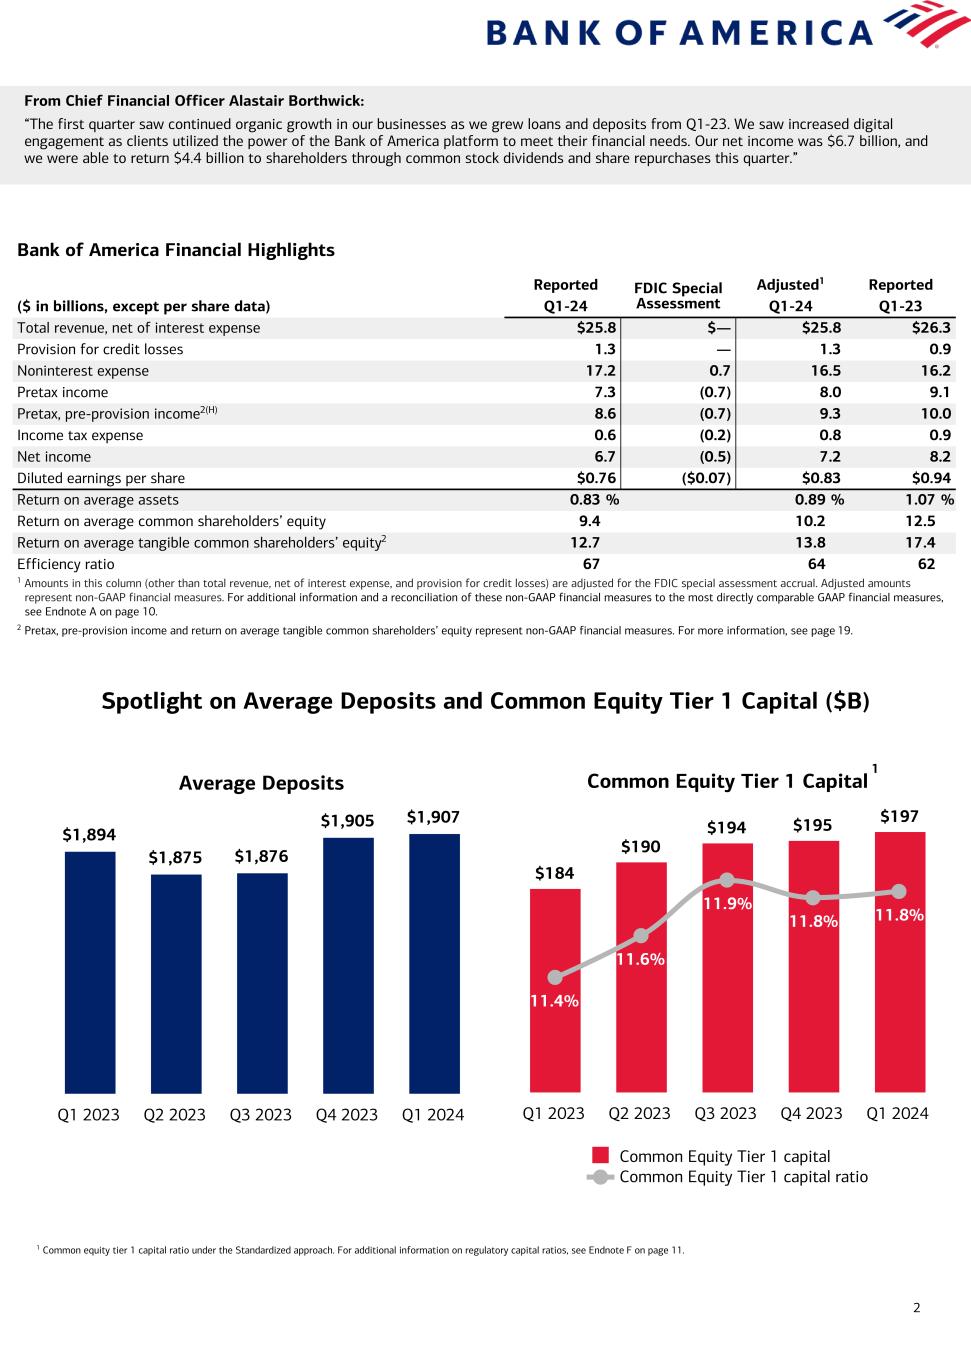
2 Bank of America Financial Highlights Reported FDIC Special Assessment Adjusted1 Reported ($ in billions, except per share data) Q1-24 Q1-24 Q1-23 Total revenue, net of interest expense $25.8 $— $25.8 $26.3 Provision for credit losses 1.3 — 1.3 0.9 Noninterest expense 17.2 0.7 16.5 16.2 Pretax income 7.3 (0.7) 8.0 9.1 Pretax, pre-provision income2(H) 8.6 (0.7) 9.3 10.0 Income tax expense 0.6 (0.2) 0.8 0.9 Net income 6.7 (0.5) 7.2 8.2 Diluted earnings per share $0.76 ($0.07) $0.83 $0.94 Return on average assets 0.83 % 0.89 % 1.07 % Return on average common shareholders’ equity 9.4 10.2 12.5 Return on average tangible common shareholders’ equity2 12.7 13.8 17.4 Efficiency ratio 67 64 62 1 Amounts in this column (other than total revenue, net of interest expense, and provision for credit losses) are adjusted for the FDIC special assessment accrual. Adjusted amounts represent non-GAAP financial measures. For additional information and a reconciliation of these non-GAAP financial measures to the most directly comparable GAAP financial measures, see Endnote A on page 10. 2 Pretax, pre-provision income and return on average tangible common shareholders’ equity represent non-GAAP financial measures. For more information, see page 19. From Chief Financial Officer Alastair Borthwick: “The first quarter saw continued organic growth in our businesses as we grew loans and deposits from Q1-23. We saw increased digital engagement as clients utilized the power of the Bank of America platform to meet their financial needs. Our net income was $6.7 billion, and we were able to return $4.4 billion to shareholders through common stock dividends and share repurchases this quarter.” Common Equity Tier 1 Capital $184 $190 $194 $195 $197 11.4% 11.6% 11.9% 11.8% 11.8% Common Equity Tier 1 capital Common Equity Tier 1 capital ratio Q1 2023 Q2 2023 Q3 2023 Q4 2023 Q1 2024 Average Deposits $1,894 $1,875 $1,876 $1,905 $1,907 Q1 2023 Q2 2023 Q3 2023 Q4 2023 Q1 2024 Spotlight on Average Deposits and Common Equity Tier 1 Capital ($B) 1 1 Common equity tier 1 capital ratio under the Standardized approach. For additional information on regulatory capital ratios, see Endnote F on page 11.
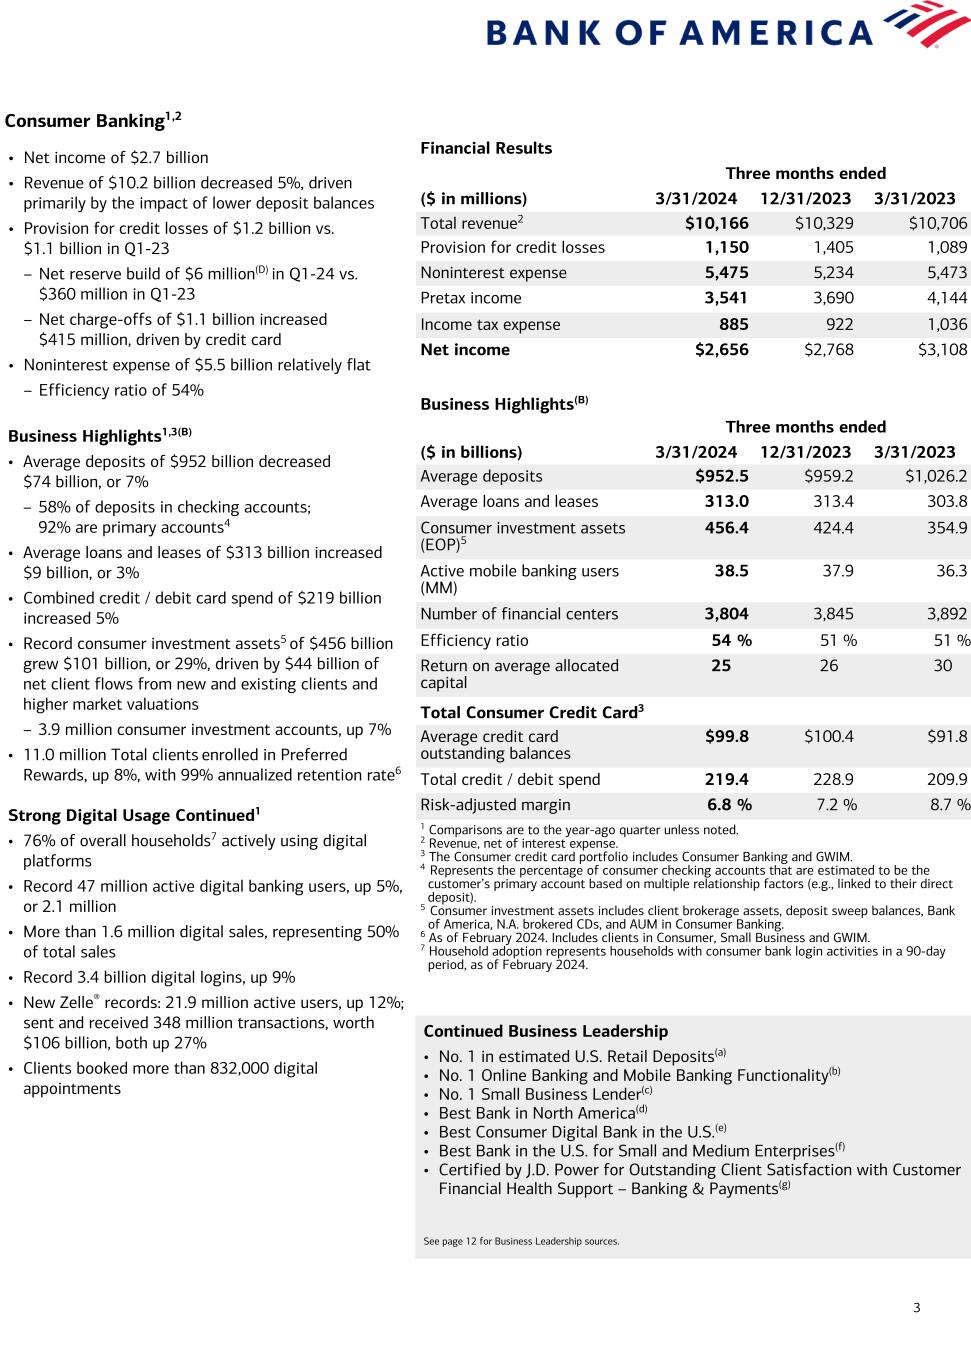
3 Consumer Banking1,2 Financial Results Three months ended ($ in millions) 3/31/2024 12/31/2023 3/31/2023 Total revenue2 $10,166 $10,329 $10,706 Provision for credit losses 1,150 1,405 1,089 Noninterest expense 5,475 5,234 5,473 Pretax income 3,541 3,690 4,144 Income tax expense 885 922 1,036 Net income $2,656 $2,768 $3,108 Business Highlights(B) Three months ended ($ in billions) 3/31/2024 12/31/2023 3/31/2023 Average deposits $952.5 $959.2 $1,026.2 Average loans and leases 313.0 313.4 303.8 Consumer investment assets (EOP)5 456.4 424.4 354.9 Active mobile banking users (MM) 38.5 37.9 36.3 Number of financial centers 3,804 3,845 3,892 Efficiency ratio 54 % 51 % 51 % Return on average allocated capital 25 26 30 Total Consumer Credit Card3 Average credit card outstanding balances $99.8 $100.4 $91.8 Total credit / debit spend 219.4 228.9 209.9 Risk-adjusted margin 6.8 % 7.2 % 8.7 % 1 Comparisons are to the year-ago quarter unless noted. 2 Revenue, net of interest expense. 3 The Consumer credit card portfolio includes Consumer Banking and GWIM. 4 Represents the percentage of consumer checking accounts that are estimated to be the customer’s primary account based on multiple relationship factors (e.g., linked to their direct deposit). 5 Consumer investment assets includes client brokerage assets, deposit sweep balances, Bank of America, N.A. brokered CDs, and AUM in Consumer Banking. 6 As of February 2024. Includes clients in Consumer, Small Business and GWIM. 7 Household adoption represents households with consumer bank login activities in a 90-day period, as of February 2024. • Net income of $2.7 billion • Revenue of $10.2 billion decreased 5%, driven primarily by the impact of lower deposit balances • Provision for credit losses of $1.2 billion vs. $1.1 billion in Q1-23 – Net reserve build of $6 million(D) in Q1-24 vs. $360 million in Q1-23 – Net charge-offs of $1.1 billion increased $415 million, driven by credit card • Noninterest expense of $5.5 billion relatively flat – Efficiency ratio of 54% Business Highlights1,3(B) • Average deposits of $952 billion decreased $74 billion, or 7% – 58% of deposits in checking accounts; 92% are primary accounts4 • Average loans and leases of $313 billion increased $9 billion, or 3% • Combined credit / debit card spend of $219 billion increased 5% • Record consumer investment assets5 of $456 billion grew $101 billion, or 29%, driven by $44 billion of net client flows from new and existing clients and higher market valuations – 3.9 million consumer investment accounts, up 7% • 11.0 million Total clients enrolled in Preferred Rewards, up 8%, with 99% annualized retention rate6 Strong Digital Usage Continued1 • 76% of overall households7 actively using digital platforms • Record 47 million active digital banking users, up 5%, or 2.1 million • More than 1.6 million digital sales, representing 50% of total sales • Record 3.4 billion digital logins, up 9% • New Zelle® records: 21.9 million active users, up 12%; sent and received 348 million transactions, worth $106 billion, both up 27% • Clients booked more than 832,000 digital appointments Continued Business Leadership • No. 1 in estimated U.S. Retail Deposits(a) • No. 1 Online Banking and Mobile Banking Functionality(b) • No. 1 Small Business Lender(c) • Best Bank in North America(d) • Best Consumer Digital Bank in the U.S.(e) • Best Bank in the U.S. for Small and Medium Enterprises(f) • Certified by J.D. Power for Outstanding Client Satisfaction with Customer Financial Health Support – Banking & Payments(g) See page 12 for Business Leadership sources.
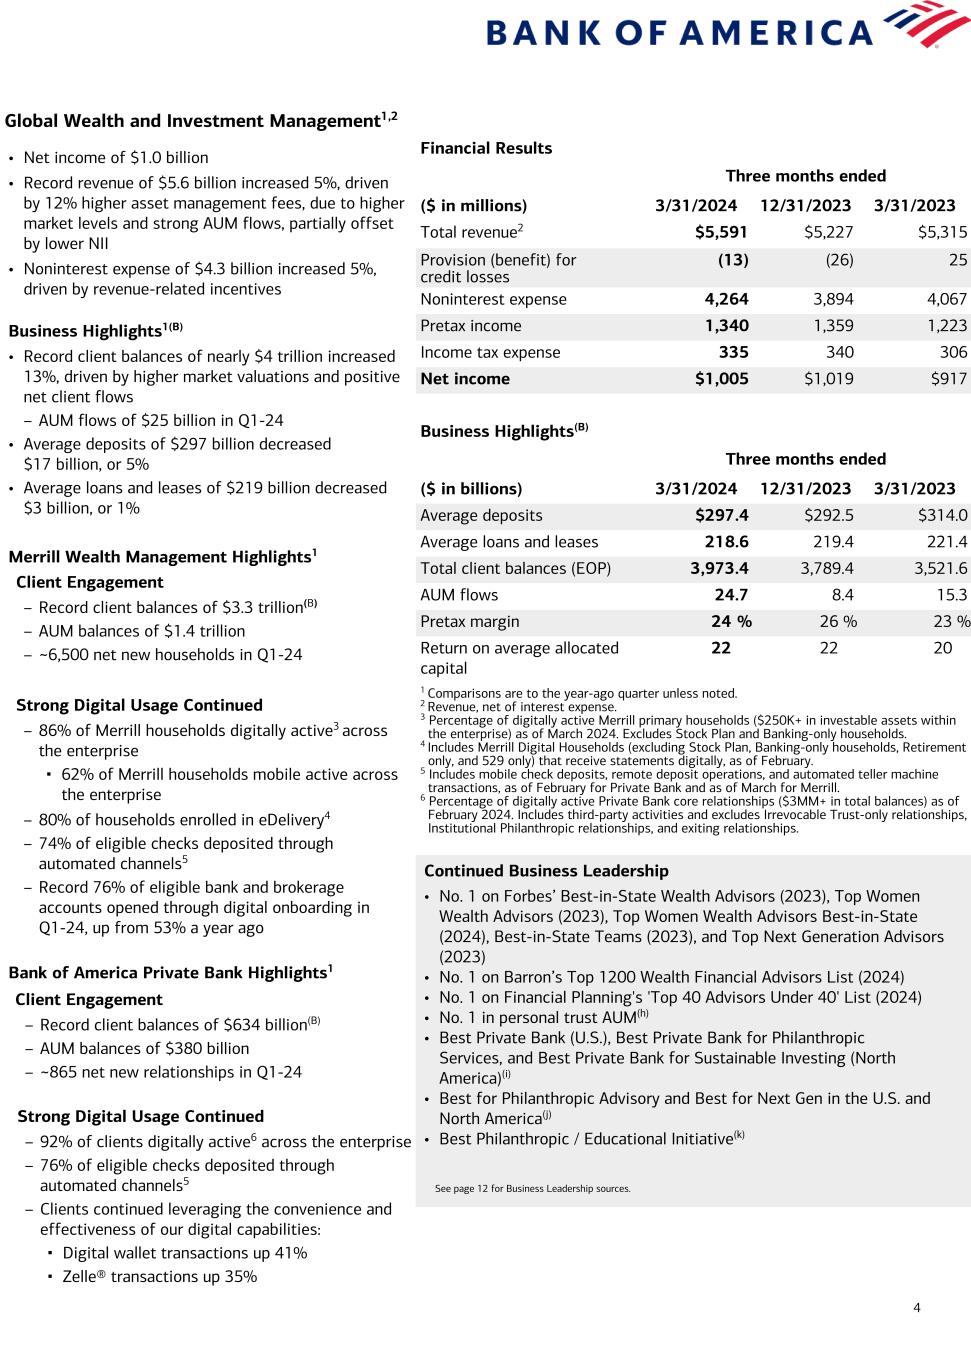
4 Global Wealth and Investment Management1,2 Financial Results Three months ended ($ in millions) 3/31/2024 12/31/2023 3/31/2023 Total revenue2 $5,591 $5,227 $5,315 Provision (benefit) for credit losses (13) (26) 25 Noninterest expense 4,264 3,894 4,067 Pretax income 1,340 1,359 1,223 Income tax expense 335 340 306 Net income $1,005 $1,019 $917 Business Highlights(B) Three months ended ($ in billions) 3/31/2024 12/31/2023 3/31/2023 Average deposits $297.4 $292.5 $314.0 Average loans and leases 218.6 219.4 221.4 Total client balances (EOP) 3,973.4 3,789.4 3,521.6 AUM flows 24.7 8.4 15.3 Pretax margin 24 % 26 % 23 % Return on average allocated capital 22 22 20 1 Comparisons are to the year-ago quarter unless noted. 2 Revenue, net of interest expense. 3 Percentage of digitally active Merrill primary households ($250K+ in investable assets within the enterprise) as of March 2024. Excludes Stock Plan and Banking-only households. 4 Includes Merrill Digital Households (excluding Stock Plan, Banking-only households, Retirement only, and 529 only) that receive statements digitally, as of February. 5 Includes mobile check deposits, remote deposit operations, and automated teller machine transactions, as of February for Private Bank and as of March for Merrill. 6 Percentage of digitally active Private Bank core relationships ($3MM+ in total balances) as of February 2024. Includes third-party activities and excludes Irrevocable Trust-only relationships, Institutional Philanthropic relationships, and exiting relationships. Continued Business Leadership • No. 1 on Forbes’ Best-in-State Wealth Advisors (2023), Top Women Wealth Advisors (2023), Top Women Wealth Advisors Best-in-State (2024), Best-in-State Teams (2023), and Top Next Generation Advisors (2023) • No. 1 on Barron’s Top 1200 Wealth Financial Advisors List (2024) • No. 1 on Financial Planning's 'Top 40 Advisors Under 40' List (2024) • No. 1 in personal trust AUM(h) • Best Private Bank (U.S.), Best Private Bank for Philanthropic Services, and Best Private Bank for Sustainable Investing (North America)(i) • Best for Philanthropic Advisory and Best for Next Gen in the U.S. and North America(j) • Best Philanthropic / Educational Initiative(k) See page 12 for Business Leadership sources. • Net income of $1.0 billion • Record revenue of $5.6 billion increased 5%, driven by 12% higher asset management fees, due to higher market levels and strong AUM flows, partially offset by lower NII • Noninterest expense of $4.3 billion increased 5%, driven by revenue-related incentives Business Highlights1(B) • Record client balances of nearly $4 trillion increased 13%, driven by higher market valuations and positive net client flows – AUM flows of $25 billion in Q1-24 • Average deposits of $297 billion decreased $17 billion, or 5% • Average loans and leases of $219 billion decreased $3 billion, or 1% Merrill Wealth Management Highlights1 Client Engagement – Record client balances of $3.3 trillion(B) – AUM balances of $1.4 trillion – ~6,500 net new households in Q1-24 Strong Digital Usage Continued – 86% of Merrill households digitally active3 across the enterprise ▪ 62% of Merrill households mobile active across the enterprise – 80% of households enrolled in eDelivery4 – 74% of eligible checks deposited through automated channels5 – Record 76% of eligible bank and brokerage accounts opened through digital onboarding in Q1-24, up from 53% a year ago Client Engagement – Record client balances of $634 billion(B) – AUM balances of $380 billion – ~865 net new relationships in Q1-24 Bank of America Private Bank Highlights1 Strong Digital Usage Continued – 92% of clients digitally active6 across the enterprise – 76% of eligible checks deposited through automated channels5 – Clients continued leveraging the convenience and effectiveness of our digital capabilities: ▪ Digital wallet transactions up 41% ▪ Zelle® transactions up 35%
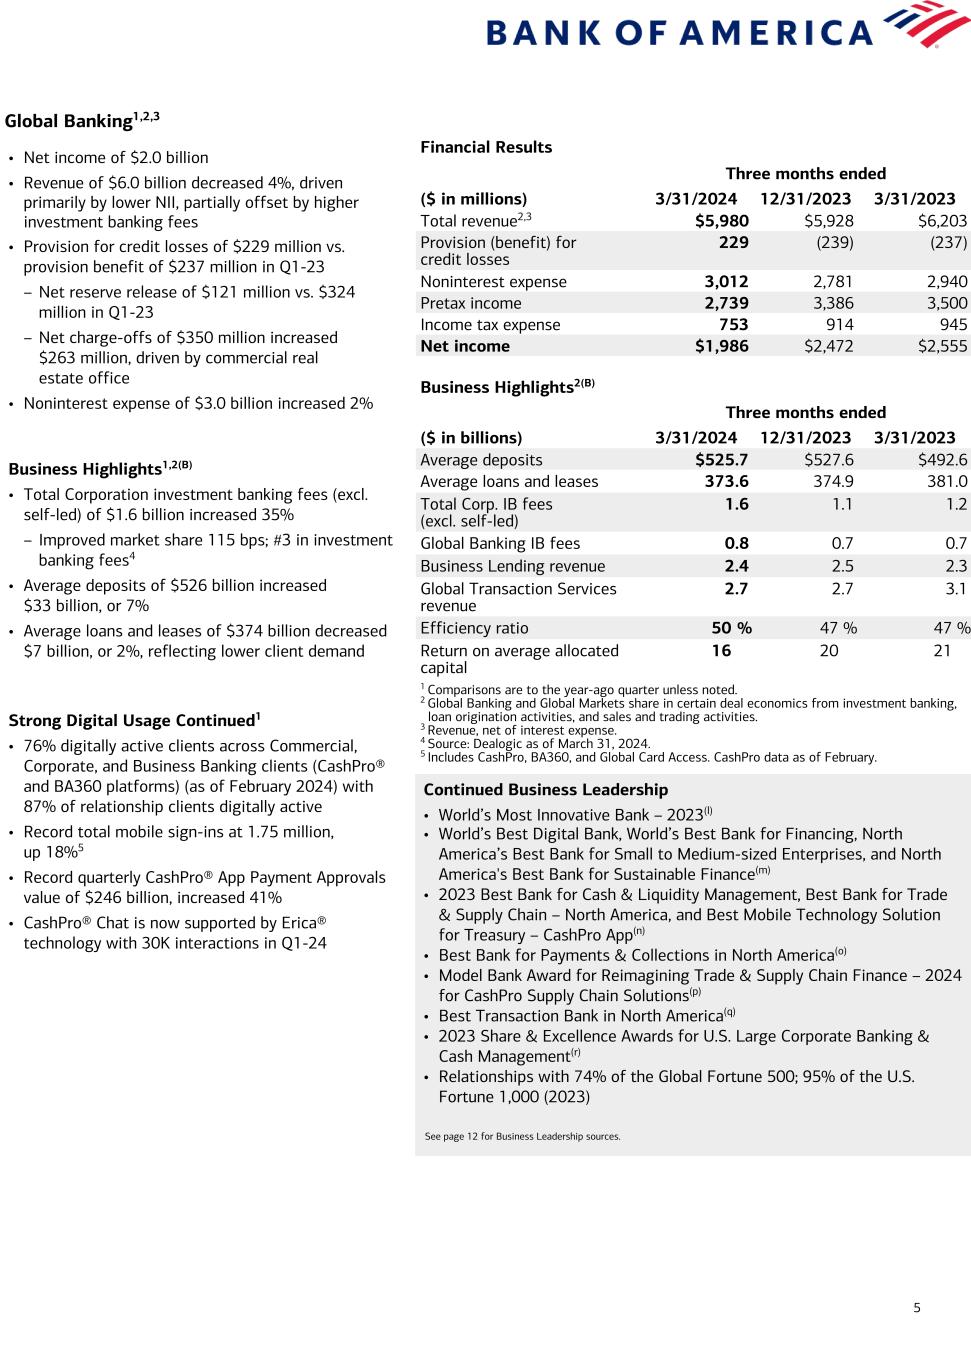
5 Global Banking1,2,3 Financial Results Three months ended ($ in millions) 3/31/2024 12/31/2023 3/31/2023 Total revenue2,3 $5,980 $5,928 $6,203 Provision (benefit) for credit losses 229 (239) (237) Noninterest expense 3,012 2,781 2,940 Pretax income 2,739 3,386 3,500 Income tax expense 753 914 945 Net income $1,986 $2,472 $2,555 Business Highlights2(B) Three months ended ($ in billions) 3/31/2024 12/31/2023 3/31/2023 Average deposits $525.7 $527.6 $492.6 Average loans and leases 373.6 374.9 381.0 Total Corp. IB fees (excl. self-led) 1.6 1.1 1.2 Global Banking IB fees 0.8 0.7 0.7 Business Lending revenue 2.4 2.5 2.3 Global Transaction Services revenue 2.7 2.7 3.1 Efficiency ratio 50 % 47 % 47 % Return on average allocated capital 16 20 21 1 Comparisons are to the year-ago quarter unless noted. 2 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 3 Revenue, net of interest expense. 4 Source: Dealogic as of March 31, 2024. 5 Includes CashPro, BA360, and Global Card Access. CashPro data as of February. • Net income of $2.0 billion • Revenue of $6.0 billion decreased 4%, driven primarily by lower NII, partially offset by higher investment banking fees • Provision for credit losses of $229 million vs. provision benefit of $237 million in Q1-23 – Net reserve release of $121 million vs. $324 million in Q1-23 – Net charge-offs of $350 million increased $263 million, driven by commercial real estate office • Noninterest expense of $3.0 billion increased 2% Continued Business Leadership • World’s Most Innovative Bank – 2023(l) • World’s Best Digital Bank, World’s Best Bank for Financing, North America’s Best Bank for Small to Medium-sized Enterprises, and North America's Best Bank for Sustainable Finance(m) • 2023 Best Bank for Cash & Liquidity Management, Best Bank for Trade & Supply Chain – North America, and Best Mobile Technology Solution for Treasury – CashPro App(n) • Best Bank for Payments & Collections in North America(o) • Model Bank Award for Reimagining Trade & Supply Chain Finance – 2024 for CashPro Supply Chain Solutions(p) • Best Transaction Bank in North America(q) • 2023 Share & Excellence Awards for U.S. Large Corporate Banking & Cash Management(r) • Relationships with 74% of the Global Fortune 500; 95% of the U.S. Fortune 1,000 (2023) See page 12 for Business Leadership sources. Strong Digital Usage Continued1 • 76% digitally active clients across Commercial, Corporate, and Business Banking clients (CashPro® and BA360 platforms) (as of February 2024) with 87% of relationship clients digitally active • Record total mobile sign-ins at 1.75 million, up 18%5 • Record quarterly CashPro® App Payment Approvals value of $246 billion, increased 41% • CashPro® Chat is now supported by Erica® technology with 30K interactions in Q1-24 Business Highlights1,2(B) • Total Corporation investment banking fees (excl. self-led) of $1.6 billion increased 35% – Improved market share 115 bps; #3 in investment banking fees4 • Average deposits of $526 billion increased $33 billion, or 7% • Average loans and leases of $374 billion decreased $7 billion, or 2%, reflecting lower client demand
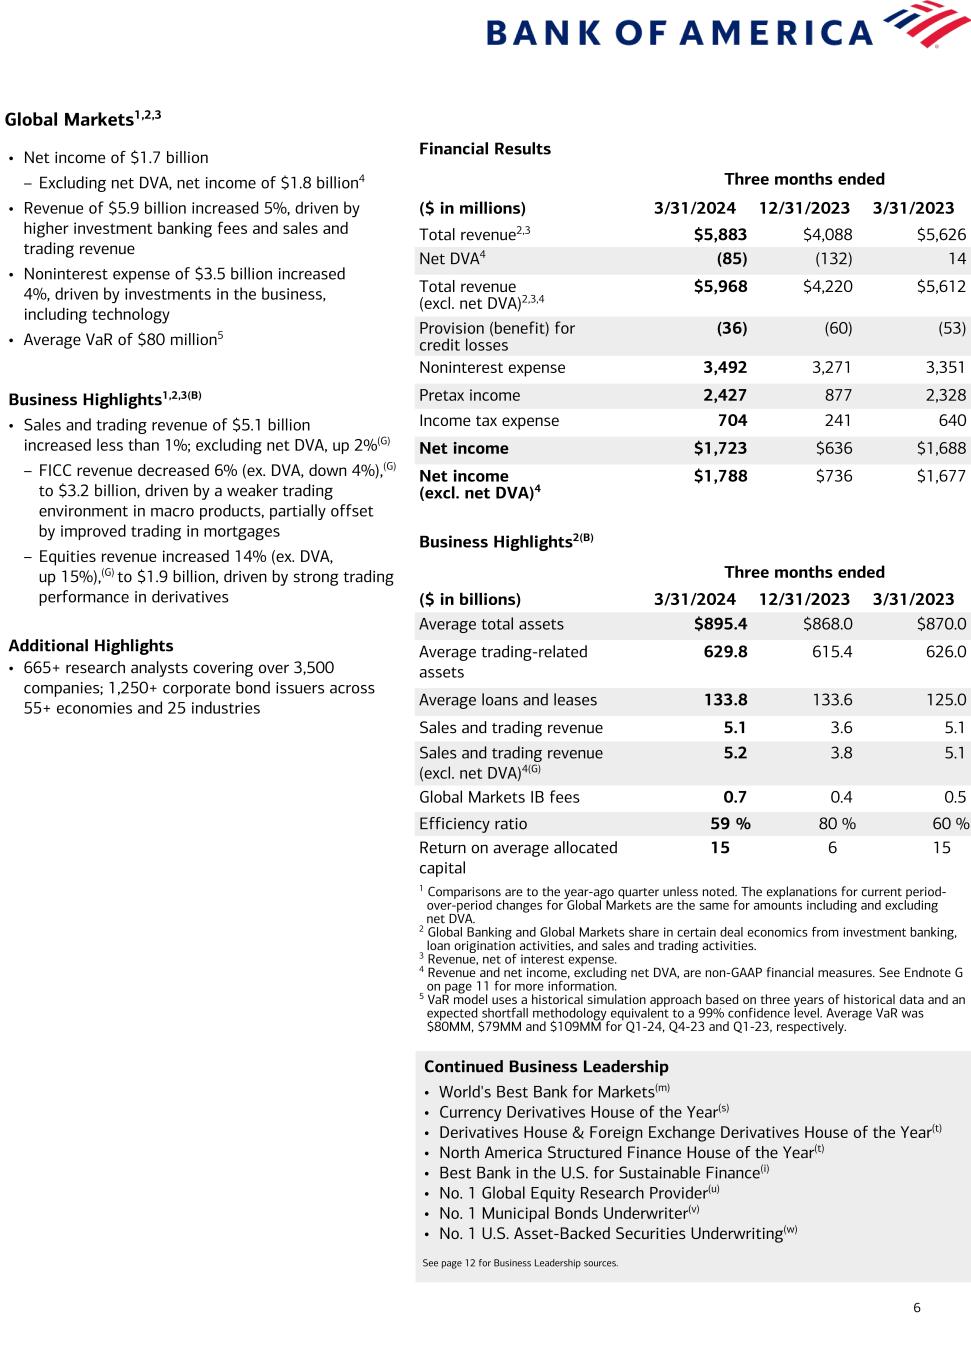
6 Global Markets1,2,3 Financial Results Three months ended ($ in millions) 3/31/2024 12/31/2023 3/31/2023 Total revenue2,3 $5,883 $4,088 $5,626 Net DVA4 (85) (132) 14 Total revenue (excl. net DVA)2,3,4 $5,968 $4,220 $5,612 Provision (benefit) for credit losses (36) (60) (53) Noninterest expense 3,492 3,271 3,351 Pretax income 2,427 877 2,328 Income tax expense 704 241 640 Net income $1,723 $636 $1,688 Net income (excl. net DVA)4 $1,788 $736 $1,677 Business Highlights2(B) Three months ended ($ in billions) 3/31/2024 12/31/2023 3/31/2023 Average total assets $895.4 $868.0 $870.0 Average trading-related assets 629.8 615.4 626.0 Average loans and leases 133.8 133.6 125.0 Sales and trading revenue 5.1 3.6 5.1 Sales and trading revenue (excl. net DVA)4(G) 5.2 3.8 5.1 Global Markets IB fees 0.7 0.4 0.5 Efficiency ratio 59 % 80 % 60 % Return on average allocated capital 15 6 15 1 Comparisons are to the year-ago quarter unless noted. The explanations for current period- over-period changes for Global Markets are the same for amounts including and excluding net DVA. 2 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 3 Revenue, net of interest expense. 4 Revenue and net income, excluding net DVA, are non-GAAP financial measures. See Endnote G on page 11 for more information. 5 VaR model uses a historical simulation approach based on three years of historical data and an expected shortfall methodology equivalent to a 99% confidence level. Average VaR was $80MM, $79MM and $109MM for Q1-24, Q4-23 and Q1-23, respectively. • Net income of $1.7 billion – Excluding net DVA, net income of $1.8 billion4 • Revenue of $5.9 billion increased 5%, driven by higher investment banking fees and sales and trading revenue • Noninterest expense of $3.5 billion increased 4%, driven by investments in the business, including technology • Average VaR of $80 million5 Business Highlights1,2,3(B) • Sales and trading revenue of $5.1 billion increased less than 1%; excluding net DVA, up 2%(G) – FICC revenue decreased 6% (ex. DVA, down 4%),(G) to $3.2 billion, driven by a weaker trading environment in macro products, partially offset by improved trading in mortgages – Equities revenue increased 14% (ex. DVA, up 15%),(G) to $1.9 billion, driven by strong trading performance in derivatives Additional Highlights • 665+ research analysts covering over 3,500 companies; 1,250+ corporate bond issuers across 55+ economies and 25 industries Continued Business Leadership • World's Best Bank for Markets(m) • Currency Derivatives House of the Year(s) • Derivatives House & Foreign Exchange Derivatives House of the Year(t) • North America Structured Finance House of the Year(t) • Best Bank in the U.S. for Sustainable Finance(i) • No. 1 Global Equity Research Provider(u) • No. 1 Municipal Bonds Underwriter(v) • No. 1 U.S. Asset-Backed Securities Underwriting(w) See page 12 for Business Leadership sources.
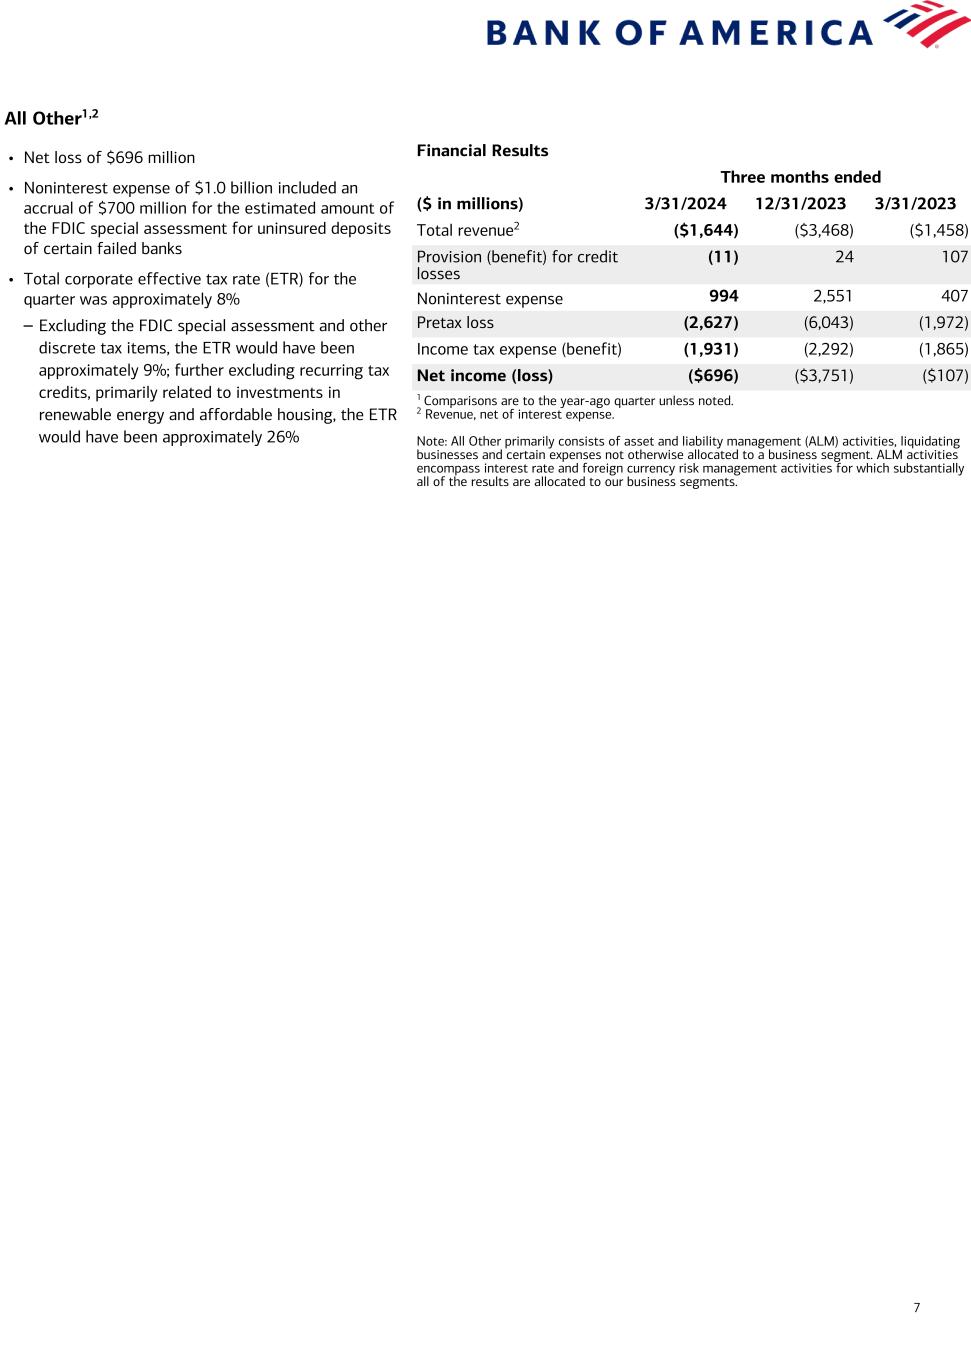
7 All Other1,2 Financial Results Three months ended ($ in millions) 3/31/2024 12/31/2023 3/31/2023 Total revenue2 ($1,644) ($3,468) ($1,458) Provision (benefit) for credit losses (11) 24 107 Noninterest expense 994 2,551 407 Pretax loss (2,627) (6,043) (1,972) Income tax expense (benefit) (1,931) (2,292) (1,865) Net income (loss) ($696) ($3,751) ($107) 1 Comparisons are to the year-ago quarter unless noted. 2 Revenue, net of interest expense. Note: All Other primarily consists of asset and liability management (ALM) activities, liquidating businesses and certain expenses not otherwise allocated to a business segment. ALM activities encompass interest rate and foreign currency risk management activities for which substantially all of the results are allocated to our business segments. • Net loss of $696 million • Noninterest expense of $1.0 billion included an accrual of $700 million for the estimated amount of the FDIC special assessment for uninsured deposits of certain failed banks • Total corporate effective tax rate (ETR) for the quarter was approximately 8% – Excluding the FDIC special assessment and other discrete tax items, the ETR would have been approximately 9%; further excluding recurring tax credits, primarily related to investments in renewable energy and affordable housing, the ETR would have been approximately 26%
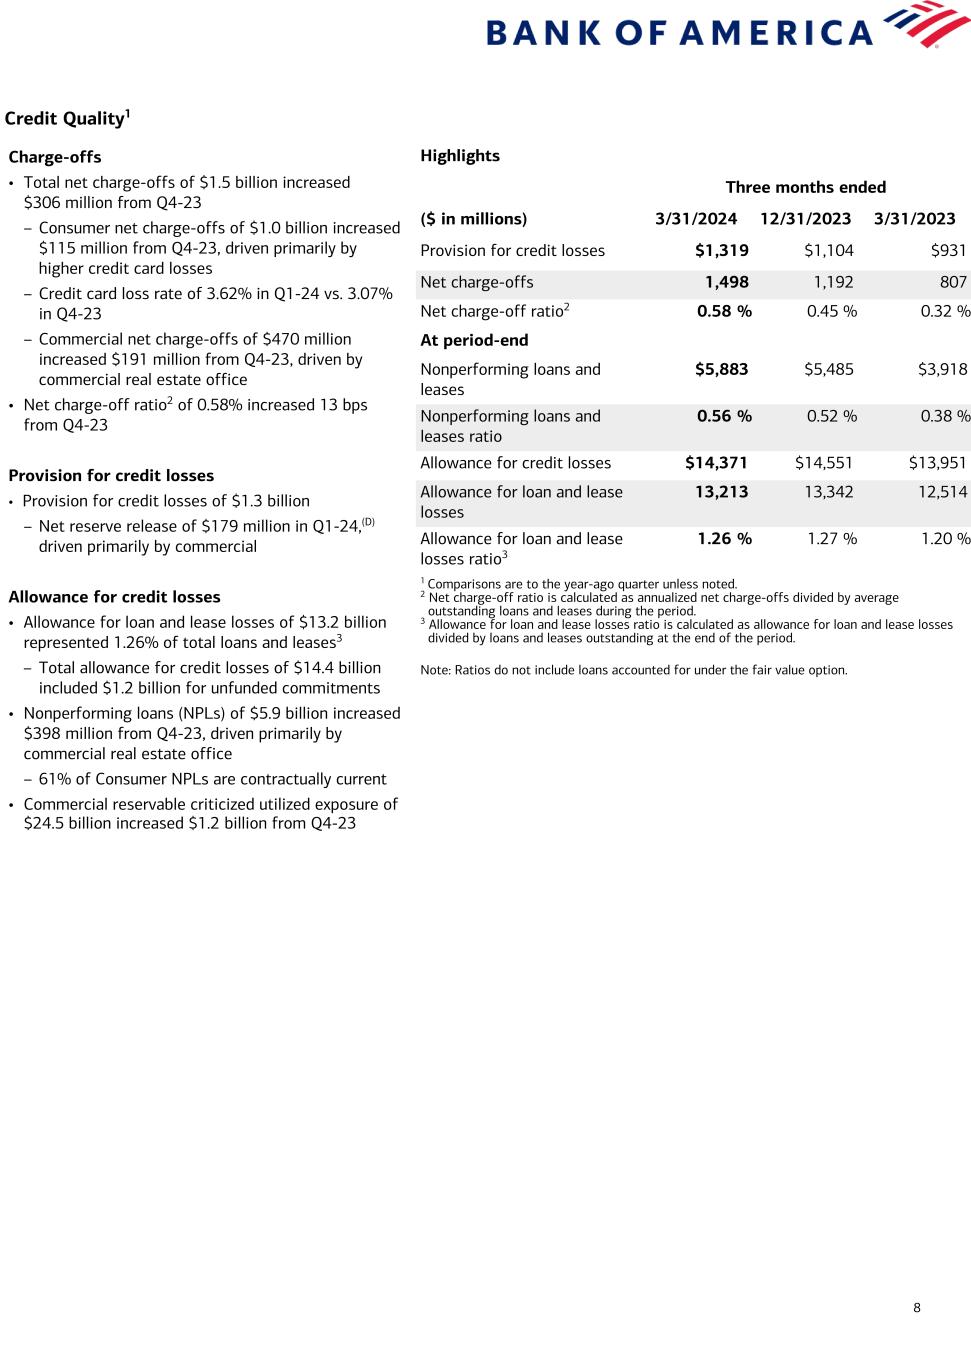
8 Credit Quality1 Highlights Three months ended ($ in millions) 3/31/2024 12/31/2023 3/31/2023 Provision for credit losses $1,319 $1,104 $931 Net charge-offs 1,498 1,192 807 Net charge-off ratio2 0.58 % 0.45 % 0.32 % At period-end Nonperforming loans and leases $5,883 $5,485 $3,918 Nonperforming loans and leases ratio 0.56 % 0.52 % 0.38 % Allowance for credit losses $14,371 $14,551 $13,951 Allowance for loan and lease losses 13,213 13,342 12,514 Allowance for loan and lease losses ratio3 1.26 % 1.27 % 1.20 % 1 Comparisons are to the year-ago quarter unless noted. 2 Net charge-off ratio is calculated as annualized net charge-offs divided by average outstanding loans and leases during the period. 3 Allowance for loan and lease losses ratio is calculated as allowance for loan and lease losses divided by loans and leases outstanding at the end of the period. Note: Ratios do not include loans accounted for under the fair value option. Charge-offs • Total net charge-offs of $1.5 billion increased $306 million from Q4-23 – Consumer net charge-offs of $1.0 billion increased $115 million from Q4-23, driven primarily by higher credit card losses – Credit card loss rate of 3.62% in Q1-24 vs. 3.07% in Q4-23 – Commercial net charge-offs of $470 million increased $191 million from Q4-23, driven by commercial real estate office • Net charge-off ratio2 of 0.58% increased 13 bps from Q4-23 Provision for credit losses • Provision for credit losses of $1.3 billion – Net reserve release of $179 million in Q1-24,(D) driven primarily by commercial Allowance for credit losses • Allowance for loan and lease losses of $13.2 billion represented 1.26% of total loans and leases3 – Total allowance for credit losses of $14.4 billion included $1.2 billion for unfunded commitments • Nonperforming loans (NPLs) of $5.9 billion increased $398 million from Q4-23, driven primarily by commercial real estate office – 61% of Consumer NPLs are contractually current • Commercial reservable criticized utilized exposure of $24.5 billion increased $1.2 billion from Q4-23
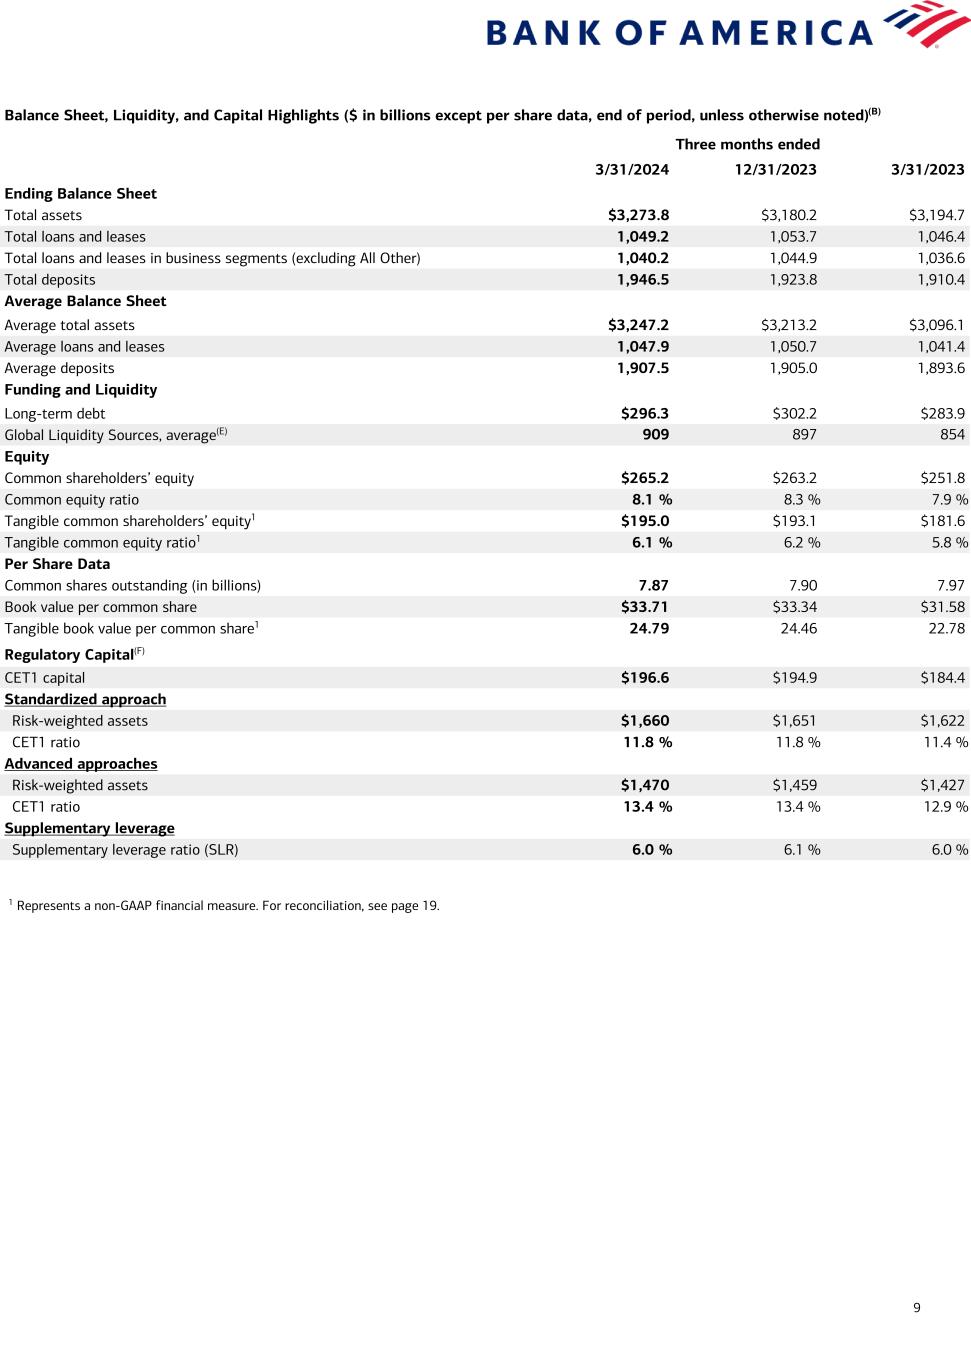
9 Balance Sheet, Liquidity, and Capital Highlights ($ in billions except per share data, end of period, unless otherwise noted)(B) Three months ended 3/31/2024 12/31/2023 3/31/2023 Ending Balance Sheet Total assets $3,273.8 $3,180.2 $3,194.7 Total loans and leases 1,049.2 1,053.7 1,046.4 Total loans and leases in business segments (excluding All Other) 1,040.2 1,044.9 1,036.6 Total deposits 1,946.5 1,923.8 1,910.4 Average Balance Sheet Average total assets $3,247.2 $3,213.2 $3,096.1 Average loans and leases 1,047.9 1,050.7 1,041.4 Average deposits 1,907.5 1,905.0 1,893.6 Funding and Liquidity Long-term debt $296.3 $302.2 $283.9 Global Liquidity Sources, average(E) 909 897 854 Equity Common shareholders’ equity $265.2 $263.2 $251.8 Common equity ratio 8.1 % 8.3 % 7.9 % Tangible common shareholders’ equity1 $195.0 $193.1 $181.6 Tangible common equity ratio1 6.1 % 6.2 % 5.8 % Per Share Data Common shares outstanding (in billions) 7.87 7.90 7.97 Book value per common share $33.71 $33.34 $31.58 Tangible book value per common share1 24.79 24.46 22.78 Regulatory Capital(F) CET1 capital $196.6 $194.9 $184.4 Standardized approach Risk-weighted assets $1,660 $1,651 $1,622 CET1 ratio 11.8 % 11.8 % 11.4 % Advanced approaches Risk-weighted assets $1,470 $1,459 $1,427 CET1 ratio 13.4 % 13.4 % 12.9 % Supplementary leverage Supplementary leverage ratio (SLR) 6.0 % 6.1 % 6.0 % 1 Represents a non-GAAP financial measure. For reconciliation, see page 19.
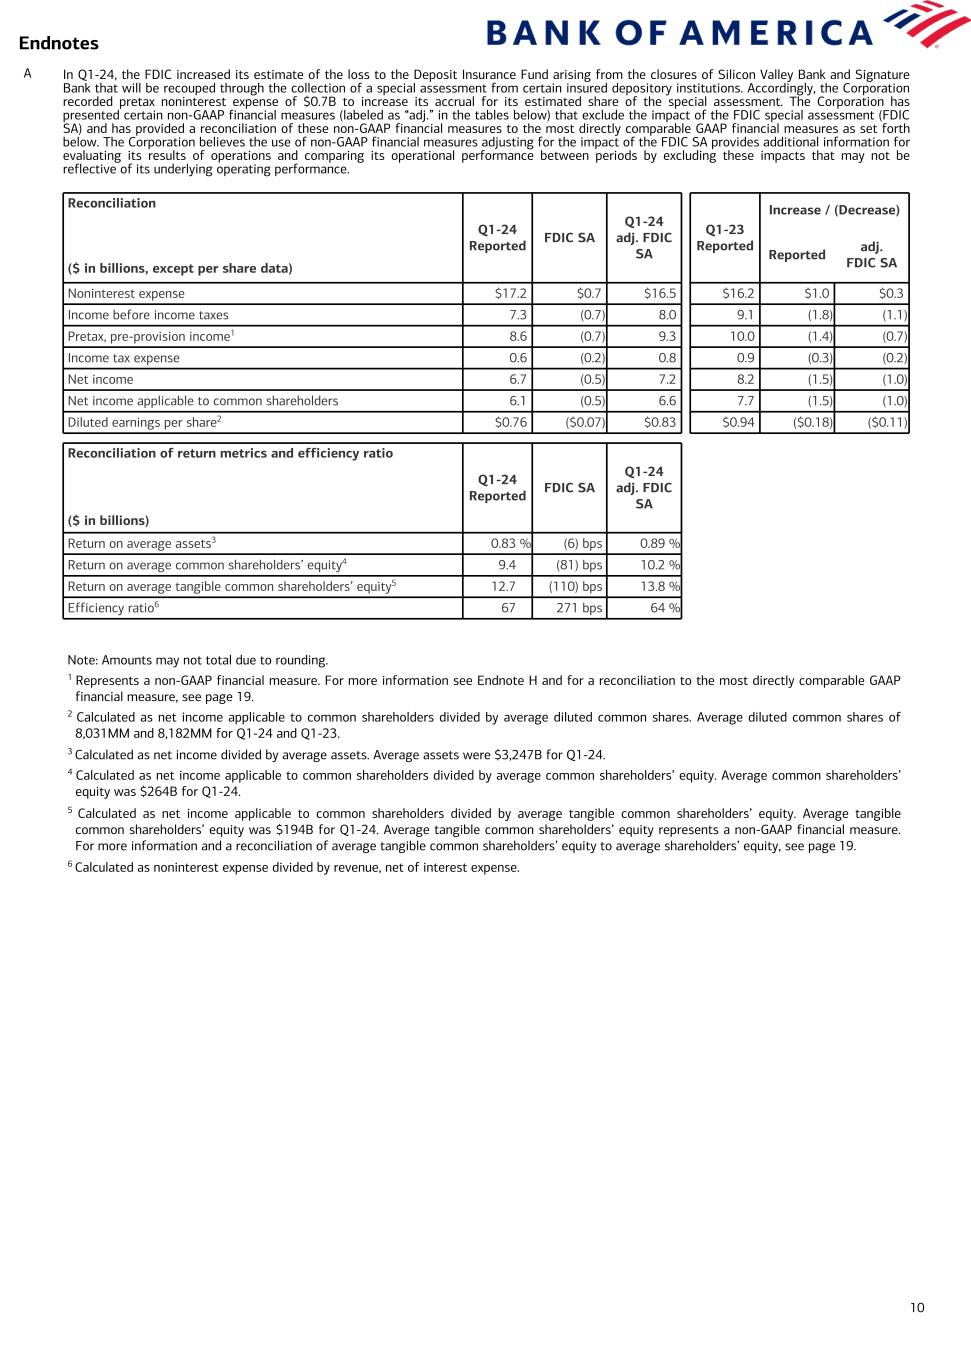
10 Endnotes A In Q1-24, the FDIC increased its estimate of the loss to the Deposit Insurance Fund arising from the closures of Silicon Valley Bank and Signature Bank that will be recouped through the collection of a special assessment from certain insured depository institutions. Accordingly, the Corporation recorded pretax noninterest expense of $0.7B to increase its accrual for its estimated share of the special assessment. The Corporation has presented certain non-GAAP financial measures (labeled as “adj.” in the tables below) that exclude the impact of the FDIC special assessment (FDIC SA) and has provided a reconciliation of these non-GAAP financial measures to the most directly comparable GAAP financial measures as set forth below. The Corporation believes the use of non-GAAP financial measures adjusting for the impact of the FDIC SA provides additional information for evaluating its results of operations and comparing its operational performance between periods by excluding these impacts that may not be reflective of its underlying operating performance. Note: Amounts may not total due to rounding. 1 Represents a non-GAAP financial measure. For more information see Endnote H and for a reconciliation to the most directly comparable GAAP financial measure, see page 19. 2 Calculated as net income applicable to common shareholders divided by average diluted common shares. Average diluted common shares of 8,031MM and 8,182MM for Q1-24 and Q1-23. 3 Calculated as net income divided by average assets. Average assets were $3,247B for Q1-24. 4 Calculated as net income applicable to common shareholders divided by average common shareholders’ equity. Average common shareholders’ equity was $264B for Q1-24. 5 Calculated as net income applicable to common shareholders divided by average tangible common shareholders’ equity. Average tangible common shareholders’ equity was $194B for Q1-24. Average tangible common shareholders’ equity represents a non-GAAP financial measure. For more information and a reconciliation of average tangible common shareholders’ equity to average shareholders’ equity, see page 19. 6 Calculated as noninterest expense divided by revenue, net of interest expense. Reconciliation Q1-24 Reported FDIC SA Q1-24 adj. FDIC SA Q1-23 Reported Increase / (Decrease) ($ in billions, except per share data) Reported adj. FDIC SA Noninterest expense $17.2 $0.7 $16.5 $16.2 $1.0 $0.3 Income before income taxes 7.3 (0.7) 8.0 9.1 (1.8) (1.1) Pretax, pre-provision income1 8.6 (0.7) 9.3 10.0 (1.4) (0.7) Income tax expense 0.6 (0.2) 0.8 0.9 (0.3) (0.2) Net income 6.7 (0.5) 7.2 8.2 (1.5) (1.0) Net income applicable to common shareholders 6.1 (0.5) 6.6 7.7 (1.5) (1.0) Diluted earnings per share2 $0.76 ($0.07) $0.83 $0.94 ($0.18) ($0.11) Reconciliation of return metrics and efficiency ratio ($ in billions) Q1-24 Reported FDIC SA Q1-24 adj. FDIC SA Return on average assets3 0.83 % (6) bps 0.89 % Return on average common shareholders’ equity4 9.4 (81) bps 10.2 % Return on average tangible common shareholders’ equity5 12.7 (110) bps 13.8 % Efficiency ratio6 67 271 bps 64 %

11 Endnotes Three months ended (Dollars in millions) 3/31/2024 12/31/2023 3/31/2023 Sales and trading revenue Fixed-income, currencies and commodities $ 3,231 $ 2,079 $ 3,440 Equities 1,861 1,540 1,627 Total sales and trading revenue $ 5,092 $ 3,619 $ 5,067 Sales and trading revenue, excluding net debit valuation adjustment1 Fixed-income, currencies and commodities $ 3,307 $ 2,206 $ 3,429 Equities 1,870 1,545 1,624 Total sales and trading revenue, excluding net debit valuation adjustment $ 5,177 $ 3,751 $ 5,053 B We present certain key financial and nonfinancial performance indicators (KPIs) that management uses when assessing consolidated and/or segment results. We believe this information is useful because it provides management and investors with information about underlying operational performance and trends. KPIs are presented in Consolidated and Business Segment Highlights on page 1, Balance Sheet, Liquidity, and Capital Highlights on page 9 and on the Segment pages for each segment. C We also measure NII on an FTE basis, which is a non-GAAP financial measure. FTE basis is a performance measure used in operating the business that management believes provides investors with meaningful information on the interest margin for comparative purposes. We believe that this presentation allows for comparison of amounts from both taxable and tax-exempt sources and is consistent with industry practice. NII on an FTE basis was $14.2 billion, $14.1 billion and $14.6 billion for the three months ended March 31, 2024, December 31, 2023 and March 31, 2023, respectively. The FTE adjustment was $158 million, $145 million and $134 million for the three months ended March 31, 2024, December 31, 2023 and March 31, 2023, respectively. D Reserve Build (or Release) is calculated by subtracting net charge-offs for the period from the provision for credit losses recognized in that period. The period-end allowance, or reserve, for credit losses reflects the beginning of the period allowance adjusted for net charge-offs recorded in that period plus the provision for credit losses and other valuation accounts recognized in that period. E Global Liquidity Sources (GLS) include cash and high-quality, liquid, unencumbered securities, inclusive of U.S. government securities, U.S. agency securities, U.S. agency mortgage-backed securities, and a select group of non-U.S. government and supranational securities, and other investment-grade securities, and are readily available to meet funding requirements as they arise. It does not include Federal Reserve Discount Window or Federal Home Loan Bank borrowing capacity. Transfers of liquidity among legal entities may be subject to certain regulatory and other restrictions. F Regulatory capital ratios at March 31, 2024 are preliminary. The Corporation reports regulatory capital ratios under both the Standardized and Advanced approaches. Capital adequacy is evaluated against the lower of the Standardized or Advanced approaches compared to their respective regulatory capital ratio requirements. The Corporation’s binding ratio was Total capital ratio under the Standardized approach for March 31, 2024 and December 31, 2023; and the Common equity tier 1 ratio under the Standardized approach for March 31, 2023. G The below table includes Global Markets sales and trading revenue, excluding net DVA, which is a non-GAAP financial measure. We believe that the presentation of measures that exclude this item is useful because such measures provide additional information to assess the underlying operational performance and trends of our businesses and to allow better comparison of period-to-period operating performance. 1 For the three months ended March 31, 2024, December 31, 2023 and March 31, 2023, net DVA gains (losses) were ($85) million, ($132) million and $14 million, FICC net DVA gains (losses) were ($76) million, ($127) million and $11 million, and Equities net DVA gains (losses) were ($9) million, ($5) million and $3 million, respectively. H Pretax, pre-provision income (PTPI) is a non-GAAP financial measure calculated by adjusting consolidated pretax income to add back provision for credit losses. Management believes that PTPI is a useful financial measure as it enables an assessment of the Company’s ability to generate earnings to cover credit losses through a credit cycle and provides an additional basis for comparing the Company's results of operations between periods by isolating the impact of provision for credit losses, which can vary significantly between periods. For Reconciliations to GAAP Financial Measures, see page 19.
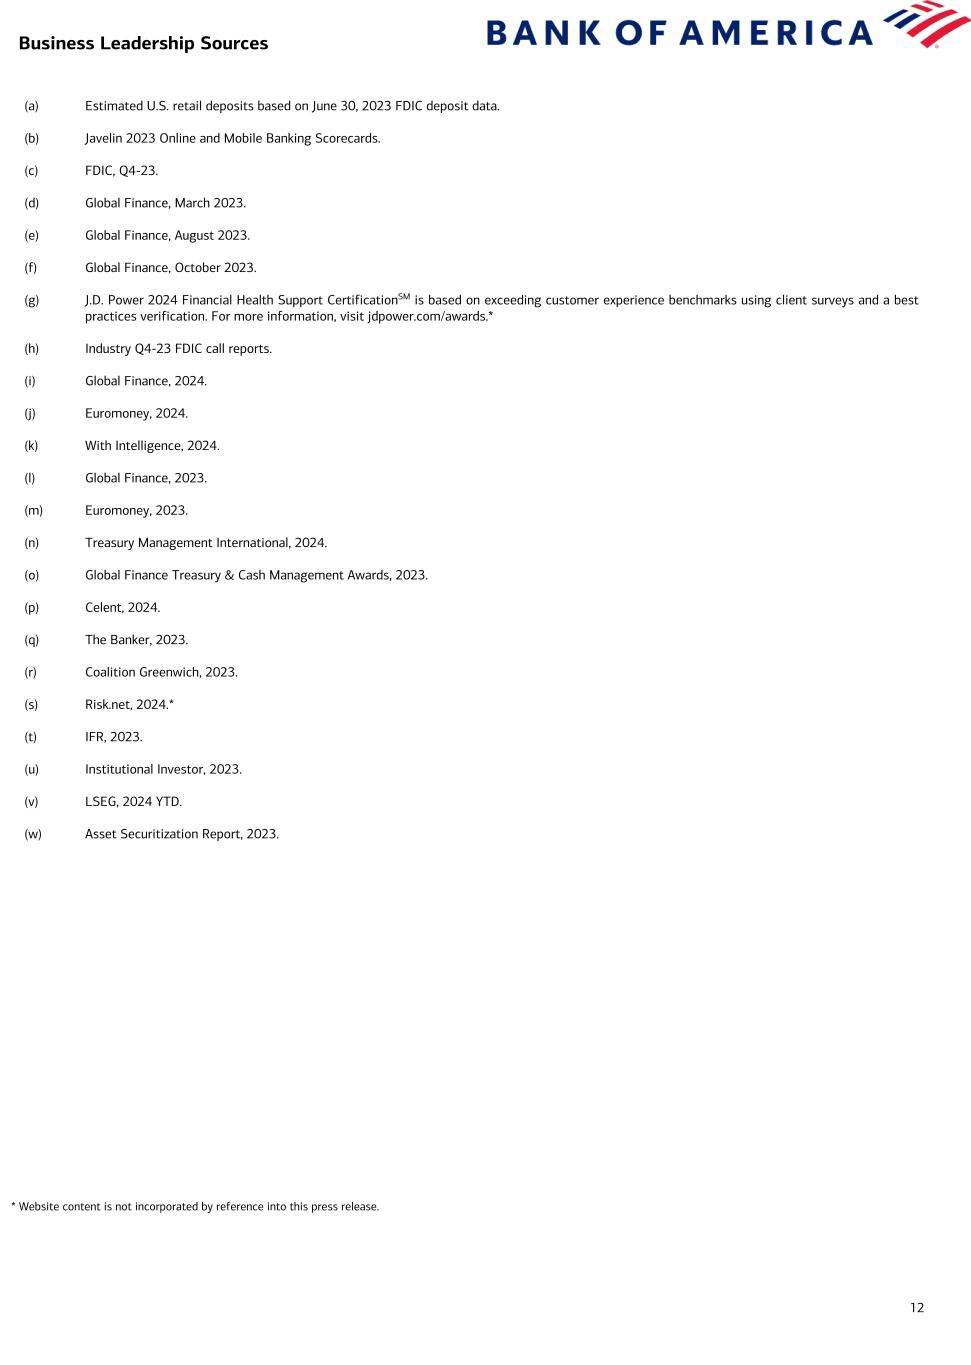
12 (a) Estimated U.S. retail deposits based on June 30, 2023 FDIC deposit data. (b) Javelin 2023 Online and Mobile Banking Scorecards. (c) FDIC, Q4-23. (d) Global Finance, March 2023. (e) Global Finance, August 2023. (f) Global Finance, October 2023. (g) J.D. Power 2024 Financial Health Support CertificationSM is based on exceeding customer experience benchmarks using client surveys and a best practices verification. For more information, visit jdpower.com/awards.* (h) Industry Q4-23 FDIC call reports. (i) Global Finance, 2024. (j) Euromoney, 2024. (k) With Intelligence, 2024. (l) Global Finance, 2023. (m) Euromoney, 2023. (n) Treasury Management International, 2024. (o) Global Finance Treasury & Cash Management Awards, 2023. (p) Celent, 2024. (q) The Banker, 2023. (r) Coalition Greenwich, 2023. (s) Risk.net, 2024.* (t) IFR, 2023. (u) Institutional Investor, 2023. (v) LSEG, 2024 YTD. (w) Asset Securitization Report, 2023. Business Leadership Sources * Website content is not incorporated by reference into this press release.

13 Contact Information and Investor Conference Call Invitation Investor Call Information Chief Executive Officer Brian Moynihan and Chief Financial Officer Alastair Borthwick will discuss first-quarter 2024 financial results in a conference call at 8:30 a.m. ET today. The presentation and supporting materials can be accessed on the Bank of America Investor Relations website at https://investor.bankofamerica.com.* For a listen-only connection to the conference call, dial 1.877.200.4456 (U.S.) or 1.785.424.1732 (international). The conference ID is 79795. Please dial in 10 minutes prior to the start of the call. Investors can access replays of the conference call by visiting the Investor Relations website or by calling 1.800.934.4850 (U.S.) or 1.402.220.1178 (international) from noon April 16 through 11:59 p.m. ET on April 26. Investors May Contact: Lee McEntire, Bank of America Phone: 1.980.388.6780 [email protected] Jonathan G. Blum, Bank of America (Fixed Income) Phone: 1.212.449.3112 [email protected] Bank of America Bank of America is one of the world’s leading financial institutions, serving individual consumers, small and middle-market businesses and large corporations with a full range of banking, investing, asset management and other financial and risk management products and services. The company provides unmatched convenience in the United States, serving approximately 69 million consumer and small business clients with approximately 3,800 retail financial centers, approximately 15,000 ATMs (automated teller machines) and award-winning digital banking with approximately 57 million verified digital users. Bank of America is a global leader in wealth management, corporate and investment banking and trading across a broad range of asset classes, serving corporations, governments, institutions and individuals around the world. Bank of America offers industry-leading support to approximately 4 million small business households through a suite of innovative, easy-to-use online products and services. The company serves clients through operations across the United States, its territories and more than 35 countries. Bank of America Corporation stock (NYSE: BAC) is listed on the New York Stock Exchange. Forward-Looking Statements Bank of America Corporation (the Corporation) and its management may make certain statements that constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These statements can be identified by the fact that they do not relate strictly to historical or current facts. Forward-looking statements often use words such as “anticipates,” “targets,” “expects,” “hopes,” “estimates,” “intends,” “plans,” “goals,” “believes,” “continue” and other similar expressions or future or conditional verbs such as “will,” “may,” “might,” “should,” “would” and “could.” Forward-looking statements represent the Corporation’s current expectations, plans or forecasts of its future results, revenues, liquidity, net interest income, provision for credit losses, expenses, efficiency ratio, capital measures, strategy, deposits, assets, and future business and economic conditions more generally, and other future matters. These statements are not guarantees of future results or performance and involve certain known and unknown risks, uncertainties and assumptions that are difficult to predict and are often beyond the Corporation’s control. Actual outcomes and results may differ materially from those expressed in, or implied by, any of these forward-looking statements. * Website content is not incorporated by reference into this press release. Reporters May Contact: Bill Halldin, Bank of America Phone: 1.916.724.0093 [email protected]
14 You should not place undue reliance on any forward-looking statement and should consider the following uncertainties and risks, as well as the risks and uncertainties more fully discussed under Item 1A. Risk Factors of the Corporation’s 2023 Annual Report on Form 10-K and in any of the Corporation’s subsequent Securities and Exchange Commission filings: the Corporation’s potential judgments, orders, settlements, penalties, fines and reputational damage resulting from pending or future litigation and regulatory investigations, proceedings and enforcement actions, including as a result of our participation in and execution of government programs related to the Coronavirus Disease 2019 (COVID-19) pandemic, such as the processing of unemployment benefits for California and certain other states; the possibility that the Corporation's future liabilities may be in excess of its recorded liability and estimated range of possible loss for litigation, and regulatory and government actions; the possibility that the Corporation could face increased claims from one or more parties involved in mortgage securitizations; the Corporation’s ability to resolve representations and warranties repurchase and related claims; the risks related to the discontinuation of reference rates, including increased expenses and litigation and the effectiveness of hedging strategies; uncertainties about the financial stability and growth rates of non-U.S. jurisdictions, the risk that those jurisdictions may face difficulties servicing their sovereign debt, and related stresses on financial markets, currencies and trade, and the Corporation’s exposures to such risks, including direct, indirect and operational; the impact of U.S. and global interest rates, inflation, currency exchange rates, economic conditions, trade policies and tensions, including tariffs, and potential geopolitical instability; the impact of the interest rate, inflationary, macroeconomic, banking and regulatory environment on the Corporation’s assets, business, financial condition and results of operations; the impact of adverse developments affecting the U.S. or global banking industry, including bank failures and liquidity concerns, resulting in worsening economic and market volatility, and regulatory responses thereto; the possibility that future credit losses may be higher than currently expected due to changes in economic assumptions, customer behavior, adverse developments with respect to U.S. or global economic conditions and other uncertainties, including the impact of supply chain disruptions, inflationary pressures and labor shortages on economic conditions and our business; potential losses related to the Corporation’s concentration of credit risk; the Corporation's ability to achieve its expense targets and expectations regarding revenue, net interest income, provision for credit losses, net charge-offs, effective tax rate, loan growth or other projections; adverse changes to the Corporation’s credit ratings from the major credit rating agencies; an inability to access capital markets or maintain deposits or borrowing costs; estimates of the fair value and other accounting values, subject to impairment assessments, of certain of the Corporation’s assets and liabilities; the estimated or actual impact of changes in accounting standards or assumptions in applying those standards; uncertainty regarding the content, timing and impact of regulatory capital and liquidity requirements; the impact of adverse changes to total loss-absorbing capacity requirements, stress capital buffer requirements and / or global systemically important bank surcharges; the potential impact of actions of the Board of Governors of the Federal Reserve System on the Corporation’s capital plans; the effect of changes in or interpretations of income tax laws and regulations; the impact of implementation and compliance with U.S. and international laws, regulations and regulatory interpretations, including, but not limited to, recovery and resolution planning requirements, Federal Deposit Insurance Corporation assessments, the Volcker Rule, fiduciary standards, derivatives regulations and potential changes to loss allocations between financial institutions and customers, including for losses incurred from the use of our products and services, including electronic payments and payment of checks, that were authorized by the customer but induced by fraud; the impact of failures or disruptions in or breaches of the Corporation’s operations or information systems, or those of third parties, including as a result of cybersecurity incidents; the risks related to the development, implementation, use and management of emerging technologies, including artificial intelligence and machine learning; the risks related to the transition and physical impacts of climate change; our ability to achieve environmental, social and governance goals and commitments or the impact of any changes in the Corporation's sustainability strategy or commitments generally; the impact of any future federal government shutdown and uncertainty regarding the federal government’s debt limit or changes in fiscal, monetary or regulatory policy; the emergence or continuation of widespread health emergencies or pandemics; the impact of natural disasters, extreme weather events, military conflicts (including the Russia / Ukraine conflict, the conflict in the Middle East, the possible expansion of such conflicts and potential geopolitical consequences), terrorism or other geopolitical events; and other matters. Forward-looking statements speak only as of the date they are made, and the Corporation undertakes no obligation to update any forward- looking statement to reflect the impact of circumstances or events that arise after the date the forward-looking statement was made. “Bank of America” and “BofA Securities” are the marketing names used by the Global Banking and Global Markets divisions of Bank of America Corporation. Lending, other commercial banking activities, and trading in certain financial instruments are performed globally by banking affiliates of Bank of America Corporation, including Bank of America, N.A., Member FDIC. Trading in securities and financial instruments, and strategic advisory, and other investment banking activities, are performed globally by investment banking affiliates of Bank of America Corporation (“Investment Banking Affiliates”) or other affiliates, including, in the United States, BofA Securities, Inc. and Merrill Lynch, Pierce, Fenner & Smith Incorporated, each of which are registered broker-dealers and Members of SIPC, and, in other jurisdictions, by locally registered entities. BofA Securities, Inc. is registered as a futures commission merchant with the CFTC and is a member of the NFA. Investment products offered by Investment Banking Affiliates: Are Not FDIC Insured · May Lose Value · Are Not Bank Guaranteed. Bank of America Corporation’s broker-dealers are not banks and are separate legal entities from their bank affiliates. The obligations of the broker- dealers are not obligations of their bank affiliates (unless explicitly stated otherwise), and these bank affiliates are not responsible for securities sold, offered, or recommended by the broker-dealers. The foregoing also applies to other non-bank affiliates. For more Bank of America news, including dividend announcements and other important information, visit the Bank of America newsroom at https://newsroom.bankofamerica.com.* www.bankofamerica.com* * Website content is not incorporated by reference into this press release.
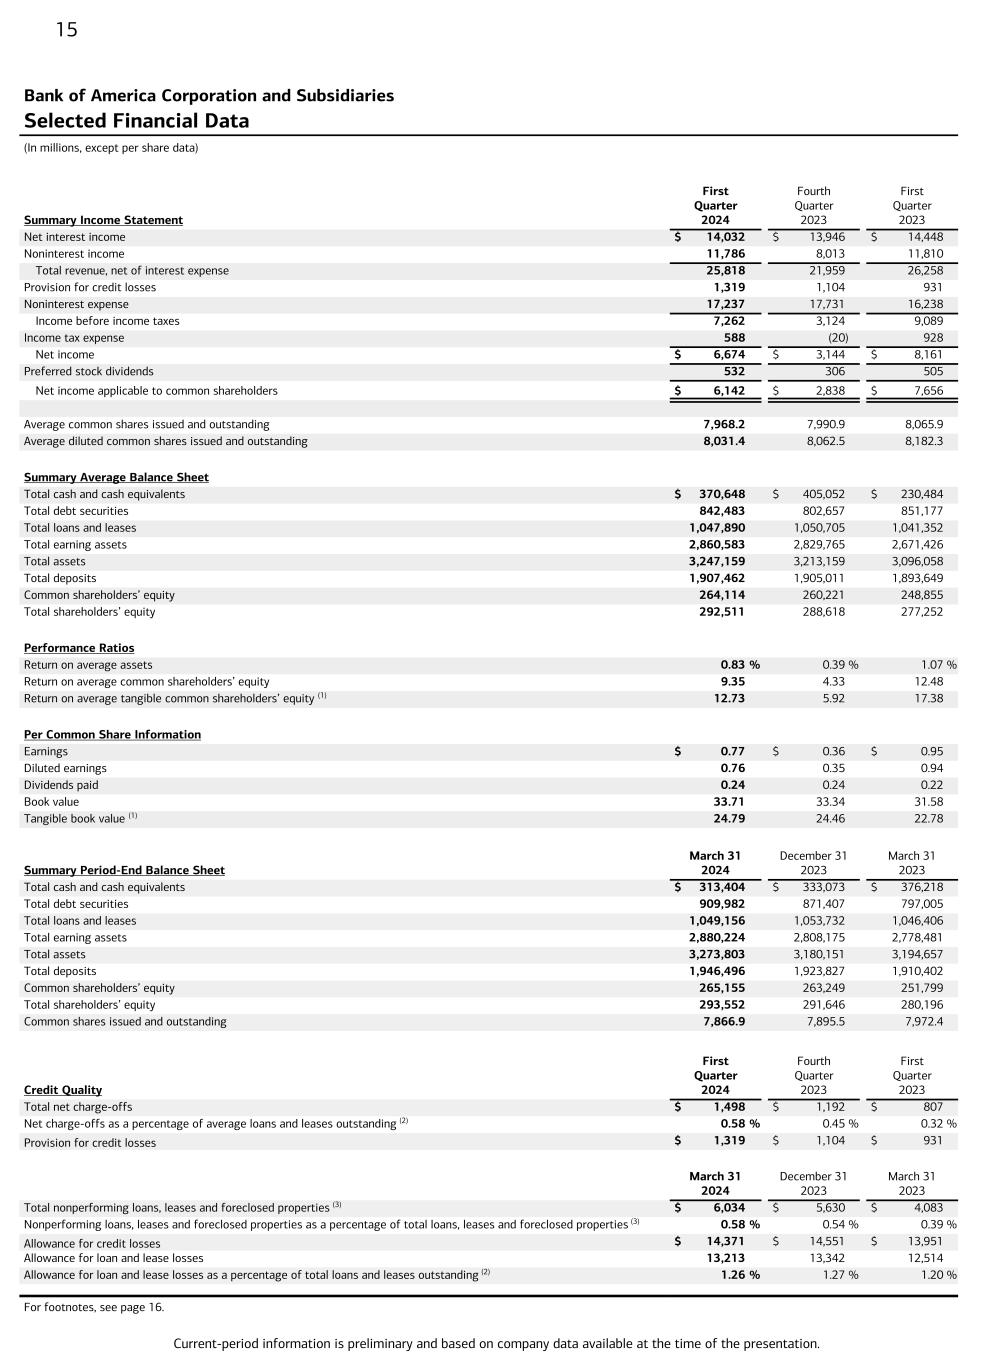
Current-period information is preliminary and based on company data available at the time of the presentation. 15 Bank of America Corporation and Subsidiaries Selected Financial Data (In millions, except per share data) First Quarter 2024 Fourth Quarter 2023 First Quarter 2023Summary Income Statement Net interest income $ 14,032 $ 13,946 $ 14,448 Noninterest income 11,786 8,013 11,810 Total revenue, net of interest expense 25,818 21,959 26,258 Provision for credit losses 1,319 1,104 931 Noninterest expense 17,237 17,731 16,238 Income before income taxes 7,262 3,124 9,089 Income tax expense 588 (20) 928 Net income $ 6,674 $ 3,144 $ 8,161 Preferred stock dividends 532 306 505 Net income applicable to common shareholders $ 6,142 $ 2,838 $ 7,656 Average common shares issued and outstanding 7,968.2 7,990.9 8,065.9 Average diluted common shares issued and outstanding 8,031.4 8,062.5 8,182.3 Summary Average Balance Sheet Total cash and cash equivalents $ 370,648 $ 405,052 $ 230,484 Total debt securities 842,483 802,657 851,177 Total loans and leases 1,047,890 1,050,705 1,041,352 Total earning assets 2,860,583 2,829,765 2,671,426 Total assets 3,247,159 3,213,159 3,096,058 Total deposits 1,907,462 1,905,011 1,893,649 Common shareholders’ equity 264,114 260,221 248,855 Total shareholders’ equity 292,511 288,618 277,252 Performance Ratios Return on average assets 0.83 % 0.39 % 1.07 % Return on average common shareholders’ equity 9.35 4.33 12.48 Return on average tangible common shareholders’ equity (1) 12.73 5.92 17.38 Per Common Share Information Earnings $ 0.77 $ 0.36 $ 0.95 Diluted earnings 0.76 0.35 0.94 Dividends paid 0.24 0.24 0.22 Book value 33.71 33.34 31.58 Tangible book value (1) 24.79 24.46 22.78 Summary Period-End Balance Sheet March 31 2024 December 31 2023 March 31 2023 Total cash and cash equivalents $ 313,404 $ 333,073 $ 376,218 Total debt securities 909,982 871,407 797,005 Total loans and leases 1,049,156 1,053,732 1,046,406 Total earning assets 2,880,224 2,808,175 2,778,481 Total assets 3,273,803 3,180,151 3,194,657 Total deposits 1,946,496 1,923,827 1,910,402 Common shareholders’ equity 265,155 263,249 251,799 Total shareholders’ equity 293,552 291,646 280,196 Common shares issued and outstanding 7,866.9 7,895.5 7,972.4 First Quarter 2024 Fourth Quarter 2023 First Quarter 2023Credit Quality Total net charge-offs $ 1,498 $ 1,192 $ 807 Net charge-offs as a percentage of average loans and leases outstanding (2) 0.58 % 0.45 % 0.32 % Provision for credit losses $ 1,319 $ 1,104 $ 931 March 31 2024 December 31 2023 March 31 2023 Total nonperforming loans, leases and foreclosed properties (3) $ 6,034 $ 5,630 $ 4,083 Nonperforming loans, leases and foreclosed properties as a percentage of total loans, leases and foreclosed properties (3) 0.58 % 0.54 % 0.39 % Allowance for credit losses $ 14,371 $ 14,551 $ 13,951 Allowance for loan and lease losses 13,213 13,342 12,514 Allowance for loan and lease losses as a percentage of total loans and leases outstanding (2) 1.26 % 1.27 % 1.20 % For footnotes, see page 16.
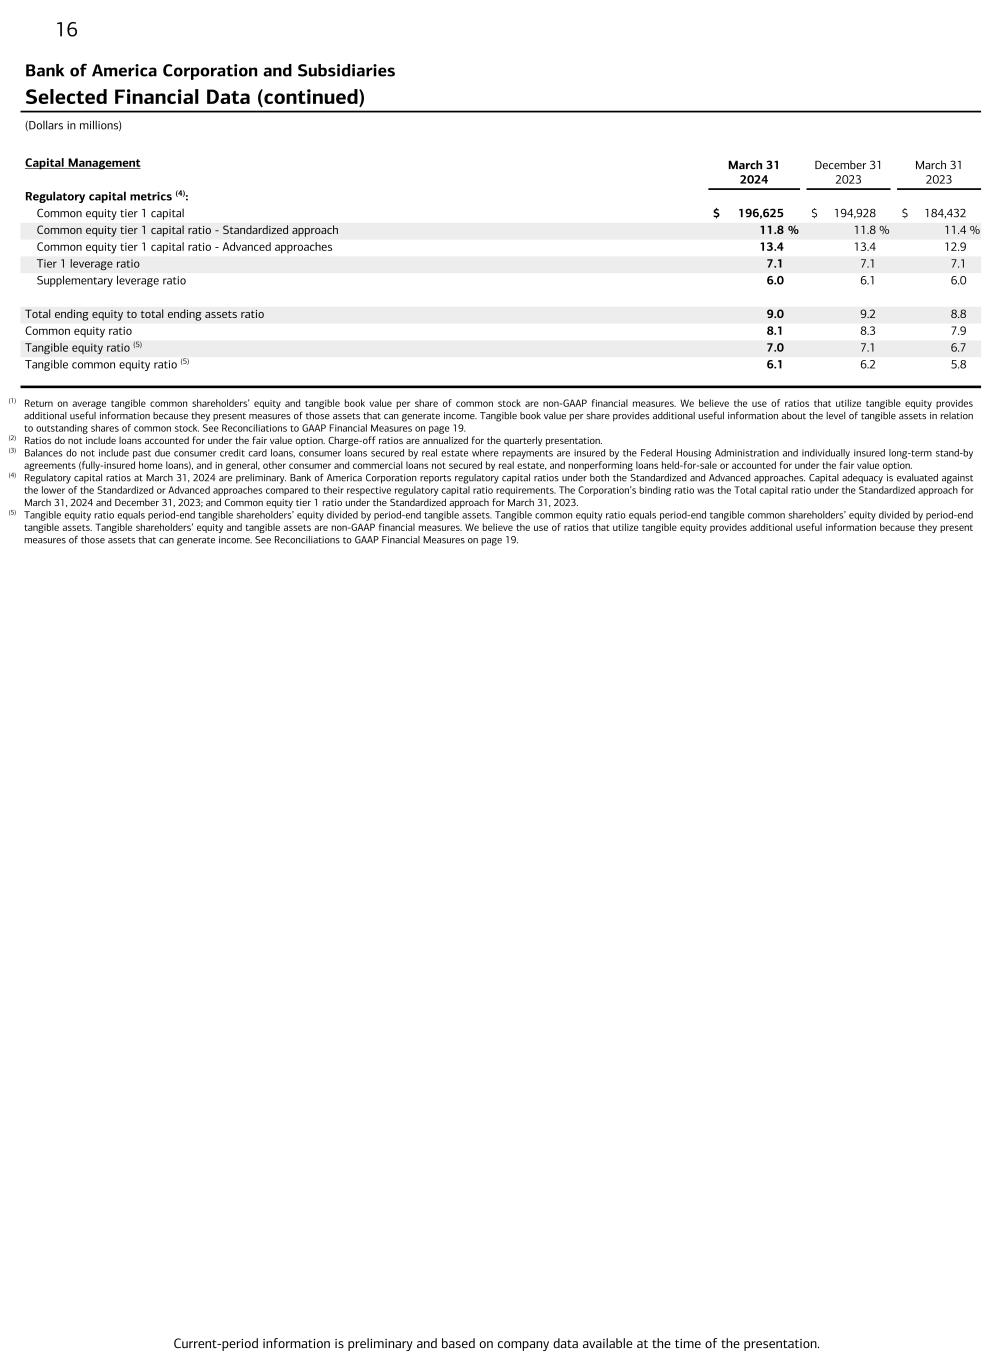
Current-period information is preliminary and based on company data available at the time of the presentation. 16 Bank of America Corporation and Subsidiaries Selected Financial Data (continued) (Dollars in millions) Capital Management March 31 2024 December 31 2023 March 31 2023 Regulatory capital metrics (4): Common equity tier 1 capital $ 196,625 $ 194,928 $ 184,432 Common equity tier 1 capital ratio - Standardized approach 11.8 % 11.8 % 11.4 % Common equity tier 1 capital ratio - Advanced approaches 13.4 13.4 12.9 Tier 1 leverage ratio 7.1 7.1 7.1 Supplementary leverage ratio 6.0 6.1 6.0 Total ending equity to total ending assets ratio 9.0 9.2 8.8 Common equity ratio 8.1 8.3 7.9 Tangible equity ratio (5) 7.0 7.1 6.7 Tangible common equity ratio (5) 6.1 6.2 5.8 (1) Return on average tangible common shareholders’ equity and tangible book value per share of common stock are non-GAAP financial measures. We believe the use of ratios that utilize tangible equity provides additional useful information because they present measures of those assets that can generate income. Tangible book value per share provides additional useful information about the level of tangible assets in relation to outstanding shares of common stock. See Reconciliations to GAAP Financial Measures on page 19. (2) Ratios do not include loans accounted for under the fair value option. Charge-off ratios are annualized for the quarterly presentation. (3) Balances do not include past due consumer credit card loans, consumer loans secured by real estate where repayments are insured by the Federal Housing Administration and individually insured long-term stand-by agreements (fully-insured home loans), and in general, other consumer and commercial loans not secured by real estate, and nonperforming loans held-for-sale or accounted for under the fair value option. (4) Regulatory capital ratios at March 31, 2024 are preliminary. Bank of America Corporation reports regulatory capital ratios under both the Standardized and Advanced approaches. Capital adequacy is evaluated against the lower of the Standardized or Advanced approaches compared to their respective regulatory capital ratio requirements. The Corporation’s binding ratio was the Total capital ratio under the Standardized approach for March 31, 2024 and December 31, 2023; and Common equity tier 1 ratio under the Standardized approach for March 31, 2023. (5) Tangible equity ratio equals period-end tangible shareholders’ equity divided by period-end tangible assets. Tangible common equity ratio equals period-end tangible common shareholders’ equity divided by period-end tangible assets. Tangible shareholders’ equity and tangible assets are non-GAAP financial measures. We believe the use of ratios that utilize tangible equity provides additional useful information because they present measures of those assets that can generate income. See Reconciliations to GAAP Financial Measures on page 19.
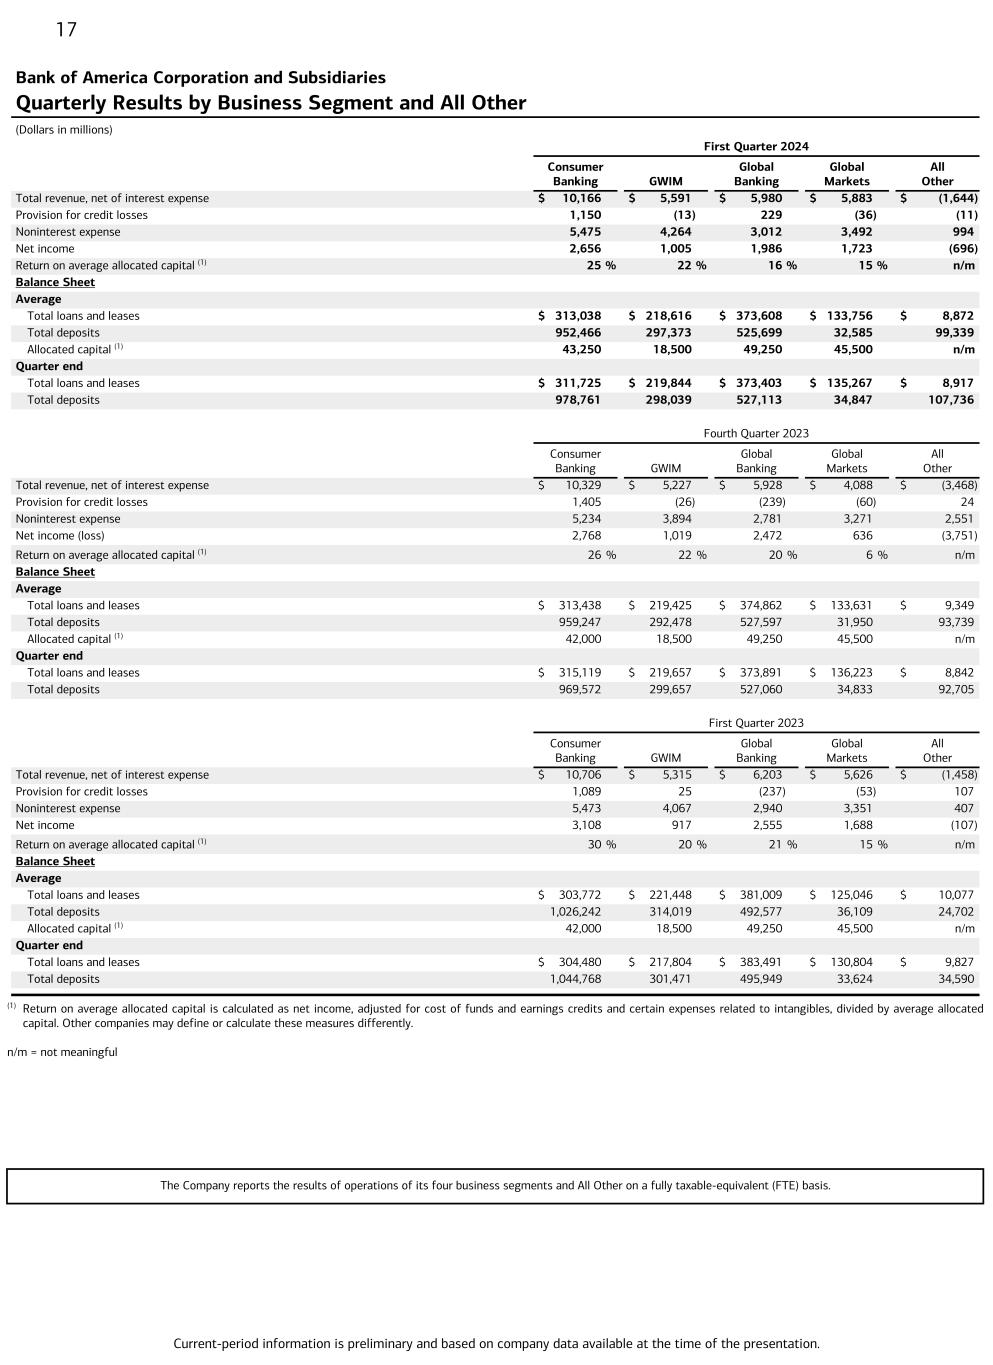
Current-period information is preliminary and based on company data available at the time of the presentation. 17 Bank of America Corporation and Subsidiaries Quarterly Results by Business Segment and All Other (Dollars in millions) First Quarter 2024 Consumer Banking GWIM Global Banking Global Markets All Other Total revenue, net of interest expense $ 10,166 $ 5,591 $ 5,980 $ 5,883 $ (1,644) Provision for credit losses 1,150 (13) 229 (36) (11) Noninterest expense 5,475 4,264 3,012 3,492 994 Net income 2,656 1,005 1,986 1,723 (696) Return on average allocated capital (1) 25 % 22 % 16 % 15 % n/m Balance Sheet Average Total loans and leases $ 313,038 $ 218,616 $ 373,608 $ 133,756 $ 8,872 Total deposits 952,466 297,373 525,699 32,585 99,339 Allocated capital (1) 43,250 18,500 49,250 45,500 n/m Quarter end Total loans and leases $ 311,725 $ 219,844 $ 373,403 $ 135,267 $ 8,917 Total deposits 978,761 298,039 527,113 34,847 107,736 Fourth Quarter 2023 Consumer Banking GWIM Global Banking Global Markets All Other Total revenue, net of interest expense $ 10,329 $ 5,227 $ 5,928 $ 4,088 $ (3,468) Provision for credit losses 1,405 (26) (239) (60) 24 Noninterest expense 5,234 3,894 2,781 3,271 2,551 Net income (loss) 2,768 1,019 2,472 636 (3,751) Return on average allocated capital (1) 26 % 22 % 20 % 6 % n/m Balance Sheet Average Total loans and leases $ 313,438 $ 219,425 $ 374,862 $ 133,631 $ 9,349 Total deposits 959,247 292,478 527,597 31,950 93,739 Allocated capital (1) 42,000 18,500 49,250 45,500 n/m Quarter end Total loans and leases $ 315,119 $ 219,657 $ 373,891 $ 136,223 $ 8,842 Total deposits 969,572 299,657 527,060 34,833 92,705 First Quarter 2023 Consumer Banking GWIM Global Banking Global Markets All Other Total revenue, net of interest expense $ 10,706 $ 5,315 $ 6,203 $ 5,626 $ (1,458) Provision for credit losses 1,089 25 (237) (53) 107 Noninterest expense 5,473 4,067 2,940 3,351 407 Net income 3,108 917 2,555 1,688 (107) Return on average allocated capital (1) 30 % 20 % 21 % 15 % n/m Balance Sheet Average Total loans and leases $ 303,772 $ 221,448 $ 381,009 $ 125,046 $ 10,077 Total deposits 1,026,242 314,019 492,577 36,109 24,702 Allocated capital (1) 42,000 18,500 49,250 45,500 n/m Quarter end Total loans and leases $ 304,480 $ 217,804 $ 383,491 $ 130,804 $ 9,827 Total deposits 1,044,768 301,471 495,949 33,624 34,590 (1) Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently. n/m = not meaningful The Company reports the results of operations of its four business segments and All Other on a fully taxable-equivalent (FTE) basis.

Current-period information is preliminary and based on company data available at the time of the presentation. 18 Bank of America Corporation and Subsidiaries Supplemental Financial Data (Dollars in millions) First Quarter 2024 Fourth Quarter 2023 First Quarter 2023FTE basis data (1) Net interest income $ 14,190 $ 14,091 $ 14,582 Total revenue, net of interest expense 25,977 22,104 26,392 Net interest yield 1.99 % 1.97 % 2.20 % Efficiency ratio 66.36 80.22 61.53 Other Data March 31 2024 December 31 2023 March 31 2023 Number of financial centers - U.S. 3,804 3,845 3,892 Number of branded ATMs - U.S. 15,028 15,168 15,407 Headcount 212,335 212,985 217,059 (1) FTE basis is a non-GAAP financial measure. FTE basis is a performance measure used by management in operating the business that management believes provides investors with meaningful information on the interest margin for comparative purposes. The Corporation believes that this presentation allows for comparison of amounts from both taxable and tax- exempt sources and is consistent with industry practices. Net interest income includes FTE adjustments of $158 million, $145 million and $134 million for the first quarter of 2024 and the fourth and first quarters of 2023, respectively.
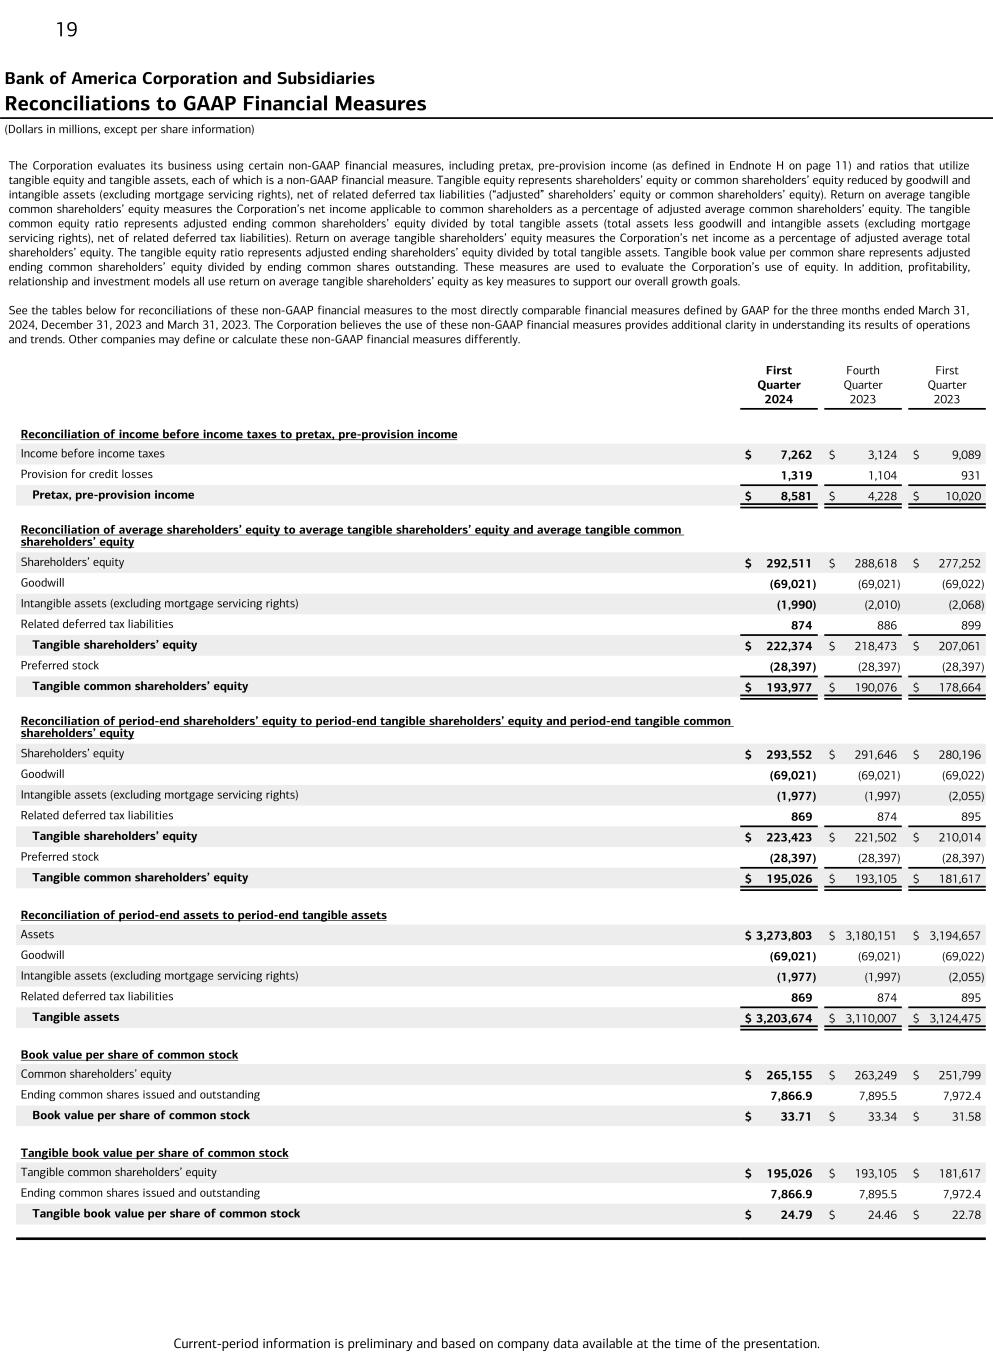
Current-period information is preliminary and based on company data available at the time of the presentation. 19 The Corporation evaluates its business using certain non-GAAP financial measures, including pretax, pre-provision income (as defined in Endnote H on page 11) and ratios that utilize tangible equity and tangible assets, each of which is a non-GAAP financial measure. Tangible equity represents shareholders’ equity or common shareholders’ equity reduced by goodwill and intangible assets (excluding mortgage servicing rights), net of related deferred tax liabilities (“adjusted” shareholders’ equity or common shareholders’ equity). Return on average tangible common shareholders’ equity measures the Corporation’s net income applicable to common shareholders as a percentage of adjusted average common shareholders’ equity. The tangible common equity ratio represents adjusted ending common shareholders’ equity divided by total tangible assets (total assets less goodwill and intangible assets (excluding mortgage servicing rights), net of related deferred tax liabilities). Return on average tangible shareholders’ equity measures the Corporation’s net income as a percentage of adjusted average total shareholders’ equity. The tangible equity ratio represents adjusted ending shareholders’ equity divided by total tangible assets. Tangible book value per common share represents adjusted ending common shareholders’ equity divided by ending common shares outstanding. These measures are used to evaluate the Corporation’s use of equity. In addition, profitability, relationship and investment models all use return on average tangible shareholders’ equity as key measures to support our overall growth goals. See the tables below for reconciliations of these non-GAAP financial measures to the most directly comparable financial measures defined by GAAP for the three months ended March 31, 2024, December 31, 2023 and March 31, 2023. The Corporation believes the use of these non-GAAP financial measures provides additional clarity in understanding its results of operations and trends. Other companies may define or calculate these non-GAAP financial measures differently. Bank of America Corporation and Subsidiaries Reconciliations to GAAP Financial Measures (Dollars in millions, except per share information) First Quarter 2024 Fourth Quarter 2023 First Quarter 2023 Reconciliation of income before income taxes to pretax, pre-provision income Income before income taxes $ 7,262 $ 3,124 $ 9,089 Provision for credit losses 1,319 1,104 931 Pretax, pre-provision income $ 8,581 $ 4,228 $ 10,020 Reconciliation of average shareholders’ equity to average tangible shareholders’ equity and average tangible common shareholders’ equity Shareholders’ equity $ 292,511 $ 288,618 $ 277,252 Goodwill (69,021) (69,021) (69,022) Intangible assets (excluding mortgage servicing rights) (1,990) (2,010) (2,068) Related deferred tax liabilities 874 886 899 Tangible shareholders’ equity $ 222,374 $ 218,473 $ 207,061 Preferred stock (28,397) (28,397) (28,397) Tangible common shareholders’ equity $ 193,977 $ 190,076 $ 178,664 Reconciliation of period-end shareholders’ equity to period-end tangible shareholders’ equity and period-end tangible common shareholders’ equity Shareholders’ equity $ 293,552 $ 291,646 $ 280,196 Goodwill (69,021) (69,021) (69,022) Intangible assets (excluding mortgage servicing rights) (1,977) (1,997) (2,055) Related deferred tax liabilities 869 874 895 Tangible shareholders’ equity $ 223,423 $ 221,502 $ 210,014 Preferred stock (28,397) (28,397) (28,397) Tangible common shareholders’ equity $ 195,026 $ 193,105 $ 181,617 Reconciliation of period-end assets to period-end tangible assets Assets $ 3,273,803 $ 3,180,151 $ 3,194,657 Goodwill (69,021) (69,021) (69,022) Intangible assets (excluding mortgage servicing rights) (1,977) (1,997) (2,055) Related deferred tax liabilities 869 874 895 Tangible assets $ 3,203,674 $ 3,110,007 $ 3,124,475 Book value per share of common stock Common shareholders’ equity $ 265,155 $ 263,249 $ 251,799 Ending common shares issued and outstanding 7,866.9 7,895.5 7,972.4 Book value per share of common stock $ 33.71 $ 33.34 $ 31.58 Tangible book value per share of common stock Tangible common shareholders’ equity $ 195,026 $ 193,105 $ 181,617 Ending common shares issued and outstanding 7,866.9 7,895.5 7,972.4 Tangible book value per share of common stock $ 24.79 $ 24.46 $ 22.78
Bank of America 1Q24 Financial Results April 16, 2024
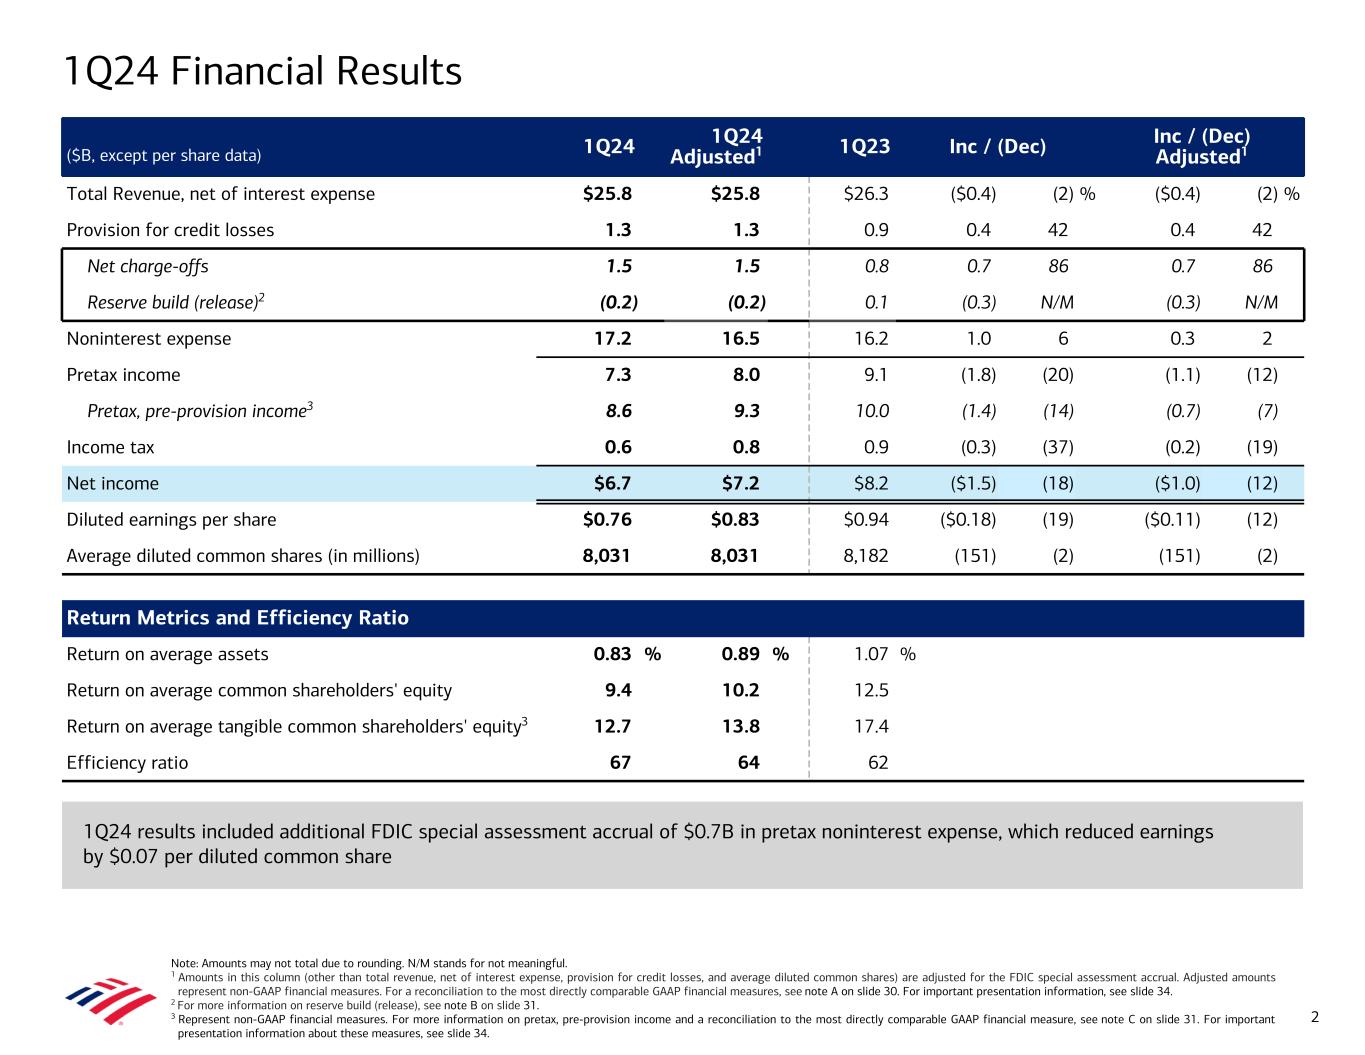
1Q24 results included additional FDIC special assessment accrual of $0.7B in pretax noninterest expense, which reduced earnings by $0.07 per diluted common share Note: Amounts may not total due to rounding. N/M stands for not meaningful. 1 Amounts in this column (other than total revenue, net of interest expense, provision for credit losses, and average diluted common shares) are adjusted for the FDIC special assessment accrual. Adjusted amounts represent non-GAAP financial measures. For a reconciliation to the most directly comparable GAAP financial measures, see note A on slide 30. For important presentation information, see slide 34. 2 For more information on reserve build (release), see note B on slide 31. 3 Represent non-GAAP financial measures. For more information on pretax, pre-provision income and a reconciliation to the most directly comparable GAAP financial measure, see note C on slide 31. For important presentation information about these measures, see slide 34. ($B, except per share data) 1Q24 1Q24 Adjusted1 1Q23 Inc / (Dec) Inc / (Dec) Adjusted1 Total Revenue, net of interest expense $25.8 $25.8 $26.3 ($0.4) (2) % ($0.4) (2) % Provision for credit losses 1.3 1.3 0.9 0.4 42 0.4 42 Net charge-offs 1.5 1.5 0.8 0.7 86 0.7 86 Reserve build (release)2 (0.2) (0.2) 0.1 (0.3) N/M (0.3) N/M Noninterest expense 17.2 16.5 16.2 1.0 6 0.3 2 Pretax income 7.3 8.0 9.1 (1.8) (20) (1.1) (12) Pretax, pre-provision income3 8.6 9.3 10.0 (1.4) (14) (0.7) (7) Income tax 0.6 0.8 0.9 (0.3) (37) (0.2) (19) Net income $6.7 $7.2 $8.2 ($1.5) (18) ($1.0) (12) Diluted earnings per share $0.76 $0.83 $0.94 ($0.18) (19) ($0.11) (12) Average diluted common shares (in millions) 8,031 8,031 8,182 (151) (2) (151) (2) Return Metrics and Efficiency Ratio Return on average assets 0.83 % 0.89 % 1.07 % Return on average common shareholders' equity 9.4 10.2 12.5 Return on average tangible common shareholders' equity3 12.7 13.8 17.4 Efficiency ratio 67 64 62 1Q24 Financial Results 2
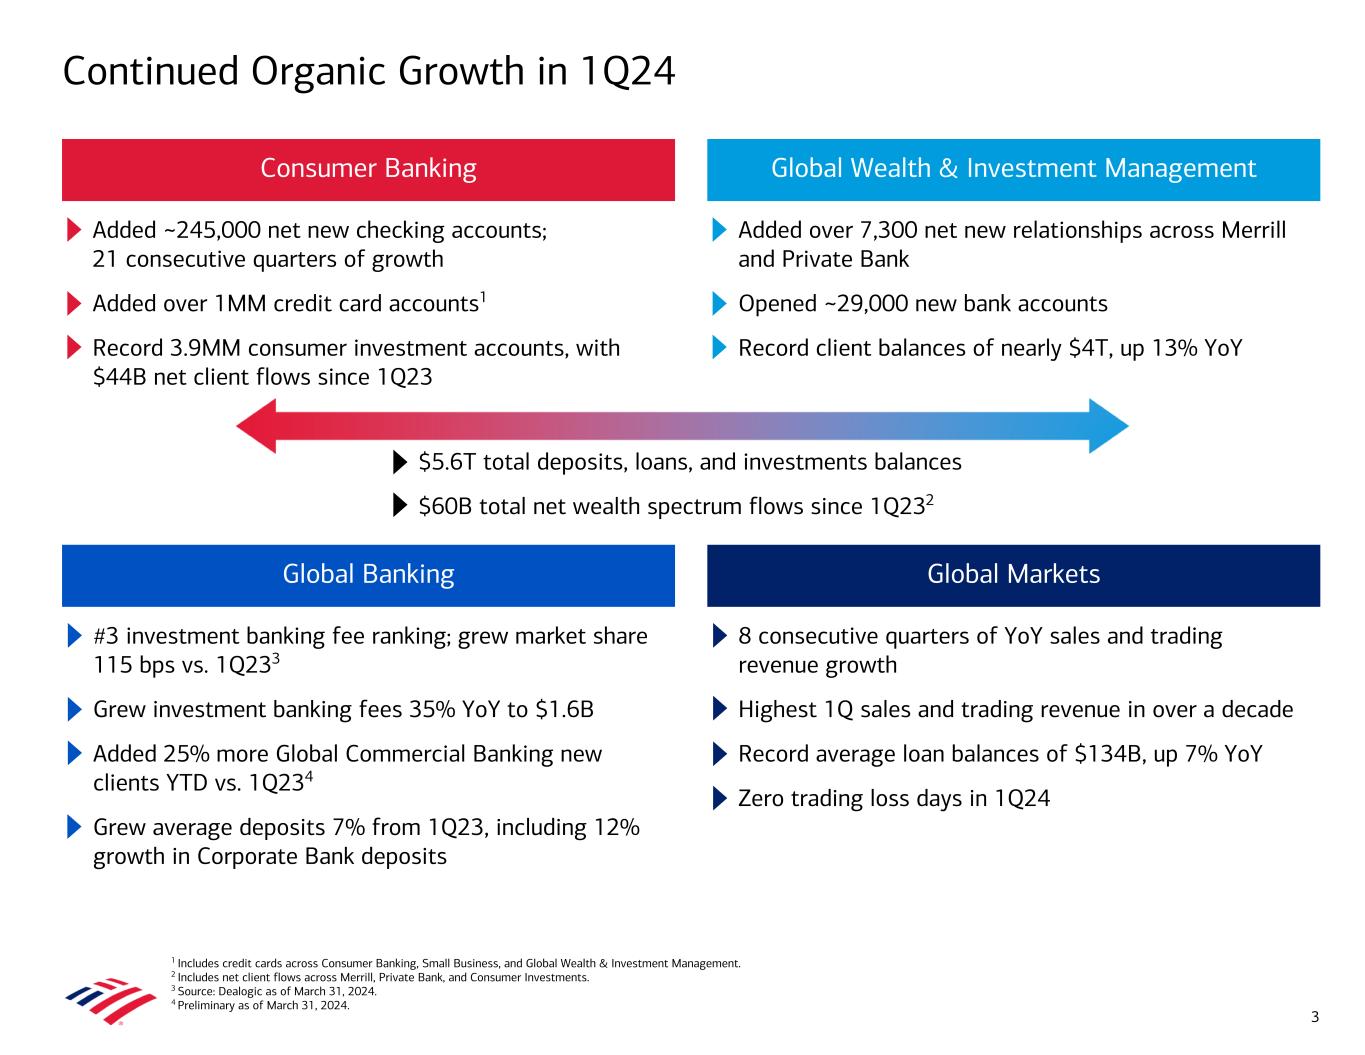
1 Includes credit cards across Consumer Banking, Small Business, and Global Wealth & Investment Management. 2 Includes net client flows across Merrill, Private Bank, and Consumer Investments. 3 Source: Dealogic as of March 31, 2024. 4 Preliminary as of March 31, 2024. #3 investment banking fee ranking; grew market share 115 bps vs. 1Q233 Grew investment banking fees 35% YoY to $1.6B Added 25% more Global Commercial Banking new clients YTD vs. 1Q234 Grew average deposits 7% from 1Q23, including 12% growth in Corporate Bank deposits Added over 7,300 net new relationships across Merrill and Private Bank Opened ~29,000 new bank accounts Record client balances of nearly $4T, up 13% YoY Continued Organic Growth in 1Q24 3 Consumer Banking Global Wealth & Investment Management Global Banking Global Markets Added ~245,000 net new checking accounts; 21 consecutive quarters of growth Added over 1MM credit card accounts1 Record 3.9MM consumer investment accounts, with $44B net client flows since 1Q23 $5.6T total deposits, loans, and investments balances $60B total net wealth spectrum flows since 1Q232 8 consecutive quarters of YoY sales and trading revenue growth Highest 1Q sales and trading revenue in over a decade Record average loan balances of $134B, up 7% YoY Zero trading loss days in 1Q24
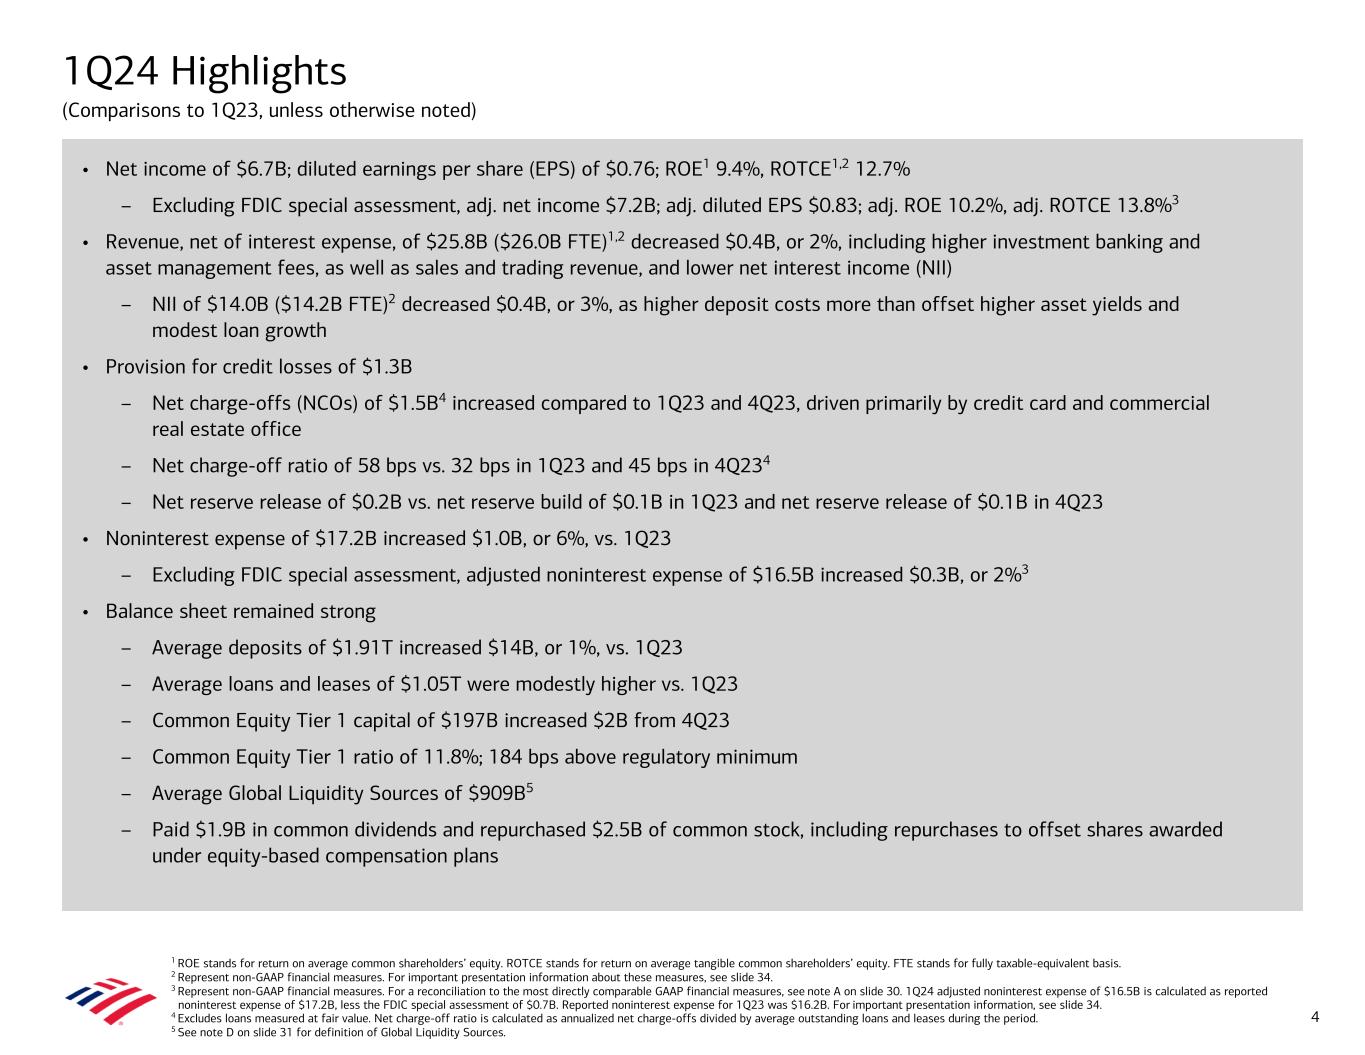
1 ROE stands for return on average common shareholders’ equity. ROTCE stands for return on average tangible common shareholders’ equity. FTE stands for fully taxable-equivalent basis. 2 Represent non-GAAP financial measures. For important presentation information about these measures, see slide 34. 3 Represent non-GAAP financial measures. For a reconciliation to the most directly comparable GAAP financial measures, see note A on slide 30. 1Q24 adjusted noninterest expense of $16.5B is calculated as reported noninterest expense of $17.2B, less the FDIC special assessment of $0.7B. Reported noninterest expense for 1Q23 was $16.2B. For important presentation information, see slide 34. 4 Excludes loans measured at fair value. Net charge-off ratio is calculated as annualized net charge-offs divided by average outstanding loans and leases during the period. 5 See note D on slide 31 for definition of Global Liquidity Sources. 1Q24 Highlights (Comparisons to 1Q23, unless otherwise noted) • Net income of $6.7B; diluted earnings per share (EPS) of $0.76; ROE1 9.4%, ROTCE1,2 12.7% – Excluding FDIC special assessment, adj. net income $7.2B; adj. diluted EPS $0.83; adj. ROE 10.2%, adj. ROTCE 13.8%3 • Revenue, net of interest expense, of $25.8B ($26.0B FTE)1,2 decreased $0.4B, or 2%, including higher investment banking and asset management fees, as well as sales and trading revenue, and lower net interest income (NII) – NII of $14.0B ($14.2B FTE)2 decreased $0.4B, or 3%, as higher deposit costs more than offset higher asset yields and modest loan growth • Provision for credit losses of $1.3B – Net charge-offs (NCOs) of $1.5B4 increased compared to 1Q23 and 4Q23, driven primarily by credit card and commercial real estate office – Net charge-off ratio of 58 bps vs. 32 bps in 1Q23 and 45 bps in 4Q234 – Net reserve release of $0.2B vs. net reserve build of $0.1B in 1Q23 and net reserve release of $0.1B in 4Q23 • Noninterest expense of $17.2B increased $1.0B, or 6%, vs. 1Q23 – Excluding FDIC special assessment, adjusted noninterest expense of $16.5B increased $0.3B, or 2%3 • Balance sheet remained strong – Average deposits of $1.91T increased $14B, or 1%, vs. 1Q23 – Average loans and leases of $1.05T were modestly higher vs. 1Q23 – Common Equity Tier 1 capital of $197B increased $2B from 4Q23 – Common Equity Tier 1 ratio of 11.8%; 184 bps above regulatory minimum – Average Global Liquidity Sources of $909B5 – Paid $1.9B in common dividends and repurchased $2.5B of common stock, including repurchases to offset shares awarded under equity-based compensation plans 4
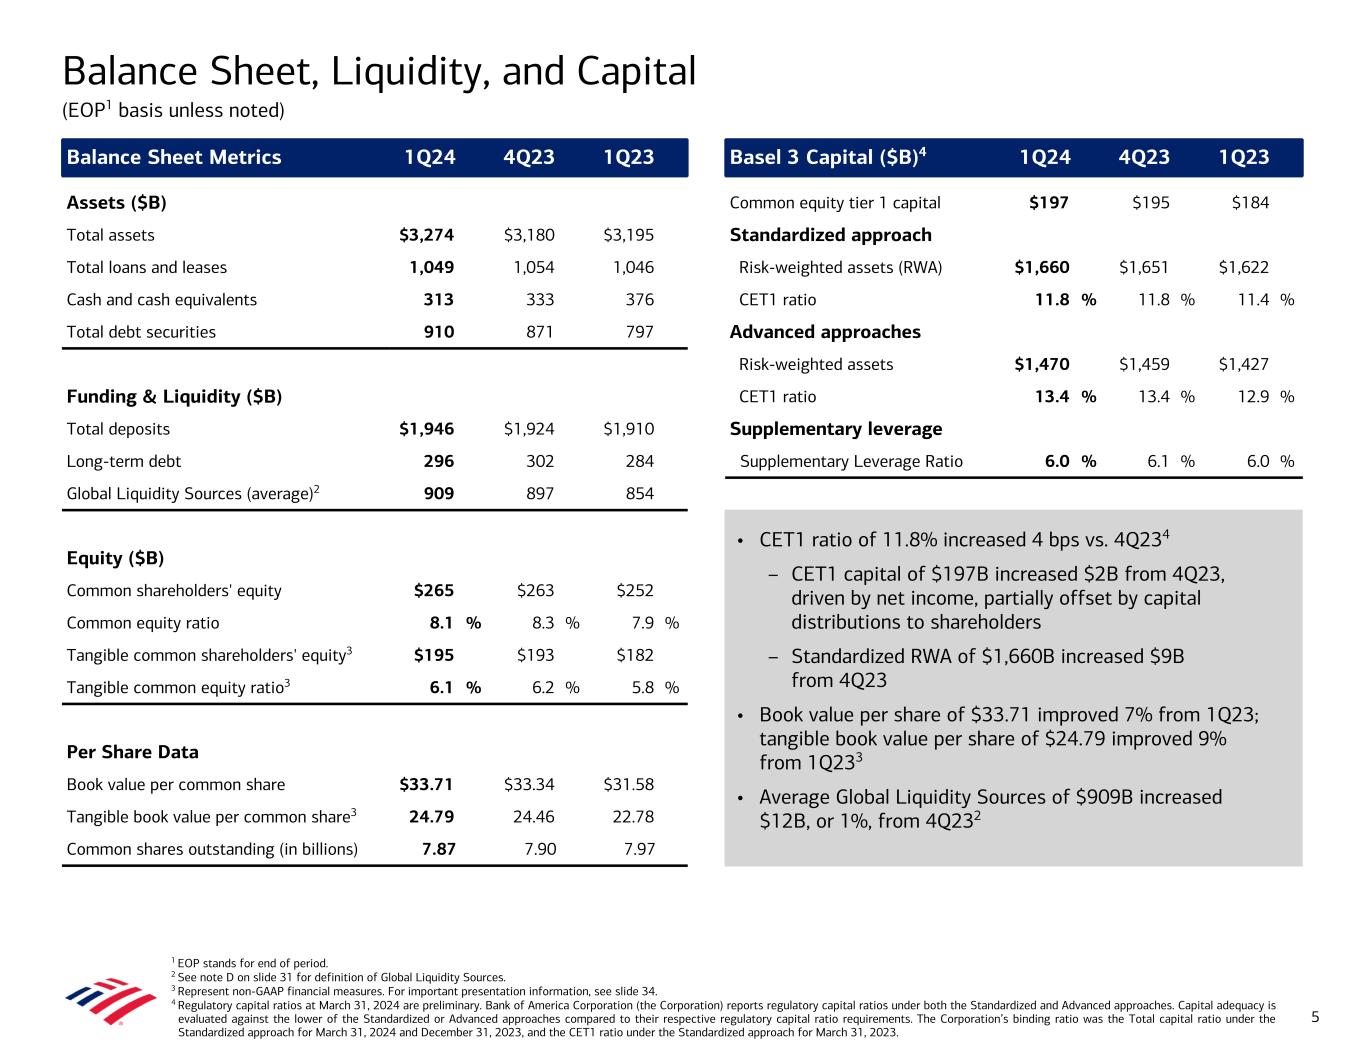
Balance Sheet Metrics 1Q24 4Q23 1Q23 Basel 3 Capital ($B)4 1Q24 4Q23 1Q23 Assets ($B) Common equity tier 1 capital $197 $195 $184 Total assets $3,274 $3,180 $3,195 Standardized approach Total loans and leases 1,049 1,054 1,046 Risk-weighted assets (RWA) $1,660 $1,651 $1,622 Cash and cash equivalents 313 333 376 CET1 ratio 11.8 % 11.8 % 11.4 % Total debt securities 910 871 797 Advanced approaches Risk-weighted assets $1,470 $1,459 $1,427 Funding & Liquidity ($B) CET1 ratio 13.4 % 13.4 % 12.9 % Total deposits $1,946 $1,924 $1,910 Supplementary leverage Long-term debt 296 302 284 Supplementary Leverage Ratio 6.0 % 6.1 % 6.0 % Global Liquidity Sources (average)2 909 897 854 Equity ($B) Common shareholders' equity $265 $263 $252 Common equity ratio 8.1 % 8.3 % 7.9 % Tangible common shareholders' equity3 $195 $193 $182 Tangible common equity ratio3 6.1 % 6.2 % 5.8 % Per Share Data Book value per common share $33.71 $33.34 $31.58 Tangible book value per common share3 24.79 24.46 22.78 Common shares outstanding (in billions) 7.87 7.90 7.97 1 EOP stands for end of period. 2 See note D on slide 31 for definition of Global Liquidity Sources. 3 Represent non-GAAP financial measures. For important presentation information, see slide 34. 4 Regulatory capital ratios at March 31, 2024 are preliminary. Bank of America Corporation (the Corporation) reports regulatory capital ratios under both the Standardized and Advanced approaches. Capital adequacy is evaluated against the lower of the Standardized or Advanced approaches compared to their respective regulatory capital ratio requirements. The Corporation’s binding ratio was the Total capital ratio under the Standardized approach for March 31, 2024 and December 31, 2023, and the CET1 ratio under the Standardized approach for March 31, 2023. Balance Sheet, Liquidity, and Capital (EOP1 basis unless noted) 5 • CET1 ratio of 11.8% increased 4 bps vs. 4Q234 – CET1 capital of $197B increased $2B from 4Q23, driven by net income, partially offset by capital distributions to shareholders – Standardized RWA of $1,660B increased $9B from 4Q23 • Book value per share of $33.71 improved 7% from 1Q23; tangible book value per share of $24.79 improved 9% from 1Q233 • Average Global Liquidity Sources of $909B increased $12B, or 1%, from 4Q232
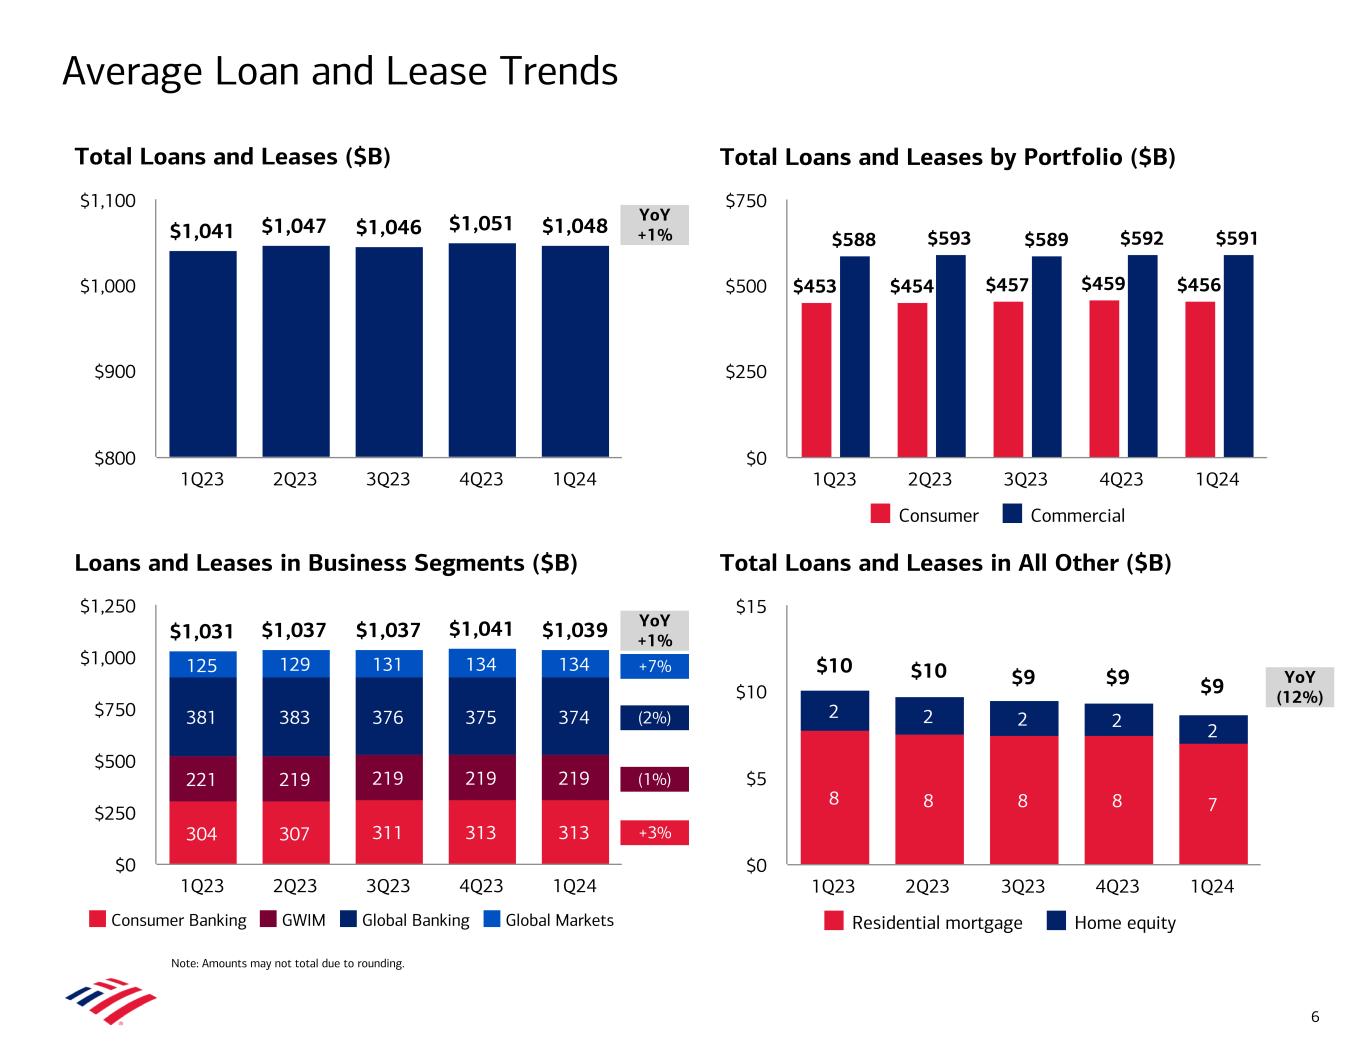
$1,031 $1,037 $1,037 $1,041 $1,039 304 307 311 313 313 221 219 219 219 219 381 383 376 375 374 125 129 131 134 134 Consumer Banking GWIM Global Banking Global Markets 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $250 $500 $750 $1,000 $1,250 $1,041 $1,047 $1,046 $1,051 $1,048 1Q23 2Q23 3Q23 4Q23 1Q24 $800 $900 $1,000 $1,100 +3% (1%) (2%) +7% Average Loan and Lease Trends YoY +1% YoY +1% YoY (12%) Note: Amounts may not total due to rounding. Total Loans and Leases in All Other ($B) Loans and Leases in Business Segments ($B) Total Loans and Leases by Portfolio ($B)Total Loans and Leases ($B) $453 $454 $457 $459 $456 $588 $593 $589 $592 $591 Consumer Commercial 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $250 $500 $750 6 8 8 8 8 7 2 2 2 2 2 $10 $10 $9 $9 $9 Residential mortgage Home equity 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $5 $10 $15
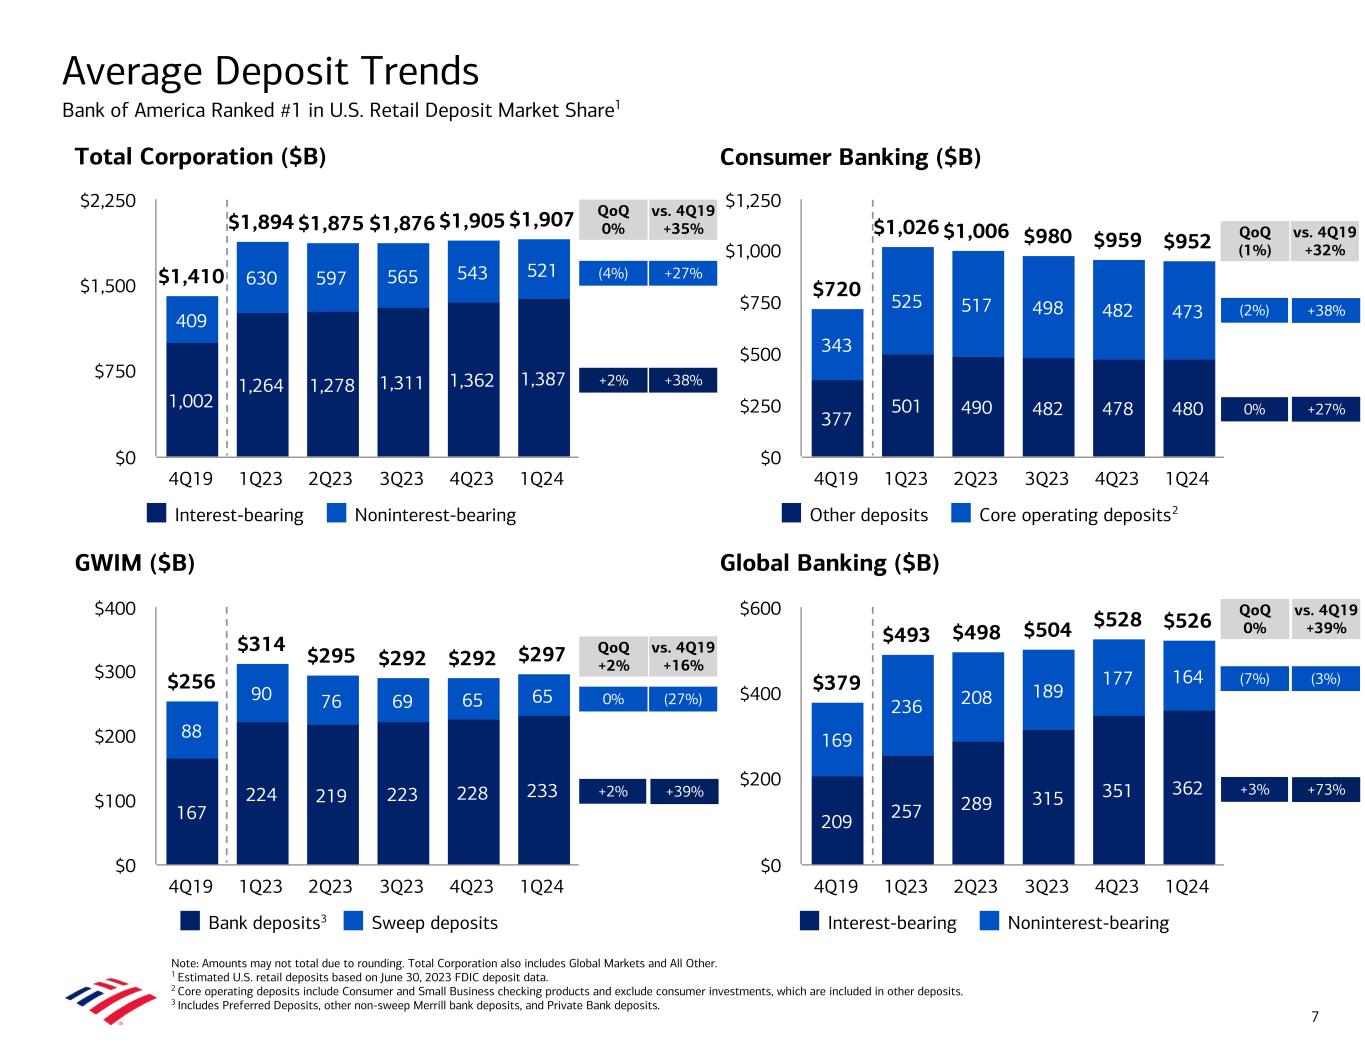
Consumer Banking ($B) GWIM ($B) Global Banking ($B) Total Corporation ($B) Average Deposit Trends Bank of America Ranked #1 in U.S. Retail Deposit Market Share1 Note: Amounts may not total due to rounding. Total Corporation also includes Global Markets and All Other. 1 Estimated U.S. retail deposits based on June 30, 2023 FDIC deposit data. 2 Core operating deposits include Consumer and Small Business checking products and exclude consumer investments, which are included in other deposits. 3 Includes Preferred Deposits, other non-sweep Merrill bank deposits, and Private Bank deposits. $256 $314 $295 $292 $292 $297 167 224 219 223 228 233 88 90 76 69 65 65 Bank deposits Sweep deposits 4Q19 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $100 $200 $300 $400 $1,410 $1,894 $1,875 $1,876 $1,905 $1,907 1,002 1,264 1,278 1,311 1,362 1,387 409 630 597 565 543 521 Interest-bearing Noninterest-bearing 4Q19 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $750 $1,500 $2,250 $379 $493 $498 $504 $528 $526 209 257 289 315 351 362 169 236 208 189 177 164 Interest-bearing Noninterest-bearing 4Q19 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $200 $400 $600 +2% 0% +2% (4%) QoQ 0% QoQ +2% QoQ (1%) +3% (7%) 0% QoQ 0% 7 $720 $1,026 $1,006 $980 $959 $952 377 501 490 482 478 480 343 525 517 498 482 473 Other deposits Core operating deposits 4Q19 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $250 $500 $750 $1,000 $1,250 (2%) 2 +38% +27% vs. 4Q19 +35% +39% (27%) vs. 4Q19 +16% +27% +38% vs. 4Q19 +32% +73% (3%) vs. 4Q19 +39% 3
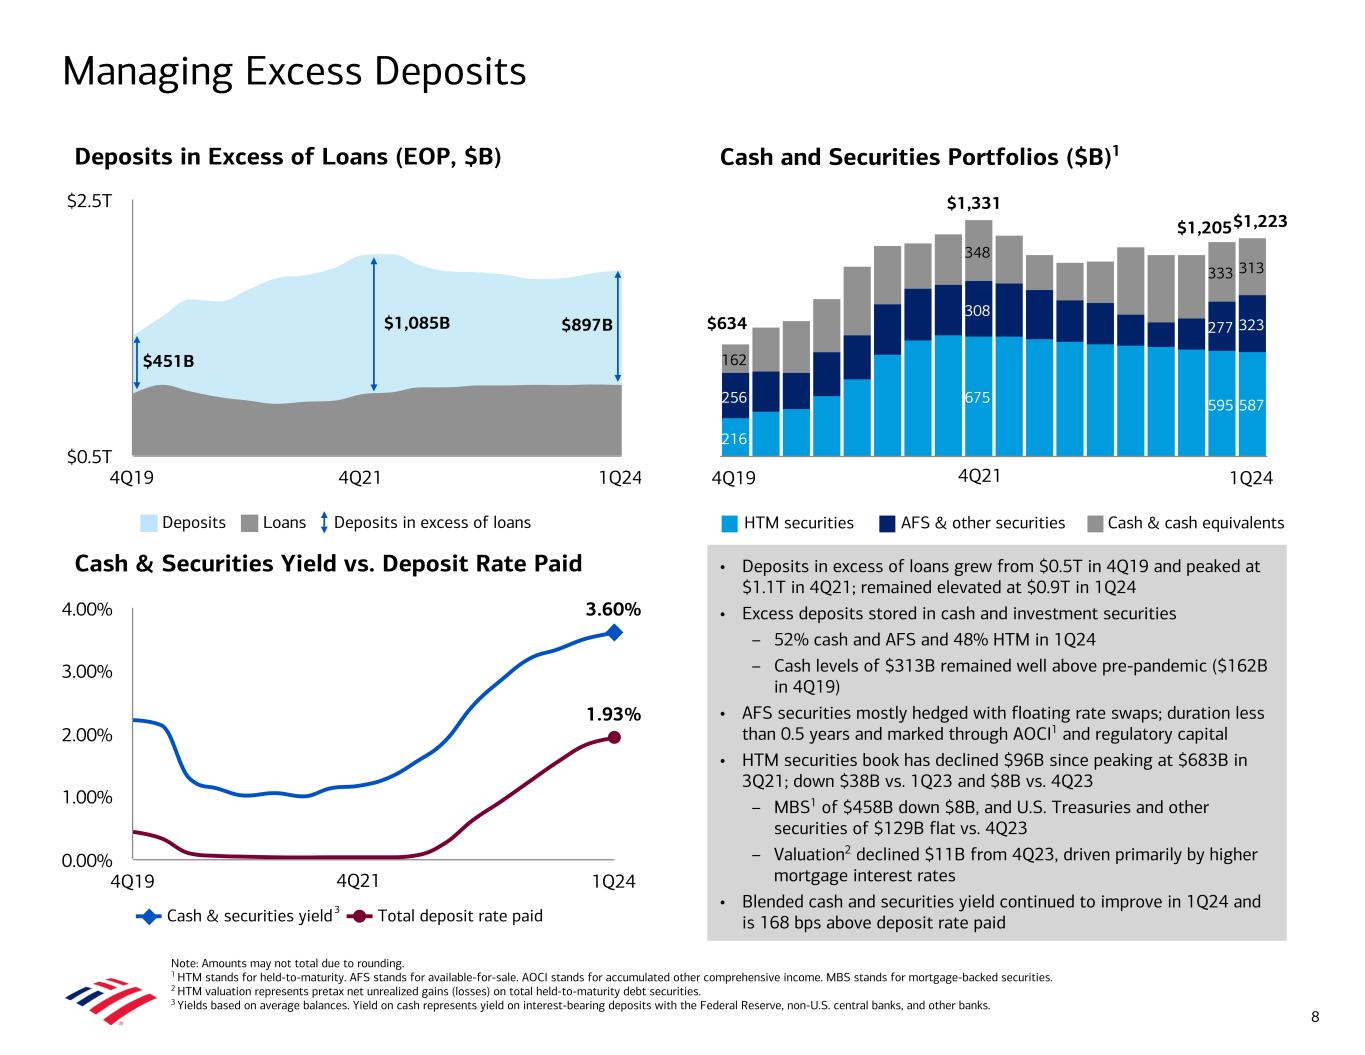
• Deposits in excess of loans grew from $0.5T in 4Q19 and peaked at $1.1T in 4Q21; remained elevated at $0.9T in 1Q24 • Excess deposits stored in cash and investment securities – 52% cash and AFS and 48% HTM in 1Q24 – Cash levels of $313B remained well above pre-pandemic ($162B in 4Q19) • AFS securities mostly hedged with floating rate swaps; duration less than 0.5 years and marked through AOCI1 and regulatory capital • HTM securities book has declined $96B since peaking at $683B in 3Q21; down $38B vs. 1Q23 and $8B vs. 4Q23 – MBS1 of $458B down $8B, and U.S. Treasuries and other securities of $129B flat vs. 4Q23 – Valuation2 declined $11B from 4Q23, driven primarily by higher mortgage interest rates • Blended cash and securities yield continued to improve in 1Q24 and is 168 bps above deposit rate paid 4Q19 4Q21 1Q24 $0.5T $2.5T 216 675 595 587256 308 277 323 162 348 333 313 4Q19 1Q24 8 3.60% 1.93% Cash & securities yield Total deposit rate paid 4Q19 1Q24 0.00% 1.00% 2.00% 3.00% 4.00% Managing Excess Deposits Deposits in Excess of Loans (EOP, $B) Cash and Securities Portfolios ($B)1 Cash & Securities Yield vs. Deposit Rate Paid 3 $451B $1,085B $897B Deposits Loans HTM securities AFS & other securities Cash & cash equivalentsDeposits in excess of loans 4Q21 4Q21 $1,223$1,205 $1,331 $634 Note: Amounts may not total due to rounding. 1 HTM stands for held-to-maturity. AFS stands for available-for-sale. AOCI stands for accumulated other comprehensive income. MBS stands for mortgage-backed securities. 2 HTM valuation represents pretax net unrealized gains (losses) on total held-to-maturity debt securities. 3 Yields based on average balances. Yield on cash represents yield on interest-bearing deposits with the Federal Reserve, non-U.S. central banks, and other banks.

• Net interest income of $14.0B ($14.2B FTE)1 decreased $0.4B YoY, as higher deposit costs more than offset higher asset yields, higher NII related to Global Markets (GM) activity, and modest loan growth – Increased $0.1B from 4Q23, driven primarily by higher asset yields and NII related to GM activity, partially offset by higher deposit costs and one fewer day of interest accrual – NII related to GM activity increased approximately $0.6B YoY and $0.1B from 4Q23 • Net interest yield of 1.99% decreased 21 bps YoY and increased 2 bps from 4Q23 – Excluding GM, net interest yield of 2.50%1 • As of March 31, 2024, a +100 bps parallel shift above the interest rate yield curve was estimated to benefit NII by $3.0B over the next 12 months; a -100bps parallel shift was estimated to decrease NII by $2.9B2 Net Interest Income (FTE, $B)1 Net Interest Income Net Interest Yield (FTE)1 Note: Amounts may not total due to rounding. FTE stands for fully taxable-equivalent basis. 1 Represent non-GAAP financial measures. Net interest yield adjusted to exclude Global Markets NII of $0.7B, $0.6B, $0.7B, $0.3B, and $0.1B and average earning assets of $692.9B, $667.1B, $656.0B, $657.9B, and $627.9B for 1Q24, 4Q23, 3Q23, 2Q23, and 1Q23, respectively. The Corporation believes the presentation of NII and net interest yield excluding Global Markets provides investors with transparency of NII and net interest yield in core banking activities. For important presentation information, see slide 34. 2 NII asset sensitivity represents banking book positions. See note E on slide 31 for information on asset sensitivity assumptions. 2.20% 2.06% 2.11% 1.97% 1.99% 2.85% 2.65% 2.64% 2.47% 2.50% Reported net interest yield Net interest yield excl. GM 1Q23 2Q23 3Q23 4Q23 1Q24 1.00% 2.00% 3.00% 4.00% $14.6 $14.3 $14.5 $14.1 $14.2 $14.4 $14.2 $14.4 $13.9 $14.0 Net interest income (GAAP) FTE adjustment 1Q23 2Q23 3Q23 4Q23 1Q24 $0.0 $5.0 $10.0 $15.0 9 Net Interest Income excl. GM (FTE, $B)1 $14.6 $14.3 $14.5 $14.1 $14.2 $14.5 $14.0 $13.9 $13.5 $13.5 NII excl. GM GM NII 1Q23 2Q23 3Q23 4Q23 1Q24 $0.0 $5.0 $10.0 $15.0
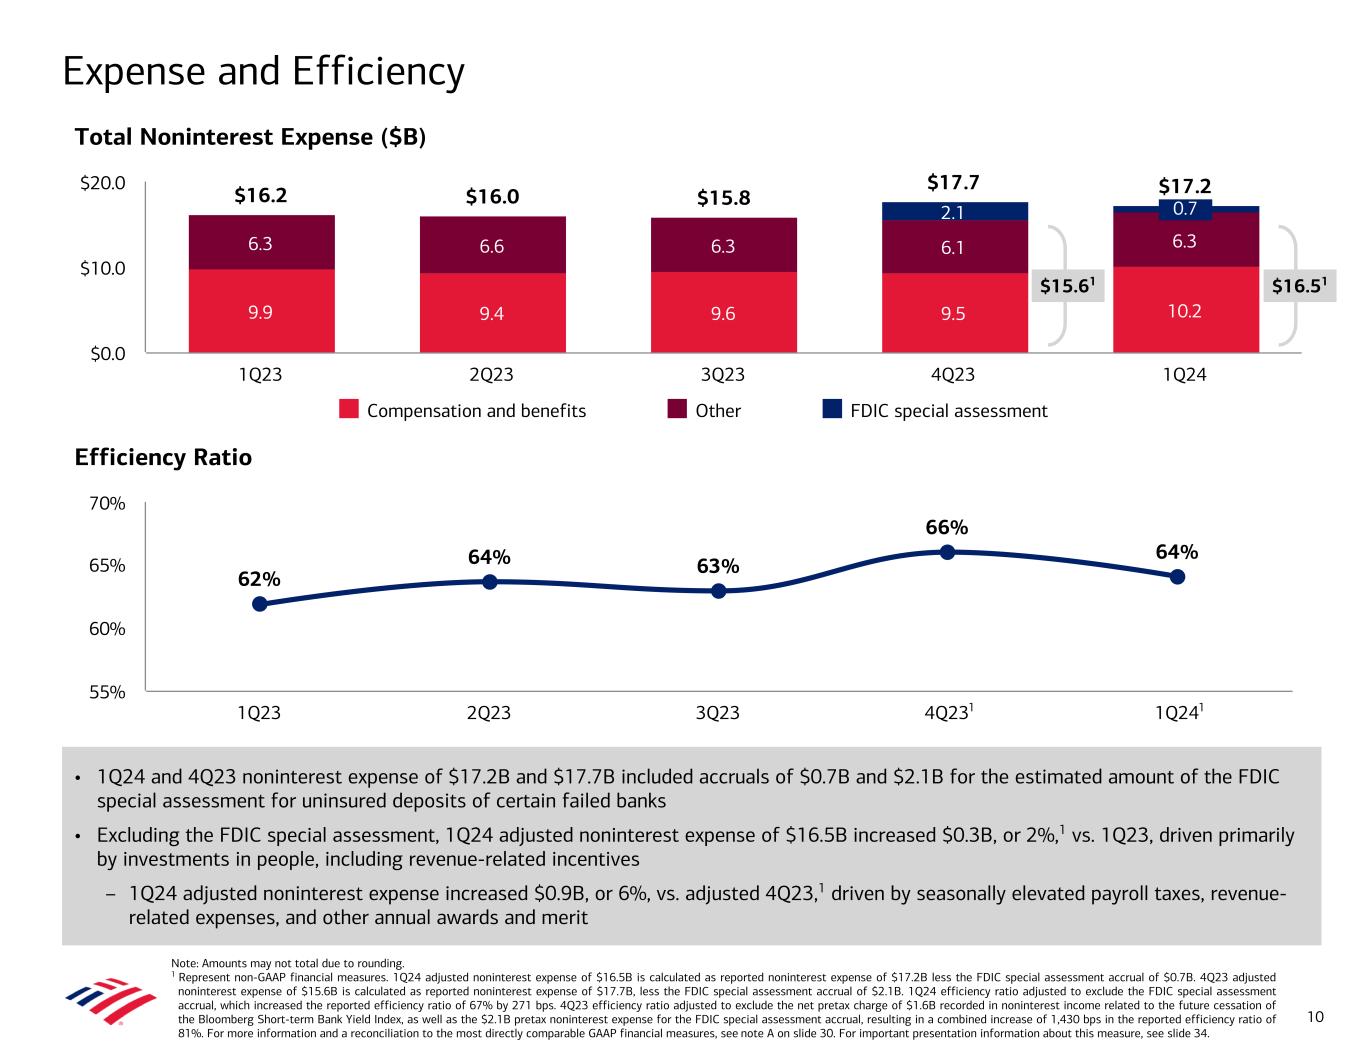
$16.2 $16.0 $15.8 $17.7 $17.2 9.9 9.4 9.6 9.5 10.2 6.3 6.6 6.3 6.1 6.3 2.1 0.7 Compensation and benefits Other FDIC special assessment 1Q23 2Q23 3Q23 4Q23 1Q24 $0.0 $10.0 $20.0 62% 64% 63% 66% 64% 1Q23 2Q23 3Q23 4Q23 1Q24 55% 60% 65% 70% Total Noninterest Expense ($B) Efficiency Ratio Expense and Efficiency 10 • 1Q24 and 4Q23 noninterest expense of $17.2B and $17.7B included accruals of $0.7B and $2.1B for the estimated amount of the FDIC special assessment for uninsured deposits of certain failed banks • Excluding the FDIC special assessment, 1Q24 adjusted noninterest expense of $16.5B increased $0.3B, or 2%,1 vs. 1Q23, driven primarily by investments in people, including revenue-related incentives – 1Q24 adjusted noninterest expense increased $0.9B, or 6%, vs. adjusted 4Q23,1 driven by seasonally elevated payroll taxes, revenue- related expenses, and other annual awards and merit 1 $16.51 Note: Amounts may not total due to rounding. 1 Represent non-GAAP financial measures. 1Q24 adjusted noninterest expense of $16.5B is calculated as reported noninterest expense of $17.2B less the FDIC special assessment accrual of $0.7B. 4Q23 adjusted noninterest expense of $15.6B is calculated as reported noninterest expense of $17.7B, less the FDIC special assessment accrual of $2.1B. 1Q24 efficiency ratio adjusted to exclude the FDIC special assessment accrual, which increased the reported efficiency ratio of 67% by 271 bps. 4Q23 efficiency ratio adjusted to exclude the net pretax charge of $1.6B recorded in noninterest income related to the future cessation of the Bloomberg Short-term Bank Yield Index, as well as the $2.1B pretax noninterest expense for the FDIC special assessment accrual, resulting in a combined increase of 1,430 bps in the reported efficiency ratio of 81%. For more information and a reconciliation to the most directly comparable GAAP financial measures, see note A on slide 30. For important presentation information about this measure, see slide 34. $15.61 1 .
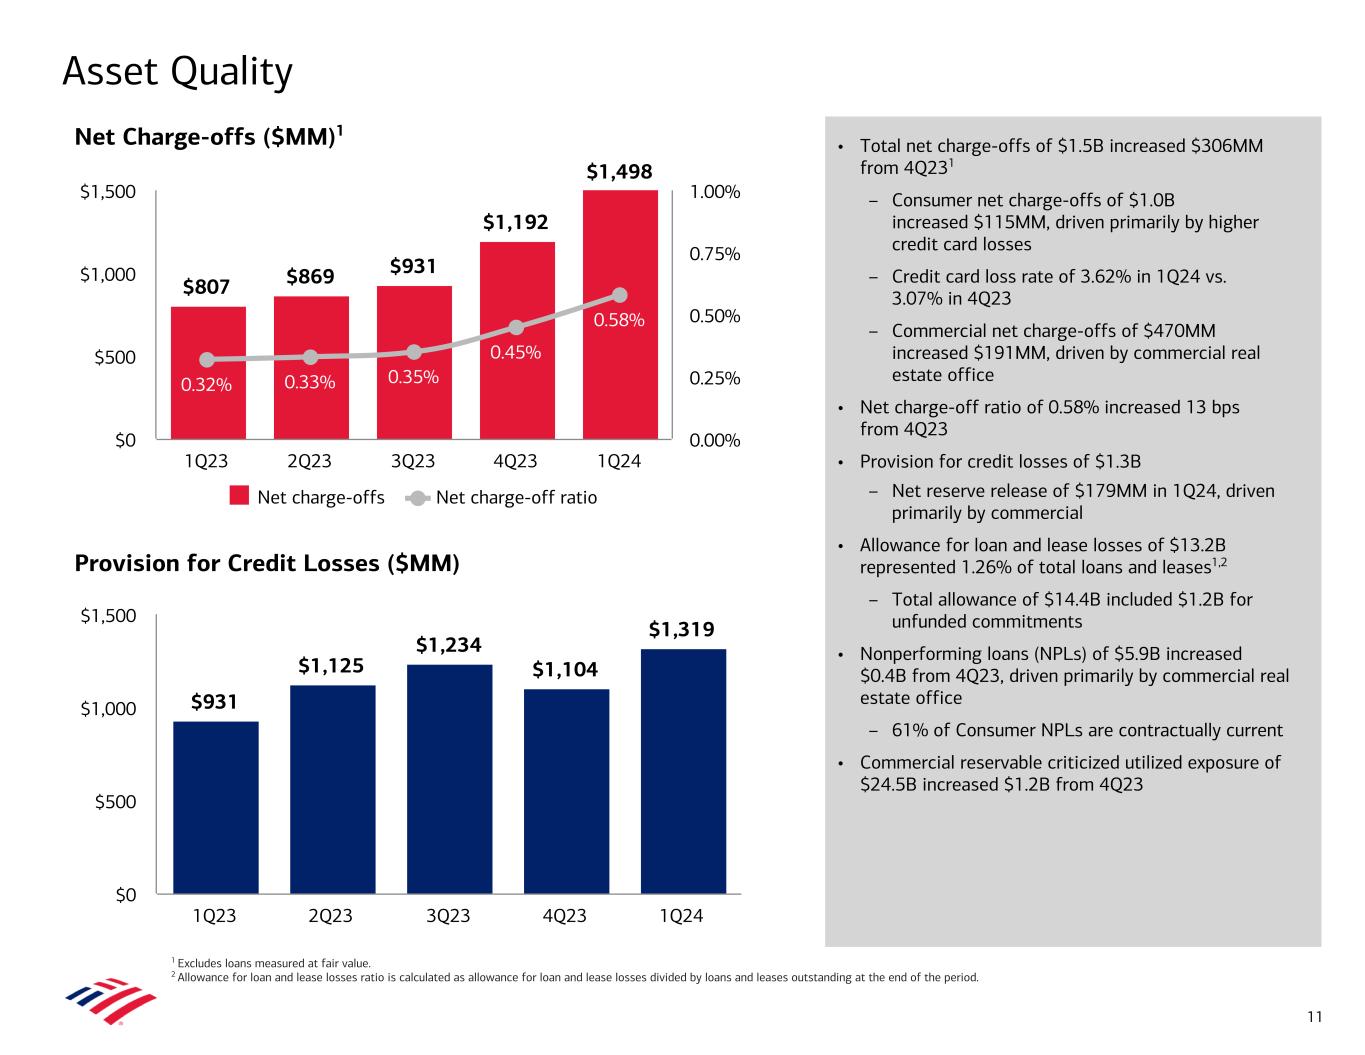
Asset Quality 1 Excludes loans measured at fair value. 2 Allowance for loan and lease losses ratio is calculated as allowance for loan and lease losses divided by loans and leases outstanding at the end of the period. Provision for Credit Losses ($MM) Net Charge-offs ($MM)1 $931 $1,125 $1,234 $1,104 $1,319 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $500 $1,000 $1,500 $807 $869 $931 $1,192 $1,498 0.32% 0.33% 0.35% 0.45% 0.58% Net charge-offs Net charge-off ratio 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $500 $1,000 $1,500 0.00% 0.25% 0.50% 0.75% 1.00% 11 • Total net charge-offs of $1.5B increased $306MM from 4Q231 – Consumer net charge-offs of $1.0B increased $115MM, driven primarily by higher credit card losses – Credit card loss rate of 3.62% in 1Q24 vs. 3.07% in 4Q23 – Commercial net charge-offs of $470MM increased $191MM, driven by commercial real estate office • Net charge-off ratio of 0.58% increased 13 bps from 4Q23 • Provision for credit losses of $1.3B – Net reserve release of $179MM in 1Q24, driven primarily by commercial • Allowance for loan and lease losses of $13.2B represented 1.26% of total loans and leases1,2 – Total allowance of $14.4B included $1.2B for unfunded commitments • Nonperforming loans (NPLs) of $5.9B increased $0.4B from 4Q23, driven primarily by commercial real estate office – 61% of Consumer NPLs are contractually current • Commercial reservable criticized utilized exposure of $24.5B increased $1.2B from 4Q23
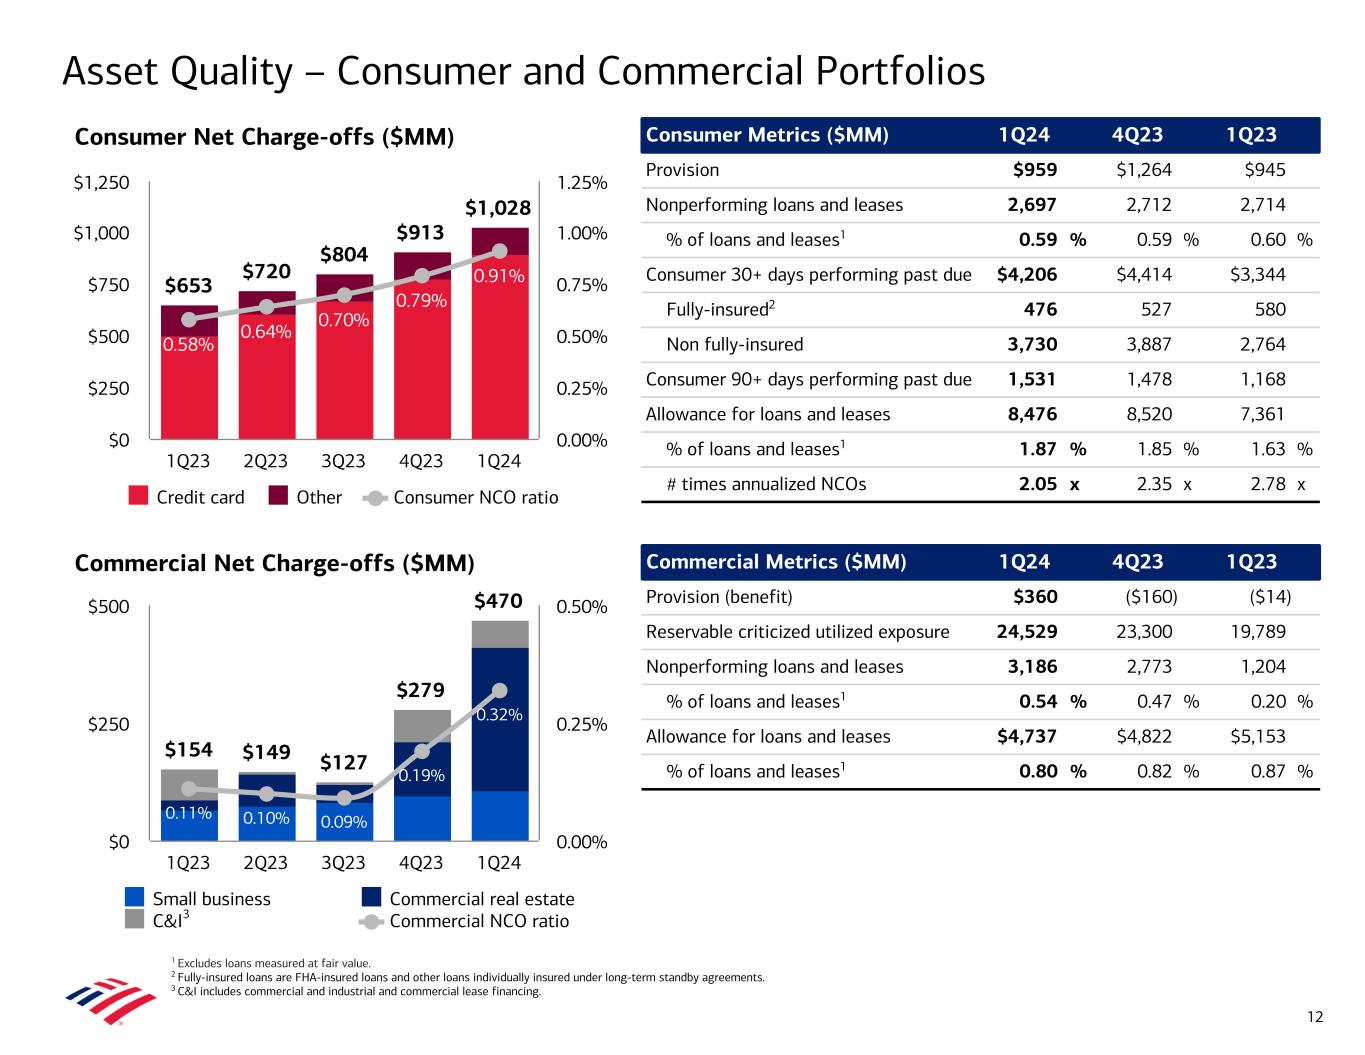
Commercial Net Charge-offs ($MM) Consumer Net Charge-offs ($MM) Asset Quality – Consumer and Commercial Portfolios 1 Excludes loans measured at fair value. 2 Fully-insured loans are FHA-insured loans and other loans individually insured under long-term standby agreements. 3 C&I includes commercial and industrial and commercial lease financing. $154 $149 $127 $279 $470 0.11% 0.10% 0.09% 0.19% 0.32% Small business Commercial real estate C&I Commercial NCO ratio 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $250 $500 0.00% 0.25% 0.50% $653 $720 $804 $913 $1,028 0.58% 0.64% 0.70% 0.79% 0.91% Credit card Other Consumer NCO ratio 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $250 $500 $750 $1,000 $1,250 0.00% 0.25% 0.50% 0.75% 1.00% 1.25% Commercial Metrics ($MM) 1Q24 4Q23 1Q23 Provision (benefit) $360 ($160) ($14) Reservable criticized utilized exposure 24,529 23,300 19,789 Nonperforming loans and leases 3,186 2,773 1,204 % of loans and leases1 0.54 % 0.47 % 0.20 % Allowance for loans and leases $4,737 $4,822 $5,153 % of loans and leases1 0.80 % 0.82 % 0.87 % Consumer Metrics ($MM) 1Q24 4Q23 1Q23 Provision $959 $1,264 $945 Nonperforming loans and leases 2,697 2,712 2,714 % of loans and leases1 0.59 % 0.59 % 0.60 % Consumer 30+ days performing past due $4,206 $4,414 $3,344 Fully-insured2 476 527 580 Non fully-insured 3,730 3,887 2,764 Consumer 90+ days performing past due 1,531 1,478 1,168 Allowance for loans and leases 8,476 8,520 7,361 % of loans and leases1 1.87 % 1.85 % 1.63 % # times annualized NCOs 2.05 x 2.35 x 2.78 x 12 3
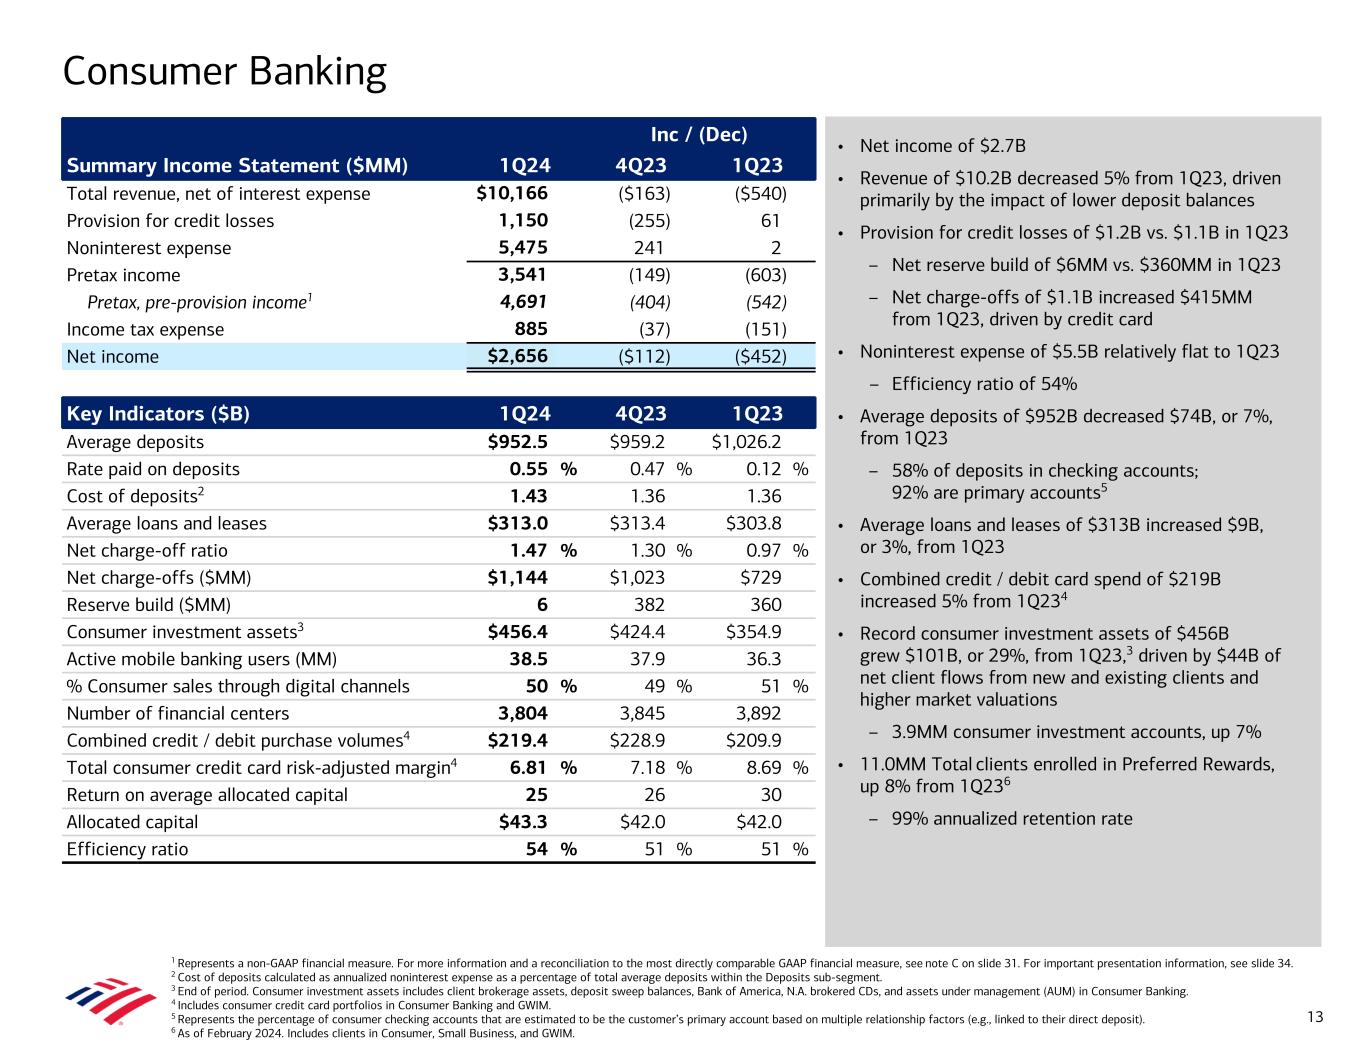
• Net income of $2.7B • Revenue of $10.2B decreased 5% from 1Q23, driven primarily by the impact of lower deposit balances • Provision for credit losses of $1.2B vs. $1.1B in 1Q23 – Net reserve build of $6MM vs. $360MM in 1Q23 – Net charge-offs of $1.1B increased $415MM from 1Q23, driven by credit card • Noninterest expense of $5.5B relatively flat to 1Q23 – Efficiency ratio of 54% • Average deposits of $952B decreased $74B, or 7%, from 1Q23 – 58% of deposits in checking accounts; 92% are primary accounts5 • Average loans and leases of $313B increased $9B, or 3%, from 1Q23 • Combined credit / debit card spend of $219B increased 5% from 1Q234 • Record consumer investment assets of $456B grew $101B, or 29%, from 1Q23,3 driven by $44B of net client flows from new and existing clients and higher market valuations – 3.9MM consumer investment accounts, up 7% • 11.0MM Total clients enrolled in Preferred Rewards, up 8% from 1Q236 – 99% annualized retention rate Consumer Banking 1 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP financial measure, see note C on slide 31. For important presentation information, see slide 34. 2 Cost of deposits calculated as annualized noninterest expense as a percentage of total average deposits within the Deposits sub-segment. 3 End of period. Consumer investment assets includes client brokerage assets, deposit sweep balances, Bank of America, N.A. brokered CDs, and assets under management (AUM) in Consumer Banking. 4 Includes consumer credit card portfolios in Consumer Banking and GWIM. 5 Represents the percentage of consumer checking accounts that are estimated to be the customer’s primary account based on multiple relationship factors (e.g., linked to their direct deposit). 6 As of February 2024. Includes clients in Consumer, Small Business, and GWIM. Inc / (Dec) Summary Income Statement ($MM) 1Q24 4Q23 1Q23 Total revenue, net of interest expense $10,166 ($163) ($540) Provision for credit losses 1,150 (255) 61 Noninterest expense 5,475 241 2 Pretax income 3,541 (149) (603) Pretax, pre-provision income1 4,691 (404) (542) Income tax expense 885 (37) (151) Net income $2,656 ($112) ($452) Key Indicators ($B) 1Q24 4Q23 1Q23 Average deposits $952.5 $959.2 $1,026.2 Rate paid on deposits 0.55 % 0.47 % 0.12 % Cost of deposits2 1.43 1.36 1.36 Average loans and leases $313.0 $313.4 $303.8 Net charge-off ratio 1.47 % 1.30 % 0.97 % Net charge-offs ($MM) $1,144 $1,023 $729 Reserve build ($MM) 6 382 360 Consumer investment assets3 $456.4 $424.4 $354.9 Active mobile banking users (MM) 38.5 37.9 36.3 % Consumer sales through digital channels 50 % 49 % 51 % Number of financial centers 3,804 3,845 3,892 Combined credit / debit purchase volumes4 $219.4 $228.9 $209.9 Total consumer credit card risk-adjusted margin4 6.81 % 7.18 % 8.69 % Return on average allocated capital 25 26 30 Allocated capital $43.3 $42.0 $42.0 Efficiency ratio 54 % 51 % 51 % 13
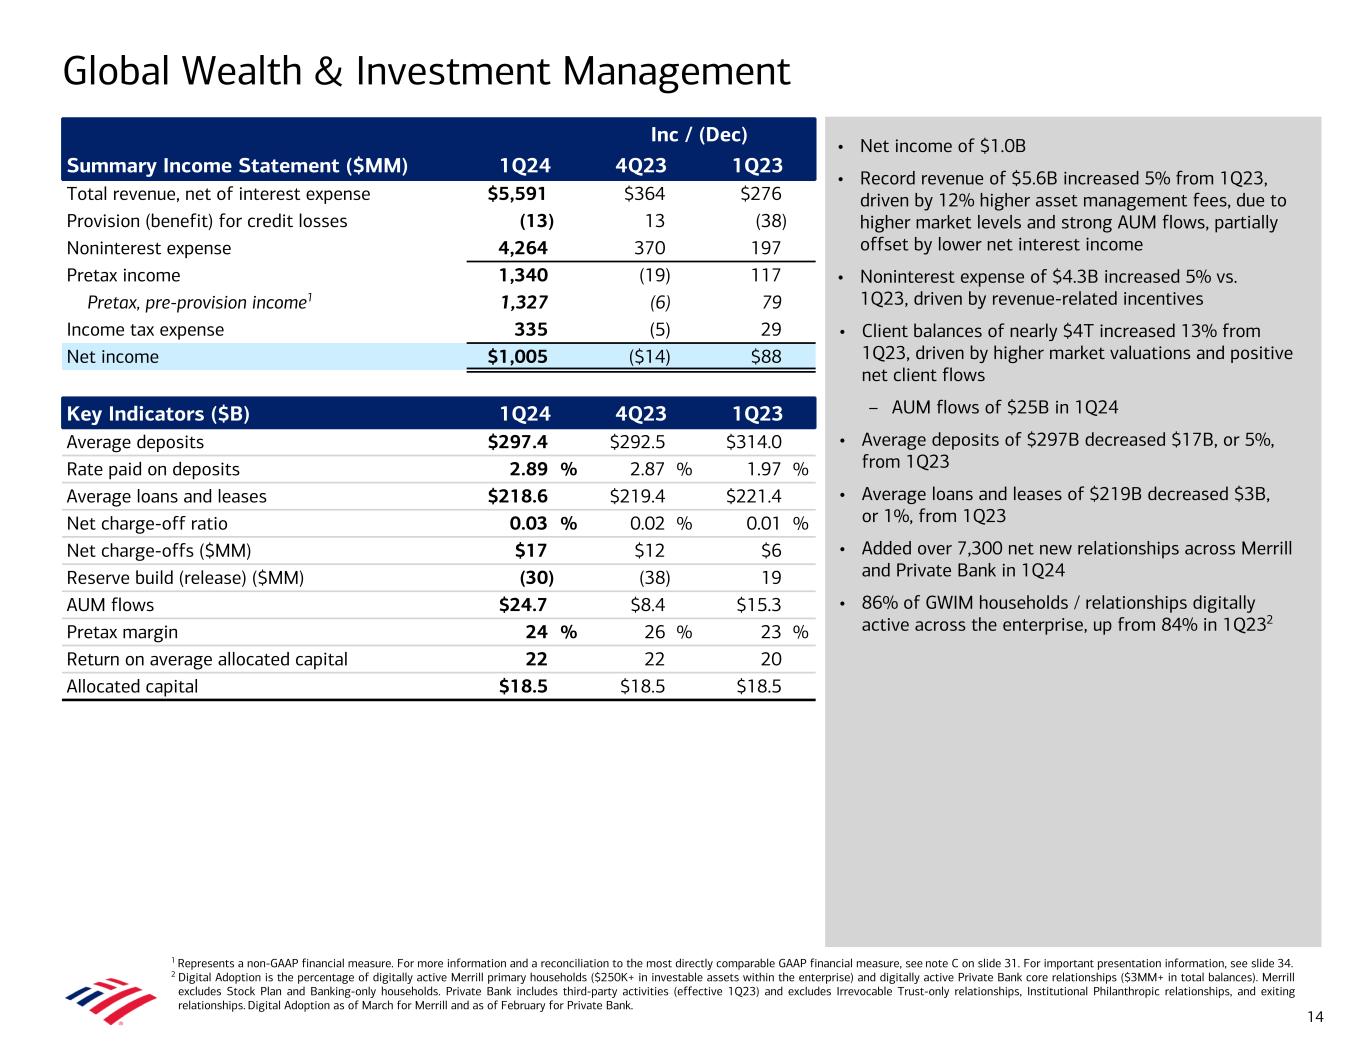
• Net income of $1.0B • Record revenue of $5.6B increased 5% from 1Q23, driven by 12% higher asset management fees, due to higher market levels and strong AUM flows, partially offset by lower net interest income • Noninterest expense of $4.3B increased 5% vs. 1Q23, driven by revenue-related incentives • Client balances of nearly $4T increased 13% from 1Q23, driven by higher market valuations and positive net client flows – AUM flows of $25B in 1Q24 • Average deposits of $297B decreased $17B, or 5%, from 1Q23 • Average loans and leases of $219B decreased $3B, or 1%, from 1Q23 • Added over 7,300 net new relationships across Merrill and Private Bank in 1Q24 • 86% of GWIM households / relationships digitally active across the enterprise, up from 84% in 1Q232 Global Wealth & Investment Management 1 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP financial measure, see note C on slide 31. For important presentation information, see slide 34. 2 Digital Adoption is the percentage of digitally active Merrill primary households ($250K+ in investable assets within the enterprise) and digitally active Private Bank core relationships ($3MM+ in total balances). Merrill excludes Stock Plan and Banking-only households. Private Bank includes third-party activities (effective 1Q23) and excludes Irrevocable Trust-only relationships, Institutional Philanthropic relationships, and exiting relationships. Digital Adoption as of March for Merrill and as of February for Private Bank. Inc / (Dec) Summary Income Statement ($MM) 1Q24 4Q23 1Q23 Total revenue, net of interest expense $5,591 $364 $276 Provision (benefit) for credit losses (13) 13 (38) Noninterest expense 4,264 370 197 Pretax income 1,340 (19) 117 Pretax, pre-provision income1 1,327 (6) 79 Income tax expense 335 (5) 29 Net income $1,005 ($14) $88 Key Indicators ($B) 1Q24 4Q23 1Q23 Average deposits $297.4 $292.5 $314.0 Rate paid on deposits 2.89 % 2.87 % 1.97 % Average loans and leases $218.6 $219.4 $221.4 Net charge-off ratio 0.03 % 0.02 % 0.01 % Net charge-offs ($MM) $17 $12 $6 Reserve build (release) ($MM) (30) (38) 19 AUM flows $24.7 $8.4 $15.3 Pretax margin 24 % 26 % 23 % Return on average allocated capital 22 22 20 Allocated capital $18.5 $18.5 $18.5 14
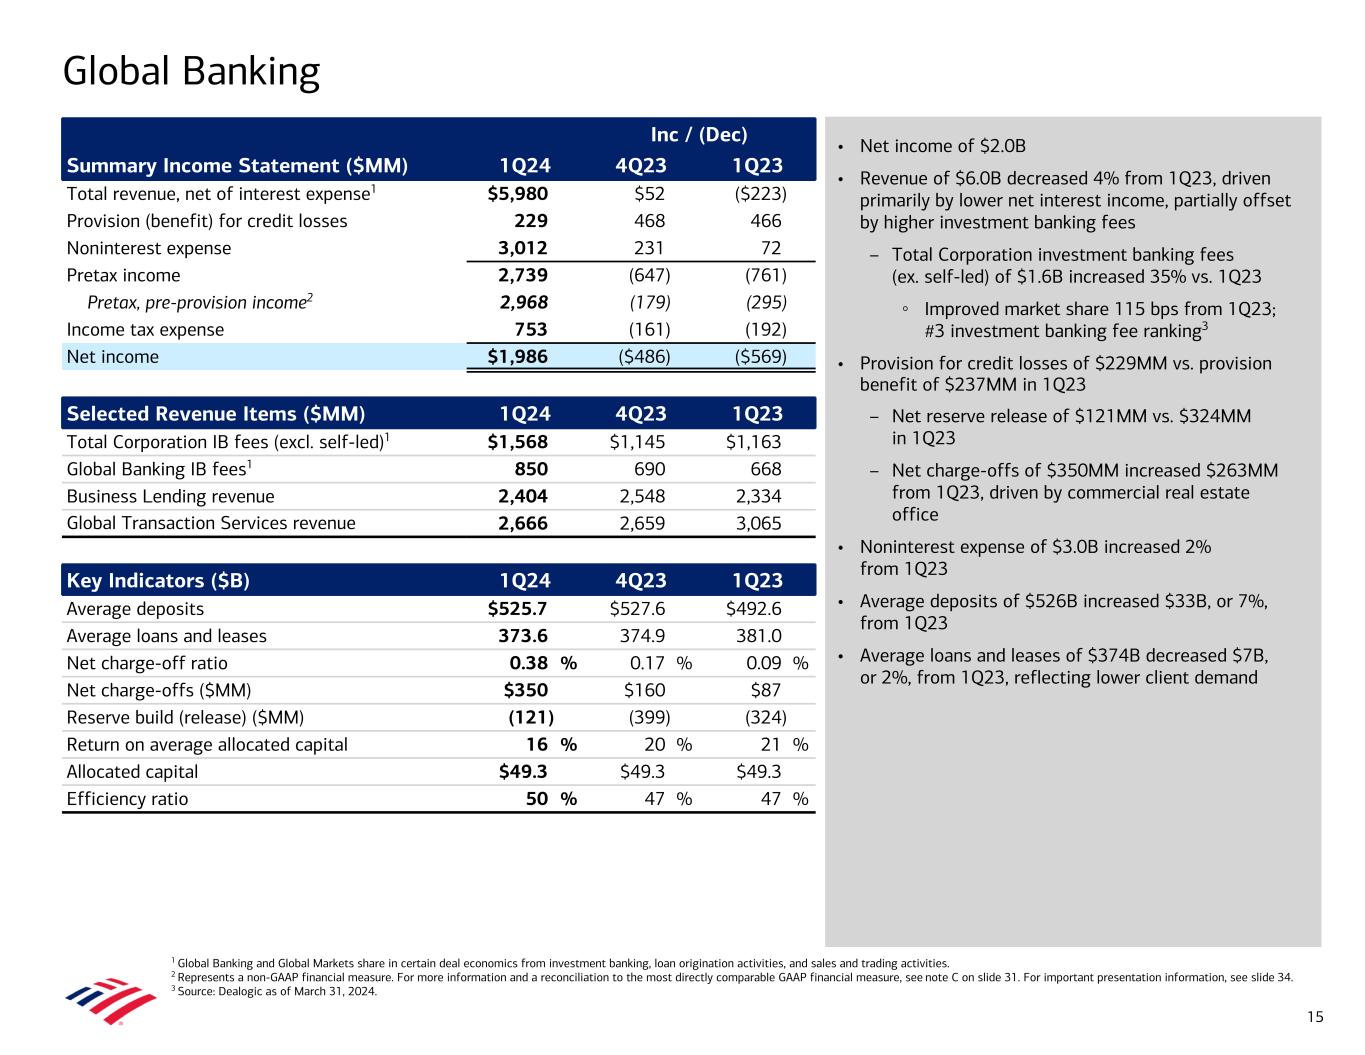
• Net income of $2.0B • Revenue of $6.0B decreased 4% from 1Q23, driven primarily by lower net interest income, partially offset by higher investment banking fees – Total Corporation investment banking fees (ex. self-led) of $1.6B increased 35% vs. 1Q23 ◦ Improved market share 115 bps from 1Q23; #3 investment banking fee ranking3 • Provision for credit losses of $229MM vs. provision benefit of $237MM in 1Q23 – Net reserve release of $121MM vs. $324MM in 1Q23 – Net charge-offs of $350MM increased $263MM from 1Q23, driven by commercial real estate office • Noninterest expense of $3.0B increased 2% from 1Q23 • Average deposits of $526B increased $33B, or 7%, from 1Q23 • Average loans and leases of $374B decreased $7B, or 2%, from 1Q23, reflecting lower client demand Global Banking 1 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 2 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP financial measure, see note C on slide 31. For important presentation information, see slide 34. 3 Source: Dealogic as of March 31, 2024. Inc / (Dec) Summary Income Statement ($MM) 1Q24 4Q23 1Q23 Total revenue, net of interest expense1 $5,980 $52 ($223) Provision (benefit) for credit losses 229 468 466 Noninterest expense 3,012 231 72 Pretax income 2,739 (647) (761) Pretax, pre-provision income2 2,968 (179) (295) Income tax expense 753 (161) (192) Net income $1,986 ($486) ($569) Selected Revenue Items ($MM) 1Q24 4Q23 1Q23 Total Corporation IB fees (excl. self-led)1 $1,568 $1,145 $1,163 Global Banking IB fees1 850 690 668 Business Lending revenue 2,404 2,548 2,334 Global Transaction Services revenue 2,666 2,659 3,065 Key Indicators ($B) 1Q24 4Q23 1Q23 Average deposits $525.7 $527.6 $492.6 Average loans and leases 373.6 374.9 381.0 Net charge-off ratio 0.38 % 0.17 % 0.09 % Net charge-offs ($MM) $350 $160 $87 Reserve build (release) ($MM) (121) (399) (324) Return on average allocated capital 16 % 20 % 21 % Allocated capital $49.3 $49.3 $49.3 Efficiency ratio 50 % 47 % 47 % 15
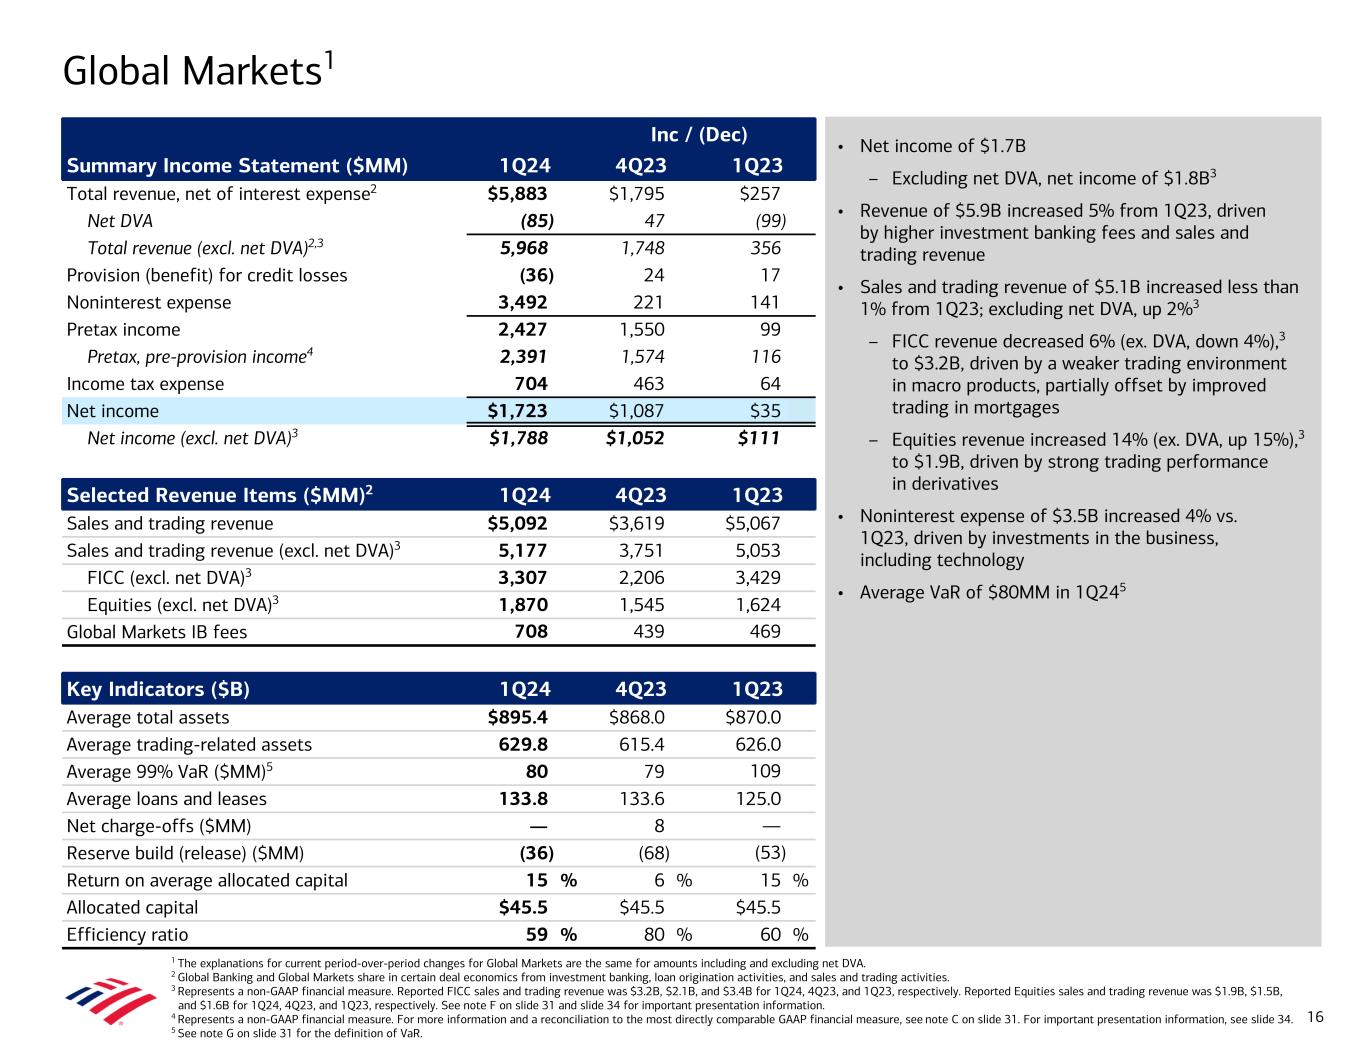
Global Markets1 • Net income of $1.7B – Excluding net DVA, net income of $1.8B3 • Revenue of $5.9B increased 5% from 1Q23, driven by higher investment banking fees and sales and trading revenue • Sales and trading revenue of $5.1B increased less than 1% from 1Q23; excluding net DVA, up 2%3 – FICC revenue decreased 6% (ex. DVA, down 4%),3 to $3.2B, driven by a weaker trading environment in macro products, partially offset by improved trading in mortgages – Equities revenue increased 14% (ex. DVA, up 15%),3 to $1.9B, driven by strong trading performance in derivatives • Noninterest expense of $3.5B increased 4% vs. 1Q23, driven by investments in the business, including technology • Average VaR of $80MM in 1Q245 1 The explanations for current period-over-period changes for Global Markets are the same for amounts including and excluding net DVA. 2 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 3 Represents a non-GAAP financial measure. Reported FICC sales and trading revenue was $3.2B, $2.1B, and $3.4B for 1Q24, 4Q23, and 1Q23, respectively. Reported Equities sales and trading revenue was $1.9B, $1.5B, and $1.6B for 1Q24, 4Q23, and 1Q23, respectively. See note F on slide 31 and slide 34 for important presentation information. 4 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP financial measure, see note C on slide 31. For important presentation information, see slide 34. 5 See note G on slide 31 for the definition of VaR. Inc / (Dec) Summary Income Statement ($MM) 1Q24 4Q23 1Q23 Total revenue, net of interest expense2 $5,883 $1,795 $257 Net DVA (85) 47 (99) Total revenue (excl. net DVA)2,3 5,968 1,748 356 Provision (benefit) for credit losses (36) 24 17 Noninterest expense 3,492 221 141 Pretax income 2,427 1,550 99 Pretax, pre-provision income4 2,391 1,574 116 Income tax expense 704 463 64 Net income $1,723 $1,087 $35 Net income (excl. net DVA)3 $1,788 $1,052 $111 Selected Revenue Items ($MM)2 1Q24 4Q23 1Q23 Sales and trading revenue $5,092 $3,619 $5,067 Sales and trading revenue (excl. net DVA)3 5,177 3,751 5,053 FICC (excl. net DVA)3 3,307 2,206 3,429 Equities (excl. net DVA)3 1,870 1,545 1,624 Global Markets IB fees 708 439 469 Key Indicators ($B) 1Q24 4Q23 1Q23 Average total assets $895.4 $868.0 $870.0 Average trading-related assets 629.8 615.4 626.0 Average 99% VaR ($MM)5 80 79 109 Average loans and leases 133.8 133.6 125.0 Net charge-offs ($MM) — 8 — Reserve build (release) ($MM) (36) (68) (53) Return on average allocated capital 15 % 6 % 15 % Allocated capital $45.5 $45.5 $45.5 Efficiency ratio 59 % 80 % 60 % 16
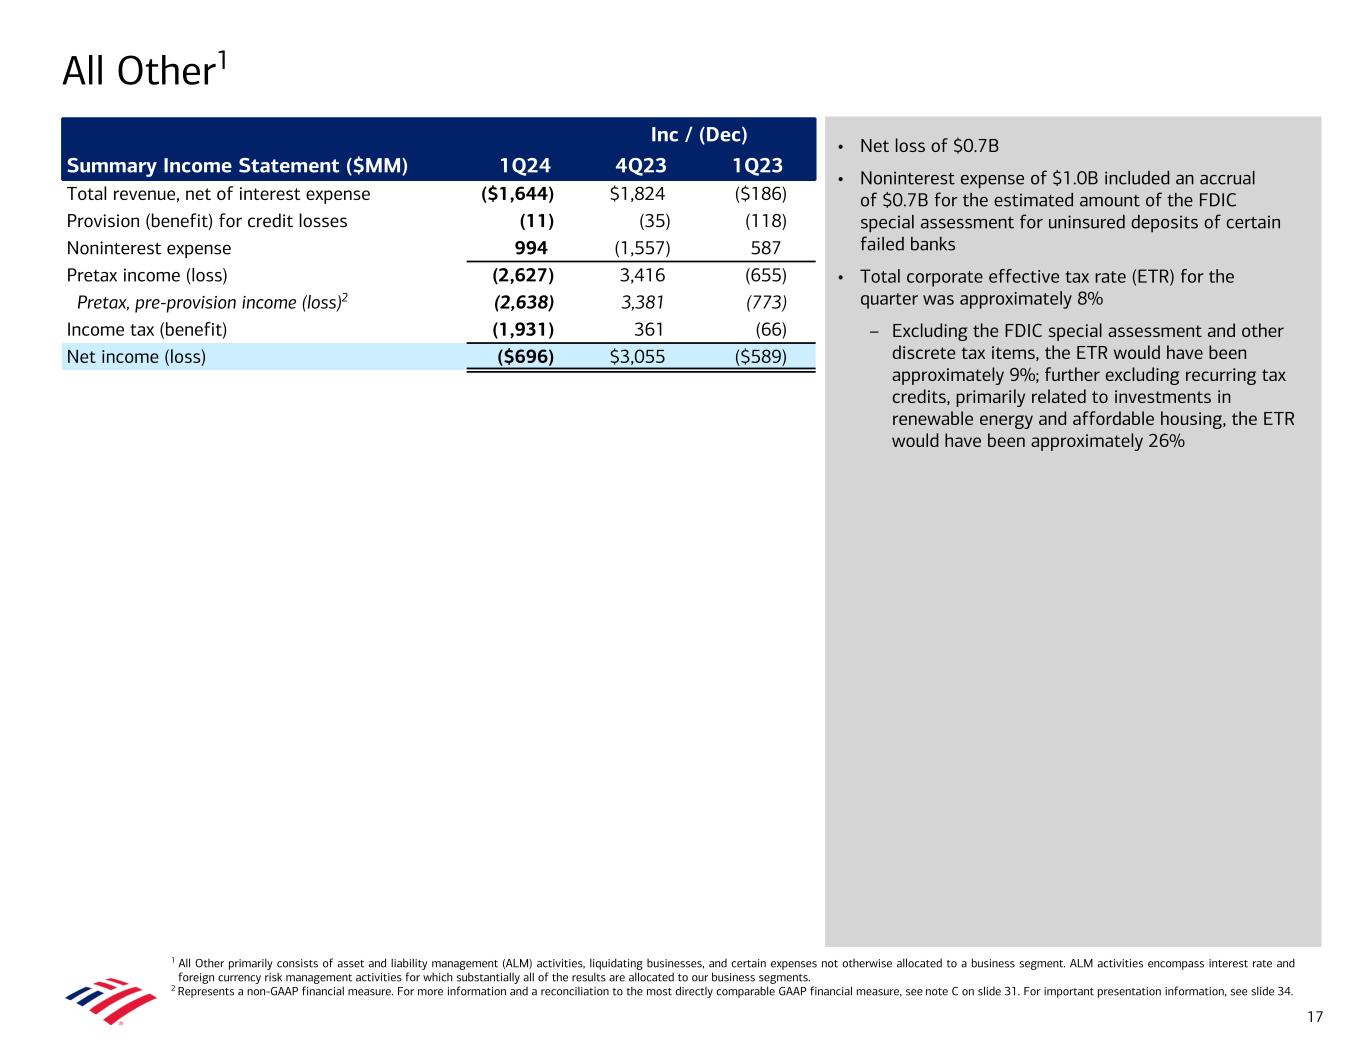
All Other1 1 All Other primarily consists of asset and liability management (ALM) activities, liquidating businesses, and certain expenses not otherwise allocated to a business segment. ALM activities encompass interest rate and foreign currency risk management activities for which substantially all of the results are allocated to our business segments. 2 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP financial measure, see note C on slide 31. For important presentation information, see slide 34. Inc / (Dec) Summary Income Statement ($MM) 1Q24 4Q23 1Q23 Total revenue, net of interest expense ($1,644) $1,824 ($186) Provision (benefit) for credit losses (11) (35) (118) Noninterest expense 994 (1,557) 587 Pretax income (loss) (2,627) 3,416 (655) Pretax, pre-provision income (loss)2 (2,638) 3,381 (773) Income tax (benefit) (1,931) 361 (66) Net income (loss) ($696) $3,055 ($589) 17 • Net loss of $0.7B • Noninterest expense of $1.0B included an accrual of $0.7B for the estimated amount of the FDIC special assessment for uninsured deposits of certain failed banks • Total corporate effective tax rate (ETR) for the quarter was approximately 8% – Excluding the FDIC special assessment and other discrete tax items, the ETR would have been approximately 9%; further excluding recurring tax credits, primarily related to investments in renewable energy and affordable housing, the ETR would have been approximately 26%
Supplemental Business Segment Trends
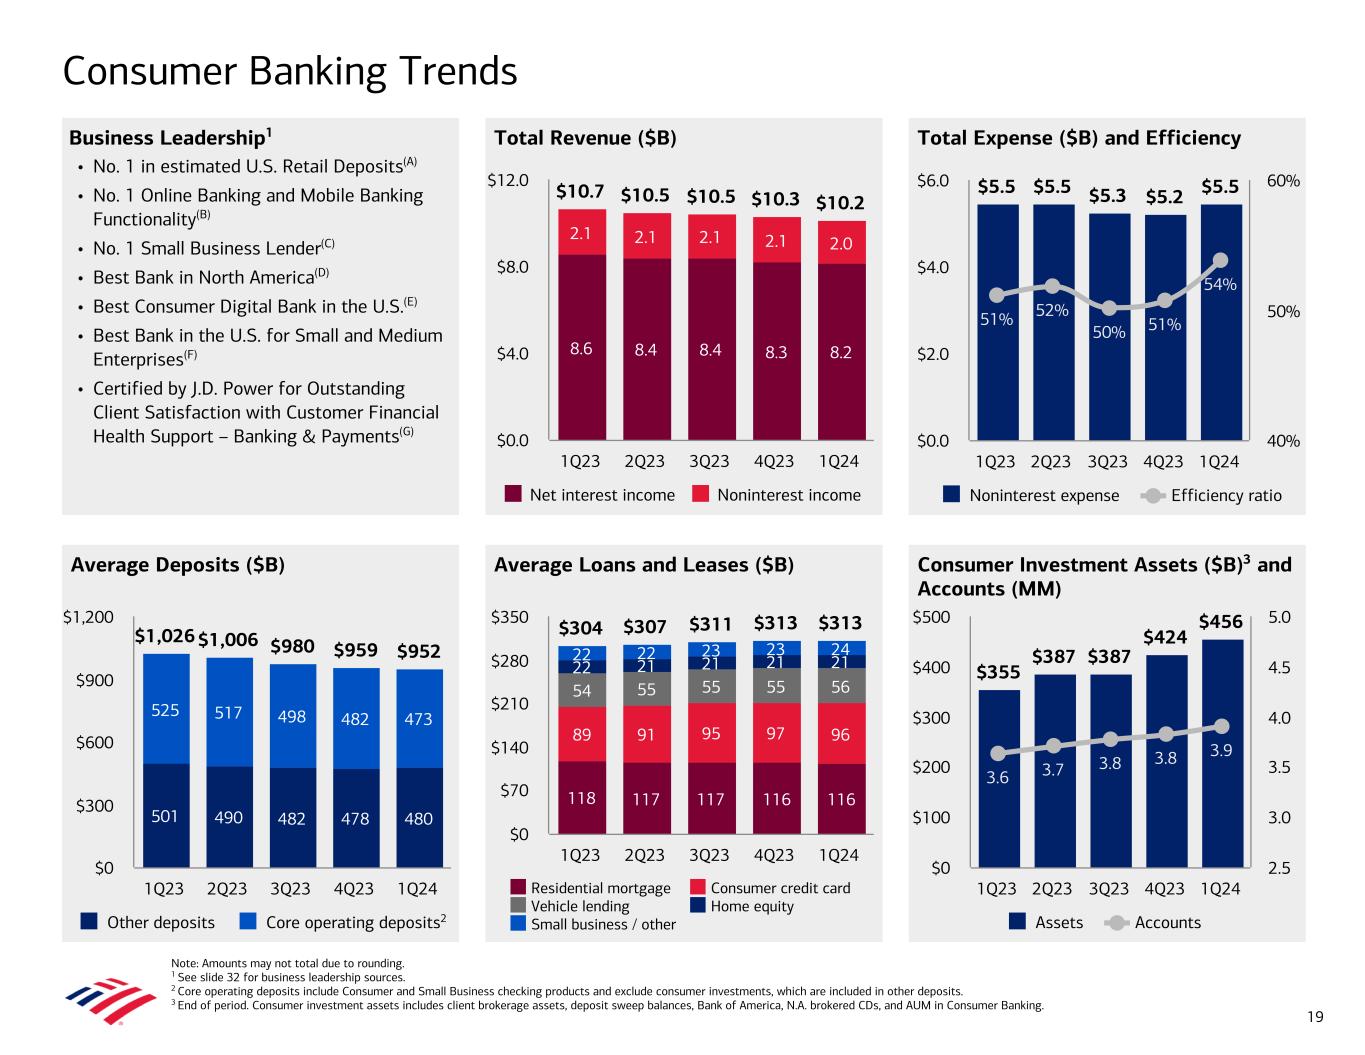
Total Expense ($B) and Efficiency Total Revenue ($B) Average Deposits ($B) Consumer Investment Assets ($B)3 and Accounts (MM) Average Loans and Leases ($B) Consumer Banking Trends Note: Amounts may not total due to rounding. 1 See slide 32 for business leadership sources. 2 Core operating deposits include Consumer and Small Business checking products and exclude consumer investments, which are included in other deposits. 3 End of period. Consumer investment assets includes client brokerage assets, deposit sweep balances, Bank of America, N.A. brokered CDs, and AUM in Consumer Banking. $10.7 $10.5 $10.5 $10.3 $10.2 8.6 8.4 8.4 8.3 8.2 2.1 2.1 2.1 2.1 2.0 Net interest income Noninterest income 1Q23 2Q23 3Q23 4Q23 1Q24 $0.0 $4.0 $8.0 $12.0 $5.5 $5.5 $5.3 $5.2 $5.5 51% 52% 50% 51% 54% Noninterest expense Efficiency ratio 1Q23 2Q23 3Q23 4Q23 1Q24 $0.0 $2.0 $4.0 $6.0 40% 50% 60% $1,026$1,006 $980 $959 $952 501 490 482 478 480 525 517 498 482 473 Other deposits Core operating deposits 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $300 $600 $900 $1,200 $304 $307 $311 $313 $313 118 117 117 116 116 89 91 95 97 96 54 55 55 55 56 22 21 21 21 2122 22 23 23 24 Residential mortgage Consumer credit card Vehicle lending Home equity Small business / other 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $70 $140 $210 $280 $350 19 $355 $387 $387 $424 $456 3.6 3.7 3.8 3.8 3.9 Assets Accounts 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $100 $200 $300 $400 $500 2.5 3.0 3.5 4.0 4.5 5.0 Business Leadership1 • No. 1 in estimated U.S. Retail Deposits(A) • No. 1 Online Banking and Mobile Banking Functionality(B) • No. 1 Small Business Lender(C) • Best Bank in North America(D) • Best Consumer Digital Bank in the U.S.(E) • Best Bank in the U.S. for Small and Medium Enterprises(F) • Certified by J.D. Power for Outstanding Client Satisfaction with Customer Financial Health Support – Banking & Payments(G) 2
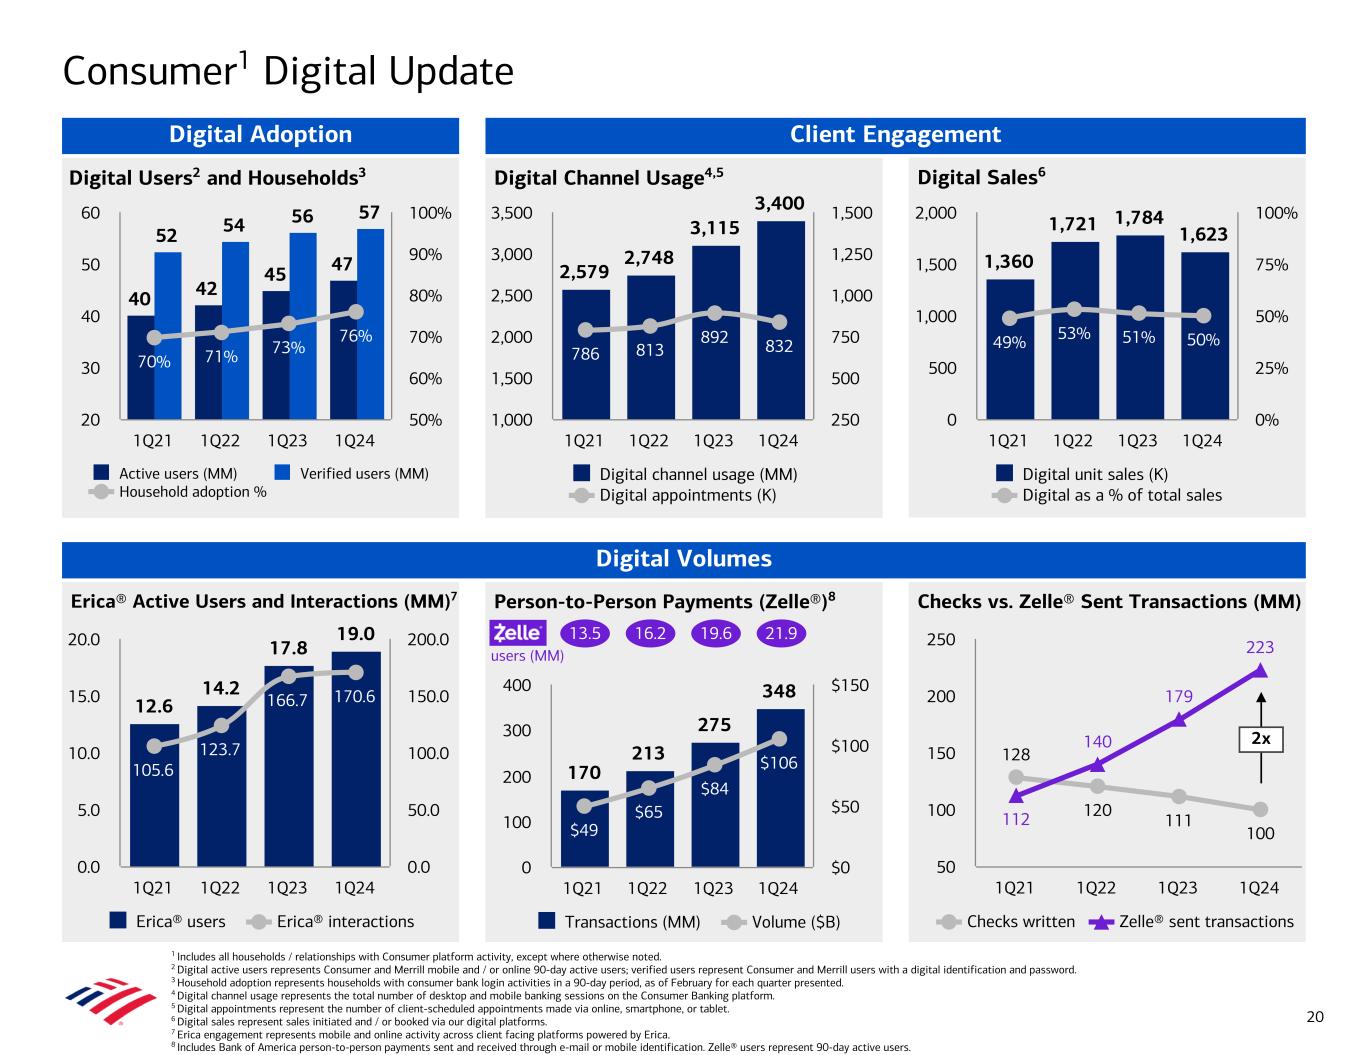
Erica® Active Users and Interactions (MM)7 Checks vs. Zelle® Sent Transactions (MM) Digital Sales6Digital Users2 and Households3 Digital Channel Usage4,5 1,360 1,721 1,784 1,623 49% 53% 51% 50% Digital unit sales (K) Digital as a % of total sales 1Q21 1Q22 1Q23 1Q24 0 500 1,000 1,500 2,000 0% 25% 50% 75% 100% 2,579 2,748 3,115 3,400 786 813 892 832 Digital channel usage (MM) Digital appointments (K) 1Q21 1Q22 1Q23 1Q24 1,000 1,500 2,000 2,500 3,000 3,500 250 500 750 1,000 1,250 1,500 40 42 45 47 52 54 56 57 70% 71% 73% 76% Active users (MM) Verified users (MM) Household adoption % 1Q21 1Q22 1Q23 1Q24 20 30 40 50 60 50% 60% 70% 80% 90% 100% Client Engagement Person-to-Person Payments (Zelle®)8 Digital Volumes 170 213 275 348 $49 $65 $84 $106 Transactions (MM) Volume ($B) 1Q21 1Q22 1Q23 1Q24 0 100 200 300 400 $0 $50 $100 $150 Consumer1 Digital Update 1 Includes all households / relationships with Consumer platform activity, except where otherwise noted. 2 Digital active users represents Consumer and Merrill mobile and / or online 90-day active users; verified users represent Consumer and Merrill users with a digital identification and password. 3 Household adoption represents households with consumer bank login activities in a 90-day period, as of February for each quarter presented. 4 Digital channel usage represents the total number of desktop and mobile banking sessions on the Consumer Banking platform. 5 Digital appointments represent the number of client-scheduled appointments made via online, smartphone, or tablet. 6 Digital sales represent sales initiated and / or booked via our digital platforms. 7 Erica engagement represents mobile and online activity across client facing platforms powered by Erica. 8 Includes Bank of America person-to-person payments sent and received through e-mail or mobile identification. Zelle® users represent 90-day active users. 13.5 16.2 19.6 21.9 users (MM) 20 Digital Adoption 12.6 14.2 17.8 19.0 105.6 123.7 166.7 170.6 Erica® users Erica® interactions 1Q21 1Q22 1Q23 1Q24 0.0 5.0 10.0 15.0 20.0 0.0 50.0 100.0 150.0 200.0 128 120 111 100 112 140 179 223 Checks written Zelle® sent transactions 1Q21 1Q22 1Q23 1Q24 50 100 150 200 250 2x
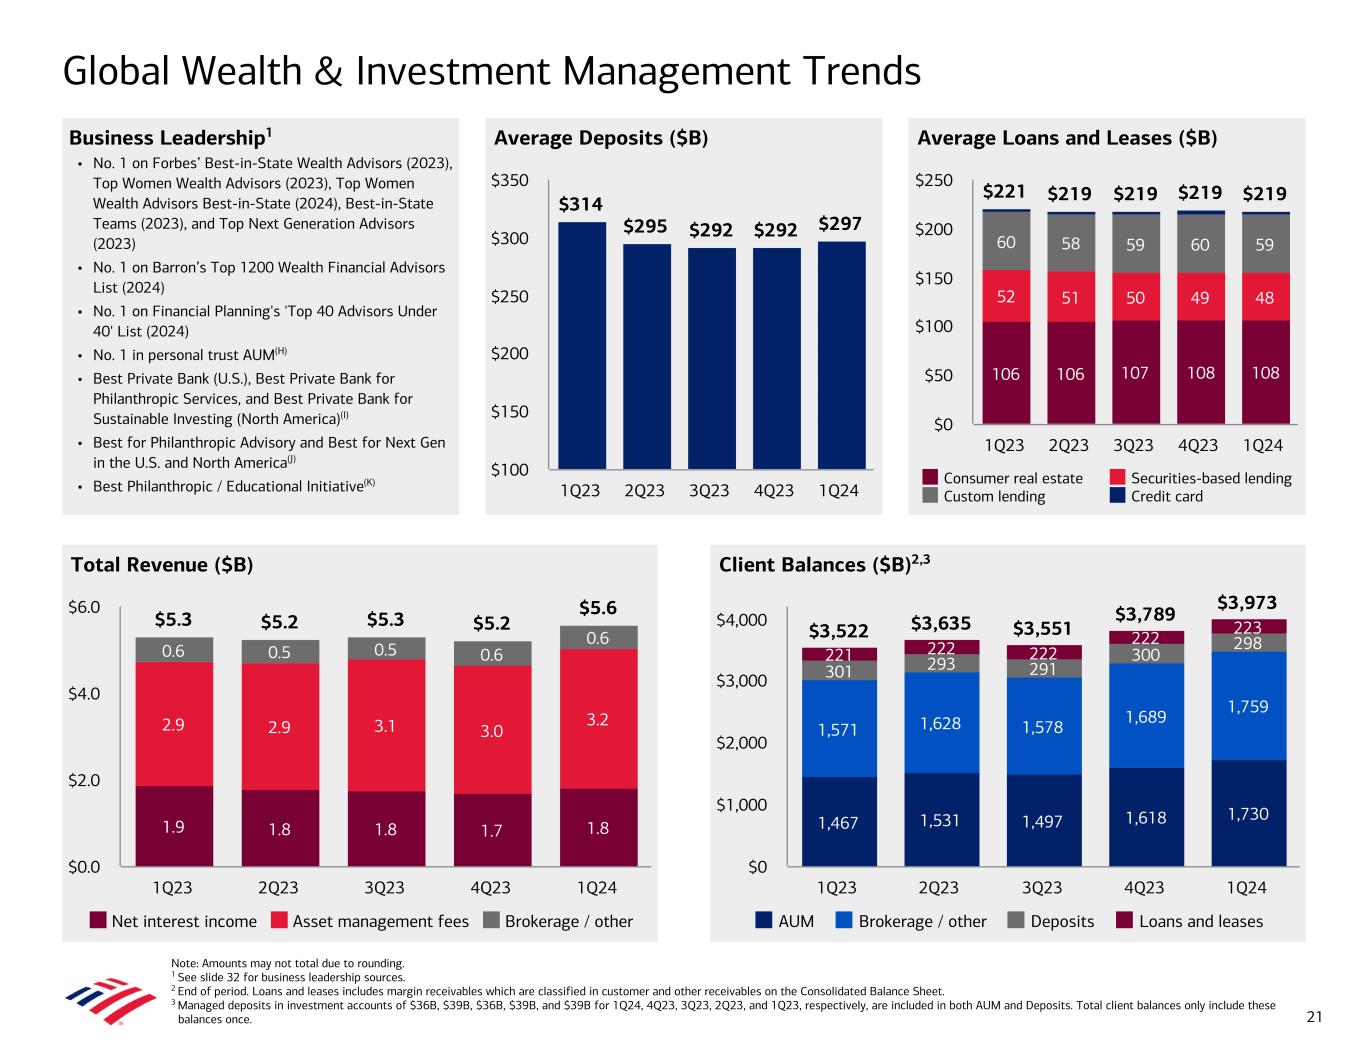
Note: Amounts may not total due to rounding. 1 See slide 32 for business leadership sources. 2 End of period. Loans and leases includes margin receivables which are classified in customer and other receivables on the Consolidated Balance Sheet. 3 Managed deposits in investment accounts of $36B, $39B, $36B, $39B, and $39B for 1Q24, 4Q23, 3Q23, 2Q23, and 1Q23, respectively, are included in both AUM and Deposits. Total client balances only include these balances once. Average Deposits ($B) Global Wealth & Investment Management Trends Business Leadership1 • No. 1 on Forbes’ Best-in-State Wealth Advisors (2023), Top Women Wealth Advisors (2023), Top Women Wealth Advisors Best-in-State (2024), Best-in-State Teams (2023), and Top Next Generation Advisors (2023) • No. 1 on Barron’s Top 1200 Wealth Financial Advisors List (2024) • No. 1 on Financial Planning's 'Top 40 Advisors Under 40' List (2024) • No. 1 in personal trust AUM(H) • Best Private Bank (U.S.), Best Private Bank for Philanthropic Services, and Best Private Bank for Sustainable Investing (North America)(I) • Best for Philanthropic Advisory and Best for Next Gen in the U.S. and North America(J) • Best Philanthropic / Educational Initiative(K) Average Loans and Leases ($B) Total Revenue ($B) Client Balances ($B)2,3 $5.3 $5.2 $5.3 $5.2 $5.6 1.9 1.8 1.8 1.7 1.8 2.9 2.9 3.1 3.0 3.2 0.6 0.5 0.5 0.6 0.6 Net interest income Asset management fees Brokerage / other 1Q23 2Q23 3Q23 4Q23 1Q24 $0.0 $2.0 $4.0 $6.0 1,467 1,531 1,497 1,618 1,730 1,571 1,628 1,578 1,689 1,759 301 293 291 300 298 221 222 222 222 223$3,522 $3,635 $3,551 $3,789 $3,973 AUM Brokerage / other Deposits Loans and leases 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $1,000 $2,000 $3,000 $4,000 $221 $219 $219 $219 $219 106 106 107 108 108 52 51 50 49 48 60 58 59 60 59 Consumer real estate Securities-based lending Custom lending Credit card 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $50 $100 $150 $200 $250 $314 $295 $292 $292 $297 1Q23 2Q23 3Q23 4Q23 1Q24 $100 $150 $200 $250 $300 $350 21

Erica® Interactions (MM)5 1.6 1.8 2.6 3.0 1Q21 1Q22 1Q23 1Q24 0.0 1.0 2.0 3.0 Person-to-Person Payments (Zelle®)6 Check Deposits7 eDelivery4Digital Households / Relationships2 Digital Channel Adoption3 71% 74% 77% 79% 1Q21 1Q22 1Q23 1Q24 0% 25% 50% 75% 100% 53% 56% 58% 62% 74% 75% 77% 80% Mobile adoption Online adoption 1Q21 1Q22 1Q23 1Q24 0% 25% 50% 75% 100% 667 688 717 748 79% 81% 84% 86% Digital households / relationships (K) Digital adoption % 1Q21 1Q22 1Q23 1Q24 500 600 700 800 60% 70% 80% 90% 100% Client Engagement Digital Volumes Global Wealth & Investment Management Digital Update 1 Digital Adoption is the percentage of digitally active Merrill primary households ($250K+ in investable assets within the enterprise) and digitally active Private Bank core relationships ($3MM+ in total balances). Merrill excludes Stock Plan and Banking-only households. Private Bank includes third-party activities (effective 1Q23) and excludes Irrevocable Trust-only relationships, Institutional Philanthropic relationships, and exiting relationships. 2 Digital Adoption as of February for 1Q21 and 1Q22. 1Q23 and 1Q24 as of March for Merrill and as of February for Private Bank. 3 Digital channel adoption represents the percentage of desktop and mobile banking engagement, as of February for 1Q21, 1Q22, and 1Q23. 1Q24 as of March for Merrill and as of February for Private Bank. 4 GWIM eDelivery percentage includes Merrill Digital Households (excluding Stock Plan, Banking-only households, Retirement only, and 529 only) and Private Bank relationships that receive statements digitally, as of February for each quarter presented. 5 Erica engagement represents mobile and online activity across client-facing platforms powered by Erica. 6 Includes Bank of America person-to-person payments sent and received through e-mail or mobile identification. 7 As of February for Private Bank and as of March for Merrill for each quarter presented. Automated check deposits include mobile check deposits, remote deposit operations, and automated teller machine transactions. 22 Digital Adoption1 1.4 1.3 1.3 1.2 73% 74% 74% 75% Physical (MM) Automated 1Q21 1Q22 1Q23 1Q24 0.0 0.5 1.0 1.5 60% 70% 80% 90% 1.2 2.0 2.7 3.6 $0.7 $1.2 $1.6 $2.2 Transactions (MM) Volume ($B) 1Q21 1Q22 1Q23 1Q24 0.0 1.0 2.0 3.0 4.0 $0.0 $1.0 $2.0 $3.0
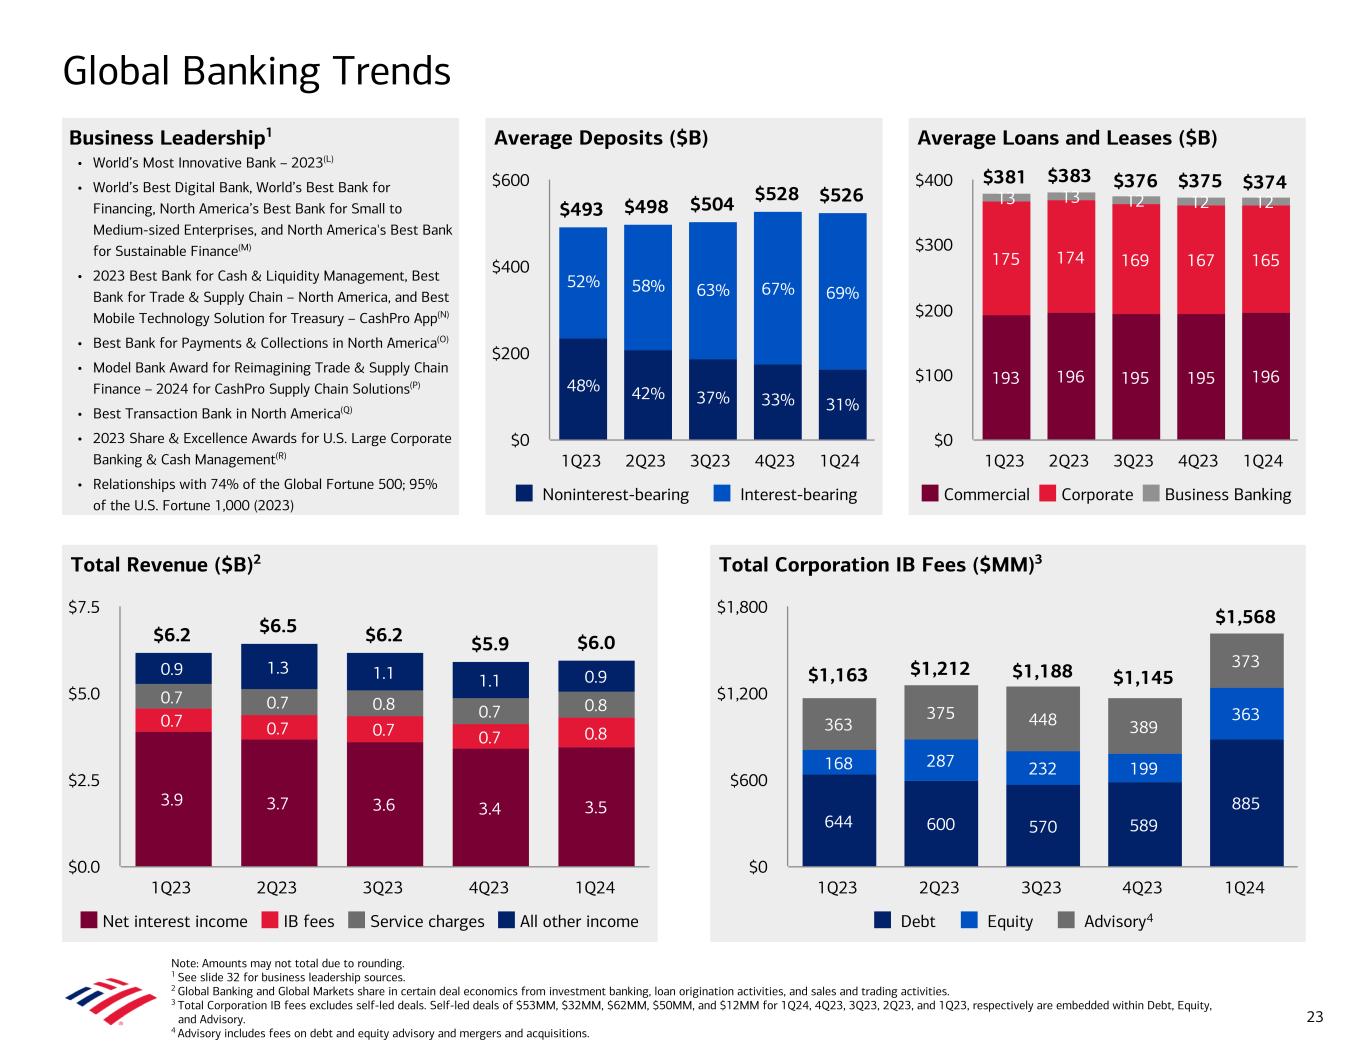
Global Banking Trends Note: Amounts may not total due to rounding. 1 See slide 32 for business leadership sources. 2 Global Banking and Global Markets share in certain deal economics from investment banking, loan origination activities, and sales and trading activities. 3 Total Corporation IB fees excludes self-led deals. Self-led deals of $53MM, $32MM, $62MM, $50MM, and $12MM for 1Q24, 4Q23, 3Q23, 2Q23, and 1Q23, respectively are embedded within Debt, Equity, and Advisory. 4 Advisory includes fees on debt and equity advisory and mergers and acquisitions. Average Deposits ($B)Business Leadership1 • World’s Most Innovative Bank – 2023(L) • World’s Best Digital Bank, World’s Best Bank for Financing, North America’s Best Bank for Small to Medium-sized Enterprises, and North America's Best Bank for Sustainable Finance(M) • 2023 Best Bank for Cash & Liquidity Management, Best Bank for Trade & Supply Chain – North America, and Best Mobile Technology Solution for Treasury – CashPro App(N) • Best Bank for Payments & Collections in North America(O) • Model Bank Award for Reimagining Trade & Supply Chain Finance – 2024 for CashPro Supply Chain Solutions(P) • Best Transaction Bank in North America(Q) • 2023 Share & Excellence Awards for U.S. Large Corporate Banking & Cash Management(R) • Relationships with 74% of the Global Fortune 500; 95% of the U.S. Fortune 1,000 (2023) Average Loans and Leases ($B) Total Revenue ($B)2 Total Corporation IB Fees ($MM)3 $6.2 $6.5 $6.2 $5.9 $6.0 3.9 3.7 3.6 3.4 3.5 0.7 0.7 0.7 0.7 0.8 0.7 0.7 0.8 0.7 0.8 0.9 1.3 1.1 1.1 0.9 Net interest income IB fees Service charges All other income 1Q23 2Q23 3Q23 4Q23 1Q24 $0.0 $2.5 $5.0 $7.5 644 600 570 589 885 168 287 232 199 363 363 375 448 389 373 $1,163 $1,212 $1,188 $1,145 $1,568 Debt Equity Advisory 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $600 $1,200 $1,800 193 196 195 195 196 175 174 169 167 165 13 13 12 12 12 $381 $383 $376 $375 $374 Commercial Corporate Business Banking 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $100 $200 $300 $400 4 $493 $498 $504 $528 $526 Noninterest-bearing Interest-bearing 1Q23 2Q23 3Q23 4Q23 1Q24 $0 $200 $400 $600 23 48% 42% 37% 33% 31% 52% 58% 63% 67% 69%

1 Digital active clients represents 90-day active clients across CashPro and BA360 platforms. Data as of February for each quarter presented. Relationship clients defined as clients meeting revenue threshold for Global Commercial Banking and Business Banking, and all clients in Global Corporate and Investment Banking. 2 Includes CashPro, BA360, and Global Card Access. CashPro data as of February for each quarter presented. 1Q21 Global Card Access sign-ins include only February and March, 2021. 3 Erica technology integrated into CashPro Chat starting in August 2023. 4 Includes CashPro alert volume and CashPro online reports and statements scheduled, BA360 90-day Erica Insights and alerts, and Global Card Access alert volume for online and mobile. 5 Percent of U.S. Dollar Investment Grade Debt Global Capital Markets investor bond orders received and fully processed digitally. Capital Markets Digital Bond Orders (%)5 Erica® Interactions on CashPro® Chat (K)3 Proactive Alerts and Insights (MM)2,4 5% 15% 23% 1Q22 1Q23 1Q24 0% 10% 20% 30% 16.0 17.5 19.0 21.2 1Q21 1Q22 1Q23 1Q24 0.0 6.0 12.0 18.0 24.0 21.9 30.6 30.0 3Q23 4Q23 1Q24 0.0 10.0 20.0 30.0 40.0 CashPro® App PaymentsBusiness Adoption % Mobile App Sign-ins (K)2 $62 $136 $174 $246 1.3 2.4 3.3 3.5 Value ($B) Volume (MM) 1Q21 1Q22 1Q23 1Q24 $0 $100 $200 $300 0.0 2.0 4.0 6.0 8.0 651 931 1,482 1,752 1Q21 1Q22 1Q23 1Q24 0 500 1,000 1,500 2,000 74% 74% 76% 76% 1Q21 1Q22 1Q23 1Q24 0% 25% 50% 75% 100% Client Engagement Digital Volumes Global Banking Digital Update 24 Digital Adoption1 87%Relationship clients:

Global Markets Trends and Revenue Mix Note: Amounts may not total due to rounding. 1 See slide 32 for business leadership sources. 2 Represents a non-GAAP financial measure. Reported Global Markets revenue was $5.9B for 1Q24. Reported sales and trading revenue was $5.1B, $5.1B, $4.7B, and $5.1B for 1Q24, 1Q23, 1Q22, and 1Q21, respectively. Reported FICC sales and trading revenue was $3.2B, $3.4B, $2.7B, and $3.2B for 1Q24, 1Q23, 1Q22, and 1Q21, respectively. Reported Equities sales and trading revenue was $1.9B, $1.6B, $2.0B, and $1.8B for 1Q24, 1Q23, 1Q22, and 1Q21, respectively. Reported Global Markets revenue mix and FICC sales and trading revenue mix are the same including and excluding DVA. See note F on slide 31 and slide 34 for important presentation information. 3 Macro includes currencies, interest rates, and commodities products. 4 See note G on slide 31 for definition of VaR. 1Q24 Global Markets Revenue Mix (excl. net DVA)2 Business Leadership1 • World's Best Bank for Markets(M) • Currency Derivatives House of the Year(S) • Derivatives House & Foreign Exchange Derivatives House of the Year(T) • North America Structured Finance House of the Year(T) • Best Bank in the U.S. for Sustainable Finance(I) • No. 1 Global Equity Research Provider(U) • No. 1 Municipal Bonds Underwriter(V) • No. 1 U.S. Asset-Backed Securities Underwriting(W) 1Q24 Total FICC Sales and Trading Revenue Mix (excl. net DVA)2 Total Sales and Trading Revenue (excl. net DVA) ($B)2 Average Trading-Related Assets ($B) and VaR ($MM)4 $5.1 $4.7 $5.1 $5.2 3.3 2.6 3.4 3.3 1.8 2.0 1.6 1.9 FICC Equities 1Q21 1Q22 1Q23 1Q24 $0.0 $2.0 $4.0 $6.0 $502 $596 $626 $630 $74 $79 $109 $80 Avg. trading-related assets Avg. VaR 1Q21 1Q22 1Q23 1Q24 $0 $250 $500 $750 $0 $50 $100 $150 63% 37% U.S. / Canada International 49% 51% Credit / Other Macro3 25
Additional Presentation Information
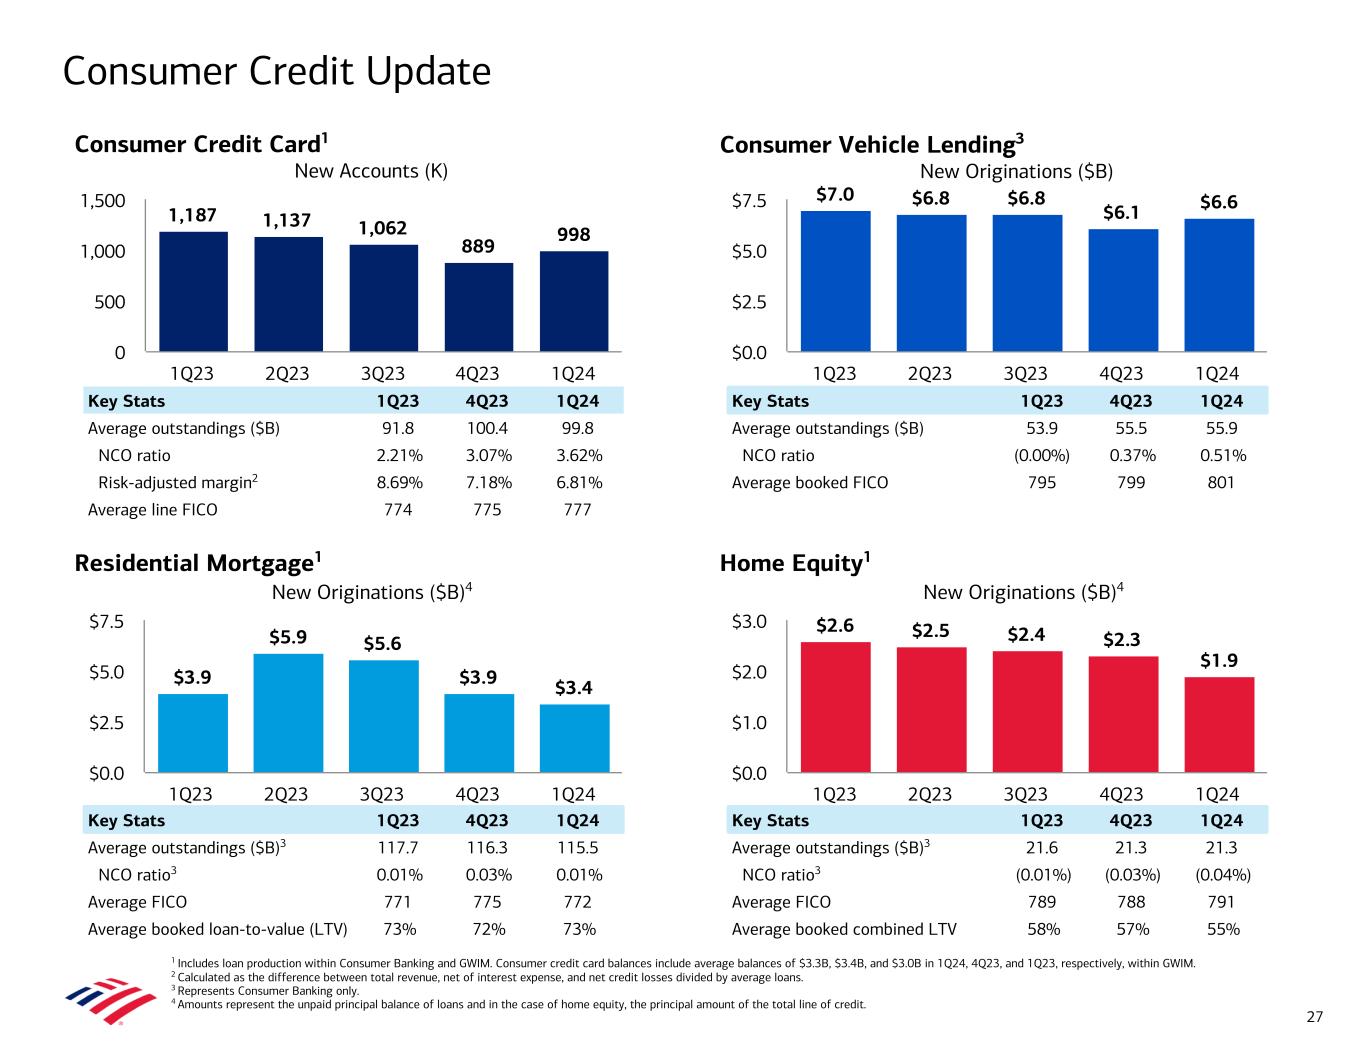
1,187 1,137 1,062 889 998 1Q23 2Q23 3Q23 4Q23 1Q24 0 500 1,000 1,500 Home Equity1 New Originations ($B)4 Consumer Credit Update 1 Includes loan production within Consumer Banking and GWIM. Consumer credit card balances include average balances of $3.3B, $3.4B, and $3.0B in 1Q24, 4Q23, and 1Q23, respectively, within GWIM. 2 Calculated as the difference between total revenue, net of interest expense, and net credit losses divided by average loans. 3 Represents Consumer Banking only. 4 Amounts represent the unpaid principal balance of loans and in the case of home equity, the principal amount of the total line of credit. Consumer Vehicle Lending3 New Originations ($B) Consumer Credit Card1 New Accounts (K) 27 Residential Mortgage1 New Originations ($B)4 Key Stats 1Q23 4Q23 1Q24 Average outstandings ($B) 91.8 100.4 99.8 NCO ratio 2.21% 3.07% 3.62% Risk-adjusted margin2 8.69% 7.18% 6.81% Average line FICO 774 775 777 $7.0 $6.8 $6.8 $6.1 $6.6 1Q23 2Q23 3Q23 4Q23 1Q24 $0.0 $2.5 $5.0 $7.5 Key Stats 1Q23 4Q23 1Q24 Average outstandings ($B) 53.9 55.5 55.9 NCO ratio (0.00%) 0.37% 0.51% Average booked FICO 795 799 801 $3.9 $5.9 $5.6 $3.9 $3.4 1Q23 2Q23 3Q23 4Q23 1Q24 $0.0 $2.5 $5.0 $7.5 Key Stats 1Q23 4Q23 1Q24 Average outstandings ($B)3 117.7 116.3 115.5 NCO ratio3 0.01% 0.03% 0.01% Average FICO 771 775 772 Average booked loan-to-value (LTV) 73% 72% 73% $2.6 $2.5 $2.4 $2.3 $1.9 1Q23 2Q23 3Q23 4Q23 1Q24 $0.0 $1.0 $2.0 $3.0 Key Stats 1Q23 4Q23 1Q24 Average outstandings ($B)3 21.6 21.3 21.3 NCO ratio3 (0.01%) (0.03%) (0.04%) Average FICO 789 788 791 Average booked combined LTV 58% 57% 55%

• Beginning in 4Q20, we saw early stage delinquencies recede below pre-pandemic levels, as expired deferrals worked through the delinquency periods and payment rates increased, fueled by stimulus payments • Credit card delinquencies have increased off historic lows over the past several quarters • In 1Q24, early stage (5-29 days past due) delinquency rate declined 18 bps from 4Q23 vs. a decline of 11 bps in 1Q23 – 30+ days past due increased 11 bps vs. an increase of 20 bps in 1Q23 D ec -1 9 M ar -2 0 Ju n- 20 Se p- 20 D ec -2 0 M ar -2 1 Ju n- 21 Se p- 21 D ec -2 1 M ar -2 2 Ju n- 22 Se p- 22 D ec -2 2 M ar -2 3 Ju n- 23 Se p- 23 D ec -2 3 M ar -2 4 $0 $1,000 $2,000 $3,000 Credit Card Days Past Due Trend Credit Card 30+ Days Past Due ($MM) 5-29 Days ($MM) Dec-19 Mar-24 $0 $1,000 $2,000 $3,000 30-59 Days ($MM) 60-89 Days ($MM) Dec-19 Mar-24 $0 $200 $400 $600 $800 Dec-19 Mar-24 $0 $200 $400 $600 Dec-19 Mar-24 $0 $500 $1,000 $1,500 90+ Days ($MM) 28 2.06% 2.02% 2.09% 2.48% Delinquency rate
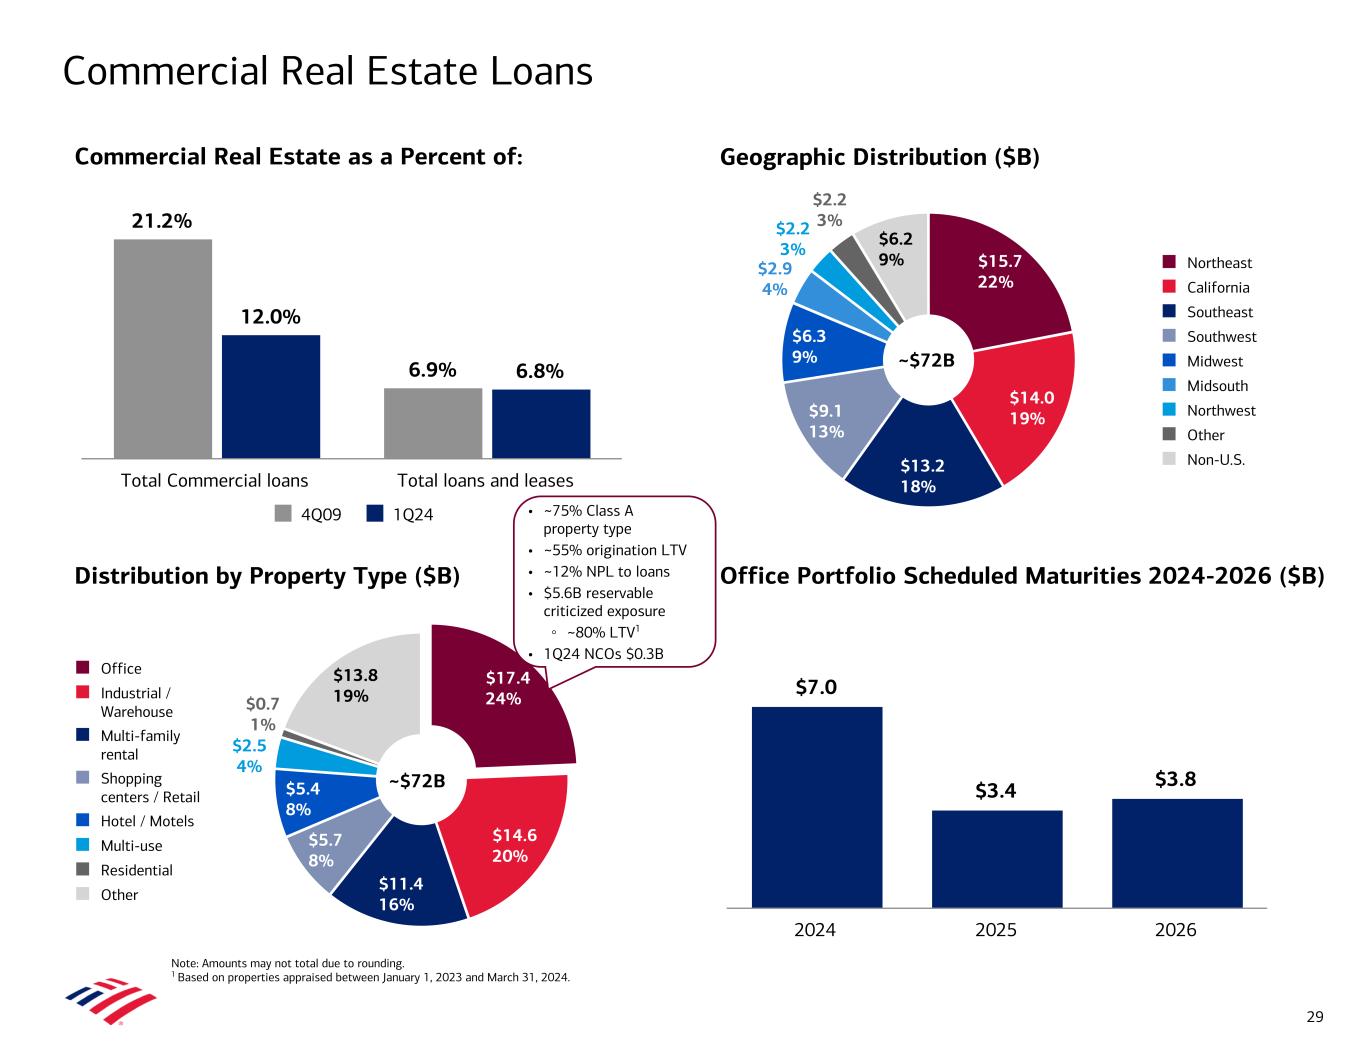
Commercial Real Estate Loans 29 21.2% 6.9% 12.0% 6.8% 4Q09 1Q24 Total Commercial loans Total loans and leases Commercial Real Estate as a Percent of: Geographic Distribution ($B) $15.7 22% $14.0 19% $13.2 18% $9.1 13% $6.3 9% $6.2 9% Northeast California Southeast Southwest Midwest Midsouth Northwest Other Non-U.S. Office Portfolio Scheduled Maturities 2024-2026 ($B) $17.4 24% $14.6 20% $11.4 16% $5.7 8% $5.4 8% $13.8 19% Office Industrial / Warehouse Multi-family rental Shopping centers / Retail Hotel / Motels Multi-use Residential Other ~$72B Distribution by Property Type ($B) $2.2 3%$2.2 3% $2.9 4% $0.7 1% $2.5 4% $7.0 $3.4 $3.8 2024 2025 2026 • ~75% Class A property type • ~55% origination LTV • ~12% NPL to loans • $5.6B reservable criticized exposure ◦ ~80% LTV1 • 1Q24 NCOs $0.3B ~$72B Note: Amounts may not total due to rounding. 1 Based on properties appraised between January 1, 2023 and March 31, 2024.

Note: Amounts may not total due to rounding. 1 Represents a non-GAAP financial measure. For more information and a reconciliation to the most directly comparable GAAP financial measure, see note C on slide 31. For important presentation information about these measures, see slide 34. 2 Calculated as net income applicable to common shareholders divided by average diluted common shares. Average diluted common shares of 8,031MM, 8,062MM, and 8,182MM for 1Q24, 4Q23, and 1Q23, respectively. 3 Calculated as net income divided by average assets. Average assets were $3,247B for 1Q24. 4 Calculated as net income applicable to common shareholders divided by average common shareholders’ equity. Average common shareholders’ equity was $264B for 1Q24. 5 Calculated as net income applicable to common shareholders divided by average tangible common shareholders’ equity. Average tangible common shareholders’ equity was $194B for 1Q24. Average tangible common shareholders’ equity represents a non- GAAP financial measure. For important presentation information on non-GAAP measures, see slide 34. 6 Calculated as noninterest expense divided by revenue, net of interest expense. A In 1Q24, the FDIC increased its estimate of the loss to the Deposit Insurance Fund arising from the closures of Silicon Valley Bank and Signature Bank that will be recouped through the collection of a special assessment from certain insured depository institutions. Accordingly, the Corporation recorded pretax noninterest expense of $0.7B to increase its accrual for its estimated share of the special assessment. The Corporation has presented certain non-GAAP financial measures (labeled as “adj.” in the tables below) that exclude the impact of the FDIC special assessment (FDIC SA) and has provided a reconciliation of these non-GAAP financial measures to the most directly comparable GAAP financial measures as set forth below. The Corporation believes the use of non-GAAP financial measures adjusting for the impact of the FDIC SA provides additional information for evaluating its results of operations and comparing its operational performance between periods by excluding these impacts that may not be reflective of its underlying operating performance. Notes 30 Reconciliation of return metrics and efficiency ratio ($ in billions) 1Q24 Reported FDIC SA 1Q24 adj. FDIC SA Return on average assets3 0.83 % (6) bps 0.89 % Return on average common shareholders’ equity4 9.4 % (81) bps 10.2 % Return on average tangible common shareholders’ equity5 12.7 % (110) bps 13.8 % Efficiency ratio6 67 % 271 bps 64 % Reconciliation 1Q24 Reported FDIC SA 1Q24 adj. FDIC SA 4Q23 Reported FDIC SA 4Q23 adj. FDIC SA Increase / (Decrease) 1Q23 Reported Increase / (Decrease) ($ in billions, except per share data) Reported adj. FDIC SA Reported adj. FDIC SA Noninterest expense $17.2 $0.7 $16.5 $17.7 $2.1 $15.6 ($0.5) $0.9 $16.2 $1.0 $0.3 Income before income taxes 7.3 (0.7) 8.0 3.1 (2.1) 5.2 4.1 2.8 9.1 (1.8) (1.1) Pretax, pre-provision income1 8.6 (0.7) 9.3 4.2 (2.1) 6.3 4.4 3.0 10.0 (1.4) (0.7) Income tax expense (benefit) 0.6 (0.2) 0.8 — (0.5) 0.5 0.6 0.3 0.9 (0.3) (0.2) Net income 6.7 (0.5) 7.2 3.1 (1.6) 4.7 3.5 2.5 8.2 (1.5) (1.0) Net income applicable to common shareholders 6.1 (0.5) 6.6 2.8 (1.6) 4.4 3.3 2.2 7.7 (1.5) (1.0) Diluted earnings per share2 $0.76 ($0.07) $0.83 $0.35 ($0.20) $0.55 $0.41 $0.28 $0.94 ($0.18) ($0.11)
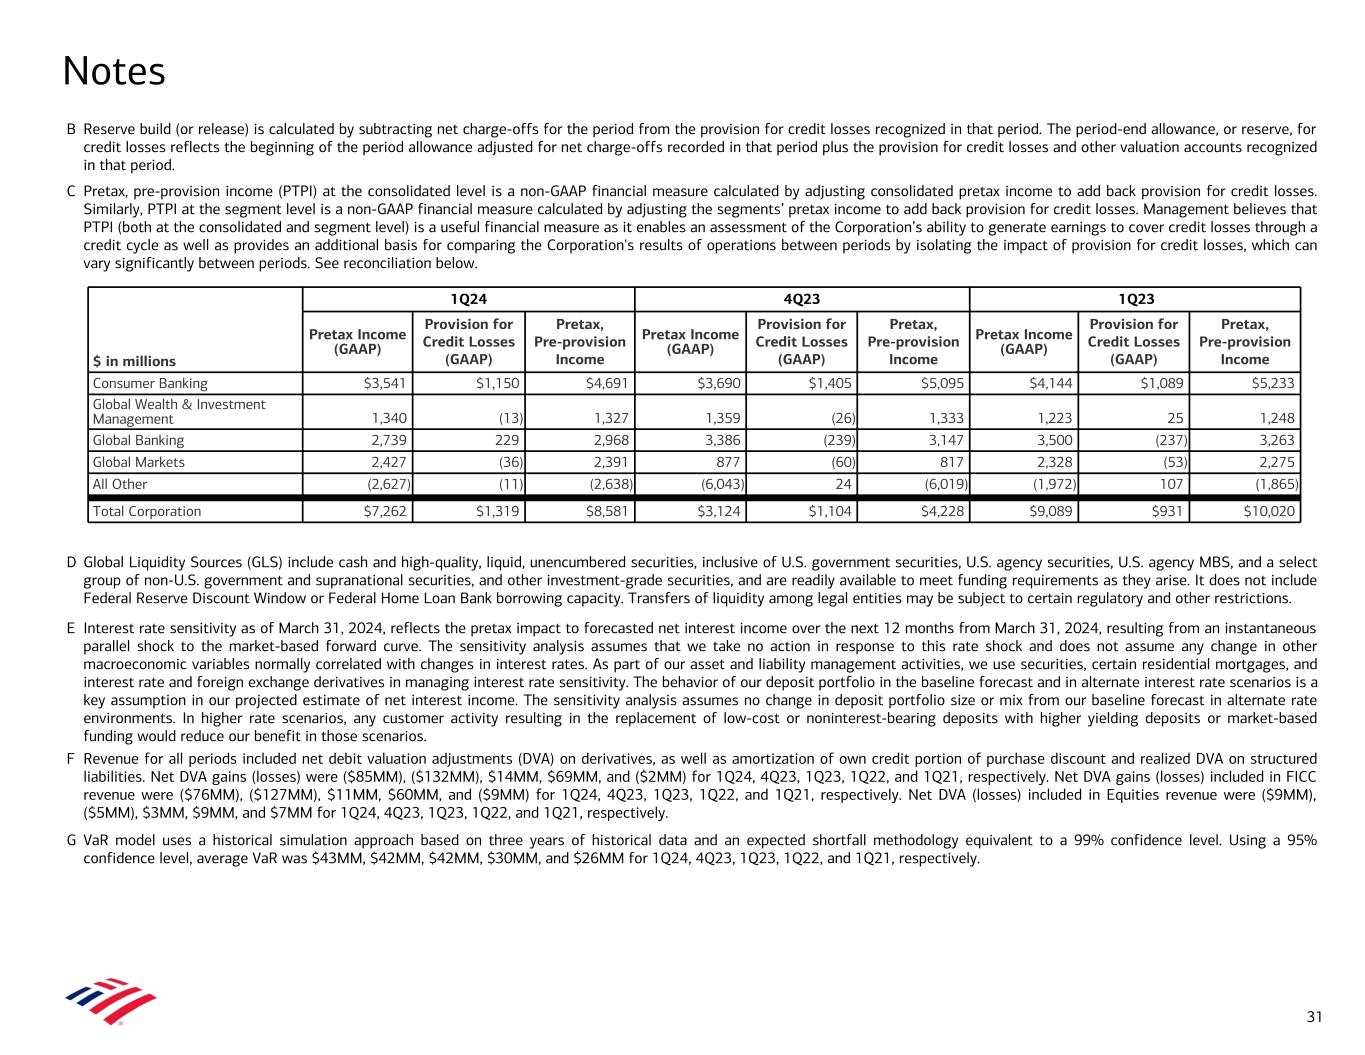
B Reserve build (or release) is calculated by subtracting net charge-offs for the period from the provision for credit losses recognized in that period. The period-end allowance, or reserve, for credit losses reflects the beginning of the period allowance adjusted for net charge-offs recorded in that period plus the provision for credit losses and other valuation accounts recognized in that period. C Pretax, pre-provision income (PTPI) at the consolidated level is a non-GAAP financial measure calculated by adjusting consolidated pretax income to add back provision for credit losses. Similarly, PTPI at the segment level is a non-GAAP financial measure calculated by adjusting the segments’ pretax income to add back provision for credit losses. Management believes that PTPI (both at the consolidated and segment level) is a useful financial measure as it enables an assessment of the Corporation’s ability to generate earnings to cover credit losses through a credit cycle as well as provides an additional basis for comparing the Corporation's results of operations between periods by isolating the impact of provision for credit losses, which can vary significantly between periods. See reconciliation below. D Global Liquidity Sources (GLS) include cash and high-quality, liquid, unencumbered securities, inclusive of U.S. government securities, U.S. agency securities, U.S. agency MBS, and a select group of non-U.S. government and supranational securities, and other investment-grade securities, and are readily available to meet funding requirements as they arise. It does not include Federal Reserve Discount Window or Federal Home Loan Bank borrowing capacity. Transfers of liquidity among legal entities may be subject to certain regulatory and other restrictions. E Interest rate sensitivity as of March 31, 2024, reflects the pretax impact to forecasted net interest income over the next 12 months from March 31, 2024, resulting from an instantaneous parallel shock to the market-based forward curve. The sensitivity analysis assumes that we take no action in response to this rate shock and does not assume any change in other macroeconomic variables normally correlated with changes in interest rates. As part of our asset and liability management activities, we use securities, certain residential mortgages, and interest rate and foreign exchange derivatives in managing interest rate sensitivity. The behavior of our deposit portfolio in the baseline forecast and in alternate interest rate scenarios is a key assumption in our projected estimate of net interest income. The sensitivity analysis assumes no change in deposit portfolio size or mix from our baseline forecast in alternate rate environments. In higher rate scenarios, any customer activity resulting in the replacement of low-cost or noninterest-bearing deposits with higher yielding deposits or market-based funding would reduce our benefit in those scenarios. F Revenue for all periods included net debit valuation adjustments (DVA) on derivatives, as well as amortization of own credit portion of purchase discount and realized DVA on structured liabilities. Net DVA gains (losses) were ($85MM), ($132MM), $14MM, $69MM, and ($2MM) for 1Q24, 4Q23, 1Q23, 1Q22, and 1Q21, respectively. Net DVA gains (losses) included in FICC revenue were ($76MM), ($127MM), $11MM, $60MM, and ($9MM) for 1Q24, 4Q23, 1Q23, 1Q22, and 1Q21, respectively. Net DVA (losses) included in Equities revenue were ($9MM), ($5MM), $3MM, $9MM, and $7MM for 1Q24, 4Q23, 1Q23, 1Q22, and 1Q21, respectively. G VaR model uses a historical simulation approach based on three years of historical data and an expected shortfall methodology equivalent to a 99% confidence level. Using a 95% confidence level, average VaR was $43MM, $42MM, $42MM, $30MM, and $26MM for 1Q24, 4Q23, 1Q23, 1Q22, and 1Q21, respectively. Notes $ in millions 1Q24 4Q23 1Q23 Pretax Income (GAAP) Provision for Credit Losses (GAAP) Pretax, Pre-provision Income Pretax Income (GAAP) Provision for Credit Losses (GAAP) Pretax, Pre-provision Income Pretax Income (GAAP) Provision for Credit Losses (GAAP) Pretax, Pre-provision Income Consumer Banking $3,541 $1,150 $4,691 $3,690 $1,405 $5,095 $4,144 $1,089 $5,233 Global Wealth & Investment Management 1,340 (13) 1,327 1,359 (26) 1,333 1,223 25 1,248 Global Banking 2,739 229 2,968 3,386 (239) 3,147 3,500 (237) 3,263 Global Markets 2,427 (36) 2,391 877 (60) 817 2,328 (53) 2,275 All Other (2,627) (11) (2,638) (6,043) 24 (6,019) (1,972) 107 (1,865) Total Corporation $7,262 $1,319 $8,581 $3,124 $1,104 $4,228 $9,089 $931 $10,020 31
Business Leadership Sources (A) Estimated U.S. retail deposits based on June 30, 2023 FDIC deposit data. (B) Javelin 2023 Online and Mobile Banking Scorecards. (C) FDIC, 4Q23. (D) Global Finance, March 2023. (E) Global Finance, August 2023. (F) Global Finance, October 2023. (G) J.D. Power 2024 Financial Health Support CertificationSM is based on exceeding customer experience benchmarks using client surveys and a best practices verification. For more information, visit jdpower.com/awards.* (H) Industry 4Q23 FDIC call reports. (I) Global Finance, 2024. (J) Euromoney, 2024. (K) With Intelligence, 2024. (L) Global Finance, 2023. (M) Euromoney, 2023. (N) Treasury Management International, 2024. (O) Global Finance Treasury & Cash Management Awards, 2023. (P) Celent, 2024. (Q) The Banker, 2023. (R) Coalition Greenwich, 2023. (S) Risk.net, 2024.* (T) IFR, 2023. (U) Institutional Investor, 2023. (V) LSEG, 2024 YTD. (W) Asset Securitization Report, 2023. 32 * Website content is not incorporated by reference into this presentation.
Forward-Looking Statements Bank of America Corporation (the Corporation) and its management may make certain statements that constitute “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. These statements can be identified by the fact that they do not relate strictly to historical or current facts. Forward-looking statements often use words such as “anticipates,” “targets,” “expects,” “hopes,” “estimates,” “intends,” “plans,” “goals,” “believes,” “continue” and other similar expressions or future or conditional verbs such as “will,” “may,” “might,” “should,” “would” and “could.” Forward-looking statements represent the Corporation’s current expectations, plans or forecasts of its future results, revenues, liquidity, net interest income, provision for credit losses, expenses, efficiency ratio, capital measures, strategy, deposits, assets, and future business and economic conditions more generally, and other future matters. These statements are not guarantees of future results or performance and involve certain known and unknown risks, uncertainties and assumptions that are difficult to predict and are often beyond the Corporation’s control. Actual outcomes and results may differ materially from those expressed in, or implied by, any of these forward-looking statements. You should not place undue reliance on any forward-looking statement and should consider the following uncertainties and risks, as well as the risks and uncertainties more fully discussed under Item 1A. Risk Factors of the Corporation’s 2023 Annual Report on Form 10-K and in any of the Corporation’s subsequent Securities and Exchange Commission filings: the Corporation’s potential judgments, orders, settlements, penalties, fines and reputational damage resulting from pending or future litigation and regulatory investigations, proceedings and enforcement actions, including as a result of our participation in and execution of government programs related to the Coronavirus Disease 2019 (COVID-19) pandemic, such as the processing of unemployment benefits for California and certain other states; the possibility that the Corporation's future liabilities may be in excess of its recorded liability and estimated range of possible loss for litigation, and regulatory and government actions; the possibility that the Corporation could face increased claims from one or more parties involved in mortgage securitizations; the Corporation’s ability to resolve representations and warranties repurchase and related claims; the risks related to the discontinuation of reference rates, including increased expenses and litigation and the effectiveness of hedging strategies; uncertainties about the financial stability and growth rates of non-U.S. jurisdictions, the risk that those jurisdictions may face difficulties servicing their sovereign debt, and related stresses on financial markets, currencies and trade, and the Corporation’s exposures to such risks, including direct, indirect and operational; the impact of U.S. and global interest rates, inflation, currency exchange rates, economic conditions, trade policies and tensions, including tariffs, and potential geopolitical instability; the impact of the interest rate, inflationary, macroeconomic, banking and regulatory environment on the Corporation’s assets, business, financial condition and results of operations; the impact of adverse developments affecting the U.S. or global banking industry, including bank failures and liquidity concerns, resulting in worsening economic and market volatility, and regulatory responses thereto; the possibility that future credit losses may be higher than currently expected due to changes in economic assumptions, customer behavior, adverse developments with respect to U.S. or global economic conditions and other uncertainties, including the impact of supply chain disruptions, inflationary pressures and labor shortages on economic conditions and our business; potential losses related to the Corporation’s concentration of credit risk; the Corporation's ability to achieve its expense targets and expectations regarding revenue, net interest income, provision for credit losses, net charge-offs, effective tax rate, loan growth or other projections; adverse changes to the Corporation’s credit ratings from the major credit rating agencies; an inability to access capital markets or maintain deposits or borrowing costs; estimates of the fair value and other accounting values, subject to impairment assessments, of certain of the Corporation’s assets and liabilities; the estimated or actual impact of changes in accounting standards or assumptions in applying those standards; uncertainty regarding the content, timing and impact of regulatory capital and liquidity requirements; the impact of adverse changes to total loss-absorbing capacity requirements, stress capital buffer requirements and / or global systemically important bank surcharges; the potential impact of actions of the Board of Governors of the Federal Reserve System on the Corporation’s capital plans; the effect of changes in or interpretations of income tax laws and regulations; the impact of implementation and compliance with U.S. and international laws, regulations and regulatory interpretations, including, but not limited to, recovery and resolution planning requirements, Federal Deposit Insurance Corporation assessments, the Volcker Rule, fiduciary standards, derivatives regulations and potential changes to loss allocations between financial institutions and customers, including for losses incurred from the use of our products and services, including electronic payments and payment of checks, that were authorized by the customer but induced by fraud; the impact of failures or disruptions in or breaches of the Corporation’s operations or information systems, or those of third parties, including as a result of cybersecurity incidents; the risks related to the development, implementation, use and management of emerging technologies, including artificial intelligence and machine learning; the risks related to the transition and physical impacts of climate change; our ability to achieve environmental, social and governance goals and commitments or the impact of any changes in the Corporation's sustainability strategy or commitments generally; the impact of any future federal government shutdown and uncertainty regarding the federal government’s debt limit or changes in fiscal, monetary or regulatory policy; the emergence or continuation of widespread health emergencies or pandemics; the impact of natural disasters, extreme weather events, military conflicts (including the Russia / Ukraine conflict, the conflict in the Middle East, the possible expansion of such conflicts and potential geopolitical consequences), terrorism or other geopolitical events; and other matters. Forward-looking statements speak only as of the date they are made, and the Corporation undertakes no obligation to update any forward-looking statement to reflect the impact of circumstances or events that arise after the date the forward-looking statement was made. 33
Important Presentation Information 34 • The information contained herein is preliminary and based on Corporation data available at the time of the earnings presentation. It speaks only as of the particular date or dates included in the accompanying slides. Bank of America does not undertake an obligation to, and disclaims any duty to, update any of the information provided. • The Corporation may present certain metrics and ratios, including year-over-year comparisons of revenue, noninterest expense, and pretax income, excluding certain items (e.g., DVA) that are non-GAAP financial measures. The Corporation believes the use of these non-GAAP financial measures provides additional clarity in understanding its results of operations and trends. For more information about the non-GAAP financial measures contained herein, please see the presentation of the most directly comparable financial measures calculated in accordance with GAAP and accompanying reconciliations in the earnings press release for the quarter ended March 31, 2024, and other earnings-related information available through the Bank of America Investor Relations website at: https://investor.bankofamerica.com/quarterly-earnings, the content of which is not incorporated by reference into this presentation. • The Corporation presents certain key financial and nonfinancial performance indicators (KPIs) that management uses when assessing consolidated and / or segment results. The Corporation believes this information is useful because it provides management with information about underlying operational performance and trends. KPIs are presented in 1Q24 Financial Results on slide 2 and on the Summary Income Statement for each segment. • The Corporation also views net interest income and related ratios and analyses on a fully taxable-equivalent (FTE) basis, which when presented on a consolidated basis are non-GAAP financial measures. The Corporation believes managing the business with net interest income on an FTE basis provides investors with meaningful information on the interest margin for comparative purposes. The Corporation believes that the presentation allows for comparison of amounts from both taxable and tax-exempt sources and is consistent with industry practices. The FTE adjustment was $158MM, $145MM, $153MM, $135MM, and $134MM for 1Q24, 4Q23, 3Q23, 2Q23, and 1Q23, respectively. • The Corporation allocates capital to its business segments using a methodology that considers the effect of regulatory capital requirements in addition to internal risk-based capital models. Allocated capital is reviewed periodically and refinements are made based on multiple considerations that include, but are not limited to, risk-weighted assets measured under Basel 3 Standardized and Advanced approaches, business segment exposures and risk profile, and strategic plans. As a result of this process, in the first quarter of 2024, the Corporation adjusted the amount of capital being allocated to its business segments.

Supplemental Information
First Quarter 2024
Current-period information is preliminary and based on company data available at the time of the earnings presentation. It speaks only as of the particular date or dates included in the accompanying pages. Bank of America Corporation (the Corporation) does not undertake an obligation to, and disclaims any duty to, update any of the information provided. Any forward-looking statements in this information are subject to the forward-looking language contained in the Corporation’s reports filed with the SEC pursuant to the Securities Exchange Act of 1934, which are available at the SEC’s website (www.sec.gov) or at the Corporation’s website (www.bankofamerica.com). The Corporation’s future financial performance is subject to risks and uncertainties as described in its SEC filings.
| Bank of America Corporation and Subsidiaries | |||||
| Table of Contents | Page | ||||
| Consumer Banking | |||||
| Global Wealth & Investment Management | |||||
| Global Banking | |||||
| Global Markets | |||||
| All Other | |||||
Key Performance Indicators | |||||
| The Corporation presents certain key financial and nonfinancial performance indicators that management uses when assessing consolidated and/or segment results. The Corporation believes this information is useful because it provides management with information about underlying operational performance and trends. Key performance indicators are presented in Consolidated Financial Highlights on page 2 and on the Key Indicators pages for each segment. | |||||
Business Segment Operations | |||||
The Corporation reports the results of operations of its four business segments and All Other on a fully taxable-equivalent (FTE) basis. Additionally, the results for the total Corporation as presented on pages 11 - 12 are reported on an FTE basis. | |||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Consolidated Financial Highlights | |||||||||||||||||||||||||||||
| (In millions, except per share information) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Income statement | |||||||||||||||||||||||||||||
| Net interest income | $ | 14,032 | $ | 13,946 | $ | 14,379 | $ | 14,158 | $ | 14,448 | |||||||||||||||||||
| Noninterest income | 11,786 | 8,013 | 10,788 | 11,039 | 11,810 | ||||||||||||||||||||||||
| Total revenue, net of interest expense | 25,818 | 21,959 | 25,167 | 25,197 | 26,258 | ||||||||||||||||||||||||
| Provision for credit losses | 1,319 | 1,104 | 1,234 | 1,125 | 931 | ||||||||||||||||||||||||
| Noninterest expense | 17,237 | 17,731 | 15,838 | 16,038 | 16,238 | ||||||||||||||||||||||||
| Income before income taxes | 7,262 | 3,124 | 8,095 | 8,034 | 9,089 | ||||||||||||||||||||||||
Pretax, pre-provision income (1) | 8,581 | 4,228 | 9,329 | 9,159 | 10,020 | ||||||||||||||||||||||||
| Income tax expense (benefit) | 588 | (20) | 293 | 626 | 928 | ||||||||||||||||||||||||
| Net income | 6,674 | 3,144 | 7,802 | 7,408 | 8,161 | ||||||||||||||||||||||||
| Preferred stock dividends | 532 | 306 | 532 | 306 | 505 | ||||||||||||||||||||||||
| Net income applicable to common shareholders | 6,142 | 2,838 | 7,270 | 7,102 | 7,656 | ||||||||||||||||||||||||
| Diluted earnings per common share | 0.76 | 0.35 | 0.90 | 0.88 | 0.94 | ||||||||||||||||||||||||
| Average diluted common shares issued and outstanding | 8,031.4 | 8,062.5 | 8,075.9 | 8,080.7 | 8,182.3 | ||||||||||||||||||||||||
| Dividends paid per common share | $ | 0.24 | $ | 0.24 | $ | 0.24 | $ | 0.22 | $ | 0.22 | |||||||||||||||||||
| Performance ratios | |||||||||||||||||||||||||||||
| Return on average assets | 0.83 | % | 0.39 | % | 0.99 | % | 0.94 | % | 1.07 | % | |||||||||||||||||||
| Return on average common shareholders’ equity | 9.35 | 4.33 | 11.24 | 11.21 | 12.48 | ||||||||||||||||||||||||
| Return on average shareholders’ equity | 9.18 | 4.32 | 10.86 | 10.52 | 11.94 | ||||||||||||||||||||||||
Return on average tangible common shareholders’ equity (2) | 12.73 | 5.92 | 15.47 | 15.49 | 17.38 | ||||||||||||||||||||||||
Return on average tangible shareholders’ equity (2) | 12.07 | 5.71 | 14.41 | 14.00 | 15.98 | ||||||||||||||||||||||||
| Efficiency ratio | 66.77 | 80.75 | 62.93 | 63.65 | 61.84 | ||||||||||||||||||||||||
| At period end | |||||||||||||||||||||||||||||
| Book value per share of common stock | $ | 33.71 | $ | 33.34 | $ | 32.65 | $ | 32.05 | $ | 31.58 | |||||||||||||||||||
Tangible book value per share of common stock (2) | 24.79 | 24.46 | 23.79 | 23.23 | 22.78 | ||||||||||||||||||||||||
| Market capitalization | 298,312 | 265,840 | 216,942 | 228,188 | 228,012 | ||||||||||||||||||||||||
| Number of financial centers - U.S. | 3,804 | 3,845 | 3,862 | 3,887 | 3,892 | ||||||||||||||||||||||||
| Number of branded ATMs - U.S. | 15,028 | 15,168 | 15,253 | 15,335 | 15,407 | ||||||||||||||||||||||||
| Headcount | 212,335 | 212,985 | 212,752 | 215,546 | 217,059 | ||||||||||||||||||||||||
(1) Pretax, pre-provision income (PTPI) is a non-GAAP financial measure calculated by adjusting pretax income to add back provision for credit losses. Management believes that PTPI is a useful financial measure because it enables an assessment of the Corporation's ability to generate earnings to cover credit losses through a credit cycle. (See Exhibit A: Non-GAAP Reconciliations - Reconciliations to GAAP Financial Measures on page 30.)
(2) Tangible equity ratios and tangible book value per share of common stock are non-GAAP financial measures. We believe the use of ratios that utilize tangible equity provides additional useful information because they present measures of those assets that can generate income. Tangible book value per share provides additional useful information about the level of tangible assets in relation to outstanding shares of common stock. (See Exhibit A: Non-GAAP Reconciliations - Reconciliations to GAAP Financial Measures on page 30.)
| Current-period information is preliminary and based on company data available at the time of the presentation. | 2 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Consolidated Statement of Income | |||||||||||||||||||||||||||||
| (In millions, except per share information) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Net interest income | |||||||||||||||||||||||||||||
| Interest income | $ | 36,285 | $ | 35,629 | $ | 33,624 | $ | 32,354 | $ | 28,655 | |||||||||||||||||||
| Interest expense | 22,253 | 21,683 | 19,245 | 18,196 | 14,207 | ||||||||||||||||||||||||
| Net interest income | 14,032 | 13,946 | 14,379 | 14,158 | 14,448 | ||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||
| Fees and commissions | 8,660 | 8,019 | 8,135 | 7,961 | 7,894 | ||||||||||||||||||||||||
| Market making and similar activities | 3,888 | 998 | 3,325 | 3,697 | 4,712 | ||||||||||||||||||||||||
| Other income (loss) | (762) | (1,004) | (672) | (619) | (796) | ||||||||||||||||||||||||
| Total noninterest income | 11,786 | 8,013 | 10,788 | 11,039 | 11,810 | ||||||||||||||||||||||||
| Total revenue, net of interest expense | 25,818 | 21,959 | 25,167 | 25,197 | 26,258 | ||||||||||||||||||||||||
| Provision for credit losses | 1,319 | 1,104 | 1,234 | 1,125 | 931 | ||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||
| Compensation and benefits | 10,195 | 9,460 | 9,551 | 9,401 | 9,918 | ||||||||||||||||||||||||
| Occupancy and equipment | 1,811 | 1,794 | 1,795 | 1,776 | 1,799 | ||||||||||||||||||||||||
| Information processing and communications | 1,800 | 1,690 | 1,676 | 1,644 | 1,697 | ||||||||||||||||||||||||
| Product delivery and transaction related | 851 | 882 | 880 | 956 | 890 | ||||||||||||||||||||||||
| Professional fees | 548 | 550 | 545 | 527 | 537 | ||||||||||||||||||||||||
| Marketing | 455 | 455 | 501 | 513 | 458 | ||||||||||||||||||||||||
| Other general operating | 1,577 | 2,900 | 890 | 1,221 | 939 | ||||||||||||||||||||||||
| Total noninterest expense | 17,237 | 17,731 | 15,838 | 16,038 | 16,238 | ||||||||||||||||||||||||
| Income before income taxes | 7,262 | 3,124 | 8,095 | 8,034 | 9,089 | ||||||||||||||||||||||||
| Income tax expense (benefit) | 588 | (20) | 293 | 626 | 928 | ||||||||||||||||||||||||
| Net income | $ | 6,674 | $ | 3,144 | $ | 7,802 | $ | 7,408 | $ | 8,161 | |||||||||||||||||||
| Preferred stock dividends | 532 | 306 | 532 | 306 | 505 | ||||||||||||||||||||||||
| Net income applicable to common shareholders | $ | 6,142 | $ | 2,838 | $ | 7,270 | $ | 7,102 | $ | 7,656 | |||||||||||||||||||
| Per common share information | |||||||||||||||||||||||||||||
| Earnings | $ | 0.77 | $ | 0.36 | $ | 0.91 | $ | 0.88 | $ | 0.95 | |||||||||||||||||||
| Diluted earnings | 0.76 | 0.35 | 0.90 | 0.88 | 0.94 | ||||||||||||||||||||||||
| Average common shares issued and outstanding | 7,968.2 | 7,990.9 | 8,017.1 | 8,040.9 | 8,065.9 | ||||||||||||||||||||||||
| Average diluted common shares issued and outstanding | 8,031.4 | 8,062.5 | 8,075.9 | 8,080.7 | 8,182.3 | ||||||||||||||||||||||||
| Consolidated Statement of Comprehensive Income | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Net income | $ | 6,674 | $ | 3,144 | $ | 7,802 | $ | 7,408 | $ | 8,161 | |||||||||||||||||||
| Other comprehensive income (loss), net-of-tax: | |||||||||||||||||||||||||||||
| Net change in debt securities | 332 | 492 | (642) | 168 | 555 | ||||||||||||||||||||||||
| Net change in debit valuation adjustments | (188) | (267) | (25) | (404) | 10 | ||||||||||||||||||||||||
| Net change in derivatives | (416) | 4,236 | (366) | (1,993) | 2,042 | ||||||||||||||||||||||||
| Employee benefit plan adjustments | 23 | (464) | 6 | 9 | 10 | ||||||||||||||||||||||||
| Net change in foreign currency translation adjustments | (20) | 7 | (23) | 5 | 12 | ||||||||||||||||||||||||
| Other comprehensive income (loss) | (269) | 4,004 | (1,050) | (2,215) | 2,629 | ||||||||||||||||||||||||
| Comprehensive income (loss) | $ | 6,405 | $ | 7,148 | $ | 6,752 | $ | 5,193 | $ | 10,790 | |||||||||||||||||||
| Current-period information is preliminary and based on company data available at the time of the presentation. | 3 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Net Interest Income and Noninterest Income | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Net interest income | |||||||||||||||||||||||||||||
| Interest income | |||||||||||||||||||||||||||||
| Loans and leases | $ | 15,240 | $ | 15,227 | $ | 14,830 | $ | 13,970 | $ | 13,097 | |||||||||||||||||||
| Debt securities | 6,137 | 5,417 | 4,658 | 4,691 | 5,460 | ||||||||||||||||||||||||
| Federal funds sold and securities borrowed or purchased under agreements to resell | 5,175 | 5,124 | 4,888 | 4,955 | 3,712 | ||||||||||||||||||||||||
| Trading account assets | 2,455 | 2,452 | 2,217 | 2,076 | 2,028 | ||||||||||||||||||||||||
| Other interest income | 7,278 | 7,409 | 7,031 | 6,662 | 4,358 | ||||||||||||||||||||||||
| Total interest income | 36,285 | 35,629 | 33,624 | 32,354 | 28,655 | ||||||||||||||||||||||||
| Interest expense | |||||||||||||||||||||||||||||
| Deposits | 9,138 | 8,724 | 7,340 | 5,785 | 4,314 | ||||||||||||||||||||||||
| Short-term borrowings | 8,535 | 8,389 | 7,629 | 8,355 | 6,180 | ||||||||||||||||||||||||
| Trading account liabilities | 546 | 557 | 510 | 472 | 504 | ||||||||||||||||||||||||
| Long-term debt | 4,034 | 4,013 | 3,766 | 3,584 | 3,209 | ||||||||||||||||||||||||
| Total interest expense | 22,253 | 21,683 | 19,245 | 18,196 | 14,207 | ||||||||||||||||||||||||
| Net interest income | $ | 14,032 | $ | 13,946 | $ | 14,379 | $ | 14,158 | $ | 14,448 | |||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||
| Fees and commissions | |||||||||||||||||||||||||||||
| Card income | |||||||||||||||||||||||||||||
Interchange fees (1) | $ | 931 | $ | 1,010 | $ | 994 | $ | 1,023 | $ | 956 | |||||||||||||||||||
| Other card income | 532 | 509 | 526 | 523 | 513 | ||||||||||||||||||||||||
| Total card income | 1,463 | 1,519 | 1,520 | 1,546 | 1,469 | ||||||||||||||||||||||||
| Service charges | |||||||||||||||||||||||||||||
| Deposit-related fees | 1,122 | 1,116 | 1,124 | 1,045 | 1,097 | ||||||||||||||||||||||||
| Lending-related fees | 320 | 330 | 340 | 319 | 313 | ||||||||||||||||||||||||
| Total service charges | 1,442 | 1,446 | 1,464 | 1,364 | 1,410 | ||||||||||||||||||||||||
| Investment and brokerage services | |||||||||||||||||||||||||||||
| Asset management fees | 3,270 | 3,012 | 3,103 | 2,969 | 2,918 | ||||||||||||||||||||||||
| Brokerage fees | 917 | 897 | 860 | 870 | 934 | ||||||||||||||||||||||||
| Total investment and brokerage services | 4,187 | 3,909 | 3,963 | 3,839 | 3,852 | ||||||||||||||||||||||||
| Investment banking fees | |||||||||||||||||||||||||||||
| Underwriting income | 901 | 478 | 531 | 657 | 569 | ||||||||||||||||||||||||
| Syndication fees | 294 | 278 | 209 | 180 | 231 | ||||||||||||||||||||||||
| Financial advisory services | 373 | 389 | 448 | 375 | 363 | ||||||||||||||||||||||||
| Total investment banking fees | 1,568 | 1,145 | 1,188 | 1,212 | 1,163 | ||||||||||||||||||||||||
| Total fees and commissions | 8,660 | 8,019 | 8,135 | 7,961 | 7,894 | ||||||||||||||||||||||||
| Market making and similar activities | 3,888 | 998 | 3,325 | 3,697 | 4,712 | ||||||||||||||||||||||||
| Other income (loss) | (762) | (1,004) | (672) | (619) | (796) | ||||||||||||||||||||||||
| Total noninterest income | $ | 11,786 | $ | 8,013 | $ | 10,788 | $ | 11,039 | $ | 11,810 | |||||||||||||||||||
(1)Gross interchange fees and merchant income were $3.2 billion, $3.4 billion, $3.4 billion, $3.4 billion and $3.2 billion and are presented net of $2.3 billion, $2.4 billion, $2.4 billion, $2.4 billion and $2.2 billion of expenses for rewards and partner payments as well as certain other card costs for the first quarter of 2024 and the fourth, third, second and first quarters of 2023, respectively.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 4 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||
| Consolidated Balance Sheet | ||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||
| March 31 2024 | December 31 2023 | March 31 2023 | ||||||||||||||||||
| Assets | ||||||||||||||||||||
| Cash and due from banks | $ | 23,550 | $ | 27,892 | $ | 29,327 | ||||||||||||||
| Interest-bearing deposits with the Federal Reserve, non-U.S. central banks and other banks | 289,854 | 305,181 | 346,891 | |||||||||||||||||
| Cash and cash equivalents | 313,404 | 333,073 | 376,218 | |||||||||||||||||
| Time deposits placed and other short-term investments | 7,859 | 8,346 | 11,637 | |||||||||||||||||
| Federal funds sold and securities borrowed or purchased under agreements to resell | 316,093 | 280,624 | 298,078 | |||||||||||||||||
| Trading account assets | 318,172 | 277,354 | 314,978 | |||||||||||||||||
| Derivative assets | 36,236 | 39,323 | 40,947 | |||||||||||||||||
| Debt securities: | ||||||||||||||||||||
| Carried at fair value | 323,119 | 276,852 | 172,510 | |||||||||||||||||
| Held-to-maturity, at cost | 586,863 | 594,555 | 624,495 | |||||||||||||||||
| Total debt securities | 909,982 | 871,407 | 797,005 | |||||||||||||||||
| Loans and leases | 1,049,156 | 1,053,732 | 1,046,406 | |||||||||||||||||
| Allowance for loan and lease losses | (13,213) | (13,342) | (12,514) | |||||||||||||||||
| Loans and leases, net of allowance | 1,035,943 | 1,040,390 | 1,033,892 | |||||||||||||||||
| Premises and equipment, net | 11,901 | 11,855 | 11,708 | |||||||||||||||||
| Goodwill | 69,021 | 69,021 | 69,022 | |||||||||||||||||
| Loans held-for-sale | 8,762 | 6,002 | 6,809 | |||||||||||||||||
| Customer and other receivables | 86,106 | 81,881 | 79,902 | |||||||||||||||||
| Other assets | 160,324 | 160,875 | 154,461 | |||||||||||||||||
| Total assets | $ | 3,273,803 | $ | 3,180,151 | $ | 3,194,657 | ||||||||||||||
| Liabilities | ||||||||||||||||||||
| Deposits in U.S. offices: | ||||||||||||||||||||
| Noninterest-bearing | $ | 524,982 | $ | 530,619 | $ | 617,922 | ||||||||||||||
| Interest-bearing | 1,304,508 | 1,273,904 | 1,183,106 | |||||||||||||||||
| Deposits in non-U.S. offices: | ||||||||||||||||||||
| Noninterest-bearing | 16,502 | 16,427 | 17,686 | |||||||||||||||||
| Interest-bearing | 100,504 | 102,877 | 91,688 | |||||||||||||||||
| Total deposits | 1,946,496 | 1,923,827 | 1,910,402 | |||||||||||||||||
| Federal funds purchased and securities loaned or sold under agreements to repurchase | 329,658 | 283,887 | 314,380 | |||||||||||||||||
| Trading account liabilities | 114,326 | 95,530 | 92,452 | |||||||||||||||||
| Derivative liabilities | 40,401 | 43,432 | 40,169 | |||||||||||||||||
| Short-term borrowings | 38,895 | 32,098 | 56,564 | |||||||||||||||||
| Accrued expenses and other liabilities | 214,129 | 207,527 | 216,621 | |||||||||||||||||
| Long-term debt | 296,346 | 302,204 | 283,873 | |||||||||||||||||
| Total liabilities | 2,980,251 | 2,888,505 | 2,914,461 | |||||||||||||||||
| Shareholders’ equity | ||||||||||||||||||||
Preferred stock, $0.01 par value; authorized –100,000,000 shares; issued and outstanding – 4,088,099, 4,088,099 and 4,088,099 shares | 28,397 | 28,397 | 28,397 | |||||||||||||||||
Common stock and additional paid-in capital, $0.01 par value; authorized – 12,800,000,000 shares; issued and outstanding – 7,866,868,200, 7,895,457,665 and 7,972,438,148 shares | 54,310 | 56,365 | 57,264 | |||||||||||||||||
| Retained earnings | 228,902 | 224,672 | 213,062 | |||||||||||||||||
| Accumulated other comprehensive income (loss) | (18,057) | (17,788) | (18,527) | |||||||||||||||||
| Total shareholders’ equity | 293,552 | 291,646 | 280,196 | |||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 3,273,803 | $ | 3,180,151 | $ | 3,194,657 | ||||||||||||||
| Assets of consolidated variable interest entities included in total assets above (isolated to settle the liabilities of the variable interest entities) | ||||||||||||||||||||
| Trading account assets | $ | 5,838 | $ | 6,054 | $ | 4,276 | ||||||||||||||
| Loans and leases | 19,250 | 18,276 | 15,754 | |||||||||||||||||
| Allowance for loan and lease losses | (920) | (826) | (797) | |||||||||||||||||
| Loans and leases, net of allowance | 18,330 | 17,450 | 14,957 | |||||||||||||||||
| All other assets | 256 | 269 | 129 | |||||||||||||||||
| Total assets of consolidated variable interest entities | $ | 24,424 | $ | 23,773 | $ | 19,362 | ||||||||||||||
| Liabilities of consolidated variable interest entities included in total liabilities above | ||||||||||||||||||||
| Short-term borrowings | $ | 3,387 | $ | 2,957 | $ | 1,339 | ||||||||||||||
| Long-term debt | 8,157 | 8,456 | 4,883 | |||||||||||||||||
| All other liabilities | 18 | 19 | 7 | |||||||||||||||||
| Total liabilities of consolidated variable interest entities | $ | 11,562 | $ | 11,432 | $ | 6,229 | ||||||||||||||
| Current-period information is preliminary and based on company data available at the time of the presentation. | 5 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||
| Capital Management | |||||||||||||||||
| (Dollars in millions) | |||||||||||||||||
| March 31 2024 | December 31 2023 | March 31 2023 | |||||||||||||||
Risk-based capital metrics (1): | |||||||||||||||||
| Standardized Approach | |||||||||||||||||
| Common equity tier 1 capital | $ | 196,625 | $ | 194,928 | $ | 184,432 | |||||||||||
| Tier 1 capital | 225,021 | 223,323 | 212,825 | ||||||||||||||
| Total capital | 252,390 | 251,399 | 242,743 | ||||||||||||||
| Risk-weighted assets | 1,660,396 | 1,651,232 | 1,621,900 | ||||||||||||||
| Common equity tier 1 capital ratio | 11.8 | % | 11.8 | % | 11.4 | % | |||||||||||
| Tier 1 capital ratio | 13.6 | 13.5 | 13.1 | ||||||||||||||
| Total capital ratio | 15.2 | 15.2 | 15.0 | ||||||||||||||
| Advanced Approaches | |||||||||||||||||
| Common equity tier 1 capital | $ | 196,625 | $ | 194,928 | $ | 184,432 | |||||||||||
| Tier 1 capital | 225,021 | 223,323 | 212,825 | ||||||||||||||
| Total capital | 242,452 | 241,449 | 233,877 | ||||||||||||||
| Risk-weighted assets | 1,470,041 | 1,458,746 | 1,427,494 | ||||||||||||||
| Common equity tier 1 capital ratio | 13.4 | % | 13.4 | % | 12.9 | % | |||||||||||
| Tier 1 capital ratio | 15.3 | 15.3 | 14.9 | ||||||||||||||
| Total capital ratio | 16.5 | 16.6 | 16.4 | ||||||||||||||
Leverage-based metrics (1): | |||||||||||||||||
| Adjusted average assets | $ | 3,168,595 | $ | 3,135,468 | $ | 3,018,318 | |||||||||||
| Tier 1 leverage ratio | 7.1 | % | 7.1 | % | 7.1 | % | |||||||||||
| Supplementary leverage exposure | $ | 3,725,480 | $ | 3,676,365 | $ | 3,554,884 | |||||||||||
| Supplementary leverage ratio | 6.0 | % | 6.1 | % | 6.0 | % | |||||||||||
| Total ending equity to total ending assets ratio | 9.0 | 9.2 | 8.8 | ||||||||||||||
| Common equity ratio | 8.1 | 8.3 | 7.9 | ||||||||||||||
Tangible equity ratio (2) | 7.0 | 7.1 | 6.7 | ||||||||||||||
Tangible common equity ratio (2) | 6.1 | 6.2 | 5.8 | ||||||||||||||
(1)Regulatory capital ratios at March 31, 2024 are preliminary. The Corporation reports regulatory capital ratios under both the Standardized and Advanced approaches. Capital adequacy is evaluated against the lower of the Standardized or Advanced approaches compared to their respective regulatory capital ratio requirements. The Corporation's binding ratio was the Total capital ratio under the Standardized approach for March 31, 2024 and December 31, 2023, and the Common equity tier 1 ratio under the Standardized approach for March 31, 2023.
(2)Tangible equity ratio equals period-end tangible shareholders’ equity divided by period-end tangible assets. Tangible common equity ratio equals period-end tangible common shareholders’ equity divided by period-end tangible assets. Tangible shareholders’ equity and tangible assets are non-GAAP financial measures. We believe the use of ratios that utilize tangible equity provides additional useful information because they present measures of those assets that can generate income. (See Exhibit A: Non-GAAP Reconciliations - Reconciliation to GAAP Financial Measures on page 30.)
| Current-period information is preliminary and based on company data available at the time of the presentation. | 6 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||
| Capital Composition under Basel 3 | |||||||||||||||||
| (Dollars in millions) | |||||||||||||||||
| March 31 2024 | December 31 2023 | March 31 2023 | |||||||||||||||
| Total common shareholders' equity | $ | 265,155 | $ | 263,249 | $ | 251,799 | |||||||||||
CECL transitional amount (1) | 627 | 1,254 | 1,254 | ||||||||||||||
| Goodwill, net of related deferred tax liabilities | (68,648) | (68,648) | (68,644) | ||||||||||||||
| Deferred tax assets arising from net operating loss and tax credit carryforwards | (8,148) | (7,912) | (7,835) | ||||||||||||||
| Intangibles, other than mortgage servicing rights, net of related deferred tax liabilities | (1,481) | (1,496) | (1,538) | ||||||||||||||
| Defined benefit pension plan net assets, net-of-tax | (775) | (764) | (882) | ||||||||||||||
| Cumulative unrealized net (gain) loss related to changes in fair value of financial liabilities attributable to own creditworthiness, net-of-tax | 1,584 | 1,342 | 484 | ||||||||||||||
Accumulated net (gain) loss on certain cash flow hedges (2) | 8,449 | 8,025 | 9,886 | ||||||||||||||
| Other | (138) | (122) | (92) | ||||||||||||||
| Common equity tier 1 capital | 196,625 | 194,928 | 184,432 | ||||||||||||||
| Qualifying preferred stock, net of issuance cost | 28,396 | 28,396 | 28,396 | ||||||||||||||
| Other | — | (1) | (3) | ||||||||||||||
| Tier 1 capital | 225,021 | 223,323 | 212,825 | ||||||||||||||
| Tier 2 capital instruments | 14,176 | 15,340 | 17,845 | ||||||||||||||
Qualifying allowance for credit losses (3) | 13,592 | 12,920 | 12,449 | ||||||||||||||
| Other | (399) | (184) | (376) | ||||||||||||||
| Total capital under the Standardized approach | 252,390 | 251,399 | 242,743 | ||||||||||||||
Adjustment in qualifying allowance for credit losses under the Advanced approaches (3) | (9,938) | (9,950) | (8,866) | ||||||||||||||
| Total capital under the Advanced approaches | $ | 242,452 | $ | 241,449 | $ | 233,877 | |||||||||||
(1)March 31, 2024, December 31, 2023 and March 31, 2023 include 25 percent, 50 percent and 50 percent of the current expected credit losses (CECL) transition provision’s impact as of December 31, 2021, respectively.
(2)Includes amounts in accumulated other comprehensive income related to the hedging of items that are not recognized at fair value on the Consolidated Balance Sheet.
(3)Includes the impact of transition provisions related to the CECL accounting standard.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 7 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Quarterly Average Balances and Interest Rates – Fully Taxable-equivalent Basis | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | First Quarter 2023 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Balance | Interest Income/ Expense (1) | Yield/ Rate | Average Balance | Interest Income/ Expense (1) | Yield/ Rate | Average Balance | Interest Income/ Expense (1) | Yield/ Rate | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Earning assets | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits with the Federal Reserve, non-U.S. central banks and other banks | $ | 346,463 | $ | 4,531 | 5.26 | % | $ | 380,362 | $ | 5,050 | 5.27 | % | $ | 202,700 | $ | 1,999 | 4.00 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Time deposits placed and other short-term investments | 9,728 | 116 | 4.80 | 8,370 | 115 | 5.48 | 10,581 | 108 | 4.16 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Federal funds sold and securities borrowed or purchased under agreements to resell | 304,821 | 5,175 | 6.83 | 297,149 | 5,124 | 6.84 | 287,532 | 3,712 | 5.24 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Trading account assets | 202,461 | 2,482 | 4.93 | 194,551 | 2,474 | 5.05 | 183,657 | 2,040 | 4.50 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Debt securities | 842,483 | 6,162 | 2.92 | 802,657 | 5,445 | 2.68 | 851,177 | 5,485 | 2.58 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Loans and leases (2) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | 227,748 | 1,803 | 3.17 | 228,975 | 1,790 | 3.12 | 229,275 | 1,684 | 2.94 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 25,522 | 390 | 6.14 | 25,756 | 411 | 6.34 | 26,513 | 317 | 4.84 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 99,815 | 2,786 | 11.22 | 100,389 | 2,778 | 10.98 | 91,775 | 2,426 | 10.72 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Direct/Indirect and other consumer | 103,371 | 1,399 | 5.45 | 103,606 | 1,386 | 5.31 | 105,657 | 1,186 | 4.55 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total consumer | 456,456 | 6,378 | 5.61 | 458,726 | 6,365 | 5.52 | 453,220 | 5,613 | 5.00 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. commercial | 379,566 | 5,236 | 5.55 | 379,215 | 5,176 | 5.42 | 376,852 | 4,471 | 4.81 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 125,024 | 2,170 | 6.98 | 125,371 | 2,208 | 6.99 | 127,003 | 1,778 | 5.68 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 71,986 | 1,311 | 7.33 | 73,140 | 1,351 | 7.33 | 70,591 | 1,144 | 6.57 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial lease financing | 14,858 | 200 | 5.41 | 14,253 | 184 | 5.14 | 13,686 | 147 | 4.33 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 591,434 | 8,917 | 6.06 | 591,979 | 8,919 | 5.98 | 588,132 | 7,540 | 5.20 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | 1,047,890 | 15,295 | 5.87 | 1,050,705 | 15,284 | 5.78 | 1,041,352 | 13,153 | 5.11 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other earning assets | 106,737 | 2,682 | 10.10 | 95,971 | 2,282 | 9.43 | 94,427 | 2,292 | 9.82 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total earning assets | 2,860,583 | 36,443 | 5.12 | 2,829,765 | 35,774 | 5.02 | 2,671,426 | 28,789 | 4.36 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 24,185 | 24,690 | 27,784 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other assets, less allowance for loan and lease losses | 362,391 | 358,704 | 396,848 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 3,247,159 | $ | 3,213,159 | $ | 3,096,058 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. interest-bearing deposits | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Demand and money market deposits | $ | 956,716 | $ | 5,012 | 2.11 | % | $ | 942,561 | $ | 4,868 | 2.05 | % | $ | 975,085 | $ | 2,790 | 1.16 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Time and savings deposits | 325,765 | 3,059 | 3.78 | 317,971 | 2,846 | 3.55 | 196,984 | 919 | 1.89 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total U.S. interest-bearing deposits | 1,282,481 | 8,071 | 2.53 | 1,260,532 | 7,714 | 2.43 | 1,172,069 | 3,709 | 1.28 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-U.S. interest-bearing deposits | 104,373 | 1,067 | 4.11 | 101,766 | 1,010 | 3.94 | 91,603 | 605 | 2.68 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 1,386,854 | 9,138 | 2.65 | 1,362,298 | 8,724 | 2.54 | 1,263,672 | 4,314 | 1.38 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Federal funds purchased and securities loaned or sold under agreements to repurchase | 350,507 | 6,026 | 6.92 | 329,696 | 5,883 | 7.08 | 256,015 | 3,551 | 5.63 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings and other interest-bearing liabilities | 141,091 | 2,509 | 7.15 | 149,273 | 2,506 | 6.67 | 156,887 | 2,629 | 6.79 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Trading account liabilities | 51,757 | 546 | 4.24 | 47,294 | 557 | 4.67 | 43,953 | 504 | 4.65 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Long-term debt | 254,782 | 4,034 | 6.35 | 256,262 | 4,013 | 6.24 | 244,759 | 3,209 | 5.28 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 2,184,991 | 22,253 | 4.10 | 2,144,823 | 21,683 | 4.01 | 1,965,286 | 14,207 | 2.93 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing sources | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 520,608 | 542,713 | 629,977 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Other liabilities (3) | 249,049 | 237,005 | 223,543 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 292,511 | 288,618 | 277,252 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 3,247,159 | $ | 3,213,159 | $ | 3,096,058 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest spread | 1.02 | % | 1.01 | % | 1.43 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Impact of noninterest-bearing sources | 0.97 | 0.96 | 0.77 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Net interest income/yield on earning assets (4) | $ | 14,190 | 1.99 | % | $ | 14,091 | 1.97 | % | $ | 14,582 | 2.20 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
(1)Includes the impact of interest rate risk management contracts.
(2)Nonperforming loans are included in the respective average loan balances. Income on these nonperforming loans is generally recognized on a cost recovery basis.
(3)Includes $44.1 billion, $42.3 billion and $37.3 billion of structured notes and liabilities for the first quarter of 2024 and the fourth and first quarters of 2023, respectively.
(4)Net interest income includes FTE adjustments of $158 million, $145 million and $134 million for the first quarter of 2024 and the fourth and first quarters of 2023, respectively.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 8 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||
| Debt Securities | |||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||
| March 31, 2024 | |||||||||||||||||||||||
| Amortized Cost | Gross Unrealized Gains | Gross Unrealized Losses | Fair Value | ||||||||||||||||||||
| Available-for-sale debt securities | |||||||||||||||||||||||
| Mortgage-backed securities: | |||||||||||||||||||||||
| Agency | $ | 37,971 | $ | 28 | $ | (1,487) | $ | 36,512 | |||||||||||||||
| Agency-collateralized mortgage obligations | 2,661 | 8 | (219) | 2,450 | |||||||||||||||||||
| Commercial | 10,978 | 66 | (469) | 10,575 | |||||||||||||||||||
| Non-agency residential | 310 | 46 | (58) | 298 | |||||||||||||||||||
| Total mortgage-backed securities | 51,920 | 148 | (2,233) | 49,835 | |||||||||||||||||||
| U.S. Treasury and government agencies | 229,830 | 81 | (1,072) | 228,839 | |||||||||||||||||||
| Non-U.S. securities | 21,249 | 23 | (21) | 21,251 | |||||||||||||||||||
| Other taxable securities | 3,285 | 2 | (49) | 3,238 | |||||||||||||||||||
| Tax-exempt securities | 10,134 | 11 | (235) | 9,910 | |||||||||||||||||||
| Total available-for-sale debt securities | 316,418 | 265 | (3,610) | 313,073 | |||||||||||||||||||
Other debt securities carried at fair value (1) | 10,035 | 90 | (79) | 10,046 | |||||||||||||||||||
| Total debt securities carried at fair value | 326,453 | 355 | (3,689) | 323,119 | |||||||||||||||||||
| Held-to-maturity debt securities | |||||||||||||||||||||||
| Agency mortgage-backed securities | 457,841 | — | (88,505) | 369,336 | |||||||||||||||||||
| U.S. Treasury and government agencies | 121,658 | — | (19,526) | 102,132 | |||||||||||||||||||
| Other taxable securities | 7,400 | — | (1,120) | 6,280 | |||||||||||||||||||
| Total held-to-maturity debt securities | 586,899 | — | (109,151) | 477,748 | |||||||||||||||||||
| Total debt securities | $ | 913,352 | $ | 355 | $ | (112,840) | $ | 800,867 | |||||||||||||||
| December 31, 2023 | |||||||||||||||||||||||
| Available-for-sale debt securities | |||||||||||||||||||||||
| Mortgage-backed securities: | |||||||||||||||||||||||
| Agency | $ | 39,195 | $ | 37 | $ | (1,420) | $ | 37,812 | |||||||||||||||
| Agency-collateralized mortgage obligations | 2,739 | 6 | (201) | 2,544 | |||||||||||||||||||
| Commercial | 10,909 | 40 | (514) | 10,435 | |||||||||||||||||||
| Non-agency residential | 449 | 3 | (70) | 382 | |||||||||||||||||||
| Total mortgage-backed securities | 53,292 | 86 | (2,205) | 51,173 | |||||||||||||||||||
| U.S. Treasury and government agencies | 179,108 | 19 | (1,461) | 177,666 | |||||||||||||||||||
| Non-U.S. securities | 22,868 | 27 | (20) | 22,875 | |||||||||||||||||||
| Other taxable securities | 4,910 | 1 | (76) | 4,835 | |||||||||||||||||||
| Tax-exempt securities | 10,304 | 17 | (221) | 10,100 | |||||||||||||||||||
| Total available-for-sale debt securities | 270,482 | 150 | (3,983) | 266,649 | |||||||||||||||||||
Other debt securities carried at fair value (1) | 10,202 | 56 | (55) | 10,203 | |||||||||||||||||||
| Total debt securities carried at fair value | 280,684 | 206 | (4,038) | 276,852 | |||||||||||||||||||
| Held-to-maturity debt securities | |||||||||||||||||||||||
| Agency mortgage-backed securities | 465,456 | — | (78,930) | 386,526 | |||||||||||||||||||
| U.S. Treasury and government agencies | 121,645 | — | (17,963) | 103,682 | |||||||||||||||||||
| Other taxable securities | 7,490 | — | (1,101) | 6,389 | |||||||||||||||||||
| Total held-to-maturity debt securities | 594,591 | — | (97,994) | 496,597 | |||||||||||||||||||
| Total debt securities | $ | 875,275 | $ | 206 | $ | (102,032) | $ | 773,449 | |||||||||||||||
(1) Primarily includes non-U.S. securities used to satisfy certain international regulatory requirements.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 9 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Supplemental Financial Data | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
FTE basis data (1) | |||||||||||||||||||||||||||||
| Net interest income | $ | 14,190 | $ | 14,091 | $ | 14,532 | $ | 14,293 | $ | 14,582 | |||||||||||||||||||
| Total revenue, net of interest expense | 25,977 | 22,104 | 25,320 | 25,332 | 26,392 | ||||||||||||||||||||||||
| Net interest yield | 1.99 | % | 1.97 | % | 2.11 | % | 2.06 | % | 2.20 | % | |||||||||||||||||||
| Efficiency ratio | 66.36 | 80.22 | 62.55 | 63.31 | 61.53 | ||||||||||||||||||||||||
(1)FTE basis is a non-GAAP financial measure. FTE basis is a performance measure used by management in operating the business that management believes provides investors with meaningful information on the interest margin for comparative purposes. The Corporation believes that this presentation allows for comparison of amounts from both taxable and tax-exempt sources and is consistent with industry practices. Net interest income includes FTE adjustments of $158 million, $145 million, $153 million, $135 million and $134 million for the first quarter of 2024 and the fourth, third, second and first quarters of 2023, respectively.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 10 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||||||||||||||
| Quarterly Results by Business Segment and All Other | |||||||||||||||||||||||||||||||||||||||||
(Dollars in millions) | |||||||||||||||||||||||||||||||||||||||||
| First Quarter 2024 | |||||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | ||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 14,190 | $ | 8,197 | $ | 1,814 | $ | 3,460 | $ | 681 | $ | 38 | |||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||
| Fees and commissions: | |||||||||||||||||||||||||||||||||||||||||
| Card income | 1,463 | 1,272 | 10 | 188 | 17 | (24) | |||||||||||||||||||||||||||||||||||
| Service charges | 1,442 | 578 | 23 | 750 | 90 | 1 | |||||||||||||||||||||||||||||||||||
| Investment and brokerage services | 4,187 | 78 | 3,600 | 18 | 495 | (4) | |||||||||||||||||||||||||||||||||||
| Investment banking fees | 1,568 | — | 63 | 850 | 708 | (53) | |||||||||||||||||||||||||||||||||||
| Total fees and commissions | 8,660 | 1,928 | 3,696 | 1,806 | 1,310 | (80) | |||||||||||||||||||||||||||||||||||
| Market making and similar activities | 3,888 | 5 | 34 | 68 | 3,830 | (49) | |||||||||||||||||||||||||||||||||||
Other income (loss) | (762) | 36 | 47 | 646 | 62 | (1,553) | |||||||||||||||||||||||||||||||||||
| Total noninterest income (loss) | 11,786 | 1,969 | 3,777 | 2,520 | 5,202 | (1,682) | |||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 25,976 | 10,166 | 5,591 | 5,980 | 5,883 | (1,644) | |||||||||||||||||||||||||||||||||||
| Provision for credit losses | 1,319 | 1,150 | (13) | 229 | (36) | (11) | |||||||||||||||||||||||||||||||||||
| Noninterest expense | 17,237 | 5,475 | 4,264 | 3,012 | 3,492 | 994 | |||||||||||||||||||||||||||||||||||
| Income (loss) before income taxes | 7,420 | 3,541 | 1,340 | 2,739 | 2,427 | (2,627) | |||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | 746 | 885 | 335 | 753 | 704 | (1,931) | |||||||||||||||||||||||||||||||||||
| Net income (loss) | $ | 6,674 | $ | 2,656 | $ | 1,005 | $ | 1,986 | $ | 1,723 | $ | (696) | |||||||||||||||||||||||||||||
| Average | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,047,890 | $ | 313,038 | $ | 218,616 | $ | 373,608 | $ | 133,756 | $ | 8,872 | |||||||||||||||||||||||||||||
Total assets (1) | 3,247,159 | 1,033,101 | 341,119 | 623,073 | 895,382 | 354,484 | |||||||||||||||||||||||||||||||||||
| Total deposits | 1,907,462 | 952,466 | 297,373 | 525,699 | 32,585 | 99,339 | |||||||||||||||||||||||||||||||||||
| Quarter end | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,049,156 | $ | 311,725 | $ | 219,844 | $ | 373,403 | $ | 135,267 | $ | 8,917 | |||||||||||||||||||||||||||||
Total assets (1) | 3,273,803 | 1,060,482 | 343,718 | 623,204 | 902,741 | 343,658 | |||||||||||||||||||||||||||||||||||
| Total deposits | 1,946,496 | 978,761 | 298,039 | 527,113 | 34,847 | 107,736 | |||||||||||||||||||||||||||||||||||
| Fourth Quarter 2023 | |||||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | ||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 14,091 | $ | 8,268 | $ | 1,711 | $ | 3,435 | $ | 598 | $ | 79 | |||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||
| Fees and commissions: | |||||||||||||||||||||||||||||||||||||||||
| Card income | 1,519 | 1,324 | 12 | 194 | 15 | (26) | |||||||||||||||||||||||||||||||||||
| Service charges | 1,446 | 588 | 20 | 749 | 87 | 2 | |||||||||||||||||||||||||||||||||||
| Investment and brokerage services | 3,909 | 78 | 3,328 | 20 | 486 | (3) | |||||||||||||||||||||||||||||||||||
| Investment banking fees | 1,145 | — | 47 | 690 | 439 | (31) | |||||||||||||||||||||||||||||||||||
| Total fees and commissions | 8,019 | 1,990 | 3,407 | 1,653 | 1,027 | (58) | |||||||||||||||||||||||||||||||||||
| Market making and similar activities | 998 | 5 | 37 | 55 | 2,428 | (1,527) | |||||||||||||||||||||||||||||||||||
| Other income (loss) | (1,004) | 66 | 72 | 785 | 35 | (1,962) | |||||||||||||||||||||||||||||||||||
| Total noninterest income (loss) | 8,013 | 2,061 | 3,516 | 2,493 | 3,490 | (3,547) | |||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 22,104 | 10,329 | 5,227 | 5,928 | 4,088 | (3,468) | |||||||||||||||||||||||||||||||||||
| Provision for credit losses | 1,104 | 1,405 | (26) | (239) | (60) | 24 | |||||||||||||||||||||||||||||||||||
| Noninterest expense | 17,731 | 5,234 | 3,894 | 2,781 | 3,271 | 2,551 | |||||||||||||||||||||||||||||||||||
| Income (loss) before income taxes | 3,269 | 3,690 | 1,359 | 3,386 | 877 | (6,043) | |||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | 125 | 922 | 340 | 914 | 241 | (2,292) | |||||||||||||||||||||||||||||||||||
| Net income (loss) | $ | 3,144 | $ | 2,768 | $ | 1,019 | $ | 2,472 | $ | 636 | $ | (3,751) | |||||||||||||||||||||||||||||
| Average | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,050,705 | $ | 313,438 | $ | 219,425 | $ | 374,862 | $ | 133,631 | $ | 9,349 | |||||||||||||||||||||||||||||
Total assets (1) | 3,213,159 | 1,038,418 | 336,067 | 624,093 | 867,953 | 346,628 | |||||||||||||||||||||||||||||||||||
| Total deposits | 1,905,011 | 959,247 | 292,478 | 527,597 | 31,950 | 93,739 | |||||||||||||||||||||||||||||||||||
| Quarter end | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,053,732 | $ | 315,119 | $ | 219,657 | $ | 373,891 | $ | 136,223 | $ | 8,842 | |||||||||||||||||||||||||||||
Total assets (1) | 3,180,151 | 1,049,830 | 344,626 | 621,751 | 817,588 | 346,356 | |||||||||||||||||||||||||||||||||||
| Total deposits | 1,923,827 | 969,572 | 299,657 | 527,060 | 34,833 | 92,705 | |||||||||||||||||||||||||||||||||||
(1)Total assets include asset allocations to match liabilities (i.e., deposits).
| Current-period information is preliminary and based on company data available at the time of the presentation. | 11 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||||||||||||||
| Quarterly Results by Business Segment and All Other (continued) | |||||||||||||||||||||||||||||||||||||||||
(Dollars in millions) | |||||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | |||||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | ||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 14,582 | $ | 8,593 | $ | 1,876 | $ | 3,907 | $ | 109 | $ | 97 | |||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||
| Fees and commissions: | |||||||||||||||||||||||||||||||||||||||||
| Card income | 1,469 | 1,274 | 12 | 190 | 16 | (23) | |||||||||||||||||||||||||||||||||||
| Service charges | 1,410 | 599 | 19 | 714 | 78 | — | |||||||||||||||||||||||||||||||||||
| Investment and brokerage services | 3,852 | 74 | 3,238 | 9 | 533 | (2) | |||||||||||||||||||||||||||||||||||
| Investment banking fees | 1,163 | — | 39 | 668 | 469 | (13) | |||||||||||||||||||||||||||||||||||
| Total fees and commissions | 7,894 | 1,947 | 3,308 | 1,581 | 1,096 | (38) | |||||||||||||||||||||||||||||||||||
| Market making and similar activities | 4,712 | 5 | 34 | 45 | 4,398 | 230 | |||||||||||||||||||||||||||||||||||
| Other income (loss) | (796) | 161 | 97 | 670 | 23 | (1,747) | |||||||||||||||||||||||||||||||||||
| Total noninterest income (loss) | 11,810 | 2,113 | 3,439 | 2,296 | 5,517 | (1,555) | |||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 26,392 | 10,706 | 5,315 | 6,203 | 5,626 | (1,458) | |||||||||||||||||||||||||||||||||||
| Provision for credit losses | 931 | 1,089 | 25 | (237) | (53) | 107 | |||||||||||||||||||||||||||||||||||
| Noninterest expense | 16,238 | 5,473 | 4,067 | 2,940 | 3,351 | 407 | |||||||||||||||||||||||||||||||||||
| Income (loss) before income taxes | 9,223 | 4,144 | 1,223 | 3,500 | 2,328 | (1,972) | |||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | 1,062 | 1,036 | 306 | 945 | 640 | (1,865) | |||||||||||||||||||||||||||||||||||
| Net income (loss) | $ | 8,161 | $ | 3,108 | $ | 917 | $ | 2,555 | $ | 1,688 | $ | (107) | |||||||||||||||||||||||||||||
| Average | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,041,352 | $ | 303,772 | $ | 221,448 | $ | 381,009 | $ | 125,046 | $ | 10,077 | |||||||||||||||||||||||||||||
Total assets (1) | 3,096,058 | 1,105,245 | 359,164 | 588,886 | 870,038 | 172,725 | |||||||||||||||||||||||||||||||||||
| Total deposits | 1,893,649 | 1,026,242 | 314,019 | 492,577 | 36,109 | 24,702 | |||||||||||||||||||||||||||||||||||
| Quarter end | |||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,046,406 | $ | 304,480 | $ | 217,804 | $ | 383,491 | $ | 130,804 | $ | 9,827 | |||||||||||||||||||||||||||||
Total assets (1) | 3,194,657 | 1,124,438 | 349,888 | 591,231 | 861,477 | 267,623 | |||||||||||||||||||||||||||||||||||
| Total deposits | 1,910,402 | 1,044,768 | 301,471 | 495,949 | 33,624 | 34,590 | |||||||||||||||||||||||||||||||||||
(1)Total assets include asset allocations to match liabilities (i.e., deposits).
| Current-period information is preliminary and based on company data available at the time of the presentation. | 12 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Consumer Banking Segment Results | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Net interest income | $ | 8,197 | $ | 8,268 | $ | 8,391 | $ | 8,437 | $ | 8,593 | |||||||||||||||||||
| Noninterest income: | |||||||||||||||||||||||||||||
| Card income | 1,272 | 1,324 | 1,325 | 1,341 | 1,274 | ||||||||||||||||||||||||
| Service charges | 578 | 588 | 605 | 525 | 599 | ||||||||||||||||||||||||
| All other income | 119 | 149 | 151 | 221 | 240 | ||||||||||||||||||||||||
| Total noninterest income | 1,969 | 2,061 | 2,081 | 2,087 | 2,113 | ||||||||||||||||||||||||
| Total revenue, net of interest expense | 10,166 | 10,329 | 10,472 | 10,524 | 10,706 | ||||||||||||||||||||||||
| Provision for credit losses | 1,150 | 1,405 | 1,397 | 1,267 | 1,089 | ||||||||||||||||||||||||
| Noninterest expense | 5,475 | 5,234 | 5,256 | 5,453 | 5,473 | ||||||||||||||||||||||||
| Income before income taxes | 3,541 | 3,690 | 3,819 | 3,804 | 4,144 | ||||||||||||||||||||||||
| Income tax expense | 885 | 922 | 955 | 951 | 1,036 | ||||||||||||||||||||||||
| Net income | $ | 2,656 | $ | 2,768 | $ | 2,864 | $ | 2,853 | $ | 3,108 | |||||||||||||||||||
| Net interest yield | 3.31 | % | 3.28 | % | 3.26 | % | 3.24 | % | 3.27 | % | |||||||||||||||||||
Return on average allocated capital (1) | 25 | 26 | 27 | 27 | 30 | ||||||||||||||||||||||||
| Efficiency ratio | 53.86 | 50.71 | 50.18 | 51.81 | 51.12 | ||||||||||||||||||||||||
| Balance Sheet | |||||||||||||||||||||||||||||
| Average | |||||||||||||||||||||||||||||
| Total loans and leases | $ | 313,038 | $ | 313,438 | $ | 310,761 | $ | 306,662 | $ | 303,772 | |||||||||||||||||||
Total earning assets (2) | 995,556 | 1,000,032 | 1,019,980 | 1,045,743 | 1,065,202 | ||||||||||||||||||||||||
Total assets (2) | 1,033,101 | 1,038,418 | 1,059,152 | 1,085,469 | 1,105,245 | ||||||||||||||||||||||||
| Total deposits | 952,466 | 959,247 | 980,051 | 1,006,337 | 1,026,242 | ||||||||||||||||||||||||
Allocated capital (1) | 43,250 | 42,000 | 42,000 | 42,000 | 42,000 | ||||||||||||||||||||||||
| Period end | |||||||||||||||||||||||||||||
| Total loans and leases | $ | 311,725 | $ | 315,119 | $ | 313,216 | $ | 309,735 | $ | 304,480 | |||||||||||||||||||
Total earning assets (2) | 1,022,320 | 1,009,360 | 1,023,162 | 1,043,228 | 1,081,780 | ||||||||||||||||||||||||
Total assets (2) | 1,060,482 | 1,049,830 | 1,062,038 | 1,084,512 | 1,124,438 | ||||||||||||||||||||||||
| Total deposits | 978,761 | 969,572 | 982,302 | 1,004,482 | 1,044,768 | ||||||||||||||||||||||||
(1) Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently.
(2) Total earning assets and total assets include asset allocations to match liabilities (i.e., deposits) and allocated shareholders’ equity.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 13 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Consumer Banking Key Indicators | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Average deposit balances | |||||||||||||||||||||||||||||
| Checking | $ | 548,604 | $ | 551,890 | $ | 562,319 | $ | 575,792 | $ | 580,910 | |||||||||||||||||||
| Savings | 57,401 | 58,975 | 62,352 | 66,142 | 68,327 | ||||||||||||||||||||||||
| MMS | 266,056 | 277,912 | 296,833 | 317,942 | 339,823 | ||||||||||||||||||||||||
| CDs and IRAs | 76,621 | 66,758 | 54,596 | 42,445 | 33,098 | ||||||||||||||||||||||||
| Other | 3,784 | 3,712 | 3,951 | 4,016 | 4,084 | ||||||||||||||||||||||||
| Total average deposit balances | $ | 952,466 | $ | 959,247 | $ | 980,051 | $ | 1,006,337 | $ | 1,026,242 | |||||||||||||||||||
| Deposit spreads (excludes noninterest costs) | |||||||||||||||||||||||||||||
| Checking | 2.50 | % | 2.47 | % | 2.38 | % | 2.30 | % | 2.22 | % | |||||||||||||||||||
| Savings | 2.80 | 2.90 | 2.77 | 2.65 | 2.53 | ||||||||||||||||||||||||
| MMS | 3.20 | 3.64 | 3.49 | 3.28 | 2.99 | ||||||||||||||||||||||||
| CDs and IRAs | 2.04 | 2.25 | 2.55 | 2.96 | 3.27 | ||||||||||||||||||||||||
| Other | 5.19 | 5.21 | 5.05 | 4.80 | 4.37 | ||||||||||||||||||||||||
| Total deposit spreads | 2.69 | 2.83 | 2.76 | 2.67 | 2.54 | ||||||||||||||||||||||||
| Consumer investment assets | $ | 456,391 | $ | 424,410 | $ | 387,467 | $ | 386,761 | $ | 354,892 | |||||||||||||||||||
Active digital banking users (in thousands) (1) | 47,079 | 46,265 | 45,797 | 45,713 | 44,962 | ||||||||||||||||||||||||
Active mobile banking users (in thousands) (2) | 38,544 | 37,927 | 37,487 | 37,329 | 36,322 | ||||||||||||||||||||||||
| Financial centers | 3,804 | 3,845 | 3,862 | 3,887 | 3,892 | ||||||||||||||||||||||||
| ATMs | 15,028 | 15,168 | 15,253 | 15,335 | 15,407 | ||||||||||||||||||||||||
Total credit card (3) | |||||||||||||||||||||||||||||
| Loans | |||||||||||||||||||||||||||||
| Average credit card outstandings | $ | 99,815 | $ | 100,389 | $ | 98,049 | $ | 94,431 | $ | 91,775 | |||||||||||||||||||
| Ending credit card outstandings | 98,453 | 102,200 | 99,686 | 97,009 | 92,469 | ||||||||||||||||||||||||
| Credit quality | |||||||||||||||||||||||||||||
| Net charge-offs | $ | 899 | $ | 777 | $ | 673 | $ | 610 | $ | 501 | |||||||||||||||||||
| 3.62 | % | 3.07 | % | 2.72 | % | 2.60 | % | 2.21 | % | ||||||||||||||||||||
| 30+ delinquency | $ | 2,446 | $ | 2,419 | $ | 2,097 | $ | 1,810 | $ | 1,674 | |||||||||||||||||||
| 2.48 | % | 2.37 | % | 2.10 | % | 1.87 | % | 1.81 | % | ||||||||||||||||||||
| 90+ delinquency | $ | 1,299 | $ | 1,224 | $ | 1,016 | $ | 897 | $ | 828 | |||||||||||||||||||
| 1.32 | % | 1.20 | % | 1.02 | % | 0.92 | % | 0.90 | % | ||||||||||||||||||||
Other total credit card indicators (3) | |||||||||||||||||||||||||||||
| Gross interest yield | 12.24 | % | 11.97 | % | 12.03 | % | 11.66 | % | 11.85 | % | |||||||||||||||||||
| Risk-adjusted margin | 6.81 | 7.18 | 7.70 | 7.83 | 8.69 | ||||||||||||||||||||||||
| New accounts (in thousands) | 998 | 889 | 1,062 | 1,137 | 1,187 | ||||||||||||||||||||||||
| Purchase volumes | $ | 87,011 | $ | 92,759 | $ | 91,711 | $ | 93,103 | $ | 85,544 | |||||||||||||||||||
| Debit card data | |||||||||||||||||||||||||||||
| Purchase volumes | $ | 132,407 | $ | 136,183 | $ | 133,553 | $ | 132,962 | $ | 124,376 | |||||||||||||||||||
Loan production (4) | |||||||||||||||||||||||||||||
| Consumer Banking: | |||||||||||||||||||||||||||||
| First mortgage | $ | 1,688 | $ | 1,753 | $ | 2,547 | $ | 2,889 | $ | 1,956 | |||||||||||||||||||
| Home equity | 1,600 | 1,939 | 2,035 | 2,171 | 2,183 | ||||||||||||||||||||||||
Total (5): | |||||||||||||||||||||||||||||
| First mortgage | $ | 3,443 | $ | 3,932 | $ | 5,596 | $ | 5,940 | $ | 3,937 | |||||||||||||||||||
| Home equity | 1,891 | 2,255 | 2,421 | 2,542 | 2,596 | ||||||||||||||||||||||||
(1) Represents mobile and/or online active users over the past 90 days.
(2) Represents mobile active users over the past 90 days.
(3) In addition to the credit card portfolio in Consumer Banking, the remaining credit card portfolio is in GWIM.
(4) Loan production amounts represent the unpaid principal balance of loans and, in the case of home equity, the principal amount of the total line of credit.
(5) In addition to loan production in Consumer Banking, there is also first mortgage and home equity loan production in GWIM.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 14 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||||||||
| Consumer Banking Quarterly Results | ||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | |||||||||||||||||||||||||||||||||||||||||||
| Total Consumer Banking | Deposits | Consumer Lending | Total Consumer Banking | Deposits | Consumer Lending | |||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 8,197 | $ | 5,269 | $ | 2,928 | $ | 8,268 | $ | 5,425 | $ | 2,843 | ||||||||||||||||||||||||||||||||
| Noninterest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Card income | 1,272 | (10) | 1,282 | 1,324 | (9) | 1,333 | ||||||||||||||||||||||||||||||||||||||
| Service charges | 578 | 577 | 1 | 588 | 588 | — | ||||||||||||||||||||||||||||||||||||||
| All other income | 119 | 102 | 17 | 149 | 116 | 33 | ||||||||||||||||||||||||||||||||||||||
| Total noninterest income | 1,969 | 669 | 1,300 | 2,061 | 695 | 1,366 | ||||||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 10,166 | 5,938 | 4,228 | 10,329 | 6,120 | 4,209 | ||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 1,150 | 76 | 1,074 | 1,405 | 77 | 1,328 | ||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 5,475 | 3,378 | 2,097 | 5,234 | 3,269 | 1,965 | ||||||||||||||||||||||||||||||||||||||
| Income before income taxes | 3,541 | 2,484 | 1,057 | 3,690 | 2,774 | 916 | ||||||||||||||||||||||||||||||||||||||
| Income tax expense | 885 | 621 | 264 | 922 | 693 | 229 | ||||||||||||||||||||||||||||||||||||||
| Net income | $ | 2,656 | $ | 1,863 | $ | 793 | $ | 2,768 | $ | 2,081 | $ | 687 | ||||||||||||||||||||||||||||||||
| Net interest yield | 3.31 | % | 2.23 | % | 3.81 | % | 3.28 | % | 2.25 | % | 3.64 | % | ||||||||||||||||||||||||||||||||
Return on average allocated capital (1) | 25 | 55 | 11 | 26 | 60 | 10 | ||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 53.86 | 56.89 | 49.60 | 50.71 | 53.51 | 46.65 | ||||||||||||||||||||||||||||||||||||||
| Balance Sheet | ||||||||||||||||||||||||||||||||||||||||||||
| Average | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 313,038 | $ | 4,241 | $ | 308,797 | $ | 313,438 | $ | 4,183 | $ | 309,255 | ||||||||||||||||||||||||||||||||
Total earning assets (2) | 995,556 | 950,194 | 308,914 | 1,000,032 | 955,931 | 309,503 | ||||||||||||||||||||||||||||||||||||||
Total assets (2) | 1,033,101 | 982,857 | 313,795 | 1,038,418 | 988,956 | 314,864 | ||||||||||||||||||||||||||||||||||||||
| Total deposits | 952,466 | 947,843 | 4,623 | 959,247 | 954,228 | 5,019 | ||||||||||||||||||||||||||||||||||||||
Allocated capital (1) | 43,250 | 13,700 | 29,550 | 42,000 | 13,700 | 28,300 | ||||||||||||||||||||||||||||||||||||||
| Period end | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 311,725 | $ | 4,260 | $ | 307,465 | $ | 315,119 | $ | 4,218 | $ | 310,901 | ||||||||||||||||||||||||||||||||
Total earning assets (2) | 1,022,320 | 976,167 | 307,634 | 1,009,360 | 965,088 | 311,008 | ||||||||||||||||||||||||||||||||||||||
Total assets (2) | 1,060,482 | 1,008,366 | 313,598 | 1,049,830 | 999,372 | 317,194 | ||||||||||||||||||||||||||||||||||||||
| Total deposits | 978,761 | 972,906 | 5,855 | 969,572 | 964,136 | 5,436 | ||||||||||||||||||||||||||||||||||||||
| First Quarter 2023 | ||||||||||||||||||||||||||||||||||||||||||||
| Total Consumer Banking | Deposits | Consumer Lending | ||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 8,593 | $ | 5,816 | $ | 2,777 | ||||||||||||||||||||||||||||||||||||||
| Noninterest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Card income | 1,274 | (10) | 1,284 | |||||||||||||||||||||||||||||||||||||||||
| Service charges | 599 | 598 | 1 | |||||||||||||||||||||||||||||||||||||||||
| All other income | 240 | 197 | 43 | |||||||||||||||||||||||||||||||||||||||||
| Total noninterest income | 2,113 | 785 | 1,328 | |||||||||||||||||||||||||||||||||||||||||
| Total revenue, net of interest expense | 10,706 | 6,601 | 4,105 | |||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 1,089 | 183 | 906 | |||||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 5,473 | 3,415 | 2,058 | |||||||||||||||||||||||||||||||||||||||||
| Income before income taxes | 4,144 | 3,003 | 1,141 | |||||||||||||||||||||||||||||||||||||||||
| Income tax expense | 1,036 | 751 | 285 | |||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 3,108 | $ | 2,252 | $ | 856 | ||||||||||||||||||||||||||||||||||||||
| Net interest yield | 3.27 | % | 2.31 | % | 3.76 | % | ||||||||||||||||||||||||||||||||||||||
Return on average allocated capital (1) | 30 | 67 | 12 | |||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 51.12 | 51.76 | 50.10 | |||||||||||||||||||||||||||||||||||||||||
| Balance Sheet | ||||||||||||||||||||||||||||||||||||||||||||
| Average | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 303,772 | $ | 4,119 | $ | 299,653 | ||||||||||||||||||||||||||||||||||||||
Total earning assets (2) | 1,065,202 | 1,022,445 | 299,794 | |||||||||||||||||||||||||||||||||||||||||
Total assets (2) | 1,105,245 | 1,056,007 | 306,275 | |||||||||||||||||||||||||||||||||||||||||
| Total deposits | 1,026,242 | 1,021,374 | 4,868 | |||||||||||||||||||||||||||||||||||||||||
Allocated capital (1) | 42,000 | 13,700 | 28,300 | |||||||||||||||||||||||||||||||||||||||||
| Period end | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 304,480 | $ | 4,065 | $ | 300,415 | ||||||||||||||||||||||||||||||||||||||
Total earning assets (2) | 1,081,780 | 1,038,545 | 300,595 | |||||||||||||||||||||||||||||||||||||||||
Total assets (2) | 1,124,438 | 1,074,571 | 307,227 | |||||||||||||||||||||||||||||||||||||||||
| Total deposits | 1,044,768 | 1,039,744 | 5,024 | |||||||||||||||||||||||||||||||||||||||||
(1) Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently.
(2) For presentation purposes, in segments or businesses where the total of liabilities and equity exceeds assets, the Corporation allocates assets from All Other to match the segments’ and businesses’ liabilities and allocated shareholders’ equity. As a result, total earning assets and total assets of the businesses may not equal total Consumer Banking.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 15 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Global Wealth & Investment Management Segment Results | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Net interest income | $ | 1,814 | $ | 1,711 | $ | 1,755 | $ | 1,805 | $ | 1,876 | |||||||||||||||||||
| Noninterest income: | |||||||||||||||||||||||||||||
| Investment and brokerage services | 3,600 | 3,328 | 3,396 | 3,251 | 3,238 | ||||||||||||||||||||||||
| All other income | 177 | 188 | 170 | 186 | 201 | ||||||||||||||||||||||||
| Total noninterest income | 3,777 | 3,516 | 3,566 | 3,437 | 3,439 | ||||||||||||||||||||||||
| Total revenue, net of interest expense | 5,591 | 5,227 | 5,321 | 5,242 | 5,315 | ||||||||||||||||||||||||
| Provision for credit losses | (13) | (26) | (6) | 13 | 25 | ||||||||||||||||||||||||
| Noninterest expense | 4,264 | 3,894 | 3,950 | 3,925 | 4,067 | ||||||||||||||||||||||||
| Income before income taxes | 1,340 | 1,359 | 1,377 | 1,304 | 1,223 | ||||||||||||||||||||||||
| Income tax expense | 335 | 340 | 344 | 326 | 306 | ||||||||||||||||||||||||
| Net income | $ | 1,005 | $ | 1,019 | $ | 1,033 | $ | 978 | $ | 917 | |||||||||||||||||||
| Net interest yield | 2.23 | % | 2.10 | % | 2.16 | % | 2.21 | % | 2.20 | % | |||||||||||||||||||
Return on average allocated capital (1) | 22 | 22 | 22 | 21 | 20 | ||||||||||||||||||||||||
| Efficiency ratio | 76.27 | 74.41 | 74.28 | 74.86 | 76.53 | ||||||||||||||||||||||||
| Balance Sheet | |||||||||||||||||||||||||||||
| Average | |||||||||||||||||||||||||||||
| Total loans and leases | $ | 218,616 | $ | 219,425 | $ | 218,569 | $ | 218,604 | $ | 221,448 | |||||||||||||||||||
Total earning assets (2) | 327,692 | 322,827 | 322,032 | 327,066 | 346,384 | ||||||||||||||||||||||||
Total assets (2) | 341,119 | 336,067 | 335,124 | 340,105 | 359,164 | ||||||||||||||||||||||||
| Total deposits | 297,373 | 292,478 | 291,770 | 295,380 | 314,019 | ||||||||||||||||||||||||
Allocated capital (1) | 18,500 | 18,500 | 18,500 | 18,500 | 18,500 | ||||||||||||||||||||||||
| Period end | |||||||||||||||||||||||||||||
| Total loans and leases | $ | 219,844 | $ | 219,657 | $ | 218,913 | $ | 219,208 | $ | 217,804 | |||||||||||||||||||
Total earning assets (2) | 329,515 | 330,653 | 320,196 | 324,820 | 336,560 | ||||||||||||||||||||||||
Total assets (2) | 343,718 | 344,626 | 333,779 | 338,184 | 349,888 | ||||||||||||||||||||||||
| Total deposits | 298,039 | 299,657 | 290,732 | 292,526 | 301,471 | ||||||||||||||||||||||||
(1)Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently.
(2)Total earning assets and total assets include asset allocations to match liabilities (i.e., deposits) and allocated shareholders’ equity.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 16 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Global Wealth & Investment Management Key Indicators | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Revenue by Business | |||||||||||||||||||||||||||||
| Merrill Wealth Management | $ | 4,647 | $ | 4,326 | $ | 4,398 | $ | 4,340 | $ | 4,397 | |||||||||||||||||||
| Bank of America Private Bank | 944 | 901 | 923 | 902 | 918 | ||||||||||||||||||||||||
| Total revenue, net of interest expense | $ | 5,591 | $ | 5,227 | $ | 5,321 | $ | 5,242 | $ | 5,315 | |||||||||||||||||||
| Client Balances by Business, at period end | |||||||||||||||||||||||||||||
| Merrill Wealth Management | $ | 3,339,693 | $ | 3,182,735 | $ | 2,978,229 | $ | 3,057,680 | $ | 2,952,681 | |||||||||||||||||||
| Bank of America Private Bank | 633,697 | 606,639 | 572,624 | 577,514 | 568,925 | ||||||||||||||||||||||||
| Total client balances | $ | 3,973,390 | $ | 3,789,374 | $ | 3,550,853 | $ | 3,635,194 | $ | 3,521,606 | |||||||||||||||||||
| Client Balances by Type, at period end | |||||||||||||||||||||||||||||
Assets under management (1) | $ | 1,730,005 | $ | 1,617,740 | $ | 1,496,601 | $ | 1,531,042 | $ | 1,467,242 | |||||||||||||||||||
| Brokerage and other assets | 1,758,642 | 1,688,923 | 1,578,123 | 1,628,294 | 1,571,409 | ||||||||||||||||||||||||
| Deposits | 298,039 | 299,657 | 290,732 | 292,526 | 301,471 | ||||||||||||||||||||||||
Loans and leases (2) | 222,528 | 222,287 | 221,684 | 222,280 | 220,633 | ||||||||||||||||||||||||
| Less: Managed deposits in assets under management | (35,824) | (39,233) | (36,287) | (38,948) | (39,149) | ||||||||||||||||||||||||
| Total client balances | $ | 3,973,390 | $ | 3,789,374 | $ | 3,550,853 | $ | 3,635,194 | $ | 3,521,606 | |||||||||||||||||||
| Assets Under Management Rollforward | |||||||||||||||||||||||||||||
| Assets under management, beginning balance | $ | 1,617,740 | $ | 1,496,601 | $ | 1,531,042 | $ | 1,467,242 | $ | 1,401,474 | |||||||||||||||||||
| Net client flows | 24,655 | 8,443 | 14,226 | 14,296 | 15,262 | ||||||||||||||||||||||||
| Market valuation/other | 87,610 | 112,696 | (48,667) | 49,504 | 50,506 | ||||||||||||||||||||||||
| Total assets under management, ending balance | $ | 1,730,005 | $ | 1,617,740 | $ | 1,496,601 | $ | 1,531,042 | $ | 1,467,242 | |||||||||||||||||||
(1)Defined as managed assets under advisory and/or discretion of GWIM.
(2)Includes margin receivables which are classified in customer and other receivables on the Consolidated Balance Sheet.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 17 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Global Banking Segment Results | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Net interest income | $ | 3,460 | $ | 3,435 | $ | 3,613 | $ | 3,690 | $ | 3,907 | |||||||||||||||||||
| Noninterest income: | |||||||||||||||||||||||||||||
| Service charges | 750 | 749 | 754 | 735 | 714 | ||||||||||||||||||||||||
| Investment banking fees | 850 | 690 | 743 | 718 | 668 | ||||||||||||||||||||||||
| All other income | 920 | 1,054 | 1,093 | 1,319 | 914 | ||||||||||||||||||||||||
| Total noninterest income | 2,520 | 2,493 | 2,590 | 2,772 | 2,296 | ||||||||||||||||||||||||
| Total revenue, net of interest expense | 5,980 | 5,928 | 6,203 | 6,462 | 6,203 | ||||||||||||||||||||||||
| Provision for credit losses | 229 | (239) | (119) | 9 | (237) | ||||||||||||||||||||||||
| Noninterest expense | 3,012 | 2,781 | 2,804 | 2,819 | 2,940 | ||||||||||||||||||||||||
| Income before income taxes | 2,739 | 3,386 | 3,518 | 3,634 | 3,500 | ||||||||||||||||||||||||
| Income tax expense | 753 | 914 | 950 | 981 | 945 | ||||||||||||||||||||||||
| Net income | $ | 1,986 | $ | 2,472 | $ | 2,568 | $ | 2,653 | $ | 2,555 | |||||||||||||||||||
| Net interest yield | 2.50 | % | 2.45 | % | 2.68 | % | 2.80 | % | 3.03 | % | |||||||||||||||||||
Return on average allocated capital (1) | 16 | 20 | 21 | 22 | 21 | ||||||||||||||||||||||||
| Efficiency ratio | 50.37 | 46.92 | 45.22 | 43.59 | 47.41 | ||||||||||||||||||||||||
| Balance Sheet | |||||||||||||||||||||||||||||
| Average | |||||||||||||||||||||||||||||
| Total loans and leases | $ | 373,608 | $ | 374,862 | $ | 376,214 | $ | 383,058 | $ | 381,009 | |||||||||||||||||||
Total earning assets (2) | 555,957 | 557,147 | 534,153 | 527,959 | 522,374 | ||||||||||||||||||||||||
Total assets (2) | 623,073 | 624,093 | 601,378 | 595,585 | 588,886 | ||||||||||||||||||||||||
| Total deposits | 525,699 | 527,597 | 504,432 | 497,533 | 492,577 | ||||||||||||||||||||||||
Allocated capital (1) | 49,250 | 49,250 | 49,250 | 49,250 | 49,250 | ||||||||||||||||||||||||
| Period end | |||||||||||||||||||||||||||||
| Total loans and leases | $ | 373,403 | $ | 373,891 | $ | 373,351 | $ | 381,609 | $ | 383,491 | |||||||||||||||||||
Total earning assets (2) | 554,253 | 552,453 | 521,423 | 518,547 | 524,299 | ||||||||||||||||||||||||
Total assets (2) | 623,204 | 621,751 | 588,578 | 586,397 | 591,231 | ||||||||||||||||||||||||
| Total deposits | 527,113 | 527,060 | 494,938 | 492,734 | 495,949 | ||||||||||||||||||||||||
(1)Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently.
(2)Total earning assets and total assets include asset allocations to match liabilities (i.e., deposits) and allocated shareholders’ equity.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 18 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Global Banking Key Indicators | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
Investment Banking fees (1) | |||||||||||||||||||||||||||||
Advisory (2) | $ | 317 | $ | 350 | $ | 396 | $ | 333 | $ | 313 | |||||||||||||||||||
| Debt issuance | 383 | 265 | 255 | 263 | 290 | ||||||||||||||||||||||||
| Equity issuance | 150 | 75 | 92 | 122 | 65 | ||||||||||||||||||||||||
Total Investment Banking fees (3) | $ | 850 | $ | 690 | $ | 743 | $ | 718 | $ | 668 | |||||||||||||||||||
| Business Lending | |||||||||||||||||||||||||||||
| Corporate | $ | 1,065 | $ | 1,235 | $ | 1,300 | $ | 1,359 | $ | 1,034 | |||||||||||||||||||
| Commercial | 1,280 | 1,251 | 1,262 | 1,270 | 1,233 | ||||||||||||||||||||||||
| Business Banking | 59 | 62 | 61 | 63 | 67 | ||||||||||||||||||||||||
| Total Business Lending revenue | $ | 2,404 | $ | 2,548 | $ | 2,623 | $ | 2,692 | $ | 2,334 | |||||||||||||||||||
| Global Transaction Services | |||||||||||||||||||||||||||||
| Corporate | $ | 1,335 | $ | 1,322 | $ | 1,392 | $ | 1,483 | $ | 1,549 | |||||||||||||||||||
| Commercial | 970 | 967 | 998 | 1,045 | 1,129 | ||||||||||||||||||||||||
| Business Banking | 361 | 370 | 379 | 395 | 387 | ||||||||||||||||||||||||
| Total Global Transaction Services revenue | $ | 2,666 | $ | 2,659 | $ | 2,769 | $ | 2,923 | $ | 3,065 | |||||||||||||||||||
| Average deposit balances | |||||||||||||||||||||||||||||
| Interest-bearing | $ | 362,100 | $ | 351,007 | $ | 315,289 | $ | 289,187 | $ | 257,012 | |||||||||||||||||||
| Noninterest-bearing | 163,599 | 176,590 | 189,143 | 208,346 | 235,565 | ||||||||||||||||||||||||
| Total average deposits | $ | 525,699 | $ | 527,597 | $ | 504,432 | $ | 497,533 | $ | 492,577 | |||||||||||||||||||
| Provision for credit losses | $ | 229 | $ | (239) | $ | (119) | $ | 9 | $ | (237) | |||||||||||||||||||
Credit quality (4, 5) | |||||||||||||||||||||||||||||
| Reservable criticized utilized exposure | $ | 22,530 | $ | 21,597 | $ | 22,025 | $ | 19,714 | $ | 18,104 | |||||||||||||||||||
| 5.70 | % | 5.46 | % | 5.58 | % | 4.89 | % | 4.46 | % | ||||||||||||||||||||
| Nonperforming loans, leases and foreclosed properties | $ | 3,075 | $ | 2,673 | $ | 1,908 | $ | 1,248 | $ | 1,023 | |||||||||||||||||||
| 0.83 | % | 0.72 | % | 0.51 | % | 0.33 | % | 0.27 | % | ||||||||||||||||||||
| Average loans and leases by product | |||||||||||||||||||||||||||||
| U.S. commercial | $ | 226,470 | $ | 225,070 | $ | 225,758 | $ | 230,111 | $ | 229,558 | |||||||||||||||||||
| Non-U.S. commercial | 76,284 | 78,483 | 78,748 | 81,546 | 82,412 | ||||||||||||||||||||||||
| Commercial real estate | 55,683 | 56,735 | 57,573 | 57,449 | 55,019 | ||||||||||||||||||||||||
| Commercial lease financing | 15,170 | 14,573 | 14,134 | 13,951 | 14,019 | ||||||||||||||||||||||||
| Other | 1 | 1 | 1 | 1 | 1 | ||||||||||||||||||||||||
| Total average loans and leases | $ | 373,608 | $ | 374,862 | $ | 376,214 | $ | 383,058 | $ | 381,009 | |||||||||||||||||||
| Total Corporation Investment Banking fees | |||||||||||||||||||||||||||||
Advisory (2) | $ | 373 | $ | 389 | $ | 448 | $ | 375 | $ | 363 | |||||||||||||||||||
| Debt issuance | 885 | 589 | 570 | 600 | 644 | ||||||||||||||||||||||||
| Equity issuance | 363 | 199 | 232 | 287 | 168 | ||||||||||||||||||||||||
| Total investment banking fees including self-led deals | 1,621 | 1,177 | 1,250 | 1,262 | 1,175 | ||||||||||||||||||||||||
| Self-led deals | (53) | (32) | (62) | (50) | (12) | ||||||||||||||||||||||||
| Total Investment Banking fees | $ | 1,568 | $ | 1,145 | $ | 1,188 | $ | 1,212 | $ | 1,163 | |||||||||||||||||||
(1)Investment banking fees represent total investment banking fees for Global Banking inclusive of self-led deals and fees included within Business Lending.
(2)Advisory includes fees on debt and equity advisory and mergers and acquisitions.
(3)Investment banking fees represent only the fee component in Global Banking and do not include certain other items shared with the Investment Banking Group under internal revenue sharing agreements.
(4)Criticized exposure corresponds to the Special Mention, Substandard and Doubtful asset categories defined by regulatory authorities. The reservable criticized exposure is on an end-of-period basis and is also shown as a percentage of total commercial reservable utilized exposure, including loans and leases, standby letters of credit, financial guarantees, commercial letters of credit and bankers’ acceptances.
(5)Nonperforming loans, leases and foreclosed properties are on an end-of-period basis. The nonperforming ratio is nonperforming assets divided by loans, leases and foreclosed properties.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 19 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Global Markets Segment Results | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Net interest income | $ | 681 | $ | 598 | $ | 674 | $ | 297 | $ | 109 | |||||||||||||||||||
| Noninterest income: | |||||||||||||||||||||||||||||
| Investment and brokerage services | 495 | 486 | 475 | 499 | 533 | ||||||||||||||||||||||||
| Investment banking fees | 708 | 439 | 463 | 503 | 469 | ||||||||||||||||||||||||
| Market making and similar activities | 3,830 | 2,428 | 3,195 | 3,409 | 4,398 | ||||||||||||||||||||||||
| All other income | 169 | 137 | 135 | 163 | 117 | ||||||||||||||||||||||||
| Total noninterest income | 5,202 | 3,490 | 4,268 | 4,574 | 5,517 | ||||||||||||||||||||||||
Total revenue, net of interest expense (1) | 5,883 | 4,088 | 4,942 | 4,871 | 5,626 | ||||||||||||||||||||||||
| Provision for credit losses | (36) | (60) | (14) | (4) | (53) | ||||||||||||||||||||||||
| Noninterest expense | 3,492 | 3,271 | 3,235 | 3,349 | 3,351 | ||||||||||||||||||||||||
| Income before income taxes | 2,427 | 877 | 1,721 | 1,526 | 2,328 | ||||||||||||||||||||||||
| Income tax expense | 704 | 241 | 473 | 420 | 640 | ||||||||||||||||||||||||
| Net income | $ | 1,723 | $ | 636 | $ | 1,248 | $ | 1,106 | $ | 1,688 | |||||||||||||||||||
Return on average allocated capital (2) | 15 | % | 6 | % | 11 | % | 10 | % | 15 | % | |||||||||||||||||||
| Efficiency ratio | 59.38 | 80.00 | 65.47 | 68.74 | 59.56 | ||||||||||||||||||||||||
| Balance Sheet | |||||||||||||||||||||||||||||
| Average | |||||||||||||||||||||||||||||
| Total trading-related assets | $ | 629,826 | $ | 615,414 | $ | 609,744 | $ | 621,125 | $ | 626,035 | |||||||||||||||||||
| Total loans and leases | 133,756 | 133,631 | 131,298 | 128,539 | 125,046 | ||||||||||||||||||||||||
| Total earning assets | 692,851 | 667,094 | 655,971 | 657,947 | 627,935 | ||||||||||||||||||||||||
| Total assets | 895,382 | 867,953 | 863,653 | 877,471 | 870,038 | ||||||||||||||||||||||||
| Total deposits | 32,585 | 31,950 | 31,890 | 33,222 | 36,109 | ||||||||||||||||||||||||
Allocated capital (2) | 45,500 | 45,500 | 45,500 | 45,500 | 45,500 | ||||||||||||||||||||||||
| Period end | |||||||||||||||||||||||||||||
| Total trading-related assets | $ | 628,890 | $ | 542,544 | $ | 613,009 | $ | 599,787 | $ | 599,841 | |||||||||||||||||||
| Total loans and leases | 135,267 | 136,223 | 134,386 | 131,128 | 130,804 | ||||||||||||||||||||||||
| Total earning assets | 698,279 | 637,955 | 660,172 | 640,712 | 632,873 | ||||||||||||||||||||||||
| Total assets | 902,741 | 817,588 | 864,792 | 851,771 | 861,477 | ||||||||||||||||||||||||
| Total deposits | 34,847 | 34,833 | 31,041 | 33,049 | 33,624 | ||||||||||||||||||||||||
| Trading-related assets (average) | |||||||||||||||||||||||||||||
| Trading account securities | $ | 323,210 | $ | 309,051 | $ | 307,990 | $ | 317,928 | $ | 339,248 | |||||||||||||||||||
| Reverse repurchases | 134,081 | 133,209 | 135,401 | 139,480 | 126,760 | ||||||||||||||||||||||||
| Securities borrowed | 134,852 | 129,365 | 119,936 | 120,481 | 116,280 | ||||||||||||||||||||||||
| Derivative assets | 37,683 | 43,789 | 46,417 | 43,236 | 43,747 | ||||||||||||||||||||||||
| Total trading-related assets | $ | 629,826 | $ | 615,414 | $ | 609,744 | $ | 621,125 | $ | 626,035 | |||||||||||||||||||
(1)Substantially all of Global Markets total revenue is sales and trading revenue and investment banking fees, with a small portion related to certain revenue sharing agreements with other business segments. For additional sales and trading revenue information, see page 21.
(2)Return on average allocated capital is calculated as net income, adjusted for cost of funds and earnings credits and certain expenses related to intangibles, divided by average allocated capital. Other companies may define or calculate these measures differently.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 20 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Global Markets Key Indicators | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
Sales and trading revenue (1) | |||||||||||||||||||||||||||||
| Fixed-income, currencies and commodities | $ | 3,231 | $ | 2,079 | $ | 2,710 | $ | 2,667 | $ | 3,440 | |||||||||||||||||||
| Equities | 1,861 | 1,540 | 1,695 | 1,618 | 1,627 | ||||||||||||||||||||||||
| Total sales and trading revenue | $ | 5,092 | $ | 3,619 | $ | 4,405 | $ | 4,285 | $ | 5,067 | |||||||||||||||||||
Sales and trading revenue, excluding net debit valuation adjustment (2,3) | |||||||||||||||||||||||||||||
| Fixed-income, currencies and commodities | $ | 3,307 | $ | 2,206 | $ | 2,723 | $ | 2,764 | $ | 3,429 | |||||||||||||||||||
| Equities | 1,870 | 1,545 | 1,698 | 1,623 | 1,624 | ||||||||||||||||||||||||
| Total sales and trading revenue, excluding net debit valuation adjustment | $ | 5,177 | $ | 3,751 | $ | 4,421 | $ | 4,387 | $ | 5,053 | |||||||||||||||||||
| Sales and trading revenue breakdown | |||||||||||||||||||||||||||||
| Net interest income | $ | 512 | $ | 432 | $ | 518 | $ | 137 | $ | (74) | |||||||||||||||||||
| Commissions | 494 | 486 | 474 | 492 | 529 | ||||||||||||||||||||||||
| Trading | 3,830 | 2,428 | 3,194 | 3,407 | 4,398 | ||||||||||||||||||||||||
| Other | 256 | 273 | 219 | 249 | 214 | ||||||||||||||||||||||||
| Total sales and trading revenue | $ | 5,092 | $ | 3,619 | $ | 4,405 | $ | 4,285 | $ | 5,067 | |||||||||||||||||||
(1) Includes Global Banking sales and trading revenue of $144 million, $190 million, $133 million, $154 million and $177 million for the first quarter of 2024 and the fourth, third, second and first quarters of 2023, respectively.
(2) For this presentation, sales and trading revenue excludes net debit valuation adjustment (DVA) gains (losses) which include net DVA on derivatives, as well as amortization of own credit portion of purchase discount and realized DVA on structured liabilities. Sales and trading revenue excluding net DVA gains (losses) represents a non-GAAP financial measure. We believe the use of this non-GAAP financial measure provides additional useful information to assess the underlying performance of these businesses and to allow better comparison of period-to-period operating performance.
(3)Net DVA gains (losses) were $(85) million, $(132) million, $(16) million, $(102) million and $14 million for the first quarter of 2024 and the fourth, third, second and first quarters of 2023, respectively. FICC net DVA gains (losses) were $(76) million, $(127) million, $(13) million, $(97) million and $11 million for the first quarter of 2024 and the fourth, third, second and first quarters of 2023, respectively. Equities net DVA gains (losses) were $(9) million, $(5) million, $(3) million, $(5) million and $3 million for the first quarter of 2024 and the fourth, third, second and first quarters of 2023, respectively.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 21 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
All Other Results (1) | |||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Net interest income | $ | 38 | $ | 79 | $ | 99 | $ | 64 | $ | 97 | |||||||||||||||||||
| Noninterest income (loss) | (1,682) | (3,547) | (1,717) | (1,831) | (1,555) | ||||||||||||||||||||||||
| Total revenue, net of interest expense | (1,644) | (3,468) | (1,618) | (1,767) | (1,458) | ||||||||||||||||||||||||
| Provision for credit losses | (11) | 24 | (24) | (160) | 107 | ||||||||||||||||||||||||
| Noninterest expense | 994 | 2,551 | 593 | 492 | 407 | ||||||||||||||||||||||||
| Loss before income taxes | (2,627) | (6,043) | (2,187) | (2,099) | (1,972) | ||||||||||||||||||||||||
| Income tax expense (benefit) | (1,931) | (2,292) | (2,276) | (1,917) | (1,865) | ||||||||||||||||||||||||
| Net income (loss) | $ | (696) | $ | (3,751) | $ | 89 | $ | (182) | $ | (107) | |||||||||||||||||||
| Balance Sheet | |||||||||||||||||||||||||||||
| Average | |||||||||||||||||||||||||||||
| Total loans and leases | $ | 8,872 | $ | 9,349 | $ | 9,412 | $ | 9,745 | $ | 10,077 | |||||||||||||||||||
Total assets (2) | 354,484 | 346,628 | 269,159 | 276,728 | 172,725 | ||||||||||||||||||||||||
| Total deposits | 99,339 | 93,739 | 68,010 | 42,881 | 24,702 | ||||||||||||||||||||||||
| Period end | |||||||||||||||||||||||||||||
| Total loans and leases | $ | 8,917 | $ | 8,842 | $ | 9,283 | $ | 9,544 | $ | 9,827 | |||||||||||||||||||
Total assets (3) | 343,658 | 346,356 | 303,903 | 262,334 | 267,623 | ||||||||||||||||||||||||
| Total deposits | 107,736 | 92,705 | 85,588 | 54,418 | 34,590 | ||||||||||||||||||||||||
(1)All Other primarily consists of asset and liability management (ALM) activities, liquidating businesses and certain expenses not otherwise allocated to a business segment. ALM activities encompass interest rate and foreign currency risk management activities for which substantially all of the results are allocated to our business segments.
(2)Includes elimination of segments’ excess asset allocations to match liabilities (i.e., deposits) and allocated shareholders’ equity of $958.0 billion, $958.4 billion, $955.7 billion, $977.8 billion and $1.0 trillion for the first quarter of 2024 and the fourth, third, second and first quarters of 2023, respectively.
(3)Includes elimination of segments’ excess asset allocations to match liabilities (i.e., deposits) and allocated shareholders’ equity of $987.1 billion, $972.9 billion, $945.7 billion, $963.6 billion and $1.0 trillion at March 31, 2024, December 31, 2023, September 30, 2023, June 30, 2023 and March 31, 2023, respectively.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 22 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||
| Outstanding Loans and Leases | |||||||||||||||||
| (Dollars in millions) | |||||||||||||||||
| March 31 2024 | December 31 2023 | March 31 2023 | |||||||||||||||
| Consumer | |||||||||||||||||
| Residential mortgage | $ | 227,435 | $ | 228,403 | $ | 228,827 | |||||||||||
| Home equity | 25,185 | 25,527 | 25,868 | ||||||||||||||
| Credit card | 98,453 | 102,200 | 92,469 | ||||||||||||||
Direct/Indirect consumer (1) | 102,849 | 103,468 | 104,540 | ||||||||||||||
Other consumer (2) | 115 | 124 | 120 | ||||||||||||||
| Total consumer loans excluding loans accounted for under the fair value option | 454,037 | 459,722 | 451,824 | ||||||||||||||
Consumer loans accounted for under the fair value option (3) | 235 | 243 | 334 | ||||||||||||||
| Total consumer | 454,272 | 459,965 | 452,158 | ||||||||||||||
| Commercial | |||||||||||||||||
| U.S. commercial | 362,744 | 358,931 | 360,655 | ||||||||||||||
| Non-U.S. commercial | 123,073 | 124,581 | 124,827 | ||||||||||||||
Commercial real estate (4) | 71,652 | 72,878 | 73,051 | ||||||||||||||
| Commercial lease financing | 14,781 | 14,854 | 13,448 | ||||||||||||||
| 572,250 | 571,244 | 571,981 | |||||||||||||||
U.S. small business commercial (5) | 19,931 | 19,197 | 18,204 | ||||||||||||||
| Total commercial loans excluding loans accounted for under the fair value option | 592,181 | 590,441 | 590,185 | ||||||||||||||
Commercial loans accounted for under the fair value option (3) | 2,703 | 3,326 | 4,063 | ||||||||||||||
| Total commercial | 594,884 | 593,767 | 594,248 | ||||||||||||||
| Total loans and leases | $ | 1,049,156 | $ | 1,053,732 | $ | 1,046,406 | |||||||||||
(1)Includes primarily auto and specialty lending loans and leases of $54.1 billion, $53.9 billion and $52.7 billion, U.S. securities-based lending loans of $45.3 billion, $46.0 billion and $48.1 billion and non-U.S. consumer loans of $2.7 billion, $2.8 billion and $2.8 billion at March 31, 2024, December 31, 2023 and March 31, 2023, respectively.
(2)Substantially all of other consumer is consumer overdrafts.
(3)Consumer loans accounted for under the fair value option includes residential mortgage loans of $62 million, $66 million and $72 million and home equity loans of $173 million, $177 million and $262 million at March 31, 2024, December 31, 2023 and March 31, 2023, respectively. Commercial loans accounted for under the fair value option includes U.S. commercial loans of $1.7 billion, $2.2 billion and $2.2 billion and non-U.S. commercial loans of $1.0 billion, $1.2 billion and $1.9 billion at March 31, 2024, December 31, 2023 and March 31, 2023, respectively.
(4)Includes U.S. commercial real estate loans of $65.5 billion, $66.8 billion and $67.2 billion and non-U.S. commercial real estate loans of $6.2 billion, $6.1 billion and $5.8 billion at March 31, 2024, December 31, 2023 and March 31, 2023, respectively.
(5)Includes card-related products and Paycheck Protection Program (PPP) loans.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 23 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||
| Quarterly Average Loans and Leases by Business Segment and All Other | ||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||
| First Quarter 2024 | ||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | |||||||||||||||||||||||||||||||||
| Consumer | ||||||||||||||||||||||||||||||||||||||
| Residential mortgage | $ | 227,748 | $ | 115,536 | $ | 105,177 | $ | 1 | $ | — | $ | 7,034 | ||||||||||||||||||||||||||
| Home equity | 25,522 | 21,289 | 2,402 | — | 159 | 1,672 | ||||||||||||||||||||||||||||||||
| Credit card | 99,815 | 96,480 | 3,335 | — | — | — | ||||||||||||||||||||||||||||||||
| Direct/Indirect and other consumer | 103,371 | 54,413 | 48,956 | — | — | 2 | ||||||||||||||||||||||||||||||||
| Total consumer | 456,456 | 287,718 | 159,870 | 1 | 159 | 8,708 | ||||||||||||||||||||||||||||||||
| Commercial | ||||||||||||||||||||||||||||||||||||||
| U.S. commercial | 379,566 | 25,310 | 51,029 | 226,470 | 76,590 | 167 | ||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 125,024 | — | 572 | 76,284 | 47,861 | 307 | ||||||||||||||||||||||||||||||||
| Commercial real estate | 71,986 | 10 | 7,145 | 55,683 | 9,146 | 2 | ||||||||||||||||||||||||||||||||
| Commercial lease financing | 14,858 | — | — | 15,170 | — | (312) | ||||||||||||||||||||||||||||||||
| Total commercial | 591,434 | 25,320 | 58,746 | 373,607 | 133,597 | 164 | ||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,047,890 | $ | 313,038 | $ | 218,616 | $ | 373,608 | $ | 133,756 | $ | 8,872 | ||||||||||||||||||||||||||
| Fourth Quarter 2023 | ||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | |||||||||||||||||||||||||||||||||
| Consumer | ||||||||||||||||||||||||||||||||||||||
| Residential mortgage | $ | 228,975 | $ | 116,278 | $ | 105,184 | $ | 1 | $ | — | $ | 7,512 | ||||||||||||||||||||||||||
| Home equity | 25,756 | 21,307 | 2,419 | — | 165 | 1,865 | ||||||||||||||||||||||||||||||||
| Credit card | 100,389 | 97,013 | 3,378 | — | — | (2) | ||||||||||||||||||||||||||||||||
| Direct/Indirect and other consumer | 103,606 | 54,035 | 49,568 | — | — | 3 | ||||||||||||||||||||||||||||||||
| Total consumer | 458,726 | 288,633 | 160,549 | 1 | 165 | 9,378 | ||||||||||||||||||||||||||||||||
| Commercial | ||||||||||||||||||||||||||||||||||||||
| U.S. commercial | 379,215 | 24,794 | 51,196 | 225,070 | 77,959 | 196 | ||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 125,371 | — | 535 | 78,483 | 46,258 | 95 | ||||||||||||||||||||||||||||||||
| Commercial real estate | 73,140 | 11 | 7,145 | 56,735 | 9,249 | — | ||||||||||||||||||||||||||||||||
| Commercial lease financing | 14,253 | — | — | 14,573 | — | (320) | ||||||||||||||||||||||||||||||||
| Total commercial | 591,979 | 24,805 | 58,876 | 374,861 | 133,466 | (29) | ||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,050,705 | $ | 313,438 | $ | 219,425 | $ | 374,862 | $ | 133,631 | $ | 9,349 | ||||||||||||||||||||||||||
| First Quarter 2023 | ||||||||||||||||||||||||||||||||||||||
| Total Corporation | Consumer Banking | GWIM | Global Banking | Global Markets | All Other | |||||||||||||||||||||||||||||||||
| Consumer | ||||||||||||||||||||||||||||||||||||||
| Residential mortgage | $ | 229,275 | $ | 117,747 | $ | 103,700 | $ | 1 | $ | — | $ | 7,827 | ||||||||||||||||||||||||||
| Home equity | 26,513 | 21,571 | 2,444 | — | 200 | 2,298 | ||||||||||||||||||||||||||||||||
| Credit card | 91,775 | 88,731 | 3,045 | — | — | (1) | ||||||||||||||||||||||||||||||||
| Direct/Indirect and other consumer | 105,657 | 52,728 | 52,927 | — | — | 2 | ||||||||||||||||||||||||||||||||
| Total consumer | 453,220 | 280,777 | 162,116 | 1 | 200 | 10,126 | ||||||||||||||||||||||||||||||||
| Commercial | ||||||||||||||||||||||||||||||||||||||
| U.S. commercial | 376,852 | 22,985 | 52,067 | 229,558 | 72,074 | 168 | ||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 127,003 | — | 999 | 82,412 | 43,478 | 114 | ||||||||||||||||||||||||||||||||
| Commercial real estate | 70,591 | 10 | 6,266 | 55,019 | 9,294 | 2 | ||||||||||||||||||||||||||||||||
| Commercial lease financing | 13,686 | — | — | 14,019 | — | (333) | ||||||||||||||||||||||||||||||||
| Total commercial | 588,132 | 22,995 | 59,332 | 381,008 | 124,846 | (49) | ||||||||||||||||||||||||||||||||
| Total loans and leases | $ | 1,041,352 | $ | 303,772 | $ | 221,448 | $ | 381,009 | $ | 125,046 | $ | 10,077 | ||||||||||||||||||||||||||
| Current-period information is preliminary and based on company data available at the time of the presentation. | 24 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||||||||
Commercial Credit Exposure by Industry (1, 2, 3, 4) | |||||||||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||||||||
| Commercial Utilized | Total Commercial Committed | ||||||||||||||||||||||||||||||||||
| March 31 2024 | December 31 2023 | March 31 2023 | March 31 2024 | December 31 2023 | March 31 2023 | ||||||||||||||||||||||||||||||
| Asset managers and funds | $ | 104,602 | $ | 103,138 | $ | 102,345 | $ | 172,321 | $ | 169,318 | $ | 164,480 | |||||||||||||||||||||||
Real estate (5) | 72,992 | 73,150 | 73,515 | 99,338 | 100,269 | 101,072 | |||||||||||||||||||||||||||||
| Capital goods | 49,292 | 49,698 | 48,146 | 94,710 | 97,044 | 88,060 | |||||||||||||||||||||||||||||
| Finance companies | 60,501 | 62,906 | 58,226 | 89,253 | 89,119 | 81,811 | |||||||||||||||||||||||||||||
| Healthcare equipment and services | 35,013 | 35,037 | 34,245 | 61,827 | 61,766 | 59,280 | |||||||||||||||||||||||||||||
| Materials | 25,257 | 25,223 | 27,224 | 54,935 | 55,296 | 56,244 | |||||||||||||||||||||||||||||
| Retailing | 25,399 | 24,561 | 26,021 | 53,193 | 54,523 | 54,127 | |||||||||||||||||||||||||||||
| Consumer services | 29,287 | 27,355 | 27,475 | 51,724 | 49,105 | 48,491 | |||||||||||||||||||||||||||||
| Food, beverage and tobacco | 23,624 | 23,865 | 24,307 | 48,283 | 49,426 | 46,838 | |||||||||||||||||||||||||||||
| Government and public education | 31,453 | 31,051 | 33,443 | 47,041 | 45,873 | 46,931 | |||||||||||||||||||||||||||||
| Individuals and trusts | 32,800 | 32,481 | 31,874 | 44,587 | 43,938 | 43,488 | |||||||||||||||||||||||||||||
| Commercial services and supplies | 23,073 | 22,642 | 24,136 | 41,480 | 41,473 | 41,711 | |||||||||||||||||||||||||||||
| Utilities | 17,571 | 18,610 | 19,118 | 39,298 | 39,481 | 39,209 | |||||||||||||||||||||||||||||
| Energy | 12,143 | 12,450 | 13,667 | 37,978 | 36,996 | 34,923 | |||||||||||||||||||||||||||||
| Transportation | 23,868 | 24,200 | 22,051 | 35,924 | 36,267 | 33,846 | |||||||||||||||||||||||||||||
| Technology hardware and equipment | 11,363 | 11,951 | 10,500 | 29,605 | 29,160 | 29,807 | |||||||||||||||||||||||||||||
| Global commercial banks | 22,816 | 22,749 | 26,910 | 25,667 | 25,684 | 29,047 | |||||||||||||||||||||||||||||
| Software and services | 9,904 | 9,830 | 11,678 | 25,257 | 22,381 | 25,300 | |||||||||||||||||||||||||||||
| Media | 12,944 | 13,033 | 15,102 | 24,998 | 24,908 | 29,006 | |||||||||||||||||||||||||||||
| Vehicle dealers | 17,365 | 16,283 | 13,281 | 23,370 | 22,570 | 21,237 | |||||||||||||||||||||||||||||
| Consumer durables and apparel | 8,948 | 9,184 | 10,167 | 20,771 | 20,732 | 21,784 | |||||||||||||||||||||||||||||
| Pharmaceuticals and biotechnology | 7,202 | 6,852 | 6,581 | 20,428 | 22,169 | 21,419 | |||||||||||||||||||||||||||||
| Insurance | 8,499 | 9,371 | 10,007 | 19,423 | 19,322 | 19,109 | |||||||||||||||||||||||||||||
| Telecommunication services | 9,396 | 9,224 | 9,646 | 17,186 | 17,269 | 17,666 | |||||||||||||||||||||||||||||
| Automobiles and components | 7,508 | 7,049 | 8,163 | 15,724 | 16,459 | 15,910 | |||||||||||||||||||||||||||||
| Food and staples retailing | 7,512 | 7,423 | 7,331 | 13,200 | 12,496 | 12,507 | |||||||||||||||||||||||||||||
| Financial markets infrastructure (clearinghouses) | 2,687 | 4,229 | 3,013 | 5,008 | 6,503 | 8,526 | |||||||||||||||||||||||||||||
| Religious and social organizations | 2,734 | 2,754 | 2,542 | 4,643 | 4,565 | 4,557 | |||||||||||||||||||||||||||||
| Total commercial credit exposure by industry | $ | 695,753 | $ | 696,299 | $ | 700,714 | $ | 1,217,172 | $ | 1,214,112 | $ | 1,196,386 | |||||||||||||||||||||||
(1)Includes loans and leases, standby letters of credit and financial guarantees, derivative assets, assets held-for-sale, commercial letters of credit, bankers’ acceptances, securitized assets, foreclosed properties and other collateral acquired. Derivative assets are carried at fair value, reflect the effects of legally enforceable master netting agreements and have been reduced by cash collateral of $57.7 billion, $55.8 billion and $29.1 billion at March 31, 2024, December 31, 2023 and March 31, 2023, respectively. Not reflected in utilized and committed exposure is additional non-cash derivative collateral held of $27.9 billion, $29.4 billion and $51.0 billion, which consists primarily of other marketable securities, at March 31, 2024, December 31, 2023 and March 31, 2023, respectively.
(2)Total utilized and total committed exposure includes loans of $2.7 billion, $3.3 billion and $4.1 billion and issued letters of credit with a notional amount of $25 million, $14 million and $15 million accounted for under the fair value option at March 31, 2024, December 31, 2023 and March 31, 2023, respectively. In addition, total committed exposure includes unfunded loan commitments accounted for under the fair value option with a notional amount of $3.1 billion, $2.6 billion and $3.1 billion at March 31, 2024, December 31, 2023 and March 31, 2023, respectively.
(3)Includes U.S. small business commercial exposure.
(4)Includes the notional amount of unfunded legally binding lending commitments net of amounts distributed (e.g., syndicated or participated) to other financial institutions.
(5)Industries are viewed from a variety of perspectives to best isolate the perceived risks. For purposes of this table, the real estate industry is defined based on the primary business activity of the borrowers or the counterparties using operating cash flows and primary source of repayment as key factors.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 25 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
| Nonperforming Loans, Leases and Foreclosed Properties | |||||||||||||||||||||||||||||
(Dollars in millions) | |||||||||||||||||||||||||||||
| March 31 2024 | December 31 2023 | September 30 2023 | June 30 2023 | March 31 2023 | |||||||||||||||||||||||||
| Residential mortgage | $ | 2,112 | $ | 2,114 | $ | 2,185 | $ | 2,140 | $ | 2,125 | |||||||||||||||||||
| Home equity | 438 | 450 | 479 | 482 | 488 | ||||||||||||||||||||||||
| Direct/Indirect consumer | 147 | 148 | 128 | 107 | 101 | ||||||||||||||||||||||||
| Total consumer | 2,697 | 2,712 | 2,792 | 2,729 | 2,714 | ||||||||||||||||||||||||
| U.S. commercial | 720 | 636 | 561 | 476 | 559 | ||||||||||||||||||||||||
| Non-U.S. commercial | 157 | 175 | 102 | 84 | 125 | ||||||||||||||||||||||||
| Commercial real estate | 2,273 | 1,927 | 1,343 | 816 | 502 | ||||||||||||||||||||||||
| Commercial lease financing | 16 | 19 | 18 | 6 | 4 | ||||||||||||||||||||||||
| 3,166 | 2,757 | 2,024 | 1,382 | 1,190 | |||||||||||||||||||||||||
| U.S. small business commercial | 20 | 16 | 17 | 15 | 14 | ||||||||||||||||||||||||
| Total commercial | 3,186 | 2,773 | 2,041 | 1,397 | 1,204 | ||||||||||||||||||||||||
| Total nonperforming loans and leases | 5,883 | 5,485 | 4,833 | 4,126 | 3,918 | ||||||||||||||||||||||||
Foreclosed properties (1) | 151 | 145 | 160 | 148 | 165 | ||||||||||||||||||||||||
Total nonperforming loans, leases, and foreclosed properties(2, 3) | $ | 6,034 | $ | 5,630 | $ | 4,993 | $ | 4,274 | $ | 4,083 | |||||||||||||||||||
| Fully-insured home loans past due 30 days or more and still accruing | $ | 476 | $ | 527 | $ | 523 | $ | 525 | $ | 580 | |||||||||||||||||||
| Consumer credit card past due 30 days or more and still accruing | 2,446 | 2,419 | 2,097 | 1,811 | 1,674 | ||||||||||||||||||||||||
| Other loans past due 30 days or more and still accruing | 2,907 | 2,974 | 2,848 | 2,920 | 3,146 | ||||||||||||||||||||||||
Total loans past due 30 days or more and still accruing (4, 5) | $ | 5,829 | $ | 5,920 | $ | 5,468 | $ | 5,256 | $ | 5,400 | |||||||||||||||||||
| Fully-insured home loans past due 90 days or more and still accruing | $ | 230 | $ | 252 | $ | 265 | $ | 288 | $ | 338 | |||||||||||||||||||
Consumer credit card past due 90 days or more and still accruing | 1,299 | 1,224 | 1,016 | 896 | 828 | ||||||||||||||||||||||||
| Other loans past due 90 days or more and still accruing | 343 | 280 | 286 | 356 | 508 | ||||||||||||||||||||||||
Total loans past due 90 days or more and still accruing (5) | $ | 1,872 | $ | 1,756 | $ | 1,567 | $ | 1,540 | $ | 1,674 | |||||||||||||||||||
Nonperforming loans, leases and foreclosed properties/Total assets (6) | 0.18 | % | 0.18 | % | 0.16 | % | 0.14 | % | 0.13 | % | |||||||||||||||||||
Nonperforming loans, leases and foreclosed properties/Total loans, leases and foreclosed properties (5) | 0.58 | 0.54 | 0.48 | 0.41 | 0.39 | ||||||||||||||||||||||||
Nonperforming loans and leases/Total loans and leases (6) | 0.56 | 0.52 | 0.46 | 0.39 | 0.38 | ||||||||||||||||||||||||
Commercial reservable criticized utilized exposure (7) | $ | 24,529 | $ | 23,300 | $ | 23,722 | $ | 21,469 | $ | 19,789 | |||||||||||||||||||
Commercial reservable criticized utilized exposure/Commercial reservable utilized exposure (6) | 3.93 | % | 3.74 | % | 3.83 | % | 3.44 | % | 3.17 | % | |||||||||||||||||||
Total commercial criticized utilized exposure/Commercial utilized exposure (7) | 4.13 | 4.00 | 4.12 | 3.79 | 3.67 | ||||||||||||||||||||||||
(1)Includes repossessed assets of $23 million for the first quarter of 2024, $22 million and $20 million for the fourth and third quarters of 2023 and $0 for the remaining quarters.
(2)Balances do not include past due consumer credit card, consumer loans secured by real estate where repayments are insured by the FHA and individually insured long-term stand-by agreements (fully-insured home loans), and in general, other consumer and commercial loans not secured by real estate.
(3)Balances do not include nonperforming loans held-for-sale of $379 million, $161 million, $173 million, $174 million and $250 million at March 31, 2024, December 31, 2023, September 30, 2023, June 30, 2023 and March 31, 2023, respectively.
(4)Balances do not include loans held-for-sale past due 30 days or more and still accruing of $106 million, $72 million, $22 million, $39 million and $36 million at March 31, 2024, December 31, 2023, September 30, 2023, June 30, 2023 and March 31, 2023, respectively.
(5)These balances are excluded from total nonperforming loans, leases and foreclosed properties.
(6)Total assets and total loans and leases do not include loans accounted for under the fair value option of $2.9 billion, $3.6 billion, $4.3 billion, $4.3 billion and $4.4 billion at March 31, 2024, December 31, 2023, September 30, 2023, June 30, 2023 and March 31, 2023, respectively.
(7)Criticized exposure corresponds to the Special Mention, Substandard and Doubtful asset categories defined by regulatory authorities. The reservable criticized exposure excludes loans held-for-sale, exposure accounted for under the fair value option and other nonreservable exposure.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 26 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||
Nonperforming Loans, Leases and Foreclosed Properties Activity (1) | |||||||||||||||||||||||||||||
(Dollars in millions) | |||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Nonperforming Consumer Loans and Leases: | |||||||||||||||||||||||||||||
| Balance, beginning of period | $ | 2,712 | $ | 2,792 | $ | 2,729 | $ | 2,714 | $ | 2,754 | |||||||||||||||||||
| Additions | 254 | 247 | 297 | 258 | 253 | ||||||||||||||||||||||||
| Reductions: | |||||||||||||||||||||||||||||
| Paydowns and payoffs | (131) | (129) | (117) | (131) | (103) | ||||||||||||||||||||||||
| Sales | (1) | (57) | (2) | (2) | (2) | ||||||||||||||||||||||||
Returns to performing status (2) | (113) | (122) | (91) | (92) | (170) | ||||||||||||||||||||||||
Charge-offs (3) | (10) | (15) | (13) | (13) | (12) | ||||||||||||||||||||||||
| Transfers to foreclosed properties | (14) | (4) | (11) | (5) | (6) | ||||||||||||||||||||||||
| Total net additions (reductions) to nonperforming loans and leases | (15) | (80) | 63 | 15 | (40) | ||||||||||||||||||||||||
| Total nonperforming consumer loans and leases, end of period | 2,697 | 2,712 | 2,792 | 2,729 | 2,714 | ||||||||||||||||||||||||
Foreclosed properties (4) | 112 | 103 | 112 | 97 | 117 | ||||||||||||||||||||||||
| Nonperforming consumer loans, leases and foreclosed properties, end of period | $ | 2,809 | $ | 2,815 | $ | 2,904 | $ | 2,826 | $ | 2,831 | |||||||||||||||||||
Nonperforming Commercial Loans and Leases (5): | |||||||||||||||||||||||||||||
| Balance, beginning of period | $ | 2,773 | $ | 2,041 | $ | 1,397 | $ | 1,204 | $ | 1,054 | |||||||||||||||||||
| Additions | 1,006 | 1,085 | 875 | 484 | 419 | ||||||||||||||||||||||||
| Reductions: | |||||||||||||||||||||||||||||
| Paydowns | (220) | (121) | (153) | (171) | (72) | ||||||||||||||||||||||||
| Sales | (1) | (1) | — | (3) | — | ||||||||||||||||||||||||
Returns to performing status (6) | (4) | (45) | (2) | (7) | (52) | ||||||||||||||||||||||||
| Charge-offs | (368) | (186) | (67) | (87) | (88) | ||||||||||||||||||||||||
| Transfers to foreclosed properties | — | — | — | (23) | — | ||||||||||||||||||||||||
| Transfers to loans held-for-sale | — | — | (9) | — | (57) | ||||||||||||||||||||||||
| Total net additions (reductions) to nonperforming loans and leases | 413 | 732 | 644 | 193 | 150 | ||||||||||||||||||||||||
| Total nonperforming commercial loans and leases, end of period | 3,186 | 2,773 | 2,041 | 1,397 | 1,204 | ||||||||||||||||||||||||
Foreclosed properties (4) | 39 | 42 | 48 | 51 | 48 | ||||||||||||||||||||||||
| Nonperforming commercial loans, leases and foreclosed properties, end of period | $ | 3,225 | $ | 2,815 | $ | 2,089 | $ | 1,448 | $ | 1,252 | |||||||||||||||||||
(1)For amounts excluded from nonperforming loans, leases and foreclosed properties, see footnotes to Nonperforming Loans, Leases and Foreclosed Properties table on page 26.
(2)Consumer loans and leases may be returned to performing status when all principal and interest is current and full repayment of the remaining contractual principal and interest is expected, or when the loan otherwise becomes well-secured and is in the process of collection.
(3)Our policy is not to classify consumer credit card and non-bankruptcy related consumer loans not secured by real estate as nonperforming; therefore, the charge-offs on these loans have no impact on nonperforming activity and, accordingly, are excluded from this table.
(4)Includes repossessed assets of $22 million in consumer loans and $1 million in commercial loans for the first quarter of 2024. Includes $20 million and $19 million in consumer loans and $2 million and $1 million in commercial loans for the fourth and third quarters of 2023 and $0 for the remaining quarters.
(5)Includes U.S. small business commercial activity. Small business card loans are excluded as they are not classified as nonperforming.
(6)Commercial loans and leases may be returned to performing status when all principal and interest is current and full repayment of the remaining contractual principal and interest is expected, or when the loan otherwise becomes well-secured and is in the process of collection.
| Current-period information is preliminary and based on company data available at the time of the presentation. | 27 | ||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Quarterly Net Charge-offs and Net Charge-off Ratios (1) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Amount | Percent | Amount | Percent | Amount | Percent | Amount | Percent | Amount | Percent | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Charge-offs | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Residential mortgage (2) | $ | 3 | 0.01 | % | $ | 11 | 0.02 | % | $ | 2 | — | % | $ | 2 | — | % | $ | 1 | — | % | |||||||||||||||||||||||||||||||||||||||
Home equity (3) | (13) | (0.20) | (17) | (0.26) | (14) | (0.22) | (16) | (0.25) | (12) | (0.18) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 899 | 3.62 | 777 | 3.07 | 673 | 2.72 | 610 | 2.60 | 501 | 2.21 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Direct/Indirect consumer | 65 | 0.26 | 49 | 0.19 | 25 | 0.10 | 17 | 0.06 | 1 | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other consumer | 74 | n/m | 93 | n/m | 118 | n/m | 107 | n/m | 162 | n/m | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total consumer | 1,028 | 0.91 | 913 | 0.79 | 804 | 0.70 | 720 | 0.64 | 653 | 0.58 | |||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. commercial | 66 | 0.07 | 67 | 0.07 | 5 | 0.01 | 5 | 0.01 | 47 | 0.05 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Non-U.S. commercial | (9) | (0.03) | 1 | — | (2) | (0.01) | — | — | 20 | 0.07 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial and industrial | 57 | 0.05 | 68 | 0.06 | 3 | — | 5 | — | 67 | 0.06 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 304 | 1.70 | 115 | 0.62 | 39 | 0.21 | 69 | 0.37 | 22 | 0.12 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial lease financing | 1 | 0.03 | (1) | — | 3 | 0.08 | 1 | — | (1) | (0.01) | |||||||||||||||||||||||||||||||||||||||||||||||||
| 362 | 0.26 | 182 | 0.13 | 45 | 0.03 | 75 | 0.05 | 88 | 0.06 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. small business commercial | 108 | 2.22 | 97 | 1.99 | 82 | 1.74 | 74 | 1.62 | 66 | 1.48 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 470 | 0.32 | 279 | 0.19 | 127 | 0.09 | 149 | 0.10 | 154 | 0.11 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total net charge-offs | $ | 1,498 | 0.58 | $ | 1,192 | 0.45 | $ | 931 | 0.35 | $ | 869 | 0.33 | $ | 807 | 0.32 | ||||||||||||||||||||||||||||||||||||||||||||
| By Business Segment and All Other | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Consumer Banking | $ | 1,144 | 1.47 | % | $ | 1,023 | 1.30 | % | $ | 911 | 1.16 | % | $ | 819 | 1.07 | % | $ | 729 | 0.97 | % | |||||||||||||||||||||||||||||||||||||||
| Global Wealth & Investment Management | 17 | 0.03 | 12 | 0.02 | 4 | 0.01 | 3 | 0.01 | 6 | 0.01 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Global Banking | 350 | 0.38 | 160 | 0.17 | 20 | 0.02 | 59 | 0.06 | 87 | 0.09 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Global Markets | — | — | 8 | 0.02 | 13 | 0.04 | 5 | 0.02 | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| All Other | (13) | (0.59) | (11) | (0.48) | (17) | (0.68) | (17) | (0.74) | (15) | (0.59) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total net charge-offs | $ | 1,498 | 0.58 | $ | 1,192 | 0.45 | $ | 931 | 0.35 | $ | 869 | 0.33 | $ | 807 | 0.32 | ||||||||||||||||||||||||||||||||||||||||||||
(1)Net charge-off ratios are calculated as annualized net charge-offs divided by average outstanding loans and leases excluding loans accounted for under the fair value option during the period for each loan and lease category.
(2)Includes loan sale net charge-offs (recoveries) of $8 million for the fourth quarter of 2023 and $0 for the remaining quarters.
(3)Includes loan sale net charge-offs (recoveries) of $(3) million for the fourth quarter of 2023 and $0 for the remaining quarters.
n/m = not meaningful
| Current-period information is preliminary and based on company data available at the time of the presentation. | 28 | ||||
| Bank of America Corporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||
| Allocation of the Allowance for Credit Losses by Product Type | ||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | ||||||||||||||||||||||||||||||||||||||
| March 31, 2024 | December 31, 2023 | March 31, 2023 | ||||||||||||||||||||||||||||||||||||
| Amount | Percent of Loans and Leases Outstanding (1) | Amount | Percent of Loans and Leases Outstanding (1) | Amount | Percent of Loans and Leases Outstanding (1) | |||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses | ||||||||||||||||||||||||||||||||||||||
| Residential mortgage | $ | 292 | 0.13% | $ | 339 | 0.15% | $ | 305 | 0.13% | |||||||||||||||||||||||||||||
| Home equity | 63 | 0.25 | 47 | 0.19 | 98 | 0.38 | ||||||||||||||||||||||||||||||||
| Credit card | 7,296 | 7.41 | 7,346 | 7.19 | 6,220 | 6.73 | ||||||||||||||||||||||||||||||||
| Direct/Indirect consumer | 751 | 0.73 | 715 | 0.69 | 628 | 0.60 | ||||||||||||||||||||||||||||||||
| Other consumer | 74 | n/m | 73 | n/m | 110 | n/m | ||||||||||||||||||||||||||||||||
| Total consumer | 8,476 | 1.87 | 8,520 | 1.85 | 7,361 | 1.63 | ||||||||||||||||||||||||||||||||
U.S. commercial (2) | 2,596 | 0.68 | 2,600 | 0.69 | 2,835 | 0.75 | ||||||||||||||||||||||||||||||||
| Non-U.S. commercial | 812 | 0.66 | 842 | 0.68 | 1,019 | 0.82 | ||||||||||||||||||||||||||||||||
| Commercial real estate | 1,292 | 1.80 | 1,342 | 1.84 | 1,253 | 1.72 | ||||||||||||||||||||||||||||||||
| Commercial lease financing | 37 | 0.25 | 38 | 0.26 | 46 | 0.34 | ||||||||||||||||||||||||||||||||
| Total commercial | 4,737 | 0.80 | 4,822 | 0.82 | 5,153 | 0.87 | ||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses | 13,213 | 1.26 | 13,342 | 1.27 | 12,514 | 1.20 | ||||||||||||||||||||||||||||||||
| Reserve for unfunded lending commitments | 1,158 | 1,209 | 1,437 | |||||||||||||||||||||||||||||||||||
| Allowance for credit losses | $ | 14,371 | $ | 14,551 | $ | 13,951 | ||||||||||||||||||||||||||||||||
Asset Quality Indicators | ||||||||||||||||||||||||||||||||||||||
Allowance for loan and lease losses/Total loans and leases (1) | 1.26% | 1.27% | 1.20% | |||||||||||||||||||||||||||||||||||
Allowance for loan and lease losses/Total nonperforming loans and leases | 225 | 243 | 319 | |||||||||||||||||||||||||||||||||||
| Ratio of the allowance for loan and lease losses/Annualized net charge-offs | 2.19 | 2.82 | 3.83 | |||||||||||||||||||||||||||||||||||
(1)Ratios are calculated as allowance for loan and lease losses as a percentage of loans and leases outstanding excluding loans accounted for under the fair value option. For fair value option amounts, see Outstanding Loans and Leases and related footnotes on page 23.
(2)Includes allowance for loan and lease losses for U.S. small business commercial loans of $1.1 billion, $1.0 billion and $864 million at March 31, 2024, December 31, 2023 and March 31, 2023, respectively.
n/m = not meaningful
| Current-period information is preliminary and based on company data available at the time of the presentation. | 29 | ||||
| Exhibit A: Non-GAAP Reconciliations | |||||||||||||||||
| Bank of America Corporation and Subsidiaries | |||||||||||||||||
| Reconciliations to GAAP Financial Measures | |||||||||||||||||
| (Dollars in millions, except per share information) | |||||||||||||||||
The Corporation evaluates its business using certain non-GAAP financial measures, including pretax, pre-provision income and ratios that utilize tangible equity and tangible assets, each of which is a non-GAAP financial measure. Tangible equity represents shareholders’ equity or common shareholders’ equity reduced by goodwill and intangible assets (excluding mortgage servicing rights), net of related deferred tax liabilities ("adjusted" shareholders' equity or common shareholders’ equity). Return on average tangible common shareholders’ equity measures the Corporation’s net income applicable to common shareholders as a percentage of adjusted average common shareholders’ equity. The tangible common equity ratio represents adjusted ending common shareholders’ equity divided by total tangible assets (total assets less goodwill and intangible assets (excluding mortgage servicing rights), net of related deferred tax liabilities). Return on average tangible shareholders’ equity measures the Corporation’s net income as a percentage of adjusted average total shareholders’ equity. The tangible equity ratio represents adjusted ending shareholders’ equity divided by total tangible assets. Tangible book value per common share represents adjusted ending common shareholders’ equity divided by ending common shares outstanding. These measures are used to evaluate the Corporation’s use of equity. In addition, profitability, relationship and investment models all use return on average tangible shareholders’ equity as key measures to support our overall growth goals.
See the tables below for reconciliations of these non-GAAP financial measures to the most directly comparable financial measures defined by GAAP for the three months ended March 31, 2024, December 31, 2023, September 30, 2023, June 30, 2023 and March 31, 2023. The Corporation believes the use of these non-GAAP financial measures provides additional clarity in understanding its results of operations and trends. Other companies may define or calculate these non-GAAP financial measures differently.
| First Quarter 2024 | Fourth Quarter 2023 | Third Quarter 2023 | Second Quarter 2023 | First Quarter 2023 | |||||||||||||||||||||||||
| Reconciliation of income before income taxes to pretax, pre-provision income | |||||||||||||||||||||||||||||
| Income before income taxes | $ | 7,262 | $ | 3,124 | $ | 8,095 | $ | 8,034 | $ | 9,089 | |||||||||||||||||||
| Provision for credit losses | 1,319 | 1,104 | 1,234 | 1,125 | 931 | ||||||||||||||||||||||||
| Pretax, pre-provision income | $ | 8,581 | $ | 4,228 | $ | 9,329 | $ | 9,159 | $ | 10,020 | |||||||||||||||||||
| Reconciliation of average shareholders’ equity to average tangible shareholders’ equity and average tangible common shareholders’ equity | |||||||||||||||||||||||||||||
| Shareholders’ equity | $ | 292,511 | $ | 288,618 | $ | 284,975 | $ | 282,425 | $ | 277,252 | |||||||||||||||||||
| Goodwill | (69,021) | (69,021) | (69,021) | (69,022) | (69,022) | ||||||||||||||||||||||||
| Intangible assets (excluding mortgage servicing rights) | (1,990) | (2,010) | (2,029) | (2,049) | (2,068) | ||||||||||||||||||||||||
| Related deferred tax liabilities | 874 | 886 | 890 | 895 | 899 | ||||||||||||||||||||||||
| Tangible shareholders’ equity | $ | 222,374 | $ | 218,473 | $ | 214,815 | $ | 212,249 | $ | 207,061 | |||||||||||||||||||
| Preferred stock | (28,397) | (28,397) | (28,397) | (28,397) | (28,397) | ||||||||||||||||||||||||
| Tangible common shareholders’ equity | $ | 193,977 | $ | 190,076 | $ | 186,418 | $ | 183,852 | $ | 178,664 | |||||||||||||||||||
| Reconciliation of period-end shareholders’ equity to period-end tangible shareholders’ equity and period-end tangible common shareholders’ equity | |||||||||||||||||||||||||||||
| Shareholders’ equity | $ | 293,552 | $ | 291,646 | $ | 287,064 | $ | 283,319 | $ | 280,196 | |||||||||||||||||||
| Goodwill | (69,021) | (69,021) | (69,021) | (69,021) | (69,022) | ||||||||||||||||||||||||
| Intangible assets (excluding mortgage servicing rights) | (1,977) | (1,997) | (2,016) | (2,036) | (2,055) | ||||||||||||||||||||||||
| Related deferred tax liabilities | 869 | 874 | 886 | 890 | 895 | ||||||||||||||||||||||||
| Tangible shareholders’ equity | $ | 223,423 | $ | 221,502 | $ | 216,913 | $ | 213,152 | $ | 210,014 | |||||||||||||||||||
| Preferred stock | (28,397) | (28,397) | (28,397) | (28,397) | (28,397) | ||||||||||||||||||||||||
| Tangible common shareholders’ equity | $ | 195,026 | $ | 193,105 | $ | 188,516 | $ | 184,755 | $ | 181,617 | |||||||||||||||||||
| Reconciliation of period-end assets to period-end tangible assets | |||||||||||||||||||||||||||||
| Assets | $ | 3,273,803 | $ | 3,180,151 | $ | 3,153,090 | $ | 3,123,198 | $ | 3,194,657 | |||||||||||||||||||
| Goodwill | (69,021) | (69,021) | (69,021) | (69,021) | (69,022) | ||||||||||||||||||||||||
| Intangible assets (excluding mortgage servicing rights) | (1,977) | (1,997) | (2,016) | (2,036) | (2,055) | ||||||||||||||||||||||||
| Related deferred tax liabilities | 869 | 874 | 886 | 890 | 895 | ||||||||||||||||||||||||
| Tangible assets | $ | 3,203,674 | $ | 3,110,007 | $ | 3,082,939 | $ | 3,053,031 | $ | 3,124,475 | |||||||||||||||||||
| Book value per share of common stock | |||||||||||||||||||||||||||||
| Common shareholders’ equity | $ | 265,155 | $ | 263,249 | $ | 258,667 | $ | 254,922 | $ | 251,799 | |||||||||||||||||||
| Ending common shares issued and outstanding | 7,866.9 | 7,895.5 | 7,923.4 | 7,953.6 | 7,972.4 | ||||||||||||||||||||||||
| Book value per share of common stock | $ | 33.71 | $ | 33.34 | $ | 32.65 | $ | 32.05 | $ | 31.58 | |||||||||||||||||||
| Tangible book value per share of common stock | |||||||||||||||||||||||||||||
| Tangible common shareholders’ equity | $ | 195,026 | $ | 193,105 | $ | 188,516 | $ | 184,755 | $ | 181,617 | |||||||||||||||||||
| Ending common shares issued and outstanding | 7,866.9 | 7,895.5 | 7,923.4 | 7,953.6 | 7,972.4 | ||||||||||||||||||||||||
| Tangible book value per share of common stock | $ | 24.79 | $ | 24.46 | $ | 23.79 | $ | 23.23 | $ | 22.78 | |||||||||||||||||||
| Current-period information is preliminary and based on company data available at the time of the presentation. | 30 | ||||