
BANC 8-K
Banc Of California, Inc. (BANC)
8-K
2025-04-23
For: 2025-04-23
View Original
Added on
April 10, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, DC 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the
Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): April 23, 2025
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||
| (Address of principal executive offices) | (Zip Code) | |||||||
Registrant’s telephone number, including area code: (855 ) 361-2262
N/A
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2.):
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Conditions.
On April 23, 2025, Banc of California, Inc. (the “Company”) issued a press release announcing 2025 first quarter financial results.
A copy of the press release is furnished herewith as Exhibit 99.1 and is incorporated by reference herein.
Item 7.01 Regulation FD Disclosure.
The Company will host a conference call to discuss its first quarter results at 10:00 A.M. Pacific Time on Thursday, April 23, 2025. Interested parties may attend the conference call by dialing (888) 317-6003 and referencing event code 8785621. A live audio webcast will be available through the webcast link to be posted on the Company’s Investor Relations website at www.bancofcal.com/investor, in addition to the slide presentation for investor review prior to the call. A copy of the presentation materials is furnished herewith as Exhibit 99.2 and is incorporated by reference herein.
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits.
104 Cover Page Interactive Data File (embedded within the Inline XBRL document)
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| BANC OF CALIFORNIA, INC. | ||
| /s/ Joseph Kauder | ||
| Joseph Kauder | ||
| Executive Vice President and Chief Financial Officer | ||
Date: April 23, 2025
Banc of California, Inc. Reports First Quarter Diluted Earnings per Share of $0.26 and Loan Growth of 6% Annualized in the First Quarter; Upsizes Stock Buyback Program to $300 Million
Company Release – 4/23/2025
$0.26 Earnings Per Share | $18.17 Book Value Per Share $16.12 Tangible Book Value Per Share(1) | 10.43% CET1 Ratio | 6% Annualized Loan Growth | |||||||||||||||||
LOS ANGELES, Calif.--(BUSINESS WIRE)--Banc of California, Inc. (NYSE: BANC) (“Banc of California” or the “Company”), the parent company of wholly-owned subsidiary Banc of California (the “Bank”), today reported financial results for the first quarter ended March 31, 2025. The Company reported net earnings available to common and equivalent stockholders of $43.6 million, or $0.26 per diluted common share, for the first quarter of 2025. This compares to net earnings available to common and equivalent stockholders of $47.0 million, or $0.28 per diluted common share, for the fourth quarter of 2024.
The Company also announced today an upsize of its stock repurchase program, first announced on March 17, 2025, from $150 million to $300 million, inclusive of $150.0 million purchased through April 21, 2025, and expanded to cover both the Company's common stock and depositary shares representing its preferred stock.
First Quarter of 2025 Financial Highlights:
•Total loans of $24.1 billion grew by 6% annualized or $344.9 million from 4Q24 driven by increases in nearly all loan segments and highlighted by commercial and industrial ("C&I") growth in the lender finance, fund finance, and warehouse loan portfolios.
•New loan originations totaled $2.6 billion including production, purchased loans, and unfunded new commitments with a weighted average interest rate on production of 7.20%.
•Repurchase of $38.5 million of common stock with a weighted average price per share of $14.36 during the first quarter, and $150.0 million with a weighted average price per share of $13.05 cumulatively through April 21, 2025, or 6.8% of common shares outstanding as of March 17, 2025, the date that the $150 million authorization was announced.
•Net interest margin up 4 basis points vs 4Q24 to 3.08% mainly driven by lower average costs of deposits.
•Average total cost of deposits declined by 14 basis points to 2.12% vs 4Q24.
•Average noninterest-bearing deposits stable at 29% of average total deposits.
•High liquidity levels, with available on-balance sheet liquidity and unused borrowing capacity of $15.1 billion at March 31, 2025, which was 2.1 times greater than uninsured and uncollateralized deposits.
•Strong capital ratios(1) well above the regulatory thresholds for "well capitalized" banks, including an estimated 12.83% Tier 1 capital ratio and 10.43% CET 1 capital ratio.
•Continued growth in book value per share to $18.17, up 2.2% vs 4Q24 and tangible book value per share(2) to $16.12, up 2.5% vs 4Q24
•Strong credit quality with low net charge-offs at 0.24% of average loans and leases. Appropriate credit reserves with the ACL ratio mostly flat at 1.10% of total loans and leases and the economic coverage ratio(2) at 1.66%.
(1)Capital ratio for March 31, 2025 is preliminary
(2)Non-GAAP measure; refer to section 'Non-GAAP Measures'
 1

Jared Wolff, President & CEO of Banc of California, commented, “Our first quarter results came in as expected, with positive trends in our core earnings drivers including net interest margin expansion, solid loan growth, and prudent expense management. We have continued to capitalize on our strong market position to bring in new attractive client relationships, providing us with high quality lending opportunities and stable deposits. As a result, both book value and tangible book value per share increased, and liquidity levels remained high. Given our healthy capital and liquidity position, and our commitment to delivering excellent, sustainable returns to our shareholders, we announced an opportunistic share buyback program in mid-March and have repurchased 6.8% of our shares as of April 21."
Mr. Wolff continued, “While the economic outlook remains uncertain, demand in our key markets continues to support expansion in our net interest margin, loan and deposit growth, and improvement in operating efficiency as we grow revenue while managing our expense levels. Our capital, liquidity, and credit loss coverage positions remain healthy, allowing us to operate comfortably under a variety of economic scenarios, including the market volatility we are currently experiencing. We remain committed to leveraging our position of strength to serve our customers and help them navigate successfully through these volatile times.”
2 INCOME STATEMENT HIGHLIGHTS
| Three Months Ended | ||||||||||||||||||||
| March 31, | December 31, | March 31, | ||||||||||||||||||
| Summary Income Statement | 2025 | 2024 | 2024 | |||||||||||||||||
| (In thousands) | ||||||||||||||||||||
| Total interest income | $ | 406,655 | $ | 424,519 | $ | 478,704 | ||||||||||||||
| Total interest expense | 174,291 | 189,234 | 249,602 | |||||||||||||||||
| Net interest income | 232,364 | 235,285 | 229,102 | |||||||||||||||||
| Provision for credit losses | 9,300 | 12,801 | 10,000 | |||||||||||||||||
| Gain (loss) on sale of loans | 211 | 20 | (448) | |||||||||||||||||
| Loss on sale of securities | — | (454) | — | |||||||||||||||||
| Other noninterest income | 33,439 | 29,423 | 34,264 | |||||||||||||||||
| Total noninterest income | 33,650 | 28,989 | 33,816 | |||||||||||||||||
| Total revenue | 266,014 | 264,274 | 262,918 | |||||||||||||||||
| Acquisition, integration and | ||||||||||||||||||||
| reorganization costs | — | (1,023) | — | |||||||||||||||||
| Other noninterest expense | 183,653 | 182,393 | 210,518 | |||||||||||||||||
| Total noninterest expense | 183,653 | 181,370 | 210,518 | |||||||||||||||||
| Earnings before income taxes | 73,061 | 70,103 | 42,400 | |||||||||||||||||
| Income tax expense | 19,493 | 13,184 | 11,548 | |||||||||||||||||
| Net earnings | 53,568 | 56,919 | 30,852 | |||||||||||||||||
| Preferred stock dividends | 9,947 | 9,947 | 9,947 | |||||||||||||||||
| Net earnings available to common | ||||||||||||||||||||
| and equivalent stockholders | $ | 43,621 | $ | 46,972 | $ | 20,905 | ||||||||||||||
| Diluted earnings per share | $ | 0.26 | $ | 0.28 | $ | 0.12 | ||||||||||||||
Net Interest Income and Margin
Q1-2025 vs Q4-2024
Net interest income decreased by $2.9 million to $232.4 million for the first quarter from $235.3 million for the fourth quarter attributable primarily to the following:
•A decrease of $11.2 million in interest income from loans due primarily to lower day count, lower loan prepayments, and lower market interest rates reflective of a full quarter impact of the 50 basis points federal funds rate cuts in the fourth quarter.
•A decrease of $6.8 million in interest income from deposits in financial institutions driven by lower balances, as we maintained a lower cash target level in the first quarter, and lower market interest rates.
This was partially offset by:
•A decrease of $13.6 million in interest expense due primarily to lower interest paid on interest-bearing deposits as a result of deposit rate repricing driven by the federal funds rate cuts in the fourth quarter and lower day count.
•A decrease of $1.4 million in interest expense paid on our borrowings and subordinated debt driven by lower market interest rates.
3 The net interest margin was 3.08% for the first quarter compared to 3.04% for the fourth quarter. Our net interest margin increased by 4 basis points primarily driven by lower average total cost of funds, offset partially by lower average yield on interest-earning assets as described below:
•The average total cost of funds decreased by 13 basis points to 2.42% for the first quarter compared to 2.55% for the fourth quarter due mainly to lower market interest rates and a lower average balance of interest-bearing deposits, offset partially by a lower balance of average noninterest-bearing deposits. The average cost of deposits decreased by 14 basis points to 2.12% in the first quarter from 2.26% for the fourth quarter reflecting a full quarter impact of the federal funds rate cuts. Average total deposits decreased by $247.0 million, with average noninterest-bearing deposits decreasing by $190.9 million for the first quarter compared to the fourth quarter, and average interest-bearing deposits decreasing by $56.1 million for those same comparative periods. Average noninterest-bearing deposits represented 29% of average total deposits in both the first quarter and the fourth quarter.
•The average yield on interest-earning assets decreased by 9 basis points to 5.39% for the first quarter compared to 5.48% for the fourth quarter due mainly to the average yield on deposits in financial institutions decreasing by 33 basis points and the average yield on loans and leases decreasing by 11 basis points, offset partially by the average yield on investment securities increasing by 5 basis points. The average yield on deposits in financial institutions was 4.41% for the first quarter compared to 4.74% for the fourth quarter, driven by the federal funds rate cuts as described above. The average yield on loans and leases was 5.90% for the first quarter compared to 6.01% for the fourth quarter due primarily to aforementioned lower loan prepayments and lower market interest rates. These decreases were partially offset by an increase in the average yield on investment securities, which was 3.24% in the first quarter compared to 3.19% in the fourth quarter as we continued to benefit from the balance sheet repositioning actions taken in 2024 and the purchase of and reinvestment into higher-yielding securities. Additionally, average deposits in financial institutions decreased by $386.6 million to $2.1 billion in the first quarter from $2.5 billion in the fourth quarter as we maintained a lower cash target level.
| Three Months Ended | Increase (Decrease) | |||||||||||||||||||||||||||||||
| March 31, 2025 | December 31, 2024 | QoQ | ||||||||||||||||||||||||||||||
| Summary | Interest | Average | Interest | Average | Average | |||||||||||||||||||||||||||
| Average Balance | Average | Income/ | Yield/ | Average | Income/ | Yield/ | Average | Yield/ | ||||||||||||||||||||||||
| and Yield/Cost Data | Balance | Expense | Cost | Balance | Expense | Cost | Balance | Cost | ||||||||||||||||||||||||
| (Dollars in thousands) | ||||||||||||||||||||||||||||||||
| Assets: | ||||||||||||||||||||||||||||||||
Loans and leases(1) | $ | 23,788,647 | $ | 346,103 | 5.90 | % | $ | 23,649,271 | $ | 357,303 | 6.01 | % | $ | 139,376 | (0.11) | % | ||||||||||||||||
| Investment securities | 4,734,037 | 37,862 | 3.24 | % | 4,700,742 | 37,743 | 3.19 | % | 33,295 | 0.05 | % | |||||||||||||||||||||
| Deposits in financial institutions | 2,088,139 | 22,690 | 4.41 | % | 2,474,732 | 29,473 | 4.74 | % | (386,593) | (0.33) | % | |||||||||||||||||||||
| Total interest-earning assets | $ | 30,610,823 | $ | 406,655 | 5.39 | % | $ | 30,824,745 | $ | 424,519 | 5.48 | % | $ | (213,922) | (0.09) | % | ||||||||||||||||
| Liabilities: | ||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | ||||||||||||||||||||||||||||||||
| deposits | $ | 7,714,830 | $ | 7,905,750 | $ | (190,920) | ||||||||||||||||||||||||||
| Total interest-bearing deposits | 19,206,084 | $ | 140,530 | 2.97 | % | 19,262,178 | $ | 154,085 | 3.18 | % | (56,094) | (0.21) | % | |||||||||||||||||||
| Total deposits | $ | 26,920,914 | 140,530 | 2.12 | % | $ | 27,167,928 | 154,085 | 2.26 | % | $ | (247,014) | (0.14) | % | ||||||||||||||||||
| Total interest-bearing liabilities | $ | 21,546,621 | $ | 174,291 | 3.28 | % | $ | 21,603,479 | $ | 189,234 | 3.48 | % | $ | (56,858) | (0.20) | % | ||||||||||||||||
Net interest income(1) | $ | 232,364 | $ | 235,285 | ||||||||||||||||||||||||||||
| Net interest margin | 3.08 | % | 3.04 | % | 0.04 | % | ||||||||||||||||||||||||||
Total funds(2) | $ | 29,261,451 | $ | 174,291 | 2.42 | % | $ | 29,509,229 | $ | 189,234 | 2.55 | % | $ | (247,778) | (0.13) | % | ||||||||||||||||
______________
(1) Includes net loan discount accretion of $16.0 million and $20.7 million for the three months ended March 31, 2025 and December 31, 2024.
(2) Total funds is the sum of total interest-bearing liabilities and noninterest-bearing demand deposits. The cost of total funds is calculated as annualized total interest expense divided by average total funds.
4 Provision For Credit Losses
Q1-2025 vs Q4-2024
The provision for credit losses was $9.3 million for the first quarter compared to $12.8 million for the fourth quarter. The first quarter provision included a $9.7 million provision for loan losses and a $0.5 million provision for unfunded loan commitments, offset partially by a $0.9 million reversal of the provision for credit losses related to held-to-maturity ("HTM") securities. The first quarter provision for loans and unfunded loan commitments was primarily driven by net charge-off activity experienced during the quarter, partially offset by lower specific reserves and changes in portfolio mix driven by growth in loan segments with low expected credit losses.
The fourth quarter provision included an $11.5 million provision for loan losses and a $1.5 million provision for unfunded loan commitments, offset partially by a $0.2 million reversal of the provision for credit losses related to available-for-sale ("AFS") securities. The fourth quarter provision for loans and unfunded loan commitments was driven primarily by net charge-off activity during the quarter.
Noninterest Income
Q1-2025 vs Q4-2024
Noninterest income increased by $4.7 million to $33.7 million for the first quarter from $29.0 million for the fourth quarter due mainly to a $2.3 million increase in dividends and gains on equity investments, a $1.7 million increase in other commissions and fees, and a $0.8 million increase in other income. The increase in dividends and gains on equity investments was due to higher gains from Small Business Investment Company (“SBIC”) investments. The increase in other commissions and fees was due to higher loan-related fee income and higher customer service fees. The increase in other income was mainly driven by a $0.7 million increase in the fair value mark on credit-linked notes.
Noninterest Expense
Q1-2025 vs Q4-2024
Noninterest expense increased by $2.3 million to $183.7 million for the first quarter from $181.4 million for the fourth quarter due mainly to increases of $8.8 million in compensation expenses and $3.9 million in other expenses, offset partially by decreases of $3.9 million in customer related expenses, $3.9 million in insurance and assessments expenses, and $1.6 million in loan expense. The increase in compensation was primarily due to seasonality as resets of accruals for incentive compensation, payroll taxes and benefits occur during the first quarter of the year. The increase in other expenses was primarily due to higher donations including a $1.0 million donation to the Banc of California Wildfire Relief and Recovery Fund. The decrease in customer related expenses was driven by lower earnings credit rate expenses which were impacted by the lower federal funds rate. The decrease in insurance and assessments expense was mainly due to a lower FDIC assessment and FDIC expense true-ups. The decrease in loan expenses was mostly attributable to lower legal fees driven by higher recoveries in the first quarter.
Income Taxes
Q1-2025 vs Q4-2024
Income tax expense of $19.5 million was recorded for the first quarter resulting in an effective tax rate of 26.7% compared to income tax expense of $13.2 million for the fourth quarter and an effective tax rate of 18.8%. The lower fourth quarter effective tax rate was due primarily to tax benefits resulting from recording deferred tax assets at higher state tax rates.
5 BALANCE SHEET HIGHLIGHTS
| March 31, | December 31, | March 31, | Increase (Decrease) | ||||||||||||||||||||||||||
| Selected Balance Sheet Items | 2025 | 2024 | 2024 | QoQ | YoY | ||||||||||||||||||||||||
| (In thousands) | |||||||||||||||||||||||||||||
| Cash and cash equivalents | $ | 2,343,889 | $ | 2,502,212 | $ | 3,085,228 | $ | (158,323) | $ | (741,339) | |||||||||||||||||||
| Securities available-for-sale | 2,334,058 | 2,246,839 | 2,286,682 | 87,219 | 47,376 | ||||||||||||||||||||||||
| Securities held-to-maturity | 2,311,912 | 2,306,149 | 2,291,984 | 5,763 | 19,928 | ||||||||||||||||||||||||
| Loans held for sale | 25,797 | 26,331 | 80,752 | (534) | (54,955) | ||||||||||||||||||||||||
| Loans and leases held for investment | 24,126,527 | 23,781,663 | 25,473,022 | 344,864 | (1,346,495) | ||||||||||||||||||||||||
| Total assets | 33,779,918 | 33,542,864 | 36,073,516 | 237,054 | (2,293,598) | ||||||||||||||||||||||||
| Noninterest-bearing deposits | $ | 7,593,950 | $ | 7,719,913 | $ | 7,833,608 | $ | (125,963) | $ | (239,658) | |||||||||||||||||||
| Total deposits | 27,193,191 | 27,191,909 | 28,892,407 | 1,282 | (1,699,216) | ||||||||||||||||||||||||
| Borrowings | 1,670,782 | 1,391,814 | 2,139,498 | 278,968 | (468,716) | ||||||||||||||||||||||||
| Total liabilities | 30,258,262 | 30,042,915 | 32,679,366 | 215,347 | (2,421,104) | ||||||||||||||||||||||||
| Total stockholders' equity | 3,521,656 | 3,499,949 | 3,394,150 | 21,707 | 127,506 | ||||||||||||||||||||||||
Securities
AFS securities increased by $87.2 million during the first quarter to $2.3 billion at March 31, 2025. AFS securities had aggregate unrealized net after-tax losses in accumulated other comprehensive income (loss) ("AOCI") of $172.5 million. These AFS unrealized net losses related primarily to changes in overall interest rates and spreads and the resulting impact on valuations.
The balance of HTM securities increased by $5.8 million in the first quarter to $2.3 billion at March 31, 2025. As of March 31, 2025, HTM securities had aggregate unrealized net after-tax losses in AOCI of $151.9 million remaining from the balance established at the time of transfer from AFS on June 1, 2022.
6 Loans and Leases
The following table sets forth the composition, by loan category, of our loan and lease portfolio held for investment as of the dates indicated:
| March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||||||||||||||||
| 2025 | 2024 | 2024 | 2024 | 2024 | |||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| Composition of Loans and Leases | |||||||||||||||||||||||||||||
| Real estate mortgage: | |||||||||||||||||||||||||||||
| Commercial | $ | 4,489,543 | $ | 4,578,772 | $ | 4,557,939 | $ | 4,722,585 | $ | 4,896,544 | |||||||||||||||||||
| Multi-family | 6,216,084 | 6,041,713 | 6,009,280 | 5,984,930 | 6,121,472 | ||||||||||||||||||||||||
| Other residential | 2,787,031 | 2,807,174 | 2,767,187 | 2,866,085 | 4,949,383 | ||||||||||||||||||||||||
| Total real estate mortgage | 13,492,658 | 13,427,659 | 13,334,406 | 13,573,600 | 15,967,399 | ||||||||||||||||||||||||
| Real estate construction and land: | |||||||||||||||||||||||||||||
| Commercial | 733,684 | 799,131 | 836,902 | 784,166 | 775,021 | ||||||||||||||||||||||||
| Residential | 2,127,354 | 2,373,162 | 2,622,507 | 2,573,431 | 2,470,333 | ||||||||||||||||||||||||
| Total real estate construction and land | 2,861,038 | 3,172,293 | 3,459,409 | 3,357,597 | 3,245,354 | ||||||||||||||||||||||||
| Total real estate | 16,353,696 | 16,599,952 | 16,793,815 | 16,931,197 | 19,212,753 | ||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||
| Asset-based | 2,305,325 | 2,087,969 | 2,115,311 | 1,968,713 | 2,061,016 | ||||||||||||||||||||||||
| Venture capital | 1,733,074 | 1,537,776 | 1,353,626 | 1,456,122 | 1,513,641 | ||||||||||||||||||||||||
| Other commercial | 3,340,400 | 3,153,084 | 2,850,535 | 2,446,974 | 2,245,910 | ||||||||||||||||||||||||
| Total commercial | 7,378,799 | 6,778,829 | 6,319,472 | 5,871,809 | 5,820,567 | ||||||||||||||||||||||||
| Consumer | 394,032 | 402,882 | 414,490 | 425,903 | 439,702 | ||||||||||||||||||||||||
| Total loans and leases held for | |||||||||||||||||||||||||||||
| investment | $ | 24,126,527 | $ | 23,781,663 | $ | 23,527,777 | $ | 23,228,909 | $ | 25,473,022 | |||||||||||||||||||
| Total unfunded loan commitments | $ | 4,858,960 | $ | 4,887,690 | $ | 5,008,449 | $ | 5,256,473 | $ | 5,482,672 | |||||||||||||||||||
| Composition as % of Total | |||||||||||||||||||||||||||||
| Loans and Leases | |||||||||||||||||||||||||||||
| Real estate mortgage: | |||||||||||||||||||||||||||||
| Commercial | 19 | % | 19 | % | 19 | % | 20 | % | 19 | % | |||||||||||||||||||
| Multi-family | 26 | % | 26 | % | 25 | % | 26 | % | 24 | % | |||||||||||||||||||
| Other residential | 11 | % | 12 | % | 12 | % | 12 | % | 19 | % | |||||||||||||||||||
| Total real estate mortgage | 56 | % | 57 | % | 56 | % | 58 | % | 62 | % | |||||||||||||||||||
| Real estate construction and land: | |||||||||||||||||||||||||||||
| Commercial | 3 | % | 3 | % | 4 | % | 4 | % | 3 | % | |||||||||||||||||||
| Residential | 9 | % | 10 | % | 11 | % | 11 | % | 10 | % | |||||||||||||||||||
| Total real estate construction and land | 12 | % | 13 | % | 15 | % | 15 | % | 13 | % | |||||||||||||||||||
| Total real estate | 68 | % | 70 | % | 71 | % | 73 | % | 75 | % | |||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||
| Asset-based | 9 | % | 9 | % | 9 | % | 8 | % | 8 | % | |||||||||||||||||||
| Venture capital | 7 | % | 6 | % | 6 | % | 6 | % | 6 | % | |||||||||||||||||||
| Other commercial | 14 | % | 13 | % | 12 | % | 11 | % | 9 | % | |||||||||||||||||||
| Total commercial | 30 | % | 28 | % | 27 | % | 25 | % | 23 | % | |||||||||||||||||||
| Consumer | 2 | % | 2 | % | 2 | % | 2 | % | 2 | % | |||||||||||||||||||
| Total loans and leases held for | |||||||||||||||||||||||||||||
| investment | 100 | % | 100 | % | 100 | % | 100 | % | 100 | % | |||||||||||||||||||
7 Total loans and leases held for investment increased by $344.9 million in the first quarter and totaled $24.1 billion at March 31, 2025. The increase in loans and leases held for investment was due primarily to increased balances in the asset-based, venture capital, other commercial, and multi-family loan portfolios, offset partially by a decrease in the real estate construction and land loan segment, and the commercial real estate mortgage and other residential real estate mortgage loan portfolios. Loan originations including production, purchased loans, and unfunded new commitments were $2.6 billion in the first quarter, most of which onboarded towards the end of the quarter, with a weighted average interest rate on production of 7.20%.
Credit Quality
| March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||||||||||||||||
| Asset Quality Information and Ratios | 2025 | 2024 | 2024 | 2024 | 2024 | ||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| Delinquent loans and leases held for | |||||||||||||||||||||||||||||
| investment: | |||||||||||||||||||||||||||||
| 30 to 89 days delinquent | $ | 100,664 | $ | 91,347 | $ | 52,927 | $ | 27,962 | $ | 178,421 | |||||||||||||||||||
| 90+ days delinquent | 99,976 | 88,846 | 72,037 | 55,792 | 57,573 | ||||||||||||||||||||||||
| Total delinquent loans and leases | $ | 200,640 | $ | 180,193 | $ | 124,964 | $ | 83,754 | $ | 235,994 | |||||||||||||||||||
| Total delinquent loans and leases to | |||||||||||||||||||||||||||||
| loans and leases held for investment | 0.83 | % | 0.76 | % | 0.53 | % | 0.36 | % | 0.93 | % | |||||||||||||||||||
| Nonperforming assets, excluding loans | |||||||||||||||||||||||||||||
| held for sale: | |||||||||||||||||||||||||||||
| Nonaccrual loans and leases | $ | 213,480 | $ | 189,605 | $ | 168,341 | $ | 117,070 | $ | 145,785 | |||||||||||||||||||
| 90+ days delinquent loans and still | |||||||||||||||||||||||||||||
| accruing | — | — | — | — | — | ||||||||||||||||||||||||
| Total nonperforming loans and | |||||||||||||||||||||||||||||
| leases ("NPLs") | 213,480 | 189,605 | 168,341 | 117,070 | 145,785 | ||||||||||||||||||||||||
| Foreclosed assets, net | 5,474 | 9,734 | 8,661 | 13,302 | 12,488 | ||||||||||||||||||||||||
| Total nonperforming assets ("NPAs") | $ | 218,954 | $ | 199,339 | $ | 177,002 | $ | 130,372 | $ | 158,273 | |||||||||||||||||||
| Classified loans and leases held for | |||||||||||||||||||||||||||||
| investment | $ | 764,723 | $ | 563,502 | $ | 533,591 | $ | 415,498 | $ | 366,729 | |||||||||||||||||||
| Allowance for loan and lease losses | $ | 234,986 | $ | 239,360 | $ | 254,345 | $ | 247,762 | $ | 291,503 | |||||||||||||||||||
| Allowance for loan and lease losses | |||||||||||||||||||||||||||||
| to NPLs | 110.07 | % | 126.24 | % | 151.09 | % | 211.64 | % | 199.95 | % | |||||||||||||||||||
| NPLs to loans and leases held for | |||||||||||||||||||||||||||||
| investment | 0.88 | % | 0.80 | % | 0.72 | % | 0.50 | % | 0.57 | % | |||||||||||||||||||
| NPAs to total assets | 0.65 | % | 0.59 | % | 0.53 | % | 0.37 | % | 0.44 | % | |||||||||||||||||||
| Classified loans and leases to loans | |||||||||||||||||||||||||||||
| and leases held for investment | 3.17 | % | 2.37 | % | 2.27 | % | 1.79 | % | 1.44 | % | |||||||||||||||||||
The overall quality of our loan portfolio remains strong, supported by disciplined underwriting, borrower strength, and robust credit metrics. In light of the current economic uncertainty, we enhanced our credit monitoring process to more proactively manage potential risks. In the first quarter, credit downgrades were primarily driven by rate-sensitive loans in the higher interest rate environment, although these loans are well-collateralized with low loan-to-value ("LTV") ratios that we believe mitigates the risk of potential losses. Classified inflows were mainly driven by migration of rate-sensitive multifamily loans, all of which remain current, maintain strong collateral values, and are in attractive California locations. Nonperforming and delinquent loan inflows in the quarter were mainly driven by one commercial real estate loan which is full recourse to the guarantor and we believe has adequate collateral coverage.
8 At March 31, 2025, total delinquent loans and leases were $200.6 million, compared to $180.2 million at December 31, 2024. The $20.4 million increase in total delinquent loans was due mainly to an increase in the 30 to 89 days delinquent category of $27.0 million in commercial real estate mortgage loans, offset partially by decreases of $8.6 million in multi-family real estate mortgage loans and $5.5 million in venture capital loans. In the 90 or more days delinquent category, there was a $14.9 million increase in commercial real estate mortgage loans, offset partially by decreases of $2.6 million in other residential real estate mortgage loans and $2.4 million in other commercial loans. Total delinquent loans and leases as a percentage of loans and leases held for investment increased to 0.83% at March 31, 2025, compared to 0.76% at December 31, 2024.
At March 31, 2025, nonperforming loans and leases were $213.5 million, compared to $189.6 million at December 31, 2024. During the first quarter, nonperforming loans and leases increased by $23.9 million due to additions of $67.8 million, offset partially by charge-offs of $12.6 million and payoffs, paydowns, and other reductions of $31.3 million. The addition to nonperforming loans and leases was mainly related to the one commercial real estate loan as described above.
Nonperforming loans and leases as a percentage of loans and leases held for investment increased to 0.88% at March 31, 2025 compared to 0.80% at December 31, 2024.
At March 31, 2025, nonperforming assets were $219.0 million, or 0.65% of total assets, compared to $199.3 million, or 0.59% of total assets, as of December 31, 2024. At March 31, 2025, nonperforming assets included $5.5 million of foreclosed assets, consisting primarily of single-family residences.
9 Allowance for Credit Losses – Loans
| Three Months Ended | |||||||||||||||||
| March 31, | December 31, | March 31, | |||||||||||||||
| Allowance for Credit Losses - Loans | 2025 | 2024 | 2024 | ||||||||||||||
| (Dollars in thousands) | |||||||||||||||||
| Allowance for loan and lease losses | |||||||||||||||||
| ("ALLL"): | |||||||||||||||||
| Balance at beginning of period | $ | 239,360 | $ | 254,345 | $ | 281,687 | |||||||||||
| Charge-offs | (16,551) | (27,696) | (5,014) | ||||||||||||||
| Recoveries | 2,477 | 1,211 | 3,830 | ||||||||||||||
| Net charge-offs | (14,074) | (26,485) | (1,184) | ||||||||||||||
| Provision for loan losses | 9,700 | 11,500 | 11,000 | ||||||||||||||
| Balance at end of period | $ | 234,986 | $ | 239,360 | $ | 291,503 | |||||||||||
| Reserve for unfunded loan commitments | |||||||||||||||||
| ("RUC"): | |||||||||||||||||
| Balance at beginning of period | $ | 29,071 | $ | 27,571 | $ | 29,571 | |||||||||||
| Provision for credit losses | 500 | 1,500 | (1,000) | ||||||||||||||
| Balance at end of period | $ | 29,571 | $ | 29,071 | $ | 28,571 | |||||||||||
| Allowance for credit losses ("ACL") - | |||||||||||||||||
| Loans: | |||||||||||||||||
| Balance at beginning of period | $ | 268,431 | $ | 281,916 | $ | 311,258 | |||||||||||
| Charge-offs | (16,551) | (27,696) | (5,014) | ||||||||||||||
| Recoveries | 2,477 | 1,211 | 3,830 | ||||||||||||||
| Net charge-offs | (14,074) | (26,485) | (1,184) | ||||||||||||||
| Provision for credit losses | 10,200 | 13,000 | 10,000 | ||||||||||||||
| Balance at end of period | $ | 264,557 | $ | 268,431 | $ | 320,074 | |||||||||||
| ALLL to loans and leases held for | |||||||||||||||||
| investment | 0.97 | % | 1.01 | % | 1.14 | % | |||||||||||
| ACL to loans and leases held for | |||||||||||||||||
| investment | 1.10 | % | 1.13 | % | 1.26 | % | |||||||||||
| ACL to NPLs | 123.93 | % | 141.57 | % | 219.55 | % | |||||||||||
| ACL to NPAs | 120.83 | % | 134.66 | % | 202.23 | % | |||||||||||
| Annualized net charge-offs to average | |||||||||||||||||
| loans and leases | 0.24 | % | 0.45 | % | 0.02 | % | |||||||||||
The allowance for credit losses - loans, which includes the reserve for unfunded loan commitments, totaled $264.6 million, or 1.10% of total loans and leases, at March 31, 2025, compared to $268.4 million, or 1.13% of total loans and leases, at December 31, 2024. The $3.9 million decrease in the allowance was due to net charge-offs of $14.1 million, offset partially by a $10.2 million provision. The decrease in the ACL coverage ratio was driven by improvement in the economic forecast compared to the fourth quarter, a shift in the portfolio mix driven by growth in loan categories with lower expected losses, and the impact of charge-offs, offset partially by the impact of changes in risk ratings in the venture lending and commercial construction loan portfolios.
Our ability to absorb credit losses is also bolstered by (i) $115.2 million of loss coverage from the credit-linked notes, pursuant to which the bank sold the first 5% of any losses on $2.3 billion of single-family residential mortgage loans in our portfolio; and (ii) unearned credit marks of $20.9 million on approximately $1.5 billion of purchased loans without credit deterioration that were originated by Banc of California prior to the merger. When the loss coverage from the credit-linked notes and unearned credit marks is added to our allowance for credit losses, this provides additional economic coverage on top of our ACL ratio. We refer to this adjusted ACL ratio as our economic coverage ratio(1), which equaled 1.66% of total loans and leases at March 31, 2025 compared to 1.72% at December 31, 2024.
(1) Non-GAAP measure; refer to section 'Non-GAAP Measures'
10 The ACL coverage of nonperforming loans and leases was 124% at March 31, 2025 compared to 142% at December 31, 2024.
Net charge-offs were 0.24% of average loans and leases (annualized) for the first quarter, compared to 0.45% for the fourth quarter. The decrease in net charge-offs in the first quarter was attributable primarily to two commercial loans, one loan secured by an office property and another commercial real estate loan. One of the charge-offs recognized during the quarter was specifically reserved for in December 2024.
Deposits and Client Investment Funds
The following table sets forth the composition of our deposits at the dates indicated:
| March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||||||||||||||||
| 2025 | 2024 | 2024 | 2024 | 2024 | |||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||
| Composition of Deposits | |||||||||||||||||||||||||||||
| Noninterest-bearing checking | $ | 7,593,950 | $ | 7,719,913 | $ | 7,811,796 | $ | 7,825,007 | $ | 7,833,608 | |||||||||||||||||||
| Interest-bearing: | |||||||||||||||||||||||||||||
| Checking | 7,747,051 | 7,610,705 | 7,539,899 | 7,309,833 | 7,836,097 | ||||||||||||||||||||||||
| Money market | 5,367,788 | 5,361,635 | 5,039,607 | 4,837,025 | 5,020,110 | ||||||||||||||||||||||||
| Savings | 1,999,062 | 1,933,232 | 1,992,364 | 2,040,461 | 2,016,398 | ||||||||||||||||||||||||
| Time deposits: | |||||||||||||||||||||||||||||
| Non-brokered | 2,490,639 | 2,488,217 | 2,451,340 | 2,758,067 | 2,761,836 | ||||||||||||||||||||||||
| Brokered | 1,994,701 | 2,078,207 | 1,993,263 | 4,034,057 | 3,424,358 | ||||||||||||||||||||||||
| Total time deposits | 4,485,340 | 4,566,424 | 4,444,603 | 6,792,124 | 6,186,194 | ||||||||||||||||||||||||
| Total interest-bearing | 19,599,241 | 19,471,996 | 19,016,473 | 20,979,443 | 21,058,799 | ||||||||||||||||||||||||
| Total deposits | $ | 27,193,191 | $ | 27,191,909 | $ | 26,828,269 | $ | 28,804,450 | $ | 28,892,407 | |||||||||||||||||||
| Composition as % of | |||||||||||||||||||||||||||||
| Total Deposits | |||||||||||||||||||||||||||||
| Noninterest-bearing checking | 28 | % | 28 | % | 29 | % | 27 | % | 27 | % | |||||||||||||||||||
| Interest-bearing: | |||||||||||||||||||||||||||||
| Checking | 29 | % | 28 | % | 28 | % | 25 | % | 27 | % | |||||||||||||||||||
| Money market | 20 | % | 20 | % | 19 | % | 17 | % | 17 | % | |||||||||||||||||||
| Savings | 7 | % | 7 | % | 7 | % | 7 | % | 7 | % | |||||||||||||||||||
| Time deposits: | |||||||||||||||||||||||||||||
| Non-brokered | 9 | % | 9 | % | 9 | % | 10 | % | 10 | % | |||||||||||||||||||
| Brokered | 7 | % | 8 | % | 8 | % | 14 | % | 12 | % | |||||||||||||||||||
| Total time deposits | 16 | % | 17 | % | 17 | % | 24 | % | 22 | % | |||||||||||||||||||
| Total interest-bearing | 72 | % | 72 | % | 71 | % | 73 | % | 73 | % | |||||||||||||||||||
| Total deposits | 100 | % | 100 | % | 100 | % | 100 | % | 100 | % | |||||||||||||||||||
Total deposits remained mostly flat in the first quarter from the fourth quarter and totaled $27.2 billion at March 31, 2025.
Noninterest-bearing checking totaled $7.6 billion and represented 28% of total deposits at March 31, 2025, compared to $7.7 billion, or 28% of total deposits, at December 31, 2024.
Uninsured and uncollateralized deposits of $7.4 billion represented 27% of total deposits at March 31, 2025 compared to uninsured and uncollateralized deposits of $7.2 billion, or 26% of total deposits, at December 31, 2024.
11 In addition to deposit products, we also offer alternative, non-depository corporate treasury solutions for select clients to invest excess liquidity. These alternative options include investments managed by BofCal Asset Management Inc. (“BAM”), our registered investment advisor subsidiary, and third-party sweep products. Total off-balance sheet client investment funds were $1.6 billion as of March 31, 2025, of which $813.2 million was managed by BAM.
Borrowings
Borrowings increased by $279.0 million to $1.7 billion at March 31, 2025 from $1.4 billion at December 31, 2024 due to higher short-term borrowings.
Equity
During the first quarter, total stockholders’ equity increased by $21.7 million to $3.5 billion and tangible common equity(1) increased by $28.7 million to $2.7 billion at March 31, 2025. The increase in total stockholders’ equity for the first quarter resulted primarily from net earnings of $53.6 million and a decrease in the unrealized after-tax net loss in AOCI for AFS and HTM securities of $33.5 million, offset partially by the repurchase of common stock of $38.5 million and common and preferred stock dividends of $27.3 million.
At March 31, 2025, book value per common share increased to $18.17 compared to $17.78 at December 31, 2024, and tangible book value per common share(1) increased to $16.12 compared to $15.72 at December 31, 2024.
During the first quarter of 2025, common stock repurchased under the Company's stock repurchase program authorized on March 17, 2025 totaled 2,684,823 shares at a weighted average price per share of $14.36, or $38.5 million. Through April 21, 2025, repurchases of Company common stock totaled 11,494,637 shares at a weighted average price of $13.05 per share, or $150.0 million.
The Company also announced today an upsize of its stock repurchase program, first announced on March 17, 2025, from $150 million to $300 million, inclusive of $150.0 million purchased through April 21, 2025, and expanded to cover both the Company's common stock and depositary shares representing its preferred stock. As before, the repurchase authorization expires in March 2026. Purchases may be made in open-market transactions, in block transactions on or off an exchange, in privately negotiated transactions or by other means as determined by the Company's management and in accordance with the regulations of the Securities and Exchange Commission (the "SEC"). The timing of purchases and the number of shares repurchased under the program will depend on a variety of factors including price, trading volume, market conditions, and corporate and regulatory requirements.
(1) Non-GAAP measure; refer to section 'Non-GAAP Measures'
•
12 CAPITAL AND LIQUIDITY
Capital ratios remain strong with total risk-based capital at 16.90% and a tier 1 leverage ratio of 10.19% at March 31, 2025.
The following table sets forth our regulatory capital ratios as of the dates indicated:
| March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||||||||||||||||
| 2025 | 2024 | 2024 | 2024 | 2024 | |||||||||||||||||||||||||
Capital Ratios(1) | |||||||||||||||||||||||||||||
| Banc of California, Inc. | |||||||||||||||||||||||||||||
| Total risk-based capital ratio | 16.90 | % | 17.05 | % | 17.00 | % | 16.57 | % | 16.40 | % | |||||||||||||||||||
| Tier 1 risk-based capital ratio | 12.83 | % | 12.97 | % | 12.88 | % | 12.62 | % | 12.38 | % | |||||||||||||||||||
| Common equity tier 1 capital ratio | 10.43 | % | 10.55 | % | 10.46 | % | 10.27 | % | 10.09 | % | |||||||||||||||||||
| Tier 1 leverage ratio | 10.19 | % | 10.15 | % | 9.83 | % | 9.51 | % | 9.12 | % | |||||||||||||||||||
| Banc of California | |||||||||||||||||||||||||||||
| Total risk-based capital ratio | 16.19 | % | 16.65 | % | 16.61 | % | 16.19 | % | 15.88 | % | |||||||||||||||||||
| Tier 1 risk-based capital ratio | 13.72 | % | 14.17 | % | 14.08 | % | 13.77 | % | 13.34 | % | |||||||||||||||||||
| Common equity tier 1 capital ratio | 13.72 | % | 14.17 | % | 14.08 | % | 13.77 | % | 13.34 | % | |||||||||||||||||||
| Tier 1 leverage ratio | 10.88 | % | 11.08 | % | 10.74 | % | 10.38 | % | 9.84 | % | |||||||||||||||||||
(1)March 31, 2025 capital ratios are preliminary.
At March 31, 2025, cash and cash equivalents decreased by $158.3 million to $2.3 billion from $2.5 billion at December 31, 2024 as we maintained a lower cash target level in the first quarter.
Our immediately available cash and cash equivalents excluding restricted cash were $2.2 billion. Combined with total available borrowing capacity of $10.8 billion and unpledged AFS securities of $2.1 billion, total available liquidity was $15.1 billion at the end of the first quarter.
13 Conference Call
The Company will host a conference call to discuss its first quarter 2025 financial results at 10:00 a.m. Pacific Time (PT) on Thursday, April 24, 2025. Interested parties are welcome to attend the conference call by dialing (888) 317-6003 and referencing event code 8785621. A live audio webcast will also be available, and the webcast link will be posted on the Company’s Investor Relations website at www.bancofcal.com/investor. The slide presentation for the call will also be available on the Company's Investor Relations website prior to the call. A replay of the call will be made available approximately one hour after the call has ended on the Company’s Investor Relations website at www.bancofcal.com/investor or by dialing (877) 344-7529 and referencing event code 8013520.
About Banc of California, Inc.
Banc of California, Inc. (NYSE: BANC) is a bank holding company with over $33 billion in assets and the parent company of Banc of California. Banc of California is one of the nation’s premier relationship-based business banks, providing banking and treasury management services to small-, middle-market, and venture-backed businesses. Banc of California is the largest independent bank headquartered in Los Angeles and the third largest bank headquartered in California and offers a broad range of loan and deposit products and services through 80 full-service branches located throughout California and in Denver, Colorado, and Durham, North Carolina, as well as through regional offices nationwide. The bank also provides full-stack payment processing solutions through its subsidiary, Deepstack Technologies, and serves the Community Association Management industry nationwide with its technology-forward platform, SmartStreet™. The bank is committed to its local communities through the Banc of California Charitable Foundation, and by supporting organizations that provide financial literacy and job training, small business support, affordable housing, and more. For more information, please visit us at www.bancofcal.com.
Forward-Looking Statements
This press release includes forward-looking statements within the meaning of the “Safe-Harbor” provisions of the Private Securities Litigation Reform Act of 1995. These statements include, but are not limited to, statements related to our expectations regarding the performance of our business, liquidity and capital ratios and other non-historical statements. Words or phrases such as “believe,” “will,” “should,” “will likely result,” “are expected to,” “will continue,” “is anticipated,” “estimate,” “project,” “plans,” “strategy,” or similar expressions are intended to identify these forward-looking statements. You are cautioned not to place undue reliance on any forward-looking statements. These statements are necessarily subject to risk and uncertainty and actual results could differ materially from those anticipated due to various factors, including those set forth from time to time in the documents filed or furnished by the Company with the SEC. The Company undertakes no obligation to revise or publicly release any revision or update to these forward-looking statements to reflect events or circumstances that occur after the date on which such statements were made, except as required by law.
14 Factors that could cause actual results to differ materially from the results anticipated or projected include, but are not limited to: (i) changes in general economic conditions, either nationally or in our market areas, including the impact of tariffs, supply chain disruptions, and the risk of recession or an economic downturn; (ii) changes in the interest rate environment, including the recent and potential future changes in the FRB benchmark rate, which could adversely affect our revenue and expenses, the value of assets and obligations, the realization of deferred tax assets, the availability and cost of capital and liquidity, and the impacts of continuing or renewed inflation; (iii) the credit risks of lending activities, which may be affected by deterioration in real estate markets and the financial condition of borrowers, and the operational risk of lending activities, including the effectiveness of our underwriting practices and the risk of fraud, any of which may lead to increased loan delinquencies, losses, and non-performing assets, and may result in our allowance for credit losses not being adequate; (iv) fluctuations in the demand for loans, and fluctuations in commercial and residential real estate values in our market area; (v) the quality and composition of our securities portfolio; (vi) our ability to develop and maintain a strong core deposit base, including among our venture banking clients, or other low cost funding sources necessary to fund our activities particularly in a rising or high interest rate environment; (vii) the rapid withdrawal of a significant amount of demand deposits over a short period of time; (viii) the costs and effects of litigation; (ix) risks related to the Company’s acquisitions, including disruption to current plans and operations; difficulties in customer and employee retention; fees, expenses and charges related to these transactions being significantly higher than anticipated; and our inability to achieve expected revenues, cost savings, synergies, and other benefits; (x) results of examinations by regulatory authorities of the Company and the possibility that any such regulatory authority may, among other things, limit our business activities, restrict our ability to invest in certain assets, refrain from issuing an approval or non-objection to certain capital or other actions, increase our allowance for credit losses, result in write-downs of asset values, restrict our ability or that of our bank subsidiary to pay dividends, or impose fines, penalties or sanctions; (xi) legislative or regulatory changes that adversely affect our business, including changes in tax laws and policies, accounting policies and practices, privacy laws, and regulatory capital or other rules; (xii) the risk that our enterprise risk management framework may not be effective in mitigating risk and reducing the potential for losses; (xiii) errors in estimates of the fair values of certain of our assets and liabilities, which may result in significant changes in valuation; (xiv) failures or security breaches with respect to the network, applications, vendors and computer systems on which we depend, including due to cybersecurity threats; (xv) our ability to attract and retain key members of our senior management team; (xvi) the effects of climate change, severe weather events, natural disasters such as earthquakes and wildfires, pandemics, epidemics and other public health crises, acts of war or terrorism, and other external events on our business; (xvii) the impact of bank failures or other adverse developments at other banks on general depositor and investor sentiment regarding the stability and liquidity of banks; (xviii) the possibility that our recorded goodwill could become impaired, which may have an adverse impact on our earnings and capital; (xix) our existing indebtedness, together with any future incurrence of additional indebtedness, could adversely affect our ability to raise additional capital and to meet our debt obligations; (xx) the risk that we may incur significant losses on future asset sales; and (xxi) other economic, competitive, governmental, regulatory, and technological factors affecting our operations, pricing, products and services and the other risks described in our Annual Report on Form 10-K for the fiscal year ended December 31, 2024 and from time to time in other documents that we file with or furnish to the SEC.
Non-GAAP Financial Measures
Included in this press release are certain non-GAAP financial measures, such as tangible common equity, tangible book value per common share, return on average tangible common equity, adjusted return on average tangible common equity, adjusted return on average assets, efficiency ratio, and economic coverage ratio, designed to complement the financial information presented in accordance with U.S. GAAP because management believes such measures are useful to investors. These non-GAAP financial measures should be considered only as supplemental to, and not superior to, financial measures provided in accordance with GAAP. Please refer to the “Non-GAAP Measures” section of this release for additional detail including reconciliations of the non-GAAP financial measures included in this press release to the most directly comparable financial measures prepared in accordance with GAAP.
15 | Investor Relations Inquiries: | ||
| Banc of California, Inc. | ||
| (855) 361-2262 | ||
| Jared Wolff, (310) 424-1230 | ||
Joe Kauder, (310) 844-5224 | ||
| Ann DeVries, (646) 376-7011 | ||
| Media Contact: | ||
| Debora Vrana, Banc of California | ||
| (213) 533-3122 | ||
| [email protected] | ||
Source: Banc of California, Inc. | ||
16 | BANC OF CALIFORNIA, INC. | |||||||||||||||||||||||||||||
| CONSOLIDATED STATEMENTS OF FINANCIAL CONDITION (UNAUDITED) | |||||||||||||||||||||||||||||
| March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||||||||||||||||
| 2025 | 2024 | 2024 | 2024 | 2024 | |||||||||||||||||||||||||
| ASSETS: | (Dollars in thousands) | ||||||||||||||||||||||||||||
| Cash and due from banks | $ | 215,591 | $ | 192,006 | $ | 251,869 | $ | 203,467 | $ | 199,922 | |||||||||||||||||||
| Interest-earning deposits in financial | |||||||||||||||||||||||||||||
| institutions | 2,128,298 | 2,310,206 | 2,302,358 | 2,495,343 | 2,885,306 | ||||||||||||||||||||||||
| Total cash and cash equivalents | 2,343,889 | 2,502,212 | 2,554,227 | 2,698,810 | 3,085,228 | ||||||||||||||||||||||||
| Securities available-for-sale | 2,334,058 | 2,246,839 | 2,300,284 | 2,244,031 | 2,286,682 | ||||||||||||||||||||||||
| Securities held-to-maturity | 2,311,912 | 2,306,149 | 2,301,263 | 2,296,708 | 2,291,984 | ||||||||||||||||||||||||
| FRB and FHLB stock | 155,330 | 147,773 | 145,123 | 132,380 | 129,314 | ||||||||||||||||||||||||
| Total investment securities | 4,801,300 | 4,700,761 | 4,746,670 | 4,673,119 | 4,707,980 | ||||||||||||||||||||||||
| Loans held for sale | 25,797 | 26,331 | 28,639 | 1,935,455 | 80,752 | ||||||||||||||||||||||||
| Loans and leases held for investment | 24,126,527 | 23,781,663 | 23,527,777 | 23,228,909 | 25,473,022 | ||||||||||||||||||||||||
| Allowance for loan and lease losses | (234,986) | (239,360) | (254,345) | (247,762) | (291,503) | ||||||||||||||||||||||||
| Total loans and leases held for | |||||||||||||||||||||||||||||
| investment, net | 23,891,541 | 23,542,303 | 23,273,432 | 22,981,147 | 25,181,519 | ||||||||||||||||||||||||
| Equipment leased to others under | |||||||||||||||||||||||||||||
| operating leases | 295,032 | 307,188 | 314,998 | 335,968 | 339,925 | ||||||||||||||||||||||||
| Premises and equipment, net | 140,347 | 142,546 | 143,200 | 145,734 | 144,912 | ||||||||||||||||||||||||
| Bank owned life insurance | 342,810 | 339,517 | 343,212 | 341,779 | 341,806 | ||||||||||||||||||||||||
| Goodwill | 214,521 | 214,521 | 216,770 | 215,925 | 198,627 | ||||||||||||||||||||||||
| Intangible assets, net | 125,937 | 132,944 | 140,562 | 148,894 | 157,226 | ||||||||||||||||||||||||
| Deferred tax asset, net | 702,323 | 720,587 | 706,849 | 738,534 | 741,158 | ||||||||||||||||||||||||
| Other assets | 896,421 | 913,954 | 964,054 | 1,028,474 | 1,094,383 | ||||||||||||||||||||||||
| Total assets | $ | 33,779,918 | $ | 33,542,864 | $ | 33,432,613 | $ | 35,243,839 | $ | 36,073,516 | |||||||||||||||||||
| LIABILITIES: | |||||||||||||||||||||||||||||
| Noninterest-bearing deposits | $ | 7,593,950 | $ | 7,719,913 | $ | 7,811,796 | $ | 7,825,007 | $ | 7,833,608 | |||||||||||||||||||
| Interest-bearing deposits | 19,599,241 | 19,471,996 | 19,016,473 | 20,979,443 | 21,058,799 | ||||||||||||||||||||||||
| Total deposits | 27,193,191 | 27,191,909 | 26,828,269 | 28,804,450 | 28,892,407 | ||||||||||||||||||||||||
| Borrowings | 1,670,782 | 1,391,814 | 1,591,833 | 1,440,875 | 2,139,498 | ||||||||||||||||||||||||
| Subordinated debt | 944,908 | 941,923 | 942,151 | 939,287 | 937,717 | ||||||||||||||||||||||||
| Accrued interest payable and other | |||||||||||||||||||||||||||||
| liabilities | 449,381 | 517,269 | 574,162 | 651,379 | 709,744 | ||||||||||||||||||||||||
| Total liabilities | 30,258,262 | 30,042,915 | 29,936,415 | 31,835,991 | 32,679,366 | ||||||||||||||||||||||||
| STOCKHOLDERS' EQUITY: | |||||||||||||||||||||||||||||
| Preferred stock | 498,516 | 498,516 | 498,516 | 498,516 | 498,516 | ||||||||||||||||||||||||
| Common stock | 1,561 | 1,586 | 1,586 | 1,583 | 1,583 | ||||||||||||||||||||||||
| Class B non-voting common stock | 5 | 5 | 5 | 5 | 5 | ||||||||||||||||||||||||
| Non-voting common stock equivalents | 98 | 98 | 98 | 101 | 101 | ||||||||||||||||||||||||
| Additional paid-in-capital | 3,732,376 | 3,785,725 | 3,802,314 | 3,813,312 | 3,827,777 | ||||||||||||||||||||||||
| Retained deficit | (387,580) | (431,201) | (478,173) | (477,010) | (497,396) | ||||||||||||||||||||||||
| Accumulated other comprehensive | |||||||||||||||||||||||||||||
| loss, net | (323,320) | (354,780) | (328,148) | (428,659) | (436,436) | ||||||||||||||||||||||||
| Total stockholders’ equity | 3,521,656 | 3,499,949 | 3,496,198 | 3,407,848 | 3,394,150 | ||||||||||||||||||||||||
| Total liabilities and stockholders’ | |||||||||||||||||||||||||||||
| equity | $ | 33,779,918 | $ | 33,542,864 | $ | 33,432,613 | $ | 35,243,839 | $ | 36,073,516 | |||||||||||||||||||
Common shares outstanding (1) | 166,403,086 | 168,825,656 | 168,879,566 | 168,875,712 | 169,013,629 | ||||||||||||||||||||||||
(1) Common shares outstanding include non-voting common equivalents that are participating securities.
17 | BANC OF CALIFORNIA, INC. | |||||||||||||||||
| CONSOLIDATED STATEMENTS OF EARNINGS (UNAUDITED) | |||||||||||||||||
| Three Months Ended | |||||||||||||||||
| March 31, | December 31, | March 31, | |||||||||||||||
| 2025 | 2024 | 2024 | |||||||||||||||
| (In thousands, except per share amounts) | |||||||||||||||||
| Interest income: | |||||||||||||||||
| Loans and leases | $ | 346,103 | $ | 357,303 | $ | 385,465 | |||||||||||
| Investment securities | 37,862 | 37,743 | 34,303 | ||||||||||||||
| Deposits in financial institutions | 22,690 | 29,473 | 58,936 | ||||||||||||||
| Total interest income | 406,655 | 424,519 | 478,704 | ||||||||||||||
| Interest expense: | |||||||||||||||||
| Deposits | 140,530 | 154,085 | 194,807 | ||||||||||||||
| Borrowings | 18,421 | 18,993 | 38,124 | ||||||||||||||
| Subordinated debt | 15,340 | 16,156 | 16,671 | ||||||||||||||
| Total interest expense | 174,291 | 189,234 | 249,602 | ||||||||||||||
| Net interest income | 232,364 | 235,285 | 229,102 | ||||||||||||||
| Provision for credit losses | 9,300 | 12,801 | 10,000 | ||||||||||||||
| Net interest income after provision | |||||||||||||||||
| for credit losses | 223,064 | 222,484 | 219,102 | ||||||||||||||
| Noninterest income: | |||||||||||||||||
| Service charges on deposit accounts | 4,543 | 4,770 | 4,705 | ||||||||||||||
| Other commissions and fees | 9,958 | 8,231 | 8,142 | ||||||||||||||
| Leased equipment income | 10,784 | 10,730 | 11,716 | ||||||||||||||
| Gain (loss) on sale of loans and leases | 211 | 20 | (448) | ||||||||||||||
| Loss on sale of securities | — | (454) | — | ||||||||||||||
| Dividends and gains on equity investments | 2,323 | 18 | 3,068 | ||||||||||||||
| Warrant (loss) income | (295) | 343 | 178 | ||||||||||||||
| LOCOM HFS adjustment | — | (3) | 330 | ||||||||||||||
| Other income | 6,126 | 5,334 | 6,125 | ||||||||||||||
| Total noninterest income | 33,650 | 28,989 | 33,816 | ||||||||||||||
| Noninterest expense: | |||||||||||||||||
| Compensation | 86,417 | 77,661 | 92,236 | ||||||||||||||
| Occupancy | 15,010 | 15,678 | 17,968 | ||||||||||||||
| Information technology and data processing | 15,099 | 14,546 | 15,418 | ||||||||||||||
| Other professional services | 4,513 | 5,498 | 5,075 | ||||||||||||||
| Insurance and assessments | 7,283 | 11,179 | 20,461 | ||||||||||||||
| Intangible asset amortization | 7,160 | 7,770 | 8,404 | ||||||||||||||
| Leased equipment depreciation | 6,741 | 7,096 | 7,520 | ||||||||||||||
| Acquisition, integration and reorganization costs | — | (1,023) | — | ||||||||||||||
| Customer related expense | 27,751 | 31,672 | 30,919 | ||||||||||||||
| Loan expense | 2,930 | 4,489 | 4,491 | ||||||||||||||
| Other expense | 10,749 | 6,804 | 8,026 | ||||||||||||||
| Total noninterest expense | 183,653 | 181,370 | 210,518 | ||||||||||||||
| Earnings before income taxes | 73,061 | 70,103 | 42,400 | ||||||||||||||
| Income tax expense | 19,493 | 13,184 | 11,548 | ||||||||||||||
| Net earnings | 53,568 | 56,919 | 30,852 | ||||||||||||||
| Preferred stock dividends | 9,947 | 9,947 | 9,947 | ||||||||||||||
| Net earnings available to common | |||||||||||||||||
| and equivalent stockholders | $ | 43,621 | $ | 46,972 | $ | 20,905 | |||||||||||
| Earnings per common share: | |||||||||||||||||
| Basic | $ | 0.26 | $ | 0.28 | $ | 0.12 | |||||||||||
| Diluted | $ | 0.26 | $ | 0.28 | $ | 0.12 | |||||||||||
Weighted average number of common shares (1) | |||||||||||||||||
| outstanding: | |||||||||||||||||
| Basic | 168,495 | 168,604 | 168,143 | ||||||||||||||
| Diluted | 169,434 | 169,732 | 168,143 | ||||||||||||||
(1) Common shares outstanding include non-voting common equivalents that are participating securities.
18 | BANC OF CALIFORNIA, INC. | |||||||||||||||||
| SELECTED FINANCIAL DATA | |||||||||||||||||
| (UNAUDITED) | |||||||||||||||||
| Three Months Ended | |||||||||||||||||
| March 31, | December 31, | March 31, | |||||||||||||||
| Profitability and Other Ratios | 2025 | 2024 | 2024 | ||||||||||||||
Return on average assets (1) | 0.65 | % | 0.67 | % | 0.33 | % | |||||||||||
Adjusted ROAA (1)(2) | 0.65 | % | 0.67 | % | 0.37 | % | |||||||||||
Return on average equity (1) | 6.16 | % | 6.50 | % | 3.66 | % | |||||||||||
| Return on average tangible common | |||||||||||||||||
equity (1)(2) | 7.56 | % | 7.35 | % | 4.36 | % | |||||||||||
| Adjusted return on average tangible | |||||||||||||||||
common equity (1)(2) | 7.56 | % | 7.35 | % | 4.92 | % | |||||||||||
Dividend payout ratio (3) | 36.46 | % | 35.71 | % | 83.33 | % | |||||||||||
Average yield on loans and leases (1) | 5.90 | % | 6.01 | % | 6.08 | % | |||||||||||
Average yield on interest-earning assets (1) | 5.39 | % | 5.48 | % | 5.56 | % | |||||||||||
| Average cost of interest-bearing deposits (1) | 2.97 | % | 3.18 | % | 3.60 | % | |||||||||||
Average total cost of deposits (1) | 2.12 | % | 2.26 | % | 2.66 | % | |||||||||||
Average cost of interest-bearing liabilities (1) | 3.28 | % | 3.48 | % | 3.92 | % | |||||||||||
Average total cost of funds (1) | 2.42 | % | 2.55 | % | 3.02 | % | |||||||||||
| Net interest spread | 2.11 | % | 2.00 | % | 1.64 | % | |||||||||||
Net interest margin (1) | 3.08 | % | 3.04 | % | 2.66 | % | |||||||||||
Noninterest income to total revenue (4) | 12.65 | % | 10.97 | % | 12.86 | % | |||||||||||
| Noninterest expense to average total | |||||||||||||||||
assets (1) | 2.24 | % | 2.15 | % | 2.26 | % | |||||||||||
| Noninterest expense to total revenue (4) | 69.04 | % | 68.63 | % | 80.07 | % | |||||||||||
| Efficiency ratio (2)(5) | 66.35 | % | 65.96 | % | 76.87 | % | |||||||||||
| Loans to deposits ratio | 88.82 | % | 87.56 | % | 88.44 | % | |||||||||||
| Average loans and leases to average deposits | 88.36 | % | 87.05 | % | 86.65 | % | |||||||||||
| Average investment securities to average | |||||||||||||||||
| total assets | 14.21 | % | 14.01 | % | 12.58 | % | |||||||||||
| Average stockholders' equity to average | |||||||||||||||||
| total assets | 10.58 | % | 10.39 | % | 9.03 | % | |||||||||||
______________
(1) Annualized.
(2) Non-GAAP measure.
(3) Ratio calculated by dividing dividends declared per common and equivalent share by basic earnings per common and equivalent share.
(4) Total revenue equals the sum of net interest income and noninterest income.
(5) Ratio calculated by dividing noninterest expense (less intangible asset amortization and acquisition, integration and reorganization costs) by total revenue (less gain (loss) on sale of securities).
19 | BANC OF CALIFORNIA, INC. | |||||||||||||||||||||||||||||||||||
| AVERAGE BALANCE, AVERAGE YIELD EARNED, AND AVERAGE COST PAID | |||||||||||||||||||||||||||||||||||
| (UNAUDITED) | |||||||||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||||||||
| March 31, 2025 | December 31, 2024 | March 31, 2024 | |||||||||||||||||||||||||||||||||
| Interest | Average | Interest | Average | Interest | Average | ||||||||||||||||||||||||||||||
| Average | Income/ | Yield/ | Average | Income/ | Yield/ | Average | Income/ | Yield/ | |||||||||||||||||||||||||||
| Balance | Expense | Cost | Balance | Expense | Cost | Balance | Expense | Cost | |||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Assets: | |||||||||||||||||||||||||||||||||||
Loans and leases (1) | $ | 23,788,647 | $ | 346,103 | 5.90 | % | $ | 23,649,271 | $ | 357,303 | 6.01 | % | $ | 25,518,590 | $ | 385,465 | 6.08 | % | |||||||||||||||||
| Investment securities | 4,734,037 | 37,862 | 3.24 | % | 4,700,742 | 37,743 | 3.19 | % | 4,721,556 | 34,303 | 2.92 | % | |||||||||||||||||||||||
| Deposits in financial | |||||||||||||||||||||||||||||||||||
| institutions | 2,088,139 | 22,690 | 4.41 | % | 2,474,732 | 29,473 | 4.74 | % | 4,374,968 | 58,936 | 5.42 | % | |||||||||||||||||||||||
| Total interest-earning | |||||||||||||||||||||||||||||||||||
| assets | 30,610,823 | 406,655 | 5.39 | % | 30,824,745 | 424,519 | 5.48 | % | 34,615,114 | 478,704 | 5.56 | % | |||||||||||||||||||||||
| Other assets | 2,697,562 | 2,737,283 | 2,925,593 | ||||||||||||||||||||||||||||||||
| Total assets | $ | 33,308,385 | $ | 33,562,028 | $ | 37,540,707 | |||||||||||||||||||||||||||||
| Liabilities and | |||||||||||||||||||||||||||||||||||
| Stockholders' Equity: | |||||||||||||||||||||||||||||||||||
| Interest checking | $ | 7,343,451 | 47,879 | 2.64 | % | $ | 7,659,320 | 56,408 | 2.93 | % | $ | 7,883,177 | 61,549 | 3.14 | % | ||||||||||||||||||||
| Money market | 5,415,716 | 33,003 | 2.47 | % | 5,003,118 | 31,688 | 2.52 | % | 5,737,837 | 41,351 | 2.90 | % | |||||||||||||||||||||||
| Savings | 1,948,649 | 12,857 | 2.68 | % | 1,954,625 | 14,255 | 2.90 | % | 2,036,129 | 18,030 | 3.56 | % | |||||||||||||||||||||||
| Time | 4,498,268 | 46,791 | 4.22 | % | 4,645,115 | 51,734 | 4.43 | % | 6,108,321 | 73,877 | 4.86 | % | |||||||||||||||||||||||
| Total interest-bearing | |||||||||||||||||||||||||||||||||||
| deposits | 19,206,084 | 140,530 | 2.97 | % | 19,262,178 | 154,085 | 3.18 | % | 21,765,464 | 194,807 | 3.60 | % | |||||||||||||||||||||||
| Borrowings | 1,397,720 | 18,421 | 5.34 | % | 1,399,080 | 18,993 | 5.40 | % | 2,892,406 | 38,124 | 5.30 | % | |||||||||||||||||||||||
| Subordinated debt | 942,817 | 15,340 | 6.60 | % | 942,221 | 16,156 | 6.82 | % | 937,005 | 16,671 | 7.16 | % | |||||||||||||||||||||||
| Total interest-bearing | |||||||||||||||||||||||||||||||||||
| liabilities | 21,546,621 | 174,291 | 3.28 | % | 21,603,479 | 189,234 | 3.48 | % | 25,594,875 | 249,602 | 3.92 | % | |||||||||||||||||||||||
| Noninterest-bearing | |||||||||||||||||||||||||||||||||||
| demand deposits | 7,714,830 | 7,905,750 | 7,685,027 | ||||||||||||||||||||||||||||||||
| Other liabilities | 522,753 | 566,635 | 870,273 | ||||||||||||||||||||||||||||||||
| Total liabilities | 29,784,204 | 30,075,864 | 34,150,175 | ||||||||||||||||||||||||||||||||
| Stockholders' equity | 3,524,181 | 3,486,164 | 3,390,532 | ||||||||||||||||||||||||||||||||
| Total liabilities and | |||||||||||||||||||||||||||||||||||
| stockholders' equity | $ | 33,308,385 | $ | 33,562,028 | $ | 37,540,707 | |||||||||||||||||||||||||||||
Net interest income (1) | $ | 232,364 | $ | 235,285 | $ | 229,102 | |||||||||||||||||||||||||||||
| Net interest spread | 2.11 | % | 2.00 | % | 1.64 | % | |||||||||||||||||||||||||||||
| Net interest margin | 3.08 | % | 3.04 | % | 2.66 | % | |||||||||||||||||||||||||||||
Total deposits (2) | $ | 26,920,914 | $ | 140,530 | 2.12 | % | $ | 27,167,928 | $ | 154,085 | 2.26 | % | $ | 29,450,491 | $ | 194,807 | 2.66 | % | |||||||||||||||||
Total funds (3) | $ | 29,261,451 | $ | 174,291 | 2.42 | % | $ | 29,509,229 | $ | 189,234 | 2.55 | % | $ | 33,279,902 | $ | 249,602 | 3.02 | % | |||||||||||||||||
______________
(1) Includes net loan discount accretion of $16.0 million, $20.7 million, and $22.4 million for the three months ended March 31, 2025, December 31, 2024, and March 31, 2024.
(2) Total deposits is the sum of total interest-bearing deposits and noninterest-bearing demand deposits. The cost of total deposits is calculated as annualized interest expense on total deposits divided by average total deposits.
(3) Total funds is the sum of total interest-bearing liabilities and noninterest-bearing demand deposits. The cost of total funds is calculated as annualized total interest expense divided by average total funds.
20 BANC OF CALIFORNIA, INC.
NON-GAAP MEASURES
We refer to certain financial measures that are not recognized under U.S. generally accepted accounting principles (“GAAP”) in this press release, including: tangible common equity, tangible book value per common share, return on average tangible common equity, adjusted return on average tangible common equity, adjusted return on average assets, efficiency ratio, and economic coverage ratio. These non-GAAP measures are used by management in its analysis of the Company's performance.
Tangible common equity is calculated by subtracting preferred stock, as applicable, from total common equity. Return on average tangible common equity is calculated by dividing net earnings available to common stockholders, after adjustment for amortization of intangible assets and any goodwill impairment, by average tangible common equity. Adjusted return on average tangible common equity is calculated by dividing adjusted net earnings available to common stockholders, after adjustment for amortization of intangible assets, any goodwill impairment, and any unusual one-time items, by average tangible common equity. Banking regulators also exclude goodwill and other intangible assets from stockholders' equity when assessing the capital adequacy of a financial institution.
Adjusted return on average assets ("Adjusted ROAA") is calculated by dividing annualized adjusted net earnings, after adjustment for any unusual one-time items, by average assets.
Efficiency ratio is calculated by dividing noninterest expense (less intangible asset amortization and acquisition, integration and reorganization costs) by total revenue (the sum of net interest income and noninterest income, less gain (loss) on sale of securities).
Economic coverage ratio is calculated by dividing the allowance for credit losses adjusted for the impact of the credit-linked notes and unearned credit mark from purchase accounting by loans and leases held for investment.
Management believes the presentation of these financial measures adjusting the impact of these items provides useful supplemental information that is essential to a proper understanding of the financial results and operating performance of the Company. This disclosure should not be viewed as a substitute for results determined in accordance with GAAP, nor is it necessarily comparable to non-GAAP performance measures that may be presented by other companies.
The following tables provide reconciliations of the non-GAAP measures to financial measures defined by GAAP.
21 | BANC OF CALIFORNIA, INC. | |||||||||||||||||||||||||||||
| NON-GAAP MEASURES | |||||||||||||||||||||||||||||
| (UNAUDITED) | |||||||||||||||||||||||||||||
| Tangible Common Equity | March 31, | December 31, | September 30, | June 30, | March 31, | ||||||||||||||||||||||||
| and Tangible Book Value Per Share | 2025 | 2024 | 2024 | 2024 | 2024 | ||||||||||||||||||||||||
| (Dollars in thousands, except per share amounts) | |||||||||||||||||||||||||||||
| Stockholders' equity | $ | 3,521,656 | $ | 3,499,949 | $ | 3,496,198 | $ | 3,407,848 | $ | 3,394,150 | |||||||||||||||||||
| Less: Preferred stock | 498,516 | 498,516 | 498,516 | 498,516 | 498,516 | ||||||||||||||||||||||||
| Total common equity | 3,023,140 | 3,001,433 | 2,997,682 | 2,909,332 | 2,895,634 | ||||||||||||||||||||||||
| Less: Intangible assets | 340,458 | 347,465 | 357,332 | 364,819 | 355,853 | ||||||||||||||||||||||||
| Tangible common equity | 2,682,682 | 2,653,968 | 2,640,350 | 2,544,513 | 2,539,781 | ||||||||||||||||||||||||
Book value per common share (1) | $ | 18.17 | $ | 17.78 | $ | 17.75 | $ | 17.23 | $ | 17.13 | |||||||||||||||||||
Tangible book value per common share (2) | $ | 16.12 | $ | 15.72 | $ | 15.63 | $ | 15.07 | $ | 15.03 | |||||||||||||||||||
| Common shares outstanding (3) | 166,403,086 | 168,825,656 | 168,879,566 | 168,875,712 | 169,013,629 | ||||||||||||||||||||||||
(1) Total common equity divided by common shares outstanding.
(2) Tangible common equity divided by common shares outstanding.
(3) Common shares outstanding include non-voting common equivalents that are participating securities.
22 | BANC OF CALIFORNIA, INC. | |||||||||||||||||
| NON-GAAP MEASURES | |||||||||||||||||
| (UNAUDITED) | |||||||||||||||||
| Three Months Ended | |||||||||||||||||
| Return on Average Tangible | March 31, | December 31, | March 31, | ||||||||||||||
| Common Equity ("ROATCE") | 2025 | 2024 | 2024 | ||||||||||||||
| (Dollars in thousands) | |||||||||||||||||
| Net earnings | $ | 53,568 | $ | 56,919 | $ | 30,852 | |||||||||||
| Earnings before income taxes | $ | 73,061 | $ | 70,103 | $ | 42,400 | |||||||||||
| Add: Intangible asset amortization | 7,160 | 7,770 | 8,404 | ||||||||||||||
| Adjusted earnings before | |||||||||||||||||
| income taxes used for ROATCE | 80,221 | 77,873 | 50,804 | ||||||||||||||
Adjusted income tax expense (1) | 20,296 | 19,281 | 13,412 | ||||||||||||||
| Adjusted net earnings for ROATCE | 59,925 | 58,592 | 37,392 | ||||||||||||||
| Less: Preferred stock dividends | 9,947 | 9,947 | 9,947 | ||||||||||||||
| Adjusted net earnings available | |||||||||||||||||
| to common and equivalent | |||||||||||||||||
| stockholders for ROATCE | $ | 49,978 | $ | 48,645 | $ | 27,445 | |||||||||||
| Average stockholders' equity | $ | 3,524,181 | $ | 3,486,164 | $ | 3,390,532 | |||||||||||
| Less: Average goodwill and intangible | |||||||||||||||||
| assets | 344,610 | 352,907 | 360,680 | ||||||||||||||
| Less: Average preferred stock | 498,516 | 498,516 | 498,516 | ||||||||||||||
| Average tangible common equity | $ | 2,681,055 | $ | 2,634,741 | $ | 2,531,336 | |||||||||||
Return on average equity (2) | 6.16 | % | 6.50 | % | 3.66 | % | |||||||||||
ROATCE (3) | 7.56 | % | 7.35 | % | 4.36 | % | |||||||||||
______________
(1) Effective tax rates of 25.30%, 24.76%, and 26.40% used for the three months ended March 31, 2025, December 31, 2024, and March 31, 2024, respectively.
(2) Annualized net earnings divided by average stockholders' equity.
(3) Annualized adjusted net earnings available to common and equivalent stockholders for ROATCE divided by average tangible
common equity.
23 | BANC OF CALIFORNIA, INC. | |||||||||||||||||
| NON-GAAP MEASURES | |||||||||||||||||
| (UNAUDITED) | |||||||||||||||||
| Three Months Ended | |||||||||||||||||
| Adjusted Return on Average | March 31, | December 31, | March 31, | ||||||||||||||
| Tangible Common Equity ("ROATCE") | 2025 | 2024 | 2024 | ||||||||||||||
| (Dollars in thousands) | |||||||||||||||||
| Net earnings | $ | 53,568 | $ | 56,919 | $ | 30,852 | |||||||||||
| Earnings before income taxes | $ | 73,061 | $ | 70,103 | $ | 42,400 | |||||||||||
| Add: Intangible asset amortization | 7,160 | 7,770 | 8,404 | ||||||||||||||
| Add: FDIC special assessment | — | — | 4,814 | ||||||||||||||
| Adjusted earnings before income | |||||||||||||||||
| taxes used for adjusted ROATCE | 80,221 | 77,873 | 55,618 | ||||||||||||||
Adjusted income tax expense (1) | 20,296 | 19,281 | 14,683 | ||||||||||||||
| Adjusted net earnings for adjusted | |||||||||||||||||
| ROATCE | 59,925 | 58,592 | 40,935 | ||||||||||||||
| Less: Preferred stock dividends | 9,947 | 9,947 | 9,947 | ||||||||||||||
| Adjusted net earnings available to | |||||||||||||||||
| common and equivalent stockholders | |||||||||||||||||
| for adjusted ROATCE | $ | 49,978 | $ | 48,645 | $ | 30,988 | |||||||||||
| Average stockholders' equity | $ | 3,524,181 | $ | 3,486,164 | $ | 3,390,532 | |||||||||||
| Less: Average goodwill and intangible | |||||||||||||||||
| assets | 344,610 | 352,907 | 360,680 | ||||||||||||||
| Less: Average preferred stock | 498,516 | 498,516 | 498,516 | ||||||||||||||
| Average tangible common equity | $ | 2,681,055 | $ | 2,634,741 | $ | 2,531,336 | |||||||||||
Adjusted ROATCE (2) | 7.56 | % | 7.35 | % | 4.92 | % | |||||||||||
______________
(1) Effective tax rates of 25.30%, 24.76%, and 26.40% used for the three months ended March 31, 2025, December 31, 2024, and March 31, 2024, respectively.
(2) Annualized adjusted net earnings (loss) available to common and equivalent stockholders for adjusted ROATCE divided by average tangible common equity.
24 | BANC OF CALIFORNIA, INC. | |||||||||||||||||
| NON-GAAP MEASURES | |||||||||||||||||
| (UNAUDITED) | |||||||||||||||||
| Three Months Ended | |||||||||||||||||
| Return on Average Assets ("ROAA") | March 31, | December 31, | March 31, | ||||||||||||||
| and Adjusted Return on Average Assets | 2025 | 2024 | 2024 | ||||||||||||||
| (Dollars in thousands) | |||||||||||||||||
| Net earnings | $ | 53,568 | $ | 56,919 | $ | 30,852 | |||||||||||
| Earnings before income taxes | $ | 73,061 | $ | 70,103 | $ | 42,400 | |||||||||||
| Add: FDIC special assessment | — | — | 4,814 | ||||||||||||||
| Adjusted earnings before income taxes | 73,061 | 70,103 | 47,214 | ||||||||||||||
| Adjusted income tax expense (1) | 19,493 | 13,184 | 12,464 | ||||||||||||||
| Adjusted net earnings | 53,568 | 56,919 | 34,750 | ||||||||||||||
| Average total assets | $ | 33,308,385 | $ | 33,562,028 | $ | 37,540,707 | |||||||||||
| Return on average assets ("ROAA") (2) | 0.65 | % | 0.67 | % | 0.33 | % | |||||||||||
| Adjusted ROAA (3) | 0.65 | % | 0.67 | % | 0.37 | % | |||||||||||
______________
(1) Effective tax rates of 25.30%, 24.76%, and 26.40% used for the three months ended March 31, 2025, December 31, 2024, and March 31, 2024, respectively.
(2) Annualized net earnings divided by average assets.
(3) Annualized adjusted net earnings divided by average assets.
25 | BANC OF CALIFORNIA, INC. | |||||||||||||||||
| NON-GAAP MEASURES | |||||||||||||||||
| (UNAUDITED) | |||||||||||||||||
| Three Months Ended | |||||||||||||||||
| March 31, | December 31, | March 31, | |||||||||||||||
| Efficiency Ratio | 2025 | 2024 | 2024 | ||||||||||||||
| (Dollars in thousands) | |||||||||||||||||
| Noninterest expense | $ | 183,653 | $ | 181,370 | $ | 210,518 | |||||||||||
| Less: Intangible asset amortization | (7,160) | (7,770) | (8,404) | ||||||||||||||
| Less: Acquisition, integration, and | |||||||||||||||||
| reorganization costs | — | 1,023 | — | ||||||||||||||
| Noninterest expense used for | |||||||||||||||||
| efficiency ratio | $ | 176,493 | $ | 174,623 | $ | 202,114 | |||||||||||
| Net interest income | $ | 232,364 | $ | 235,285 | $ | 229,102 | |||||||||||
| Noninterest income | 33,650 | 28,989 | 33,816 | ||||||||||||||
| Total revenue | 266,014 | 264,274 | 262,918 | ||||||||||||||
| Add: Loss on sale of securities | — | 454 | — | ||||||||||||||
| Total revenue used for efficiency ratio | $ | 266,014 | $ | 264,728 | $ | 262,918 | |||||||||||
| Noninterest expense to total revenue | 69.04 | % | 68.63 | % | 80.07 | % | |||||||||||
| Efficiency ratio (1) | 66.35 | % | 65.96 | % | 76.87 | % | |||||||||||
______________
(1) Noninterest expense used for efficiency ratio divided by total revenue used for efficiency ratio.
26 | BANC OF CALIFORNIA, INC. | |||||||||||||||||
| NON-GAAP MEASURES | |||||||||||||||||
| (UNAUDITED) | |||||||||||||||||
| March 31, | December 31, | March 31, | |||||||||||||||
| Economic Coverage Ratio | 2025 | 2024 | 2024 | ||||||||||||||
| (Dollars in thousands) | |||||||||||||||||
| Allowance for credit losses ("ACL) | $ | 264,557 | $ | 268,431 | $ | 320,074 | |||||||||||
| Add: Unearned credit mark from purchase accounting (1) | 20,870 | 22,473 | 28,980 | ||||||||||||||
| Add: Credit-linked notes (2) | 115,188 | 116,991 | 122,782 | ||||||||||||||
| Adjusted allowance for credit losses | $ | 400,615 | $ | 407,895 | $ | 471,836 | |||||||||||
| Loans and leases held for investment | $ | 24,126,527 | $ | 23,781,663 | $ | 25,473,022 | |||||||||||
| ACL to loans and leases held for investment (3) | 1.10 | % | 1.13 | % | 1.26 | % | |||||||||||
| Economic coverage ratio (4) | 1.66 | % | 1.72 | % | 1.85 | % | |||||||||||
______________
(1) Unearned credit mark from purchase accounting estimated by using the same pro rata split between the credit and yield marks associated with non-PCD loans (purchased loans without credit deterioration at the time of purchase).
(2) Credit-linked notes loss coverage equal to 5% of the unpaid principal balance of the pledged loans.
(3) Allowance for credit losses divided by loans and leases held for investment.
(4) Adjusted allowance for credit losses divided by loans and leases held for investment.
27 
Investor Presentation First Quarter 2025 Results Draft v4.5 1/21/24
Forward-Looking Statements and Other Matters This presentation includes forward-looking statements within the meaning of the “Safe-Harbor” provisions of the Private Securities Litigation Reform Act of 1995. These statements include, but are not limited to, statements related to our expectations regarding the performance of our business, liquidity and capital ratios and other non-historical statements. Words or phrases such as “believe,” “will,” “should,” “will likely result,” “are expected to,” “will continue,” “is anticipated,” “estimate,” “project,” “plans,” “strategy,” or similar expressions are intended to identify these forward-looking statements. You are cautioned not to place undue reliance on any forward-looking statements. These statements are necessarily subject to risk and uncertainty and actual results could differ materially from those anticipated due to various factors, including those set forth from time to time in the documents filed or furnished by Banc of California, Inc. (the “Company”) with the Securities and Exchange Commission (“SEC”). The Company undertakes no obligation to revise or publicly release any revision or update to these forward-looking statements to reflect events or circumstances that occur after the date on which such statements were made, except as required by law. Factors that could cause actual results to differ materially from the results anticipated or projected include, but are not l imited to: (i) changes in general economic conditions, either nationally or in our market areas, including the impact of tariffs, supply chain disruptions, and the risk of recession or an economic downturn; (ii) changes in the interest rate environment, including the recent and potential future changes in the FRB benchmark rate, which could adversely affect our revenue and expenses, the value of assets and obligations, the realization of deferred tax assets, the availability and cost of capital and liquidity, and the impacts of continuing or renewed inflation; (iii) the credit risks of lending activities, which may be affected by deterioration in real estate markets and the financial condition of borrowers, and the operational risk of lending activities, including the effectiveness of our underwriting practices and the risk of fraud, any of which may lead to increased loan delinquencies, losses, and non-performing assets, and may result in our allowance for credit losses not being adequate; (iv) fluctuations in the demand for loans, and fluctuations in commercial and residential real estate values in our market area; (v) the quality and composition of our securities portfolio; (vi) our ability to develop and maintain a strong core deposit base, including among our venture banking clients, or other low cost funding sources necessary to fund our activities particularly in a rising or high interest rate environment; (vii) the rapid withdrawal of a significant amount of demand deposits over a short period of time; (viii) the costs and effects of litigation; (ix) risks related to the Company’s acquisitions, including disruption to current plans and operations; difficulties in customer and employee retention; fees, expenses and charges related to these transactions being significantly higher than anticipated; and our inability to achieve expected revenues, cost savings, synergies, and other benefits; (x) results of examinations by regulatory authorities of the Company and the possibility that any such regulatory authority may, among other things, limit our business activities, restrict our ability to invest in certain assets, refrain from issuing an approval or non-objection to certain capital or other actions, increase our allowance for credit losses, result in write-downs of asset values, restrict our ability or that of our bank subsidiary to pay dividends, or impose fines, penalties or sanctions; (xi) legislative or regulatory changes that adversely affect our business, including changes in tax laws and policies, accounting policies and practices, privacy laws, and regulatory capital or other rules; (xii) the risk that our enterprise risk management framework may not be effective in mitigating risk and reducing the potential for losses; (xiii) errors in estimates of the fair values of certain of our assets and liabilities, which may result in significant changes in valuation; (xiv) failures or security breaches with respect to the network, applications, vendors and computer systems on which we depend, including due to cybersecurity threats; (xv) our ability to attract and retain key members of our senior management team; (xvi) the effects of climate change, severe weather events, natural disasters such as earthquakes and wildfires, pandemics, epidemics and other public health crises, acts of war or terrorism, and other external events on our business; (xvii) the impact of bank failures or other adverse developments at other banks on general depositor and investor sentiment regarding the stability and liquidity of banks; (xviii) the possibility that our recorded goodwill could become impaired, which may have an adverse impact on our earnings and capital; (xix) our existing indebtedness, together with any future incurrence of additional indebtedness, could adversely affect our ability to raise additional capital and to meet our debt obligations; (xx) the risk that we may incur significant losses on future asset sales; and (xxi) other economic, competitive, governmental, regulatory, and technological factors affecting our operations, pricing, products and services and the other risks described in our Annual Report on Form 10-K for the fiscal year ended December 31, 2024 and from time to time in other documents that we file with or furnish to the SEC. Included in this presentation are certain non-GAAP financial measures, such as tangible assets, tangible common equity ratio, tangible book value per common share, adjusted net earnings, return on average tangible common equity, adjusted return on average tangible common equity, pre-tax pre-provision income, adjusted noninterest expense, adjusted noninterest expense to average assets, adjusted efficiency ratio, economic coverage ratio, and adjusted ACL for lower-risk loan portfolio ratio, designed to complement the financial information presented in accordance with U.S. GAAP because management believes such measures are useful to investors. These non-GAAP financial measures should be considered only as supplemental to, and not superior to, financial measures provided in accordance with GAAP. Please refer to the “Non-GAAP Financial Information” and “Non-GAAP Reconciliation” sections of the appendix of this presentation for additional detail including reconciliations of non-GAAP financial measures included in this presentation to the most directly comparable financial measures prepared in accordance with GAAP. First Quarter 2025 Earnings | 2
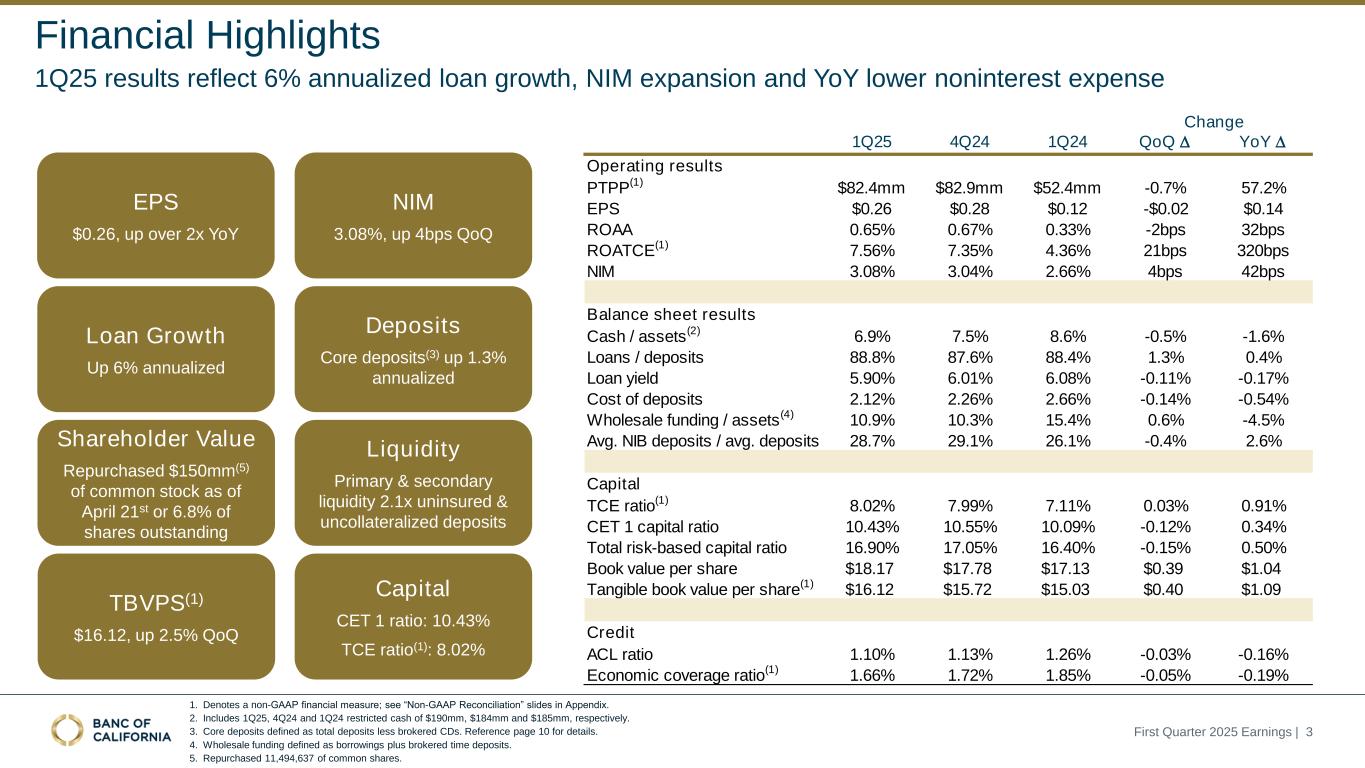
First Quarter 2025 Earnings | 3 1Q25 results reflect 6% annualized loan growth, NIM expansion and YoY lower noninterest expense 1. Denotes a non-GAAP financial measure; see “Non-GAAP Reconciliation” slides in Appendix. 2. Includes 1Q25, 4Q24 and 1Q24 restricted cash of $190mm, $184mm and $185mm, respectively. 3. Core deposits defined as total deposits less brokered CDs. Reference page 10 for details. 4. Wholesale funding defined as borrowings plus brokered time deposits. 5. Repurchased 11,494,637 of common shares. Financial Highlights EPS $0.26, up over 2x YoY NIM 3.08%, up 4bps QoQ Shareholder Value Repurchased $150mm(5) of common stock as of April 21st or 6.8% of shares outstanding Liquidity Primary & secondary liquidity 2.1x uninsured & uncollateralized deposits Loan Growth Up 6% annualized Deposits Core deposits(3) up 1.3% annualized TBVPS(1) $16.12, up 2.5% QoQ Capital CET 1 ratio: 10.43% TCE ratio(1): 8.02% Change 1Q25 4Q24 1Q24 QoQ D YoY D Operating results PTPP(1) $82.4mm $82.9mm $52.4mm -0.7% 57.2% EPS $0.26 $0.28 $0.12 -$0.02 $0.14 ROAA 0.65% 0.67% 0.33% -2bps 32bps ROATCE(1) 7.56% 7.35% 4.36% 21bps 320bps NIM 3.08% 3.04% 2.66% 4bps 42bps Balance sheet results Cash / assets(2) 6.9% 7.5% 8.6% -0.5% -1.6% Loans / deposits 88.8% 87.6% 88.4% 1.3% 0.4% Loan yield 5.90% 6.01% 6.08% -0.11% -0.17% Cost of deposits 2.12% 2.26% 2.66% -0.14% -0.54% Wholesale funding / assets(4) 10.9% 10.3% 15.4% 0.6% -4.5% Avg. NIB deposits / avg. deposits 28.7% 29.1% 26.1% -0.4% 2.6% Capital TCE ratio(1) 8.02% 7.99% 7.11% 0.03% 0.91% CET 1 capital ratio 10.43% 10.55% 10.09% -0.12% 0.34% Total risk-based capital ratio 16.90% 17.05% 16.40% -0.15% 0.50% Book value per share $18.17 $17.78 $17.13 $0.39 $1.04 Tangible book value per share(1) $16.12 $15.72 $15.03 $0.40 $1.09 Credit ACL ratio 1.10% 1.13% 1.26% -0.03% -0.16% Economic coverage ratio(1) 1.66% 1.72% 1.85% -0.05% -0.19%
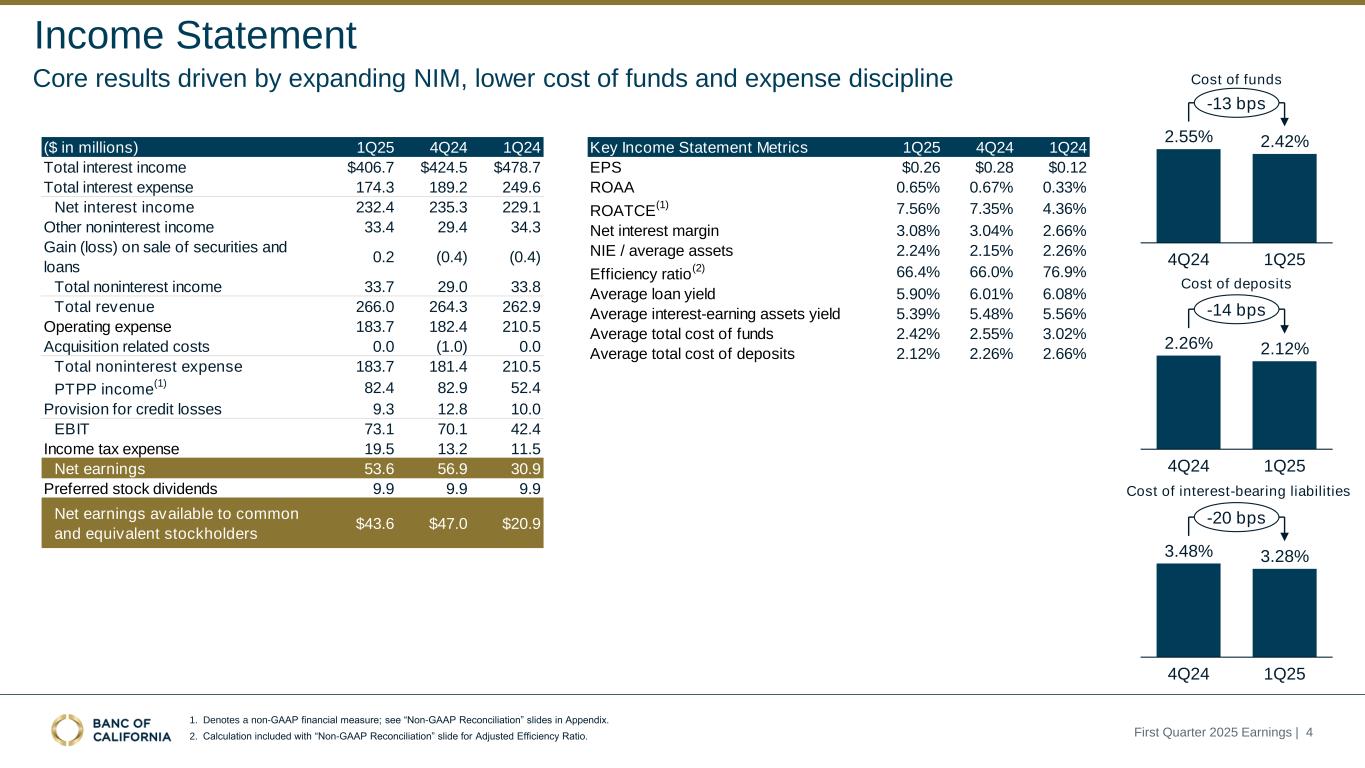
2.26% 2.12% 4Q24 1Q25 -28 bps 3.48% 3.28% 4Q24 1Q25 -32 bps 2.55% 2.42% 4Q24 1Q25 -27 bps First Quarter 2025 Earnings | 4 1. Denotes a non-GAAP financial measure; see “Non-GAAP Reconciliation” slides in Appendix. 2. Calculation included with “Non-GAAP Reconciliation” slide for Adjusted Efficiency Ratio. Core results driven by expanding NIM, lower cost of funds and expense discipline Income Statement 14 20 13 Cost of funds Cost of deposits Cost of interest-bearing liabilities Key Income Statement Metrics 1Q25 4Q24 1Q24 EPS $0.26 $0.28 $0.12 ROAA 0.65% 0.67% 0.33% ROATCE (1) 7.56% 7.35% 4.36% Net interest margin 3.08% 3.04% 2.66% NIE / average assets 2.24% 2.15% 2.26% Efficiency ratio (2) 66.4% 66.0% 76.9% Average loan yield 5.90% 6.01% 6.08% Average interest-earning assets yield 5.39% 5.48% 5.56% Average total cost of funds 2.42% 2.55% 3.02% Average total cost of deposits 2.12% 2.26% 2.66% ($ in millions) 1Q25 4Q24 1Q24 Total interest income $406.7 $424.5 $478.7 Total interest expense 174.3 189.2 249.6 Net interest income 232.4 235.3 229.1 Other noninterest income 33.4 29.4 34.3 Gain (loss) on sale of securities and loans 0.2 (0.4) (0.4) Total noninterest income 33.7 29.0 33.8 Total revenue 266.0 264.3 262.9 Operating expense 183.7 182.4 210.5 Acquisition related costs 0.0 (1.0) 0.0 Total noninterest expense 183.7 181.4 210.5 PTPP income (1) 82.4 82.9 52.4 Provision for credit losses 9.3 12.8 10.0 EBIT 73.1 70.1 42.4 Income tax expense 19.5 13.2 11.5 Net earnings 53.6 56.9 30.9 Preferred stock dividends 9.9 9.9 9.9 Net earnings available to common and equivalent stockholders $43.6 $47.0 $20.9
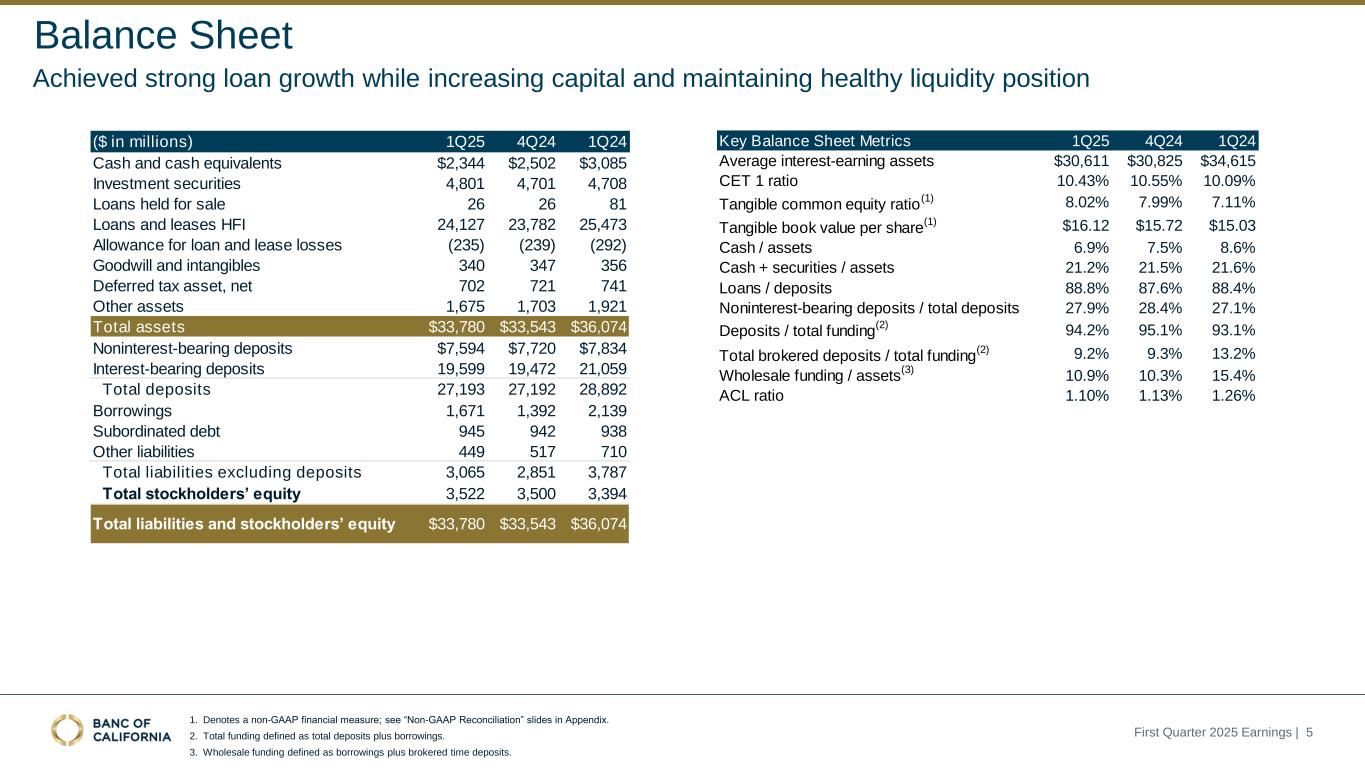
Balance Sheet First Quarter 2025 Earnings | 5 1. Denotes a non-GAAP financial measure; see “Non-GAAP Reconciliation” slides in Appendix. 2. Total funding defined as total deposits plus borrowings. 3. Wholesale funding defined as borrowings plus brokered time deposits. Achieved strong loan growth while increasing capital and maintaining healthy liquidity position ($ in millions) 1Q25 4Q24 1Q24 Cash and cash equivalents $2,344 $2,502 $3,085 Investment securities 4,801 4,701 4,708 Loans held for sale 26 26 81 Loans and leases HFI 24,127 23,782 25,473 Allowance for loan and lease losses (235) (239) (292) Goodwill and intangibles 340 347 356 Deferred tax asset, net 702 721 741 Other assets 1,675 1,703 1,921 Total assets $33,780 $33,543 $36,074 Noninterest-bearing deposits $7,594 $7,720 $7,834 Interest-bearing deposits 19,599 19,472 21,059 Total deposits 27,193 27,192 28,892 Borrowings 1,671 1,392 2,139 Subordinated debt 945 942 938 Other liabilities 449 517 710 Total liabilities excluding deposits 3,065 2,851 3,787 Total stockholders’ equity 3,522 3,500 3,394 Total liabilities and stockholders’ equity $33,780 $33,543 $36,074 Key Balance Sheet Metrics 1Q25 4Q24 1Q24 Average interest-earning assets $30,611 $30,825 $34,615 CET 1 ratio 10.43% 10.55% 10.09% Tangible common equity ratio (1) 8.02% 7.99% 7.11% Tangible book value per share (1) $16.12 $15.72 $15.03 Cash / assets 6.9% 7.5% 8.6% Cash + securities / assets 21.2% 21.5% 21.6% Loans / deposits 88.8% 87.6% 88.4% Noninterest-bearing deposits / total deposits 27.9% 28.4% 27.1% Deposits / total funding (2) 94.2% 95.1% 93.1% Total brokered deposits / total funding (2) 9.2% 9.3% 13.2% Wholesale funding / assets (3) 10.9% 10.3% 15.4% ACL ratio 1.10% 1.13% 1.26%
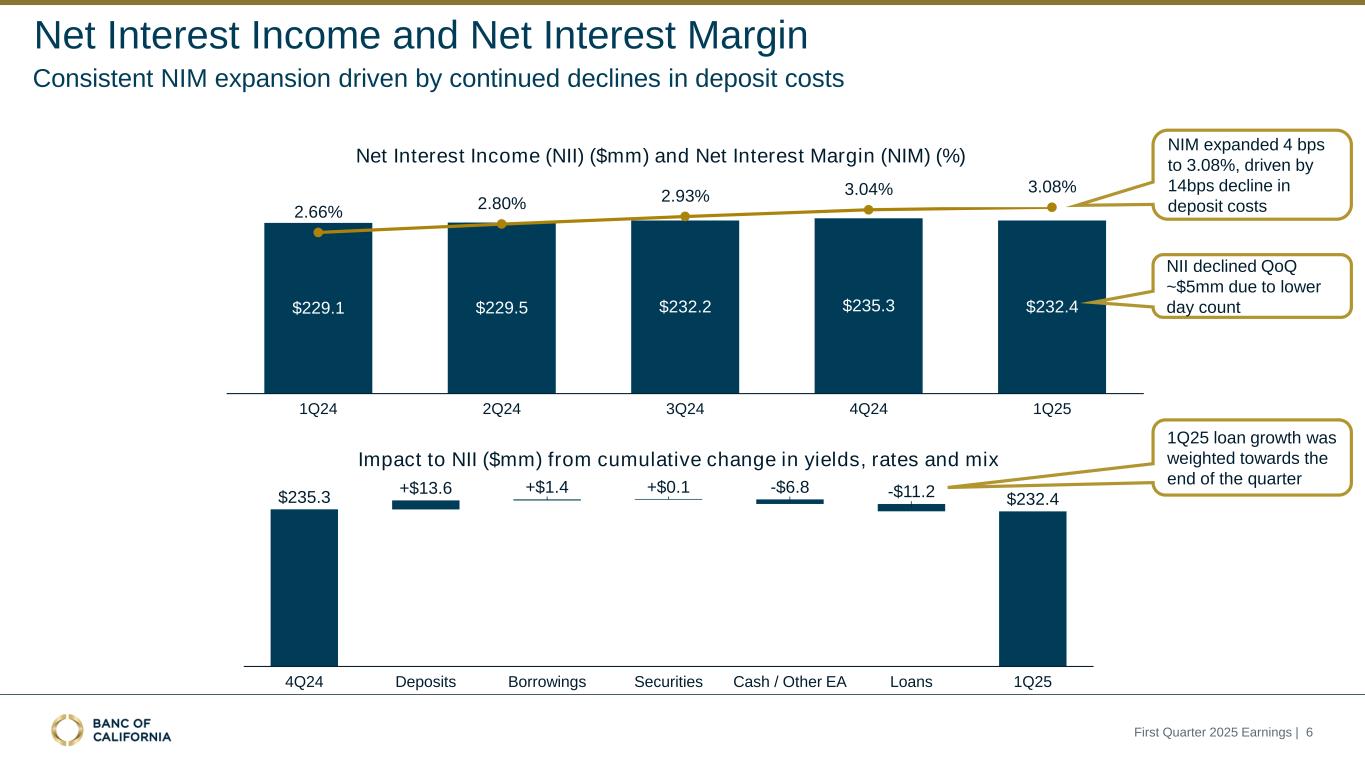
First Quarter 2025 Earnings | 6 Net Interest Income (NII) ($mm) and Net Interest Margin (NIM) (%) Impact to NII ($mm) from cumulative change in yields, rates and mix 4Q24 Deposits +$1.4 Borrowings +$0.1 Securities -$6.8 Cash / Other EA -$11.2 Loans 1Q25 $235.3 +$13.6 $232.4 2.66% $229.1 1Q24 2.80% $229.5 2Q24 2.93% $232.2 3Q24 3.04% $235.3 4Q24 3.08% $232.4 1Q25 Consistent NIM expansion driven by continued declines in deposit costs Net Interest Income and Net Interest Margin NIM expanded 4 bps to 3.08%, driven by 14bps decline in deposit costs 1Q25 loan growth was weighted towards the end of the quarter NII declined QoQ ~$5mm due to lower day count
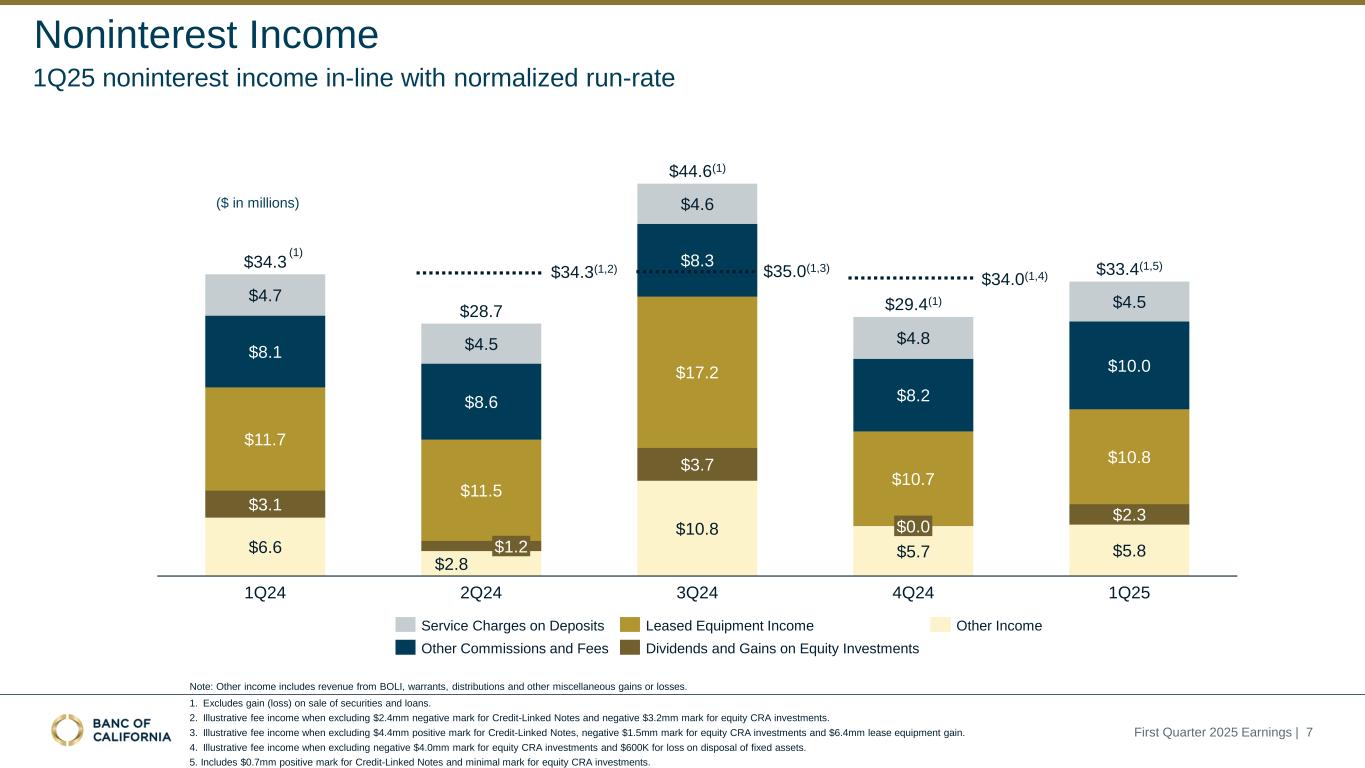
First Quarter 2025 Earnings | 7 $6.6 $2.8 $10.8 $5.7 $5.8 $3.1 $3.7 $2.3 $11.7 $11.5 $17.2 $10.7 $10.8 $8.1 $8.6 $8.3 $8.2 $10.0 $4.7 $4.5 $4.6 $4.8 $4.5 1Q24 $1.2 2Q24 3Q24 $0.0 4Q24 1Q25 $34.3 $28.7 $44.6(1) $29.4(1) $33.4(1,5) Service Charges on Deposits Other Commissions and Fees Leased Equipment Income Dividends and Gains on Equity Investments Other Income ($ in millions) (1) $34.3(1,2) $35.0(1,3) $34.0(1,4) 1. Excludes gain (loss) on sale of securities and loans. 2. Illustrative fee income when excluding $2.4mm negative mark for Credit-Linked Notes and negative $3.2mm mark for equity CRA investments. 3. Illustrative fee income when excluding $4.4mm positive mark for Credit-Linked Notes, negative $1.5mm mark for equity CRA investments and $6.4mm lease equipment gain. 4. Illustrative fee income when excluding negative $4.0mm mark for equity CRA investments and $600K for loss on disposal of fixed assets. 5. Includes $0.7mm positive mark for Credit-Linked Notes and minimal mark for equity CRA investments. Noninterest Income 1Q25 noninterest income in-line with normalized run-rate Note: Other income includes revenue from BOLI, warrants, distributions and other miscellaneous gains or losses.
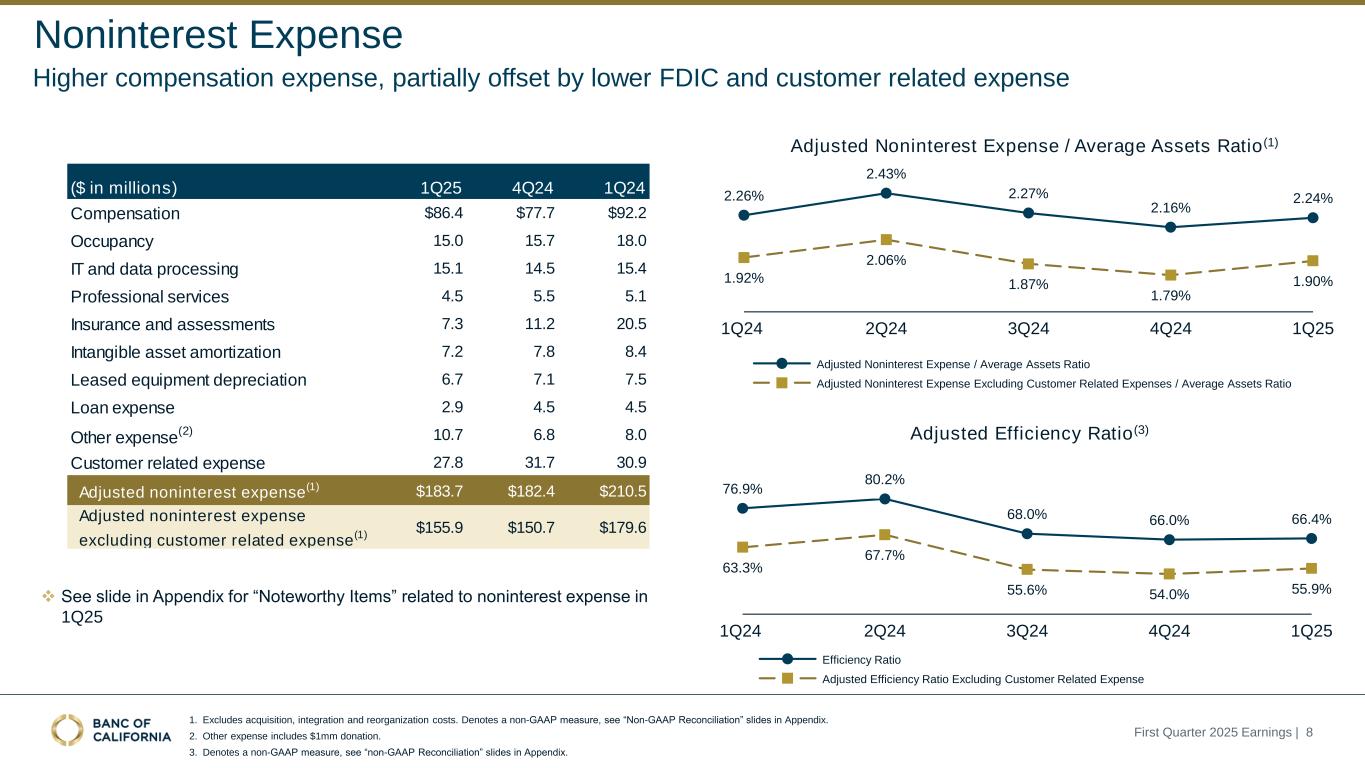
First Quarter 2025 Earnings | 8 ❖ See slide in Appendix for “Noteworthy Items” related to noninterest expense in 1Q25 2.26% 2.43% 2.27% 2.16% 2.24% 1.92% 2.06% 1.87% 1.79% 1.90% 1Q24 2Q24 3Q24 4Q24 1Q25 Adjusted Noninterest Expense / Average Assets Ratio Adjusted Noninterest Expense Excluding Customer Related Expenses / Average Assets Ratio Adjusted Noninterest Expense / Average Assets Ratio(1) 1. Excludes acquisition, integration and reorganization costs. Denotes a non-GAAP measure, see “Non-GAAP Reconciliation” slides in Appendix. 2. Other expense includes $1mm donation. 3. Denotes a non-GAAP measure, see “non-GAAP Reconciliation” slides in Appendix. Noninterest Expense Higher compensation expense, partially offset by lower FDIC and customer related expense 76.9% 80.2% 68.0% 66.0% 66.4% 63.3% 67.7% 55.6% 54.0% 55.9% 1Q24 2Q24 3Q24 4Q24 1Q25 Efficiency Ratio Adjusted Efficiency Ratio Excluding Customer Related Expense Adjusted Efficiency Ratio(3) ($ in millions) 1Q25 4Q24 1Q24 Compensation $86.4 $77.7 $92.2 Occupancy 15.0 15.7 18.0 IT and data processing 15.1 14.5 15.4 Professional services 4.5 5.5 5.1 Insurance and assessments 7.3 11.2 20.5 Intangible asset amortization 7.2 7.8 8.4 Leased equipment depreciation 6.7 7.1 7.5 Loan expense 2.9 4.5 4.5 Other expense (2) 10.7 6.8 8.0 Customer related expense 27.8 31.7 30.9 Adjusted noninterest expense(1) $183.7 $182.4 $210.5 Adjusted noninterest expense excluding customer related expense(1) $155.9 $150.7 $179.6
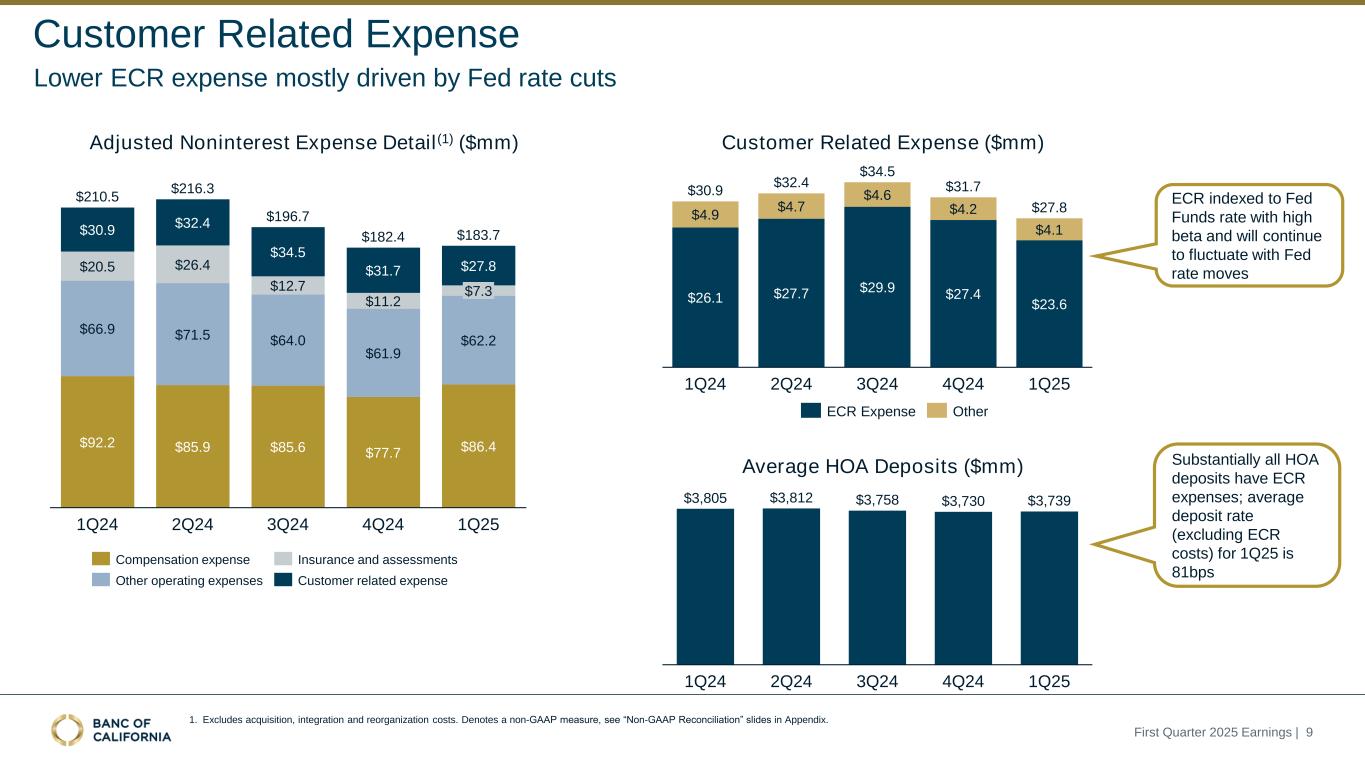
First Quarter 2025 Earnings | 9 Adjusted Noninterest Expense Detail(1) ($mm) $30.9 $20.5 $66.9 $92.2 1Q24 $32.4 $26.4 $71.5 $85.9 2Q24 $34.5 $12.7 $64.0 $85.6 3Q24 $31.7 $11.2 $61.9 $77.7 4Q24 $27.8 $7.3 $62.2 $86.4 1Q25 $210.5 $216.3 $196.7 $182.4 $183.7 Compensation expense Other operating expenses Insurance and assessments Customer related expense Customer Related Expense ($mm) $26.1 $4.9 1Q24 $27.7 $4.7 2Q24 $29.9 $4.6 3Q24 $27.4 $4.2 4Q24 $23.6 $4.1 1Q25 $30.9 $32.4 $34.5 $31.7 $27.8 ECR Expense Other 1. Excludes acquisition, integration and reorganization costs. Denotes a non-GAAP measure, see “Non-GAAP Reconciliation” slides in Appendix. Customer Related Expense Lower ECR expense mostly driven by Fed rate cuts 1Q24 2Q24 3Q24 4Q24 1Q25 $3,805 $3,812 $3,758 $3,730 $3,739 Average HOA Deposits ($mm) ECR indexed to Fed Funds rate with high beta and will continue to fluctuate with Fed rate moves Substantially all HOA deposits have ECR expenses; average deposit rate (excluding ECR costs) for 1Q25 is 81bps
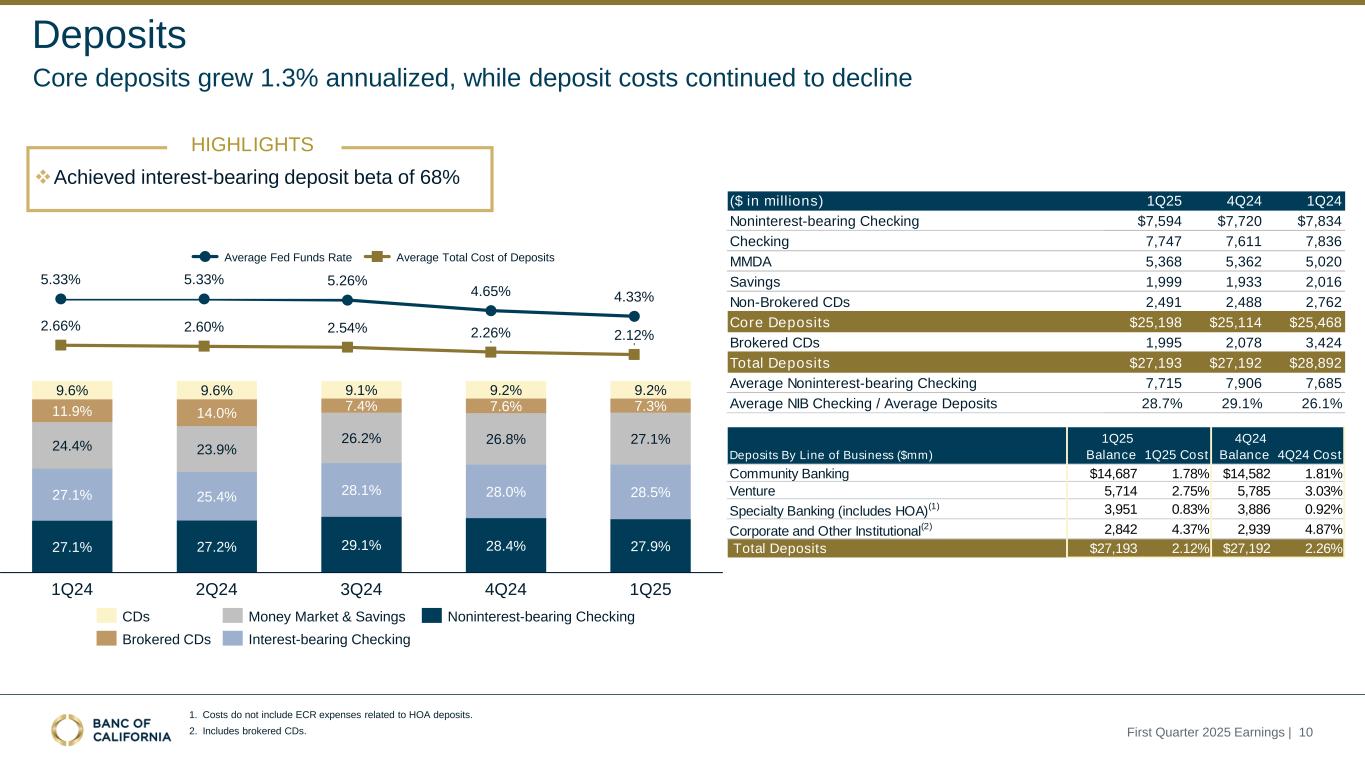
First Quarter 2025 Earnings | 10 Deposits Core deposits grew 1.3% annualized, while deposit costs continued to decline 5.33% 5.33% 5.26% 4.65% 4.33% 2.66% 2.60% 2.54% 2.26% 2.12% Average Fed Funds Rate Average Total Cost of Deposits Deposits By Line of Business ($mm) 1Q25 Balance 1Q25 Cost 4Q24 Balance 4Q24 Cost Community Banking $14,687 1.78% $14,582 1.81% Venture 5,714 2.75% 5,785 3.03% Specialty Banking (includes HOA)(1) 3,951 0.83% 3,886 0.92% Corporate and Other Institutional(2) 2,842 4.37% 2,939 4.87% Total Deposits $27,193 2.12% $27,192 2.26%27.1% 27.2% 29.1% 28.4% 27.9% 27.1% 25.4% 28.1% 28.0% 28.5% 24.4% 23.9% 26.2% 26.8% 27.1% 11.9% 14.0% 7.4% 7.6% 7.3% 9.6% 9.6% 9.1% 9.2% 9.2% 1Q24 2Q24 3Q24 4Q24 1Q25 CDs Brokered CDs Money Market & Savings Interest-bearing Checking Noninterest-bearing Checking 1. Costs do not include ECR expenses related to HOA deposits. 2. Includes brokered CDs. ($ in millions) 1Q25 4Q24 1Q24 Noninterest-bearing Checking $7,594 $7,720 $7,834 Checking 7,747 7,611 7,836 MMDA 5,368 5,362 5,020 Savings 1,999 1,933 2,016 Non-Brokered CDs 2,491 2,488 2,762 Core Deposits $25,198 $25,114 $25,468 Brokered CDs 1,995 2,078 3,424 Total Deposits $27,193 $27,192 $28,892 Average Noninterest-bearing Checking 7,715 7,906 7,685 Average NIB Checking / Average Deposits 28.7% 29.1% 26.1% ❖Achieved interest-bearing deposit beta of 68% HIGHLIGHTS
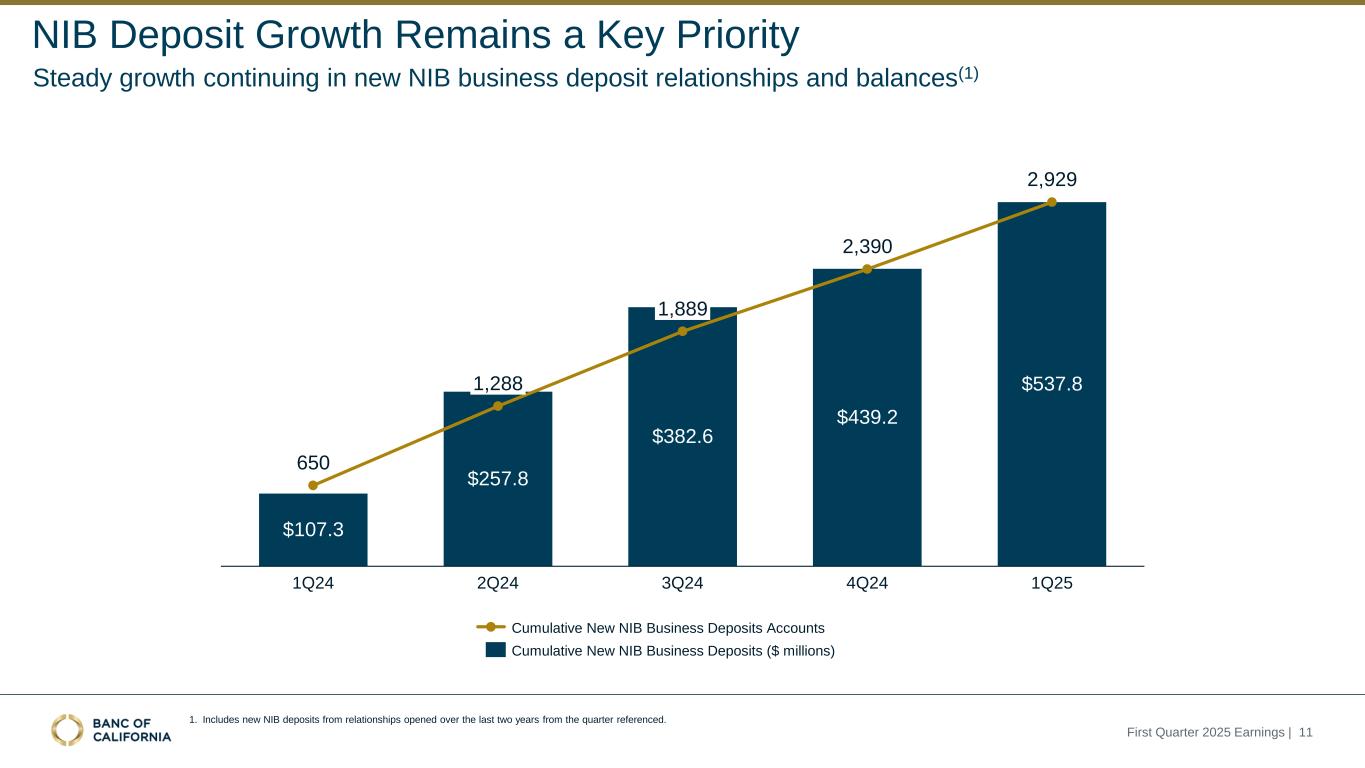
First Quarter 2025 Earnings | 11 650 2,390 2,929 $107.3 1Q24 1,288 $257.8 2Q24 1,889 $382.6 3Q24 $439.2 4Q24 $537.8 1Q25 Cumulative New NIB Business Deposits Accounts Cumulative New NIB Business Deposits ($ millions) NIB Deposit Growth Remains a Key Priority Steady growth continuing in new NIB business deposit relationships and balances(1) 1. Includes new NIB deposits from relationships opened over the last two years from the quarter referenced.
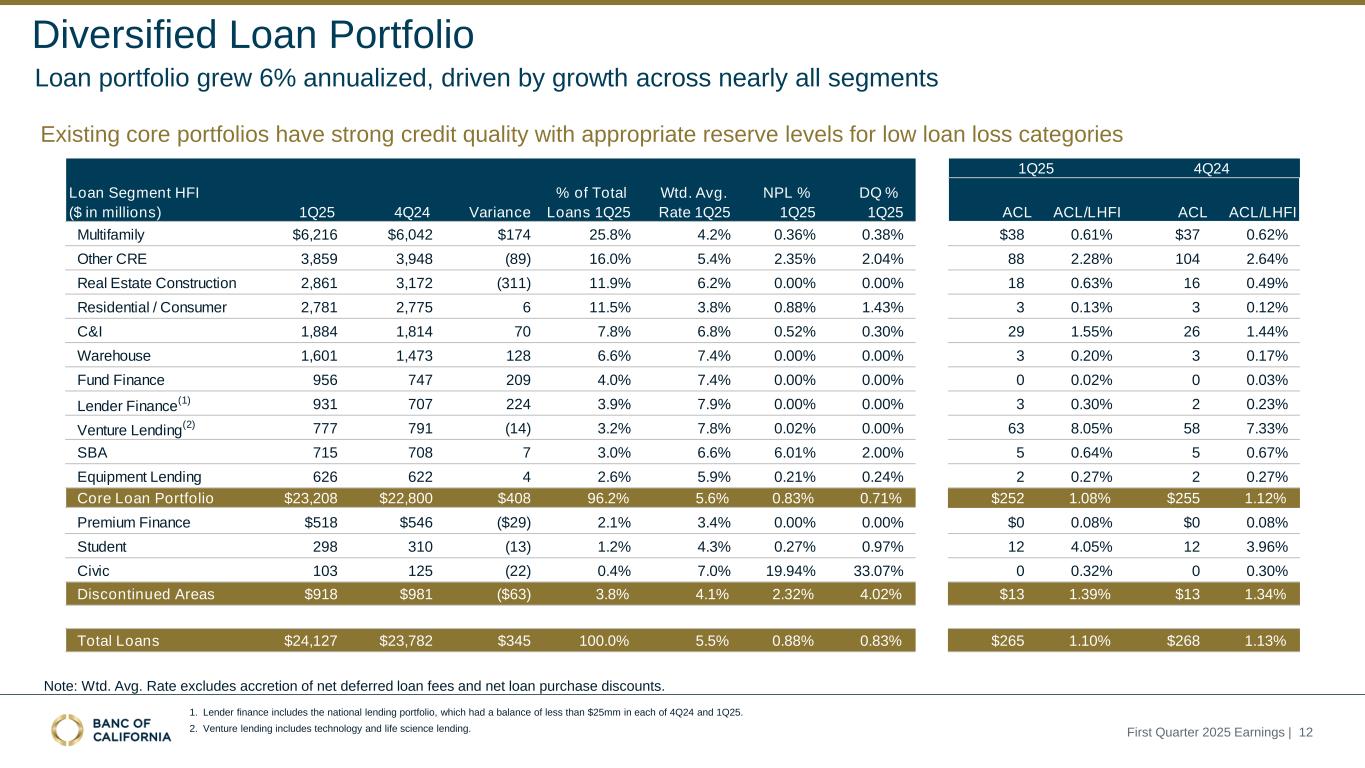
Diversified Loan Portfolio First Quarter 2025 Earnings | 12 Existing core portfolios have strong credit quality with appropriate reserve levels for low loan loss categories Note: Wtd. Avg. Rate excludes accretion of net deferred loan fees and net loan purchase discounts. 1. Lender finance includes the national lending portfolio, which had a balance of less than $25mm in each of 4Q24 and 1Q25. 2. Venture lending includes technology and life science lending. Loan portfolio grew 6% annualized, driven by growth across nearly all segments 1Q25 4Q24 1Q25 4Q24 Variance % of Total Loans 1Q25 Wtd. Avg. Rate 1Q25 NPL % 1Q25 DQ % 1Q25 ACL ACL/LHFI ACL ACL/LHFI Multifamily $6,216 $6,042 $174 25.8% 4.2% 0.36% 0.38% $38 0.61% $37 0.62% Other CRE 3,859 3,948 (89) 16.0% 5.4% 2.35% 2.04% 88 2.28% 104 2.64% Real Estate Construction 2,861 3,172 (311) 11.9% 6.2% 0.00% 0.00% 18 0.63% 16 0.49% Residential / Consumer 2,781 2,775 6 11.5% 3.8% 0.88% 1.43% 3 0.13% 3 0.12% C&I 1,884 1,814 70 7.8% 6.8% 0.52% 0.30% 29 1.55% 26 1.44% Warehouse 1,601 1,473 128 6.6% 7.4% 0.00% 0.00% 3 0.20% 3 0.17% Fund Finance 956 747 209 4.0% 7.4% 0.00% 0.00% 0 0.02% 0 0.03% Lender Finance (1) 931 707 224 3.9% 7.9% 0.00% 0.00% 3 0.30% 2 0.23% Venture Lending (2) 777 791 (14) 3.2% 7.8% 0.02% 0.00% 63 8.05% 58 7.33% SBA 715 708 7 3.0% 6.6% 6.01% 2.00% 5 0.64% 5 0.67% Equipment Lending 626 622 4 2.6% 5.9% 0.21% 0.24% 2 0.27% 2 0.27% Core Loan Portfolio $23,208 $22,800 $408 96.2% 5.6% 0.83% 0.71% $252 1.08% $255 1.12% Premium Finance $518 $546 ($29) 2.1% 3.4% 0.00% 0.00% $0 0.08% $0 0.08% Student 298 310 (13) 1.2% 4.3% 0.27% 0.97% 12 4.05% 12 3.96% Civic 103 125 (22) 0.4% 7.0% 19.94% 33.07% 0 0.32% 0 0.30% Discontinued Areas $918 $981 ($63) 3.8% 4.1% 2.32% 4.02% $13 1.39% $13 1.34% Total Loans $24,127 $23,782 $345 100.0% 5.5% 0.88% 0.83% $265 1.10% $268 1.13% Loan Segment HFI ($ in millions)
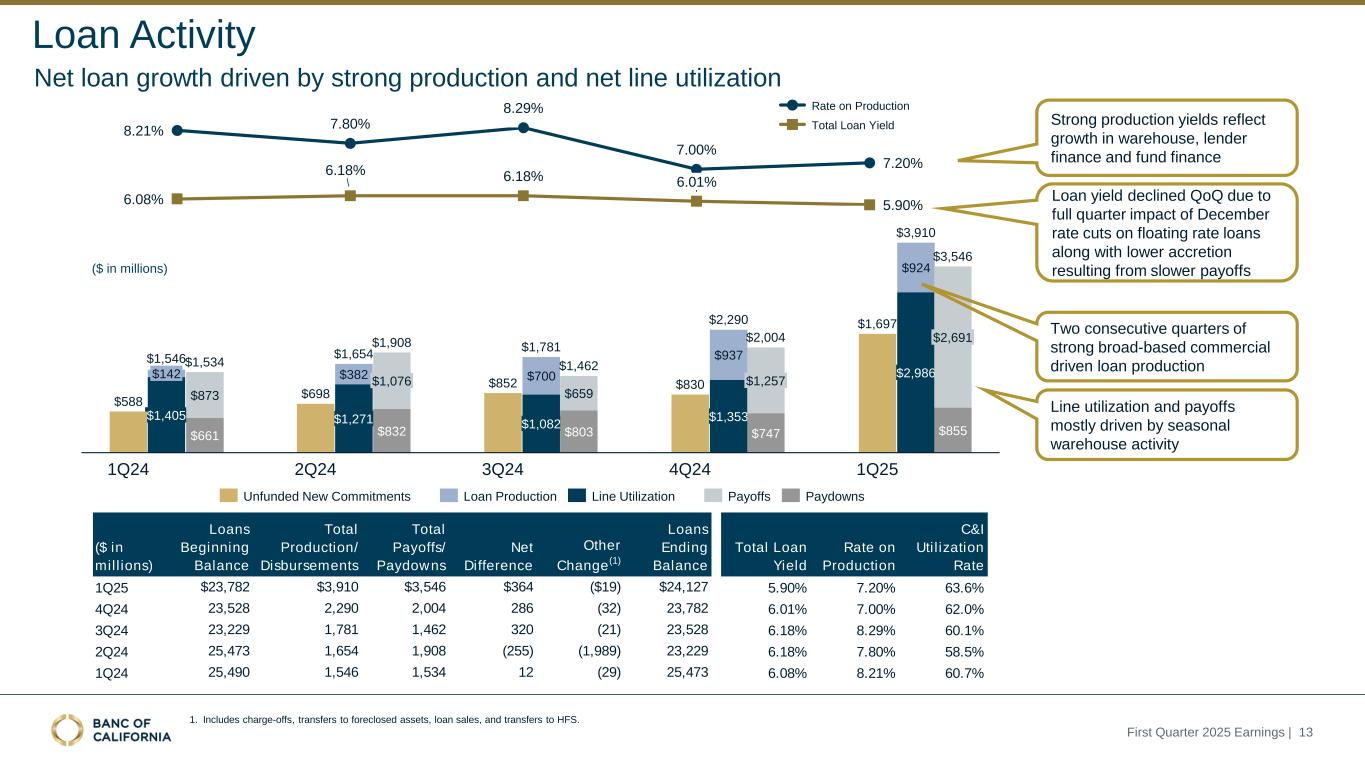
$142 $1,405 $382 $1,271 $700 $1,082 $937 $1,353 $924 $2,986 $1,546 $1,654 $1,781 $2,290 $3,910 $873 $661 $1,076 $832 $659 $803 $1,257 $747 $2,691 $855 $1,534 $1,908 $1,462 $2,004 $3,546 First Quarter 2025 Earnings | 13 1Q24 2Q24 3Q24 4Q24 1Q25 $588 $698 $852 $830 $1,697 Loan Production Line Utilization Payoffs Paydowns 8.21% 7.80% 8.29% 7.00% 7.20% 6.08% 6.18% 6.18% 5.90% 6.01% Rate on Production Total Loan Yield ($ in millions) Unfunded New Commitments 1. Includes charge-offs, transfers to foreclosed assets, loan sales, and transfers to HFS. Loan Activity Net loan growth driven by strong production and net line utilization Line utilization and payoffs mostly driven by seasonal warehouse activity Two consecutive quarters of strong broad-based commercial driven loan production Strong production yields reflect growth in warehouse, lender finance and fund finance ($ in millions) Loans Beginning Balance Total Production/ Disbursements Total Payoffs/ Paydowns Net Difference Other Change(1) Loans Ending Balance Total Loan Yield Rate on Production C&I Utilization Rate 1Q25 $23,782 $3,910 $3,546 $364 ($19) $24,127 5.90% 7.20% 63.6% 4Q24 23,528 2,290 2,004 286 (32) 23,782 6.01% 7.00% 62.0% 3Q24 23,229 1,781 1,462 320 (21) 23,528 6.18% 8.29% 60.1% 2Q24 25,473 1,654 1,908 (255) (1,989) 23,229 6.18% 7.80% 58.5% 1Q24 25,490 1,546 1,534 12 (29) 25,473 6.08% 8.21% 60.7% Loan yield declined QoQ due to full quarter impact of December rate cuts on floating rate loans along with lower accretion resulting from slower payoffs
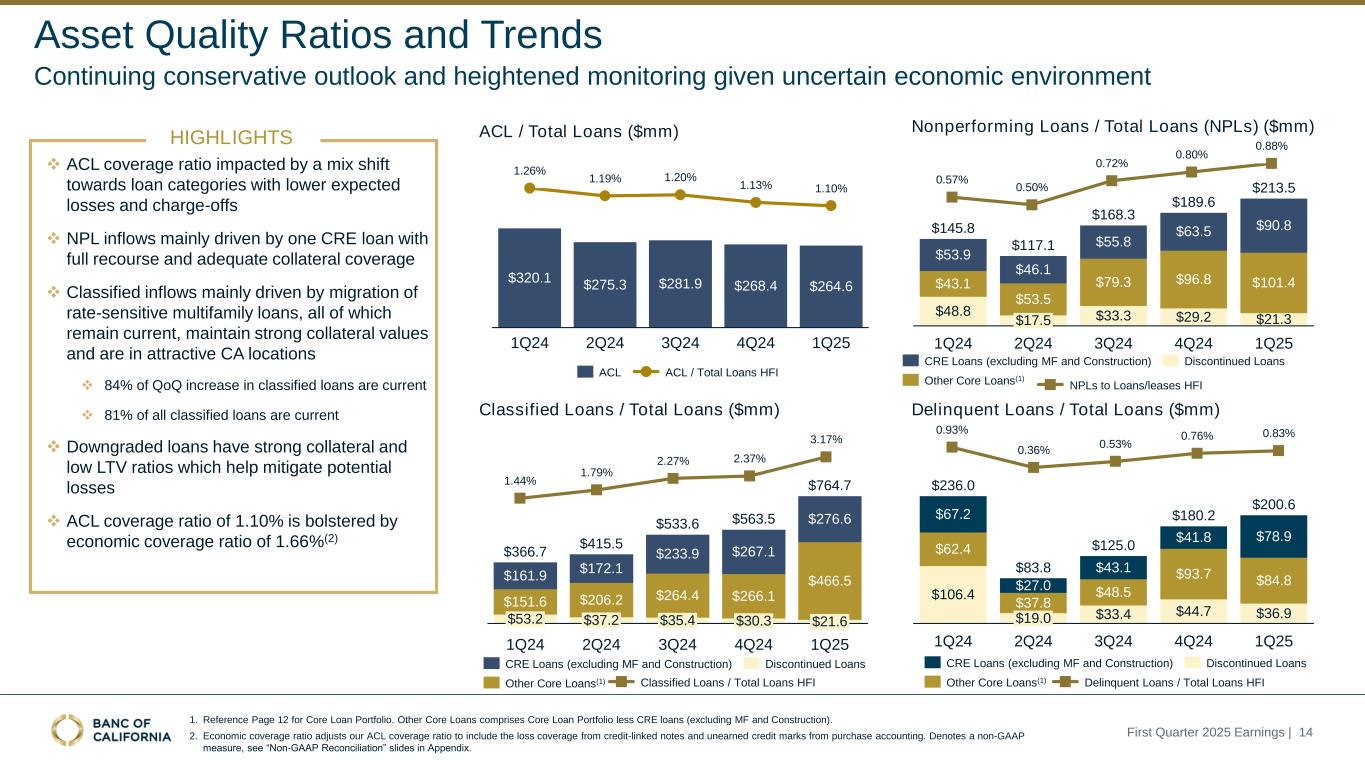
Asset Quality Ratios and Trends First Quarter 2025 Earnings | 14 ❖ ACL coverage ratio impacted by a mix shift towards loan categories with lower expected losses and charge-offs ❖ NPL inflows mainly driven by one CRE loan with full recourse and adequate collateral coverage ❖ Classified inflows mainly driven by migration of rate-sensitive multifamily loans, all of which remain current, maintain strong collateral values and are in attractive CA locations ❖ 84% of QoQ increase in classified loans are current ❖ 81% of all classified loans are current ❖ Downgraded loans have strong collateral and low LTV ratios which help mitigate potential losses ❖ ACL coverage ratio of 1.10% is bolstered by economic coverage ratio of 1.66%(2) Nonperforming Loans / Total Loans (NPLs) ($mm) Delinquent Loans / Total Loans ($mm)Classified Loans / Total Loans ($mm) ACL / Total Loans ($mm) $311.3 $320.1 $275.3 $281.9$320.1 1.26% 1Q24 $275.3 1.19% 2Q24 $281.9 1.20% 3Q24 $268.4 1.13% 4Q24 $264.6 1.10% 1Q25 ACL ACL / Total Loans HFI $53.9 $43.1 $48.8 1Q24 $46.1 $53.5 $17.5 2Q24 $55.8 $79.3 $33.3 3Q24 $63.5 $96.8 $29.2 4Q24 $90.8 $101.4 $21.3 1Q25 $145.8 $117.1 $168.3 $189.6 $213.5 CRE Loans (excluding MF and Construction) Other Core Loans(1) Discontinued Loans 0.57% 0.50% 0.72% 0.80% 0.88% NPLs to Loans/leases HFI $161.9 $151.6 $53.2 1Q24 $172.1 $206.2 $37.2 2Q24 $233.9 $264.4 $35.4 3Q24 $267.1 $266.1 $30.3 4Q24 $276.6 $466.5 $21.6 1Q25 $366.7 $415.5 $533.6 $563.5 $764.71.44% 1.79% 2.27% 2.37% 3.17% Classified Loans / Total Loans HFI CRE Loans (excluding MF and Construction) Other Core Loans(1) Discontinued Loans $67.2 $62.4 $106.4 1Q24 $27.0 $37.8 $19.0 2Q24 $43.1 $48.5 $33.4 3Q24 $41.8 $93.7 $44.7 4Q24 $78.9 $84.8 $36.9 1Q25 $236.0 $83.8 $125.0 $180.2 $200.6 0.93% 0.36% 0.53% 0.76% 0.83% CRE Loans (excluding MF and Construction) Other Core Loans(1) Discontinued Loans Delinquent Loans / Total Loans HFI 1. Reference Page 12 for Core Loan Portfolio. Other Core Loans comprises Core Loan Portfolio less CRE loans (excluding MF and Construction). 2. Economic coverage ratio adjusts our ACL coverage ratio to include the loss coverage from credit-linked notes and unearned credit marks from purchase accounting. Denotes a non-GAAP measure, see “Non-GAAP Reconciliation” slides in Appendix. Continuing conservative outlook and heightened monitoring given uncertain economic environment HIGHLIGHTS
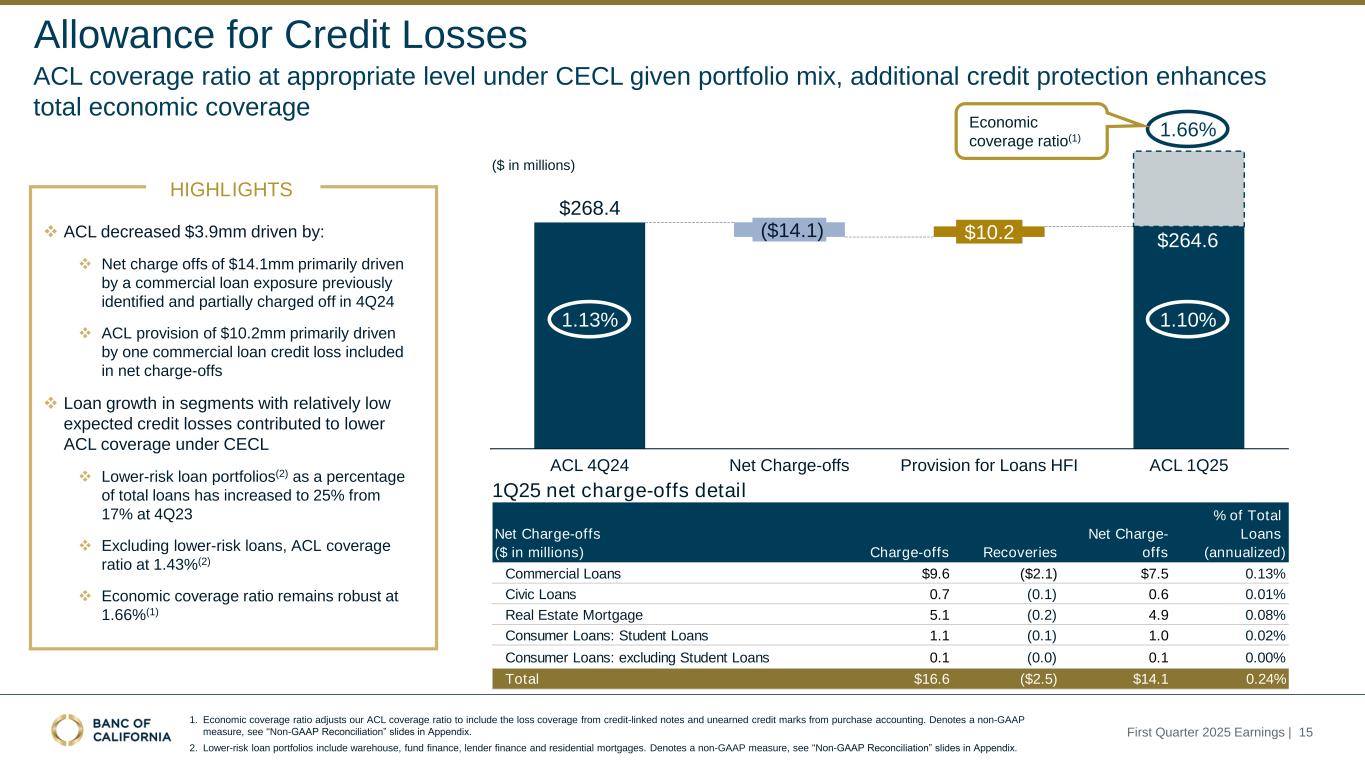
First Quarter 2025 Earnings | 15 ❖ ACL decreased $3.9mm driven by: ❖ Net charge offs of $14.1mm primarily driven by a commercial loan exposure previously identified and partially charged off in 4Q24 ❖ ACL provision of $10.2mm primarily driven by one commercial loan credit loss included in net charge-offs ❖ Loan growth in segments with relatively low expected credit losses contributed to lower ACL coverage under CECL ❖ Lower-risk loan portfolios(2) as a percentage of total loans has increased to 25% from 17% at 4Q23 ❖ Excluding lower-risk loans, ACL coverage ratio at 1.43%(2) ❖ Economic coverage ratio remains robust at 1.66%(1) 1.19% 1.20% ($ in millions) 1Q25 net charge-offs detail $268.4 ACL 4Q24 ($14.1) Net Charge-offs $10.2 Provision for Loans HFI ACL 1Q25 1.13% 1.10% Allowance for Credit Losses ACL coverage ratio at appropriate level under CECL given portfolio mix, additional credit protection enhances total economic coverage HIGHLIGHTS Net Charge-offs ($ in millions) Charge-offs Recoveries Net Charge- offs % of Total Loans (annualized) Commercial Loans $9.6 ($2.1) $7.5 0.13% Civic Loans 0.7 (0.1) 0.6 0.01% Real Estate Mortgage 5.1 (0.2) 4.9 0.08% Consumer Loans: Student Loans 1.1 (0.1) 1.0 0.02% Consumer Loans: excluding Student Loans 0.1 (0.0) 0.1 0.00% Total $16.6 ($2.5) $14.1 0.24% 1. Economic coverage ratio adjusts our ACL coverage ratio to include the loss coverage from credit-linked notes and unearned credit marks from purchase accounting. Denotes a non-GAAP measure, see "Non-GAAP Reconciliation” slides in Appendix. 2. Lower-risk loan portfolios include warehouse, fund finance, lender finance and residential mortgages. Denotes a non-GAAP measure, see "Non-GAAP Reconciliation” slides in Appendix. 1.66% Economic coverage ratio(1) $264.6
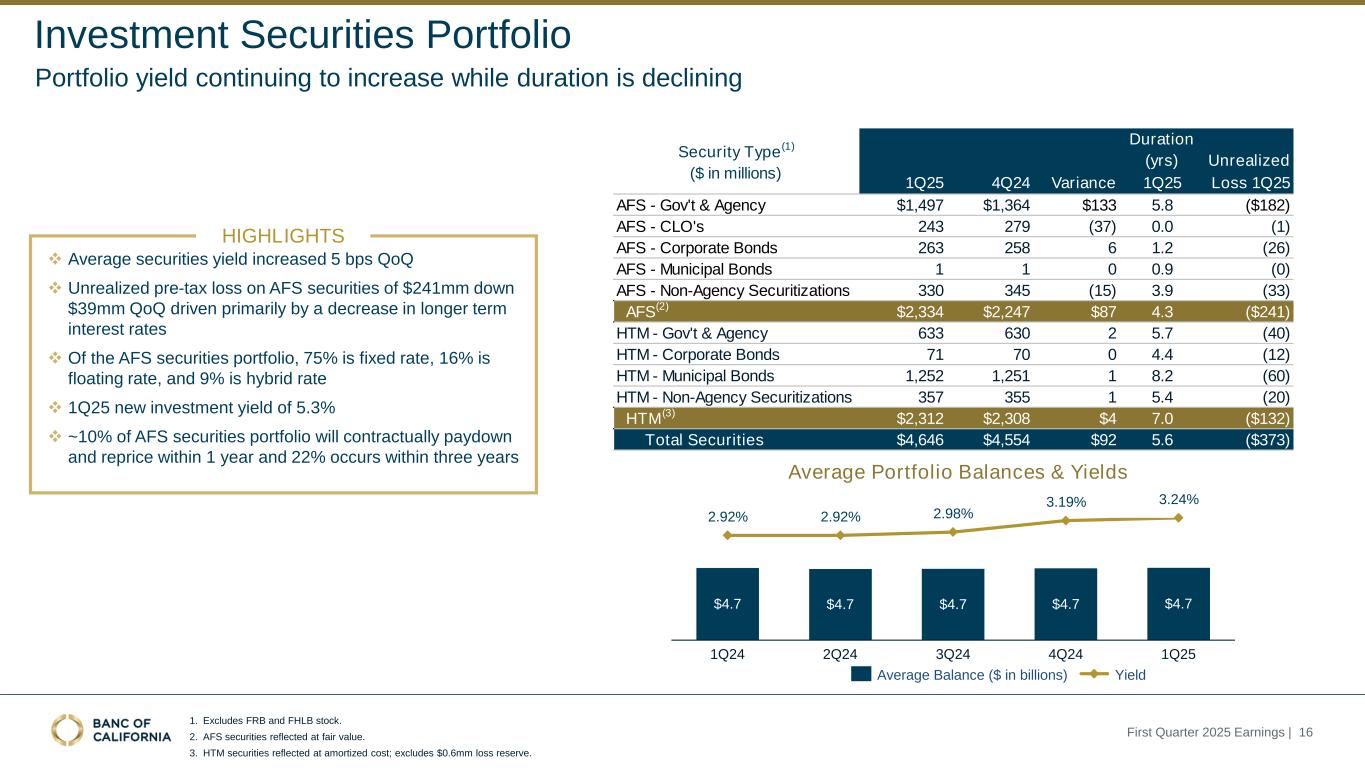
First Quarter 2025 Earnings | 16 Average Portfolio Balances & Yields 1. Excludes FRB and FHLB stock. 2. AFS securities reflected at fair value. 3. HTM securities reflected at amortized cost; excludes $0.6mm loss reserve. Investment Securities Portfolio Portfolio yield continuing to increase while duration is declining ❖ Average securities yield increased 5 bps QoQ ❖ Unrealized pre-tax loss on AFS securities of $241mm down $39mm QoQ driven primarily by a decrease in longer term interest rates ❖ Of the AFS securities portfolio, 75% is fixed rate, 16% is floating rate, and 9% is hybrid rate ❖ 1Q25 new investment yield of 5.3% ❖ ~10% of AFS securities portfolio will contractually paydown and reprice within 1 year and 22% occurs within three years HIGHLIGHTS $4.7 2.92% 1Q24 $4.7 2.92% 2Q24 $4.7 2.98% 3Q24 $4.7 3.19% 4Q24 $4.7 3.24% 1Q25 Average Balance ($ in billions) Yield Duration (yrs) Unrealized 1Q25 4Q24 Variance 1Q25 Loss 1Q25 AFS - Gov't & Agency $1,497 $1,364 $133 5.8 ($182) AFS - CLO's 243 279 (37) 0.0 (1) AFS - Corporate Bonds 263 258 6 1.2 (26) AFS - Municipal Bonds 1 1 0 0.9 (0) AFS - Non-Agency Securitizations 330 345 (15) 3.9 (33) AFS(2) $2,334 $2,247 $87 4.3 ($241) HTM - Gov't & Agency 633 630 2 5.7 (40) HTM - Corporate Bonds 71 70 0 4.4 (12) HTM - Municipal Bonds 1,252 1,251 1 8.2 (60) HTM - Non-Agency Securitizations 357 355 1 5.4 (20) HTM(3) $2,312 $2,308 $4 7.0 ($132) Total Securities $4,646 $4,554 $92 5.6 ($373) Security Type(1) ($ in millions)
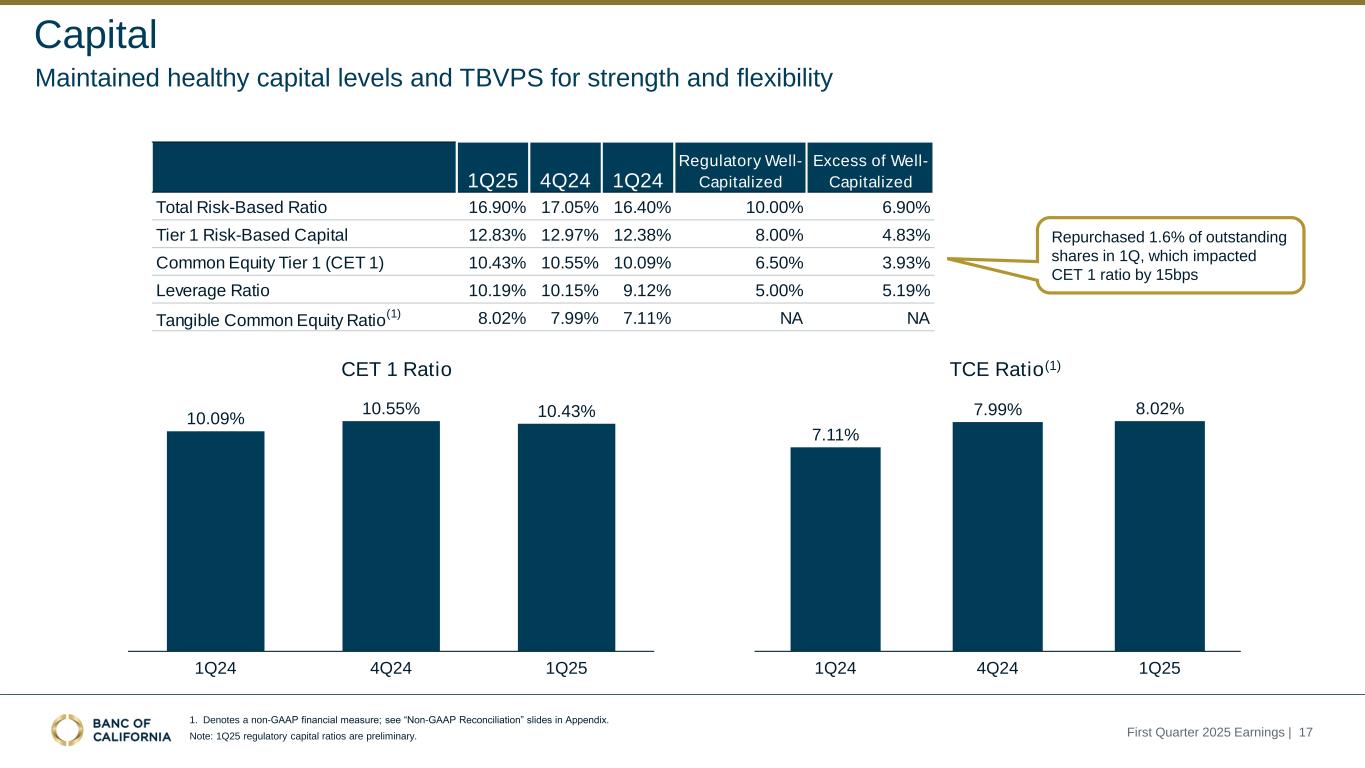
First Quarter 2025 Earnings | 17 10.09% 10.55% 10.43% 1Q24 4Q24 1Q25 7.11% 7.99% 8.02% 1Q24 4Q24 1Q25 CET 1 Ratio TCE Ratio(1) 1. Denotes a non-GAAP financial measure; see “Non-GAAP Reconciliation” slides in Appendix. Note: 1Q25 regulatory capital ratios are preliminary. Capital Maintained healthy capital levels and TBVPS for strength and flexibility Repurchased 1.6% of outstanding shares in 1Q, which impacted CET 1 ratio by 15bps 1Q25 4Q24 1Q24 Regulatory Well- Capitalized Excess of Well- Capitalized Total Risk-Based Ratio 16.90% 17.05% 16.40% 10.00% 6.90% Tier 1 Risk-Based Capital 12.83% 12.97% 12.38% 8.00% 4.83% Common Equity Tier 1 (CET 1) 10.43% 10.55% 10.09% 6.50% 3.93% Leverage Ratio 10.19% 10.15% 9.12% 5.00% 5.19% Tangible Common Equity Ratio (1) 8.02% 7.99% 7.11% NA NA
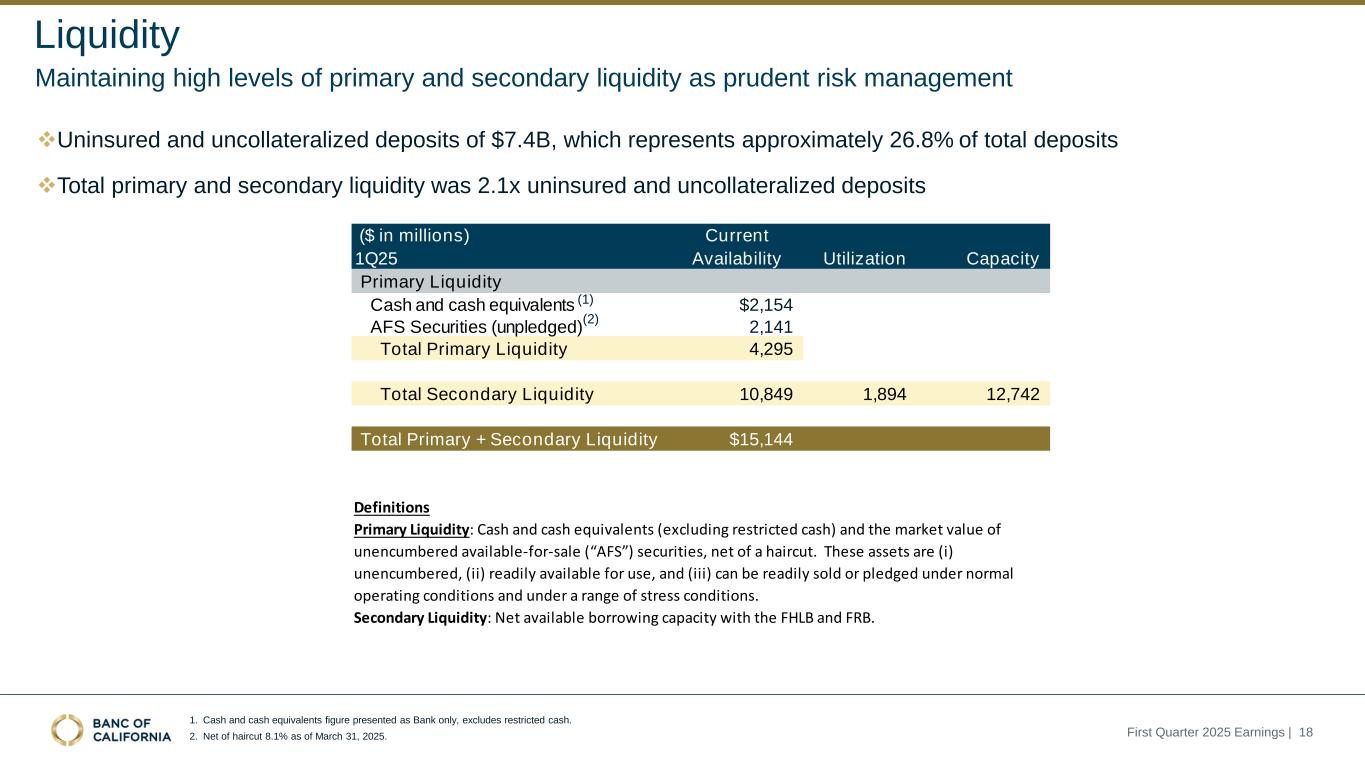
($ in millions) 1Q25 Current Availability Utilization Capacity Primary Liquidity Cash and cash equivalents $2,154 AFS Securities (unpledged) 2,141 Total Primary Liquidity 4,295 Total Secondary Liquidity 10,849 1,894 12,742 Total Primary + Secondary Liquidity $15,144 Definitions Secondary Liquidity: Net available borrowing capacity with the FHLB and FRB. Primary Liquidity: Cash and cash equivalents (excluding restricted cash) and the market value of unencumbered available-for-sale (“AFS”) securities, net of a haircut. These assets are (i) unencumbered, (ii) readily available for use, and (iii) can be readily sold or pledged under normal operating conditions and under a range of stress conditions. (2) (1) ❖Uninsured and uncollateralized deposits of $7.4B, which represents approximately 26.8% of total deposits ❖Total primary and secondary liquidity was 2.1x uninsured and uncollateralized deposits First Quarter 2025 Earnings | 18 Liquidity Maintaining high levels of primary and secondary liquidity as prudent risk management 1. Cash and cash equivalents figure presented as Bank only, excludes restricted cash. 2. Net of haircut 8.1% as of March 31, 2025.
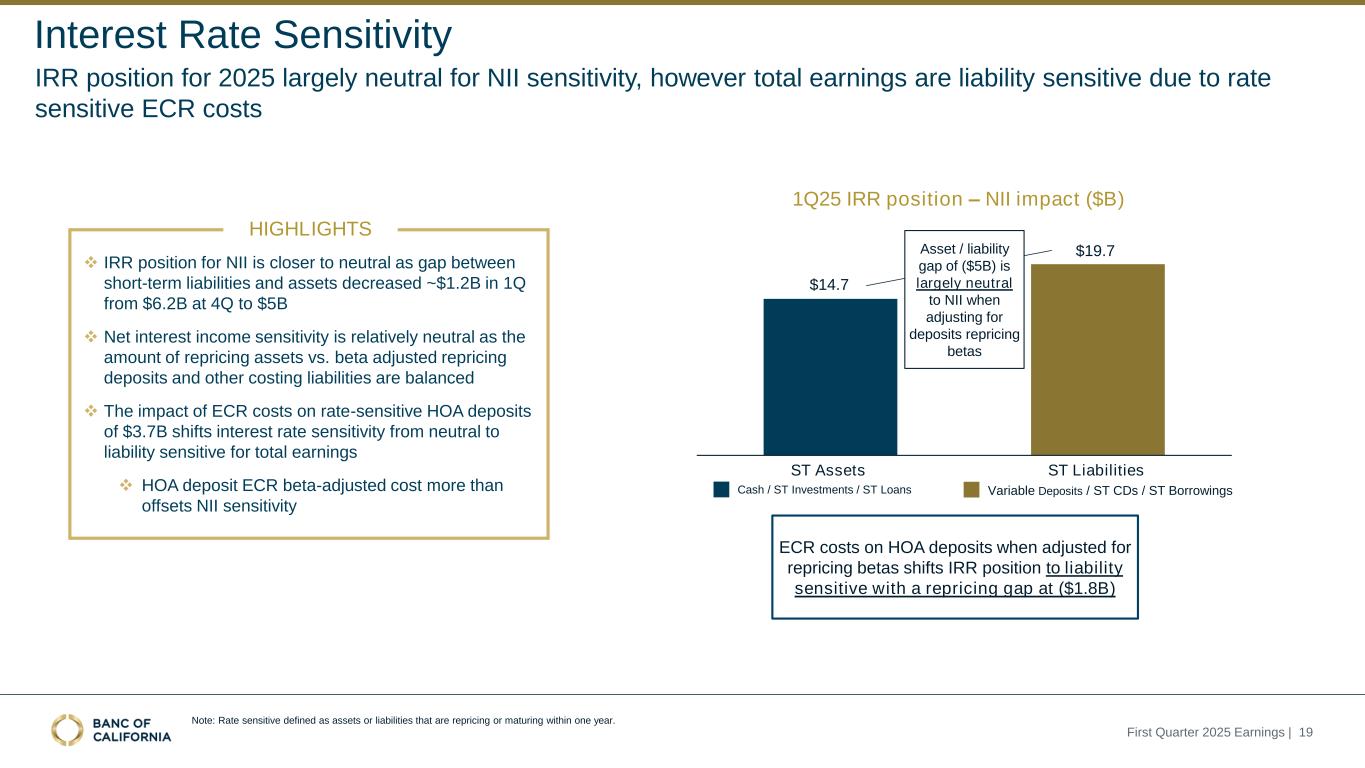
First Quarter 2025 Earnings | 19 Note: Rate sensitive defined as assets or liabilities that are repricing or maturing within one year. Interest Rate Sensitivity IRR position for 2025 largely neutral for NII sensitivity, however total earnings are liability sensitive due to rate sensitive ECR costs 1Q25 IRR position – NII impact ($B) ❖ IRR position for NII is closer to neutral as gap between short-term liabilities and assets decreased ~$1.2B in 1Q from $6.2B at 4Q to $5B ❖ Net interest income sensitivity is relatively neutral as the amount of repricing assets vs. beta adjusted repricing deposits and other costing liabilities are balanced ❖ The impact of ECR costs on rate-sensitive HOA deposits of $3.7B shifts interest rate sensitivity from neutral to liability sensitive for total earnings ❖ HOA deposit ECR beta-adjusted cost more than offsets NII sensitivity $14.7 $19.7 ST Assets ST Liabilities Asset / liability gap of ($5B) is largely neutral to NII when adjusting for deposits repricing betas ECR costs on HOA deposits when adjusted for repricing betas shifts IRR position to liability sensitive with a repricing gap at ($1.8B) Cash / ST Investments / ST Loans Variable Deposits / ST CDs / ST Borrowings HIGHLIGHTS
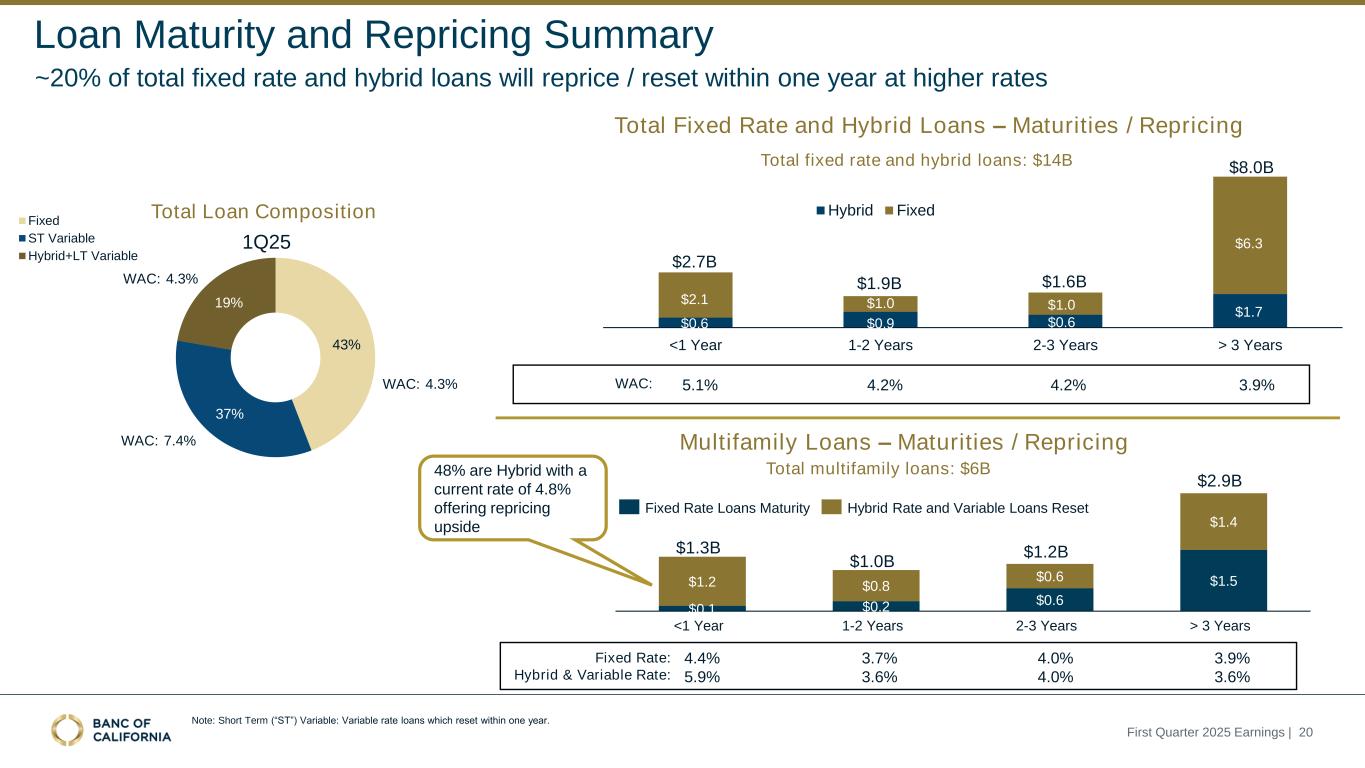
<1 Year 1-2 Years 2-3 Years > 3 Years Hybrid Fixed First Quarter 2025 Earnings | 20 Loan Maturity and Repricing Summary 3.7% 3.6% 4.0% 4.0% 3.9% 3.6% 4.4% 5.9% Multifamily Loans – Maturities / Repricing $0.1 $0.2 $0.6 $1.5$1.2 $0.8 $0.6 $1.4 <1 Year 1-2 Years 2-3 Years > 3 Years $1.3B $1.0B $1.2B $2.9B Fixed Rate Loans Maturity Hybrid Rate and Variable Loans Reset Fixed Rate: Hybrid & Variable Rate: Total Fixed Rate and Hybrid Loans – Maturities / Repricing $2.7B $1.9B $1.6B $8.0B $2.1 $1.0 $1.0 $6.3 $1.7 $0.6$0.9$0.6 ~20% of total fixed rate and hybrid loans will reprice / reset within one year at higher rates Total fixed rate and hybrid loans: $14B Total multifamily loans: $6B 43% 37% 19% 1Q25 Fixed ST Variable Hybrid+LT Variable Total Loan Composition WAC: 4.3% WAC: 7.4% WAC: 4.3% 48% are Hybrid with a current rate of 4.8% offering repricing upside 4.2% 4.2% 3.9%5.1%WAC: Note: Short Term (“ST”) Variable: Variable rate loans which reset within one year.
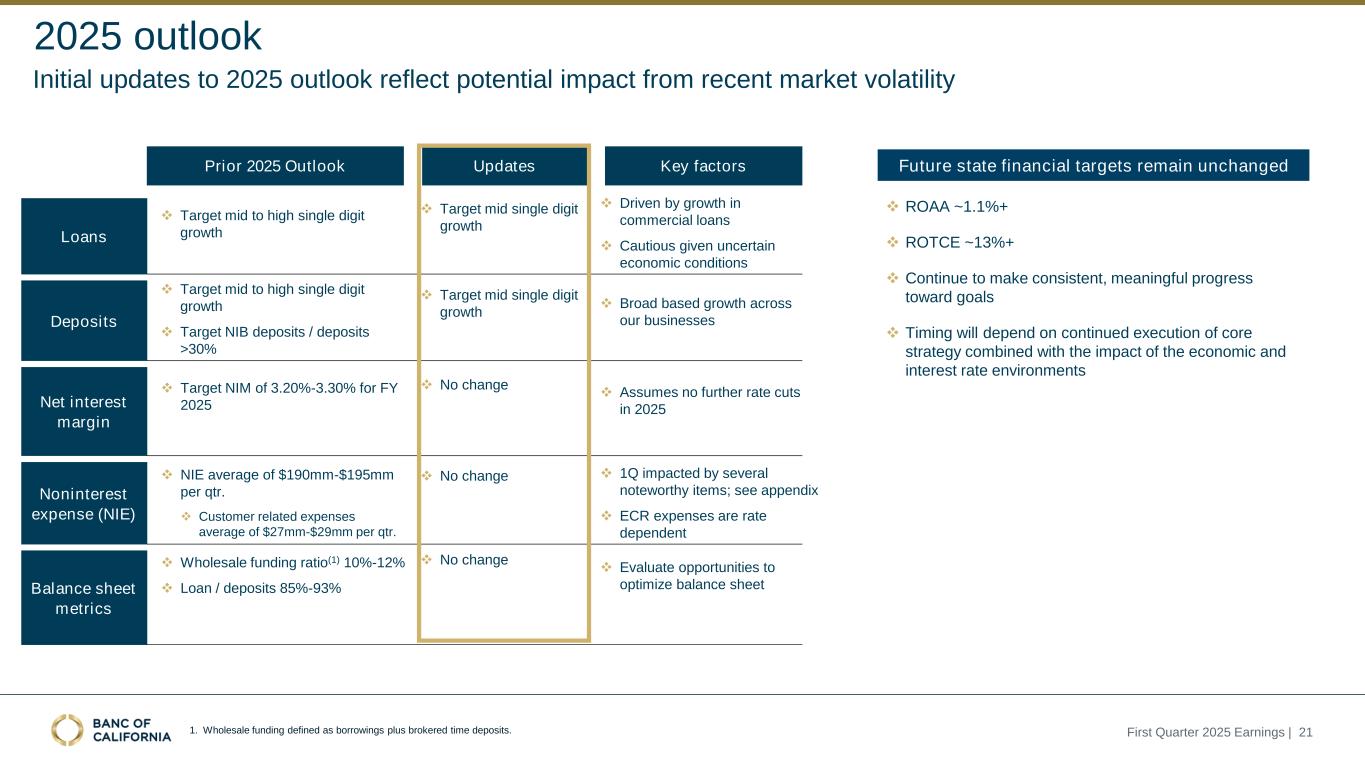
Prior 2025 Outlook Updates Key factors Loans Deposits Net interest margin Noninterest expense (NIE) Balance sheet metrics First Quarter 2025 Earnings | 21 ❖ Target NIM of 3.20%-3.30% for FY 2025 ❖ Assumes no further rate cuts in 2025 ❖ NIE average of $190mm-$195mm per qtr. ❖ Customer related expenses average of $27mm-$29mm per qtr. ❖ 1Q impacted by several noteworthy items; see appendix ❖ ECR expenses are rate dependent ❖ Wholesale funding ratio(1) 10%-12% ❖ Loan / deposits 85%-93% ❖ Evaluate opportunities to optimize balance sheet ❖ ROAA ~1.1%+ ❖ ROTCE ~13%+ ❖ Continue to make consistent, meaningful progress toward goals ❖ Timing will depend on continued execution of core strategy combined with the impact of the economic and interest rate environments ❖ Target mid to high single digit growth ❖ Driven by growth in commercial loans ❖ Cautious given uncertain economic conditions ❖ Target mid to high single digit growth ❖ Target NIB deposits / deposits >30% ❖ Broad based growth across our businesses 1. Wholesale funding defined as borrowings plus brokered time deposits. Initial updates to 2025 outlook reflect potential impact from recent market volatility 2025 outlook ❖ Target mid single digit growth ❖ Target mid single digit growth ❖ No change ❖ No change ❖ No change Future state financial targets remain unchanged
Supplemental Information
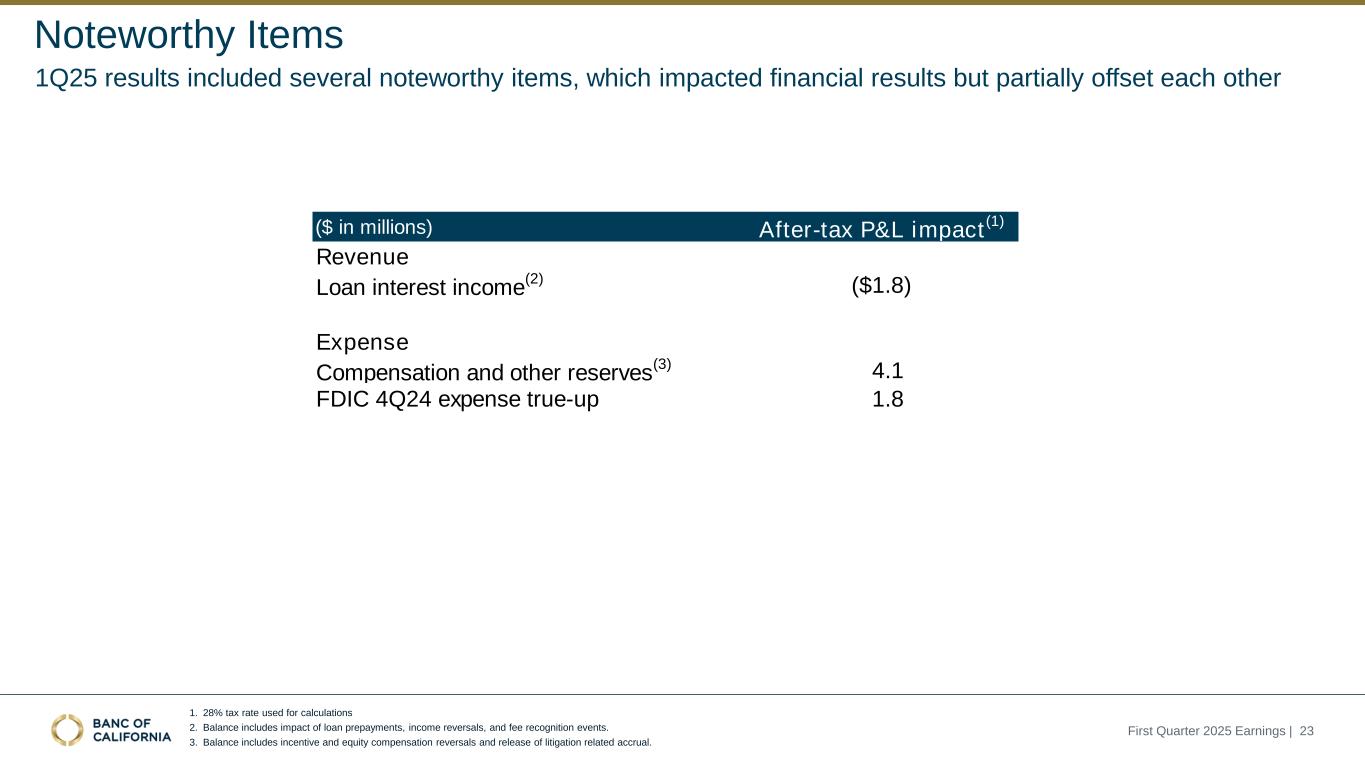
1. 28% tax rate used for calculations 2. Balance includes impact of loan prepayments, income reversals, and fee recognition events. 3. Balance includes incentive and equity compensation reversals and release of litigation related accrual. Noteworthy Items 1Q25 results included several noteworthy items, which impacted financial results but partially offset each other ($ in millions) After-tax P&L impact (1) Revenue Loan interest income (2) ($1.8) Expense Compensation and other reserves (3) 4.1 FDIC 4Q24 expense true-up 1.8 First Quarter 2025 Earnings | 23
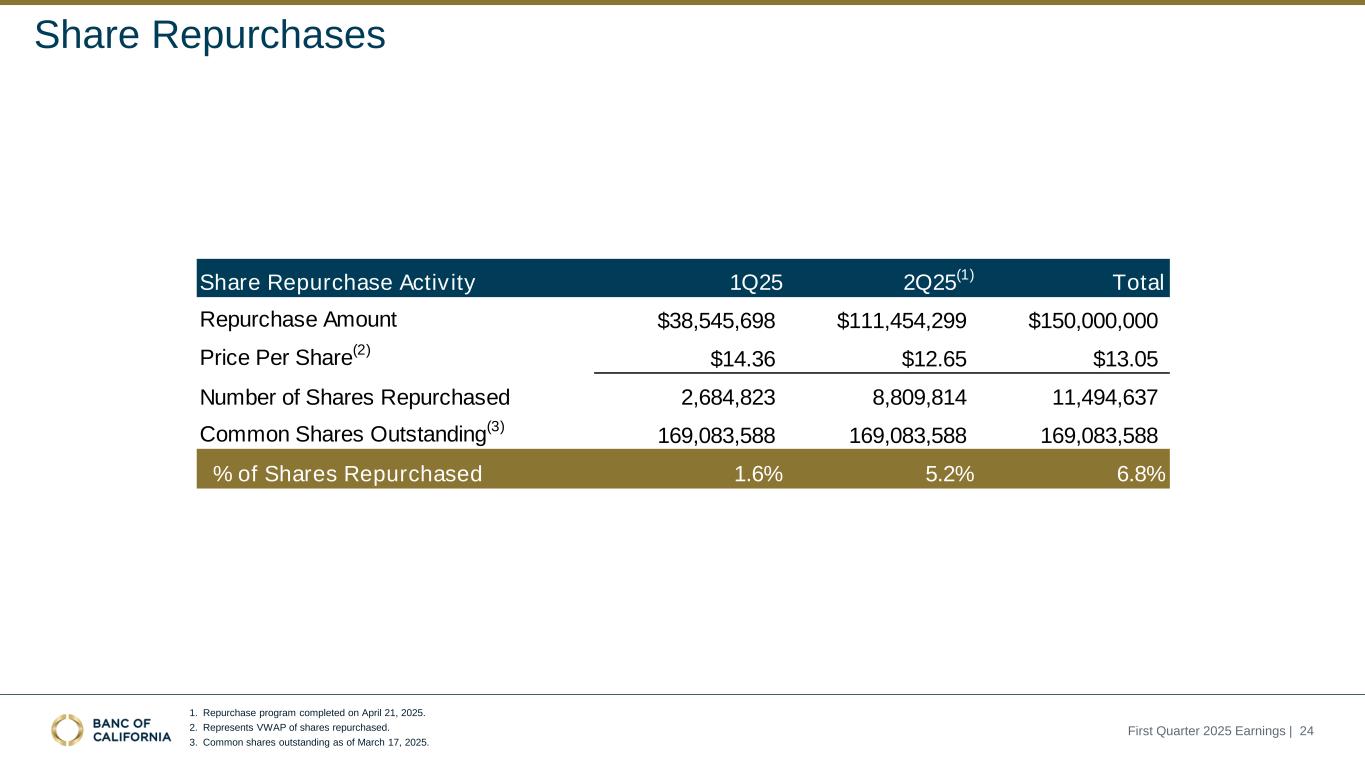
1. Repurchase program completed on April 21, 2025. 2. Represents VWAP of shares repurchased. 3. Common shares outstanding as of March 17, 2025. Share Repurchases First Quarter 2025 Earnings | 24 Share Repurchase Activity 1Q25 2Q25(1) Total Repurchase Amount $38,545,698 $111,454,299 $150,000,000 Price Per Share(2) $14.36 $12.65 $13.05 Number of Shares Repurchased 2,684,823 8,809,814 11,494,637 Common Shares Outstanding(3) 169,083,588 169,083,588 169,083,588 % of Shares Repurchased 1.6% 5.2% 6.8%
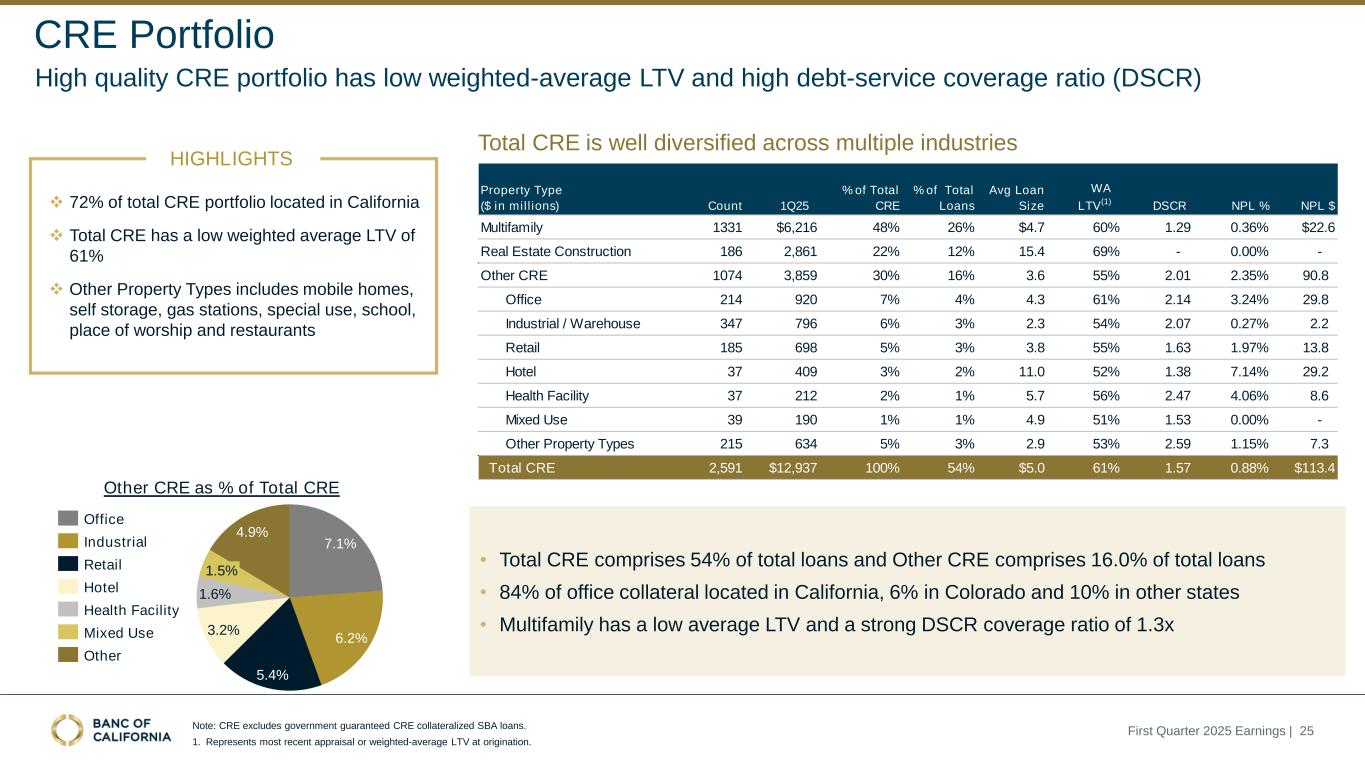
❖ 72% of total CRE portfolio located in California ❖ Total CRE has a low weighted average LTV of 61% ❖ Other Property Types includes mobile homes, self storage, gas stations, special use, school, place of worship and restaurants 7.1% 6.2% 5.4% 3.2% 1.6% 4.9% 1.5% Office Industrial Retail Hotel Health Facility Mixed Use Other Other CRE as % of Total CRE Total CRE is well diversified across multiple industries • Total CRE comprises 54% of total loans and Other CRE comprises 16.0% of total loans • 84% of office collateral located in California, 6% in Colorado and 10% in other states • Multifamily has a low average LTV and a strong DSCR coverage ratio of 1.3x Note: CRE excludes government guaranteed CRE collateralized SBA loans. 1. Represents most recent appraisal or weighted-average LTV at origination. CRE Portfolio High quality CRE portfolio has low weighted-average LTV and high debt-service coverage ratio (DSCR) HIGHLIGHTS Property Type ($ in millions) Count 1Q25 % of Total CRE % of Total Loans Avg Loan Size WA LTV(1) DSCR NPL % NPL $ Multifamily 1331 $6,216 48% 26% $4.7 60% 1.29 0.36% $22.6 Real Estate Construction 186 2,861 22% 12% 15.4 69% - 0.00% - Other CRE 1074 3,859 30% 16% 3.6 55% 2.01 2.35% 90.8 Office 214 920 7% 4% 4.3 61% 2.14 3.24% 29.8 Industrial / Warehouse 347 796 6% 3% 2.3 54% 2.07 0.27% 2.2 Retail 185 698 5% 3% 3.8 55% 1.63 1.97% 13.8 Hotel 37 409 3% 2% 11.0 52% 1.38 7.14% 29.2 Health Facility 37 212 2% 1% 5.7 56% 2.47 4.06% 8.6 Mixed Use 39 190 1% 1% 4.9 51% 1.53 0.00% - Other Property Types 215 634 5% 3% 2.9 53% 2.59 1.15% 7.3 Total CRE 2,591 $12,937 100% 54% $5.0 61% 1.57 0.88% $113.4 First Quarter 2025 Earnings | 25
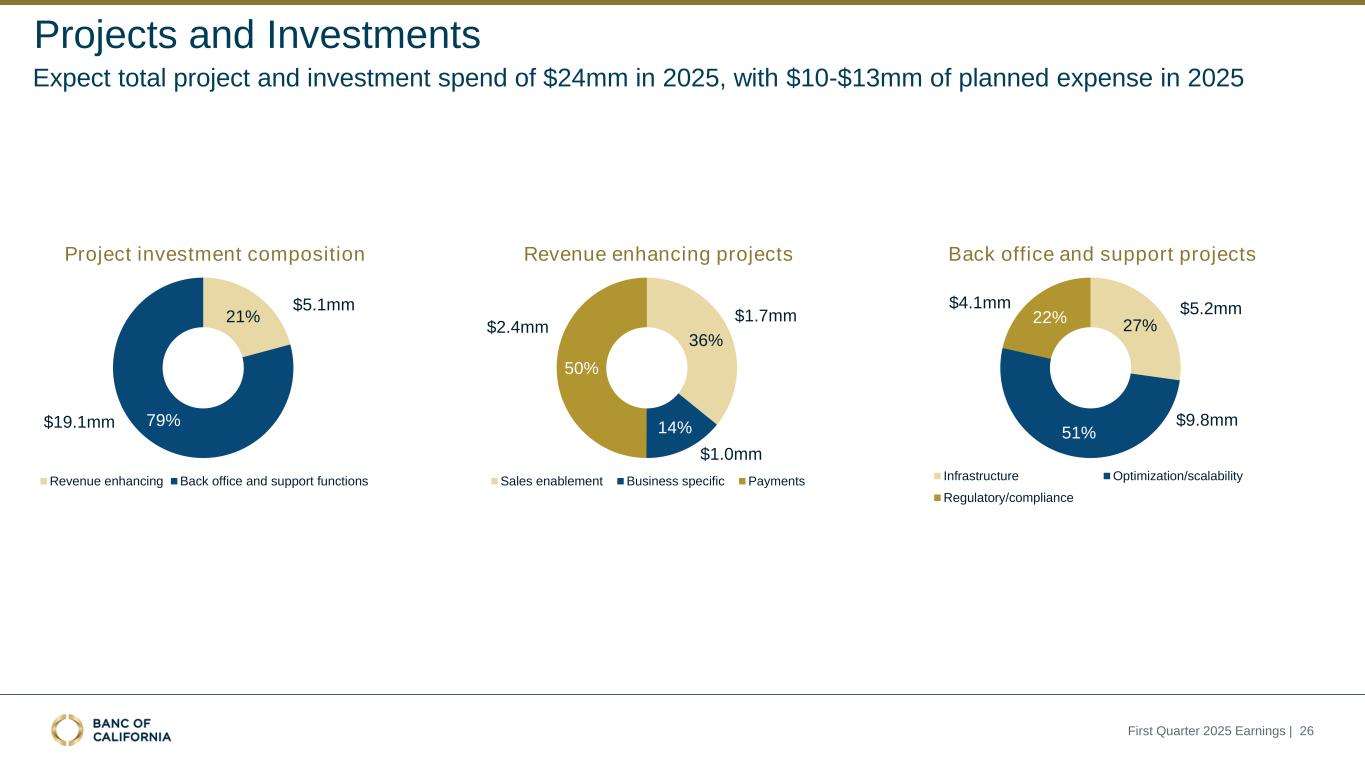
Projects and Investments Expect total project and investment spend of $24mm in 2025, with $10-$13mm of planned expense in 2025 21% 79% Revenue enhancing Back office and support functions Project investment composition 36% 14% 50% Sales enablement Business specific Payments Revenue enhancing projects 27% 51% 22% Infrastructure Optimization/scalability Regulatory/compliance Back office and support projects $5.1mm $19.1mm $2.4mm $1.7mm $1.0mm $4.1mm $5.2mm $9.8mm First Quarter 2025 Earnings | 26
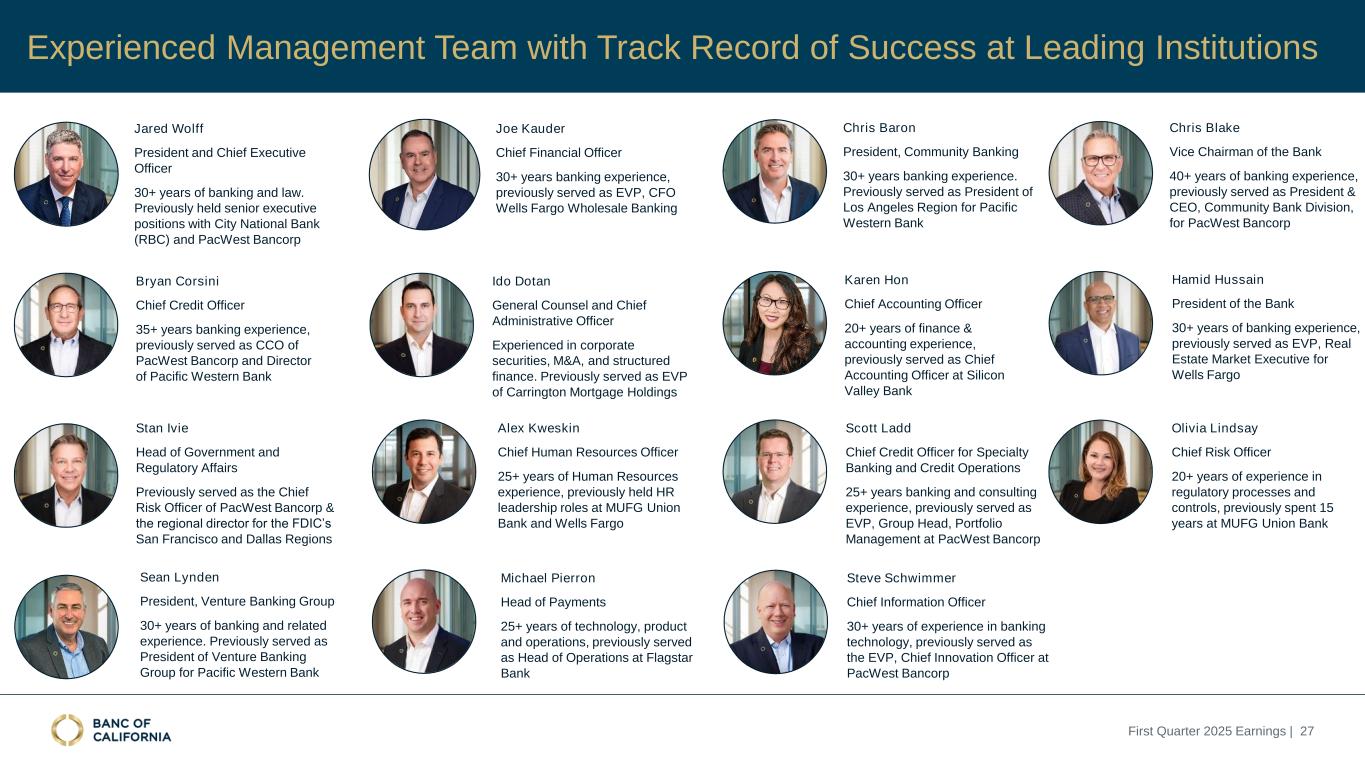
Experienced Management Team with Track Record of Success at Leading Institutions Alex Kweskin Chief Human Resources Officer 25+ years of Human Resources experience, previously held HR leadership roles at MUFG Union Bank and Wells Fargo Chris Blake Vice Chairman of the Bank 40+ years of banking experience, previously served as President & CEO, Community Bank Division, for PacWest Bancorp Scott Ladd Chief Credit Officer for Specialty Banking and Credit Operations 25+ years banking and consulting experience, previously served as EVP, Group Head, Portfolio Management at PacWest Bancorp Hamid Hussain President of the Bank 30+ years of banking experience, previously served as EVP, Real Estate Market Executive for Wells Fargo Bryan Corsini Chief Credit Officer 35+ years banking experience, previously served as CCO of PacWest Bancorp and Director of Pacific Western Bank Ido Dotan General Counsel and Chief Administrative Officer Experienced in corporate securities, M&A, and structured finance. Previously served as EVP of Carrington Mortgage Holdings Olivia Lindsay Chief Risk Officer 20+ years of experience in regulatory processes and controls, previously spent 15 years at MUFG Union Bank Steve Schwimmer Chief Information Officer 30+ years of experience in banking technology, previously served as the EVP, Chief Innovation Officer at PacWest Bancorp Stan Ivie Head of Government and Regulatory Affairs Previously served as the Chief Risk Officer of PacWest Bancorp & the regional director for the FDIC’s San Francisco and Dallas Regions Michael Pierron Head of Payments 25+ years of technology, product and operations, previously served as Head of Operations at Flagstar Bank Sean Lynden President, Venture Banking Group 30+ years of banking and related experience. Previously served as President of Venture Banking Group for Pacific Western Bank Chris Baron President, Community Banking 30+ years banking experience. Previously served as President of Los Angeles Region for Pacific Western Bank Karen Hon Chief Accounting Officer 20+ years of finance & accounting experience, previously served as Chief Accounting Officer at Silicon Valley Bank Jared Wolff President and Chief Executive Officer 30+ years of banking and law. Previously held senior executive positions with City National Bank (RBC) and PacWest Bancorp Joe Kauder Chief Financial Officer 30+ years banking experience, previously served as EVP, CFO Wells Fargo Wholesale Banking First Quarter 2025 Earnings | 27
Appendix
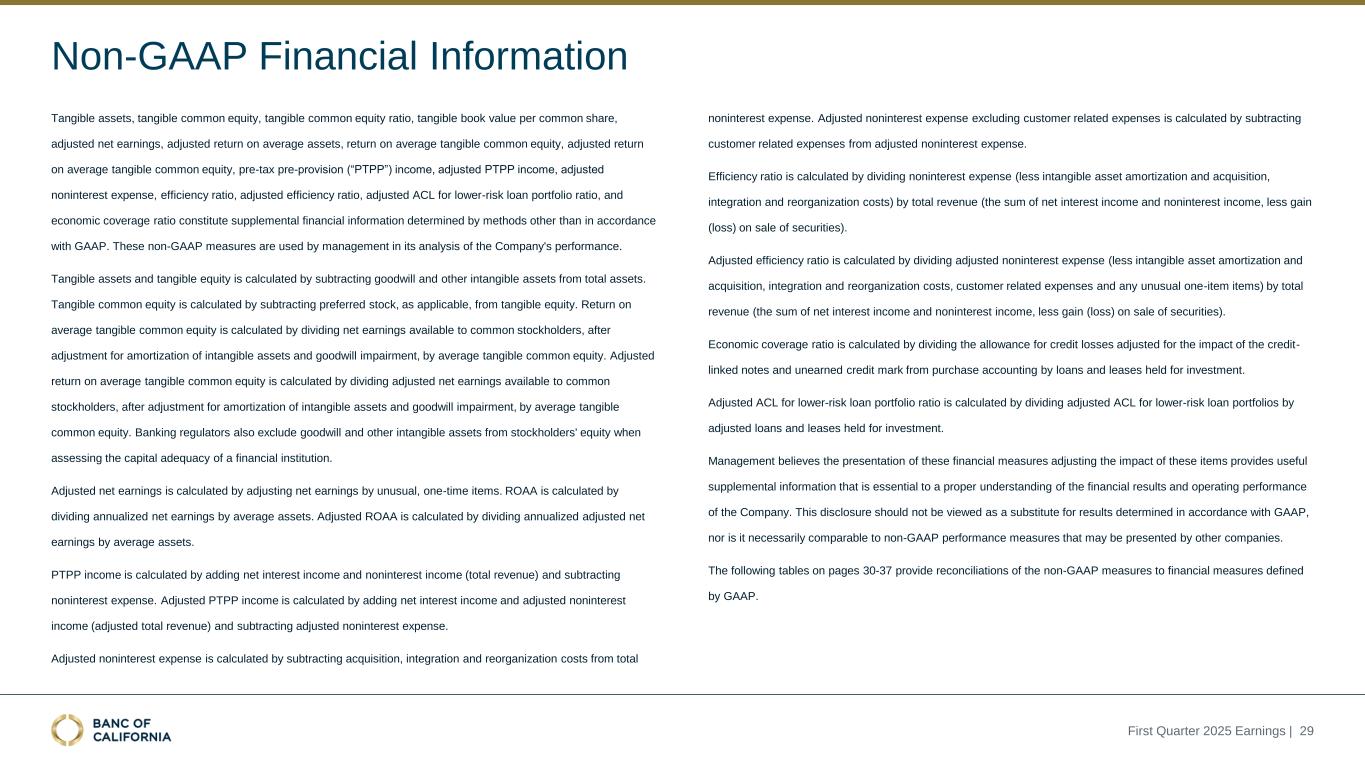
Non-GAAP Financial Information First Quarter 2025 Earnings | 29 Tangible assets, tangible common equity, tangible common equity ratio, tangible book value per common share, adjusted net earnings, adjusted return on average assets, return on average tangible common equity, adjusted return on average tangible common equity, pre-tax pre-provision (“PTPP”) income, adjusted PTPP income, adjusted noninterest expense, efficiency ratio, adjusted efficiency ratio, adjusted ACL for lower-risk loan portfolio ratio, and economic coverage ratio constitute supplemental financial information determined by methods other than in accordance with GAAP. These non-GAAP measures are used by management in its analysis of the Company's performance. Tangible assets and tangible equity is calculated by subtracting goodwill and other intangible assets from total assets. Tangible common equity is calculated by subtracting preferred stock, as applicable, from tangible equity. Return on average tangible common equity is calculated by dividing net earnings available to common stockholders, after adjustment for amortization of intangible assets and goodwill impairment, by average tangible common equity. Adjusted return on average tangible common equity is calculated by dividing adjusted net earnings available to common stockholders, after adjustment for amortization of intangible assets and goodwill impairment, by average tangible common equity. Banking regulators also exclude goodwill and other intangible assets from stockholders' equity when assessing the capital adequacy of a financial institution. Adjusted net earnings is calculated by adjusting net earnings by unusual, one-time items. ROAA is calculated by dividing annualized net earnings by average assets. Adjusted ROAA is calculated by dividing annualized adjusted net earnings by average assets. PTPP income is calculated by adding net interest income and noninterest income (total revenue) and subtracting noninterest expense. Adjusted PTPP income is calculated by adding net interest income and adjusted noninterest income (adjusted total revenue) and subtracting adjusted noninterest expense. Adjusted noninterest expense is calculated by subtracting acquisition, integration and reorganization costs from total noninterest expense. Adjusted noninterest expense excluding customer related expenses is calculated by subtracting customer related expenses from adjusted noninterest expense. Efficiency ratio is calculated by dividing noninterest expense (less intangible asset amortization and acquisition, integration and reorganization costs) by total revenue (the sum of net interest income and noninterest income, less gain (loss) on sale of securities). Adjusted efficiency ratio is calculated by dividing adjusted noninterest expense (less intangible asset amortization and acquisition, integration and reorganization costs, customer related expenses and any unusual one-item items) by total revenue (the sum of net interest income and noninterest income, less gain (loss) on sale of securities). Economic coverage ratio is calculated by dividing the allowance for credit losses adjusted for the impact of the credit- linked notes and unearned credit mark from purchase accounting by loans and leases held for investment. Adjusted ACL for lower-risk loan portfolio ratio is calculated by dividing adjusted ACL for lower-risk loan portfolios by adjusted loans and leases held for investment. Management believes the presentation of these financial measures adjusting the impact of these items provides useful supplemental information that is essential to a proper understanding of the financial results and operating performance of the Company. This disclosure should not be viewed as a substitute for results determined in accordance with GAAP, nor is it necessarily comparable to non-GAAP performance measures that may be presented by other companies. The following tables on pages 30-37 provide reconciliations of the non-GAAP measures to financial measures defined by GAAP.
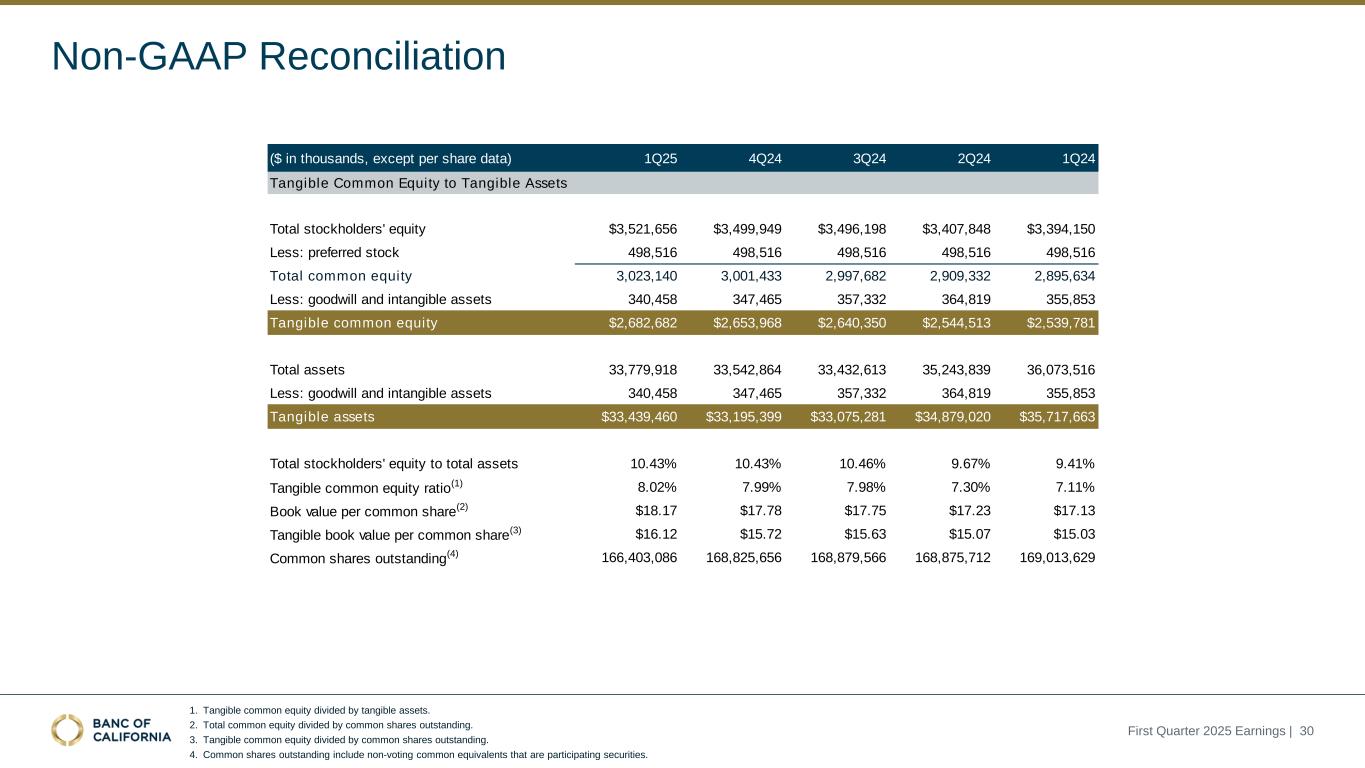
Non-GAAP Reconciliation 1. Tangible common equity divided by tangible assets. 2. Total common equity divided by common shares outstanding. 3. Tangible common equity divided by common shares outstanding. 4. Common shares outstanding include non-voting common equivalents that are participating securities. First Quarter 2025 Earnings | 30 ($ in thousands, except per share data) 1Q25 4Q24 3Q24 2Q24 1Q24 Tangible Common Equity to Tangible Assets Total stockholders' equity $3,521,656 $3,499,949 $3,496,198 $3,407,848 $3,394,150 Less: preferred stock 498,516 498,516 498,516 498,516 498,516 Total common equity 3,023,140 3,001,433 2,997,682 2,909,332 2,895,634 Less: goodwill and intangible assets 340,458 347,465 357,332 364,819 355,853 Tangible common equity $2,682,682 $2,653,968 $2,640,350 $2,544,513 $2,539,781 Total assets 33,779,918 33,542,864 33,432,613 35,243,839 36,073,516 Less: goodwill and intangible assets 340,458 347,465 357,332 364,819 355,853 Tangible assets $33,439,460 $33,195,399 $33,075,281 $34,879,020 $35,717,663 Total stockholders' equity to total assets 10.43% 10.43% 10.46% 9.67% 9.41% Tangible common equity ratio(1) 8.02% 7.99% 7.98% 7.30% 7.11% Book value per common share(2) $18.17 $17.78 $17.75 $17.23 $17.13 Tangible book value per common share(3) $16.12 $15.72 $15.63 $15.07 $15.03 Common shares outstanding(4) 166,403,086 168,825,656 168,879,566 168,875,712 169,013,629
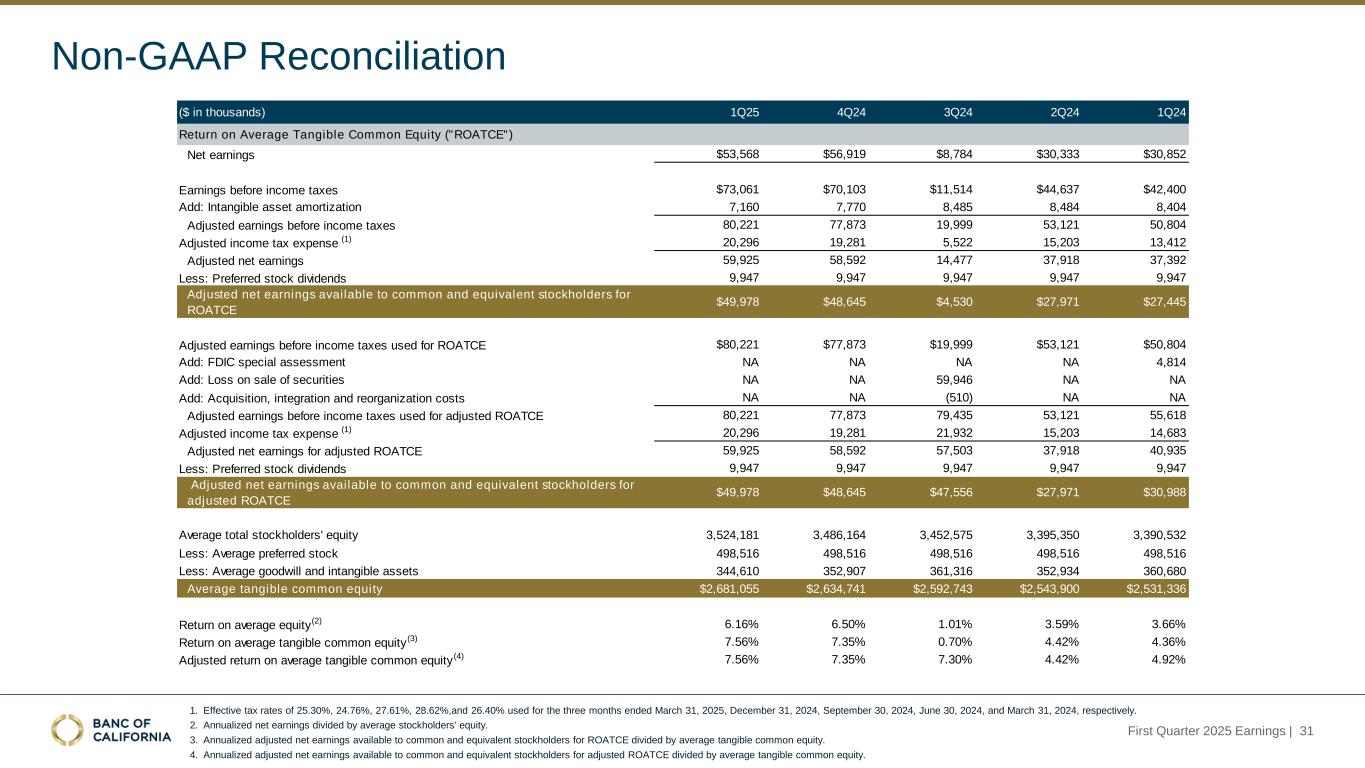
Non-GAAP Reconciliation 1. Effective tax rates of 25.30%, 24.76%, 27.61%, 28.62%,and 26.40% used for the three months ended March 31, 2025, December 31, 2024, September 30, 2024, June 30, 2024, and March 31, 2024, respectively. 2. Annualized net earnings divided by average stockholders' equity. 3. Annualized adjusted net earnings available to common and equivalent stockholders for ROATCE divided by average tangible common equity. 4. Annualized adjusted net earnings available to common and equivalent stockholders for adjusted ROATCE divided by average tangible common equity. First Quarter 2025 Earnings | 31 ($ in thousands) 1Q25 4Q24 3Q24 2Q24 1Q24 Return on Average Tangible Common Equity ("ROATCE") Net earnings $53,568 $56,919 $8,784 $30,333 $30,852 Earnings before income taxes $73,061 $70,103 $11,514 $44,637 $42,400 Add: Intangible asset amortization 7,160 7,770 8,485 8,484 8,404 Adjusted earnings before income taxes 80,221 77,873 19,999 53,121 50,804 Adjusted income tax expense (1) 20,296 19,281 5,522 15,203 13,412 Adjusted net earnings 59,925 58,592 14,477 37,918 37,392 Less: Preferred stock dividends 9,947 9,947 9,947 9,947 9,947 Adjusted net earnings available to common and equivalent stockholders for ROATCE $49,978 $48,645 $4,530 $27,971 $27,445 Adjusted earnings before income taxes used for ROATCE $80,221 $77,873 $19,999 $53,121 $50,804 Add: FDIC special assessment NA NA NA NA 4,814 Add: Loss on sale of securities NA NA 59,946 NA NA Add: Acquisition, integration and reorganization costs NA NA (510) NA NA Adjusted earnings before income taxes used for adjusted ROATCE 80,221 77,873 79,435 53,121 55,618 Adjusted income tax expense (1) 20,296 19,281 21,932 15,203 14,683 Adjusted net earnings for adjusted ROATCE 59,925 58,592 57,503 37,918 40,935 Less: Preferred stock dividends 9,947 9,947 9,947 9,947 9,947 Adjusted net earnings available to common and equivalent stockholders for adjusted ROATCE $49,978 $48,645 $47,556 $27,971 $30,988 Average total stockholders' equity 3,524,181 3,486,164 3,452,575 3,395,350 3,390,532 Less: Average preferred stock 498,516 498,516 498,516 498,516 498,516 Less: Average goodwill and intangible assets 344,610 352,907 361,316 352,934 360,680 Average tangible common equity $2,681,055 $2,634,741 $2,592,743 $2,543,900 $2,531,336 Return on average equity(2) 6.16% 6.50% 1.01% 3.59% 3.66% Return on average tangible common equity (3) 7.56% 7.35% 0.70% 4.42% 4.36% Adjusted return on average tangible common equity (4) 7.56% 7.35% 7.30% 4.42% 4.92%
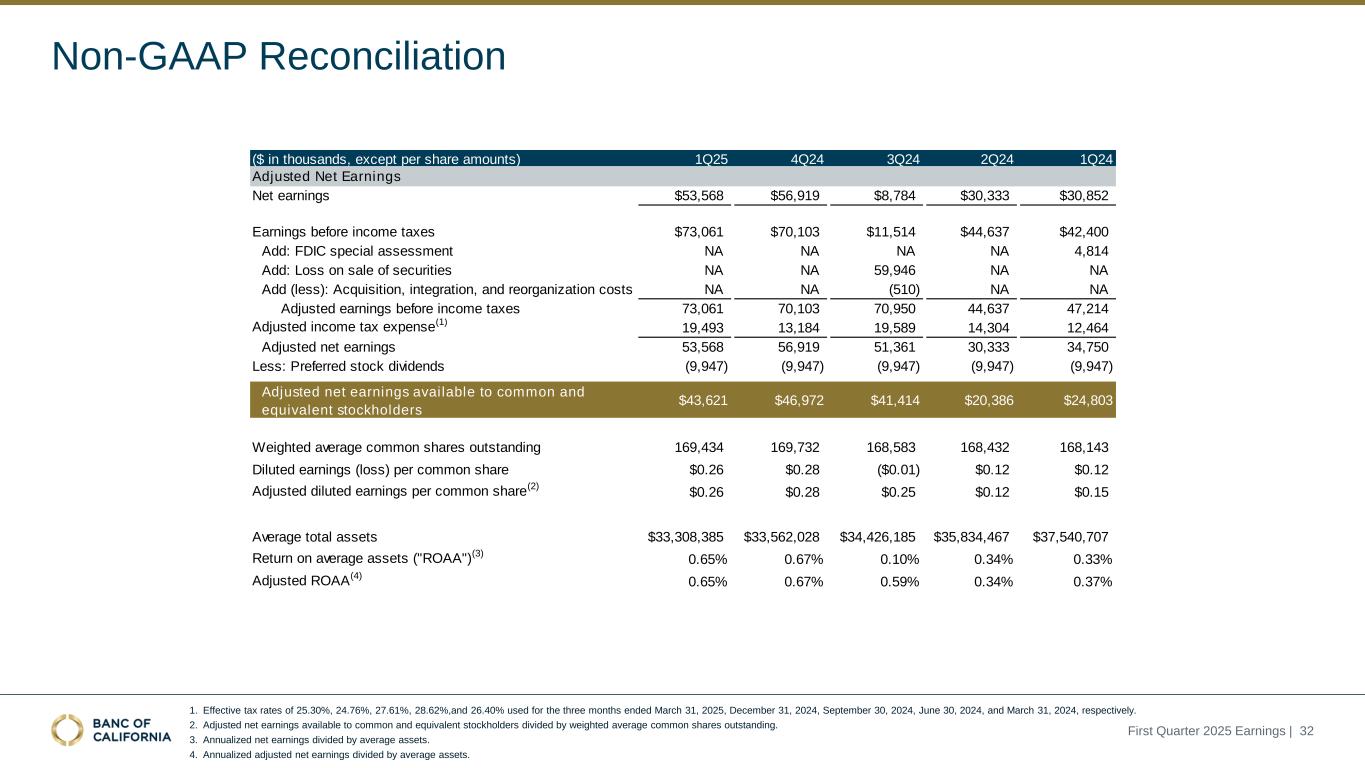
1. Effective tax rates of 25.30%, 24.76%, 27.61%, 28.62%,and 26.40% used for the three months ended March 31, 2025, December 31, 2024, September 30, 2024, June 30, 2024, and March 31, 2024, respectively. 2. Adjusted net earnings available to common and equivalent stockholders divided by weighted average common shares outstanding. 3. Annualized net earnings divided by average assets. 4. Annualized adjusted net earnings divided by average assets. Non-GAAP Reconciliation First Quarter 2025 Earnings | 32 ($ in thousands, except per share amounts) 1Q25 4Q24 3Q24 2Q24 1Q24 Net earnings $53,568 $56,919 $8,784 $30,333 $30,852 Earnings before income taxes $73,061 $70,103 $11,514 $44,637 $42,400 Add: FDIC special assessment NA NA NA NA 4,814 Add: Loss on sale of securities NA NA 59,946 NA NA Add (less): Acquisition, integration, and reorganization costs NA NA (510) NA NA Adjusted earnings before income taxes 73,061 70,103 70,950 44,637 47,214 Adjusted income tax expense(1) 19,493 13,184 19,589 14,304 12,464 Adjusted net earnings 53,568 56,919 51,361 30,333 34,750 Less: Preferred stock dividends (9,947) (9,947) (9,947) (9,947) (9,947) Adjusted net earnings available to common and equivalent stockholders $43,621 $46,972 $41,414 $20,386 $24,803 Weighted average common shares outstanding 169,434 169,732 168,583 168,432 168,143 Diluted earnings (loss) per common share $0.26 $0.28 ($0.01) $0.12 $0.12 Adjusted diluted earnings per common share(2) $0.26 $0.28 $0.25 $0.12 $0.15 Average total assets $33,308,385 $33,562,028 $34,426,185 $35,834,467 $37,540,707 Return on average assets ("ROAA")(3) 0.65% 0.67% 0.10% 0.34% 0.33% Adjusted ROAA(4) 0.65% 0.67% 0.59% 0.34% 0.37% Adjusted Net Earnings
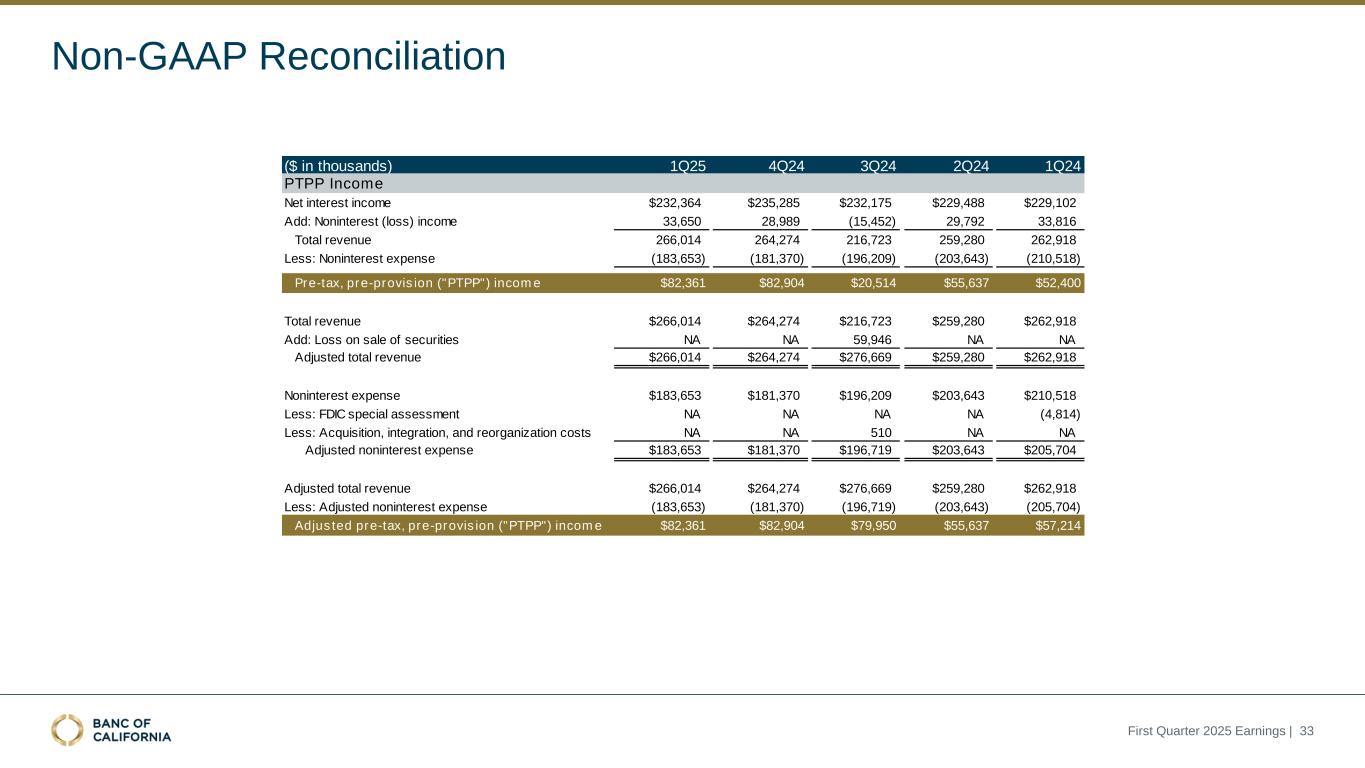
Non-GAAP Reconciliation First Quarter 2025 Earnings | 33 ($ in thousands) 1Q25 4Q24 3Q24 2Q24 1Q24 PTPP Income Net interest income $232,364 $235,285 $232,175 $229,488 $229,102 Add: Noninterest (loss) income 33,650 28,989 (15,452) 29,792 33,816 Total revenue 266,014 264,274 216,723 259,280 262,918 Less: Noninterest expense (183,653) (181,370) (196,209) (203,643) (210,518) Pre-tax, pre-provision ("PTPP") income $82,361 $82,904 $20,514 $55,637 $52,400 Total revenue $266,014 $264,274 $216,723 $259,280 $262,918 Add: Loss on sale of securities NA NA 59,946 NA NA Adjusted total revenue $266,014 $264,274 $276,669 $259,280 $262,918 Noninterest expense $183,653 $181,370 $196,209 $203,643 $210,518 Less: FDIC special assessment NA NA NA NA (4,814) Less: Acquisition, integration, and reorganization costs NA NA 510 NA NA Adjusted noninterest expense $183,653 $181,370 $196,719 $203,643 $205,704 Adjusted total revenue $266,014 $264,274 $276,669 $259,280 $262,918 Less: Adjusted noninterest expense (183,653) (181,370) (196,719) (203,643) (205,704) Adjusted pre-tax, pre-provision ("PTPP") income $82,361 $82,904 $79,950 $55,637 $57,214
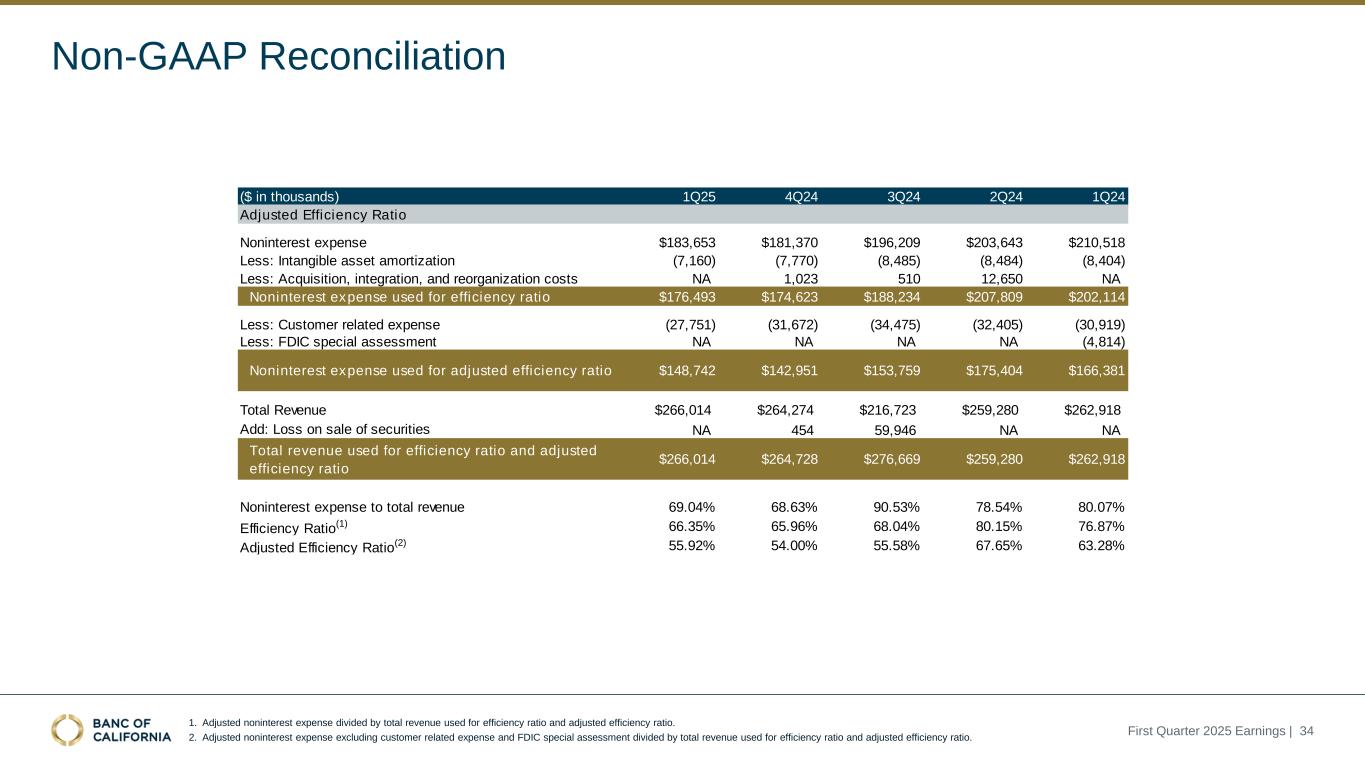
Non-GAAP Reconciliation First Quarter 2025 Earnings | 34 1. Adjusted noninterest expense divided by total revenue used for efficiency ratio and adjusted efficiency ratio. 2. Adjusted noninterest expense excluding customer related expense and FDIC special assessment divided by total revenue used for efficiency ratio and adjusted efficiency ratio. ($ in thousands) 1Q25 4Q24 3Q24 2Q24 1Q24 Noninterest expense $183,653 $181,370 $196,209 $203,643 $210,518 Less: Intangible asset amortization (7,160) (7,770) (8,485) (8,484) (8,404) Less: Acquisition, integration, and reorganization costs NA 1,023 510 12,650 NA Noninterest expense used for efficiency ratio $176,493 $174,623 $188,234 $207,809 $202,114 Less: Customer related expense (27,751) (31,672) (34,475) (32,405) (30,919) Less: FDIC special assessment NA NA NA NA (4,814) Noninterest expense used for adjusted efficiency ratio $148,742 $142,951 $153,759 $175,404 $166,381 Total Revenue $266,014 $264,274 $216,723 $259,280 $262,918 Add: Loss on sale of securities NA 454 59,946 NA NA Total revenue used for efficiency ratio and adjusted efficiency ratio $266,014 $264,728 $276,669 $259,280 $262,918 Noninterest expense to total revenue 69.04% 68.63% 90.53% 78.54% 80.07% Efficiency Ratio(1) 66.35% 65.96% 68.04% 80.15% 76.87% Adjusted Efficiency Ratio(2) 55.92% 54.00% 55.58% 67.65% 63.28% Adjusted Efficiency Ratio
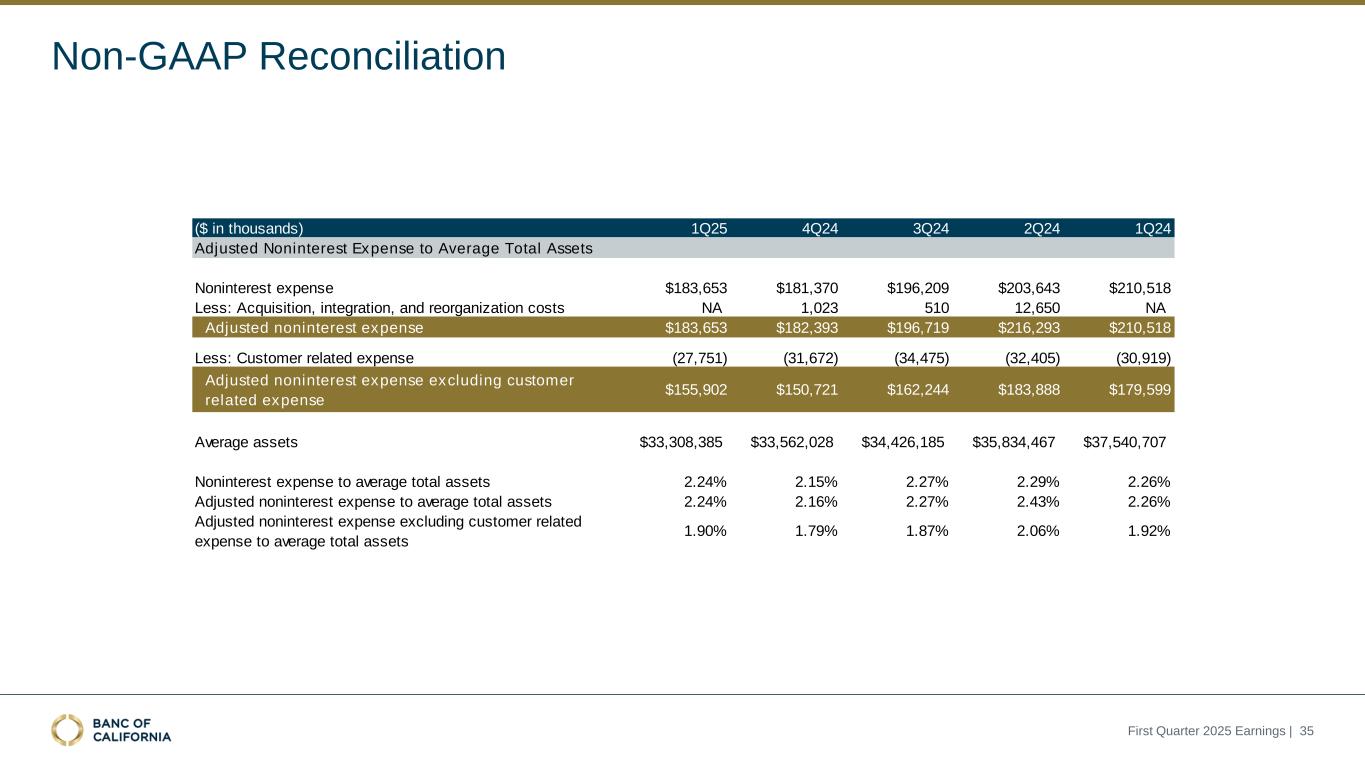
Non-GAAP Reconciliation First Quarter 2025 Earnings | 35 ($ in thousands) 1Q25 4Q24 3Q24 2Q24 1Q24 Noninterest expense $183,653 $181,370 $196,209 $203,643 $210,518 Less: Acquisition, integration, and reorganization costs NA 1,023 510 12,650 NA Adjusted noninterest expense $183,653 $182,393 $196,719 $216,293 $210,518 Less: Customer related expense (27,751) (31,672) (34,475) (32,405) (30,919) Adjusted noninterest expense excluding customer related expense $155,902 $150,721 $162,244 $183,888 $179,599 Average assets $33,308,385 $33,562,028 $34,426,185 $35,834,467 $37,540,707 Noninterest expense to average total assets 2.24% 2.15% 2.27% 2.29% 2.26% Adjusted noninterest expense to average total assets 2.24% 2.16% 2.27% 2.43% 2.26% Adjusted noninterest expense excluding customer related expense to average total assets 1.90% 1.79% 1.87% 2.06% 1.92% Adjusted Noninterest Expense to Average Total Assets
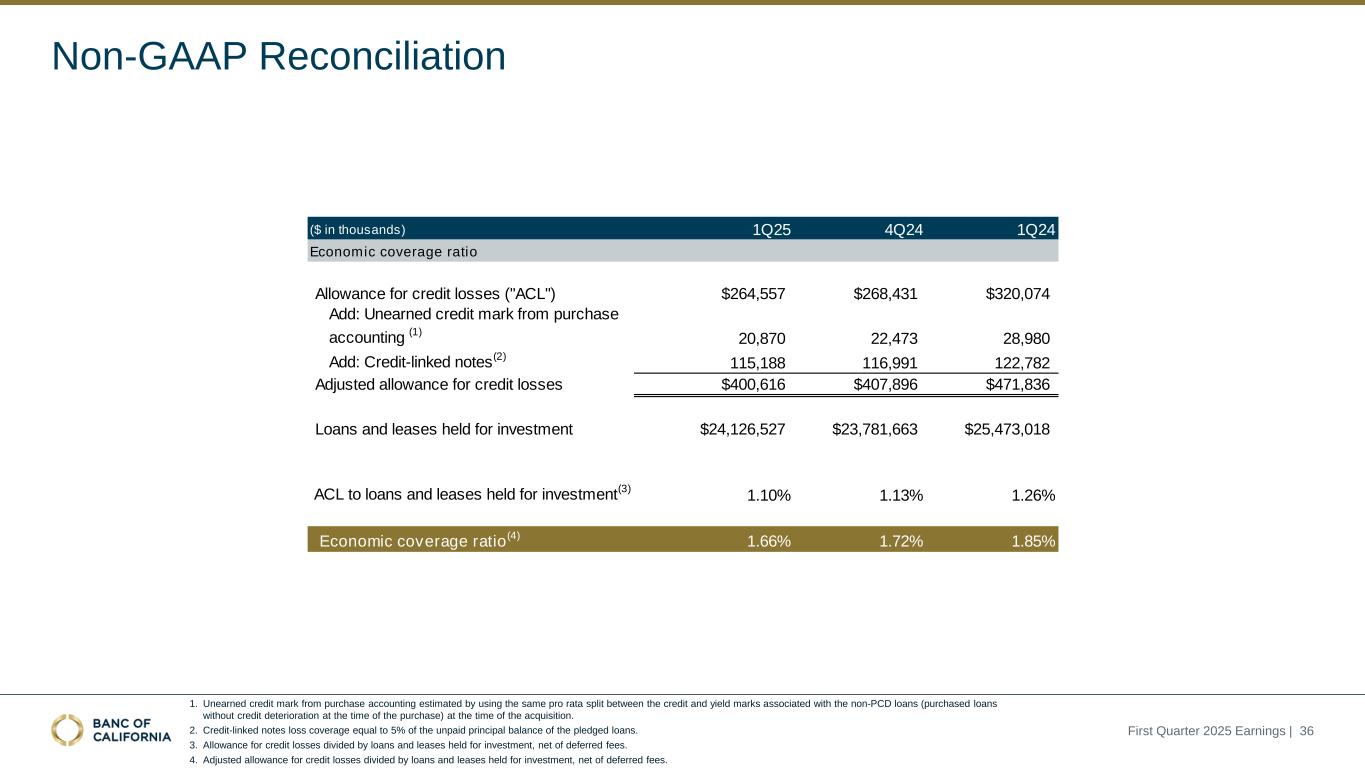
Non-GAAP Reconciliation First Quarter 2025 Earnings | 36 1. Unearned credit mark from purchase accounting estimated by using the same pro rata split between the credit and yield marks associated with the non-PCD loans (purchased loans without credit deterioration at the time of the purchase) at the time of the acquisition. 2. Credit-linked notes loss coverage equal to 5% of the unpaid principal balance of the pledged loans. 3. Allowance for credit losses divided by loans and leases held for investment, net of deferred fees. 4. Adjusted allowance for credit losses divided by loans and leases held for investment, net of deferred fees. ($ in thousands) 1Q25 4Q24 1Q24 Allowance for credit losses ("ACL") $264,557 $268,431 $320,074 Add: Unearned credit mark from purchase accounting (1) 20,870 22,473 28,980 Add: Credit-linked notes(2) 115,188 116,991 122,782 Adjusted allowance for credit losses $400,616 $407,896 $471,836 Loans and leases held for investment $24,126,527 $23,781,663 $25,473,018 ACL to loans and leases held for investment(3) 1.10% 1.13% 1.26% Economic coverage ratio(4) 1.66% 1.72% 1.85% Economic coverage ratio
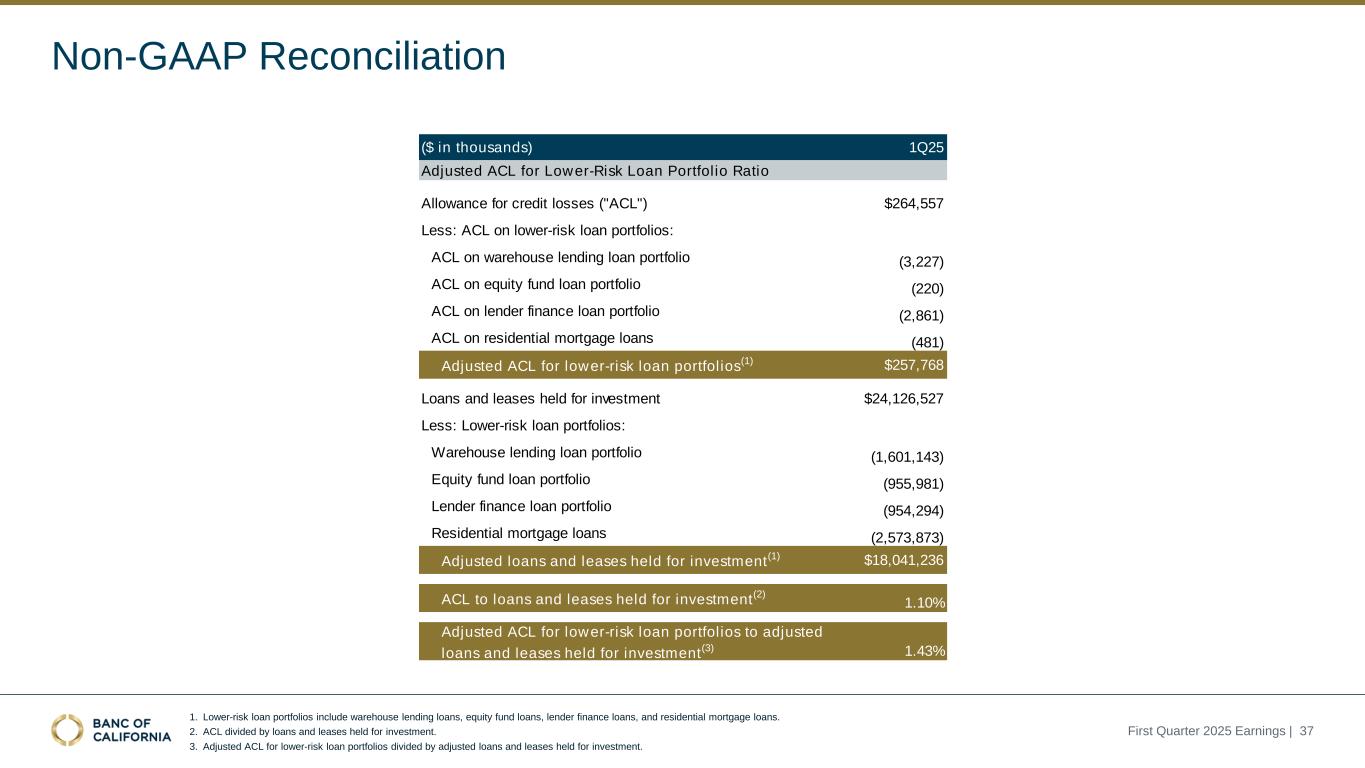
Non-GAAP Reconciliation First Quarter 2025 Earnings | 37 1. Lower-risk loan portfolios include warehouse lending loans, equity fund loans, lender finance loans, and residential mortgage loans. 2. ACL divided by loans and leases held for investment. 3. Adjusted ACL for lower-risk loan portfolios divided by adjusted loans and leases held for investment. ($ in thousands) 1Q25 Allowance for credit losses ("ACL") $264,557 Less: ACL on lower-risk loan portfolios: ACL on warehouse lending loan portfolio (3,227) ACL on equity fund loan portfolio (220) ACL on lender finance loan portfolio (2,861) ACL on residential mortgage loans (481) Adjusted ACL for lower-risk loan portfolios(1) $257,768 $- Loans and leases held for investment $24,126,527 Less: Lower-risk loan portfolios: Warehouse lending loan portfolio (1,601,143) Equity fund loan portfolio (955,981) Lender finance loan portfolio (954,294) Residential mortgage loans (2,573,873) Adjusted loans and leases held for investment(1) $18,041,236 ACL to loans and leases held for investment(2) 1.10% Adjusted ACL for lower-risk loan portfolios to adjusted loans and leases held for investment(3) 1.43% Adjusted ACL for Lower-Risk Loan Portfolio Ratio