
BANR 8-K
Banner Corp (BANR)
8-K
2026-04-22
For: 2026-04-22
View Original
Added on
April 22, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported): April 22, 2026
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) | ||||||||||||
(Address of principal executive offices) (Zip Code)
Registrant's telephone number (including area code) (509 ) 527-3636
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
[
[
[
[
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition.*
On April 22, 2026, Banner Corporation issued its earnings release for the quarter ended March 31, 2026. A copy of the earnings release is furnished herewith as Exhibit 99.1, and is incorporated herein by reference.
Item 7.01 Regulation FD Disclosure.*
Banner Corporation intends to review the investor presentation attached as Exhibit 99.2 to this Current Report on Form 8-K in conjunction with its earnings release conference call on April 23, 2026, and from time to time in presentations to investors and other stakeholders.
Item 8.01 Other Events.
On April 22, 2026, Banner Corporation announced its Board of Directors declared a regular quarterly cash dividend on Banner Corporation common stock of $0.52 per share, payable on May 15, 2026 to stockholders of record as of the close of business on May 5, 2026.
Item 9.01 Financial Statements and Exhibits.*
(d) Exhibits
104 Cover Page Interactive Data File (embedded within the Inline XBRL document)
* The information furnished under Item 2.02, Item 7.01 and Item 9.01 of this Current Report on Form 8-K, including the exhibits, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to liabilities under that Section, nor shall it be deemed incorporated by reference in any registration statement or other filings of Banner Corporation under the Securities Act of 1933, as amended, except as shall be set forth by specific reference in such filing.
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| BANNER CORPORATION | |||||
| Date: April 22, 2026 | By: /s/ Robert G Butterfield | ||||
| Robert G Butterfield | |||||
| Executive Vice President, Treasurer and Chief Financial Officer | |||||
Exhibit 99.1
 |  | CONTACT: | MARK J. GRESCOVICH, | ||||||||
| PRESIDENT & CEO | |||||||||||
| ROBERT G. BUTTERFIELD, CFO | |||||||||||
| (509) 527-3636 | |||||||||||
| NEWS RELEASE | |||||||||||
Banner Corporation Reports Net Income of $54.7 Million, or $1.60 Per Diluted Share, for First Quarter 2026;
Increases Quarterly Cash Dividend Declared by 4% to $0.52 Per Share
Walla Walla, WA - April 22, 2026 - Banner Corporation (NASDAQ GSM: BANR) (“Banner”), the parent company of Banner Bank, today reported net income of $54.7 million, or $1.60 per diluted share, for the first quarter of 2026, compared to $51.2 million, or $1.49 per diluted share, for the preceding quarter, and $45.1 million, or $1.30 per diluted share, for the first quarter of 2025. Net interest income was $150.2 million for the first quarter of 2026, compared to $152.4 million in the preceding quarter and $141.1 million for the first quarter a year ago. Net interest margin expanded by eight basis points to 4.11%, driven by continued reductions in funding costs. The decrease in net interest income compared to the prior quarter primarily reflects two fewer calendar days in the current quarter and a slight decrease in average earning assets, both of which were largely offset by the margin improvement. The increase in net interest income compared to the first quarter a year ago primarily reflects a decrease in overall funding costs and an increase in the average balance of interest-earning assets. First quarter 2026 results included a $796,000 recapture of provision for credit losses, compared to $2.4 million of provision for credit losses in the preceding quarter and $3.1 million of provision for credit losses in the first quarter of 2025.
Banner announced that its Board of Directors increased its regular quarterly cash dividend by 4% to $0.52 per share payable May 15, 2026, to common shareholders of record on May 5, 2026.
“Banner’s first quarter results demonstrate the continued strength of our super community bank strategy, which focuses on building client relationships, preserving a strong funding base, and delivering exceptional service while sustaining a moderate risk profile,” said Mark Grescovich, President and CEO. “Our earnings for the first quarter of 2026 benefited from an improved net interest margin, increased non-interest income and decreased non-interest expense. The strategic investments we have made across the organization are delivering tangible returns and are further strengthening Banner for long-term success. Additionally, Banner’s credit quality remains solid, supported by a well-funded reserve for loan losses and a robust capital position that provides resilience and flexibility for future growth. We also continue to benefit from a strong core deposit base, with core deposits representing 89% of total deposits at quarter-end. For 135 years, Banner has upheld its core values by consistently doing the right thing for our clients, communities, colleagues, company and shareholders. Our long-standing commitment has enabled us to earn trust, navigate change with confidence and continue building a strong foundation for the future.”
At March 31, 2026, Banner, on a consolidated basis, had $16.34 billion in assets, $11.55 billion in net loans and $13.84 billion in deposits. Banner operates 135 full-service branch offices, including branches located in eight of the top 20 largest western Metropolitan Statistical Areas by population.
BANR - First Quarter 2026 Results
April 22, 2026
Page 2
First Quarter 2026 Highlights
•Net interest margin, on a tax equivalent basis, was 4.11% for the current quarter, compared to 4.03% in the preceding quarter and 3.92% in the first quarter a year ago.
•Revenue was $169.3 million for the first quarter of 2026, compared to $167.7 million in the preceding quarter and an increase of 6% from $160.2 million in the first quarter a year ago.
•Net interest income was $150.2 million in the first quarter of 2026, compared to $152.4 million in the preceding quarter and $141.1 million in the first quarter a year ago.
•Mortgage banking operations revenue was $3.2 million for the first quarter of 2026, compared to $3.6 million in the preceding quarter and $3.1 million the first quarter a year ago.
•Return on average assets was 1.37% for the first quarter of 2026, compared to 1.24% in the preceding quarter and 1.15% in the first quarter a year ago.
•Net loans receivable were $11.55 billion at March 31, 2026, compared to $11.56 billion at December 31, 2025, and compared to $11.28 billion at March 31, 2025.
•Total deposits were $13.84 billion at March 31, 2026, compared to $13.74 billion at December 31, 2025 and $13.59 billion at March 31, 2025.
•Core deposits represented 89% of total deposits at March 31, 2026.
•Non-performing assets were $51.7 million, or 0.32% of total assets, at March 31, 2026, compared to $51.2 million, or 0.31% of total assets, at December 31, 2025, and $42.7 million, or 0.26% of total assets, at March 31, 2025.
•The allowance for credit losses - loans was $160.4 million, or 1.37% of total loans receivable, as of March 31, 2026, compared to $160.3 million, or 1.37% of total loans receivable, as of December 31, 2025, and $157.3 million, or 1.38% of total loans receivable, as of March 31, 2025.
•Dividends paid to shareholders were $0.50 per share in the quarter ended March 31, 2026.
•Common shareholders’ equity per share increased 2% to $58.06 at March 31, 2026, compared to $57.08 at the preceding quarter end, and increased 9% from $53.16 at March 31, 2025.
•Tangible common shareholders’ equity per share* increased 2% to $47.00 at March 31, 2026, compared to $46.09 at December 31, 2025, and increased 11% from $42.27 at March 31, 2025.
•Repurchased 250,000 shares of Banner common stock during the first quarter of 2026 at an average price of $64.56 per share.
*Non-GAAP (Generally Accepted Accounting Principles) financial measure; See, “Additional Financial Information - Non-GAAP Financial Measures” on the final two pages of this press release for a reconciliation of non-GAAP financial measures.
Income Statement Review
Net interest income was $150.2 million in the first quarter of 2026, compared to $152.4 million in the preceding quarter and $141.1 million in the first quarter a year ago. Net interest margin, on a tax equivalent basis, increased eight basis points to 4.11% for the first quarter of 2026, compared to 4.03% in the preceding quarter, and increased 19 basis points from 3.92% in the first quarter a year ago. The net interest margin for the current quarter benefited from lower funding costs.
Interest income was $197.8 million in the first quarter of 2026, compared to $205.0 million in the preceding quarter and $193.9 million in the first quarter of 2025. Average yields on interest-earning assets were 5.39% for both the first quarter of 2026 and the preceding quarter. Compared to the first quarter a year ago, average yields on interest-earning assets increased by four basis points from 5.35%, primarily due to increases in the average balance of loans. Average loan yields decreased by three basis points to 6.07% in the first quarter of 2026, compared to 6.10% in the preceding quarter, and was consistent with 6.07% in the first quarter a year ago.
Interest expense was $47.6 million in the first quarter of 2026, compared to $52.5 million in the preceding quarter and $52.8 million in the first quarter a year ago. Total deposit costs decreased by eight basis points to 1.35% in the first quarter of 2026, compared to 1.43% in the preceding quarter, and decreased by 12 basis points compared to 1.47% in the first quarter a year ago. The decrease in deposit costs in the current quarter compared to the prior quarter was primarily due to a decrease in market interest rates, as well as a lower percentage of interest-bearing deposits being held in higher cost certificates of deposits. The decrease in deposit costs in the current quarter compared to the same quarter a year ago was primarily due to the decreases in market interest rates, partially offset by an increase in the average balance of interest-bearing deposits. The average rate paid on borrowings decreased three basis points to 3.90% in the first quarter of 2026, compared to 3.93% in the preceding quarter, and decreased by 42 basis points compared to 4.32% in the first quarter a year ago. The year-over-year decrease was primarily due to declines in both interest rates paid and the average balance of higher costing FHLB advances. The total cost of funding liabilities decreased nine basis points to 1.38% in the first quarter of 2026, compared to 1.47% in the preceding quarter, and decreased 17 basis points from 1.55% in the first quarter a year ago, primarily due to deposit interest rate declines.
A $796,000 recapture of provision for credit losses was recorded in the current quarter (comprised of a $1.3 million provision for credit losses - loans and a $2.1 million recapture of provision for credit losses - unfunded loan commitments). This compares to a $2.4 million provision for credit losses in the prior quarter (comprised of a $1.5 million provision for credit losses - loans and a $945,000 provision for credit losses - unfunded loan commitments) and a $3.1 million provision for credit losses in the first quarter a year ago (comprised of a $4.5 million provision for credit losses - loans and a $1.4 million recapture of provision for credit losses - unfunded loan commitments).
BANR - First Quarter 2026 Results
April 22, 2026
Page 3
Total non-interest income was $19.2 million in the first quarter of 2026, compared to $15.2 million in the preceding quarter and $19.1 million in the first quarter a year ago. The sequential increase was driven primarily by a $3.7 million favorable shift in fair value adjustments on financial instruments. This was partially offset by a $1.2 million net loss on the sale of securities during the current quarter. Compared to the prior year quarter, the slight increase in non-interest income was primarily attributable to an increase in fair value adjustments on financial instruments carried at fair value, partially offset by the net loss recognized on the sale of securities during the current quarter.
Total non-interest expense was $102.6 million in the first quarter of 2026, compared to $104.1 million in the preceding quarter and $101.3 million in the first quarter of 2025. The decrease from the previous quarter reflected a $1.2 million decrease in occupancy and equipment costs, primarily due to lower rent expense as well as lower building repair and maintenance expenses, a $988,000 decrease in professional and legal expenses, primarily due to expenses recognized on a pending legal settlement during the prior quarter and lower audit and regulatory exam expenses, and a $1.0 million decrease in advertising and marketing expense, primarily due to decreases in direct mail marketing and community development expenses. These decreases were partially offset by a $2.3 million increase in salary and employee benefits, resulting from increased medical premiums and payroll tax expenses. The increase compared to the same quarter a year ago primarily reflects increases in salary and employee benefits, partially offset by a decrease in occupancy and equipment costs.
Banner’s efficiency ratio was 60.60% for the first quarter of 2026, compared to 62.11% in the preceding quarter and 63.21% in the same quarter a year ago. Banner’s adjusted efficiency ratio, a non-GAAP financial measure, was 59.45% for the first quarter of 2026, compared to 59.87% in the preceding quarter and 62.18% in the year-ago quarter. See, “Additional Financial Information - Non-GAAP Financial Measures” on the final two pages of this press release for a discussion and reconciliation of non-GAAP financial measures.
Balance Sheet Review
Total assets were $16.34 billion at March 31, 2026, compared to $16.35 billion at December 31, 2025, and $16.17 billion at March 31, 2025. The decrease compared to the prior quarter was primarily due to decreases in both loans held for sale and loans receivable and a reduction in FHLB stock resulting from the repayment of FHLB advances, partially offset by growth in interest-bearing deposits held at other banks. Securities and interest-bearing deposits held at other banks totaled $3.24 billion at March 31, 2026, compared to $3.22 billion at December 31, 2025 and $3.33 billion at March 31, 2025. The average effective duration of the securities portfolio was approximately 6.1 years and 6.5 years at March 31, 2026 and March 31, 2025, respectively.
Total loans receivable were $11.71 billion at March 31, 2026, compared to $11.72 billion at December 31, 2025, and increased from $11.44 billion at March 31, 2025. Commercial real estate loans totaled $4.11 billion at March 31, 2026, an increase of 2% compared to $4.05 billion at December 31, 2025, and an increase of 7% from $3.84 billion at March 31, 2025. The increases from both periods reflected a combination of new loan production and the conversion of commercial construction loans to the commercial real estate portfolio upon completion of the construction phase. Multifamily real estate loans decreased 6% to $798.2 million at March 31, 2026, compared to $850.8 million at December 31, 2025, and decreased 9% from $877.7 million at March 31, 2025. The decreases from both periods were primarily due to payoffs and paydowns. Agricultural business loans decreased 6% to $332.4 million at March 31, 2026, compared to $353.2 million at December 31, 2025, and decreased from $334.9 million at March 31, 2025. The decrease was primarily due to operating line paydowns and payoffs exceeding new production. Consumer loans increased to $774.0 million at March 31, 2026, compared to $768.5 million at December 31, 2025, and increased 8% compared to $717.2 million at March 31, 2025. The increases resulted from both new loan production and advances, primarily related to home equity revolving lines of credit.
Loans held for sale were $33.8 million at March 31, 2026, compared to $42.9 million at December 31, 2025, and $24.5 million at March 31, 2025. One- to four- family residential mortgage held for sale loans sold in the current quarter totaled $132.6 million, compared to $104.2 million in the preceding quarter, and $108.1 million in the first quarter a year ago. The decrease in loans held for sale at March 31, 2026, compared to the preceding quarter, was primarily attributable to higher sales volumes of one- to four-family residential mortgage loans held for sale during the current quarter. The increase in loans held for sale at March 31, 2026, compared to the prior-year quarter, was primarily attributable to increased originations of one- to four- family residential mortgage loans held for sale.
Total deposits were $13.84 billion at March 31, 2026, compared to $13.74 billion at December 31, 2025, and $13.59 billion a year ago. Core deposits increased to $12.38 billion at March 31, 2026, compared to $12.21 billion at December 31, 2025, and $12.09 billion at March 31, 2025. The increase compared to the preceding quarter primarily reflects increases in non-interest-bearing deposits and interest-bearing transaction and savings accounts. The increase compared to the prior year quarter primarily reflects increases in interest-bearing transaction and savings accounts. Core deposits remained stable at 89% of total deposits at March 31, 2026, December 31, 2025 and March 31, 2025. Certificates of deposit decreased 4% to $1.46 billion at March 31, 2026, compared to $1.53 billion at December 31, 2025, and decreased 3% from $1.50 billion a year earlier.
There were no outstanding FHLB advances at March 31, 2026, compared to $150.0 million at December 31, 2025, and $168.0 million a year ago, as the increase in core deposits was used to pay off FHLB advances during the current quarter. At March 31, 2026, off-balance sheet liquidity included additional borrowing capacity of $3.76 billion at the FHLB and $1.74 billion at the Federal Reserve, as well as federal funds line of credit agreements with other financial institutions of $125.0 million.
At March 31, 2026, total common shareholders’ equity was $1.97 billion, or 12.03% of total assets, compared to $1.95 billion, or 11.90% of total assets at December 31, 2025, and $1.83 billion, or 11.34% of total assets at March 31, 2025. The increase in total common shareholders’ equity from December 31, 2025, was primarily attributable to a $37.4 million increase in retained earnings resulting from $54.7 million in net income, partially offset by the accrual of $17.3 million in cash dividends during the first quarter of 2026. In addition, Banner repurchased 250,000 shares of its common stock in the first quarter of 2026 at an average price of $64.56 per share. At March 31, 2026, tangible common shareholders’ equity, a non-GAAP financial measure, was $1.59 billion, or 9.97% of tangible assets, compared to $1.57 billion, or 9.84% of tangible assets, at December 31, 2025, and $1.46 billion, or 9.23% of tangible assets, a year ago. See “Additional Financial Information - Non-GAAP Financial Measures” on the final two pages of this press release for a reconciliation of non-GAAP financial measures.
BANR - First Quarter 2026 Results
April 22, 2026
Page 4
Banner and Banner Bank continue to maintain capital levels in excess of the requirements to be categorized as “well-capitalized.” At March 31, 2026, Banner’s estimated common equity Tier 1 capital ratio was 12.97%, its estimated Tier 1 leverage capital to average assets ratio was 11.68%, and its estimated total capital to risk-weighted assets ratio was 14.85%. These regulatory capital ratios are estimates, pending completion and filing of Banner’s regulatory reports.
Credit Quality
The allowance for credit losses - loans was $160.4 million, or 1.37% of total loans receivable and 353% of non-performing loans, at March 31, 2026, compared to $160.3 million, or 1.37% of total loans receivable and 351% of non-performing loans, at December 31, 2025, and $157.3 million, or 1.38% of total loans receivable and 404% of non-performing loans, at March 31, 2025. The allowance ratio remained stable compared to both prior periods, reflecting consistent portfolio composition and credit performance. Coverage of non-performing loans remained strong at 353% at March 31, 2026, compared to 351% at December 31, 2025. The year-over-year decline from 404% at March 31, 2025 reflects moderate growth in non-performing loans over the past year, from $39.0 million to $45.4 million, while the allowance level has remained stable and commensurate with the portfolio’s risk profile. In addition to the allowance for credit losses - loans, Banner maintains an allowance for credit losses - unfunded loan commitments, which was $12.9 million at March 31, 2026, compared to $15.0 million at December 31, 2025, and $12.2 million at March 31, 2025. Net loan charge-offs remained low at $1.2 million in the first quarter of 2026, compared to net loan charge-offs of $934,000 and $2.7 million in the preceding quarter and first quarter a year ago, respectively. Non-performing loans were $45.4 million at March 31, 2026, compared to $45.6 million at December 31, 2025, and $39.0 million a year ago. Substandard loans were $235.0 million as of March 31, 2026, compared to $193.1 million as of December 31, 2025, and $197.8 million a year ago. Total non-performing assets were $51.7 million, or 0.32% of total assets, at March 31, 2026, compared to $51.2 million, or 0.31% of total assets, at December 31, 2025, and $42.7 million, or 0.26% of total assets, a year ago.
Conference Call
Banner will host a conference call on Thursday, April 23, 2026, at 8:00 a.m. PDT, to discuss its first quarter results. Interested investors may listen to the call live at www.bannerbank.com. Investment professionals are invited to dial (800) 715-9871 to participate in the call. A replay of the call will be available at www.bannerbank.com.
About the Company
Banner Corporation is a $16.34 billion bank holding company operating a commercial bank primarily in Washington, Oregon, California and Idaho through a network of branches offering a full range of deposit services and business, commercial real estate, construction, residential, agricultural and consumer loans. Visit Banner Bank on the Web at www.bannerbank.com.
BANR - First Quarter 2026 Results
April 22, 2026
Page 5
Forward-Looking Statements
When used in this press release and in other documents filed with or furnished to the Securities and Exchange Commission (the “SEC”), in press releases or other public stockholder communications, or in oral statements made with the approval of an authorized executive officer, the words or phrases “may,” “believe,” “will,” “will likely result,” “are expected to,” “will continue,” “is anticipated,” “estimate,” “project,” “plans,” “potential,” or similar expressions are intended to identify “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995. You are cautioned not to place undue reliance on any forward-looking statements, which speak only as of the date such statements are made and based only on information then actually known to Banner. Banner does not undertake and specifically disclaims any obligation to revise any forward-looking statements to reflect the occurrence of anticipated or unanticipated events or circumstances after the date of such statements.
Forward-looking statements may relate to, among other things, future financial performance, strategic plans or objectives, revenues or earnings projections, and other financial or operational information. These statements are inherently subject to numerous risks and uncertainties, including ongoing market volatility and evolving global conditions, which may cause actual results to differ materially from those expressed or implied. These factors include, but are not limited to: (1) adverse impacts to economic conditions in our local market areas, other markets where the Company has lending relationships, or other aspects of the Company’s business operations or financial markets, including, without limitation, as a result of labor shortages, elevated inflation, recessionary pressures, or slowing economic growth; (2) changes in interest rate levels, volatility, and the timing and pace of such changes, including actions by the Federal Reserve, which could materially affect our net interest margin, funding costs, asset values, access to capital and liquidity; (3) the impact of inflation and monetary and fiscal policy responses thereto, and their impact on consumer and business behavior; (4) geopolitical developments and international conflicts, including but not limited to tensions or instability in Eastern Europe, South America, the Middle East, and Asia, or the imposition of new or increased tariffs and trade restrictions, which may disrupt financial markets, global supply chains, commodity prices, or economic activity in specific industry sectors, including, but not limited to, agriculture-based lending; (5) the effects of a federal government shutdown, debt ceiling standoff, or other fiscal policy uncertainty; (6) the impact of bank failures or adverse developments at other banks and related negative publicity about the banking industry in general on investor and depositor sentiment; (7) expectations regarding key growth initiatives and strategic priorities; (8) credit risks from lending activities, including changes in the level and direction of loan delinquencies and write-offs and changes in estimates of the adequacy of the allowance for credit losses, which could necessitate additional provisions for credit losses, resulting both from loans originated and loans acquired from other financial institutions; (9) results of examinations by regulatory authorities, which could result in the imposition of penalties, required changes to our business practices, or additional reserves; (10) competitive pressures among depository and non-depository institutions that adversely affect pricing, market share, deposit flows or product offerings; (11) fluctuations in real estate values; (12) the ability to adapt to rapid technological changes, including advancements in artificial intelligence, digital banking platforms, and cybersecurity; (13) vulnerabilities in information systems or third-party service providers, including disruptions, breaches, or attacks; (14) market volatility or deterioration in capital markets affecting liquidity, valuations, or investor confidence; (15) the costs, effects and outcomes of litigation or other legal proceedings involving the Company; (16) legislation or regulatory changes, including but not limited to shifts in capital requirements, banking regulation, tax laws, or consumer protection laws; (17) climate-related risks and natural disasters, which may affect loan collateral, operations, or compliance obligations; (18) changes in accounting principles, policies or guidelines; (19) the impact of future acquisitions or business combinations, including related goodwill impairment risks and integration challenges; (20) effects of critical accounting policies and judgments, including the use of estimates in determining fair value of certain of our assets, which estimates may prove to be incorrect and result in significant declines in valuation; (21) other economic, competitive, governmental, regulatory, and technological factors affecting our operations, pricing, products and services; and (22) other risks detailed from time to time in Banner’s other reports filed with and furnished to the Securities and Exchange Commission including Banner’s Quarterly Reports on Form 10-Q and Annual Reports on Form 10-K.
BANR - First Quarter 2026 Results
April 22, 2026
Page 6
| RESULTS OF OPERATIONS | Quarters Ended | |||||||||||||||||||
| (in thousands except shares and per share data) | Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | |||||||||||||||||
| INTEREST INCOME: | ||||||||||||||||||||
| Loans receivable | $ | 173,703 | $ | 178,908 | $ | 168,677 | ||||||||||||||
| Mortgage-backed securities | 14,316 | 14,750 | 15,744 | |||||||||||||||||
| Securities and cash equivalents | 9,799 | 11,322 | 9,447 | |||||||||||||||||
| Total interest income | 197,818 | 204,980 | 193,868 | |||||||||||||||||
| INTEREST EXPENSE: | ||||||||||||||||||||
| Deposits | 45,678 | 50,494 | 48,737 | |||||||||||||||||
| Federal Home Loan Bank (FHLB) advances | 40 | 17 | 860 | |||||||||||||||||
| Other borrowings | 697 | 693 | 694 | |||||||||||||||||
Subordinated debt | 1,234 | 1,328 | 2,494 | |||||||||||||||||
| Total interest expense | 47,649 | 52,532 | 52,785 | |||||||||||||||||
| Net interest income | 150,169 | 152,448 | 141,083 | |||||||||||||||||
| (RECAPTURE) PROVISION FOR CREDIT LOSSES | (796) | 2,441 | 3,139 | |||||||||||||||||
| Net interest income after (recapture) provision for credit losses | 150,965 | 150,007 | 137,944 | |||||||||||||||||
| NON-INTEREST INCOME: | ||||||||||||||||||||
| Deposit fees and other service charges | 11,391 | 10,681 | 10,769 | |||||||||||||||||
| Mortgage banking operations | 3,212 | 3,617 | 3,103 | |||||||||||||||||
| Bank-owned life insurance | 2,312 | 2,491 | 2,575 | |||||||||||||||||
| Miscellaneous | 1,826 | 446 | 2,346 | |||||||||||||||||
| 18,741 | 17,235 | 18,793 | ||||||||||||||||||
| Net loss on sale of securities | (1,242) | — | — | |||||||||||||||||
| Net change in valuation of financial instruments carried at fair value | 1,662 | (2,010) | 315 | |||||||||||||||||
| Total non-interest income | 19,161 | 15,225 | 19,108 | |||||||||||||||||
| NON-INTEREST EXPENSE: | ||||||||||||||||||||
| Salary and employee benefits | 67,732 | 65,428 | 64,857 | |||||||||||||||||
| Less capitalized loan origination costs | (3,886) | (4,163) | (3,330) | |||||||||||||||||
| Occupancy and equipment | 10,697 | 11,852 | 12,097 | |||||||||||||||||
| Information and computer data services | 8,313 | 9,041 | 7,628 | |||||||||||||||||
| Payment and card processing services | 6,041 | 6,239 | 5,750 | |||||||||||||||||
| Professional and legal expenses | 1,613 | 2,601 | 2,430 | |||||||||||||||||
| Advertising and marketing | 673 | 1,676 | 590 | |||||||||||||||||
| Deposit insurance | 2,717 | 2,850 | 2,797 | |||||||||||||||||
| State and municipal business and use taxes | 1,820 | 1,751 | 1,454 | |||||||||||||||||
| Real estate operations, net | 109 | (43) | (61) | |||||||||||||||||
| Amortization of core deposit intangibles | 256 | 315 | 456 | |||||||||||||||||
| Miscellaneous | 6,523 | 6,598 | 6,591 | |||||||||||||||||
| Total non-interest expense | 102,608 | 104,145 | 101,259 | |||||||||||||||||
| Income before provision for income taxes | 67,518 | 61,087 | 55,793 | |||||||||||||||||
| PROVISION FOR INCOME TAXES | 12,802 | 9,838 | 10,658 | |||||||||||||||||
| NET INCOME | $ | 54,716 | $ | 51,249 | $ | 45,135 | ||||||||||||||
| Earnings per common share: | ||||||||||||||||||||
| Basic | $ | 1.61 | $ | 1.50 | $ | 1.31 | ||||||||||||||
| Diluted | $ | 1.60 | $ | 1.49 | $ | 1.30 | ||||||||||||||
| Cumulative dividends declared per common share | $ | 0.50 | $ | 0.50 | $ | 0.48 | ||||||||||||||
| Weighted average number of common shares outstanding: | ||||||||||||||||||||
| Basic | 34,039,234 | 34,214,220 | 34,509,815 | |||||||||||||||||
| Diluted | 34,254,587 | 34,408,587 | 34,778,687 | |||||||||||||||||
BANR - First Quarter 2026 Results
April 22, 2026
Page 7
| FINANCIAL CONDITION | Percentage Change | |||||||||||||||||||||||||||||||
| (in thousands except shares and per share data) | Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | Prior Qtr | Prior Yr Qtr | |||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||
| Cash and due from banks | $ | 180,158 | $ | 182,772 | $ | 213,574 | (1) | % | (16) | % | ||||||||||||||||||||||
| Interest-bearing deposits | 259,081 | 239,868 | 228,371 | 8 | % | 13 | % | |||||||||||||||||||||||||
Total cash and cash equivalents | 439,239 | 422,640 | 441,945 | 4 | % | (1) | % | |||||||||||||||||||||||||
Securities - available for sale, amortized cost $2,294,225, $2,271,471 and $2,426,395, respectively | 2,035,021 | 2,016,261 | 2,108,945 | 1 | % | (4) | % | |||||||||||||||||||||||||
Securities - held to maturity, fair value $791,763, $814,668 and $819,261, respectively | 943,688 | 961,196 | 991,796 | (2) | % | (5) | % | |||||||||||||||||||||||||
Total securities | 2,978,709 | 2,977,457 | 3,100,741 | — | % | (4) | % | |||||||||||||||||||||||||
| FHLB stock | 9,809 | 16,476 | 17,286 | (40) | % | (43) | % | |||||||||||||||||||||||||
| Loans held for sale | 33,778 | 42,902 | 24,536 | (21) | % | 38 | % | |||||||||||||||||||||||||
| Loans receivable | 11,707,626 | 11,721,687 | 11,438,796 | — | % | 2 | % | |||||||||||||||||||||||||
| Allowance for credit losses – loans | (160,352) | (160,276) | (157,323) | — | % | 2 | % | |||||||||||||||||||||||||
Net loans receivable | 11,547,274 | 11,561,411 | 11,281,473 | — | % | 2 | % | |||||||||||||||||||||||||
| Accrued interest receivable | 63,736 | 60,525 | 63,987 | 5 | % | — | % | |||||||||||||||||||||||||
| Property and equipment, net | 108,303 | 111,522 | 119,649 | (3) | % | (9) | % | |||||||||||||||||||||||||
| Goodwill | 373,121 | 373,121 | 373,121 | — | % | — | % | |||||||||||||||||||||||||
| Other intangibles, net | 1,235 | 1,491 | 2,602 | (17) | % | (53) | % | |||||||||||||||||||||||||
| Bank-owned life insurance | 321,660 | 319,347 | 313,942 | 1 | % | 2 | % | |||||||||||||||||||||||||
| Operating lease right-of-use assets | 31,056 | 32,736 | 37,134 | (5) | % | (16) | % | |||||||||||||||||||||||||
| Other assets | 436,352 | 434,860 | 394,396 | — | % | 11 | % | |||||||||||||||||||||||||
Total assets | $ | 16,344,272 | $ | 16,354,488 | $ | 16,170,812 | — | % | 1 | % | ||||||||||||||||||||||
| LIABILITIES | ||||||||||||||||||||||||||||||||
| Deposits: | ||||||||||||||||||||||||||||||||
| Non-interest-bearing | $ | 4,532,639 | $ | 4,489,839 | $ | 4,571,598 | 1 | % | (1) | % | ||||||||||||||||||||||
| Interest-bearing transaction and savings accounts | 7,842,911 | 7,721,003 | 7,517,617 | 2 | % | 4 | % | |||||||||||||||||||||||||
| Interest-bearing certificates | 1,464,814 | 1,532,304 | 1,504,050 | (4) | % | (3) | % | |||||||||||||||||||||||||
| Total deposits | 13,840,364 | 13,743,146 | 13,593,265 | 1 | % | 2 | % | |||||||||||||||||||||||||
| Advances from FHLB | — | 150,000 | 168,000 | (100) | % | (100) | % | |||||||||||||||||||||||||
| Other borrowings | 115,723 | 107,715 | 130,588 | 7 | % | (11) | % | |||||||||||||||||||||||||
| Subordinated notes, net | — | — | 80,389 | — | % | (100) | % | |||||||||||||||||||||||||
| Junior subordinated debentures at fair value | 79,472 | 79,151 | 67,711 | — | % | 17 | % | |||||||||||||||||||||||||
| Operating lease liabilities | 33,794 | 35,755 | 40,466 | (5) | % | (16) | % | |||||||||||||||||||||||||
| Accrued expenses and other liabilities | 261,295 | 245,266 | 210,771 | 7 | % | 24 | % | |||||||||||||||||||||||||
| Deferred compensation | 46,990 | 47,158 | 46,169 | — | % | 2 | % | |||||||||||||||||||||||||
| Total liabilities | 14,377,638 | 14,408,191 | 14,337,359 | — | % | — | % | |||||||||||||||||||||||||
| SHAREHOLDERS’ EQUITY | ||||||||||||||||||||||||||||||||
| Common stock | 1,268,298 | 1,282,505 | 1,308,967 | (1) | % | (3) | % | |||||||||||||||||||||||||
| Retained earnings | 909,222 | 871,803 | 772,412 | 4 | % | 18 | % | |||||||||||||||||||||||||
| Accumulated other comprehensive loss | (210,886) | (208,011) | (247,926) | 1 | % | (15) | % | |||||||||||||||||||||||||
| Total shareholders’ equity | 1,966,634 | 1,946,297 | 1,833,453 | 1 | % | 7 | % | |||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 16,344,272 | $ | 16,354,488 | $ | 16,170,812 | — | % | 1 | % | ||||||||||||||||||||||
| Common Shares Issued: | ||||||||||||||||||||||||||||||||
| Shares outstanding at end of period | 33,875,098 | 34,097,856 | 34,489,972 | |||||||||||||||||||||||||||||
Common shareholders’ equity per share (1) | $ | 58.06 | $ | 57.08 | $ | 53.16 | ||||||||||||||||||||||||||
Common shareholders’ tangible equity per share (1) (2) | $ | 47.00 | $ | 46.09 | $ | 42.27 | ||||||||||||||||||||||||||
| Common shareholders’ equity to total assets | 12.03 | % | 11.90 | % | 11.34 | % | ||||||||||||||||||||||||||
Common shareholders’ tangible equity to tangible assets (2) | 9.97 | % | 9.84 | % | 9.23 | % | ||||||||||||||||||||||||||
| Consolidated Tier 1 leverage capital ratio | 11.68 | % | 11.41 | % | 11.22 | % | ||||||||||||||||||||||||||
| (1) | Calculation is based on number of common shares outstanding at the end of the period rather than weighted average shares outstanding. | ||||||||||||||||
| (2) | Common shareholders’ tangible equity and tangible assets exclude goodwill and other intangible assets. These ratios represent non-GAAP financial measures. See, “Additional Financial Information - Non-GAAP Financial Measures” on the final two pages of this press release for a reconciliation of non-GAAP financial measures. | ||||||||||||||||
BANR - First Quarter 2026 Results
April 22, 2026
Page 8
| ADDITIONAL FINANCIAL INFORMATION | ||||||||||||||||||||||||||||||||
| (dollars in thousands) | ||||||||||||||||||||||||||||||||
| LOANS | Percentage Change | |||||||||||||||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | Prior Qtr | Prior Yr Qtr | ||||||||||||||||||||||||||||
| Commercial real estate (CRE): | ||||||||||||||||||||||||||||||||
| Owner-occupied | $ | 1,176,035 | $ | 1,138,298 | $ | 1,020,829 | 3 | % | 15 | % | ||||||||||||||||||||||
| Investment properties | 1,719,220 | 1,701,413 | 1,598,387 | 1 | % | 8 | % | |||||||||||||||||||||||||
| Small balance CRE | 1,218,388 | 1,212,357 | 1,217,458 | — | % | — | % | |||||||||||||||||||||||||
| Multifamily real estate | 798,230 | 850,789 | 877,716 | (6) | % | (9) | % | |||||||||||||||||||||||||
| Construction, land and land development: | ||||||||||||||||||||||||||||||||
| Commercial construction | 174,761 | 156,021 | 146,467 | 12 | % | 19 | % | |||||||||||||||||||||||||
| Multifamily construction | 502,166 | 514,330 | 618,942 | (2) | % | (19) | % | |||||||||||||||||||||||||
| One- to four-family construction | 617,233 | 607,447 | 504,265 | 2 | % | 22 | % | |||||||||||||||||||||||||
| Land and land development | 400,959 | 433,678 | 396,009 | (8) | % | 1 | % | |||||||||||||||||||||||||
| Commercial business: | ||||||||||||||||||||||||||||||||
| Commercial business | 1,231,154 | 1,225,108 | 1,283,754 | — | % | (4) | % | |||||||||||||||||||||||||
| Small business scored | 1,199,913 | 1,187,360 | 1,122,550 | 1 | % | 7 | % | |||||||||||||||||||||||||
| Agricultural business, including secured by farmland: | ||||||||||||||||||||||||||||||||
| Agricultural business, including secured by farmland | 332,440 | 353,152 | 334,899 | (6) | % | (1) | % | |||||||||||||||||||||||||
| One- to four-family residential | 1,563,088 | 1,573,191 | 1,600,283 | (1) | % | (2) | % | |||||||||||||||||||||||||
| Consumer: | ||||||||||||||||||||||||||||||||
| Consumer—home equity revolving lines of credit | 682,692 | 679,489 | 620,483 | — | % | 10 | % | |||||||||||||||||||||||||
| Consumer—other | 91,347 | 89,054 | 96,754 | 3 | % | (6) | % | |||||||||||||||||||||||||
| Total loans receivable | $ | 11,707,626 | $ | 11,721,687 | $ | 11,438,796 | — | % | 2 | % | ||||||||||||||||||||||
| Loans 30 - 89 days past due and on accrual | $ | 30,177 | $ | 26,767 | $ | 37,339 | ||||||||||||||||||||||||||
| Total delinquent loans (including loans on non-accrual), net | $ | 65,632 | $ | 63,093 | $ | 71,927 | ||||||||||||||||||||||||||
| Total delinquent loans / Total loans receivable | 0.56 | % | 0.54 | % | 0.63 | % | ||||||||||||||||||||||||||
| LOANS BY GEOGRAPHIC LOCATION | Percentage Change | |||||||||||||||||||||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | Prior Qtr | Prior Yr Qtr | ||||||||||||||||||||||||||||||||||
| Amount | Percentage | Amount | Amount | |||||||||||||||||||||||||||||||||||
| Washington | $ | 5,313,022 | 45 | % | $ | 5,371,200 | $ | 5,260,906 | (1) | % | 1 | % | ||||||||||||||||||||||||||
| California | 3,159,842 | 27 | % | 3,105,405 | 2,927,835 | 2 | % | 8 | % | |||||||||||||||||||||||||||||
| Oregon | 2,166,750 | 18 | % | 2,159,404 | 2,122,953 | — | % | 2 | % | |||||||||||||||||||||||||||||
| Idaho | 690,608 | 6 | % | 667,343 | 665,625 | 3 | % | 4 | % | |||||||||||||||||||||||||||||
| Utah | 77,046 | 1 | % | 82,594 | 88,858 | (7) | % | (13) | % | |||||||||||||||||||||||||||||
| Other | 300,358 | 3 | % | 335,741 | 372,619 | (11) | % | (19) | % | |||||||||||||||||||||||||||||
| Total loans receivable | $ | 11,707,626 | 100 | % | $ | 11,721,687 | $ | 11,438,796 | — | % | 2 | % | ||||||||||||||||||||||||||
BANR - First Quarter 2026 Results
April 22, 2026
Page 9
ADDITIONAL FINANCIAL INFORMATION
(dollars in thousands)
| LOAN ORIGINATIONS | Quarters Ended | ||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | |||||||||||||||
| Commercial real estate | $ | 220,193 | $ | 136,604 | $ | 37,041 | |||||||||||
| Multifamily real estate | 3,869 | 4,300 | 9,555 | ||||||||||||||
| Construction and land | 323,941 | 362,199 | 287,565 | ||||||||||||||
| Commercial business | 168,324 | 219,592 | 103,739 | ||||||||||||||
| Agricultural business | 22,562 | 28,815 | 12,765 | ||||||||||||||
| One-to four-family residential | 13,416 | 7,219 | 5,139 | ||||||||||||||
| Consumer | 110,913 | 108,578 | 80,030 | ||||||||||||||
| Total loan originations (excluding loans held for sale) | $ | 863,218 | $ | 867,307 | $ | 535,834 | |||||||||||
BANR - First Quarter 2026 Results
April 22, 2026
Page 10
| ADDITIONAL FINANCIAL INFORMATION | ||||||||||||||||||||
| (dollars in thousands) | ||||||||||||||||||||
| CHANGE IN THE ALLOWANCE FOR CREDIT LOSSES – LOANS | Quarters Ended | |||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | ||||||||||||||||||
| Balance, beginning of period | $ | 160,276 | $ | 159,707 | $ | 155,521 | ||||||||||||||
| Provision for credit losses – loans | 1,292 | 1,503 | 4,549 | |||||||||||||||||
| Recoveries of loans previously charged off: | ||||||||||||||||||||
| Commercial real estate | 11 | 48 | 57 | |||||||||||||||||
| Construction and land | 4 | 4 | — | |||||||||||||||||
| One- to four-family real estate | 13 | 14 | 188 | |||||||||||||||||
| Commercial business | 81 | 93 | 557 | |||||||||||||||||
| Agricultural business, including secured by farmland | 4 | 68 | 10 | |||||||||||||||||
| Consumer | 140 | 83 | 119 | |||||||||||||||||
| 253 | 310 | 931 | ||||||||||||||||||
| Loans charged off: | ||||||||||||||||||||
| One- to four-family real estate | — | — | (13) | |||||||||||||||||
| Commercial business | (863) | (837) | (3,301) | |||||||||||||||||
| Consumer | (606) | (407) | (364) | |||||||||||||||||
| (1,469) | (1,244) | (3,678) | ||||||||||||||||||
| Net charge-offs | (1,216) | (934) | (2,747) | |||||||||||||||||
| Balance, end of period | $ | 160,352 | $ | 160,276 | $ | 157,323 | ||||||||||||||
| Net charge-offs / average loans receivable | (0.010) | % | (0.008) | % | (0.024) | % | ||||||||||||||
| ALLOCATION OF ALLOWANCE FOR CREDIT LOSSES – LOANS | Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | |||||||||||||||||
| Commercial real estate | $ | 41,788 | $ | 41,599 | $ | 40,076 | ||||||||||||||
| Multifamily real estate | 9,201 | 9,805 | 10,109 | |||||||||||||||||
| Construction and land | 34,589 | 35,508 | 32,042 | |||||||||||||||||
| One- to four-family real estate | 19,640 | 19,552 | 20,752 | |||||||||||||||||
| Commercial business | 39,452 | 37,785 | 38,665 | |||||||||||||||||
| Agricultural business, including secured by farmland | 4,930 | 5,567 | 5,641 | |||||||||||||||||
| Consumer | 10,752 | 10,460 | 10,038 | |||||||||||||||||
| Total allowance for credit losses – loans | $ | 160,352 | $ | 160,276 | $ | 157,323 | ||||||||||||||
| Allowance for credit losses - loans / Total loans receivable | 1.37 | % | 1.37 | % | 1.38 | % | ||||||||||||||
| Allowance for credit losses - loans / Non-performing loans | 353 | % | 351 | % | 404 | % | ||||||||||||||
| CHANGE IN THE ALLOWANCE FOR CREDIT LOSSES - UNFUNDED LOAN COMMITMENTS | Quarters Ended | ||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | |||||||||||||||
| Balance, beginning of period | $ | 14,985 | $ | 14,040 | $ | 13,562 | |||||||||||
| (Recapture) provision for credit losses - unfunded loan commitments | (2,082) | 945 | (1,400) | ||||||||||||||
| Balance, end of period | $ | 12,903 | $ | 14,985 | $ | 12,162 | |||||||||||
BANR - First Quarter 2026 Results
April 22, 2026
Page 11
| ADDITIONAL FINANCIAL INFORMATION | |||||||||||||||||
| (dollars in thousands) | |||||||||||||||||
| NON-PERFORMING ASSETS | Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | ||||||||||||||
| Loans on non-accrual status: | |||||||||||||||||
| Secured by real estate: | |||||||||||||||||
| Commercial | $ | 2,027 | $ | 525 | $ | 2,182 | |||||||||||
| Construction and land | 4,321 | 5,175 | 4,359 | ||||||||||||||
| One- to four-family | 20,945 | 19,855 | 10,448 | ||||||||||||||
| Commercial business | 6,988 | 6,751 | 6,425 | ||||||||||||||
| Agricultural business, including secured by farmland | 5,511 | 4,609 | 10,301 | ||||||||||||||
| Consumer | 4,214 | 4,610 | 4,874 | ||||||||||||||
| 44,006 | 41,525 | 38,589 | |||||||||||||||
| Loans more than 90 days delinquent, still on accrual: | |||||||||||||||||
| Secured by real estate: | |||||||||||||||||
| Construction and land | — | 1,268 | — | ||||||||||||||
| One- to four-family | 636 | 2,698 | 9 | ||||||||||||||
| Commercial business | — | — | 206 | ||||||||||||||
| Consumer | 795 | 148 | 155 | ||||||||||||||
| 1,431 | 4,114 | 370 | |||||||||||||||
| Total non-performing loans | 45,437 | 45,639 | 38,959 | ||||||||||||||
| REO | 6,248 | 5,578 | 3,468 | ||||||||||||||
| Other repossessed assets | — | 18 | 300 | ||||||||||||||
| Total non-performing assets | $ | 51,685 | $ | 51,235 | $ | 42,727 | |||||||||||
| Total non-performing assets to total assets | 0.32 | % | 0.31 | % | 0.26 | % | |||||||||||
| LOANS BY CREDIT RISK RATING | Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | ||||||||||||||
| Pass | $ | 11,416,687 | $ | 11,446,550 | $ | 11,207,852 | |||||||||||
| Special Mention | 55,981 | 82,060 | 33,133 | ||||||||||||||
| Substandard | 234,958 | 193,077 | 197,811 | ||||||||||||||
| Total | $ | 11,707,626 | $ | 11,721,687 | $ | 11,438,796 | |||||||||||
BANR - First Quarter 2026 Results
April 22, 2026
Page 12
| ADDITIONAL FINANCIAL INFORMATION | ||||||||||||||||||||||||||||||||
| (dollars in thousands) | ||||||||||||||||||||||||||||||||
| DEPOSIT COMPOSITION | Percentage Change | |||||||||||||||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | Prior Qtr | Prior Yr Qtr | ||||||||||||||||||||||||||||
| Non-interest-bearing | $ | 4,532,639 | $ | 4,489,839 | $ | 4,571,598 | 1 | % | (1) | % | ||||||||||||||||||||||
| Interest-bearing checking | 2,628,731 | 2,609,080 | 2,431,279 | 1 | % | 8 | % | |||||||||||||||||||||||||
| Regular savings accounts | 3,859,530 | 3,723,922 | 3,542,005 | 4 | % | 9 | % | |||||||||||||||||||||||||
| Money market accounts | 1,354,650 | 1,388,001 | 1,544,333 | (2) | % | (12) | % | |||||||||||||||||||||||||
| Total interest-bearing transaction and savings accounts | 7,842,911 | 7,721,003 | 7,517,617 | 2 | % | 4 | % | |||||||||||||||||||||||||
| Total core deposits | 12,375,550 | 12,210,842 | 12,089,215 | 1 | % | 2 | % | |||||||||||||||||||||||||
| Interest-bearing certificates | 1,464,814 | 1,532,304 | 1,504,050 | (4) | % | (3) | % | |||||||||||||||||||||||||
| Total deposits | $ | 13,840,364 | $ | 13,743,146 | $ | 13,593,265 | 1 | % | 2 | % | ||||||||||||||||||||||
| GEOGRAPHIC CONCENTRATION OF DEPOSITS | Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | Percentage Change | ||||||||||||||||||||||||||||||||||
| Amount | Percentage | Amount | Amount | Prior Qtr | Prior Yr Qtr | |||||||||||||||||||||||||||||||||
| Washington | $ | 7,429,406 | 54 | % | $ | 7,500,215 | $ | 7,394,201 | (1) | % | — | % | ||||||||||||||||||||||||||
| Oregon | 3,125,040 | 23 | % | 3,035,104 | 3,045,078 | 3 | % | 3 | % | |||||||||||||||||||||||||||||
| California | 2,558,466 | 18 | % | 2,483,948 | 2,463,012 | 3 | % | 4 | % | |||||||||||||||||||||||||||||
| Idaho | 727,452 | 5 | % | 723,879 | 690,974 | — | % | 5 | % | |||||||||||||||||||||||||||||
| Total deposits | $ | 13,840,364 | 100 | % | $ | 13,743,146 | $ | 13,593,265 | 1 | % | 2 | % | ||||||||||||||||||||||||||
| INCLUDED IN TOTAL DEPOSITS | Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | |||||||||||||||||
| Public non-interest-bearing accounts | $ | 146,846 | $ | 138,860 | $ | 146,390 | ||||||||||||||
| Public interest-bearing transaction & savings accounts | 237,776 | 234,669 | 239,707 | |||||||||||||||||
| Public interest-bearing certificates | 36,125 | 34,431 | 24,226 | |||||||||||||||||
| Total public deposits | $ | 420,747 | $ | 407,960 | $ | 410,323 | ||||||||||||||
| Collateralized public deposits | $ | 325,675 | $ | 312,310 | $ | 313,445 | ||||||||||||||
| Total brokered deposits | $ | — | $ | 50,002 | $ | 75,321 | ||||||||||||||
| AVERAGE ACCOUNT BALANCE PER DEPOSIT ACCOUNT | Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | |||||||||||||||||
| Number of deposit accounts | 444,250 | 445,989 | 453,808 | |||||||||||||||||
| Average account balance per account | $ | 32 | $ | 31 | $ | 30 | ||||||||||||||
BANR - First Quarter 2026 Results
April 22, 2026
Page 13
| ADDITIONAL FINANCIAL INFORMATION | ||||||||||||||||||||||||||||||||||||||
| (dollars in thousands) | ||||||||||||||||||||||||||||||||||||||
| ESTIMATED REGULATORY CAPITAL RATIOS AS OF MARCH 31, 2026 | Actual | Minimum to be categorized as "Adequately Capitalized" | Minimum to be categorized as "Well Capitalized" | |||||||||||||||||||||||||||||||||||
| Amount | Ratio | Amount | Ratio | Amount | Ratio | |||||||||||||||||||||||||||||||||
| Banner Corporation-consolidated: | ||||||||||||||||||||||||||||||||||||||
| Total capital to risk-weighted assets | $ | 2,055,876 | 14.85 | % | $ | 1,107,753 | 8.00 | % | $ | 1,384,692 | 10.00 | % | ||||||||||||||||||||||||||
| Tier 1 capital to risk-weighted assets | 1,882,784 | 13.60 | % | 830,815 | 6.00 | % | 830,815 | 6.00 | % | |||||||||||||||||||||||||||||
| Tier 1 leverage capital to average assets | 1,882,784 | 11.68 | % | 644,575 | 4.00 | % | n/a | n/a | ||||||||||||||||||||||||||||||
| Common equity tier 1 capital to risk-weighted assets | 1,796,284 | 12.97 | % | 623,111 | 4.50 | % | n/a | n/a | ||||||||||||||||||||||||||||||
| Banner Bank: | ||||||||||||||||||||||||||||||||||||||
| Total capital to risk-weighted assets | 1,959,652 | 14.16 | % | 1,107,375 | 8.00 | % | 1,384,219 | 10.00 | % | |||||||||||||||||||||||||||||
| Tier 1 capital to risk-weighted assets | 1,786,618 | 12.91 | % | 830,531 | 6.00 | % | 1,107,375 | 8.00 | % | |||||||||||||||||||||||||||||
| Tier 1 leverage capital to average assets | 1,786,618 | 11.09 | % | 644,332 | 4.00 | % | 805,415 | 5.00 | % | |||||||||||||||||||||||||||||
| Common equity tier 1 capital to risk-weighted assets | 1,786,618 | 12.91 | % | 622,898 | 4.50 | % | 899,742 | 6.50 | % | |||||||||||||||||||||||||||||
These regulatory capital ratios are estimates, pending completion and filing of Banner’s regulatory reports.
BANR - First Quarter 2026 Results
April 22, 2026
Page 14
| ADDITIONAL FINANCIAL INFORMATION | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| (rates / ratios annualized) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| ANALYSIS OF NET INTEREST SPREAD | Quarters Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Balance | Interest and Dividends | Yield / Cost (3) | Average Balance | Interest and Dividends | Yield / Cost (3) | Average Balance | Interest and Dividends | Yield / Cost (3) | |||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Held for sale loans | $ | 26,051 | $ | 381 | 5.93 | % | $ | 31,892 | $ | 487 | 6.06 | % | $ | 22,457 | $ | 357 | 6.45 | % | |||||||||||||||||||||||||||||||||||
| Real estate secured loans | 9,754,431 | 144,369 | 6.00 | % | 9,759,170 | 148,310 | 6.03 | % | 9,366,213 | 137,724 | 5.96 | % | |||||||||||||||||||||||||||||||||||||||||
Commercial/agricultural loans | 1,853,248 | 29,153 | 6.38 | % | 1,877,966 | 30,430 | 6.43 | % | 1,907,212 | 30,752 | 6.54 | % | |||||||||||||||||||||||||||||||||||||||||
Consumer and other loans | 116,147 | 2,040 | 7.12 | % | 119,212 | 2,076 | 6.91 | % | 121,492 | 2,092 | 6.98 | % | |||||||||||||||||||||||||||||||||||||||||
Total loans (1) | 11,749,877 | 175,943 | 6.07 | % | 11,788,240 | 181,303 | 6.10 | % | 11,417,374 | 170,925 | 6.07 | % | |||||||||||||||||||||||||||||||||||||||||
Mortgage-backed securities | 2,326,123 | 14,509 | 2.53 | % | 2,379,784 | 14,943 | 2.49 | % | 2,542,983 | 15,895 | 2.53 | % | |||||||||||||||||||||||||||||||||||||||||
Other securities | 878,650 | 9,040 | 4.17 | % | 869,066 | 9,141 | 4.17 | % | 902,732 | 9,687 | 4.35 | % | |||||||||||||||||||||||||||||||||||||||||
Interest-bearing deposits with banks | 184,204 | 1,518 | 3.34 | % | 293,188 | 2,786 | 3.77 | % | 65,758 | 484 | 2.99 | % | |||||||||||||||||||||||||||||||||||||||||
FHLB stock | 9,912 | 148 | 6.06 | % | 9,849 | 300 | 12.08 | % | 12,804 | 149 | 4.72 | % | |||||||||||||||||||||||||||||||||||||||||
| Total investment securities | 3,398,889 | 25,215 | 3.01 | % | 3,551,887 | 27,170 | 3.03 | % | 3,524,277 | 26,215 | 3.02 | % | |||||||||||||||||||||||||||||||||||||||||
Total interest-earning assets | 15,148,766 | 201,158 | 5.39 | % | 15,340,127 | 208,473 | 5.39 | % | 14,941,651 | 197,140 | 5.35 | % | |||||||||||||||||||||||||||||||||||||||||
| Non-interest-earning assets | 1,106,533 | 1,081,392 | 1,006,497 | ||||||||||||||||||||||||||||||||||||||||||||||||||
Total assets | $ | 16,255,299 | $ | 16,421,519 | $ | 15,948,148 | |||||||||||||||||||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Interest-bearing checking accounts | $ | 2,631,917 | 9,273 | 1.43 | % | $ | 2,671,378 | 10,550 | 1.57 | % | $ | 2,381,106 | 8,537 | 1.45 | % | ||||||||||||||||||||||||||||||||||||||
Savings accounts | 3,792,427 | 18,388 | 1.97 | % | 3,739,496 | 19,623 | 2.08 | % | 3,450,908 | 18,103 | 2.13 | % | |||||||||||||||||||||||||||||||||||||||||
Money market accounts | 1,387,870 | 6,151 | 1.80 | % | 1,430,674 | 6,926 | 1.92 | % | 1,555,262 | 7,860 | 2.05 | % | |||||||||||||||||||||||||||||||||||||||||
Certificates of deposit | 1,481,349 | 11,866 | 3.25 | % | 1,539,845 | 13,395 | 3.45 | % | 1,531,428 | 14,237 | 3.77 | % | |||||||||||||||||||||||||||||||||||||||||
Total interest-bearing deposits | 9,293,563 | 45,678 | 1.99 | % | 9,381,393 | 50,494 | 2.14 | % | 8,918,704 | 48,737 | 2.22 | % | |||||||||||||||||||||||||||||||||||||||||
Non-interest-bearing deposits | 4,470,629 | — | — | % | 4,584,612 | — | — | % | 4,526,596 | — | — | % | |||||||||||||||||||||||||||||||||||||||||
Total deposits | 13,764,192 | 45,678 | 1.35 | % | 13,966,005 | 50,494 | 1.43 | % | 13,445,300 | 48,737 | 1.47 | % | |||||||||||||||||||||||||||||||||||||||||
| Other interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
FHLB advances | 4,089 | 40 | 3.97 | % | 1,630 | 17 | 4.14 | % | 75,300 | 860 | 4.63 | % | |||||||||||||||||||||||||||||||||||||||||
Other borrowings | 111,569 | 697 | 2.53 | % | 114,685 | 693 | 2.40 | % | 134,761 | 694 | 2.09 | % | |||||||||||||||||||||||||||||||||||||||||
Junior subordinated debentures and subordinated notes | 89,178 | 1,234 | 5.61 | % | 89,178 | 1,328 | 5.91 | % | 169,678 | 2,494 | 5.96 | % | |||||||||||||||||||||||||||||||||||||||||
Total borrowings | 204,836 | 1,971 | 3.90 | % | 205,493 | 2,038 | 3.93 | % | 379,739 | 4,048 | 4.32 | % | |||||||||||||||||||||||||||||||||||||||||
Total funding liabilities | 13,969,028 | 47,649 | 1.38 | % | 14,171,498 | 52,532 | 1.47 | % | 13,825,039 | 52,785 | 1.55 | % | |||||||||||||||||||||||||||||||||||||||||
Other non-interest-bearing liabilities (2) | 320,808 | 324,492 | 324,031 | ||||||||||||||||||||||||||||||||||||||||||||||||||
Total liabilities | 14,289,836 | 14,495,990 | 14,149,070 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 1,965,463 | 1,925,529 | 1,799,078 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 16,255,299 | $ | 16,421,519 | $ | 15,948,148 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income/rate spread (tax equivalent) | 153,509 | 4.01 | % | 155,941 | 3.92 | % | 144,355 | 3.80 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin (tax equivalent) | 4.11 | % | 4.03 | % | 3.92 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Reconciliation to reported net interest income: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Adjustments for taxable equivalent basis | (3,340) | (3,493) | (3,272) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income and margin, as reported | $ | 150,169 | 4.02 | % | $ | 152,448 | 3.94 | % | $ | 141,083 | 3.83 | % | |||||||||||||||||||||||||||||||||||||||||
| Additional Key Financial Ratios: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Return on average assets | 1.37 | % | 1.24 | % | 1.15 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Adjusted return on average assets (4) | 1.36 | % | 1.29 | % | 1.14 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Return on average equity | 11.29 | % | 10.56 | % | 10.17 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Adjusted return on average equity (4) | 11.23 | % | 10.97 | % | 10.12 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Return on average tangible common equity (4) | 14.00 | % | 13.17 | % | 12.96 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Average equity/average assets | 12.09 | % | 11.73 | % | 11.28 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Average interest-earning assets/average interest-bearing liabilities | 159.49 | % | 160.01 | % | 160.69 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Average interest-earning assets/average funding liabilities | 108.45 | % | 108.25 | % | 108.08 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest income/average assets | 0.48 | % | 0.37 | % | 0.49 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest expense/average assets | 2.56 | % | 2.52 | % | 2.57 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 60.60 | % | 62.11 | % | 63.21 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Adjusted efficiency ratio (4) | 59.45 | % | 59.87 | % | 62.18 | % | |||||||||||||||||||||||||||||||||||||||||||||||
(1)Average balances include loans accounted for on a nonaccrual basis and accruing loans 90 days or more past due. Amortization of net deferred loan fees/costs is included with interest on loans.
(2)Average other non-interest-bearing liabilities include fair value adjustments related to junior subordinated debentures.
(3)Tax-exempt income is calculated on a tax equivalent basis, which Banner believes provides comparability of net interest income and net interest margin arising from both taxable and tax-exempt sources and is consistent with industry practice. The tax equivalent yield adjustment to interest earned on loans was $2.2 million, $2.4 million and $2.2 million for the quarters ended March 31, 2026, December 31, 2025 and March 31, 2025, respectively. The tax equivalent yield adjustment to interest earned on tax exempt securities was $1.1 million for both the quarters ended March 31, 2026 and December 31, 2025 and $1.0 million for the quarter ended March 31, 2025.
(4)Represent non-GAAP financial measures. See, “Additional Financial Information - Non-GAAP Financial Measures” on the final two pages of this press release for a reconciliation of non-GAAP financial measures.
BANR - First Quarter 2026 Results
April 22, 2026
Page 15
| ADDITIONAL FINANCIAL INFORMATION | |||||||||||||||||
| (dollars in thousands) | |||||||||||||||||
| * Non-GAAP Financial Measures | |||||||||||||||||
| In addition to results presented in accordance with generally accepted accounting principles in the United States of America (GAAP), this earnings release contains certain non-GAAP financial measures. Tangible common shareholders’ equity per share, the ratio of tangible common equity to tangible assets and the return on average tangible common equity, and references to adjusted revenue, adjusted earnings, the adjusted return on average assets, the adjusted return on average equity and the adjusted efficiency ratio represent non-GAAP financial measures. Management has presented these non-GAAP financial measures in this earnings release because it believes that they provide useful and comparative information to assess trends in Banner’s core operations reflected in the current quarter’s results and facilitate the comparison of our performance with the performance of our peers. However, these non-GAAP financial measures are supplemental and are not a substitute for any analysis based on GAAP. Where applicable, comparable earnings information using GAAP financial measures is also presented. Because not all companies use the same calculations, our presentation may not be comparable to other similarly titled measures as calculated by other companies. For a reconciliation of these non-GAAP financial measures, see the tables below: | |||||||||||||||||
| ADJUSTED REVENUE | Quarters Ended | ||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | |||||||||||||||
| Net interest income (GAAP) | $ | 150,169 | $ | 152,448 | $ | 141,083 | |||||||||||
| Non-interest income (GAAP) | 19,161 | 15,225 | 19,108 | ||||||||||||||
| Total revenue (GAAP) | 169,330 | 167,673 | 160,191 | ||||||||||||||
| Exclude: Net loss on sale of securities | 1,242 | — | — | ||||||||||||||
| Net change in valuation of financial instruments carried at fair value | (1,662) | 2,010 | (315) | ||||||||||||||
| Losses incurred on building and lease exits | — | 169 | — | ||||||||||||||
| Adjusted revenue (non-GAAP) | $ | 168,910 | $ | 169,852 | $ | 159,876 | |||||||||||
| ADJUSTED EARNINGS | Quarters Ended | ||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | |||||||||||||||
| Net income (GAAP) | $ | 54,716 | $ | 51,249 | $ | 45,135 | |||||||||||
| Exclude: Net loss on sale of securities | 1,242 | — | — | ||||||||||||||
| Net change in valuation of financial instruments carried at fair value | (1,662) | 2,010 | (315) | ||||||||||||||
| Building and lease exit costs | 9 | 603 | — | ||||||||||||||
| Related net tax expense (benefit) | 99 | (627) | 76 | ||||||||||||||
| Total adjusted earnings (non-GAAP) | $ | 54,404 | $ | 53,235 | $ | 44,896 | |||||||||||
| Diluted earnings per share (GAAP) | $ | 1.60 | $ | 1.49 | $ | 1.30 | |||||||||||
| Diluted adjusted earnings per share (non-GAAP) | $ | 1.59 | $ | 1.55 | $ | 1.29 | |||||||||||
| Return on average assets | 1.37 | % | 1.24 | % | 1.15 | % | |||||||||||
Adjusted return on average assets (1) | 1.36 | % | 1.29 | % | 1.14 | % | |||||||||||
| Return on average equity | 11.29 | % | 10.56 | % | 10.17 | % | |||||||||||
Adjusted return on average equity (2) | 11.23 | % | 10.97 | % | 10.12 | % | |||||||||||
| AVERAGE TANGIBLE COMMON EQUITY | Quarters Ended | ||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | |||||||||||||||
| Net Income (GAAP) | $ | 54,716 | $ | 51,249 | $ | 45,135 | |||||||||||
| Exclude: Amortization of intangibles, net of tax | $ | 202 | $ | 249 | $ | 360 | |||||||||||
| Tangible net income available to common shareholders (non-GAAP) | $ | 54,918 | $ | 51,498 | $ | 45,495 | |||||||||||
| Average common shareholder’s equity | $ | 1,965,463 | $ | 1,925,529 | $ | 1,799,078 | |||||||||||
| Exclude: Average goodwill and other intangible assets, net | 374,477 | 374,764 | 375,943 | ||||||||||||||
| Average tangible common equity | $ | 1,590,986 | $ | 1,550,765 | $ | 1,423,135 | |||||||||||
Return on average tangible common equity (3) | 14.00 | % | 13.17 | % | 12.96 | % | |||||||||||
(1)Adjusted earnings (non-GAAP) divided by average assets.
(2)Adjusted earnings (non-GAAP) divided by average equity.
(3)Tangible net income (non-GAAP) divided by average tangible common equity (non-GAAP).
BANR - First Quarter 2026 Results
April 22, 2026
Page 16
| ADDITIONAL FINANCIAL INFORMATION | ||||||||||||||||||||
| (dollars in thousands) | ||||||||||||||||||||
| ADJUSTED EFFICIENCY RATIO | Quarters Ended | |||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | ||||||||||||||||||
| Non-interest expense (GAAP) | $ | 102,608 | $ | 104,145 | $ | 101,259 | ||||||||||||||
| Exclude: CDI amortization | (256) | (315) | (456) | |||||||||||||||||
| State/municipal tax expense | (1,820) | (1,751) | (1,454) | |||||||||||||||||
| REO operations | (109) | 43 | 61 | |||||||||||||||||
| Building and lease exit costs | (9) | (434) | — | |||||||||||||||||
| Adjusted non-interest expense (non-GAAP) | $ | 100,414 | $ | 101,688 | $ | 99,410 | ||||||||||||||
| Net interest income (GAAP) | $ | 150,169 | $ | 152,448 | $ | 141,083 | ||||||||||||||
| Non-interest income (GAAP) | 19,161 | 15,225 | 19,108 | |||||||||||||||||
| Total revenue (GAAP) | 169,330 | 167,673 | 160,191 | |||||||||||||||||
| Exclude: Net loss on sale of securities | 1,242 | — | — | |||||||||||||||||
| Net change in valuation of financial instruments carried at fair value | (1,662) | 2,010 | (315) | |||||||||||||||||
| Losses incurred on building and lease exits | — | 169 | — | |||||||||||||||||
| Adjusted revenue (non-GAAP) | $ | 168,910 | $ | 169,852 | $ | 159,876 | ||||||||||||||
| Efficiency ratio (GAAP) | 60.60 | % | 62.11 | % | 63.21 | % | ||||||||||||||
Adjusted efficiency ratio (non-GAAP) (1) | 59.45 | % | 59.87 | % | 62.18 | % | ||||||||||||||
(1)Adjusted non-interest expense (non-GAAP) divided by adjusted revenue (non-GAAP).
| TANGIBLE COMMON SHAREHOLDERS’ EQUITY TO TANGIBLE ASSETS | ||||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Mar 31, 2025 | ||||||||||||||||||
| Shareholders’ equity (GAAP) | $ | 1,966,634 | $ | 1,946,297 | $ | 1,833,453 | ||||||||||||||
| Exclude goodwill and other intangible assets, net | 374,356 | 374,612 | 375,723 | |||||||||||||||||
| Tangible common shareholders’ equity (non-GAAP) | $ | 1,592,278 | $ | 1,571,685 | $ | 1,457,730 | ||||||||||||||
| Total assets (GAAP) | $ | 16,344,272 | $ | 16,354,488 | $ | 16,170,812 | ||||||||||||||
| Exclude goodwill and other intangible assets, net | 374,356 | 374,612 | 375,723 | |||||||||||||||||
| Total tangible assets (non-GAAP) | $ | 15,969,916 | $ | 15,979,876 | $ | 15,795,089 | ||||||||||||||
| Common shareholders’ equity to total assets (GAAP) | 12.03 | % | 11.90 | % | 11.34 | % | ||||||||||||||
| Tangible common shareholders’ equity to tangible assets (non-GAAP) | 9.97 | % | 9.84 | % | 9.23 | % | ||||||||||||||
| TANGIBLE COMMON SHAREHOLDERS’ EQUITY PER SHARE | ||||||||||||||||||||
| Shareholders’ equity (GAAP) | $ | 1,966,634 | $ | 1,946,297 | $ | 1,833,453 | ||||||||||||||
| Tangible common shareholders’ equity (non-GAAP) | $ | 1,592,278 | $ | 1,571,685 | $ | 1,457,730 | ||||||||||||||
| Common shares outstanding at end of period | 33,875,098 | 34,097,856 | 34,489,972 | |||||||||||||||||
| Common shareholders’ equity (book value) per share (GAAP) | $ | 58.06 | $ | 57.08 | $ | 53.16 | ||||||||||||||
| Tangible common shareholders’ equity (tangible book value) per share (non-GAAP) | $ | 47.00 | $ | 46.09 | $ | 42.27 | ||||||||||||||
F i r s t Q u a r t e r 2 0 2 6 Since 1890
Disclosure Statement 1 This presentation includes forward-looking statements. These statements include descriptions of management’s plans, objectives or goals for future operations, products or services, forecast of financial or other performance measures and statements about Banner’s general outlook for economic and other conditions. Additional forward-looking statements may be made in the question-and-answer period following the presentation. These forward-looking statements are subject to several risks and uncertainties and actual results may differ materially from those discussed today. Information on the risk factors that could cause actual results to differ are available from the earnings press release that was released April 22, 2026 as well as the Form 10-K for the year ended December 31, 2025. Forward-looking statements are effective only as of the date they are made, and Banner assumes no obligation to update information concerning its expectations.
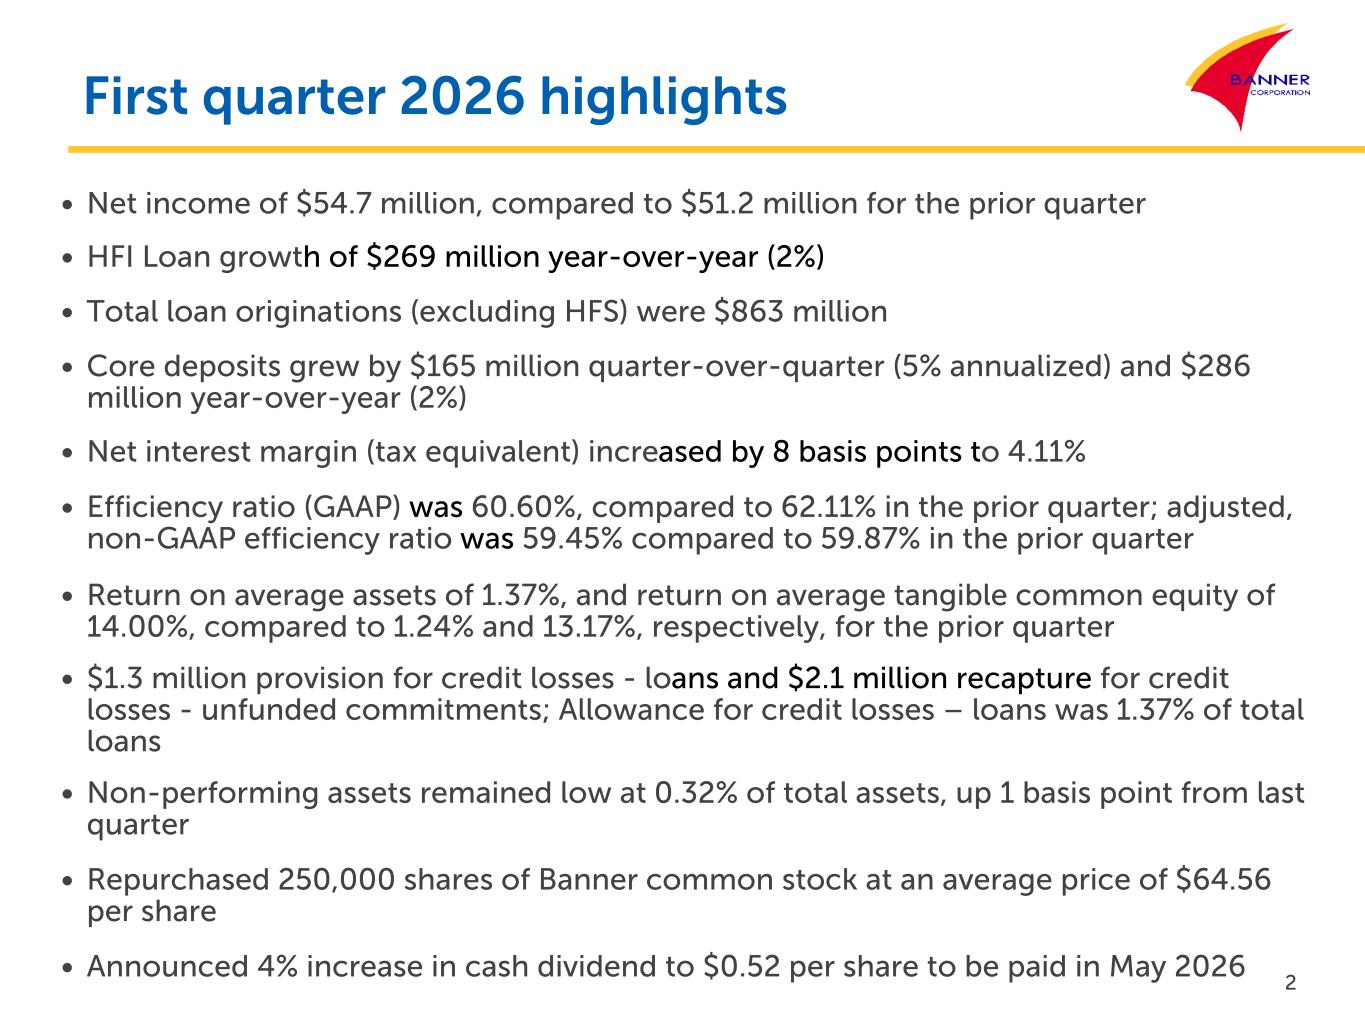
First quarter 2026 highlights 2 • Net income of $54.7 million, compared to $51.2 million for the prior quarter • HFI Loan growth of $269 million year-over-year (2%) • Total loan originations (excluding HFS) were $863 million • Core deposits grew by $165 million quarter-over-quarter (5% annualized) and $286 million year-over-year (2%) • Net interest margin (tax equivalent) increased by 8 basis points to 4.11% • Efficiency ratio (GAAP) was 60.60%, compared to 62.11% in the prior quarter; adjusted, non-GAAP efficiency ratio was 59.45% compared to 59.87% in the prior quarter • Return on average assets of 1.37%, and return on average tangible common equity of 14.00%, compared to 1.24% and 13.17%, respectively, for the prior quarter • $1.3 million provision for credit losses - loans and $2.1 million recapture for credit losses - unfunded commitments; Allowance for credit losses – loans was 1.37% of total loans • Non-performing assets remained low at 0.32% of total assets, up 1 basis point from last quarter • Repurchased 250,000 shares of Banner common stock at an average price of $64.56 per share • Announced 4% increase in cash dividend to $0.52 per share to be paid in May 2026
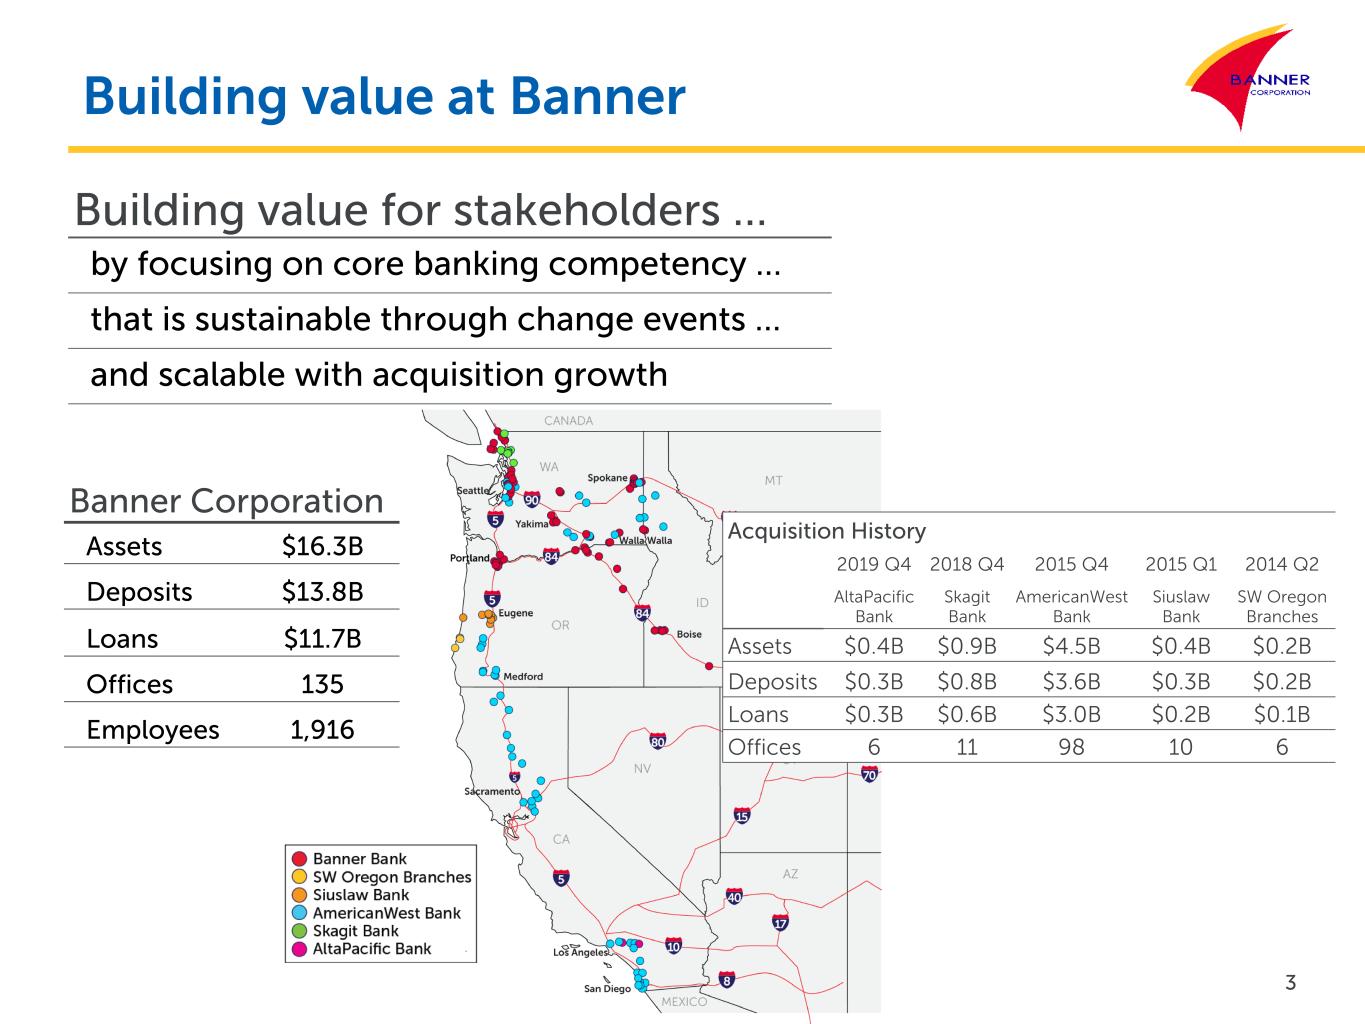
Building value at Banner Building value for stakeholders … by focusing on core banking competency … that is sustainable through change events … and scalable with acquisition growth Banner Corporation Assets $16.3B Deposits $13.8B Loans $11.7B Offices 135 Employees 1,916 3 Acquisition History 2019 Q4 2018 Q4 2015 Q4 2015 Q1 2014 Q2 AltaPacific Bank Skagit Bank AmericanWest Bank Siuslaw Bank SW Oregon Branches Assets $0.4B $0.9B $4.5B $0.4B $0.2B Deposits $0.3B $0.8B $3.6B $0.3B $0.2B Loans $0.3B $0.6B $3.0B $0.2B $0.1B Offices 6 11 98 10 6
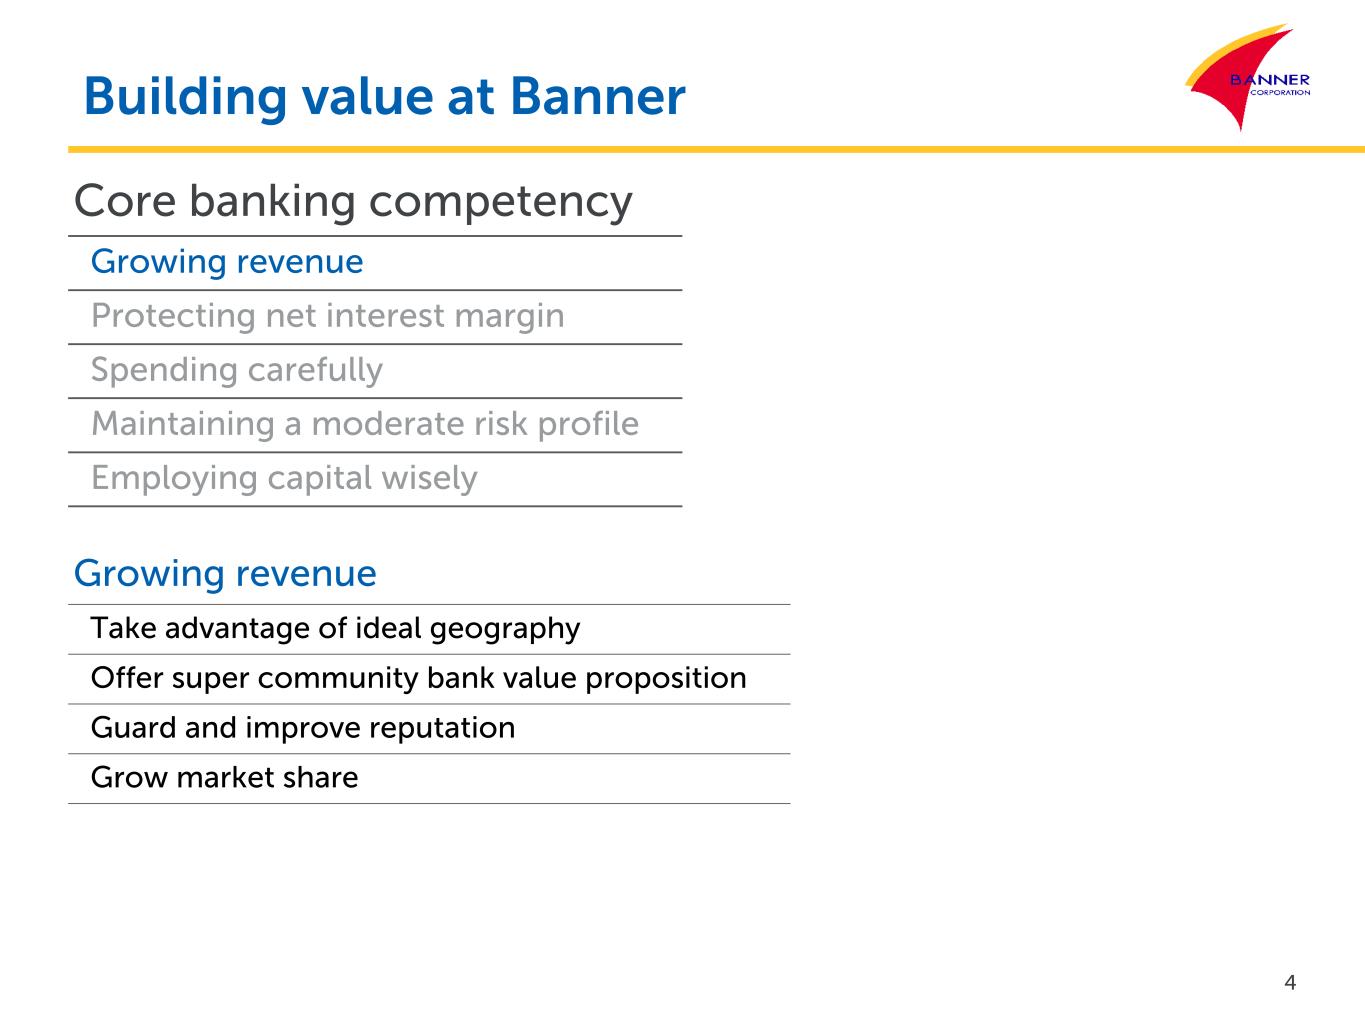
Building value at Banner Core banking competency Growing revenue Protecting net interest margin Spending carefully Maintaining a moderate risk profile Employing capital wisely Growing revenue Take advantage of ideal geography Offer super community bank value proposition Guard and improve reputation Grow market share 4
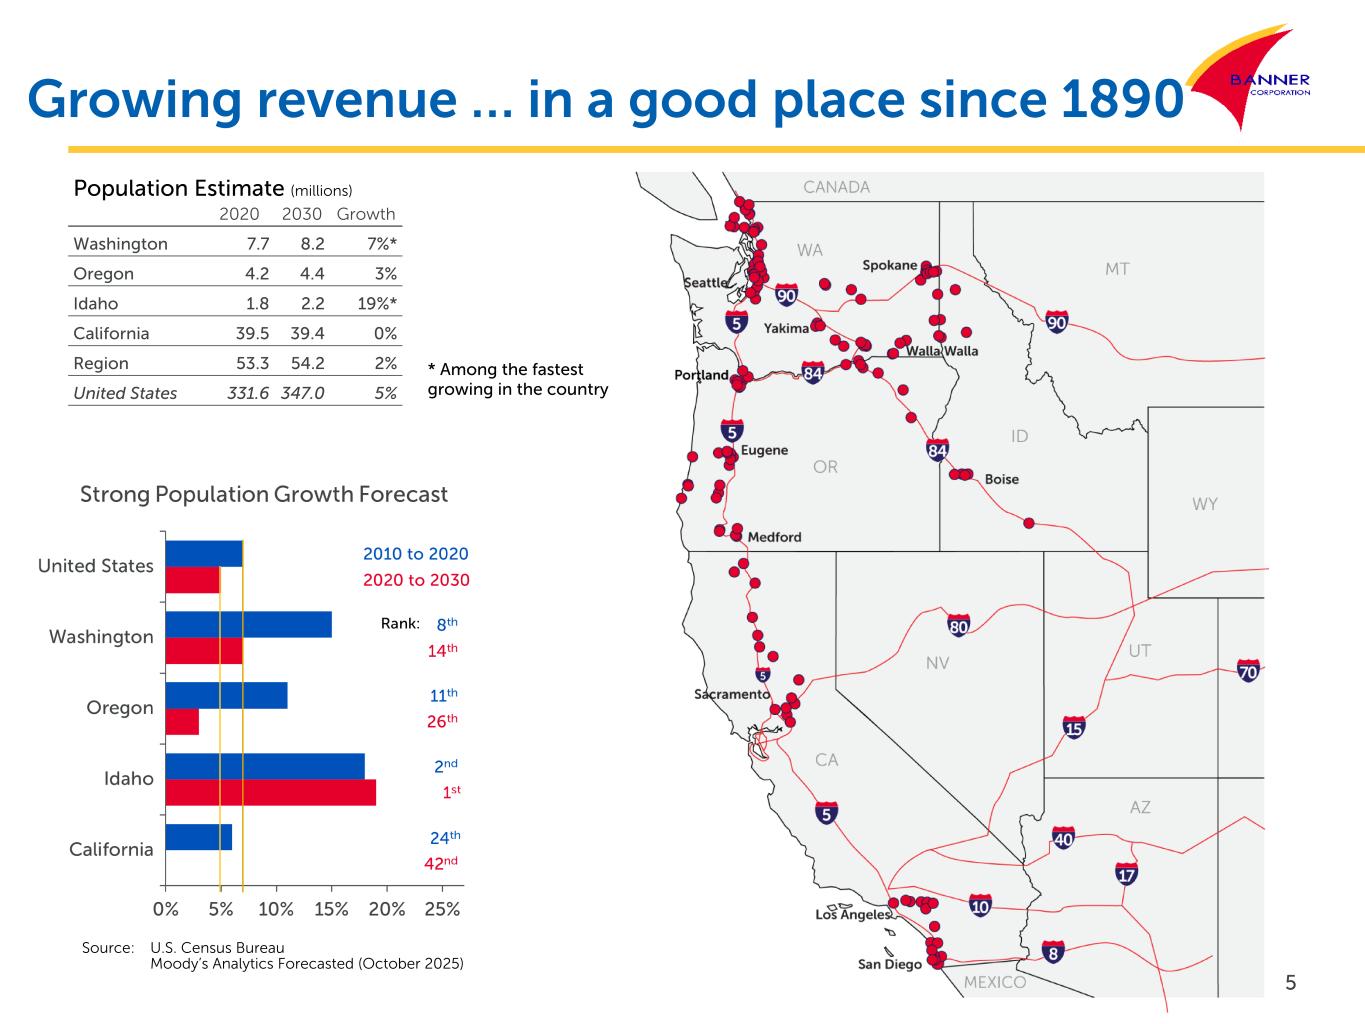
Growing revenue … in a good place since 1890 5 Source: U.S. Census Bureau Moody’s Analytics Forecasted (October 2025) Population Estimate (millions) 2020 2030 Growth Washington 7.7 8.2 7%* Oregon 4.2 4.4 3% Idaho 1.8 2.2 19%* California 39.5 39.4 0% Region 53.3 54.2 2% United States 331.6 347.0 5% * Among the fastest growing in the country
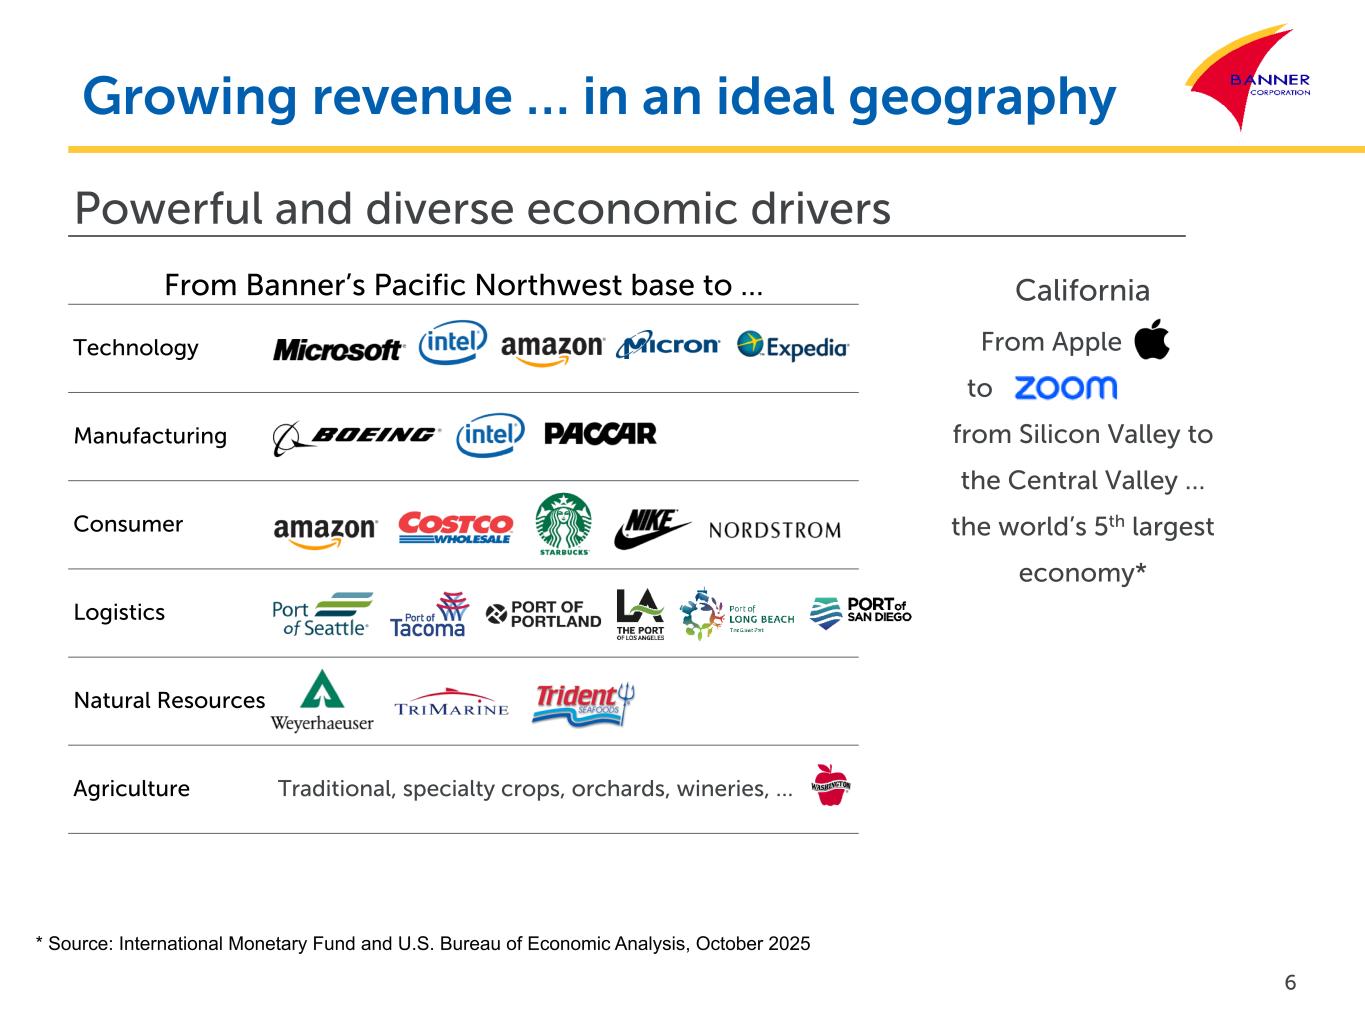
Growing revenue … in an ideal geography Powerful and diverse economic drivers From Banner’s Pacific Northwest base to … Technology Manufacturing Consumer Logistics Natural Resources Agriculture Traditional, specialty crops, orchards, wineries, … California From Apple to from Silicon Valley to the Central Valley … the world’s 5th largest economy* 6 * Source: International Monetary Fund and U.S. Bureau of Economic Analysis, October 2025
Growing revenue Our super community bank value proposition Broad product offerings serving middle market, small business and consumer client base Decision-making as close to client as possible Delivery channels aligned to maximize tactical execution of strategic plan Community investment 7
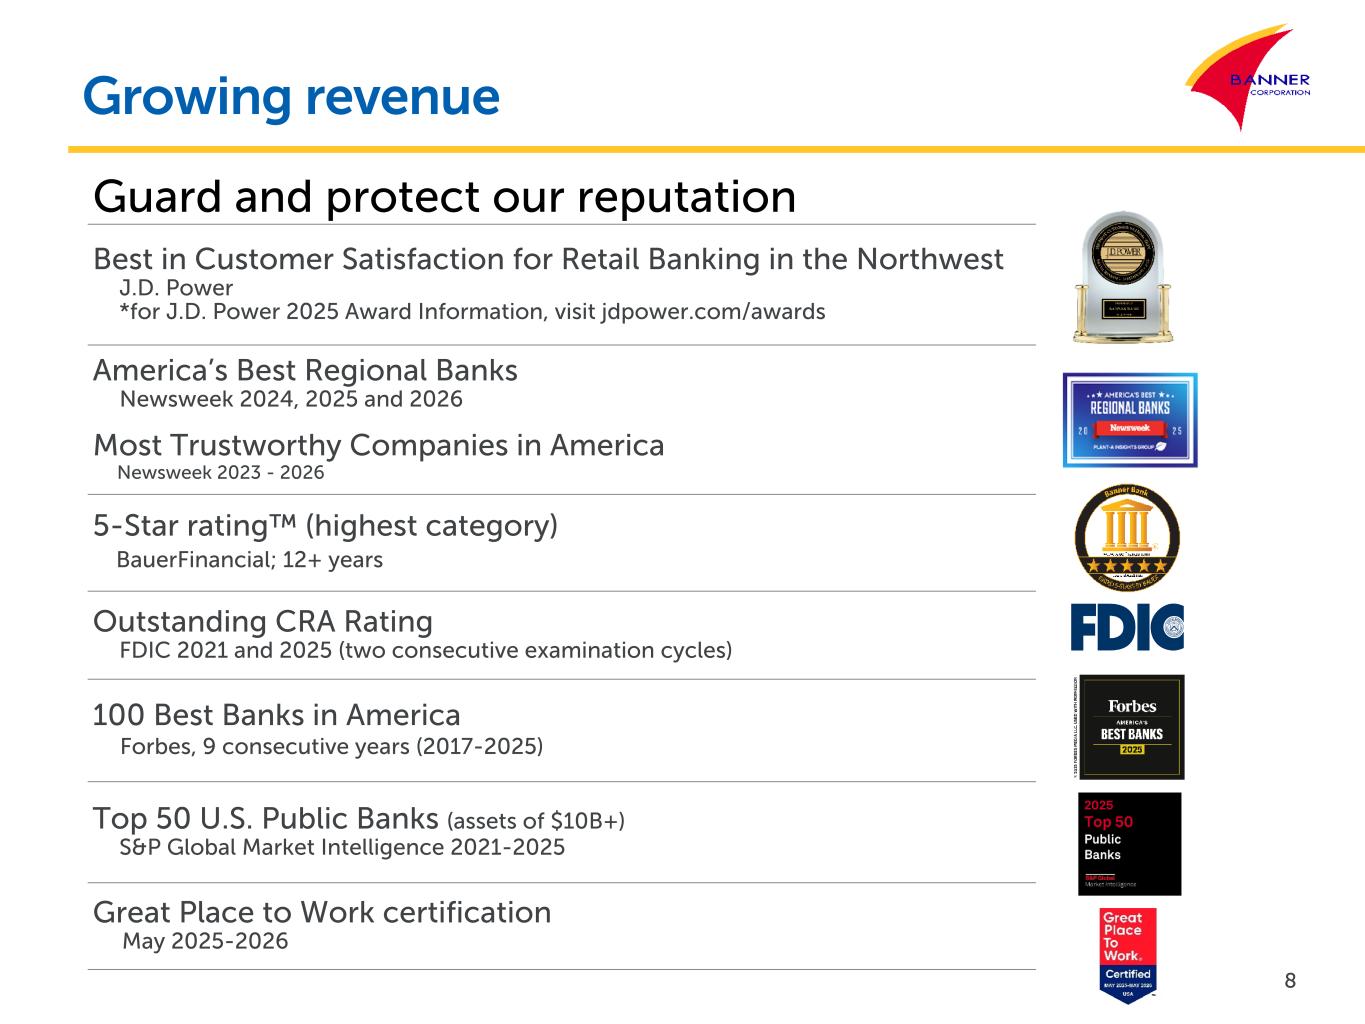
Growing revenue Guard and protect our reputation Best in Customer Satisfaction for Retail Banking in the Northwest J.D. Power *for J.D. Power 2025 Award Information, visit jdpower.com/awards America’s Best Regional Banks Newsweek 2024, 2025 and 2026 Most Trustworthy Companies in America Newsweek 2023 - 2026 5-Star rating™ (highest category) BauerFinancial; 12+ years Outstanding CRA Rating FDIC 2021 and 2025 (two consecutive examination cycles) 100 Best Banks in America Forbes, 9 consecutive years (2017-2025) Top 50 U.S. Public Banks (assets of $10B+) S&P Global Market Intelligence 2021-2025 Great Place to Work certification May 2025-2026 8
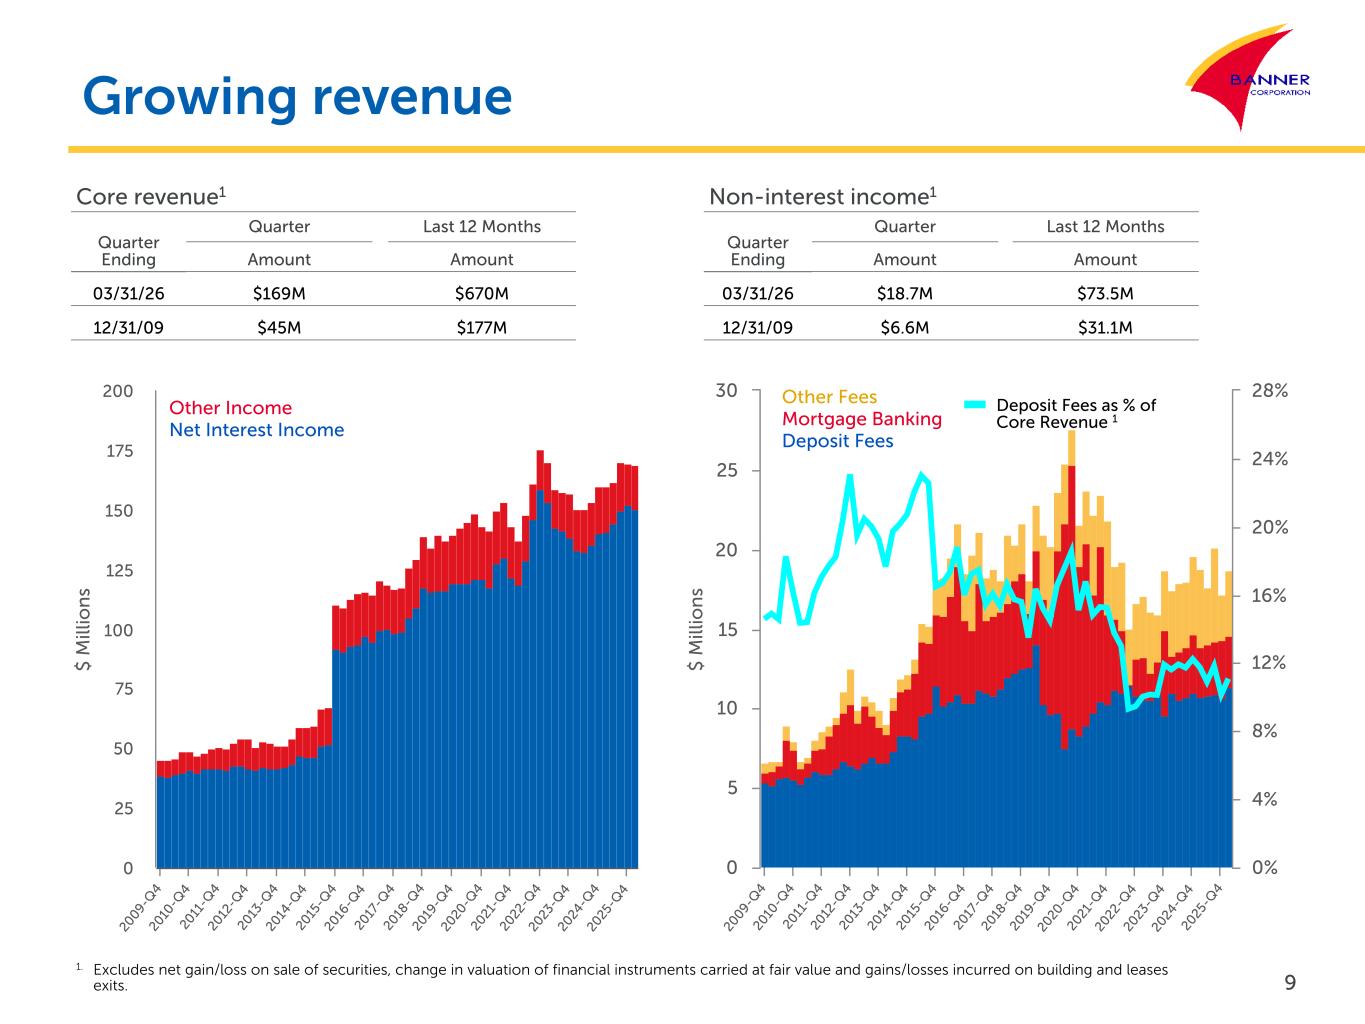
$ M ill io n s 20 09- Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 0 5 10 15 20 25 30 0% 4% 8% 12% 16% 20% 24% 28% $ M ill io n s 20 09- Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 0 25 50 75 100 125 150 175 200 Growing revenue Deposit Fees as % of Core Revenue 1 Other Fees Mortgage Banking Deposit Fees 9 1. Excludes net gain/loss on sale of securities, change in valuation of financial instruments carried at fair value and gains/losses incurred on building and leases exits. Core revenue1 Quarter Ending Quarter Last 12 Months Amount Amount 03/31/26 $169M $670M 12/31/09 $45M $177M Non-interest income1 Quarter Ending Quarter Last 12 Months Amount Amount 03/31/26 $18.7M $73.5M 12/31/09 $6.6M $31.1M Other Income Net Interest Income
Building value at Banner Core banking competency Growing revenue Protecting net interest margin Spending carefully Maintaining a moderate risk profile Employing capital wisely Protecting net interest margin Improve earning asset mix Improve funding mix Reduce deposit costs Maintain loan-to-deposit ratio 10
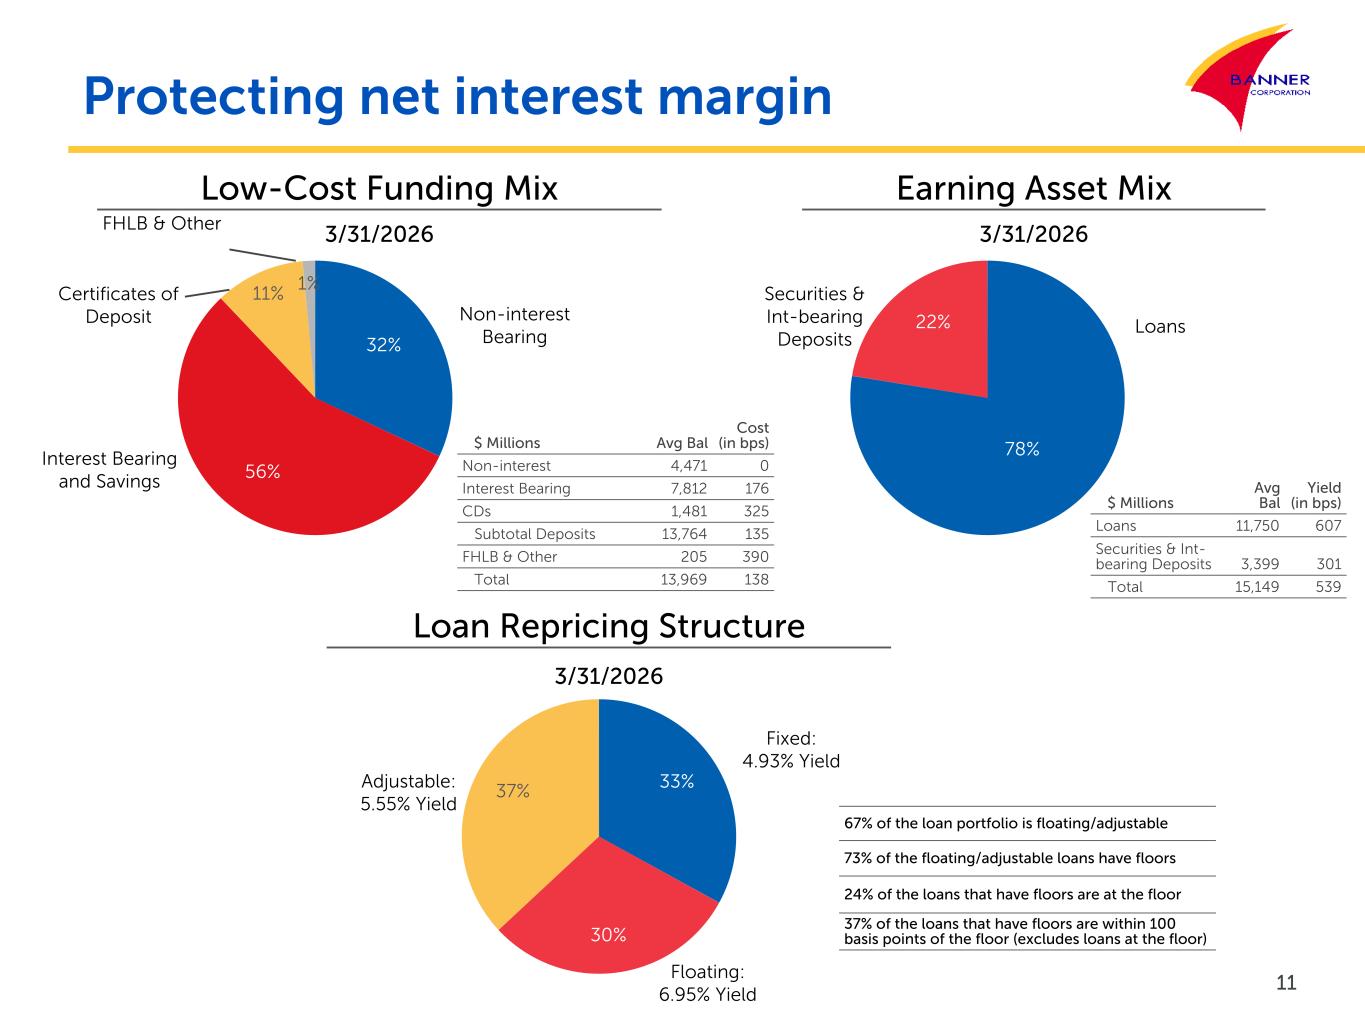
Protecting net interest margin $ Millions Avg Bal Cost (in bps) Non-interest 4,471 0 Interest Bearing 7,812 176 CDs 1,481 325 Subtotal Deposits 13,764 135 FHLB & Other 205 390 Total 13,969 138 11 32% 56% 11% 1% 78% 22% 33% 30% 37% Non-interest Bearing Certificates of Deposit Interest Bearing and Savings Securities & Int-bearing Deposits Loans Fixed: 4.93% Yield Floating: 6.95% Yield Low-Cost Funding Mix 3/31/2026 Adjustable: 5.55% Yield Earning Asset Mix 3/31/2026 Loan Repricing Structure 3/31/2026 $ Millions Avg Bal Yield (in bps) Loans 11,750 607 Securities & Int- bearing Deposits 3,399 301 Total 15,149 539 67% of the loan portfolio is floating/adjustable 73% of the floating/adjustable loans have floors 24% of the loans that have floors are at the floor 37% of the loans that have floors are within 100 basis points of the floor (excludes loans at the floor) FHLB & Other
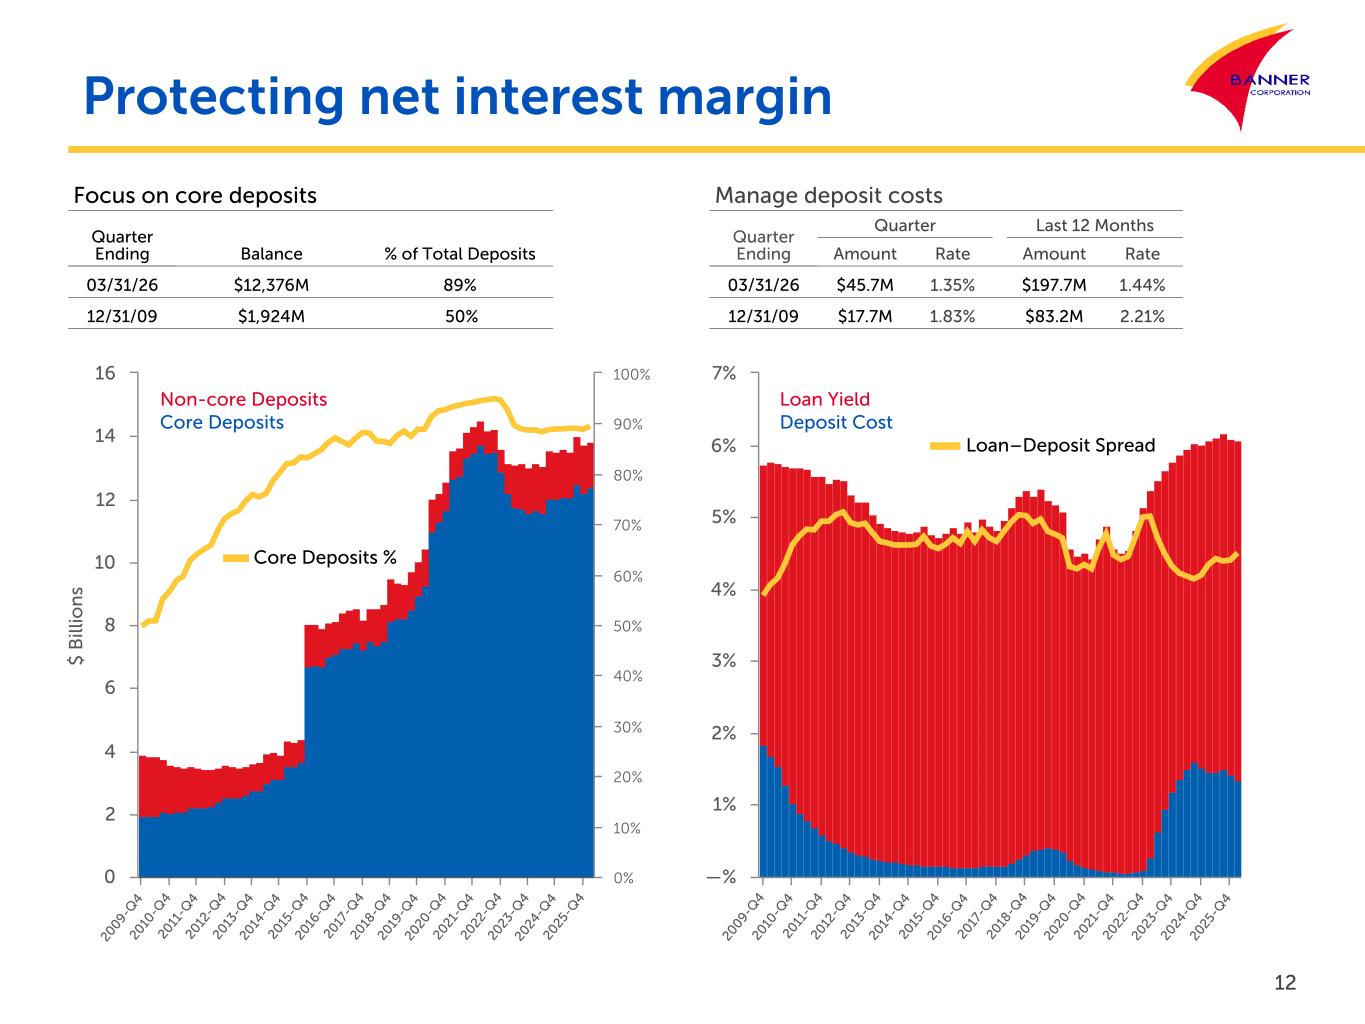
20 09- Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 —% 1% 2% 3% 4% 5% 6% 7% $ B ill io n s 20 09- Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 0 2 4 6 8 10 12 14 16 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% Protecting net interest margin Non-core Deposits Core Deposits Manage deposit costs Quarter Ending Quarter Last 12 Months Amount Rate Amount Rate 03/31/26 $45.7M 1.35% $197.7M 1.44% 12/31/09 $17.7M 1.83% $83.2M 2.21% 12 Focus on core deposits Quarter Ending Balance % of Total Deposits 03/31/26 $12,376M 89% 12/31/09 $1,924M 50% Loan Yield Deposit Cost Core Deposits % Loan–Deposit Spread
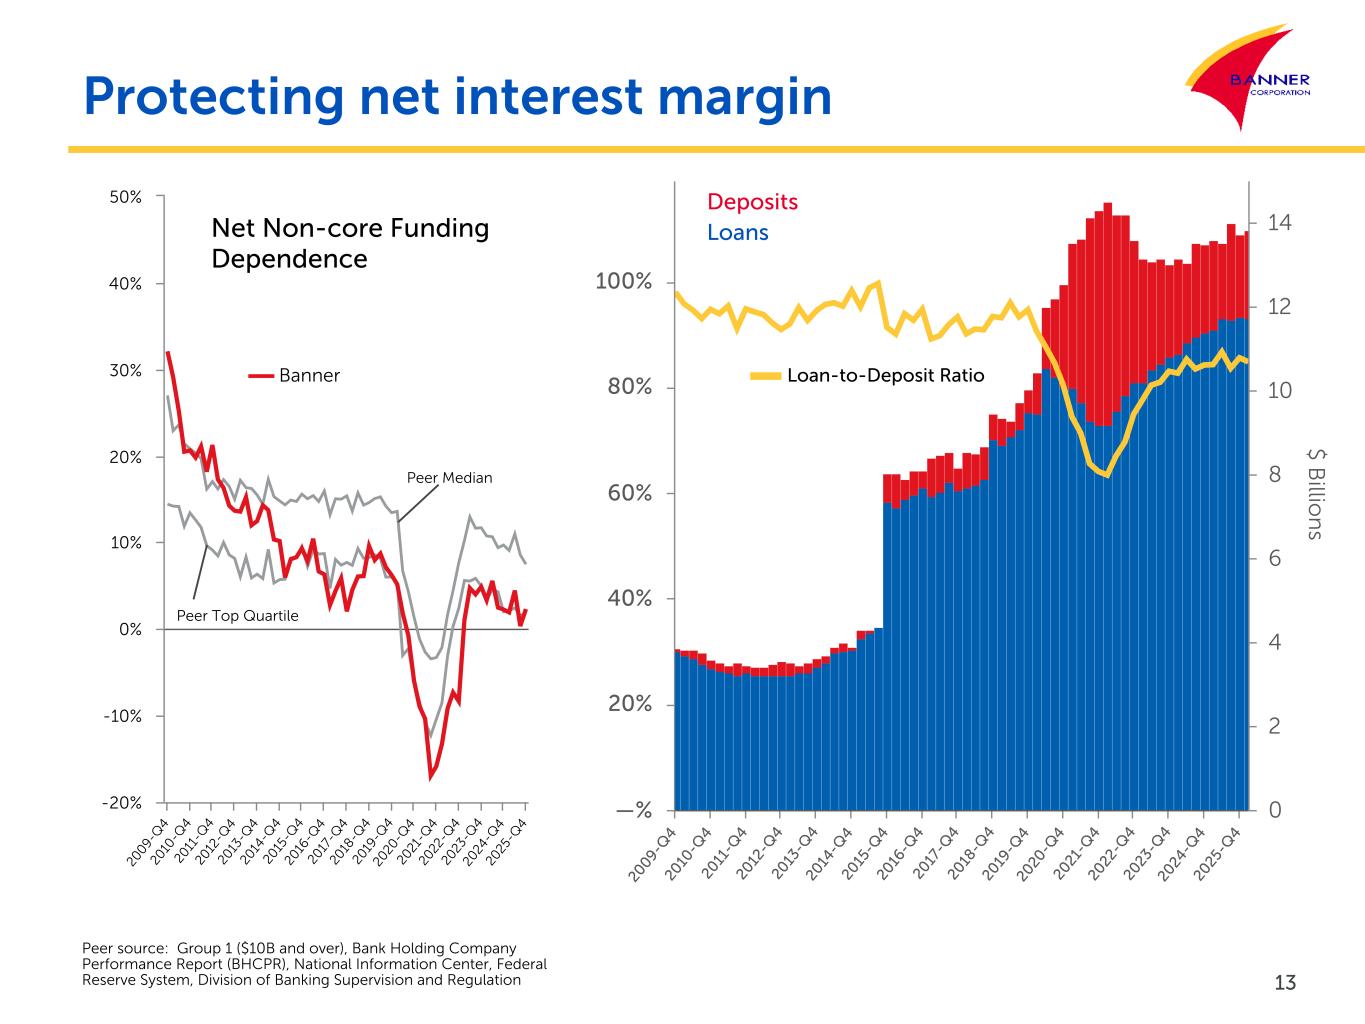
20 09 -Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 -20% -10% 0% 10% 20% 30% 40% 50% Protecting net interest margin Peer Median Peer source: Group 1 ($10B and over), Bank Holding Company Performance Report (BHCPR), National Information Center, Federal Reserve System, Division of Banking Supervision and Regulation Net Non-core Funding Dependence Peer Top Quartile 13 $ B illio n s 20 09- Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 —% 20% 40% 60% 80% 100% 0 2 4 6 8 10 12 14 Banner Loan-to-Deposit Ratio Deposits Loans
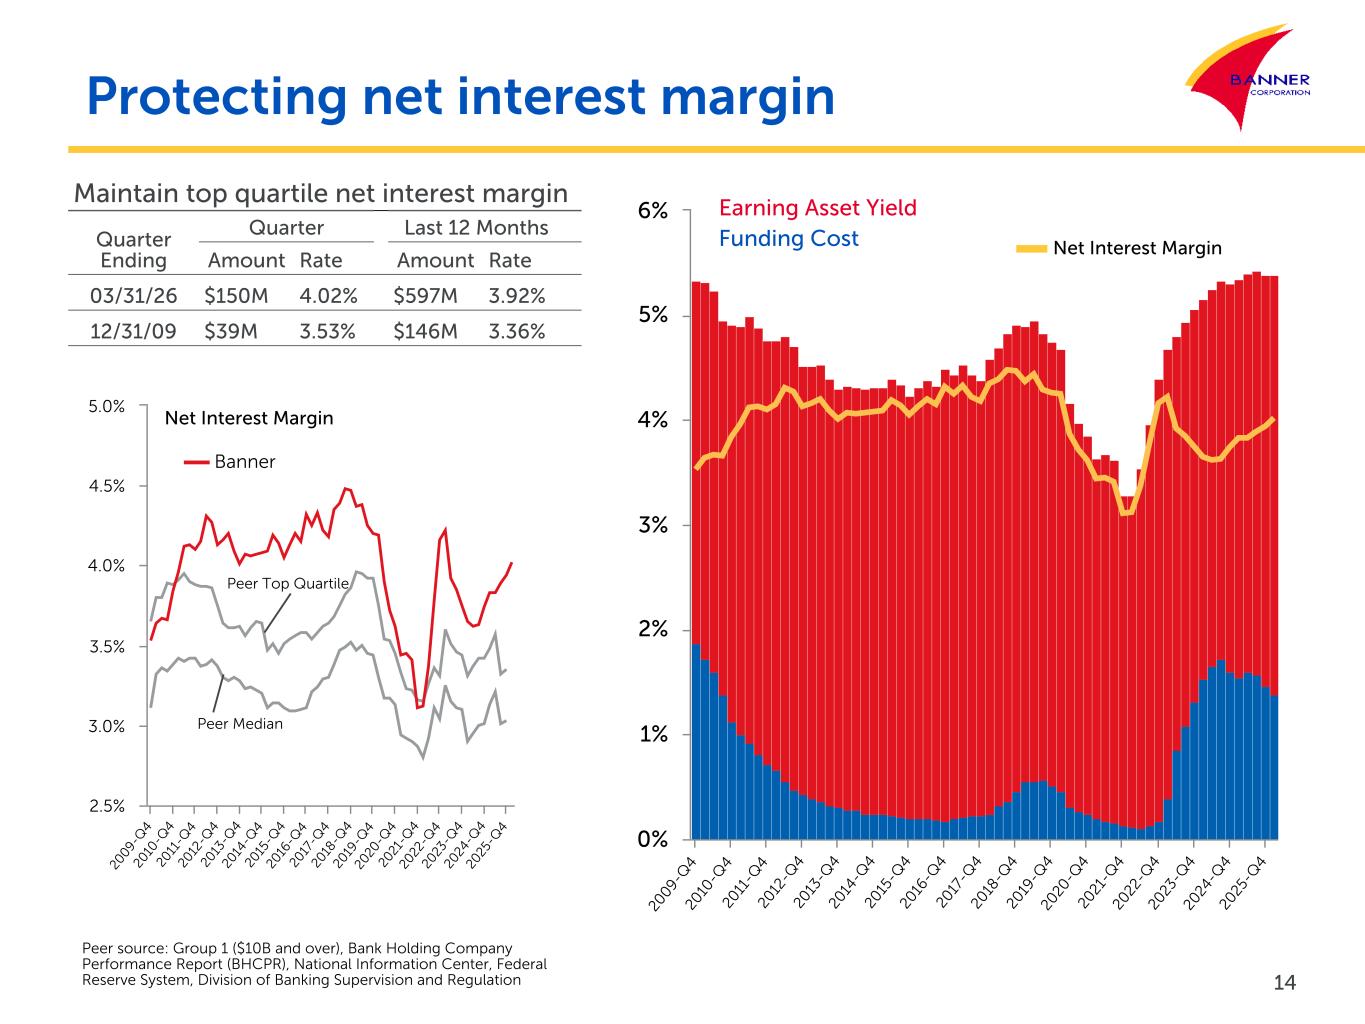
20 09 -Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 0% 1% 2% 3% 4% 5% 6% 20 09 -Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 2.5% 3.0% 3.5% 4.0% 4.5% 5.0% Protecting net interest margin Maintain top quartile net interest margin Quarter Ending Quarter Last 12 Months Amount Rate Amount Rate 03/31/26 $150M 4.02% $597M 3.92% 12/31/09 $39M 3.53% $146M 3.36% Peer source: Group 1 ($10B and over), Bank Holding Company Performance Report (BHCPR), National Information Center, Federal Reserve System, Division of Banking Supervision and Regulation 14 Peer Top Quartile Peer Median Net Interest Margin Banner Net Interest Margin Earning Asset Yield Funding Cost
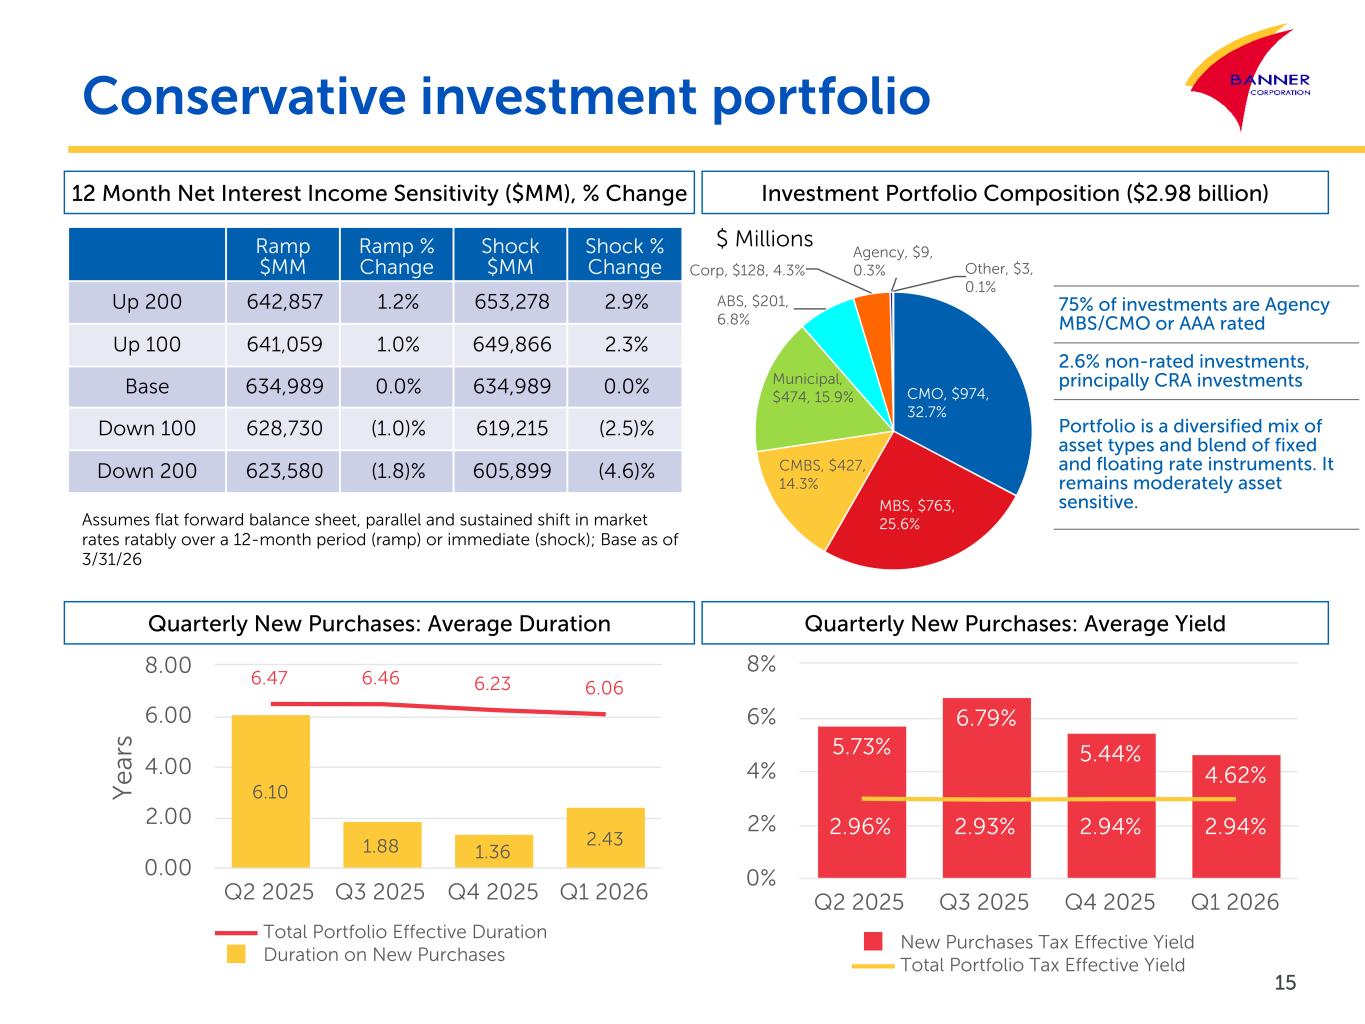
Conservative investment portfolio 15 Assumes flat forward balance sheet, parallel and sustained shift in market rates ratably over a 12-month period (ramp) or immediate (shock); Base as of 3/31/26 CMO, $974, 32.7% MBS, $763, 25.6% CMBS, $427, 14.3% Municipal, $474, 15.9% ABS, $201, 6.8% Corp, $128, 4.3% Agency, $9, 0.3% Other, $3, 0.1% Y e ar s 6.10 1.88 1.36 2.43 6.47 6.46 6.23 6.06 Total Portfolio Effective Duration Duration on New Purchases Q2 2025 Q3 2025 Q4 2025 Q1 2026 0.00 2.00 4.00 6.00 8.00 5.73% 6.79% 5.44% 4.62% 2.96% 2.93% 2.94% 2.94% New Purchases Tax Effective Yield Total Portfolio Tax Effective Yield Q2 2025 Q3 2025 Q4 2025 Q1 2026 0% 2% 4% 6% 8% 12 Month Net Interest Income Sensitivity ($MM), % Change Quarterly New Purchases: Average Duration Investment Portfolio Composition ($2.98 billion) 75% of investments are Agency MBS/CMO or AAA rated 2.6% non-rated investments, principally CRA investments Portfolio is a diversified mix of asset types and blend of fixed and floating rate instruments. It remains moderately asset sensitive. Quarterly New Purchases: Average Yield $ MillionsRamp $MM Ramp % Change Shock $MM Shock % Change Up 200 642,857 1.2% 653,278 2.9% Up 100 641,059 1.0% 649,866 2.3% Base 634,989 0.0% 634,989 0.0% Down 100 628,730 (1.0)% 619,215 (2.5)% Down 200 623,580 (1.8)% 605,899 (4.6)%
Building value at Banner Core banking competency Growing revenue Protecting net interest margin Spending carefully Maintaining a moderate risk profile Employing capital wisely Spending carefully Benefit from scale Control core operating expense 16
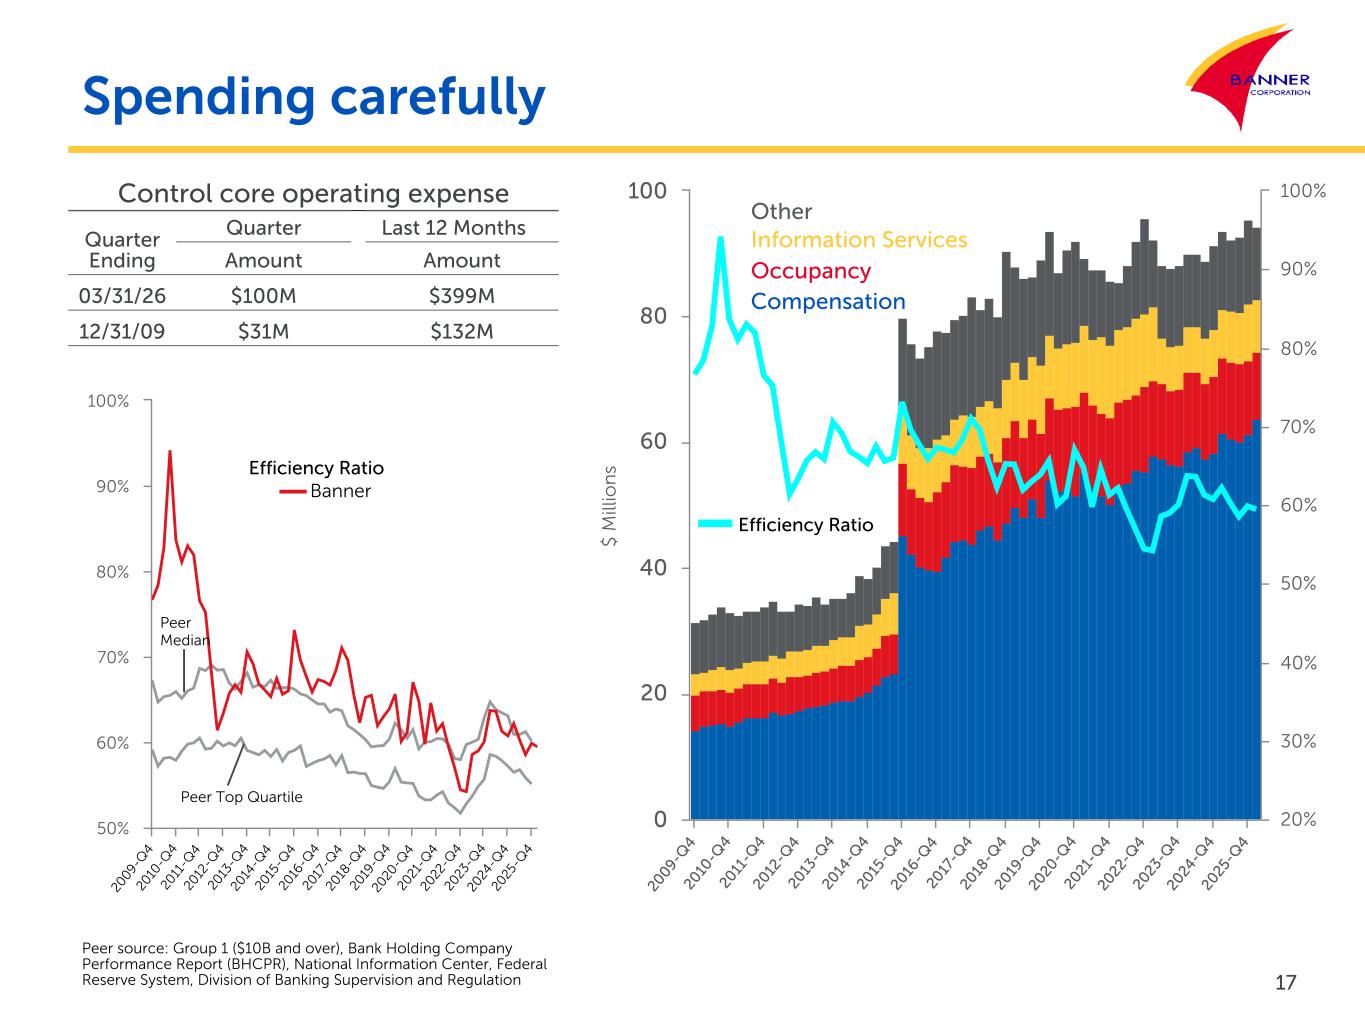
$ M ill io n s 20 09- Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 0 20 40 60 80 100 20% 30% 40% 50% 60% 70% 80% 90% 100% 20 09 -Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 50% 60% 70% 80% 90% 100% Spending carefully Peer source: Group 1 ($10B and over), Bank Holding Company Performance Report (BHCPR), National Information Center, Federal Reserve System, Division of Banking Supervision and Regulation 17 Control core operating expense Quarter Ending Quarter Last 12 Months Amount Amount 03/31/26 $100M $399M 12/31/09 $31M $132M Peer Top Quartile Peer Median Banner Efficiency Ratio Occupancy Compensation Information Services Other Efficiency Ratio
Maintaining a moderate risk profile Embrace effective enterprise risk management Minimize non-performing assets Maintain appropriate loan loss reserve Maintain appropriate risk capital Building value at Banner Core banking competency Growing revenue Protecting net interest margin Spending carefully Maintaining a moderate risk profile Employing capital wisely 18
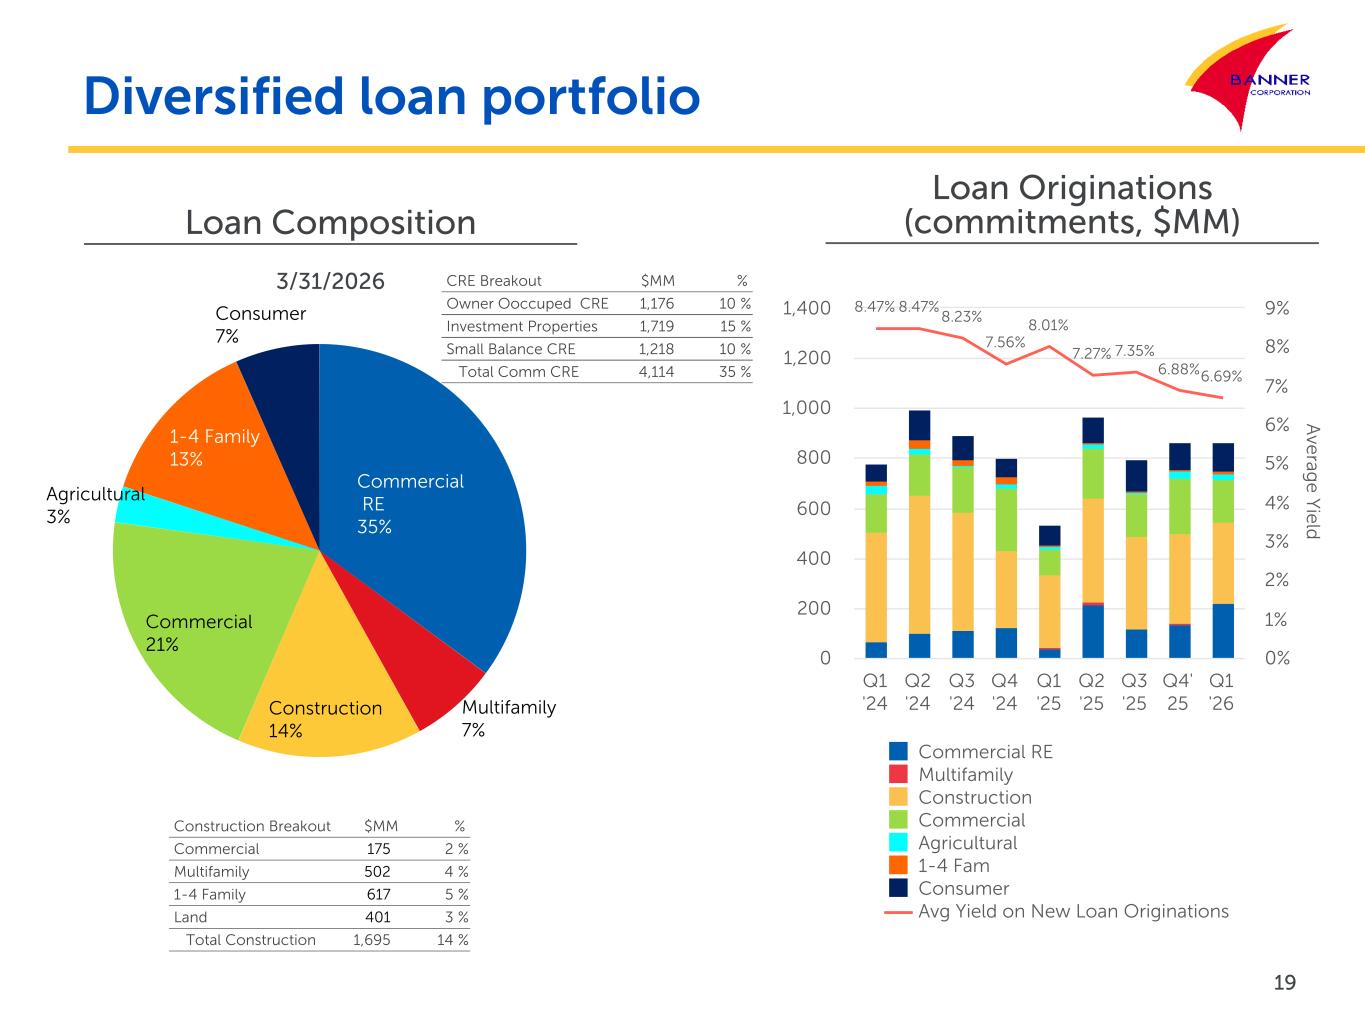
Commercial RE 35% Multifamily 7% Construction 14% Commercial 21% Agricultural 3% 1-4 Family 13% Consumer 7% Diversified loan portfolio 19 Loan Composition 3/31/2026 CRE Breakout $MM % Owner Ooccuped CRE 1,176 10 % Investment Properties 1,719 15 % Small Balance CRE 1,218 10 % Total Comm CRE 4,114 35 % Construction Breakout $MM % Commercial 175 2 % Multifamily 502 4 % 1-4 Family 617 5 % Land 401 3 % Total Construction 1,695 14 % Loan Originations (commitments, $MM) A ve rag e Y ie ld 8.47% 8.47% 8.23% 7.56% 8.01% 7.27% 7.35% 6.88%6.69% Commercial RE Multifamily Construction Commercial Agricultural 1-4 Fam Consumer Avg Yield on New Loan Originations Q1 '24 Q2 '24 Q3 '24 Q4 '24 Q1 '25 Q2 '25 Q3 '25 Q4' 25 Q1 '26 0 200 400 600 800 1,000 1,200 1,400 0% 1% 2% 3% 4% 5% 6% 7% 8% 9%
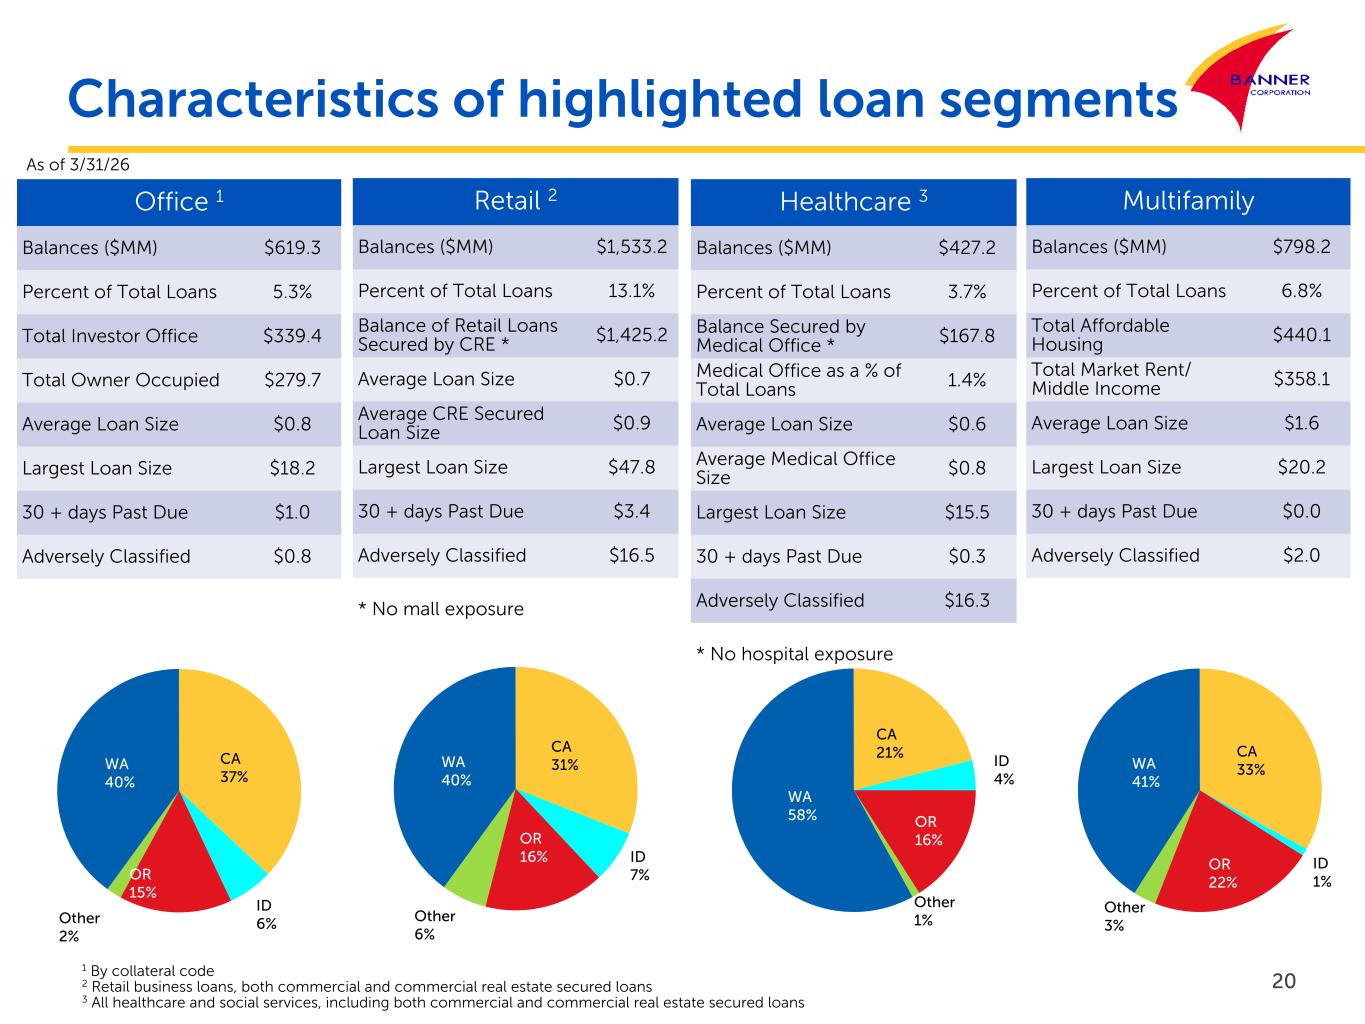
20 Characteristics of highlighted loan segments Office 1 Balances ($MM) $619.3 Percent of Total Loans 5.3% Total Investor Office $339.4 Total Owner Occupied $279.7 Average Loan Size $0.8 Largest Loan Size $18.2 30 + days Past Due $1.0 Adversely Classified $0.8 Retail 2 Balances ($MM) $1,533.2 Percent of Total Loans 13.1% Balance of Retail Loans Secured by CRE * $1,425.2 Average Loan Size $0.7 Average CRE Secured Loan Size $0.9 Largest Loan Size $47.8 30 + days Past Due $3.4 Adversely Classified $16.5 * No mall exposure Healthcare 3 Balances ($MM) $427.2 Percent of Total Loans 3.7% Balance Secured by Medical Office * $167.8 Medical Office as a % of Total Loans 1.4% Average Loan Size $0.6 Average Medical Office Size $0.8 Largest Loan Size $15.5 30 + days Past Due $0.3 Adversely Classified $16.3 * No hospital exposure 1 By collateral code 2 Retail business loans, both commercial and commercial real estate secured loans 3 All healthcare and social services, including both commercial and commercial real estate secured loans Multifamily Balances ($MM) $798.2 Percent of Total Loans 6.8% Total Affordable Housing $440.1 Total Market Rent/ Middle Income $358.1 Average Loan Size $1.6 Largest Loan Size $20.2 30 + days Past Due $0.0 Adversely Classified $2.0 CA 37% ID 6% OR 15% Other 2% WA 40% CA 31% ID 7% OR 16% Other 6% WA 40% CA 21% ID 4% OR 16% Other 1% WA 58% CA 33% ID 1% OR 22% Other 3% WA 41% As of 3/31/26
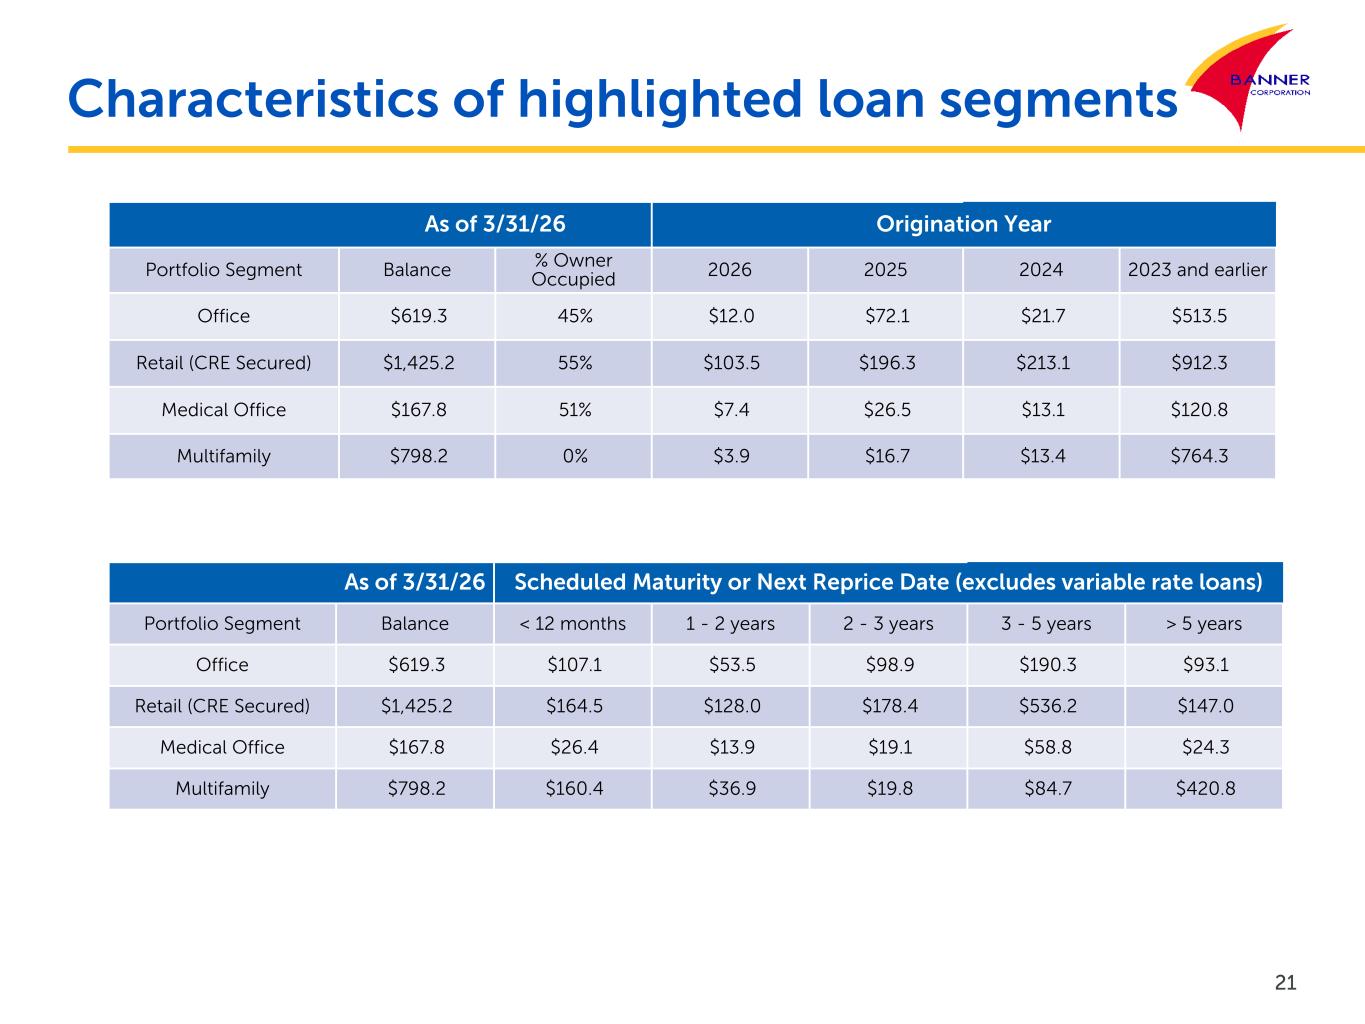
21 As of 3/31/26 Origination Year Portfolio Segment Balance % Owner Occupied 2026 2025 2024 2023 and earlier Office $619.3 45% $12.0 $72.1 $21.7 $513.5 Retail (CRE Secured) $1,425.2 55% $103.5 $196.3 $213.1 $912.3 Medical Office $167.8 51% $7.4 $26.5 $13.1 $120.8 Multifamily $798.2 0% $3.9 $16.7 $13.4 $764.3 As of 3/31/26 Scheduled Maturity or Next Reprice Date (excludes variable rate loans) Portfolio Segment Balance < 12 months 1 - 2 years 2 - 3 years 3 - 5 years > 5 years Office $619.3 $107.1 $53.5 $98.9 $190.3 $93.1 Retail (CRE Secured) $1,425.2 $164.5 $128.0 $178.4 $536.2 $147.0 Medical Office $167.8 $26.4 $13.9 $19.1 $58.8 $24.3 Multifamily $798.2 $160.4 $36.9 $19.8 $84.7 $420.8 Characteristics of highlighted loan segments
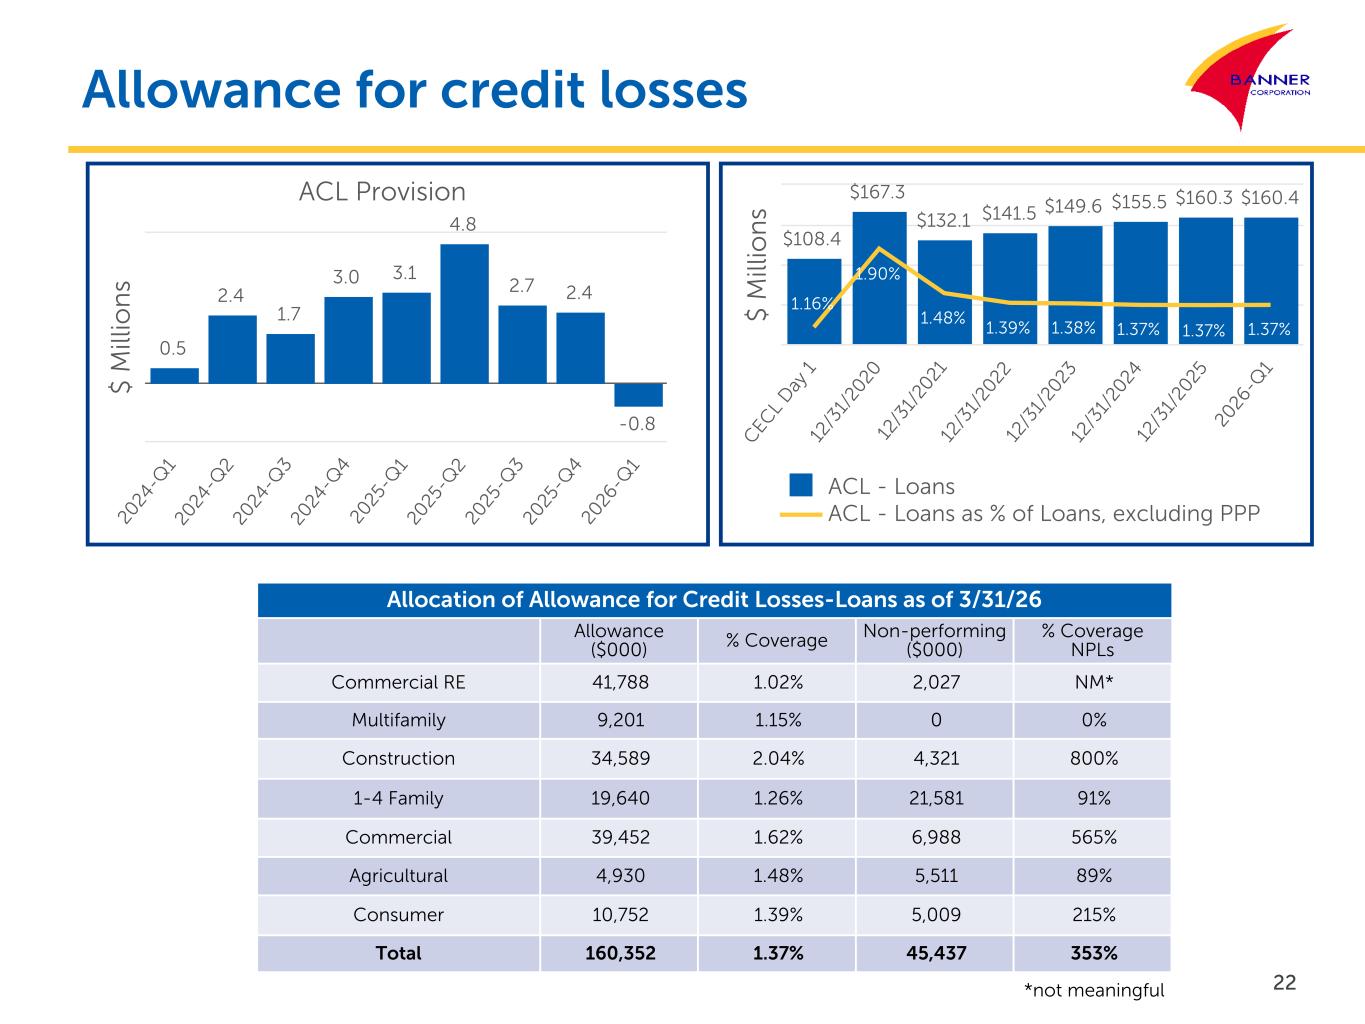
Allowance for credit losses 22 $ M ill io n s ACL Provision 0.5 2.4 1.7 3.0 3.1 4.8 2.7 2.4 -0.8 20 24 -Q 1 20 24 -Q 2 20 24 -Q 3 20 24 -Q 4 20 25 -Q 1 20 25 -Q 2 20 25 -Q 3 20 25 -Q 4 20 26 -Q 1 $ M ill io n s $108.4 $167.3 $132.1 $141.5 $149.6 $155.5 $160.3 $160.4 1.16% 1.90% 1.48% 1.39% 1.38% 1.37% 1.37% 1.37% ACL - Loans ACL - Loans as % of Loans, excluding PPP C EC L D ay 1 12 /3 1/ 20 20 12 /3 1/ 20 21 12 /3 1/ 20 22 12 /3 1/ 20 23 12 /3 1/ 20 24 12 /3 1/ 20 25 20 26 -Q 1 Allocation of Allowance for Credit Losses-Loans as of 3/31/26 Allowance ($000) % Coverage Non-performing ($000) % Coverage NPLs Commercial RE 41,788 1.02% 2,027 NM* Multifamily 9,201 1.15% 0 0% Construction 34,589 2.04% 4,321 800% 1-4 Family 19,640 1.26% 21,581 91% Commercial 39,452 1.62% 6,988 565% Agricultural 4,930 1.48% 5,511 89% Consumer 10,752 1.39% 5,009 215% Total 160,352 1.37% 45,437 353% *not meaningful
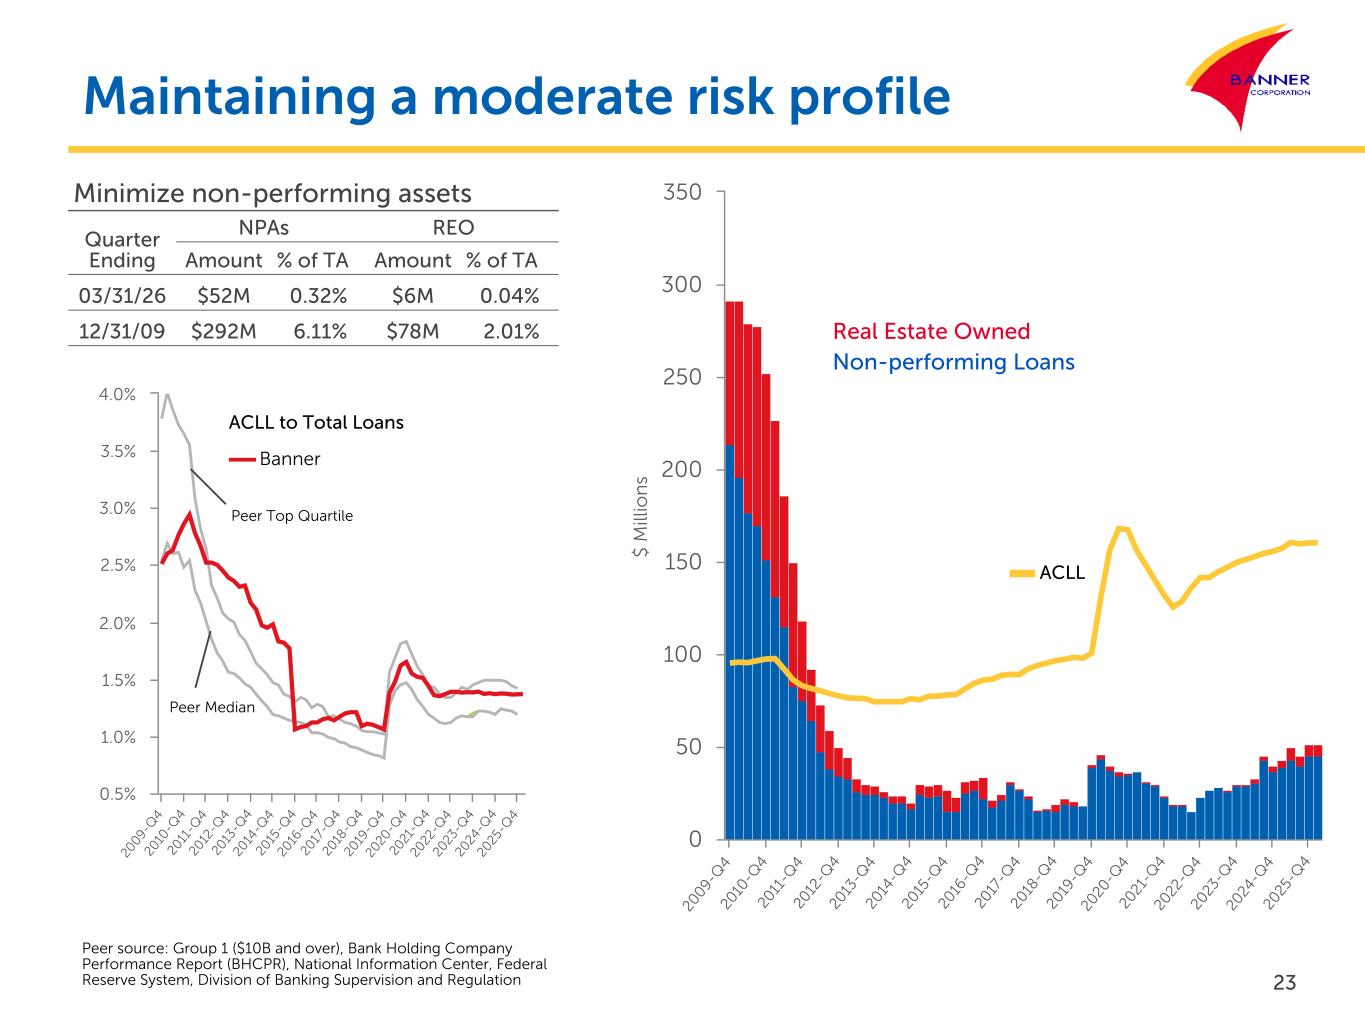
20 09 -Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 0.5% 1.0% 1.5% 2.0% 2.5% 3.0% 3.5% 4.0% $ M ill io n s 20 09 -Q 4 20 10 -Q 4 20 11 -Q 4 20 12 -Q 4 20 13 -Q 4 20 14 -Q 4 20 15 -Q 4 20 16 -Q 4 20 17 -Q 4 20 18 -Q 4 20 19 -Q 4 20 20 -Q 4 20 21 -Q 4 20 22 -Q 4 20 23 -Q 4 20 24 -Q 4 20 25 -Q 4 0 50 100 150 200 250 300 350Minimize non-performing assets Quarter Ending NPAs REO Amount % of TA Amount % of TA 03/31/26 $52M 0.32% $6M 0.04% 12/31/09 $292M 6.11% $78M 2.01% Peer source: Group 1 ($10B and over), Bank Holding Company Performance Report (BHCPR), National Information Center, Federal Reserve System, Division of Banking Supervision and Regulation Maintaining a moderate risk profile ACLL Real Estate Owned Non-performing Loans Peer Top Quartile Peer Median Banner ACLL to Total Loans 23
Building value at Banner Core banking competency Growing revenue Protecting net interest margin Spending carefully Maintaining a moderate risk profile Employing capital wisely Employing capital wisely Maintain premium to tangible book value Pay appropriate dividends Prepare for future opportunities 24
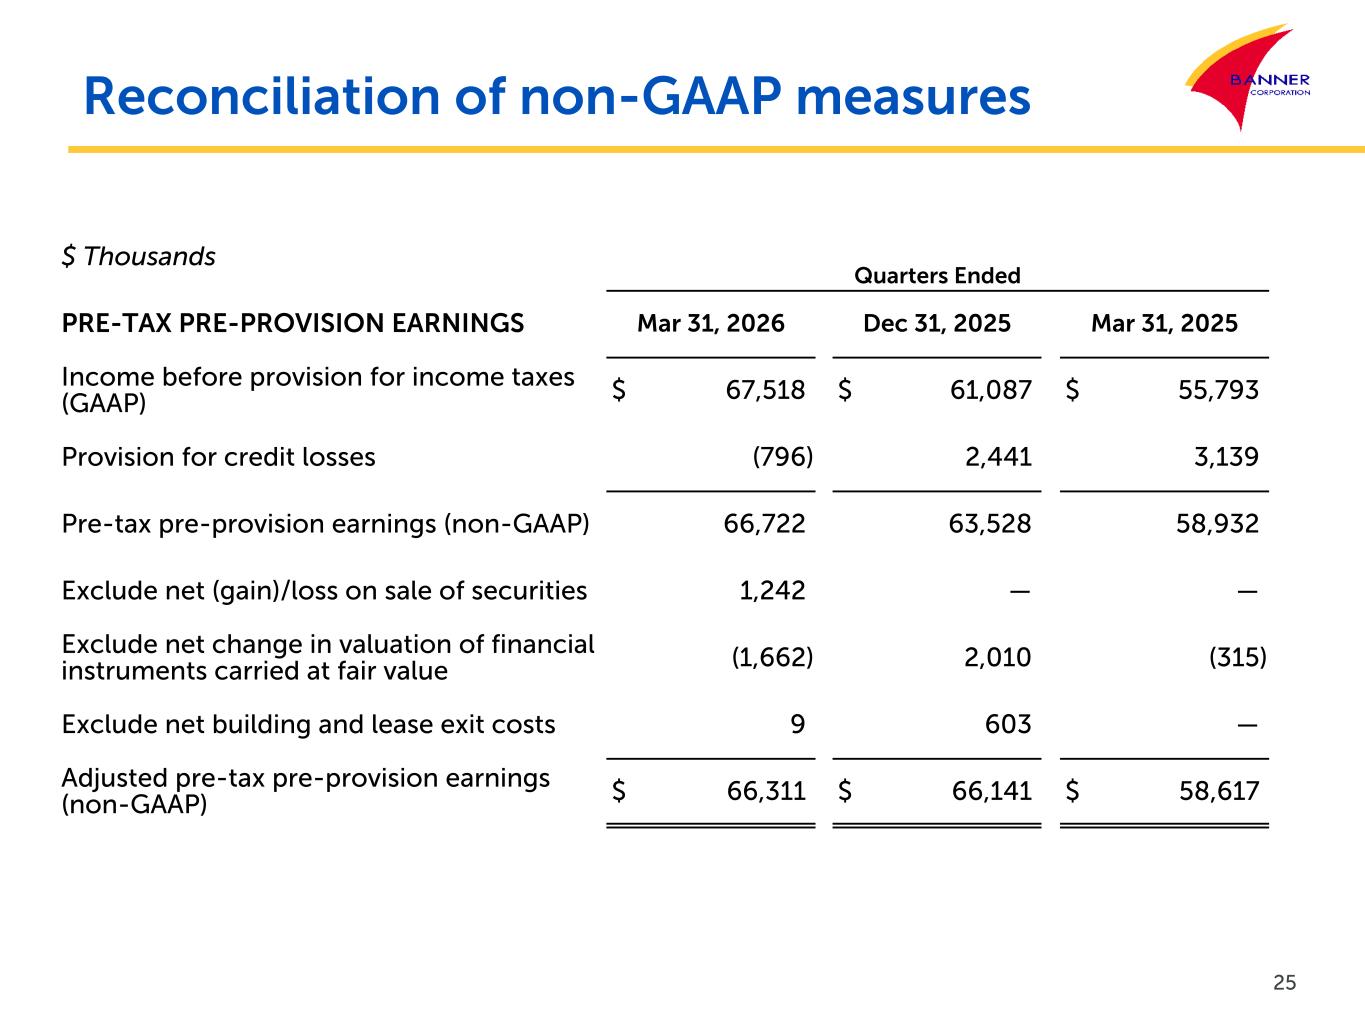
Reconciliation of non-GAAP measures 25 $ Thousands Quarters Ended PRE-TAX PRE-PROVISION EARNINGS Mar 31, 2026 Dec 31, 2025 Mar 31, 2025 Income before provision for income taxes (GAAP) $ 67,518 $ 61,087 $ 55,793 Provision for credit losses (796) 2,441 3,139 Pre-tax pre-provision earnings (non-GAAP) 66,722 63,528 58,932 Exclude net (gain)/loss on sale of securities 1,242 — — Exclude net change in valuation of financial instruments carried at fair value (1,662) 2,010 (315) Exclude net building and lease exit costs 9 603 — Adjusted pre-tax pre-provision earnings (non-GAAP) $ 66,311 $ 66,141 $ 58,617
Building value at Banner Building value for … Shareholders by delivering top quartile financial performance Clients by delivering super community bank service and products Employees by offering opportunity and reward Communities by providing capital and staying involved 26