
BMRC 8-K
Bank of Marin Bancorp (BMRC)
8-K
2025-07-28
For: 2025-07-24
View Original
Added on
July 04, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of
the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported) July 24, 2025
(Exact name of Registrant as specified in its charter)
| | ||||||||
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||
| (Address of principal executive office) | (Zip Code) | ||||
Registrant’s telephone number, including area code: (415 ) 763-4520
Not Applicable
(Former name or former address, if changes since last report)
| Check the appropriate box below if the Form 8-K filing is to simultaneously satisfy the filing obligation of the registrant under any of the following provisions: | |||||
| Securities registered pursuant to 12(b) of the Act: | ||||||||
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||||||
| Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). | |||||
Emerging growth company | |||||
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐ | |||||
Section 2 - Financial Information
Item 2.02 Results of Operations and Financial Condition
On July 28, 2025, Bank of Marin Bancorp, "Bancorp" (Nasdaq: BMRC), parent company of Bank of Marin, released its financial results for the quarter ended June 30, 2025. A copy of the press release is included as Exhibit 99.1 and the related Second Quarter 2025 Earnings Presentation is included as Exhibit 99.2.
The press release and presentation will be available on Bank of Marin's website at http://www.bankofmarin.com under “Investor Relations/News & Market Data/Press Releases" and "Presentations” on July 28, 2025.
Section 8 - Other Events
Item 8.01 Other Events
In the press release, Bancorp announced that on July 24, 2025, its Board of Directors approved a quarterly cash dividend of $0.25 per share. The cash dividend is payable on August 14, 2025, to shareholders of record at the close of business on August 7, 2025.
Following a review of industry practice and consultation with Bancorp’s legal counsel, certain revisions to Bancorp’s Insider Trading Policy were approved by the board of directors at a meeting on July 24, 2025. Among the revisions, the commencement of the regular quarterly blackout period was changed from three weeks prior to quarter end to two weeks prior to quarter end. Additionally, provisions were added covering the use of 10b5-1 trading plans by Bancorp employees and directors requiring pre-approval of any such plans by Bancorp and mandating that such plans conform to Securities and Exchange Commission rules.
A copy of the press release is attached to this report as Exhibit 99.1.
Section 9 - Financial Statements and Exhibits
Item 9.01 Financial Statements and Exhibits
(d) Exhibits.
| Exhibit No. | Description | Page Number | ||||||
| 99.1 | 1-12 | |||||||
| 99.2 | ||||||||
| 104 | Cover Page Interactive Data File (formatted as inline XBRL and contained in Exhibit 101) | |||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Date: | July 28, 2025 | BANK OF MARIN BANCORP | ||||||||||||
| By: | /s/ David Bonaccorso | |||||||||||||
| David Bonaccorso | ||||||||||||||
| Executive Vice President | ||||||||||||||
| and Chief Financial Officer | ||||||||||||||
EXHIBIT 99.1
 | |||||
| FOR IMMEDIATE RELEASE | MEDIA CONTACT: | ||||
| Yahaira Garcia-Perea | |||||
| Marketing & Corporate Communications Manager | |||||
| 916-823-7214 | [email protected] | |||||
BANK OF MARIN BANCORP REPORTS SECOND QUARTER FINANCIAL RESULTS
CONTINUED NET INTEREST MARGIN EXPANSION FROM ACTIVE BALANCE SHEET MANAGEMENT
NOVATO, CA, July 28, 2025 - Bank of Marin Bancorp, "Bancorp" (Nasdaq: BMRC), parent company of Bank of Marin, "Bank," announced a net loss of $8.5 million for the second quarter of 2025, compared to net income of $4.9 million for the first quarter of 2025. Diluted loss per share was $0.53 for the second quarter, compared to diluted earnings per share of $0.30 for the prior quarter. The loss was attributable to the previously announced securities repositioning which is more fully described below. Net income and diluted earnings per share for the second quarter excluding the loss on sale of securities was $4.7 million and $0.29, respectively, all other factors unchanged and with adjustments made based on the Company's blended statutory tax rate of 29.56%. See Reconciliation of GAAP and Non-GAAP Financial Measures below. If the adjustments were made using the Company's second quarter 2025 effective tax rate of 23.78%, net income and diluted earnings per share for the second quarter of 2025 excluding the loss on sale of securities was $5.7 million and $0.36, respectively, all other factors unchanged.
Comparable (non-GAAP) Excluding Loss on Sale of Securities
| Three months ended | Six months ended | ||||||||||||||||
(in thousands, except per share amounts; unaudited) | June 30, 2025 | March 31, 2025 | June 30, 2025 | June 30, 2024 | |||||||||||||
Pre-tax, pre-provision net (loss) income | |||||||||||||||||
Pre-tax, pre-provision net (loss) income (GAAP) | $ | (11,199) | $ | 6,556 | $ | (4,643) | $ | (24,903) | |||||||||
Comparable pre-tax, pre-provision net income (non-GAAP) | 7,537 | 6,556 | 14,093 | 7,639 | |||||||||||||
| Net (loss) income | |||||||||||||||||
Net (loss) income (GAAP) | (8,536) | 4,876 | (3,660) | (18,980) | |||||||||||||
| Comparable net income (non-GAAP) | 4,662 | 4,876 | 9,538 | 3,942 | |||||||||||||
Diluted (loss) earnings per share | |||||||||||||||||
Diluted (loss) earnings per share (GAAP) | (0.53) | 0.30 | (0.23) | (1.18) | |||||||||||||
| Comparable diluted earnings per share (non-GAAP) | 0.29 | 0.30 | 0.59 | 0.24 | |||||||||||||
| See complete Reconciliation of GAAP and Non-GAAP Financial Measures below | |||||||||||||||||
Related tax benefit calculated using blended statutory rate of 29.5636% | |||||||||||||||||
Concurrent with this release, Bancorp issued presentation slides providing supplemental information, some of which will be discussed during the second quarter 2025 earnings call. The earnings release and presentation slides are intended to be reviewed together and can be found online on Bank of Marin’s website at www.bankofmarin.com. under “Investor Relations.”
"We continue to take steps to improve our core financial performance as demonstrated by pre-tax pre-provision net income growth of 15% and 85% compared to the prior quarter and prior year to date, respectively," said Tim Myers, President and Chief Executive Officer. "Our recent securities repositioning, which was made possible by our strong capital and liquidity levels, should lead to further net interest margin expansion.
"With stable asset quality, the continued addition of new loan and deposit relationships, and a healthy loan pipeline, we expect further improvement in our financial performance in the coming quarters," said Myers.
Bancorp also provided the following highlights for the second quarter of 2025:
1
•As previously announced, the Bank sold available-for-sale ("AFS") securities with a book value of $185.8 million, resulting in a pre-tax loss of $18.7 million. Redeployment of the proceeds is expected to provide a 13 basis point increase in annualized net interest margin beginning in the third quarter and $0.20 of estimated earnings per share accretion over the next four quarters, assuming a 5.0% average yield on reinvestment. The securities repositioning is expected to have an approximate four-year earn back. The sale is part of a continued strategy to improve future earnings and increase return on equity. Excluding the loss on security sales, net income and diluted earnings per share for the second quarter would have been $4.7 million and $0.29, respectively, all other factors unchanged. See Reconciliation of GAAP and Non-GAAP Financial Measures below.
•The second quarter tax-equivalent net interest margin improved 7 basis points over the preceding quarter to 2.93% from 2.86%, largely due to the effects of new loan production at higher rates. The tax-equivalent net interest margin for the six months ended June 30, 2025 improved 39 basis points over the same period of the prior year due to the favorable impact of the securities repositioned in the second quarter of 2024, which resulted in higher yielding assets during the first six months of 2025.
•Return on average assets ("ROA") was (0.92)% (non-GAAP 0.50%) for the second quarter of 2025, compared to 0.53% for the prior quarter. Return on average equity ("ROE") was (7.80)% (non-GAAP 4.26%), compared to 4.52% for the prior quarter. The efficiency ratio for the second quarter of 2025 was 208.81% (non-GAAP 74.03%), compared to 76.44% last quarter. Non-GAAP ratios exclude the loss on security sales, all other factors unchanged, and with adjustments made based on the Company's blended statutory tax rate of 29.56%. See Reconciliation of GAAP and Non-GAAP Financial Measures below.
Comparable (non-GAAP) Excluding Loss on Sale of Securities
| Three months ended | Six months ended | |||||||||||||||||||
(in thousands, except per share amounts; unaudited) | June 30, 2025 | March 31, 2025 | June 30, 2024 | June 30, 2025 | June 30, 2024 | |||||||||||||||
| Return on average assets | ||||||||||||||||||||
| Return on average assets (GAAP) | (0.92) | % | 0.53 | % | (2.35) | % | (0.20) | % | (1.01) | % | ||||||||||
| Comparable return on average assets (non-GAAP) | 0.50 | % | 0.53 | % | 0.11 | % | 0.52 | % | 0.21 | % | ||||||||||
| Return on average equity | ||||||||||||||||||||
| Return on average equity (GAAP) | (7.80) | % | 4.52 | % | (20.36) | % | (1.68) | % | (8.79) | % | ||||||||||
| Comparable return on average equity (non-GAAP) | 4.26 | % | 4.52 | % | 0.95 | % | 4.39 | % | 1.83 | % | ||||||||||
| Efficiency ratio | ||||||||||||||||||||
| Efficiency ratio (GAAP) | 208.81 | % | 76.44 | % | (300.37) | % | 112.18 | % | 237.13 | % | ||||||||||
| Comparable efficiency ratio (non-GAAP) | 74.03 | % | 76.44 | % | 86.70 | % | 75.21 | % | 84.93 | % | ||||||||||
| See complete Reconciliation of GAAP and Non-GAAP Financial Measures below | ||||||||||||||||||||
Related tax benefit calculated using blended statutory rate of 29.5636% | ||||||||||||||||||||
•The average cost of total deposits and of interest-bearing deposits decreased by 1 and 3 basis points, respectively, to 1.28% and 2.24%, in the second quarter of 2025, compared to the prior quarter. Non-interest bearing deposits continued to make up a strong portion of total deposits at 42.5% as of June 30, 2025, compared to 43.2% last quarter.
•There was no provision for credit losses on loans in the second quarter of 2025 compared to a $75 thousand provision in the previous quarter. The allowance for credit losses was 1.44% of total loans at June 30, 2025, consistent with March 31, 2025.
•Classified loans were 2.95% of total loans compared to 2.77% last quarter largely due to downgrades from special mention in two commercial real estate relationships during the quarter totaling $3.9 million.
•Non-accrual loans were 1.57% of total loans at quarter-end, down from 1.59% at March 31, 2025.
•Total deposits of $3.245 billion as of June 30, 2025 compared to $3.302 billion as of March 31, 2025, the decrease mainly due to business expenses, payroll and distributions, asset purchases and seasonal outflows for tax payments.
2
•Capital was above well-capitalized regulatory thresholds with total risk-based capital ratios of 16.25% as of June 30, 2025 for Bancorp compared to 16.69% as of March 31, 2025. Bancorp's tangible common equity to tangible assets ("TCE ratio") was 9.95% as of June 30, 2025. Bancorp's TCE ratio net of after-tax unrealized losses on held-to-maturity securities as if the losses were realized1 was 8.26% as of June 30, 2025.
•Bancorp repurchased 100,000 in shares for $2.2 million during the second quarter of 2025, contributing to an increase in the book value per share to $27.21 at June 30, 2025 compared to $27.13 at March 31, 2025, and the tangible book value per share2 to $22.55 at June 30, 2025 compared to $22.48 at March 31, 2025.
•The Board of Directors declared a cash dividend of $0.25 per share on July 24, 2025, which represents the 81st consecutive quarterly dividend paid by Bancorp. The dividend is payable on August 14, 2025, to shareholders of record at the close of business on August 7, 2025.
“Expenses grew 1.1% compared to the prior quarter, which was in line with a roughly 4% annual expense growth rate in recent years," said Chief Financial Officer Dave Bonaccorso. "The expense increases included technology-related expenditures that are expected to drive future efficiency as well as costs for branch upgrades, annual events, and regulatory agencies. This increase was partially offset by a decline in contributions expense from the acceleration of most of our annual charitable contributions from the second quarter into the first quarter. Looking ahead, we expect that expenses for the second half of 2025 will be similar to the first half of the year.”
Loans and Credit Quality
Loans totaled $2.074 billion as of June 30, 2025, a net increase of $90 thousand from March 31, 2025. Loan originations for the second quarter were $68.8 million ($50.2 million funded) including $49.1 million ($41.6 million funded) in commercial loans, which includes commercial and industrial and commercial real estate loans. In the prior quarter, loan originations were $63.6 million ($47.4 million funded) including $50.2 million ($43.2 million funded) in commercial loans. The second quarter of the prior year included total originations of $94.5 million ($64.1 million funded) including $43.1 million ($30.0 million funded) in commercial loans.
Loan payoffs were $36.5 million for the second quarter of 2025, compared to $25.5 million for the first quarter of 2025 and $31.2 million in the second quarter of the prior year. In addition, there was $18.6 million of loan amortization from scheduled repayments and a net increase of $4.7 million in credit line utilization during the quarter ended June 30, 2025.
Accruing loans past due 30 to 89 days totaled $2.7 million as of June 30, 2025, compared to $6.0 million as of March 31, 2025. Contributing to the decrease were two commercial loans totaling $3.6 million, of which $2.8 million was paid off and the remaining was reclassified as non-accrual.
Non-accrual loans totaled $32.5 million, or 1.57% of the loan portfolio, at June 30, 2025, compared to $32.9 million, or 1.59% at March 31, 2025. Of the total non-accrual loans as of June 30, 2025, approximately 60% were paying as agreed, 89% were real estate secured, and all are being closely managed and monitored.
The Bank continues to uphold its prudent underwriting standards. In response to current market conditions, we continue to closely monitor our portfolio for signs of potential weakness to ensure proactive risk management and actively work towards a resolution on our classified loans. Classified loans increased by $3.7 million to $61.1 million as of June 30, 2025, from $57.4 million as of March 31, 2025. The increase was largely due to downgrades of two commercial real estate loans totaling $3.9 million, partially offset by paydowns and payoffs totaling $1.1 million.
Loans designated special mention, which are not considered adversely classified, increased by $2.6 million to $91.5 million as of June 30, 2025, from $88.9 million as of March 31, 2025. The increase was largely due to downgrades
1 Refer to the discussion and reconciliation of this non-GAAP financial measure in the section below entitled Statement Regarding Use of Non-GAAP Financial Measures.
2 Tangible book value per share is a non-GAAP financial measure used by Bancorp, as well as investors and analysts, in assessing Bancorp’s use of equity. Refer to the reconciliation of common equity to tangible common equity and resulting calculation of tangible book value per share in the section below entitled Statement Regarding Use of Non-GAAP Financial Measures.
3
from pass or watch of $9.4 million, slightly offset by contractual paydowns and payoffs of $2.6 million and the downgrade of $4.2 million to substandard.
There were $52 thousand in net charge-offs for the second quarter of 2025. This compared to net charge-offs of $825 thousand for the first quarter of 2025.
There was no provision for credit losses on loans in the second quarter of 2025 and a $75 thousand provision in the prior quarter. The ratio of allowance for credit losses to total loans was unchanged at 1.44% at June 30, 2025, compared to 1.44% at March 31, 2025.
Cash, Cash Equivalents and Restricted Cash
Total cash, cash equivalents and restricted cash were $228.9 million at June 30, 2025, a decrease of $31.1 million compared to $259.9 million at March 31, 2025 largely due to the $56.9 million decrease in deposits, partially offset by paydowns and maturities of investment securities.
Investments
The investment securities portfolio totaled $1.215 billion at June 30, 2025, a decrease of $25.4 million from March 31, 2025. The decrease was primarily the result of the sale of available-for-sale securities with a book value of $185.8 million along with principal repayments and maturities of $57.0 million and $20.1 million, respectively, offset by the purchase of $219.2 million in available-for-sale securities and the reduction of the unrealized loss of $18.3 million in the portfolio which included the reduction of $18.7 million unrealized loss that was realized and recognized in the sale. Both the available-for-sale and held-to-maturity portfolios are eligible for pledging to FHLB or the Federal Reserve as collateral for borrowing. The portfolios are comprised of high credit quality investments with average effective durations of 2.55 on available-for-sale securities and 5.58 on held-to-maturity securities. Both portfolios generate cash flows monthly from interest, principal amortization and payoffs, which supports the Bank's liquidity. Those cash flows totaled $85.4 million and $72.8 million in the second and first quarters of 2025, respectively.
Deposits
Deposits decreased $56.9 million to $3.245 billion at June 30, 2025, compared to $3.302 billion at March 31, 2025. The majority of this decrease was $46.6 million in non-interest bearing deposits, largely affected by business expenses, payroll and distributions, asset purchases and seasonal outflows for tax payments. Despite that, non-interest bearing deposits continued to make up a strong 42.5% of total deposits at June 30, 2025, compared to 43.2% at March 31, 2025. The Bank's competitive and balanced approach to relationship management and focused outreach to customers seeking alternative options for banking solutions generated over 1,000 new accounts during the second quarter, 40% of which were new relationships (excluding new reciprocal accounts).
Borrowings and Liquidity
At June 30, 2025, the Bank had no outstanding borrowings, consistent with March 31, 2025. While available as a liquidity source, we have not utilized brokered deposits. Net available funding sources, including unrestricted cash, unencumbered available-for-sale securities and total available borrowing capacity totaled $1.863 billion, or 57% of total deposits and 200% of estimated uninsured and/or uncollateralized deposits as of June 30, 2025.
4
The following table details the components of our contingent liquidity sources as of June 30, 2025.
(in millions) | Total Available | Amount Used | Net Availability | ||||||||
| Internal Sources | |||||||||||
Unrestricted cash 1 | $ | 201.1 | $ | — | $ | 201.1 | |||||
| Unencumbered securities at market value | 271.0 | — | 271.0 | ||||||||
| External Sources | |||||||||||
| FHLB line of credit | 946.0 | — | 946.0 | ||||||||
| FRB line of credit | 319.8 | — | 319.8 | ||||||||
| Lines of credit at correspondent banks | 125.0 | — | 125.0 | ||||||||
| Total Liquidity | $ | 1,862.9 | $ | — | $ | 1,862.9 | |||||
1 Excludes cash items in transit as of June 30, 2025.
Note: Brokered deposits available through third-party networks are not included above.
Capital Resources
The total risk-based capital ratio for Bancorp was 16.25% at June 30, 2025, compared to 16.69% at March 31, 2025. The decrease was largely due to losses realized on the sale of available-for-sale securities associated with the portfolio repositioning. The total risk-based capital ratio for the Bank was 15.00% at June 30, 2025, compared to 16.45% at March 31, 2025. The decrease was mainly due to a dividend of $32.0 million that was paid by the Bank to Bancorp during the second quarter of 2025.
Bancorp's tangible common equity to tangible assets ("TCE ratio") was 9.95% at June 30, 2025, compared to 9.82% at March 31, 2025. Our capital plan and point-in-time capital stress tests indicate that Bank of Marin and Bancorp capital ratios will remain above regulatory well-capitalized and internal policy minimums throughout a five-year forecast horizon and across stress scenarios such as additional unrealized losses on the investment portfolio, additional deposit growth or decline, loan credit quality deterioration, and potential share repurchases.
Earnings
Net Interest Income
Net interest income totaled $25.9 million for the second quarter of 2025, a $966 thousand increase from the prior quarter. This was driven by an increase of $9.6 million in average earning assets including a $678 thousand increase in loan interest income due to the continued replenishment of the loan portfolio at higher rates.
The tax-equivalent net interest margin increased to 2.93% for the second quarter of 2025, compared to 2.86% for the prior quarter. Loan originations at higher rates contributed to 4 basis points growth in the second quarter. Higher average interest-earning deposit balances with banks increased the margin by 2 basis points and the repositioning of securities added 1 basis point to the margin, with more impact to come.
Non-Interest Income (Loss)
Non-interest income was in a loss position of $15.6 million for the second quarter of 2025, compared to net interest income of $2.9 million for the prior quarter. The decrease of $18.5 million from the prior quarter was primarily attributable to a loss of $18.7 million on the sale of available-for-sale investment securities during the second quarter, slightly offset by the recording of a bank owned life insurance death benefit receivable. Excluding the loss on sale of securities, non-interest income for the quarter was $3.1 million, an increase of $241 thousand from prior quarter.
Non-Interest Expense
Non-interest expense totaled $21.5 million for the second quarter of 2025, compared to $21.3 million for the prior quarter, an increase of $226 thousand. This was mainly due to increased information technology expense and other expenses including the annual shareholders meeting and other events, partially offset by reduced charitable contribution expense in the second quarter which was paid out mostly in the first quarter for the 2025 year.
5
Statement Regarding use of Non-GAAP Financial Measures
Financial results are presented in accordance with GAAP and with reference to certain non-GAAP financial measures. Management believes that, given industry turmoil that largely began in the first quarter of 2023, the presentation of Bancorp's non-GAAP TCE ratio reflecting the after tax impact of unrealized losses on held-to-maturity securities provides useful supplemental information to investors because it reflects the level of capital remaining after a hypothetical liquidation of the entire securities portfolio. In addition, management believes that providing selected financial measures excluding the loss on sale of securities discussed above is useful to investors as the strategic short-term loss taken for long-term profitability makes the operational performance difficult to compare to other periods. Because there are limits to the usefulness of this or any other non-GAAP measure to investors, Bancorp encourages readers to consider its annual and quarterly consolidated financial statements and notes related thereto for their entirety, as filed with the Securities and Exchange Commission, and not to rely on any single financial measure. A reconciliation of the GAAP financial measures to comparable non-GAAP financial measures is presented below.
Reconciliation of GAAP and Non-GAAP Financial Measures
(in thousands, except per share amounts; unaudited) | June 30, 2025 | March 31, 2025 | December 31, 2024 | |||||||||||
| Tangible Common Equity - Bancorp | ||||||||||||||
| Total stockholders' equity | $ | 438,538 | $ | 439,566 | $ | 435,407 | ||||||||
| Goodwill and core deposit intangible | (75,098) | (75,319) | (75,546) | |||||||||||
| Total TCE | a | 363,440 | 364,247 | 359,861 | ||||||||||
Unrealized losses on HTM securities, net of tax1 | (74,625) | (77,768) | (89,171) | |||||||||||
Unrealized losses on HTM securities included in AOCI, net of tax 2 | 7,205 | 7,462 | 7,701 | |||||||||||
| TCE, net of unrealized losses on HTM securities (non-GAAP) | b | $ | 296,020 | $ | 293,941 | $ | 278,391 | |||||||
| Total assets | $ | 3,726,193 | $ | 3,784,243 | $ | 3,701,335 | ||||||||
| Goodwill and core deposit intangible | (75,098) | (75,319) | (75,546) | |||||||||||
| Total tangible assets | c | 3,651,095 | 3,708,924 | 3,625,789 | ||||||||||
Unrealized losses on HTM securities, net of tax1 | (74,625) | (77,768) | (89,171) | |||||||||||
| Unrealized losses on HTM securities included in AOCI, net of tax | 7,205 | 7,462 | 7,701 | |||||||||||
| Total tangible assets, net of unrealized losses on HTM securities (non-GAAP) | d | $ | 3,583,675 | $ | 3,638,618 | $ | 3,544,319 | |||||||
| Bancorp TCE ratio | a / c | 10.0 | % | 9.8 | % | 9.9 | % | |||||||
| Bancorp TCE ratio, net of unrealized losses on HTM securities (non-GAAP) | b / d | 8.3 | % | 8.1 | % | 7.9 | % | |||||||
Tangible Book Value Per Share | ||||||||||||||
Common shares outstanding | e | 16,116 | 16,203 | 16,089 | ||||||||||
Book value per share | $ | 27.21 | $ | 27.13 | $ | 27.06 | ||||||||
Tangible book value per share | a / e | $ | 22.55 | $ | 22.48 | $ | 22.37 | |||||||
1 Unrealized losses on held-to-maturity securities as of June 30, 2025, March 31, 2025 and December 31, 2024 of $105.9 million, $110.4 million and $126.6 million, respectively, including the unrealized losses that resulted from the transfer of securities from AFS to HTM, net of an estimated $31.3 million, $32.6 million and $37.4 million, respectively, in deferred tax benefits based on a blended state and federal statutory tax rate of 29.56%. 2 The remaining unrealized losses that resulted from the transfer of securities from AFS to HTM, as of June 30, 2025, March 31, 2025 and December 31, 2024, net of an estimated $3.0 million, $3.1 million and $3.2 million, respectively, in deferred tax benefits based on a blended state and federal statutory tax rate of 29.56% are added back as they are already included in AOCI. | ||||||||||||||
6
Reconciliation of GAAP and Non-GAAP Financial Measures (continued)
(in thousands, except per share amounts; unaudited) | Three months ended | Six months ended | ||||||||||||||||||
Pre-tax, pre-provision net (loss) income | June 30, 2025 | March 31, 2025 | June 30, 2024 | June 30, 2025 | June 30, 2024 | |||||||||||||||
| (Loss) income before (benefit from) provision for income taxes | $ | (11,199) | $ | 6,481 | $ | (34,382) | $ | (4,718) | $ | (30,453) | ||||||||||
| Provision for credit losses on loans | — | 75 | 5,200 | 75 | 5,550 | |||||||||||||||
Pre-tax, pre-provision net (loss) income (GAAP) | (11,199) | 6,556 | (29,182) | (4,643) | (24,903) | |||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Losses on sale of investment securities from portfolio repositioning | 18,736 | — | 32,542 | 18,736 | 32,542 | |||||||||||||||
Comparable pre-tax, pre-provision net income (non-GAAP) | $ | 7,537 | $ | 6,556 | $ | 3,360 | $ | 14,093 | $ | 7,639 | ||||||||||
Net (loss) income | ||||||||||||||||||||
Net (loss) income (GAAP) | $ | (8,536) | $ | 4,876 | $ | (21,902) | $ | (3,660) | $ | (18,980) | ||||||||||
| Adjustments: | ||||||||||||||||||||
| Losses on sale of investment securities from portfolio repositioning | 18,736 | — | 32,542 | 18,736 | 32,542 | |||||||||||||||
Related income tax benefit1 | (5,538) | — | (9,620) | (5,538) | (9,620) | |||||||||||||||
| Adjustments, net of taxes | 13,198 | — | 22,922 | 13,198 | 22,922 | |||||||||||||||
| Comparable net income (non-GAAP) | $ | 4,662 | $ | 4,876 | $ | 1,020 | $ | 9,538 | $ | 3,942 | ||||||||||
Diluted (loss) earnings per share | ||||||||||||||||||||
| Weighted average diluted shares | 15,989 | 16,002 | 16,108 | 15,983 | 16,095 | |||||||||||||||
Diluted (loss) earnings per share (GAAP) | $ | (0.53) | $ | 0.30 | $ | (1.36) | $ | (0.23) | $ | (1.18) | ||||||||||
| Comparable diluted earnings per share (non-GAAP) | $ | 0.29 | $ | 0.30 | $ | 0.06 | $ | 0.60 | $ | 0.24 | ||||||||||
| Return on average assets | ||||||||||||||||||||
| Average assets | $ | 3,737,794 | $ | 3,728,066 | $ | 3,751,159 | $ | 3,732,957 | $ | 3,781,214 | ||||||||||
| Return on average assets (GAAP) | (0.92) | % | 0.53 | % | (2.35) | % | (0.20) | % | (1.01) | % | ||||||||||
| Comparable return on average assets (non-GAAP) | 0.50 | % | 0.53 | % | 0.11 | % | 0.52 | % | 0.21 | % | ||||||||||
| Return on average equity | ||||||||||||||||||||
| Average stockholders' equity | $ | 439,187 | $ | 437,176 | $ | 432,962 | $ | 438,187 | $ | 434,332 | ||||||||||
| Return on average equity (GAAP) | (7.80) | % | 4.52 | % | (20.36) | % | (1.68) | % | (8.79) | % | ||||||||||
| Comparable return on average equity (non-GAAP) | 4.26 | % | 4.52 | % | 0.95 | % | 4.39 | % | 1.83 | % | ||||||||||
| Efficiency ratio | ||||||||||||||||||||
| Non-interest expense | $ | 21,490 | $ | 21,264 | $ | 21,894 | $ | 42,754 | $ | 43,063 | ||||||||||
| Net interest income | $ | 25,912 | $ | 24,946 | $ | 22,467 | $ | 50,858 | $ | 45,161 | ||||||||||
| Non-interest income (GAAP) | $ | (15,621) | $ | 2,874 | $ | (29,755) | $ | (12,747) | $ | (27,001) | ||||||||||
| Losses on sale of investment securities from portfolio repositioning | 18,736 | — | 32,542 | 18,736 | 32,542 | |||||||||||||||
| Non-interest income (non-GAAP) | $ | 3,115 | $ | 2,874 | $ | 2,787 | $ | 5,989 | $ | 5,541 | ||||||||||
| Efficiency ratio (GAAP) | 208.81 | % | 76.44 | % | (300.37) | % | 112.18 | % | 237.13 | % | ||||||||||
| Comparable efficiency ratio (non-GAAP) | 74.03 | % | 76.44 | % | 86.70 | % | 75.21 | % | 84.93 | % | ||||||||||
1Related tax benefit calculated using blended statutory rate of 29.5636% | ||||||||||||||||||||
Share Repurchase Program
Bancorp repurchased 100,000 shares totaling $2.2 million at an average price of $21.72 per share during the second quarter of 2025 under our existing share repurchase program expiring July 31, 2025. As announced in the Form 8-K filed simultaneously today, the board of directors has authorized the repurchase of up to $25.0 million of its common stock effective July 24, 2025 through July 31, 2027. This stock buyback program replaces the existing program approved in 2023 and expiring July 31, 2025 under which Bancorp repurchased $6.4 million worth in shares.
Insider Trading Policy Revisions
Following a review of industry practice and consultation with Bancorp’s legal counsel, certain revisions to Bancorp’s Insider Trading Policy were approved by the board of directors at a meeting on July 24, 2025. Among the revisions, the commencement of the regular quarterly blackout period was changed from three weeks prior to quarter end to two weeks prior to quarter end. Additionally, provisions were added covering the use of 10b5-1 trading plans by
7
Bancorp employees and directors requiring pre-approval of any such plans by Bancorp and mandating that such plans conform to Securities and Exchange Commission rules.
Earnings Call and Webcast Information
Bank of Marin Bancorp (Nasdaq: BMRC) will present its second quarter financial results call via webcast on Monday, July 28, 2025 at 8:30 a.m. PT/11:30 a.m. ET. Investors can listen to the webcast online through Bank of Marin’s website at www.bankofmarin.com. under “Investor Relations.” To listen to the live call, please go to the website at least 15 minutes early to register, download and install any necessary audio software. For those who cannot listen to the live broadcast, a replay will be available at the same website location shortly after the call. Closed captioning will be available during the live webcast, as well as on the webcast replay.
About Bank of Marin Bancorp
Founded in 1990 and headquartered in Novato, Bank of Marin is the wholly owned subsidiary of Bank of Marin Bancorp (Nasdaq: BMRC). A leading business and community bank with assets of $3.7 billion, Bank of Marin provides commercial and personal banking, specialty lending, and wealth management and trust services throughout its network of 27 branches and eight commercial banking offices serving Northern California. Specializing in providing legendary service to its clients and investing in its local communities, Bank of Marin has consistently been ranked one of the “Top Corporate Philanthropists" by San Francisco Business Times since 2003, was inducted into NorthBay Biz’s “Best of” Hall of Fame in 2024, and ranked top 13 in Sacramento Business Journal’s 2025 Corporate Direct Giving List.. Bank of Marin Bancorp is included in the Russell 2000 Small-Cap Index and Nasdaq ABA Community Bank Index. For more information, visit www.bankofmarin.com.
Forward-Looking Statements
This release may contain certain forward-looking statements that are based on management's current expectations regarding economic, legislative, and regulatory issues that may impact Bancorp's earnings in future periods. Forward-looking statements can be identified by the fact that they do not relate strictly to historical or current facts. They often include the words “believe,” “expect,” “intend,” “estimate” or words of similar meaning, or future or conditional verbs such as “will,” “would,” “should,” “could” or “may.” Factors that could cause future results to vary materially from current management expectations include, but are not limited to, general economic conditions and the economic uncertainty in the United States and abroad, including economic or other disruptions to financial markets caused by the Trump administration's approach to tariffs and trade, acts of terrorism, war or other conflicts, impacts from inflation, supply chain disruptions, changes in interest rates (including the actions taken by the Federal Reserve to control inflation), California's unemployment rate, deposit flows, real estate values, and expected future cash flows on loans and securities; the impact of adverse developments at other banks, including bank failures, that impact general sentiment regarding the stability and liquidity of banks; costs or effects of acquisitions; competition; changes in accounting principles, policies or guidelines; changes in legislation or regulation; natural disasters (such as wildfires and earthquakes in our area); adverse weather conditions; interruptions of utility service in our markets for sustained periods; and other economic, competitive, governmental, regulatory and technological factors (including external fraud and cybersecurity threats) affecting our operations, pricing, products and services; and successful integration of acquisitions. These and other important factors are detailed in various securities law filings made periodically by Bancorp, copies of which are available from Bancorp without charge. Bancorp undertakes no obligation to release publicly the result of any revisions to these forward-looking statements that may be made to reflect events or circumstances after the date of this press release or to reflect the occurrence of unanticipated events.
8
| BANK OF MARIN BANCORP FINANCIAL HIGHLIGHTS | ||||||||||||||||||||
| Three months ended | Six months ended | |||||||||||||||||||
| (in thousands, except per share amounts; unaudited) | June 30, 2025 | March 31, 2025 | June 30, 2024 | June 30, 2025 | June 30, 2024 | |||||||||||||||
| Selected operating data and performance ratios: | ||||||||||||||||||||
| Net income (loss) | $ | (8,536) | $ | 4,876 | $ | (21,902) | $ | (3,660) | $ | (18,980) | ||||||||||
| Diluted earnings (loss) per common share | $ | (0.53) | $ | 0.30 | $ | (1.36) | $ | (0.23) | $ | (1.18) | ||||||||||
| Return on average assets | (0.92) | % | 0.53 | % | (2.35) | % | (0.20) | % | (1.01) | % | ||||||||||
| Return on average equity | (7.80) | % | 4.52 | % | (20.36) | % | (1.68) | % | (8.79) | % | ||||||||||
| Efficiency ratio | 208.81 | % | 76.44 | % | (300.37) | % | 112.18 | % | 237.13 | % | ||||||||||
Tax-equivalent net interest margin | 2.93 | % | 2.86 | % | 2.52 | % | 2.90 | % | 2.51 | % | ||||||||||
| Cost of deposits | 1.28 | % | 1.29 | % | 1.45 | % | 1.28 | % | 1.41 | % | ||||||||||
Cost of funds | 1.28 | % | 1.29 | % | 1.46 | % | 1.28 | % | 1.42 | % | ||||||||||
Net charge-offs (recoveries) | $ | 52 | $ | 825 | $ | 26 | $ | 877 | $ | 47 | ||||||||||
Net charge-offs to average loans | NM | 0.04 | % | NM | 0.04 | % | NM | |||||||||||||
| (in thousands; unaudited) | June 30, 2025 | March 31, 2025 | December 31, 2024 | ||||||||
| Selected financial condition data: | |||||||||||
| Total assets | $ | 3,726,193 | $ | 3,784,243 | $ | 3,701,335 | |||||
| Loans: | |||||||||||
| Commercial and industrial | $ | 154,576 | $ | 147,291 | $ | 152,263 | |||||
| Real estate: | |||||||||||
| Commercial owner-occupied | 320,439 | 319,112 | 321,962 | ||||||||
| Commercial non-owner occupied | 1,285,803 | 1,292,281 | 1,273,596 | ||||||||
| Construction | 25,018 | 25,745 | 36,970 | ||||||||
| Home equity | 95,242 | 89,240 | 88,325 | ||||||||
| Other residential | 127,946 | 133,960 | 143,207 | ||||||||
| Installment and other consumer loans | 64,614 | 65,919 | 66,933 | ||||||||
| Total loans | $ | 2,073,638 | $ | 2,073,548 | $ | 2,083,256 | |||||
Non-accrual loans: 1 | |||||||||||
| Commercial and industrial | $ | 2,793 | $ | 2,845 | $ | 2,845 | |||||
| Real estate: | |||||||||||
| Commercial owner-occupied | 1,554 | 1,493 | $ | 1,537 | |||||||
| Commercial non-owner occupied | 26,012 | 26,826 | 28,525 | ||||||||
| Home equity | 1,456 | 1,353 | 752 | ||||||||
| Other residential | 282 | 206 | — | ||||||||
| Installment and other consumer loans | 375 | 198 | 222 | ||||||||
| Total non-accrual loans | $ | 32,472 | $ | 32,921 | $ | 33,881 | |||||
| Non-accrual loans to total loans | 1.57 | % | 1.59 | % | 1.63 | % | |||||
| Classified loans (graded substandard and doubtful) | $ | 61,090 | $ | 57,435 | $ | 45,104 | |||||
| Classified loans as a percentage of total loans | 2.95 | % | 2.77 | % | 2.17 | % | |||||
| Total accruing loans 30-89 days past due | $ | 2,702 | $ | 5,965 | $ | 2,231 | |||||
Total accruing loans 90+ days past due 1 | $ | — | $ | — | $ | — | |||||
| Allowance for credit losses to total loans | 1.44 | % | 1.44 | % | 1.47 | % | |||||
| Allowance for credit losses to non-accrual loans | 0.92x | 0.91x | 0.90x | ||||||||
| Total deposits | $ | 3,245,048 | $ | 3,301,971 | $ | 3,220,015 | |||||
| Loan-to-deposit ratio | 63.90 | % | 62.80 | % | 64.70 | % | |||||
| Stockholders' equity | $ | 438,538 | $ | 439,566 | $ | 435,407 | |||||
| Book value per share | $ | 27.21 | $ | 27.13 | $ | 27.06 | |||||
Tangible book value per share | $ | 22.55 | $ | 22.48 | $ | 22.37 | |||||
Tangible common equity to tangible assets - Bank | 9.09 | % | 9.66 | % | 9.64 | % | |||||
Tangible common equity to tangible assets - Bancorp | 9.95 | % | 9.82 | % | 9.93 | % | |||||
| Total risk-based capital ratio - Bank | 15.00 | % | 16.45 | % | 16.13 | % | |||||
| Total risk-based capital ratio - Bancorp | 16.25 | % | 16.69 | % | 16.54 | % | |||||
| Full-time equivalent employees | 302 | 291 | 285 | ||||||||
1 There were no non-performing loans over 90 days past due and accruing interest as of June 30, 2025, March 31, 2025 and December 31, 2024. | |||||||||||
NM - Not meaningful | |||||||||||
9
BANK OF MARIN BANCORP CONSOLIDATED STATEMENTS OF CONDITION | ||
| (in thousands, except share data; unaudited) | June 30, 2025 | March 31, 2025 | December 31, 2024 | ||||||||
| Assets | |||||||||||
| Cash, cash equivalents and restricted cash | $ | 228,863 | $ | 259,924 | $ | 137,304 | |||||
| Investment securities: | |||||||||||
Held-to-maturity, at amortized cost (net of zero allowance for credit losses at June 30, 2025, March 31, 2025 and December 31, 2024) | 823,314 | 834,640 | 879,199 | ||||||||
Available-for-sale (at fair value; amortized cost of $402,205, $434,479 and $419,292 at June 30, 2025, March 31, 2025 and December 31, 2024, respectively; net of zero allowance for credit losses at June 30, 2025, March 31, 2025 and December 31, 2024) | 391,985 | 406,009 | 387,534 | ||||||||
| Total investment securities | 1,215,299 | 1,240,649 | 1,266,733 | ||||||||
| Loans, at amortized cost | 2,073,638 | 2,073,548 | 2,083,256 | ||||||||
| Allowance for credit losses on loans | (29,854) | (29,906) | (30,656) | ||||||||
| Loans, net of allowance for credit losses on loans | 2,043,784 | 2,043,642 | 2,052,600 | ||||||||
| Goodwill | 72,754 | 72,754 | 72,754 | ||||||||
| Bank-owned life insurance | 70,432 | 71,066 | 71,026 | ||||||||
| Operating lease right-of-use assets | 18,316 | 19,076 | 19,025 | ||||||||
| Bank premises and equipment, net | 7,472 | 6,824 | 6,832 | ||||||||
| Core deposit intangible, net | 2,344 | 2,565 | 2,792 | ||||||||
| Interest receivable and other assets | 66,929 | 67,743 | 72,269 | ||||||||
| Total assets | $ | 3,726,193 | $ | 3,784,243 | $ | 3,701,335 | |||||
| Liabilities and Stockholders' Equity | |||||||||||
| Liabilities | |||||||||||
| Deposits: | |||||||||||
| Non-interest bearing | $ | 1,379,814 | $ | 1,426,446 | $ | 1,399,900 | |||||
| Interest bearing: | |||||||||||
| Transaction accounts | 180,444 | 184,322 | 198,301 | ||||||||
| Savings accounts | 221,172 | 228,038 | 225,691 | ||||||||
| Money market accounts | 1,246,013 | 1,246,739 | 1,153,746 | ||||||||
| Time accounts | 217,605 | 216,426 | 242,377 | ||||||||
| Total deposits | 3,245,048 | 3,301,971 | 3,220,015 | ||||||||
| Borrowings and other obligations | 77 | 116 | 154 | ||||||||
| Operating lease liabilities | 20,668 | 21,497 | 21,509 | ||||||||
| Interest payable and other liabilities | 21,862 | 21,093 | 24,250 | ||||||||
| Total liabilities | 3,287,655 | 3,344,677 | 3,265,928 | ||||||||
| Stockholders' Equity | |||||||||||
Preferred stock, no par value, Authorized - 5,000,000 shares, none issued | — | — | — | ||||||||
Common stock, no par value, Authorized - 30,000,000 shares; issued and outstanding - 16,116,470, 16,202,869 and 16,089,454 at June 30, 2025, March 31, 2025 and December 31, 2024, respectively | 214,713 | 216,263 | 215,511 | ||||||||
| Retained earnings | 238,225 | 250,815 | 249,964 | ||||||||
| Accumulated other comprehensive loss, net of taxes | (14,400) | (27,512) | (30,068) | ||||||||
| Total stockholders' equity | 438,538 | 439,566 | 435,407 | ||||||||
| Total liabilities and stockholders' equity | $ | 3,726,193 | $ | 3,784,243 | $ | 3,701,335 | |||||
10
BANK OF MARIN BANCORP CONSOLIDATED STATEMENTS OF COMPREHENSIVE INCOME | ||
| Three months ended | Six months ended | ||||||||||||||||
| (in thousands, except per share amounts; unaudited) | June 30, 2025 | March 31, 2025 | June 30, 2025 | June 30, 2024 | |||||||||||||
| Interest income | |||||||||||||||||
| Interest and fees on loans | $ | 25,861 | $ | 25,183 | $ | 51,044 | $ | 50,129 | |||||||||
| Interest on investment securities | 8,423 | 8,261 | 16,684 | 17,104 | |||||||||||||
| Interest on federal funds sold and due from banks | 2,004 | 1,795 | 3,799 | 1,245 | |||||||||||||
| Total interest income | 36,288 | 35,239 | 71,527 | 68,478 | |||||||||||||
| Interest expense | |||||||||||||||||
| Interest on interest-bearing transaction accounts | 351 | 343 | 694 | 535 | |||||||||||||
| Interest on savings accounts | 587 | 533 | 1,120 | 882 | |||||||||||||
| Interest on money market accounts | 7,878 | 7,626 | 15,504 | 17,090 | |||||||||||||
| Interest on time accounts | 1,559 | 1,790 | 3,349 | 4,571 | |||||||||||||
| Interest on borrowings and other obligations | 1 | 1 | 2 | 239 | |||||||||||||
| Total interest expense | 10,376 | 10,293 | 20,669 | 23,317 | |||||||||||||
| Net interest income | 25,912 | 24,946 | 50,858 | 45,161 | |||||||||||||
| Provision for credit losses on loans | — | 75 | 75 | 5,550 | |||||||||||||
| Net interest income after provision for credit losses | 25,912 | 24,871 | 50,783 | 39,611 | |||||||||||||
| Non-interest income | |||||||||||||||||
| Earnings on bank-owned life insurance, net | 667 | 544 | 1,211 | 856 | |||||||||||||
| Wealth management and trust services | 612 | 563 | 1,175 | 1,138 | |||||||||||||
| Service charges on deposit accounts | 550 | 548 | 1,098 | 1,070 | |||||||||||||
| Debit card interchange fees, net | 410 | 396 | 806 | 852 | |||||||||||||
| Dividends on Federal Home Loan Bank stock | 362 | 375 | 737 | 743 | |||||||||||||
| Merchant interchange fees, net | 90 | 96 | 186 | 177 | |||||||||||||
| Losses on sale of investment securities | (18,736) | — | (18,736) | (32,542) | |||||||||||||
| Other income | 424 | 352 | 776 | 705 | |||||||||||||
| Total non-interest income | (15,621) | 2,874 | (12,747) | (27,001) | |||||||||||||
| Non-interest expense | |||||||||||||||||
| Salaries and related benefits | 12,045 | 12,050 | 24,095 | 24,448 | |||||||||||||
| Occupancy and equipment | 2,226 | 2,106 | 4,332 | 4,018 | |||||||||||||
| Deposit network fees | 1,054 | 932 | 1,986 | 1,761 | |||||||||||||
| Data processing | 1,041 | 1,136 | 2,177 | 2,075 | |||||||||||||
| Professional services | 908 | 937 | 1,845 | 2,121 | |||||||||||||
| Information technology | 563 | 413 | 976 | 850 | |||||||||||||
| Federal Deposit Insurance Corporation insurance | 421 | 388 | 809 | 861 | |||||||||||||
| Depreciation and amortization | 320 | 322 | 642 | 767 | |||||||||||||
| Directors' expense | 279 | 304 | 583 | 623 | |||||||||||||
| Amortization of core deposit intangible | 220 | 227 | 447 | 497 | |||||||||||||
| Charitable contributions | 116 | 403 | 519 | 617 | |||||||||||||
| Other expense | 2,297 | 2,046 | 4,343 | 4,425 | |||||||||||||
| Total non-interest expense | 21,490 | 21,264 | 42,754 | 43,063 | |||||||||||||
| (Loss) income before (benefit from) provision for income taxes | (11,199) | 6,481 | (4,718) | (30,453) | |||||||||||||
| (Benefit from) provision for income taxes | (2,663) | 1,605 | (1,058) | (11,473) | |||||||||||||
| Net (loss) income | $ | (8,536) | $ | 4,876 | $ | (3,660) | $ | (18,980) | |||||||||
| Net (loss) income per common share | |||||||||||||||||
| Basic | $ | (0.53) | $ | 0.31 | $ | (0.23) | $ | (1.18) | |||||||||
| Diluted | $ | (0.53) | $ | 0.30 | $ | (0.23) | $ | (1.18) | |||||||||
| Weighted average shares: | |||||||||||||||||
| Basic | 15,989 | 15,977 | 15,983 | 16,095 | |||||||||||||
| Diluted | 15,989 | 16,002 | 15,983 | 16,095 | |||||||||||||
| Comprehensive income: | |||||||||||||||||
| Net (loss) income | $ | (8,536) | $ | 4,876 | $ | (3,660) | $ | (18,980) | |||||||||
| Other comprehensive income: | |||||||||||||||||
| Change in net unrealized gains or losses on available-for-sale securities | (486) | 3,289 | 2,803 | (4,009) | |||||||||||||
| Reclassification adjustment for realized losses on available-for-sale securities in net income | 18,736 | — | 18,736 | 32,542 | |||||||||||||
| Reclassification adjustment for gains or losses on fair value hedges | — | — | — | 1,499 | |||||||||||||
| Amortization of net unrealized losses on securities transferred from available-for-sale to held-to-maturity | 365 | 340 | 705 | 764 | |||||||||||||
| Other comprehensive income, before tax | 18,615 | 3,629 | 22,244 | 30,796 | |||||||||||||
| Deferred tax expense | 5,503 | 1,073 | 6,576 | 9,097 | |||||||||||||
| Other comprehensive income, net of tax | 13,112 | 2,556 | 15,668 | 21,699 | |||||||||||||
| Total comprehensive income | $ | 4,576 | $ | 7,432 | $ | 12,008 | $ | 2,719 | |||||||||
11
| BANK OF MARIN BANCORP | ||
| AVERAGE STATEMENTS OF CONDITION AND ANALYSIS OF NET INTEREST INCOME | ||
| Three months ended | Three months ended | |||||||||||||||||||||||||
| June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
| Interest | Interest | |||||||||||||||||||||||||
| Average | Income/ | Yield/ | Average | Income/ | Yield/ | |||||||||||||||||||||
| (in thousands) | Balance | Expense | Rate | Balance | Expense | Rate | ||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||
Interest-earning deposits with banks 1 | $ | 180,730 | $ | 2,004 | 4.39 | % | $ | 163,446 | $ | 1,795 | 4.39 | % | ||||||||||||||
Investment securities 2, 3 | 1,266,317 | 8,495 | 2.68 | % | 1,273,422 | 8,331 | 2.62 | % | ||||||||||||||||||
Loans 1, 3, 4, 5 | 2,073,110 | 25,965 | 4.95 | % | 2,073,739 | 25,289 | 4.88 | % | ||||||||||||||||||
Total interest-earning assets 1 | 3,520,157 | 36,464 | 4.10 | % | 3,510,607 | 35,415 | 4.04 | % | ||||||||||||||||||
| Cash and non-interest-bearing due from banks | 37,721 | 37,493 | ||||||||||||||||||||||||
| Bank premises and equipment, net | 7,259 | 6,831 | ||||||||||||||||||||||||
| Interest receivable and other assets, net | 172,657 | 173,135 | ||||||||||||||||||||||||
| Total assets | $ | 3,737,794 | $ | 3,728,066 | ||||||||||||||||||||||
| Liabilities and Stockholders' Equity | ||||||||||||||||||||||||||
| Interest-bearing transaction accounts | $ | 187,297 | $ | 351 | 0.75 | % | $ | 191,089 | $ | 343 | 0.73 | % | ||||||||||||||
| Savings accounts | 222,524 | 587 | 1.06 | % | 227,098 | 533 | 0.95 | % | ||||||||||||||||||
| Money market accounts | 1,227,506 | 7,878 | 2.57 | % | 1,192,956 | 7,626 | 2.59 | % | ||||||||||||||||||
| Time accounts including CDARS | 218,150 | 1,559 | 2.87 | % | 228,018 | 1,790 | 3.18 | % | ||||||||||||||||||
Borrowings and other obligations 1 | 91 | 1 | 3.39 | % | 130 | 1 | 2.86 | % | ||||||||||||||||||
| Total interest-bearing liabilities | 1,855,568 | 10,376 | 2.24 | % | 1,839,291 | 10,293 | 2.27 | % | ||||||||||||||||||
| Demand accounts | 1,398,570 | 1,406,648 | ||||||||||||||||||||||||
| Interest payable and other liabilities | 44,469 | 44,951 | ||||||||||||||||||||||||
| Stockholders' equity | 439,187 | 437,176 | ||||||||||||||||||||||||
| Total liabilities & stockholders' equity | $ | 3,737,794 | $ | 3,728,066 | ||||||||||||||||||||||
Tax-equivalent net interest income/margin 1 | $ | 26,088 | 2.93 | % | $ | 25,122 | 2.86 | % | ||||||||||||||||||
Reported net interest income/margin 1 | $ | 25,912 | 2.91 | % | $ | 24,946 | 2.84 | % | ||||||||||||||||||
| Tax-equivalent net interest rate spread | 1.86 | % | 1.77 | % | ||||||||||||||||||||||
| Six months ended | Six months ended | |||||||||||||||||||||||||
| June 30, 2025 | June 30, 2024 | |||||||||||||||||||||||||
| Interest | Interest | |||||||||||||||||||||||||
| Average | Income/ | Yield/ | Average | Income/ | Yield/ | |||||||||||||||||||||
| (in thousands) | Balance | Expense | Rate | Balance | Expense | Rate | ||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||
Interest-earning deposits with banks 1 | $ | 172,136 | $ | 3,799 | 4.39 | % | $ | 45,613 | $ | 1,245 | 5.40 | % | ||||||||||||||
Investment securities 2, 3 | 1,269,850 | 16,821 | 2.65 | % | 1,480,462 | 17,247 | 2.33 | % | ||||||||||||||||||
Loans 1, 3, 4, 5 | 2,073,423 | 51,254 | 4.92 | % | 2,063,351 | 50,346 | 4.83 | % | ||||||||||||||||||
Total interest-earning assets 1 | 3,515,409 | 71,874 | 4.07 | % | 3,589,426 | 68,838 | 3.79 | % | ||||||||||||||||||
| Cash and non-interest-bearing due from banks | 37,608 | 36,275 | ||||||||||||||||||||||||
| Bank premises and equipment, net | 7,046 | 7,564 | ||||||||||||||||||||||||
| Interest receivable and other assets, net | 172,894 | 147,949 | ||||||||||||||||||||||||
| Total assets | $ | 3,732,957 | $ | 3,781,214 | ||||||||||||||||||||||
| Liabilities and Stockholders' Equity | ||||||||||||||||||||||||||
| Interest-bearing transaction accounts | $ | 189,182 | $ | 694 | 0.74 | % | $ | 206,268 | $ | 535 | 0.52 | % | ||||||||||||||
| Savings accounts | 224,798 | 1,120 | 1.00 | % | 228,559 | 882 | 0.78 | % | ||||||||||||||||||
| Money market accounts | 1,210,327 | 15,504 | 2.58 | % | 1,152,492 | 17,090 | 2.98 | % | ||||||||||||||||||
| Time accounts including CDARS | 223,057 | 3,349 | 3.03 | % | 262,598 | 4,571 | 3.50 | % | ||||||||||||||||||
Borrowings and other obligations 1 | 110 | 2 | 3.08 | % | 9,116 | 239 | 5.18 | % | ||||||||||||||||||
| Total interest-bearing liabilities | 1,847,474 | 20,669 | 2.26 | % | 1,859,033 | 23,317 | 2.52 | % | ||||||||||||||||||
| Demand accounts | 1,402,587 | 1,440,114 | ||||||||||||||||||||||||
| Interest payable and other liabilities | 44,709 | 47,735 | ||||||||||||||||||||||||
| Stockholders' equity | 438,187 | 434,332 | ||||||||||||||||||||||||
| Total liabilities & stockholders' equity | $ | 3,732,957 | $ | 3,781,214 | ||||||||||||||||||||||
Tax-equivalent net interest income/margin 1 | $ | 51,205 | 2.90 | % | $ | 45,521 | 2.51 | % | ||||||||||||||||||
Reported net interest income/margin 1 | $ | 50,858 | 2.88 | % | $ | 45,161 | 2.49 | % | ||||||||||||||||||
| Tax-equivalent net interest rate spread | 1.81 | % | 1.27 | % | ||||||||||||||||||||||
1 Interest income/expense is divided by actual number of days in the period times 360 days to correspond to stated interest rate terms, where applicable. | ||||||||||||||||||||||||||
2 Yields on available-for-sale securities are calculated based on amortized cost balances rather than fair value, as changes in fair value are reflected as a component of stockholders' equity. Investment security interest is earned on 30/360 day basis monthly. | ||||||||||||||||||||||||||
3 Yields and interest income on tax-exempt securities and loans are presented on a taxable-equivalent basis using the Federal statutory rate of 21 percent. | ||||||||||||||||||||||||||
4 Average balances on loans outstanding include non-performing loans. The amortized portion of net loan origination fees is included in interest income on loans, representing an adjustment to the yield. | ||||||||||||||||||||||||||
5 Net loan origination costs in interest income totaled $399 thousand and $364 thousand for the three months ended June 30, 2025 and March 31, 2025, and totaled $764 thousand and $811 thousand for the six months ended June 30, 2025 and 2024, respectively. | ||||||||||||||||||||||||||
12
Second Quarter 2025 Earnings Presentation
2 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Forward-Looking Statements This discussion of financial results includes forward-looking statements within the meaning of Section 27A of the Securities Act of 1933, as amended, (the "1933 Act") and Section 21E of the Securities Exchange Act of 1934, as amended, (the "1934 Act"). Those sections of the 1933 Act and 1934 Act provide a "safe harbor" for forward-looking statements to encourage companies to provide prospective information about their financial performance so long as they provide meaningful, cautionary statements identifying important factors that could cause actual results to differ significantly from projected results. Our forward-looking statements include descriptions of plans or objectives of management for future operations, products or services, and forecasts of revenues, earnings or other measures of economic performance. Forward-looking statements can be identified by the fact that they do not relate strictly to historical or current facts. They often include the words "believe," "expect," "intend," "estimate" or words of similar meaning, or future or conditional verbs preceded by "will," "would," "should," "could" or "may." Forward-looking statements are based on management's current expectations regarding economic, legislative, and regulatory issues that may affect our earnings in future periods. Factors that could cause future results to vary materially from current management expectations include, but are not limited to, general economic conditions and the economic uncertainty in the United States and abroad, including economic or other disruptions to financial markets caused by the Trump administration's approach to tariffs and trade, acts of terrorism, war, impacts from inflation, supply chain disruptions, changes in interest rates (including the actions taken by the Federal Reserve to control inflation), California's unemployment rate, deposit flows, real estate values, and expected future cash flows on loans and securities; the impact of adverse developments at other banks, including bank failures, that impact general sentiment regarding the stability and liquidity of banks; costs or effects of acquisitions; competition; changes in accounting principles, policies or guidelines; changes in legislation or regulation; natural disasters (such as wildfires and earthquakes in our area); adverse weather conditions; interruptions of utility service in our markets for sustained periods; and other economic, competitive, governmental, regulatory and technological factors (including external fraud and cybersecurity threats) affecting our operations, pricing, products and services; and successful integration of acquisitions. These and other important factors detailed in various securities law filings made periodically by Bancorp, copies of which are available from us at no charge. Forward-looking statements speak only as of the date they are made. Bancorp undertakes no obligation to release publicly the result of any revisions to these forward-looking statements that may be made to reflect events or circumstances that occur after the date of this press release or to reflect the occurrence of unanticipated events. GAAP to Non-GAAP Financial Measures This presentation includes some non-GAAP financial measures as shown in the Appendix of this presentation. Please refer to the reconciliation of GAAP to Non-GAAP financial measures included in our Form 8-K under Item 9 - Financial Statements and Exhibit 99.1 filed with the SEC on July 28, 2025.
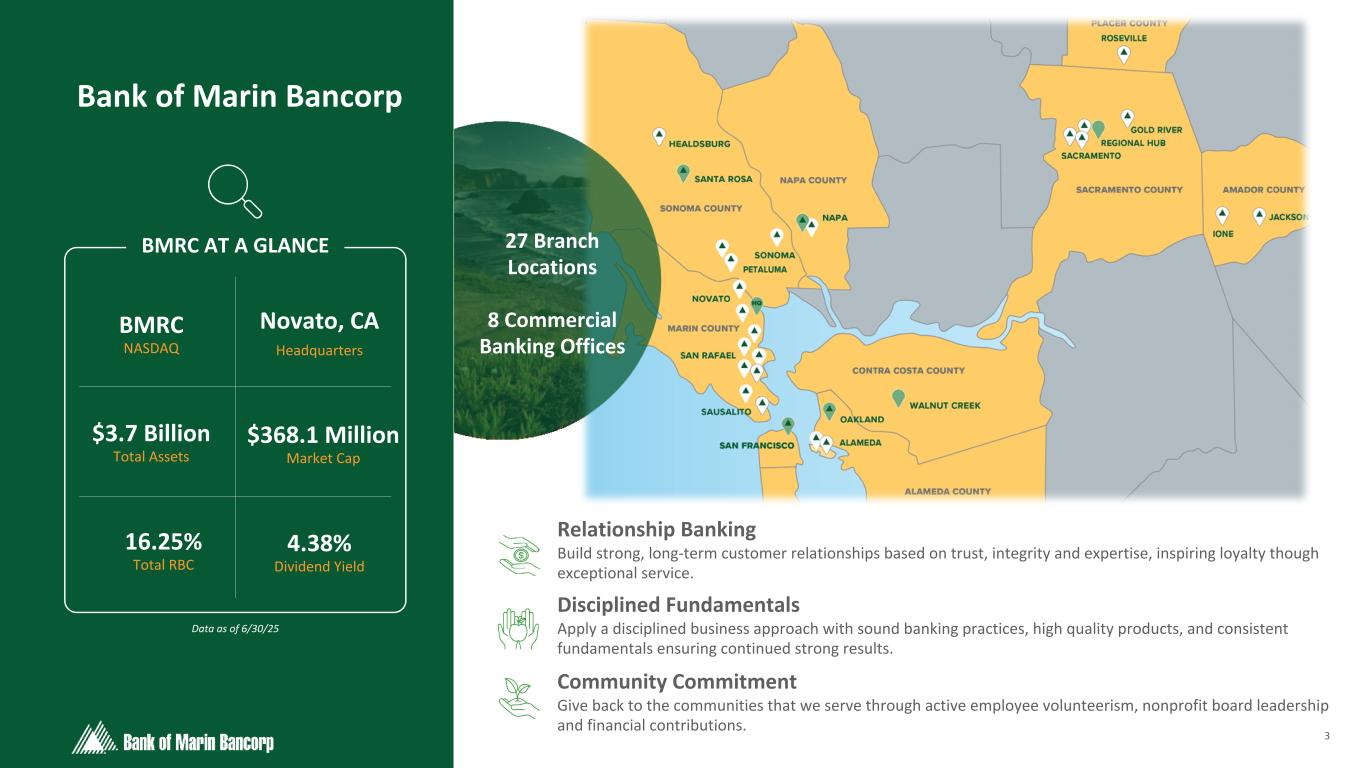
3 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Bank of Marin Bancorp Novato, CA Headquarters BMRC NASDAQ $368.1 Million Market Cap $3.7 Billion Total Assets 4.38% Dividend Yield 16.25% Total RBC BMRC AT A GLANCE O P T I O N 2 Data as of 6/30/25 Relationship Banking Build strong, long-term customer relationships based on trust, integrity and expertise, inspiring loyalty though exceptional service. Disciplined Fundamentals Apply a disciplined business approach with sound banking practices, high quality products, and consistent fundamentals ensuring continued strong results. Community Commitment Give back to the communities that we serve through active employee volunteerism, nonprofit board leadership and financial contributions. 27 Branch Locations 8 Commercial Banking Offices
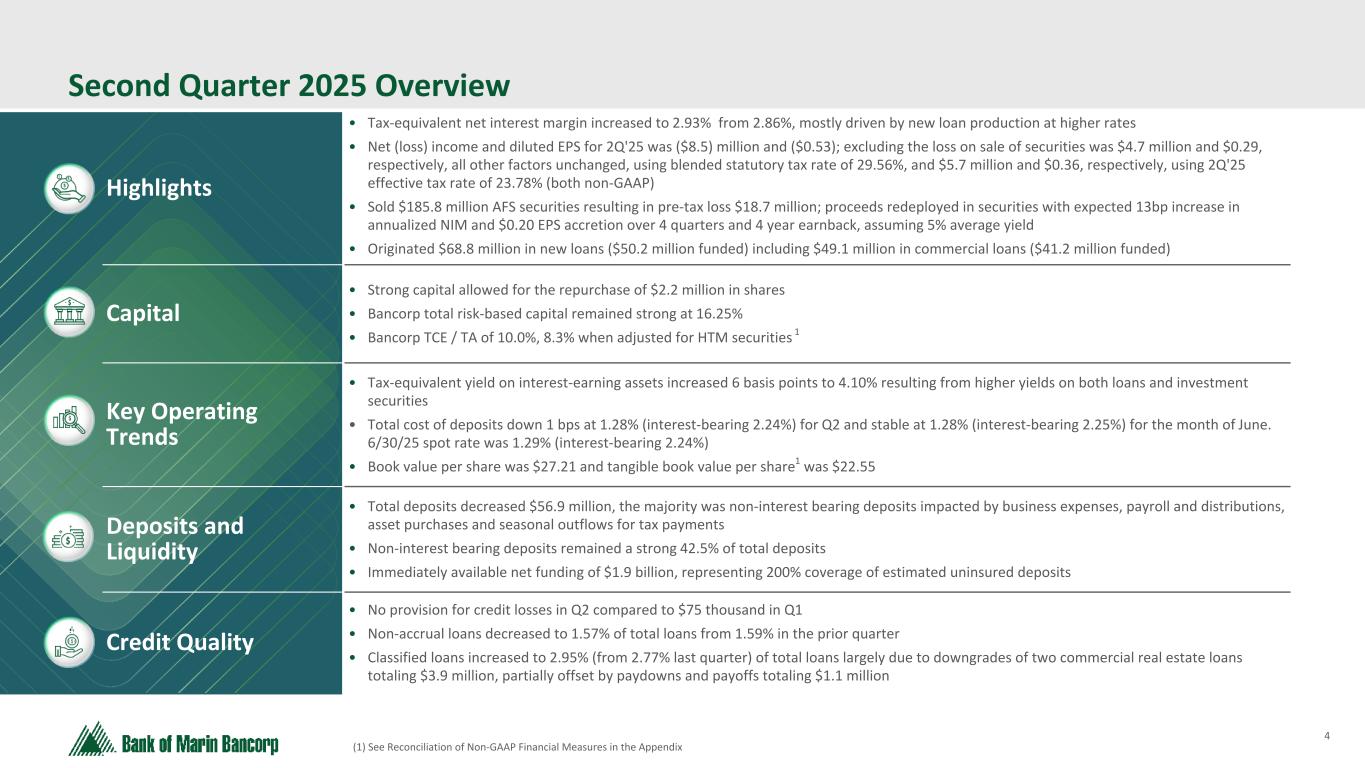
4 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Second Quarter 2025 Overview (1) See Reconciliation of Non-GAAP Financial Measures in the Appendix Highlights • Tax-equivalent net interest margin increased to 2.93% from 2.86%, mostly driven by new loan production at higher rates • Net (loss) income and diluted EPS for 2Q'25 was ($8.5) million and ($0.53); excluding the loss on sale of securities was $4.7 million and $0.29, respectively, all other factors unchanged, using blended statutory tax rate of 29.56%, and $5.7 million and $0.36, respectively, using 2Q'25 effective tax rate of 23.78% (both non-GAAP) • Sold $185.8 million AFS securities resulting in pre-tax loss $18.7 million; proceeds redeployed in securities with expected 13bp increase in annualized NIM and $0.20 EPS accretion over 4 quarters and 4 year earnback, assuming 5% average yield • Originated $68.8 million in new loans ($50.2 million funded) including $49.1 million in commercial loans ($41.2 million funded) Capital • Strong capital allowed for the repurchase of $2.2 million in shares • Bancorp total risk-based capital remained strong at 16.25% • Bancorp TCE / TA of 10.0%, 8.3% when adjusted for HTM securities 1 Key Operating Trends • Tax-equivalent yield on interest-earning assets increased 6 basis points to 4.10% resulting from higher yields on both loans and investment securities • Total cost of deposits down 1 bps at 1.28% (interest-bearing 2.24%) for Q2 and stable at 1.28% (interest-bearing 2.25%) for the month of June. 6/30/25 spot rate was 1.29% (interest-bearing 2.24%) • Book value per share was $27.21 and tangible book value per share1 was $22.55 Deposits and Liquidity • Total deposits decreased $56.9 million, the majority was non-interest bearing deposits impacted by business expenses, payroll and distributions, asset purchases and seasonal outflows for tax payments • Non-interest bearing deposits remained a strong 42.5% of total deposits • Immediately available net funding of $1.9 billion, representing 200% coverage of estimated uninsured deposits Credit Quality • No provision for credit losses in Q2 compared to $75 thousand in Q1 • Non-accrual loans decreased to 1.57% of total loans from 1.59% in the prior quarter • Classified loans increased to 2.95% (from 2.77% last quarter) of total loans largely due to downgrades of two commercial real estate loans totaling $3.9 million, partially offset by paydowns and payoffs totaling $1.1 million
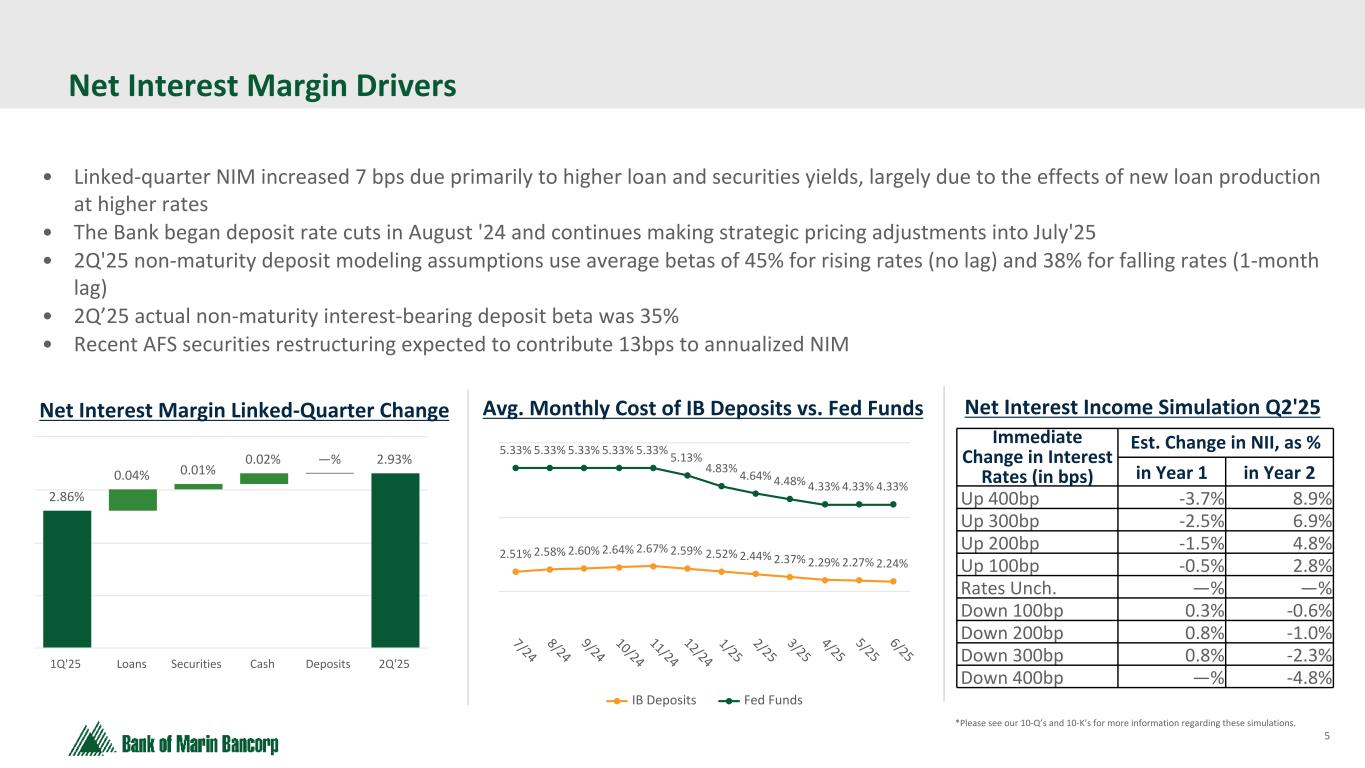
5 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 • Linked-quarter NIM increased 7 bps due primarily to higher loan and securities yields, largely due to the effects of new loan production at higher rates • The Bank began deposit rate cuts in August '24 and continues making strategic pricing adjustments into July'25 • 2Q'25 non-maturity deposit modeling assumptions use average betas of 45% for rising rates (no lag) and 38% for falling rates (1-month lag) • 2Q’25 actual non-maturity interest-bearing deposit beta was 35% • Recent AFS securities restructuring expected to contribute 13bps to annualized NIM Net Interest Margin Drivers 2.86% 0.04% 0.01% 0.02% —% 2.93% 1Q'25 Loans Securities Cash Deposits 2Q'25 Net Interest Margin Linked-Quarter Change 2.51% 2.58% 2.60% 2.64% 2.67% 2.59% 2.52% 2.44% 2.37% 2.29% 2.27% 2.24% 5.33% 5.33% 5.33% 5.33% 5.33% 5.13% 4.83% 4.64% 4.48% 4.33% 4.33% 4.33% IB Deposits Fed Funds 7/24 8/24 9/24 10/24 11/24 12/24 1/25 2/25 3/25 4/25 5/25 6/25 Avg. Monthly Cost of IB Deposits vs. Fed Funds Immediate Change in Interest Rates (in bps) Est. Change in NII, as % in Year 1 in Year 2 Up 400bp -3.7 % 8.9 % Up 300bp -2.5 % 6.9 % Up 200bp -1.5 % 4.8 % Up 100bp -0.5 % 2.8 % Rates Unch. — % — % Down 100bp 0.3 % -0.6 % Down 200bp 0.8 % -1.0 % Down 300bp 0.8 % -2.3 % Down 400bp — % -4.8 % *Please see our 10-Q’s and 10-K’s for more information regarding these simulations. Net Interest Income Simulation Q2'25
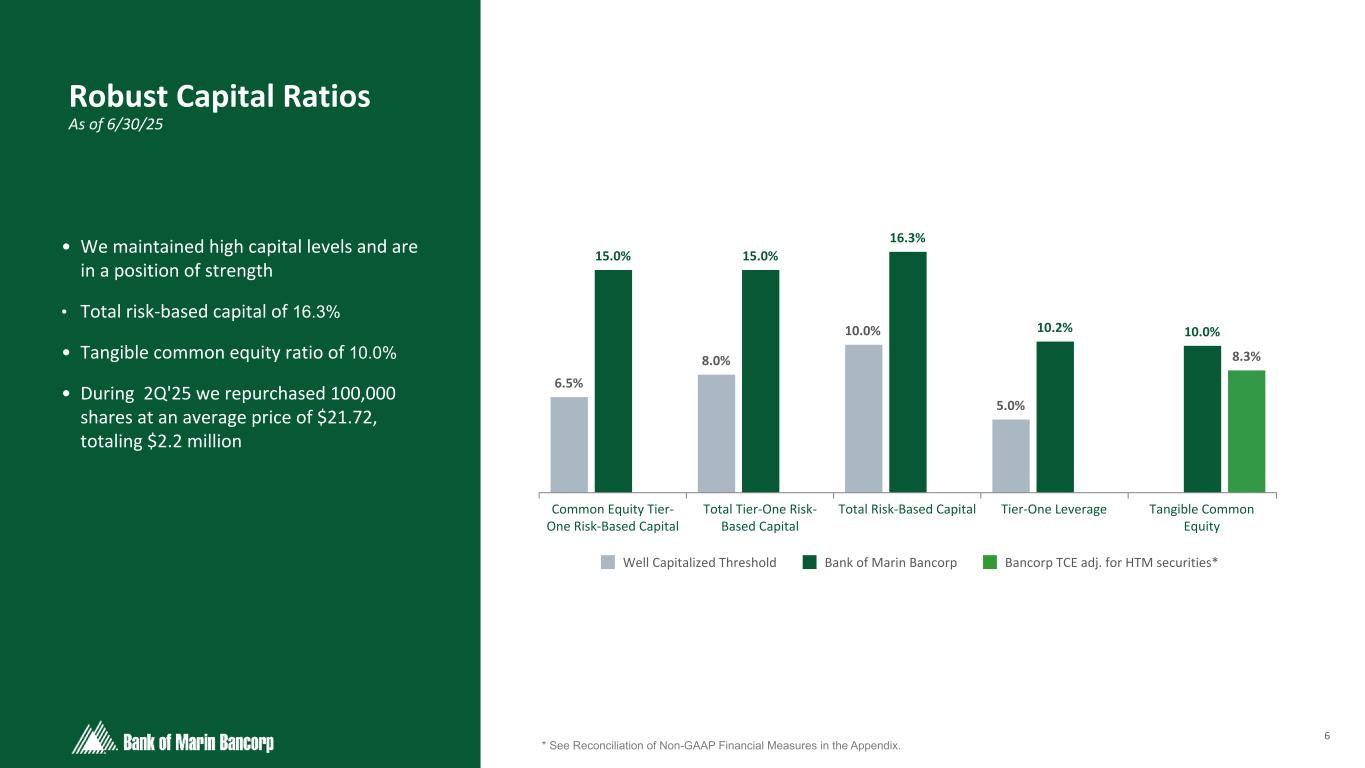
6 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Robust Capital Ratios As of 6/30/25 • We maintained high capital levels and are in a position of strength • Total risk-based capital of 16.3% • Tangible common equity ratio of 10.0% • During 2Q'25 we repurchased 100,000 shares at an average price of $21.72, totaling $2.2 million * See Reconciliation of Non-GAAP Financial Measures in the Appendix. 6.5% 8.0% 10.0% 5.0% 15.0% 15.0% 16.3% 10.2% 10.0% 8.3% Well Capitalized Threshold Bank of Marin Bancorp Bancorp TCE adj. for HTM securities* Common Equity Tier- One Risk-Based Capital Total Tier-One Risk- Based Capital Total Risk-Based Capital Tier-One Leverage Tangible Common Equity
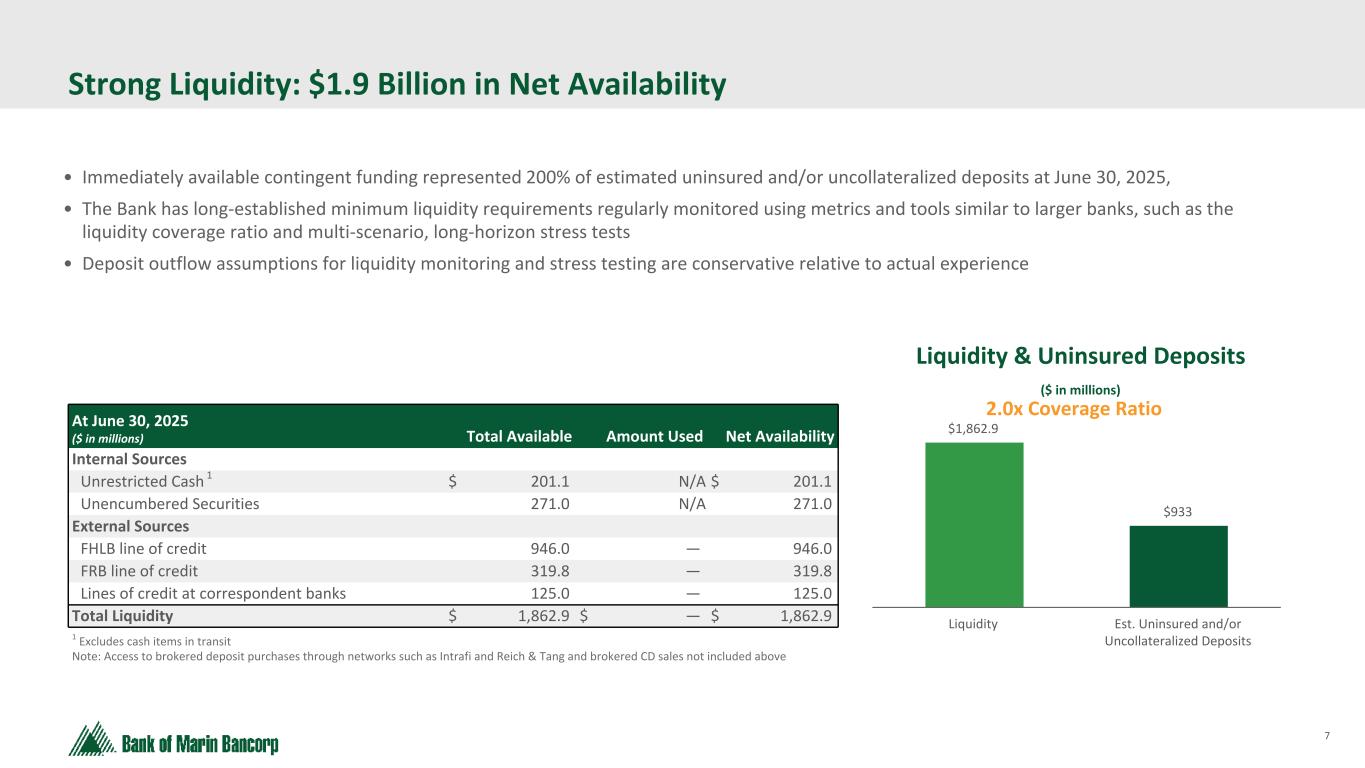
7 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Strong Liquidity: $1.9 Billion in Net Availability • Immediately available contingent funding represented 200% of estimated uninsured and/or uncollateralized deposits at June 30, 2025, • The Bank has long-established minimum liquidity requirements regularly monitored using metrics and tools similar to larger banks, such as the liquidity coverage ratio and multi-scenario, long-horizon stress tests • Deposit outflow assumptions for liquidity monitoring and stress testing are conservative relative to actual experience Liquidity & Uninsured Deposits ($ in millions) 2.0x Coverage Ratio At June 30, 2025 ($ in millions) Total Available Amount Used Net Availability Internal Sources Unrestricted Cash 1 $ 201.1 N/A $ 201.1 Unencumbered Securities 271.0 N/A 271.0 External Sources FHLB line of credit 946.0 — 946.0 FRB line of credit 319.8 — 319.8 Lines of credit at correspondent banks 125.0 — 125.0 Total Liquidity $ 1,862.9 $ — $ 1,862.9 1 Excludes cash items in transit Note: Access to brokered deposit purchases through networks such as Intrafi and Reich & Tang and brokered CD sales not included above $1,862.9 $933 Liquidity Est. Uninsured and/or Uncollateralized Deposits
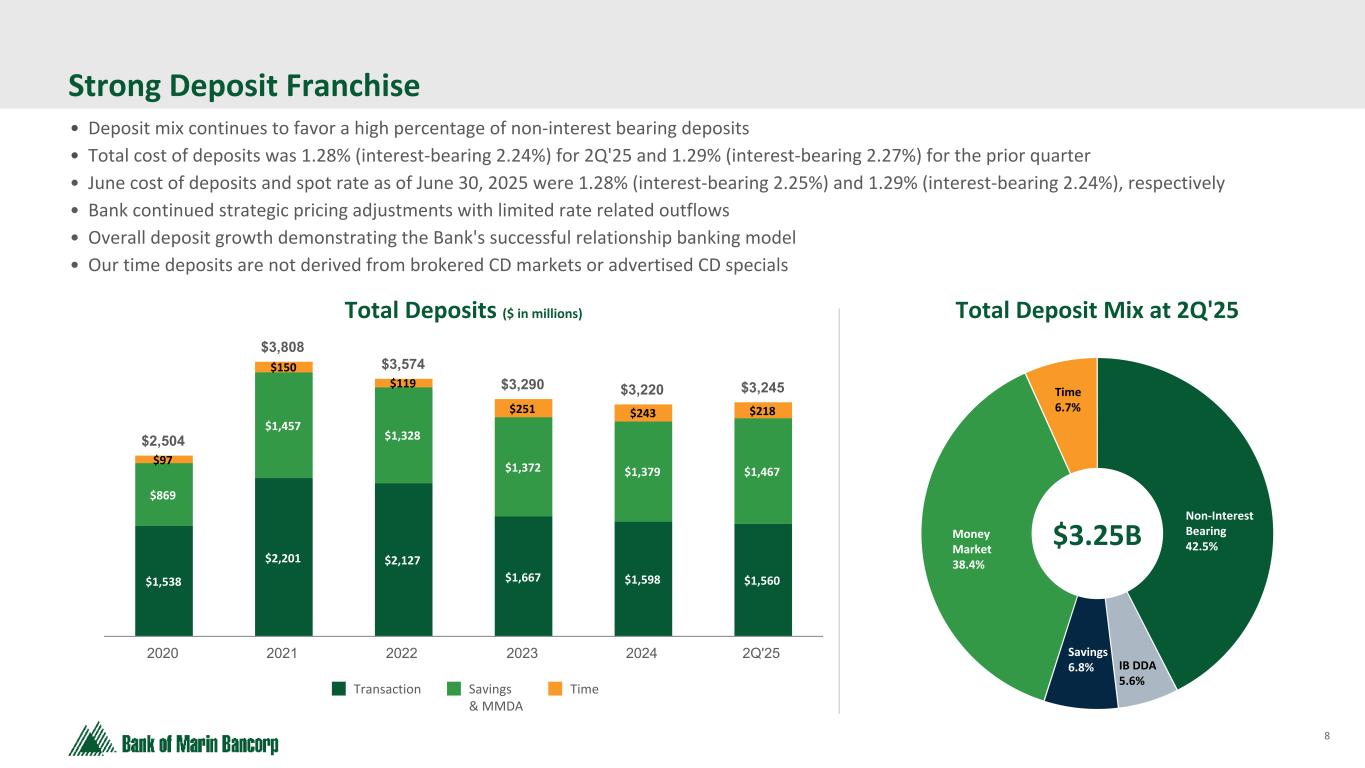
8 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Strong Deposit Franchise • Deposit mix continues to favor a high percentage of non-interest bearing deposits • Total cost of deposits was 1.28% (interest-bearing 2.24%) for 2Q'25 and 1.29% (interest-bearing 2.27%) for the prior quarter • June cost of deposits and spot rate as of June 30, 2025 were 1.28% (interest-bearing 2.25%) and 1.29% (interest-bearing 2.24%), respectively • Bank continued strategic pricing adjustments with limited rate related outflows • Overall deposit growth demonstrating the Bank's successful relationship banking model • Our time deposits are not derived from brokered CD markets or advertised CD specials Total Deposit Mix at 2Q'25Total Deposits ($ in millions) $2,504 $3,808 $3,574 $3,290 $3,220 $3,245 $1,538 $2,201 $2,127 $1,667 $1,598 $1,560 $869 $1,457 $1,328 $1,372 $1,379 $1,467 $97 $150 $119 $251 $243 $218 Transaction Savings & MMDA Time 2020 2021 2022 2023 2024 2Q'25 Non-Interest Bearing 42.5% IB DDA 5.6% Savings 6.8% Money Market 38.4% Time 6.7% $3.25B
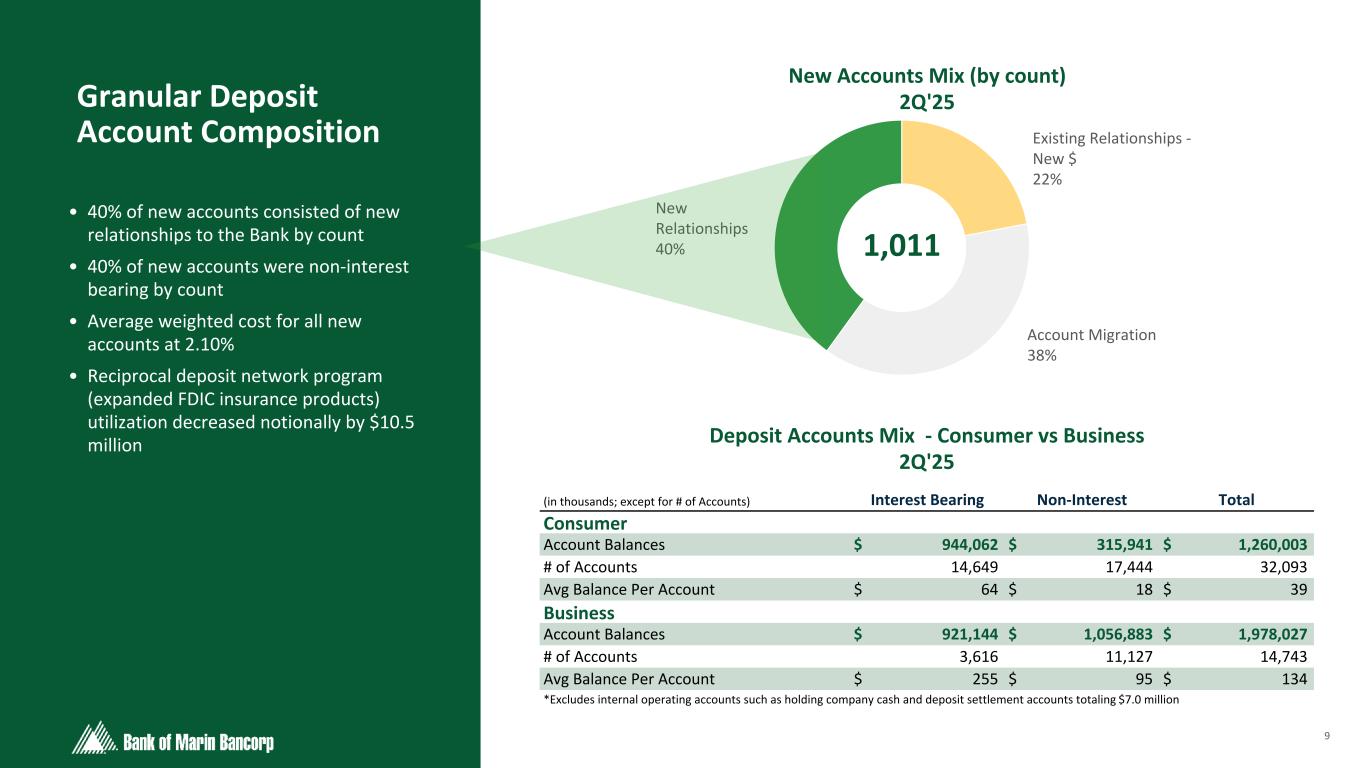
9 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 • 40% of new accounts consisted of new relationships to the Bank by count • 40% of new accounts were non-interest bearing by count • Average weighted cost for all new accounts at 2.10% • Reciprocal deposit network program (expanded FDIC insurance products) utilization decreased notionally by $10.5 million New Accounts Mix (by count) 2Q'25Granular Deposit Account Composition Existing Relationships - New $ 22% Account Migration 38% New Relationships 40% 1,011 (in thousands; except for # of Accounts) Interest Bearing Non-Interest Bearing Total Consumer Account Balances $ 944,062 $ 315,941 $ 1,260,003 # of Accounts 14,649 17,444 32,093 Avg Balance Per Account $ 64 $ 18 $ 39 Business Account Balances $ 921,144 $ 1,056,883 $ 1,978,027 # of Accounts 3,616 11,127 14,743 Avg Balance Per Account $ 255 $ 95 $ 134 *Excludes internal operating accounts such as holding company cash and deposit settlement accounts totaling $7.0 million Deposit Accounts Mix - Consumer vs Business 2Q'25
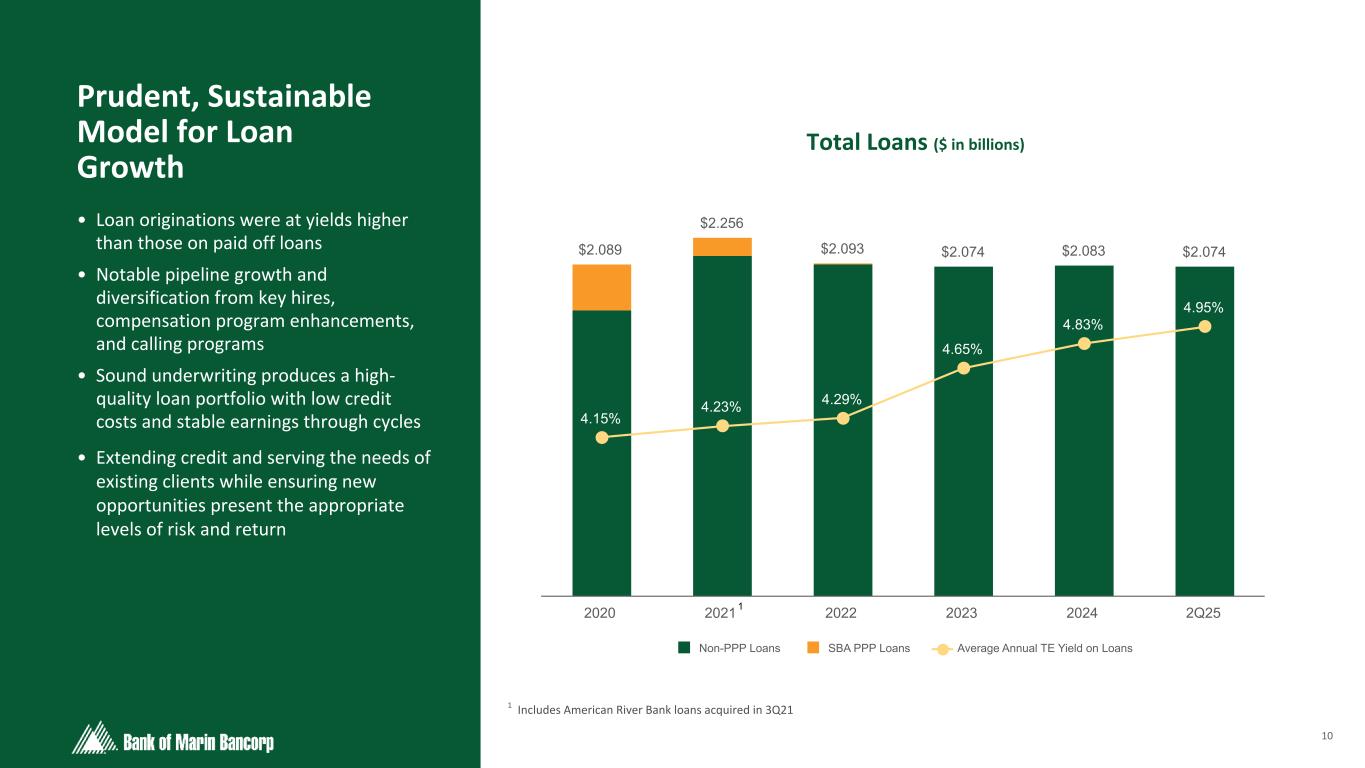
10 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 • Loan originations were at yields higher than those on paid off loans • Notable pipeline growth and diversification from key hires, compensation program enhancements, and calling programs • Sound underwriting produces a high- quality loan portfolio with low credit costs and stable earnings through cycles • Extending credit and serving the needs of existing clients while ensuring new opportunities present the appropriate levels of risk and return Prudent, Sustainable Model for Loan Growth $2.089 $2.256 $2.093 $2.074 $2.083 $2.074 4.15% 4.23% 4.29% 4.65% 4.83% 4.95% Non-PPP Loans SBA PPP Loans Average Annual TE Yield on Loans 2020 2021 2022 2023 2024 2Q25 Total Loans ($ in billions) 1 Includes American River Bank loans acquired in 3Q21 1
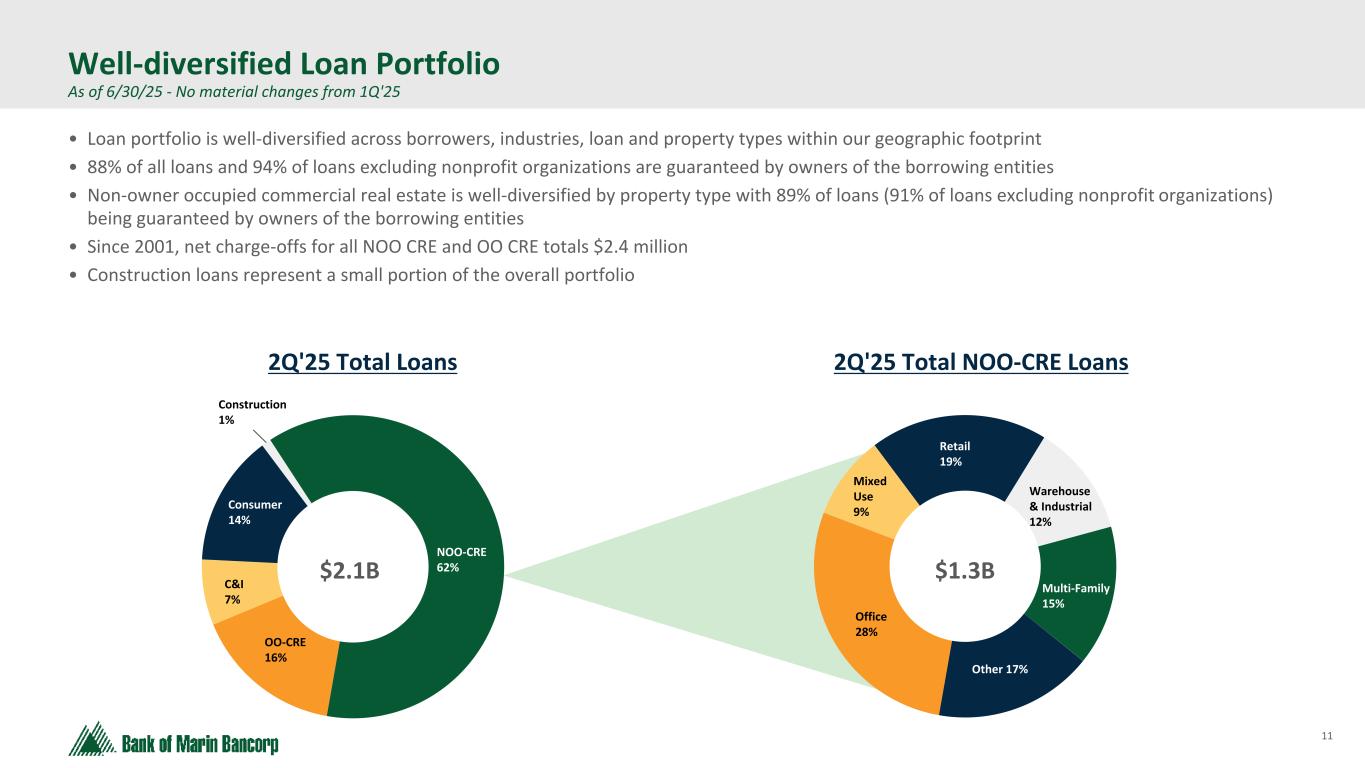
11 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Well-diversified Loan Portfolio As of 6/30/25 - No material changes from 1Q'25 • Loan portfolio is well-diversified across borrowers, industries, loan and property types within our geographic footprint • 88% of all loans and 94% of loans excluding nonprofit organizations are guaranteed by owners of the borrowing entities • Non-owner occupied commercial real estate is well-diversified by property type with 89% of loans (91% of loans excluding nonprofit organizations) being guaranteed by owners of the borrowing entities • Since 2001, net charge-offs for all NOO CRE and OO CRE totals $2.4 million • Construction loans represent a small portion of the overall portfolio OO-CRE 16% C&I 7% Consumer 14% Construction 1% NOO-CRE 62% 2Q'25 Total Loans $2.1B Office 28% Mixed Use 9% Retail 19% Warehouse & Industrial 12% Multi-Family 15% Other 17% 2Q'25 Total NOO-CRE Loans $1.3B
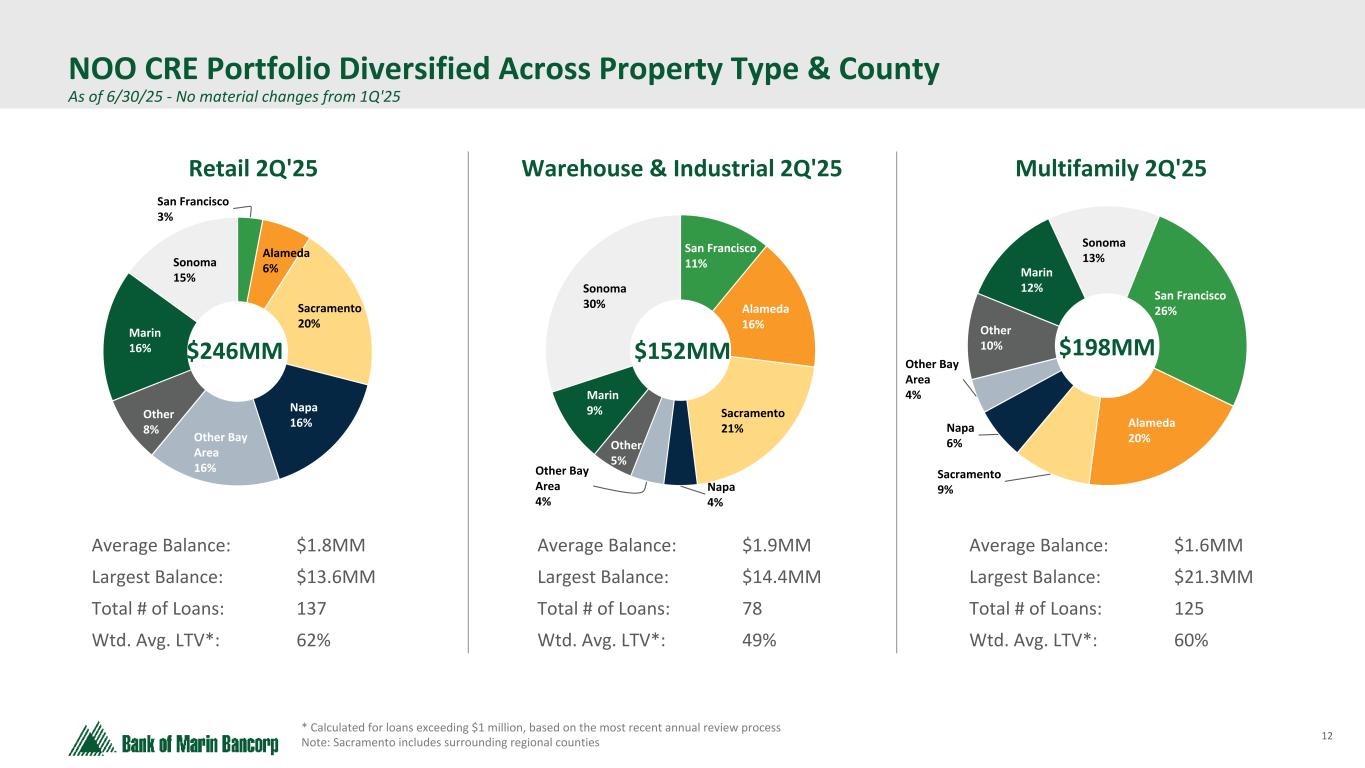
12 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 * Calculated for loans exceeding $1 million, based on the most recent annual review process Note: Sacramento includes surrounding regional counties NOO CRE Portfolio Diversified Across Property Type & County As of 6/30/25 - No material changes from 1Q'25 Average Balance: $1.8MM Largest Balance: $13.6MM Total # of Loans: 137 Wtd. Avg. LTV*: 62% Average Balance: $1.9MM Largest Balance: $14.4MM Total # of Loans: 78 Wtd. Avg. LTV*: 49% Average Balance: $1.6MM Largest Balance: $21.3MM Total # of Loans: 125 Wtd. Avg. LTV*: 60% San Francisco 3% Alameda 6% Sacramento 20% Napa 16% Other Bay Area 16% Other 8% Marin 16% Sonoma 15% San Francisco 11% Alameda 16% Sacramento 21% Napa 4% Other Bay Area 4% Other 5% Marin 9% Sonoma 30% San Francisco 26% Alameda 20% Sacramento 9% Napa 6% Other Bay Area 4% Other 10% Marin 12% Sonoma 13% Retail 2Q'25 Warehouse & Industrial 2Q'25 Multifamily 2Q'25 $246MM $152MM $198MM
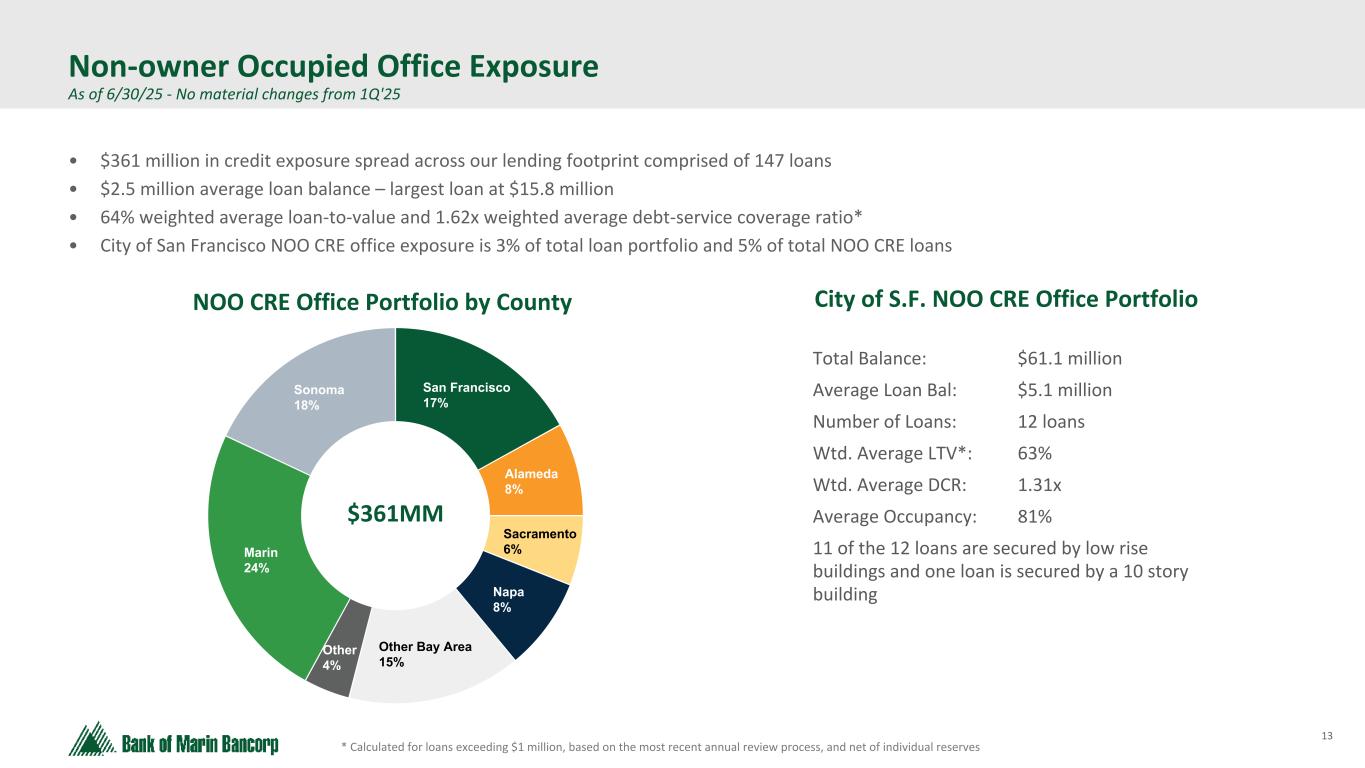
13 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 • $361 million in credit exposure spread across our lending footprint comprised of 147 loans • $2.5 million average loan balance – largest loan at $15.8 million • 64% weighted average loan-to-value and 1.62x weighted average debt-service coverage ratio* • City of San Francisco NOO CRE office exposure is 3% of total loan portfolio and 5% of total NOO CRE loans NOO CRE Office Portfolio by County * Calculated for loans exceeding $1 million, based on the most recent annual review process, and net of individual reserves Non-owner Occupied Office Exposure As of 6/30/25 - No material changes from 1Q'25 San Francisco 17% Alameda 8% Sacramento 6% Napa 8% Other Bay Area 15% Other 4% Marin 24% Sonoma 18% $361MM City of S.F. NOO CRE Office Portfolio Total Balance: $61.1 million Average Loan Bal: $5.1 million Number of Loans: 12 loans Wtd. Average LTV*: 63% Wtd. Average DCR: 1.31x Average Occupancy: 81% 11 of the 12 loans are secured by low rise buildings and one loan is secured by a 10 story building
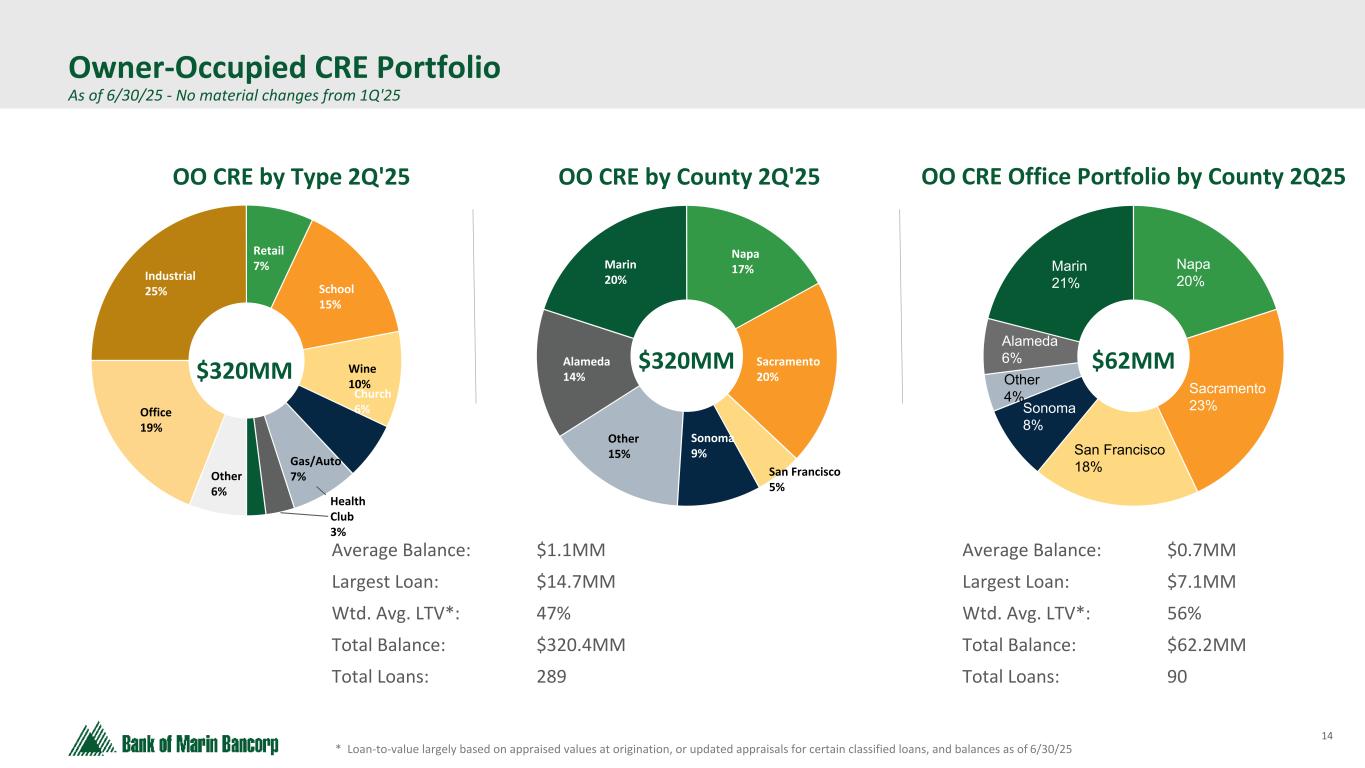
14 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 ($ in millions at Fair Value) * Loan-to-value largely based on appraised values at origination, or updated appraisals for certain classified loans, and balances as of 6/30/25 Owner-Occupied CRE Portfolio As of 6/30/25 - No material changes from 1Q'25 Retail 7% School 15% Wine 10% Church 6% Gas/Auto 7% Health Club 3% Other 6% Office 19% Industrial 25% Napa 17% Sacramento 20% San Francisco 5% Sonoma 9% Other 15% Alameda 14% Marin 20% OO CRE by County 2Q'25 Average Balance: $1.1MM Largest Loan: $14.7MM Wtd. Avg. LTV*: 47% Total Balance: $320.4MM Total Loans: 289 OO CRE by Type 2Q'25 $320MM $320MM Napa 20% Sacramento 23% San Francisco 18% Sonoma 8% Other 4% Alameda 6% Marin 21% Average Balance: $0.7MM Largest Loan: $7.1MM Wtd. Avg. LTV*: 56% Total Balance: $62.2MM Total Loans: 90 OO CRE Office Portfolio by County 2Q25 $62MM
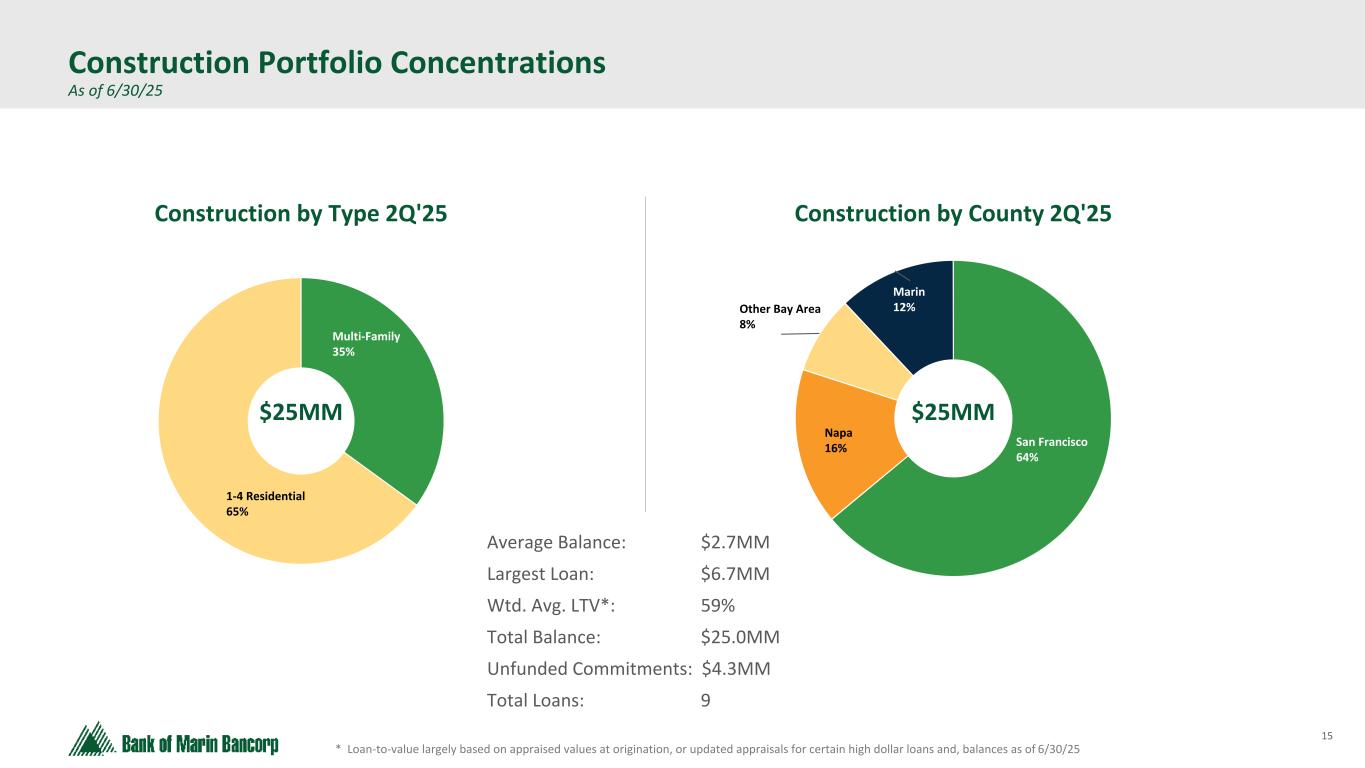
15 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 ($ in millions at Fair Value) * Loan-to-value largely based on appraised values at origination, or updated appraisals for certain high dollar loans and, balances as of 6/30/25 Construction Portfolio Concentrations As of 6/30/25 Construction by Type 2Q'25 Construction by County 2Q'25 Multi-Family 35% 1-4 Residential 65% San Francisco 64% Napa 16% Other Bay Area 8% Marin 12% Average Balance: $2.7MM Largest Loan: $6.7MM Wtd. Avg. LTV*: 59% Total Balance: $25.0MM Unfunded Commitments: $4.3MM Total Loans: 9 $25MM $25MM
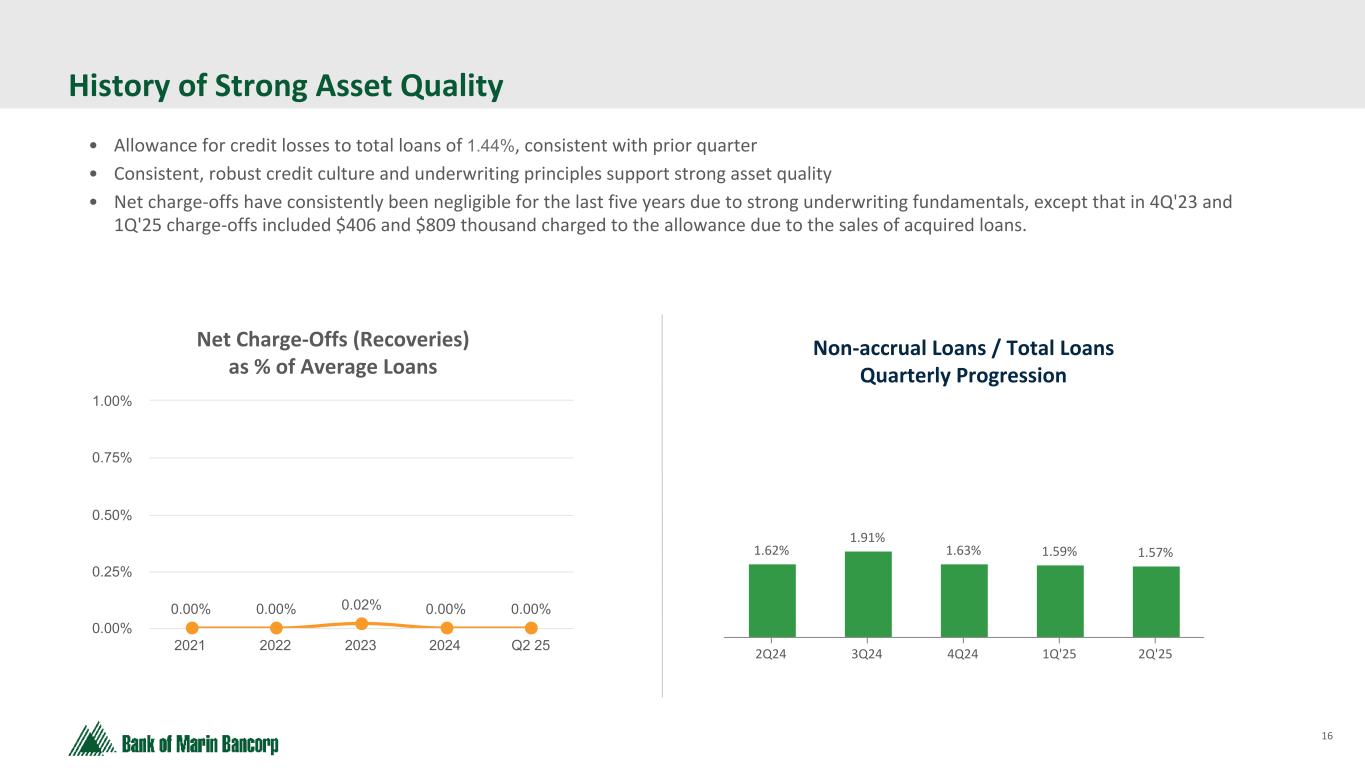
16 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 ($ in millions at Fair Value) History of Strong Asset Quality • Allowance for credit losses to total loans of 1.44%, consistent with prior quarter • Consistent, robust credit culture and underwriting principles support strong asset quality • Net charge-offs have consistently been negligible for the last five years due to strong underwriting fundamentals, except that in 4Q'23 and 1Q'25 charge-offs included $406 and $809 thousand charged to the allowance due to the sales of acquired loans. Non-accrual Loans / Total Loans Quarterly Progression 1.62% 1.91% 1.63% 1.59% 1.57% 2Q24 3Q24 4Q24 1Q'25 2Q'25 Net Charge-Offs (Recoveries) as % of Average Loans 0.00% 0.00% 0.02% 0.00% 0.00% 2021 2022 2023 2024 Q2 25 0.00% 0.25% 0.50% 0.75% 1.00%
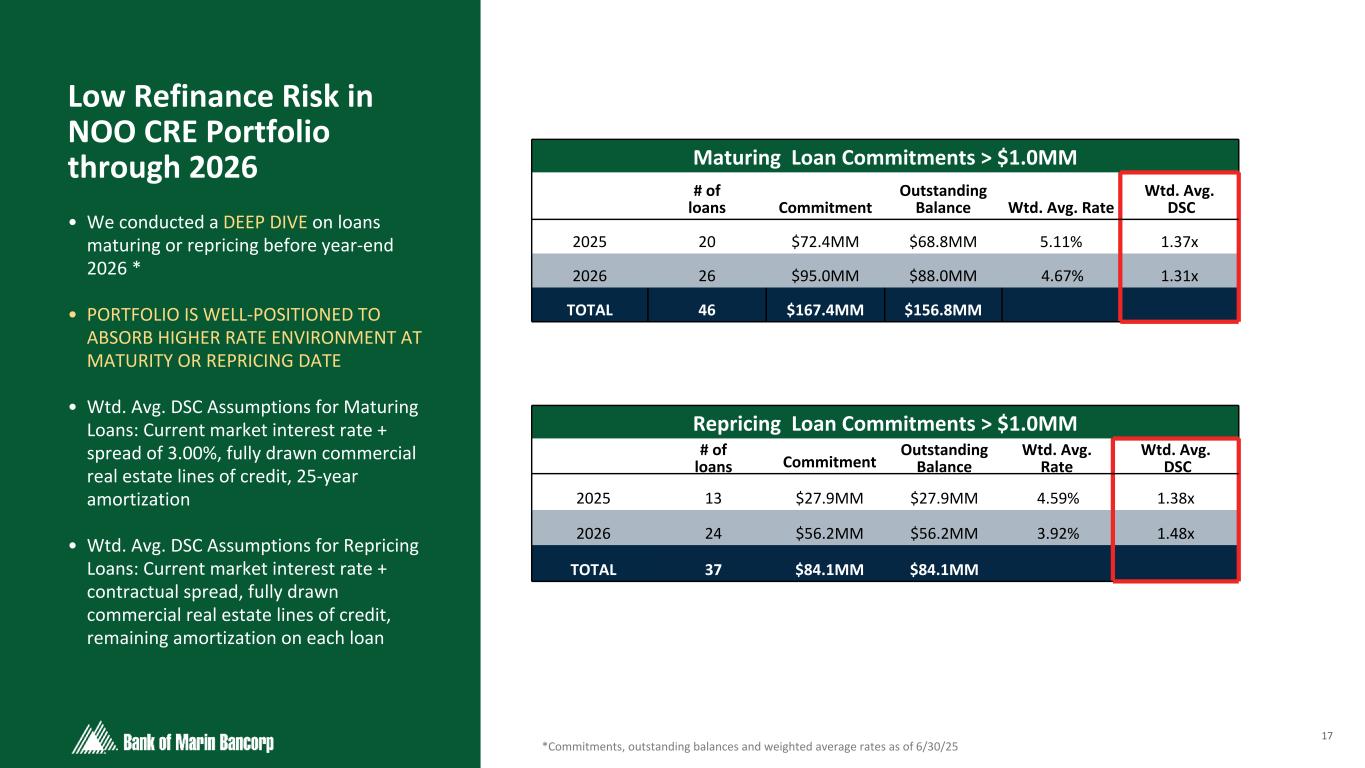
17 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Low Refinance Risk in NOO CRE Portfolio through 2026 • We conducted a DEEP DIVE on loans maturing or repricing before year-end 2026 * • PORTFOLIO IS WELL-POSITIONED TO ABSORB HIGHER RATE ENVIRONMENT AT MATURITY OR REPRICING DATE • Wtd. Avg. DSC Assumptions for Maturing Loans: Current market interest rate + spread of 3.00%, fully drawn commercial real estate lines of credit, 25-year amortization • Wtd. Avg. DSC Assumptions for Repricing Loans: Current market interest rate + contractual spread, fully drawn commercial real estate lines of credit, remaining amortization on each loan Maturing Loan Commitments > $1.0MM # of loans Commitment Outstanding Balance Wtd. Avg. Rate Wtd. Avg. DSC 2025 20 $72.4MM $68.8MM 5.11% 1.37x 2026 26 $95.0MM $88.0MM 4.67% 1.31x TOTAL 46 $167.4MM $156.8MM Repricing Loan Commitments > $1.0MM # of loans Commitment Outstanding Balance Wtd. Avg. Rate Wtd. Avg. DSC 2025 13 $27.9MM $27.9MM 4.59% 1.38x 2026 24 $56.2MM $56.2MM 3.92% 1.48x TOTAL 37 $84.1MM $84.1MM *Commitments, outstanding balances and weighted average rates as of 6/30/25
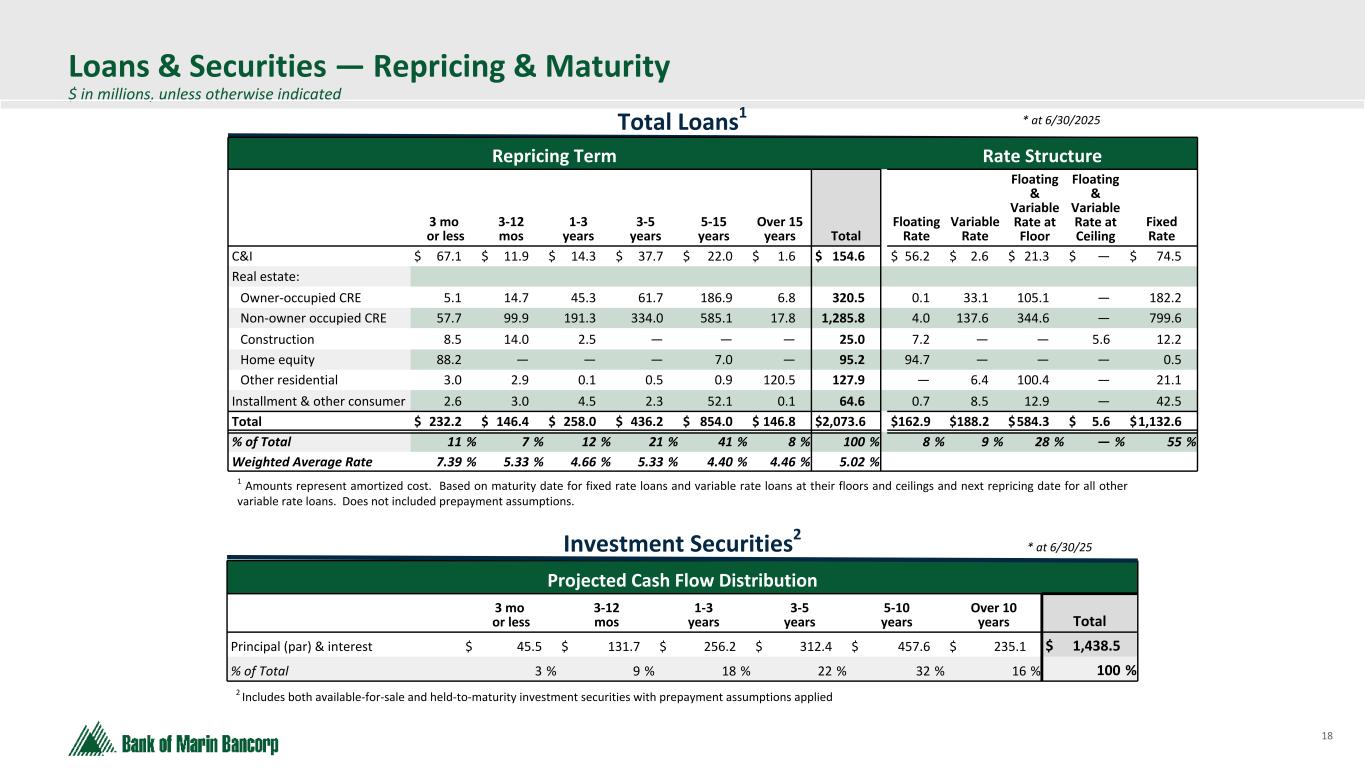
18 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Loans & Securities — Repricing & Maturity $ in millions, unless otherwise indicated Total Loans1 * at 6/30/2025 Repricing Term Rate Structure 3 mo or less 3-12 mos 1-3 years 3-5 years 5-15 years Over 15 years Total Floating Rate Variable Rate Floating & Variable Rate at Floor Floating & Variable Rate at Ceiling Fixed Rate C&I $ 67.1 $ 11.9 $ 14.3 $ 37.7 $ 22.0 $ 1.6 $ 154.6 $ 56.2 $ 2.6 $ 21.3 $ — $ 74.5 Real estate: Owner-occupied CRE 5.1 14.7 45.3 61.7 186.9 6.8 320.5 0.1 33.1 105.1 — 182.2 Non-owner occupied CRE 57.7 99.9 191.3 334.0 585.1 17.8 1,285.8 4.0 137.6 344.6 — 799.6 Construction 8.5 14.0 2.5 — — — 25.0 7.2 — — 5.6 12.2 Home equity 88.2 — — — 7.0 — 95.2 94.7 — — — 0.5 Other residential 3.0 2.9 0.1 0.5 0.9 120.5 127.9 — 6.4 100.4 — 21.1 Installment & other consumer 2.6 3.0 4.5 2.3 52.1 0.1 64.6 0.7 8.5 12.9 — 42.5 Total $ 232.2 $ 146.4 $ 258.0 $ 436.2 $ 854.0 $ 146.8 $ 2,073.6 $ 162.9 $ 188.2 $ 584.3 $ 5.6 $ 1,132.6 % of Total 11 % 7 % 12 % 21 % 41 % 8 % 100 % 8 % 9 % 28 % — % 55 % Weighted Average Rate 7.39 % 5.33 % 4.66 % 5.33 % 4.40 % 4.46 % 5.02 % 1 Amounts represent amortized cost. Based on maturity date for fixed rate loans and variable rate loans at their floors and ceilings and next repricing date for all other variable rate loans. Does not included prepayment assumptions. Investment Securities2 * at 6/30/25 2 Includes both available-for-sale and held-to-maturity investment securities with prepayment assumptions applied Projected Cash Flow Distribution 3 mo or less 3-12 mos 1-3 years 3-5 years 5-10 years Over 10 years Total Principal (par) & interest $ 45.5 $ 131.7 $ 256.2 $ 312.4 $ 457.6 $ 235.1 $ 1,438.5 % of Total 3 % 9 % 18 % 22 % 32 % 16 % 100 %
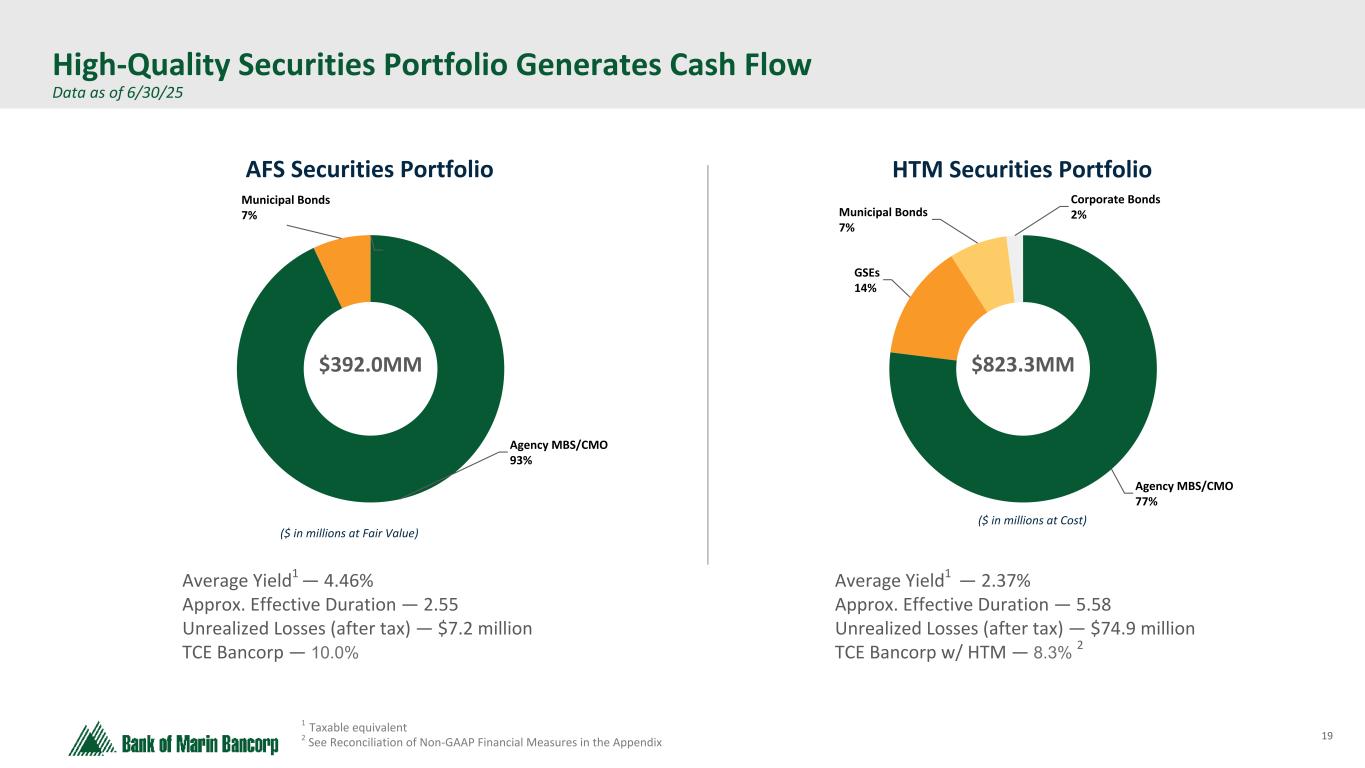
19 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 1 Taxable equivalent 2 See Reconciliation of Non-GAAP Financial Measures in the Appendix High-Quality Securities Portfolio Generates Cash Flow Data as of 6/30/25 AFS Securities Portfolio Agency MBS/CMO 93% Municipal Bonds 7% ($ in millions at Fair Value) $392.0MM HTM Securities Portfolio Agency MBS/CMO 77% GSEs 14% Municipal Bonds 7% Corporate Bonds 2% $823.3MM ($ in millions at Cost) Average Yield1 — 4.46% Approx. Effective Duration — 2.55 Unrealized Losses (after tax) — $7.2 million TCE Bancorp — 10.0% Average Yield1 — 2.37% Approx. Effective Duration — 5.58 Unrealized Losses (after tax) — $74.9 million TCE Bancorp w/ HTM — 8.3% 2
Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Appendix
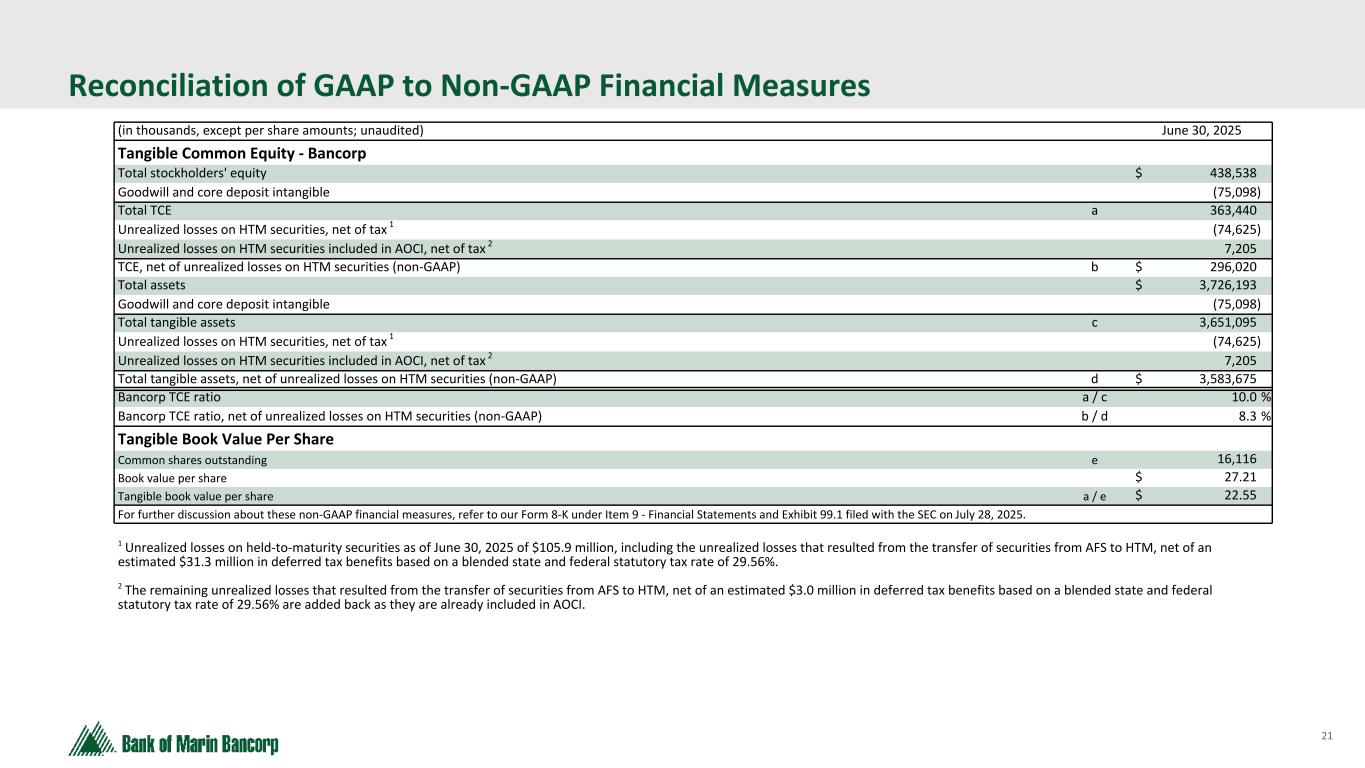
21 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Reconciliation of GAAP to Non-GAAP Financial Measures (in thousands, except per share amounts; unaudited) June 30, 2025 Tangible Common Equity - Bancorp Total stockholders' equity $ 438,538 Goodwill and core deposit intangible (75,098) Total TCE a 363,440 Unrealized losses on HTM securities, net of tax 1 (74,625) Unrealized losses on HTM securities included in AOCI, net of tax 2 7,205 TCE, net of unrealized losses on HTM securities (non-GAAP) b $ 296,020 Total assets $ 3,726,193 Goodwill and core deposit intangible (75,098) Total tangible assets c 3,651,095 Unrealized losses on HTM securities, net of tax 1 (74,625) Unrealized losses on HTM securities included in AOCI, net of tax 2 7,205 Total tangible assets, net of unrealized losses on HTM securities (non-GAAP) d $ 3,583,675 Bancorp TCE ratio a / c 10.0 % Bancorp TCE ratio, net of unrealized losses on HTM securities (non-GAAP) b / d 8.3 % Tangible Book Value Per Share Common shares outstanding e 16,116 Book value per share $ 27.21 Tangible book value per share a / e $ 22.55 For further discussion about these non-GAAP financial measures, refer to our Form 8-K under Item 9 - Financial Statements and Exhibit 99.1 filed with the SEC on July 28, 2025. 1 Unrealized losses on held-to-maturity securities as of June 30, 2025 of $105.9 million, including the unrealized losses that resulted from the transfer of securities from AFS to HTM, net of an estimated $31.3 million in deferred tax benefits based on a blended state and federal statutory tax rate of 29.56%. 2 The remaining unrealized losses that resulted from the transfer of securities from AFS to HTM, net of an estimated $3.0 million in deferred tax benefits based on a blended state and federal statutory tax rate of 29.56% are added back as they are already included in AOCI.
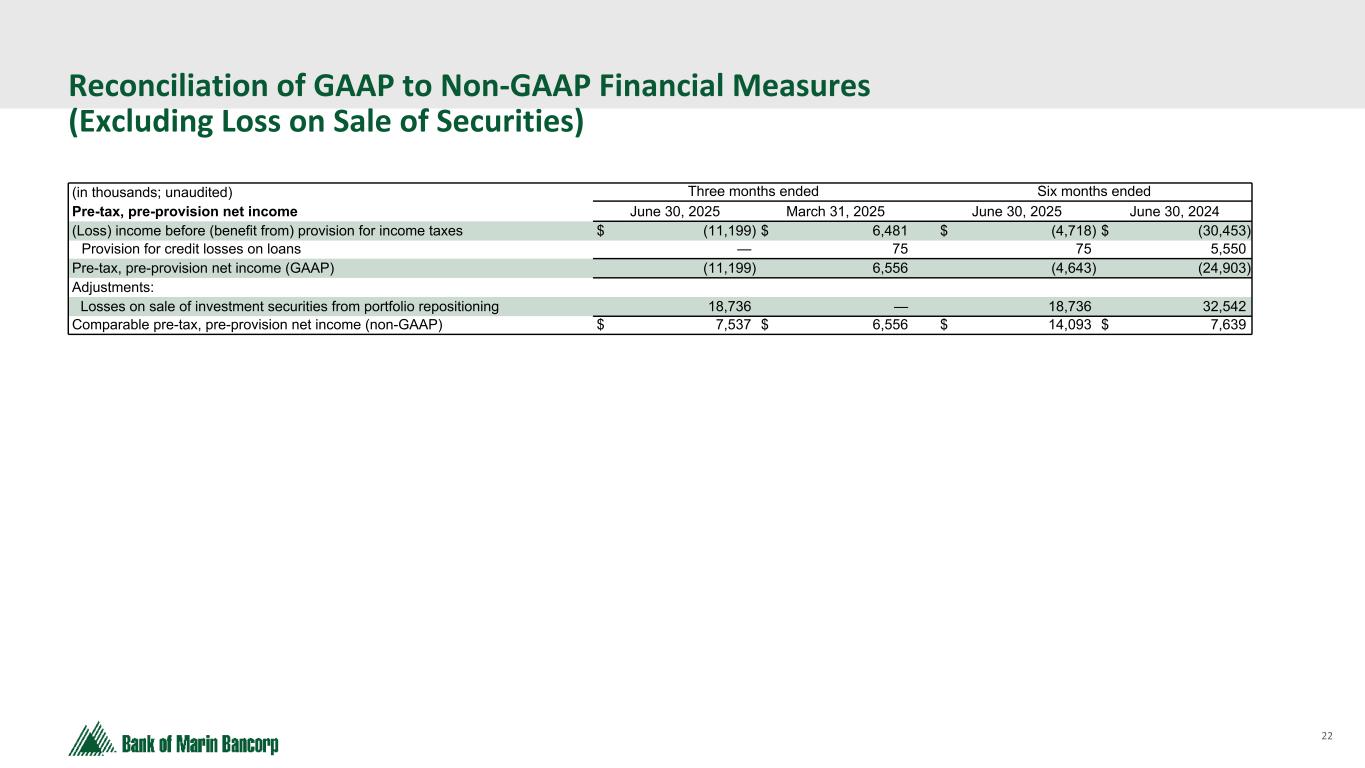
22 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Reconciliation of GAAP to Non-GAAP Financial Measures (Excluding Loss on Sale of Securities) (in thousands; unaudited) Three months ended Six months ended Pre-tax, pre-provision net income June 30, 2025 March 31, 2025 June 30, 2025 June 30, 2024 (Loss) income before (benefit from) provision for income taxes $ (11,199) $ 6,481 $ (4,718) $ (30,453) Provision for credit losses on loans — 75 75 5,550 Pre-tax, pre-provision net income (GAAP) (11,199) 6,556 (4,643) (24,903) Adjustments: Losses on sale of investment securities from portfolio repositioning 18,736 — 18,736 32,542 Comparable pre-tax, pre-provision net income (non-GAAP) $ 7,537 $ 6,556 $ 14,093 $ 7,639
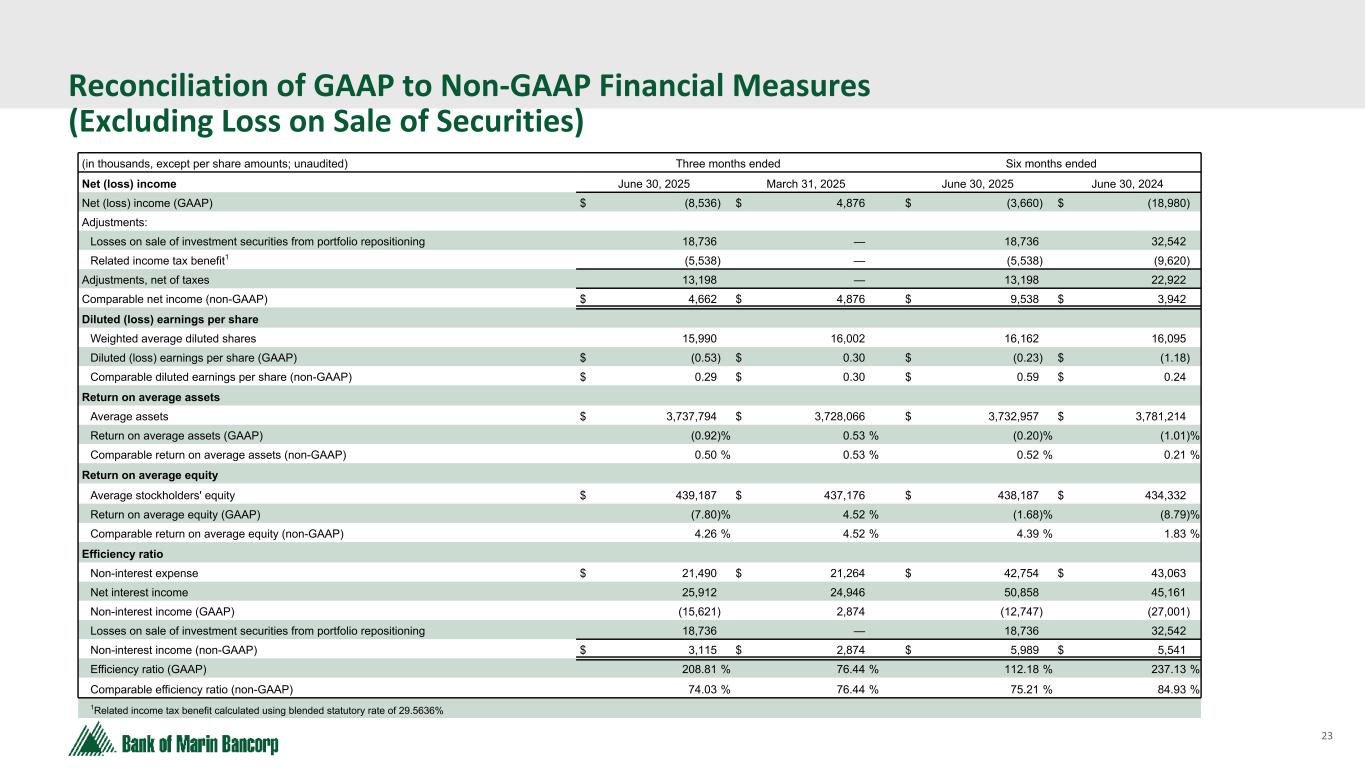
23 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Reconciliation of GAAP to Non-GAAP Financial Measures (Excluding Loss on Sale of Securities) (in thousands, except per share amounts; unaudited) Three months ended Six months ended Net (loss) income June 30, 2025 March 31, 2025 June 30, 2025 June 30, 2024 Net (loss) income (GAAP) $ (8,536) $ 4,876 $ (3,660) $ (18,980) Adjustments: Losses on sale of investment securities from portfolio repositioning 18,736 — 18,736 32,542 Related income tax benefit1 (5,538) — (5,538) (9,620) Adjustments, net of taxes 13,198 — 13,198 22,922 Comparable net income (non-GAAP) $ 4,662 $ 4,876 $ 9,538 $ 3,942 Diluted (loss) earnings per share Weighted average diluted shares 15,990 16,002 16,162 16,095 Diluted (loss) earnings per share (GAAP) $ (0.53) $ 0.30 $ (0.23) $ (1.18) Comparable diluted earnings per share (non-GAAP) $ 0.29 $ 0.30 $ 0.59 $ 0.24 Return on average assets Average assets $ 3,737,794 $ 3,728,066 $ 3,732,957 $ 3,781,214 Return on average assets (GAAP) (0.92) % 0.53 % (0.20) % (1.01) % Comparable return on average assets (non-GAAP) 0.50 % 0.53 % 0.52 % 0.21 % Return on average equity Average stockholders' equity $ 439,187 $ 437,176 $ 438,187 $ 434,332 Return on average equity (GAAP) (7.80) % 4.52 % (1.68) % (8.79) % Comparable return on average equity (non-GAAP) 4.26 % 4.52 % 4.39 % 1.83 % Efficiency ratio Non-interest expense $ 21,490 $ 21,264 $ 42,754 $ 43,063 Net interest income 25,912 24,946 50,858 45,161 Non-interest income (GAAP) (15,621) 2,874 (12,747) (27,001) Losses on sale of investment securities from portfolio repositioning 18,736 — 18,736 32,542 Non-interest income (non-GAAP) $ 3,115 $ 2,874 $ 5,989 $ 5,541 Efficiency ratio (GAAP) 208.81 % 76.44 % 112.18 % 237.13 % Comparable efficiency ratio (non-GAAP) 74.03 % 76.44 % 75.21 % 84.93 % 1Related income tax benefit calculated using blended statutory rate of 29.5636%
24 Text 95,96,96 Light Gray 232, 232, 232 Black 0, 0, 0 White 255, 255, 255 Accent 1 7,89,52 Accent 2 248,153,40 Accent 3 254,217,129 Accent 4 52,153,70 Accent 5 5,39,67 Accent 6 171,184,195 Contact Us Tim Myers President and Chief Executive Officer (415) 763-4970 [email protected] Dave Bonaccorso EVP, Chief Financial Officer (415) 884-4758 [email protected] Media Requests: Yahaira Garcia-Perea Marketing & Corporate Communications Manager (916) 231-6703 [email protected]