
CAKE 8-K
Cheesecake Factory Inc (CAKE)
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM
CURRENT REPORT
Pursuant to Section 13 OR 15(d) of The Securities Exchange Act of 1934
Date of Report (Date of earliest event reported):
THE
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction | (Commission | (IRS Employer | ||
| of incorporation) | File Number) | Identification No.) |
| (Address of principal executive offices) | (Zip Code) |
Registrant’s telephone number, including
area code (
Not Applicable
(Former name or former address, if changed since last report.)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class: | Trading Symbol(s) | Name of each exchange on which registered: | ||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging
growth company
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
The following information under Item 2.02 of Form 8-K, “Results of Operations and Financial Condition” and Item 7.01 “Regulation FD Disclosure” is intended to be furnished. This information shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), or incorporated by reference in any filing under the Securities Act of 1933, as amended, or the Exchange Act, whether made before or after the date of this report, regardless of any general incorporation language in the filing.
| ITEM 2.02 | RESULTS OF OPERATIONS AND FINANCIAL CONDITION |
In a press release dated October 29, 2020, a copy of which is furnished as Exhibit 99.1 to this report, the Company reported third quarter fiscal 2020 financial results.
| ITEM 7.01 | REGULATION FD DISCLOSURE |
On October 29, 2020, the Company posted an updated Investor Presentation on the Company’s Investor Relations website at investors.thecheesecakefactory.com. A copy of the presentation is furnished as Exhibit 99.2 hereto and is incorporated by reference herein.
| ITEM 9.01 | FINANCIAL STATEMENTS AND EXHIBITS |
| (d) | Exhibits |
| 99.1 | Press Release dated October 29, 2020, entitled, “The Cheesecake Factory Reports Results for Third Quarter of Fiscal 2020 and Provides Business Update” | |
| 99.2 | The Cheesecake Factory Investor Presentation dated October 29, 2020 | |
| 104.1 | Cover Page Interactive Data File (embedded within the inline XBRL document) |
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Date: October 29, 2020 | THE CHEESECAKE FACTORY INCORPORATED | |
| By: | /s/ Matthew E. Clark | |
| Matthew E. Clark | ||
| Executive Vice President and Chief Financial Officer | ||
Exhibit 99.1
PRESS RELEASE
| FOR IMMEDIATE RELEASE | Contact: Stacy Feit |
| (818) 871-3000 | |
| [email protected] |
THE CHEESECAKE FACTORY REPORTS RESULTS FOR
THIRD QUARTER OF FISCAL 2020 AND PROVIDES BUSINESS UPDATE
CALABASAS HILLS, Calif., – October 29, 2020 – The Cheesecake Factory Incorporated (NASDAQ: CAKE) today reported financial results for the third quarter of fiscal 2020, which ended on September 29, 2020.
Total revenues were $517.7 million in the third quarter of fiscal 2020 compared to $586.5 million in the third quarter of fiscal 2019. Net loss and diluted net loss per share were $28.3 million and $0.76, respectively, in the third quarter of fiscal 2020, reflecting the impact of COVID-19. The results in this press release include the acquisition of North Italia and the remaining business of Fox Restaurant Concepts LLC (“FRC”) on October 2, 2019.
During the third quarter of fiscal 2020, the Company recorded pre-tax impairment of assets and lease termination expense of $10.4 million, $5.4 million of which was cash lease termination expense associated with one Grand Lux Cafe location that discontinued operations during the third quarter and RockSugar Southeast Asian Kitchen, which is scheduled to discontinue operations at the end of the year. The remainder was primarily related to non-cash accelerated depreciation associated with the closed Grand Lux Cafe location and accrued lease termination expense associated with another Grand Lux Cafe location that the Company expects to close by the end of the year. The Company also recorded COVID-19 related charges of $2.6 million, for costs such as sick pay, additional sanitation and personal protective equipment.
Excluding the after-tax impact of these and certain other items, and reflecting the potential impact of the conversion of the Company’s convertible preferred stock into common stock, adjusted net loss and adjusted net loss per share for the third quarter of fiscal 2020 were $17.7 million and $0.33, respectively. Please see the Company’s reconciliation of non-GAAP financial measures at the end of this press release.
Comparable restaurant sales at The Cheesecake Factory restaurants decreased 23.3% in the third quarter of fiscal 2020, reflecting the impact of COVID-19.
Fiscal fourth quarter-to-date through October 27, 2020, The Cheesecake Factory restaurants with reopened indoor dining rooms have recaptured, on average, approximately 90% of prior year annualized sales volumes, supported by approximately 40% off-premise sales mix. In aggregate, including locations with only reopened patios and off-premise only operating models, fiscal fourth quarter to-date through October 27, 2020 comparable sales at The Cheesecake Factory restaurants are down approximately 7%.
26901 Malibu Hills Road, Calabasas Hills, CA 91301 · Telephone (818) 871-3000 · Fax (818) 871-3100
As of today, approximately 90% of the Company’s restaurants across its concepts, including 187 Cheesecake Factory locations, are operating with reopened indoor dining rooms with limited capacity in accordance with local mandates and social distancing protocols. On average, Cheesecake Factory restaurants with reopened dining rooms are operating at 50% capacity. Approximately 7% of the Company’s restaurants across its concepts, including 17 Cheesecake Factory locations, are operating with reopened patios with social distancing in accordance with California and Toronto dining restrictions. Currently, two locations, including one Cheesecake Factory restaurant, are operating an off-premise only model and five locations across the Company’s concepts are currently closed.
“We have continued to drive sales at The Cheesecake Factory restaurants despite mandated capacity restrictions as many of our guests have been eager to return to our restaurants and we have continued to sustain strength in the off-premise channel. In fact, we were able to maintain the vast majority of off-premise sales from the second quarter, even with additional restaurants able to reopen indoor dining rooms during the third quarter,” said David Overton, Chairman and Chief Executive Officer. “We believe this underscores the broad consumer appeal and strong guest affinity for The Cheesecake Factory brand.”
Overton continued, “We have seen a continued sales recovery at North Italia and the FRC concepts, underscoring the strength of these brands as well. Operational execution was solid across our concepts, reinforcing our financial position. In turn, we believe we are poised to continue to manage through the COVID-19 environment and emerge in a competitively strong position.”
Development
During the third quarter of fiscal 2020, two Flower Child locations opened in Houston and Oklahoma City. Subsequent to quarter-end, Culinary Dropout opened in Scottsdale, Arizona. No new restaurants were opened by the Company’s international licensees during the third quarter of fiscal 2020.
Balance Sheet & Cash Flow
During the third quarter, the Company generated $3.0 million in cash flow from operating activities.
As of September 29, 2020, cash and cash equivalents totaled $243.8 million and total debt was $376.0 million. Subsequent to quarter-end, the Company repaid $96.0 million of its revolving credit facility, bringing its debt balance to $280.0 million.
A $4.8 million dividend for the third quarter of fiscal 2020 was paid in-kind to holders of the Company’s convertible preferred stock.
Conference Call and Webcast
The Company will hold a conference call to review its results for the third quarter of fiscal 2020 today at 2:00 p.m. Pacific Time. The conference call will be webcast live on the Company’s website at investors.thecheesecakefactory.com and a replay of the webcast will be available through November 28, 2020.
About The Cheesecake Factory Incorporated
The Cheesecake Factory Incorporated is a leader in experiential dining. We are culinary forward and relentlessly focused on hospitality. Delicious, memorable experiences created by passionate people – this defines who we are and where we are going. We currently own and operate 295 restaurants throughout the United States and Canada under brands including The Cheesecake Factory®, North Italia® and a collection within the Fox Restaurant Concepts subsidiary. Internationally, 26 The Cheesecake Factory® restaurants operate under licensing agreements. Our bakery division operates two facilities that produce quality cheesecakes and other baked products for our restaurants, international licensees and third-party bakery customers. In 2020, we were named to the FORTUNE Magazine “100 Best Companies to Work For®” list for the seventh consecutive year. To learn more, visit www.thecheesecakefactory.com, www.northitalia.com and www.foxrc.com.
From FORTUNE. ©2020 Fortune Media IP Limited. FORTUNE 100 Best Companies to Work For is a trademark of Fortune Media IP Limited and is used under license. FORTUNE and Fortune Media IP Limited are not affiliated with, and do not endorse products or services of, Licensee.
26901 Malibu Hills Road, Calabasas Hills, CA 91301 · Telephone (818) 871-3000 · Fax (818) 871-3100
Safe Harbor Statement
This press release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995, as codified in Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. These statements include, without limitation, statements regarding the expected closure of a Grand Luxe Cafe location, fourth quarter to-date comparable restaurant sales, continued strength in off-premise sales, the Company’s ability to maximize sales at The Cheesecake Factory restaurants despite mandated capacity restrictions, sales recovery at North Italia and the FRC concepts, and the Company’s ability to manage through the COVID-19 environment and emerge in a competitively strong position. Such forward-looking statements include all other statements that are not historical facts, as well as statements that are preceded by, followed by or that include words or phrases such as “believe,” “plan,” “will likely result,” “expect,” “intend,” “will continue,” “is anticipated,” “estimate,” “project,” “may,” “could,” “would,” “should” and similar expressions. These statements are based on current expectations and involve risks and uncertainties which may cause results to differ materially from those set forth in such statements. Investors are cautioned that forward-looking statements are not guarantees of future performance and that undue reliance should not be placed on such statements. These forward-looking statements may be affected by various factors including: the rapidly evolving nature of the COVID-19 outbreak and related containment measures, including the potential for a complete shutdown of the Company’s restaurants, international licensee restaurants and the Company’s bakery operations; demonstrations, political unrest, potential damage to or closure of the Company’s restaurants and potential reputational damage to the Company or any of its brands; economic, public health and political conditions that impact consumer confidence and spending, including the impact of COVID-19 and other health epidemics or pandemics on the global economy; acceptance and success of The Cheesecake Factory in international markets; acceptance and success of North Italia and the Fox Restaurant Concepts restaurants; the risks of doing business abroad through Company-owned restaurants and/or licensees; foreign exchange rates, tariffs and cross border taxation; changes in unemployment rates; changes in laws impacting the Company’s business, including laws and regulations related to COVID-19 impacting restaurant operations and customer access to off- and on-premise dining; increases in minimum wages and benefit costs; the economic health of the Company’s landlords and other tenants in retail centers in which its restaurants are located, and the Company’s ability to successfully manage its lease arrangements with landlords; unanticipated costs that may arise due to a return to normal course of business including potential negative impacts from furlough actions; the economic health of suppliers, licensees, vendors and other third parties providing goods or services to the Company; compliance with debt covenants; adverse weather conditions in regions in which the Company’s restaurants are located; factors that are under the control of government agencies, landlords and other third parties; the risk, costs and uncertainties associated with opening new restaurants; and other risks and uncertainties detailed from time to time in the Company’s filings with the Securities and Exchange Commission (“SEC”). Forward-looking statements speak only as of the dates on which they are made and the Company undertakes no obligation to publicly update or revise any forward-looking statements or to make any other forward-looking statements, whether as a result of new information, future events or otherwise, unless required to do so by law. Investors are referred to the full discussion of risks and uncertainties associated with forward-looking statements and the discussion of risk factors contained in the Company’s latest Annual Report on Form 10-K, Quarterly Reports on Form 10-Q and Current Reports on Form 8-K as filed with the SEC, which are available at www.sec.gov.
26901 Malibu Hills Road, Calabasas Hills, CA 91301 · Telephone (818) 871-3000 · Fax (818) 871-3100
The Cheesecake Factory Incorporated
Condensed Consolidated Financial Statements
(unaudited; in thousands, except per share and statistical data)
| 13 Weeks Ended | 13 Weeks Ended | 39 Weeks Ended | 39 Weeks Ended | |||||||||||||||||||||||||||||
| September 29, 2020(1) | October 1, 2019 | September 29, 2020(1) | October 1, 2019 | |||||||||||||||||||||||||||||
| Consolidated Statements of Income | Amount | Percent of Revenues | Amount | Percent of Revenues | Amount | Percent of Revenues | Amount | Percent of Revenues | ||||||||||||||||||||||||
| Revenues | $ | 517,716 | 100.0 | % | $ | 586,536 | 100.0 | % | $ | 1,428,673 | 100.0 | % | $ | 1,788,662 | 100.0 | % | ||||||||||||||||
| Costs and expenses: | ||||||||||||||||||||||||||||||||
| Cost of sales | 118,093 | 22.8 | % | 132,941 | 22.7 | % | 331,137 | 23.2 | % | 403,566 | 22.6 | % | ||||||||||||||||||||
| Labor expenses | 200,666 | 38.7 | % | 213,600 | 36.4 | % | 560,460 | 39.2 | % | 648,831 | 36.3 | % | ||||||||||||||||||||
| Other operating costs and expenses | 159,095 | 30.7 | % | 149,397 | 25.5 | % | 448,740 | 31.4 | % | 451,724 | 25.2 | % | ||||||||||||||||||||
| General and administrative expenses | 37,795 | 7.3 | % | 36,556 | 6.2 | % | 117,467 | 8.2 | % | 112,926 | 6.3 | % | ||||||||||||||||||||
| Depreciation and amortization expenses | 22,651 | 4.4 | % | 21,342 | 3.6 | % | 68,803 | 4.8 | % | 64,363 | 3.6 | % | ||||||||||||||||||||
| Impairment of assets and lease terminations(2) | 10,402 | 2.0 | % | - | 0.0 | % | 204,731 | 14.3 | % | - | 0.0 | % | ||||||||||||||||||||
| Acquisition-related costs | 39 | 0.0 | % | 3,190 | 0.6 | % | 2,343 | 0.2 | % | 3,190 | 0.2 | % | ||||||||||||||||||||
| Acquisition-related contingent consideration, compensation and amortization expenses | 1,439 | 0.3 | % | - | 0.0 | % | (3,992 | ) | (0.3 | )% | - | 0.0 | % | |||||||||||||||||||
| Preopening costs | 2,394 | 0.5 | % | 2,546 | 0.4 | % | 7,610 | 0.6 | % | 6,851 | 0.4 | % | ||||||||||||||||||||
| Total costs and expenses | 552,574 | 106.7 | % | 559,572 | 95.4 | % | 1,737,299 | 121.6 | % | 1,691,451 | 94.6 | % | ||||||||||||||||||||
| (Loss)/income from operations | (34,858 | ) | (6.7 | )% | 26,964 | 4.6 | % | (308,626 | ) | (21.6 | )% | 97,211 | 5.4 | % | ||||||||||||||||||
| Loss on investment in unconsolidated affiliates | - | 0.0 | % | (10,345 | ) | (1.8 | )% | - | 0.0 | % | (13,439 | ) | (0.7 | )% | ||||||||||||||||||
| Interest and other (expense)/income, net | (2,935 | ) | (0.6 | )% | 6 | 0.0 | % | (7,019 | ) | (0.5 | )% | (17 | ) | (0.0 | )% | |||||||||||||||||
| (Loss)/income before income taxes | (37,793 | ) | (7.3 | )% | 16,625 | 2.8 | % | (315,645 | ) | (22.1 | )% | 83,755 | 4.7 | % | ||||||||||||||||||
| Income tax (benefit)/provision | (9,447 | ) | (1.8 | )% | 535 | 0.1 | % | (94,597 | ) | (6.6 | )% | 5,171 | 0.3 | % | ||||||||||||||||||
| Net (loss)/income | $ | (28,346 | ) | (5.5 | )% | $ | 16,090 | 2.7 | % | $ | (221,048 | ) | (15.5 | )% | $ | 78,584 | 4.4 | % | ||||||||||||||
| Basic net (loss)/income per share | $ | (0.76 | ) | $ | 0.37 | $ | (5.47 | ) | $ | 1.78 | ||||||||||||||||||||||
| Basic weighted average shares outstanding | 43,900 | 43,682 | 43,849 | 44,034 | ||||||||||||||||||||||||||||
| Diluted net (loss)/income per share | $ | (0.76 | ) | $ | 0.36 | $ | (5.47 | ) | $ | 1.76 | ||||||||||||||||||||||
| Diluted weighted average shares outstanding | 43,900 | 44,186 | 43,849 | 44,643 | ||||||||||||||||||||||||||||
(1) Results include the acquisition of North Italia and the remaining business of Fox Restaurant Concepts LLC (“FRC”) on October 2, 2019.
(2) Includes $10.4 million of impairment of assets and lease terminations expense in the thirteen weeks and thirty-nine weeks ended September 29, 2020 related to lease terminations for two Grand Lux Cafe locations, RockSugar Southeast Asian Kitchen and one Flower Child location. The thirty-nine weeks ended September 29, 2020 also includes $194.3 million of impairment of assets and lease terminations expense related to a lease termination for one The Cheesecake Factory restaurant, impairment of goodwill, trade names, trademarks and licensing agreements associated with the North Italia and FRC acquisition and impairment of long-lived assets for one The Cheesecake Factory, one North Italia, two Other FRC and four Other restaurants.
| 13 Weeks Ended | 13 Weeks Ended | 39 Weeks Ended | 39 Weeks Ended | |||||||||||||
| Net (Loss)/Income Per Share | September 29, 2020 | October 1, 2019 | September 29, 2020 | October 1, 2019 | ||||||||||||
| | (In thousands, except per share data) | |||||||||||||||
| Basic net (loss)/income per common share: | ||||||||||||||||
| Net (loss)/income | $ | (28,346 | ) | $ | 16,090 | $ | (221,048 | ) | $ | 78,584 | ||||||
| Dividends on preferred stock | (4,838 | ) | - | (8,532 | ) | - | ||||||||||
| Direct and incremental preferred stock issuance costs | - | - | (10,257 | ) | - | |||||||||||
| Net (loss)/income available to common stockholders | (33,184 | ) | 16,090 | (239,837 | ) | 78,584 | ||||||||||
| Basic weighted-average shares outstanding | 43,900 | 43,682 | 43,849 | 44,034 | ||||||||||||
| Basic net (loss)/income per common share | $ | (0.76 | ) | $ | 0.37 | $ | (5.47 | ) | $ | 1.78 | ||||||
| | | | | | ||||||||||||
| Diluted net (loss)/income per common share: | ||||||||||||||||
| Net (loss)/income available to common stockholders | (33,184 | ) | 16,090 | (239,837 | ) | 78,584 | ||||||||||
| Basic weighted-average shares outstanding | 43,900 | 43,682 | 43,849 | 44,034 | ||||||||||||
| Dilutive effect of equity awards (1) | - | 504 | - | 609 | ||||||||||||
| Diluted weighted-average shares outstanding | 43,900 | 44,186 | 43,849 | 44,643 | ||||||||||||
| Diluted net (loss)/income per common share | $ | (0.76 | ) | $ | 0.36 | $ | (5.47 | ) | $ | 1.76 | ||||||
(1) Shares of common stock equivalents of 4.0 million and 2.1 million as of September 29, 2020 and October 1, 2019, respectively, were excluded from the diluted calculation due to their anti-dilutive effect.
26901 Malibu Hills Road, Calabasas Hills, CA 91301 · Telephone (818) 871-3000 · Fax (818) 871-3100
| 13 Weeks Ended | 13 Weeks Ended | 39 Weeks Ended | 39 Weeks Ended | |||||||||||||
| Selected Segment Information | September 29, 2020 | October 1, 2019 | September 29, 2020 | October 1, 2019 | ||||||||||||
| Revenues: | ||||||||||||||||
| The Cheesecake Factory restaurants | $ | 416,984 | $ | 536,101 | $ | 1,146,524 | $ | 1,636,253 | ||||||||
| North Italia | 27,990 | - | 72,262 | - | ||||||||||||
| Other FRC | 20,273 | - | 68,063 | - | ||||||||||||
| Other | 52,469 | 50,435 | 141,824 | 152,409 | ||||||||||||
| Total | $ | 517,716 | $ | 586,536 | $ | 1,428,673 | $ | 1,788,662 | ||||||||
| (Loss)/income from operations(1): | ||||||||||||||||
| The Cheesecake Factory restaurants | $ | 18,836 | $ | 64,254 | $ | 31,208 | $ | 203,803 | ||||||||
| North Italia | (831 | ) | - | (77,321 | ) | - | ||||||||||
| Other FRC | (1,901 | ) | - | (77,077 | ) | - | ||||||||||
| Other | (50,962 | ) | (37,290 | ) | (185,436 | ) | (106,592 | ) | ||||||||
| Total | $ | (34,858 | ) | $ | 26,964 | $ | (308,626 | ) | $ | 97,211 | ||||||
| Preopening costs: | ||||||||||||||||
| The Cheesecake Factory restaurants | $ | 976 | $ | 2,437 | $ | 3,157 | $ | 5,874 | ||||||||
| North Italia | 631 | - | 1,895 | - | ||||||||||||
| Other FRC | 306 | - | 527 | - | ||||||||||||
| Other | 481 | 109 | 2,031 | 977 | ||||||||||||
| Total | $ | 2,394 | $ | 2,546 | $ | 7,610 | $ | 6,851 | ||||||||
| Depreciation and amortization: | ||||||||||||||||
| The Cheesecake Factory restaurants | $ | 16,713 | $ | 17,728 | $ | 50,857 | $ | 53,340 | ||||||||
| North Italia | 901 | - | 2,767 | - | ||||||||||||
| Other FRC | 987 | - | 3,002 | - | ||||||||||||
| Other | 4,050 | 3,614 | 12,177 | 11,023 | ||||||||||||
| Total | $ | 22,651 | $ | 21,342 | $ | 68,803 | $ | 64,363 | ||||||||
(1) During the thirteen weeks ended September 29, 2020, the Company recorded impairment of assets and lease terminations expense of $10.4 million in the Other segment. During the thirty-nine weeks ended September 29, 2020, the Company recorded impairment of assets and lease terminations expense of $3.0 million for The Cheesecake Factory restaurants, $71.5 million for North Italia, $72.9 million for Other FRC and $57.3 million for Other.
| The Cheesecake Factory restaurants operating information: | ||||||||||||||||
| Comparable restaurant sales | (23.3 | )% | 0.4 | % | (31.1 | )% | 0.9 | % | ||||||||
| Restaurants opened during period | - | 1 | - | 2 | ||||||||||||
| Restaurants open at period-end | 205 | 203 | 205 | 203 | ||||||||||||
| Restaurant operating weeks | 2,662 | 2,628 | 7,976 | 7,865 | ||||||||||||
| North Italia operating information: | ||||||||||||||||
| Comparable restaurant sales | (22 | )% | - | (32 | )% | - | ||||||||||
| Restaurants opened during period | - | - | 1 | - | ||||||||||||
| Restaurants open at period-end | 23 | - | 23 | - | ||||||||||||
| Restaurant operating weeks | 296 | - | 847 | - | ||||||||||||
| Other Fox Restaurant Concepts (FRC) operating information:(1) | ||||||||||||||||
| Restaurants opened during period | - | - | - | - | ||||||||||||
| Restaurants open at period-end | 25 | - | 25 | - | ||||||||||||
| Restaurant operating weeks | 275 | - | 809 | - | ||||||||||||
| Other operating information:(2) | ||||||||||||||||
| Restaurants opened during period | 2 | - | 3 | 1 | ||||||||||||
| Restaurants open at period-end | 41 | 17 | 41 | 17 | ||||||||||||
| Restaurant operating weeks | 437 | 221 | 1,242 | 655 | ||||||||||||
| Number of company-owned restaurants: | ||||||||||||||||
| The Cheesecake Factory | 205 | |||||||||||||||
| North Italia | 23 | |||||||||||||||
| Other FRC | 25 | |||||||||||||||
| Other | 41 | |||||||||||||||
| Total | 294 | |||||||||||||||
| Number of international-licensed restaurants: | ||||||||||||||||
| The Cheesecake Factory | 26 | |||||||||||||||
(1) The Other FRC segment includes all FRC brands except Flower Child.
(2) The Other segment includes the Flower Child, Grand Lux Cafe, RockSugar Southeast Asian Kitchen and Social Monk Asian Kitchen concepts, as well as the Company's third-party bakery, international and consumer packaged goods businesses.
| Selected Consolidated Balance Sheet Information | September 29, 2020 | December 31, 2019 | ||||||
| Cash and cash equivalents | $ | 243,768 | $ | 58,416 | ||||
| Long-term debt | 376,000 | 290,000 | ||||||
26901 Malibu Hills Road, Calabasas Hills, CA 91301 · Telephone (818) 871-3000 · Fax (818) 871-3100
Reconciliation of Non-GAAP Results to GAAP Results
In addition to the results provided in accordance with accounting principles generally accepted in the United States of America (“GAAP”) in this press release, the Company is providing non-GAAP measurements which present net (loss)/income and net (loss)/income per share excluding the impact of certain items. The non-GAAP measurements are intended to supplement the presentation of the Company’s financial results in accordance with GAAP. These non-GAAP measures are calculated by eliminating from net (loss)/income and diluted net (loss)/income per share the impact of items the Company does not consider indicative of its ongoing operations. To reflect the potential impact of the conversion of the Company’s convertible preferred stock into common stock, the Company excludes the preferred dividend and direct and incremental preferred stock issuance costs, and assumes all convertible preferred shares convert to common stock. The Company uses these non-GAAP financial measures for financial and operational decision-making and as a means to evaluate period-to-period comparisons.
The Cheesecake Factory Incorporated
Reconciliation of Non-GAAP Financial Measures
(unaudited; in thousands, except per share data)
| 13 Weeks Ended | 13 Weeks Ended | 39 Weeks Ended | 39 Weeks Ended | |||||||||||||
| September 29, 2020 | October 1, 2019 | September 29, 2020 | October 1, 2019 | |||||||||||||
| Net (loss)/income available to common stockholders (GAAP) | $ | (33,184 | ) | $ | 16,090 | $ | (239,837 | ) | $ | 78,584 | ||||||
| Dividends on preferred stock | 4,838 | - | 8,532 | - | ||||||||||||
| Direct and incremental preferred stock issuance costs | - | - | 10,257 | - | ||||||||||||
| COVID-19 related costs(1) | 2,558 | - | 17,579 | - | ||||||||||||
| Impairment of assets and lease terminations(2) | 10,402 | - | 204,731 | - | ||||||||||||
| Acquisition-related costs(3) | 39 | 3,190 | 2,343 | 3,190 | ||||||||||||
| Acquisition-related contingent consideration, compensation and amortization expenses(4) | 1,439 | - | (3,992 | ) | - | |||||||||||
| Loss on investment in unconsolidated affiliates(5) | - | 10,345 | - | 13,439 | ||||||||||||
| Tax effect of adjustments(6) | (3,754 | ) | (3,519 | ) | (57,372 | ) | (4,323 | ) | ||||||||
| Adjusted net (loss)/income (non-GAAP) | $ | (17,662 | ) | $ | 26,106 | $ | (57,759 | ) | $ | 90,890 | ||||||
| Diluted net (loss)/income per common share (GAAP) | $ | (0.76 | ) | $ | 0.36 | $ | (5.47 | ) | $ | 1.76 | ||||||
| Dividends on preferred stock | 0.09 | - | 0.17 | - | ||||||||||||
| Direct and incremental preferred stock issuance costs | - | - | 0.21 | - | ||||||||||||
| Assumed impact of potential conversion of preferred stock into common stock(7) | 0.13 | - | 0.60 | - | ||||||||||||
| COVID-19 related costs | 0.05 | - | 0.36 | - | ||||||||||||
| Impairment of assets and lease terminations | 0.20 | - | 4.16 | - | ||||||||||||
| Acquisition-related costs | 0.00 | 0.07 | 0.05 | 0.07 | ||||||||||||
| Acquisition-related contingent consideration, compensation and amortization expenses | 0.03 | - | (0.08 | ) | - | |||||||||||
| Loss on investment in unconsolidated affiliates | - | 0.23 | - | 0.30 | ||||||||||||
| Tax effect of adjustments | (0.07 | ) | (0.08 | ) | (1.17 | ) | (0.10 | ) | ||||||||
| Adjusted net (loss)/income per share (non-GAAP)(8) | $ | (0.33 | ) | $ | 0.59 | $ | (1.17 | ) | $ | 2.04 | ||||||
(1) Represents incremental costs associated with COVID-19 such as additional sanitation, personal protective equipment, and healthcare benefits and other expenses associated with furloughed staff members. For the thirteen weeks ended September 29, 2020, the Company recorded $2.6 million for these costs with approximately $0.4 million reflected in labor expenses, $2.1 million in other operating expenses and $0.1 million in General & Administrative expenses. For the thirty-nine weeks ended September 29, 2020, the Company recorded $17.6 million for these costs with approximately $2.2 million in cost of sales, $9.9 million reflected in labor expenses, $5.1 million in other operating expenses and $0.4 million in General & Administrative expenses.
(2) Includes $10.4 million of impairment of assets and lease terminations expense in the thirteen weeks and thirty-nine weeks ended September 29, 2020 related to lease terminations for two Grand Lux Cafe locations, RockSugar Southeast Asian Kitchen and one Flower Child location. The thirty-nine weeks ended September 29, 2020 also includes $194.3 million of impairment of assets and lease terminations expense related to a lease termination for one The Cheesecake Factory restaurant, impairment of goodwill, trade names, trademarks and licensing agreements associated with the North Italia and FRC acquisition and impairment of long-lived assets for one The Cheesecake Factory, one North Italia, two Other FRC and four Other restaurants.
(3) Represents costs incurred to effect and integrate the North and FRC acquisition.
(4) Represents changes in the fair value of the deferred consideration and contingent consideration and compensation liabilities related to the North and FRC acquisition, as well as amortization of acquired definite-lived licensing agreements.
(5) Represents the Company's share of pre-acquisition losses incurred by North Italia and Flower Child.
(6) Based on the federal statutory rate and an estimated blended state tax rate, the tax effect on all adjustments assumes a 26% tax rate for fiscal 2020 and 2019.
(7) Represents the impact of assuming the conversion of preferred stock into common stock (9,163,043 shares and 5,394,188 shares for the thirteen weeks and thirty-nine weeks ended September 29, 2020, respectively), resulting in an assumption of 53,062,945 and 49,243,370 weighted-average common shares outstanding, respectively, for the thirteen weeks and thirty-nine weeks ended September 29, 2020. Beginning in the third quarter of fiscal 2020, the Company revised the method used to calculate the potential impact of the conversion of the Company’s preferred stock to common stock for purposes of determining adjusted net (loss)/income per share (non-GAAP). Instead of assuming preferred shares are converted to common shares as of the beginning of each period presented, the Company now utilizes a weighted average shares outstanding approach to be consistent with the approach used for outstanding common shares. Under this methodology, the revised adjusted net loss per share for the second quarter of fiscal 2020 was $0.90.
(8) Adjusted net (loss)/income per share may not add due to rounding.
26901 Malibu Hills Road, Calabasas Hills, CA 91301 · Telephone (818) 871-3000 · Fax (818) 871-3100
Exhibit 99.2
Investor Presentation October 29, 2020
This presentation contains forward - looking statements within the meaning of Section 27 A of the Securities Act of 1933 , as amended, and Section 21 E of the Securities Exchange Act of 1934 , as amended . This includes, without limitation, financial guidance and projections and statements with respect to expectations of the Company’s future financial condition, results of operations, cash flows, plans, targets, goals, objectives, performance, growth potential, competitive position and business ; the Company’s strong foothold in the off - premise channel supporting the business in the COVID - 19 environment ; the Company’s ability to successfully reopen its dining rooms ; the opportunity for additional domestic and foreign locations and licensees and territories ; target returns for new restaurant openings ; performance of international licensed locations ; the acquisitions of North Italia and Fox Restaurant Concepts (“FRC”) ; FRC as an incubation engine ; steady - state restaurant level margins and anticipated unit growth roadmap . Such forward - looking statements include all other statements that are not historical facts, as well as statements that are preceded by, followed by or that include words or phrases such as “believe,” “plan,” “will likely result,” “expect,” “intend,” “will continue,” “is anticipated,” “estimate,” “project,” “may,” “could,” “would,” “should” and similar expressions . These statements are based on the Company’s current expectations and involve risks and uncertainties which may cause results to differ materially from those set forth in such statements . These forward - looking statements also may be affected by various factors control including : the rapidly evolving nature of the COVID - 19 pandemic and related containment measures, including the potential for a complete shutdown of the Company’s restaurants, international licensee restaurants and the Company’s bakery operations ; demonstrations, political unrest, potential damage to or closure of the Company’s restaurants and potential reputational damage to the Company or any of its brands ; economic, public health and political conditions that impact consumer confidence and spending, including the impact of the COVID - 19 pandemic and other health epidemics or pandemics on the global economy ; acceptance and success of The Cheesecake Factory in international markets ; acceptance and success of North Italia and the FRC concepts, Social Monk Asian Kitchen and other concepts ; the risks of doing business abroad through Company - owned restaurants and/or licensees ; foreign exchange rates, tariffs and cross border taxation ; changes in unemployment rates ; changes in laws impacting the Company’s business, including laws and regulations related to COVID - 19 impacting restaurant operations and customer access to off - and on - premise dining ; increases in minimum wages and benefit costs ; the economic health of the Company’s landlords and other tenants in retail centers in which its restaurants are located, and the Company’s ability to successfully manage its lease arrangements with landlords ; unanticipated costs that may arise in connection with a return to normal course of business including potential negative impacts from furlough actions ; the economic health of suppliers, licensees, vendors and other third parties providing goods or services to the Company ; the timing of the resumption of the Company’s new unit development ; compliance with debt covenants ; strategic capital allocation decisions including share repurchases and dividends ; the ability to achieve projected financial results ; economic and political conditions that impact consumer confidence and spending ; impact of tax reform legislation ; adverse weather conditions in regions in which the Company’s restaurants are located ; factors that are under the control of government agencies, landlords and other third parties ; the risk, costs and uncertainties associated with opening new restaurants ; and other risks and uncertainties detailed from time to time in the Company’s filings with the Securities and Exchange Commission (“SEC”) . Forward - looking statements speak only as of the dates on which they are made and the Company undertakes no obligation to publicly update or revise any forward - looking statements or to make any other forward - looking statements, whether as a result of new information, future events or otherwise, unless required to do so by law . Investors are referred to the full discussion of risks and uncertainties associated with forward - looking statements and the discussion of risk factors contained in the Company’s latest Annual Report on Form 10 - K, Quarterly Reports on Form 10 - Q and Current Reports on Form 8 - K as filed with the SEC, which are available at www . sec . gov . Safe Harbor Statement 2
Initial Response to COVID - 19 3 • Pivoted very quickly to maximize sales, manage costs and preserve cash • Shifted to an off - premise only model in March – began reopening dining rooms in mid - May • Eliminated non - essential spending and suspended new unit development – resumed new unit development on a limited basis during 3Q20 • Reduced board, executive and corporate support staff compensation – restored compensation during 3Q20 • Made difficult decision to furlough a significant number of staff members – during 3Q20, called back to work a majority of staff members who were previously furloughed • Increased liquidity with $200 million convertible preferred equity – ended 3Q20 with cash balance of $244 million • Amended credit facility to provide for certain covenant relief through 1Q21 • Suspended dividend on common stock and share repurchases
Managing Through COVID - 19 4 • Have taken a deliberate approach in our dining room reopening strategy as the health and safety of our teams and guests remain our top priority • Secured PPE; implemented additional safety protocols; and made a number of operational changes and technology upgrades, including contactless menu & payment technology and text paging, in order to help ensure the best and safest possible experiences for our guests and staff • Strategic decision to maintain our restaurant management teams has enabled us to reopen our dining rooms effectively • Leveraging our large restaurant footprints, patio space and flexible seating layouts, we have captured meaningful sales levels at Cheesecake Factory restaurants despite capacity restrictions • Locations with partially reopened indoor dining rooms have recaptured, on average quarter - to - date through October 27th, approximately 90 % of prior year annualized sales levels • Quarter - to - date through October 27th, we continued to maintain nearly 90 % of elevated COVID off - premise sales at Cheesecake Factory restaurants with partially reopened dining rooms • Restaurants in jurisdictions with outdoor dining - only restrictions were doing volumes of over 90 %, on average quarter - to - date through October 27th, of Cheesecake Factory locations with indoor dining rooms partially open
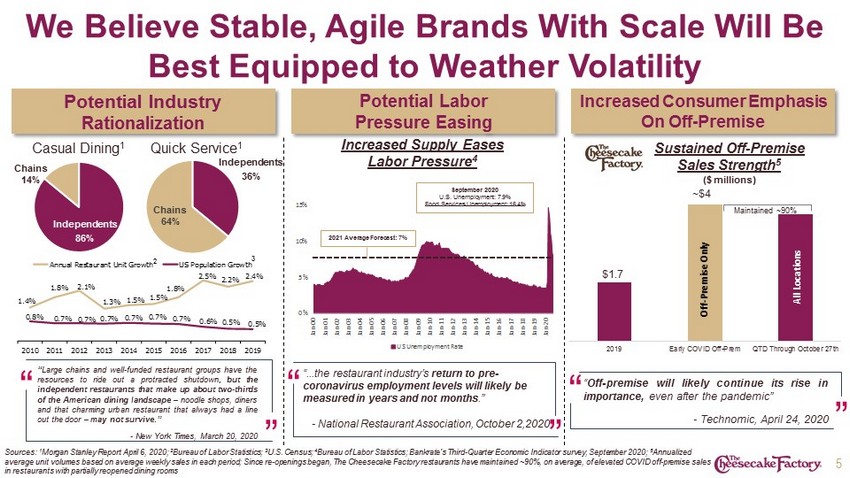
Sustained Off - Premise Sales Strength 5 ($ millions) ~$4 2019 Early COVID Off-Prem QTD Through October 27th Off - Premise Only $1.7 1.4% 1.8% 2.1% 1.3% 1.5% 1.5% 1.8% 2.5% 2.2% 2.4% 0.8% 0.7% 0.7% 0.7% 0.7% 0.7% 0.7% 0.6% 0.5% 0.5% 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 Annual Restaurant Unit Growth US Population Growth We Believe Stable, Agile Brands With Scale Will Be Best Equipped to Weather Volatility 5 Potential Industry Rationalization Shifting Industry Dynamics “ ” “ Large chains and well - funded restaurant groups have the resources to ride out a protracted shutdown , but the independent restaurants that make up about two - thirds of the American dining landscape – noodle shops, diners and that charming urban restaurant that always had a line out the door – may not survive . ” - New York Times, March 20, 2020 Quick Service 1 Casual Dining 1 Sources: 1 Morgan Stanley Report April 6, 2020; 2 Bureau of Labor Statistics; 3 U.S. Census; 4 Bureau of Labor Statistics; Bankrate's Third - Quarter Economic Indicator survey, September 2020; 5 Annualized average unit volumes based on average weekly sales in each period; Since re - openings began, The Cheesecake Factory restaurants h ave maintained ~90%, on average, of elevated COVID off - premise sales in restaurants with partially reopened dining rooms Increased Supply Eases Labor Pressure 4 Potential Labor Pressure Easing Increased Consumer Emphasis On Off - Premise “ Off - premise will likely continue its rise in importance, even after the pandemic” - Technomic, April 24, 2020 ” “ Independents 86% Chains 14% Independents 36% Chains 64% 3 2 “ ” “...the restaurant industry’s return to pre - coronavirus employment levels will likely be measured in years and not months .” - National Restaurant Association, October 2,2020 All Locations Maintained ~90% 0% 5% 10% 15% Jan-00 Jan-01 Jan-02 Jan-03 Jan-04 Jan-05 Jan-06 Jan-07 Jan-08 Jan-09 Jan-10 Jan-11 Jan-12 Jan-13 Jan-14 Jan-15 Jan-16 Jan-17 Jan-18 Jan-19 Jan-20 US Unemployment Rate 2021 Average Forecast: 7% September 2020 U.S. Unemployment: 7.9% Food Services Unemployment: 16.4%
• Experiential dining category leader with diversified growth drivers • Leveraging the Company’s strong foothold in the off - premise channel to support the business in the COVID - 19 environment • Durable business over time - sustained track record of consistent financial performance • Historically robust cash flow provides several levers to support long - term growth Investment Highlights 6
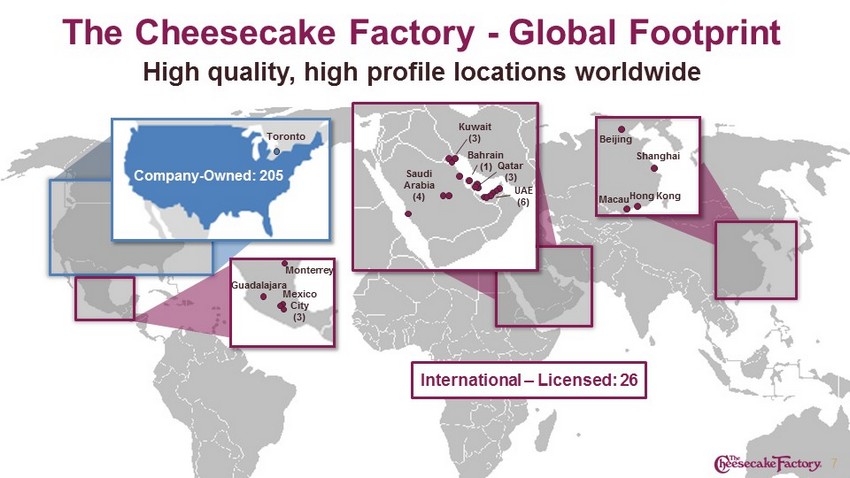
The Cheesecake Factory - Global Footprint 7 High quality, high profile locations worldwide Company - Owned: 205 Toronto International – Licensed: 26 Mexico City (3) Guadalajara Saudi Arabia (4) UAE (6) Kuwait (3) Qatar (3) Bahrain (1) Shanghai Hong Kong Beijing Monterrey Macau
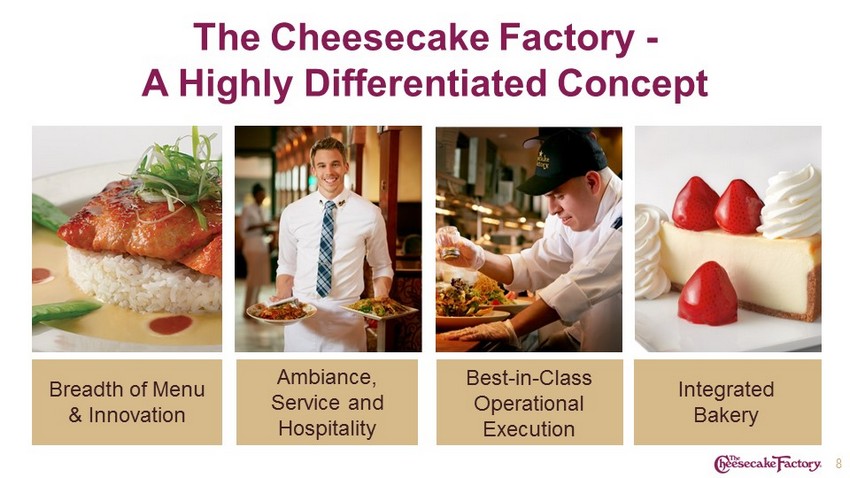
Breadth of Menu & Innovation Ambiance, Service and Hospitality The Cheesecake Factory - A Highly Differentiated Concept Best - in - Class Operational Execution Integrated Bakery 8
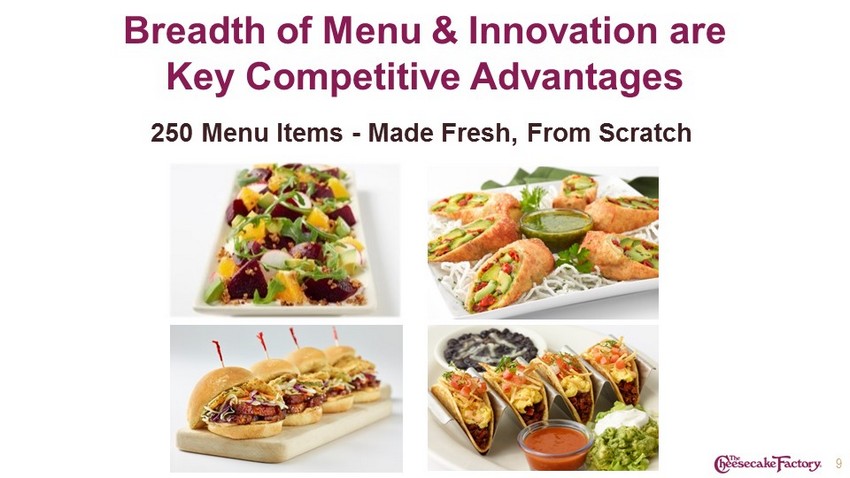
Breadth of Menu & Innovation are Key Competitive Advantages 250 Menu Items - Made Fresh, From Scratch 9
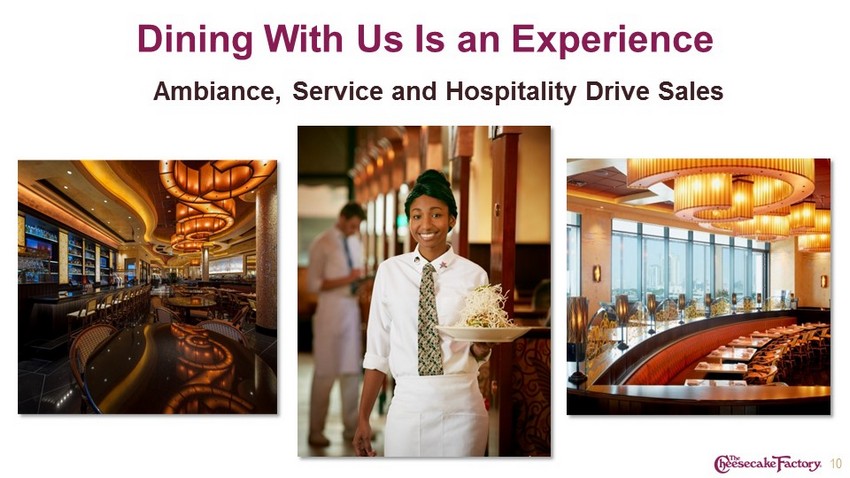
Dining With Us Is an Experience Ambiance, Service and Hospitality Drive Sales 10
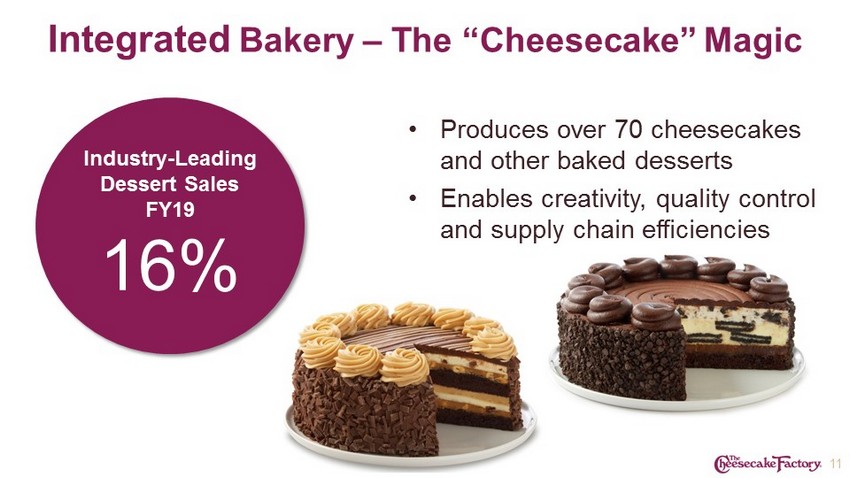
Integrated Bakery – The “Cheesecake” Magic • Produces over 70 cheesecakes and other baked desserts • Enables creativity, quality control and supply chain efficiencies Industry - Leading Dessert Sales FY19 16% 11
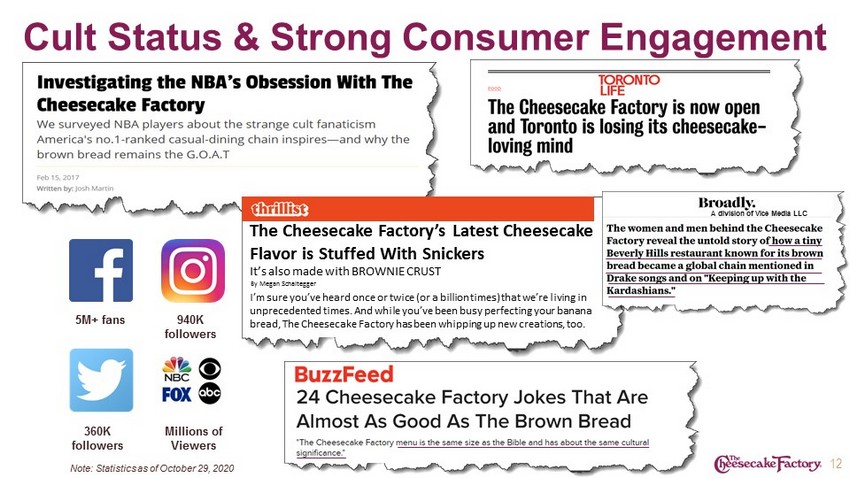
Cult Status & Strong Consumer Engagement 940K followers 5M+ fans 360K followers Millions of Viewers 12 Note: Statistics as of October 29, 2020 The Cheesecake Factory’s Latest Cheesecake Flavor is Stuffed With Snickers It’s also made with BROWNIE CRUST By Megan Schaltegger I’m sure you’ve heard once or twice (or a billion times) that we’re living in unprecedented times. And while you’ve been busy perfecting your banana bread, The Cheesecake Factory has been whipping up new creations, too. A division of Vice Media LLC
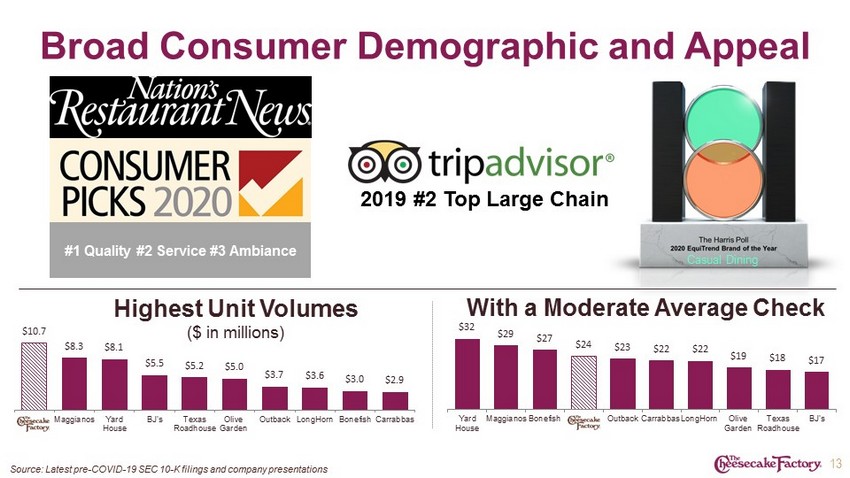
Broad Consumer Demographic and Appeal With a Moderate Average Check Highest Unit Volumes ($ in millions) Source: Latest pre - COVID - 19 SEC 10 - K filings and company presentations 2019 #2 Top Large Chain 13 Casual Dining $10.7 $8.3 $8.1 $5.5 $5.2 $5.0 $3.7 $3.6 $3.0 $2.9 Maggianos Yard House BJ's Texas Roadhouse Olive Garden Outback LongHorn Bonefish Carrabbas $32 $29 $27 $24 $23 $22 $22 $19 $18 $17 Yard House Maggianos Bonefish Outback Carrabbas LongHorn Olive Garden Texas Roadhouse BJ's #1 Quality #2 Service #3 Ambiance
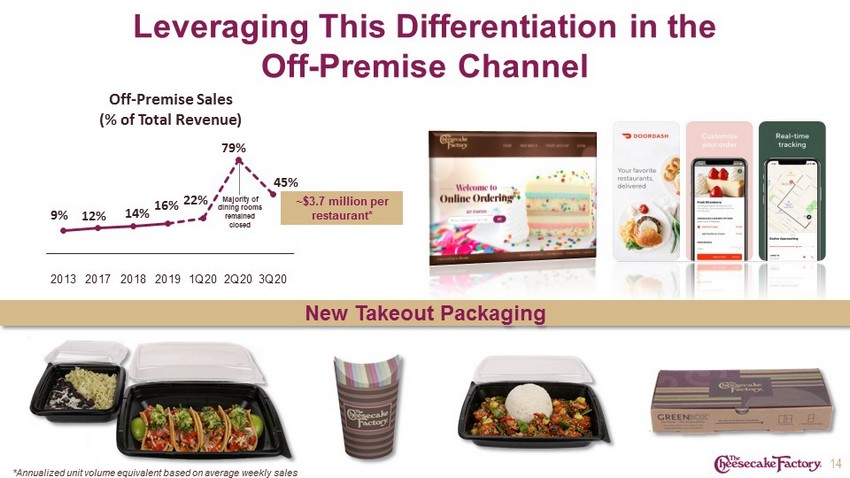
9% 12% 14% 16% 22% 79% 45% 2013 2017 2018 2019 1Q20 2Q20 3Q20 Off - Premise Sales (% of Total Revenue) Leveraging This Differentiation in the Off - Premise Channel New Takeout Packaging 14 *Annualized unit volume equivalent based on average weekly sales ~$3.7 million per restaurant* Majority of dining rooms remained closed
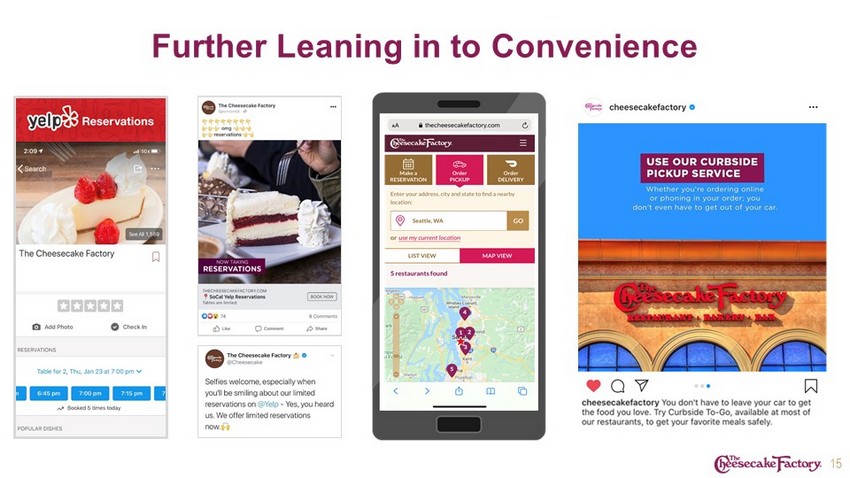
Further Leaning in to Convenience 15
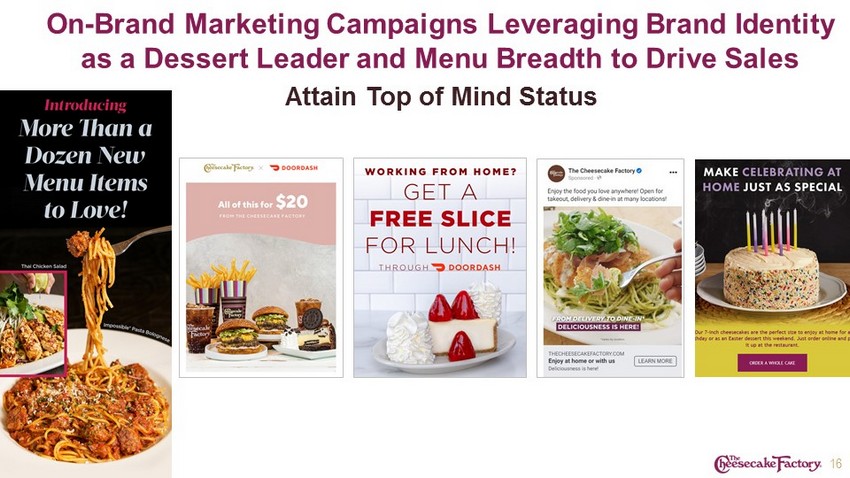
On - Brand Marketing Campaigns Leveraging Brand Identity as a Dessert Leader and Menu Breadth to Drive Sales 16 Attain Top of Mind Status
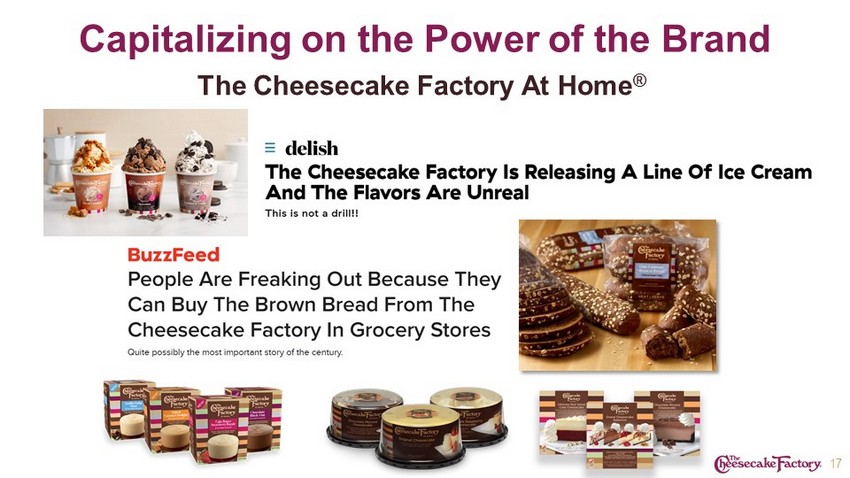
Capitalizing on the Power of the Brand The Cheesecake Factory At Home ® 17
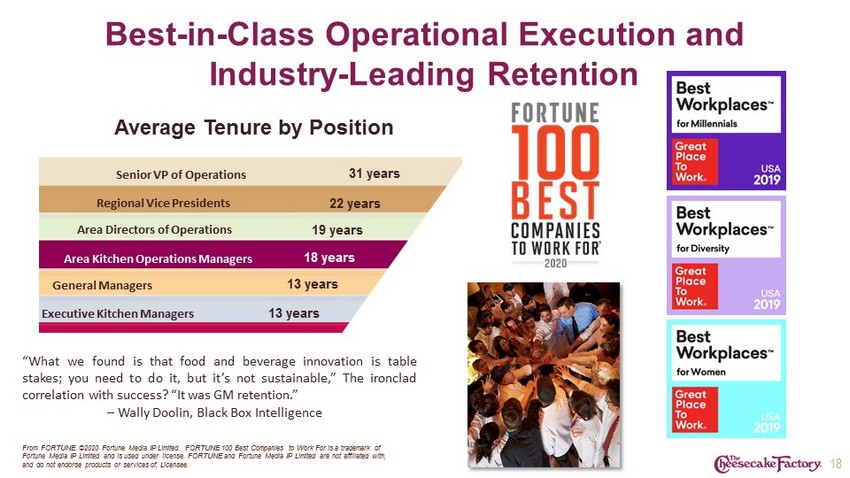
Best - in - Class Operational Execution and Industry - Leading Retention Average Tenure by Position 31 years 22 years 19 years 18 years 13 years 13 years Senior VP of Operations Regional Vice Presidents Area Directors of Operations Area Kitchen Operations Managers General Managers Executive Kitchen Managers “What we found is that food and beverage innovation is table stakes ; you need to do it, but it’s not sustainable,” The ironclad correlation with success? “It was GM retention . ” – Wally Doolin, Black Box Intelligence From FORTUNE. ©2020 Fortune Media IP Limited. FORTUNE 100 Best Companies to Work For is a trademark of Fortune Media IP Limited and is used under license. FORTUNE and Fortune Media IP Limited are not affiliated with, and do not endorse products or services of, Licensee. 18
Looking Ahead: Post - COVID - 19 Diversified growth drivers once the restaurant industry operating environment normalizes 19 19 *The following targets assume full capacity conditions are ultimately permitted by state and local jurisdictions
An Experiential Dining Category Leader 20 Culinary forward. First class hospitality. Concepts like no other.
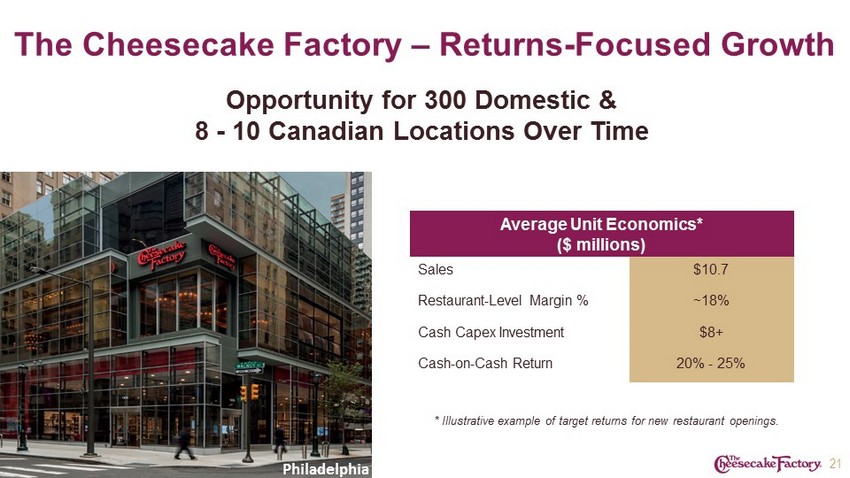
The Cheesecake Factory – Returns - Focused Growth Opportunity for 300 Domestic & 8 - 10 Canadian Locations Over Time Average Unit Economics* ($ millions) Sales $10.7 Restaurant - Level Margin % ~18% Cash Capex Investment $8+ Cash - on - Cash Return 20% - 25% * Illustrative example of target returns for new restaurant openings. Philadelphia 21
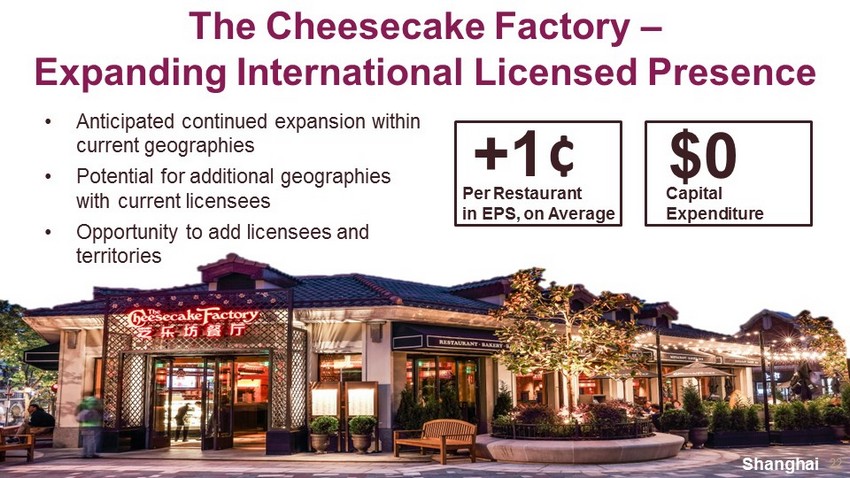
The Cheesecake Factory – Expanding International Licensed Presence • Anticipated continued expansion within current geographies • Potential for additional geographies with current licensees • Opportunity to add licensees and territories +1 ¢ Per Restaurant in EPS, on Average $0 Capital Expenditure Shanghai 22
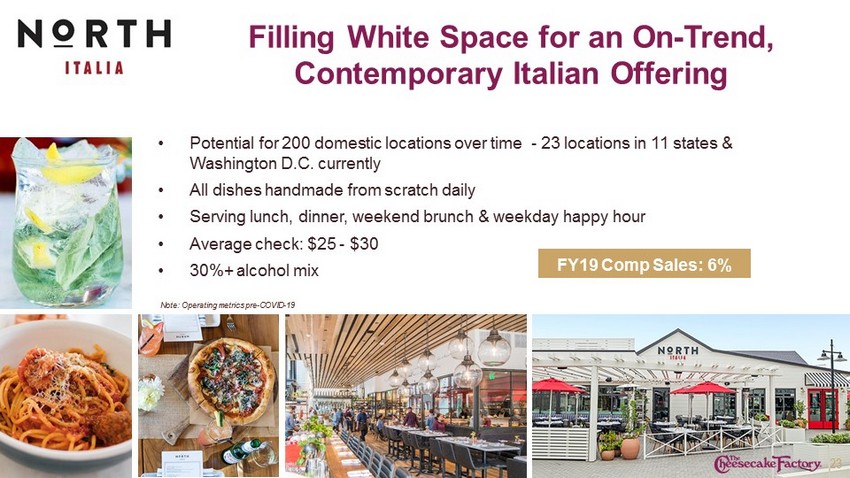
Filling White Space for an On - Trend, Contemporary Italian Offering 23 • Potential for 200 domestic locations over time - 23 locations in 11 states & Washington D.C. currently • All dishes handmade from scratch daily • Serving lunch, dinner, weekend brunch & weekday happy hour • Average check: $25 - $30 • 30%+ alcohol mix FY19 Comp Sales: 6% Note: Operating metrics pre - COVID - 19
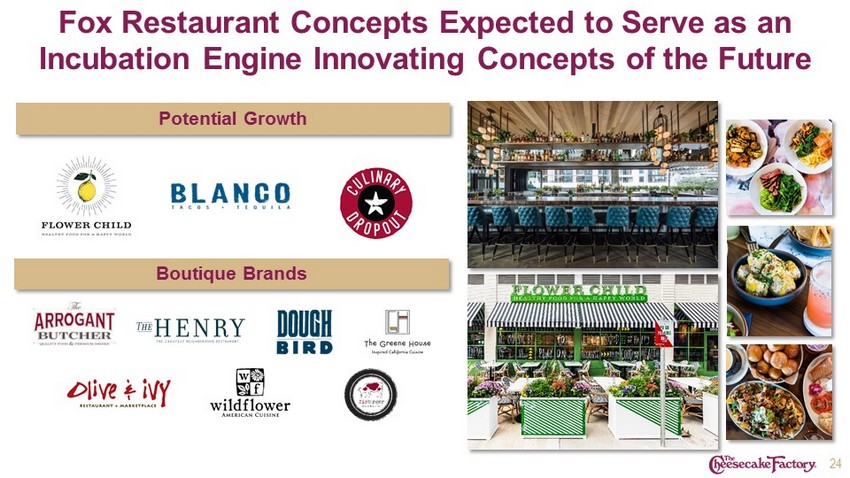
Fox Restaurant Concepts Expected to Serve as an Incubation Engine Innovating Concepts of the Future 24 Potential Growth Boutique Brands
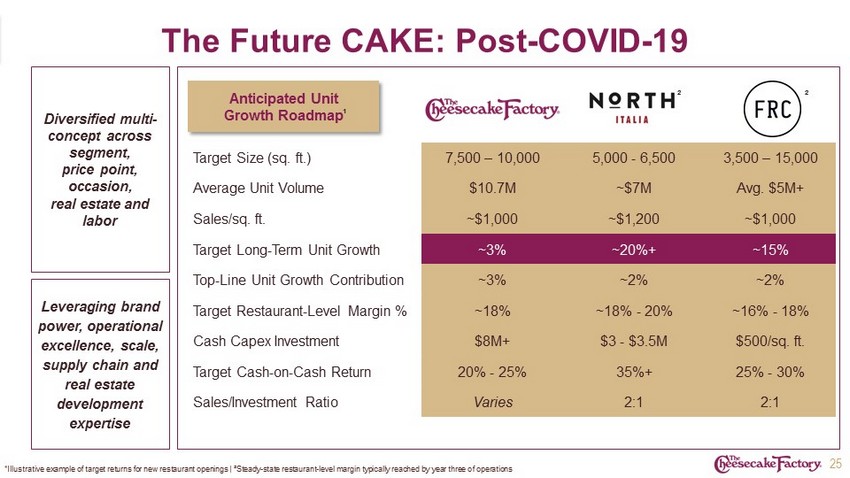
The Future CAKE: Post - COVID - 19 Target Size (sq. ft.) 7,500 – 10,000 5,000 - 6,500 3,500 – 15,000 Average Unit Volume $10.7M ~$7M Avg. $5M+ Sales/sq. ft. ~$1,000 ~$1,200 ~$1,000 Target Long - Term Unit Growth ~3% ~20%+ ~15% Top - Line Unit Growth Contribution ~3% ~2% ~2% Target Restaurant - Level Margin % ~18% ~18% - 20% ~16% - 18% Cash Capex Investment $8M+ $3 - $3.5M $500/sq. ft. Target Cash - on - Cash Return 20% - 25% 35%+ 25% - 30% Sales/Investment Ratio Varies 2:1 2:1 25 Diversified multi - concept across segment, price point, occasion, real estate and labor Leveraging brand power, operational excellence, scale, supply chain and real estate development expertise Anticipated Unit Growth Roadmap ¹Illustrative example of target returns for new restaurant openings | ²Steady - state restaurant - level margin typically reached by year three of operations ¹ ² ²
Track Record of Consistent Financial Performance 26
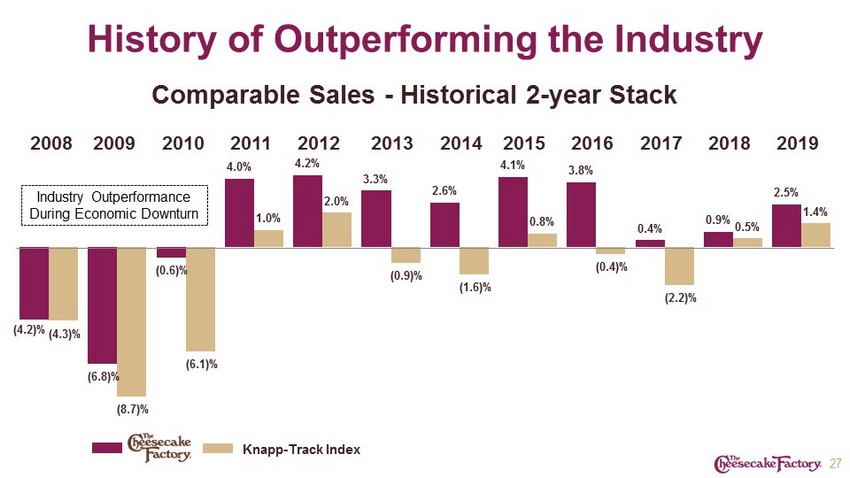
(4.2)% (6.8)% (0.6)% 4.0% 4.2% 3.3% 2.6% 4.1% 3.8% 0.4% 0.9% 2.5% (4.3)% (8.7)% (6.1)% 1.0% 2.0% (0.9)% (1.6)% 0.8% (0.4)% (2.2)% 0.5% 1.4% History of Outperforming the Industry 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 Knapp - Track Index Comparable Sales - Historical 2 - year Stack 27 Industry Outperformance During Economic Downturn
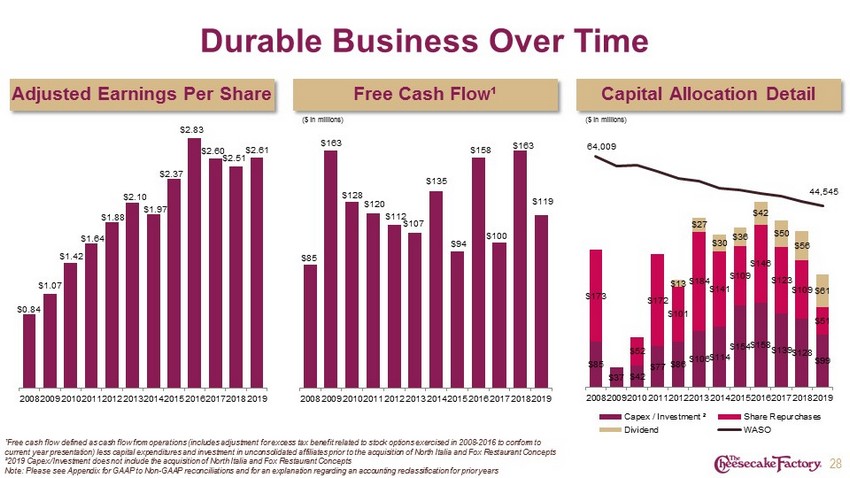
28 $0.84 $1.07 $1.42 $1.64 $1.88 $2.10 $1.97 $2.37 $2.83 $2.60 $2.51 $2.61 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 Capital Allocation Detail $85 $163 $128 $120 $112 $107 $135 $94 $158 $100 $163 $119 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 ¹Free cash flow defined as cash flow from operations (includes adjustment for excess tax benefit related to stock options exe rci sed in 2008 - 2016 to conform to current year presentation) less capital expenditures and investment in unconsolidated affiliates prior to the acquisition of Nor th Italia and Fox Restaurant Concepts ²2019 Capex/Investment does not include the acquisition of North Italia and Fox Restaurant Concepts Note: Please see Appendix for GAAP to Non - GAAP reconciliations and for an explanation regarding an accounting reclassification f or prior years $85 $37 $42 $77 $86 $106 $114 $154 $158 $139 $128 $99 $173 $52 $172 $101 $184 $141 $109 $146 $123 $109 $51 $13 $27 $30 $36 $42 $50 $56 $61 64,009 44,545 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 Capex / Investment ² Share Repurchases Dividend WASO Durable Business Over Time Free Cash Flow¹ Adjusted Earnings Per Share ($ in millions) ($ in millions)
• Experiential dining category leader with diversified growth drivers • Leveraging the Company’s strong foothold in the off - premise channel to support the business in the COVID - 19 environment • Durable business over time - sustained track record of consistent financial performance • Historically robust cash flow provides several levers to support long - term growth Investment Highlights 29
Appendix
Non - GAAP Reconciliations In addition to the results provided in accordance with the Generally Accepted Accounting Principles (“GAAP”) in this presentation, the Company is providing non - GAAP measurements which present diluted net income per share excluding the impact of certain items and free cash flow . The non - GAAP measurements are intended to supplement the presentation of the Company’s financial results in accordance with GAAP. The Company believes that the presentation of these items provides additional information to facilitate the comparison of past and present financial results. 31
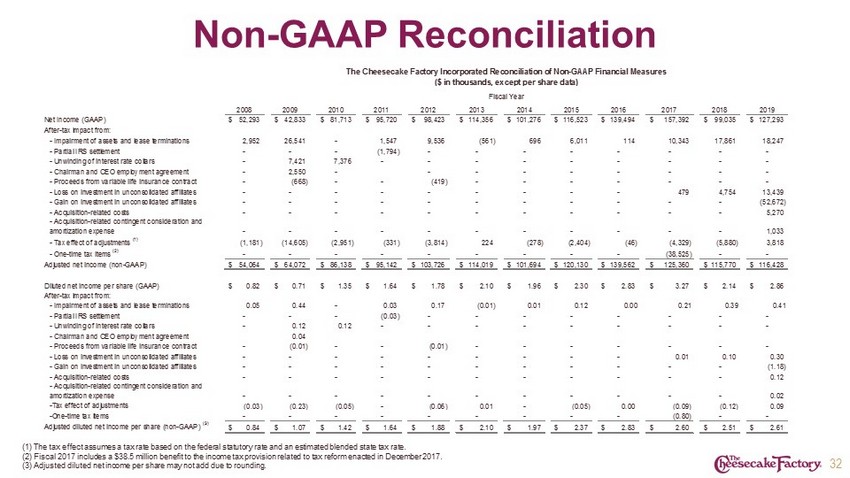
Non - GAAP Reconciliation (1) The tax effect assumes a tax rate based on the federal statutory rate and an estimated blended state tax rate. (2) Fiscal 2017 includes a $38.5 million benefit to the income tax provision related to tax reform enacted in December 2017. (3) Adjusted diluted net income per share may not add due to rounding. 32 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 Net Income (GAAP) 52,293$ 42,833$ 81,713$ 95,720$ 98,423$ 114,356$ 101,276$ 116,523$ 139,494$ 157,392$ 99,035$ 127,293$ After-tax impact from: - Impairment of assets and lease terminations 2,952 26,541 - 1,547 9,536 (561) 696 6,011 114 10,343 17,861 18,247 - Partial IRS settlement - - - (1,794) - - - - - - - - - Unwinding of interest rate collars - 7,421 7,376 - - - - - - - - - - Chairman and CEO employment agreement - 2,550 - - - - - - - - - - Proceeds from variable life insurance contract - (668) - - (419) - - - - - - - - Loss on investment in unconsolidated affiliates - - - - - - - - - 479 4,754 13,439 - Gain on investment in unconsolidated affiliates - - - - - - - - - - - (52,672) - Acquisition-related costs - - - - - - - - - - - 5,270 - Acquisition-related contingent consideration and amortization expense - - - - - - - - - - - 1,033 - Tax effect of adjustments (1) (1,181) (14,605) (2,951) (331) (3,814) 224 (278) (2,404) (46) (4,329) (5,880) 3,818 - One-time tax items (2) - - - - - - - - - (38,525) - - Adjusted net income (non-GAAP) 54,064$ 64,072$ 86,138$ 95,142$ 103,726$ 114,019$ 101,694$ 120,130$ 139,562$ 125,360$ 115,770$ 116,428$ Diluted net income per share (GAAP) 0.82$ 0.71$ 1.35$ 1.64$ 1.78$ 2.10$ 1.96$ 2.30$ 2.83$ 3.27$ 2.14$ 2.86$ After-tax impact from: - Impairment of assets and lease terminations 0.05 0.44 - 0.03 0.17 (0.01) 0.01 0.12 0.00 0.21 0.39 0.41 - Partial IRS settlement - - - (0.03) - - - - - - - - - Unwinding of interest rate collars - 0.12 0.12 - - - - - - - - - - Chairman and CEO employment agreement 0.04 - Proceeds from variable life insurance contract - (0.01) - - (0.01) - - - - - - - - Loss on investment in unconsolidated affiliates - - - - - - - - - 0.01 0.10 0.30 - Gain on investment in unconsolidated affiliates - - - - - - - - - - - (1.18) - Acquisition-related costs - - - - - - - - - - - 0.12 - Acquisition-related contingent consideration and amortization expense - - - - - - - - - - - 0.02 -Tax effect of adjustments (0.03) (0.23) (0.05) - (0.06) 0.01 - (0.05) 0.00 (0.09) (0.12) 0.09 -One-time tax items - - - - - - - - - (0.80) - - Adjusted diluted net income per share (non-GAAP) (3) 0.84$ 1.07$ 1.42$ 1.64$ 1.88$ 2.10$ 1.97$ 2.37$ 2.83$ 2.60$ 2.51$ 2.61$ The Cheesecake Factory Incorporated Reconciliation of Non-GAAP Financial Measures ($ in thousands, except per share data) Fiscal Year
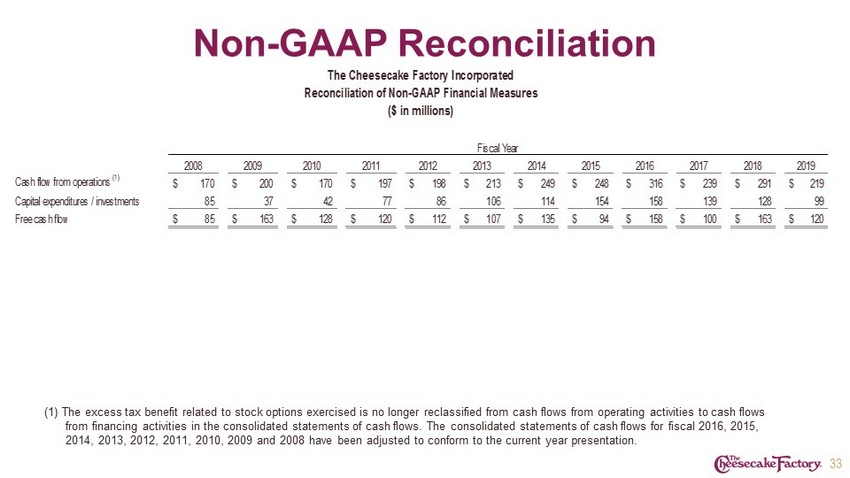
Non - GAAP Reconciliation (1) The excess tax benefit related to stock options exercised is no longer reclassified from cash flows from operating activi tie s to cash flows from financing activities in the consolidated statements of cash flows. The consolidated statements of cash flows for fiscal 201 6, 2015, 2014, 2013, 2012, 2011, 2010, 2009 and 2008 have been adjusted to conform to the current year presentation. 33 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 Cash flow from operations (1) 170$ 200$ 170$ 197$ 198$ 213$ 249$ 248$ 316$ 239$ 291$ 219$ Capital expenditures / investments 85 37 42 77 86 106 114 154 158 139 128 99 Free cash flow 85$ 163$ 128$ 120$ 112$ 107$ 135$ 94$ 158$ 100$ 163$ 120$ The Cheesecake Factory Incorporated Reconciliation of Non-GAAP Financial Measures ($ in millions) Fiscal Year