
CBAN 8-K
Colony Bankcorp Inc (CBAN)
8-K
2025-07-23
For: 2025-07-23
View Original
Added on
July 07, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
Form 8-K
CURRENT REPORT
Pursuant to Section 13 OR 15(d) of The Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): July 23, 2025
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||
(Address of principal executive offices) (Zip Code)
(229 ) 426-6000
(Registrant's telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | ||||||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | ||||||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | ||||||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | ||||||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each Class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operation and Financial Condition
On July 23, 2025 , Colony Bankcorp, Inc. issued a press release announcing its consolidated financial results for the second quarter ended June 30, 2025, as well as the announcement of a regular quarterly cash dividend. A copy of the press release is attached hereto as Exhibit 99.1 and is incorporated herein by reference.
Item 7.01. Regulation FD Disclosure
The Company is furnishing a copy of its most recent investor presentation, which it intends to use in connection with certain community group presentations. A copy of the presentation materials to be used by the Company is furnished as Exhibit 99.2 to this Current Report and is incorporated herein by reference. The Company will also host an investor earnings call at 9:00 a.m. ET on Thursday, July 24, 2025.
In accordance with General Instruction B.2 of Form 8-K, the information in this Current Report on Form 8-K, including Exhibits 99.1 and 99.2 attached hereto, is being furnished and shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”) or otherwise subject to the liabilities of that section, nor shall it be deemed incorporated by reference in any filing under the Securities Act of 1933, as amended, or the Exchange Act, except as expressly set forth by specific reference in such filing.
Item 9.01 Financial Statements and Exhibits
(d)Exhibits.
| Exhibit Number | Description | |||||||
| 99.1 | ||||||||
| 99.2 | ||||||||
| 104 | Cover Page Interactive Data File - the cover page XBRL tags are embedded within the Inline XBRL document. | |||||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| COLONY BANKCORP, INC. | ||||||||
Date: | By: | /s/ Derek Shelnutt | ||||||
| Derek Shelnutt | ||||||||
| Executive Vice President and Chief Financial Officer | ||||||||
For additional information, contact:
Derek Shelnutt
EVP & Chief Financial Officer
229-426-6000, extension 6119
COLONY BANKCORP REPORTS SECOND QUARTER 2025 RESULTS
DECLARES QUARTERLY CASH DIVIDEND OF $0.1150 PER SHARE
FITZGERALD, GA. (July 23, 2025) – Colony Bankcorp, Inc. (NYSE: CBAN) (“Colony” or the “Company”) today reported financial results for the second quarter of 2025. Financial highlights are shown below.
Financial Highlights:
•Net income increased to $8.0 million, or $0.46 per diluted share, for the second quarter of 2025, compared to $6.6 million, or $0.38 per diluted share, for the first quarter of 2025, and $5.5 million, or $0.31 per diluted share, for the second quarter of 2024.
•Operating net income was $8.0 million, or $0.46 of adjusted earnings per diluted share, for the second quarter of 2025, compared to $6.6 million, or $0.38 of adjusted earnings per diluted share, for the first quarter of 2025, and $6.0 million, or $0.34 of adjusted earnings per diluted share, for the second quarter of 2024. (See Reconciliation of Non-GAAP Measures).
•Provision for credit losses of $450,000 was recorded in the second quarter of 2025 compared to $1.5 million in the first quarter of 2025, and $650,000 in the second quarter of 2024.
•Total loans, excluding loans held for sale, were $1.99 billion at June 30, 2025, an increase of $72.3 million, or 3.76%, from the prior quarter.
•Total deposits were $2.56 billion and $2.62 billion at June 30, 2025 and March 31, 2025, respectively, a decrease of $66.3 million.
•Mortgage production was $94.9 million, and mortgage sales totaled $65.3 million in the second quarter of 2025 compared to $72.0 million and $55.9 million, respectively, for the first quarter of 2025.
•Small Business Specialty Lending (“SBSL”) closed $15.8 million in Small Business Administration (“SBA”) loans and sold $17.9 million in SBA loans in the second quarter of 2025 compared to $15.4 million and $12.1 million, respectively, for the first quarter of 2025.
The Company also announced that on July 22, 2025, the Board of Directors declared a quarterly cash dividend of $0.1150 per share, to be paid on its common stock on August 20, 2025, to shareholders of record as of the close of business on August 6, 2025. The Company had 17,461,032 shares of its common stock outstanding as of July 21, 2025.
“We are very pleased with our second-quarter results reflecting continued strength in core earnings and disciplined execution across the organization. Net interest margin expanded meaningfully, supported by a well-positioned balance sheet and stable funding costs, while return on assets improved as we maintained strong operating leverage. Additionally, our sustained loan growth demonstrates healthy demand across our markets,” said Heath Fountain, Chief Executive Officer.
“Credit quality remains solid, with improvements in several key metrics, underscoring the resilience of our portfolio and prudent underwriting. We remain focused on driving long-term value through consistent, high-quality growth.”
“In addition to our strong financial performance, we’re also excited to announce our strategic acquisition of TC Bancshares, Inc., detailed in a separate release issued today. This combination represents a compelling opportunity to further strengthen our franchise, expand our reach in key markets, and enhance long-term value for our shareholders.”
1
Balance Sheet
•Total assets were $3.12 billion at June 30, 2025, a decrease of $56.2 million from March 31, 2025.
•Total loans, excluding loans held for sale, were $1.99 billion at June 30, 2025, an increase of $72.3 million from the quarter ended March 31, 2025.
•Total deposits were $2.56 billion and $2.62 billion at June 30, 2025 and March 31, 2025, respectively, a decrease of $66.3 million. Decreases were seen in interest bearing demand deposits of $34.6 million and savings and money market deposits of $22.3 million, partially offset by an increase in time deposits of $5.7 million, from March 31, 2025 to June 30, 2025. Total deposits increased $96.0 million from the period ended June 30, 2024, with increases seen in interest bearing demand deposits of $49.9 million and time deposits of $52.7 million, partially offset by a decrease in savings and money market deposits of $3.7 million.
•Total borrowings at June 30, 2025 totaled $248.1 million, an increase of $24,000 compared to March 31, 2025, related to a minimal increase in other borrowed money.
Capital
•Colony continues to maintain a strong capital position, with ratios that exceed regulatory minimums required to be considered as “well-capitalized.”
•Under the Company’s approved stock repurchase program, a total of 62,017 shares of Company common stock were repurchased during the second quarter of 2025 at an average price of $15.46 per share and a total value of $959,092.
•Preliminary tier one leverage ratio, tier one capital ratio, total risk-based capital ratio and common equity tier one capital ratio were 9.61%, 13.42%, 16.06%, and 12.34%, respectively, at June 30, 2025.
Second Quarter 2025 Results of Operations
•Net interest income, on a tax-equivalent basis, totaled $22.6 million for the second quarter ended June 30, 2025 compared to $18.6 million for the same period in 2024. Net interest income, on a tax-equivalent basis, for the six months ended June 30, 2025 totaled $43.7 million, compared to $37.4 million for the six months ended June 30, 2024. For both periods, increases occurred in income on interest earning assets while expenses on interest bearing liabilities decreased slightly. Income on interest earning assets increased $3.5 million, to $37.0 million for the second quarter of 2025 compared to the respective period in 2024. Expense on interest bearing liabilities decreased $477,000, to $14.4 million for the second quarter of 2025 compared to the respective period in 2024. Income on interest earning assets increased $5.7 million to $72.7 million for the six month period ended June 30, 2025 compared to the respective period in 2024. Expense on interest bearing liabilities decreased $559,000, to $29.0 million for the six month period ended June 30, 2025 compared to the respective period in 2024.
•Net interest margin for the second quarter of 2025 was 3.12% compared to 2.68% for the second quarter of 2024. Net interest margin was 3.02% for the six months ended June 30, 2025 compared to 2.69% for the six months ended June 30, 2024. The increase for both periods was primarily related to increases in interest earning assets period over period, partially offset by the rate decreases in interest bearing liabilities.
•Noninterest income totaled $10.1 million for the second quarter ended June 30, 2025, an increase of $601,000, or 6.33%, compared to the same period in 2024. Noninterest income totaled $19.1 million for the six months ended June 30, 2025, an increase of $158,000, or 0.83%, compared to the same period in 2024. These increases were primarily related to increases in mortgage fee income, insurance commissions and decreases on losses on the sales of investment securities partially offset by decreases in service charges on deposit accounts and gains on sales of SBA loans.
•Noninterest expense totaled $22.0 million for the second quarter ended June 30, 2025, compared to $20.3 million for the same period in 2024. Noninterest expense totaled $42.2 million for the six months ended June 30, 2025, compared to $40.7 million for the same period in 2024. These increases were a result of increases in salaries and employee benefits, occupancy and equipment, information technology expenses along with the valuation on SBSL servicing assets partially offset by decreases in advertising and public relations and communications expense.
Asset Quality
•Nonperforming assets totaled $11.4 million and $13.0 million at June 30, 2025 and March 31, 2025, respectively, a decrease of $1.6 million.
•Other real estate owned and repossessed assets totaled $731,000 at June 30, 2025 and $528,000 at March 31, 2025.
2
•Net loans charged-off were $1.0 million, or 0.21% of average loans for the second quarter of 2025, compared to $606,000, or 0.13% for the first quarter of 2025.
•The credit loss reserve was $19.2 million, or 0.96% of total loans, at June 30, 2025, compared to $20.0 million, or 1.04% of total loans at March 31, 2025.
Earnings call information
The Company will host an earnings conference call at 9:00 a.m. ET on Thursday, July 24, 2025, to discuss the recent results and answer relevant questions. The conference call can be accessed by dialing 1-800-549-8228 and using the Conference ID: 22154. A replay of the call will be available until Thursday, July 31, 2025. To listen to the replay, dial 1-888-660-6264 and entering the passcode 22154#.
About Colony Bankcorp
Colony Bankcorp, Inc. is the bank holding company for Colony Bank. Founded in Fitzgerald, Georgia in 1975, Colony operates locations throughout Georgia as well as in Birmingham, Alabama; Tallahassee, Florida; and the Florida Panhandle. Colony Bank offers a range of banking solutions for personal and business customers. In addition to traditional banking services, Colony provides specialized solutions including mortgage lending, government guaranteed lending, consumer insurance, wealth management, credit cards and merchant services. Colony’s common stock is traded on the New York Stock Exchange (“NYSE”) under the symbol “CBAN.” For more information, please visit www.colony.bank. You can also follow the Company on social media.
Forward-Looking Statements
Certain statements contained in this press release that are not statements of historical fact constitute “forward-looking statements” within the meaning of, and subject to the protections of, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. In addition, certain statements may be contained in the Company’s future filings with the Securities and Exchange Commission (the “SEC”), in press releases, and in oral and written statements made by or with the approval of the Company that are not statements of historical fact and constitute “forward-looking statements” within the meaning of, and subject to the protections of, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Examples of forward-looking statements include, but are not limited to: (i) projections and/or expectations of revenues, income or loss, earnings or loss per share, the payment or nonpayment of dividends, capital structure and other financial items; (ii) statement of plans and objectives of Colony Bankcorp, Inc. or its management or Board of Directors, including those relating to products or services; (iii) statements of future economic performance; (iv) statements regarding growth strategy, capital management, liquidity and funding, and future profitability; and (v) statements of assumptions underlying such statements. Words such as “may”, “will”, “anticipate”, “assume”, “should”, “support”, “indicate”, “would”, “believe”, “contemplate”, “expect”, “estimate”, “continue”, “further”, “plan”, “point to”, “project”, “could”, “intend”, “target” and similar expressions are intended to identify forward-looking statements but are not the exclusive means of identifying such statements.
Prospective investors are cautioned that any such forward-looking statements are not guarantees of future performance and involve known and unknown risks and uncertainties. Factors that might cause such differences include, but are not limited to: the impact of current and future economic conditions, particularly those affecting the financial services industry, including the effects of declines in the real estate market, tariffs or trade wars (including the resulting reduced consumer spending, lower economic growth or recession, reduced demand for U.S. exports, disruptions to supply chains, and decreased demand for other banking products and services), high unemployment rates, inflationary pressures, changes in interest rates (including the impact of prolonged elevated interest rates on our financial projections and models) and slowdowns in economic growth, as well as the financial stress on borrowers as a result of the foregoing; the risk of reductions in benchmark interest rates and the resulting impacts on net interest income; potential impacts of adverse developments in the banking industry highlighted by high-profile bank failures, including impacts on customer confidence, deposit outflows, liquidity and the regulatory response thereto; risks arising from media coverage of the banking industry; risks arising from perceived instability in the banking sector; the risks of changes in interest rates and their effects on the level, cost, and composition of, and competition for, deposits, loan demand and timing of payments, the values of loan collateral, securities, and interest sensitive assets and liabilities; the ability to attract new or retain existing deposits, to retain or grow loans or additional interest and fee income, or to control noninterest expense; the effect of pricing pressures on the Company’s net interest margin; the failure of assumptions underlying the establishment of reserves for possible credit losses, fair value for loans and other real estate owned; changes in real estate values; the Company’s ability to implement its various strategic and growth initiatives; increased competition in the financial services industry, particularly from regional and national institutions, as well as from fintech companies; economic conditions, either
3
nationally or locally, in areas in which the Company conducts operations being less favorable than expected; changes in the prices, values and sales volumes of residential and commercial real estate; developments in our mortgage banking business, including loan modifications, general demand, and the effects of judicial or regulatory requirements or guidance; legislation or regulatory changes which adversely affect the ability of the consolidated Company to conduct business combinations or new operations; adverse results from current or future litigation, regulatory examinations or other legal and/or regulatory actions, including as a result of the Company’s participation in and execution of government programs; significant turbulence or a disruption in the capital or financial markets and the effect of a fall in the stock market prices on our investment securities; the effects of war or other conflicts; general risks related to the Company’s merger and acquisition activity, including risks associated with integrating and realizing the expected financial benefits of previous or pending acquisitions, and the Company’s pursuit of future acquisitions; the impact of generative artificial intelligence; fraud or misconduct by internal or external actors, and system failures, cybersecurity threats or security breaches and the cost of defending against them; a deterioration of the credit rating for U.S. long-term sovereign debt, actions that the U.S. government may take to avoid exceeding the debt ceiling, and uncertainties surrounding debt ceiling and the federal budget; a potential U.S. federal government shutdown and the resulting impacts; and general competitive, economic, political and market conditions or other unexpected factors or events. These and other factors, risks and uncertainties could cause the actual results, performance or achievements of the Company to be materially different from the future results, performance or achievements expressed or implied by such forward-looking statements. Many of these factors are beyond the Company’s ability to control or predict.
Forward-looking statements speak only as of the date on which such statements are made. These forward-looking statements are based upon information presently known to the Company’s management and are inherently subjective, uncertain and subject to change due to any number of risks and uncertainties, including, without limitation, the risks and other factors set forth in the Company’s filings with the Securities and Exchange Commission, the Company’s Annual Report on Form 10-K for the year ended December 31, 2024, under the captions “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors,” and in the Company’s quarterly reports on Form 10-Q and current reports on Form 8-K. The Company undertakes no obligation to update any forward-looking statement to reflect events or circumstances after the date on which such statement is made, or to reflect the occurrence of unanticipated events. Readers are cautioned not to place undue reliance on these forward-looking statements.
Additional Information About the Proposed Merger and Where to Find It
This document does not constitute an offer to sell or the solicitation of an offer to buy any securities, or a solicitation of any vote or approval, nor shall there be any sale of securities in any jurisdiction in which such offer, solicitation or sale would be unlawful prior to registration or qualification under the securities laws of any such jurisdiction. In connection with the proposed merger, the Company will file with the SEC a registration statement on Form S-4 that will include a joint proxy statement of TC Bancshares, Inc. (“TC Bancshares”) and the Company and a prospectus of the Company, as well as other relevant documents concerning the proposed transaction. WE URGE INVESTORS AND SECURITY HOLDERS TO READ THE REGISTRATION STATEMENT ON FORM S-4, THE JOINT PROXY STATEMENT/PROSPECTUS INCLUDED WITHIN THE REGISTRATION STATEMENT ON FORM S-4 AND ANY OTHER RELEVANT DOCUMENTS TO BE FILED WITH THE SEC IN CONNECTION WITH THE PROPOSED MERGER BECAUSE THEY WILL CONTAIN IMPORTANT INFORMATION ABOUT THE COMPANY, TC BANCSHARES AND THE PROPOSED MERGER. The joint proxy statement/prospectus will be sent to the shareholders of TC Bancshares seeking the required shareholder approval. Investors and security holders will be able to obtain free copies of the registration statement on Form S-4 and the related joint proxy statement/prospectus, when filed, as well as other documents filed with the SEC by the Company through the web site maintained by the SEC at www.sec.gov. Documents filed with the SEC by the Company will also be available free of charge by directing a written request to Colony Bankcorp, Inc., 115 South Grant Street, Fitzgerald, Georgia 31750, Attn: Derek Shelnutt and on the Company’s website, colony.bank, under Investor Relations. The Company’s telephone number is (229) 426-6000.
4
Explanation of Certain Unaudited Non-GAAP Financial Measures
The measures entitled operating noninterest income, operating noninterest expense, operating net income, adjusted earnings per diluted share, operating return on average assets, operating return on average equity, tangible book value per common share, tangible equity to tangible assets, operating efficiency ratio, operating net noninterest expense to average assets and pre-provision net revenue are not measures recognized under U.S. generally accepted accounting principles (GAAP) and therefore are considered non-GAAP financial measures. The most comparable GAAP measures are noninterest income, noninterest expense, net income, diluted earnings per share, return on average assets, return on average equity, book value per common share, total equity to total assets, efficiency ratio, net noninterest expense to average assets and net interest income before provision for credit losses, respectively. Operating noninterest income excludes gain on sale of bank premises and loss on sales of securities. Operating noninterest expense excludes acquisition-related expenses and severance costs. Operating net income, operating return on average assets, operating return on average equity and operating efficiency ratio all exclude acquisition-related expenses, severance costs, gain on sale of bank premises and loss on sales of securities from net income, return on average assets, return on average equity and efficiency ratio, respectively. Operating net noninterest expense to average assets ratio excludes from net noninterest expense, severance costs, acquisition-related expenses, gain on sale of bank premises and loss on sales of securities. Acquisition-related expenses includes fees associated with acquisitions and vendor contract buyouts. Severance costs includes costs associated with termination and retirement of employees. Adjusted earnings per diluted share includes the adjustments to operating net income. Tangible book value per common share and tangible equity to tangible assets exclude goodwill and other intangibles from book value per common share and total equity to total assets, respectively. Pre-provision net revenue is calculated by adding noninterest income to net interest income before provision for credit losses, and subtracting noninterest expense.
Management uses these non-GAAP financial measures in its analysis of the Company's performance and believes these presentations provide useful supplemental information, and a clearer understanding of the Company's performance, and if not provided would be requested by the investor community. The Company believes the non-GAAP measures enhance investors' understanding of the Company's business and performance. These measures are also useful in understanding performance trends and facilitate comparisons with the performance of other financial institutions. The limitations associated with operating measures are the risk that persons might disagree as to the appropriateness of items comprising these measures and that different companies might calculate these measures differently.
These disclosures should not be considered an alternative to GAAP. The computations of operating noninterest income, operating noninterest expense, operating net income, adjusted earnings per diluted share, operating return on average assets, operating return on average equity, tangible book value per common share, tangible equity to tangible assets, operating efficiency ratio, operating net noninterest expense to average assets and pre-provision net revenue and the reconciliation of these measures to noninterest income, noninterest expense, net income, diluted earnings per share, return on average assets, return on average equity, book value per common share, total equity to total assets, efficiency ratio, net noninterest expense to average assets and net interest income before provision for credit losses are set forth in the table below.
5
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||
| Reconciliation of Non-GAAP Measures | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
(dollars in thousands, except per share data) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||
| Operating noninterest income reconciliation | ||||||||||||||||||||||||||||||||
| Noninterest income (GAAP) | $ | 10,098 | $ | 9,044 | $ | 10,309 | $ | 10,082 | $ | 9,497 | ||||||||||||||||||||||
| Writedown of bank premises | — | — | — | — | 197 | |||||||||||||||||||||||||||
| Loss on sales of securities | — | — | 401 | 454 | 425 | |||||||||||||||||||||||||||
| Operating noninterest income | $ | 10,098 | $ | 9,044 | $ | 10,710 | $ | 10,536 | $ | 10,119 | ||||||||||||||||||||||
| Operating noninterest expense reconciliation | ||||||||||||||||||||||||||||||||
| Noninterest expense (GAAP) | $ | 22,004 | $ | 20,221 | $ | 21,272 | $ | 20,835 | $ | 20,330 | ||||||||||||||||||||||
| Severance costs | — | — | — | (265) | — | |||||||||||||||||||||||||||
| Operating noninterest expense | $ | 22,004 | $ | 20,221 | $ | 21,272 | $ | 20,570 | $ | 20,330 | ||||||||||||||||||||||
| Operating net income reconciliation | ||||||||||||||||||||||||||||||||
| Net income (GAAP) | $ | 7,978 | $ | 6,613 | $ | 7,432 | $ | 5,629 | $ | 5,474 | ||||||||||||||||||||||
| Severance costs | — | — | — | 265 | — | |||||||||||||||||||||||||||
| Writedown of bank premises | — | — | — | — | 197 | |||||||||||||||||||||||||||
| Loss on sales of securities | — | — | 401 | 454 | 425 | |||||||||||||||||||||||||||
| Income tax benefit | — | — | (77) | (143) | (129) | |||||||||||||||||||||||||||
| Operating net income | $ | 7,978 | $ | 6,613 | $ | 7,756 | $ | 6,205 | $ | 5,967 | ||||||||||||||||||||||
| Weighted average diluted shares | 17,448,945 | 17,509,059 | 17,531,808 | 17,587,902 | 17,551,007 | |||||||||||||||||||||||||||
| Adjusted earnings per diluted share | $ | 0.46 | $ | 0.38 | $ | 0.44 | $ | 0.35 | $ | 0.34 | ||||||||||||||||||||||
| Operating return on average assets reconciliation | ||||||||||||||||||||||||||||||||
| Return on average assets (GAAP) | 1.02 | % | 0.85 | % | 0.95 | % | 0.74 | % | 0.73 | % | ||||||||||||||||||||||
| Severance costs | — | — | — | 0.03 | — | |||||||||||||||||||||||||||
| Writedown of bank premises | — | — | — | — | 0.03 | |||||||||||||||||||||||||||
| Loss on sales of securities | — | — | 0.05 | 0.06 | 0.06 | |||||||||||||||||||||||||||
| Tax effect of adjustment items | — | — | (0.01) | (0.02) | (0.02) | |||||||||||||||||||||||||||
| Operating return on average assets | 1.02 | % | 0.85 | % | 0.99 | % | 0.81 | % | 0.80 | % | ||||||||||||||||||||||
| Operating return on average equity reconciliation | ||||||||||||||||||||||||||||||||
| Return on average equity (GAAP) | 11.14 | % | 9.63 | % | 10.71 | % | 8.33 | % | 8.46 | % | ||||||||||||||||||||||
| Severance costs | — | — | — | 0.39 | — | |||||||||||||||||||||||||||
| Writedown of bank premises | — | — | — | — | 0.30 | |||||||||||||||||||||||||||
| Loss on sales of securities | — | — | 0.58 | 0.67 | 0.66 | |||||||||||||||||||||||||||
| Tax effect of adjustment items | — | — | (0.11) | (0.21) | (0.20) | |||||||||||||||||||||||||||
| Operating return on average equity | 11.14 | % | 9.63 | % | 11.18 | % | 9.18 | % | 9.22 | % | ||||||||||||||||||||||
| Tangible book value per common share reconciliation | ||||||||||||||||||||||||||||||||
| Book value per common share (GAAP) | $ | 16.87 | $ | 16.41 | $ | 15.91 | $ | 15.73 | $ | 15.09 | ||||||||||||||||||||||
| Effect of goodwill and other intangibles | (3.14) | (2.95) | (2.96) | (2.97) | (2.99) | |||||||||||||||||||||||||||
Tangible book value per common share | $ | 13.73 | $ | 13.46 | $ | 12.95 | $ | 12.76 | $ | 12.10 | ||||||||||||||||||||||
| Tangible equity to tangible assets reconciliation | ||||||||||||||||||||||||||||||||
| Equity to assets (GAAP) | 9.43 | % | 9.05 | % | 8.96 | % | 9.01 | % | 8.80 | % | ||||||||||||||||||||||
| Effect of goodwill and other intangibles | (1.62) | (1.51) | (1.54) | (1.58) | (1.62) | |||||||||||||||||||||||||||
Tangible equity to tangible assets | 7.81 | % | 7.54 | % | 7.42 | % | 7.43 | % | 7.18 | % | ||||||||||||||||||||||
6
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||
| Reconciliation of Non-GAAP Measures | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
(dollars in thousands, except per share data) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||
| Operating efficiency ratio calculation | ||||||||||||||||||||||||||||||||
| Efficiency ratio (GAAP) | 67.74 | % | 67.41 | % | 69.11 | % | 72.79 | % | 72.85 | % | ||||||||||||||||||||||
| Severance costs | — | — | — | (0.93) | — | |||||||||||||||||||||||||||
| Writedown of bank premises | — | — | — | — | (0.71) | |||||||||||||||||||||||||||
| Loss on sales of securities | — | — | (1.31) | (1.59) | (1.52) | |||||||||||||||||||||||||||
| Operating efficiency ratio | 67.74 | % | 67.41 | % | 67.80 | % | 70.27 | % | 70.62 | % | ||||||||||||||||||||||
Operating net noninterest expense(1) to average assets calculation | ||||||||||||||||||||||||||||||||
| Net noninterest expense to average assets | 1.52 | % | 1.44 | % | 1.40 | % | 1.41 | % | 1.45 | % | ||||||||||||||||||||||
| Severance costs | — | — | — | (0.03) | — | |||||||||||||||||||||||||||
| Writedown of bank premises | — | — | — | — | (0.03) | |||||||||||||||||||||||||||
| Loss on sales of securities | — | — | (0.05) | (0.06) | (0.06) | |||||||||||||||||||||||||||
| Operating net noninterest expense to average assets | 1.52 | % | 1.44 | % | 1.35 | % | 1.32 | % | 1.36 | % | ||||||||||||||||||||||
| Pre-provision net revenue | ||||||||||||||||||||||||||||||||
| Net interest income before provision for credit losses | $ | 22,385 | $ | 20,952 | $ | 20,472 | $ | 18,541 | $ | 18,409 | ||||||||||||||||||||||
| Noninterest income | 10,098 | 9,044 | 10,309 | 10,082 | 9,497 | |||||||||||||||||||||||||||
| Total income | 32,483 | 29,996 | 30,781 | 28,623 | 27,906 | |||||||||||||||||||||||||||
| Noninterest expense | 22,004 | 20,221 | 21,272 | 20,835 | 20,330 | |||||||||||||||||||||||||||
| Pre-provision net revenue | $ | 10,479 | $ | 9,775 | $ | 9,509 | $ | 7,788 | $ | 7,576 | ||||||||||||||||||||||
(1) Net noninterest expense is defined as noninterest expense less noninterest income. | ||||||||||||||||||||||||||||||||
7
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||
| Selected Financial Information | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
| (dollars in thousands, except per share data) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||
| EARNINGS SUMMARY | ||||||||||||||||||||||||||||||||
| Net interest income | $ | 22,385 | $ | 20,952 | $ | 20,472 | $ | 18,541 | $ | 18,409 | ||||||||||||||||||||||
| Provision for credit losses | 450 | 1,500 | 650 | 750 | 650 | |||||||||||||||||||||||||||
| Noninterest income | 10,098 | 9,044 | 10,309 | 10,082 | 9,497 | |||||||||||||||||||||||||||
| Noninterest expense | 22,004 | 20,221 | 21,272 | 20,835 | 20,330 | |||||||||||||||||||||||||||
| Income taxes | 2,051 | 1,662 | 1,427 | 1,409 | 1,452 | |||||||||||||||||||||||||||
| Net income | $ | 7,978 | $ | 6,613 | $ | 7,432 | $ | 5,629 | $ | 5,474 | ||||||||||||||||||||||
| PERFORMANCE MEASURES | ||||||||||||||||||||||||||||||||
| Per common share: | ||||||||||||||||||||||||||||||||
| Common shares outstanding | 17,416,702 | 17,481,709 | 17,519,884 | 17,554,884 | 17,538,611 | |||||||||||||||||||||||||||
| Weighted average basic shares | 17,448,945 | 17,509,059 | 17,531,808 | 17,587,902 | 17,551,007 | |||||||||||||||||||||||||||
| Weighted average diluted shares | 17,448,945 | 17,509,059 | 17,531,808 | 17,587,902 | 17,551,007 | |||||||||||||||||||||||||||
| Earnings per basic share | $ | 0.46 | $ | 0.38 | $ | 0.42 | $ | 0.32 | $ | 0.31 | ||||||||||||||||||||||
| Earnings per diluted share | 0.46 | 0.38 | 0.42 | 0.32 | 0.31 | |||||||||||||||||||||||||||
Adjusted earnings per diluted share(b) | 0.46 | 0.38 | 0.44 | 0.35 | 0.34 | |||||||||||||||||||||||||||
| Cash dividends declared per share | 0.1150 | 0.1150 | 0.1125 | 0.1125 | 0.1125 | |||||||||||||||||||||||||||
| Common book value per share | 16.87 | 16.41 | 15.91 | 15.73 | 15.09 | |||||||||||||||||||||||||||
Tangible book value per common share(b) | 13.73 | 13.46 | 12.95 | 12.76 | 12.10 | |||||||||||||||||||||||||||
Pre-provision net revenue(b) | $ | 10,479 | $ | 9,775 | $ | 9,509 | $ | 7,788 | $ | 7,576 | ||||||||||||||||||||||
| Performance ratios: | ||||||||||||||||||||||||||||||||
Net interest margin (a) | 3.12 | % | 2.93 | % | 2.84 | % | 2.64 | % | 2.68 | % | ||||||||||||||||||||||
| Return on average assets | 1.02 | 0.85 | 0.95 | 0.74 | 0.73 | |||||||||||||||||||||||||||
Operating return on average assets (b) | 1.02 | 0.85 | 0.99 | 0.81 | 0.80 | |||||||||||||||||||||||||||
| Return on average total equity | 11.14 | 9.63 | 10.71 | 8.33 | 8.46 | |||||||||||||||||||||||||||
Operating return on average total equity (b) | 11.14 | 9.63 | 11.18 | 9.18 | 9.22 | |||||||||||||||||||||||||||
| Total equity to total assets | 9.43 | 9.05 | 8.96 | 9.01 | 8.80 | |||||||||||||||||||||||||||
Tangible equity to tangible assets (b) | 7.81 | 7.54 | 7.42 | 7.43 | 7.18 | |||||||||||||||||||||||||||
Efficiency ratio | 67.74 | 67.41 | 69.11 | 72.79 | 72.85 | |||||||||||||||||||||||||||
Operating efficiency ratio (b) | 67.74 | 67.41 | 67.80 | 70.27 | 70.62 | |||||||||||||||||||||||||||
| Net noninterest expense to average assets | 1.52 | 1.44 | 1.40 | 1.41 | 1.45 | |||||||||||||||||||||||||||
Operating net noninterest expense to average assets(b) | 1.52 | 1.44 | 1.35 | 1.32 | 1.36 | |||||||||||||||||||||||||||
8
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||
| Selected Financial Information | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
| (dollars in thousands, except per share data) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||
| ASSET QUALITY | ||||||||||||||||||||||||||||||||
| Nonperforming portfolio loans | $ | 4,760 | $ | 7,538 | $ | 5,024 | $ | 6,273 | $ | 3,653 | ||||||||||||||||||||||
| Nonperforming SBA government loans-guaranteed portion | 4,583 | 3,647 | 4,293 | 4,514 | 2,309 | |||||||||||||||||||||||||||
| Nonperforming SBA government loans-unguaranteed portion | 1,241 | 1,271 | 1,343 | 1,428 | 707 | |||||||||||||||||||||||||||
| Loans 90 days past due and still accruing | 107 | 22 | 152 | 44 | 41 | |||||||||||||||||||||||||||
| Total nonperforming loans (NPLs) | 10,691 | 12,478 | 10,812 | 12,259 | 6,710 | |||||||||||||||||||||||||||
| Other real estate owned | 710 | 522 | 202 | 227 | 582 | |||||||||||||||||||||||||||
| Repossessed assets | 21 | 6 | 328 | 9 | 13 | |||||||||||||||||||||||||||
| Total nonperforming assets (NPAs) | 11,422 | 13,006 | 11,342 | 12,495 | 7,305 | |||||||||||||||||||||||||||
| Classified loans | 25,112 | 26,453 | 20,103 | 20,918 | 22,355 | |||||||||||||||||||||||||||
| Criticized loans | 54,814 | 55,823 | 49,387 | 52,062 | 44,850 | |||||||||||||||||||||||||||
| Net loan charge-offs (recoveries) | 1,049 | 606 | 1,534 | 139 | 667 | |||||||||||||||||||||||||||
| Allowance for credit losses to total loans | 0.96 | % | 1.04 | % | 1.03 | % | 1.04 | % | 1.01 | % | ||||||||||||||||||||||
| Allowance for credit losses to total NPLs | 179.15 | 160.26 | 175.55 | 160.40 | 280.27 | |||||||||||||||||||||||||||
| Allowance for credit losses to total NPAs | 167.69 | 153.75 | 167.34 | 157.37 | 257.44 | |||||||||||||||||||||||||||
| Net charge-offs (recoveries) to average loans, net | 0.21 | 0.13 | 0.33 | 0.03 | 0.14 | |||||||||||||||||||||||||||
| NPLs to total loans | 0.54 | 0.65 | 0.59 | 0.65 | 0.36 | |||||||||||||||||||||||||||
| NPAs to total assets | 0.37 | 0.41 | 0.36 | 0.41 | 0.24 | |||||||||||||||||||||||||||
| NPAs to total loans and foreclosed assets | 0.57 | 0.68 | 0.62 | 0.66 | 0.39 | |||||||||||||||||||||||||||
| ACTUAL BALANCES | ||||||||||||||||||||||||||||||||
| Total assets | $ | 3,115,617 | $ | 3,171,825 | $ | 3,109,782 | $ | 3,065,103 | $ | 3,007,907 | ||||||||||||||||||||||
| Loans held for sale | 22,163 | 24,844 | 39,786 | 27,760 | 40,132 | |||||||||||||||||||||||||||
| Loans, net of unearned income | 1,993,580 | 1,921,263 | 1,842,980 | 1,886,037 | 1,865,574 | |||||||||||||||||||||||||||
| Deposits | 2,556,230 | 2,622,531 | 2,567,943 | 2,524,970 | 2,460,225 | |||||||||||||||||||||||||||
| Total stockholders’ equity | 293,857 | 286,925 | 278,675 | 276,052 | 264,743 | |||||||||||||||||||||||||||
| AVERAGE BALANCES | ||||||||||||||||||||||||||||||||
| Total assets | $ | 3,138,125 | $ | 3,149,321 | $ | 3,108,762 | $ | 3,038,947 | $ | 3,010,486 | ||||||||||||||||||||||
| Loans held for sale | 22,495 | 23,253 | 35,299 | 34,533 | 33,024 | |||||||||||||||||||||||||||
| Loans, net of unearned income | 1,960,025 | 1,869,476 | 1,851,628 | 1,881,842 | 1,869,178 | |||||||||||||||||||||||||||
| Deposits | 2,586,620 | 2,606,706 | 2,568,824 | 2,504,101 | 2,492,479 | |||||||||||||||||||||||||||
| Total stockholders’ equity | 287,325 | 278,551 | 276,082 | 268,769 | 260,162 | |||||||||||||||||||||||||||
| (a) Computed using fully taxable-equivalent net income. | ||||||||||||||||||||||||||||||||
| (b) Non-GAAP measure - see “Explanation of Certain Unaudited Non-GAAP Financial Measures” for more information and reconciliation to GAAP. | ||||||||||||||||||||||||||||||||
9
| Colony Bankcorp, Inc. | |||||||||||||||||||||||||||||||||||
| Average Balance Sheet and Net Interest Analysis | |||||||||||||||||||||||||||||||||||
| Three Months Ended June 30, | |||||||||||||||||||||||||||||||||||
| 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| (dollars in thousands) | Average Balances | Income/ Expense | Yields/ Rates | Average Balances | Income/ Expense | Yields/ Rates | |||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||
| Interest-earning assets: | |||||||||||||||||||||||||||||||||||
| Loans held for sale | $ | 22,495 | $ | 325 | 5.79 | % | $ | 33,024 | $ | 647 | 7.88 | % | |||||||||||||||||||||||
| Loans, net of unearned income 1 | 1,960,025 | 30,139 | 6.17 | % | 1,869,178 | 27,014 | 5.81 | % | |||||||||||||||||||||||||||
| Investment securities, taxable | 698,416 | 4,759 | 2.73 | % | 722,535 | 4,616 | 2.57 | % | |||||||||||||||||||||||||||
| Investment securities, tax-exempt 2 | 93,082 | 492 | 2.12 | % | 100,143 | 547 | 2.20 | % | |||||||||||||||||||||||||||
| Deposits in banks and short term investments | 134,806 | 1,326 | 3.95 | % | 62,614 | 684 | 4.39 | % | |||||||||||||||||||||||||||
| Total interest-earning assets | 2,908,824 | 37,041 | 5.11 | % | 2,787,494 | 33,508 | 4.83 | % | |||||||||||||||||||||||||||
| Noninterest-earning assets | 229,300 | 222,992 | |||||||||||||||||||||||||||||||||
| Total assets | $ | 3,138,125 | $ | 3,010,486 | |||||||||||||||||||||||||||||||
| Liabilities and stockholders' equity | |||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||
| Interest-bearing demand and savings | $ | 1,529,608 | $ | 6,310 | 1.65 | % | $ | 1,451,300 | $ | 6,784 | 1.88 | % | |||||||||||||||||||||||
| Other time | 615,303 | 5,322 | 3.47 | % | 577,173 | 5,322 | 3.71 | % | |||||||||||||||||||||||||||
| Total interest-bearing deposits | 2,144,911 | 11,632 | 2.18 | % | 2,028,473 | 12,106 | 2.40 | % | |||||||||||||||||||||||||||
| Federal Home Loan Bank advances | 185,000 | 1,889 | 4.10 | % | 178,516 | 1,821 | 4.10 | % | |||||||||||||||||||||||||||
| Other borrowings | 63,072 | 929 | 5.91 | % | 63,638 | 1,000 | 6.32 | % | |||||||||||||||||||||||||||
| Total other interest-bearing liabilities | 248,072 | 2,818 | 4.56 | % | 242,154 | 2,821 | 4.69 | % | |||||||||||||||||||||||||||
| Total interest-bearing liabilities | 2,392,983 | 14,450 | 2.42 | % | 2,270,627 | 14,927 | 2.64 | % | |||||||||||||||||||||||||||
| Noninterest-bearing liabilities: | |||||||||||||||||||||||||||||||||||
| Demand deposits | 441,709 | $ | 464,007 | ||||||||||||||||||||||||||||||||
| Other liabilities | 16,108 | 15,690 | |||||||||||||||||||||||||||||||||
| Stockholders' equity | 287,325 | 260,162 | |||||||||||||||||||||||||||||||||
| Total noninterest-bearing liabilities and stockholders' equity | 745,142 | 739,859 | |||||||||||||||||||||||||||||||||
| Total liabilities and stockholders' equity | $ | 3,138,125 | $ | 3,010,486 | |||||||||||||||||||||||||||||||
| Interest rate spread | 2.69 | % | 2.19 | % | |||||||||||||||||||||||||||||||
| Net interest income | $ | 22,591 | $ | 18,581 | |||||||||||||||||||||||||||||||
| Net interest margin | 3.12 | % | 2.68 | % | |||||||||||||||||||||||||||||||
3
1The average balance of loans includes the average balance of nonaccrual loans. Income on such loans is recognized and recorded on the cash basis. Taxable-equivalent adjustments totaling $102,000 and $56,000 for the quarters ended June 30, 2025 and 2024, respectively, are calculated using the statutory federal tax rate and are included in income and fees on loans. Accretion income of $17,000 and $15,000 for the quarters ended June 30, 2025 and 2024, respectively, are also included in income and fees on loans.
2Taxable-equivalent adjustments totaling $103,000 and $115,000 for the quarters ended June 30, 2025 and 2024, respectively, are calculated using the statutory federal tax rate and are included in tax-exempt interest on investment securities.
3
10
| Colony Bankcorp, Inc. | |||||||||||||||||||||||||||||||||||
| Average Balance Sheet and Net Interest Analysis | |||||||||||||||||||||||||||||||||||
| Six Months Ended June 30, | |||||||||||||||||||||||||||||||||||
| 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| (dollars in thousands) | Average Balances | Income/ Expense | Yields/ Rates | Average Balances | Income/ Expense | Yields/ Rates | |||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||
| Interest-earning assets: | |||||||||||||||||||||||||||||||||||
| Loans held for sale | $ | 22,872 | $ | 653 | 5.76 | % | $ | 28,818 | $ | 1,081 | 7.54 | % | |||||||||||||||||||||||
| Loans, net of unearned income3 | 1,915,001 | 57,854 | 6.09 | % | 1,870,290 | 53,723 | 5.78 | % | |||||||||||||||||||||||||||
| Investment securities, taxable | 704,322 | 9,595 | 2.75 | % | 729,896 | 9,658 | 2.66 | % | |||||||||||||||||||||||||||
| Investment securities, tax-exempt 4 | 93,727 | 986 | 2.12 | % | 103,481 | 1,152 | 2.24 | % | |||||||||||||||||||||||||||
| Deposits in banks and short term investments | 181,651 | 3,648 | 4.05 | % | 67,023 | 1,376 | 4.13 | % | |||||||||||||||||||||||||||
| Total interest-earning assets | 2,917,573 | 72,736 | 5.03 | % | 2,799,508 | 66,990 | 4.81 | % | |||||||||||||||||||||||||||
| Noninterest-earning assets | 226,120 | 223,781 | |||||||||||||||||||||||||||||||||
| Total assets | $ | 3,143,693 | $ | 3,023,289 | |||||||||||||||||||||||||||||||
| Liabilities and stockholders' equity | |||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||
| Interest-bearing demand and savings | $ | 1,539,504 | $ | 12,779 | 1.67 | % | $ | 1,451,395 | $ | 13,193 | 1.83 | % | |||||||||||||||||||||||
| Other time | 608,648 | 10,627 | 3.52 | % | 594,707 | 11,005 | 3.72 | % | |||||||||||||||||||||||||||
| Total interest-bearing deposits | 2,148,152 | 23,406 | 2.20 | % | 2,046,102 | 24,198 | 2.38 | % | |||||||||||||||||||||||||||
| Federal funds purchased | — | — | — | % | 6 | — | — | % | |||||||||||||||||||||||||||
| Federal Home Loan Bank advances | 185,000 | 3,762 | 4.10 | % | 167,747 | 3,392 | 4.07 | % | |||||||||||||||||||||||||||
| Other borrowings | 63,060 | 1,856 | 5.94 | % | 63,362 | 1,993 | 6.33 | % | |||||||||||||||||||||||||||
| Total other interest-bearing liabilities | 248,060 | 5,618 | 4.57 | % | 231,115 | 5,385 | 4.69 | % | |||||||||||||||||||||||||||
| Total interest-bearing liabilities | 2,396,212 | 29,024 | 2.44 | % | 2,277,217 | 29,583 | 2.61 | % | |||||||||||||||||||||||||||
| Noninterest-bearing liabilities: | |||||||||||||||||||||||||||||||||||
| Demand deposits | 448,457 | $ | 471,768 | ||||||||||||||||||||||||||||||||
| Other liabilities | 16,062 | 16,259 | |||||||||||||||||||||||||||||||||
| Stockholders' equity | 282,962 | 258,045 | |||||||||||||||||||||||||||||||||
| Total noninterest-bearing liabilities and stockholders' equity | 747,481 | 746,072 | |||||||||||||||||||||||||||||||||
| Total liabilities and stockholders' equity | $ | 3,143,693 | $ | 3,023,289 | |||||||||||||||||||||||||||||||
| Interest rate spread | 2.59 | % | 2.20 | % | |||||||||||||||||||||||||||||||
| Net interest income | $ | 43,712 | $ | 37,407 | |||||||||||||||||||||||||||||||
| Net interest margin | 3.02 | % | 2.69 | % | |||||||||||||||||||||||||||||||
5
3The average balance of loans includes the average balance of nonaccrual loans. Income on such loans is recognized and recorded on the cash basis. Taxable-equivalent adjustments totaling $170,000 and $103,000 for the six months ended June 30, 2025 and 2024, respectively, are calculated using the statutory federal tax rate and are included in income and fees on loans. Accretion income of $36,000 and $10,000 for the six months ended June 30, 2025 and 2024, respectively, are also included in income and fees on loans.
4Taxable-equivalent adjustments totaling $207,000 and $242,000 for the six months ended June 30, 2025 and 2024, respectively, are calculated using the statutory federal tax rate and are included in tax-exempt interest on investment securities.
5
11
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||
| Segment Reporting | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
(dollars in thousands) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||
| Banking Division | ||||||||||||||||||||||||||||||||
| Net interest income | $ | 21,319 | $ | 19,989 | $ | 19,191 | $ | 17,152 | $ | 17,217 | ||||||||||||||||||||||
| Provision for credit losses | (330) | 1,221 | 309 | 698 | 96 | |||||||||||||||||||||||||||
| Noninterest income | 5,969 | 5,774 | 5,452 | 5,494 | 5,086 | |||||||||||||||||||||||||||
| Noninterest expenses | 18,269 | 16,790 | 17,616 | 17,075 | 17,135 | |||||||||||||||||||||||||||
| Income taxes | 1,908 | 1,551 | 927 | 1,017 | 1,060 | |||||||||||||||||||||||||||
| Segment income | $ | 7,441 | $ | 6,201 | $ | 5,791 | $ | 3,856 | $ | 4,012 | ||||||||||||||||||||||
Total segment assets | $ | 3,010,416 | $ | 3,065,385 | $ | 2,985,856 | $ | 2,955,145 | $ | 2,889,013 | ||||||||||||||||||||||
Full time employees | 390 | 366 | 376 | 375 | 385 | |||||||||||||||||||||||||||
| Mortgage Banking Division | ||||||||||||||||||||||||||||||||
| Net interest income | $ | 44 | $ | 53 | $ | 53 | $ | 67 | $ | 50 | ||||||||||||||||||||||
| Provision for credit losses | — | — | — | — | — | |||||||||||||||||||||||||||
| Noninterest income | 1,984 | 1,579 | 1,545 | 1,812 | 1,456 | |||||||||||||||||||||||||||
| Noninterest expenses | 1,710 | 1,601 | 1,699 | 1,533 | 1,326 | |||||||||||||||||||||||||||
| Income taxes | 69 | 10 | (12) | 71 | 42 | |||||||||||||||||||||||||||
| Segment income | $ | 249 | $ | 21 | $ | (89) | $ | 275 | $ | 138 | ||||||||||||||||||||||
Total segment assets | $ | 14,296 | $ | 16,041 | $ | 17,970 | $ | 9,300 | $ | 19,004 | ||||||||||||||||||||||
Variable noninterest expense(1) | $ | 1,157 | $ | 880 | $ | 764 | $ | 1,005 | $ | 807 | ||||||||||||||||||||||
| Fixed noninterest expense | 553 | 721 | 935 | 528 | 519 | |||||||||||||||||||||||||||
| Full time employees | 43 | 42 | 45 | 44 | 42 | |||||||||||||||||||||||||||
| Small Business Specialty Lending Division | ||||||||||||||||||||||||||||||||
| Net interest income | $ | 1,022 | $ | 910 | $ | 1,228 | $ | 1,322 | $ | 1,142 | ||||||||||||||||||||||
| Provision for credit losses | 780 | 279 | 341 | 52 | 554 | |||||||||||||||||||||||||||
| Noninterest income | 2,145 | 1,691 | 3,312 | 2,776 | 2,955 | |||||||||||||||||||||||||||
| Noninterest expenses | 2,025 | 1,830 | 1,957 | 2,227 | 1,869 | |||||||||||||||||||||||||||
| Income taxes | 74 | 101 | 512 | 321 | 350 | |||||||||||||||||||||||||||
| Segment income | $ | 288 | $ | 391 | $ | 1,730 | $ | 1,498 | $ | 1,324 | ||||||||||||||||||||||
Total segment assets | $ | 90,905 | $ | 90,399 | $ | 105,956 | $ | 100,658 | $ | 99,890 | ||||||||||||||||||||||
| Full time employees | 34 | 35 | 34 | 33 | 33 | |||||||||||||||||||||||||||
| Total Consolidated | ||||||||||||||||||||||||||||||||
| Net interest income | $ | 22,385 | $ | 20,952 | $ | 20,472 | $ | 18,541 | $ | 18,409 | ||||||||||||||||||||||
| Provision for credit losses | 450 | 1,500 | 650 | 750 | 650 | |||||||||||||||||||||||||||
| Noninterest income | 10,098 | 9,044 | 10,309 | 10,082 | 9,497 | |||||||||||||||||||||||||||
| Noninterest expenses | 22,004 | 20,221 | 21,272 | 20,835 | 20,330 | |||||||||||||||||||||||||||
| Income taxes | 2,051 | 1,662 | 1,427 | 1,409 | 1,452 | |||||||||||||||||||||||||||
| Segment income | $ | 7,978 | $ | 6,613 | $ | 7,432 | $ | 5,629 | $ | 5,474 | ||||||||||||||||||||||
Total segment assets | $ | 3,115,617 | $ | 3,171,825 | $ | 3,109,782 | $ | 3,065,103 | $ | 3,007,907 | ||||||||||||||||||||||
| Full time employees | 467 | 443 | 455 | 452 | 460 | |||||||||||||||||||||||||||
(1) Variable noninterest expense includes commission based salary expenses and volume based loan related fees. | ||||||||||||||||||||||||||||||||
12
| Colony Bankcorp, Inc. | ||||||||||||||
| Consolidated Balance Sheets | ||||||||||||||
| June 30, 2025 | December 31, 2024 | |||||||||||||
(dollars in thousands) | (unaudited) | (audited) | ||||||||||||
| ASSETS | ||||||||||||||
| Cash and due from banks | $ | 27,590 | $ | 26,045 | ||||||||||
| Interest-bearing deposits in banks and federal funds sold | 84,555 | 204,989 | ||||||||||||
| Cash and cash equivalents | 112,145 | 231,034 | ||||||||||||
| Investment securities available for sale, at fair value | 373,572 | 366,049 | ||||||||||||
| Investment securities held to maturity, at amortized cost | 409,634 | 430,077 | ||||||||||||
| Other investments | 17,927 | 17,694 | ||||||||||||
| Loans held for sale | 22,163 | 39,786 | ||||||||||||
| Loans, net of unearned income | 1,993,580 | 1,842,980 | ||||||||||||
| Allowance for credit losses | (19,153) | (18,980) | ||||||||||||
| Loans, net | 1,974,427 | 1,824,000 | ||||||||||||
| Premises and equipment | 35,909 | 37,831 | ||||||||||||
| Other real estate | 710 | 202 | ||||||||||||
| Goodwill | 50,871 | 48,923 | ||||||||||||
| Other intangible assets | 3,799 | 2,975 | ||||||||||||
| Bank owned life insurance | 58,811 | 57,970 | ||||||||||||
| Deferred income taxes, net | 19,401 | 21,891 | ||||||||||||
| Other assets | 36,248 | 31,350 | ||||||||||||
| Total assets | $ | 3,115,617 | $ | 3,109,782 | ||||||||||
| LIABILITIES AND STOCKHOLDERS’ EQUITY | ||||||||||||||
| Liabilities: | ||||||||||||||
| Deposits: | ||||||||||||||
| Noninterest-bearing | $ | 434,785 | $ | 462,283 | ||||||||||
| Interest-bearing | 2,121,445 | 2,105,660 | ||||||||||||
Total deposits | 2,556,230 | 2,567,943 | ||||||||||||
| Federal Home Loan Bank advances | 185,000 | 185,000 | ||||||||||||
| Other borrowed money | 63,086 | 63,039 | ||||||||||||
| Accrued expenses and other liabilities | 17,444 | 15,125 | ||||||||||||
| Total liabilities | 2,821,760 | 2,831,107 | ||||||||||||
| Stockholders’ equity | ||||||||||||||
| Common stock, $1 par value; 50,000,000 shares authorized, 17,416,702 and 17,519,884 issued and outstanding, respectively | 17,417 | 17,520 | ||||||||||||
| Paid in capital | 167,160 | 168,353 | ||||||||||||
| Retained earnings | 150,938 | 140,369 | ||||||||||||
| Accumulated other comprehensive loss, net of tax | (41,658) | (47,567) | ||||||||||||
| Total stockholders’ equity | 293,857 | 278,675 | ||||||||||||
| Total liabilities and stockholders’ equity | $ | 3,115,617 | $ | 3,109,782 | ||||||||||
13
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||
Consolidated Statements of Income (unaudited) | ||||||||||||||||||||||||||
| Three months ended June 30, | Six months ended June 30, | |||||||||||||||||||||||||
| 2025 | 2024 | 2025 | 2024 | |||||||||||||||||||||||
(dollars in thousands, except per share data) | ||||||||||||||||||||||||||
| Interest income: | ||||||||||||||||||||||||||
| Loans, including fees | $ | 30,361 | $ | 27,604 | $ | 58,337 | $ | 54,701 | ||||||||||||||||||
| Investment securities | 5,148 | 5,048 | 10,375 | 10,568 | ||||||||||||||||||||||
| Deposits in banks and short term investments | 1,326 | 684 | 3,648 | 1,377 | ||||||||||||||||||||||
| Total interest income | 36,835 | 33,336 | 72,360 | 66,646 | ||||||||||||||||||||||
| Interest expense: | ||||||||||||||||||||||||||
| Deposits | 11,632 | 12,106 | 23,405 | 24,197 | ||||||||||||||||||||||
| Federal Home Loan Bank advances | 1,889 | 1,821 | 3,762 | 3,393 | ||||||||||||||||||||||
| Other borrowings | 929 | 1,000 | 1,856 | 1,993 | ||||||||||||||||||||||
| Total interest expense | 14,450 | 14,927 | 29,023 | 29,583 | ||||||||||||||||||||||
Net interest income | 22,385 | 18,409 | 43,337 | 37,063 | ||||||||||||||||||||||
| Provision for credit losses | 450 | 650 | 1,950 | 1,650 | ||||||||||||||||||||||
| Net interest income after provision for credit losses | 21,935 | 17,759 | 41,387 | 35,413 | ||||||||||||||||||||||
| Noninterest income: | ||||||||||||||||||||||||||
| Service charges on deposits | 2,219 | 2,289 | 4,391 | 4,662 | ||||||||||||||||||||||
| Mortgage fee income | 1,984 | 1,442 | 3,563 | 2,691 | ||||||||||||||||||||||
| Gain on sales of SBA loans | 1,550 | 2,347 | 2,585 | 4,393 | ||||||||||||||||||||||
| Loss on sales of securities | — | (425) | — | (980) | ||||||||||||||||||||||
| Interchange fees | 2,073 | 2,078 | 4,011 | 4,106 | ||||||||||||||||||||||
| BOLI income | 423 | 397 | 819 | 930 | ||||||||||||||||||||||
| Insurance commissions | 766 | 420 | 1,235 | 885 | ||||||||||||||||||||||
| Other | 1,083 | 949 | 2,538 | 2,297 | ||||||||||||||||||||||
Total noninterest income | 10,098 | 9,497 | 19,142 | 18,984 | ||||||||||||||||||||||
| Noninterest expense: | ||||||||||||||||||||||||||
| Salaries and employee benefits | 12,865 | 12,278 | 24,770 | 24,296 | ||||||||||||||||||||||
| Occupancy and equipment | 1,683 | 1,474 | 3,263 | 2,981 | ||||||||||||||||||||||
| Information technology expenses | 2,592 | 2,227 | 5,069 | 4,337 | ||||||||||||||||||||||
| Professional fees | 742 | 704 | 1,490 | 1,538 | ||||||||||||||||||||||
| Advertising and public relations | 942 | 966 | 1,747 | 1,926 | ||||||||||||||||||||||
| Communications | 188 | 216 | 393 | 442 | ||||||||||||||||||||||
| Other | 2,992 | 2,465 | 5,493 | 5,207 | ||||||||||||||||||||||
Total noninterest expense | 22,004 | 20,330 | 42,225 | 40,727 | ||||||||||||||||||||||
| Income before income taxes | 10,029 | 6,926 | 18,304 | 13,670 | ||||||||||||||||||||||
| Income taxes | 2,051 | 1,452 | 3,713 | 2,863 | ||||||||||||||||||||||
| Net income | $ | 7,978 | $ | 5,474 | $ | 14,591 | $ | 10,807 | ||||||||||||||||||
| Earnings per common share: | ||||||||||||||||||||||||||
| Basic | $ | 0.46 | $ | 0.31 | $ | 0.83 | $ | 0.62 | ||||||||||||||||||
| Diluted | 0.46 | 0.31 | 0.83 | 0.62 | ||||||||||||||||||||||
| Dividends declared per share | 0.1150 | 0.1125 | 0.2300 | 0.2250 | ||||||||||||||||||||||
| Weighted average common shares outstanding: | ||||||||||||||||||||||||||
| Basic | 17,448,945 | 17,551,007 | 17,478,836 | 17,555,609 | ||||||||||||||||||||||
| Diluted | 17,448,945 | 17,551,007 | 17,478,836 | 17,555,609 | ||||||||||||||||||||||
14
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||
| Quarterly Consolidated Statements of Income | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
| Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | ||||||||||||||||||||||||||||
(dollars in thousands, except per share data) | (unaudited) | (unaudited) | (unaudited) | (unaudited) | (unaudited) | |||||||||||||||||||||||||||
| Interest income: | ||||||||||||||||||||||||||||||||
| Loans, including fees | $ | 30,361 | $ | 27,976 | $ | 28,473 | $ | 28,501 | $ | 27,604 | ||||||||||||||||||||||
| Investment securities | 5,148 | 5,227 | 5,158 | 5,248 | 5,048 | |||||||||||||||||||||||||||
| Deposits in banks and short term investments | 1,326 | 2,322 | 2,360 | 855 | 684 | |||||||||||||||||||||||||||
| Total interest income | 36,835 | 35,525 | 35,991 | 34,604 | 33,336 | |||||||||||||||||||||||||||
| Interest expense: | ||||||||||||||||||||||||||||||||
| Deposits | 11,632 | 11,773 | 12,656 | 13,154 | 12,106 | |||||||||||||||||||||||||||
| Federal Home Loan Bank advances | 1,889 | 1,873 | 1,905 | 1,913 | 1,821 | |||||||||||||||||||||||||||
| Other borrowings | 929 | 927 | 958 | 996 | 1,000 | |||||||||||||||||||||||||||
| Total interest expense | 14,450 | 14,573 | 15,519 | 16,063 | 14,927 | |||||||||||||||||||||||||||
Net interest income | 22,385 | 20,952 | 20,472 | 18,541 | 18,409 | |||||||||||||||||||||||||||
| Provision for credit losses | 450 | 1,500 | 650 | 750 | 650 | |||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 21,935 | 19,452 | 19,822 | 17,791 | 17,759 | |||||||||||||||||||||||||||
| Noninterest income: | ||||||||||||||||||||||||||||||||
| Service charges on deposits | 2,219 | 2,172 | 2,302 | 2,401 | 2,289 | |||||||||||||||||||||||||||
| Mortgage fee income | 1,984 | 1,579 | 1,545 | 1,812 | 1,442 | |||||||||||||||||||||||||||
| Gain on sales of SBA loans | 1,550 | 1,035 | 2,622 | 2,227 | 2,347 | |||||||||||||||||||||||||||
| Loss on sales of securities | — | — | (401) | (454) | (425) | |||||||||||||||||||||||||||
| Interchange fees | 2,073 | 1,938 | 2,030 | 2,163 | 2,078 | |||||||||||||||||||||||||||
| BOLI income | 423 | 396 | 412 | 383 | 397 | |||||||||||||||||||||||||||
| Insurance commissions | 766 | 469 | 471 | 433 | 420 | |||||||||||||||||||||||||||
| Other | 1,083 | 1,455 | 1,328 | 1,117 | 949 | |||||||||||||||||||||||||||
Total noninterest income | 10,098 | 9,044 | 10,309 | 10,082 | 9,497 | |||||||||||||||||||||||||||
| Noninterest expense: | ||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 12,865 | 11,905 | 12,877 | 12,594 | 12,278 | |||||||||||||||||||||||||||
| Occupancy and equipment | 1,683 | 1,580 | 1,645 | 1,523 | 1,474 | |||||||||||||||||||||||||||
| Information technology expenses | 2,592 | 2,477 | 2,491 | 2,150 | 2,227 | |||||||||||||||||||||||||||
| Professional fees | 742 | 748 | 539 | 748 | 704 | |||||||||||||||||||||||||||
| Advertising and public relations | 942 | 805 | 1,118 | 965 | 966 | |||||||||||||||||||||||||||
| Communications | 188 | 205 | 213 | 210 | 216 | |||||||||||||||||||||||||||
| Other | 2,992 | 2,501 | 2,389 | 2,645 | 2,465 | |||||||||||||||||||||||||||
Total noninterest expense | 22,004 | 20,221 | 21,272 | 20,835 | 20,330 | |||||||||||||||||||||||||||
| Income before income taxes | 10,029 | 8,275 | 8,859 | 7,038 | 6,926 | |||||||||||||||||||||||||||
| Income taxes | 2,051 | 1,662 | 1,427 | 1,409 | 1,452 | |||||||||||||||||||||||||||
| Net income | $ | 7,978 | $ | 6,613 | $ | 7,432 | $ | 5,629 | $ | 5,474 | ||||||||||||||||||||||
| Earnings per common share: | ||||||||||||||||||||||||||||||||
| Basic | $ | 0.46 | $ | 0.38 | $ | 0.42 | $ | 0.32 | $ | 0.31 | ||||||||||||||||||||||
| Diluted | 0.46 | 0.38 | 0.42 | 0.32 | 0.31 | |||||||||||||||||||||||||||
| Dividends declared per share | 0.1150 | 0.1150 | 0.1125 | 0.1125 | 0.1125 | |||||||||||||||||||||||||||
| Weighted average common shares outstanding: | ||||||||||||||||||||||||||||||||
| Basic | 17,448,945 | 17,509,059 | 17,531,808 | 17,587,902 | 17,551,007 | |||||||||||||||||||||||||||
| Diluted | 17,448,945 | 17,509,059 | 17,531,808 | 17,587,902 | 17,551,007 | |||||||||||||||||||||||||||
15
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||
| Quarterly Deposits Composition Comparison | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
| (dollars in thousands) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 434,785 | $ | 449,818 | $ | 462,283 | $ | 439,892 | $ | 437,623 | ||||||||||||||||||||||
| Interest-bearing demand | 838,540 | 873,156 | 813,783 | 769,123 | 788,674 | |||||||||||||||||||||||||||
| Savings | 667,135 | 689,446 | 687,603 | 684,371 | 670,848 | |||||||||||||||||||||||||||
| Time over $250,000 | 193,427 | 189,466 | 185,176 | 198,942 | 168,856 | |||||||||||||||||||||||||||
| Other time | 422,343 | 420,645 | 419,098 | 432,642 | 394,224 | |||||||||||||||||||||||||||
| Total | $ | 2,556,230 | $ | 2,622,531 | $ | 2,567,943 | $ | 2,524,970 | $ | 2,460,225 | ||||||||||||||||||||||
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||
| Quarterly Deposits by Location Comparison | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
| (dollars in thousands) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||
| Coastal Georgia | $ | 138,838 | $ | 142,230 | $ | 145,828 | $ | 142,580 | $ | 144,021 | ||||||||||||||||||||||
| Middle Georgia | 277,880 | 283,149 | 279,360 | 269,144 | 275,758 | |||||||||||||||||||||||||||
| Atlanta and North Georgia | 344,329 | 333,845 | 318,927 | 321,808 | 336,338 | |||||||||||||||||||||||||||
| South Georgia | 1,203,732 | 1,249,192 | 1,217,433 | 1,165,529 | 1,110,049 | |||||||||||||||||||||||||||
| West Georgia | 325,946 | 335,438 | 337,818 | 357,450 | 365,380 | |||||||||||||||||||||||||||
| Brokered deposits | 59,494 | 59,499 | 59,499 | 70,999 | 39,240 | |||||||||||||||||||||||||||
| Reciprocal deposits | 206,011 | 219,178 | 209,078 | 197,460 | 189,439 | |||||||||||||||||||||||||||
| Total | $ | 2,556,230 | $ | 2,622,531 | $ | 2,567,943 | $ | 2,524,970 | $ | 2,460,225 | ||||||||||||||||||||||
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||
| Quarterly Loan Comparison | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
| (dollars in thousands) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||
| Core | $ | 1,887,456 | $ | 1,808,879 | $ | 1,720,444 | $ | 1,759,600 | $ | 1,732,843 | ||||||||||||||||||||||
| Purchased | 106,124 | 112,384 | 122,536 | 126,437 | 132,731 | |||||||||||||||||||||||||||
| Loans, net of unearned income | $ | 1,993,580 | $ | 1,921,263 | $ | 1,842,980 | $ | 1,886,037 | $ | 1,865,574 | ||||||||||||||||||||||
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||
| Quarterly Loans by Composition Comparison | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
| (dollars in thousands) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||
| Construction, land & land development | $ | 238,078 | $ | 208,872 | $ | 205,046 | $ | 196,390 | $ | 199,916 | ||||||||||||||||||||||
| Other commercial real estate | 1,059,149 | 1,052,967 | 990,648 | 1,012,466 | 985,102 | |||||||||||||||||||||||||||
| Total commercial real estate | 1,297,227 | 1,261,839 | 1,195,694 | 1,208,856 | 1,185,018 | |||||||||||||||||||||||||||
| Residential real estate | 356,515 | 345,521 | 344,167 | 349,777 | 360,847 | |||||||||||||||||||||||||||
| Commercial, financial & agricultural | 212,872 | 213,355 | 213,910 | 242,389 | 242,205 | |||||||||||||||||||||||||||
| Consumer and other | 126,966 | 100,548 | 89,209 | 85,015 | 77,504 | |||||||||||||||||||||||||||
| Loans, net of unearned income | $ | 1,993,580 | $ | 1,921,263 | $ | 1,842,980 | $ | 1,886,037 | $ | 1,865,574 | ||||||||||||||||||||||
16
| Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||
| Quarterly Loans by Location Comparison | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
| (dollars in thousands) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||
| Alabama | $ | 50,856 | $ | 52,183 | $ | 45,365 | $ | 46,630 | $ | 44,575 | ||||||||||||||||||||||
| Florida | 24,562 | 19,490 | 13,135 | 12,280 | 2,753 | |||||||||||||||||||||||||||
| Augusta | 95,246 | 91,758 | 76,492 | 59,557 | 64,465 | |||||||||||||||||||||||||||
| Coastal Georgia | 253,177 | 230,242 | 224,609 | 220,452 | 228,844 | |||||||||||||||||||||||||||
| Middle Georgia | 125,435 | 130,302 | 121,059 | 120,843 | 124,268 | |||||||||||||||||||||||||||
| Atlanta and North Georgia | 445,921 | 441,323 | 427,046 | 432,377 | 427,568 | |||||||||||||||||||||||||||
| South Georgia | 408,954 | 398,295 | 384,907 | 427,887 | 413,098 | |||||||||||||||||||||||||||
| West Georgia | 168,968 | 168,851 | 169,699 | 184,634 | 184,365 | |||||||||||||||||||||||||||
| Small Business Specialty Lending | 81,242 | 79,517 | 81,636 | 79,967 | 75,182 | |||||||||||||||||||||||||||
| Consumer Portfolio Mortgages | 262,846 | 251,816 | 250,555 | 253,481 | 257,772 | |||||||||||||||||||||||||||
| Marine/RV Lending | 75,649 | 55,033 | 46,941 | 45,785 | 41,922 | |||||||||||||||||||||||||||
| Other | 724 | 2,453 | 1,536 | 2,144 | 762 | |||||||||||||||||||||||||||
| Loans, net of unearned income | $ | 1,993,580 | $ | 1,921,263 | $ | 1,842,980 | $ | 1,886,037 | $ | 1,865,574 | ||||||||||||||||||||||
17
Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||||||||
| Classified Loans | ||||||||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||||||||
(dollars in thousands) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||||||||
| $ | # | $ | # | $ | # | $ | # | $ | # | |||||||||||||||||||||||||||||
| Construction, land & land development | $ | 126 | 4 | $ | 126 | 4 | $ | — | — | $ | — | — | $ | 54 | 3 | |||||||||||||||||||||||
| Other commercial real estate | 16,687 | 48 | 18,578 | 51 | 13,367 | 38 | 13,338 | 36 | 13,990 | 34 | ||||||||||||||||||||||||||||
| Residential real estate | 1,222 | 73 | 1,670 | 76 | 1,265 | 83 | 1,554 | 85 | 2,168 | 104 | ||||||||||||||||||||||||||||
| Commercial, financial & agricultural | 7,071 | 64 | 6,077 | 58 | 5,407 | 70 | 6,005 | 61 | 6,075 | 54 | ||||||||||||||||||||||||||||
| Consumer and other | 6 | 25 | 2 | 25 | 64 | 22 | 21 | 23 | 68 | 24 | ||||||||||||||||||||||||||||
| TOTAL | $ | 25,112 | 214 | $ | 26,453 | 214 | $ | 20,103 | 213 | $ | 20,918 | 205 | $ | 22,355 | 219 | |||||||||||||||||||||||
| Classified loans to total loans | 1.26 | % | 1.38 | % | 1.09 | % | 1.11 | % | 1.20 | % | ||||||||||||||||||||||||||||
Colony Bankcorp, Inc. | ||||||||||||||||||||||||||||||||||||||
| Criticized Loans | ||||||||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||||||||
(dollars in thousands) | Second Quarter | First Quarter | Fourth Quarter | Third Quarter | Second Quarter | |||||||||||||||||||||||||||||||||
| $ | # | $ | # | $ | # | $ | # | $ | # | |||||||||||||||||||||||||||||
| Construction, land & land development | $ | 2,207 | 10 | $ | 4,028 | 11 | $ | 2,865 | 9 | $ | 4,418 | 9 | $ | 626 | 6 | |||||||||||||||||||||||
| Other commercial real estate | 30,034 | 69 | 28,869 | 70 | 32,077 | 65 | 32,790 | 64 | 31,544 | 59 | ||||||||||||||||||||||||||||
| Residential real estate | 7,224 | 79 | 8,289 | 83 | 5,504 | 89 | 5,389 | 90 | 5,431 | 107 | ||||||||||||||||||||||||||||
| Commercial, financial & agricultural | 15,212 | 85 | 14,501 | 82 | 8,877 | 76 | 9,444 | 68 | 7,181 | 59 | ||||||||||||||||||||||||||||
| Consumer and other | 137 | 26 | 136 | 26 | 64 | 22 | 21 | 23 | 68 | 24 | ||||||||||||||||||||||||||||
| TOTAL | $ | 54,814 | 269 | $ | 55,823 | 272 | $ | 49,387 | 261 | $ | 52,062 | 254 | $ | 44,850 | 255 | |||||||||||||||||||||||
| Criticized loans to total loans | 2.75 | % | 2.91 | % | 2.68 | % | 2.76 | % | 2.40 | % | ||||||||||||||||||||||||||||
18
INVESTOR PRESENTATION Second Quarter 2025
2 CAUTIONARY STATEMENTS This presentation contains "forward-looking statements“ within the meaning of, and subject to the protections of, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. In addition, certain statements may be contained in Colony Bankcorp, Inc's (the "Company") future filings with the Securities and Exchange Commission (the "SEC"), in press releases, and in oral and written statements made by or with the approval of the Company that are not statements of historical fact and constitute “forward-looking statements” within the meaning of, and subject to the protections of, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Examples of forward-looking statements include, but are not limited to: (i) projections and/or expectations of revenues, income or loss, earnings or loss per share, the payment or nonpayment of dividends, capital structure and other financial items; (ii) statement of plans and objectives of Colony Bankcorp, Inc. or its management or Board of Directors, including those relating to products or services; (iii) statements of future economic performance; (iv) statements regarding growth strategy, capital management, liquidity and funding and future profitability; and (v) statements of assumptions underlying such statements. Words such as “may”, “will”, “anticipate”, “assume”, “should”, “support”, “indicate”, “would”, “believe”, “contemplate”, “expect”, “estimate”, “continue”, “further”, “plan”, “point to”, “project”, “could”, “intend”, “target” and similar expressions are intended to identify forward-looking statements but are not the exclusive means of identifying such statements. Prospective investors are cautioned that any such forward-looking statements are not guarantees of future performance and involve known and unknown risks and uncertainties. Factors that might cause such differences include, but are not limited to: the impact of current and future economic conditions, particularly those affecting the financial services industry, including the effects of declines in the real estate market, tariffs or trade wars (including the resulting reduced consumer spending, lower economic growth or recession, reduced demand for U.S. exports, disruptions to supply chains, and decreased demand for other banking products and services), high unemployment rates, inflationary pressures, changes in interest rates (including the impact of prolonged elevated interest rates on our financial projections and models) and slowdowns in economic growth, as well as the financial stress on borrowers as a result of the foregoing; the risk of reductions in benchmark interest rates and the resulting impacts on net interest income; potential impacts of adverse developments in the banking industry highlighted by high-profile bank failures, including impacts on customer confidence, deposit outflows, liquidity and the regulatory response thereto; risks arising from media coverage of the banking industry; risks arising from perceived instability in the banking sector; the risks of changes in interest rates and their effects on the level, cost, and composition of, and competition for, deposits, loan demand and timing of payments, the values of loan collateral, securities, and interest sensitive assets and liabilities; the ability to attract new or retain existing deposits, to retain or grow loans or additional interest and fee income, or to control noninterest expense; the effect of pricing pressures on the Company’s net interest margin; the failure of assumptions underlying the establishment of reserves for possible credit losses, fair value for loans and other real estate owned; changes in real estate values; the Company’s ability to implement its various strategic and growth initiatives; increased competition in the financial services industry, particularly from regional and national institutions, as well as from fintech companies; economic conditions, either nationally or locally, in areas in which the Company conducts operations being less favorable than expected; changes in the prices, values and sales volumes of residential and commercial real estate; developments in our mortgage banking business, including loan modifications, general demand, and the effects of judicial or regulatory requirements or guidance; legislation or regulatory changes which adversely affect the ability of the consolidated Company to conduct business combinations or new operations; adverse results from current or future litigation, regulatory examinations or other legal and/or regulatory actions, including as a result of the Company's participation in and execution of government programs; significant turbulence or a disruption in the capital or financial markets and the effect of a fall in stock market prices on our investment securities; the effects of war or other conflicts; general risks related to the Company’s merger and acquisition activity, including risks associated with integrating and realizing the expected financial benefits of previous or pending acquisitions, and the Company’s pursuit of future acquisitions; the impact of generative artificial intelligence; fraud or misconduct by internal or external actors, and system failures, cybersecurity threats or security breaches and the cost of defending against them; a deterioration of the credit rating for U.S. long- term sovereign debt, actions that the U.S. government may take to avoid exceeding the debt ceiling, and uncertainties surrounding debt ceiling and the federal budget; a potential U.S. federal government shutdown and the resulting impacts; and general competitive, economic, political and market conditions or other unexpected factors or events. These and other factors, risks and uncertainties could cause the actual results, performance or achievements of the Company to be materially different from the future results, performance or achievements expressed or implied by such forward-looking statements. Many of these factors are beyond the Company’s ability to control or predict. Forward-looking statements speak only as of the date on which such statements are made. These forward-looking statements are based upon information presently known to the Company’s management and are inherently subjective, uncertain and subject to change due to any number of risks and uncertainties, including, without limitation, the risks and other factors set forth in the Company’s filings with the Securities and Exchange Commission, the Company’s Annual Report on Form 10-K for the year ended December 31, 2024, under the captions “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors,” and in the Company’s quarterly reports on Form 10-Q and current reports on Form 8-K. The Company undertakes no obligation to update any forward-looking statement to reflect events or circumstances after the date on which such statement is made, or to reflect the occurrence of unanticipated events. Readers are cautioned not to place undue reliance on these forward- looking statements.
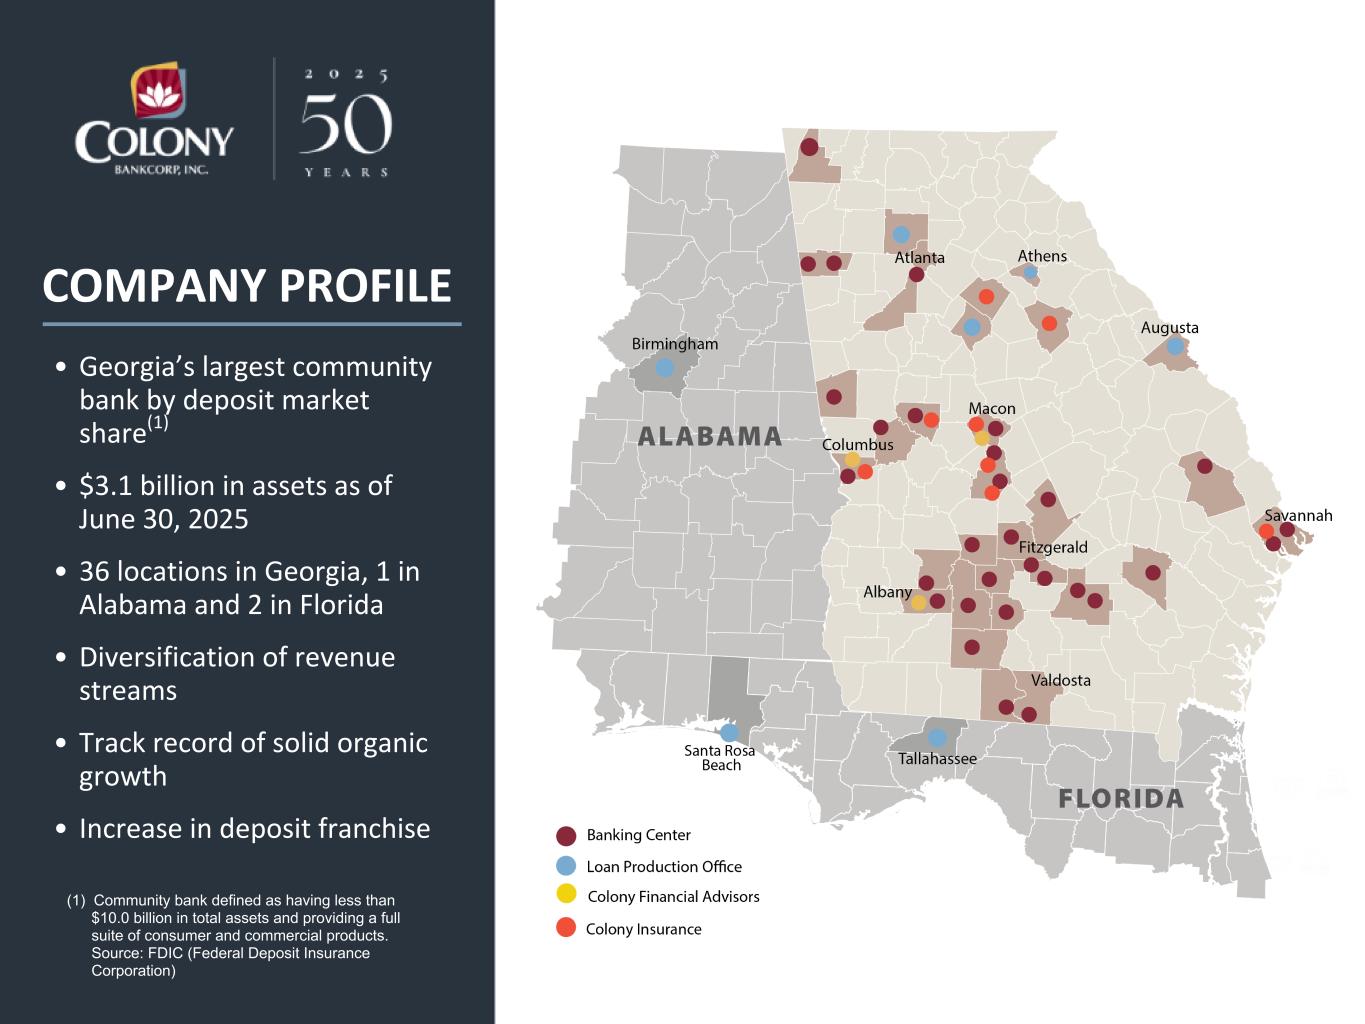
3 (1) Community bank defined as having less than $10.0 billion in total assets and providing a full suite of consumer and commercial products. Source: FDIC (Federal Deposit Insurance Corporation) • Georgia’s largest community bank by deposit market share(1) • $3.1 billion in assets as of June 30, 2025 • 36 locations in Georgia, 1 in Alabama and 2 in Florida • Diversification of revenue streams • Track record of solid organic growth • Increase in deposit franchise COMPANY PROFILE
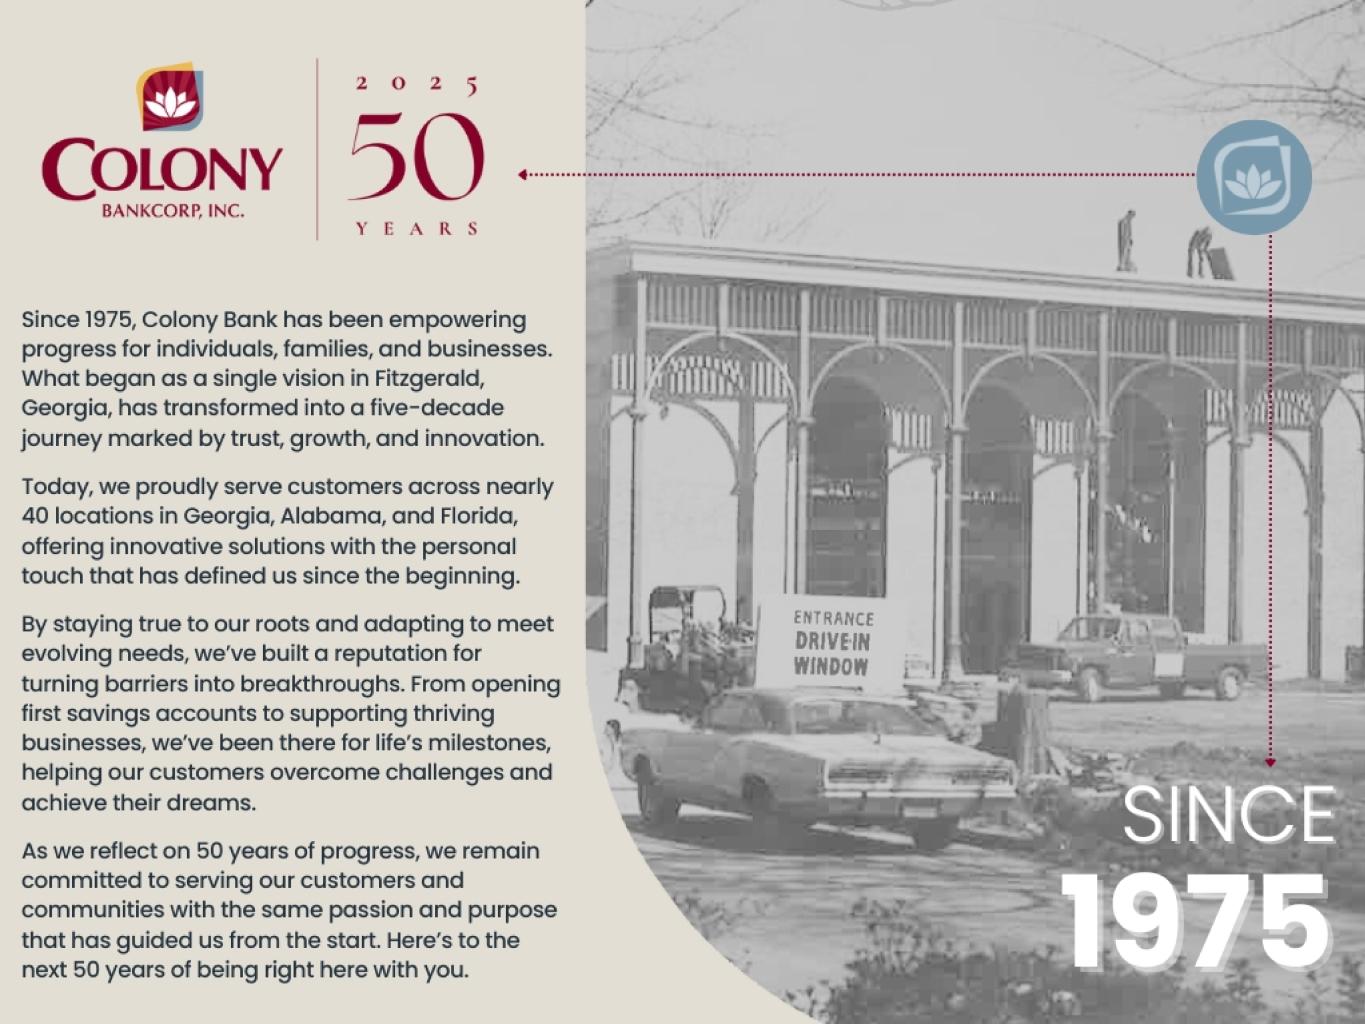
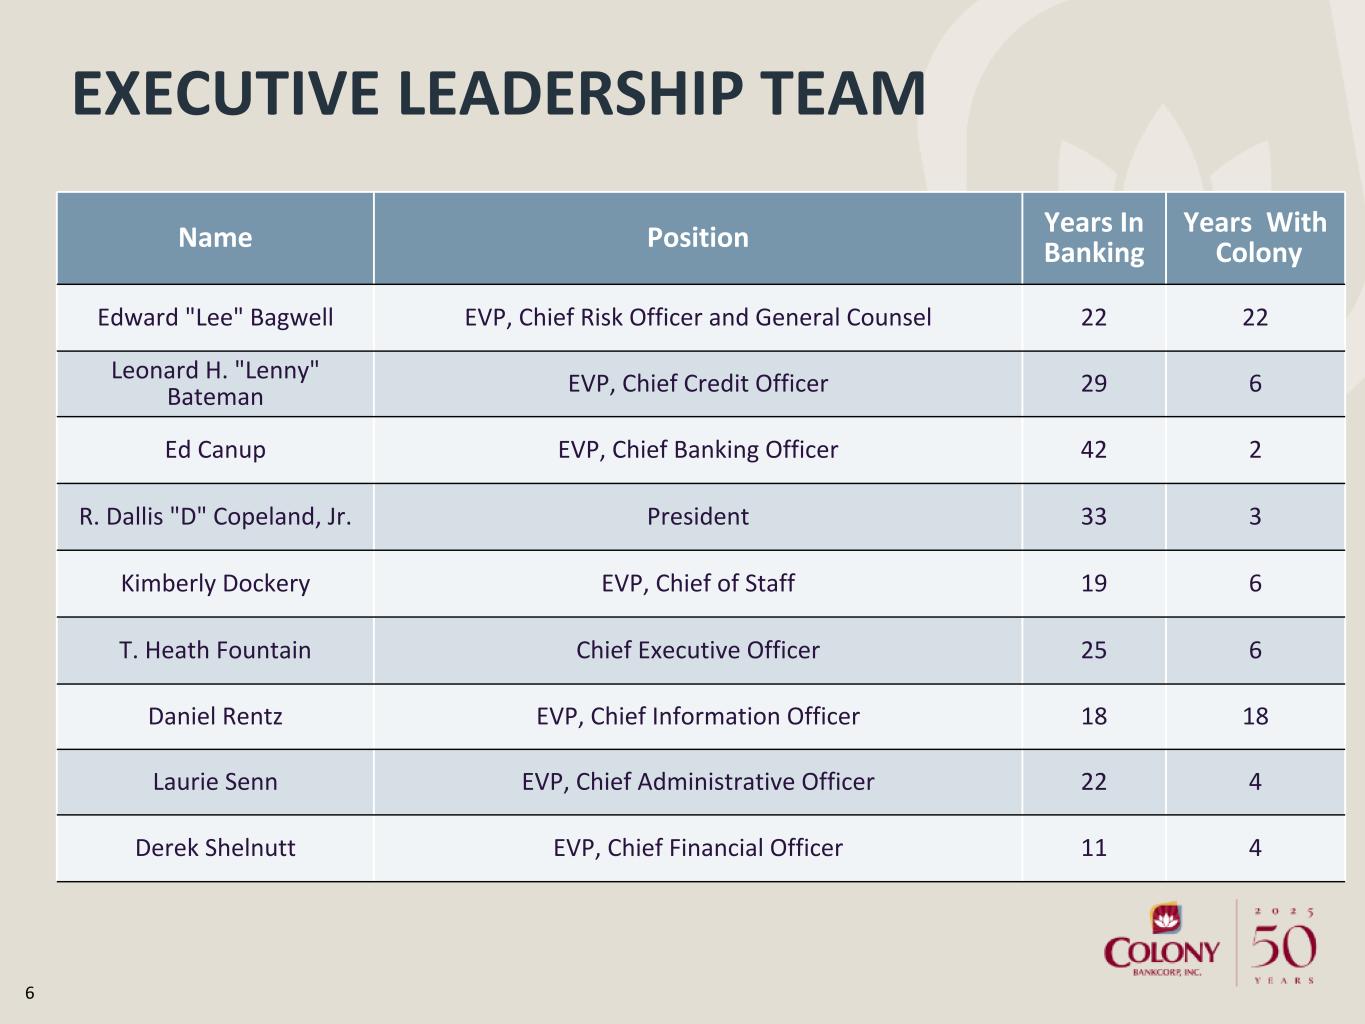
6 Name Position Years In Banking Years With Colony Edward "Lee" Bagwell EVP, Chief Risk Officer and General Counsel 22 22 Leonard H. "Lenny" Bateman EVP, Chief Credit Officer 29 6 Ed Canup EVP, Chief Banking Officer 42 2 R. Dallis "D" Copeland, Jr. President 33 3 Kimberly Dockery EVP, Chief of Staff 19 6 T. Heath Fountain Chief Executive Officer 25 6 Daniel Rentz EVP, Chief Information Officer 18 18 Laurie Senn EVP, Chief Administrative Officer 22 4 Derek Shelnutt EVP, Chief Financial Officer 11 4 EXECUTIVE LEADERSHIP TEAM
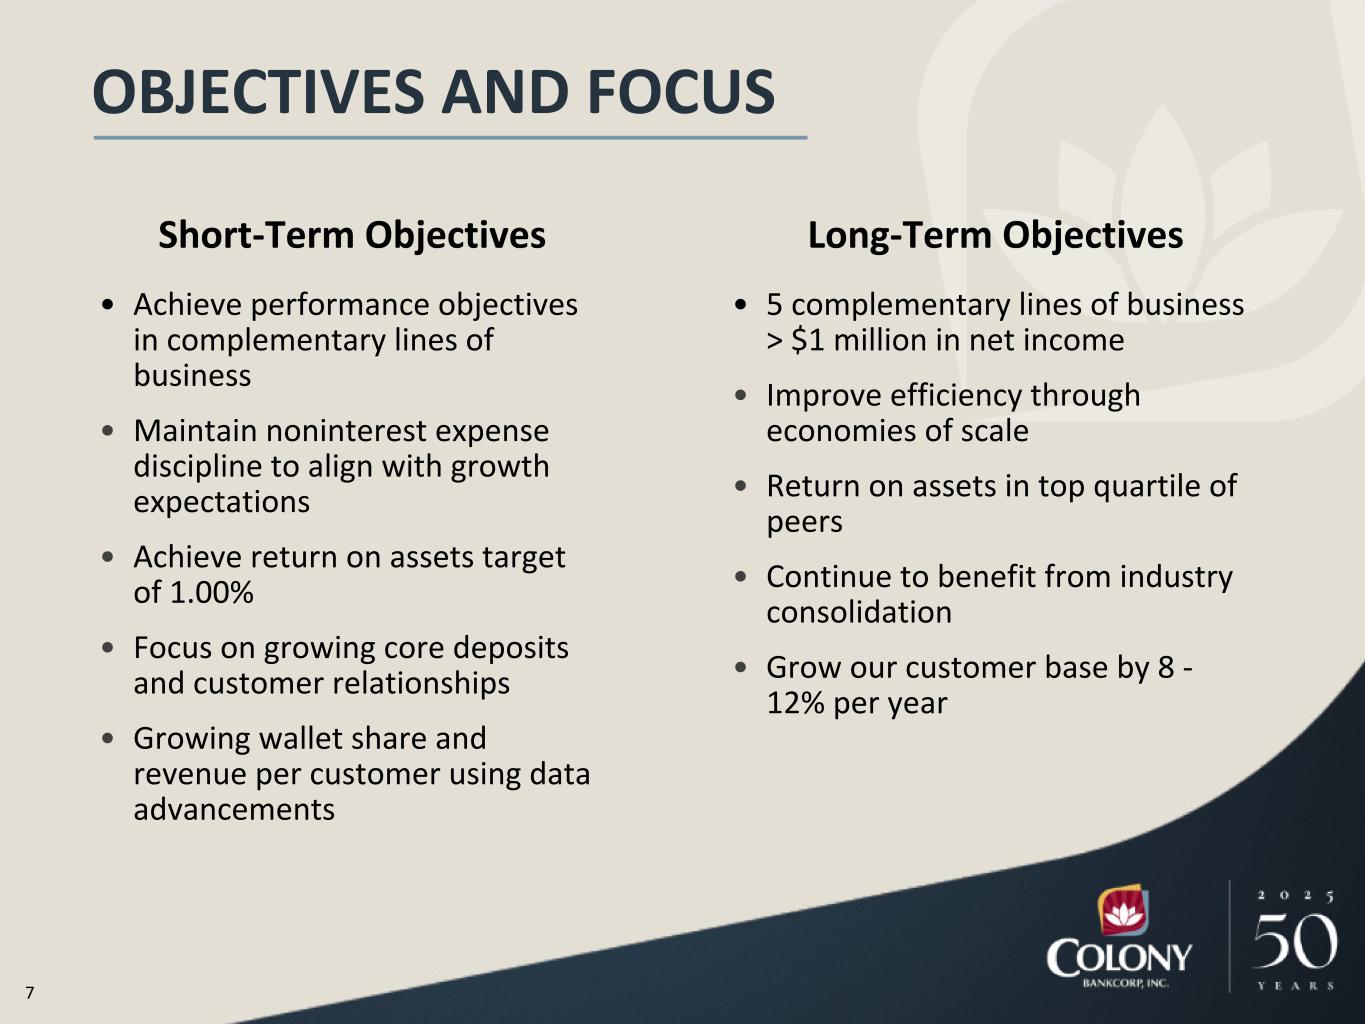
7 OBJECTIVES AND FOCUS • Achieve performance objectives in complementary lines of business • Maintain noninterest expense discipline to align with growth expectations • Achieve return on assets target of 1.00% • Focus on growing core deposits and customer relationships • Growing wallet share and revenue per customer using data advancements Short-Term Objectives Long-Term Objectives • 5 complementary lines of business > $1 million in net income • Improve efficiency through economies of scale • Return on assets in top quartile of peers • Continue to benefit from industry consolidation • Grow our customer base by 8 - 12% per year
8 ORGANIC GROWTH • Presence in dynamic growth markets of Atlanta, Augusta, Birmingham, North Florida and Savannah provides opportunity for above average growth • Second-tier MSA markets of Albany, Columbus, Macon and Valdosta have significant market share held by large regional and national banks, creating the opportunity for growth in market share • Smaller markets where Colony has stable deposits and significant market shares creates the opportunity to grow insurance, wealth management and other complementary lines of business • Utilization of data improves the effectiveness of marketing and business development activity • Proactive calling effort by bankers, including executive and senior management, to develop new business and deepen relationships • Expect to return to 8 - 12% organic growth run rate by the end of 2025
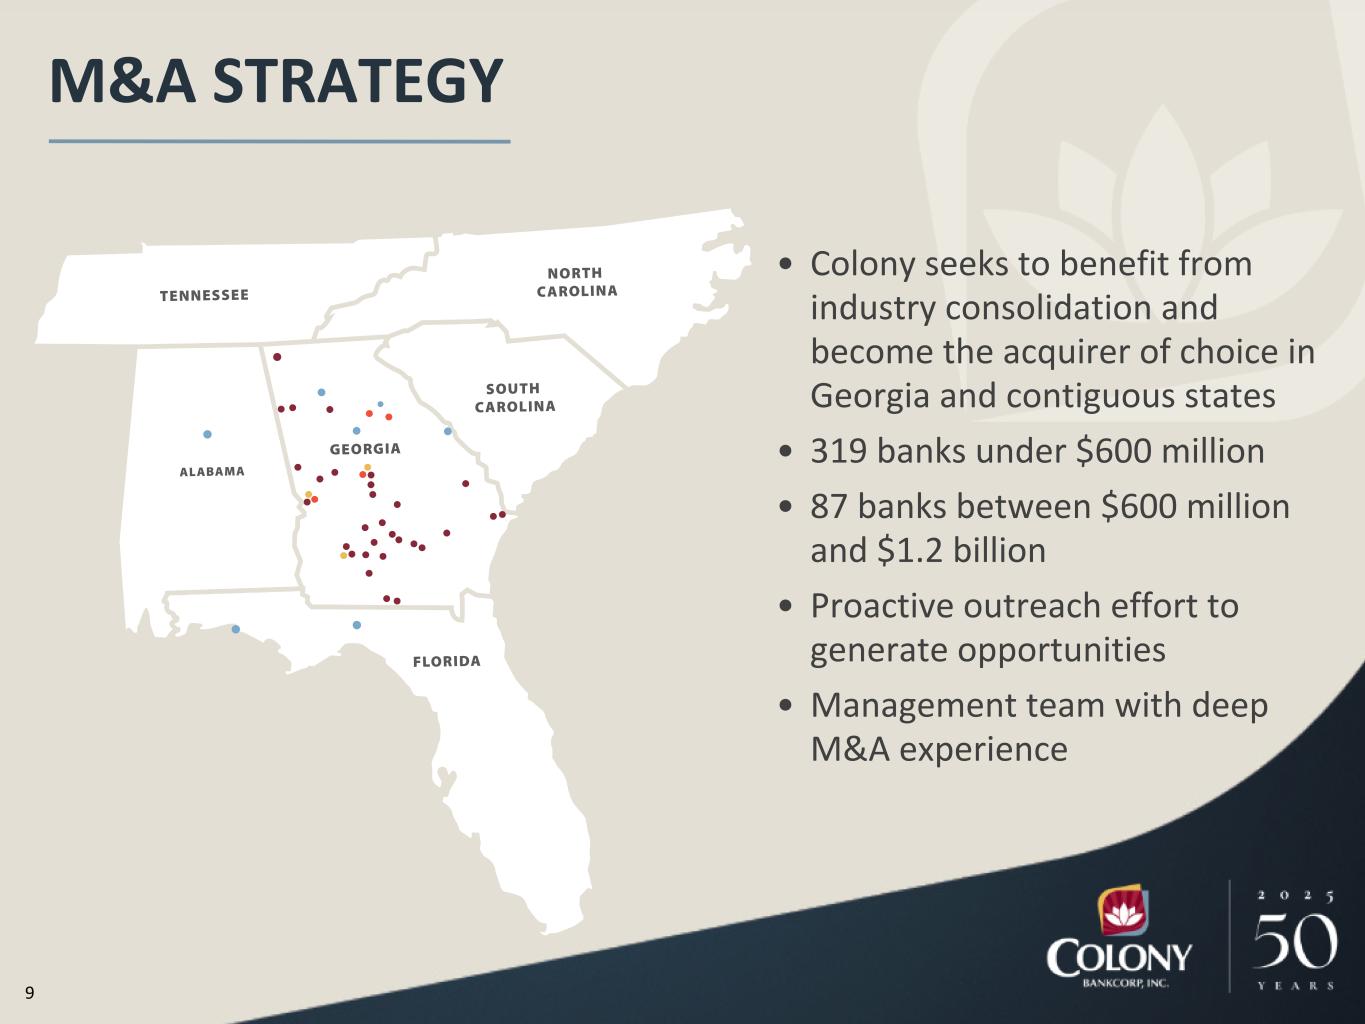
9 M&A STRATEGY • Colony seeks to benefit from industry consolidation and become the acquirer of choice in Georgia and contiguous states • 319 banks under $600 million • 87 banks between $600 million and $1.2 billion • Proactive outreach effort to generate opportunities • Management team with deep M&A experience
10 EFFICIENCY AND SCALING • Focused on process improvement and ensuring it is easy to do business with Colony Bank • Hired a Director of Optimization with experience from a large regional bank to oversee process improvement and customer experience • Utilization of Robotic Process Automation ("RPA") and other innovative technology to improve the customer experience • Implementation of cross functional teams to reduce friction and improve the customer experience • Building operational capacity in order to maintain efficiency through organic growth and M&A
11 INNOVATION AND DATA STRATEGY • Successful digital banking implementation offering customers an elevated, seamless and convenient banking experience • Research and develop all potential technology-based opportunities • Increase customer wallet share through data gathering and analytics • Full implementation of Salesforce based customer relationship management ("CRM") system to influence a more complete customer relationship through calling efforts and targeted marketing • Implemented nCino to allow an upgrade of the customer loan experience and reduce operational friction, leading to increased production capacity and efficiency • Implemented middleware for applying API-based technology to allow seamless integration for Fintech partnerships • Implement data warehouse to allow improved data usage across all lines of business
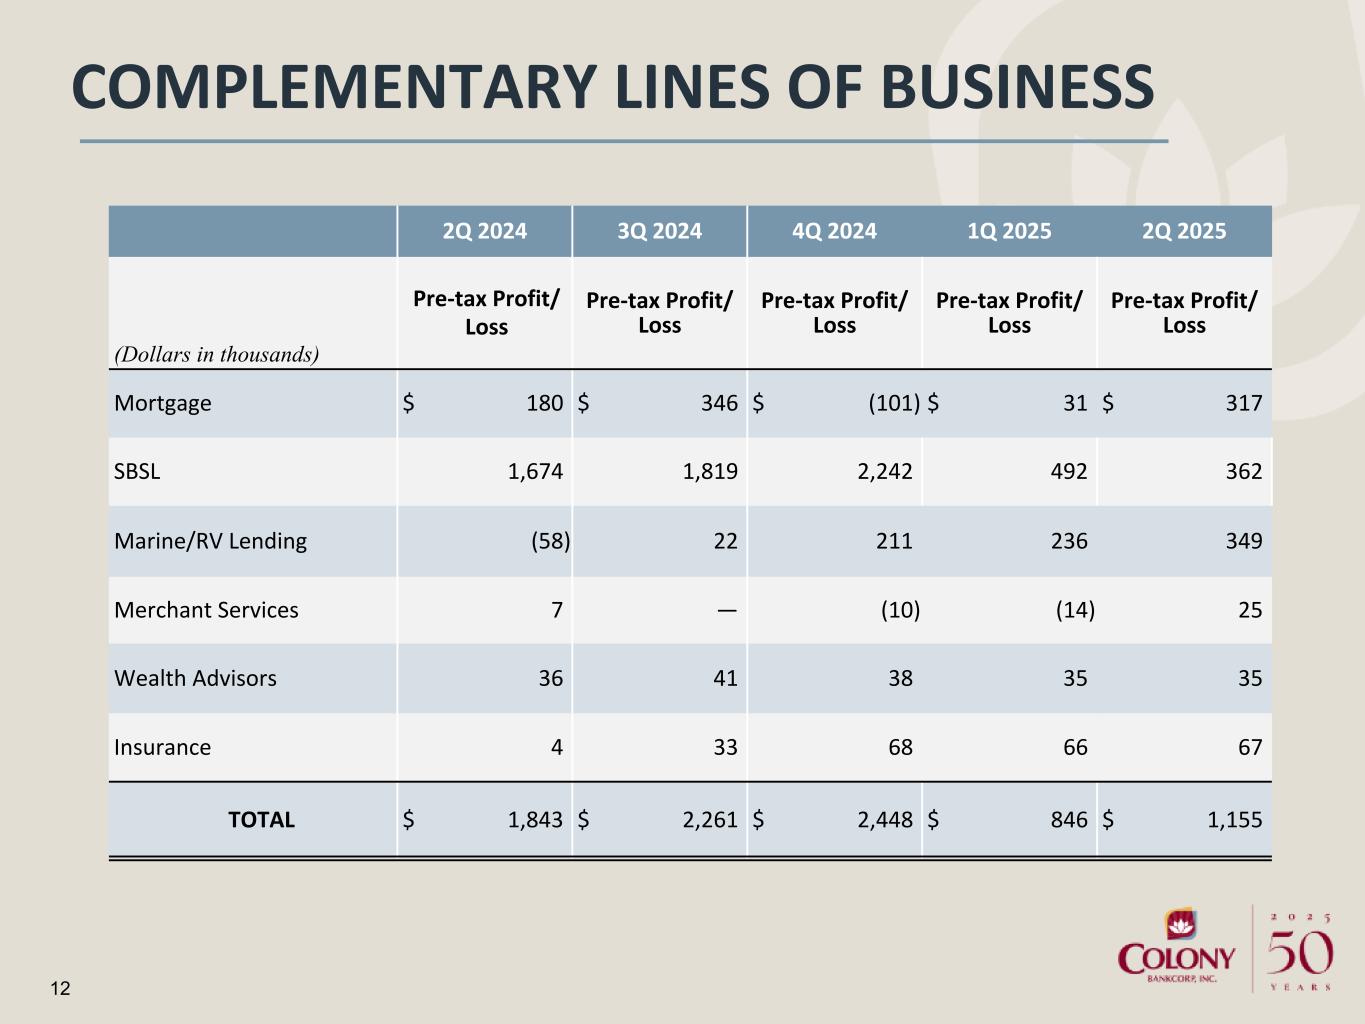
12 COMPLEMENTARY LINES OF BUSINESS 2Q 2024 3Q 2024 4Q 2024 1Q 2025 2Q 2025 (Dollars in thousands) Pre-tax Profit/ Loss Pre-tax Profit/ Loss Pre-tax Profit/ Loss Pre-tax Profit/ Loss Pre-tax Profit/ Loss Mortgage $ 180 $ 346 $ (101) $ 31 $ 317 SBSL 1,674 1,819 2,242 492 362 Marine/RV Lending (58) 22 211 236 349 Merchant Services 7 — (10) (14) 25 Wealth Advisors 36 41 38 35 35 Insurance 4 33 68 66 67 TOTAL $ 1,843 $ 2,261 $ 2,448 $ 846 $ 1,155 12
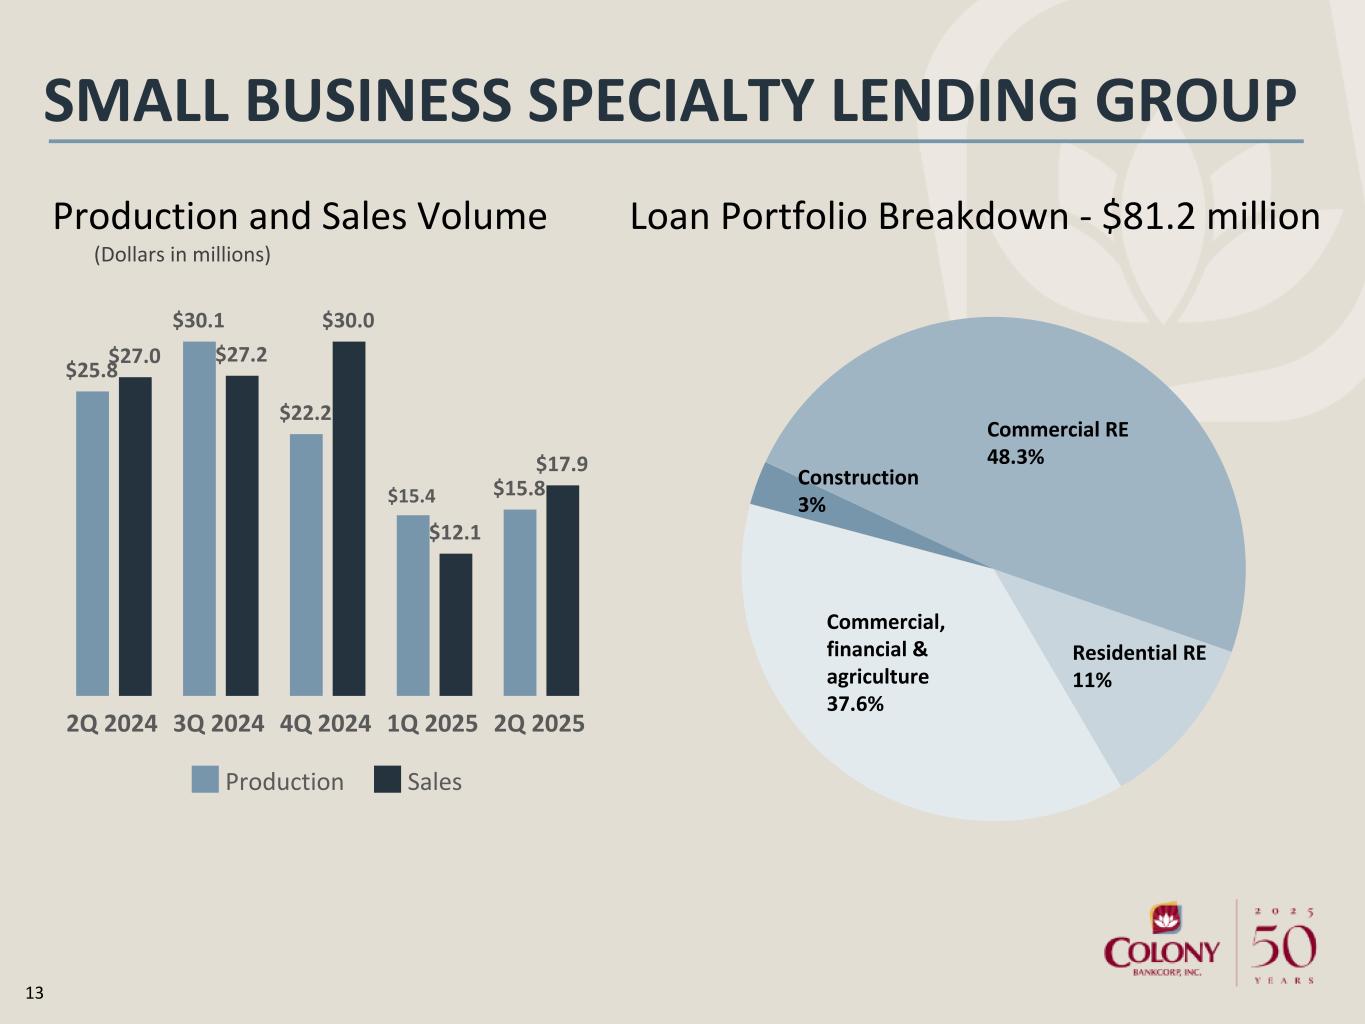
13 SMALL BUSINESS SPECIALTY LENDING GROUP (Dollars in millions) Production and Sales Volume $25.8 $30.1 $22.2 $15.4 $15.8 $27.0 $27.2 $30.0 $12.1 $17.9 Production Sales 2Q 2024 3Q 2024 4Q 2024 1Q 2025 2Q 2025 Loan Portfolio Breakdown - $81.2 million Construction 3% Commercial RE 48.3% Residential RE 11% Commercial, financial & agriculture 37.6%
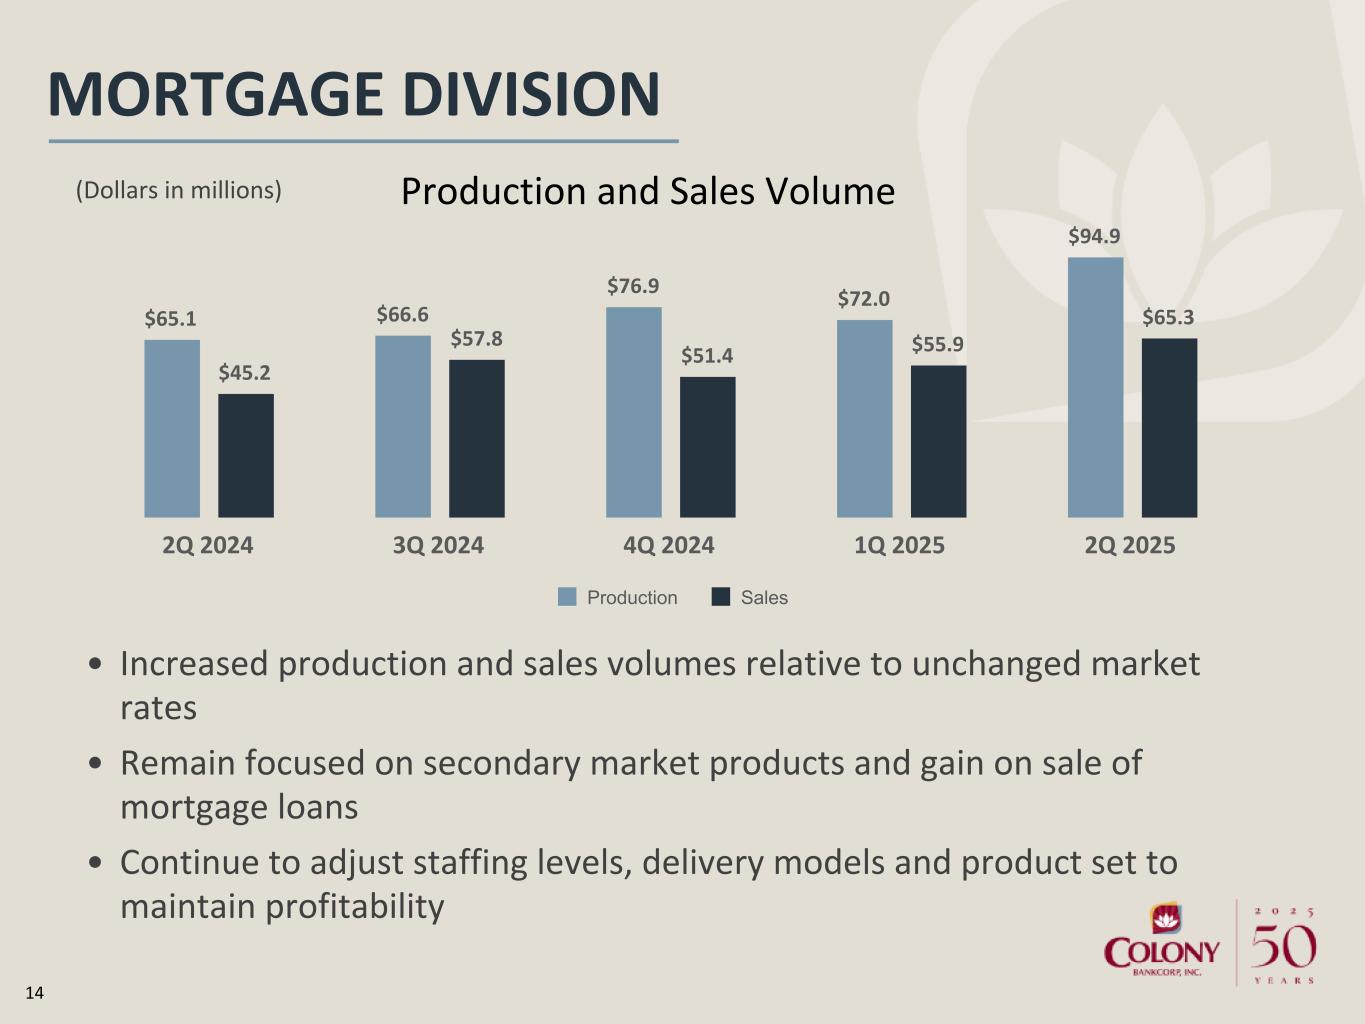
14 MORTGAGE DIVISION (Dollars in millions) • Increased production and sales volumes relative to unchanged market rates • Remain focused on secondary market products and gain on sale of mortgage loans • Continue to adjust staffing levels, delivery models and product set to maintain profitability $65.1 $66.6 $76.9 $72.0 $94.9 $45.2 $57.8 $51.4 $55.9 $65.3 Production Sales 2Q 2024 3Q 2024 4Q 2024 1Q 2025 2Q 2025 Production and Sales Volume
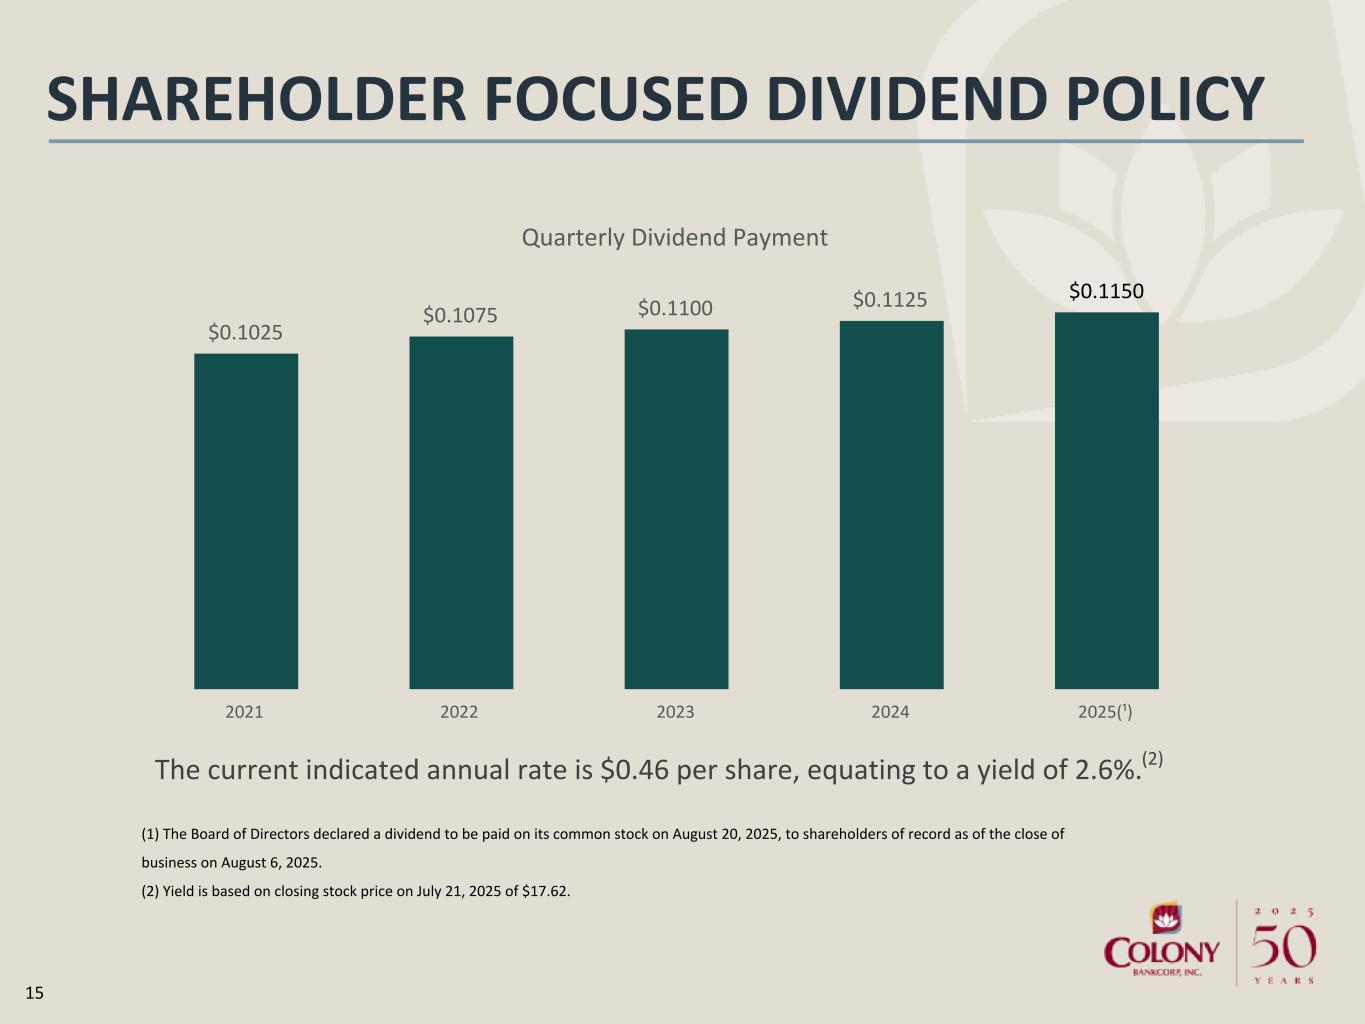
15 The current indicated annual rate is $0.46 per share, equating to a yield of 2.6%.(2) SHAREHOLDER FOCUSED DIVIDEND POLICY (1) The Board of Directors declared a dividend to be paid on its common stock on August 20, 2025, to shareholders of record as of the close of business on August 6, 2025. (2) Yield is based on closing stock price on July 21, 2025 of $17.62. Quarterly Dividend Payment $0.1025 $0.1075 $0.1100 $0.1125 $0.1150 2021 2022 2023 2024 2025(¹)
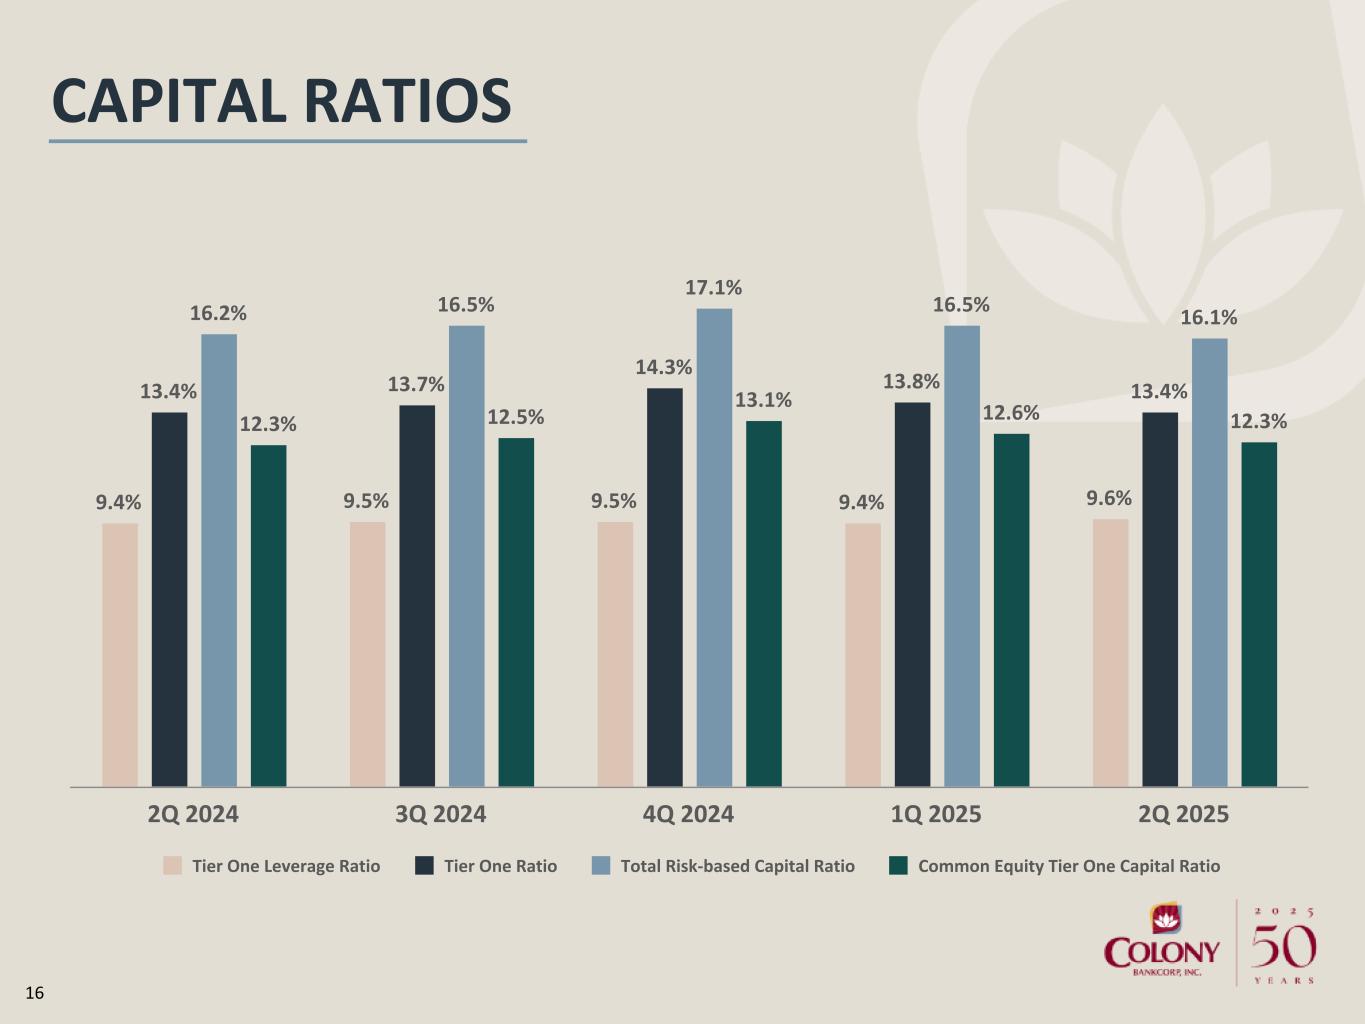
16 CAPITAL RATIOS 9.4% 9.5% 9.5% 9.4% 9.6% 13.4% 13.7% 14.3% 13.8% 13.4% 16.2% 16.5% 17.1% 16.5% 16.1% 12.3% 12.5% 13.1% 12.6% 12.3% Tier One Leverage Ratio Tier One Ratio Total Risk-based Capital Ratio Common Equity Tier One Capital Ratio 2Q 2024 3Q 2024 4Q 2024 1Q 2025 2Q 2025
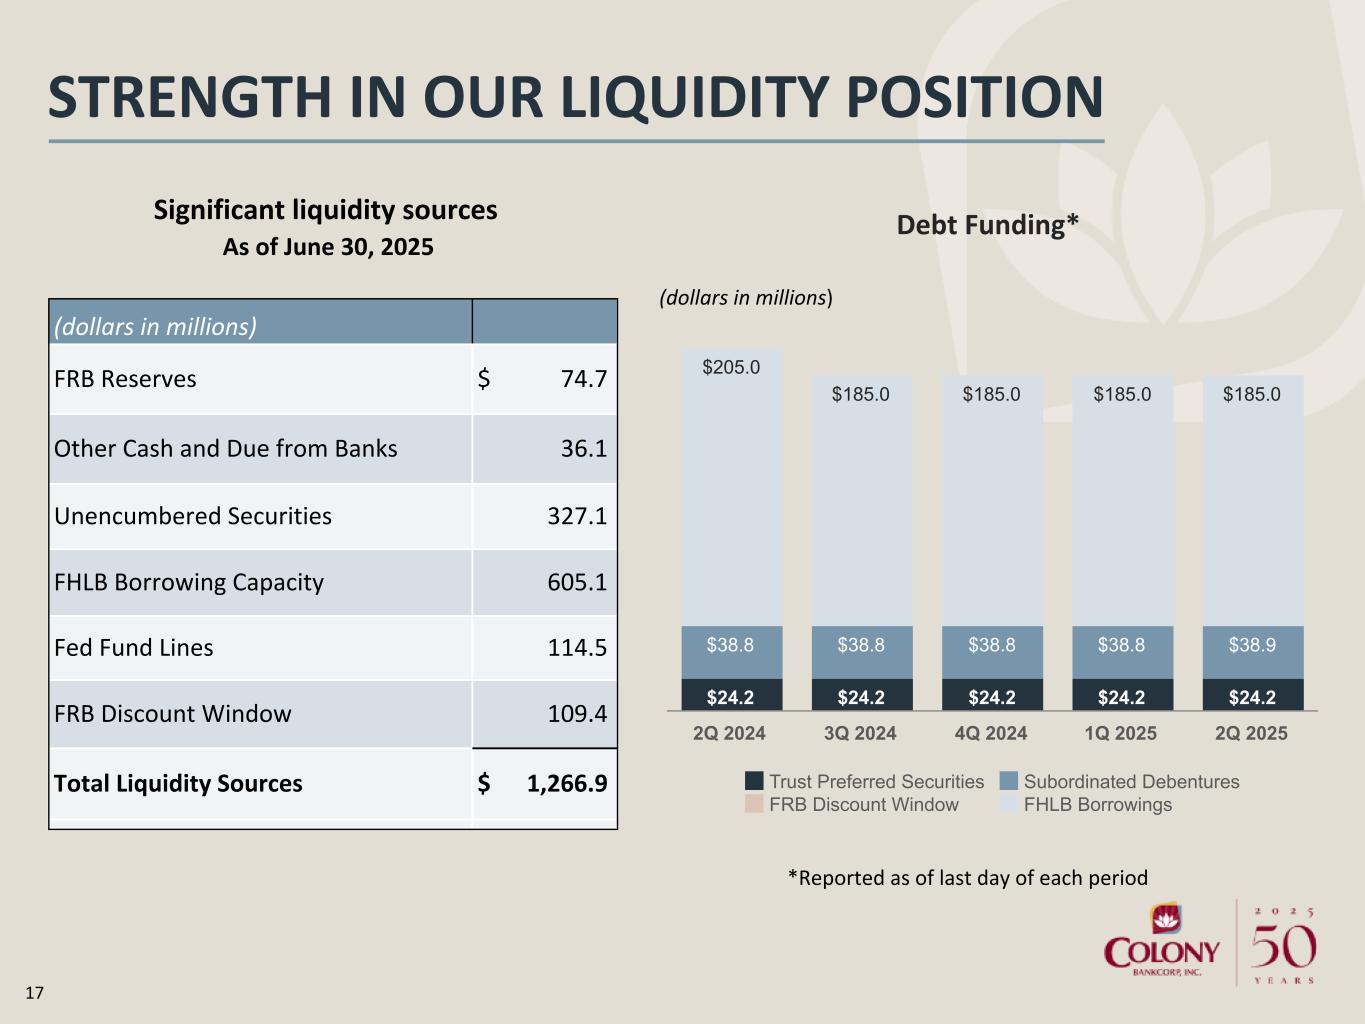
17 STRENGTH IN OUR LIQUIDITY POSITION Significant liquidity sources (dollars in millions) FRB Reserves $ 74.7 Other Cash and Due from Banks 36.1 Unencumbered Securities 327.1 FHLB Borrowing Capacity 605.1 Fed Fund Lines 114.5 FRB Discount Window 109.4 Total Liquidity Sources $ 1,266.9 $24.2 $24.2 $24.2 $24.2 $24.2 $38.8 $38.8 $38.8 $38.8 $38.9 $205.0 $185.0 $185.0 $185.0 $185.0 Trust Preferred Securities Subordinated Debentures FRB Discount Window FHLB Borrowings 2Q 2024 3Q 2024 4Q 2024 1Q 2025 2Q 2025 Debt Funding* (dollars in millions) *Reported as of last day of each period As of June 30, 2025
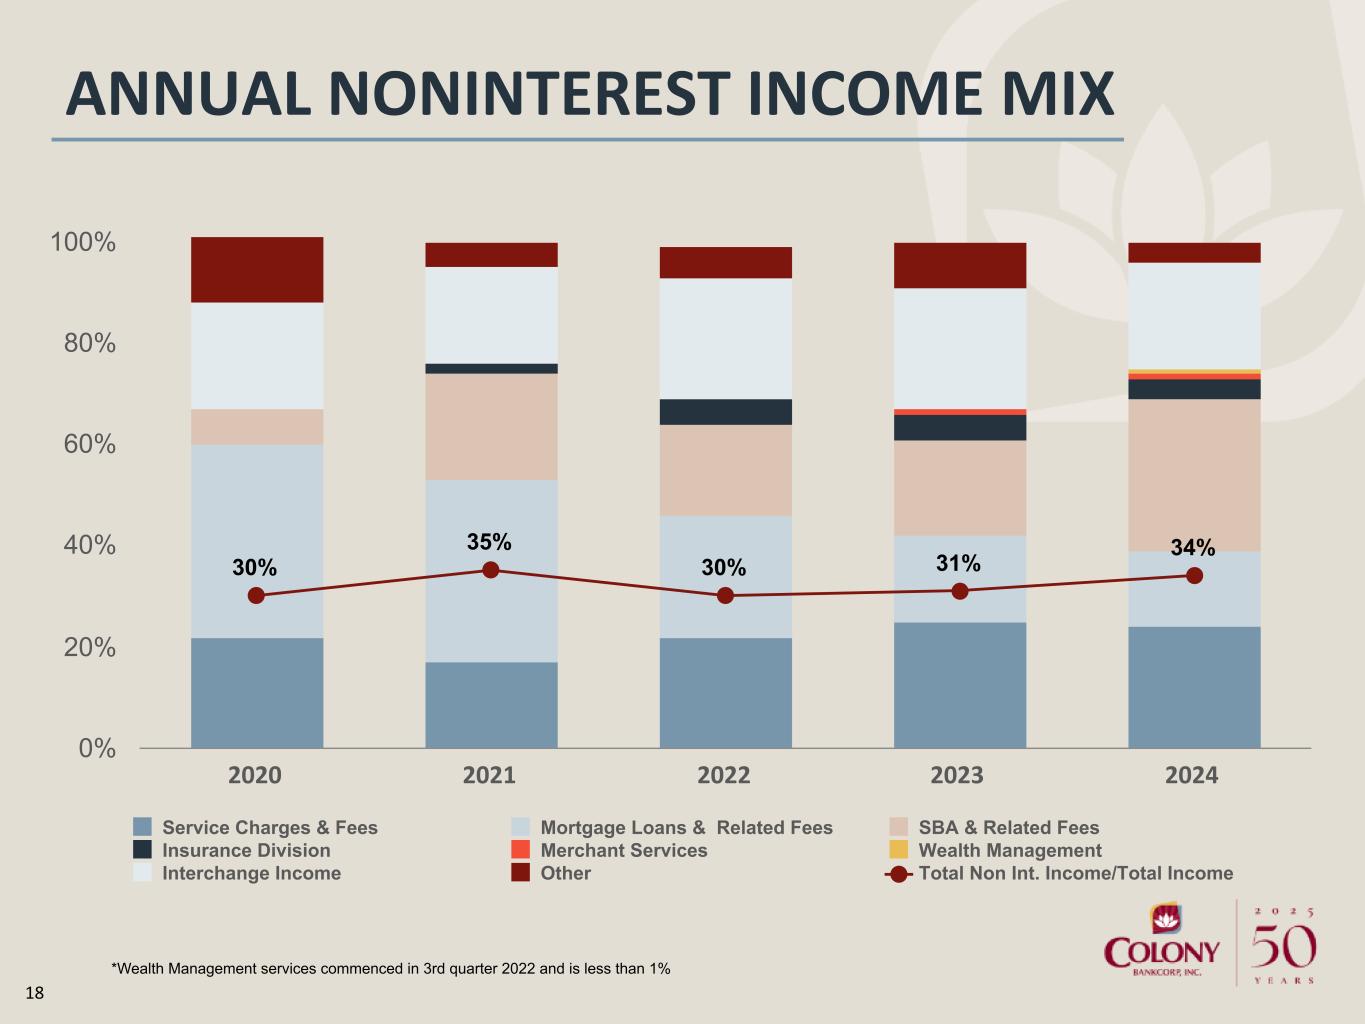
18 30% 35% 30% 31% 34% Service Charges & Fees Mortgage Loans & Related Fees SBA & Related Fees Insurance Division Merchant Services Wealth Management Interchange Income Other Total Non Int. Income/Total Income 2020 2021 2022 2023 2024 0% 20% 40% 60% 80% 100% ANNUAL NONINTEREST INCOME MIX *Wealth Management services commenced in 3rd quarter 2022 and is less than 1%
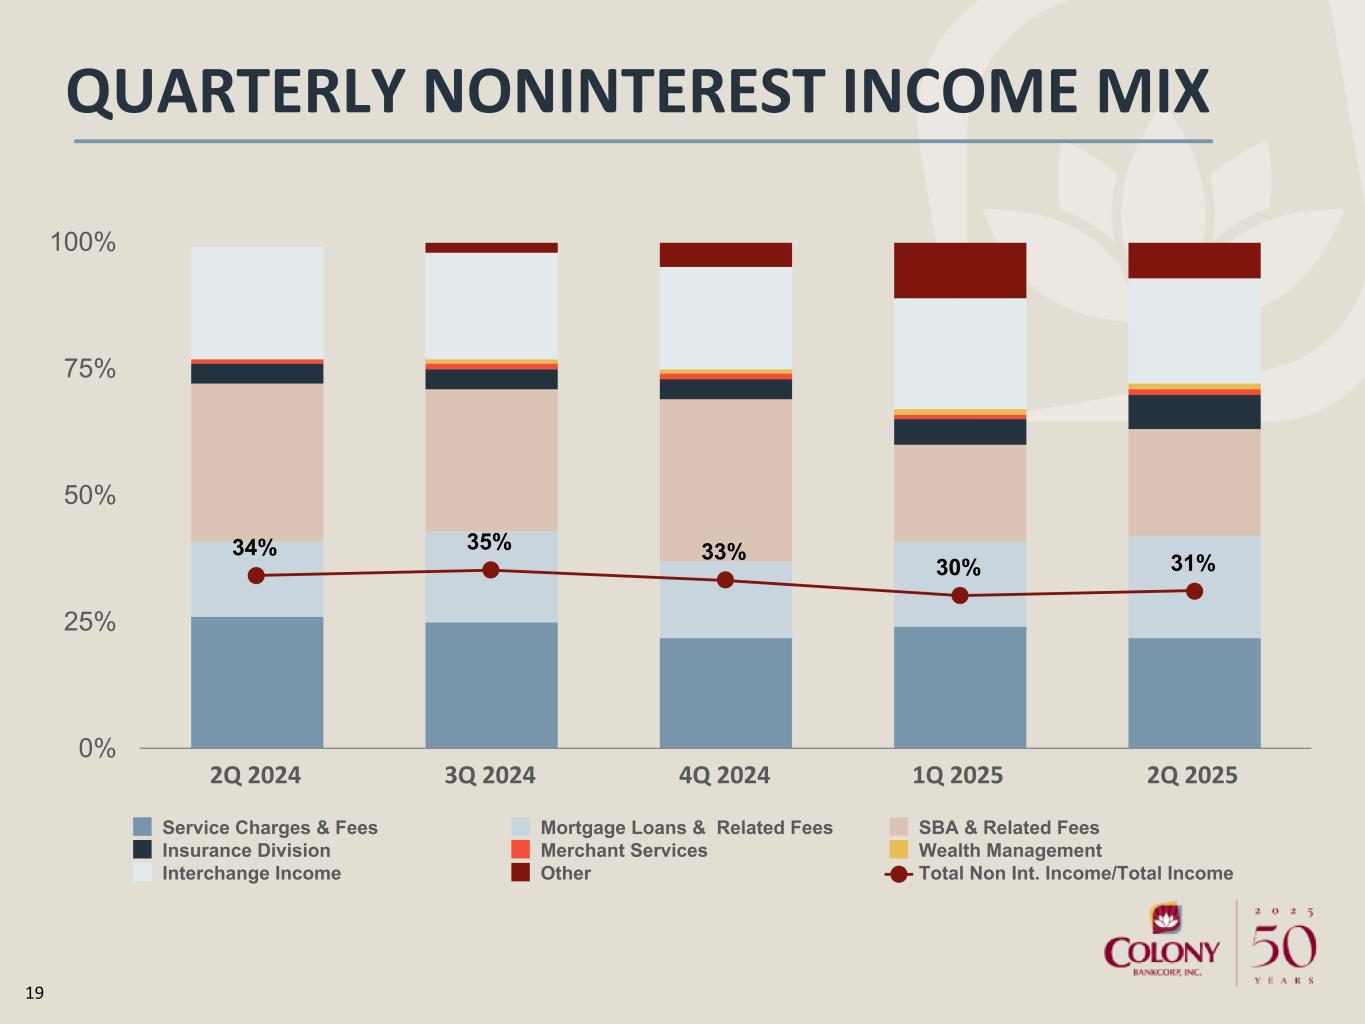
19 34% 35% 33% 30% 31% Service Charges & Fees Mortgage Loans & Related Fees SBA & Related Fees Insurance Division Merchant Services Wealth Management Interchange Income Other Total Non Int. Income/Total Income 2Q 2024 3Q 2024 4Q 2024 1Q 2025 2Q 2025 0% 25% 50% 75% 100% QUARTERLY NONINTEREST INCOME MIX
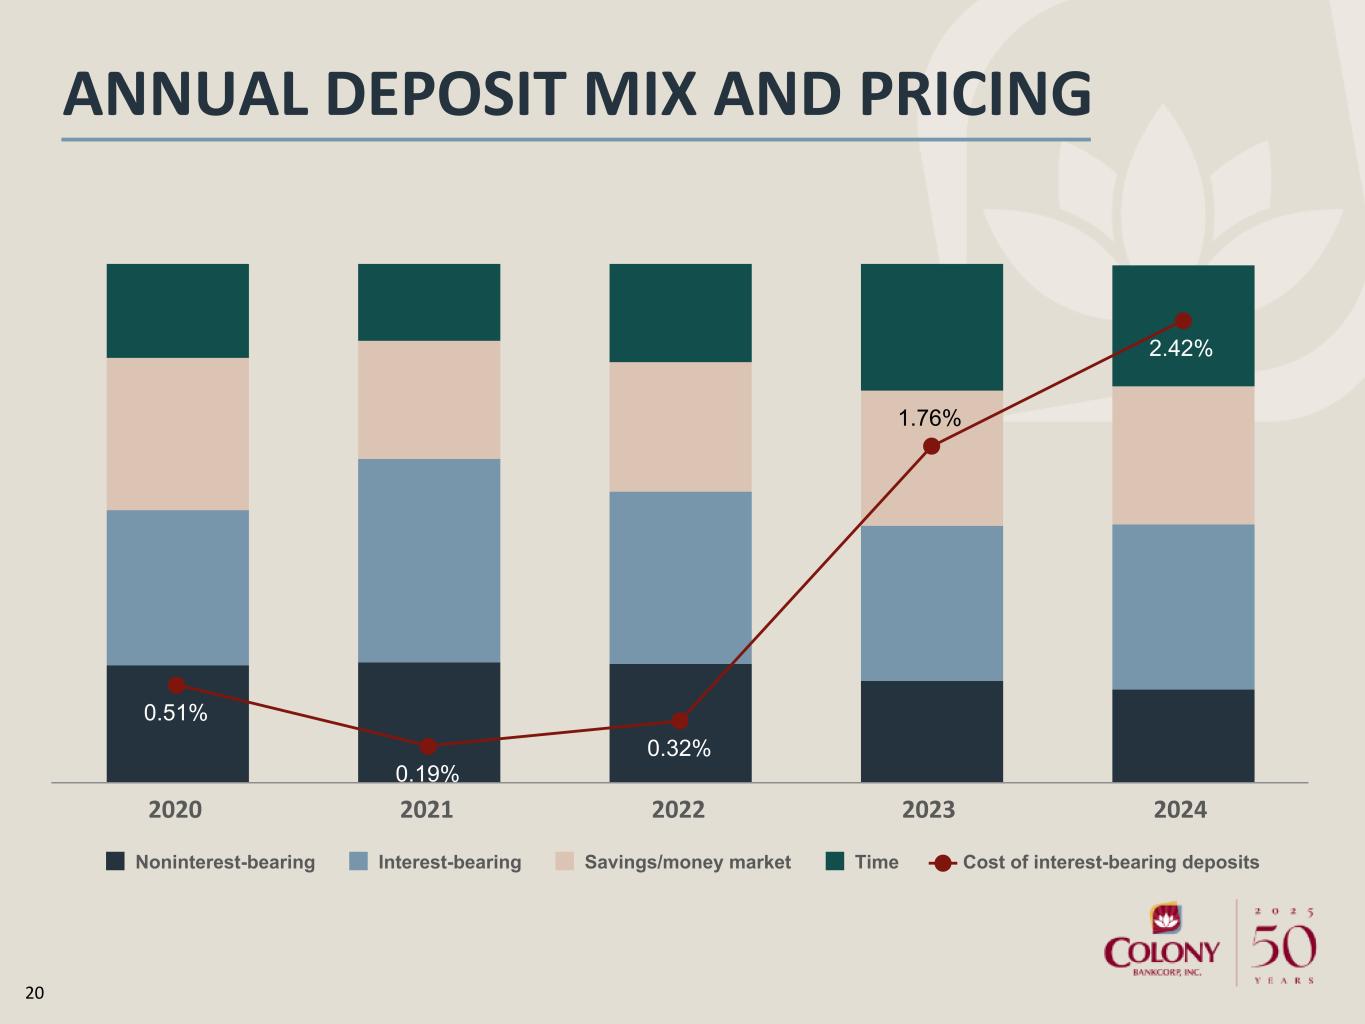
20 0.51% 0.19% 0.32% 1.76% 2.42% Noninterest-bearing Interest-bearing Savings/money market Time Cost of interest-bearing deposits 2020 2021 2022 2023 2024 ANNUAL DEPOSIT MIX AND PRICING
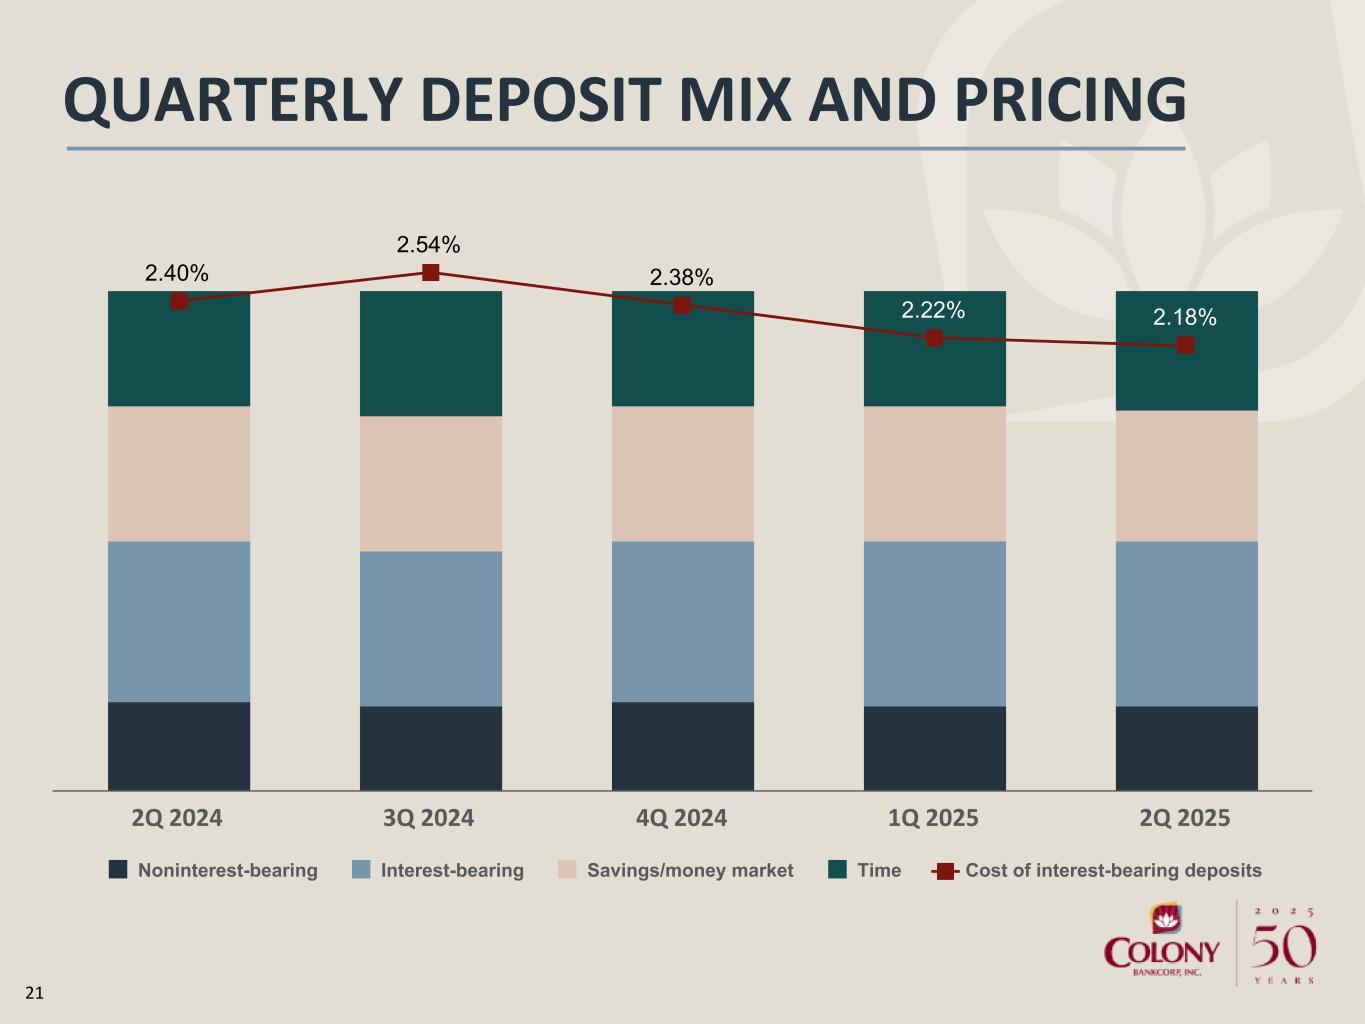
21 2.40% 2.54% 2.38% 2.22% 2.18% Noninterest-bearing Interest-bearing Savings/money market Time Cost of interest-bearing deposits 2Q 2024 3Q 2024 4Q 2024 1Q 2025 2Q 2025 QUARTERLY DEPOSIT MIX AND PRICING
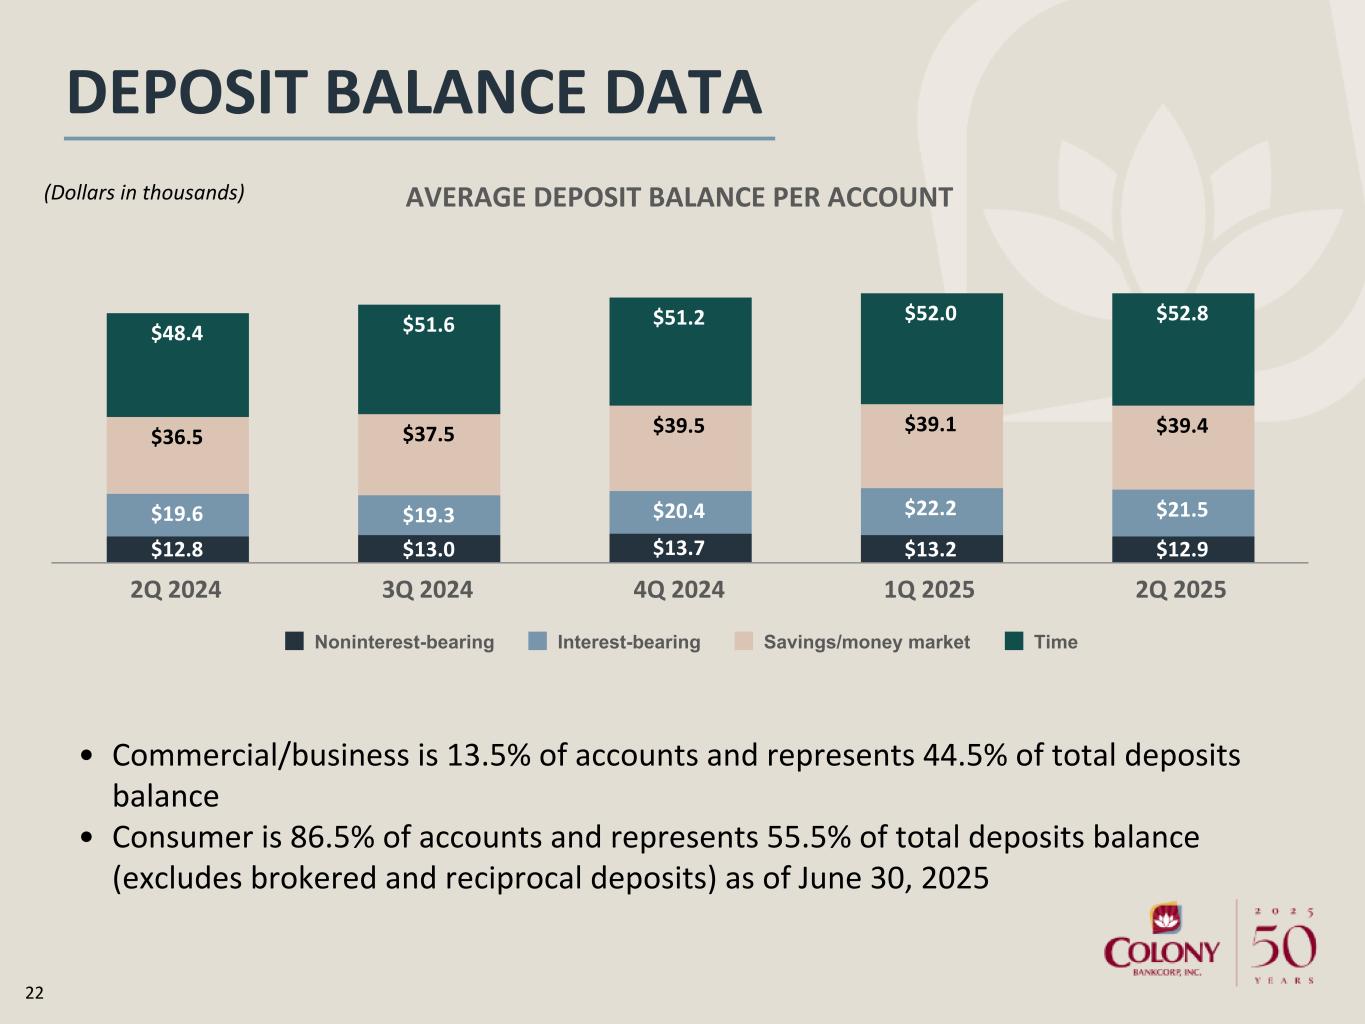
22 AVERAGE DEPOSIT BALANCE PER ACCOUNT $12.8 $13.0 $13.7 $13.2 $12.9 $19.6 $19.3 $20.4 $22.2 $21.5 $36.5 $37.5 $39.5 $39.1 $39.4 $48.4 $51.6 $51.2 $52.0 $52.8 Noninterest-bearing Interest-bearing Savings/money market Time 2Q 2024 3Q 2024 4Q 2024 1Q 2025 2Q 2025 DEPOSIT BALANCE DATA • Commercial/business is 13.5% of accounts and represents 44.5% of total deposits balance • Consumer is 86.5% of accounts and represents 55.5% of total deposits balance (excludes brokered and reciprocal deposits) as of June 30, 2025 (Dollars in thousands)
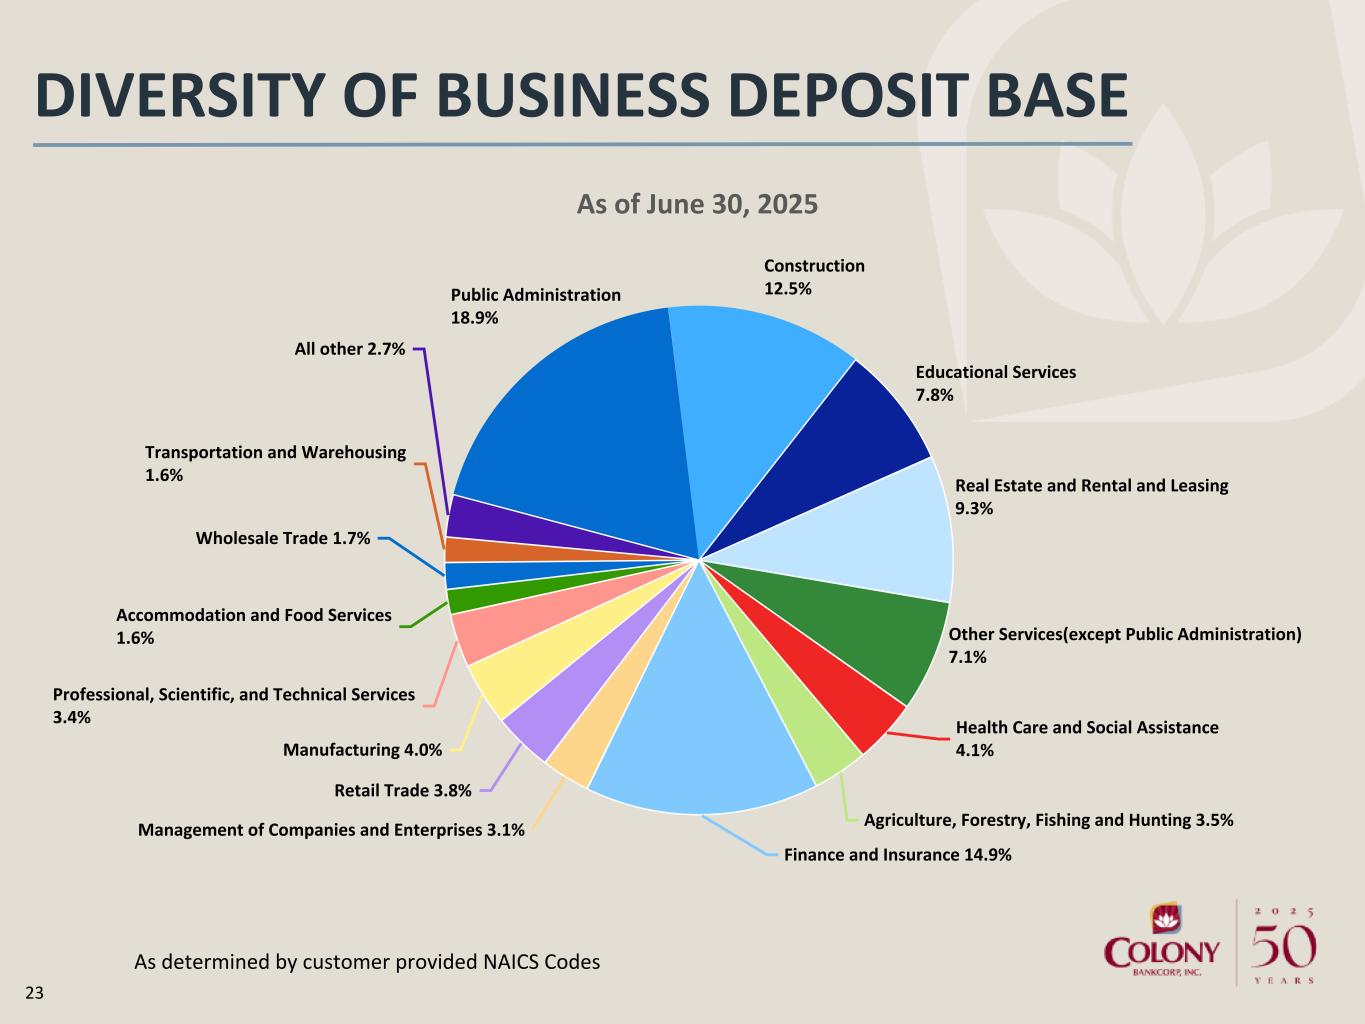
23 DIVERSITY OF BUSINESS DEPOSIT BASE As of June 30, 2025 Public Administration 18.9% Construction 12.5% Educational Services 7.8% Real Estate and Rental and Leasing 9.3% Other Services(except Public Administration) 7.1% Health Care and Social Assistance 4.1% Agriculture, Forestry, Fishing and Hunting 3.5% Finance and Insurance 14.9% Management of Companies and Enterprises 3.1% Retail Trade 3.8% Manufacturing 4.0% Professional, Scientific, and Technical Services 3.4% Accommodation and Food Services 1.6% Wholesale Trade 1.7% Transportation and Warehousing 1.6% All other 2.7% As determined by customer provided NAICS Codes
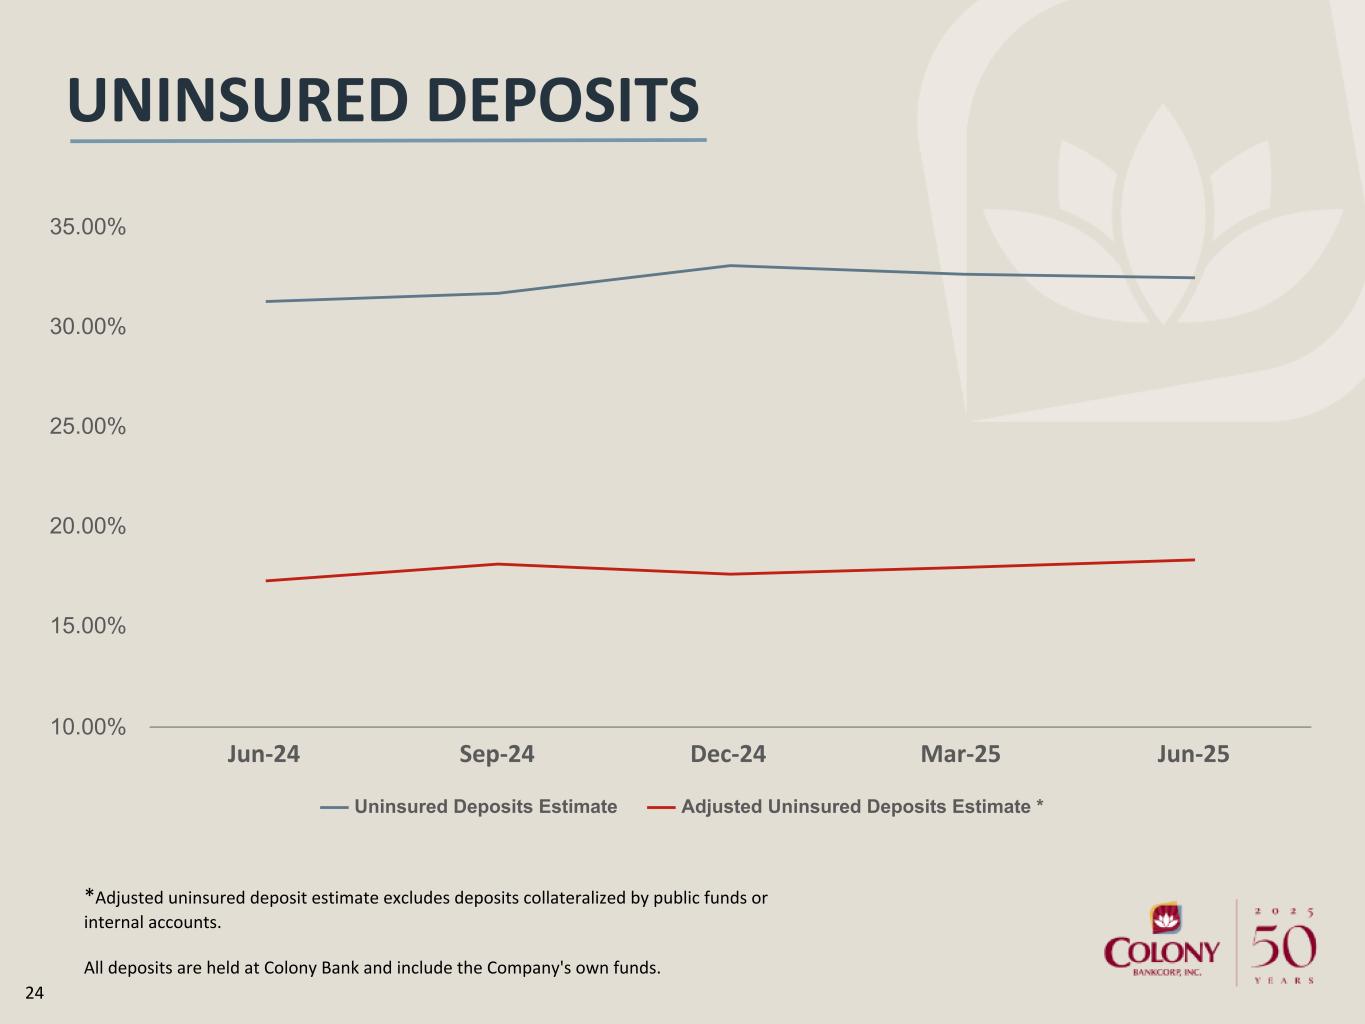
24 Uninsured Deposits Estimate Adjusted Uninsured Deposits Estimate * Jun-24 Sep-24 Dec-24 Mar-25 Jun-25 10.00% 15.00% 20.00% 25.00% 30.00% 35.00% UNINSURED DEPOSITS *Adjusted uninsured deposit estimate excludes deposits collateralized by public funds or internal accounts. All deposits are held at Colony Bank and include the Company's own funds.
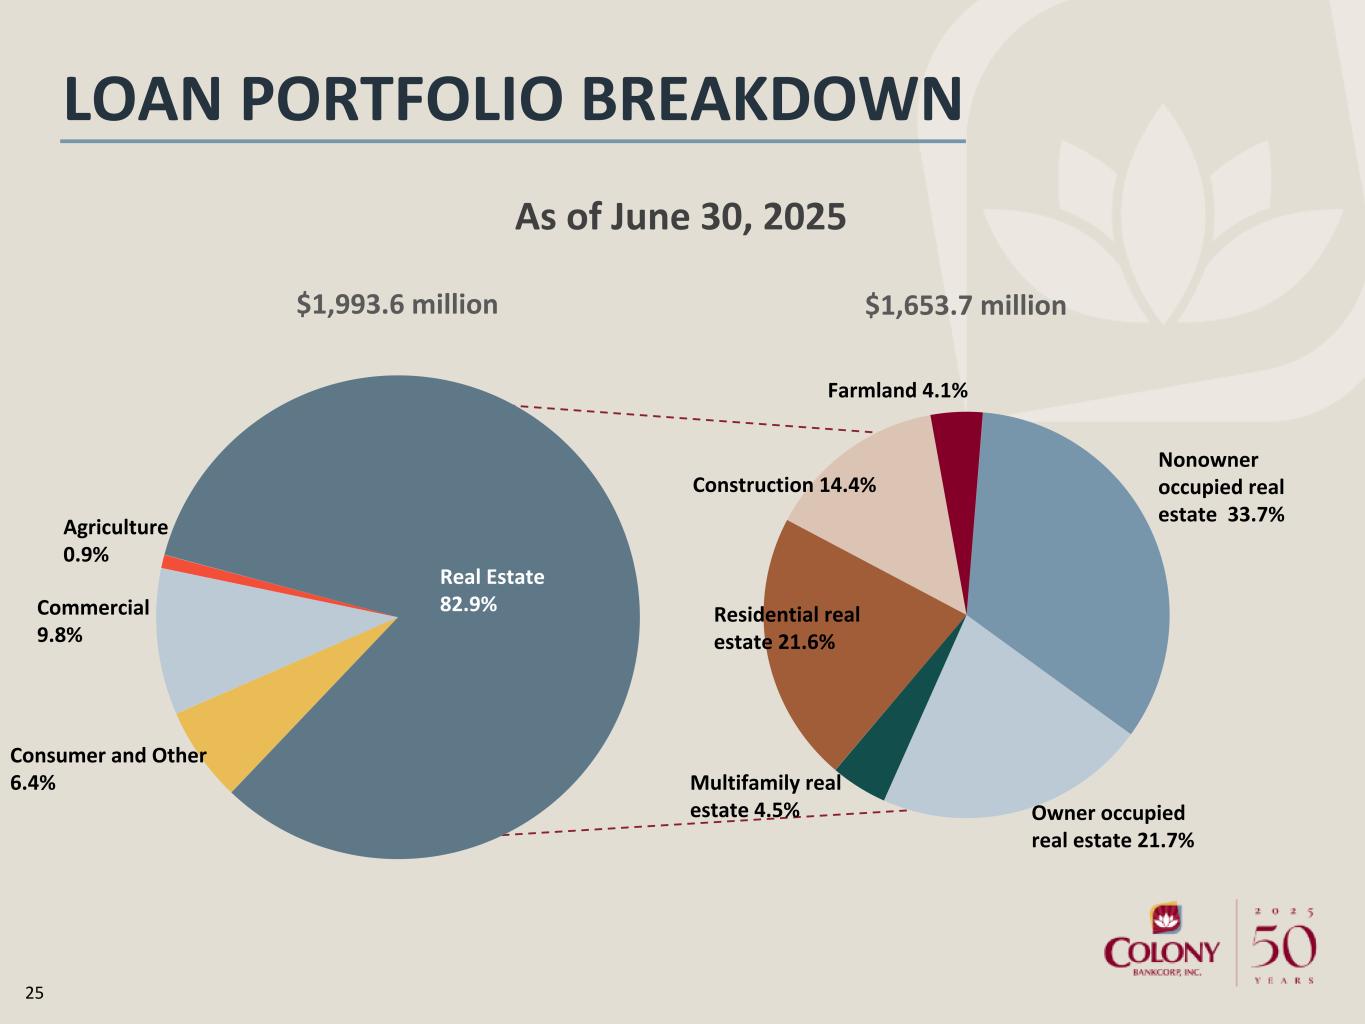
25 LOAN PORTFOLIO BREAKDOWN As of June 30, 2025 $1,993.6 million Real Estate 82.9% Consumer and Other 6.4% Commercial 9.8% Agriculture 0.9% $1,653.7 million Multifamily real estate 4.5% Residential real estate 21.6% Construction 14.4% Farmland 4.1% Nonowner occupied real estate 33.7% Owner occupied real estate 21.7%
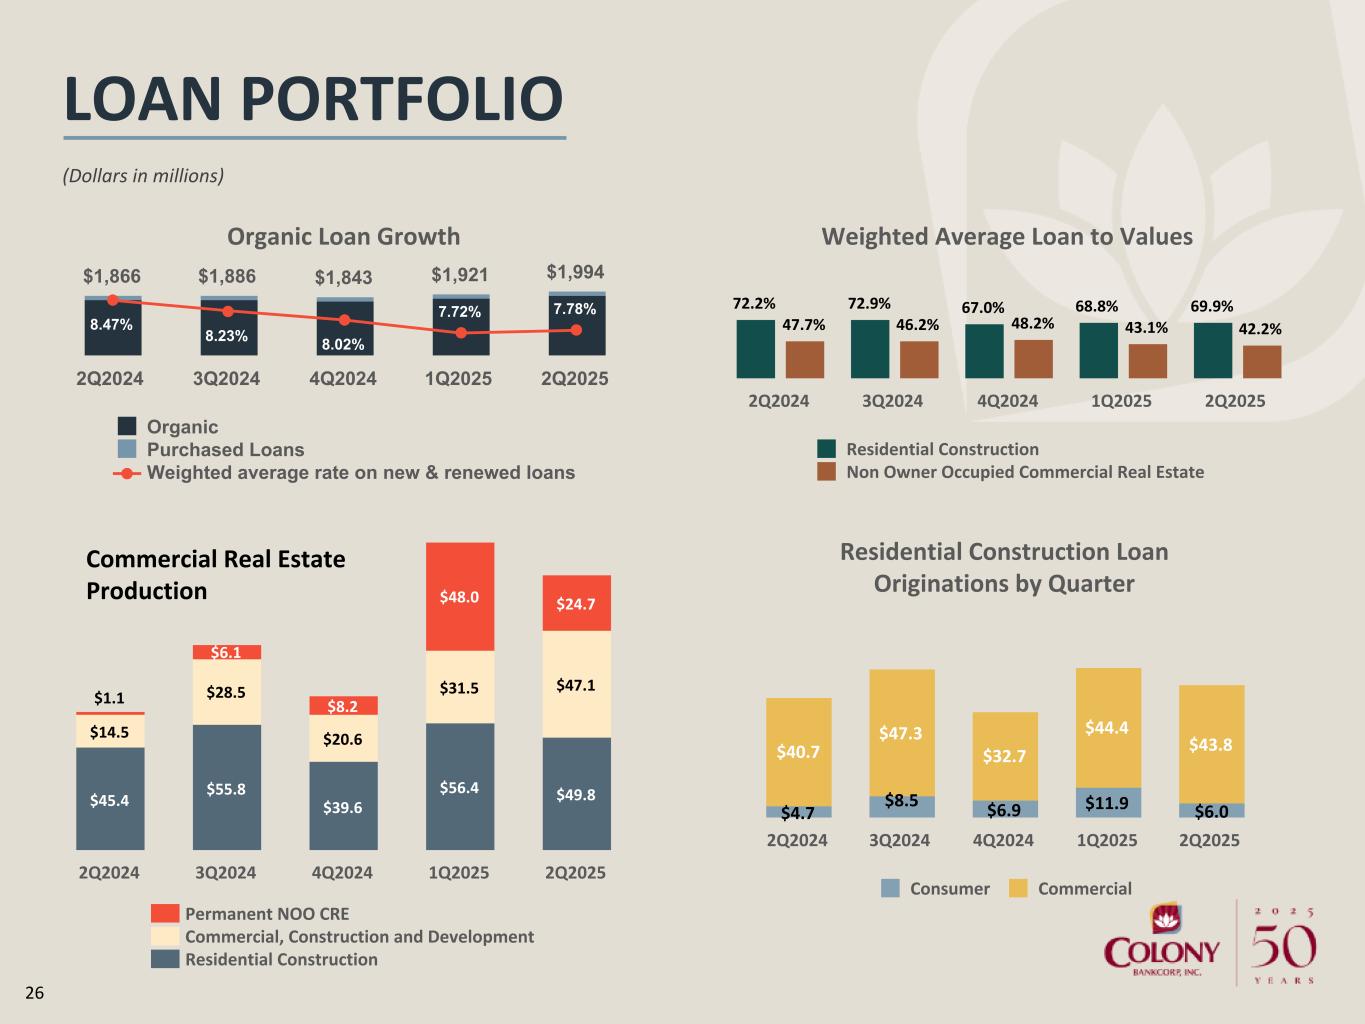
26 LOAN PORTFOLIO (Dollars in millions) Organic Loan Growth $1,866 $1,886 $1,843 $1,921 $1,994 8.47% 8.23% 8.02% 7.72% 7.78% Organic Purchased Loans Weighted average rate on new & renewed loans 2Q2024 3Q2024 4Q2024 1Q2025 2Q2025 Weighted Average Loan to Values 72.2% 72.9% 67.0% 68.8% 69.9% 47.7% 46.2% 48.2% 43.1% 42.2% Residential Construction Non Owner Occupied Commercial Real Estate 2Q2024 3Q2024 4Q2024 1Q2025 2Q2025 $45.4 $55.8 $39.6 $56.4 $49.8 $14.5 $28.5 $20.6 $31.5 $47.1 $1.1 $6.1 $8.2 $48.0 $24.7 Permanent NOO CRE Commercial, Construction and Development Residential Construction 2Q2024 3Q2024 4Q2024 1Q2025 2Q2025 Commercial Real Estate Production Residential Construction Loan Originations by Quarter $4.7 $8.5 $6.9 $11.9 $6.0 $40.7 $47.3 $32.7 $44.4 $43.8 Consumer Commercial 2Q2024 3Q2024 4Q2024 1Q2025 2Q2025
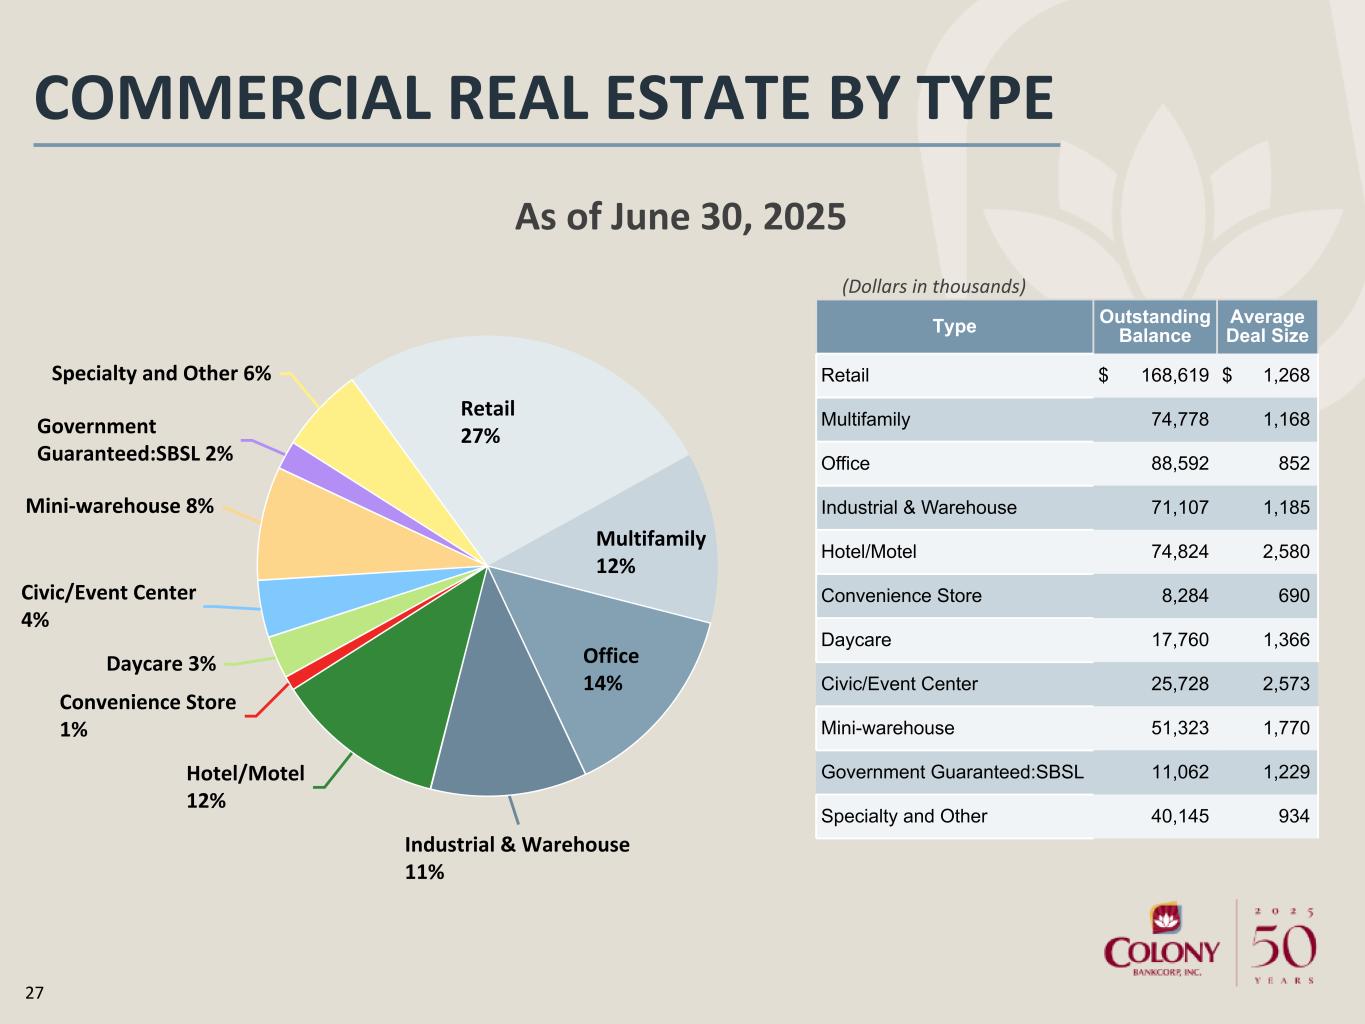
27 COMMERCIAL REAL ESTATE BY TYPE Retail 27% Multifamily 12% Office 14% Industrial & Warehouse 11% Hotel/Motel 12% Convenience Store 1% Daycare 3% Civic/Event Center 4% Mini-warehouse 8% Government Guaranteed:SBSL 2% Specialty and Other 6% Type Outstanding Balance Average Deal Size Retail $ 168,619 $ 1,268 Multifamily 74,778 1,168 Office 88,592 852 Industrial & Warehouse 71,107 1,185 Hotel/Motel 74,824 2,580 Convenience Store 8,284 690 Daycare 17,760 1,366 Civic/Event Center 25,728 2,573 Mini-warehouse 51,323 1,770 Government Guaranteed:SBSL 11,062 1,229 Specialty and Other 40,145 934 (Dollars in thousands) As of June 30, 2025
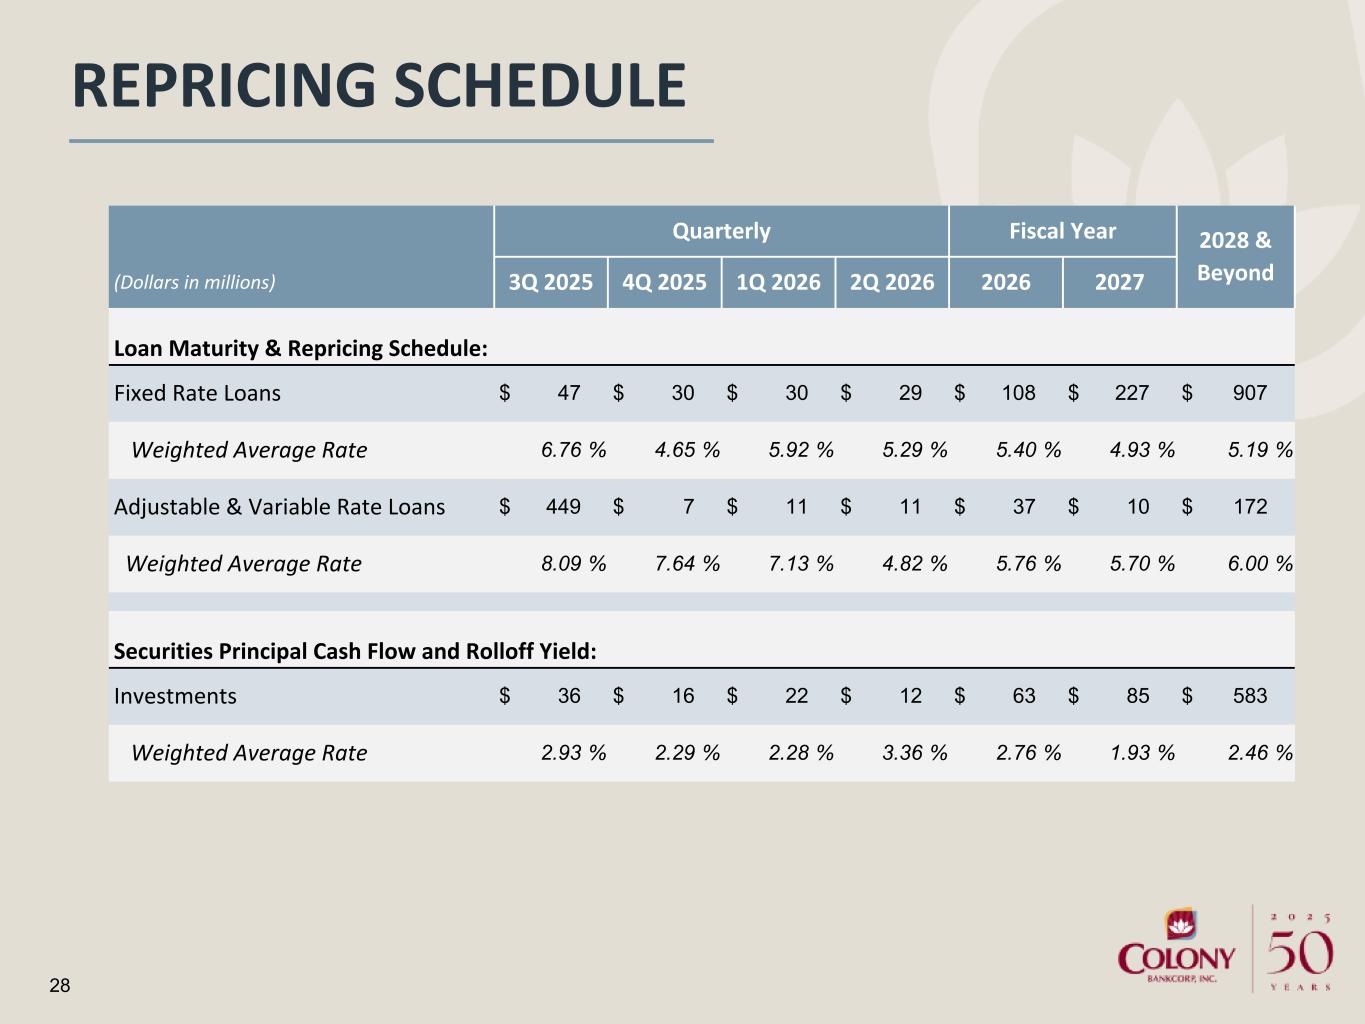
28 REPRICING SCHEDULE Quarterly Fiscal Year 2028 & (Dollars in millions) 3Q 2025 4Q 2025 1Q 2026 2Q 2026 2026 2027 Beyond Loan Maturity & Repricing Schedule: Fixed Rate Loans $ 47 $ 30 $ 30 $ 29 $ 108 $ 227 $ 907 Weighted Average Rate 6.76 % 4.65 % 5.92 % 5.29 % 5.40 % 4.93 % 5.19 % Adjustable & Variable Rate Loans $ 449 $ 7 $ 11 $ 11 $ 37 $ 10 $ 172 Weighted Average Rate 8.09 % 7.64 % 7.13 % 4.82 % 5.76 % 5.70 % 6.00 % Securities Principal Cash Flow and Rolloff Yield: Investments $ 36 $ 16 $ 22 $ 12 $ 63 $ 85 $ 583 Weighted Average Rate 2.93 % 2.29 % 2.28 % 3.36 % 2.76 % 1.93 % 2.46 % 28
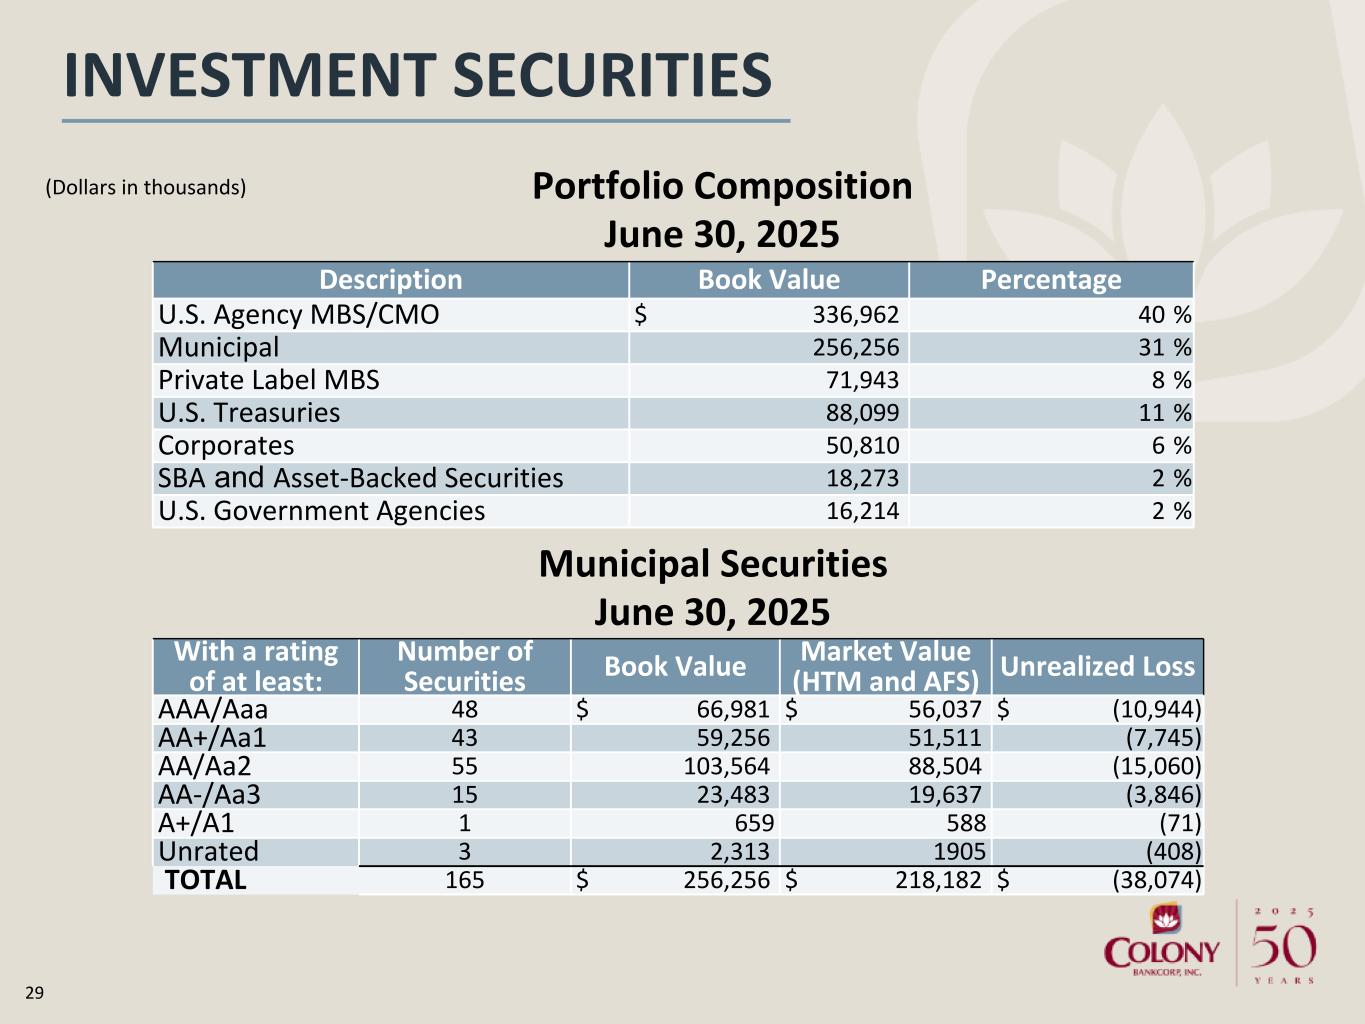
29 INVESTMENT SECURITIES Description Book Value Percentage U.S. Agency MBS/CMO $ 336,962 40 % Municipal 256,256 31 % Private Label MBS 71,943 8 % U.S. Treasuries 88,099 11 % Corporates 50,810 6 % SBA and Asset-Backed Securities 18,273 2 % U.S. Government Agencies 16,214 2 % (Dollars in thousands) Portfolio Composition June 30, 2025 Municipal Securities June 30, 2025 With a rating of at least: Number of Securities Book Value Market Value (HTM and AFS) Unrealized Loss AAA/Aaa 48 $ 66,981 $ 56,037 $ (10,944) AA+/Aa1 43 59,256 51,511 (7,745) AA/Aa2 55 103,564 88,504 (15,060) AA-/Aa3 15 23,483 19,637 (3,846) A+/A1 1 659 588 (71) Unrated 3 2,313 1905 (408) TOTAL 165 $ 256,256 $ 218,182 $ (38,074)
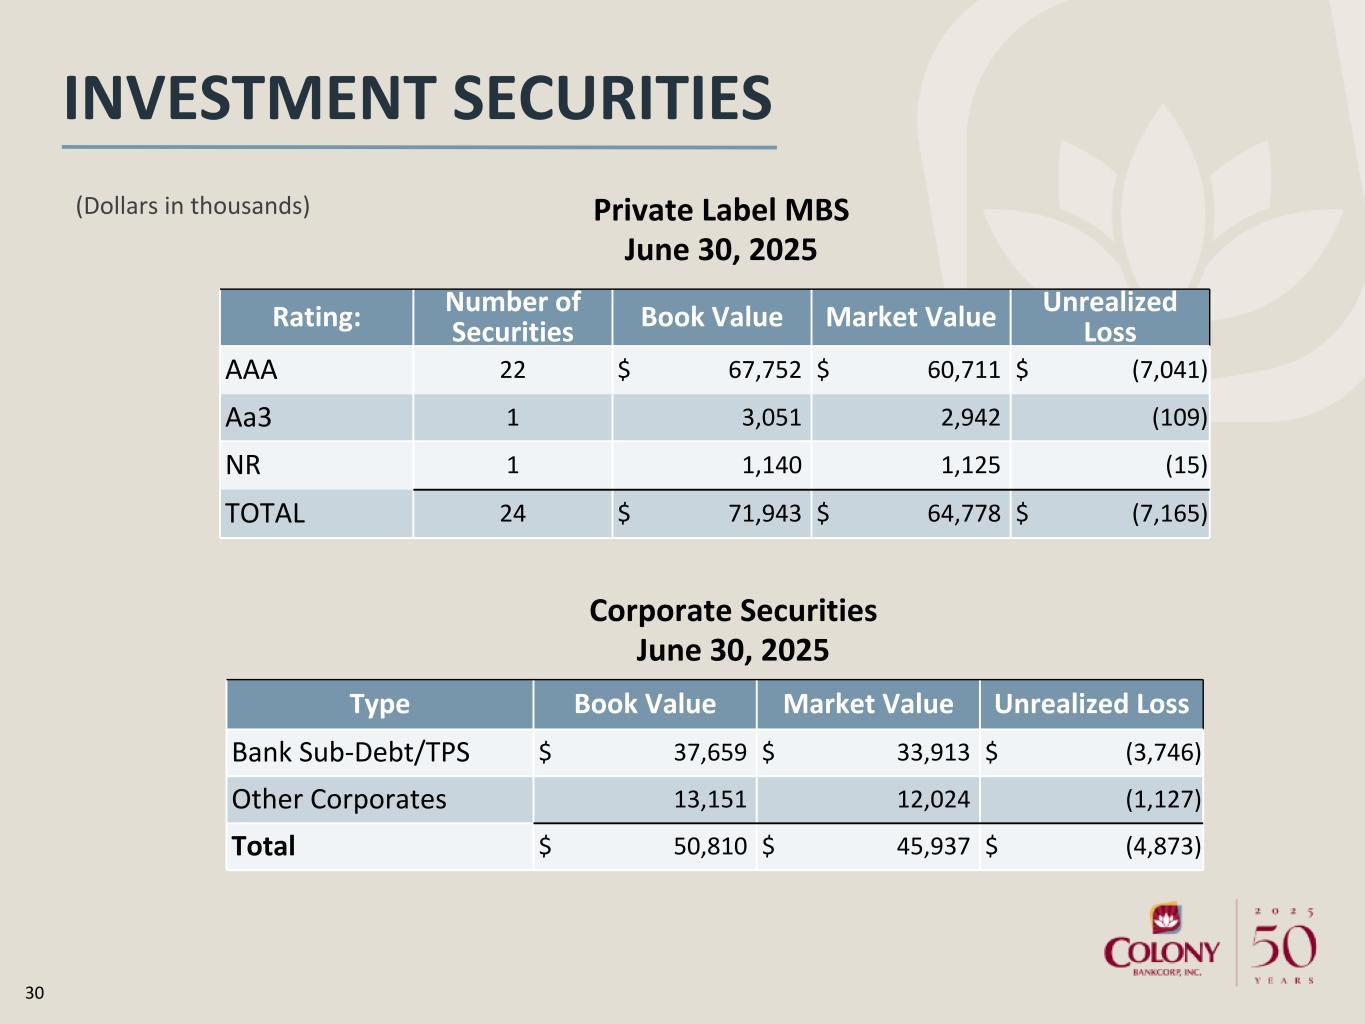
30 INVESTMENT SECURITIES (Dollars in thousands) Rating: Number of Securities Book Value Market Value Unrealized Loss AAA 22 $ 67,752 $ 60,711 $ (7,041) Aa3 1 3,051 2,942 (109) NR 1 1,140 1,125 (15) TOTAL 24 $ 71,943 $ 64,778 $ (7,165) Private Label MBS June 30, 2025 Type Book Value Market Value Unrealized Loss Bank Sub-Debt/TPS $ 37,659 $ 33,913 $ (3,746) Other Corporates 13,151 12,024 (1,127) Total $ 50,810 $ 45,937 $ (4,873) Corporate Securities June 30, 2025
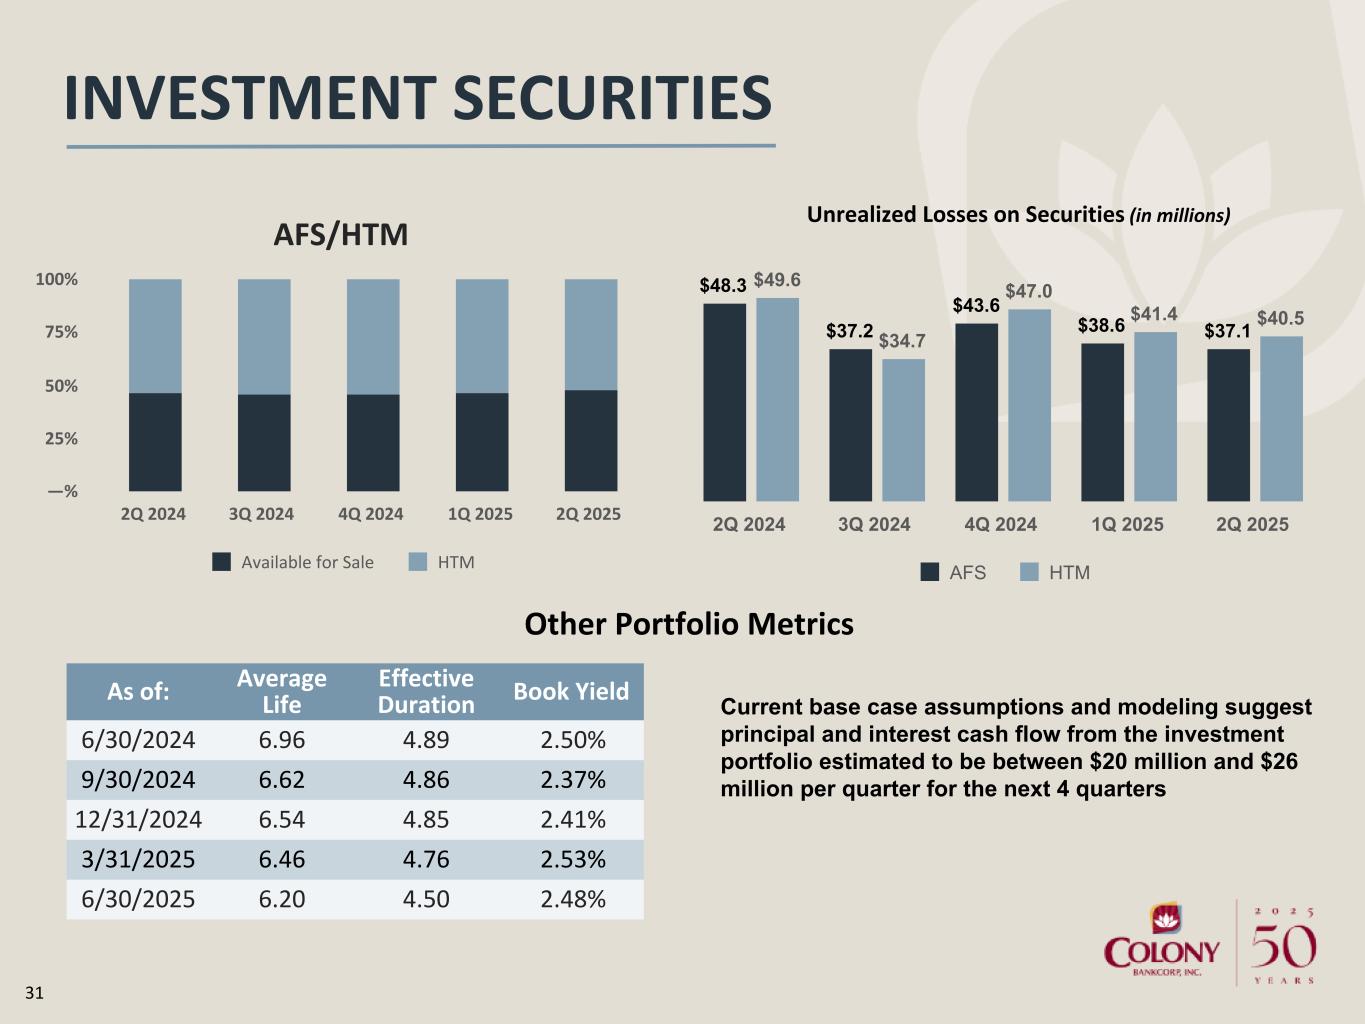
31 INVESTMENT SECURITIES As of: Average Life Effective Duration Book Yield 6/30/2024 6.96 4.89 2.50% 9/30/2024 6.62 4.86 2.37% 12/31/2024 6.54 4.85 2.41% 3/31/2025 6.46 4.76 2.53% 6/30/2025 6.20 4.50 2.48% Other Portfolio Metrics Unrealized Losses on Securities (in millions) AFS/HTM Available for Sale HTM 2Q 2024 3Q 2024 4Q 2024 1Q 2025 2Q 2025 —% 25% 50% 75% 100% $48.3 $37.2 $43.6 $38.6 $37.1 $49.6 $34.7 $47.0 $41.4 $40.5 AFS HTM 2Q 2024 3Q 2024 4Q 2024 1Q 2025 2Q 2025 Current base case assumptions and modeling suggest principal and interest cash flow from the investment portfolio estimated to be between $20 million and $26 million per quarter for the next 4 quarters
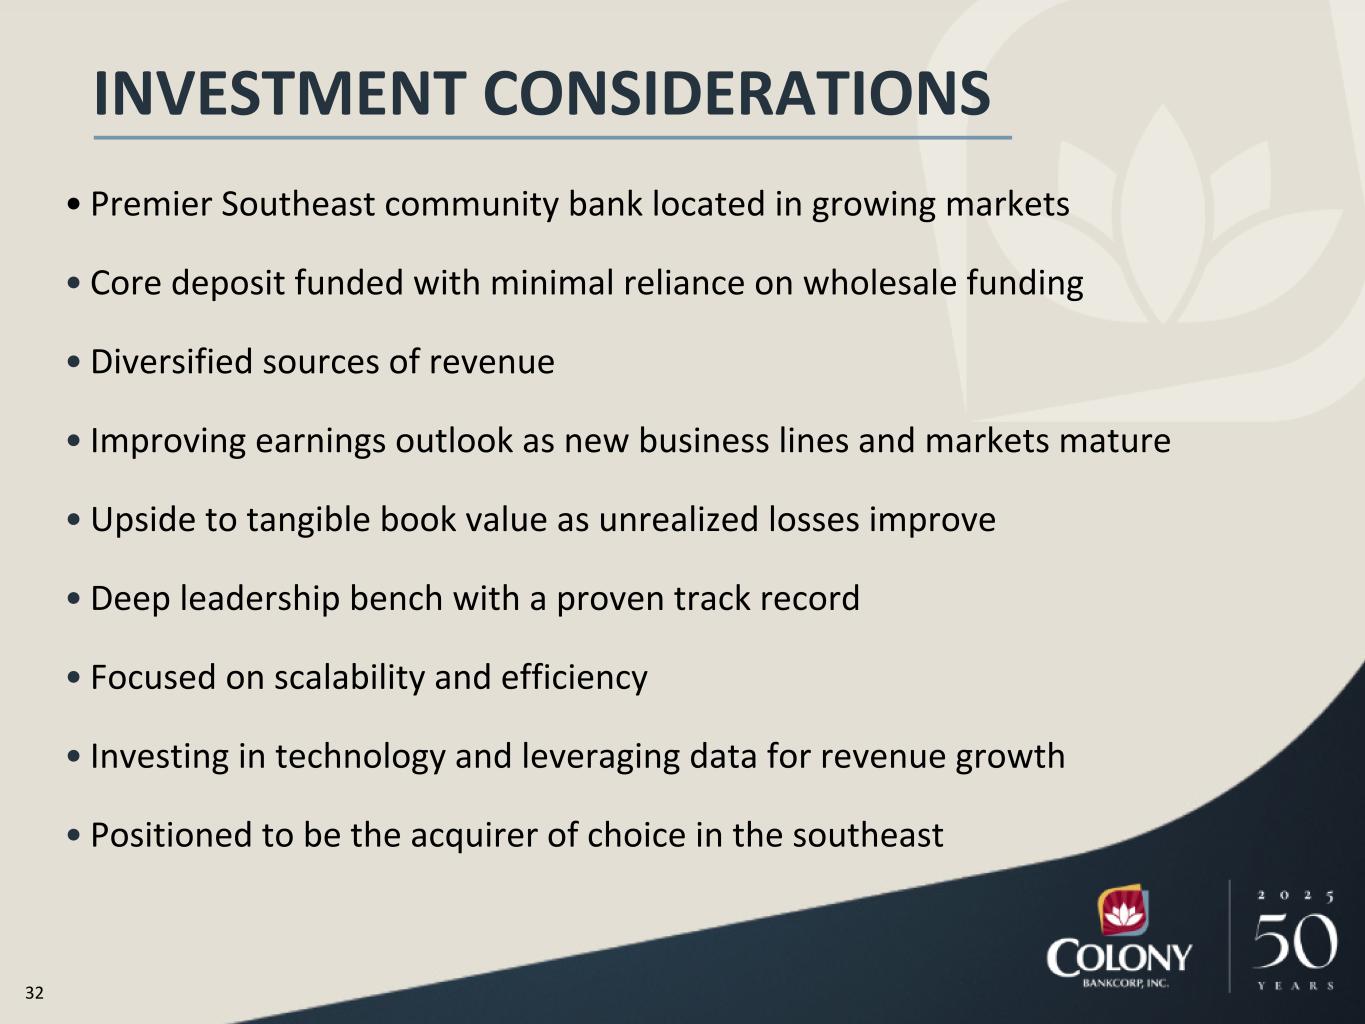
32 INVESTMENT CONSIDERATIONS • Premier Southeast community bank located in growing markets • Core deposit funded with minimal reliance on wholesale funding • Diversified sources of revenue • Improving earnings outlook as new business lines and markets mature • Upside to tangible book value as unrealized losses improve • Deep leadership bench with a proven track record • Focused on scalability and efficiency • Investing in technology and leveraging data for revenue growth • Positioned to be the acquirer of choice in the southeast
NYSE: CBAN