
CBSH 8-K
Commerce Bancshares Inc /Mo/ (CBSH)
8-K
2020-10-20
For: 2020-10-20
View Original
Added on
April 11, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
__________________________
Form 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported): October 20, 2020
(Exact name of registrant as specified in its charter)
| (State of Incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||||||||
| (Address of principal executive offices) | (Zip Code) | ||||||||||
(816 ) 234-2000
(Registrant’s telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Securities registered pursuant to Section 12(b) of the Act: | ||||||||
| Title of class | Trading symbol(s) | Name of exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 or Rule 12b-2 of the Securities Exchange Act of 1934.
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition
A copy of the press release issued October 20, 2020 by Commerce Bancshares, Inc. announcing Third Quarter 2020 earnings is furnished under Item 2.02 of this Current Report on Form 8-K as Exhibit 99.1. Additionally, a slide presentation for investors and analysts is being furnished as Exhibit 99.2 to this Current Report on Form 8-K.
The information in this Current Report on Form 8-K, including the exhibits, is furnished pursuant to Item 2.02 and shall not be deemed “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities under that Section. Furthermore, the information in this Current Report on Form 8-K, including the exhibit, shall not be deemed to be incorporated by reference into the filings of Commerce Bancshares, Inc. under the Securities Act of 1933, as amended.
All information included in this Current Report on Form 8-K is available on the Company’s Internet site at http://www.commercebank.com.
Item 9.01 Financial Statements and Exhibits
Exhibits
104 The XBRL tags on the cover page of this Form 8-K are embedded within the Inline XBRL document.
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| COMMERCE BANCSHARES, INC. | |||||||||||
| By: | /s/ Paul A. Steiner | ||||||||||
| Paul A. Steiner | |||||||||||
Controller (Chief Accounting Officer) | |||||||||||
Date: October 20, 2020
Exhibit 99.1
 | CBSH | ||||
| 1000 Walnut Street / Suite 700 / Kansas City, Missouri 64106 / 816.234.2000 | |||||
 | |||||
FOR IMMEDIATE RELEASE:
Tuesday, October 20, 2020
COMMERCE BANCSHARES, INC. REPORTS
THIRD QUARTER EARNINGS PER SHARE OF $1.11
Commerce Bancshares, Inc. announced earnings of $1.11 per common share for the three months ended September 30, 2020, compared to $.93 per share in the same quarter last year and $.34 per share in the prior quarter. Net income attributable to Commerce Bancshares, Inc. (net income) for the third quarter of 2020 amounted to $132.4 million, compared to $109.2 million in the third quarter of 2019 and $39.9 million in the prior quarter. For the quarter, the return on average assets was 1.71%, the return on average common equity was 15.21% and the efficiency ratio was 55.0%.
For the nine months ended September 30, 2020, earnings per common share totaled $1.89 compared to $2.65 for the first nine months of 2019. Net income amounted to $224.2 million for the nine months ended September 30, 2020 compared to $314.4 million in the same period last year. Year to date, the return on average assets was 1.04% and the return on average common equity was 8.93%.
In announcing these results, John Kemper, Chief Executive Officer, said, “We are pleased to report a healthy rebound in earnings this quarter. Net income grew significantly compared to the second quarter, driven by low provision expense and by increases in net interest income, fee income, and investment securities gains. Compared to the prior quarter, net interest income grew $12.9 million supported by our larger balance sheet and historically low funding costs. Fee income from our bank card, trust and mortgage banking businesses rebounded nicely from the prior quarter. While our bank card fees have not yet fully recovered from the impact of COVID-19, trust and mortgage banking fees were at record levels. Prudent expense management remains in focus as we prepare for a prolonged low interest rate environment. We continued our efforts of providing relief to customers who have been impacted by COVID-19. Loans on active deferral declined significantly throughout the quarter. Fewer customers requested first-time relief, and just a small percentage of our customers required extensions of their initial relief requests. We remain cautiously optimistic about the recovery of the economy and are encouraged by the resiliency of our customers and communities.”
Mr. Kemper continued, “Net loan charge-offs this quarter totaled $7.6 million, compared to $8.4 million in the prior quarter and $11.5 million in the third quarter of 2019. The ratio of annualized net loan charge-offs to average loans was .18% in the current quarter, .21% in the prior quarter and .32% in the third quarter of last year. Net loan charge-offs on commercial loans totaled $194 thousand this quarter compared to $3.2 million in the prior quarter. Net loan charge-offs on personal banking loans increased $2.2 million to $7.4 million. Non-performing assets increased this quarter from $23.1 million to $40.3 million. At September 30, 2020, the allowance for credit losses on loans decreased slightly to $236.4 million, partly due to an improved economic forecast utilized in our CECL model compared to the prior quarter.”
Total assets at September 30, 2020 were $31.5 billion, total loans were $16.4 billion, and total deposits were $25.7 billion. During the quarter, the Company paid a common cash dividend of $.27 per share, representing an 8.9% increase over the rate paid in 2019, and also paid an annualized 6% cash dividend on its preferred stock. On September 1, 2020, the Company redeemed all outstanding shares of its preferred stock.
Commerce Bancshares, Inc. is a regional bank holding company offering a full line of banking services, including payment solutions, investment management and securities brokerage. Commerce Bank, a subsidiary of Commerce Bancshares, Inc., leverages more than 150 years of proven strength and experience to help individuals and businesses solve financial challenges. In addition to offering payment solutions across the U.S., Commerce Bank currently operates full service banking facilities across the Midwest including the St. Louis and Kansas City metropolitan areas, Springfield, Central Missouri, Central Illinois, Wichita, Tulsa, Oklahoma City, and Denver. It also maintains commercial offices in Dallas, Houston, Cincinnati, Nashville, Des Moines, Indianapolis, and Grand Rapids. Commerce delivers high-touch service and sophisticated financial solutions at regional branches, commercial offices, ATMs, online, mobile and through a 24/7 customer service line.
This financial news release, including management's discussion of third quarter results, is posted to the Company's web site at www.commercebank.com.
* * * * * * * * * * * * * * *
For additional information, contact
Matthew Burkemper, Investor Relations
at 8000 Forsyth, Mailstop: CBIR-1
Clayton, MO 63105
or by telephone at (314) 746-7485
Web Site: http://www.commercebank.com
Email: [email protected]
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
FINANCIAL HIGHLIGHTS
| For the Three Months Ended | For the Nine Months Ended | |||||||||||||||||||
| (Unaudited) (Dollars in thousands, except per share data) | September 30, 2020 | June 30, 2020 | September 30, 2019 | September 30, 2020 | September 30, 2019 | |||||||||||||||
FINANCIAL SUMMARY | ||||||||||||||||||||
| Net interest income | $215,962 | $203,057 | $203,512 | $620,084 | $618,634 | |||||||||||||||
| Non-interest income | 129,572 | 117,515 | 132,743 | 370,750 | 381,242 | |||||||||||||||
Total revenue | 345,534 | 320,572 | 336,255 | 990,834 | 999,876 | |||||||||||||||
| Investment securities gains (losses), net | 16,155 | (4,129) | 4,909 | (1,275) | 3,874 | |||||||||||||||
| Provision for credit losses | 3,101 | 80,539 | 10,963 | 141,593 | 35,232 | |||||||||||||||
| Non-interest expense | 190,858 | 187,512 | 191,020 | 572,068 | 572,224 | |||||||||||||||
Income before taxes | 167,730 | 48,392 | 139,181 | 275,898 | 396,294 | |||||||||||||||
| Income taxes | 34,375 | 9,661 | 29,101 | 54,209 | 80,860 | |||||||||||||||
| Non-controlling interest (income) expense | 907 | (1,132) | 838 | (2,479) | 1,083 | |||||||||||||||
Net income attributable to Commerce Bancshares, Inc. | 132,448 | 39,863 | 109,242 | 224,168 | 314,351 | |||||||||||||||
| Preferred stock dividends | 7,466 | 2,250 | 2,250 | 11,966 | 6,750 | |||||||||||||||
Net income available to common shareholders | $124,982 | $37,613 | $106,992 | $212,202 | $307,601 | |||||||||||||||
| Earnings per common share: | ||||||||||||||||||||
| Net income — basic | $1.12 | $.34 | $.93 | $1.90 | $2.65 | |||||||||||||||
| Net income — diluted | $1.11 | $.34 | $.93 | $1.89 | $2.65 | |||||||||||||||
| Effective tax rate | 20.61 | % | 19.51 | % | 21.04 | % | 19.47 | % | 20.46 | % | ||||||||||
| Tax equivalent net interest income | $219,118 | $206,253 | $206,958 | $629,773 | $629,265 | |||||||||||||||
Average total interest earning assets (1) | $ | 29,352,970 | $ | 28,193,312 | $ | 23,947,084 | $ | 27,419,514 | $ | 23,920,745 | ||||||||||
| Diluted wtd. average shares outstanding | 110,899,197 | 110,896,858 | 113,249,070 | 111,056,754 | 114,758,916 | |||||||||||||||
| RATIOS | ||||||||||||||||||||
Average loans to deposits (2) | 66.23 | % | 69.22 | % | 72.48 | % | 69.12 | % | 71.47 | % | ||||||||||
| Return on total average assets | 1.71 | .54 | 1.72 | 1.04 | 1.68 | |||||||||||||||
Return on average common equity (3) | 15.21 | 4.77 | 14.21 | 8.93 | 14.11 | |||||||||||||||
| Non-interest income to total revenue | 37.50 | 36.66 | 39.48 | 37.42 | 38.13 | |||||||||||||||
Efficiency ratio (4) | 55.00 | 58.10 | 56.66 | 57.37 | 57.08 | |||||||||||||||
| Net yield on interest earning assets | 2.97 | 2.94 | 3.43 | 3.07 | 3.52 | |||||||||||||||
| EQUITY SUMMARY | ||||||||||||||||||||
| Cash dividends per common share | $.270 | $.270 | $.248 | $.810 | $.744 | |||||||||||||||
| Cash dividends on common stock | $30,174 | $30,174 | $27,993 | $90,640 | $85,533 | |||||||||||||||
Cash dividends on preferred stock (7) | $7,466 | $2,250 | $2,250 | $11,966 | $6,750 | |||||||||||||||
Book value per common share (5) | $29.64 | $28.81 | $26.27 | |||||||||||||||||
Market value per common share (5) | $56.29 | $59.47 | $57.76 | |||||||||||||||||
| High market value per common share | $62.09 | $69.77 | $58.90 | |||||||||||||||||
| Low market value per common share | $53.03 | $48.06 | $52.05 | |||||||||||||||||
Common shares outstanding (5) | 111,532,580 | 111,533,315 | 112,732,983 | |||||||||||||||||
Tangible common equity to tangible assets (6) | 10.11 | % | 10.12 | % | 10.95 | % | ||||||||||||||
| Tier I leverage ratio | 9.39 | % | 9.88 | % | 11.32 | % | ||||||||||||||
| OTHER QTD INFORMATION | ||||||||||||||||||||
| Number of bank/ATM locations | 308 | 312 | 316 | |||||||||||||||||
| Full-time equivalent employees | 4,825 | 4,856 | 4,873 | |||||||||||||||||
(1)Excludes allowance for credit losses on loans and unrealized gains/(losses) on available for sale debt securities.
(2)Includes loans held for sale.
(3)Annualized net income available to common shareholders divided by average total equity less preferred stock.
(4)The efficiency ratio is calculated as non-interest expense (excluding intangibles amortization) as a percent of revenue.
(5)As of period end.
(6)The tangible common equity ratio is calculated as stockholders’ equity reduced by preferred stock, goodwill and other intangible assets (excluding mortgage servicing rights) divided by total assets reduced by goodwill and other intangible assets (excluding mortgage servicing rights).
(7)For the period ended September 30, 2020, preferred stock dividends includes $5.2 million related to the preferred stock redemption. The $5.2 million is the excess of the redemption costs over the book value of the preferred stock and is considered a dividend.
All share and per share amounts have been restated to reflect the 5% stock dividend distributed in December 2019.
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
CONSOLIDATED STATEMENTS OF INCOME
| For the Three Months Ended | For the Nine Months Ended | |||||||||||||||||||||||||
| (Unaudited) (In thousands, except per share data) | September 30, 2020 | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | September 30, 2020 | September 30, 2019 | |||||||||||||||||||
| Interest income | $223,114 | $213,323 | $221,485 | $226,665 | $231,743 | $657,922 | $698,020 | |||||||||||||||||||
| Interest expense | 7,152 | 10,266 | 20,420 | 24,006 | 28,231 | 37,838 | 79,386 | |||||||||||||||||||
| Net interest income | 215,962 | 203,057 | 201,065 | 202,659 | 203,512 | 620,084 | 618,634 | |||||||||||||||||||
| Provision for credit losses | 3,101 | 80,539 | 57,953 | 15,206 | 10,963 | 141,593 | 35,232 | |||||||||||||||||||
Net interest income after credit losses | 212,861 | 122,518 | 143,112 | 187,453 | 192,549 | 478,491 | 583,402 | |||||||||||||||||||
| NON-INTEREST INCOME | ||||||||||||||||||||||||||
| Bank card transaction fees | 37,873 | 33,745 | 40,200 | 41,079 | 44,510 | 111,818 | 126,800 | |||||||||||||||||||
| Trust fees | 40,769 | 37,942 | 39,965 | 40,405 | 39,592 | 118,676 | 115,223 | |||||||||||||||||||
| Deposit account charges and other fees | 23,107 | 22,279 | 23,677 | 24,974 | 24,032 | 69,063 | 71,009 | |||||||||||||||||||
| Capital market fees | 3,194 | 3,772 | 3,790 | 2,536 | 1,787 | 10,756 | 5,610 | |||||||||||||||||||
| Consumer brokerage services | 4,011 | 3,011 | 4,077 | 4,139 | 4,030 | 11,099 | 11,665 | |||||||||||||||||||
| Loan fees and sales | 9,769 | 4,649 | 3,235 | 3,465 | 4,755 | 17,653 | 12,302 | |||||||||||||||||||
| Other | 10,849 | 12,117 | 8,719 | 26,863 | 14,037 | 31,685 | 38,633 | |||||||||||||||||||
| Total non-interest income | 129,572 | 117,515 | 123,663 | 143,461 | 132,743 | 370,750 | 381,242 | |||||||||||||||||||
INVESTMENT SECURITIES GAINS (LOSSES), NET | 16,155 | (4,129) | (13,301) | (248) | 4,909 | (1,275) | 3,874 | |||||||||||||||||||
| NON-INTEREST EXPENSE | ||||||||||||||||||||||||||
| Salaries and employee benefits | 127,308 | 126,759 | 128,937 | 126,901 | 123,836 | 383,004 | 366,026 | |||||||||||||||||||
| Net occupancy | 12,058 | 11,269 | 11,748 | 12,218 | 12,293 | 35,075 | 34,939 | |||||||||||||||||||
| Equipment | 4,737 | 4,755 | 4,821 | 4,859 | 4,941 | 14,313 | 14,202 | |||||||||||||||||||
| Supplies and communication | 4,141 | 4,427 | 4,658 | 4,851 | 5,106 | 13,226 | 15,543 | |||||||||||||||||||
| Data processing and software | 23,610 | 23,837 | 23,555 | 23,934 | 23,457 | 71,002 | 68,965 | |||||||||||||||||||
| Marketing | 4,926 | 3,801 | 5,979 | 3,951 | 6,048 | 14,706 | 17,963 | |||||||||||||||||||
| Other | 14,078 | 12,664 | 14,000 | 18,460 | 15,339 | 40,742 | 54,586 | |||||||||||||||||||
| Total non-interest expense | 190,858 | 187,512 | 193,698 | 195,174 | 191,020 | 572,068 | 572,224 | |||||||||||||||||||
| Income before income taxes | 167,730 | 48,392 | 59,776 | 135,492 | 139,181 | 275,898 | 396,294 | |||||||||||||||||||
| Less income taxes | 34,375 | 9,661 | 10,173 | 28,214 | 29,101 | 54,209 | 80,860 | |||||||||||||||||||
| Net income | 133,355 | 38,731 | 49,603 | 107,278 | 110,080 | 221,689 | 315,434 | |||||||||||||||||||
Less non-controlling interest expense (income) | 907 | (1,132) | (2,254) | 398 | 838 | (2,479) | 1,083 | |||||||||||||||||||
Net income attributable to Commerce Bancshares, Inc. | 132,448 | 39,863 | 51,857 | 106,880 | 109,242 | 224,168 | 314,351 | |||||||||||||||||||
| Less preferred stock dividends | 7,466 | 2,250 | 2,250 | 2,250 | 2,250 | 11,966 | 6,750 | |||||||||||||||||||
Net income available to common shareholders | $124,982 | $37,613 | $49,607 | $104,630 | $106,992 | $212,202 | $307,601 | |||||||||||||||||||
| Net income per common share — basic | $1.12 | $.34 | $.44 | $.94 | $.93 | $1.90 | $2.65 | |||||||||||||||||||
| Net income per common share — diluted | $1.11 | $.34 | $.44 | $.93 | $.93 | $1.89 | $2.65 | |||||||||||||||||||
| OTHER INFORMATION | ||||||||||||||||||||||||||
| Return on total average assets | 1.71 | % | .54 | % | .80 | % | 1.65 | % | 1.72 | % | 1.04 | % | 1.68 | % | ||||||||||||
Return on average common equity (1) | 15.21 | 4.77 | 6.48 | 13.90 | 14.21 | 8.93 | 14.11 | |||||||||||||||||||
Efficiency ratio (2) | 55.00 | 58.10 | 59.17 | 56.29 | 56.66 | 57.37 | 57.08 | |||||||||||||||||||
| Effective tax rate | 20.61 | 19.51 | 16.40 | 20.88 | 21.04 | 19.47 | 20.46 | |||||||||||||||||||
| Net yield on interest earning assets | 2.97 | 2.94 | 3.33 | 3.36 | 3.43 | 3.07 | 3.52 | |||||||||||||||||||
| Tax equivalent net interest income | $219,118 | $206,253 | $204,402 | $206,156 | $206,958 | $629,773 | $629,265 | |||||||||||||||||||
(1)Annualized net income available to common shareholders divided by average total equity less preferred stock.
(2)The efficiency ratio is calculated as non-interest expense (excluding intangibles amortization) as a percent of revenue.
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
CONSOLIDATED BALANCE SHEETS - PERIOD END
| (Unaudited) (In thousands) | September 30, 2020 | June 30, 2020 | September 30, 2019 | |||||||||||
| ASSETS | ||||||||||||||
| Loans | ||||||||||||||
| Business | $ | 6,683,413 | $ | 6,858,217 | $ | 5,393,268 | ||||||||
| Real estate — construction and land | 1,009,729 | 932,022 | 932,737 | |||||||||||
| Real estate — business | 2,993,192 | 2,941,163 | 2,833,146 | |||||||||||
| Real estate — personal | 2,753,867 | 2,690,542 | 2,226,663 | |||||||||||
| Consumer | 2,006,360 | 1,966,707 | 1,953,690 | |||||||||||
| Revolving home equity | 324,203 | 334,627 | 349,111 | |||||||||||
| Consumer credit card | 647,893 | 666,597 | 766,743 | |||||||||||
| Overdrafts | 2,270 | 5,179 | 7,236 | |||||||||||
| Total loans | 16,420,927 | 16,395,054 | 14,462,594 | |||||||||||
| Allowance for credit losses on loans | (236,360) | (240,744) | (160,682) | |||||||||||
Net loans | 16,184,567 | 16,154,310 | 14,301,912 | |||||||||||
| Loans held for sale | 39,483 | 12,785 | 20,064 | |||||||||||
| Investment securities: | ||||||||||||||
| Available for sale debt securities | 11,539,061 | 10,317,427 | 8,660,419 | |||||||||||
| Trading debt securities | 25,805 | 28,813 | 35,918 | |||||||||||
| Equity securities | 4,203 | 4,128 | 4,186 | |||||||||||
| Other securities | 122,532 | 117,761 | 147,211 | |||||||||||
Total investment securities | 11,691,601 | 10,468,129 | 8,847,734 | |||||||||||
Federal funds sold and short-term securities purchased under agreements to resell | 2,275 | — | 2,850 | |||||||||||
Long-term securities purchased under agreements to resell | 850,000 | 850,000 | 850,000 | |||||||||||
| Interest earning deposits with banks | 1,171,697 | 1,404,968 | 344,129 | |||||||||||
| Cash and due from banks | 357,616 | 391,268 | 512,254 | |||||||||||
| Premises and equipment — net | 377,853 | 368,565 | 365,949 | |||||||||||
| Goodwill | 138,921 | 138,921 | 138,921 | |||||||||||
| Other intangible assets — net | 7,183 | 7,179 | 9,139 | |||||||||||
| Other assets | 632,621 | 699,996 | 483,527 | |||||||||||
Total assets | $ | 31,453,817 | $ | 30,496,121 | $ | 25,876,479 | ||||||||
| LIABILITIES AND STOCKHOLDERS’ EQUITY | ||||||||||||||
| Deposits: | ||||||||||||||
| Non-interest bearing | $ | 10,727,827 | $ | 9,700,261 | $ | 6,816,527 | ||||||||
| Savings, interest checking and money market | 12,983,505 | 12,792,993 | 11,424,404 | |||||||||||
| Certificates of deposit of less than $100,000 | 556,870 | 590,635 | 627,630 | |||||||||||
| Certificates of deposit of $100,000 and over | 1,433,577 | 1,443,078 | 1,441,590 | |||||||||||
Total deposits | 25,701,779 | 24,526,967 | 20,310,151 | |||||||||||
Federal funds purchased and securities sold under agreements to repurchase | 1,653,064 | 1,740,438 | 1,641,274 | |||||||||||
| Other borrowings | 782 | 1,475 | 257,383 | |||||||||||
| Other liabilities | 791,928 | 869,072 | 561,657 | |||||||||||
Total liabilities | 28,147,553 | 27,137,952 | 22,770,465 | |||||||||||
| Stockholders’ equity: | ||||||||||||||
| Preferred stock | — | 144,784 | 144,784 | |||||||||||
| Common stock | 563,978 | 563,978 | 559,432 | |||||||||||
| Capital surplus | 2,140,410 | 2,136,874 | 2,042,643 | |||||||||||
| Retained earnings | 326,890 | 232,082 | 463,231 | |||||||||||
| Treasury stock | (69,050) | (69,112) | (251,663) | |||||||||||
| Accumulated other comprehensive income | 343,435 | 349,261 | 144,173 | |||||||||||
Total stockholders’ equity | 3,305,663 | 3,357,867 | 3,102,600 | |||||||||||
| Non-controlling interest | 601 | 302 | 3,414 | |||||||||||
Total equity | 3,306,264 | 3,358,169 | 3,106,014 | |||||||||||
Total liabilities and equity | $ | 31,453,817 | $ | 30,496,121 | $ | 25,876,479 | ||||||||
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
AVERAGE BALANCE SHEETS
| (Unaudited) (In thousands) | For the Three Months Ended | ||||||||||||||||
| September 30, 2020 | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | |||||||||||||
| ASSETS: | |||||||||||||||||
| Loans: | |||||||||||||||||
| Business | $ | 6,709,200 | $ | 6,760,827 | $ | 5,493,657 | $ | 5,362,020 | $ | 5,263,312 | |||||||
| Real estate — construction and land | 974,346 | 895,648 | 924,086 | 901,367 | 920,206 | ||||||||||||
| Real estate — business | 2,989,652 | 2,962,076 | 2,853,632 | 2,820,189 | 2,883,379 | ||||||||||||
| Real estate — personal | 2,722,300 | 2,582,484 | 2,390,716 | 2,283,530 | 2,175,156 | ||||||||||||
| Consumer | 1,992,314 | 1,944,265 | 1,950,491 | 1,961,631 | 1,924,434 | ||||||||||||
| Revolving home equity | 329,361 | 343,210 | 350,256 | 347,527 | 354,040 | ||||||||||||
| Consumer credit card | 646,185 | 663,911 | 727,569 | 749,056 | 763,377 | ||||||||||||
| Overdrafts | 2,689 | 2,912 | 4,044 | 18,322 | 9,240 | ||||||||||||
Total loans | 16,366,047 | 16,155,333 | 14,694,451 | 14,443,642 | 14,293,144 | ||||||||||||
| Allowance for credit losses on loans | (240,286) | (171,616) | (139,482) | (159,776) | (160,387) | ||||||||||||
| Net loans | 16,125,761 | 15,983,717 | 14,554,969 | 14,283,866 | 14,132,757 | ||||||||||||
| Loans held for sale | 24,728 | 6,363 | 12,875 | 15,363 | 19,882 | ||||||||||||
| Investment securities: | |||||||||||||||||
U.S. government and federal agency obligations | 770,361 | 776,240 | 802,556 | 826,702 | 825,544 | ||||||||||||
Government-sponsored enterprise obligations | 102,749 | 114,518 | 134,296 | 184,973 | 181,929 | ||||||||||||
| State and municipal obligations | 1,767,526 | 1,285,427 | 1,222,595 | 1,207,584 | 1,172,259 | ||||||||||||
Mortgage-backed securities | 6,259,926 | 5,325,720 | 4,685,782 | 4,685,794 | 4,712,508 | ||||||||||||
| Asset-backed securities | 1,520,988 | 1,342,518 | 1,182,556 | 1,258,297 | 1,297,685 | ||||||||||||
Other debt securities | 514,166 | 406,665 | 321,733 | 331,167 | 334,218 | ||||||||||||
| Unrealized gain (loss) on debt securities | 368,154 | 281,457 | 191,275 | 149,591 | 152,706 | ||||||||||||
| Total available for sale debt securities | 11,303,870 | 9,532,545 | 8,540,793 | 8,644,108 | 8,676,849 | ||||||||||||
Trading debt securities | 27,267 | 31,981 | 34,055 | 32,518 | 29,622 | ||||||||||||
| Equity securities | 4,193 | 4,137 | 4,273 | 4,200 | 4,705 | ||||||||||||
| Other securities | 120,253 | 139,250 | 144,096 | 141,501 | 134,896 | ||||||||||||
| Total investment securities | 11,455,583 | 9,707,913 | 8,723,217 | 8,822,327 | 8,846,072 | ||||||||||||
Federal funds sold and short-term securities purchased under agreements to resell | 337 | 92 | 326 | 714 | 1,080 | ||||||||||||
| Long-term securities purchased under agreements to resell | 849,994 | 850,000 | 850,000 | 849,986 | 713,030 | ||||||||||||
| Interest earning deposits with banks | 1,024,435 | 1,755,068 | 601,420 | 390,134 | 226,582 | ||||||||||||
| Other assets | 1,389,683 | 1,461,528 | 1,368,464 | 1,315,395 | 1,292,191 | ||||||||||||
| Total assets | $ | 30,870,521 | $ | 29,764,681 | $ | 26,111,271 | $ | 25,677,785 | $ | 25,231,594 | |||||||
| LIABILITIES AND EQUITY: | |||||||||||||||||
Non-interest bearing deposits | $ | 9,801,562 | $ | 8,843,408 | $ | 6,615,108 | $ | 6,552,862 | $ | 6,290,036 | |||||||
| Savings | 1,193,079 | 1,111,397 | 952,709 | 924,282 | 924,581 | ||||||||||||
| Interest checking and money market | 11,731,494 | 11,441,694 | 10,777,400 | 10,618,347 | 10,409,111 | ||||||||||||
Certificates of deposit of less than $100,000 | 573,207 | 605,136 | 622,840 | 626,944 | 620,138 | ||||||||||||
Certificates of deposit of $100,000 and over | 1,447,968 | 1,346,069 | 1,299,443 | 1,434,309 | 1,503,805 | ||||||||||||
| Total deposits | 24,747,310 | 23,347,704 | 20,267,500 | 20,156,744 | 19,747,671 | ||||||||||||
| Borrowings: | |||||||||||||||||
Federal funds purchased and securities sold under agreements to repurchase | 1,855,971 | 1,991,971 | 1,990,051 | 1,836,982 | 1,884,939 | ||||||||||||
| Other borrowings | 1,225 | 345,162 | 161,698 | 94,471 | 77,248 | ||||||||||||
| Total borrowings | 1,857,196 | 2,337,133 | 2,151,749 | 1,931,453 | 1,962,187 | ||||||||||||
| Other liabilities | 899,890 | 763,524 | 466,980 | 458,094 | 390,560 | ||||||||||||
| Total liabilities | 27,504,396 | 26,448,361 | 22,886,229 | 22,546,291 | 22,100,418 | ||||||||||||
| Equity | 3,366,125 | 3,316,320 | 3,225,042 | 3,131,494 | 3,131,176 | ||||||||||||
| Total liabilities and equity | $ | 30,870,521 | $ | 29,764,681 | $ | 26,111,271 | $ | 25,677,785 | $ | 25,231,594 | |||||||
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
AVERAGE RATES
| (Unaudited) | For the Three Months Ended | |||||||||||||||||||
| September 30, 2020 | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | ||||||||||||||||
| ASSETS: | ||||||||||||||||||||
| Loans: | ||||||||||||||||||||
Business (1) | 2.95 | % | 2.91 | % | 3.50 | % | 3.59 | % | 3.85 | % | ||||||||||
| Real estate — construction and land | 3.74 | 3.95 | 4.78 | 5.05 | 5.46 | |||||||||||||||
| Real estate — business | 3.53 | 3.71 | 4.16 | 4.22 | 4.42 | |||||||||||||||
| Real estate — personal | 3.56 | 3.69 | 3.83 | 3.85 | 3.91 | |||||||||||||||
| Consumer | 4.19 | 4.48 | 4.78 | 4.76 | 4.88 | |||||||||||||||
| Revolving home equity | 3.29 | 3.50 | 4.61 | 4.76 | 5.17 | |||||||||||||||
| Consumer credit card | 11.40 | 11.76 | 12.26 | 12.11 | 12.42 | |||||||||||||||
| Overdrafts | — | — | — | — | — | |||||||||||||||
| Total loans | 3.69 | 3.80 | 4.39 | 4.47 | 4.71 | |||||||||||||||
| Loans held for sale | 4.25 | 8.03 | 6.15 | 5.32 | 6.15 | |||||||||||||||
| Investment securities: | ||||||||||||||||||||
U.S. government and federal agency obligations | 3.71 | .46 | 2.09 | 2.16 | 2.36 | |||||||||||||||
Government-sponsored enterprise obligations | 2.17 | 3.51 | 4.19 | 2.17 | 2.69 | |||||||||||||||
State and municipal obligations (1) | 2.53 | 2.97 | 3.11 | 3.05 | 3.14 | |||||||||||||||
Mortgage-backed securities | 1.95 | 2.17 | 2.37 | 2.72 | 2.61 | |||||||||||||||
| Asset-backed securities | 1.90 | 2.25 | 2.63 | 2.62 | 2.80 | |||||||||||||||
| Other debt securities | 2.35 | 2.49 | 2.94 | 2.82 | 2.63 | |||||||||||||||
| Total available for sale debt securities | 2.18 | 2.18 | 2.54 | 2.69 | 2.69 | |||||||||||||||
Trading debt securities (1) | 1.66 | 2.93 | 2.52 | 2.81 | 2.91 | |||||||||||||||
Equity securities (1) | 47.15 | 48.42 | 46.78 | 49.40 | 35.67 | |||||||||||||||
Other securities (1) | 6.74 | 4.36 | 5.31 | 6.58 | 6.19 | |||||||||||||||
| Total investment securities | 2.24 | 2.24 | 2.61 | 2.78 | 2.76 | |||||||||||||||
Federal funds sold and short-term securities purchased under agreements to resell | — | — | 2.47 | 2.22 | 2.57 | |||||||||||||||
Long-term securities purchased under agreements to resell | 5.26 | 5.08 | 3.53 | 2.26 | 2.01 | |||||||||||||||
| Interest earning deposits with banks | .10 | .10 | .86 | 1.61 | 2.17 | |||||||||||||||
| Total interest earning assets | 3.07 | 3.09 | 3.66 | 3.75 | 3.90 | |||||||||||||||
| LIABILITIES AND EQUITY: | ||||||||||||||||||||
| Interest bearing deposits: | ||||||||||||||||||||
| Savings | .09 | .09 | .11 | .11 | .11 | |||||||||||||||
| Interest checking and money market | .10 | .13 | .30 | .35 | .38 | |||||||||||||||
Certificates of deposit of less than $100,000 | .71 | .93 | 1.15 | 1.16 | 1.11 | |||||||||||||||
Certificates of deposit of $100,000 and over | .69 | 1.08 | 1.62 | 1.79 | 1.99 | |||||||||||||||
| Total interest bearing deposits | .18 | .25 | .45 | .52 | .58 | |||||||||||||||
| Borrowings: | ||||||||||||||||||||
Federal funds purchased and securities sold under agreements to repurchase | .09 | .12 | .96 | 1.20 | 1.74 | |||||||||||||||
| Other borrowings | — | .82 | .82 | 2.05 | 2.33 | |||||||||||||||
| Total borrowings | .09 | .22 | .95 | 1.25 | 1.76 | |||||||||||||||
| Total interest bearing liabilities | .17 | % | .25 | % | .52 | % | .61 | % | .73 | % | ||||||||||
| Net yield on interest earning assets | 2.97 | % | 2.94 | % | 3.33 | % | 3.36 | % | 3.43 | % | ||||||||||
(1) Stated on a tax equivalent basis using a federal income tax rate of 21%.
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
CREDIT QUALITY
| For the Three Months Ended | For the Nine Months Ended | |||||||||||||||||||||||||
| (Unaudited) (In thousands, except per share data) | September 30, 2020 | June 30, 2020 | March 31, 2020 | December 31, 2019 | September 30, 2019 | September 30, 2020 | September 30, 2019 | |||||||||||||||||||
| ALLOWANCE FOR CREDIT LOSSES ON LOANS | ||||||||||||||||||||||||||
| Balance at beginning of period | $ | 240,744 | $ | 171,653 | $ | 160,682 | $ | 160,682 | $ | 161,182 | $ | 160,682 | $ | 159,932 | ||||||||||||
| Adoption of ASU 2016-13 | — | — | (21,039) | — | — | (21,039) | — | |||||||||||||||||||
| Provision for credit losses on loans | 3,200 | 77,491 | 42,868 | 15,206 | 10,963 | 123,559 | 35,232 | |||||||||||||||||||
| Net charge-offs (recoveries): | ||||||||||||||||||||||||||
| Commercial portfolio: | ||||||||||||||||||||||||||
Business | 208 | 3,249 | (373) | 3,036 | 335 | 3,084 | 1,066 | |||||||||||||||||||
Real estate — construction and land | (1) | — | — | — | — | (1) | (117) | |||||||||||||||||||
Real estate — business | (13) | (6) | (21) | 35 | (44) | (40) | (95) | |||||||||||||||||||
| 194 | 3,243 | (394) | 3,071 | 291 | 3,043 | 854 | ||||||||||||||||||||
| Personal banking portfolio: | ||||||||||||||||||||||||||
Consumer credit card | 7,263 | 3,584 | 9,157 | 8,829 | 8,568 | 20,004 | 26,592 | |||||||||||||||||||
Consumer | 211 | 1,362 | 1,711 | 2,838 | 2,069 | 3,284 | 5,716 | |||||||||||||||||||
Overdraft | 200 | 316 | 426 | 507 | 446 | 942 | 1,016 | |||||||||||||||||||
Real estate — personal | (198) | (71) | (4) | 6 | (30) | (273) | 50 | |||||||||||||||||||
Revolving home equity | (86) | (34) | (38) | (45) | 119 | (158) | 254 | |||||||||||||||||||
| 7,390 | 5,157 | 11,252 | 12,135 | 11,172 | 23,799 | 33,628 | ||||||||||||||||||||
| Total net loan charge-offs | 7,584 | 8,400 | 10,858 | 15,206 | 11,463 | 26,842 | 34,482 | |||||||||||||||||||
| Balance at end of period | $ | 236,360 | $ | 240,744 | $ | 171,653 | $ | 160,682 | $ | 160,682 | $ | 236,360 | $ | 160,682 | ||||||||||||
| LIABILITY FOR UNFUNDED LENDING COMMITMENTS | $ | 35,200 | $ | 35,299 | $ | 32,250 | $ | 1,075 | $ | 1,075 | ||||||||||||||||
NET CHARGE-OFF RATIOS (1) | ||||||||||||||||||||||||||
| Commercial portfolio: | ||||||||||||||||||||||||||
| Business | .01 | % | .19 | % | (.03 | %) | .22 | % | .03 | % | .07 | % | .03 | % | ||||||||||||
| Real estate — construction and land | — | — | — | — | — | — | (.02) | |||||||||||||||||||
| Real estate — business | — | — | — | — | (.01) | — | — | |||||||||||||||||||
| .01 | .12 | (.02) | .13 | .01 | .04 | .01 | ||||||||||||||||||||
| Personal banking portfolio: | ||||||||||||||||||||||||||
| Consumer credit card | 4.47 | 2.17 | 5.06 | 4.68 | 4.45 | 3.93 | 4.62 | |||||||||||||||||||
| Consumer | .04 | .28 | .35 | .57 | .43 | .22 | .40 | |||||||||||||||||||
| Overdraft | 29.59 | 43.65 | 42.37 | 10.98 | 19.15 | 39.16 | 22.16 | |||||||||||||||||||
| Real estate — personal | (.03) | (.01) | — | — | (.01) | (.01) | — | |||||||||||||||||||
| Revolving home equity | (.10) | (.04) | (.04) | (.05) | .13 | (.06) | .09 | |||||||||||||||||||
| .52 | .37 | .83 | .90 | .85 | .57 | .86 | ||||||||||||||||||||
| Total | .18 | % | .21 | % | .30 | % | .42 | % | .32 | % | .23 | % | .33 | % | ||||||||||||
| CREDIT QUALITY RATIOS | ||||||||||||||||||||||||||
| Non-performing assets to total loans | .25 | % | .14 | % | .07 | % | .07 | % | .08 | % | ||||||||||||||||
| Non-performing assets to total assets | .13 | .08 | .04 | .04 | .05 | |||||||||||||||||||||
Allowance for credit losses on loans to total loans(2) | 1.44 | 1.47 | 1.14 | 1.09 | 1.11 | |||||||||||||||||||||
| NON-PERFORMING ASSETS | ||||||||||||||||||||||||||
| Non-accrual loans: | ||||||||||||||||||||||||||
| Business | $ | 37,295 | $ | 19,034 | $ | 7,356 | $ | 7,489 | $ | 7,753 | ||||||||||||||||
| Real estate — construction and land | 1 | 1 | 2 | 2 | 3 | |||||||||||||||||||||
| Real estate — business | 1,063 | 1,921 | 1,532 | 1,030 | 2,359 | |||||||||||||||||||||
| Real estate — personal | 1,911 | 1,679 | 1,743 | 1,699 | 1,618 | |||||||||||||||||||||
| Total | 40,270 | 22,635 | 10,633 | 10,220 | 11,733 | |||||||||||||||||||||
| Foreclosed real estate | 57 | 422 | 422 | 365 | 502 | |||||||||||||||||||||
| Total non-performing assets | $ | 40,327 | $ | 23,057 | $ | 11,055 | $ | 10,585 | $ | 12,235 | ||||||||||||||||
| Loans past due 90 days and still accruing interest | $ | 14,436 | $ | 24,583 | $ | 16,520 | $ | 19,859 | $ | 16,308 | ||||||||||||||||
(1) As a percentage of average loans (excluding loans held for sale).
(2) Excluding PPP loans, the allowance for credit losses on loans to total loans was 1.59% and 1.62% as of September 30, 2020 and June 30, 2020, respectively.
COMMERCE BANCSHARES, INC.
Management Discussion of Third Quarter Results
September 30, 2020
For the quarter ended September 30, 2020, net income attributable to Commerce Bancshares, Inc. (net income) amounted to $132.4 million, compared to $39.9 million in the previous quarter and $109.2 million in the same quarter last year. The increase in net income over the previous quarter was primarily the result of a significant decrease in the provision for credit losses, coupled with higher net securities gains, net interest income and non-interest income, partly offset by higher income taxes. The economic forecast used to estimate the allowance for credit losses in September was slightly more optimistic than the forecast utilized in June, which resulted in no additional increase to the allowance for credit losses as of September 30, 2020, and significantly decreased the provision for credit losses this quarter, compared to the prior quarter. Net interest income increased this quarter and the net interest margin increased three basis points, partly due to an increase of $6.3 million in inflation income on our Treasury inflation-protected securities (TIPs). Excluding TIPs inflation income, the net yield on interest earning assets declined five basis points. Average loans increased $210.7 million over the previous quarter, while average available for sale investment securities grew $1.8 billion, and average deposits increased $1.4 billion. For the quarter, the return on average assets was 1.71%, the return on average common equity was 15.21%, and the efficiency ratio was 55.0%.
Balance Sheet Review
During the 3rd quarter of 2020, average loans totaled $16.4 billion, and increased $210.7 million over the prior quarter, and grew $2.1 billion, or 14.5%, over the same quarter last year. Period end loans grew $25.9 million over the prior quarter and $2.0 billion over September 30, 2019. Compared to the previous quarter, average loan growth was primarily driven by increases in personal real estate, construction and land, and consumer loans of $139.8 million, $78.7 million, and $48.0 million, respectively. This growth was partly offset by a decline in business loans of $51.6 million. The period-end balance of Paycheck Protection Loans (PPP) loans (included in business loans) was approximately $1.5 billion at both September 30, 2020 and June 30, 2020, but the average PPP loan balance at September 30, 2020 increased $261.6 million compared to the prior quarter. Growth in personal real estate loan balances was due to a continuation of strong demand for residential mortgage loans in this low interest rate environment. During the current quarter, the Company sold certain fixed rate personal real estate loans totaling $98.9 million, compared to $832 thousand in the prior quarter.
Total average available for sale debt securities increased $1.8 billion over the previous quarter to $11.3 billion, at fair value. The increase in investment securities was mainly the result of growth in mortgage-backed and state and municipal securities. During the quarter, purchases of securities totaled $2.3 billion with a weighted average yield of approximately 1.42%. Sales, maturities and pay downs were $1.0 billion. At September 30, 2020, the duration of the investment portfolio was 3.4 years, and maturities and pay downs of approximately $1.7 billion are expected to occur during the next 12 months.
Total average deposits increased $1.4 billion this quarter compared to the previous quarter. The increase in deposits resulted from growth in demand ($958.2 million), interest checking and money market ($289.8 million), savings deposits ($81.7 million), and certificates of deposit ($70.0 million). Compared to the previous quarter, total average commercial, consumer and wealth deposits (including private banking) grew $840.8 million, $237.5 million and $286.1 million, respectively.
The average loans to deposits ratio was 66.2% in the current quarter and 69.2% in the prior quarter. The Company’s average borrowings, which includes customer repurchase agreements, were $1.9 billion in the 3rd quarter of 2020 and $2.3 billion in the prior quarter.
Net Interest Income
Net interest income in the 3rd quarter of 2020 amounted to $216.0 million, an increase of $12.9 million compared to the previous quarter. On a tax equivalent basis, net interest income for the current quarter increased $12.9 million over the previous quarter to $219.1 million. The increase in net interest income was mainly due to higher income on interest earning assets, supplemented by lower interest expense on interest bearing liabilities. The Company recorded a $1.0 million adjustment to premium amortization on mortgage-backed securities for prepayment speed changes, which increased interest income this quarter. The net yield on earning assets (tax equivalent) increased to 2.97%, compared to 2.94% in the prior quarter.
Compared to the previous quarter, interest income on loans (tax equivalent) decreased $794 thousand, mostly as a result of lower yields on loans, mainly business real estate and consumer banking loans, and lower average balances of consumer credit card loans. Growth in average personal real estate, construction and consumer loan balances and higher yields on business loans increased net interest income and partially offset the impact of lower yields. The average tax-equivalent yield on the loan portfolio declined to 3.69%, compared to 3.80% in the previous quarter.
Interest income on investment securities (tax equivalent) increased $10.1 million over the previous quarter, mainly due to higher average balances. Decreasing rates on the investment securities portfolio were entirely offset by higher interest income earned on U.S. government and federal agency securities as TIPs inflation income grew $6.3 million this quarter. The yield on total investment securities was 2.24% in both the current and previous quarters.
Interest costs on deposits totaled 18 basis points in the 3rd quarter of 2020, compared to 25 basis points in the prior quarter. Interest expense on deposits decreased $2.2 million this quarter compared to the previous quarter mainly due to lower rates paid on all deposit categories. Borrowing costs decreased $880 thousand this quarter due to lower average balances of Federal Home Loan Bank borrowings and lower rates paid on borrowings, mainly securities sold under agreements to repurchase. The overall rate paid on interest bearing liabilities was .17% in the current quarter, compared to .25% in the prior quarter.
Non-Interest Income
In the 3rd quarter of 2020, total non-interest income amounted to $129.6 million, a decrease of $3.2 million, or 2.4%, compared to the same period last year and increased $12.1 million, or 10.3%, compared to the prior quarter. The decrease in non-interest income from the same period last year was mainly due to lower bank card fees, partly offset by growth in loan fees and sales.
Total net bank card fees in the current quarter decreased $6.6 million, or 14.9%, from the same period last year, and increased $4.1 million, or 12.2%, compared to the prior quarter. Net corporate card fees decreased $5.6 million from the same quarter of last year mainly due to lower transaction volume. Net debit card fees decreased $769 thousand, or 7.3%, mainly due to lower
COMMERCE BANCSHARES, INC.
Management Discussion of Third Quarter Results
September 30, 2020
interchange income. Net merchant income increased $56 thousand, or 1.2%, while net credit card fees decreased $283 thousand, or 7.8%, due to lower fee income, partly offset by lower rewards expense. Total net bank card fees this quarter were comprised of fees on corporate card ($20.2 million), debit card ($9.7 million), merchant ($4.6 million) and credit card ($3.4 million) transactions.
In the current quarter, trust fees increased $1.2 million, or 3.0%, over the same period last year, resulting from higher private client fee income. Compared to the same period last year, deposit account fees decreased $925 thousand, or 3.8%, mainly due to lower overdraft and return item fees, partly offset by an increase in corporate cash management fees. Additionally, capital market fees grew $1.4 million, or 78.7%, while loan fees and sales, mostly mortgage banking revenue, grew $5.0 million, or 105.4%, over amounts recorded in the same quarter last year.
Other non-interest income decreased in the 3rd quarter of 2020 compared to the previous quarter mainly due to lower cash sweep commissions, swap fees, and gains on sales of assets. These decreases were partly offset by increases in tax credit sales fees. For the 3rd quarter of 2020, non-interest income comprised 37.5% of the Company’s total revenue.
Investment Securities Gains and Losses
The Company recorded net securities gains of $16.2 million in the current quarter, compared to losses of $4.1 million in the prior quarter and gains of $4.9 million in the 3rd quarter of 2019. Net securities gains in the current quarter primarily resulted from gains of $13.4 million on the sales of mortgage-backed securities coupled with unrealized gains of $2.4 million in the Company’s private equity investment portfolio.
Non-Interest Expense
Non-interest expense for the current quarter amounted to $190.9 million, compared to $191.0 million in the same period last year and $187.5 million in the prior quarter. The decrease in non-interest expense compared to the same period last year was mainly due to lower travel and entertainment, marketing, and supplies and communication expense. These decreases were partially offset by higher salaries and employee benefits expense.
Compared to the 3rd quarter of last year, salaries and employee benefits expense increased $3.5 million, or 2.8%, driven mainly by growth in full-time salary costs, incentive compensation expense, and medical costs. Full-time equivalent employees totaled 4,825 and 4,873 at September 30, 2020 and 2019, respectively.
For the current quarter compared to the same quarter of last year, marketing expense decreased $1.1 million, or 18.6%. Supplies and communication expense decreased $965 thousand due to lower supplies, postage and bank card issuance expense. Other non-interest expense decreased mainly due to a $2.9 million decrease in travel and entertainment expense. FDIC insurance expense, also within other non-interest expense, increased due to higher deposit balances during the current quarter than in the 3rd quarter of 2019.
Income Taxes
The effective tax rate for the Company was 20.6% in the current quarter, 19.5% in the previous quarter, and 21.0% in the 3rd quarter of 2019.
Credit Quality
Net loan charge-offs in the 3rd quarter of 2020 amounted to $7.6 million, compared to $8.4 million in the prior quarter and $11.5 million in the same period last year. The ratio of annualized net loan charge-offs to total average loans was .18% in the current quarter, .21% in the previous quarter, and .32% in the 3rd quarter of last year. Compared to the prior quarter, net loan charge-offs on commercial loans decreased $3.0 million to $194 thousand, while net loan charge-offs on personal banking loans increased $2.2 million to $7.4 million.
In the 3rd quarter of 2020, annualized net loan charge-offs on average consumer credit card loans were 4.47%, compared to 2.17% in the previous quarter, and 4.45% in the same quarter last year. Consumer loan net charge-offs were .04% of average consumer loans in the current quarter, .28% in the prior quarter and .43% in the same quarter last year.
This quarter, the provision for credit losses on loans totaled $3.2 million and was $4.4 million lower than net loan charge-offs. At September 30, 2020, the allowance for credit losses on loans totaled $236.4 million, or 1.44% of total loans and 1.59% of total loans excluding PPP loans. Additionally, the liability for unfunded lending commitments at September 30, 2020 was $35.2 million.
At September 30, 2020, total non-performing assets amounted to $40.3 million, an increase of $17.3 million over the previous quarter. Non-performing assets are comprised of non-accrual loans and foreclosed real estate ($40.3 million and $57 thousand, respectively). At September 30, 2020, the balance of non-accrual loans, which represented .25% of loans outstanding, included business loans of $37.3 million, business real estate loans of $1.1 million, and personal real estate loans of $1.9 million. Loans more than 90 days past due and still accruing interest totaled $14.4 million at September 30, 2020.
Other
During the 3rd quarter of 2020, the Company paid a cash dividend of $.27 per common share, representing an 8.9% increase over the same period last year. The Company also paid an annualized 6% cash dividend on its preferred stock. On September 1, 2020, the Company redeemed all outstanding shares of its Series B preferred stock.
Forward Looking Information
This information contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements include future financial and operating results, expectations, intentions and other statements that are not historical facts. Such statements are based on current beliefs and expectations of the Company’s management and are subject to significant risks and uncertainties. Actual results may differ materially from those set forth in the forward-looking statements.
Embracing a Growth Mindset COMMERCE BANCSHARES, INC. INVESTOR UPDATE 3rd Quarter 2020
CAUTIONARY STATEMENT A number of statements we will be making in our presentation and in the accompanying slides are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, such as statements of the Corporation’s plans, goals, objectives, expectations, projections, estimates and intentions. These forward- looking statements involve significant risks and uncertainties and are subject to change based on various factors (some of which are beyond the Corporation’s control). Factors that could cause the Corporation’s actual results to differ materially from such forward- looking statements made herein or by management of the Corporation are set forth in the Corporation’s 2019 Annual Report on Form 10-K, 2ND Quarter 2020 Report on Form 10-Q and the Corporation’s Current Reports on Form 8-K. 2 2
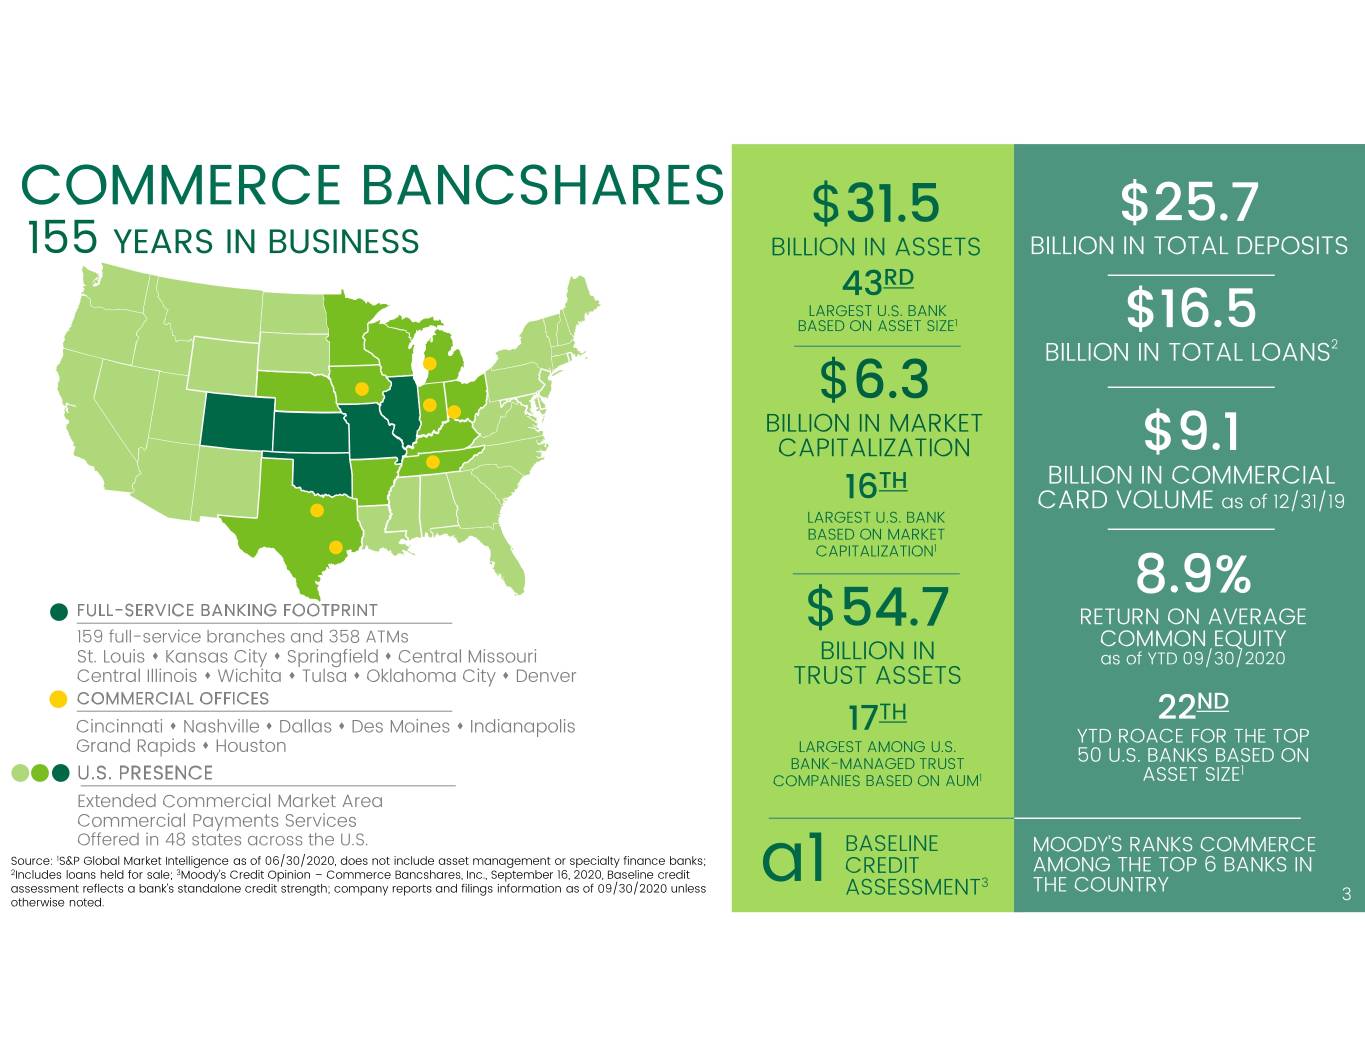
COMMERCE BANCSHARES $31.5 $25.7 155 YEARS IN BUSINESS BILLION IN ASSETS BILLION IN TOTAL DEPOSITS 43RD LARGEST U.S. BANK BASED ON ASSET SIZE1 $16.5 BILLION IN TOTAL LOANS2 $6.3 BILLION IN MARKET CAPITALIZATION $9.1 TH BILLION IN COMMERCIAL 16 CARD VOLUME as of 12/31/19 LARGEST U.S. BANK BASED ON MARKET CAPITALIZATION1 8.9% FULL-SERVICE BANKING FOOTPRINT RETURN ON AVERAGE 159 full-service branches and 358 ATMs $54.7 COMMON EQUITY St. Louis Kansas City Springfield Central Missouri BILLION IN as of YTD 09/30/2020 Central Illinois Wichita Tulsa Oklahoma City Denver TRUST ASSETS COMMERCIAL OFFICES TH ND Cincinnati Nashville Dallas Des Moines Indianapolis 17 22 Grand Rapids Houston LARGEST AMONG U.S. YTD ROACE FOR THE TOP 50 U.S. BANKS BASED ON BANK-MANAGED TRUST 1 U.S. PRESENCE COMPANIES BASED ON AUM1 ASSET SIZE Extended Commercial Market Area Commercial Payments Services Offered in 48 states across the U.S. BASELINE MOODY’S RANKS COMMERCE Source: 1S&P Global Market Intelligence as of 06/30/2020, does not include asset management or specialty finance banks; 2Includes loans held for sale; 3Moody’s Credit Opinion – Commerce Bancshares, Inc., September 16, 2020, Baseline credit CREDIT AMONG THE TOP 6 BANKS IN assessment reflects a bank’s standalone credit strength; company reports and filings information as of 09/30/2020 unless ASSESSMENT3 THE COUNTRY otherwise noted. a1 3
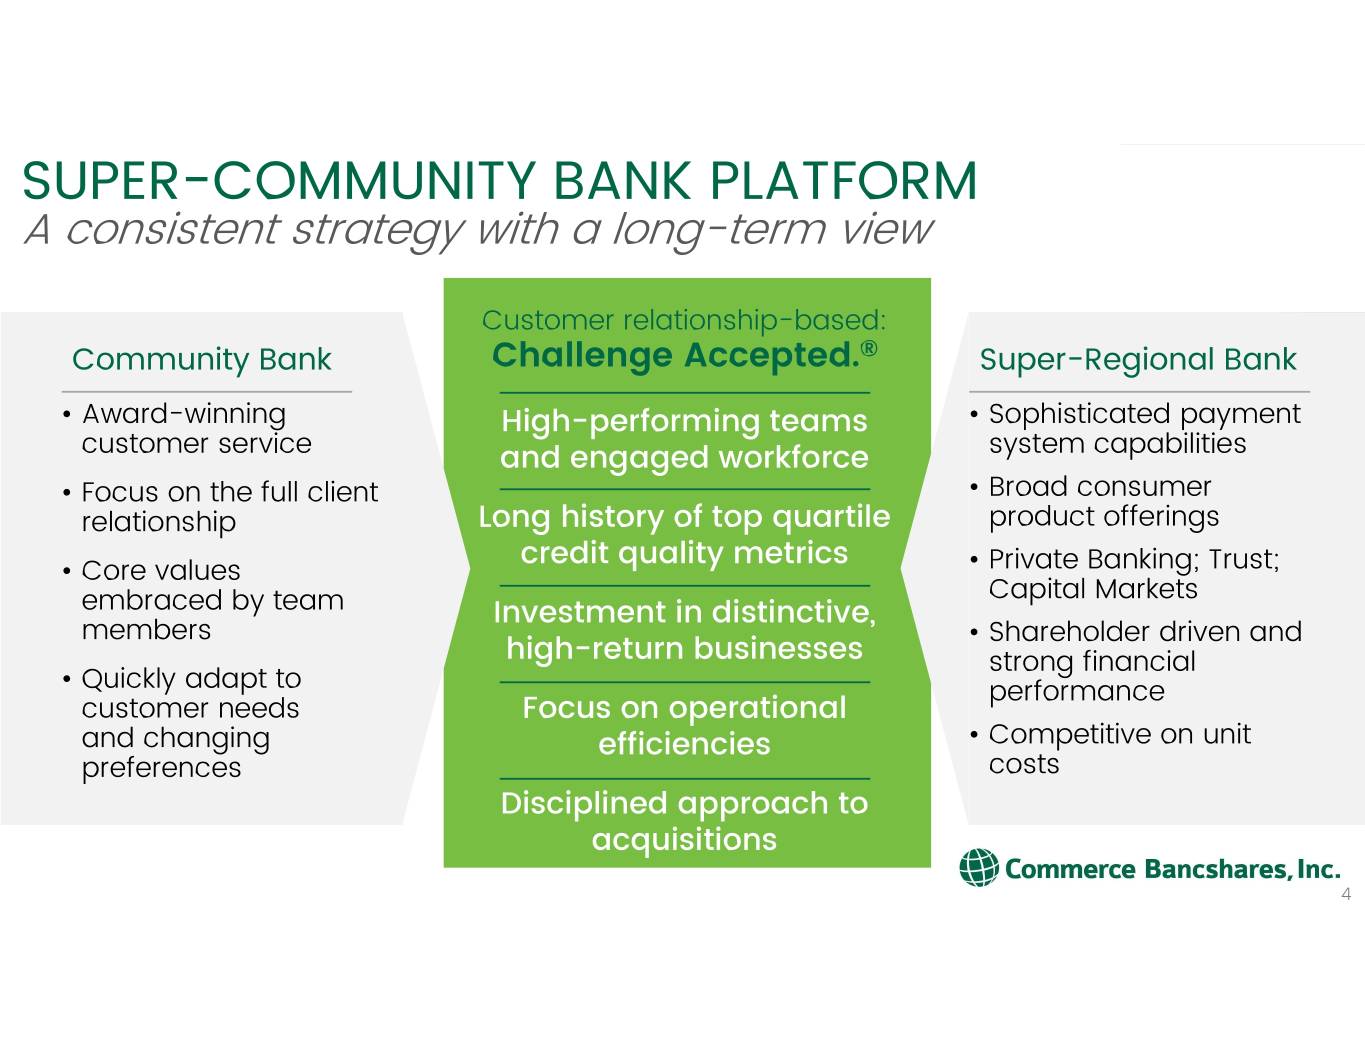
SUPER-COMMUNITY BANK PLATFORM A consistent strategy with a long-term view Customer relationship-based: Community Bank Challenge Accepted.® Super-Regional Bank • • Award-winning High-performing teams Sophisticated payment customer service and engaged workforce system capabilities • • Focus on the full client Broad consumer relationship Long history of top quartile product offerings credit quality metrics • • Core values Private Banking; Trust; Capital Markets embraced by team Investment in distinctive, members • Shareholder driven and high-return businesses • strong financial Quickly adapt to performance customer needs Focus on operational • and changing efficiencies Competitive on unit preferences costs Disciplined approach to acquisitions 4
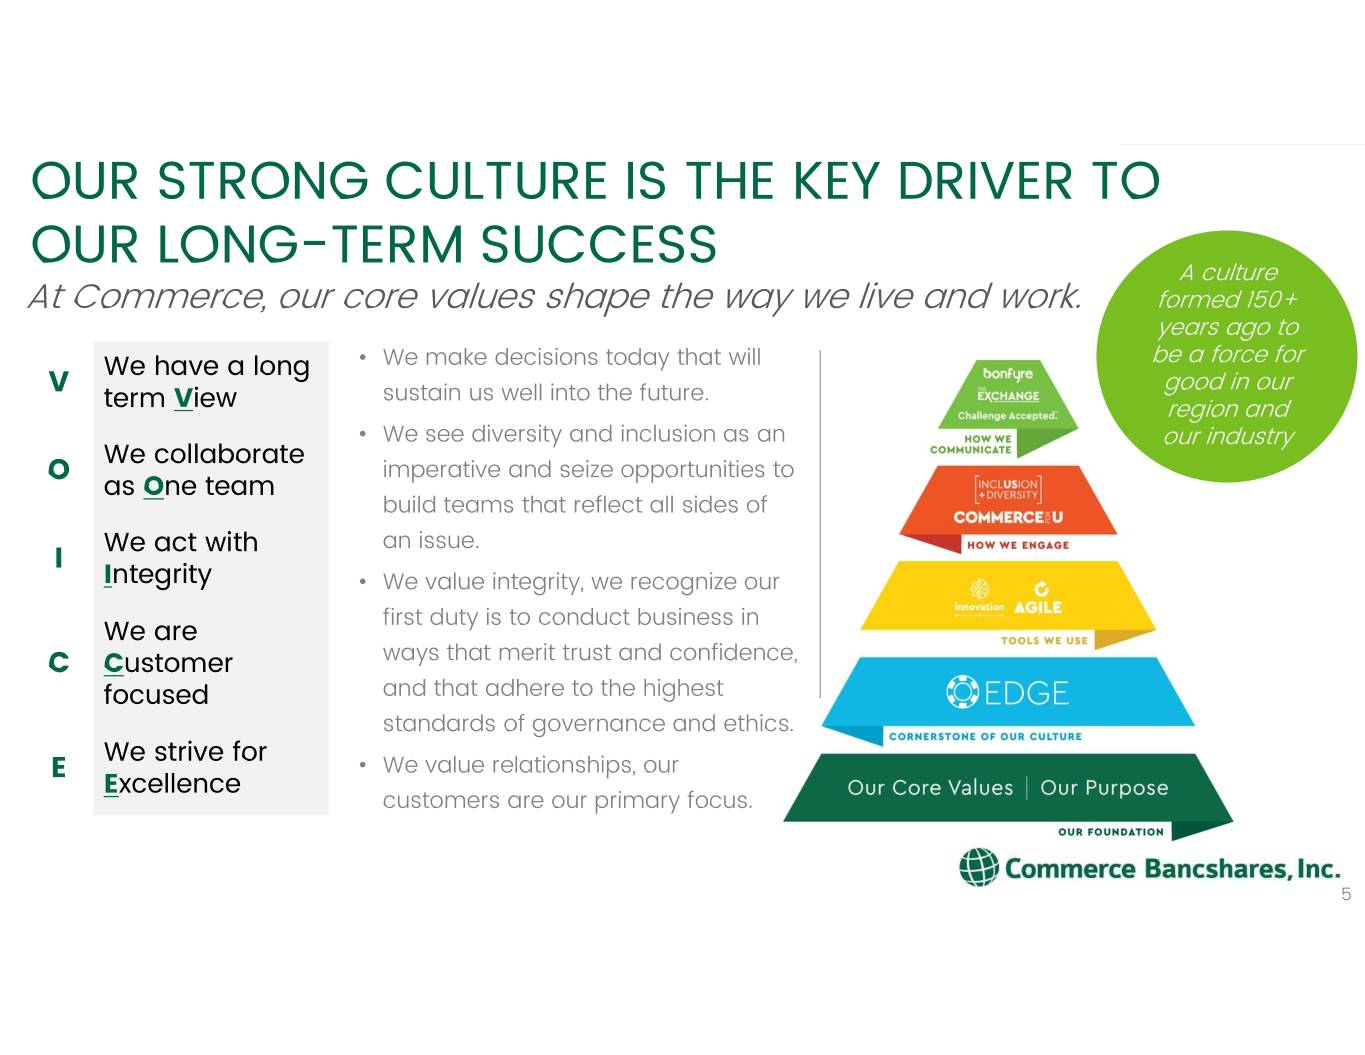
OUR STRONG CULTURE IS THE KEY DRIVER TO OUR LONG-TERM SUCCESS A culture At Commerce, our core values shape the way we live and work. formed 150+ years ago to • We have a long We make decisions today that will be a force for V sustain us well into the future. good in our term View region and • We see diversity and inclusion as an our industry We collaborate O imperative and seize opportunities to as One team build teams that reflect all sides of We act with an issue. I Integrity • We value integrity, we recognize our first duty is to conduct business in We are C Customer ways that merit trust and confidence, focused and that adhere to the highest standards of governance and ethics. We strive for E • We value relationships, our Excellence customers are our primary focus. 5
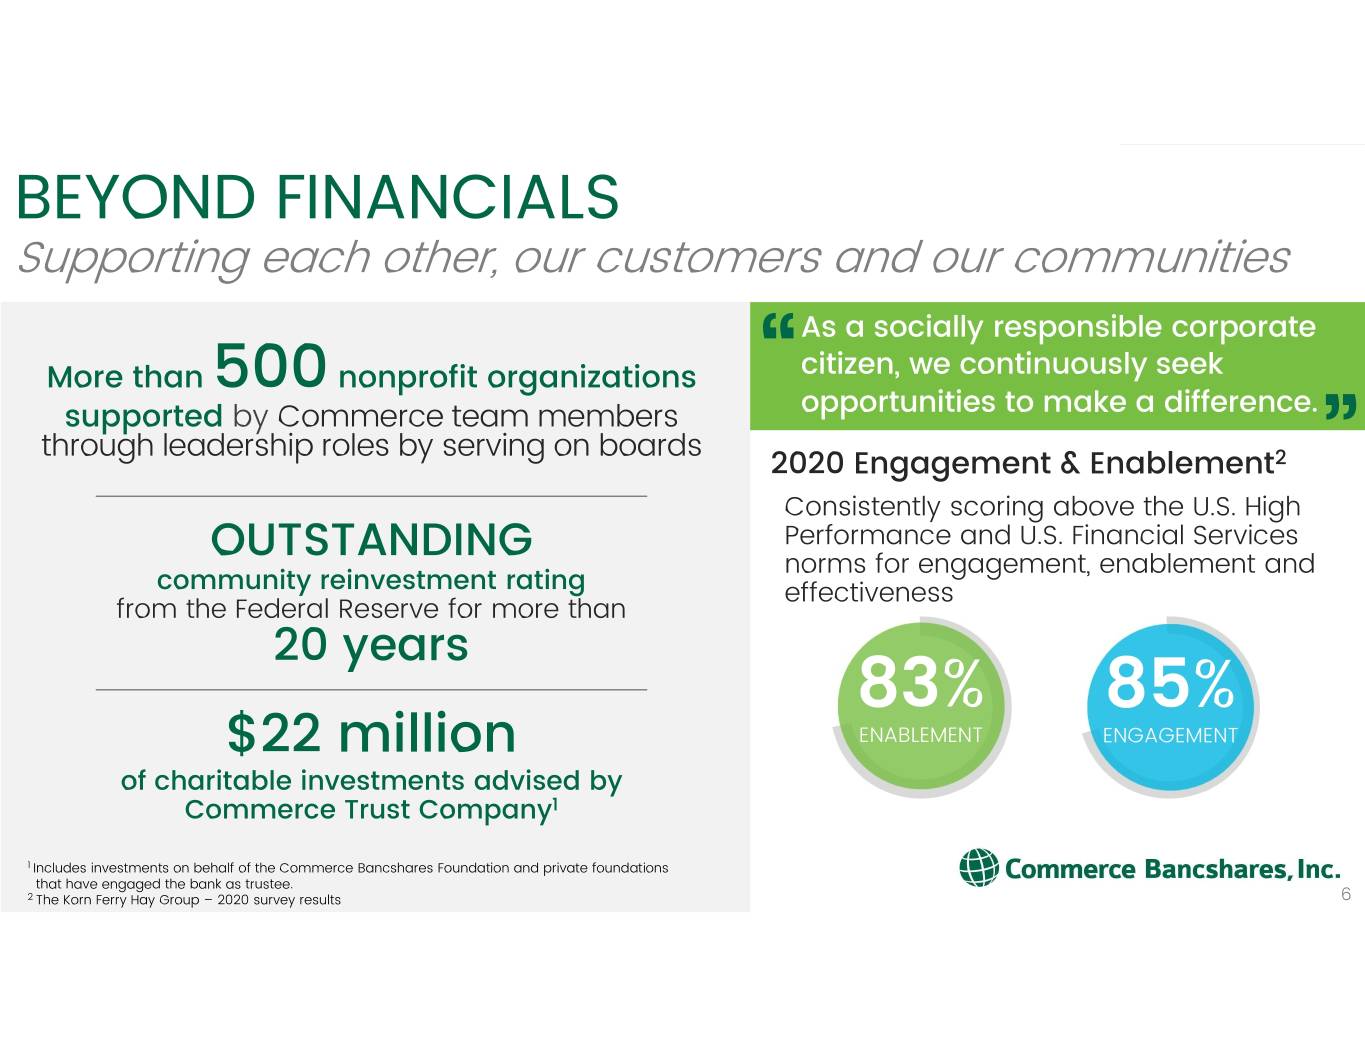
BEYOND FINANCIALS Supporting each other, our customers and our communities As a socially responsible corporate More than 500 nonprofit organizations citizen, we continuously seek supported by Commerce team members opportunities to make a difference. through leadership roles by serving on boards 2020 Engagement & Enablement2 Consistently scoring above the U.S. High Performance and U.S. Financial Services OUTSTANDING norms for engagement, enablement and community reinvestment rating effectiveness from the Federal Reserve for more than 20 years 83% 85% $22 million ENABLEMENT ENGAGEMENT of charitable investments advised by Commerce Trust Company1 1 Includes investments on behalf of the Commerce Bancshares Foundation and private foundations that have engaged the bank as trustee. 2 The Korn Ferry Hay Group – 2020 survey results 6
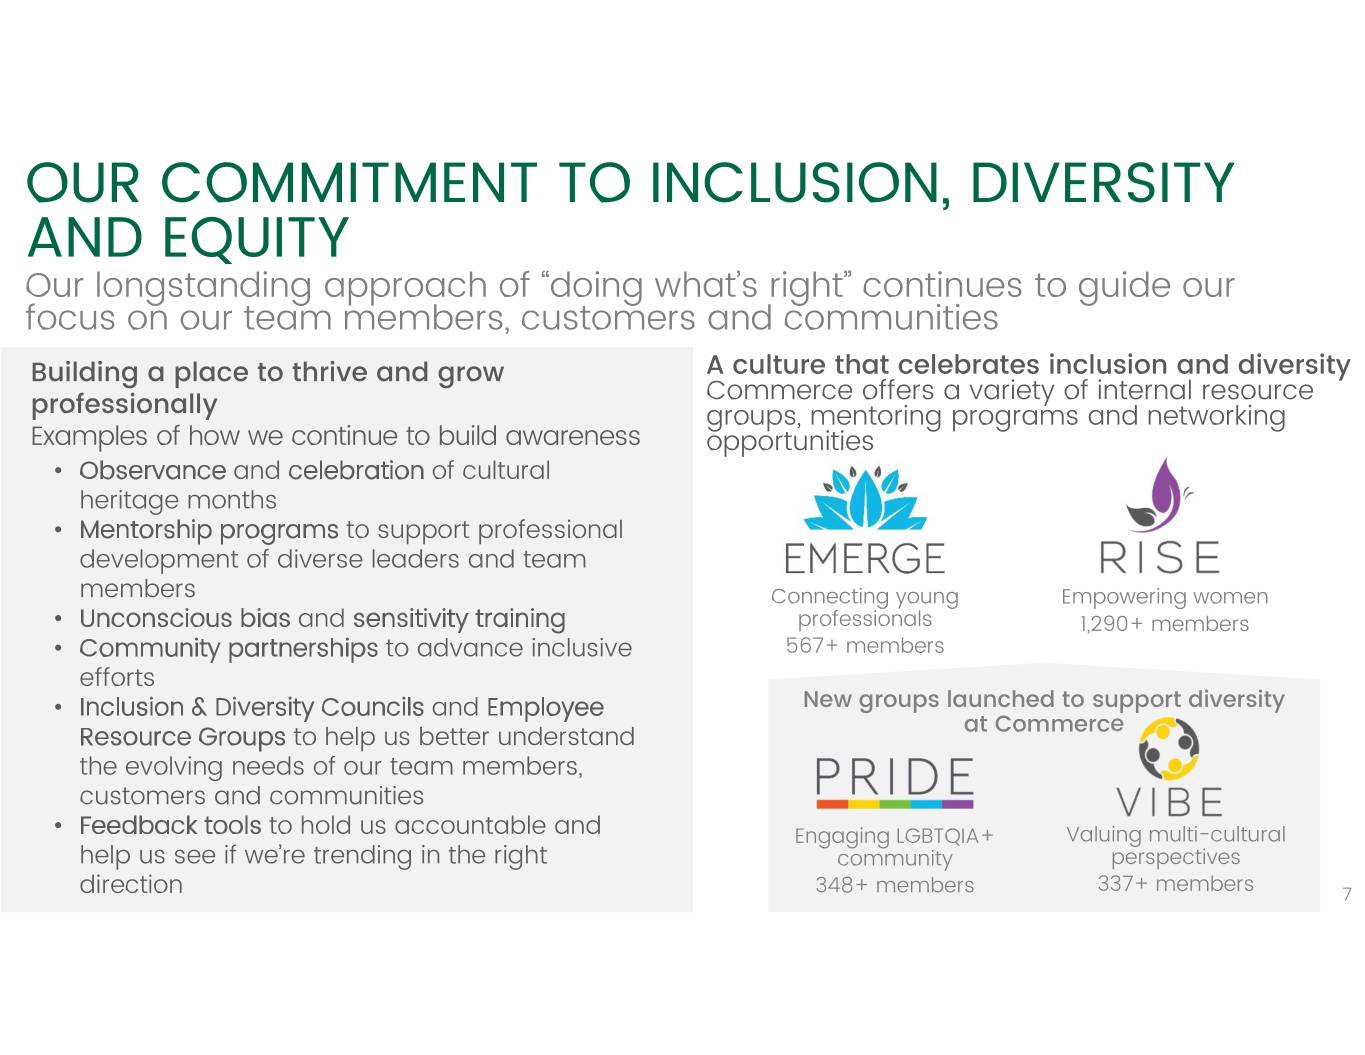
OUR COMMITMENT TO INCLUSION, DIVERSITY AND EQUITY Our longstanding approach of “doing what’s right” continues to guide our focus on our team members, customers and communities Building a place to thrive and grow A culture that celebrates inclusion and diversity Commerce offers a variety of internal resource professionally groups, mentoring programs and networking Examples of how we continue to build awareness opportunities • Observance and celebration of cultural heritage months • Mentorship programs to support professional development of diverse leaders and team members Connecting young Empowering women • Unconscious bias and sensitivity training professionals 1,290+ members • Community partnerships to advance inclusive 567+ members efforts • Inclusion & Diversity Councils and Employee New groups launched to support diversity at Commerce Resource Groups to help us better understand the evolving needs of our team members, customers and communities • Feedback tools to hold us accountable and Engaging LGBTQIA+ Valuing multi-cultural help us see if we’re trending in the right community perspectives direction 348+ members 337+ members 7
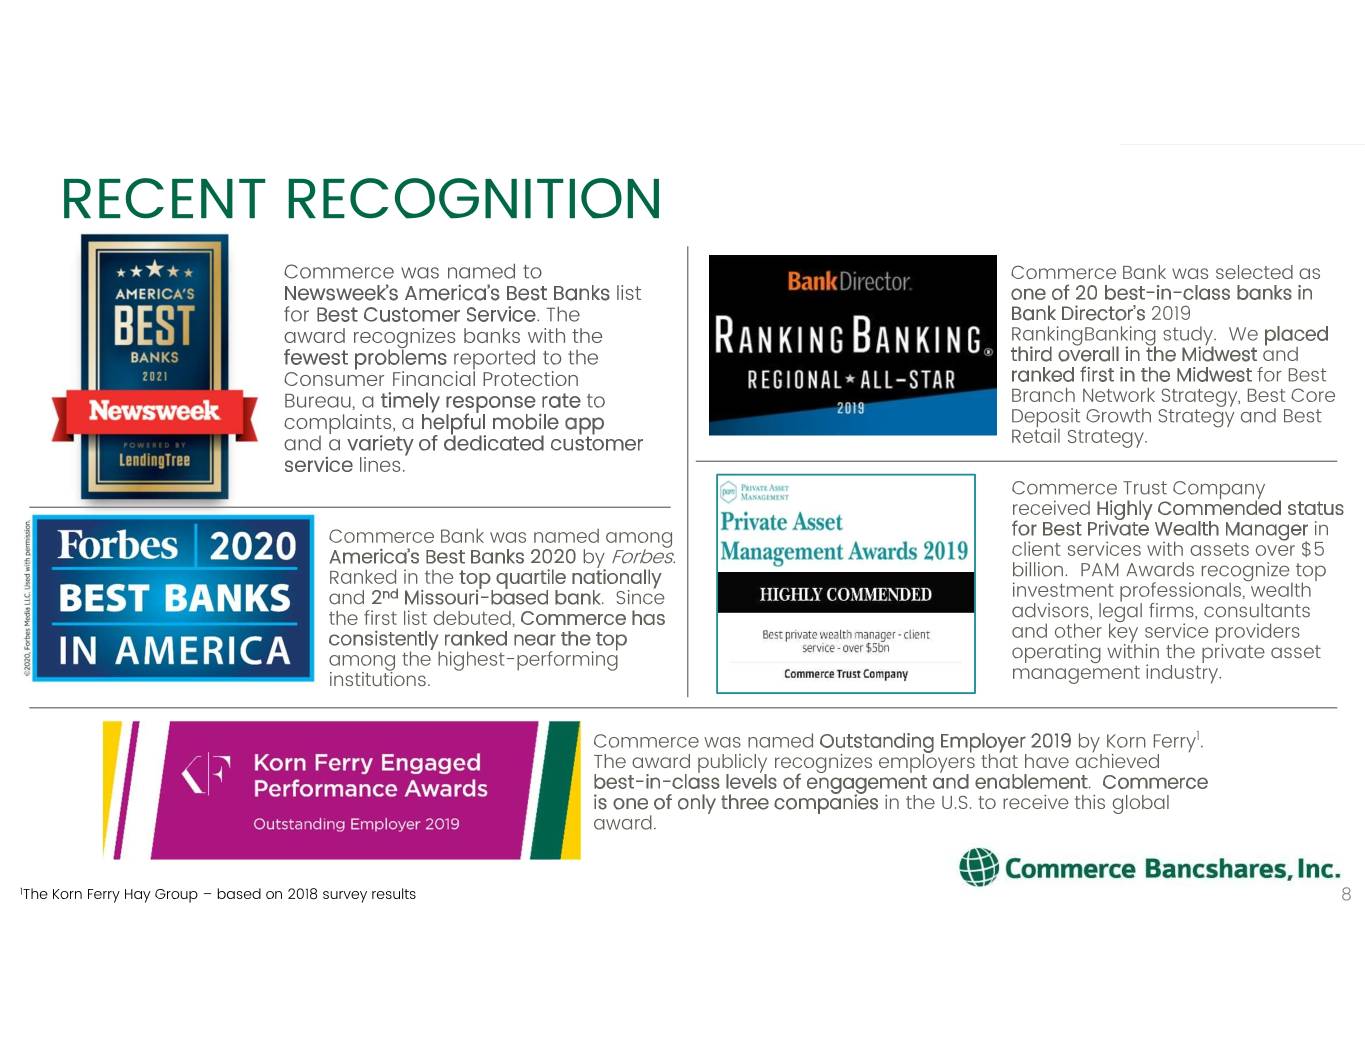
RECENT RECOGNITION Commerce was named to Commerce Bank was selected as Newsweek’s America’s Best Banks list one of 20 best-in-class banks in for Best Customer Service. The Bank Director’s 2019 award recognizes banks with the RankingBanking study. We placed fewest problems reported to the third overall in the Midwest and Consumer Financial Protection ranked first in the Midwest for Best Bureau, a timely response rate to Branch Network Strategy, Best Core complaints, a helpful mobile app Deposit Growth Strategy and Best and a variety of dedicated customer Retail Strategy. service lines. Commerce Trust Company received Highly Commended status Commerce Bank was named among for Best Private Wealth Manager in America’s Best Banks 2020 by Forbes. client services with assets over $5 Ranked in the top quartile nationally billion. PAM Awards recognize top and 2nd Missouri-based bank. Since investment professionals, wealth the first list debuted, Commerce has advisors, legal firms, consultants consistently ranked near the top and other key service providers among the highest-performing operating within the private asset institutions. management industry. Commerce was named Outstanding Employer 2019 by Korn Ferry1. The award publicly recognizes employers that have achieved best-in-class levels of engagement and enablement. Commerce is one of only three companies in the U.S. to receive this global award. 1The Korn Ferry Hay Group – based on 2018 survey results 8
Q3 FINANCIAL RESULTS 9
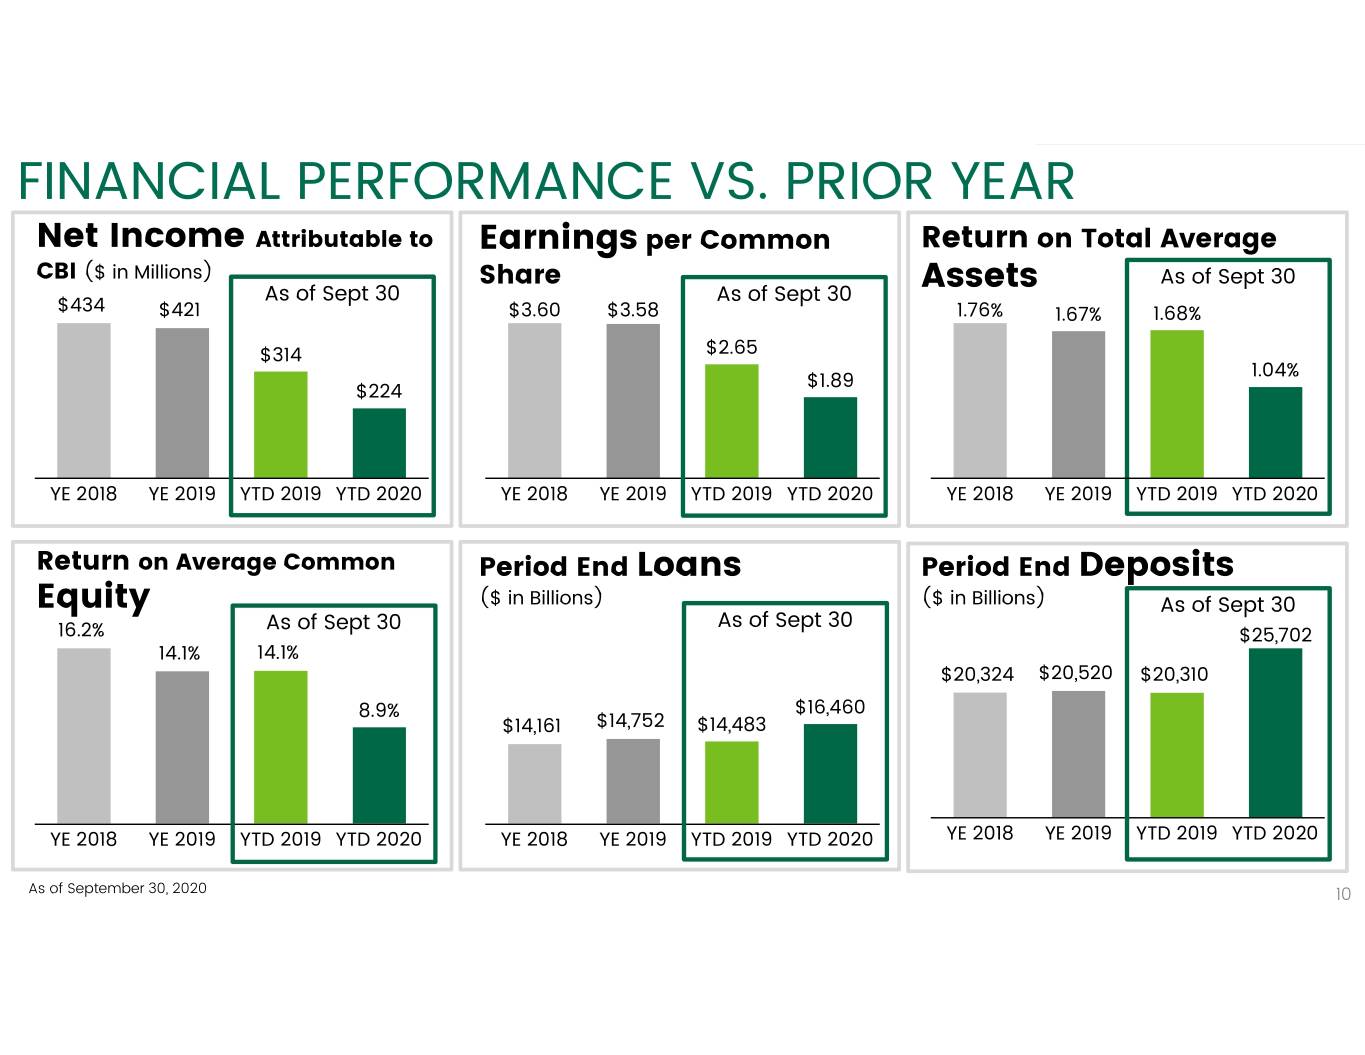
FINANCIAL PERFORMANCE VS. PRIOR YEAR Net Income Attributable to Earnings per Common Return on Total Average CBI ($ in Millions) Share As of Sept 30 As of Sept 30 As of Sept 30 Assets $434 $421 $3.60 $3.58 1.76% 1.67% 1.68% $314 $2.65 1.04% $1.89 $224 YE 2018 YE 2019 YTD 2019 YTD 2020 YE 2018 YE 2019 YTD 2019 YTD 2020 YE 2018 YE 2019 YTD 2019 YTD 2020 Return on Average Common Period End Loans Period End Deposits Equity ($ in Billions) ($ in Billions) As of Sept 30 As of Sept 30 As of Sept 30 16.2% $25,702 14.1% 14.1% $20,324 $20,520 $20,310 8.9% $16,460 $14,161 $14,752 $14,483 YE 2018YE 2019 YTD 2019 YTD 2020 YE 2018 YE 2019 YTD 2019 YTD 2020 YE 2018YE 2019 YTD 2019 YTD 2020 As of September 30, 2020 10
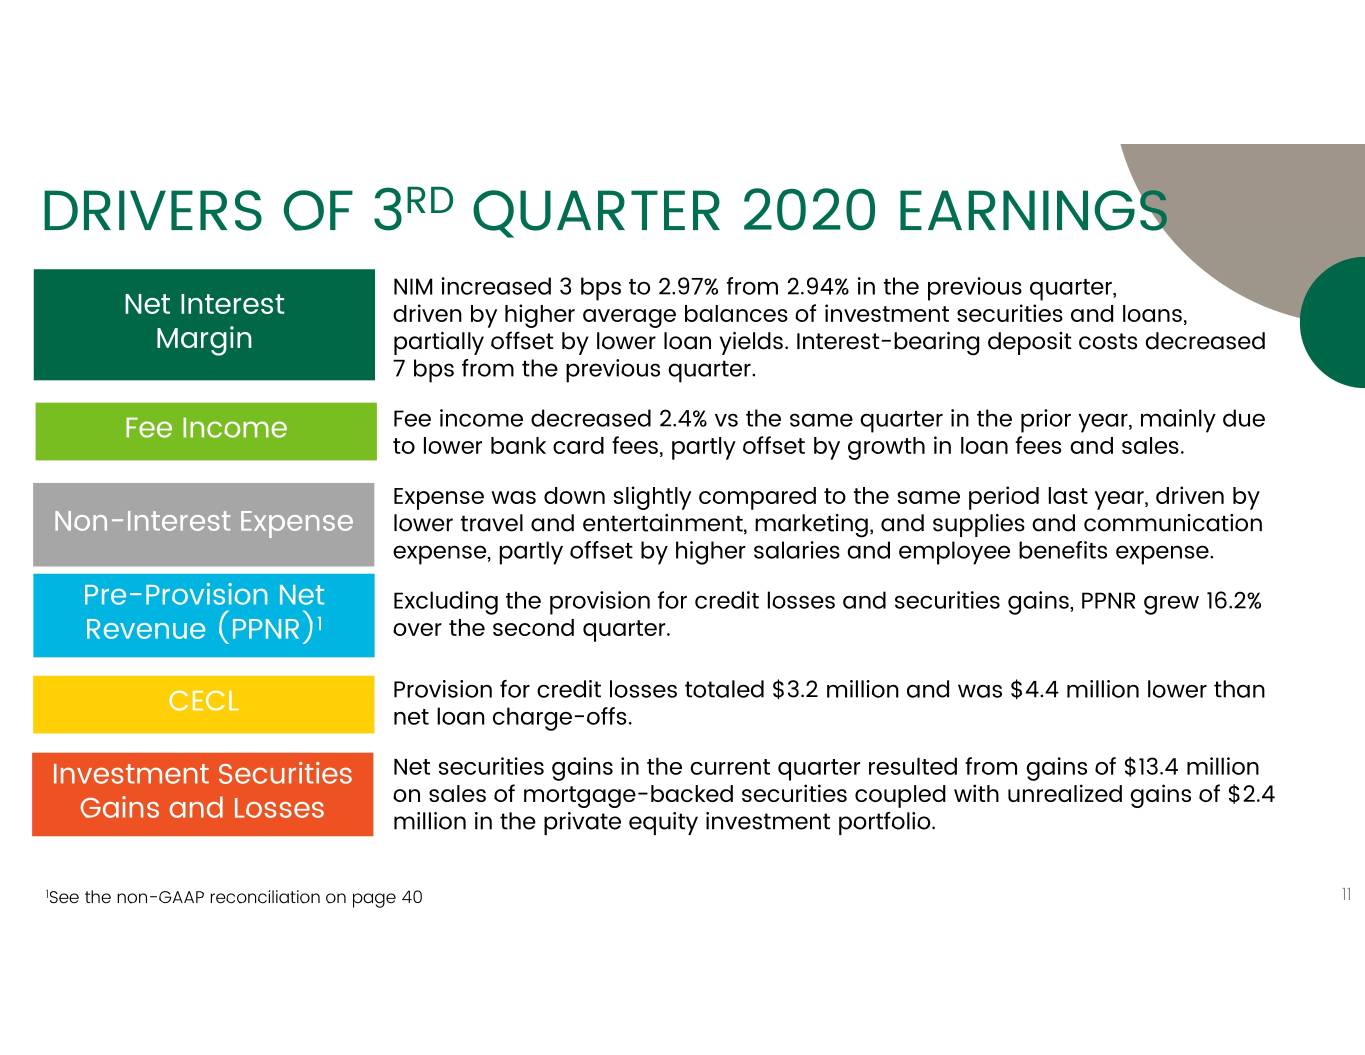
DRIVERS OF 3RD QUARTER 2020 EARNINGS NIM increased 3 bps to 2.97% from 2.94% in the previous quarter, Net Interest driven by higher average balances of investment securities and loans, Margin partially offset by lower loan yields. Interest-bearing deposit costs decreased 7 bps from the previous quarter. Fee Income Fee income decreased 2.4% vs the same quarter in the prior year, mainly due to lower bank card fees, partly offset by growth in loan fees and sales. Expense was down slightly compared to the same period last year, driven by Non-Interest Expense lower travel and entertainment, marketing, and supplies and communication expense, partly offset by higher salaries and employee benefits expense. Pre-Provision Net Excluding the provision for credit losses and securities gains, PPNR grew 16.2% Revenue (PPNR)1 over the second quarter. Provision for credit losses totaled $3.2 million and was $4.4 million lower than CECL net loan charge-offs. Investment Securities Net securities gains in the current quarter resulted from gains of $13.4 million on sales of mortgage-backed securities coupled with unrealized gains of $2.4 Gains and Losses million in the private equity investment portfolio. 1See the non-GAAP reconciliation on page 40 11
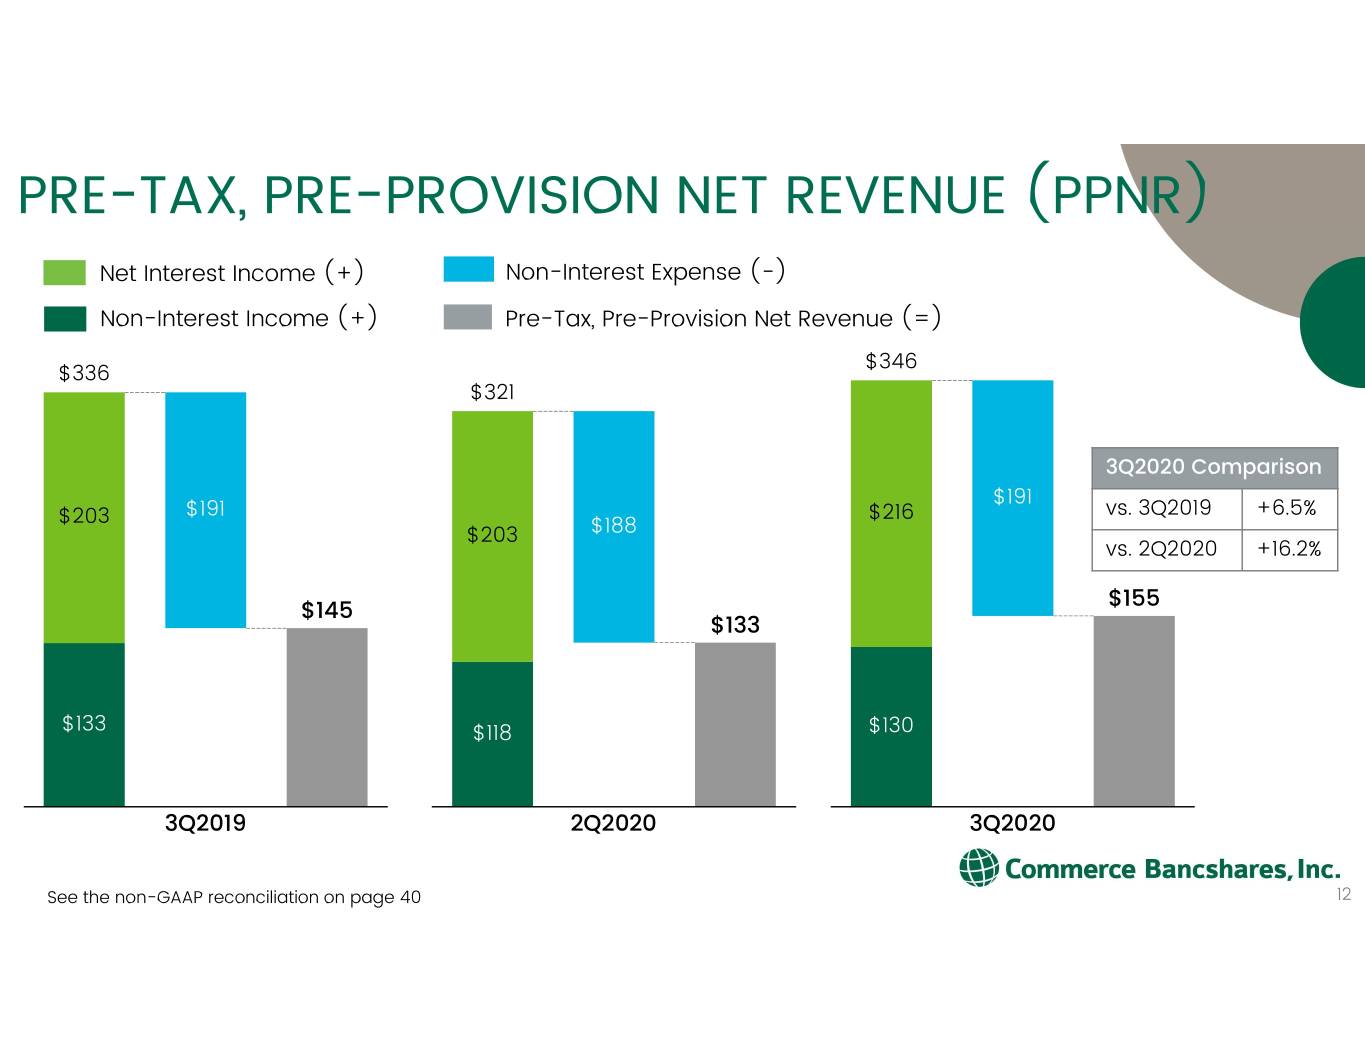
PRE-TAX, PRE-PROVISION NET REVENUE (PPNR) Net Interest Income (+) Non-Interest Expense (-) Non-Interest Income (+) Pre-Tax, Pre-Provision Net Revenue (=) $346 $336 $321 3Q2020 Comparison $191 $203 $191 $216 vs. 3Q2019 +6.5% $203 $188 vs. 2Q2020 +16.2% $155 $145 $133 $133 $118 $130 3Q2019 2Q2020 3Q2020 See the non-GAAP reconciliation on page 40 12
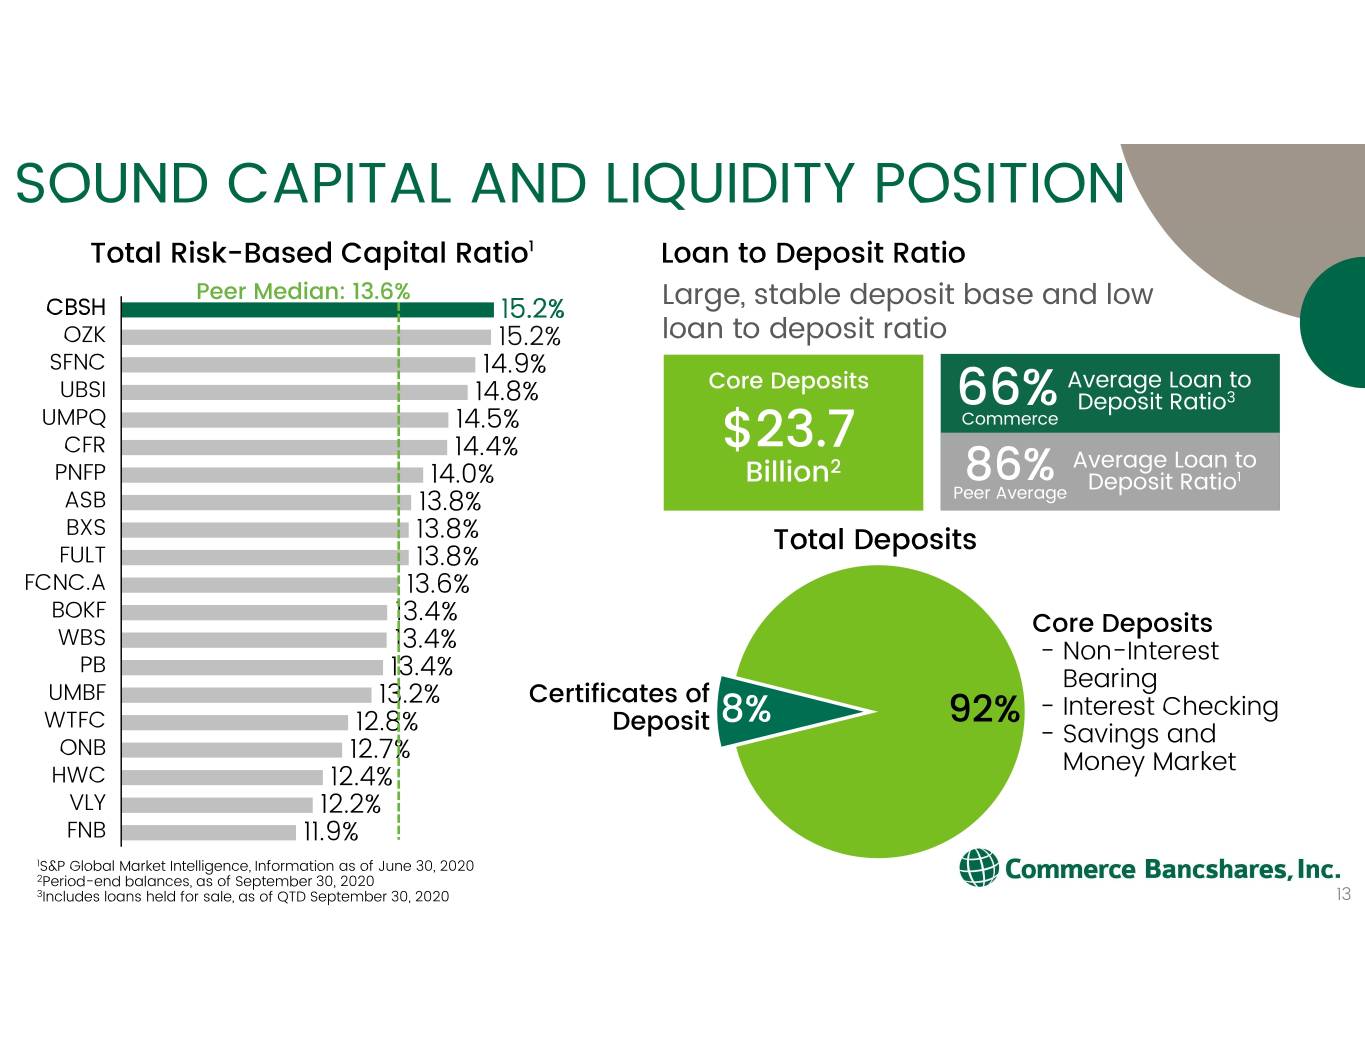
SOUND CAPITAL AND LIQUIDITY POSITION Total Risk-Based Capital Ratio1 Loan to Deposit Ratio Peer Median: 13.6% CBSH 15.2% Large, stable deposit base and low OZK 15.2% loan to deposit ratio SFNC 14.9% UBSI Core Deposits Average Loan to 14.8% Deposit Ratio3 UMPQ 14.5% 66%Commerce CFR 14.4% $23.72 Average Loan to PNFP 14.0% Billion 86% Deposit Ratio1 ASB 13.8% Peer Average BXS 13.8% Total Deposits FULT 13.8% FCNC.A 13.6% BOKF 13.4% Core Deposits WBS 13.4% - Non-Interest PB 13.4% UMBF Bearing 13.2% Certificates of - Interest Checking WTFC 12.8% Deposit 8% 92% ONB - Savings and 12.7% Money Market HWC 12.4% VLY 12.2% FNB 11.9% 1S&P Global Market Intelligence, Information as of June 30, 2020 2Period-end balances, as of September 30, 2020 3Includes loans held for sale, as of QTD September 30, 2020 13
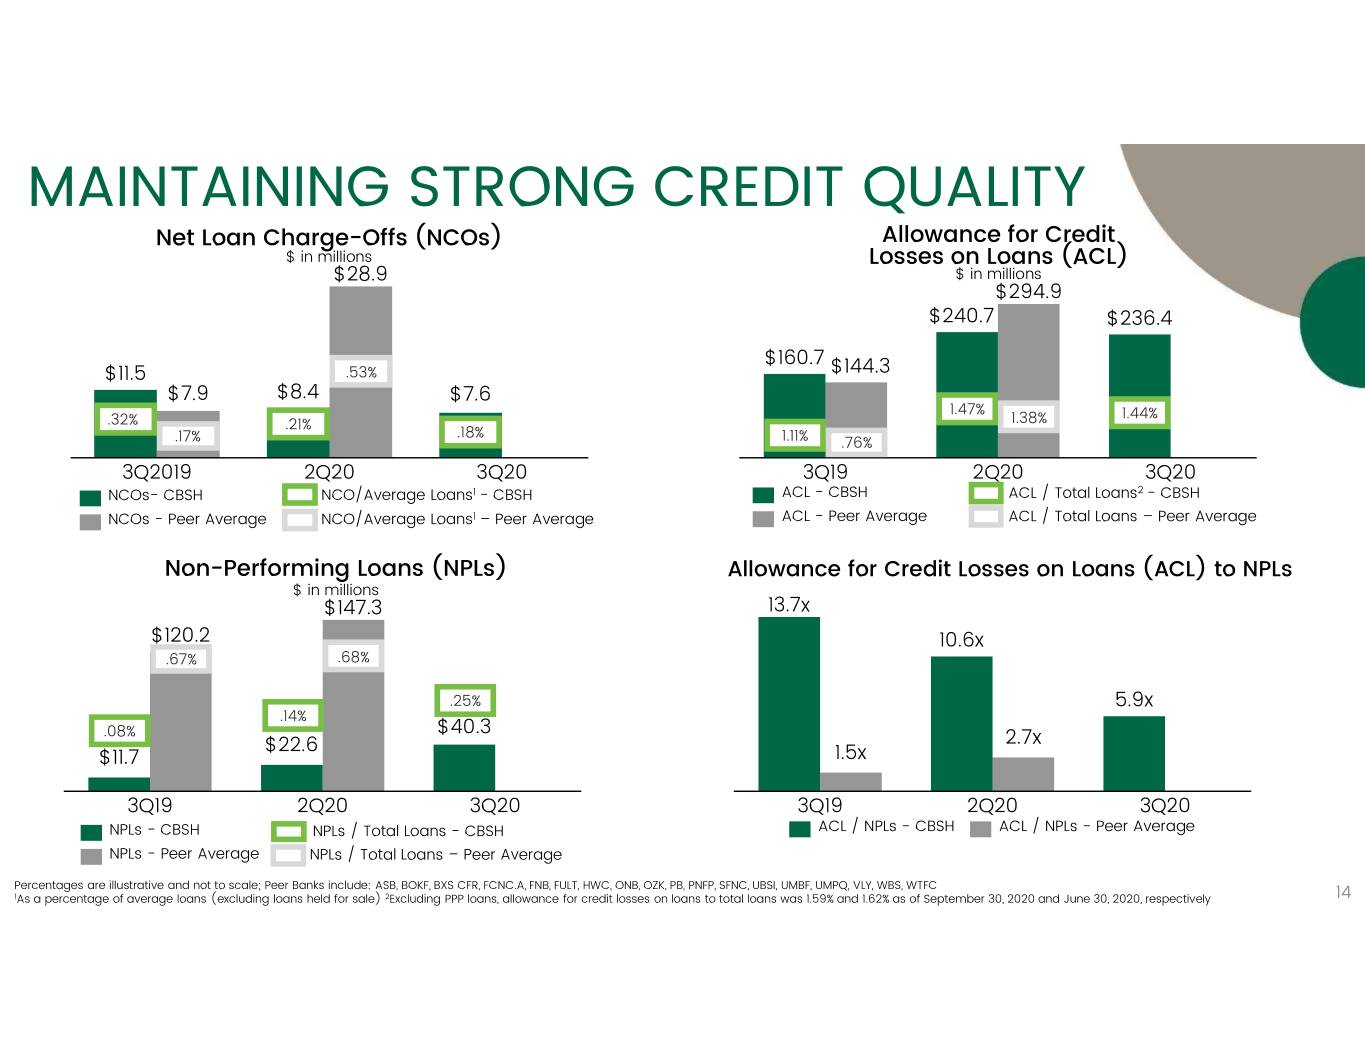
MAINTAINING STRONG CREDIT QUALITY Net Loan Charge-Offs (NCOs) Allowance for Credit $ in millions Losses on Loans (ACL) $28.9 $ in millions $294.9 $240.7 $236.4 $160.7 $11.5 .53% $144.3 $7.9 $8.4 $7.6 1.47% 1.44% .32% .21% 1.38% .18% .17% 1.11% .76% 3Q2019 2Q20 3Q20 3Q19 2Q20 3Q20 NCOs- CBSH NCO/Average Loans1 - CBSH ACL - CBSH ACL / Total Loans2 - CBSH NCOs - Peer Average NCO/Average Loans1 – Peer Average ACL - Peer Average ACL / Total Loans – Peer Average Non-Performing Loans (NPLs) Allowance for Credit Losses on Loans (ACL) to NPLs $ in millions $147.3 13.7x $120.2 10.6x .67% .68% .25% 5.9x .14% .08% $40.3 $22.6 2.7x $11.7 1.5x 3Q19 2Q20 3Q20 3Q19 2Q20 3Q20 NPLs - CBSH NPLs / Total Loans - CBSH ACL / NPLs - CBSH ACL / NPLs - Peer Average NPLs - Peer Average NPLs / Total Loans – Peer Average Percentages are illustrative and not to scale; Peer Banks include: ASB, BOKF, BXS CFR, FCNC.A, FNB, FULT, HWC, ONB, OZK, PB, PNFP, SFNC, UBSI, UMBF, UMPQ, VLY, WBS, WTFC 1As a percentage of average loans (excluding loans held for sale) 2Excluding PPP loans, allowance for credit losses on loans to total loans was 1.59% and 1.62% as of September 30, 2020 and June 30, 2020, respectively 14
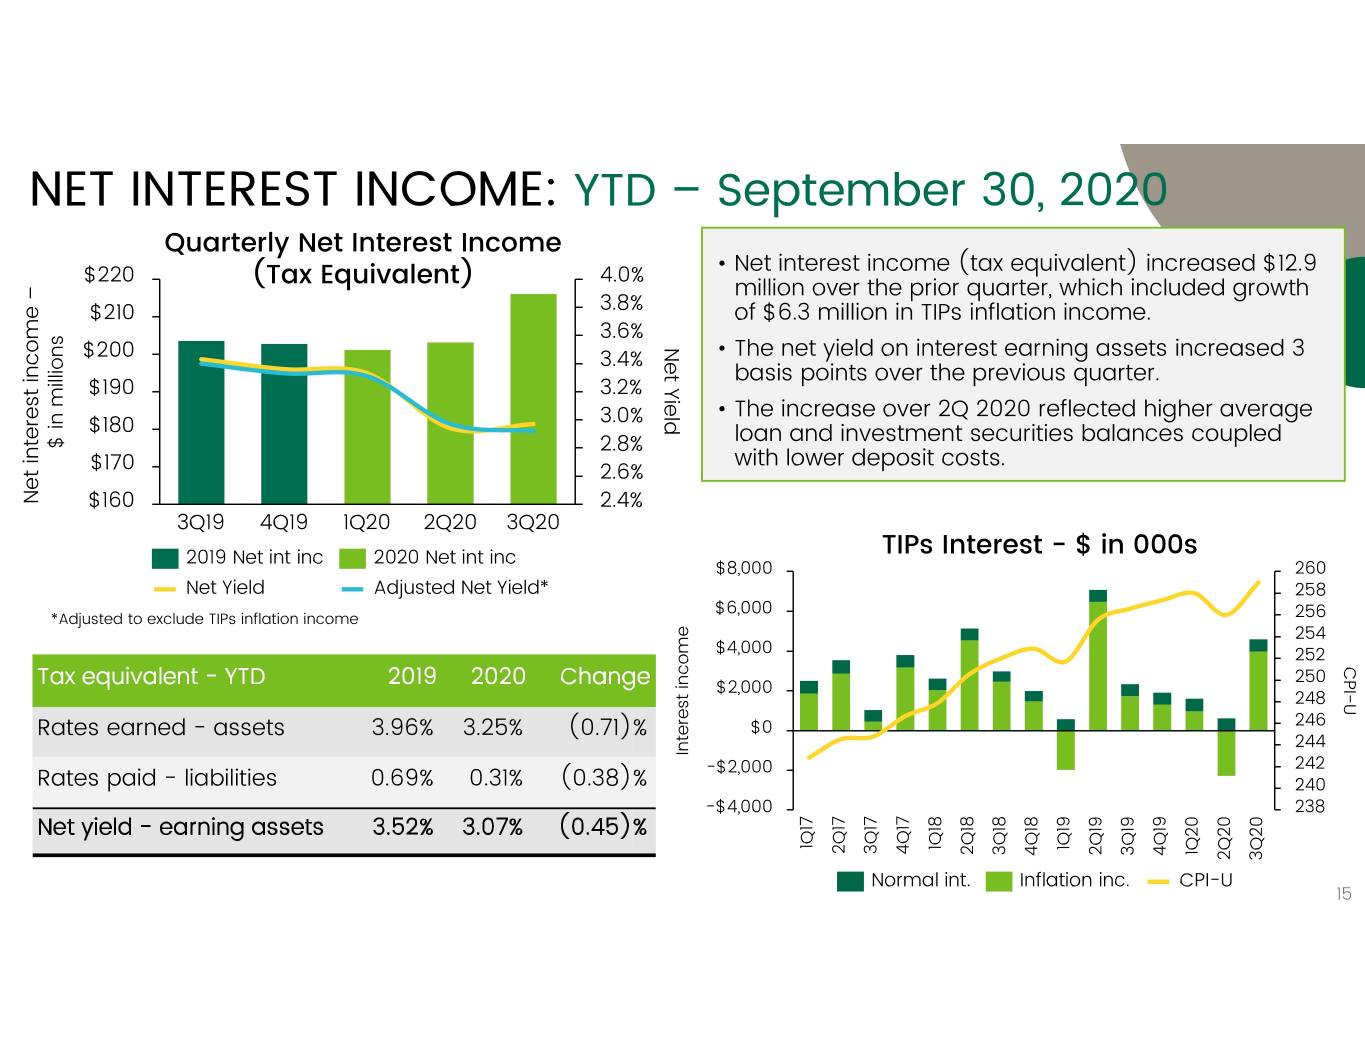
NET INTEREST INCOME: YTD – September 30, 2020 Quarterly Net Interest Income $220 4.0% • Net interest income (tax equivalent) increased $12.9 (Tax Equivalent) million over the prior quarter, which included growth $210 3.8% of $6.3 million in TIPs inflation income. 3.6% NetYield $200 3.4% • The net yield on interest earning assets increased 3 basis points over the previous quarter. $190 3.2% • The increase over 2Q 2020 reflected higher average $180 3.0% $ in millions $ in 2.8% loan and investment securities balances coupled with lower deposit costs. $170 2.6% Net interest income – income interestNet $160 2.4% 3Q19 4Q19 1Q20 2Q20 3Q20 2019 Net int inc 2020 Net int inc TIPs Interest - $ in 000s $8,000 260 Net Yield Adjusted Net Yield* 258 $6,000 *Adjusted to exclude TIPs inflation income 256 254 $4,000 252 CPI-U 250 Tax equivalent -YTD 2019 2020 Change $2,000 248 Rates earned - assets 3.96% 3.25% (0.71)% $0 246 Interest income Interest 244 -$2,000 242 Rates paid - liabilities 0.69% 0.31% (0.38)% 240 -$4,000 238 Net yield - earning assets 3.52% 3.07% (0.45)% 1Q17 1Q18 1Q19 2Q17 3Q17 4Q17 2Q18 3Q18 1Q20 2Q19 3Q19 4Q18 4Q19 2Q20 3Q20 Normal int. Inflation inc. CPI-U 1515
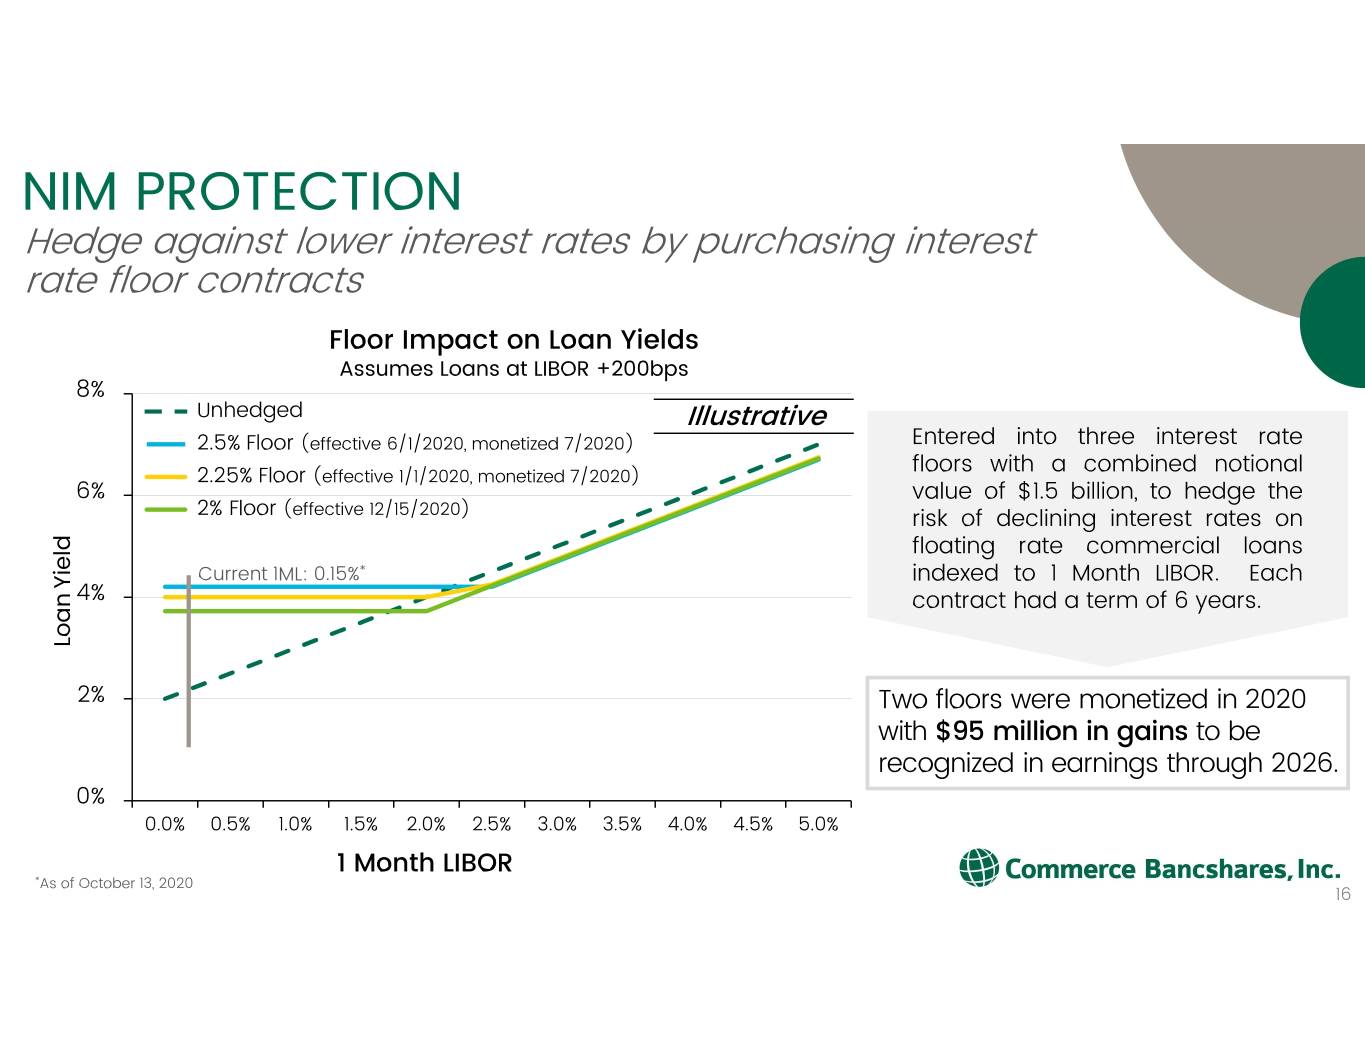
NIM PROTECTION Hedge against lower interest rates by purchasing interest rate floor contracts Floor Impact on Loan Yields Assumes Loans at LIBOR +200bps 8% Unhedged Illustrative 2.5% Floor (effective 6/1/2020, monetized 7/2020) Entered into three interest rate floors with a combined notional 2.25% Floor (effective 1/1/2020, monetized 7/2020) 6% value of $1.5 billion, to hedge the 2% Floor (effective 12/15/2020) risk of declining interest rates on floating rate commercial loans Current 1ML: 0.15%* indexed to 1 Month LIBOR. Each 4% contract had a term of 6 years. Loan Yield 2% Two floors were monetized in 2020 with $95 million in gains to be recognized in earnings through 2026. 0% 0.0%0.5% 1.0% 1.5%2.0% 2.5%3.0% 3.5% 4.0% 4.5% 5.0% 1 Month LIBOR *As of October 13, 2020 16 16
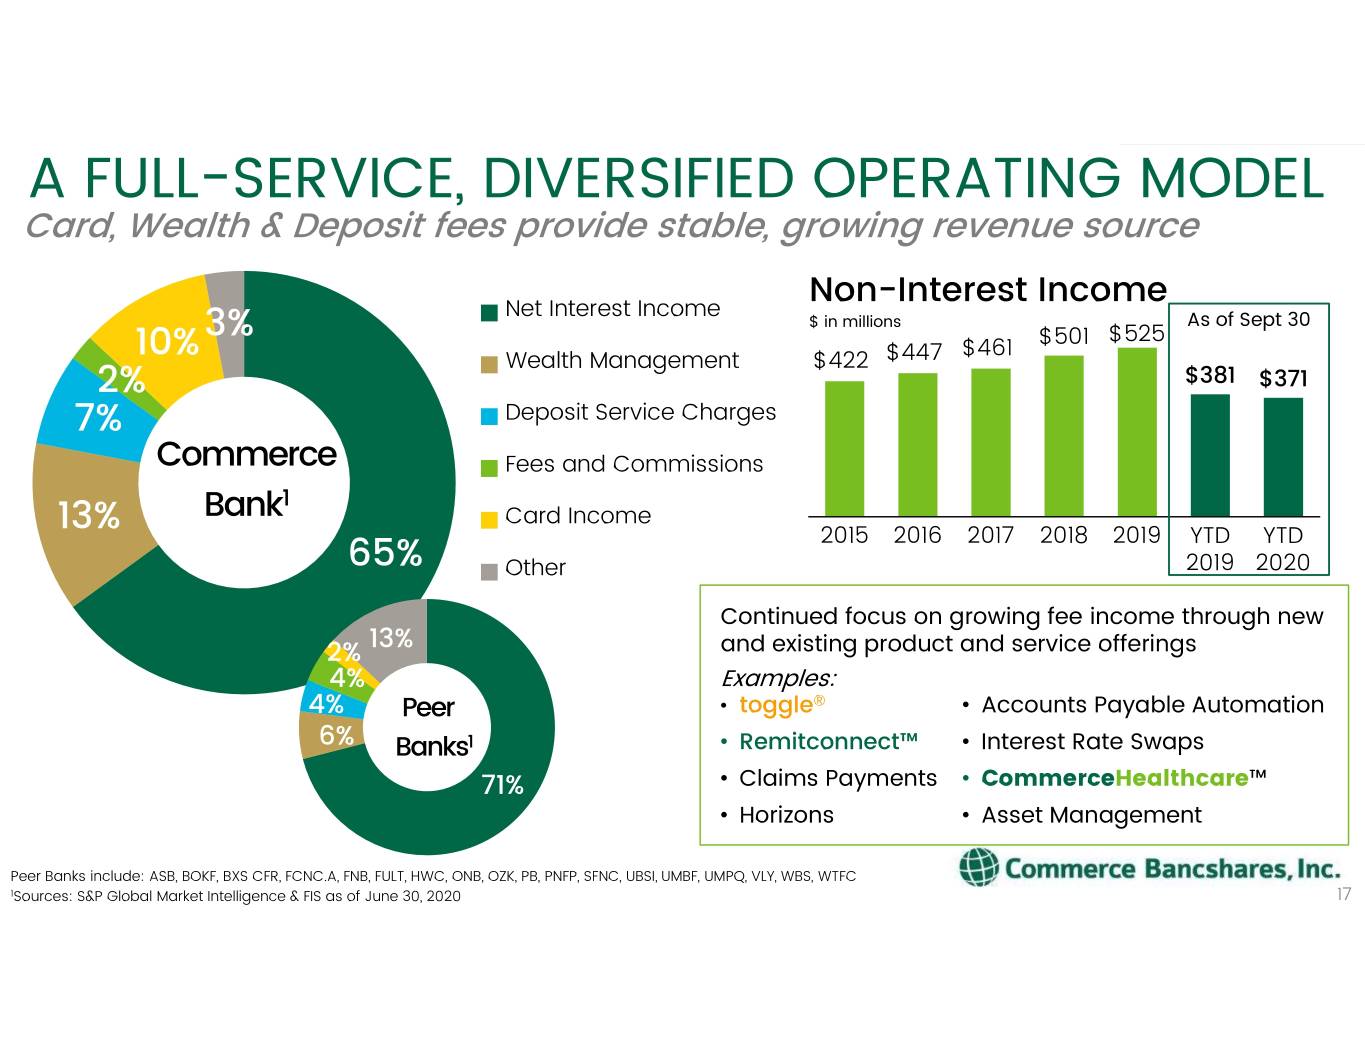
A FULL-SERVICE, DIVERSIFIED OPERATING MODEL Card, Wealth & Deposit fees provide stable, growing revenue source Non-Interest Income Net Interest Income $ in millions As of Sept 30 3% $525 $461 $501 10% Wealth Management $422 $447 2% $381 $371 7% Deposit Service Charges Commerce Fees and Commissions 1 Bank Card Income 13% 2015 201620172018 2019 YTD YTD 65% Other 2019 2020 Continued focus on growing fee income through new 13% 2% and existing product and service offerings 4% Examples: 4% Peer • toggle® • Accounts Payable Automation • • 6% Banks1 Remitconnect™ Interest Rate Swaps • • 71% Claims Payments CommerceHealthcare™ • Horizons • Asset Management Peer Banks include: ASB, BOKF, BXS CFR, FCNC.A, FNB, FULT, HWC, ONB, OZK, PB, PNFP, SFNC, UBSI, UMBF, UMPQ, VLY, WBS, WTFC 1Sources: S&P Global Market Intelligence & FIS as of June 30, 2020 17
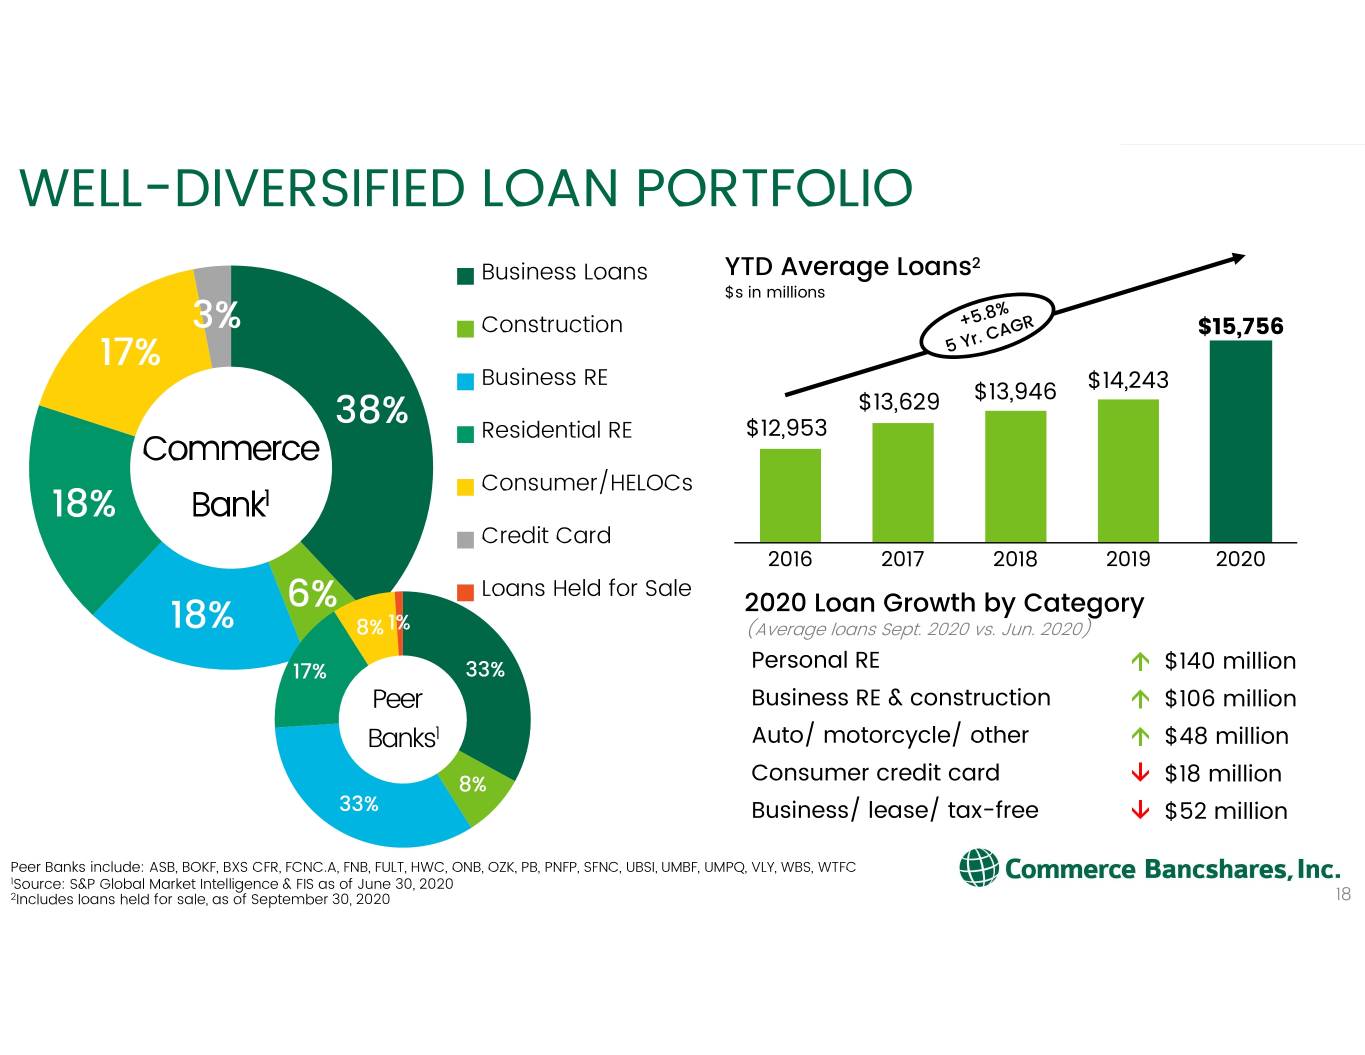
WELL-DIVERSIFIED LOAN PORTFOLIO Business Loans YTD Average Loans2 $s in millions 3% Construction $15,756 17% Business RE $14,243 $13,629 $13,946 38% Residential RE $12,953 Commerce Consumer/HELOCs 18% Bank1 Credit Card 2016 2017 20182019 2020 Loans Held for Sale 6% 2020 Loan Growth by Category 18% 8% 1% (Average loans Sept. 2020 vs. Jun. 2020) 17% 33% Personal RE $140 million Peer Business RE & construction $106 million Banks1 Auto/ motorcycle/ other $48 million 8% Consumer credit card $18 million 33% Business/ lease/ tax-free $52 million Peer Banks include: ASB, BOKF, BXS CFR, FCNC.A, FNB, FULT, HWC, ONB, OZK, PB, PNFP, SFNC, UBSI, UMBF, UMPQ, VLY, WBS, WTFC 1Source: S&P Global Market Intelligence & FIS as of June 30, 2020 2Includes loans held for sale, as of September 30, 2020 18
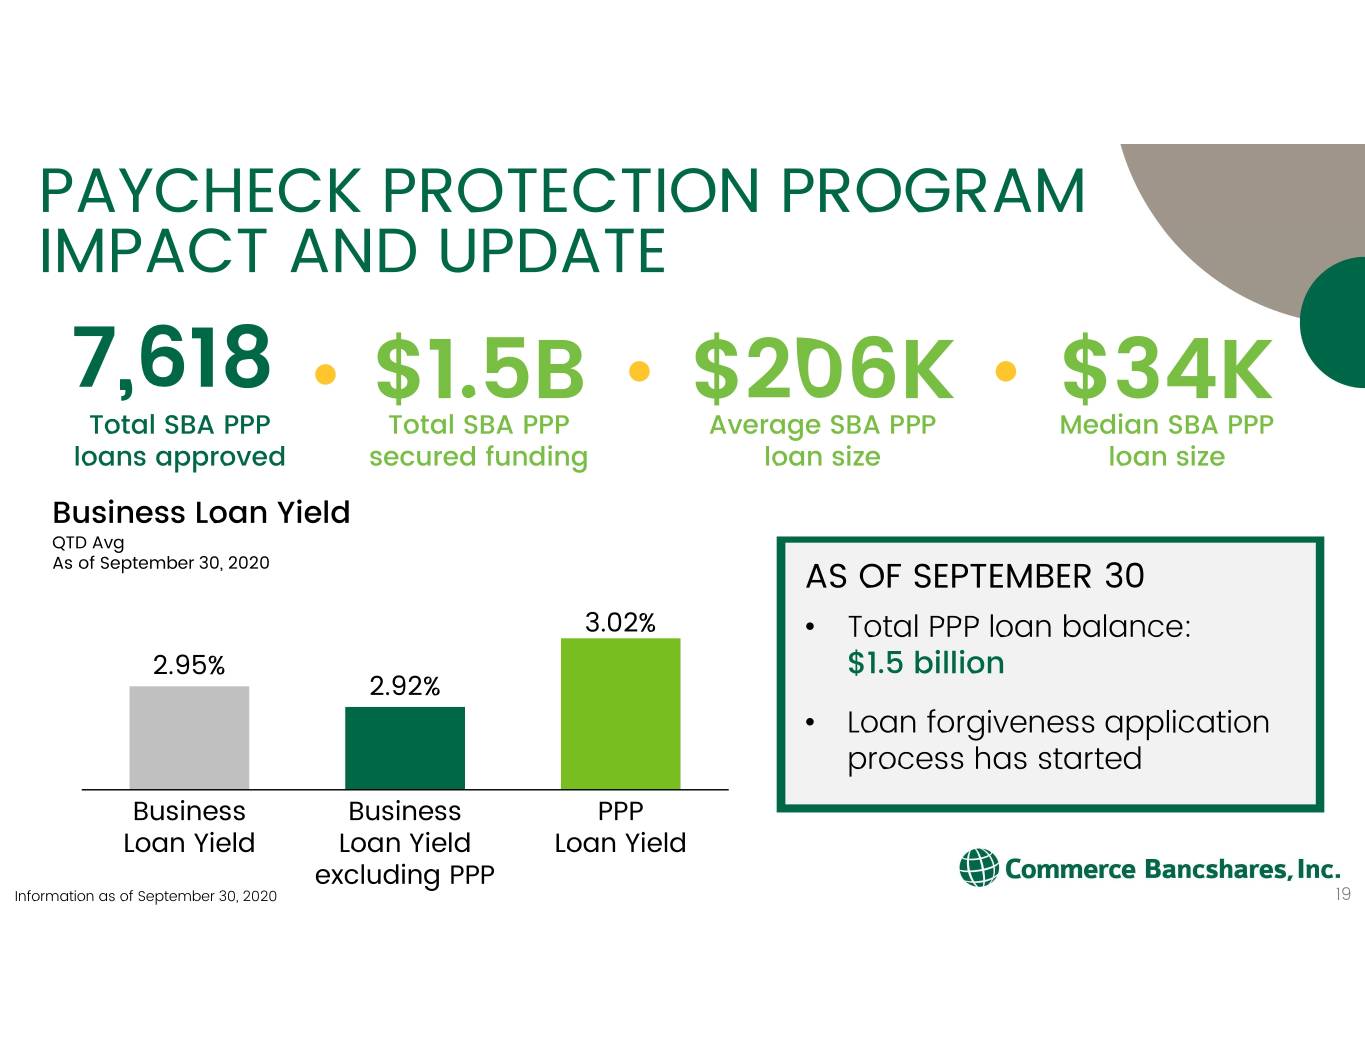
PAYCHECK PROTECTION PROGRAM IMPACT AND UPDATE 7,618 Total SBA PPP $1.5BTotal SBA PPP $206KAverage SBA PPP $34KMedian SBA PPP loans approved secured funding loan size loan size Business Loan Yield QTD Avg As of September 30, 2020 AS OF SEPTEMBER 30 3.02% • Total PPP loan balance: 2.95% $1.5 billion 2.92% • Loan forgiveness application process has started Business Business PPP Loan Yield Loan Yield Loan Yield excluding PPP Information as of September 30, 2020 19
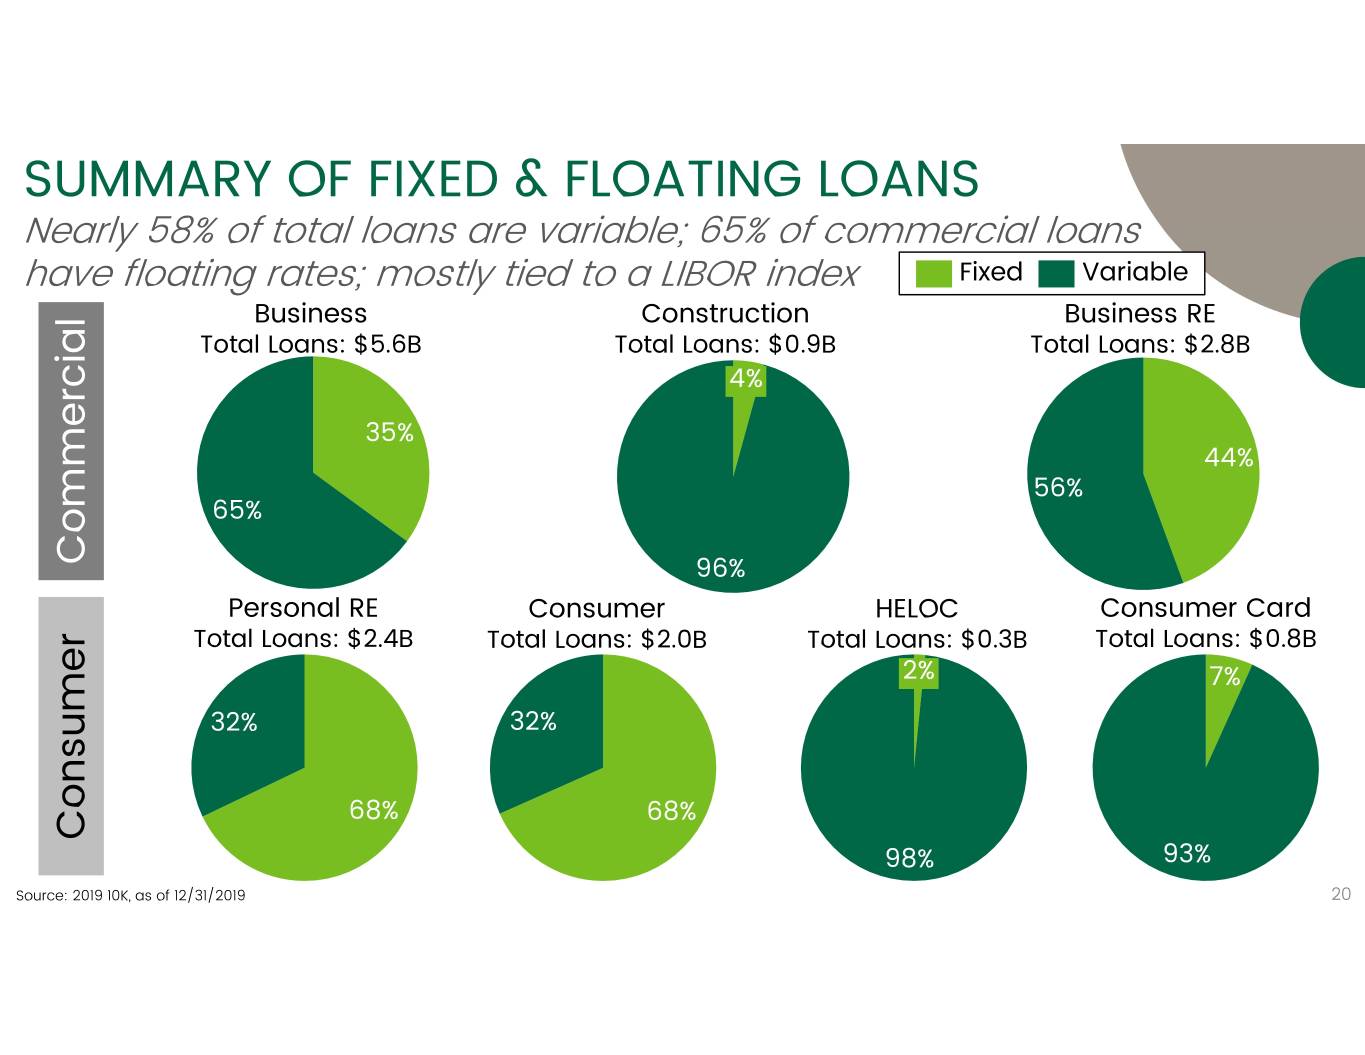
SUMMARY OF FIXED & FLOATING LOANS Nearly 58% of total loans are variable; 65% of commercial loans have floating rates; mostly tied to a LIBOR index Fixed Variable Business Construction Business RE Total Loans: $5.6B Total Loans: $0.9B Total Loans: $2.8B 4% 35% 44% 56% 65% Commercial 96% Personal RE Consumer HELOC Consumer Card Total Loans: $2.4B Total Loans: $2.0B Total Loans: $0.3B Total Loans: $0.8B 2% 7% 32% 32% 68% 68% Consumer 98% 93% 20 Source: 2019 10K, as of 12/31/2019 20
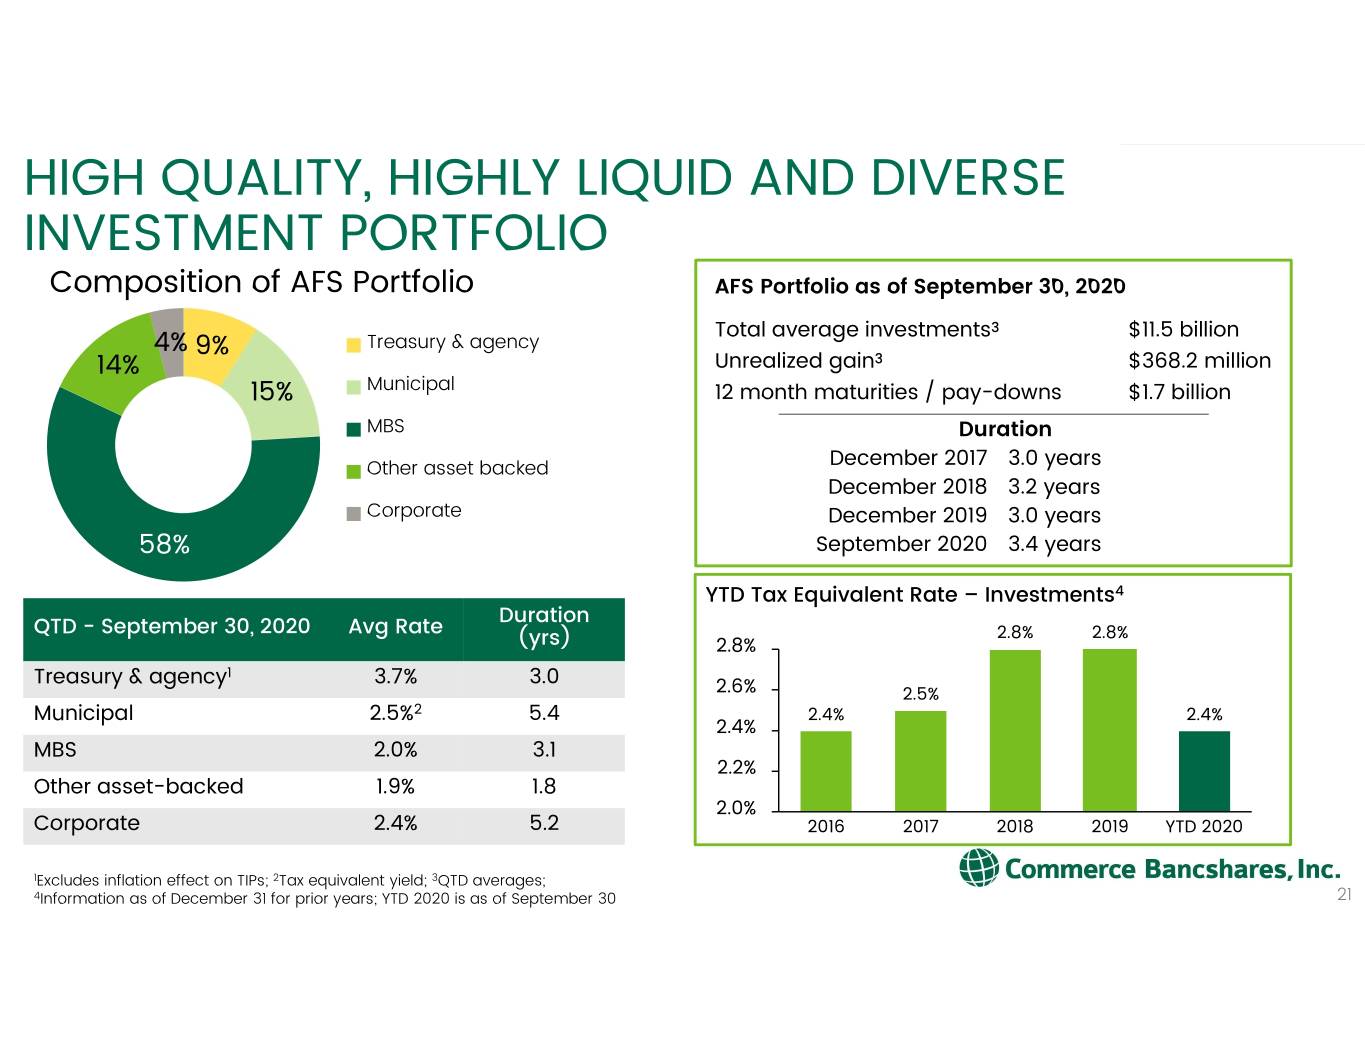
HIGH QUALITY, HIGHLY LIQUID AND DIVERSE INVESTMENT PORTFOLIO Composition of AFS Portfolio AFS Portfolio as of September 30, 2020 Total average investments3 $11.5 billion 4% 9% Treasury & agency 14% Unrealized gain3 $368.2 million 15% Municipal 12 month maturities / pay-downs $1.7 billion MBS Duration Other asset backed December 2017 3.0 years December 2018 3.2 years Corporate December 2019 3.0 years 58% September 2020 3.4 years YTD Tax Equivalent Rate – Investments4 Duration QTD - September 30, 2020 Avg Rate 2.8% 2.8% (yrs) 2.8% Treasury & agency1 3.7% 3.0 2.6% 2.5% Municipal 2.5%2 5.4 2.4% 2.4% 2.4% MBS 2.0% 3.1 2.2% Other asset-backed 1.9% 1.8 2.0% Corporate 2.4% 5.2 2016 20172018 2019 YTD 2020 1 2 3 Excludes inflation effect on TIPs; Tax equivalent yield; QTD averages; 21 4Information as of December 31 for prior years; YTD 2020 is as of September 30 21
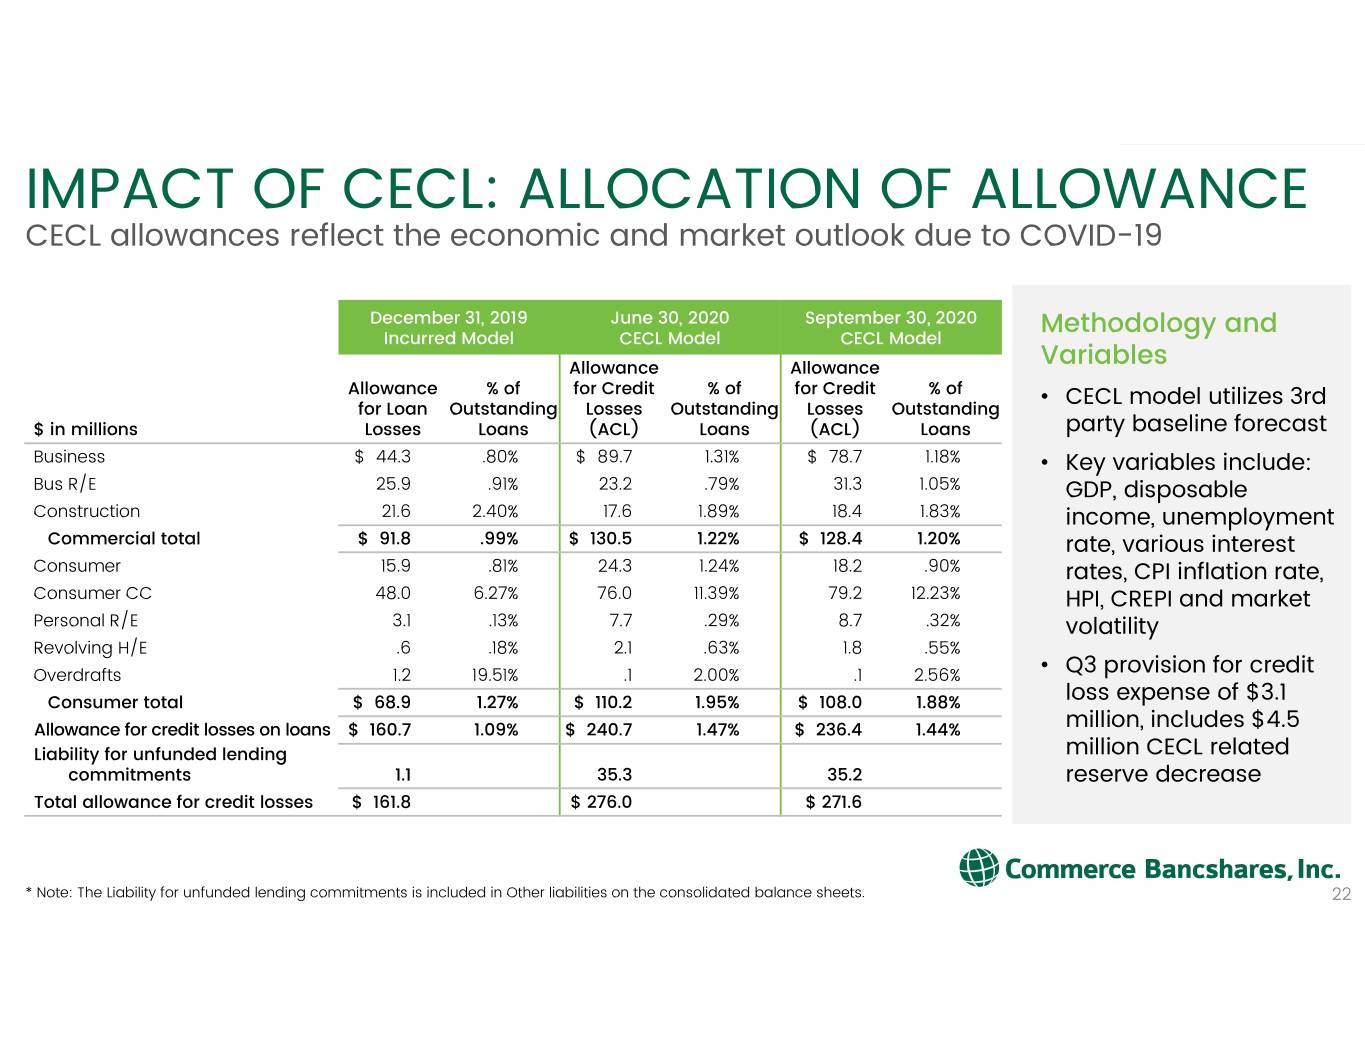
IMPACT OF CECL: ALLOCATION OF ALLOWANCE CECL allowances reflect the economic and market outlook due to COVID-19 December 31, 2019 June 30, 2020 September 30, 2020 Incurred Model CECL Model CECL Model Methodology and Allowance Allowance Variables Allowance % of for Credit % of for Credit % of • for Loan Outstanding Losses Outstanding Losses Outstanding CECL model utilizes 3rd $ in millions Losses Loans (ACL) Loans (ACL) Loans party baseline forecast Business $ 44.3 .80% $ 89.7 1.31% $ 78.7 1.18% • Key variables include: Bus R/E 25.9 .91% 23.2 .79% 31.3 1.05% GDP, disposable Construction 21.6 2.40% 17.6 1.89% 18.4 1.83% income, unemployment Commercial total $ 91.8 .99% $ 130.5 1.22% $ 128.4 1.20% rate, various interest Consumer 15.9 .81% 24.3 1.24% 18.2 .90% rates, CPI inflation rate, Consumer CC 48.0 6.27% 76.0 11.39% 79.2 12.23% HPI, CREPI and market Personal R/E 3.1 .13% 7.7 .29% 8.7 .32% volatility Revolving H/E .6 .18% 2.1 .63% 1.8 .55% • Overdrafts 1.2 19.51% .1 2.00% .1 2.56% Q3 provision for credit Consumer total $ 68.9 1.27% $ 110.2 1.95% $ 108.0 1.88% loss expense of $3.1 Allowance for credit losses on loans $ 160.7 1.09% $ 240.7 1.47% $ 236.4 1.44% million, includes $4.5 Liability for unfunded lending million CECL related commitments 1.1 35.3 35.2 reserve decrease Total allowance for credit losses $ 161.8 $ 276.0 $ 271.6 * Note: The Liability for unfunded lending commitments is included in Other liabilities on the consolidated balance sheets. 22
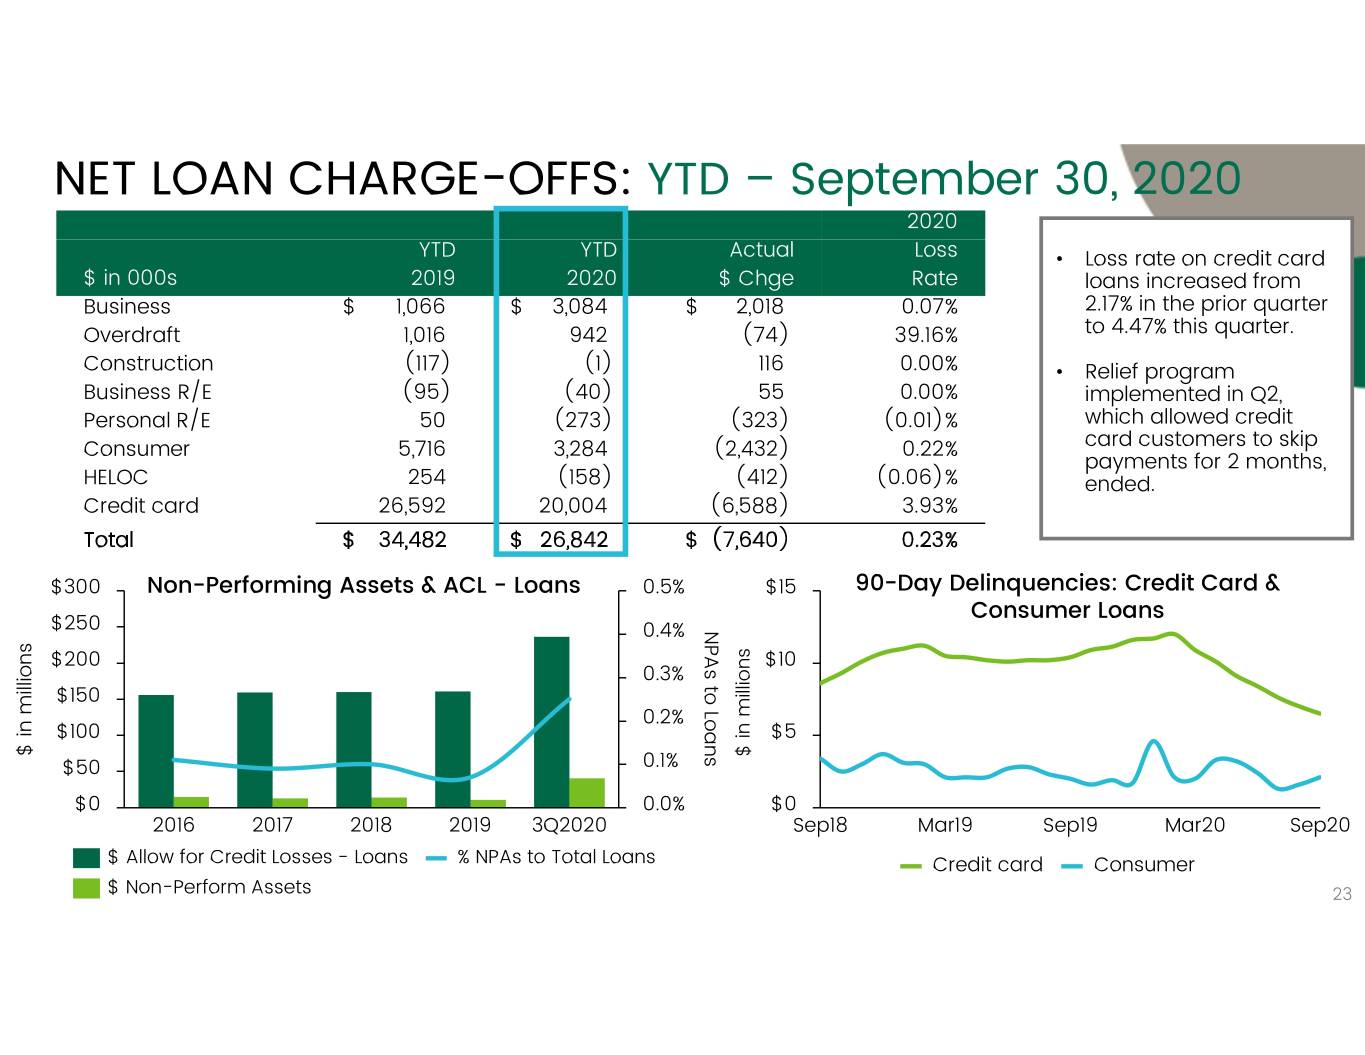
NET LOAN CHARGE-OFFS: YTD – September 30, 2020 2020 YTD YTD Actual Loss • Loss rate on credit card $ in 000s 2019 2020 $ Chge Rate loans increased from Business $ 1,066 $ 3,084 $ 2,018 0.07% 2.17% in the prior quarter Overdraft 1,016 942 (74) 39.16% to 4.47% this quarter. Construction (117) (1) 116 0.00% • Relief program Business R/E (95) (40) 55 0.00% implemented in Q2, Personal R/E 50 (273) (323) (0.01)% which allowed credit Consumer 5,716 3,284 (2,432) 0.22% card customers to skip payments for 2 months, HELOC 254 (158) (412) (0.06)% ended. Credit card 26,592 20,004 (6,588) 3.93% Total $ 34,482 $26,842 $(7,640) 0.23% $300 Non-Performing Assets & ACL - Loans 0.5% $15 90-Day Delinquencies: Credit Card & Consumer Loans $250 0.4% to Loans NPAs $200 $10 0.3% $150 0.2% $100 $5 $ in millions $ in $ in in millions $ $50 0.1% $0 0.0% $0 2016 2017 2018 2019 3Q2020 Sep18Mar19 Sep19 Mar20 Sep20 $ Allow for Credit Losses - Loans % NPAs to Total Loans Credit card Consumer $ Non-Perform Assets 23
COMMERCE AND COVID-19 24
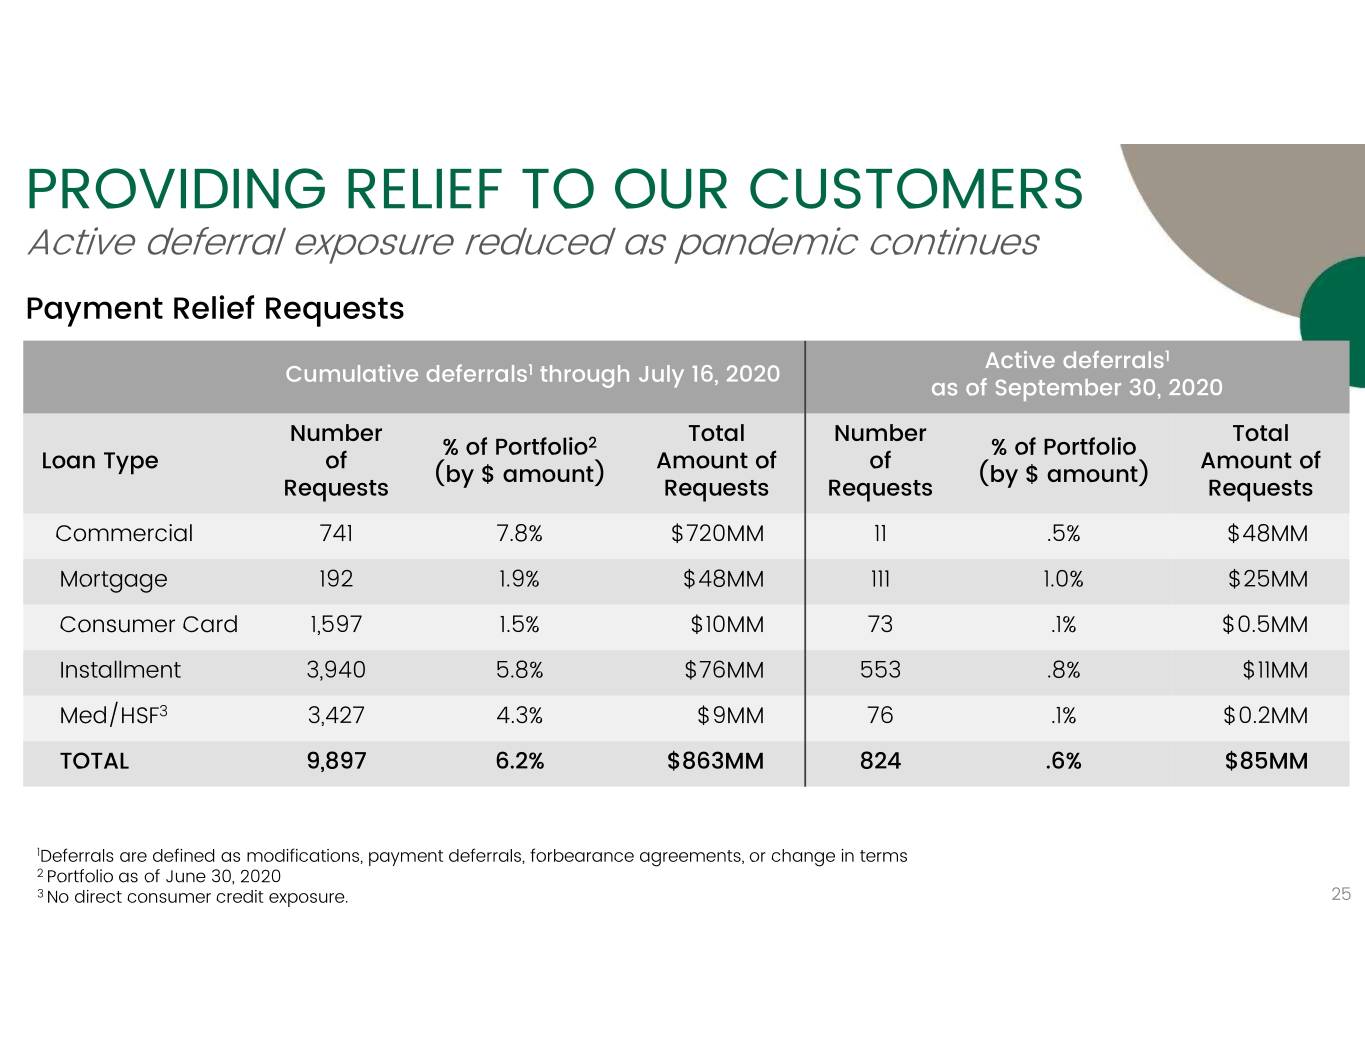
PROVIDING RELIEF TO OUR CUSTOMERS Active deferral exposure reduced as pandemic continues Payment Relief Requests Active deferrals1 Cumulative deferrals1 through July 16, 2020 as of September 30, 2020 Number Total Number Total % of Portfolio2 % of Portfolio Loan Type of Amount of of Amount of (by $ amount) (by $ amount) Requests Requests Requests Requests Commercial 741 7.8% $720MM 11 .5% $48MM Mortgage 192 1.9% $48MM 111 1.0% $25MM Consumer Card 1,597 1.5% $10MM 73 .1% $0.5MM Installment 3,940 5.8% $76MM 553 .8% $11MM Med/HSF3 3,427 4.3% $9MM 76 .1% $0.2MM TOTAL 9,897 6.2% $863MM 824 .6% $85MM 1Deferrals are defined as modifications, payment deferrals, forbearance agreements, or change in terms 2 Portfolio as of June 30, 2020 3 No direct consumer credit exposure. 25
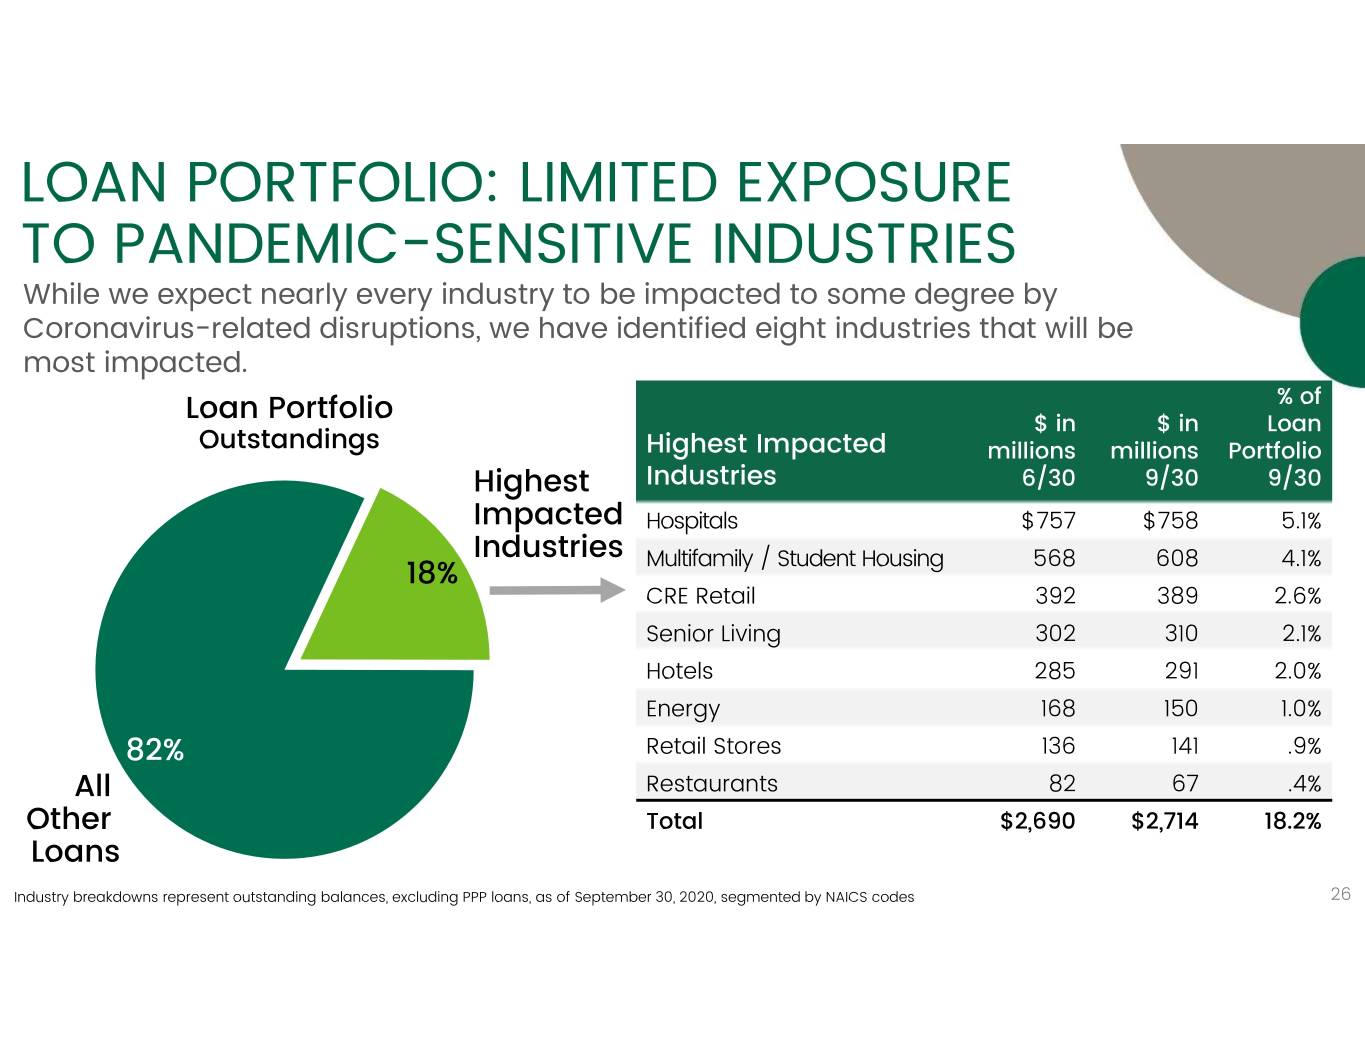
LOAN PORTFOLIO: LIMITED EXPOSURE TO PANDEMIC-SENSITIVE INDUSTRIES While we expect nearly every industry to be impacted to some degree by Coronavirus-related disruptions, we have identified eight industries that will be most impacted. % of Loan Portfolio $ in $ in Loan Outstandings Highest Impacted millions millions Portfolio Highest Industries 6/30 9/30 9/30 Impacted Hospitals $757 $758 5.1% Industries Multifamily / Student Housing 568 608 4.1% 18% CRE Retail 392 389 2.6% Senior Living 302 310 2.1% Hotels 285 291 2.0% Energy 168 150 1.0% 82% Retail Stores 136 141 .9% All Restaurants 82 67 .4% Other Total $2,690 $2,714 18.2% Loans Industry breakdowns represent outstanding balances, excluding PPP loans, as of September 30, 2020, segmented by NAICS codes 26
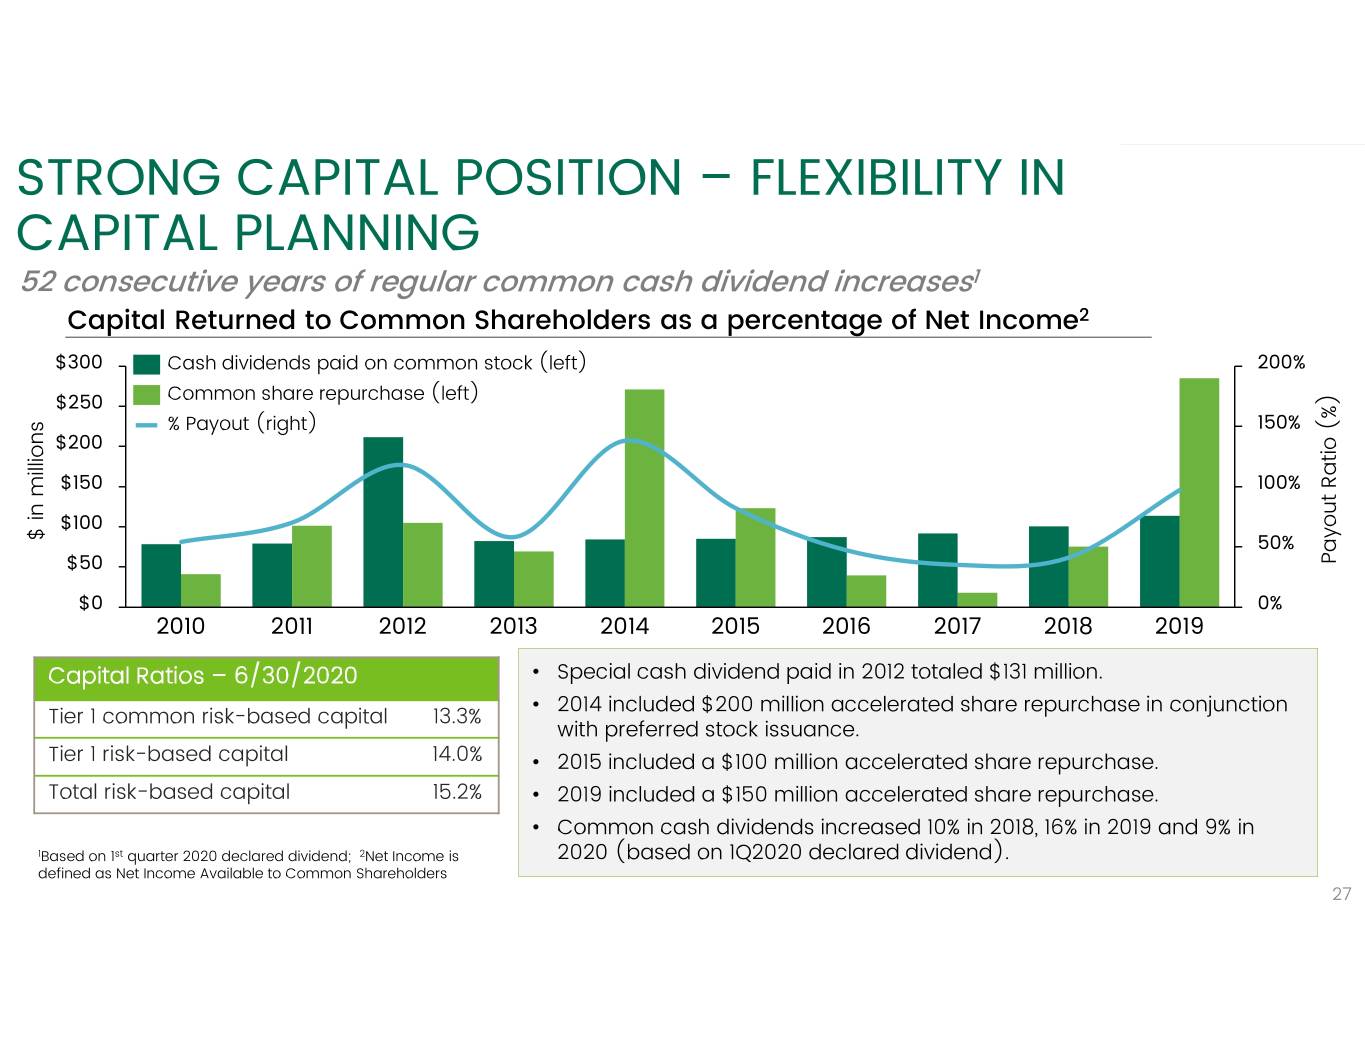
STRONG CAPITAL POSITION – FLEXIBILITY IN CAPITAL PLANNING 52 consecutive years of regular common cash dividend increases1 Capital Returned to Common Shareholders as a percentage of Net Income2 $300 Cash dividends paid on common stock (left) 200% $250 Common share repurchase (left) % Payout (right) 150% $200 $150 100% $100 $ in millions $ 50% $50 (%) Ratio Payout $0 0% 201020112012 2013 2014 2015 2016 20172018 2019 Capital Ratios – 6/30/2020 • Special cash dividend paid in 2012 totaled $131 million. • 2014 included $200 million accelerated share repurchase in conjunction Tier 1 common risk-based capital 13.3% with preferred stock issuance. Tier 1 risk-based capital 14.0% • 2015 included a $100 million accelerated share repurchase. Total risk-based capital 15.2% • 2019 included a $150 million accelerated share repurchase. • Common cash dividends increased 10% in 2018, 16% in 2019 and 9% in 1Based on 1st quarter 2020 declared dividend; 2Net Income is 2020 (based on 1Q2020 declared dividend). defined as Net Income Available to Common Shareholders 27 27
STRATEGIC POSITION 28
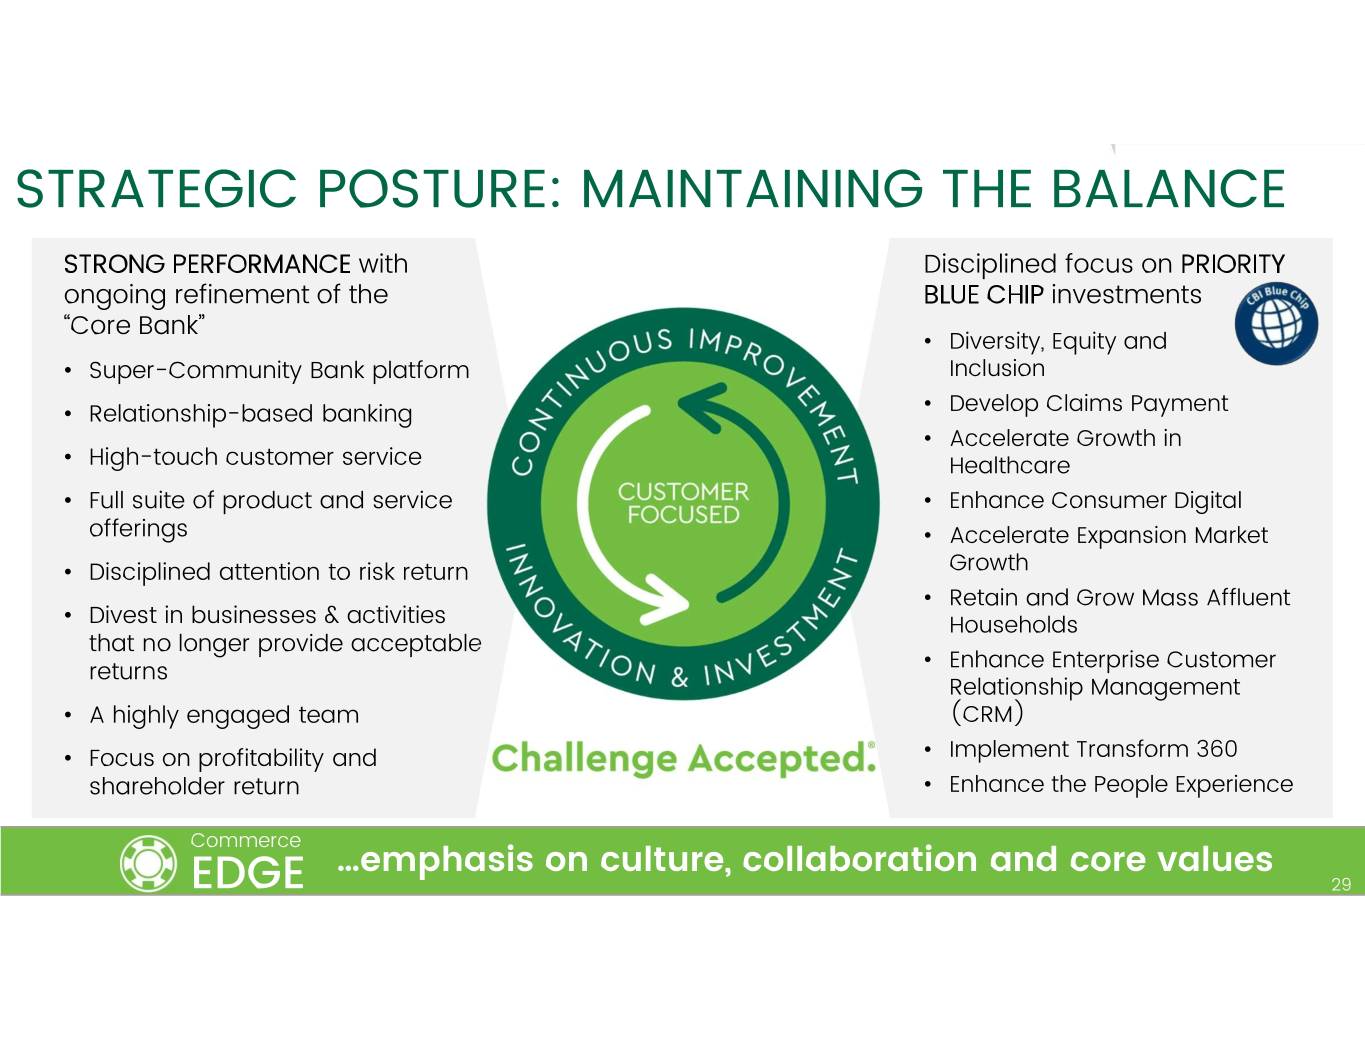
STRATEGIC POSTURE: MAINTAINING THE BALANCE STRONG PERFORMANCE with Disciplined focus on PRIORITY ongoing refinement of the BLUE CHIP investments “Core Bank” • Diversity, Equity and • Super-Community Bank platform Inclusion • • Relationship-based banking Develop Claims Payment • • Accelerate Growth in High-touch customer service Healthcare • Full suite of product and service • Enhance Consumer Digital offerings • Accelerate Expansion Market • Disciplined attention to risk return Growth • • Retain and Grow Mass Affluent Divest in businesses & activities Households that no longer provide acceptable • Enhance Enterprise Customer returns Relationship Management • A highly engaged team (CRM) • • Focus on profitability and Implement Transform 360 shareholder return • Enhance the People Experience Commerce …emphasis on culture, collaboration and core values EDGE 29
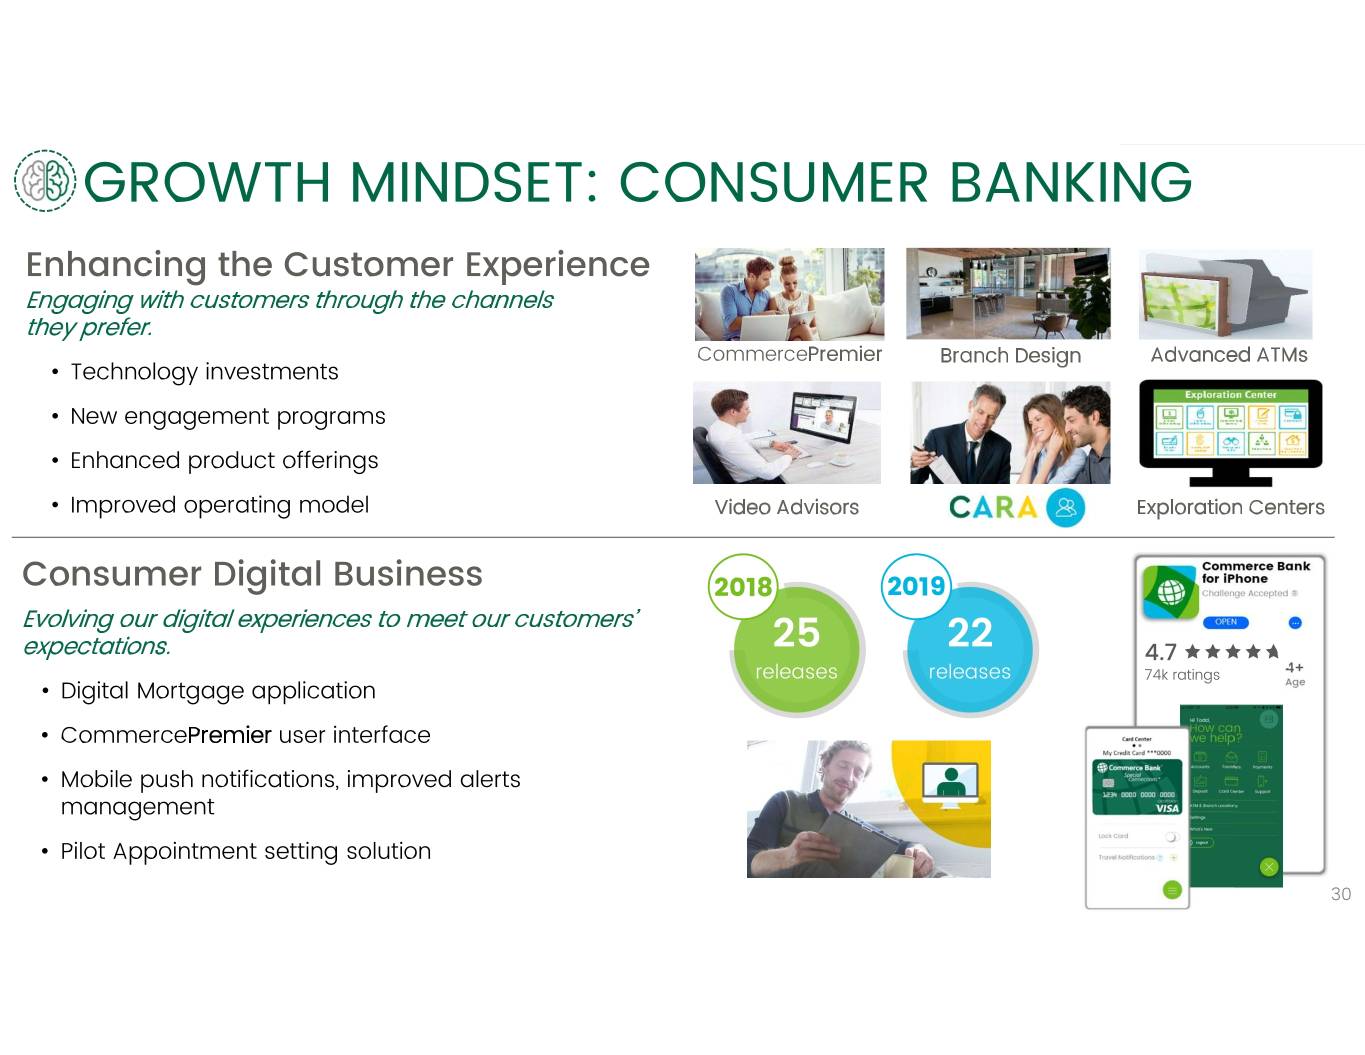
GROWTH MINDSET: CONSUMER BANKING Enhancing the Customer Experience Engaging with customers through the channels they prefer. CommercePremier Branch Design Advanced ATMs • Technology investments • New engagement programs • Enhanced product offerings • Improved operating model Video Advisors Exploration Centers Consumer Digital Business 2018 2019 Evolving our digital experiences to meet our customers’ expectations. 25 22 4.7 releases releases 74k ratings • Digital Mortgage application • CommercePremier user interface • Mobile push notifications, improved alerts management • Pilot Appointment setting solution 30
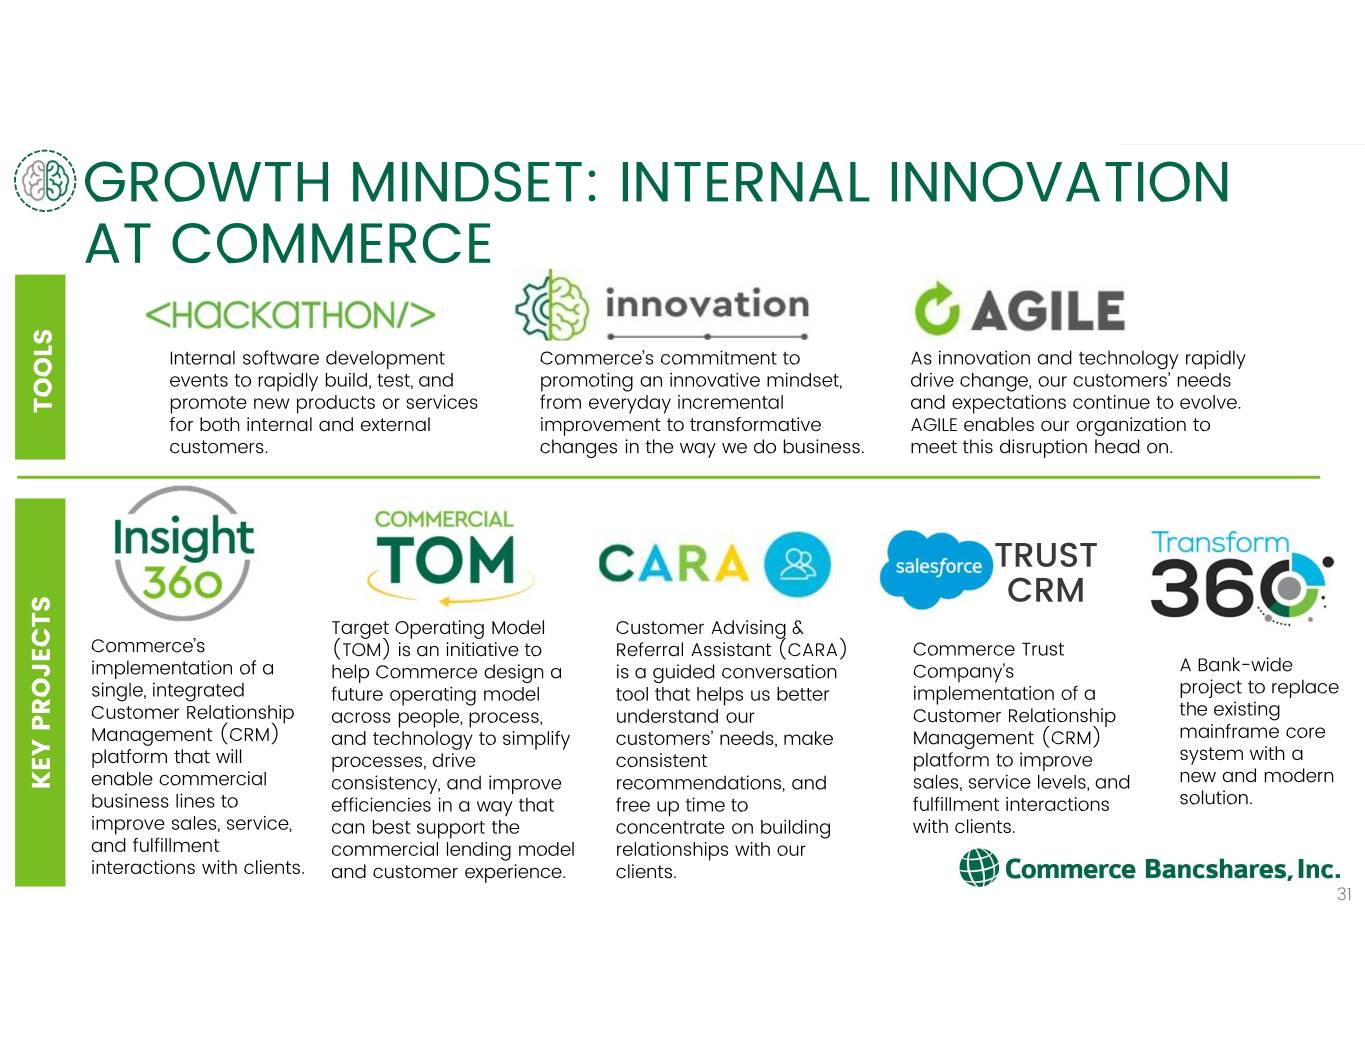
GROWTH MINDSET: INTERNAL INNOVATION AT COMMERCE Internal software development Commerce’s commitment to As innovation and technology rapidly events to rapidly build, test, and promoting an innovative mindset, drive change, our customers’ needs TOOLS promote new products or services from everyday incremental and expectations continue to evolve. for both internal and external improvement to transformative AGILE enables our organization to customers. changes in the way we do business. meet this disruption head on. TRUST CRM Target Operating Model Customer Advising & Commerce’s (TOM) is an initiative to Referral Assistant (CARA) Commerce Trust implementation of a help Commerce design a is a guided conversation Company’s A Bank-wide single, integrated future operating model tool that helps us better implementation of a project to replace Customer Relationship across people, process, understand our Customer Relationship the existing Management (CRM) and technology to simplify customers’ needs, make Management (CRM) mainframe core platform that will processes, drive consistent platform to improve system with a KEY PROJECTS KEY enable commercial consistency, and improve recommendations, and sales, service levels, and new and modern business lines to efficiencies in a way that free up time to fulfillment interactions solution. improve sales, service, can best support the concentrate on building with clients. and fulfillment commercial lending model relationships with our interactions with clients. and customer experience. clients. 31
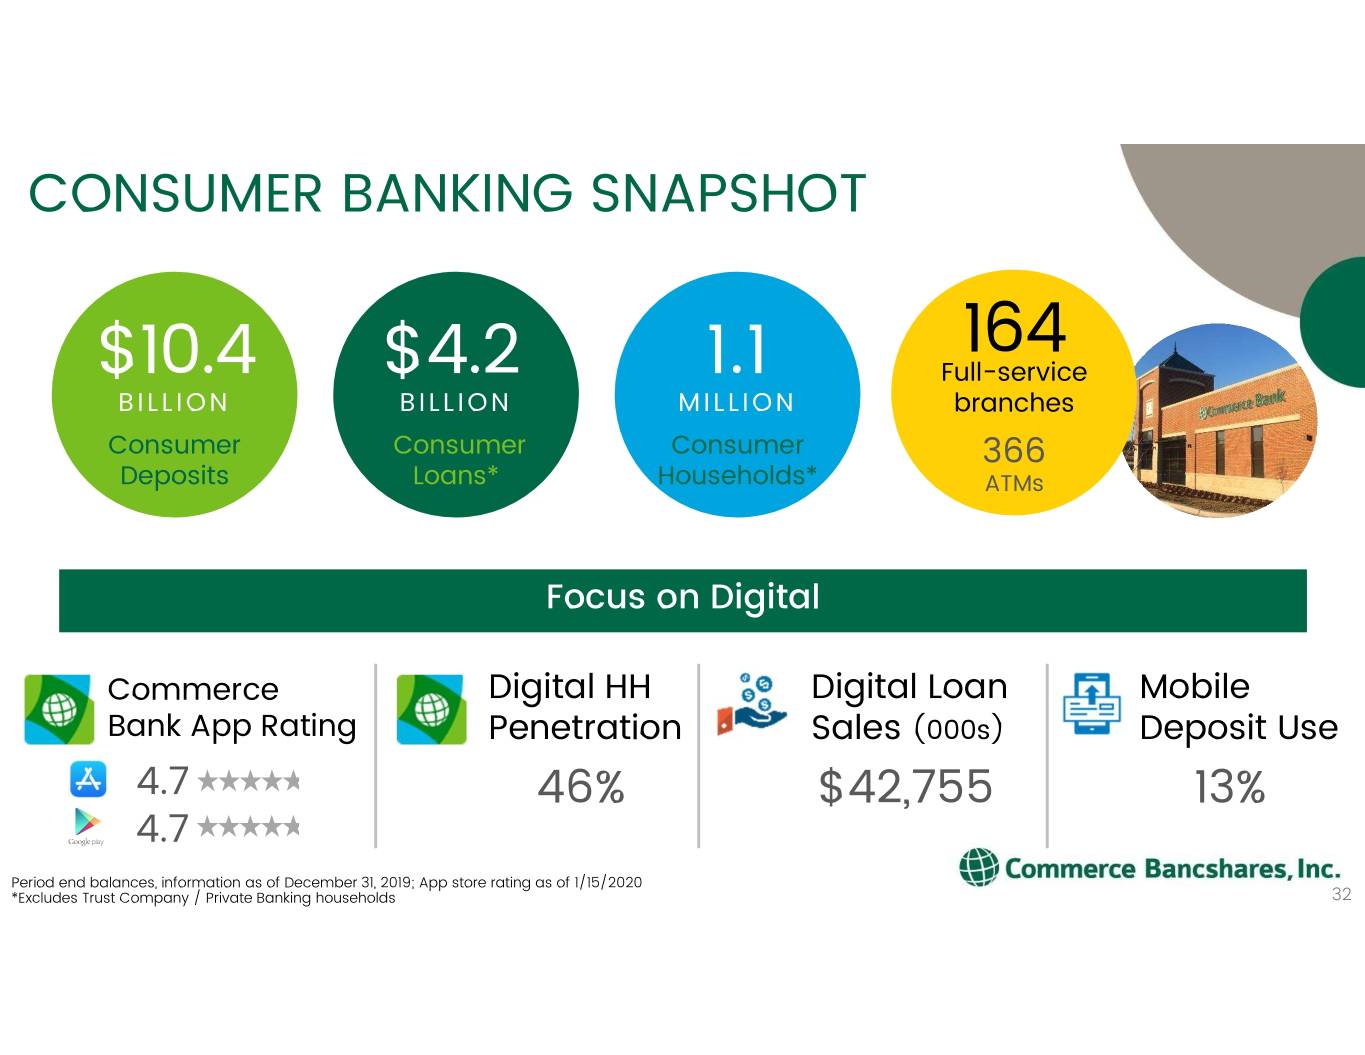
CONSUMER BANKING SNAPSHOT 164 $10.4 $4.2 1.1 Full-service BILLION BILLION MILLION branches Consumer Consumer Consumer 366 Deposits Loans* Households* ATMs Focus on Digital Commerce Digital HH Digital Loan Mobile Bank App Rating Penetration Sales (000s) Deposit Use 4.7 46% $42,755 13% 4.7 Period end balances, information as of December 31, 2019; App store rating as of 1/15/2020 32 *Excludes Trust Company / Private Banking households 32
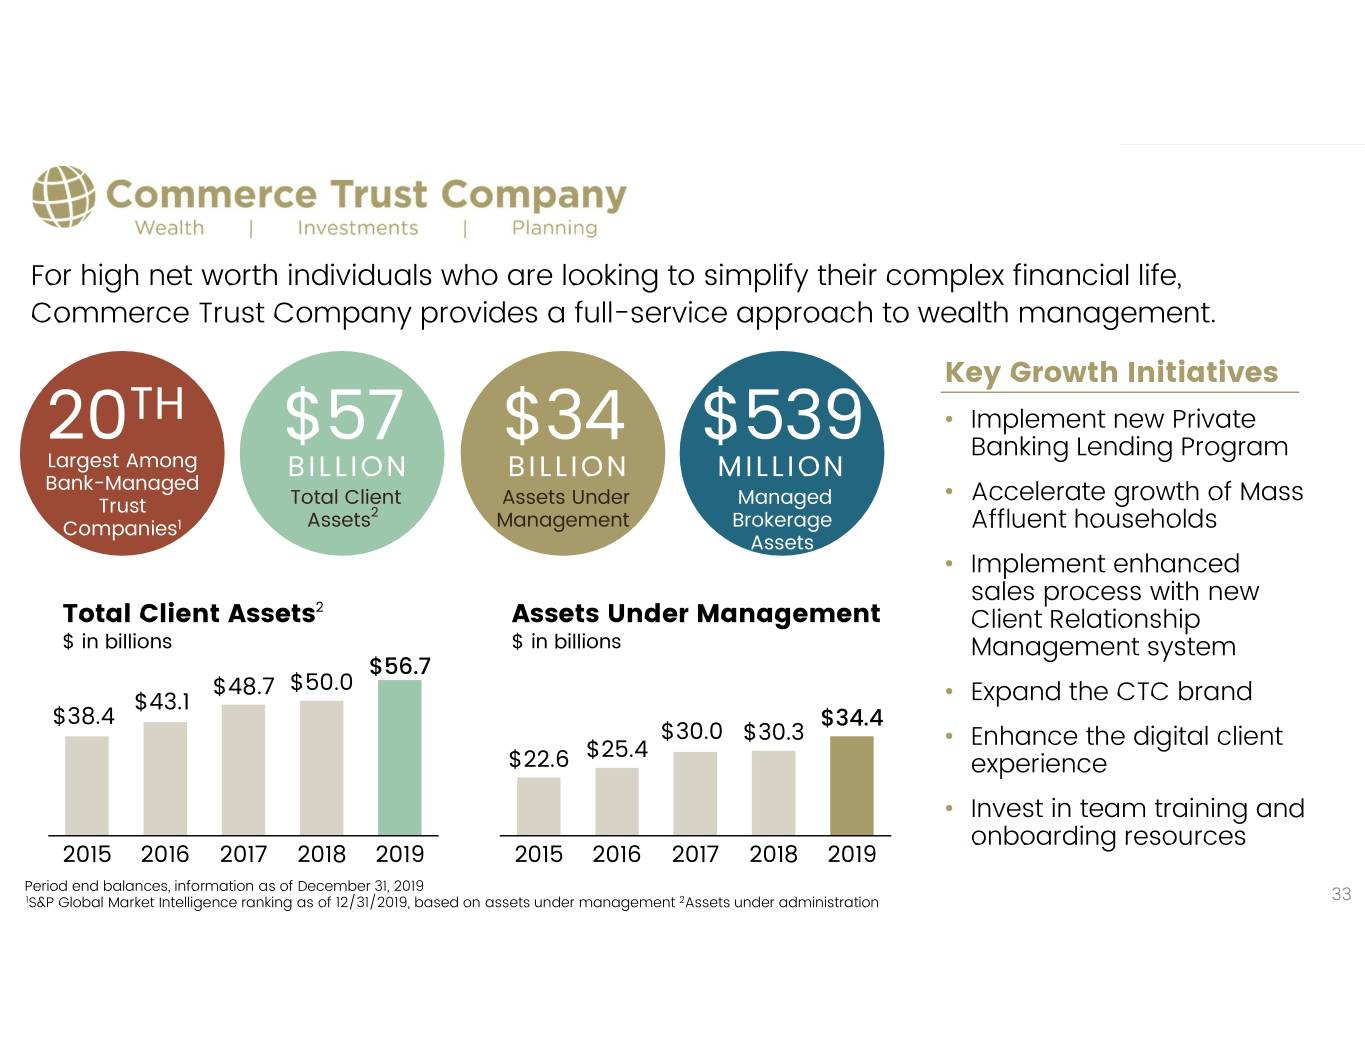
For high net worth individuals who are looking to simplify their complex financial life, Commerce Trust Company provides a full-service approach to wealth management. Key Growth Initiatives TH • Implement new Private 20Largest Among $57 $34 $539 Banking Lending Program Bank-Managed BILLION BILLION MILLION Total Client Assets Under Managed • Accelerate growth of Mass Trust 2 Companies1 Assets Management Brokerage Affluent households Assets • Implement enhanced 2 sales process with new Total Client Assets Assets Under Management Client Relationship $ in billions $ in billions Management system $56.7 $48.7 $50.0 • $43.1 Expand the CTC brand $38.4 $34.4 $30.0 $30.3 • $25.4 Enhance the digital client $22.6 experience • Invest in team training and onboarding resources 2015 2016 2017 2018 2019 2015 2016 2017 2018 2019 Period end balances, information as of December 31, 2019 33 1S&P Global Market Intelligence ranking as of 12/31/2019, based on assets under management 2Assets under administration 33
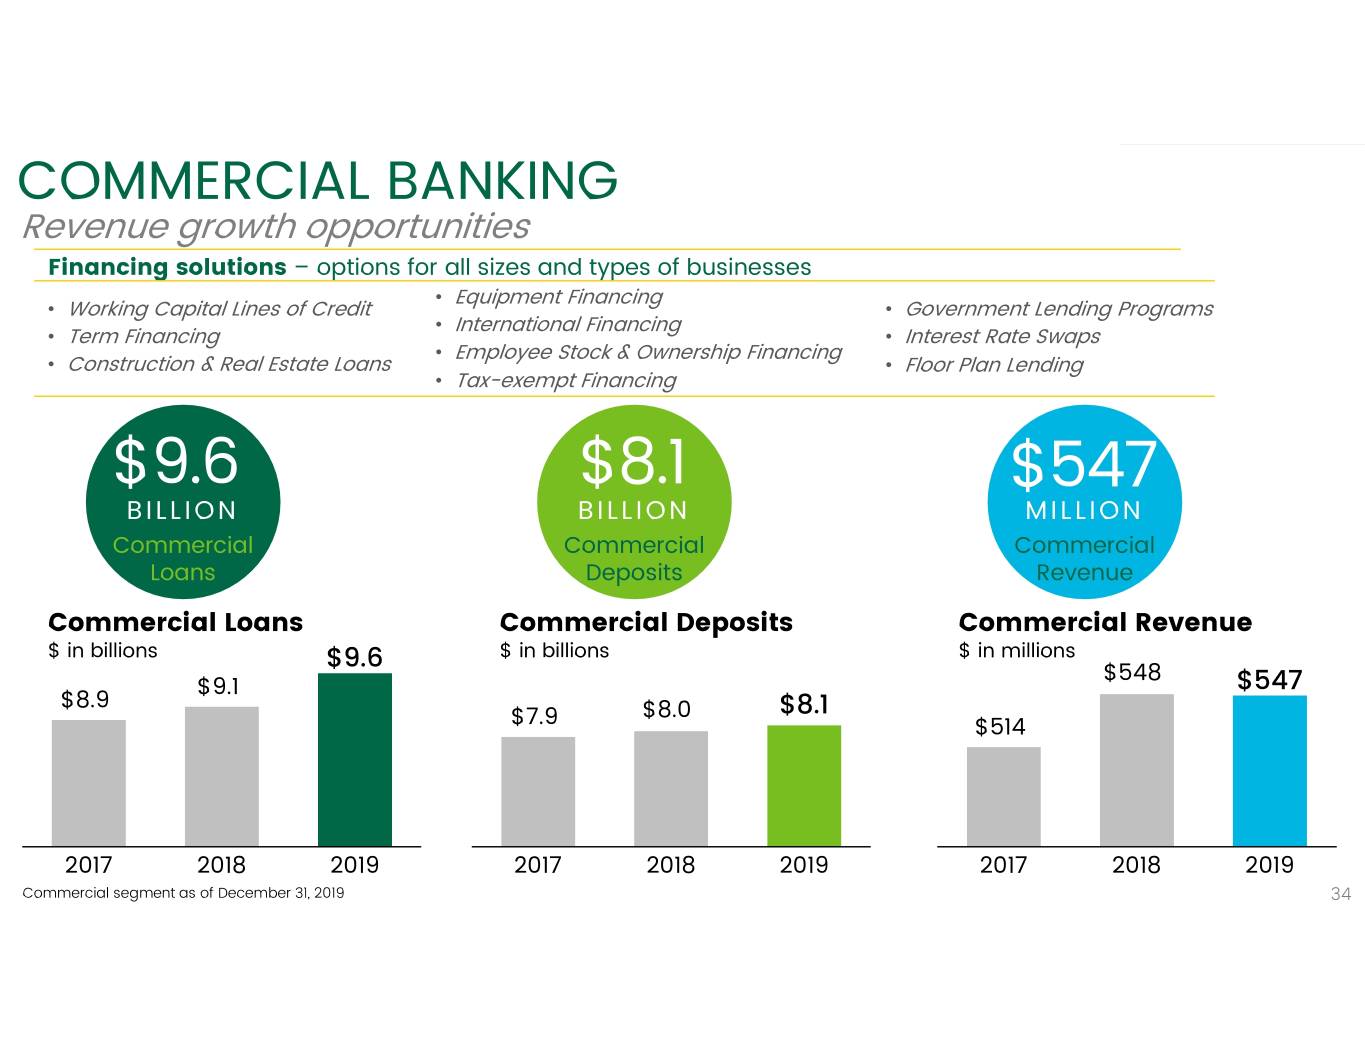
COMMERCIAL BANKING Revenue growth opportunities Financing solutions – options for all sizes and types of businesses • Equipment Financing • Working Capital Lines of Credit • Government Lending Programs • International Financing • Term Financing • Interest Rate Swaps • Employee Stock & Ownership Financing • Construction & Real Estate Loans • Floor Plan Lending • Tax-exempt Financing $9.6 $8.1 $547 BILLION BILLION MILLION Commercial Commercial Commercial Loans Deposits Revenue Commercial Loans Commercial Deposits Commercial Revenue $ in billions $9.6 $ in billions $ in millions $548 $9.1 $547 $8.9 $8.0 $8.1 $7.9 $514 2017 2018 2019 20172018 2019 2017 2018 2019 Commercial segment as of December 31, 2019 34
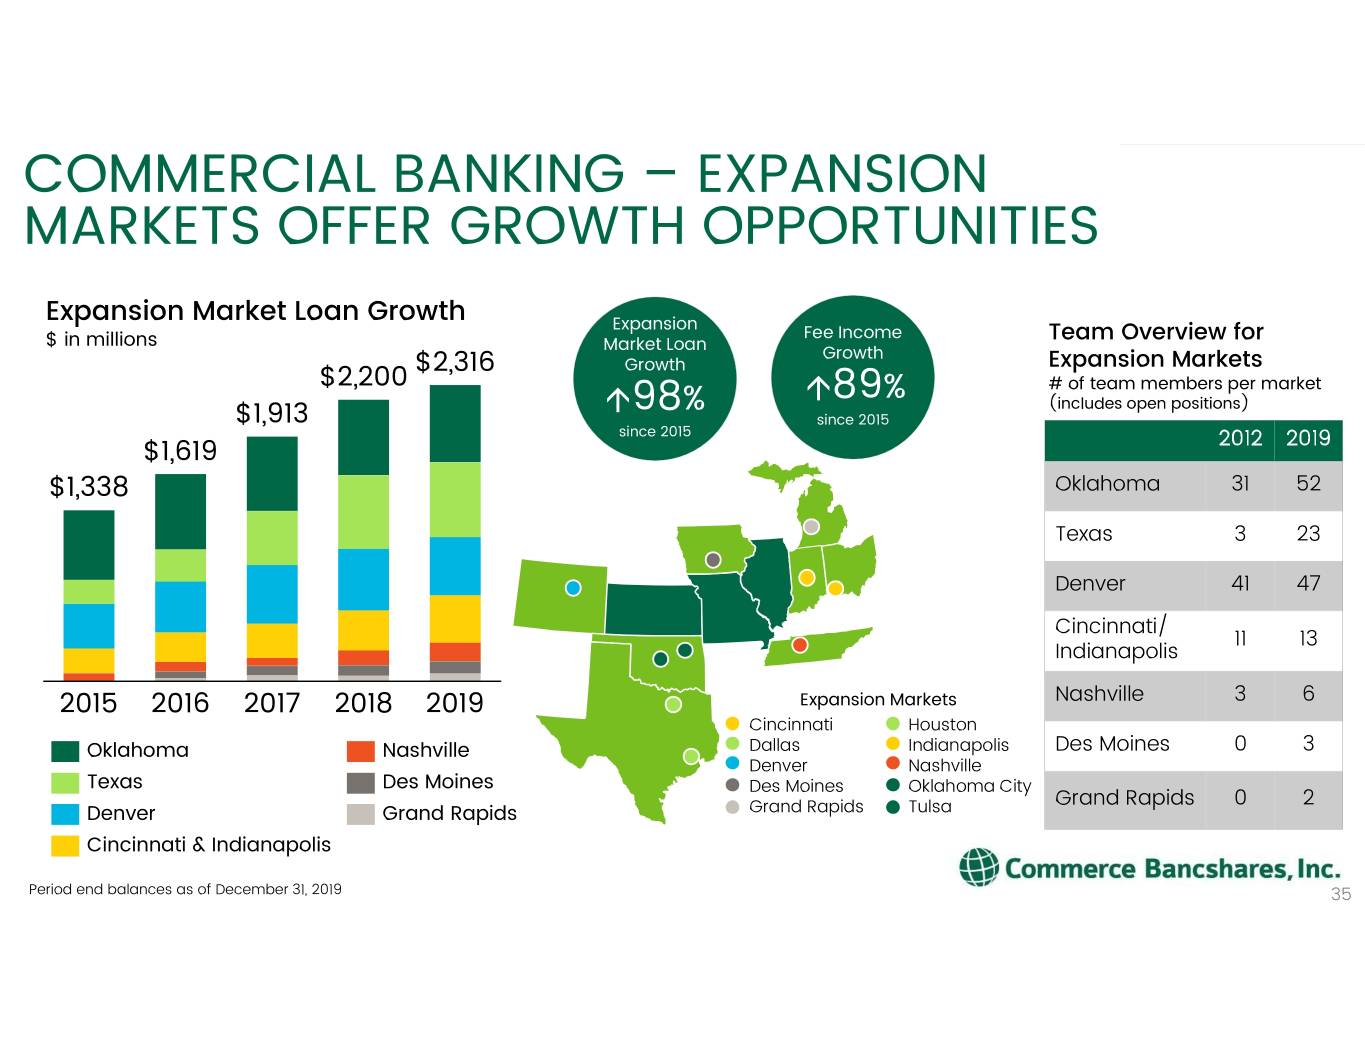
COMMERCIAL BANKING – EXPANSION MARKETS OFFER GROWTH OPPORTUNITIES Expansion Market Loan Growth Expansion Fee Income $ in millions Market Loan Team Overview for Growth $2,316 Growth Expansion Markets $2,200 # of team members per market 89% (includes open positions) $1,913 98% since 2015 since 2015 2012 2019 $1,619 $1,338 Oklahoma 31 52 Texas 3 23 Denver 41 47 Cincinnati/ 11 13 Indianapolis 2015 2016 2017 2018 2019 Expansion Markets Nashville 3 6 • Cincinnati • Houston • • Oklahoma Nashville Dallas Indianapolis Des Moines 0 3 • Denver • Nashville Texas Des Moines • Des Moines • Oklahoma City • • Grand Rapids 0 2 Denver Grand Rapids Grand Rapids Tulsa Cincinnati & Indianapolis Period end balances as of December 31, 2019 35
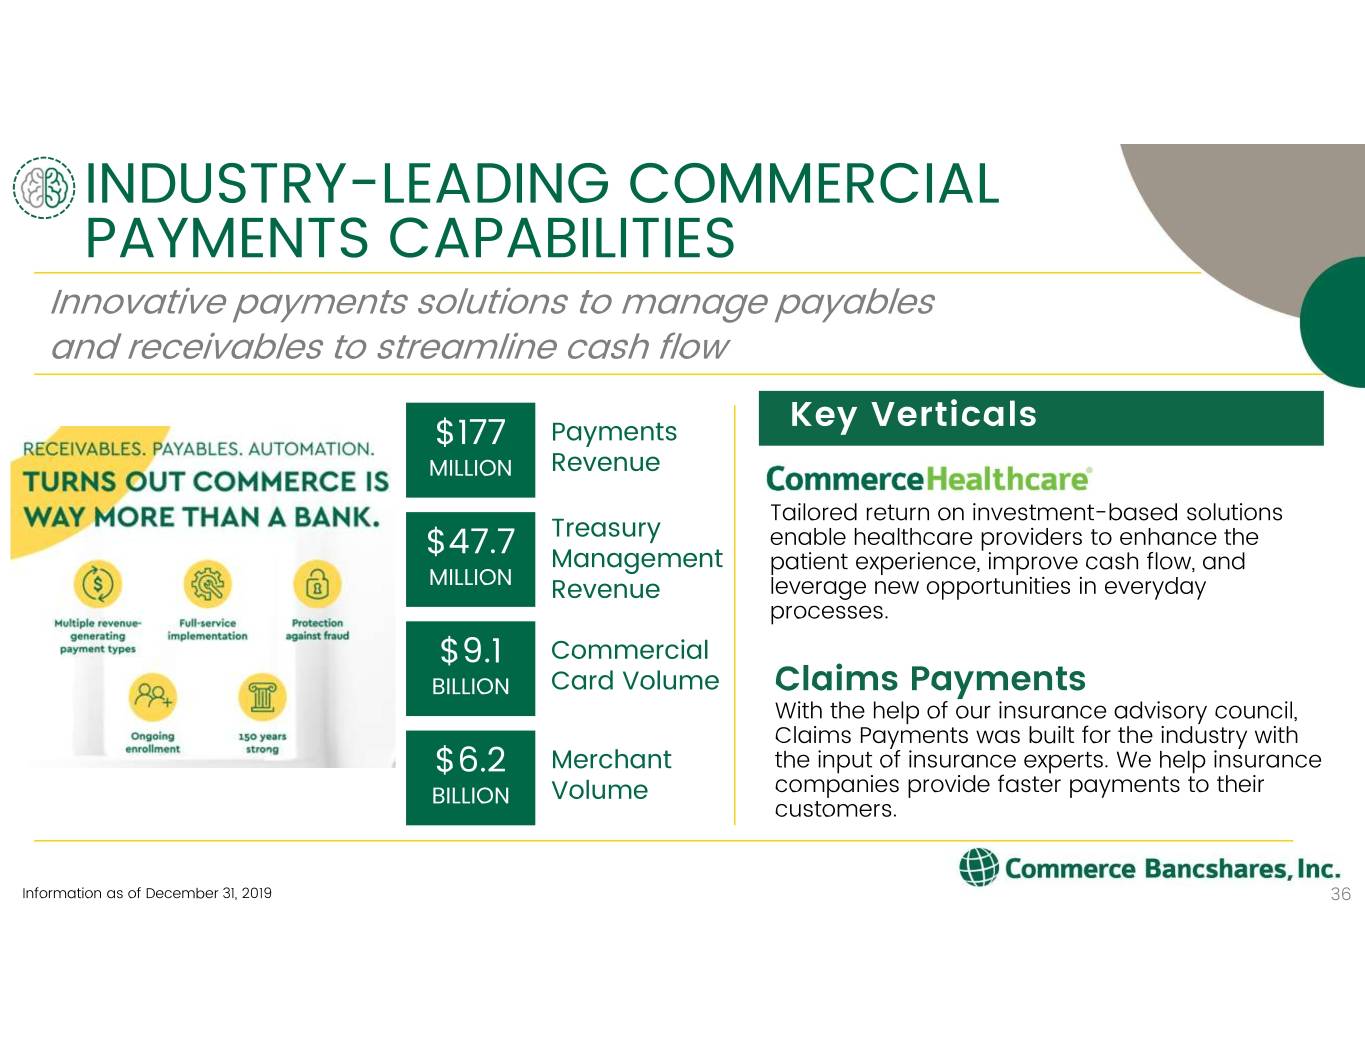
INDUSTRY-LEADING COMMERCIAL PAYMENTS CAPABILITIES Innovative payments solutions to manage payables and receivables to streamline cash flow Key Verticals $177 Payments MILLION Revenue Tailored return on investment-based solutions Treasury enable healthcare providers to enhance the $47.7 Management patient experience, improve cash flow, and MILLION Revenue leverage new opportunities in everyday processes. $9.1 Commercial BILLION Card Volume Claims Payments With the help of our insurance advisory council, Claims Payments was built for the industry with $6.2 Merchant the input of insurance experts. We help insurance companies provide faster payments to their BILLION Volume customers. Information as of December 31, 2019 36
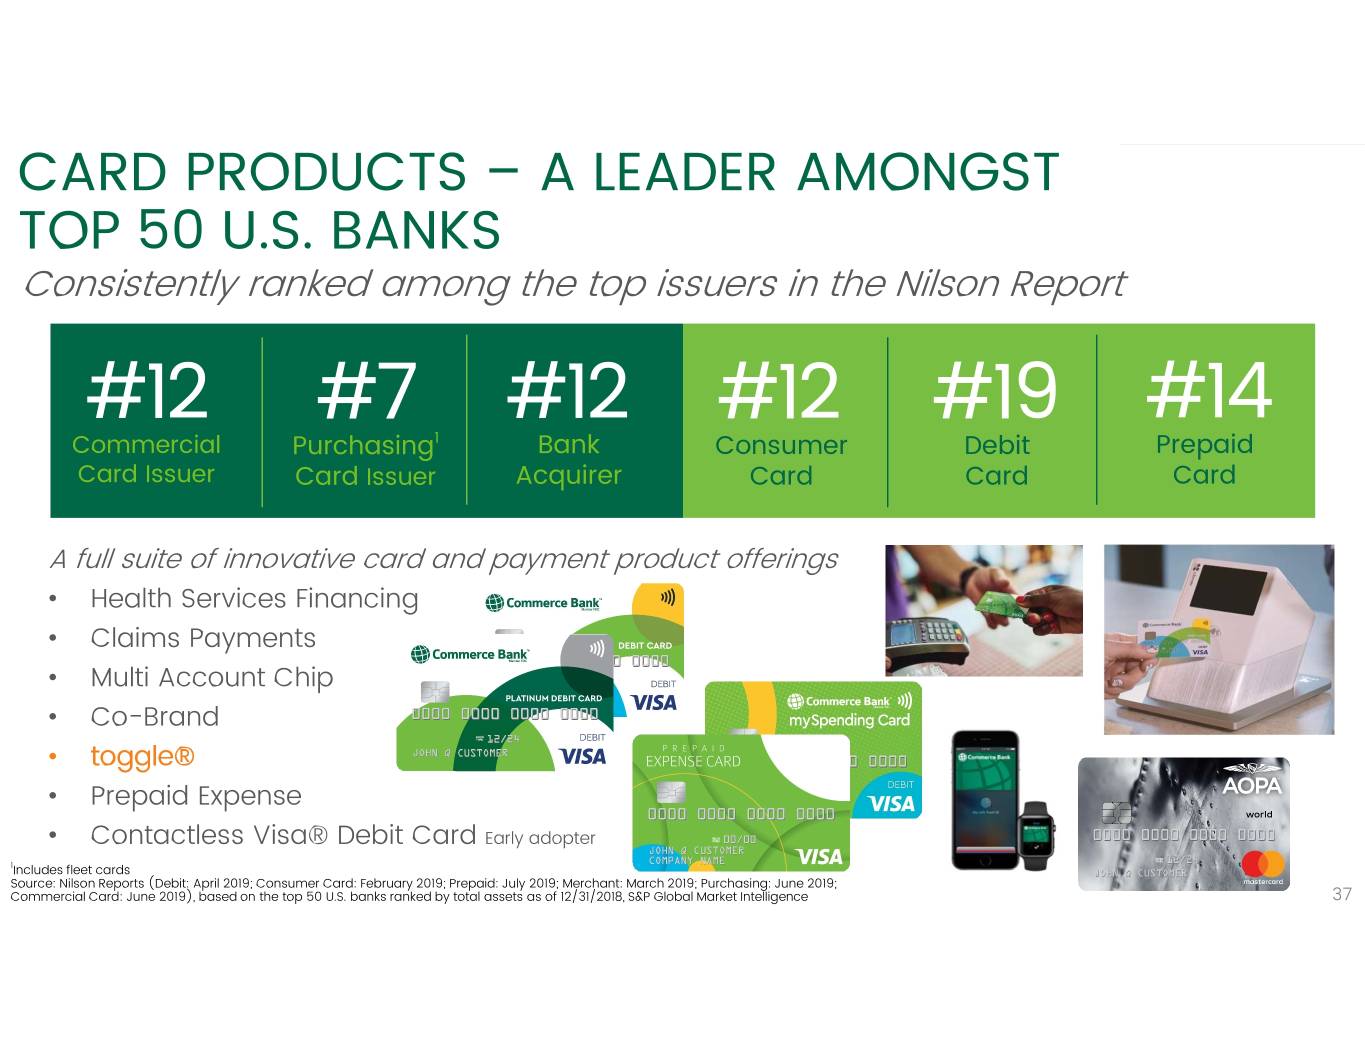
CARD PRODUCTS – A LEADER AMONGST TOP 50 U.S. BANKS Consistently ranked among the top issuers in the Nilson Report Commercial Consumer Commercial#12 Purchasing#7 1 #12Bank Consumer#12 #19Debit #14Prepaid Card Issuer Card Issuer Acquirer Card Card Card A full suite of innovative card and payment product offerings • Health Services Financing • Claims Payments • Multi Account Chip • Co-Brand • toggle® • Prepaid Expense • Contactless Visa® Debit Card Early adopter 1 Includes fleet cards Source: Nilson Reports (Debit: April 2019; Consumer Card: February 2019; Prepaid: July 2019; Merchant: March 2019; Purchasing: June 2019; Commercial Card: June 2019), based on the top 50 U.S. banks ranked by total assets as of 12/31/2018, S&P Global Market Intelligence 37
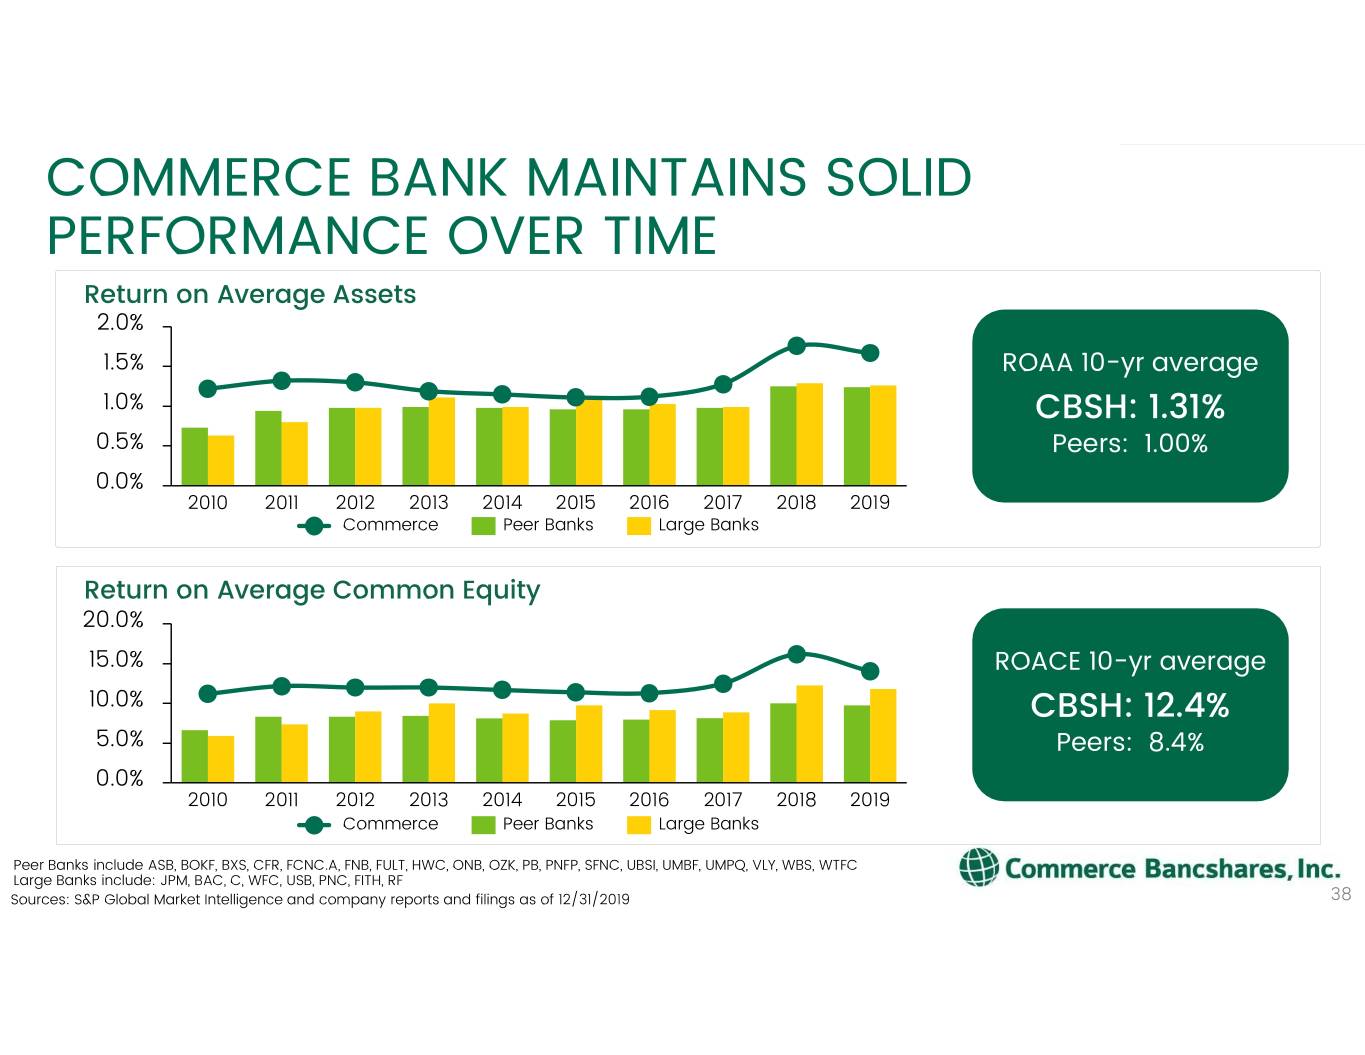
COMMERCE BANK MAINTAINS SOLID PERFORMANCE OVER TIME Return on Average Assets 2.0% 1.5% ROAA 10-yr average 1.0% CBSH: 1.31% 0.5% Peers: 1.00% 0.0% 20102011 2012 2013 2014 2015 2016 20172018 2019 Commerce Peer Banks Large Banks Return on Average Common Equity 20.0% 15.0% ROACE 10-yr average 10.0% CBSH: 12.4% 5.0% Peers: 8.4% 0.0% 201020112012 20132014 2015 2016 2017 2018 2019 CommercePeer Banks Large Banks Peer Banks include ASB, BOKF, BXS, CFR, FCNC.A, FNB, FULT, HWC, ONB, OZK, PB, PNFP, SFNC, UBSI, UMBF, UMPQ, VLY, WBS, WTFC Large Banks include: JPM, BAC, C, WFC, USB, PNC, FITH, RF Sources: S&P Global Market Intelligence and company reports and filings as of 12/31/2019 38
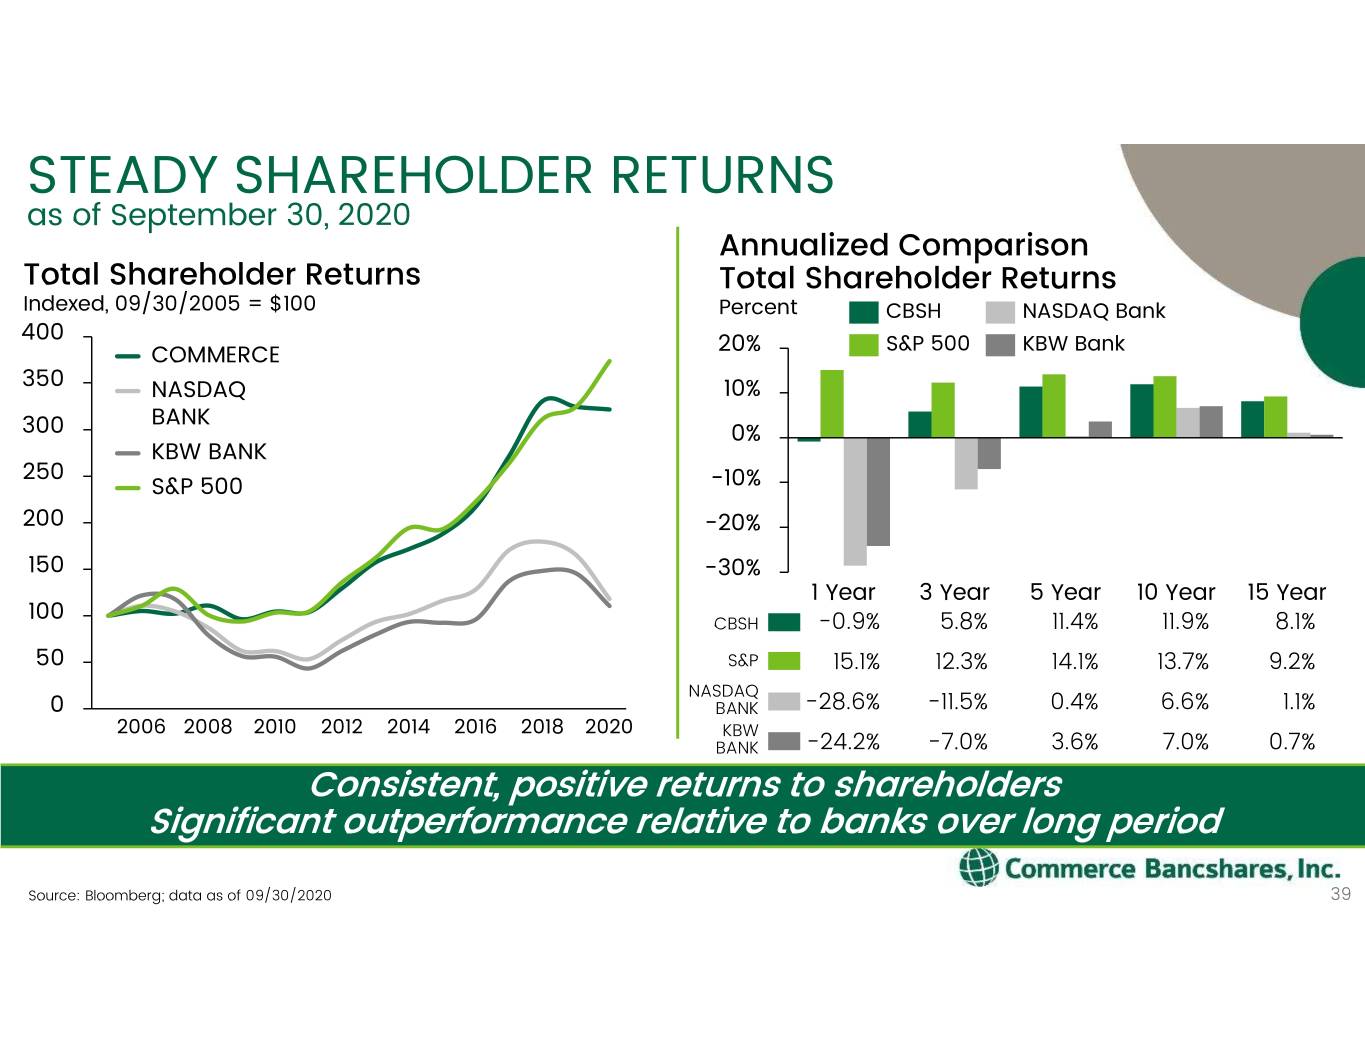
STEADY SHAREHOLDER RETURNS as of September 30, 2020 Annualized Comparison Total Shareholder Returns Total Shareholder Returns Indexed, 09/30/2005 = $100 Percent CBSH NASDAQ Bank 400 S&P 500 KBW Bank COMMERCE 20% 350 NASDAQ 10% BANK 300 0% KBW BANK 250 S&P 500 -10% 200 -20% 150 -30% 1 Year 3 Year5 Year 10 Year 15 Year 100 CBSH -0.9% 5.8% 11.4% 11.9% 8.1% 50 S&P 15.1% 12.3% 14.1% 13.7% 9.2% NASDAQ 0 BANK -28.6% -11.5% 0.4% 6.6% 1.1% 20062008 2010 20122014 2016 2018 2020 KBW BANK -24.2% -7.0% 3.6% 7.0% 0.7% Consistent, positive returns to shareholders Significant outperformance relative to banks over long period Source: Bloomberg; data as of 09/30/2020 39
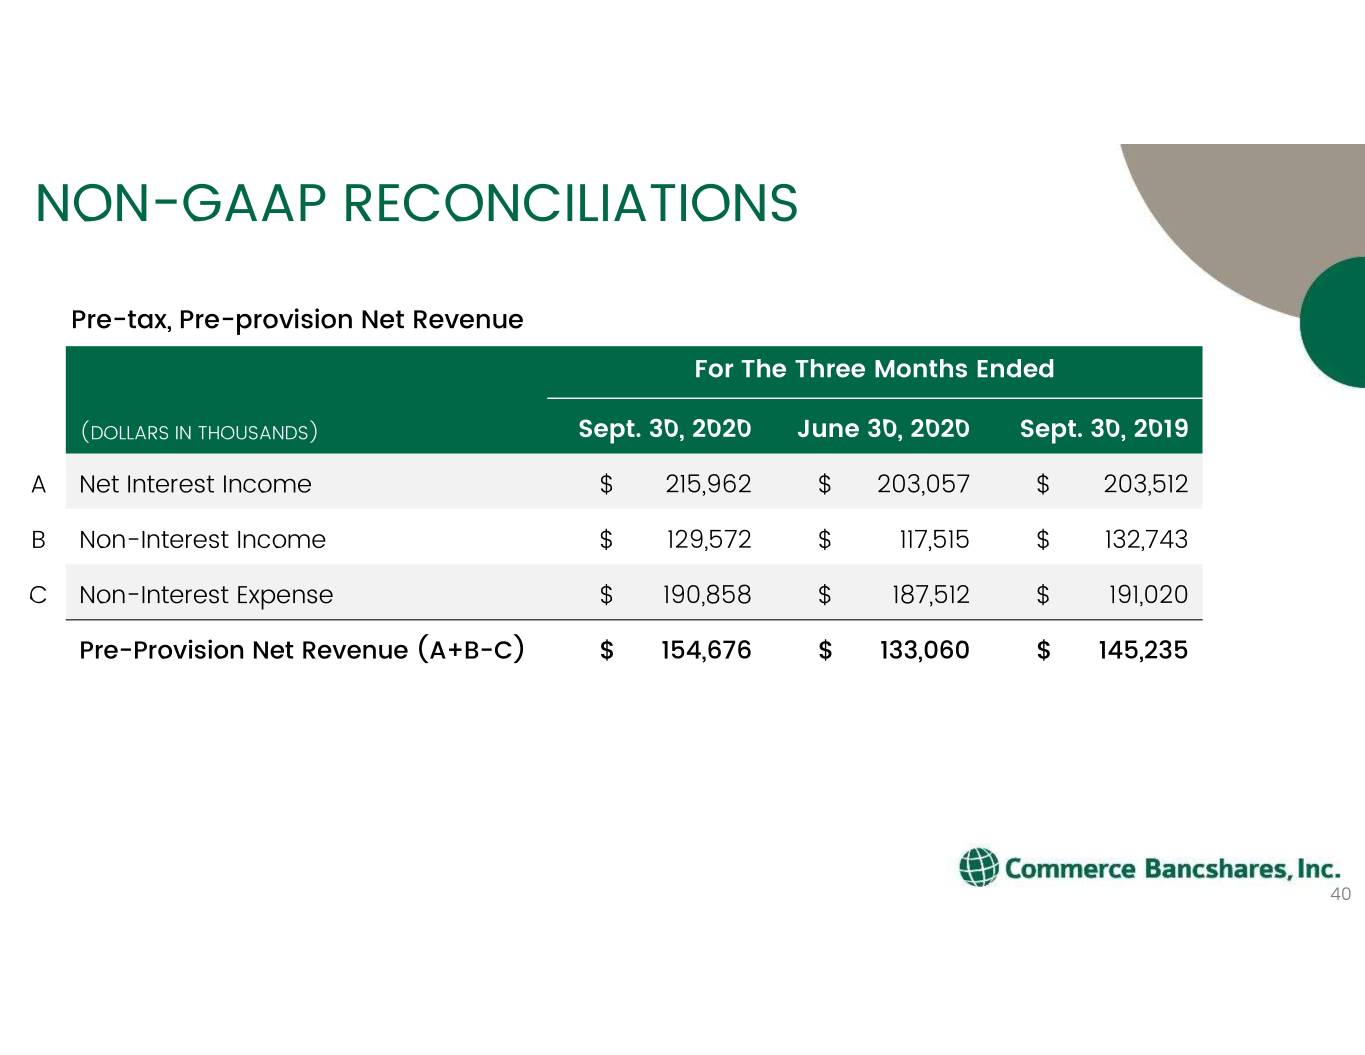
NON-GAAP RECONCILIATIONS Pre-tax, Pre-provision Net Revenue For The Three Months Ended (DOLLARS IN THOUSANDS) Sept. 30, 2020 June 30, 2020 Sept. 30, 2019 A Net Interest Income $ 215,962 $ 203,057 $ 203,512 B Non-Interest Income $ 129,572 $ 117,515 $ 132,743 C Non-Interest Expense $ 190,858 $ 187,512 $ 191,020 Pre-Provision Net Revenue (A+B-C) $ 154,676 $ 133,060 $ 145,235 40
Contact Information: Matthew Burkemper Senior Vice President, Commerce Bank Corporate Development and Investor Relations 314.746.7485 [email protected] Commerce Bancshares, Inc. Investor Relations website: http://investor.commercebank.com/
Embracing a Growth Mindset