CBSH 8-K
Commerce Bancshares Inc /Mo/ (CBSH)
8-K
2022-04-19
For: 2022-04-19
View Original
Added on
April 11, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
__________________________
Form 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported): April 19, 2022
(Exact name of registrant as specified in its charter)
| (State of Incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||||||||
| (Address of principal executive offices) | (Zip Code) | ||||||||||
(816 ) 234-2000
(Registrant’s telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Securities registered pursuant to Section 12(b) of the Act: | ||||||||
| Title of class | Trading symbol(s) | Name of exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 or Rule 12b-2 of the Securities Exchange Act of 1934.
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition
A copy of the press release issued April 19, 2022 by Commerce Bancshares, Inc. announcing First Quarter 2022 earnings is furnished under Item 2.02 of this Current Report on Form 8-K as Exhibit 99.1. Additionally, a slide presentation for investors and analysts is being furnished as Exhibit 99.2 to this Current Report on Form 8-K.
The information in this Current Report on Form 8-K, including the exhibits, is furnished pursuant to Item 2.02 and shall not be deemed “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities under that Section. Furthermore, the information in this Current Report on Form 8-K, including the exhibits, shall not be deemed to be incorporated by reference into the filings of Commerce Bancshares, Inc. under the Securities Act of 1933, as amended.
All information included in this Current Report on Form 8-K is available on the Company’s website at https://investor.commercebank.com/news-info/financial-news-releases/default.aspx.
Item 9.01 Financial Statements and Exhibits
Exhibits
104 The XBRL tags on the cover page of this Form 8-K are embedded within the Inline XBRL document.
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| COMMERCE BANCSHARES, INC. | |||||||||||
| By: | /s/ Paul A. Steiner | ||||||||||
| Paul A. Steiner | |||||||||||
Controller (Chief Accounting Officer) | |||||||||||
Date: April 19, 2022
Exhibit 99.1
 | CBSH | ||||
1000 Walnut Street / Suite 700 / Kansas City, Missouri 64106 / 816.234.2000 | |||||
FOR IMMEDIATE RELEASE:
Tuesday, April 19, 2022
COMMERCE BANCSHARES, INC. REPORTS
FIRST QUARTER EARNINGS PER SHARE OF $.97
Commerce Bancshares, Inc. announced earnings of $.97 per share for the three months ended March 31, 2022, compared to $1.06 per share in the same quarter last year and $.94 per share in the fourth quarter of 2021. Net income for the first quarter of 2022 amounted to $118.2 million, compared to $131.0 million in the first quarter of 2021 and $114.9 million in the prior quarter.
"Commerce had strong financial performance for the quarter, including an expanding net interest margin and increasing loan demand,” said John Kemper, Chief Executive Officer. “Loan demand increased across our commercial loan categories, reflecting higher seasonal business activity and good overall momentum in our markets."
“The increase in interest rates and the steepening of the yield curve provided opportunities to optimize the mix of earning assets on our balance sheet. While net interest income grew, non-interest income comprised 39% of total revenue, a reflection of our diversified business model.”
First Quarter 2022 Financial Highlights:
•Net interest income was $208.8 million, a slight increase over the prior quarter. Net interest margin increased 2 basis points to 2.45%.
•Non-interest income totaled $131.8 million, a decrease of $15.9 million compared to the prior quarter.
•Net investment securities gains of $7.2 million were driven by net fair value gains of $7.5 million in the Company’s portfolio of private equity investments.
•Non-interest expense totaled $205.6 million, an increase of $2.1 million compared to the prior quarter.
•Average loan balances totaled $15.2 billion, an increase of $130.1 million, or .9%, over the prior quarter (average Paycheck Protection Program (PPP) loan balances declined $132.0 million).
•Total average available for sale debt securities increased 2.9%, or $418.0 million, over the prior quarter to $14.9 billion, at fair value. Purchases of securities during the quarter totaled $1.8 billion, with a weighted average yield of approximately 2.06%.
•Compared to the prior quarter, average deposits grew $501.7 million, or 1.7%. The average rate paid on interest bearing deposits was 5 basis points.
1
•The ratio of annualized net loan charge-offs to average loans was .12% compared to .11% in the prior quarter.
•Non-accrual loans totaled $8.3 million compared to $9.2 million in the prior quarter. Non-accrual loans were .05% of total loans.
•At March 31, 2022, the allowance for credit losses on loans decreased to $134.7 million. The allowance for credit losses on loans to total loans was .87% at March 31, 2022.
•The Company purchased 795,387 shares of its common stock this quarter at an average price of $70.22.
•Total assets at March 31, 2022 were $35.0 billion, a decrease of $1.7 billion, or 4.6%, from the prior quarter.
•For the quarter, the return on average assets was 1.33%, the return on average equity was 14.41%, and the efficiency ratio was 60.3%.
Commerce Bancshares, Inc. is a regional bank holding company offering a full line of banking services, including payment solutions, investment management and securities brokerage. Commerce Bank, a subsidiary of Commerce Bancshares, Inc., leverages more than 155 years of proven strength and experience to help individuals and businesses solve financial challenges. In addition to offering payment solutions across the U.S., Commerce Bank currently operates full-service banking facilities across the Midwest including the St. Louis and Kansas City metropolitan areas, Springfield, Central Missouri, Central Illinois, Wichita, Tulsa, Oklahoma City, and Denver. It also maintains commercial offices in Dallas, Houston, Cincinnati, Nashville, Des Moines, Indianapolis, and Grand Rapids. Commerce delivers high-touch service and sophisticated financial solutions at regional branches, commercial offices, ATMs, online, mobile and through a 24/7 customer service line.
This financial news release and the supplementary Earnings Highlights presentation are available on the Company’s website at https://investor.commercebank.com/news-info/financial-news-releases/default.aspx.
* * * * * * * * * * * * * * *
For additional information, contact
Matt Burkemper, Investor Relations
(314) 746-7485
www.commercebank.com
2
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
FINANCIAL HIGHLIGHTS
| For the Three Months Ended | ||||||||||||||
| (Unaudited) (Dollars in thousands, except per share data) | Mar. 31, 2022 | Dec. 31, 2021 | Mar. 31, 2021 | |||||||||||
| FINANCIAL SUMMARY | ||||||||||||||
| Net interest income | $208,786 | $207,657 | $205,748 | |||||||||||
| Non-interest income | 131,769 | 147,699 | 136,045 | |||||||||||
| Total revenue | 340,555 | 355,356 | 341,793 | |||||||||||
| Investment securities gains (losses), net | 7,163 | (9,706) | 9,853 | |||||||||||
| Provision for credit losses | (9,858) | (7,054) | (6,232) | |||||||||||
| Non-interest expense | 205,648 | 203,582 | 192,573 | |||||||||||
| Income before taxes | 151,928 | 149,122 | 165,305 | |||||||||||
| Income taxes | 31,902 | 33,764 | 32,076 | |||||||||||
| Non-controlling interest expense | 1,872 | 452 | 2,257 | |||||||||||
| Net income attributable to Commerce Bancshares, Inc. | $118,154 | $114,906 | $130,972 | |||||||||||
| Earnings per common share: | ||||||||||||||
| Net income — basic | $0.97 | $0.94 | $1.06 | |||||||||||
| Net income — diluted | $0.97 | $0.94 | $1.06 | |||||||||||
| Effective tax rate | 21.26 | % | 22.71 | % | 19.67 | % | ||||||||
| Tax equivalent net interest income | $211,393 | $210,424 | $208,774 | |||||||||||
Average total interest earning assets (1) | $34,937,086 | $34,318,520 | $31,278,721 | |||||||||||
| Diluted wtd. average shares outstanding | 120,616,095 | 121,221,482 | 122,402,075 | |||||||||||
| RATIOS | ||||||||||||||
Average loans to deposits (2) | 51.90 | % | 52.36 | % | 61.79 | % | ||||||||
| Return on total average assets | 1.33 | 1.28 | 1.63 | |||||||||||
Return on average equity (3) | 14.41 | 13.11 | 15.69 | |||||||||||
| Non-interest income to total revenue | 38.69 | 41.56 | 39.80 | |||||||||||
Efficiency ratio (4) | 60.29 | 57.29 | 56.37 | |||||||||||
| Net yield on interest earning assets | 2.45 | 2.43 | 2.71 | |||||||||||
| EQUITY SUMMARY | ||||||||||||||
| Cash dividends per share | $.265 | $.250 | $.250 | |||||||||||
| Cash dividends on common stock | $32,143 | $30,489 | $30,799 | |||||||||||
Book value per share (5) | $24.60 | $28.40 | $26.99 | |||||||||||
Market value per share (5) | $71.59 | $68.74 | $72.96 | |||||||||||
| High market value per share | $74.72 | $71.50 | $79.10 | |||||||||||
| Low market value per share | $66.28 | $64.85 | $61.68 | |||||||||||
Common shares outstanding (5) | 120,881,120 | 121,436,734 | 122,931,140 | |||||||||||
Tangible common equity to tangible assets (6) | 8.09 | % | 9.01 | % | 9.57 | % | ||||||||
| Tier I leverage ratio | 9.07 | % | 9.13 | % | 9.38 | % | ||||||||
| OTHER QTD INFORMATION | ||||||||||||||
| Number of bank/ATM locations | 285 | 287 | 298 | |||||||||||
| Full-time equivalent employees | 4,563 | 4,567 | 4,619 | |||||||||||
(1)Excludes allowance for credit losses on loans and unrealized gains/(losses) on available for sale debt securities.
(2)Includes loans held for sale.
(3)Annualized net income attributable to Commerce Bancshares, Inc. divided by average total equity.
(4)The efficiency ratio is calculated as non-interest expense (excluding intangibles amortization) as a percent of revenue.
(5)As of period end.
(6)The tangible common equity ratio is calculated as stockholders’ equity reduced by goodwill and other intangible assets (excluding mortgage servicing rights) divided by total assets reduced by goodwill and other intangible assets (excluding mortgage servicing rights).
All share and per share amounts have been restated to reflect the 5% stock dividend distributed in December 2021.
3
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
CONSOLIDATED STATEMENTS OF INCOME
| (Unaudited) (In thousands, except per share data) | For the Three Months Ended | |||||||||||||||||||
| Mar. 31, 2022 | Dec. 31, 2021 | Sep. 30, 2021 | Jun. 30, 2021 | Mar. 31, 2021 | ||||||||||||||||
| Interest income | $211,782 | $210,479 | $216,981 | $211,133 | $209,697 | |||||||||||||||
| Interest expense | 2,996 | 2,822 | 2,944 | 3,151 | 3,949 | |||||||||||||||
| Net interest income | 208,786 | 207,657 | 214,037 | 207,982 | 205,748 | |||||||||||||||
| Provision for credit losses | (9,858) | (7,054) | (7,385) | (45,655) | (6,232) | |||||||||||||||
| Net interest income after credit losses | 218,644 | 214,711 | 221,422 | 253,637 | 211,980 | |||||||||||||||
| NON-INTEREST INCOME | ||||||||||||||||||||
| Bank card transaction fees | 42,045 | 44,773 | 42,815 | 42,608 | 37,695 | |||||||||||||||
| Trust fees | 47,811 | 48,893 | 48,950 | 46,257 | 44,127 | |||||||||||||||
| Deposit account charges and other fees | 22,307 | 25,493 | 25,161 | 23,988 | 22,575 | |||||||||||||||
| Capital market fees | 4,125 | 3,841 | 3,794 | 3,327 | 4,981 | |||||||||||||||
| Consumer brokerage services | 4,446 | 4,878 | 4,900 | 4,503 | 4,081 | |||||||||||||||
| Loan fees and sales | 4,235 | 5,248 | 6,842 | 7,446 | 10,184 | |||||||||||||||
| Other | 6,800 | 14,573 | 5,044 | 11,014 | 12,402 | |||||||||||||||
| Total non-interest income | 131,769 | 147,699 | 137,506 | 139,143 | 136,045 | |||||||||||||||
| INVESTMENT SECURITIES GAINS (LOSSES), NET | 7,163 | (9,706) | 13,108 | 16,804 | 9,853 | |||||||||||||||
| NON-INTEREST EXPENSE | ||||||||||||||||||||
| Salaries and employee benefits | 135,953 | 132,640 | 132,824 | 130,751 | 129,033 | |||||||||||||||
| Net occupancy | 12,296 | 12,308 | 12,329 | 11,527 | 12,021 | |||||||||||||||
| Equipment | 4,568 | 4,691 | 4,440 | 4,605 | 4,353 | |||||||||||||||
| Supplies and communication | 4,713 | 4,430 | 4,530 | 4,033 | 4,125 | |||||||||||||||
| Data processing and software | 27,016 | 25,777 | 25,598 | 24,954 | 25,463 | |||||||||||||||
| Marketing | 6,344 | 5,395 | 5,623 | 5,680 | 5,158 | |||||||||||||||
| Other | 14,758 | 18,341 | 26,276 | 16,576 | 12,420 | |||||||||||||||
| Total non-interest expense | 205,648 | 203,582 | 211,620 | 198,126 | 192,573 | |||||||||||||||
| Income before income taxes | 151,928 | 149,122 | 160,416 | 211,458 | 165,305 | |||||||||||||||
| Less income taxes | 31,902 | 33,764 | 34,662 | 45,209 | 32,076 | |||||||||||||||
| Net income | 120,026 | 115,358 | 125,754 | 166,249 | 133,229 | |||||||||||||||
| Less non-controlling interest expense | 1,872 | 452 | 3,193 | 3,923 | 2,257 | |||||||||||||||
| Net income attributable to Commerce Bancshares, Inc. | $118,154 | $114,906 | $122,561 | $162,326 | $130,972 | |||||||||||||||
| Net income per common share — basic | $0.97 | $0.94 | $1.00 | $1.32 | $1.06 | |||||||||||||||
| Net income per common share — diluted | $0.97 | $0.94 | $0.99 | $1.32 | $1.06 | |||||||||||||||
| OTHER INFORMATION | ||||||||||||||||||||
| Return on total average assets | 1.33 | % | 1.28 | % | 1.40 | % | 1.93 | % | 1.63 | % | ||||||||||
Return on average equity (1) | 14.41 | 13.11 | 13.74 | 19.12 | 15.69 | |||||||||||||||
Efficiency ratio (2) | 60.29 | 57.29 | 59.95 | 56.90 | 56.37 | |||||||||||||||
| Effective tax rate | 21.26 | 22.71 | 22.05 | 21.78 | 19.67 | |||||||||||||||
| Net yield on interest earning assets | 2.45 | 2.43 | 2.58 | 2.60 | 2.71 | |||||||||||||||
| Tax equivalent net interest income | $211,393 | $210,424 | $216,858 | $211,060 | $208,774 | |||||||||||||||
(1)Annualized net income attributable to Commerce Bancshares, Inc. divided by average total equity.
(2)The efficiency ratio is calculated as non-interest expense (excluding intangibles amortization) as a percent of revenue.
4
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
CONSOLIDATED BALANCE SHEETS - PERIOD END
| (Unaudited) (In thousands) | Mar. 31, 2022 | Dec. 31, 2021 | Mar. 31, 2021 | |||||||||||
| ASSETS | ||||||||||||||
| Loans | ||||||||||||||
| Business | $ | 5,508,508 | $ | 5,303,535 | $ | 6,624,209 | ||||||||
| Real estate — construction and land | 1,144,411 | 1,118,266 | 1,073,036 | |||||||||||
| Real estate — business | 3,109,668 | 3,058,837 | 3,017,242 | |||||||||||
| Real estate — personal | 2,820,076 | 2,805,401 | 2,828,418 | |||||||||||
| Consumer | 2,053,160 | 2,032,225 | 1,966,833 | |||||||||||
| Revolving home equity | 264,401 | 275,945 | 285,261 | |||||||||||
| Consumer credit card | 544,579 | 575,410 | 593,833 | |||||||||||
| Overdrafts | 14,211 | 6,740 | 3,239 | |||||||||||
| Total loans | 15,459,014 | 15,176,359 | 16,392,071 | |||||||||||
| Allowance for credit losses on loans | (134,710) | (150,044) | (200,527) | |||||||||||
| Net loans | 15,324,304 | 15,026,315 | 16,191,544 | |||||||||||
| Loans held for sale | 8,908 | 8,615 | 38,076 | |||||||||||
| Investment securities: | ||||||||||||||
| Available for sale debt securities | 14,780,494 | 14,450,027 | 12,528,203 | |||||||||||
| Trading debt securities | 31,380 | 46,235 | 26,925 | |||||||||||
| Equity securities | 9,284 | 9,202 | 4,337 | |||||||||||
| Other securities | 199,576 | 194,047 | 155,913 | |||||||||||
| Total investment securities | 15,020,734 | 14,699,511 | 12,715,378 | |||||||||||
| Federal funds sold | — | 2,800 | 500 | |||||||||||
| Securities purchased under agreements to resell | 1,825,000 | 1,625,000 | 850,000 | |||||||||||
| Interest earning deposits with banks | 1,260,813 | 3,971,217 | 2,017,128 | |||||||||||
| Cash and due from banks | 326,549 | 305,539 | 338,666 | |||||||||||
| Premises and equipment — net | 394,028 | 388,738 | 371,737 | |||||||||||
| Goodwill | 138,921 | 138,921 | 138,921 | |||||||||||
| Other intangible assets — net | 15,885 | 15,570 | 13,098 | |||||||||||
| Other assets | 671,651 | 506,862 | 594,738 | |||||||||||
| Total assets | $ | 34,986,793 | $ | 36,689,088 | $ | 33,269,786 | ||||||||
| LIABILITIES AND STOCKHOLDERS’ EQUITY | ||||||||||||||
| Deposits: | ||||||||||||||
| Non-interest bearing | $ | 11,428,372 | $ | 11,772,374 | $ | 11,076,556 | ||||||||
| Savings, interest checking and money market | 16,751,632 | 16,598,085 | 14,572,378 | |||||||||||
| Certificates of deposit of less than $100,000 | 422,992 | 435,960 | 504,472 | |||||||||||
| Certificates of deposit of $100,000 and over | 716,345 | 1,006,654 | 1,267,219 | |||||||||||
| Total deposits | 29,319,341 | 29,813,073 | 27,420,625 | |||||||||||
| Federal funds purchased and securities sold under agreements to repurchase | 2,317,461 | 3,022,967 | 1,938,110 | |||||||||||
| Other borrowings | 9,057 | 12,560 | 3,791 | |||||||||||
| Other liabilities | 367,532 | 392,164 | 589,875 | |||||||||||
| Total liabilities | 32,013,391 | 33,240,764 | 29,952,401 | |||||||||||
| Stockholders’ equity: | ||||||||||||||
| Common stock | 610,804 | 610,804 | 589,352 | |||||||||||
| Capital surplus | 2,678,025 | 2,689,894 | 2,420,393 | |||||||||||
| Retained earnings | 178,504 | 92,493 | 173,173 | |||||||||||
| Treasury stock | (72,293) | (32,973) | (39,080) | |||||||||||
| Accumulated other comprehensive income | (434,400) | 77,080 | 168,752 | |||||||||||
| Total stockholders’ equity | 2,960,640 | 3,437,298 | 3,312,590 | |||||||||||
| Non-controlling interest | 12,762 | 11,026 | 4,795 | |||||||||||
| Total equity | 2,973,402 | 3,448,324 | 3,317,385 | |||||||||||
| Total liabilities and equity | $ | 34,986,793 | $ | 36,689,088 | $ | 33,269,786 | ||||||||
5
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
AVERAGE BALANCE SHEETS
| (Unaudited) (In thousands) | For the Three Months Ended | ||||||||||||||||
| Mar. 31, 2022 | Dec. 31, 2021 | Sep. 30, 2021 | Jun. 30, 2021 | Mar. 31, 2021 | |||||||||||||
| ASSETS: | |||||||||||||||||
| Loans: | |||||||||||||||||
| Business | $ | 5,324,172 | $ | 5,191,844 | $ | 5,437,498 | $ | 6,211,610 | $ | 6,532,921 | |||||||
| Real estate — construction and land | 1,134,902 | 1,228,237 | 1,168,566 | 1,088,433 | 1,091,969 | ||||||||||||
| Real estate — business | 3,095,068 | 3,003,459 | 2,982,847 | 3,014,955 | 3,022,979 | ||||||||||||
| Real estate — personal | 2,808,980 | 2,785,095 | 2,775,638 | 2,804,388 | 2,826,112 | ||||||||||||
| Consumer | 2,040,200 | 2,043,690 | 2,041,263 | 2,004,625 | 1,947,322 | ||||||||||||
| Revolving home equity | 273,859 | 276,464 | 281,689 | 287,031 | 299,371 | ||||||||||||
| Consumer credit card | 540,844 | 559,429 | 566,406 | 575,725 | 608,747 | ||||||||||||
| Overdrafts | 5,178 | 4,926 | 5,110 | 3,735 | 3,546 | ||||||||||||
Total loans | 15,223,203 | 15,093,144 | 15,259,017 | 15,990,502 | 16,332,967 | ||||||||||||
| Allowance for credit losses on loans | (149,685) | (162,428) | (172,112) | (200,801) | (220,512) | ||||||||||||
| Net loans | 15,073,518 | 14,930,716 | 15,086,905 | 15,789,701 | 16,112,455 | ||||||||||||
| Loans held for sale | 9,383 | 11,203 | 16,021 | 23,389 | 35,814 | ||||||||||||
| Investment securities: | |||||||||||||||||
| U.S. government and federal agency obligations | 1,103,749 | 1,009,025 | 727,566 | 719,849 | 725,367 | ||||||||||||
| Government-sponsored enterprise obligations | 51,770 | 50,777 | 50,785 | 50,793 | 50,801 | ||||||||||||
| State and municipal obligations | 2,077,600 | 2,095,517 | 2,039,942 | 1,966,673 | 1,958,637 | ||||||||||||
| Mortgage-backed securities | 7,316,609 | 7,141,249 | 7,115,419 | 6,685,407 | 6,998,521 | ||||||||||||
| Asset-backed securities | 3,933,061 | 3,514,541 | 3,028,076 | 2,653,928 | 2,085,491 | ||||||||||||
Other debt securities | 636,247 | 629,643 | 608,642 | 605,772 | 570,115 | ||||||||||||
| Unrealized gain on debt securities | (174,297) | 86,020 | 230,058 | 197,124 | 283,511 | ||||||||||||
| Total available for sale debt securities | 14,944,739 | 14,526,772 | 13,800,488 | 12,879,546 | 12,672,443 | ||||||||||||
Trading debt securities | 40,686 | 46,513 | 32,238 | 34,955 | 32,320 | ||||||||||||
| Equity securities | 9,498 | 9,171 | 8,756 | 4,914 | 4,321 | ||||||||||||
| Other securities | 192,311 | 190,346 | 183,397 | 156,984 | 154,030 | ||||||||||||
| Total investment securities | 15,187,234 | 14,772,802 | 14,024,879 | 13,076,399 | 12,863,114 | ||||||||||||
| Federal funds sold | 1,053 | 564 | 792 | 1,338 | 7 | ||||||||||||
| Securities purchased under agreements to resell | 1,733,887 | 1,669,835 | 1,633,205 | 937,372 | 849,999 | ||||||||||||
| Interest earning deposits with banks | 2,608,029 | 2,856,992 | 2,602,896 | 2,724,782 | 1,480,331 | ||||||||||||
| Other assets | 1,304,400 | 1,288,323 | 1,261,277 | 1,258,989 | 1,308,105 | ||||||||||||
| Total assets | $ | 35,917,504 | $ | 35,530,435 | $ | 34,625,975 | $ | 33,811,970 | $ | 32,649,825 | |||||||
| LIABILITIES AND EQUITY: | |||||||||||||||||
| Non-interest bearing deposits | $ | 11,544,701 | $ | 11,919,268 | $ | 11,475,113 | $ | 11,109,198 | $ | 10,438,637 | |||||||
| Savings | 1,563,093 | 1,507,199 | 1,484,923 | 1,474,391 | 1,333,177 | ||||||||||||
| Interest checking and money market | 14,949,727 | 13,873,985 | 13,343,180 | 13,283,481 | 12,970,629 | ||||||||||||
| Certificates of deposit of less than $100,000 | 429,852 | 441,920 | 464,367 | 491,446 | 516,728 | ||||||||||||
| Certificates of deposit of $100,000 and over | 862,232 | 1,105,480 | 1,289,665 | 1,354,685 | 1,230,075 | ||||||||||||
| Total deposits | 29,349,605 | 28,847,852 | 28,057,248 | 27,713,201 | 26,489,246 | ||||||||||||
| Borrowings: | |||||||||||||||||
| Federal funds purchased | 23,356 | 20,848 | 13,606 | 23,291 | 37,034 | ||||||||||||
| Securities sold under agreements to repurchase | 2,712,468 | 2,620,348 | 2,347,270 | 2,142,405 | 2,129,038 | ||||||||||||
| Other borrowings | 768 | 1,078 | 347 | 978 | 831 | ||||||||||||
| Total borrowings | 2,736,592 | 2,642,274 | 2,361,223 | 2,166,674 | 2,166,903 | ||||||||||||
| Other liabilities | 505,644 | 562,102 | 667,786 | 527,401 | 608,212 | ||||||||||||
| Total liabilities | 32,591,841 | 32,052,228 | 31,086,257 | 30,407,276 | 29,264,361 | ||||||||||||
| Equity | 3,325,663 | 3,478,207 | 3,539,718 | 3,404,694 | 3,385,464 | ||||||||||||
| Total liabilities and equity | $ | 35,917,504 | $ | 35,530,435 | $ | 34,625,975 | $ | 33,811,970 | $ | 32,649,825 | |||||||
6
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
AVERAGE RATES
| (Unaudited) | For the Three Months Ended | ||||||||||||||||
| Mar. 31, 2022 | Dec. 31, 2021 | Sep. 30, 2021 | Jun. 30, 2021 | Mar. 31, 2021 | |||||||||||||
| ASSETS: | |||||||||||||||||
| Loans: | |||||||||||||||||
Business (1) | 2.93 | % | 3.16 | % | 3.43 | % | 3.15 | % | 3.09 | % | |||||||
| Real estate — construction and land | 3.76 | 3.61 | 3.51 | 3.56 | 3.54 | ||||||||||||
| Real estate — business | 3.38 | 3.41 | 3.46 | 3.49 | 3.52 | ||||||||||||
| Real estate — personal | 3.28 | 3.21 | 3.27 | 3.31 | 3.40 | ||||||||||||
| Consumer | 3.59 | 3.65 | 3.71 | 3.84 | 4.02 | ||||||||||||
| Revolving home equity | 3.48 | 3.47 | 3.46 | 3.43 | 3.38 | ||||||||||||
| Consumer credit card | 11.35 | 11.06 | 11.29 | 11.22 | 10.97 | ||||||||||||
| Overdrafts | — | — | — | — | — | ||||||||||||
| Total loans | 3.54 | 3.62 | 3.74 | 3.65 | 3.66 | ||||||||||||
| Loans held for sale | 6.48 | 5.10 | 4.63 | 4.20 | 3.44 | ||||||||||||
| Investment securities: | |||||||||||||||||
| U.S. government and federal agency obligations | 3.42 | 3.11 | 5.74 | 5.52 | 2.54 | ||||||||||||
| Government-sponsored enterprise obligations | 2.33 | 2.30 | 2.30 | 2.33 | 2.36 | ||||||||||||
State and municipal obligations (1) | 2.29 | 2.26 | 2.35 | 2.41 | 2.46 | ||||||||||||
| Mortgage-backed securities | 1.98 | 1.40 | 1.53 | 1.11 | 1.39 | ||||||||||||
| Asset-backed securities | 1.13 | 1.03 | 1.08 | 1.25 | 1.39 | ||||||||||||
| Other debt securities | 2.00 | 2.07 | 2.04 | 2.06 | 2.15 | ||||||||||||
| Total available for sale debt securities | 1.91 | 1.59 | 1.80 | 1.64 | 1.67 | ||||||||||||
Trading debt securities (1) | 1.84 | 1.54 | 1.01 | 1.19 | 1.08 | ||||||||||||
Equity securities (1) | 26.00 | 27.64 | 23.92 | 43.10 | 49.56 | ||||||||||||
Other securities (1) | 5.91 | 18.39 | 7.46 | 11.90 | 5.26 | ||||||||||||
| Total investment securities | 1.97 | 1.82 | 1.89 | 1.78 | 1.72 | ||||||||||||
| Federal funds sold | .39 | .70 | .50 | .60 | — | ||||||||||||
| Securities purchased under agreements to resell | 1.24 | 1.62 | 2.19 | 4.46 | 5.31 | ||||||||||||
| Interest earning deposits with banks | .18 | .15 | .15 | .11 | .10 | ||||||||||||
| Total interest earning assets | 2.49 | 2.47 | 2.62 | 2.64 | 2.76 | ||||||||||||
| LIABILITIES AND EQUITY: | |||||||||||||||||
| Interest bearing deposits: | |||||||||||||||||
| Savings | .05 | .08 | .08 | .08 | .08 | ||||||||||||
| Interest checking and money market | .04 | .04 | .05 | .05 | .06 | ||||||||||||
| Certificates of deposit of less than $100,000 | .13 | .14 | .18 | .27 | .37 | ||||||||||||
| Certificates of deposit of $100,000 and over | .20 | .14 | .14 | .20 | .35 | ||||||||||||
| Total interest bearing deposits | .05 | .05 | .06 | .07 | .09 | ||||||||||||
| Borrowings: | |||||||||||||||||
| Federal funds purchased | .12 | .11 | .10 | .05 | .05 | ||||||||||||
| Securities sold under agreements to repurchase | .10 | .08 | .08 | .06 | .06 | ||||||||||||
| Other borrowings | .53 | — | 1.14 | .82 | .98 | ||||||||||||
| Total borrowings | .10 | .08 | .08 | .06 | .06 | ||||||||||||
| Total interest bearing liabilities | .06 | % | .06 | % | .06 | % | .07 | % | .09 | % | |||||||
| Net yield on interest earning assets | 2.45 | % | 2.43 | % | 2.58 | % | 2.60 | % | 2.71 | % | |||||||
(1) Stated on a tax equivalent basis using a federal income tax rate of 21%.
7
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
CREDIT QUALITY
| For the Three Months Ended | ||||||||||||||||||||
| (Unaudited) (In thousands, except ratios) | Mar. 31, 2022 | Dec. 31, 2021 | Sep. 30, 2021 | Jun. 30, 2021 | Mar. 31, 2021 | |||||||||||||||
| ALLOWANCE FOR CREDIT LOSSES ON LOANS | ||||||||||||||||||||
| Balance at beginning of period | $150,044 | $162,775 | $172,395 | $200,527 | $220,834 | |||||||||||||||
| Adoption of ASU 2016-13 | — | — | — | — | — | |||||||||||||||
| Provision for credit losses on loans | (10,686) | (8,474) | (5,961) | (27,433) | (10,355) | |||||||||||||||
| Net charge-offs (recoveries): | ||||||||||||||||||||
| Commercial portfolio: | ||||||||||||||||||||
| Business | 77 | 90 | 65 | (4,909) | (4) | |||||||||||||||
| Real estate — construction and land | — | — | — | — | 1 | |||||||||||||||
| Real estate — business | (7) | 6 | (5) | (85) | 20 | |||||||||||||||
| 70 | 96 | 60 | (4,994) | 17 | ||||||||||||||||
| Personal banking portfolio: | ||||||||||||||||||||
| Consumer credit card | 3,372 | 2,964 | 2,908 | 5,155 | 8,981 | |||||||||||||||
| Consumer | 808 | 919 | 496 | 378 | 763 | |||||||||||||||
| Overdraft | 358 | 375 | 243 | 148 | 153 | |||||||||||||||
| Real estate — personal | 22 | (71) | (26) | (16) | 15 | |||||||||||||||
| Revolving home equity | 18 | (26) | (22) | 28 | 23 | |||||||||||||||
| 4,578 | 4,161 | 3,599 | 5,693 | 9,935 | ||||||||||||||||
| Total net loan charge-offs | 4,648 | 4,257 | 3,659 | 699 | 9,952 | |||||||||||||||
| Balance at end of period | $134,710 | $150,044 | $162,775 | $172,395 | $200,527 | |||||||||||||||
| LIABILITY FOR UNFUNDED LENDING COMMITMENTS | $25,032 | $24,204 | $22,784 | $24,208 | $42,430 | |||||||||||||||
NET CHARGE-OFF RATIOS (1) | ||||||||||||||||||||
| Commercial portfolio: | ||||||||||||||||||||
| Business | .01 | % | .01 | % | — | % | (.32 | %) | — | % | ||||||||||
| Real estate — construction and land | — | — | — | — | — | |||||||||||||||
| Real estate — business | — | — | — | (.01) | — | |||||||||||||||
| — | — | — | (.19) | — | ||||||||||||||||
| Personal banking portfolio: | ||||||||||||||||||||
| Consumer credit card | 2.53 | 2.10 | 2.04 | 3.59 | 5.98 | |||||||||||||||
| Consumer | .16 | .18 | .10 | .08 | .16 | |||||||||||||||
| Overdraft | 28.04 | 30.20 | 18.87 | 15.89 | 17.50 | |||||||||||||||
| Real estate — personal | — | (.01) | — | — | — | |||||||||||||||
| Revolving home equity | .03 | (.04) | (.03) | .04 | .03 | |||||||||||||||
| .33 | .29 | .25 | .40 | .71 | ||||||||||||||||
| Total | .12 | % | .11 | % | .10 | % | .02 | % | .25 | % | ||||||||||
| CREDIT QUALITY RATIOS | ||||||||||||||||||||
| Non-accrual loans to total loans | .05 | % | .06 | % | .07 | % | .07 | % | .14 | % | ||||||||||
Allowance for credit losses on loans to total loans(2) | .87 | .99 | 1.07 | 1.10 | 1.22 | |||||||||||||||
| NON-ACCRUAL AND PAST DUE LOANS | ||||||||||||||||||||
| Non-accrual loans: | ||||||||||||||||||||
| Business | $6,756 | $7,312 | $8,293 | $8,839 | $20,215 | |||||||||||||||
| Real estate — construction and land | — | — | — | — | — | |||||||||||||||
| Real estate — business | 190 | 214 | 577 | 655 | 1,572 | |||||||||||||||
| Real estate — personal | 1,389 | 1,631 | 1,551 | 1,672 | 1,719 | |||||||||||||||
| Total | 8,335 | 9,157 | 10,421 | 11,166 | 23,506 | |||||||||||||||
| Loans past due 90 days and still accruing interest | $10,670 | $11,726 | $10,496 | $12,338 | $21,512 | |||||||||||||||
(1) Net charge-offs are annualized and calculated as a percentage of average loans (excluding loans held for sale).
(2) Excluding PPP loans, the allowance for credit losses on loans to total loans was .87% and 1.00% as of March 31, 2022 and December 31, 2021, respectively.
8
COMMERCE BANCSHARES, INC.
Management Discussion of First Quarter Results
March 31, 2022
For the quarter ended March 31, 2022, net income amounted to $118.2 million, compared to $114.9 million in the previous quarter and $131.0 million in the same quarter last year. The increase in net income compared to the previous quarter was primarily the result of net investment securities gains recorded this quarter compared to net losses recorded in the prior quarter, mostly offset by lower non-interest income. The net yield on interest earning assets grew two basis points to 2.45%. Average loans grew $130.1 million compared to the previous quarter, while average available for sale debt securities grew $418.0 million, and average deposits increased $501.7 million. For the quarter, the return on average assets was 1.33%, the return on average equity was 14.41%, and the efficiency ratio was 60.3%.
Balance Sheet Review
During the 1st quarter of 2022, average loans totaled $15.2 billion, an increase of $130.1 million over the prior quarter, and declined $1.1 billion, or 6.8%, from the same quarter last year. Compared to the previous quarter, average balances of business loans grew $132.3 million (includes a decline of $132.0 million in Paycheck Protection Program (PPP) average loan balances). Average business real estate loan balances grew $91.6 million, while construction loan balances declined $93.3 million. Period end loans increased $282.7 million compared to the prior quarter, including PPP loan balances that decreased $75.7 million this quarter and totaled $53.4 million at March 31, 2022. Excluding PPP loans, period end business loans increased $280.7 million. As of March 31, 2022, 97% of PPP loan balances have been forgiven. During the current quarter, the Company sold certain fixed rate personal real estate loans totaling $55.6 million, compared to $119.3 million in the prior quarter.
Total average available for sale debt securities increased $418.0 million over the previous quarter to $14.9 billion, at fair value. The increase in investment securities was mainly the result of growth in asset-backed securities. During the current quarter, purchases of securities totaled $1.8 billion with a weighted average yield of approximately 2.06%. Maturities and pay downs were $806.5 million. At March 31, 2022, the duration of the investment portfolio was 3.6 years, and maturities and pay downs of approximately $3.1 billion are expected to occur during the next 12 months.
Total average deposits increased $501.7 million this quarter compared to the previous quarter. The increase in deposits mostly resulted from growth in interest checking and money market deposits of $1.1 billion, partially offset by lower demand deposits and certificates of deposit of $374.6 million and $255.3 million, respectively. Compared to the previous quarter, total average consumer and wealth deposits grew $290.2 million and $213.6 million, respectively. The average loans to deposits ratio was 51.9% in the current quarter and 52.4% in the prior
quarter. The Company’s average borrowings, which include customer repurchase agreements, were $2.7 billion in the 1st quarter of 2022 and $2.6 billion in the prior quarter.
Net Interest Income
Net interest income in the 1st quarter of 2022 amounted to $208.8 million, an increase of $1.1 million compared to the previous quarter. On a tax equivalent basis, net interest income for the current quarter increased $969 thousand compared to the previous quarter to $211.4 million. The increase in net interest income was mainly due to higher income earned on investment securities, partially offset by lower income earned on loans and securities purchased under agreements to resell. The net yield on earning assets (tax equivalent) increased to 2.45%, compared to 2.43% in the prior quarter.
Compared to the previous quarter, interest income on loans (tax equivalent) decreased $4.8 million, mostly due to $4.0 million of lower income recognized from PPP loans this quarter, partly offset by higher average loan balances. Interest on construction and consumer card loans declined mostly due to lower average loan balances, while consumer banking loans declined mostly due to lower average rates. The yield on PPP loans decreased from 10.80% to 9.36% this quarter. Excluding PPP loans, the yield on business loans was 2.82% in the 1st quarter of 2022 compared to 2.83% in the prior quarter. The average tax-equivalent yield on the loan portfolio decreased six basis points to 3.54% this quarter.
Interest income on investment securities (tax equivalent) increased $7.4 million compared to the prior quarter, due to higher rates earned coupled with higher average balances. At March 31, 2022, the Company recorded a $7.5 million adjustment to premium amortization compared to a $2.6 million adjustment in the prior quarter, which increased interest income to reflect considerably slower forward prepayment speed estimates on mortgage-backed securities. Interest income earned on U.S. government and federal agency securities increased due to higher average balances and rates earned, including the impact of $1.4 million in higher inflation income from Treasury inflation-protected securities. These increases were partly offset by $5.5 million in dividends received from private equity portfolio investments last quarter that did not reoccur. The yield on total investment securities was 1.97% in the current quarter, compared to 1.82% in the previous quarter.
The average rate paid on interest bearing deposits totaled .05% in both the current and prior quarters. Interest expense on deposits increased $25 thousand this quarter compared to the previous quarter. The overall rate paid on interest bearing liabilities was .06% in both the current and prior quarters.
COMMERCE BANCSHARES, INC.
Management Discussion of First Quarter Results
March 31, 2022
Non-Interest Income
In the 1st quarter of 2022, total non-interest income amounted to $131.8 million, a decrease of $4.3 million, or 3.1%, compared to the same period last year and decreased $15.9 million compared to the prior quarter. The decrease in non-interest income compared to the same period last year was mainly due to lower loan fees and sales and less income from branch sales, partly offset by higher bank card and trust fee income. The decrease in non-interest income compared to the prior quarter was mainly due to lower income from branch sales, deposit account, trust and bank card fees.
Total net bank card fees in the current quarter increased $4.4 million, or 11.5%, over the same period last year, and decreased $2.7 million compared to the prior quarter. Net corporate card fees increased $3.5 million, or 17.2%, over the same quarter of last year mainly due to higher interchange fee income, partly offset by higher rewards expense. Net debit card fees increased $185 thousand, or 2.0%, mainly due to higher interchange fees. Net merchant income increased $366 thousand, or 7.9%, and net credit card fees increased $300 thousand, or 8.8%. Total net bank card fees this quarter were comprised of fees on corporate card ($23.8 million), debit card ($9.6 million), merchant ($5.0 million) and credit card ($3.7 million) transactions.
In the current quarter, trust fees increased $3.7 million, or 8.3%, over the same period last year, resulting mostly from higher private client fee income. Compared to the same period last year, deposit account fees decreased $268 thousand, or 1.2%, mainly due to lower personal deposit account fees, partially offset by higher corporate cash management fees. Loan fees and sales, mostly mortgage banking revenue, declined $5.9 million, or 58.4%, compared to amounts recorded in the same quarter last year. Capital markets fees decreased $856 thousand, or 17.2%, while consumer brokerage fees increased $365 thousand, or 8.9%, compared to the same quarter last year.
Other non-interest income decreased from the same period last year mainly due to a $2.4 million gain on the sale of a branch location recorded last year compared to a $965 thousand write down on a branch location recorded this quarter. In addition, swap fees and cash sweep commissions declined $637 thousand and $403 thousand, respectively. Fair value adjustments on the Company’s deferred compensation plan assets, which are held in a trust and recorded as both an asset and liability, decreased $1.9 million from the same quarter last year, affecting both other income and other expense. For the 1st quarter of 2022, non-interest income comprised 38.7% of the Company’s total revenue.
Investment Securities Gains and Losses
The Company recorded investment net gains of $7.2 million in the current quarter, compared to net losses of $9.7 million in the prior quarter and net gains of $9.9 million in the 1st quarter of 2021. Net gains on investments in the current quarter primarily resulted from net fair value gains of $7.5 million in the Company’s private equity investment portfolio.
Non-Interest Expense
Non-interest expense for the current quarter amounted to $205.6 million, compared to $192.6 million in the same period last year and $203.6 million in the prior quarter. The increase in non-interest expense compared to the same period last year was mainly due to higher salaries and benefits expense, data processing and software expense, marketing expense, and travel and entertainment expense. The increase in non-interest expense compared to the prior quarter was mainly due to higher payroll taxes and 401(k) contributions expense, partly offset by fair value adjustments on the Company’s deferred compensation plan and lower salaries expense.
Compared to the 1st quarter of last year, salaries and employee benefits expense increased $6.9 million, mostly due to higher full-time salaries expense. Employee benefits expense also increased $2.5 million compared to the prior quarter. Full-time equivalent employees totaled 4,563 and 4,619 at March 31, 2022 and 2021, respectively.
Compared to the same period last year, data processing and software expense increased $1.6 million due to higher software amortization, bank card processing fees and increased costs for service providers this quarter. Marketing expense increased $1.2 million. Additionally, other non-interest expense increased $2.3 million, mainly due to an increase of $1.1 million in travel and entertainment expense and lower deferred origination costs of $1.1 million, partially offset by a $1.9 million deferred compensation adjustment previously mentioned.
Income Taxes
The effective tax rate for the Company was 21.3% in the current quarter, 22.7% in the previous quarter, and 19.7% in the 1st quarter of 2021. The effective tax rate in the first quarter of 2022 is higher than the first quarter of 2021 mostly due to the executive compensation limitation on equity-based compensation.
Credit Quality
Net loan charge-offs in the 1st quarter of 2022 amounted to $4.6 million, compared to $4.3 million in the prior quarter and $10.0 million in the same period last year. The ratio of annualized net loan charge-offs to total average loans was .12% in the current quarter, .11% in the previous quarter, and .25% in the 1st quarter of last year. Net loan charge-offs on personal banking loans increased $417 thousand to
10
COMMERCE BANCSHARES, INC.
Management Discussion of First Quarter Results
March 31, 2022
$4.6 million.
In the 1st quarter of 2022, annualized net loan charge-offs on average consumer credit card loans were 2.53%, compared to 2.10% in the previous quarter, and 5.98% in the same quarter last year. Consumer loan net charge-offs were .16% of average consumer loans in the current quarter, .18% in the prior quarter and .16% in the same quarter last year.
During the 1st quarter of 2022, the economy continued to recover from the pandemic and the economic forecast utilized in the allowance for credit loss model also continued to improve. This improvement, coupled with other model inputs, resulted in a decrease in the allowance for credit losses as of March 31, 2022, primarily in the consumer credit card portfolio as consumer credit continued to prove resistant to pandemic related hardships. At March 31, 2022, the allowance for credit losses on loans totaled $134.7 million, or .87% of total loans. Additionally, the liability for unfunded lending commitments at March 31, 2022 was $25.0 million, an increase of $828 thousand compared to the liability at December 31, 2021.
At March 31, 2022, total non-accrual loans amounted to $8.3 million, a decrease of $822 thousand from the previous quarter. At March 31, 2022, the balance of non-accrual loans, which represented .05% of loans outstanding, included business loans of $6.8 million, personal real estate loans of $1.4 million, and business real estate loans of $190 thousand. Loans more than 90 days past due and still accruing interest totaled $10.7 million at March 31, 2022.
Other
During the 1st quarter of 2022, the Company paid a cash dividend of $.265 per common share, representing a 6.0% increase over the same period last year. The Company purchased 795,387 shares of treasury stock during the current quarter at an average price of $70.22.
Forward Looking Information
This information contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements include future financial and operating results, expectations, intentions and other statements that are not historical facts. Such statements are based on current beliefs and expectations of the Company’s management and are subject to significant risks and uncertainties. Actual results may differ materially from those set forth in the forward-looking statements.
11
COMMERCE BANCSHARES, INC. EARNINGS HIGHLIGHTS 1st Quarter 2022
CAUTIONARY STATEMENT A number of statements we will be making in our presentation and in the accompanying slides are “forward-looking statements” within the meaning of the Private Securities Litigation Reform Act of 1995, such as statements of the Corporation’s plans, goals, objectives, expectations, projections, estimates and intentions. These forward- looking statements involve significant risks and uncertainties and are subject to change based on various factors (some of which are beyond the Corporation’s control). Factors that could cause the Corporation’s actual results to differ materially from such forward- looking statements made herein or by management of the Corporation are set forth in the Corporation’s 2021 Annual Report on Form 10-K and the Corporation’s Current Reports on Form 8-K. 2
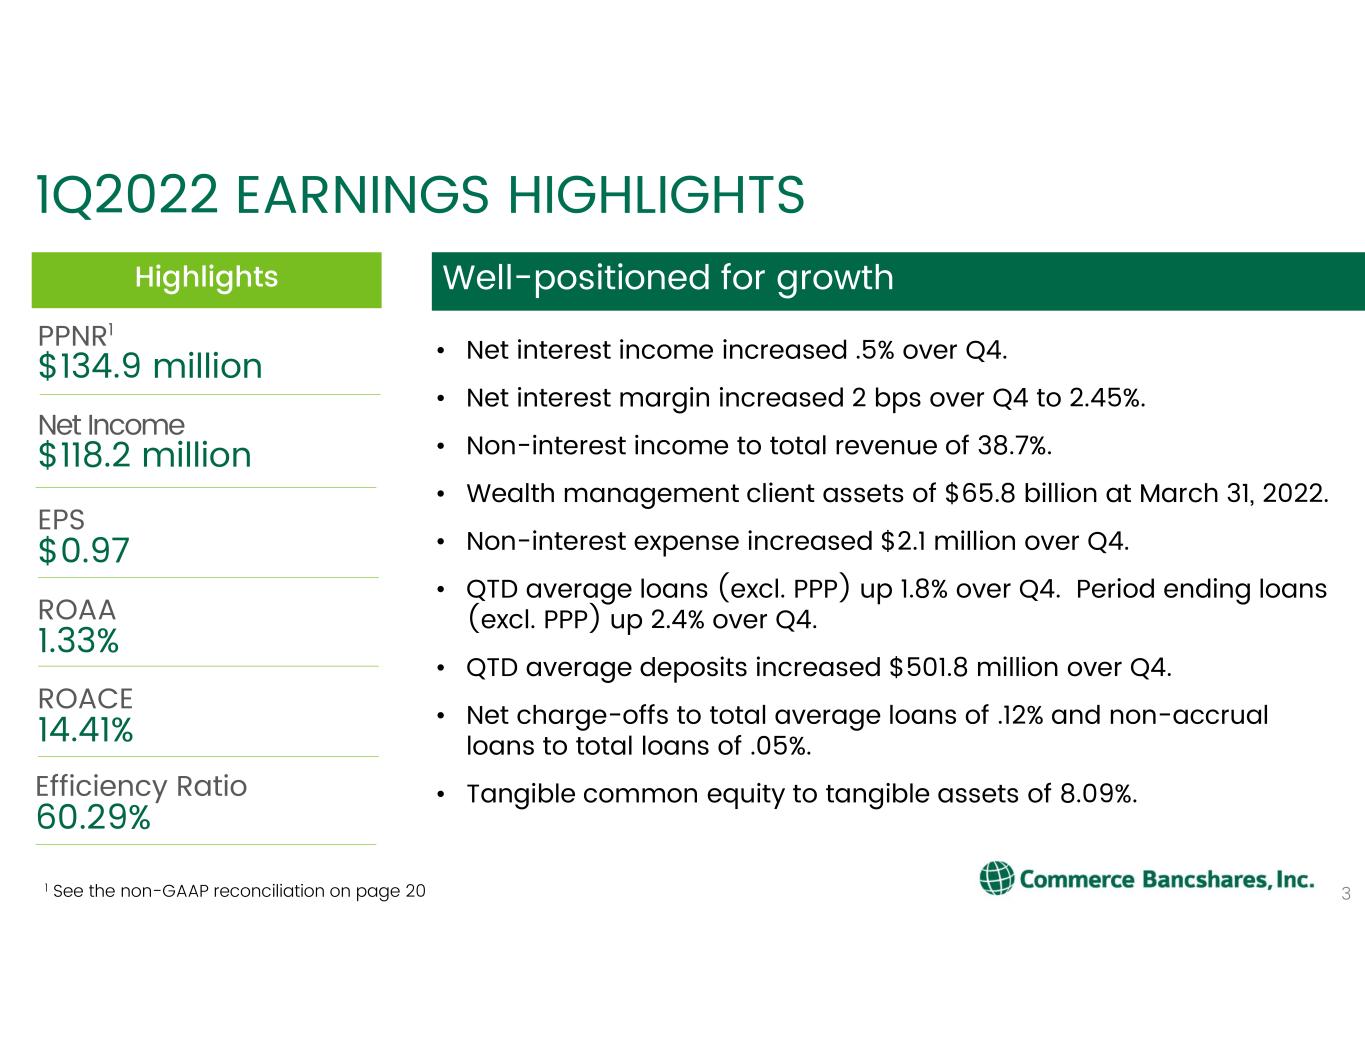
$0.97 EPS 3 • Net interest income increased .5% over Q4. • Net interest margin increased 2 bps over Q4 to 2.45%. • Non-interest income to total revenue of 38.7%. • Wealth management client assets of $65.8 billion at March 31, 2022. • Non-interest expense increased $2.1 million over Q4. • QTD average loans (excl. PPP) up 1.8% over Q4. Period ending loans (excl. PPP) up 2.4% over Q4. • QTD average deposits increased $501.8 million over Q4. • Net charge-offs to total average loans of .12% and non-accrual loans to total loans of .05%. • Tangible common equity to tangible assets of 8.09%. Highlights Well-positioned for growth 1Q2022 EARNINGS HIGHLIGHTS $134.9 million PPNR1 $118.2 million Net Income 14.41% ROACE 1 See the non-GAAP reconciliation on page 20 1.33% ROAA 60.29% Efficiency Ratio
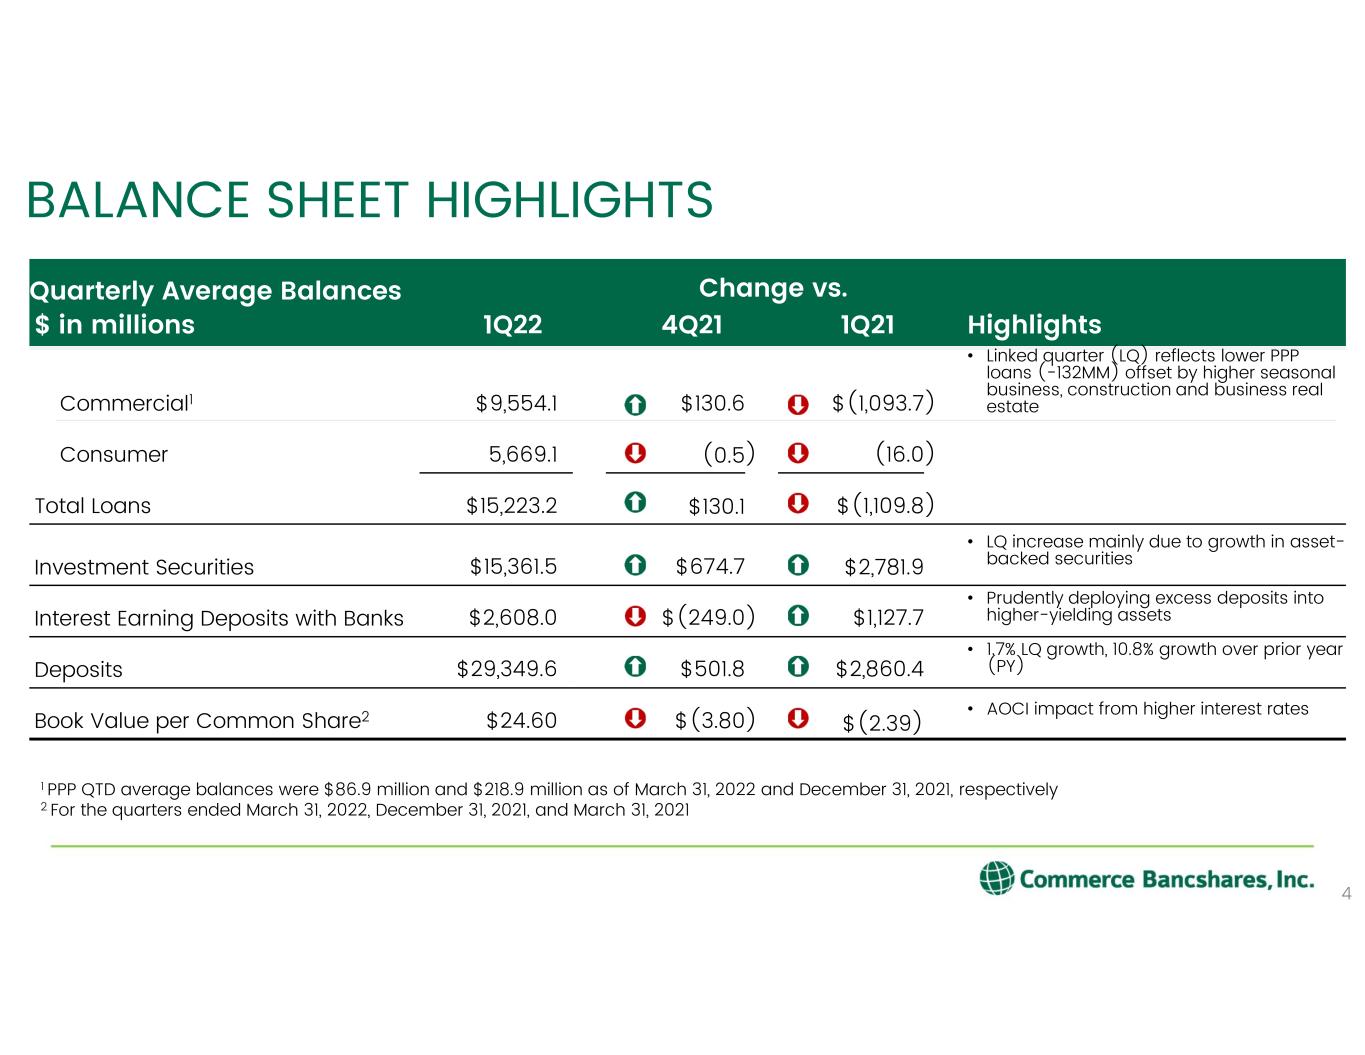
Quarterly Average Balances Change vs. $ in millions 1Q22 4Q21 1Q21 Highlights Commercial1 $9,554.1 $130.6 $(1,093.7) • Linked quarter (LQ) reflects lower PPP loans (-132MM) offset by higher seasonal business, construction and business real estate Consumer 5,669.1 (0.5) (16.0) Total Loans $15,223.2 $130.1 $(1,109.8) Investment Securities $15,361.5 $674.7 $2,781.9 • LQ increase mainly due to growth in asset- backed securities Interest Earning Deposits with Banks $2,608.0 $(249.0) $1,127.7 • Prudently deploying excess deposits into higher-yielding assets Deposits $29,349.6 $501.8 $2,860.4 • 1.7% LQ growth, 10.8% growth over prior year (PY) Book Value per Common Share2 $24.60 $(3.80) $(2.39) • AOCI impact from higher interest rates BALANCE SHEET HIGHLIGHTS 4 1 PPP QTD average balances were $86.9 million and $218.9 million as of March 31, 2022 and December 31, 2021, respectively 2 For the quarters ended March 31, 2022, December 31, 2021, and March 31, 2021
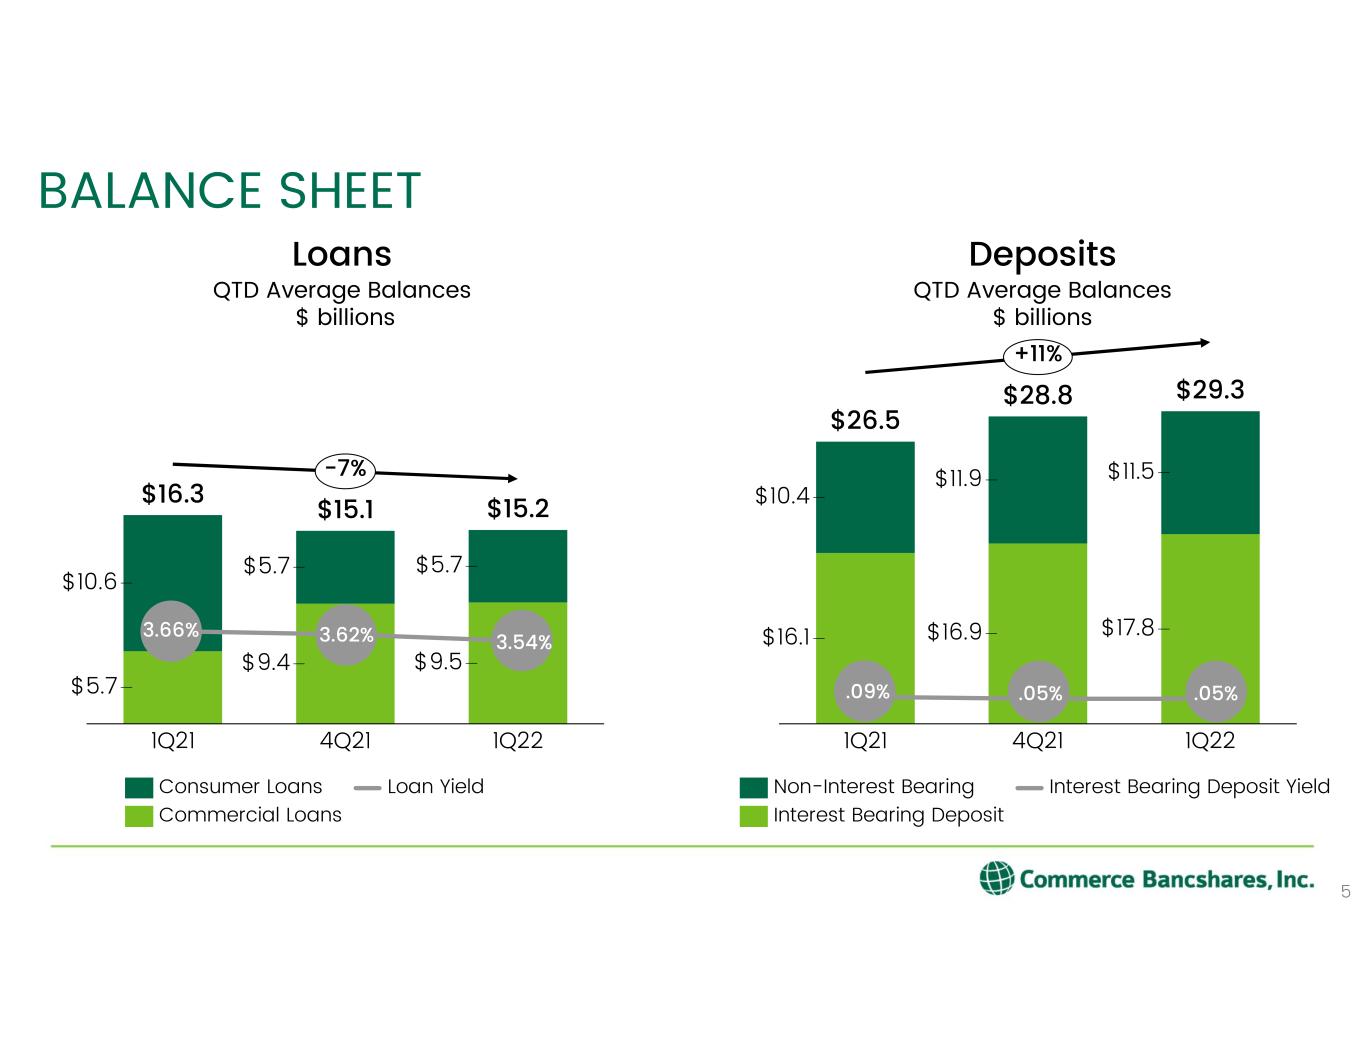
$16.1 $16.9 $17.8 $10.4 $11.9 $11.5 1Q224Q211Q21 $26.5 $29.3$28.8 +11% $5.7 $9.4 $9.5 $10.6 $5.7 $5.7 4Q21 $16.3 1Q21 $15.2 1Q22 $15.1 -7% BALANCE SHEET 5 Loans Loan Yield Commercial Loans Consumer Loans Deposits QTD Average Balances $ billions Non-Interest Bearing Interest Bearing Deposit Interest Bearing Deposit Yield QTD Average Balances $ billions 3.66% 3.62% 3.54% .09% .05% .05%
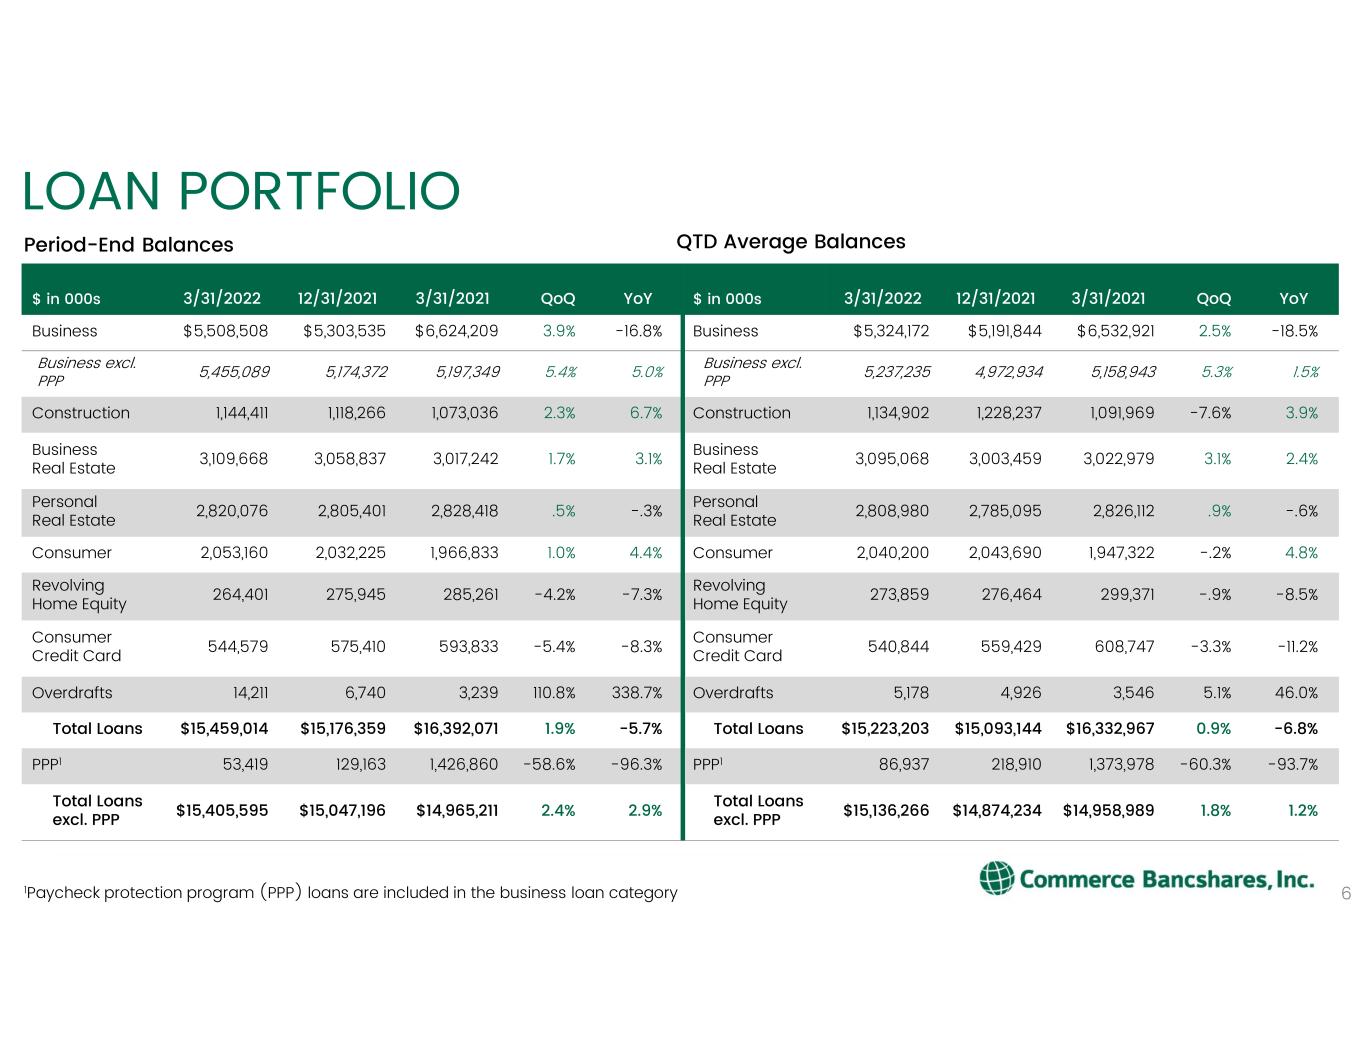
LOAN PORTFOLIO 6 $ in 000s 3/31/2022 12/31/2021 3/31/2021 QoQ YoY Business $5,508,508 $5,303,535 $6,624,209 3.9% -16.8% Business excl. PPP 5,455,089 5,174,372 5,197,349 5.4% 5.0% Construction 1,144,411 1,118,266 1,073,036 2.3% 6.7% Business Real Estate 3,109,668 3,058,837 3,017,242 1.7% 3.1% Personal Real Estate 2,820,076 2,805,401 2,828,418 .5% -.3% Consumer 2,053,160 2,032,225 1,966,833 1.0% 4.4% Revolving Home Equity 264,401 275,945 285,261 -4.2% -7.3% Consumer Credit Card 544,579 575,410 593,833 -5.4% -8.3% Overdrafts 14,211 6,740 3,239 110.8% 338.7% Total Loans $15,459,014 $15,176,359 $16,392,071 1.9% -5.7% PPP1 53,419 129,163 1,426,860 -58.6% -96.3% Total Loans excl. PPP $15,405,595 $15,047,196 $14,965,211 2.4% 2.9% Period-End Balances $ in 000s 3/31/2022 12/31/2021 3/31/2021 QoQ YoY Business $5,324,172 $5,191,844 $6,532,921 2.5% -18.5% Business excl. PPP 5,237,235 4,972,934 5,158,943 5.3% 1.5% Construction 1,134,902 1,228,237 1,091,969 -7.6% 3.9% Business Real Estate 3,095,068 3,003,459 3,022,979 3.1% 2.4% Personal Real Estate 2,808,980 2,785,095 2,826,112 .9% -.6% Consumer 2,040,200 2,043,690 1,947,322 -.2% 4.8% Revolving Home Equity 273,859 276,464 299,371 -.9% -8.5% Consumer Credit Card 540,844 559,429 608,747 -3.3% -11.2% Overdrafts 5,178 4,926 3,546 5.1% 46.0% Total Loans $15,223,203 $15,093,144 $16,332,967 0.9% -6.8% PPP1 86,937 218,910 1,373,978 -60.3% -93.7% Total Loans excl. PPP $15,136,266 $14,874,234 $14,958,989 1.8% 1.2% QTD Average Balances 1Paycheck protection program (PPP) loans are included in the business loan category
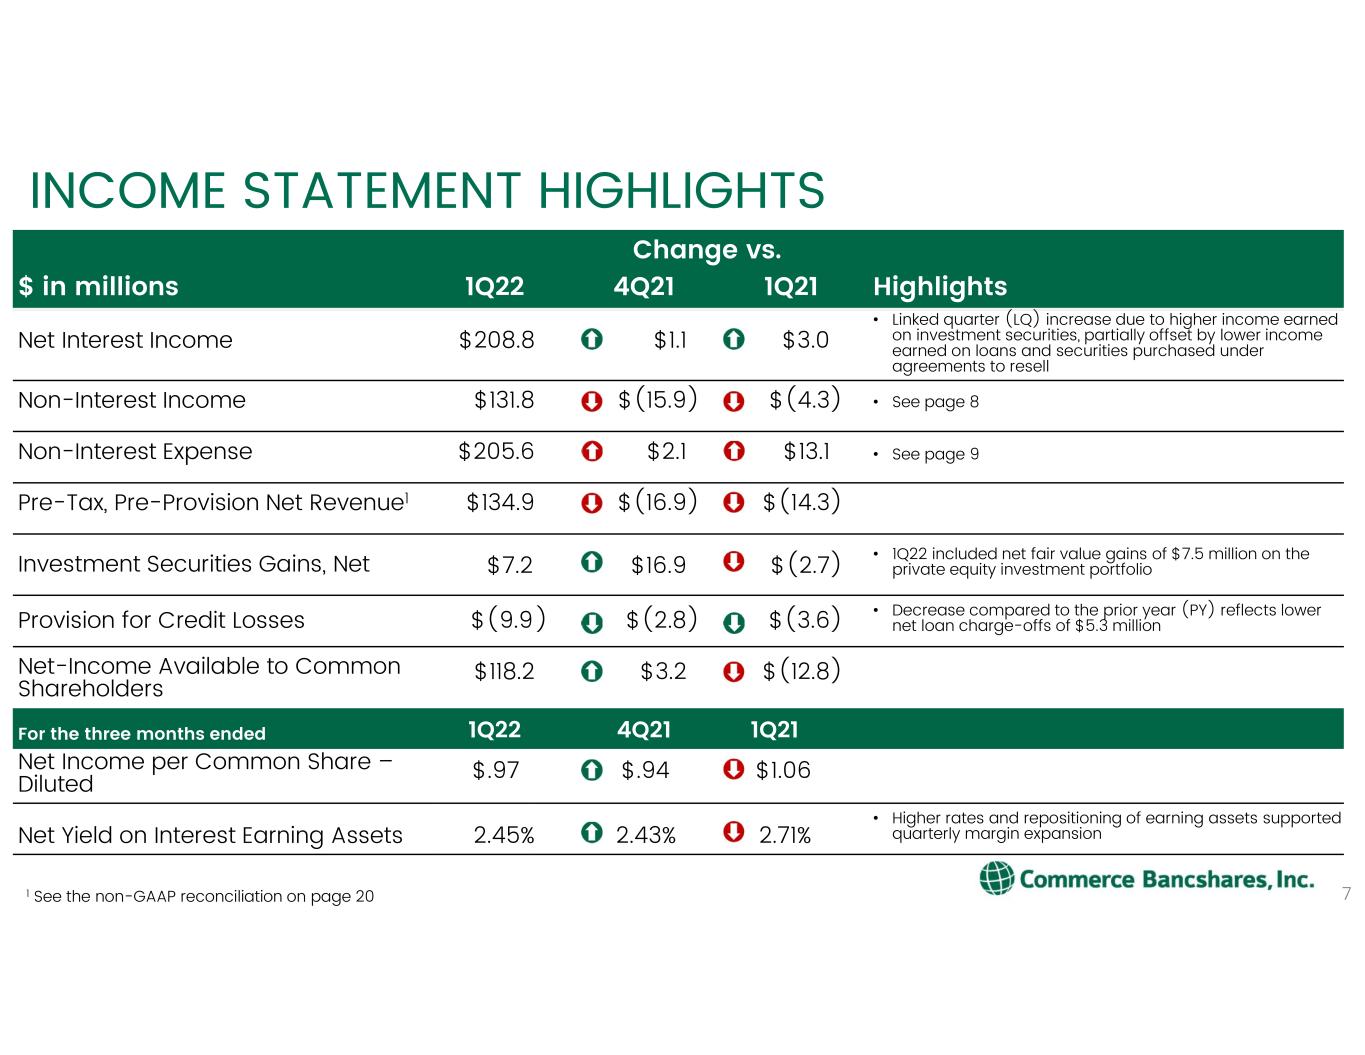
Change vs. $ in millions 1Q22 4Q21 1Q21 Highlights Net Interest Income $208.8 $1.1 $3.0 • Linked quarter (LQ) increase due to higher income earned on investment securities, partially offset by lower income earned on loans and securities purchased under agreements to resell Non-Interest Income $131.8 $(15.9) $(4.3) • See page 8 Non-Interest Expense $205.6 $2.1 $13.1 • See page 9 Pre-Tax, Pre-Provision Net Revenue1 $134.9 $(16.9) $(14.3) Investment Securities Gains, Net $7.2 $16.9 $(2.7) • 1Q22 included net fair value gains of $7.5 million on the private equity investment portfolio Provision for Credit Losses $(9.9) $(2.8) $(3.6) • Decrease compared to the prior year (PY) reflects lower net loan charge-offs of $5.3 million Net-Income Available to Common Shareholders $118.2 $3.2 $(12.8) For the three months ended 1Q22 4Q21 1Q21 Net Income per Common Share – Diluted $.97 $.94 $1.06 Net Yield on Interest Earning Assets 2.45% 2.43% 2.71% • Higher rates and repositioning of earning assets supported quarterly margin expansion INCOME STATEMENT HIGHLIGHTS 1 See the non-GAAP reconciliation on page 20 7
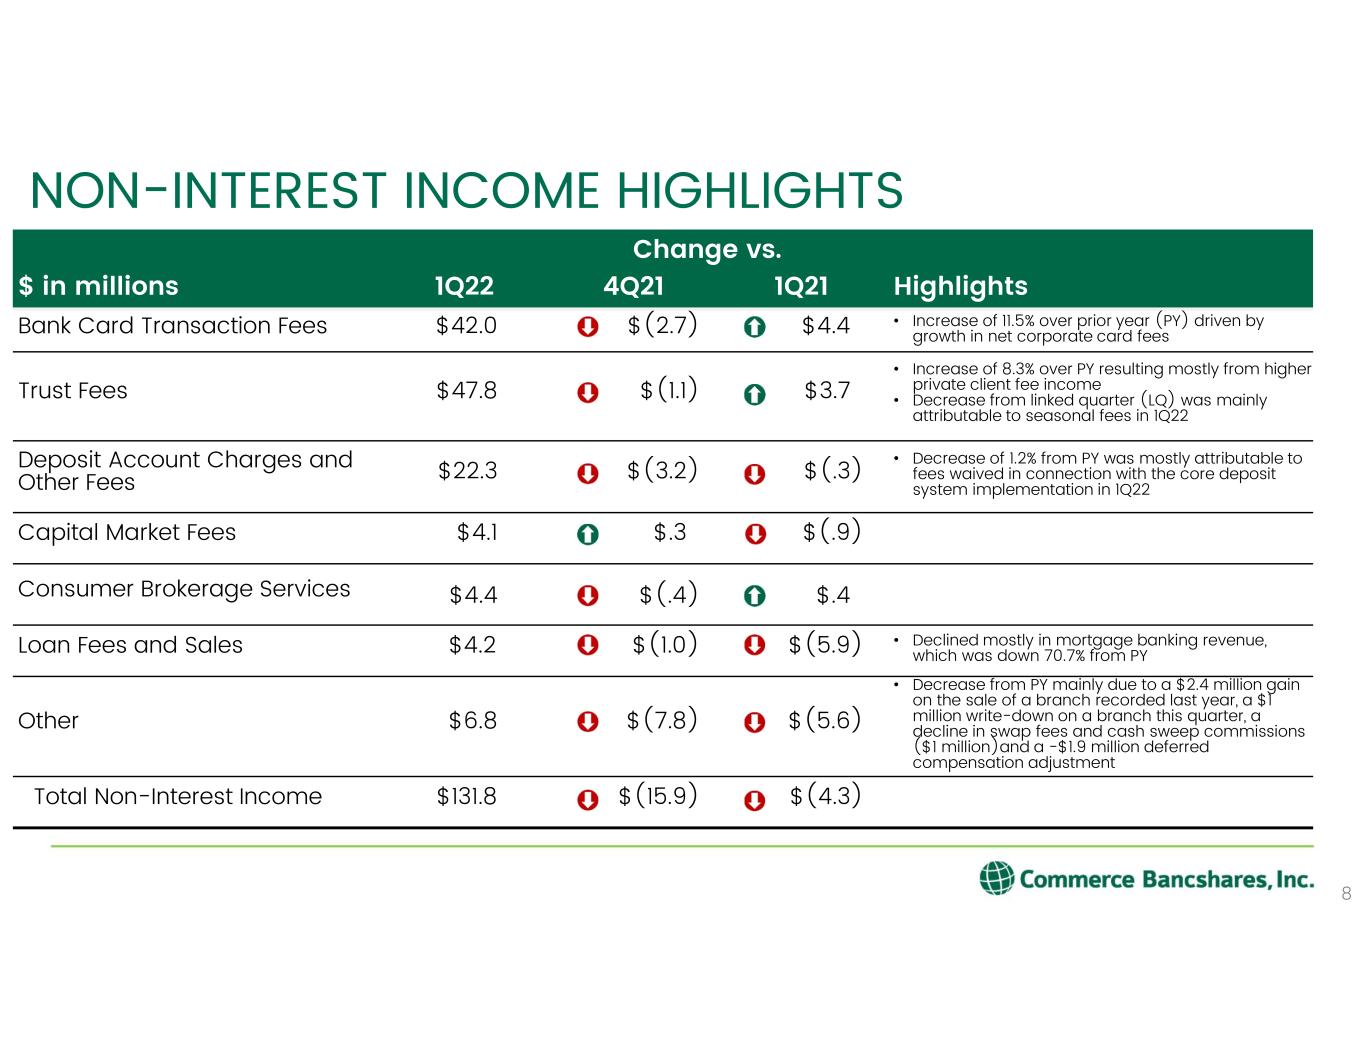
Change vs. $ in millions 1Q22 4Q21 1Q21 Highlights Bank Card Transaction Fees $42.0 $(2.7) $4.4 • Increase of 11.5% over prior year (PY) driven by growth in net corporate card fees Trust Fees $47.8 $(1.1) $3.7 • Increase of 8.3% over PY resulting mostly from higher private client fee income • Decrease from linked quarter (LQ) was mainly attributable to seasonal fees in 1Q22 Deposit Account Charges and Other Fees $22.3 $(3.2) $(.3) • Decrease of 1.2% from PY was mostly attributable to fees waived in connection with the core deposit system implementation in 1Q22 Capital Market Fees $4.1 $.3 $(.9) Consumer Brokerage Services $4.4 $(.4) $.4 Loan Fees and Sales $4.2 $(1.0) $(5.9) • Declined mostly in mortgage banking revenue, which was down 70.7% from PY Other $6.8 $(7.8) $(5.6) • Decrease from PY mainly due to a $2.4 million gain on the sale of a branch recorded last year, a $1 million write-down on a branch this quarter, a decline in swap fees and cash sweep commissions ($1 million)and a -$1.9 million deferred compensation adjustment Total Non-Interest Income $131.8 $(15.9) $(4.3) NON-INTEREST INCOME HIGHLIGHTS 8
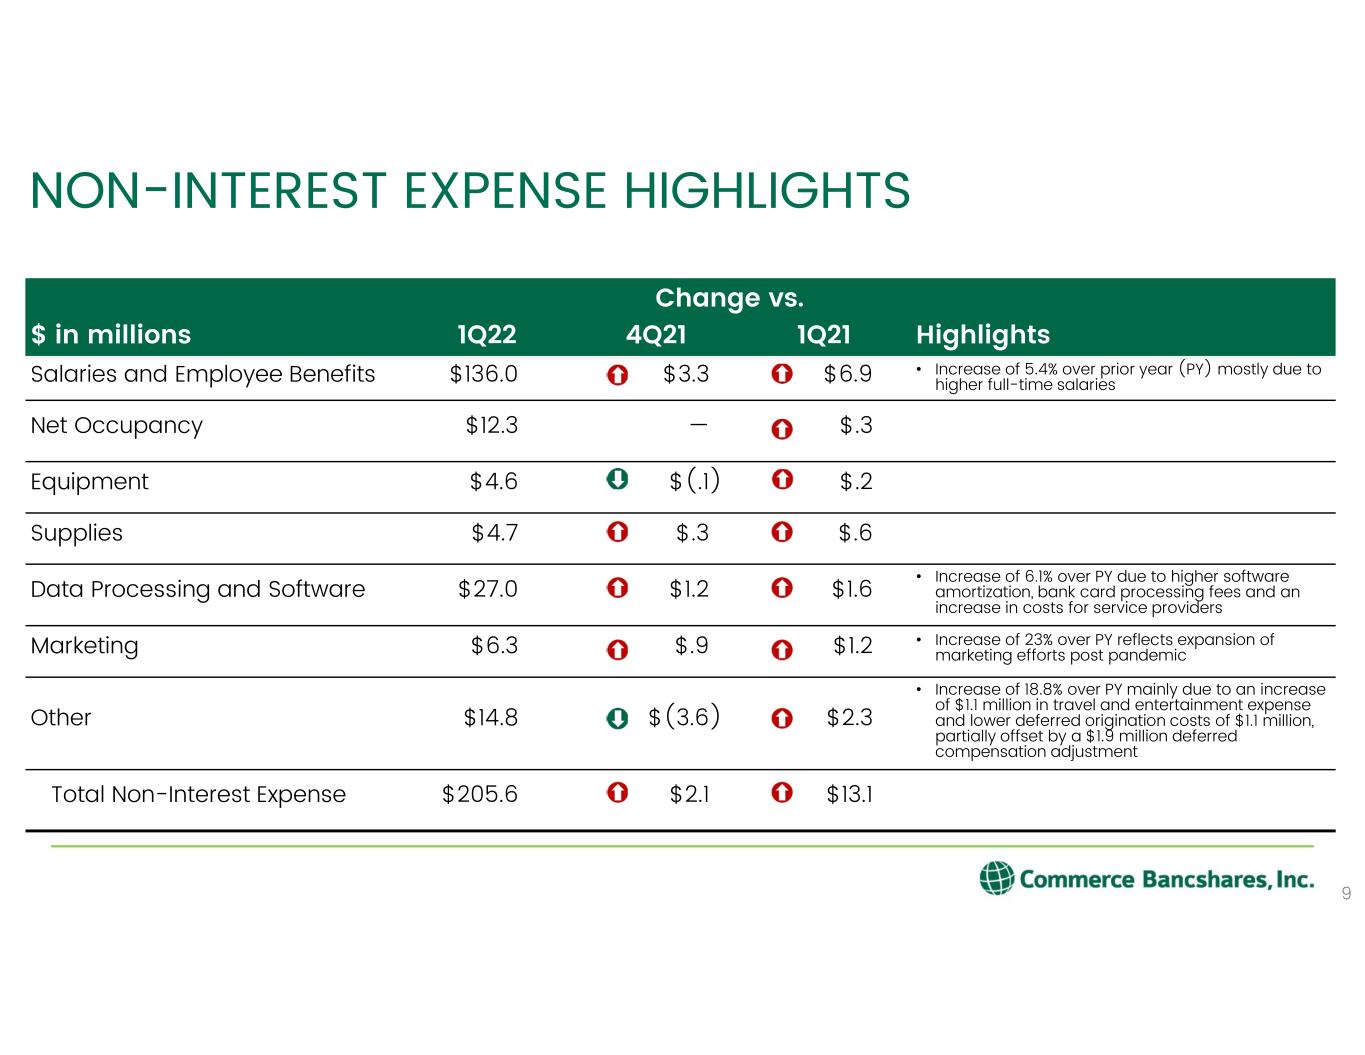
Change vs. $ in millions 1Q22 4Q21 1Q21 Highlights Salaries and Employee Benefits $136.0 $3.3 $6.9 • Increase of 5.4% over prior year (PY) mostly due to higher full-time salaries Net Occupancy $12.3 — $.3 Equipment $4.6 $(.1) $.2 Supplies $4.7 $.3 $.6 Data Processing and Software $27.0 $1.2 $1.6 • Increase of 6.1% over PY due to higher software amortization, bank card processing fees and an increase in costs for service providers Marketing $6.3 $.9 $1.2 • Increase of 23% over PY reflects expansion of marketing efforts post pandemic Other $14.8 $(3.6) $2.3 • Increase of 18.8% over PY mainly due to an increase of $1.1 million in travel and entertainment expense and lower deferred origination costs of $1.1 million, partially offset by a $1.9 million deferred compensation adjustment Total Non-Interest Expense $205.6 $2.1 $13.1 NON-INTEREST EXPENSE HIGHLIGHTS 9
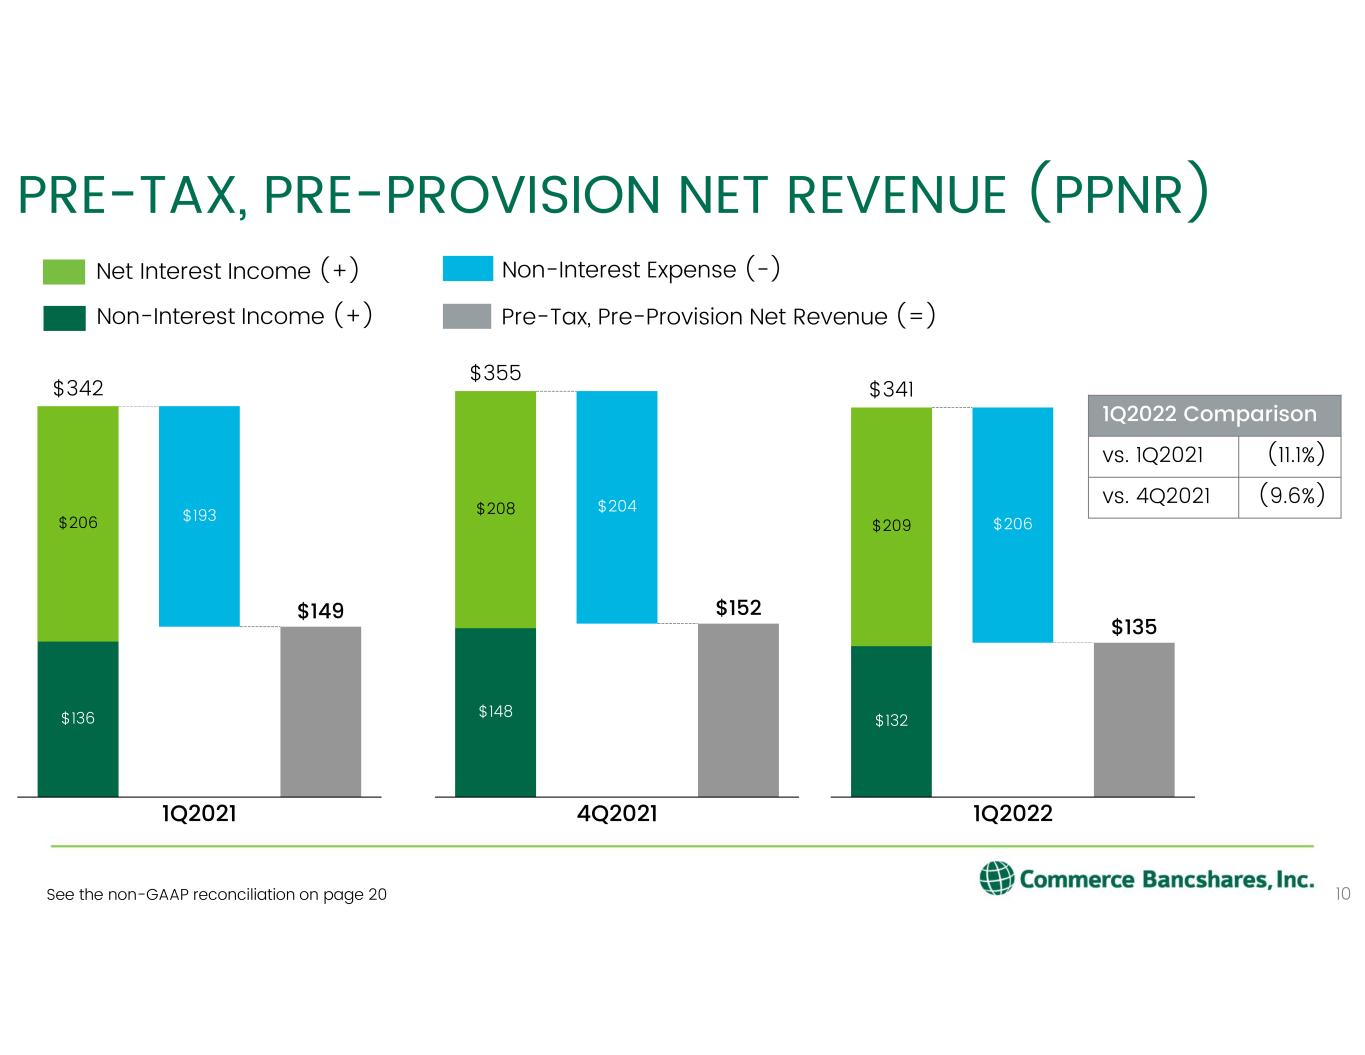
10 PRE-TAX, PRE-PROVISION NET REVENUE (PPNR) $136 $149 $206 $193 1Q2021 $342 $148 $152 $208 $204 4Q2021 $355 $132 $135 $209 $206 $341 1Q2022 Non-Interest Income (+) Net Interest Income (+) Non-Interest Expense (-) Pre-Tax, Pre-Provision Net Revenue (=) 1Q2022 Comparison vs. 1Q2021 (11.1%) vs. 4Q2021 (9.6%) See the non-GAAP reconciliation on page 20
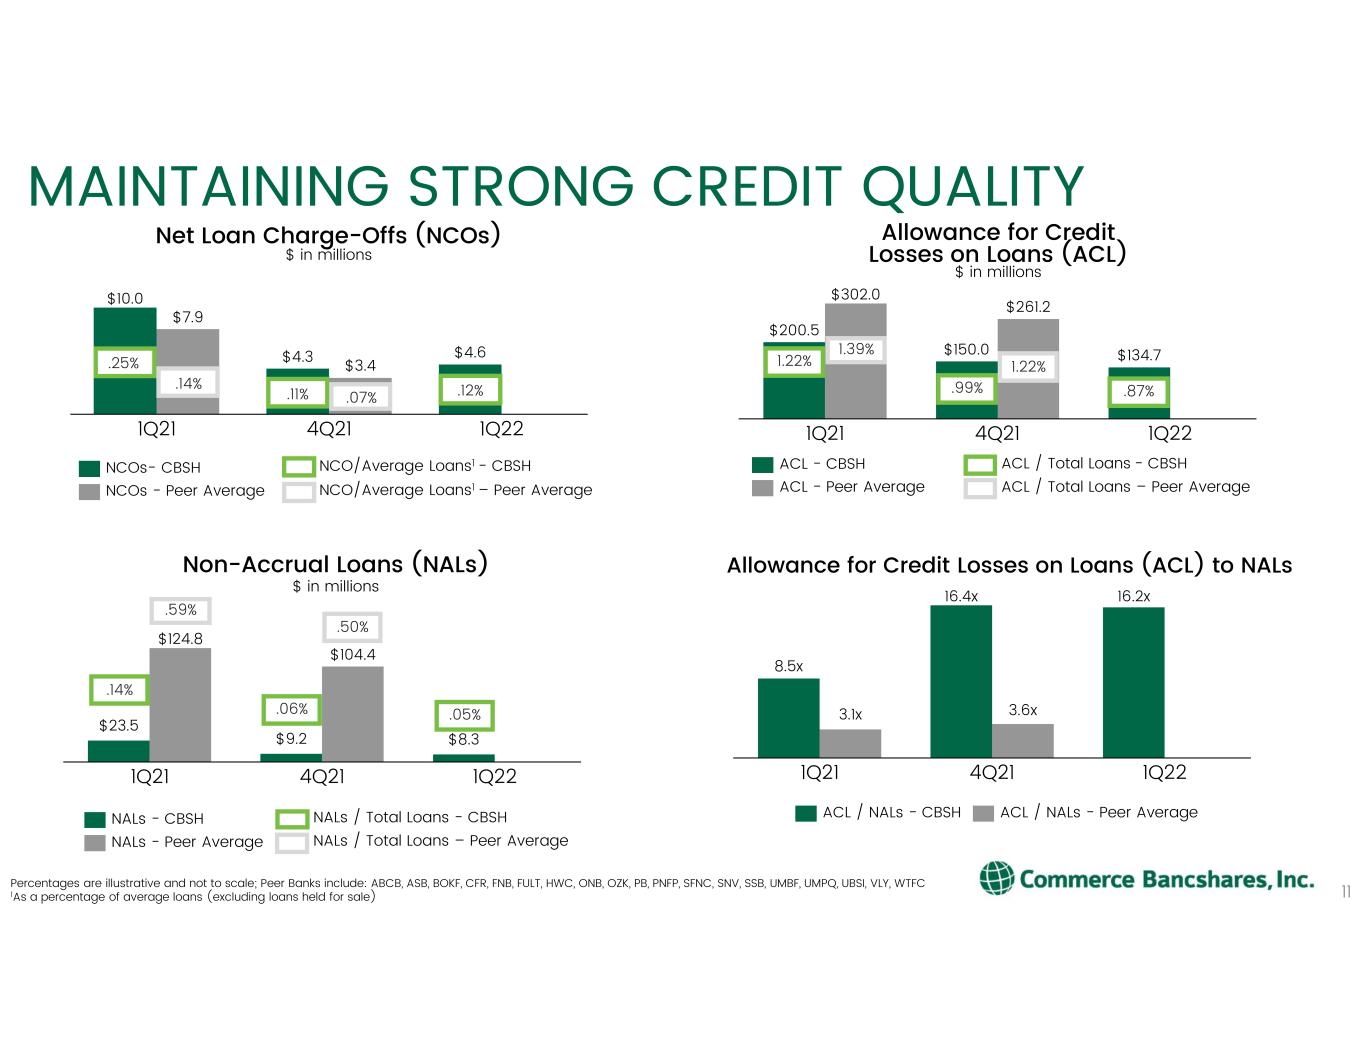
$10.0 $4.3 $4.6 $7.9 $3.4 1Q21 4Q21 1Q22 MAINTAINING STRONG CREDIT QUALITY 11 Net Loan Charge-Offs (NCOs) $ in millions NCOs- CBSH NCOs - Peer Average NCO/Average Loans1 - CBSH $200.5 $150.0 $134.7 $302.0 $261.2 1Q21 4Q21 1Q22 Allowance for Credit Losses on Loans (ACL) $ in millions ACL - CBSH ACL - Peer Average ACL / Total Loans - CBSH $23.5 $9.2 $8.3 $124.8 $104.4 1Q21 4Q21 1Q22 Non-Accrual Loans (NALs) $ in millions NALs - CBSH NALs - Peer Average 8.5x 16.4x 16.2x 3.1x 3.6x 1Q21 4Q21 1Q22 Allowance for Credit Losses on Loans (ACL) to NALs ACL / NALs - CBSH ACL / NALs - Peer Average Percentages are illustrative and not to scale; Peer Banks include: ABCB, ASB, BOKF, CFR, FNB, FULT, HWC, ONB, OZK, PB, PNFP, SFNC, SNV, SSB, UMBF, UMPQ, UBSI, VLY, WTFC 1As a percentage of average loans (excluding loans held for sale) NALs / Total Loans - CBSH NCO/Average Loans1 – Peer Average .14% NALs / Total Loans – Peer Average .06% .05% .59% .50% ACL / Total Loans – Peer Average 1.22% .99% .87% 1.39% 1.22%.25% .11% .12%.14% .07%
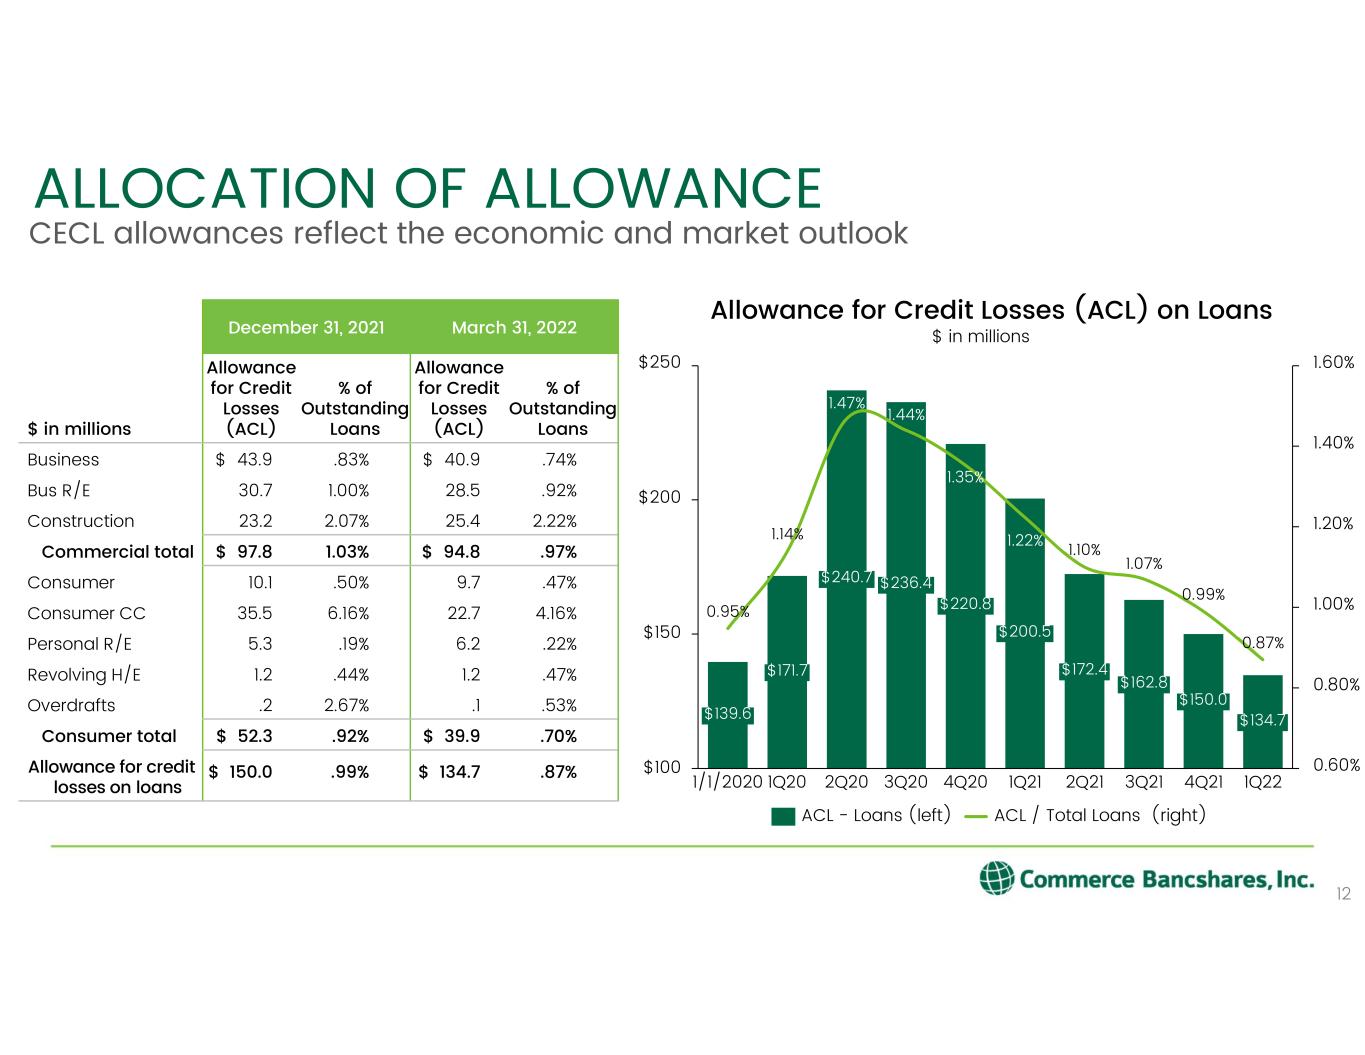
ALLOCATION OF ALLOWANCE 12 CECL allowances reflect the economic and market outlook December 31, 2021 March 31, 2022 $ in millions Allowance for Credit Losses (ACL) % of Outstanding Loans Allowance for Credit Losses (ACL) % of Outstanding Loans Business $ 43.9 .83% $ 40.9 .74% Bus R/E 30.7 1.00% 28.5 .92% Construction 23.2 2.07% 25.4 2.22% Commercial total $ 97.8 1.03% $ 94.8 .97% Consumer 10.1 .50% 9.7 .47% Consumer CC 35.5 6.16% 22.7 4.16% Personal R/E 5.3 .19% 6.2 .22% Revolving H/E 1.2 .44% 1.2 .47% Overdrafts .2 2.67% .1 .53% Consumer total $ 52.3 .92% $ 39.9 .70% Allowance for credit losses on loans $ 150.0 .99% $ 134.7 .87% 1.47% 1.44% 1.22% 1.07% 0.60% 0.80% 1.00% 1.20% 1.40% 1.60% $100 $150 $200 $250 1/1/2020 $220.8 1Q22 $172.4 $139.6 1Q20 $171.7 0.87% $240.7 1.35% 2Q20 $236.4 3Q20 4Q20 $200.5 1Q21 2Q21 $162.8 3Q21 $150.0 0.99% 4Q21 $134.7 0.95% 1.14% 1.10% Allowance for Credit Losses (ACL) on Loans ACL - Loans (left) ACL / Total Loans (right) $ in millions
13 WELL-POSITIONED FOR A RISING RATE ENVIRONMENT
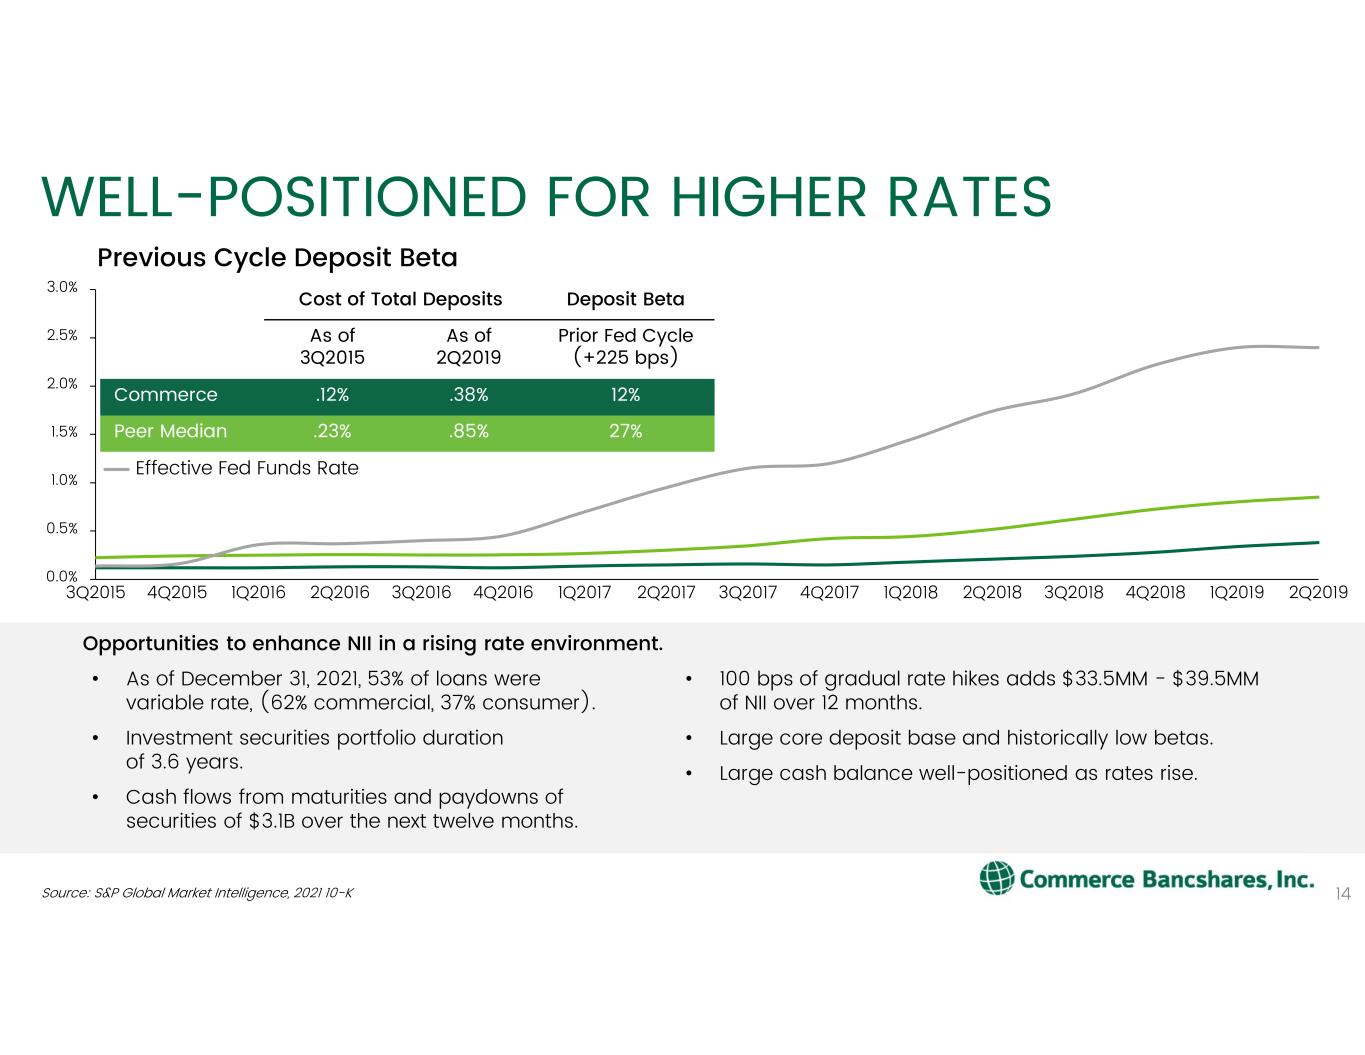
0.0% 0.5% 1.0% 1.5% 2.0% 2.5% 3.0% 3Q20182Q20173Q2015 4Q2015 2Q20161Q2016 4Q20173Q2016 4Q2016 1Q2017 3Q2017 1Q2018 2Q2018 4Q2018 1Q2019 2Q2019 WELL-POSITIONED FOR HIGHER RATES 14 Opportunities to enhance NII in a rising rate environment. • As of December 31, 2021, 53% of loans were variable rate, (62% commercial, 37% consumer). • Investment securities portfolio duration of 3.6 years. • Cash flows from maturities and paydowns of securities of $3.1B over the next twelve months. • 100 bps of gradual rate hikes adds $33.5MM - $39.5MM of NII over 12 months. • Large core deposit base and historically low betas. • Large cash balance well-positioned as rates rise. Previous Cycle Deposit Beta Cost of Total Deposits Deposit Beta As of 3Q2015 As of 2Q2019 Prior Fed Cycle (+225 bps) Commerce .12% .38% 12% Peer Median .23% .85% 27% Effective Fed Funds Rate Source: S&P Global Market Intelligence, 2021 10-K
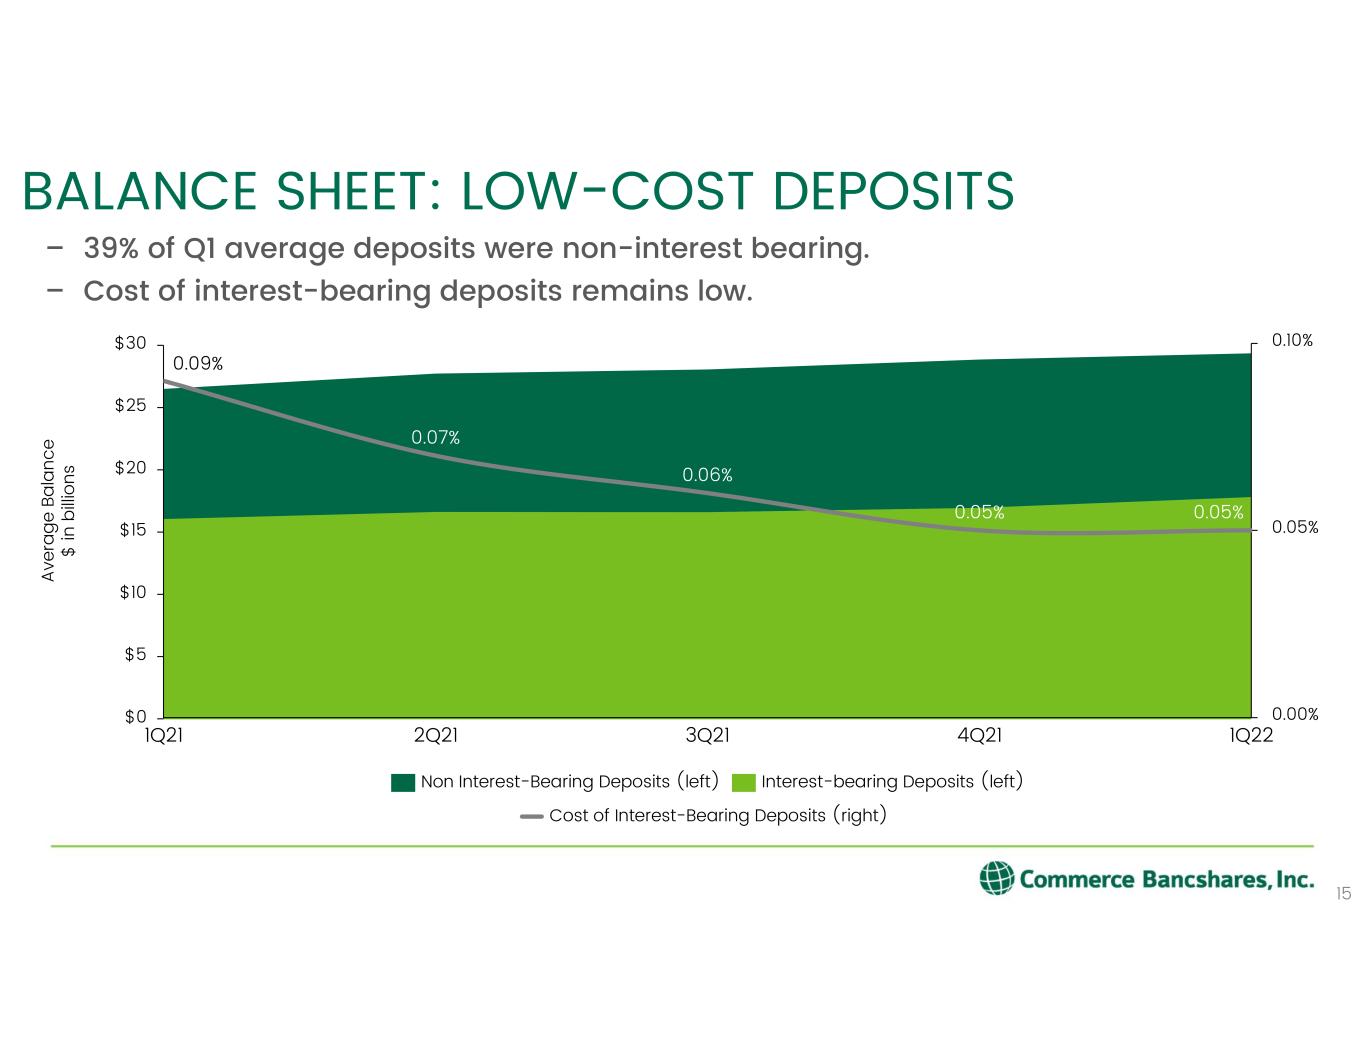
$10 $0 $5 $15 $20 $25 $30 4Q211Q21 2Q21 3Q21 1Q22 0.09% 0.07% 0.06% 0.05% 0.05% 0.00% 0.05% 0.10% BALANCE SHEET: LOW-COST DEPOSITS Interest-bearing Deposits (left)Non Interest-Bearing Deposits (left) Av er ag e Ba la nc e $ in b illi on s Cost of Interest-Bearing Deposits (right) 15 – 39% of Q1 average deposits were non-interest bearing. – Cost of interest-bearing deposits remains low.
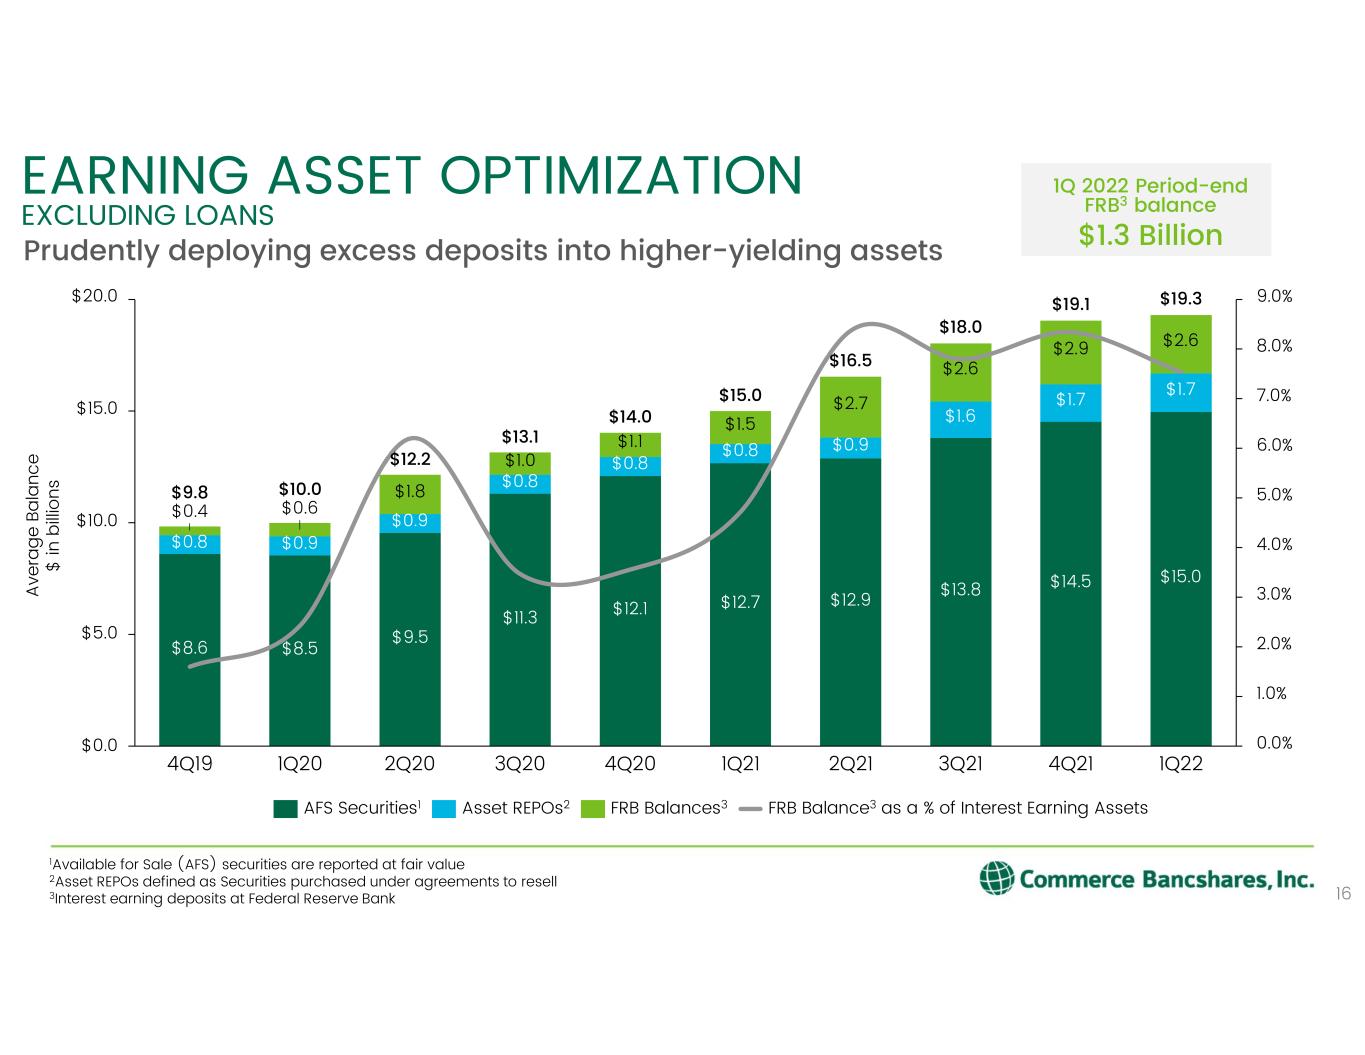
0.0% 1.0% 2.0% 3.0% 4.0% 5.0% 6.0% 7.0% 8.0% 9.0% $10.0 $15.0 $0.0 $20.0 $5.0 $13.8 $0.8 $2.6 $0.9 $0.8 $8.6 $0.4 $19.1 4Q19 1Q20 $8.5 $0.9 1Q22 $0.6 $9.5 $10.0 $2.6 $2.7 $0.9 $1.8 $11.3 2Q20 $0.8 $1.0 3Q20 $12.1 $15.0 $1.6 $0.8 $1.1 4Q20 $1.5 1Q21 $12.9 2Q21 $12.7 $14.5 $1.7 $2.9 4Q21 $1.7 $15.0 3Q21 $16.5 $12.2 $19.3 $13.1 $14.0 $18.0 $9.8 EARNING ASSET OPTIMIZATION EXCLUDING LOANS 16 Av er ag e Ba la nc e $ in b illi on s AFS Securities1 FRB Balance3 as a % of Interest Earning AssetsFRB Balances3Asset REPOs2 1Available for Sale (AFS) securities are reported at fair value 2Asset REPOs defined as Securities purchased under agreements to resell 3Interest earning deposits at Federal Reserve Bank Prudently deploying excess deposits into higher-yielding assets 1Q 2022 Period-end FRB3 balance $1.3 Billion
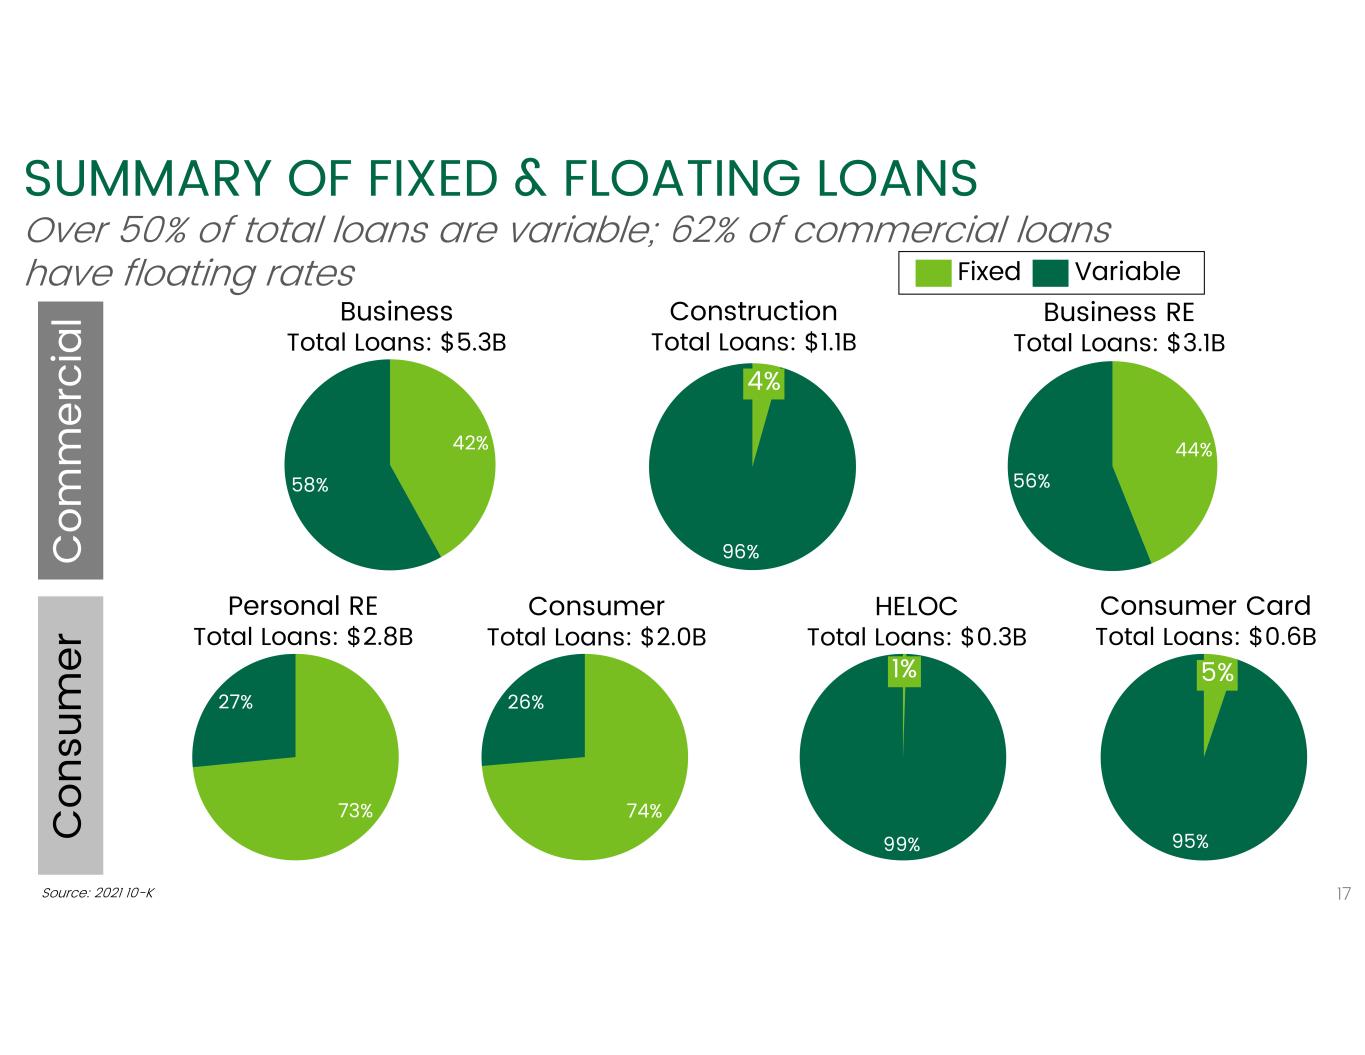
Over 50% of total loans are variable; 62% of commercial loans have floating rates SUMMARY OF FIXED & FLOATING LOANS 42% 58% Business Total Loans: $5.3B Fixed Variable C om m er ci al 73% 27% Personal RE Total Loans: $2.8B C on su m er 99% 1% HELOC Total Loans: $0.3B 44% 56% Business RE Total Loans: $3.1B 95% 5% Consumer Card Total Loans: $0.6B 74% 26% Consumer Total Loans: $2.0B 17 96% 4% Construction Total Loans: $1.1B Source: 2021 10-K
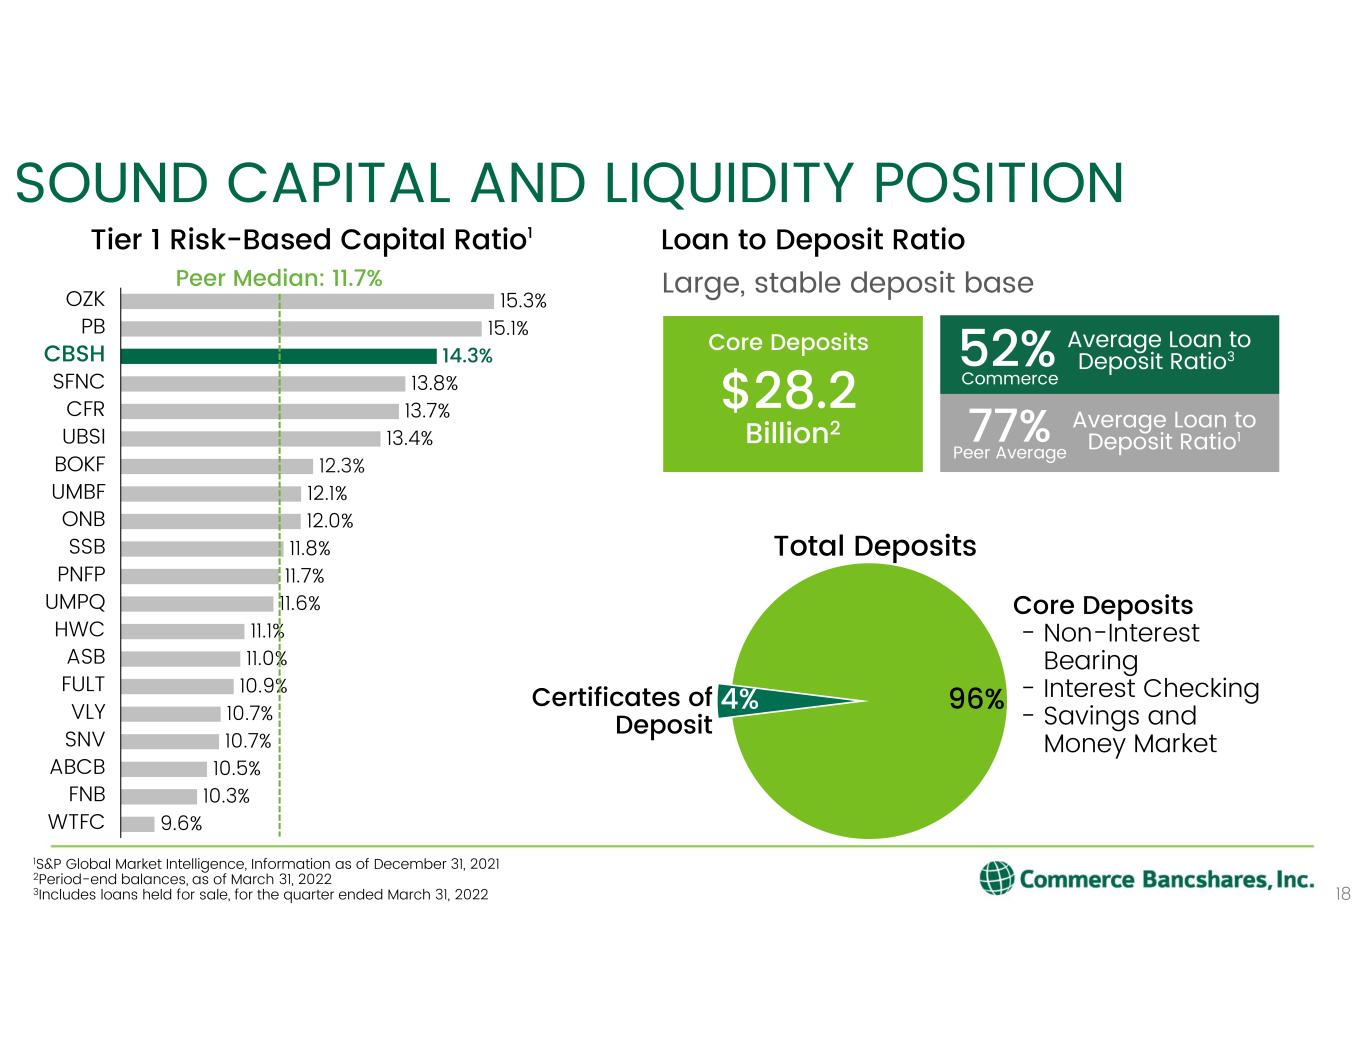
Average Loan to Deposit Ratio3 SOUND CAPITAL AND LIQUIDITY POSITION 18 Tier 1 Risk-Based Capital Ratio1 1S&P Global Market Intelligence, Information as of December 31, 2021 2Period-end balances, as of March 31, 2022 3Includes loans held for sale, for the quarter ended March 31, 2022 15.3% 15.1% 14.3% 13.8% 13.7% 13.4% 12.3% 12.1% 12.0% 11.8% 11.7% 11.6% 11.1% 11.0% 10.9% 10.7% 10.7% 10.5% 10.3% 9.6% PB ABCB VLY UMBF UBSI SSB OZK CBSH SFNC CFR BOKF PNFP ONB UMPQ HWC ASB FULT SNV FNB WTFC Peer Median: 11.7% Core Deposits $28.2 Billion2 Large, stable deposit base Loan to Deposit Ratio Total Deposits 52% Average Loan to Deposit Ratio177% Peer Average Commerce 96%4%Certificates of Deposit Core Deposits - Non-Interest Bearing - Interest Checking - Savings and Money Market
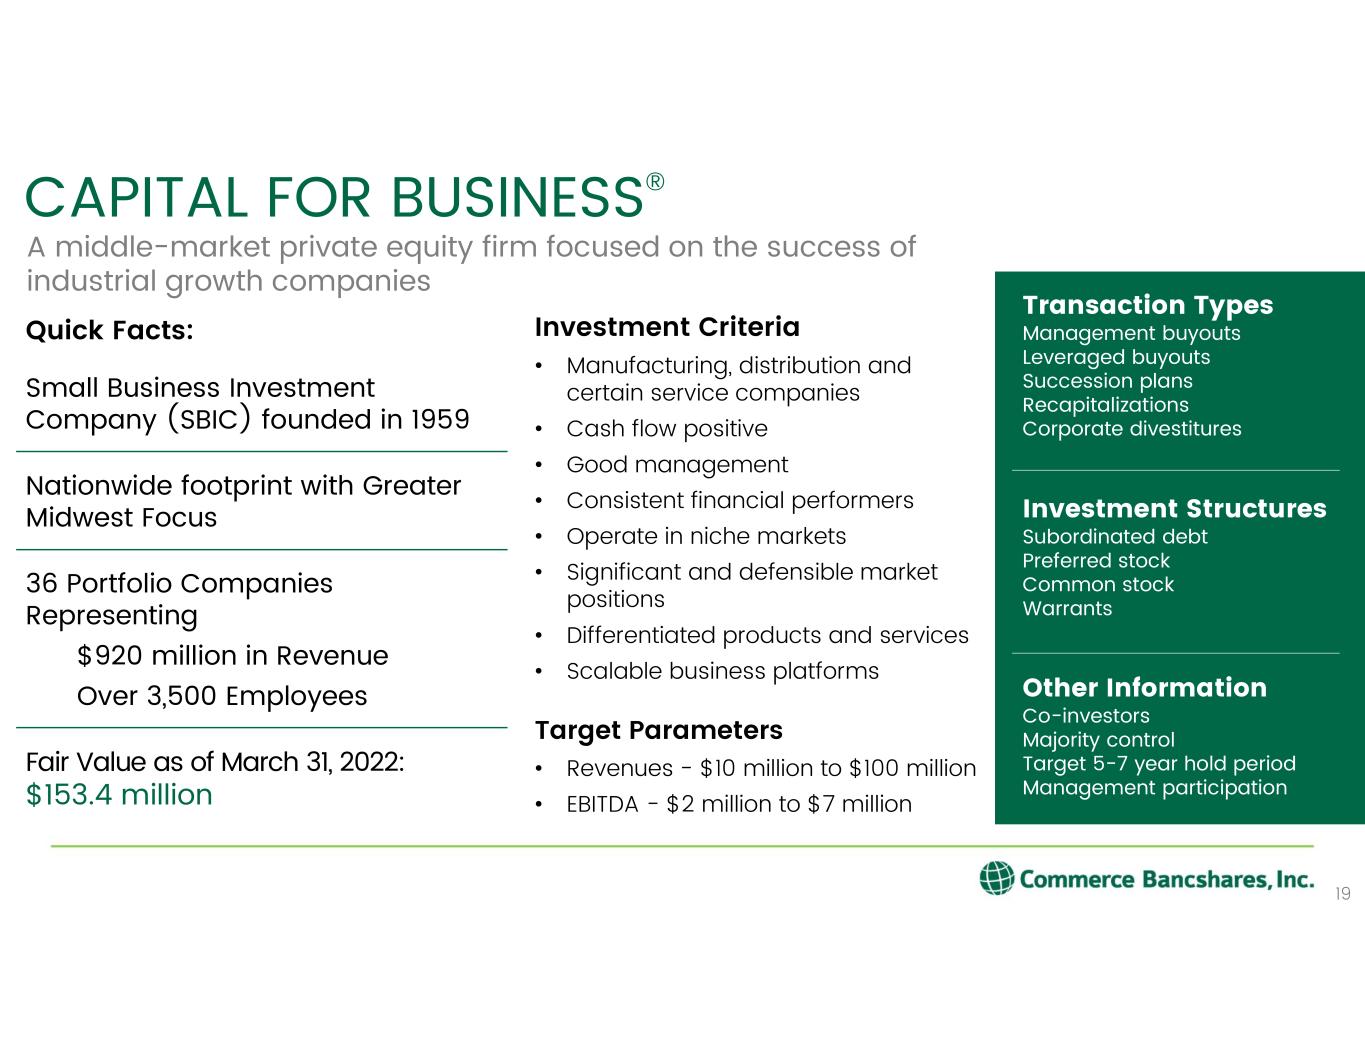
Quick Facts: Small Business Investment Company (SBIC) founded in 1959 Nationwide footprint with Greater Midwest Focus 36 Portfolio Companies Representing $920 million in Revenue Over 3,500 Employees Fair Value as of March 31, 2022: $153.4 million Investment Criteria • Manufacturing, distribution and certain service companies • Cash flow positive • Good management • Consistent financial performers • Operate in niche markets • Significant and defensible market positions • Differentiated products and services • Scalable business platforms Target Parameters • Revenues - $10 million to $100 million • EBITDA - $2 million to $7 million CAPITAL FOR BUSINESS® A middle-market private equity firm focused on the success of industrial growth companies Transaction Types Management buyouts Leveraged buyouts Succession plans Recapitalizations Corporate divestitures Investment Structures Subordinated debt Preferred stock Common stock Warrants Other Information Co-investors Majority control Target 5-7 year hold period Management participation 19
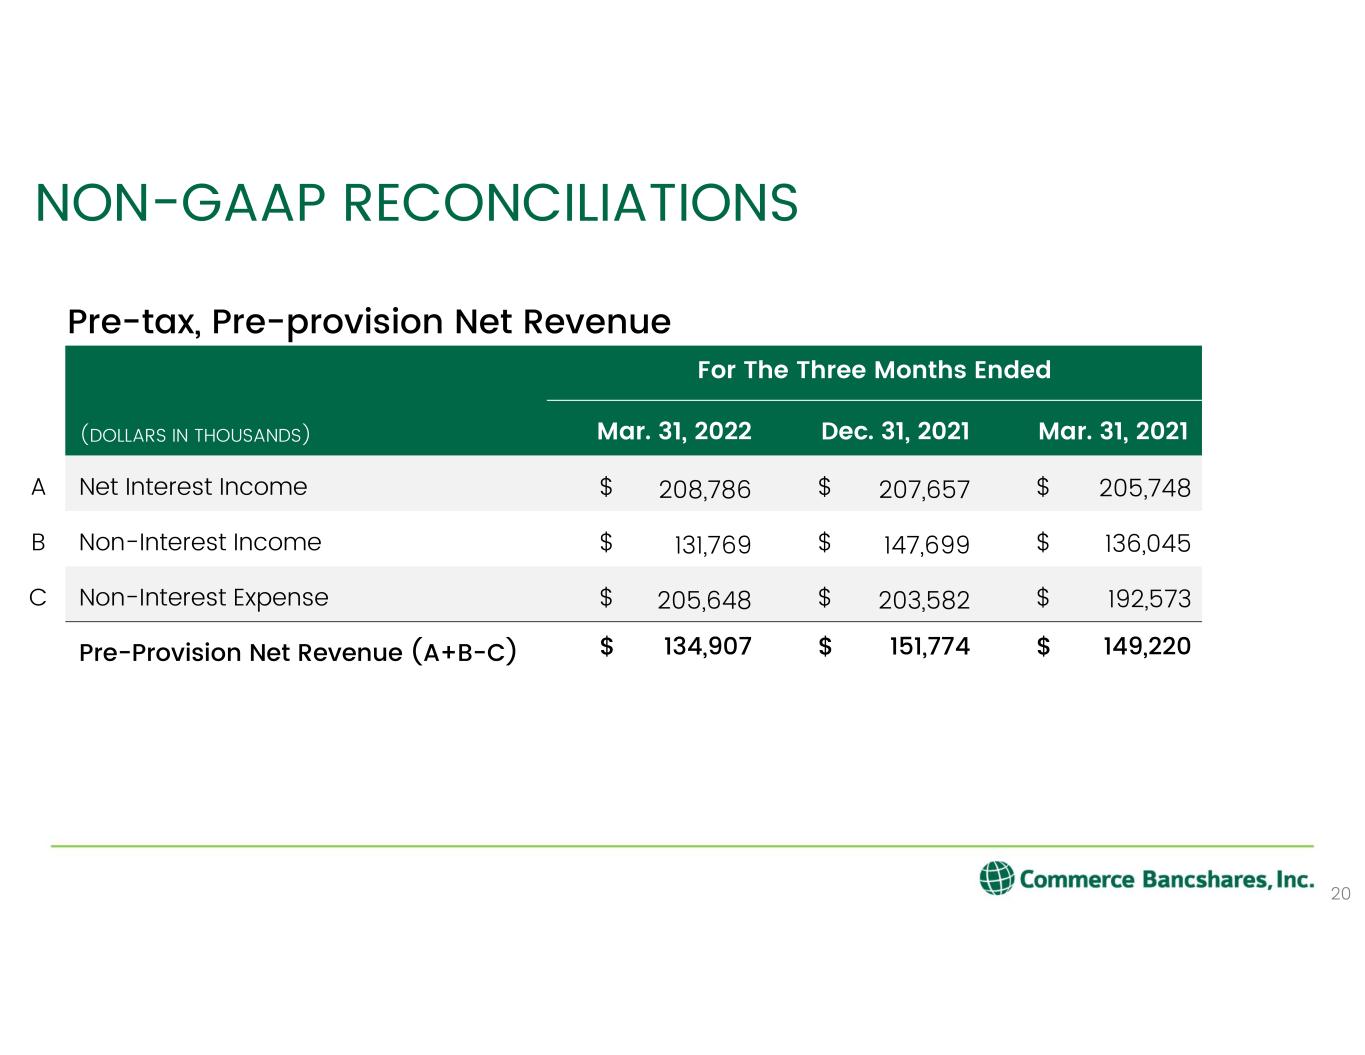
NON-GAAP RECONCILIATIONS 20 For The Three Months Ended (DOLLARS IN THOUSANDS) Mar. 31, 2022 Dec. 31, 2021 Mar. 31, 2021 A Net Interest Income $ 208,786 $ 207,657 $ 205,748 B Non-Interest Income $ 131,769 $ 147,699 $ 136,045 C Non-Interest Expense $ 205,648 $ 203,582 $ 192,573 Pre-Provision Net Revenue (A+B-C) $ 134,907 $ 151,774 $ 149,220 Pre-tax, Pre-provision Net Revenue