
CPF 8-K
Central Pacific Financial Corp (CPF)
8-K
2026-07-24
For: 2026-07-24
View Original
Added on
July 24, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
___________________________________
FORM 8-K
___________________________________
CURRENT REPORT
Pursuant to Section 13 or 15(d)
of the Securities Exchange Act of 1934
Date of Report (date of earliest event reported)
___________________________________
(Exact name of registrant as specified in its charter)
___________________________________
| (State or other jurisdiction of incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) | ||||||||||||
(Address of principal executive offices and zip code)
(808 ) 544-0500
(Registrant’s telephone number, including area code)
___________________________________
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act.
☐
Item 2.02. Results of Operations and Financial Condition
On July 24, 2026, Central Pacific Financial Corp. (the "Company") issued a press release regarding its results of operations and financial condition for the quarter ended June 30, 2026. A copy of the press release is furnished herewith as Exhibit 99.1 and incorporated herein by reference.
Item 7.01. Regulation FD Disclosure
On July 24, 2026, the Company will hold an investor conference call and webcast to discuss financial results for the quarter ended June 30, 2026, including the attached press release and other matters relating to the Company.
The Company has also made available on its website a slide presentation containing certain additional information about the Company's financial results for the quarter ended June 30, 2026 (the "Earnings Supplement"). The Earnings Supplement is furnished herewith as Exhibit 99.2 and is incorporated herein by reference. All information in Exhibit 99.2 is presented as of the particular date or dates referenced therein, and the Company does not undertake any obligation to, and disclaims any duty to, update any of the information provided except as required by law.
The Earnings Supplement contains forward-looking statements within the meaning of Section 27A of the Securities Act and Section 21E of the Exchange Act and, as such, may involve known and unknown risks, uncertainties and assumptions. These forward-looking statements relate to the Company’s current expectations and are subject to the limitations and qualifications set forth in the attached presentation as well as in the Company’s other documents filed with the Securities and Exchange Commission, including, without limitation, that actual events and/or results may differ materially from those projected in such forward-looking statements.
The information provided in Items 2.02 and 7.01 of this Current Report, including Exhibits 99.1 and 99.2, shall not be deemed "filed" for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, nor shall the information in Exhibits 99.1 and 99.2 be deemed incorporated by reference in any filings under the Securities Act of 1933, as amended.
Item 9.01 Financial Statements and Exhibits
| Exhibit No. | ||||||||
| 99.1 | ||||||||
| 99.2 | ||||||||
| 104 | Cover Page Interactive Data File (embedded in the cover page formatted in Inline XBRL) | |||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Central Pacific Financial Corp. | ||||||||
| (Registrant) | ||||||||
| Date: | July 24, 2026 | /s/ Dayna N. Matsumoto | ||||||
| Dayna N. Matsumoto | ||||||||
| Executive Vice President and Chief Financial Officer | ||||||||
Exhibit 99.1
| Investor Contact: | Jayrald Rabago | Media Contact: | Tim Sakahara | ||||||||
| Senior Strategic Financial Officer | Corporate Communications Manager | ||||||||||
| (808) 544-3556 | (808) 544-5125 | ||||||||||
| [email protected] | [email protected] | ||||||||||
FOR IMMEDIATE RELEASE
NEWS RELEASE
CENTRAL PACIFIC FINANCIAL REPORTS SECOND QUARTER 2026 EARNINGS OF $20.8 MILLION
Highlights:
•Net income of $20.8 million, or $0.80 per diluted share
•Return on average assets of 1.12% and return on average equity of 13.94%
•Net interest margin increased by 4 bps to 3.57% from the prior quarter
•Repurchased 321,858 shares of common stock at a total cost of $11.3 million during the quarter
•Board of Directors declared a third quarter cash dividend of $0.30 per share, an increase of 3.4% from prior quarter
•Central Pacific Bank was the highest-ranked company in Hawaii on America's Best Companies 2026 list, published by TIME magazine, and named Best Bank in Hawaii by Forbes Magazine in 2026 for the third consecutive year
HONOLULU, HI, July 24, 2026 – Central Pacific Financial Corp. (NYSE: CPF) (the "Company"), parent company of Central Pacific Bank (the "Bank" or "CPB"), today reported net income of $20.8 million, or $0.80 diluted earnings per share ("EPS"), for the second quarter of 2026. This compares to net income of $20.7 million, or EPS of $0.78, in the prior quarter and $18.3 million, or EPS of $0.67, in the same period last year.
“We delivered another strong quarter of performance, backed by our team’s dedication and commitment," said Arnold Martines, Chairman, President and CEO. "Our robust capital position supports future organic growth, while returning value to shareholders through our increased dividend and continued share repurchases. We are also honored to be the highest-ranked company in Hawaii on America’s Best Companies 2026 list, published by TIME magazine, and recognized by Forbes as the Best Bank in Hawaii for the third consecutive year. We are grateful for the support of our customers and the communities we serve.”
Earnings Highlights
Net interest income for the second quarter of 2026 totaled $62.8 million, which increased by $1.5 million, or 2.4% from the prior quarter, and increased by $3.0 million, or 5.1%, compared to the same quarter last year. Net interest margin ("NIM") for the second quarter of 2026 was 3.57%, an increase of 4 basis points ("bp" or "bps") from the prior quarter, and an increase of 13 bps from the same quarter last year. The sequential quarter increase in net interest income and NIM was primarily driven by higher average balances and yields earned on loans and investment securities, combined with a decline in average rates paid on interest-bearing deposits.
The Company recorded a provision for credit losses of $4.4 million in the second quarter of 2026, compared to a provision of $2.4 million in the prior quarter, and a provision of $5.0 million in the same quarter last year. The current quarter provision included a
Central Pacific Financial Reports Second Quarter 2026 Earnings of $20.8 Million
Page 2
provision for credit loss on loans of $3.3 million and a $1.1 million reserve for off-balance sheet credit exposures. The increase from the prior quarter was primarily driven by changes in the economic forecast used in our current expected credit losses model, combined with higher unfunded loan commitments.
Other operating income for the second quarter of 2026 totaled $14.6 million, compared to $11.6 million in the prior quarter, and $13.0 million in the same quarter last year. The sequential quarter increase was primarily due to a $2.6 million increase in income from bank-owned life insurance ("BOLI") due to favorable equity market performance.
Other operating expense for the second quarter of 2026 totaled $46.2 million, compared to $43.7 million in the prior quarter, and $43.9 million in the same quarter last year. The increase from the prior quarter was primarily attributable to higher salaries and employee benefits of $2.3 million due to higher deferred compensation expense and incentive accruals. The increase in deferred compensation expense was related to equity market performance.
The efficiency ratio was 59.62% in the second quarter of 2026, compared to 59.87% in the prior quarter and 60.36% in the same quarter last year.
The effective tax rate for the second quarter of 2026 was 22.6%, compared to 23.0% in the prior quarter, and 23.5% in the same quarter last year. The decrease in the Company's effective tax rate was primarily attributable to an increase in tax-exempt income.
Balance Sheet Highlights
As of June 30, 2026, total assets were $7.50 billion, generally consistent with $7.50 billion at March 31, 2026, and increased $131.5 million, or 1.8% from $7.37 billion at June 30, 2025.
Total loans, net of deferred fees and costs, were $5.31 billion at June 30, 2026, and remained relatively stable compared to $5.32 billion at March 31, 2026, and $5.29 billion at June 30, 2025. The average yield earned on loans during the second quarter of 2026 was 4.96%, compared to 4.93% in the prior quarter and 4.96% in the same quarter last year.
Total deposits were $6.70 billion at June 30, 2026, relatively unchanged from $6.70 billion at March 31, 2026, and increased by $150.8 million, or 2.3% from $6.54 billion at June 30, 2025. Core deposits, which include demand deposits, savings and money market deposits and time deposits up to $250,000, totaled $6.12 billion at June 30, 2026, generally consistent with $6.13 billion at March 31, 2026, and increased by $167.1 million, or 2.8% from $5.96 billion at June 30, 2025. The average rate paid on total deposits during the second quarter of 2026 was 0.90%, consistent with 0.90% in the prior quarter, and decreased from 1.02% in the same quarter last year.
Asset Quality
Nonperforming assets totaled $16.5 million, or 0.22% of total assets at June 30, 2026, compared to $14.5 million, or 0.19% of total assets at March 31, 2026 and $14.9 million, or 0.20% of total assets at June 30, 2025.
Net charge-offs in the second quarter of 2026 totaled $2.7 million, compared to net charge-offs of $2.4 million in the prior quarter, and net charge-offs of $4.7 million in the same quarter last year. On an annualized basis, net charge-offs as a percentage of average loans was 0.20% in the second quarter of 2026, compared to 0.18% in the prior quarter, and 0.35% in the same quarter last year.
The allowance for credit losses on loans was 1.14% of total loans as of June 30, 2026, compared to 1.13% at March 31, 2026 and June 30, 2025.
Capital
Total shareholders' equity at June 30, 2026 was $596.3 million, compared to $593.9 million at March 31, 2026 and $568.9 million at June 30, 2025.
During the second quarter of 2026, the Company repurchased 321,858 shares of common stock at a total cost of $11.3 million, or an average price of $35.01 per share. As of June 30, 2026, $33.2 million remained available under the Company's share repurchase authorization.
The Company's regulatory capital ratios remained strong, with a leverage ratio of 9.7%, a Common Equity Tier 1 ratio of 12.7%, a Tier 1 risk-based capital ratio of 13.6%, and a total risk-based capital ratio of 14.8% at June 30, 2026.
Central Pacific Financial Reports Second Quarter 2026 Earnings of $20.8 Million
Page 3
On July 23, 2026, the Board of Directors increased its quarterly cash dividend by 3.4% to $0.30 per share. The dividend will be payable on September 15, 2026, to shareholders of record as of August 31, 2026.
Conference Call
The Company's management will host a conference call today at 2:00 p.m. Eastern Time (8:00 a.m. Hawaii Time) to discuss its second quarter of 2026 financial results. Interested parties may listen to the conference by calling 1-833-461-5787 and entering the meeting ID: 719 331 929 or by registering for the webcast at the following link: https://events.q4inc.com/attendee/719331929. The Company’s investor relations website, https://ir.cpb.bank, will also include a link to the webcast and a slide presentation.
A replay of the call will be available on the Company's investor relations website until July 24, 2027.
About Central Pacific Financial Corp.
Central Pacific Financial Corp. is a Hawaii-based bank holding company with approximately $7.50 billion in assets as of June 30, 2026. Its primary subsidiary, Central Pacific Bank, operates 27 branches and 56 ATMs in the State of Hawaii. Central Pacific Financial Corp. is listed on the New York Stock Exchange under the symbol "CPF." For additional information, please visit: cpb.bank.

**********
Central Pacific Financial Reports Second Quarter 2026 Earnings of $20.8 Million
Page 4
Forward-Looking Statements
This document may contain forward-looking statements ("FLS") concerning, among other things: projections of revenues, expenses, income or loss, earnings or loss per share, capital expenditures, payment or nonpayment of dividends, net interest income, capital position, credit losses, net interest margin, or other financial items. These statements may also include the plans, objectives, and expectations of Central Pacific Financial Corp. (the "Company") or its management or Board of Directors, including those relating to business plans, use of capital resources, products or services, and regulatory developments or actions. In addition, such statements may address anticipated economic performance, the expected impact of business initiatives, and the assumptions underlying any of the foregoing.
Words such as "believe," "plan," "anticipate," "aim," "seek," "expect," "intend," "forecast," "hope," "target," "continue," "remain," "estimate," "will," "should," "may," and other similar expressions are intended to identify FLS, although such terminology is not the exclusive means of doing so.
While we believe that our FLS and their underlying assumptions are reasonably based, such statements are inherently subject to risks and uncertainties that may cause actual results to differ materially from expectations. Factors that may lead to such differences, include, but are not limited to: the persistence or resurgence of inflationary pressures in the United States and our market areas, and their effect on market interest rates, economic conditions, and credit quality; the impact of the current U.S. administration’s economic policies, including potential international tariffs, geopolitical instability, trade tensions,and other cost-cutting or fiscal initiatives; the adverse effects of bank failures on customer confidence, deposit behavior, liquidity, and regulatory responses; the effects of pandemics, epidemics, and other public health emergencies, including their impact on Hawaii's tourism and construction sectors and on our borrowers, customers, vendors and employees; supply chain disruptions, labor contract disputes, strikes; adverse trends in the real estate or construction industries, including rising inventory levels or declining property values; deterioration in borrowers' financial performance leading to increased loan delinquencies, asset quality issues, or loan losses; the impact of local, national, and international economic conditions and natural disasters (such as wildfires, volcanic eruptions, hurricanes, tsunamis, storms, floods, or earthquakes) on our markets and major industries within Hawaii; weakness in domestic economic conditions, including instability in the financial industry, deterioration in real estate markets, and declines in consumer or business confidence; revisions to estimates of reserve requirements under applicable regulatory and accounting standards; the impact of legislative and regulatory developments, changing capital and consumer protection rules, and new regulations affecting our operations and competitiveness; the costs and effects of legal and regulatory proceedings, including actual or threatened litigation and the results of governmental and regulatory exams and orders, as well as the costs of ongoing or potential compliance efforts; the effect of accounting standard changes adopted by regulatory agencies, the PCAOB, or the FASB, and the cost and resources associated with implementation; changes in trade, monetary, or fiscal policy, including actions by the Federal Reserve; market volatility and monetary fluctuations, including the transition away from the LIBOR Index; declines in our market capitalization or the price of our common stock; the effects and cost of acquisitions, dispositions, or strategic transactions we may make or evaluate; political instability, acts of war or terrorism, or other geopolitical conflicts; shifts in consumer spending, borrowing, and savings behaviors; technological changes and developments; cybersecurity incidents, data privacy breaches, or fraud involving us or third-party vendors; deficiencies in internal control over financial reporting or disclosure controls and procedures, and our ability to remediate them; increased competition among financial institutions and other financial service providers; our ability to achieve efficiency ratio improvement goals; our ability to attract and retain key personnel; changes in our personnel, organization, compensation and benefit plans; and related reputational or regulatory exposures; and risks related to the United States fiscal debt, deficit, and budget uncertainties.
For further information on factors that could cause actual results to differ materially from the expectations or projections expressed in our FLS, please refer to the Company's filings with the U.S. Securities and Exchange Commission, including the Company's most recent Form 10-K, particularly, the discussion of "Risk Factors" set forth therein.
We urge investors to consider all of these factors carefully in evaluating the FLS contained in this document. FLS speak only as of the date on which such statements are made. We undertake no obligation to update any FLS to reflect events or circumstances occurring after the date on which such statements are made, or to reflect the occurrence of unanticipated events, except as required by law.
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Financial Highlights | |||||
| (Unaudited) | TABLE 1 | ||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | Jun 30, | Jun 30, | ||||||||||||||||||||||||||||||||||||||
| except for per share amounts) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||
| CONDENSED INCOME STATEMENT | ||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 62,834 | $ | 61,358 | $ | 62,087 | $ | 61,301 | $ | 59,796 | $ | 124,192 | $ | 117,495 | ||||||||||||||||||||||||||||||
| Provision for credit losses | 4,382 | 2,353 | 2,396 | 4,157 | 4,987 | 6,735 | 9,159 | |||||||||||||||||||||||||||||||||||||
| Total other operating income | 14,620 | 11,574 | 14,201 | 13,507 | 13,013 | 26,194 | 24,109 | |||||||||||||||||||||||||||||||||||||
| Total other operating expense | 46,180 | 43,666 | 45,680 | 47,009 | 43,946 | 89,846 | 86,018 | |||||||||||||||||||||||||||||||||||||
| Income tax expense | 6,070 | 6,188 | 5,337 | 5,068 | 5,605 | 12,258 | 10,396 | |||||||||||||||||||||||||||||||||||||
| Net income | 20,822 | 20,725 | 22,875 | 18,574 | 18,271 | 41,547 | 36,031 | |||||||||||||||||||||||||||||||||||||
| Basic earnings per share | $ | 0.80 | $ | 0.79 | $ | 0.86 | $ | 0.69 | $ | 0.68 | $ | 1.59 | $ | 1.33 | ||||||||||||||||||||||||||||||
| Diluted earnings per share | 0.80 | 0.78 | 0.85 | 0.69 | 0.67 | 1.58 | 1.33 | |||||||||||||||||||||||||||||||||||||
| Dividends declared per share | 0.29 | 0.29 | 0.28 | 0.27 | 0.27 | 0.58 | 0.54 | |||||||||||||||||||||||||||||||||||||
| PERFORMANCE RATIOS | ||||||||||||||||||||||||||||||||||||||||||||
| Return on average assets (ROA) [1] | 1.12 | % | 1.12 | % | 1.25 | % | 1.01 | % | 1.00 | % | 1.12 | % | 0.98 | % | ||||||||||||||||||||||||||||||
| Return on average equity (ROE) [1] | 13.94 | 13.90 | 15.41 | 12.89 | 13.04 | 13.92 | 13.04 | |||||||||||||||||||||||||||||||||||||
| Average equity to average assets | 8.03 | 8.07 | 8.12 | 7.85 | 7.66 | 8.05 | 7.52 | |||||||||||||||||||||||||||||||||||||
| Efficiency ratio [2] | 59.62 | 59.87 | 59.88 | 62.84 | 60.36 | 59.74 | 60.75 | |||||||||||||||||||||||||||||||||||||
| Net interest margin (NIM) [1] | 3.57 | 3.53 | 3.56 | 3.49 | 3.44 | 3.55 | 3.37 | |||||||||||||||||||||||||||||||||||||
| Dividend payout ratio [3] | 36.25 | 37.18 | 32.94 | 39.13 | 40.30 | 36.71 | 40.60 | |||||||||||||||||||||||||||||||||||||
| SELECTED AVERAGE BALANCES | ||||||||||||||||||||||||||||||||||||||||||||
| Average loans, including loans held for sale | $ | 5,300,949 | $ | 5,268,482 | $ | 5,328,499 | $ | 5,332,656 | $ | 5,307,946 | $ | 5,284,805 | $ | 5,309,768 | ||||||||||||||||||||||||||||||
| Average interest-earning assets | 7,076,331 | 7,022,759 | 6,964,796 | 7,011,753 | 6,985,097 | 7,049,694 | 7,019,602 | |||||||||||||||||||||||||||||||||||||
| Average assets | 7,433,822 | 7,396,084 | 7,310,098 | 7,341,281 | 7,314,144 | 7,415,057 | 7,351,257 | |||||||||||||||||||||||||||||||||||||
| Average deposits | 6,630,910 | 6,592,361 | 6,499,119 | 6,509,692 | 6,503,463 | 6,611,742 | 6,532,122 | |||||||||||||||||||||||||||||||||||||
| Average interest-bearing liabilities | 4,876,776 | 4,846,057 | 4,757,686 | 4,807,225 | 4,807,669 | 4,861,501 | 4,860,738 | |||||||||||||||||||||||||||||||||||||
| Average equity | 597,299 | 596,524 | 593,750 | 576,531 | 560,248 | 596,913 | 552,610 | |||||||||||||||||||||||||||||||||||||
| [1] ROA and ROE are annualized based on a 30/360 day convention. Annualized net interest income and expense in the NIM calculation are based on the day count interest payment conventions at the interest-earning asset or interest-bearing liability level (i.e. 30/360, actual/actual). | ||||||||||||||||||||||||||||||||||||||||||||
| [2] Efficiency ratio is defined as total other operating expense divided by total revenue (net interest income and total other operating income). | ||||||||||||||||||||||||||||||||||||||||||||
| [3] Dividend payout ratio is defined as dividends declared per share divided by diluted earnings per share. | ||||||||||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Financial Highlights | |||||
| (Unaudited) | TABLE 1 (CONTINUED) | ||||
| Jun 30, | Mar 31, | Dec 31, | Sep 30, | Jun 30, | ||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||||||
| REGULATORY CAPITAL RATIOS | ||||||||||||||||||||||||||||||||
| Central Pacific Financial Corp. | ||||||||||||||||||||||||||||||||
| Leverage ratio | 9.7 | % | 9.7 | % | 9.8 | % | 9.7 | % | 9.6 | % | ||||||||||||||||||||||
| Common equity tier 1 capital ratio | 12.7 | 12.6 | 12.7 | 12.6 | 12.6 | |||||||||||||||||||||||||||
| Tier 1 risk-based capital ratio | 13.6 | 13.5 | 13.6 | 13.5 | 13.5 | |||||||||||||||||||||||||||
| Total risk-based capital ratio | 14.8 | 14.7 | 14.8 | 15.7 | 15.8 | |||||||||||||||||||||||||||
| Central Pacific Bank | ||||||||||||||||||||||||||||||||
| Leverage ratio | 9.6 | 9.6 | 9.7 | 10.2 | 10.1 | |||||||||||||||||||||||||||
| Common equity tier 1 capital ratio | 13.4 | 13.4 | 13.5 | 14.1 | 14.1 | |||||||||||||||||||||||||||
| Tier 1 risk-based capital ratio | 13.4 | 13.4 | 13.5 | 14.1 | 14.1 | |||||||||||||||||||||||||||
| Total risk-based capital ratio | 14.7 | 14.6 | 14.7 | 15.3 | 15.3 | |||||||||||||||||||||||||||
| Jun 30, | Mar 31, | Dec 31, | Sep 30, | Jun 30, | ||||||||||||||||||||||||||||
| (dollars in thousands, except for per share amounts) | 2026 | 2026 | 2025 | 2025 | 2025 | |||||||||||||||||||||||||||
| BALANCE SHEET | ||||||||||||||||||||||||||||||||
| Total loans, net of deferred fees and costs | $ | 5,308,322 | $ | 5,320,349 | $ | 5,289,096 | $ | 5,367,202 | $ | 5,289,809 | ||||||||||||||||||||||
| Total assets | 7,501,060 | 7,495,363 | 7,409,241 | 7,421,478 | 7,369,567 | |||||||||||||||||||||||||||
| Total deposits | 6,695,754 | 6,699,354 | 6,609,764 | 6,577,684 | 6,544,989 | |||||||||||||||||||||||||||
| Long-term debt | 76,547 | 76,547 | 76,547 | 131,527 | 131,466 | |||||||||||||||||||||||||||
| Total equity | 596,331 | 593,879 | 592,581 | 588,066 | 568,874 | |||||||||||||||||||||||||||
| Tangible common equity to tangible assets [4] | 7.95 | % | 7.92 | % | 8.00 | % | 7.92 | % | 7.72 | % | ||||||||||||||||||||||
| ASSET QUALITY | ||||||||||||||||||||||||||||||||
| Allowance for credit losses (ACL) | $ | 60,581 | $ | 59,933 | $ | 59,621 | $ | 60,393 | $ | 59,611 | ||||||||||||||||||||||
| Nonaccrual loans | 15,622 | 14,524 | 14,386 | 14,319 | 14,895 | |||||||||||||||||||||||||||
| Non-performing assets (NPA) | 16,546 | 14,524 | 14,386 | 14,319 | 14,895 | |||||||||||||||||||||||||||
| Ratio of ACL to total loans | 1.14 | % | 1.13 | % | 1.13 | % | 1.13 | % | 1.13 | % | ||||||||||||||||||||||
| Ratio of NPA to total assets | 0.22 | % | 0.19 | % | 0.19 | % | 0.19 | % | 0.20 | % | ||||||||||||||||||||||
| PER SHARE OF COMMON STOCK OUTSTANDING | ||||||||||||||||||||||||||||||||
| Book value per common share | $ | 23.11 | $ | 22.74 | $ | 22.47 | $ | 21.86 | $ | 21.08 | ||||||||||||||||||||||
| Closing market price per common share | 38.20 | 31.96 | 31.16 | 30.34 | 28.03 | |||||||||||||||||||||||||||
| [4] The tangible common equity ratio is a non-GAAP measure which should be read in conjunction with the Company’s GAAP financial information. Comparison of our ratio with those of other companies may not be possible because other companies may calculate the ratio differently. See Reconciliation of Non-GAAP Financial Measures in Table 10. | ||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Consolidated Balance Sheets | |||||
| (Unaudited) | TABLE 2 | ||||
| Jun 30, | Mar 31, | Dec 31, | Sep 30, | Jun 30, | ||||||||||||||||||||||||||||
| (Dollars in thousands, except share data) | 2026 | 2026 | 2025 | 2025 | 2025 | |||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||
| Cash and due from financial institutions | $ | 96,678 | $ | 88,880 | $ | 88,200 | $ | 102,859 | $ | 110,935 | ||||||||||||||||||||||
| Interest-bearing deposits in other financial institutions | 286,593 | 317,716 | 290,453 | 207,034 | 206,035 | |||||||||||||||||||||||||||
| Investment securities: | ||||||||||||||||||||||||||||||||
| Debt securities available-for-sale, at fair value | 835,378 | 779,156 | 748,212 | 758,683 | 765,213 | |||||||||||||||||||||||||||
| Debt securities held-to-maturity, at amortized cost; fair value of: $474,928 at June 30, 2026, $486,018 at March 31, 2026, $495,845 at December 31, 2025, $500,859 at September 30, 2025, and $499,833 at June 30, 2025 | 545,215 | 554,548 | 562,391 | 570,886 | 580,476 | |||||||||||||||||||||||||||
| Total investment securities | 1,380,593 | 1,333,704 | 1,310,603 | 1,329,569 | 1,345,689 | |||||||||||||||||||||||||||
| Loans held for sale | 2,364 | 2,536 | 1,084 | 1,557 | — | |||||||||||||||||||||||||||
| Loans, net of deferred fees and costs | 5,308,322 | 5,320,349 | 5,289,096 | 5,367,202 | 5,289,809 | |||||||||||||||||||||||||||
| Less: allowance for credit losses | (60,581) | (59,933) | (59,621) | (60,393) | (59,611) | |||||||||||||||||||||||||||
| Loans, net of allowance for credit losses | 5,247,741 | 5,260,416 | 5,229,475 | 5,306,809 | 5,230,198 | |||||||||||||||||||||||||||
| Premises and equipment, net | 100,231 | 99,942 | 100,620 | 100,992 | 103,657 | |||||||||||||||||||||||||||
| Accrued interest receivable | 23,419 | 24,320 | 23,559 | 25,232 | 23,518 | |||||||||||||||||||||||||||
| Investment in unconsolidated entities | 57,738 | 59,548 | 61,349 | 52,987 | 49,370 | |||||||||||||||||||||||||||
| Other real estate owned | 924 | — | — | — | — | |||||||||||||||||||||||||||
| Mortgage servicing rights | 8,364 | 8,520 | 8,672 | 8,459 | 8,436 | |||||||||||||||||||||||||||
| Bank-owned life insurance | 185,134 | 181,298 | 180,717 | 179,743 | 177,639 | |||||||||||||||||||||||||||
| Federal Home Loan Bank of Des Moines ("FHLB") and Federal Reserve Bank ("FRB") stock | 24,744 | 24,682 | 25,836 | 25,215 | 24,816 | |||||||||||||||||||||||||||
| Right-of-use lease assets | 23,311 | 24,320 | 24,822 | 25,570 | 30,693 | |||||||||||||||||||||||||||
| Other assets | 63,226 | 69,481 | 63,851 | 55,452 | 58,581 | |||||||||||||||||||||||||||
| Total assets | $ | 7,501,060 | $ | 7,495,363 | $ | 7,409,241 | $ | 7,421,478 | $ | 7,369,567 | ||||||||||||||||||||||
| LIABILITIES | ||||||||||||||||||||||||||||||||
| Deposits: | ||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 1,917,502 | $ | 1,897,593 | $ | 1,891,198 | $ | 1,903,614 | $ | 1,938,226 | ||||||||||||||||||||||
| Interest-bearing demand | 1,407,574 | 1,428,323 | 1,388,107 | 1,340,725 | 1,336,620 | |||||||||||||||||||||||||||
| Savings and money market | 2,376,831 | 2,378,834 | 2,346,522 | 2,292,881 | 2,242,122 | |||||||||||||||||||||||||||
| Time | 993,847 | 994,604 | 983,937 | 1,040,464 | 1,028,021 | |||||||||||||||||||||||||||
| Total deposits | 6,695,754 | 6,699,354 | 6,609,764 | 6,577,684 | 6,544,989 | |||||||||||||||||||||||||||
| Long-term debt, net of unamortized debt issuance costs | 76,547 | 76,547 | 76,547 | 131,527 | 131,466 | |||||||||||||||||||||||||||
| Lease liabilities | 24,063 | 25,073 | 25,549 | 26,288 | 31,981 | |||||||||||||||||||||||||||
| Accrued interest payable | 6,044 | 6,433 | 7,068 | 8,604 | 8,755 | |||||||||||||||||||||||||||
| Other liabilities | 102,321 | 94,077 | 97,732 | 89,309 | 83,502 | |||||||||||||||||||||||||||
| Total liabilities | 6,904,729 | 6,901,484 | 6,816,660 | 6,833,412 | 6,800,693 | |||||||||||||||||||||||||||
| EQUITY | ||||||||||||||||||||||||||||||||
| Shareholders' equity: | ||||||||||||||||||||||||||||||||
| Preferred stock, no par value, authorized 1,000,000 shares; issued and outstanding: none at June 30, 2026, March 31, 2026, December 31, 2025, September 30, 2025, and June 30, 2025 | — | — | — | — | — | |||||||||||||||||||||||||||
| Common stock, no par value, authorized 185,000,000 shares; issued and outstanding: 25,806,418 at June 30, 2026, 26,115,229 at March 31, 2026, 26,374,967 at December 31, 2025, 26,903,512 at September 30, 2025, and 26,981,436 at June 30, 2025 | 359,364 | 370,633 | 381,158 | 397,479 | 399,823 | |||||||||||||||||||||||||||
| Additional paid-in capital | 107,534 | 106,501 | 107,308 | 106,675 | 106,033 | |||||||||||||||||||||||||||
| Retained earnings | 217,789 | 204,494 | 191,383 | 175,968 | 164,676 | |||||||||||||||||||||||||||
| Accumulated other comprehensive loss | (88,356) | (87,749) | (87,268) | (92,056) | (101,658) | |||||||||||||||||||||||||||
| Total equity | 596,331 | 593,879 | 592,581 | 588,066 | 568,874 | |||||||||||||||||||||||||||
| Total liabilities and equity | $ | 7,501,060 | $ | 7,495,363 | $ | 7,409,241 | $ | 7,421,478 | $ | 7,369,567 | ||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Consolidated Statements of Income | |||||
| (Unaudited) | TABLE 3 | ||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| Jun 30, | Mar 31, | Dec 31, | Sep 30, | Jun 30, | Jun 30, | |||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||
| Interest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 65,553 | $ | 64,323 | $ | 66,897 | $ | 67,222 | $ | 65,668 | $ | 129,876 | $ | 129,787 | ||||||||||||||||||||||||||||||
| Interest and dividends on investment securities: | ||||||||||||||||||||||||||||||||||||||||||||
| Taxable investment securities | 9,732 | 9,210 | 9,401 | 9,776 | 9,871 | 18,942 | 19,672 | |||||||||||||||||||||||||||||||||||||
| Tax-exempt investment securities | 684 | 682 | 696 | 709 | 709 | 1,366 | 1,417 | |||||||||||||||||||||||||||||||||||||
| Interest on deposits in other financial institutions | 2,331 | 2,500 | 1,501 | 1,857 | 1,484 | 4,831 | 3,738 | |||||||||||||||||||||||||||||||||||||
| Dividend income on FHLB and FRB stock | 389 | 381 | 382 | 395 | 388 | 770 | 712 | |||||||||||||||||||||||||||||||||||||
| Total interest income | 78,689 | 77,096 | 78,877 | 79,959 | 78,120 | 155,785 | 155,326 | |||||||||||||||||||||||||||||||||||||
| Interest expense: | ||||||||||||||||||||||||||||||||||||||||||||
| Interest on deposits: | ||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand | 757 | 522 | 441 | 490 | 443 | 1,279 | 895 | |||||||||||||||||||||||||||||||||||||
| Savings and money market | 7,554 | 7,502 | 8,004 | 8,898 | 8,414 | 15,056 | 17,276 | |||||||||||||||||||||||||||||||||||||
| Time | 6,488 | 6,665 | 6,999 | 7,410 | 7,616 | 13,153 | 15,723 | |||||||||||||||||||||||||||||||||||||
| Interest on long-term debt | 1,056 | 1,049 | 1,346 | 1,860 | 1,851 | 2,105 | 3,937 | |||||||||||||||||||||||||||||||||||||
| Total interest expense | 15,855 | 15,738 | 16,790 | 18,658 | 18,324 | 31,593 | 37,831 | |||||||||||||||||||||||||||||||||||||
| Net interest income | 62,834 | 61,358 | 62,087 | 61,301 | 59,796 | 124,192 | 117,495 | |||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 4,382 | 2,353 | 2,396 | 4,157 | 4,987 | 6,735 | 9,159 | |||||||||||||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 58,452 | 59,005 | 59,691 | 57,144 | 54,809 | 117,457 | 108,336 | |||||||||||||||||||||||||||||||||||||
| Other operating income: | ||||||||||||||||||||||||||||||||||||||||||||
| Mortgage banking income | 693 | 649 | 1,186 | 958 | 744 | 1,342 | 1,341 | |||||||||||||||||||||||||||||||||||||
| Service charges on deposit accounts | 2,250 | 2,299 | 2,423 | 2,330 | 2,124 | 4,549 | 4,271 | |||||||||||||||||||||||||||||||||||||
| Other service charges and fees | 6,330 | 5,789 | 5,570 | 6,472 | 5,957 | 12,119 | 11,723 | |||||||||||||||||||||||||||||||||||||
| Income from fiduciary activities | 1,580 | 1,423 | 1,529 | 1,547 | 1,501 | 3,003 | 3,125 | |||||||||||||||||||||||||||||||||||||
| Income from bank-owned life insurance | 2,999 | 399 | 2,816 | 1,879 | 2,260 | 3,398 | 2,757 | |||||||||||||||||||||||||||||||||||||
| Net loss on sales of investment securities | — | — | — | (30) | — | — | — | |||||||||||||||||||||||||||||||||||||
| Other | 768 | 1,015 | 677 | 351 | 427 | 1,783 | 892 | |||||||||||||||||||||||||||||||||||||
| Total other operating income | 14,620 | 11,574 | 14,201 | 13,507 | 13,013 | 26,194 | 24,109 | |||||||||||||||||||||||||||||||||||||
| Other operating expense: | ||||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 25,372 | 23,085 | 24,490 | 24,749 | 22,696 | 48,457 | 44,515 | |||||||||||||||||||||||||||||||||||||
| Net occupancy | 4,299 | 4,322 | 4,432 | 4,598 | 4,253 | 8,621 | 8,645 | |||||||||||||||||||||||||||||||||||||
| Computer software | 4,952 | 5,045 | 5,442 | 5,151 | 5,320 | 9,997 | 10,034 | |||||||||||||||||||||||||||||||||||||
| Legal and professional services | 2,607 | 2,384 | 2,878 | 2,669 | 2,873 | 4,991 | 5,671 | |||||||||||||||||||||||||||||||||||||
| Equipment | 822 | 807 | 825 | 867 | 950 | 1,629 | 2,032 | |||||||||||||||||||||||||||||||||||||
| Advertising | 762 | 997 | 943 | 730 | 832 | 1,759 | 1,719 | |||||||||||||||||||||||||||||||||||||
| Communication | 840 | 823 | 495 | 791 | 901 | 1,663 | 1,934 | |||||||||||||||||||||||||||||||||||||
| Other | 6,526 | 6,203 | 6,175 | 7,454 | 6,121 | 12,729 | 11,468 | |||||||||||||||||||||||||||||||||||||
| Total other operating expense | 46,180 | 43,666 | 45,680 | 47,009 | 43,946 | 89,846 | 86,018 | |||||||||||||||||||||||||||||||||||||
| Income before income taxes | 26,892 | 26,913 | 28,212 | 23,642 | 23,876 | 53,805 | 46,427 | |||||||||||||||||||||||||||||||||||||
| Income tax expense | 6,070 | 6,188 | 5,337 | 5,068 | 5,605 | 12,258 | 10,396 | |||||||||||||||||||||||||||||||||||||
| Net income | $ | 20,822 | $ | 20,725 | $ | 22,875 | $ | 18,574 | $ | 18,271 | $ | 41,547 | $ | 36,031 | ||||||||||||||||||||||||||||||
| Per common share data: | ||||||||||||||||||||||||||||||||||||||||||||
| Basic earnings per share | $ | 0.80 | $ | 0.79 | $ | 0.86 | $ | 0.69 | $ | 0.68 | $ | 1.59 | $ | 1.33 | ||||||||||||||||||||||||||||||
| Diluted earnings per share | 0.80 | 0.78 | 0.85 | 0.69 | 0.67 | 1.58 | 1.33 | |||||||||||||||||||||||||||||||||||||
| Cash dividends declared | 0.29 | 0.29 | 0.28 | 0.27 | 0.27 | 0.58 | 0.54 | |||||||||||||||||||||||||||||||||||||
| Basic weighted average shares outstanding | 25,999,122 | 26,277,749 | 26,687,551 | 26,968,163 | 26,988,169 | 26,137,665 | 27,037,388 | |||||||||||||||||||||||||||||||||||||
| Diluted weighted average shares outstanding | 26,109,241 | 26,414,880 | 26,827,551 | 27,083,280 | 27,069,677 | 26,261,252 | 27,139,969 | |||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Average Balances, Interest Income & Expense, Yields and Rates (Taxable Equivalent) | |||||
| (Unaudited) | TABLE 4 | ||||
| Three Months Ended | Three Months Ended | Three Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| June 30, 2026 | March 31, 2026 | June 30, 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | Average | Average | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Balance | Yield/Rate | Interest | Balance | Yield/Rate | Interest | Balance | Yield/Rate | Interest | |||||||||||||||||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in other financial institutions | $ | 253,598 | 3.69 | % | $ | 2,331 | $ | 274,885 | 3.69 | % | $ | 2,500 | $ | 134,270 | 4.43 | % | $ | 1,484 | ||||||||||||||||||||||||||||||||||||||
| Investment securities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Taxable [1] | 1,362,100 | 2.86 | 9,732 | 1,318,722 | 2.80 | 9,210 | 1,379,213 | 2.86 | 9,871 | |||||||||||||||||||||||||||||||||||||||||||||||
| Tax-exempt [1] [3] | 134,964 | 2.56 | 866 | 135,519 | 2.55 | 863 | 139,103 | 2.58 | 897 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total investment securities | 1,497,064 | 2.83 | 10,598 | 1,454,241 | 2.77 | 10,073 | 1,518,316 | 2.84 | 10,768 | |||||||||||||||||||||||||||||||||||||||||||||||
| Loans, including loans held for sale [2] | 5,300,949 | 4.96 | 65,553 | 5,268,482 | 4.93 | 64,323 | 5,307,946 | 4.96 | 65,668 | |||||||||||||||||||||||||||||||||||||||||||||||
| FHLB and FRB stock | 24,720 | 6.28 | 389 | 25,151 | 6.07 | 381 | 24,565 | 6.33 | 388 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 7,076,331 | 4.47 | 78,871 | 7,022,759 | 4.44 | 77,277 | 6,985,097 | 4.49 | 78,308 | |||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-earning assets | 357,491 | 373,325 | 329,047 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 7,433,822 | $ | 7,396,084 | $ | 7,314,144 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| LIABILITIES AND EQUITY | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand deposits | $ | 1,442,933 | 0.21 | % | $ | 757 | $ | 1,407,877 | 0.15 | % | $ | 522 | $ | 1,357,049 | 0.13 | % | $ | 443 | ||||||||||||||||||||||||||||||||||||||
| Savings and money market deposits | 2,367,169 | 1.28 | 7,554 | 2,371,217 | 1.28 | 7,502 | 2,275,799 | 1.48 | 8,414 | |||||||||||||||||||||||||||||||||||||||||||||||
| Time deposits up to $250,000 | 428,642 | 2.14 | 2,290 | 432,745 | 2.18 | 2,331 | 439,738 | 2.32 | 2,546 | |||||||||||||||||||||||||||||||||||||||||||||||
| Time deposits over $250,000 | 561,485 | 3.00 | 4,198 | 557,671 | 3.15 | 4,334 | 603,652 | 3.37 | 5,070 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 4,800,229 | 1.24 | 14,799 | 4,769,510 | 1.25 | 14,689 | 4,676,238 | 1.41 | 16,473 | |||||||||||||||||||||||||||||||||||||||||||||||
| Long-term debt | 76,547 | 5.53 | 1,056 | 76,547 | 5.56 | 1,049 | 131,431 | 5.65 | 1,851 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 4,876,776 | 1.30 | 15,855 | 4,846,057 | 1.32 | 15,738 | 4,807,669 | 1.53 | 18,324 | |||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 1,830,681 | 1,822,851 | 1,827,225 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 129,066 | 130,652 | 119,002 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities | 6,836,523 | 6,799,560 | 6,753,896 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total equity | 597,299 | 596,524 | 560,248 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 7,433,822 | $ | 7,396,084 | $ | 7,314,144 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income (taxable-equivalent) | 63,016 | 61,539 | 59,984 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Taxable-equivalent adjustment [3] | (182) | (181) | (188) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income (GAAP) | $ | 62,834 | $ | 61,358 | $ | 59,796 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest rate spread | 3.17 | % | 3.12 | % | 2.96 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin (taxable-equivalent) [4] | 3.57 | % | 3.53 | % | 3.44 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| [1] At amortized cost. | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| [2] Includes nonaccrual loans. | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| [3] Interest income and resultant yield information for tax-exempt investment securities is expressed on a taxable-equivalent basis using a federal statutory tax rate of 21%. | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| [4] Annualized net interest income and expense in the NIM calculation are based on the day count interest payment conventions at the interest-earning asset or interest-bearing liability level (i.e. 30/360, actual/actual). | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Average Balances, Interest Income & Expense, Yields and Rates (Taxable Equivalent) | |||||
| (Unaudited) | TABLE 5 | ||||
| Six Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||
| June 30, 2026 | June 30, 2025 | |||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | |||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Balance | Yield/Rate | Interest | Balance | Yield/Rate | Interest | ||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in other financial institutions | $ | 264,183 | 3.69 | % | $ | 4,831 | $ | 169,991 | 4.43 | % | $ | 3,738 | ||||||||||||||||||||||||||
| Investment securities: | ||||||||||||||||||||||||||||||||||||||
| Taxable [1] | 1,340,531 | 2.83 | 18,942 | 1,377,957 | 2.86 | 19,672 | ||||||||||||||||||||||||||||||||
| Tax-exempt [1] [3] | 135,240 | 2.55 | 1,729 | 139,345 | 2.57 | 1,794 | ||||||||||||||||||||||||||||||||
| Total investment securities | 1,475,771 | 2.80 | 20,671 | 1,517,302 | 2.83 | 21,466 | ||||||||||||||||||||||||||||||||
| Loans, including loans held for sale [2] | 5,284,805 | 4.94 | 129,876 | 5,309,768 | 4.92 | 129,787 | ||||||||||||||||||||||||||||||||
| FHLB and FRB stock | 24,935 | 6.17 | 770 | 22,541 | 6.32 | 712 | ||||||||||||||||||||||||||||||||
| Total interest-earning assets | 7,049,694 | 4.45 | 156,148 | 7,019,602 | 4.46 | 155,703 | ||||||||||||||||||||||||||||||||
| Noninterest-earning assets | 365,363 | 331,655 | ||||||||||||||||||||||||||||||||||||
| Total assets | $ | 7,415,057 | $ | 7,351,257 | ||||||||||||||||||||||||||||||||||
| LIABILITIES AND EQUITY | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand deposits | $ | 1,425,501 | 0.18 | % | $ | 1,279 | $ | 1,356,209 | 0.13 | % | $ | 895 | ||||||||||||||||||||||||||
| Savings and money market deposits | 2,369,182 | 1.28 | 15,056 | 2,310,429 | 1.51 | 17,276 | ||||||||||||||||||||||||||||||||
| Time deposits up to $250,000 | 430,682 | 2.16 | 4,621 | 448,557 | 2.42 | 5,377 | ||||||||||||||||||||||||||||||||
| Time deposits over $250,000 | 559,589 | 3.07 | 8,532 | 603,785 | 3.46 | 10,346 | ||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 4,784,954 | 1.24 | 29,488 | 4,718,980 | 1.45 | 33,894 | ||||||||||||||||||||||||||||||||
| Long-term debt | 76,547 | 5.55 | 2,105 | 141,758 | 5.60 | 3,937 | ||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 4,861,501 | 1.31 | 31,593 | 4,860,738 | 1.57 | 37,831 | ||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 1,826,788 | 1,813,142 | ||||||||||||||||||||||||||||||||||||
| Other liabilities | 129,855 | 124,767 | ||||||||||||||||||||||||||||||||||||
| Total liabilities | 6,818,144 | 6,798,647 | ||||||||||||||||||||||||||||||||||||
| Total equity | 596,913 | 552,610 | ||||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 7,415,057 | $ | 7,351,257 | ||||||||||||||||||||||||||||||||||
| Net interest income (taxable-equivalent) | 124,555 | 117,872 | ||||||||||||||||||||||||||||||||||||
| Taxable-equivalent adjustment [3] | (363) | (377) | ||||||||||||||||||||||||||||||||||||
| Net interest income (GAAP) | $ | 124,192 | $ | 117,495 | ||||||||||||||||||||||||||||||||||
| Interest rate spread | 3.14 | % | 2.89 | % | ||||||||||||||||||||||||||||||||||
| Net interest margin (taxable-equivalent) [4] | 3.55 | % | 3.37 | % | ||||||||||||||||||||||||||||||||||
| [1] At amortized cost. | ||||||||||||||||||||||||||||||||||||||
| [2] Includes nonaccrual loans. | ||||||||||||||||||||||||||||||||||||||
| [3] Interest income and resultant yield information for tax-exempt investment securities is expressed on a taxable-equivalent basis using a federal statutory tax rate of 21%. | ||||||||||||||||||||||||||||||||||||||
| [4] Annualized net interest income and expense in the NIM calculation are based on the day count interest payment conventions at the interest-earning asset or interest-bearing liability level (i.e. 30/360, actual/actual). | ||||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
Loans | |||||
| (Unaudited) | TABLE 6 | ||||
| Jun 30, | Mar 31, | Dec 31, | Sep 30, | Jun 30, | ||||||||||||||||||||||||||||
| (Dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | |||||||||||||||||||||||||||
| Commercial and industrial | $ | 590,404 | $ | 590,810 | $ | 594,592 | $ | 608,814 | $ | 608,130 | ||||||||||||||||||||||
| Construction | 211,007 | 204,368 | 213,191 | 217,610 | 190,008 | |||||||||||||||||||||||||||
| Residential mortgage | 1,815,342 | 1,806,965 | 1,839,191 | 1,839,535 | 1,851,690 | |||||||||||||||||||||||||||
| Home equity | 577,283 | 582,380 | 600,082 | 610,889 | 627,834 | |||||||||||||||||||||||||||
| Commercial mortgage | 1,686,361 | 1,703,760 | 1,594,433 | 1,613,187 | 1,540,523 | |||||||||||||||||||||||||||
| Consumer | 427,925 | 432,066 | 447,607 | 477,167 | 471,624 | |||||||||||||||||||||||||||
| Total loans, net of deferred fees and costs | 5,308,322 | 5,320,349 | 5,289,096 | 5,367,202 | 5,289,809 | |||||||||||||||||||||||||||
| Less: Allowance for credit losses | (60,581) | (59,933) | (59,621) | (60,393) | (59,611) | |||||||||||||||||||||||||||
| Loans, net of allowance for credit losses | $ | 5,247,741 | $ | 5,260,416 | $ | 5,229,475 | $ | 5,306,809 | $ | 5,230,198 | ||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Deposits | |||||
| (Unaudited) | TABLE 7 | ||||
| Jun 30, | Mar 31, | Dec 31, | Sep 30, | Jun 30, | ||||||||||||||||||||||||||||
| (Dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | |||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 1,917,502 | $ | 1,897,593 | $ | 1,891,198 | $ | 1,903,614 | $ | 1,938,226 | ||||||||||||||||||||||
| Interest-bearing demand | 1,407,574 | 1,428,323 | 1,388,107 | 1,340,725 | 1,336,620 | |||||||||||||||||||||||||||
| Savings and money market | 2,376,831 | 2,378,834 | 2,346,522 | 2,292,881 | 2,242,122 | |||||||||||||||||||||||||||
| Time deposits up to $250,000 | 421,811 | 429,564 | 433,629 | 444,005 | 439,687 | |||||||||||||||||||||||||||
| Core deposits | 6,123,718 | 6,134,314 | 6,059,456 | 5,981,225 | 5,956,655 | |||||||||||||||||||||||||||
| Other time deposits greater than $250,000 | 441,059 | 431,013 | 412,188 | 458,339 | 459,945 | |||||||||||||||||||||||||||
| Government time deposits | 130,977 | 134,027 | 138,120 | 138,120 | 128,389 | |||||||||||||||||||||||||||
| Total time deposits greater than $250,000 | 572,036 | 565,040 | 550,308 | 596,459 | 588,334 | |||||||||||||||||||||||||||
| Total deposits | $ | 6,695,754 | $ | 6,699,354 | $ | 6,609,764 | $ | 6,577,684 | $ | 6,544,989 | ||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Nonperforming Assets and Accruing Loans 90+ Days Past Due | |||||
| (Unaudited) | TABLE 8 | ||||
| Jun 30, | Mar 31, | Dec 31, | Sep 30, | Jun 30, | ||||||||||||||||||||||||||||
| (Dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | |||||||||||||||||||||||||||
| Nonaccrual loans: | ||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 192 | $ | 490 | $ | 591 | $ | 357 | $ | 110 | ||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Residential mortgage | 9,268 | 10,518 | 10,572 | 11,413 | 12,327 | |||||||||||||||||||||||||||
| Home equity | 5,619 | 2,986 | 2,608 | 2,119 | 1,889 | |||||||||||||||||||||||||||
| Consumer | 543 | 530 | 615 | 430 | 569 | |||||||||||||||||||||||||||
| Total nonaccrual loans | 15,622 | 14,524 | 14,386 | 14,319 | 14,895 | |||||||||||||||||||||||||||
| Other real estate owned ("OREO"): | ||||||||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Residential mortgage | 924 | — | — | — | — | |||||||||||||||||||||||||||
| Total OREO | 924 | — | — | — | — | |||||||||||||||||||||||||||
| Total nonperforming assets ("NPAs") | 16,546 | 14,524 | 14,386 | 14,319 | 14,895 | |||||||||||||||||||||||||||
| Accruing loans 90+ days past due: | ||||||||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Residential mortgage | — | — | 664 | 1,159 | 1,625 | |||||||||||||||||||||||||||
| Home equity | — | — | 485 | — | 21 | |||||||||||||||||||||||||||
| Consumer | 286 | 290 | 403 | 349 | 418 | |||||||||||||||||||||||||||
| Total accruing loans 90+ days past due | 286 | 290 | 1,552 | 1,508 | 2,064 | |||||||||||||||||||||||||||
| Total NPAs and accruing loans 90+ days past due | $ | 16,832 | $ | 14,814 | $ | 15,938 | $ | 15,827 | $ | 16,959 | ||||||||||||||||||||||
| Ratio of total nonaccrual loans to total loans | 0.29 | % | 0.27 | % | 0.27 | % | 0.27 | % | 0.28 | % | ||||||||||||||||||||||
| Ratio of total NPAs to total assets | 0.22 | 0.19 | 0.19 | 0.19 | 0.20 | |||||||||||||||||||||||||||
| Ratio of total NPAs to total loans and OREO | 0.31 | 0.27 | 0.27 | 0.27 | 0.28 | |||||||||||||||||||||||||||
| Ratio of total NPAs and accruing loans 90+ days past due to total loans and OREO | 0.32 | 0.28 | 0.30 | 0.29 | 0.32 | |||||||||||||||||||||||||||
| Quarter-to-quarter changes in NPAs: | ||||||||||||||||||||||||||||||||
| Balance at beginning of quarter | $ | 14,524 | $ | 14,386 | $ | 14,319 | $ | 14,895 | $ | 11,085 | ||||||||||||||||||||||
| Additions | 4,202 | 2,094 | 2,549 | 838 | 5,879 | |||||||||||||||||||||||||||
| Reductions: | ||||||||||||||||||||||||||||||||
| Payments | (782) | (284) | (397) | (286) | (585) | |||||||||||||||||||||||||||
| Return to accrual status | (16) | (883) | (1,098) | (821) | (861) | |||||||||||||||||||||||||||
| Charge-offs, valuation adjustments and other reductions | (1,382) | (789) | (987) | (307) | (623) | |||||||||||||||||||||||||||
| Total reductions | (2,180) | (1,956) | (2,482) | (1,414) | (2,069) | |||||||||||||||||||||||||||
| Balance at end of quarter | $ | 16,546 | $ | 14,524 | $ | 14,386 | $ | 14,319 | $ | 14,895 | ||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Allowance for Credit Losses on Loans | |||||
| (Unaudited) | TABLE 9 | ||||
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| Jun 30, | Mar 31, | Dec 31, | Sep 30, | Jun 30, | Jun 30, | |||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||||
| Allowance for credit losses ("ACL") on loans: | ||||||||||||||||||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 59,933 | $ | 59,621 | $ | 60,393 | $ | 59,611 | $ | 60,469 | $ | 59,621 | $ | 59,182 | ||||||||||||||||||||||||||||||
| Provision for credit losses on loans | 3,304 | 2,724 | 1,685 | 3,440 | 3,810 | 6,028 | 7,715 | |||||||||||||||||||||||||||||||||||||
| Charge-offs: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | (1,353) | (1,056) | (678) | (1,071) | (2,858) | (2,409) | (3,438) | |||||||||||||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | (23) | — | — | — | — | (23) | — | |||||||||||||||||||||||||||||||||||||
| Consumer | (2,283) | (2,301) | (2,831) | (2,824) | (2,864) | (4,584) | (5,841) | |||||||||||||||||||||||||||||||||||||
| Total charge-offs | (3,659) | (3,357) | (3,509) | (3,895) | (5,722) | (7,016) | (9,279) | |||||||||||||||||||||||||||||||||||||
| Recoveries: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 198 | 175 | 266 | 204 | 195 | 373 | 366 | |||||||||||||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||||||||||||||
| Construction | — | 2 | 1 | — | 3 | 2 | 3 | |||||||||||||||||||||||||||||||||||||
| Residential mortgage | 10 | 8 | 9 | 8 | 7 | 18 | 17 | |||||||||||||||||||||||||||||||||||||
| Home equity | 6 | 6 | 9 | 9 | 9 | 12 | 12 | |||||||||||||||||||||||||||||||||||||
| Consumer | 789 | 754 | 767 | 1,016 | 840 | 1,543 | 1,595 | |||||||||||||||||||||||||||||||||||||
| Total recoveries | 1,003 | 945 | 1,052 | 1,237 | 1,054 | 1,948 | 1,993 | |||||||||||||||||||||||||||||||||||||
Net charge-offs | (2,656) | (2,412) | (2,457) | (2,658) | (4,668) | (5,068) | (7,286) | |||||||||||||||||||||||||||||||||||||
| Balance at end of period | $ | 60,581 | $ | 59,933 | $ | 59,621 | $ | 60,393 | $ | 59,611 | $ | 60,581 | $ | 59,611 | ||||||||||||||||||||||||||||||
| Average loans, net of deferred fees and costs | $ | 5,300,949 | $ | 5,268,482 | $ | 5,328,499 | $ | 5,332,656 | $ | 5,307,946 | $ | 5,284,805 | $ | 5,309,768 | ||||||||||||||||||||||||||||||
| Ratio of annualized net charge-offs to average loans | 0.20 | % | 0.18 | % | 0.18 | % | 0.20 | % | 0.35 | % | 0.19 | % | 0.27 | % | ||||||||||||||||||||||||||||||
| Ratio of ACL to total loans | 1.14 | 1.13 | 1.13 | 1.13 | 1.13 | 1.14 | 1.13 | |||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Reconciliation of Non-GAAP Financial Measures | |||||
| (Unaudited) | TABLE 10 | ||||
To supplement its consolidated financial information, the Company utilizes certain non-GAAP financial measures. These measures are not intended to be considered in isolation or as a substitute for comparable GAAP results. The Company believes these non-GAAP financial measures provide meaningful insight to investors and other stakeholders in understanding its financial performance and position, by excluding certain transactions that may be non-recurring, non-operational, or not indicative of ongoing results. The Company believes that these non-GAAP measures offer a useful perspective for evaluating performance trends over time and are intended to support period-to-period comparisons. The Company believes they are valuable tools for both investors and management in assessing historical results and forecasting future performance. Non-GAAP financial measures may not be comparable to similarly entitled measures reported by other companies. The results for the three months ended June 30, 2026 were not materially impacted by items outside of the normal course of business.
A key measure of operating efficiency monitored by the Company is the efficiency ratio, which is derived from GAAP-based amounts. It is calculated by dividing total other operating expenses by total pre-provision revenue (defined as net interest income plus total other operating income). The Company believes that the efficiency ratio, a non-GAAP financial measure, provides a useful supplemental metric that enhances understanding of its business performance and operating efficiency. However, this ratio should not be viewed as a substitute for GAAP results and may not be comparable to similarly titled measures reported by other companies. The following table presents the Company's efficiency ratio for the periods indicated:
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||
| (dollars in thousands) | Jun 30, 2026 | Dec 31, 2025 | Jun 30, 2025 | Jun 30, 2026 | Jun 30, 2025 | |||||||||||||||||||||||||||
| Total other operating expense | $ | 46,180 | $ | 45,680 | $ | 43,946 | $ | 89,846 | $ | 86,018 | ||||||||||||||||||||||
| Net interest income | $ | 62,834 | $ | 62,087 | $ | 59,796 | $ | 124,192 | $ | 117,495 | ||||||||||||||||||||||
| Total other operating income | 14,620 | 14,201 | 13,013 | 26,194 | 24,109 | |||||||||||||||||||||||||||
| Total revenue | $ | 77,454 | $ | 76,288 | $ | 72,809 | $ | 150,386 | $ | 141,604 | ||||||||||||||||||||||
| Efficiency ratio (non-GAAP) | 59.62 | % | 59.88 | % | 60.36 | % | 59.74 | % | 60.75 | % | ||||||||||||||||||||||
The table below presents the Tangible Common Equity ("TCE") ratio, a non-GAAP financial measure, as of the dates indicated. The TCE ratio is calculated by dividing tangible common equity by tangible assets.
| (dollars in thousands) | Jun 30, 2026 | Mar 31, 2026 | Dec 31, 2025 | Sep 30, 2025 | Jun 30, 2025 | |||||||||||||||||||||||||||
| Total equity | $ | 596,331 | $ | 593,879 | $ | 592,581 | $ | 588,066 | $ | 568,874 | ||||||||||||||||||||||
| Less: Intangible assets | — | — | — | — | — | |||||||||||||||||||||||||||
| TCE | $ | 596,331 | $ | 593,879 | $ | 592,581 | $ | 588,066 | $ | 568,874 | ||||||||||||||||||||||
| Total assets | $ | 7,501,060 | $ | 7,495,363 | $ | 7,409,241 | $ | 7,421,478 | $ | 7,369,567 | ||||||||||||||||||||||
| Less: Intangible assets | — | — | — | — | — | |||||||||||||||||||||||||||
| Tangible assets | $ | 7,501,060 | $ | 7,495,363 | $ | 7,409,241 | $ | 7,421,478 | $ | 7,369,567 | ||||||||||||||||||||||
| TCE ratio (non-GAAP) | 7.95 | % | 7.92 | % | 8.00 | % | 7.92 | % | 7.72 | % | ||||||||||||||||||||||

2nd Quarter 2026 Earnings Supplement and Investor Presentation July 24, 2026
2Central Pacific Financial Corp. Forward-Looking Statements This document may contain forward-looking statements ("FLS") concerning, among other things: projections of revenues, expenses, income or loss, earnings or loss per share, capital expenditures, payment or nonpayment of dividends, net interest income, capital position, credit losses, net interest margin, or other financial items. These statements may also include the plans, objectives, and expectations of Central Pacific Financial Corp. (the "Company") or its management or Board of Directors, including those relating to business plans, use of capital resources, products or services, and regulatory developments or actions. In addition, such statements may address anticipated economic performance, the expected impact of business initiatives, and the assumptions underlying any of the foregoing. Words such as "believe," "plan," "anticipate," "aim," "seek," "expect," "intend," "forecast," "hope," "target," "continue," "remain," "estimate," "will," "should," "may," and other similar expressions are intended to identify FLS, although such terminology is not the exclusive means of doing so. While we believe that our FLS and their underlying assumptions are reasonably based, such statements are inherently subject to risks and uncertainties that may cause actual results to differ materially from expectations. Factors that may lead to such differences, include, but are not limited to: the persistence or resurgence of inflationary pressures in the United States and our market areas, and their effect on market interest rates, economic conditions, and credit quality; the impact of the current U.S. administration’s economic policies, including potential international tariffs, geopolitical instability, trade tensions, and other cost- cutting or fiscal initiatives; the adverse effects of bank failures on customer confidence, deposit behavior, liquidity, and regulatory responses; the effects of pandemics, epidemics, and other public health emergencies, including their impact on Hawaii's tourism and construction sectors and on our borrowers, customers, vendors and employees; supply chain disruptions, labor contract disputes, strikes; adverse trends in the real estate or construction industries, including rising inventory levels or declining property values; deterioration in borrowers' financial performance leading to increased loan delinquencies, asset quality issues, or loan losses; the impact of local, national, and international economic conditions and natural disasters (such as wildfires, volcanic eruptions, hurricanes, tsunamis, storms, floods, or earthquakes) on our markets and major industries within Hawaii; weakness in domestic economic conditions, including instability in the financial industry, deterioration in real estate markets, and declines in consumer or business confidence; revisions to estimates of reserve requirements under applicable regulatory and accounting standards; the impact of legislative and regulatory developments, changing capital and consumer protection rules, and new regulations affecting our operations and competitiveness; the costs and effects of legal and regulatory proceedings, including actual or threatened litigation and the results of governmental and regulatory exams and orders, as well as the costs of ongoing or potential compliance efforts; the effect of accounting standard changes adopted by regulatory agencies, the PCAOB, or the FASB, and the cost and resources associated with implementation; changes in trade, monetary, or fiscal policy, including actions by the Federal Reserve; market volatility and monetary fluctuations, including the transition away from the LIBOR Index; declines in our market capitalization or the price of our common stock; the effects and cost of acquisitions, dispositions, or strategic transactions we may make or evaluate; political instability, acts of war or terrorism, or other geopolitical conflicts; shifts in consumer spending, borrowing, and savings behaviors; technological changes and developments; cybersecurity incidents, data privacy breaches, or fraud involving us or third-party vendors; deficiencies in internal control over financial reporting or disclosure controls and procedures, and our ability to remediate them; increased competition among financial institutions and other financial service providers; our ability to achieve efficiency ratio improvement goals; our ability to attract and retain key personnel; changes in our personnel, organization, compensation and benefit plans; and related reputational or regulatory exposures; and risks related to the United States fiscal debt, deficit, and budget uncertainties. For further information on factors that could cause actual results to differ materially from the expectations or projections expressed in our FLS, please refer to the Company's filings with the U.S. Securities and Exchange Commission, including the Company's most recent Form 10-K, particularly, the discussion of "Risk Factors" set forth therein. We urge investors to consider all of these factors carefully in evaluating the FLS contained in this document. FLS speak only as of the date on which such statements are made. We undertake no obligation to update any FLS to reflect events or circumstances occurring after the date on which such statements are made, or to reflect the occurrence of unanticipated events, except as required by law.
3Central Pacific Financial Corp. Central Pacific Financial Corp. Overview Who We Are Strategic Focus Financial Results Appendix
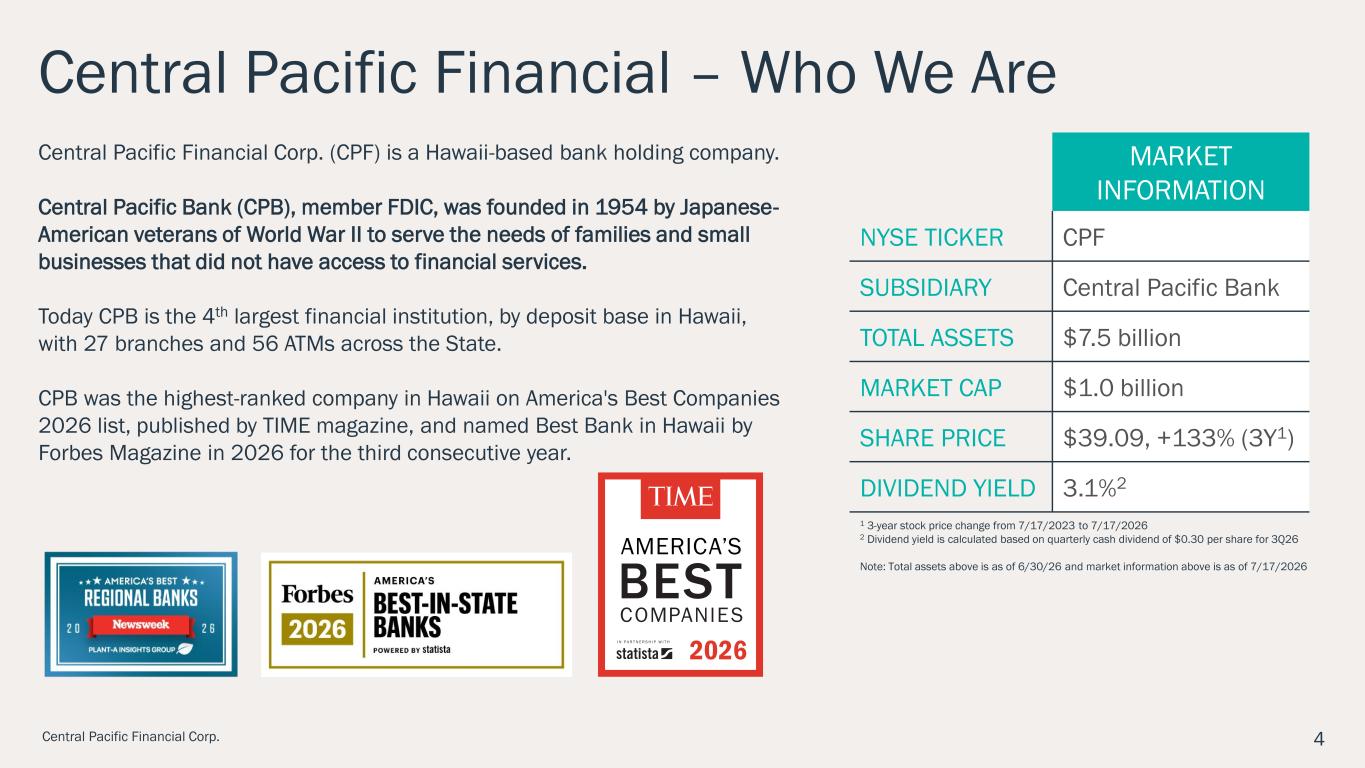
4Central Pacific Financial Corp. MARKET INFORMATION NYSE TICKER CPF SUBSIDIARY Central Pacific Bank TOTAL ASSETS $7.5 billion MARKET CAP $1.0 billion SHARE PRICE $39.09, +133% (3Y1) DIVIDEND YIELD 3.1%2 Central Pacific Financial Corp. (CPF) is a Hawaii-based bank holding company. Central Pacific Bank (CPB), member FDIC, was founded in 1954 by Japanese- American veterans of World War II to serve the needs of families and small businesses that did not have access to financial services. Today CPB is the 4th largest financial institution, by deposit base in Hawaii, with 27 branches and 56 ATMs across the State. CPB was the highest-ranked company in Hawaii on America's Best Companies 2026 list, published by TIME magazine, and named Best Bank in Hawaii by Forbes Magazine in 2026 for the third consecutive year. Central Pacific Financial – Who We Are 1 3-year stock price change from 7/17/2023 to 7/17/2026 2 Dividend yield is calculated based on quarterly cash dividend of $0.30 per share for 3Q26 Note: Total assets above is as of 6/30/26 and market information above is as of 7/17/2026
Strategic Focus

6Central Pacific Financial Corp. CPF Strategic Focus Our objective is to operate as a high performing bank that delivers sustainable, growing returns and provides enhanced value to positively impact our employees, customers, community and long- term shareholders. Our focus is on our core business. We believe we are positioned to drive strong results organically. Strengthen our brand and reputation to enhance customer trust, loyalty and community relevance which drives sustained deposit growth, lower customer acquisition costs and long-term shareholder value. Brand and Reputation Relationship-based Hawaii retail and small business deposits provide stable, low-cost funding to support balance sheet growth and margin optimization. Diversify funding sources through strategic partnerships with customers in Japan and Korea. Stable, Low-Cost Funding Focus on high-quality, relationship-driven lending and selective investments. Prioritize durable spreads over rate speculation to drive consistent earnings and capital growth. Disciplined Asset Deployment Seek diversification through selective indirect and wholesale credit exposure to reduce concentration risk, access larger markets, and enhance returns, while maintaining disciplined, deposit-funded growth anchored in our Hawaii core franchise. Thoughtful Diversification
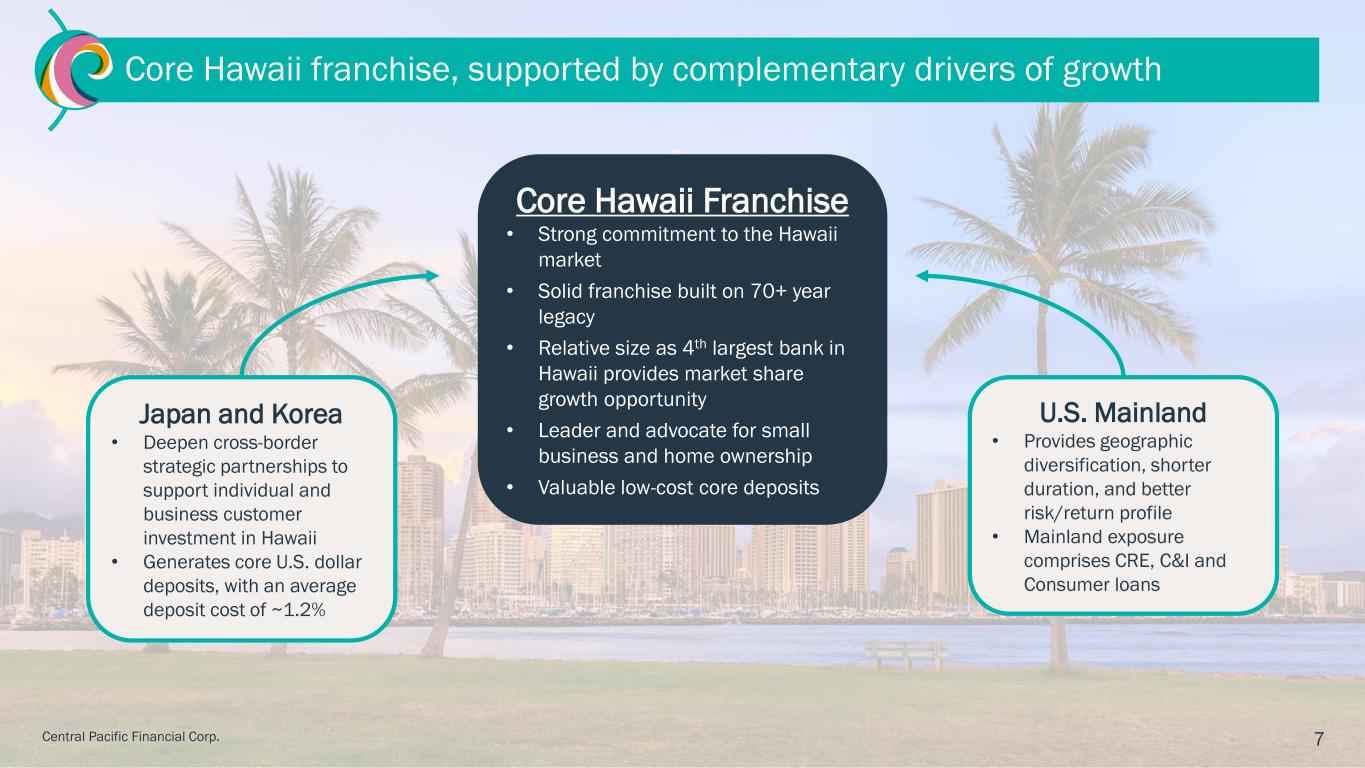
7Central Pacific Financial Corp. Core Hawaii franchise, supported by complementary drivers of growth Core Hawaii Franchise • Strong commitment to the Hawaii market • Solid franchise built on 70+ year legacy • Relative size as 4th largest bank in Hawaii provides market share growth opportunity • Leader and advocate for small business and home ownership • Valuable low-cost core deposits Japan and Korea • Deepen cross-border strategic partnerships to support individual and business customer investment in Hawaii • Generates core U.S. dollar deposits, with an average deposit cost of ~1.2% U.S. Mainland • Provides geographic diversification, shorter duration, and better risk/return profile • Mainland exposure comprises CRE, C&I and Consumer loans

Operational Excellence – Positive Operating Leverage Execution Proof Points: • Strategic vendor renewals: successfully negotiated large contracts which provide expense savings/incentives while also strengthening system capabilities, service levels, and scalability. • Branch & Sales system enhancements: reduced teller balancing time by over 80%. Sales and customer relationship management (CRM) tools being implemented. • Expense optimization: consolidation of employees from Operations Center into our main office for an annual savings of ~$1 million. • Data Center & Data Platform Modernization: upgraded Data Center with enhanced resiliency and disaster recovery. Migrating data warehouse to modern, cloud- based solution. 59.62% 50% 52% 54% 56% 58% 60% 62% 64% 66% - 10 20 30 40 50 60 70 80 90 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Efficiency Trend1 ($ in millions) Other Operating Expense Total Revenue Efficiency ratio 14Q24 is presented on a non-GAAP basis, normalized for non-recurring items. Refer to Appendix for non-GAAP reconciliation. 2Total Revenue = Net Interest Income + Other Operating Income Central Pacific Financial Corp. 8 59.6% Efficiency Ratio1 5.0% lower vs 4Q24 +13% Total Revenue2 Growth $68 mil to $77 mil from 4Q24 to 2Q26
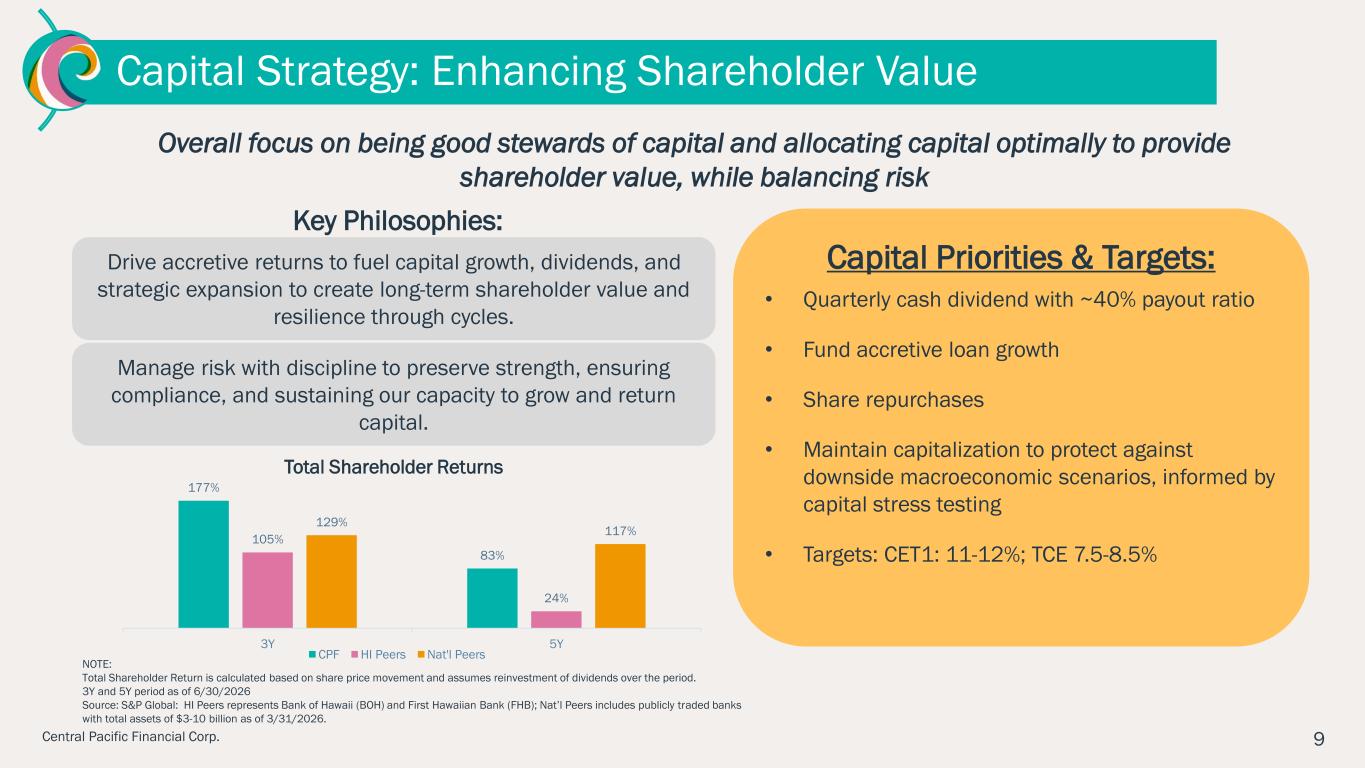
9Central Pacific Financial Corp. 177% 83% 105% 24% 129% 117% 3Y 5Y Total Shareholder Returns CPF HI Peers Nat'l Peers Capital Strategy: Enhancing Shareholder Value Overall focus on being good stewards of capital and allocating capital optimally to provide shareholder value, while balancing risk Drive accretive returns to fuel capital growth, dividends, and strategic expansion to create long-term shareholder value and resilience through cycles. Manage risk with discipline to preserve strength, ensuring compliance, and sustaining our capacity to grow and return capital. Key Philosophies: NOTE: Total Shareholder Return is calculated based on share price movement and assumes reinvestment of dividends over the period. 3Y and 5Y period as of 6/30/2026 Source: S&P Global: HI Peers represents Bank of Hawaii (BOH) and First Hawaiian Bank (FHB); Nat’l Peers includes publicly traded banks with total assets of $3-10 billion as of 3/31/2026. Capital Priorities & Targets: • Quarterly cash dividend with ~40% payout ratio • Fund accretive loan growth • Share repurchases • Maintain capitalization to protect against downside macroeconomic scenarios, informed by capital stress testing • Targets: CET1: 11-12%; TCE 7.5-8.5%

2Q 2026 Financial Results

11Central Pacific Financial Corp. • Net interest margin increased by 4bps, driven by $75 million growth in average loan and securities balances, at higher weighted average yields • Loan production of $200 million in 2Q, at weighted average new loan yield of 6.2%, leading to a 3bps increase in loan portfolio yield • Deposit cost remained steady at 0.90%, with NIB deposit growth of $20 million in 2Q • Repurchased 322 thousand shares of CPF common stock for $11.3 million in 2Q 2Q 2026 Financial Highlights 2Q26 1Q26 NET INCOME / DILUTED EPS $20.8mil $0.80 $20.7mil $0.78 RETURN ON ASSETS (ROA) 1.12% 1.12% RETURN ON EQUITY (ROE) 13.94% 13.90% NET INTEREST MARGIN (NIM) 3.57% 3.53% EFFICIENCY RATIO1 59.62% 59.87% TANGIBLE COMMON EQUITY (TCE)1 7.95% 7.92% 1 Refer to non-GAAP table in the appendix

12Central Pacific Financial Corp. Key Actions & Drivers of Stronger Financial Performance •Improved loan portfolio mix with $146 million YoY growth in commercial mortgage loans, offset by $87 million YoY reduction in residential mortgage and home equity loans •Loan portfolio mix improved to 57% fixed/43% variable from 62% fixed/38% variable in 2024 •Existing swap on $115 million municipal securities portfolio - pay fixed at 2.1%, receive float at the effective Fed Funds rate. In the money position added $0.8 million to interest income YTD as of 2Q26 Balance Sheet Optimization/Asset Liability Management •Total loan portfolio cashflows of approximately $200 million in 2Q26 •New loan weighted average yield of 6.2% in 2Q26 •Deposit costs held at 0.90%, reflecting disciplined deposit pricing and retention strategies Favorable Asset/Liability Repricing •Paid quarterly cash dividend of $0.29 per share in 2Q26 •322 thousand shares repurchased, totaling $11.3 million in 2Q26; $33.2 million remaining authorization •Declared quarterly cash dividend of $0.30 per share for 3Q26 Capital Optimization

13Central Pacific Financial Corp. Profitability Improvements Transitioned from post-pandemic normalization to sustainable profitability and capital generation 1CPF Historical trend = post-pandemic average from 1Q21 to 4Q25 depicted by pink dashed line 2Metrics are normalized for non-recurring items and are non-GAAP for 3Q24, 4Q24, and 3Q25. Refer to non-GAAP table in the appendix 1.12 0.50 0.60 0.70 0.80 0.90 1.00 1.10 1.20 1.30 1Q24 4Q24 3Q25 2Q26 ROA2 % GAAP Normalized (non-GAAP) Historical Trend 1 13.94 8.00 10.00 12.00 14.00 16.00 18.00 1Q24 4Q24 3Q25 2Q26 ROE2 % GAAP Normalized (non-GAAP) Historical Trend 1 3.57 2.50 2.70 2.90 3.10 3.30 3.50 3.70 3.90 1Q24 4Q24 3Q25 2Q26 NIM % GAAP Historical Trend 1 59.62 57.00 60.00 63.00 66.00 69.00 72.00 75.00 1Q24 4Q24 3Q25 2Q26 EFFICIENCY RATIO2 % Efficiency Ratio (non-GAAP) Normalized (non-GAAP) Historical Trend 1
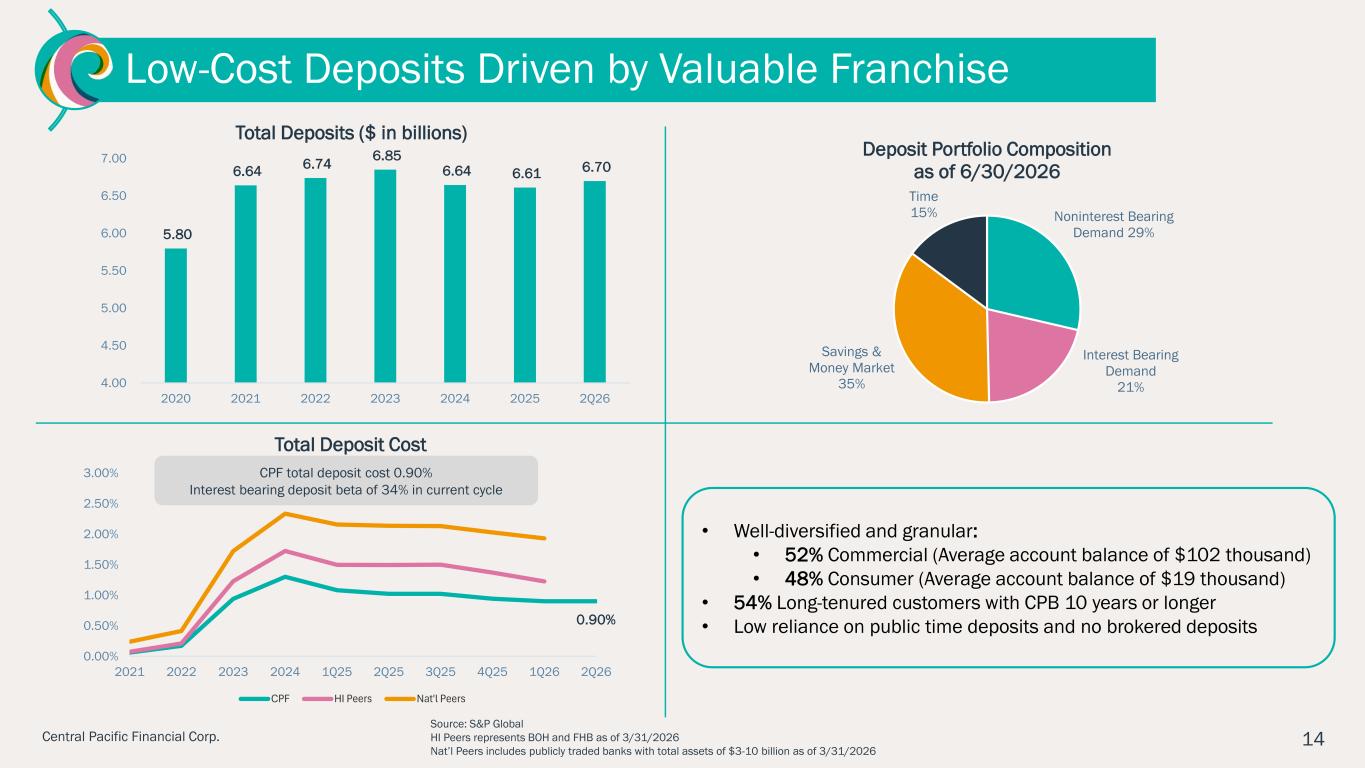
14Central Pacific Financial Corp. 0.90% 0.00% 0.50% 1.00% 1.50% 2.00% 2.50% 3.00% 2021 2022 2023 2024 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Total Deposit Cost CPF HI Peers Nat'l Peers Low-Cost Deposits Driven by Valuable Franchise CPF total deposit cost 0.90% Interest bearing deposit beta of 34% in current cycle • Well-diversified and granular: • 52% Commercial (Average account balance of $102 thousand) • 48% Consumer (Average account balance of $19 thousand) • 54% Long-tenured customers with CPB 10 years or longer • Low reliance on public time deposits and no brokered deposits Source: S&P Global HI Peers represents BOH and FHB as of 3/31/2026 Nat’l Peers includes publicly traded banks with total assets of $3-10 billion as of 3/31/2026 5.80 6.64 6.74 6.85 6.64 6.61 6.70 4.00 4.50 5.00 5.50 6.00 6.50 7.00 2020 2021 2022 2023 2024 2025 2Q26 Total Deposits ($ in billions) Noninterest Bearing Demand 29% Interest Bearing Demand 21% Savings & Money Market 35% Time 15% Deposit Portfolio Composition as of 6/30/2026
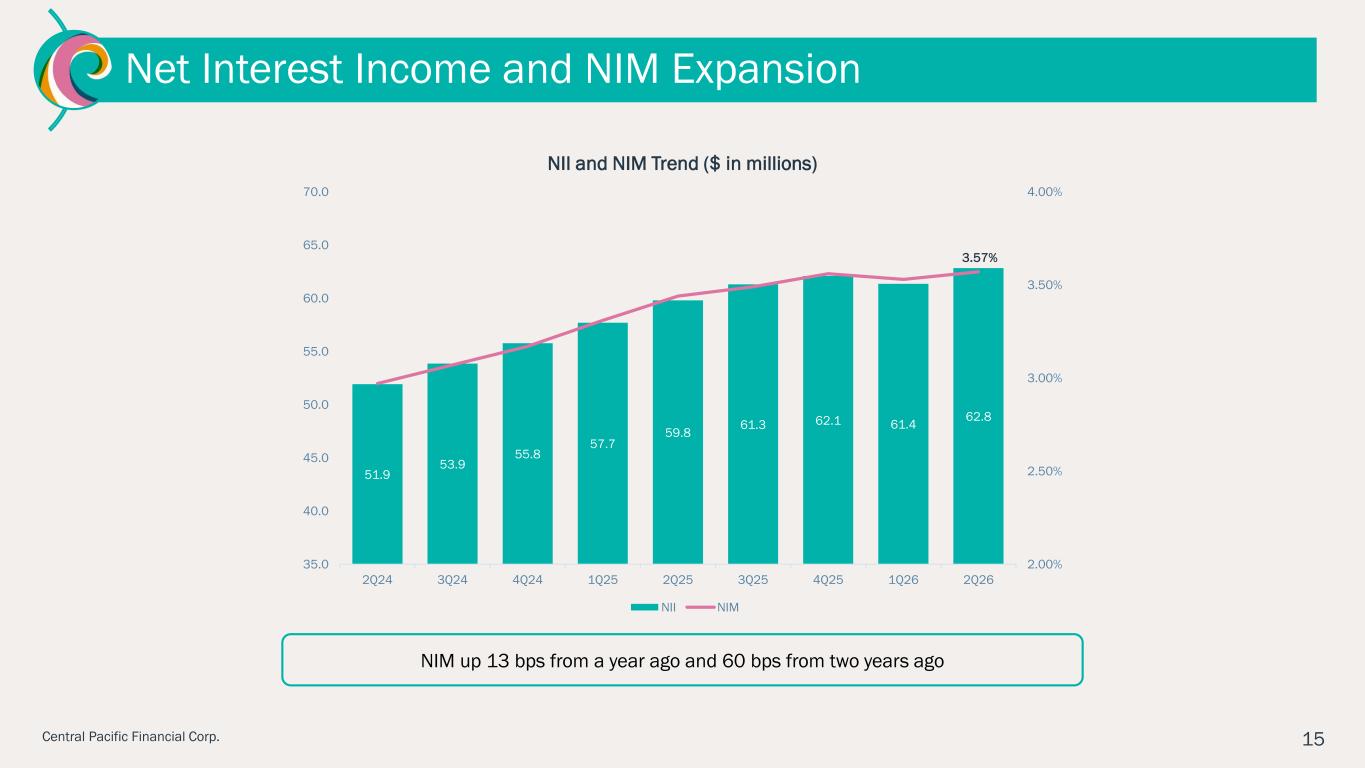
15Central Pacific Financial Corp. Net Interest Income and NIM Expansion NIM up 13 bps from a year ago and 60 bps from two years ago 51.9 53.9 55.8 57.7 59.8 61.3 62.1 61.4 62.8 3.57% 2.00% 2.50% 3.00% 3.50% 4.00% 35.0 40.0 45.0 50.0 55.0 60.0 65.0 70.0 2Q24 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 NII and NIM Trend ($ in millions) NII NIM
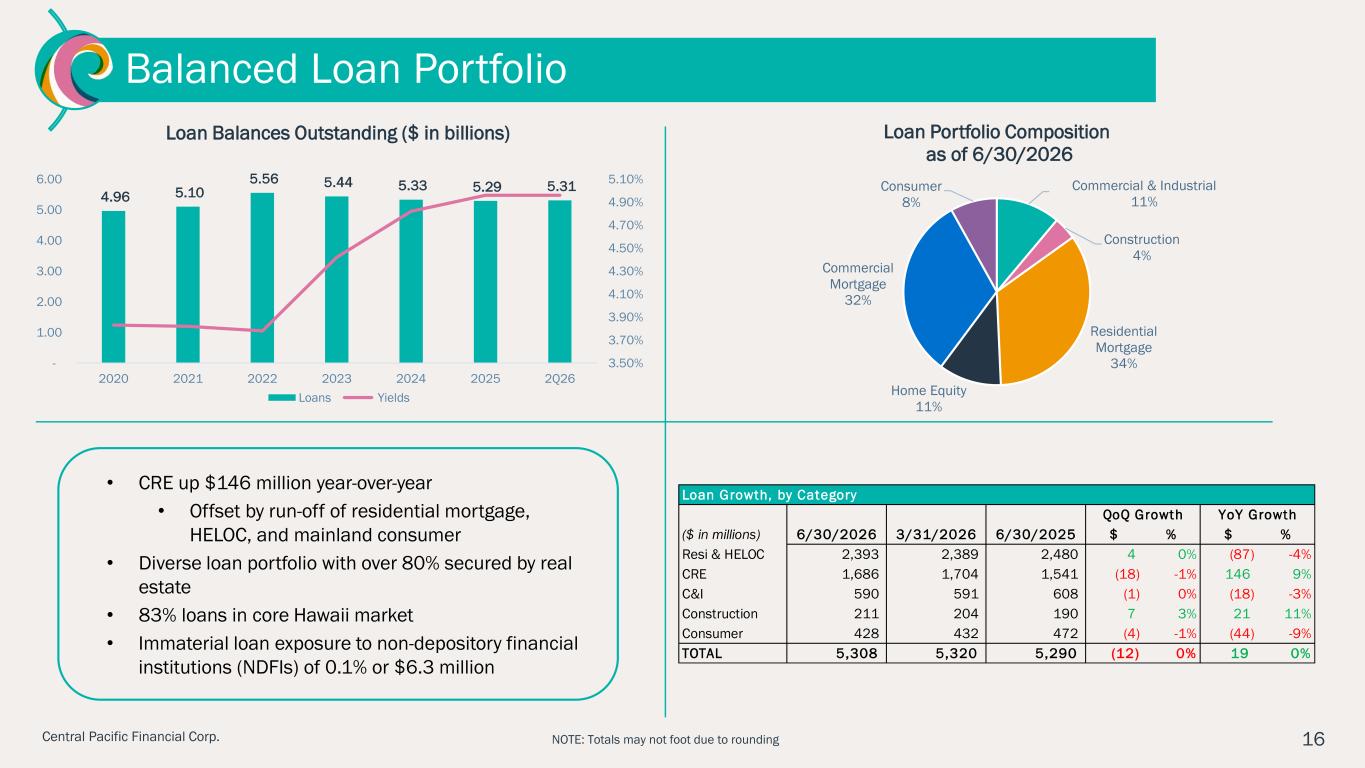
16Central Pacific Financial Corp. Balanced Loan Portfolio NOTE: Totals may not foot due to rounding • CRE up $146 million year-over-year • Offset by run-off of residential mortgage, HELOC, and mainland consumer • Diverse loan portfolio with over 80% secured by real estate • 83% loans in core Hawaii market • Immaterial loan exposure to non-depository financial institutions (NDFIs) of 0.1% or $6.3 million Commercial & Industrial 11% Construction 4% Residential Mortgage 34% Home Equity 11% Commercial Mortgage 32% Consumer 8% Loan Portfolio Composition as of 6/30/2026 4.96 5.10 5.56 5.44 5.33 5.29 5.31 3.50% 3.70% 3.90% 4.10% 4.30% 4.50% 4.70% 4.90% 5.10% - 1.00 2.00 3.00 4.00 5.00 6.00 2020 2021 2022 2023 2024 2025 2Q26 Loan Balances Outstanding ($ in billions) Loans Yields ($ in millions) 6/30/2026 3/31/2026 6/30/2025 $ % $ % Resi & HELOC 2,393 2,389 2,480 4 0% (87) -4% CRE 1,686 1,704 1,541 (18) -1% 146 9% C&I 590 591 608 (1) 0% (18) -3% Construction 211 204 190 7 3% 21 11% Consumer 428 432 472 (4) -1% (44) -9% TOTAL 5,308 5,320 5,290 (12) 0% 19 0% Loan Growth, by Category QoQ Growth YoY Growth

17Central Pacific Financial Corp. Balance Sheet Sensitivity 557 311 102 23 0 250 500 750 1000 ≤3m 3-6m 6-12m 1-3yr CD Maturity ($ in millions) as of 6/30/2026 1,426 27% 285 5% 610 12% 688 13% 798 15% 1,488 28% 0 500 1,000 1,500 2,000 ≤3m 3m-12m 1yr-3yr 3yr-5yr 5-15yr >15yr Loan Repricing Schedule1 ($ in millions) as of 6/30/2026 ▪ Contractual maturity ▪ Rate sensitive ▪ Non-rate sensitive 1Represents loan repricing or maturing. Excludes nonaccrual loans. • 32% or $1.7B of the loan portfolio contractually reprices within 1 year • Over 95% or $1.0B CDs reprice within 1 year • Interest Bearing Deposit repricing beta in current falling-rates cycle is 34% NOTE: Totals may not foot due to rounding Non-Int Bearing Demand, $1.9B Int Bearing Demand - WAR 0.21%, $1.4B Savings & MM - WAR 1.28%, $2.4B CDs - WAR 2.63%, $1.0B Deposit Portfolio Composition
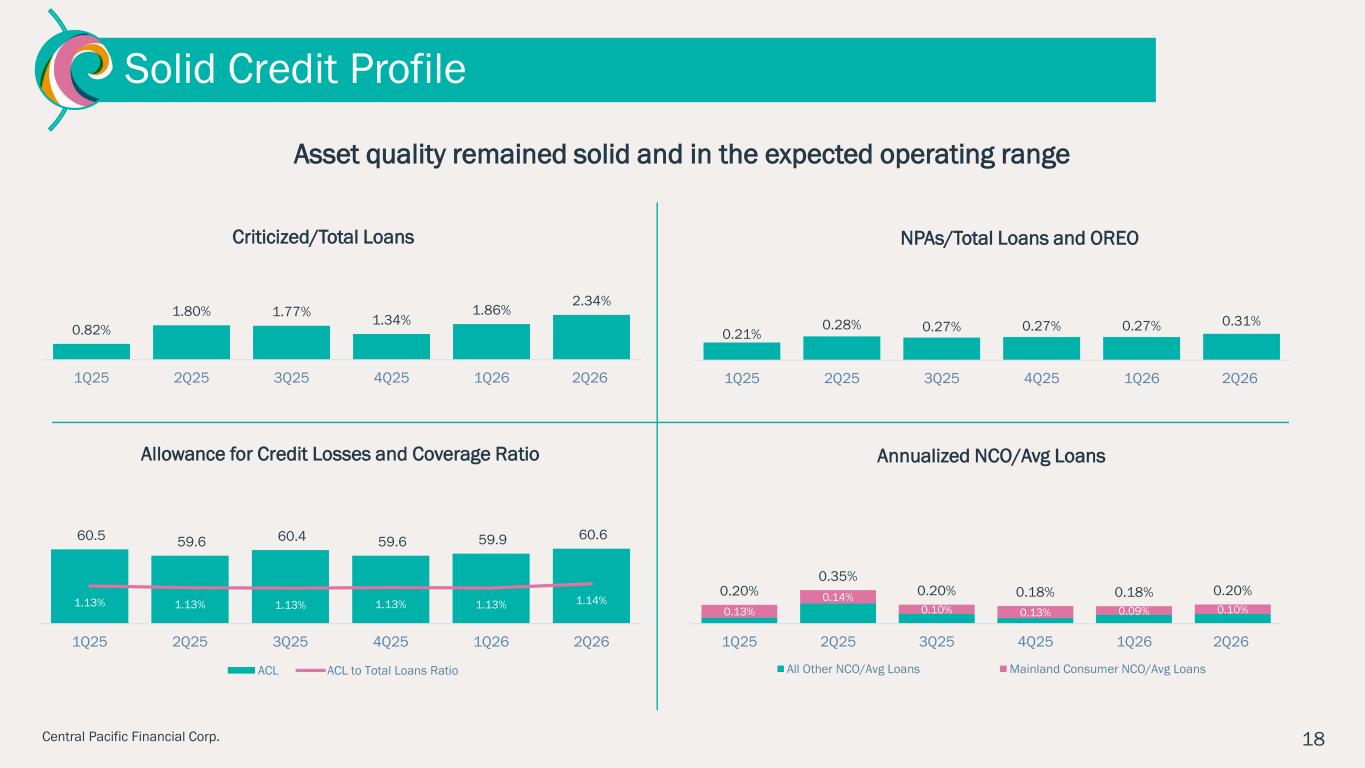
18Central Pacific Financial Corp. 0.13% 0.14% 0.10% 0.13% 0.09% 0.10% 0.20% 0.35% 0.20% 0.18% 0.18% 0.20% 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Annualized NCO/Avg Loans All Other NCO/Avg Loans Mainland Consumer NCO/Avg Loans 5 Asset quality remained solid and in the expected operating range Solid Credit Profile 0.82% 1.80% 1.77% 1.34% 1.86% 2.34% 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Criticized/Total Loans 0.21% 0.28% 0.27% 0.27% 0.27% 0.31% 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 NPAs/Total Loans and OREO 60.5 59.6 60.4 59.6 59.9 60.6 1.13% 1.13% 1.13% 1.13% 1.13% 1.14% 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Allowance for Credit Losses and Coverage Ratio ACL ACL to Total Loans Ratio

19Central Pacific Financial Corp. 45.7 43.7 46.2 1.5 0.0 10.0 20.0 30.0 40.0 50.0 60.0 3Q25 4Q25 1Q26 2Q26 Other Operating Expense ($ in millions) Other Operating Expense Non-recurring 13.5 11.6 14.6 1.4 0.0 2.0 4.0 6.0 8.0 10.0 12.0 14.0 16.0 18.0 3Q25 4Q25 1Q26 2Q26 Other Operating Income ($ in millions) Other Operating Income Non-recurring • 2Q26 increase was primarily driven by BOLI income • 4Q25 $1.4 million death benefit proceeds for BOLI income • Focused on growing long-term fee income from wealth management and advisory offerings • 2Q26 increase was primarily driven by higher deferred compensation expense (offsetting BOLI income) • 3Q25 $1.5 million in one-time expenses related to Operations Center consolidation • Focused on process improvements and driving positive operating leverage Other Operating Income and Expense 14.2 47.0

202Central Pacific Financial Corp. Strong Capital Position Supporting Organic Growth & Capital Return • Repurchased 322 thousand shares of CPF common stock for $11.3 million in 2Q26 • Quarterly cash dividend declared of $0.30 per share for 3Q26 • Capital Ratio Targets: • CET1: 11-12% • TCE: 7.5-8.5% 49.2 30.7 29.1 52.7 36.9 0 10 20 30 40 50 60 2022 2023 2024 2025 2Q26 YTD Capital Return ($ in millions) Cash Dividends Share repurchases 9.7% 12.7% 14.8% 0.0% 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 14.0% 16.0% Tier 1 Leverage CET1 Total Capital Regulatory Capital Ratios as of 6/30/2026

Appendix
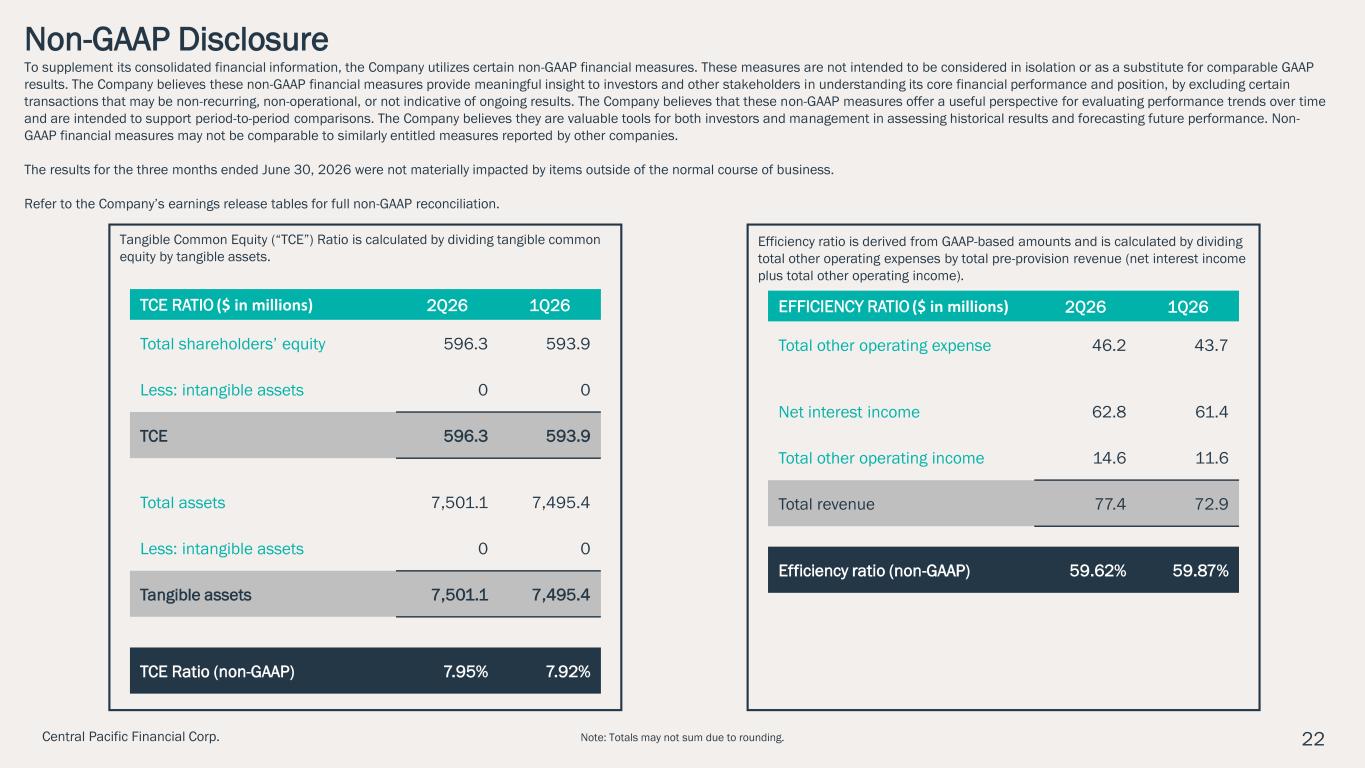
22Central Pacific Financial Corp. Non-GAAP Disclosure To supplement its consolidated financial information, the Company utilizes certain non-GAAP financial measures. These measures are not intended to be considered in isolation or as a substitute for comparable GAAP results. The Company believes these non-GAAP financial measures provide meaningful insight to investors and other stakeholders in understanding its core financial performance and position, by excluding certain transactions that may be non-recurring, non-operational, or not indicative of ongoing results. The Company believes that these non-GAAP measures offer a useful perspective for evaluating performance trends over time and are intended to support period-to-period comparisons. The Company believes they are valuable tools for both investors and management in assessing historical results and forecasting future performance. Non- GAAP financial measures may not be comparable to similarly entitled measures reported by other companies. The results for the three months ended June 30, 2026 were not materially impacted by items outside of the normal course of business. Refer to the Company’s earnings release tables for full non-GAAP reconciliation. EFFICIENCY RATIO ($ in millions) 2Q26 1Q26 Total other operating expense 46.2 43.7 Net interest income 62.8 61.4 Total other operating income 14.6 11.6 Total revenue 77.4 72.9 Efficiency ratio (non-GAAP) 59.62% 59.87% TCE RATIO ($ in millions) 2Q26 1Q26 Total shareholders’ equity 596.3 593.9 Less: intangible assets 0 0 TCE 596.3 593.9 Total assets 7,501.1 7,495.4 Less: intangible assets 0 0 Tangible assets 7,501.1 7,495.4 TCE Ratio (non-GAAP) 7.95% 7.92% Efficiency ratio is derived from GAAP-based amounts and is calculated by dividing total other operating expenses by total pre-provision revenue (net interest income plus total other operating income). Tangible Common Equity (“TCE”) Ratio is calculated by dividing tangible common equity by tangible assets. Note: Totals may not sum due to rounding.

23Central Pacific Financial Corp. Non-GAAP Disclosure (cont’d) To supplement our consolidated financial information, the Company uses certain non-GAAP financial measures, which are not meant to be considered in isolation or as a substitute for comparable GAAP financial measures. The Company believes these non-GAAP financial measures provide useful information to investors and others, which excludes transactions that are not meaningful in comparison to our past operating performance or not reflective of ongoing financial results. The Company believes that these measures offer a supplemental measure for period-to-period comparisons and can be used to evaluate our historical and prospective financial performance. These non-GAAP financial measures may not be comparable to similarly entitled measures reported by other companies. The following reconciling adjustments from GAAP or reported financial measures to non-GAAP adjusted financial measures are limited to: • 3Q25: net pre-tax expenses of $1.5 million related to the consolidation of the Company's former operations center into its main office in the three months ended September 30, 2025 • 4Q24: net pre-tax loss on sales of investment securities related to an investment portfolio repositioning of $9.9 million • 3Q24: pre-tax expenses of $3.1 million related to the evaluation and assessment of a strategic opportunity in the three months ended September 30, 2024 Management does not consider these transactions to be representative of the Company's core operating performance. The income tax effect was calculated assuming a 23% effective tax rate. Refer to the Company’s earnings release tables for full non-GAAP reconciliation. 3Q25 GAAP 3Q25 Adjustment 3Q25 Non-GAAP 4Q24 GAAP 4Q24 Adjustment 4Q24 Non-GAAP 3Q24 GAAP 3Q24 Adjustment 3Q24 Non-GAAP NET INCOME ($ in millions) $18.6 +$1.2 $19.7 $11.3 +$7.6 $19.0 $13.3 +$2.4 $15.7 DILUTED EARNINGS PER SHARE (EPS) $0.69 +$0.04 $0.73 $0.42 +$0.28 $0.70 $0.49 +$0.09 $0.58 RETURN ON ASSETS (ROA) 1.01% +0.07% 1.08% 0.62% +0.41% 1.03% 0.72% +0.13% 0.85% RETURN ON EQUITY (ROE) 12.89% +0.78% 13.67% 8.37% +5.45% 13.82% 10.02% +1.73% 11.75% TANGIBLE COMMON EQUITY (NON-GAAP) 7.92% +0.02% 7.94% 7.21% +0.12% 7.33% 7.31% +0.03% 7.34% EFFICIENCY RATIO (NON-GAAP) 62.84% -2.03% 60.81% 75.65% -11.00% 64.65% 70.12% -4.61% 65.51%
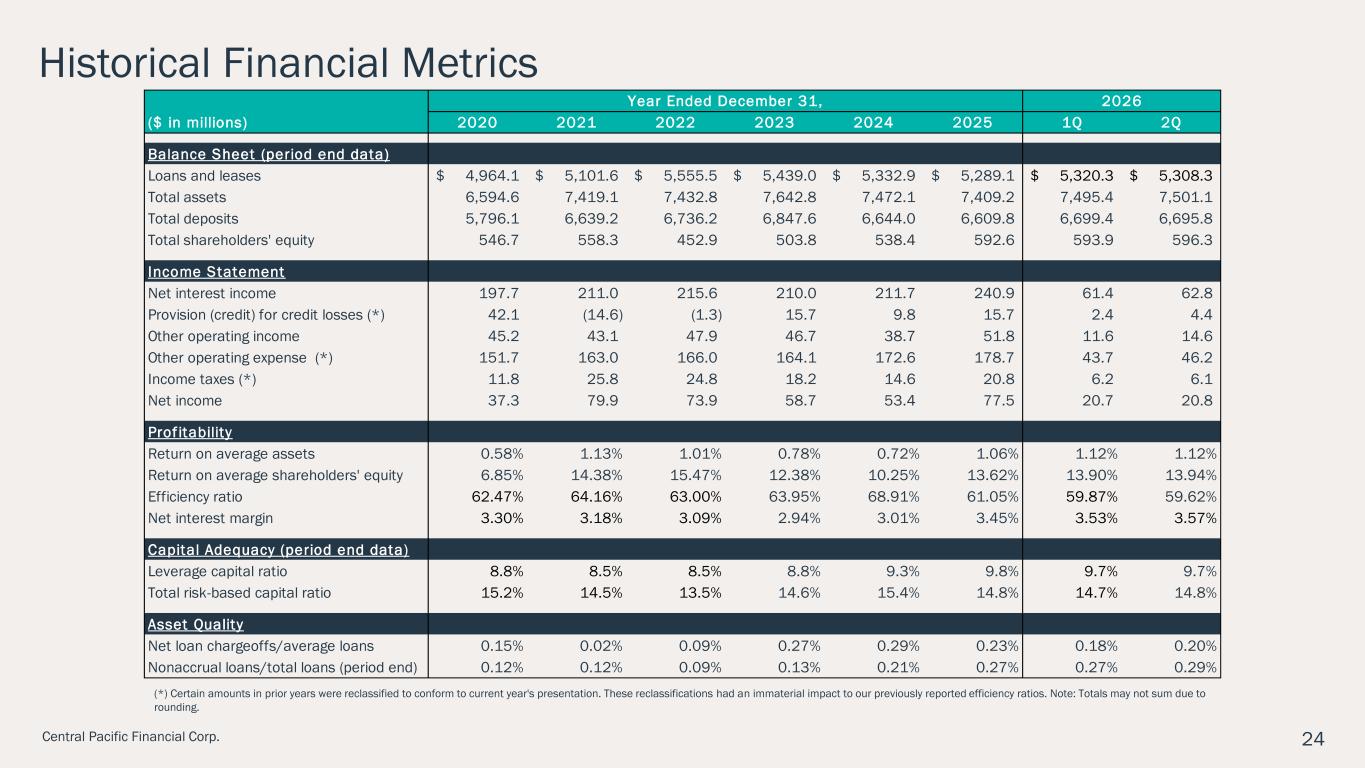
24Central Pacific Financial Corp. (*) Certain amounts in prior years were reclassified to conform to current year's presentation. These reclassifications had an immaterial impact to our previously reported efficiency ratios. Note: Totals may not sum due to rounding. Historical Financial Metrics ($ in millions) 2020 2021 2022 2023 2024 2025 1Q 2Q Balance Sheet (period end data) Loans and leases 4,964.1$ 5,101.6$ 5,555.5$ 5,439.0$ 5,332.9$ 5,289.1$ 5,320.3$ 5,308.3$ Total assets 6,594.6 7,419.1 7,432.8 7,642.8 7,472.1 7,409.2 7,495.4 7,501.1 Total deposits 5,796.1 6,639.2 6,736.2 6,847.6 6,644.0 6,609.8 6,699.4 6,695.8 Total shareholders' equity 546.7 558.3 452.9 503.8 538.4 592.6 593.9 596.3 Income Statement Net interest income 197.7 211.0 215.6 210.0 211.7 240.9 61.4 62.8 Provision (credit) for credit losses (*) 42.1 (14.6) (1.3) 15.7 9.8 15.7 2.4 4.4 Other operating income 45.2 43.1 47.9 46.7 38.7 51.8 11.6 14.6 Other operating expense (*) 151.7 163.0 166.0 164.1 172.6 178.7 43.7 46.2 Income taxes (*) 11.8 25.8 24.8 18.2 14.6 20.8 6.2 6.1 Net income 37.3 79.9 73.9 58.7 53.4 77.5 20.7 20.8 Prof itability Return on average assets 0.58% 1.13% 1.01% 0.78% 0.72% 1.06% 1.12% 1.12% Return on average shareholders' equity 6.85% 14.38% 15.47% 12.38% 10.25% 13.62% 13.90% 13.94% Efficiency ratio 62.47% 64.16% 63.00% 63.95% 68.91% 61.05% 59.87% 59.62% Net interest margin 3.30% 3.18% 3.09% 2.94% 3.01% 3.45% 3.53% 3.57% Capital Adequacy (period end data) Leverage capital ratio 8.8% 8.5% 8.5% 8.8% 9.3% 9.8% 9.7% 9.7% Total risk-based capital ratio 15.2% 14.5% 13.5% 14.6% 15.4% 14.8% 14.7% 14.8% Asset Quality Net loan chargeoffs/average loans 0.15% 0.02% 0.09% 0.27% 0.29% 0.23% 0.18% 0.20% Nonaccrual loans/total loans (period end) 0.12% 0.12% 0.09% 0.13% 0.21% 0.27% 0.27% 0.29% Year Ended December 31, 2026

25Central Pacific Financial Corp. CPB’s Branch Footprint 70+ year legacy 27 branches on 4 islands Kauai (1), Oahu (20), Maui (4), and Hawaii (2) & 56 ATMs Kauai Oahu Molokai Maui Hawaii Island Niihau Kahoolawe Lanai Note: Map is not to scale
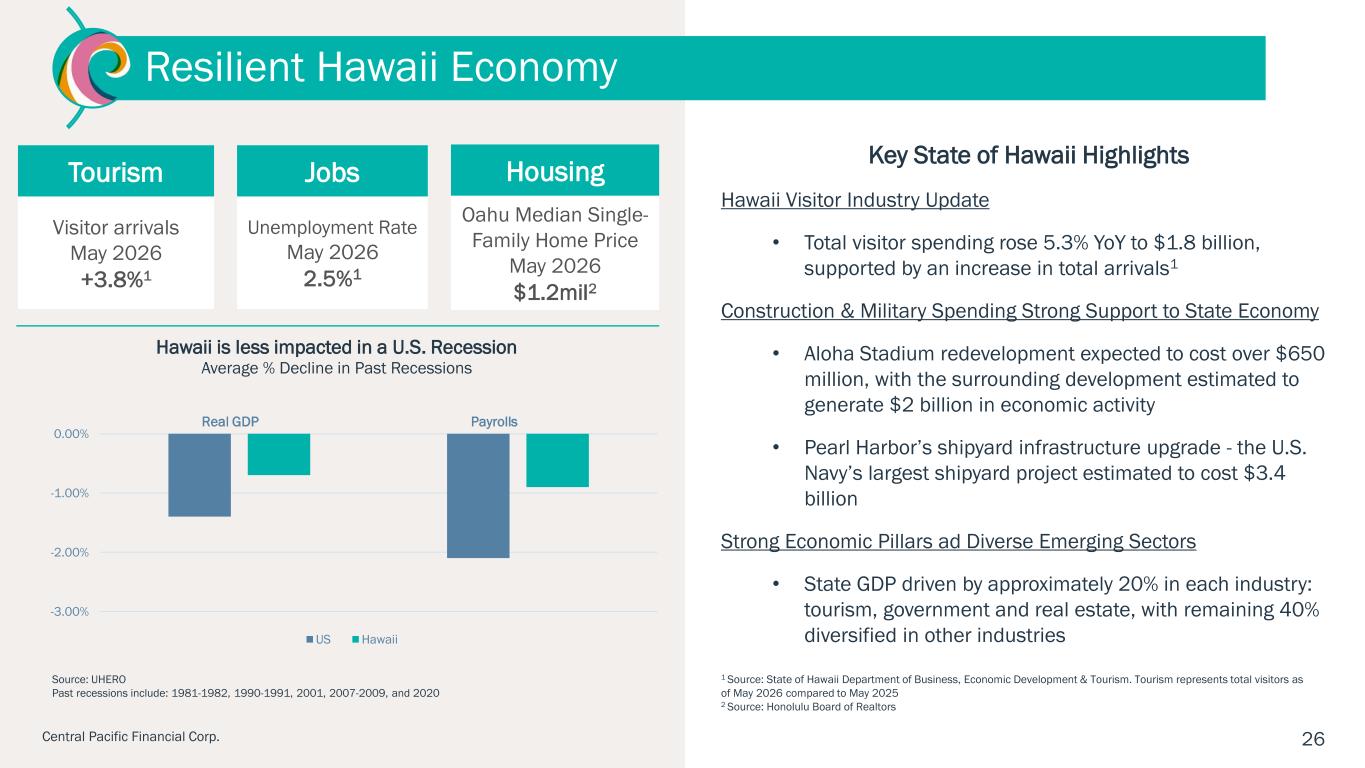
262Central Pacific Financial Corp. Tourism Visitor arrivals May 2026 +3.8%1 Jobs Unemployment Rate May 2026 2.5%1 Key State of Hawaii Highlights Hawaii Visitor Industry Update • Total visitor spending rose 5.3% YoY to $1.8 billion, supported by an increase in total arrivals1 Construction & Military Spending Strong Support to State Economy • Aloha Stadium redevelopment expected to cost over $650 million, with the surrounding development estimated to generate $2 billion in economic activity • Pearl Harbor’s shipyard infrastructure upgrade - the U.S. Navy’s largest shipyard project estimated to cost $3.4 billion Strong Economic Pillars ad Diverse Emerging Sectors • State GDP driven by approximately 20% in each industry: tourism, government and real estate, with remaining 40% diversified in other industries 1 Source: State of Hawaii Department of Business, Economic Development & Tourism. Tourism represents total visitors as of May 2026 compared to May 2025 2 Source: Honolulu Board of Realtors Resilient Hawaii Economy Housing Oahu Median Single- Family Home Price May 2026 $1.2mil2 -3.00% -2.00% -1.00% 0.00% Hawaii is less impacted in a U.S. Recession Average % Decline in Past Recessions US Hawaii Real GDP Source: UHERO Past recessions include: 1981-1982, 1990-1991, 2001, 2007-2009, and 2020 Payrolls

27Central Pacific Financial Corp. CPB Named Best Bank in Hawaii by Times, Forbes, Newsweek, and Honolulu Star-Advertiser • TIME’s America’s Best Companies of 2026 List • Forbes’ Best-In-State Banks 2026 • Newsweek’s America’s Best Regional Banks 2026 • SBA Lender of the year for 2025
Mahalo