
FBNC 8-K
First Bancorp /Nc/ (FBNC)
8-K
2026-07-22
For: 2026-07-22
View Original
Added on
July 22, 2026
UNITED STATES SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
__________________
Form 8-K
__________________
CURRENT REPORT PURSUANT TO SECTION 13 OR 15(d) OF
THE SECURITIES EXCHANGE ACT OF 1934
| Date of Report (Date of earliest event reported): | ||||||||
(Exact Name of Registrant as Specified in its Charter)
| (State or Other Jurisdiction | (Commission | (I.R.S. Employer | ||||||||||||
| of Incorporation) | File Number) | Identification Number) | ||||||||||||
| | ||||||||||||||
| (Address of Principal Executive Offices) | (Zip Code) | |||||||||||||
____________________
(Registrant’s telephone number, including area code)
Not Applicable
___________________
(Former Name or Former Address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | ||||||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | ||||||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | ||||||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | ||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Securities registered pursuant to Section 12(b) of the Act:
Title of each class Trading symbol Name of each exchange on which registered:
1
First Bancorp
INDEX
| Page | |||||
| Item 2.02 – Results of Operations and Financial Condition | 3 | ||||
| Item 9.01 – Financial Statements and Exhibits | 3 | ||||
| Signatures | 3 | ||||
| 4 | |||||
| 21 | |||||
2
Item 2.02 - Results of Operations and Financial Condition
On July 22, 2026, First Bancorp (the “Registrant” or “Company”) issued an earnings release to announce its financial results for the three month period ended June 30, 2026. The earnings release contains forward-looking statements regarding the Company and includes cautionary language identifying important factors that could cause actual results to differ materially from those anticipated. The earnings release is furnished as Exhibit 99.1. Consequently, it is not deemed "filed" for purposes of Section 18 of the Securities Exchange Act of 1934 or otherwise subject to the liabilities of that section. Such materials may only be incorporated by reference into another filing under the Exchange Act or Securities Act of 1933 if such subsequent filing specifically references this Form 8-K.
Item 9.01 – Financial Statements and Exhibits
(d) Exhibits
Disclosures About Forward Looking Statements
This news release contains forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934 and the Private Securities Litigation Reform Act of 1995, which statements are inherently subject to risks and uncertainties. Forward-looking statements are statements that include projections, predictions, expectations or beliefs about future events or results or otherwise are not statements of historical fact. Such statements are often characterized by the use of qualifying words (and their derivatives) such as “expect,” “believe,” “estimate,” “plan,” “project,” “anticipate,” or other statements concerning opinions or judgments of the Company and its management about future events. Factors that could influence the accuracy of such forward-looking statements include, but are not limited to, the financial success or changing strategies of the Company’s customers, the Company’s level of success in integrating acquisitions, actions of government regulators, the level of market interest rates, and general economic conditions. For additional information about the factors that could affect the matters discussed in this paragraph, see the “Risk Factors” section of the Company’s most recent Annual Report on Form 10-K. Forward-looking statements speak only as of the date they are made, and the Company undertakes no obligation to update or revise forward-looking statements. The Company is also not responsible for changes made to the press release by wire services, internet services or other media.
Signatures
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized.
| First Bancorp | ||||||||||||||||||||
| July 22, 2026 | By: | /s/ Richard H. Moore | ||||||||||||||||||
| Richard H. Moore | ||||||||||||||||||||
| Chief Executive Officer | ||||||||||||||||||||
3

News Release
| For Immediate Release: | For More Information, Contact: | ||||||||||
| July 22, 2026 | Katie Doyle | ||||||||||
336-286-8741 | |||||||||||
First Bancorp Reports Second Quarter Results
Second Quarter 2026 Financial Data | |||||||||||||||||
| (Dollars in 000s, except per share data) | Q2-2026 | Q1-2026 | Q2-2025 | ||||||||||||||
| Summary Income Statement | |||||||||||||||||
| Total interest income | $ | 148,315 | $ | 142,390 | $ | 136,731 | |||||||||||
| Total interest expense | 37,049 | 35,274 | 40,065 | ||||||||||||||
| Net interest income | 111,266 | 107,116 | 96,666 | ||||||||||||||
| Provision for credit losses | 1,169 | 3,083 | 2,212 | ||||||||||||||
| Noninterest income | 16,034 | 15,178 | 14,292 | ||||||||||||||
| Noninterest expenses | 62,761 | 60,218 | 58,924 | ||||||||||||||
| Income tax expense | 12,851 | 12,334 | 11,256 | ||||||||||||||
| Net income | $ | 50,519 | $ | 46,659 | $ | 38,566 | |||||||||||
| Key Metrics | |||||||||||||||||
| Diluted EPS | $ | 1.22 | $ | 1.13 | $ | 0.93 | |||||||||||
| Book value per share | 41.49 | 40.68 | 37.53 | ||||||||||||||
| Tangible book value per share | 29.84 | 29.01 | 25.82 | ||||||||||||||
| ROA | 1.56 | % | 1.48 | % | 1.24 | % | |||||||||||
| ROCE | 11.89 | % | 11.22 | % | 10.11 | % | |||||||||||
| ROTCE | 16.88 | % | 16.05 | % | 15.25 | % | |||||||||||
| NIM | 3.71 | % | 3.67 | % | 3.32 | % | |||||||||||
| NIM- T/E | 3.73 | % | 3.69 | % | 3.32 | % | |||||||||||
| Efficiency ratio | 49.12 | % | 49.05 | % | 53.00 | % | |||||||||||
| Quarterly NCO ratio | 0.04 | % | 0.06 | % | 0.06 | % | |||||||||||
| ACL ratio | 1.39 | % | 1.42 | % | 1.47 | % | |||||||||||
| Capital Ratios (1) | |||||||||||||||||
| Tangible common equity to tangible assets | 9.83 | % | 9.63 | % | 8.83 | % | |||||||||||
| Common equity tier I capital ratio | 14.09 | % | 14.13 | % | 14.64 | % | |||||||||||
| Total risk-based capital ratio | 16.06 | % | 16.12 | % | 16.90 | % | |||||||||||
(1) June 30, 2026 ratios are preliminary. | |||||||||||||||||
Second Quarter 2026 Highlights | ||
• D-EPS was $1.22 per share for the second quarter of 2026 compared to $1.13 for the linked quarter and $0.93 for the like quarter.
•The net interest margin was 3.71% for the quarter ended June 30, 2026, an expansion of 0.04% from the linked quarter and 0.39% from the like quarter.
•The efficiency ratio for the quarter ended June 30, 2026 was 49.12%, compared to 49.05% for the linked quarter and 53.00% for the like quarter.
•Total assets exceeded $13 billion at June 30, 2026, the highest level in First Bancorp's history.
•Total loans were $9.0 billion at June 30, 2026, representing an increase of $194.9 million, or 8.9% annualized.
•Total loan yield was 5.67%, up 10 basis points from the linked quarter and 14 basis points from the like quarter.
•The yield on securities decreased 3 basis points to 2.71% from 2.74% for the linked quarter.
•Total cost of funds increased 3 basis points to 1.34% for the quarter ended June 30, 2026 from 1.31% for the linked quarter and decreased 14 basis points from the like quarter.
•Average core deposits were $11.0 billion, an increase of $181.0 million for the linked quarter and $268.1 million from the like quarter. Total cost of deposits was 1.31%, an increase of 3 basis points for the linked quarter and a decrease of 12 basis points from the like quarter.
•Noninterest expenses of $62.8 million represented a $2.5 million increase from the linked quarter and a $3.8 million increase from the like quarter. The linked quarter increase was driven by a $2.0 million increase in Total personnel expense.
•Noninterest-bearing demand deposits were $3.6 billion, representing 32% of total deposits at June 30, 2026. During the second quarter of 2026, period end customer deposits grew by 2.6% annualized.
•The loan-to-deposit ratio was 81.1% as of June 30, 2026.
•On July 14, 2026, First Bancorp announced its pending acquisition of First Carolina Bancshares Corporation, scheduled to close in late 2026 or early 2027.
1
 | Second Quarter 2026 Results | ||||
SOUTHERN PINES, N.C. - First Bancorp (the "Company") (NASDAQ - FBNC), the parent company of First Bank, reported unaudited second quarter earnings today. The Company reported net income of $50.5 million, or $1.22 diluted earnings per share ("D-EPS"), for the three months ended June 30, 2026 compared to $46.7 million, or $1.13 D-EPS, for the three months ended March 31, 2026 ("linked quarter") and $38.6 million, or $0.93 D-EPS, for the second quarter of 2025 ("like quarter").
On July 14, 2026, the Company announced an agreement to acquire First Carolina Bancshares Corporation ("First Carolina"), and its subsidiary, Carolina Bank & Trust Company ("Carolina Bank") headquartered in Florence, South Carolina, in a 75% stock and 25% cash transaction. This transaction is subject to regulatory approvals and approval of First Carolina's shareholders, and is expected to close in the late fourth quarter of 2026 or early first quarter of 2027. Carolina Bank operates 14 branches throughout the Pee Dee region of South Carolina and had approximately $831 million in total assets, $596 million in loans, and $714 million in deposits at June 30, 2026.
The Company continued to enhance net interest income and net interest margin ("NIM") during the second quarter of 2026. The Company recorded net interest income of $111.3 million for the current quarter, compared to $107.1 million for the linked quarter and $96.7 million for the like quarter. NIM for the second quarter of 2026 expanded to 3.71% from 3.67% for the linked quarter and 3.32% for the like quarter.
Noninterest expenses were $62.8 million for the second quarter of 2026, up from $60.2 million for the linked quarter, and $58.9 million for the like quarter. The efficiency ratio was 49.12% for the quarter ended June 30, 2026 , compared to 49.05% for the linked quarter and 53.00% for the like quarter.
Richard H. Moore, Chairman and CEO of the Company, stated, “First Bancorp continued to build on its positive start to 2026 with strong second quarter financial results driven by continued margin expansion, prudent balance sheet execution, high quality loans and a controlled efficiency ratio. Earnings continue to benefit from the repositioning of lower-yielding assets into higher-yielding opportunities, while our liquidity position, capital levels, and credit quality remain strong. We are pleased with our performance through the first half of the year and remain confident in our ability to sustain positive momentum and deliver continued success in 2026. We are excited about the acquisition of First Carolina which brings talented bankers and will help us accelerate our South Carolina growth expansion."
| Net Interest Income and Net Interest Margin | ||
Net interest income for the second quarter of 2026 was $111.3 million, an increase of 3.9% from the linked quarter of $107.1 million and an increase of 15.1% from the like quarter of $96.7 million. The increase in net interest income from the linked and like quarters resulted from additional loan volume and increasing loan yield through originations as well as one additional earning day compared to the linked quarter. The increase from the like quarter also resulted from our focused efforts to manage deposit costs after the rate cuts by the Federal Reserve in 2025.
The Company’s NIM for the second quarter of 2026 was 3.71%, an increase of 4 basis points from the linked quarter and 39 basis points from the like quarter.
The linked quarter expansion of NIM was driven a $114.9 million increase in average loans along with a 10 basis points expansion in loan yield. Additionally, short-term investments contributed an additional $1.5 million from increased balances partially reduced by lower yields. Offsetting these increases, the cost of interest bearing deposits increased 5 basis points on growth of $98.8 million in average balances. Driving these increases, the average balance of money market deposits increased $99.6 million while the cost of those deposits increased 8 basis points.
The like quarter expansion of NIM was driven by growth of $708.9 million in average loans, coupled with a 14 basis point yield increase as well as the cost of interest bearing deposits decreasing 20 basis points. The Company shifted its mix of interest-earning assets to higher yielding assets from the like quarter, with loans increasing from
2
| Second Quarter 2026 Results | ||||
70.1% of average interest-earning assets to 74.1% in the current quarter, while securities contracted from 25.6% of average interest-earning assets to 22.3% and short-term investments contracted from 4.3% of average interest-bearing assets to 3.7% .
| For the Three Months Ended | ||||||||||||||||||||
| YIELD INFORMATION | June 30, 2026 | March 31, 2026 | June 30, 2025 | |||||||||||||||||
| Yield on loans | 5.67% | 5.57% | 5.53% | |||||||||||||||||
| Yield on securities | 2.71% | 2.74% | 2.41% | |||||||||||||||||
| Yield on other earning assets | 3.99% | 4.36% | 4.63% | |||||||||||||||||
| Yield on total interest-earning assets | 4.95% | 4.88% | 4.69% | |||||||||||||||||
| Cost of interest-bearing deposits | 1.94% | 1.89% | 2.14% | |||||||||||||||||
| Cost of borrowings | 6.64% | 6.68% | 7.22% | |||||||||||||||||
| Cost of total interest-bearing liabilities | 1.99% | 1.94% | 2.20% | |||||||||||||||||
| Total cost of funds | 1.34% | 1.31% | 1.48% | |||||||||||||||||
| Cost of total deposits | 1.31% | 1.28% | 1.43% | |||||||||||||||||
| Net interest margin (1) | 3.71% | 3.67% | 3.32% | |||||||||||||||||
| Net interest margin - tax-equivalent (2) | 3.73% | 3.69% | 3.32% | |||||||||||||||||
| Average prime rate | 6.75% | 6.75% | 7.50% | |||||||||||||||||
| (1) Calculated by dividing annualized net interest income by average earning assets for the period. | ||||||||||||||||||||
(2) Calculated by dividing annualized tax-equivalent net interest income by average earning assets for the period. The tax-equivalent amount reflects the tax benefit that the Company receives related to its tax-exempt loans and securities, which carry interest rates lower than similar taxable investments due to their tax-exempt status. This amount has been computed using the expected tax rate and is reduced by the related nondeductible portion of interest expense. | ||||||||||||||||||||
See Appendix H regarding loan purchase discount accretion and its impact on the Company's NIM.
| Provision for Credit Losses and Credit Quality | ||
For the three months ended June 30, 2026, March 31, 2026 and June 30, 2025, the Company recorded $1.2 million, $3.1 million and $2.2 million in provision for credit losses, respectively. The provision for the second quarter of 2026 was driven by net charge-offs of $1.0 million. The Allowance for Credit Losses increased $0.2 million to $124.9 million, or 1.39% of loans. Additionally, the $22 thousand provision for unfunded commitments during the quarter was the result of additional unfunded lending commitments.
The Company did not adjust its incremental reserve for potential exposure from Hurricane Helene, maintaining a $1.9 million reserve as of June 30, 2026. The remaining incremental reserve contributed two basis points to the Allowance for Credit Losses at period end.
Asset quality remained strong with annualized net loan charge-offs of 0.04% for the second quarter of 2026. Total nonperforming assets ("NPAs") totaled $44.9 million at June 30, 2026, or 0.34% of total assets, up slightly from 0.32% at March 31, 2026 and 0.28% at June 30, 2025.
3
| Second Quarter 2026 Results | ||||
The following table presents the summary of NPAs and asset quality ratios for each period.
ASSET QUALITY DATA ($ in thousands) | June 30, 2026 | March 31, 2026 | June 30, 2025 | |||||||||||||||||
| Nonperforming assets | ||||||||||||||||||||
| Nonaccrual loans | $ | 44,283 | $ | 41,032 | $ | 34,625 | ||||||||||||||
| Accruing loans > 90 days past due | — | — | — | |||||||||||||||||
| Total nonperforming loans | 44,283 | 41,032 | 34,625 | |||||||||||||||||
| Foreclosed real estate | 659 | 740 | 1,218 | |||||||||||||||||
| Total nonperforming assets | $ | 44,942 | $ | 41,772 | $ | 35,843 | ||||||||||||||
| Asset Quality Ratios | ||||||||||||||||||||
| Quarterly net charge-offs to average loans - annualized | 0.04 | % | 0.06 | % | 0.06 | % | ||||||||||||||
| Nonperforming loans to total loans | 0.49 | % | 0.47 | % | 0.42 | % | ||||||||||||||
| Nonperforming assets to total assets | 0.34 | % | 0.32 | % | 0.28 | % | ||||||||||||||
| Allowance for credit losses to total loans | 1.39 | % | 1.42 | % | 1.47 | % | ||||||||||||||
| Noninterest Income | ||
Total noninterest income for the second quarter of 2026 was $16.0 million, a $0.9 million increase from the linked quarter, primarily related to a $0.7 million increase in Other income, net. The current quarter reflected a 12.2% increase from $14.3 million for the like quarter, primarily related to a $1.0 million increase in Other income net.
| Noninterest Expenses | ||
Noninterest expenses amounted to $62.8 million for the second quarter of 2026 compared to $60.2 million for the linked quarter and $58.9 million for the like quarter. The $2.5 million, or 4.2%, increase in noninterest expense from the linked quarter was driven by a $2.0 million increase in Total personnel expenses. The $3.8 million increase from the like quarter was driven by a $3.3 million increase in Total personnel expenses. While noninterest expenses have been increasing, they are the result of the Company's continued growth as the efficiency ratio was 49.12% for the quarter ended June 30, 2026, compared to 49.05% for the linked quarter and 53.00% for the like quarter.
| Income Taxes | ||
Income tax expense totaled $12.9 million for the second quarter of 2026 compared to $12.3 million for the linked quarter and $11.3 million for the like quarter, reflecting effective tax rates of 20.3%, 20.9% and 22.6% for the respective periods.
| Balance Sheet | ||
Total assets at June 30, 2026 were $13.0 billion, an increase of $93.9 million, or 2.9% annualized, from the linked quarter and $433.4 million, or 3.4%, from a year earlier.
4
| Second Quarter 2026 Results | ||||
Key period end balance sheet components are presented below.
BALANCES ($ in thousands) | June 30, 2026 | March 31, 2026 | June 30, 2025 | Change 2Q26 vs 1Q26 | Change 2Q26 vs 2Q25 | |||||||||||||||||||||||||||
| Total assets | $ | 13,041,615 | $ | 12,947,734 | $ | 12,608,265 | 0.7% | 3.4% | ||||||||||||||||||||||||
| Loans | 8,988,748 | 8,793,814 | 8,225,650 | 2.2% | 9.3% | |||||||||||||||||||||||||||
| Investment securities | 2,448,787 | 2,491,035 | 2,661,236 | (1.7)% | (8.0)% | |||||||||||||||||||||||||||
| Total cash and cash equivalents | 550,332 | 597,991 | 711,286 | (8.0)% | (22.6)% | |||||||||||||||||||||||||||
| Noninterest-bearing deposits | 3,597,565 | 3,596,629 | 3,542,626 | —% | 1.6% | |||||||||||||||||||||||||||
| Interest-bearing deposits | 7,487,302 | 7,415,854 | 7,287,754 | 1.0% | 2.7% | |||||||||||||||||||||||||||
| Borrowings | 74,717 | 74,643 | 92,237 | 0.1% | (19.0)% | |||||||||||||||||||||||||||
| Shareholders’ equity | 1,716,460 | 1,682,950 | 1,556,180 | 2.0% | 10.3% | |||||||||||||||||||||||||||
Driven by principal paydowns and maturities, total investment securities decreased to $2.4 billion at June 30, 2026, a $42.2 million decrease from the linked quarter. Total unrealized losses on available for sale investment securities were $204.5 million at June 30, 2026, as compared to $197.7 million at March 31, 2026 and $298.9 million at June 30, 2025.
Total loans were $9.0 billion at June 30, 2026, an increase of $194.9 million, or 8.9% annualized, from March 31, 2026 and an increase of $763.1 million, or 9.3%, from June 30, 2025. Adjusting for the paydown of one larger seasonal loan, loan growth for the current quarter was 10.9% annualized. Please see the below table for total loan portfolio mix. As of June 30, 2026, there were no notable concentrations in geographies within North Carolina or South Carolina or within industries, including in office or hospitality categories, which are included in the "commercial real estate - non-owner occupied" category in the table below. The Company's exposure to non-owner occupied office loans represented approximately 6.2% of the total portfolio at June 30, 2026, with the largest loan being $33.0 million and with an average loan outstanding balance of $1.4 million. Non-owner occupied office loans are generally in non-metro markets and the ten largest loans in this category represent less than 2% of the total loan portfolio.
The following table presents the period end balance and portfolio percentage by loan category.
| LOAN PORTFOLIO | June 30, 2026 | March 31, 2026 | June 30, 2025 | |||||||||||||||||||||||||||||||||||
| ($ in thousands) | Amount | Percentage | Amount | Percentage | Amount | Percentage | ||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 1,014,295 | 11 | % | $ | 1,000,037 | 11 | % | $ | 911,227 | 11 | % | ||||||||||||||||||||||||||
| Construction, development & other land loans | 847,912 | 10 | % | 821,826 | 10 | % | 633,529 | 8 | % | |||||||||||||||||||||||||||||
| Commercial real estate - owner occupied | 1,358,100 | 15 | % | 1,352,473 | 15 | % | 1,254,596 | 15 | % | |||||||||||||||||||||||||||||
| Commercial real estate - non-owner occupied | 2,974,749 | 33 | % | 2,921,210 | 33 | % | 2,758,629 | 34 | % | |||||||||||||||||||||||||||||
| Multi-family real estate | 619,489 | 7 | % | 545,586 | 6 | % | 509,419 | 6 | % | |||||||||||||||||||||||||||||
| Residential 1-4 family real estate | 1,728,367 | 19 | % | 1,717,550 | 20 | % | 1,731,397 | 21 | % | |||||||||||||||||||||||||||||
| Home equity loans/lines of credit | 377,949 | 4 | % | 369,062 | 4 | % | 355,876 | 4 | % | |||||||||||||||||||||||||||||
| Consumer loans | 68,692 | 1 | % | 66,430 | 1 | % | 70,137 | 1 | % | |||||||||||||||||||||||||||||
| Loans, gross | 8,989,553 | 100 | % | 8,794,174 | 100 | % | 8,224,810 | 100 | % | |||||||||||||||||||||||||||||
| Unamortized net deferred loan fees/(costs) | (805) | (360) | 840 | |||||||||||||||||||||||||||||||||||
| Total loans | $ | 8,988,748 | $ | 8,793,814 | $ | 8,225,650 | ||||||||||||||||||||||||||||||||
Total deposits were $11.1 billion at June 30, 2026, an increase of $72.4 million, or 2.6% annualized, from March 31, 2026 and $254.5 million, or 2.3%, from June 30, 2025.
5
| Second Quarter 2026 Results | ||||
The Company has a diversified and granular deposit base which has remained a stable funding source with noninterest-bearing deposits comprising 32% of total deposits at June 30, 2026. As presented in the table below, our deposit mix has remained relatively consistent.
| DEPOSIT PORTFOLIO | June 30, 2026 | March 31, 2026 | June 30, 2025 | |||||||||||||||||||||||||||||||||||
| ($ in thousands) | Amount | Percentage | Amount | Percentage | Amount | Percentage | ||||||||||||||||||||||||||||||||
| Noninterest-bearing checking accounts | $ | 3,597,565 | 32 | % | $ | 3,596,629 | 33 | % | $ | 3,542,626 | 33 | % | ||||||||||||||||||||||||||
| Interest-bearing checking accounts | 1,422,592 | 13 | % | 1,462,606 | 13 | % | 1,443,010 | 13 | % | |||||||||||||||||||||||||||||
| Money market accounts | 4,754,782 | 43 | % | 4,631,619 | 42 | % | 4,446,485 | 41 | % | |||||||||||||||||||||||||||||
| Savings accounts | 510,392 | 5 | % | 519,266 | 5 | % | 536,247 | 5 | % | |||||||||||||||||||||||||||||
| Other time deposits | 475,744 | 4 | % | 489,257 | 4 | % | 514,865 | 5 | % | |||||||||||||||||||||||||||||
| Time deposits >$250,000 | 318,821 | 3 | % | 308,177 | 3 | % | 337,382 | 3 | % | |||||||||||||||||||||||||||||
| Total customer deposits | 11,079,896 | 100 | % | 11,007,554 | 100 | % | 10,820,615 | 100 | % | |||||||||||||||||||||||||||||
| Brokered deposits | 4,971 | — | % | 4,929 | — | % | 9,765 | — | % | |||||||||||||||||||||||||||||
| Total deposits | $ | 11,084,867 | 100 | % | $ | 11,012,483 | 100 | % | $ | 10,830,380 | 100 | % | ||||||||||||||||||||||||||
As of June 30, 2026 and March 31, 2026, estimated insured deposits totaled $6.5 billion, or 58.9%, and $6.5 billion, or 59.0%, of total deposits, respectively. In addition, at June 30, 2026 and March 31, 2026, there were collateralized deposits of $748.7 million and $723.8 million, respectively, such that approximately 65.7% and 65.6%, respectively, of our total deposits were insured or collateralized at those dates.
| Capital | ||
The Company maintains capital in excess of well-capitalized regulatory requirements, with an estimated total risk-based capital ratio at June 30, 2026 of 16.06%, down from the linked quarter ratio of 16.12% and from the like quarter ratio of 16.90%.
The Company has elected to exclude accumulated other comprehensive income ("AOCI") related primarily to available for sale securities from common equity tier 1 capital. AOCI is included in the Company’s tangible common equity ("TCE") to tangible assets ratio (a non-GAAP financial measure) which was 9.83% at June 30, 2026, an increase of 20 basis points from the linked quarter and 100 basis points from June 30, 2025. The increase in TCE from the like quarter was driven by improvements in the level of unrealized losses on the available for sale securities portfolio, arising from market value improvements and the 2025 securities loss-earnback transactions. Please refer to Appendix A for a reconciliation of common equity to TCE (a non-GAAP measure) and Appendix C for a calculation of the TCE ratio (a non-GAAP measure).
| CAPITAL RATIOS | June 30, 2026 (estimated) | March 31, 2026 | June 30, 2025 | |||||||||||||||||
| Tangible common equity to tangible assets (non-GAAP) | 9.83% | 9.63% | 8.83% | |||||||||||||||||
| Common equity tier I capital ratio | 14.09% | 14.13% | 14.64% | |||||||||||||||||
| Tier I leverage ratio | 11.60% | 11.46% | 11.23% | |||||||||||||||||
| Tier I risk-based capital ratio | 14.81% | 14.87% | 15.45% | |||||||||||||||||
| Total risk-based capital ratio | 16.06% | 16.12% | 16.90% | |||||||||||||||||
| Liquidity | ||
Liquidity is evaluated as both on-balance sheet (primarily cash and cash-equivalents, unpledged securities and other marketable assets) and off-balance sheet (readily available lines of credit and other funding sources). The
6
| Second Quarter 2026 Results | ||||
Company continues to manage liquidity sources, including unused lines of credit, at levels believed to be adequate to meet its operating needs for the foreseeable future.
The Company's on-balance sheet liquidity ratio (net liquid assets as a percent of net liabilities) at June 30, 2026 was 15.7%. In addition, the Company had approximately $2.4 billion in available lines of credit at that date resulting in a total liquidity ratio of 32.8%.
7
| Second Quarter 2026 Results | ||||
| About First Bancorp | ||
First Bancorp is a bank holding company headquartered in Southern Pines, North Carolina, with total assets of $13.0 billion. Its principal activity is the ownership and operation of First Bank, a state-chartered community bank that operates 113 branches in North Carolina and South Carolina. Since 1935, First Bank has taken a tailored approach to banking, combining best-in-class financial solutions, helpful local expertise, and technology to manage a home or business. First Bank also provides SBA loans to customers through its nationwide network of lenders. Member FDIC, Equal Housing Lender.
Please visit our website at www.LocalFirstBank.com for more information.
First Bancorp's common stock is traded on The NASDAQ Global Select Market under the symbol "FBNC."
Caution about Forward-Looking Statements: This News Release release contains forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934 and the Private Securities Litigation Reform Act of 1995, which statements are inherently subject to risks and uncertainties. Forward-looking statements are statements that include projections, predictions, expectations or beliefs about future events or results or otherwise are not statements of historical fact. Such statements are often characterized by the use of qualifying words (and their derivatives) such as “expect,” “believe,” “estimate,” “plan,” “project,” “anticipate,” or other words or phrases concerning opinions or judgments of the Company and its management about future events. Factors that could influence the accuracy of such forward-looking statements include, but are not limited to, the financial success or changing strategies of the Company’s customers, the risks and uncertainties relating to the level of success in integrating acquisitions, (including the ability to successfully integrate First Carolina into First Bank; to realize the anticipated benefits of the acquisition; deposit attrition, customer loss or other revenue loss following completed acquisitions may be greater than anticipated; and the integration of operations and personnel may require more time and expense); actions of government regulators; the level of market interest rates; and general economic conditions. For additional information about the factors that could affect the matters discussed in this paragraph, see the “Risk Factors” section of the Company’s most recent Annual Report on Form 10-K available at www.sec.gov. Forward-looking statements speak only as of the date they are made, and the Company undertakes no obligation to update or revise forward-looking statements. The Company is also not responsible for changes made to this press release by wire services, internet services or other media.
| Non-GAAP Measures | ||
In this Earnings Release, we present certain measures of our performance that are calculated by methods other than in accordance with generally accepted accounting principles (“GAAP”). Company management uses these non-GAAP measures for purposes of evaluating our performance. Non-GAAP measures exclude or include amounts that are not normally excluded or included in the most directly comparable measure determined in accordance with GAAP. Company management believes an appropriate analysis of the Company's financial performance requires an understanding of the factors underlying such performance. Non-GAAP financial measures should not be viewed as substitutes for the most directly comparable financial measures calculated in accordance with GAAP. Please see the Appendices attached to this Earnings Release for reconciliations of return on tangible common equity, tangible common equity, tangible book value per share, the tangible common equity ratio, adjusted net income and adjusted diluted earnings per share.
8
| Second Quarter 2026 Results | ||||
| First Bancorp and Subsidiaries Financial Summary | ||
| CONSOLIDATED INCOME STATEMENT | ||||||||||||||||||||||||||||||||
| For the Three Months Ended | For the Six Months Ended | |||||||||||||||||||||||||||||||
| ($ in thousands, except per share data - unaudited) | June 30, 2026 | March 31, 2026 | June 30, 2025 | June 30, 2026 | June 30, 2025 | |||||||||||||||||||||||||||
| Interest income | ||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 125,845 | $ | 120,747 | $ | 112,921 | $ | 246,592 | $ | 223,418 | ||||||||||||||||||||||
| Interest on investment securities: | ||||||||||||||||||||||||||||||||
| Taxable interest income | 16,925 | 17,556 | 16,857 | 34,481 | 32,381 | |||||||||||||||||||||||||||
| Tax-exempt interest income | 1,115 | 1,115 | 1,116 | 2,230 | 2,232 | |||||||||||||||||||||||||||
| Other, principally overnight investments | 4,430 | 2,972 | 5,837 | 7,402 | 11,324 | |||||||||||||||||||||||||||
| Total interest income | 148,315 | 142,390 | 136,731 | 290,705 | 269,355 | |||||||||||||||||||||||||||
| Interest expense | ||||||||||||||||||||||||||||||||
| Interest on deposits | 35,812 | 34,046 | 38,405 | 69,858 | 76,524 | |||||||||||||||||||||||||||
| Interest on borrowings | 1,237 | 1,228 | 1,660 | 2,465 | 3,318 | |||||||||||||||||||||||||||
| Total interest expense | 37,049 | 35,274 | 40,065 | 72,323 | 79,842 | |||||||||||||||||||||||||||
| Net interest income | 111,266 | 107,116 | 96,666 | 218,382 | 189,513 | |||||||||||||||||||||||||||
| Provision for credit losses | 1,169 | 3,083 | 2,212 | 4,252 | 3,328 | |||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 110,097 | 104,033 | 94,454 | 214,130 | 186,185 | |||||||||||||||||||||||||||
| Noninterest income | ||||||||||||||||||||||||||||||||
| Service charges on deposit accounts | 4,205 | 3,954 | 3,976 | 8,159 | 7,743 | |||||||||||||||||||||||||||
| Other service charges and fees | 5,986 | 5,942 | 6,605 | 11,928 | 12,524 | |||||||||||||||||||||||||||
| Presold mortgage loan fees and gains on sale | 660 | 669 | 315 | 1,329 | 765 | |||||||||||||||||||||||||||
| Commissions from sales of financial products | 1,707 | 1,492 | 1,388 | 3,199 | 2,796 | |||||||||||||||||||||||||||
| SBA loan sale gains | 529 | 903 | 151 | 1,432 | 203 | |||||||||||||||||||||||||||
| Bank-owned life insurance income | 1,358 | 1,340 | 1,221 | 2,698 | 2,449 | |||||||||||||||||||||||||||
| Other Income, net | 1,589 | 878 | 636 | 2,467 | 768 | |||||||||||||||||||||||||||
| Total noninterest income | 16,034 | 15,178 | 14,292 | 31,212 | 27,248 | |||||||||||||||||||||||||||
| Noninterest expenses | ||||||||||||||||||||||||||||||||
| Salaries, incentives and commissions expense | 31,529 | 29,978 | 29,005 | 61,507 | 57,666 | |||||||||||||||||||||||||||
| Employee benefit expense | 6,958 | 6,516 | 6,187 | 13,474 | 12,282 | |||||||||||||||||||||||||||
| Total personnel expense | 38,487 | 36,494 | 35,192 | 74,981 | 69,948 | |||||||||||||||||||||||||||
| Occupancy and equipment expense | 4,961 | 5,355 | 5,195 | 10,316 | 10,387 | |||||||||||||||||||||||||||
| Intangibles amortization expense | 1,199 | 1,247 | 1,468 | 2,446 | 2,984 | |||||||||||||||||||||||||||
| Other operating expenses | 18,114 | 17,122 | 17,069 | 35,236 | 33,516 | |||||||||||||||||||||||||||
| Total noninterest expenses | 62,761 | 60,218 | 58,924 | 122,979 | 116,835 | |||||||||||||||||||||||||||
| Income before income taxes | 63,370 | 58,993 | 49,822 | 122,363 | 96,598 | |||||||||||||||||||||||||||
| Income tax expense | 12,851 | 12,334 | 11,256 | 25,185 | 21,626 | |||||||||||||||||||||||||||
| Net income | $ | 50,519 | $ | 46,659 | $ | 38,566 | $ | 97,178 | $ | 74,972 | ||||||||||||||||||||||
| Earnings per common share: | ||||||||||||||||||||||||||||||||
| Basic | $ | 1.22 | $ | 1.13 | $ | 0.93 | $ | 2.35 | $ | 1.81 | ||||||||||||||||||||||
| Diluted | 1.22 | 1.13 | 0.93 | 2.35 | 1.81 | |||||||||||||||||||||||||||
9
| Second Quarter 2026 Results | ||||
| First Bancorp and Subsidiaries Financial Summary | ||
CONSOLIDATED BALANCE SHEETS | ||||||||||||||||||||
| ($ in thousands - unaudited) | June 30, 2026 | March 31, 2026 | June 30, 2025 | |||||||||||||||||
| Assets | ||||||||||||||||||||
| Cash and due from banks, noninterest-bearing | $ | 128,424 | $ | 135,176 | $ | 139,486 | ||||||||||||||
| Due from banks, interest-bearing | 421,908 | 462,815 | 571,800 | |||||||||||||||||
| Total cash and cash equivalents | 550,332 | 597,991 | 711,286 | |||||||||||||||||
| Securities available for sale | 1,939,075 | 1,979,606 | 2,144,831 | |||||||||||||||||
| Securities held to maturity | 509,712 | 511,429 | 516,405 | |||||||||||||||||
| Presold mortgages and SBA loans held for sale | 12,304 | 11,191 | 8,928 | |||||||||||||||||
| Loans | 8,988,748 | 8,793,814 | 8,225,650 | |||||||||||||||||
| Allowance for credit losses on loans | (124,894) | (124,734) | (120,545) | |||||||||||||||||
| Net loans | 8,863,854 | 8,669,080 | 8,105,105 | |||||||||||||||||
| Premises and equipment, net | 138,129 | 139,374 | 141,661 | |||||||||||||||||
| Accrued interest receivable | 38,272 | 37,296 | 36,681 | |||||||||||||||||
| Goodwill | 478,750 | 478,750 | 478,750 | |||||||||||||||||
| Other intangible assets, net | 14,786 | 15,985 | 19,920 | |||||||||||||||||
| Bank-owned life insurance | 195,984 | 194,626 | 190,817 | |||||||||||||||||
| Other assets | 300,417 | 312,406 | 253,881 | |||||||||||||||||
| Total assets | $ | 13,041,615 | $ | 12,947,734 | $ | 12,608,265 | ||||||||||||||
| Liabilities | ||||||||||||||||||||
| Deposits: | ||||||||||||||||||||
| Noninterest-bearing deposits | $ | 3,597,565 | $ | 3,596,629 | $ | 3,542,626 | ||||||||||||||
| Interest-bearing deposits | 7,487,302 | 7,415,854 | 7,287,754 | |||||||||||||||||
| Total deposits | 11,084,867 | 11,012,483 | 10,830,380 | |||||||||||||||||
| Borrowings | 74,717 | 74,643 | 92,237 | |||||||||||||||||
| Accrued interest payable | 3,813 | 3,733 | 4,340 | |||||||||||||||||
| Other liabilities | 161,758 | 173,925 | 125,128 | |||||||||||||||||
| Total liabilities | 11,325,155 | 11,264,784 | 11,052,085 | |||||||||||||||||
| Shareholders’ equity | ||||||||||||||||||||
| Common stock | 966,777 | 968,675 | 973,041 | |||||||||||||||||
| Retained earnings | 906,976 | 866,387 | 812,657 | |||||||||||||||||
| Stock in rabbi trust assumed in acquisition | (534) | (893) | (869) | |||||||||||||||||
| Rabbi trust obligation | 534 | 893 | 869 | |||||||||||||||||
| Accumulated other comprehensive loss | (157,293) | (152,112) | (229,518) | |||||||||||||||||
| Total shareholders’ equity | 1,716,460 | 1,682,950 | 1,556,180 | |||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 13,041,615 | $ | 12,947,734 | $ | 12,608,265 | ||||||||||||||
10
| Second Quarter 2026 Results | ||||
| First Bancorp and Subsidiaries Financial Summary | ||
| TREND INFORMATION | ||||||||||||||||||||||||||||||||
| For the Three Months Ended | ||||||||||||||||||||||||||||||||
| June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | ||||||||||||||||||||||||||||
PERFORMANCE RATIOS (annualized) | ||||||||||||||||||||||||||||||||
ROA (1) | 1.56 | % | 1.48 | % | 0.49 | % | 0.64 | % | 1.24 | % | ||||||||||||||||||||||
Adjusted ROA (2) | 1.56 | % | 1.48 | % | 1.54 | % | 1.31 | % | 1.24 | % | ||||||||||||||||||||||
ROCE (3) | 11.89 | % | 11.22 | % | 3.83 | % | 5.14 | % | 10.11 | % | ||||||||||||||||||||||
Adjusted ROCE (4) | 11.89 | % | 11.22 | % | 12.01 | % | 10.55 | % | 10.11 | % | ||||||||||||||||||||||
ROTCE (5) | 16.88 | % | 16.05 | % | 5.80 | % | 7.83 | % | 15.25 | % | ||||||||||||||||||||||
Adjusted ROTCE (6) | 16.88 | % | 16.05 | % | 17.45 | % | 15.66 | % | 15.25 | % | ||||||||||||||||||||||
Efficiency ratio (7) | 49.12 | % | 49.05 | % | 73.75 | % | 66.95 | % | 53.00 | % | ||||||||||||||||||||||
Adjusted efficiency ratio (7) | 49.12 | % | 49.05 | % | 48.53 | % | 51.09 | % | 53.00 | % | ||||||||||||||||||||||
| COMMON SHARE DATA | ||||||||||||||||||||||||||||||||
| Cash dividends declared - common | $ | 0.24 | $ | 0.24 | $ | 0.23 | $ | 0.23 | $ | 0.23 | ||||||||||||||||||||||
| Book value per common share | $ | 41.49 | $ | 40.68 | $ | 39.89 | $ | 38.67 | $ | 37.53 | ||||||||||||||||||||||
Tangible book value per share (8) | $ | 29.84 | $ | 29.01 | $ | 28.23 | $ | 26.98 | $ | 25.82 | ||||||||||||||||||||||
| Common shares outstanding at end of period | 41,374,221 | 41,375,026 | 41,466,227 | 41,465,437 | 41,468,098 | |||||||||||||||||||||||||||
| Weighted average shares outstanding - diluted | 41,375,377 | 41,459,357 | 41,481,132 | 41,481,542 | 41,441,393 | |||||||||||||||||||||||||||
CAPITAL INFORMATION (preliminary for current quarter) | ||||||||||||||||||||||||||||||||
Tangible common equity to tangible assets (9) | 9.83 | % | 9.63 | % | 9.61 | % | 9.12 | % | 8.83 | % | ||||||||||||||||||||||
| Common equity tier I capital ratio | 14.09 | % | 14.13 | % | 14.10 | % | 14.35 | % | 14.64 | % | ||||||||||||||||||||||
| Total risk-based capital ratio | 16.06 | % | 16.12 | % | 16.12 | % | 16.58 | % | 16.90 | % | ||||||||||||||||||||||
| (1) Calculated by dividing annualized net income by average assets. | ||||||||||||||||||||||||||||||||
(2) See Appendix D for a reconciliation of ROA to adjusted ROA. | ||||||||||||||||||||||||||||||||
(3) Calculated by dividing annualized tangible net income (net income adjusted for intangible asset amortization, net of tax), by average common equity. See Appendix E for the components of the calculation. | ||||||||||||||||||||||||||||||||
(4) See Appendix E for a reconciliation of ROCE to adjusted ROCE. | ||||||||||||||||||||||||||||||||
(5) Return on average tangible common equity is a non-GAAP financial measure. See Appendix F for the components of the calculation and the reconciliation of average common equity to average TCE. | ||||||||||||||||||||||||||||||||
(6) See Appendix F for a reconciliation of ROTCE to adjusted ROTCE. | ||||||||||||||||||||||||||||||||
(7) See Appendix G for a reconciliation of the efficiency ratio to the adjusted efficiency ratio. | ||||||||||||||||||||||||||||||||
(8) Tangible book value per share is a non-GAAP financial measure. See Appendix A for a reconciliation of common equity to tangible common equity and Appendix B for the resulting calculation. | ||||||||||||||||||||||||||||||||
(9) Tangible common equity ratio is a non-GAAP financial measure. See Appendix A for a reconciliation of common equity to tangible common equity and Appendix C for the resulting calculation. | ||||||||||||||||||||||||||||||||
11
| Second Quarter 2026 Results | ||||
| For the Three Months Ended | ||||||||||||||||||||||||||||||||
INCOME STATEMENT ($ in thousands except per share data) | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | |||||||||||||||||||||||||||
| Net interest income | $ | 111,266 | $ | 107,116 | $ | 106,199 | $ | 102,489 | $ | 96,666 | ||||||||||||||||||||||
| Provision for credit losses | 1,169 | 3,083 | 4,732 | 3,442 | 2,212 | |||||||||||||||||||||||||||
| Noninterest income | 16,034 | 15,178 | (22,299) | (12,879) | 14,292 | |||||||||||||||||||||||||||
| Noninterest expense | 62,761 | 60,218 | 62,223 | 60,211 | 58,924 | |||||||||||||||||||||||||||
| Income before income taxes | 63,370 | 58,993 | 16,945 | 25,957 | 49,822 | |||||||||||||||||||||||||||
| Income tax expense | 12,851 | 12,334 | 1,232 | 5,594 | 11,256 | |||||||||||||||||||||||||||
| Net income | $ | 50,519 | $ | 46,659 | $ | 15,713 | $ | 20,363 | $ | 38,566 | ||||||||||||||||||||||
| Earnings per common share - diluted | $ | 1.22 | $ | 1.13 | $ | 0.38 | $ | 0.49 | $ | 0.93 | ||||||||||||||||||||||
12
| Second Quarter 2026 Results | ||||
| First Bancorp and Subsidiaries Financial Summary | ||
AVERAGE BALANCES AND NET INTEREST INCOME ANALYSIS - QUARTERS
| For the Three Months Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| June 30, 2026 | March 31, 2026 | June 30, 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Average Volume | Interest Earned or Paid | Average Rate | Average Volume | Interest Earned or Paid | Average Rate | Average Volume | Interest Earned or Paid | Average Rate | ||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans (1) (2) | $ | 8,896,592 | $ | 125,845 | 5.67 | % | $ | 8,781,728 | $ | 120,747 | 5.57 | % | $ | 8,187,662 | $ | 112,921 | 5.53 | % | |||||||||||||||||||||||||||||||||||
| Taxable securities | 2,384,076 | 16,925 | 2.84 | % | 2,442,140 | 17,556 | 2.88 | % | 2,697,338 | 16,857 | 2.50 | % | |||||||||||||||||||||||||||||||||||||||||
| Non-taxable securities | 283,645 | 1,115 | 1.57 | % | 284,712 | 1,115 | 1.57 | % | 287,848 | 1,116 | 1.55 | % | |||||||||||||||||||||||||||||||||||||||||
| Short-term investments, primarily interest-bearing cash | 444,845 | 4,430 | 3.99 | % | 276,471 | 2,972 | 4.36 | % | 505,912 | 5,837 | 4.63 | % | |||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 12,009,158 | 148,315 | 4.95 | % | 11,785,051 | 142,390 | 4.88 | % | 11,678,760 | 136,731 | 4.69 | % | |||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 136,181 | 147,124 | 153,074 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Premises and equipment | 139,177 | 139,775 | 142,090 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Other assets | 664,823 | 690,864 | 484,448 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 12,949,339 | $ | 12,762,814 | $ | 12,458,372 | |||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing checking | $ | 1,420,738 | $ | 2,233 | 0.63 | % | $ | 1,416,600 | $ | 2,230 | 0.64 | % | $ | 1,434,559 | $ | 2,426 | 0.68 | % | |||||||||||||||||||||||||||||||||||
| Money market deposits | 4,666,044 | 28,268 | 2.43 | % | 4,566,409 | 26,516 | 2.35 | % | 4,358,877 | 29,947 | 2.76 | % | |||||||||||||||||||||||||||||||||||||||||
| Savings deposits | 516,779 | 250 | 0.19 | % | 524,123 | 241 | 0.19 | % | 538,843 | 252 | 0.19 | % | |||||||||||||||||||||||||||||||||||||||||
| Other time deposits | 487,071 | 2,790 | 2.30 | % | 495,115 | 2,819 | 2.31 | % | 534,242 | 3,088 | 2.32 | % | |||||||||||||||||||||||||||||||||||||||||
| Time deposits >$250,000 | 314,506 | 2,271 | 2.90 | % | 304,089 | 2,240 | 2.99 | % | 345,916 | 2,692 | 3.12 | % | |||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 7,405,138 | 35,812 | 1.94 | % | 7,306,336 | 34,046 | 1.89 | % | 7,212,437 | 38,405 | 2.14 | % | |||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings | 757 | 1 | 0.72 | % | 745 | 1 | 0.61 | % | 848 | 2 | 1.09 | % | |||||||||||||||||||||||||||||||||||||||||
| Long-term borrowings | 73,950 | 1,236 | 6.70 | % | 73,858 | 1,227 | 6.74 | % | 91,351 | 1,658 | 7.28 | % | |||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 7,479,845 | 37,049 | 1.99 | % | 7,380,939 | 35,274 | 1.94 | % | 7,304,636 | 40,065 | 2.20 | % | |||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing checking | 3,597,511 | 3,515,359 | 3,522,117 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 167,595 | 179,753 | 101,069 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 1,704,388 | 1,686,763 | 1,530,550 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 12,949,339 | $ | 12,762,814 | $ | 12,458,372 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net yield on interest-earning assets and net interest income | $ | 111,266 | 3.71 | % | $ | 107,116 | 3.67 | % | $ | 96,666 | 3.32 | % | |||||||||||||||||||||||||||||||||||||||||
| Net yield on interest-earning assets and net interest income – tax-equivalent (3) | $ | 111,732 | 3.73 | % | $ | 107,595 | 3.69 | % | $ | 96,877 | 3.32 | % | |||||||||||||||||||||||||||||||||||||||||
| Interest rate spread | 2.96 | % | 2.94 | % | 2.49 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Average prime rate | 6.75 | % | 6.75 | % | 7.50 | % | |||||||||||||||||||||||||||||||||||||||||||||||
(1) Average loans include nonaccruing loans, the effect of which is to lower the average rate shown.
(2) Includes accretion of discount on acquired loans of $1.1 million, $1.1 million and $1.5 million for the three months ended June 30, 2026, March 31, 2026 and June 30, 2025, respectively.
(3) Includes tax-equivalent adjustments to reflect the net tax benefit that we receive related to tax-exempt securities and loans as reduced by the related nondeductible portion of interest expense.
13
| Second Quarter 2026 Results | ||||
| First Bancorp and Subsidiaries Financial Summary | ||
AVERAGE BALANCES AND NET INTEREST INCOME ANALYSIS - YEAR-TO-DATE
| For the Six Months Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| June 30, 2026 | June 30, 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Average Volume | Interest Earned or Paid | Average Rate | Average Volume | Interest Earned or Paid | Average Rate | |||||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans (1) (2) | $ | 8,839,477 | $ | 246,592 | 5.62 | % | $ | 8,147,750 | $ | 223,418 | 5.52 | % | |||||||||||||||||||||||||||||||||||||||||
| Taxable securities | 2,412,948 | 34,481 | 2.86 | % | 2,663,390 | 32,381 | 2.43 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Non-taxable securities | 284,176 | 2,230 | 1.57 | % | 288,373 | 2,232 | 1.55 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Short-term investments, primarily interest-bearing cash | 361,123 | 7,402 | 4.13 | % | 504,652 | 11,324 | 4.52 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 11,897,724 | 290,705 | 4.92 | % | 11,604,165 | 269,355 | 4.67 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 141,622 | 143,469 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Premises and equipment | 139,474 | 142,574 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Other assets | 677,771 | 453,023 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 12,856,591 | $ | 12,343,231 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing checking | $ | 1,418,681 | $ | 4,462 | 0.63 | % | $ | 1,433,066 | $ | 4,923 | 0.69 | % | |||||||||||||||||||||||||||||||||||||||||
| Money market deposits | 4,616,502 | 54,785 | 2.39 | % | 4,348,277 | 59,126 | 2.74 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Savings deposits | 520,429 | 491 | 0.19 | % | 538,973 | 493 | 0.18 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Other time deposits | 491,071 | 5,609 | 2.30 | % | 546,377 | 6,441 | 2.38 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Time deposits >$250,000 | 309,327 | 4,511 | 2.94 | % | 349,028 | 5,541 | 3.20 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 7,356,010 | 69,858 | 1.92 | % | 7,215,721 | 76,524 | 2.14 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings | 751 | 2 | 0.66 | % | 822 | 3 | 0.86 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Long-term borrowings | 73,904 | 2,463 | 6.72 | % | 91,259 | 3,315 | 7.32 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 7,430,665 | 72,323 | 1.96 | % | 7,307,802 | 79,842 | 2.20 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing checking | 3,556,662 | 3,449,013 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 173,640 | 87,032 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 1,695,624 | 1,499,384 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 12,856,591 | $ | 12,343,231 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Net yield on interest-earning assets and net interest income | $ | 218,382 | 3.69 | % | $ | 189,513 | 3.28 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Net yield on interest-earning assets and net interest income – tax-equivalent (3) | $ | 219,327 | 3.71 | % | $ | 190,161 | 3.30 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Interest rate spread | 2.96 | % | 2.47 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
| Average prime rate | 6.75 | % | 7.50 | % | |||||||||||||||||||||||||||||||||||||||||||||||||
(1) Average loans include nonaccruing loans, the effect of which is to lower the average rate shown.
(2) Includes accretion of discount on acquired loans of $2.1 million and $3.2 million for the six months ended June 30, 2026 and June 30, 2025, respectively.
(3) Includes tax-equivalent adjustments to reflect the net tax benefit that we receive related to tax-exempt securities and loans as reduced by the related nondeductible portion of interest expense.
14
| Second Quarter 2026 Results | ||||
| Reconciliation of non-GAAP measures | ||
APPENDIX A: Reconciliation of Common Equity to Tangible Common Equity ("TCE")
| For the Three Months Ended | ||||||||||||||||||||||||||||||||
| ($ in thousands) | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | |||||||||||||||||||||||||||
Total shareholders' common equity | $ | 1,716,460 | $ | 1,682,950 | $ | 1,654,168 | $ | 1,603,323 | $ | 1,556,180 | ||||||||||||||||||||||
| Less: Goodwill and other intangibles, net of related taxes | (481,673) | (482,640) | (483,644) | (484,623) | (485,657) | |||||||||||||||||||||||||||
| Tangible common equity | $ | 1,234,787 | $ | 1,200,310 | $ | 1,170,524 | $ | 1,118,700 | $ | 1,070,523 | ||||||||||||||||||||||
APPENDIX B: Calculation of Tangible Book Value Per Share ("TBVPS")
| For the Three Months Ended | ||||||||||||||||||||||||||||||||
| ($ in thousands except per share data) | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | |||||||||||||||||||||||||||
Tangible common equity (Appendix A) | $ | 1,234,787 | $ | 1,200,310 | $ | 1,170,524 | $ | 1,118,700 | $ | 1,070,523 | ||||||||||||||||||||||
Common shares outstanding | 41,374,221 | 41,375,026 | 41,466,227 | 41,465,437 | 41,468,098 | |||||||||||||||||||||||||||
| Tangible book value per common share | $ | 29.84 | $ | 29.01 | $ | 28.23 | $ | 26.98 | $ | 25.82 | ||||||||||||||||||||||
APPENDIX C: TCE Ratio
| For the Three Months Ended | ||||||||||||||||||||||||||||||||
| ($ in thousands) | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | |||||||||||||||||||||||||||
Tangible common equity (Appendix A) | $ | 1,234,787 | $ | 1,200,310 | $ | 1,170,524 | $ | 1,118,700 | $ | 1,070,523 | ||||||||||||||||||||||
Total assets | 13,041,615 | 12,947,734 | 12,668,339 | 12,750,263 | 12,608,265 | |||||||||||||||||||||||||||
| Less: Goodwill and other intangibles, net of related taxes | (481,673) | (482,640) | (483,644) | (484,623) | (485,657) | |||||||||||||||||||||||||||
| Tangible assets ("TA") | $ | 12,559,942 | $ | 12,465,094 | $ | 12,184,695 | $ | 12,265,640 | $ | 12,122,608 | ||||||||||||||||||||||
| TCE to TA ratio | 9.83 | % | 9.63 | % | 9.61 | % | 9.12 | % | 8.83 | % | ||||||||||||||||||||||
APPENDIX D: Calculation of Return on Average Assets ("ROA") and Adjusted ROA
| For the Three Months Ended | ||||||||||||||||||||||||||||||||
| ($ in thousands) | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | |||||||||||||||||||||||||||
| Net income (A) | $ | 50,519 | $ | 46,659 | $ | 15,713 | $ | 20,363 | $ | 38,566 | ||||||||||||||||||||||
| After-tax impact of loss-earnback | — | — | 33,581 | 21,433 | — | |||||||||||||||||||||||||||
| Adjusted net income (B) | $ | 50,519 | $ | 46,659 | $ | 49,294 | $ | 41,796 | $ | 38,566 | ||||||||||||||||||||||
| Average total assets (C) | $ | 12,949,339 | $ | 12,762,814 | $ | 12,716,139 | $ | 12,640,016 | $ | 12,458,372 | ||||||||||||||||||||||
| ROA (A/C) | 1.56 | % | 1.48 | % | 0.49 | % | 0.64 | % | 1.24 | % | ||||||||||||||||||||||
| Adjusted ROA (B/C) | 1.56 | % | 1.48 | % | 1.54 | % | 1.31 | % | 1.24 | % | ||||||||||||||||||||||
15
| Second Quarter 2026 Results | ||||
| Reconciliation of non-GAAP measures, continued | ||
APPENDIX E: Calculation of Return on Common Equity ("ROCE") and Adjusted ROCE
| For the Three Months Ended | ||||||||||||||||||||||||||||||||
| ($ in thousands) | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | |||||||||||||||||||||||||||
| Net income (A) | $ | 50,519 | $ | 46,659 | $ | 15,713 | $ | 20,363 | $ | 38,566 | ||||||||||||||||||||||
| After-tax impact of loss-earnback | — | — | 33,581 | 21,433 | — | |||||||||||||||||||||||||||
| Adjusted net income (B) | $ | 50,519 | $ | 46,659 | $ | 49,294 | $ | 41,796 | $ | 38,566 | ||||||||||||||||||||||
| Average common equity (C) | $ | 1,704,388 | $ | 1,686,763 | $ | 1,627,976 | $ | 1,571,104 | $ | 1,530,550 | ||||||||||||||||||||||
| ROCE (A/C) | 11.89 | % | 11.22 | % | 3.83 | % | 5.14 | % | 10.11 | % | ||||||||||||||||||||||
| Adjusted ROCE (B/C) | 11.89 | % | 11.22 | % | 12.01 | % | 10.55 | % | 10.11 | % | ||||||||||||||||||||||
APPENDIX F: Calculation of Return on TCE ("ROTCE") and Adjusted ROTCE
| For the Three Months Ended | ||||||||||||||||||||||||||||||||
| ($ in thousands) | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | |||||||||||||||||||||||||||
Net Income | $ | 50,519 | $ | 46,659 | $ | 15,713 | $ | 20,363 | $ | 38,566 | ||||||||||||||||||||||
| Intangible asset amortization, net of taxes | 923 | 960 | 994 | 1,066 | 1,123 | |||||||||||||||||||||||||||
| Tangible Net income (A) | 51,442 | 47,619 | 16,707 | 21,429 | 39,689 | |||||||||||||||||||||||||||
| After-tax impact of loss-earnback | — | — | 33,581 | 21,433 | — | |||||||||||||||||||||||||||
| Adjusted tangible net income (B) | $ | 51,442 | $ | 47,619 | $ | 50,288 | $ | 42,862 | $ | 39,689 | ||||||||||||||||||||||
| Average common equity | $ | 1,704,388 | $ | 1,686,763 | $ | 1,627,976 | $ | 1,571,104 | $ | 1,530,550 | ||||||||||||||||||||||
| Less: Average goodwill and other intangibles, net of related taxes | (482,326) | (483,314) | (484,313) | (485,331) | (486,393) | |||||||||||||||||||||||||||
| Average TCE (C) | $ | 1,222,062 | $ | 1,203,449 | $ | 1,143,663 | $ | 1,085,773 | $ | 1,044,157 | ||||||||||||||||||||||
| ROTCE (A/C) | 16.88 | % | 16.05 | % | 5.80 | % | 7.83 | % | 15.25 | % | ||||||||||||||||||||||
| Adjusted ROTCE (B/C) | 16.88 | % | 16.05 | % | 17.45 | % | 15.66 | % | 15.25 | % | ||||||||||||||||||||||
APPENDIX G: Efficiency Ratio and Adjusted Efficiency Ratio
| For the Three Months Ended | ||||||||||||||||||||||||||||||||
| June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | ||||||||||||||||||||||||||||
| Noninterest expenses (A) | $ | 62,761 | $ | 60,218 | $ | 62,043 | $ | 60,171 | $ | 58,924 | ||||||||||||||||||||||
| Nointerest income (B) | 16,034 | 15,178 | (22,479) | (12,951) | 14,292 | |||||||||||||||||||||||||||
| Securities losses, net | — | — | (43,722) | (27,905) | — | |||||||||||||||||||||||||||
| Adjusted nointerest income (C) | 16,034 | 15,178 | 21,243 | 14,954 | 14,292 | |||||||||||||||||||||||||||
| Net interest income – tax-equivalent (D) | 111,732 | 107,595 | 106,601 | 102,829 | 96,877 | |||||||||||||||||||||||||||
| Efficiency ratio A/(B+D) | 49.12 | % | 49.05 | % | 73.75 | % | 66.95 | % | 53.00 | % | ||||||||||||||||||||||
| Adjusted efficiency ratio A/(C+D) | 49.12 | % | 49.05 | % | 48.53 | % | 51.09 | % | 53.00 | % | ||||||||||||||||||||||
16
| Second Quarter 2026 Results | ||||
| Supplemental information | ||
APPENDIX H: Loan purchase discount accretion and its impact on the Company's NIM
Included in interest income for the second quarter of 2026 was loan purchase accounting discount accretion of $1.1 million compared to $1.1 million for the linked quarter and $1.5 million for the like quarter, with the activity primarily related to the continued repayments/reduction of the loan portfolio acquired from GrandSouth Bancorporation in January of 2023. Loan discount accretion had positive impacts of three basis points, three basis points and four basis points, respectively, on the Company's NIM and NIM-T/E in the second quarter of 2026, the linked quarter and the like quarter.
The following table presents the impact to net interest income of the purchase accounting adjustments for each period.
| For the Three Months Ended | ||||||||||||||||||||
NET INTEREST INCOME PURCHASE ACCOUNTING ADJUSTMENTS ($ in thousands) | June 30, 2026 | March 31, 2026 | June 30, 2025 | |||||||||||||||||
| Interest income - increased by accretion of loan discount on acquired loans | $ | 1,083 | $ | 1,065 | $ | 1,457 | ||||||||||||||
| Total interest income impact | 1,083 | 1,065 | 1,457 | |||||||||||||||||
| Interest expense - increased by discount accretion on deposits | (62) | (61) | (102) | |||||||||||||||||
| Interest expense - increased by discount accretion on borrowings | (87) | (86) | (194) | |||||||||||||||||
| Total net interest expense impact | (149) | (147) | (296) | |||||||||||||||||
| Total impact on net interest income | $ | 934 | $ | 918 | $ | 1,161 | ||||||||||||||
17
Second Quarter Update 2026
Important information Caution Regarding Forward-Looking Statements This presentation contains certain forward-looking statements within the meaning of Section 21E of the Securities Exchange Act of 1934 and the Private Securities Litigation Reform Act of 1995, including those regarding First Bancorp's expectations or predictions of future financial or business performance or conditions. The forward-looking statements are inherently subject to risks and uncertainties. Forward-looking statements are typically identified by words such as "believe," "expect," "anticipate," "intend," "target," "estimate," "continue," "positions," "prospects" or "potential," by future conditional verbs such as "will," "would," "should," "could" or "may", or by variations of such words or by similar expressions. Such forward-looking statements include, but are not limited to, statements about future financial and operating results, expected cost savings, expected impact on future earnings, the Company's plans, objectives, expectations and intentions and other statements that are not historical facts. These forward-looking statements are subject to numerous assumptions, risks and uncertainties which change over time. Forward-looking statements speak only as of the date they are made and you are cautioned not to place undue reliance on any forward-looking statements. We assume no duty to update forward-looking statements. In addition to factors previously disclosed in First Bancorp’s reports filed with the Securities and Exchange Commission (“SEC”), including without limitation its Annual Reports on Form 10-K, its Quarterly Reports on Form 10-Q, and its Current Reports on Form 8-K, factors that could influence the accuracy of such forward- looking statements include, but are not limited to, the financial success or changing strategies of the Company’s customers, the risks and uncertainties relating to the level of success in integrating acquisitions, (including the ability to successfully integrate First Carolina into First Bank; to realize the anticipated benefits of the acquisition; deposit attrition, customer loss or other revenue loss following completed acquisitions may be greater than anticipated; and the integration of operations and personnel may require more time and expense); actions of government regulators; the level of market interest rates; and general economic conditions. This presentation contains financial information, performance measures and statements that include non-GAAP (Generally Accepted Accounting Principles) measures and should be read along with related earnings releases and Forms 10-Q/K for the respective quarters and period ends, which provide a reconciliation of non-GAAP measures to GAAP measures. Management believes that these non-GAAP measures provide additional useful information that allows readers to evaluate the ongoing performance of First Bancorp. Non-GAAP measures should not be considered as an alternative to any measure of performance or financial condition as determined in accordance with GAAP, and investors should consider the Company’s performance and financial condition as reported under GAAP and all other relevant information when assessing the performance or financial condition of First Bancorp. Non-GAAP measures have limitations as analytical tools, and investors should not consider them in isolation or as a substitute for analysis of the Company’s results or financial condition as reported under GAAP. Non-GAAP Measures
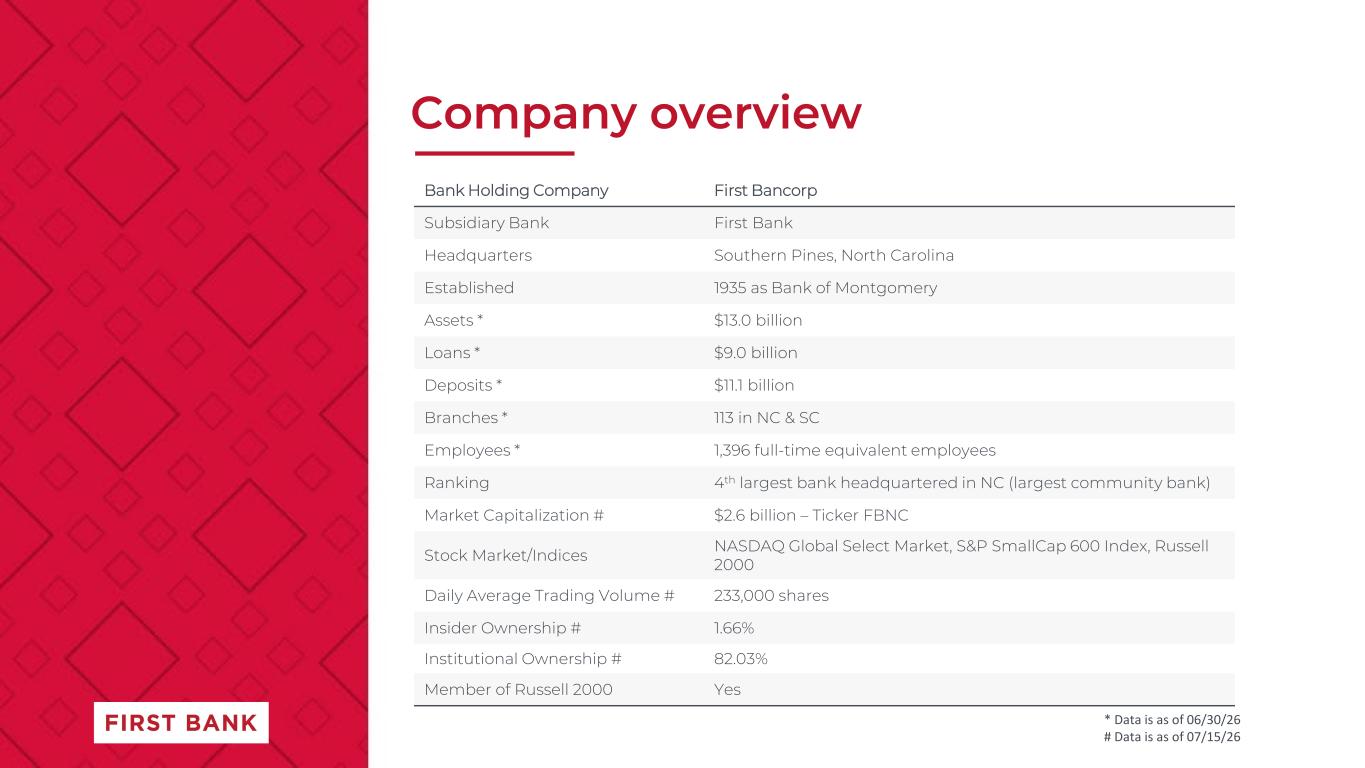
Company overview Bank Holding Company First Bancorp Subsidiary Bank First Bank Headquarters Southern Pines, North Carolina Established 1935 as Bank of Montgomery Assets * $13.0 billion Loans * $9.0 billion Deposits * $11.1 billion Branches * 113 in NC & SC Employees * 1,396 full-time equivalent employees Ranking 4th largest bank headquartered in NC (largest community bank) Market Capitalization # $2.6 billion – Ticker FBNC Stock Market/Indices NASDAQ Global Select Market, S&P SmallCap 600 Index, Russell 2000 Daily Average Trading Volume # 233,000 shares Insider Ownership # 1.66% Institutional Ownership # 82.03% Member of Russell 2000 Yes * Data is as of 06/30/26 # Data is as of 07/15/26
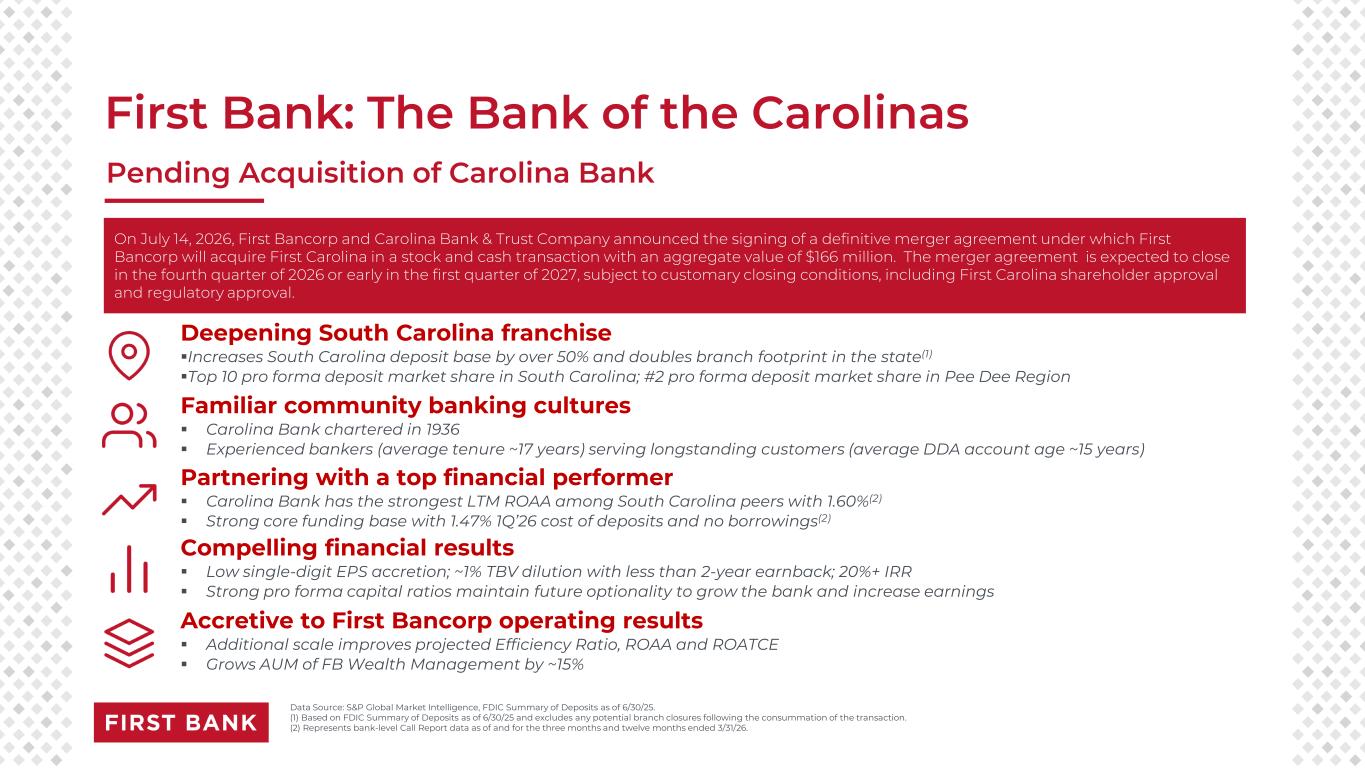
First Bank: The Bank of the Carolinas Deepening South Carolina franchise Increases South Carolina deposit base by over 50% and doubles branch footprint in the state(1) Top 10 pro forma deposit market share in South Carolina; #2 pro forma deposit market share in Pee Dee Region Familiar community banking cultures Carolina Bank chartered in 1936 Experienced bankers (average tenure ~17 years) serving longstanding customers (average DDA account age ~15 years) Partnering with a top financial performer Carolina Bank has the strongest LTM ROAA among South Carolina peers with 1.60%(2) Strong core funding base with 1.47% 1Q’26 cost of deposits and no borrowings(2) Compelling financial results Low single-digit EPS accretion; ~1% TBV dilution with less than 2-year earnback; 20%+ IRR Strong pro forma capital ratios maintain future optionality to grow the bank and increase earnings Accretive to First Bancorp operating results Additional scale improves projected Efficiency Ratio, ROAA and ROATCE Grows AUM of FB Wealth Management by ~15% Data Source: S&P Global Market Intelligence, FDIC Summary of Deposits as of 6/30/25. (1) Based on FDIC Summary of Deposits as of 6/30/25 and excludes any potential branch closures following the consummation of the transaction. (2) Represents bank-level Call Report data as of and for the three months and twelve months ended 3/31/26. On July 14, 2026, First Bancorp and Carolina Bank & Trust Company announced the signing of a definitive merger agreement under which First Bancorp will acquire First Carolina in a stock and cash transaction with an aggregate value of $166 million. The merger agreement is expected to close in the fourth quarter of 2026 or early in the first quarter of 2027, subject to customary closing conditions, including First Carolina shareholder approval and regulatory approval. Pending Acquisition of Carolina Bank
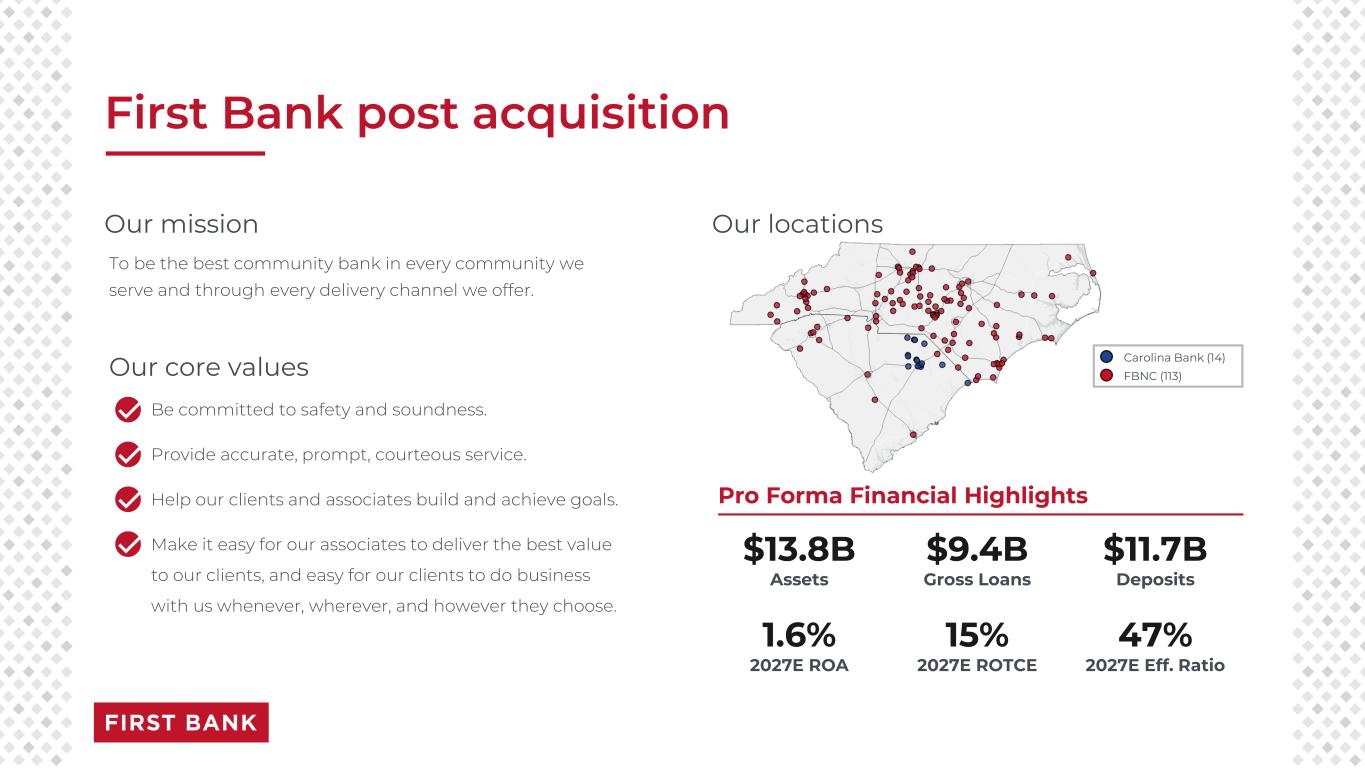
First Bank post acquisition Our mission To be the best community bank in every community we serve and through every delivery channel we offer. Our core values Be committed to safety and soundness. Provide accurate, prompt, courteous service. Help our clients and associates build and achieve goals. Make it easy for our associates to deliver the best value to our clients, and easy for our clients to do business with us whenever, wherever, and however they choose. Our locations Carolina Bank (14) FBNC (113) $13.8B Assets $9.4B Gross Loans $11.7B Deposits 1.6% 2027E ROA 15% 2027E ROTCE 47% 2027E Eff. Ratio Pro Forma Financial Highlights
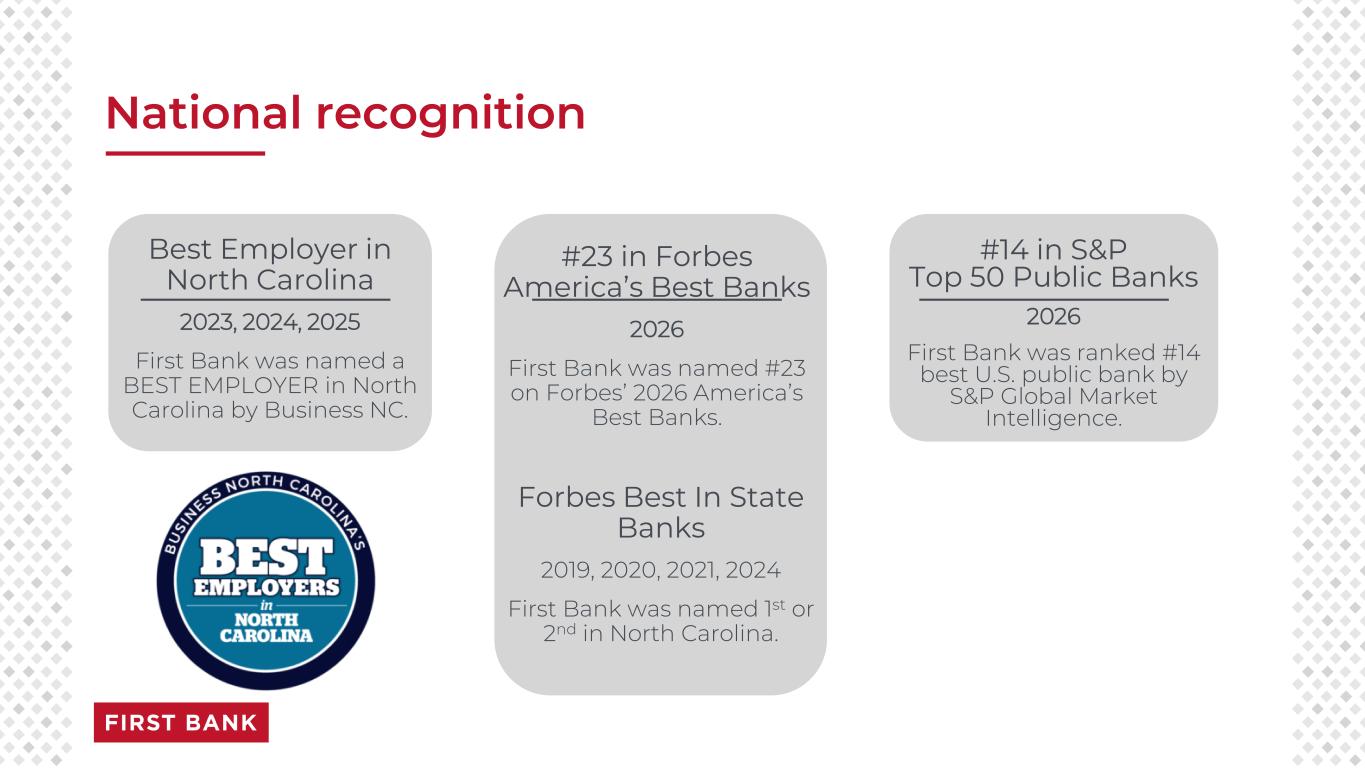
Best Employer in North Carolina 2023, 2024, 2025 First Bank was named a BEST EMPLOYER in North Carolina by Business NC. National recognition #14 in S&P Top 50 Public Banks 2026 First Bank was ranked #14 best U.S. public bank by S&P Global Market Intelligence. #23 in Forbes America’s Best Banks 2026 First Bank was named #23 on Forbes’ 2026 America’s Best Banks. Forbes Best In State Banks 2019, 2020, 2021, 2024 First Bank was named 1st or 2nd in North Carolina.
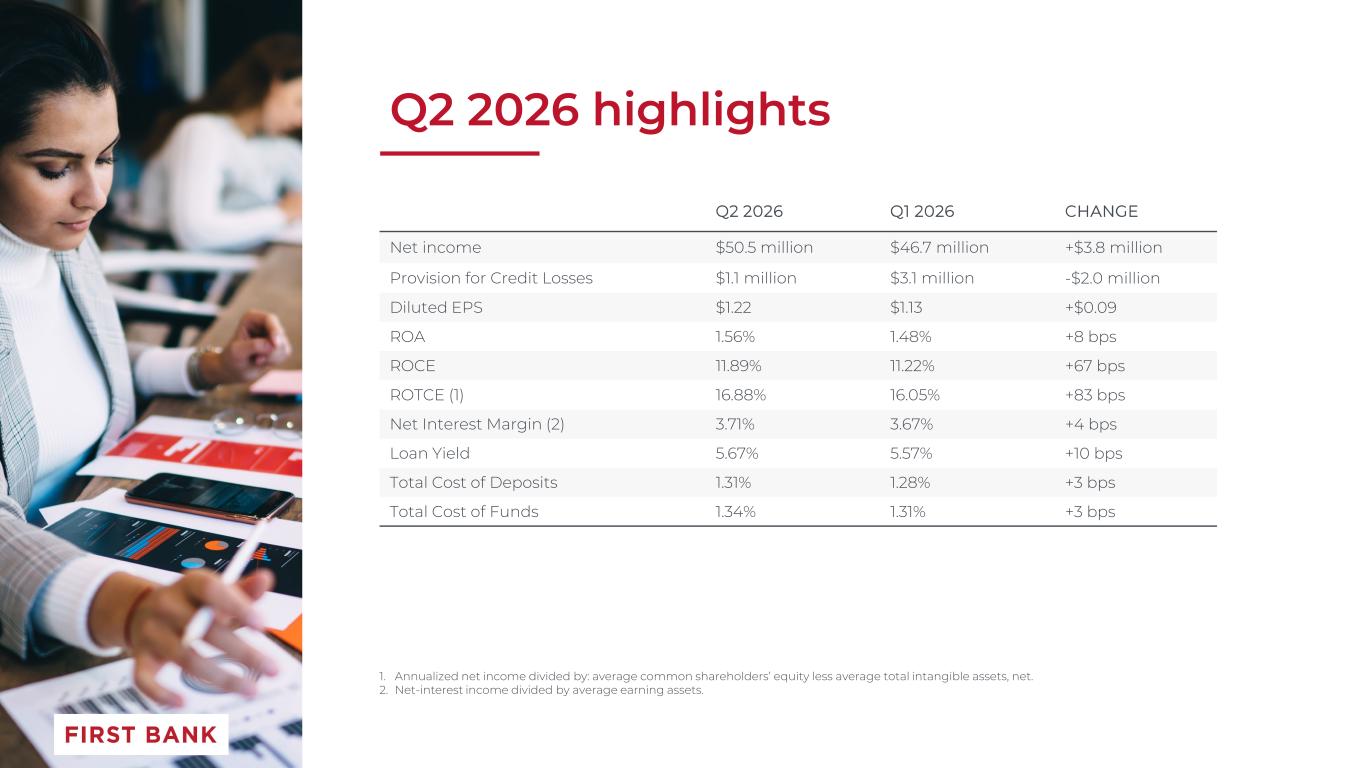
Q2 2026 highlights 1. Annualized net income divided by: average common shareholders’ equity less average total intangible assets, net. 2. Net-interest income divided by average earning assets. Q2 2026 Q1 2026 CHANGE Net income $50.5 million $46.7 million +$3.8 million Provision for Credit Losses $1.1 million $3.1 million -$2.0 million Diluted EPS $1.22 $1.13 +$0.09 ROA 1.56% 1.48% +8 bps ROCE 11.89% 11.22% +67 bps ROTCE (1) 16.88% 16.05% +83 bps Net Interest Margin (2) 3.71% 3.67% +4 bps Loan Yield 5.67% 5.57% +10 bps Total Cost of Deposits 1.31% 1.28% +3 bps Total Cost of Funds 1.34% 1.31% +3 bps
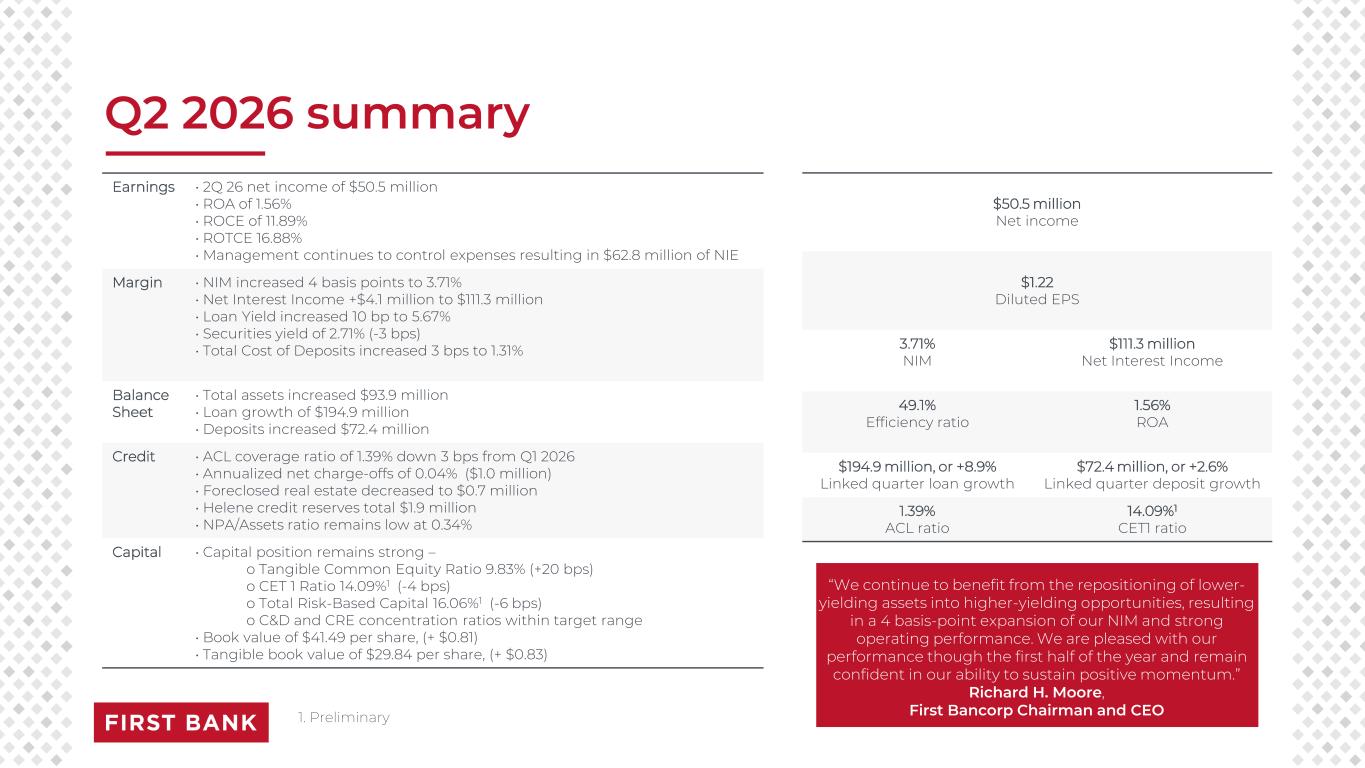
Q2 2026 summary 1. Preliminary Earnings • 2Q 26 net income of $50.5 million • ROA of 1.56% • ROCE of 11.89% • ROTCE 16.88% • Management continues to control expenses resulting in $62.8 million of NIE Margin • NIM increased 4 basis points to 3.71% • Net Interest Income +$4.1 million to $111.3 million • Loan Yield increased 10 bp to 5.67% • Securities yield of 2.71% (-3 bps) • Total Cost of Deposits increased 3 bps to 1.31% Balance Sheet • Total assets increased $93.9 million • Loan growth of $194.9 million • Deposits increased $72.4 million Credit • ACL coverage ratio of 1.39% down 3 bps from Q1 2026 • Annualized net charge-offs of 0.04% ($1.0 million) • Foreclosed real estate decreased to $0.7 million • Helene credit reserves total $1.9 million • NPA/Assets ratio remains low at 0.34% Capital • Capital position remains strong – o Tangible Common Equity Ratio 9.83% (+20 bps) o CET 1 Ratio 14.09%1 (-4 bps) o Total Risk-Based Capital 16.06%1 (-6 bps) o C&D and CRE concentration ratios within target range • Book value of $41.49 per share, (+ $0.81) • Tangible book value of $29.84 per share, (+ $0.83) “We continue to benefit from the repositioning of lower- yielding assets into higher-yielding opportunities, resulting in a 4 basis-point expansion of our NIM and strong operating performance. We are pleased with our performance though the first half of the year and remain confident in our ability to sustain positive momentum.” Richard H. Moore, First Bancorp Chairman and CEO $50.5 million Net income $1.22 Diluted EPS 3.71% NIM $111.3 million Net Interest Income 49.1% Efficiency ratio 1.56% ROA $194.9 million, or +8.9% Linked quarter loan growth $72.4 million, or +2.6% Linked quarter deposit growth 1.39% ACL ratio 14.09%1 CET1 ratio
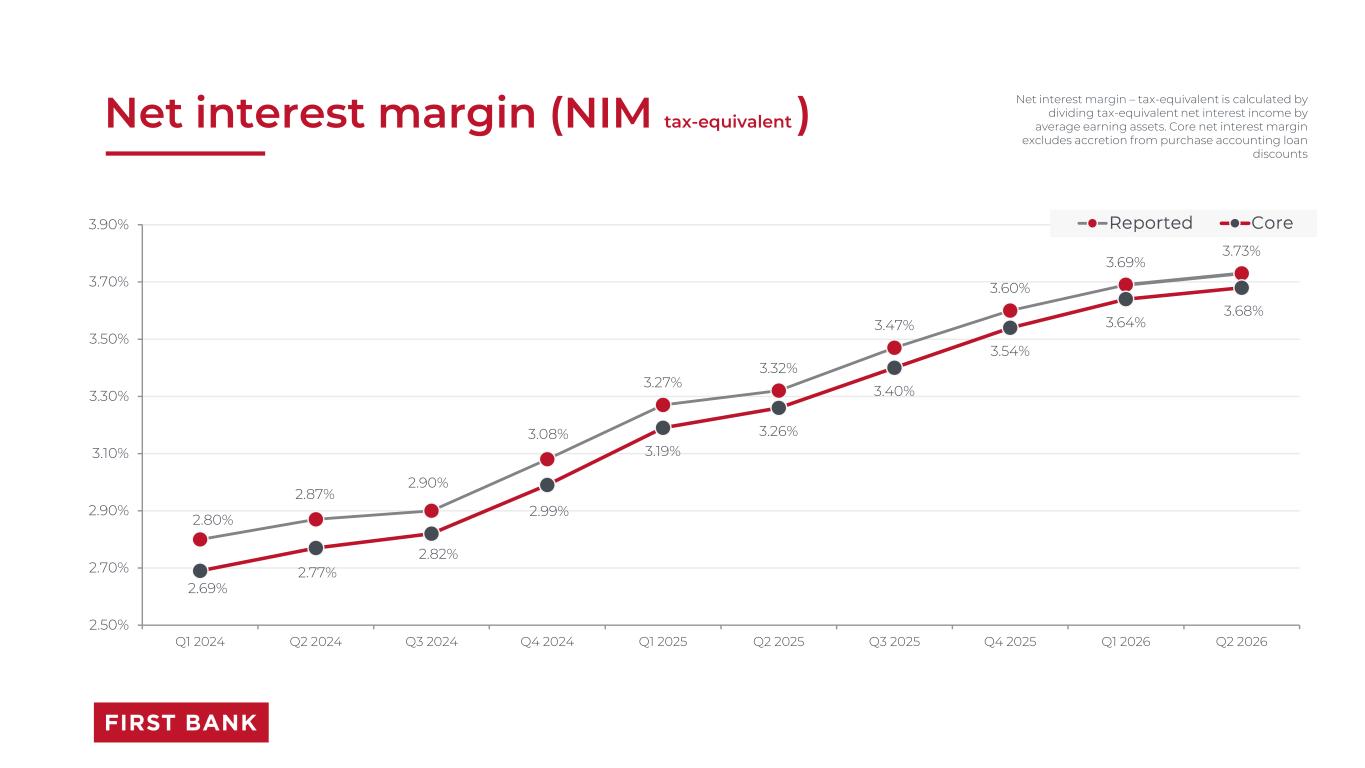
Net interest margin (NIM tax-equivalent ) 2.80% 2.87% 2.90% 3.08% 3.27% 3.32% 3.47% 3.60% 3.69% 3.73% 2.69% 2.77% 2.82% 2.99% 3.19% 3.26% 3.40% 3.54% 3.64% 3.68% 2.50% 2.70% 2.90% 3.10% 3.30% 3.50% 3.70% 3.90% Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Reported Core Net interest margin – tax-equivalent is calculated by dividing tax-equivalent net interest income by average earning assets. Core net interest margin excludes accretion from purchase accounting loan discounts
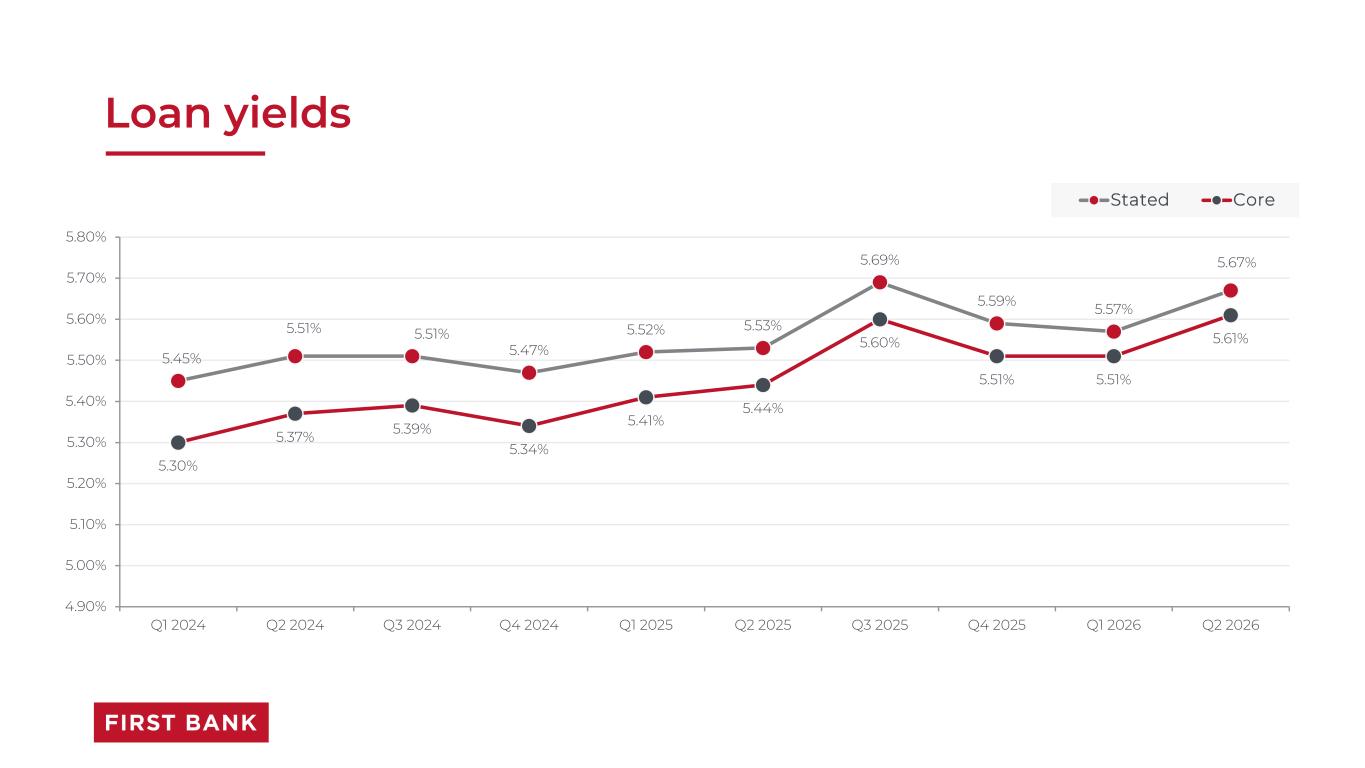
Loan yields 5.45% 5.51% 5.51% 5.47% 5.52% 5.53% 5.69% 5.59% 5.57% 5.67% 5.30% 5.37% 5.39% 5.34% 5.41% 5.44% 5.60% 5.51% 5.51% 5.61% 4.90% 5.00% 5.10% 5.20% 5.30% 5.40% 5.50% 5.60% 5.70% 5.80% Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Stated Core
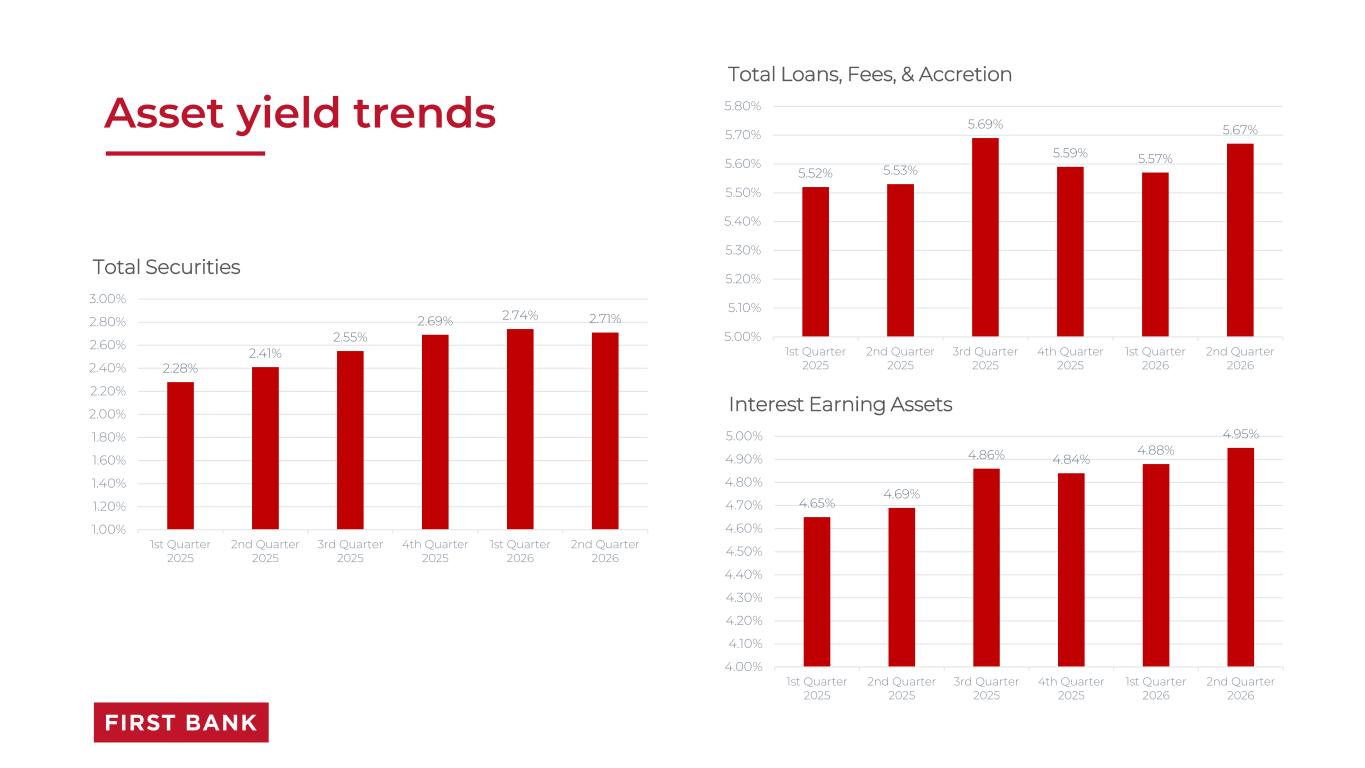
Asset yield trends 2.28% 2.41% 2.55% 2.69% 2.74% 2.71% 1.00% 1.20% 1.40% 1.60% 1.80% 2.00% 2.20% 2.40% 2.60% 2.80% 3.00% 1st Quarter 2025 2nd Quarter 2025 3rd Quarter 2025 4th Quarter 2025 1st Quarter 2026 2nd Quarter 2026 Total Securities 4.65% 4.69% 4.86% 4.84% 4.88% 4.95% 4.00% 4.10% 4.20% 4.30% 4.40% 4.50% 4.60% 4.70% 4.80% 4.90% 5.00% 1st Quarter 2025 2nd Quarter 2025 3rd Quarter 2025 4th Quarter 2025 1st Quarter 2026 2nd Quarter 2026 Interest Earning Assets 5.52% 5.53% 5.69% 5.59% 5.57% 5.67% 5.00% 5.10% 5.20% 5.30% 5.40% 5.50% 5.60% 5.70% 5.80% 1st Quarter 2025 2nd Quarter 2025 3rd Quarter 2025 4th Quarter 2025 1st Quarter 2026 2nd Quarter 2026 Total Loans, Fees, & Accretion
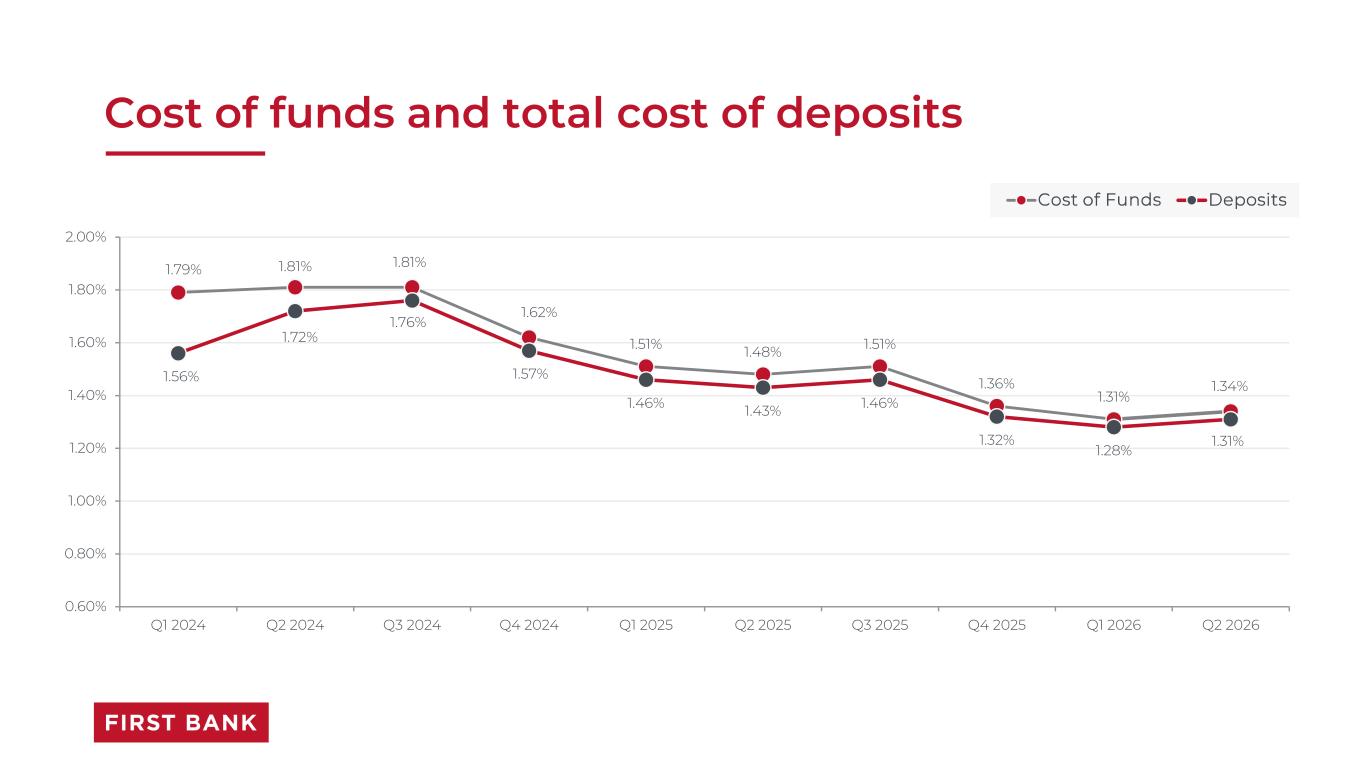
Cost of funds and total cost of deposits 1.79% 1.81% 1.81% 1.62% 1.51% 1.48% 1.51% 1.36% 1.31% 1.34% 1.56% 1.72% 1.76% 1.57% 1.46% 1.43% 1.46% 1.32% 1.28% 1.31% 0.60% 0.80% 1.00% 1.20% 1.40% 1.60% 1.80% 2.00% Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Cost of Funds Deposits
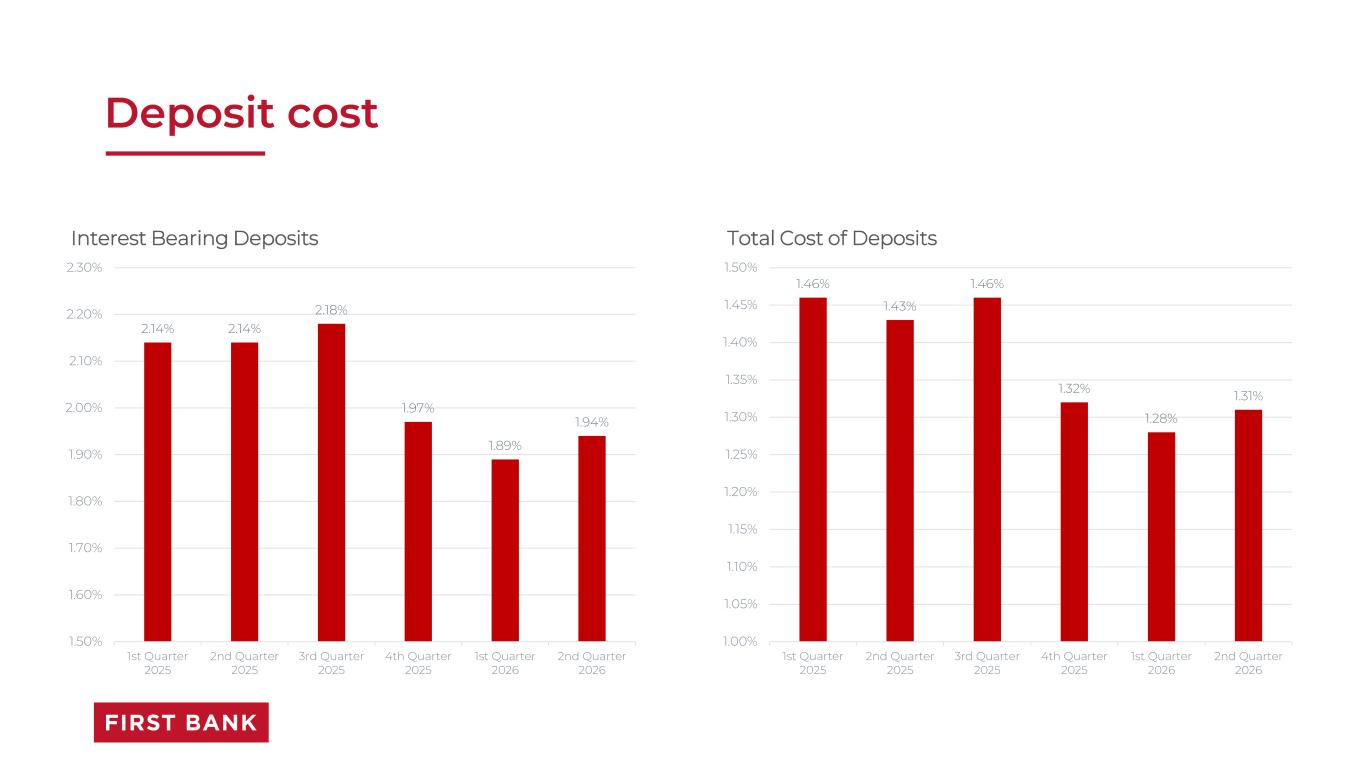
Deposit cost 2.14% 2.14% 2.18% 1.97% 1.89% 1.94% 1.50% 1.60% 1.70% 1.80% 1.90% 2.00% 2.10% 2.20% 2.30% 1st Quarter 2025 2nd Quarter 2025 3rd Quarter 2025 4th Quarter 2025 1st Quarter 2026 2nd Quarter 2026 Interest Bearing Deposits 1.46% 1.43% 1.46% 1.32% 1.28% 1.31% 1.00% 1.05% 1.10% 1.15% 1.20% 1.25% 1.30% 1.35% 1.40% 1.45% 1.50% 1st Quarter 2025 2nd Quarter 2025 3rd Quarter 2025 4th Quarter 2025 1st Quarter 2026 2nd Quarter 2026 Total Cost of Deposits
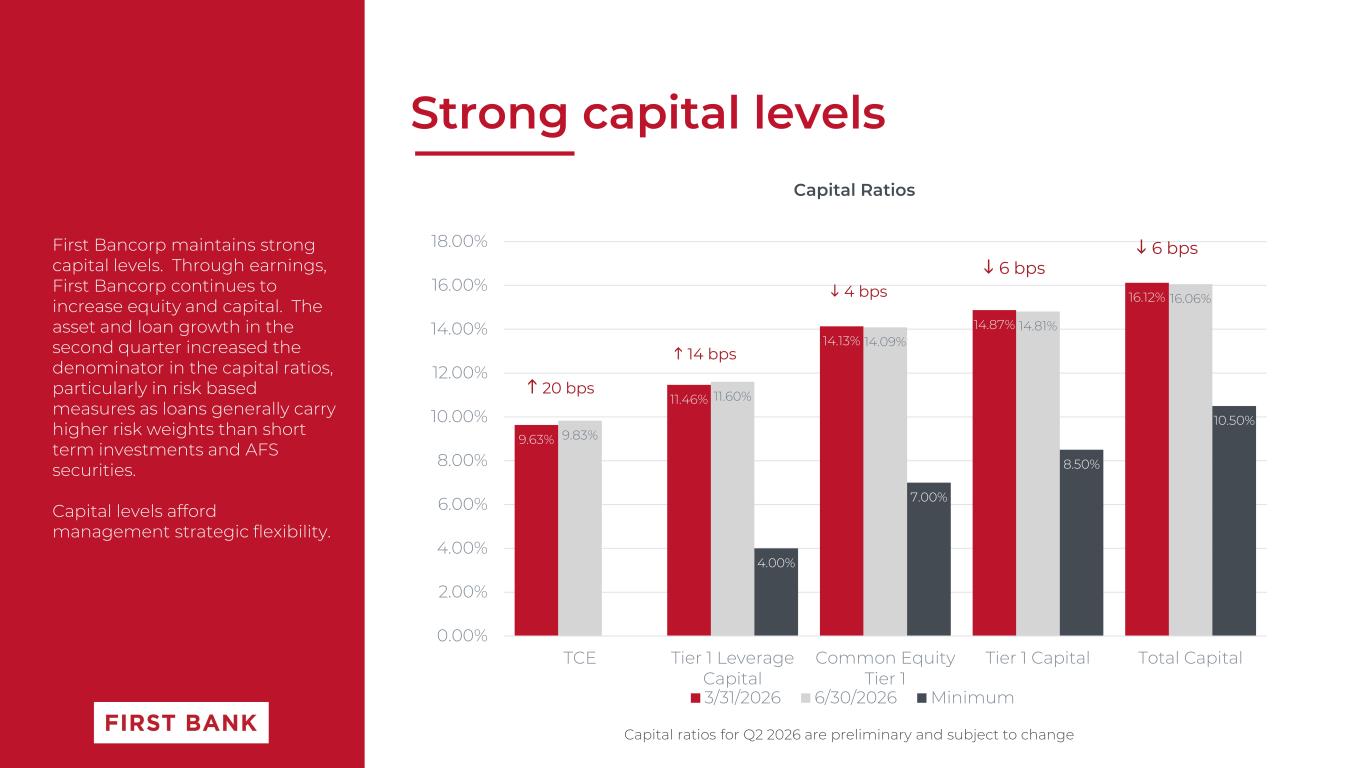
Strong capital levels First Bancorp maintains strong capital levels. Through earnings, First Bancorp continues to increase equity and capital. The asset and loan growth in the second quarter increased the denominator in the capital ratios, particularly in risk based measures as loans generally carry higher risk weights than short term investments and AFS securities. Capital levels afford management strategic flexibility. Capital ratios for Q2 2026 are preliminary and subject to change 9.63% 11.46% 14.13% 14.87% 16.12% 9.83% 11.60% 14.09% 14.81% 16.06% 4.00% 7.00% 8.50% 10.50% 0.00% 2.00% 4.00% 6.00% 8.00% 10.00% 12.00% 14.00% 16.00% 18.00% TCE Tier 1 Leverage Capital Common Equity Tier 1 Tier 1 Capital Total Capital 3/31/2026 6/30/2026 Minimum 20 bps 14 bps 6 bps 6 bps 4 bps Capital Ratios
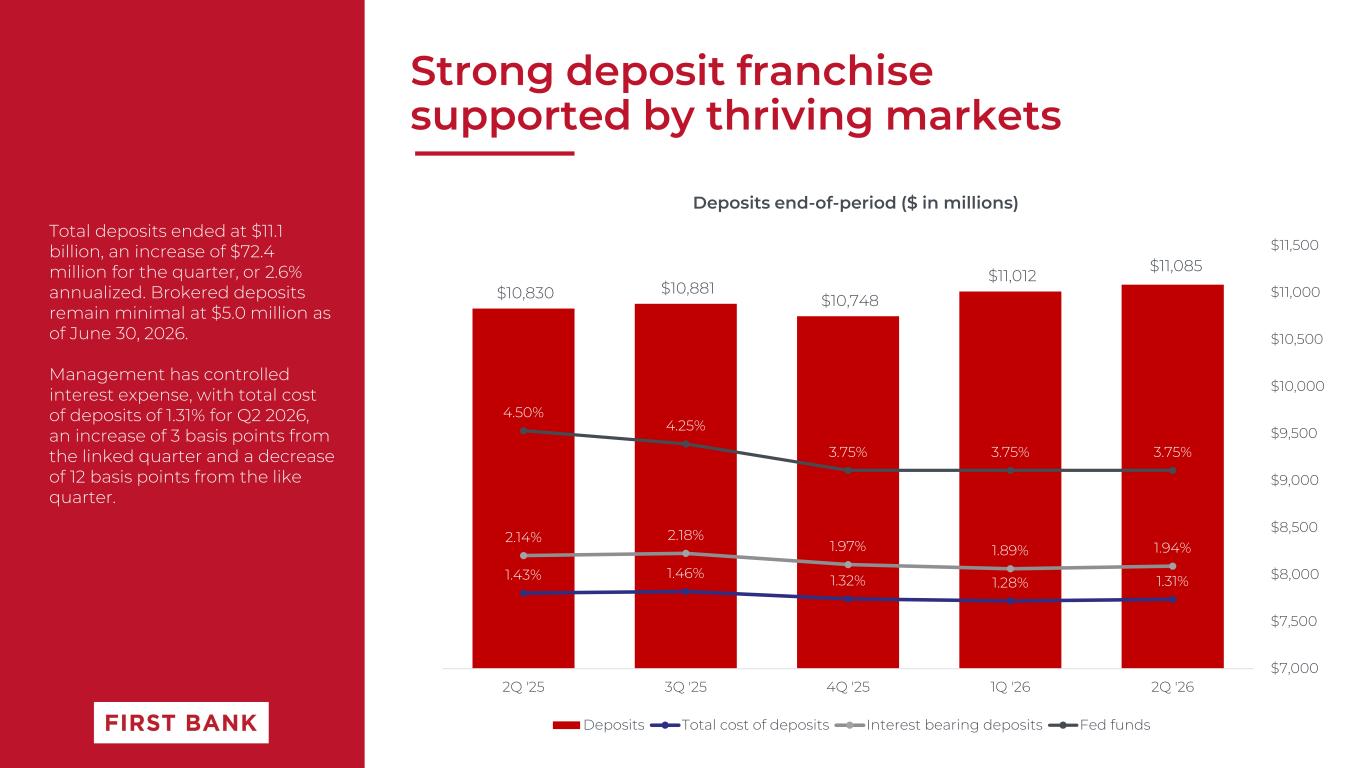
Strong deposit franchise supported by thriving markets Total deposits ended at $11.1 billion, an increase of $72.4 million for the quarter, or 2.6% annualized. Brokered deposits remain minimal at $5.0 million as of June 30, 2026. Management has controlled interest expense, with total cost of deposits of 1.31% for Q2 2026, an increase of 3 basis points from the linked quarter and a decrease of 12 basis points from the like quarter. $10,830 $10,881 $10,748 $11,012 $11,085 1.43% 1.46% 1.32% 1.28% 1.31% 2.14% 2.18% 1.97% 1.89% 1.94% 4.50% 4.25% 3.75% 3.75% 3.75% $7,000 $7,500 $8,000 $8,500 $9,000 $9,500 $10,000 $10,500 $11,000 $11,500 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% 7.00% 8.00% 2Q '25 3Q '25 4Q '25 1Q '26 2Q '26 Deposits Total cost of deposits Interest bearing deposits Fed funds Deposits end-of-period ($ in millions)
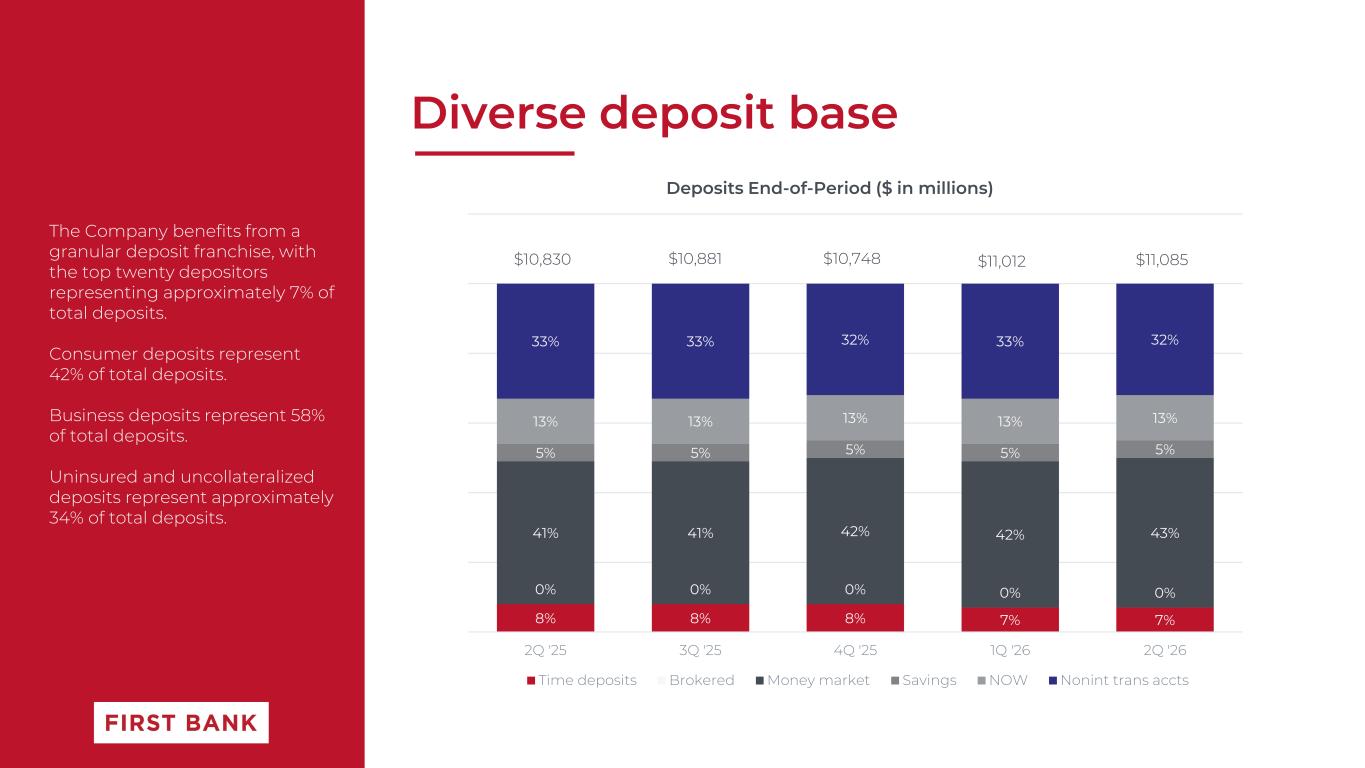
Diverse deposit base The Company benefits from a granular deposit franchise, with the top twenty depositors representing approximately 7% of total deposits. Consumer deposits represent 42% of total deposits. Business deposits represent 58% of total deposits. Uninsured and uncollateralized deposits represent approximately 34% of total deposits. 8% 8% 8% 7% 7% 0% 0% 0% 0% 0% 41% 41% 42% 42% 43% 5% 5% 5% 5% 5% 13% 13% 13% 13% 13% 33% 33% 32% 33% 32% 2Q '25 3Q '25 4Q '25 1Q '26 2Q '26 Time deposits Brokered Money market Savings NOW Nonint trans accts Deposits End-of-Period ($ in millions) $10,830 $10,881 $10,748 $11,012 $11,085
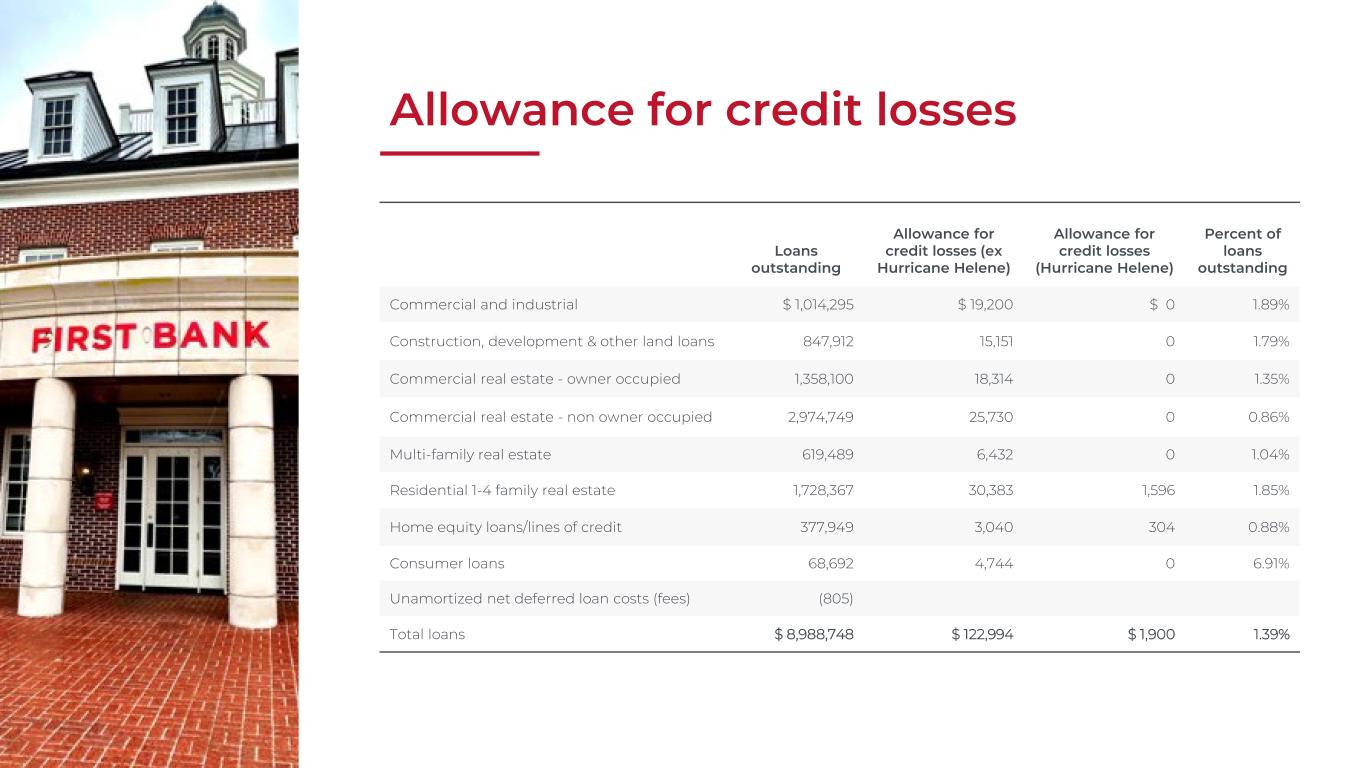
Allowance for credit losses Loans outstanding Allowance for credit losses (ex Hurricane Helene) Allowance for credit losses (Hurricane Helene) Percent of loans outstanding Commercial and industrial $ 1,014,295 $ 19,200 $ 0 1.89% Construction, development & other land loans 847,912 15,151 0 1.79% Commercial real estate - owner occupied 1,358,100 18,314 0 1.35% Commercial real estate - non owner occupied 2,974,749 25,730 0 0.86% Multi-family real estate 619,489 6,432 0 1.04% Residential 1-4 family real estate 1,728,367 30,383 1,596 1.85% Home equity loans/lines of credit 377,949 3,040 304 0.88% Consumer loans 68,692 4,744 0 6.91% Unamortized net deferred loan costs (fees) (805) Total loans $ 8,988,748 $ 122,994 $ 1,900 1.39%
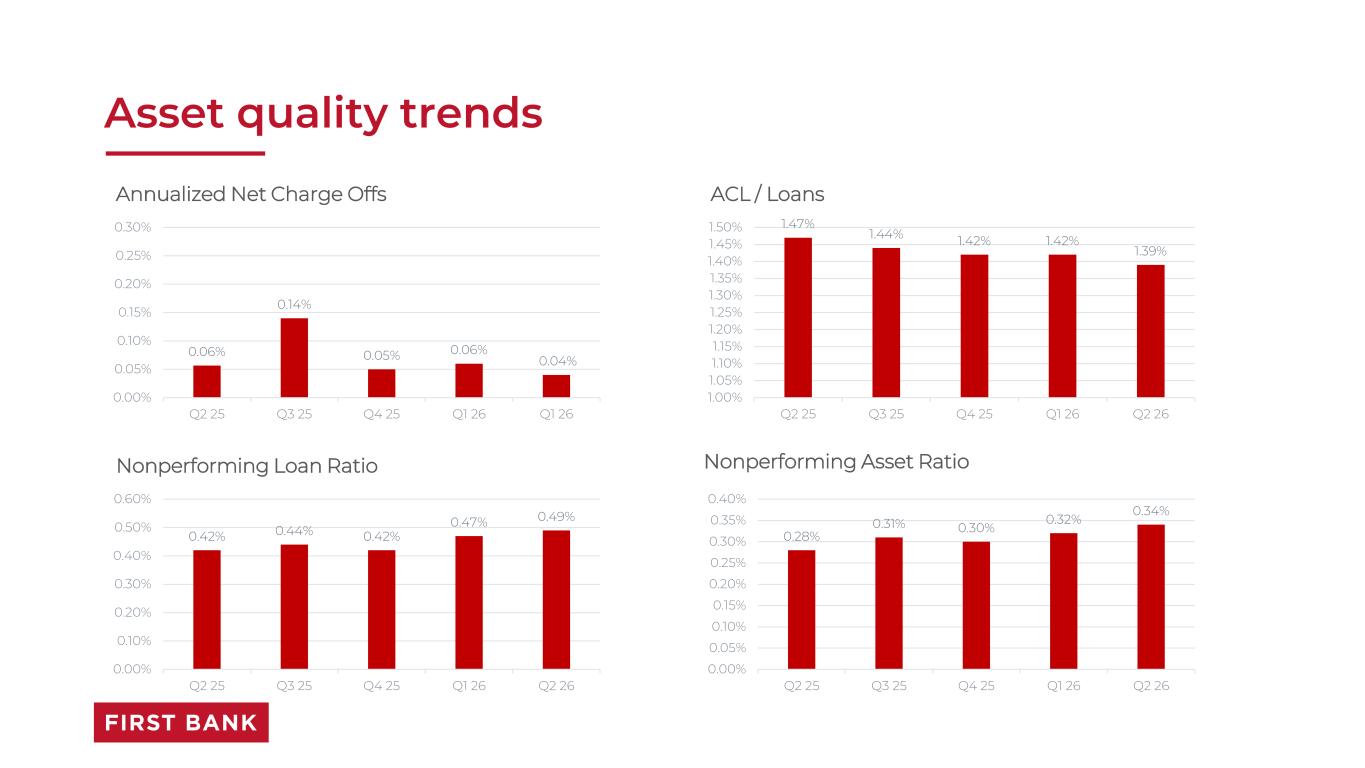
Asset quality trends 0.06% 0.14% 0.05% 0.06% 0.04% 0.00% 0.05% 0.10% 0.15% 0.20% 0.25% 0.30% Q2 25 Q3 25 Q4 25 Q1 26 Q1 26 Annualized Net Charge Offs 0.42% 0.44% 0.42% 0.47% 0.49% 0.00% 0.10% 0.20% 0.30% 0.40% 0.50% 0.60% Q2 25 Q3 25 Q4 25 Q1 26 Q2 26 Nonperforming Loan Ratio 1.47% 1.44% 1.42% 1.42% 1.39% 1.00% 1.05% 1.10% 1.15% 1.20% 1.25% 1.30% 1.35% 1.40% 1.45% 1.50% Q2 25 Q3 25 Q4 25 Q1 26 Q2 26 ACL / Loans 0.28% 0.31% 0.30% 0.32% 0.34% 0.00% 0.05% 0.10% 0.15% 0.20% 0.25% 0.30% 0.35% 0.40% Q2 25 Q3 25 Q4 25 Q1 26 Q2 26 Nonperforming Asset Ratio
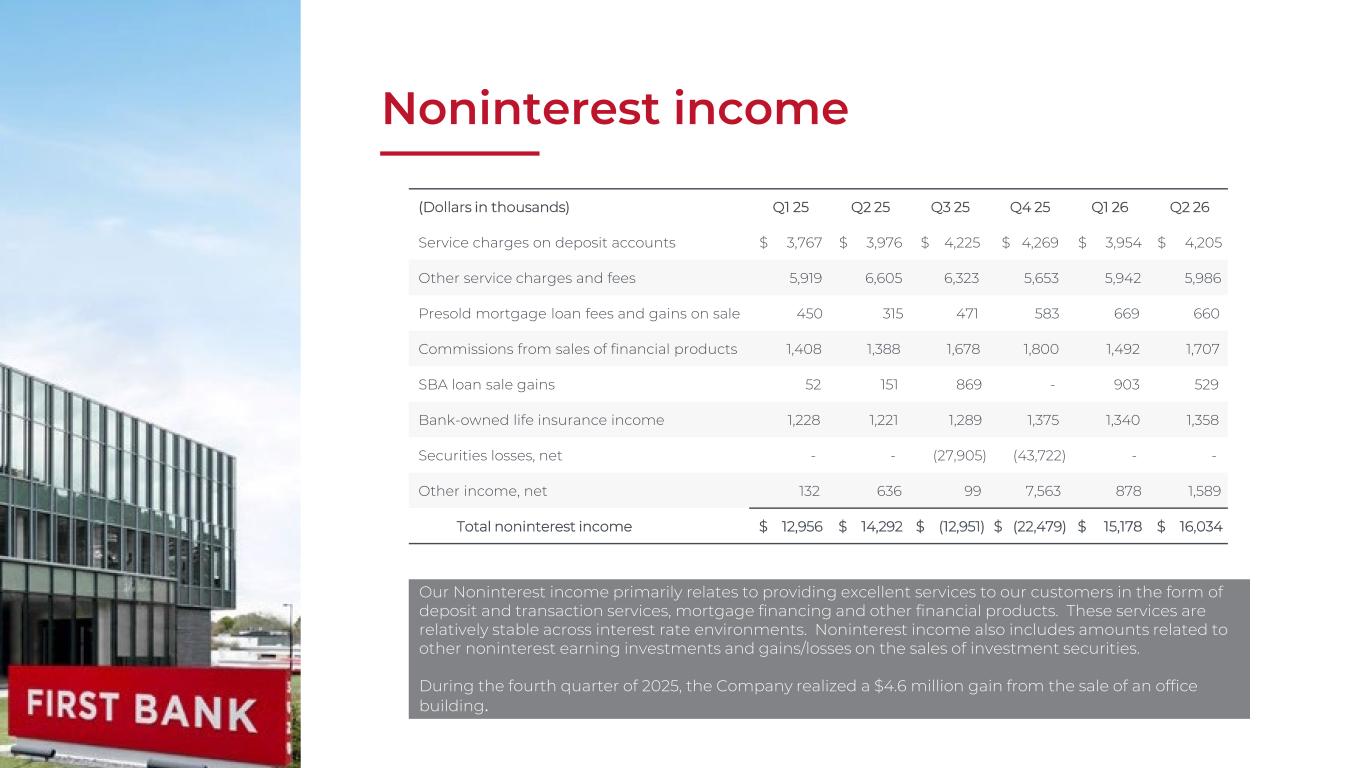
Noninterest income (Dollars in thousands) Q1 25 Q2 25 Q3 25 Q4 25 Q1 26 Q2 26 Service charges on deposit accounts $ 3,767 $ 3,976 $ 4,225 $ 4,269 $ 3,954 $ 4,205 Other service charges and fees 5,919 6,605 6,323 5,653 5,942 5,986 Presold mortgage loan fees and gains on sale 450 315 471 583 669 660 Commissions from sales of financial products 1,408 1,388 1,678 1,800 1,492 1,707 SBA loan sale gains 52 151 869 - 903 529 Bank-owned life insurance income 1,228 1,221 1,289 1,375 1,340 1,358 Securities losses, net - - (27,905) (43,722) - - Other income, net 132 636 99 7,563 878 1,589 Total noninterest income $ 12,956 $ 14,292 $ (12,951) $ (22,479) $ 15,178 $ 16,034 Our Noninterest income primarily relates to providing excellent services to our customers in the form of deposit and transaction services, mortgage financing and other financial products. These services are relatively stable across interest rate environments. Noninterest income also includes amounts related to other noninterest earning investments and gains/losses on the sales of investment securities. During the fourth quarter of 2025, the Company realized a $4.6 million gain from the sale of an office building.
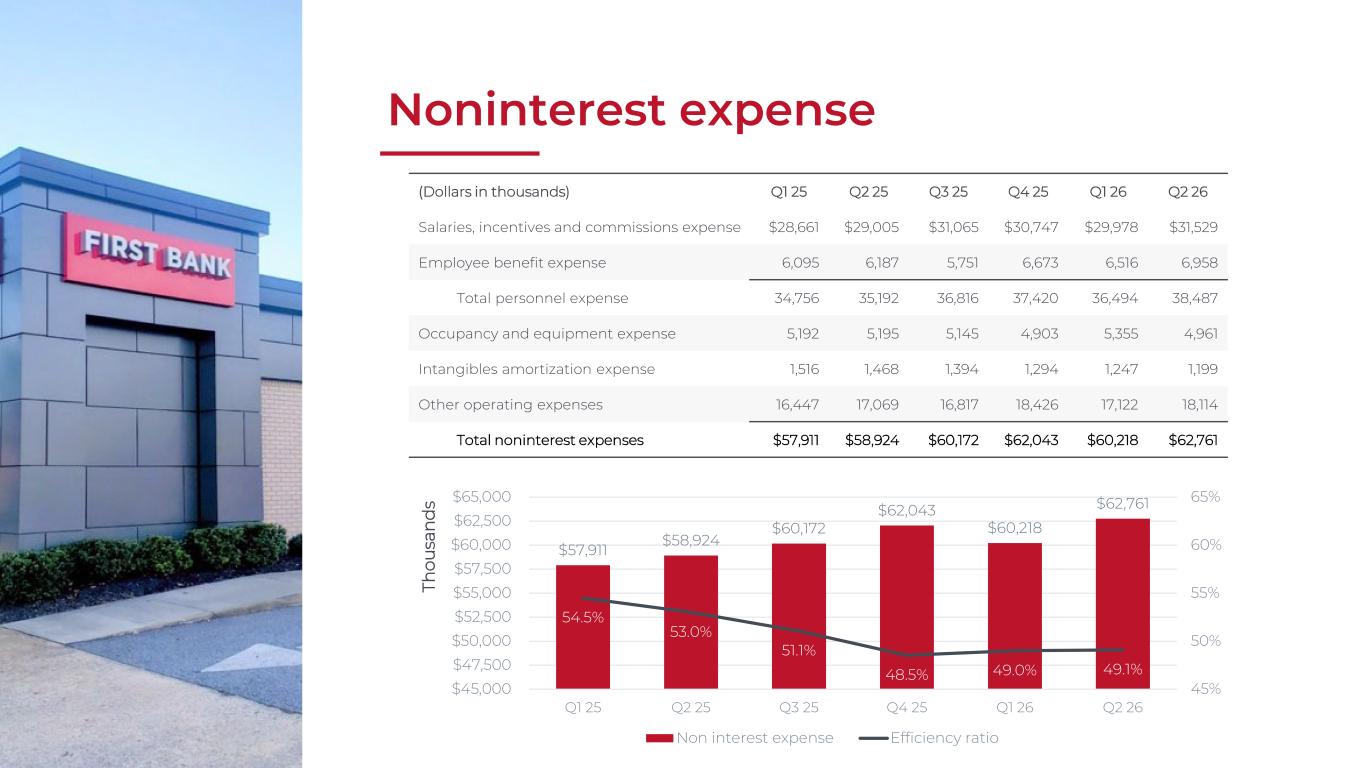
Noninterest expense (Dollars in thousands) Q1 25 Q2 25 Q3 25 Q4 25 Q1 26 Q2 26 Salaries, incentives and commissions expense $28,661 $29,005 $31,065 $30,747 $29,978 $31,529 Employee benefit expense 6,095 6,187 5,751 6,673 6,516 6,958 Total personnel expense 34,756 35,192 36,816 37,420 36,494 38,487 Occupancy and equipment expense 5,192 5,195 5,145 4,903 5,355 4,961 Intangibles amortization expense 1,516 1,468 1,394 1,294 1,247 1,199 Other operating expenses 16,447 17,069 16,817 18,426 17,122 18,114 Total noninterest expenses $57,911 $58,924 $60,172 $62,043 $60,218 $62,761 $57,911 $58,924 $60,172 $62,043 $60,218 $62,761 54.5% 53.0% 51.1% 48.5% 49.0% 49.1% 45% 50% 55% 60% 65% $45,000 $47,500 $50,000 $52,500 $55,000 $57,500 $60,000 $62,500 $65,000 Q1 25 Q2 25 Q3 25 Q4 25 Q1 26 Q2 26 Th ou sa n d s Non interest expense Efficiency ratio
Investment thesis Regional bank with strong culture that offers many of the product capabilities found in larger national banks but delivers those services with a local community bank focus. Capabilities include Mobile Banking, Wealth Management, Credit Card, Treasury Services, and Mortgage Banking. Centered in one of the fastest-growing regions in the U.S. and focused on high growth markets. Stable, low-cost core deposit franchise • Built over 90 years of serving our communities • Strength of rural markets • Q2 2026 Total Cost of Deposits was 1.31% • Minimal wholesale funding Conservative Balance Sheet • Minimal credit risk in investment portfolio • Core funded • In market loan portfolio – almost no participations Market disruptions provide opportunity
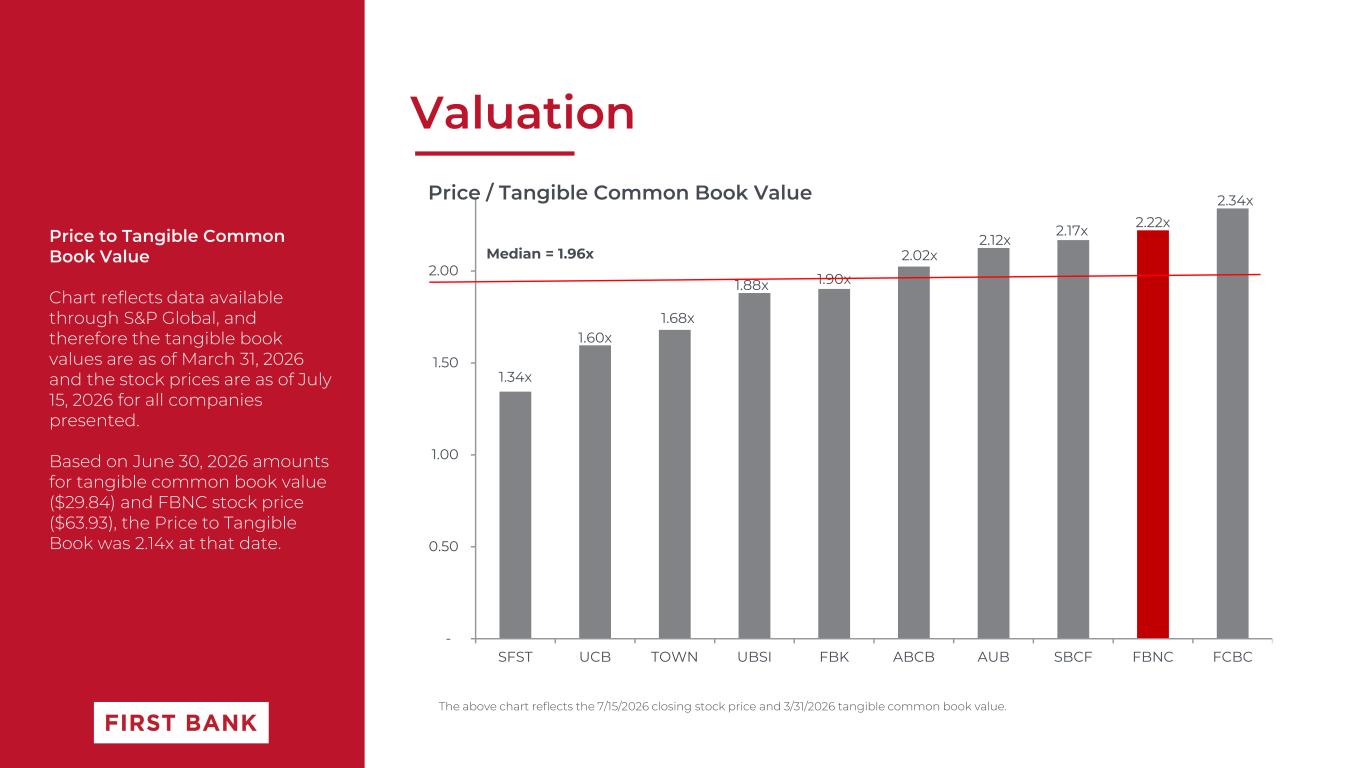
Valuation Price to Tangible Common Book Value Chart reflects data available through S&P Global, and therefore the tangible book values are as of March 31, 2026 and the stock prices are as of July 15, 2026 for all companies presented. Based on June 30, 2026 amounts for tangible common book value ($29.84) and FBNC stock price ($63.93), the Price to Tangible Book was 2.14x at that date. 1.34x 1.60x 1.68x 1.88x 1.90x 2.02x 2.12x 2.17x 2.22x 2.34x - 0.50 1.00 1.50 2.00 SFST UCB TOWN UBSI FBK ABCB AUB SBCF FBNC FCBC Price / Tangible Common Book Value Median = 1.96x The above chart reflects the 7/15/2026 closing stock price and 3/31/2026 tangible common book value.
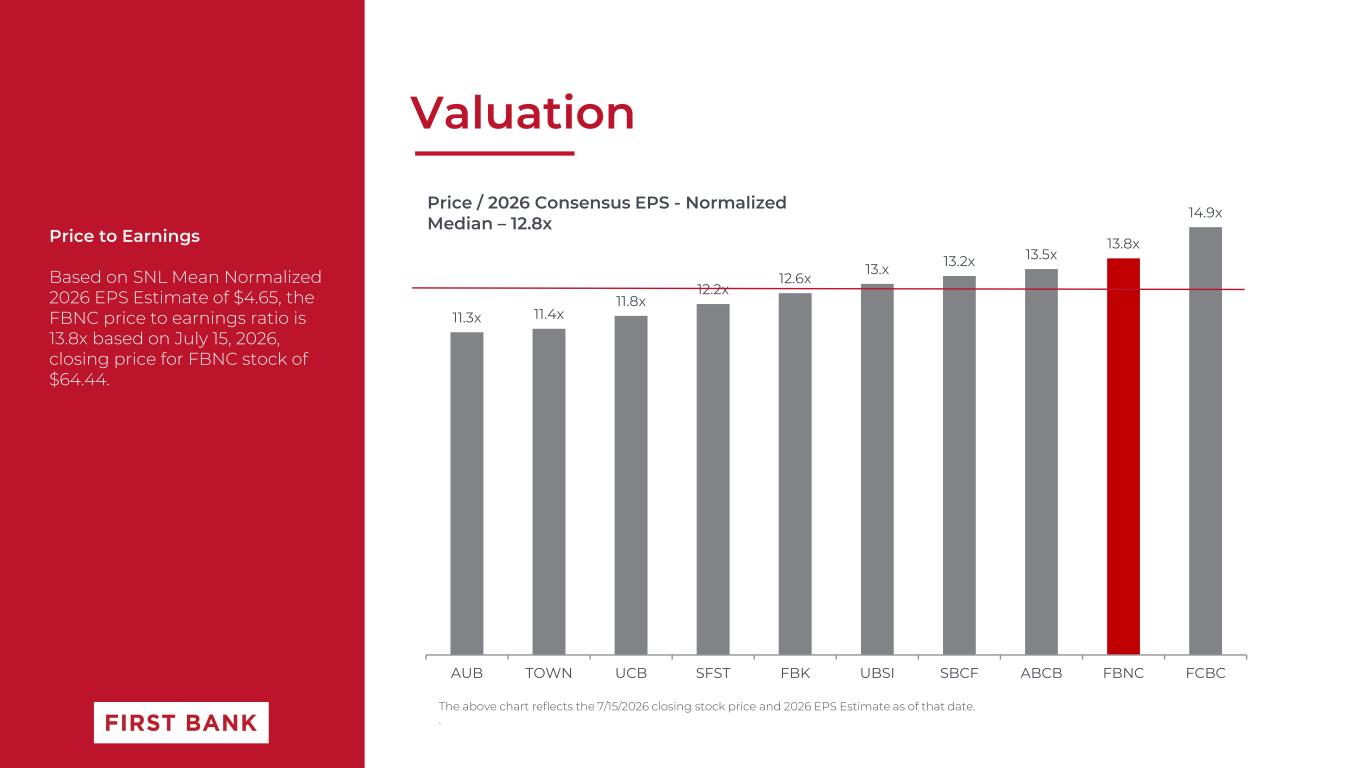
Valuation Price to Earnings Based on SNL Mean Normalized 2026 EPS Estimate of $4.65, the FBNC price to earnings ratio is 13.8x based on July 15, 2026, closing price for FBNC stock of $64.44. The above chart reflects the 7/15/2026 closing stock price and 2026 EPS Estimate as of that date. . 11.3x 11.4x 11.8x 12.2x 12.6x 13.x 13.2x 13.5x 13.8x 14.9x AUB TOWN UCB SFST FBK UBSI SBCF ABCB FBNC FCBC Price / 2026 Consensus EPS - Normalized Median – 12.8x
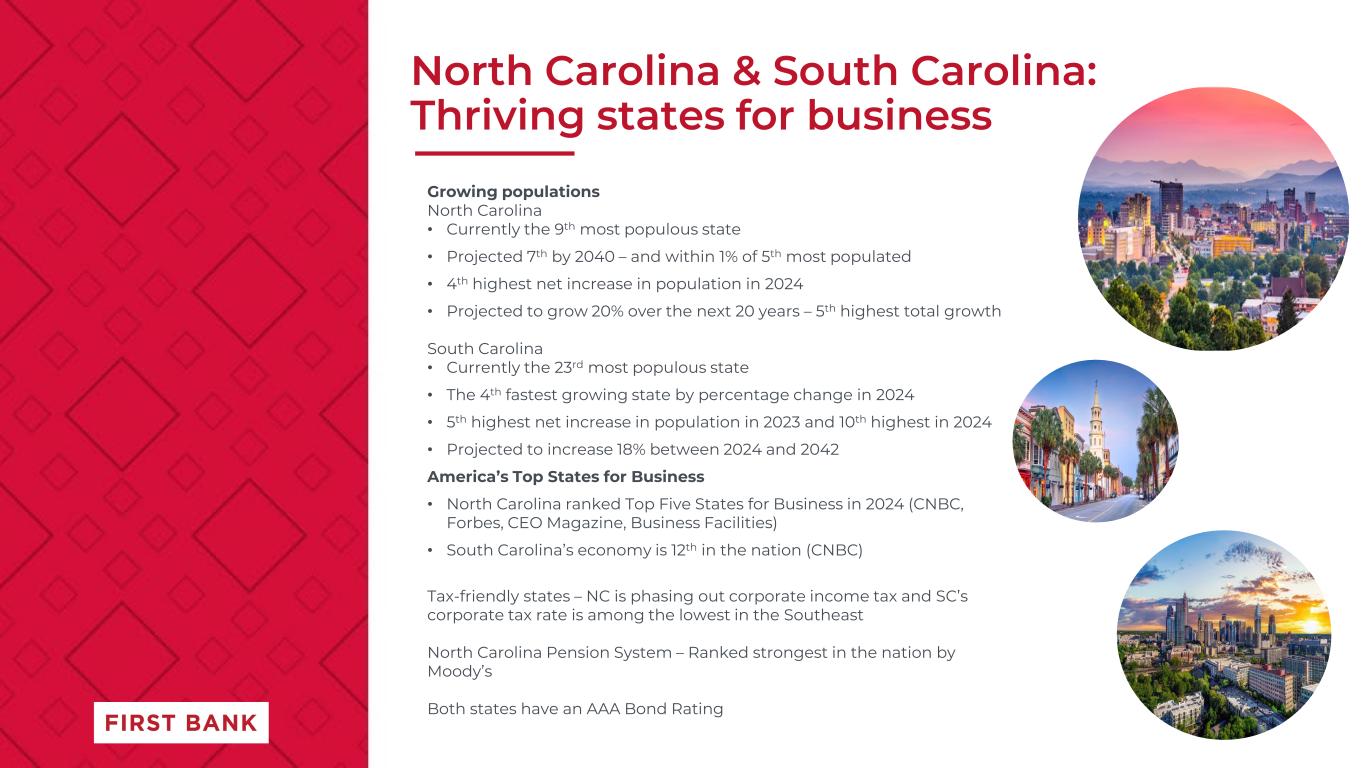
North Carolina & South Carolina: Thriving states for business Growing populations North Carolina • Currently the 9th most populous state • Projected 7th by 2040 – and within 1% of 5th most populated • 4th highest net increase in population in 2024 • Projected to grow 20% over the next 20 years – 5th highest total growth South Carolina • Currently the 23rd most populous state • The 4th fastest growing state by percentage change in 2024 • 5th highest net increase in population in 2023 and 10th highest in 2024 • Projected to increase 18% between 2024 and 2042 America’s Top States for Business • North Carolina ranked Top Five States for Business in 2024 (CNBC, Forbes, CEO Magazine, Business Facilities) • South Carolina’s economy is 12th in the nation (CNBC) Tax-friendly states – NC is phasing out corporate income tax and SC’s corporate tax rate is among the lowest in the Southeast North Carolina Pension System – Ranked strongest in the nation by Moody’s Both states have an AAA Bond Rating
Corporate citizenship
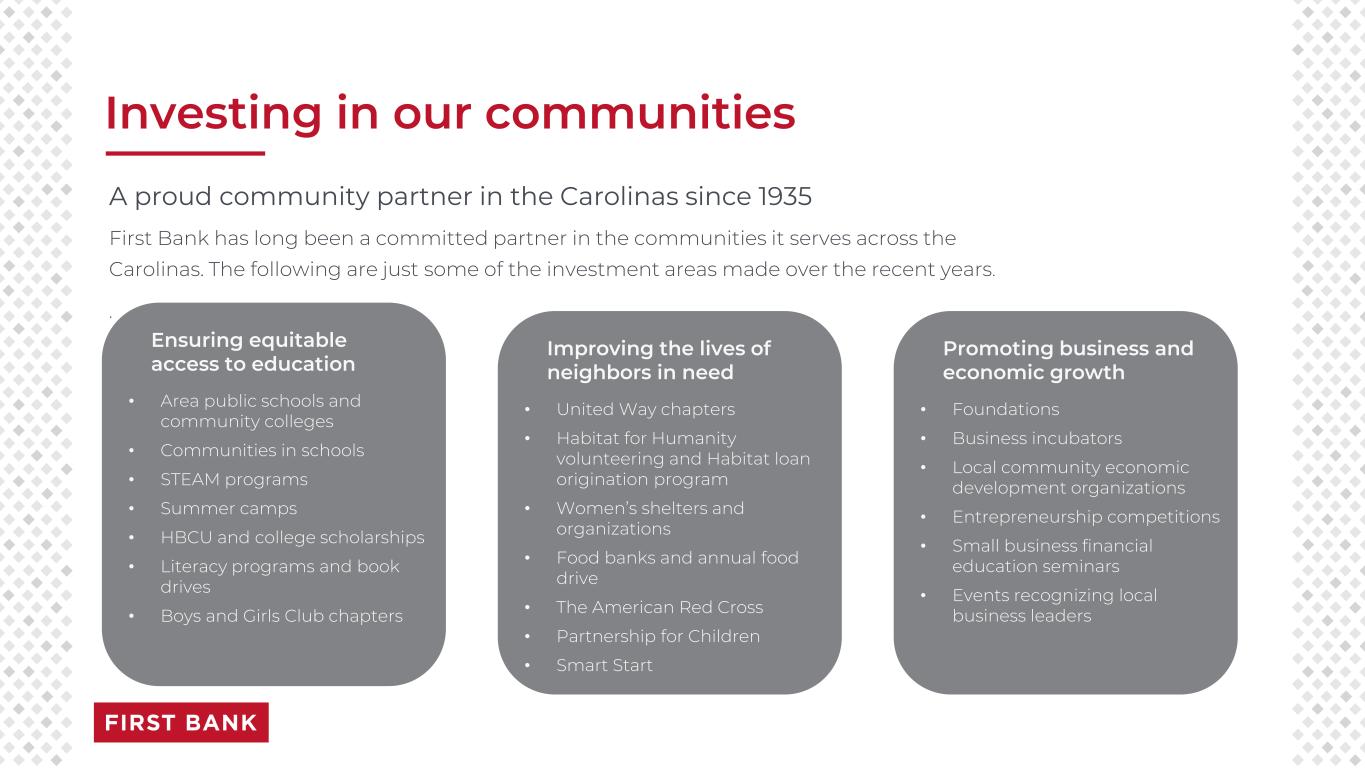
Investing in our communities A proud community partner in the Carolinas since 1935 First Bank has long been a committed partner in the communities it serves across the Carolinas. The following are just some of the investment areas made over the recent years. . Ensuring equitable access to education • Area public schools and community colleges • Communities in schools • STEAM programs • Summer camps • HBCU and college scholarships • Literacy programs and book drives • Boys and Girls Club chapters Improving the lives of neighbors in need • United Way chapters • Habitat for Humanity volunteering and Habitat loan origination program • Women’s shelters and organizations • Food banks and annual food drive • The American Red Cross • Partnership for Children • Smart Start Promoting business and economic growth • Foundations • Business incubators • Local community economic development organizations • Entrepreneurship competitions • Small business financial education seminars • Events recognizing local business leaders
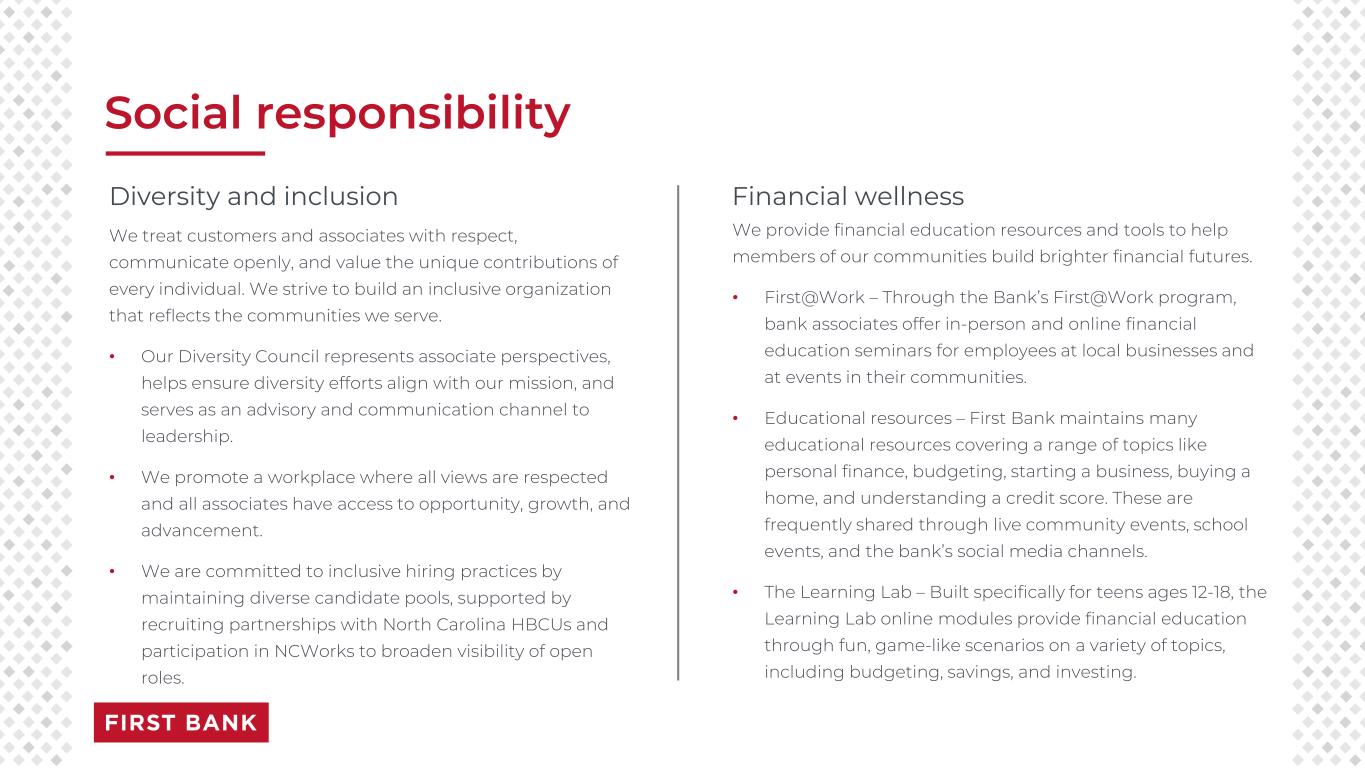
Social responsibility Diversity and inclusion We treat customers and associates with respect, communicate openly, and value the unique contributions of every individual. We strive to build an inclusive organization that reflects the communities we serve. • Our Diversity Council represents associate perspectives, helps ensure diversity efforts align with our mission, and serves as an advisory and communication channel to leadership. • We promote a workplace where all views are respected and all associates have access to opportunity, growth, and advancement. • We are committed to inclusive hiring practices by maintaining diverse candidate pools, supported by recruiting partnerships with North Carolina HBCUs and participation in NCWorks to broaden visibility of open roles. Financial wellness We provide financial education resources and tools to help members of our communities build brighter financial futures. • First@Work – Through the Bank’s First@Work program, bank associates offer in-person and online financial education seminars for employees at local businesses and at events in their communities. • Educational resources – First Bank maintains many educational resources covering a range of topics like personal finance, budgeting, starting a business, buying a home, and understanding a credit score. These are frequently shared through live community events, school events, and the bank’s social media channels. • The Learning Lab – Built specifically for teens ages 12-18, the Learning Lab online modules provide financial education through fun, game-like scenarios on a variety of topics, including budgeting, savings, and investing.
Thank you!