
FBP 8-K
First Bancorp /Pr/ (FBP)
8-K
2026-04-22
For: 2026-04-22
View Original
Added on
April 22, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, DC 20549
Form
CURRENT REPORT
Pursuant to Section 13 or 15(d) of
the Securities Exchange Act of 1934
Date of Report (Date of Earliest Event Reported):
(Exact Name of Registrant as Specified in its Charter)
(State or Other Jurisdiction
of Incorporation)
(Commission
File Number)
(I.R.S. Employer
Identification No.)
,
(Address of Principal Executive Offices)
(Zip Code)
(
)
(Registrant’s Telephone Number, including Area Code)
Not applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of
the registrant under any of the following provisions:
☐
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)
☐
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a -12)
☐
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))
☐
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))
Securities registered pursuant to Section 12(b) of the Act:
Title of each class
Trading
Symbol(s)
Name of each exchange on which
registered
New York Stock Exchange
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the
Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2
of this chapter).
Emerging growth company
☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition
period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of
the Exchange Act.
☐
Item 2.02
Results of Operations and Financial Condition.
On April 22, 2026, First BanCorp. (the “Corporation”), the bank holding company for FirstBank Puerto Rico
(“FirstBank” or the “Bank”), issued a press release announcing its unaudited results of operations for the quarter ended
March 31, 2026. A copy of the press release is attached hereto as Exhibit 99.1 and is incorporated herein by reference.
A copy of the presentation that the Corporation will use at its conference call to discuss its financial results for the
quarter ended March 31, 2026 is attached hereto as Exhibit 99.2 and is incorporated herein by reference. As announced
in a press release dated March 16, 2026, the call may be accessed via a live Internet webcast at 10:00 a.m. Eastern
time on Wednesday, April 22, 2026, through the Corporation’s investor relations website: www. fbpinvestor.com or
through the dial-in telephone number 800-715-9871 or 646 -307-1963. The participant access code is 5351564.
Item 9.01
Financial Statements and Exhibits
(d) Exhibits
Exhibit
Description of Exhibit
99.1 Press Release dated April 22, 2026 - First BanCorp Announces Earnings for the quarter ended
March 31, 2026
99.2 First BanCorp Conference Call Presentation – Financial Results for the quarter ended March 31,
2026
104 Cover Page Interactive Data File (embedded within the Inline XBRL document).
of the Securities Exchange Act of 1934, as amended, nor shall Exhibits 99.1 and 99.2 be deemed
incorporated by reference in any filings under the Securities Act of 1933, as amended.
Exhibit Index
Exhibit
Description of Exhibit
Press Release dated April 22, 2026 - First BanCorp Announces Earnings for the quarter ended March 31,
2026
First BanCorp Conference Call Presentation – Financial Results for the quarter ended March 31, 2026
104
Cover Page Interactive Data File (embedded within the Inline XBRL document).
Exhibits 99.1 and 99.2 referenced therein, shall not be deemed “filed” for purposes of Section 18 of the
Securities Exchange Act of 1934, as amended, nor shall Exhibits 99.1 and 99.2 be deemed incorporated
by reference in any filings under the Securities Act of 1933, as amended.
SIGNATURE
to be signed on its behalf by the undersigned hereunto duly authorized.
Date: April 22, 2026
First BanCorp.
Exhibit 99.1
FIRST BANCORP. ANNOUNCES EARNINGS FOR THE QUARTER ENDED MARCH 31, 2026
SAN JUAN, Puerto Rico – April 22, 2026
Rico (“FirstBank” or “the Bank”), today reported a net income of $88.8 million, or $0.57 per diluted share, for the first quarter of 2026, compared to $87.1 million, or
$0.55 per diluted share, for the fourth quarter of 2025, and $77.1 million, or $0.47 per diluted share, for the first quarter of 2025.
Aurelio Alemán, President and Chief Executive Officer of First BanCorp,
commented:
“We began the year with another quarter of strong operating
results, delivering consistent performance across our franchise. Earnings per
share increased 21% year-over-year, reflecting strong revenue generation and
disciplined expense management, which translated into a return on average
assets of 1.89%—our 17th consecutive quarter posting a ROAA above 1.5%.
Underlying revenue trends remained very strong during the quarter, with
pre‑tax, pre‑provision income reaching an all‑time high of $131 million, up 2%
from the prior quarter and 5% from a year ago. Core customer deposits
continued to grow, reinforcing the strength of our relationship‑driven franchise
while allowing us to proactively manage funding costs. Loan pipelines remain
healthy and continue to support our confidence in achieving our established loan
growth targets for the full year. Credit performance was strong, with stable
charge‑offs, record‑low levels of non‑performing assets, and very encouraging
early‑stage delinquency trends, which declined 24% from the prior quarter.
Supported by a resilient labor market and stable economic backdrop, we remain
focused on serving our customers across a range of environments while closely
monitoring key risks, including energy costs and their potential impact on
consumers. Our thoughtful and consistent approach to capital deployment
resulted in a net payout ratio of 92% during the quarter achieved through share
buybacks and dividends. Our disciplined approach to capital allocation,
responsible growth, and ongoing execution of our omnichannel strategy continue
to position First BanCorp to deliver sustainable long‑term value for all our
stakeholders.”
(In thousands)
Q1 '26
Q4 '25
Q1 '25
Financial Highlights
Net interest income
$
220,956
$
222,768
$
212,397
Provision for credit losses
17,273
22,971
24,810
Non-interest income
37,685
34,400
35,734
Non-interest expenses
127,105
126,870
123,022
Income before income taxes
114,263
107,327
100,299
Income tax expense
25,485
20,226
23,240
Net income
$
88,778
$
87,101
$
77,059
Selected Financial Data
Net interest margin
4.75%
4.68%
4.52%
Efficiency ratio
49.14%
49.33%
49.58%
Diluted earnings per share
$
0.57
$
0.55
$
0.47
Book value per share
$
12.72
$
12.56
$
10.91
Tangible book value per share
(1)
$
12.45
$
12.29
$
10.64
Return on average equity
17.92%
17.84%
17.90%
Return on average assets
1.89%
1.81%
1.64%
Results for the First Quarter of 2026 compared to the Fourth Quarter of 2025
Profitability
Net income –
of 2025 included a reversal of $1.1 million ($0.7 million after-tax) related to the Federal Deposit Insurance Corporation (“FDIC”) special
assessment.
Income before income taxes
–
Adjusted pre-tax, pre-provision income (Non-GAAP)
(1)
Net interest income –
two less days in the first quarter of 2026, $2.2 million associated to the downward repricing of variable-rate commercial loans and cash held at
the Federal Reserve Bank (“FED”), partially offset by the continued deployment of cash flows from lower-yielding investment securities to
higher-yielding assets and a decrease in the cost of interest-bearing deposits. Net interest margin increased to 4.75%, compared to 4.68%.
Provision for credit losses –
variables and improvements in delinquency in the consumer loan portfolios, partially offset by higher qualitative reserves associated with
geopolitical uncertainty driven by, among other things, higher oil prices as a result of the conflict in the Middle East.
Non-interest income –
commissions recorded in the first quarter of 2026.
Non-interest expenses
Income tax expense
– $25.5 million compared to $20.2 million, mainly due to higher pre-tax income and an adjustment in the fourth quarter of
2025 due to a lower than estimated annual effective tax rate.
Balance
Sheet
Total loans –
and finance leases portfolios in the Puerto Rico region. Total loan originations of $1.2 billion, down $143.0 million, mainly in commercial and
construction loans.
Core deposits (other than brokered and government deposits) –
increased by $158.5 million to $13.2 billion, mainly in interest-bearing
deposits in the Puerto Rico region.
Government deposits (fully collateralized) –
Brokered certificates of deposits (“CDs”)
Asset
Quality
Allowance for credit losses (“ACL”) coverage ratio –
Annualized net charge-offs to average loans ratio
Non-performing assets –
Liquidity
and
Capital
Liquidity –
Cash and cash equivalents amounted to $550.9 million, compared to $658.6 million. When adding $2.3 billion of free high-quality
liquid securities that could be liquidated or pledged within one day and $1.0 billion in available lending capacity at the Federal Home Loan Bank
(“FHLB”), available liquidity amounted to 20.14% of total assets, compared to 19.39%.
Capital –
Repurchased $50.0 million in common stock and declared $31.5 million in common stock dividends. Capital ratios exceeded required
regulatory levels. The Corporation’s estimated total capital, common equity tier 1 (“CET1”) capital, tier 1 capital, and leverage ratios were
18.19%, 16.93%, 16.93%, and 11.66%, respectively, as of March 31, 2026. On a non-GAAP basis, the tangible common equity ratio
(1)
to 10.11%, compared to 10.08%.
(1) Represents non-GAAP financial measures. Refer to
Non-GAAP Disclosures - Non-GAAP Financial Measures
financial measures.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 2 of 27
NET INTEREST INCOME
The following table sets forth information concerning net interest income for the last five quarters:
Quarter Ended
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
March 31, 2025
(Dollars in thousands)
Net Interest Income
Interest income
$
279,849
$
285,158
$
282,743
$
278,190
$
277,065
Interest expense
58,893
62,390
64,827
62,331
64,668
Net interest income
$
220,956
$
222,768
$
217,916
$
215,859
$
212,397
Average Balances
Loans and leases
$
13,068,874
$
13,032,081
$
12,876,239
$
12,742,809
$
12,632,501
Total securities, other short-term investments and interest-bearing cash
balances
5,776,844
5,871,091
6,037,726
6,245,844
6,444,016
Average interest-earning assets
$
18,845,718
$
18,903,172
$
18,913,965
$
18,988,653
$
19,076,517
Average interest-bearing liabilities
$
11,409,037
$
11,531,091
$
11,669,135
$
11,670,411
$
11,749,011
Average Yield/Rate
Average yield on interest-earning assets
6.02%
5.98%
5.93%
5.88%
5.89%
Average rate on interest-bearing liabilities
2.09%
2.15%
2.20%
2.14%
2.23%
Net interest spread
3.93%
3.83%
3.73%
3.74%
3.66%
Net interest margin
4.75%
4.68%
4.57%
4.56%
4.52%
Net interest income amounted to $221.0 million for the first quarter of 2026, a decrease of $1.8 million, compared to $222.8 million
for the fourth quarter of 2025, which includes a reduction of approximately $2.7 million associated with the effect of two less days in
the first quarter of 2026. The decrease in net interest income reflects the following:
●
A $6.5 million decrease in interest income on loans, driven by:
-
A $4.1 million decrease in interest income on commercial and construction loans, driven by a $2.2 million reduction
associated with the effect of two less days in the first quarter of 2026, and a $1.7 million decrease due to the effect of
lower interest rates on the downward repricing of variable-rate loans. Also, the fourth quarter of 2025 included $0.8
million of interest income and a $0.5 million prepayment penalty in connection with the payoffs of a $12.0 million
nonaccrual commercial mortgage loan and a $23.8 million construction loan, respectively, both in the Florida region.
These variances were partially offset by a $1.1 million increase associated with a $65.8 million increase in the average
balance.
As of March 31, 2026, the interest rate on approximately 51% of the Corporation’s commercial and construction loans
was tied to variable rates, with 32% based upon SOFR of 3 months or less, 12% based upon the Prime rate index, and
7% based on other indexes. For the quarter ended March 31, 2026, the average one-month SOFR decreased 24 basis
points, the average three-month SOFR decreased 15 basis points, and the average Prime rate decreased 27 basis points,
when compared to the fourth quarter of 2025.
-
A $2.7 million decrease in interest income on consumer loans and finance leases, due to a $1.7 million decrease
associated with the effect of two less days in the first quarter of 2026, and a $1.0 million decrease associated with a
$36.1 million decline in the average balance.
Partially offset by:
●
A
$3.3 million decrease in interest expense on interest-bearing deposits, consisting of:
-
A $1.5 million decrease in interest expense on interest-bearing checking and saving accounts, mainly due to a decrease
of approximately $0.6 million associated with lower interest rates paid in the first quarter of 2026, a $0.5 million
decrease driven by the effect of two less days in the first quarter of 2026, and a $0.4 million decrease associated with a
$66.4 million net reduction in the average balance. The average cost of interest-bearing checking and saving accounts in
the first quarter of 2026 decreased 4 basis points to 1.21% when compared to the previous quarter, driven by a decrease
in the cost of government deposits. Excluding government deposits, the average cost of interest-bearing checking and
saving accounts in the first quarter of 2026 was 0.66%, compared to 0.68% for the previous quarter.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 3 of 27
-
A $0.9 million decrease in interest expense on time deposits, excluding brokered CDs, mainly due to a $0.7 million
decrease associated with the effect of two less days in the first quarter of 2026.
-
A $0.9 million decrease in interest expense on brokered CDs, of which $0.7 million was associated with a $61.3 million
decline in the average balance.
●
A $1.2 million increase in interest income on investment securities and interest-bearing cash balances, a net effect of:
o
A $2.8 million increase in interest income on debt securities, mainly due to a 22 basis points improvement in yield
resulting from purchases of higher-yielding available-for-sale debt securities replacing maturities of lower-yielding
debt securities.
Partially offset by:
o
A $1.6 million decrease in interest income from interest-bearing cash balances, mainly due to a $1.1 million
decrease associated with a $108.6 million decrease in the average balances, which consisted primarily of cash
maintained at the FED, and a $0.5 million decrease associated with the reduction of the federal funds rate.
Net interest margin for the first quarter of 2026 was 4.75%, a 7 basis points increase when compared to the fourth quarter of 2025,
mostly reflecting the deployment of cash flows from lower-yielding investment securities to higher-yielding assets and the decrease in
the cost of interest-bearing deposits. These factors were partially offset by the downward repricing of variable-rate commercial loans
and a decrease of 3 basis points associated with the aforementioned interest income collected on a nonaccrual commercial loan and a
prepayment penalty during the fourth quarter of 2025.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 4 of 27
NON-INTEREST INCOME
The following table sets forth information concerning non-interest income for the last five quarters:
Quarter Ended
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
March 31, 2025
(In thousands)
Service charges and fees on deposit accounts
$
9,932
$
9,861
$
9,811
$
9,756
$
9,640
Mortgage banking activities
4,043
4,219
3,309
3,401
3,177
Insurance commission income
5,944
2,265
2,618
2,538
5,805
Card and processing income
11,758
12,353
11,682
11,880
11,475
Other non-interest income
6,008
5,702
3,374
3,375
5,637
Non-interest income
$
37,685
$
34,400
$
30,794
$
30,950
$
35,734
Non-interest income increased by $3.3 million to $37.7 million for the first quarter of 2026, compared to $34.4 million for the fourth
quarter of 2025, mainly due to $3.6 million in seasonal contingent commissions recorded as part of insurance commission income in
the first quarter of 2026 based on the prior year’s production of insurance policies. Other variances included a $0.8 million increase in
realized gains from purchased income tax credits reported as part of other non-interest income, partially offset by a $0.6 million
decrease in debit and credit card processing income driven by higher transactional fee income from point-of-sale terminals during the
fourth quarter of 2025.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 5 of 27
NON-INTEREST EXPENSES
The following table sets forth information concerning non-interest expenses for the last five quarters:
Quarter Ended
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
March 31, 2025
(In thousands)
Employees’ compensation and benefits
$
65,299
$
63,196
$
59,761
$
60,058
$
62,137
Occupancy and equipment
22,063
21,797
22,185
22,297
22,630
Business promotion
3,555
5,944
3,884
3,495
3,278
Professional service fees:
Collections, appraisals and other credit-related fees
734
1,007
856
634
598
Outsourcing technology services
8,585
8,433
8,107
8,324
7,921
Other professional fees
3,593
3,671
2,940
2,651
2,967
Taxes, other than income taxes
6,184
6,272
6,092
5,712
5,878
FDIC deposit insurance
2,058
961
2,236
2,235
2,236
Other insurance and supervisory fees
1,206
1,327
1,344
1,566
1,551
Net (gain) loss on other real estate owned (“OREO”) operations
(937)
(838)
1,033
(591)
(1,129)
Credit and debit card processing expenses
7,327
7,728
7,889
7,747
5,110
Communications
2,288
2,284
2,294
2,208
2,245
Other non-interest expenses
5,150
5,088
6,273
7,001
7,600
Total non-interest expenses
$
127,105
$
126,870
$
124,894
$
123,337
$
123,022
Non-interest expenses amounted to $127.1 million in the first quarter of 2026, an increase of $0.2 million, from $126.9 million in the
fourth quarter of 2025. Non-interest expenses for the first quarter of 2026 reflect the following significant variances:
●
A $2.1 million increase in employees’ compensation and benefits expenses, driven by a $1.5 million increase in payroll
taxes, and a $1.8 million increase in stock-based compensation expense, mostly for stock grants during the first quarter of
2026 for retirement-eligible employees, partially offset by a $1.3 million decrease in salary compensation mainly due to the
effect of two less working days in the first quarter of 2026.
●
A $1.1 million increase in the FDIC deposit insurance expense driven by the aforementioned $1.1 million reversal
recognized in the fourth quarter of 2025 related to the FDIC special assessment.
Partially offset by:
●
A $2.4 million decrease in business promotion expenses as a result of certain marketing efforts during the fourth quarter of
2025.
●
A $0.4 million decrease in credit and debit card processing expenses, mainly due to $1.1 million in debit card expense
reimbursements recognized during the first quarter of 2026, partially offset by a $0.7 million increase driven by higher
transactional volumes.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 6 of 27
INCOME TAXES
The Corporation recorded an income tax expense of $25.5 million for the first quarter of 2026, compared to $20.2 million for the
fourth quarter of 2025. The increase in income tax expense was driven by higher pre-tax income and an adjustment in the fourth
quarter of 2025 due to a lower than estimated annual effective tax rate.
For the year, the Corporation’s annual effective tax rate, excluding discrete items, was estimated at 21.9% for the first quarter of 2026,
compared to 21.6% for the fourth quarter of 2025. As of March 31, 2026, the Corporation had a net deferred tax asset of $143.6
million, net of a valuation allowance of $75.9 million, compared to a net deferred tax asset of $149.0 million, net of a valuation
allowance of $75.0 million as of December 31, 2025.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 7 of 27
CREDIT QUALITY
Non-Performing Assets
The following table sets forth information concerning non-performing assets for the last five quarters:
(Dollars in thousands)
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
March 31, 2025
Nonaccrual loans held for investment:
$
28,071
$
29,169
$
28,866
$
30,790
$
30,793
5,414
5,536
5,591
5,718
1,356
7,442
8,382
21,437
22,905
23,155
27,100
28,042
19,650
20,349
20,344
19,717
21,434
20,717
20,336
22,813
$
87,744
$
92,563
$
96,261
$
100,098
$
98,461
OREO
6,344
7,522
9,343
14,449
15,880
Other repossessed property
13,124
12,389
12,234
11,868
13,444
Other assets
(1)
1,609
1,620
1,579
1,576
1,599
(2)
$
108,821
$
114,094
$
119,417
$
127,991
$
129,384
Past due loans 90 days and still accruing
(3)
$
28,949
$
31,913
$
28,891
$
29,535
$
37,117
Nonaccrual loans held for investment to total loans held for investment
0.67%
0.71%
0.74%
0.78%
0.78%
Nonaccrual loans to total loans
0.67%
0.70%
0.74%
0.78%
0.78%
Non-performing assets to total assets
0.57%
0.60%
0.62%
0.68%
0.68%
(1)
Residential pass-through MBS issued by the Puerto Rico Housing Finance Authority (“PRHFA”) held as part of the available-for-sale debt securities portfolio.
(2)
Excludes purchased-credit deteriorated (“PCD”) loans previously accounted for under Accounting Standards Codification (“ASC”) Subtopic 310-30 for which the Corporation made the accounting policy election of
maintaining pools of loans as “units of account” both at the time of adoption of current expected credit losses (“CECL”) on January 1, 2020 and on an ongoing basis for credit loss measurement. These loans will
continue to be excluded from nonaccrual loan statistics as long as the Corporation can reasonably estimate the timing and amount of cash flows expected to be collected on the loan pools. The portion of such loans
contractually past due 90 days or more amounted to $4.2 million as of March 31, 2026 (December 31, 2025 - $4.8 million; September 30, 2025 - $5.0 million; June 30, 2025 - $4.9 million; March 31, 2025 - $5.7
million).
(3)
These include rebooked loans, which were previously pooled into GNMA securities, amounting to $6.7 million as of March 31, 2026 (December 31, 2025 - $6.7 million; September 30, 2025 - $3.8 million; June 30,
2025 - $5.5 million; March 31, 2025 - $6.4 million). Under the GNMA program, the Corporation has the option but not the obligation to repurchase loans that meet GNMA’s specified delinquency criteria. For
accounting purposes, the loans subject to the repurchase option are required to be reflected on the financial statements with an offsetting liability.
Variances in credit quality metrics:
●
Total non-performing assets decreased by $5.3 million to $108.8 million as of March 31, 2026, driven by a $4.8 million
decrease in nonaccrual loans. Nonaccrual commercial and construction loans decreased by $2.0 million, driven by a $1.2
million repayment of a C&I loan in the Puerto Rico region in the food retail industry, and a $0.6 million charge-off of a
commercial mortgage loan in the Virgin Islands region. Nonaccrual consumer loans decreased by $1.7 million, mainly in the
auto loan portfolio, and nonaccrual residential mortgage loans decreased by $1.1 million. In addition, the OREO portfolio
balance decreased by $1.2 million, mainly attributable to the sale of residential properties in the Puerto Rico region, partially
offset by an increase of $0.7 million in other repossessed properties.
●
Inflows to nonaccrual loans held for investment were $34.3 million in the first quarter of 2026, a decrease of $11.9 million,
compared to inflows of $46.2 million in the fourth quarter of 2025. Inflows to nonaccrual commercial and construction loans
were $1.2 million in the first quarter of 2026, a decrease of $11.2 million, compared to inflows of $12.4 million in the fourth
quarter of 2025, mostly associated with a $10.0 million C&I loan in the Puerto Rico region in the telecommunications
industry. Inflows to nonaccrual residential mortgage loans were $3.4 million in the first quarter of 2026, a decrease of $0.9
million, compared to inflows of $4.3 million in the fourth quarter of 2025. Inflows to nonaccrual consumer loans were $29.7
million in the first quarter of 2026, an increase of $0.2 million, compared to inflows of $29.5 million in the fourth quarter of
2025. See
Early Delinquency
below
for additional information.
●
Adversely classified commercial and construction loans decreased by $5.4 million to $76.0 million as of March 31, 2026,
compared to $81.4 million as of December 31, 2025, driven by $3.8 million in repayments on three C&I loans, including the
aforementioned repayment of a nonaccrual C&I loan in the Puerto Rico region.
Early Delinquency
Total loans held for investment in early delinquency (i.e., 30-89 days past due accruing loans, as defined in regulatory reporting
instructions) amounted to $110.5 million as of March 31, 2026, a decrease of $34.5 million, compared to $145.0 million as of
December 31, 2025, driven by a $31.0 million decrease in consumer loans, primarily in the auto loan portfolio.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 8 of 27
Allowance for Credit Losses
The following table summarizes the activity of the ACL for on-balance sheet and off-balance sheet exposures during the first quarter
of 2026 and fourth quarter of 2025:
Quarter Ended March 31, 2026
Loans and Finance Leases
Debt Securities
(Dollars in thousands)
Residential
Mortgage
Loans
Commercial and
Construction
Loans
Consumer
Loans and
Finance Leases
Total Loans and
Finance Leases
Unfunded
Loans
Commitments
Held-to-
Maturity
Available-
for-Sale
Total ACL
Allowance for Credit Losses
Allowance for credit losses, beginning balance
$
41,071
$
70,920
$
137,046
$
249,037
$
3,013
$
733
$
763
$
253,546
Provision for credit losses - expense (benefit)
239
(984)
17,915
17,170
107
(92)
88
17,273
Net recoveries (charge-offs)
224
(818)
(20,553)
(21,147)
-
-
(12)
(21,159)
Allowance for credit losses, end of period
$
41,534
$
69,118
$
134,408
$
245,060
$
3,120
$
641
$
839
$
249,660
Amortized cost of loans and finance leases
$
2,914,898
$
6,517,223
$
3,658,956
$
13,091,077
Allowance for credit losses on loans to amortized cost
1.42%
1.06%
3.67%
1.87%
Quarter Ended December 31, 2025
Loans and Finance Leases
Debt Securities
(Dollars in thousands)
Residential
Mortgage
Loans
Commercial and
Construction
Loans
Consumer
Loans and
Finance Leases
Total Loans and
Finance Leases
Unfunded
Loans
Commitments
Held-to-
Maturity
Available-
for-Sale
Total ACL
Allowance for Credit Losses
Allowance for credit losses, beginning balance
$
40,272
$
68,580
$
138,138
$
246,990
$
2,611
$
698
$
658
$
250,957
Provision for credit losses - expense
644
2,393
19,381
22,418
402
35
116
22,971
Net recoveries (charge-offs)
155
(53)
(20,473)
(20,371)
-
-
(11)
(20,382)
Allowance for credit losses, end of period
$
41,071
$
70,920
$
137,046
$
249,037
$
3,013
$
733
$
763
$
253,546
Amortized cost of loans and finance leases
$
2,908,302
$
6,508,178
$
3,708,876
$
13,125,356
Allowance for credit losses on loans to amortized cost
1.41%
1.09%
3.70%
1.90%
Allowance for Credit Losses for Loans and Finance Leases
As of March 31, 2026, the ACL for loans and finance leases was $245.1 million, a decrease of $3.9 million, from $249.0 million as of
December 31, 2025. The ratio of the ACL for loans and finance leases to total loans held for investment was 1.87% as of March 31,
2026, compared to 1.90% as of December 31, 2025.
The decrease was mainly related to the ACL for consumer loans, which decreased by $2.6 million, driven by improvements in
macroeconomic variables, mainly in the projection of the unemployment rate, and lower delinquency levels, partially offset by higher
qualitative reserves associated with geopolitical uncertainty driven by, among other things, higher oil prices as a result of the conflict
in the Middle East. In addition, the ACL for commercial and construction loans decreased by $1.8 million, mainly due to
improvements in the projections of the unemployment rate and the CRE price index, net of aforementioned qualitative reserves,
partially offset by renewals and refinancings. Meanwhile, the ACL for residential mortgage loans increased by $0.5 million, driven by
loan growth and the aforementioned geopolitical uncertainty, partially offset by an improvement in the unemployment rate.
The provision for credit losses on loans and finance leases was $17.2 million for the first quarter of 2026, compared to $22.4 million
in the fourth quarter of 2025, as detailed below:
●
Provision for credit losses on the commercial and construction loan portfolios was a net benefit of $1.0 million for the
first quarter of 2026, compared to an expense of $2.4 million for the fourth quarter of 2025. The net benefit recorded
during the first quarter of 2026 was driven primarily by the aforementioned improvement in macroeconomic variables.
●
Provision for credit losses on the consumer loan and finance lease portfolios was an expense of $18.0 million for the first
quarter of 2026, compared to an expense of $19.4 million for the fourth quarter of 2025. The $1.4 million decrease in
provision expense was driven by the aforementioned factors.
●
Provision for credit losses on the residential mortgage loan portfolio was an expense of $0.2 million for the first quarter
of 2026, compared to an expense of $0.6 million for the fourth quarter of 2025. The $0.4 million decrease in provision
expense was driven by lower loan growth than the previous quarter, partially offset by the aforementioned qualitative
reserves for the geopolitical uncertainty discussed above.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 9 of 27
Net Charge-Offs
The following table presents ratios of net (recoveries) charge-offs to average loans held-in-portfolio for the last five quarters:
Quarter Ended
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
March 31, 2025
Residential mortgage
-0.03%
-0.02%
-0.00%
-0.00%
0.00%
Construction
-0.02%
-0.02%
-0.50%
-0.02%
-0.02%
Commercial mortgage
0.08%
0.01%
-0.02%
-0.01%
-0.01%
C&I
0.03%
0.00%
0.01%
-0.09%
-0.01%
Consumer loans and finance leases
2.23%
2.20%
2.16%
2.12%
2.31%
(1)
Total loans
0.65%
0.63%
0.62%
0.60%
0.68%
(1)
(1)
Includes $2.4 million in recoveries associated with the bulk sale of fully charged-off consumer loans and finance leases, which reduced the ratios of consumer loans and finance
leases and total net charge-offs to related average loans by 25 basis points and 8 basis points, respectively.
The ratios above are based on annualized net charge-offs and are not necessarily indicative of the results expected in subsequent
periods.
Net charge-offs were $21.1 million for the first quarter of 2026, or an annualized 0.65% of average loans, compared to $20.4 million,
or an annualized 0.63% of average loans, in the fourth quarter of 2025. The $0.7 million increase in net charge-offs was driven by a
$0.6 million charge-off associated with a nonaccrual commercial mortgage loan in the Virgin Islands region.
Allowance for Credit Losses for Unfunded Loan Commitments
As of March 31, 2026, the ACL for off-balance sheet credit exposures increased to $3.1 million, compared to $3.0 million as of
December 31, 2025.
Allowance for Credit Losses for Debt Securities
As of March 31, 2026, the ACL for debt securities was $1.5 million, of which $0.6 million was related to Puerto Rico municipal bonds
classified as held-to-maturity, compared to $1.5 million and $0.7 million, respectively, as of December 31, 2025.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 10 of 27
STATEMENT OF FINANCIAL CONDITION
Total assets were approximately $19.1 billion as of March 31, 2026, down $46.8 million from December 31, 2025. The following
variances within the main components of total assets are noted:
●
A $107.7 million decrease in cash and cash equivalents, mainly related to the net cash outflow for the purchase of investment
securities, capital deployment actions, and the overall decrease in deposits, partially offset by the net income generated in the
first quarter of 2026.
●
A $38.2 million decrease in total loans , driven by a $49.9 million decrease in consumer loans, of which $28.6 million was in
auto loans and finance leases in the Puerto Rico region. In terms of geography, the decline consisted of a $112.9 million
decrease in the Puerto Rico region, driven by the aforementioned decrease in consumer loans and lower utilization of C&I
lines of credit, mainly in automotive lending, partially offset by increase s of $47.2 million in the Florida region and $27.5
million in the Virgin Islands region.
Total loan originations, including refinancings, renewals, and draws from existing commitments, amounted to $1.2 billion in
the first quarter of 2026, a decrease of $143.0 million compared to the fourth quarter of 2025.
Total loan originations in the Puerto Rico region amounted to $848.9 million in the first quarter of 2026, compared to $1.1
billion in the fourth quarter of 2025. The decrease of $219.9 million in total loan originations was mainly related to a $192.7
million decrease in commercial and construction loans, of which $174.0 million was in C&I loans, driven by multiple term
loan originations in the fourth quarter of 2025 totaling $114.7 million and the aforementioned lower utilization of lines of
credit.
Total loan originations in the Florida region amounted to $228.4 million in the first quarter of 2026, compared to $295.8
million in the fourth quarter of 2025. The $67.4 million decrease in total loan originations was mainly related to a $66.5
million decrease in commercial and construction loan originations, of which $42.1 million was in commercial mortgage loan
originations and $23.5 million was in C&I loan originations.
Total loan originations in the Virgin Islands region amounted to $170.9 million in the first quarter of 2026, compared to
$26.6 million in the fourth quarter of 2025. The increase of $144.3 million in total loan originations was mainly related to the
origination of a $138.1 million government line of credit during the first quarter of 2026, of which $108.1 million was a
refinancing.
Partially offset by:
●
A $108.7 million increase in investment securities, driven by purchases during the first quarter of 2026 of $437.0 million in
U.S. agencies’ MBS and debentures at an average yield of 4.57%, partially offset by repayments of $322.2 million of U.S.
agencies’ MBS and debentures, of which $125.7 million was associated with matured securities, and a $6.2 million decrease
in the fair value of available -for-sale debt securities attributable to changes in market interest rates. In addition, during the
first quarter of 2026, $375.0 million in matured U.S. Treasury bills were replaced with $370.6 million in U.S. Treasury bills.
Total liabilities were approximately $17.1 billion as of March 31, 2026, a decrease of $47.2 million from December 31, 2025. The
following variances within the main components of total liabilities are noted:
●
Total deposits decreased by $74.3 million consisting of:
o
A
$146.3 million decrease in government deposits, driven by a decline of $134.2 million in the Puerto Rico region.
o
An $86.5 million decrease in brokered CDs in the Florida region. The decrease consisted of maturing brokered CDs
amounting to $119.6 million with an all-in cost of 4.42% that were paid off during the first quarter of 2026, partially
offset by $33.1 million of new issuances with original average maturities of approximately 1.2 years and an all-in
cost of 3.77%.
Partially offset by:
o
A $158.5 million increase in deposits, excluding brokered CDs and government deposits, consisting of increases of
$97.0 million in the Puerto Rico region, $37.8 million in the Virgin Islands region, and $23.7 million in the Florida
region. The increase in such deposits consists of a $115.4 million increase in interest-bearing deposits, of which
$73.1 million was in the Puerto Rico region, and a $43.1 million increase in non-interest-bearing deposits.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 11 of 27
Total stockholders’ equity amounted to $2.0 billion as of March 31, 2026, an increase of $0.4 million from December 31, 2025, driven
by the net income generated in the first quarter of 2026, partially offset by $50.0 million in common stock repurchases at an average
price of $20.75, $31.5 million in common stock dividends declared in the first quarter of 2026, and a $6.2 million decrease in the fair
value of available-for-sale debt securities due to changes in market interest rates recognized as part of accumulated other
comprehensive loss.
As of March 31, 2026, capital ratios exceeded the required regulatory levels for bank holding companies and well-capitalized banks.
The Corporation’s estimated CET1 capital, tier 1 capital, total capital and leverage ratios under the Basel III rules were 16.93%,
16.93%, 18.19%, and 11.66%, respectively, as of March 31, 2026, compared to CET1 capital, tier 1 capital, total capital, and leverage
ratios of 16.76%, 16.76%, 18.01%, and 11.58% , respectively, as of December 31, 2025.
Meanwhile, estimated CET1 capital, tier 1 capital, total capital and leverage ratios of our banking subsidiary, FirstBank, were 15.76%,
16.51%, 17.77%, and 11.37%, respectively, as of March 31, 2026, compared to CET1 capital, tier 1 capital, total capital and leverage
ratios of 15.60%, 16.35%, 17.61%, and 11.30%, respectively, as of December 31, 2025.
Liquidity
Cash and cash equivalents decreased by $107.7 million to $550.9 million as of March 31, 2026. When adding $2.3 billion of free
high-quality liquid securities that could be liquidated or pledged within one day, total core liquidity amounted to $2.9 billion as of
March 31, 2026, or 14.66% of total assets, compared to $2.6 billion, or 13.54% of total assets as of December 31, 2025. In addition, as
of March 31, 2026, the Corporation had $1.0 billion available for credit with the FHLB based on the value of the collateral pledged
with the FHLB. As such, the basic liquidity ratio (which includes cash, free high-quality liquid assets such as U.S. government and
government-sponsored enterprises’ obligations that could be liquidated or pledged within one day, and available secured lines of credit
with the FHLB to total assets) was approximately 20.14% as of March 31, 2026, compared to 19.39% as of December 31, 2025.
In addition to the aforementioned available credit from the FHLB, the Corporation also maintains borrowing capacity at the FED
Discount Window Program. The Corporation had approximately $2.6 billion available for funding under the FED’s Borrower-In-
Custody Program as of March 31, 2026. In the aggregate, as of March 31, 2026, the Corporation had $6.5 billion available to meet
liquidity needs, or 134% of estimated uninsured deposits (excluding fully collateralized government deposits).
The Corporation’s total deposits, excluding brokered CDs, amounted to $16.1 billion as of each of March 31, 2026 and December 31,
2025, which included $2.9 billion and $3.0 billion, respectively, in government deposits that are fully collateralized. Excluding fully
collateralized government deposits and FDIC-insured deposits, the estimated amount of uninsured deposits was $4.8 billion as of each
of March 31, 2026 and December 31, 2025, which represents 30.12% and 29.79% of total deposits, respectively. Refer to Table 9 in
the accompanying tables (Exhibit A) for additional information about the deposits composition.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 12 of 27
Tangible Common Equity (Non-GAAP)
On a non-GAAP basis, the Corporation’s tangible common equity ratio increased to 10.11% as of March 31, 2026, compared to
10.08% as of December 31, 2025. Refer to
Non-GAAP Disclosures- Non-GAAP Financial Measures
additional information about this non-GAAP financial measure.
The following table presents a reconciliation of the Corporation’s tangible common equity and tangible assets to the most comparable
GAAP items as of the indicated dates:
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
March 31, 2025
(In thousands, except ratios and per share information)
Tangible Equity:
Total common equity - GAAP
$
1,967,239
$
1,966,865
$
1,918,045
$
1,845,455
$
1,779,342
Goodwill
(38,611)
(38,611)
(38,611)
(38,611)
(38,611)
Other intangible assets
(3,240)
(3,458)
(3,676)
(4,535)
(5,715)
Tangible common equity - non-GAAP
$
1,925,388
$
1,924,796
$
1,875,758
$
1,802,309
$
1,735,016
Tangible Assets:
Total assets - GAAP
$
19,086,105
$
19,132,892
$
19,321,335
$
18,897,529
$
19,106,983
Goodwill
(38,611)
(38,611)
(38,611)
(38,611)
(38,611)
Other intangible assets
(3,240)
(3,458)
(3,676)
(4,535)
(5,715)
Tangible assets - non-GAAP
$
19,044,254
$
19,090,823
$
19,279,048
$
18,854,383
$
19,062,657
Common shares outstanding
154,694
156,619
159,135
161,508
163,104
Tangible common equity ratio - non-GAAP
10.11%
10.08%
9.73%
9.56%
9.10%
Tangible book value per common share - non-GAAP
$
12.45
$
12.29
$
11.79
$
11.16
$
10.64
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 13 of 27
Exposure to Puerto Rico Government
Direct Exposure
As of March 31, 2026, the Corporation had $297.5 million of direct exposure to the Puerto Rico government, its municipalities, and
public corporations, a decrease of $0.3 million compared to $297.8 million as of December 31, 2025. As of March 31, 2026,
approximately $211.5 million of the exposure consisted of loans and obligations of municipalities in Puerto Rico that are supported by
assigned property tax revenues and for which, in most cases, the good faith, credit, and unlimited taxing power of the applicable
municipality have been pledged to their repayment, and $42.3 million consisted of loans and obligations which are supported by one
or more specific sources of municipal revenues. The Corporation’s total direct exposure to the Puerto Rico government also included
$8.6 million in a loan extended to an affiliate of the Puerto Rico Electric Power Authority and $32.4 million in loans to a public
corporation of Puerto Rico. In addition, the total direct exposure included an obligation of the Puerto Rico government, specifically a
residential pass-through MBS issued by the PRHFA, at an amortized cost of $2.7 million (fair value of $1.6 million as of March 31,
2026), included as part of the Corporation’s available-for-sale debt securities portfolio. This residential pass-through MBS issued by
the PRHFA is collateralized by certain second mortgages and had an unrealized loss of $1.1 million as of March 31, 2026, of which
$0.3 million is due to credit deterioration.
The aforementioned exposure to municipalities in Puerto Rico included $79.8 million of financing arrangements with Puerto Rico
municipalities that were issued in bond form but underwritten as loans with features that are typically found in commercial loans.
These bonds are accounted for as held-to-maturity debt securities.
Indirect Exposure
As of March 31, 2026 and December 31, 2025, the Corporation had $2.4 billion and $2.5 billion, respectively, of public sector
deposits in Puerto Rico. Approximately 20% of the public sector deposits as of March 31, 2026 were from municipalities and
municipal agencies in Puerto Rico, and 80% were from public corporations, the Puerto Rico central government and agencies, and
U.S. federal government agencies in Puerto Rico.
Additionally, as of March 31, 2026, the outstanding balance of construction loans funded through conduit financing structures to
support the federal programs of Low-Income Housing Tax Credit combined with other federal programs amounted to $81.6 million,
compared to $92.4 million as of December 31, 2025. The main objective of these programs is to spur development in new or
rehabilitated and affordable rental housing. PRHFA , as program subrecipient and conduit issuer, issues tax-exempt obligations which
are acquired by private financial institutions and are required to co-underwrite with PRHFA a mirror construction loan agreement for
the specific project loan to which the Corporation will serve as ultimate lender but where the PRHFA will be the lender of record. The
total amount of unfunded loan commitments related to these loans as of March 31, 2026 was $55.3 million.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 14 of 27
NON-GAAP DISCLOSURES
This press release contains GAAP financial measures and non-GAAP financial measures. Non-GAAP financial measures are used
when management believes that the presentation of these non-GAAP financial measures enhances the ability of analysts and investors
to analyze trends in the Corporation’s business and understand the performance of the Corporation. The Corporation may utilize these
non-GAAP financial measures as guides in its budgeting and long-term planning process. Where non-GAAP financial measures are
used, the most comparable GAAP financial measure, as well as the reconciliation of the non-GAAP financial measure to the most
comparable GAAP financial measure, can be found in the text or in the tables in or attached to this press release. Any analysis of these
non-GAAP financial measures should be used only in conjunction with results presented in accordance with GAAP.
Certain non-GAAP financial measures, such as adjusted non-interest expenses, adjusted net income, adjusted earnings per share, and
adjusted pre-tax, pre-provision income, exclude the effect of items that management believes are not reflective of core operating
performance (the “Special Items”). Other non-GAAP financial measures include net interest income, interest rate spread, and net
interest margin each presented on a tax-equivalent basis; tangible common equity; tangible book value per common share; and certain
capital ratios. These measures should be read in conjunction with the accompanying tables (Exhibit A), which are an integral part of
this press release, and the Corporation’s other financial information that is presented in accordance with GAAP.
Special Items
The financial results for the quarters ended March 31, 2026 and December 31, 2025 included the following Special Item:
FDIC Special Assessment Reversal
-
A benefit of $0.1 million ($0.1 million after-tax, calculated based on the statutory tax rate of 37.5%) and $1.1 million ($0.7
million after-tax) were recorded during the first quarter of 2026 and fourth quarter of 2025, respectively, as a result of
amendments to the FDIC special assessment collection terms. On December 16, 2025, the FDIC issued an interim final rule
amending the collection terms of the special assessment, which included reducing the collection rate in the eighth collection
quarter from 3.36 basis points to 2.97 basis points, removing the previously established extended assessment period
provisions, and providing offsets to regular quarterly deposit insurance assessments if aggregate collections exceed actual
losses. This update follows the FDIC’s 2023 final rule, which initially imposed the special assessment to recover certain
estimated losses incurred by the Deposit Insurance Fund following the failures of certain financial institutions in the first half
of 2023. The FDIC deposit special assessment is reflected in the condensed consolidated statements of income as part of
“FDIC deposit insurance” expenses.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 15 of 27
Non-GAAP Financial Measures
Tangible Common Equity Ratio and Tangible Book Value per Common Share
The tangible common equity ratio and tangible book value per common share are non-GAAP financial measures that management
believes are generally used by the financial community to evaluate capital adequacy. Tangible common equity is total common equity
less goodwill and other intangible assets. Tangible assets are total assets less goodwill and other intangible assets. Tangible common
equity ratio is tangible common equity divided by tangible assets. Tangible book value per common share is tangible assets divided by
common shares outstanding. Refer to
Statement of Financial Condition – Tangible Common Equity (Non-GAAP)
of the Corporation’s total stockholders’ equity and total assets in accordance with GAAP to the non-GAAP financial measures of
tangible common equity and tangible assets, respectively. Management uses and believes that many stock analysts use the tangible
common equity ratio and tangible book value per common share in conjunction with other more traditional bank capital ratios to
compare the capital adequacy of banking organizations with significant amounts of goodwill or other intangible assets, typically
stemming from the use of the purchase method of accounting for mergers and acquisitions. Accordingly, the Corporation believes that
disclosure of these financial measures may be useful to investors. Neither tangible common equity nor tangible assets, or the related
measures, should be considered in isolation or as a substitute for stockholders’ equity, total assets, or any other measure calculated in
accordance with GAAP. Moreover, the manner in which the Corporation calculates its tangible common equity, tangible assets, and
any other related measures may differ from that of other companies reporting measures with similar names.
Adjusted Net Income and Adjusted Non-Interest Expenses
To supplement the Corporation’s financial statements presented in accordance with GAAP, the Corporation uses, and believes that
investors benefit from disclosure of, non -GAAP financial measures that reflect adjustments to net income and non-interest expenses to
exclude Special Items.
Adjusted Pre-Tax, Pre-Provision Income
Adjusted pre-tax, pre-provision income is a non-GAAP performance metric that management uses and believes that investors may
find useful in analyzing underlying performance trends, particularly in times of economic stress, including as a result of natural
catastrophes or health epidemics. Adjusted pre-tax, pre-provision income, as defined by management, represents income before
income taxes adjusted to exclude the provisions for credit losses on loans, unfunded loan commitments and debt securities. In
addition, from time to time, earnings are also adjusted for certain items that management believes are not reflective of core operating
performance, which are regarded as Special Items.
Net Interest Income on a Tax -Equivalent Basis
Net interest income, interest rate spread, and net interest margin are reported on a tax-equivalent basis in order to provide to investors
additional information about the Corporation’s net interest income that management uses and believes should facilitate comparability
and analysis of the periods presented. The tax-equivalent adjustment to net interest income recognizes the income tax savings when
comparing taxable and tax-exempt assets and assumes a marginal income tax rate. Income from tax-exempt earning assets is increased
by an amount equivalent to the taxes that would have been paid if this income had been taxable at statutory rates. Refer to Table 4 in
the accompanying tables (Exhibit A) for a reconciliation of the Corporation’s net interest income on a tax-equivalent basis.
Management believes that it is a standard practice in the banking industry to present net interest income, interest rate spread, and net
interest margin on a fully tax-equivalent basis. This adjustment puts all earning assets, most notably tax-exempt securities and tax-
exempt loans, on a common basis that management believes facilitates comparison of results to the results of peers.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 16 of 27
NET INCOME AND RECONCILIATION TO ADJUSTED NET INCOME (NON-GAAP)
The following table reconciles, for the first quarter of 2026 and fourth quarter of 2025, net income to adjusted net income and adjusted
earnings per diluted share, which are non-GAAP financial measures that exclude the significant Special Item discussed in the
Non-
GAAP Disclosures – Special Items
Quarter Ended
March 31, 2026
December 31, 2025
March 31, 2025
(In thousands, except per share information)
Net income, as reported (GAAP)
$
88,778
$
87,101
$
77,059
Adjustment:
FDIC special assessment reversal
(92)
(1,099)
-
(1)
35
412
-
Adjusted net income attributable to common stockholders (Non-GAAP)
$
88,721
$
86,414
$
77,059
Weighted-average diluted shares outstanding
156,101
157,675
163,749
Earnings per share - diluted (GAAP)
$
0.57
$
0.55
$
0.47
Adjusted earnings per share - diluted (non-GAAP)
$
0.57
$
0.55
$
0.47
(1) See
Non-GAAP Disclosures —
Special Items
above for a discussion of the individual tax impact related to the above adjustment.
INCOME BEFORE INCOME TAXES AND RECONCILIATION TO ADJUSTED PRE-TAX, PRE-PROVISION INCOME
(NON-GAAP)
The following table reconciles income before income taxes to adjusted pre-tax, pre-provision income for the last five quarters:
Quarter Ended
March 31, 2026
December 31, 2025
September 30, 2025
June 30, 2025
March 31, 2025
(Dollars in thousands)
Income before income taxes
$
114,263
$
107,327
$
106,223
$
102,885
$
100,299
Add: Provision for credit losses expense
17,273
22,971
17,593
20,587
24,810
Less: FDIC special assessment reversal
(92)
(1,099)
-
-
-
Less: Employee retention credit
-
-
(2,358)
-
-
Adjusted pre-tax, pre-provision income
(1)
$
131,444
$
129,199
$
121,458
$
123,472
$
125,109
Change from most recent prior period (amount)
$
2,245
$
7,741
$
(2,014)
$
(1,637)
$
8,176
Change from most recent prior period (percentage)
1.7%
6.4%
-1.6%
-1.3%
7.0%
(1)
Non-GAAP financial measure. See
Non-GAAP Disclosures
above for the definition and additional information about this non-GAAP financial measure.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 17 of 27
Conference Call / Webcast Information
First BanCorp.’s senior management will host an earnings conference call and live webcast on Wednesday, April 22, 2026, at 10:00
a.m. (Eastern Time). The call may be accessed via a live Internet webcast through the Corporation’s investor relations website,
fbpinvestor.com, or through a dial-in telephone number at (800) 715-9871 or (646) 307-1963. The participant access code is 5351564.
The Corporation recommends that listeners go to the web site at least 15 minutes prior to the call to download and install any
necessary software. Following the webcast presentation, a question and answer session will be made available to research analysts and
institutional investors. A replay of the webcast will be archived in the Corporation’s investor relations website, fbpinvestor.com, until
April 22, 2027. A telephone replay will be available one hour after the end of the conference call through May 22, 2026, at (800) 770-
2030. The replay access code is 5351564.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 18 of 27
Safe Harbor
This press release may contain “forward-looking statements” concerning the Corporation’s future economic, operational, and financial
performance. The words or phrases “expect,” “anticipate,” “intend,” “should,” “would,” “will,” “plans,” “forecast,” “believe,” and
similar expressions are meant to identify “forward-looking statements” within the meaning of Section 27A of the Securities Act of
1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, and are subject to the safe harbor created by
such sections. The Corporation cautions readers not to place undue reliance on any such forward-looking statements, which speak only
as of the date hereof, and advises readers that any such forward-looking statements are not guarantees of future performance and
involve certain risks, uncertainties, estimates, and assumptions by us that are difficult to predict. Various factors, some of which are
beyond our control, including, but not limited to, the uncertainties more fully discussed in Part I, Item 1A, “Risk Factors” of the
Corporation’s Annual Report on Form 10-K for the year ended December 31, 2025, and the following, could cause actual results to
differ materially from those expressed in, or implied by, such forward-looking statements: the effect of changes in the interest rate
environment and inflation levels on the level, composition and performance of the Corporation’s assets and liabilities, and
corresponding effects on the Corporation’s net interest income, net interest margin, loan originations, deposit attrition, overall results
of operations, and liquidity position; volatility in the financial services industry, which could result in, among other things, bank
deposit runoffs, liquidity constraints, and increased regulatory requirements and costs; the effect of continued changes in the fiscal,
monetary and trade policies and regulations of the U.S. federal government, the Puerto Rico government and other governments,
including those determined by the Federal Reserve Board, the Federal Reserve Bank of New York, the FDIC, government -sponsored
housing agencies and regulators in Puerto Rico, the U.S., and the U.S. and British Virgin Islands, that may affect the future results of
the Corporation; uncertainty as to the ability of FirstBank to retain its core deposits and generate sufficient cash flow through its
wholesale funding sources, such as securities sold under agreements to repurchase, FHLB advances, and brokered CDs, which may
require us to sell investment securities at a loss; adverse changes in general political and economic conditions in Puerto Rico, the U.S.,
and the U.S. and British Virgin Islands, including in the interest rate environment, unemployment rates, market liquidity and volatility,
trade policies, housing absorption rates, real estate markets , and U.S. capital markets, which may affect funding sources, loan portfolio
performance and credit quality, market prices of investment securities, and demand for the Corporation’s products and services,
and which may reduce the Corporation’s revenues and earnings and the value of the Corporation’s assets; the impact of litigation or
the threat of litigation or other dispute resolutions, including any adverse settlements or judgments against the Corporation, and the
potential resulting liabilities, costs, negative publicity or other reputational harm; the effects of asserted and unasserted claims and the
extent of available insurance coverage; the impact of government financial assistance for hurricane recovery and other disaster relief
on economic activity in Puerto Rico, and the timing and pace of disbursements of funds earmarked for disaster relief; the ability of the
Corporation, FirstBank, and third-party service providers to identify and prevent cyber-security incidents, such as data security
breaches, ransomware, malware, “denial of service” attacks, “hacking,” identity theft, and state-sponsored cyberthreats, and the
occurrence of and response to any incidents that occur, which may result in misuse or misappropriation of confidential or proprietary
information, disruption, or damage to our systems or those of third-party service providers on which we rely, increased costs and
losses and/ or adverse effects to our reputation; general competitive factors and other market risks as well as the implementation of
existing or planned strategic growth opportunities, including risks, uncertainties, and other factors or events related to any business
acquisitions, dispositions, strategic partnerships, strategic operational investments, including systems conversions, and any anticipated
efficiencies or other expected results related thereto; uncertainty regarding the implementation of Puerto Rico’s debt restructuring plan
and the revised fiscal plan for Puerto Rico, as certified on June 6, 2025, by the oversight board established by the Puerto Rico
Oversight, Management, and Economic Stability Act, or any revisions to it, on our clients and loan portfolios, and any potential
impact of future economic or political developments and tax regulations in Puerto Rico; the impact of changes in accounting
standards, or determinations and assumptions in applying those standards, and of forecasts of economic variables considered for the
determination of the ACL; the ability of FirstBank to realize the benefits of its net deferred tax assets; the ability of FirstBank to
generate sufficient cash flow to pay dividends to the Corporation; environmental, social, and governance (“ESG”) matters, including
our climate-related initiatives and commitments, as well as the impact and potential cost to us of any policies, legislation, or initiatives
in opposition to our ESG policies; the impacts of natural or man-made disasters, widespread health emergencies, geopolitical conflicts
(including sanctions, war or armed conflict, such as the ongoing conflict in Ukraine, ongoing conflicts in the Middle East, such as the
war in Iran, recent conflicts in South America, the possible expansion of such conflicts in surrounding areas and potential geopolitical
consequences, and the threat of conflict from neighboring countries in our region), terrorist attacks, or other catastrophic external
events, including impacts of such events on general economic conditions and on the Corporation’s assumptions regarding forecasts of
economic variables; the risk that additional portions of the unrealized losses in the Corporation’s debt securities portfolio are
determined to be credit-related, resulting in additional charges to the provision for credit losses on the Corporation’s debt securities
portfolio, and the potential for additional credit losses that could emerge from further downgrades of the U.S.’s Long-Term Foreign-
Currency Issuer Default Rating and negative ratings outlooks; the impacts of applicable legislative, tax, or regulatory changes or
changes in legislative, tax, or regulatory priorities, including as a result of the One Big Beautiful Bill Act, signed into law on July 4,
2025, the reduction in staffing at U.S. governmental agencies, the effects of U.S. federal government shutdowns and political
impasses, and uncertainties regarding the U.S. debt ceiling and federal budget, on the Corporation’s financial condition or
performance; the risk of possible failure or circumvention of the Corporation’s internal controls and procedures and the risk that the
Corporation’s risk management policies may not be adequate; the risk that the FDIC may further increase the deposit insurance
premium and/or require further special assessments, causing an additional increase in the Corporation’s non-interest expenses; any
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 19 of 27
need to recognize impairments on the Corporation’s financial instruments, goodwill, and other intangible assets; the risk that the
impact of the occurrence of any of these uncertainties on the Corporation’s capital would preclude further growth of FirstBank and
preclude the Corporation’s Board of Directors from declaring dividends; and uncertainty as to whether FirstBank will be able to
continue to satisfy its regulators regarding, among other things, its asset quality, liquidity plans, maintenance of capital levels, and
compliance with applicable laws, regulations and related requirements. The Corporation does not undertake to, and specifically
disclaims any obligation to update any “forward-looking statements” to reflect occurrences or unanticipated events or circumstances
after the date of such statements, except as required by the federal securities laws.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 20 of 27
About First BanCorp.
First BanCorp. is the parent corporation of FirstBank Puerto Rico, a state-chartered commercial bank with operations in Puerto Rico,
the U.S., and the British Virgin Islands and Florida, and of FirstBank Insurance Agency. First BanCorp.’s shares of common stock
trade on the New York Stock Exchange under the symbol FBP. Additional information about First BanCorp. may be found at
www.1firstbank.com .
###
First BanCorp.
Ramon Rodriguez
Senior Vice President
Corporate Strategy and Investor Relations
(787) 729-8200 Ext. 82179
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 21 of 27
EXHIBIT A
Table 1 – Condensed Consolidated Statements of Financial Condition
As of
March 31, 2026
December 31, 2025
(In thousands, except for share information)
ASSETS
Cash and due from banks
549,199
657,149
Money market investments:
1,000
750
700
700
1,700
1,450
Available-for-sale debt securities, at fair value (ACL of $839 as of March 31, 2026 and $763 as of December 31, 2025)
4,668,697
4,554,032
Held-to-maturity debt securities, at amortized cost, net of ACL of $641 as of March 31, 2026 and $733 as of
256,881
264,563
4,925,578
4,818,595
Equity securities
46,432
44,753
4,972,010
4,863,348
Loans held for investment, net of ACL of $245,060 as of March 31, 2026 and $249,037 as of December 31, 2025
12,846,017
12,876,319
Mortgage loans held for sale, at lower of cost or market
12,805
16,697
12,858,822
12,893,016
Accrued interest receivable on loans and investments
67,722
71,351
Premises and equipment, net
127,865
126,920
OREO
6,344
7,522
Deferred tax asset, net
143,565
149,012
Goodwill
38,611
38,611
Other intangible assets
3,240
3,458
Other assets
317,027
321,055
19,086,105
19,132,892
LIABILITIES
Deposits:
$
5,554,751
$
5,549,416
11,041,070
11,120,727
16,595,821
16,670,143
Advances from the FHLB
290,000
290,000
Accounts payable and other liabilities
233,045
205,884
17,118,866
17,166,027
STOCKHOLDERSʼ EQUITY
Common stock, $0.10 par value, 223,663,116 shares issued (March 31, 2026 - 154,693,926 shares outstanding
22,366
22,366
Additional paid-in capital
952,773
963,543
Retained earnings
2,325,256
2,268,011
Treasury stock, at cost (March 31, 2026 - 68,969,190 shares; and December 31, 2025 - 67,044,120 shares)
(972,438)
(932,505)
Accumulated other comprehensive loss
(360,718)
(354,550)
1,967,239
1,966,865
19,086,105
19,132,892
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 22 of 27
Table 2 – Condensed Consolidated Statements of Income
Quarter Ended
March 31, 2026
December 31, 2025
March 31, 2025
(In thousands, except per share information)
Net interest income:
Interest income
$
279,849
$
285,158
$
277,065
Interest expense
58,893
62,390
64,668
Net interest income
220,956
222,768
212,397
Provision for credit losses - expense (benefit):
Loans
17,170
22,418
24,837
Unfunded loan commitments
107
402
(63)
Debt securities
(4)
151
36
Provision for credit losses - expense
17,273
22,971
24,810
Net interest income after provision for credit losses
203,683
199,797
187,587
Non-interest income:
Service charges and fees on deposit accounts
9,932
9,861
9,640
Mortgage banking activities
4,043
4,219
3,177
Card and processing income
11,758
12,353
11,475
Other non-interest income
11,952
7,967
11,442
Total non-interest income
37,685
34,400
35,734
Non-interest expenses:
Employees’ compensation and benefits
65,299
63,196
62,137
Occupancy and equipment
22,063
21,797
22,630
Business promotion
3,555
5,944
3,278
Professional service fees
12,912
13,111
11,486
Taxes, other than income taxes
6,184
6,272
5,878
FDIC deposit insurance
2,058
961
2,236
Net gain on OREO operations
(937)
(838)
(1,129)
Credit and debit card processing expenses
7,327
7,728
5,110
Other non-interest expenses
8,644
8,699
11,396
Total non-interest expenses
127,105
126,870
123,022
Income before income taxes
114,263
107,327
100,299
Income tax expense
25,485
20,226
23,240
Net income
$
88,778
$
87,101
$
77,059
Net income attributable to common stockholders
$
88,778
$
87,101
$
77,059
Earnings per common share:
Basic
$
0.57
$
0.56
$
0.47
Diluted
$
0.57
$
0.55
$
0.47
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 23 of 27
Table 3 – Selected Financial Data
Quarter Ended
March 31, 2026
December 31, 2025
March 31, 2025
(Shares in thousands)
Per Common Share Results:
Net earnings per share - basic
$
0.57
$
0.56
$
0.47
Net earnings per share - diluted
$
0.57
$
0.55
$
0.47
Cash dividends declared
$
0.20
$
0.18
$
0.18
Average shares outstanding
155,262
156,792
162,934
Average shares outstanding diluted
156,101
157,675
163,749
Book value per common share
$
12.72
$
12.56
$
10.91
Tangible book value per common share
(1)
$
12.45
$
12.29
$
10.64
Common stock price: end of period
$
21.36
$
20.73
$
19.17
Selected Financial Ratios (In Percent):
Profitability:
Average yield on loans and leases
7.49
7.55
7.75
Average yield on investment securities, other short-term investments and interest-earning
cash balances
2.69
2.51
2.25
Average yield on interest-earning assets
6.02
5.98
5.89
Average rate on interest-bearing liabilities
2.09
2.15
2.23
Average cost of funds
1.42
1.46
1.53
Interest rate spread
3.93
3.83
3.66
Interest rate spread - non-GAAP
(2)
4.18
4.04
3.79
Net interest margin
4.75
4.68
4.52
Net interest margin - non-GAAP
(2)
5.00
4.88
4.65
Return on average assets
1.89
1.81
1.64
Return on average equity
17.92
17.84
17.90
Efficiency ratio
(3)
49.14
49.33
49.58
Capital and Other:
Average total equity to average total assets
10.54
10.15
9.14
Total capital
18.19
18.01
17.96
Common equity Tier 1 capital
16.93
16.76
16.62
Tier 1 capital
16.93
16.76
16.62
Leverage
11.66
11.58
11.20
Tangible common equity ratio
(1)
10.11
10.08
9.10
Dividend payout ratio
34.98
32.40
38.06
Basic liquidity ratio
(4)
20.14
19.39
18.76
Core liquidity ratio
(5)
14.66
13.54
14.25
Loan to deposit ratio
78.96
78.84
75.44
Uninsured deposits, excluding fully collateralized deposits, to total deposits
(6)
30.12
29.79
28.44
Average Balances (In thousands):
Loan and leases
$
13,068,874
$
13,032,081
$
12,632,501
Investment securities, other short-term investments and interest-earning cash balances
5,776,844
5,871,091
6,444,016
Interest-earning assets
$
18,845,718
$
18,903,172
$
19,076,517
Total assets
$
19,069,238
$
19,081,259
$
19,107,102
Interest-bearing liabilities
$
11,409,037
$
11,531,091
$
11,749,011
Non-interest-bearing deposits
5,441,443
5,419,990
5,425,836
Total funding sources
$
16,850,480
$
16,951,081
$
17,174,847
Total stockholders’ equity
$
2,009,137
$
1,936,808
$
1,745,899
Asset Quality:
Allowance for credit losses for loans and finance leases to total loans
1.87
1.90
1.95
Net charge-offs (annualized) to average loans outstanding
0.65
0.63
0.68
Provision for credit losses for loans and finance leases
81.19
110.05
115.47
Non-performing assets to total assets
0.57
0.60
0.68
Nonaccrual loans held for investment to total loans held for investment
0.67
0.71
0.78
Allowance for credit losses for loans and finance leases to total nonaccrual loans
279.29
269.05
251.13
Allowance for credit losses for loans and finance leases to total nonaccrual loans
410.67
392.84
365.41
(1)
Non-GAAP financial measures. Refer to
Non-GAAP Disclosures
and
Tangible Common Equity (Non-GAAP) above
the components and a reconciliation of these measures.
(2)
Non-GAAP financial measures reported on a tax-equivalent basis. Refer to
Non-GAAP Disclosures
and Table 4 below for additional information and reconciliation of this measure.
(3)
Non-interest expenses divided by the sum of net interest income and non-interest income.
(4)
Defined as the sum of cash and cash equivalents, free high-quality liquid assets that could be liquidated within one day, and available secured lines of credit with the FHLB to total assets.
(5)
Defined as the sum of cash and cash equivalents and free high-quality liquid assets that could be liquidated within one day to total assets.
(6)
Exclude insured deposits not covered by federal deposit insurance.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 24 of 27
Table 4 – Quarterly Statement of Average Interest-Earning Assets and Average Interest-Bearing Liabilities (On a Tax-
Equivalent Basis, with GAAP reconciliation)
Average Volume
Interest Income
(1)
Average Rate
(1)
Quarter Ended
March 31,
December 31,
March 31,
March 31,
December 31,
March 31,
March 31,
December 31,
March 31,
2026
2025
2025
2026
2025
2025
2026
2025
2025
(Dollars in thousands)
Interest-earning assets:
Money market and other short-term investments
$
618,371
$
727,018
$
1,111,087
$
5,630
$
7,300
$
12,205
3.69%
3.98%
4.45%
Government obligations
(2)
1,467,672
1,595,962
1,971,327
11,426
11,211
6,970
3.16%
2.79%
1.43%
MBS
3,645,699
3,502,688
3,308,964
26,814
22,891
17,497
2.98%
2.59%
2.14%
FHLB stock
24,150
24,735
32,661
474
493
790
7.96%
7.91%
9.81%
Other investments
20,952
20,688
19,977
139
83
247
2.69%
1.59%
5.01%
Total investments
(3)
5,776,844
5,871,091
6,444,016
44,483
41,978
37,709
3.12%
2.84%
2.37%
Residential mortgage loans
2,911,731
2,904,714
2,841,918
43,249
42,960
41,484
6.02%
5.87%
5.92%
Construction loans
247,415
250,338
232,295
5,791
6,398
5,596
9.49%
10.14%
9.77%
C&I and commercial mortgage loans
6,225,066
6,156,312
5,806,929
101,920
105,174
99,756
6.64%
6.78%
6.97%
Consumer loans and finance leases
3,684,662
3,720,717
3,751,359
95,871
98,542
98,752
10.55%
10.51%
10.68%
Total loans
(4) (5)
13,068,874
13,032,081
12,632,501
246,831
253,074
245,588
7.66%
7.70%
7.88%
Total interest-earning assets
$
18,845,718
$
18,903,172
$
19,076,517
$
291,314
$
295,052
$
283,297
6.27%
6.19%
6.02%
Tax-equivalent adjustment
(11,465)
(9,894)
(6,232)
Interest income - GAAP
$
279,849
$
285,158
$
277,065
6.02%
5.98%
5.89%
Interest-bearing liabilities:
Time deposits
$
3,542,960
$
3,524,261
$
3,048,778
$
29,237
$
30,169
$
25,468
3.35%
3.40%
3.39%
Brokered CDs
555,938
617,217
483,774
5,759
6,644
5,461
4.20%
4.27%
4.58%
Other interest-bearing deposits
7,033,139
7,099,613
7,693,900
20,935
22,390
27,568
1.21%
1.25%
1.45%
Advances from the FHLB
277,000
290,000
468,667
2,962
3,187
5,190
4.34%
4.36%
4.49%
Other borrowings
-
-
53,892
-
-
981
0.00%
0.00%
7.38%
Total interest-bearing liabilities
$
11,409,037
$
11,531,091
$
11,749,011
$
58,893
$
62,390
$
64,668
2.09%
2.15%
2.23%
Net interest income / margin- non-GAAP
(1)
$
232,421
$
232,662
$
218,629
5.00%
4.88%
4.65%
Net interest income / margin - GAAP
$
220,956
$
222,768
$
212,397
4.75%
4.68%
4.52%
Net interest spread - non-GAAP
(1)
4.18%
4.04%
3.79%
Net interest spread - GAAP
3.93%
3.83%
3.66%
(1)
Non-GAAP financial measures reported on a tax-equivalent basis. The tax-equivalent yield was estimated by dividing the interest rate spread on exempt assets by 1 less the Puerto Rico statutory tax rate of 37.5% and
adding to it the cost of interest-bearing liabilities. When adjusted to a tax-equivalent basis, yields on taxable and exempt assets are comparable. Refer to
Non-GAAP Disclosures - Non-GAAP Financial Measures
additional information.
(2)
Government obligations include debt issued by government-sponsored agencies.
(3)
Unrealized gains and losses on available-for-sale debt securities are excluded from the average volumes.
(4)
Average loan balances include the average of non-performing loans.
(5)
Interest income on loans includes $4.0 million, $4.4 million, and $5.4 million, for the quarters ended March 31, 2026, December 31, 2025, and March 31, 2025, respectively, of income from prepayment penalties and late
fees related to the Corporation’s loan portfolio. The results for the first quarter of 2025 include a prepayment penalties associated with the payoff of a $73.8 million commercial mortgage loan and higher income from late
fees in the consumer loans and finance leases portfolios.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 25 of 27
Table 5 – Loan Portfolio by Geography
As of March 31, 2026
Puerto Rico
Virgin Islands
United States
Total
(In thousands)
Residential mortgage loans
$
2,231,306
$
147,082
$
536,510
$
2,914,898
Commercial loans:
Construction loans
178,810
14,167
2,290
195,267
Commercial mortgage loans
1,753,712
72,837
800,564
2,627,113
C&I loans
2,290,891
203,810
1,200,142
3,694,843
Commercial loans
4,223,413
290,814
2,002,996
6,517,223
Consumer loans and finance leases
3,587,266
65,834
5,856
3,658,956
Loans held for investment
10,041,985
503,730
2,545,362
13,091,077
Mortgage loans held for sale
12,805
-
-
12,805
Total loans
$
10,054,790
$
503,730
$
2,545,362
$
13,103,882
As of December 31, 2025
Puerto Rico
Virgin Islands
United States
Total
(In thousands)
Residential mortgage loans
$
2,227,053
$
150,551
$
530,698
$
2,908,302
Commercial loans:
Construction loans
249,466
14,174
1,928
265,568
Commercial mortgage loans
1,690,176
73,751
790,325
2,554,252
C&I loans
2,348,274
170,728
1,169,356
3,688,358
Commercial loans
4,287,916
258,653
1,961,609
6,508,178
Consumer loans and finance leases
3,636,072
66,947
5,857
3,708,876
Loans held for investment
10,151,041
476,151
2,498,164
13,125,356
Mortgage loans held for sale
16,697
-
-
16,697
Total loans
$
10,167,738
$
476,151
$
2,498,164
$
13,142,053
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 26 of 27
Table 6 – Non-Performing Assets by Geography
As of March 31, 2026
(In thousands)
Puerto Rico
Virgin Islands
United States
Total
Nonaccrual loans held for investment:
$
11,875
$
4,923
$
11,273
$
28,071
4,458
956
-
5,414
1,581
5,861
-
7,442
26,010
611
479
27,100
19,316
356
45
19,717
Total nonaccrual loans held for investment
63,240
12,707
11,797
87,744
OREO
5,685
659
-
6,344
Other repossessed property
13,055
69
-
13,124
Other assets
(1)
1,609
-
-
1,609
Total non-performing assets
(2)
$
83,589
$
13,435
$
11,797
$
108,821
Past due loans 90 days and still accruing
(3)
$
28,078
$
871
$
-
$
28,949
As of December 31, 2025
(In thousands)
Puerto Rico
Virgin Islands
United States
Total
Nonaccrual loans held for investment:
$
12,637
$
5,407
$
11,125
$
29,169
4,581
955
-
5,536
1,913
6,469
-
8,382
27,211
644
187
28,042
20,891
529
14
21,434
Total nonaccrual loans held for investment
67,233
14,004
11,326
92,563
OREO
6,661
861
-
7,522
Other repossessed property
12,216
173
-
12,389
Other assets
(1)
1,620
-
-
1,620
Total non-performing assets
(2)
$
87,730
$
15,038
$
11,326
$
114,094
Past due loans 90 days and still accruing
(3)
$
30,643
$
1,270
$
-
$
31,913
(1)
Residential pass-through MBS issued by the PRHFA held as part of the available-for-sale debt securities portfolio.
(2)
Excludes PCD loans previously accounted for under ASC Subtopic 310-30 for which the Corporation made the accounting policy election of maintaining pools of loans as “units of account” both at the time of
adoption of CECL on January 1, 2020 and on an ongoing basis for credit loss measurement. These loans will continue to be excluded from nonaccrual loan statistics as long as the Corporation can reasonably estimate
the timing and amount of cash flows expected to be collected on the loan pools. The portion of such loans contractually past due 90 days or more amounted to $4.2 million as of March 31, 2026 (December 31, 2025 -
$4.8 million).
(3)
These include rebooked loans, which were previously pooled into GNMA securities, amounting to $6.7 million as of each of March 31, 2026 and December 31, 2025. Under the GNMA program, the Corporation has
the option but not the obligation to repurchase loans that meet GNMA's specified delinquency criteria. For accounting purposes, the loans subject to the repurchase option are required to be reflected on the financial
statements with an offsetting liability.
First BanCorp. Announces Earnings for the Quarter Ended March 31, 2026
– Page 27 of 27
Table 7 – Allowance for Credit Losses on Loans and Finance Leases
Quarter Ended
March 31, 2026
December 31, 2025
March 31, 2025
(Dollars in thousands)
Allowance for credit losses on loans and finance leases, beginning of period
$
249,037
$
246,990
$
243,942
Provision for credit losses on loans and finance leases expense
17,170
22,418
24,837
Net recoveries (charge-offs) of loans and finance leases:
Residential mortgage
224
155
(18)
Construction
13
14
14
Commercial mortgage
(522)
(53)
40
C&I
(309)
(14)
77
Consumer loans and finance leases
(20,553)
(20,473)
(21,623)
Net charge-offs
(21,147)
(20,371)
(21,510)
Allowance for credit losses on loans and finance leases, end of period
$
245,060
$
249,037
$
247,269
Allowance for credit losses on loans and finance leases to period end total
1.87%
1.90%
1.95%
Net charge-offs (annualized) to average loans outstanding during the period
0.65%
0.63%
0.68%
Provision for credit losses on loans and finance leases to net charge-offs during the period
0.81x
1.10x
1.15x
(1)
Includes recoveries totaling $2.4 million associated with the bulk sale of fully charged-off consumer loans and finance leases.
Table 8 – Annualized Net (Recoveries) Charge-Offs to Average Loans
Quarter Ended
March 31, 2026
December 31, 2025
March 31, 2025
Residential mortgage
-0.03%
-0.02%
0.00%
Construction
-0.02%
-0.02%
-0.02%
Commercial mortgage
0.08%
0.01%
-0.01%
C&I
0.03%
0.00%
-0.01%
Consumer loans and finance leases
2.23%
2.20%
2.31%
(1)
Total loans
0.65%
0.63%
0.68%
(1)
(1)
The recoveries associated with the aforementioned bulk sale reduced the ratios of consumer loans and finance leases and total net charge-offs to related average loans by 25 basis points and 8 basis points, respectively.
Table 9 – Deposits
As of
March 31, 2026
December 31, 2025
(In thousands)
Time deposits
$
3,482,968
$
3,562,331
Interest-bearing saving and checking accounts
7,051,091
6,964,841
Non-interest-bearing deposits
5,554,751
5,549,416
Total deposits, excluding brokered CDs
(1)
16,088,810
16,076,588
Brokered CDs
507,011
593,555
Total deposits
$
16,595,821
$
16,670,143
Total deposits, excluding brokered CDs and government deposits
$
13,219,627
$
13,061,068
(1)
As of March 31, 2026 and December 31, 2025, government deposits amounted to $2.9 billion and $3.0 billion, respectively.
Exhibit 99.2
1First BanCorp Financial Results First Quarter 2026 April 22, 2026
Forward Looking Statements This presentation contains “forward -looking statements” concerning the Corporation’s future economic, operational and financial performance. The words or phrases “expect,” “anticipate,” “intend,” “should,” “would,” “will,” “plans,” “forecast,” “believe” and similar expressions are meant to identify “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, and are subject to the safe harbor created by such sections. The Corporation cautions readers not to place undue reliance on any such forward -looking statements, which speak only as of the date hereof, and advises readers that any such forward-looking statements are not guarantees of future performance and involve certain risks, uncertainties, estimates and assumptions by us that are difficult to predict. Various factors, some of which are beyond our control, including, but not limited to, the uncertainties more fully discussed in Part I, Item 1A, “Risk Factors” of the Corporation’s Annual Report on Form 10-K for the year ended December 31, 2025, and the following, could cause actual results to differ materially from those expressed in, or implied by, such forward-looking statements: the effect of the current global interest rate environment (including the potential for ongoing reductions in interest rates) and inflation levels on the level, composition and performance of the Corporation’s assets and liabilities, and corresponding effects on the Corporation’s net interest income, net interest margin, loan originations, deposit attrition, overall results of operations, and liquidity position; the effects of changes in the interest rate environment, including any adverse change in the Corporation’s ability to attract and retain clients and gain acceptance from current and prospective customers for new products and services,
including those related to the offering of digital banking and financial services; volatility in the financial services industry, which could result in, among other things, bank deposit runoffs, liquidity constraints, and increased regulatory requirements and costs; uncertainty as to the ability of FirstBank to retain its core deposits and generate sufficient cash flow through its wholesale funding sources, which may require us to sell investment securities at a loss; the impacts of natural or man-made disasters, widespread health emergencies, geopolitical conflicts (including sanctions, war or armed conflict such as the ongoing conflict in Ukraine, ongoing conflicts in the Middle East, such as the war in Iran); adverse changes in general political and economic conditions in Puerto Rico, the U.S., and the U.S. and British Virgin Islands, including in the interest rate environment, unemployment rates, market liquidity, housing absorption rates, real estate markets and U.S. capital markets; general competitive factors and other market risks as well as the implementation of existent or planned strategic growth opportunities, including risks, uncertainties, and other factors or events related to any business acquisitions, dispositions , strategic partnerships, strategic operational investments including system conversions, and any anticipated efficiencies or other expected results related thereto; the impact of litigation or the threat of litigation, including any settlements or judgments against the Corporation, and the potential resulting liabilities, costs, negative publicity or other reputational harm; the effects of asserted and unasserted claims and the extent of available insurance coverage; uncertainty as to the implementation of the debt restructuring plan of Puerto Rico and the Fiscal Plan for Puerto Rico as certified on June 6, 2025 by the Financial Oversight and Management Board for Puerto Rico, or any revisions to it, on our clients and
loan portfolios, and any potential impact from future economic or political developments and tax regulations in Puerto Rico; the impact of government financial assistance for hurricane recovery and other disaster relief on economic activity in Puerto Rico; the timing of sales of properties from our other real estate owned (“OREO”) portfolio; the impacts of applicable legislative, tax or regulatory changes on the Corporation’s financial condition or performance; and the effect of continued changes in the fiscal, monetary, and trade policies and regulations of the U.S. federal government, the Puerto Rico government and other governments. The Corporation does not undertake and specifically disclaims any obligation to update any “forward-looking statements” to reflect occurrences or unanticipated events or circumstances after the date of such statements, except as required by the federal securities laws. Non-GAAP Financial Measures In addition to the Corporation’s financial information presented in accordance with GAAP, management uses certain “non-GAAP” financial measures” within the meaning of Regulation G promulgated by the SEC, to clarify and enhance understanding of past performance and prospects for the future. Please refer to pages 14-16 for a reconciliation of GAAP to non-GAAP measures and calculations. 2
Agenda 1 1Q 2026 – Quarter Highlights Aurelio Alemán, President and Chief Executive Officer 2 1Q 2026 – Results of Operations Orlando Berges, Executive Vice President and Chief Financial Officer 3 1Q 2026 – Questions and Answers 3
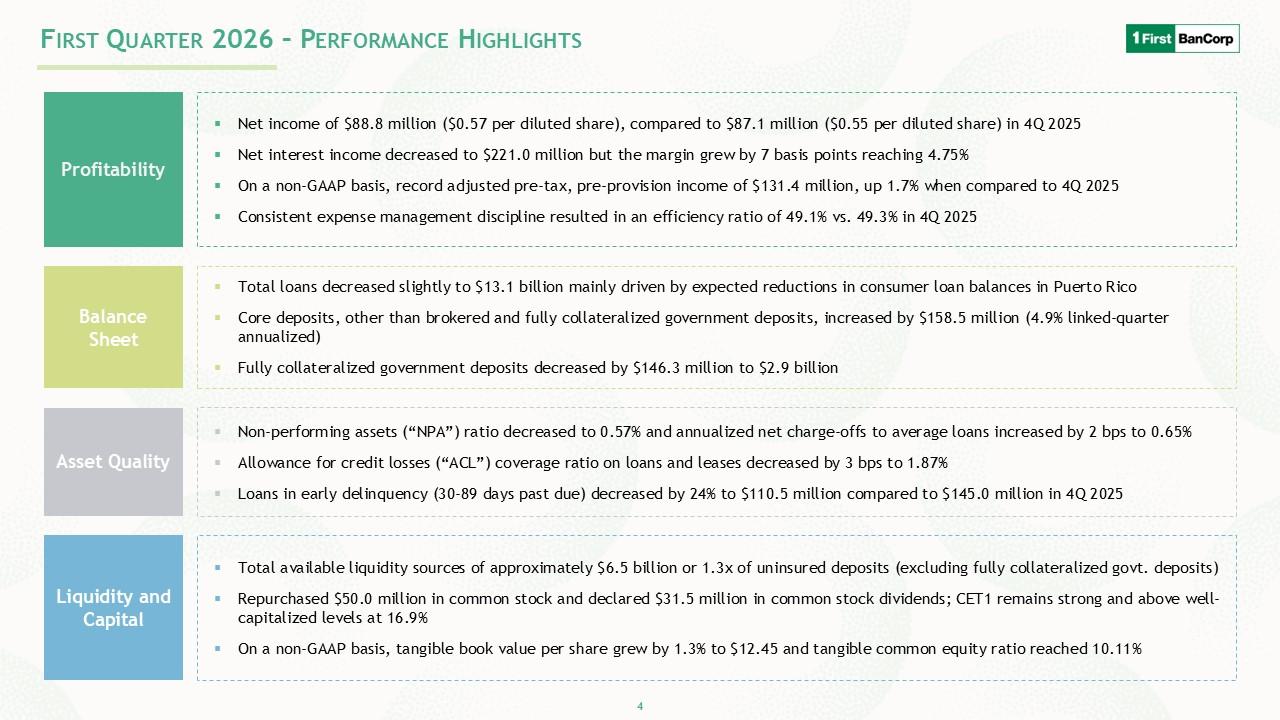
First Quarter 2026 – Performance Highlights Profitability Net income of $88.8 million ($0.57 per diluted share), compared to $87.1 million ($0.55 per diluted share) in 4Q 2025 Net interest income decreased to $221.0 million but the margin grew by 7 basis points reaching 4.75% On a non-GAAP basis, record adjusted pre-tax, pre-provision income of $131.4 million, up 1.7% when compared to 4Q 2025 Consistent expense management discipline resulted in an efficiency ratio of 49.1% vs. 49.3% in 4Q 2025 Balance Sheet Total loans decreased slightly to $13.1 billion mainly driven by expected reductions in consumer loan balances in Puerto Rico Core deposits, other than brokered and fully collateralized government deposits, increased by $158.5 million (1.2% vs. prior quarter) Fully collateralized government deposits decreased by $146.3 million to $2.9 billion Asset Quality Non -performing assets (“NPA”) ratio decreased to 0.57% and annualized net charge-offs to average loans increased by 2 bps to 0.65% Allowance for credit losses (“ACL”) coverage ratio on loans and leases decreased by 3 bps to 1.87% Liquidity and Capital Loans in early delinquency (30-89 days past due) decreased by 24% to $110.5 million compared to $145.0 million in 4Q 2025 Total available liquidity sources of approximately $6.5 billion or 1.3x of uninsured deposits (excluding fully collateralized govt. deposits) Repurchased $50.0 million in common stock and declared $31.5 million in common stock dividends; CET1 remains strong and above well-capitalized levels at 16.9% On a non-GAAP basis, tangible book value per share grew by 1.3% to $12.45 and tangible common equity ratio reached 10.11% 4
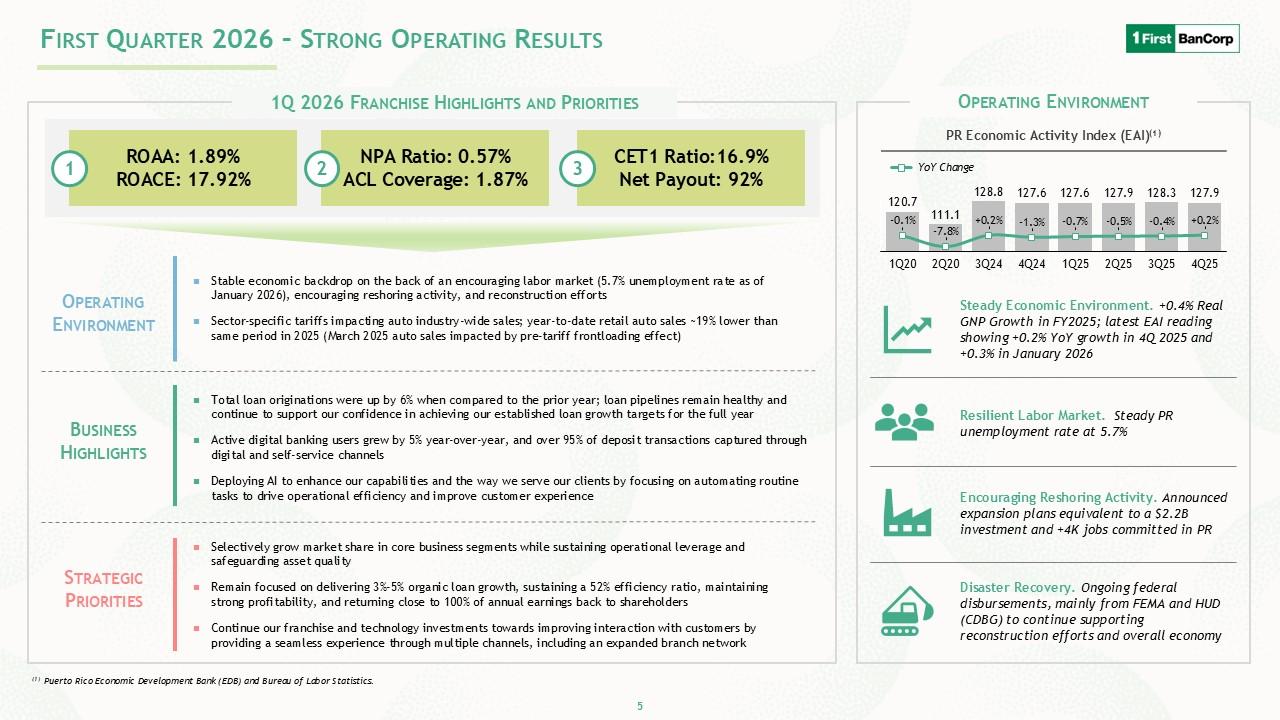
First Quarter 2026 – Strong Operating Results 1Q 2026 Franchise Highlights and Priorities 1 ROAA: 1.89% ROACE: 17.92% 2 NPA Ratio: 0.57% ACL Coverage: 1.87% 3 CET1 Ratio:16.9% Net Payout: 92% Operating Environment Stable economic backdrop on the back of an encouraging labor market (5.7% unemployment rate as of January 2026), encouraging reshoring activity, and reconstruction efforts Sector-specific tariffs impacting auto industry-wide sales; year-to-date retail auto sales ~19% lower than same period in 2025 (March 2025 auto sales impacted by pre-tariff frontloading effect) Business Highlights Linked-quarter loan originations declined by 10% but increased by 6% when compared to the first quarter of 2025; core customer deposits grew by 4.9% on a linked-quarter annualized basis Active digital banking users grew by 5% year -over-year, and over 95% of deposit transactions captured through digital and self-service channels Deploying AI to enhance our capabilities and the way we serve our clients by focusing on automating routine tasks to drive operational efficiency and improve customer experience Strategic Priorities Selectively grow market share in core business segments while sustaining operational leverage and safeguarding asset quality Remain focused on delivering 3%-5% organic loan growth, sustaining a 52% efficiency ratio, maintaining strong profitability, and returning close to 100% of annual earnings back to shareholders Continue our franchise and technology investments towards improving interaction with customers by providing a seamless experi ence through multiple channels, including an expanded branch network Operating Environment PR Economic Activity Index (EAI)(1) 120.7 111.1 128.8 127.6 127.6 127.9 128.3 127.9 -0.1% -7.8% 0.2% -1.3% -0.7% -0.5% -0.4% 0.2% 1Q20 2Q20 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 Steady Economic Environment.
+0.4% Real GNP Growth in FY2025; latest EAI reading showing +0.2% YoY growth in 4Q 2025 and +0.3% in January 2026 Resilient Labor Market. Steady PR unemployment rate at 5.7% Encouraging Reshoring Activity. Announced expansion plans equivalent to a $2.2B investment and +4K jobs committed in PR Disaster Recovery. Ongoing federal disbursements, mainly from FEMA and HUD (CDBG) to continue supporting reconstruction efforts and overall economy (1) Puerto Rico Economic Development Bank (EDB) and Bureau of Labor Statistics. 5
Results of Operations
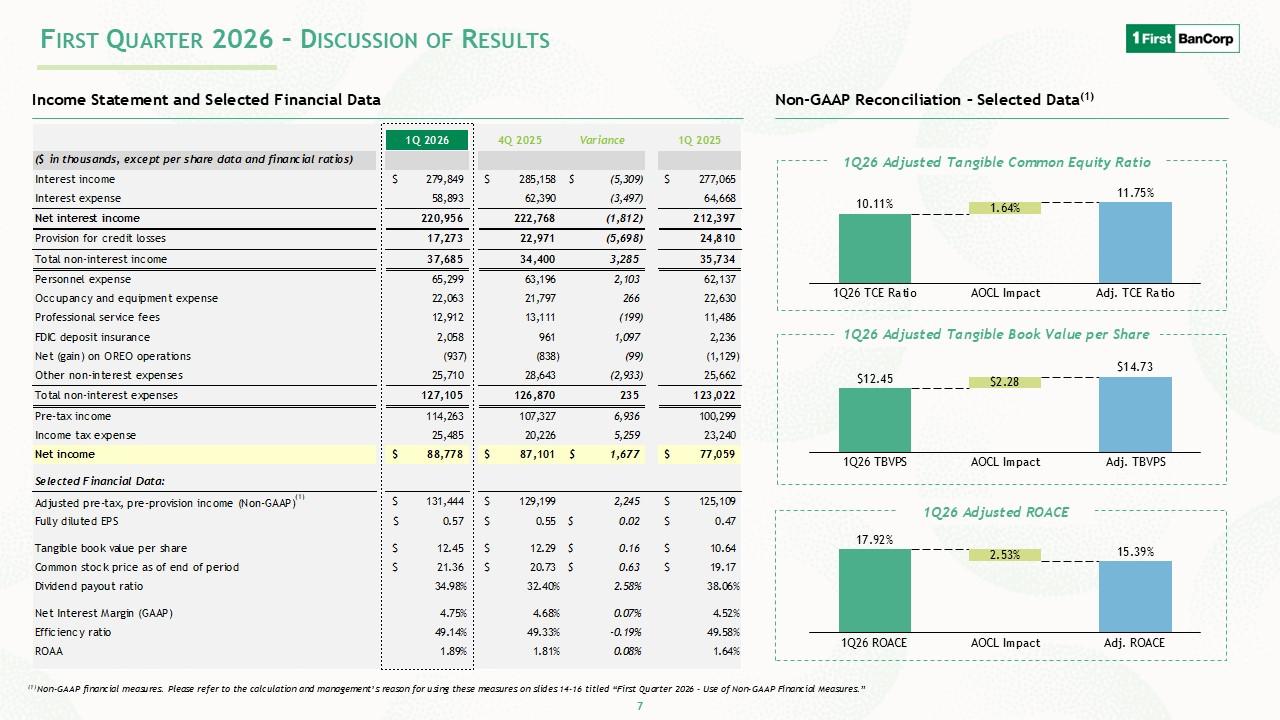
Income Statement and Selected Financial Data I 10 2026 I vl 40n (0 F ($ in thousands, except per share data and financial ratios) Interest income S 279,849 S 285,158 $ (5,309) S 277,065 Interest expense 58,893 62,390 (3,497) 64,668 Net interest income 220,956 222,768 (1,812) 212,397 Provision for credit losses 17,273 22,971 (5,698) 24,8 10 Total non-interest income 37,685 34,400 3,285 35,734 Personnel expense 65,299 63,196 2,103 62,137 Occupancy and equipment expense 22,063 21,797 266 22,630 Professional service fees 12,912 13,111 (199) 11,486 FDIC deposit insurance 2,058 961 1,097 2,236 Net (gain) on OREO operations (937) (838) (99) (1,129) Other non-interest expenses 25,710 28,643 _2,933) 25,662 Total non-interest expenses 127,1 05 126,870 23 5 123,022 Pre-tax income 114,263 107,327 6,936 100,299 Income tax expense 25,485 20,226 5,259 23,240 Net i ncome $ 88,778 $ 87,101 $ 1,677 $ 77,059 Selected Financial Data: Adjusted pre-tax, pre-provision income (Non-GAAP) S 131,444 S 129,199 2,245 S 125,109 Fully diluted EPS S 0.57 S 0.55 0.02 S 0.47 Tangible bookvaue per share S 12.45 S 12.29 0.16 S 10.64 Common stock price as of end of period S 21.36 S 20.73 0.63 S 19.17 Dividend payout ratio 34.98% 32.40% 2.58% 38.06% Net interest Margin (GAAP) 4.75% 4.68% 0.07% 4.52% Efficiency ratio 49.14% 49.33% 0. 19% 49.58% ROAA 1.89% 1.81% 0.08% 1.64% Non-GAAP Reconciliation – Selected Data(1) 1Q26 Adjusted Tangible Common Equity Ratio 10.11% 1.64% 11.75% 1Q26 TCE Ratio AOCL Impact Adj. TCE Ratio 1Q26 Adjusted Tangible Book Value per Share $12.45 $2.28 $14.73 1Q26 TBVPS AOCL Impact Adj. TBVPS 1Q26 Adjusted ROACE 17.92% 2.53% 15.39% 1Q26 ROACE AOCL Impact Adj. ROACE (1) Non-GAAP financial measures. Please refer to the calculation and management’s reason for using these measures on slides 14-16
titled “First Quarter 2026 - Use of Non-GAAP Financial Measures.” 7
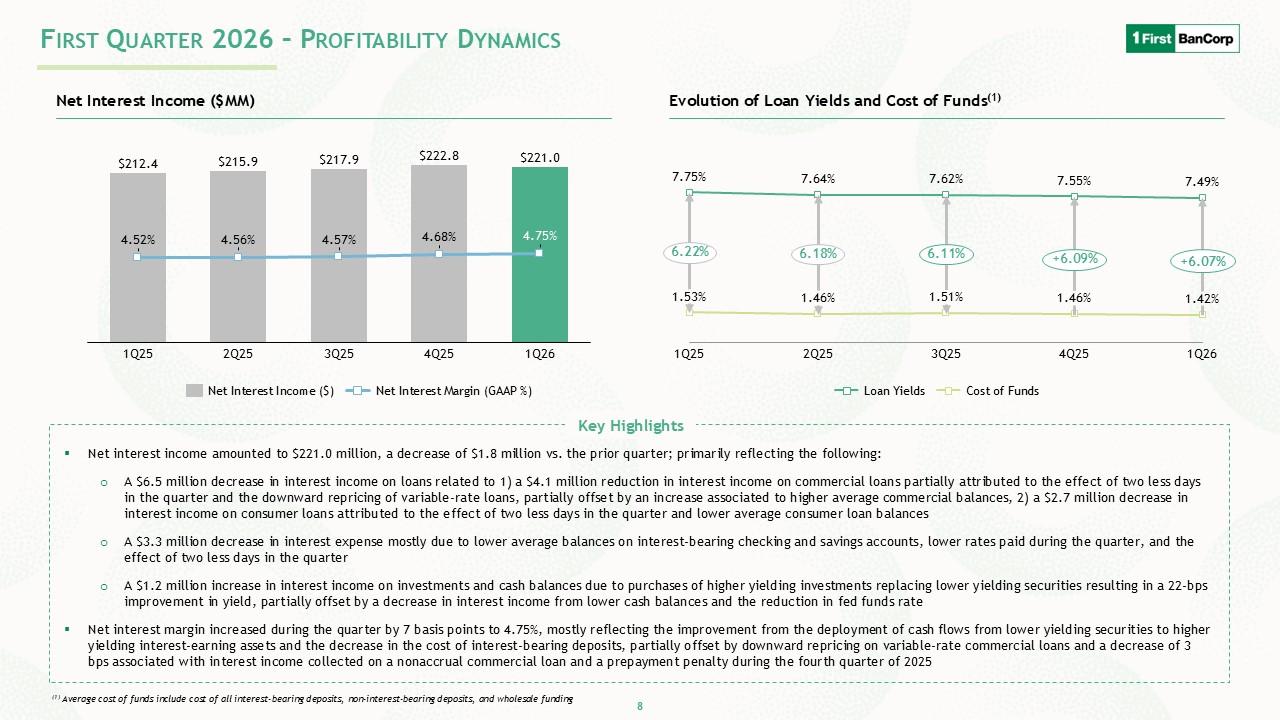
First Quarter 2026 – Profitability Dynamics Net Interest Income ($MM) $212.4 $215.9 $217.9 $222.8 $221.0 4.52% 4.56% 4.57% 4.68% 4.75% 1Q25 2Q25 3Q25 4Q25 1Q26 Net Interest Income ($) Net Interest Margin (GAAP %) Evolution of Loan Yields and Cost of Funds(1) 7.75% 7.64% 7.62% 7.55% 7.49% 6.22% 6.18% 6.11% 6.09% 6.07% 1.53% 1.46% 1.51% 1.46% 1.42% 1Q25 2Q25 3Q25 4Q25 1Q26 Loan Yields Cost of Funds Key Highlights Net interest income amounted to $221.0 million, a decrease of $1.8 million vs. the prior quarter; primarily reflecting the following: A $6.5 million decrease in interest income on loans related to 1) a $4.1 million reduction in interest income on commercial loans partially attributed to the effect of two less days in the quarter and the downward repricing of variable-rate loans, partially offset by an increase associated to higher average commercial balances, 2) a $2.7 million decrease in interest income on consumer loans attributed to the effect of two less days in the quarter and lower average consumer loan balances A $3.3 million decrease in interest expense mostly due to lower average balances on interest-bearing checking and savings accounts, lower rates paid during the quarter, and the effect of two less days in the quarter A $1.2 million increase in interest income on investments and cash balances due to purchases of higher yielding investments replacing lower yielding securities resulting in a 22-bps improvement in yield, partially offset by a decrease in interest income from lower cash balances and the reduction in fed funds rate Net interest margin increased during the quarter by 7 basis points to 4.75%, mostly reflecting the improvement from the deployment of cash flows from lower yielding securities to higher yielding interest -earning assets and the decrease in the cost of interest-bearing deposits, partially offset by downward repricing on variable-rate
commercial loans and a decrease of 3 bps associated with interest income collected on a nonaccrual commercial loan and a prepayment penalty during the fourth quarter of 2025 (1) Average cost of funds include cost of all interest-bearing deposits, non-interest-bearing deposits, and wholesale funding 8
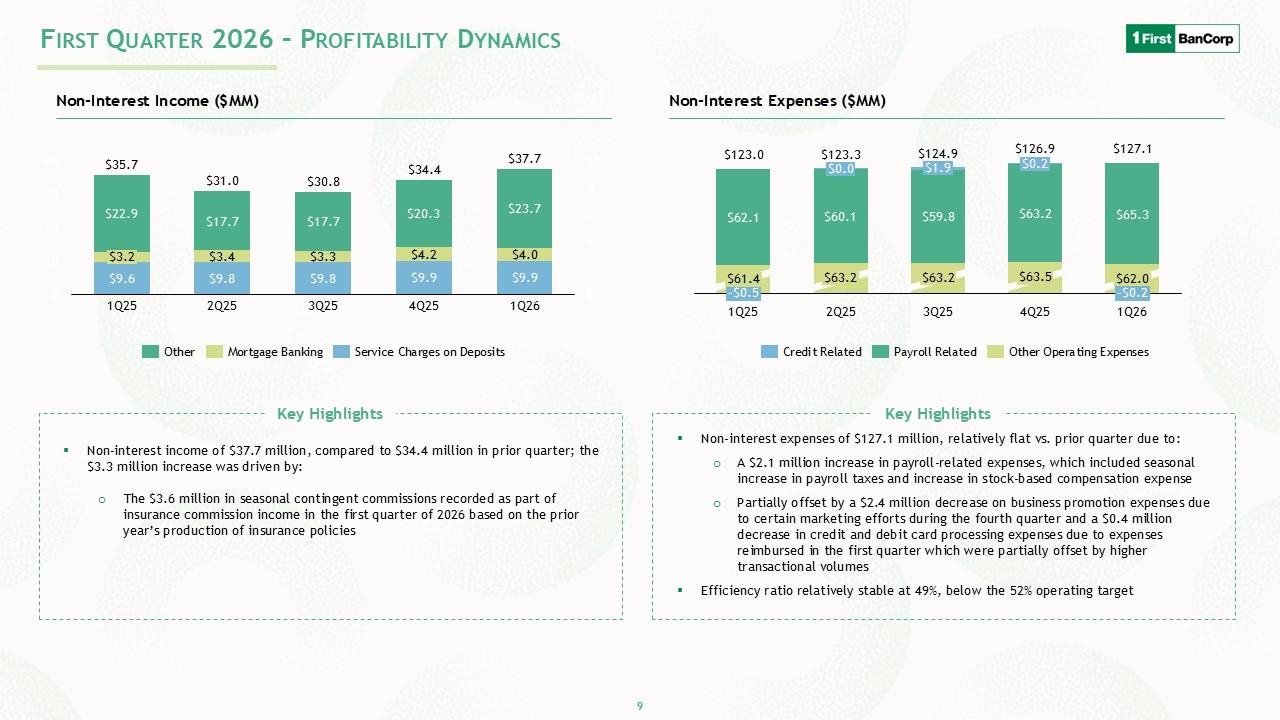
First Quarter 2026 – Profitability Dynamics Non-Interest Income ($MM) $35.7 $31.0 $30.8 $34.4 $37.7 $22.9 $17.7 $17.7 $20.3 $23.7 $3.2 $3.4 $3.3 $4.2 $4.0 $9.6 $9.8 $9.8 $9.9 $9.9 1Q25 2Q25 3Q25 4Q25 1Q26 Other Mortgage Banking Service Charges on Deposits Key Highlights Non-interest income of $37.7 million, compared to $34.4 million in prior quarter; the $3.3 million increase was driven by: The $3.6 million in seasonal contingent commissions recorded as part of insurance commission income in the first quarter of 2026 based on the prior year’s production of insurance policies Non-Interest Expenses ($MM) $123.0 $123.3 $124.9 $126.9 $127.1 -$0.5 $0.0 $1.9 $0.2 -$0.2 $62.1 $60.1 $59.8 $63.2 $65.3 $61.4 $63.2 $63.2 $63.5 $62.0 1Q25 2Q25 3Q25 4Q25 1Q26 Credit Related Payroll Related Other Operating Expenses Key Highlights Non-interest expenses of $127.1 million, relatively flat vs. prior quarter due to: A $2.1 million increase in payroll-related expenses, which included seasonal increase in payroll taxes and increase in stock-based compensation expense Partially offset by a $2.4 million decrease on business promotion expenses due to certain marketing efforts during the fourth quarter and a $0.4 million decrease in credit and debit card processing expenses due to expenses reimbursed in the first quarter which were partially offset by higher transactional volumes Efficiency ratio relatively stable at 49%, below the 52% operating target 9
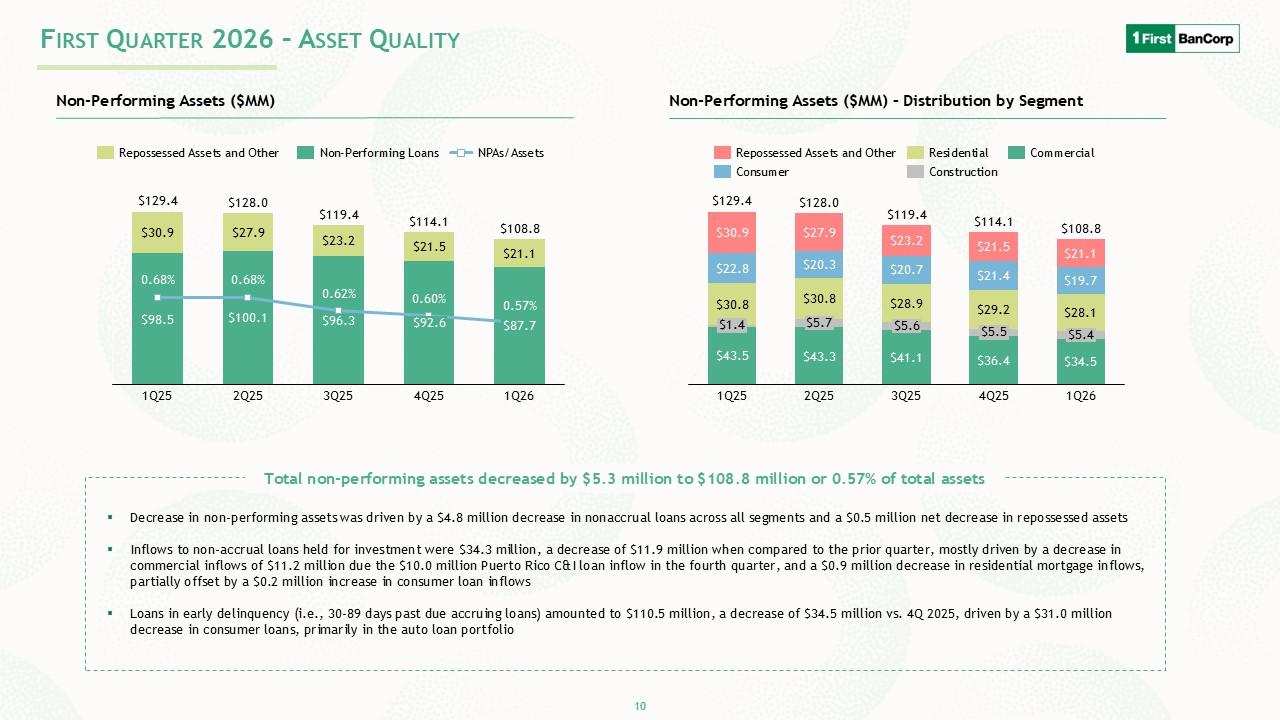
First Quarter 2026 – Asset Quality Repossessed Assets and Other Non-Performing Loans NPAs/Assets Non-Performing Assets ($MM) $129.4 $128.0 $119.4 $114.1 $108.8 $30.9 $27.9 $23.2 $21.5 $21.1 0.68% 0.68% 0.62% 0.60% 0.57% $98.5 $100.1 $69.3 $92.6 $87.7 1Q25 2Q25 3Q25 4Q25 1Q26 Repossessed Assets and Other Consumer Residential Construction Commercial $129.4 $128.0 $119.4 $114.1 $108.8 $30.9 $27.9 $23.2 $21.5 21.1. $22.8 $20.3 $20.7 $21.4 $19.7 $30.8 $30.8 $28.9 $29.2 $285.1 $1.4 $5.7 $5.6 $5.5 $5.4 $43.5 $43.3 $41.1 $36.4 $34.5 1Q25 2Q25 3Q25 4Q25 1Q26 Non-Performing Assets ($MM) – Distribution by Segment Total non-performing assets decreased by $5.3 million to $108.8 million or 0.57% of total assets Decrease in non-performing assets was driven by a $4.8 million decrease in nonaccrual loans across all segments and a $0.5 million net decrease in repossessed assets Inflows to non-accrual loans held for investment were $34.3 million, a decrease of $11.9 million when compared to the prior quarter, mostly driven by a decrease in commercial inflows of $11.2 million due the $10.0 million Puerto Rico C&I loan inflow in the fourth quarter, and a $0.9 million decrease in residential mortgage inflows, partially offset by a $0.2 million increase in consumer loan inflows Loans in early delinquency (i.e., 30-89 days past due accruing loans) amounted to $110.5 million, a decrease of $34.5 million vs. 4Q 2025, driven by a $31.0 million decrease in consumer loans, primarily in the auto loan portfolio 10
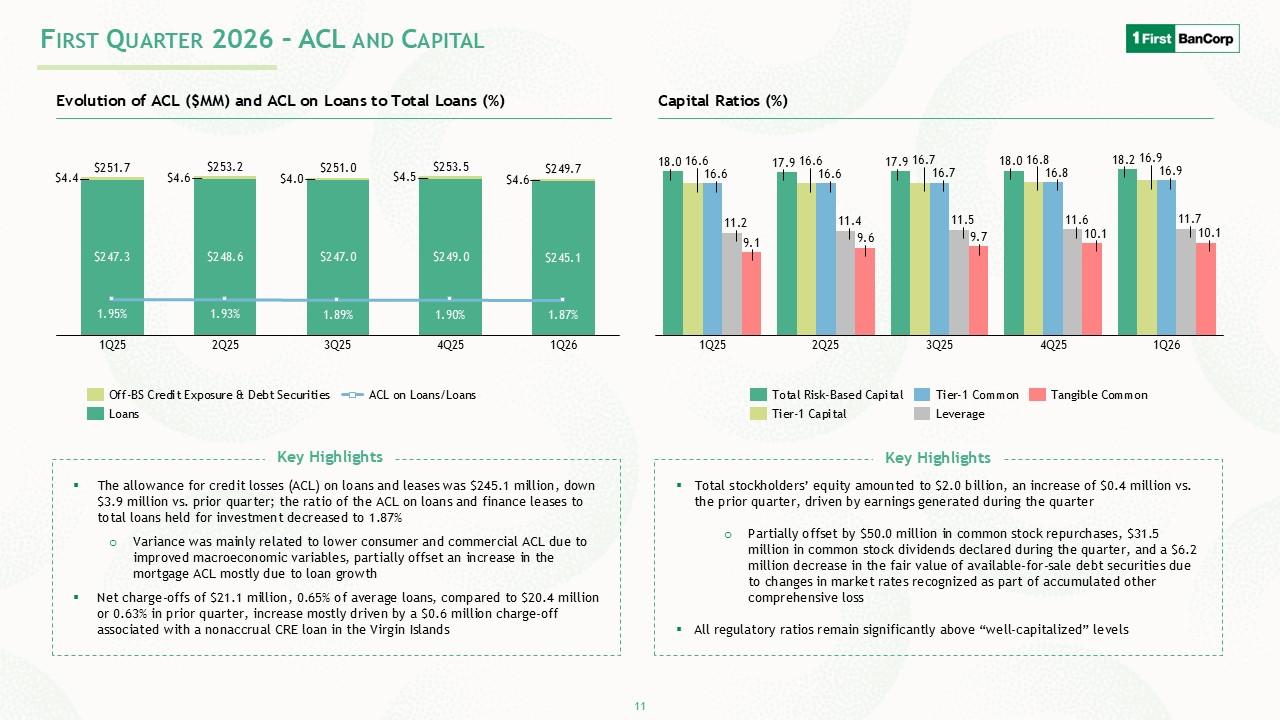
First Quarter 2026 – ACL and Capital Evolution of ACL ($MM) and ACL on Loans to Total Loans (%) $251.7 $253.2 $251.0 $253.5 $249.7 $4.4 $4.6 $4.0 $4.5 $4.6 $247.3 $248.6 $247.0 $249.0 $245.1 1.95% 1.93% 18.90% 1.90% 1.87% 1Q25 2Q25 3Q25 4Q25 1Q26 Off-BS Credit Exposure & Debt Securities Loans ACL on Loans/Loans Key Highlights The allowance for credit losses (ACL) on loans and leases was $245.1 million, down $3.9 million vs. prior quarter; the ratio of the ACL on loans and finance leases to total loans held for investment decreased to 1.87% Variance was mainly related to lower consumer and commercial ACL due to improved macroeconomic variables, partially offset an increase in the mortgage ACL mostly due to loan growth Net charge-offs of $21.1 million, 0.65% of average loans, compared to $20.4 million or 0.63% in prior quarter, increase mostly driven by a $0.6 million charge-off associated with a nonaccrual CRE loan in the Virgin Islands Capital Ratios (%) $18.0 $16.6 $16.6 $11.2 $9.1 $17.9 $16.6 $16.6 $11.4 $9.6 $17.9 $16.7 $16.7 $11.5 $9.7 $18.0 $16.8 $16.8 $11.6 $10.1 $18.2 $16.9 $16.9 $11.7 $10.1 1Q25 2Q25 3Q25 4Q25 1Q26 Total Risk-Based Capital Tier-1 Capital Tier-1 Common Leverage Tangible Common Key Highlights Total stockholders’ equity amounted to $2.0 billion, an increase of $0.4 million vs. the prior quarter, driven by earnings generated during the quarter Partially offset by $50.0 million in common stock repurchases, $31.5 million in common stock dividends declared during the quarter, and a $6.2 million decrease in the fair value of available-for-sale debt securities due to changes in market rates recognized as part of accumulated other comprehensive loss All regulatory ratios remain significantly above “well-capitalized” levels 11
1Q 2026 Financial Results Appendix and Non-GAAP Financial Measures
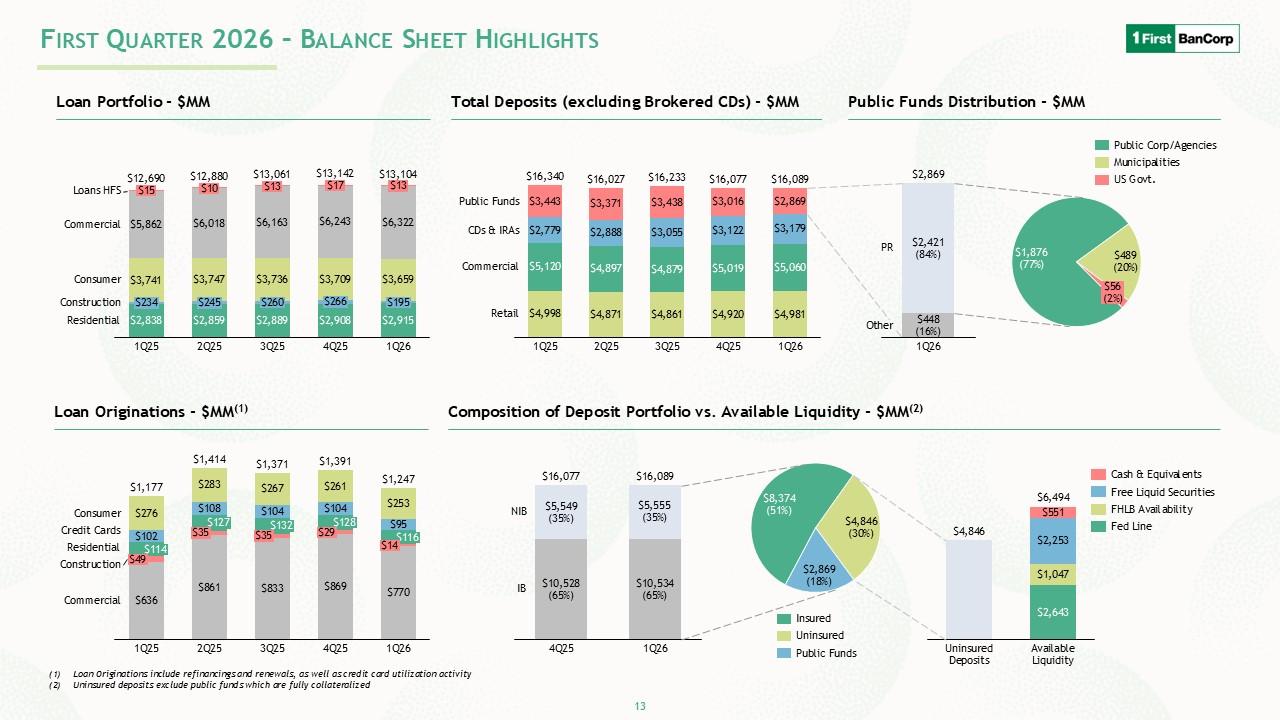
First Quarter 2026 – Balance Sheet Highlights Loan Portfolio - $MM $12,690.0 $12,880.0 $13,061.0 $13,142.0 $13,104.0 Loans HFS $15 $10 $13 $17 $13 Commercial $5,862 $6,018 $6,163 $6,243 $6,322 Consumer $3,741 $3,747 $3,736 $3,709 $3,659 Construction $234 $245 $260 $260 $195 Residential $2,838 $2,859 $2,889 $2,908 $2,915 1Q25 2Q25 3Q25 4Q25 1Q26 Total Deposits (excluding Brokered CDs) - $MM $16 $16,027 $16,233 $16,077 $16,089 Public Funds $3,443 $3,371 $3,438 $3,016 $2,869 CDs & IRAs $2,779 $2,888 $3,055 $3,122 $3,179 Commercial $5,120 $4,897 $4,879 $5,019 $5,060 Retail $4,998 $4,871 $4,861 $4,920 $4,981 1Q25 2Q25 3Q25 4Q25 1Q26 Public Funds Distribution - $MM $2 -84% PR $448 Other -16% 1Q26 $1,876 $489 $56 -77% -20% -2% Public Corp/Agencies Municipalities US Govt. Loan Originations - $MM(1) $1,177 $1,414 $1,371 $1,391 $1,247 Consumer $276 $283 $267 $261 $253 Credit Card $102 $106 $104 $104 $95 Residential $114 $127 $132 $128 $116 Construction $49 $35 $35 $29 $14 Commercial $4,998 $861 $833 $869 $770 1Q25 2Q25 3Q25 4Q25 1Q26 Composition of Deposit Portfolio vs. Available Liquidity - $MM(2) $16,077 $16,089 $5,549 $5,555 -35% -35% NIB $10,528 $10,534 IB -65% -65% 4Q25 1Q26 $8,374 $4,846 $2,869 -51% -30% -18% Cash & Equivalents Free Liquid Securities PHLB Avaialbility Fed Line (1) Loan Originations include refinancing and renewals, as well as credit card utilization activity (2) Uninsured deposits exclude public funds which are fully collateralized 13
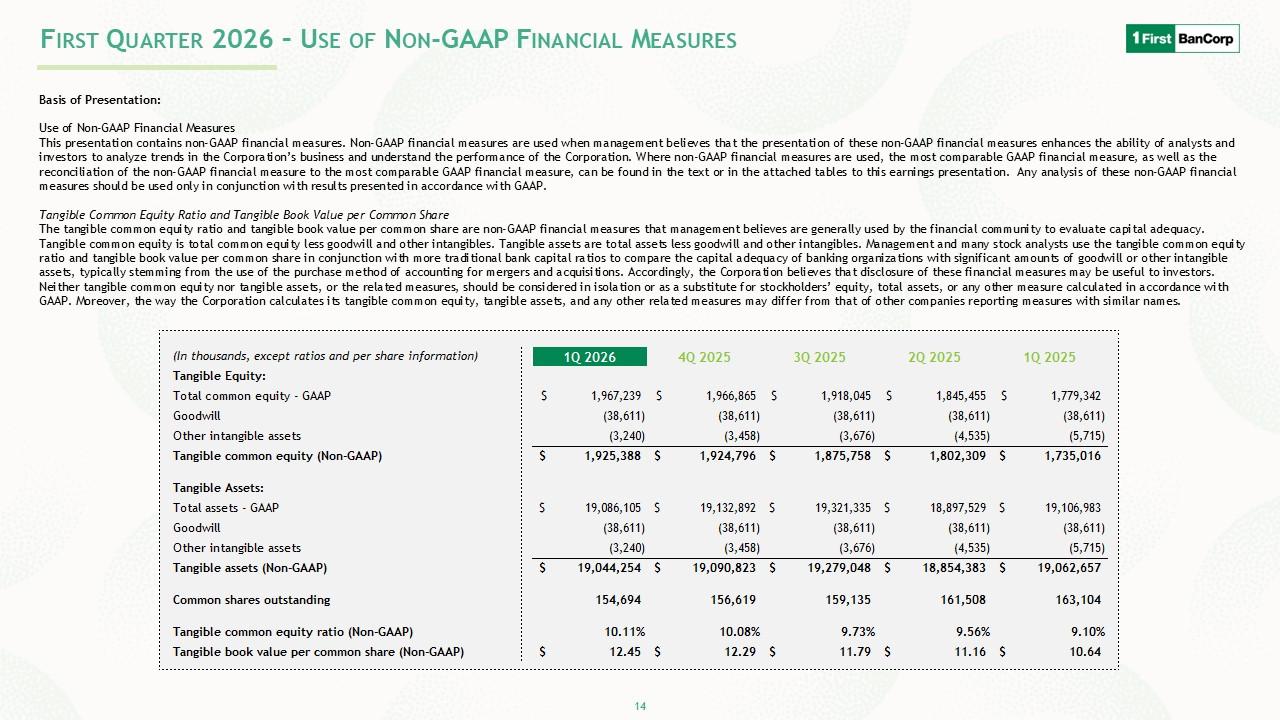
First Quarter 2026 – Use of Non-GAAP Financial Measures Basis of Presentation: Use of Non-GAAP Financial Measures This presentation contains non-GAAP financial measures. Non-GAAP financial measures are used when management believes that the presentation of these non-GAAP financial measures enhances the ability of analysts and investors to analyze trends in the Corporation’s business and understand the performance of the Corporation. Where non-GAAP financial measures are used, the most comparable GAAP financial measure, as well as the reconciliation of the non-GAAP financial measure to the most comparable GAAP financial measure, can be found in the text or in the attached tables to this earnings presentation. Any analysis of these non-GAAP financial measures should be used only in conjunction with results presented in accordance with GAAP. Tangible Common Equity Ratio and Tangible Book Value per Common Share The tangible common equity ratio and tangible book value per common share are non-GAAP financial measures that management believes are generally used by the financial community to evaluate capital adequacy. Tangible common equity is total common equity less goodwill and other intangibles. Tangible assets are total assets less goodwill and other intangibles. Management and many stock analysts use the tangible common equity ratio and tangible book value per common share in conjunction with more traditional bank capital ratios to compare the capital adequacy of banking organizations with significant amounts of goodwill or other intangible assets, typically stemming from the use of the purchase method of accounting for mergers and acquisitions. Accordingly, the Corporation believes that disclosure of these financial measures may be useful to investors. Neither tangible common equity nor tangible assets, or the related measures, should be
considered in isolation or as a substitute for stockholders’ equity, total assets, or any other measure calculated in accordance with GAAP. Moreover, the way the Corporation calculates its tangible common equity, tangible assets, and any other related measures may differ from that of other companies reporting measures with similar names. (In thousands, except ratios and per share information) 10 2026 1 40 2025 3Q2025 20 2025 10 2025 Tangible Equity: Total common equity - GAAP s 1,967,239 S 1,966,865 S 1,918,045 S 1,845,455 S 1,779,342 Goodwill (38,611) (38,611) (38,611) (38,611) (38,611) Other intangible assets (3,240) (3,458) (3,676) (4,535) (5,715) Tangible common equity (Non-GAAP) $ 1,925,388 $ 1,924,796 $ 1,875,758 $ 1,802,309 $ 1,735,016 Tangible Assets: Total assets - GAAP s 19,086,105 S 19,132,892 S 19,321,335 S 18,897,529 S 19,106,983 Goodwill (38,611) (38,611) (38,611) (38,611) (38,611) Other intangible assets (3,240) (3,458) (3,676) (4,535) (5,715) Tangible assets (Non-GAAP) $ 19,044,254 $ 19,090,823 $ 19,279,048 $ 18,854,383 $ 19,062,657 Common shares outstanding 154,694 156,619 159,135 161,508 163,104 Tangible common equity ratio (Non-GAAP) 10.11% 10.08% 9.73% 9.56% 9.10% Tangible book value per common share (Non-GAAP) $ 12.45 $ 12.29 $ 11.79 $ 11.16 $ 10.64 14
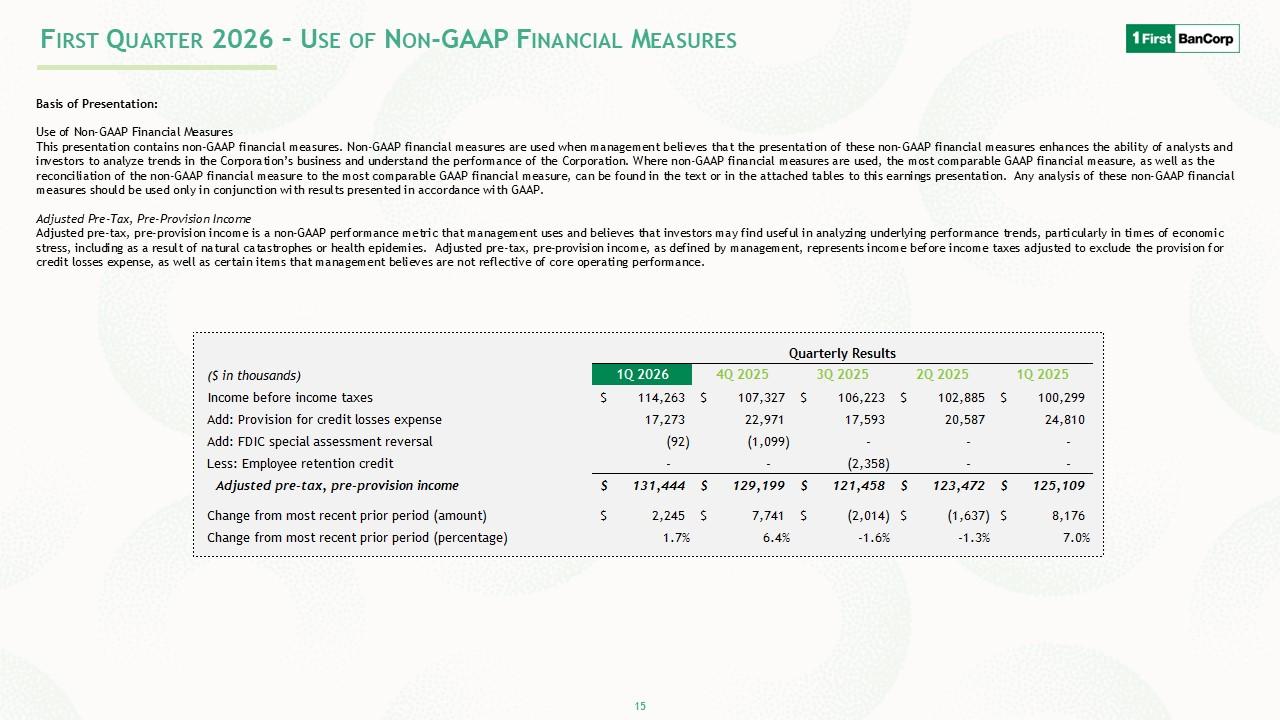
First Quarter 2026 – Use of Non-GAAP Financial Measures Basis of Presentation: Use of Non-GAAP Financial Measures This presentation contains non-GAAP financial measures. Non-GAAP financial measures are used when management believes that the presentation of these non-GAAP financial measures enhances the ability of analysts and investors to analyze trends in the Corporation’s business and understand the performance of the Corporation. Where non-GAAP financial measures are used, the most comparable GAAP financial measure, as well as the reconciliation of the non-GAAP financial measure to the most comparable GAAP financial measure, can be found in the text or in the attached tables to this earnings presentation. Any analysis of these non-GAAP financial measures should be used only in conjunction with results presented in accordance with GAAP. Adjusted Pre-Tax, Pre-Provision Income Adjusted pre-tax, pre-provision income is a non-GAAP performance metric that management uses and believes that investors may find useful in analyzing underlying performance trends, particularly in times of economic stress, including as a result of natural cat astrophes or health epidemies. Adjusted pre-tax, pre-provision income, as defined by management, represents income before income taxes adjusted to exclude the provision for credit losses expense, as well as certain items that management believes are not reflective of core operating performance. (S in thousands) Income before income taxes Add: Provision for credit losses expense Add: FDIC special assessment reversal Less: Employee retention credit Adjusted pre-tax, pre-provision income Change from most recent prior period (amount) Change from most recent prior period (percentage) Quarterly Results 10 2026 ! 40 2025 3Q2025 20 2025 1Q2025 S 114,263 S 107,327 S 106,223 S 102,885 S 100,299 17,273 22,971 17,593 20,587
24,810 (92) (1,099) - -s - - (-5 (2,358) - S 131,444 S 129,199 S 121,458 S 123,472 S 125,109 s 2,245 s 7,741 s (2,014) S (1,637) S 8,176 1.7% 6.4% -1.6% -1.3% 7.0% 15
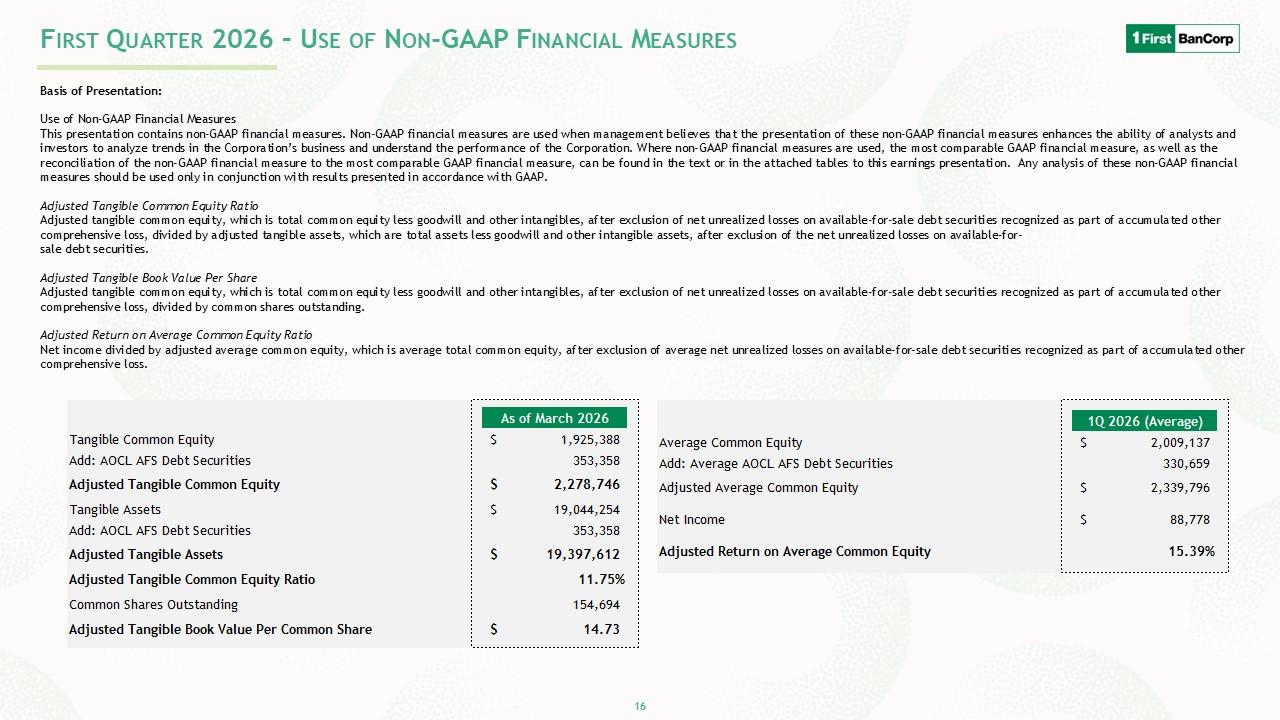
First Quarter 2026 – Use of Non-GAAP Financial Measures Basis of Presentation: Use of Non-GAAP Financial Measures This presentation contains non-GAAP financial measures. Non-GAAP financial measures are used when management believes that the presentation of these non-GAAP financial measures enhances the ability of analysts and investors to analyze trends in the Corporation’s business and understand the performance of the Corporation. Where non-GAAP financial measures are used, the most comparable GAAP financial measure, as well as the reconciliation of the non-GAAP financial measure to the most comparable GAAP financial measure, can be found in the text or in the attached tables to this earnings presentation. Any analysis of these non-GAAP financial measures should be used only in conjunction with results presented in accordance with GAAP. Adjusted Tangible Common Equity Ratio Adju sted tangible common equity, which is total common equity less goodwill and other intangibles, after exclusion of net unreali zed losses on available-for-sale debt securities recognized as part of accumulated other comprehensive loss and Special Items, divided by adjusted tangible assets, which are total assets less goodwill and other intangible assets, after exclusion of the net unrealized losses on available-for- sale debt securities. Adjusted Tangible Book Value Per Share Adjusted tangible common equity, which is total common equity less goodwill and other intangibles, after exclusion of net unrealized losses on available-for-sale debt securities recognized as part of accumulated other comprehensive loss, divided by common shares outstanding. Adjusted Return on Average Common Equity Ratio Net income divided by adjusted average common equity, which is average total common equity, after exclusion of average net unrealized losses on available-for-sale debt securities recognized as
part of accumulated other comprehensive loss. Tangible Common Equity Add: AOCL AFS Debt Securities Adjusted Tangible Common Equity Tangible Assets Add: AOCL AFS Debt Securities Adjusted Tangible Assets Adjusted Tangible Common Equity Ratio Common Shares Outstanding Adjusted Tangible Book Value Per Common Share As of March 2026 S 1,925,388 353,358 $ 2,278,746 s 19,044,254 353,358 $ 19,397,612 11.75% 154,694 s 14.73 Average Common Equity Add: Average AOCL AFS Debt Securities Adjusted Average Common Equity Net Income Adjusted Return on Average Common Equity 1Q2026 (Average) S 2,009,137 330,659 $ 2,339,796 s 88,778 15.39% 16
Financial Results First Quarter 2026 April 22, 2026