
FFBC 8-K
First Financial Bancorp /Oh/ (FFBC)
8-K
2020-04-20
For: 2020-04-20
View Original
Added on
April 07, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the
Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): April 20, 2020
(Exact name of registrant as specified in its charter)
(State or other jurisdiction of incorporation or organization) | (Commission File Number) | (I.R.S. employer identification number) | |||
(Address of principal executive offices) | (Zip Code) | ||||
Registrant's telephone number, including area code: (877 ) 322-9530
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
Securities registered pursuant to Section 12(b) of the Act:
Title of each class | Trading symbol | Name of exchange on which registered | ||
Indicate by check mark whether the registrant is an emerging growth company as defined in as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition.
On April 20, 2020, First Financial Bancorp. (the "Company") issued its earnings press release that included its results of operations and financial condition for the first three months of 2020. A copy of the earnings press release is attached as Exhibit 99.1.
The Company also provided electronic presentation slides that will be used in connection with the earnings conference call. A copy of the electronic presentation slides is included in this Report as Exhibit 99.2 and will be available on the Company's website, www.bankatfirst.com.
The information set forth in this Current Report on Form 8-K (including the information in Exhibits 99.1 and 99.2 attached hereto) is being furnished to the Securities and Exchange Commission and is not deemed to be "filed" for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the "Exchange Act") , or otherwise subject to the liabilities under the Exchange Act. Such information shall not be incorporated by reference into any registration statement or other document filed under the Securities Act of 1933, as amended, or the Exchange Act, except as shall be expressly set forth by specific reference in such filing.
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits:
The following exhibits shall not be deemed to be "filed" for purposes of the Exchange Act:
Exhibit No. Description
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
FIRST FINANCIAL BANCORP.
By: /s/ James M. Anderson | ||
James M. Anderson | ||
Executive Vice President and Chief Financial Officer | ||
Date: | April 20, 2020 | |
Exhibit 99.1


First Financial Bancorp Announces First Quarter 2020 Financial Results
• | Earnings per Diluted Share of $0.29; $0.31 on an Adjusted Basis |
• | 4.6% Loan Growth on an Annualized Basis |
• | 3.77% Fully Tax Equivalent Net Interest Margin |
• | $25.4 million total provision for credit losses |
Cincinnati, Ohio - April 20, 2020 - First Financial Bancorp. (Nasdaq: FFBC) (“First Financial” or the “Company”) announced financial results for the first quarter 2020. In addition, the Company has highlighted client and associate outreach initiatives related to the COVID-19 pandemic.
For the three months ended March 31, 2020, the Company reported net income of $28.6 million, or $0.29 per diluted common share. These results compare to net income of $48.7 million, or $0.49 per diluted common share, for the fourth quarter of 2019 and $45.8 million, or $0.47 per diluted common share, for the first quarter of 2019.
Return on average assets for the first quarter of 2020 was 0.79% while return on average tangible common equity was 9.71%. These compare to returns on average assets of 1.34% and 1.33%, and returns on average tangible common equity of 15.84% and 15.95%, in the fourth quarter of 2019 and the first quarter of 2019, respectively.
First quarter 2020 highlights include:
• | After adjustments(1) for merger-related, nonrecurring and certain COVID-19 related items: |
◦ | Net income of $0.31 per diluted common share |
◦ | 0.85% return on average assets; 10.41% return on average tangible common equity |
• | Adjustments(1) to net income include: |
◦ | $1.0 million contribution to First Financial Foundation for COVID-19 relief |
◦ | $1.5 million of other nonrecurring costs such as branch consolidation costs |
• | Total Allowance for Credit Losses of $158.2 million; Total quarterly provision for credit losses of $25.4 million |
◦ | Adopted CECL as of January 1 |
◦ | Loans and leases - ACL of $143.9 million, 1.55% of total loans; $23.9 provision expense |
◦ | Unfunded Commitments - ACL of $14.3 million; $1.6 million provision expense |
◦ | Substantially all of first quarter provision expense related to expected economic impact from COVID-19 |
• | Loan balances grew 4.6% on an annualized basis |
◦ | $106.2 million increase compared to the linked quarter driven by commercial real estate |
• | Net interest margin of 3.77% on a fully tax-equivalent basis(1) |
◦ | 12 basis point reduction from the linked quarter |
◦ | Impact of lower interest rates on asset yields, lower loan fees and lower purchase accounting accretion partially offset by funding cost reductions |
• | Noninterest income of $35.4 million |
◦ | $4.0 million, or 65.7% increase in foreign exchange income |
◦ | Continued strong client derivative fee income |
◦ | Record trust and wealth management fees; increased $0.6 million, or 14.2% |
____________________________________________________________________________________________(1) Financial information in this release that is described as “adjusted” or that is presented on a fully tax equivalent basis is non-GAAP. For details on the calculation of these non-GAAP financial measures and a reconciliation to the GAAP financial measure, see the sections titled “Use of Non-GAAP Financial Measures” in this release and “Appendix: Non-GAAP to GAAP Reconciliation” in the accompanying slide presentation.
1
• | Noninterest expenses of $89.7 million, or $87.2 million as adjusted(1) |
◦ | Efficiency ratio of 59.9%; 58.2% as adjusted(1) |
◦ | $1.0 million contribution to First Financial Foundation for COVID-19 relief |
◦ | Elevated healthcare costs, seasonal increases in payroll taxes and incentive compensation related to the increase in foreign exchange income drove higher salary and benefits expense |
• | Strong capital ratios |
◦ | Total capital of 13.54%; Tier 1 common equity of 11.27%; Tangible common equity of 8.25% |
◦ | Tangible book value per share of $11.82 |
To date, the Company has performed the following In response to COVID-19:
• | Introduced hardship relief programs that include payment deferrals, fee-waivers and suspension of foreclosures |
◦ | Processed modifications for over $950 million, or 10% of total loans |
◦ | Successfully modified over $45 million in consumer loans |
• | Participant in CARES Act SBA Paycheck Protection Program |
◦ | Received in excess of 5,700 PPP applications; over $1 billion in requests |
◦ | Approximately 3,600 PPP requests, or 63% of applicants, approved by SBA |
• | Accelerated adoption of new processes and technologies to ease customer access to banking services |
Archie Brown, President and Chief Executive Officer, commented, “The first quarter of 2020 proved to be one of the most unique and challenging quarters in our industry's history. While the first half of the quarter was marked by strong financial performance, March was characterized by economic, logistical and social upheaval. In a rapidly changing operational and economic landscape, we successfully implemented a comprehensive business continuity plan without sacrificing the performance and service our borrowers and shareholders have come to expect and were pleased that pre-provision financial results exceeded our expectations, despite a 150 basis point drop in interest rates."
Mr. Brown continued, “First quarter earnings were solid, although they were obviously negatively impacted by COVID's influence on our CECL model. To date, credit stress on the loan portfolio has been limited, evidenced by net recoveries during the period, however the quarterly provision expense reflects our expectation for that to change during the remainder of the year. We were pleased with our ability to manage the margin despite strong interest rate headwinds, as we successfully lowered deposit costs to help alleviate the pressure from declining asset yields, fewer loan fees and lower purchase accounting accretion. In addition, a record quarter from Bannockburn combined with a relatively flat expense base to offset expected seasonal declines in noninterest income to result in a sub-60% adjusted efficiency ratio."
Mr. Brown further remarked, "We began monitoring the pandemic early and preparing in the event it affected our markets. As a result, in response to the pandemic, our executive committee was able to immediately shift to crisis management, working to develop plans and products to assist our clients and communities in a meaningful way. This included the development of our Hardship Relief program, which includes various payment deferral options for borrowers, as well as making a $1.0 million contribution to help fund COVID-19 relief efforts in communities throughout our footprint. We are also actively engaged in extending loans under the U.S. Government's Paycheck Protection Program to our loan and deposit customers. We continue to actively monitor the actions of the federal and state governments, and are proactively assisting our clients to ensure they are aware of every program and level of financial assistance available to them."
Mr. Brown concluded, "The end of the first quarter was certainly unprecedented, and one we will never forget. Our agile response to these trying circumstances has truly highlighted our strength as a Company. In the face of a pandemic, we were able to deliver solid financial performance while maintaining focus on our customers and communities. Although certain performance metrics are difficult to forecast for the remainder of the year, we pledge to remain diligent and manage the Company in a way that continues to deliver maximum shareholder value while prioritizing the physical and financial well-being of our clients and associates."
Full detail of the Company’s first quarter performance is provided in the accompanying financial statements and slide presentation.
Teleconference / Webcast Information
First Financial’s executive management will host a conference call to discuss the Company’s financial and operating results on Tuesday, April 21, 2020 at 8:30 a.m. Eastern Time. Members of the public who would like to listen to the conference call should dial (877) 506-6873 (U.S. toll free), (855) 669-9657 (Canada toll free) or +1 (412) 380-2003 (International) (no passcode required). The number should be dialed five to ten minutes prior to the start of the conference call. The conference call will also be accessible as an audio webcast via the Investor Relations section of the Company’s website at www.bankatfirst.com. A replay of the conference call will be available beginning one hour after the completion of the live call at (877) 344-7529 (U.S. toll free), (855) 669-9658 (Canada toll free) and +1 (412) 317-0088 (International); conference number 10141642. The webcast will be archived on the Investor Relations section of the Company’s website for 12 months.
Press Release and Additional Information on Website
This press release as well as supplemental information are available to the public through the Investor Relations section of First Financial's website at www.bankatfirst.com.
Use of Non-GAAP Financial Measures
This earnings release contains GAAP financial measures and Non-GAAP financial measures where management believes it to be helpful in understanding the Company’s results of operations or financial position. Where Non-GAAP financial measures are used, the comparable GAAP financial measures, as well as a reconciliation to the
2
comparable GAAP financial measure, can be found in the section titled “Appendix: Non-GAAP to GAAP Reconciliation” in the accompanying slide presentation.
3
Forward-Looking Statement
Certain statements contained in this report which are not statements of historical fact constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Words such as ‘‘believes,’’ ‘‘anticipates,’’ “likely,” “expected,” “estimated,” ‘‘intends’’ and other similar expressions are intended to identify forward-looking statements but are not the exclusive means of identifying such statements. Examples of forward-looking statements include, but are not limited to, statements we make about (i) our future operating or financial performance, including revenues, income or loss and earnings or loss per share, (ii) future common stock dividends, (iii) our capital structure, including future capital levels, (iv) our plans, objectives and strategies, and (v) the assumptions that underlie our forward-looking statements.
As with any forecast or projection, forward-looking statements are subject to inherent uncertainties, risks and changes in circumstances that may cause actual results to differ materially from those set forth in the forward-looking statements. Forward-looking statements are not historical facts but instead express only management’s beliefs regarding future results or events, many of which, by their nature, are inherently uncertain and outside of management’s control. It is possible that actual results and outcomes may differ, possibly materially, from the anticipated results or outcomes indicated in these forward-looking statements. Important factors that could cause actual results to differ materially from those in our forward-looking statements include the following, without limitation:
• | economic, market, liquidity, credit, interest rate, operational and technological risks associated with the Company’s business; |
• | future credit quality and performance, including our expectations regarding future loan losses and our allowance for credit losses |
• | the effect of and changes in policies and laws or regulatory agencies, including the Dodd-Frank Wall Street Reform and Consumer Protection Act and other legislation and regulation relating to the banking industry; (iv) management’s ability to effectively execute its business plans; |
• | mergers and acquisitions, including costs or difficulties related to the integration of acquired companies; |
• | the possibility that any of the anticipated benefits of the Company’s acquisitions will not be realized or will not be realized within the expected time period; |
• | the effect of changes in accounting policies and practices; |
• | changes in consumer spending, borrowing and saving and changes in unemployment; |
• | changes in customers’ performance and creditworthiness; |
• | the costs and effects of litigation and of unexpected or adverse outcomes in such litigation; |
• | current and future economic and market conditions, including the effects of declines in housing prices, high unemployment rates, U.S. fiscal debt, budget and tax matters, geopolitical matters, and any slowdown in global economic growth; |
• | the adverse impact on the U.S. economy, including the markets in which we operate, of the novel coronavirus, which causes the Coronavirus disease 2019 (“COVID-19”), global pandemic, and the impact of a slowing U.S. economy and increased unemployment on the performance of our loan and lease portfolio, the market value of our investment securities, the availability of sources of funding and the demand for our products; |
• | our capital and liquidity requirements (including under regulatory capital standards, such as the Basel III capital standards) and our ability to generate capital internally or raise capital on favorable terms; |
• | financial services reform and other current, pending or future legislation or regulation that could have a negative effect on our revenue and businesses, including the Dodd-Frank Act and other legislation and regulation relating to bank products and services; |
• | the effect of the current interest rate environment or changes in interest rates or in the level or composition of our assets or liabilities on our net interest income, net interest margin and our mortgage originations, mortgage servicing rights and mortgage loans held for sale; |
• | the effect of a fall in stock market prices on our brokerage, asset and wealth management businesses; |
• | a failure in or breach of our operational or security systems or infrastructure, or those of our third-party vendors or other service providers, including as a result of cyber attacks; |
• | the effect of changes in the level of checking or savings account deposits on our funding costs and net interest margin; and |
• | our ability to develop and execute effective business plans and strategies. |
4
Additional factors that may cause our actual results to differ materially from those described in our forward-looking statements can be found in our Form 10-K for the year ended December 31, 2019, as well as our other filings with the SEC, which are available on the SEC website at www.sec.gov.
All forward-looking statements included in this filing are made as of the date hereof and are based on information available at the time of the filing. Except as required by law, the Company does not assume any obligation to update any forward-looking statement.
About First Financial Bancorp.
First Financial Bancorp. is a Cincinnati, Ohio based bank holding company. As of March 31, 2020, the Company had $15.1 billion in assets, $9.3 billion in loans, $10.6 billion in deposits and $2.2 billion in shareholders’ equity. The Company’s subsidiary, First Financial Bank, founded in 1863, provides banking and financial services products through its six lines of business: Commercial, Retail Banking, Investment Commercial Real Estate, Mortgage Banking, Commercial Finance and Wealth Management. These business units provide traditional banking services to business and retail clients. Wealth Management provides wealth planning, portfolio management, trust and estate, brokerage and retirement plan services and had approximately $2.6 billion in assets under management as of March 31, 2020. The Company operated 145 full service banking centers as of March 31, 2020, primarily in Ohio, Indiana and Kentucky, while the Commercial Finance business lends into targeted industry verticals on a nationwide basis. Additional information about the Company, including its products, services and banking locations, is available at www.bankatfirst.com.
Contact Information
Investors/Analysts Media
Jamie Anderson Tim Condron
Chief Financial Officer Marketing Communications Manager
(513) 887-5400 (513) 979-5796
5
Selected Financial Information
March 31, 2020
(unaudited)
Contents | Page |
Consolidated Financial Highlights | 2 |
Consolidated Quarterly Statements of Income | 3 |
Consolidated Statements of Condition | 4 |
Average Consolidated Statements of Condition | 5 |
Net Interest Margin Rate / Volume Analysis | 6 |
Credit Quality | 7 |
Capital Adequacy | 8 |
FIRST FINANCIAL BANCORP. | |||||||||||||||||||
CONSOLIDATED FINANCIAL HIGHLIGHTS | |||||||||||||||||||
(Dollars in thousands, except per share data) | |||||||||||||||||||
(Unaudited) | |||||||||||||||||||
Three Months Ended, | |||||||||||||||||||
Mar. 31, | Dec. 31, | Sep. 30, | Jun. 30, | Mar. 31, | |||||||||||||||
2020 | 2019 | 2019 | 2019 | 2019 | |||||||||||||||
RESULTS OF OPERATIONS | |||||||||||||||||||
Net income | $ | 28,628 | $ | 48,677 | $ | 50,856 | $ | 52,703 | $ | 45,839 | |||||||||
Net earnings per share - basic | $ | 0.29 | $ | 0.49 | $ | 0.52 | $ | 0.54 | $ | 0.47 | |||||||||
Net earnings per share - diluted | $ | 0.29 | $ | 0.49 | $ | 0.51 | $ | 0.53 | $ | 0.47 | |||||||||
Dividends declared per share | $ | 0.23 | $ | 0.23 | $ | 0.23 | $ | 0.22 | $ | 0.22 | |||||||||
KEY FINANCIAL RATIOS | |||||||||||||||||||
Return on average assets | 0.79 | % | 1.34 | % | 1.41 | % | 1.50 | % | 1.33 | % | |||||||||
Return on average shareholders' equity | 5.21 | % | 8.60 | % | 9.13 | % | 9.85 | % | 8.88 | % | |||||||||
Return on average tangible shareholders' equity | 9.71 | % | 15.84 | % | 16.15 | % | 17.33 | % | 15.95 | % | |||||||||
Net interest margin | 3.71 | % | 3.84 | % | 3.91 | % | 3.99 | % | 4.05 | % | |||||||||
Net interest margin (fully tax equivalent) (1) | 3.77 | % | 3.89 | % | 3.96 | % | 4.04 | % | 4.10 | % | |||||||||
Ending shareholders' equity as a percent of ending assets | 14.47 | % | 15.49 | % | 15.62 | % | 15.16 | % | 15.14 | % | |||||||||
Ending tangible shareholders' equity as a percent of: | |||||||||||||||||||
Ending tangible assets | 8.25 | % | 9.07 | % | 9.17 | % | 9.34 | % | 9.15 | % | |||||||||
Risk-weighted assets | 10.50 | % | 11.09 | % | 11.34 | % | 11.82 | % | 11.61 | % | |||||||||
Average shareholders' equity as a percent of average assets | 15.21 | % | 15.53 | % | 15.43 | % | 15.22 | % | 15.01 | % | |||||||||
Average tangible shareholders' equity as a percent of | |||||||||||||||||||
average tangible assets | 8.79 | % | 9.07 | % | 9.35 | % | 9.26 | % | 8.95 | % | |||||||||
Book value per share | $ | 22.25 | $ | 22.82 | $ | 22.59 | $ | 22.18 | $ | 21.60 | |||||||||
Tangible book value per share | $ | 11.82 | $ | 12.42 | $ | 12.33 | $ | 12.79 | $ | 12.19 | |||||||||
Common equity tier 1 ratio (2) | 11.27 | % | 11.30 | % | 11.52 | % | 12.00 | % | 12.03 | % | |||||||||
Tier 1 ratio (2) | 11.66 | % | 11.69 | % | 11.91 | % | 12.40 | % | 12.43 | % | |||||||||
Total capital ratio (2) | 13.54 | % | 13.39 | % | 13.62 | % | 14.20 | % | 14.24 | % | |||||||||
Leverage ratio (2) | 9.49 | % | 9.58 | % | 9.75 | % | 10.02 | % | 9.84 | % | |||||||||
AVERAGE BALANCE SHEET ITEMS | |||||||||||||||||||
Loans (3) | $ | 9,220,643 | $ | 9,149,222 | $ | 9,014,092 | $ | 8,852,662 | $ | 8,773,310 | |||||||||
Investment securities | 3,115,723 | 3,102,867 | 3,290,666 | 3,408,994 | 3,355,732 | ||||||||||||||
Interest-bearing deposits with other banks | 39,332 | 36,672 | 38,569 | 33,255 | 34,709 | ||||||||||||||
Total earning assets | $ | 12,375,698 | $ | 12,288,761 | $ | 12,343,327 | $ | 12,294,911 | $ | 12,163,751 | |||||||||
Total assets | $ | 14,524,422 | $ | 14,460,288 | $ | 14,320,514 | $ | 14,102,733 | $ | 13,952,551 | |||||||||
Noninterest-bearing deposits | $ | 2,643,240 | $ | 2,638,908 | $ | 2,513,458 | $ | 2,484,214 | $ | 2,457,587 | |||||||||
Interest-bearing deposits | 7,590,791 | 7,583,531 | 7,504,708 | 7,612,146 | 7,610,092 | ||||||||||||||
Total deposits | $ | 10,234,031 | $ | 10,222,439 | $ | 10,018,166 | $ | 10,096,360 | $ | 10,067,679 | |||||||||
Borrowings | $ | 1,735,767 | $ | 1,613,696 | $ | 1,816,983 | $ | 1,656,570 | $ | 1,587,068 | |||||||||
Shareholders' equity | $ | 2,209,733 | $ | 2,245,107 | $ | 2,210,327 | $ | 2,146,997 | $ | 2,094,234 | |||||||||
CREDIT QUALITY RATIOS | |||||||||||||||||||
Allowance to ending loans | 1.55 | % | 0.63 | % | 0.62 | % | 0.69 | % | 0.64 | % | |||||||||
Allowance to nonaccrual loans | 296.51 | % | 119.69 | % | 93.18 | % | 119.86 | % | 95.40 | % | |||||||||
Allowance to nonperforming loans | 203.42 | % | 96.73 | % | 71.46 | % | 69.33 | % | 68.94 | % | |||||||||
Nonperforming loans to total loans | 0.76 | % | 0.65 | % | 0.87 | % | 0.99 | % | 0.93 | % | |||||||||
Nonperforming assets to ending loans, plus OREO | 0.78 | % | 0.67 | % | 0.89 | % | 1.00 | % | 0.95 | % | |||||||||
Nonperforming assets to total assets | 0.48 | % | 0.42 | % | 0.56 | % | 0.62 | % | 0.60 | % | |||||||||
Classified assets to total assets | 0.83 | % | 0.62 | % | 0.92 | % | 1.02 | % | 1.01 | % | |||||||||
Net charge-offs to average loans (annualized) | (0.04 | )% | 0.15 | % | 0.45 | % | 0.08 | % | 0.64 | % | |||||||||
(1) The tax equivalent adjustment to net interest income recognizes the income tax savings when comparing taxable and tax-exempt assets and assumes a 21% tax rate. Management believes that it is a standard practice in the banking industry to present net interest margin and net interest income on a fully tax equivalent basis. Therefore, management believes these measures provide useful information to investors by allowing them to make peer comparisons. Management also uses these measures to make peer comparisons.
(2) March 31, 2020 regulatory capital ratios are preliminary.
(3) Includes loans held for sale.
2
FIRST FINANCIAL BANCORP. | |||||||||||||||||||||||
CONSOLIDATED QUARTERLY STATEMENTS OF INCOME | |||||||||||||||||||||||
(Dollars in thousands, except per share data) | |||||||||||||||||||||||
(Unaudited) | |||||||||||||||||||||||
2020 | 2019 | ||||||||||||||||||||||
First | Fourth | Third | Second | First | Full | ||||||||||||||||||
Quarter | Quarter | Quarter | Quarter | Quarter | Year | ||||||||||||||||||
Interest income | |||||||||||||||||||||||
Loans and leases, including fees | $ | 115,775 | $ | 122,802 | $ | 126,786 | $ | 126,365 | $ | 123,056 | $ | 499,009 | |||||||||||
Investment securities | |||||||||||||||||||||||
Taxable | 19,005 | 20,137 | 22,180 | 23,616 | 24,235 | 90,168 | |||||||||||||||||
Tax-exempt | 4,582 | 4,545 | 4,457 | 4,336 | 4,258 | 17,596 | |||||||||||||||||
Total investment securities interest | 23,587 | 24,682 | 26,637 | 27,952 | 28,493 | 107,764 | |||||||||||||||||
Other earning assets | 142 | 167 | 222 | 206 | 210 | 805 | |||||||||||||||||
Total interest income | 139,504 | 147,651 | 153,645 | 154,523 | 151,759 | 607,578 | |||||||||||||||||
Interest expense | |||||||||||||||||||||||
Deposits | 16,365 | 19,026 | 20,151 | 20,612 | 19,243 | 79,032 | |||||||||||||||||
Short-term borrowings | 5,087 | 5,430 | 7,199 | 6,646 | 5,960 | 25,235 | |||||||||||||||||
Long-term borrowings | 3,770 | 4,293 | 4,760 | 4,963 | 5,041 | 19,057 | |||||||||||||||||
Total interest expense | 25,222 | 28,749 | 32,110 | 32,221 | 30,244 | 123,324 | |||||||||||||||||
Net interest income | 114,282 | 118,902 | 121,535 | 122,302 | 121,515 | 484,254 | |||||||||||||||||
Provision for credit losses-loans and leases (1) | 23,880 | 4,629 | 5,228 | 6,658 | 14,083 | 30,598 | |||||||||||||||||
Provision for credit losses-unfunded commitments (1) | 1,568 | 177 | (216 | ) | (132 | ) | 6 | (165 | ) | ||||||||||||||
Net interest income after provision for credit losses | 88,834 | 114,096 | 116,523 | 115,776 | 107,426 | 453,821 | |||||||||||||||||
Noninterest income | |||||||||||||||||||||||
Service charges on deposit accounts | 8,435 | 9,343 | 9,874 | 9,819 | 8,903 | 37,939 | |||||||||||||||||
Trust and wealth management fees | 4,469 | 3,913 | 3,718 | 3,943 | 4,070 | 15,644 | |||||||||||||||||
Bankcard income | 2,698 | 3,405 | 3,316 | 6,497 | 5,586 | 18,804 | |||||||||||||||||
Client derivative fees | 3,105 | 4,194 | 4,859 | 4,905 | 1,704 | 15,662 | |||||||||||||||||
Foreign exchange income | 9,966 | 6,014 | 1,708 | 17 | 0 | 7,739 | |||||||||||||||||
Net gains from sales of loans | 2,831 | 4,723 | 4,806 | 3,432 | 1,890 | 14,851 | |||||||||||||||||
Net gains on sale of investment securities | (59 | ) | (296 | ) | 105 | (37 | ) | (178 | ) | (406 | ) | ||||||||||||
Other | 3,939 | 5,472 | 4,754 | 6,062 | 4,852 | 21,140 | |||||||||||||||||
Total noninterest income | 35,384 | 36,768 | 33,140 | 34,638 | 26,827 | 131,373 | |||||||||||||||||
Noninterest expenses | |||||||||||||||||||||||
Salaries and employee benefits | 54,822 | 53,952 | 53,212 | 53,985 | 47,912 | 209,061 | |||||||||||||||||
Net occupancy | 6,104 | 6,334 | 5,509 | 5,596 | 6,630 | 24,069 | |||||||||||||||||
Furniture and equipment | 4,053 | 4,145 | 4,120 | 4,222 | 3,416 | 15,903 | |||||||||||||||||
Data processing | 6,389 | 5,996 | 5,774 | 4,984 | 5,127 | 21,881 | |||||||||||||||||
Marketing | 1,220 | 1,980 | 1,346 | 1,976 | 1,606 | 6,908 | |||||||||||||||||
Communication | 890 | 882 | 910 | 747 | 728 | 3,267 | |||||||||||||||||
Professional services | 2,275 | 2,192 | 4,771 | 2,039 | 2,252 | 11,254 | |||||||||||||||||
State intangible tax | 1,516 | 1,767 | 1,445 | 1,307 | 1,310 | 5,829 | |||||||||||||||||
FDIC assessments | 1,405 | 1,055 | (1,097 | ) | 1,065 | 950 | 1,973 | ||||||||||||||||
Intangible amortization | 2,792 | 3,150 | 2,432 | 2,044 | 2,045 | 9,671 | |||||||||||||||||
Other | 8,200 | 11,434 | 8,020 | 6,545 | 6,517 | 32,516 | |||||||||||||||||
Total noninterest expenses | 89,666 | 92,887 | 86,442 | 84,510 | 78,493 | 342,332 | |||||||||||||||||
Income before income taxes | 34,552 | 57,977 | 63,221 | 65,904 | 55,760 | 242,862 | |||||||||||||||||
Income tax expense (benefit) | 5,924 | 9,300 | 12,365 | 13,201 | 9,921 | 44,787 | |||||||||||||||||
Net income | $ | 28,628 | $ | 48,677 | $ | 50,856 | $ | 52,703 | $ | 45,839 | $ | 198,075 | |||||||||||
ADDITIONAL DATA | |||||||||||||||||||||||
Net earnings per share - basic | $ | 0.29 | $ | 0.49 | $ | 0.52 | $ | 0.54 | $ | 0.47 | $ | 2.01 | |||||||||||
Net earnings per share - diluted | $ | 0.29 | $ | 0.49 | $ | 0.51 | $ | 0.53 | $ | 0.47 | $ | 2.00 | |||||||||||
Dividends declared per share | $ | 0.23 | $ | 0.23 | $ | 0.23 | $ | 0.22 | $ | 0.22 | $ | 0.90 | |||||||||||
Return on average assets | 0.79 | % | 1.34 | % | 1.41 | % | 1.50 | % | 1.33 | % | 1.39 | % | |||||||||||
Return on average shareholders' equity | 5.21 | % | 8.60 | % | 9.13 | % | 9.85 | % | 8.88 | % | 9.11 | % | |||||||||||
Interest income | $ | 139,504 | $ | 147,651 | $ | 153,645 | $ | 154,523 | $ | 151,759 | $ | 607,578 | |||||||||||
Tax equivalent adjustment | 1,624 | 1,630 | 1,759 | 1,416 | 1,523 | 6,328 | |||||||||||||||||
Interest income - tax equivalent | 141,128 | 149,281 | 155,404 | 155,939 | 153,282 | 613,906 | |||||||||||||||||
Interest expense | 25,222 | 28,749 | 32,110 | 32,221 | 30,244 | 123,324 | |||||||||||||||||
Net interest income - tax equivalent | $ | 115,906 | $ | 120,532 | $ | 123,294 | $ | 123,718 | $ | 123,038 | $ | 490,582 | |||||||||||
Net interest margin | 3.71 | % | 3.84 | % | 3.91 | % | 3.99 | % | 4.05 | % | 3.95 | % | |||||||||||
Net interest margin (fully tax equivalent) (2) | 3.77 | % | 3.89 | % | 3.96 | % | 4.04 | % | 4.10 | % | 4.00 | % | |||||||||||
Full-time equivalent employees | 2,067 | 2,065 | 2,064 | 2,076 | 2,087 | ||||||||||||||||||
(1) Beginning January 1,2020, calculation is based on current expected loss methodology. Prior to January 1, 2020, calculation was based on the incurred loss methodology. | |||||||||||||||||||||||
(2) The tax equivalent adjustment to net interest income recognizes the income tax savings when comparing taxable and tax-exempt assets and assumes a 21% tax rate. Management believes that it is a standard practice in the banking industry to present net interest income on a fully tax equivalent basis. Therefore, management believes these measures provide useful information to investors by allowing them to make peer comparisons. Management also uses these measures to make peer comparisons. | |||||||||||||||||||||||
3
FIRST FINANCIAL BANCORP. | |||||||||||||||||||||||||
CONSOLIDATED STATEMENTS OF CONDITION | |||||||||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||||||||
(Unaudited) | |||||||||||||||||||||||||
Mar. 31, | Dec. 31, | Sep. 30, | Jun. 30, | Mar. 31, | % Change | % Change | |||||||||||||||||||
2020 | 2019 | 2019 | 2019 | 2019 | Linked Qtr. | Comp Qtr. | |||||||||||||||||||
ASSETS | |||||||||||||||||||||||||
Cash and due from banks | $ | 261,892 | $ | 200,691 | $ | 242,482 | $ | 169,694 | $ | 169,004 | 30.5 | % | 55.0 | % | |||||||||||
Interest-bearing deposits with other banks | 71,071 | 56,948 | 39,669 | 101,668 | 50,224 | 24.8 | % | 41.5 | % | ||||||||||||||||
Investment securities available-for-sale | 2,908,688 | 2,852,084 | 2,850,502 | 3,152,970 | 3,113,811 | 2.0 | % | (6.6 | )% | ||||||||||||||||
Investment securities held-to-maturity | 136,744 | 142,862 | 148,778 | 154,327 | 158,305 | (4.3 | )% | (13.6 | )% | ||||||||||||||||
Other investments | 143,581 | 125,020 | 124,965 | 127,439 | 115,731 | 14.8 | % | 24.1 | % | ||||||||||||||||
Loans held for sale | 27,334 | 13,680 | 23,528 | 20,244 | 8,217 | 99.8 | % | 232.7 | % | ||||||||||||||||
Loans and leases | |||||||||||||||||||||||||
Commercial and industrial | 2,477,773 | 2,465,877 | 2,470,017 | 2,547,997 | 2,543,427 | 0.5 | % | (2.6 | )% | ||||||||||||||||
Lease financing | 82,602 | 88,364 | 92,616 | 90,638 | 95,573 | (6.5 | )% | (13.6 | )% | ||||||||||||||||
Construction real estate | 500,311 | 493,182 | 515,960 | 497,683 | 458,113 | 1.4 | % | 9.2 | % | ||||||||||||||||
Commercial real estate | 4,278,257 | 4,194,651 | 4,015,908 | 3,903,654 | 3,802,179 | 2.0 | % | 12.5 | % | ||||||||||||||||
Residential real estate | 1,061,792 | 1,055,949 | 1,055,007 | 1,015,820 | 975,120 | 0.6 | % | 8.9 | % | ||||||||||||||||
Home equity | 781,243 | 771,869 | 776,885 | 787,139 | 797,118 | 1.2 | % | (2.0 | )% | ||||||||||||||||
Installment | 80,085 | 82,589 | 88,275 | 89,149 | 90,689 | (3.0 | )% | (11.7 | )% | ||||||||||||||||
Credit card | 45,756 | 49,184 | 49,010 | 48,706 | 46,982 | (7.0 | )% | (2.6 | )% | ||||||||||||||||
Total loans | 9,307,819 | 9,201,665 | 9,063,678 | 8,980,786 | 8,809,201 | 1.2 | % | 5.7 | % | ||||||||||||||||
Less: | |||||||||||||||||||||||||
Allowance for credit losses (1) | 143,885 | 57,650 | 56,552 | 61,549 | 56,722 | 149.6 | % | 153.7 | % | ||||||||||||||||
Net loans | 9,163,934 | 9,144,015 | 9,007,126 | 8,919,237 | 8,752,479 | 0.2 | % | 4.7 | % | ||||||||||||||||
Premises and equipment | 212,787 | 214,506 | 213,681 | 211,313 | 210,676 | (0.8 | )% | 1.0 | % | ||||||||||||||||
Goodwill | 937,771 | 937,771 | 937,689 | 879,727 | 879,727 | 0.0 | % | 6.6 | % | ||||||||||||||||
Other intangibles | 73,258 | 76,201 | 79,506 | 36,349 | 38,571 | (3.9 | )% | 89.9 | % | ||||||||||||||||
Accrued interest and other assets | 1,120,507 | 747,847 | 812,519 | 664,695 | 577,518 | 49.8 | % | 94.0 | % | ||||||||||||||||
Total Assets | $ | 15,057,567 | $ | 14,511,625 | $ | 14,480,445 | $ | 14,437,663 | $ | 14,074,263 | 3.8 | % | 7.0 | % | |||||||||||
LIABILITIES | |||||||||||||||||||||||||
Deposits | |||||||||||||||||||||||||
Interest-bearing demand | $ | 2,498,109 | $ | 2,364,881 | $ | 2,316,301 | $ | 2,332,692 | $ | 2,235,036 | 5.6 | % | 11.8 | % | |||||||||||
Savings | 2,978,250 | 2,960,979 | 2,924,200 | 2,953,114 | 3,100,894 | 0.6 | % | (4.0 | )% | ||||||||||||||||
Time | 2,435,858 | 2,240,441 | 2,308,617 | 2,321,908 | 2,309,810 | 8.7 | % | 5.5 | % | ||||||||||||||||
Total interest-bearing deposits | 7,912,217 | 7,566,301 | 7,549,118 | 7,607,714 | 7,645,740 | 4.6 | % | 3.5 | % | ||||||||||||||||
Noninterest-bearing | 2,723,341 | 2,643,928 | 2,534,739 | 2,501,290 | 2,488,157 | 3.0 | % | 9.5 | % | ||||||||||||||||
Total deposits | 10,635,558 | 10,210,229 | 10,083,857 | 10,109,004 | 10,133,897 | 4.2 | % | 5.0 | % | ||||||||||||||||
Federal funds purchased and securities sold | |||||||||||||||||||||||||
under agreements to repurchase | 215,824 | 165,181 | 85,286 | 260,621 | 95,015 | 30.7 | % | 127.1 | % | ||||||||||||||||
FHLB short-term borrowings | 1,181,900 | 1,151,000 | 1,128,900 | 1,052,700 | 952,400 | 2.7 | % | 24.1 | % | ||||||||||||||||
Total short-term borrowings | 1,397,724 | 1,316,181 | 1,214,186 | 1,313,321 | 1,047,415 | 6.2 | % | 33.4 | % | ||||||||||||||||
Long-term debt | 325,566 | 414,376 | 498,778 | 547,042 | 546,423 | (21.4 | )% | (40.4 | )% | ||||||||||||||||
Total borrowed funds | 1,723,290 | 1,730,557 | 1,712,964 | 1,860,363 | 1,593,838 | (0.4 | )% | 8.1 | % | ||||||||||||||||
Accrued interest and other liabilities | 519,336 | 323,134 | 422,311 | 280,107 | 216,109 | 60.7 | % | 140.3 | % | ||||||||||||||||
Total Liabilities | 12,878,184 | 12,263,920 | 12,219,132 | 12,249,474 | 11,943,844 | 5.0 | % | 7.8 | % | ||||||||||||||||
SHAREHOLDERS' EQUITY | |||||||||||||||||||||||||
Common stock | 1,633,950 | 1,640,771 | 1,639,333 | 1,623,699 | 1,622,554 | (0.4 | )% | 0.7 | % | ||||||||||||||||
Retained earnings | 660,653 | 711,249 | 685,368 | 657,730 | 626,408 | (7.1 | )% | 5.5 | % | ||||||||||||||||
Accumulated other comprehensive income (loss) | 11,788 | 13,323 | 15,450 | 5,193 | (19,635 | ) | (11.5 | )% | 160.0 | % | |||||||||||||||
Treasury stock, at cost | (127,008 | ) | (117,638 | ) | (78,838 | ) | (98,433 | ) | (98,908 | ) | 8.0 | % | 28.4 | % | |||||||||||
Total Shareholders' Equity | 2,179,383 | 2,247,705 | 2,261,313 | 2,188,189 | 2,130,419 | (3.0 | )% | 2.3 | % | ||||||||||||||||
Total Liabilities and Shareholders' Equity | $ | 15,057,567 | $ | 14,511,625 | $ | 14,480,445 | $ | 14,437,663 | $ | 14,074,263 | 3.8 | % | 7.0 | % | |||||||||||
(1) Beginning January 1,2020, calculation is based on current expected loss methodology. Prior to January 1, 2020, calculation was based on the incurred loss methodology. | |||||||||||||||||||||||||
4
FIRST FINANCIAL BANCORP. | |||||||||||||||||||
AVERAGE CONSOLIDATED STATEMENTS OF CONDITION | |||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||
(Unaudited) | |||||||||||||||||||
Quarterly Averages | |||||||||||||||||||
Mar. 31, | Dec. 31, | Sep. 30, | Jun. 30, | Mar. 31, | |||||||||||||||
2020 | 2019 | 2019 | 2019 | 2019 | |||||||||||||||
ASSETS | |||||||||||||||||||
Cash and due from banks | $ | 235,696 | $ | 221,060 | $ | 191,000 | $ | 173,278 | $ | 181,695 | |||||||||
Interest-bearing deposits with other banks | 39,332 | 36,672 | 38,569 | 33,255 | 34,709 | ||||||||||||||
Investment securities | 3,115,723 | 3,102,867 | 3,290,666 | 3,408,994 | 3,355,732 | ||||||||||||||
Loans held for sale | 13,174 | 21,050 | 18,197 | 13,258 | 6,392 | ||||||||||||||
Loans and leases | |||||||||||||||||||
Commercial and industrial | 2,450,893 | 2,469,810 | 2,509,782 | 2,533,981 | 2,509,274 | ||||||||||||||
Lease financing | 85,782 | 91,225 | 94,858 | 94,458 | 91,043 | ||||||||||||||
Construction real estate | 501,471 | 501,892 | 509,742 | 457,962 | 496,153 | ||||||||||||||
Commercial real estate | 4,209,345 | 4,102,288 | 3,925,028 | 3,834,404 | 3,762,314 | ||||||||||||||
Residential real estate | 1,055,456 | 1,053,707 | 1,035,975 | 989,923 | 961,584 | ||||||||||||||
Home equity | 773,082 | 773,119 | 781,340 | 789,087 | 807,768 | ||||||||||||||
Installment | 81,234 | 85,515 | 88,760 | 89,778 | 91,270 | ||||||||||||||
Credit card | 50,206 | 50,616 | 50,410 | 49,811 | 47,512 | ||||||||||||||
Total loans | 9,207,469 | 9,128,172 | 8,995,895 | 8,839,404 | 8,766,918 | ||||||||||||||
Less: | |||||||||||||||||||
Allowance for credit losses (1) | 121,126 | 56,649 | 61,911 | 58,335 | 57,088 | ||||||||||||||
Net loans | 9,086,343 | 9,071,523 | 8,933,984 | 8,781,069 | 8,709,830 | ||||||||||||||
Premises and equipment | 215,545 | 215,171 | 215,671 | 211,714 | 213,208 | ||||||||||||||
Goodwill | 937,771 | 937,710 | 899,888 | 879,726 | 878,541 | ||||||||||||||
Other intangibles | 75,014 | 78,190 | 51,365 | 37,666 | 39,900 | ||||||||||||||
Accrued interest and other assets | 805,824 | 776,045 | 681,174 | 563,773 | 532,544 | ||||||||||||||
Total Assets | $ | 14,524,422 | $ | 14,460,288 | $ | 14,320,514 | $ | 14,102,733 | $ | 13,952,551 | |||||||||
LIABILITIES | |||||||||||||||||||
Deposits | |||||||||||||||||||
Interest-bearing demand | $ | 2,418,193 | $ | 2,373,962 | $ | 2,325,405 | $ | 2,334,322 | $ | 2,269,948 | |||||||||
Savings | 2,976,518 | 2,995,395 | 2,945,076 | 3,057,100 | 3,115,557 | ||||||||||||||
Time | 2,196,080 | 2,214,174 | 2,234,227 | 2,220,724 | 2,224,587 | ||||||||||||||
Total interest-bearing deposits | 7,590,791 | 7,583,531 | 7,504,708 | 7,612,146 | 7,610,092 | ||||||||||||||
Noninterest-bearing | 2,643,240 | 2,638,908 | 2,513,458 | 2,484,214 | 2,457,587 | ||||||||||||||
Total deposits | 10,234,031 | 10,222,439 | 10,018,166 | 10,096,360 | 10,067,679 | ||||||||||||||
Federal funds purchased and securities sold | |||||||||||||||||||
under agreements to repurchase | 164,093 | 206,800 | 185,156 | 126,872 | 103,147 | ||||||||||||||
FHLB short-term borrowings | 1,189,765 | 952,625 | 1,112,091 | 982,993 | 913,974 | ||||||||||||||
Total short-term borrowings | 1,353,858 | 1,159,425 | 1,297,247 | 1,109,865 | 1,017,121 | ||||||||||||||
Long-term debt | 381,909 | 454,271 | 519,736 | 546,705 | 569,947 | ||||||||||||||
Total borrowed funds | 1,735,767 | 1,613,696 | 1,816,983 | 1,656,570 | 1,587,068 | ||||||||||||||
Accrued interest and other liabilities | 344,891 | 379,046 | 275,038 | 202,806 | 203,570 | ||||||||||||||
Total Liabilities | 12,314,689 | 12,215,181 | 12,110,187 | 11,955,736 | 11,858,317 | ||||||||||||||
SHAREHOLDERS' EQUITY | |||||||||||||||||||
Common stock | 1,638,851 | 1,640,066 | 1,629,286 | 1,622,994 | 1,625,228 | ||||||||||||||
Retained earnings | 660,108 | 691,236 | 662,899 | 635,629 | 610,737 | ||||||||||||||
Accumulated other comprehensive loss | 31,200 | 13,986 | 11,985 | (12,889 | ) | (39,796 | ) | ||||||||||||
Treasury stock, at cost | (120,426 | ) | (100,181 | ) | (93,843 | ) | (98,737 | ) | (101,935 | ) | |||||||||
Total Shareholders' Equity | 2,209,733 | 2,245,107 | 2,210,327 | 2,146,997 | 2,094,234 | ||||||||||||||
Total Liabilities and Shareholders' Equity | $ | 14,524,422 | $ | 14,460,288 | $ | 14,320,514 | $ | 14,102,733 | $ | 13,952,551 | |||||||||
(1) Beginning January 1,2020, calculation is based on current expected loss methodology. Prior to January 1, 2020, calculation was based on the incurred loss methodology. | |||||||||||||||||||
5
FIRST FINANCIAL BANCORP. | |||||||||||||||||||||||||||||||||||||||||||||
NET INTEREST MARGIN RATE/VOLUME ANALYSIS | |||||||||||||||||||||||||||||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||
(Unaudited) | |||||||||||||||||||||||||||||||||||||||||||||
Quarterly Averages | |||||||||||||||||||||||||||||||||||||||||||||
March 31, 2020 | December 31, 2019 | March 31, 2019 | Linked Qtr. Income Variance | Comparable Qtr. Income Variance | |||||||||||||||||||||||||||||||||||||||||
Balance | Yield | Balance | Yield | Balance | Yield | Rate | Volume | Total | Rate | Volume | Total | ||||||||||||||||||||||||||||||||||
Earning assets | |||||||||||||||||||||||||||||||||||||||||||||
Investments: | |||||||||||||||||||||||||||||||||||||||||||||
Investment securities | $ | 3,115,723 | 3.04 | % | $ | 3,102,867 | 3.16 | % | $ | 3,355,732 | 3.44 | % | $ | (934 | ) | $ | (161 | ) | $ | (1,095 | ) | $ | (3,368 | ) | $ | (1,538 | ) | $ | (4,906 | ) | |||||||||||||||
Interest-bearing deposits with other banks | 39,332 | 1.45 | % | 36,672 | 1.81 | % | 34,709 | 2.45 | % | (33 | ) | 8 | (25 | ) | (86 | ) | 18 | (68 | ) | ||||||||||||||||||||||||||
Gross loans (1) | 9,220,643 | 5.04 | % | 9,149,222 | 5.33 | % | 8,773,310 | 5.69 | % | (6,661 | ) | (366 | ) | (7,027 | ) | (14,108 | ) | 6,827 | (7,281 | ) | |||||||||||||||||||||||||
Total earning assets | 12,375,698 | 4.52 | % | 12,288,761 | 4.77 | % | 12,163,751 | 5.06 | % | (7,628 | ) | (519 | ) | (8,147 | ) | (17,562 | ) | 5,307 | (12,255 | ) | |||||||||||||||||||||||||
Nonearning assets | |||||||||||||||||||||||||||||||||||||||||||||
Allowance for credit losses | (121,126 | ) | (56,649 | ) | (57,088 | ) | |||||||||||||||||||||||||||||||||||||||
Cash and due from banks | 235,696 | 221,060 | 181,695 | ||||||||||||||||||||||||||||||||||||||||||
Accrued interest and other assets | 2,034,154 | 2,007,116 | 1,664,193 | ||||||||||||||||||||||||||||||||||||||||||
Total assets | $ | 14,524,422 | $ | 14,460,288 | $ | 13,952,551 | |||||||||||||||||||||||||||||||||||||||
Interest-bearing liabilities | |||||||||||||||||||||||||||||||||||||||||||||
Deposits: | |||||||||||||||||||||||||||||||||||||||||||||
Interest-bearing demand | $ | 2,418,193 | 0.45 | % | $ | 2,373,962 | 0.53 | % | $ | 2,269,948 | 0.50 | % | |||||||||||||||||||||||||||||||||
Savings | 2,976,518 | 0.45 | % | 2,995,395 | 0.60 | % | 3,115,557 | 0.76 | % | ||||||||||||||||||||||||||||||||||||
Time | 2,196,080 | 1.88 | % | 2,214,174 | 2.03 | % | 2,224,587 | 1.94 | % | ||||||||||||||||||||||||||||||||||||
Total interest-bearing deposits | 7,590,791 | 0.86 | % | 7,583,531 | 1.00 | % | 7,610,092 | 1.03 | % | $ | (2,497 | ) | $ | (164 | ) | $ | (2,661 | ) | $ | (3,017 | ) | $ | 139 | $ | (2,878 | ) | |||||||||||||||||||
Borrowed funds | |||||||||||||||||||||||||||||||||||||||||||||
Short-term borrowings | 1,353,858 | 1.51 | % | 1,159,425 | 1.86 | % | 1,017,121 | 2.38 | % | (1,026 | ) | 683 | (343 | ) | (2,180 | ) | 1,307 | (873 | ) | ||||||||||||||||||||||||||
Long-term debt | 381,909 | 3.96 | % | 454,271 | 3.75 | % | 569,947 | 3.59 | % | 241 | (764 | ) | (523 | ) | 523 | (1,794 | ) | (1,271 | ) | ||||||||||||||||||||||||||
Total borrowed funds | 1,735,767 | 2.05 | % | 1,613,696 | 2.39 | % | 1,587,068 | 2.81 | % | (785 | ) | (81 | ) | (866 | ) | (1,657 | ) | (487 | ) | (2,144 | ) | ||||||||||||||||||||||||
Total interest-bearing liabilities | 9,326,558 | 1.08 | % | 9,197,227 | 1.24 | % | 9,197,160 | 1.33 | % | (3,282 | ) | (245 | ) | (3,527 | ) | (4,674 | ) | (348 | ) | (5,022 | ) | ||||||||||||||||||||||||
Noninterest-bearing liabilities | |||||||||||||||||||||||||||||||||||||||||||||
Noninterest-bearing demand deposits | 2,643,240 | 2,638,908 | 2,457,587 | ||||||||||||||||||||||||||||||||||||||||||
Other liabilities | 344,891 | 379,046 | 203,570 | ||||||||||||||||||||||||||||||||||||||||||
Shareholders' equity | 2,209,733 | 2,245,107 | 2,094,234 | ||||||||||||||||||||||||||||||||||||||||||
Total liabilities & shareholders' equity | $ | 14,524,422 | $ | 14,460,288 | $ | 13,952,551 | |||||||||||||||||||||||||||||||||||||||
Net interest income | $ | 114,282 | $ | 118,902 | $ | 121,515 | $ | (4,346 | ) | $ | (274 | ) | $ | (4,620 | ) | $ | (12,888 | ) | $ | 5,655 | $ | (7,233 | ) | ||||||||||||||||||||||
Net interest spread | 3.44 | % | 3.53 | % | 3.73 | % | |||||||||||||||||||||||||||||||||||||||
Net interest margin | 3.71 | % | 3.84 | % | 4.05 | % | |||||||||||||||||||||||||||||||||||||||
Tax equivalent adjustment | 0.06 | % | 0.05 | % | 0.05 | % | |||||||||||||||||||||||||||||||||||||||
Net interest margin (fully tax equivalent) | 3.77 | % | 3.89 | % | 4.10 | % | |||||||||||||||||||||||||||||||||||||||
(1) Loans held for sale and nonaccrual loans are included in gross loans. | |||||||||||||||||||||||||||||||||||||||||||||
6
FIRST FINANCIAL BANCORP. | |||||||||||||||||||
CREDIT QUALITY | |||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||
(Unaudited) | |||||||||||||||||||
Mar. 31, | Dec. 31, | Sep. 30, | Jun. 30, | Mar. 31, | |||||||||||||||
2020 | 2019 | 2019 | 2019 | 2019 | |||||||||||||||
ALLOWANCE FOR CREDIT LOSS ACTIVITY | |||||||||||||||||||
Balance at beginning of period, prior to adoption of ASC 326 | $ | 57,650 | $ | 56,552 | $ | 61,549 | $ | 56,722 | $ | 56,542 | |||||||||
Impact of adopting ASC 326 | 61,505 | 0 | 0 | 0 | 0 | ||||||||||||||
Provision for credit losses | 23,880 | 4,629 | 5,228 | 6,658 | 14,083 | ||||||||||||||
Gross charge-offs | |||||||||||||||||||
Commercial and industrial | 1,091 | 2,919 | 9,556 | 1,873 | 12,328 | ||||||||||||||
Lease financing | 0 | 62 | 0 | 0 | 100 | ||||||||||||||
Construction real estate | 0 | 0 | 0 | 0 | 0 | ||||||||||||||
Commercial real estate | 4 | 1,854 | 535 | 86 | 1,214 | ||||||||||||||
Residential real estate | 115 | 167 | 278 | 150 | 82 | ||||||||||||||
Home equity | 267 | 807 | 627 | 689 | 468 | ||||||||||||||
Installment | 61 | 31 | 65 | 78 | 49 | ||||||||||||||
Credit card | 311 | 319 | 598 | 289 | 341 | ||||||||||||||
Total gross charge-offs | 1,849 | 6,159 | 11,659 | 3,165 | 14,582 | ||||||||||||||
Recoveries | |||||||||||||||||||
Commercial and industrial | 2,000 | 1,796 | 556 | 291 | 240 | ||||||||||||||
Lease financing | 0 | 0 | 0 | 0 | 0 | ||||||||||||||
Construction real estate | 0 | 0 | 0 | 5 | 63 | ||||||||||||||
Commercial real estate | 234 | 439 | 347 | 254 | 73 | ||||||||||||||
Residential real estate | 52 | 72 | 64 | 101 | 36 | ||||||||||||||
Home equity | 339 | 243 | 335 | 572 | 185 | ||||||||||||||
Installment | 31 | 49 | 93 | 61 | 48 | ||||||||||||||
Credit card | 43 | 29 | 39 | 50 | 34 | ||||||||||||||
Total recoveries | 2,699 | 2,628 | 1,434 | 1,334 | 679 | ||||||||||||||
Total net charge-offs | (850 | ) | 3,531 | 10,225 | 1,831 | 13,903 | |||||||||||||
Ending allowance for credit losses | $ | 143,885 | $ | 57,650 | $ | 56,552 | $ | 61,549 | $ | 56,722 | |||||||||
NET CHARGE-OFFS TO AVERAGE LOANS AND LEASES (ANNUALIZED) | |||||||||||||||||||
Commercial and industrial | (0.15 | )% | 0.18 | % | 1.42 | % | 0.25 | % | 1.95 | % | |||||||||
Lease financing | 0.00 | % | 0.27 | % | 0.00 | % | 0.00 | % | 0.45 | % | |||||||||
Construction real estate | 0.00 | % | 0.00 | % | 0.00 | % | 0.00 | % | (0.05 | )% | |||||||||
Commercial real estate | (0.02 | )% | 0.14 | % | 0.02 | % | (0.02 | )% | 0.12 | % | |||||||||
Residential real estate | 0.02 | % | 0.04 | % | 0.08 | % | 0.02 | % | 0.02 | % | |||||||||
Home equity | (0.04 | )% | 0.29 | % | 0.15 | % | 0.06 | % | 0.14 | % | |||||||||
Installment | 0.15 | % | (0.08 | )% | (0.13 | )% | 0.08 | % | 0.00 | % | |||||||||
Credit card | 2.15 | % | 2.27 | % | 4.40 | % | 1.92 | % | 2.62 | % | |||||||||
Total net charge-offs | (0.04 | )% | 0.15 | % | 0.45 | % | 0.08 | % | 0.64 | % | |||||||||
COMPONENTS OF NONPERFORMING LOANS, NONPERFORMING ASSETS, AND UNDERPERFORMING ASSETS | |||||||||||||||||||
Nonaccrual loans (1) | |||||||||||||||||||
Commercial and industrial | $ | 21,126 | $ | 24,346 | $ | 28,358 | $ | 18,502 | $ | 19,263 | |||||||||
Lease financing | 222 | 223 | 284 | 295 | 301 | ||||||||||||||
Construction real estate | 0 | 0 | 5 | 6 | 7 | ||||||||||||||
Commercial real estate | 10,050 | 7,295 | 14,889 | 15,981 | 21,082 | ||||||||||||||
Residential real estate | 11,163 | 10,892 | 11,655 | 11,627 | 13,052 | ||||||||||||||
Home equity | 5,821 | 5,242 | 5,427 | 4,745 | 5,581 | ||||||||||||||
Installment | 145 | 167 | 75 | 195 | 170 | ||||||||||||||
Nonaccrual loans | 48,527 | 48,165 | 60,693 | 51,351 | 59,456 | ||||||||||||||
Accruing troubled debt restructurings (TDRs) | 22,206 | 11,435 | 18,450 | 37,420 | 22,817 | ||||||||||||||
Total nonperforming loans | 70,733 | 59,600 | 79,143 | 88,771 | 82,273 | ||||||||||||||
Other real estate owned (OREO) | 1,467 | 2,033 | 1,613 | 1,421 | 1,665 | ||||||||||||||
Total nonperforming assets | 72,200 | 61,633 | 80,756 | 90,192 | 83,938 | ||||||||||||||
Accruing loans past due 90 days or more | 120 | 201 | 287 | 107 | 178 | ||||||||||||||
Total underperforming assets | $ | 72,320 | $ | 61,834 | $ | 81,043 | $ | 90,299 | $ | 84,116 | |||||||||
Total classified assets | $ | 124,510 | $ | 89,250 | $ | 132,500 | $ | 147,753 | $ | 142,014 | |||||||||
CREDIT QUALITY RATIOS | |||||||||||||||||||
Allowance for credit losses to | |||||||||||||||||||
Nonaccrual loans | 296.51 | % | 119.69 | % | 93.18 | % | 119.86 | % | 95.40 | % | |||||||||
Nonperforming loans | 203.42 | % | 96.73 | % | 71.46 | % | 69.33 | % | 68.94 | % | |||||||||
Total ending loans | 1.55 | % | 0.63 | % | 0.62 | % | 0.69 | % | 0.64 | % | |||||||||
Nonperforming loans to total loans | 0.76 | % | 0.65 | % | 0.87 | % | 0.99 | % | 0.93 | % | |||||||||
Nonperforming assets to | |||||||||||||||||||
Ending loans, plus OREO | 0.78 | % | 0.67 | % | 0.89 | % | 1.00 | % | 0.95 | % | |||||||||
Total assets | 0.48 | % | 0.42 | % | 0.56 | % | 0.62 | % | 0.60 | % | |||||||||
Nonperforming assets, excluding accruing TDRs to | |||||||||||||||||||
Ending loans, plus OREO | 0.54 | % | 0.55 | % | 0.69 | % | 0.59 | % | 0.69 | % | |||||||||
Total assets | 0.33 | % | 0.35 | % | 0.43 | % | 0.37 | % | 0.43 | % | |||||||||
Classified assets to total assets | 0.83 | % | 0.62 | % | 0.92 | % | 1.02 | % | 1.01 | % | |||||||||
(1) Nonaccrual loans include nonaccrual TDRs of $18.4 million, $18.5 million, $21.5 million, $11.0 million, and $13.1 million, as of March 31, 2020, December 31, 2019, September 30, 2019, June 30, 2019, and March 31, 2019, respectively. | |||||||||||||||||||
7
FIRST FINANCIAL BANCORP. | |||||||||||||||||||
CAPITAL ADEQUACY | |||||||||||||||||||
(Dollars in thousands, except per share data) | |||||||||||||||||||
(Unaudited) | |||||||||||||||||||
Mar. 31, | Dec. 31, | Sep. 30, | Jun. 30, | Mar. 31, | |||||||||||||||
2020 | 2019 | 2019 | 2019 | 2019 | |||||||||||||||
PER COMMON SHARE | |||||||||||||||||||
Market Price | |||||||||||||||||||
High | $ | 25.52 | $ | 26.04 | $ | 25.49 | $ | 25.80 | $ | 28.56 | |||||||||
Low | $ | 12.67 | $ | 23.24 | $ | 22.37 | $ | 22.16 | $ | 23.02 | |||||||||
Close | $ | 14.91 | $ | 25.44 | $ | 24.48 | $ | 24.22 | $ | 24.06 | |||||||||
Average shares outstanding - basic | 97,736,690 | 98,684,706 | 98,517,025 | 98,083,799 | 97,926,088 | ||||||||||||||
Average shares outstanding - diluted | 98,356,214 | 99,232,167 | 99,077,723 | 98,648,384 | 98,436,311 | ||||||||||||||
Ending shares outstanding | 97,968,958 | 98,490,998 | 100,094,819 | 98,647,690 | 98,613,872 | ||||||||||||||
Total shareholders' equity | $ | 2,179,383 | $ | 2,247,705 | $ | 2,261,313 | $ | 2,188,189 | $ | 2,130,419 | |||||||||
REGULATORY CAPITAL | Preliminary | ||||||||||||||||||
Common equity tier 1 capital | $ | 1,243,152 | $ | 1,245,746 | $ | 1,253,803 | $ | 1,281,406 | $ | 1,246,004 | |||||||||
Common equity tier 1 capital ratio | 11.27 | % | 11.30 | % | 11.52 | % | 12.00 | % | 12.03 | % | |||||||||
Tier 1 capital | $ | 1,285,705 | $ | 1,288,185 | $ | 1,296,399 | $ | 1,323,905 | $ | 1,287,757 | |||||||||
Tier 1 ratio | 11.66 | % | 11.69 | % | 11.91 | % | 12.40 | % | 12.43 | % | |||||||||
Total capital | $ | 1,493,100 | $ | 1,475,813 | $ | 1,482,708 | $ | 1,515,382 | $ | 1,474,723 | |||||||||
Total capital ratio | 13.54 | % | 13.39 | % | 13.62 | % | 14.20 | % | 14.24 | % | |||||||||
Total capital in excess of minimum requirement | $ | 335,229 | $ | 318,315 | $ | 339,935 | $ | 394,571 | $ | 387,048 | |||||||||
Total risk-weighted assets | $ | 11,027,347 | $ | 11,023,795 | $ | 10,883,554 | $ | 10,674,393 | $ | 10,358,805 | |||||||||
Leverage ratio | 9.49 | % | 9.58 | % | 9.75 | % | 10.02 | % | 9.84 | % | |||||||||
OTHER CAPITAL RATIOS | |||||||||||||||||||
Ending shareholders' equity to ending assets | 14.47 | % | 15.49 | % | 15.62 | % | 15.16 | % | 15.14 | % | |||||||||
Ending tangible shareholders' equity to ending tangible assets | 8.25 | % | 9.07 | % | 9.17 | % | 9.34 | % | 9.15 | % | |||||||||
Average shareholders' equity to average assets | 15.21 | % | 15.53 | % | 15.43 | % | 15.22 | % | 15.01 | % | |||||||||
Average tangible shareholders' equity to average tangible assets | 8.79 | % | 9.07 | % | 9.35 | % | 9.26 | % | 8.95 | % | |||||||||
REPURCHASE PROGRAM (1) | |||||||||||||||||||
Shares repurchased | 880,000 | 1,609,778 | 1,143,494 | 0 | 0 | ||||||||||||||
Average share repurchase price | $ | 18.96 | $ | 24.13 | $ | 23.94 | N/A | N/A | |||||||||||
Total cost of shares repurchased | $ | 16,686 | $ | 38,846 | $ | 27,372 | N/A | N/A | |||||||||||
(1) Represents share repurchases as part of publicly announced plans. | |||||||||||||||||||
N/A = Not applicable | |||||||||||||||||||
8
Exhibit 99.2 Earnings Presentation First Quarter 2020
Forward Looking Statement Disclosure Certain statements contained in this report which are not statements of historical fact constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Words such as ‘‘believes,’’ ‘‘anticipates,’’ “likely,” “expected,” “estimated,” ‘‘intends’’ and other similar expressions are intended to identify forward-looking statements but are not the exclusive means of identifying such statements. Examples of forward-looking statements include, but are not limited to, statements we make about (i) our future operating or financial performance, including revenues, income or loss and earnings or loss per share, (ii) future common stock dividends, (iii) our capital structure, including future capital levels, (iv) our plans, objectives and strategies, and (v) the assumptions that underlie our forward-looking statements. As with any forecast or projection, forward-looking statements are subject to inherent uncertainties, risks and changes in circumstances that may cause actual results to differ materially from those set forth in the forward-looking statements. Forward-looking statements are not historical facts but instead express only management’s beliefs regarding future results or events, many of which, by their nature, are inherently uncertain and outside of management’s control. It is possible that actual results and outcomes may differ, possibly materially, from the anticipated results or outcomes indicated in these forward-looking statements. Important factors that could cause actual results to differ materially from those in our forward-looking statements include the following, without limitation: • economic, market, liquidity, credit, interest rate, operational and technological risks associated with the Company’s business; • future credit quality and performance, including our expectations regarding future loan losses and our allowance for credit losses; • the effect of and changes in policies and laws or regulatory agencies, including the Dodd-Frank Wall Street Reform and Consumer Protection Act and other legislation and regulation relating to the banking industry; (iv) management’s ability to effectively execute its business plans; • mergers and acquisitions, including costs or difficulties related to the integration of acquired companies; • the possibility that any of the anticipated benefits of the Company’s acquisitions will not be realized or will not be realized within the expected time period; • the effect of changes in accounting policies and practices; • changes in consumer spending, borrowing and saving and changes in unemployment; • changes in customers’ performance and creditworthiness; • the costs and effects of litigation and of unexpected or adverse outcomes in such litigation; • current and future economic and market conditions, including the effects of declines in housing prices, high unemployment rates, U.S. fiscal debt, budget and tax matters, geopolitical matters, and any slowdown in global economic growth; • the adverse impact on the U.S. economy, including the markets in which we operate, of the novel coronavirus, which causes the Coronavirus disease 2019 (“COVID-19”), global pandemic, and the impact of a slowing U.S. economy and increased unemployment on the performance of our loan and lease portfolio, the market value of our investment securities, the availability of sources of funding and the demand for our products; • our capital and liquidity requirements (including under regulatory capital standards, such as the Basel III capital standards) and our ability to generate capital internally or raise capital on favorable terms; 2
Forward Looking Statement Disclosure • financial services reform and other current, pending or future legislation or regulation that could have a negative effect on our revenue and businesses, including the Dodd-Frank Act and other legislation and regulation relating to bank products and services; • the effect of the current interest rate environment or changes in interest rates or in the level or composition of our assets or liabilities on our net interest income, net interest margin and our mortgage originations, mortgage servicing rights and mortgage loans held for sale; • the effect of a fall in stock market prices on our brokerage, asset and wealth management businesses; • a failure in or breach of our operational or security systems or infrastructure, or those of our third-party vendors or other service providers, including as a result of cyber attacks; • the effect of changes in the level of checking or savings account deposits on our funding costs and net interest margin; and • our ability to develop and execute effective business plans and strategies. Additional factors that may cause our actual results to differ materially from those described in our forward-looking statements can be found in our Form 10-K for the year ended December 31, 2019, as well as our other filings with the SEC, which are available on the SEC website at www.sec.gov. All forward-looking statements included in this filing are made as of the date hereof and are based on information available at the time of the filing. Except as required by law, the Company does not assume any obligation to update any forward-looking statement. 3
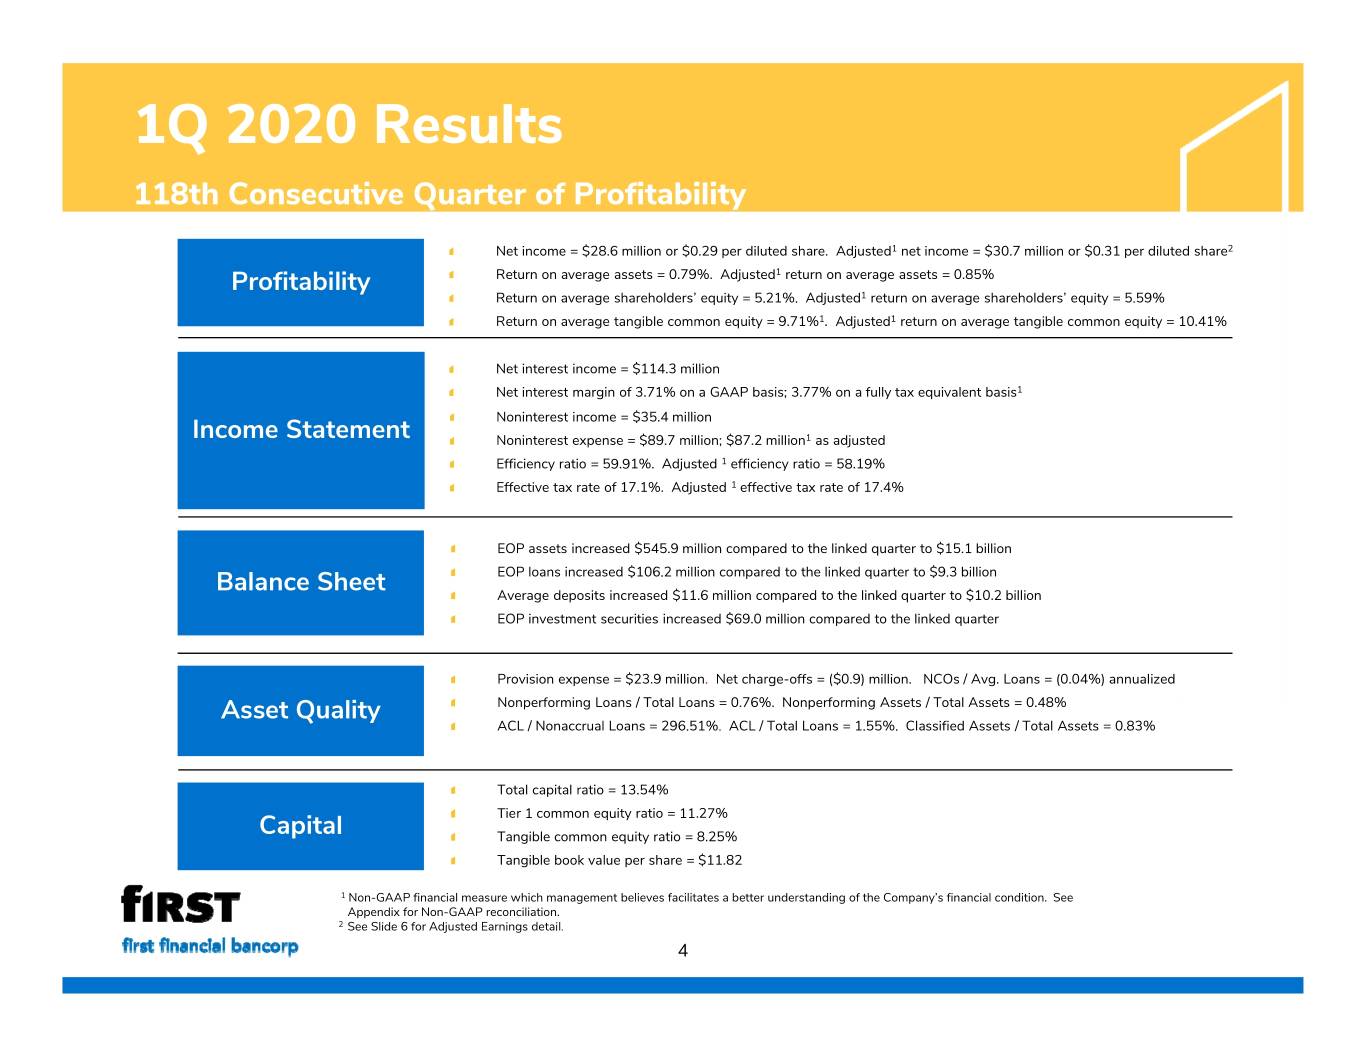
1Q 2020 Results 118th Consecutive Quarter of Profitability Net income = $28.6 million or $0.29 per diluted share. Adjusted1 net income = $30.7 million or $0.31 per diluted share2 Profitability Return on average assets = 0.79%. Adjusted1 return on average assets = 0.85% Return on average shareholders’ equity = 5.21%. Adjusted1 return on average shareholders’ equity = 5.59% Return on average tangible common equity = 9.71%1. Adjusted1 return on average tangible common equity = 10.41% Net interest income = $114.3 million Net interest margin of 3.71% on a GAAP basis; 3.77% on a fully tax equivalent basis1 Noninterest income = $35.4 million Income Statement Noninterest expense = $89.7 million; $87.2 million1 as adjusted Efficiency ratio = 59.91%. Adjusted 1 efficiency ratio = 58.19% Effective tax rate of 17.1%. Adjusted 1 effective tax rate of 17.4% EOP assets increased $545.9 million compared to the linked quarter to $15.1 billion EOP loans increased $106.2 million compared to the linked quarter to $9.3 billion Balance Sheet Average deposits increased $11.6 million compared to the linked quarter to $10.2 billion EOP investment securities increased $69.0 million compared to the linked quarter Provision expense = $23.9 million. Net charge-offs = ($0.9) million. NCOs / Avg. Loans = (0.04%) annualized Asset Quality Nonperforming Loans / Total Loans = 0.76%. Nonperforming Assets / Total Assets = 0.48% ACL / Nonaccrual Loans = 296.51%. ACL / Total Loans = 1.55%. Classified Assets / Total Assets = 0.83% Total capital ratio = 13.54% Tier 1 common equity ratio = 11.27% Capital Tangible common equity ratio = 8.25% Tangible book value per share = $11.82 1 Non-GAAP financial measure which management believes facilitates a better understanding of the Company’s financial condition. See Appendix for Non-GAAP reconciliation. 2 See Slide 6 for Adjusted Earnings detail. 4
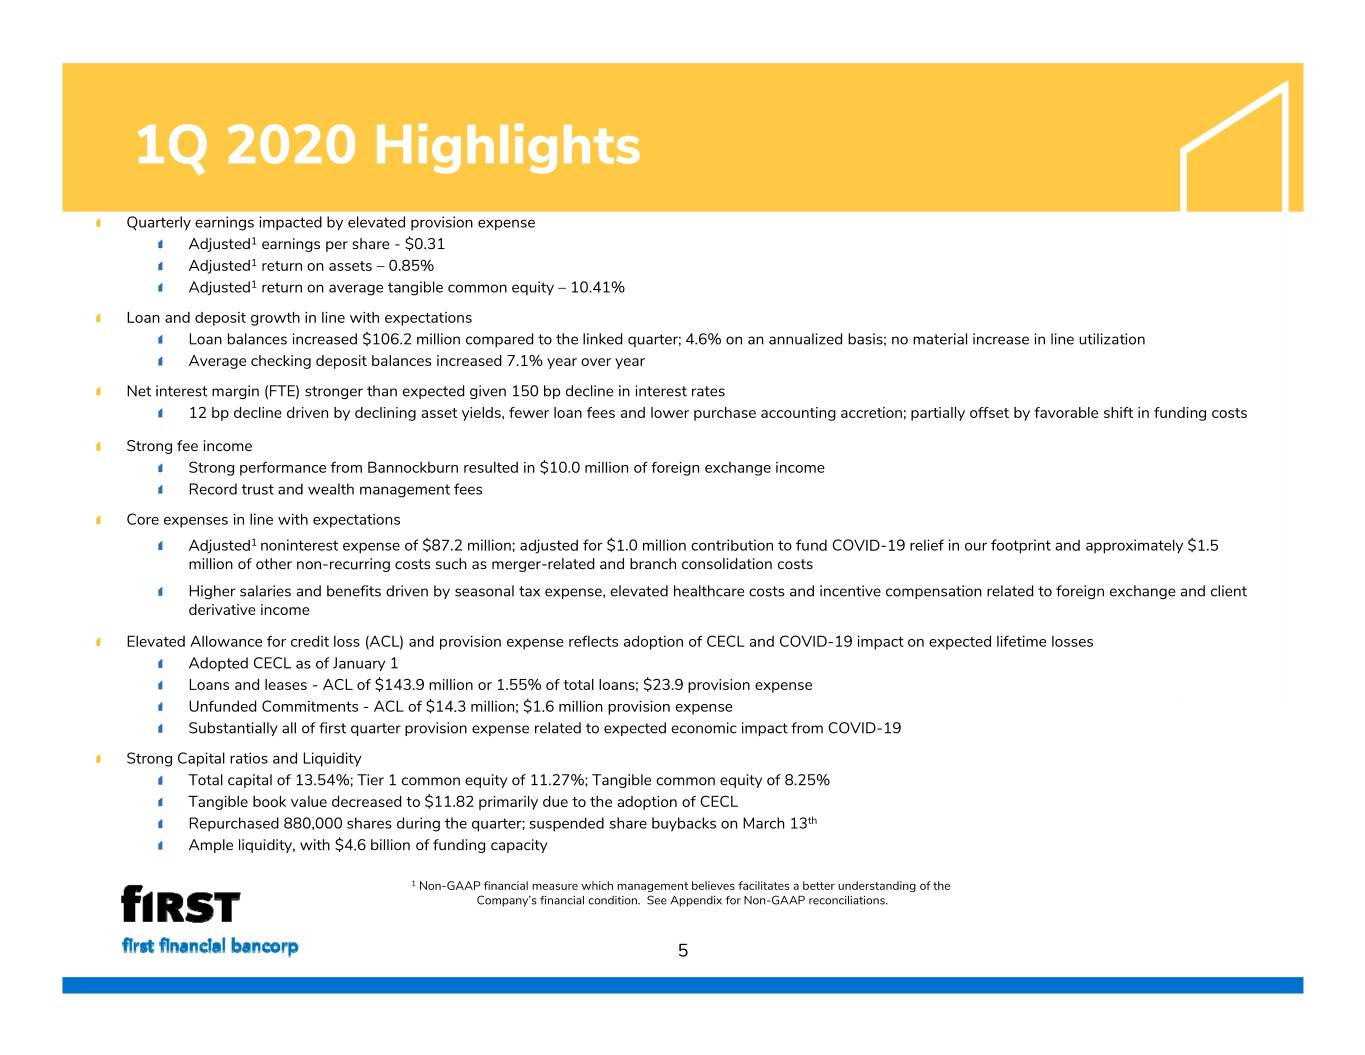
1Q 2020 Highlights Quarterly earnings impacted by elevated provision expense Adjusted1 earnings per share - $0.31 Adjusted1 return on assets – 0.85% Adjusted1 return on average tangible common equity – 10.41% Loan and deposit growth in line with expectations Loan balances increased $106.2 million compared to the linked quarter; 4.6% on an annualized basis; no material increase in line utilization Average checking deposit balances increased 7.1% year over year Net interest margin (FTE) stronger than expected given 150 bp decline in interest rates 12 bp decline driven by declining asset yields, fewer loan fees and lower purchase accounting accretion; partially offset by favorable shift in funding costs Strong fee income Strong performance from Bannockburn resulted in $10.0 million of foreign exchange income Record trust and wealth management fees Core expenses in line with expectations Adjusted1 noninterest expense of $87.2 million; adjusted for $1.0 million contribution to fund COVID-19 relief in our footprint and approximately $1.5 million of other non-recurring costs such as merger-related and branch consolidation costs Higher salaries and benefits driven by seasonal tax expense, elevated healthcare costs and incentive compensation related to foreign exchange and client derivative income Elevated Allowance for credit loss (ACL) and provision expense reflects adoption of CECL and COVID-19 impact on expected lifetime losses Adopted CECL as of January 1 Loans and leases - ACL of $143.9 million or 1.55% of total loans; $23.9 provision expense Unfunded Commitments - ACL of $14.3 million; $1.6 million provision expense Substantially all of first quarter provision expense related to expected economic impact from COVID-19 Strong Capital ratios and Liquidity Total capital of 13.54%; Tier 1 common equity of 11.27%; Tangible common equity of 8.25% Tangible book value decreased to $11.82 primarily due to the adoption of CECL Repurchased 880,000 shares during the quarter; suspended share buybacks on March 13th Ample liquidity, with $4.6 billion of funding capacity 1 Non-GAAP financial measure which management believes facilitates a better understanding of the Company’s financial condition. See Appendix for Non-GAAP reconciliations. 5
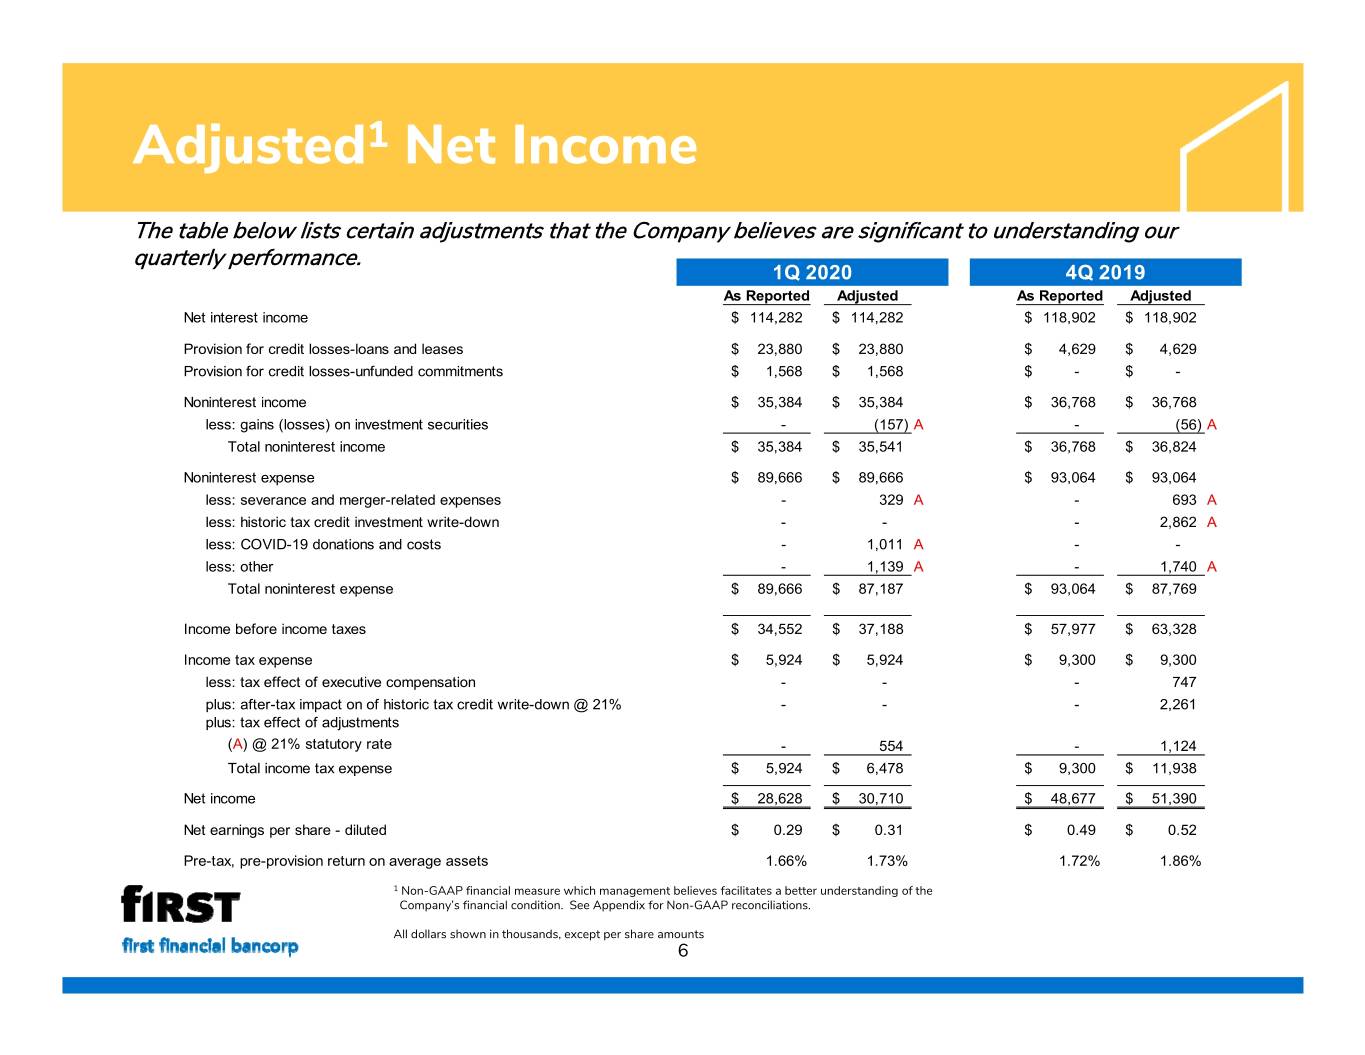
Adjusted1 Net Income The table below lists certain adjustments that the Co quarterly performance. 1Q 2020 4Q 2019 As Reported Adjusted As Reported Adjusted Net interest income$ 114,282 $ 114,282 $ 118,902 $ 118,902 Provision for credit losses-loans and leases$ 23,880 $ 23,880 $ 4,629 $ 4,629 Provision for credit losses-unfunded commitments$ 1,568 $ 1,568 $ - $ - Noninterest incomempany $believes 35,384 are$ 35,384signific $ 36,768 $ 36,768 less: gains (losses) on investment securities - (157) A - (56) A Total noninterest income$ 35,384 $ 35,541 $ 36,768 $ 36,824 Noninterest expense$ 89,666 $ 89,666 $ 93,064 $ 93,064 less: severance and merger-related expenses - 329 A ant to understanding - our 693 A less: historic tax credit investment write-down - - - 2,862 A less: COVID-19 donations and costs - 1,011 A - - less: other - 1,139 A - 1,740 A Total noninterest expense$ 89,666 $ 87,187 $ 93,064 $ 87,769 Income before income taxes$ 34,552 $ 37,188 $ 57,977 $ 63,328 Income tax expense$ 5,924 $ 5,924 $ 9,300 $ 9,300 less: tax effect of executive compensation - - - 747 plus: after-tax impact on of historic tax credit write-down @ 21% - - - 2,261 plus: tax effect of adjustments - 1,124 (A) @ 21% statutory rate - 554 Total income tax expense$ 5,924 $ 6,478 $ 9,300 $ 11,938 Net income $ 28,628 $ 30,710 $ 48,677 $ 51,390 Net earnings per share - diluted$ 0.29 $ 0.31 $ 0.49 $ 0.52 Pre-tax, pre-provision return on average assets 1.66% 1.73% 1.72% 1.86% 1 Non-GAAP financial measure which management believes facilitates a better understanding of the Company’s financial condition. See Appendix for Non-GAAP reconciliations. All dollars shown in thousands, except per share amounts 6
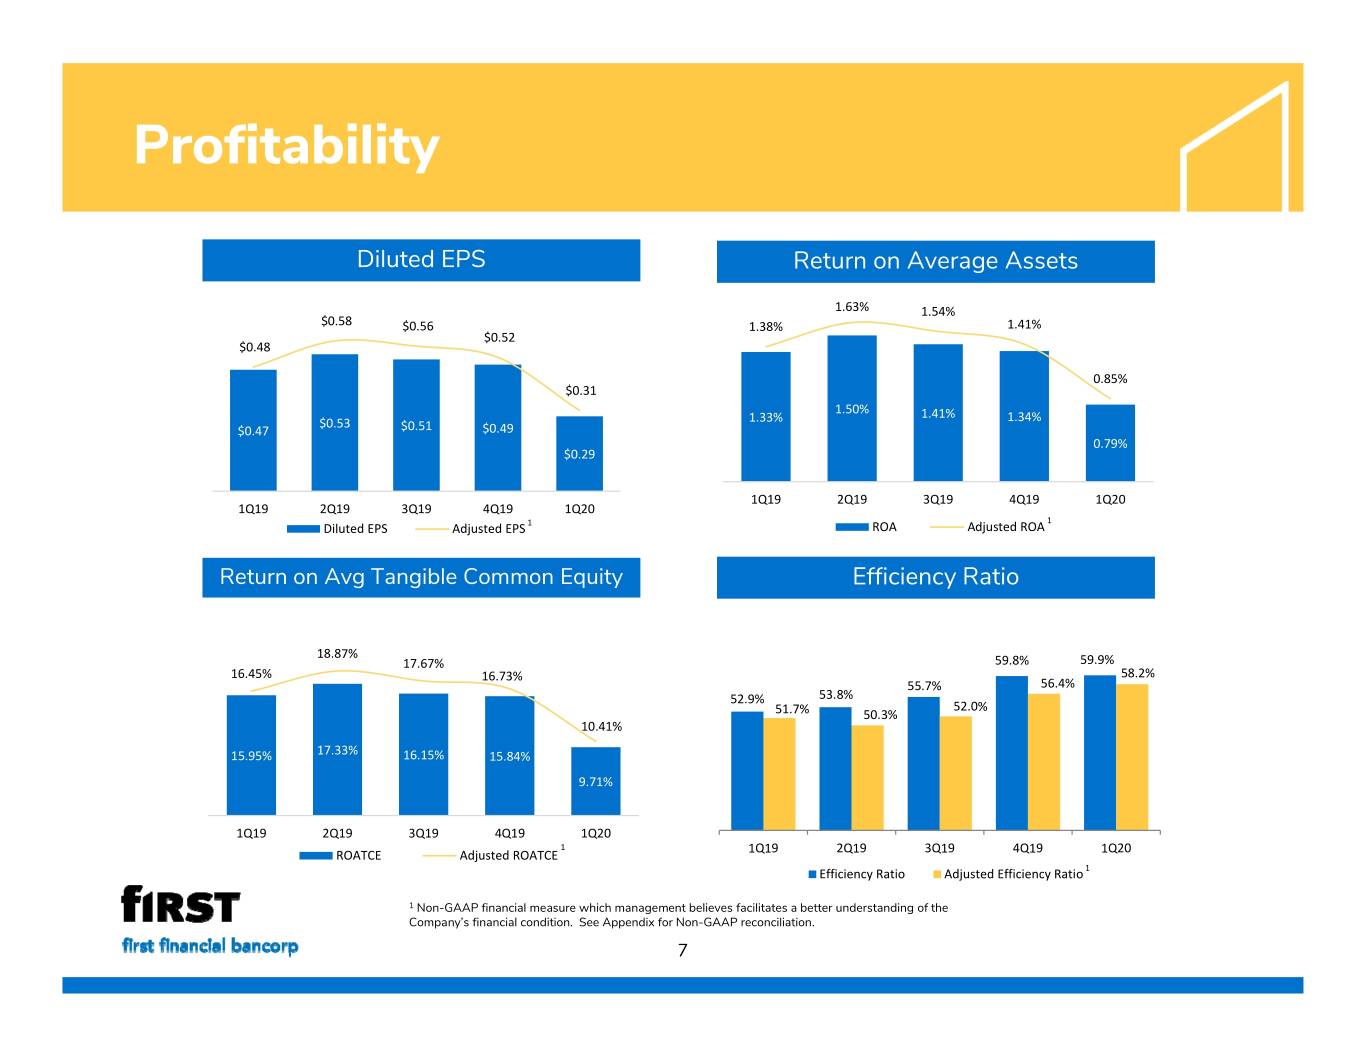
Profitability Diluted EPS Return on Average Assets 1.63% 1.54% $0.58 $0.56 1.38% 1.41% $0.52 $0.48 0.85% $0.31 1.50% 1.41% $0.53 1.33% 1.34% $0.47 $0.51 $0.49 0.79% $0.29 1Q19 2Q19 3Q19 4Q19 1Q20 1Q19 2Q19 3Q19 4Q19 1Q20 1 Diluted EPS Adjusted EPS 1 ROA Adjusted ROA Return on Avg Tangible Common Equity Efficiency Ratio 18.87% 17.67% 59.8% 59.9% 16.45% 16.73% 58.2% 55.7% 56.4% 52.9% 53.8% 52.0% 51.7% 50.3% 10.41% 15.95% 17.33% 16.15% 15.84% 9.71% 1Q19 2Q19 3Q19 4Q19 1Q20 1 1Q19 2Q19 3Q19 4Q19 1Q20 ROATCE Adjusted ROATCE Efficiency Ratio Adjusted Efficiency Ratio 1 1 Non-GAAP financial measure which management believes facilitates a better understanding of the Company’s financial condition. See Appendix for Non-GAAP reconciliation. 7
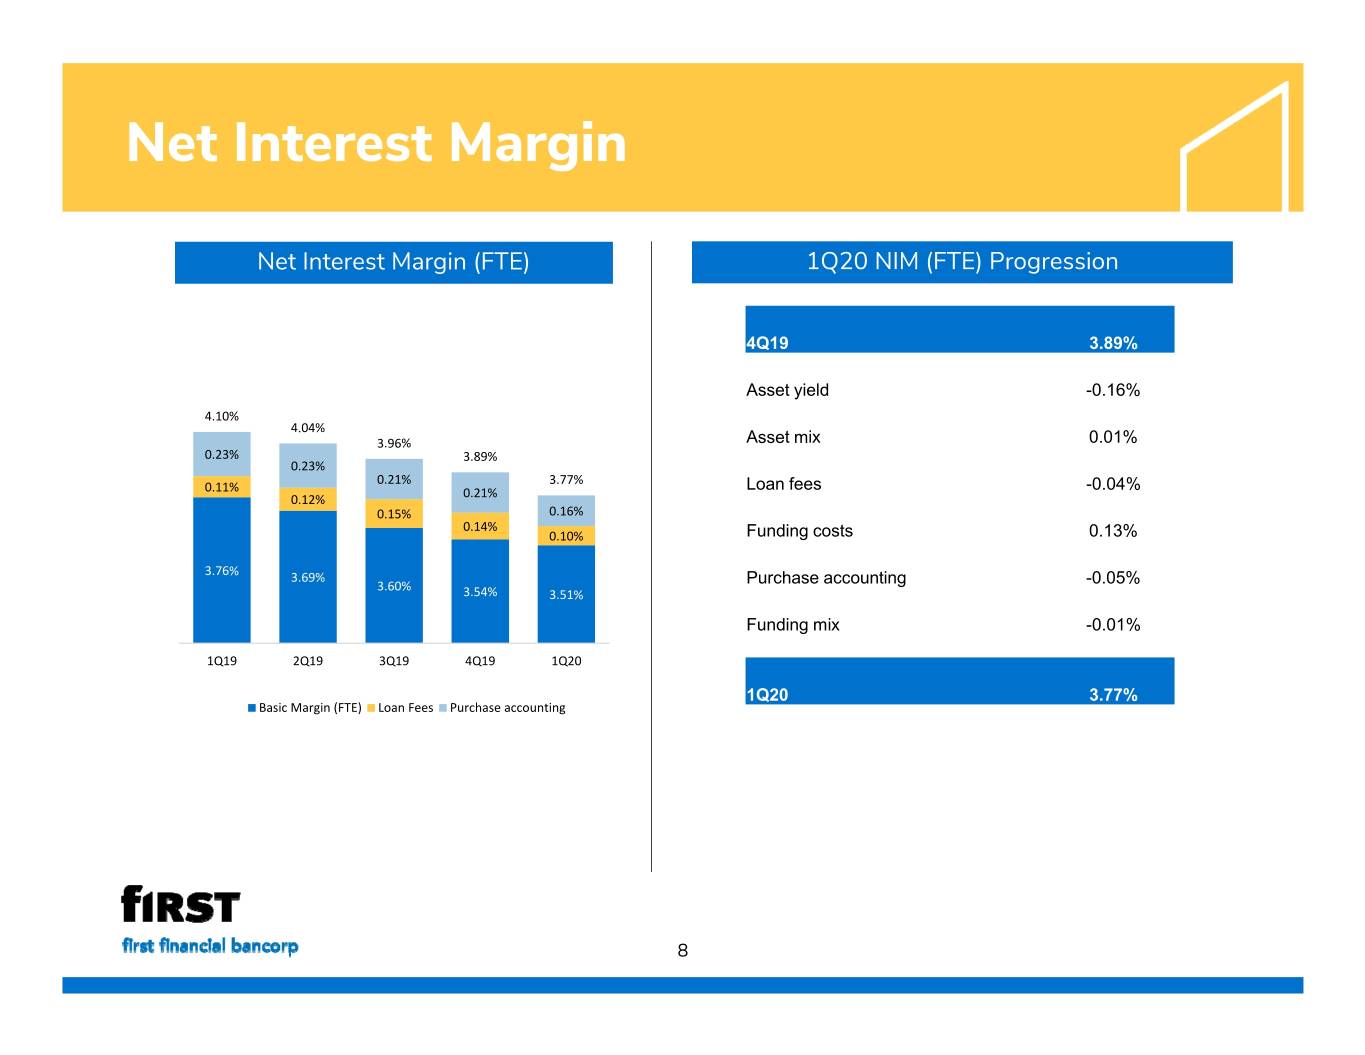
Net Interest Margin Net Interest Margin (FTE) 1Q20 NIM (FTE) Progression 4Q19 3.89% Asset yield -0.16% 4.10% 4.04% 3.96% Asset mix 0.01% 0.23% 3.89% 0.23% 0.21% 3.77% 0.11% Loan fees -0.04% 0.12% 0.21% 0.15% 0.16% 0.14% 0.10% Funding costs 0.13% 3.76% 3.69% 3.60% Purchase accounting -0.05% 3.54% 3.51% Funding mix -0.01% 1Q19 2Q19 3Q19 4Q19 1Q20 1Q20 3.77% Basic Margin (FTE) Loan Fees Purchase accounting 8
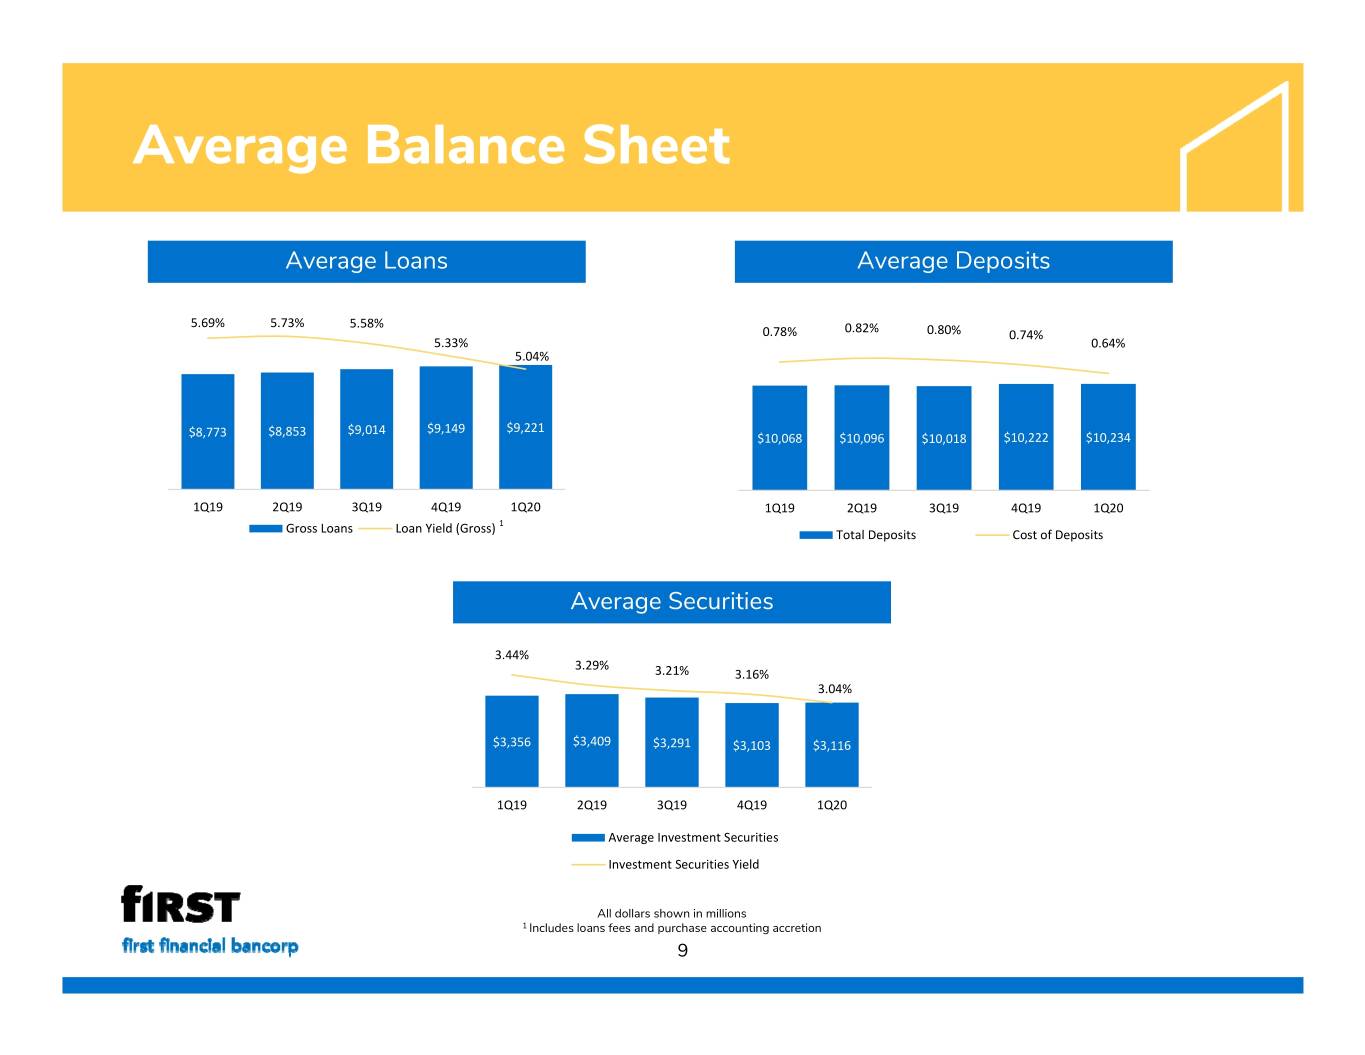
Average Balance Sheet Average Loans Average Deposits 5.69% 5.73% 5.58% 0.82% 0.78% 0.80% 0.74% 5.33% 0.64% 5.04% $8,853 $9,014 $9,149 $9,221 $8,773 $10,068 $10,096 $10,018 $10,222 $10,234 1Q19 2Q19 3Q19 4Q19 1Q20 1Q19 2Q19 3Q19 4Q19 1Q20 1 Gross Loans Loan Yield (Gross) Total Deposits Cost of Deposits Average Securities 3.44% 3.29% 3.21% 3.16% 3.04% $3,356 $3,409 $3,291 $3,103 $3,116 1Q19 2Q19 3Q19 4Q19 1Q20 Average Investment Securities Investment Securities Yield All dollars shown in millions 1 Includes loans fees and purchase accounting accretion 9
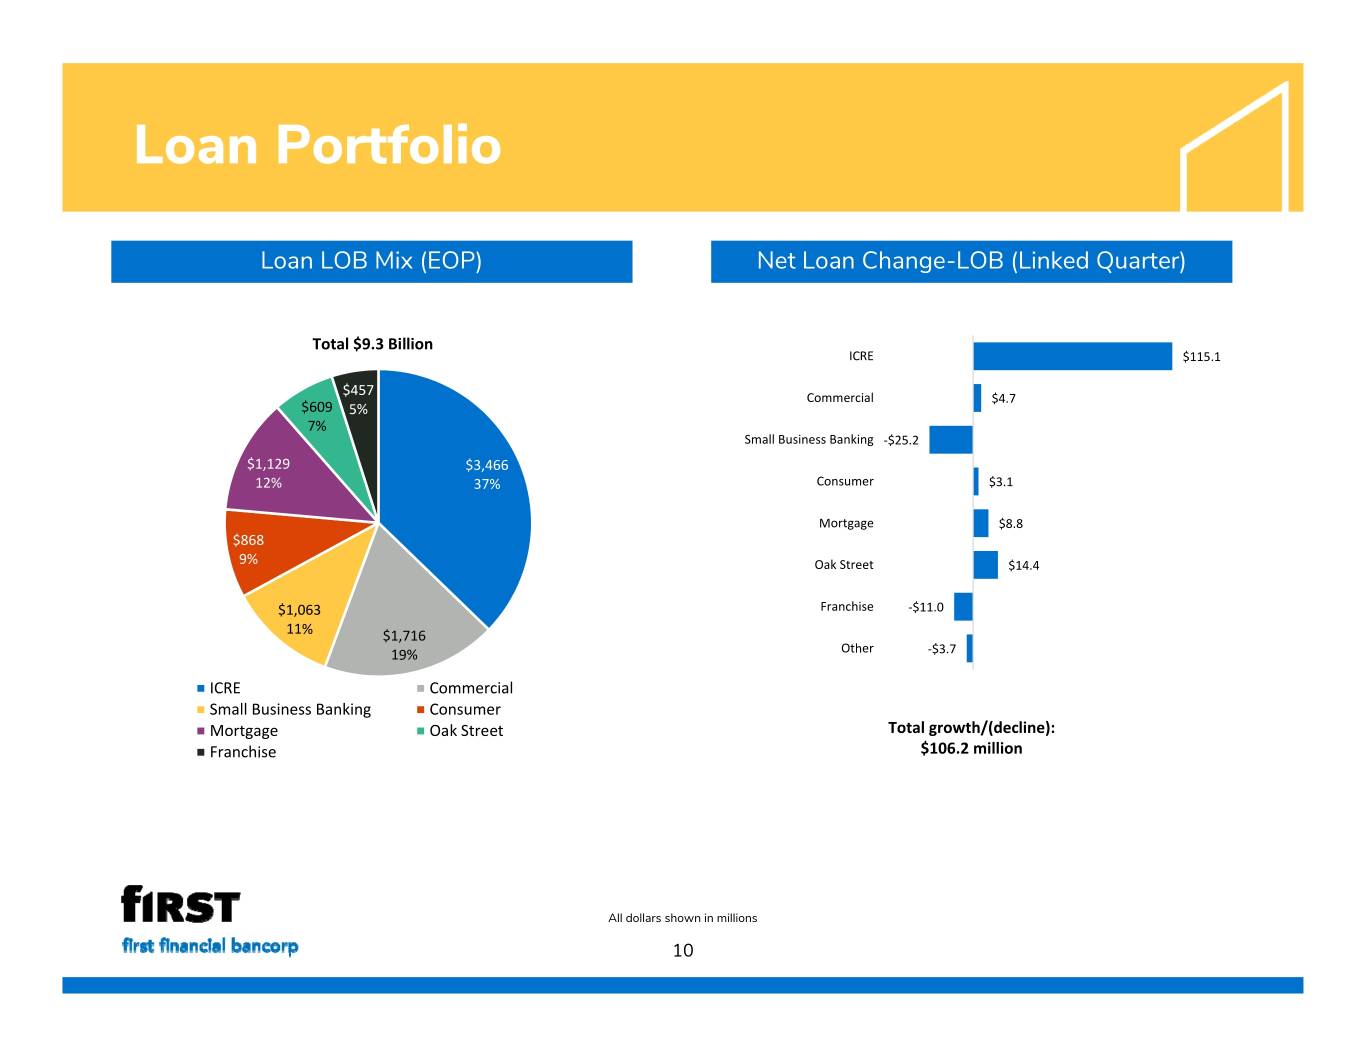
Loan Portfolio Loan LOB Mix (EOP) Net Loan Change-LOB (Linked Quarter) Total $9.3 Billion ICRE $115.1 $457 Commercial $4.7 $609 5% 7% Small Business Banking ‐$25.2 $1,129 $3,466 12% 37% Consumer $3.1 Mortgage $8.8 $868 9% Oak Street $14.4 $1,063 Franchise ‐$11.0 11% $1,716 19% Other ‐$3.7 ICRE Commercial Small Business Banking Consumer Mortgage Oak Street Total growth/(decline): Franchise $106.2 million All dollars shown in millions 10
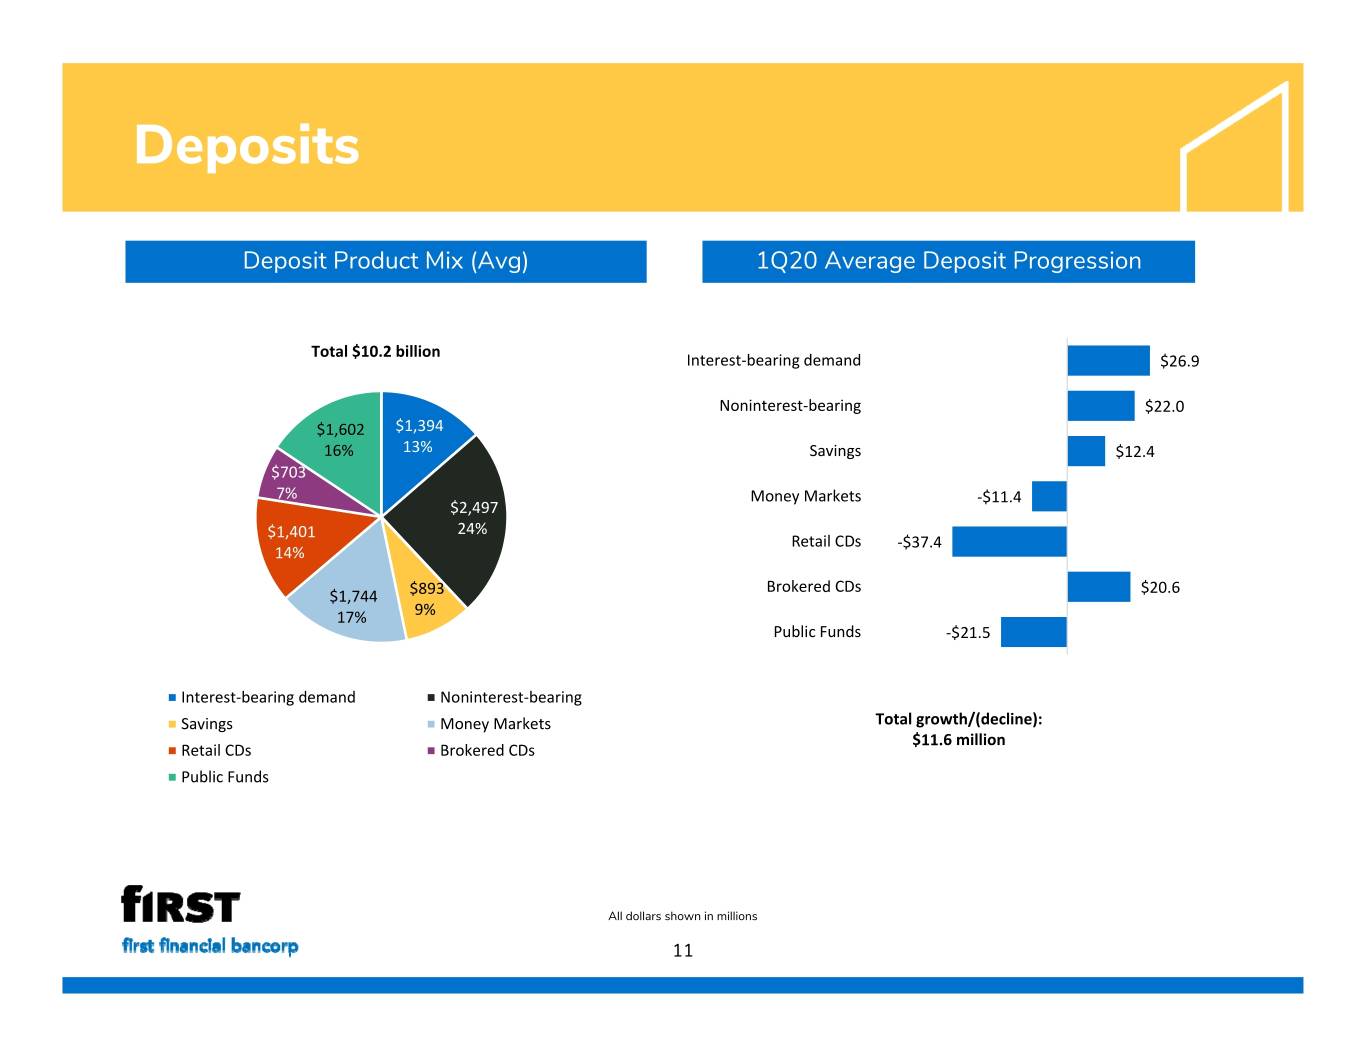
Deposits Deposit Product Mix (Avg) 1Q20 Average Deposit Progression Total $10.2 billion Interest‐bearing demand $26.9 Noninterest‐bearing $22.0 $1,602 $1,394 16% 13% Savings $12.4 $703 7% Money Markets ‐$11.4 $2,497 $1,401 24% Retail CDs ‐$37.4 14% Brokered CDs $20.6 $1,744 $893 17% 9% Public Funds ‐$21.5 Interest‐bearing demand Noninterest‐bearing Savings Money Markets Total growth/(decline): $11.6 million Retail CDs Brokered CDs Public Funds All dollars shown in millions 11
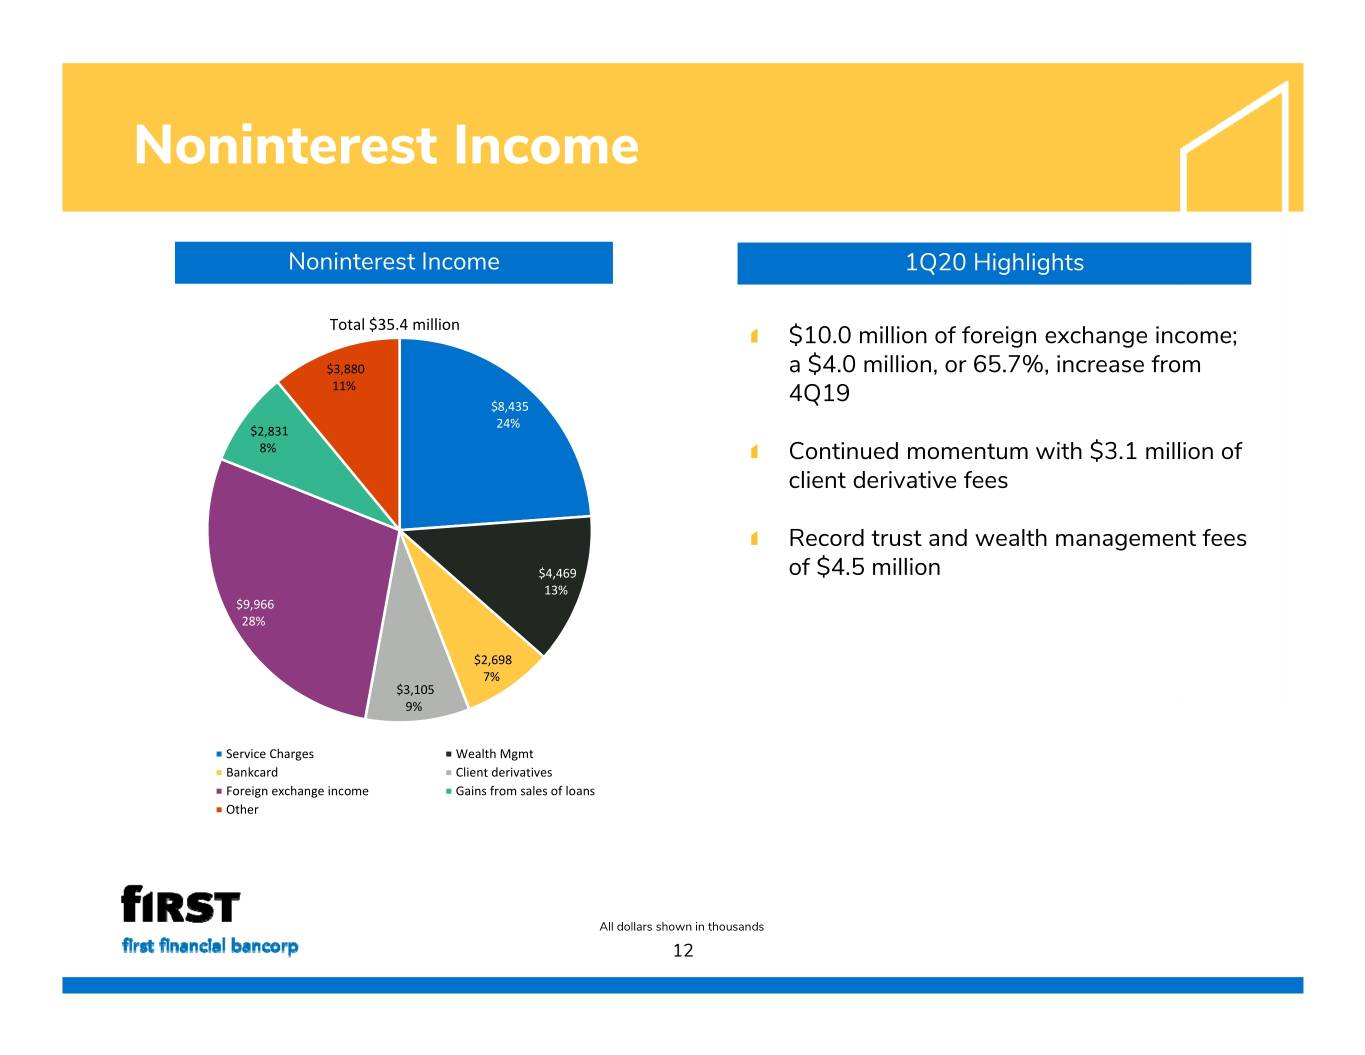
Noninterest Income Noninterest Income 1Q20 Highlights Total $35.4 million $10.0 million of foreign exchange income; $3,880 a $4.0 million, or 65.7%, increase from 11% $8,435 4Q19 24% $2,831 8% Continued momentum with $3.1 million of client derivative fees Record trust and wealth management fees $4,469 of $4.5 million 13% $9,966 28% $2,698 7% $3,105 9% Service Charges Wealth Mgmt Bankcard Client derivatives Foreign exchange income Gains from sales of loans Other All dollars shown in thousands 12
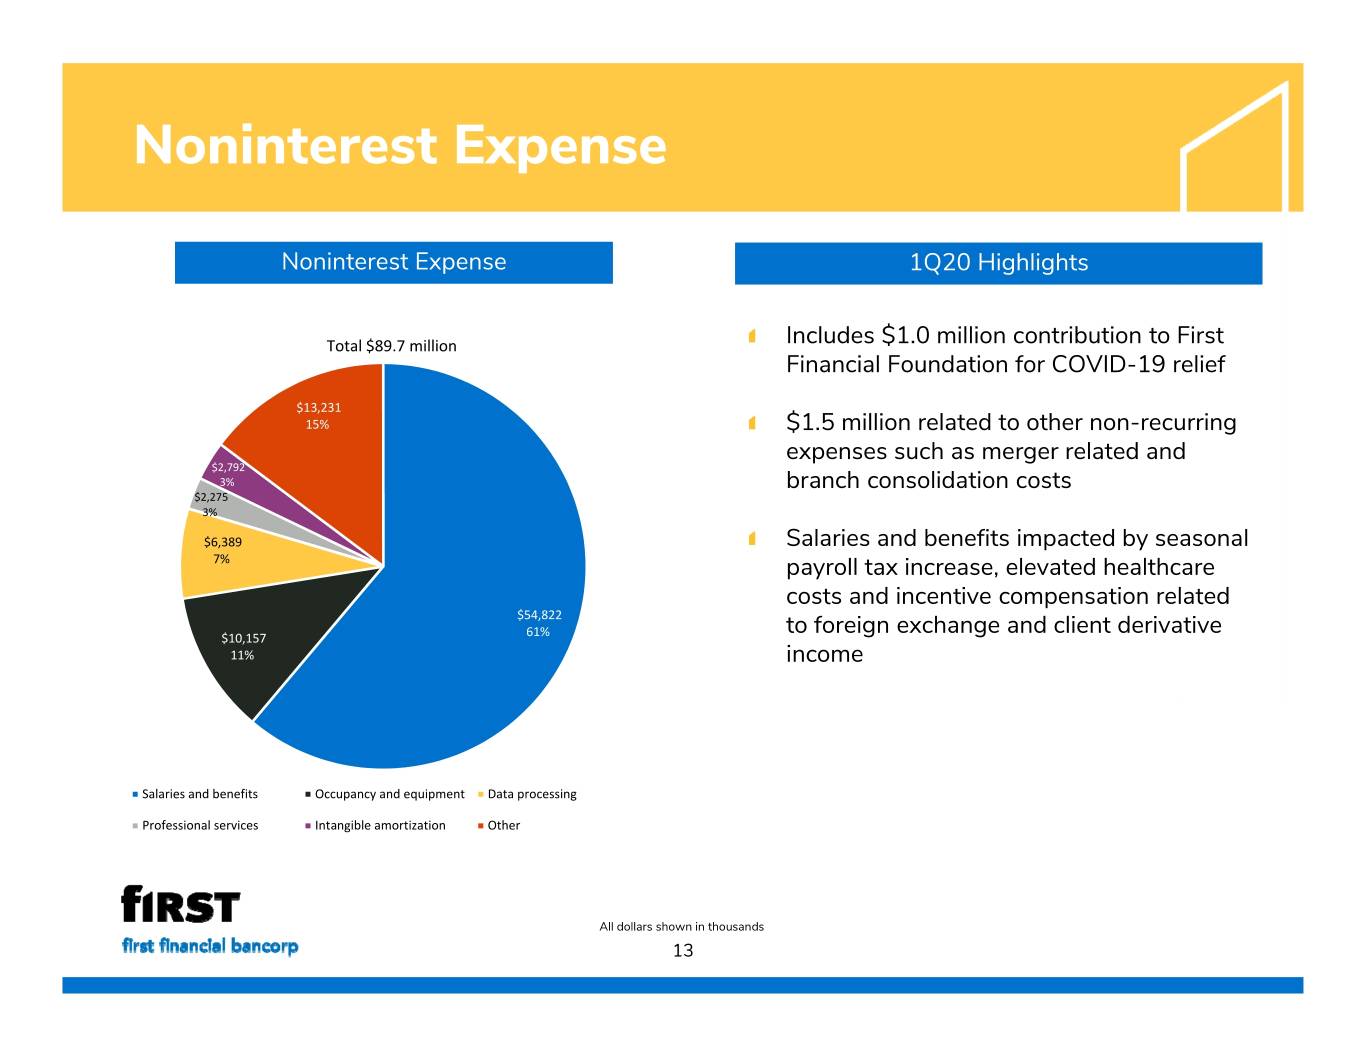
Noninterest Expense Noninterest Expense 1Q20 Highlights Total $89.7 million Includes $1.0 million contribution to First Financial Foundation for COVID-19 relief $13,231 15% $1.5 million related to other non-recurring expenses such as merger related and $2,792 3% branch consolidation costs $2,275 3% $6,389 Salaries and benefits impacted by seasonal 7% payroll tax increase, elevated healthcare costs and incentive compensation related $54,822 $10,157 61% to foreign exchange and client derivative 11% income Salaries and benefits Occupancy and equipment Data processing Professional services Intangible amortization Other All dollars shown in thousands 13
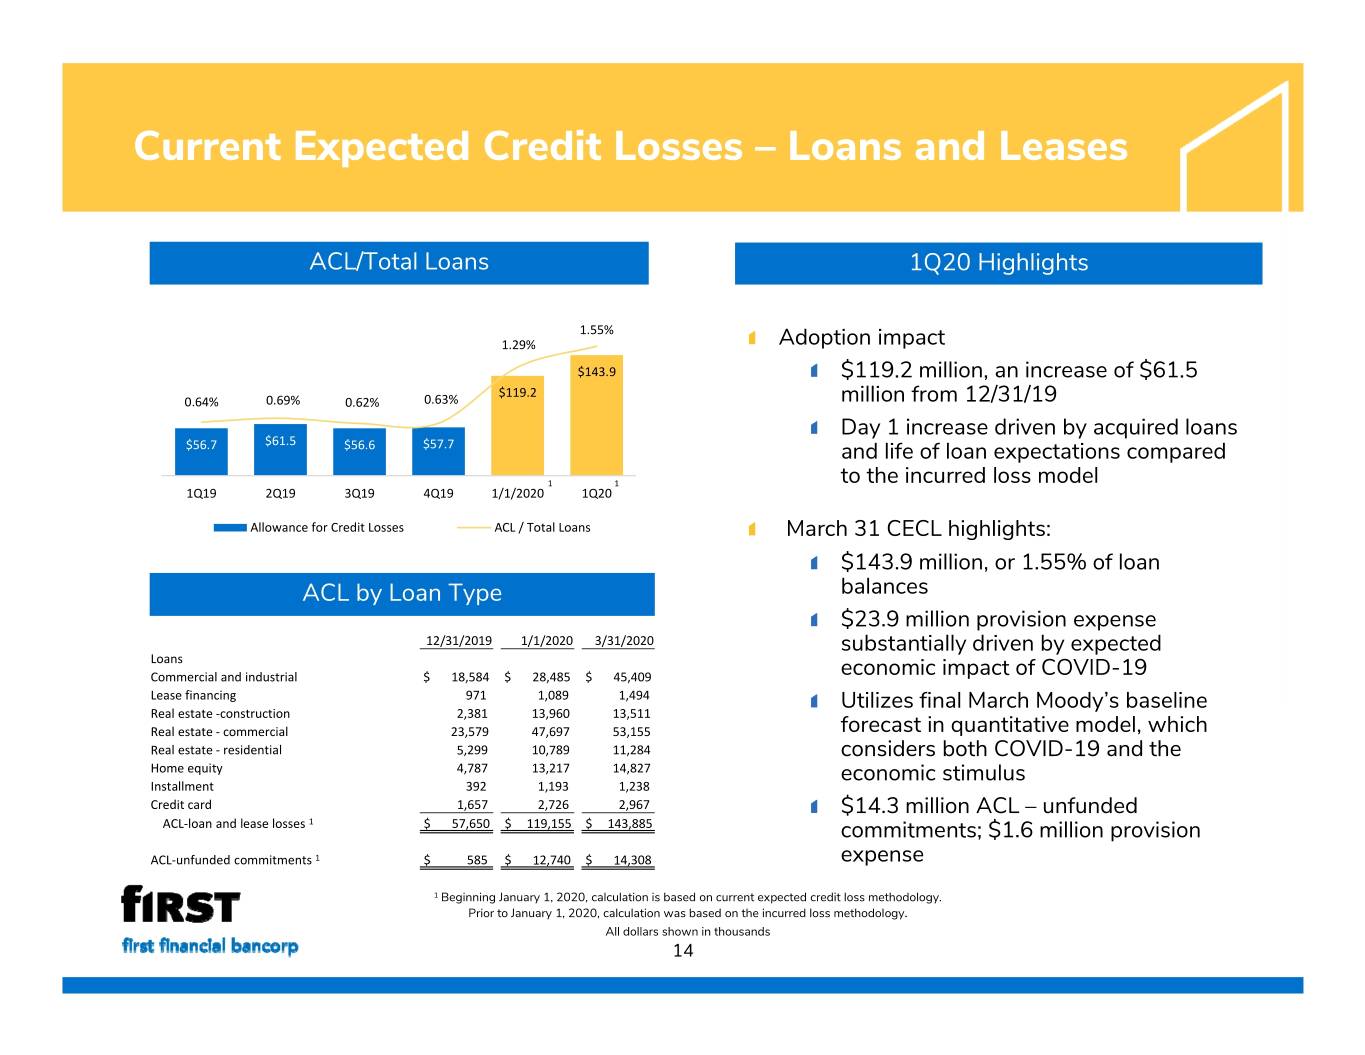
Current Expected Credit Losses – Loans and Leases ACL/Total Loans 1Q20 Highlights 1.55% 1.29% Adoption impact $143.9 $119.2 million, an increase of $61.5 $119.2 0.64% 0.69% 0.62% 0.63% million from 12/31/19 $61.5 Day 1 increase driven by acquired loans $56.7 $56.6 $57.7 and life of loan expectations compared 11 to the incurred loss model 1Q19 2Q19 3Q19 4Q19 1/1/2020 1Q20 Allowance for Credit Losses ACL / Total Loans March 31 CECL highlights: $143.9 million, or 1.55% of loan ACL by Loan Type balances $23.9 million provision expense 12/31/2019 1/1/2020 3/31/2020 substantially driven by expected Loans Commercial and industrial $ 18,584 $ 28,485 $ 45,409 economic impact of COVID-19 Lease financing 971 1,089 1,494 Real estate ‐construction 2,381 13,960 13,511 Utilizes final March Moody’s baseline Real estate ‐ commercial 23,579 47,697 53,155 forecast in quantitative model, which Real estate ‐ residential 5,299 10,789 11,284 considers both COVID-19 and the Home equity 4,787 13,217 14,827 Installment 392 1,193 1,238 economic stimulus Credit card 1,657 2,726 2,967 $14.3 million ACL – unfunded 1 ACL‐loan and lease losses $ 57,650 $ 119,155 $ 143,885 commitments; $1.6 million provision ACL‐unfunded commitments 1 $ 585 $ 12,740 $ 14,308 expense 1 Beginning January 1, 2020, calculation is based on current expected credit loss methodology. Prior to January 1, 2020, calculation was based on the incurred loss methodology. All dollars shown in thousands 14
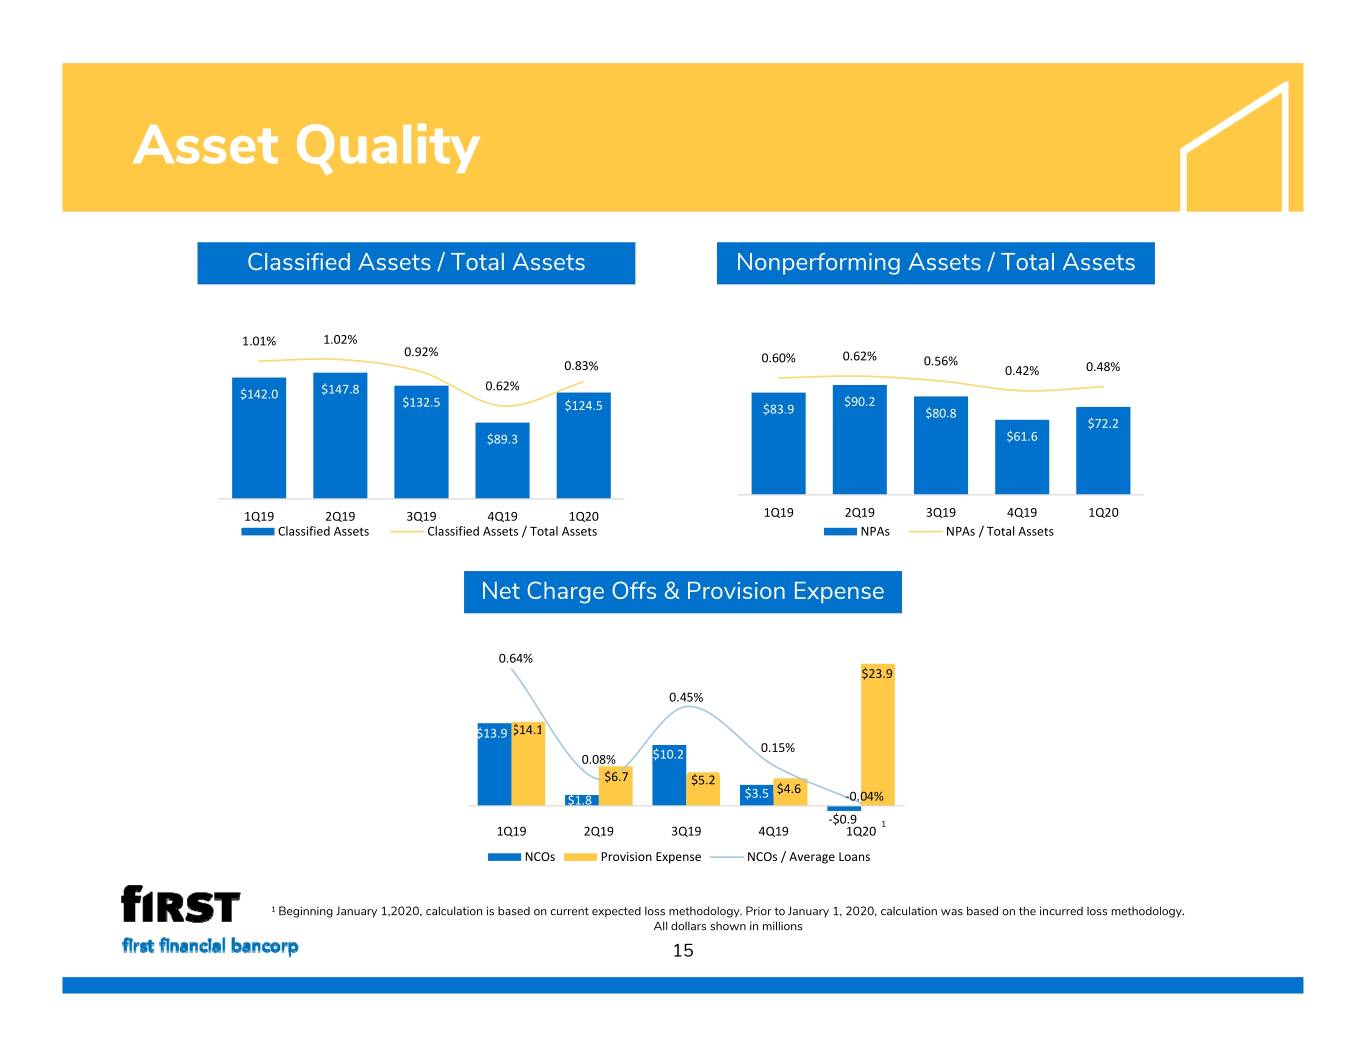
Asset Quality Classified Assets / Total Assets Nonperforming Assets / Total Assets 1.01% 1.02% 0.92% 0.60% 0.62% 0.56% 0.83% 0.42% 0.48% 0.62% $142.0 $147.8 $132.5 $124.5 $90.2 $83.9 $80.8 $72.2 $89.3 $61.6 1Q19 2Q19 3Q19 4Q19 1Q20 1Q19 2Q19 3Q19 4Q19 1Q20 Classified Assets Classified Assets / Total Assets NPAs NPAs / Total Assets Net Charge Offs & Provision Expense 0.64% $23.9 0.45% $13.9 $14.1 0.15% 0.08% $10.2 $6.7 $5.2 $4.6 $1.8 $3.5 ‐0.04% ‐$0.9 1 1Q19 2Q19 3Q19 4Q19 1Q20 NCOs Provision Expense NCOs / Average Loans 1 Beginning January 1,2020, calculation is based on current expected loss methodology. Prior to January 1, 2020, calculation was based on the incurred loss methodology. All dollars shown in millions 15
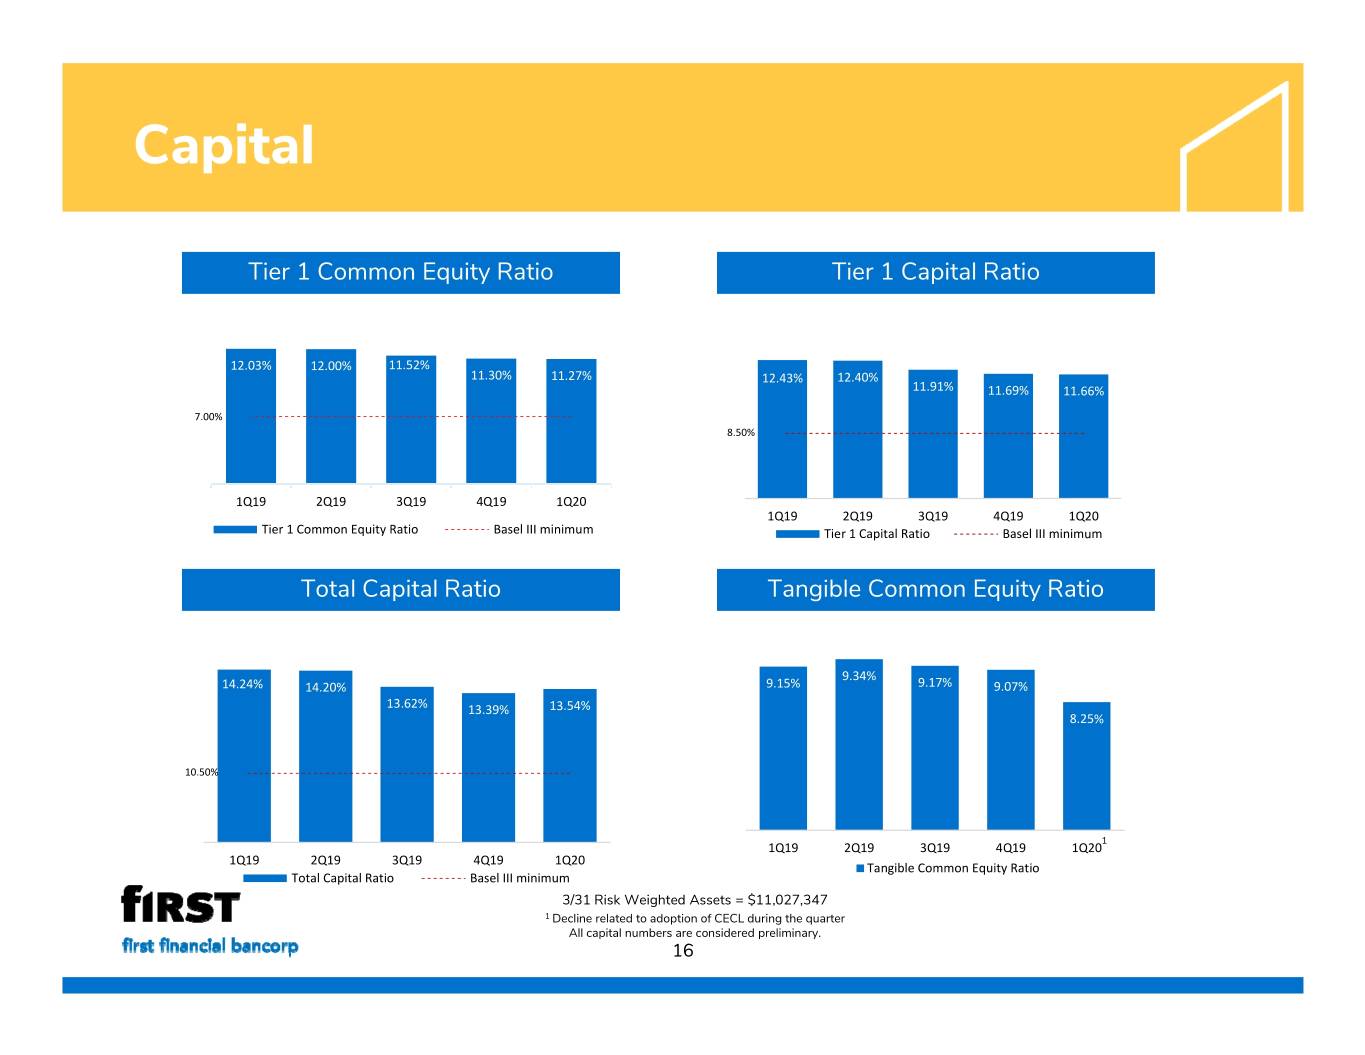
Capital Tier 1 Common Equity Ratio Tier 1 Capital Ratio 12.03% 12.00% 11.52% 11.30% 11.27% 12.43% 12.40% 11.91% 11.69% 11.66% 7.00% 8.50% 1Q19 2Q19 3Q19 4Q19 1Q20 1Q19 2Q19 3Q19 4Q19 1Q20 Tier 1 Common Equity Ratio Basel III minimum Tier 1 Capital Ratio Basel III minimum Total Capital Ratio Tangible Common Equity Ratio 9.34% 14.24% 14.20% 9.15% 9.17% 9.07% 13.62% 13.39% 13.54% 8.25% 10.50% 1 1Q19 2Q19 3Q19 4Q19 1Q20 1Q19 2Q19 3Q19 4Q19 1Q20 Tangible Common Equity Ratio Total Capital Ratio Basel III minimum 3/31 Risk Weighted Assets = $11,027,347 1 Decline related to adoption of CECL during the quarter All capital numbers are considered preliminary. 16
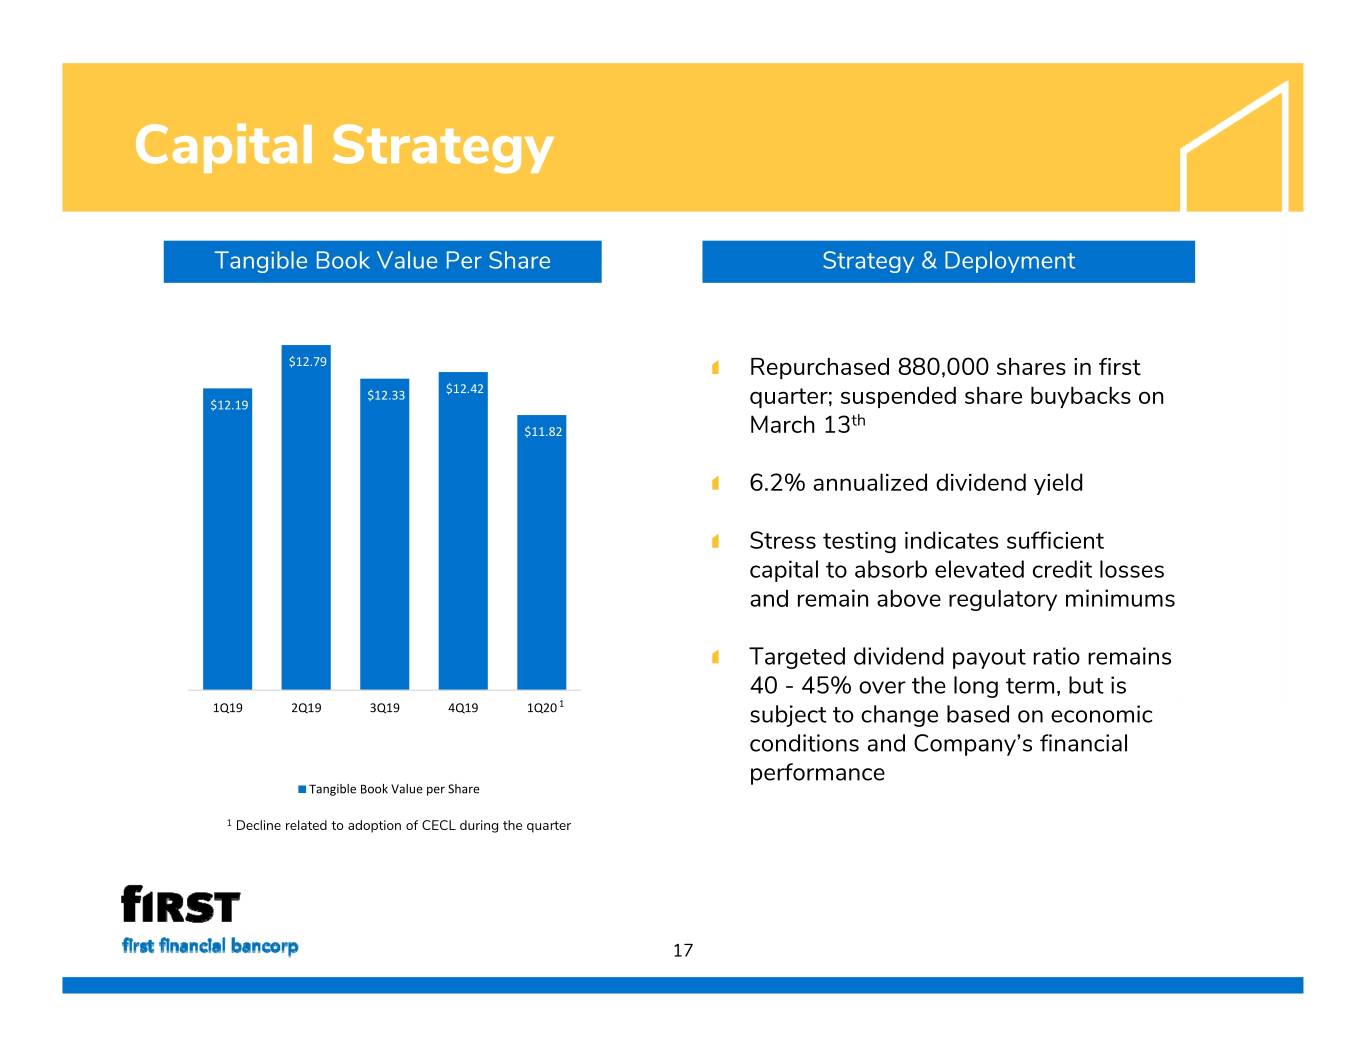
Capital Strategy Tangible Book Value Per Share Strategy & Deployment $12.79 Repurchased 880,000 shares in first $12.33 $12.42 $12.19 quarter; suspended share buybacks on th $11.82 March 13 6.2% annualized dividend yield Stress testing indicates sufficient capital to absorb elevated credit losses and remain above regulatory minimums Targeted dividend payout ratio remains 40 - 45% over the long term, but is 1 1Q19 2Q19 3Q19 4Q19 1Q20 subject to change based on economic conditions and Company’s financial performance Tangible Book Value per Share 1 Decline related to adoption of CECL during the quarter 17
COVID – 19 Related Information
Leading our Response We were prepared to immediately implement our Pandemic Plan and adapt our business continuity planning to navigate the evolving circumstances of our associates, clients and communities. 19
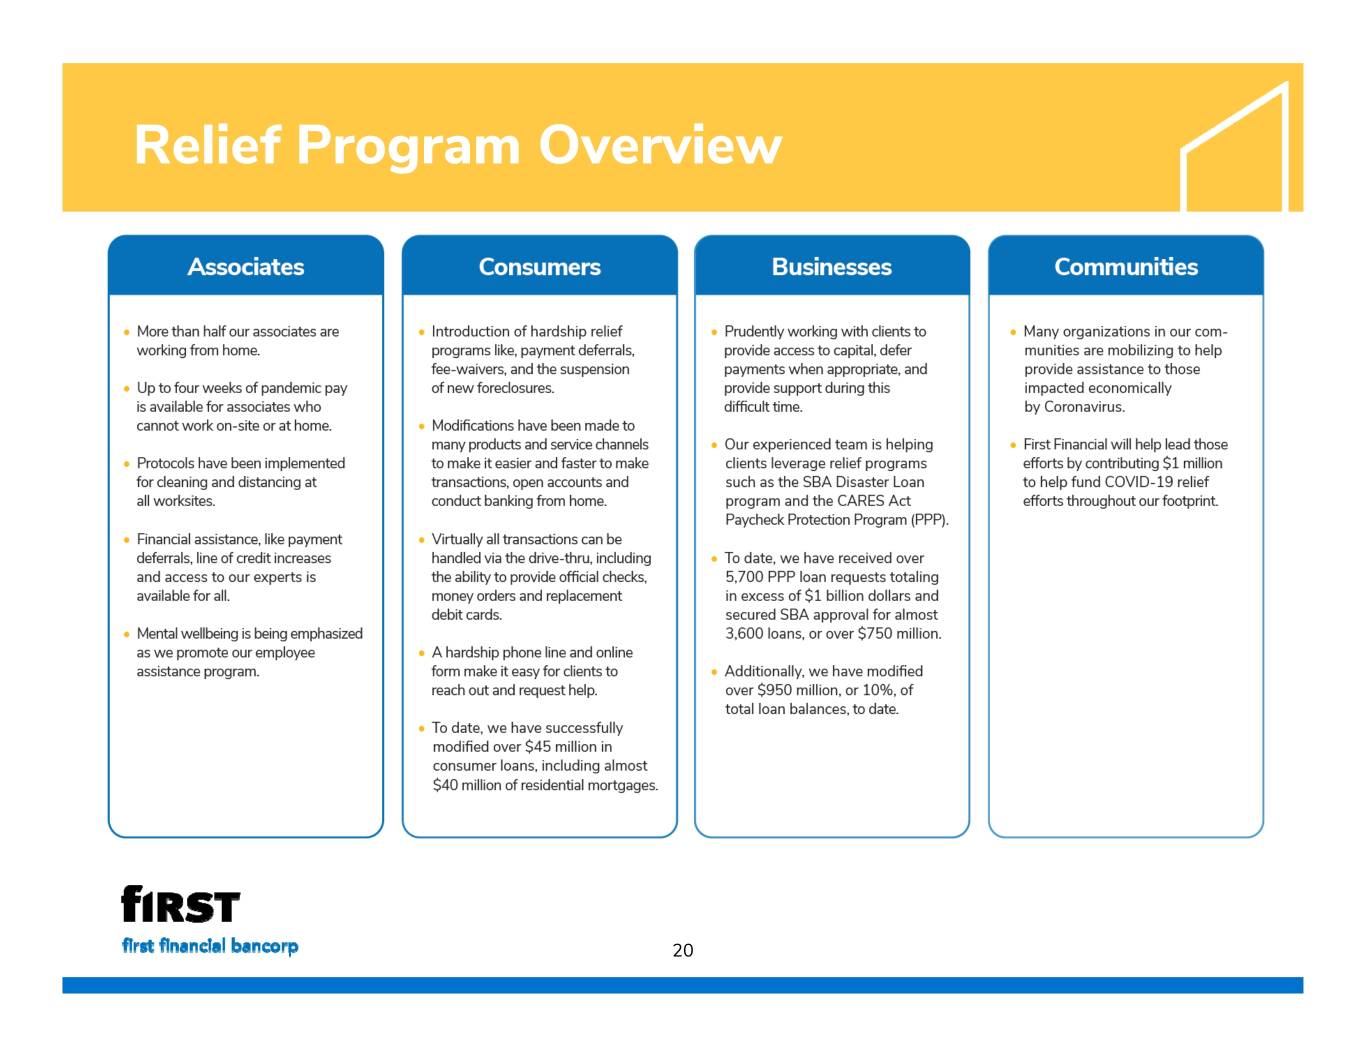
Relief Program Overview 20
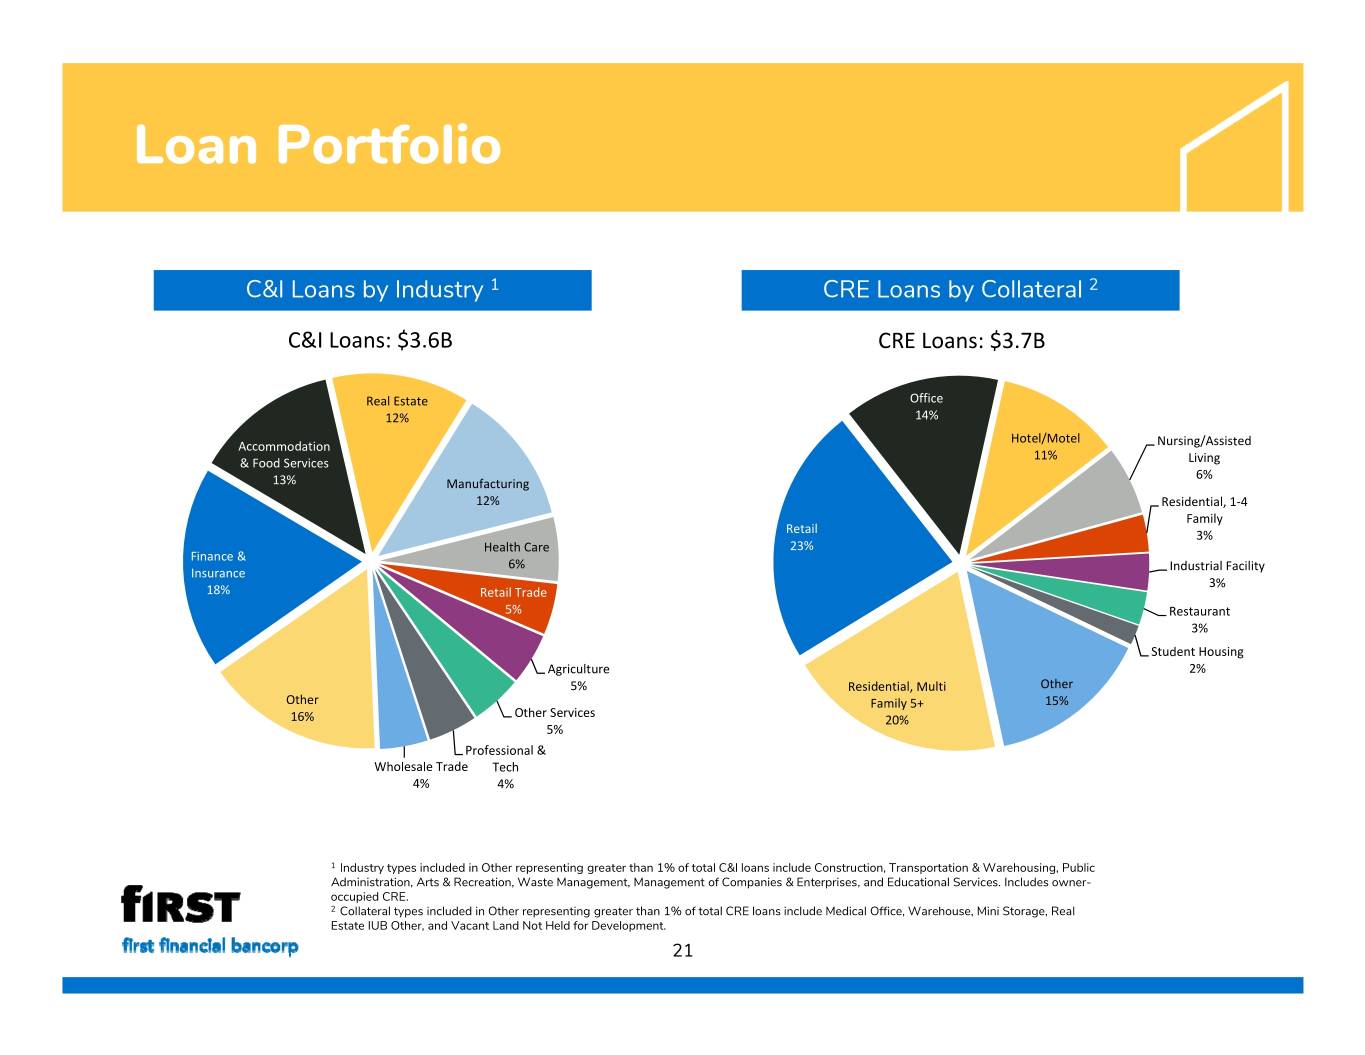
Loan Portfolio C&I Loans by Industry 1 CRE Loans by Collateral 2 C&I Loans: $3.6B CRE Loans: $3.7B Real Estate Office 12% 14% Hotel/Motel Accommodation Nursing/Assisted 11% & Food Services Living 6% 13% Manufacturing 12% Residential, 1‐4 Family Retail 3% Health Care 23% Finance & 6% Industrial Facility Insurance 3% 18% Retail Trade 5% Restaurant 3% Student Housing Agriculture 2% 5% Residential, Multi Other Other Family 5+ 15% Other Services 16% 20% 5% Professional & Wholesale Trade Tech 4% 4% 1 Industry types included in Other representing greater than 1% of total C&I loans include Construction, Transportation & Warehousing, Public Administration, Arts & Recreation, Waste Management, Management of Companies & Enterprises, and Educational Services. Includes owner- occupied CRE. 2 Collateral types included in Other representing greater than 1% of total CRE loans include Medical Office, Warehouse, Mini Storage, Real Estate IUB Other, and Vacant Land Not Held for Development. 21
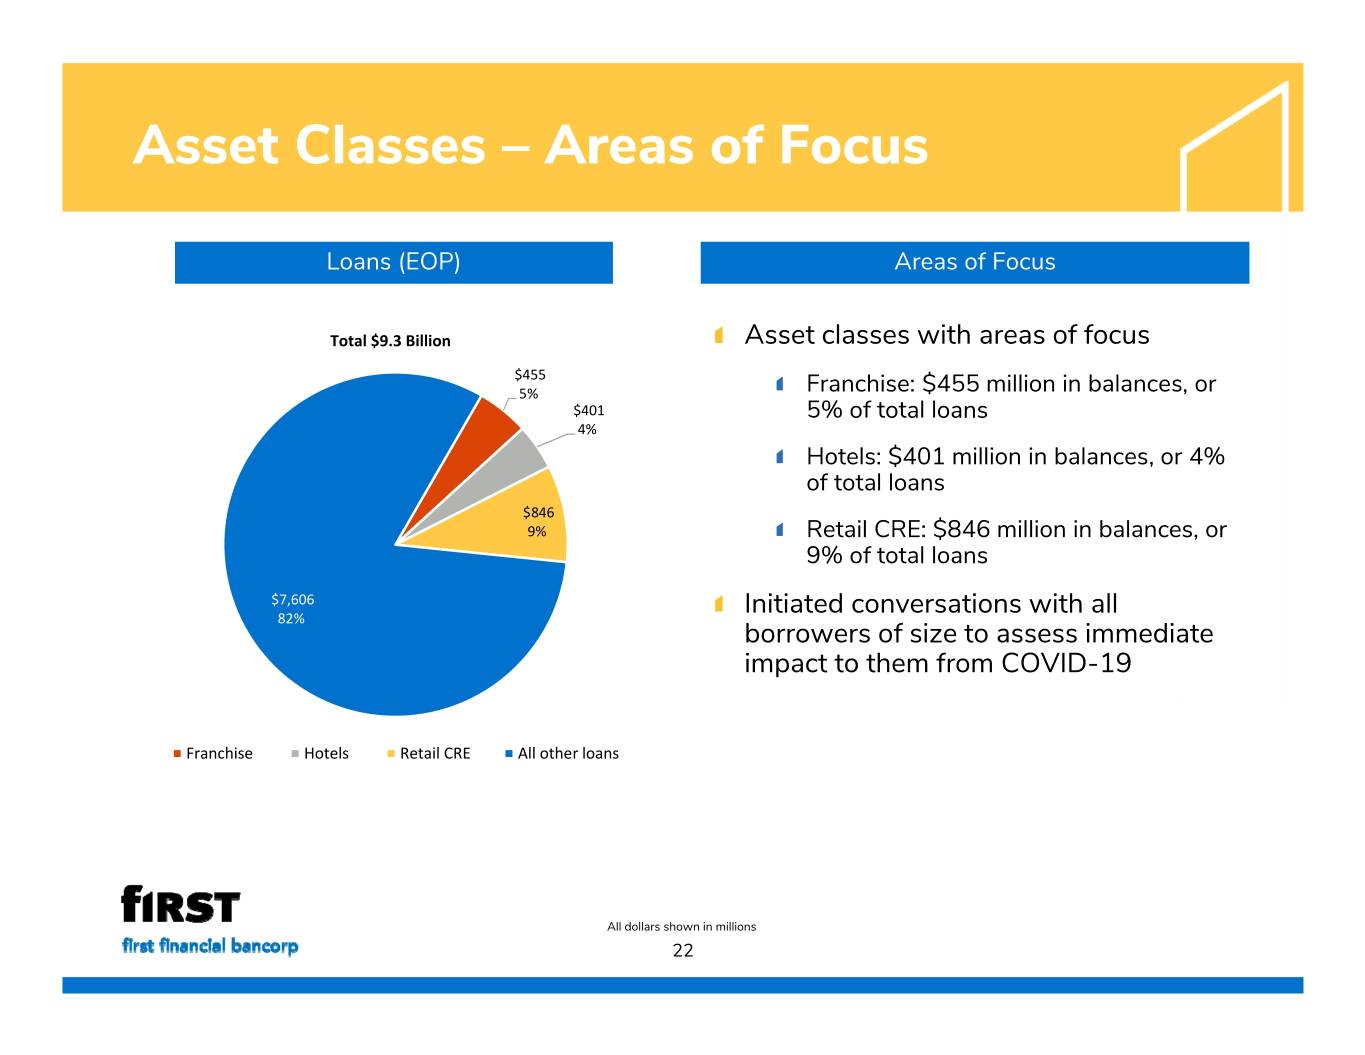
Asset Classes – Areas of Focus Loans (EOP) Areas of Focus Total $9.3 Billion Asset classes with areas of focus $455 5% Franchise: $455 million in balances, or $401 5% of total loans 4% Hotels: $401 million in balances, or 4% of total loans $846 9% Retail CRE: $846 million in balances, or 9% of total loans $7,606 82% Initiated conversations with all borrowers of size to assess immediate impact to them from COVID-19 Franchise Hotels Retail CRE All other loans All dollars shown in millions 22
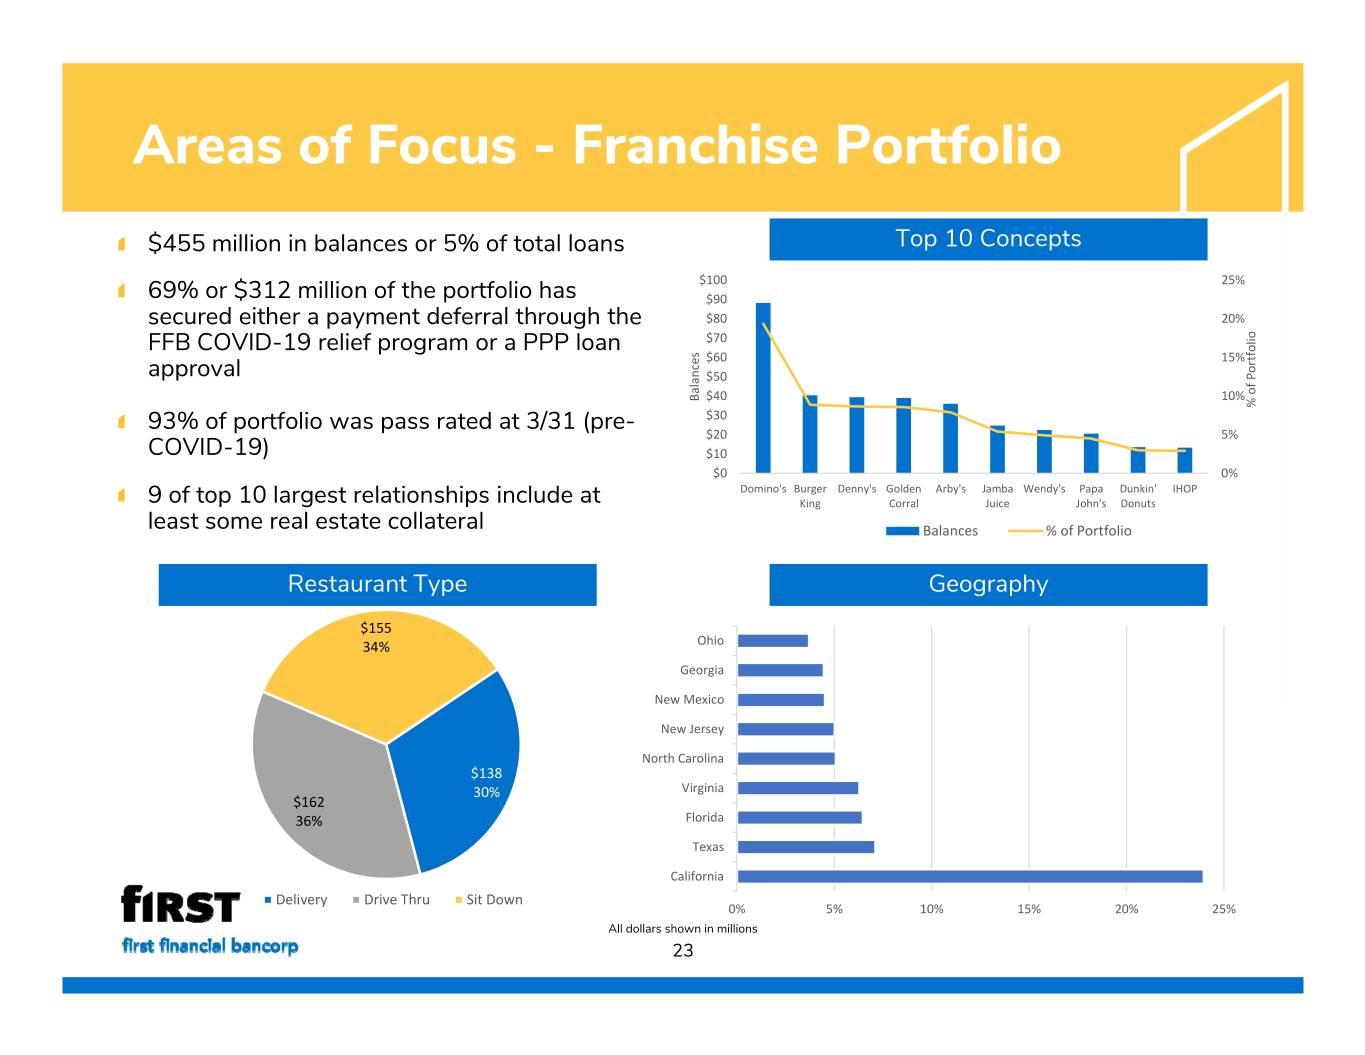
Areas of Focus - Franchise Portfolio $455 million in balances or 5% of total loans Top 10 Concepts $100 25% 69% or $312 million of the portfolio has $90 secured either a payment deferral through the $80 20% $70 FFB COVID-19 relief program or a PPP loan $60 15% approval $50 Balances $40 10% % of Portfolio $30 93% of portfolio was pass rated at 3/31 (pre- $20 5% COVID-19) $10 $0 0% Domino's Burger Denny's Golden Arby's Jamba Wendy's Papa Dunkin' IHOP 9 of top 10 largest relationships include at King Corral Juice John's Donuts least some real estate collateral Balances % of Portfolio Restaurant Type Geography $155 34% Ohio Georgia New Mexico New Jersey North Carolina $138 30% Virginia $162 36% Florida Texas California Delivery Drive Thru Sit Down 0% 5% 10% 15% 20% 25% All dollars shown in millions 23
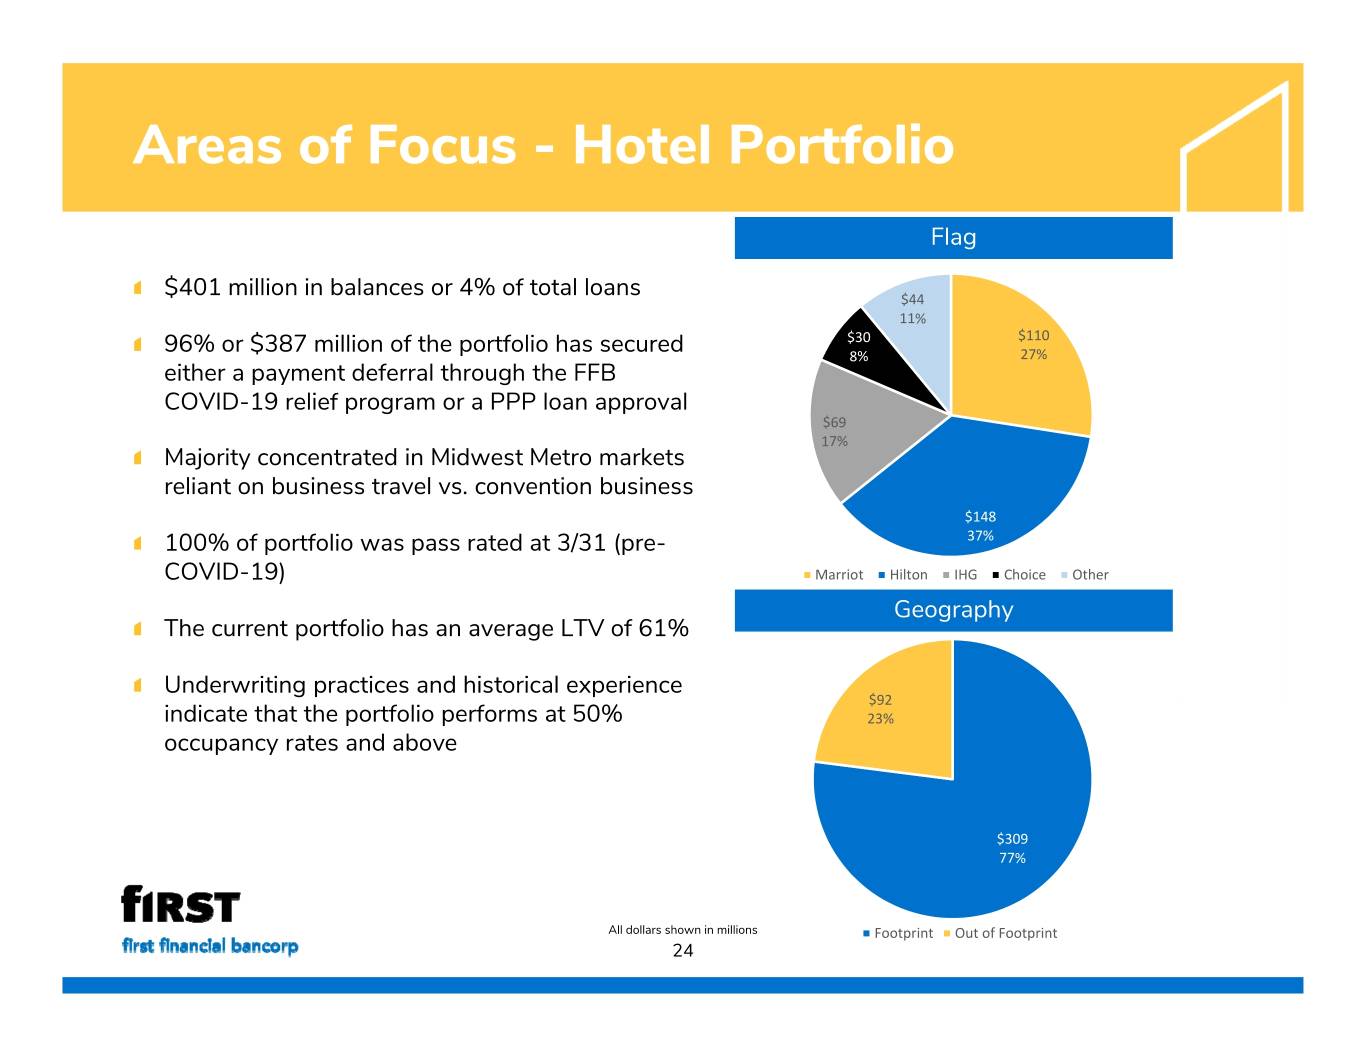
Areas of Focus - Hotel Portfolio Flag $401 million in balances or 4% of total loans $44 11% $30 $110 96% or $387 million of the portfolio has secured 8% 27% either a payment deferral through the FFB COVID-19 relief program or a PPP loan approval $69 17% Majority concentrated in Midwest Metro markets reliant on business travel vs. convention business $148 100% of portfolio was pass rated at 3/31 (pre- 37% COVID-19) Marriot Hilton IHG Choice Other Geography The current portfolio has an average LTV of 61% Underwriting practices and historical experience $92 indicate that the portfolio performs at 50% 23% occupancy rates and above $309 77% All dollars shown in millions Footprint Out of Footprint 24
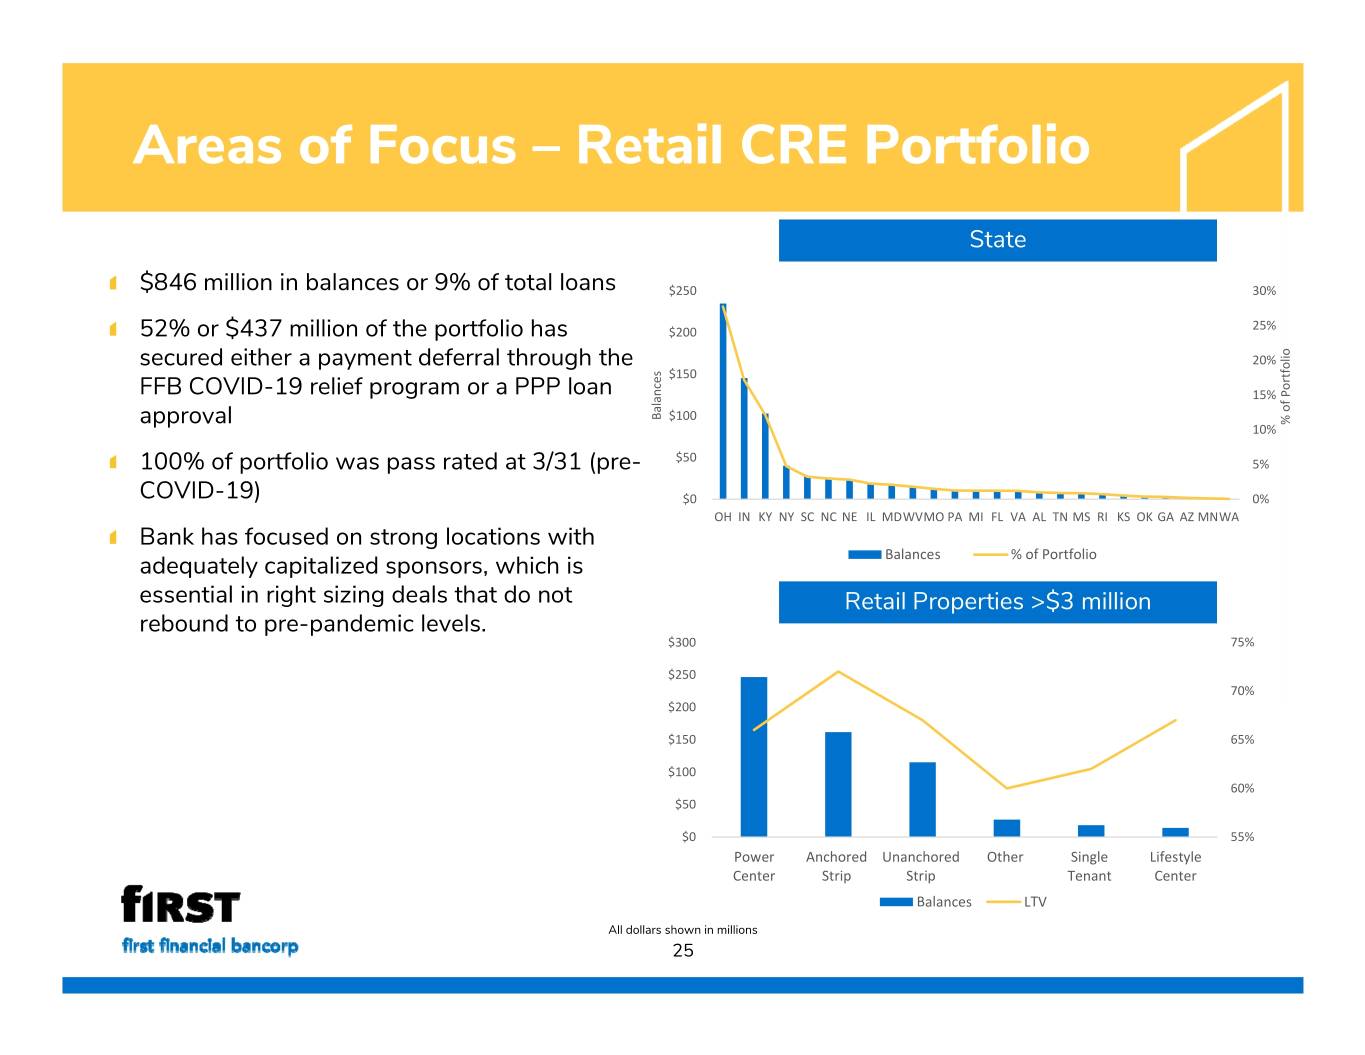
Areas of Focus – Retail CRE Portfolio State $846 million in balances or 9% of total loans $250 30% 25% 52% or $437 million of the portfolio has $200 secured either a payment deferral through the 20% $150 FFB COVID-19 relief program or a PPP loan 15% Balances $100 approval 10% % of Portfolio $50 100% of portfolio was pass rated at 3/31 (pre- 5% COVID-19) $0 0% OH IN KY NY SC NC NE IL MDWVMO PA MI FL VA AL TN MS RI KS OK GA AZ MNWA Bank has focused on strong locations with Balances % of Portfolio adequately capitalized sponsors, which is essential in right sizing deals that do not Retail Properties >$3 million rebound to pre-pandemic levels. $300 75% $250 70% $200 $150 65% $100 60% $50 $0 55% Power Anchored Unanchored Other Single Lifestyle Center Strip Strip Tenant Center Balances LTV All dollars shown in millions 25
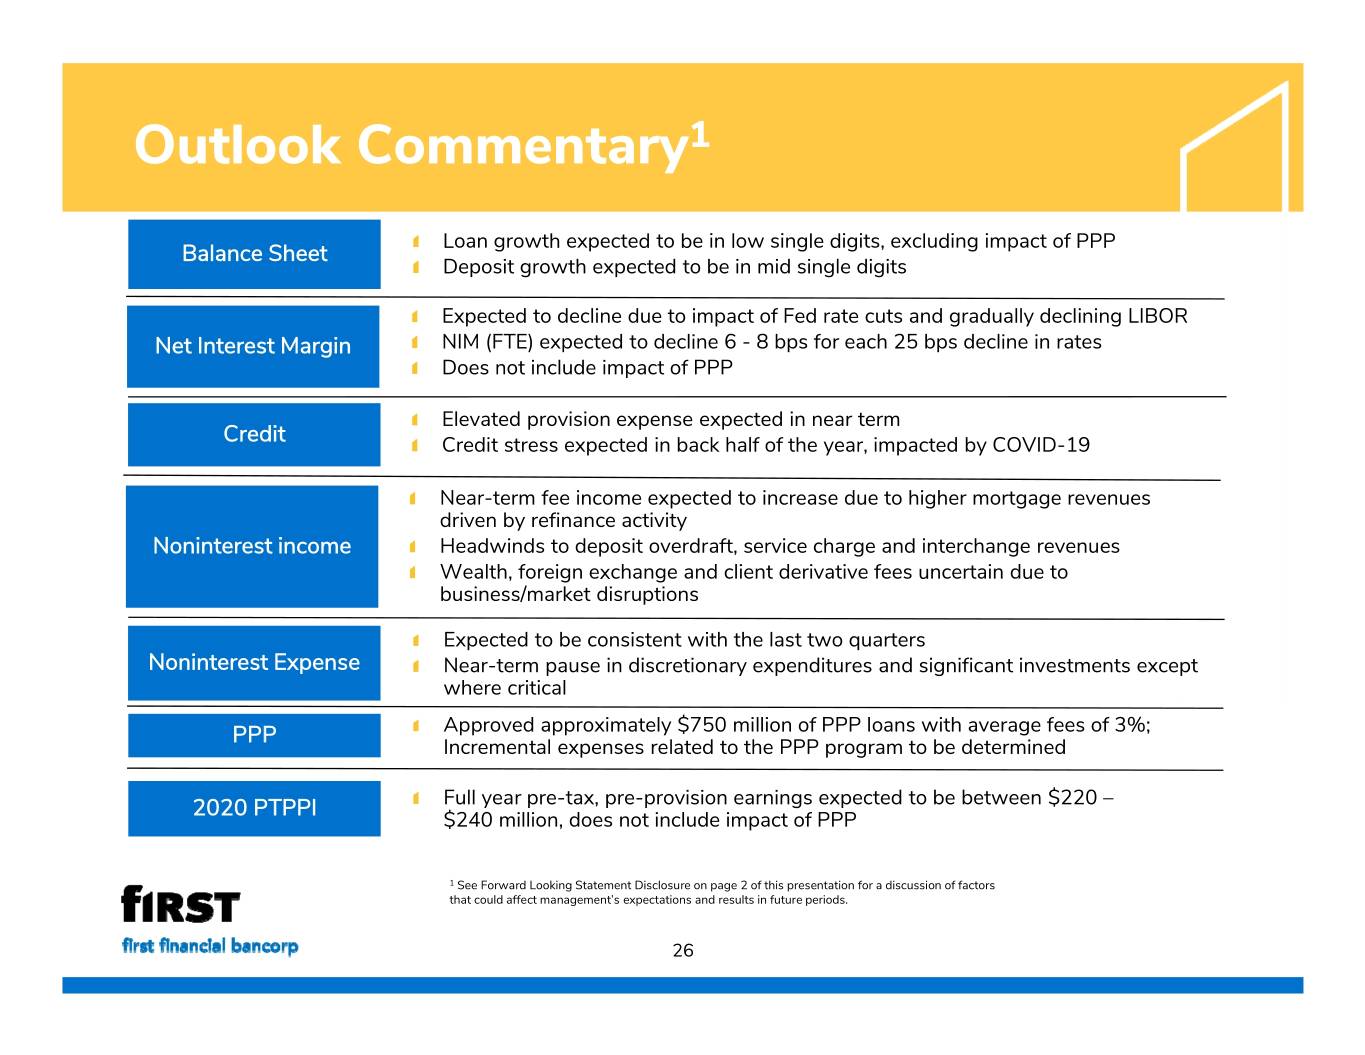
Outlook Commentary1 Loan growth expected to be in low single digits, excluding impact of PPP Balance Sheet Deposit growth expected to be in mid single digits Expected to decline due to impact of Fed rate cuts and gradually declining LIBOR Net Interest Margin NIM (FTE) expected to decline 6 - 8 bps for each 25 bps decline in rates Does not include impact of PPP Elevated provision expense expected in near term Credit Credit stress expected in back half of the year, impacted by COVID-19 Near-term fee income expected to increase due to higher mortgage revenues driven by refinance activity Noninterest income Headwinds to deposit overdraft, service charge and interchange revenues Wealth, foreign exchange and client derivative fees uncertain due to business/market disruptions Expected to be consistent with the last two quarters Noninterest Expense Near-term pause in discretionary expenditures and significant investments except where critical PPP Approved approximately $750 million of PPP loans with average fees of 3%; Incremental expenses related to the PPP program to be determined 2020 PTPPI Full year pre-tax, pre-provision earnings expected to be between $220 – $240 million, does not include impact of PPP 1 See Forward Looking Statement Disclosure on page 2 of this presentation for a discussion of factors that could affect management’s expectations and results in future periods. 26
Appendix: Non-GAAP Measures The Company’s earnings release and accompanying presentation contain certain financial information determined by methods other than in accordance with accounting principles generally accepted in the United States (GAAP). Such non-GAAP financial information should be considered supplemental to, and not as a substitute for, or superior to, financial measures calculated in accordance with GAAP. However, we believe that non-GAAP reporting provides meaningful information and therefore we use it to supplement our GAAP information. We have chosen to provide this supplemental information to investors, analysts and other interested parties to enable them to perform additional analyses of operating results, to illustrate the results of operations giving effect to the non-GAAP adjustments and to provide an additional measure of performance. We believe this information is helpful in understanding the results of operations separate and apart from items that may, or could, have a disproportional positive or negative impact in any given period. For a reconciliation of the differences between the non-GAAP financial measures and the most comparable GAAP measures, please refer to the following reconciliation tables. to GAAP Reconciliation 27
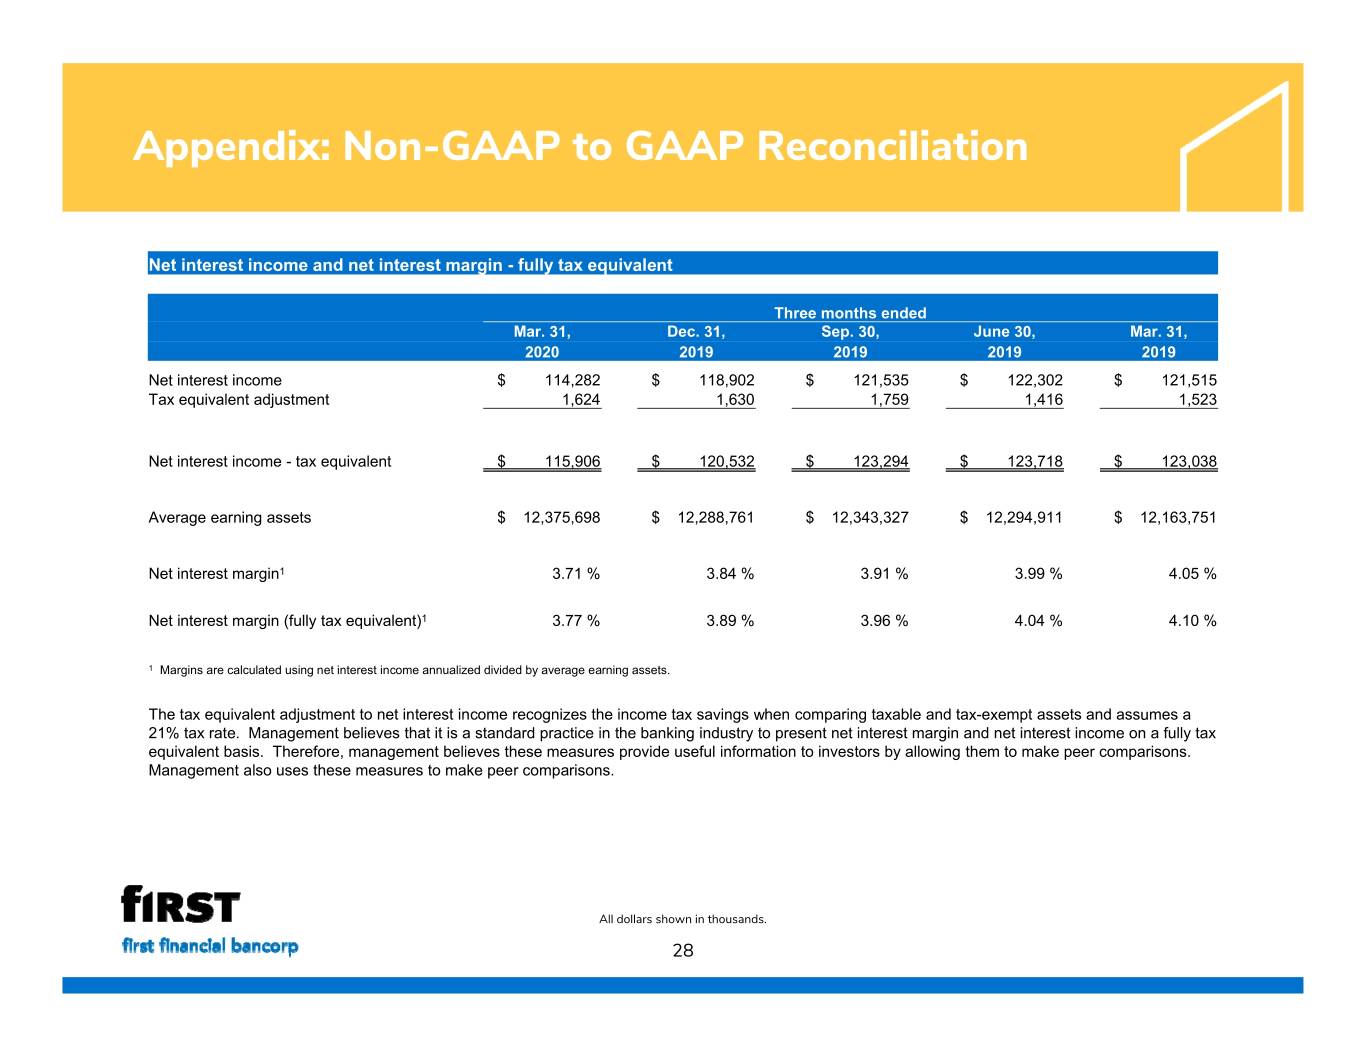
Appendix: Non-GAAP to GAAP Reconciliation Net interest income and net interest margin - fully tax equivalent Three months ended Mar. 31, Dec. 31, Sep. 30, June 30, Mar. 31, 2020 2019 2019 2019 2019 Net interest income $ 114,282 $ 118,902 $ 121,535 $ 122,302 $ 121,515 Tax equivalent adjustment 1,624 1,630 1,759 1,416 1,523 Net interest income - tax equivalent $ 115,906 $ 120,532 $ 123,294 $ 123,718 $ 123,038 Average earning assets $ 12,375,698 $ 12,288,761 $ 12,343,327 $ 12,294,911 $ 12,163,751 Net interest margin1 3.71 % 3.84 % 3.91 % 3.99 % 4.05 % Net interest margin (fully tax equivalent)1 3.77 % 3.89 % 3.96 % 4.04 % 4.10 % 1 Margins are calculated using net interest income annualized divided by average earning assets. The tax equivalent adjustment to net interest income recognizes the income tax savings when comparing taxable and tax-exempt assets and assumes a 21% tax rate. Management believes that it is a standard practice in the banking industry to present net interest margin and net interest income on a fully tax equivalent basis. Therefore, management believes these measures provide useful information to investors by allowing them to make peer comparisons. Management also uses these measures to make peer comparisons. All dollars shown in thousands. 28
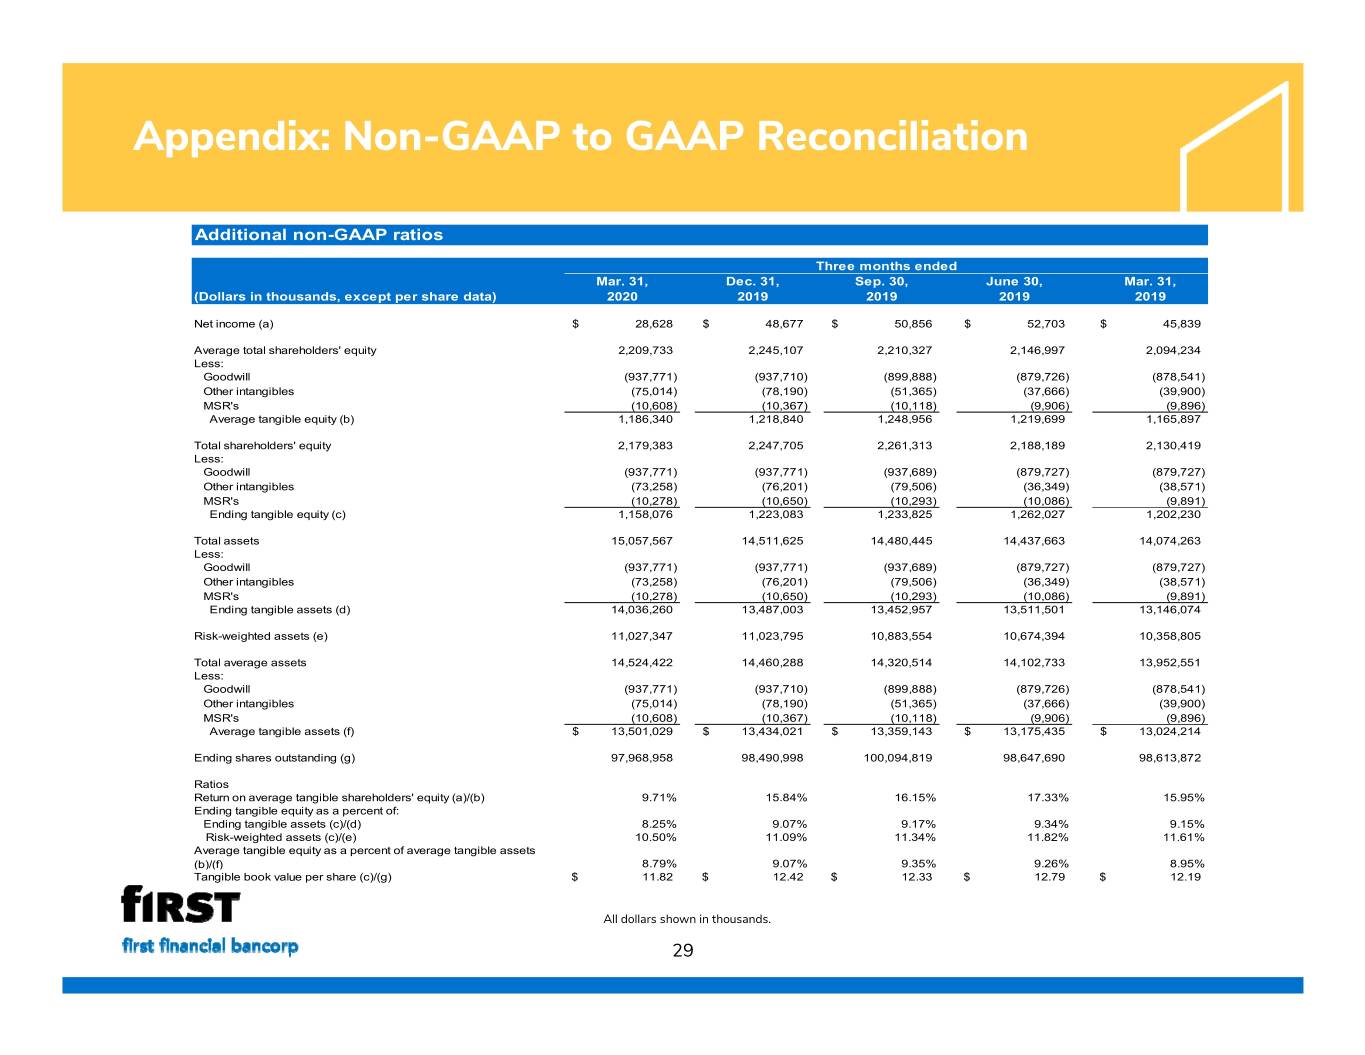
Appendix: Non-GAAP to GAAP Reconciliation Additional non-GAAP ratios Three months ended Mar. 31, Dec. 31, Sep. 30, June 30, Mar. 31, (Dollars in thousands, except per share data) 2020 2019 2019 2019 2019 Net income (a)$ 28,628 $ 48,677 $ 50,856 $ 52,703 $ 45,839 Average total shareholders' equity 2,209,733 2,245,107 2,210,327 2,146,997 2,094,234 Less: Goodwill (937,771) (937,710) (899,888) (879,726) (878,541) Other intangibles (75,014) (78,190) (51,365) (37,666) (39,900) MSR's (10,608) (10,367) (10,118) (9,906) (9,896) Average tangible equity (b) 1,186,340 1,218,840 1,248,956 1,219,699 1,165,897 Total shareholders' equity 2,179,383 2,247,705 2,261,313 2,188,189 2,130,419 Less: Goodwill (937,771) (937,771) (937,689) (879,727) (879,727) Other intangibles (73,258) (76,201) (79,506) (36,349) (38,571) MSR's (10,278) (10,650) (10,293) (10,086) (9,891) Ending tangible equity (c) 1,158,076 1,223,083 1,233,825 1,262,027 1,202,230 Total assets 15,057,567 14,511,625 14,480,445 14,437,663 14,074,263 Less: Goodwill (937,771) (937,771) (937,689) (879,727) (879,727) Other intangibles (73,258) (76,201) (79,506) (36,349) (38,571) MSR's (10,278) (10,650) (10,293) (10,086) (9,891) Ending tangible assets (d) 14,036,260 13,487,003 13,452,957 13,511,501 13,146,074 Total average assets 14,524,422 14,460,288 14,320,514 14,102,733 13,952,551 Less: Risk-weighted assets (e) 11,027,347 11,023,795 10,883,554 10,674,394 10,358,805 Goodwill (937,771) (937,710) (899,888) (879,726) (878,541) Other intangibles (75,014) (78,190) (51,365) (37,666) (39,900) MSR's (10,608) (10,367) (10,118) (9,906) (9,896) Average tangible assets (f)$ 13,501,029 $ 13,434,021 $ 13,359,143 $ 13,175,435 $ 13,024,214 Ending shares outstanding (g) 97,968,958 98,490,998 100,094,819 98,647,690 98,613,872 Ratios Return on average tangible shareholders' equity (a)/(b) 9.71% 15.84% 16.15% 17.33% 15.95% Ending tangible equity as a percent of: Ending tangible assets (c)/(d) 8.25% 9.07% 9.17% 9.34% 9.15% (b)/(f) 8.79% 9.07% 9.35% 9.26% 8.95% Risk-weighted assets (c)/(e) 10.50% 11.09% 11.34% 11.82% 11.61% Tangible book value per share (c)/(g)$ 11.82 $ 12.42 $ 12.33 $ 12.79 $ 12.19 Average tangible equity as a percent of average tangible assets All dollars shown in thousands. 29
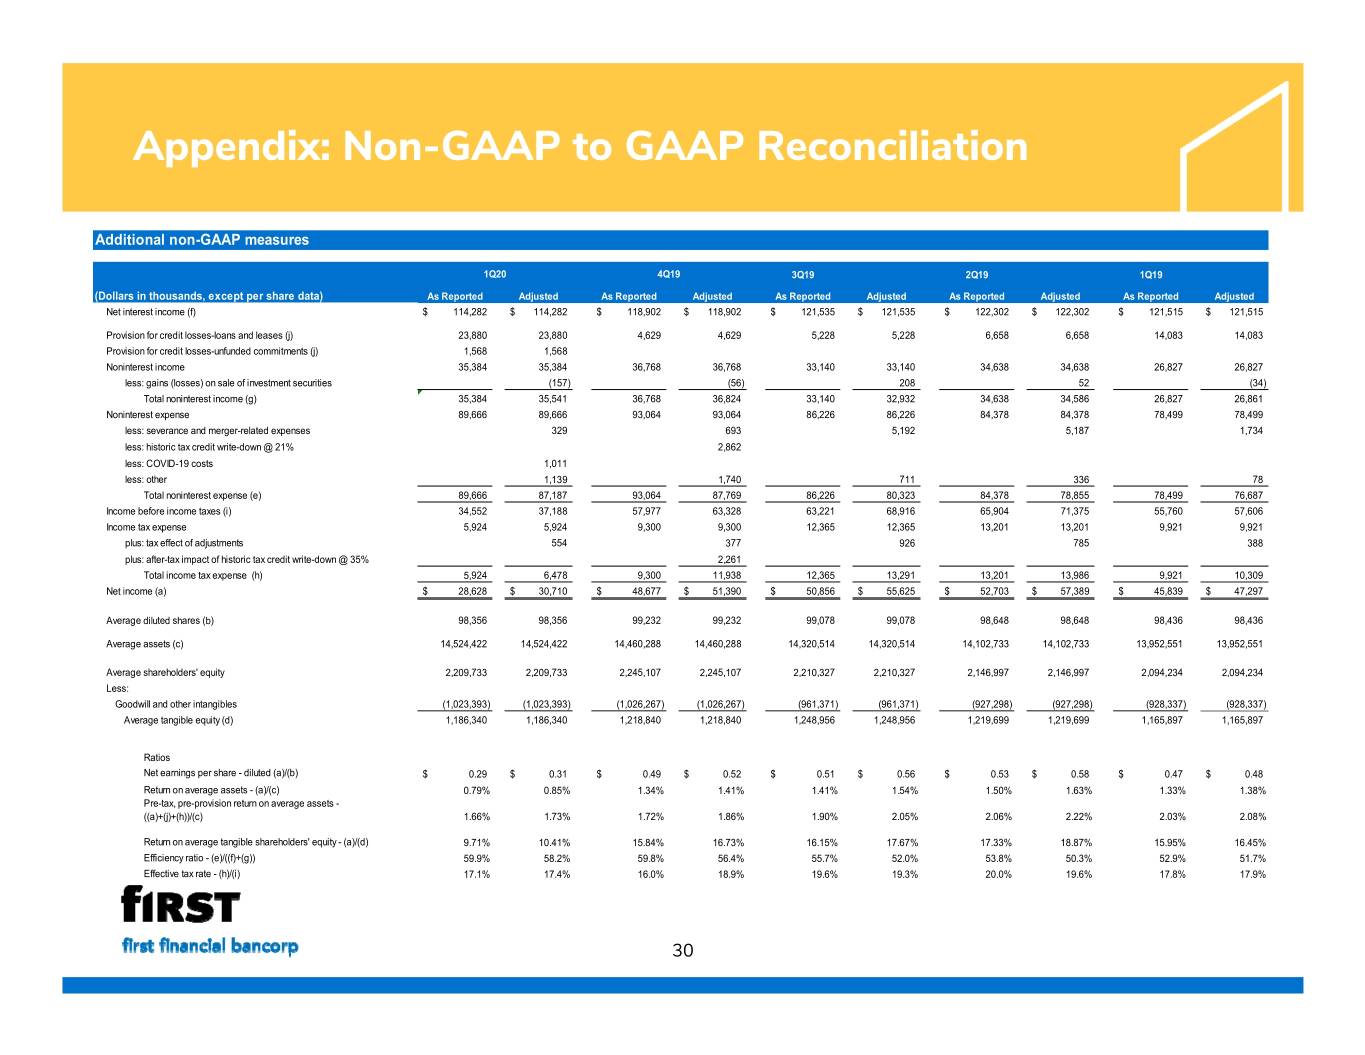
Appendix: Non-GAAP to GAAP Reconciliation Additional non-GAAP measures 1Q20 4Q19 3Q19 2Q19 1Q19 (Dollars in thousands, except per share data) As Reported Adjusted As Reported Adjusted As Reported Adjusted As Reported Adjusted As Reported Adjusted Net interest income (f)$ 114,282 $ 114,282 $ 118,902 $ 118,902 $ 121,535 $ 121,535 $ 122,302 $ 122,302 $ 121,515 $ 121,515 Provision for credit losses-loans and leases (j) 23,880 23,880 4,629 4,629 5,228 5,228 6,658 6,658 14,083 14,083 Provision for credit losses-unfunded commitments (j) 1,568 1,568 Noninterest income 35,384 35,384 36,768 36,768 33,140 33,140 34,638 34,638 26,827 26,827 less: gains (losses) on sale of investment securities (157) (56) 208 52 (34) Total noninterest income (g) 35,384 35,541 36,768 36,824 33,140 32,932 34,638 34,586 26,827 26,861 Noninterest expense 89,666 89,666 93,064 93,064 86,226 86,226 84,378 84,378 78,499 78,499 less: severance and merger-related expenses 329 693 5,192 5,187 1,734 less: historic tax credit write-down @ 21% 2,862 less: COVID-19 costs 1,011 less: other 1,139 1,740 711 336 78 Total noninterest expense (e) 89,666 87,187 93,064 87,769 86,226 80,323 84,378 78,855 78,499 76,687 Income before income taxes (i) 34,552 37,188 57,977 63,328 63,221 68,916 65,904 71,375 55,760 57,606 Income tax expense 5,924 5,924 9,300 9,300 12,365 12,365 13,201 13,201 9,921 9,921 plus: tax effect of adjustments 554 377 926 785 388 plus: after-tax impact of historic tax credit write-down @ 35% 2,261 Total income tax expense (h) 5,924 6,478 9,300 11,938 12,365 13,291 13,201 13,986 9,921 10,309 Net income (a)$ 28,628 $ 30,710 $ 48,677 $ 51,390 $ 50,856 $ 55,625 $ 52,703 $ 57,389 $ 45,839 $ 47,297 Average diluted shares (b) 98,356 98,356 99,232 99,232 99,078 99,078 98,648 98,648 98,436 98,436 Average assets (c) 14,524,422 14,524,422 14,460,288 14,460,288 14,320,514 14,320,514 14,102,733 14,102,733 13,952,551 13,952,551 Average shareholders' equity 2,209,733 2,209,733 2,245,107 2,245,107 2,210,327 2,210,327 2,146,997 2,146,997 2,094,234 2,094,234 Less: Goodwill and other intangibles (1,023,393) (1,023,393) (1,026,267) (1,026,267) (961,371) (961,371) (927,298) (927,298) (928,337) (928,337) Average tangible equity (d) 1,186,340 1,186,340 1,218,840 1,218,840 1,248,956 1,248,956 1,219,699 1,219,699 1,165,897 1,165,897 Ratios Net earnings per share - diluted (a)/(b) $ 0.29 $ 0.31 $ 0.49 $ 0.52 $ 0.51 $ 0.56 $ 0.53 $ 0.58 $ 0.47 $ 0.48 Return on average assets - (a)/(c) 0.79% 0.85% 1.34% 1.41% 1.41% 1.54% 1.50% 1.63% 1.33% 1.38% Pre-tax, pre-provision return on average assets - ((a)+(j)+(h))/(c) 1.66% 1.73% 1.72% 1.86% 1.90% 2.05% 2.06% 2.22% 2.03% 2.08% Return on average tangible shareholders' equity - (a)/(d) 9.71% 10.41% 15.84% 16.73% 16.15% 17.67% 17.33% 18.87% 15.95% 16.45% Efficiency ratio - (e)/((f)+(g)) 59.9% 58.2% 59.8% 56.4% 55.7% 52.0% 53.8% 50.3% 52.9% 51.7% Effective tax rate - (h)/(i) 17.1% 17.4% 16.0% 18.9% 19.6% 19.3% 20.0% 19.6% 17.8% 17.9% 30
Update ‐New colors 31