
IBCP 8-K
Independent Bank Corp /Mi/ (IBCP)
8-K
2021-01-28
For: 2021-01-28
View Original
Added on
July 07, 2026
SECURITIES AND EXCHANGE COMMISSION
Washington, DC 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report: January 28, 2021
(Exact name of registrant as specified in its charter)
|
|
|
|
|
(State or other jurisdiction of incorporation)
|
(Commission File Number)
|
(IRS Employer Identification No.)
|
|
|
|
|
|
(Address of principal executive office)
|
(Zip Code)
|
Registrant's telephone number,
including area code:
(616 ) 527-5820
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following
provisions (see General Instruction A.2. below):
|
|
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425)
|
|
|
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12)
|
|
|
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b))
|
|
|
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c))
|
Securities registered pursuant to Section 12(b) of the Act:
|
Title of each class
|
Trading symbol(s)
|
Name of each exchange on which registered
|
|
|
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of
the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised
financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
| Item 2.02. |
Results of Operations and Financial Condition
|
On January 28, 2021, Independent Bank Corporation issued a press release announcing its financial results for the quarter ended December 31, 2020. A copy of the press
release is attached as Exhibit 99.1. Attached Exhibit 99.2 contains supplemental data to that press release and attached Exhibit 99.3 contains a slide presentation for our earnings conference call.
The information in this Form 8-K and the attached Exhibits shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, nor
shall they be deemed incorporated by reference in any filing under the Securities Act of 1933, as amended, except as shall be expressly set forth by specific reference in such filing.
| Item 9.01. |
Financial Statements and Exhibits
|
Exhibits.
|
Press release dated January 28, 2021.
|
|
|
Supplemental data to the Registrant's press release dated January 28, 2021.
|
|
|
Earnings conference call presentation.
|
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned thereunto
duly authorized.
|
INDEPENDENT BANK CORPORATION
|
||||||
|
(Registrant)
|
||||||
|
Date
|
January 28, 2021
|
By
|
s/Gavin A. Mohr
|
||||
|
Gavin A. Mohr, Principal Financial Officer
|
|||||||
2
Exhibit 99.1
News Release
Independent Bank Corporation
4200 East Beltline
Grand Rapids, MI 49525
616.527.5820
|
For Release:
|
Immediately
|
|
Contact:
|
William B. Kessel, President and CEO, 616.447.3933
|
|
Gavin A. Mohr, Chief Financial Officer, 616.447.3929
|
INDEPENDENT BANK CORPORATION REPORTS
2020 FOURTH QUARTER AND FULL YEAR RESULTS
GRAND RAPIDS, Mich., Jan. 28, 2021 - Independent Bank Corporation (NASDAQ:
IBCP) reported fourth quarter 2020 net income of $17.0 million, or $0.77 per diluted share, versus net income of $13.9 million, or $0.61 per diluted share, in the
prior-year period. For the year ended December 31, 2020, the Company reported net income of $56.2 million, or $2.53 per diluted share, compared to net income of $46.4 million, or $2.00 per diluted share, in 2019. The increase in 2020 fourth quarter
and full-year 2020 earnings as compared to 2019 primarily reflects increases in non-interest income that were partially offset by a decrease in interest income and an increase in non-interest expense and income tax expense.
Fourth quarter 2020 highlights include:
| • |
Increases in net income and diluted earnings per share of 22.4% and 26.2%, respectively, compared to 2019;
|
| • |
Return on average assets and return on average equity of 1.61% and 17.82%, respectively, compared to 1.56% and 15.92%, respectively, in 2019;
|
| • |
Net gains on mortgage loans of $15.9 million (up 148.5% over 2019) and total mortgage loan origination volume of $502.5 million;
|
| • |
Deposit net growth of $39.6 million (or 1.1%);
|
| • |
Continued strong asset quality metrics as evidenced by net loan recoveries during the quarter, a low level of non-performing loans and non-performing assets;
|
| • |
COVID related forbearances declined to 0.83% of total loans; and
|
| • |
The payment of a 20 cent per share dividend on common stock on November 16, 2020.
|
Full year 2020 highlights include:
| • |
Increases in net income and diluted earnings per share of 20.9% and 26.3%, respectively, compared to 2019;
|
| • |
Return on average assets and return on average equity of 1.43% and 15.68 %, respectively, compared to 1.35% and 13.63%, respectively, in 2019;
|
| • |
Net gains on mortgage loans of $62.6 million (up 213.1% over 2019) and total mortgage loan origination volume of $1.8 billion;
|
| • |
Deposit net growth of $600.6 million (or 19.8 %); and
|
| • |
Tangible common equity per share increased by 16% to $16.33 from $14.08.
|
1
Significant items impacting comparable quarterly and year to date 2020 and 2019 results include the following:
| • |
As a result of hedge de-designation the company realized an increase in interest expense of $1.6 million ($0.06 per diluted share, after tax) due to accelerated amortization of
deferred losses on certain derivative instruments. As cash flow hedges these losses were previously recorded in accumulated other comprehensive income (loss).
|
| • |
Changes in the fair value due to price of capitalized mortgage loan servicing rights (the “MSR Changes”) of a negative $0.9 million ($0.03 per diluted share, after taxes) and a
negative $10.8 million ($0.39 per diluted share, after taxes) for the three-months and full-year ended December 31, 2020, respectively, as compared to a positive $0.6 million ($0.02 per diluted share, after taxes) and a negative $6.4 million
($0.22 per diluted share, after taxes) for the three-months and full year ended December 31, 2019, respectively.
|
| • |
Approximately $1.54 million ($0.06 per diluted share, after taxes) and $3.0 million ($0.11 per diluted share, after taxes) of expenses related to the ongoing data processing
conversion and the completed bank branch closures (as described further below under “Operating Results”) for the three-months and full-year ended December 31, 2020, respectively.
|
William B. (“Brad”) Kessel, the President and Chief Executive Officer of Independent Bank
Corporation, commented: “We are pleased to report very strong financial performance in the fourth quarter and for the full-year 2020 as we continue to navigate the many challenges brought on by the COVID-19 pandemic. Our associates continued their
amazing efforts during this quarter! We closed over one-half billion dollars of mortgage loans, helping our customers buy new homes or refinance existing mortgage loans. We assisted our customers in completing and submitting PPP forgiveness
applications to the SBA, with over 38% of outstanding balances submitted. We continued to effectively operate our Business Continuity Plan to safely serve our customers and protect our employees. Finally, we maintained solid asset quality metrics
during the fourth quarter of 2020. COVID-19 related loan forbearance balances decreased by 62.7% during the fourth quarter of 2020. As we look ahead to 2021 and beyond, we are mindful of the ongoing challenges from the COVID-19 pandemic,
however, we are confident of our continued ability to effectively respond to these challenges and remain optimistic about our future.”
COVID-19 Pandemic Update
The Company continues to respond to the challenges arising from the COVID-19
pandemic. Our response was initially formulated during the month of February 2020 as we prepared our infrastructure to allow the majority of our associates to work remotely. In March 2020 we activated our Business Continuity Plan to protect our
customers, employees and business. We will continue to take the necessary steps to serve our communities while doing our part to minimize the spread of COVID-19. The following is a brief description of our current initiatives:
| • |
Customer Safety and Service Levels – From mid-March 2020 to mid-June 2020 we limited our branch lobbies to appointment only and kept drive-through windows open. In mid-June 2020 our
bank branch lobbies fully reopened. On November 13, 2020 we again limited our branch lobbies to appointment only in response to increasing COVID-19 cases in the State of Michigan. Branch lobbies were reopened January 4, 2021. With the
ability to use drive through service, ATMs or our electronic banking solutions there was minimal disruption to our customers.
|
| • |
Employee Safety – For employees that are in our bank branches servicing our customers, we have expanded sick and vacation time. All non-branch employees either have the option or
are required to work remotely. We currently have approximately 38% of our total staff working remotely every day. We have installed “customer friendly” shields throughout our delivery network and have implemented a variety of other
protective processes to promote the safety of our employees and put both customers and staff at ease.
|
| • |
Loan Forbearances – We have forbearance programs in place to proactively work with our customers who have experienced financial difficulty due to the COVID-19 pandemic. Totals for
these programs by loan type are presented in the table below under the caption “Asset Quality”. The level of these loans is down significantly after peaking in mid-June 2020, as many customers’ economic situations have improved, allowing them
to pay their loans current or return to their original payment terms.
|
| • |
U.S. Small Business Administration (“SBA”) Paycheck Protection Program (“PPP”) – We built an effective process to manage the high volume of applications that we received. Customer
demand for this program was extraordinary. As of December 31, 2020, we had 1,483 PPP loans outstanding with a total balance of $169.8 million. The average balance of PPP loans in the fourth quarter of 2020 was $220.2 million with an average
yield of 6.91% (including the accretion of approximately $3.3 million of net of fees). At December 31, 2020, there was $3.2 million remaining unaccreted net fees related to PPP loans. These net fees are expected to be accreted into interest
income over the next 6 months, and the pace of such accretion will depend on payment activity (including loan forgiveness) within the PPP loan portfolio. As of December 31, 2020, 808 forgiveness applications (totaling $123.0 million) have
been submitted to the SBA with 751 (totaling $92.0 million) applications approved. We are currently taking applications for the second round of the Paycheck Protection Program.
|
2
Operating Results
The Company’s net interest income totaled $31.0 million during the fourth quarter of 2020, an increase of $0.3 million, or 0.9% from the year-ago period, and down $1.0
million, or 3.0%, from the third quarter of 2020. The Company realized an increase in interest expense of $1.6 million due to accelerated amortization of deferred loss on certain derivative instruments that have been de-designated. The Company’s tax
equivalent net interest income as a percent of average interest-earning assets (the “net interest margin”) was 3.12% during the fourth quarter of 2020, compared to 3.70% in the year-ago period, and 3.31% in the third quarter of 2020. The
year-over-year quarterly increase in net interest income is due to an increase in average interest-earning assets that was partially offset by a decline in the net interest margin. Average interest-earning assets were $3.98 billion in the fourth
quarter of 2020, compared to $3.32 billion in the year ago quarter and $3.89 billion in the third quarter of 2020.
For the full year 2020, net interest income totaled $123.6 million, an increase of $1.0 million, or 0.8% from 2019. The Company’s net interest margin for the full year
of 2020 was 3.34% compared to 3.80% in 2019. The increase in net interest income for the full year of 2020 compared to 2019 is also due to an increase in average interest-earning assets that was largely offset by a decline in the net interest
margin.
Due to the economic impact of COVID-19, the Federal Reserve has taken a variety of actions to stimulate the economy, including significantly lowering short-term interest
rates. These actions have placed continued pressure on the Company’s net interest margin.
Non-interest income totaled $22.4 million and $80.7 million, respectively, for the fourth quarter and full year 2020, compared to $15.6 million and $47.7 million in the
respective comparable year ago periods. These changes were primarily due to variances in mortgage banking related revenues (net gains on mortgage loans and mortgage loan servicing, net).
Net gains on mortgage loans in the fourth quarters of 2020 and 2019, were approximately $15.9 million and $6.4 million, respectively. For full year 2020, net gains on
mortgage loans totaled $62.6 million compared to $20.0 million in 2019. The increase in net gains on mortgage loans in 2020 was primarily due to a significant increase in mortgage loan sales volume (principally reflecting the rise in mortgage loan
refinance levels), as well as improved profit margins on mortgage loan sales and fair value adjustments on the mortgage loan pipeline.
Mortgage loan servicing, net, generated a loss of $0.4 million and a gain of $1.3 million in the fourth quarters of 2020 and 2019, respectively. For full year 2020 and
2019, mortgage loan servicing, net, generated a loss of $9.4 million and $3.3 million, respectively. The significant variances in mortgage loan servicing, net are primarily due to changes in the fair value of capitalized mortgage loan servicing
rights associated with changes in mortgage loan interest rates and expected future prepayment levels. Mortgage loan servicing, net activity is summarized in the following table:
|
Three Months Ended
|
Twelve Months Ended
|
|||||||||||||||
|
12/31/2020
|
12/31/2019
|
12/31/2020
|
12/31/2019
|
|||||||||||||
|
Mortgage loan servicing, net:
|
(Dollars in thousands)
|
|||||||||||||||
|
Revenue, net
|
$
|
1,812
|
$
|
1,622
|
$
|
6,874
|
$
|
6,196
|
||||||||
|
Fair value change due to price
|
(892
|
)
|
628
|
(10,833
|
)
|
(6,408
|
)
|
|||||||||
|
Fair value change due to pay-downs
|
(1,304
|
)
|
(902
|
)
|
(5,391
|
)
|
(3,124
|
)
|
||||||||
|
Total
|
$
|
(384
|
)
|
$
|
1,348
|
$
|
(9,350
|
)
|
$
|
(3,336
|
)
|
|||||
Non-interest expenses totaled $32.7 million in the fourth quarter of 2020, compared to $29.3 million in the year-ago period. For full year 2020, non-interest expenses
totaled $122.4 million versus $111.7 million in 2019. These year-over-year increases in non-interest expense are primarily due to increases in compensation and employee benefits, FDIC deposit insurance and data processing conversion related
expenses. Full year 2020 performance based compensation expense increased $7.7 million primarily as a result of actual performance relative to established management incentive plan targets. The fourth quarter and full year 2020 includes $1.5 million
and $2.6 million, respectively, of expenses related to the Company’s core data processing conversion that is in process (this conversion is expected to be completed in April 2021). The full-year 2020 non-interest expense also includes $0.4 million of
expenses (primarily write-downs of fixed assets and leases) related to the closures of eight bank branch offices that occurred in June and July 2020.
The Company recorded an income tax expense of $4.1 million and $13.3 million in the fourth quarter and full-year 2020, respectively. This compares to an income tax
expense of $3.3 million and $11.3 million in the fourth quarter and full-year 2019, respectively. The changes in income tax expense primarily reflect changes in pre-tax earnings in 2020 relative to 2019.
3
Asset Quality
A breakdown of loan forbearance totals by loan type is as follows:
|
12/31/20
|
9/30/20
|
% change vs. prior quarter
|
||||||||||||||||||||||||||||||
|
Loan Type
|
#
|
|
$(000’s)
|
|
% of portfolio
|
#
|
$ (000's)
|
% of portfolio
|
#
|
|
$ |
|||||||||||||||||||||
|
Loans serviced for others
|
288
|
$
|
42,897
|
1.4
|
%
|
416
|
$
|
66,279
|
2.3
|
%
|
(30.8
|
)%
|
(35.3
|
)%
|
||||||||||||||||||
|
Commercial
|
2
|
$
|
163
|
0.0
|
%
|
17
|
$
|
25,105
|
1.9
|
%
|
(88.2
|
%)
|
(99.4
|
%)
|
||||||||||||||||||
|
Mortgage
|
134
|
19,830
|
2.0
|
%
|
197
|
32,091
|
3.1
|
%
|
(32.0
|
)%
|
(38.2
|
)%
|
||||||||||||||||||||
|
Installment
|
48
|
1,412
|
0.3
|
%
|
97
|
2,631
|
0.5
|
%
|
(50.5
|
)%
|
(46.3
|
)%
|
||||||||||||||||||||
|
Total
|
184
|
$
|
21,405
|
0.8
|
%
|
311
|
$
|
59,827
|
2.1
|
%
|
(40.8
|
)%
|
(64.2
|
)%
|
||||||||||||||||||
Note: The % of portfolio is based on the dollar amount of forbearances to the total for the loan portfolio segment.
A breakdown of non-performing loans(1) by loan type is as follows:
|
Loan Type
|
12/31/2020
|
12/31/2019
|
12/31/2018
|
|||||||||
|
(Dollars in thousands)
|
||||||||||||
|
Commercial
|
$
|
1,440
|
$
|
1,377
|
$
|
2,220
|
||||||
|
Mortgage
|
6,353
|
7,996
|
6,033
|
|||||||||
|
Installment
|
519
|
805
|
781
|
|||||||||
|
Subtotal
|
8,312
|
10,178
|
9,034
|
|||||||||
|
Less – government guaranteed loans
|
439
|
646
|
460
|
|||||||||
|
Total non-performing loans
|
$
|
7,873
|
$
|
9,532
|
$
|
8,574
|
||||||
|
Ratio of non-performing loans to total portfolio loans
|
0.29
|
%
|
0.35
|
%
|
0.33
|
%
|
||||||
|
Ratio of non-performing assets to total assets
|
0.21
|
%
|
0.32
|
%
|
0.29
|
%
|
||||||
|
Ratio of the allowance for loan losses to non-performing loans
|
450.01
|
%
|
274.32
|
%
|
290.27
|
%
|
||||||
| (1) |
Excludes loans that are classified as “troubled debt restructured” that are still performing.
|
Non-performing loans have decreased $1.7 million from December 31, 2019, due primarily to a decrease in non-performing mortgage loans.
The provision for loan losses was a credit of $0.4 million and $0.2 million in the fourth quarters of 2020 and 2019, respectively. The provision for loan losses was an
expense of $12.5 million and 0.8 million for the full-year 2020 and 2019, respectively. The level of the provision for loan losses in each period reflects the Company’s overall assessment of the allowance for loan losses, taking into consideration
factors such as loan growth, loan mix, levels of non-performing and classified loans, loan forbearances and loan net charge-offs. In addition, the higher 2020 full-year provision for loan losses includes an $11.2 million (or 128.3%) increase in the
qualitative/subjective portion of the allowance for loan losses. This increase principally reflects the unique challenges and economic uncertainty resulting from the COVID-19 pandemic and the potential impact on the loan portfolio that is not
otherwise captured elsewhere within the allowance for loan losses. The Company recorded loan net recoveries of $0.1 million and loan net charge offs of $3.2 million in the fourth quarter and full-year 2020, respectively. This compares to loan net
recoveries of $0.2 million and $0.4 million, in the fourth quarter and full-year 2019, respectively. At December 31, 2020, the allowance for loan losses totaled $35.4 million, or 1.30% of total portfolio loans, compared to $26.1 million, or 0.96% of
total portfolio loans, at December 31, 2019. Excluding PPP loans and the remaining Traverse City State Bank acquired loan balances, the allowance for loan losses was equal to 1.43% of portfolio loans at December 31, 2020.
The provision for the loan loss was calculated utilizing the incurred model for the full year 2020. The adoption of CECL was delayed following the updated guidance
included in the second COVID-19 relief bill passed in December 2020. The Company is expecting to adopt CECL on January 1, 2021 as allowed under the CARES Act extension. We expect to recognize an cumulative effect adjustment through retained earnings
increasing the allowance for loan losses. We are estimating this increase to the allowance for loan losses to be in the range of $10.5 million to $12.5 million.
4
Balance Sheet, Liquidity and Capital
Total assets were $4.2 billion at December 31, 2020, an increase of $639.3 million from December 31, 2019. Loans, excluding loans held for sale, were $2.73 billion at
December 31, 2020, compared to $2.73 billion at December 31, 2019. Deposits totaled $3.64 billion at December 31, 2020, an increase of $600.6 million from December 31, 2019. This increase is primarily due to growth in non-interest bearing, savings
and interest-bearing checking and reciprocal deposit account balances.
Cash and cash equivalents totaled $118.7 million at December 31, 2020, versus $65.3 million at December 31, 2019. Securities available for sale totaled $1.1 billion at
December 31, 2020, versus $518.4 million at December 31, 2019. The significant increase in securities available for sale is due to the deployment of funds generated from the growth in deposits.
In May 2020, the Company issued $40.0 million of subordinated notes with a ten year maturity, a five year call option and an initial coupon interest rate (fixed for the
first five years) of 5.95%.
Total shareholders’ equity was $389.5 million at December 31, 2020, or 9.27% of total assets. Tangible common equity totaled $356.9 million at December 31, 2020, or
$16.33 per share. The Company’s wholly owned subsidiary, Independent Bank, remains significantly above “well capitalized” for regulatory purposes with the following ratios:
|
Regulatory Capital Ratios
|
12/31/2020
|
12/31/2019
|
Well
Capitalized Minimum
|
|||||||||
|
Tier 1 capital to average total assets
|
8.81
|
%
|
9.49
|
%
|
5.00
|
%
|
||||||
|
Tier 1 common equity to risk-weighted assets
|
12.81
|
%
|
11.96
|
%
|
6.50
|
%
|
||||||
|
Tier 1 capital to risk-weighted assets
|
12.81
|
%
|
11.96
|
%
|
8.00
|
%
|
||||||
|
Total capital to risk-weighted assets
|
14.06
|
%
|
12.96
|
%
|
10.00
|
%
|
||||||
Share Repurchase Plan
On December 18, 2020, the Board of Directors of the Company authorized the 2021 share repurchase plan. Under the terms of the 2021 share repurchase plan, the Company is
authorized to purchase up to 1,100,000 shares, or approximately 5% of its outstanding common stock. The repurchase plan is authorized to last through December 31, 2021.
Due primarily to the economic uncertainty brought on by the COVID-19 pandemic, the Company suspended its share repurchase plan in March 2020. However, as a result of the
Company’s strong financial performance and improved economic conditions, the Company reactivated the share repurchased plan in the fourth quarter of 2020 and acquired 30,027 shares at a weighted average price of $14.90. For the full-year 2020 the
Company repurchased 708,956 shares at a weighted average price of $20.07.
Earnings Conference Call
Brad Kessel, President and CEO and Gavin A. Mohr, CFO will review the quarterly results in a conference call for investors and analysts beginning at
11:00 am ET on Thursday, January 28, 2021.
To participate in the live conference call, please dial 1-866-200-8394. Also the
conference call will be accessible through an audio webcast with user-controlled slides via the following site/URL: https://services.choruscall.com/links/ibcp210128.html.
A playback of the call can be accessed by dialing 1-877-344-7529 (Conference ID # 10150378). The replay will be available through February 4, 2021.
About Independent Bank Corporation
Independent Bank Corporation (NASDAQ: IBCP) is a Michigan-based bank holding company with total assets of approximately $4.2 billion. Founded as First National Bank of
Ionia in 1864, Independent Bank Corporation operates a branch network across Michigan's Lower Peninsula through one state-chartered bank subsidiary. This subsidiary (Independent Bank) provides a full range of financial services, including commercial
banking, mortgage lending, investments and insurance. Independent Bank Corporation is committed to providing exceptional personal service and value to its customers, stockholders and the communities it serves.
For more information, please visit our Web site at: IndependentBank.com.
5
Forward-Looking Statements
This press release contains forward-looking statements about Independent Bank Corporation. Statements that are not historical or current facts,
including statements about beliefs and expectations, are forward-looking statements and are based on the information available to, and assumptions and estimates made by, management as of the date hereof. These forward-looking statements cover, among
other things, anticipated future revenue and expenses and the future plans and prospects of Independent Bank Corporation. Forward-looking statements involve inherent risks and uncertainties, and important factors could cause actual results to differ
materially from those anticipated. The COVID-19 pandemic is adversely affecting Independent Bank Corporation, its customers, counterparties, employees, and third-party service providers, and the ultimate extent of the impacts on its business,
financial position, results of operations, liquidity, and prospects is uncertain. Continued deterioration in general business and economic conditions or turbulence in domestic or global financial markets could adversely affect Independent Bank
Corporation’s revenues and the values of its assets and liabilities, reduce the availability of funding from certain financial institutions, lead to a tightening of credit, and increase stock price volatility. In addition, changes to statutes,
regulations, or regulatory policies or practices could affect Independent Bank Corporation in substantial and unpredictable ways. Independent Bank Corporation’s results could also be adversely affected by changes in interest rates; further increases
in unemployment rates; deterioration in the credit quality of its loan portfolios or in the value of the collateral securing those loans; deterioration in the value of its investment securities; legal and regulatory developments; litigation;
increased competition from both banks and non-banks; changes in the level of tariffs and other trade policies of the United States and its global trading partners; changes in customer behavior and preferences; breaches in data security; failures to
safeguard personal information; effects of mergers and acquisitions and related integration; effects of critical accounting policies and judgments; and management’s ability to effectively manage credit risk, market risk, operational risk, compliance
risk, strategic risk, interest rate risk, liquidity risk and reputation risk.
Certain risks and important factors that could affect Independent Bank Corporation's future results are identified in its Annual
Report on Form 10-K for the year ended December 31, 2019 and other reports filed with the SEC, including among other things under the heading “Risk Factors” in such Annual Report on Form 10-K. Any forward-looking statement speaks only as of the date
on which it is made, and Independent Bank Corporation undertakes no obligation to update any forward-looking statement, whether to reflect events or circumstances, after the date on which the statement is made, to reflect new information or the
occurrence of unanticipated events, or otherwise.
6
INDEPENDENT BANK CORPORATION AND SUBSIDIARIES
Consolidated Statements of Financial Condition
|
December 31,
|
||||||||
|
2020
|
2019
|
|||||||
|
(unaudited)
|
||||||||
|
(In thousands, except share
|
||||||||
|
amounts)
|
||||||||
|
Assets
|
||||||||
|
Cash and due from banks
|
$
|
56,006
|
$
|
53,295
|
||||
|
Interest bearing deposits
|
62,699
|
12,009
|
||||||
|
Cash and Cash Equivalents
|
118,705
|
65,304
|
||||||
|
Interest bearing deposits - time
|
-
|
350
|
||||||
|
Securities available for sale
|
1,072,159
|
518,400
|
||||||
|
Federal Home Loan Bank and Federal Reserve Bank stock, at cost
|
18,427
|
18,359
|
||||||
|
Loans held for sale, carried at fair value
|
92,434
|
69,800
|
||||||
|
Loans
|
||||||||
|
Commercial
|
1,242,415
|
1,166,695
|
||||||
|
Mortgage
|
1,015,926
|
1,098,911
|
||||||
|
Installment
|
475,337
|
459,417
|
||||||
|
Total Loans
|
2,733,678
|
2,725,023
|
||||||
|
Allowance for loan losses
|
(35,429
|
)
|
(26,148
|
)
|
||||
|
Net Loans
|
2,698,249
|
2,698,875
|
||||||
|
Other real estate and repossessed assets
|
766
|
1,865
|
||||||
|
Property and equipment, net
|
36,127
|
38,411
|
||||||
|
Bank-owned life insurance
|
55,180
|
55,710
|
||||||
|
Capitalized mortgage loan servicing rights
|
16,904
|
19,171
|
||||||
|
Other intangibles
|
4,306
|
5,326
|
||||||
|
Goodwill
|
28,300
|
28,300
|
||||||
|
Accrued income and other assets
|
62,456
|
44,823
|
||||||
|
Total Assets
|
$
|
4,204,013
|
$
|
3,564,694
|
||||
|
Liabilities and Shareholders' Equity
|
||||||||
|
Deposits
|
||||||||
|
Non-interest bearing
|
$
|
1,153,473
|
$
|
852,076
|
||||
|
Savings and interest-bearing checking
|
1,526,465
|
1,186,745
|
||||||
|
Reciprocal
|
556,185
|
431,027
|
||||||
|
Time
|
287,402
|
376,877
|
||||||
|
Brokered time
|
113,830
|
190,002
|
||||||
|
Total Deposits
|
3,637,355
|
3,036,727
|
||||||
|
Other borrowings
|
30,012
|
88,646
|
||||||
|
Subordinated debt
|
39,281
|
-
|
||||||
|
Subordinated debentures
|
39,524
|
39,456
|
||||||
|
Accrued expenses and other liabilities
|
68,319
|
49,696
|
||||||
|
Total Liabilities
|
3,814,491
|
3,214,525
|
||||||
|
Shareholders’ Equity
|
||||||||
|
Preferred stock, no par value, 200,000 shares authorized; none issued or outstanding
|
-
|
-
|
||||||
|
Common stock, no par value, 500,000,000 shares authorized; issued and outstanding: 21,853,800 shares at December 31, 2020
and 22,481,643 shares at December 31, 2019
|
339,353
|
352,344
|
||||||
|
Retained earnings
|
40,145
|
1,611
|
||||||
|
Accumulated other comprehensive income (loss)
|
10,024
|
(3,786
|
)
|
|||||
|
Total Shareholders’ Equity
|
389,522
|
350,169
|
||||||
|
Total Liabilities and Shareholders’ Equity
|
$
|
4,204,013
|
$
|
3,564,694
|
||||
7
INDEPENDENT BANK CORPORATION AND SUBSIDIARIES
Consolidated Statements of Operations
|
Three Months Ended
|
Twelve Months Ended
|
|||||||||||||||||||
|
December 31,
|
September 30,
|
December 31,
|
December 31,
|
|||||||||||||||||
|
2020
|
2020
|
2019
|
2020
|
2019
|
||||||||||||||||
|
(unaudited)
|
||||||||||||||||||||
|
Interest Income
|
(In thousands, except per share amounts)
|
|||||||||||||||||||
|
Interest and fees on loans
|
$
|
31,139
|
$
|
30,393
|
$
|
33,140
|
$
|
123,159
|
$
|
133,883
|
||||||||||
|
Interest on securities available for sale
|
||||||||||||||||||||
|
Taxable
|
3,299
|
3,450
|
3,031
|
12,655
|
11,842
|
|||||||||||||||
|
Tax-exempt
|
789
|
954
|
325
|
2,926
|
1,342
|
|||||||||||||||
|
Other investments
|
235
|
237
|
412
|
1,089
|
1,861
|
|||||||||||||||
|
Total Interest Income
|
35,462
|
35,034
|
36,908
|
139,829
|
148,928
|
|||||||||||||||
|
Interest Expense
|
||||||||||||||||||||
|
Deposits
|
3,516
|
2,062
|
5,487
|
12,666
|
23,425
|
|||||||||||||||
|
Other borrowings and subordinated debt and debentures
|
953
|
1,006
|
711
|
3,551
|
2,922
|
|||||||||||||||
|
Total Interest Expense
|
4,469
|
3,068
|
6,198
|
16,217
|
26,347
|
|||||||||||||||
|
Net Interest Income
|
30,993
|
31,966
|
30,710
|
123,612
|
122,581
|
|||||||||||||||
|
Provision for loan losses
|
(421
|
)
|
975
|
(221
|
)
|
12,463
|
824
|
|||||||||||||
|
Net Interest Income After Provision for Loan Losses
|
31,414
|
30,991
|
30,931
|
111,149
|
121,757
|
|||||||||||||||
|
Non-interest Income
|
||||||||||||||||||||
|
Service charges on deposit accounts
|
2,218
|
2,085
|
2,885
|
8,517
|
11,208
|
|||||||||||||||
|
Interchange income
|
2,819
|
3,428
|
2,553
|
11,230
|
10,297
|
|||||||||||||||
|
Net gains on assets
|
||||||||||||||||||||
|
Mortgage loans
|
15,873
|
20,205
|
6,388
|
62,560
|
19,978
|
|||||||||||||||
|
Securities available for sale
|
14
|
-
|
3
|
267
|
307
|
|||||||||||||||
|
Mortgage loan servicing, net
|
(384
|
)
|
(644
|
)
|
1,348
|
(9,350
|
)
|
(3,336
|
)
|
|||||||||||
|
Other
|
1,823
|
1,937
|
2,420
|
7,521
|
9,282
|
|||||||||||||||
|
Total Non-interest Income
|
22,363
|
27,011
|
15,597
|
80,745
|
47,736
|
|||||||||||||||
|
Non-interest Expense
|
||||||||||||||||||||
|
Compensation and employee benefits
|
20,039
|
21,954
|
18,546
|
74,781
|
67,501
|
|||||||||||||||
|
Occupancy, net
|
2,120
|
2,199
|
2,216
|
8,938
|
9,013
|
|||||||||||||||
|
Data processing
|
2,374
|
2,215
|
2,308
|
8,534
|
8,905
|
|||||||||||||||
|
Furniture, fixtures and equipment
|
964
|
999
|
1,055
|
4,089
|
4,113
|
|||||||||||||||
|
Interchange expense
|
926
|
831
|
883
|
3,342
|
3,215
|
|||||||||||||||
|
Communications
|
785
|
806
|
728
|
3,194
|
2,947
|
|||||||||||||||
|
Loan and collection
|
708
|
768
|
709
|
3,037
|
2,685
|
|||||||||||||||
|
Conversion related expenses
|
1,541
|
643
|
-
|
2,586
|
-
|
|||||||||||||||
|
Advertising
|
594
|
589
|
515
|
2,230
|
2,450
|
|||||||||||||||
|
Legal and professional
|
600
|
566
|
533
|
2,027
|
1,814
|
|||||||||||||||
|
FDIC deposit insurance
|
385
|
411
|
(38
|
)
|
1,596
|
685
|
||||||||||||||
|
Branch closure costs
|
-
|
-
|
417
|
-
|
||||||||||||||||
|
Correspondent bank service fees
|
101
|
101
|
111
|
395
|
411
|
|||||||||||||||
|
Net (gains) losses on other real estate and repossessed assets
|
(82
|
)
|
46
|
(63
|
)
|
64
|
(90
|
)
|
||||||||||||
|
Other
|
1,652
|
1,513
|
1,800
|
7,183
|
8,084
|
|||||||||||||||
|
Total Non-interest Expense
|
32,707
|
33,641
|
29,303
|
122,413
|
111,733
|
|||||||||||||||
|
Income Before Income Tax
|
21,070
|
24,361
|
17,225
|
69,481
|
57,760
|
|||||||||||||||
|
Income tax expense
|
4,084
|
4,777
|
3,346
|
13,329
|
11,325
|
|||||||||||||||
|
Net Income
|
$
|
16,986
|
$
|
19,584
|
$
|
13,879
|
$
|
56,152
|
$
|
46,435
|
||||||||||
|
Net Income Per Common Share
|
||||||||||||||||||||
|
Basic
|
$
|
0.78
|
$
|
0.90
|
$
|
0.62
|
$
|
2.56
|
$
|
2.03
|
||||||||||
|
Diluted
|
$
|
0.77
|
$
|
0.89
|
$
|
0.61
|
$
|
2.53
|
$
|
2.00
|
||||||||||
8
INDEPENDENT BANK CORPORATION AND SUBSIDIARIES
Selected Financial Data
|
December 31,
2020
|
September 30,
2020
|
June 30,
2020
|
March 31,
2020
|
December 31,
2019
|
||||||||||||||||
|
(unaudited)
|
||||||||||||||||||||
|
(Dollars in thousands except per share data)
|
||||||||||||||||||||
|
Three Months Ended
|
||||||||||||||||||||
|
Net interest income
|
$
|
30,993
|
$
|
31,966
|
$
|
30,462
|
$
|
30,191
|
$
|
30,710
|
||||||||||
|
Provision for loan losses
|
(421
|
)
|
975
|
5,188
|
6,721
|
(221
|
)
|
|||||||||||||
|
Non-interest income
|
22,363
|
27,011
|
20,367
|
11,004
|
15,597
|
|||||||||||||||
|
Non-interest expense
|
32,707
|
33,641
|
27,346
|
28,719
|
29,303
|
|||||||||||||||
|
Income before income tax
|
21,070
|
24,361
|
18,295
|
5,755
|
17,225
|
|||||||||||||||
|
Income tax expense
|
4,084
|
4,777
|
3,523
|
945
|
3,346
|
|||||||||||||||
|
Net income
|
$
|
16,986
|
$
|
19,584
|
$
|
14,772
|
$
|
4,810
|
$
|
13,879
|
||||||||||
|
Basic earnings per share
|
$
|
0.78
|
$
|
0.90
|
$
|
0.67
|
$
|
0.22
|
$
|
0.62
|
||||||||||
|
Diluted earnings per share
|
0.77
|
0.89
|
0.67
|
0.21
|
0.61
|
|||||||||||||||
|
Cash dividend per share
|
0.20
|
0.20
|
0.20
|
0.20
|
0.18
|
|||||||||||||||
|
Average shares outstanding
|
21,866,326
|
21,881,562
|
21,890,761
|
22,271,412
|
22,481,551
|
|||||||||||||||
|
Average diluted shares outstanding
|
22,112,829
|
22,114,692
|
22,113,187
|
22,529,370
|
22,776,908
|
|||||||||||||||
|
Performance Ratios
|
||||||||||||||||||||
|
Return on average assets
|
1.61
|
%
|
1.90
|
%
|
1.54
|
%
|
0.54
|
%
|
1.56
|
%
|
||||||||||
|
Return on average equity
|
17.82
|
21.36
|
17.39
|
5.54
|
15.92
|
|||||||||||||||
|
Efficiency ratio (1)
|
60.59
|
56.36
|
53.07
|
69.32
|
62.56
|
|||||||||||||||
|
As a Percent of Average Interest-Earning Assets (1)
|
||||||||||||||||||||
|
Interest income
|
3.57
|
%
|
3.62
|
%
|
3.72
|
%
|
4.28
|
%
|
4.44
|
%
|
||||||||||
|
Interest expense
|
0.45
|
0.31
|
0.36
|
0.65
|
0.74
|
|||||||||||||||
|
Net interest income
|
3.12
|
3.31
|
3.36
|
3.63
|
3.70
|
|||||||||||||||
|
Average Balances
|
||||||||||||||||||||
|
Loans
|
$
|
2,876,795
|
$
|
2,925,872
|
$
|
2,913,857
|
$
|
2,766,770
|
$
|
2,776,037
|
||||||||||
|
Securities available for sale
|
1,009,578
|
891,975
|
660,126
|
527,395
|
488,016
|
|||||||||||||||
|
Total earning assets
|
3,984,080
|
3,887,455
|
3,659,614
|
3,350,948
|
3,320,828
|
|||||||||||||||
|
Total assets
|
4,195,546
|
4,102,318
|
3,868,408
|
3,565,829
|
3,529,744
|
|||||||||||||||
|
Deposits
|
3,632,758
|
3,559,070
|
3,303,302
|
3,066,298
|
3,040,099
|
|||||||||||||||
|
Interest bearing liabilities
|
2,574,306
|
2,532,481
|
2,402,361
|
2,309,995
|
2,251,928
|
|||||||||||||||
|
Shareholders' equity
|
379,232
|
364,714
|
341,606
|
348,963
|
345,910
|
|||||||||||||||
|
End of Period
|
||||||||||||||||||||
|
Capital
|
||||||||||||||||||||
|
Tangible common equity ratio
|
8.56
|
%
|
8.23
|
%
|
8.03
|
%
|
8.40
|
%
|
8.96
|
%
|
||||||||||
|
Average equity to average assets
|
9.04
|
8.89
|
8.83
|
9.79
|
9.80
|
|||||||||||||||
|
Common shareholders' equity per share of common stock
|
$
|
17.82
|
$
|
17.05
|
$
|
16.23
|
$
|
15.33
|
$
|
15.58
|
||||||||||
|
Tangible common equity per share of common stock
|
16.33
|
15.55
|
14.72
|
13.81
|
14.08
|
|||||||||||||||
|
Total shares outstanding
|
21,853,800
|
21,885,368
|
21,880,183
|
21,892,001
|
22,481,643
|
|||||||||||||||
|
Selected Balances
|
||||||||||||||||||||
|
Loans
|
$
|
2,733,678
|
$
|
2,855,479
|
$
|
2,866,663
|
$
|
2,718,115
|
$
|
2,725,023
|
||||||||||
|
Securities available for sale
|
1,072,159
|
985,050
|
856,280
|
594,284
|
518,400
|
|||||||||||||||
|
Total earning assets
|
3,979,397
|
3,962,824
|
3,833,523
|
3,416,845
|
3,343,941
|
|||||||||||||||
|
Total assets
|
4,204,013
|
4,168,944
|
4,043,315
|
3,632,387
|
3,564,694
|
|||||||||||||||
|
Deposits
|
3,637,355
|
3,597,745
|
3,485,125
|
3,083,564
|
3,036,727
|
|||||||||||||||
|
Interest bearing liabilities
|
2,553,418
|
2,515,185
|
2,456,193
|
2,350,056
|
2,312,753
|
|||||||||||||||
|
Shareholders' equity
|
389,522
|
373,092
|
355,123
|
335,618
|
350,169
|
|||||||||||||||
|
(1)
|
Presented on a fully tax equivalent basis assuming a marginal tax rate of 21%.
|
9
Reconciliation of Non-GAAP Financial Measures
Independent Bank Corporation
Independent Bank Corporation believes non-GAAP measures are meaningful because they reflect adjustments commonly made by management, investors, regulators and analysts
to evaluate the adequacy of common equity and performance trends. Tangible common equity is used by the Company to measure the quality of capital.
Reconciliation of Non-GAAP Financial Measures
|
Three Months Ended
December 31,
|
Twelve Months Ended
December 31,
|
|||||||||||||||
|
2020
|
2019
|
2020
|
2019
|
|||||||||||||
|
(Dollars in thousands)
|
||||||||||||||||
|
Net Interest Margin, Fully Taxable Equivalent ("FTE")
|
||||||||||||||||
|
Net interest income
|
$
|
30,993
|
$
|
30,710
|
$
|
123,612
|
$
|
122,581
|
||||||||
|
Add: taxable equivalent adjustment
|
221
|
104
|
823
|
423
|
||||||||||||
|
Net interest income - taxable equivalent
|
$
|
31,214
|
$
|
30,814
|
$
|
124,435
|
$
|
123,004
|
||||||||
|
Net interest margin (GAAP) (1)
|
3.10
|
%
|
3.68
|
%
|
3.32
|
%
|
3.79
|
%
|
||||||||
|
Net interest margin (FTE) (1)
|
3.12
|
%
|
3.70
|
%
|
3.34
|
%
|
3.80
|
%
|
||||||||
|
(1)
|
Annualized for three months ended December 31, 2020 and 2019.
|
Tangible Common Equity Ratio
|
December 31,
2020
|
September 30,
2020
|
June 30,
2020
|
March 31,
2020
|
December 31,
2019
|
||||||||||||||||
|
(Dollars in thousands)
|
||||||||||||||||||||
|
Common shareholders' equity
|
$
|
389,522
|
$
|
373,092
|
$
|
355,123
|
$
|
335,618
|
$
|
350,169
|
||||||||||
|
Less:
|
||||||||||||||||||||
|
Goodwill
|
28,300
|
28,300
|
28,300
|
28,300
|
28,300
|
|||||||||||||||
|
Other intangibles
|
4,306
|
4,561
|
4,816
|
5,071
|
5,326
|
|||||||||||||||
|
Tangible common equity
|
$
|
356,916
|
$
|
340,231
|
$
|
322,007
|
$
|
302,247
|
$
|
316,543
|
||||||||||
|
Total assets
|
$
|
4,204,013
|
$
|
4,168,944
|
$
|
4,043,315
|
$
|
3,632,387
|
$
|
3,564,694
|
||||||||||
|
Less:
|
||||||||||||||||||||
|
Goodwill
|
28,300
|
28,300
|
28,300
|
28,300
|
28,300
|
|||||||||||||||
|
Other intangibles
|
4,306
|
4,561
|
4,816
|
5,071
|
5,326
|
|||||||||||||||
|
Tangible assets
|
$
|
4,171,407
|
$
|
4,136,083
|
$
|
4,010,199
|
$
|
3,599,016
|
$
|
3,531,068
|
||||||||||
|
Common equity ratio
|
9.27
|
%
|
8.95
|
%
|
8.78
|
%
|
9.24
|
%
|
9.82
|
%
|
||||||||||
|
Tangible common equity ratio
|
8.56
|
%
|
8.23
|
%
|
8.03
|
%
|
8.40
|
%
|
8.96
|
%
|
||||||||||
|
Tangible Common Equity per Share of Common Stock:
|
||||||||||||||||||||
|
Common shareholders' equity
|
$
|
389,522
|
$
|
373,092
|
$
|
355,123
|
$
|
335,618
|
$
|
350,169
|
||||||||||
|
Tangible common equity
|
$
|
356,916
|
$
|
340,231
|
$
|
322,007
|
$
|
302,247
|
$
|
316,543
|
||||||||||
|
Shares of common stock outstanding (in thousands)
|
21,854
|
21,885
|
21,880
|
21,892
|
22,482
|
|||||||||||||||
|
Common shareholders' equity per share of common stock
|
$
|
17.82
|
$
|
17.05
|
$
|
16.23
|
$
|
15.33
|
$
|
15.58
|
||||||||||
|
Tangible common equity per share of common stock
|
$
|
16.33
|
$
|
15.55
|
$
|
14.72
|
$
|
13.81
|
$
|
14.08
|
||||||||||
The tangible common equity ratio removes the effect of goodwill and other intangible assets from capital and total assets. Tangible common equity per share of common stock removes the effect of goodwill and other intangible assets from common shareholders’ equity per share of common stock.
10
Exhibit 99.2
INDEPENDENT BANK CORPORATION AND SUBSIDIARIES
Supplemental Data
Non-performing assets (1)
|
December 31,
2020
|
September 30,
2020
|
June 30,
2020
|
March 31,
2020
|
December 31,
2019
|
||||||||||||||||
|
(Dollars in thousands)
|
||||||||||||||||||||
|
Non-accrual loans
|
$
|
8,312
|
$
|
10,481
|
$
|
12,938
|
$
|
17,454
|
$
|
10,178
|
||||||||||
|
Loans 90 days or more past due and still accruing interest
|
-
|
266
|
5
|
-
|
-
|
|||||||||||||||
|
Subtotal
|
8,312
|
10,747
|
12,943
|
17,454
|
10,178
|
|||||||||||||||
|
Less: Government guaranteed loans
|
439
|
510
|
604
|
676
|
646
|
|||||||||||||||
|
Total non-performing loans
|
7,873
|
10,237
|
12,339
|
16,778
|
9,532
|
|||||||||||||||
|
Other real estate and repossessed assets
|
766
|
1,487
|
1,569
|
1,494
|
1,865
|
|||||||||||||||
|
Total non-performing assets
|
$
|
8,639
|
$
|
11,724
|
$
|
13,908
|
$
|
18,272
|
$
|
11,397
|
||||||||||
|
As a percent of Portfolio Loans
|
||||||||||||||||||||
|
Non-performing loans
|
0.29
|
%
|
0.36
|
%
|
0.43
|
%
|
0.62
|
%
|
0.35
|
%
|
||||||||||
|
Allowance for loan losses
|
1.30
|
1.25
|
1.20
|
1.20
|
0.96
|
|||||||||||||||
|
Non-performing assets to total assets
|
0.21
|
0.28
|
0.34
|
0.50
|
0.32
|
|||||||||||||||
|
Allowance for loan losses as a percent of non-performing loans
|
450.01
|
349.43
|
279.60
|
193.68
|
274.32
|
|||||||||||||||
|
(1)
|
Excludes loans classified as "trouble debt restructured" that are not past due.
|
Troubled debt restructurings ("TDR")
|
December 31, 2020
|
||||||||||||
|
Commercial
|
Retail (1)
|
Total
|
||||||||||
|
(In thousands)
|
||||||||||||
|
Performing TDR's
|
$
|
7,956
|
$
|
36,385
|
$
|
44,341
|
||||||
|
Non-performing TDR's (2)
|
1,148
|
1,584
|
(3)
|
2,732
|
||||||||
|
Total
|
$
|
9,104
|
$
|
37,969
|
$
|
47,073
|
||||||
|
December 31, 2019
|
||||||||||||
|
Commercial
|
Retail (1)
|
Total
|
||||||||||
|
(In thousands)
|
||||||||||||
|
Performing TDR's
|
$
|
7,974
|
$
|
39,601
|
$
|
47,575
|
||||||
|
Non-performing TDR's (2)
|
540
|
2,607
|
(3)
|
3,147
|
||||||||
|
Total
|
$
|
8,514
|
$
|
42,208
|
$
|
50,722
|
||||||
|
(1)
|
Retail loans include mortgage and installment loan segments.
|
|
(2)
|
Included in non-performing assets table above.
|
|
(3)
|
Also includes loans on non-accrual at the time of modification until six payments are received on a timely basis.
|
1
Allowance for loan losses
|
Twelve months ended
December 31,
|
||||||||||||||||
|
2020
|
2019
|
|||||||||||||||
|
Loans
|
Unfunded
Commitments
|
Loans
|
Unfunded
Commitments
|
|||||||||||||
|
(Dollars in thousands)
|
||||||||||||||||
|
Balance at beginning of period
|
$
|
26,148
|
$
|
1,542
|
$
|
24,888
|
$
|
1,296
|
||||||||
|
Additions (deductions)
|
||||||||||||||||
|
Provision for loan losses
|
12,463
|
-
|
824
|
-
|
||||||||||||
|
Recoveries credited to allowance
|
3,069
|
-
|
3,961
|
-
|
||||||||||||
|
Loans charged against the allowance
|
(6,251
|
)
|
-
|
(3,525
|
)
|
-
|
||||||||||
|
Additions included in non-interest expense
|
-
|
263
|
-
|
246
|
||||||||||||
|
Balance at end of period
|
$
|
35,429
|
$
|
1,805
|
$
|
26,148
|
$
|
1,542
|
||||||||
|
Net loans charged against the allowance to average Portfolio Loans
|
0.11
|
%
|
(0.02
|
)%
|
||||||||||||
Capitalization
|
December 31,
|
||||||||
|
2020
|
2019
|
|||||||
|
(In thousands)
|
||||||||
|
Subordinated debt
|
$
|
39,281
|
$
|
-
|
||||
|
Subordinated debentures
|
39,524
|
39,456
|
||||||
|
Amount not qualifying as regulatory capital
|
(505
|
)
|
(1,224
|
)
|
||||
|
Amount qualifying as regulatory capital
|
78,300
|
38,232
|
||||||
|
Shareholders’ equity
|
||||||||
|
Common stock
|
339,353
|
352,344
|
||||||
|
Retained earnings
|
40,145
|
1,611
|
||||||
|
Accumulated other comprehensive income (loss)
|
10,024
|
(3,786
|
)
|
|||||
|
Total shareholders’ equity
|
389,522
|
350,169
|
||||||
|
Total capitalization
|
$
|
467,822
|
$
|
388,401
|
||||
2
Non-Interest Income
|
Three months ended
|
Twelve months ended
|
|||||||||||||||||||
|
December 31,
|
September 30,
|
December 31,
|
December 31,
|
|||||||||||||||||
|
2020
|
2020
|
2019
|
2020
|
2019
|
||||||||||||||||
|
(In thousands)
|
||||||||||||||||||||
|
Service charges on deposit accounts
|
$
|
2,218
|
$
|
2,085
|
$
|
2,885
|
$
|
8,517
|
$
|
11,208
|
||||||||||
|
Interchange income
|
2,819
|
3,428
|
2,553
|
$
|
11,230
|
$
|
10,297
|
|||||||||||||
|
Net gains on assets
|
||||||||||||||||||||
|
Mortgage loans
|
15,873
|
20,205
|
6,388
|
62,560
|
19,978
|
|||||||||||||||
|
Securities
|
14
|
-
|
3
|
267
|
307
|
|||||||||||||||
|
Mortgage loan servicing, net
|
(384
|
)
|
(644
|
)
|
1,348
|
(9,350
|
)
|
(3,336
|
)
|
|||||||||||
|
Investment and insurance commissions
|
493
|
530
|
461
|
1,971
|
1,658
|
|||||||||||||||
|
Bank owned life insurance
|
160
|
215
|
298
|
910
|
1,111
|
|||||||||||||||
|
Other
|
1,170
|
1,192
|
1,661
|
4,640
|
6,513
|
|||||||||||||||
|
Total non-interest income
|
$
|
22,363
|
$
|
27,011
|
$
|
15,597
|
$
|
80,745
|
$
|
47,736
|
||||||||||
Capitalized Mortgage Loan Servicing Rights
|
Three months ended
|
Twelve months ended
|
|||||||||||||||
|
December 31,
|
December 31,
|
|||||||||||||||
|
2020
|
2019
|
2020
|
2019
|
|||||||||||||
|
(In thousands)
|
||||||||||||||||
|
Balance at beginning of period
|
$
|
15,403
|
$
|
16,906
|
$
|
19,171
|
$
|
21,400
|
||||||||
|
Originated servicing rights capitalized
|
3,697
|
2,539
|
13,957
|
7,303
|
||||||||||||
|
Change in fair value
|
(2,196
|
)
|
(274
|
)
|
(16,224
|
)
|
(9,532
|
)
|
||||||||
|
Balance at end of period
|
$
|
16,904
|
$
|
19,171
|
$
|
16,904
|
$
|
19,171
|
||||||||
3
|
Three months ended
|
Twelve months ended
|
|||||||||||||||||||
|
December 31,
|
September 30,
|
December 31,
|
December 31,
|
|||||||||||||||||
|
2020
|
2020
|
2019
|
2020
|
2019
|
||||||||||||||||
|
(Dollars in thousands)
|
||||||||||||||||||||
|
Mortgage loans originated
|
$
|
502,491
|
$
|
536,502
|
$
|
302,520
|
$
|
1,820,697
|
$
|
1,011,141
|
||||||||||
|
Mortgage loans sold
|
388,631
|
417,092
|
248,691
|
1,447,031
|
738,910
|
|||||||||||||||
|
Net gains on mortgage loans
|
15,873
|
20,205
|
6,388
|
62,560
|
19,978
|
|||||||||||||||
|
Net gains as a percent of mortgage loans sold ("Loan Sales Margin")
|
4.08
|
%
|
4.84
|
%
|
2.57
|
%
|
4.32
|
%
|
2.70
|
%
|
||||||||||
|
Fair value adjustments included in the Loan Sales Margin
|
(0.53
|
)
|
0.50
|
(0.38
|
)
|
0.47
|
0.22
|
|||||||||||||
Non-Interest Expense
|
Three months ended
|
Twelve months ended
|
|||||||||||||||||||
|
December 31,
|
September 30,
|
December 31,
|
December 31,
|
|||||||||||||||||
|
2020
|
2020
|
2019
|
2020
|
2019
|
||||||||||||||||
|
(In thousands)
|
||||||||||||||||||||
|
Compensation
|
$
|
10,852
|
$
|
10,294
|
$
|
10,726
|
$
|
41,517
|
$
|
41,719
|
||||||||||
|
Performance-based compensation
|
5,485
|
8,310
|
4,336
|
19,725
|
12,066
|
|||||||||||||||
|
Payroll taxes and employee benefits
|
3,702
|
3,350
|
3,484
|
13,539
|
13,716
|
|||||||||||||||
|
Compensation and employee benefits
|
20,039
|
21,954
|
18,546
|
74,781
|
67,501
|
|||||||||||||||
|
Occupancy, net
|
2,120
|
2,199
|
2,216
|
8,938
|
9,013
|
|||||||||||||||
|
Data processing
|
2,374
|
2,215
|
2,308
|
8,534
|
8,905
|
|||||||||||||||
|
Furniture, fixtures and equipment
|
964
|
999
|
1,055
|
4,089
|
4,113
|
|||||||||||||||
|
Interchange expense
|
926
|
831
|
883
|
3,342
|
3,215
|
|||||||||||||||
|
Communications
|
785
|
806
|
728
|
3,194
|
2,947
|
|||||||||||||||
|
Loan and collection
|
708
|
768
|
709
|
3,037
|
2,685
|
|||||||||||||||
|
Conversion related expenses
|
1,541
|
643
|
-
|
2,586
|
-
|
|||||||||||||||
|
Advertising
|
594
|
589
|
515
|
2,230
|
2,450
|
|||||||||||||||
|
Legal and professional fees
|
600
|
566
|
533
|
2,027
|
1,814
|
|||||||||||||||
|
FDIC deposit insurance
|
385
|
411
|
(38
|
)
|
1,596
|
685
|
||||||||||||||
|
Amortization of intangible assets
|
255
|
255
|
272
|
1,020
|
1,089
|
|||||||||||||||
|
Supplies
|
167
|
126
|
164
|
680
|
638
|
|||||||||||||||
|
Branch closure costs
|
-
|
-
|
417
|
|||||||||||||||||
|
Correspondent bank service fees
|
101
|
101
|
111
|
395
|
411
|
|||||||||||||||
|
Costs (recoveries) related to unfunded lending commitments
|
(8
|
)
|
41
|
(95
|
)
|
263
|
246
|
|||||||||||||
|
Provision for loss reimbursement on sold loans
|
40
|
46
|
50
|
200
|
229
|
|||||||||||||||
|
Net (gains) losses on other real estate and repossessed assets
|
(82
|
)
|
46
|
(63
|
)
|
64
|
(90
|
)
|
||||||||||||
|
Other
|
1,198
|
1,045
|
1,409
|
5,020
|
5,882
|
|||||||||||||||
|
Total non-interest expense
|
$
|
32,707
|
$
|
33,641
|
$
|
29,303
|
$
|
122,413
|
$
|
111,733
|
||||||||||
4
|
Three Months Ended
December 31,
|
||||||||||||||||||||||||
2020
|
2019
|
|||||||||||||||||||||||
|
Average
|
Average
|
|||||||||||||||||||||||
|
Balance
|
Interest
|
Rate (2)
|
Balance
|
Interest
|
Rate (2)
|
|||||||||||||||||||
|
(Dollars in thousands)
|
||||||||||||||||||||||||
|
Assets
|
||||||||||||||||||||||||
|
Taxable loans
|
$
|
2,870,011
|
$
|
31,071
|
4.31
|
%
|
$
|
2,767,857
|
$
|
33,061
|
4.75
|
%
|
||||||||||||
|
Tax-exempt loans (1)
|
6,784
|
87
|
5.10
|
8,180
|
100
|
4.85
|
||||||||||||||||||
|
Taxable securities
|
803,322
|
3,299
|
1.64
|
437,087
|
3,031
|
2.77
|
||||||||||||||||||
|
Tax-exempt securities (1)
|
206,256
|
991
|
1.92
|
50,929
|
408
|
3.20
|
||||||||||||||||||
|
Interest bearing cash
|
79,280
|
24
|
0.12
|
38,416
|
163
|
1.68
|
||||||||||||||||||
|
Other investments
|
18,427
|
211
|
4.56
|
18,359
|
249
|
5.38
|
||||||||||||||||||
|
Interest Earning Assets
|
3,984,080
|
35,683
|
3.57
|
3,320,828
|
37,012
|
4.44
|
||||||||||||||||||
|
Cash and due from banks
|
51,497
|
48,095
|
||||||||||||||||||||||
|
Other assets, net
|
159,969
|
160,821
|
||||||||||||||||||||||
|
Total Assets
|
$
|
4,195,546
|
$
|
3,529,744
|
||||||||||||||||||||
|
Liabilities
|
||||||||||||||||||||||||
|
Savings and interest-bearing checking
|
$
|
1,988,438
|
761
|
0.15
|
$
|
1,547,860
|
2,441
|
0.63
|
||||||||||||||||
|
Time deposits
|
477,079
|
2,755
|
2.30
|
611,914
|
3,046
|
1.97
|
||||||||||||||||||
|
Other borrowings
|
108,789
|
953
|
3.48
|
92,154
|
711
|
3.06
|
||||||||||||||||||
|
Interest Bearing Liabilities
|
2,574,306
|
4,469
|
0.69
|
2,251,928
|
6,198
|
1.09
|
||||||||||||||||||
|
Non-interest bearing deposits
|
1,167,241
|
880,325
|
||||||||||||||||||||||
|
Other liabilities
|
74,767
|
51,581
|
||||||||||||||||||||||
|
Shareholders’ equity
|
379,232
|
345,910
|
||||||||||||||||||||||
|
Total liabilities and shareholders’ equity
|
$
|
4,195,546
|
$
|
3,529,744
|
||||||||||||||||||||
|
Net Interest Income
|
$
|
31,214
|
$
|
30,814
|
||||||||||||||||||||
|
Net Interest Income as a Percent of Average Interest Earning Assets
|
3.12
|
%
|
3.70
|
%
|
||||||||||||||||||||
|
(1)
|
Interest on tax-exempt loans and securities is presented on a fully tax equivalent basis assuming a marginal tax rate of 21%.
|
|
(2)
|
Annualized
|
5
Average Balances and Tax Equivalent Rates
|
Twelve Months Ended
December 31,
|
||||||||||||||||||||||||
2020
|
2019
|
|||||||||||||||||||||||
|
Average
|
Average
|
|||||||||||||||||||||||
|
Balance
|
Interest
|
Rate
|
Balance
|
Interest
|
Rate
|
|||||||||||||||||||
|
(Dollars in thousands)
|
||||||||||||||||||||||||
|
Assets
|
||||||||||||||||||||||||
|
Taxable loans
|
$
|
2,863,846
|
$
|
122,875
|
4.29
|
%
|
$
|
2,713,690
|
$
|
133,574
|
4.92
|
%
|
||||||||||||
|
Tax-exempt loans (1)
|
7,145
|
360
|
5.04
|
7,937
|
391
|
4.93
|
||||||||||||||||||
|
Taxable securities
|
635,914
|
12,655
|
1.99
|
397,598
|
11,842
|
2.98
|
||||||||||||||||||
|
Tax-exempt securities (1)
|
137,330
|
3,673
|
2.67
|
52,324
|
1,683
|
3.22
|
||||||||||||||||||
|
Interest bearing cash
|
59,056
|
184
|
0.31
|
48,023
|
818
|
1.70
|
||||||||||||||||||
|
Other investments
|
18,410
|
905
|
4.92
|
18,359
|
1,043
|
5.68
|
||||||||||||||||||
|
Interest Earning Assets
|
3,721,701
|
140,652
|
3.78
|
3,237,931
|
149,351
|
4.61
|
||||||||||||||||||
|
Cash and due from banks
|
49,886
|
37,575
|
||||||||||||||||||||||
|
Other assets, net
|
162,068
|
164,726
|
||||||||||||||||||||||
|
Total Assets
|
$
|
3,933,655
|
$
|
3,440,232
|
||||||||||||||||||||
|
Liabilities
|
||||||||||||||||||||||||
|
Savings and interest-bearing checking
|
$
|
1,821,115
|
3,882
|
0.21
|
$
|
1,453,061
|
10,228
|
0.70
|
||||||||||||||||
|
Time deposits
|
516,306
|
8,784
|
1.70
|
655,718
|
13,197
|
2.01
|
||||||||||||||||||
|
Other borrowings
|
117,904
|
3,551
|
3.01
|
77,254
|
2,922
|
3.78
|
||||||||||||||||||
|
Interest Bearing Liabilities
|
2,455,325
|
16,217
|
0.66
|
2,186,033
|
26,347
|
1.21
|
||||||||||||||||||
|
Non-interest bearing deposits
|
1,054,230
|
867,314
|
||||||||||||||||||||||
|
Other liabilities
|
65,943
|
46,153
|
||||||||||||||||||||||
|
Shareholders’ equity
|
358,157
|
340,732
|
||||||||||||||||||||||
|
Total liabilities and shareholders’ equity
|
$
|
3,933,655
|
$
|
3,440,232
|
||||||||||||||||||||
|
Net Interest Income
|
$
|
124,435
|
$
|
123,004
|
||||||||||||||||||||
|
Net Interest Income as a Percent of Average Interest Earning Assets
|
3.34
|
%
|
3.80
|
%
|
||||||||||||||||||||
|
(1)
|
Interest on tax-exempt loans and securities is presented on a fully tax equivalent basis assuming a marginal tax rate of 21%.
|
6
Commercial Loan Portfolio Analysis as of December 31, 2020
|
Total Commercial Loans
|
||||||||||||||||||||
|
Watch Credits
|
Percent of Loan
|
|||||||||||||||||||
|
Loan Category
|
All Loans
|
Performing
|
Non-accrual
|
Total
|
Category in Watch Credit
|
|||||||||||||||
|
(Dollars in thousands)
|
||||||||||||||||||||
|
Land
|
$
|
14,567
|
$
|
116
|
$
|
-
|
$
|
116
|
0.8
|
%
|
||||||||||
|
Land Development
|
12,176
|
36
|
-
|
36
|
0.3
|
|||||||||||||||
|
Construction
|
68,724
|
36
|
-
|
36
|
0.1
|
|||||||||||||||
|
Income Producing
|
358,603
|
3,699
|
-
|
3,699
|
1.0
|
|||||||||||||||
|
Owner Occupied
|
360,510
|
24,693
|
745
|
25,438
|
7.1
|
|||||||||||||||
|
Total Commercial Real Estate Loans
|
$
|
814,580
|
$
|
28,580
|
745
|
$
|
29,325
|
3.6
|
||||||||||||
|
Other Commercial Loans
|
$
|
427,835
|
$
|
16,059
|
695
|
$
|
16,754
|
3.9
|
||||||||||||
|
Total non-performing commercial loans
|
$
|
1,440
|
||||||||||||||||||
Commercial Loan Portfolio Analysis as of December 31, 2019
|
Total Commercial Loans
|
||||||||||||||||||||
|
Watch Credits
|
Percent of Loan
|
|||||||||||||||||||
|
Loan Category
|
All Loans
|
Performing
|
Non-accrual
|
Total
|
Category in
Watch Credit
|
|||||||||||||||
|
(Dollars in thousands)
|
||||||||||||||||||||
|
Land
|
$
|
11,235
|
$
|
275
|
$
|
735
|
$
|
1,010
|
9.0
|
%
|
||||||||||
|
Land Development
|
12,899
|
-
|
-
|
-
|
0.0
|
|||||||||||||||
|
Construction
|
97,463
|
-
|
-
|
-
|
0.0
|
|||||||||||||||
|
Income Producing
|
409,897
|
15,347
|
-
|
15,347
|
3.7
|
|||||||||||||||
|
Owner Occupied
|
323,694
|
35,485
|
295
|
35,780
|
11.1
|
|||||||||||||||
|
Total Commercial Real Estate Loans
|
$
|
855,188
|
$
|
51,107
|
1,030
|
$
|
52,137
|
6.1
|
||||||||||||
|
Other Commercial Loans
|
$
|
311,507
|
$
|
20,580
|
347
|
$
|
20,927
|
6.7
|
||||||||||||
|
Total non-performing commercial loans
|
$
|
1,377
|
||||||||||||||||||
7
Exhibit 99.3
Q4 EARNINGS Independent Bank Corporation (IBCP)Conference Call – January 28, 2021
Cautionary note regarding forward-looking statements This presentation contains forward-looking
statements about Independent Bank Corporation. Statements that are not historical or current facts, including statements about beliefs and expectations, are forward-looking statements and are based on the information available to, and
assumptions and estimates made by, management as of the date hereof. These forward-looking statements cover, among other things, anticipated future revenue and expenses and the future plans and prospects of Independent Bank Corporation.
Forward-looking statements involve inherent risks and uncertainties, and important factors could cause actual results to differ materially from those anticipated. The COVID-19 pandemic is adversely affecting Independent Bank Corporation, its
customers, counterparties, employees, and third-party service providers, and the ultimate extent of the impacts on its business, financial position, results of operations, liquidity, and prospects is uncertain. Continued deterioration in
general business and economic conditions or turbulence in domestic or global financial markets could adversely affect Independent Bank Corporation’s revenues and the values of its assets and liabilities, reduce the availability of funding
from certain financial institutions, lead to a tightening of credit, and increase stock price volatility. In addition, changes to statutes, regulations, or regulatory policies or practices could affect Independent Bank Corporation in
substantial and unpredictable ways. Independent Bank Corporation’s results could also be adversely affected by changes in interest rates; further increases in unemployment rates; deterioration in the credit quality of its loan portfolios or
in the value of the collateral securing those loans; deterioration in the value of its investment securities; legal and regulatory developments; litigation; increased competition from both banks and non-banks; changes in the level of tariffs
and other trade policies of the United States and its global trading partners; changes in customer behavior and preferences; breaches in data security; failures to safeguard personal information; effects of mergers and acquisitions and
related integration; effects of critical accounting policies and judgments; and management’s ability to effectively manage credit risk, market risk, operational risk, compliance risk, strategic risk, interest rate risk, liquidity risk and
reputation risk. Certain risks and important factors that could affect Independent Bank Corporation's future results are identified in its Annual Report on Form 10-K for the year ended December 31, 2019 and other reports filed with the SEC,
including among other things under the heading “Risk Factors” in such Annual Report on Form 10-K. Any forward-looking statement speaks only as of the date on which it is made, and Independent Bank Corporation undertakes no obligation to
update any forward-looking statement, whether to reflect events or circumstances after the date on which the statement is made, to reflect new information or the occurrence of unanticipated events, or otherwise. 2
Agenda Formal Remarks.William B. (Brad) Kessel, President and Chief Executive OfficerGavin A. Mohr,
Executive Vice President and Chief Financial OfficerQuestion and Answer session.Closing Remarks.Note: This presentation is available at www.IndependentBank.com in the Investor Relations area under the “Presentations” tab. 3
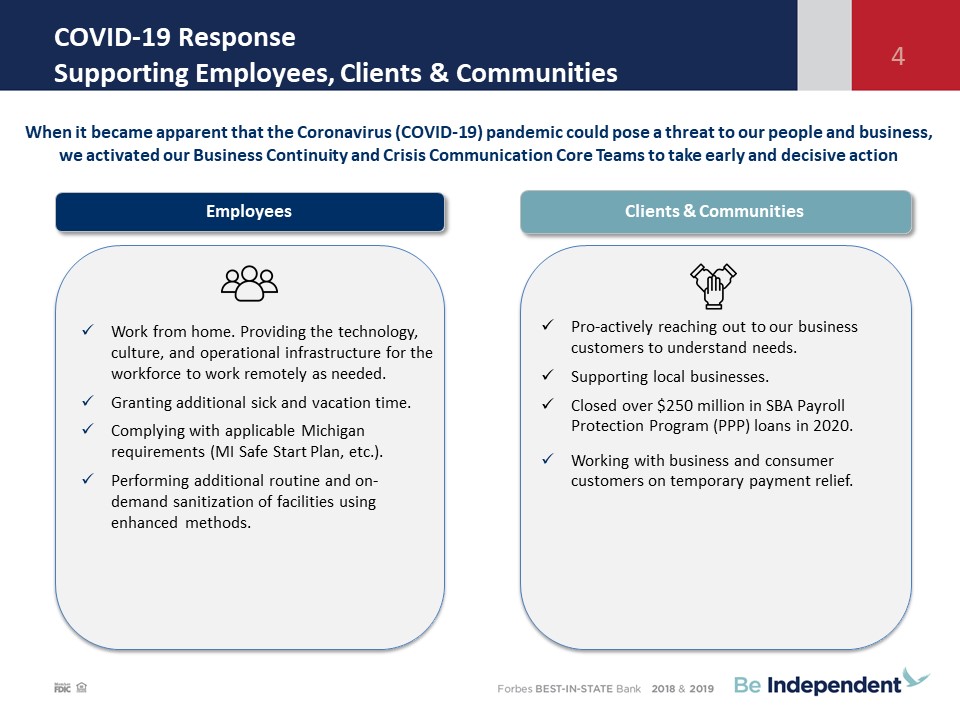
COVID-19 ResponseSupporting Employees, Clients & Communities 4 Employees Clients &
Communities Work from home. Providing the technology, culture, and operational infrastructure for the workforce to work remotely as needed.Granting additional sick and vacation time. Complying with applicable Michigan requirements (MI
Safe Start Plan, etc.).Performing additional routine and on-demand sanitization of facilities using enhanced methods. Pro-actively reaching out to our business customers to understand needs. Supporting local businesses. Closed over $250
million in SBA Payroll Protection Program (PPP) loans in 2020. Working with business and consumer customers on temporary payment relief. When it became apparent that the Coronavirus (COVID-19) pandemic could pose a threat to our people and
business, we activated our Business Continuity and Crisis Communication Core Teams to take early and decisive action
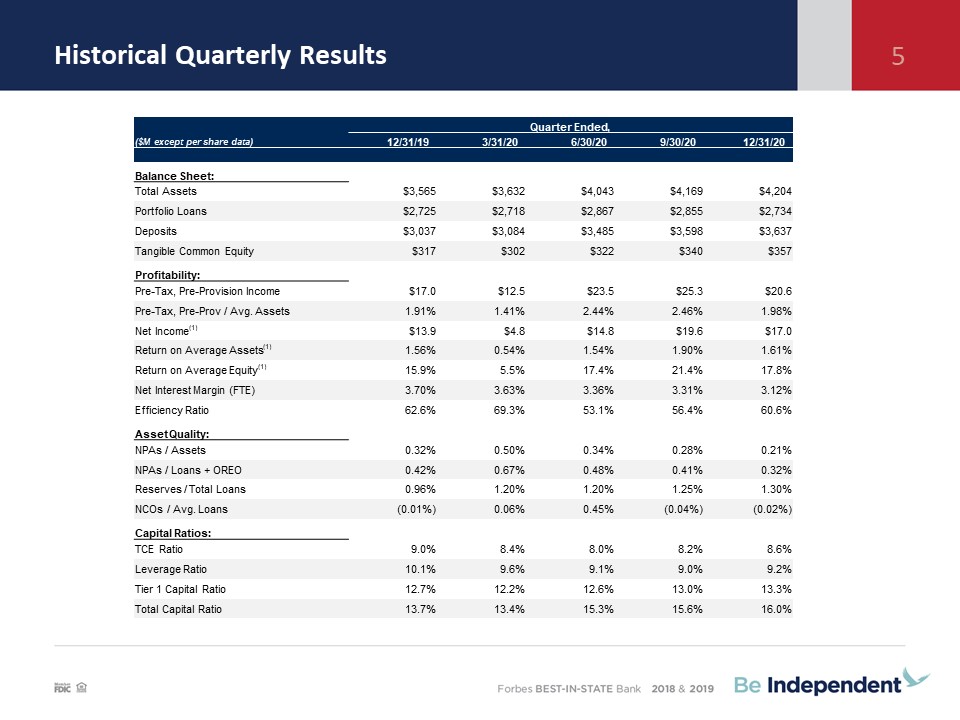
Historical Quarterly Results 5 Quarter Ended, ($M except per share
data) 12/31/19 3/31/20 6/30/20 9/30/20 12/31/20 Balance Sheet: Total Assets $3,565 $3,632 $4,043 $4,169 $4,204 Portfolio Loans $2,725 $2,718 $2,867 $2,855 $2,734
Deposits $3,037 $3,084 $3,485 $3,598 $3,637 Tangible Common Equity $317 $302 $322 $340 $357 Profitability: Pre-Tax, Pre-Provision Income $17.0 $12.5 $23.5 $25.3 $20.6 Pre-Tax, Pre-Prov /
Avg. Assets 1.91% 1.41% 2.44% 2.46% 1.98% Net Income(1) $13.9 $4.8 $14.8 $19.6 $17.0 Return on Average Assets(1) 1.56% 0.54% 1.54% 1.90% 1.61% Return on Average Equity(1) 15.9% 5.5% 17.4% 21.4% 17.8% Net
Interest Margin (FTE) 3.70% 3.63% 3.36% 3.31% 3.12% Efficiency Ratio 62.6% 69.3% 53.1% 56.4% 60.6% Asset Quality: NPAs / Assets 0.32% 0.50% 0.34% 0.28% 0.21% NPAs / Loans +
OREO 0.42% 0.67% 0.48% 0.41% 0.32% Reserves / Total Loans 0.96% 1.20% 1.20% 1.25% 1.30% NCOs / Avg. Loans (0.01%) 0.06% 0.45% (0.04%) (0.02%) Capital Ratios: TCE
Ratio 9.0% 8.4% 8.0% 8.2% 8.6% Leverage Ratio 10.1% 9.6% 9.1% 9.0% 9.2% Tier 1 Capital Ratio 12.7% 12.2% 12.6% 13.0% 13.3% Total Capital Ratio 13.7% 13.4% 15.3% 15.6% 16.0%
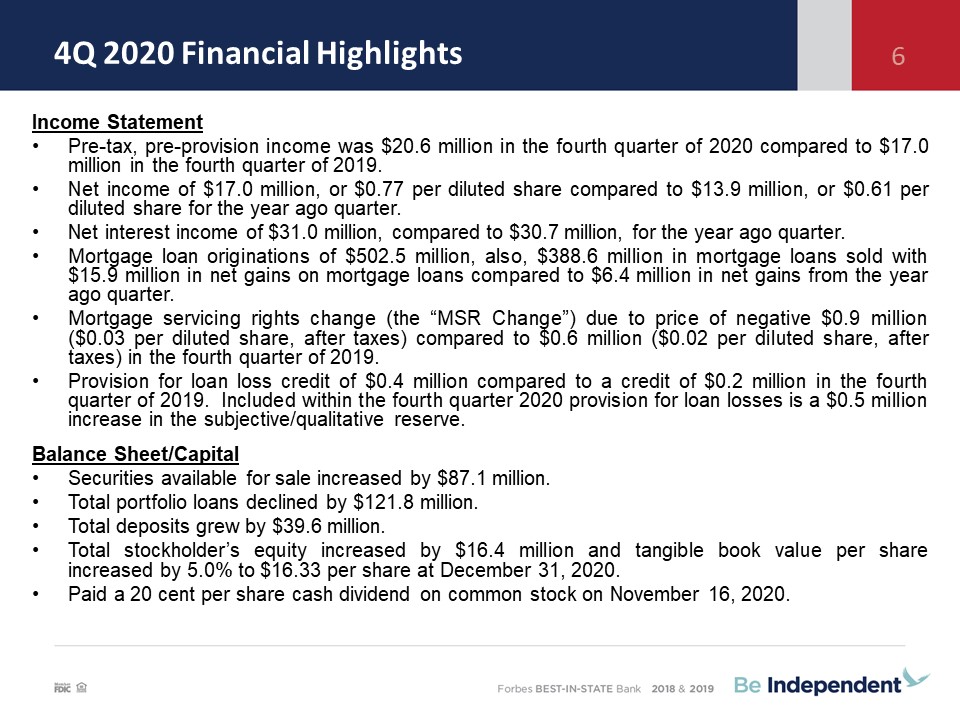
4Q 2020 Financial Highlights Income StatementPre-tax, pre-provision income was $20.6 million in
the fourth quarter of 2020 compared to $17.0 million in the fourth quarter of 2019.Net income of $17.0 million, or $0.77 per diluted share compared to $13.9 million, or $0.61 per diluted share for the year ago quarter.Net interest
income of $31.0 million, compared to $30.7 million, for the year ago quarter.Mortgage loan originations of $502.5 million, also, $388.6 million in mortgage loans sold with $15.9 million in net gains on mortgage loans compared to $6.4
million in net gains from the year ago quarter. Mortgage servicing rights change (the “MSR Change”) due to price of negative $0.9 million ($0.03 per diluted share, after taxes) compared to $0.6 million ($0.02 per diluted share, after
taxes) in the fourth quarter of 2019. Provision for loan loss credit of $0.4 million compared to a credit of $0.2 million in the fourth quarter of 2019. Included within the fourth quarter 2020 provision for loan losses is a $0.5 million
increase in the subjective/qualitative reserve.Balance Sheet/CapitalSecurities available for sale increased by $87.1 million.Total portfolio loans declined by $121.8 million.Total deposits grew by $39.6 million.Total stockholder’s
equity increased by $16.4 million and tangible book value per share increased by 5.0% to $16.33 per share at December 31, 2020. Paid a 20 cent per share cash dividend on common stock on November 16, 2020. 6
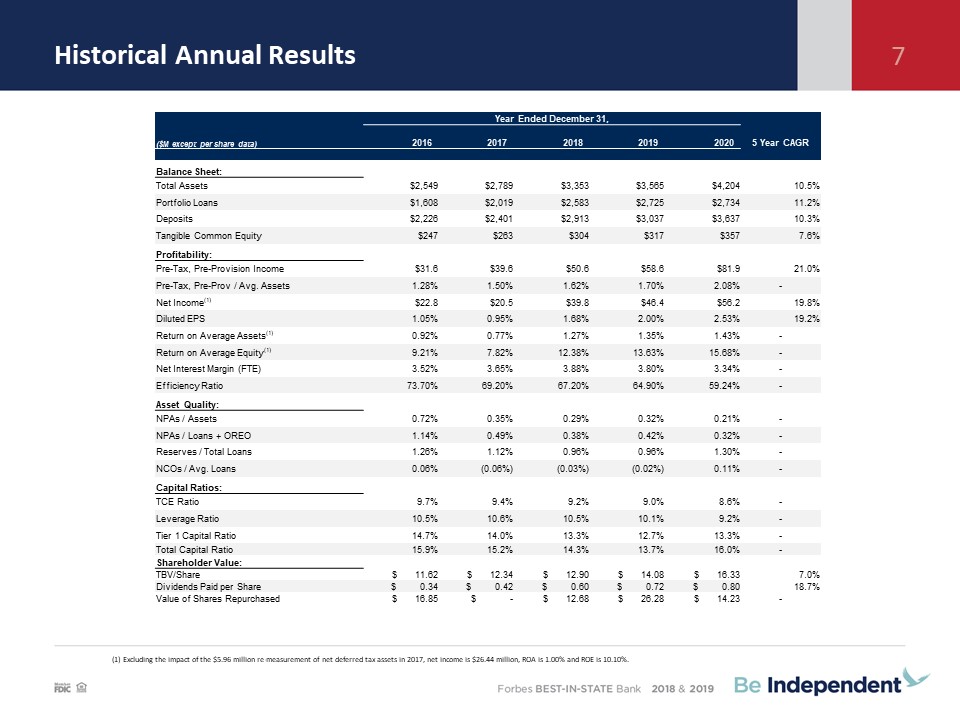
Historical Annual Results 7 (1) Excluding the impact of the $5.96 million re-measurement of net
deferred tax assets in 2017, net income is $26.44 million, ROA is 1.00% and ROE is 10.10%. Year Ended December 31, ($M except per share data) 2016 2017 2018 2019 2020 5 Year
CAGR Balance Sheet: Total Assets $2,549 $2,789 $3,353 $3,565 $4,204 10.5% Portfolio Loans $1,608 $2,019 $2,583 $2,725 $2,734 11.2% Deposits $2,226 $2,401
$2,913 $3,037 $3,637 10.3% Tangible Common Equity $247 $263 $304 $317 $357 7.6% Profitability: Pre-Tax, Pre-Provision Income $31.6 $39.6 $50.6 $58.6 $81.9 21.0% Pre-Tax, Pre-Prov /
Avg. Assets 1.28% 1.50% 1.62% 1.70% 2.08% - Net Income(1) $22.8 $20.5 $39.8 $46.4 $56.2 19.8% Diluted EPS 1.05% 0.95% 1.68% 2.00% 2.53% 19.2% Return on Average
Assets(1) 0.92% 0.77% 1.27% 1.35% 1.43% - Return on Average Equity(1) 9.21% 7.82% 12.38% 13.63% 15.68% - Net Interest Margin (FTE) 3.52% 3.65% 3.88% 3.80% 3.34% - Efficiency
Ratio 73.70% 69.20% 67.20% 64.90% 59.24% - Asset Quality: NPAs / Assets 0.72% 0.35% 0.29% 0.32% 0.21% - NPAs / Loans + OREO 1.14% 0.49% 0.38% 0.42% 0.32% - Reserves / Total
Loans 1.26% 1.12% 0.96% 0.96% 1.30% - NCOs / Avg. Loans 0.06% (0.06%) (0.03%) (0.02%) 0.11% - Capital Ratios: TCE Ratio 9.7% 9.4% 9.2% 9.0% 8.6% - Leverage
Ratio 10.5% 10.6% 10.5% 10.1% 9.2% - Tier 1 Capital Ratio 14.7% 14.0% 13.3% 12.7% 13.3% - Total Capital Ratio 15.9% 15.2% 14.3% 13.7% 16.0% - Shareholder Value: TBV/Share $ 11.62 $
12.34 $ 12.90 $ 14.08 $ 16.33 7.0% Dividends Paid per Share $ 0.34 $ 0.42 $ 0.60 $ 0.72 $ 0.80 18.7% Value of Shares Repurchased $ 16.85 $ - $ 12.68 $ 26.28 $ 14.23 -
Incurred Loss Model vs CECL 25 Incurred vs. CECL ($ in Thousands) 12/31/20 “As If” ACL
and percent of loans calculated at midpoint of incremental range with additional $11.5 million at Day. The ACL to total loans ratio is approximately 1.80% excluding PPP loans. % Loans 0.96% 1.30% 1.72%(1) “As-if CECL” Illustrative
Only Incurred Loss Build We delayed adopting CECL under the CARES Act:Increased visibility into the economic (local, regional, national) impact of the COVID-19 pandemic. Unemployment forecast sources exhibiting wide
disparity.Relationship between unemployment and credit impacted by non-traditional factors, including “stay at home” executive orders, increased unemployment eligibility as well as supplemental unemployment benefits. Incurred
Model:4Q’20 provision was a credit of $0.4 millionDecember 31, 2020 allowance for loan losses of $35.4 million or,1.30% of portfolio loans;1.43% of portfolio loans excluding PPP loans and remaining Traverse City State Bank acquired
loans; and450% of non-performing loans.Qualitative/subjective allocation increased $0.5 million in 4Q’20 (and by $11.2 million for full-year 2020) due to impact of: increased economic shock to high risk industries, elevated unemployment
claims and the level of retail forbearance requests.CECL:Expect to adopt CECL on January 1, 2021 as allowed under the CARES Act extension. ECL day 1 impact range is $10.5 million to $12.5 million with $0.5 million to $1.5 million for
unfunded commitments.Increase in the estimated day 1 adjustment range is due to certain discounted cash flow model enhancements.CECL Model Details:Discounted cash flow model with fourteen loan segments.Probability of default and loss
given default based on long-term average for commercial loans and regression for mortgage and installment loans.Regression uses one year forecast / with immediate reversion to mean driven primarily by unemployment.Unemployment data:
median of Bloomberg survey: 6.7% Q4, falls to 5.9% at the end of the one year forecast.Q factors: economic shock, forbearance activity, and loans in high risk industries. Allocation of Incurred ALLL $26,148 $35,429
$46,929 (1) $9,281 $10,500 to $12,500 12/31/19 ALLL Reserve Build Under Incurred Loss 12/31/20 Incurred Loss Reserve "As If" Day 1 CECL Reserve 1/1/21 "As If" ACL
Historical Annual Results 6 (1) Excluding the impact of the $5.96 million re-measurement of net
deferred tax assets in 2017, net income is $26.44 million, ROA is 1.00% and ROE is 10.10%. Year Ended December 31, ($M except per share data) 2016 2017 2018 2019 2020 5 Year CAGR Balance
Sheet: Total Assets $2,549 $2,789 $3,353 $3,565 $4,204 10.5% Portfolio Loans $1,608 $2,019 $2,583 $2,725 $2,734 11.2% Deposits $2,226 $2,401 $2,913 $3,037 $3,637 10.3% Tangible Common
Equity $247 $263 $304 $317 $357 7.6% Profitability: Pre-Tax, Pre-Provision Income $31.6 $39.6 $50.6 $58.6 $81.9 21.0% Pre-Tax, Pre-Prov / Avg. Assets 1.28% 1.50% 1.62% 1.70% 2.08% - Net
Income(1) $22.8 $20.5 $39.8 $46.4 $56.2 19.8% Diluted EPS 1.05% 0.95% 1.68% 2.00% 2.53% 19.2% Return on Average Assets(1) 0.92% 0.77% 1.27% 1.35% 1.43% - Return on Average
Equity(1) 9.21% 7.82% 12.38% 13.63% 15.68% - Net Interest Margin (FTE) 3.52% 3.65% 3.88% 3.80% 3.34% - Efficiency Ratio 73.70% 69.20% 67.20% 64.90% 59.24% - Asset Quality: NPAs /
Assets 0.72% 0.35% 0.29% 0.32% 0.21% - NPAs / Loans + OREO 1.14% 0.49% 0.38% 0.42% 0.32% - Reserves / Total Loans 1.26% 1.12% 0.96% 0.96% 1.30% - NCOs / Avg.
Loans 0.06% (0.06%) (0.03%) (0.02%) 0.11% - Capital Ratios: TCE Ratio 9.7% 9.4% 9.2% 9.0% 8.6% - Leverage Ratio 10.5% 10.6% 10.5% 10.1% 9.2% - Tier 1 Capital
Ratio 14.7% 14.0% 13.3% 12.7% 13.3% - Total Capital Ratio 15.9% 15.2% 14.3% 13.7% 16.0% - Shareholder Value: TBV/Share $ 11.62 $ 12.34 $ 12.90 $ 14.08 $ 16.33 7.0% Dividends Paid per
Share $ 0.34 $ 0.42 $ 0.60 $ 0.72 $ 0.80 18.7% Value of Shares Repurchased $ 16.85 $ - $ 12.68 $ 26.28 $ 14.23 -
4Q 2020 Financial Highlights Income StatementPre-tax, pre-provision income was $20.6 million in the
fourth quarter of 2020 compared to $17.0 million in the fourth quarter of 2019.Net income of $17.0 million, or $0.77 per diluted share compared to $13.9 million, or $0.61 per diluted share for the year ago quarter.Net interest income of $31.0
million, compared to $30.7 million, for the year ago quarter.Mortgage loan originations of $502.5 million, also, $388.6 million in mortgage loans sold with $15.9 million in net gains on mortgage loans compared to $6.4 million in net gains
from the year ago quarter. Mortgage servicing rights change (the “MSR Change”) due to price of negative $0.9 million ($0.03 per diluted share, after taxes) compared to $0.6 million ($0.02 per diluted share, after taxes) in the fourth quarter
of 2019. Provision for loan loss credit of $0.4 million compared to a credit of $0.2 million in the fourth quarter of 2019. Included within the fourth quarter 2020 provision for loan losses is a $0.5 million increase in the
subjective/qualitative reserve.Balance Sheet/CapitalSecurities available for sale increased by $87.1 million.Total portfolio loans declined by $121.8 million.Total deposits grew by $39.6 million.Total stockholder’s equity increased by $16.4
million and tangible book value per share increased by 5.0% to $16.33 per share at December 31, 2020. Paid a 20 cent per share cash dividend on common stock on November 16, 2020. 7
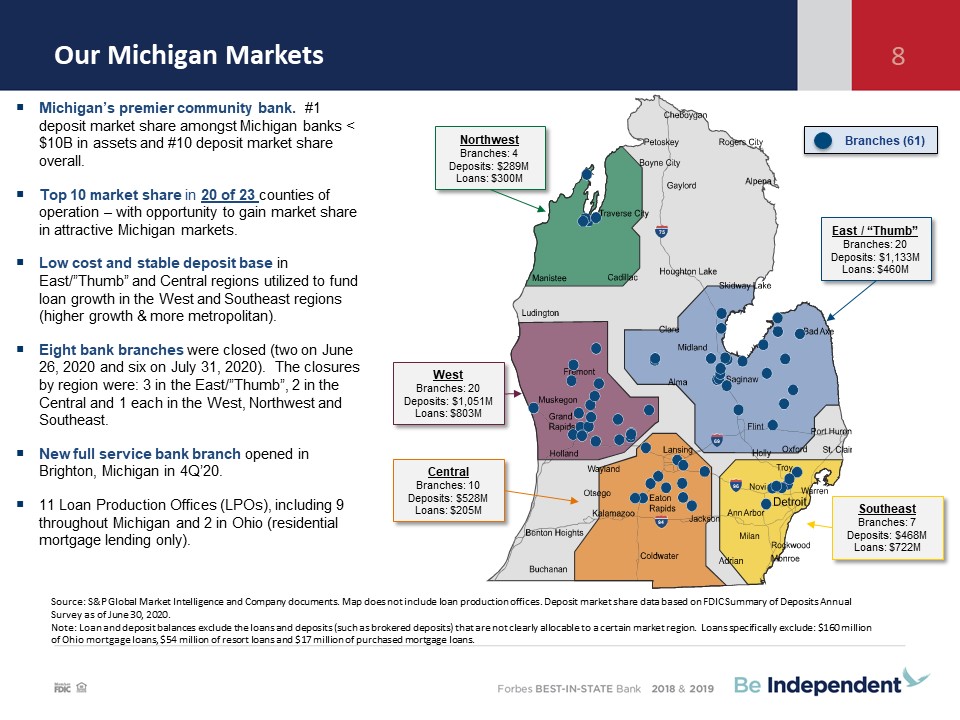
Our Michigan Markets 8 Source: S&P Global Market Intelligence and Company documents. Map does not
include loan production offices. Deposit market share data based on FDIC Summary of Deposits Annual Survey as of June 30, 2020.Note: Loan and deposit balances exclude the loans and deposits (such as brokered deposits) that are not clearly
allocable to a certain market region. Loans specifically exclude: $160 million of Ohio mortgage loans, $54 million of resort loans and $17 million of purchased mortgage loans. 94 96 75 69 Michigan’s
premier community bank. #1 deposit market share amongst Michigan banks < $10B in assets and #10 deposit market share overall. Top 10 market share in 20 of 23 counties of operation – with opportunity to gain market share in attractive
Michigan markets.Low cost and stable deposit base in East/”Thumb” and Central regions utilized to fund loan growth in the West and Southeast regions (higher growth & more metropolitan).Eight bank branches were closed (two on June 26, 2020
and six on July 31, 2020). The closures by region were: 3 in the East/”Thumb”, 2 in the Central and 1 each in the West, Northwest and Southeast. New full service bank branch opened in Brighton, Michigan in 4Q’20.11 Loan Production Offices
(LPOs), including 9 throughout Michigan and 2 in Ohio (residential mortgage lending only). Branches (61) East / “Thumb”Branches: 20Deposits: $1,133MLoans: $460M SoutheastBranches: 7Deposits: $468MLoans: $722M CentralBranches:
10Deposits: $528MLoans: $205M WestBranches: 20Deposits: $1,051MLoans: $803M NorthwestBranches: 4Deposits: $289MLoans: $300M
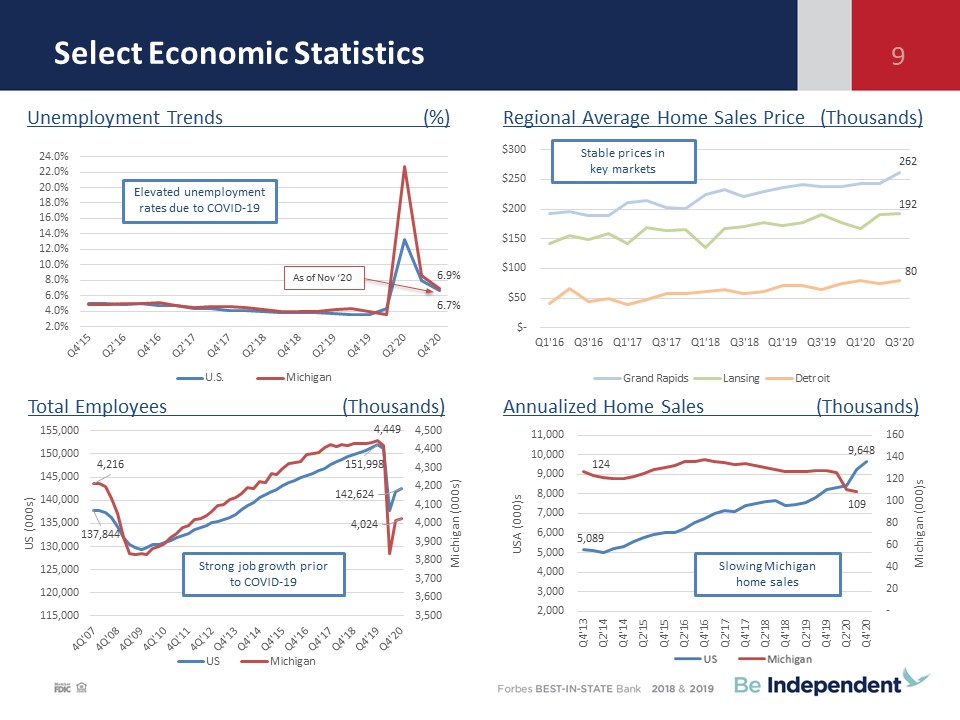
Select Economic Statistics Unemployment Trends (%) Total Employees (Thousands) Regional Average
Home Sales Price (Thousands) Annualized Home Sales (Thousands) 9 Elevated unemployment rates due to COVID-19 As of Nov ‘20 Stable prices in key markets Strong job growth prior to COVID-19 Slowing Michigan home sales
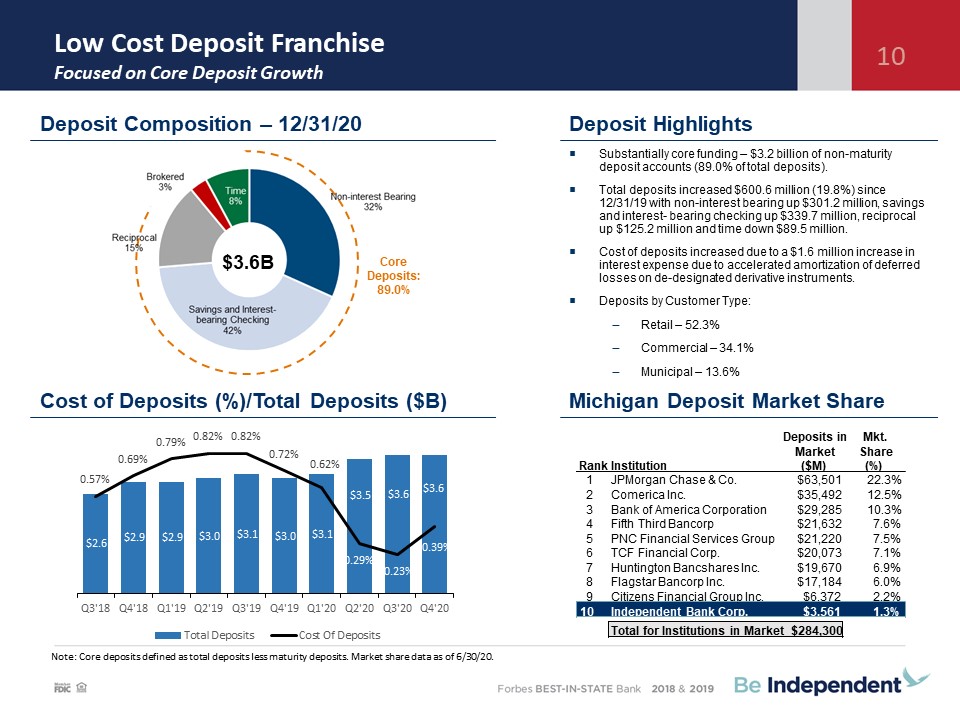
Low Cost Deposit Franchise Focused on Core Deposit Growth 10 Substantially core funding – $3.2
billion of non-maturity deposit accounts (89.0% of total deposits).Total deposits increased $600.6 million (19.8%) since 12/31/19 with non-interest bearing up $301.2 million, savings and interest- bearing checking up $339.7 million,
reciprocal up $125.2 million and time down $89.5 million.Cost of deposits increased due to a $1.6 million increase in interest expense due to accelerated amortization of deferred losses on de-designated derivative instruments. Deposits by
Customer Type:Retail – 52.3%Commercial – 34.1%Municipal – 13.6% Deposit Composition – 12/31/20 Deposit Highlights Michigan Deposit Market Share $3.6B Core Deposits: 89.0% Cost of Deposits (%)/Total Deposits ($B) Note: Core deposits
defined as total deposits less maturity deposits. Market share data as of 6/30/20. Deposits in Mkt. Market Share Rank Institution ($M) (%) 1 JPMorgan Chase & Co. $63,501 22.3% 2 Comerica Inc. $35,492 12.5% 3 Bank
of America Corporation $29,285 10.3% 4 Fifth Third Bancorp $21,632 7.6% 5 PNC Financial Services Group $21,220 7.5% 6 TCF Financial Corp. $20,073 7.1% 7 Huntington Bancshares Inc. $19,670 6.9% 8 Flagstar Bancorp Inc.
$17,184 6.0% 9 Citizens Financial Group Inc. $6,372 2.2% 10 Independent Bank Corp. $3,561 1.3% Total for Institutions in Market $284,300
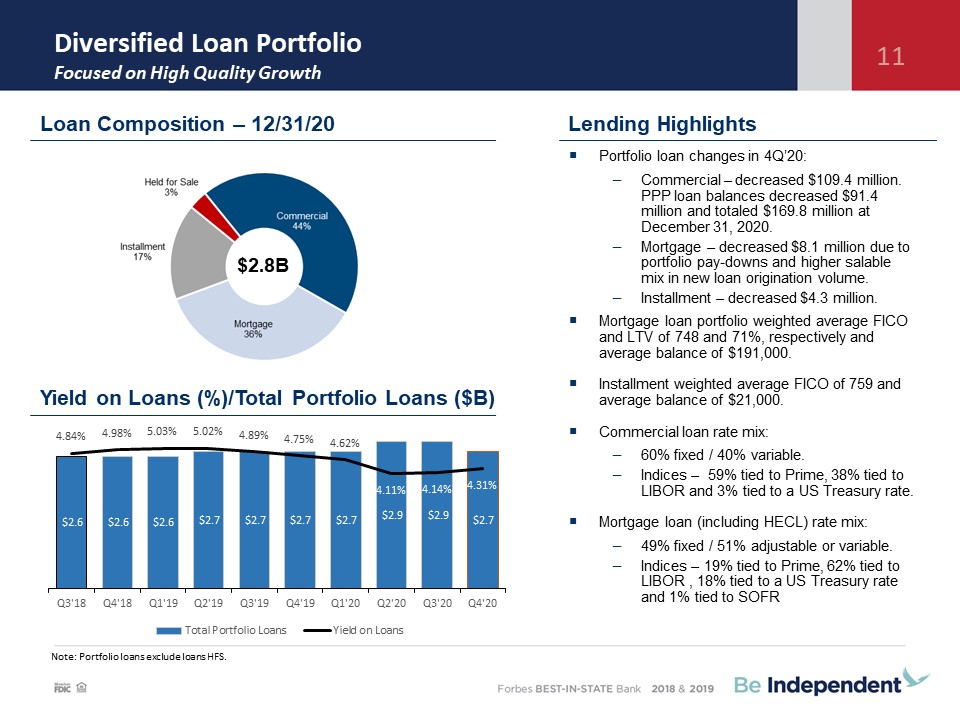
Diversified Loan PortfolioFocused on High Quality Growth 11 Lending Highlights Note: Portfolio loans
exclude loans HFS. Portfolio loan changes in 4Q’20:Commercial – decreased $109.4 million. PPP loan balances decreased $91.4 million and totaled $169.8 million at December 31, 2020.Mortgage – decreased $8.1 million due to portfolio pay-downs
and higher salable mix in new loan origination volume. Installment – decreased $4.3 million.Mortgage loan portfolio weighted average FICO and LTV of 748 and 71%, respectively and average balance of $191,000.Installment weighted average FICO
of 759 and average balance of $21,000.Commercial loan rate mix:60% fixed / 40% variable.Indices – 59% tied to Prime, 38% tied to LIBOR and 3% tied to a US Treasury rate.Mortgage loan (including HECL) rate mix: 49% fixed / 51% adjustable or
variable. Indices – 19% tied to Prime, 62% tied to LIBOR , 18% tied to a US Treasury rate and 1% tied to SOFR Loan Composition – 12/31/20 $2.8B Yield on Loans (%)/Total Portfolio Loans ($B)
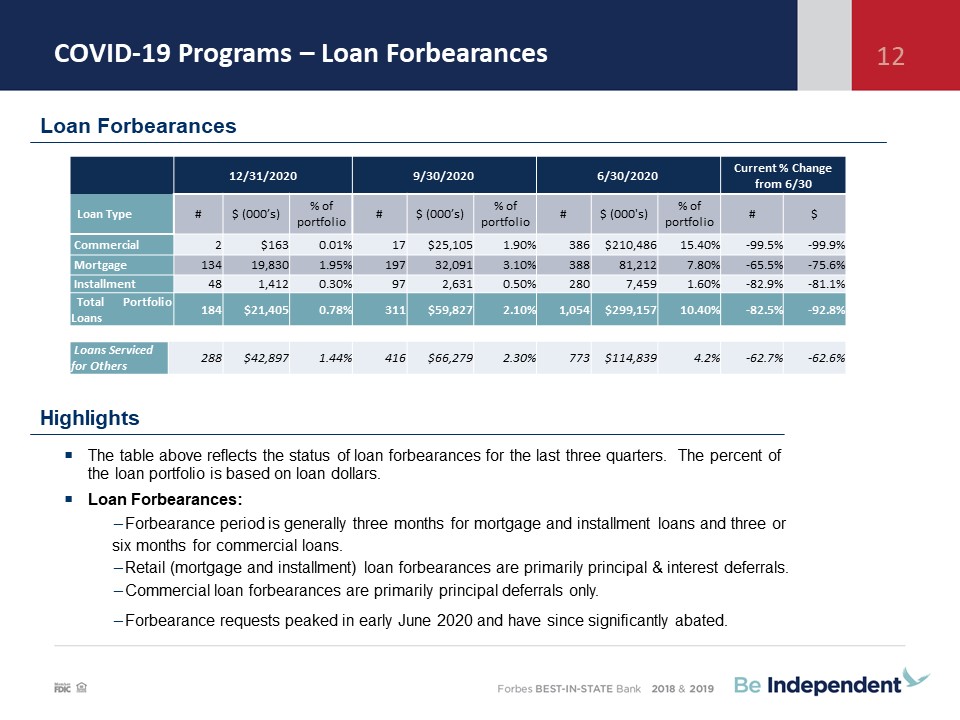
COVID-19 Programs – Loan Forbearances 12 Highlights Loan
Forbearances 12/31/2020 9/30/2020 6/30/2020 Current % Change from 6/30 Loan Type # $ (000’s) % of portfolio # $ (000’s) % of portfolio # $ (000's) % of portfolio # $ Commercial 2 $163
0.01% 17 $25,105 1.90% 386 $210,486 15.40% -99.5% -99.9% Mortgage 134 19,830 1.95% 197 32,091 3.10% 388 81,212 7.80% -65.5% -75.6% Installment 48 1,412 0.30% 97 2,631 0.50% 280 7,459 1.60% -82.9% -81.1%
Total Portfolio Loans 184 $21,405 0.78% 311 $59,827 2.10% 1,054 $299,157 10.40% -82.5% -92.8% Loans Serviced for Others 288 $42,897 1.44% 416 $66,279 2.30% 773 $114,839 4.2% -62.7% -62.6% The table
above reflects the status of loan forbearances for the last three quarters. The percent of the loan portfolio is based on loan dollars.Loan Forbearances:Forbearance period is generally three months for mortgage and installment loans and three
or six months for commercial loans. Retail (mortgage and installment) loan forbearances are primarily principal & interest deferrals.Commercial loan forbearances are primarily principal deferrals only.Forbearance requests peaked in early
June 2020 and have since significantly abated.
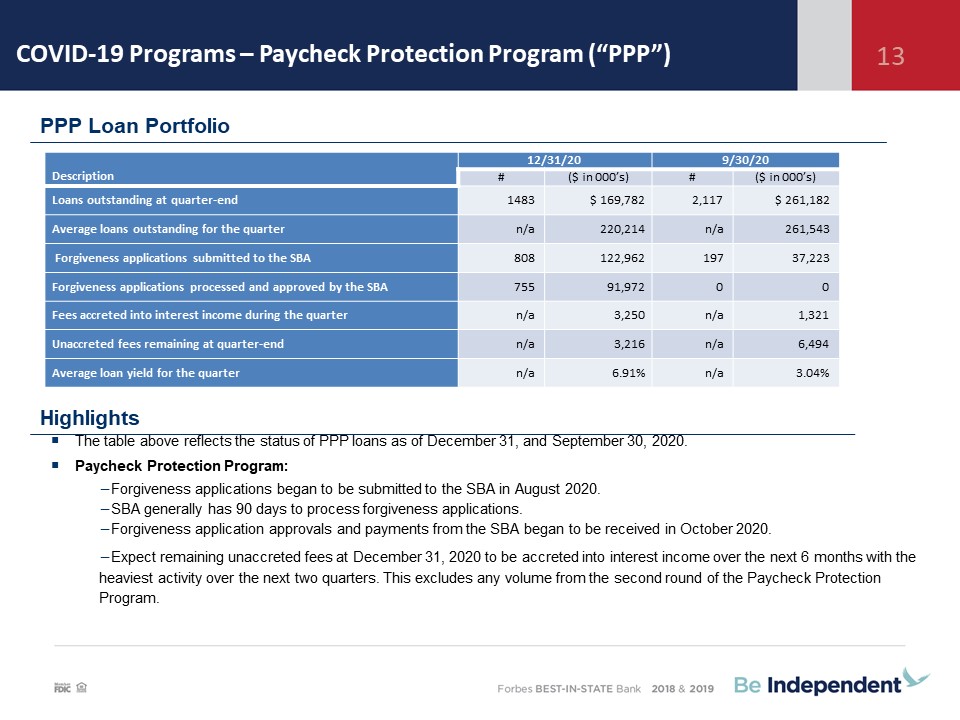
COVID-19 Programs – Paycheck Protection Program (“PPP”) 13 Highlights PPP Loan Portfolio The table
above reflects the status of PPP loans as of December 31, and September 30, 2020.Paycheck Protection Program:Forgiveness applications began to be submitted to the SBA in August 2020. SBA generally has 90 days to process forgiveness
applications.Forgiveness application approvals and payments from the SBA began to be received in October 2020.Expect remaining unaccreted fees at December 31, 2020 to be accreted into interest income over the next 6 months with the heaviest
activity over the next two quarters. This excludes any volume from the second round of the Paycheck Protection Program. Description 12/31/20 9/30/20 # ($ in 000’s) # ($ in 000’s) Loans outstanding at quarter-end 1483 $
169,782 2,117 $ 261,182 Average loans outstanding for the quarter n/a 220,214 n/a 261,543 Forgiveness applications submitted to the SBA 808 122,962 197 37,223 Forgiveness applications processed and approved by the
SBA 755 91,972 0 0 Fees accreted into interest income during the quarter n/a 3,250 n/a 1,321 Unaccreted fees remaining at quarter-end n/a 3,216 n/a 6,494 Average loan yield for the quarter n/a 6.91% n/a 3.04%
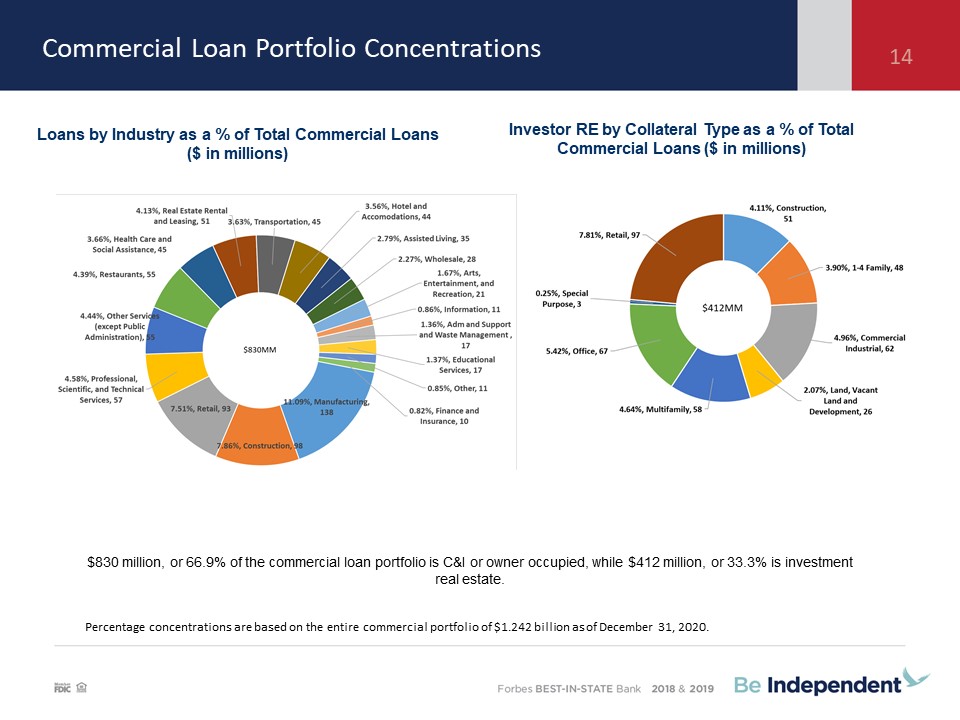
Loan Portfolio Concentrations by Industry Percentage concentrations are based on the entire
commercial portfolio of $1.242 billion as of December 31, 2020. Loans by Industry as a % of Total Commercial Loans ($ in millions) Investor RE by Collateral Type as a % of Total Commercial Loans ($ in millions) $830 million, or 66.9% of
the commercial loan portfolio is C&I or owner occupied, while $412 million, or 33.3% is investment real estate. 14 Commercial Loan Portfolio Concentrations
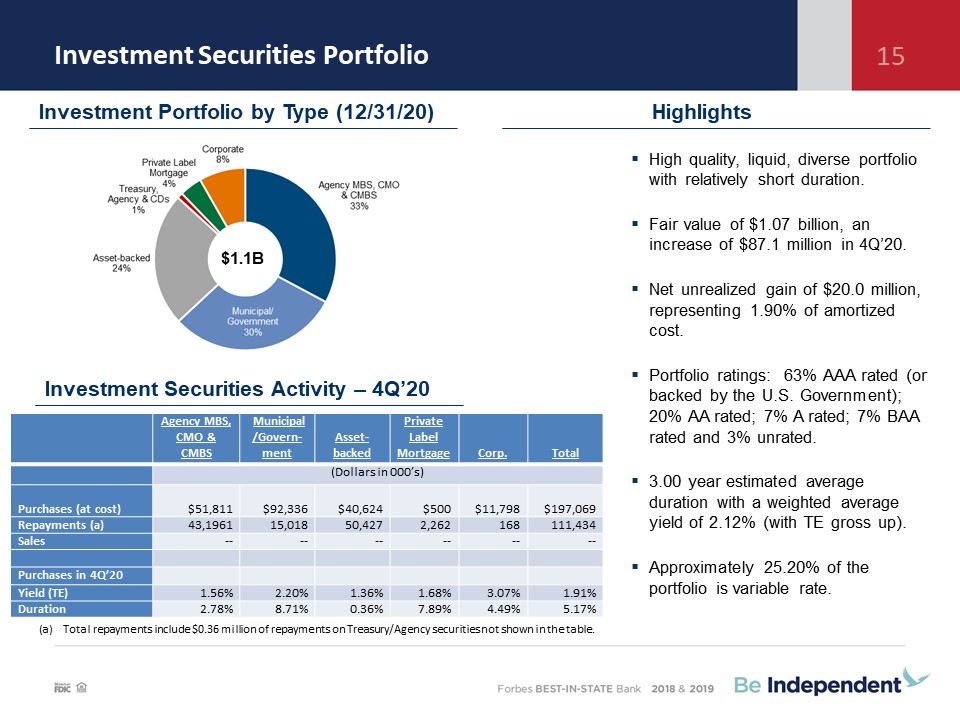
Investment Securities Portfolio 15 Highlights High quality, liquid, diverse portfolio with
relatively short duration.Fair value of $1.07 billion, an increase of $87.1 million in 4Q’20.Net unrealized gain of $20.0 million, representing 1.90% of amortized cost.Portfolio ratings: 63% AAA rated (or backed by the U.S. Government); 20%
AA rated; 7% A rated; 7% BAA rated and 3% unrated.3.00 year estimated average duration with a weighted average yield of 2.12% (with TE gross up).Approximately 25.20% of the portfolio is variable rate. $1.1B Investment Portfolio by Type
(12/31/20) Investment Securities Activity – 4Q’20 Agency MBS, CMO & CMBS Municipal/Govern-ment Asset-backed Private Label Mortgage Corp. Total (Dollars in 000’s) Purchases (at
cost) $51,811 $92,336 $40,624 $500 $11,798 $197,069 Repayments (a) 43,1961 15,018 50,427 2,262 168 111,434 Sales -- -- -- -- -- -- Purchases in 4Q’20 Yield
(TE) 1.56% 2.20% 1.36% 1.68% 3.07% 1.91% Duration 2.78% 8.71% 0.36% 7.89% 4.49% 5.17% Total repayments include $0.36 million of repayments on Treasury/Agency securities not shown in the table.
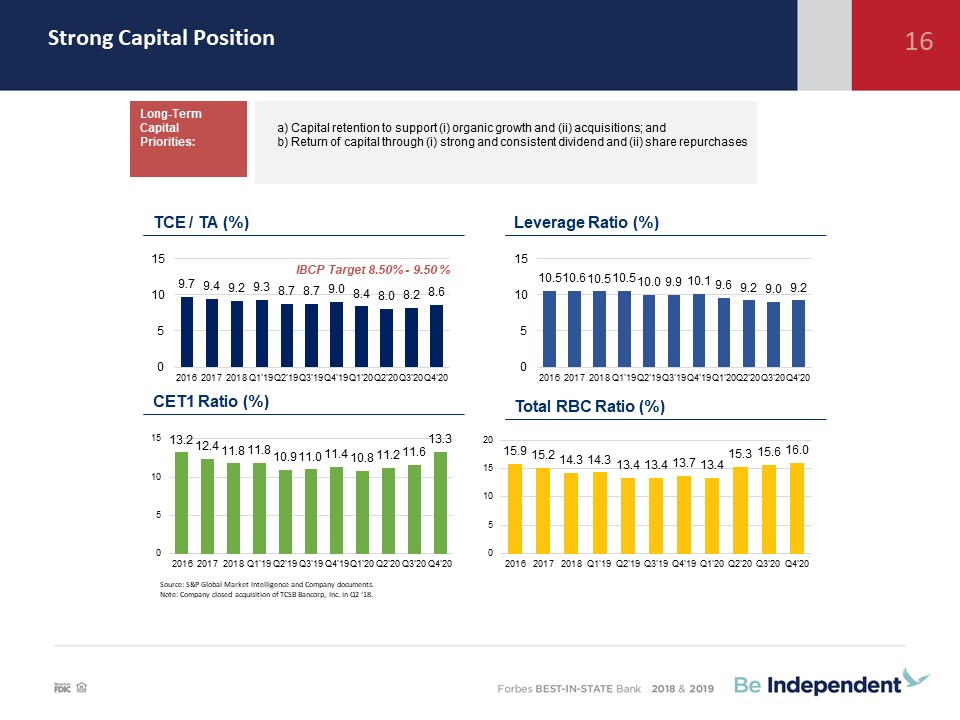
Strong Capital Position 16 Source: S&P Global Market Intelligence and Company documents.Note:
Company closed acquisition of TCSB Bancorp, Inc. in Q2 ‘18. TCE / TA (%) Leverage Ratio (%) CET1 Ratio (%) Total RBC Ratio (%) IBCP Target 8.50% - 9.50 % Capital retention to support (i) organic growth and (ii) acquisitions; and
Return of capital through (i) strong and consistent dividend and (ii) share repurchases Long-Term Capital Priorities: Strong Capital Position
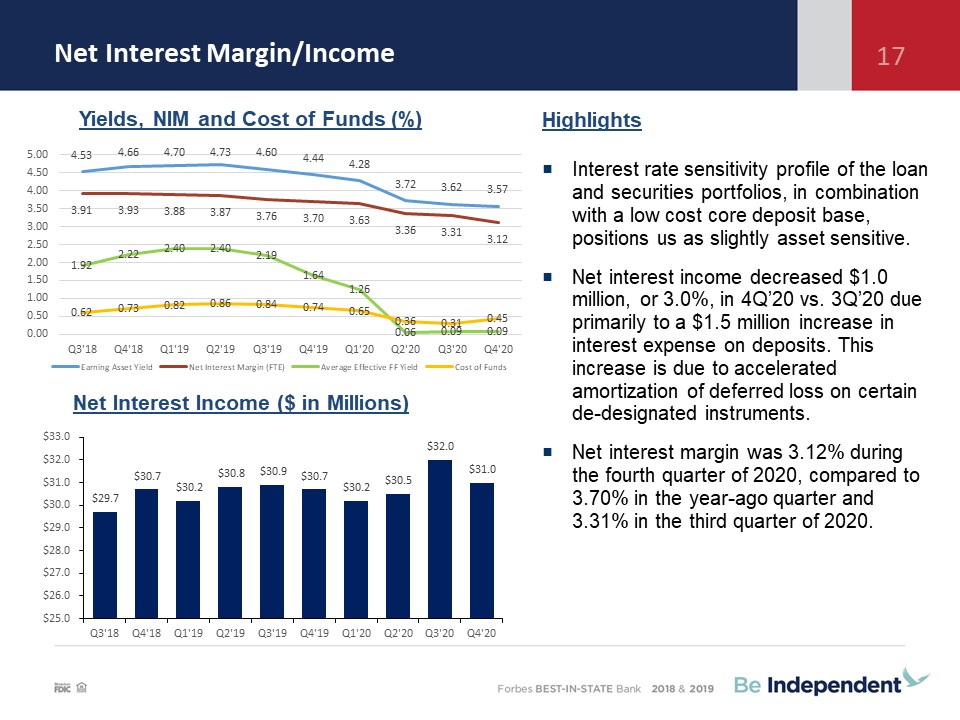
HighlightsInterest rate sensitivity profile of the loan and securities portfolios, in combination with
a low cost core deposit base, positions us as slightly asset sensitive.Net interest income decreased $1.0 million, or 3.0%, in 4Q’20 vs. 3Q’20 due primarily to a $1.5 million increase in interest expense on deposits. This increase is due to
accelerated amortization of deferred loss on certain de-designated instruments. Net interest margin was 3.12% during the fourth quarter of 2020, compared to 3.70% in the year-ago quarter and 3.31% in the third quarter of 2020. Yields, NIM
and Cost of Funds (%) Net Interest Income ($ in Millions) Net Interest Margin/Income 17
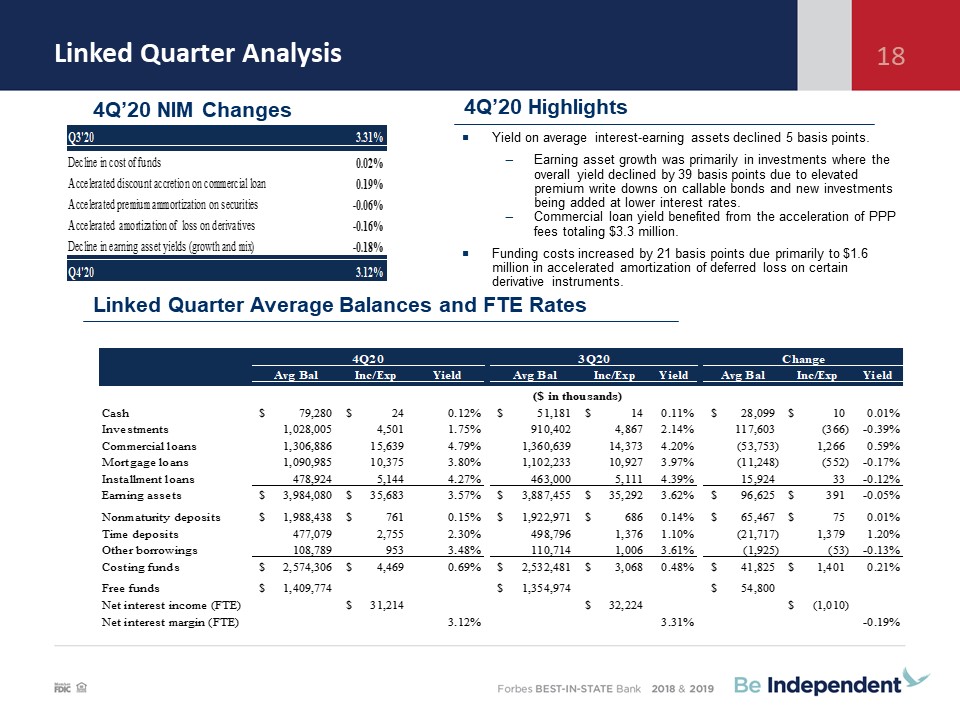
Linked Quarter Analysis 18 4Q’20 NIM Changes Linked Quarter Average Balances and FTE Rates Yield on
average interest-earning assets declined 5 basis points.Earning asset growth was primarily in investments where the overall yield declined by 39 basis points due to elevated premium write downs on callable bonds and new investments being
added at lower interest rates.Commercial loan yield benefited from the acceleration of PPP fees totaling $3.3 million. Funding costs increased by 21 basis points due primarily to $1.6 million in accelerated amortization of deferred loss on
certain derivative instruments. 4Q’20 Highlights
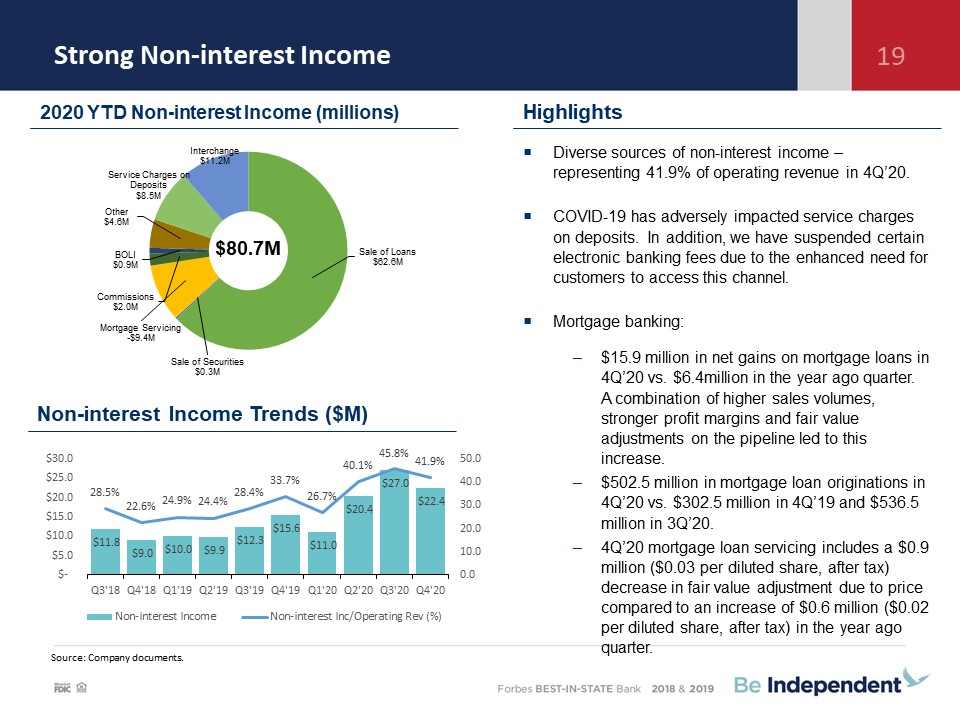
Strong Non-interest Income 19 Diverse sources of non-interest income – representing 41.9% of
operating revenue in 4Q’20.COVID-19 has adversely impacted service charges on deposits. In addition, we have suspended certain electronic banking fees due to the enhanced need for customers to access this channel.Mortgage banking: $15.9
million in net gains on mortgage loans in 4Q’20 vs. $6.4million in the year ago quarter. A combination of higher sales volumes, stronger profit margins and fair value adjustments on the pipeline led to this increase.$502.5 million in mortgage
loan originations in 4Q’20 vs. $302.5 million in 4Q’19 and $536.5 million in 3Q’20.4Q’20 mortgage loan servicing includes a $0.9 million ($0.03 per diluted share, after tax) decrease in fair value adjustment due to price compared to an
increase of $0.6 million ($0.02 per diluted share, after tax) in the year ago quarter. Source: Company documents. $80.7M 2020 YTD Non-interest Income (millions) Non-interest Income Trends ($M) Highlights
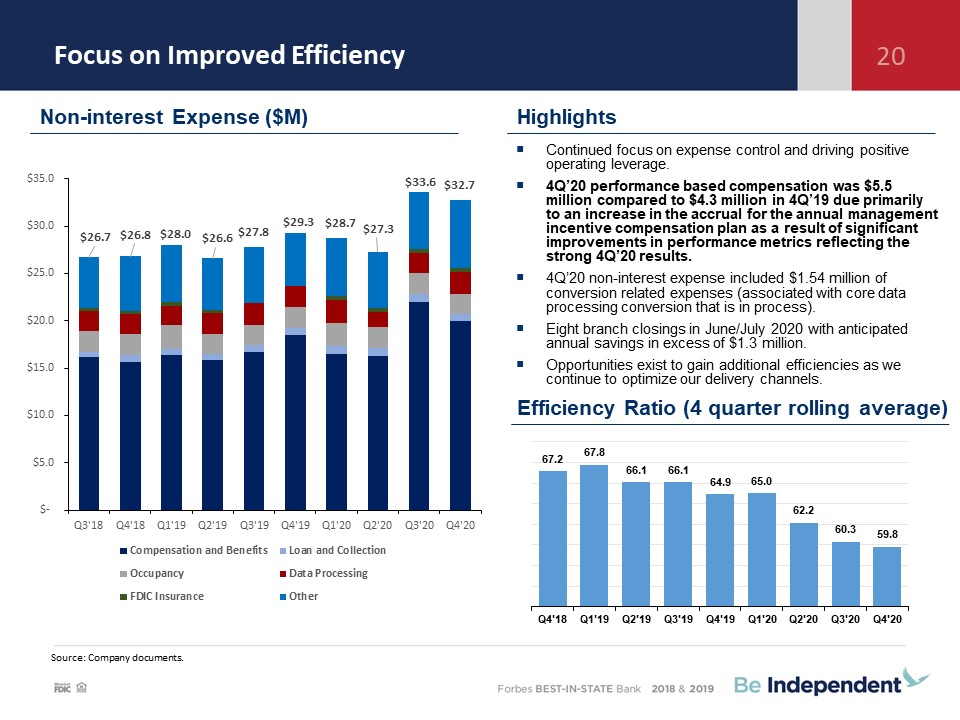
Focus on Improved Efficiency 20 Source: Company documents. Non-interest Expense ($M) Highlights
Efficiency Ratio (4 quarter rolling average) Continued focus on expense control and driving positive operating leverage. 4Q’20 performance based compensation was $5.5 million compared to $4.3 million in 4Q’19 due primarily to an increase in
the accrual for the annual management incentive compensation plan as a result of significant improvements in performance metrics reflecting the strong 4Q’20 results.4Q’20 non-interest expense included $1.54 million of conversion related
expenses (associated with core data processing conversion that is in process).Eight branch closings in June/July 2020 with anticipated annual savings in excess of $1.3 million.Opportunities exist to gain additional efficiencies as we continue
to optimize our delivery channels.
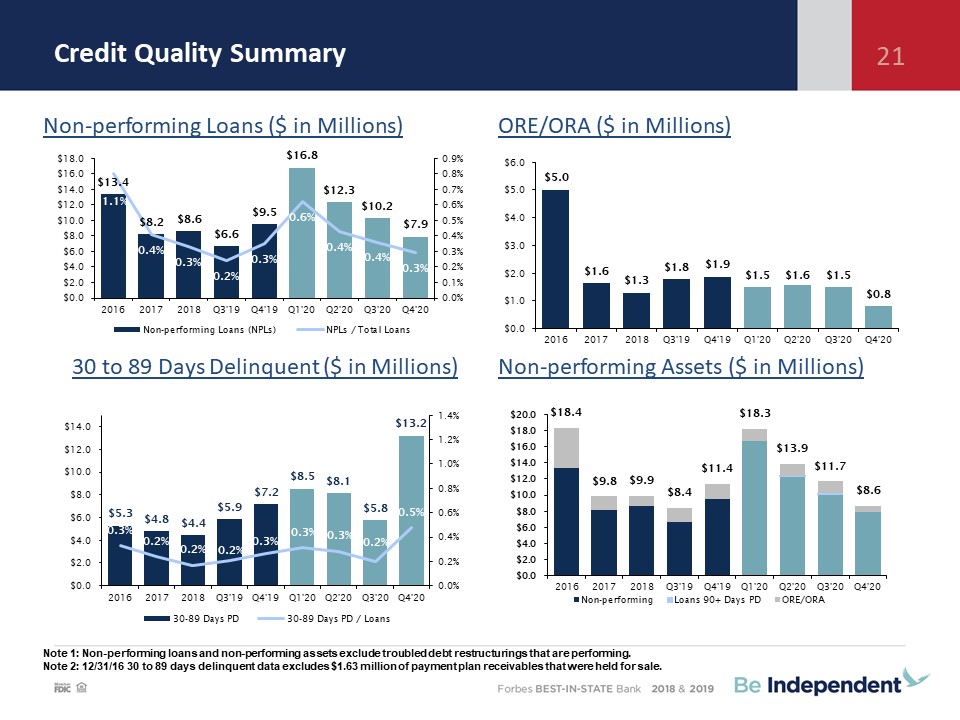
Credit Quality Summary Note 1: Non-performing loans and non-performing assets exclude troubled debt
restructurings that are performing.Note 2: 12/31/16 30 to 89 days delinquent data excludes $1.63 million of payment plan receivables that were held for sale. Non-performing Assets ($ in Millions) ORE/ORA ($ in Millions) Non-performing
Loans ($ in Millions) 30 to 89 Days Delinquent ($ in Millions) 21
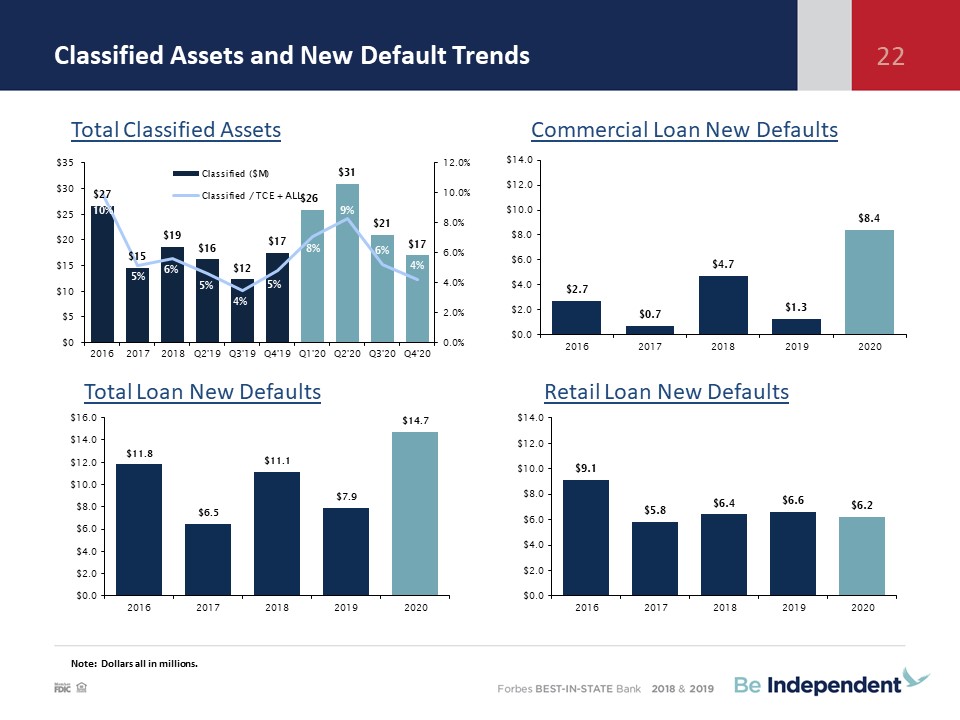
Classified Assets and New Default Trends Note: Dollars all in millions. Total Classified
Assets Commercial Loan New Defaults Total Loan New Defaults Retail Loan New Defaults 22
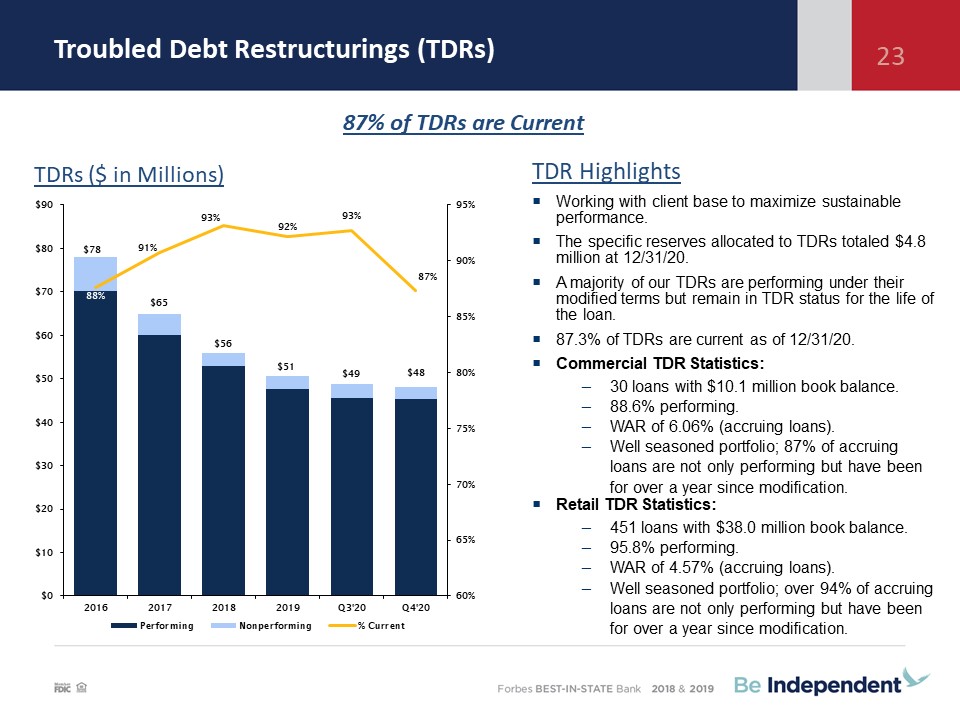
Troubled Debt Restructurings (TDRs) TDR HighlightsWorking with client base to maximize sustainable
performance.The specific reserves allocated to TDRs totaled $4.8 million at 12/31/20.A majority of our TDRs are performing under their modified terms but remain in TDR status for the life of the loan.87.3% of TDRs are current as of
12/31/20.Commercial TDR Statistics:30 loans with $10.1 million book balance.88.6% performing.WAR of 6.06% (accruing loans).Well seasoned portfolio; 87% of accruing loans are not only performing but have been for over a year since
modification.Retail TDR Statistics:451 loans with $38.0 million book balance.95.8% performing.WAR of 4.57% (accruing loans).Well seasoned portfolio; over 94% of accruing loans are not only performing but have been for over a year since
modification. TDRs ($ in Millions) 87% of TDRs are Current 23
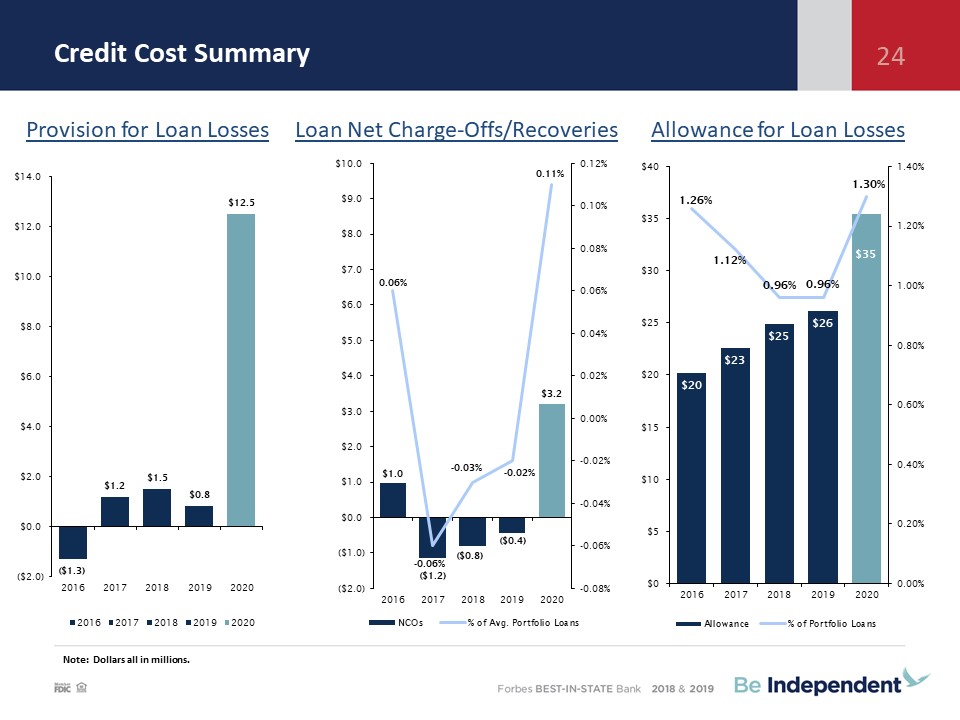
Note: Dollars all in millions. Provision for Loan Losses Loan Net Charge-Offs/Recoveries
Allowance for Loan Losses Credit Cost Summary 24
Incurred Loss Model vs CECL 25 Incurred vs. CECL ($ in Thousands) 12/31/20 “As If” ACL and percent
of loans calculated at midpoint of incremental range with additional $11.5 million at Day. The ACL to total loans ratio is approximately 1.80% excluding PPP loans. % Loans 0.96% 1.30% 1.72%(1) “As-if CECL” Illustrative Only Incurred
Loss Build We delayed adopting CECL under the CARES Act:Increased visibility into the economic (local, regional, national) impact of the COVID-19 pandemic. Unemployment forecast sources exhibiting wide disparity.Relationship between
unemployment and credit impacted by non-traditional factors, including “stay at home” executive orders, increased unemployment eligibility as well as supplemental unemployment benefits. Incurred Model:4Q’20 provision was a credit of $0.4
millionDecember 31, 2020 allowance for loan losses of $35.4 million or,1.30% of portfolio l
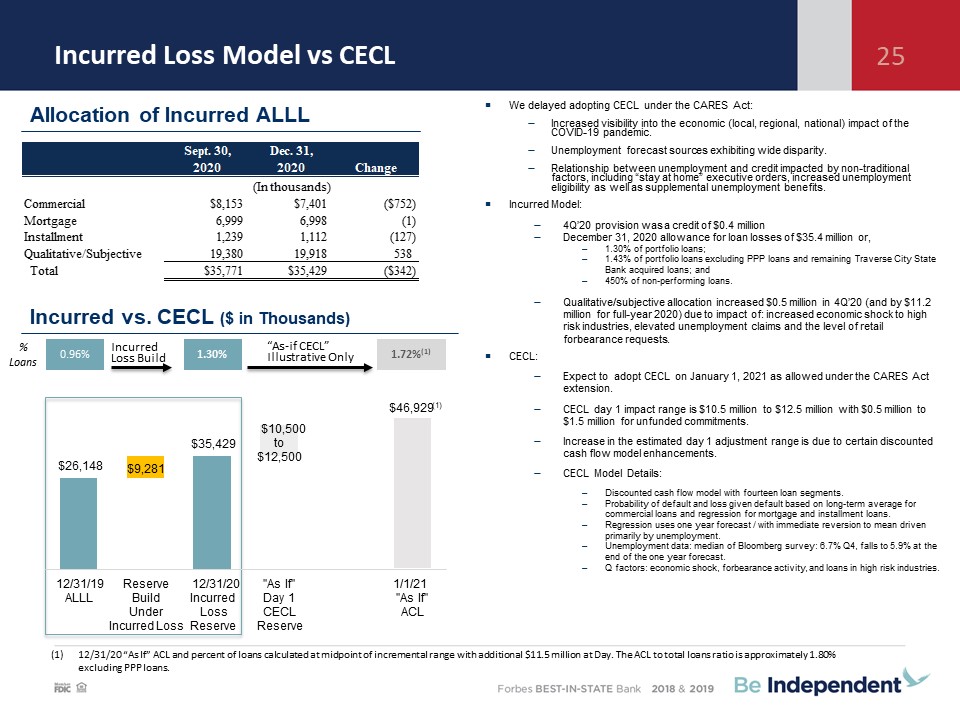
oans;1.38% of portfolio loans excluding PPP loans and remaining Traverse City State Bank acquired loans; and450% of non-performing loans.Qualitative/subjective allocation increased $0.5 million in 4Q’20 (and by $11.2 million for full-year
2020) due to impact of: increased economic shock to high risk industries, elevated unemployment claims and the level of retail forbearance requests.CECL:Expect to adopt CECL on January 1, 2021 as allowed under the CARES Act extension. CECL
day 1 impact range is $10.5 million to $12.5 million with $0.5 million to $1.5 million for unfunded commitments.Increase in the estimated day 1 adjustment range is due to certain discounted cash flow model enhancements.CECL Model
Details:Discounted cash flow model with fourteen loan segments.Probability of default and loss given default based on long-term average for commercial loans and regression for mortgage and installment loans.Regression uses one year forecast /
with immediate reversion to mean driven primarily by unemployment.Unemployment data: median of Bloomberg survey: 6.7% Q4, falls to 5.9% at the end of the one year forecast.Q factors: economic shock, forbearance activity, and loans in high
risk industries. Allocation of Incurred ALLL $26,148 $35,429 $46,929 (1) $9,281 $10,500 to $12,500 12/31/19 ALLL Reserve Build Under Incurred Loss 12/31/20 Incurred Loss Reserve "As If" Day
1 CECL Reserve 1/1/21 "As If" ACL
Incurred Loss Model vs CECL 25 Incurred vs. CECL ($ in Thousands) 12/31/20 “As If” ACL and
percent of loans calculated at midpoint of incremental range with additional $11.5 million at Day. The ACL to total loans ratio is approximately 1.80% excluding PPP loans. % Loans 0.96% 1.30% 1.72%(1) “As-if CECL” Illustrative
Only Incurred Loss Build We delayed adopting CECL under the CARES Act:Increased visibility into the economic (local, regional, national) impact of the COVID-19 pandemic. Unemployment forecast sources exhibiting wide
disparity.Relationship between unemployment and credit impacted by non-traditional factors, including “stay at home” executive orders, increased unemployment eligibility as well as supplemental unemployment benefits. Incurred
Model:4Q’20 provision was a credit of $0.4 millionDecember 31, 2020 allowance for loan losses of $35.4 million or,1.30% of portfolio loans;1.43% of portfolio loans excluding PPP loans and remaining Traverse City State Bank acquired
loans; and450% of non-performing loans.Qualitative/subjective allocation increased $0.5 million in 4Q’20 (and by $11.2 million for full-year 2020) due to impact of: increased economic shock to high risk industries, elevated
unemployment claims and the level of retail forbearance requests.CECL:Expect to adopt CECL on January 1, 2021 as allowed under the CARES Act extension. CECL day 1 impact range is $10.5 million to $12.5 million with $0.5 million to
$1.5 million for unfunded commitments.Increase in the estimated day 1 adjustment range is due to certain discounted cash flow model enhancements.CECL Model Details:Discounted cash flow model with fourteen loan segments.Probability of
default and loss given default based on long-term average for commercial loans and regression for mortgage and installment loans.Regression uses one year forecast / with immediate reversion to mean driven primarily by
unemployment.Unemployment data: median of Bloomberg survey: 6.7% Q4, falls to 5.9% at the end of the one year forecast.Q factors: economic shock, forbearance activity, and loans in high risk industries. Allocation of Incurred
ALLL $26,148 $35,429 $46,929 (1) $9,281 $10,500 to $12,500 12/31/19 ALLL Reserve Build Under Incurred Loss 12/31/20 Incurred Loss Reserve "As If" Day 1 CECL Reserve 1/1/21 "As If" ACL
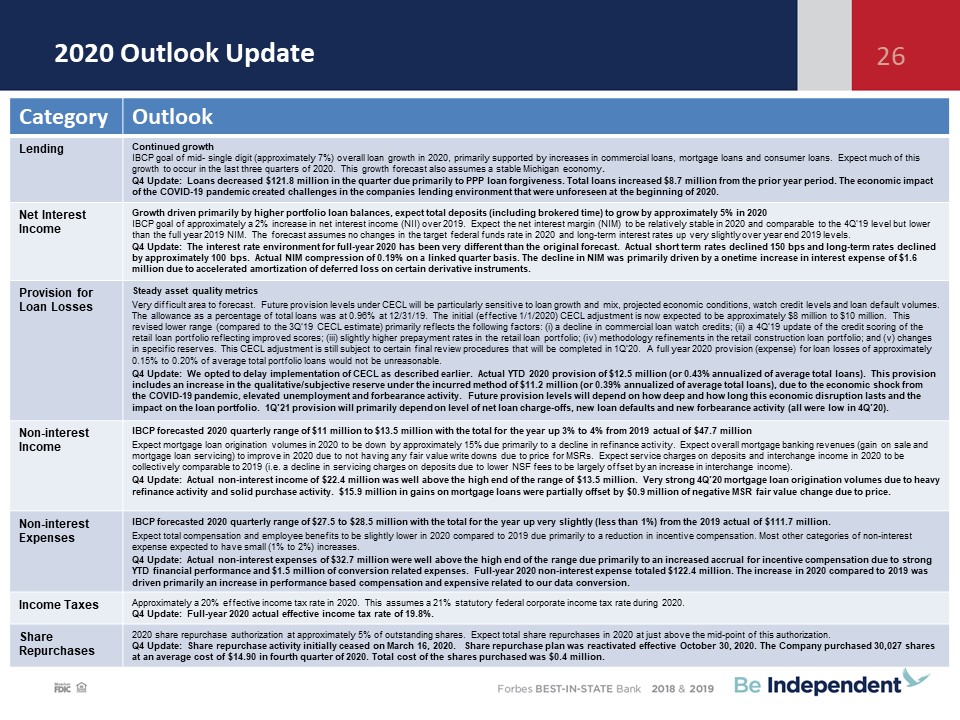
2020 Outlook Update Category Outlook Lending Continued growthIBCP goal of mid- single digit
(approximately 7%) overall loan growth in 2020, primarily supported by increases in commercial loans, mortgage loans and consumer loans. Expect much of this growth to occur in the last three quarters of 2020. This growth forecast also assumes
a stable Michigan economy.Q4 Update: Loans decreased $121.8 million in the quarter due primarily to PPP loan forgiveness. Total loans increased $8.7 million from the prior year period. The economic impact of the COVID-19 pandemic created
challenges in the companies lending environment that were unforeseen at the beginning of 2020. Net Interest Income Growth driven primarily by higher portfolio loan balances, expect total deposits (including brokered time) to grow by
approximately 5% in 2020 IBCP goal of approximately a 2% increase in net interest income (NII) over 2019. Expect the net interest margin (NIM) to be relatively stable in 2020 and comparable to the 4Q’19 level but lower than the full year 2019
NIM. The forecast assumes no changes in the target federal funds rate in 2020 and long-term interest rates up very slightly over year end 2019 levels. Q4 Update: The interest rate environment for full-year 2020 has been very different than
the original forecast. Actual short term rates declined 150 bps and long-term rates declined by approximately 100 bps. Actual NIM compression of 0.19% on a linked quarter basis. The decline in NIM was primarily driven by a onetime increase in
interest expense of $1.6 million due to accelerated amortization of deferred loss on certain derivative instruments. Provision for Loan Losses Steady asset quality metricsVery difficult area to forecast. Future provision levels under CECL
will be particularly sensitive to loan growth and mix, projected economic conditions, watch credit levels and loan default volumes. The allowance as a percentage of total loans was at 0.96% at 12/31/19. The initial (effective 1/1/2020) CECL
adjustment is now expected to be approximately $8 million to $10 million. This revised lower range (compared to the 3Q’19 CECL estimate) primarily reflects the following factors: (i) a decline in commercial loan watch credits; (ii) a 4Q’19
update of the credit scoring of the retail loan portfolio reflecting improved scores; (iii) slightly higher prepayment rates in the retail loan portfolio; (iv) methodology refinements in the retail construction loan portfolio; and (v) changes
in specific reserves. This CECL adjustment is still subject to certain final review procedures that will be completed in 1Q’20. A full year 2020 provision (expense) for loan losses of approximately 0.15% to 0.20% of average total portfolio
loans would not be unreasonable.Q4 Update: We opted to delay implementation of CECL as described earlier. Actual YTD 2020 provision of $12.5 million (or 0.43% annualized of average total loans). This provision includes an increase in the
qualitative/subjective reserve under the incurred method of $11.2 million (or 0.39% annualized of average total loans), due to the economic shock from the COVID-19 pandemic, elevated unemployment and forbearance activity. Future provision
levels will depend on how deep and how long this economic disruption lasts and the impact on the loan portfolio. 1Q’21 provision will primarily depend on level of net loan charge-offs, new loan defaults and new forbearance activity (all were
low in 4Q’20). Non-interest Income IBCP forecasted 2020 quarterly range of $11 million to $13.5 million with the total for the year up 3% to 4% from 2019 actual of $47.7 millionExpect mortgage loan origination volumes in 2020 to be down by
approximately 15% due primarily to a decline in refinance activity. Expect overall mortgage banking revenues (gain on sale and mortgage loan servicing) to improve in 2020 due to not having any fair value write downs due to price for MSRs.
Expect service charges on deposits and interchange income in 2020 to be collectively comparable to 2019 (i.e. a decline in servicing charges on deposits due to lower NSF fees to be largely offset by an increase in interchange income). Q4
Update: Actual non-interest income of $22.4 million was well above the high end of the range of $13.5 million. Very strong 4Q’20 mortgage loan origination volumes due to heavy refinance activity and solid purchase activity. $15.9 million in
gains on mortgage loans were partially offset by $0.9 million of negative MSR fair value change due to price. Non-interest Expenses IBCP forecasted 2020 quarterly range of $27.5 to $28.5 million with the total for the year up very slightly
(less than 1%) from the 2019 actual of $111.7 million.Expect total compensation and employee benefits to be slightly lower in 2020 compared to 2019 due primarily to a reduction in incentive compensation. Most other categories of non-interest
expense expected to have small (1% to 2%) increases.Q4 Update: Actual non-interest expenses of $32.7 million were well above the high end of the range due primarily to an increased accrual for incentive compensation due to strong YTD
financial performance and $1.5 million of conversion related expenses. Full-year 2020 non-interest expense totaled $122.4 million. The increase in 2020 compared to 2019 was driven primarily an increase in performance based compensation and
expensive related to our data conversion. Income Taxes Approximately a 20% effective income tax rate in 2020. This assumes a 21% statutory federal corporate income tax rate during 2020.Q4 Update: Full-year 2020 actual effective income tax
rate of 19.8%. Share Repurchases 2020 share repurchase authorization at approximately 5% of outstanding shares. Expect total share repurchases in 2020 at just above the mid-point of this authorization.Q4 Update: Share repurchase activity
initially ceased on March 16, 2020. Share repurchase plan was reactivated effective October 30, 2020. The Company purchased 30,027 shares at an average cost of $14.90 in fourth quarter of 2020. Total cost of the shares purchased was $0.4
million. 26
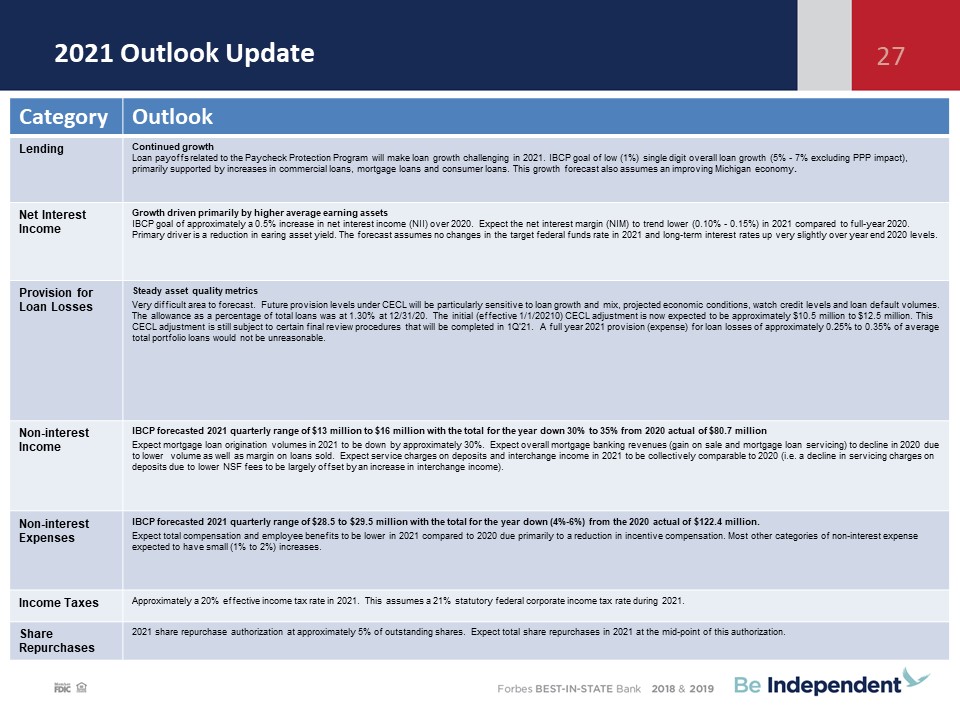
2021 Outlook Update Category Outlook Lending Continued growthLoan payoffs related to the Paycheck
Protection Program will make loan growth challenging in 2021. IBCP goal of low (1%) single digit overall loan growth (5% - 7% excluding PPP impact), primarily supported by increases in commercial loans, mortgage loans and consumer loans. This
growth forecast also assumes an improving Michigan economy. Net Interest Income Growth driven primarily by higher average earning assetsIBCP goal of approximately a 0.5% increase in net interest income (NII) over 2020. Expect the net
interest margin (NIM) to trend lower (0.10% - 0.15%) in 2021 compared to full-year 2020. Primary driver is a reduction in earing asset yield. The forecast assumes no changes in the target federal funds rate in 2021 and long-term interest
rates up very slightly over year end 2020 levels. Provision for Loan Losses Steady asset quality metricsVery difficult area to forecast. Future provision levels under CECL will be particularly sensitive to loan growth and mix, projected
economic conditions, watch credit levels and loan default volumes. The allowance as a percentage of total loans was at 1.30% at 12/31/20. The initial (effective 1/1/20210) CECL adjustment is now expected to be approximately $10.5 million to
$12.5 million. This CECL adjustment is still subject to certain final review procedures that will be completed in 1Q’21. A full year 2021 provision (expense) for loan losses of approximately 0.25% to 0.35% of average total portfolio loans
would not be unreasonable. Non-interest Income IBCP forecasted 2021 quarterly range of $13 million to $16 million with the total for the year down 30% to 35% from 2020 actual of $80.7 millionExpect mortgage loan origination volumes in 2021
to be down by approximately 30%. Expect overall mortgage banking revenues (gain on sale and mortgage loan servicing) to decline in 2020 due to lower volume as well as margin on loans sold. Expect service charges on deposits and interchange
income in 2021 to be collectively comparable to 2020 (i.e. a decline in servicing charges on deposits due to lower NSF fees to be largely offset by an increase in interchange income). Non-interest Expenses IBCP forecasted 2021 quarterly
range of $28.5 to $29.5 million with the total for the year down (4%-6%) from the 2020 actual of $122.4 million.Expect total compensation and employee benefits to be lower in 2021 compared to 2020 due primarily to a reduction in incentive
compensation. Most other categories of non-interest expense expected to have small (1% to 2%) increases. Income Taxes Approximately a 20% effective income tax rate in 2021. This assumes a 21% statutory federal corporate income tax rate
during 2021. Share Repurchases 2021 share repurchase authorization at approximately 5% of outstanding shares. Expect total share repurchases in 2021 at the mid-point of this authorization. 27
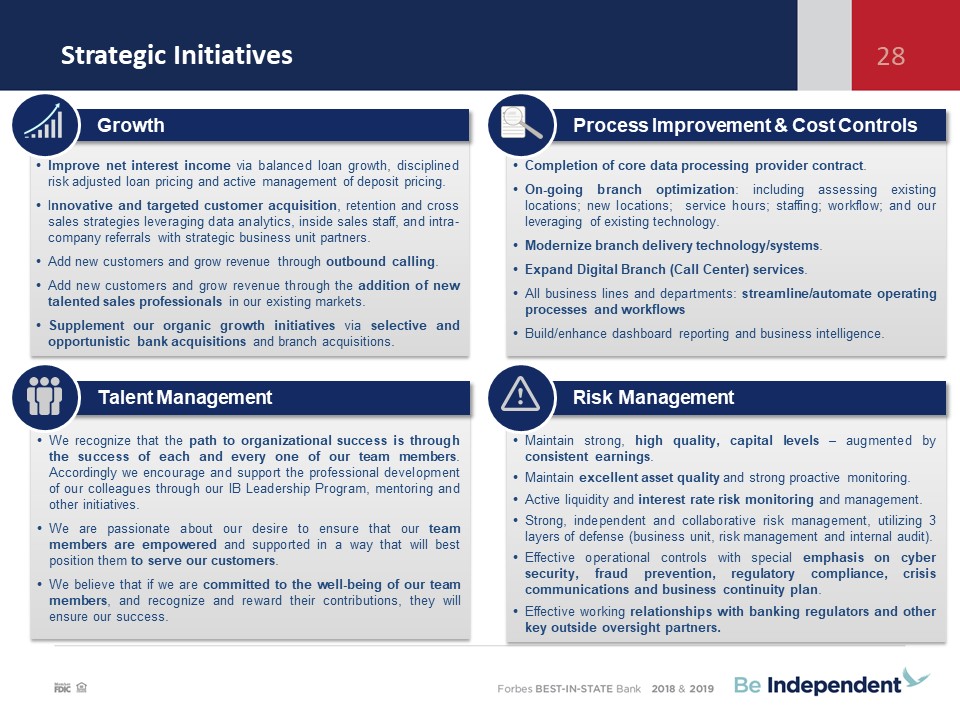
Strategic Initiatives 28 Improve net interest income via balanced loan growth, disciplined risk
adjusted loan pricing and active management of deposit pricing. Innovative and targeted customer acquisition, retention and cross sales strategies leveraging data analytics, inside sales staff, and intra-company referrals with strategic
business unit partners.Add new customers and grow revenue through outbound calling.Add new customers and grow revenue through the addition of new talented sales professionals in our existing markets. Supplement our organic growth initiatives
via selective and opportunistic bank acquisitions and branch acquisitions. Growth Completion of core data processing provider contract.On-going branch optimization: including assessing existing locations; new locations; service hours;
staffing; workflow; and our leveraging of existing technology. Modernize branch delivery technology/systems.Expand Digital Branch (Call Center) services.All business lines and departments: streamline/automate operating processes and workflows
Build/enhance dashboard reporting and business intelligence. Process Improvement & Cost Controls We recognize that the path to organizational success is through the success of each and every one of our team members. Accordingly we
encourage and support the professional development of our colleagues through our IB Leadership Program, mentoring and other initiatives. We are passionate about our desire to ensure that our team members are empowered and supported in a way
that will best position them to serve our customers. We believe that if we are committed to the well-being of our team members, and recognize and reward their contributions, they will ensure our success. Talent Management Maintain
strong, high quality, capital levels – augmented by consistent earnings. Maintain excellent asset quality and strong proactive monitoring.Active liquidity and interest rate risk monitoring and management.Strong, independent and collaborative
risk management, utilizing 3 layers of defense (business unit, risk management and internal audit). Effective operational controls with special emphasis on cyber security, fraud prevention, regulatory compliance, crisis communications and
business continuity plan.Effective working relationships with banking regulators and other key outside oversight partners. Risk Management
Q&A and Closing Remarks Question and Answer SessionClosing RemarksThank you for attending!NASDAQ:
IBCP 29