
MSBI 8-K
Midland States Bancorp, Inc. (MSBI)
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
_________________
FORM
_________________
CURRENT REPORT
Pursuant to Section 13 or 15(d)
of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported):
_______________________________
(Exact name of registrant as specified in its charter)
_______________________________
| (State or Other Jurisdiction of Incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) |
(Address of Principal Executive Offices) (Zip Code)
(
(Registrant's telephone number, including area code)
N/A
(Former name or former address, if changed since last report)
_______________________________
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) |
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered |
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
On October 22, 2020, Midland States Bancorp, Inc. (the "Company") issued a press release announcing its financial results for the third quarter of 2020. The press release is attached as Exhibit 99.1.
On October 22, 2020, the Company made available on its website a slide presentation regarding the Company's third quarter 2020 financial results, which will be used as part of a publicly accessible conference call on October 23, 2020. The slide presentation is attached as Exhibit 99.2.
The information in this Form 8-K and the attached exhibits shall not be deemed "filed" for purposes of Section 18 of the Securities Exchange Act of 1934, nor shall it be deemed incorporated by reference in any filing under the Securities Act of 1933, except as shall be expressly set forth by specific reference in any such filing.
(d) Exhibits.
| Exhibit No. | Description | |||
| 99.1 | Press Release of Midland States Bancorp, Inc., dated October 22, 2020 | |||
| 99.2 | Slide Presentation of Midland States Bancorp, Inc. regarding third quarter 2020 financial results | |||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) |
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Midland States Bancorp, Inc. | ||
| Date: October 22, 2020 | By: | /s/ Douglas J. Tucker |
| Douglas J. Tucker | ||
| Senior Vice President and Corporate Counsel | ||
EXHIBIT 99.1
Midland States Bancorp, Inc. Announces 2020 Third Quarter Results
Summary
- Net income of $86 thousand, or $0.00 diluted earnings per share
- Adjusted earnings of $12.0 million, or $0.52 diluted earnings per share, primarily reflects the exclusion of $13.9 million of charges related to branch and facilities optimization plan
- Total loans increased $102.0 million, or 2.1%, from June 30, 2020
- Total deposits increased $85.6 million, or 1.7%, from June 30, 2020
- Allowance for credit losses increased to 1.07% of total loans
- COVID-19 related loan deferral requests declined 68.9% from June 30, 2020
EFFINGHAM, Ill., Oct. 22, 2020 (GLOBE NEWSWIRE) -- Midland States Bancorp, Inc. (Nasdaq: MSBI) (the “Company”) today reported net income of $86 thousand, or $0.00 diluted earnings per share, for the third quarter of 2020, which includes $13.9 million of charges primarily related to the Company’s previously announced branch and facilities optimization plan. This compares to net income of $12.6 million, or $0.53 diluted earnings per share, for the second quarter of 2020, and net income of $12.7 million, or $0.51 diluted earnings per share, for the third quarter of 2019.
Jeffrey G. Ludwig, President and Chief Executive Officer of the Company, said, “Excluding the charges related to our branch and facilities optimization plan, we delivered a strong quarter highlighted by solid balance sheet growth, significant contributions from many of our sources of noninterest income, and disciplined expense management. Our diverse lending businesses enabled us to capitalize on pockets of strength in the economy where there is good demand, including equipment financing, small dollar consumer loans, and warehouse lines to commercial FHA lenders. As a result, our total loan balances increased at an annualized rate of more than 8% in the third quarter and helped drive an increase in net interest income.”
“We are seeing general improvement in the financial health of our borrowers as the economy continues to strengthen. Our deferred loans declined from 18.6% of total loans at the end of the second quarter to 5.7% of total loans at September 30, 2020. While the return to scheduled payments by many borrowers is encouraging, we remain cautious about the pace of the economic recovery and continued to add to our loan loss reserves, resulting in our allowance for credit losses increasing to 1.07% of total loans at September 30, 2020, from 0.97% at June 30, 2020.”
“As previously disclosed, during the third quarter we also made adjustments to our operations with the sale of our commercial FHA loan origination platform and the announcement of a series of planned branch and corporate office reductions. We believe the collective impact of these actions will help drive further improvement in our efficiency ratio and provide more operating leverage as we continue to grow our balance sheet in the future, resulting in more consistent financial performance, a higher level of returns, and greater franchise value,” said Mr. Ludwig.
Factors Affecting Comparability
Effective January 1, 2020, the Company adopted the new current expected credit loss (“CECL”) accounting standard, which replaced the incurred loss methodology with an estimated life of loan credit loss methodology.
Adjusted Earnings
Financial results for the third quarter of 2020 were impacted by $13.9 million in charges primarily related to the branch and facilities optimization plan (integration and acquisition expenses), $1.7 million in gains on sales of investment securities, and a $0.2 million loss on residential mortgage servicing rights (“MSRs”) held-for-sale. Excluding these amounts and certain income, adjusted earnings were $12.0 million, or $0.52 diluted earnings per share, for the third quarter of 2020.
Financial results for the second quarter of 2020 were impacted by a $0.4 million loss on residential MSRs held-for-sale and $0.1 million in integration and acquisition expenses. Excluding these amounts and certain income, adjusted earnings were $12.9 million, or $0.55 diluted earnings per share, for the second quarter of 2020.
A reconciliation of adjusted earnings to net income according to accounting principles generally accepted in the United States (“GAAP”) is provided in the financial tables at the end of this press release.
Net Interest Margin
Net interest margin for the third quarter of 2020 was 3.33%, compared to 3.32% for the second quarter of 2020. The Company’s net interest margin benefits from accretion income on purchased loan portfolios, which contributed 14 and 12 basis points to net interest margin in the third quarter of 2020 and second quarter of 2020, respectively. Excluding the impact of accretion income, net interest margin decreased 1 basis point from the second quarter of 2020, as a decline in the average yield on earning assets was largely offset by a reduction in the average cost of deposits.
Relative to the third quarter of 2019, net interest margin decreased from 3.70%. Accretion income on purchased loan portfolios contributed 20 basis points to net interest margin in the third quarter of 2019. Excluding the impact of accretion income, net interest margin decreased 31 basis points compared to the third quarter of 2019, primarily due to the impact of new subordinated debt issued in September 2019 and a decline in the average yield on earning assets, partially offset by a reduction in the average cost of deposits.
Net Interest Income
Net interest income for the third quarter of 2020 was $50.0 million, an increase of 2.0% from $49.0 million for the second quarter of 2020. Excluding accretion income, net interest income increased $0.6 million from the prior quarter. Accretion income associated with purchased loan portfolios totaled $2.1 million for the third quarter of 2020, compared with $1.8 million for the second quarter of 2020.
Relative to the third quarter of 2019, net interest income increased $0.5 million, or 1.1%. Accretion income for the third quarter of 2019 was $3.1 million. Excluding the impact of accretion income, net interest income increased primarily due to organic loan growth and a significant decline in cost of funds.
Noninterest Income
Noninterest income for the third quarter of 2020 was $18.9 million, a decrease of 2.5% from $19.4 million for the second quarter of 2020. Impairment on commercial MSRs impacted noninterest income by $1.4 million and $0.1 million in the third quarter of 2020 and second quarter of 2020, respectively. Excluding the impairment, noninterest income increased due to higher levels of residential mortgage banking revenue, service charges on deposit accounts, and other income.
Relative to the third quarter of 2019, noninterest income decreased 3.5% from $19.6 million. The decrease was primarily attributable to lower commercial FHA revenue and service charges on deposit accounts, partially offset by higher residential mortgage banking revenue.
Wealth management revenue for the third quarter of 2020 was $5.6 million, a decrease of 2.4% from the second quarter of 2020. Compared to the third quarter of 2019, wealth management revenue decreased 7.3%.
Commercial FHA revenue for the third quarter of 2020 was $0.9 million, compared to $3.4 million in the second quarter of 2020. The Company originated $50.9 million in rate lock commitments during the third quarter of 2020, prior to the sale of the origination platform on August 28, 2020, compared to $134.8 million in the prior quarter. Compared to the third quarter of 2019, commercial FHA revenue decreased $3.0 million.
Noninterest Expense
Noninterest expense for the third quarter of 2020 was $54.7 million, which included $13.9 million in charges primarily related to the branch and facilities optimization plan (integration and acquisition expenses), and a $0.2 million loss on residential MSRs held-for-sale, compared with $40.8 million in the second quarter of 2020, which included a $0.4 million loss on residential MSRs held-for-sale and $0.1 million in integration and acquisition expenses. Excluding the integration and acquisition expenses and losses on residential MSRs held-for-sale, noninterest expense was relatively unchanged from the prior quarter.
Relative to the third quarter of 2019, noninterest expense increased 13.8% from $48.0 million, which included $5.3 million in integration and acquisition expenses and a $0.1 million gain on residential MSRs held-for-sale. Excluding integration and acquisition expenses and gains/losses on MSRs held-for-sale, noninterest expense decreased 5.1% due principally to the Company’s expense reduction and efficiency improvement initiatives implemented over the past year.
Loan Portfolio
Total loans outstanding were $4.94 billion at September 30, 2020, compared with $4.84 billion at June 30, 2020 and $4.33 billion at September 30, 2019. The increase in total loans from June 30, 2020 was primarily attributable to an increase in equipment finance loans and leases, commercial FHA warehouse lines of credit, and consumer loans.
Equipment finance balances increased $65.0 million from June 30, 2020 to $815.5 million, which are booked within the commercial loans and leases portfolio, reflecting management’s efforts to grow the equipment finance business.
The increase in total loans from September 30, 2019 was primarily attributable to the growth in equipment finance balances, consumer loans, and loans originated under the Paycheck Protection Program (“PPP”).
Deposits
Total deposits were $5.03 billion at September 30, 2020, compared with $4.94 billion at June 30, 2020, and $4.45 billion at September 30, 2019. The increase in total deposits from the end of the prior quarter was primarily attributable to an increase in commercial FHA servicing deposits.
Asset Quality
Nonperforming loans totaled $67.4 million, or 1.36% of total loans, at September 30, 2020, compared with $60.5 million, or 1.25% of total loans, at June 30, 2020. The increase in nonperforming loans was primarily attributable to the addition of three commercial real estate loans. At September 30, 2019, nonperforming loans totaled $45.2 million, or 1.04% of total loans.
Net charge-offs for the third quarter of 2020 were $5.3 million, or 0.44% of average loans on an annualized basis, which primarily represents charge-offs taken against the three commercial real estate loans moved to nonperforming status referenced above.
The Company recorded a provision for credit losses on loans of $11.0 million for the third quarter of 2020, which reflects the higher level of net charge-offs experienced in the quarter.
The Company’s allowance for credit losses on loans was 1.07% of total loans and 78.3% of nonperforming loans at September 30, 2020, compared with 0.97% of total loans and 77.8% of nonperforming loans at June 30, 2020. Approximately 96.3% of the allowance for credit losses on loans at September 30, 2020 was allocated to general reserves.
Capital
At September 30, 2020, Midland States Bank and the Company exceeded all regulatory capital requirements under Basel III, and Midland States Bank met the qualifications to be a ‘‘well-capitalized’’ financial institution, as summarized in the following table:
Bank Level Ratios as of September 30, 2020 | Consolidated Ratios as of September 30, 2020 | Minimum Regulatory Requirements (2) | |
| Total capital to risk-weighted assets | 11.82% | 13.34% | 10.50% |
| Tier 1 capital to risk-weighted assets | 10.96% | 9.40% | 8.50% |
| Tier 1 leverage ratio | 9.01% | 7.72% | 4.00% |
| Common equity Tier 1 capital | 10.96% | 8.18% | 7.00% |
| Tangible common equity to tangible assets (1) | NA | 6.61% | NA |
(1) A non-GAAP financial measure. Refer to page 15 for a reconciliation to the comparable GAAP financial measure.
(2) Includes the capital conservation buffer of 2.5%.
Stock Repurchase Program
During the third quarter of 2020, the Company repurchased 352,932 shares of its common stock at a weighted average price of $14.20 under its stock repurchase program, which authorized the repurchase of up to $50 million of its common stock. As of September 30, 2020, the Company had $13.3 million remaining under the current stock repurchase authorization.
Conference Call, Webcast and Slide Presentation
The Company will host a conference call and webcast at 7:30 a.m. Central Time on Friday, October 23, 2020, to discuss its financial results. The call can be accessed via telephone at (877) 516-3531; conference ID: 1996893. A recorded replay can be accessed through October 30, 2020, by dialing (855) 859-2056; conference ID: 1996893.
A slide presentation relating to the third quarter 2020 results will be accessible prior to the scheduled conference call. This earnings release should be read together with the slide presentation, which contains important information related to the impact of COVID-19. The slide presentation and webcast of the conference call can be accessed on the Webcasts and Presentations page of the Company’s investor relations website at investors.midlandsb.com under the “News and Events” tab.
About Midland States Bancorp, Inc.
Midland States Bancorp, Inc. is a community-based financial holding company headquartered in Effingham, Illinois, and is the sole shareholder of Midland States Bank. As of September 30, 2020, the Company had total assets of approximately $6.70 billion, and its Wealth Management Group had assets under administration of approximately $3.26 billion. Midland provides a full range of commercial and consumer banking products and services, business equipment financing, merchant credit card services, trust and investment management, insurance and financial planning services. For additional information, visit https://www.midlandsb.com/ or https://www.linkedin.com/company/midland-states-bank.
Non-GAAP Financial Measures
Some of the financial measures included in this press release are not measures of financial performance recognized in accordance with GAAP. These non-GAAP financial measures include “Adjusted Earnings,” “Adjusted Diluted Earnings Per Common Share,” “Adjusted Return on Average Assets,” “Adjusted Return on Average Shareholders’ Equity,” “Adjusted Return on Average Tangible Common Equity,” “Efficiency Ratio,” “Tangible Common Equity to Tangible Assets,” “Tangible Book Value Per Share” and “Return on Average Tangible Common Equity.” The Company believes these non-GAAP financial measures provide both management and investors a more complete understanding of the Company’s funding profile and profitability. These non-GAAP financial measures are supplemental and are not a substitute for any analysis based on GAAP financial measures. Not all companies use the same calculation of these measures; therefore, this presentation may not be comparable to other similarly titled measures as presented by other companies.
Forward-Looking Statements
Readers should note that in addition to the historical information contained herein, this press release includes "forward-looking statements" within the meanings of the Private Securities Litigation Reform Act of 1995, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, including but not limited to statements about the Company’s plans, objectives, future performance, goals and future earnings levels. These statements are subject to many risks and uncertainties, including changes in interest rates and other general economic, business and political conditions, including the effects of the COVID-19 pandemic including its potential effects on the economic environment, our customers and our operations, as well as any changes to federal, state and local government laws, regulations and orders in connection with the pandemic; changes in the financial markets; changes in business plans as circumstances warrant; risks relating to acquisitions; and other risks detailed from time to time in filings made by the Company with the Securities and Exchange Commission. Readers should note that the forward-looking statements included in this press release are not a guarantee of future events, and that actual events may differ materially from those made in or suggested by the forward-looking statements. Forward-looking statements generally can be identified by the use of forward-looking terminology such as "will," "propose," "may," "plan," "seek," "expect," "intend," "estimate," "anticipate," "believe," "continue," or similar terminology. Any forward-looking statements presented herein are made only as of the date of this press release, and the Company does not undertake any obligation to update or revise any forward-looking statements to reflect changes in assumptions, the occurrence of unanticipated events, or otherwise.
CONTACTS:
Jeffrey G. Ludwig, President and CEO, at [email protected] or (217) 342-7321
Eric T. Lemke, Chief Financial Officer, at [email protected] or (217) 342-7321
Douglas J. Tucker, SVP and Corporate Counsel, at [email protected] or (217) 342-7321
| MIDLAND STATES BANCORP, INC. | ||||||||||||||||||||||
| CONSOLIDATED FINANCIAL SUMMARY (unaudited) | ||||||||||||||||||||||
| For the Quarter Ended | ||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||
| (dollars in thousands, except per share data) | 2020 | 2020 | 2020 | 2019 | 2019 | |||||||||||||||||
| Earnings Summary | ||||||||||||||||||||||
| Net interest income | $ | 49,980 | $ | 48,989 | $ | 46,651 | $ | 48,687 | $ | 49,450 | ||||||||||||
| Provision for credit losses on loans | 10,970 | 11,610 | 10,569 | 5,305 | 4,361 | |||||||||||||||||
| Noninterest income | 18,919 | 19,396 | 8,598 | 19,014 | 19,606 | |||||||||||||||||
| Noninterest expense | 54,659 | 40,782 | 42,675 | 46,325 | 48,025 | |||||||||||||||||
| Income before income taxes | 3,270 | 15,993 | 2,005 | 16,071 | 16,670 | |||||||||||||||||
| Income taxes | 3,184 | 3,424 | 456 | 3,279 | 4,015 | |||||||||||||||||
| Net income | 86 | 12,569 | 1,549 | 12,792 | 12,655 | |||||||||||||||||
| Preferred stock dividends, net | - | - | - | - | (22 | ) | ||||||||||||||||
| Net income available to common shareholders | $ | 86 | $ | 12,569 | $ | 1,549 | $ | 12,792 | $ | 12,677 | ||||||||||||
| Diluted earnings per common share | $ | - | $ | 0.53 | $ | 0.06 | $ | 0.51 | $ | 0.51 | ||||||||||||
| Weighted average shares outstanding - diluted | 22,937,837 | 23,339,964 | 24,538,002 | 24,761,960 | 24,684,529 | |||||||||||||||||
| Return on average assets | 0.01 | % | 0.77 | % | 0.10 | % | 0.83 | % | 0.84 | % | ||||||||||||
| Return on average shareholders' equity | 0.05 | % | 8.00 | % | 0.96 | % | 7.71 | % | 7.71 | % | ||||||||||||
| Return on average tangible common equity (1) | 0.08 | % | 11.84 | % | 1.39 | % | 11.24 | % | 11.19 | % | ||||||||||||
| Net interest margin | 3.33 | % | 3.32 | % | 3.48 | % | 3.56 | % | 3.70 | % | ||||||||||||
| Efficiency ratio (1) | 58.83 | % | 58.53 | % | 63.78 | % | 59.46 | % | 60.63 | % | ||||||||||||
| Adjusted Earnings Performance Summary | ||||||||||||||||||||||
| Adjusted earnings (1) | $ | 12,023 | $ | 12,884 | $ | 2,806 | $ | 16,110 | $ | 16,422 | ||||||||||||
| Adjusted diluted earnings per common share (1) | $ | 0.52 | $ | 0.55 | $ | 0.11 | $ | 0.64 | $ | 0.66 | ||||||||||||
| Adjusted return on average assets (1) | 0.72 | % | 0.78 | % | 0.19 | % | 1.04 | % | 1.09 | % | ||||||||||||
| Adjusted return on average shareholders' equity (1) | 7.56 | % | 8.20 | % | 1.73 | % | 9.71 | % | 10.01 | % | ||||||||||||
| Adjusted return on average tangible common equity (1) | 11.04 | % | 12.14 | % | 2.53 | % | 14.15 | % | 14.52 | % | ||||||||||||
| (1) Non-GAAP financial measures. Refer to pages 13 - 15 for a reconciliation to the comparable GAAP financial measures. | ||||||||||||||||||||||
| MIDLAND STATES BANCORP, INC. | ||||||||||||||||||||||||||
| CONSOLIDATED FINANCIAL SUMMARY (unaudited) (continued) | ||||||||||||||||||||||||||
| For the Quarter Ended | ||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||
| (in thousands, except per share data) | 2020 | 2020 | 2020 | 2019 | 2019 | |||||||||||||||||||||
| Net interest income: | ||||||||||||||||||||||||||
| Interest income | $ | 60,314 | $ | 60,548 | $ | 61,314 | $ | 64,444 | $ | 65,006 | ||||||||||||||||
| Interest expense | 10,334 | 11,559 | 14,663 | 15,757 | 15,556 | |||||||||||||||||||||
| Net interest income | 49,980 | 48,989 | 46,651 | 48,687 | 49,450 | |||||||||||||||||||||
| Provision for credit losses on loans | 10,970 | 11,610 | 10,569 | 5,305 | 4,361 | |||||||||||||||||||||
| Net interest income after provision for credit losses on loans | 39,010 | 37,379 | 36,082 | 43,382 | 45,089 | |||||||||||||||||||||
| Noninterest income: | ||||||||||||||||||||||||||
| Wealth management revenue | 5,559 | 5,698 | 5,677 | 5,377 | 5,998 | |||||||||||||||||||||
| Commercial FHA revenue | 926 | 3,414 | 1,267 | 3,702 | 3,954 | |||||||||||||||||||||
| Residential mortgage banking revenue | 3,049 | 2,723 | 1,755 | 763 | 720 | |||||||||||||||||||||
| Service charges on deposit accounts | 2,092 | 1,706 | 2,656 | 2,860 | 3,008 | |||||||||||||||||||||
| Interchange revenue | 3,283 | 3,013 | 2,833 | 3,053 | 3,249 | |||||||||||||||||||||
| Gain on sales of investment securities, net | 1,721 | - | - | 635 | 25 | |||||||||||||||||||||
| Impairment on commercial mortgage servicing rights | (1,418 | ) | (107 | ) | (8,468 | ) | (1,613 | ) | (1,060 | ) | ||||||||||||||||
| Other income | 3,707 | 2,949 | 2,878 | 4,237 | 3,712 | |||||||||||||||||||||
| Total noninterest income | 18,919 | 19,396 | 8,598 | 19,014 | 19,606 | |||||||||||||||||||||
| Noninterest expense: | ||||||||||||||||||||||||||
| Salaries and employee benefits | 21,118 | 20,740 | 21,063 | 23,650 | 25,083 | |||||||||||||||||||||
| Occupancy and equipment | 4,866 | 4,286 | 4,869 | 4,654 | 4,793 | |||||||||||||||||||||
| Data processing | 5,396 | 5,300 | 5,334 | 6,074 | 5,271 | |||||||||||||||||||||
| Professional | 1,861 | 1,606 | 1,855 | 1,952 | 2,348 | |||||||||||||||||||||
| Amortization of intangible assets | 1,557 | 1,629 | 1,762 | 1,804 | 1,803 | |||||||||||||||||||||
| Loss (gain) on mortgage servicing rights held for sale | 188 | 391 | 496 | 95 | (70 | ) | ||||||||||||||||||||
| Impairment related to branch optimization | 12,651 | 60 | 146 | - | 3,229 | |||||||||||||||||||||
| Other expense | 7,022 | 6,770 | 7,150 | 8,096 | 5,568 | |||||||||||||||||||||
| Total noninterest expense | 54,659 | 40,782 | 42,675 | 46,325 | 48,025 | |||||||||||||||||||||
| Income before income taxes | 3,270 | 15,993 | 2,005 | 16,071 | 16,670 | |||||||||||||||||||||
| Income taxes | 3,184 | 3,424 | 456 | 3,279 | 4,015 | |||||||||||||||||||||
| Net income | 86 | 12,569 | 1,549 | 12,792 | 12,655 | |||||||||||||||||||||
| Preferred stock dividends, net | - | - | - | - | (22 | ) | ||||||||||||||||||||
| Net income available to common shareholders | $ | 86 | $ | 12,569 | $ | 1,549 | $ | 12,792 | $ | 12,677 | ||||||||||||||||
| Basic earnings per common share | $ | 0.00 | $ | 0.53 | $ | 0.06 | $ | 0.52 | $ | 0.51 | ||||||||||||||||
| Diluted earnings per common share | $ | 0.00 | $ | 0.53 | $ | 0.06 | $ | 0.51 | $ | 0.51 | ||||||||||||||||
| MIDLAND STATES BANCORP, INC. | |||||||||||||||||||||||||
| CONSOLIDATED FINANCIAL SUMMARY (unaudited) (continued) | |||||||||||||||||||||||||
| As of | |||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | |||||||||||||||||||||
| (in thousands) | 2020 | 2020 | 2020 | 2019 | 2019 | ||||||||||||||||||||
| Assets | |||||||||||||||||||||||||
| Cash and cash equivalents | $ | 461,196 | $ | 519,868 | $ | 449,396 | $ | 394,505 | $ | 409,346 | |||||||||||||||
| Investment securities | 618,974 | 639,693 | 661,894 | 655,054 | 668,630 | ||||||||||||||||||||
| Loans | 4,941,466 | 4,839,423 | 4,376,204 | 4,401,410 | 4,328,835 | ||||||||||||||||||||
| Allowance for credit losses on loans | (52,771 | ) | (47,093 | ) | (38,545 | ) | (28,028 | ) | (24,917 | ) | |||||||||||||||
| Total loans, net | 4,888,695 | 4,792,330 | 4,337,659 | 4,373,382 | 4,303,918 | ||||||||||||||||||||
| Loans held for sale | 62,500 | 32,403 | 113,852 | 16,431 | 88,322 | ||||||||||||||||||||
| Premises and equipment, net | 74,967 | 89,046 | 90,118 | 91,055 | 93,896 | ||||||||||||||||||||
| Other real estate owned | 15,961 | 12,728 | 7,892 | 6,745 | 4,890 | ||||||||||||||||||||
| Loan servicing rights, at lower of cost or fair value | 42,465 | 44,239 | 44,566 | 53,824 | 54,124 | ||||||||||||||||||||
| Mortgage servicing rights held for sale | 1,308 | 1,244 | 1,460 | 1,972 | 1,860 | ||||||||||||||||||||
| Goodwill | 161,904 | 172,796 | 172,796 | 171,758 | 171,074 | ||||||||||||||||||||
| Other intangible assets, net | 29,938 | 31,495 | 33,124 | 34,886 | 36,690 | ||||||||||||||||||||
| Cash surrender value of life insurance policies | 145,112 | 144,215 | 143,323 | 142,423 | 141,510 | ||||||||||||||||||||
| Other assets | 197,025 | 164,441 | 152,150 | 144,982 | 139,644 | ||||||||||||||||||||
| Total assets | $ | 6,700,045 | $ | 6,644,498 | $ | 6,208,230 | $ | 6,087,017 | $ | 6,113,904 | |||||||||||||||
| Liabilities and Shareholders' Equity | |||||||||||||||||||||||||
| Noninterest-bearing deposits | $ | 1,355,188 | $ | 1,273,267 | $ | 1,052,726 | $ | 1,019,472 | $ | 1,015,081 | |||||||||||||||
| Interest-bearing deposits | 3,673,548 | 3,669,840 | 3,597,914 | 3,524,782 | 3,430,090 | ||||||||||||||||||||
| Total deposits | 5,028,736 | 4,943,107 | 4,650,640 | 4,544,254 | 4,445,171 | ||||||||||||||||||||
| Short-term borrowings | 58,625 | 77,136 | 43,578 | 82,029 | 122,294 | ||||||||||||||||||||
| FHLB advances and other borrowings | 693,640 | 693,865 | 593,089 | 493,311 | 559,932 | ||||||||||||||||||||
| Subordinated debt | 169,702 | 169,610 | 169,505 | 176,653 | 192,689 | ||||||||||||||||||||
| Trust preferred debentures | 48,682 | 48,551 | 48,420 | 48,288 | 48,165 | ||||||||||||||||||||
| Other liabilities | 78,780 | 78,640 | 71,838 | 80,571 | 90,131 | ||||||||||||||||||||
| Total liabilities | 6,078,165 | 6,010,909 | 5,577,070 | 5,425,106 | 5,458,382 | ||||||||||||||||||||
| Total shareholders’ equity | 621,880 | 633,589 | 631,160 | 661,911 | 655,522 | ||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 6,700,045 | $ | 6,644,498 | $ | 6,208,230 | $ | 6,087,017 | $ | 6,113,904 | |||||||||||||||
| MIDLAND STATES BANCORP, INC. | |||||||||||||||||||||
| CONSOLIDATED FINANCIAL SUMMARY (unaudited) (continued) | |||||||||||||||||||||
| As of | |||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | |||||||||||||||||
| (in thousands) | 2020 | 2020 | 2020 | 2019 | 2019 | ||||||||||||||||
| Loan Portfolio | |||||||||||||||||||||
| Commercial loans and leases | $ | 1,938,691 | $ | 1,856,435 | $ | 1,439,145 | $ | 1,387,766 | $ | 1,292,511 | |||||||||||
| Commercial real estate | 1,496,758 | 1,495,183 | 1,507,280 | 1,526,504 | 1,622,363 | ||||||||||||||||
| Construction and land development | 177,894 | 207,593 | 208,361 | 208,733 | 215,978 | ||||||||||||||||
| Residential real estate | 470,829 | 509,453 | 548,014 | 568,291 | 587,984 | ||||||||||||||||
| Consumer | 857,294 | 770,759 | 673,404 | 710,116 | 609,999 | ||||||||||||||||
| Total loans | $ | 4,941,466 | $ | 4,839,423 | $ | 4,376,204 | $ | 4,401,410 | $ | 4,328,835 | |||||||||||
| Deposit Portfolio | |||||||||||||||||||||
| Noninterest-bearing demand | $ | 1,355,188 | $ | 1,273,267 | $ | 1,052,726 | $ | 1,019,472 | $ | 1,015,081 | |||||||||||
| Interest-bearing: | |||||||||||||||||||||
| Checking | 1,581,216 | 1,484,728 | 1,425,022 | 1,342,788 | 1,222,599 | ||||||||||||||||
| Money market | 826,454 | 877,675 | 849,642 | 787,662 | 753,869 | ||||||||||||||||
| Savings | 580,748 | 594,685 | 534,457 | 522,456 | 526,938 | ||||||||||||||||
| Time | 661,872 | 689,841 | 765,870 | 822,160 | 833,038 | ||||||||||||||||
| Brokered time | 23,258 | 22,911 | 22,923 | 49,716 | 93,646 | ||||||||||||||||
| Total deposits | $ | 5,028,736 | $ | 4,943,107 | $ | 4,650,640 | $ | 4,544,254 | $ | 4,445,171 | |||||||||||
| MIDLAND STATES BANCORP, INC. | |||||||||||||||||||||
| CONSOLIDATED FINANCIAL SUMMARY (unaudited) (continued) | |||||||||||||||||||||
| For the Quarter Ended | |||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | |||||||||||||||||
| (dollars in thousands) | 2020 | 2020 | 2020 | 2019 | 2019 | ||||||||||||||||
| Average Balance Sheets | |||||||||||||||||||||
| Cash and cash equivalents | $ | 491,728 | $ | 489,941 | $ | 337,851 | $ | 406,526 | $ | 259,427 | |||||||||||
| Investment securities | 628,705 | 650,356 | 662,450 | 631,294 | 666,157 | ||||||||||||||||
| Loans | 4,803,940 | 4,696,288 | 4,384,206 | 4,359,144 | 4,352,635 | ||||||||||||||||
| Loans held for sale | 44,880 | 99,169 | 19,844 | 36,974 | 31,664 | ||||||||||||||||
| Nonmarketable equity securities | 50,765 | 50,661 | 45,124 | 43,745 | 44,010 | ||||||||||||||||
| Total interest-earning assets | 6,020,018 | 5,986,415 | 5,449,475 | 5,477,683 | 5,353,893 | ||||||||||||||||
| Non-earning assets | 625,522 | 619,411 | 624,594 | 649,169 | 636,028 | ||||||||||||||||
| Total assets | $ | 6,645,540 | $ | 6,605,826 | $ | 6,074,069 | $ | 6,126,852 | $ | 5,989,921 | |||||||||||
| Interest-bearing deposits | $ | 3,656,833 | $ | 3,651,406 | $ | 3,549,515 | $ | 3,490,165 | $ | 3,429,063 | |||||||||||
| Short-term borrowings | 64,010 | 59,103 | 55,616 | 104,598 | 124,183 | ||||||||||||||||
| FHLB advances and other borrowings | 693,721 | 692,470 | 532,733 | 531,419 | 591,516 | ||||||||||||||||
| Subordinated debt | 169,657 | 169,560 | 170,026 | 182,149 | 106,090 | ||||||||||||||||
| Trust preferred debentures | 48,618 | 48,487 | 48,357 | 48,229 | 48,105 | ||||||||||||||||
| Total interest-bearing liabilities | 4,632,839 | 4,621,026 | 4,356,247 | 4,356,560 | 4,298,957 | ||||||||||||||||
| Noninterest-bearing deposits | 1,303,963 | 1,280,983 | 986,178 | 1,028,670 | 967,192 | ||||||||||||||||
| Other noninterest-bearing liabilities | 75,859 | 71,853 | 78,943 | 83,125 | 72,610 | ||||||||||||||||
| Shareholders' equity | 632,879 | 631,964 | 652,701 | 658,497 | 651,162 | ||||||||||||||||
| Total liabilities and shareholders' equity | $ | 6,645,540 | $ | 6,605,826 | $ | 6,074,069 | $ | 6,126,852 | $ | 5,989,921 | |||||||||||
| Yields | |||||||||||||||||||||
| Earning Assets | |||||||||||||||||||||
| Cash and cash equivalents | 0.10 | % | 0.14 | % | 1.26 | % | 1.62 | % | 2.14 | % | |||||||||||
| Investment securities | 2.86 | % | 3.05 | % | 3.23 | % | 3.10 | % | 3.00 | % | |||||||||||
| Loans | 4.57 | % | 4.64 | % | 5.01 | % | 5.22 | % | 5.31 | % | |||||||||||
| Loans held for sale | 2.92 | % | 4.07 | % | 3.87 | % | 4.12 | % | 3.02 | % | |||||||||||
| Nonmarketable equity securities | 5.26 | % | 5.40 | % | 5.39 | % | 5.31 | % | 5.33 | % | |||||||||||
| Total interest-earning assets | 4.01 | % | 4.10 | % | 4.56 | % | 4.70 | % | 4.85 | % | |||||||||||
| Interest-Bearing Liabilities | |||||||||||||||||||||
| Interest-bearing deposits | 0.46 | % | 0.61 | % | 0.95 | % | 1.03 | % | 1.08 | % | |||||||||||
| Short-term borrowings | 0.17 | % | 0.19 | % | 0.73 | % | 0.67 | % | 0.68 | % | |||||||||||
| FHLB advances and other borrowings | 1.85 | % | 1.69 | % | 2.24 | % | 2.26 | % | 2.36 | % | |||||||||||
| Subordinated debt | 5.58 | % | 5.85 | % | 5.90 | % | 5.94 | % | 6.30 | % | |||||||||||
| Trust preferred debentures | 4.16 | % | 4.86 | % | 6.02 | % | 6.41 | % | 6.83 | % | |||||||||||
| Total interest-bearing liabilities | 0.89 | % | 1.01 | % | 1.35 | % | 1.43 | % | 1.44 | % | |||||||||||
| Cost of Deposits | 0.34 | % | 0.45 | % | 0.74 | % | 0.80 | % | 0.84 | % | |||||||||||
| Net Interest Margin | 3.33 | % | 3.32 | % | 3.48 | % | 3.56 | % | 3.70 | % | |||||||||||
| MIDLAND STATES BANCORP, INC. | |||||||||||||||||||||
| CONSOLIDATED FINANCIAL SUMMARY (unaudited) (continued) | |||||||||||||||||||||
| As of and for the Quarter Ended | |||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | |||||||||||||||||
| (dollars in thousands, except per share data) | 2020 | 2020 | 2020 | 2019 | 2019 | ||||||||||||||||
| Asset Quality | |||||||||||||||||||||
| Loans 30-89 days past due | $ | 28,188 | $ | 36,551 | $ | 40,392 | $ | 29,876 | $ | 23,118 | |||||||||||
| Nonperforming loans | 67,443 | 60,513 | 58,166 | 42,082 | 45,168 | ||||||||||||||||
| Nonperforming assets | 84,795 | 74,707 | 67,158 | 50,027 | 50,058 | ||||||||||||||||
| Net charge-offs | 5,292 | 3,062 | 12,835 | 2,194 | 5,369 | ||||||||||||||||
| Loans 30-89 days past due to total loans | 0.57 | % | 0.76 | % | 0.92 | % | 0.68 | % | 0.53 | % | |||||||||||
| Nonperforming loans to total loans | 1.36 | % | 1.25 | % | 1.33 | % | 0.96 | % | 1.04 | % | |||||||||||
| Nonperforming assets to total assets | 1.27 | % | 1.12 | % | 1.08 | % | 0.82 | % | 0.82 | % | |||||||||||
| Allowance for credit losses to total loans | 1.07 | % | 0.97 | % | 0.88 | % | 0.64 | % | 0.58 | % | |||||||||||
| Allowance for credit losses to nonperforming loans | 78.25 | % | 77.82 | % | 66.27 | % | 66.60 | % | 55.29 | % | |||||||||||
| Net charge-offs to average loans | 0.44 | % | 0.26 | % | 1.18 | % | 0.20 | % | 0.49 | % | |||||||||||
| Wealth Management | |||||||||||||||||||||
| Trust assets under administration | $ | 3,260,893 | $ | 3,253,784 | $ | 2,967,536 | $ | 3,409,959 | $ | 3,281,260 | |||||||||||
| Market Data | |||||||||||||||||||||
| Book value per share at period end | $ | 27.51 | $ | 27.62 | $ | 26.99 | $ | 27.10 | $ | 26.93 | |||||||||||
| Tangible book value per share at period end (1) | $ | 19.03 | $ | 18.72 | $ | 18.19 | $ | 18.64 | $ | 18.40 | |||||||||||
| Market price at period end | $ | 12.85 | $ | 14.95 | $ | 17.49 | $ | 28.96 | $ | 26.05 | |||||||||||
| Shares outstanding at period end | 22,602,844 | 22,937,296 | 23,381,496 | 24,420,345 | 24,338,748 | ||||||||||||||||
| Capital | |||||||||||||||||||||
| Total capital to risk-weighted assets | 13.34 | % | 13.67 | % | 13.73 | % | 14.72 | % | 14.82 | % | |||||||||||
| Tier 1 capital to risk-weighted assets | 9.40 | % | 9.71 | % | 9.76 | % | 10.52 | % | 10.35 | % | |||||||||||
| Tier 1 leverage ratio | 7.72 | % | 7.75 | % | 8.39 | % | 8.74 | % | 8.77 | % | |||||||||||
| Tier 1 common capital to risk-weighted assets | 8.18 | % | 8.44 | % | 8.47 | % | 9.20 | % | 9.02 | % | |||||||||||
| Tangible common equity to tangible assets (1) | 6.61 | % | 6.67 | % | 7.08 | % | 7.74 | % | 7.58 | % | |||||||||||
| (1) Non-GAAP financial measures. Refer to pages 13 - 15 for a reconciliation to the comparable GAAP financial measures. | |||||||||||||||||||||
| MIDLAND STATES BANCORP, INC. | ||||||||||||||||||||||||||
| RECONCILIATIONS OF NON-GAAP FINANCIAL MEASURES (unaudited) | ||||||||||||||||||||||||||
| Adjusted Earnings Reconciliation | ||||||||||||||||||||||||||
| For the Quarter Ended | ||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||
| (dollars in thousands, except per share data) | 2020 | 2020 | 2020 | 2019 | 2019 | |||||||||||||||||||||
| Income before income taxes - GAAP | $ | 3,270 | $ | 15,993 | $ | 2,005 | $ | 16,071 | $ | 16,670 | ||||||||||||||||
| Adjustments to noninterest income: | ||||||||||||||||||||||||||
| Gain on sales of investment securities, net | 1,721 | - | - | 635 | 25 | |||||||||||||||||||||
| Other | (17 | ) | 11 | (13 | ) | (6 | ) | - | ||||||||||||||||||
| Total adjustments to noninterest income | 1,704 | 11 | (13 | ) | 629 | 25 | ||||||||||||||||||||
| Adjustments to noninterest expense: | ||||||||||||||||||||||||||
| Loss (gain) on mortgage servicing rights held for sale | 188 | 391 | 496 | 95 | (70 | ) | ||||||||||||||||||||
| Loss on repurchase of subordinated debt | - | - | 193 | 1,778 | - | |||||||||||||||||||||
| Impairment related to branch optimization | 12,651 | 60 | 146 | - | 3,229 | |||||||||||||||||||||
| Integration and acquisition expenses | 1,199 | (6 | ) | 885 | 3,332 | 2,063 | ||||||||||||||||||||
| Total adjustments to noninterest expense | 14,038 | 445 | 1,720 | 5,205 | 5,222 | |||||||||||||||||||||
| Adjusted earnings pre tax | 15,604 | 16,427 | 3,738 | 20,647 | 21,867 | |||||||||||||||||||||
| Adjusted earnings tax | 3,581 | 3,543 | 932 | 4,537 | 5,445 | |||||||||||||||||||||
| Adjusted earnings - non-GAAP | 12,023 | 12,884 | 2,806 | 16,110 | 16,422 | |||||||||||||||||||||
| Preferred stock dividends, net | - | - | - | - | (22 | ) | ||||||||||||||||||||
| Adjusted earnings available to common shareholders - non-GAAP | $ | 12,023 | $ | 12,884 | $ | 2,806 | $ | 16,110 | $ | 16,444 | ||||||||||||||||
| Adjusted diluted earnings per common share | $ | 0.52 | $ | 0.55 | $ | 0.11 | $ | 0.64 | $ | 0.66 | ||||||||||||||||
| Adjusted return on average assets | 0.72 | % | - | 0.78 | % | - | 0.19 | % | - | 1.04 | % | - | 1.09 | % | ||||||||||||
| Adjusted return on average shareholders' equity | 7.56 | % | - | 8.20 | % | - | 1.73 | % | - | 9.71 | % | - | 10.01 | % | ||||||||||||
| Adjusted return on average tangible common equity | 11.04 | % | - | 12.14 | % | - | 2.53 | % | - | 14.15 | % | - | 14.52 | % | ||||||||||||
| MIDLAND STATES BANCORP, INC. | ||||||||||||||||||||||||||
| RECONCILIATIONS OF NON-GAAP FINANCIAL MEASURES (unaudited) (continued) | ||||||||||||||||||||||||||
| Efficiency Ratio Reconciliation | ||||||||||||||||||||||||||
| For the Quarter Ended | ||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||
| (dollars in thousands) | 2020 | 2020 | 2020 | 2019 | 2019 | |||||||||||||||||||||
| Noninterest expense - GAAP | $ | 54,659 | $ | 40,782 | $ | 42,675 | $ | 46,325 | $ | 48,025 | ||||||||||||||||
| (Loss) gain on mortgage servicing rights held for sale | (188 | ) | (391 | ) | (496 | ) | (95 | ) | 70 | |||||||||||||||||
| Loss on repurchase of subordinated debt | - | - | (193 | ) | (1,778 | ) | - | |||||||||||||||||||
| Impairment related to branch optimization | (12,651 | ) | (60 | ) | (146 | ) | - | (3,229 | ) | |||||||||||||||||
| Integration and acquisition expenses | (1,199 | ) | 6 | (885 | ) | (3,332 | ) | (2,063 | ) | |||||||||||||||||
| Adjusted noninterest expense | $ | 40,621 | $ | 40,337 | $ | 40,955 | $ | 41,120 | $ | 42,803 | ||||||||||||||||
| Net interest income - GAAP | $ | 49,980 | $ | 48,989 | $ | 46,651 | $ | 48,687 | $ | 49,450 | ||||||||||||||||
| Effect of tax-exempt income | 430 | 438 | 485 | 474 | 502 | |||||||||||||||||||||
| Adjusted net interest income | 50,410 | 49,427 | 47,136 | 49,161 | 49,952 | |||||||||||||||||||||
| Noninterest income - GAAP | $ | 18,919 | $ | 19,396 | $ | 8,598 | $ | 19,014 | $ | 19,606 | ||||||||||||||||
| Loan servicing rights impairment | 1,418 | 107 | 8,468 | 1,613 | 1,060 | |||||||||||||||||||||
| Gain on sales of investment securities, net | (1,721 | ) | - | - | (635 | ) | (25 | ) | ||||||||||||||||||
| Other | 17 | (11 | ) | 13 | 6 | - | ||||||||||||||||||||
| Adjusted noninterest income | 18,633 | 19,492 | 17,079 | 19,998 | 20,641 | |||||||||||||||||||||
| Adjusted total revenue | $ | 69,043 | $ | 68,919 | $ | 64,215 | $ | 69,159 | $ | 70,593 | ||||||||||||||||
| Efficiency ratio | 58.83 | % | 58.53 | % | 63.78 | % | 59.46 | % | 60.63 | % | ||||||||||||||||
| MIDLAND STATES BANCORP, INC. | ||||||||||||||||||||||||||
| RECONCILIATIONS OF NON-GAAP FINANCIAL MEASURES (unaudited) (continued) | ||||||||||||||||||||||||||
| Tangible Common Equity to Tangible Assets Ratio and Tangible Book Value Per Share | ||||||||||||||||||||||||||
| As of | ||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||
| (dollars in thousands, except per share data) | 2020 | 2020 | 2020 | 2019 | 2019 | |||||||||||||||||||||
| Shareholders' Equity to Tangible Common Equity | ||||||||||||||||||||||||||
| Total shareholders' equity—GAAP | $ | 621,880 | $ | 633,589 | $ | 631,160 | $ | 661,911 | $ | 655,522 | ||||||||||||||||
| Adjustments: | ||||||||||||||||||||||||||
| Preferred stock | - | - | - | - | - | |||||||||||||||||||||
| Goodwill | (161,904 | ) | (172,796 | ) | (172,796 | ) | (171,758 | ) | (171,074 | ) | ||||||||||||||||
| Other intangibles, net | (29,938 | ) | (31,495 | ) | (33,124 | ) | (34,886 | ) | (36,690 | ) | ||||||||||||||||
| Tangible common equity | $ | 430,038 | $ | 429,298 | $ | 425,240 | $ | 455,267 | $ | 447,758 | ||||||||||||||||
| Total Assets to Tangible Assets: | ||||||||||||||||||||||||||
| Total assets—GAAP | $ | 6,700,045 | $ | 6,644,498 | $ | 6,208,230 | $ | 6,087,017 | $ | 6,113,904 | ||||||||||||||||
| Adjustments: | ||||||||||||||||||||||||||
| Goodwill | (161,904 | ) | (172,796 | ) | (172,796 | ) | (171,758 | ) | (171,074 | ) | ||||||||||||||||
| Other intangibles, net | (29,938 | ) | (31,495 | ) | (33,124 | ) | (34,886 | ) | (36,690 | ) | ||||||||||||||||
| Tangible assets | $ | 6,508,203 | $ | 6,440,207 | $ | 6,002,310 | $ | 5,880,373 | $ | 5,906,140 | ||||||||||||||||
| Common Shares Outstanding | 22,602,844 | 22,937,296 | 23,381,496 | 24,420,345 | 24,338,748 | |||||||||||||||||||||
| Tangible Common Equity to Tangible Assets | 6.61 | % | 6.67 | % | 7.08 | % | 7.74 | % | 7.58 | % | ||||||||||||||||
| Tangible Book Value Per Share | $ | 19.03 | $ | 18.72 | $ | 18.19 | $ | 18.64 | $ | 18.40 | ||||||||||||||||
| Return on Average Tangible Common Equity (ROATCE) | ||||||||||||||||||||||||||
| For the Quarter Ended | ||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||
| (dollars in thousands) | 2020 | 2020 | 2020 | 2019 | 2019 | |||||||||||||||||||||
| Net income available to common shareholders | $ | 86 | $ | 12,569 | $ | 1,549 | $ | 12,792 | $ | 12,677 | ||||||||||||||||
| Average total shareholders' equity—GAAP | $ | 632,879 | $ | 631,964 | $ | 652,701 | $ | 658,497 | $ | 651,162 | ||||||||||||||||
| Adjustments: | ||||||||||||||||||||||||||
| Preferred stock | - | - | - | - | (814 | ) | ||||||||||||||||||||
| Goodwill | (168,771 | ) | (172,796 | ) | (171,890 | ) | (171,082 | ) | (166,389 | ) | ||||||||||||||||
| Other intangibles, net | (30,690 | ) | (32,275 | ) | (33,951 | ) | (35,745 | ) | (34,519 | ) | ||||||||||||||||
| Average tangible common equity | $ | 433,418 | $ | 426,893 | $ | 446,860 | $ | 451,670 | $ | 449,440 | ||||||||||||||||
| ROATCE | 0.08 | % | 11.84 | % | 1.39 | % | 11.24 | % | 11.19 | % | ||||||||||||||||
Exhibit 99.2
1 Midland States Bancorp, Inc. NASDAQ: MSBI Third Quarter 2020 Earnings Call
2 Forward - Looking Statements. This presentation may contain forward - looking statements within the meaning of the federal securities laws. Forward - looking statements expressing management’s current expectations, forecasts of future events or long - te rm goals may be based upon beliefs, expectations and assumptions of Midland’s management, and are generally identifiable by the use of words such as “believe,” “expect,” “anticipate,” “plan,” “intend,” “estimate,” “may,” “will,” “would,” “could,” “should” o r o ther similar expressions. All statements in this presentation speak only as of the date they are made, and Midland undertakes no obligation to update any statement. A number of factors, many of which are beyond the ability of Midland to control or predic t, could cause actual results to differ materially from those in its forward - looking statements including the effects of the Corona virus Disease 2019 (COVID - 19) pandemic, including its potential effects on the economic environment, our customers and our operations, as well as any changes to federal, state or local government laws, regulations or orders in connection with the pandemic. These risks and uncertainties should be considered in evaluating forward - looking statements, and undue reliance should not be placed o n such statements. Additional information concerning Midland and its businesses, including additional factors that could materi all y affect Midland’s financial results, are included in Midland’s filings with the Securities and Exchange Commission. Use of Non - GAAP Financial Measures. This presentation may contain certain financial information determined by methods other than in accordance with accounting principles generally accepted in the United States (“GAAP”). These non - GAAP financial measure s include “Adjusted Earnings,” “Adjusted Diluted Earnings Per Share,” “Adjusted Return on Average Assets,” “Adjusted Return on Average Shareholders’ Equity,” “Adjusted Return on Average Tangible Common Equity,” “Efficiency Ratio,” “Tangible Common Equ ity to Tangible Assets,” “Tangible Book Value Per Share,” and “Return on Average Tangible Common Equity.” The Company believes th at these non - GAAP financial measures provide both management and investors a more complete understanding of the Company’s funding profile and profitability. These non - GAAP financial measures are supplemental and are not a substitute for any analysis based on GAAP financial measures. Not all companies use the same calculation of these measures; therefore this presentation m ay not be comparable to other similarly titled measures as presented by other companies. Reconciliations of these non - GAAP measures are provided in the Appendix section of this presentation.
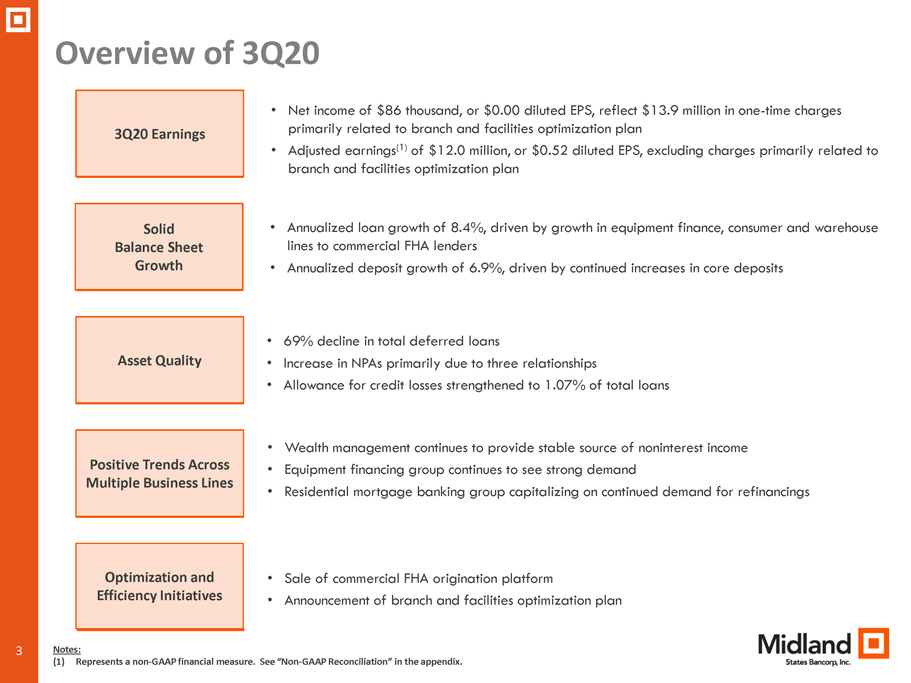
3 Overview of 3Q20 3 Positive Trends Across Multiple Business Lines 3Q20 Earnings Optimization and Efficiency Initiatives • Wealth management continues to provide stable source of noninterest income • Equipment financing group continues to see strong demand • Residential mortgage banking group capitalizing on continued demand for refinancings • Sale of commercial FHA origination platform • Announcement of branch and facilities optimization plan Asset Quality • 69% decline in total deferred loans • Increase in NPAs primarily due to three relationships • Allowance for credit losses strengthened to 1.07% of total loans • Net income of $86 thousand, or $0.00 diluted EPS, reflect $13.9 million in one - time charges primarily related to branch and facilities optimization plan • Adjusted earnings (1) of $12.0 million, or $0.52 diluted EPS, excluding charges primarily related to branch and facilities optimization plan Notes: (1) Represents a non - GAAP financial measure. See “Non - GAAP Reconciliation” in the appendix. Solid Balance Sheet Growth • Annualized loan growth of 8.4%, driven by growth in equipment finance, consumer and warehouse lines to commercial FHA lenders • Annualized deposit growth of 6.9%, driven by continued increases in core deposits
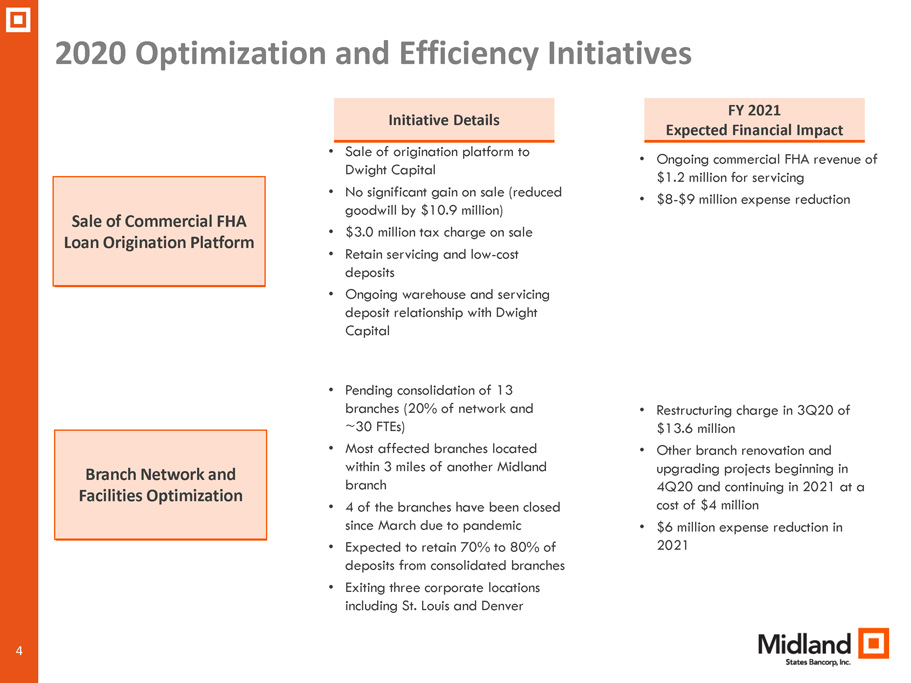
4 2020 Optimization and Efficiency Initiatives 4 Sale of Commercial FHA Loan Origination Platform • Sale of origination platform to Dwight Capital • No significant gain on sale (reduced goodwill by $10.9 million) • $3.0 million tax charge on sale • Retain servicing and low - cost deposits • Ongoing warehouse and servicing deposit relationship with Dwight Capital • Ongoing commercial FHA revenue of $1.2 million for servicing • $8 - $9 million expense reduction Branch Network and Facilities Optimization • Pending consolidation of 13 branches (20% of network and ~30 FTEs) • Most affected branches located within 3 miles of another Midland branch • 4 of the branches have been closed since March due to pandemic • Expected to retain 70% to 80% of deposits from consolidated branches • Exiting three corporate locations including St. Louis and Denver • Restructuring charge in 3Q20 of $13.6 million • Other branch renovation and upgrading projects beginning in 4Q20 and continuing in 2021 at a cost of $4 million • $6 million expense reduction in 2021 Initiative Details FY 2021 Expected Financial Impact
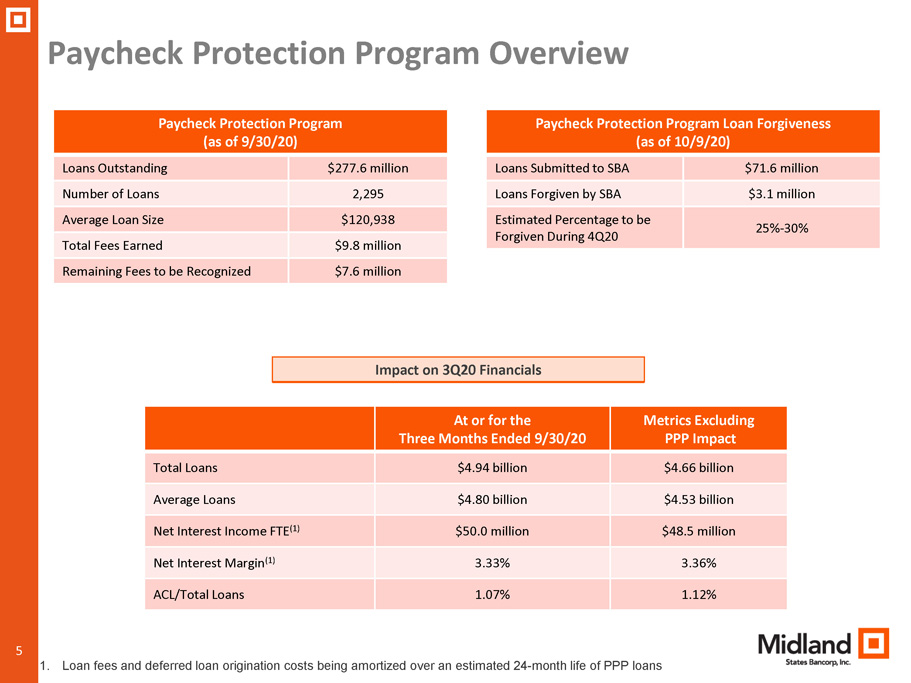
5 Paycheck Protection Program Overview Paycheck Protection Program (as of 9/30/20) Loans Outstanding $277.6 million Number of Loans 2,295 Average Loan Size $120,938 Total Fees Earned $9.8 million Remaining Fees to be Recognized $7.6 million Impact on 3Q20 Financials At or for the Three Months Ended 9/30/20 Metrics Excluding PPP Impact Total Loans $4.94 billion $4.66 billion Average Loans $4.80 billion $4.53 billion Net Interest Income FTE (1) $50.0 million $48.5 million Net Interest Margin (1) 3.33% 3.36% ACL/Total Loans 1.07% 1.12% 1. Loan fees and deferred loan origination costs being amortized over an estimated 24 - month life of PPP loans Paycheck Protection Program Loan Forgiveness (as of 10/9/20) Loans Submitted to SBA $71.6 million Loans Forgiven by SBA $3.1 million Estimated Percentage to be Forgiven During 4Q20 25% - 30%
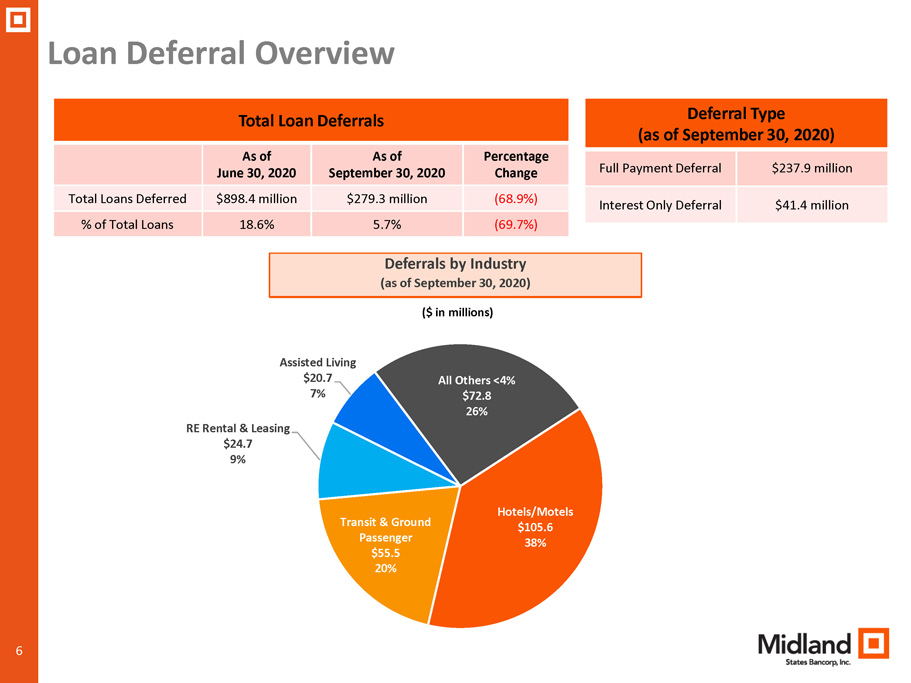
6 Loan Deferral Overview Total Loan Deferrals As of June 30, 2020 As of September 30, 2020 Percentage Change Total Loans Deferred $898.4 million $279.3 million (68.9%) % of Total Loans 18.6% 5.7% (69.7%) Deferrals by Industry (as of September 30, 2020) Hotels/Motels $105.6 38% Transit & Ground Passenger $55.5 20% RE Rental & Leasing $24.7 9% Assisted Living $20.7 7% All Others <4% $72.8 26% ($ in millions) Deferral Type (as of September 30, 2020) Full Payment Deferral $237.9 million Interest Only Deferral $41.4 million
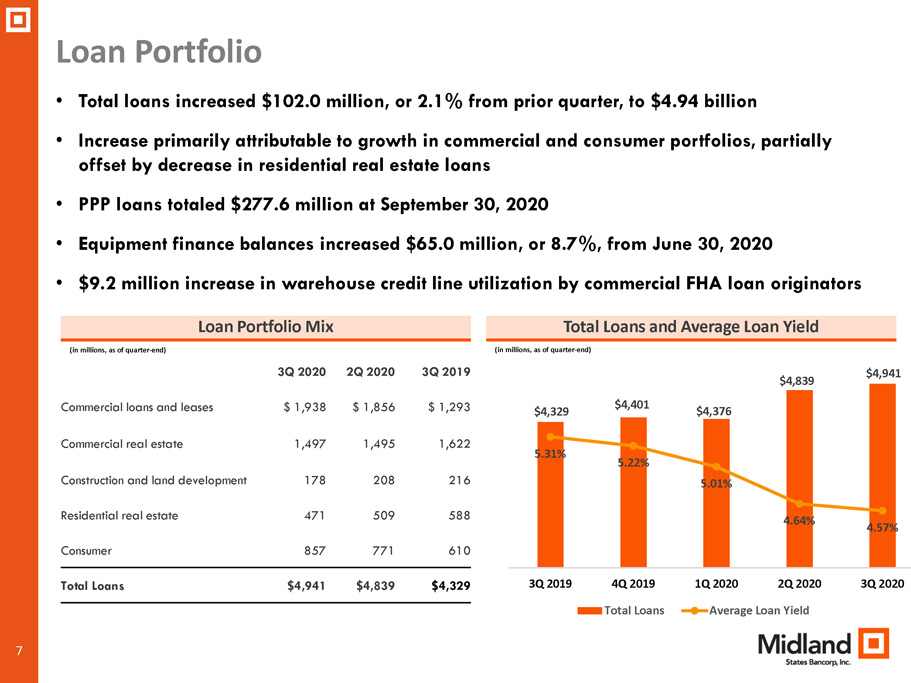
7 3Q 2020 2Q 2020 3Q 2019 Commercial loans and leases $ 1,938 $ 1,856 $ 1,293 Commercial real estate 1,497 1,495 1,622 Construction and land development 178 208 216 Residential real estate 471 509 588 Consumer 857 771 610 Total Loans $4,941 $4,839 $4,329 Loan Portfolio Total Loans and Average Loan Yield • Total loans increased $102.0 million, or 2.1% from prior quarter, to $4.94 billion • Increase primarily attributable to growth in commercial and consumer portfolios, partially offset by decrease in residential real estate loans • PPP loans totaled $277.6 million at September 30, 2020 • Equipment finance balances increased $65.0 million, or 8.7%, from June 30, 2020 • $9.2 million increase in warehouse credit line utilization by commercial FHA loan originators Loan Portfolio Mix (in millions, as of quarter - end) (in millions, as of quarter - end) $4,329 $4,401 $4,376 $4,839 $4,941 5.31% 5.22% 5.01% 4.64% 4.57% 3Q 2019 4Q 2019 1Q 2020 2Q 2020 3Q 2020 Total Loans Average Loan Yield
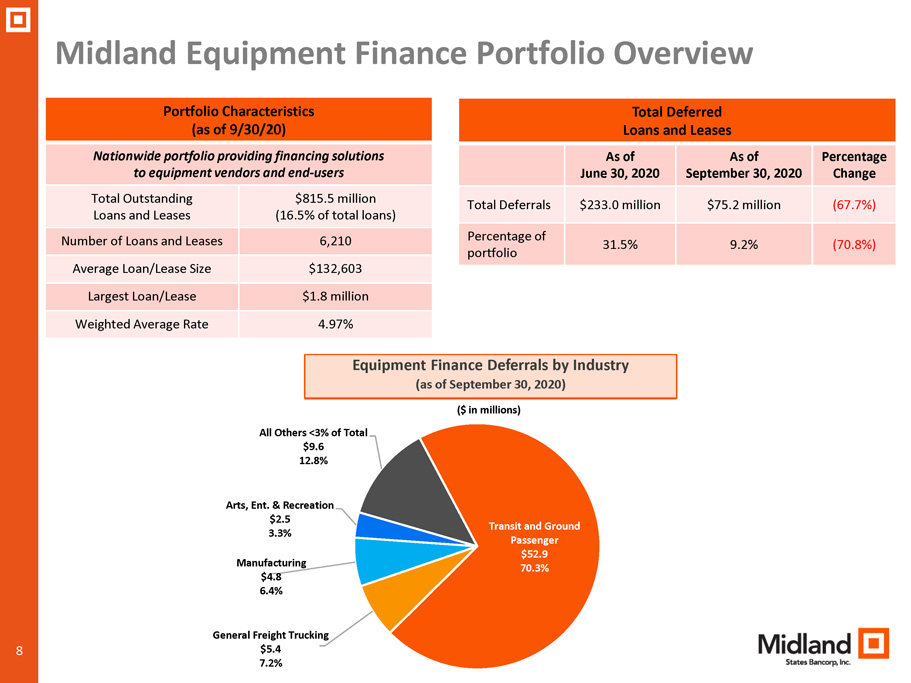
8 Midland Equipment Finance Portfolio Overview ($ in millions) Portfolio Characteristics (as of 9/30/20) Nationwide portfolio providing financing solutions to equipment vendors and end - users Total Outstanding Loans and Leases $815.5 million (16.5% of total loans) Number of Loans and Leases 6,210 Average Loan/Lease Size $132,603 Largest Loan/Lease $1.8 million Weighted Average Rate 4.97% Avg. FICO Score 604 Transit and Ground Passenger $52.9 70.3% General Freight Trucking $5.4 7.2% Manufacturing $4.8 6.4% Arts, Ent. & Recreation $2.5 3.3% All Others <3% of Total $9.6 12.8% Total Deferred Loans and Leases As of June 30, 2020 As of September 30, 2020 Percentage Change Total Deferrals $233.0 million $75.2 million (67.7%) Percentage of portfolio 31.5% 9.2% (70.8%) Equipment Finance Deferrals by Industry (as of September 30, 2020)
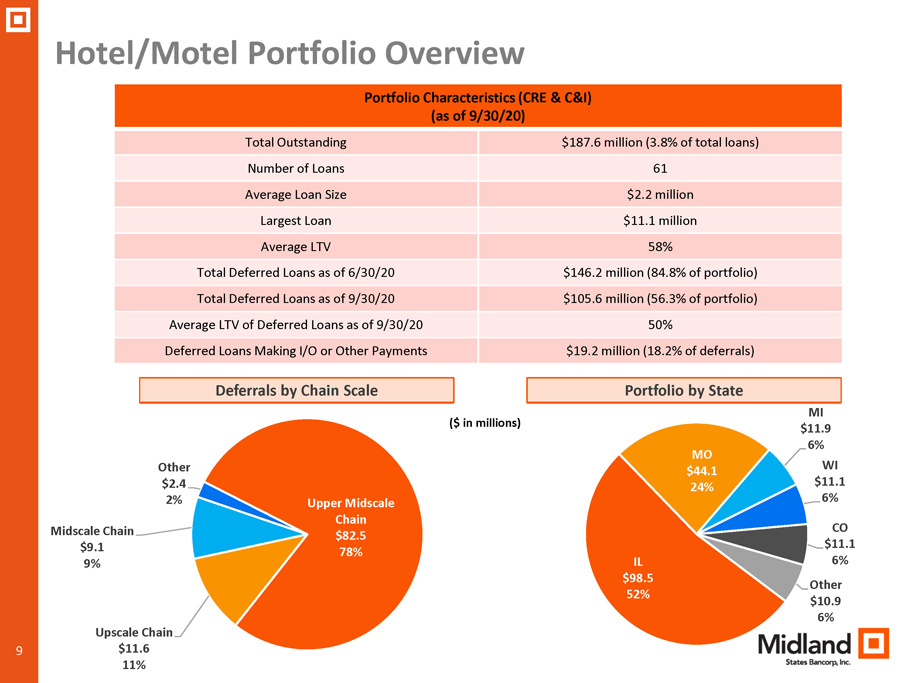
9 Hotel/Motel Portfolio Overview Deferrals by Chain Scale ($ in millions) Upper Midscale Chain $82.5 78% Upscale Chain $11.6 11% Midscale Chain $9.1 9% Other $2.4 2% Portfolio Characteristics (CRE & C&I) (as of 9/30/20) Total Outstanding $187.6 million (3.8% of total loans) Number of Loans 61 Average Loan Size $2.2 million Largest Loan $11.1 million Average LTV 58% Total Deferred Loans as of 6/30/20 $146.2 million (84.8% of portfolio) Total Deferred Loans as of 9/30/20 $105.6 million (56.3% of portfolio) Average LTV of Deferred Loans as of 9/30/20 50% Deferred Loans Making I/O or Other Payments $19.2 million (18.2% of deferrals) Portfolio by State IL $98.5 52% MO $44.1 24% MI $11.9 6% WI $11.1 6% CO $11.1 6% Other $10.9 6%
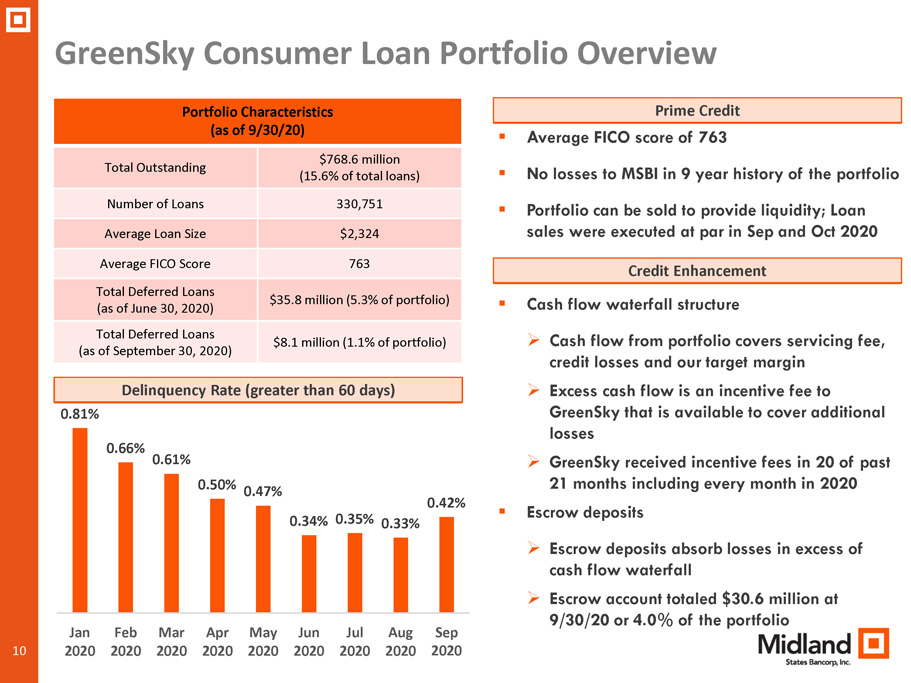
10 GreenSky Consumer Loan Portfolio Overview Delinquency Rate (greater than 60 days) Portfolio Characteristics (as of 9/30/20) Total Outstanding $768.6 million (15.6% of total loans) Number of Loans 330,751 Average Loan Size $2,324 Average FICO Score 763 Total Deferred Loans (as of June 30, 2020) $35.8 million (5.3% of portfolio) Total Deferred Loans (as of September 30, 2020) $8.1 million (1.1% of portfolio) ▪ Average FICO score of 763 ▪ No losses to MSBI in 9 year history of the portfolio ▪ Portfolio can be sold to provide liquidity; Loan sales were executed at par in Sep and Oct 2020 Prime Credit 0.81% 0.66% 0.61% 0.50% 0.47% 0.34% 0.35% 0.33% 0.42% Jan 2020 Feb 2020 Mar 2020 Apr 2020 May 2020 Jun 2020 Jul 2020 Aug 2020 Sep 2020 ▪ Cash flow waterfall structure » Cash flow from portfolio covers servicing fee, credit losses and our target margin » Excess cash flow is an incentive fee to GreenSky that is available to cover additional losses » GreenSky received incentive fees in 20 of past 21 months including every month in 2020 ▪ Escrow deposits » Escrow deposits absorb losses in excess of cash flow waterfall » Escrow account totaled $30.6 million at 9/30/20 or 4.0% of the portfolio Credit Enhancement
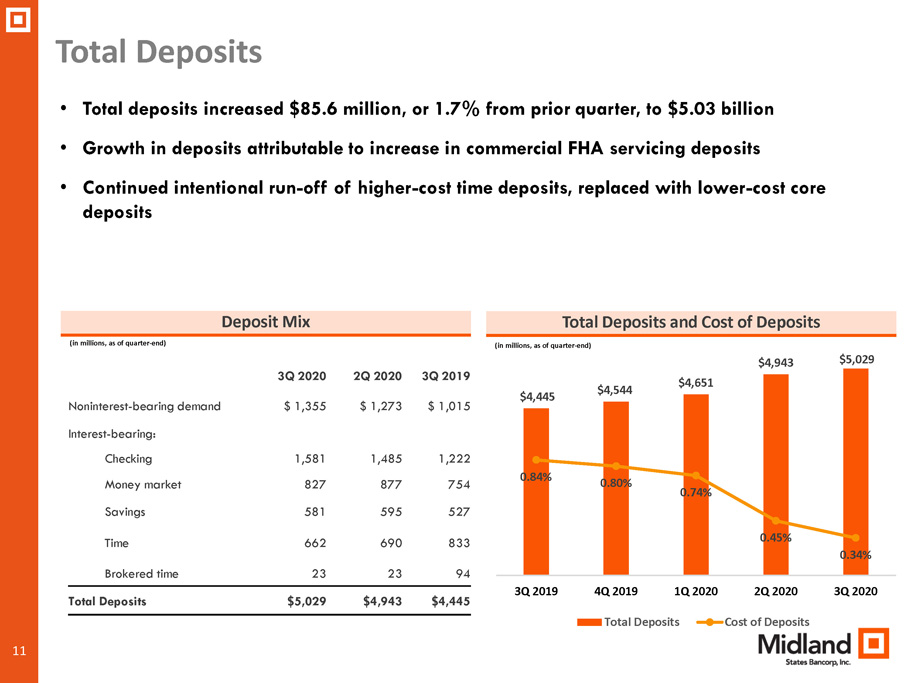
11 3Q 2020 2Q 2020 3Q 2019 Noninterest - bearing demand $ 1,355 $ 1,273 $ 1,015 Interest - bearing: Checking 1,581 1,485 1,222 Money market 827 877 754 Savings 581 595 527 Time 662 690 833 Brokered time 23 23 94 Total Deposits $5,029 $4,943 $4,445 Total Deposits Total Deposits and Cost of Deposits • Total deposits increased $85.6 million, or 1.7% from prior quarter, to $5.03 billion • Growth in deposits attributable to increase in commercial FHA servicing deposits • Continued intentional run - off of higher - cost time deposits, replaced with lower - cost core deposits Deposit Mix (in millions, as of quarter - end) (in millions, as of quarter - end) $4,445 $4,544 $4,651 $4,943 $5,029 0.84% 0.80% 0.74% 0.45% 0.34% 3Q 2019 4Q 2019 1Q 2020 2Q 2020 3Q 2020 Total Deposits Cost of Deposits
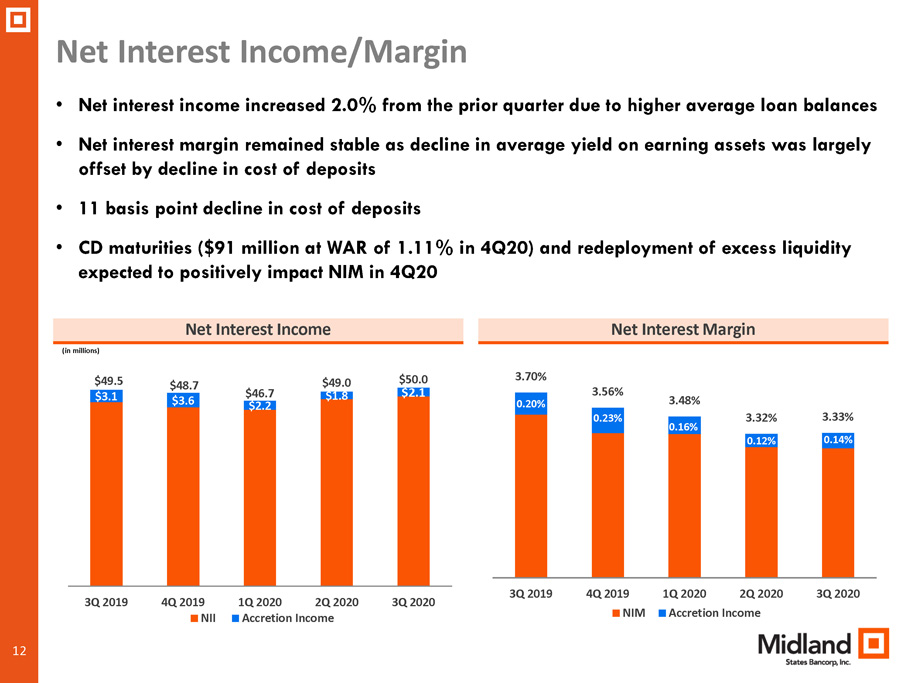
12 $3.1 $3.6 $2.2 $1.8 $2.1 $49.5 $48.7 $46.7 $49.0 $50.0 3Q 2019 4Q 2019 1Q 2020 2Q 2020 3Q 2020 NII Accretion Income 0.20% 0.23% 0.16% 0.12% 0.14% 3.70% 3.56% 3.48% 3.32% 3.33% 3Q 2019 4Q 2019 1Q 2020 2Q 2020 3Q 2020 NIM Accretion Income • Net interest income increased 2.0% from the prior quarter due to higher average loan balances • Net interest margin remained stable as decline in average yield on earning assets was largely offset by decline in cost of deposits • 11 basis point decline in cost of deposits • CD maturities ($91 million at WAR of 1.11% in 4Q20) and redeployment of excess liquidity expected to positively impact NIM in 4Q20 Net Interest Income/Margin Net Interest Margin Net Interest Income (in millions)
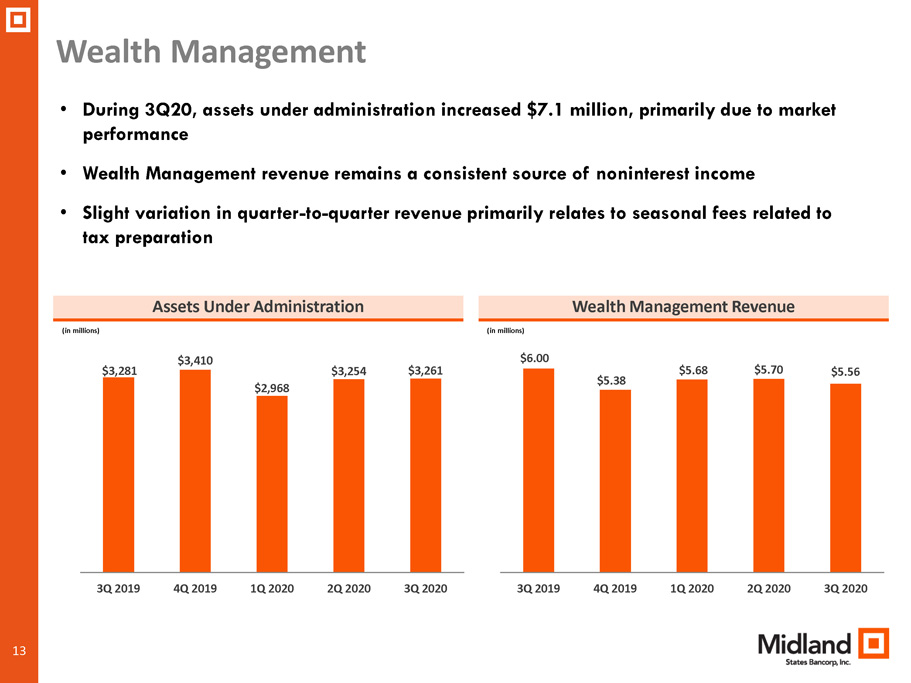
13 $6.00 $5.38 $5.68 $5.70 $5.56 3Q 2019 4Q 2019 1Q 2020 2Q 2020 3Q 2020 $3,281 $3,410 $2,968 $3,254 $3,261 3Q 2019 4Q 2019 1Q 2020 2Q 2020 3Q 2020 • During 3Q20, assets under administration increased $7.1 million, primarily due to market performance • Wealth Management revenue remains a consistent source of noninterest income • Slight variation in quarter - to - quarter revenue primarily relates to seasonal fees related to tax preparation Wealth Management Wealth Management Revenue Assets Under Administration (in millions) (in millions )
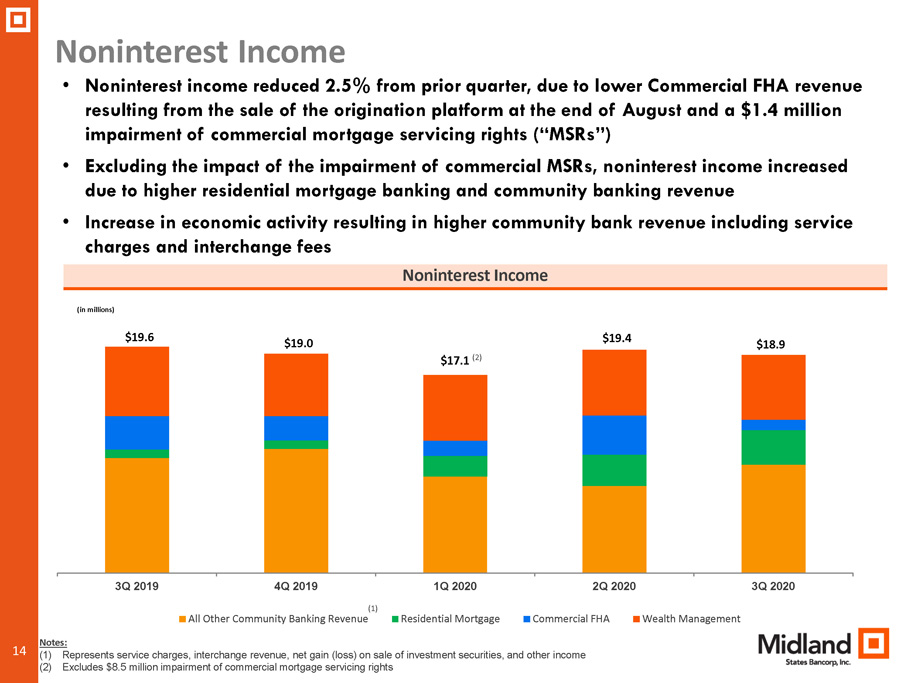
14 Noninterest Income • Noninterest income reduced 2.5% from prior quarter, due to lower Commercial FHA revenue resulting from the sale of the origination platform at the end of August and a $1.4 million impairment of commercial mortgage servicing rights (“MSRs”) • Excluding the impact of the impairment of commercial MSRs, noninterest income increased due to higher residential mortgage banking and community banking revenue • Increase in economic activity resulting in higher community bank revenue including service charges and interchange fees Noninterest Income (in millions) $19.6 $19.0 $17.1 $19.4 $18.9 3Q 2019 4Q 2019 1Q 2020 2Q 2020 3Q 2020 All Other Community Banking Revenue Residential Mortgage Commercial FHA Wealth Management Notes: (1) Represents service charges, interchange revenue, net gain (loss) on sale of investment securities, and other income (2) Excludes $8.5 million impairment of commercial mortgage servicing rights (1) (2)
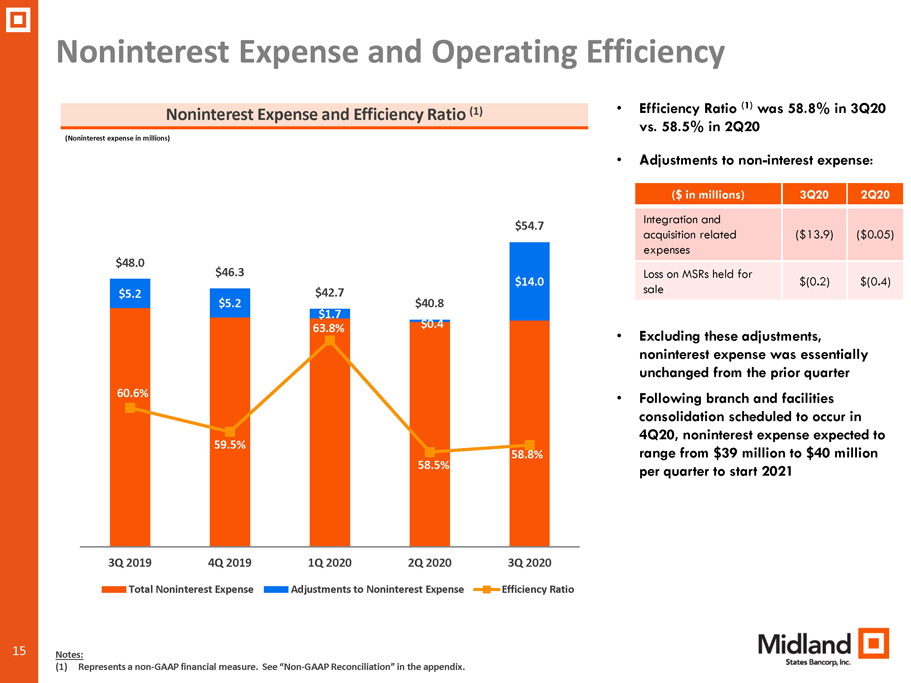
15 Noninterest Expense and Operating Efficiency • Efficiency Ratio (1) was 58.8% in 3Q20 vs. 58.5% in 2Q20 • Adjustments to non - interest expense: • Excluding these adjustments, noninterest expense was essentially unchanged from the prior quarter • Following branch and facilities consolidation scheduled to occur in 4Q20, noninterest expense expected to range from $39 million to $40 million per quarter to start 2021 Noninterest Expense and Efficiency Ratio (1) (Noninterest expense in millions) $5.2 $5.2 $1.7 $0.4 $14.0 $48.0 $46.3 $42.7 $40.8 $54.7 60.6% 59.5% 63.8% 58.5% 58.8% 3Q 2019 4Q 2019 1Q 2020 2Q 2020 3Q 2020 Total Noninterest Expense Adjustments to Noninterest Expense Efficiency Ratio Notes: (1) Represents a non - GAAP financial measure. See “Non - GAAP Reconciliation” in the appendix. ($ in millions) 3Q20 2Q20 Integration and acquisition related expenses ($13.9) ($0.05) Loss on MSRs held for sale $(0.2) $(0.4)
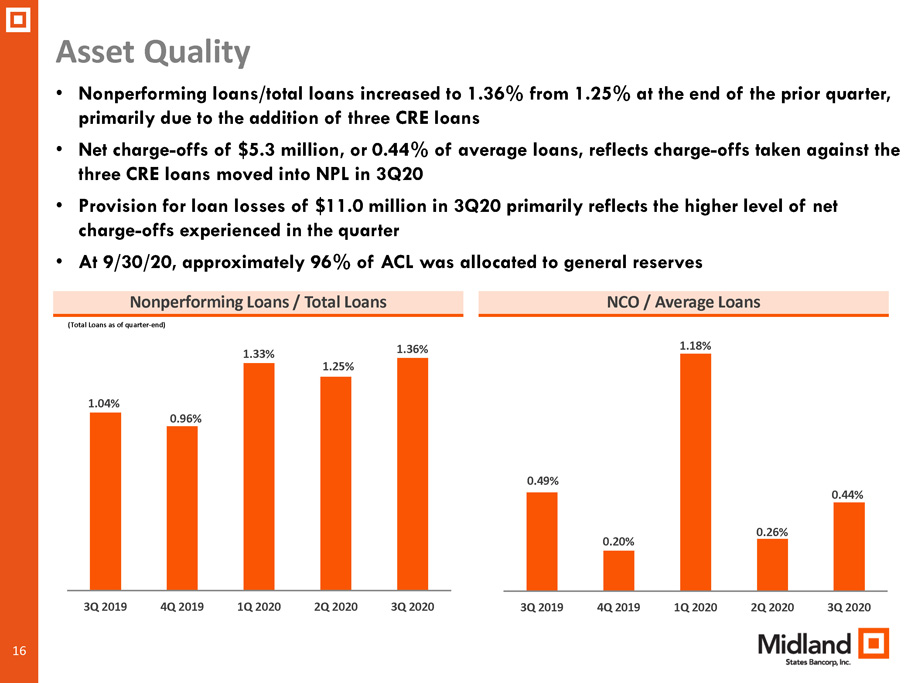
16 Asset Quality NCO / Average Loans • Nonperforming loans/total loans increased to 1.36% from 1.25% at the end of the prior quarter, primarily due to the addition of three CRE loans • Net charge - offs of $5.3 million, or 0.44% of average loans, reflects charge - offs taken against the three CRE loans moved into NPL in 3Q20 • Provision for loan losses of $11.0 million in 3Q20 primarily reflects the higher level of net charge - offs experienced in the quarter • At 9/30/20, approximately 96% of ACL was allocated to general reserves Nonperforming Loans / Total Loans (Total Loans as of quarter - end) 1.04% 0.96% 1.33% 1.25% 1.36% 3Q 2019 4Q 2019 1Q 2020 2Q 2020 3Q 2020 0.49% 0.20% 1.18% 0.26% 0.44% 3Q 2019 4Q 2019 1Q 2020 2Q 2020 3Q 2020
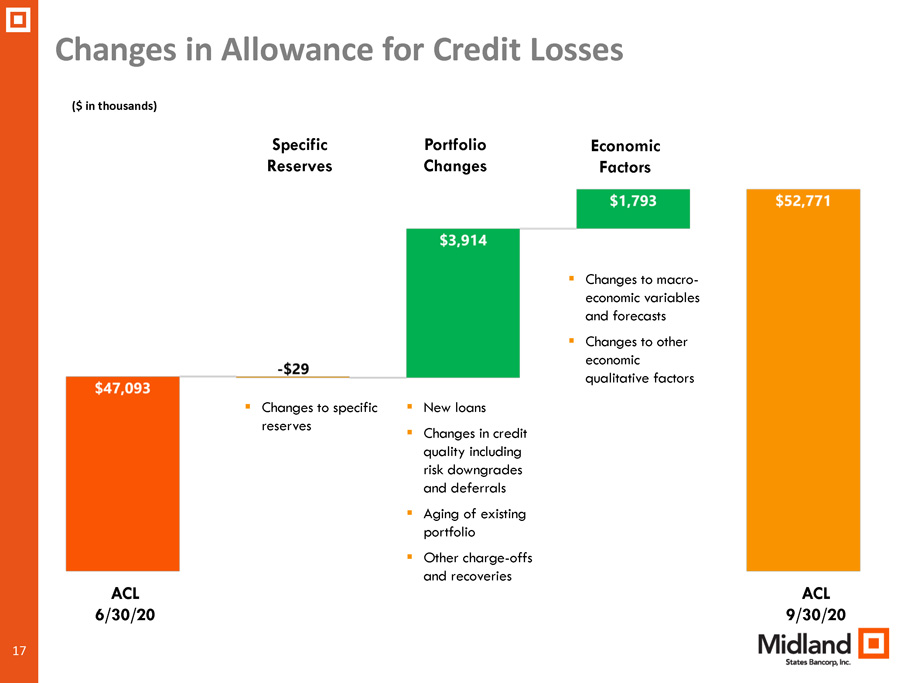
17 Changes in Allowance for Credit Losses ACL 6/30/20 ACL 9/30/20 ($ in thousands) Specific Reserves Portfolio Changes Economic Factors ▪ Changes to specific reserves ▪ New loans ▪ Changes in credit quality including risk downgrades and deferrals ▪ Aging of existing portfolio ▪ Other charge - offs and recoveries ▪ Changes to macro - economic variables and forecasts ▪ Changes to other economic qualitative factors
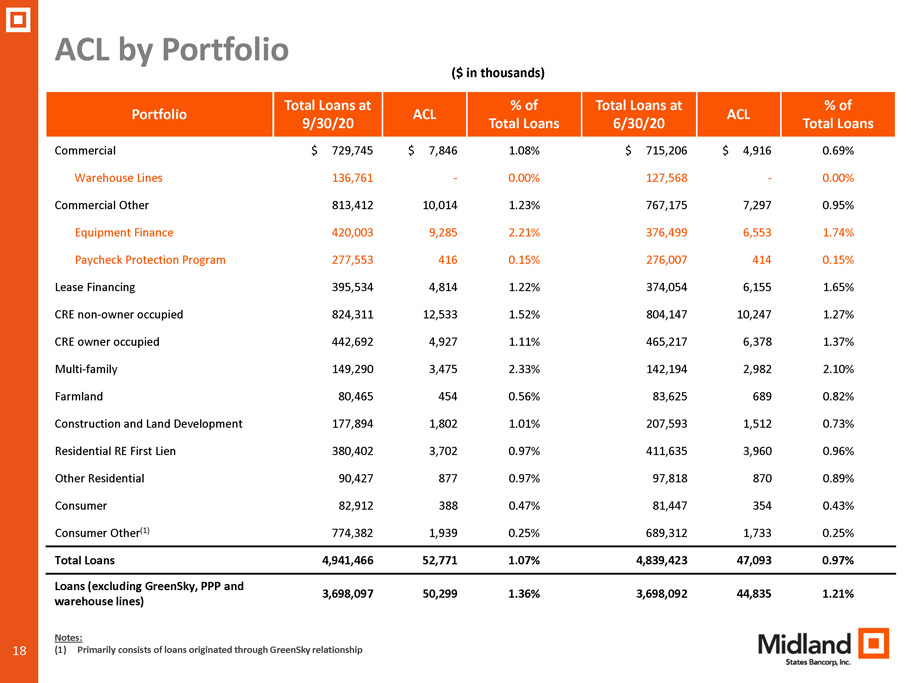
18 ACL by Portfolio Portfolio Total Loans at 9/30/20 ACL % of Total Loans Total Loans at 6/30/20 ACL % of Total Loans Commercial $ 729,745 $ 7,846 1.08% $ 715,206 $ 4,916 0.69% Warehouse Lines 136,761 - 0.00% 127,568 - 0.00% Commercial Other 813,412 10,014 1.23% 767,175 7,297 0.95% Equipment Finance 420,003 9,285 2.21% 376,499 6,553 1.74% Paycheck Protection Program 277,553 416 0.15% 276,007 414 0.15% Lease Financing 395,534 4,814 1.22% 374,054 6,155 1.65% CRE non - owner occupied 824,311 12,533 1.52% 804,147 10,247 1.27% CRE owner occupied 442,692 4,927 1.11% 465,217 6,378 1.37% Multi - family 149,290 3,475 2.33% 142,194 2,982 2.10% Farmland 80,465 454 0.56% 83,625 689 0.82% Construction and Land Development 177,894 1,802 1.01% 207,593 1,512 0.73% Residential RE First Lien 380,402 3,702 0.97% 411,635 3,960 0.96% Other Residential 90,427 877 0.97% 97,818 870 0.89% Consumer 82,912 388 0.47% 81,447 354 0.43% Consumer Other (1) 774,382 1,939 0.25% 689,312 1,733 0.25% Total Loans 4,941,466 52,771 1.07% 4,839,423 47,093 0.97% Loans (excluding GreenSky, PPP and warehouse lines) 3,698,097 50,299 1.36% 3,698,092 44,835 1.21% ($ in thousands) Notes: (1) Primarily consists of loans originated through GreenSky relationship
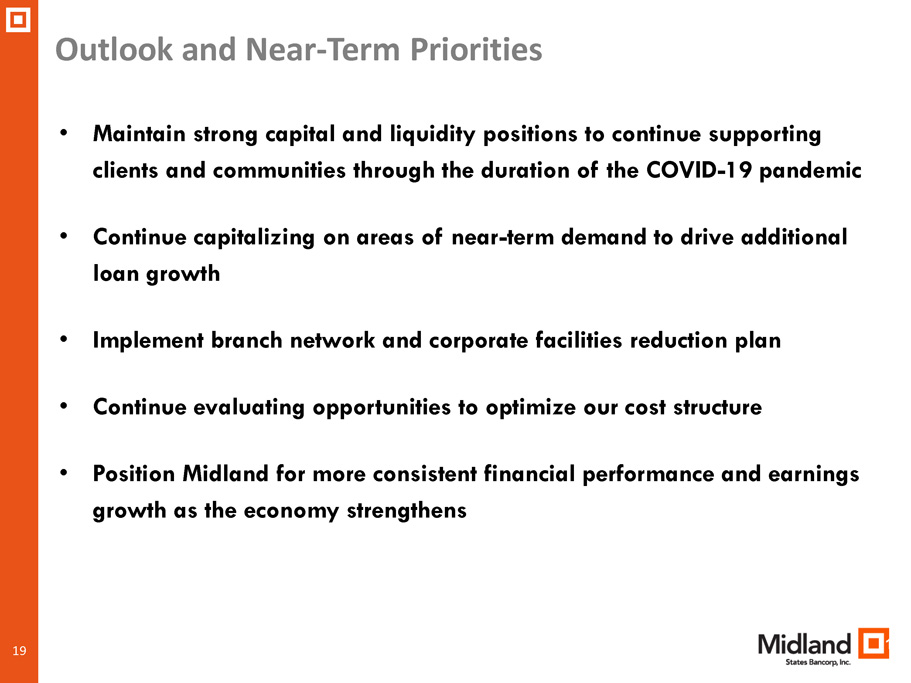
19 Outlook and Near - Term Priorities • Maintain strong capital and liquidity positions to continue supporting clients and communities through the duration of the COVID - 19 pandemic • Continue capitalizing on areas of near - term demand to drive additional loan growth • Implement branch network and corporate facilities reduction plan • Continue evaluating opportunities to optimize our cost structure • Position Midland for more consistent financial performance and earnings growth as the economy strengthens 19
20 APPENDIX
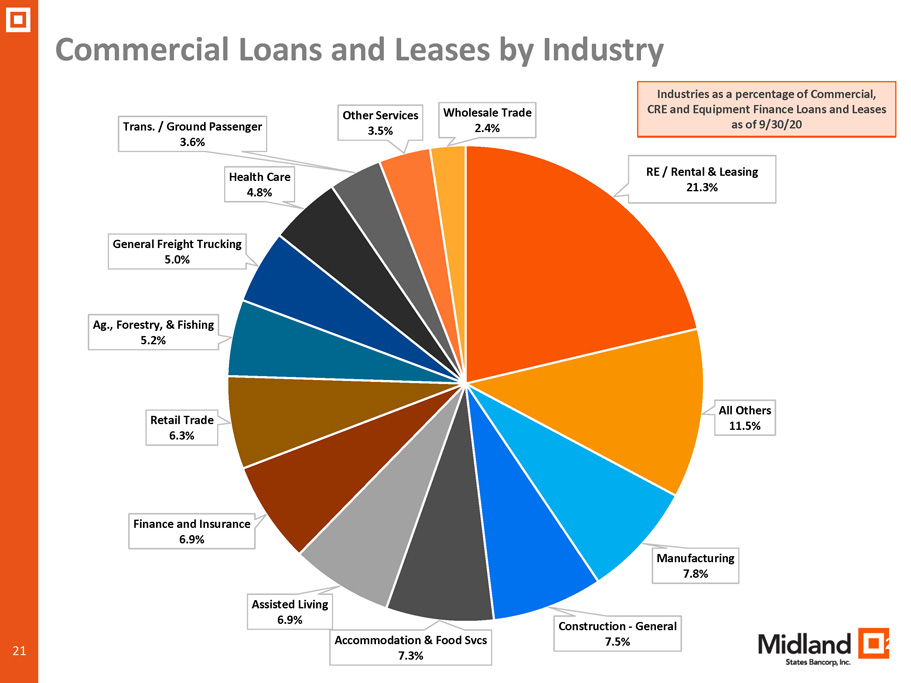
21 Commercial Loans and Leases by Industry 21 RE / Rental & Leasing 21.3% All Others 11.5% Manufacturing 7.8% Construction - General 7.5% Accommodation & Food Svcs 7.3% Assisted Living 6.9% Finance and Insurance 6.9% Retail Trade 6.3% Ag., Forestry, & Fishing 5.2% General Freight Trucking 5.0% Health Care 4.8% Trans. / Ground Passenger 3.6% Other Services 3.5% Wholesale Trade 2.4% Industries as a percentage of Commercial, CRE and Equipment Finance Loans and Leases as of 9/30/20
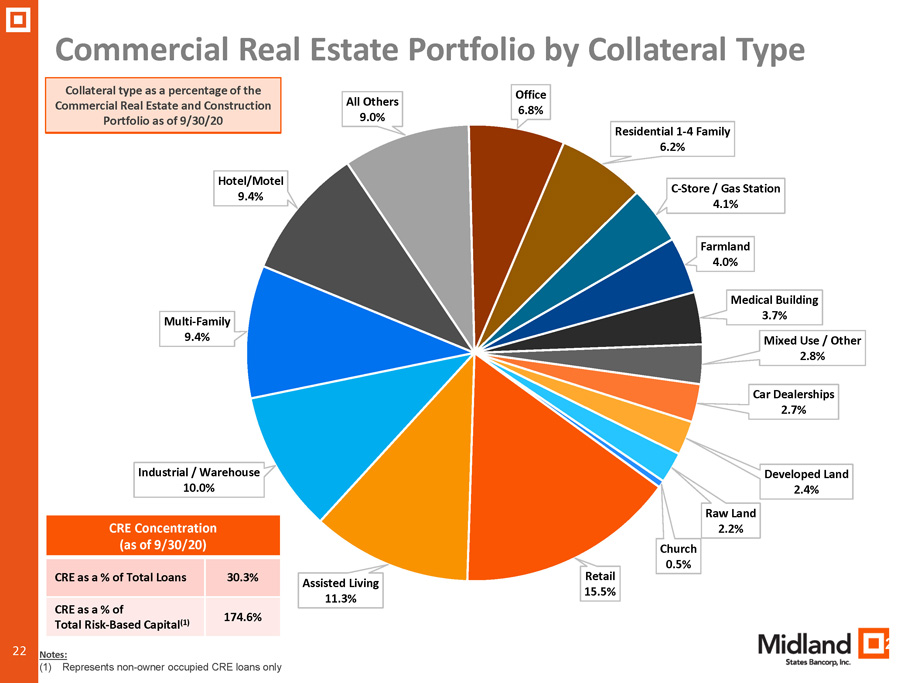
22 Commercial Real Estate Portfolio by Collateral Type 22 Retail 15.5% Assisted Living 11.3% Industrial / Warehouse 10.0% Multi - Family 9.4% Hotel/Motel 9.4% All Others 9.0% Office 6.8% Residential 1 - 4 Family 6.2% C - Store / Gas Station 4.1% Farmland 4.0% Medical Building 3.7% Mixed Use / Other 2.8% Car Dealerships 2.7% Developed Land 2.4% Raw Land 2.2% Church 0.5% Collateral type as a percentage of the Commercial Real Estate and Construction Portfolio as of 9/30/20 CRE Concentration (as of 9/30/20) CRE as a % of Total Loans 30.3% CRE as a % of Total Risk - Based Capital (1) 174.6% Notes: (1) Represents non - owner occupied CRE loans only
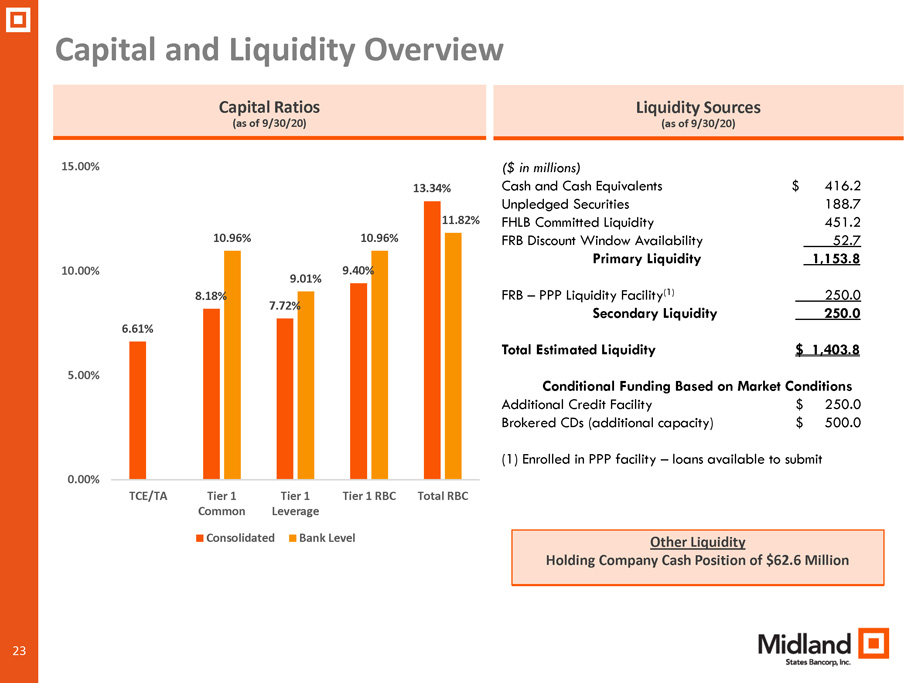
23 Capital and Liquidity Overview Capital Ratios (as of 9/30/20) Liquidity Sources (as of 9/30/20) 6.61% 8.18% 7.72% 9.40% 13.34% 10.96% 9.01% 10.96% 11.82% 0.00% 5.00% 10.00% 15.00% TCE/TA Tier 1 Common Tier 1 Leverage Tier 1 RBC Total RBC Consolidated Bank Level ($ in millions) Cash and Cash Equivalents $ 416.2 Unpledged Securities 188.7 FHLB Committed Liquidity 451.2 FRB Discount Window Availability 52.7 Primary Liquidity 1,153.8 FRB – PPP Liquidity Facility (1) 250.0 Secondary Liquidity 250.0 Total Estimated Liquidity $ 1,403.8 Conditional Funding Based on Market Conditions Additional Credit Facility $ 250.0 Brokered CDs (additional capacity) $ 500.0 (1) Enrolled in PPP facility – loans available to submit Other Liquidity Holding Company Cash Position of $62.6 Million
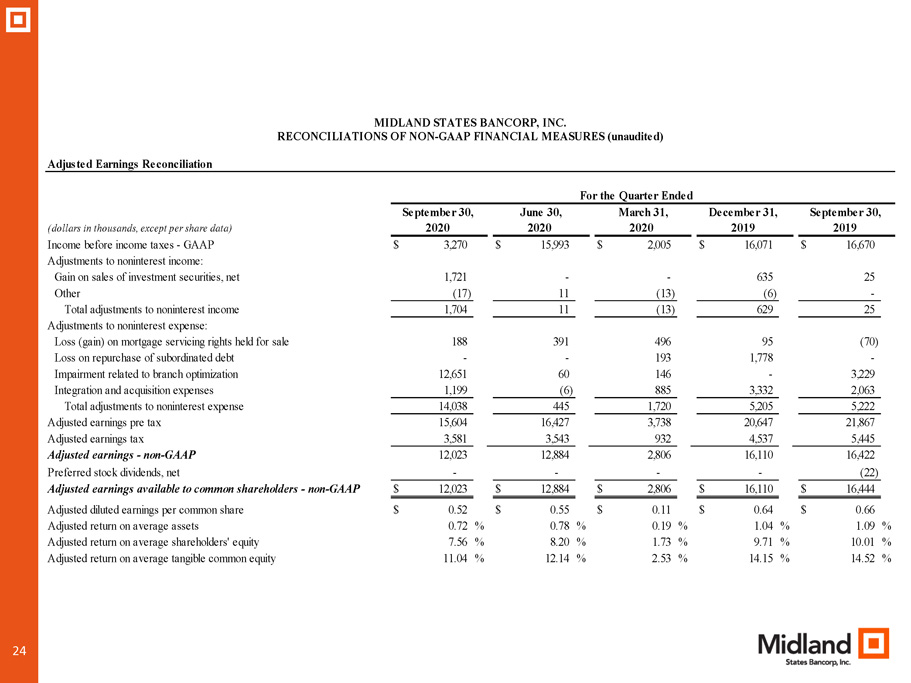
24 Adjusted Earnings Reconciliation (dollars in thousands, except per share data) Income before income taxes - GAAP $ 3,270 $ 15,993 $ 2,005 $ 16,071 $ 16,670 Adjustments to noninterest income: Gain on sales of investment securities, net 1,721 - - 635 25 Other (17) 11 (13) (6) - Total adjustments to noninterest income 1,704 11 (13) 629 25 Adjustments to noninterest expense: Loss (gain) on mortgage servicing rights held for sale 188 391 496 95 (70) Loss on repurchase of subordinated debt - - 193 1,778 - Impairment related to branch optimization 12,651 60 146 - 3,229 Integration and acquisition expenses 1,199 (6) 885 3,332 2,063 Total adjustments to noninterest expense 14,038 445 1,720 5,205 5,222 Adjusted earnings pre tax 15,604 16,427 3,738 20,647 21,867 Adjusted earnings tax 3,581 3,543 932 4,537 5,445 Adjusted earnings - non-GAAP 12,023 12,884 2,806 16,110 16,422 Preferred stock dividends, net - - - - (22) Adjusted earnings available to common shareholders - non-GAAP $ 12,023 $ 12,884 $ 2,806 $ 16,110 $ 16,444 Adjusted diluted earnings per common share $ 0.52 $ 0.55 $ 0.11 $ 0.64 $ 0.66 Adjusted return on average assets 0.72 % 0.78 % 0.19 % 1.04 % 1.09 % Adjusted return on average shareholders' equity 7.56 % 8.20 % 1.73 % 9.71 % 10.01 % Adjusted return on average tangible common equity 11.04 % 12.14 % 2.53 % 14.15 % 14.52 % 2020 2020 2020 2019 2019 September 30, June 30, March 31, December 31, September 30, MIDLAND STATES BANCORP, INC.RECONCILIATIONS OF NON-GAAP FINANCIAL MEASURES (unaudited) For the Quarter Ended
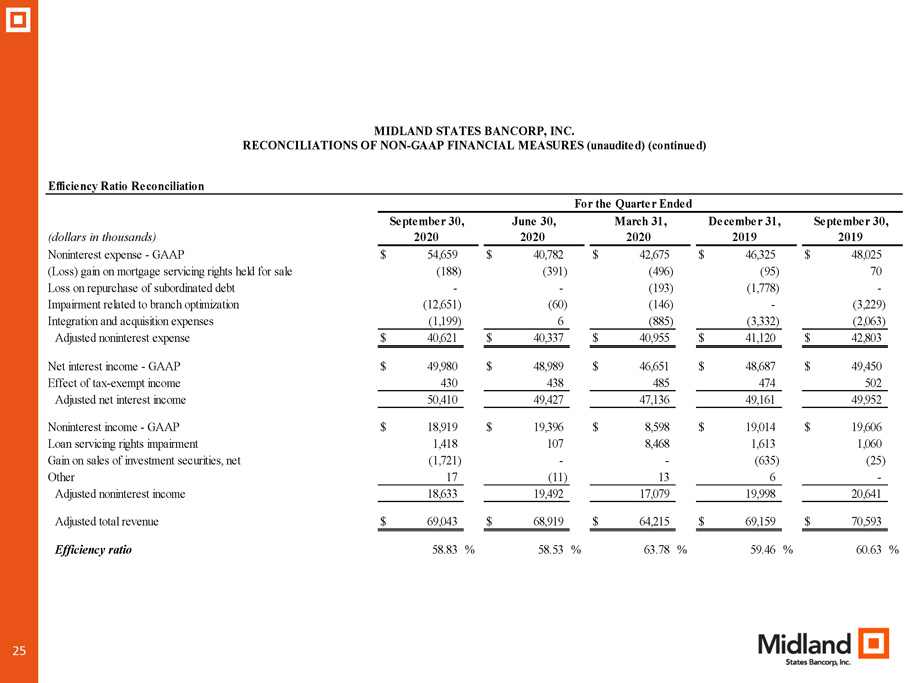
25 Efficiency Ratio Reconciliation (dollars in thousands) Noninterest expense - GAAP $ 54,659 $ 40,782 $ 42,675 $ 46,325 $ 48,025 (Loss) gain on mortgage servicing rights held for sale (188) (391) (496) (95) 70 Loss on repurchase of subordinated debt - - (193) (1,778) - Impairment related to branch optimization (12,651) (60) (146) - (3,229) Integration and acquisition expenses (1,199) 6 (885) (3,332) (2,063) Adjusted noninterest expense $ 40,621 $ 40,337 $ 40,955 $ 41,120 $ 42,803 Net interest income - GAAP $ 49,980 $ 48,989 $ 46,651 $ 48,687 $ 49,450 Effect of tax-exempt income 430 438 485 474 502 Adjusted net interest income 50,410 49,427 47,136 49,161 49,952 Noninterest income - GAAP $ 18,919 $ 19,396 $ 8,598 $ 19,014 $ 19,606 Loan servicing rights impairment 1,418 107 8,468 1,613 1,060 Gain on sales of investment securities, net (1,721) - - (635) (25) Other 17 (11) 13 6 - Adjusted noninterest income 18,633 19,492 17,079 19,998 20,641 Adjusted total revenue $ 69,043 $ 68,919 $ 64,215 $ 69,159 $ 70,593 Efficiency ratio 58.83 % 58.53 % 63.78 % 59.46 % 60.63 % 2020 2020 2020 2019 2019 September 30, June 30, March 31, December 31, September 30, MIDLAND STATES BANCORP, INC.RECONCILIATIONS OF NON-GAAP FINANCIAL MEASURES (unaudited) (continued) For the Quarter Ended
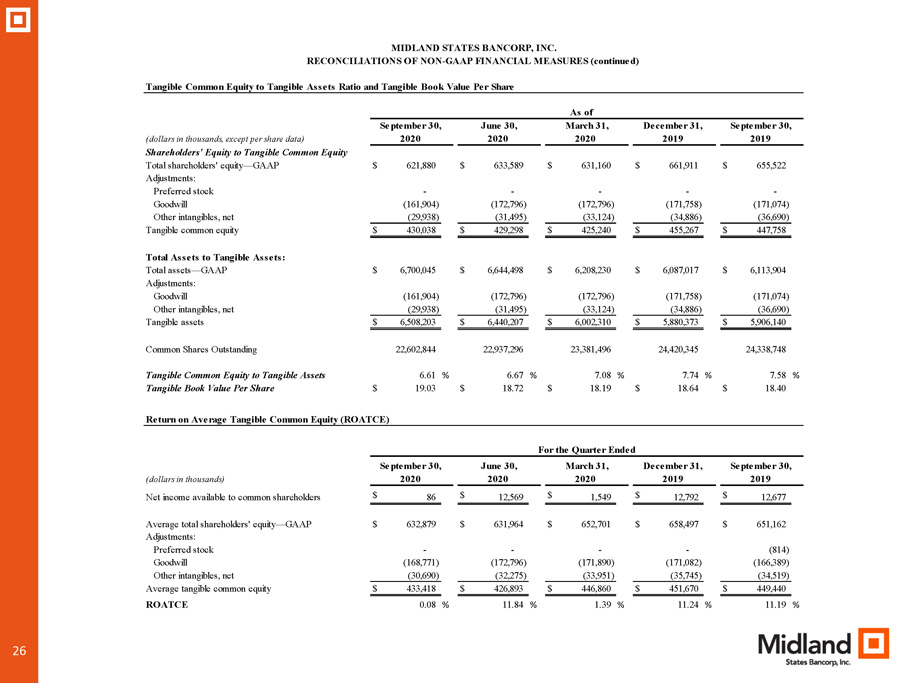
26 Tangible Common Equity to Tangible Assets Ratio and Tangible Book Value Per Share (dollars in thousands, except per share data) Shareholders' Equity to Tangible Common Equity Total shareholders' equity—GAAP $ 621,880 $ 633,589 $ 631,160 $ 661,911 $ 655,522 Adjustments: Preferred stock - - - - - Goodwill (161,904) (172,796) (172,796) (171,758) (171,074) Other intangibles, net (29,938) (31,495) (33,124) (34,886) (36,690) Tangible common equity $ 430,038 $ 429,298 $ 425,240 $ 455,267 $ 447,758 Total Assets to Tangible Assets: Total assets—GAAP $ 6,700,045 $ 6,644,498 $ 6,208,230 $ 6,087,017 $ 6,113,904 Adjustments: Goodwill (161,904) (172,796) (172,796) (171,758) (171,074) Other intangibles, net (29,938) (31,495) (33,124) (34,886) (36,690) Tangible assets $ 6,508,203 $ 6,440,207 $ 6,002,310 $ 5,880,373 $ 5,906,140 Common Shares Outstanding 22,602,844 22,937,296 23,381,496 24,420,345 24,338,748 Tangible Common Equity to Tangible Assets 6.61 % 6.67 % 7.08 % 7.74 % 7.58 % Tangible Book Value Per Share $ 19.03 $ 18.72 $ 18.19 $ 18.64 $ 18.40 Return on Average Tangible Common Equity (ROATCE) (dollars in thousands) Net income available to common shareholders $ 86 $ 12,569 $ 1,549 $ 12,792 $ 12,677 Average total shareholders' equity—GAAP $ 632,879 $ 631,964 $ 652,701 $ 658,497 $ 651,162 Adjustments: Preferred stock - - - - (814) Goodwill (168,771) (172,796) (171,890) (171,082) (166,389) Other intangibles, net (30,690) (32,275) (33,951) (35,745) (34,519) Average tangible common equity $ 433,418 $ 426,893 $ 446,860 $ 451,670 $ 449,440 ROATCE 0.08 % 11.84 % 1.39 % 11.24 % 11.19 % MIDLAND STATES BANCORP, INC. RECONCILIATIONS OF NON-GAAP FINANCIAL MEASURES (continued) As of September 30, June 30, March 31, December 31, September 30, 2020 2020 2020 2019 2019 For the Quarter Ended 2020 2020 2020 2019 2019 September 30, June 30, March 31, December 31, September 30,