
NPB 8-K
Northpointe Bancshares Inc (NPB)
8-K
2025-10-21
For: 2025-10-21
View Original
Added on
April 10, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 OR 15(d) of The Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): October 21, 2025
(Exact name of registrant as specified in its charter)
No. | ||||||||
| (State or other jurisdiction of | (Commission File Number) | (IRS Employer | ||||||
| incorporation) | Identification No.) | |||||||
| (Address of principal executive offices) | (Zip Code) | |||||||
(616 ) 940‑9400
(Registrant’s telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| | ||
| | ||
| | ||
| | ||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 under the Securities Act (17 CFR 230.405) or Rule 12b-2 under the Exchange Act (17 CFR 240.12b-2).
Item 2.02 Results of Operations and Financial Condition.
On October 21, 2025, Northpointe Bancshares, Inc. (the “Company”) issued a press release announcing its financial results for the quarter ended September 30, 2025. A copy of the press release is furnished herewith as Exhibit 99.1 and is incorporated herein by reference.
Item 7.01 Regulation FD Disclosure.
On October 21, 2025, the Company made available supplemental financial information containing additional information about the Company’s financial results for the quarter ended September 30, 2025. A copy of the supplemental financial information is furnished herewith as Exhibit 99.2 and is incorporated herein by reference.
On October 22, 2025, the Company will host a conference call to discuss financial results for the quarter ended September 30, 2025.
The information in Item 2.02 and 7.01, including the information incorporated herein from Exhibits 99.1 and 99.2, is furnished and shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), or incorporated by reference in any filing under the Securities Act of 1933, as amended, or the Exchange Act, except as shall be expressly set forth by specific reference in such a filing.
Item 9.01. Financial Statements and Exhibits.
| (d) | Exhibits | ||||||||||
| Exhibit No. | Description | ||||||||||
| 99.1 | |||||||||||
| 99.2 | |||||||||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document). | ||||||||||
* * * * * *
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| NORTHPOINTE BANCSHARES, INC. | |||||||||||
| Date: October 21, 2025 | By: | /s/ Brad T. Howes | |||||||||
| Brad T. Howes | |||||||||||
| Executive Vice President and Chief Financial Officer | |||||||||||
NORTHPOINTE BANCSHARES, INC. REPORTS THIRD QUARTER 2025 RESULTS
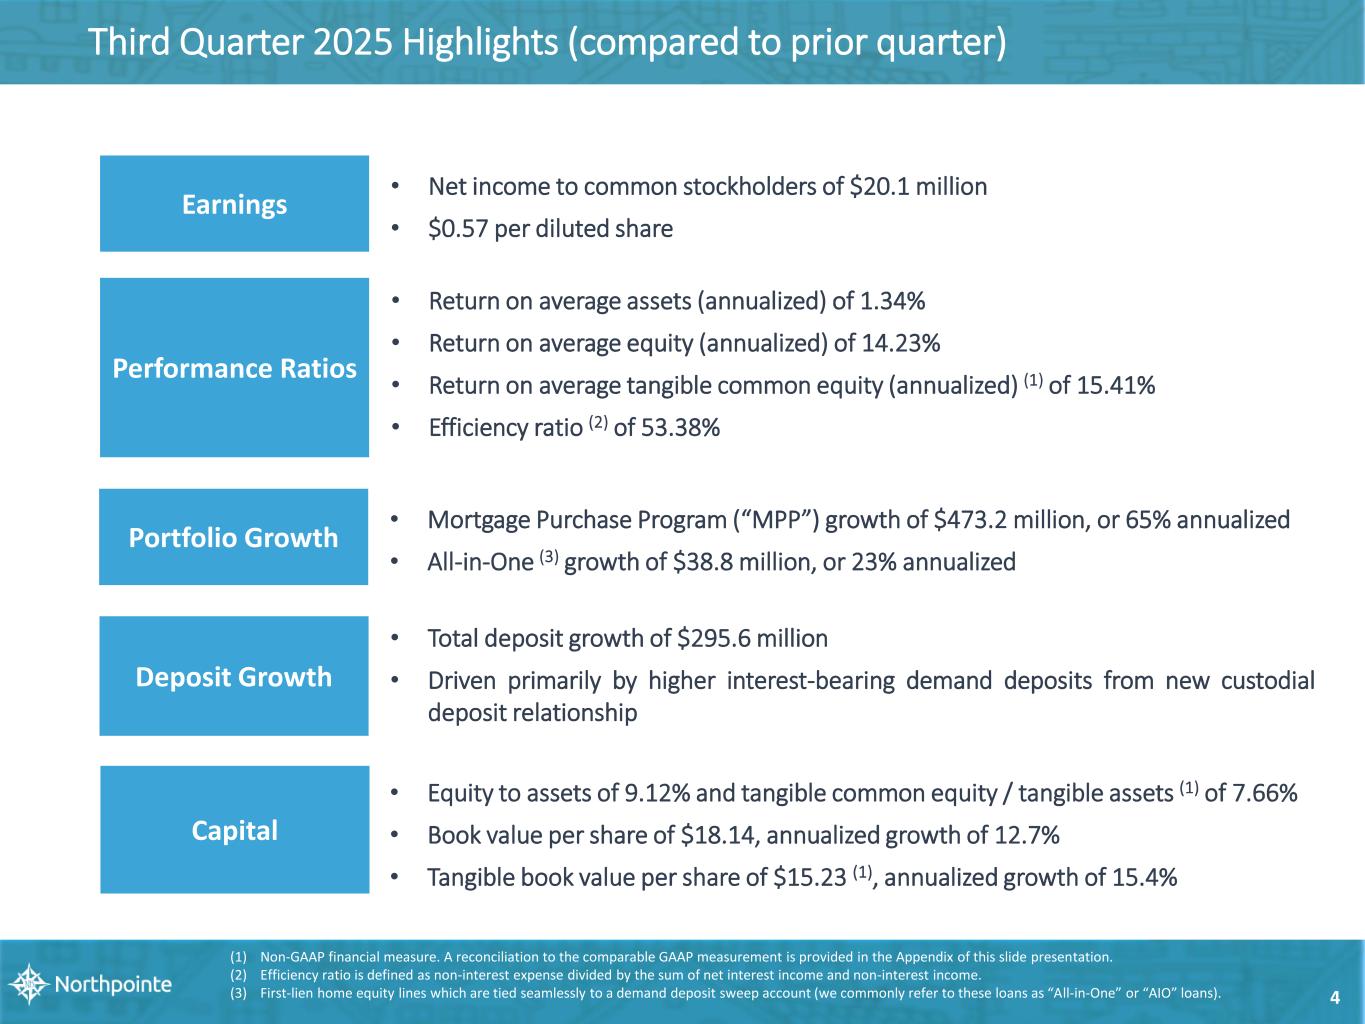
GRAND RAPIDS, MICHIGAN, October 21, 2025 – Northpointe Bancshares, Inc. (NYSE: NPB) ("Northpointe" or the "Company"), holding company for Northpointe Bank, today reported net income to common stockholders of $20.1 million, or $0.57 per diluted share, for the third quarter of 2025. This compares to $18.0 million, or $0.51 per diluted share, for the second quarter of 2025, and $17.1 million, or $0.67 per diluted share, for the third quarter of 2024. The decrease in earnings per diluted share from the prior year quarter reflects additional common shares issued from the initial public offering completed on February 13, 2025.
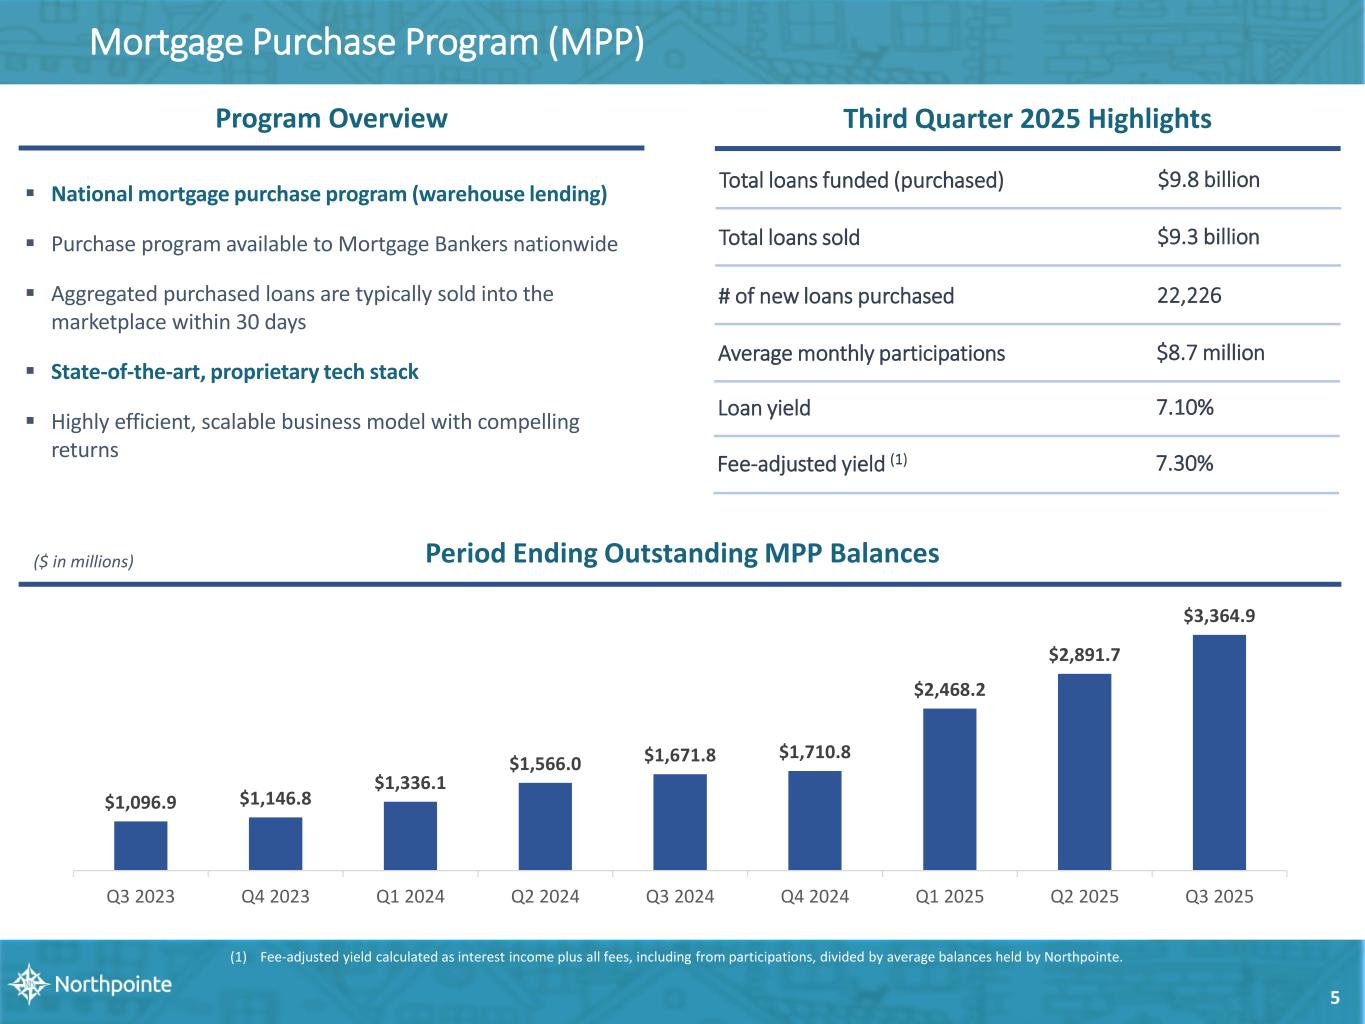
"The momentum we are building across our business lines resulted in strong financial performance in the third quarter, highlighted by strong balance sheet growth and an improvement in net income from the prior quarter and year," remarked Chuck Williams, Chairman and Chief Executive Officer. "We've continued to experience exceptional performance in our Mortgage Purchase Program business, increasing balances by $1.7 billion over the prior year level and funding $9.8 billion in total loans during the third quarter. In the residential lending channel, both mortgage locks and applications increased from the prior quarter, and all-in-one loan balances increased by 23% annualized. On the funding side, interest-bearing demand deposits increased by over $300 million from the prior quarter as we completed an initiative to bring in valuable new custodial deposits during the third quarter."
Third Quarter 2025 Highlights
•Net income to common stockholders of $20.1 million, up $2.1 million from the prior quarter.
•Delivered improved financial performance from the prior quarter, including:
•Return on average equity of 14.23%, compared to 13.60% in the prior quarter.
•Return on average tangible common equity of 15.41%, compared to 14.49% in the prior quarter (see non-GAAP reconciliation).
•Return on average assets of 1.34%, flat from the prior quarter.
•Efficiency ratio of 53.38%, compared to 53.80% in the prior quarter.
•Net interest income after provision increased by $3.6 million from the prior quarter, reflecting strong growth in average interest-earning assets and expansion in net interest margin, partially offset by an increase in the provision for credit losses.
•Non-interest income increased by $1.6 million from the prior quarter driven primarily by increases in the fair value of loans held for investment and lender risk account ("LRA") attributable to changes in market interest rates.
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
2 of 18
•Non-interest expense increased by $2.6 million from the prior quarter driven primarily by higher salaries and benefits, including a $935,000 increase in expense related to a legacy stock appreciation rights plan resulting from the increase in stock price, as well as higher other taxes and insurance expense related to FDIC insurance premiums.
•Loans held for investment increased by $470.4 million, or 34% annualized, from the prior quarter, reflecting strong growth in Mortgage Purchase Program ("MPP") and first-lien home equity lines which are tied seamlessly to a demand deposit sweep account (the Company commonly refers to these loans as “All-in-One” or “AIO” loans) balances.
•Total deposits increased by $295.6 million from the prior quarter driven primarily by new custodial account balances onboarded during the third quarter of 2025.
•Wholesale funding ratio improved to 67.58% from 70.71% in the prior quarter.
•Total delinquent loans (including non-performing loans and loans past due 31 to 89 days) decreased by $4.6 million from the prior quarter.
•The Company's Board of Directors declared a regular quarterly cash dividend of $0.025 per share, payable on November 3, 2025 to shareholders of record as of October 15, 2025.
Net Interest Income
Net interest income before provision was $40.3 million for the third quarter of 2025, an increase of $3.8 million compared to the second quarter of 2025. The linked quarter increase reflects a 3 basis point improvement in net interest margin and a $465.6 million increase in average interest-earning assets. As compared to the third quarter of 2024, net interest income before provision increased by $11.9 million, driven primarily by a 27 basis point improvement in net interest margin and a $1.33 billion increase in average interest-earning assets.
Net interest margin was 2.47% for the third quarter of 2025, an increase of 3 basis points compared to 2.44% in the second quarter of 2025. This increase was driven primarily by an improvement in loan yields and the mix of interest-earning assets, along with flat overall funding costs. As compared to the third quarter of 2024, net interest margin increased by 27 bps, as the decrease in the yield earned on interest-earning assets was outpaced by a larger decrease in the rate paid on interest-bearing liabilities.
Average interest-earning assets increased by $465.6 million from June 30, 2025 and by $1.33 billion compared to September 30, 2024. The increases from both comparable periods reflect the strong growth in MPP and AIO balances, partially offset by continued run-off in the remainder of the loan portfolio.
Provision for Credit Losses
The Company recorded a total provision for credit losses (including provisions for loans and unfunded commitments) of $828,000 in the third quarter of 2025, compared to $583,000 in the second quarter of 2025 and $178,000 in the third quarter of 2024. The Company's quarterly provision for credit losses reflects loan charge-offs, along with factors such as loan growth, portfolio mix, reserves on individually evaluated loans, credit migration trends, and changes in the economic forecasts used in the credit models. The increases from both comparable periods were driven primarily by higher loan charge-offs, largely attributable to two larger mortgage loans.
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
3 of 18
Non-interest Income
Non-interest income was $24.0 million for the third quarter of 2025, an increase of $1.6 million compared to the second quarter of 2025 and a decrease of $1.7 million compared to the third quarter of 2024.
MPP fees were $1.5 million for the third quarter of 2025, an increase of $102,000 compared to the second quarter of 2025 and a decrease of $81,000 compared to the third quarter of 2024. The linked quarter increase reflects higher levels of funded loans in the MPP business and the decrease from prior year quarter reflects lower levels of participations.
Loan servicing fees were $1.1 million for the third quarter of 2025, a decrease of $408,000 compared to the second quarter of 2025 and an increase of $1.4 million compared to the third quarter of 2024. Both the linked quarter increase and decrease from prior year quarter were driven primarily by changes in the fair value of mortgage servicing rights ("MSRs") primarily attributable to the movement in market interest rates during the respective periods.
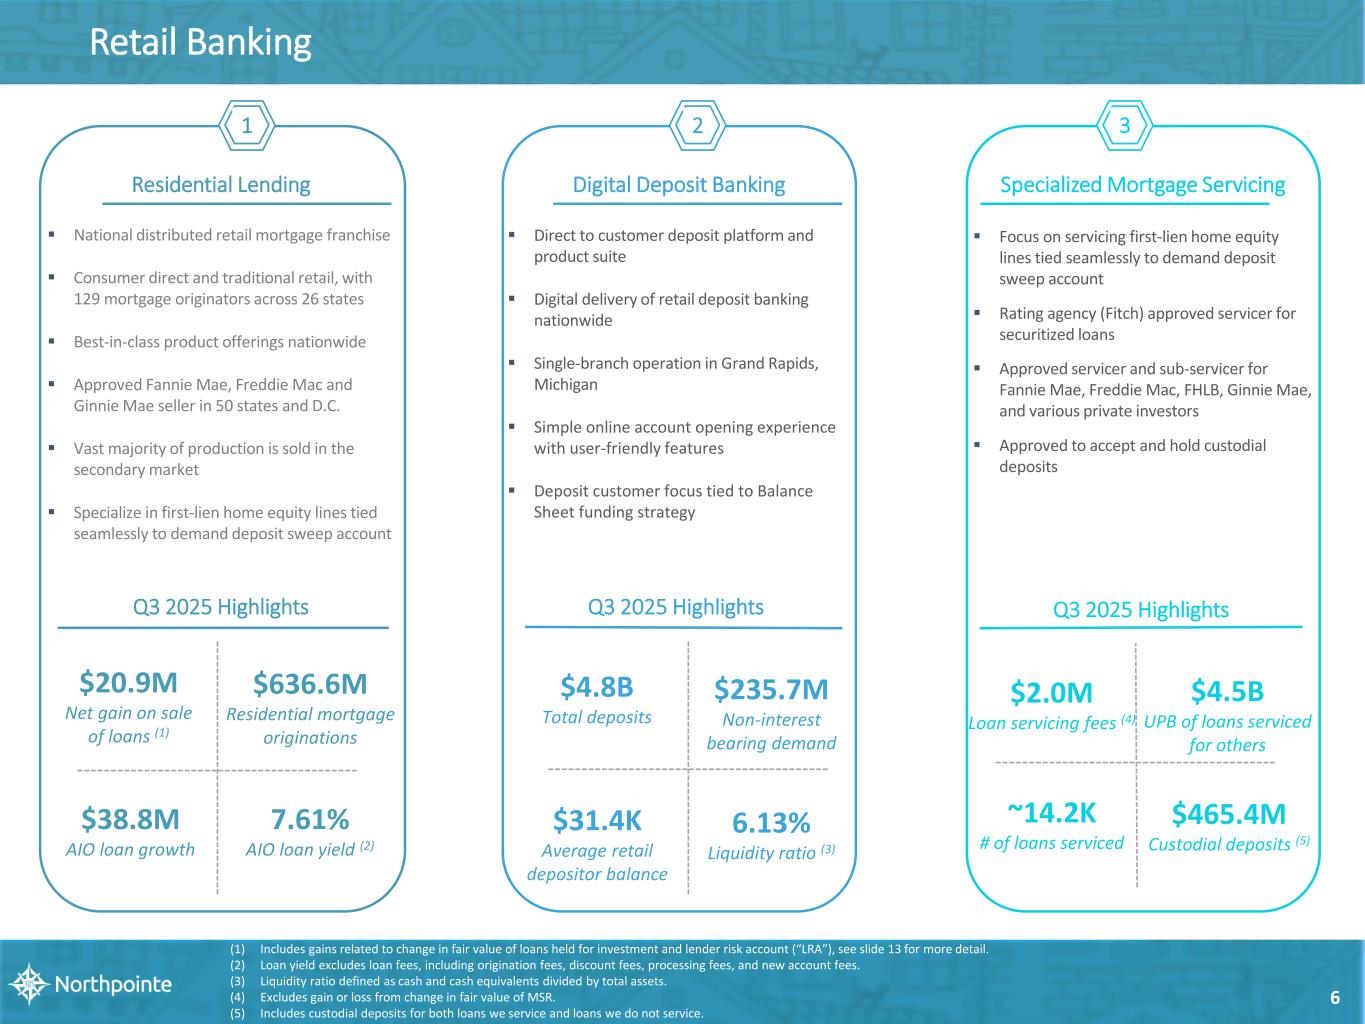
Net gain on sale of loans was $21.0 million for the third quarter of 2025, compared to $19.4 million for the second quarter of 2025 and $24.6 million for the third quarter of 2024. Net gain on sale of loans includes the capitalization of new MSRs, gains or losses on the sale of portfolio loans, changes in fair value of loans, and gains on the sale of loans.
The net gain on sale of loans for the third quarter of 2025 included an increase of $2.2 million from the combined change in fair value of loans held for investment and LRA, both attributable to changes in market interest rates, and a $1.2 million gain on the sale of portfolio loans. Excluding these items (see Net Gain on Sale of Loans table below for a reconciliation), net gain on sale of loans was $17.5 million, flat on a comparative basis from the second quarter of 2025 and up from $14.8 million on a comparative basis in the third quarter of 2024. The increase from the prior year quarter was driven primarily by higher saleable residential mortgage rate lock commitments and originations.
Other non-interest income was $285,000 for the third quarter of 2025, compared to a loss of $32,000 for the second quarter of 2025 and a loss of $445,000 for the third quarter of 2024. The Company recognized net gains on sale of other real estate owned of $282,000 in the third quarter of 2025 compared to net losses of $30,000 in the second quarter of 2025 and net losses of $180,000 in the third quarter of 2024. Other non-interest income in the third quarter of 2024 also included $312,000 in losses on lease termination and sale of assets.
Non-interest Expense
Non-interest expense was $34.4 million for the third quarter of 2025, an increase of $2.6 million compared to the second quarter of 2025 and an increase of $5.0 million compared to the third quarter of 2024.
Salaries and benefits expense was $24.3 million for the third quarter of 2025, an increase of $2.1 million compared to the second quarter of 2025. This increase was driven primarily by bonus and incentive compensation, which increased by $1.9 million, and included a $935,000 increase in expense related to a legacy stock appreciation rights plan resulting from the increase in stock price, along with higher incentive compensation from the improvement in business activity over the same period. As compared to the third quarter of 2024, salaries and benefits expense increased by $3.6 million, driven primarily by higher bonus and incentive compensation (up $1.7 million), reflecting higher expense
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
4 of 18
related to the legacy stock appreciation rights plan and additional restricted stock expense from the initial public offering, as well as higher variable compensation on mortgage production (up $946,000).
Professional fees decreased by $92,000 on a linked quarter basis, and increased by $561,000 compared to the third quarter of 2024. The increase compared to the prior year quarter was driven primarily by higher ongoing customary public company compliance costs.
Other taxes and insurance increased by $808,000 on a linked quarter basis, and by $396,000 compared to the third quarter of 2024. The increase for both compared periods was driven primarily by higher FDIC assessment expense resulting from the growth in assets and continued utilization of capital.
All other categories of non-interest expense decreased by $182,000 on a linked quarter basis and increased by $474,000 compared to the third quarter of 2024. The linked quarter decrease was driven primarily by lower servicing expenses related to additional fees incurred during the prior quarter. As compared to the third quarter of 2024, the increase was driven primarily by additional expenses associated with the Company's private label outsourcing of its non-specialized mortgage servicing to a scaled sub-servicer.
Taxes
Income tax expense for the third quarter of 2025 was $7.0 million, compared to $6.3 million for the second quarter of 2025 and $5.9 million for the third quarter of 2024. The Company's effective tax rate was 24.00% for the third quarter of 2025, compared to 23.67% for the second quarter of 2025 and 24.02% for the third quarter of 2024.
Balance Sheet Highlights
Total assets were $6.84 billion at September 30, 2025, representing an increase of $408.7 million compared to June 30, 2025 and an increase of $1.45 billion compared to September 30, 2024. The increase in total assets at September 30, 2025, compared to both June 30, 2025 and September 30, 2024, was driven primarily by an increase in total loans, particularly growth in MPP and AIO balances.
Gross loans held for investment were $5.97 billion at September 30, 2025, an increase of $470.4 million, or 34% annualized, compared to June 30, 2025 and an increase of $1.56 billion, or 35%, compared to September 30, 2024. The linked quarter increase in gross loans held for investment was driven primarily by growth in MPP balances, which were up 65% annualized and growth in AIO loans, which were up 23% annualized. These increases were partially offset by a decrease of $41.5 million in the remainder of the loans held for investment portfolio. Loans held for sale totaled $259.8 million at September 30, 2025, compared to $331.2 million at June 30, 2025 and $345.0 million at September 30, 2024, and reflect the timing of closing saleable residential mortgage originations and any portfolio loan sales (which are temporarily moved to held for sale) completed during the quarter.
The Company continues to focus on growing its two main loan portfolios, AIO and MPP. Outside of these two portfolios, no other significant loans are being added to the loans held for investment portfolio. At September 30, 2025, virtually all of the loan portfolio was comprised of loans collateralized by residential property.
Total deposits were $4.77 billion at September 30, 2025, an increase of $295.6 million, or 26% annualized, compared to June 30, 2025 and an increase of $1.24 billion, or 35%, compared to September 30, 2024. The linked quarter increase was driven primarily by higher interest-bearing
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
5 of 18
demand deposits as the Company completed its initiative to bring in a new custodial account relationship during the third quarter. As compared to September 30, 2024, the increase reflected a higher level of brokered CDs, along with increases in the Company's diversified digital deposit banking platform including non-interest bearing demand, interest-bearing demand, retail CDs and rateboard CDs, including the new custodial account relationship.
Total borrowings were $1.37 billion at September 30, 2025, an increase of $94.1 million compared to June 30, 2025 and an increase of $60.3 million compared to September 30, 2024. The increase for both compared periods was driven primarily by utilization of the Company's short-term line of credit borrowing facilities.
Asset Quality
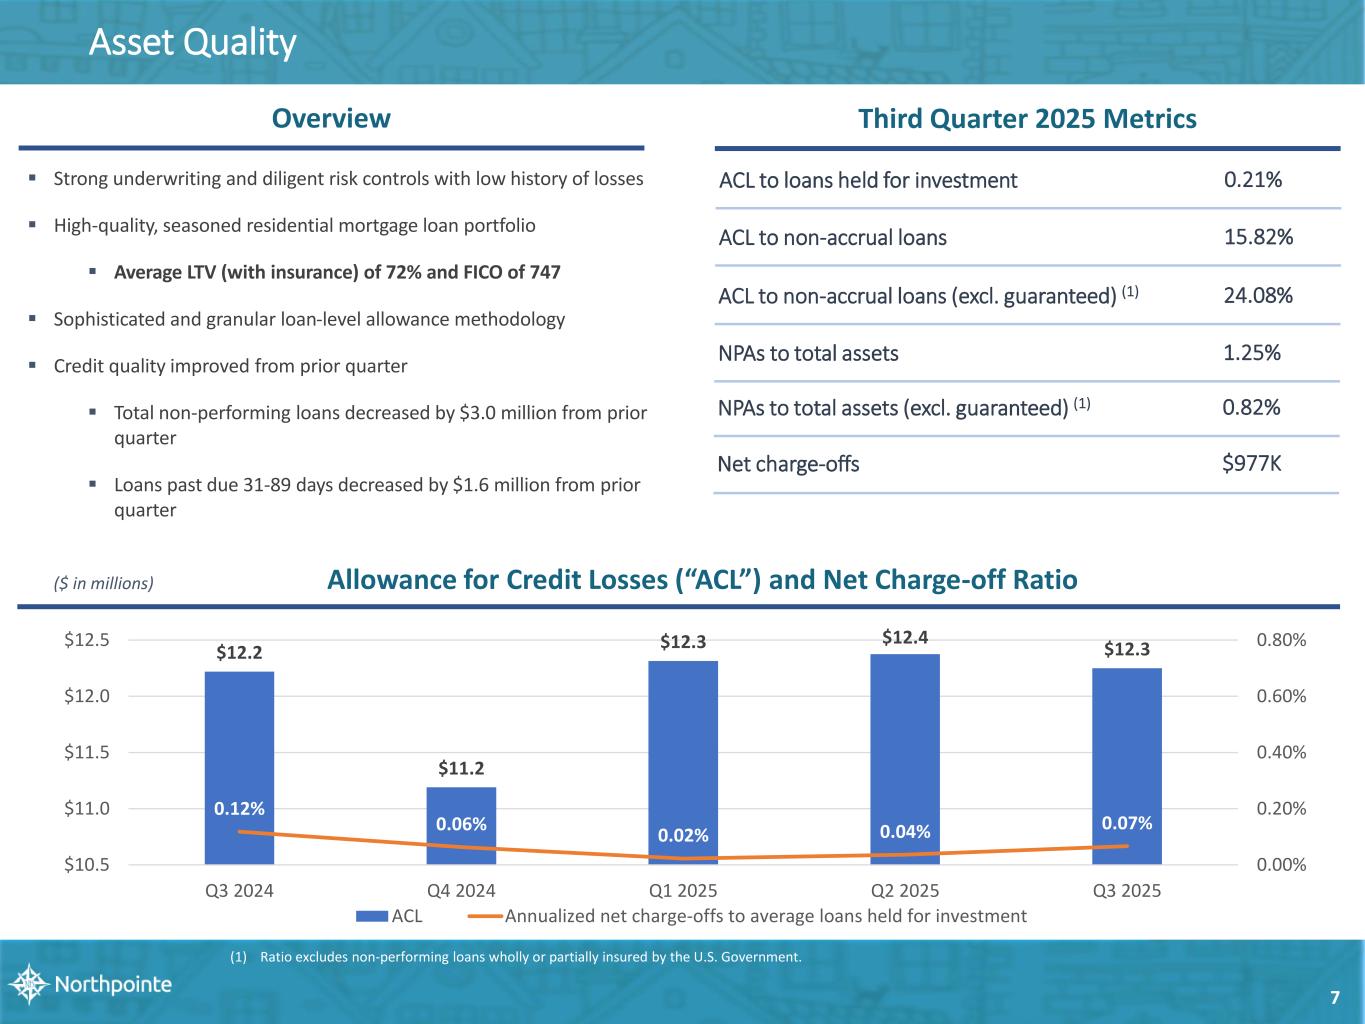
The Company’s allowance for credit losses was $12.3 million at September 30, 2025, $12.4 million at June 30, 2025 and $12.2 million at September 30, 2024. The allowance for credit losses represented 0.21% of loans held for investment at September 30, 2025, 0.23% of loans held for investment at June 30, 2025 and 0.28% of loans held for investment at September 30, 2024.
Net charge-offs were $977,000, or 7 basis points annualized as a percentage of average loans, for the third quarter of 2025. This compares to $488,000, or 4 basis points annualized as a percentage of average loans, for the second quarter of 2025, and $554,000, or 5 basis points annualized as a percentage of average loans, for the third quarter of 2024.
A substantial portion of the Company's non-performing loans are wholly or partially guaranteed by the U.S. Government, so asset quality metrics within this earnings release are shown with and without these guaranteed loans. Non-performing assets were $85.2 million at September 30, 2025 ($57.7 million excluding guaranteed loans), $87.1 million at June 30, 2025 ($58.5 million excluding guaranteed loans) and $81.9 million at September 30, 2024 ($44.7 million excluding guaranteed loans). Non-performing assets represented 1.25% of total assets at September 30, 2025 (0.85% excluding guaranteed loans), 1.35% at June 30, 2025 (0.91% excluding guaranteed loans) and 1.52% at September 30, 2024 (0.84% excluding guaranteed loans).
Capital
At September 30, 2025, the estimated capital levels for the Company and its subsidiary bank, Northpointe Bank (the “Bank”), remained well in excess of the minimum amounts needed for capital adequacy purposes and the Bank’s capital levels met the necessary requirements to be considered "well-capitalized". The regulatory capital ratios as of September 30, 2025 are estimates, pending completion and filing of the Bank's regulatory reports.
Earnings Presentation and Conference Call
Northpointe will host its third quarter of 2025 earnings conference call on October 22, 2025 at 10:00 a.m. E.T. During the call, management will discuss the third quarter of 2025 financial results and provide an update on recent activities. There will be a live question-and-answer session following the presentation. It is recommended you join 10 minutes prior to the start time. Participants may access the live conference call by dialing 1-877-413-2414 and requesting “Northpointe Bancshares, Inc. Conference Call”. The conference call will also be webcast live at ir.northpointe.com. An audio archive will be available on the website following the call.
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
6 of 18
Forward Looking Statements
Statements in this earnings release regarding future events and our expectations and beliefs about our future financial performance and financial condition, as well as trends in our business and markets, constitute “forward-looking statements” within the meaning of, and subject to the protections of, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements are not historical in nature and may be identified by references to a future period or periods by the use of the words “believe,” “expect,” “anticipate,” “intend,” “plan,” “estimate,” “project,” “outlook,” or words of similar meaning, or future or conditional verbs such as “will,” “would,” “should,” “could,” or “may.” The forward-looking statements in this earnings release should not be relied on because they are based on current information and on assumptions that we make about future events and circumstances that are subject to a number of known and unknown risks and uncertainties that are often difficult to predict and beyond our control. As a result of those risks and uncertainties, and other factors, our actual financial results in the future could differ, possibly materially, from those expressed in or implied by the forward-looking statements contained in this earnings release and could cause us to make changes to our future plans. Factors that might cause such differences include, but are not limited to: the impact of current and future economic conditions, particularly those affecting the financial services industry, including the effects of declines in the real estate market, tariffs or trade wars (including reduced consumer spending, lower economic growth or recession, reduced demand for U.S. exports, disruptions to supply chains, and decreased demand for other banking products and services), high unemployment rates, inflationary pressures, increasing insurance costs, elevated interest rates, including the impact of changes in interest rates on our financial projections, models and guidance and slowdowns in economic growth, as well as the financial stress on borrowers as a result of the foregoing; uncertain duration of trade conflicts; potential impacts of adverse developments in the banking and mortgage industries, including impacts on deposits, liquidity and the regulatory rules and regulations; risks arising from media coverage of the banking and mortgage industries; risks arising from perceived instability in the banking and mortgage sectors; changes in the interest rate environment, including changes to the federal funds rate, which could have an adverse effect on the Company’s profitability; changes in prices, values and sales volumes of residential real estate; developments in our mortgage banking business, including loan modifications, general demand, and the effects of judicial or regulatory requirements or guidance; competition in our markets that may result in increased funding costs or reduced earning assets yields, thus reducing margins and net interest income; legislation or regulatory changes which could adversely affect the ability of the consolidated Company to conduct business combinations or new operations; changes in tax laws; significant turbulence or a disruption in the capital or financial markets and the effect of a fall in stock market prices on our investment securities; the ability to keep pace with technological changes, including changes regarding maintaining cybersecurity and the impact of generative artificial intelligence; increased competition in the financial services industry, particularly from regional and national institutions; the impact of a failure in, or breach of, the Company's operational or security systems or infrastructure, or those of third parties with whom the Company does business, including as a result of cyber-attacks or an increase in the incidence or severity of fraud, illegal payments, security breaches or other illegal acts impacting the Company or the Company's customers; the effects of war or other conflicts; the impact of action or inaction by the federal government, including as a result of any prolonged government shutdown; and adverse results from current or future litigation, regulatory examinations or other legal and/or regulatory actions, including as a result of the Company’s participation in and execution of government programs.
Therefore, the Company can give no assurance that the results contemplated in the forward-looking statements will be realized. Additional information regarding these and other risks and uncertainties to which our business and future financial performance are subject is contained in the sections titled “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors” in the Company’s most recent Annual Report on Form 10-K and Quarterly Reports on Form 10-Q on file with the U.S.
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
7 of 18
Securities and Exchange Commission (the “SEC”), and in other documents that we file with the SEC from time to time, which are available on the SEC’s website, http://www.sec.gov. Due to these and other possible uncertainties and risks, readers are cautioned not to place undue reliance on the forward-looking statements contained in this earnings release or to make predictions based solely on historical financial performance. Any forward-looking statement speaks only as of the date on which it is made, and we do not undertake any obligation to update or review any forward-looking statement, whether as a result of new information, future developments or otherwise, except as required by law. All forward-looking statements, express or implied, included in this earnings release are qualified in their entirety by this cautionary statement.
About Northpointe
Headquartered in Grand Rapids, Michigan, Northpointe Bancshares, Inc. is the holding company of Northpointe Bank, a client-focused company that provides home loans and retail banking products to communities across the nation. Our mission is to be the best bank in America by bringing value and innovation to the people we serve. To learn more visit www.northpointe.com.
Contacts:
Kevin Comps | President | 616-974-8491 | [email protected]
Brad Howes | CFO | 616-726-2585 | [email protected]
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
8 of 18
| NORTHPOINTE BANCSHARES, INC. | ||||||||||||||||||||||||||||||||
| (unaudited, dollars in thousands except per share data) | ||||||||||||||||||||||||||||||||
| Consolidated Statements of Income | ||||||||||||||||||||||||||||||||
| Three Months Ended | Nine Months Ended | |||||||||||||||||||||||||||||||
| Sept 30, 2025 | June 30, 2025 | Sept 30, 2024 | Sept 30, 2025 | Sept 30, 2024 | ||||||||||||||||||||||||||||
| Interest income | ||||||||||||||||||||||||||||||||
| Loans - including fees | $ | 94,044 | $ | 86,260 | $ | 75,033 | $ | 252,376 | $ | 210,660 | ||||||||||||||||||||||
| Investment securities - taxable | 87 | 158 | 157 | 399 | 477 | |||||||||||||||||||||||||||
| Federal Home Loan Bank ("FHLB") stock - taxable | 1,605 | 1,553 | 1,641 | 4,786 | 4,751 | |||||||||||||||||||||||||||
| Interest bearing deposits | 6,100 | 5,122 | 6,520 | 16,518 | 18,943 | |||||||||||||||||||||||||||
| Total interest income | 101,836 | 93,093 | 83,351 | 274,079 | 234,831 | |||||||||||||||||||||||||||
| Interest expense | ||||||||||||||||||||||||||||||||
| Deposits | 48,169 | 43,582 | 40,937 | 128,061 | 111,968 | |||||||||||||||||||||||||||
| Subordinated debentures | 679 | 678 | 1,271 | 2,244 | 2,855 | |||||||||||||||||||||||||||
| Borrowings | 12,657 | 12,313 | 12,740 | 36,534 | 35,815 | |||||||||||||||||||||||||||
| Total interest expense | 61,505 | 56,573 | 54,948 | 166,839 | 150,638 | |||||||||||||||||||||||||||
| Net interest income | 40,331 | 36,520 | 28,403 | 107,240 | 84,193 | |||||||||||||||||||||||||||
| Provision for credit losses | 852 | 548 | 484 | 2,785 | 1,212 | |||||||||||||||||||||||||||
| Provision (benefit) for unfunded commitments | (24) | 35 | (306) | (79) | (1,094) | |||||||||||||||||||||||||||
| Net interest income after provision (benefit) for credit losses | 39,503 | 35,937 | 28,225 | 104,534 | 84,075 | |||||||||||||||||||||||||||
| Non-Interest Income | ||||||||||||||||||||||||||||||||
| Service charges on deposits and fees | 217 | 239 | 363 | 635 | 1,387 | |||||||||||||||||||||||||||
| Loan servicing fees | 1,117 | 1,525 | (289) | 3,637 | 5,970 | |||||||||||||||||||||||||||
| MPP fees | 1,457 | 1,355 | 1,538 | 3,952 | 3,823 | |||||||||||||||||||||||||||
| Net gain on sale of loans | 20,953 | 19,351 | 24,591 | 58,892 | 49,656 | |||||||||||||||||||||||||||
| Other non-interest income | 285 | (32) | (445) | 2,224 | (1,527) | |||||||||||||||||||||||||||
| Total Non-Interest Income | 24,029 | 22,438 | 25,758 | 69,340 | 59,309 | |||||||||||||||||||||||||||
| Non-Interest Expense | ||||||||||||||||||||||||||||||||
| Salaries and benefits | 24,336 | 22,234 | 20,779 | 67,012 | 58,817 | |||||||||||||||||||||||||||
| Occupancy and equipment | 811 | 918 | 1,014 | 2,701 | 3,456 | |||||||||||||||||||||||||||
| Data processing expense | 2,190 | 2,155 | 2,207 | 6,451 | 7,047 | |||||||||||||||||||||||||||
| Professional fees | 1,701 | 1,793 | 1,140 | 4,722 | 3,341 | |||||||||||||||||||||||||||
| Other taxes and insurance | 1,998 | 1,190 | 1,602 | 4,974 | 4,894 | |||||||||||||||||||||||||||
| Other non-interest expense | 3,322 | 3,432 | 2,628 | 9,590 | 7,599 | |||||||||||||||||||||||||||
| Total Non-Interest Expense | 34,358 | 31,722 | 29,370 | 95,450 | 85,154 | |||||||||||||||||||||||||||
| Income before income taxes | 29,174 | 26,653 | 24,613 | 78,424 | 58,230 | |||||||||||||||||||||||||||
| Income tax expense | 7,001 | 6,309 | 5,913 | 18,658 | 14,061 | |||||||||||||||||||||||||||
| Net Income | $ | 22,173 | $ | 20,344 | $ | 18,700 | $ | 59,766 | $ | 44,169 | ||||||||||||||||||||||
| Preferred stock dividends | 2,041 | 2,296 | 1,601 | 6,544 | 5,853 | |||||||||||||||||||||||||||
| Net Income Available To Common Stockholders | $ | 20,132 | $ | 18,048 | $ | 17,099 | $ | 53,222 | $ | 38,316 | ||||||||||||||||||||||
| Basic Earnings Per Share | $ | 0.58 | $ | 0.52 | $ | 0.67 | $ | 1.61 | $ | 1.49 | ||||||||||||||||||||||
| Diluted Earnings Per Share | $ | 0.57 | $ | 0.51 | $ | 0.67 | $ | 1.58 | $ | 1.49 | ||||||||||||||||||||||
| Weighted Average Shares Outstanding | 34,602,289 | 34,574,086 | 25,689,560 | 33,006,655 | 25,689,560 | |||||||||||||||||||||||||||
| Diluted Weighted Average Shares Outstanding | 35,337,136 | 35,218,962 | 25,756,431 | 33,668,316 | 25,756,431 | |||||||||||||||||||||||||||
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
9 of 18
| NORTHPOINTE BANCSHARES, INC. | ||||||||||||||||||||
| (unaudited, dollars in thousands except per share data) | ||||||||||||||||||||
| Consolidated Balance Sheets | ||||||||||||||||||||
| Sept 30, 2025 | June 30, 2025 | Sept 30, 2024 | ||||||||||||||||||
| Assets | ||||||||||||||||||||
| Cash and cash equivalents | $ | 419,162 | $ | 415,659 | $ | 440,751 | ||||||||||||||
| Equity securities | 1,342 | 1,329 | 1,346 | |||||||||||||||||
| Debt securities available for sale | 4,752 | 8,785 | 8,411 | |||||||||||||||||
| FHLB stock | 80,109 | 69,574 | 69,574 | |||||||||||||||||
| Loans held for sale, at fair value | 259,835 | 331,199 | 345,024 | |||||||||||||||||
Loans (1) | 5,967,235 | 5,496,806 | 4,412,061 | |||||||||||||||||
| Allowance for credit losses | (12,250) | (12,375) | (12,220) | |||||||||||||||||
| Net loans | 5,954,985 | 5,484,431 | 4,399,841 | |||||||||||||||||
| Mortgage servicing rights | 16,763 | 16,388 | 11,671 | |||||||||||||||||
| Intangible assets, net | 1,660 | 1,806 | 3,811 | |||||||||||||||||
| Premises and equipment | 27,658 | 27,479 | 27,877 | |||||||||||||||||
| Other assets | 73,314 | 74,244 | 77,693 | |||||||||||||||||
| Total Assets | $ | 6,839,580 | $ | 6,430,894 | $ | 5,385,999 | ||||||||||||||
| Liabilities | ||||||||||||||||||||
| Non-interest-bearing | $ | 235,733 | $ | 201,449 | $ | 221,928 | ||||||||||||||
| Interest-bearing | 4,533,904 | 4,272,622 | 3,309,950 | |||||||||||||||||
| Total Deposits | 4,769,637 | 4,474,071 | 3,531,878 | |||||||||||||||||
| Borrowings | 1,369,034 | 1,274,929 | 1,308,750 | |||||||||||||||||
| Subordinated debentures | 24,203 | 24,181 | 38,897 | |||||||||||||||||
| Subordinated debentures issued through trusts | 5,000 | 5,000 | 5,000 | |||||||||||||||||
| Deferred tax liability | 2,651 | 3,141 | 4,539 | |||||||||||||||||
| Other liabilities | 45,530 | 45,295 | 42,153 | |||||||||||||||||
| Total Liabilities | 6,216,055 | 5,826,617 | 4,931,217 | |||||||||||||||||
| Stockholders' Equity | ||||||||||||||||||||
| Preferred stock, Common stock and Additional paid in capital | 276,885 | 276,885 | 167,462 | |||||||||||||||||
| Retained earnings | 346,829 | 327,556 | 287,765 | |||||||||||||||||
| Accumulated other comprehensive loss | (189) | (164) | (445) | |||||||||||||||||
| Total Stockholders' Equity | 623,525 | 604,277 | 454,782 | |||||||||||||||||
| Total Liabilities and Stockholders' Equity | $ | 6,839,580 | $ | 6,430,894 | $ | 5,385,999 | ||||||||||||||
| (1) Includes $179.4 million, $175.1 million and $175.5 million of loans carried at fair value at September 30, 2025, June 30, 2025 and September 30, 2024, respectively. | ||||||||||||||||||||
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
10 of 18
| NORTHPOINTE BANCSHARES, INC. | ||||||||||||||||||||||||||||||||
| (unaudited, dollars in thousands except per share data) | ||||||||||||||||||||||||||||||||
| Selected Financial Highlights | ||||||||||||||||||||||||||||||||
| Three Months Ended | Nine Months Ended | |||||||||||||||||||||||||||||||
| Sept 30, 2025 | June 30, 2025 | Sept 30, 2024 | Sept 30, 2025 | Sept 30, 2024 | ||||||||||||||||||||||||||||
| PER COMMON SHARE | ||||||||||||||||||||||||||||||||
| Diluted earnings per share | $ | 0.57 | $ | 0.51 | $ | 0.67 | $ | 1.58 | $ | 1.49 | ||||||||||||||||||||||
| Book value | $ | 18.14 | $ | 17.58 | $ | 17.70 | $ | 18.14 | $ | 17.70 | ||||||||||||||||||||||
Tangible book value (1) | $ | 15.23 | $ | 14.67 | $ | 13.56 | $ | 15.23 | $ | 13.56 | ||||||||||||||||||||||
| PERFORMANCE RATIOS | ||||||||||||||||||||||||||||||||
| Return on average assets (annualized) | 1.34 | % | 1.34 | % | 1.41 | % | 1.33 | % | 1.17 | % | ||||||||||||||||||||||
| Return on average equity (annualized) | 14.23 | % | 13.60 | % | 16.32 | % | 13.70 | % | 13.20 | % | ||||||||||||||||||||||
Return on average tangible common equity (annualized) (1) | 15.41 | % | 14.49 | % | 19.56 | % | 14.77 | % | 15.44 | % | ||||||||||||||||||||||
| Net interest margin | 2.47 | % | 2.44 | % | 2.20 | % | 2.43 | % | 2.30 | % | ||||||||||||||||||||||
Efficiency ratio (2) | 53.38 | % | 53.80 | % | 54.23 | % | 54.05 | % | 59.34 | % | ||||||||||||||||||||||
| ASSET QUALITY AND RATIOS | ||||||||||||||||||||||||||||||||
| Allowance for credit losses to loans held for investment ("HFI") | 0.21 | % | 0.23 | % | 0.28 | % | 0.21 | % | 0.28 | % | ||||||||||||||||||||||
| Allowance for credit losses to loans HFI (excluding fair value loans) | 0.21 | % | 0.24 | % | 0.29 | % | 0.21 | % | 0.29 | % | ||||||||||||||||||||||
| Allowance for credit losses to non-accrual loans | 15.82 | % | 15.10 | % | 17.28 | % | 15.82 | % | 17.28 | % | ||||||||||||||||||||||
Allowance for credit losses to non-accrual loans (excluding guaranteed) (3) | 24.08 | % | 22.75 | % | 36.32 | % | 24.08 | % | 36.32 | % | ||||||||||||||||||||||
| Net charge-offs | $ | 977 | $ | 488 | $ | 554 | $ | 1,728 | $ | 1,286 | ||||||||||||||||||||||
| Annualized net charge-offs to average loans | 0.07 | % | 0.04 | % | 0.05 | % | 0.03 | % | 0.04 | % | ||||||||||||||||||||||
| Non-performing assets to total assets | 1.25 | % | 1.35 | % | 1.52 | % | 1.25 | % | 1.52 | % | ||||||||||||||||||||||
Non-performing assets to total assets (excluding guaranteed) (3) | 0.85 | % | 0.91 | % | 0.84 | % | 0.85 | % | 0.84 | % | ||||||||||||||||||||||
| Non-performing loans to total gross loans | 1.35 | % | 1.49 | % | 1.68 | % | 1.35 | % | 1.68 | % | ||||||||||||||||||||||
Non-performing loans to total gross loans (excluding guaranteed) (3) | 0.91 | % | 1.01 | % | 0.90 | % | 0.91 | % | 0.90 | % | ||||||||||||||||||||||
| SELECTED OTHER INFORMATION | ||||||||||||||||||||||||||||||||
| Equity / assets | 9.12 | % | 9.40 | % | 8.44 | % | 9.12 | % | 8.44 | % | ||||||||||||||||||||||
Tangible common equity / tangible assets (1) | 7.66 | % | 7.84 | % | 6.47 | % | 7.66 | % | 6.47 | % | ||||||||||||||||||||||
Loans / deposits (4) | 125.11 | % | 122.86 | % | 124.92 | % | 125.11 | % | 124.92 | % | ||||||||||||||||||||||
Liquidity ratio (5) | 6.13 | % | 6.46 | % | 8.18 | % | 6.13 | % | 8.18 | % | ||||||||||||||||||||||
Wholesale funding ratio (6) | 67.58 | % | 70.71 | % | 74.00 | % | 67.58 | % | 74.00 | % | ||||||||||||||||||||||
| SELECTED MORTGAGE DATA | ||||||||||||||||||||||||||||||||
| Residential mortgage originations | $ | 636,600 | $ | 665,515 | $ | 583,471 | $ | 1,787,620 | $ | 1,557,955 | ||||||||||||||||||||||
| Residential mortgage interest rate lock commitments | $ | 823,261 | $ | 753,317 | $ | 797,052 | $ | 2,306,015 | $ | 2,107,284 | ||||||||||||||||||||||
| Residential mortgage applications | $ | 1,113,569 | $ | 1,096,299 | $ | 1,157,023 | $ | 3,283,606 | $ | 2,010,634 | ||||||||||||||||||||||
| MPP total loans funded | $ | 9,822,322 | $ | 9,009,750 | $ | 6,559,838 | $ | 25,576,189 | $ | 17,380,555 | ||||||||||||||||||||||
Total loans serviced for others (UPB) (7) | $ | 4,542,688 | $ | 4,019,138 | $ | 4,082,232 | $ | 4,542,688 | $ | 4,082,232 | ||||||||||||||||||||||
| Loans serviced for others (UPB) | $ | 1,754,235 | $ | 1,596,367 | $ | 1,169,711 | $ | 1,754,235 | $ | 1,169,711 | ||||||||||||||||||||||
| Loans sub-serviced for others (UPB) | $ | 2,788,453 | $ | 2,422,771 | $ | 2,912,521 | $ | 2,788,453 | $ | 2,912,521 | ||||||||||||||||||||||
(1)See non-GAAP reconciliation.
(2)Efficiency ratio is defined as non-interest expense divided by the sum of net interest income and non-interest income.
(3)Ratio excludes non-performing loans wholly or partially insured by the U.S. Government (see non-performing asset table within for more detail).
(4)Loan/deposit ratio reflects loans held for investments as a percentage of total deposits.
(5)Liquidity ratio defined as cash and cash equivalents divided by total assets.
(6)Wholesale funding ratio defined as brokered CDs plus borrowings divided by total deposits plus borrowings.
(7)Excludes UPB of loans held for investment and loans held for sale.
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
11 of 18
| Summary Average Balance Sheet | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Three Months Ended | Three Months Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| September 30, 2025 | June 30, 2025 | September 30, 2024 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Principal Balance | Income/ Expense | Yield/ Rate | Average Principal Balance | Income/ Expense | Yield/ Rate | Average Principal Balance | Income/ Expense | Yield/ Rate | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Loans (1)(2) | $ | 5,835,496 | $ | 94,044 | 6.39 | % | $ | 5,462,596 | $ | 86,260 | 6.33 | % | $ | 4,581,283 | $ | 75,033 | 6.52 | % | |||||||||||||||||||||||||||||||||||||||||
Securities, AFS (3) | 7,116 | 87 | 4.85 | % | 9,916 | 158 | 6.39 | % | 9,514 | 157 | 6.56 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Securities, FHLB Stock | 78,621 | 1,605 | 8.10 | % | 69,574 | 1,553 | 8.95 | % | 69,574 | 1,641 | 9.38 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest bearing deposits | 549,657 | 6,100 | 4.40 | % | 463,199 | 5,122 | 4.44 | % | 482,059 | 6,520 | 5.38 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Total Interest Earning Assets | 6,470,890 | 101,836 | 6.24 | % | 6,005,285 | 93,093 | 6.22 | % | 5,142,430 | 83,351 | 6.45 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Noninterest Earning Assets (4) | 103,976 | 105,120 | 115,250 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Assets | $ | 6,574,866 | $ | 6,110,405 | $ | 5,257,680 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Transaction accounts | $ | 1,009,709 | $ | 11,246 | 4.42 | % | $ | 765,245 | $ | 8,394 | 4.40 | % | $ | 386,912 | $ | 4,744 | 4.88 | % | |||||||||||||||||||||||||||||||||||||||||
| Money Market & Savings | 325,660 | 3,143 | 3.83 | % | 326,396 | 3,114 | 3.83 | % | 373,262 | 4,194 | 4.47 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Time | 3,063,371 | 33,780 | 4.37 | % | 2,903,158 | 32,074 | 4.43 | % | 2,411,450 | 31,999 | 5.28 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 4,398,740 | 48,169 | 4.34 | % | 3,994,799 | 43,582 | 4.38 | % | 3,171,624 | 40,937 | 5.13 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Sub Debt | 29,189 | 679 | 9.23 | % | 29,166 | 678 | 9.32 | % | 43,485 | 1,271 | 11.63 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Borrowings | 1,245,949 | 12,657 | 4.03 | % | 1,249,314 | 12,313 | 3.95 | % | 1,309,177 | 12,740 | 3.87 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 5,673,878 | 61,505 | 4.30 | % | 5,273,279 | 56,573 | 4.30 | % | 4,524,286 | 54,948 | 4.83 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 234,252 | 195,275 | 220,747 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other noninterest-bearing liabilities | 48,425 | 41,998 | 56,819 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total noninterest-bearing liabilities | 282,677 | 237,273 | 277,566 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity | 618,311 | 599,853 | 455,828 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | 6,574,866 | $ | 6,110,405 | $ | 5,257,680 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Interest Income | $ | 40,331 | $ | 36,520 | $ | 28,403 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Net Interest Spread (5) | 1.94 | % | 1.91 | % | 1.62 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Net Interest Margin (6) | 2.47 | % | 2.44 | % | 2.20 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
(1) Loan balance includes loans held for investment and held for sale. Nonaccrual loans are included in total loan balances and no adjustment has been made for these loans in the yield calculation. Interest income on loans includes amortization of deferred loan fees, net of deferred loan costs.
(2) Loan fees of $45,000, $30,000, and $83,000 for the quarters ended September 30, 2025, June 30, 2025 and September 30, 2024, respectively, are included in interest income.
(3) Average yield based on carrying value and there are no tax-exempt securities in the portfolio.
(4) Noninterest-earning assets includes the allowance for credit losses.
(5) Net interest spread is the average yield on total interest-earning assets minus the average rate on total interest-bearing liabilities.
(6) Net interest margin is annualized net interest income divided by total average interest-earning assets.
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
12 of 18
| Summary Average Balance Sheet | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Nine Months Ended | Nine Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| September 30, 2025 | September 30, 2024 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Principal Balance | Income/ Expense | Yield/ Rate | Average Principal Balance | Income/ Expense | Yield/ Rate | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Loans (1)(2) | $ | 5,327,769 | $ | 252,376 | 6.33 | % | $ | 4,347,308 | $ | 210,660 | 6.47 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Securities, AFS (3) | 8,970 | 399 | 5.95 | % | 9,884 | 477 | 6.45 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Securities, FHLB Stock | 72,623 | 4,786 | 8.81 | % | 69,132 | 4,751 | 9.18 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest bearing deposits | 500,241 | 16,518 | 4.41 | % | 466,277 | 18,943 | 5.43 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Interest Earning Assets | 5,909,603 | 274,079 | 6.20 | % | 4,892,601 | 234,831 | 6.41 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
Noninterest Earning Assets (4) | 105,949 | 149,263 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Assets | $ | 6,015,552 | $ | 5,041,864 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Transaction accounts | $ | 839,210 | $ | 27,630 | 4.40 | % | $ | 395,765 | $ | 14,639 | 4.94 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Money Market & Savings | 329,685 | 9,506 | 3.86 | % | 395,580 | 13,152 | 4.44 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Time | 2,743,269 | 90,925 | 4.43 | % | 2,131,676 | 84,177 | 5.27 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 3,912,164 | 128,061 | 4.38 | % | 2,923,021 | 111,968 | 5.12 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Sub Debt | 29,166 | 2,244 | 10.29 | % | 40,767 | 2,855 | 9.35 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Borrowings | 1,235,247 | 36,534 | 3.95 | % | 1,321,471 | 35,815 | 3.62 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 5,176,577 | 166,839 | 4.31 | % | 4,285,259 | 150,638 | 4.70 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 214,521 | 251,850 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other noninterest-bearing liabilities | 41,027 | 57,697 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total noninterest-bearing liabilities | 255,548 | 309,547 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Equity | 583,427 | 447,058 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total Liabilities and Equity | $ | 6,015,552 | $ | 5,041,864 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net Interest Income | $ | 107,240 | $ | 84,193 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
Net Interest Spread (5) | 1.89 | % | 1.72 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
Net Interest Margin (6) | 2.43 | % | 2.30 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
(1) Loan balance includes loans held for investment and held for sale. Nonaccrual loans are included in total loan balances and no adjustment has been made for these loans in the yield calculation. Interest income on loans includes amortization of deferred loan fees, net of deferred loan costs.
(2) Loan fees of $114,000 and $216,000 for the nine months ended September 30, 2025 and 2024, respectively, are included in interest income.
(3) Average yield based on carrying value and there are no tax-exempt securities in the portfolio.
(4) Noninterest-earning assets includes the allowance for credit losses.
(5) Net interest spread is the average yield on total interest-earning assets minus the average rate on total interest-bearing liabilities.
(6) Net interest margin is annualized net interest income divided by total average interest-earning assets.
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
13 of 18
| End of Period Loan Balances | ||||||||||||||||||||
| (Dollars in thousands) | September 30, 2025 | June 30, 2025 | September 30, 2024 | |||||||||||||||||
| Residential: | ||||||||||||||||||||
| Construction | $ | 18,973 | $ | 27,144 | $ | 86,300 | ||||||||||||||
| All-in-One (AIO) | 701,580 | 662,829 | 581,728 | |||||||||||||||||
| Other Consumer/Home Equity | 56,592 | 54,495 | 99,547 | |||||||||||||||||
Residential Mortgage (1) | 1,814,623 | 1,859,814 | 1,971,907 | |||||||||||||||||
| Commercial | 10,581 | 856 | 750 | |||||||||||||||||
| MPP | 3,364,886 | 2,891,668 | 1,671,829 | |||||||||||||||||
| Total Loans Held for Investment (HFI) | 5,967,235 | 5,496,806 | 4,412,061 | |||||||||||||||||
| Total Loans Held for Sale (HFS) | 259,835 | 331,199 | 345,024 | |||||||||||||||||
| Total Gross Loans (HFI and HFS) | $ | 6,227,070 | $ | 5,828,005 | $ | 4,757,085 | ||||||||||||||
| (1) Residential Mortgage loans consist of Closed end first liens, Closed end second liens, and Land development loans. | ||||||||||||||||||||
| End of Period Deposit Balances | ||||||||||||||||||||
| (Dollars in thousands) | September 30, 2025 | June 30, 2025 | September 30, 2024 | |||||||||||||||||
| Noninterest-bearing demand | $ | 235,733 | $ | 201,449 | $ | 221,928 | ||||||||||||||
| Interest-bearing demand | 1,056,372 | 749,479 | 383,517 | |||||||||||||||||
| Savings & money market | 321,077 | 327,244 | 330,076 | |||||||||||||||||
| Brokered time deposits | 2,779,204 | 2,790,399 | 2,273,538 | |||||||||||||||||
| Other time deposits | 377,253 | 405,500 | 322,819 | |||||||||||||||||
| Total deposits | $ | 4,769,639 | $ | 4,474,071 | $ | 3,531,878 | ||||||||||||||
| Loan Servicing Fees | Three Months Ended | Nine Months Ended | ||||||||||||||||||||||||||||||
| (Dollars in thousands) | Sept 30, 2025 | June 30, 2025 | Sept 30, 2024 | Sept 30, 2025 | Sept 30, 2024 | |||||||||||||||||||||||||||
| Fees on servicing | $ | 2,027 | $ | 1,827 | $ | 1,584 | $ | 5,556 | $ | 10,565 | ||||||||||||||||||||||
Change in fair value of MSRs (1) | (910) | (302) | (1,873) | (1,919) | (4,595) | |||||||||||||||||||||||||||
| Total loan servicing fees | $ | 1,117 | $ | 1,525 | $ | (289) | $ | 3,637 | $ | 5,970 | ||||||||||||||||||||||
| (1) Includes change in fair value and paid in full MSRs. | ||||||||||||||||||||||||||||||||
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
14 of 18
| Net Gain on Sale of Loans | Three Months Ended | Nine Months Ended | ||||||||||||||||||||||||||||||
| (Dollars in thousands) | Sept 30, 2025 | June 30, 2025 | Sept 30, 2024 | Sept 30, 2025 | Sept 30, 2024 | |||||||||||||||||||||||||||
| Capitalized MSRs | $ | 1,285 | $ | 902 | $ | 643 | $ | 3,254 | $ | 2,736 | ||||||||||||||||||||||
Change in fair value of loans (1) | 725 | 3,340 | 21,084 | 8,743 | 19,242 | |||||||||||||||||||||||||||
Gain (loss) on sale of portfolio loans (2) | 1,234 | — | (8,025) | 1,234 | (8,025) | |||||||||||||||||||||||||||
Gain on sale of loans, net (3) | 17,709 | 15,109 | 10,889 | 45,661 | 35,703 | |||||||||||||||||||||||||||
| Total net gain on sale of loans | $ | 20,953 | $ | 19,351 | $ | 24,591 | $ | 58,892 | $ | 49,656 | ||||||||||||||||||||||
| Total net gain on sale of loans | $ | 20,953 | $ | 19,351 | $ | 24,591 | $ | 58,892 | $ | 49,656 | ||||||||||||||||||||||
| Less: change in fair value of loans HFI and LRA | (2,229) | (1,812) | (17,844) | (7,739) | (16,837) | |||||||||||||||||||||||||||
| Less: Gain (loss) on sale of portfolio loans | (1,234) | — | 8,025 | (1,234) | 8,025 | |||||||||||||||||||||||||||
| Total net gain on sale of loans, excluding portfolio sales and LRA / HFI fair value adjustments | $ | 17,490 | $ | 17,539 | $ | 14,772 | $ | 49,919 | $ | 40,844 | ||||||||||||||||||||||
| (1) Includes the change in fair value of interest rate locks, loans held for sale, and loans HFI. | ||||||||||||||||||||||||||||||||
| (2) Includes proceeds from portfolio loans sales, which are netted against any associated changes in fair value of loans to determine total gain or loss on sale. | ||||||||||||||||||||||||||||||||
| (3) Includes (a) net gain on sale of loans, (b) loan origination fees, points and costs, (c) provision from investor reserves, (d) gain or loss from forward commitments from hedging, and (e) fair value of LRA. | ||||||||||||||||||||||||||||||||
| Salaries and employee benefits | Three Months Ended | Nine Months Ended | ||||||||||||||||||||||||||||||
| (Dollars in thousands) | Sept 30, 2025 | June 30, 2025 | Sept 30, 2024 | Sept 30, 2025 | Sept 30, 2024 | |||||||||||||||||||||||||||
| Salaries and other compensation | $ | 9,252 | $ | 8,737 | $ | 8,786 | $ | 26,596 | $ | 26,968 | ||||||||||||||||||||||
| Salary deferral from loan origination | (1,151) | (991) | (836) | (3,110) | (2,974) | |||||||||||||||||||||||||||
| Bonus and incentive compensation | 5,425 | 3,564 | 3,730 | 12,631 | 7,688 | |||||||||||||||||||||||||||
| Mortgage production - variable compensation | 7,578 | 7,730 | 6,632 | 21,365 | 19,119 | |||||||||||||||||||||||||||
| Employee benefits | 3,232 | 3,194 | 2,467 | 9,530 | 8,016 | |||||||||||||||||||||||||||
| Total salaries and employee benefits | $ | 24,336 | $ | 22,234 | $ | 20,779 | $ | 67,012 | $ | 58,817 | ||||||||||||||||||||||
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
15 of 18
| Non-performing Assets | ||||||||||||||||||||
| (Dollars in thousands) | Sept 30, 2025 | June 30, 2025 | Sept 30, 2025 | |||||||||||||||||
| Unguaranteed | $ | 50,870 | $ | 54,402 | $ | 33,641 | ||||||||||||||
| Wholly or partially guaranteed | 26,568 | 27,577 | 37,064 | |||||||||||||||||
| Total non-accrual loans | $ | 77,438 | $ | 81,979 | $ | 70,705 | ||||||||||||||
| Unguaranteed | $ | 5,522 | $ | 3,938 | $ | 9,041 | ||||||||||||||
| Wholly or partially guaranteed | 941 | 974 | 171 | |||||||||||||||||
| Total past due loans (90 days or more and still accruing) | $ | 6,463 | $ | 4,912 | $ | 9,212 | ||||||||||||||
| Unguaranteed | $ | 56,392 | $ | 58,340 | $ | 42,682 | ||||||||||||||
| Wholly or partially guaranteed | 27,509 | 28,551 | 37,235 | |||||||||||||||||
| Total non-performing loans | $ | 83,901 | $ | 86,891 | $ | 79,917 | ||||||||||||||
| Other real estate | $ | 1,339 | $ | 203 | $ | 1,990 | ||||||||||||||
| Total non-performing assets | $ | 85,240 | $ | 87,094 | $ | 81,907 | ||||||||||||||
| Total non-performing assets (excluding wholly or partially guaranteed) | $ | 57,731 | $ | 58,543 | $ | 44,672 | ||||||||||||||
| Loans past due 31-89 days | $ | 43,016 | $ | 44,626 | $ | 32,795 | ||||||||||||||
| Ratios: | ||||||||||||||||||||
| Non-accrual loans to total gross loans | 1.24 | % | 1.41 | % | 1.49 | % | ||||||||||||||
| Non-performing loans to total gross loans | 1.35 | % | 1.49 | % | 1.68 | % | ||||||||||||||
| Non-performing assets to total assets | 1.25 | % | 1.35 | % | 1.52 | % | ||||||||||||||
| Ratios excluding loans wholly or partially guaranteed: | ||||||||||||||||||||
| Non-accrual loans to total gross loans | 0.82 | % | 0.93 | % | 0.71 | % | ||||||||||||||
| Non-performing loans to total gross loans | 0.91 | % | 1.01 | % | 0.90 | % | ||||||||||||||
| Non-performing assets to total assets | 0.85 | % | 0.91 | % | 0.84 | % | ||||||||||||||
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
16 of 18
Regulatory Capital Ratios (1) | Sept 30, 2025 Ratio | June 30, 2025 Ratio | Sept 30, 2024 Ratio | |||||||||||||||||
| Total Capital (to Risk Weighted Assets) | ||||||||||||||||||||
| Consolidated | 11.32 | % | 11.80 | % | 11.36 | % | ||||||||||||||
| Bank | 11.14 | % | 11.34 | % | 11.22 | % | ||||||||||||||
| Tier 1 (Core) Capital (to Risk Weighted Assets) | ||||||||||||||||||||
| Consolidated | 10.72 | % | 11.15 | % | 10.37 | % | ||||||||||||||
| Bank | 10.96 | % | 11.15 | % | 10.78 | % | ||||||||||||||
| CET 1 Capital Ratio (to Risk Weighted Assets) | ||||||||||||||||||||
| Consolidated | 8.96 | % | 9.25 | % | 7.93 | % | ||||||||||||||
| Bank | 10.96 | % | 11.15 | % | 10.78 | % | ||||||||||||||
| Tier 1 Capital (to Average Assets) | ||||||||||||||||||||
| Consolidated | 9.57 | % | 9.98 | % | 8.77 | % | ||||||||||||||
| Bank | 9.79 | % | 9.98 | % | 9.11 | % | ||||||||||||||
| (1) The regulatory capital ratios as of September 30, 2025 are estimates, pending completion and filing of the Bank's regulatory reports. | ||||||||||||||||||||
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
17 of 18
Non-GAAP Financial Measures
This earnings release contains certain financial measures that are not measures recognized under U.S. generally accepted accounting principles (“GAAP”) and therefore are considered non-GAAP financial measures. The measures entitled tangible common equity, tangible book value, tangible assets, tangible common equity to tangible assets and return on average tangible common equity are not measures recognized under GAAP and therefore are considered non-GAAP financial measures. The most comparable GAAP measures to these measures are stockholders’ equity, book value per share, total assets, equity to assets and return on average equity, respectively.
The Company believes that non-GAAP financial measures provide useful information to management and investors that is supplementary to its financial condition, results of operations and cash flows computed in accordance with GAAP; however the Company acknowledges that the non-GAAP financial measures have inherent limitations. As such, these disclosures should not be viewed as a substitute for results determined in accordance with GAAP, and these disclosures are not necessarily comparable to non-GAAP financial measures that other companies use.
The Company calculates tangible common equity as stockholders' equity less goodwill and intangible assets (net of deferred tax liability ("DTL") and preferred stock. The Company calculates tangible book value ("TBV") per share as tangible common equity divided by the number of shares of common stock outstanding at the end of the relevant period. The Company calculates tangible assets as total assets less intangible assets (net of DTL). The Company calculates tangible common equity/tangible assets as tangible common equity divided by tangible assets. The Company calculates return on average tangible common equity as annualized net income available to common stockholders divided by average tangible equity. The most directly comparable GAAP financial measures are outlined in the non-GAAP reconciliation table below.
Northpointe Bancshares, Inc. Reports Third Quarter 2025 Results
October 21, 2025
18 of 18
| Non-GAAP Measures Reconciliation | ||||||||||||||||||||||||||||||||
| As of or for the Three Months Ended | As of or for the Nine Months Ended | |||||||||||||||||||||||||||||||
| (Dollars in thousands) | Sept 30, 2025 | June 30, 2025 | Sept 30, 2024 | Sept 30, 2025 | Sept 30, 2024 | |||||||||||||||||||||||||||
| Stockholders' equity (GAAP) | $ | 623,525 | $ | 604,277 | $ | 454,782 | $ | 623,525 | $ | 454,782 | ||||||||||||||||||||||
| Less: Preferred stock | 98,734 | 98,734 | 103,573 | 98,734 | 103,573 | |||||||||||||||||||||||||||
| Less: Intangible assets, net of DTL | 1,267 | 1,379 | 2,909 | 1,267 | 2,909 | |||||||||||||||||||||||||||
| Tangible common equity | 523,524 | 504,164 | 348,300 | 523,524 | 348,300 | |||||||||||||||||||||||||||
| Common shares at end of period | 34,364,659 | 34,364,659 | 25,689,560 | 34,364,659 | 25,689,560 | |||||||||||||||||||||||||||
| Tangible book value per share | $ | 15.23 | $ | 14.67 | $ | 13.56 | $ | 15.23 | $ | 13.56 | ||||||||||||||||||||||
| Book value per share (GAAP) | $ | 18.14 | $ | 17.58 | $ | 17.70 | $ | 18.14 | $ | 17.70 | ||||||||||||||||||||||
| Total assets (GAAP) | $ | 6,839,580 | $ | 6,430,894 | $ | 5,385,999 | $ | 6,839,580 | $ | 5,385,999 | ||||||||||||||||||||||
| Less: Intangible assets, net of DTL | 1,267 | 1,379 | 2,909 | 1,267 | 2,909 | |||||||||||||||||||||||||||
| Tangible assets | $ | 6,838,313 | $ | 6,429,515 | $ | 5,383,090 | $ | 6,838,313 | $ | 5,383,090 | ||||||||||||||||||||||
| Tangible common equity/tangible assets | 7.66 | % | 7.84 | % | 6.47 | % | 7.66 | % | 6.47 | % | ||||||||||||||||||||||
| Equity to assets (GAAP) | 9.12 | % | 9.40 | % | 8.44 | % | 9.12 | % | 8.44 | % | ||||||||||||||||||||||
| Net income | $ | 22,173 | $ | 20,344 | $ | 18,700 | $ | 59,766 | $ | 44,169 | ||||||||||||||||||||||
| Less: Preferred stock dividends | 2,041 | 2,296 | 1,601 | 6,544 | 5,853 | |||||||||||||||||||||||||||
| Net income available to common stockholders | 20,132 | 18,048 | 17,099 | 53,222 | 38,316 | |||||||||||||||||||||||||||
| Annualized net income available to common stockholders | 79,872 | 72,390 | 67,293 | 71,158 | 51,181 | |||||||||||||||||||||||||||
| Average tangible common equity | 518,238 | 499,667 | 343,981 | 481,665 | 331,531 | |||||||||||||||||||||||||||
| Return on average tangible common equity | 15.41 | % | 14.49 | % | 19.56 | % | 14.77 | % | 15.44 | % | ||||||||||||||||||||||
| Annualized net income | 87,969 | 81,600 | 73,594 | 79,907 | 58,999 | |||||||||||||||||||||||||||
| Average equity | 618,312 | 599,853 | 455,828 | 583,427 | 447,058 | |||||||||||||||||||||||||||
| Return on average equity (GAAP) | 14.23 | % | 13.60 | % | 16.15 | % | 13.70 | % | 13.20 | % | ||||||||||||||||||||||
October 22, 2025 Third Quarter 2025 Earnings Call Presentation
Disclaimer Forward-Looking Statements Statements in this presentation regarding future events and our expectations and beliefs about our future financial performance and financial condition, as well as trends in our business and markets, constitute “forward-looking statements” within the meaning of, and subject to the protections of, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements are not historical in nature and may be identified by references to a future period or periods by the use of the words “believe,” “expect,” “anticipate,” “intend,” “plan,” “estimate,” “project,” “outlook,” or words of similar meaning, or future or conditional verbs such as “will,” “would,” “should,” “could,” or “may.” The forward-looking statements in this presentation should not be relied on because they are based on current information and on assumptions that we make about future events and circumstances that are subject to a number of known and unknown risks and uncertainties that are often difficult to predict and beyond our control. As a result of those risks and uncertainties, and other factors, our actual financial results in the future could differ, possibly materially, from those expressed in or implied by the forward-looking statements contained in this presentation and could cause us to make changes to our future plans. Factors that might cause such differences include, but are not limited to: the impact of current and future economic conditions, particularly those affecting the financial services industry, including the effects of declines in the real estate market, tariffs or trade wars (including reduced consumer spending, lower economic growth or recession, reduced demand for U.S. exports, disruptions to supply chains, and decreased demand for other banking products and services), high unemployment rates, inflationary pressures, increasing insurance costs, elevated interest rates, including the impact of changes in interest rates on our financial projections, models and guidance and slowdowns in economic growth, as well as the financial stress on borrowers as a result of the foregoing; uncertain duration of trade conflicts; potential impacts of adverse developments in the banking and mortgage industries, including impacts on deposits, liquidity and the regulatory rules and regulations; risks arising from media coverage of the banking and mortgage industries; risks arising from perceived instability in the banking and mortgage sectors; changes in the interest rate environment, including changes to the federal funds rate, which could have an adverse effect on the Company’s profitability; changes in prices, values and sales volumes of residential real estate; developments in our mortgage banking business, including loan modifications, general demand, and the effects of judicial or regulatory requirements or guidance; competition in our markets that may result in increased funding costs or reduced earning assets yields, thus reducing margins and net interest income; legislation or regulatory changes which could adversely affect the ability of the consolidated Company to conduct business combinations or new operations; changes in tax laws; significant turbulence or a disruption in the capital or financial markets and the effect of a fall in stock market prices on our investment securities; the ability to keep pace with technological changes, including changes regarding maintaining cybersecurity and the impact of generative artificial intelligence; increased competition in the financial services industry, particularly from regional and national institutions; the impact of a failure in, or breach of, the Company's operational or security systems or infrastructure, or those of third parties with whom the Company does business, including as a result of cyber-attacks or an increase in the incidence or severity of fraud, illegal payments, security breaches or other illegal acts impacting the Company or the Company's customers; the effects of war or other conflicts; the impact of action or inaction by the federal government, including as a result of any prolonged government shutdown; and adverse results from current or future litigation, regulatory examinations or other legal and/or regulatory actions, including as a result of the Company’s participation in and execution of government programs. Therefore, the Company can give no assurance that the results contemplated in the forward-looking statements will be realized. Additional information regarding these and other risks and uncertainties to which our business and future financial performance are subject is contained in the sections titled “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors” in the Company’s most recent Annual Report on Form 10-K and Quarterly Reports on Form 10-Q on file with the U.S. Securities and Exchange Commission (the “SEC”), and in other documents that we file with the SEC from time to time, which are available on the SEC’s website, http://www.sec.gov. Due to these and other possible uncertainties and risks, readers are cautioned not to place undue reliance on the forward-looking statements contained in this presentation or to make predictions based solely on historical financial performance. Any forward-looking statement speaks only as of the date on which it is made, and we do not undertake any obligation to update or review any forward-looking statement, whether as a result of new information, future developments or otherwise, except as required by law. All forward-looking statements, express or implied, included in this presentation are qualified in their entirety by this cautionary statement. 2 Use of Non-GAAP Financial Measures This presentation contains certain financial measures that are not measures recognized under U.S. generally accepted accounting principles (“GAAP”) and therefore are considered non-GAAP financial measures. The measures entitled tangible common equity, tangible book value, tangible assets, tangible common equity to tangible assets and return on average tangible common equity are not measures recognized under GAAP and therefore are considered non-GAAP financial measures. The most comparable GAAP measures to these measures are stockholders’ equity, book value per share, total assets, equity to assets and return on average equity, respectively. The Company calculates tangible common equity as stockholders' equity less goodwill and intangible assets (net of deferred tax liability ("DTL") and preferred stock. The Company calculates tangible book value ("TBV") per share as tangible common equity divided by the number of shares of common stock outstanding at the end of the relevant period. The Company calculates tangible assets as total assets less intangible assets (net of DTL). The Company calculates tangible common equity to tangible assets as tangible common equity divided by tangible assets. The Company calculates return on average tangible common equity as annualized net income available to common stockholders divided by average tangible equity. The most directly comparable GAAP financial measures are outlined in the non-GAAP reconciliation in the Appendix of this slide presentation. The Company believes that non-GAAP financial measures provide useful information to management and investors that is supplementary to its financial condition, results of operations and cash flows computed in accordance with GAAP; however the Company acknowledges that the non-GAAP financial measures have inherent limitations. As such, these disclosures should not be viewed as a substitute for results determined in accordance with GAAP, and these disclosures are not necessarily comparable to non-GAAP financial measures that other companies use. The Company calculates tangible common equity as stockholders' equity less goodwill and intangible assets (net of deferred tax liability ("DTL") and preferred stock. The Company calculates tangible book value ("TBV") per share as tangible common equity divided by the number of shares of common stock outstanding at the end of the relevant period. The Company calculates tangible assets as total assets less intangible assets (net of DTL). The Company calculates tangible common equity to tangible assets as tangible common equity divided by tangible assets. The Company calculates return on average tangible common equity as annualized net income available to common stockholders divided by average tangible equity. The most directly comparable GAAP financial measures are outlined in the non-GAAP reconciliation in the Appendix of this slide presentation.
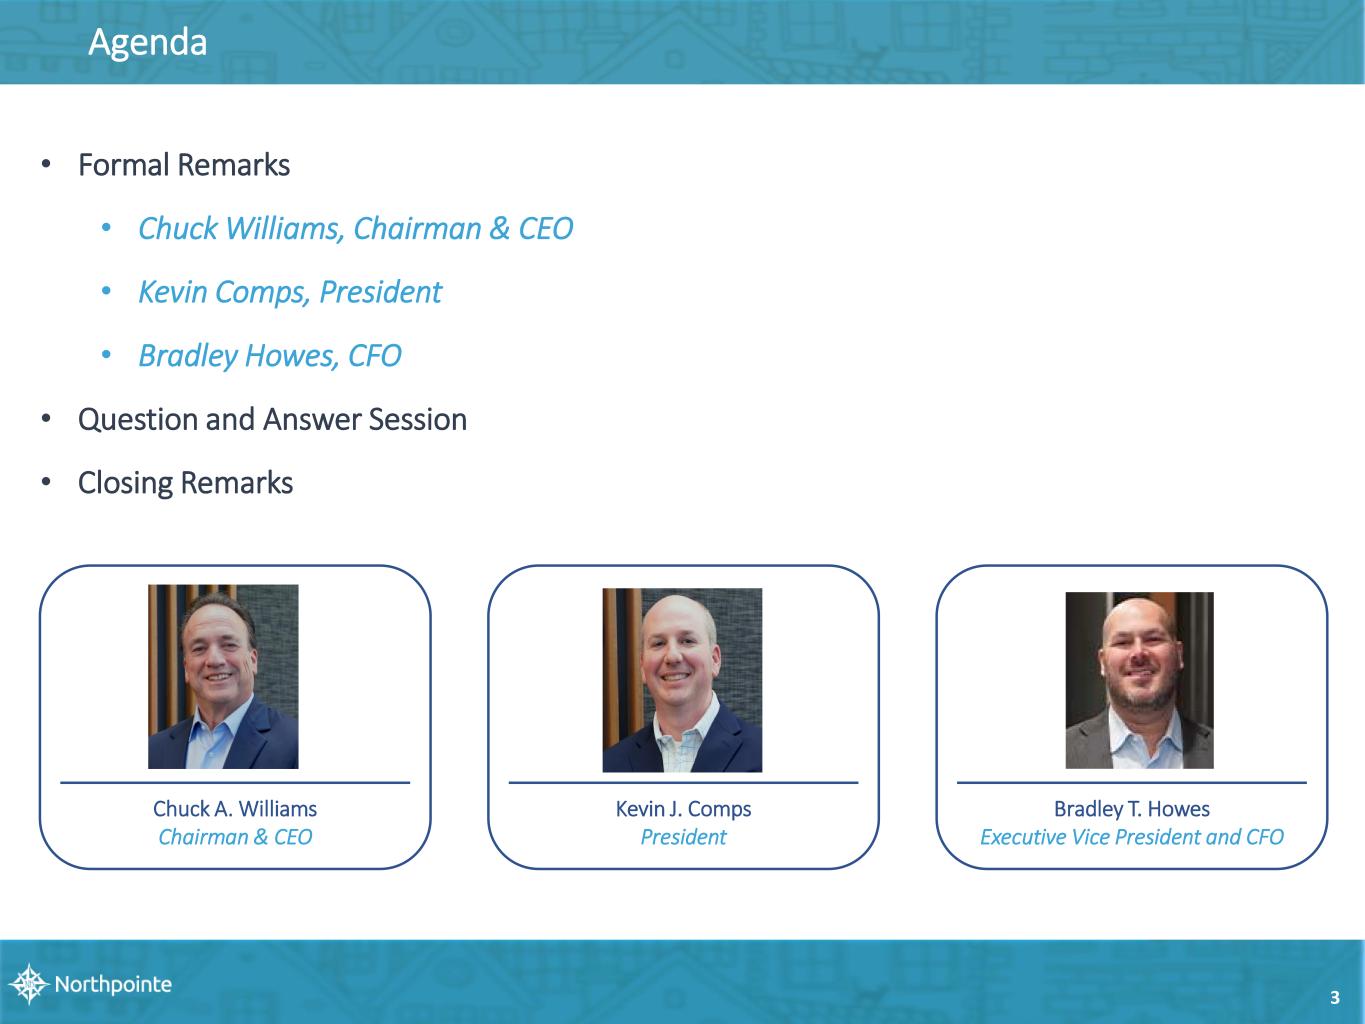
Agenda 3 Chuck A. Williams Chairman & CEO Kevin J. Comps President Bradley T. Howes Executive Vice President and CFO • Formal Remarks • Chuck Williams, Chairman & CEO • Kevin Comps, President • Bradley Howes, CFO • Question and Answer Session • Closing Remarks
Third Quarter 2025 Highlights (compared to prior quarter) 4 Earnings • Net income to common stockholders of $20.1 million • $0.57 per diluted share Performance Ratios • Return on average assets (annualized) of 1.34% • Return on average equity (annualized) of 14.23% • Return on average tangible common equity (annualized) (1) of 15.41% • Efficiency ratio (2) of 53.38% Portfolio Growth • Mortgage Purchase Program (“MPP”) growth of $473.2 million, or 65% annualized • All-in-One (3) growth of $38.8 million, or 23% annualized Deposit Growth • Total deposit growth of $295.6 million • Driven primarily by higher interest-bearing demand deposits from new custodial deposit relationship (1) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided in the Appendix of this slide presentation. (2) Efficiency ratio is defined as non-interest expense divided by the sum of net interest income and non-interest income. (3) First-lien home equity lines which are tied seamlessly to a demand deposit sweep account (we commonly refer to these loans as “All-in-One” or “AIO” loans). • Equity to assets of 9.12% and tangible common equity / tangible assets (1) of 7.66% • Book value per share of $18.14, annualized growth of 12.7% • Tangible book value per share of $15.23 (1), annualized growth of 15.4% Capital
5 Mortgage Purchase Program (MPP) Period Ending Outstanding MPP Balances($ in millions) $1,096.9 $1,146.8 $1,336.1 $1,566.0 $1,671.8 $1,710.8 $2,468.2 $2,891.7 $3,364.9 Q3 2023 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 Q2 2025 Q3 2025 Third Quarter 2025 Highlights Total loans funded (purchased) $9.8 billion Total loans sold $9.3 billion # of new loans purchased 22,226 Average monthly participations $8.7 million Loan yield 7.10% Fee-adjusted yield (1) 7.30% (1) Fee-adjusted yield calculated as interest income plus all fees, including from participations, divided by average balances held by Northpointe. Program Overview ▪ National mortgage purchase program (warehouse lending) ▪ Purchase program available to Mortgage Bankers nationwide ▪ Aggregated purchased loans are typically sold into the marketplace within 30 days ▪ State-of-the-art, proprietary tech stack ▪ Highly efficient, scalable business model with compelling returns
▪ National distributed retail mortgage franchise ▪ Consumer direct and traditional retail, with 129 mortgage originators across 26 states ▪ Best-in-class product offerings nationwide ▪ Approved Fannie Mae, Freddie Mac and Ginnie Mae seller in 50 states and D.C. ▪ Vast majority of production is sold in the secondary market ▪ Specialize in first-lien home equity lines tied seamlessly to demand deposit sweep account $20.9M Net gain on sale of loans (1) $636.6M Residential mortgage originations 7.61% AIO loan yield (2) Residential Lending Q3 2025 Highlights $38.8M AIO loan growth ▪ Focus on servicing first-lien home equity lines tied seamlessly to demand deposit sweep account ▪ Rating agency (Fitch) approved servicer for securitized loans ▪ Approved servicer and sub-servicer for Fannie Mae, Freddie Mac, FHLB, Ginnie Mae, and various private investors ▪ Approved to accept and hold custodial deposits $4.5B UPB of loans serviced for others $2.0M Loan servicing fees (4) Specialized Mortgage Servicing Q3 2025 Highlights ▪ Direct to customer deposit platform and product suite ▪ Digital delivery of retail deposit banking nationwide ▪ Single-branch operation in Grand Rapids, Michigan ▪ Simple online account opening experience with user-friendly features ▪ Deposit customer focus tied to Balance Sheet funding strategy $4.8B Total deposits $235.7M Non-interest bearing demand Digital Deposit Banking Q3 2025 Highlights $31.4K Average retail depositor balance 6.13% Liquidity ratio (3) ~14.2K # of loans serviced 6 Retail Banking 1 2 3 (1) Includes gains related to change in fair value of loans held for investment and lender risk account (“LRA”), see slide 13 for more detail. (2) Loan yield excludes loan fees, including origination fees, discount fees, processing fees, and new account fees. (3) Liquidity ratio defined as cash and cash equivalents divided by total assets. (4) Excludes gain or loss from change in fair value of MSR. (5) Includes custodial deposits for both loans we service and loans we do not service. $465.4M Custodial deposits (5)
Allowance for Credit Losses (“ACL”) and Net Charge-off Ratio 7 Asset Quality Third Quarter 2025 Metrics ACL to loans held for investment 0.21% ACL to non-accrual loans 15.82% ACL to non-accrual loans (excl. guaranteed) (1) 24.08% NPAs to total assets 1.25% NPAs to total assets (excl. guaranteed) (1) 0.82% Net charge-offs $977K ($ in millions) Overview ▪ Strong underwriting and diligent risk controls with low history of losses ▪ High-quality, seasoned residential mortgage loan portfolio ▪ Average LTV (with insurance) of 72% and FICO of 747 ▪ Sophisticated and granular loan-level allowance methodology ▪ Credit quality improved from prior quarter ▪ Total non-performing loans decreased by $3.0 million from prior quarter ▪ Loans past due 31-89 days decreased by $1.6 million from prior quarter $12.2 $11.2 $12.3 $12.4 $12.3 0.12% 0.06% 0.02% 0.04% 0.07% 0.00% 0.20% 0.40% 0.60% 0.80% $10.5 $11.0 $11.5 $12.0 $12.5 Q3 2024 Q4 2024 Q1 2025 Q2 2025 Q3 2025 ACL Annualized net charge-offs to average loans held for investment (1) Ratio excludes non-performing loans wholly or partially insured by the U.S. Government.
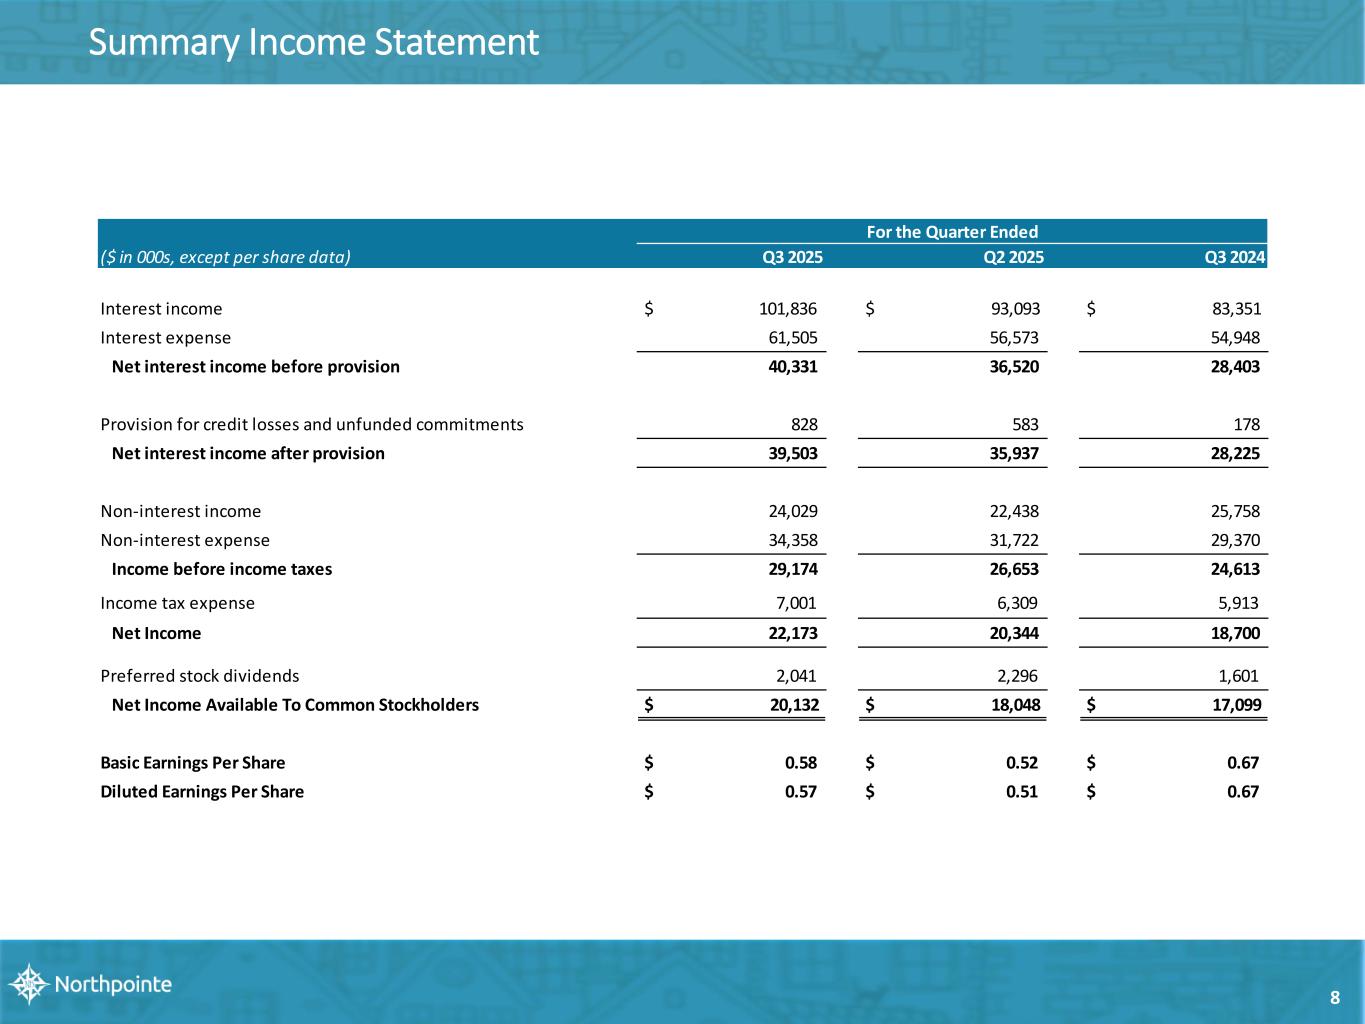
8 Summary Income Statement ($ in 000s, except per share data) Q3 2025 Q2 2025 Q3 2024 Interest income $ 101,836 $ 93,093 $ 83,351 Interest expense 61,505 56,573 54,948 Net interest income before provision 40,331 36,520 28,403 Provision for credit losses and unfunded commitments 828 583 178 Net interest income after provision 39,503 35,937 28,225 Non-interest income 24,029 22,438 25,758 Non-interest expense 34,358 31,722 29,370 Income before income taxes 29,174 26,653 24,613 Income tax expense 7,001 6,309 5,913 Net Income 22,173 20,344 18,700 Preferred stock dividends 2,041 2,296 1,601 Net Income Available To Common Stockholders $ 20,132 $ 18,048 $ 17,099 Basic Earnings Per Share $ 0.58 $ 0.52 $ 0.67 Diluted Earnings Per Share $ 0.57 $ 0.51 $ 0.67 For the Quarter Ended
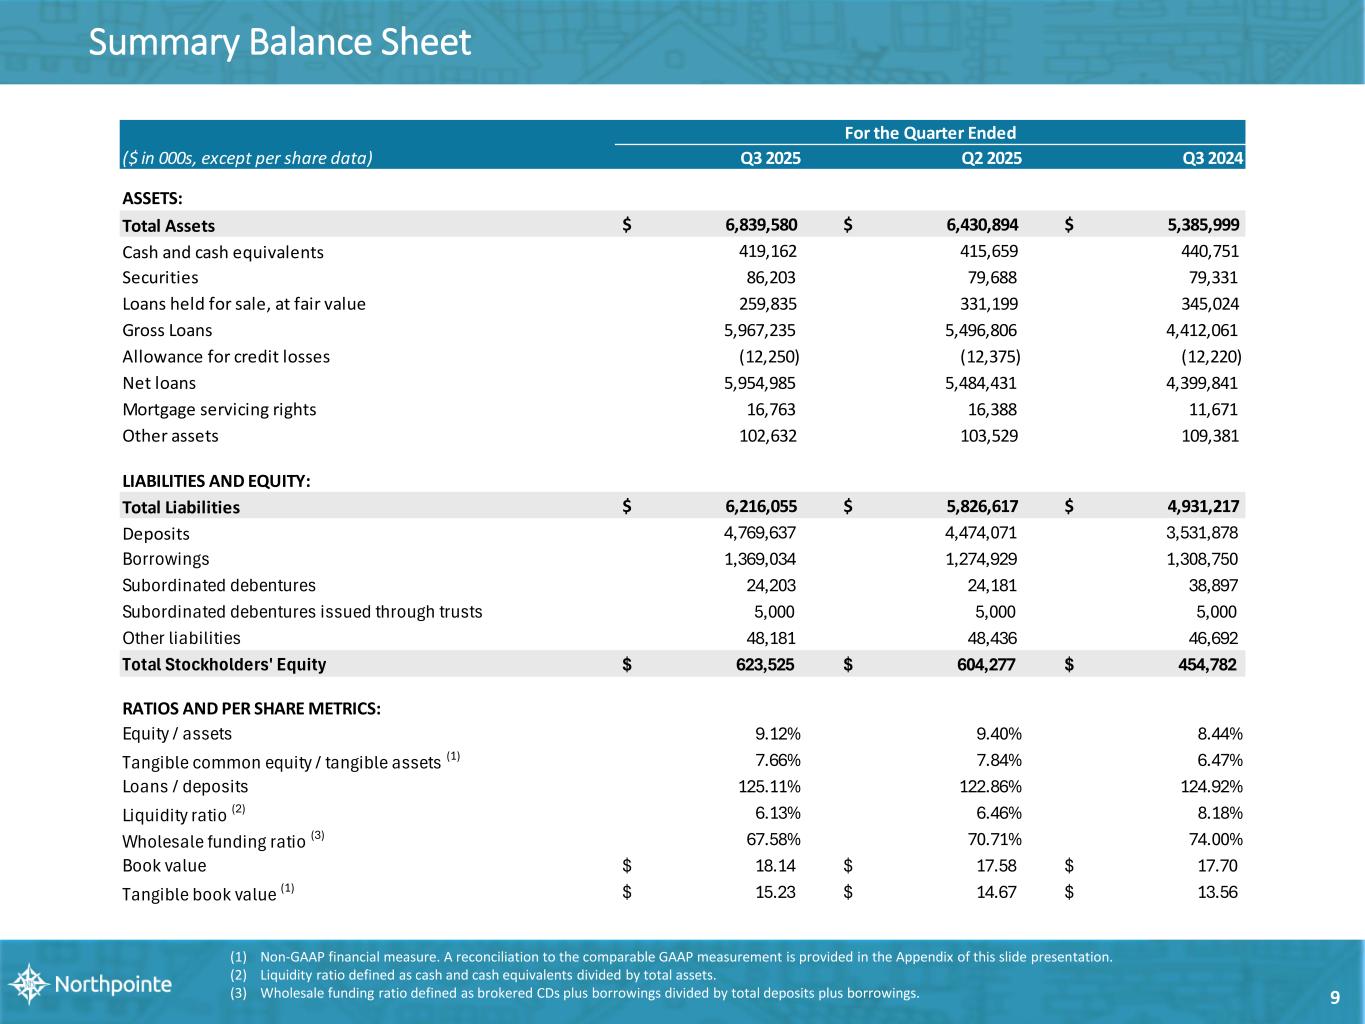
9 Summary Balance Sheet (1) Non-GAAP financial measure. A reconciliation to the comparable GAAP measurement is provided in the Appendix of this slide presentation. (2) Liquidity ratio defined as cash and cash equivalents divided by total assets. (3) Wholesale funding ratio defined as brokered CDs plus borrowings divided by total deposits plus borrowings. ($ in 000s, except per share data) Q3 2025 Q2 2025 Q3 2024 ASSETS: Total Assets $ 6,839,580 $ 6,430,894 $ 5,385,999 Cash and cash equivalents 419,162 415,659 440,751 Securities 86,203 79,688 79,331 Loans held for sale, at fair value 259,835 331,199 345,024 Gross Loans 5,967,235 5,496,806 4,412,061 Allowance for credit losses (12,250) (12,375) (12,220) Net loans 5,954,985 5,484,431 4,399,841 Mortgage servicing rights 16,763 16,388 11,671 Other assets 102,632 103,529 109,381 LIABILITIES AND EQUITY: Total Liabilities $ 6,216,055 $ 5,826,617 $ 4,931,217 Deposits 4,769,637 4,474,071 3,531,878 Borrowings 1,369,034 1,274,929 1,308,750 Subordinated debentures 24,203 24,181 38,897 Subordinated debentures issued through trusts 5,000 5,000 5,000 Other liabilities 48,181 48,436 46,692 Total Stockholders' Equity $ 623,525 $ 604,277 $ 454,782 RATIOS AND PER SHARE METRICS: Equity / assets 9.12% 9.40% 8.44% Tangible common equity / tangible assets (1) 7.66% 7.84% 6.47% Loans / deposits 125.11% 122.86% 124.92% Liquidity ratio (2) 6.13% 6.46% 8.18% Wholesale funding ratio (3) 67.58% 70.71% 74.00% Book value $ 18.14 $ 17.58 $ 17.70 Tangible book value (1) $ 15.23 $ 14.67 $ 13.56 For the Quarter Ended
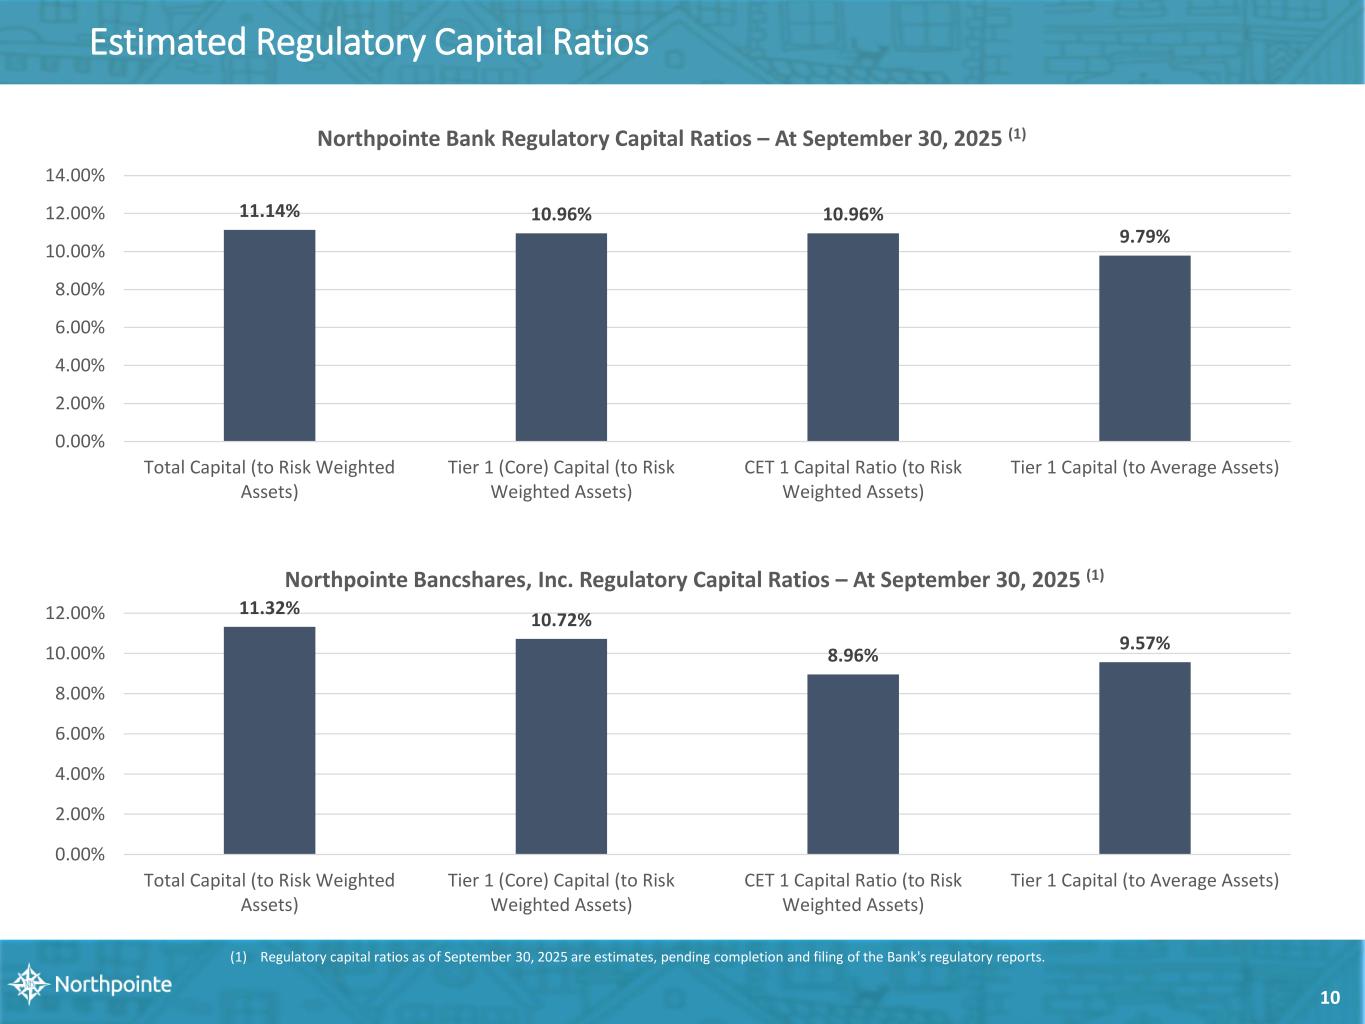
10 Estimated Regulatory Capital Ratios 11.14% 10.96% 10.96% 9.79% 0.00% 2.00% 4.00% 6.00% 8.00% 10.00% 12.00% 14.00% Total Capital (to Risk Weighted Assets) Tier 1 (Core) Capital (to Risk Weighted Assets) CET 1 Capital Ratio (to Risk Weighted Assets) Tier 1 Capital (to Average Assets) Northpointe Bank Regulatory Capital Ratios – At September 30, 2025 (1) (1) Regulatory capital ratios as of September 30, 2025 are estimates, pending completion and filing of the Bank's regulatory reports. 11.32% 10.72% 8.96% 9.57% 0.00% 2.00% 4.00% 6.00% 8.00% 10.00% 12.00% Total Capital (to Risk Weighted Assets) Tier 1 (Core) Capital (to Risk Weighted Assets) CET 1 Capital Ratio (to Risk Weighted Assets) Tier 1 Capital (to Average Assets) Northpointe Bancshares, Inc. Regulatory Capital Ratios – At September 30, 2025 (1)
APPENDIX
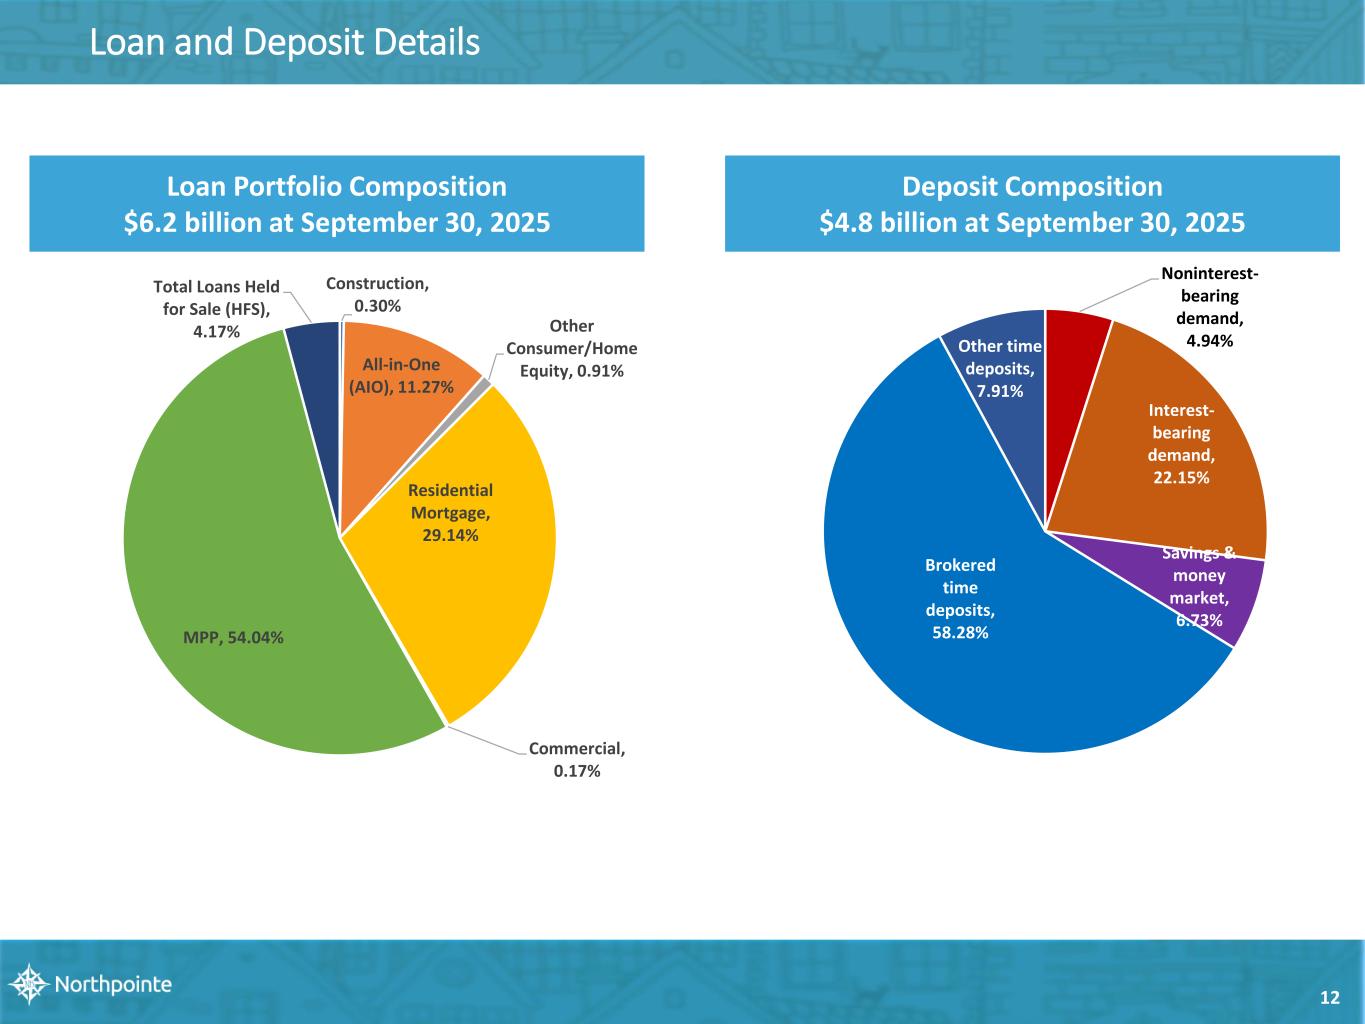
12 Loan and Deposit Details Loan Portfolio Composition $6.2 billion at September 30, 2025 Deposit Composition $4.8 billion at September 30, 2025 Construction, 0.30% All-in-One (AIO), 11.27% Other Consumer/Home Equity, 0.91% Residential Mortgage, 29.14% Commercial, 0.17% MPP, 54.04% Total Loans Held for Sale (HFS), 4.17% Noninterest- bearing demand, 4.94% Interest- bearing demand, 22.15% Savings & money market, 6.73% Brokered time deposits, 58.28% Other time deposits, 7.91%
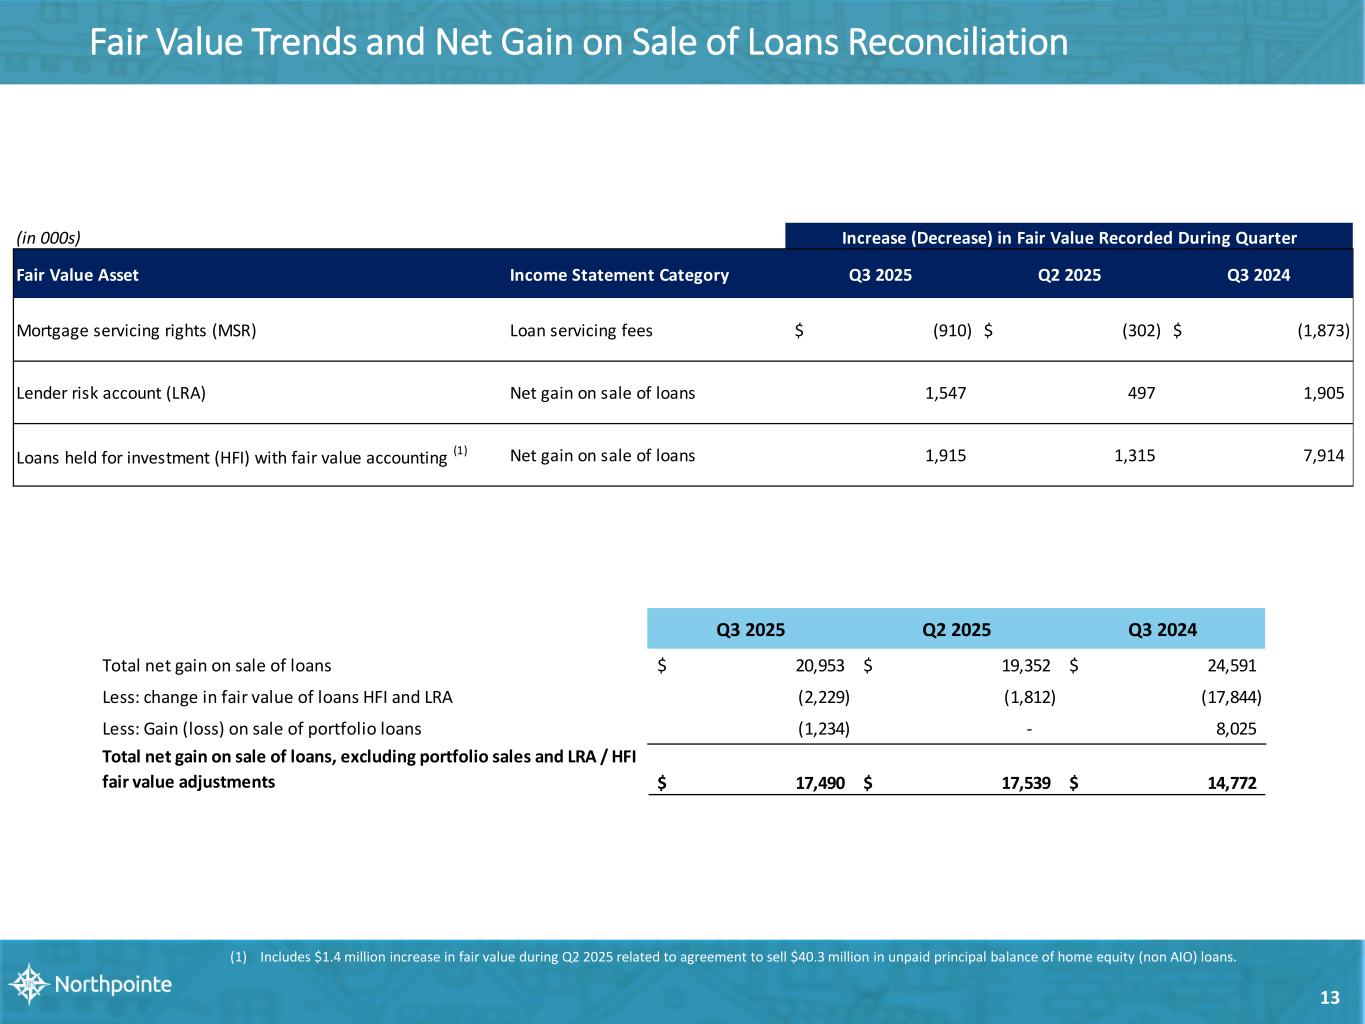
13 Fair Value Trends and Net Gain on Sale of Loans Reconciliation (1) Includes $1.4 million increase in fair value during Q2 2025 related to agreement to sell $40.3 million in unpaid principal balance of home equity (non AIO) loans. (in 000s) Fair Value Asset Income Statement Category Q3 2025 Q2 2025 Q3 2024 Mortgage servicing rights (MSR) Loan servicing fees (910)$ (302)$ (1,873)$ Lender risk account (LRA) Net gain on sale of loans 1,547 497 1,905 Loans held for investment (HFI) with fair value accounting (1) Net gain on sale of loans 1,915 1,315 7,914 Increase (Decrease) in Fair Value Recorded During Quarter Q3 2025 Q2 2025 Q3 2024 Total net gain on sale of loans 20,953$ 19,352$ 24,591$ Less: change in fair value of loans HFI and LRA (2,229) (1,812) (17,844) Less: Gain (loss) on sale of portfolio loans (1,234) - 8,025 Total net gain on sale of loans, excluding portfolio sales and LRA / HFI fair value adjustments 17,490$ 17,539$ 14,772$
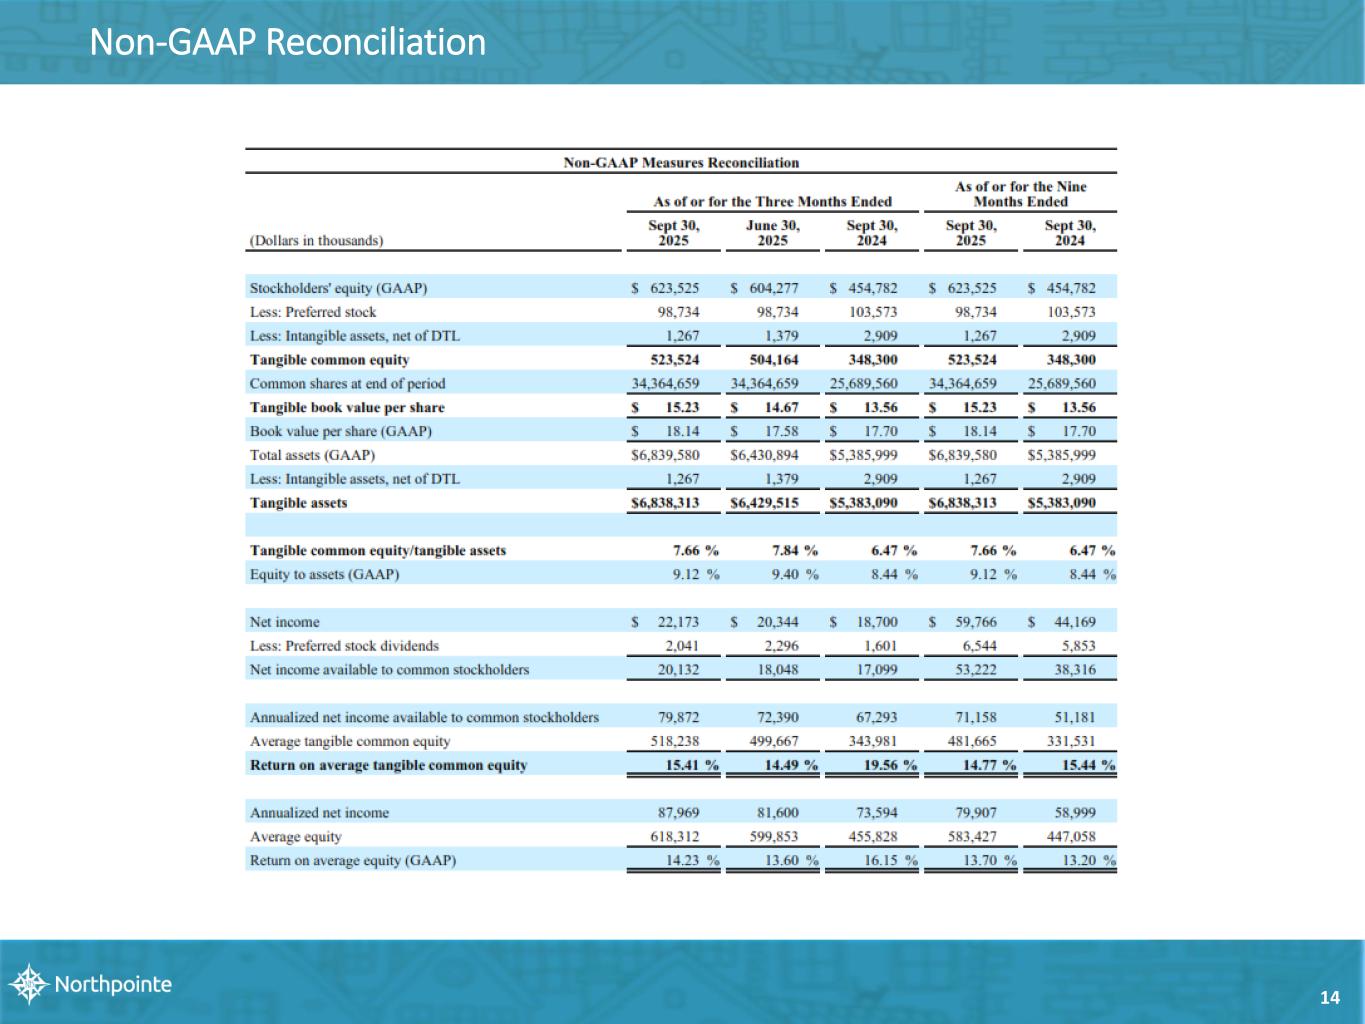
14 Non-GAAP Reconciliation