
SVC 8-K
Service Properties Trust (SVC)
8-K
2021-11-04
For: 2021-11-04
View Original
Added on
April 12, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT PURSUANT
TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported): November 4, 2021
(Exact Name of Registrant as Specified in Its Charter)
(State or Other Jurisdiction of Incorporation)
| (Commission File Number) | (IRS Employer Identification No.) | |||||||
(Address of Principal Executive Offices) (Zip Code)
(Registrant’s Telephone Number, Including Area Code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Trading Symbol | Name of each Exchange on which Registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition.
On November 4, 2021, Service Properties Trust, or the Company, issued a press release regarding the Company’s results of operations and financial condition for the quarter and nine months ended September 30, 2021, and also provided certain supplemental operating and financial data for the quarter and nine months ended September 30, 2021. Copies of the Company’s press release and supplemental operating and financial data are furnished as Exhibits 99.1 and 99.2 hereto, respectively.
Item 9.01. Financial Statements and Exhibits.
(d) Exhibits
104 Cover Page Interactive Data File (Embedded within the Inline XBRL document.)
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| SERVICE PROPERTIES TRUST | ||||||||||||||
| By: | /s/ Brian E. Donley | |||||||||||||
| Name: | Brian E. Donley | |||||||||||||
| Title: | Chief Financial Officer and Treasurer | |||||||||||||
| Dated: | ||||||||||||||
EXHIBIT 99.1
FOR IMMEDIATE RELEASE
Service Properties Trust Announces Third Quarter 2021 Results
Third Quarter Net Loss of $(0.36) Per Common Share
Third Quarter Normalized FFO of $0.27 Per Common Share
Third Quarter Adjusted EBITDAre of $137.3 million
Newton, MA (November 4, 2021). Service Properties Trust (Nasdaq: SVC) today announced its financial results for the quarter ended September 30, 2021.
John Murray, President and Chief Executive Officer of SVC, made the following statement:
“The third quarter marked a period of continued recovery for SVC’s hotel portfolio. SVC’s monthly hotel EBITDA has been positive since April and increased 71.0% versus the second quarter. Over the same period, portfolio-wide occupancy increased to 60.1% from 56.6% and RevPAR for comparable hotels increased by 18.2%, supported by stable extended stay occupancy and continued leisure demand. Comparable RevPAR for the 2021 third quarter was 70.1% of the pre-COVID-19 comparable RevPAR for the 2019 third quarter. With weekly COVID-19 cases on the decline, we expect to benefit from a rebound in business travel in the coming quarters, particularly at our full service hotels as urban centers re-open. We collected all of the rents due from our net lease tenants during the third quarter and our largest net lease tenant, TravelCenters of America, continues to benefit from healthy trucking activity and improved operating efficiencies.
With our previously announced hotel sales in process and expected to close in the first quarter of 2022, over $900 million of cash on our balance sheet, no debt maturities until the third quarter of 2022, and positive cash flow from our hotel portfolio before capital expenditures, we believe we have ample liquidity and financial flexibility as lodging trends continue to rebound.”
Results for the Quarter Ended September 30, 2021:
| Three Months Ended September 30, | |||||||||||
| 2021 | 2020 | ||||||||||
| ($ in thousands, except per share data) | |||||||||||
| Net loss | $ | (59,714) | $ | (102,642) | |||||||
| Net loss per common share | $ | (0.36) | $ | (0.62) | |||||||
Normalized FFO (1) | $ | 43,781 | $ | 23,195 | |||||||
Normalized FFO per common share (1) | $ | 0.27 | $ | 0.14 | |||||||
Adjusted EBITDAre (1) | $ | 137,324 | $ | 103,611 | |||||||
(1)Additional information and reconciliations of net loss determined in accordance with U.S. generally accepted accounting principles, or GAAP, to certain non-GAAP measures, including FFO, Normalized FFO, EBITDA, EBITDAre and Adjusted EBITDAre for the quarters ended September 30, 2021 and 2020 appear later in this press release.
A Maryland Real Estate Investment Trust with transferable shares of beneficial interest listed on the Nasdaq.
No shareholder, Trustee or officer is personally liable for any act or obligation of the Trust.
•Net loss: Net loss for the quarter ended September 30, 2021 was $59.7 million, or $0.36 per diluted common share, compared to a net loss of $102.6 million, or $0.62 per diluted common share, for the quarter ended September 30, 2020. Net loss for the quarter ended September 30, 2021 includes $24.3 million, or $0.15 per diluted common share, of net unrealized gains on equity securities and $3.1 million, or $0.02 per diluted common share, of transaction related costs. Net loss for the quarter ended September 30, 2020 includes a $10.2 million, or $0.06 per diluted common share, loss on asset impairment, and $5.6 million, or $0.03 per diluted common share, of net unrealized gains on equity securities. The weighted average number of diluted common shares outstanding was 164.6 million and 164.4 million for the quarters ended September 30, 2021 and 2020, respectively.
•Normalized FFO: Normalized FFO for the quarter ended September 30, 2021 were $43.8 million, or $0.27 per diluted common share, compared to Normalized FFO of $23.2 million, or $0.14 per diluted common share, for the quarter ended September 30, 2020.
•Adjusted EBITDAre: Adjusted EBITDAre for the quarter ended September 30, 2021 compared to the same period in 2020 increased 32.5% to $137.3 million.
Hotel Portfolio:
As of September 30, 2021, SVC’s 304 hotels were operated by subsidiaries of Sonesta Holdco Corporation, or Sonesta (261 hotels), Hyatt Hotels Corporation, or Hyatt (17 hotels), Radisson Hospitality, Inc., or Radisson (nine hotels), Marriott International, Inc., or Marriott (16 hotels), and InterContinental Hotels Group, plc (one hotel).
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||||||||||||||
| 2021 | 2020 | Change | 2021 | 2020 | Change | |||||||||||||||||||||||||||||||||
| ($ in thousands, except hotel statistics) | ||||||||||||||||||||||||||||||||||||||
| Comparable Hotels | ||||||||||||||||||||||||||||||||||||||
| No. of hotels | 292 | 292 | — | 282 | 282 | — | ||||||||||||||||||||||||||||||||
| No. of rooms or suites | 45,020 | 45,020 | — | 42,292 | 42,292 | — | ||||||||||||||||||||||||||||||||
| Occupancy | 60.9 | % | 45.5 | % | 15.4 | pts | 53.5 | % | 44.9 | % | 8.6 | pts | ||||||||||||||||||||||||||
ADR | $ | 111.18 | $ | 90.87 | 22.4 | % | $ | 95.50 | $ | 100.17 | (4.7) | % | ||||||||||||||||||||||||||
Hotel RevPAR | $ | 67.71 | $ | 41.35 | 63.7 | % | $ | 51.09 | $ | 44.98 | 13.6 | % | ||||||||||||||||||||||||||
Hotel operating revenues (1) | $ | 308,399 | $ | 188,314 | 63.8 | % | $ | 633,739 | $ | 579,240 | 9.4 | % | ||||||||||||||||||||||||||
Hotel operating expenses (1) | $ | 256,160 | $ | 182,408 | 40.4 | % | $ | 602,313 | $ | 566,341 | 6.4 | % | ||||||||||||||||||||||||||
Hotel EBITDA (1) | $ | 52,239 | $ | 5,906 | n/m | $ | 31,426 | $ | 12,899 | n/m | ||||||||||||||||||||||||||||
| Hotel EBITDA margin | 16.9 | % | 3.1 | % | n/m | 5.0 | % | 2.2 | % | n/m | ||||||||||||||||||||||||||||
All Hotels (2) | ||||||||||||||||||||||||||||||||||||||
| No. of hotels | 304 | 329 | (25) | 304 | 329 | (25) | ||||||||||||||||||||||||||||||||
| No. of rooms or suites | 48,439 | 51,404 | (2,965) | 48,439 | 51,404 | (2,965) | ||||||||||||||||||||||||||||||||
| Occupancy | 60.1 | % | 43.6 | % | 16.5 | pts | 52.2 | % | 42.7 | % | 9.5 | pts | ||||||||||||||||||||||||||
| ADR | $ | 114.55 | $ | 89.88 | 27.4 | % | $ | 102.84 | $ | 103.30 | (0.4) | % | ||||||||||||||||||||||||||
| Hotel RevPAR | $ | 68.84 | $ | 39.19 | 75.7 | % | $ | 53.68 | $ | 44.11 | 21.7 | % | ||||||||||||||||||||||||||
Hotel operating revenues (1) | $ | 338,375 | $ | 202,047 | 67.5 | % | $ | 787,463 | $ | 712,323 | 10.5 | % | ||||||||||||||||||||||||||
Hotel operating expenses (1) | $ | 287,265 | $ | 208,336 | 37.9 | % | $ | 744,638 | $ | 736,541 | 1.1 | % | ||||||||||||||||||||||||||
Hotel EBITDA (1) | $ | 51,110 | $ | (6,289) | n/m | $ | 42,825 | $ | (24,218) | n/m | ||||||||||||||||||||||||||||
| Hotel EBITDA margin | 15.1 | % | (3.1) | % | n/m | 5.4 | % | (3.4) | % | n/m | ||||||||||||||||||||||||||||
2
(1) Reconciliations of hotel operating revenues and hotel operating expenses used to determine Hotel EBITDA from hotel operating revenues and hotel operating expenses determined in accordance with GAAP for the quarters ended September 30, 2021 and 2020 appear later in this press release.
(2) Results of all hotels as owned during the periods presented, including the results of hotels sold by SVC for the period owned by SVC.
Recent operating statistics for SVC’s hotels are as follows:
| Comparable Hotels | All Hotels | |||||||||||||||||||||||||||||||||||||
| July 2021 | August 2021 | September 2021 | July 2021 | August 2021 | September 2021 | |||||||||||||||||||||||||||||||||
| Occupancy | 64.0 | % | 58.1 | % | 60.6 | % | 62.9 | % | 56.8 | % | 60.8 | % | ||||||||||||||||||||||||||
| ADR | $ | 113.73 | $ | 109.43 | $ | 110.09 | $ | 117.40 | $ | 112.68 | $ | 113.22 | ||||||||||||||||||||||||||
| RevPAR | $ | 72.79 | $ | 63.58 | $ | 68.71 | $ | 73.84 | $ | 64.00 | $ | 68.84 | ||||||||||||||||||||||||||
For SVC’s 304 hotels, preliminary October 2021 occupancy, ADR and RevPAR are projected to be 59.2%, $116.07 and $68.73, respectively.
Hotel Agreements:
As previously announced, on November 1, 2021, SVC and Radisson amended their previous management agreement for nine hotels owned by SVC. As a result of the amendment, Radisson continues to manage eight of the nine hotels for a 10-year term effective August 1, 2021. The amended agreement sets the annual minimum return due to SVC at $10.2 million and Radisson has provided SVC with a new $22.0 million limited guarantee for 75% of the aggregate annual minimum returns beginning in 2023. Under the amended agreement, a management fee of 5% of gross room revenues for each hotel operated under the Country Inn & Suites brand and a management fee of 3% of gross room revenues for each hotel managed under the Radisson Hotel brand payable to Radisson will be an operating cost paid senior to SVC’s annual minimum return. Radisson may also earn a 20% incentive management fee after payment of SVC’s annual minimum return and reimbursement of certain advances, if any. SVC has also agreed to fund approximately $12.0 million of renovations that are expected to be completed by the end of 2022. The management and branding of the ninth hotel previously managed by Radisson was transitioned to Sonesta on November 1, 2021 on terms substantially consistent with SVC’s Sonesta management agreements for the hotels it transitioned the branding of and management to Sonesta in the fourth quarter of 2020 and first and second quarters of 2021.
Net Lease Retail Portfolio:
SVC’s net lease retail portfolio is summarized as follows:
| As of September 30, 2021 | ||||||||
| Number of properties | 794 | |||||||
| Industries | 21 | |||||||
| Tenants | 175 | |||||||
| Brands | 134 | |||||||
| Square feet | 13.6 million | |||||||
| Occupancy | 98.2% | |||||||
| Weighted average lease term (by annual minimum rent) | 10.3 years | |||||||
| Rent Coverage | 2.37x | |||||||
3
Recent Investment Activities:
During the quarter ended September 30, 2021, SVC sold two net lease properties with an aggregate of 6,639 rentable square feet for an aggregate sales price of $0.7 million, excluding closing costs. In October 2021, SVC sold one net lease property with 7,070 rentable square feet for a sales price of $0.9 million, excluding closing costs.
SVC is currently marketing for sale 68 Sonesta branded hotels (46 extended stay hotels with 5,404 keys, 19 select service hotels with 2,461 keys and three full service hotels with 895 keys) located in 27 states with an aggregate net carrying value of $579.0 million as of September 30, 2021. SVC expects these sales to be completed by the end of the first quarter of 2022.
SVC has also entered agreements to sell four net lease properties with an aggregate of 14,630 square feet located in three states for an aggregate sales price of $2.3 million, excluding closing costs. SVC expects these sales to be completed by the end of the fourth quarter of 2021.
Capital expenditures made at certain of SVC’s properties for the quarter ended September 30, 2021 were $19.8 million.
Liquidity and Financing Activities:
As of September 30, 2021, SVC had $912.5 million of cash and cash equivalents.
Conference Call:
On November 5, 2021 at 10:00 a.m. Eastern Time, John Murray, Chief Executive Officer, Brian Donley, Chief Financial Officer, and Todd Hargreaves, Chief Investment Officer, will host a conference call to discuss SVC’s third quarter 2021 financial results. The conference call telephone number is (877) 329-3720. Participants calling from outside the United States and Canada should dial (412) 317-5434. No pass code is necessary to access the call from either number. Participants should dial in about 15 minutes prior to the scheduled start of the call. A replay of the conference call will be available through Friday, November 12, 2021. To access the replay, dial (412) 317-0088. The replay pass code is 10160343.
A live audio webcast of the conference call will also be available in a listen-only mode on SVC’s website, www.svcreit.com. Participants wanting to access the webcast should visit SVC’s website about five minutes before the call. The archived webcast will be available for replay on SVC’s website for about one week after the call. The transcription, recording and retransmission in any way of SVC’s third quarter conference call is strictly prohibited without the prior written consent of SVC.
Supplemental Data:
A copy of SVC’s Third Quarter 2021 Supplemental Operating and Financial Data is available for download at SVC’s website, www.svcreit.com. SVC’s website is not incorporated as part of this press release.
Service Properties Trust (Nasdaq: SVC) is a real estate investment trust, or REIT, with more than $12 billion invested in two asset categories: hotels and service-focused retail net lease properties. SVC owns more than 300 hotels with over 48,000 guest rooms throughout the United States and in Puerto Rico and Canada, the majority of which are extended stay and select service. SVC owns nearly 800 retail service-focused net lease properties totaling over 13 million square feet throughout United States. SVC is managed by an operating subsidiary of The RMR Group Inc. (Nasdaq: RMR), an alternative asset management company with more than $32 billion in assets under management and more than 35 years of institutional experience in buying, selling, financing and operating commercial real estate. SVC is headquartered in Newton, MA. For more information, visit svcreit.com.
4
Non-GAAP Financial Measures and Certain Definitions:
SVC presents certain “non-GAAP financial measures” within the meaning of the applicable Securities and Exchange Commission, or SEC, rules, including funds from operations, or FFO, Normalized FFO, earnings before interest, taxes, depreciation and amortization, or EBITDA, Hotel EBITDA, EBITDA for real estate, or EBITDAre, and Adjusted EBITDAre. These measures do not represent cash generated by operating activities in accordance with GAAP and should not be considered alternatives to net income (loss) as indicators of SVC’s operating performance or as measures of SVC’s liquidity. These measures should be considered in conjunction with net income (loss) as presented in SVC’s condensed consolidated statements of income (loss). SVC considers these non-GAAP measures to be appropriate supplemental measures of operating performance for a REIT, along with net income (loss). SVC believes these measures provide useful information to investors because by excluding the effects of certain historical amounts, such as depreciation and amortization expense, they may facilitate a comparison of SVC’s operating performance between periods and with other REITs and, in the case of Hotel EBITDA, reflecting only those income and expense items that are generated and incurred at the hotel level may help both investors and management to understand the operations of SVC’s hotels.
Please see the pages attached hereto for a more detailed statement of SVC’s operating results and financial condition and for an explanation of SVC’s calculation of FFO and Normalized FFO, EBITDA, Hotel EBITDA, EBITDAre and Adjusted EBITDAre and a reconciliation of those amounts to amounts determined in accordance with GAAP.
Occupancy represents the total number of room nights sold divided by the total number of room nights available at a hotel or group of hotels. Occupancy is an important measure of the utilization rate and demand of SVC’s hotels.
Average Daily Rate, or ADR, represents rooms revenue divided by the total number of room nights sold in a given period. ADR provides useful insight on pricing at SVC’s hotels and is a measure widely used in the hotel industry.
Revenue per Available Room, or RevPAR, represents rooms revenue divided by the total number of room nights available to guests for a given period. RevPAR is an industry metric correlated to occupancy and ADR and helps measure revenue performance over comparable periods.
Hotel EBITDA: Hotel EBITDA is calculated as hotel operating revenues less hotel operating expenses of all managed and leased hotels, prior to any adjustments required for presentation in SVC’s condensed consolidated statements of income (loss) in accordance with GAAP.
Hotel EBITDA Margin: Hotel EBITDA Margin is Hotel EBITDA as a percentage of hotel operating revenues.
Comparable Hotels Data: SVC presents RevPAR, ADR, and occupancy for the periods presented on a comparable basis to facilitate comparisons between periods. SVC generally defines comparable hotels as those that were owned by it on September 30, 2021 and were open and operating for the entire periods being compared. For the three months ended September 30, 2021 and 2020, SVC’s comparable results excluded 12 hotels that had suspended operations during part of the periods presented. For the nine months ended September 30, 2021 and 2020, SVC’s comparable results excluded 22 hotels that had suspended operations during part of the periods presented.
5
Rent Coverage: SVC defines Rent Coverage as earnings before interest, taxes, depreciation, amortization and rent, or EBITDAR, divided by the annual minimum rent due to SVC weighted by the minimum rent of the property to total minimum rents of the net lease portfolio. EBITDAR amounts used to determine rent coverage are generally for the latest twelve-month period reported based on the most recent operating information, if any, furnished by the tenant. Operating statements furnished by the tenant often are unaudited and, in certain cases, may not have been prepared in accordance with GAAP and are not independently verified by SVC. Tenants that do not report operating information are excluded from the rent coverage calculations. In instances where SVC does not have financial information for the most recent quarter from its tenants, it has calculated an implied EBITDAR for the 2021 third quarter using industry benchmark data to reflect current operating trends. SVC believes using this industry benchmark data provides a reasonable estimate of recent operating results and rent coverage for those tenants.
6
SERVICE PROPERTIES TRUST
CONDENSED CONSOLIDATED BALANCE SHEETS
(dollars in thousands, except share data)
(unaudited)
| September 30, 2021 | December 31, 2020 | |||||||||||||
| ASSETS | ||||||||||||||
| Real estate properties: | ||||||||||||||
| Land | $ | 2,036,297 | $ | 2,030,440 | ||||||||||
| Buildings, improvements and equipment | 9,109,518 | 9,131,832 | ||||||||||||
Total real estate properties, gross | 11,145,815 | 11,162,272 | ||||||||||||
Accumulated depreciation | (3,517,771) | (3,280,110) | ||||||||||||
Total real estate properties, net | 7,628,044 | 7,882,162 | ||||||||||||
| Acquired real estate leases and other intangibles, net | 288,852 | 325,845 | ||||||||||||
| Assets held for sale | 3,707 | 13,543 | ||||||||||||
| Cash and cash equivalents | 912,532 | 73,332 | ||||||||||||
| Restricted cash | 1,657 | 18,124 | ||||||||||||
| Due from related persons | 46,660 | 55,530 | ||||||||||||
| Other assets, net | 453,379 | 318,783 | ||||||||||||
Total assets | $ | 9,334,831 | $ | 8,687,319 | ||||||||||
| LIABILITIES AND SHAREHOLDERS’ EQUITY | ||||||||||||||
| Revolving credit facility | $ | 1,000,000 | $ | 78,424 | ||||||||||
| Senior unsecured notes, net | 6,139,787 | 6,130,166 | ||||||||||||
| Accounts payable and other liabilities | 430,694 | 345,373 | ||||||||||||
| Due to related persons | 10,608 | 30,566 | ||||||||||||
Total liabilities | 7,581,089 | 6,584,529 | ||||||||||||
| Commitments and contingencies | ||||||||||||||
| Shareholders’ equity: | ||||||||||||||
Common shares of beneficial interest, $.01 par value; 200,000,000 shares authorized; 165,092,638 and 164,823,833 shares issued and outstanding, respectively | 1,651 | 1,648 | ||||||||||||
Additional paid in capital | 4,552,087 | 4,550,385 | ||||||||||||
Cumulative other comprehensive loss | (755) | (760) | ||||||||||||
Cumulative net income available for common shareholders | 2,834,449 | 3,180,263 | ||||||||||||
Cumulative common distributions | (5,633,690) | (5,628,746) | ||||||||||||
Total shareholders’ equity | 1,753,742 | 2,102,790 | ||||||||||||
Total liabilities and shareholders’ equity | $ | 9,334,831 | $ | 8,687,319 | ||||||||||
7
SERVICE PROPERTIES TRUST
CONDENSED CONSOLIDATED STATEMENTS OF INCOME (LOSS)
(amounts in thousands, except per share data)
(unaudited)
| Three Months Ended September 30, | Nine Months Ended September 30, | |||||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | |||||||||||||||||||||||
Revenues: | ||||||||||||||||||||||||||
Hotel operating revenues (1) | $ | 338,375 | $ | 199,719 | $ | 787,463 | $ | 700,578 | ||||||||||||||||||
Rental income (2) | 98,724 | 96,776 | 286,742 | 294,633 | ||||||||||||||||||||||
Total revenues | 437,099 | 296,495 | 1,074,205 | 995,211 | ||||||||||||||||||||||
Expenses: | ||||||||||||||||||||||||||
Hotel operating expenses (1)(3) | 285,233 | 174,801 | 723,769 | 492,906 | ||||||||||||||||||||||
Other operating expenses | 4,437 | 3,705 | 11,758 | 11,029 | ||||||||||||||||||||||
Depreciation and amortization | 124,163 | 122,204 | 370,208 | 377,557 | ||||||||||||||||||||||
| General and administrative | 14,231 | 12,295 | 40,840 | 37,621 | ||||||||||||||||||||||
Transaction related costs (4) | 3,149 | — | 28,934 | — | ||||||||||||||||||||||
Loss on asset impairment (5) | — | 10,248 | 2,110 | 55,502 | ||||||||||||||||||||||
Total expenses | 431,213 | 323,253 | 1,177,619 | 974,615 | ||||||||||||||||||||||
Gain (loss) on sale of real estate, net (6) | 94 | 109 | 10,934 | (9,655) | ||||||||||||||||||||||
Unrealized gain on equity securities, net (7) | 24,348 | 5,606 | 20,367 | 4,409 | ||||||||||||||||||||||
Gain on insurance settlement (8) | — | — | — | 62,386 | ||||||||||||||||||||||
Interest income | 203 | 6 | 485 | 283 | ||||||||||||||||||||||
Interest expense (including amortization of debt issuance costs and debt discounts and premiums of $5,877, $3,877, $15,123 and $10,651, respectively) | (92,458) | (80,532) | (273,227) | (223,679) | ||||||||||||||||||||||
Loss on early extinguishment of debt (9) | — | — | — | (6,970) | ||||||||||||||||||||||
| Loss before income taxes and equity in earnings (losses) of an investee | (61,927) | (101,569) | (344,855) | (152,630) | ||||||||||||||||||||||
Income tax benefit (expense) (8) | 55 | 296 | (1,009) | (16,706) | ||||||||||||||||||||||
Equity in earnings (losses) of an investee (10) | 2,158 | (1,369) | 50 | (4,305) | ||||||||||||||||||||||
| Net loss | $ | (59,714) | $ | (102,642) | $ | (345,814) | $ | (173,641) | ||||||||||||||||||
| Weighted average common shares outstanding (basic and diluted) | 164,590 | 164,435 | 164,532 | 164,397 | ||||||||||||||||||||||
| Net loss per common share (basic and diluted) | $ | (0.36) | $ | (0.62) | $ | (2.10) | $ | (1.06) | ||||||||||||||||||
See Notes on page 13.
8
SERVICE PROPERTIES TRUST
RECONCILIATIONS OF FUNDS FROM OPERATIONS, NORMALIZED FUNDS
FROM OPERATIONS
(amounts in thousands, except per share data)
(unaudited)
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||
Calculation of FFO and Normalized FFO: (11) | |||||||||||||||||||||||
| Net loss | $ | (59,714) | $ | (102,642) | $ | (345,814) | $ | (173,641) | |||||||||||||||
| Add (Less): Depreciation and amortization | 124,163 | 122,204 | 370,208 | 377,557 | |||||||||||||||||||
Loss on asset impairment (5) | — | 10,248 | 2,110 | 55,502 | |||||||||||||||||||
(Gain) loss on sale of real estate, net (6) | (94) | (109) | (10,934) | 9,655 | |||||||||||||||||||
Unrealized gain on equity securities, net (7) | (24,348) | (5,606) | (20,367) | (4,409) | |||||||||||||||||||
Adjustments to reflect SVC’s share of FFO attributable to an investee (10) | 369 | (900) | 1,868 | (461) | |||||||||||||||||||
| FFO | 40,376 | 23,195 | (2,929) | 264,203 | |||||||||||||||||||
| Add (Less): | |||||||||||||||||||||||
Transaction related costs (4) | 3,149 | — | 28,934 | — | |||||||||||||||||||
Gain on insurance settlement, net of tax (8) | — | — | — | (46,736) | |||||||||||||||||||
Loss on early extinguishment of debt (9) | — | — | — | 6,970 | |||||||||||||||||||
Adjustments to reflect SVC's share of Normalized FFO attributable to an investee (10) | 256 | — | 1,619 | — | |||||||||||||||||||
| Normalized FFO | $ | 43,781 | $ | 23,195 | $ | 27,624 | $ | 224,437 | |||||||||||||||
| Weighted average common shares outstanding (basic and diluted) | 164,590 | 164,435 | 164,532 | 164,397 | |||||||||||||||||||
| Basic and diluted per common share amounts: | |||||||||||||||||||||||
| Net loss per share | $ | (0.36) | $ | (0.62) | $ | (2.10) | $ | (1.06) | |||||||||||||||
| FFO | $ | 0.25 | $ | 0.14 | $ | (0.02) | $ | 1.61 | |||||||||||||||
| Normalized FFO | $ | 0.27 | $ | 0.14 | $ | 0.17 | $ | 1.37 | |||||||||||||||
| Distributions declared per share | $ | 0.01 | $ | 0.01 | $ | 0.03 | $ | 0.56 | |||||||||||||||
See Notes on page 13.
9
SERVICE PROPERTIES TRUST
RECONCILIATIONS OF EBITDA, EBITDAre AND ADJUSTED EBITDAre
(amounts in thousands, except per share data)
(unaudited)
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||
Calculation of EBITDA, EBITDAre and Adjusted EBITDAre:(12) | |||||||||||||||||||||||
| Net loss | $ | (59,714) | $ | (102,642) | $ | (345,814) | $ | (173,641) | |||||||||||||||
| Add (Less): Interest expense | 92,458 | 80,532 | 273,227 | 223,679 | |||||||||||||||||||
Income tax (benefit) expense (8) | (55) | (296) | 1,009 | 16,706 | |||||||||||||||||||
| Depreciation and amortization | 124,163 | 122,204 | 370,208 | 377,557 | |||||||||||||||||||
| EBITDA | 156,852 | 99,798 | 298,630 | 444,301 | |||||||||||||||||||
Add (Less): Loss on asset impairment (5) | — | 10,248 | 2,110 | 55,502 | |||||||||||||||||||
(Gain) loss on sale of real estate, net (6) | (94) | (109) | (10,934) | 9,655 | |||||||||||||||||||
Adjustments to reflect SVC’s share of EBITDAre attributable to an investee (10) | 464 | — | 2,123 | — | |||||||||||||||||||
EBITDAre | 157,222 | 109,937 | 291,929 | 509,458 | |||||||||||||||||||
Add (Less): Transaction related costs (4) | 3,149 | — | 28,934 | — | |||||||||||||||||||
Unrealized gain on equity securities, net (7) | (24,348) | (5,606) | (20,367) | (4,409) | |||||||||||||||||||
Gain on insurance settlement (8) | — | — | — | (62,386) | |||||||||||||||||||
Loss on early extinguishment of debt (9) | — | — | — | 6,970 | |||||||||||||||||||
Adjustments to reflect SVC’s share of Adjusted EBITDAre attributable to an investee (10) | 256 | (1,583) | 1,619 | (1,004) | |||||||||||||||||||
General and administrative expense paid in common shares (13) | 1,045 | 863 | 2,490 | 2,285 | |||||||||||||||||||
Adjusted EBITDAre | $ | 137,324 | $ | 103,611 | $ | 304,605 | $ | 450,914 | |||||||||||||||
See Notes on page 13.
10
SERVICE PROPERTIES TRUST
CALCULATION AND RECONCILIATION OF HOTEL EBITDA
Comparable Hotels
(amounts in thousands)
(unaudited)
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||
| Number of hotels | 292 | 292 | 282 | 282 | |||||||||||||||||||
| Room revenues | $ | 276,288 | $ | 171,017 | $ | 586,755 | $ | 520,527 | |||||||||||||||
| Food and beverage revenues | 20,658 | 6,556 | 27,166 | 36,577 | |||||||||||||||||||
| Other revenues | 11,453 | 10,741 | 19,818 | 22,136 | |||||||||||||||||||
| Hotel operating revenues - comparable hotels | 308,399 | 188,314 | 633,739 | 579,240 | |||||||||||||||||||
| Rooms expenses | 84,283 | 54,975 | 193,119 | 173,246 | |||||||||||||||||||
| Food and beverage expenses | 16,517 | 8,822 | 23,581 | 37,065 | |||||||||||||||||||
| Other direct and indirect expenses | 115,454 | 91,152 | 285,749 | 271,407 | |||||||||||||||||||
| Management fees | 11,821 | 1,641 | 24,256 | 3,854 | |||||||||||||||||||
| Real estate taxes, insurance and other | 26,719 | 25,556 | 72,655 | 70,925 | |||||||||||||||||||
FF&E reserves (14) | 1,366 | 262 | 2,953 | 9,844 | |||||||||||||||||||
| Hotel operating expenses - comparable hotels | 256,160 | 182,408 | 602,313 | 566,341 | |||||||||||||||||||
| Hotel EBITDA - comparable hotels | $ | 52,239 | $ | 5,906 | $ | 31,426 | $ | 12,899 | |||||||||||||||
| Hotel EBITDA Margin | 16.9 | % | 3.1 | % | 5.0 | % | 2.2 | % | |||||||||||||||
Hotel operating revenues (GAAP) (1) | $ | 338,375 | $ | 199,719 | $ | 787,463 | $ | 700,578 | |||||||||||||||
| Add (Less): | |||||||||||||||||||||||
| Hotel operating revenues from leased hotels | — | 2,328 | — | 11,745 | |||||||||||||||||||
| Hotel operating revenues from non-comparable hotels | (29,976) | (13,733) | (153,724) | (133,083) | |||||||||||||||||||
| Hotel operating revenues - comparable hotels | $ | 308,399 | $ | 188,314 | $ | 633,739 | $ | 579,240 | |||||||||||||||
Hotel operating expenses (GAAP) (1) | $ | 285,233 | $ | 174,801 | $ | 723,769 | $ | 492,906 | |||||||||||||||
| Add (Less): | |||||||||||||||||||||||
| Hotel operating expenses from non-comparable hotels | (31,105) | (25,666) | (141,190) | (170,200) | |||||||||||||||||||
Reduction for security deposit and guaranty fundings, net (3) | — | 30,474 | 15,696 | 222,134 | |||||||||||||||||||
| Hotel operating expenses of leased hotels | — | 2,178 | — | 8,848 | |||||||||||||||||||
FF&E reserves from managed hotel operations (14) | 1,411 | — | 2,175 | 11,205 | |||||||||||||||||||
Other (15) | 621 | 621 | 1,863 | 1,448 | |||||||||||||||||||
| Hotel operating expenses - comparable hotels | $ | 256,160 | $ | 182,408 | $ | 602,313 | $ | 566,341 | |||||||||||||||
See Notes on page 13.
11
SERVICE PROPERTIES TRUST
CALCULATION AND RECONCILIATION OF HOTEL EBITDA
All Hotels
(amounts in thousands)
(unaudited)
| Three Months Ended September 30, | Nine Months Ended September 30, | ||||||||||||||||||||||
| 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||
| Room revenues | $ | 298,607 | $ | 182,366 | $ | 699,953 | $ | 614,550 | |||||||||||||||
| Food and beverage revenues | 25,822 | 6,786 | 52,927 | 58,919 | |||||||||||||||||||
| Other revenues | 13,946 | 12,895 | 34,583 | 38,854 | |||||||||||||||||||
| Hotel operating revenues | 338,375 | 202,047 | 787,463 | 712,323 | |||||||||||||||||||
| Rooms expenses | 93,035 | 59,711 | 230,523 | 211,044 | |||||||||||||||||||
| Food and beverage expenses | 21,415 | 11,420 | 46,116 | 65,790 | |||||||||||||||||||
| Other direct and indirect expenses | 125,080 | 97,993 | 332,378 | 325,489 | |||||||||||||||||||
| Management fees | 12,710 | 1,781 | 28,609 | 5,614 | |||||||||||||||||||
| Real estate taxes, insurance and other | 33,614 | 37,169 | 103,702 | 117,720 | |||||||||||||||||||
FF&E reserves (14) | 1,411 | 262 | 3,310 | 10,884 | |||||||||||||||||||
| Hotel operating expenses | 287,265 | 208,336 | 744,638 | 736,541 | |||||||||||||||||||
| Hotel EBITDA | $ | 51,110 | $ | (6,289) | $ | 42,825 | $ | (24,218) | |||||||||||||||
| Hotel EBITDA Margin | 15.1 | % | (3.1) | % | 5.4 | % | (3.4) | % | |||||||||||||||
Hotel operating revenues (GAAP) (1) | $ | 338,375 | $ | 199,719 | $ | 787,463 | $ | 700,578 | |||||||||||||||
Add: hotel revenues of leased hotels (1) | — | 2,328 | — | 11,745 | |||||||||||||||||||
| Hotel operating revenues | $ | 338,375 | $ | 202,047 | $ | 787,463 | $ | 712,323 | |||||||||||||||
Hotel operating expenses (GAAP) (1) | $ | 285,233 | $ | 174,801 | $ | 723,769 | $ | 492,906 | |||||||||||||||
| Add (Less): | |||||||||||||||||||||||
Reduction for security deposit and guaranty fundings, net (3) | — | 30,474 | 15,696 | 222,134 | |||||||||||||||||||
| Hotel operating expenses of leased hotels | — | 2,178 | — | 8,848 | |||||||||||||||||||
FF&E reserves from managed hotels operations (14) | 1,411 | 262 | 3,310 | 11,205 | |||||||||||||||||||
Other (15) | 621 | 621 | 1,863 | 1,448 | |||||||||||||||||||
| Hotel operating expenses | $ | 287,265 | $ | 208,336 | $ | 744,638 | $ | 736,541 | |||||||||||||||
See Notes on page 13.
12
(1)As of September 30, 2021, SVC owned 304 hotels. SVC’s condensed consolidated statements of income (loss) include hotel operating revenues and expenses of managed hotels and rental income from leased hotels.
(2)SVC reduced rental income by $905 and increased rental income by $2,370 for the three months ended September 30, 2021 and 2020, respectively, and reduced rental income by $3,087 and $298 for the nine months ended September 30, 2021 and 2020, respectively, to record scheduled rent changes under certain of SVC’s leases, the deferred rent obligations under SVC’s leases with TA and the estimated future payments to SVC under its leases with TA for the cost of removing underground storage tanks on a straight-line basis.
(3)When managers of SVC’s hotels are required to fund the shortfalls of minimum returns under the terms of SVC’s management agreements or their guarantees, SVC reflects such fundings (including security deposit applications) in its condensed consolidated statements of income (loss) as a reduction of hotel operating expenses. The net reduction to hotel operating expenses was $30,474 for the three months ended September 30, 2020 and $15,696 and $222,134 for the nine months ended September 30, 2021 and 2020, respectively. There was no net reduction to hotel operating expenses during the three months ended September 30, 2021.
(4)Transaction related costs for the three months ended September 30, 2021 of $3,149 are primarily related to legal costs related to SVC’s arbitration proceeding with Marriott. Transaction related costs for the nine months ended September 30, 2021 included $19,971 of hotel manager transition related costs resulting from the rebranding of 88 hotels during the period, $5,263 of legal costs related to SVC’s arbitration proceeding with Marriott and $3,700 of working capital SVC previously funded under its agreement with Hyatt as a result of the amount no longer expected to be recoverable.
(5)SVC recorded a $10,248 loss on asset impairment during the three months ended September 30, 2020 to reduce the carrying value of one hotel and two net lease properties to their estimated fair value less costs to sell. SVC recorded a $2,110 loss on asset impairment during the nine months ended September 30, 2021 to reduce the carrying value of five net lease properties to their estimated fair value less costs to sell and a $55,502 loss on asset impairment during the nine months ended September 30, 2020 to reduce the carrying value of 18 hotel properties and eight net lease properties to their estimated fair value less costs to sell.
(6)SVC recorded a $94 net gain on sale of real estate during the three months ended September 30, 2021 in connection with the sale of two net lease properties. SVC recorded a $109 net gain on sale of real estate during the three months ended September 30, 2020 in connection with the sale of five net lease properties. SVC recorded a $10,934 net gain on sale of real estate during the nine months ended September 30, 2021 in connection with the sale of six hotels and five net lease properties and recorded a net loss on sale of real estate of $9,655 during the nine months ended September 30, 2020 in connection with the sale of 15 net lease properties.
(7)Unrealized gain on equity securities, net represents the adjustment required to adjust the carrying value of SVC’s investment in shares of TA common stock to its fair value.
(8)SVC recorded a $62,386 gain on insurance settlement during the nine months ended September 30, 2020 for insurance proceeds received for its then leased hotel in San Juan, PR related to Hurricane Maria. Under GAAP, SVC was required to increase the building basis of this hotel for the amount of the insurance proceeds. SVC also recorded a $15,650 deferred tax liability as a result of the book value to tax basis difference related to this accounting during the nine months ended September 30, 2020.
(9)SVC recorded a $6,970 loss on early extinguishment of debt, net of unamortized discount and deferred financing costs, relating to its repurchase of certain of its senior notes, during the three months ended September 30, 2020.
(10)Represents SVC’s proportionate share from its equity investment in Sonesta.
(11)SVC calculates FFO and Normalized FFO as shown above. FFO is calculated on the basis defined by The National Association of Real Estate Investment Trusts, or Nareit, which is net income (loss), calculated in accordance with GAAP, excluding any gain or loss on sale of properties and loss on impairment of real estate assets, if any, plus real estate depreciation and amortization, less any unrealized gains and losses on equity securities, as well as adjustments to reflect SVC’s share of FFO attributable to an investee and certain other adjustments currently not applicable to SVC. In calculating Normalized FFO, SVC adjusts for the items shown above. FFO and Normalized FFO are among the factors considered by SVC’s Board of Trustees when determining the amount of distributions to its shareholders. Other factors include, but are not limited to, requirements to satisfy SVC’s REIT distribution requirements, limitations in its credit agreement and public debt covenants, the availability to SVC of debt and equity capital, SVC’s distribution rate as a percentage of the trading price of its common shares, or dividend yield, and to the dividend yield of other REITs, SVC’s expectation of its future capital requirements and operating performance and SVC’s expected needs for and availability of cash to pay its obligations. Other real estate companies and REITs may calculate FFO and Normalized FFO differently than SVC does.
(12)SVC calculates EBITDA, EBITDAre, and Adjusted EBITDAre as shown above. EBITDAre is calculated on the basis defined by Nareit which is EBITDA, excluding gains and losses on the sale of real estate, loss on impairment of real estate assets, if any, and adjustments to reflect SVC’s share of EBITDAre attributable to an investee. In calculating Adjusted EBITDAre, SVC adjusts for the items shown above. Other real estate companies and REITs may calculate EBITDA, EBITDAre and Adjusted EBITDAre differently than SVC does.
(13)Amounts represent the equity compensation for SVC’s Trustees, officers and certain other employees of SVC’s manager.
(14)Various percentages of total sales at certain of SVC’s hotels are escrowed as reserves for future renovations or refurbishments, or FF&E reserve escrows. SVC owns all the FF&E reserve escrows for its hotels.
(15)SVC is amortizing a liability it recorded for the fair value of its initial investment in Sonesta as a reduction to hotel operating expenses in its condensed consolidated statements of income (loss). SVC reduced hotel operating expenses by $621 for each of the three months ended September 30, 2021 and 2020, and $1,863 and $1,448 for the nine months ended September 30, 2021 and 2020, respectively, for this liability.
13
Warning Concerning Forward-Looking Statements
This press release contains statements that constitute forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 and other securities laws. Whenever SVC uses words such as “believe,” “expect,” “anticipate,” “intend,” “plan,” “estimate,” “will,” “may” and negatives or derivatives of these or similar expressions, SVC is making forward-looking statements. These forward-looking statements are based upon SVC’s present intent, beliefs or expectations, but forward-looking statements are not guaranteed to occur and may not occur. Actual results may differ materially from those contained in or implied by SVC’s forward-looking statements. Forward-looking statements involve known and unknown risks, uncertainties and other factors, some of which are beyond SVC’s control. For example:
•Mr. Murray indicates SVC’s monthly hotel EBITDA has been positive since April and increased versus the second quarter; further Mr. Murray states that SVC’s portfolio-wide occupancy for the 2021 third quarter has increased and RevPAR for SVC’s comparable properties has increased for the third quarter of 2021. He also stated that comparable RevPAR for the third quarter of 2021 increased over the third quarter of 2019. This may imply that metrics will continue to improve; however, SVC’s business is subject to various risks, including risks beyond its control, such as the impact of COVID-19 pandemic. As a result, hotel EBITDA, hotel occupancy and hotel performance may not improve at SVC’s hotels and may decline in the future;
•Mr. Murray states that SVC collected all of the rents when due from its net lease tenants during the third quarter, which may imply that SVC will continue to maintain its rent collections in the future; however, if any of SVC’s tenants’ businesses are negatively affected, including by the ongoing COVID-19 pandemic or a decline in economic activity, rent collections may decline;
•Mr. Murray indicates that TA continues to benefit from healthy trucking activity; however, if trucking activity slows or decreases in importance, TA’s business may be negatively impacted, which could adversely impact SVC and the value of its travel center properties;
•Mr. Murray states that SVC believes that it has ample liquidity and financial flexibility; however, if lodging and other economic trends relating to SVC and its operators and tenants do not continue to improve or decline, SVC’s current liquidity position may not be sufficient to meet its future obligations;
•Mr. Murray indicates that SVC expects to benefit from a rebound in business travel in the coming quarters. However, that rebound may not occur or may not be as strong as SVC expects. Further, the hotel industry is highly competitive and the hotel industry is experiencing labor supply challenges and other cost pressures. As a result, SVC may not be able to attain the benefits it expects from any such rebound in business travel;
•Mr. Murray indicates SVC has ample liquidity and financial flexibility as lodging trends continue to rebound. However SVC’s waiver for compliance with all financial covenants on its revolving credit facility expires on July 15, 2022 when the revolving credit facility becomes due. SVC may be unable to repay its debt obligations and may not be able to meet the conditions required to exercise the extension option available to it under the agreement or be able to refinance the balance with new debt. SVC may need to seek additional waivers or amendments with its lenders and there is no assurance it will be granted such relief;
•This press release provides projected operating metrics for October 2021. These estimates may differ from actual results;
•SVC is marketing for sale 68 hotels with a net book value as of September 30, 2021 of $579.0 million and expects to complete these sales by the end of the first quarter of 2022. SVC also expects to complete $2.5 million of net lease property sales by the end of the fourth quarter of 2021. The sales of SVC’s properties are subject to conditions; accordingly, SVC cannot provide any assurance that it will sell any of these properties and the sales may be delayed, may not occur or their terms may change. Any sales it may complete may be at prices less than SVC expects and less than its net book value; and
14
•SVC has entered agreements to sell four net lease properties for an aggregate sales price of $2.3 million, excluding closing costs and expects to complete these sales by the end of the fourth quarter of 2021. The sales of these properties are subject to conditions; accordingly, SVC cannot provide any assurance that it will sell any of these properties and the sales may be delayed, may not occur or their terms may change. Any sales it may complete may be at prices less than SVC expects and less than its net book value.
The information contained in SVC’s filings with the SEC, including under the caption “Risk Factors” in SVC’s periodic reports, or incorporated therein, identifies other important factors that could cause differences from SVC’s forward-looking statements. SVC’s filings with the SEC are available on the SEC’s website at www.sec.gov.
You should not place undue reliance upon forward-looking statements.
Except as required by law, SVC does not intend to update or change any forward-looking statements as a result of new information, future events or otherwise.
Contact:
Kristin Brown, Director, Investor Relations
(617) 658-0776
(end)
15
Royal Sonesta Chase Park Plaza St. Louis, MO THIRD QUARTER 2021 Supplemental Operating and Financial Data ALL AMOUNTS IN THIS REPORT ARE UNAUDITED. Exhibit 99.2 Royal Sonesta Chicago Downtown Chicago, IL
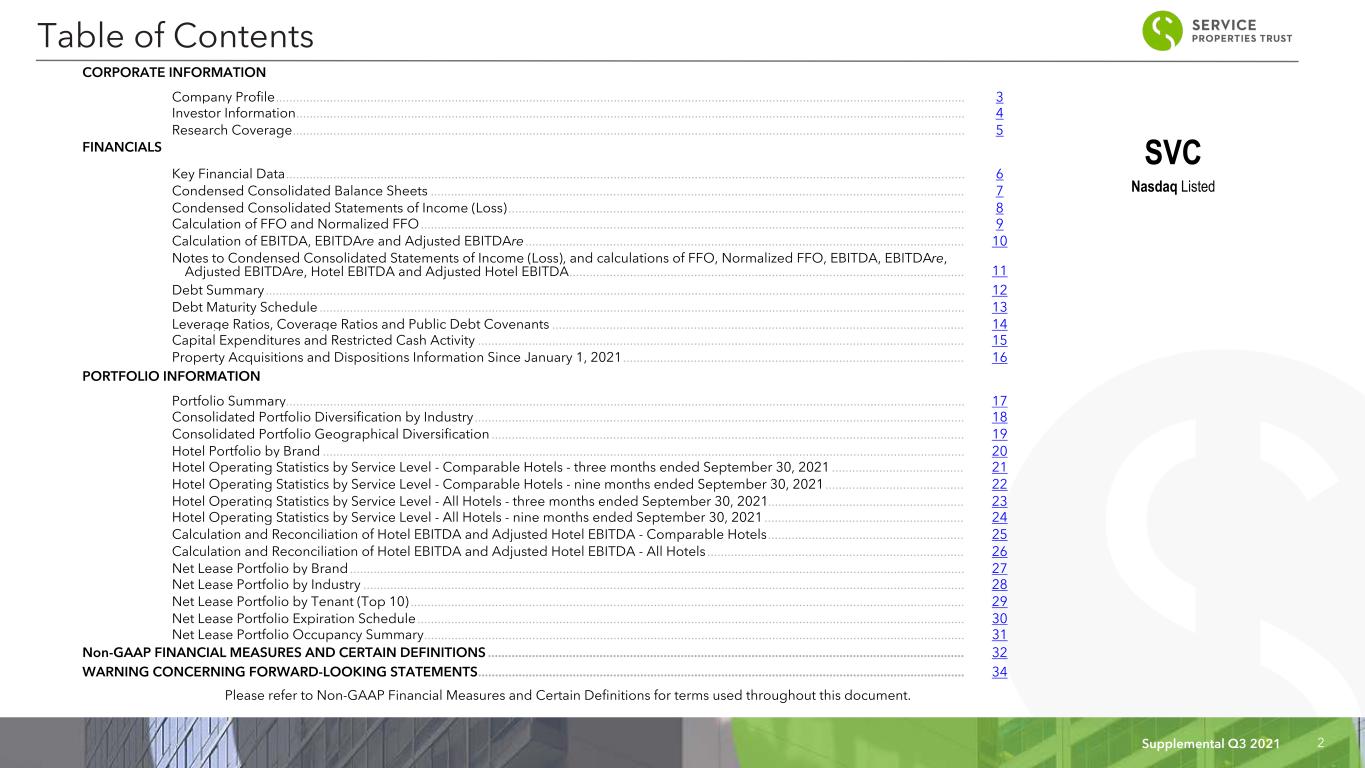
Supplemental Q3 2021 2 Table of Contents CORPORATE INFORMATION Company Profile ............................................................................................................................................................................................................ 3 Investor Information ...................................................................................................................................................................................................... 4 Research Coverage ....................................................................................................................................................................................................... 5 FINANCIALS Key Financial Data ......................................................................................................................................................................................................... 6 Condensed Consolidated Balance Sheets .............................................................................................................................................................. 7 Condensed Consolidated Statements of Income (Loss) ....................................................................................................................................... 8 Calculation of FFO and Normalized FFO ................................................................................................................................................................. 9 Calculation of EBITDA, EBITDAre and Adjusted EBITDAre .................................................................................................................................. 10 Notes to Condensed Consolidated Statements of Income (Loss), and calculations of FFO, Normalized FFO, EBITDA, EBITDAre, Adjusted EBITDAre, Hotel EBITDA and Adjusted Hotel EBITDA ..................................................................................................................... 11 Debt Summary ............................................................................................................................................................................................................... 12 Debt Maturity Schedule ............................................................................................................................................................................................... 13 Leverage Ratios, Coverage Ratios and Public Debt Covenants .......................................................................................................................... 14 Capital Expenditures and Restricted Cash Activity ................................................................................................................................................ 15 Property Acquisitions and Dispositions Information Since January 1, 2021 ..................................................................................................... 16 PORTFOLIO INFORMATION Portfolio Summary ......................................................................................................................................................................................................... 17 Consolidated Portfolio Diversification by Industry ................................................................................................................................................. 18 Consolidated Portfolio Geographical Diversification ............................................................................................................................................ 19 Hotel Portfolio by Brand .............................................................................................................................................................................................. 20 Hotel Operating Statistics by Service Level - Comparable Hotels - three months ended September 30, 2021 ....................................... 21 Hotel Operating Statistics by Service Level - Comparable Hotels - nine months ended September 30, 2021 ......................................... 22 Hotel Operating Statistics by Service Level - All Hotels - three months ended September 30, 2021 .......................................................... 23 Hotel Operating Statistics by Service Level - All Hotels - nine months ended September 30, 2021 ........................................................... 24 Calculation and Reconciliation of Hotel EBITDA and Adjusted Hotel EBITDA - Comparable Hotels .......................................................... 25 Calculation and Reconciliation of Hotel EBITDA and Adjusted Hotel EBITDA - All Hotels ............................................................................ 26 Net Lease Portfolio by Brand ...................................................................................................................................................................................... 27 Net Lease Portfolio by Industry .................................................................................................................................................................................. 28 Net Lease Portfolio by Tenant (Top 10) .................................................................................................................................................................... 29 Net Lease Portfolio Expiration Schedule .................................................................................................................................................................. 30 Net Lease Portfolio Occupancy Summary ................................................................................................................................................................ 31 Non-GAAP FINANCIAL MEASURES AND CERTAIN DEFINITIONS ............................................................................................................................................. 32 WARNING CONCERNING FORWARD-LOOKING STATEMENTS ................................................................................................................................................ 34 Please refer to Non-GAAP Financial Measures and Certain Definitions for terms used throughout this document. SVC Nasdaq Listed
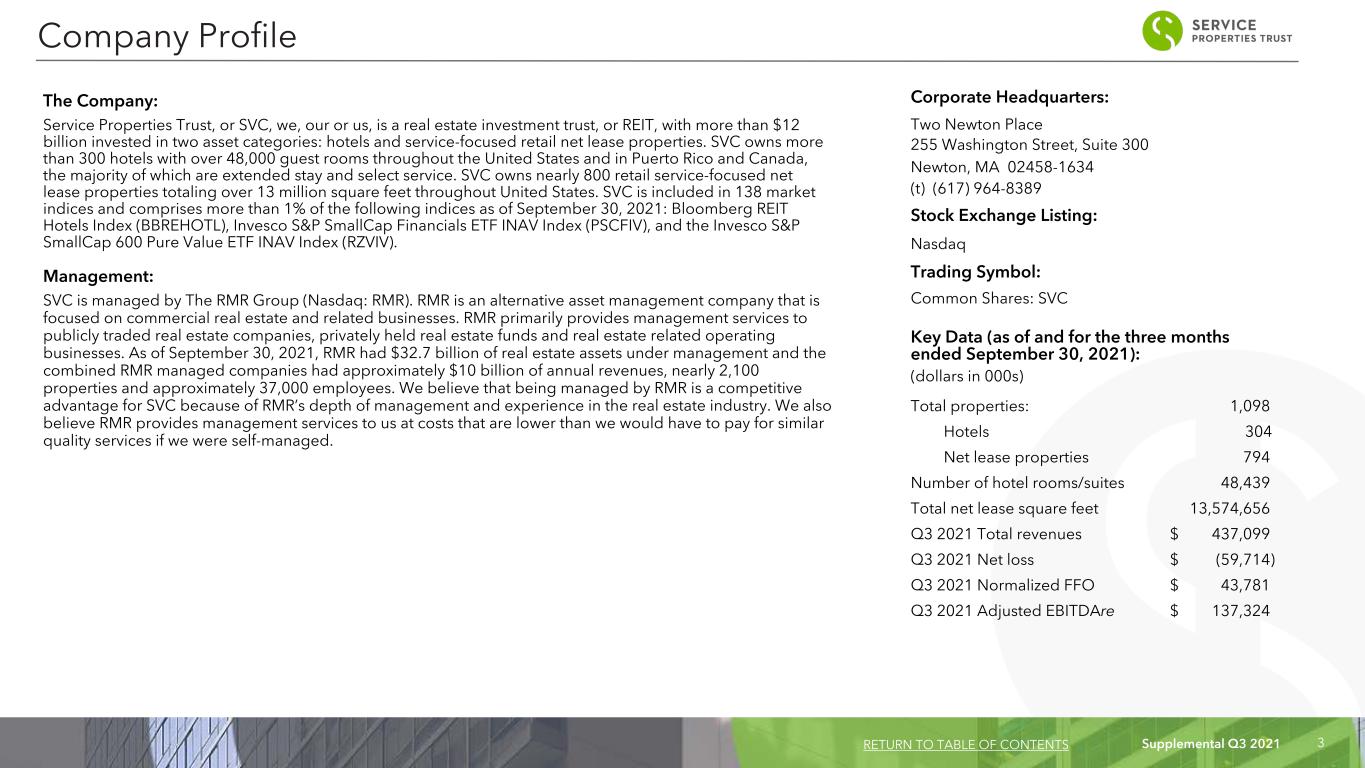
Supplemental Q3 2021 3 Corporate Headquarters: Two Newton Place 255 Washington Street, Suite 300 Newton, MA 02458-1634 (t) (617) 964-8389 Stock Exchange Listing: Nasdaq Trading Symbol: Common Shares: SVC Key Data (as of and for the three months ended September 30, 2021): (dollars in 000s) Total properties: 1,098 Hotels 304 Net lease properties 794 Number of hotel rooms/suites 48,439 Total net lease square feet 13,574,656 Q3 2021 Total revenues $ 437,099 Q3 2021 Net loss $ (59,714) Q3 2021 Normalized FFO $ 43,781 Q3 2021 Adjusted EBITDAre $ 137,324 The Company: Service Properties Trust, or SVC, we, our or us, is a real estate investment trust, or REIT, with more than $12 billion invested in two asset categories: hotels and service-focused retail net lease properties. SVC owns more than 300 hotels with over 48,000 guest rooms throughout the United States and in Puerto Rico and Canada, the majority of which are extended stay and select service. SVC owns nearly 800 retail service-focused net lease properties totaling over 13 million square feet throughout United States. SVC is included in 138 market indices and comprises more than 1% of the following indices as of September 30, 2021: Bloomberg REIT Hotels Index (BBREHOTL), Invesco S&P SmallCap Financials ETF INAV Index (PSCFIV), and the Invesco S&P SmallCap 600 Pure Value ETF INAV Index (RZVIV). Management: SVC is managed by The RMR Group (Nasdaq: RMR). RMR is an alternative asset management company that is focused on commercial real estate and related businesses. RMR primarily provides management services to publicly traded real estate companies, privately held real estate funds and real estate related operating businesses. As of September 30, 2021, RMR had $32.7 billion of real estate assets under management and the combined RMR managed companies had approximately $10 billion of annual revenues, nearly 2,100 properties and approximately 37,000 employees. We believe that being managed by RMR is a competitive advantage for SVC because of RMR’s depth of management and experience in the real estate industry. We also believe RMR provides management services to us at costs that are lower than we would have to pay for similar quality services if we were self-managed. Company Profile RETURN TO TABLE OF CONTENTS
Supplemental Q3 2021 4 Board of Trustees Laurie B. Burns Robert E. Cramer Donna D. Fraiche Independent Trustee Independent Trustee Lead Independent Trustee John L. Harrington William A. Lamkin John G. Murray Independent Trustee Independent Trustee Managing Trustee Adam D. Portnoy Chair of the Board & Managing Trustee Senior Management John G. Murray Brian E. Donley Todd W. Hargreaves President and Chief Executive Officer Chief Financial Officer and Treasurer Vice President and Chief Investment Officer Contact Information Investor Relations Inquiries Service Properties Trust Financial, investor and media inquiries should be directed to: Two Newton Place Kristin Brown, Director, Investor Relations at 255 Washington Street/Suite 300 (617) 796-8232, or [email protected]. Newton, MA 02458-1634 (t) (617) 964-8389 (email) [email protected] (website) www.svcreit.com Investor Information RETURN TO TABLE OF CONTENTS Royal Sonesta Harbor Court Baltimore Baltimore, MD
Supplemental Q3 2021 5 Equity Research Coverage (1) B. Riley Securities, Inc. BTIG Janney Montgomery Scott Wells Fargo Securities Bryan Maher James Sullivan Tyler Batory Dori Kesten (646) 885-5423 (212) 738-6139 (215) 665-4448 (617) 603-4233 [email protected] [email protected] [email protected] [email protected] Rating Agencies (1) Senior Unsecured Debt Ratings Moody’s Investors Service S&P Global Standard & Poor's: BB-/BB* Reed Valutas Michael Souers Moody's: Ba2/ Ba1* (212) 553-4169 (212) 438-2508 * BB/ Ba1 rating assigned to guaranteed Senior Unsecured Notes. [email protected] [email protected] Research Coverage (1) SVC is followed by the analysts and its publicly held debt is rated by the rating agencies listed above. Please note that any opinions, estimates or forecasts regarding SVC's performance made by these analysts or agencies do not represent opinions, forecasts or predictions of SVC or its management. SVC does not by its reference above imply its endorsement of or concurrence with any information, conclusions or recommendations provided by any of these analysts or agencies. RETURN TO TABLE OF CONTENTS The Royal Sonesta Chicago River North Chicago, IL
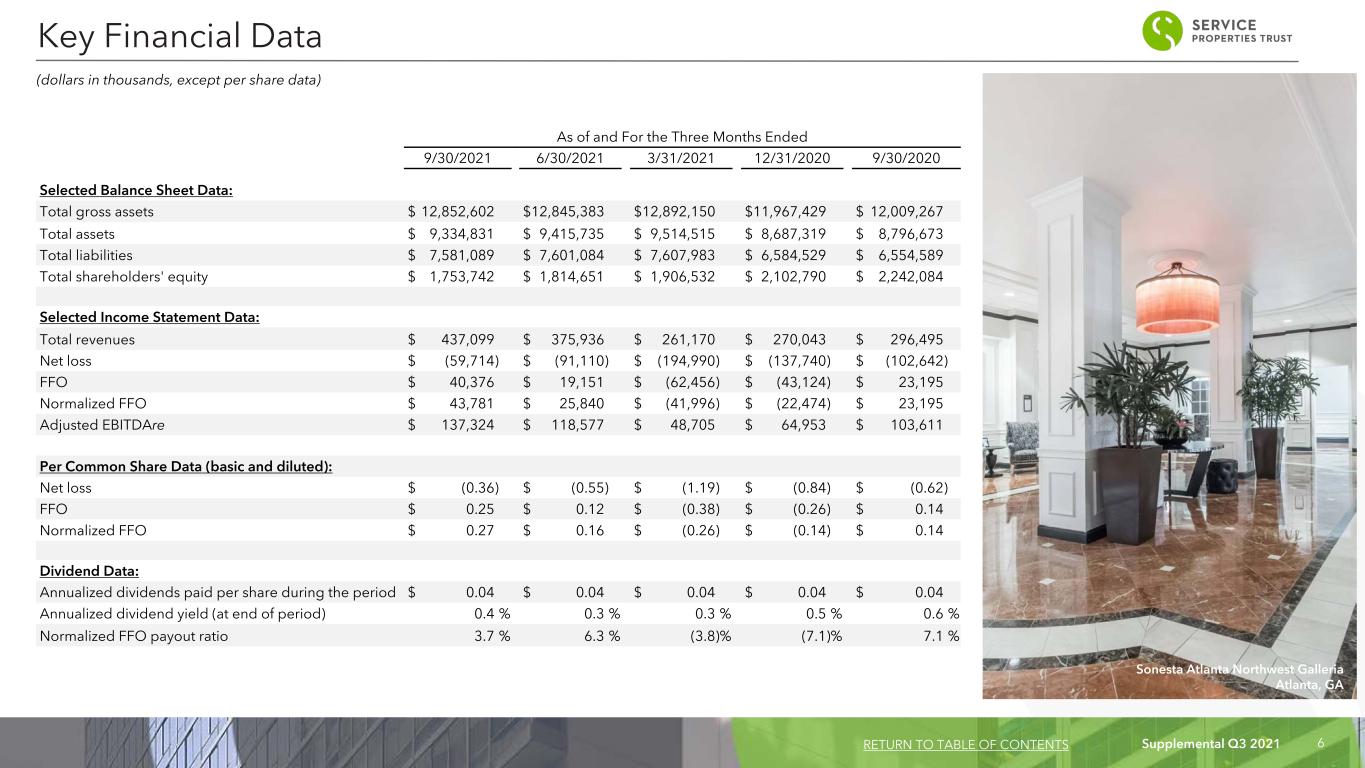
Supplemental Q3 2021 6 As of and For the Three Months Ended 9/30/2021 6/30/2021 3/31/2021 12/31/2020 9/30/2020 Selected Balance Sheet Data: Total gross assets $ 12,852,602 $ 12,845,383 $ 12,892,150 $ 11,967,429 $ 12,009,267 Total assets $ 9,334,831 $ 9,415,735 $ 9,514,515 $ 8,687,319 $ 8,796,673 Total liabilities $ 7,581,089 $ 7,601,084 $ 7,607,983 $ 6,584,529 $ 6,554,589 Total shareholders' equity $ 1,753,742 $ 1,814,651 $ 1,906,532 $ 2,102,790 $ 2,242,084 Selected Income Statement Data: Total revenues $ 437,099 $ 375,936 $ 261,170 $ 270,043 $ 296,495 Net loss $ (59,714) $ (91,110) $ (194,990) $ (137,740) $ (102,642) FFO $ 40,376 $ 19,151 $ (62,456) $ (43,124) $ 23,195 Normalized FFO $ 43,781 $ 25,840 $ (41,996) $ (22,474) $ 23,195 Adjusted EBITDAre $ 137,324 $ 118,577 $ 48,705 $ 64,953 $ 103,611 Per Common Share Data (basic and diluted): Net loss $ (0.36) $ (0.55) $ (1.19) $ (0.84) $ (0.62) FFO $ 0.25 $ 0.12 $ (0.38) $ (0.26) $ 0.14 Normalized FFO $ 0.27 $ 0.16 $ (0.26) $ (0.14) $ 0.14 Dividend Data: Annualized dividends paid per share during the period $ 0.04 $ 0.04 $ 0.04 $ 0.04 $ 0.04 Annualized dividend yield (at end of period) 0.4 % 0.3 % 0.3 % 0.5 % 0.6 % Normalized FFO payout ratio 3.7 % 6.3 % (3.8) % (7.1) % 7.1 % (dollars in thousands, except per share data) Key Financial Data RETURN TO TABLE OF CONTENTS Sonesta Atlanta Northwest Galleria Atlanta, GA
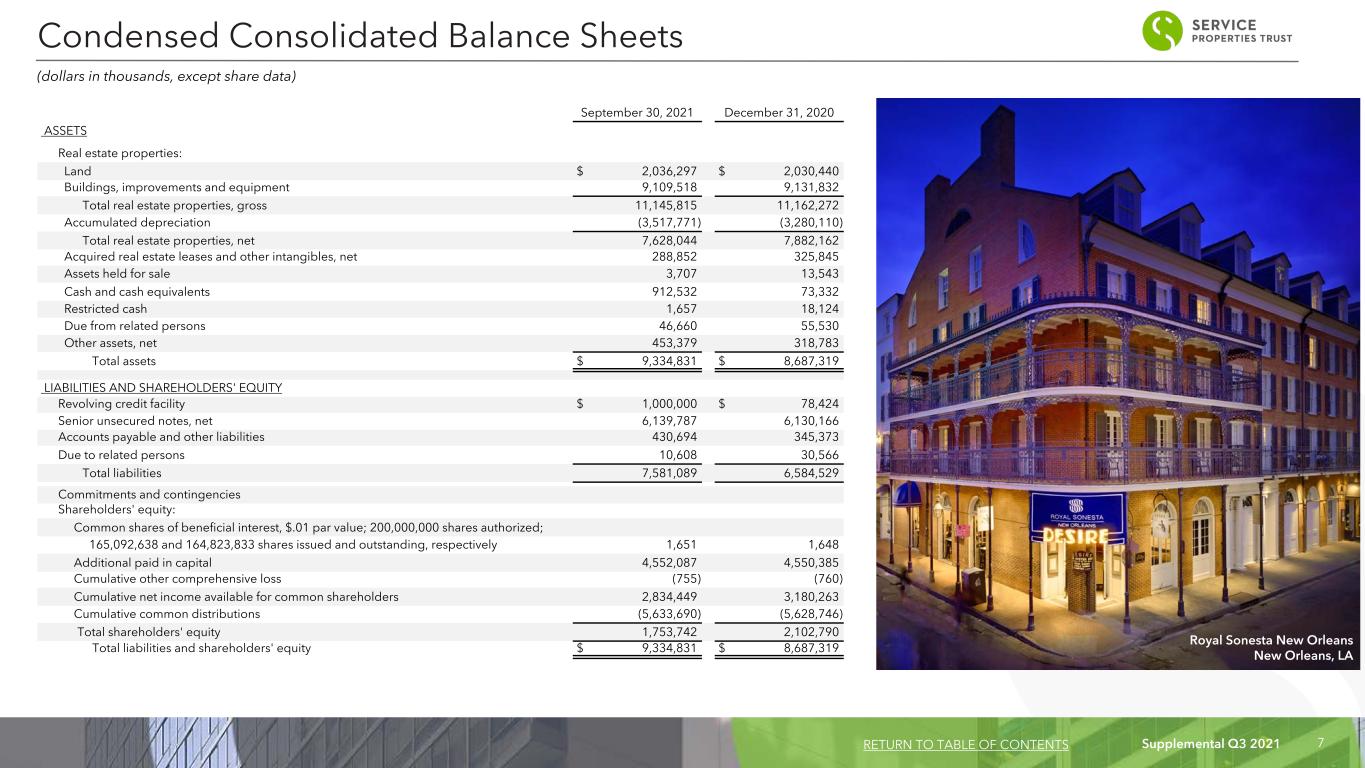
Supplemental Q3 2021 7 September 30, 2021 December 31, 2020 ASSETS Real estate properties: Land $ 2,036,297 $ 2,030,440 Buildings, improvements and equipment 9,109,518 9,131,832 Total real estate properties, gross 11,145,815 11,162,272 Accumulated depreciation (3,517,771) (3,280,110) Total real estate properties, net 7,628,044 7,882,162 Acquired real estate leases and other intangibles, net 288,852 325,845 Assets held for sale 3,707 13,543 Cash and cash equivalents 912,532 73,332 Restricted cash 1,657 18,124 Due from related persons 46,660 55,530 Other assets, net 453,379 318,783 Total assets $ 9,334,831 $ 8,687,319 LIABILITIES AND SHAREHOLDERS' EQUITY Revolving credit facility $ 1,000,000 $ 78,424 Senior unsecured notes, net 6,139,787 6,130,166 Accounts payable and other liabilities 430,694 345,373 Due to related persons 10,608 30,566 Total liabilities 7,581,089 6,584,529 Commitments and contingencies Shareholders' equity: Common shares of beneficial interest, $.01 par value; 200,000,000 shares authorized; 165,092,638 and 164,823,833 shares issued and outstanding, respectively 1,651 1,648 Additional paid in capital 4,552,087 4,550,385 Cumulative other comprehensive loss (755) (760) Cumulative net income available for common shareholders 2,834,449 3,180,263 Cumulative common distributions (5,633,690) (5,628,746) Total shareholders' equity 1,753,742 2,102,790 Total liabilities and shareholders' equity $ 9,334,831 $ 8,687,319 Condensed Consolidated Balance Sheets (dollars in thousands, except share data) RETURN TO TABLE OF CONTENTS Royal Sonesta New Orleans New Orleans, LA
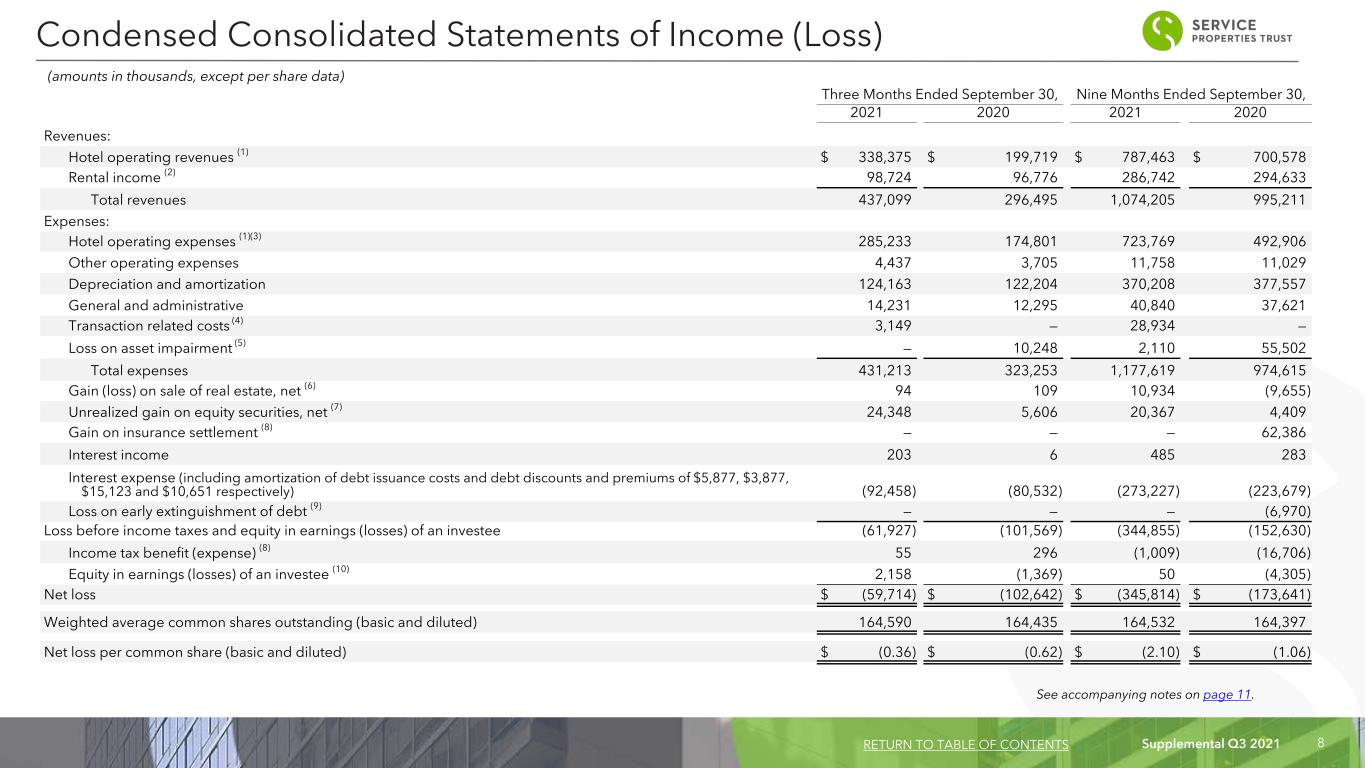
Supplemental Q3 2021 8 Three Months Ended September 30, Nine Months Ended September 30, 2021 2020 2021 2020 Revenues: Hotel operating revenues (1) $ 338,375 $ 199,719 $ 787,463 $ 700,578 Rental income (2) 98,724 96,776 286,742 294,633 Total revenues 437,099 296,495 1,074,205 995,211 Expenses: Hotel operating expenses (1)(3) 285,233 174,801 723,769 492,906 Other operating expenses 4,437 3,705 11,758 11,029 Depreciation and amortization 124,163 122,204 370,208 377,557 General and administrative 14,231 12,295 40,840 37,621 Transaction related costs (4) 3,149 — 28,934 — Loss on asset impairment (5) — 10,248 2,110 55,502 Total expenses 431,213 323,253 1,177,619 974,615 Gain (loss) on sale of real estate, net (6) 94 109 10,934 (9,655) Unrealized gain on equity securities, net (7) 24,348 5,606 20,367 4,409 Gain on insurance settlement (8) — — — 62,386 Interest income 203 6 485 283 Interest expense (including amortization of debt issuance costs and debt discounts and premiums of $5,877, $3,877, $15,123 and $10,651 respectively) (92,458) (80,532) (273,227) (223,679) Loss on early extinguishment of debt (9) — — — (6,970) Loss before income taxes and equity in earnings (losses) of an investee (61,927) (101,569) (344,855) (152,630) Income tax benefit (expense) (8) 55 296 (1,009) (16,706) Equity in earnings (losses) of an investee (10) 2,158 (1,369) 50 (4,305) Net loss $ (59,714) $ (102,642) $ (345,814) $ (173,641) Weighted average common shares outstanding (basic and diluted) 164,590 164,435 164,532 164,397 Net loss per common share (basic and diluted) $ (0.36) $ (0.62) $ (2.10) $ (1.06) (amounts in thousands, except per share data) Condensed Consolidated Statements of Income (Loss) RETURN TO TABLE OF CONTENTS See accompanying notes on page 11.
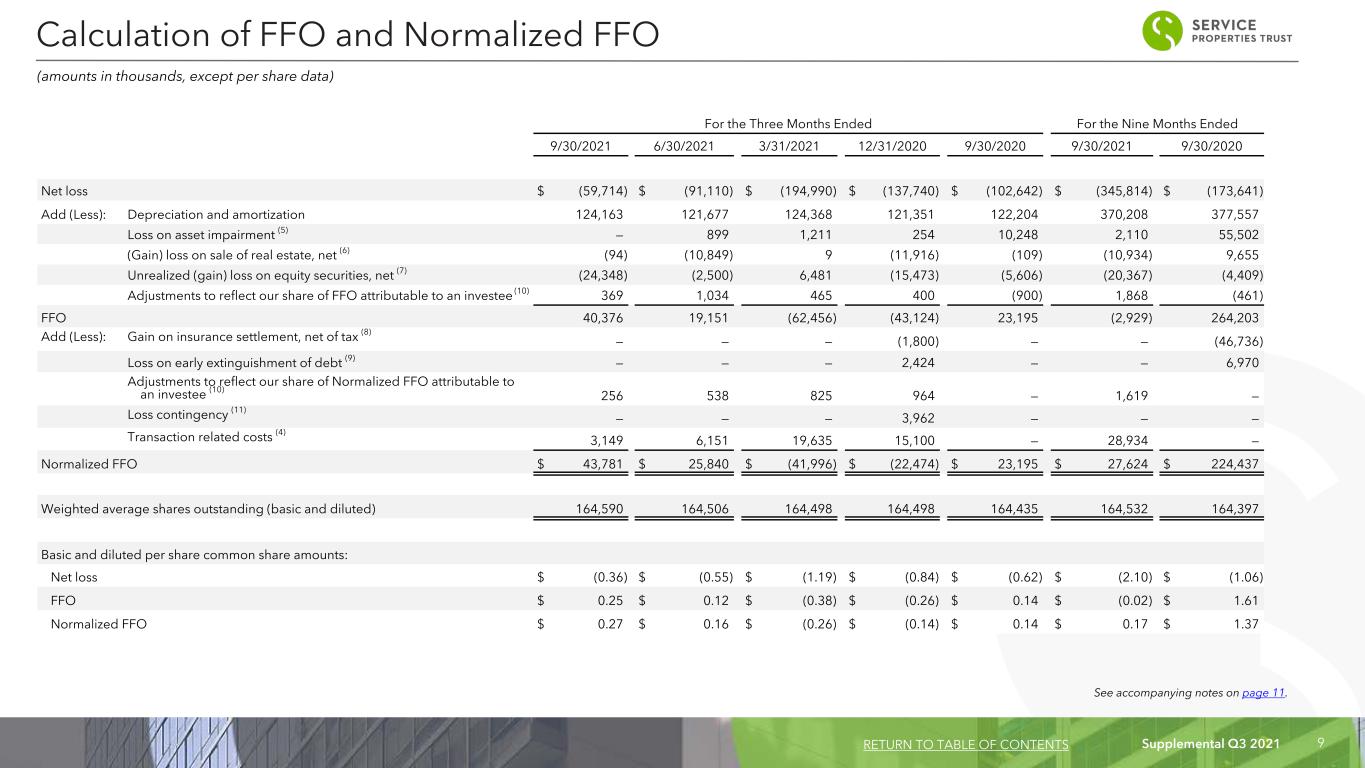
Supplemental Q3 2021 9 For the Three Months Ended For the Nine Months Ended 9/30/2021 6/30/2021 3/31/2021 12/31/2020 9/30/2020 9/30/2021 9/30/2020 Net loss $ (59,714) $ (91,110) $ (194,990) $ (137,740) $ (102,642) $ (345,814) $ (173,641) Add (Less): Depreciation and amortization 124,163 121,677 124,368 121,351 122,204 370,208 377,557 Loss on asset impairment (5) — 899 1,211 254 10,248 2,110 55,502 (Gain) loss on sale of real estate, net (6) (94) (10,849) 9 (11,916) (109) (10,934) 9,655 Unrealized (gain) loss on equity securities, net (7) (24,348) (2,500) 6,481 (15,473) (5,606) (20,367) (4,409) Adjustments to reflect our share of FFO attributable to an investee (10) 369 1,034 465 400 (900) 1,868 (461) FFO 40,376 19,151 (62,456) (43,124) 23,195 (2,929) 264,203 Add (Less): Gain on insurance settlement, net of tax (8) — — — (1,800) — — (46,736) Loss on early extinguishment of debt (9) — — — 2,424 — — 6,970 Adjustments to reflect our share of Normalized FFO attributable to an investee (10) 256 538 825 964 — 1,619 — Loss contingency (11) — — — 3,962 — — — Transaction related costs (4) 3,149 6,151 19,635 15,100 — 28,934 — Normalized FFO $ 43,781 $ 25,840 $ (41,996) $ (22,474) $ 23,195 $ 27,624 $ 224,437 Weighted average shares outstanding (basic and diluted) 164,590 164,506 164,498 164,498 164,435 164,532 164,397 Basic and diluted per share common share amounts: Net loss $ (0.36) $ (0.55) $ (1.19) $ (0.84) $ (0.62) $ (2.10) $ (1.06) FFO $ 0.25 $ 0.12 $ (0.38) $ (0.26) $ 0.14 $ (0.02) $ 1.61 Normalized FFO $ 0.27 $ 0.16 $ (0.26) $ (0.14) $ 0.14 $ 0.17 $ 1.37 Calculation of FFO and Normalized FFO (amounts in thousands, except per share data) RETURN TO TABLE OF CONTENTS See accompanying notes on page 11.
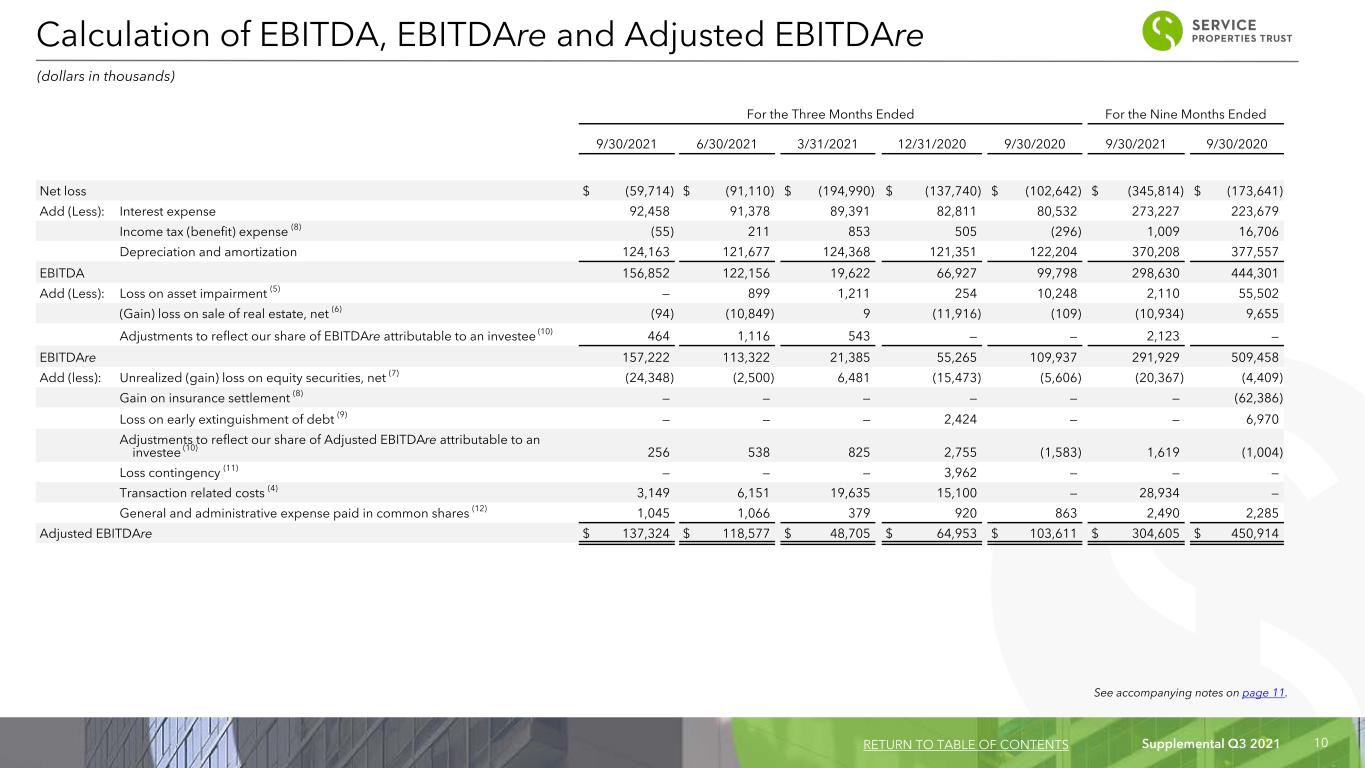
Supplemental Q3 2021 10 For the Three Months Ended For the Nine Months Ended 9/30/2021 6/30/2021 3/31/2021 12/31/2020 9/30/2020 9/30/2021 9/30/2020 Net loss $ (59,714) $ (91,110) $ (194,990) $ (137,740) $ (102,642) $ (345,814) $ (173,641) Add (Less): Interest expense 92,458 91,378 89,391 82,811 80,532 273,227 223,679 Income tax (benefit) expense (8) (55) 211 853 505 (296) 1,009 16,706 Depreciation and amortization 124,163 121,677 124,368 121,351 122,204 370,208 377,557 EBITDA 156,852 122,156 19,622 66,927 99,798 298,630 444,301 Add (Less): Loss on asset impairment (5) — 899 1,211 254 10,248 2,110 55,502 (Gain) loss on sale of real estate, net (6) (94) (10,849) 9 (11,916) (109) (10,934) 9,655 Adjustments to reflect our share of EBITDAre attributable to an investee (10) 464 1,116 543 — — 2,123 — EBITDAre 157,222 113,322 21,385 55,265 109,937 291,929 509,458 Add (less): Unrealized (gain) loss on equity securities, net (7) (24,348) (2,500) 6,481 (15,473) (5,606) (20,367) (4,409) Gain on insurance settlement (8) — — — — — — (62,386) Loss on early extinguishment of debt (9) — — — 2,424 — — 6,970 Adjustments to reflect our share of Adjusted EBITDAre attributable to an investee (10) 256 538 825 2,755 (1,583) 1,619 (1,004) Loss contingency (11) — — — 3,962 — — — Transaction related costs (4) 3,149 6,151 19,635 15,100 — 28,934 — General and administrative expense paid in common shares (12) 1,045 1,066 379 920 863 2,490 2,285 Adjusted EBITDAre $ 137,324 $ 118,577 $ 48,705 $ 64,953 $ 103,611 $ 304,605 $ 450,914 Calculation of EBITDA, EBITDAre and Adjusted EBITDAre (dollars in thousands) See accompanying notes on page 11. RETURN TO TABLE OF CONTENTS
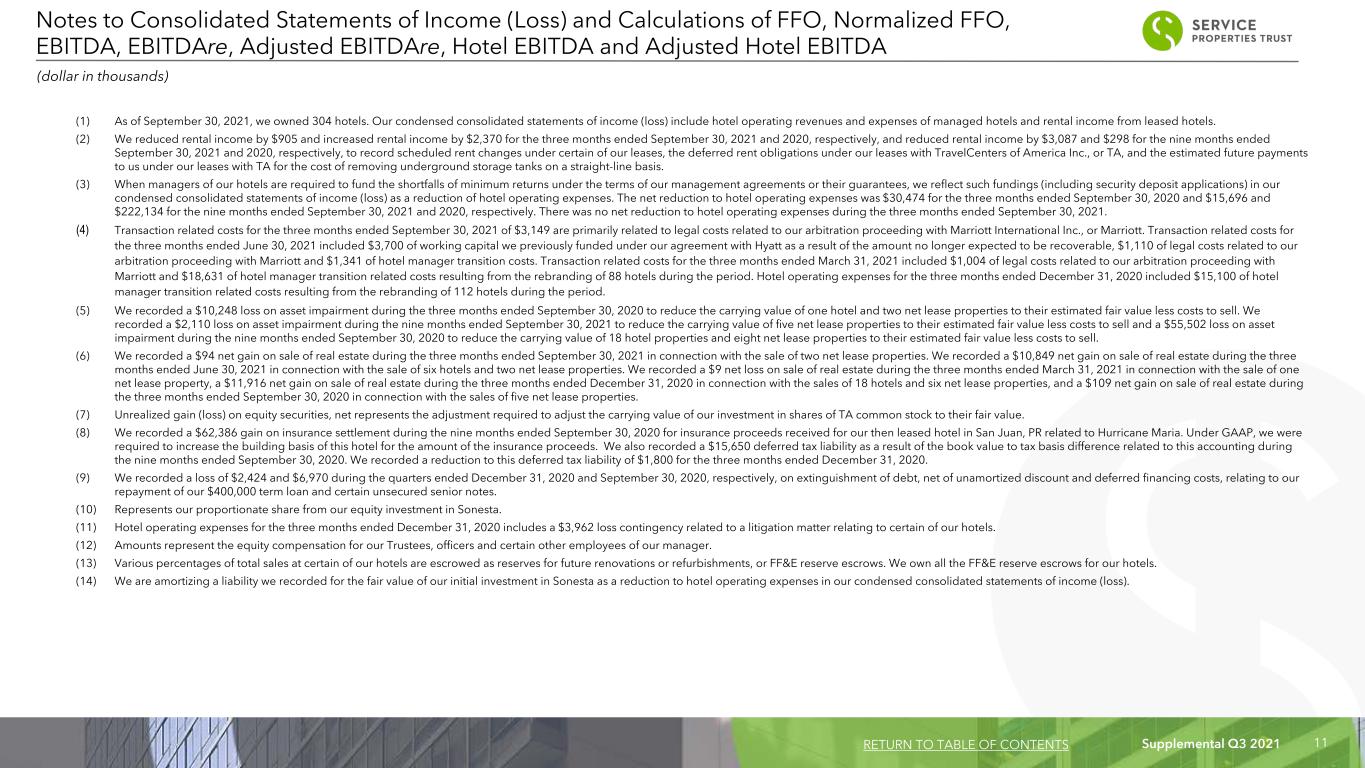
Supplemental Q3 2021 11 Notes to Consolidated Statements of Income (Loss) and Calculations of FFO, Normalized FFO, EBITDA, EBITDAre, Adjusted EBITDAre, Hotel EBITDA and Adjusted Hotel EBITDA (dollar in thousands) RETURN TO TABLE OF CONTENTS (1) As of September 30, 2021, we owned 304 hotels. Our condensed consolidated statements of income (loss) include hotel operating revenues and expenses of managed hotels and rental income from leased hotels. (2) We reduced rental income by $905 and increased rental income by $2,370 for the three months ended September 30, 2021 and 2020, respectively, and reduced rental income by $3,087 and $298 for the nine months ended September 30, 2021 and 2020, respectively, to record scheduled rent changes under certain of our leases, the deferred rent obligations under our leases with TravelCenters of America Inc., or TA, and the estimated future payments to us under our leases with TA for the cost of removing underground storage tanks on a straight-line basis. (3) When managers of our hotels are required to fund the shortfalls of minimum returns under the terms of our management agreements or their guarantees, we reflect such fundings (including security deposit applications) in our condensed consolidated statements of income (loss) as a reduction of hotel operating expenses. The net reduction to hotel operating expenses was $30,474 for the three months ended September 30, 2020 and $15,696 and $222,134 for the nine months ended September 30, 2021 and 2020, respectively. There was no net reduction to hotel operating expenses during the three months ended September 30, 2021. (4) Transaction related costs for the three months ended September 30, 2021 of $3,149 are primarily related to legal costs related to our arbitration proceeding with Marriott International Inc., or Marriott. Transaction related costs for the three months ended June 30, 2021 included $3,700 of working capital we previously funded under our agreement with Hyatt as a result of the amount no longer expected to be recoverable, $1,110 of legal costs related to our arbitration proceeding with Marriott and $1,341 of hotel manager transition costs. Transaction related costs for the three months ended March 31, 2021 included $1,004 of legal costs related to our arbitration proceeding with Marriott and $18,631 of hotel manager transition related costs resulting from the rebranding of 88 hotels during the period. Hotel operating expenses for the three months ended December 31, 2020 included $15,100 of hotel manager transition related costs resulting from the rebranding of 112 hotels during the period. (5) We recorded a $10,248 loss on asset impairment during the three months ended September 30, 2020 to reduce the carrying value of one hotel and two net lease properties to their estimated fair value less costs to sell. We recorded a $2,110 loss on asset impairment during the nine months ended September 30, 2021 to reduce the carrying value of five net lease properties to their estimated fair value less costs to sell and a $55,502 loss on asset impairment during the nine months ended September 30, 2020 to reduce the carrying value of 18 hotel properties and eight net lease properties to their estimated fair value less costs to sell. (6) We recorded a $94 net gain on sale of real estate during the three months ended September 30, 2021 in connection with the sale of two net lease properties. We recorded a $10,849 net gain on sale of real estate during the three months ended June 30, 2021 in connection with the sale of six hotels and two net lease properties. We recorded a $9 net loss on sale of real estate during the three months ended March 31, 2021 in connection with the sale of one net lease property, a $11,916 net gain on sale of real estate during the three months ended December 31, 2020 in connection with the sales of 18 hotels and six net lease properties, and a $109 net gain on sale of real estate during the three months ended September 30, 2020 in connection with the sales of five net lease properties. (7) Unrealized gain (loss) on equity securities, net represents the adjustment required to adjust the carrying value of our investment in shares of TA common stock to their fair value. (8) We recorded a $62,386 gain on insurance settlement during the nine months ended September 30, 2020 for insurance proceeds received for our then leased hotel in San Juan, PR related to Hurricane Maria. Under GAAP, we were required to increase the building basis of this hotel for the amount of the insurance proceeds. We also recorded a $15,650 deferred tax liability as a result of the book value to tax basis difference related to this accounting during the nine months ended September 30, 2020. We recorded a reduction to this deferred tax liability of $1,800 for the three months ended December 31, 2020. (9) We recorded a loss of $2,424 and $6,970 during the quarters ended December 31, 2020 and September 30, 2020, respectively, on extinguishment of debt, net of unamortized discount and deferred financing costs, relating to our repayment of our $400,000 term loan and certain unsecured senior notes. (10) Represents our proportionate share from our equity investment in Sonesta. (11) Hotel operating expenses for the three months ended December 31, 2020 includes a $3,962 loss contingency related to a litigation matter relating to certain of our hotels. (12) Amounts represent the equity compensation for our Trustees, officers and certain other employees of our manager. (13) Various percentages of total sales at certain of our hotels are escrowed as reserves for future renovations or refurbishments, or FF&E reserve escrows. We own all the FF&E reserve escrows for our hotels. (14) We are amortizing a liability we recorded for the fair value of our initial investment in Sonesta as a reduction to hotel operating expenses in our condensed consolidated statements of income (loss).
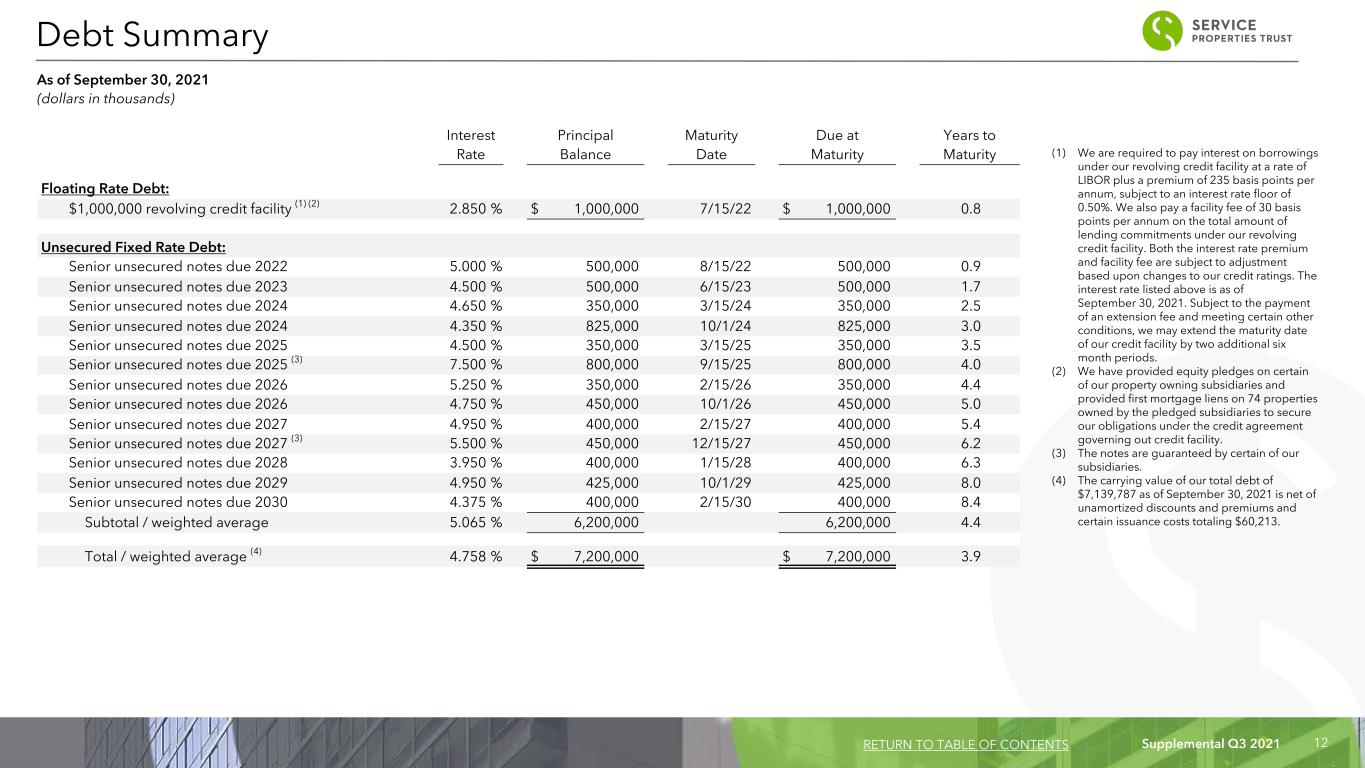
Supplemental Q3 2021 12 (1) We are required to pay interest on borrowings under our revolving credit facility at a rate of LIBOR plus a premium of 235 basis points per annum, subject to an interest rate floor of 0.50%. We also pay a facility fee of 30 basis points per annum on the total amount of lending commitments under our revolving credit facility. Both the interest rate premium and facility fee are subject to adjustment based upon changes to our credit ratings. The interest rate listed above is as of September 30, 2021. Subject to the payment of an extension fee and meeting certain other conditions, we may extend the maturity date of our credit facility by two additional six month periods. (2) We have provided equity pledges on certain of our property owning subsidiaries and provided first mortgage liens on 74 properties owned by the pledged subsidiaries to secure our obligations under the credit agreement governing out credit facility. (3) The notes are guaranteed by certain of our subsidiaries. (4) The carrying value of our total debt of $7,139,787 as of September 30, 2021 is net of unamortized discounts and premiums and certain issuance costs totaling $60,213. Interest Principal Maturity Due at Years to Rate Balance Date Maturity Maturity Floating Rate Debt: $1,000,000 revolving credit facility (1) (2) 2.850 % $ 1,000,000 7/15/22 $ 1,000,000 0.8 Unsecured Fixed Rate Debt: Senior unsecured notes due 2022 5.000 % 500,000 8/15/22 500,000 0.9 Senior unsecured notes due 2023 4.500 % 500,000 6/15/23 500,000 1.7 Senior unsecured notes due 2024 4.650 % 350,000 3/15/24 350,000 2.5 Senior unsecured notes due 2024 4.350 % 825,000 10/1/24 825,000 3.0 Senior unsecured notes due 2025 4.500 % 350,000 3/15/25 350,000 3.5 Senior unsecured notes due 2025 (3) 7.500 % 800,000 9/15/25 800,000 4.0 Senior unsecured notes due 2026 5.250 % 350,000 2/15/26 350,000 4.4 Senior unsecured notes due 2026 4.750 % 450,000 10/1/26 450,000 5.0 Senior unsecured notes due 2027 4.950 % 400,000 2/15/27 400,000 5.4 Senior unsecured notes due 2027 (3) 5.500 % 450,000 12/15/27 450,000 6.2 Senior unsecured notes due 2028 3.950 % 400,000 1/15/28 400,000 6.3 Senior unsecured notes due 2029 4.950 % 425,000 10/1/29 425,000 8.0 Senior unsecured notes due 2030 4.375 % 400,000 2/15/30 400,000 8.4 Subtotal / weighted average 5.065 % 6,200,000 6,200,000 4.4 Total / weighted average (4) 4.758 % $ 7,200,000 $ 7,200,000 3.9 Debt Summary As of September 30, 2021 (dollars in thousands) RETURN TO TABLE OF CONTENTS
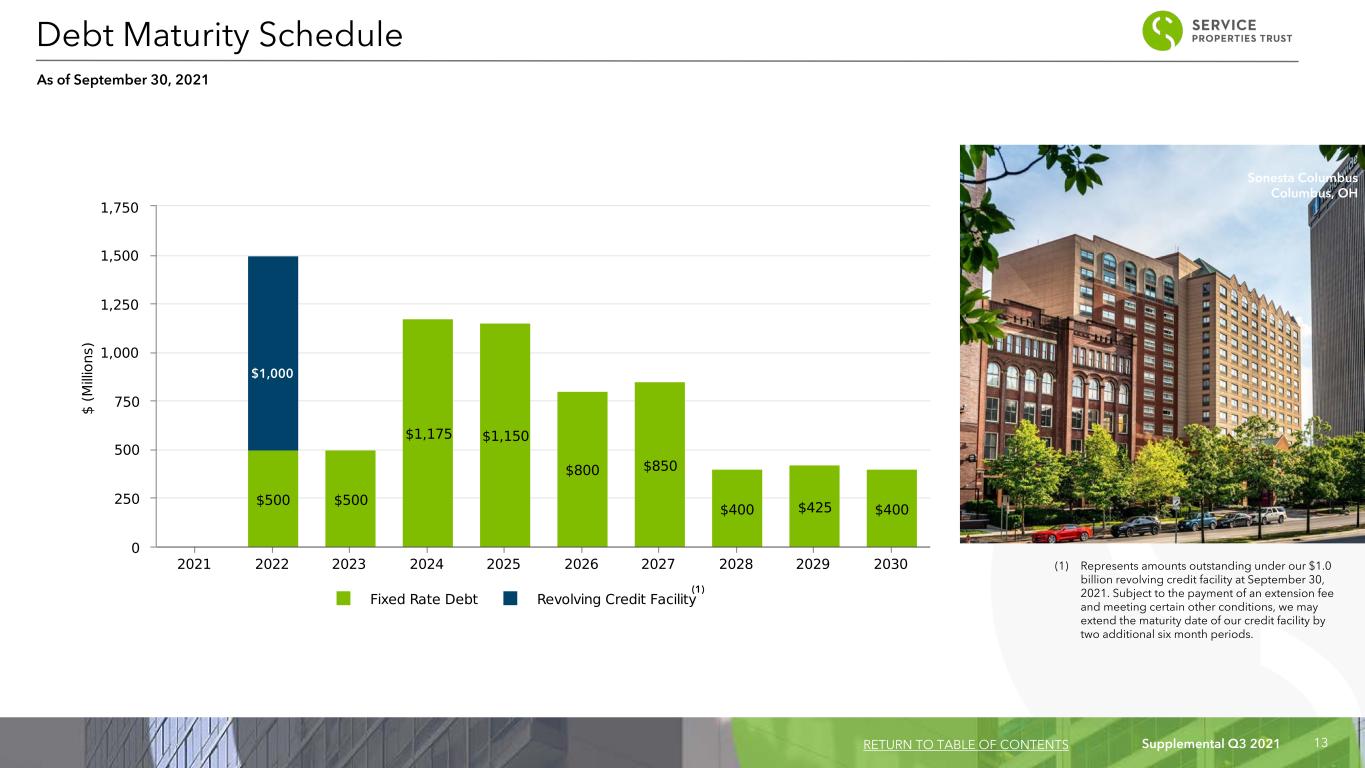
Supplemental Q3 2021 13 (1) Represents amounts outstanding under our $1.0 billion revolving credit facility at September 30, 2021. Subject to the payment of an extension fee and meeting certain other conditions, we may extend the maturity date of our credit facility by two additional six month periods. Debt Maturity Schedule As of September 30, 2021 RETURN TO TABLE OF CONTENTS (1) $1,000 Sonesta Columbus Columbus, OH
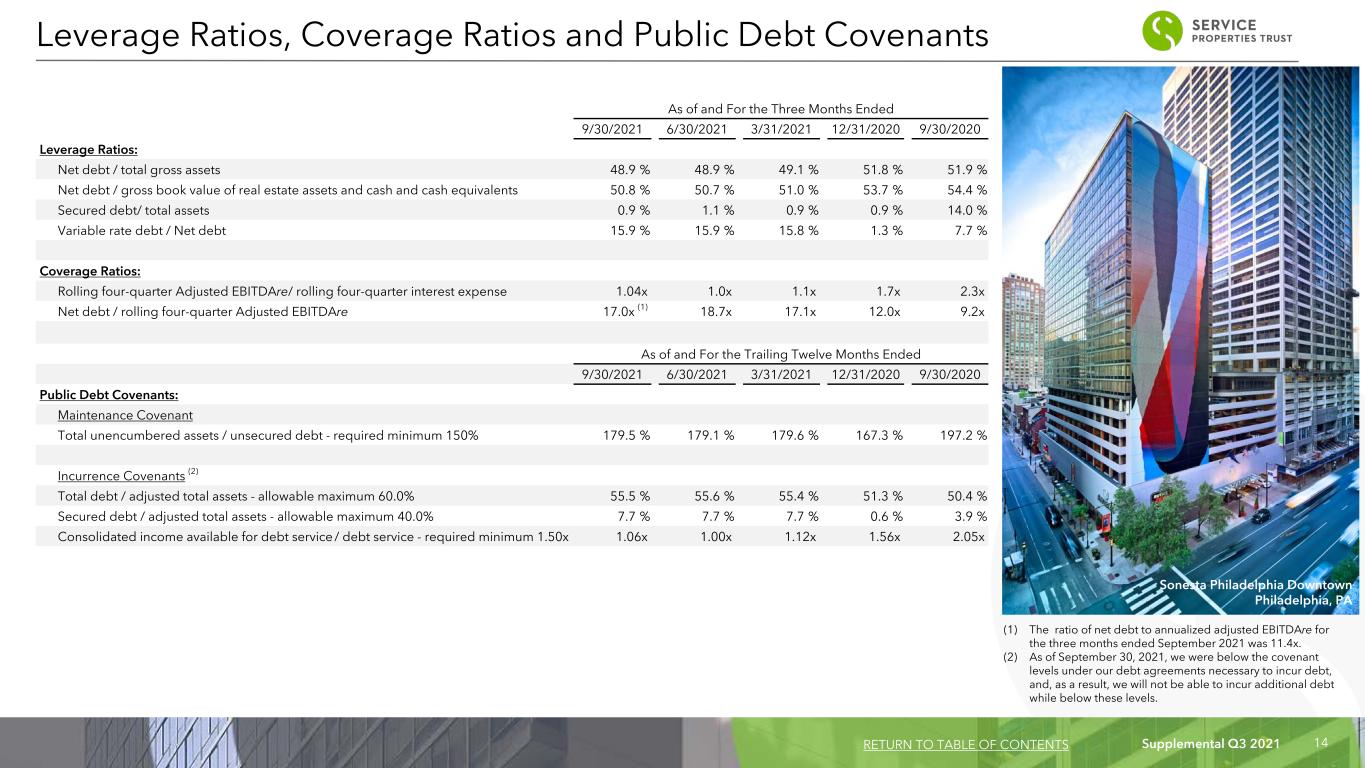
Supplemental Q3 2021 14 As of and For the Three Months Ended 9/30/2021 6/30/2021 3/31/2021 12/31/2020 9/30/2020 Leverage Ratios: Net debt / total gross assets 48.9 % 48.9 % 49.1 % 51.8 % 51.9 % Net debt / gross book value of real estate assets and cash and cash equivalents 50.8 % 50.7 % 51.0 % 53.7 % 54.4 % Secured debt/ total assets 0.9 % 1.1 % 0.9 % 0.9 % 14.0 % Variable rate debt / Net debt 15.9 % 15.9 % 15.8 % 1.3 % 7.7 % Coverage Ratios: Rolling four-quarter Adjusted EBITDAre/ rolling four-quarter interest expense 1.04x 1.0x 1.1x 1.7x 2.3x Net debt / rolling four-quarter Adjusted EBITDAre 17.0x (1) 18.7x 17.1x 12.0x 9.2x As of and For the Trailing Twelve Months Ended 9/30/2021 6/30/2021 3/31/2021 12/31/2020 9/30/2020 Public Debt Covenants: Maintenance Covenant Total unencumbered assets / unsecured debt - required minimum 150% 179.5 % 179.1 % 179.6 % 167.3 % 197.2 % Incurrence Covenants (2) Total debt / adjusted total assets - allowable maximum 60.0% 55.5 % 55.6 % 55.4 % 51.3 % 50.4 % Secured debt / adjusted total assets - allowable maximum 40.0% 7.7 % 7.7 % 7.7 % 0.6 % 3.9 % Consolidated income available for debt service / debt service - required minimum 1.50x 1.06x 1.00x 1.12x 1.56x 2.05x Leverage Ratios, Coverage Ratios and Public Debt Covenants RETURN TO TABLE OF CONTENTS (1) The ratio of net debt to annualized adjusted EBITDAre for the three months ended September 2021 was 11.4x. (2) As of September 30, 2021, we were below the covenant levels under our debt agreements necessary to incur debt, and, as a result, we will not be able to incur additional debt while below these levels. Sonesta Philadelphia Downtown Philadelphia, PA
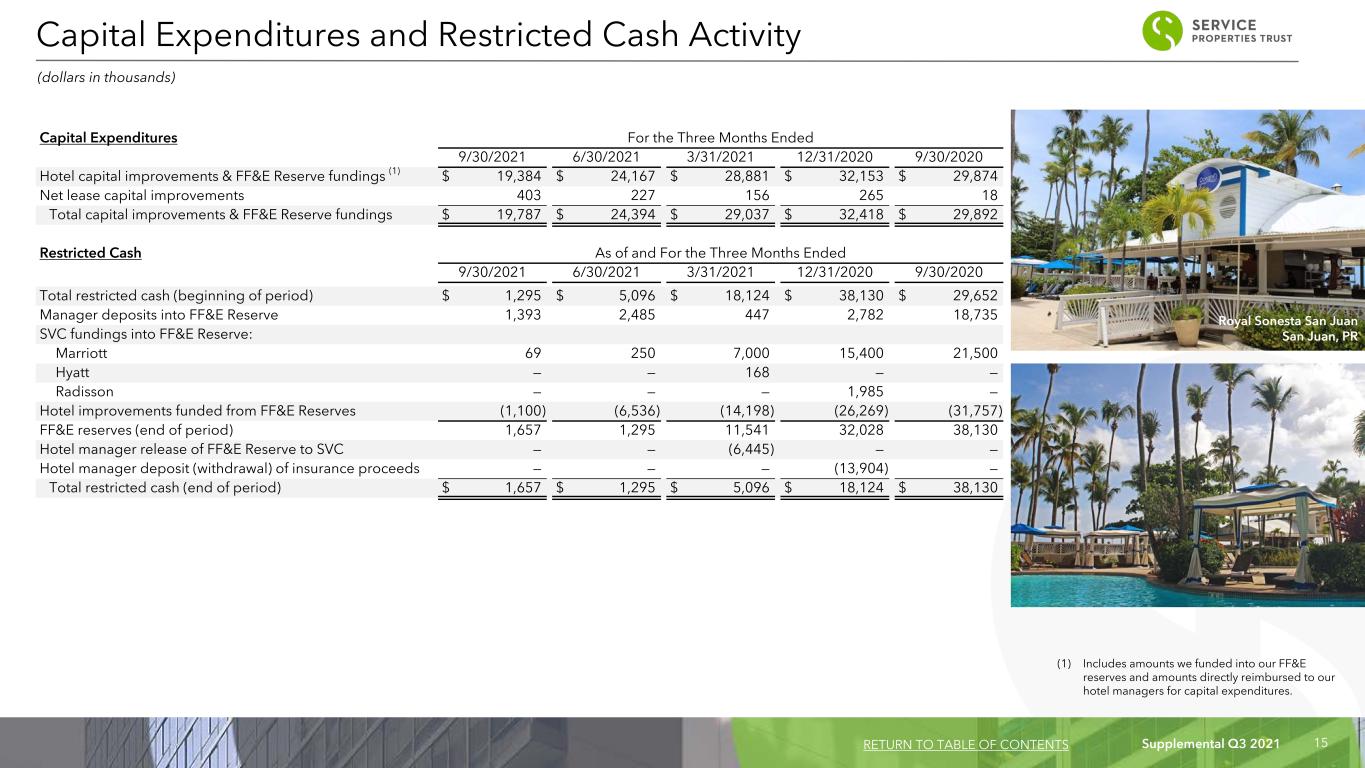
Supplemental Q3 2021 15 Capital Expenditures For the Three Months Ended 9/30/2021 6/30/2021 3/31/2021 12/31/2020 9/30/2020 Hotel capital improvements & FF&E Reserve fundings (1) $ 19,384 $ 24,167 $ 28,881 $ 32,153 $ 29,874 Net lease capital improvements 403 227 156 265 18 Total capital improvements & FF&E Reserve fundings $ 19,787 $ 24,394 $ 29,037 $ 32,418 $ 29,892 Restricted Cash As of and For the Three Months Ended 9/30/2021 6/30/2021 3/31/2021 12/31/2020 9/30/2020 Total restricted cash (beginning of period) $ 1,295 $ 5,096 $ 18,124 $ 38,130 $ 29,652 Manager deposits into FF&E Reserve 1,393 2,485 447 2,782 18,735 SVC fundings into FF&E Reserve: Marriott 69 250 7,000 15,400 21,500 Hyatt — — 168 — — Radisson — — — 1,985 — Hotel improvements funded from FF&E Reserves (1,100) (6,536) (14,198) (26,269) (31,757) FF&E reserves (end of period) 1,657 1,295 11,541 32,028 38,130 Hotel manager release of FF&E Reserve to SVC — — (6,445) — — Hotel manager deposit (withdrawal) of insurance proceeds — — — (13,904) — Total restricted cash (end of period) $ 1,657 $ 1,295 $ 5,096 $ 18,124 $ 38,130 (1) Includes amounts we funded into our FF&E reserves and amounts directly reimbursed to our hotel managers for capital expenditures. (dollars in thousands) Capital Expenditures and Restricted Cash Activity RETURN TO TABLE OF CONTENTS Royal Sonesta San Juan San Juan, PR
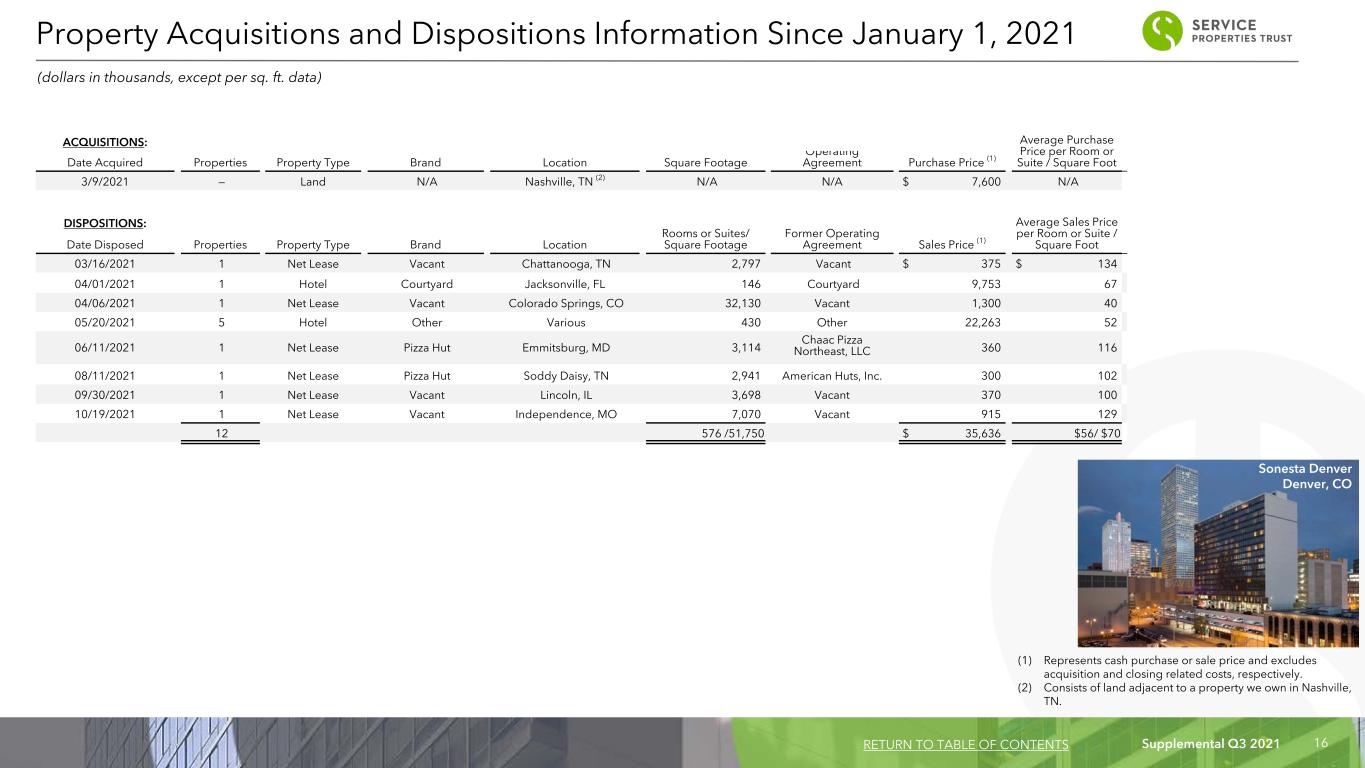
Supplemental Q3 2021 16 ACQUISITIONS: Square Footage Purchase Price (1) Average Purchase Price per Room or Suite / Square FootDate Acquired Properties Property Type Brand Location Operating Agreement 3/9/2021 — Land N/A Nashville, TN (2) N/A N/A $ 7,600 N/A DISPOSITIONS: Rooms or Suites/ Square Footage Former Operating Agreement Average Sales Price per Room or Suite / Square FootDate Disposed Properties Property Type Brand Location Sales Price (1) 03/16/2021 1 Net Lease Vacant Chattanooga, TN 2,797 Vacant $ 375 $ 134 04/01/2021 1 Hotel Courtyard Jacksonville, FL 146 Courtyard 9,753 67 04/06/2021 1 Net Lease Vacant Colorado Springs, CO 32,130 Vacant 1,300 40 05/20/2021 5 Hotel Other Various 430 Other 22,263 52 06/11/2021 1 Net Lease Pizza Hut Emmitsburg, MD 3,114 Chaac Pizza Northeast, LLC 360 116 08/11/2021 1 Net Lease Pizza Hut Soddy Daisy, TN 2,941 American Huts, Inc. 300 102 09/30/2021 1 Net Lease Vacant Lincoln, IL 3,698 Vacant 370 100 10/19/2021 1 Net Lease Vacant Independence, MO 7,070 Vacant 915 129 12 576 /51,750 $ 35,636 $56/ $70 Property Acquisitions and Dispositions Information Since January 1, 2021 (dollars in thousands, except per sq. ft. data) (1) Represents cash purchase or sale price and excludes acquisition and closing related costs, respectively. (2) Consists of land adjacent to a property we own in Nashville, TN. RETURN TO TABLE OF CONTENTS Sonesta Denver Denver, CO
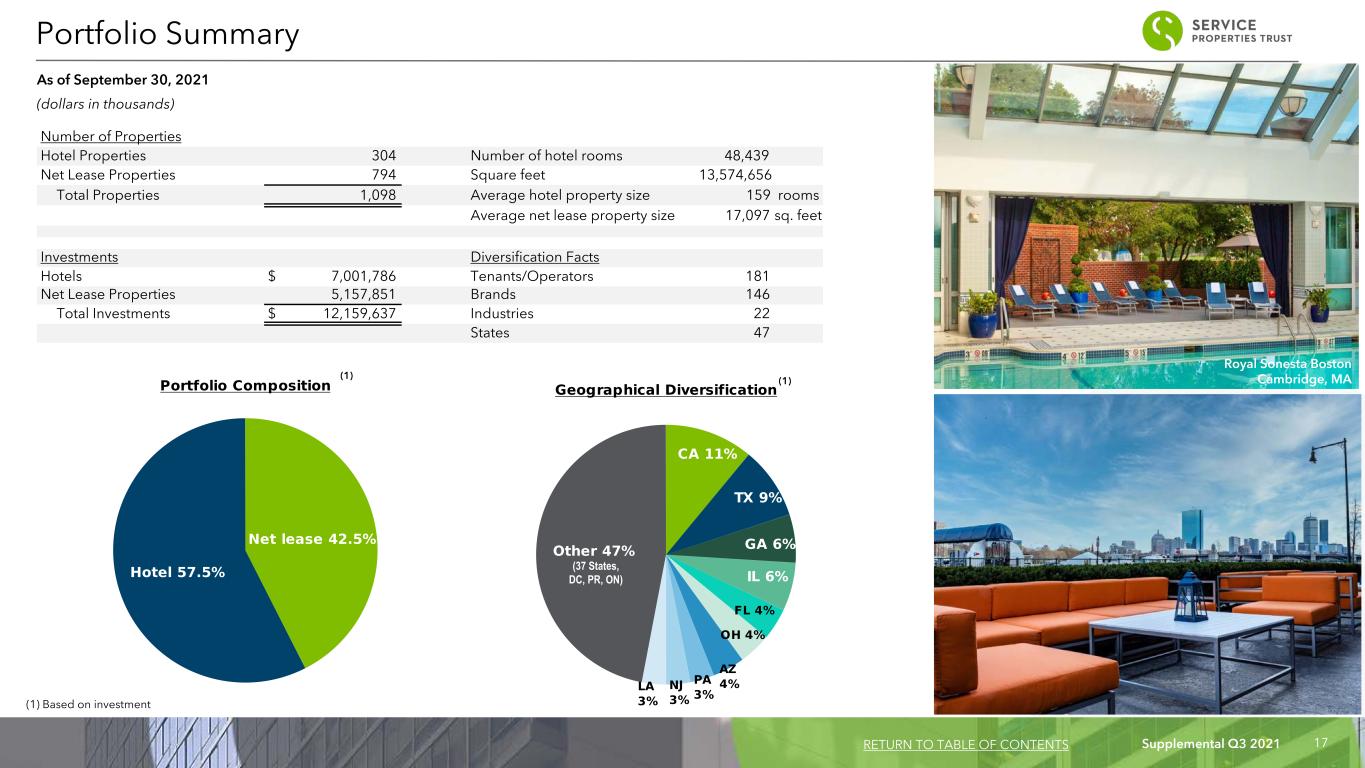
Supplemental Q3 2021 17 Number of Properties Hotel Properties 304 Number of hotel rooms 48,439 Net Lease Properties 794 Square feet 13,574,656 Total Properties 1,098 Average hotel property size 159 rooms Average net lease property size 17,097 sq. feet Investments Diversification Facts Hotels $ 7,001,786 Tenants/Operators 181 Net Lease Properties 5,157,851 Brands 146 Total Investments $ 12,159,637 Industries 22 States 47 (37 States, DC, PR, ON) Portfolio Summary As of September 30, 2021 (dollars in thousands) RETURN TO TABLE OF CONTENTS (1) Based on investment (1) (1) Royal Sonesta Boston Cambridge, MA
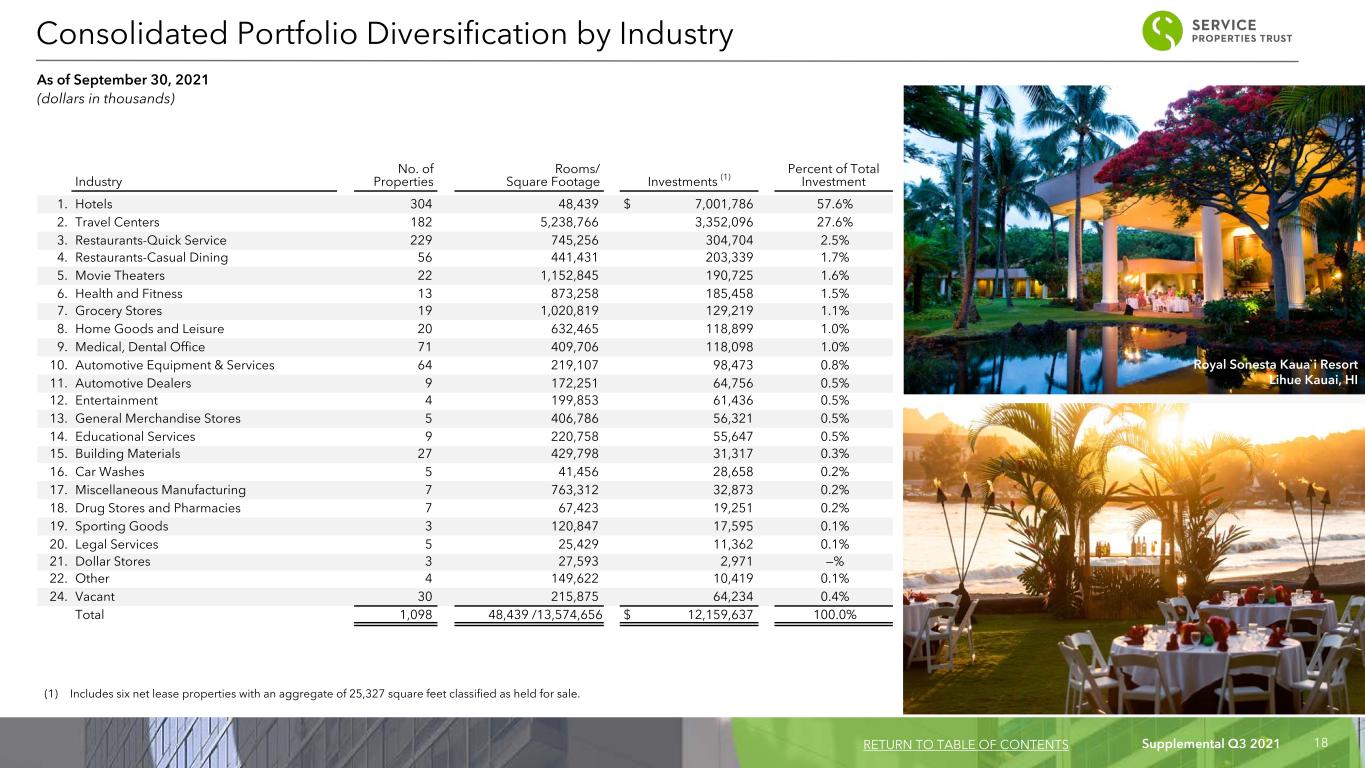
Supplemental Q3 2021 18 Industry No. of Properties Rooms/ Square Footage Investments (1) Percent of Total Investment 1. Hotels 304 48,439 $ 7,001,786 57.6% 2. Travel Centers 182 5,238,766 3,352,096 27.6% 3. Restaurants-Quick Service 229 745,256 304,704 2.5% 4. Restaurants-Casual Dining 56 441,431 203,339 1.7% 5. Movie Theaters 22 1,152,845 190,725 1.6% 6. Health and Fitness 13 873,258 185,458 1.5% 7. Grocery Stores 19 1,020,819 129,219 1.1% 8. Home Goods and Leisure 20 632,465 118,899 1.0% 9. Medical, Dental Office 71 409,706 118,098 1.0% 10. Automotive Equipment & Services 64 219,107 98,473 0.8% 11. Automotive Dealers 9 172,251 64,756 0.5% 12. Entertainment 4 199,853 61,436 0.5% 13. General Merchandise Stores 5 406,786 56,321 0.5% 14. Educational Services 9 220,758 55,647 0.5% 15. Building Materials 27 429,798 31,317 0.3% 16. Car Washes 5 41,456 28,658 0.2% 17. Miscellaneous Manufacturing 7 763,312 32,873 0.2% 18. Drug Stores and Pharmacies 7 67,423 19,251 0.2% 19. Sporting Goods 3 120,847 17,595 0.1% 20. Legal Services 5 25,429 11,362 0.1% 21. Dollar Stores 3 27,593 2,971 —% 22. Other 4 149,622 10,419 0.1% 24. Vacant 30 215,875 64,234 0.4% Total 1,098 48,439 /13,574,656 $ 12,159,637 100.0% (1) Includes six net lease properties with an aggregate of 25,327 square feet classified as held for sale. Consolidated Portfolio Diversification by Industry As of September 30, 2021 (dollars in thousands) RETURN TO TABLE OF CONTENTS Royal Sonesta Kaua`i Resort Lihue Kauai, HI
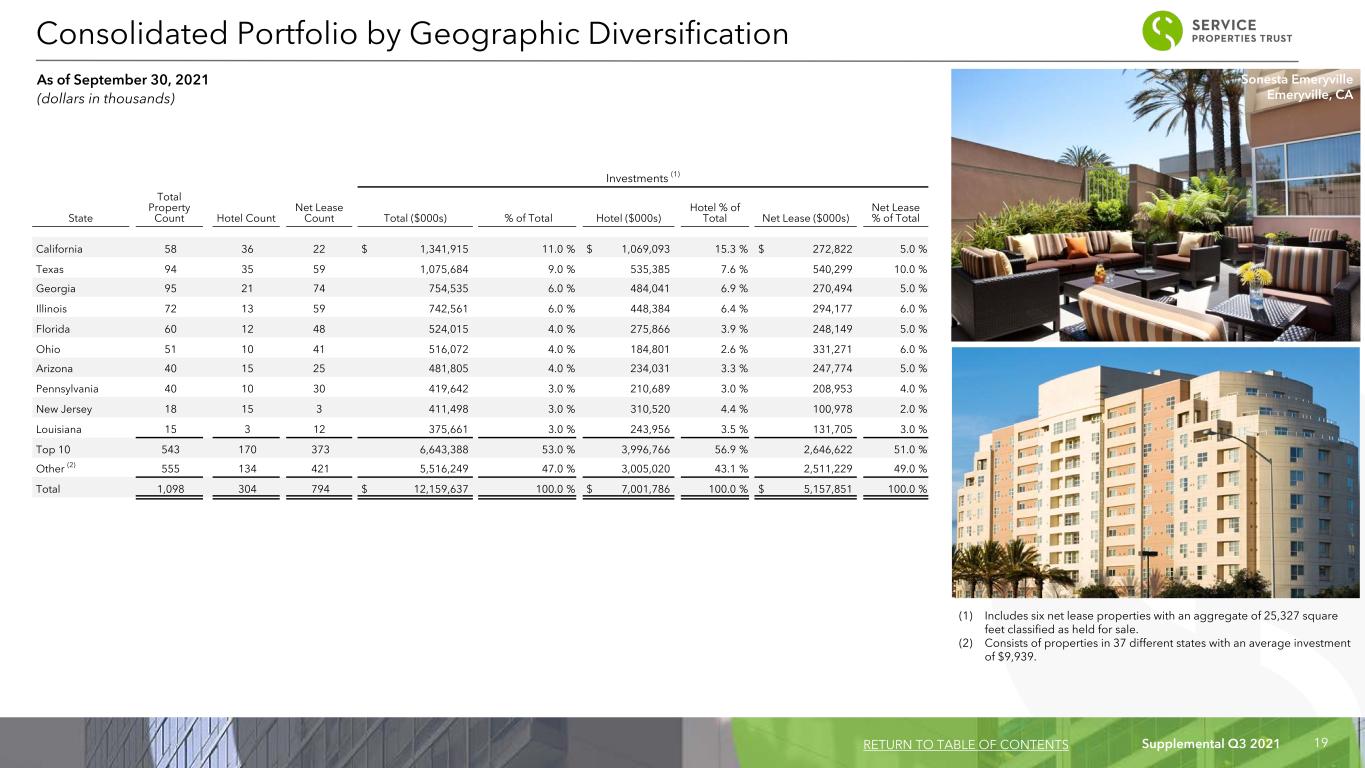
Supplemental Q3 2021 19 Investments (1) State Total Property Count Hotel Count Net Lease Count Total ($000s) % of Total Hotel ($000s) Hotel % of Total Net Lease ($000s) Net Lease % of Total California 58 36 22 $ 1,341,915 11.0 % $ 1,069,093 15.3 % $ 272,822 5.0 % Texas 94 35 59 1,075,684 9.0 % 535,385 7.6 % 540,299 10.0 % Georgia 95 21 74 754,535 6.0 % 484,041 6.9 % 270,494 5.0 % Illinois 72 13 59 742,561 6.0 % 448,384 6.4 % 294,177 6.0 % Florida 60 12 48 524,015 4.0 % 275,866 3.9 % 248,149 5.0 % Ohio 51 10 41 516,072 4.0 % 184,801 2.6 % 331,271 6.0 % Arizona 40 15 25 481,805 4.0 % 234,031 3.3 % 247,774 5.0 % Pennsylvania 40 10 30 419,642 3.0 % 210,689 3.0 % 208,953 4.0 % New Jersey 18 15 3 411,498 3.0 % 310,520 4.4 % 100,978 2.0 % Louisiana 15 3 12 375,661 3.0 % 243,956 3.5 % 131,705 3.0 % Top 10 543 170 373 6,643,388 53.0 % 3,996,766 56.9 % 2,646,622 51.0 % Other (2) 555 134 421 5,516,249 47.0 % 3,005,020 43.1 % 2,511,229 49.0 % Total 1,098 304 794 $ 12,159,637 100.0 % $ 7,001,786 100.0 % $ 5,157,851 100.0 % (1) Includes six net lease properties with an aggregate of 25,327 square feet classified as held for sale. (2) Consists of properties in 37 different states with an average investment of $9,939. Consolidated Portfolio by Geographic Diversification As of September 30, 2021 (dollars in thousands) RETURN TO TABLE OF CONTENTS Sonesta Emeryville Emeryville, CA
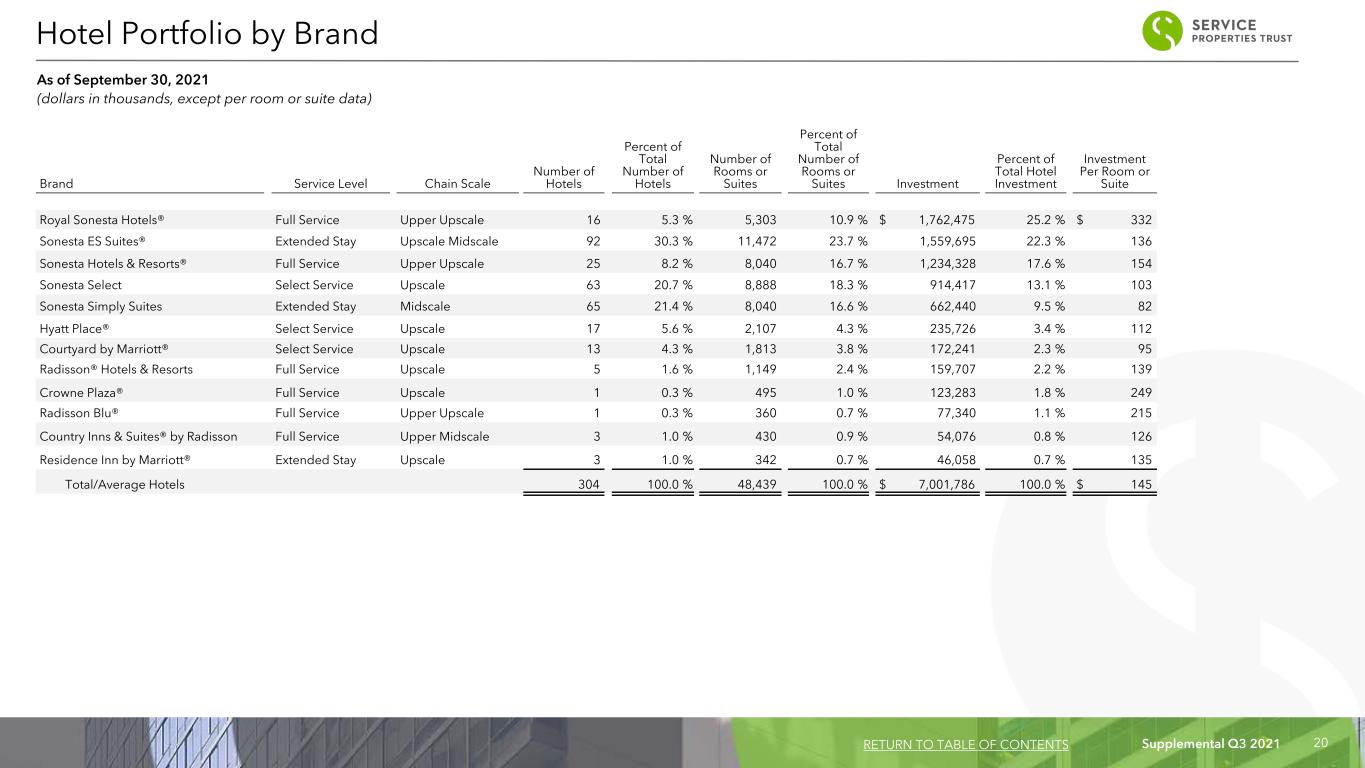
Supplemental Q3 2021 20 Brand Service Level Chain Scale Number of Hotels Percent of Total Number of Hotels Number of Rooms or Suites Percent of Total Number of Rooms or Suites Investment Percent of Total Hotel Investment Investment Per Room or Suite Royal Sonesta Hotels® Full Service Upper Upscale 16 5.3 % 5,303 10.9 % $ 1,762,475 25.2 % $ 332 Sonesta ES Suites® Extended Stay Upscale Midscale 92 30.3 % 11,472 23.7 % 1,559,695 22.3 % 136 Sonesta Hotels & Resorts® Full Service Upper Upscale 25 8.2 % 8,040 16.7 % 1,234,328 17.6 % 154 Sonesta Select Select Service Upscale 63 20.7 % 8,888 18.3 % 914,417 13.1 % 103 Sonesta Simply Suites Extended Stay Midscale 65 21.4 % 8,040 16.6 % 662,440 9.5 % 82 Hyatt Place® Select Service Upscale 17 5.6 % 2,107 4.3 % 235,726 3.4 % 112 Courtyard by Marriott® Select Service Upscale 13 4.3 % 1,813 3.8 % 172,241 2.3 % 95 Radisson® Hotels & Resorts Full Service Upscale 5 1.6 % 1,149 2.4 % 159,707 2.2 % 139 Crowne Plaza® Full Service Upscale 1 0.3 % 495 1.0 % 123,283 1.8 % 249 Radisson Blu® Full Service Upper Upscale 1 0.3 % 360 0.7 % 77,340 1.1 % 215 Country Inns & Suites® by Radisson Full Service Upper Midscale 3 1.0 % 430 0.9 % 54,076 0.8 % 126 Residence Inn by Marriott® Extended Stay Upscale 3 1.0 % 342 0.7 % 46,058 0.7 % 135 Total/Average Hotels 304 100.0 % 48,439 100.0 % $ 7,001,786 100.0 % $ 145 Hotel Portfolio by Brand As of September 30, 2021 (dollars in thousands, except per room or suite data) RETURN TO TABLE OF CONTENTS
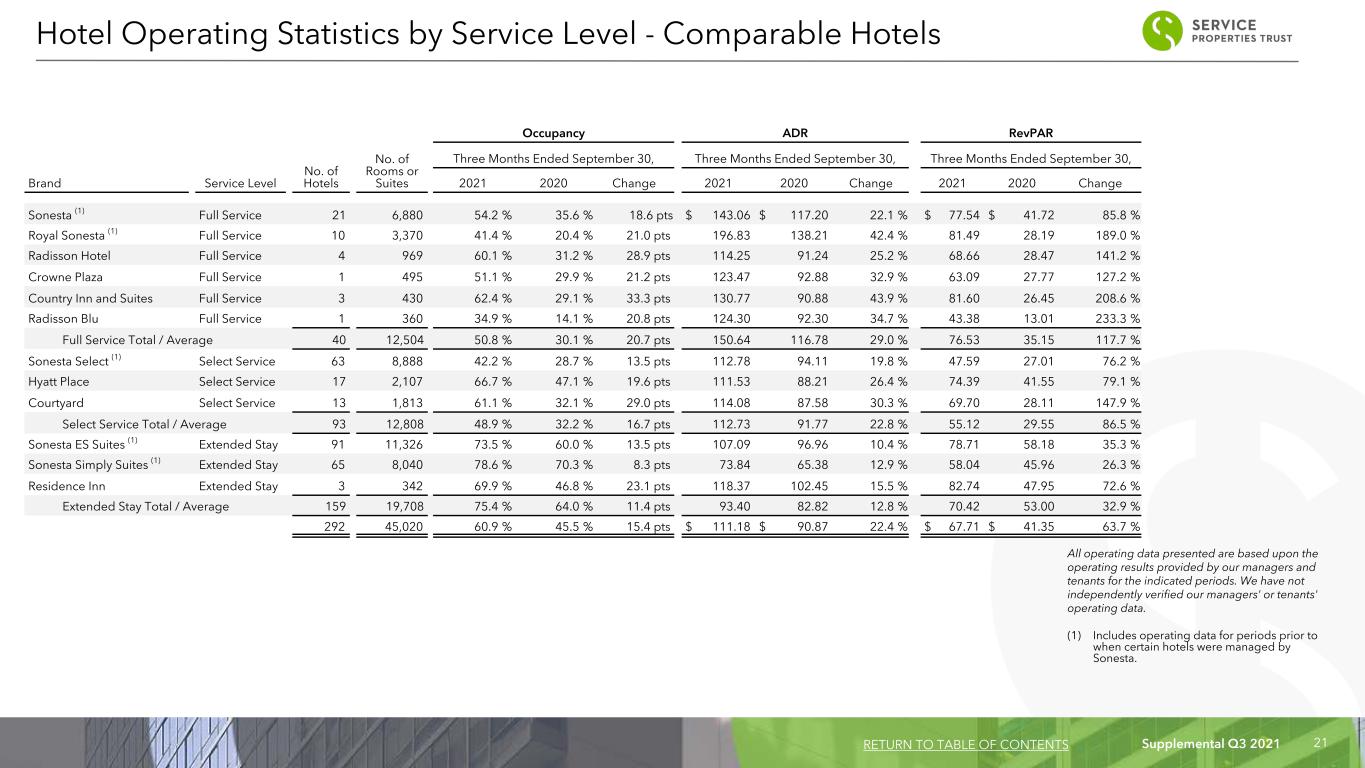
Supplemental Q3 2021 21 Occupancy ADR RevPAR No. of Hotels No. of Rooms or Suites Three Months Ended September 30, Three Months Ended September 30, Three Months Ended September 30, Brand Service Level 2021 2020 Change 2021 2020 Change 2021 2020 Change Sonesta (1) Full Service 21 6,880 54.2 % 35.6 % 18.6 pts $ 143.06 $ 117.20 22.1 % $ 77.54 $ 41.72 85.8 % Royal Sonesta (1) Full Service 10 3,370 41.4 % 20.4 % 21.0 pts 196.83 138.21 42.4 % 81.49 28.19 189.0 % Radisson Hotel Full Service 4 969 60.1 % 31.2 % 28.9 pts 114.25 91.24 25.2 % 68.66 28.47 141.2 % Crowne Plaza Full Service 1 495 51.1 % 29.9 % 21.2 pts 123.47 92.88 32.9 % 63.09 27.77 127.2 % Country Inn and Suites Full Service 3 430 62.4 % 29.1 % 33.3 pts 130.77 90.88 43.9 % 81.60 26.45 208.6 % Radisson Blu Full Service 1 360 34.9 % 14.1 % 20.8 pts 124.30 92.30 34.7 % 43.38 13.01 233.3 % Full Service Total / Average 40 12,504 50.8 % 30.1 % 20.7 pts 150.64 116.78 29.0 % 76.53 35.15 117.7 % Sonesta Select (1) Select Service 63 8,888 42.2 % 28.7 % 13.5 pts 112.78 94.11 19.8 % 47.59 27.01 76.2 % Hyatt Place Select Service 17 2,107 66.7 % 47.1 % 19.6 pts 111.53 88.21 26.4 % 74.39 41.55 79.1 % Courtyard Select Service 13 1,813 61.1 % 32.1 % 29.0 pts 114.08 87.58 30.3 % 69.70 28.11 147.9 % Select Service Total / Average 93 12,808 48.9 % 32.2 % 16.7 pts 112.73 91.77 22.8 % 55.12 29.55 86.5 % Sonesta ES Suites (1) Extended Stay 91 11,326 73.5 % 60.0 % 13.5 pts 107.09 96.96 10.4 % 78.71 58.18 35.3 % Sonesta Simply Suites (1) Extended Stay 65 8,040 78.6 % 70.3 % 8.3 pts 73.84 65.38 12.9 % 58.04 45.96 26.3 % Residence Inn Extended Stay 3 342 69.9 % 46.8 % 23.1 pts 118.37 102.45 15.5 % 82.74 47.95 72.6 % Extended Stay Total / Average 159 19,708 75.4 % 64.0 % 11.4 pts 93.40 82.82 12.8 % 70.42 53.00 32.9 % 292 45,020 60.9 % 45.5 % 15.4 pts $ 111.18 $ 90.87 22.4 % $ 67.71 $ 41.35 63.7 % Hotel Operating Statistics by Service Level - Comparable Hotels RETURN TO TABLE OF CONTENTS All operating data presented are based upon the operating results provided by our managers and tenants for the indicated periods. We have not independently verified our managers' or tenants' operating data. (1) Includes operating data for periods prior to when certain hotels were managed by Sonesta.
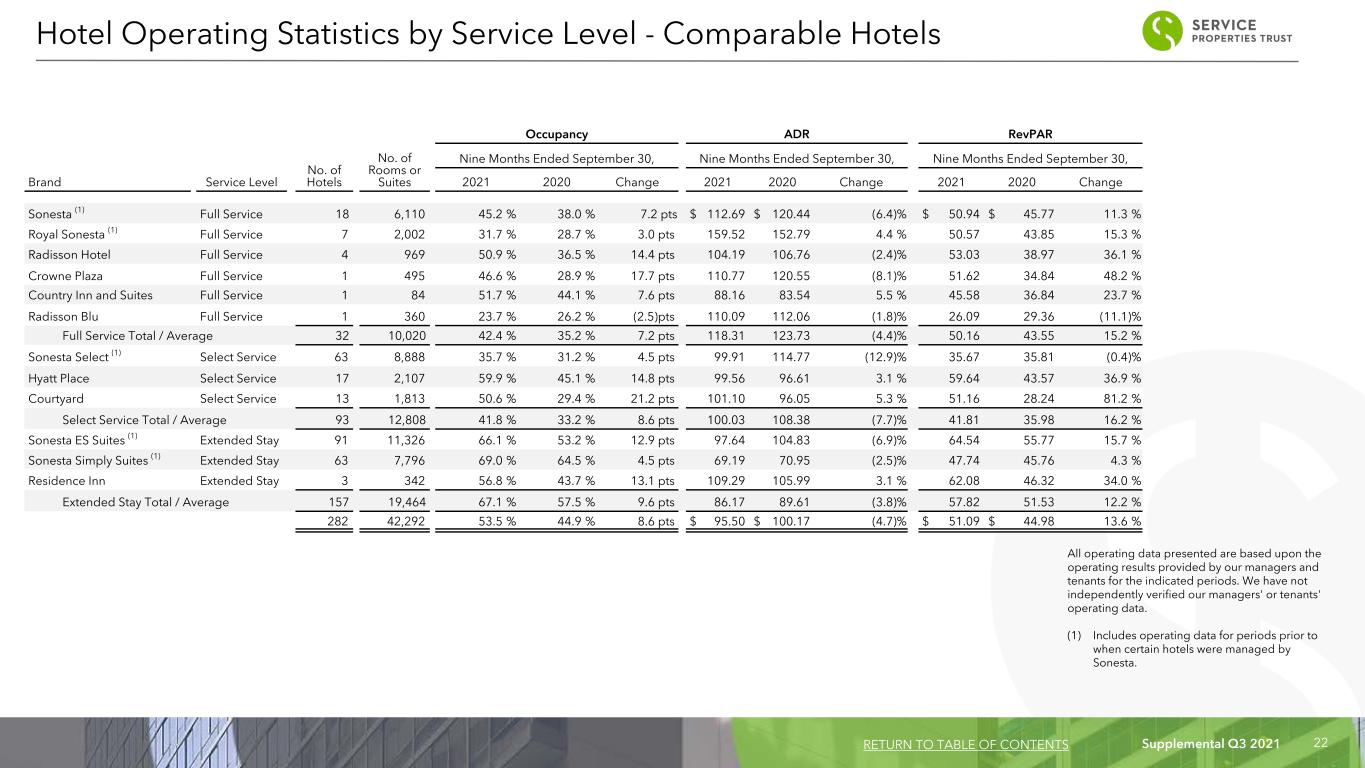
Supplemental Q3 2021 22 All operating data presented are based upon the operating results provided by our managers and tenants for the indicated periods. We have not independently verified our managers' or tenants' operating data. (1) Includes operating data for periods prior to when certain hotels were managed by Sonesta. Occupancy ADR RevPAR No. of Hotels No. of Rooms or Suites Nine Months Ended September 30, Nine Months Ended September 30, Nine Months Ended September 30, Brand Service Level 2021 2020 Change 2021 2020 Change 2021 2020 Change Sonesta (1) Full Service 18 6,110 45.2 % 38.0 % 7.2 pts $ 112.69 $ 120.44 (6.4) % $ 50.94 $ 45.77 11.3 % Royal Sonesta (1) Full Service 7 2,002 31.7 % 28.7 % 3.0 pts 159.52 152.79 4.4 % 50.57 43.85 15.3 % Radisson Hotel Full Service 4 969 50.9 % 36.5 % 14.4 pts 104.19 106.76 (2.4) % 53.03 38.97 36.1 % Crowne Plaza Full Service 1 495 46.6 % 28.9 % 17.7 pts 110.77 120.55 (8.1) % 51.62 34.84 48.2 % Country Inn and Suites Full Service 1 84 51.7 % 44.1 % 7.6 pts 88.16 83.54 5.5 % 45.58 36.84 23.7 % Radisson Blu Full Service 1 360 23.7 % 26.2 % (2.5)pts 110.09 112.06 (1.8) % 26.09 29.36 (11.1) % Full Service Total / Average 32 10,020 42.4 % 35.2 % 7.2 pts 118.31 123.73 (4.4) % 50.16 43.55 15.2 % Sonesta Select (1) Select Service 63 8,888 35.7 % 31.2 % 4.5 pts 99.91 114.77 (12.9) % 35.67 35.81 (0.4) % Hyatt Place Select Service 17 2,107 59.9 % 45.1 % 14.8 pts 99.56 96.61 3.1 % 59.64 43.57 36.9 % Courtyard Select Service 13 1,813 50.6 % 29.4 % 21.2 pts 101.10 96.05 5.3 % 51.16 28.24 81.2 % Select Service Total / Average 93 12,808 41.8 % 33.2 % 8.6 pts 100.03 108.38 (7.7) % 41.81 35.98 16.2 % Sonesta ES Suites (1) Extended Stay 91 11,326 66.1 % 53.2 % 12.9 pts 97.64 104.83 (6.9) % 64.54 55.77 15.7 % Sonesta Simply Suites (1) Extended Stay 63 7,796 69.0 % 64.5 % 4.5 pts 69.19 70.95 (2.5) % 47.74 45.76 4.3 % Residence Inn Extended Stay 3 342 56.8 % 43.7 % 13.1 pts 109.29 105.99 3.1 % 62.08 46.32 34.0 % Extended Stay Total / Average 157 19,464 67.1 % 57.5 % 9.6 pts 86.17 89.61 (3.8) % 57.82 51.53 12.2 % 282 42,292 53.5 % 44.9 % 8.6 pts $ 95.50 $ 100.17 (4.7) % $ 51.09 $ 44.98 13.6 % Hotel Operating Statistics by Service Level - Comparable Hotels RETURN TO TABLE OF CONTENTS
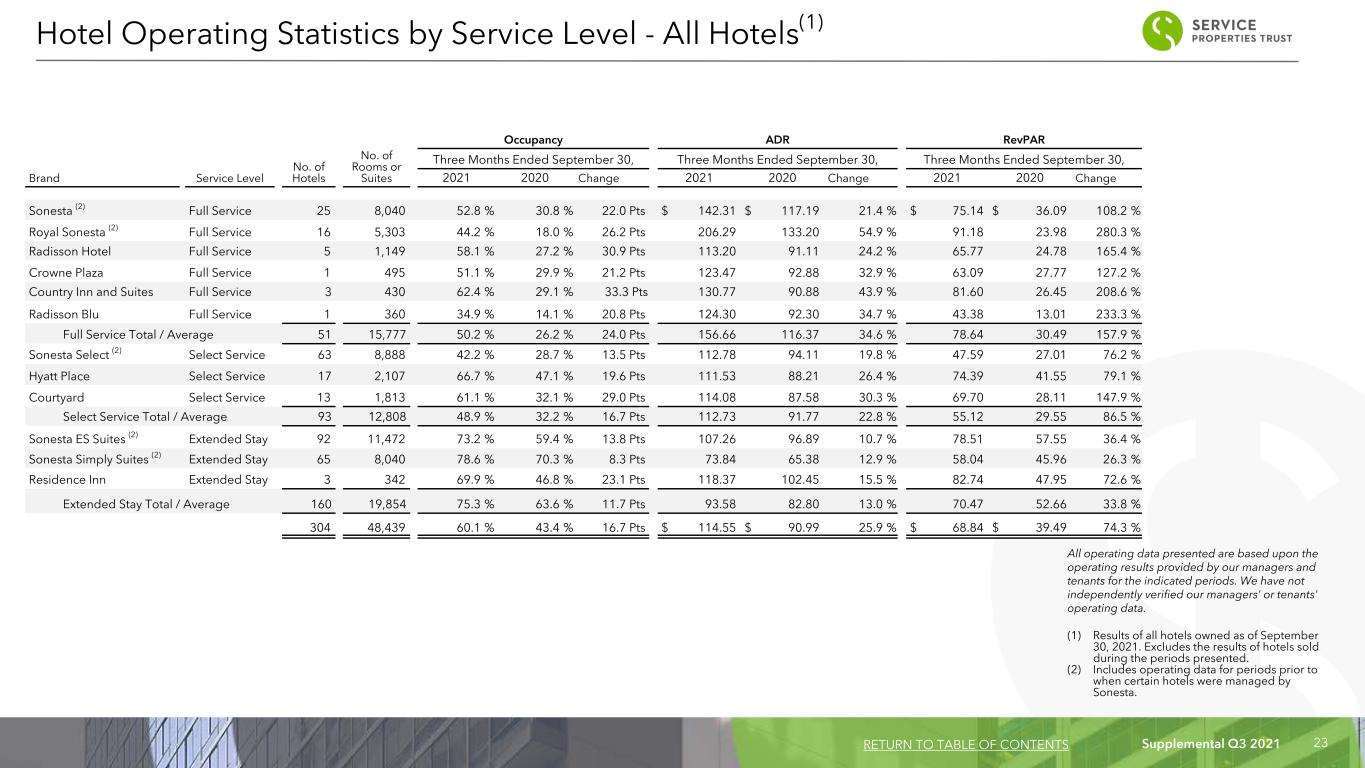
Supplemental Q3 2021 23 No. of Hotels No. of Rooms or Suites Occupancy ADR RevPAR Three Months Ended September 30, Three Months Ended September 30, Three Months Ended September 30, Brand Service Level 2021 2020 Change 2021 2020 Change 2021 2020 Change Sonesta (2) Full Service 25 8,040 52.8 % 30.8 % 22.0 Pts $ 142.31 $ 117.19 21.4 % $ 75.14 $ 36.09 108.2 % Royal Sonesta (2) Full Service 16 5,303 44.2 % 18.0 % 26.2 Pts 206.29 133.20 54.9 % 91.18 23.98 280.3 % Radisson Hotel Full Service 5 1,149 58.1 % 27.2 % 30.9 Pts 113.20 91.11 24.2 % 65.77 24.78 165.4 % Crowne Plaza Full Service 1 495 51.1 % 29.9 % 21.2 Pts 123.47 92.88 32.9 % 63.09 27.77 127.2 % Country Inn and Suites Full Service 3 430 62.4 % 29.1 % 33.3 Pts 130.77 90.88 43.9 % 81.60 26.45 208.6 % Radisson Blu Full Service 1 360 34.9 % 14.1 % 20.8 Pts 124.30 92.30 34.7 % 43.38 13.01 233.3 % Full Service Total / Average 51 15,777 50.2 % 26.2 % 24.0 Pts 156.66 116.37 34.6 % 78.64 30.49 157.9 % Sonesta Select (2) Select Service 63 8,888 42.2 % 28.7 % 13.5 Pts 112.78 94.11 19.8 % 47.59 27.01 76.2 % Hyatt Place Select Service 17 2,107 66.7 % 47.1 % 19.6 Pts 111.53 88.21 26.4 % 74.39 41.55 79.1 % Courtyard Select Service 13 1,813 61.1 % 32.1 % 29.0 Pts 114.08 87.58 30.3 % 69.70 28.11 147.9 % Select Service Total / Average 93 12,808 48.9 % 32.2 % 16.7 Pts 112.73 91.77 22.8 % 55.12 29.55 86.5 % Sonesta ES Suites (2) Extended Stay 92 11,472 73.2 % 59.4 % 13.8 Pts 107.26 96.89 10.7 % 78.51 57.55 36.4 % Sonesta Simply Suites (2) Extended Stay 65 8,040 78.6 % 70.3 % 8.3 Pts 73.84 65.38 12.9 % 58.04 45.96 26.3 % Residence Inn Extended Stay 3 342 69.9 % 46.8 % 23.1 Pts 118.37 102.45 15.5 % 82.74 47.95 72.6 % Extended Stay Total / Average 160 19,854 75.3 % 63.6 % 11.7 Pts 93.58 82.80 13.0 % 70.47 52.66 33.8 % 304 48,439 60.1 % 43.4 % 16.7 Pts $ 114.55 $ 90.99 25.9 % $ 68.84 $ 39.49 74.3 % Hotel Operating Statistics by Service Level - All Hotels(1) RETURN TO TABLE OF CONTENTS All operating data presented are based upon the operating results provided by our managers and tenants for the indicated periods. We have not independently verified our managers' or tenants' operating data. (1) Results of all hotels owned as of September 30, 2021. Excludes the results of hotels sold during the periods presented. (2) Includes operating data for periods prior to when certain hotels were managed by Sonesta.
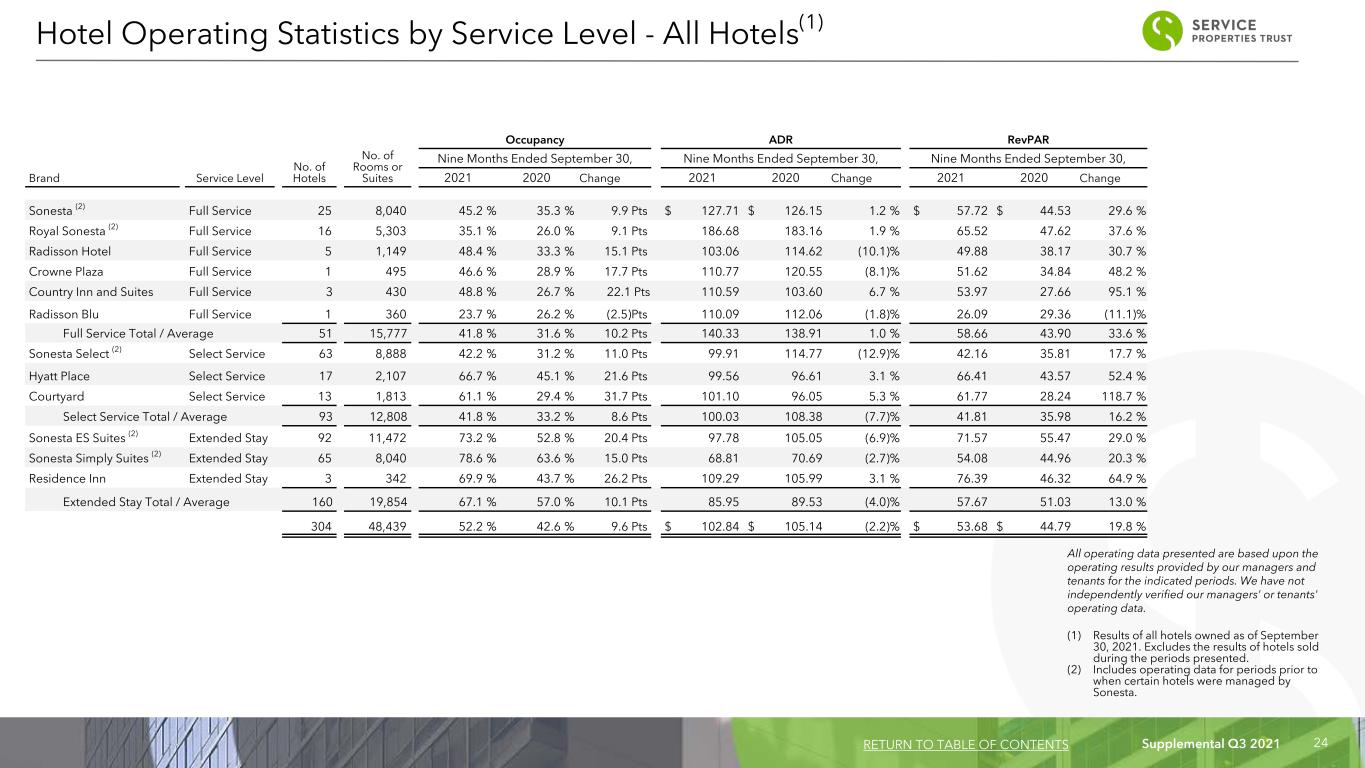
Supplemental Q3 2021 24 No. of Hotels No. of Rooms or Suites Occupancy ADR RevPAR Nine Months Ended September 30, Nine Months Ended September 30, Nine Months Ended September 30, Brand Service Level 2021 2020 Change 2021 2020 Change 2021 2020 Change Sonesta (2) Full Service 25 8,040 45.2 % 35.3 % 9.9 Pts $ 127.71 $ 126.15 1.2 % $ 57.72 $ 44.53 29.6 % Royal Sonesta (2) Full Service 16 5,303 35.1 % 26.0 % 9.1 Pts 186.68 183.16 1.9 % 65.52 47.62 37.6 % Radisson Hotel Full Service 5 1,149 48.4 % 33.3 % 15.1 Pts 103.06 114.62 (10.1) % 49.88 38.17 30.7 % Crowne Plaza Full Service 1 495 46.6 % 28.9 % 17.7 Pts 110.77 120.55 (8.1) % 51.62 34.84 48.2 % Country Inn and Suites Full Service 3 430 48.8 % 26.7 % 22.1 Pts 110.59 103.60 6.7 % 53.97 27.66 95.1 % Radisson Blu Full Service 1 360 23.7 % 26.2 % (2.5)Pts 110.09 112.06 (1.8) % 26.09 29.36 (11.1) % Full Service Total / Average 51 15,777 41.8 % 31.6 % 10.2 Pts 140.33 138.91 1.0 % 58.66 43.90 33.6 % Sonesta Select (2) Select Service 63 8,888 42.2 % 31.2 % 11.0 Pts 99.91 114.77 (12.9) % 42.16 35.81 17.7 % Hyatt Place Select Service 17 2,107 66.7 % 45.1 % 21.6 Pts 99.56 96.61 3.1 % 66.41 43.57 52.4 % Courtyard Select Service 13 1,813 61.1 % 29.4 % 31.7 Pts 101.10 96.05 5.3 % 61.77 28.24 118.7 % Select Service Total / Average 93 12,808 41.8 % 33.2 % 8.6 Pts 100.03 108.38 (7.7) % 41.81 35.98 16.2 % Sonesta ES Suites (2) Extended Stay 92 11,472 73.2 % 52.8 % 20.4 Pts 97.78 105.05 (6.9) % 71.57 55.47 29.0 % Sonesta Simply Suites (2) Extended Stay 65 8,040 78.6 % 63.6 % 15.0 Pts 68.81 70.69 (2.7) % 54.08 44.96 20.3 % Residence Inn Extended Stay 3 342 69.9 % 43.7 % 26.2 Pts 109.29 105.99 3.1 % 76.39 46.32 64.9 % Extended Stay Total / Average 160 19,854 67.1 % 57.0 % 10.1 Pts 85.95 89.53 (4.0) % 57.67 51.03 13.0 % 304 48,439 52.2 % 42.6 % 9.6 Pts $ 102.84 $ 105.14 (2.2) % $ 53.68 $ 44.79 19.8 % Hotel Operating Statistics by Service Level - All Hotels(1) RETURN TO TABLE OF CONTENTS All operating data presented are based upon the operating results provided by our managers and tenants for the indicated periods. We have not independently verified our managers' or tenants' operating data. (1) Results of all hotels owned as of September 30, 2021. Excludes the results of hotels sold during the periods presented. (2) Includes operating data for periods prior to when certain hotels were managed by Sonesta.
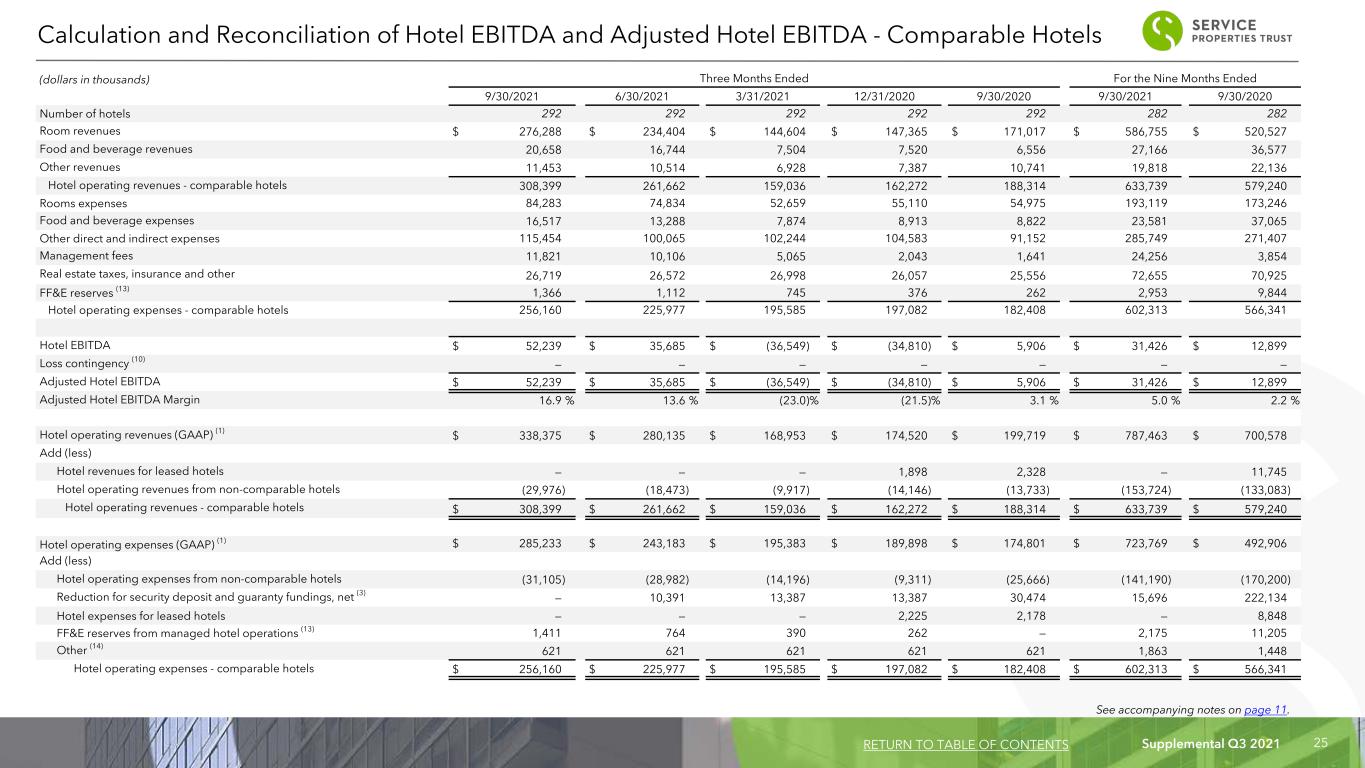
Supplemental Q3 2021 25 (dollars in thousands) Three Months Ended For the Nine Months Ended 9/30/2021 6/30/2021 3/31/2021 12/31/2020 9/30/2020 9/30/2021 9/30/2020 Number of hotels 292 292 292 292 292 282 282 Room revenues $ 276,288 $ 234,404 $ 144,604 $ 147,365 $ 171,017 $ 586,755 $ 520,527 Food and beverage revenues 20,658 16,744 7,504 7,520 6,556 27,166 36,577 Other revenues 11,453 10,514 6,928 7,387 10,741 19,818 22,136 Hotel operating revenues - comparable hotels 308,399 261,662 159,036 162,272 188,314 633,739 579,240 Rooms expenses 84,283 74,834 52,659 55,110 54,975 193,119 173,246 Food and beverage expenses 16,517 13,288 7,874 8,913 8,822 23,581 37,065 Other direct and indirect expenses 115,454 100,065 102,244 104,583 91,152 285,749 271,407 Management fees 11,821 10,106 5,065 2,043 1,641 24,256 3,854 Real estate taxes, insurance and other 26,719 26,572 26,998 26,057 25,556 72,655 70,925 FF&E reserves (13) 1,366 1,112 745 376 262 2,953 9,844 Hotel operating expenses - comparable hotels 256,160 225,977 195,585 197,082 182,408 602,313 566,341 Hotel EBITDA $ 52,239 $ 35,685 $ (36,549) $ (34,810) $ 5,906 $ 31,426 $ 12,899 Loss contingency (10) — — — — — — — Adjusted Hotel EBITDA $ 52,239 $ 35,685 $ (36,549) $ (34,810) $ 5,906 $ 31,426 $ 12,899 Adjusted Hotel EBITDA Margin 16.9 % 13.6 % (23.0) % (21.5) % 3.1 % 5.0 % 2.2 % Hotel operating revenues (GAAP) (1) $ 338,375 $ 280,135 $ 168,953 $ 174,520 $ 199,719 $ 787,463 $ 700,578 Add (less) Hotel revenues for leased hotels — — — 1,898 2,328 — 11,745 Hotel operating revenues from non-comparable hotels (29,976) (18,473) (9,917) (14,146) (13,733) (153,724) (133,083) Hotel operating revenues - comparable hotels $ 308,399 $ 261,662 $ 159,036 $ 162,272 $ 188,314 $ 633,739 $ 579,240 Hotel operating expenses (GAAP) (1) $ 285,233 $ 243,183 $ 195,383 $ 189,898 $ 174,801 $ 723,769 $ 492,906 Add (less) Hotel operating expenses from non-comparable hotels (31,105) (28,982) (14,196) (9,311) (25,666) (141,190) (170,200) Reduction for security deposit and guaranty fundings, net (3) — 10,391 13,387 13,387 30,474 15,696 222,134 Hotel expenses for leased hotels — — — 2,225 2,178 — 8,848 FF&E reserves from managed hotel operations (13) 1,411 764 390 262 — 2,175 11,205 Other (14) 621 621 621 621 621 1,863 1,448 Hotel operating expenses - comparable hotels $ 256,160 $ 225,977 $ 195,585 $ 197,082 $ 182,408 $ 602,313 $ 566,341 Calculation and Reconciliation of Hotel EBITDA and Adjusted Hotel EBITDA - Comparable Hotels RETURN TO TABLE OF CONTENTS See accompanying notes on page 11.
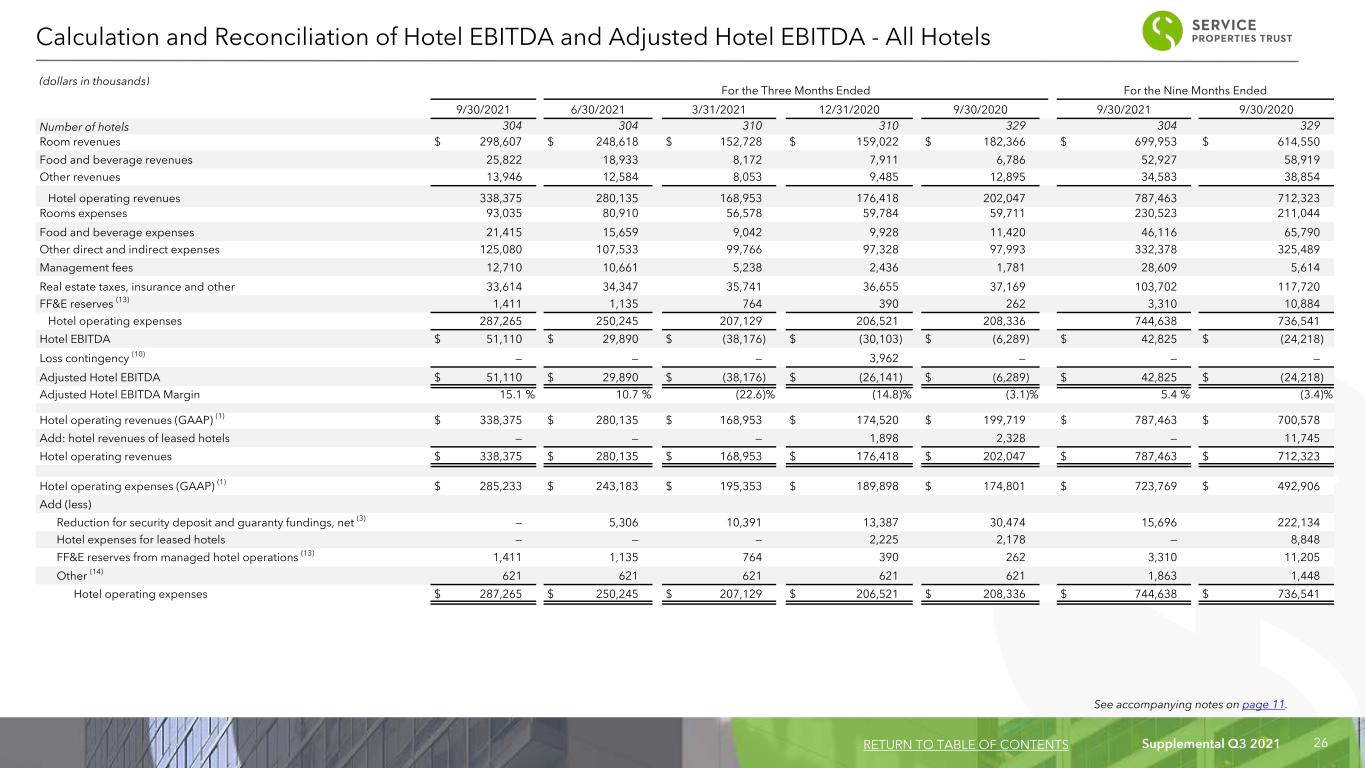
Supplemental Q3 2021 26 (dollars in thousands) For the Three Months Ended For the Nine Months Ended 9/30/2021 6/30/2021 3/31/2021 12/31/2020 9/30/2020 9/30/2021 9/30/2020 Number of hotels 304 304 310 310 329 304 329 Room revenues $ 298,607 $ 248,618 $ 152,728 $ 159,022 $ 182,366 $ 699,953 $ 614,550 Food and beverage revenues 25,822 18,933 8,172 7,911 6,786 52,927 58,919 Other revenues 13,946 12,584 8,053 9,485 12,895 34,583 38,854 Hotel operating revenues 338,375 280,135 168,953 176,418 202,047 787,463 712,323 Rooms expenses 93,035 80,910 56,578 59,784 59,711 230,523 211,044 Food and beverage expenses 21,415 15,659 9,042 9,928 11,420 46,116 65,790 Other direct and indirect expenses 125,080 107,533 99,766 97,328 97,993 332,378 325,489 Management fees 12,710 10,661 5,238 2,436 1,781 28,609 5,614 Real estate taxes, insurance and other 33,614 34,347 35,741 36,655 37,169 103,702 117,720 FF&E reserves (13) 1,411 1,135 764 390 262 3,310 10,884 Hotel operating expenses 287,265 250,245 207,129 206,521 208,336 744,638 736,541 Hotel EBITDA $ 51,110 $ 29,890 $ (38,176) $ (30,103) $ (6,289) $ 42,825 $ (24,218) Loss contingency (10) — — — 3,962 — — — Adjusted Hotel EBITDA $ 51,110 $ 29,890 $ (38,176) $ (26,141) $ (6,289) $ 42,825 $ (24,218) Adjusted Hotel EBITDA Margin 15.1 % 10.7 % (22.6) % (14.8) % (3.1) % 5.4 % (3.4) % Hotel operating revenues (GAAP) (1) $ 338,375 $ 280,135 $ 168,953 $ 174,520 $ 199,719 $ 787,463 $ 700,578 Add: hotel revenues of leased hotels — — — 1,898 2,328 — 11,745 Hotel operating revenues $ 338,375 $ 280,135 $ 168,953 $ 176,418 $ 202,047 $ 787,463 $ 712,323 Hotel operating expenses (GAAP) (1) $ 285,233 $ 243,183 $ 195,353 $ 189,898 $ 174,801 $ 723,769 $ 492,906 Add (less) Reduction for security deposit and guaranty fundings, net (3) — 5,306 10,391 13,387 30,474 15,696 222,134 Hotel expenses for leased hotels — — — 2,225 2,178 — 8,848 FF&E reserves from managed hotel operations (13) 1,411 1,135 764 390 262 3,310 11,205 Other (14) 621 621 621 621 621 1,863 1,448 Hotel operating expenses $ 287,265 $ 250,245 $ 207,129 $ 206,521 $ 208,336 $ 744,638 $ 736,541 Calculation and Reconciliation of Hotel EBITDA and Adjusted Hotel EBITDA - All Hotels RETURN TO TABLE OF CONTENTS See accompanying notes on page 11.
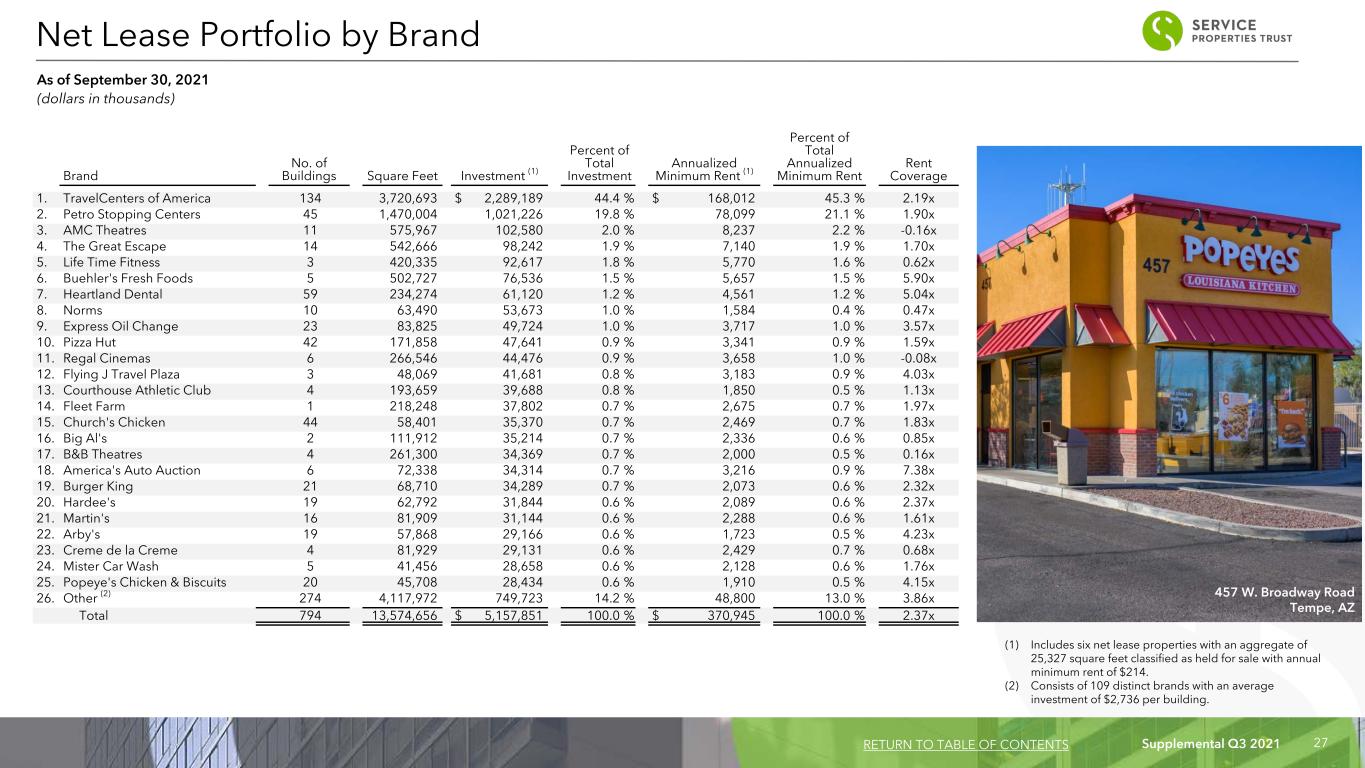
Supplemental Q3 2021 27 Brand No. of Buildings Square Feet Investment (1) Percent of Total Investment Annualized Minimum Rent (1) Percent of Total Annualized Minimum Rent Rent Coverage 1. TravelCenters of America 134 3,720,693 $ 2,289,189 44.4 % $ 168,012 45.3 % 2.19x 2. Petro Stopping Centers 45 1,470,004 1,021,226 19.8 % 78,099 21.1 % 1.90x 3. AMC Theatres 11 575,967 102,580 2.0 % 8,237 2.2 % -0.16x 4. The Great Escape 14 542,666 98,242 1.9 % 7,140 1.9 % 1.70x 5. Life Time Fitness 3 420,335 92,617 1.8 % 5,770 1.6 % 0.62x 6. Buehler's Fresh Foods 5 502,727 76,536 1.5 % 5,657 1.5 % 5.90x 7. Heartland Dental 59 234,274 61,120 1.2 % 4,561 1.2 % 5.04x 8. Norms 10 63,490 53,673 1.0 % 1,584 0.4 % 0.47x 9. Express Oil Change 23 83,825 49,724 1.0 % 3,717 1.0 % 3.57x 10. Pizza Hut 42 171,858 47,641 0.9 % 3,341 0.9 % 1.59x 11. Regal Cinemas 6 266,546 44,476 0.9 % 3,658 1.0 % -0.08x 12. Flying J Travel Plaza 3 48,069 41,681 0.8 % 3,183 0.9 % 4.03x 13. Courthouse Athletic Club 4 193,659 39,688 0.8 % 1,850 0.5 % 1.13x 14. Fleet Farm 1 218,248 37,802 0.7 % 2,675 0.7 % 1.97x 15. Church's Chicken 44 58,401 35,370 0.7 % 2,469 0.7 % 1.83x 16. Big Al's 2 111,912 35,214 0.7 % 2,336 0.6 % 0.85x 17. B&B Theatres 4 261,300 34,369 0.7 % 2,000 0.5 % 0.16x 18. America's Auto Auction 6 72,338 34,314 0.7 % 3,216 0.9 % 7.38x 19. Burger King 21 68,710 34,289 0.7 % 2,073 0.6 % 2.32x 20. Hardee's 19 62,792 31,844 0.6 % 2,089 0.6 % 2.37x 21. Martin's 16 81,909 31,144 0.6 % 2,288 0.6 % 1.61x 22. Arby's 19 57,868 29,166 0.6 % 1,723 0.5 % 4.23x 23. Creme de la Creme 4 81,929 29,131 0.6 % 2,429 0.7 % 0.68x 24. Mister Car Wash 5 41,456 28,658 0.6 % 2,128 0.6 % 1.76x 25. Popeye's Chicken & Biscuits 20 45,708 28,434 0.6 % 1,910 0.5 % 4.15x 26. Other (2) 274 4,117,972 749,723 14.2 % 48,800 13.0 % 3.86x Total 794 13,574,656 $ 5,157,851 100.0 % $ 370,945 100.0 % 2.37x (1) Includes six net lease properties with an aggregate of 25,327 square feet classified as held for sale with annual minimum rent of $214. (2) Consists of 109 distinct brands with an average investment of $2,736 per building. Net Lease Portfolio by Brand As of September 30, 2021 (dollars in thousands) RETURN TO TABLE OF CONTENTS 457 W. Broadway Road Tempe, AZ
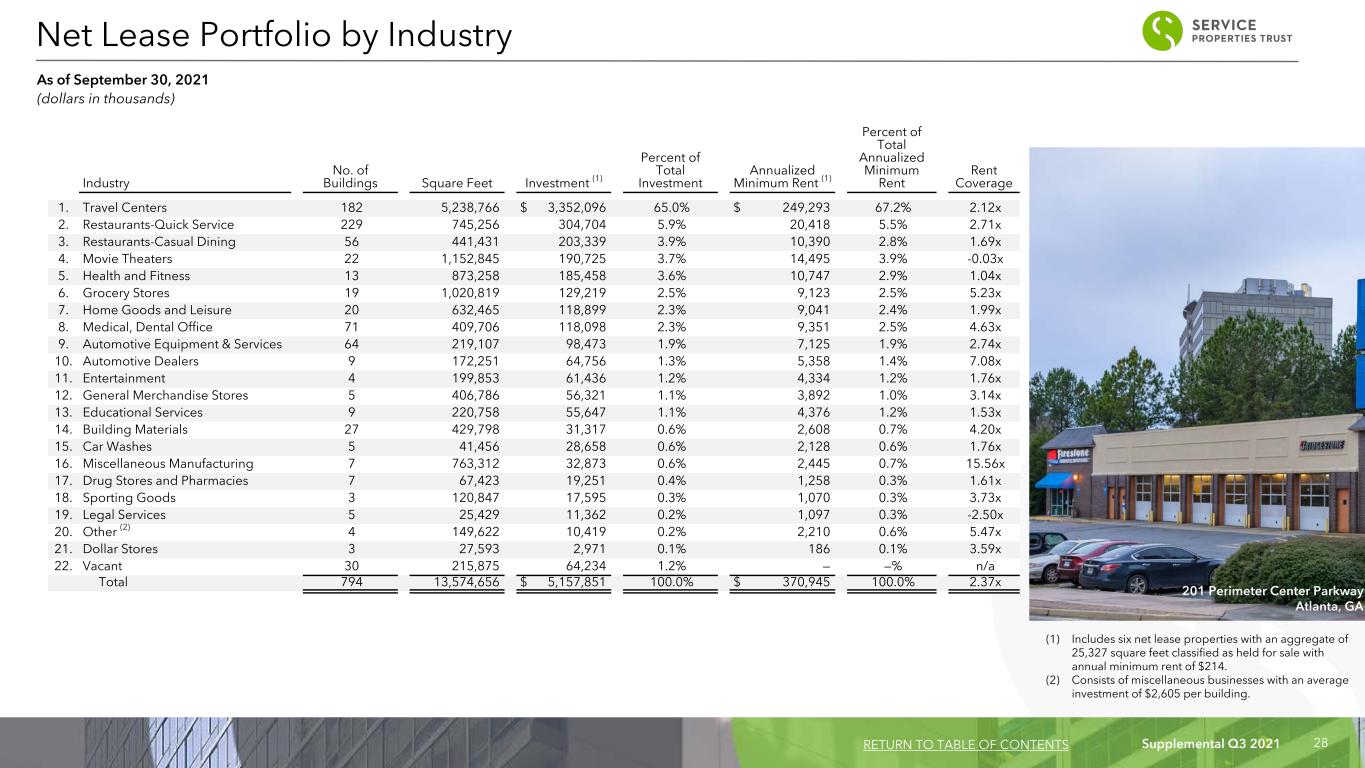
Supplemental Q3 2021 28 Industry No. of Buildings Square Feet Investment (1) Percent of Total Investment Annualized Minimum Rent (1) Percent of Total Annualized Minimum Rent Rent Coverage 1. Travel Centers 182 5,238,766 $ 3,352,096 65.0% $ 249,293 67.2% 2.12x 2. Restaurants-Quick Service 229 745,256 304,704 5.9% 20,418 5.5% 2.71x 3. Restaurants-Casual Dining 56 441,431 203,339 3.9% 10,390 2.8% 1.69x 4. Movie Theaters 22 1,152,845 190,725 3.7% 14,495 3.9% -0.03x 5. Health and Fitness 13 873,258 185,458 3.6% 10,747 2.9% 1.04x 6. Grocery Stores 19 1,020,819 129,219 2.5% 9,123 2.5% 5.23x 7. Home Goods and Leisure 20 632,465 118,899 2.3% 9,041 2.4% 1.99x 8. Medical, Dental Office 71 409,706 118,098 2.3% 9,351 2.5% 4.63x 9. Automotive Equipment & Services 64 219,107 98,473 1.9% 7,125 1.9% 2.74x 10. Automotive Dealers 9 172,251 64,756 1.3% 5,358 1.4% 7.08x 11. Entertainment 4 199,853 61,436 1.2% 4,334 1.2% 1.76x 12. General Merchandise Stores 5 406,786 56,321 1.1% 3,892 1.0% 3.14x 13. Educational Services 9 220,758 55,647 1.1% 4,376 1.2% 1.53x 14. Building Materials 27 429,798 31,317 0.6% 2,608 0.7% 4.20x 15. Car Washes 5 41,456 28,658 0.6% 2,128 0.6% 1.76x 16. Miscellaneous Manufacturing 7 763,312 32,873 0.6% 2,445 0.7% 15.56x 17. Drug Stores and Pharmacies 7 67,423 19,251 0.4% 1,258 0.3% 1.61x 18. Sporting Goods 3 120,847 17,595 0.3% 1,070 0.3% 3.73x 19. Legal Services 5 25,429 11,362 0.2% 1,097 0.3% -2.50x 20. Other (2) 4 149,622 10,419 0.2% 2,210 0.6% 5.47x 21. Dollar Stores 3 27,593 2,971 0.1% 186 0.1% 3.59x 22. Vacant 30 215,875 64,234 1.2% — —% n/a Total 794 13,574,656 $ 5,157,851 100.0% $ 370,945 100.0% 2.37x (1) Includes six net lease properties with an aggregate of 25,327 square feet classified as held for sale with annual minimum rent of $214. (2) Consists of miscellaneous businesses with an average investment of $2,605 per building. Net Lease Portfolio by Industry As of September 30, 2021 (dollars in thousands) RETURN TO TABLE OF CONTENTS 201 Perimeter Center Parkway Atlanta, GA
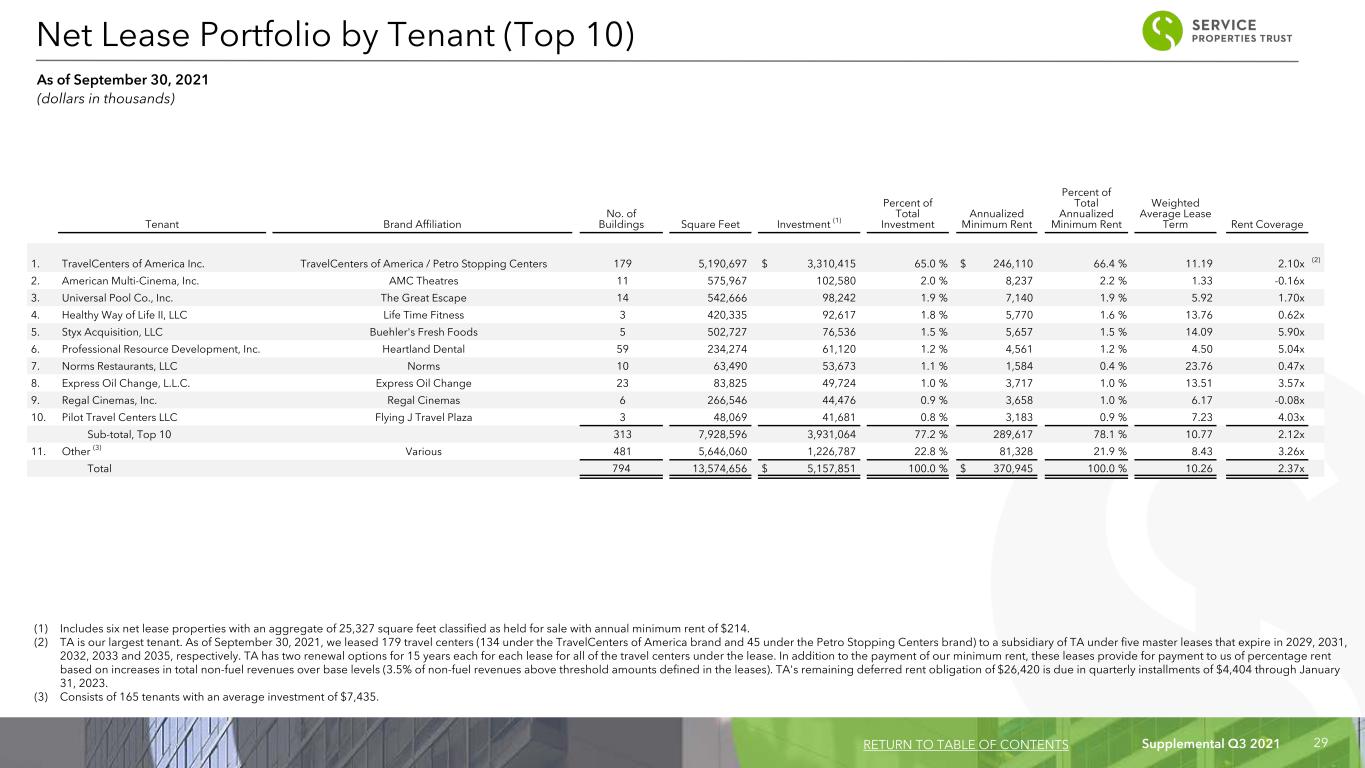
Supplemental Q3 2021 29 Tenant Brand Affiliation No. of Buildings Square Feet Investment (1) Percent of Total Investment Annualized Minimum Rent Percent of Total Annualized Minimum Rent Weighted Average Lease Term Rent Coverage 1. TravelCenters of America Inc. TravelCenters of America / Petro Stopping Centers 179 5,190,697 $ 3,310,415 65.0 % $ 246,110 66.4 % 11.19 2.10x (2) 2. American Multi-Cinema, Inc. AMC Theatres 11 575,967 102,580 2.0 % 8,237 2.2 % 1.33 -0.16x 3. Universal Pool Co., Inc. The Great Escape 14 542,666 98,242 1.9 % 7,140 1.9 % 5.92 1.70x 4. Healthy Way of Life II, LLC Life Time Fitness 3 420,335 92,617 1.8 % 5,770 1.6 % 13.76 0.62x 5. Styx Acquisition, LLC Buehler's Fresh Foods 5 502,727 76,536 1.5 % 5,657 1.5 % 14.09 5.90x 6. Professional Resource Development, Inc. Heartland Dental 59 234,274 61,120 1.2 % 4,561 1.2 % 4.50 5.04x 7. Norms Restaurants, LLC Norms 10 63,490 53,673 1.1 % 1,584 0.4 % 23.76 0.47x 8. Express Oil Change, L.L.C. Express Oil Change 23 83,825 49,724 1.0 % 3,717 1.0 % 13.51 3.57x 9. Regal Cinemas, Inc. Regal Cinemas 6 266,546 44,476 0.9 % 3,658 1.0 % 6.17 -0.08x 10. Pilot Travel Centers LLC Flying J Travel Plaza 3 48,069 41,681 0.8 % 3,183 0.9 % 7.23 4.03x Sub-total, Top 10 313 7,928,596 3,931,064 77.2 % 289,617 78.1 % 10.77 2.12x 11. Other (3) Various 481 5,646,060 1,226,787 22.8 % 81,328 21.9 % 8.43 3.26x Total 794 13,574,656 $ 5,157,851 100.0 % $ 370,945 100.0 % 10.26 2.37x (1) Includes six net lease properties with an aggregate of 25,327 square feet classified as held for sale with annual minimum rent of $214. (2) TA is our largest tenant. As of September 30, 2021, we leased 179 travel centers (134 under the TravelCenters of America brand and 45 under the Petro Stopping Centers brand) to a subsidiary of TA under five master leases that expire in 2029, 2031, 2032, 2033 and 2035, respectively. TA has two renewal options for 15 years each for each lease for all of the travel centers under the lease. In addition to the payment of our minimum rent, these leases provide for payment to us of percentage rent based on increases in total non-fuel revenues over base levels (3.5% of non-fuel revenues above threshold amounts defined in the leases). TA's remaining deferred rent obligation of $26,420 is due in quarterly installments of $4,404 through January 31, 2023. (3) Consists of 165 tenants with an average investment of $7,435. Net Lease Portfolio by Tenant (Top 10) As of September 30, 2021 (dollars in thousands) RETURN TO TABLE OF CONTENTS
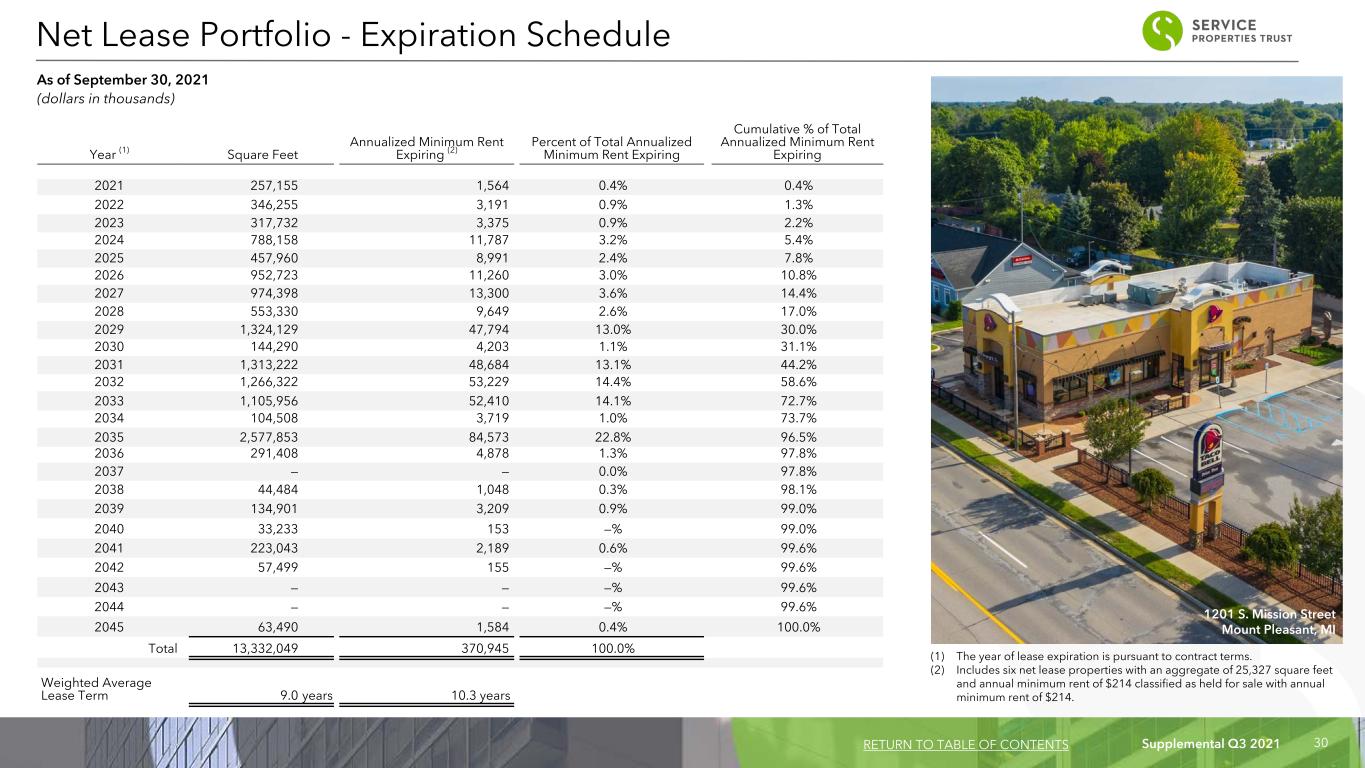
Supplemental Q3 2021 30 Year (1) Square Feet Annualized Minimum Rent Expiring (2) Percent of Total Annualized Minimum Rent Expiring Cumulative % of Total Annualized Minimum Rent Expiring 2021 257,155 1,564 0.4% 0.4% 2022 346,255 3,191 0.9% 1.3% 2023 317,732 3,375 0.9% 2.2% 2024 788,158 11,787 3.2% 5.4% 2025 457,960 8,991 2.4% 7.8% 2026 952,723 11,260 3.0% 10.8% 2027 974,398 13,300 3.6% 14.4% 2028 553,330 9,649 2.6% 17.0% 2029 1,324,129 47,794 13.0% 30.0% 2030 144,290 4,203 1.1% 31.1% 2031 1,313,222 48,684 13.1% 44.2% 2032 1,266,322 53,229 14.4% 58.6% 2033 1,105,956 52,410 14.1% 72.7% 2034 104,508 3,719 1.0% 73.7% 2035 2,577,853 84,573 22.8% 96.5% 2036 291,408 4,878 1.3% 97.8% 2037 — — 0.0% 97.8% 2038 44,484 1,048 0.3% 98.1% 2039 134,901 3,209 0.9% 99.0% 2040 33,233 153 —% 99.0% 2041 223,043 2,189 0.6% 99.6% 2042 57,499 155 —% 99.6% 2043 — — —% 99.6% 2044 — — —% 99.6% 2045 63,490 1,584 0.4% 100.0% Total 13,332,049 370,945 100.0% Weighted Average Lease Term 9.0 years 10.3 years (1) The year of lease expiration is pursuant to contract terms. (2) Includes six net lease properties with an aggregate of 25,327 square feet and annual minimum rent of $214 classified as held for sale with annual minimum rent of $214. Net Lease Portfolio - Expiration Schedule As of September 30, 2021 (dollars in thousands) RETURN TO TABLE OF CONTENTS 1201 S. Mission Street Mount Pleasant, MI
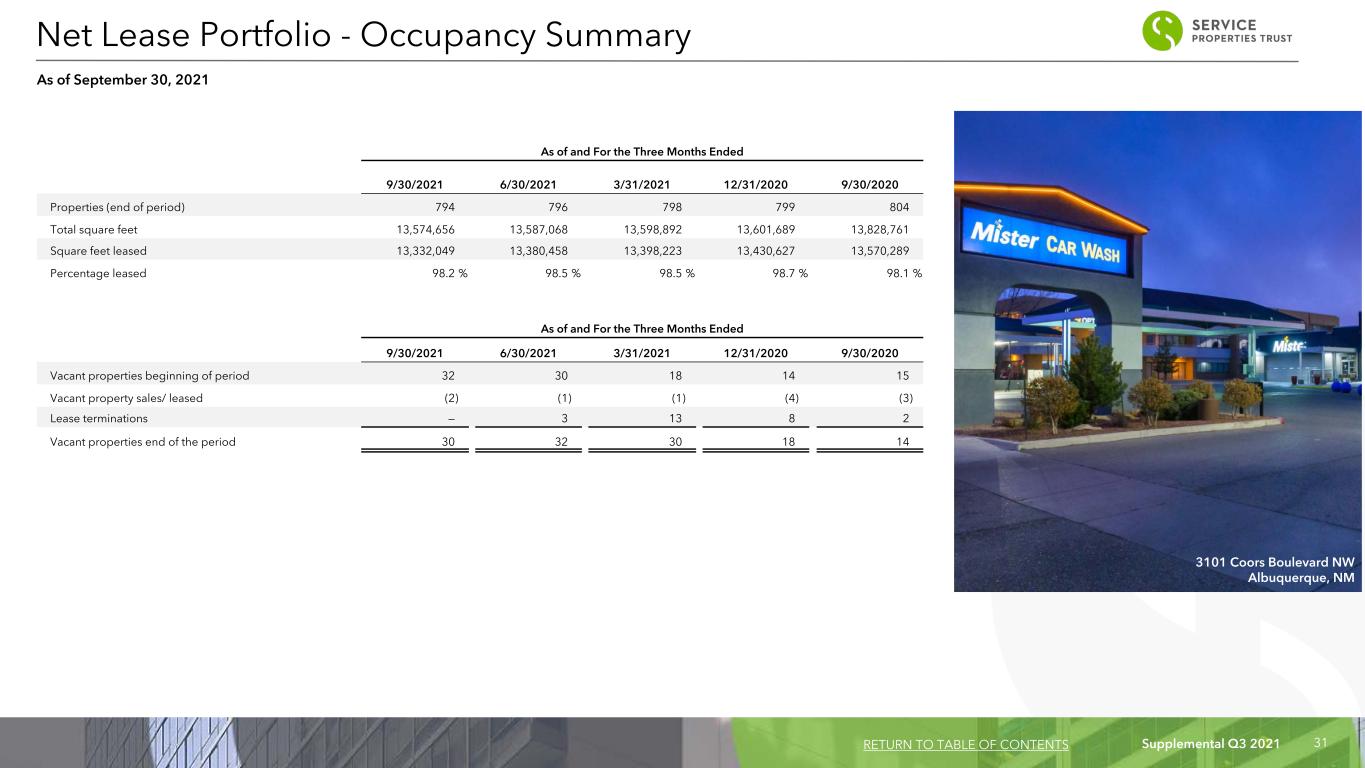
Supplemental Q3 2021 31 As of and For the Three Months Ended 9/30/2021 6/30/2021 3/31/2021 12/31/2020 9/30/2020 Properties (end of period) 794 796 798 799 804 Total square feet 13,574,656 13,587,068 13,598,892 13,601,689 13,828,761 Square feet leased 13,332,049 13,380,458 13,398,223 13,430,627 13,570,289 Percentage leased 98.2 % 98.5 % 98.5 % 98.7 % 98.1 % As of and For the Three Months Ended 9/30/2021 6/30/2021 3/31/2021 12/31/2020 9/30/2020 Vacant properties beginning of period 32 30 18 14 15 Vacant property sales/ leased (2) (1) (1) (4) (3) Lease terminations — 3 13 8 2 Vacant properties end of the period 30 32 30 18 14 Net Lease Portfolio - Occupancy Summary As of September 30, 2021 RETURN TO TABLE OF CONTENTS 3101 Coors Boulevard NW Albuquerque, NM
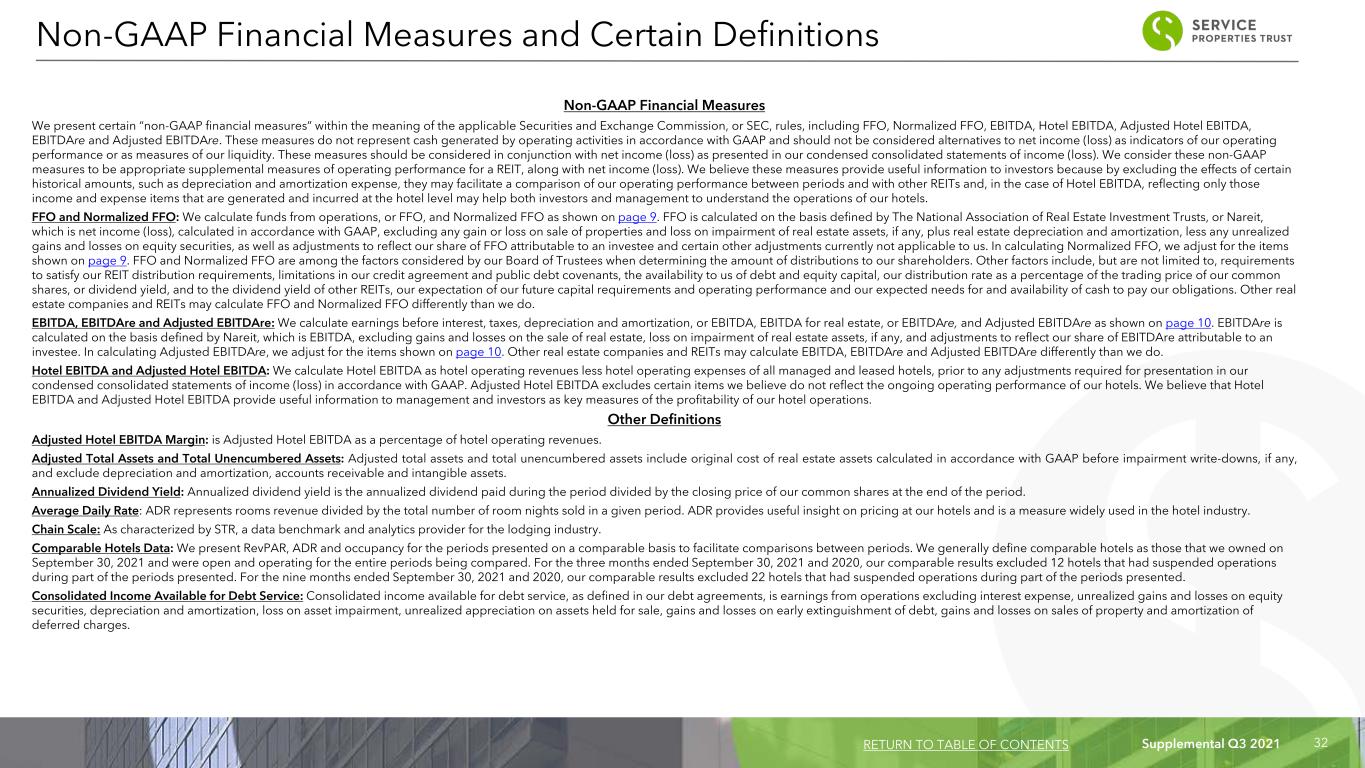
Supplemental Q3 2021 32 Non-GAAP Financial Measures We present certain “non-GAAP financial measures” within the meaning of the applicable Securities and Exchange Commission, or SEC, rules, including FFO, Normalized FFO, EBITDA, Hotel EBITDA, Adjusted Hotel EBITDA, EBITDAre and Adjusted EBITDAre. These measures do not represent cash generated by operating activities in accordance with GAAP and should not be considered alternatives to net income (loss) as indicators of our operating performance or as measures of our liquidity. These measures should be considered in conjunction with net income (loss) as presented in our condensed consolidated statements of income (loss). We consider these non-GAAP measures to be appropriate supplemental measures of operating performance for a REIT, along with net income (loss). We believe these measures provide useful information to investors because by excluding the effects of certain historical amounts, such as depreciation and amortization expense, they may facilitate a comparison of our operating performance between periods and with other REITs and, in the case of Hotel EBITDA, reflecting only those income and expense items that are generated and incurred at the hotel level may help both investors and management to understand the operations of our hotels. FFO and Normalized FFO: We calculate funds from operations, or FFO, and Normalized FFO as shown on page 9. FFO is calculated on the basis defined by The National Association of Real Estate Investment Trusts, or Nareit, which is net income (loss), calculated in accordance with GAAP, excluding any gain or loss on sale of properties and loss on impairment of real estate assets, if any, plus real estate depreciation and amortization, less any unrealized gains and losses on equity securities, as well as adjustments to reflect our share of FFO attributable to an investee and certain other adjustments currently not applicable to us. In calculating Normalized FFO, we adjust for the items shown on page 9. FFO and Normalized FFO are among the factors considered by our Board of Trustees when determining the amount of distributions to our shareholders. Other factors include, but are not limited to, requirements to satisfy our REIT distribution requirements, limitations in our credit agreement and public debt covenants, the availability to us of debt and equity capital, our distribution rate as a percentage of the trading price of our common shares, or dividend yield, and to the dividend yield of other REITs, our expectation of our future capital requirements and operating performance and our expected needs for and availability of cash to pay our obligations. Other real estate companies and REITs may calculate FFO and Normalized FFO differently than we do. EBITDA, EBITDAre and Adjusted EBITDAre: We calculate earnings before interest, taxes, depreciation and amortization, or EBITDA, EBITDA for real estate, or EBITDAre, and Adjusted EBITDAre as shown on page 10. EBITDAre is calculated on the basis defined by Nareit, which is EBITDA, excluding gains and losses on the sale of real estate, loss on impairment of real estate assets, if any, and adjustments to reflect our share of EBITDAre attributable to an investee. In calculating Adjusted EBITDAre, we adjust for the items shown on page 10. Other real estate companies and REITs may calculate EBITDA, EBITDAre and Adjusted EBITDAre differently than we do. Hotel EBITDA and Adjusted Hotel EBITDA: We calculate Hotel EBITDA as hotel operating revenues less hotel operating expenses of all managed and leased hotels, prior to any adjustments required for presentation in our condensed consolidated statements of income (loss) in accordance with GAAP. Adjusted Hotel EBITDA excludes certain items we believe do not reflect the ongoing operating performance of our hotels. We believe that Hotel EBITDA and Adjusted Hotel EBITDA provide useful information to management and investors as key measures of the profitability of our hotel operations. Other Definitions Adjusted Hotel EBITDA Margin: is Adjusted Hotel EBITDA as a percentage of hotel operating revenues. Adjusted Total Assets and Total Unencumbered Assets: Adjusted total assets and total unencumbered assets include original cost of real estate assets calculated in accordance with GAAP before impairment write-downs, if any, and exclude depreciation and amortization, accounts receivable and intangible assets. Annualized Dividend Yield: Annualized dividend yield is the annualized dividend paid during the period divided by the closing price of our common shares at the end of the period. Average Daily Rate: ADR represents rooms revenue divided by the total number of room nights sold in a given period. ADR provides useful insight on pricing at our hotels and is a measure widely used in the hotel industry. Chain Scale: As characterized by STR, a data benchmark and analytics provider for the lodging industry. Comparable Hotels Data: We present RevPAR, ADR and occupancy for the periods presented on a comparable basis to facilitate comparisons between periods. We generally define comparable hotels as those that we owned on September 30, 2021 and were open and operating for the entire periods being compared. For the three months ended September 30, 2021 and 2020, our comparable results excluded 12 hotels that had suspended operations during part of the periods presented. For the nine months ended September 30, 2021 and 2020, our comparable results excluded 22 hotels that had suspended operations during part of the periods presented. Consolidated Income Available for Debt Service: Consolidated income available for debt service, as defined in our debt agreements, is earnings from operations excluding interest expense, unrealized gains and losses on equity securities, depreciation and amortization, loss on asset impairment, unrealized appreciation on assets held for sale, gains and losses on early extinguishment of debt, gains and losses on sales of property and amortization of deferred charges. Non-GAAP Financial Measures and Certain Definitions RETURN TO TABLE OF CONTENTS
Supplemental Q3 2021 33 Debt: Debt amounts reflect the principal balance as of the date reported. Net debt means total debt less unrestricted cash and cash equivalents as of the date reported. FF&E Reserve: Various percentages of total sales at certain of our hotels are escrowed as reserves for future renovations or refurbishments, or FF&E reserve escrows. We own all the FF&E reserve escrows for our hotels. FF&E Reserve Deposits Not Funded by Hotel Operations: The operating agreements for our hotels generally provide that, if necessary, we will provide FF&E funding in excess of escrowed reserves. To the extent we make such fundings, our contractual annual minimum returns or rents generally increase by a percentage of the amounts we fund. Gross Book Value of Real Estate Assets: Gross book value of real estate assets is real estate properties at cost plus acquisition related costs, if any, before purchase price allocations, less impairment write-downs, if any. Investment: We define hotel investment as historical cost of our properties plus capital improvements funded by us less impairment write-downs, if any, and excludes capital improvements made from FF&E reserves funded from hotel operations that do not result in increases in minimum returns or rents. We define net lease investment as historical cost of our properties plus capital improvements funded by us less impairment write-downs, if any. Minimum Return/Rent: Each of our management agreements or leases with hotel operators provides for payment to us of an annual minimum return or minimum rent, respectively. Certain of these minimum payment amounts are secured by full or limited guarantees or security deposits. In addition, certain of our hotel management agreements provide for payment to us of additional amounts to the extent of available cash flows as defined in the management agreement. Payments of these additional amounts are not guaranteed or secured by deposits. Each of our agreements with our net lease tenants provides for payment to us of minimum rent. Certain of these minimum payment amounts are secured by full or limited guarantees. Annualized minimum rent amounts represent cash rent amounts due to us and exclude adjustments, if any, necessary to record scheduled rent changes under certain of our leases, the deferred rent obligations payable to us under our leases with TA and the estimated future payments to us under our TA leases for the cost of removing underground storage tanks at our travel centers on a straight line basis or any reimbursement of expenses paid by us. Occupancy: Occupancy represents the total number of room nights sold divided by the total number of room nights available at a hotel or group of hotels. Occupancy is an important measure of the utilization rate and demand of our hotels. Rent Coverage: We define rent coverage as earnings before interest, taxes, depreciation, amortization and rent, or EBITDAR, divided by the annual minimum rent due to us weighted by the minimum rent of the property to total minimum rents of the net lease portfolio. EBITDAR amounts used to determine rent coverage are generally for the latest twelve-month period reported based on the most recent operating information, if any, furnished by the tenant. Operating statements furnished by the tenant often are unaudited and, in certain cases, may not have been prepared in accordance with GAAP and are not independently verified by us. Tenants that do not report operating information are excluded from the rent coverage calculations. In instances where we do not have financial information for the most recent quarter from our tenants, we have calculated an implied EBITDAR for the 2021 third quarter using industry benchmark data to reflect current operating trends. We believe using this industry benchmark data provides a reasonable estimate of recent operating results and rent coverage for those tenants. Revenue per Available Room: RevPAR represents rooms revenue divided by the total number of room nights available to guests for a given period. RevPAR is an industry metric correlated to occupancy and ADR and helps measure revenue performance over comparable periods. Total Gross Assets: Total gross assets is total assets plus accumulated depreciation. Non-GAAP Financial Measures and Certain Definitions (Continued) RETURN TO TABLE OF CONTENTS
Supplemental Q3 2021 34 This supplemental operating and financial data may contain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 and other securities laws. Whenever we use words such as “believe,” “expect,” “anticipate,” “intend,” “plan,” “estimate,” “will,” “may” and negatives or derivatives of these or similar expressions, we are making forward-looking statements. These forward-looking statements are based upon our present intent, beliefs or expectations, but forward-looking statements are not guaranteed to occur and may not occur. Actual results may differ materially from those contained in or implied by our forward-looking statements. Forward-looking statements involve known and unknown risks, uncertainties and other factors, some of which are beyond our control. The information contained in our filings with the SEC, including under “Risk Factors” in our periodic reports, or incorporated therein, identifies important factors that could cause our actual results to differ materially from those stated in or implied by our forward-looking statements. Our filings with the SEC are available on the SEC's website at www.sec.gov. You should not place undue reliance upon our forward-looking statements. Except as required by law, we do not intend to update or change any forward-looking statements as a result of new information, future events or otherwise. Warning Concerning Forward-Looking Statements RETURN TO TABLE OF CONTENTS