
Fifth Third Bancorp 8-K, filed Oct 19, 2026
Fifth Third Bancorp (FITB)
8-K
2026-10-19
For: 2026-10-19
View Original
Added on
October 19, 2026
About this 8-K
Fifth Third Bancorp filed this 8-K on October 19, 2026.
Fifth Third Bancorp reported third quarter 2026 net income available to common shareholders of $828 million ($0.90 diluted EPS), with adjusted EPS of $1.13 and adjusted ROTCE of 20.6%. Net interest income rose 3% sequentially to $2,276 million after the completed Comerica systems conversion. AI summary
Items reported
- Item 2.02: Financial results
- Item 7.01: Regulation FD disclosure
- Item 9.01: Financial statements and exhibits
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, DC 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(D)
OF THE SECURITIES EXCHANGE ACT OF 1934
Date of report (Date of earliest event reported): October 19, 2026

(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||||||||
| , | , | |||||||||||||||||||
| (Address of Principal Executive Offices) | (Zip Code) | |||||||||||||||||||
(800 ) 972-3030
(Registrant's telephone number, including area code)
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below)
| Securities registered pursuant to Section 12(b) of the Act: | ||||||||||||||
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
| NYSE Texas | ||||||||||||||
| Depositary Shares Representing a 1/1000th Ownership Interest in a Share of | ||||||||||||||
| Depositary Shares Representing a 1/40th Ownership Interest in a Share of | ||||||||||||||
| Depositary Shares Representing a 1/1000th Ownership Interest in a Share of | ||||||||||||||
| Depositary Shares Representing a 1/40th Ownership Interest in a Share of | ||||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition.
On October 19, 2026, Fifth Third Bancorp issued a press release announcing its earnings release for the third quarter of 2026. A copy of this press release is attached as Exhibit 99.1. This information is furnished under both Item 2.02 Results of Operations and Financial Condition and Item 7.01 Regulation FD Disclosure.
The information in this Item 2.02 of Form 8-K and Exhibits attached hereto shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934, nor shall they be deemed incorporated by reference in any filing under the Securities Exchange Act of 1934 or the Securities Act of 1933, except as shall be expressly set forth by specific reference.
Item 7.01 Regulation FD Disclosure.
On October 19, 2026, Fifth Third Bancorp issued a press release announcing its earnings release for the third quarter of 2026. A copy of this press release is attached as Exhibit 99.1. This information is furnished under both Item 2.02 Results of Operations and Financial Condition and Item 7.01 Regulation FD Disclosure.
For the benefit of its investors, Fifth Third Bancorp is also furnishing a presentation regarding its earnings conference call. A copy of this item is attached as Exhibit 99.2.
The information in this Item 7.01 of Form 8-K and Exhibits attached hereto shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934, nor shall they be deemed incorporated by reference in any filing under the Securities Exchange Act of 1934 or the Securities Act of 1933, except as shall be expressly set forth by specific reference.
Item 9.01 Financial Statements and Exhibits
Exhibit 99.1 – Press release dated October 19, 2026
Exhibit 99.2 – Third Quarter 2026 Earnings Presentation
Exhibit 104 – Cover Page Interactive Data File (embedded within the Inline XBRL document)
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| FIFTH THIRD BANCORP | ||||||||
| (Registrant) | ||||||||
Date: October 19, 2026 | /s/ Bryan D. Preston | |||||||
| Bryan D. Preston | ||||||||
| Executive Vice President and Chief Financial Officer | ||||||||

Fifth Third Bancorp Reports Third Quarter 2026 Earnings
Organic momentum and successful integration advance the earnings power of the combined company
Reported EPS of $0.90; adjusted EPS(a) of $1.13 excludes $0.23 of certain items on page 2
| Key Financial Data | Key Highlights | |||||||||||||||||||||||||||||||
| $ in millions for all balance sheet and income statement items | ||||||||||||||||||||||||||||||||
3Q26 | 2Q26 | 3Q25 | Stability: •Resilient credit performance. Net charge-offs(b) of 31 bps in 3Q26 •Core deposits increased 3% sequentially; loan-to-core deposit ratio of 76% •Strong client and banker retention through the Comerica conversion Profitability: •Net interest income increased 3% sequentially •8% adjusted PPNR(a) growth and 450 bps of positive operating leverage from 2Q26 •20.6% adjusted ROTCE(a) and 1.41% adjusted ROA(a) Growth: •Generated 70% more commercial new quality relationships compared to 3Q25 •Consumer household growth of 7% in the Southeast and 8% in the Southwest •Gained deposit share in Texas and California, with capped deposits in Dallas, Houston and Austin each up more than 20% year-over-year, while Southeast deposit growth was more than five times the market rate | |||||||||||||||||||||||||||||
| Income Statement Data | ||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $828 | $763 | $608 | |||||||||||||||||||||||||||||
| Net interest income (U.S. GAAP) | 2,271 | 2,215 | 1,520 | |||||||||||||||||||||||||||||
Net interest income (FTE)(a) | 2,276 | 2,220 | 1,525 | |||||||||||||||||||||||||||||
| Noninterest income | 1,008 | 1,059 | 781 | |||||||||||||||||||||||||||||
| Noninterest expense | 2,049 | 2,109 | 1,267 | |||||||||||||||||||||||||||||
| Per Share Data | ||||||||||||||||||||||||||||||||
| Earnings per share, basic | $0.91 | $0.84 | $0.91 | |||||||||||||||||||||||||||||
| Earnings per share, diluted | 0.90 | 0.83 | 0.91 | |||||||||||||||||||||||||||||
| Book value per share | 34.31 | 35.63 | 29.26 | |||||||||||||||||||||||||||||
Tangible book value per share(a) | 22.01 | 23.22 | 21.66 | |||||||||||||||||||||||||||||
| Balance Sheet & Credit Quality | ||||||||||||||||||||||||||||||||
| Average portfolio loans and leases | $179,244 | $177,572 | $123,326 | |||||||||||||||||||||||||||||
| Average deposits | 238,344 | 231,506 | 164,754 | |||||||||||||||||||||||||||||
| Accumulated other comprehensive loss | (4,919) | (3,286) | (3,276) | |||||||||||||||||||||||||||||
Net charge-off ratio(b) | 0.31 | % | 0.30 | % | 1.09 | % | ||||||||||||||||||||||||||
Nonperforming asset ratio(c) | 0.64 | 0.60 | 0.65 | |||||||||||||||||||||||||||||
| Financial Ratios | ||||||||||||||||||||||||||||||||
| Return on average assets | 1.14 | % | 1.08 | % | 1.21 | % | ||||||||||||||||||||||||||
| Return on average common equity | 10.2 | 9.5 | 12.6 | |||||||||||||||||||||||||||||
Return on average tangible common equity(a) | 16.6 | 15.6 | 17.3 | |||||||||||||||||||||||||||||
CET1 capital(d) | 10.02 | 9.93 | 10.57 | |||||||||||||||||||||||||||||
Net interest margin(a) | 3.34 | 3.36 | 3.13 | |||||||||||||||||||||||||||||
Efficiency(a) | 62.4 | 64.3 | 54.9 | |||||||||||||||||||||||||||||
Other than the Quarterly Financial Review tables beginning on page 14, commentary is on a fully taxable-equivalent (FTE) basis unless otherwise noted. Consistent with SEC guidance in Regulation S-K that contemplates the calculation of tax-exempt income on a taxable-equivalent basis, net interest income, net interest margin, net interest rate spread, total revenue and the efficiency ratio are provided on an FTE basis. | ||||||||||||||||||||||||||||||||
| From Tim Spence, Fifth Third Chairman, CEO and President: | ||||||||||||||
Fifth Third's third quarter reflected the earnings power of the combined company. Even while integrating Comerica, our adjusted return on tangible common equity and efficiency ratio improved from the second quarter, and credit performance remained stable.
Less than a year after we announced the Comerica acquisition, we completed the systems conversion with strong client and banker retention. Most importantly, the business is growing. The latest FDIC data show sustained deposit share gains in the Southeast and new share gains in Comerica's Michigan, Texas and California markets, and household growth continues to be led by the Southeast.
We live in a more volatile world, and competition for deposits is heating up. Multiple sources of low-cost deposits and limited exposure to the borrowers most sensitive to higher rates give us flexibility regardless of the rate environment. We are building a Fifth Third that is better and not just bigger. We will continue to be guided by our operating priorities of stability, profitability and growth – in that order.
Investor contact: Matt Curoe (513) 534-2345 | Media contact: Jennifer Hendricks Sullivan (614) 744-7693 October 19, 2026
| Income Statement Highlights | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions, except per share data) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| September | June | September | ||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Condensed Statements of Income | ||||||||||||||||||||||||||||||||||||||||||||
Net interest income (NII)(a) | $2,276 | $2,220 | $1,525 | 3% | 49% | |||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 122 | 129 | 197 | (5)% | (38)% | |||||||||||||||||||||||||||||||||||||||
| Noninterest income | 1,008 | 1,059 | 781 | (5)% | 29% | |||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 2,049 | 2,109 | 1,267 | (3)% | 62% | |||||||||||||||||||||||||||||||||||||||
Income before income taxes(a) | $1,113 | $1,041 | $842 | 7% | 32% | |||||||||||||||||||||||||||||||||||||||
| Taxable equivalent adjustment | $5 | $5 | $5 | — | — | |||||||||||||||||||||||||||||||||||||||
| Applicable income tax expense | 242 | 235 | 188 | 3% | 29% | |||||||||||||||||||||||||||||||||||||||
| Net income | $866 | $801 | $649 | 8% | 33% | |||||||||||||||||||||||||||||||||||||||
| Dividends on preferred stock | 38 | 38 | 41 | — | (7)% | |||||||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $828 | $763 | $608 | 9% | 36% | |||||||||||||||||||||||||||||||||||||||
| Earnings per share, diluted | $0.90 | $0.83 | $0.91 | 8% | (1)% | |||||||||||||||||||||||||||||||||||||||
Fifth Third Bancorp (NYSE: FITB) today reported third quarter 2026 net income available to common shareholders of $828 million, or $0.90 per diluted share, compared to $763 million, or $0.83 per diluted share, in the prior quarter and $608 million, or $0.91 per diluted share, in the year-ago quarter.
Diluted earnings per share impact of certain item(s) - 3Q26 | |||||||||||||||||
(after-tax impact; $ in millions, except per share data) | |||||||||||||||||
Merger-related charges(e)1,2 | $(171) | ||||||||||||||||
Interchange litigation matters(e)3 | (26) | ||||||||||||||||
Technology-related asset impairments(e) | (14) | ||||||||||||||||
After-tax impact of certain item(s) | $(211) | ||||||||||||||||
Diluted earnings per share impact of certain item(s)4 | $(0.23) | ||||||||||||||||
Totals may not foot due to rounding; 1A portion of the adjustments related to merger-related expenses are not tax-deductible; 2Pre-tax merger-related charges increased noninterest expense by $215 million and decreased noninterest income by $10 million; 3Interchange litigation matters increased noninterest expense by $5 million and decreased noninterest income by $29 million; 4Diluted earnings per share impact reflects 917.103 million average diluted shares outstanding | |||||||||||||||||
2
| Net Interest Income | ||||||||||||||||||||||||||||||||||||||||||||
(FTE; $ in millions)(a) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| September | June | September | ||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Interest Income | ||||||||||||||||||||||||||||||||||||||||||||
| Interest income | $3,503 | $3,377 | $2,524 | 4% | 39% | |||||||||||||||||||||||||||||||||||||||
| Interest expense | 1,227 | 1,157 | 999 | 6% | 23% | |||||||||||||||||||||||||||||||||||||||
| Net interest income (NII) | $2,276 | $2,220 | $1,525 | 3% | 49% | |||||||||||||||||||||||||||||||||||||||
| Average Yield/Rate Analysis | bps Change | |||||||||||||||||||||||||||||||||||||||||||
| Yield on interest-earning assets | 5.15 | % | 5.11 | % | 5.18 | % | 4 | (3) | ||||||||||||||||||||||||||||||||||||
| Rate paid on interest-bearing liabilities | 2.50 | % | 2.44 | % | 2.77 | % | 6 | (27) | ||||||||||||||||||||||||||||||||||||
| Ratios | ||||||||||||||||||||||||||||||||||||||||||||
| Net interest rate spread | 2.65 | % | 2.67 | % | 2.41 | % | (2) | 24 | ||||||||||||||||||||||||||||||||||||
Net interest margin (NIM) | 3.34 | % | 3.36 | % | 3.13 | % | (2) | 21 | ||||||||||||||||||||||||||||||||||||
Net interest income (FTE) increased 3% sequentially to $2.28 billion, reflecting the benefit of higher market rates, continued fixed-rate asset repricing, active investment portfolio management, and loan growth. These benefits were partially offset by higher deposit costs due to higher market rates and the migration of former off-balance-sheet Comerica investment sweep balances into interest-bearing deposits.
Compared with the year-ago quarter, net interest income increased 49%, primarily reflecting the addition of Comerica, with further support from fixed-rate asset repricing and balance sheet management.
3
| Noninterest Income | ||||||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||
| September | June | September | ||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | ||||||||||||||||||||||||||||
| Noninterest Income | ||||||||||||||||||||||||||||||||
| Wealth and asset management revenue | $259 | $256 | $181 | 1% | 43% | |||||||||||||||||||||||||||
| Commercial payments revenue | 256 | 254 | 157 | 1% | 63% | |||||||||||||||||||||||||||
| Consumer banking revenue | 158 | 161 | 144 | (2)% | 10% | |||||||||||||||||||||||||||
| Capital markets fees | 147 | 154 | 115 | (5)% | 28% | |||||||||||||||||||||||||||
| Commercial banking revenue | 128 | 125 | 87 | 2% | 47% | |||||||||||||||||||||||||||
| Mortgage banking net revenue | 47 | 39 | 58 | 21% | (19)% | |||||||||||||||||||||||||||
| Other noninterest income | 18 | 50 | 29 | (64)% | (38)% | |||||||||||||||||||||||||||
| Securities (losses) gains, net | (5) | 20 | 10 | NM | NM | |||||||||||||||||||||||||||
| Total noninterest income | $1,008 | $1,059 | $781 | (5)% | 29% | |||||||||||||||||||||||||||
Noninterest income of $1.01 billion decreased $51 million, or 5%, sequentially and increased $227 million, or 29%, year-over-year. The reported results reflect the impact of certain items in the table below, including interchange litigation matters, merger-related charges, and other securities gains/losses, which incorporate the mark-to-market impacts from securities tied to non-qualified deferred compensation plans, which are offset in noninterest expense.
Higher mortgage banking, commercial banking, and wealth and asset management revenue more than offset lower capital markets and consumer banking revenue. Wealth and asset management benefited from higher institutional trust and personal asset management revenue. Commercial payments was stable, as growth in deposit fees was offset by higher earnings credits. Capital markets fees declined as late-quarter market volatility slowed M&A advisory and loan syndication activity, more than offsetting higher corporate bond fees.
| Noninterest Income excluding certain items | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| September | June | September | ||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Noninterest Income excluding certain items | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest income (U.S. GAAP) | $1,008 | $1,059 | $781 | |||||||||||||||||||||||||||||||||||||||||
| Interchange litigation matters | 29 | 1 | 18 | |||||||||||||||||||||||||||||||||||||||||
| Merger-related charges | 10 | — | — | |||||||||||||||||||||||||||||||||||||||||
| Other securities losses/(gains), net | 5 | (30) | (10) | |||||||||||||||||||||||||||||||||||||||||
| Securities repositioning losses | — | 10 | — | |||||||||||||||||||||||||||||||||||||||||
Noninterest income excluding certain items(a) | $1,052 | $1,040 | $789 | 1% | 33% | |||||||||||||||||||||||||||||||||||||||
Excluding certain items, noninterest income increased 1% sequentially to $1.05 billion.
4
| Noninterest Expense | |||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | |||||||||||||||||||||
| September | June | September | |||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | |||||||||||||||||||
| Noninterest Expense | |||||||||||||||||||||||
| Compensation and benefits | $982 | $1,129 | $685 | (13)% | 43% | ||||||||||||||||||
| Technology and communications | 300 | 250 | 128 | 20% | 134% | ||||||||||||||||||
| Net occupancy expense | 144 | 154 | 89 | (6)% | 62% | ||||||||||||||||||
| Card and processing expense | 60 | 66 | 22 | (9)% | 173% | ||||||||||||||||||
| Equipment expense | 59 | 60 | 44 | (2)% | 34% | ||||||||||||||||||
| Loan and lease expense | 47 | 53 | 39 | (11)% | 21% | ||||||||||||||||||
| Marketing expense | 57 | 65 | 34 | (12)% | 68% | ||||||||||||||||||
| Other noninterest expense | 400 | 332 | 226 | 20% | 77% | ||||||||||||||||||
| Total noninterest expense | $2,049 | $2,109 | $1,267 | (3)% | 62% | ||||||||||||||||||
Noninterest expense of $2.05 billion decreased 3% sequentially, driven primarily by lower compensation and benefits expense. The reported results reflect the impact of certain items in the table below.
| Noninterest Expense excluding certain item(s) | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| September | June | September | ||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Noninterest Expense excluding certain item(s) | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest expense (U.S. GAAP) | $2,049 | $2,109 | $1,267 | |||||||||||||||||||||||||||||||||||||||||
| Merger-related charges | (215) | (203) | — | |||||||||||||||||||||||||||||||||||||||||
| Technology-related asset impairments | (19) | (7) | — | |||||||||||||||||||||||||||||||||||||||||
| Interchange litigation matters | (5) | (1) | (9) | |||||||||||||||||||||||||||||||||||||||||
| Severance expense | — | (7) | — | |||||||||||||||||||||||||||||||||||||||||
| FDIC special assessment | — | — | 6 | |||||||||||||||||||||||||||||||||||||||||
Noninterest expense excluding certain item(s)(a) | $1,810 | $1,891 | $1,264 | (4)% | 43% | |||||||||||||||||||||||||||||||||||||||
| Non-qualified deferred compensation benefit/(expense) | 6 | (30) | (11) | |||||||||||||||||||||||||||||||||||||||||
Noninterest expense excluding certain item(s) and non-qualified deferred compensation(a) | $1,816 | $1,861 | $1,253 | (2)% | 45% | |||||||||||||||||||||||||||||||||||||||
Noninterest expense excluding certain items and non-qualified deferred compensation decreased 2% sequentially to $1.82 billion. Merger-related charges recognized in noninterest expense totaled approximately 1.04 billion year-to-date, consistent with the integration timeline.
5
| Average Interest-Earning Assets | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| September | June | September | ||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Average Portfolio Loans and Leases | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans and leases: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial loans | $85,982 | $84,967 | $54,170 | 1% | 59% | |||||||||||||||||||||||||||||||||||||||
| Commercial mortgage loans | 27,263 | 27,176 | 12,027 | — | 127% | |||||||||||||||||||||||||||||||||||||||
| Commercial construction loans | 8,744 | 8,437 | 5,541 | 4% | 58% | |||||||||||||||||||||||||||||||||||||||
| Commercial leases | 3,574 | 3,503 | 3,177 | 2% | 12% | |||||||||||||||||||||||||||||||||||||||
| Total commercial loans and leases | $125,563 | $124,083 | $74,915 | 1% | 68% | |||||||||||||||||||||||||||||||||||||||
| Consumer loans: | ||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage loans | $19,775 | $19,626 | $17,656 | 1% | 12% | |||||||||||||||||||||||||||||||||||||||
| Home equity | 7,023 | 6,830 | 4,579 | 3% | 53% | |||||||||||||||||||||||||||||||||||||||
| Indirect secured consumer loans | 18,182 | 18,239 | 17,729 | — | 3% | |||||||||||||||||||||||||||||||||||||||
| Credit card | 1,646 | 1,646 | 1,678 | — | (2)% | |||||||||||||||||||||||||||||||||||||||
| Solar energy installation loans | 4,244 | 4,384 | 4,355 | (3)% | (3)% | |||||||||||||||||||||||||||||||||||||||
| Other consumer loans | 2,811 | 2,764 | 2,414 | 2% | 16% | |||||||||||||||||||||||||||||||||||||||
| Total consumer loans | $53,681 | $53,489 | $48,411 | — | 11% | |||||||||||||||||||||||||||||||||||||||
| Total average portfolio loans and leases | $179,244 | $177,572 | $123,326 | 1% | 45% | |||||||||||||||||||||||||||||||||||||||
| Average Loans and Leases Held for Sale | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans and leases held for sale | $170 | $399 | $44 | (57)% | 286% | |||||||||||||||||||||||||||||||||||||||
| Consumer loans held for sale | 597 | 736 | 623 | (19)% | (4)% | |||||||||||||||||||||||||||||||||||||||
| Total average loans and leases held for sale | $767 | $1,135 | $667 | (32)% | 15% | |||||||||||||||||||||||||||||||||||||||
| Total average loans and leases | $180,011 | $178,707 | $123,993 | 1% | 45% | |||||||||||||||||||||||||||||||||||||||
| Securities (taxable and tax-exempt) | $68,543 | $67,924 | $54,592 | 1% | 26% | |||||||||||||||||||||||||||||||||||||||
| Other short-term investments | 21,469 | 18,358 | 14,915 | 17% | 44% | |||||||||||||||||||||||||||||||||||||||
| Total average interest-earning assets | $270,023 | $264,989 | $193,500 | 2% | 40% | |||||||||||||||||||||||||||||||||||||||
Total average portfolio loans and leases of $179 billion increased 1% sequentially and 45% year-over-year. Sequential performance was driven by approximately $1.5 billion of growth in commercial loans and leases, while average consumer loans were broadly stable. Year-over-year growth primarily reflected the addition of Comerica.
Average securities (taxable and tax-exempt; amortized cost) of $69 billion increased 1% sequentially and 26% year-over-year, with sequential growth reflecting continued investment portfolio activity. Average other short-term investments (including interest-bearing cash) increased $3.1 billion, or 17%, sequentially, primarily reflecting the migration of the previously mentioned former off-balance-sheet Comerica investment sweep balances onto the balance sheet.
6
| End of Period Interest-Earning Assets | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | As of | % Change | ||||||||||||||||||||||||||||||||||||||||||
| September | June | September | ||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| End of Period Portfolio Loans and Leases | ||||||||||||||||||||||||||||||||||||||||||||
| Total commercial loans and leases | $126,366 | $124,880 | $74,423 | 1% | 70% | |||||||||||||||||||||||||||||||||||||||
| Total consumer loans | 53,906 | 53,648 | 48,707 | — | 11% | |||||||||||||||||||||||||||||||||||||||
| Total portfolio loans and leases | $180,272 | $178,528 | $123,130 | 1% | 46% | |||||||||||||||||||||||||||||||||||||||
| End of Period Loans and Leases Held for Sale | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases held for sale | $728 | $866 | $576 | (16)% | 26% | |||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $181,000 | $179,394 | $123,706 | 1% | 46% | |||||||||||||||||||||||||||||||||||||||
| Securities (taxable and tax-exempt) | $70,769 | $68,332 | $52,680 | 4% | 34% | |||||||||||||||||||||||||||||||||||||||
| Other short-term investments | 16,520 | 19,350 | 17,215 | (15)% | (4)% | |||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | $268,289 | $267,076 | $193,601 | — | 39% | |||||||||||||||||||||||||||||||||||||||
Period-end total portfolio loans and leases increased 1% sequentially to $180 billion. Commercial growth was led by construction and C&I originations, partly offset by elevated payoffs. Consumer growth reflected continued momentum in home equity, partially offset by expected runoff in solar energy installation loans.
Total period-end securities (taxable and tax-exempt; amortized cost) increased $2.4 billion sequentially to $71 billion as a portion of the liquidity held earlier in the quarter was deployed into higher-yielding investment securities. As a result, period-end short-term investments declined $2.8 billion even though average short-term investments were higher for the quarter.
| Average Deposits | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| September | June | September | ||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Average Deposits | ||||||||||||||||||||||||||||||||||||||||||||
| Demand | $64,228 | $63,976 | $41,235 | — | 56% | |||||||||||||||||||||||||||||||||||||||
| Interest checking | 75,025 | 70,507 | 56,624 | 6% | 32% | |||||||||||||||||||||||||||||||||||||||
| Savings | 18,037 | 18,430 | 16,376 | (2)% | 10% | |||||||||||||||||||||||||||||||||||||||
Money market | 66,247 | 63,200 | 37,434 | 5% | 77% | |||||||||||||||||||||||||||||||||||||||
| Total transaction deposits | $223,537 | $216,113 | $151,669 | 3% | 47% | |||||||||||||||||||||||||||||||||||||||
CDs $250,000 or less | 12,102 | 12,403 | 10,841 | (2)% | 12% | |||||||||||||||||||||||||||||||||||||||
| Total core deposits | $235,639 | $228,516 | $162,510 | 3% | 45% | |||||||||||||||||||||||||||||||||||||||
CDs over $250,0001 | 2,705 | 2,990 | 2,244 | (10)% | 21% | |||||||||||||||||||||||||||||||||||||||
| Total average deposits | $238,344 | $231,506 | $164,754 | 3% | 45% | |||||||||||||||||||||||||||||||||||||||
1CDs over $250,000 includes $1.0MM, $0.1BN, and $1.0BN of retail brokered certificates of deposit which are fully covered by FDIC insurance for the three months ended 9/30/26, 6/30/26, and 9/30/25, respectively. | ||||||||||||||||||||||||||||||||||||||||||||
Total average deposits increased 3% sequentially to $238 billion, reflecting operational deposit growth, the Southwest retail deposit campaign, and the migration of former off-balance-sheet Comerica investment sweep balances onto the balance sheet. Additionally, certain Comerica legacy deposit products were simplified into more modern interest checking products resulting in a shift from commercial savings and money market into interest checking.
Period-end total deposits increased 2% sequentially to $239 billion, with growth in interest-checking, partially offset by lower money market and CD balances. The period-end portfolio loan-to-core deposit ratio improved to 76% from 77% last quarter, as deposit growth modestly outpaced loan growth.
7
| Average Wholesale Funding | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| September | June | September | ||||||||||||||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Average Wholesale Funding | ||||||||||||||||||||||||||||||||||||||||||||
CDs over $250,0001 | $2,705 | $2,990 | $2,244 | (10)% | 21% | |||||||||||||||||||||||||||||||||||||||
| Federal funds purchased | 181 | 160 | 198 | 13% | (9)% | |||||||||||||||||||||||||||||||||||||||
| Securities sold under repurchase agreements | 395 | 444 | 376 | (11)% | 5% | |||||||||||||||||||||||||||||||||||||||
| FHLB advances | 2,365 | 3,437 | 4,920 | (31)% | (52)% | |||||||||||||||||||||||||||||||||||||||
| Derivative collateral and other secured borrowings | 93 | 64 | 82 | 45% | 13% | |||||||||||||||||||||||||||||||||||||||
| Long-term debt | 17,513 | 18,817 | 14,001 | (7)% | 25% | |||||||||||||||||||||||||||||||||||||||
| Total average wholesale funding | $23,252 | $25,912 | $21,821 | (10)% | 7% | |||||||||||||||||||||||||||||||||||||||
1CDs over $250,000 includes $1.0MM, $0.1BN, and $1.0BN of retail brokered certificates of deposit which are fully covered by FDIC insurance for the three months ended 9/30/26, 6/30/26, and 9/30/25, respectively. | ||||||||||||||||||||||||||||||||||||||||||||
Strong deposit growth improved the overall funding mix and supported a 10% sequential reduction in average wholesale funding to $23 billion, driven primarily by decreases of $1.3 billion in long-term debt and $1.1 billion in FHLB advances.
Compared with the year-ago quarter, average wholesale funding increased 7%, reflecting the Comerica acquisition.
8
| Credit Quality Summary | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | As of and For the Three Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| September | June | March | December | September | ||||||||||||||||||||||||||||||||||||||||
| 2026 | 2026 | 2026 | 2025 | 2025 | ||||||||||||||||||||||||||||||||||||||||
| Total nonaccrual portfolio loans and leases (NPLs) | $1,070 | $1,041 | $960 | $767 | $768 | |||||||||||||||||||||||||||||||||||||||
| Repossessed property | 9 | 10 | 11 | 11 | 12 | |||||||||||||||||||||||||||||||||||||||
OREO1 | 81 | 24 | 28 | 19 | 21 | |||||||||||||||||||||||||||||||||||||||
| Total nonperforming portfolio loans and leases and OREO (NPAs) | $1,160 | $1,075 | $999 | $797 | $801 | |||||||||||||||||||||||||||||||||||||||
NPL ratio(f) | 0.59 | % | 0.58 | % | 0.54 | % | 0.62 | % | 0.62 | % | ||||||||||||||||||||||||||||||||||
NPA ratio(c) | 0.64 | % | 0.60 | % | 0.57 | % | 0.65 | % | 0.65 | % | ||||||||||||||||||||||||||||||||||
| Portfolio loans and leases 30-89 days past due (accrual) | $540 | $561 | $683 | $360 | $348 | |||||||||||||||||||||||||||||||||||||||
| Portfolio loans and leases 90 days past due (accrual) | 42 | 33 | 49 | 30 | 29 | |||||||||||||||||||||||||||||||||||||||
| 30-89 days past due as a % of portfolio loans and leases | 0.30 | % | 0.31 | % | 0.39 | % | 0.29 | % | 0.28 | % | ||||||||||||||||||||||||||||||||||
| 90 days past due as a % of portfolio loans and leases | 0.02 | % | 0.02 | % | 0.03 | % | 0.02 | % | 0.02 | % | ||||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses (ALLL), beginning | $2,918 | $2,922 | $2,253 | $2,265 | $2,412 | |||||||||||||||||||||||||||||||||||||||
| Total net losses charged-off | (139) | (135) | (144) | (125) | (339) | |||||||||||||||||||||||||||||||||||||||
| Provision for loan and lease losses | 127 | 131 | 152 | 113 | 192 | |||||||||||||||||||||||||||||||||||||||
| Allowance on PCD loans and leases at acquisition | — | (1) | 180 | — | — | |||||||||||||||||||||||||||||||||||||||
| Allowance on PSLs at acquisition | — | 1 | 481 | — | — | |||||||||||||||||||||||||||||||||||||||
| ALLL, ending | $2,906 | $2,918 | $2,922 | $2,253 | $2,265 | |||||||||||||||||||||||||||||||||||||||
| Reserve for unfunded commitments, beginning | $230 | $232 | $157 | $151 | $146 | |||||||||||||||||||||||||||||||||||||||
| (Benefit from) provision for the reserve for unfunded commitments | (5) | (2) | 75 | 6 | 5 | |||||||||||||||||||||||||||||||||||||||
| Reserve for unfunded commitments, ending | $225 | $230 | $232 | $157 | $151 | |||||||||||||||||||||||||||||||||||||||
| Total allowance for credit losses (ACL) | $3,131 | $3,148 | $3,154 | $2,410 | $2,416 | |||||||||||||||||||||||||||||||||||||||
| ACL ratios: | ||||||||||||||||||||||||||||||||||||||||||||
| As a % of portfolio loans and leases | 1.74 | % | 1.76 | % | 1.79 | % | 1.96 | % | 1.96 | % | ||||||||||||||||||||||||||||||||||
| As a % of nonperforming portfolio loans and leases | 292 | % | 303 | % | 328 | % | 314 | % | 314 | % | ||||||||||||||||||||||||||||||||||
| As a % of nonperforming portfolio assets | 270 | % | 293 | % | 316 | % | 302 | % | 302 | % | ||||||||||||||||||||||||||||||||||
| ALLL as a % of portfolio loans and leases | 1.61 | % | 1.63 | % | 1.66 | % | 1.84 | % | 1.84 | % | ||||||||||||||||||||||||||||||||||
| Total losses charged-off | $(192) | $(181) | $(187) | $(177) | $(382) | |||||||||||||||||||||||||||||||||||||||
| Total recoveries of losses previously charged-off | 53 | 46 | 43 | 52 | 43 | |||||||||||||||||||||||||||||||||||||||
Total net losses charged-off2 | $(139) | $(135) | $(144) | $(125) | $(339) | |||||||||||||||||||||||||||||||||||||||
Net charge-off ratio (NCO ratio)(b)2 | 0.31 | % | 0.30 | % | 0.37 | % | 0.40 | % | 1.09 | % | ||||||||||||||||||||||||||||||||||
| Commercial NCO ratio | 0.22 | % | 0.21 | % | 0.26 | % | 0.27 | % | 1.46 | % | ||||||||||||||||||||||||||||||||||
| Consumer NCO ratio | 0.52 | % | 0.53 | % | 0.58 | % | 0.59 | % | 0.52 | % | ||||||||||||||||||||||||||||||||||
1Includes branch-related real estate no longer intended to be used for banking purposes. | ||||||||||||||||||||||||||||||||||||||||||||
2Excludes net charge-offs of $100 million which were taken immediately at the time of acquisition. | ||||||||||||||||||||||||||||||||||||||||||||
The provision for credit losses declined to $122 million from $129 million in the prior quarter. The allowance for credit losses was $3.1 billion, or 1.74%, of total portfolio loans and leases, compared with 1.76% in the prior quarter. The modest decline in the ACL ratio reflected improvement in the commercial risk profile. The ACL coverage ratio remained strong at 292% of nonperforming portfolio loans and leases and 270% of nonperforming portfolio assets.
9
Net charge-offs totaled $139 million, or 0.31%, of average portfolio loans, compared with $135 million, or 0.30%, in the prior quarter. The commercial NCO ratio increased 1 bp sequentially to 0.22%, while the consumer NCO ratio declined 1 bp to 0.52%.
Compared with the year-ago quarter, the total NCO ratio improved 78 bps, largely because the prior year period included a $178 million asset-backed finance charge-off. Excluding that credit, the year-ago NCO ratio was 0.52%.
Credit quality remained stable, with early- and late-stage delinquencies, nonperforming portfolio loans and leases and nonperforming portfolio assets broadly unchanged sequentially. OREO was $81 million at September 30, 2026 and included $74 million of branch-related real estate no longer intended to be used for banking purposes primarily driven by the Comerica acquisition.
| Capital Position | |||||||||||||||||||||||||||||
| As of and For the Three Months Ended | |||||||||||||||||||||||||||||
| September | June | March | December | September | |||||||||||||||||||||||||
| 2026 | 2026 | 2026 | 2025 | 2025 | |||||||||||||||||||||||||
| Capital Position | |||||||||||||||||||||||||||||
Average total Bancorp shareholders' equity as a % of average assets | 11.37 | % | 11.50 | % | 11.34 | % | 10.11 | % | 10.02 | % | |||||||||||||||||||
Tangible equity(a) | 9.13 | % | 9.04 | % | 9.01 | % | 9.28 | % | 9.12 | % | |||||||||||||||||||
Tangible common equity (excluding AOCI)(a) | 8.39 | % | 8.30 | % | 8.26 | % | 8.46 | % | 8.29 | % | |||||||||||||||||||
Tangible common equity (including AOCI)(a) | 6.88 | % | 7.29 | % | 7.25 | % | 7.14 | % | 6.89 | % | |||||||||||||||||||
Regulatory Capital Ratios(d) | |||||||||||||||||||||||||||||
CET1 capital | 10.02 | % | 9.93 | % | 9.89 | % | 10.81 | % | 10.57 | % | |||||||||||||||||||
Tier 1 risk-based capital | 10.90 | % | 10.81 | % | 10.79 | % | 11.87 | % | 11.63 | % | |||||||||||||||||||
Total risk-based capital | 12.54 | % | 12.50 | % | 12.50 | % | 13.78 | % | 13.54 | % | |||||||||||||||||||
| Leverage | 9.22 | % | 9.20 | % | 10.22 | % | 9.41 | % | 9.24 | % | |||||||||||||||||||
Fifth Third's CET1 capital ratio increased to 10.02%, compared with 9.93% in the prior quarter, as capital generated through earnings was partially offset by RWA growth. Fifth Third did not repurchase common shares during the quarter or year-to-date.
10
Tax Rate
The effective tax rate for the quarter was 21.8% compared with 22.7% in the prior quarter and 22.6% in the year-ago quarter.
Conference Call
Fifth Third will host a conference call to discuss these financial results at 9:00 a.m. (Eastern Time) today. This conference call will be webcast live and may be accessed through the Fifth Third Investor Relations website at www.53.com (click on “About Us” then “Investor Relations”). Those unable to listen to the live webcast may access a webcast replay through the Fifth Third Investor Relations website at the same web address, which will be available for 30 days.
Corporate Profile
Fifth Third is a bank that's as long on innovation as it is on history. Since 1858, we've been helping individuals, families, businesses and communities grow through smart financial services that improve lives. Our list of firsts is extensive, and it's one that continues to expand as we explore the intersection of tech-driven innovation, dedicated people and focused community impact. Fifth Third is one of the few U.S.-based banks to have been named among Ethisphere's World's Most Ethical Companies® for several years. With a commitment to taking care of our customers, employees, communities and shareholders, our goal is to be the one bank people most value and trust.
Fifth Third Bank, National Association is a federally chartered institution. Fifth Third Bancorp is the indirect parent company of Fifth Third Bank, and its common stock is traded on the New York Stock Exchange under the symbol "FITB." Investor information and press releases can be viewed at www.53.com. Deposit and credit products provided by Fifth Third Bank, National Association. Member FDIC.
Earnings Release End Notes
(a)Non-GAAP measure; see discussion of non-GAAP reconciliation beginning on page 27.
(b)Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis.
(c)Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO.
(d)Current period regulatory capital ratios are estimated.
(e)Assumes a 24% tax rate.
(f)Nonperforming portfolio loans and leases as a percent of portfolio loans and leases.
11
FORWARD-LOOKING STATEMENTS
This release contains statements that we believe are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Rule 175 promulgated thereunder, and Section 21E of the Securities Exchange Act of 1934, as amended, and Rule 3b-6 promulgated thereunder. All statements other than statements of historical fact are forward-looking statements. These statements relate to our financial condition, results of operations, plans, objectives, future performance, capital actions or business. They usually can be identified by the use of forward-looking language such as “will likely result,” “may,” “are expected to,” “is anticipated,” “potential,” “estimate,” “forecast,” “projected,” “intends to,” or may include other similar words or phrases such as “believes,” “plans,” “trend,” “objective,” “continue,” “remain,” or similar expressions, or future or conditional verbs such as “will,” “would,” “should,” “could,” “might,” “can,” or similar verbs. You should not place undue reliance on these statements, as they are subject to risks and uncertainties, including but not limited to the risk factors set forth in our most recent Annual Report on Form 10-K as updated by our filings with the U.S. Securities and Exchange Commission (“SEC”).
There are a number of important factors that could cause future results to differ materially from historical performance and these forward-looking statements. Factors that might cause such a difference include, but are not limited to: (1) deteriorating credit quality; (2) loan concentration by location or industry of borrowers or collateral; (3) any instability or disruption in the financial system, including those caused by actual or perceived issues affecting the soundness of other financial institutions or market participants; (4) inadequate sources of funding or liquidity; (5) unfavorable actions of rating agencies; (6) inability to maintain or grow deposits; (7) limitations on the ability to receive dividends from subsidiaries; (8) cyber-security risks; (9) Fifth Third’s ability to secure confidential information and deliver products and services through the use of computer systems and telecommunications networks; (10) failures by third-party service providers; (11) inability to manage strategic initiatives and/or organizational changes; (12) inability to implement technology system enhancements, including the use of artificial intelligence; (13) failure of internal controls and other risk management programs; (14) losses related to fraud, theft, misappropriation or violence; (15) inability to attract and retain skilled personnel; (16) adverse impacts of government regulation; (17) governmental or regulatory changes or other actions; (18) failures to meet applicable capital requirements; (19) regulatory objections to Fifth Third’s capital plan; (20) regulation of Fifth Third’s derivatives activities; (21) deposit insurance premiums; (22) assessments for the orderly liquidation fund; (23) weakness in the national or local economies; (24) global political and economic uncertainty or negative actions; (25) changes in interest rates and the effects of inflation; (26) changes in U.S. trade policies, including the imposition of tariffs and retaliatory tariffs; (27) changes and trends in capital markets; (28) fluctuation of Fifth Third’s stock price; (29) volatility in mortgage banking revenue; (30) litigation, investigations, and enforcement proceedings; (31) breaches of contractual covenants, representations and warranties; (32) competition and changes in the financial services industry; (33) potential impacts of the adoption of real-time payment networks; (34) changing retail distribution strategies, customer preferences and behavior; (35) difficulties in identifying, acquiring or integrating suitable strategic partnerships, investments or acquisitions; (36) potential dilution from future acquisitions; (37) loss of income and/or difficulties encountered in the sale and separation of businesses, investments or other assets; (38) results of investments or acquired entities; (39) changes in accounting standards or interpretation or declines in the value of Fifth Third’s goodwill or other intangible assets; (40) inaccuracies or other failures from the use of models; (41) effects of critical accounting policies and judgments or the use of inaccurate estimates; (42) weather-related events, other natural disasters, or health emergencies (including pandemics); (43) the impact of reputational risk created by these or other developments on such matters as business generation and retention, funding and liquidity; (44) changes in law or requirements imposed by Fifth Third’s regulators impacting our capital actions, including dividend payments and stock repurchases; (45) Fifth Third's ability to meet its environmental and/or social targets, goals and commitments; and (46) risks relating to the merger with Comerica Incorporated, including Fifth Third’s inability to realize the anticipated benefits of the merger and potential disruption to Fifth Third’s business resulting from post-merger integration.
You should refer to our periodic and current reports filed with the SEC for further information on other factors, which could cause actual results to be significantly different from those expressed or implied by these forward-looking statements. Moreover, you should treat these statements as speaking only as of the date they are made and based only on information then actually known to us. We expressly disclaim any obligation or undertaking to release publicly any updates or revisions to any forward-looking statements contained herein to reflect any change in our expectations or any changes in events, conditions or circumstances on which any such statement is based, except as may be required by law, and we claim the protection of the safe harbor for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. The information contained herein is intended to be reviewed in its entirety. Any qualifications, assumptions, conditions, limitations or other disclosures that apply to a particular item of information are deemed to apply, with any necessary adjustments to all references to that information throughout this press release.
# # #
12
Quarterly Financial Review for September 30, 2026
Table of Contents
| Financial Highlights | 14-15 | ||||||||||
| Consolidated Statements of Income | 16-17 | ||||||||||
| Consolidated Balance Sheets | 18-19 | ||||||||||
| Consolidated Statements of Changes in Equity | 20 | ||||||||||
| Average Balance Sheets and Yield/Rate Analysis | 21-22 | ||||||||||
| Summary of Loans and Leases | 23 | ||||||||||
| Regulatory Capital | 24 | ||||||||||
| Summary of Credit Loss Experience | 25 | ||||||||||
| Asset Quality | 26 | ||||||||||
| Non-GAAP Reconciliation | 27-29 | ||||||||||
| Segment Presentation | 30 | ||||||||||
13
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||||||||||||||
| Financial Highlights | As of and For the Three Months Ended | % / bps | % / bps | ||||||||||||||||||||||||||
| $ in millions, except per share data | Change | Year to Date | Change | ||||||||||||||||||||||||||
| (unaudited) | September | June | September | September | September | ||||||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | 2026 | 2025 | Yr/Yr | ||||||||||||||||||||||
| Income Statement Data | |||||||||||||||||||||||||||||
| Net interest income | $2,271 | $2,215 | $1,520 | 3% | 49% | $6,420 | $4,453 | 44% | |||||||||||||||||||||
Net interest income (FTE)(a) | 2,276 | 2,220 | 1,525 | 3% | 49% | 6,435 | 4,468 | 44% | |||||||||||||||||||||
| Noninterest income | 1,008 | 1,059 | 781 | (5%) | 29% | 2,962 | 2,224 | 33% | |||||||||||||||||||||
Total revenue (FTE)(a) | 3,284 | 3,279 | 2,306 | — | 42% | 9,397 | 6,692 | 40% | |||||||||||||||||||||
| Provision for credit losses | 122 | 129 | 197 | (5%) | (38%) | 479 | 544 | (12%) | |||||||||||||||||||||
| Noninterest expense | 2,049 | 2,109 | 1,267 | (3%) | 62% | 6,553 | 3,835 | 71% | |||||||||||||||||||||
| Net income | 866 | 801 | 649 | 8% | 33% | 1,832 | 1,791 | 2% | |||||||||||||||||||||
| Net income available to common shareholders | 828 | 763 | 608 | 9% | 36% | 1,719 | 1,677 | 3% | |||||||||||||||||||||
| Earnings Per Share Data | |||||||||||||||||||||||||||||
| Net income allocated to common shareholders | $828 | $763 | $608 | 9% | 36% | $1,719 | $1,677 | 3% | |||||||||||||||||||||
| Average common shares outstanding (in thousands): | |||||||||||||||||||||||||||||
| Basic | 911,919 | 911,613 | 666,427 | — | 37% | 883,202 | 669,405 | 32% | |||||||||||||||||||||
| Diluted | 917,103 | 915,959 | 670,878 | — | 37% | 888,097 | 673,632 | 32% | |||||||||||||||||||||
| Earnings per share, basic | $0.91 | $0.84 | $0.91 | 8% | — | $1.95 | $2.51 | (22%) | |||||||||||||||||||||
| Earnings per share, diluted | 0.90 | 0.83 | 0.91 | 8% | (1%) | 1.94 | 2.49 | (22%) | |||||||||||||||||||||
| Common Share Data | |||||||||||||||||||||||||||||
| Cash dividends per common share | $0.42 | $0.40 | $0.40 | 5% | 5% | $1.22 | $1.14 | 7% | |||||||||||||||||||||
| Book value per share | 34.31 | 35.63 | 29.26 | (4%) | 17% | 34.31 | 29.26 | 17% | |||||||||||||||||||||
| Market value per share | 50.58 | 56.37 | 44.55 | (10%) | 14% | 50.58 | 44.55 | 14% | |||||||||||||||||||||
| Common shares outstanding (in thousands) | 907,367 | 906,573 | 660,973 | — | 37% | 907,367 | 660,973 | 37% | |||||||||||||||||||||
| Market capitalization | $45,895 | $51,103 | $29,446 | (10%) | 56% | $45,895 | $29,446 | 56% | |||||||||||||||||||||
| Financial Ratios | |||||||||||||||||||||||||||||
| Return on average assets | 1.14 | % | 1.08 | % | 1.21 | % | 6 | (7) | 0.85 | % | 1.13 | % | (28) | ||||||||||||||||
| Return on average common equity | 10.2 | % | 9.5 | % | 12.6 | % | 70 | (240) | 7.5 | % | 12.1 | % | (460) | ||||||||||||||||
Return on average tangible common equity(a) | 16.6 | % | 15.6 | % | 17.3 | % | 100 | (70) | 12.3 | % | 16.8 | % | (450) | ||||||||||||||||
Noninterest income as a percent of total revenue(a) | 31 | % | 32 | % | 34 | % | (100) | (300) | 32 | % | 33 | % | (100) | ||||||||||||||||
| Dividend payout | 46.2 | % | 47.6 | % | 44.0 | % | NM | NM | 62.6 | % | 45.4 | % | NM | ||||||||||||||||
Average total Bancorp shareholders’ equity as a percent of average assets | 11.37 | % | 11.50 | % | 10.02 | % | (13) | 135 | 11.40 | % | 9.78 | % | 162 | ||||||||||||||||
Tangible common equity(a) | 8.39 | % | 8.30 | % | 8.29 | % | 9 | 10 | 8.39 | % | 8.29 | % | 10 | ||||||||||||||||
Net interest margin (FTE)(a) | 3.34 | % | 3.36 | % | 3.13 | % | (2) | 21 | 3.34 | % | 3.10 | % | 24 | ||||||||||||||||
Efficiency (FTE)(a) | 62.4 | % | 64.3 | % | 54.9 | % | (190) | 750 | 69.7 | % | 57.3 | % | NM | ||||||||||||||||
| Effective tax rate | 21.8 | % | 22.7 | % | 22.6 | % | (90) | (80) | 22.0 | % | 22.1 | % | (10) | ||||||||||||||||
| Credit Quality | |||||||||||||||||||||||||||||
Net losses charged-off(h) | $139 | $135 | $339 | 3 | % | (59 | %) | $419 | $614 | (32 | %) | ||||||||||||||||||
| Net losses charged-off as a percent of average portfolio loans and leases (annualized) | 0.31 | % | 0.30 | % | 1.09 | % | 1 | (78) | 0.33 | % | 0.67 | % | (34) | ||||||||||||||||
| ALLL as a percent of portfolio loans and leases | 1.61 | % | 1.63 | % | 1.84 | % | (2) | (23) | 1.61 | % | 1.84 | % | (23) | ||||||||||||||||
ACL as a percent of portfolio loans and leases(f) | 1.74 | % | 1.76 | % | 1.96 | % | (2) | (22) | 1.74 | % | 1.96 | % | (22) | ||||||||||||||||
| Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO | 0.64 | % | 0.60 | % | 0.65 | % | 4 | (1) | 0.64 | % | 0.65 | % | (1) | ||||||||||||||||
| Average Balances | |||||||||||||||||||||||||||||
| Loans and leases, including held for sale | $180,011 | $178,707 | $123,993 | 1% | 45% | $172,414 | $123,147 | 40% | |||||||||||||||||||||
| Securities and other short-term investments | 90,012 | 86,282 | 69,507 | 4% | 30% | 85,362 | 69,853 | 22% | |||||||||||||||||||||
| Assets | 302,119 | 297,948 | 211,770 | 1% | 43% | 288,673 | 210,965 | 37% | |||||||||||||||||||||
Transaction deposits(b) | 223,537 | 216,113 | 151,669 | 3% | 47% | 211,624 | 151,327 | 40% | |||||||||||||||||||||
Core deposits(c) | 235,639 | 228,516 | 162,510 | 3% | 45% | 223,674 | 161,901 | 38% | |||||||||||||||||||||
Wholesale funding(d) | 23,252 | 25,912 | 21,821 | (10%) | 7% | 23,577 | 22,167 | 6% | |||||||||||||||||||||
Bancorp shareholders' equity | 34,338 | 34,260 | 21,216 | — | 62% | 32,917 | 20,633 | 60% | |||||||||||||||||||||
Regulatory Capital Ratios(e) | |||||||||||||||||||||||||||||
CET1 capital | 10.02 | % | 9.93 | % | 10.57 | % | 9 | (55) | 10.02 | % | 10.57 | % | (55) | ||||||||||||||||
Tier 1 risk-based capital | 10.90 | % | 10.81 | % | 11.63 | % | 9 | (73) | 10.90 | % | 11.63 | % | (73) | ||||||||||||||||
Total risk-based capital | 12.54 | % | 12.50 | % | 13.54 | % | 4 | (100) | 12.54 | % | 13.54 | % | (100) | ||||||||||||||||
| Leverage | 9.22 | % | 9.20 | % | 9.24 | % | 2 | (2) | 9.22 | % | 9.24 | % | (2) | ||||||||||||||||
| Additional Metrics | |||||||||||||||||||||||||||||
| Banking centers | 1,429 | 1,500 | 1,102 | (5%) | 30% | 1,429 | 1,102 | 30% | |||||||||||||||||||||
| ATMs | 2,549 | 2,648 | 2,184 | (4%) | 17% | 2,549 | 2,184 | 17% | |||||||||||||||||||||
| Full-time equivalent employees | 25,069 | 25,197 | 18,476 | (1%) | 36% | 25,069 | 18,476 | 36% | |||||||||||||||||||||
Assets under care ($ in billions)(g) | $880 | $902 | $681 | (2%) | 29% | $880 | $681 | 29% | |||||||||||||||||||||
Assets under management ($ in billions)(g) | 125 | 128 | 77 | (2%) | 62% | 125 | 77 | 62% | |||||||||||||||||||||
(a)Non-GAAP measure; see discussion and reconciliation of non-GAAP measures beginning on page 27.
(b)Includes demand, interest checking, savings and money market deposits..
(c)Includes transaction deposits plus CDs $250,000 or less.
(d)Includes CDs over $250,000, other deposits, federal funds purchased, other short-term borrowings and long-term debt.
(e)Current period regulatory capital ratios are estimates.
(f)The allowance for credit losses is the sum of the ALLL and the reserve for unfunded commitments.
(g)Assets under management and assets under care include trust and brokerage assets.
(h)Excludes net charge-offs of $100 million which were taken at the time of acquisition.
14
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||||||||
| Financial Highlights | ||||||||||||||||||||
| $ in millions, except per share data | As of and For the Three Months Ended | |||||||||||||||||||
| (unaudited) | September | June | March | December | September | |||||||||||||||
| 2026 | 2026 | 2026 | 2025 | 2025 | ||||||||||||||||
| Income Statement Data | ||||||||||||||||||||
| Net interest income | $2,271 | $2,215 | $1,934 | $1,529 | $1,520 | |||||||||||||||
Net interest income (FTE)(a) | 2,276 | 2,220 | 1,939 | 1,533 | 1,525 | |||||||||||||||
| Noninterest income | 1,008 | 1,059 | 895 | 811 | 781 | |||||||||||||||
Total revenue (FTE)(a) | 3,284 | 3,279 | 2,834 | 2,344 | 2,306 | |||||||||||||||
| Provision for credit losses | 122 | 129 | 227 | 119 | 197 | |||||||||||||||
| Noninterest expense | 2,049 | 2,109 | 2,395 | 1,309 | 1,267 | |||||||||||||||
| Net income | 866 | 801 | 165 | 731 | 649 | |||||||||||||||
| Net income available to common shareholders | 828 | 763 | 128 | 699 | 608 | |||||||||||||||
| Earnings Per Share Data | ||||||||||||||||||||
| Net income allocated to common shareholders | $828 | $763 | $128 | $699 | $608 | |||||||||||||||
| Average common shares outstanding (in thousands): | ||||||||||||||||||||
| Basic | 911,919 | 911,613 | 825,119 | 664,384 | 666,427 | |||||||||||||||
| Diluted | 917,103 | 915,959 | 830,274 | 669,153 | 670,878 | |||||||||||||||
| Earnings per share, basic | $0.91 | $0.84 | $0.16 | $1.05 | $0.91 | |||||||||||||||
| Earnings per share, diluted | 0.90 | 0.83 | 0.15 | 1.04 | 0.91 | |||||||||||||||
| Common Share Data | ||||||||||||||||||||
| Cash dividends per common share | $0.42 | $0.40 | $0.40 | $0.40 | $0.40 | |||||||||||||||
| Book value per share | 34.31 | 35.63 | 35.24 | 30.18 | 29.26 | |||||||||||||||
| Market value per share | 50.58 | 56.37 | 46.46 | 46.81 | 44.55 | |||||||||||||||
| Common shares outstanding (in thousands) | 907,367 | 906,573 | 905,823 | 661,198 | 660,973 | |||||||||||||||
| Market capitalization | $45,895 | $51,103 | $42,085 | $30,951 | $29,446 | |||||||||||||||
| Financial Ratios | ||||||||||||||||||||
| Return on average assets | 1.14 | % | 1.08 | % | 0.25 | % | 1.36 | % | 1.21 | % | ||||||||||
| Return on average common equity | 10.2 | % | 9.5 | % | 1.8 | % | 14.0 | % | 12.6 | % | ||||||||||
Return on average tangible common equity(a) | 16.6 | % | 15.6 | % | 3.5 | % | 19.0 | % | 17.3 | % | ||||||||||
Noninterest income as a percent of total revenue(a) | 31 | % | 32 | % | 32 | % | 35 | % | 34 | % | ||||||||||
| Dividend payout | 46.2 | % | 47.6 | % | 250.0 | % | 38.1 | % | 44.0 | % | ||||||||||
Average total Bancorp shareholders’ equity as a percent of average assets | 11.37 | % | 11.50 | % | 11.34 | % | 10.11 | % | 10.02 | % | ||||||||||
Tangible common equity(a) | 8.39 | % | 8.30 | % | 8.26 | % | 8.46 | % | 8.29 | % | ||||||||||
Net interest margin (FTE)(a) | 3.34 | % | 3.36 | % | 3.30 | % | 3.13 | % | 3.13 | % | ||||||||||
Efficiency (FTE)(a) | 62.4 | % | 64.3 | % | 84.5 | % | 55.8 | % | 54.9 | % | ||||||||||
| Effective tax rate | 21.8 | % | 22.7 | % | 20.1 | % | 19.8 | % | 22.6 | % | ||||||||||
| Credit Quality | ||||||||||||||||||||
Net losses charged-off(h) | $139 | $135 | $144 | $125 | $339 | |||||||||||||||
| Net losses charged-off as a percent of average portfolio loans and leases (annualized) | 0.31 | % | 0.30 | % | 0.37 | % | 0.40 | % | 1.09 | % | ||||||||||
| ALLL as a percent of portfolio loans and leases | 1.61 | % | 1.63 | % | 1.66 | % | 1.84 | % | 1.84 | % | ||||||||||
ACL as a percent of portfolio loans and leases(f) | 1.74 | % | 1.76 | % | 1.79 | % | 1.96 | % | 1.96 | % | ||||||||||
| Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO | 0.64 | % | 0.60 | % | 0.57 | % | 0.65 | % | 0.65 | % | ||||||||||
| Average Balances | ||||||||||||||||||||
| Loans and leases, including held for sale | $180,011 | $178,707 | $158,283 | $124,147 | $123,993 | |||||||||||||||
| Securities and other short-term investments | 90,012 | 86,282 | 79,678 | 69,997 | 69,507 | |||||||||||||||
| Assets | 302,119 | 297,948 | 265,551 | 213,021 | 211,770 | |||||||||||||||
Transaction deposits(b) | 223,537 | 216,113 | 194,904 | 155,895 | 151,669 | |||||||||||||||
Core deposits(c) | 235,639 | 228,516 | 206,545 | 166,436 | 162,510 | |||||||||||||||
Wholesale funding(d) | 23,252 | 25,912 | 21,551 | 18,853 | 21,821 | |||||||||||||||
Bancorp shareholders’ equity | 34,338 | 34,260 | 30,108 | 21,527 | 21,216 | |||||||||||||||
Regulatory Capital Ratios(e) | ||||||||||||||||||||
CET1 capital | 10.02 | % | 9.93 | % | 9.89 | % | 10.81 | % | 10.57 | % | ||||||||||
Tier 1 risk-based capital | 10.90 | % | 10.81 | % | 10.79 | % | 11.87 | % | 11.63 | % | ||||||||||
Total risk-based capital | 12.54 | % | 12.50 | % | 12.50 | % | 13.78 | % | 13.54 | % | ||||||||||
| Leverage | 9.22 | % | 9.20 | % | 10.22 | % | 9.41 | % | 9.24 | % | ||||||||||
| Additional Metrics | ||||||||||||||||||||
| Banking centers | 1,429 | 1,500 | 1,489 | 1,130 | 1,102 | |||||||||||||||
| ATMs | 2,549 | 2,648 | 2,643 | 2,199 | 2,184 | |||||||||||||||
| Full-time equivalent employees | 25,069 | 25,197 | 25,980 | 18,676 | 18,476 | |||||||||||||||
Assets under care ($ in billions)(g) | $880 | $902 | $865 | $690 | $681 | |||||||||||||||
Assets under management ($ in billions)(g) | 125 | 128 | 119 | 80 | 77 | |||||||||||||||
(a)Non-GAAP measure; see discussion and reconciliation of non-GAAP measures beginning on page 27.
(b)Includes demand, interest checking, savings and money market deposits.
(c)Includes transaction deposits plus CDs $250,000 or less.
(d)Includes CDs over $250,000, other deposits, federal funds purchased, other short-term borrowings and long-term debt.
(e)Current period regulatory capital ratios are estimates.
(f)The allowance for credit losses is the sum of the ALLL and the reserve for unfunded commitments.
(g)Assets under management and assets under care include trust and brokerage assets.
(h)Excludes net charge-offs of $100 million which were taken at the time of acquisition.
15
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||||||||||||||
| Consolidated Statements of Income | ||||||||||||||||||||||||||
| $ in millions | For the Three Months Ended | % Change | Year to Date | % Change | ||||||||||||||||||||||
| (unaudited) | September | June | September | September | September | |||||||||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | 2026 | 2025 | Yr/Yr | |||||||||||||||||||
| Interest Income | ||||||||||||||||||||||||||
| Interest and fees on loans and leases | $2,669 | $2,607 | $1,909 | 2% | 40% | $7,570 | $5,604 | 35% | ||||||||||||||||||
| Interest on securities | 631 | 598 | 444 | 6% | 42% | 1,730 | 1,354 | 28% | ||||||||||||||||||
| Interest on other short-term investments | 198 | 167 | 166 | 19% | 19% | 543 | 477 | 14% | ||||||||||||||||||
| Total interest income | 3,498 | 3,372 | 2,519 | 4% | 39% | 9,843 | 7,435 | 32% | ||||||||||||||||||
| Interest Expense | ||||||||||||||||||||||||||
| Interest on deposits | 983 | 891 | 750 | 10% | 31% | 2,688 | 2,226 | 21% | ||||||||||||||||||
Interest on short-term borrowings | 28 | 38 | 61 | (26%) | (54%) | 71 | 181 | (61%) | ||||||||||||||||||
| Interest on long-term debt | 216 | 228 | 188 | (5%) | 15% | 664 | 575 | 15% | ||||||||||||||||||
| Total interest expense | 1,227 | 1,157 | 999 | 6% | 23% | 3,423 | 2,982 | 15% | ||||||||||||||||||
| Net Interest Income | 2,271 | 2,215 | 1,520 | 3% | 49% | 6,420 | 4,453 | 44% | ||||||||||||||||||
| Provision for credit losses | 122 | 129 | 197 | (5%) | (38%) | 479 | 544 | (12%) | ||||||||||||||||||
| Net Interest Income After Provision for Credit Losses | 2,149 | 2,086 | 1,323 | 3% | 62% | 5,941 | 3,909 | 52% | ||||||||||||||||||
| Noninterest Income | ||||||||||||||||||||||||||
| Wealth and asset management revenue | 259 | 256 | 181 | 1% | 43% | 748 | 519 | 44% | ||||||||||||||||||
| Commercial payments revenue | 256 | 254 | 157 | 1% | 63% | 728 | 462 | 58% | ||||||||||||||||||
| Consumer banking revenue | 158 | 161 | 144 | (2%) | 10% | 465 | 428 | 9% | ||||||||||||||||||
| Capital markets fees | 147 | 154 | 115 | (5%) | 28% | 435 | 294 | 48% | ||||||||||||||||||
| Commercial banking revenue | 128 | 125 | 87 | 2% | 47% | 358 | 247 | 45% | ||||||||||||||||||
| Mortgage banking net revenue | 47 | 39 | 58 | 21% | (19%) | 130 | 171 | (24%) | ||||||||||||||||||
| Other noninterest income | 18 | 50 | 29 | (64%) | (38%) | 95 | 86 | 10% | ||||||||||||||||||
| Securities gains (losses), net | (5) | 20 | 10 | NM | NM | 3 | 17 | (82%) | ||||||||||||||||||
| Total noninterest income | 1,008 | 1,059 | 781 | (5%) | 29% | 2,962 | 2,224 | 33% | ||||||||||||||||||
| Noninterest Expense | ||||||||||||||||||||||||||
| Compensation and benefits | 982 | 1,129 | 685 | (13%) | 43% | 3,521 | 2,132 | 65% | ||||||||||||||||||
| Technology and communications | 300 | 250 | 128 | 20% | 134% | 753 | 378 | 99% | ||||||||||||||||||
| Net occupancy expense | 144 | 154 | 89 | (6%) | 62% | 439 | 260 | 69% | ||||||||||||||||||
| Card and processing expense | 60 | 66 | 22 | (9%) | 173% | 205 | 65 | 215% | ||||||||||||||||||
| Equipment expense | 59 | 60 | 44 | (2%) | 34% | 173 | 126 | 37% | ||||||||||||||||||
| Loan and lease expense | 47 | 53 | 39 | (11%) | 21% | 142 | 105 | 35% | ||||||||||||||||||
| Marketing expense | 57 | 65 | 34 | (12%) | 68% | 171 | 105 | 63% | ||||||||||||||||||
| Other noninterest expense | 400 | 332 | 226 | 20% | 77% | 1,149 | 664 | 73% | ||||||||||||||||||
| Total noninterest expense | 2,049 | 2,109 | 1,267 | (3%) | 62% | 6,553 | 3,835 | 71% | ||||||||||||||||||
| Income Before Income Taxes | 1,108 | 1,036 | 837 | 7% | 32% | 2,350 | 2,298 | 2% | ||||||||||||||||||
| Applicable income tax expense | 242 | 235 | 188 | 3% | 29% | 518 | 507 | 2% | ||||||||||||||||||
| Net Income | 866 | 801 | 649 | 8% | 33% | 1,832 | 1,791 | 2% | ||||||||||||||||||
| Dividends on preferred stock | 38 | 38 | 41 | — | (7%) | 113 | 114 | (1%) | ||||||||||||||||||
| Net Income Available to Common Shareholders | $828 | $763 | $608 | 9% | 36% | $1,719 | $1,677 | 3% | ||||||||||||||||||
16
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Consolidated Statements of Income | |||||||||||||||||
| $ in millions | For the Three Months Ended | ||||||||||||||||
| (unaudited) | September | June | March | December | September | ||||||||||||
| 2026 | 2026 | 2026 | 2025 | 2025 | |||||||||||||
| Interest Income | |||||||||||||||||
| Interest and fees on loans and leases | $2,669 | $2,607 | $2,293 | $1,862 | $1,909 | ||||||||||||
| Interest on securities | 631 | 598 | 501 | 431 | 444 | ||||||||||||
| Interest on other short-term investments | 198 | 167 | 178 | 175 | 166 | ||||||||||||
| Total interest income | 3,498 | 3,372 | 2,972 | 2,468 | 2,519 | ||||||||||||
| Interest Expense | |||||||||||||||||
| Interest on deposits | 983 | 891 | 813 | 726 | 750 | ||||||||||||
Interest on short-term borrowings | 28 | 38 | 5 | 34 | 61 | ||||||||||||
| Interest on long-term debt | 216 | 228 | 220 | 179 | 188 | ||||||||||||
| Total interest expense | 1,227 | 1,157 | 1,038 | 939 | 999 | ||||||||||||
| Net Interest Income | 2,271 | 2,215 | 1,934 | 1,529 | 1,520 | ||||||||||||
| Provision for credit losses | 122 | 129 | 227 | 119 | 197 | ||||||||||||
| Net Interest Income After Provision for Credit Losses | 2,149 | 2,086 | 1,707 | 1,410 | 1,323 | ||||||||||||
| Noninterest Income | |||||||||||||||||
| Wealth and asset management revenue | 259 | 256 | 233 | 185 | 181 | ||||||||||||
| Commercial payments revenue | 256 | 254 | 218 | 167 | 157 | ||||||||||||
| Consumer banking revenue | 158 | 161 | 146 | 143 | 144 | ||||||||||||
| Capital markets fees | 147 | 154 | 134 | 121 | 115 | ||||||||||||
| Commercial banking revenue | 128 | 125 | 105 | 102 | 87 | ||||||||||||
| Mortgage banking net revenue | 47 | 39 | 44 | 56 | 58 | ||||||||||||
| Other noninterest income | 18 | 50 | 27 | 42 | 29 | ||||||||||||
| Securities (losses) gains, net | (5) | 20 | (12) | (5) | 10 | ||||||||||||
| Total noninterest income | 1,008 | 1,059 | 895 | 811 | 781 | ||||||||||||
| Noninterest Expense | |||||||||||||||||
| Compensation and benefits | 982 | 1,129 | 1,410 | 683 | 685 | ||||||||||||
| Technology and communications | 300 | 250 | 204 | 138 | 128 | ||||||||||||
| Net occupancy expense | 144 | 154 | 140 | 89 | 89 | ||||||||||||
| Card and processing expense | 60 | 66 | 79 | 27 | 22 | ||||||||||||
| Equipment expense | 59 | 60 | 55 | 43 | 44 | ||||||||||||
| Loan and lease expense | 47 | 53 | 42 | 41 | 39 | ||||||||||||
| Marketing expense | 57 | 65 | 50 | 37 | 34 | ||||||||||||
| Other noninterest expense | 400 | 332 | 415 | 251 | 226 | ||||||||||||
| Total noninterest expense | 2,049 | 2,109 | 2,395 | 1,309 | 1,267 | ||||||||||||
| Income Before Income Taxes | 1,108 | 1,036 | 207 | 912 | 837 | ||||||||||||
| Applicable income tax expense | 242 | 235 | 42 | 181 | 188 | ||||||||||||
| Net Income | 866 | 801 | 165 | 731 | 649 | ||||||||||||
| Dividends on preferred stock | 38 | 38 | 37 | 32 | 41 | ||||||||||||
| Net Income Available to Common Shareholders | $828 | $763 | $128 | $699 | $608 | ||||||||||||
17
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Consolidated Balance Sheets | |||||||||||||||||
| $ in millions, except per share data | As of | % Change | |||||||||||||||
| (unaudited) | September | June | September | ||||||||||||||
| 2026 | 2026 | 2025 | Seq | Yr/Yr | |||||||||||||
| Assets | |||||||||||||||||
| Cash and due from banks | $4,086 | $4,374 | $2,901 | (7%) | 41% | ||||||||||||
| Other short-term investments | 16,520 | 19,350 | 17,215 | (15%) | (4%) | ||||||||||||
Available-for-sale debt and other securities(a) | 42,984 | 44,466 | 36,461 | (3%) | 18% | ||||||||||||
Held-to-maturity securities(b) | 20,862 | 18,404 | 11,498 | 13% | 81% | ||||||||||||
| Trading debt securities | 1,760 | 1,853 | 1,266 | (5%) | 39% | ||||||||||||
| Equity securities | 471 | 495 | 287 | (5%) | 64% | ||||||||||||
| Loans and leases held for sale | 728 | 866 | 576 | (16%) | 26% | ||||||||||||
| Portfolio loans and leases: | |||||||||||||||||
| Commercial and industrial loans | 86,144 | 85,736 | 53,947 | — | 60% | ||||||||||||
| Commercial mortgage loans | 27,486 | 27,196 | 11,932 | 1% | 130% | ||||||||||||
| Commercial construction loans | 8,957 | 8,459 | 5,326 | 6% | 68% | ||||||||||||
| Commercial leases | 3,779 | 3,489 | 3,218 | 8% | 17% | ||||||||||||
| Total commercial loans and leases | 126,366 | 124,880 | 74,423 | 1% | 70% | ||||||||||||
| Residential mortgage loans | 19,895 | 19,713 | 17,644 | 1% | 13% | ||||||||||||
| Home equity | 7,132 | 6,929 | 4,678 | 3% | 52% | ||||||||||||
| Indirect secured consumer loans | 18,196 | 18,186 | 17,885 | — | 2% | ||||||||||||
| Credit card | 1,660 | 1,683 | 1,692 | (1%) | (2%) | ||||||||||||
| Solar energy installation loans | 4,193 | 4,314 | 4,432 | (3%) | (5%) | ||||||||||||
| Other consumer loans | 2,830 | 2,823 | 2,376 | — | 19% | ||||||||||||
| Total consumer loans | 53,906 | 53,648 | 48,707 | — | 11% | ||||||||||||
| Portfolio loans and leases | 180,272 | 178,528 | 123,130 | 1% | 46% | ||||||||||||
| Allowance for loan and lease losses | (2,906) | (2,918) | (2,265) | — | 28% | ||||||||||||
| Portfolio loans and leases, net | 177,366 | 175,610 | 120,865 | 1% | 47% | ||||||||||||
| Bank premises and equipment | 3,336 | 3,343 | 2,655 | — | 26% | ||||||||||||
| Goodwill | 9,984 | 9,990 | 4,947 | — | 102% | ||||||||||||
| Intangible assets | 1,190 | 1,253 | 76 | (5%) | NM | ||||||||||||
| Servicing rights | 1,669 | 1,607 | 1,601 | 4% | 4% | ||||||||||||
| Other assets | 20,268 | 18,569 | 12,555 | 9% | 61% | ||||||||||||
| Total Assets | $301,224 | $300,180 | $212,903 | — | 41% | ||||||||||||
| Liabilities | |||||||||||||||||
| Deposits: | |||||||||||||||||
| Demand | $64,747 | $63,928 | $41,830 | 1% | 55% | ||||||||||||
| Interest checking | 81,784 | 70,527 | 57,239 | 16% | 43% | ||||||||||||
| Savings | 18,002 | 18,161 | 16,110 | (1%) | 12% | ||||||||||||
| Money market | 60,842 | 65,932 | 38,748 | (8%) | 57% | ||||||||||||
| CDs $250,000 or less | 11,576 | 12,708 | 10,667 | (9%) | 9% | ||||||||||||
| CDs over $250,000 | 2,535 | 2,885 | 1,975 | (12%) | 28% | ||||||||||||
| Total deposits | 239,486 | 234,141 | 166,569 | 2% | 44% | ||||||||||||
| Short-term borrowings | 1,200 | 4,633 | 5,260 | (74%) | (77%) | ||||||||||||
| Accrued taxes, interest and expenses | 2,955 | 3,022 | 1,943 | (2%) | 52% | ||||||||||||
| Other liabilities | 7,330 | 6,266 | 4,347 | 17% | 69% | ||||||||||||
| Long-term debt | 16,938 | 17,636 | 13,677 | (4%) | 24% | ||||||||||||
| Total Liabilities | 267,909 | 265,698 | 191,796 | 1% | 40% | ||||||||||||
| Equity | |||||||||||||||||
Common stock(c) | 2,585 | 2,585 | 2,051 | — | 26% | ||||||||||||
| Preferred stock | 2,182 | 2,182 | 1,770 | — | 23% | ||||||||||||
| Capital surplus | 15,619 | 15,603 | 3,813 | — | 310% | ||||||||||||
| Retained earnings | 26,085 | 25,645 | 25,057 | 2% | 4% | ||||||||||||
| Accumulated other comprehensive loss | (4,919) | (3,286) | (3,276) | 50% | 50% | ||||||||||||
| Treasury stock | (8,237) | (8,247) | (8,308) | — | (1%) | ||||||||||||
| Total Equity | 33,315 | 34,482 | 21,107 | (3%) | 58% | ||||||||||||
| Total Liabilities and Equity | $301,224 | $300,180 | $212,903 | — | 41% | ||||||||||||
| (a) Amortized cost | $47,718 | $47,623 | $39,617 | — | 20% | ||||||||||||
| (b) Market values | 19,823 | 18,258 | 11,506 | 9 | % | 72 | % | ||||||||||
| (c) Common shares, stated value $2.22 per share (in thousands): | |||||||||||||||||
| Authorized | 2,000,000 | 2,000,000 | 2,000,000 | — | — | ||||||||||||
| Outstanding, excluding treasury | 907,367 | 906,573 | 660,973 | — | — | ||||||||||||
| Treasury | 256,872 | 257,666 | 262,919 | — | — | ||||||||||||
18
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Consolidated Balance Sheets | |||||||||||||||||
| $ in millions, except per share data | As of | ||||||||||||||||
| (unaudited) | September | June | March | December | September | ||||||||||||
| 2026 | 2026 | 2026 | 2025 | 2025 | |||||||||||||
| Assets | |||||||||||||||||
| Cash and due from banks | $4,086 | $4,374 | $4,084 | $3,499 | $2,901 | ||||||||||||
| Other short-term investments | 16,520 | 19,350 | 17,456 | 18,876 | 17,215 | ||||||||||||
Available-for-sale debt and other securities(a) | 42,984 | 44,466 | 46,161 | 36,159 | 36,461 | ||||||||||||
Held-to-maturity securities(b) | 20,862 | 18,404 | 16,389 | 11,368 | 11,498 | ||||||||||||
| Trading debt securities | 1,760 | 1,853 | 1,669 | 1,057 | 1,266 | ||||||||||||
| Equity securities | 471 | 495 | 544 | 453 | 287 | ||||||||||||
| Loans and leases held for sale | 728 | 866 | 1,365 | 733 | 576 | ||||||||||||
| Portfolio loans and leases: | |||||||||||||||||
| Commercial and industrial loans | 86,144 | 85,736 | 83,864 | 52,749 | 53,947 | ||||||||||||
| Commercial mortgage loans | 27,486 | 27,196 | 27,143 | 12,228 | 11,932 | ||||||||||||
| Commercial construction loans | 8,957 | 8,459 | 8,329 | 5,316 | 5,326 | ||||||||||||
| Commercial leases | 3,779 | 3,489 | 3,523 | 3,269 | 3,218 | ||||||||||||
| Total commercial loans and leases | 126,366 | 124,880 | 122,859 | 73,562 | 74,423 | ||||||||||||
| Residential mortgage loans | 19,895 | 19,713 | 19,507 | 17,652 | 17,644 | ||||||||||||
| Home equity | 7,132 | 6,929 | 6,735 | 4,846 | 4,678 | ||||||||||||
| Indirect secured consumer loans | 18,196 | 18,186 | 18,296 | 17,964 | 17,885 | ||||||||||||
| Credit card | 1,660 | 1,683 | 1,658 | 1,747 | 1,692 | ||||||||||||
| Solar energy installation loans | 4,193 | 4,314 | 4,465 | 4,560 | 4,432 | ||||||||||||
| Other consumer loans | 2,830 | 2,823 | 2,730 | 2,320 | 2,376 | ||||||||||||
| Total consumer loans | 53,906 | 53,648 | 53,391 | 49,089 | 48,707 | ||||||||||||
| Portfolio loans and leases | 180,272 | 178,528 | 176,250 | 122,651 | 123,130 | ||||||||||||
| Allowance for loan and lease losses | (2,906) | (2,918) | (2,922) | (2,253) | (2,265) | ||||||||||||
| Portfolio loans and leases, net | 177,366 | 175,610 | 173,328 | 120,398 | 120,865 | ||||||||||||
| Bank premises and equipment | 3,336 | 3,343 | 3,283 | 2,734 | 2,655 | ||||||||||||
| Goodwill | 9,984 | 9,990 | 9,966 | 4,947 | 4,947 | ||||||||||||
| Intangible assets | 1,190 | 1,253 | 1,233 | 69 | 76 | ||||||||||||
| Servicing rights | 1,669 | 1,607 | 1,583 | 1,598 | 1,601 | ||||||||||||
| Other assets | 20,268 | 18,569 | 19,978 | 12,485 | 12,555 | ||||||||||||
| Total Assets | $301,224 | $300,180 | $297,039 | $214,376 | $212,903 | ||||||||||||
| Liabilities | |||||||||||||||||
| Deposits: | |||||||||||||||||
| Demand | $64,747 | $63,928 | $65,335 | $42,647 | $41,830 | ||||||||||||
| Interest checking | 81,784 | 70,527 | 72,425 | 61,155 | 57,239 | ||||||||||||
| Savings | 18,002 | 18,161 | 18,610 | 16,155 | 16,110 | ||||||||||||
| Money market | 60,842 | 65,932 | 62,345 | 39,285 | 38,748 | ||||||||||||
| CDs $250,000 or less | 11,576 | 12,708 | 11,807 | 10,599 | 10,667 | ||||||||||||
| CDs over $250,000 | 2,535 | 2,885 | 3,099 | 1,978 | 1,975 | ||||||||||||
| Total deposits | 239,486 | 234,141 | 233,621 | 171,819 | 166,569 | ||||||||||||
| Short-term borrowings | 1,200 | 4,633 | 1,289 | 926 | 5,260 | ||||||||||||
| Accrued taxes, interest and expenses | 2,955 | 3,022 | 2,628 | 2,083 | 1,943 | ||||||||||||
| Other liabilities | 7,330 | 6,266 | 6,642 | 4,235 | 4,347 | ||||||||||||
| Long-term debt | 16,938 | 17,636 | 18,753 | 13,589 | 13,677 | ||||||||||||
| Total Liabilities | 267,909 | 265,698 | 262,933 | 192,652 | 191,796 | ||||||||||||
| Equity | |||||||||||||||||
Common stock(c) | 2,585 | 2,585 | 2,585 | 2,051 | 2,051 | ||||||||||||
| Preferred stock | 2,182 | 2,182 | 2,182 | 1,770 | 1,770 | ||||||||||||
| Capital surplus | 15,619 | 15,603 | 15,586 | 3,831 | 3,813 | ||||||||||||
| Retained earnings | 26,085 | 25,645 | 25,248 | 25,488 | 25,057 | ||||||||||||
| Accumulated other comprehensive loss | (4,919) | (3,286) | (3,234) | (3,110) | (3,276) | ||||||||||||
| Treasury stock | (8,237) | (8,247) | (8,261) | (8,306) | (8,308) | ||||||||||||
| Total Equity | 33,315 | 34,482 | 34,106 | 21,724 | 21,107 | ||||||||||||
| Total Liabilities and Equity | $301,224 | $300,180 | $297,039 | $214,376 | $212,903 | ||||||||||||
| (a) Amortized cost | $47,718 | $47,623 | $49,238 | $39,107 | $39,617 | ||||||||||||
| (b) Market values | 19,823 | 18,258 | 16,341 | 11,404 | 11,506 | ||||||||||||
| (c) Common shares, stated value $2.22 per share (in thousands): | |||||||||||||||||
| Authorized | 2,000,000 | 2,000,000 | 2,000,000 | 2,000,000 | 2,000,000 | ||||||||||||
| Outstanding, excluding treasury | 907,367 | 906,573 | 905,823 | 661,198 | 660,973 | ||||||||||||
| Treasury | 256,872 | 257,666 | 258,416 | 262,695 | 262,919 | ||||||||||||
19
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||||||||
| Consolidated Statements of Changes in Equity | ||||||||||||||||||||
| $ in millions | ||||||||||||||||||||
| (unaudited) | ||||||||||||||||||||
| For the Three Months Ended | Year to Date | |||||||||||||||||||
| September | September | September | September | |||||||||||||||||
| 2026 | 2025 | 2026 | 2025 | |||||||||||||||||
| Total Equity, Beginning | $34,482 | $21,124 | $21,724 | $19,645 | ||||||||||||||||
| Net income | 866 | 649 | 1,832 | 1,791 | ||||||||||||||||
| Other comprehensive (loss) income, net of tax: | ||||||||||||||||||||
| Change in unrealized (losses) gains: | ||||||||||||||||||||
| Available-for-sale debt securities | (1,203) | 230 | (1,365) | 890 | ||||||||||||||||
| Qualifying cash flow hedges | (457) | 14 | (577) | 397 | ||||||||||||||||
| Amortization of unrealized losses on securities transferred to held-to-maturity | 25 | 25 | 71 | 72 | ||||||||||||||||
| Change in accumulated other comprehensive income related to employee benefit plans | 2 | 1 | 62 | 1 | ||||||||||||||||
| Comprehensive income (loss) | (767) | 919 | 23 | 3,151 | ||||||||||||||||
| Cash dividends declared: | ||||||||||||||||||||
| Common stock | (388) | (269) | (1,122) | (770) | ||||||||||||||||
| Preferred stock | (38) | (37) | (113) | (110) | ||||||||||||||||
| Impact of Comerica acquisition | — | — | 12,676 | — | ||||||||||||||||
| Impact of stock transactions under stock compensation plans, net | 26 | 23 | 128 | 70 | ||||||||||||||||
| Shares acquired for treasury | — | (303) | — | (529) | ||||||||||||||||
| Redemption of preferred stock | — | (350) | — | (350) | ||||||||||||||||
| Other | — | — | (1) | — | ||||||||||||||||
| Total Equity, Ending | $33,315 | $21,107 | $33,315 | $21,107 | ||||||||||||||||
20
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||||||||||||||
| Average Balance Sheets and Yield/Rate Analysis | For the Three Months Ended | |||||||||||||||||||||||||
| $ in millions | September | June | September | |||||||||||||||||||||||
| (unaudited) | 2026 | 2026 | 2025 | |||||||||||||||||||||||
| Average | Average | Average | Average | Average | Average | |||||||||||||||||||||
| Balance | Yield/Rate | Balance | Yield/Rate | Balance | Yield/Rate | |||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||
| Loans and leases: | ||||||||||||||||||||||||||
Commercial and industrial loans(a) | $86,052 | 5.89 | % | $85,260 | 5.90 | % | $54,196 | 6.20 | % | |||||||||||||||||
Commercial mortgage loans(a) | 27,297 | 5.96 | % | 27,215 | 5.82 | % | 12,043 | 6.26 | % | |||||||||||||||||
Commercial construction loans(a) | 8,810 | 6.49 | % | 8,504 | 6.50 | % | 5,541 | 7.17 | % | |||||||||||||||||
Commercial leases(a) | 3,574 | 4.67 | % | 3,503 | 4.61 | % | 3,177 | 4.70 | % | |||||||||||||||||
| Total commercial loans and leases | 125,733 | 5.91 | % | 124,482 | 5.89 | % | 74,957 | 6.22 | % | |||||||||||||||||
| Residential mortgage loans | 20,372 | 4.25 | % | 20,362 | 4.16 | % | 18,279 | 4.03 | % | |||||||||||||||||
| Home equity | 7,023 | 6.90 | % | 6,830 | 6.95 | % | 4,580 | 7.43 | % | |||||||||||||||||
| Indirect secured consumer loans | 18,182 | 5.54 | % | 18,239 | 5.53 | % | 17,729 | 5.65 | % | |||||||||||||||||
| Credit card | 1,646 | 14.07 | % | 1,646 | 13.69 | % | 1,678 | 14.26 | % | |||||||||||||||||
| Solar energy installation loans | 4,244 | 7.82 | % | 4,384 | 7.93 | % | 4,355 | 8.76 | % | |||||||||||||||||
| Other consumer loans | 2,811 | 8.64 | % | 2,764 | 8.66 | % | 2,415 | 9.25 | % | |||||||||||||||||
| Total consumer loans | 54,278 | 5.83 | % | 54,225 | 5.80 | % | 49,036 | 5.96 | % | |||||||||||||||||
| Total loans and leases | 180,011 | 5.89 | % | 178,707 | 5.86 | % | 123,993 | 6.12 | % | |||||||||||||||||
| Securities: | ||||||||||||||||||||||||||
| Taxable securities | 67,170 | 3.68 | % | 66,532 | 3.55 | % | 53,244 | 3.25 | % | |||||||||||||||||
Tax exempt securities(a) | 1,373 | 3.23 | % | 1,392 | 3.25 | % | 1,348 | 3.18 | % | |||||||||||||||||
| Other short-term investments | 21,469 | 3.66 | % | 18,358 | 3.64 | % | 14,915 | 4.43 | % | |||||||||||||||||
| Total interest-earning assets | 270,023 | 5.15 | % | 264,989 | 5.11 | % | 193,500 | 5.18 | % | |||||||||||||||||
| Cash and due from banks | 3,449 | 3,307 | 2,485 | |||||||||||||||||||||||
| Other assets | 31,565 | 32,574 | 18,196 | |||||||||||||||||||||||
| Allowance for loan and lease losses | (2,918) | (2,922) | (2,411) | |||||||||||||||||||||||
| Total Assets | $302,119 | $297,948 | $211,770 | |||||||||||||||||||||||
| Liabilities | ||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||
| Interest checking deposits | $75,025 | 2.26 | % | $70,507 | 2.15 | % | $56,624 | 2.72 | % | |||||||||||||||||
| Savings deposits | 18,037 | 0.36 | % | 18,430 | 0.35 | % | 16,376 | 0.46 | % | |||||||||||||||||
| Money market deposits | 66,247 | 2.56 | % | 63,200 | 2.43 | % | 37,434 | 2.40 | % | |||||||||||||||||
| CDs $250,000 or less | 12,102 | 2.97 | % | 12,403 | 2.94 | % | 10,841 | 3.46 | % | |||||||||||||||||
| Total interest-bearing core deposits | 171,411 | 2.23 | % | 164,540 | 2.11 | % | 121,275 | 2.38 | % | |||||||||||||||||
| CDs over $250,000 | 2,705 | 3.17 | % | 2,990 | 3.25 | % | 2,244 | 4.00 | % | |||||||||||||||||
| Total interest-bearing deposits | 174,116 | 2.24 | % | 167,530 | 2.13 | % | 123,519 | 2.41 | % | |||||||||||||||||
| Federal funds purchased | 181 | 3.69 | % | 160 | 3.65 | % | 198 | 4.35 | % | |||||||||||||||||
| Securities sold under repurchase agreements | 395 | 1.63 | % | 444 | 1.69 | % | 376 | 1.65 | % | |||||||||||||||||
| FHLB advances | 2,365 | 3.89 | % | 3,437 | 3.88 | % | 4,920 | 4.51 | % | |||||||||||||||||
| Derivative collateral and other secured borrowings | 93 | 6.33 | % | 64 | 7.25 | % | 82 | 6.13 | % | |||||||||||||||||
| Long-term debt | 17,513 | 4.90 | % | 18,817 | 4.87 | % | 14,001 | 5.31 | % | |||||||||||||||||
| Total interest-bearing liabilities | 194,663 | 2.50 | % | 190,452 | 2.44 | % | 143,096 | 2.77 | % | |||||||||||||||||
| Demand deposits | 64,228 | 63,976 | 41,235 | |||||||||||||||||||||||
| Other liabilities | 8,890 | 9,260 | 6,223 | |||||||||||||||||||||||
| Total Liabilities | 267,781 | 263,688 | 190,554 | |||||||||||||||||||||||
| Total Equity | 34,338 | 34,260 | 21,216 | |||||||||||||||||||||||
| Total Liabilities and Equity | $302,119 | $297,948 | $211,770 | |||||||||||||||||||||||
| Ratios: | ||||||||||||||||||||||||||
Net interest margin (FTE)(b) | 3.34 | % | 3.36 | % | 3.13 | % | ||||||||||||||||||||
Net interest rate spread (FTE)(b) | 2.65 | % | 2.67 | % | 2.41 | % | ||||||||||||||||||||
| Interest-bearing liabilities to interest-earning assets | 72.09 | % | 71.87 | % | 73.95 | % | ||||||||||||||||||||
| (a) Average Yield/Rate of these assets are presented on an FTE basis. | ||||||||||||||||||||||||||
(b) Non-GAAP measure; see discussion and reconciliation of non-GAAP measures beginning on page 27. | ||||||||||||||||||||||||||
21
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Average Balance Sheets and Yield/Rate Analysis | Year to Date | ||||||||||||||||
| $ in millions | September | September | |||||||||||||||
| (unaudited) | 2026 | 2025 | |||||||||||||||
| Average | Average | Average | Average | ||||||||||||||
| Balance | Yield/Rate | Balance | Yield/Rate | ||||||||||||||
| Assets | |||||||||||||||||
| Interest-earning assets: | |||||||||||||||||
| Loans and leases: | |||||||||||||||||
Commercial and industrial loans(a) | $81,586 | 5.89 | % | $53,916 | 6.23 | % | |||||||||||
Commercial mortgage loans(a) | 25,524 | 5.88 | % | 12,282 | 6.12 | % | |||||||||||
Commercial construction loans(a) | 8,206 | 6.48 | % | 5,720 | 7.09 | % | |||||||||||
Commercial leases(a) | 3,476 | 4.71 | % | 3,136 | 4.77 | % | |||||||||||
| Total commercial loans and leases | 118,792 | 5.90 | % | 75,054 | 6.22 | % | |||||||||||
| Residential mortgage loans | 20,052 | 4.20 | % | 18,139 | 3.99 | % | |||||||||||
| Home equity | 6,643 | 6.95 | % | 4,396 | 7.47 | % | |||||||||||
| Indirect secured consumer loans | 18,175 | 5.54 | % | 17,156 | 5.62 | % | |||||||||||
| Credit card | 1,650 | 13.90 | % | 1,655 | 14.44 | % | |||||||||||
| Solar energy installation loans | 4,380 | 7.98 | % | 4,282 | 8.30 | % | |||||||||||
| Other consumer loans | 2,722 | 8.69 | % | 2,465 | 9.24 | % | |||||||||||
| Total consumer loans | 53,622 | 5.83 | % | 48,093 | 5.90 | % | |||||||||||
| Total loans and leases | 172,414 | 5.88 | % | 123,147 | 6.09 | % | |||||||||||
| Securities: | |||||||||||||||||
| Taxable securities | 64,128 | 3.55 | % | 54,441 | 3.26 | % | |||||||||||
Tax exempt securities(a) | 1,376 | 3.25 | % | 1,362 | 3.18 | % | |||||||||||
| Other short-term investments | 19,858 | 3.65 | % | 14,050 | 4.54 | % | |||||||||||
| Total interest-earning assets | 257,776 | 5.11 | % | 193,000 | 5.16 | % | |||||||||||
| Cash and due from banks | 3,275 | 2,437 | |||||||||||||||
| Other assets | 30,465 | 17,911 | |||||||||||||||
| Allowance for loan and lease losses | (2,843) | (2,383) | |||||||||||||||
| Total Assets | $288,673 | $210,965 | |||||||||||||||
| Liabilities | |||||||||||||||||
| Interest-bearing liabilities: | |||||||||||||||||
| Interest checking deposits | $70,996 | 2.20 | % | $57,103 | 2.70 | % | |||||||||||
| Savings deposits | 18,006 | 0.35 | % | 16,852 | 0.49 | % | |||||||||||
| Money market deposits | 61,266 | 2.47 | % | 36,731 | 2.41 | % | |||||||||||
| CDs $250,000 or less | 12,050 | 3.01 | % | 10,574 | 3.54 | % | |||||||||||
| Total interest-bearing core deposits | 162,318 | 2.16 | % | 121,260 | 2.38 | % | |||||||||||
| CDs over $250,000 | 2,833 | 3.27 | % | 2,263 | 4.17 | % | |||||||||||
| Total interest-bearing deposits | 165,151 | 2.18 | % | 123,523 | 2.41 | % | |||||||||||
| Federal funds purchased | 173 | 3.67 | % | 199 | 4.37 | % | |||||||||||
| Securities sold under repurchase agreements | 387 | 1.51 | % | 339 | 1.27 | % | |||||||||||
| FHLB advances | 1,975 | 3.89 | % | 4,888 | 4.57 | % | |||||||||||
| Derivative collateral and other secured borrowings | 80 | 6.97 | % | 85 | 6.06 | % | |||||||||||
| Long-term debt | 18,129 | 4.90 | % | 14,393 | 5.35 | % | |||||||||||
| Total interest-bearing liabilities | 185,895 | 2.46 | % | 143,427 | 2.78 | % | |||||||||||
| Demand deposits | 61,356 | 40,641 | |||||||||||||||
| Other liabilities | 8,505 | 6,264 | |||||||||||||||
| Total Liabilities | 255,756 | 190,332 | |||||||||||||||
| Total Equity | 32,917 | 20,633 | |||||||||||||||
| Total Liabilities and Equity | $288,673 | $210,965 | |||||||||||||||
| Ratios: | |||||||||||||||||
Net interest margin (FTE)(b) | 3.34 | % | 3.10 | % | |||||||||||||
Net interest rate spread (FTE)(b) | 2.65 | % | 2.38 | % | |||||||||||||
| Interest-bearing liabilities to interest-earning assets | 72.12 | % | 74.31 | % | |||||||||||||
| (a) Average Yield/Rate of these assets are presented on an FTE basis. | |||||||||||||||||
| (b) Non-GAAP measure; see discussion and reconciliation of non-GAAP measures beginning on page 27. | |||||||||||||||||
22
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Summary of Loans and Leases | |||||||||||||||||
| $ in millions | For the Three Months Ended | ||||||||||||||||
| (unaudited) | September | June | March | December | September | ||||||||||||
| 2026 | 2026 | 2026 | 2025 | 2025 | |||||||||||||
| Average Portfolio Loans and Leases | |||||||||||||||||
| Commercial loans and leases: | |||||||||||||||||
| Commercial and industrial loans | $85,982 | $84,967 | $73,264 | $53,947 | $54,170 | ||||||||||||
| Commercial mortgage loans | 27,263 | 27,176 | 21,969 | 12,079 | 12,027 | ||||||||||||
| Commercial construction loans | 8,744 | 8,437 | 7,278 | 5,399 | 5,541 | ||||||||||||
| Commercial leases | 3,574 | 3,503 | 3,347 | 3,172 | 3,177 | ||||||||||||
| Total commercial loans and leases | 125,563 | 124,083 | 105,858 | 74,597 | 74,915 | ||||||||||||
| Consumer loans: | |||||||||||||||||
| Residential mortgage loans | 19,775 | 19,626 | 18,848 | 17,660 | 17,656 | ||||||||||||
| Home equity | 7,023 | 6,830 | 6,064 | 4,769 | 4,579 | ||||||||||||
| Indirect secured consumer loans | 18,182 | 18,239 | 18,105 | 17,879 | 17,729 | ||||||||||||
| Credit card | 1,646 | 1,646 | 1,659 | 1,694 | 1,678 | ||||||||||||
| Solar energy installation loans | 4,244 | 4,384 | 4,516 | 4,486 | 4,355 | ||||||||||||
| Other consumer loans | 2,811 | 2,764 | 2,582 | 2,345 | 2,414 | ||||||||||||
| Total consumer loans | 53,681 | 53,489 | 51,774 | 48,833 | 48,411 | ||||||||||||
| Total average portfolio loans and leases | $179,244 | $177,572 | $157,632 | $123,430 | $123,326 | ||||||||||||
| Average Loans and Leases Held for Sale | |||||||||||||||||
| Commercial loans and leases held for sale | $170 | $399 | $85 | $19 | $44 | ||||||||||||
| Consumer loans held for sale | 597 | 736 | 566 | 698 | 623 | ||||||||||||
| Average loans and leases held for sale | $767 | $1,135 | $651 | $717 | $667 | ||||||||||||
| End of Period Portfolio Loans and Leases | |||||||||||||||||
| Commercial loans and leases: | |||||||||||||||||
| Commercial and industrial loans | $86,144 | $85,736 | $83,864 | $52,749 | $53,947 | ||||||||||||
| Commercial mortgage loans | 27,486 | 27,196 | 27,143 | 12,228 | 11,932 | ||||||||||||
| Commercial construction loans | 8,957 | 8,459 | 8,329 | 5,316 | 5,326 | ||||||||||||
| Commercial leases | 3,779 | 3,489 | 3,523 | 3,269 | 3,218 | ||||||||||||
| Total commercial loans and leases | 126,366 | 124,880 | 122,859 | 73,562 | 74,423 | ||||||||||||
| Consumer loans: | |||||||||||||||||
| Residential mortgage loans | 19,895 | 19,713 | 19,507 | 17,652 | 17,644 | ||||||||||||
| Home equity | 7,132 | 6,929 | 6,735 | 4,846 | 4,678 | ||||||||||||
| Indirect secured consumer loans | 18,196 | 18,186 | 18,296 | 17,964 | 17,885 | ||||||||||||
| Credit card | 1,660 | 1,683 | 1,658 | 1,747 | 1,692 | ||||||||||||
| Solar energy installation loans | 4,193 | 4,314 | 4,465 | 4,560 | 4,432 | ||||||||||||
| Other consumer loans | 2,830 | 2,823 | 2,730 | 2,320 | 2,376 | ||||||||||||
| Total consumer loans | 53,906 | 53,648 | 53,391 | 49,089 | 48,707 | ||||||||||||
| Total portfolio loans and leases | $180,272 | $178,528 | $176,250 | $122,651 | $123,130 | ||||||||||||
End of Period Loans and Leases Held for Sale | |||||||||||||||||
| Commercial loans and leases held for sale | $233 | $171 | $651 | $75 | $8 | ||||||||||||
| Consumer loans held for sale | 495 | 695 | 714 | 658 | 568 | ||||||||||||
| Loans and leases held for sale | $728 | $866 | $1,365 | $733 | $576 | ||||||||||||
| Operating lease equipment | $454 | $417 | $416 | $374 | $379 | ||||||||||||
Loans and Leases Serviced for Others(a) | |||||||||||||||||
| Commercial and industrial loans | $2,144 | $1,838 | $1,801 | $1,290 | $1,206 | ||||||||||||
| Commercial mortgage loans | 2,718 | 2,193 | 518 | 501 | 558 | ||||||||||||
| Commercial construction loans | 769 | 292 | 318 | 291 | 304 | ||||||||||||
| Commercial leases | 777 | 817 | 821 | 853 | 764 | ||||||||||||
| Residential mortgage loans | 85,091 | 85,907 | 86,733 | 87,827 | 89,639 | ||||||||||||
| Solar energy installation loans | 622 | 643 | 665 | 686 | 692 | ||||||||||||
| Other consumer loans | 76 | 81 | 86 | 92 | 98 | ||||||||||||
| Total loans and leases serviced for others | 92,197 | 91,771 | 90,942 | 91,540 | 93,261 | ||||||||||||
| Total loans and leases owned or serviced | $273,651 | $271,582 | $268,973 | $215,298 | $217,346 | ||||||||||||
(a)Fifth Third sells certain loans and leases and obtains servicing responsibilities.
23
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||||||||
| Regulatory Capital | |||||||||||||||||||||||
| $ in millions | As of | ||||||||||||||||||||||
| (unaudited) | September | June | March | December | September | ||||||||||||||||||
2026(a) | 2026 | 2026 | 2025 | 2025 | |||||||||||||||||||
| Regulatory Capital | |||||||||||||||||||||||
| CET1 capital | $25,002 | $24,508 | $24,136 | $18,099 | $17,645 | ||||||||||||||||||
| Additional tier 1 capital | 2,182 | 2,182 | 2,182 | 1,770 | 1,770 | ||||||||||||||||||
| Tier 1 capital | 27,184 | 26,690 | 26,318 | 19,869 | 19,415 | ||||||||||||||||||
| Tier 2 capital | 4,099 | 4,173 | 4,179 | 3,197 | 3,204 | ||||||||||||||||||
| Total regulatory capital | $31,283 | $30,863 | $30,497 | $23,066 | $22,619 | ||||||||||||||||||
Risk-weighted assets | $249,506 | $246,820 | $243,964 | $167,431 | $166,999 | ||||||||||||||||||
| Ratios | |||||||||||||||||||||||
Average total Bancorp shareholders' equity as a percent of average assets | 11.37 | % | 11.50 | % | 11.34 | % | 10.11 | % | 10.02 | % | |||||||||||||
Regulatory Capital Ratios | |||||||||||||||||||||||
| Fifth Third Bancorp | |||||||||||||||||||||||
CET1 capital | 10.02 | % | 9.93 | % | 9.89 | % | 10.81 | % | 10.57 | % | |||||||||||||
Tier 1 risk-based capital | 10.90 | % | 10.81 | % | 10.79 | % | 11.87 | % | 11.63 | % | |||||||||||||
Total risk-based capital | 12.54 | % | 12.50 | % | 12.50 | % | 13.78 | % | 13.54 | % | |||||||||||||
| Leverage | 9.22 | % | 9.20 | % | 10.22 | % | 9.41 | % | 9.24 | % | |||||||||||||
| Fifth Third Bank, National Association | |||||||||||||||||||||||
Tier 1 risk-based capital | 11.73 | % | 11.70 | % | 11.73 | % | 13.09 | % | 12.95 | % | |||||||||||||
Total risk-based capital | 12.96 | % | 12.95 | % | 13.00 | % | 14.33 | % | 14.19 | % | |||||||||||||
| Leverage | 9.96 | % | 9.99 | % | 11.16 | % | 10.41 | % | 10.31 | % | |||||||||||||
(a)Current period regulatory capital data and ratios are estimated.
24
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Summary of Credit Loss Experience | |||||||||||||||||
| $ in millions | For the Three Months Ended | ||||||||||||||||
| (unaudited) | September | June | March | December | September | ||||||||||||
| 2026 | 2026 | 2026 | 2025 | 2025 | |||||||||||||
| Average portfolio loans and leases: | |||||||||||||||||
| Commercial and industrial loans | $85,982 | $84,967 | $73,264 | $53,947 | $54,170 | ||||||||||||
| Commercial mortgage loans | 27,263 | 27,176 | 21,969 | 12,079 | 12,027 | ||||||||||||
| Commercial construction loans | 8,744 | 8,437 | 7,278 | 5,399 | 5,541 | ||||||||||||
| Commercial leases | 3,574 | 3,503 | 3,347 | 3,172 | 3,177 | ||||||||||||
| Total commercial loans and leases | 125,563 | 124,083 | 105,858 | 74,597 | 74,915 | ||||||||||||
| Residential mortgage loans | 19,775 | 19,626 | 18,848 | 17,660 | 17,656 | ||||||||||||
| Home equity | 7,023 | 6,830 | 6,064 | 4,769 | 4,579 | ||||||||||||
| Indirect secured consumer loans | 18,182 | 18,239 | 18,105 | 17,879 | 17,729 | ||||||||||||
| Credit card | 1,646 | 1,646 | 1,659 | 1,694 | 1,678 | ||||||||||||
| Solar energy installation loans | 4,244 | 4,384 | 4,516 | 4,486 | 4,355 | ||||||||||||
| Other consumer loans | 2,811 | 2,764 | 2,582 | 2,345 | 2,414 | ||||||||||||
| Total consumer loans | 53,681 | 53,489 | 51,774 | 48,833 | 48,411 | ||||||||||||
| Total average portfolio loans and leases | $179,244 | $177,572 | $157,632 | $123,430 | $123,326 | ||||||||||||
| Losses charged-off: | |||||||||||||||||
| Commercial and industrial loans | ($84) | ($73) | ($77) | ($61) | ($280) | ||||||||||||
| Commercial mortgage loans | — | — | — | (7) | (2) | ||||||||||||
| Commercial construction loans | — | — | — | — | — | ||||||||||||
| Commercial leases | — | — | — | (1) | — | ||||||||||||
| Total commercial loans and leases | (84) | (73) | (77) | (69) | (282) | ||||||||||||
| Residential mortgage loans | (1) | (1) | — | — | — | ||||||||||||
| Home equity | (1) | (1) | (2) | (2) | (1) | ||||||||||||
| Indirect secured consumer loans | (35) | (36) | (40) | (41) | (34) | ||||||||||||
| Credit card | (19) | (20) | (19) | (20) | (20) | ||||||||||||
| Solar energy installation loans | (29) | (29) | (26) | (22) | (20) | ||||||||||||
| Other consumer loans | (23) | (21) | (23) | (23) | (25) | ||||||||||||
| Total consumer loans | (108) | (108) | (110) | (108) | (100) | ||||||||||||
| Total losses charged-off | ($192) | ($181) | ($187) | ($177) | ($382) | ||||||||||||
| Recoveries of losses previously charged-off: | |||||||||||||||||
| Commercial and industrial loans | $9 | $8 | $8 | $17 | $6 | ||||||||||||
| Commercial mortgage loans | 6 | — | — | 1 | 1 | ||||||||||||
| Commercial construction loans | — | 1 | — | — | — | ||||||||||||
| Commercial leases | — | — | — | — | — | ||||||||||||
| Total commercial loans and leases | 15 | 9 | 8 | 18 | 7 | ||||||||||||
| Residential mortgage loans | 1 | 1 | — | 1 | 1 | ||||||||||||
| Home equity | 2 | 1 | 2 | 1 | 2 | ||||||||||||
| Indirect secured consumer loans | 18 | 18 | 16 | 14 | 16 | ||||||||||||
| Credit card | 5 | 5 | 5 | 5 | 4 | ||||||||||||
| Solar energy installation loans | 6 | 4 | 3 | 5 | 4 | ||||||||||||
| Other consumer loans | 6 | 8 | 9 | 8 | 9 | ||||||||||||
| Total consumer loans | 38 | 37 | 35 | 34 | 36 | ||||||||||||
| Total recoveries of losses previously charged-off | $53 | $46 | $43 | $52 | $43 | ||||||||||||
| Net losses charged-off: | |||||||||||||||||
| Commercial and industrial loans | ($75) | ($65) | ($69) | ($44) | ($274) | ||||||||||||
| Commercial mortgage loans | 6 | — | — | (6) | (1) | ||||||||||||
| Commercial construction loans | — | 1 | — | — | — | ||||||||||||
| Commercial leases | — | — | — | (1) | — | ||||||||||||
| Total commercial loans and leases | (69) | (64) | (69) | (51) | (275) | ||||||||||||
| Residential mortgage loans | — | — | — | 1 | 1 | ||||||||||||
| Home equity | 1 | — | — | (1) | 1 | ||||||||||||
| Indirect secured consumer loans | (17) | (18) | (24) | (27) | (18) | ||||||||||||
| Credit card | (14) | (15) | (14) | (15) | (16) | ||||||||||||
| Solar energy installation loans | (23) | (25) | (23) | (17) | (16) | ||||||||||||
| Other consumer loans | (17) | (13) | (14) | (15) | (16) | ||||||||||||
| Total consumer loans | (70) | (71) | (75) | (74) | (64) | ||||||||||||
Total net losses charged-off(a) | ($139) | ($135) | ($144) | ($125) | ($339) | ||||||||||||
| Net losses charged-off as a percent of average portfolio loans and leases (annualized): | |||||||||||||||||
| Commercial and industrial loans | 0.35 | % | 0.31 | % | 0.38 | % | 0.32 | % | 2.01 | % | |||||||
| Commercial mortgage loans | (0.09 | %) | (0.01 | %) | — | 0.21 | % | 0.04 | % | ||||||||
| Commercial construction loans | (0.01 | %) | (0.02 | %) | (0.02 | %) | — | — | |||||||||
| Commercial leases | — | (0.01 | %) | — | 0.16 | % | (0.04 | %) | |||||||||
| Total commercial loans and leases | 0.22 | % | 0.21 | % | 0.26 | % | 0.27 | % | 1.46 | % | |||||||
| Residential mortgage loans | — | — | (0.01 | %) | (0.01 | %) | (0.02 | %) | |||||||||
| Home equity | (0.03 | %) | (0.02 | %) | 0.01 | % | 0.06 | % | (0.05 | %) | |||||||
| Indirect secured consumer loans | 0.37 | % | 0.40 | % | 0.54 | % | 0.59 | % | 0.40 | % | |||||||
| Credit card | 3.45 | % | 3.60 | % | 3.51 | % | 3.62 | % | 3.70 | % | |||||||
| Solar energy installation loans | 2.18 | % | 2.25 | % | 2.03 | % | 1.45 | % | 1.47 | % | |||||||
| Other consumer loans | 2.34 | % | 1.95 | % | 2.19 | % | 2.46 | % | 2.51 | % | |||||||
| Total consumer loans | 0.52 | % | 0.53 | % | 0.58 | % | 0.59 | % | 0.52 | % | |||||||
| Total net losses charged-off as a percent of average portfolio loans and leases (annualized) | 0.31 | % | 0.30 | % | 0.37 | % | 0.40 | % | 1.09 | % | |||||||
(a)Excludes net charge-offs of $100 million which were taken at the time of acquisition.
25
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||||||||
| Asset Quality | ||||||||||||||||||||
| $ in millions | For the Three Months Ended | |||||||||||||||||||
| (unaudited) | September | June | March | December | September | |||||||||||||||
| 2026 | 2026 | 2026 | 2025 | 2025 | ||||||||||||||||
| Allowance for Credit Losses | ||||||||||||||||||||
| Allowance for loan and lease losses, beginning | $2,918 | $2,922 | $2,253 | $2,265 | $2,412 | |||||||||||||||
Total net losses charged-off(e) | (139) | (135) | (144) | (125) | (339) | |||||||||||||||
| Provision for loan and lease losses | 127 | 131 | 152 | 113 | 192 | |||||||||||||||
| Allowance on PCD loans and leases at acquisition | — | (1) | 180 | — | — | |||||||||||||||
| Allowance on PSLs at acquisition | — | 1 | 481 | — | — | |||||||||||||||
| Allowance for loan and lease losses, ending | $2,906 | $2,918 | $2,922 | $2,253 | $2,265 | |||||||||||||||
| Reserve for unfunded commitments, beginning | $230 | $232 | $157 | $151 | $146 | |||||||||||||||
| (Benefit from) provision for the reserve for unfunded commitments | (5) | (2) | 75 | 6 | 5 | |||||||||||||||
| Reserve for unfunded commitments, ending | $225 | $230 | $232 | $157 | $151 | |||||||||||||||
| Components of allowance for credit losses: | ||||||||||||||||||||
| Allowance for loan and lease losses | $2,906 | $2,918 | $2,922 | $2,253 | $2,265 | |||||||||||||||
| Reserve for unfunded commitments | 225 | 230 | 232 | 157 | 151 | |||||||||||||||
| Total allowance for credit losses | $3,131 | $3,148 | $3,154 | $2,410 | $2,416 | |||||||||||||||
| As of | ||||||||||||||||||||
| September | June | March | December | September | ||||||||||||||||
| 2026 | 2026 | 2026 | 2025 | 2025 | ||||||||||||||||
| Nonperforming Assets and Delinquent Loans | ||||||||||||||||||||
| Nonaccrual portfolio loans and leases: | ||||||||||||||||||||
| Commercial and industrial loans | $449 | $455 | $417 | $393 | $393 | |||||||||||||||
| Commercial mortgage loans | 141 | 94 | 94 | 34 | 42 | |||||||||||||||
| Commercial construction loans | 64 | 62 | 62 | — | — | |||||||||||||||
| Commercial leases | 4 | 4 | — | — | — | |||||||||||||||
| Residential mortgage loans | 159 | 176 | 164 | 149 | 142 | |||||||||||||||
| Home equity | 135 | 131 | 104 | 71 | 72 | |||||||||||||||
| Indirect secured consumer loans | 61 | 62 | 58 | 61 | 61 | |||||||||||||||
| Credit card | 29 | 29 | 30 | 29 | 29 | |||||||||||||||
| Solar energy installation loans | 23 | 23 | 26 | 22 | 22 | |||||||||||||||
| Other consumer loans | 5 | 5 | 5 | 8 | 7 | |||||||||||||||
| Total nonaccrual portfolio loans and leases | 1,070 | 1,041 | 960 | 767 | 768 | |||||||||||||||
| Repossessed property | 9 | 10 | 11 | 11 | 12 | |||||||||||||||
OREO(d) | 81 | 24 | 28 | 19 | 21 | |||||||||||||||
| Total nonperforming portfolio loans and leases and OREO | 1,160 | 1,075 | 999 | 797 | 801 | |||||||||||||||
| Nonaccrual loans held for sale | 162 | 167 | 141 | 70 | 4 | |||||||||||||||
| Total nonperforming assets | $1,322 | $1,242 | $1,140 | $867 | $805 | |||||||||||||||
| Loans and leases 90 days past due (accrual): | ||||||||||||||||||||
| Commercial and industrial loans | $5 | $4 | $3 | $2 | $2 | |||||||||||||||
| Commercial mortgage loans | 4 | 1 | 19 | — | — | |||||||||||||||
| Commercial construction loans | — | — | 2 | 1 | — | |||||||||||||||
| Commercial leases | — | — | 1 | — | — | |||||||||||||||
| Total commercial loans and leases | 9 | 5 | 25 | 3 | 2 | |||||||||||||||
Residential mortgage loans(c) | 16 | 11 | 7 | 10 | 11 | |||||||||||||||
| Credit card | 16 | 16 | 17 | 17 | 16 | |||||||||||||||
| Other consumer loans | 1 | 1 | — | — | — | |||||||||||||||
| Total consumer loans | 33 | 28 | 24 | 27 | 27 | |||||||||||||||
Total loans and leases 90 days past due (accrual)(b) | $42 | $33 | $49 | $30 | $29 | |||||||||||||||
| Ratios | ||||||||||||||||||||
| Net losses charged-off as a percent of average portfolio loans and leases (annualized) | 0.31 | % | 0.30 | % | 0.37 | % | 0.40 | % | 1.09 | % | ||||||||||
| Allowance for credit losses: | ||||||||||||||||||||
| As a percent of portfolio loans and leases | 1.74 | % | 1.76 | % | 1.79 | % | 1.96 | % | 1.96 | % | ||||||||||
As a percent of nonperforming portfolio loans and leases(a) | 292 | % | 303 | % | 328 | % | 314 | % | 314 | % | ||||||||||
As a percent of nonperforming portfolio assets(a) | 270 | % | 293 | % | 316 | % | 302 | % | 302 | % | ||||||||||
Nonperforming portfolio loans and leases as a percent of portfolio loans and leases(a) | 0.59 | % | 0.58 | % | 0.54 | % | 0.62 | % | 0.62 | % | ||||||||||
Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO(a) | 0.64 | % | 0.60 | % | 0.57 | % | 0.65 | % | 0.65 | % | ||||||||||
| Nonperforming assets as a percent of total loans and leases, OREO, and repossessed property | 0.73 | % | 0.69 | % | 0.64 | % | 0.70 | % | 0.65 | % | ||||||||||
| (a) Excludes nonaccrual loans held for sale. | ||||||||||||||||||||
| (b) Excludes loans held for sale. | ||||||||||||||||||||
| (c) Excludes government guaranteed residential mortgage loans. | ||||||||||||||||||||
| (d) Includes branch-related real estate no longer intended to be used for banking purposes. | ||||||||||||||||||||
(e) Excludes net charge-offs of $100 million which were taken at the time of acquisition. | ||||||||||||||||||||
26
Use of Non-GAAP Financial Measures
In addition to GAAP measures, management considers various non-GAAP measures when evaluating the performance of the business, including: “net interest income (FTE),” “interest income (FTE),” “net interest margin (FTE),” “net interest rate spread (FTE),” “income before income taxes (FTE),” “tangible net income available to common shareholders,” “average tangible common equity,” “return on average tangible common equity,” “tangible common equity (excluding AOCI),” “tangible common equity (including AOCI),” “tangible equity,” “tangible book value per share,” “tangible book value per share (excluding AOCI),” "adjusted earnings per share," “adjusted noninterest income,” “noninterest income excluding certain items,” “adjusted noninterest expense,” “noninterest expense excluding certain items,” “pre-provision net revenue,” “adjusted efficiency ratio,” “adjusted return on average common equity,” “adjusted return on average tangible common equity,” “adjusted return on average tangible common equity, excluding accumulated other comprehensive income", “adjusted pre-provision net revenue,” “adjusted return on average assets,” “efficiency ratio (FTE),” “total revenue (FTE),” "adjusted total revenue," “noninterest income as a percent of total revenue”, and certain ratios derived from these measures. The Bancorp believes these non-GAAP measures provide useful information to investors because these are among the measures used by the Fifth Third management team to evaluate operating performance and to make day-to-day operating decisions.
The FTE basis adjusts for the tax-favored status of income from certain loans and securities held by the Bancorp that are not taxable for federal income tax purposes. The Bancorp believes this presentation to be the preferred industry measurement of net interest income and net interest margin as it provides a relevant comparison between taxable and non-taxable amounts.
The Bancorp believes tangible net income available to common shareholders, average tangible common equity, tangible common equity (excluding AOCI), tangible common equity (including AOCI), tangible equity, tangible book value per share and return on average tangible common equity are important measures for evaluating the performance of the business without the impacts of intangible items, whether acquired or created internally, in a manner comparable to other companies in the industry that present similar measures.
The Bancorp believes noninterest income, noninterest expense, net interest income, net interest margin, pre-provision net revenue, efficiency ratio, adjusted total revenue, noninterest income as a percent of total revenue, return on average common equity, return on average tangible common equity, and return on average assets are important measures that adjust for significant, unusual, or large transactions that may occur in a reporting period which management does not consider indicative of ongoing financial performance and enhances comparability of results with prior periods.
The Bancorp believes noninterest income excluding certain items and noninterest expense excluding certain items are important measures that adjust for certain components that are prone to significant period-to-period changes in order to facilitate the explanation of variances in the noninterest income and noninterest expense line items.
Management considers various measures when evaluating capital utilization and adequacy, including the tangible equity and tangible common equity (including and excluding AOCI), in addition to capital ratios defined by U.S. banking agencies. These calculations are intended to complement the capital ratios defined by U.S. banking agencies for both absolute and comparative purposes. These ratios are not formally defined by U.S. GAAP or codified in the federal banking regulations and, therefore, are considered to be non-GAAP financial measures. Management believes that providing the tangible common equity ratio excluding AOCI on certain assets and liabilities enables investors and others to assess the Bancorp’s use of equity without the effects of changes in AOCI, some of which are uncertain; providing the tangible common equity ratio including AOCI enables investors and others to assess the Bancorp’s use of equity if components of AOCI, such as unrealized gains or losses, were to be monetized.
Please note that although non-GAAP financial measures provide useful insight, they should not be considered in isolation or relied upon as a substitute for analysis using GAAP measures.
Please see reconciliations of all historical non-GAAP measures used in this release to the most directly comparable GAAP measures, beginning on the following page.
27
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||||||||
| Non-GAAP Reconciliation | |||||||||||||||||||||||
| $ and shares in millions | As of and For the Three Months Ended | ||||||||||||||||||||||
| (unaudited) | September | June | March | December | September | ||||||||||||||||||
| 2026 | 2026 | 2026 | 2025 | 2025 | |||||||||||||||||||
| Net interest income | $2,271 | $2,215 | $1,934 | $1,529 | $1,520 | ||||||||||||||||||
| Add: Taxable equivalent adjustment | 5 | 5 | 5 | 4 | 5 | ||||||||||||||||||
| Net interest income (FTE) (a) | 2,276 | 2,220 | 1,939 | 1,533 | 1,525 | ||||||||||||||||||
| Net interest income (annualized) (b) | 9,010 | 8,884 | 7,843 | 6,066 | 6,030 | ||||||||||||||||||
| Net interest income (FTE) (annualized) (c) | 9,030 | 8,904 | 7,864 | 6,082 | 6,050 | ||||||||||||||||||
| Interest income | 3,498 | 3,372 | 2,972 | 2,468 | 2,519 | ||||||||||||||||||
| Add: Taxable equivalent adjustment | 5 | 5 | 5 | 4 | 5 | ||||||||||||||||||
| Interest income (FTE) | 3,503 | 3,377 | 2,977 | 2,472 | 2,524 | ||||||||||||||||||
| Interest income (FTE) (annualized) (d) | 13,898 | 13,545 | 12,073 | 9,807 | 10,014 | ||||||||||||||||||
| Interest expense (annualized) (e) | 4,868 | 4,641 | 4,210 | 3,725 | 3,963 | ||||||||||||||||||
| Average interest-earning assets (f) | 270,023 | 264,989 | 237,961 | 194,144 | 193,500 | ||||||||||||||||||
| Average interest-bearing liabilities (g) | 194,663 | 190,452 | 172,326 | 143,518 | 143,096 | ||||||||||||||||||
| Net interest margin (b) / (f) | 3.34 | % | 3.35 | % | 3.30 | % | 3.12 | % | 3.12 | % | |||||||||||||
| Net interest margin (FTE) (c) / (f) | 3.34 | % | 3.36 | % | 3.30 | % | 3.13 | % | 3.13 | % | |||||||||||||
| Net interest rate spread (FTE) (d) / (f) - (e) / (g) | 2.65 | % | 2.67 | % | 2.63 | % | 2.45 | % | 2.41 | % | |||||||||||||
| Income before income taxes | $1,108 | $1,036 | $207 | $912 | $837 | ||||||||||||||||||
| Add: Taxable equivalent adjustment | 5 | 5 | 5 | 4 | 5 | ||||||||||||||||||
| Income before income taxes (FTE) | 1,113 | 1,041 | 212 | 916 | 842 | ||||||||||||||||||
| Net income available to common shareholders | 828 | 763 | 128 | 699 | 608 | ||||||||||||||||||
| Add: Intangible amortization, net of tax | 48 | 48 | 34 | 5 | 5 | ||||||||||||||||||
| Tangible net income available to common shareholders (h) | 876 | 811 | 162 | 704 | 613 | ||||||||||||||||||
| Tangible net income available to common shareholders (annualized) (i) | 3,475 | 3,253 | 657 | 2,793 | 2,432 | ||||||||||||||||||
Average Bancorp shareholders’ equity | 34,338 | 34,260 | 30,108 | 21,527 | 21,216 | ||||||||||||||||||
| Less: | Average preferred stock | (2,182) | (2,182) | (2,040) | (1,770) | (2,112) | |||||||||||||||||
| Average goodwill | (9,976) | (9,973) | (8,686) | (4,947) | (4,937) | ||||||||||||||||||
| Average intangible assets | (1,221) | (1,257) | (841) | (72) | (77) | ||||||||||||||||||
| Average tangible common equity, including AOCI (j) | 20,959 | 20,848 | 18,541 | 14,738 | 14,090 | ||||||||||||||||||
| Less: | Average AOCI | 3,813 | 3,376 | 3,080 | 3,137 | 3,520 | |||||||||||||||||
| Average tangible common equity, excluding AOCI (k) | 24,772 | 24,224 | 21,621 | 17,875 | 17,610 | ||||||||||||||||||
Total Bancorp shareholders’ equity | 33,315 | 34,482 | 34,106 | 21,724 | 21,107 | ||||||||||||||||||
| Less: | Preferred stock | (2,182) | (2,182) | (2,182) | (1,770) | (1,770) | |||||||||||||||||
| Goodwill | (9,984) | (9,990) | (9,966) | (4,947) | (4,947) | ||||||||||||||||||
| Intangible assets | (1,190) | (1,253) | (1,233) | (69) | (76) | ||||||||||||||||||
| Tangible common equity, including AOCI (l) | 19,959 | 21,057 | 20,725 | 14,938 | 14,314 | ||||||||||||||||||
| Less: | AOCI | 4,919 | 3,286 | 3,234 | 3,110 | 3,276 | |||||||||||||||||
| Tangible common equity, excluding AOCI (m) | 24,878 | 24,343 | 23,959 | 18,048 | 17,590 | ||||||||||||||||||
| Add: | Preferred stock | 2,182 | 2,182 | 2,182 | 1,770 | 1,770 | |||||||||||||||||
| Tangible equity (n) | 27,060 | 26,525 | 26,141 | 19,818 | 19,360 | ||||||||||||||||||
| Total assets | 301,224 | 300,180 | 297,039 | 214,376 | 212,903 | ||||||||||||||||||
| Less: | Goodwill | (9,984) | (9,990) | (9,966) | (4,947) | (4,947) | |||||||||||||||||
| Intangible assets | (1,190) | (1,253) | (1,233) | (69) | (76) | ||||||||||||||||||
| Tangible assets, including AOCI (o) | 290,050 | 288,937 | 285,840 | 209,360 | 207,880 | ||||||||||||||||||
| Less: | AOCI, before tax | 6,472 | 4,324 | 4,255 | 4,092 | 4,311 | |||||||||||||||||
| Tangible assets, excluding AOCI (p) | $296,522 | $293,261 | $290,095 | $213,452 | $212,191 | ||||||||||||||||||
| Common shares outstanding (q) | 907 | 907 | 906 | 661 | 661 | ||||||||||||||||||
| Tangible equity (n) / (p) | 9.13 | % | 9.04 | % | 9.01 | % | 9.28 | % | 9.12 | % | |||||||||||||
| Tangible common equity (excluding AOCI) (m) / (p) | 8.39 | % | 8.30 | % | 8.26 | % | 8.46 | % | 8.29 | % | |||||||||||||
| Tangible common equity (including AOCI) (l) / (o) | 6.88 | % | 7.29 | % | 7.25 | % | 7.14 | % | 6.89 | % | |||||||||||||
| Tangible book value per share (including AOCI) (l) / (q) | $22.01 | $23.22 | $22.88 | $22.60 | $21.66 | ||||||||||||||||||
| Tangible book value per share (excluding AOCI) (m) / (q) | $27.43 | $26.84 | $26.44 | $27.30 | $26.61 | ||||||||||||||||||
28
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||||||||||||||
| Non-GAAP Reconciliation | |||||||||||||||||||||||||||||
| $ in millions | For the Three Months Ended | ||||||||||||||||||||||||||||
| (unaudited) | September | June | September | ||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | |||||||||||||||||||||||||||
| Net income (r) | $866 | $801 | $649 | ||||||||||||||||||||||||||
| Net income (annualized) (s) | 3,436 | 3,213 | 2,575 | ||||||||||||||||||||||||||
| Adjustments (pre-tax items) | |||||||||||||||||||||||||||||
| Merger-related charges | 225 | 203 | — | ||||||||||||||||||||||||||
| Interchange litigation matters | 34 | 2 | 27 | ||||||||||||||||||||||||||
| Technology-related asset impairments | 19 | 7 | — | ||||||||||||||||||||||||||
| Other securities losses/(gains), net | 5 | (30) | (10) | ||||||||||||||||||||||||||
| Securities repositioning losses | — | 10 | — | ||||||||||||||||||||||||||
| Severance expense | — | 7 | — | ||||||||||||||||||||||||||
| FDIC special assessment | — | — | (6) | ||||||||||||||||||||||||||
| Non-qualified deferred compensation expense/(benefit) | (6) | 30 | 11 | ||||||||||||||||||||||||||
| Adjustments, pre-tax | 277 | 229 | 22 | ||||||||||||||||||||||||||
| Applicable income tax expense on adjustments | 67 | 54 | 6 | ||||||||||||||||||||||||||
Adjustments, after-tax (t)(a)(b) | 210 | 175 | 16 | ||||||||||||||||||||||||||
| Noninterest income (u) | 1,008 | 1,059 | 781 | ||||||||||||||||||||||||||
| Interchange litigation matters | 29 | 1 | 18 | ||||||||||||||||||||||||||
| Merger-related charges | 10 | — | — | ||||||||||||||||||||||||||
| Securities repositioning losses | — | 10 | — | ||||||||||||||||||||||||||
| Noninterest income excluding certain item(s) | 1,047 | 1,070 | 799 | ||||||||||||||||||||||||||
| Other securities losses/(gains), net | 5 | (30) | (10) | ||||||||||||||||||||||||||
| Adjusted noninterest income, excluding certain items and securities losses (v) | 1,052 | 1,040 | 789 | ||||||||||||||||||||||||||
| Noninterest expense (w) | 2,049 | 2,109 | 1,267 | ||||||||||||||||||||||||||
| Merger-related charges | (215) | (203) | — | ||||||||||||||||||||||||||
| Technology-related asset impairments | (19) | (7) | — | ||||||||||||||||||||||||||
| Interchange litigation matters | (5) | (1) | (9) | ||||||||||||||||||||||||||
| Severance expense | — | (7) | — | ||||||||||||||||||||||||||
| FDIC special assessment | — | — | 6 | ||||||||||||||||||||||||||
| Noninterest expense excluding certain item(s) | 1,810 | 1,891 | 1,264 | ||||||||||||||||||||||||||
| Non-qualified deferred compensation (expense)/benefit | 6 | (30) | (11) | ||||||||||||||||||||||||||
| Adjusted noninterest expense, excluding certain items and non-qualified deferred compensation (x) | 1,816 | 1,861 | 1,253 | ||||||||||||||||||||||||||
| Adjusted net income (r) + (t) | 1,076 | 976 | 665 | ||||||||||||||||||||||||||
| Adjusted net income (annualized) (y) | 4,269 | 3,915 | 2,638 | ||||||||||||||||||||||||||
| Adjusted tangible net income available to common shareholders (h) + (t) | 1,086 | 986 | 629 | ||||||||||||||||||||||||||
| Adjusted tangible net income available to common shareholders (annualized) (z) | 4,309 | 3,955 | 2,495 | ||||||||||||||||||||||||||
| Average assets (aa) | $302,119 | $297,948 | $211,770 | ||||||||||||||||||||||||||
| Return on average tangible common equity (i) / (j) | 16.6 | % | 15.6 | % | 17.3 | % | |||||||||||||||||||||||
| Return on average tangible common equity excluding AOCI (i) / (k) | 14.0 | % | 13.4 | % | 13.8 | % | |||||||||||||||||||||||
| Adjusted return on average tangible common equity, including AOCI (z) / (j) | 20.6 | % | 19.0 | % | 17.7 | % | |||||||||||||||||||||||
| Adjusted return on average tangible common equity, excluding AOCI (z) / (k) | 17.4 | % | 16.3 | % | 14.2 | % | |||||||||||||||||||||||
| Return on average assets (s) / (aa) | 1.14 | % | 1.08 | % | 1.21 | % | |||||||||||||||||||||||
| Adjusted return on average assets (y) / (aa) | 1.41 | % | 1.31 | % | 1.25 | % | |||||||||||||||||||||||
| Efficiency ratio (FTE) (w) / [(a) + (u)] | 62.4 | % | 64.3 | % | 54.9 | % | |||||||||||||||||||||||
| Adjusted efficiency ratio (x) / [(a) + (v)] | 54.6 | % | 57.1 | % | 54.1 | % | |||||||||||||||||||||||
| Total revenue (FTE) (a) + (u) | $3,284 | $3,279 | $2,306 | ||||||||||||||||||||||||||
| Adjusted total revenue (FTE) (a) + (v) | $3,328 | $3,260 | $2,314 | ||||||||||||||||||||||||||
| Pre-provision net revenue (PPNR) (a) + (u) - (w) | $1,235 | $1,170 | $1,039 | ||||||||||||||||||||||||||
| Adjusted pre-provision net revenue (PPNR) (a) + (v) - (x) | $1,512 | $1,399 | $1,061 | ||||||||||||||||||||||||||
| Totals may not foot due to rounding. | |||||||||||||||||||||||||||||
| (a) Assumes a 24% tax rate. | |||||||||||||||||||||||||||||
| (b) A portion of the adjustments related to merger-related expenses are not tax-deductible. | |||||||||||||||||||||||||||||
29
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||||||||
| Segment Presentation | ||||||||||||||||||||
| $ in millions | ||||||||||||||||||||
| (unaudited) | ||||||||||||||||||||
| For the three months ended September 30, 2026 | Commercial Banking | Consumer and Small Business Banking | Wealth and Asset Management | General Corporate and Other | Total | |||||||||||||||
| Income Statement Data | ||||||||||||||||||||
Net interest income (FTE)(a) | $1,147 | $1,274 | $112 | $(257) | $2,276 | |||||||||||||||
| (Provision for) benefit from credit losses | (80) | (89) | (7) | 54 | (122) | |||||||||||||||
| Net interest income after (provision for) benefit from credit losses | 1,067 | 1,185 | 105 | (203) | 2,154 | |||||||||||||||
| Noninterest income | 512 | 326 | 183 | (13) | 1,008 | |||||||||||||||
| Noninterest expense | (761) | (855) | (182) | (251) | (2,049) | |||||||||||||||
Income (loss) before income taxes (FTE)(a) | $818 | $656 | $106 | $(467) | $1,113 | |||||||||||||||
| Average Balance Sheet Data | ||||||||||||||||||||
| Total loans and leases | $114,568 | $55,931 | $9,504 | $8 | $180,011 | |||||||||||||||
| Core deposits | $99,167 | $121,371 | $12,869 | $2,232 | $235,639 | |||||||||||||||
| For the three months ended June 30, 2026 | Commercial Banking | Consumer and Small Business Banking | Wealth and Asset Management | General Corporate and Other | Total | |||||||||||||||
| Income Statement Data | ||||||||||||||||||||
Net interest income (FTE)(a) | $1,115 | $1,237 | $113 | $(245) | $2,220 | |||||||||||||||
| (Provision for) benefit from credit losses | (25) | (82) | 4 | (26) | (129) | |||||||||||||||
| Net interest income after (provision for) benefit from credit losses | 1,090 | 1,155 | 117 | (271) | 2,091 | |||||||||||||||
| Noninterest income | 507 | 321 | 186 | 45 | 1,059 | |||||||||||||||
| Noninterest expense | (757) | (860) | (185) | (307) | (2,109) | |||||||||||||||
Income (loss) before income taxes (FTE)(a) | $840 | $616 | $118 | $(533) | $1,041 | |||||||||||||||
| Average Balance Sheet Data | ||||||||||||||||||||
| Total loans and leases | $113,297 | $55,675 | $9,709 | $26 | $178,707 | |||||||||||||||
| Core deposits | $95,241 | $117,628 | $12,961 | $2,686 | $228,516 | |||||||||||||||
For the three months ended March 31, 2026 | Commercial Banking | Consumer and Small Business Banking | Wealth and Asset Management | General Corporate and Other | Total | |||||||||||||||
| Income Statement Data | ||||||||||||||||||||
Net interest income (FTE)(a) | $878 | $1,073 | $83 | $(95) | $1,939 | |||||||||||||||
| (Provision for) benefit from credit losses | (158) | (89) | — | 20 | (227) | |||||||||||||||
| Net interest income after (provision for) benefit from credit losses | 720 | 984 | 83 | (75) | 1,712 | |||||||||||||||
| Noninterest income | 441 | 298 | 164 | (8) | 895 | |||||||||||||||
| Noninterest expense | (734) | (810) | (183) | (668) | (2,395) | |||||||||||||||
Income (loss) before income taxes (FTE)(a) | $427 | $472 | $64 | $(751) | $212 | |||||||||||||||
| Average Balance Sheet Data | ||||||||||||||||||||
| Total loans and leases | $96,110 | $54,165 | $7,970 | $38 | $158,283 | |||||||||||||||
| Core deposits | $85,160 | $107,247 | $12,069 | $2,069 | $206,545 | |||||||||||||||
For the three months ended December 31, 2025 | Commercial Banking | Consumer and Small Business Banking | Wealth and Asset Management | General Corporate and Other | Total | |||||||||||||||
| Income Statement Data | ||||||||||||||||||||
Net interest income (FTE)(a) | $581 | $1,026 | $52 | $(126) | $1,533 | |||||||||||||||
| (Provision for) benefit from credit losses | (46) | (84) | — | 11 | (119) | |||||||||||||||
| Net interest income after (provision for) benefit from credit losses | 535 | 942 | 52 | (115) | 1,414 | |||||||||||||||
| Noninterest income | 386 | 311 | 111 | 3 | 811 | |||||||||||||||
| Noninterest expense | (476) | (645) | (97) | (91) | (1,309) | |||||||||||||||
Income (loss) before income taxes (FTE)(a) | $445 | $608 | $66 | $(203) | $916 | |||||||||||||||
| Average Balance Sheet Data | ||||||||||||||||||||
| Total loans and leases | $67,425 | $52,116 | $4,590 | $16 | $124,147 | |||||||||||||||
| Core deposits | $62,984 | $92,622 | $9,567 | $1,263 | $166,436 | |||||||||||||||
For the three months ended September 30, 2025 | Commercial Banking | Consumer and Small Business Banking | Wealth and Asset Management | General Corporate and Other | Total | |||||||||||||||
| Income Statement Data | ||||||||||||||||||||
Net interest income (FTE)(a) | $594 | $1,082 | $55 | $(206) | $1,525 | |||||||||||||||
| (Provision for) benefit from credit losses | (246) | (73) | — | 122 | (197) | |||||||||||||||
| Net interest income after (provision for) benefit from credit losses | 348 | 1,009 | 55 | (84) | 1,328 | |||||||||||||||
| Noninterest income | 357 | 309 | 109 | 6 | 781 | |||||||||||||||
| Noninterest expense | (454) | (653) | (93) | (67) | (1,267) | |||||||||||||||
Income (loss) before income taxes (FTE)(a) | $251 | $665 | $71 | $(145) | $842 | |||||||||||||||
| Average Balance Sheet Data | ||||||||||||||||||||
| Total loans and leases | $68,007 | $51,367 | $4,603 | $16 | $123,993 | |||||||||||||||
| Core deposits | $60,854 | $91,110 | $9,288 | $1,258 | $162,510 | |||||||||||||||
(a) Includes taxable equivalent adjustments of $5 million for the three months ended September 30, 2026, June 30, 2026 and March 31, 2026, $4 million for the three months ended December 31, 2025 and $5 million for the three months ended September 30, 2025. | ||||||||||||||||||||
30

3Q26 Earnings Presentation October 19, 2026 Refer to earnings release dated October 19, 2026 for further information.

© Fifth Third Bancorp | All Rights Reserved This presentation contains statements that we believe are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Rule 175 promulgated thereunder, and Section 21E of the Securities Exchange Act of 1934, as amended, and Rule 3b-6 promulgated thereunder. All statements other than statements of historical fact are forward-looking statements. These statements relate to our financial condition, results of operations, plans, objectives, future performance, capital actions or business. They usually can be identified by the use of forward-looking language such as “will likely result,” “may,” “are expected to,” “is anticipated,” “potential,” “estimate,” “forecast,” “projected,” “intends to,” or may include other similar words or phrases such as “believes,” “plans,” “trend,” “objective,” “continue,” “remain,” or similar expressions, or future or conditional verbs such as “will,” “would,” “should,” “could,” “might,” “can,” or similar verbs. You should not place undue reliance on these statements, as they are subject to risks and uncertainties, including but not limited to the risk factors set forth in our most recent Annual Report on Form 10-K as updated by our filings with the U.S. Securities and Exchange Commission (“SEC”). There are a number of important factors that could cause future results to differ materially from historical performance and these forward-looking statements. Factors that might cause such a difference include, but are not limited to: (1) deteriorating credit quality; (2) loan concentration by location or industry of borrowers or collateral; (3) any instability or disruption in the financial system, including those caused by actual or perceived issues affecting the soundness of other financial institutions or market participants; (4) inadequate sources of funding or liquidity; (5) unfavorable actions of rating agencies; (6) inability to maintain or grow deposits; (7) limitations on the ability to receive dividends from subsidiaries; (8) cyber-security risks; (9) Fifth Third’s ability to secure confidential information and deliver products and services through the use of computer systems and telecommunications networks; (10) failures by third-party service providers; (11) inability to manage strategic initiatives and/or organizational changes; (12) inability to implement technology system enhancements, including the use of artificial intelligence; (13) failure of internal controls and other risk management programs; (14) losses related to fraud, theft, misappropriation or violence; (15) inability to attract and retain skilled personnel; (16) adverse impacts of government regulation; (17) governmental or regulatory changes or other actions; (18) failures to meet applicable capital requirements; (19) regulatory objections to Fifth Third’s capital plan; (20) regulation of Fifth Third’s derivatives activities; (21) deposit insurance premiums; (22) assessments for the orderly liquidation fund; (23) weakness in the national or local economies; (24) global political and economic uncertainty or negative actions; (25) changes in interest rates and the effects of inflation; (26) changes in U.S. trade policies, including the imposition of tariffs and retaliatory tariffs; (27) changes and trends in capital markets; (28) fluctuation of Fifth Third’s stock price; (29) volatility in mortgage banking revenue; (30) litigation, investigations, and enforcement proceedings; (31) breaches of contractual covenants, representations and warranties; (32) competition and changes in the financial services industry; (33) potential impacts of the adoption of real-time payment networks; (34) changing retail distribution strategies, customer preferences and behavior; (35) difficulties in identifying, acquiring or integrating suitable strategic partnerships, investments or acquisitions; (36) potential dilution from future acquisitions; (37) loss of income and/or difficulties encountered in the sale and separation of businesses, investments or other assets; (38) results of investments or acquired entities; (39) changes in accounting standards or interpretation or declines in the value of Fifth Third’s goodwill or other intangible assets; (40) inaccuracies or other failures from the use of models; (41) effects of critical accounting policies and judgments or the use of inaccurate estimates; (42) weather- related events, other natural disasters, or health emergencies (including pandemics); (43) the impact of reputational risk created by these or other developments on such matters as business generation and retention, funding and liquidity; (44) changes in law or requirements imposed by Fifth Third’s regulators impacting our capital actions, including dividend payments and stock repurchases; (45) Fifth Third's ability to meet its environmental and/or social targets, goals and commitments; and (46) risks relating to the merger with Comerica Incorporated, including Fifth Third’s inability to realize the anticipated benefits of the merger and potential disruption to Fifth Third’s business resulting from post-merger integration. You should refer to our periodic and current reports filed with the Securities and Exchange Commission, or “SEC,” for further information on other factors, which could cause actual results to be significantly different from those expressed or implied by these forward-looking statements. Moreover, you should treat these statements as speaking only as of the date they are made and based only on information then actually known to us. We expressly disclaim any obligation or undertaking to release publicly any updates or revisions to any forward-looking statements contained herein to reflect any change in our expectations or any changes in events, conditions or circumstances on which any such statement is based, except as may be required by law, and we claim the protection of the safe harbor for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. The information contained herein is intended to be reviewed in its entirety. Any qualifications, assumptions, conditions, limitations or other disclosures that apply to a particular item of information are deemed to apply, with any necessary adjustments to all references to that information throughout this presentation. Annualized, pro forma, projected and estimated numbers are used for illustrative purpose only, are not forecasts and may not reflect actual results. In this presentation, we may sometimes provide non-GAAP financial information. Please note that although non-GAAP financial measures provide useful insight to analysts, investors and regulators, they should not be considered in isolation or relied upon as a substitute for analysis using GAAP measures. We provide a discussion of non-GAAP measures and reconciliations to the most directly comparable GAAP measures in later slides in this presentation, as well as on pages 27 through 29 of our 3Q26 earnings release. Management does not provide a reconciliation for forward-looking non-GAAP financial measures where it is unable to provide a meaningful or accurate calculation or estimation of reconciling items and the information is not available without unreasonable effort. This is due to the inherent difficulty of forecasting the occurrence and the financial impact of various items that have not yet occurred, are out of the Bancorp's control or cannot be reasonably predicted. For the same reasons, Bancorp's management is unable to address the probable significance of the unavailable information. Forward-looking non-GAAP financial measures provided without the most directly comparable GAAP financial measures may vary materially from the corresponding GAAP financial measures. Cautionary statement 2

© Fifth Third Bancorp | All Rights Reserved For end note descriptions, see end note summary starting on page 42 Key Messages 3 Strong deposits, resilient credit, and disciplined balance sheet management provide flexibility across a range of economic and interest-rate environments Comerica systems integration successfully completed, with strong client and banker retention and the full $850 million expense synergy run-rate locked in for 4Q26 Earnings power of the combined company is increasingly evident, with stronger PPNR1, higher returns, and improved operating efficiency Organic growth is broadening across legacy and newly acquired markets, supported by deposit share gains, commercial relationship growth and continued Southeast momentum 1 2 3 4

© Fifth Third Bancorp | All Rights Reserved • Net interest income increased 3% • Adjusted efficiency ratio2 improved 250 bps • Net charge-offs3 of 31 basis points, with continued stability in underlying credit trends • Adjusted return on assets2 increased 10 basis points to 1.41%, the highest since 4Q22 • Adjusted ROTCE of 20.6% improved 160 bps • 3% core deposit growth and loan-to-core deposit ratio of 76% Reported1 Adjusted1 EPS $0.90 $1.13 ROA 1.14% 1.41% ROE 10.2% 12.8% ROTCE 16.6% 20.6% NIM 3.34% 3.34% Efficiency ratio 62.4% 54.6% PPNR $1,235MM $1,512MM CET14 10.0% For end note descriptions, see end note summary starting on page 42 3Q26 highlights 4 Comparisons in the bullet points are for 3Q26 versus 2Q26, unless otherwise noted
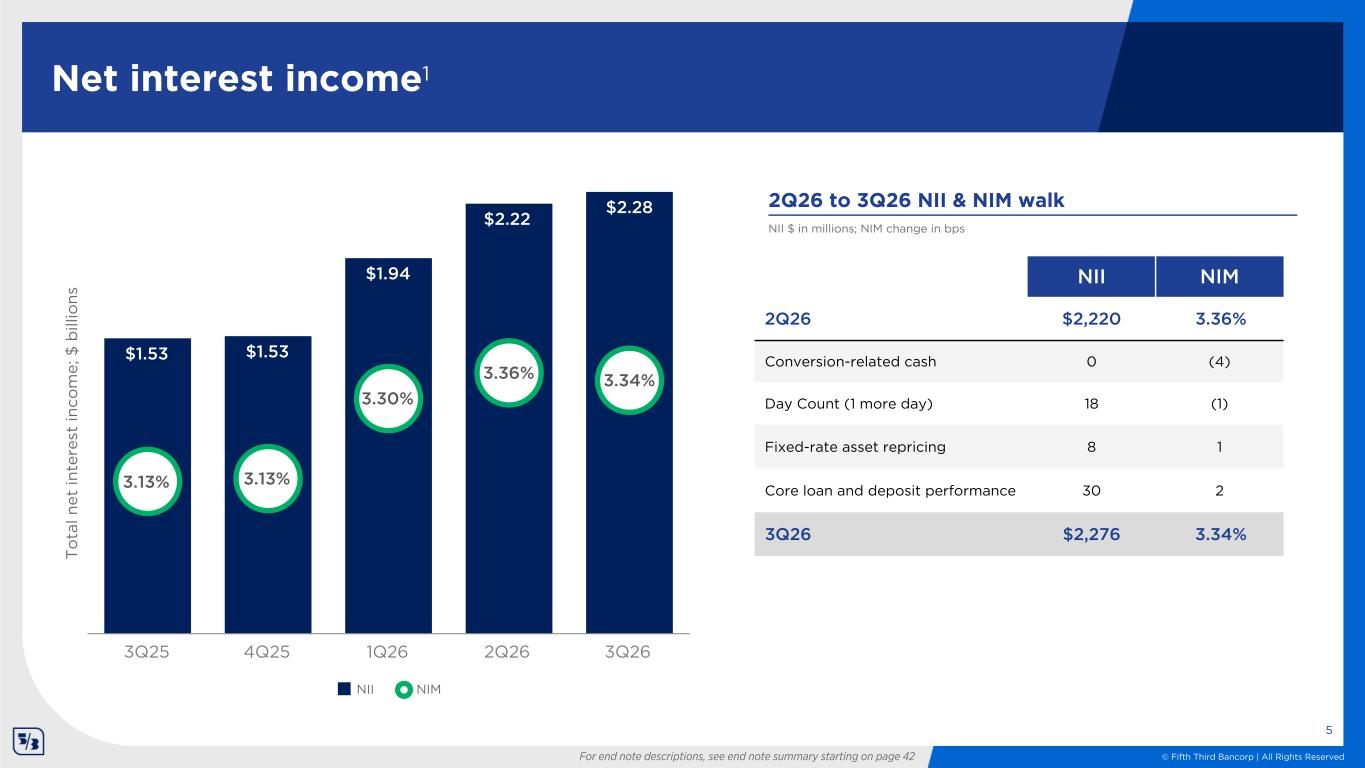
© Fifth Third Bancorp | All Rights Reserved $1.53 $1.53 $1.94 $2.22 $2.28 3.13% 3.13% 3.30% 3.36% 3.34% NII NIM 3Q25 4Q25 1Q26 2Q26 3Q26 NII $ in millions; NIM change in bps 2Q26 to 3Q26 NII & NIM walk T o ta l n et in te re st in co m e; $ b ill io ns Net interest income1 5 For end note descriptions, see end note summary starting on page 42 NII NIM 2Q26 $2,220 3.36% Conversion-related cash 0 (4) Day Count (1 more day) 18 (1) Fixed-rate asset repricing 8 1 Core loan and deposit performance 30 2 3Q26 $2,276 3.34%

© Fifth Third Bancorp | All Rights Reserved • Noninterest income excluding certain items1 of $1.05 billion increased $12 million, or 1%, compared to the prior quarter and increased $263 million, or 33%, from the year-ago quarter • Diversified fee growth across wealth and asset management, commercial payments and commercial banking, which represented 61% of adjusted fees, more than offset lower capital markets fees Noninterest income T o ta l n o ni nt er es t in co m e; $ m ill io ns For end note descriptions, see end note summary starting on page 42 6 $ millions 3Q26 PQ YoY Wealth and asset management revenue $259 1% 43% Commercial payments revenue 256 1% 63% Consumer banking revenue 158 (2)% 10% Capital markets fees 147 (5)% 28% Commercial banking revenue 128 2% 47% Mortgage banking net revenue 47 21% (19)% Other noninterest income 18 (64)% (38)% Securities (losses)/gains, net (5) NM NM Noninterest income $1,008 (5)% 29% Impact of certain items 44 Adjusted noninterest income (excl. securities gains/losses, net)1,2 $1,052 1% 33% $781 $811 $895 $1,059 $1,008 $789 $812 $921 $1,040 $1,052 Noninterest income Adjusted noninterest income (excl. securities gains/losses, net)¹² 3Q25 4Q25 1Q26 2Q26 3Q26

© Fifth Third Bancorp | All Rights Reserved $1,267 $1,309 $2,395 $2,109 $2,049 $1,253* $1,273* $1,769* $1,861* $1,816* 54.1% 54.3% 61.9% 57.1% 54.6% Adjusted noninterest expense¹* Noninterest expense Adjusted Efficiency Ratio¹ 3Q25 4Q25 1Q26 2Q26 3Q26 T o ta l n o ni nt er es t ex p en se ; $ m ill io ns Noninterest expense 7 $ in millions 3Q26 2Q26 3Q25 Non-qualified deferred compensation expense/ (benefit), primarily offset in securities gains/losses ($6) $30 $11 For end note descriptions, see end note summary starting on page 42 $ millions 3Q26 PQ YoY Compensation and benefits $982 (13)% 43% Technology and communications 300 20% 134% Net occupancy expense 144 (6)% 62% Card and processing expense 60 (9)% 173% Equipment expense 59 (2)% 34% Marketing expense 57 (12)% 68% Loan and lease expense 47 (11)% 21% Other noninterest expense 400 20% 77% Total noninterest expense $2,049 (3)% 62% Impact of certain items (239) Noninterest expense excluding certain item(s)1 $1,810 (4)% 43% Non-qualified deferred compensation (expense)/benefit 6 Adjusted noninterest expense, excluding certain item(s)1 and non-qualified deferred compensation $1,816 (2)% 45% • Adjusted noninterest expense1 decreased 2% compared to the prior quarter and increased 45% from the year-ago quarter • Lower compensation and benefits expense in the quarter was offset by higher conversion-related technology costs • Merger-related charges recognized in noninterest expense totaled approximately $1.04 billion year-to-date, consistent with the integration timeline

© Fifth Third Bancorp | All Rights Reserved Solar energy installation Average loan & lease balances excluding HFS $123.3 $123.4 $157.6 $177.6 $179.2 $74.9 $74.6 $105.9 $124.1 $125.6 $48.4 $48.8 $51.8 $53.5 $53.7 6.12% 5.96% 5.88% 5.86% 5.89% Commercial Consumer Total loan yield 3Q25 4Q25 1Q26 2Q26 3Q26 $123.1 $122.7 $176.3 $178.5 $180.3 $74.4 $73.6 $122.9 $124.9 $126.4 $48.7 $49.1 $53.4 $53.6 $53.9 Commercial Consumer 3Q25 4Q25 1Q26 2Q26 3Q26 Loans Loan portfolio compositionAverage loan & lease balances $ in billions; loan & lease balances excluding HFS Period-end loan & lease balances $ in billions; loan & lease balances excluding HFS 8 Note: totals shown above may not foot due to rounding 48% 20% 2% 11% 10% 4% 2%3% Commercial and industrial Commercial real estate Commercial leases Residential mortgage Home equity Indirect secured consumer Credit card and other % of Total Loans Commercial: 70% Consumer: 30%
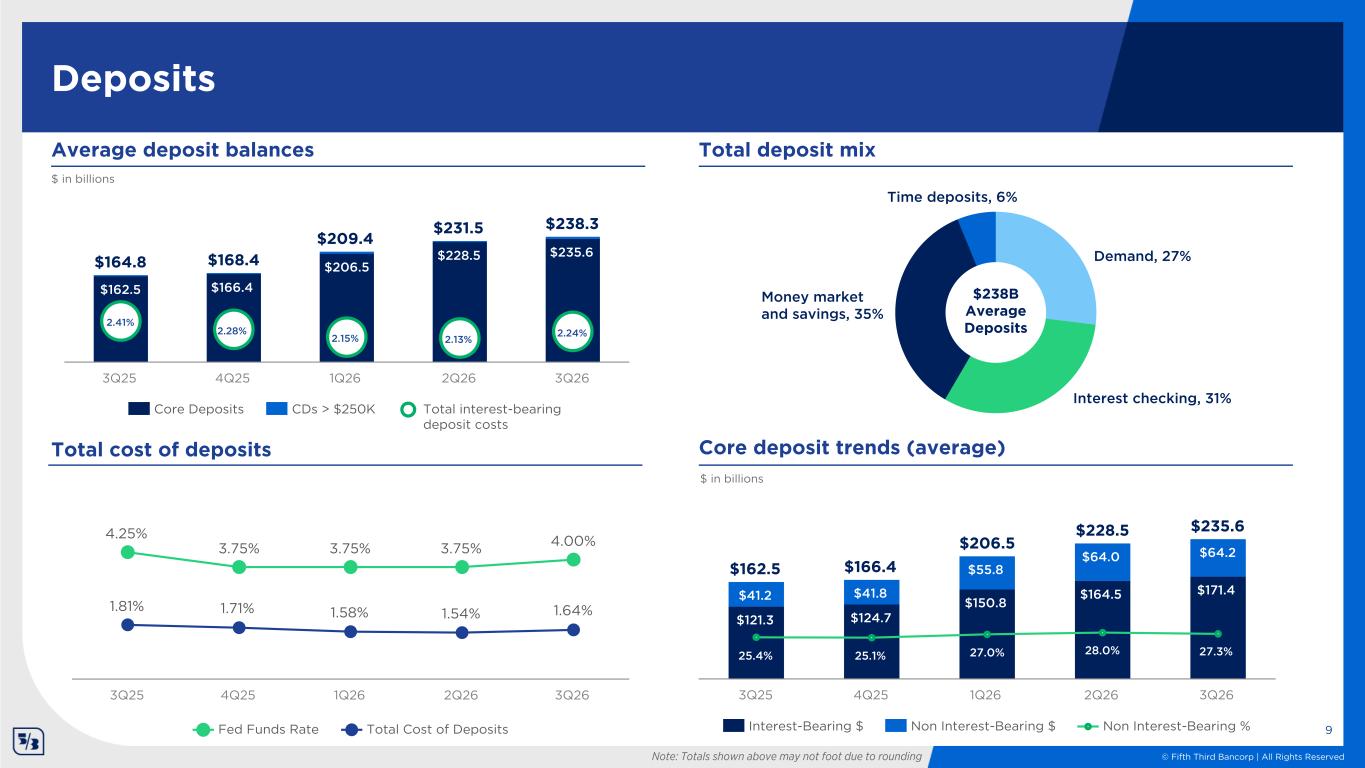
© Fifth Third Bancorp | All Rights Reserved 4.25% 3.75% 3.75% 3.75% 4.00% 1.81% 1.71% 1.58% 1.54% 1.64% Fed Funds Rate Total Cost of Deposits 3Q25 4Q25 1Q26 2Q26 3Q26 Total cost of deposits Total deposit mixAverage deposit balances $164.8 $168.4 $209.4 $231.5 $238.3 $162.5 $166.4 $206.5 $228.5 $235.6 2.41% 2.28% 2.15% 2.13% 2.24% Core Deposits CDs > $250K Total interest-bearing deposit costs 3Q25 4Q25 1Q26 2Q26 3Q26 $ in billions Demand, 27% Interest checking, 31% Money market and savings, 35% Time deposits, 6% $238B Average Deposits $162.5 $166.4 $206.5 $228.5 $235.6 $121.3 $124.7 $150.8 $164.5 $171.4$41.2 $41.8 $55.8 $64.0 $64.2 25.4% 25.1% 27.0% 28.0% 27.3% Interest-Bearing $ Non Interest-Bearing $ Non Interest-Bearing % 3Q25 4Q25 1Q26 2Q26 3Q26 Core deposit trends (average) $ in billions Deposits Note: Totals shown above may not foot due to rounding 9

© Fifth Third Bancorp | All Rights Reserved Net charge-offs (NCOs) $339 $125 $144 $135 $139 $339 $125 $144 $135 3Q25 4Q25 1Q26 2Q26 3Q26 Credit quality overview 10 3Q25 4Q25 1Q26 2Q26 3Q26 NPL ratio 0.62% 0.62% 0.54% 0.58% 0.59% NPA ratio1,2 0.65% 0.65% 0.57% 0.60% 0.64% 30-89 days past due as a % of portfolio loans and leases 0.28% 0.29% 0.39% 0.31% 0.30% NCO ratio3 1.09% 0.40% 0.37% 0.30% 0.31% ACL ratio as a % of portfolio loans and leases 1.96% 1.96% 1.79% 1.76% 1.74% Nonperforming loans (NPLs) $768 $767 $960 $1,041 $1,070 3Q25 4Q25 1Q26 2Q26 3Q26 Portfolio loans & leases 30-89 days past due $348 $360 $683 $561 $540 3Q25 4Q25 1Q26 2Q26 3Q26 $ in millions For end note descriptions, see end note summary starting on page 42

© Fifth Third Bancorp | All Rights Reserved 3Q17 3Q18 3Q19 3Q20 3Q21 3Q22 3Q23 3Q24 3Q25 3Q26 0.00% 0.50% 1.00% 1.50% Historical net charge-off and NPA ratios Net charge-off ratio Non-performing assets ratio2 3Q17 3Q18 3Q19 3Q20 3Q21 3Q22 3Q23 3Q24 3Q25 3Q26 0.00% 0.50% 1.00% 1.50% Commercial net charge-off ratio 3Q17 3Q18 3Q19 3Q20 3Q21 3Q22 3Q23 3Q24 3Q25 3Q26 0.00% 0.50% 1.00% 1.50% 3Q17 3Q18 3Q19 3Q20 3Q21 3Q22 3Q23 3Q24 3Q25 3Q26 0.00% 0.50% 1.00% 1.50% Consumer net charge-off ratio 3Q26 0.22% 3Q26 0.31% 3Q26 0.52% 10-year average excluding COVID1 10-year average excluding COVID1 10-year average excluding COVID1 10-year average excluding COVID1 For end note descriptions, see end note summary starting on page 42 11 3Q26 0.64%

© Fifth Third Bancorp | All Rights Reserved 9.9% 33 bps (11 bps) 0 bps (16 bps) 2 bps 10.0% 2Q26 Net income to common RWA Share repurchases Common dividends Other 3Q26 12 Strong liquidity and capital position Liquidity position $ in billions Capital position Common equity tier 1 ratio1 For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding Liquidity Sources 6/30/26 9/30/26 Fed reserves $18 $15 Unpledged investment securities $32 $34 Available FHLB borrowing capacity $13 $15 Current Fed discount window availability $78 $78 Total $141 $142 • Maintained full Category 1 LCR compliance during the quarter, ending at 102% • Loan-to-core deposit ratio of 76% • Robust liquidity risk management practices, including: – Daily LCR calculations – Monthly liquidity stress tests, including two FITB- specific scenarios over and above regulatory requirements – Monthly 2052a complex liquidity monitoring reporting Common equity tier 1 ratio1 Fully-phased common equity tier 1 ratio2 10.6% 10.8% 9.9% 9.9% 10.0% 9.2% Reported CET1 Ratio Fully-phased CET1 3Q25 4Q25 1Q26 2Q26 3Q263Q25 4Q25 1Q26 2Q26
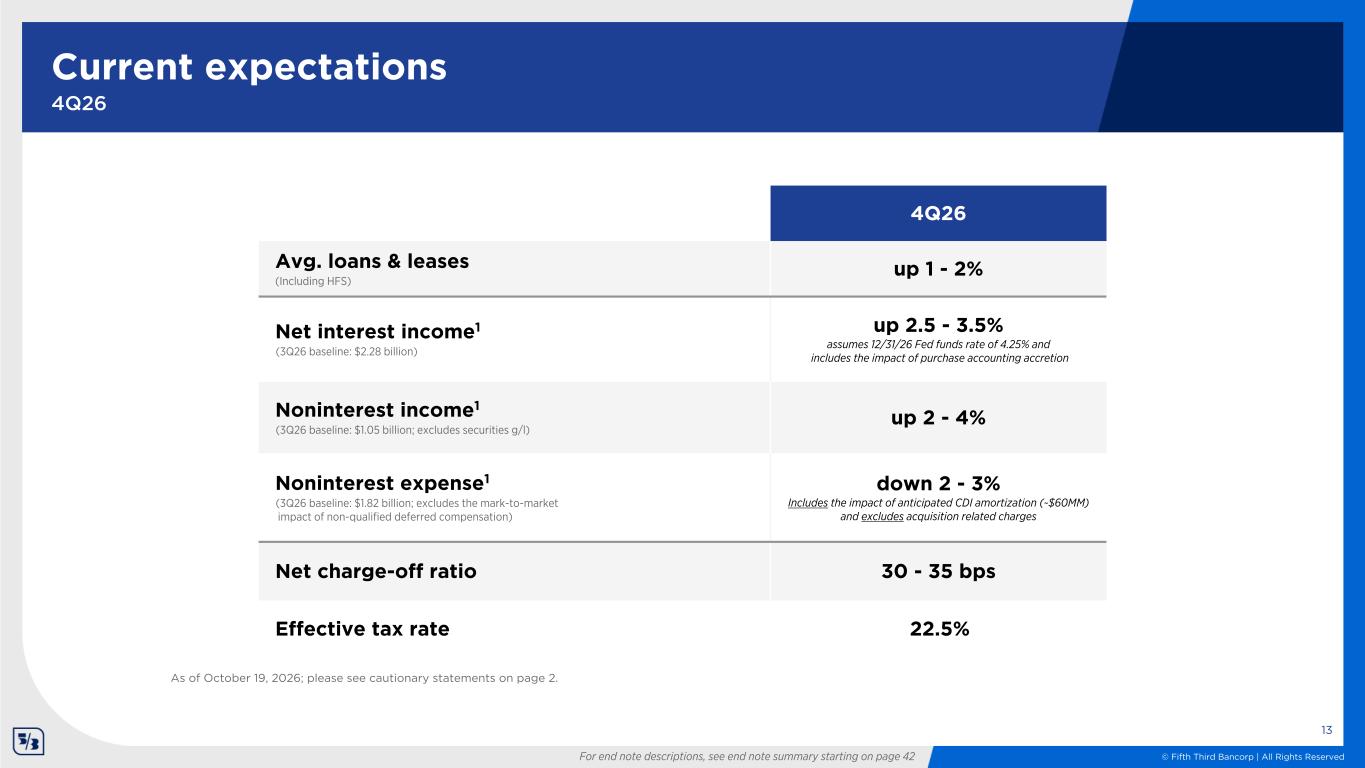
© Fifth Third Bancorp | All Rights Reserved As of October 19, 2026; please see cautionary statements on page 2. Current expectations 4Q26 13 For end note descriptions, see end note summary starting on page 42 4Q26 Avg. loans & leases (Including HFS) up 1 - 2% Net interest income1 (3Q26 baseline: $2.28 billion) up 2.5 - 3.5% assumes 12/31/26 Fed funds rate of 4.25% and includes the impact of purchase accounting accretion Noninterest income1 (3Q26 baseline: $1.05 billion; excludes securities g/l) up 2 - 4% Noninterest expense1 (3Q26 baseline: $1.82 billion; excludes the mark-to-market impact of non-qualified deferred compensation) down 2 - 3% Includes the impact of anticipated CDI amortization (~$60MM) and excludes acquisition related charges Net charge-off ratio 30 - 35 bps Effective tax rate 22.5%
© Fifth Third Bancorp | All Rights Reserved 14 Appendix

© Fifth Third Bancorp | All Rights Reserved Consumer and Business Banking Digital Metrics Average Active Digital Users (Millions) 3.19 3.19 3.25 3.27 3.49 3Q25 4Q25 1Q26 2Q26 3Q26 Digital Engagement Digital Originations Average Active Mobile Users (Millions) 2.47 2.49 2.53 2.57 2.73 3Q25 4Q25 1Q26 2Q26 3Q26 Digital Assisted Mortgage Applications 98% 98% 97% 98% 98% 3Q25 4Q25 1Q26 2Q26 3Q26 New Consumer Deposit Accounts 28% 31% 33% 29% 33% 3Q25 4Q25 1Q26 2Q26 3Q26 Award-Winning App Jeanie® named Best Chatbot by Tearsheet AI Innovation Awards 15 For end note descriptions, see end note summary starting on page 42 1 2 Mobile app serves millions of monthly users & powers more than one billion digital interactions each year
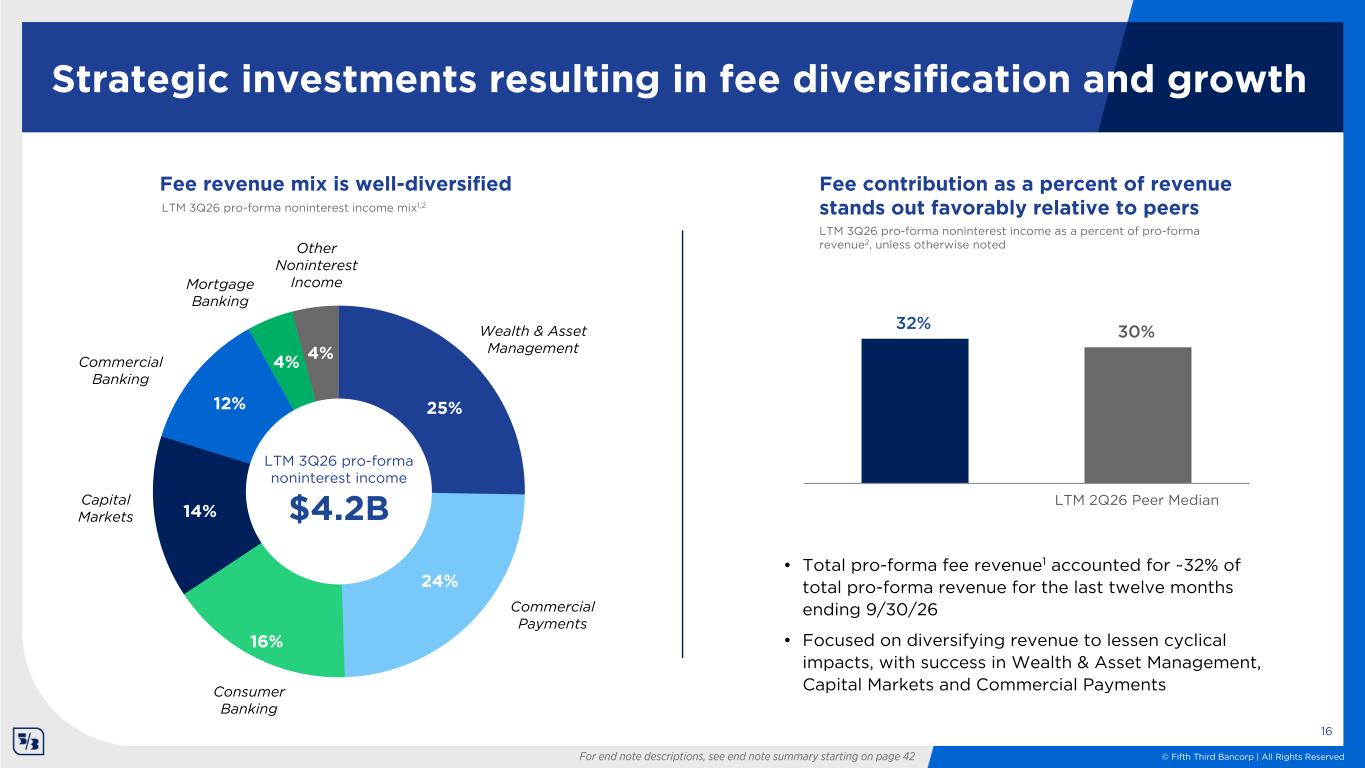
© Fifth Third Bancorp | All Rights Reserved 32% 30% LTM 2Q26 Peer Median 25% 24% 16% 14% 12% 4% 4% Strategic investments resulting in fee diversification and growth • Total pro-forma fee revenue1 accounted for ~32% of total pro-forma revenue for the last twelve months ending 9/30/26 • Focused on diversifying revenue to lessen cyclical impacts, with success in Wealth & Asset Management, Capital Markets and Commercial Payments 16 Fee revenue mix is well-diversified LTM 3Q26 pro-forma noninterest income mix1,2 Wealth & Asset Management Capital Markets Mortgage Banking Other Noninterest Income Consumer Banking Commercial Banking Commercial Payments Fee contribution as a percent of revenue stands out favorably relative to peers LTM 3Q26 pro-forma noninterest income as a percent of pro-forma revenue2, unless otherwise noted LTM 3Q26 pro-forma noninterest income $4.2B For end note descriptions, see end note summary starting on page 42

© Fifth Third Bancorp | All Rights Reserved $74.9 $74.6 $105.9 $124.1 $125.6 $74.4 $73.6 $122.9 $124.9 $126.4 Average Period-end 3Q25 4Q25 1Q26 2Q26 3Q26 3Q25 2Q26 3Q26 NCO ratio1 1.46% 0.21% 0.22% 30-89 delinquencies 0.16% 0.26% 0.24% 90+ delinquencies 0.00% 0.00% 0.01% Nonperforming loans2 0.58% 0.49% 0.52% Portfolio loans and leases $ in billions Key statistics Total commercial portfolio overview Average QoQ change (0.7%) (0.4%) 41.9% 17.2% 1.2% Period-end QoQ change 0.4% (1.2%) 67.0% 1.6% 1.2% Commercial portfolio mix 68% 22% 7% 3% C&I Commercial mortgage Commercial construction Commercial leases For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding 17
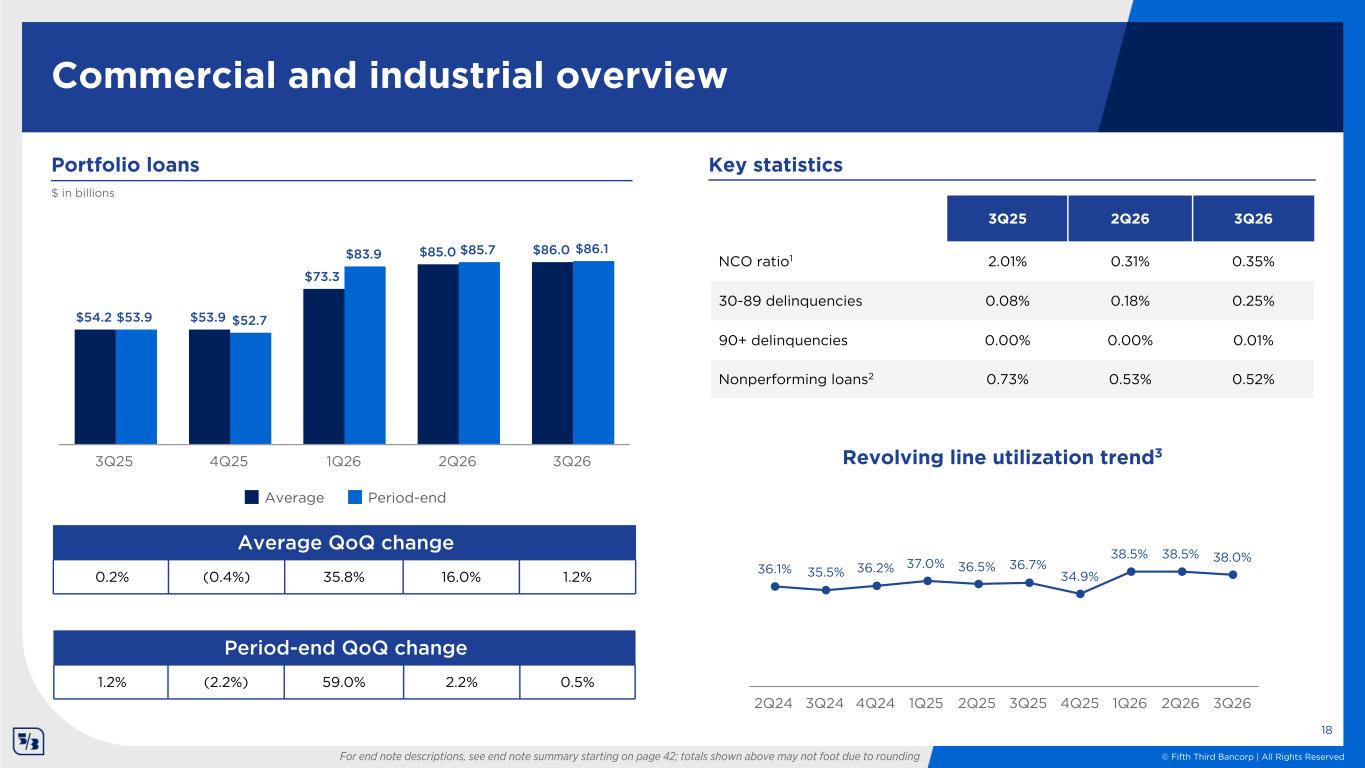
© Fifth Third Bancorp | All Rights Reserved $54.2 $53.9 $73.3 $85.0 $86.0 $53.9 $52.7 $83.9 $85.7 $86.1 Average Period-end 3Q25 4Q25 1Q26 2Q26 3Q26 18 Key statistics Revolving line utilization trend3 Commercial and industrial overview 36.1% 35.5% 36.2% 37.0% 36.5% 36.7% 34.9% 38.5% 38.5% 38.0% 2Q24 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 3Q26 Portfolio loans $ in billions Average QoQ change 0.2% (0.4%) 35.8% 16.0% 1.2% Period-end QoQ change 1.2% (2.2%) 59.0% 2.2% 0.5% For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding 3Q25 2Q26 3Q26 NCO ratio1 2.01% 0.31% 0.35% 30-89 delinquencies 0.08% 0.18% 0.25% 90+ delinquencies 0.00% 0.00% 0.01% Nonperforming loans2 0.73% 0.53% 0.52%

© Fifth Third Bancorp | All Rights Reserved Note: Totals shown above may not foot due to rounding Non-depository financial institution portfolio 30% 25% 24% 11% 10% NDFI portfolio characteristics 3Q26 $14.3B¹ 8% of loans $ in billions; as of 9/30/26 Consumer Warehouse Consumer Finance Securitization Vehicles Real Estate Institutional CRE, Residential Mortgage Warehouse, Mortgage Servicing Rights Private Capital Warehouse Corporate Debt Facilities, BDC Subscription Lines Capital Call Facilities, SBIC Funds Corporate Credit Facilities Payments, Insurance, Financial Intermediaries Relationship focused main street lender with lower NDFI exposure Private Capital Warehouse characteristics • 2nd lowest exposure to NDFIs among peers2 • 87% of the NDFI portfolio is investment grade or equivalent • 3Q26 criticized rate of 44 bps; down 10 bps sequentially • Zero losses in last 10 years across Real Estate, Subscription Lines and Private Capital Warehouse3 • Senior-positioned, well-collateralized and deliberately sized within risk appetite • Tight internal concentration limits actively monitored and enforced through independent risk governance • BDC balances limited, totaling $267 million or just 0.15% of total loans 19

© Fifth Third Bancorp | All Rights Reserved Financial Services 16% Rental and Leasing 13% Entertainment 12% Retail 11% Manufacturing 8% Business Services 8% Wholesale Trade 8% Other 24% 20 High quality Shared National Credit portfolio SNC portfolio $46.6BN ~26% of total loans Shared National Credit portfolio is well diversified Industry mix Key statistics For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding $ in billions; as of 9/30/26 • ~60% of SNC balances are at or near investment grade equivalent borrowers; independently underwrite each transaction • Lead left/lead right on ~50% of relationships • Criticized assets are lower than the rest of the commercial portfolio over a multi-year period 3Q25 2Q26 3Q26 Loan balance $32.2 $46.4 $46.6 Nonperforming loans2 0.72% 0.36% 0.40% NCO Ratio1 0.57% 0.35% 0.42%

© Fifth Third Bancorp | All Rights Reserved 21 Low concentration in leveraged lending Note: Totals shown above may not foot due to rounding Total loan portfolio composition Arts, Entertainment, and Recreation Wholesale Trade Manufacturing Accommodation & Food Services Admin, Support & Other Services Information Retail Trade Professional, Scientific, & Technical Services Healthcare & Social Assistance Mining, Quarrying, and Oil & Gas Extraction Other Diversified leveraged portfolio Total Loans $181.0 Billion as of 9/30/26 as of 9/30/26 • Significant reduction in leveraged lending portfolio as a percent of total loans – Represents ~2% of loans vs ~8% in 2015 • Leveraged criticized asset ratio remains well below the 5-year average Leveraged 2.1% $3.7 Billion

© Fifth Third Bancorp | All Rights Reserved Portfolio loans 41% 21% 19% 10% 4% 2% 2% 53%47% Commercial real estate overview CRE mortgage Balance by occupancy CRE construction Balance by property type Industrial RetailOffice Hospitality Other Home builder Non-Owner occupied Owner occupied Multifamily 28% Industrial 19% Retail 18% Medical Office 9% Office 8% Non-owner occupied property type mix $17.6 $17.5 $29.2 $35.6 $36.0 $17.3 $17.5 $35.5 $35.7 $36.4 $5.5 $5.4 $7.3 $8.4 $8.7 $12.0 $12.1 $22.0 $27.2 $27.3 $5.3 $5.3 $8.3 $8.5 $9.0 $11.9 $12.2 $27.1 $27.2 $27.5 3Q25 4Q25 1Q26 2Q26 3Q26 22 Other 7% For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding Period-end QoQ change (2.3%) 1.7% 102.2% 0.5% 2.2% $ in billions Average QoQ change (3.6%) (0.5%) 67.3% 21.8% 1.1% 3Q25 2Q26 3Q26 NCO ratio1 0.03% (0.01)% (0.07%) 30-89 delinquencies 0.37% 0.44% 0.21% 90+ delinquencies 0.00% 0.00% 0.01% Nonperforming loans2 0.24% 0.44% 0.56% Key statistics Period-end - Commercial mortgageAverage - Commercial mortgage Period-end - Commercial constructionAverage - Commercial construction Multifamily Hospitality 10%

© Fifth Third Bancorp | All Rights Reserved Period-end QoQ change 1.0% 0.8% 8.8% 0.5% 0.5% $48.4 $48.8 $51.8 $53.5 $53.7 $48.7 $49.1 $53.4 $53.6 $53.9 3Q25 4Q25 1Q26 2Q26 3Q26 15% 16% 67% 3Q25 2Q26 3Q26 NCO ratio1 0.52% 0.53% 0.52% 30-89 delinquencies 0.47% 0.45% 0.44% 90+ delinquencies 0.06% 0.05% 0.06% Nonperforming loans2 0.68% 0.79% 0.76% Weighted average FICO at origination3 768 768 768 Weighted average LTV at origination 79% 79% 79% Total consumer portfolio overview 23 Portfolio FICO score at origination3 $ in billions Portfolio loans 2% For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding Average QoQ change 1.6% 0.9% 6.0% 3.3% 0.4% Key statistics 750+720-749<660 660-719 Period-endAverage
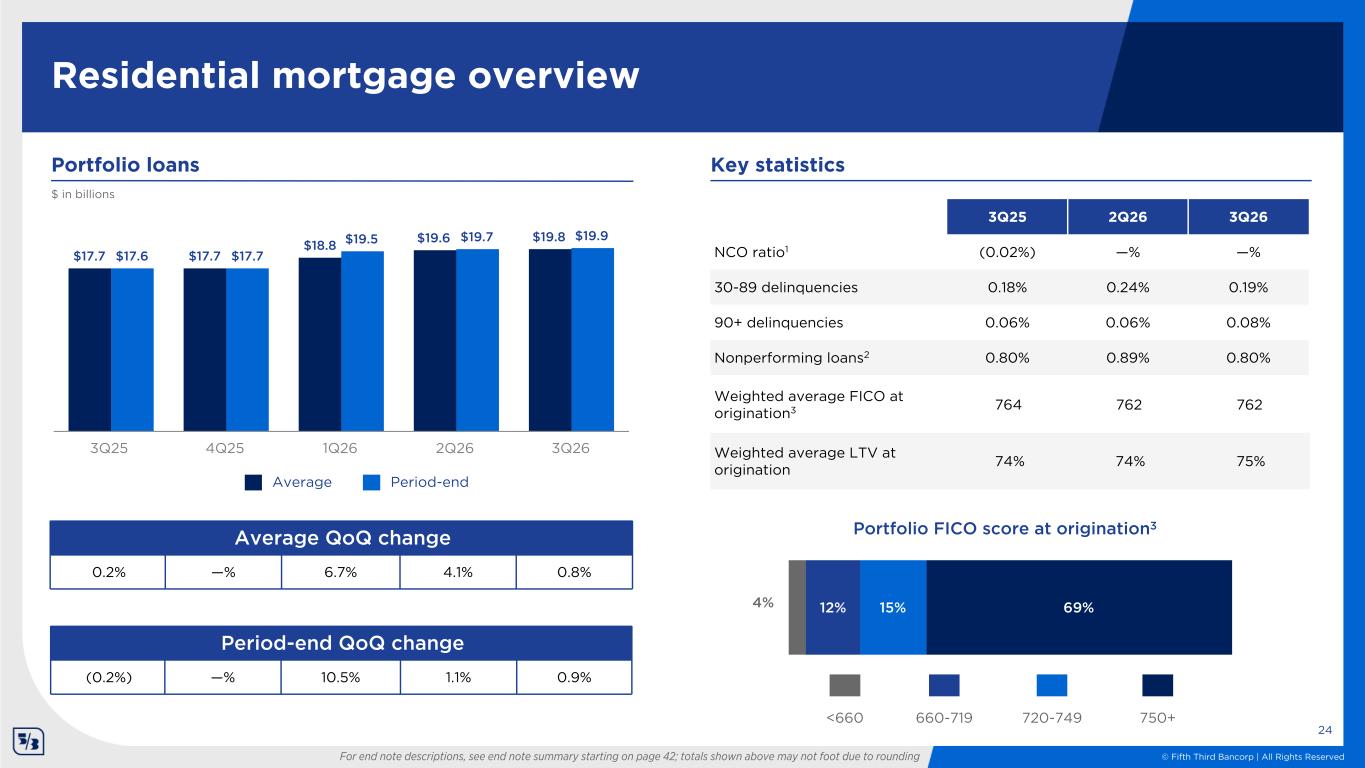
© Fifth Third Bancorp | All Rights Reserved Period-end QoQ change (0.2%) —% 10.5% 1.1% 0.9% Average QoQ change 0.2% —% 6.7% 4.1% 0.8% 12% 15% 69% Weighted average FICO at origination3 764 762 762 Weighted average LTV at origination 74% 74% 75% Residential mortgage overview 24 $17.7 $17.7 $18.8 $19.6 $19.8 $17.6 $17.7 $19.5 $19.7 $19.9 3Q25 4Q25 1Q26 2Q26 3Q26 4% For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding $ in billions Portfolio loans 3Q25 2Q26 3Q26 NCO ratio1 (0.02%) —% —% 30-89 delinquencies 0.18% 0.24% 0.19% 90+ delinquencies 0.06% 0.06% 0.08% Nonperforming loans2 0.80% 0.89% 0.80% Key statistics 750+720-749<660 660-719 Portfolio FICO score at origination3 Period-endAverage
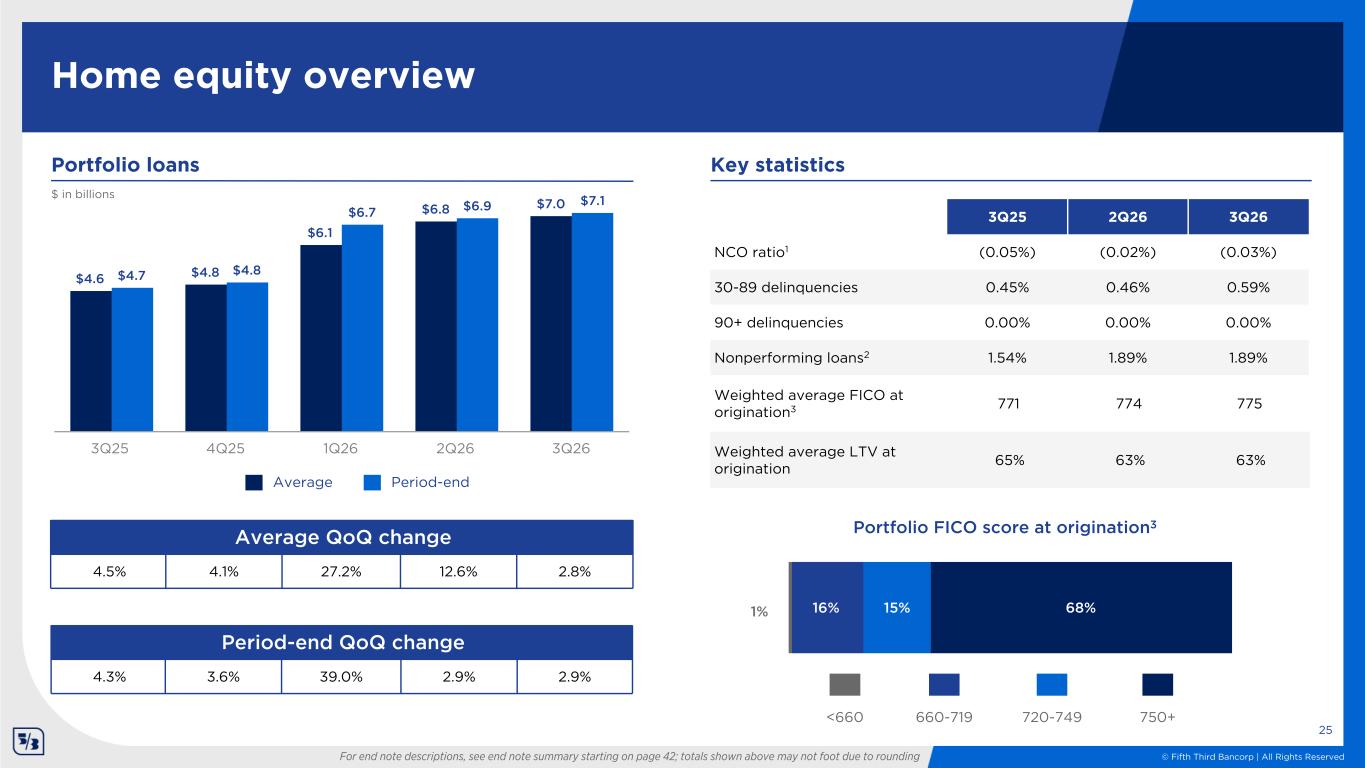
© Fifth Third Bancorp | All Rights Reserved 16% 15% 68% $4.6 $4.8 $6.1 $6.8 $7.0 $4.7 $4.8 $6.7 $6.9 $7.1 3Q25 4Q25 1Q26 2Q26 3Q26 Weighted average FICO at origination3 771 774 775 Weighted average LTV at origination 65% 63% 63% Home equity overview 25 1% For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding Period-end QoQ change 4.3% 3.6% 39.0% 2.9% 2.9% Average QoQ change 4.5% 4.1% 27.2% 12.6% 2.8% $ in billions Portfolio loans Period-endAverage 750+720-749<660 660-719 Portfolio FICO score at origination3 3Q25 2Q26 3Q26 NCO ratio1 (0.05%) (0.02%) (0.03%) 30-89 delinquencies 0.45% 0.46% 0.59% 90+ delinquencies 0.00% 0.00% 0.00% Nonperforming loans2 1.54% 1.89% 1.89% Key statistics

© Fifth Third Bancorp | All Rights Reserved 84% 16% 17% 17% 65% Indirect secured consumer overview 26 Portfolio FICO score at origination *Includes primarily RV & Marine $17.7 $17.9 $18.1 $18.2 $18.2$17.9 $18.0 $18.3 $18.2 $18.2 3Q25 4Q25 1Q26 2Q26 3Q26 1% Weighted average FICO at origination 774 773 774 Weighted average LTV at origination 88% 89% 89% For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding Period-end QoQ change 1.7% 0.4% 1.8% (0.6%) 0.1% Average QoQ change 2.8% 0.8% 1.3% 0.7% (0.3%) $ in billions Portfolio loans Period-endAverage 3Q25 2Q26 3Q26 NCO ratio1 0.40% 0.40% 0.37% 30-89 delinquencies 0.68% 0.59% 0.56% 90+ delinquencies 0.00% 0.00% 0.00% Nonperforming loans2 0.34% 0.34% 0.34% Key statistics 750+720-749<660 660-719 Portfolio FICO score at origination Auto Specialty Lending*

© Fifth Third Bancorp | All Rights Reserved 27% 19% 49% Credit card overview 27 $1.7 $1.7 $1.7 $1.6 $1.6$1.7 $1.7 $1.7 $1.7 $1.7 3Q25 4Q25 1Q26 2Q26 3Q26 Weighted average FICO at origination3 743 743 743 5% Period-end QoQ change (0.9%) 3.3% (5.1%) 1.5% (1.4%) Average QoQ change 1.1% 1.0% (2.1%) (0.8%) —% $ in billions Portfolio loans For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding Period-endAverage 3Q25 2Q26 3Q26 NCO ratio1 3.70% 3.60% 3.45% 30-89 delinquencies 1.00% 0.89% 1.02% 90+ delinquencies 0.95% 0.95% 0.96% Nonperforming loans2 1.71% 1.72% 1.75% Key statistics Portfolio FICO score at origination3 750+720-749<660 660-719
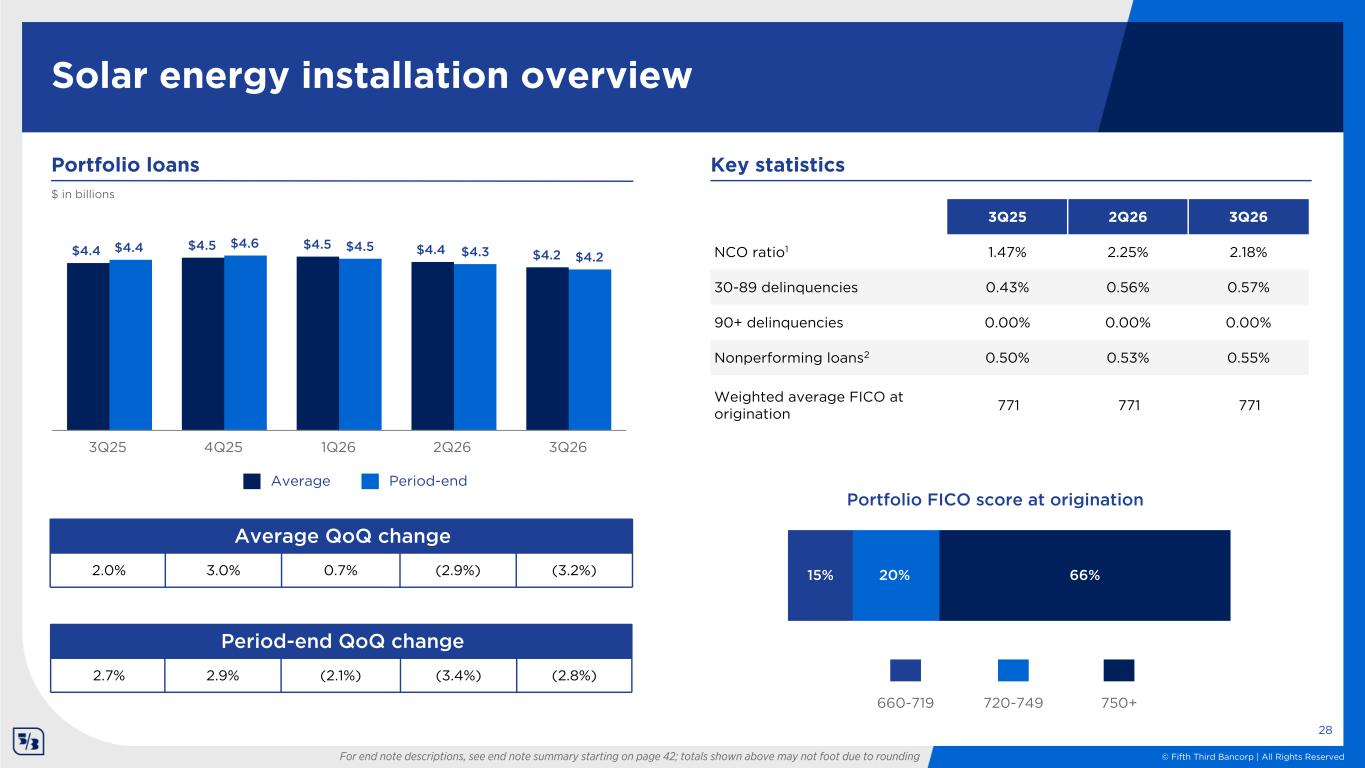
© Fifth Third Bancorp | All Rights Reserved $4.4 $4.5 $4.5 $4.4 $4.2$4.4 $4.6 $4.5 $4.3 $4.2 3Q25 4Q25 1Q26 2Q26 3Q26 15% 20% 66% Weighted average FICO at origination 771 771 771 Solar energy installation overview 28 For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding Period-end QoQ change 2.7% 2.9% (2.1%) (3.4%) (2.8%) Average QoQ change 2.0% 3.0% 0.7% (2.9%) (3.2%) $ in billions Portfolio loans 3Q25 2Q26 3Q26 NCO ratio1 1.47% 2.25% 2.18% 30-89 delinquencies 0.43% 0.56% 0.57% 90+ delinquencies 0.00% 0.00% 0.00% Nonperforming loans2 0.50% 0.53% 0.55% Key statistics Period-endAverage Portfolio FICO score at origination 750+720-749660-719
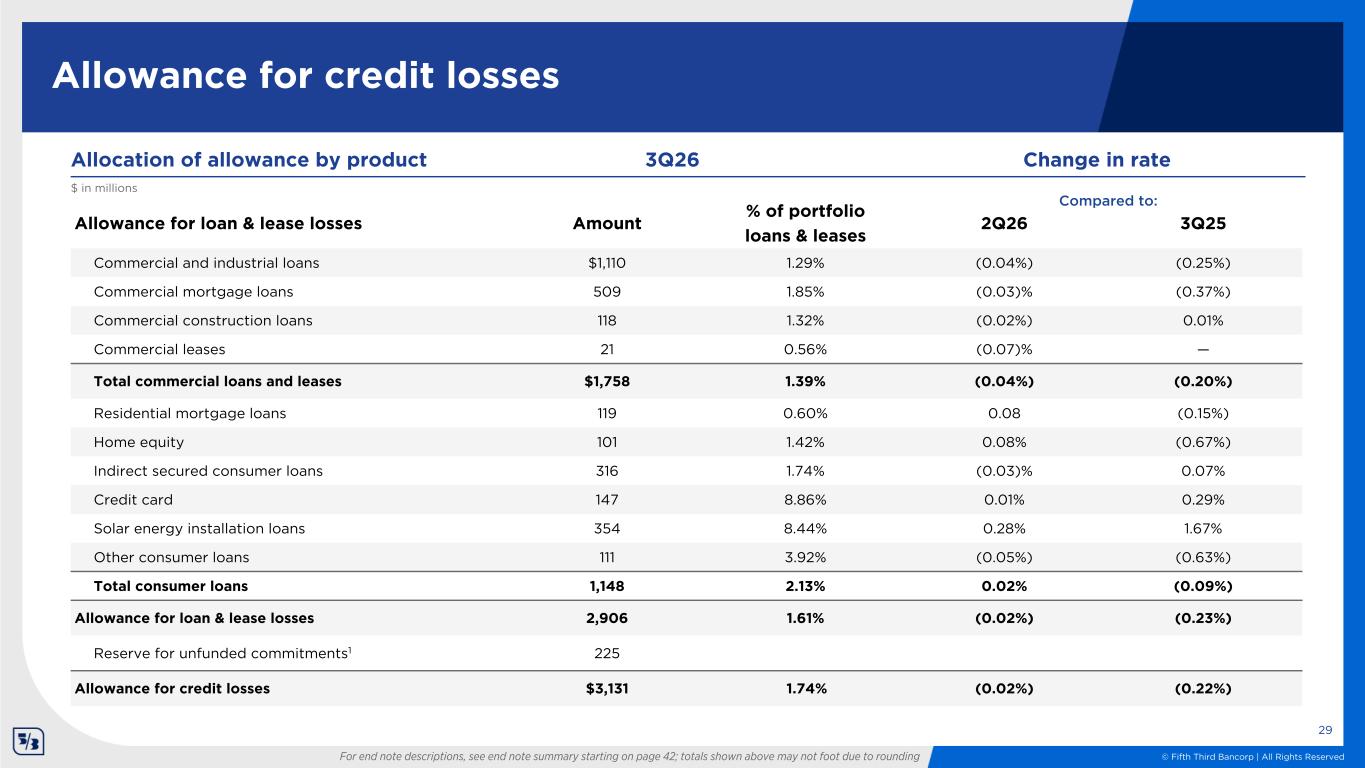
© Fifth Third Bancorp | All Rights Reserved Allowance for credit losses 29 For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding Allowance for loan & lease losses Amount % of portfolio loans & leases 2Q26 3Q25 Commercial and industrial loans $1,110 1.29% (0.04%) (0.25%) Commercial mortgage loans 509 1.85% (0.03)% (0.37%) Commercial construction loans 118 1.32% (0.02%) 0.01% Commercial leases 21 0.56% (0.07)% — Total commercial loans and leases $1,758 1.39% (0.04%) (0.20%) Residential mortgage loans 119 0.60% 0.08 (0.15%) Home equity 101 1.42% 0.08% (0.67%) Indirect secured consumer loans 316 1.74% (0.03)% 0.07% Credit card 147 8.86% 0.01% 0.29% Solar energy installation loans 354 8.44% 0.28% 1.67% Other consumer loans 111 3.92% (0.05%) (0.63%) Total consumer loans 1,148 2.13% 0.02% (0.09%) Allowance for loan & lease losses 2,906 1.61% (0.02%) (0.23%) Reserve for unfunded commitments1 225 Allowance for credit losses $3,131 1.74% (0.02%) (0.22%) Compared to: Allocation of allowance by product $ in millions 3Q26 Change in rate
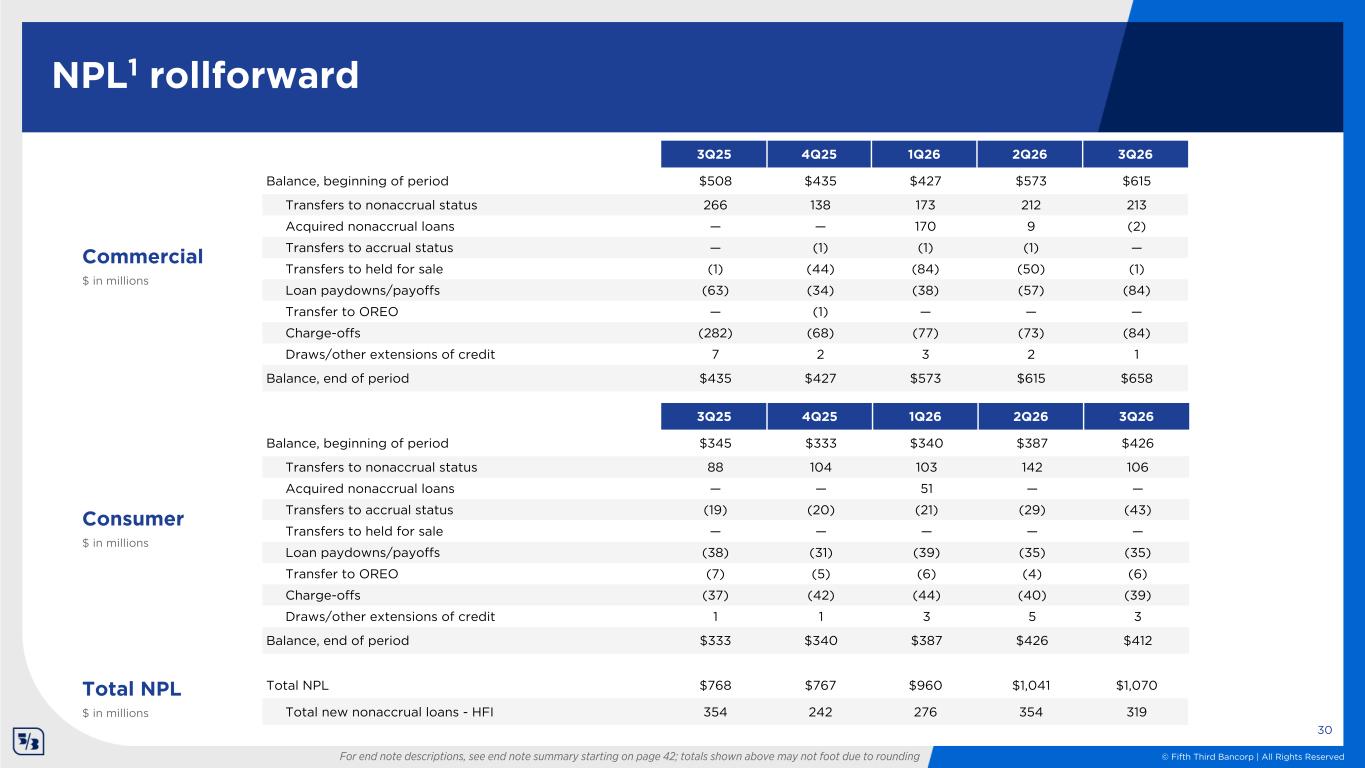
© Fifth Third Bancorp | All Rights Reserved NPL1 rollforward 30 For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding 3Q25 4Q25 1Q26 2Q26 3Q26 Balance, beginning of period $508 $435 $427 $573 $615 Transfers to nonaccrual status 266 138 173 212 213 Acquired nonaccrual loans — — 170 9 (2) Transfers to accrual status — (1) (1) (1) — Transfers to held for sale (1) (44) (84) (50) (1) Loan paydowns/payoffs (63) (34) (38) (57) (84) Transfer to OREO — (1) — — — Charge-offs (282) (68) (77) (73) (84) Draws/other extensions of credit 7 2 3 2 1 Balance, end of period $435 $427 $573 $615 $658 3Q25 4Q25 1Q26 2Q26 3Q26 Balance, beginning of period $345 $333 $340 $387 $426 Transfers to nonaccrual status 88 104 103 142 106 Acquired nonaccrual loans — — 51 — — Transfers to accrual status (19) (20) (21) (29) (43) Transfers to held for sale — — — — — Loan paydowns/payoffs (38) (31) (39) (35) (35) Transfer to OREO (7) (5) (6) (4) (6) Charge-offs (37) (42) (44) (40) (39) Draws/other extensions of credit 1 1 3 5 3 Balance, end of period $333 $340 $387 $426 $412 Commercial $ in millions Consumer $ in millions Total NPL $768 $767 $960 $1,041 $1,070 Total new nonaccrual loans - HFI 354 242 276 354 319 Total NPL $ in millions

© Fifth Third Bancorp | All Rights Reserved Balance sheet positioning 31 For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding C&I 22% Fix | 78% Variable Coml. mortgage 26% Fix | 74% Variable Coml. construction 18% Fix | 82% Variable Coml. lease 100% Fix | 0% Variable 40% 51% 9% 68% 22% 7% 3% • 58% allocation to bullet/locked- out cash flow securities • AFS & HTM spot yield: 3.71% • AFS net unrealized pre-tax loss: $4.73BN $31.6BN fixed | $94.8BN variable1,2 Commercial loans1,2 Investment portfolioConsumer loans1 Long-term debt3 $44.6BN fixed | $9.3BN variable1 $9.2BN fixed | $7.7BN variable3 • 1M based: 53%4,7 • 3M based: 7%4,7 • Prime & O/N based: 14%4,7 • Other based: 1%4,6,7 • Weighted avg. life: 1.7 years1 • 1M based: 1%5,7 • Prime: 15%5 • Other based: 1%5,7,8 • Weighted avg. life: 3.9 years1 • SOFR based: 46% • Weighted avg. life: 3.8 years Includes $2.68BN non-agency CMBS (All super-senior, AAA-rated securities; 58.6% WA LTV, ~33% WA credit enhancement) 34% 37% 13% 13% 3% 76% 9% 1% 14% The information above incorporates the impact of $8.9BN in C&I receive-fixed swaps, $4BN in CRE receive- fixed swaps2, and $7.3BN fair value hedges associated with long-term debt (receive-fixed swaps) Auto/indirect 100% Fix | 0% Variable Resi mtg. & construction 97% Fix | 3% Variable Home equity 12% Fix | 88% Variable Other 78% Fix | 22% Variable Credit card 38% Fix | 62% Variable Level 1 91% Fix | 9% Variable Level 2A 100% Fix | 0% Variable Non-HQLA/ Other 90% Fix | 10% Variable Senior debt 46% Fix | 54% Variable Sub debt 52% Fix | 48% Variable Auto securiz. proceeds 100% Fix | 0% Variable Other 98% Fix | 2% Variable

© Fifth Third Bancorp | All Rights Reserved Managing rate risk against conservative outcomes 32 For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding Estimated NII sensitivity profile and ALCO policy limits Estimated NII beta sensitivity Rate risk models assume approximately 65% effective up betas and 55-60% down betas in our baseline NII sensitivity used in IRR simulations1,2 • Models are calibrated to performance in prior rate cycles • Additionally, rate risk measures assume no deposit re-pricing lags As of September 30, 2026: • 58% of HFI loans were variable rate net of existing hedges (75% of total commercial; 17% of total consumer) • Short-term borrowings represent less than 2% of total funding • Approximately $13.8BN in non-core funding matures beyond one year % Change NII (FTE) ALCO policy limit Change in interest rates (bps) 12 months 13 to 24 months 12 months 13 to 24 months +200 Ramp over 12 months 0.2% 2.4% (9.0%) (15.0%) +100 Ramp over 12 months 0.2% 1.5% NA NA -100 Ramp over 12 months (0.8%) (3.2%) NA NA -200 Ramp over 12 months (2.3%) (8.3%) (9.0%) (15.0%) 5% Higher Beta 5% Lower Beta Change in interest rates (bps) 12 months 13 to 24 months 12 months 13 to 24 months +200 Ramp over 12 months (0.6%) 1.0% 1.0% 4.0% +100 Ramp over 12 months (0.2%) 0.8% 0.6% 2.3% -100 Ramp over 12 months (0.5%) (2.6%) (1.2%) (3.9%) -200 Ramp over 12 months (1.6%) (7.1%) (3.0%) (9.6%) Estimated NII sensitivity with demand deposit balance changes % Change in NII (FTE) $1BN balance decline $1BN balance increase Change in interest rates (bps) 12 months 13 to 24 months 12 months 13 to 24 months +200 Ramp over 12 months (0.3%) 1.8% 0.7% 2.9% +100 Ramp over 12 months (0.3%) 1.0% 0.7% 2.0% -100 Ramp over 12 months (1.2%) (3.5%) (0.5%) (2.9%) -200 Ramp over 12 months (2.6%) (8.5%) (2.0%) (8.1%)

© Fifth Third Bancorp | All Rights Reserved 33 Investment portfolio composition Investment portfolio characteristics Held-to-maturity portfolio • $20.9BN portfolio • Reclassification during 1Q24 aimed to de-risk potential AOCI volatility to capital under proposed capital rules • Securities selected for HTM meet Reg YY eligibility and inclusion requirements Available-for-sale portfolio • $47.7BN portfolio • $2.7BN Non-agency CMBS portfolio – All positions are super-senior AAA rated with WA credit enhancement of 33% – Securities are 20% risk-weighted and are pledgeable to the FHLB – Underlying loans in our structures have a WA LTV of ~59% – Credit risk team analyzes transactions at the underlying property- level, similar to what we do for all our CRE loan commitments HTM 30% AFS 70% AFS and HTM portfolio; amortized cost basis; as of 9/30/2026 Amortized cost basis; as of 9/30/2026 Securities mix Agency CMBS Agency RMBS Non- agency CMBS Treasuries Other Effective duration HTM 47% 26% — 26% —% 4.9 AFS 49% 33% 6% 5% 8% 4.2 Total 48% 31% 4% 11% 6% 4.4 Securities portfolio Securities portfolio $69BN ~26% of interest earning assets ‒ Leverage analytical tools with over 40+ years of historical data to stress the securities at an individual property level on a recurring basis, including significant market distress in real estate valuations Note: Totals shown above may not foot due to rounding
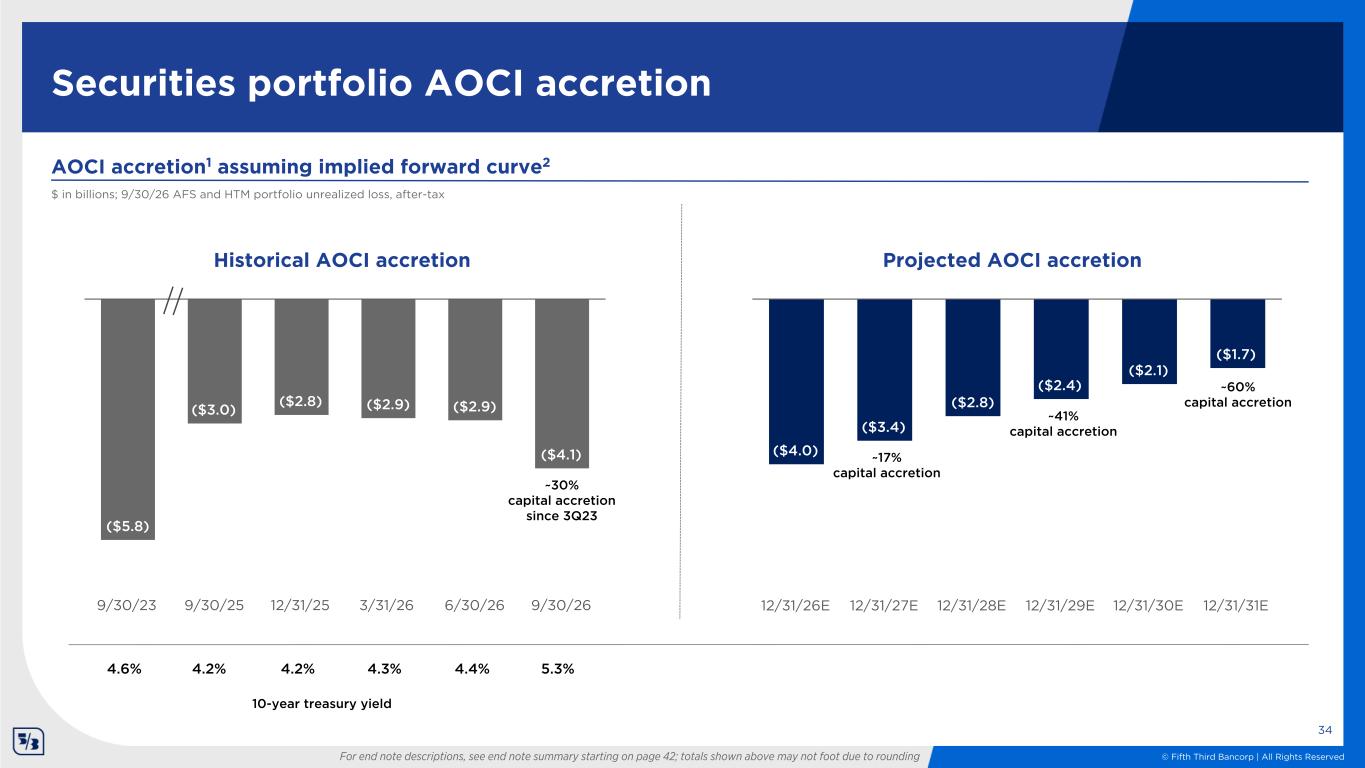
© Fifth Third Bancorp | All Rights Reserved 10-year treasury yield ($5.8) ($3.0) ($2.8) ($2.9) ($2.9) ($4.1) 9/30/23 9/30/25 12/31/25 3/31/26 6/30/26 9/30/26 Projected AOCI accretion ($4.0) ($3.4) ($2.8) ($2.4) ($2.1) ($1.7) 12/31/26E 12/31/27E 12/31/28E 12/31/29E 12/31/30E 12/31/31E Securities portfolio AOCI accretion 34 $ in billions; 9/30/26 AFS and HTM portfolio unrealized loss, after-tax ~60% capital accretion ~17% capital accretion Historical AOCI accretion ~30% capital accretion since 3Q23 AOCI accretion1 assuming implied forward curve2 5.3%4.2% 4.2% 4.3% 4.4% For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding 4.6% ~41% capital accretion
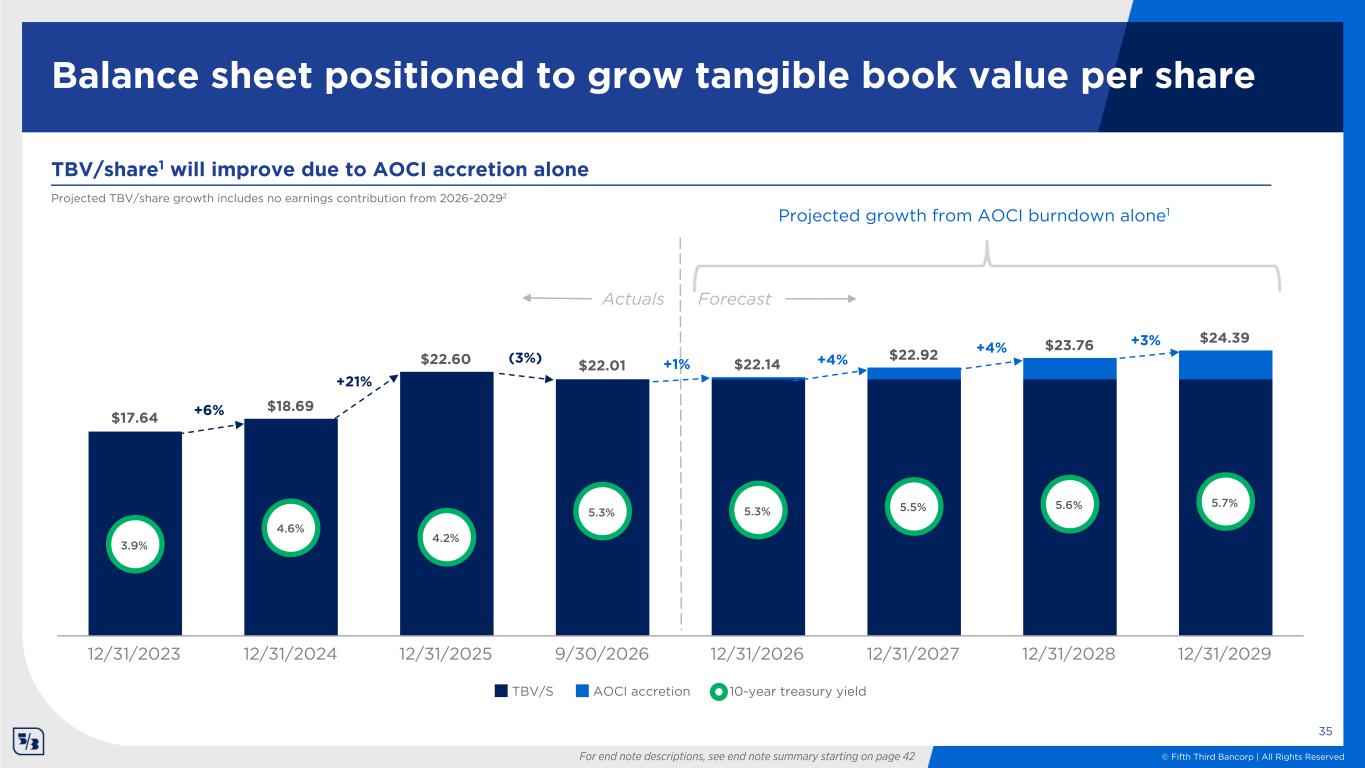
© Fifth Third Bancorp | All Rights Reserved $17.64 $18.69 $22.60 $22.01 $22.14 $22.92 $23.76 $24.39 3.9% 4.6% 4.2% 5.3% 5.3% 5.5% 5.6% 5.7% TBV/S AOCI accretion 10-year treasury yield 12/31/2023 12/31/2024 12/31/2025 9/30/2026 12/31/2026 12/31/2027 12/31/2028 12/31/2029 Balance sheet positioned to grow tangible book value per share 35 TBV/share1 will improve due to AOCI accretion alone Projected TBV/share growth includes no earnings contribution from 2026-20292 For end note descriptions, see end note summary starting on page 42 Actuals Forecast +6% +21% (3%) +4% +4% Projected growth from AOCI burndown alone1 +1% +3%
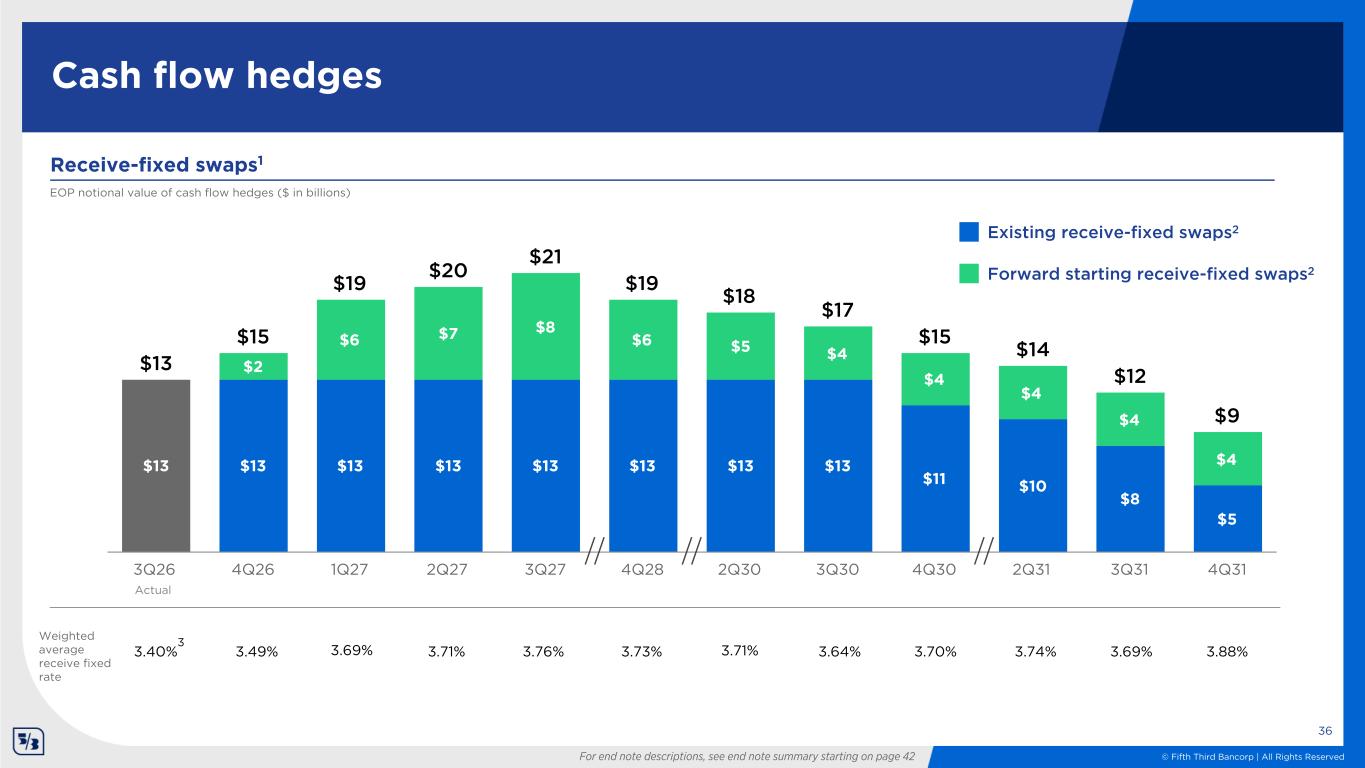
© Fifth Third Bancorp | All Rights Reserved 3.40% $13 $13 $13 $13 $13 $13 $13 $13 $11 $10 $8 $5 $2 $6 $7 $8 $6 $5 $4 $4 $4 $4 $4 $13 $15 $19 $20 $21 $19 $18 $17 $15 $14 $12 $9 3Q26 4Q26 1Q27 2Q27 3Q27 4Q28 2Q30 3Q30 4Q30 2Q31 3Q31 4Q31 Cash flow hedges Receive-fixed swaps1 EOP notional value of cash flow hedges ($ in billions) Actual 36 Existing receive-fixed swaps2 Weighted average receive fixed rate 3.71% 3.64% 3.74% 3.88% 3 For end note descriptions, see end note summary starting on page 42 3.76%3.49% 3.70% 3.69% Forward starting receive-fixed swaps2 3.69% 3.73% 3.71%

© Fifth Third Bancorp | All Rights Reserved $22 $22 $23 $21 $18 $73 $73 $70 $71 $69 $3 $3 ($10) ($11) ($40) ($42) ($39) ($42) ($40) $58 $56 $44 $39 $47Origination fees and gains on loan sale Gross servicing fees Net MSR Valuation MSR decay 3Q25 4Q25 1Q26 2Q26 3Q26 Mortgage banking results $ in millions Mortgage banking net revenue Mortgage originations and margins $ in billions Rate lock margin represents gains recorded associated with salable rate locks divided by salable rate locks. Gain-on-sale margin represents gains on all loans originated for sale divided by salable originations. 37 $1.9 $2.2 $1.9 $2.5 $2.3 $1.4 $1.6 $1.4 $1.6 $1.4 $0.6 $0.6 $0.5 $0.9 $0.8 Originations HFI Originations HFS 3Q25 4Q25 1Q26 2Q26 3Q26 Note: Totals shown above may not foot due to rounding Rate lock margin 1.28% 1.16% 1.30% 1.26% 1.28% Gain-on-sale margin 1.33% 1.17% 1.47% 0.98% 0.93% Mortgage banking net revenue $58 $56 $44 $39 $47

© Fifth Third Bancorp | All Rights Reserved Preferred dividend schedule 4Q26 1Q27 2Q27 3Q27 Series H ~$11 ~$11 ~$12 ~$12 Series I ~$9 ~$9 ~$10 ~$10 Series J ~$6 ~$6 ~$6 ~$6 Series K ~$3 ~$3 ~$3 ~$3 Series M3 ~$7 ~$7 ~$7 ~$7 Class B Series A ~$3 ~$3 ~$3 ~$3 Total ~$39 ~$39 ~$40 ~$41 Upcoming preferred dividend schedule1 $ in millions 38 Floating2 Floating2 Floating2 For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding

© Fifth Third Bancorp | All Rights Reserved 3Q26 reported EPS of $0.90 included a net negative $0.23 impact from the following notable item(s): • $225 million pre-tax (~$171 million after-tax2,3) charge related to merger-related charges • $34 million pre-tax (~$26 million after-tax2) charge related to interchange litigation • $19 million pre-tax (~$14 million after-tax2) charge related to technology-related asset impairments 3Q26 adjustments and notable items Adjusted EPS of $1.131 39 For end note descriptions, see end note summary starting on page 42

© Fifth Third Bancorp | All Rights Reserved Fifth Third Bancorp and Subsidiaries For the three months ended $ and shares in millions (unaudited) September June March December September 2026 2026 2026 2025 2025 Net income (U.S. GAAP) (a) $866 $801 $165 $731 $649 Net income (U.S. GAAP) (annualized) (b) $3,436 $3,213 $669 $2,900 $2,575 Net income available to common shareholders (U.S. GAAP) (c) $828 $763 $128 $699 $608 Add: Intangible amortization, net of tax 48 48 34 5 5 Tangible net income available to common shareholders (d) $876 $811 $162 $704 $613 Tangible net income available to common shareholders (annualized) (e) $3,475 $3,253 $657 $2,793 $2,432 Net income available to common shareholders (annualized) (f) $3,285 $3,060 $519 $2,773 $2,412 Average Bancorp shareholders' equity (U.S. GAAP) (g) $34,338 $34,260 $30,108 $21,527 $21,216 Less: Average preferred stock (h) (2,182) (2,182) (2,040) (1,770) (2,112) Average goodwill (9,976) (9,973) (8,686) (4,947) (4,937) Average intangible assets and other servicing rights (1,221) (1,257) (841) (72) (77) Average tangible common equity (i) $20,959 $20,848 $18,541 $14,738 $14,090 Less: Average accumulated other comprehensive income ("AOCI") 3,813 3,376 3,080 3,137 3,520 Average tangible common equity, excluding AOCI (j) $24,772 $24,224 $21,621 $17,875 $17,610 Adjustments (pre-tax items) Merger-related charges 225 203 657 13 — Interchange litigation matters 34 2 (8) 11 27 Technology-related asset impairments 19 7 — — — Securities (gains)/losses 5 (30) 12 5 (10) Securities repositioning losses — 10 — — — Severance expense — 7 — — — Merger-related Day 1 ACL build — — 83 — — Litigation settlements — — — (12) — FDIC special assessment — — — (25) (6) Fifth Third Foundation contribution — — — 50 — Non-qualified deferred compensation expense/(benefit) (6) 30 (9) (5) 11 Adjustments - after-tax1 (k) $210 $175 $569 $31 $16 Adjustments (tax related items) Benefit related to the resolution of certain tax matters — — — (7) — Adjustments (tax related items) (l) — — — (7) — Adjusted net income [(a) + (k)+ (l)] $1,076 $976 $734 $755 $665 Adjusted net income (annualized) (m) $4,269 $3,915 $2,977 $2,995 $2,638 Adjusted net income available to common shareholders [(c) + (k) + (l)] $1,038 $938 $697 $723 $624 Adjusted net income available to common shareholders (annualized) (n) $4,118 $3,762 $2,827 $2,868 $2,476 Adjusted tangible net income available to common shareholders [(d) + (k) + (l)] $1,086 $986 $731 $728 $629 Adjusted tangible net income available to common shareholders (annualized) (o) $4,309 $3,955 $2,965 $2,888 $2,495 Average assets (p) $302,119 $297,948 $265,551 $213,021 $211,770 Metrics: Return on assets (b) / (p) 1.14% 1.08% 0.25% 1.36% 1.21% Adjusted return on assets (m) / (p) 1.41% 1.31% 1.12% 1.41% 1.25% Return on average common equity (f) / [(g) + (h)] 10.2% 9.5% 1.8% 14.0% 12.6% Adjusted return on average common equity (n) / [(g) + (h)] 12.8% 11.7% 10.1% 14.5% 13.0% Return on average tangible common equity (e) / (i) 16.6% 15.6% 3.5% 19.0% 17.3% Adjusted return on average tangible common equity (o) / (i) 20.6% 19.0% 16.0% 19.6% 17.7% Adjusted return on average tangible common equity, excluding AOCI (o) / (j) 17.4% 16.3% 13.7% 16.2% 14.2% 40 Non-GAAP reconciliation For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding

© Fifth Third Bancorp | All Rights Reserved Non-GAAP reconciliation 41 Fifth Third Bancorp and Subsidiaries For three months ended $ and shares in millions (unaudited) September June March December September 2026 2026 2026 2025 2025 Average interest-earning assets (a) $270,023 $264,989 $237,961 $194,144 $193,500 Net interest income (U.S. GAAP) (b) $2,271 $2,215 $1,934 $1,529 $1,520 Add: Taxable equivalent adjustment 5 5 5 4 5 Net interest income (FTE) (c) $2,276 $2,220 $1,939 $1,533 $1,525 Net interest income (FTE) (annualized) (d) $9,030 $8,904 $7,864 $6,082 $6,050 Noninterest income (U.S. GAAP) (e) $1,008 $1,059 $895 $811 $781 Interchange litigation matters 29 1 (8) 8 18 Merger-related charges 10 — 22 — — Securities repositioning losses — 10 — — — Litigation settlements — — — (12) — Noninterest income excluding certain item(s) $1,047 $1,070 $909 $807 $799 Other securities (gains)/losses 5 (30) 12 5 (10) Adjusted noninterest income, excluding certain item(s) and securities (gains)/losses (f) $1,052 $1,040 $921 $812 $789 Noninterest expense (U.S. GAAP) (g) $2,049 $2,109 $2,395 $1,309 $1,267 Merger-related charges (215) (203) (635) (13) — Technology-related asset impairments (19) (7) — — — Interchange litigation matters (5) (1) — (3) (9) Severance expense — (7) — — — FDIC Special Assessment — — — 25 6 Fifth Third Foundation contribution — — — (50) — Noninterest expense excluding certain item(s) $1,810 $1,891 $1,760 $1,268 $1,264 Add: Non-qualified deferred compensation (expense)/benefit 6 (30) 9 5 (11) Adjusted noninterest expense, excluding certain item(s) and non-qualified deferred compensation (h) $1,816 $1,861 $1,769 $1,273 $1,253 Metrics: Revenue (FTE) (c) + (e) $3,284 $3,279 $2,834 $2,344 $2,306 Adjusted revenue (c) + (f) $3,328 $3,260 $2,860 $2,345 $2,314 Pre-provision net revenue [(c) + (e) - (g)] $1,235 $1,170 $439 $1,035 $1,039 Adjusted pre-provision net revenue [(c) + (f) - (h)] $1,512 $1,399 $1,091 $1,072 $1,061 Net interest margin (FTE) (d) / (a) 3.34% 3.36% 3.30% 3.13% 3.13% Efficiency ratio (FTE) (g) / [(c) + (e)] 62.4% 64.3% 84.5% 55.8% 54.9% Adjusted efficiency ratio (h) / [(c) + (f)] 54.6% 57.1% 61.9% 54.3% 54.1% For end note descriptions, see end note summary starting on page 42; totals shown above may not foot due to rounding

© Fifth Third Bancorp | All Rights Reserved 42 Earnings presentation end notes Slide 3 end notes 1. Non-GAAP measure: see reconciliation on pages 40 and 41 of this presentation and use of non-GAAP measures on pages 27-29 of the earnings release. Slide 4 end notes 1. Reported ROTCE, NIM, pre-provision net revenue, and efficiency ratio are non-GAAP measures: all adjusted figures are non-GAAP measures; see reconciliation on pages 40 and 41 of this presentation and the use of non-GAAP measures on pages 27-29 of the earnings release. 2. Non-GAAP measure: see reconciliation on pages 40 and 41 of this presentation and use of non-GAAP measures on pages 27-29 of the earnings release. 3. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 4. Current period regulatory capital ratios are estimated. Slide 5 end notes 1. Results are on a fully-taxable equivalent basis; non-GAAP measure: see reconciliation on pages 40 and 41 of this presentation and use of non-GAAP measures on pages 27-29 of the earnings release. Slide 6 end notes 1. Non-GAAP measure: see reconciliation on pages 40 and 41 of this presentation and use of non-GAAP measures on pages 27-29 of the earnings release. 2. Includes the effects of non-qualified deferred compensation. Slide 7 end notes 1. Non-GAAP measure: see reconciliation on pages 40 and 41 of this presentation and use of non-GAAP measures on pages 27-29 of the earnings release. Slide 10 end notes 1. Excludes nonaccrual loans HFS. 2. 3Q26 includes $74 million of branch-related real estate no longer intended to be used for banking purposes. 3. 1Q26 excludes net charge-offs of $21 million which were taken immediately at time of merger. Slide 11 end notes 1. Excludes 2020, 2021, and 2022 metrics. 2. Loan balances exclude nonaccrual loans HFS. Slide 12 end notes 1. Current period regulatory capital ratios are estimated. 2. Estimated fully-phased CET1 ratio based on the March 19, 2026 Basel III standardized approach regulatory capital proposal. Slide 13 end notes 1. Non-GAAP measure: see reconciliation on pages 40 and 41 of this presentation and use of non-GAAP measures on pages 27-29 of the earnings release. Slide 15 end notes 1. Digitally active defined as having at least one login to mobile or online banking during the quarter. 2. Mobile active defined as having at least one login to mobile banking during the quarter. Slide 16 end notes 1. Last‑twelve‑month (LTM) noninterest income and revenue are presented on a pro forma basis, excluding securities gains/losses, for Fifth Third and Comerica as of September 30, 2026. 2. Non-GAAP measure: see reconciliation on pages 40 and 41 of this presentation and use of non-GAAP measures on pages 27-29 of the earnings release. Slide 17 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases.
© Fifth Third Bancorp | All Rights Reserved Earnings presentation end notes 43 Slide 18 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. 3. Total commercial portfolio line utilization; 1Q26 and 2Q26 were restated to conform legacy Comerica line utilization to Fifth Third methodology upon systems conversion. Slide 19 end notes 1. Loans to NDFIs are estimated pending the filing of Fifth Third Bank's Call Report and includes the following captions within Call Report schedule RC-C Part I - mortgage credit intermediaries, business credit intermediaries, private equity funds, consumer credit intermediaries and other loans to non-depository financial institutions. 2. Peer data as of 6/30/2026. 3. Fifth Third standalone. Slide 20 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. Slide 22 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. Slide 23 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. 3. FICO distributions at origination exclude certain acquired mortgage & home equity loans, and certain credit loans on book primarily ~15+ years. Slide 24 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. 3. FICO distributions at origination exclude certain acquired mortgage loans. Slide 25 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. 3. FICO distributions at origination exclude certain acquired home equity loans. Slide 26 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. Slide 27 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. 3. FICO distributions at origination exclude certain credit loans on book primarily ~15+ years. Slide 28 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. Slide 29 end notes 1. 3Q26 commercial and consumer portfolio make up ~$185M and ~$40M, respectively, of the total reserve for unfunded commitment.
© Fifth Third Bancorp | All Rights Reserved 44 Earnings presentation end notes Slide 30 end notes 1. Loan balances exclude nonaccrual loans HFS. Slide 31 end notes Note: Data as of 9/30/2026 1. Excludes HFS Loans & Leases. 2. Fifth Third had $12.85BN of commercial variable loans classified as fixed given the impacts of $8.9BN in C&I receive-fix swaps and $4BN in CRE receive-fix swaps. Excludes $8BN in forward starting receive-fix swaps. 3. Fifth Third had $7.3BN SOFR receive-fix swaps outstanding against long-term debt, which are being included in floating long-term debt. 4. As a percent of total commercial. 5. As a percent of total consumer. 6. Includes 12M term, 6M term, and Fed Funds based loans. 7. Term points include SOFR, AMERIBOR, Treasuries & FX curves. 8. Includes overnight term, 3M term, 6M term, 12M term and Fed Funds. Slide 32 end notes Note: Data as of 9/30/2026; actual results may vary from these simulated results due to differences between forecasted and actual balance sheet composition, timing, magnitude, and frequency of interest rate changes, as well as other changes in market conditions and management strategies. 1. Re-pricing percentage or “beta” is the estimated change in yield after the 12-month ramp scenarios are fully realized and therefore reflects year-2. 2. Betas are asymmetrical as down betas assume a floor of 0%, along with rate floors, and up betas assumes a cap of 100%. Slide 34 end notes 1. See forward-looking statements on page 2 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 27-29 of the earnings release. 2. Analysis based on 9/30/2026 portfolio utilizing the implied forward curve as of 9/30/2026. Slide 35 end notes 1. See forward-looking statements on page 2 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 27-29 of the earnings release. 2. Analysis based on 9/30/2026 portfolio utilizing the implied forward curve as of 9/30/2026. Slide 36 end notes 1. Represents forward looking statement, please refer to page 2 of this presentation regarding forward-looking non-GAAP measures. 2. Existing swaps transition from receive fixed / pay 1-month LIBOR to receive fixed / pay compound SOFR + 9.666 bps on their next post-LIBOR cessation resets. 3. Reflects the weighted average receive fixed rate (swaps only) as of 9/30/2026. Slide 38 end notes 1. Represents forward looking statement, please refer to page 2 of this presentation regarding forward-looking non-GAAP measures. 2. Projected dividends for the Series J, Series H, and Series I reflect 3M term SOFR plus the applicable spread. For the periods referencing 3M term SOFR, the projections include the 26.161bps spread adjustment pursuant to the final rule adopted by the Federal Reserve. 3. Series M Preferred Stock was issued in exchange for Comerica Incorporated's 6.875 Fixed-Rate Reset Non-Cumulative Perpetual Preferred Stock, Series B as part of the closing of Comerica's merger with and into Fifth Third on February 1, 2026. The dividend payment dates will be the 1st of January, April, July, and October. Slide 39 end notes 1. Average diluted common shares outstanding (thousands); 917,103; all adjusted figures are non-GAAP measures; see reconciliation on pages 40 and 41 of this presentation and the use of non-GAAP measures on pages 27-29 of the earnings release. 2. Assumes a 24% tax rate. 3. A portion of the adjustments related to merger-related charges are not tax-deductible. Slide 40 end notes Note: See pages 27-29 of the earnings release for a discussion on the use of non-GAAP financial measures. 1. Assumes a 24% tax rate. Slide 41 end notes Note: See pages 27-29 of the earnings release for a discussion on the use of non-GAAP financial measures.