
First United Corp 8-K, filed Jul 29, 2021
First United Corp/Md/ (FUNC)
About this 8-K
First United Corp filed this 8-K on July 29, 2021, reporting on events of July 28, 2021.
Items reported
- Item 2.02: Financial results
- Item 7.01: Regulation FD disclosure
- Item 9.01: Financial statements and exhibits
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported):
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of | (Commission file number) | (IRS Employer | ||
| incorporation or organization) | Identification No.) |
(Address of principal executive offices) (Zip Code)
(
(Registrant’s telephone number, including area code)
N/A
(Former Name or Former Address, if Changed Since Last Report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligations of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) |
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) |
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) |
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) |
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered |
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (17 CFR §230.405) or Rule 12b-2 of the Securities Exchange Act of 1934 (17 CFR §240.12b-2).
Emerging growth company
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
INFORMATION TO BE INCLUDED IN THE REPORT
Item 2.02. Results of Operation and Financial Condition.
On July 28, 2021, First United Corporation (the “Corporation”) issued a press release describing its financial results for the six- and three-month periods ended June 30, 2021. A copy of the press release is furnished herewith as Exhibit 99.1.
The information contained in this Item 2.02 shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), or incorporated by reference in any filing under the Securities Act of 1933, as amended (the “Securities Act”), or the Exchange Act, except as shall be expressly set forth by specific reference in such a filing.
Item 7.01. Regulation FD Disclosure.
On July 29, 2021, the Corporation published an investor presentation that discusses certain aspects of its financial results for the six- and three-month periods ended June 30, 2021. A copy of the presentation is furnished herewith as Exhibit 99.2.
The information contained in this Item 7.01 and in Exhibit 99.1 shall not be deemed “filed” for purposes of Section 18 of the Exchange Act or incorporated by reference in any filing under the Securities Act or the Exchange Act, except as shall be expressly set forth by specific reference in such a filing.
Item 9.01. Financial Statements and Exhibits.
(d) Exhibits.
The exhibits filed or furnished with this report are listed in the following Exhibit Index:
| Exhibit No. | Description | |
| 99.1 | Press release dated July 28, 2021 (furnished herewith) | |
| 99.2 | Investor presentation dated July 29, 2021 (furnished herewith) | |
| 104 | Cover page interactive data file (embedded within the iXBRL document) |
- 2 -
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| FIRST UNITED CORPORATION | ||
| Dated: July 29, 2021 | By: | /s/ Tonya K. Sturm |
| Tonya K. Sturm | ||
| Senior Vice President & CFO | ||
- 3 -
Exhibit 99.1
FIRST UNITED CORPORATION ANNOUNCES
SECOND QUARTER and YEAR TO DATE 2021 EARNINGS
Earnings per share up 85.5% compared to the first six months of 2020 driven by wealth management, loan origination fees, gains, reduced provision and cost control
Paycheck Protection Program forgiveness of $106 million and origination fees of $2.5 million YTD
OAKLAND, MARYLAND—July 28, 2021: First United Corporation (NASDAQ: FUNC), a bank holding company and the parent company of First United Bank & Trust (the “Bank”), today announced earnings results for the three- and six-month periods ended June 30, 2021.
Second Quarter 2021 Financial Highlights:
| · | Consolidated net income increased 71% to $4.4 million compared to $2.6 million for the second quarter of 2020 |
| · | Basic and diluted net income per common share were both $0.66 compared to $0.37 for the second quarter of 2020, an 81% increase year over year |
| · | Non-GAAP, pre-tax, pre-provision earnings increased 19% for the second quarter of 2021 when compared to the second quarter of 2020 |
| · | Wealth management earnings increased 24% for the second quarter of 2021 when compared to the second quarter of 2020 |
| · | Mortgage loan production, primarily in loans sold to the secondary market, totaled $30.9 million for the quarter, leading to net gains on sales of $0.3 million |
| · | Asset quality remained strong, with low delinquency and modified loans returning to full principal and interest payments |
Financial Highlights for the Year To Date Periods Ended June 30 of 2021 and 2020:
| · | Total assets grew by $30.4 million when compared to December 31, 2020, a 1.8% increase. |
| · | When compared to December 31, 2020, loans declined 1.9%, due to $106 million of loan forgiveness under the Small Business Administration’s (“SBA’s”) Paycheck Protection Program (“PPP”), and deposits grew 2.4%. |
| · | Net interest margin, on a non-GAAP, fully tax equivalent (“FTE”) basis, declined to 3.13% at June 30, 2021 compared to 3.61% at June 30, 2020 and 3.34% at December 31, 2020, attributable to the lower interest rate environment, higher cash balances and lower yielding loans (PPP loans). |
| · | The ratio of the allowance for loan losses (“ALL”) to loans outstanding was 1.49% at June 30, 2021 as compared to 1.43% at June 30, 2020. The ALL to loans outstanding, excluding PPP loan balances of $74.1 million, was 1.60% at June 30, 2021, non-GAAP. |
| ○ | Total provision expense was $0.7 million and $4.8 million for the six-month periods ended June 30, 2021 and 2020, respectively |
| ○ | Lower provision expense was due primarily to increased provision in 2020 related to the uncertainties and risks associated with the COVID-19 pandemic |
| · | Consolidated net income increased 81.4% to $7.8 million compared to $4.3 million for the first six months of 2020, inclusive of litigation settlement expenses of $3.3 million in the first quarter of 2021. |
| ○ | Basic and diluted net income per share were both $1.15 compared to $0.62 for the six months of 2020, an 85.5% increase |
| ○ | Net income increased due to increased net interest income from recognition of deferred PPP loan origination fees, decreased provision expense, increased gains related to gains on sales of mortgage loans and investment securities’ gains, insurance proceeds and wealth income, offset by litigation settlement expenses and income taxes |
| · | Net income, exclusive of litigation settlement expenses, non-GAAP, increased to $10.4 million for the first six months of 2021. |
| ○ | Non-GAAP, basic and diluted net income per share both increased to $1.52, exclusive of litigation settlement expenses |
| ○ | Net income increased due to increased net interest income, decrease in expense, increased gains related to gains on sales of mortgage loans and investment securities’ gains, insurance proceeds recorded in the first quarter of 2021, and wealth management income and reduced operating expenses, offset by increased income taxes |
| · | Net interest income declined by $0.5 million for the six months ended June 30, 2021 when compared with the same period of 2020. |
| ○ | Margin compression caused by low yielding PPP loans, continued low-rate environment resulting in lower yields on new loans and repricing of existing loans to lower rates, and elevated cash levels |
| ○ | Growth of non-interest bearing and low-cost core deposits contributed to the elevated cash levels |
| · | Other operating income, including gains, increased $1.8 million for the first six months of 2021 when compared to same period of 2020. |
| ○ | Net gains increased $0.2 million, related to $0.1 million in gains on the sale of mortgages to the secondary market and $0.1 million in investment securities gains |
| ○ | New client relationships and increased market returns led to an increase of $0.9 million in wealth management fees |
| ○ | Increased debit card income of $0.4 million due to increased usage of electronic payment methods |
| ○ | Reduced service charge income, primarily non-sufficient funds (“NSF”) income resulting from reduced spending and increases in consumer and business cash balances from stimulus packages related to the COVID-19 pandemic |
| ○ | Other income increased due primarily to the receipt of $0.4 million in insurance proceeds related to litigation claims recorded in the first quarter of 2021 |
| · | Other operating expenses increased $1.5 million for the first six months of 2021 when compared to the same period of 2020, primarily due to $3.3 million in non-recurring litigation settlement expenses, offset by an increase in deferred PPP loan origination costs of $0.6 million credited to salary expense and a net credit of $0.6 million to expense for Other Real Estate Owned (“OREO”) related to gains on sales of properties. |
| ○ | Legal costs increased $0.6 million due to litigation that was settled in April 2021. |
| ○ | Decreased investor relations of $0.7 million and decreased other miscellaneous expenses of $0.5 million for travel and lodging, business related meals, office supplies, mileage reimbursements, schools and seminars, contract labor and in-house training. |
| · | Non-GAAP, efficiency ratio of 58.6%, exclusive of settlement expenses. The efficiency ratio benefitted from recognition of $0.8 million in gains on the sale of OREO and accrection of $1.6 million of fee income for the origination of PPP loans during the six months of 2021. |
According to Carissa Rodeheaver, President and CEO, “the second quarter produced solid results as the economies in our markets stabilized and we returned to a more normalized environment. We continued to work with our borrowers and local businesses to file forgiveness applications and to fund new PPP loans and the markets were strong, supporting increased income from our wealth division and continued growth in core deposits. Despite increased legal fees related to the litigation settlement, we continued our control over core expenses and produced strong year to date earnings per share, outpacing the same time period in 2020 by 85.5%. Our loan and wealth pipelines are robust and we continued to experience strong asset quality, causing us to be optimistic regarding the remainder of 2021.”
COVID-19
During the first six months of 2021, we continued to assist our business customers with the PPP loan forgiveness process and to originate additional PPP loans through the third round of funding. We remained diligent in protecting our associates and customers from the lingering effects of the pandemic, delaying opening our lobbies until April 1, 2021. Many of our sales and support employees continue to work remotely as we have adjusted to a hybrid work environment. We have continued to monitor our market areas, maintaining travel protocols and utilizing safety precautions while continuing to provide full banking services to our customers.
Paycheck Protection Program
The Company continues to actively participate in the SBA’s PPP program. On January 19, 2021, the SBA implemented a second round of funding for PPP loans. The Company originated $66.1 million in loans during the first six months of 2021 related to this new program, consisting of 870 loans with an average loan size of $80 thousand. New loans under this program are no longer available.
During the second and third quarters of 2020, a total of $148.5 million in PPP loans were originated under the initial program, consisting of 1,174 loans with an average loan size of $162 thousand, and 290 loans, totaling $34.5 million were forgiven, resulting in 885 loans with a remaining balance of $114.0 million at December 31, 2020.
During the first six months of 2021, an additional 1,356 loans from both programs, with an aggregate principal balance of $106.0 million, were forgiven, resulting in 858 loans with a total remaining balance of $74.1 million at June 30, 2021. Net fees recognized in the first six months of 2021 were $2.5 million due to amortization and forgiveness. Of the 1,174 loans originated in 2020, 1,057 have been forgiven totaling $132.0 million through the end of second quarter 2021, representing 90% of the number of 2020 loans originated and 88% of 2020 originated principal balances.
COVID Modifications
While the COVID-19 pandemic has had an impact on most industries, some have been more affected than others. In accordance with Section 4013 of the Coronavirus Aid, Relief, and Economic Security Act and related regulatory pronouncements, we have not accounted for modifications of loans affected by the pandemic as troubled debt restructurings nor have we designated them as past due or nonaccrual.
As of July 16, 2021, there were six commercial loans totaling $7.3 million in total loan modifications related to the real estate rental and health care sectors. These loans are scheduled to return to contractual payment terms within the next quarter.
Balance Sheet Overview
Total assets at June 30, 2021 increased to $1.8 billion, representing a $30.4 million increase since December 31, 2020. During the first six months of 2021, cash and interest-bearing deposits in other banks increased by $45.0 million, the investment portfolio increased by $12.5 million and gross loans decreased by $22.5 million. The increase in cash was due to continued deposit growth, commercial loan payoffs and normal amortization, PPP loan forgiveness, and continued refinancing of balances in our mortgage portfolio. OREO balances decreased $2.6 million due to the sale of a parcel of real estate securing a large commercial participation loan in the first quarter of 2021 and the additional sales of undeveloped lots.
Total liabilities increased by $30.9 million when compared to liabilities at December 31, 2020. The increase in the first six months of 2021 was primarily attributable to deposit growth of $33.7 million due to stimulus programs and to growth in core relationships. Total shareholders’ equity was stable during the first six months of 2021, as net income of $7.8 million was offset by the repurchase of $7.2 million (400,000 shares) of First United Corporation common stock.
Outstanding loans of $1.1 billion at June 30, 2021 reflected a decline of $22.5 million during the first six months of 2021, which was primarily attributable to core commercial loan growth offset by PPP loan forgiveness and a decline in our mortgage loan portfolio. Commercial real estate (“CRE”) loans decreased by $7.2 million, acquisition and development (“A&D”) loans increased by $14.7 million and commercial and industrial (“C&I”) loans decreased by $36.9 million, as newly originated PPP loans and growth in portfolio loans was offset by PPP loan forgiveness. The growth in the commercial portfolios was offset by a decline in residential mortgage loans of $14.8 million, as refinancing activity continued during the first six months of 2021. Given the current low interest rate environment, customers prefer longer-term fixed-rate loans and we continued to utilize the secondary market rather than hold these longer-term fixed rate mortgage loans in the portfolio. The consumer loan portfolio increased by $21.8 million due to the purchase of a pool of consumer loans in an effort to deploy excess cash into higher yielding, short-term assets.
Commercial loan production for the first six months of 2021 was approximately $89.2 million, with $39.2 million originated during the second quarter, exclusive of PPP loan production. SBA PPP loan production was approximately $64.3 million for the six months of 2021. Commercial construction funding continues to ramp up as projects are entering their larger draw periods. At June 30, 2021, unfunded, committed commercial construction loans totaled approximately $22.5 million. Commercial amortization and payoffs were approximately $69.7 million through June 30, 2021, exclusive of PPP.
Consumer mortgage loan production was approximately $57.9 million through June 30, 2021. The production and pipeline mix of in-house, portfolio loans and investor loans remained strong as of June 30, 2021, with those loans totaling $25.0 million, consisting of $22.0 million in portfolio loans and $3.0 million in investor loans. At the end of the second quarter, management implemented special promotions for residential mortgage products to shift production towards portfolio loans and utilize excess cash balances.
Total deposits at June 30, 2021 increased by $33.7 million when compared to deposits at December 31, 2020. During the first six months of 2021, non-interest-bearing deposits increased by $77.3 million, driven by retail and commercial account growth partially attributable to government stimulus programs, including the most recent PPP funding round. Traditional savings accounts increased by $32.5 million, as we continued to see significant growth in our Prime Saver product and total demand deposits increased by $6.2 million. Total money market accounts decreased by $53.6 million due primarily to management’s decision to move wealth management money market funds off balance sheet in the first quarter of 2021. We believe that these funds can be readily shifted back to in-house money market accounts should liquidity needs arise in the future. Time deposits decreased by $28.7 million, primarily in time deposits over $100,000, as we continued to reduce pricing on single-service relationships and municipal bids.
Inclusive of the $3.3 million in litigation settlement expenses, book value was $19.74 per share at June 30, 2021, compared to $18.74 per share at December 31, 2020. At June 30, 2021, there were 6,614,604 of basic outstanding shares and 6,621,677 of diluted outstanding shares of common stock.
Income Statement Overview
Consolidated net income was $7.8 million, inclusive of litigation settlement expenses of $3.3 million, for the six months ended June 30, 2021 compared to $4.3 million for the six months ended June 30, 2020. Basic and diluted net income per share for the first six months of 2021 were both $1.15, compared to basic and diluted net income per share of $0.62 for the same period of 2020, an 85.5% increase.
The increase in earnings for the first six months of 2021 was attributable to an increase in net interest income of $0.5 million, an increase in other operating income, including gains, of $1.8 million and a decrease in provision expense of $4.2 million, partially offset by an increase in other operating expenses of $1.5 million, inclusive of the $3.3 million in litigation settlement expenses.
Consolidated net income was $4.4 million for the second quarter of 2021 compared to $2.6 million for the second quarter of 2020. Basic and diluted net income per common share for the second quarter of 2021 were both $0.66, compared to basic and diluted net income per common share of $0.37 for the second quarter of 2020, an 78.4% increase.
The increase in earnings for the second quarter of 2021 was due to stable net interest income (inclusive of PPP origination fee accretion), an increase in other operating income, including gains, of approximately $0.5 million, a decrease in provision expense of $1.6 million and a decrease in other operating expenses of $0.4 million.
The net interest margins for the second quarter of 2021 and the second quarter of 2020, on a non-GAAP, FTE basis, were 3.15% and 3.53%, respectively. The reduced margin for the second quarter of 2021 was attributable to lower loan yields and increased cash levels, partially offset by lower deposit rates.
Net-Interest Income (Tax-Equivalent Basis -Non-GAAP)
Net interest income, on a non-GAAP, FTE basis, increased by $0.5 million (1.9%) during the six months ended June 30, 2021 when compared with the six months ended June 30, 2020, driven by a $1.7 million (32.4%) decrease in interest expense, partially offset by a decrease in interest income of $1.2 million. The net interest margin, on a fully-taxable equivalent (“FTE”) basis, declined for the six months ended June 30, 2021 to 3.13% compared to 3.61% for the same period of 2020.
Net interest income, on a non-GAAP, FTE basis, increased $0.1 million (0.9%) during the second quarter of 2021 over the same period in 2020 and was driven by a decrease in interest expense of approximately $0.8 million (31.7%), offset by a $0.7 million (4.4%) decrease in interest income. The net interest margin for the second quarter of 2021 was 3.15%, compared to 3.53% for the second quarter of 2020.
Participation in the PPP, with an average outstanding loan balance of $110.7 million and a loan rate of 1.0%, negatively impacted the margin for the second quarter of 2021 by 12 basis points. However, deferred fees of approximately $1.3 million recognized during the second quarter of 2021 positively impacted the margin by 28 basis points, with a net positive impact of 16 basis points. Continued elevated cash levels have also negatively impacted the margin. We expect to see continued margin compression during the remainder of 2021 as deposit rates approach floors and loans continue to reprice to lower rates.
Asset Quality
The ALL increased to $17.1 million at June 30, 2021 compared to $16.5 million at December 31, 2020. The provision for loan losses was $0.7 million for the six months ended June 30, 2021 and $4.8 million for the six months ended June 30, 2020. The higher provision expense recorded in the first six months of 2020 was driven by an increase in the qualitative factors reflecting the uncertainty of the economic environment related to the COVID-19 pandemic and its impact on our borrowers. Net charge-offs of $83 thousand were recorded for the six months ended June 30, 2021, compared to net charge offs of $0.3 million for the same period of 2020. The ratio of the ALL to loans outstanding, including PPP loan balances, was 1.49% at June 30, 2021 compared to 1.43% at June 30, 2020 and 1.41% at December 31, 2020. The ALL to loans outstanding, excluding PPP loan balances of $74.1 million, was 1.60% at June 30, 2021, non-GAAP.
The ratio of net charge-offs to average loans for the six months ended June 30, 2021 was an annualized 0.01%, compared to 0.06% for the six months ended June 30, 2020. Details of the ratio, by loan type are shown below. Our special assets team continues to effectively collect on charged-off loans, resulting in ongoing overall low net charge-off ratios.
| Ratio of Net (Charge Offs)/Recoveries to Average Loans | ||||||||
| 06/30/2021 | 06/30/2020 | |||||||
| Loan Type | (Charge Off) / Recovery | (Charge Off) / Recovery | ||||||
| Commercial Real Estate | 0.00 | % | 0.04 | % | ||||
| Acquisition & Development | 0.05 | % | (0.01 | %) | ||||
| Commercial & Industrial | 0.03 | % | (0.22 | %) | ||||
| Residential Mortgage | (0.03 | %) | (0.02 | %) | ||||
| Consumer | (0.42 | %) | (0.75 | %) | ||||
| Total Net (Charge Offs)/Recoveries | (0.01 | %) | (0.06 | %) | ||||
Non-accrual loans totaled $7.3 million at June 30, 2021 compared to $3.3 million at December 31, 2020. The increase in non-accrual balances at June 30, 2021 was due to the addition of two hospitality loans totaling approximately $4.0 million to non-accrual status during the first quarter of 2021. These loans suffered reduced cash flows due to the impact of the pandemic, received modifications and were classified as substandard at December 31, 2020. These loans have returned to their contractual payment terms but will remain on non-accrual status until they pay full contractual payments for six months.
Non-accrual loans that have been subject to partial charge-offs totaled $0.5 million at June 30, 2021 and $0.2 million at December 31, 2020. Loans secured by 1-4 family residential real estate properties in the process of foreclosure totaled $0.6 million at June 30, 2021 and $0.4 million at December 31, 2020. Foreclosure and repossession activities were temporarily suspended as a result of COVID-19. As a percentage of the loan portfolio, accruing loans past due 30 days or more increased slightly to 0.19%, including PPP loans, or 0.20% excluding PPP loans, compared to 0.17% at June 30, 2020 and 0.20% at December 31, 2020.
Non-Interest Income and Non-Interest Expense
Other operating income, including net gains, increased $1.8 million for the six months ended June 30, 2021 when compared to the six months ended June 30, 2020. Gains on the sale of mortgages to the secondary market, which we have utilized in lieu of retaining long-term fixed rate loans in our portfolio, increased $0.1 million related to continued refinancing activity. Trust and brokerage income increased $0.9 million year-over-year due to continued growth in new client relationships and assets under management. Debit card income increased $0.4 million for the six months ended June 30, 2021 when compared with the same period of 2020 as we continued to grow our deposit relationships and our customers increase use of our electronic services. Other income increased $0.4 million, due primarily to the receipt of insurance proceeds related to litigation claims recorded in the first quarter of 2021. Service charge income remained stable when comparing the six months of 2021 to the same time period of 2020.
Other operating expenses increased $1.5 million, inclusive of litigation settlement expenses, for the six months ended June 30, 2021 when compared with the same period of 2020. Salaries and benefits decreased $0.4 million when compared to the six months of 2020, primarily due to reductions of $0.2 million in life and health insurance costs, a $0.5 million offset in salary expense from deferred loan origination costs primarily attributable to PPP loans and $0.1 million of reduced executive equity compensation due to a timing difference in long-term incentive grants. These decreases were offset by an increase of $0.4 million in salaries, incentives and related payroll costs. Federal Deposit Insurance Corporation premiums increased slightly by $0.2 million due to credits received on quarterly assessments in 2020. Equipment, occupancy and technology expenses decreased $0.6 million when compared to the six months of 2020 as we began to realize cost savings from our core processor related to a new contract negotiated in the fourth quarter of 2020. OREO expenses were a net credit in the first six months of 2021 due to $0.8 million in gains attributable to the sale of OREO properties. Professional services increased $0.8 million as a result of increased legal and professional fees, partially offset by decreased investor relations expenses related to the 2021 annual meeting of shareholders and related litigation.
Other operating income, including gains, for the second quarter of 2021 increased by approximately $0.5 million when compared with the same period of 2020. Service charge income increased by $0.2 million during the second quarter of 2021 when compared with the second quarter of 2020. Trust and brokerage income increased $0.5 million due to increased production and market values on assets under management. Net gains decreased $0.4 million when comparing the second quarter of 2021 to the second quarter of 2020. While the refinancing activity continued into the second quarter of 2021, the pace of activity slowed when compared to the second quarter of 2020, which resulted in reduced gains on the sale of mortgages.
Other operating expenses decreased by $0.4 million when comparing the second quarter of 2021 to the second quarter of 2020. This decrease was driven by reduced occupancy, equipment and technology service during the second quarter of 2021 when compared with the second quarter of 2020 as we began to see reduced costs associated with our core processor due to contract negotiations during 2020. Investor relations costs decreased by $0.7 million during the second quarter of 2021 when compared with the second quarter of 2020 due to costs associated with the 2020 annual meeting of shareholders. These changes were partially offset by increased salaries and benefits related to a reduction in deferred loan origination costs and an increase in professional services related to final legal expenses associated with litigation that was settled in April 2021. Other miscellaneous expenses, such as contributions, consulting, Visa processing fees, office supplies, travel and lodging, schools and seminars, and business-related meals declined. Most of the expense reductions are related to limited operations as a result of the pandemic and management’s continued focus on cost savings and efficiencies. The decreases were offset by increases in mileage, line rentals and contract labor.
The effective income tax rates as a percentage of income for the six-month periods ended June 30, 2021 and 2020 were 25.2% and 22.2%, respectively. The increase in the tax rate was primarily due to the reduction in tax exempt income as well as the reduction in tax credits related to the expiration of a low-income housing tax credit in June 2021.
ABOUT FIRST UNITED CORPORATION
First United Corporation is the parent company of First United Bank & Trust, a Maryland trust company with commercial banking powers, and two statutory trusts that were used as financing vehicles. The Bank has four wholly-owned subsidiaries: OakFirst Loan Center, Inc., a West Virginia finance company; OakFirst Loan Center, LLC, a Maryland finance company; First OREO Trust, a Maryland statutory trust that holds and services real estate acquired by the Bank through foreclosure or by deed in lieu of foreclosure; and FUBT OREO I, LLC, a Maryland company that likewise holds and services real estate acquired by the Bank through foreclosure or by deed in lieu of foreclosure. The Bank also owns 99.9% of the limited partnership interests in Liberty Mews Limited Partnership; a Maryland limited partnership formed for the purpose of acquiring, developing and operating low-income housing units in Garrett County, Maryland. The Corporation’s website is www.mybank.com.
FORWARD-LOOKING STATEMENTS
This press release contains forward-looking statements as defined by the Private Securities Litigation Reform Act of 1995. Forward-looking statements do not represent historical facts, but are statements about management's beliefs, plans and objectives about the future, as well as its assumptions and judgments concerning such beliefs, plans and objectives. These statements are evidenced by terms such as "anticipate," "estimate," "should," "expect," "believe," "intend," and similar expressions. Although these statements reflect management's good faith beliefs and projections, they are not guarantees of future performance and they may not prove true. The beliefs, plans and objectives on which forward-looking statements are based involve risks and uncertainties that could cause actual results to differ materially from those addressed in the forward-looking statements. For a discussion of these risks and uncertainties, see the section of the periodic reports that First United Corporation files with the Securities and Exchange Commission entitled "Risk Factors," including among many others the risk factor set forth in First United’s Annual Report on Form 10-K, as amended, for the year ended December 31, 2020 entitled, “The outbreak of the recent coronavirus (‘COVID-19’), or an outbreak of another highly infectious or contagious disease, could adversely affect the Corporation’s business, financial condition and results of operations.” and any updates thereto that might be contained in subsequent reports filed by First United. The risks and uncertainties associated with the COVID-19 pandemic and its impact on First United will depend on, among other things, the length of time that the pandemic continues; the duration of the potential imposition of further restrictions on travel in the future; the effect of the pandemic on the global, national, and local economies and on the businesses of our borrowers and their ability to make payments on their obligations; the remedial actions and stimulus measures adopted by federal, state, and local governments; and the inability of employees to work due to illness, quarantine, or government mandates.
FIRST UNITED CORPORATION
Oakland, MD
Stock Symbol : FUNC
Financial Highlights - Unaudited
| (Dollars in thousands, except per share data) | ||||||||||||||||
| Three Months Ended | Six Months Ended | |||||||||||||||
| June 30, | June 30, | June 30, | ||||||||||||||
| 2021 | 2020 | 2021 | 2020 | |||||||||||||
| Results of Operations: | ||||||||||||||||
| Interest income | $ | 14,436 | $ | 15,104 | $ | 28,498 | $ | 29,720 | ||||||||
| Interest expense | 1,673 | 2,448 | 3,499 | 5,177 | ||||||||||||
| Net interest income | 12,763 | 12,656 | 24,999 | 24,543 | ||||||||||||
| Provision for loan losses | 555 | 2,167 | 665 | 4,821 | ||||||||||||
| Other operating income | 4,321 | 3,425 | 9,063 | 7,433 | ||||||||||||
| Net gains | 442 | 794 | 1,030 | 835 | ||||||||||||
| Other operating expense | 11,032 | 11,427 | 23,959 | 22,432 | ||||||||||||
| Income before taxes | $ | 5,939 | $ | 3,281 | $ | 10,468 | $ | 5,558 | ||||||||
| Income tax expense | 1,536 | 711 | 2,635 | 1,233 | ||||||||||||
| Net income | $ | 4,403 | $ | 2,570 | $ | 7,833 | $ | 4,325 | ||||||||
| Per share data: | ||||||||||||||||
| Basic/ Diluted net income | $ | 0.66 | $ | 0.37 | $ | 1.15 | $ | 0.62 | ||||||||
| Adjusted Basic/Diluted net income (1) | $ | 0.66 | $ | 0.37 | $ | 1.52 | $ | 0.62 | ||||||||
| Dividends declared per share | $ | 0.15 | $ | 0.13 | $ | 0.30 | $ | 0.26 | ||||||||
| Book value | $ | 19.74 | $ | 17.82 | ||||||||||||
| Adjusted book value (1) | $ | 20.12 | $ | 17.82 | ||||||||||||
| Diluted book value | $ | 19.72 | $ | 17.81 | ||||||||||||
| Adjusted diluted book value (1) | $ | 20.10 | $ | 17.81 | ||||||||||||
| Tangible book value per share | $ | 18.07 | $ | 16.25 | ||||||||||||
| Adjusted tangible book value per share (1) | $ | 18.46 | $ | 16.25 | ||||||||||||
| Diluted Tangible book value per share | $ | 18.05 | $ | 16.01 | ||||||||||||
| Adjusted diluted tangible book value per share (1) | $ | 18.44 | $ | 16.01 | ||||||||||||
| Closing market value | $ | 17.43 | $ | 13.34 | ||||||||||||
| Market Range: | ||||||||||||||||
| High | $ | 19.42 | $ | 15.95 | ||||||||||||
| Low | $ | 16.35 | $ | 11.00 | ||||||||||||
| Shares outstanding at period end: Basic | 6,614,604 | 6,983,523 | ||||||||||||||
| Shares outstanding at period end: Diluted | 6,621,677 | 6,988,593 | ||||||||||||||
| Performance ratios: (Year to Date Period End, annualized) | ||||||||||||||||
| Return on average assets | 0.88 | % | 0.57 | % | ||||||||||||
| Adjusted return on average assets (1) | 1.18 | % | 0.57 | % | ||||||||||||
| Return on average shareholders' equity | 12.21 | % | 6.97 | % | ||||||||||||
| Adjusted return on average shareholders' equity (1) | 15.98 | % | 6.97 | % | ||||||||||||
| Net interest margin (Non-GAAP), includes tax exempt income of $473 and $449 | 3.13 | % | 3.61 | % | ||||||||||||
| Net interest margin GAAP | 3.07 | % | 3.54 | % | ||||||||||||
| Efficiency ratio | 67.69 | % | 70.26 | % | ||||||||||||
| Adjusted efficiency ratio (1) | 58.58 | % | 70.26 | % | ||||||||||||
(1) See reconcilation of this non-GAAP financial measure provided elsewhere herein.
| June 30, | December 31, | |||||||
| 2021 | 2020 | |||||||
| Financial Condition at period end: | ||||||||
| Assets | $ | 1,763,806 | $ | 1,733,414 | ||||
| Earning assets | $ | 1,461,613 | $ | 1,473,733 | ||||
| Gross loans | $ | 1,145,343 | $ | 1,167,812 | ||||
| Commercial Real Estate | $ | 361,941 | $ | 369,176 | ||||
| Acquisition and Development | $ | 131,630 | $ | 116,961 | ||||
| Commercial and Industrial | $ | 229,852 | $ | 266,745 | ||||
| Residential Mortgage | $ | 364,408 | $ | 379,170 | ||||
| Consumer | $ | 57,512 | $ | 35,760 | ||||
| Investment securities | $ | 307,696 | $ | 295,148 | ||||
| Total deposits | $ | 1,456,111 | $ | 1,422,366 | ||||
| Noninterest bearing | $ | 497,736 | $ | 420,427 | ||||
| Interest bearing | $ | 958,375 | $ | 1,001,939 | ||||
| Shareholders' equity | $ | 130,556 | $ | 131,047 | ||||
| Capital ratios: | ||||||||
| Tier 1 to risk weighted assets | 14.48 | % | 14.83 | % | ||||
| Common Equity Tier 1 to risk weighted assets | 12.32 | % | 12.61 | % | ||||
| Tier 1 Leverage | 9.94 | % | 10.36 | % | ||||
| Total risk based capital | 15.73 | % | 16.08 | % | ||||
| Asset quality: | ||||||||
| Net charge-offs for the quarter | $ | (41 | ) | $ | (123 | ) | ||
| Nonperforming assets: (Period End) | ||||||||
| Nonaccrual loans | $ | 7,285 | $ | 3,339 | ||||
| Loans 90 days past due and accruing | 273 | 724 | ||||||
| Total nonperforming loans and 90 day past due | $ | 7,558 | $ | 4,063 | ||||
| Restructured loans | $ | 3,825 | $ | 3,958 | ||||
| Other real estate owned | $ | 6,756 | $ | 9,386 | ||||
| Allowance for loan losses to gross loans | 1.49 | % | 1.41 | % | ||||
| Allowance for loan losses to gross loans, excluding PPP loans | 1.60 | % | 1.55 | % | ||||
| Nonperforming and 90 day past due loans to total loans | 0.66 | % | 0.35 | % | ||||
| Nonperforming loans and 90 day past due loans to total assets | 0.43 | % | 0.23 | % | ||||
| Six Months Ended | ||||||||||||||||||||||||
| March 31, | ||||||||||||||||||||||||
| 2021 | 2020 | |||||||||||||||||||||||
| Average | Average | Average | Average | |||||||||||||||||||||
| (dollars in thousands) | Balance | Interest | Yield/Rate | Balance | Interest | Yield/Rate | ||||||||||||||||||
| Assets | ||||||||||||||||||||||||
| Loans | $ | 1,187,760 | $ | 25,873 | 4.39 | % | $ | 1,104,922 | $ | 26,280 | 4.77 | % | ||||||||||||
| Investment Securities: | ||||||||||||||||||||||||
| Taxable | 264,525 | 1,984 | 1.51 | % | 198,418 | 2,652 | 2.69 | % | ||||||||||||||||
| Non taxable | 25,698 | 972 | 7.63 | % | 25,974 | 954 | 7.39 | % | ||||||||||||||||
| Total | 290,223 | 2,956 | 2.05 | % | 224,392 | 3,606 | 2.23 | % | ||||||||||||||||
| Federal funds sold | 155,009 | 63 | 0.08 | % | 59,103 | 154 | 0.52 | % | ||||||||||||||||
| Interest-bearing deposits with other banks | 2,980 | 1 | 0.05 | % | 753 | 7 | 1.9 | % | ||||||||||||||||
| Other interest earning assets | 4,054 | 78 | 3.88 | % | 4,442 | 122 | 5.53 | % | ||||||||||||||||
| Total earning assets | 1,640,026 | 28,971 | 3.56 | % | 1,393,612 | 30,169 | 4.33 | % | ||||||||||||||||
| Allowance for loan losses | (16,582 | ) | (13,936 | ) | ||||||||||||||||||||
| Non-earning assets | 152,853 | 142,354 | ||||||||||||||||||||||
| Total Assets | $ | 1,776,297 | $ | 1,522,030 | ||||||||||||||||||||
| Liabilities and Shareholders’ Equity | ||||||||||||||||||||||||
| Interest-bearing demand deposits | $ | 208,930 | $ | 347 | 0.33 | % | $ | 169,055 | $ | 341 | 0.41 | % | ||||||||||||
| Interest-bearing money markets | 344,100 | 288 | 0.17 | % | 295,035 | 877 | 0.6 | % | ||||||||||||||||
| Savings deposits | 212,342 | 46 | 0.04 | % | 167,681 | 101 | 0.12 | % | ||||||||||||||||
| Time deposits: | ||||||||||||||||||||||||
| Less than $100k | 106,506 | 726 | 1.37 | % | 111,854 | 875 | 1.57 | % | ||||||||||||||||
| $100k or more | 114,908 | 738 | 1.30 | % | 132,942 | 1,288 | 1.95 | % | ||||||||||||||||
| Short-term borrowings | 50,670 | 50 | 0.20 | % | 42,975 | 49 | 0.23 | % | ||||||||||||||||
| Long-term borrowings | 100,929 | 1,304 | 2.61 | % | 100,929 | 1,646 | 3.28 | % | ||||||||||||||||
| Total interest-bearing liabilities | 1,138,385 | 3,499 | 0.62 | % | 1,020,471 | 5,177 | 1.02 | % | ||||||||||||||||
| Non-interest-bearing deposits | 481,803 | 340,904 | ||||||||||||||||||||||
| Other liabilities | 26,704 | 36,548 | ||||||||||||||||||||||
| Shareholders’ Equity | 129,405 | 124,107 | ||||||||||||||||||||||
| Total Liabilities and Shareholders’ Equity | $ | 1,776,297 | $ | 1,522,030 | ||||||||||||||||||||
| Net interest income and spread | $ | 25,472 | 2.94 | % | $ | 24,992 | 3.31 | % | ||||||||||||||||
| Net interest margin | 3.13 | % | 3.61 | % | ||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||
| March 31, | ||||||||||||||||||||||||
| 2021 | 2020 | |||||||||||||||||||||||
| (dollars in thousands) | Average Balance | Interest | Average Yield/Rate | Average Balance | Interest | Average Yield/Rate | ||||||||||||||||||
| Assets | ||||||||||||||||||||||||
| Loans | $ | 1,173,007 | $ | 13,119 | 4.49 | % | $ | 1,164,023 | $ | 13,424 | 4.61 | % | ||||||||||||
| Investment Securities: | ||||||||||||||||||||||||
| Taxable | 273,196 | 994 | 1.46 | % | 199,721 | 1,344 | 2.71 | % | ||||||||||||||||
| Non taxable | 25,325 | 480 | 7.60 | % | 26,530 | 488 | 7.40 | % | ||||||||||||||||
| Total | 298,521 | 1,474 | 1.98 | % | 226,251 | 1,832 | 3.26 | % | ||||||||||||||||
| Federal funds sold | 174,346 | 39 | 0.09 | % | 73,089 | 15 | 0.08 | % | ||||||||||||||||
| Interest-bearing deposits with other banks | 3,288 | — | 0.00 | % | 863 | 1 | 0.53 | % | ||||||||||||||||
| Other interest earning assets | 3,654 | 38 | 4.17 | % | 4,468 | 58 | 5.23 | % | ||||||||||||||||
| Total earning assets | 1,652,816 | 14,670 | 3.56 | % | 1,468,694 | 15,330 | 4.18 | % | ||||||||||||||||
| Allowance for loan losses | (16,758 | ) | (15,157 | ) | ||||||||||||||||||||
| Non-earning assets | 147,763 | 146,065 | ||||||||||||||||||||||
| Total Assets | $ | 1,783,821 | $ | 1,599,602 | ||||||||||||||||||||
| Liabilities and Shareholders’ Equity | ||||||||||||||||||||||||
| Interest-bearing demand deposits | $ | 214,310 | $ | 175 | 0.33 | % | $ | 174,498 | $ | 157 | 0.36 | % | ||||||||||||
| Interest-bearing money markets | 328,100 | 118 | 0.14 | % | 320,219 | 374 | 0.47 | % | ||||||||||||||||
| Savings deposits | 221,614 | 21 | 0.04 | % | 174,295 | 39 | 0.09 | % | ||||||||||||||||
| Time deposits: | ||||||||||||||||||||||||
| Less than $100k | 105,084 | 337 | 1.29 | % | 114,288 | 459 | 1.62 | % | ||||||||||||||||
| $100k or more | 110,265 | 348 | 1.27 | % | 125,152 | 583 | 1.87 | % | ||||||||||||||||
| Short-term borrowings | 51,035 | 26 | 0.20 | % | 40,671 | 21 | 0.21 | % | ||||||||||||||||
| Long-term borrowings | 100,929 | 648 | 2.58 | % | 100,929 | 815 | 3.25 | % | ||||||||||||||||
| Total interest-bearing liabilities | 1,131,337 | 1,673 | 0.59 | % | 1,050,052 | 2,448 | 0.94 | % | ||||||||||||||||
| Non-interest-bearing deposits | 498,130 | 392,701 | ||||||||||||||||||||||
| Other liabilities | 27,085 | 34,152 | ||||||||||||||||||||||
| Shareholders’ Equity | 127,269 | 122,697 | ||||||||||||||||||||||
| Total Liabilities and Shareholders’ Equity | $ | 1,783,821 | $ | 1,599,602 | ||||||||||||||||||||
| Net interest income and spread | $ | 12,997 | 2.97 | % | $ | 12,882 | 3.24 | % | ||||||||||||||||
| Net interest margin | 3.15 | % | 3.53 | % | ||||||||||||||||||||
FIRST UNITED CORPORATION
Oakland, MD
Stock Symbol : FUNC
Financial Highlights - Unaudited
| (Dollars in thousands, except per share data) | ||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||
| June 30, | March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||||||||
| Results of Operations: | ||||||||||||||||||||||||
| Interest income | $ | 14,436 | $ | 14,062 | 14,228 | 14,253 | 15,104 | 14,616 | ||||||||||||||||
| Interest expense | 1,673 | 1,826 | 2,127 | 2,351 | 2,448 | 2,729 | ||||||||||||||||||
| Net interest income | 12,763 | 12,236 | 12,101 | 11,902 | 12,656 | 11,887 | ||||||||||||||||||
| Provision for loan losses | 555 | 110 | 420 | 160 | 2,167 | 2,654 | ||||||||||||||||||
| Other operating income | 4,321 | 4,742 | 4,378 | 3,978 | 3,425 | 4,008 | ||||||||||||||||||
| Net gains | 442 | 588 | 777 | 1,176 | 794 | 41 | ||||||||||||||||||
| Other operating expense | 11,032 | 12,927 | 10,395 | 10,540 | 11,427 | 11,005 | ||||||||||||||||||
| Income before taxes | $ | 5,939 | $ | 4,529 | $ | 6,441 | $ | 6,356 | $ | 3,281 | $ | 2,277 | ||||||||||||
| Income tax expense | 1,536 | 1,099 | 1,469 | 1,396 | 711 | 522 | ||||||||||||||||||
| Net income | $ | 4,403 | $ | 3,430 | $ | 4,972 | $ | 4,960 | $ | 2,570 | $ | 1,755 | ||||||||||||
| Per share data: | ||||||||||||||||||||||||
| Basic/ Diluted net income | $ | 0.66 | $ | 0.49 | $ | 0.72 | $ | 0.70 | $ | 0.37 | $ | 0.25 | ||||||||||||
| Adjusted Basic/Diluted net income (1) | $ | 0.66 | $ | 0.86 | $ | 0.72 | $ | 0.70 | $ | 0.37 | $ | 0.25 | ||||||||||||
| Dividends declared per share | $ | 0.15 | $ | 0.15 | $ | 0.13 | $ | 0.13 | $ | 0.13 | $ | 0.13 | ||||||||||||
| Book value | $ | 19.74 | $ | 18.46 | $ | 18.83 | $ | 18.63 | $ | 17.82 | $ | 17.01 | ||||||||||||
| Adjusted book value (1) | $ | 20.12 | $ | 18.82 | $ | 18.83 | $ | 18.63 | $ | 17.82 | $ | 17.01 | ||||||||||||
| Diluted book value | $ | 19.72 | $ | 18.45 | $ | 18.73 | $ | 18.62 | $ | 17.81 | $ | 16.95 | ||||||||||||
| Adjusted diluted book value (1) | $ | 20.10 | $ | 18.81 | $ | 18.73 | $ | 18.62 | $ | 17.81 | $ | 16.95 | ||||||||||||
| Tangible book value per share | $ | 18.07 | $ | 16.89 | $ | 17.26 | $ | 17.06 | $ | 16.25 | $ | 15.43 | ||||||||||||
| Adjusted tangible book value per share (1) | $ | 18.46 | $ | 17.25 | $ | 17.26 | $ | 17.06 | $ | 16.25 | $ | 15.43 | ||||||||||||
| Diluted Tangible book value per share | $ | 18.05 | $ | 16.88 | $ | 17.15 | $ | 17.05 | $ | 16.01 | $ | 15.38 | ||||||||||||
| Adjusted diluted tangible book value per share (1) | $ | 18.44 | $ | 17.24 | $ | 17.15 | $ | 17.05 | $ | 16.01 | $ | 15.38 | ||||||||||||
| Closing market value | $ | 17.43 | $ | 17.62 | $ | 15.50 | $ | 11.71 | $ | 13.34 | $ | 14.29 | ||||||||||||
| Market Range: | ||||||||||||||||||||||||
| High | $ | 19.42 | $ | 20.05 | $ | 17.51 | $ | 13.88 | $ | 15.95 | $ | 24.99 | ||||||||||||
| Low | $ | 16.35 | $ | 15.30 | $ | 11.51 | $ | 10.74 | $ | 11.00 | $ | 11.09 | ||||||||||||
| Shares outstanding at period end: Basic | 6,614,604 | 6,998,617 | 6,992,911 | 6,988,998 | 6,983,523 | 6,966,898 | ||||||||||||||||||
| Shares outstanding at period end: Diluted | 6,621,677 | 7,001,997 | 6,997,981 | 6,994,068 | 6,988,593 | 6,991,902 | ||||||||||||||||||
| Performance ratios: (Year to Date Period End, annualized) | ||||||||||||||||||||||||
| Return on average assets | 0.88 | % | 0.79 | % | 0.88 | % | 0.79 | % | 0.57 | % | 0.49 | % | ||||||||||||
| Adjusted return on average assets (1) | 1.18 | % | 1.38 | % | 0.88 | % | 0.79 | % | 0.57 | % | 0.49 | % | ||||||||||||
| Return on average shareholders' equity | 12.21 | % | 10.58 | % | 11.21 | % | 9.87 | % | 6.97 | % | 5.62 | % | ||||||||||||
| Adjusted return on average shareholders' equity (1) | 15.98 | % | 18.36 | % | 11.21 | % | 9.87 | % | 6.97 | % | 5.62 | % | ||||||||||||
| Net interest margin (Non-GAAP), includes tax exempt income of $239 and $223 | 3.13 | % | 3.11 | % | 3.09 | % | 3.43 | % | 3.61 | % | 3.69 | % | ||||||||||||
| Net interest margin GAAP | 3.07 | % | 3.05 | % | 3.03 | % | 3.37 | % | 3.53 | % | 3.63 | % | ||||||||||||
| Efficiency ratio | 67.69 | % | 72.94 | % | 63.47 | % | 64.99 | % | 70.26 | % | 68.29 | % | ||||||||||||
| Adjusted efficiency ratio (1) | 58.58 | % | 54.90 | % | 63.47 | % | 64.99 | % | 70.26 | % | 68.29 | % | ||||||||||||
(1) See reconcilation of this non-GAAP financial measure provided elsewhere herein.
| June 30, | March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | 2020 | 2020 | |||||||||||||||||||
| Financial Condition at period end: | ||||||||||||||||||||||||
| Assets | $ | 1,763,806 | 1,781,833 | 1,734,030 | 1,685,907 | 1,639,636 | 1,461,482 | |||||||||||||||||
| Earning assets | $ | 1,461,613 | $ | 1,481,045 | $ | 1,473,733 | $ | 1,422,341 | $ | 1,420,433 | $ | 1,267,718 | ||||||||||||
| Gross loans | $ | 1,145,343 | $ | 1,199,325 | $ | 1,167,812 | $ | 1,192,345 | $ | 1,186,940 | # | $ | 1,053,732 | |||||||||||
| Commercial Real Estate | $ | 361,941 | $ | 365,731 | $ | 369,176 | $ | 353,272 | $ | 340,314 | $ | 337,688 | ||||||||||||
| Acquisition and Development | $ | 131,630 | $ | 123,625 | $ | 116,961 | $ | 127,299 | $ | 126,338 | $ | 121,333 | ||||||||||||
| Commercial and Industrial | $ | 229,852 | $ | 299,178 | $ | 266,745 | $ | 277,723 | $ | 272,186 | $ | 123,509 | ||||||||||||
| Residential Mortgage | $ | 364,408 | $ | 374,327 | $ | 379,170 | $ | 398,709 | $ | 412,478 | $ | 434,969 | ||||||||||||
| Consumer | $ | 57,512 | $ | 36,464 | $ | 35,760 | $ | 35,342 | $ | 35,624 | $ | 36,233 | ||||||||||||
| Investment securities | $ | 307,696 | $ | 273,363 | $ | 295,148 | $ | 222,382 | $ | 220,165 | $ | 222,192 | ||||||||||||
| Total deposits | $ | 1,456,111 | $ | 1,468,263 | $ | 1,422,366 | $ | 1,377,284 | $ | 1,351,568 | $ | 1,172,394 | ||||||||||||
| Noninterest bearing | $ | 497,736 | $ | 485,311 | $ | 420,427 | $ | 419,935 | $ | 425,274 | $ | 299,961 | ||||||||||||
| Interest bearing | $ | 958,375 | $ | 982,952 | $ | 1,001,939 | $ | 957,349 | $ | 926,294 | # | $ | 872,433 | |||||||||||
| Shareholders' equity | $ | 130,556 | $ | 129,189 | $ | 131,693 | $ | 130,237 | $ | 124,453 | $ | 118,518 | ||||||||||||
| Capital ratios: | ||||||||||||||||||||||||
| Tier 1 to risk weighted assets | 14.55 | % | 14.99 | % | 14.83 | % | 14.89 | % | 14.62 | % | 14.77 | % | ||||||||||||
| Common Equity Tier 1 to risk weighted assets | 12.37 | % | 12.76 | % | 12.61 | % | 12.59 | % | 12.33 | % | 12.44 | % | ||||||||||||
| Tier 1 Leverage | 9.94 | % | 10.22 | % | 10.36 | % | 10.37 | % | 10.46 | % | 11.52 | % | ||||||||||||
| Total risk based capital | 15.80 | % | 16.24 | % | 16.08 | % | 16.14 | % | 15.87 | % | 16.02 | % | ||||||||||||
| Asset quality: | ||||||||||||||||||||||||
| Net (charge-offs)/recoveries for the quarter | $ | (41 | ) | $ | (42 | ) | $ | (123 | ) | $ | (985 | ) | $ | 164 | $ | 178 | ||||||||
| Nonperforming assets: (Period End) | ||||||||||||||||||||||||
| Nonaccrual loans | $ | 7,285 | $ | 7,891 | $ | 3,339 | $ | 10,344 | $ | 11,081 | $ | 11,012 | ||||||||||||
| Loans 90 days past due and accruing | 273 | 6 | 724 | 813 | $ | 297 | 623 | |||||||||||||||||
| Total nonperforming loans and 90 day past due | $ | 7,558 | $ | 7,897 | $ | 4,063 | $ | 11,157 | $ | 11,378 | $ | 11,635 | ||||||||||||
| Restructured loans | $ | 3,825 | $ | 3,892 | $ | 3,958 | $ | 4,477 | $ | 4,039 | $ | 4,581 | ||||||||||||
| Other real estate owned | $ | 6,756 | $ | 7,533 | $ | 9,386 | $ | 3,787 | $ | 3,926 | $ | 4,040 | ||||||||||||
| Allowance for loan losses to gross loans | 1.49 | % | 1.38 | % | 1.41 | % | 1.36 | % | 1.43 | % | 1.42 | % | ||||||||||||
| Allowance for loan losses to gross loans, excluding PPP loans | 1.60 | % | 1.57 | % | 1.55 | % | 1.55 | % | 1.62 | % | 1.42 | % | ||||||||||||
| Nonperforming and 90 day past due loans to total loans | 0.66 | % | 0.66 | % | 0.35 | % | 0.94 | % | 0.96 | % | 1.10 | % | ||||||||||||
| Nonperforming loans and 90 day past due loans to total assets | 0.43 | % | 0.44 | % | 0.23 | % | 0.66 | % | 0.69 | % | 0.80 | % | ||||||||||||
Non-GAAP Financial Measures (unaudited)
Reconciliation of as reported (GAAP) and non-GAAP financial measures
The following tables below provide a reconciliation of certain financial measures calculated under generally accepted accounting principles ("GAAP") (as reported) and non-GAAP. A non-GAAP financial measure is a numerical measure of historical or future financial performance, financial position or cash flows that excludes or includes amounts that are required to be disclosed in the most directly comparable measure calculated and presented in accordance with GAAP in the United States. The Company’s management believes the presentation of non-GAAP financial measures provide investors with a greater understanding of the Company’s operating results in addition to the results measured in accordance with GAAP. While management uses these non-GAAP measures in its analysis of the Company’s performance, this information should not be viewed as a substitute for financial results determined in accordance with GAAP or considered to be more important than financial results determined in accordance with GAAP.
The following non-GAAP financial measures exclude settlement charges associated with the settlement with Driver Management.
| Three months ended March 31, | Three months ended June 30, | |||||||||||||||
| 2021 | 2020 | 2021 | 2020 | |||||||||||||
| (in thousands, except for per share amount) | ||||||||||||||||
| Net income - as reported | $ | 7,833 | $ | 4,325 | $ | 4,403 | $ | 2,570 | ||||||||
| Adjustments: | ||||||||||||||||
| Settlement Expense | 3,300 | — | — | — | ||||||||||||
| Income tax effect of adjustment | (735 | ) | — | — | — | |||||||||||
| Adjusted net income (non-GAAP) | $ | 10,398 | $ | 4,325 | $ | 4,403 | $ | 2,570 | ||||||||
| Basic and Diluted earnings per share - as reported | $ | 1.15 | $ | 0.62 | $ | 0.66 | $ | 0.37 | ||||||||
| Adjustments: | ||||||||||||||||
| Settlement Expense | 0.47 | — | — | — | ||||||||||||
| Income tax effect of adjustment | (0.10 | ) | — | — | — | |||||||||||
| Adjusted basic and diluted earnings per share (non-GAAP) | $ | 1.52 | $ | 0.62 | $ | 0.66 | $ | 0.37 | ||||||||
| As of or for the three months ended | ||||||||
| March 31, | ||||||||
| (in thousands, except per share data) | 2021 | 2020 | ||||||
| Per Share Data | ||||||||
| Basic net income per common share (1) - as reported | $ | 1.15 | $ | 0.62 | ||||
| Basic net income per common share (1) - non-GAAP | 1.52 | 0.62 | ||||||
| Diluted net income per common share (1) - as reported | $ | 1.15 | $ | 0.62 | ||||
| Diluted net income per common share (1) - non-GAAP | 1.52 | 0.62 | ||||||
| Basic book value per common share (1) - as reported | $ | 19.74 | $ | 17.82 | ||||
| Basic book value per common share (1) - non-GAAP | 20.12 | 17.82 | ||||||
| Diluted book value per common share (1) - as reported | $ | 19.72 | $ | 17.81 | ||||
| Diluted book value per common share (1) - non-GAAP | 20.10 | 17.81 | ||||||
| Significant Ratios: | ||||||||
| Return on Average Assets (1) - as reported | 0.88 | % | 0.57 | % | ||||
| Expenses | 0.30 | % | — | |||||
| Income tax effect of adjustment | — | — | ||||||
| Adjusted Return on Average Assets (1) (non-GAAP) | 1.18 | % | 0.57 | % | ||||
| Return on Average Equity (1) - as reported | 12.21 | % | 6.97 | % | ||||
| Expenses | 2.64 | % | — | |||||
| Income tax effect of adjustment | 1.13 | % | — | |||||
| Adjusted Return on Average Equity (1) (non-GAAP) | 15.98 | % | 6.97 | % | ||||
| Average Equity to Average Assets | 7.29 | % | 8.15 | % | ||||
(1) See reconcilation of this non-GAAP financial measure provided elsewhere herein.
Exhibit 99.2
Investor Presentation Second Quarter 2021 July 29, 2021

2 2 Forward looking statements This presentation contains forward - looking statements as defined by the Private Securities Litigation Reform Act of 1995. Forward - looking statements do not represent historical facts, but are statements about management's beliefs, plans and objectives about the future, as well as its assumptions and judgments concerning such beliefs, plans and objectives. These statements are evidenced by terms such as "anticipate," "estimate," "should," "expect," "believe," "intend," and similar expressions. Although these statements reflect management's good faith beliefs and projections, they are not guarantees of future performance and they may not prove true. The beliefs, plans and objectives on which forward - looking statements are based involve risks and uncertainties that could cause actual results to differ materially from those addressed in the forward - looking statements. For a discussion of these risks and uncertainties, see the section of the periodic reports that First United Corporation files with the Securities and Exchange Commission entitled "Risk Factors", including the risk factor set forth in First United Corporation’s Annual Report on Form 10 - K, as amended, for the year ended December 31, 2020 entitled, “The outbreak of the recent coronavirus (“COVID - 19”), or an outbreak of another highly infectious or contagious disease, could adversely affect First United Corporation’s business, financial condition and results of operations.” and any updates thereto that might be contained in subsequent reports filed by First United Corporation. The risks and uncertainties associated with the COVID - 19 pandemic and its impact on First United Corporation will depend on, among other things, the length of time that the pandemic continues; the potential imposition of further restrictions on travel in the future; the effect of the pandemic on the global, national, and local economies and on the businesses of our borrowers and their ability to make payments on their obligations; the remedial actions and stimulus measures adopted by federal, state, and local governments; and the inability of employees to work due to illness, quarantine, or government mandates. Whether actual results will conform to expectations and predictions is subject to known and unknown risks and uncertainties. Actual results could be materially different from management’s expectations. This presentation should be read in conjunction with our Annual Report on Form 10 - K, as amended, for the year ended December 31, 2020, including the sections of the report entitled “Risk Factors”, as well as the reports and other documents that we subsequently file with the Securities and Exchange Commission (“SEC”), which are available on the SEC’s website at www.sec.gov or at our website at www.mybank.com . Except as required by law, we do not intend to publish updates or revisions of any forward - looking statements we make to reflect new information, future events or otherwise.

3 3 Table of Contents I. Executive Summary Pg. 4 II. Operating and Financial Performance Pg. 13 III. Our Commitment To ESG Pg. 30 IV. Appendix Pg. 34

4 4 I. Executive Summary
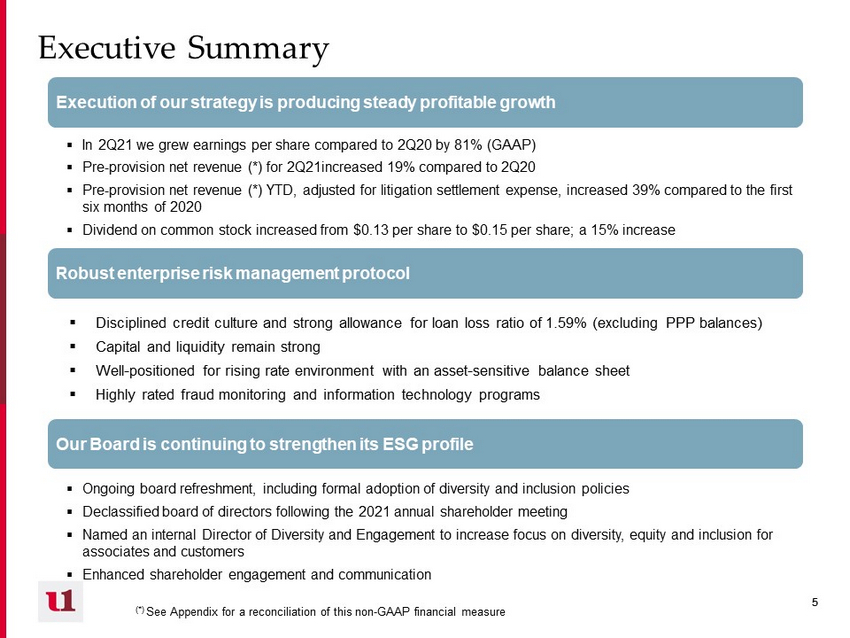
5 5 Executive Summary Robust enterprise risk management protocol Execution of our strategy is producing steady profitable growth Our Board is continuing to strengthen its ESG profile ▪ Disciplined credit culture and strong allowance for loan loss ratio of 1.59% (excluding PPP balances) ▪ Capital and liquidity remain strong ▪ Well - positioned for rising rate environment with an asset - sensitive balance sheet ▪ Highly rated fraud monitoring and information technology programs ▪ Ongoing board refreshment, including formal adoption of diversity and inclusion policies ▪ Declassified board of directors following the 2021 annual shareholder meeting ▪ Named an internal Director of Diversity and Engagement to increase focus on diversity, equity and inclusion for associates and customers ▪ Enhanced shareholder engagement and communication ▪ In 2Q21 we grew earnings per share compared to 2Q20 by 81% (GAAP) ▪ Pre - provision net revenue (*) for 2Q21increased 19% compared to 2Q20 ▪ Pre - provision net revenue (*) YTD, adjusted for litigation settlement expense, increased 39% compared to the first six months of 2020 ▪ Dividend on common stock increased from $0.13 per share to $0.15 per share; a 15% increase (*) See Appendix for a reconciliation of this non - GAAP financial measure

6 6 Mission Statement To enrich the lives of our customers, our employees and our shareholders through uncommon commitment to service and effective financial solutions Company Overview Founded: 1900 Headquarters: Oakland, Maryland Locations: 25 branches + 1 Advisory Center Business Lines: Commercial & Retail Banking, Trust Services, Wealth Management Ticker: FUNC (Nasdaq) Website: www.mybank.com Financial Highlights (as of or for the 6 months ended June 30, 2021) Assets: $1.76 billion Loans: $1.15 billion Deposits: $1.47 billion AUM: $1.41 billion Efficiency Ratio (*): 58.1 % TCE Ratio (*): 6.82% Dividends Declared Per Share : $0.30 Tangible Book Value Per Share (*): $18.07 Diluted EPS - GAAP: $1.15 Diluted EPS - non - GAAP (*): $1.52 NIM: 3.13% NPAs/Total Assets: 1.01% NCOs/Avg. Loans: 0.01% West Virginia Maryland Star denotes Oakland, Maryland Headquarters Franchise Overview (*) See Appendix for a reconciliation of these non - GAAP financial measures

7 7 2Q 2021 Highlights Highlights • Pre - provision net revenue (1) of $6.5 million in 2Q21 compared to $7.9 million in 1Q21 and $5.4 million in 2Q20 • Fee income of $3.9 million driven by strong wealth management revenue as assets under management were $1.4 billion at June 30, 2021, due to expansion of existing relationships, addition of new client relationships and favorable market returns • Mortgage production totaled $30.5 million in 2Q21 compared to $27.5 million in 1Q21 and $38.2 million in 2Q20, primarily in loans sold to the secondary market, leading to net gains of $0.3 million for 2Q21 • Net interest margin positively impacted by PPP deferred loan fees; negatively impacted by low interest environment and high cash balances • PPP deferred loan fees of $1.3 million; 28 bp positive impact • PPP average loan balance of $110.7 million; 12 bp negative impact • Loans refinanced at lower rates and mortgage loans refinanced to secondary market • New commercial loans booked at average yield of approximately 4.0% • Other operating expenses decreased $1.9 million compared to 1Q21 and $0.4 million compared to 2Q20 *2Q21 annualized $4.4 million Adj. Net Income (1) $0.66 Adj. Diluted EPS (1) .99%* ROAA (1) 15.15%* ROATCE (1) 3.15% NIM Key Facts (1) See Appendix for a reconciliation of these non - GAAP financial measures

8 8 YTD Highlights Highlights • Increased pre - provision net revenue (1) to $14.4 million in YTD 2021 from $10.4 million in YTD 2020 • Fee income of $7.9 million driven by strong wealth management revenue as assets under management were $1.4 billion at June 30, 2021, due to expansion of existing relationships, addition of new client relationships and favorable market returns • Paycheck Protection Program (“PPP”) 2020 production of $149 million and YTD 2021 production of $66 million, with $141 million forgiven for both programs at the end of June 2021 • Mortgage production totaled $57.9 million YTD 2021 compared to $62.5 million in YTD 2020, primarily in loans sold to the secondary market, leading to strong net gains of $0.9 million YTD • Allowance for Loan Losses to gross loans 1.49% including PPP loans; 1.60% excluding guaranteed PPP loans. No release of provision in 2020 or YTD 2021. Asset quality remained strong, with low delinquency and most loans returning to full principal and interest payments • Net interest margin reduced due to PPP loans, low interest rate environment and high cash balances • Opened a new Advisory Center in Cheat Lake, Monongalia County, WV *YTD 2Q21 annualized $10.4 million Adj. Net Income (1) $1.52 Adj. Diluted EPS (1) 1.17%* ROAA (1) 17.56%* ROATCE (1) 3.13% NIM Key Facts (1) See Appendix for a reconciliation of these non - GAAP financial measures
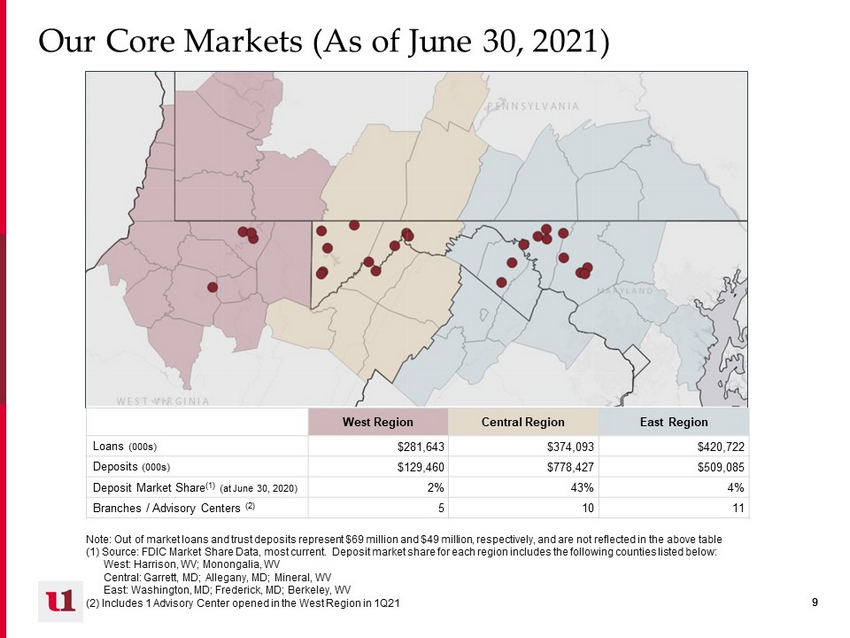
9 9 Our Core Markets (As of June 30, 2021) Note: Out of market loans and trust deposits represent $69 million and $49 million, respectively, and are not reflected in th e a bove table (1) Source: FDIC Market Share Data, most current. Deposit market share for each region includes the following counties liste d b elow: West: Harrison, WV; Monongalia, WV Central: Garrett, MD; Allegany, MD; Mineral, WV East: Washington, MD; Frederick, MD; Berkeley, WV (2) Includes 1 Advisory Center opened in the West Region in 1Q21 West Region Central Region East Region Loans (000s) $281,643 $374,093 $420,722 Deposits (000s) $129,460 $778,427 $509,085 Deposit Market Share (1) (at June 30, 2020) 2% 43% 4% Branches / Advisory Centers (2) 5 10 11
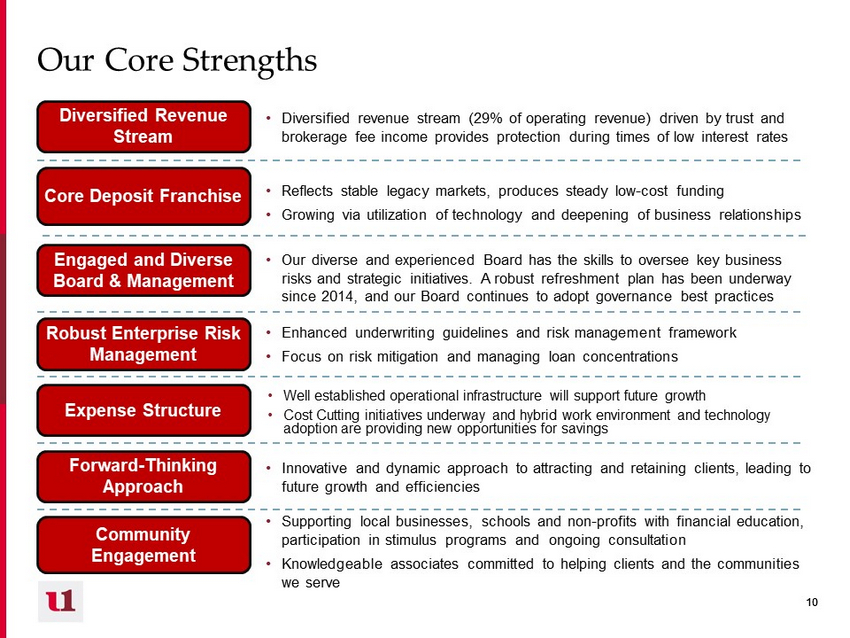
10 10 Our Core Strengths Engaged and Diverse Board & Management • Our diverse and experienced Board has the skills to oversee key business risks and strategic initiatives. A robust refreshment plan has been underway since 2014, and our Board continues to adopt governance best practices Core Deposit Franchise Diversified Revenue Stream Forward - Thinking Approach Robust Enterprise Risk Management Expense Structure • Reflects stable legacy markets, produces steady low - cost funding • Growing via utilization of technology and deepening of business relationships • Diversified revenue stream (29% of operating revenue) driven by trust and brokerage fee income provides protection during times of low interest rates • Innovative and dynamic approach to attracting and retaining clients, leading to future growth and efficiencies • Enhanced underwriting guidelines and risk management framework • Focus on risk mitigation and managing loan concentrations • Well established operational infrastructure will support future growth • Cost Cutting initiatives underway and hybrid work environment and technology adoption are providing new opportunities for savings Community Engagement • Supporting local businesses, schools and non - profits with financial education, participation in stimulus programs and ongoing consultation • Knowledgeable associates committed to helping clients and the communities we serve
11 11 Transitioning to Post - COVID Environment • Customization of Experience • Blend of technology and in - person service and solutions • Delivery of updated technology to our clients through enhanced delivery channels, including virtual closing options, mobile deposits, ATMS, cash recyclers • Enhanced communication and outreach to shareholders , clients and associates • Keen Community Focus • Supported local communities through 2,046 PPP loans totaling $215 million and 650 COVID loan modifications totaling $261 million • Supported our communities through continued support of non - profit groups and special banking accommodations • More Efficient and Flexible Employer • During COVID, assisted our associates through work - at - home accommodations, pandemic pay policies, Financial First Responder bonuses, and flexible schedules. Post COVID, we are migrating to a hybrid environment and continuing these best practices which empower our workforce and make First United an attractive place to build a career • Better Prepared for Future Business Disruption • State of the art Business Continuity Plan protecting shareholders, clients and associates
12 12 PPP and Loan Modifications • Originated 1,174 loans totaling $149 million in 2020, and an additional 870 loans totaling $66 million in 2021 • June 2021 period - end portfolio balance - $74 million, with a YTD average balance of $126.6 million and a 2Q21 average balance of $110.7 million • Based on current and projected forgiveness activity, management estimates that $16 million in balances will remain at year - end 2021 from both programs • New customers comprised 22% of the number of PPP loans granted. Actively cultivating new relationships and deepening existing relationships, adding approximately $65 million in new non - PPP loans and $40 million in new non - PPP deposits through June 2021 • Total net fees (fees assessed less deferred expenses) of $6.5 million • Recognized in 2020: $2.0 million • Recognized YTD 2021: $2.6 million: • Estimated to be recognized for the remainder of 2021:$1.4 million • Estimated to be recognized in 2022: $0.5 million • Estimated net positive impact on 2Q21 margin of 16 bps; positive impact of deferred loan fees of 28 bps offset by negative loan yield impact of 12 bps • Provided Covid - 19 loan modifications for approximately 650 loans totaling $261 million for our business and consumer clients. Active modifications remaining for 6 commercial loans totaling $3.4 million, primarily in healthcare sector. All loans expected to return to P&I in the next quarter COVID - 19 loan modifications Excellent delivery for new and existing clients on the Paycheck Protection Program
13 13 II. Operating and Financial Performance
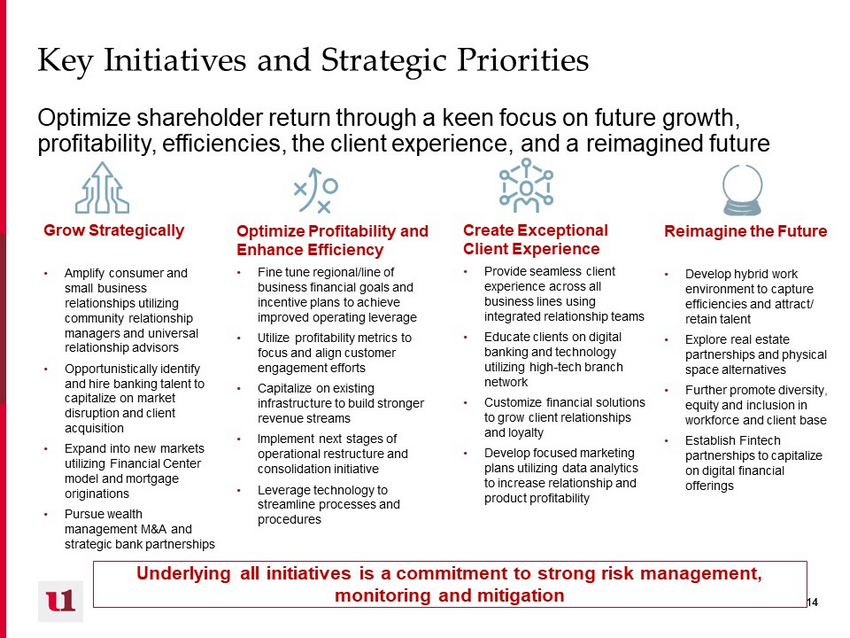
14 14 Key Initiatives and Strategic Priorities Optimize shareholder return through a keen focus on future growth, profitability, efficiencies, the client experience, and a reimagined future Create Exceptional Client Experience • Provide seamless client experience across all business lines using integrated relationship teams • Educate clients on digital banking and technology utilizing high - tech branch network • Customize financial solutions to grow client relationships and loyalty • Develop focused marketing plans utilizing data analytics to increase relationship and product profitability Grow Strategically • Amplify consumer and small business relationships utilizing community relationship managers and universal relationship advisors • Opportunistically identify and hire banking talent to capitalize on market disruption and client acquisition • Expand into new markets utilizing Financial Center model and mortgage originations • Pursue wealth management M&A and strategic bank partnerships Optimize Profitability and Enhance Efficiency • Fine tune regional/line of business financial goals and incentive plans to achieve improved operating leverage • Utilize profitability metrics to focus and align customer engagement efforts • Capitalize on existing infrastructure to build stronger revenue streams • Implement next stages of operational restructure and consolidation initiative • Leverage technology to streamline processes and procedures Underlying all initiatives is a commitment to strong risk management, monitoring and mitigation Reimagine the Future • Develop hybrid work environment to capture efficiencies and attract/ retain talent • Explore real estate partnerships and physical space alternatives • Further promote diversity, equity and inclusion in workforce and client base • Establish Fintech partnerships to capitalize on digital financial offerings
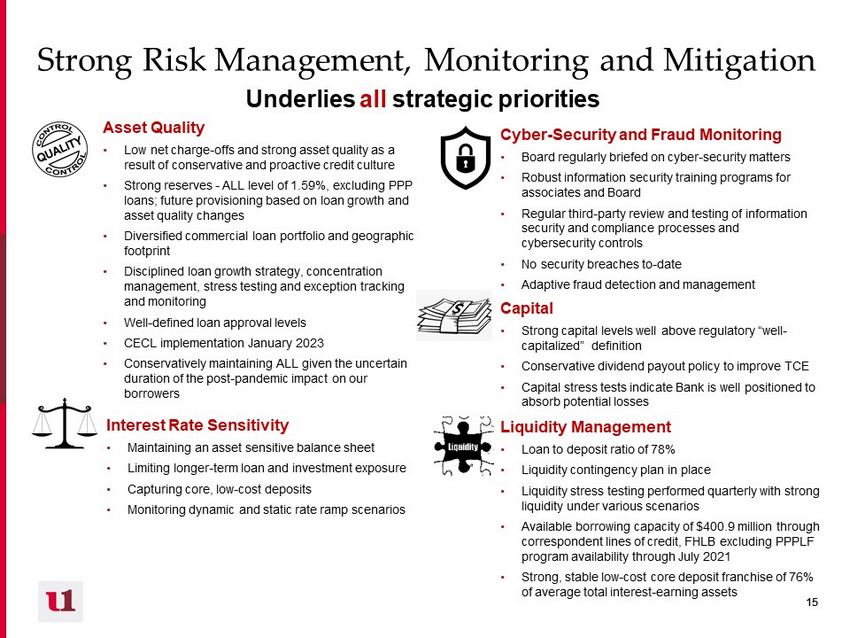
15 15 Strong Risk Management, Monitoring and Mitigation Underlies all strategic priorities Asset Quality • Low net charge - offs and strong asset quality as a result of conservative and proactive credit culture • Strong reserves - ALL level of 1.59%, excluding PPP loans; future provisioning based on loan growth and asset quality changes • Diversified commercial loan portfolio and geographic footprint • Disciplined loan growth strategy, concentration management, stress testing and exception tracking and monitoring • Well - defined loan approval levels • CECL implementation January 2023 • Conservatively maintaining ALL given the uncertain duration of the post - pandemic impact on our borrowers Liquidity Management • Loan to deposit ratio of 78% • Liquidity contingency plan in place • Liquidity stress testing performed quarterly with strong liquidity under various scenarios • Available borrowing capacity of $400.9 million through correspondent lines of credit, FHLB excluding PPPLF program availability through July 2021 • Strong, stable low - cost core deposit franchise of 76% of average total interest - earning assets Capital • Strong capital levels well above regulatory “well - capitalized” definition • Conservative dividend payout policy to improve TCE • Capital stress tests indicate Bank is well positioned to absorb potential losses Cyber - Security and Fraud Monitoring • Board regularly briefed on cyber - security matters • Robust information security training programs for associates and Board • Regular third - party review and testing of information security and compliance processes and cybersecurity controls • No security breaches to - date • Adaptive fraud detection and management Interest Rate Sensitivity • Maintaining an asset sensitive balance sheet • Limiting longer - term loan and investment exposure • Capturing core, low - cost deposits • Monitoring dynamic and static rate ramp scenarios
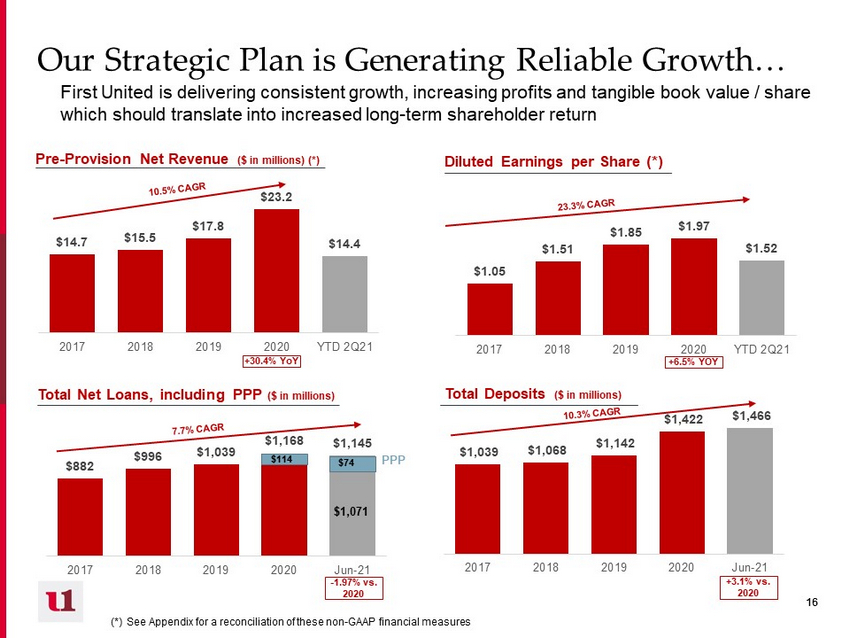
16 16 $14.7 $15.5 $17.8 $23.2 $14.4 2017 2018 2019 2020 YTD 2Q21 $1,039 $1,068 $1,142 $1,422 $1,466 2017 2018 2019 2020 Jun-21 $882 $996 $1,039 $1,168 $1,145 2017 2018 2019 2020 Jun-21 $1,071 Our Strategic Plan is Generating Reliable Growth… Pre - Provision Net Revenue ($ in millions) (*) Diluted Earnings per Share (*) Total Deposits ($ in millions) Total Net Loans, including PPP ($ in millions) First United is delivering consistent growth, increasing profits and tangible book value / share which should translate into increased long - term shareholder return $1.05 $1.51 $1.85 $1.97 $1.52 2017 2018 2019 2020 YTD 2Q21 +30.4% YoY +6.5% YOY - 1.97% vs. 2020 +3.1% vs. 2020 $74 PPP $114 (*) See Appendix for a reconciliation of these non - GAAP financial measures
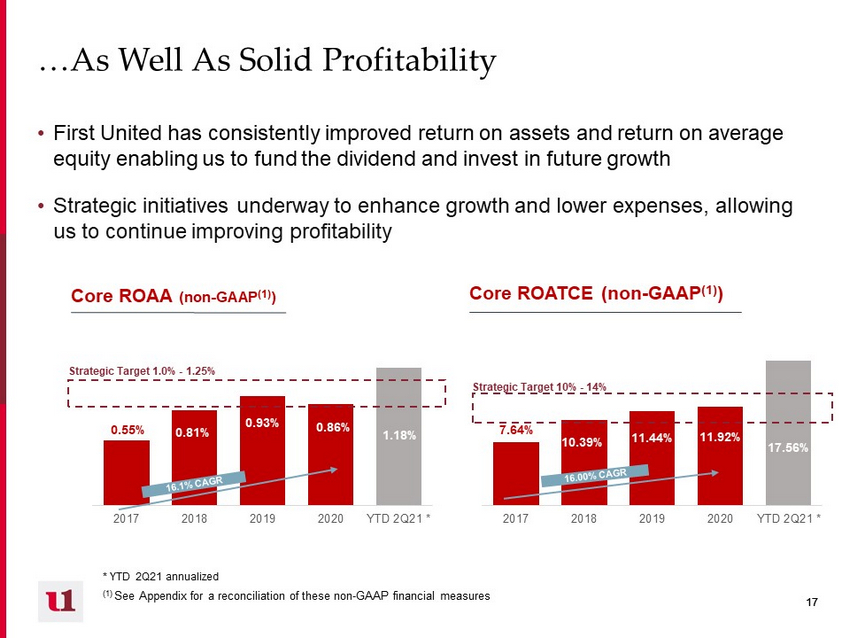
17 17 7.64% 10.39% 11.44% 11.92% 17.56% 2017 2018 2019 2020 YTD 2Q21 * 0.55% 0.81% 0.93% 0.86% 1.18% 2017 2018 2019 2020 YTD 2Q21 * …As Well As Solid Profitability • First United has consistently improved return on assets and return on average equity enabling us to fund the dividend and invest in future growth • Strategic initiatives underway to enhance growth and lower expenses, allowing us to continue improving profitability Core ROATCE (non - GAAP (1) ) Core ROAA (non - GAAP (1) ) Strategic Target 1.0% - 1.25% Strategic Target 10% - 14% * YTD 2Q21 annualized (1) See Appendix for a reconciliation of these non - GAAP financial measures
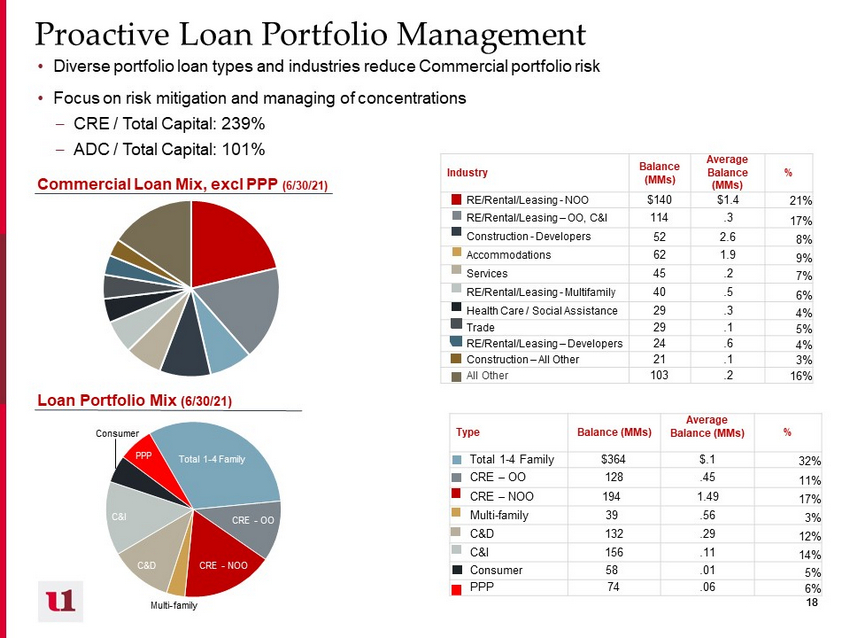
18 18 Total 1 - 4 Family CRE - OO CRE - NOO Multi - family C&D C&I Consumer PPP Proactive Loan Portfolio Management • Diverse portfolio loan types and industries reduce Commercial portfolio risk • Focus on risk mitigation and managing of concentrations – CRE / Total Capital: 239% – ADC / Total Capital: 101% Loan Portfolio Mix (6/30/21) Commercial Loan Mix, excl PPP (6/30/21) Industry Balance (MMs) Average Balance (MMs) % RE/Rental/Leasing - NOO $140 $1.4 21% RE/Rental/Leasing – OO, C&I 114 .3 17% Construction - Developers 52 2.6 8% Accommodations 62 1.9 9% Services 45 .2 7% RE/Rental/Leasing - Multifamily 40 .5 6% Health Care / Social Assistance 29 .3 4% Trade 29 .1 5% RE/Rental/Leasing – Developers 24 .6 4% Construction – All Other 21 .1 3% All Other 103 .2 16% Type Balance (MMs) Average Balance (MMs) % Total 1 - 4 Family $364 $.1 32% CRE – OO 128 .45 11% CRE – NOO 194 1.49 17% Multi - family 39 .56 3% C&D 132 .29 12% C&I 156 .11 14% Consumer 58 .01 5% PPP 74 .06 6%

19 19 Central East West Commercial Acquisition and Development Commercial Construction 1 - 4 Family Commercial Construction Amortizing Consumer Lot Loans 1 - 4 Family Residential Construction Construction and Development Portfolio • Geographically diverse construction and development portfolio mitigates risk to portfolio • Construction portfolio has been reduced from 22% of portfolio in 2007 to 12% in June 2021 By Region (6/30/21) Geography Balance (MMs) Average Balance (MMs) % Central 28 $.10 21% East 60 .47 45% West 44 1.0 34% By Purpose (6/30/21) Purpose Balance (MMs) Average Balance (MMs) % Commercial A&D $64 $1.06 49% Commercial Construction 29 3.65 22% 1 - 4 Family Commercial Construction 4 .41 3% Amortizing Consumer Lot Loans 19 .06 14% 1 - 4 Family Residential Construction 16 .27 12%

20 20 YTD Activity in Loan Portfolio • Production levels remain high YTD • Net loan production being offset by PPP payoffs • Fixed rate, longer - term mortgages being sold to secondary market (data in thousands) Production Payoffs/ Amortization 2021 Net Activity Commercial, excluding PPP 89,200.0 (69,700.0) 19,500.0 Mortgage portfolio 57,900.0 (79,353.0) (21,453.0) Consumer (*) 39,448.0 (20,130.0) 19,318.0 Total, before PPP 186,548.0 (169,183.0) 17,365.0 PPP 66,100.0 (106,000.0) (39,900.0) Total , including PPP 252,648.0 (275,183.0) (22,535.0) Mortgages sold in secondary market 22,071.0 (*) Including $20.1 million pool purchase in 2Q
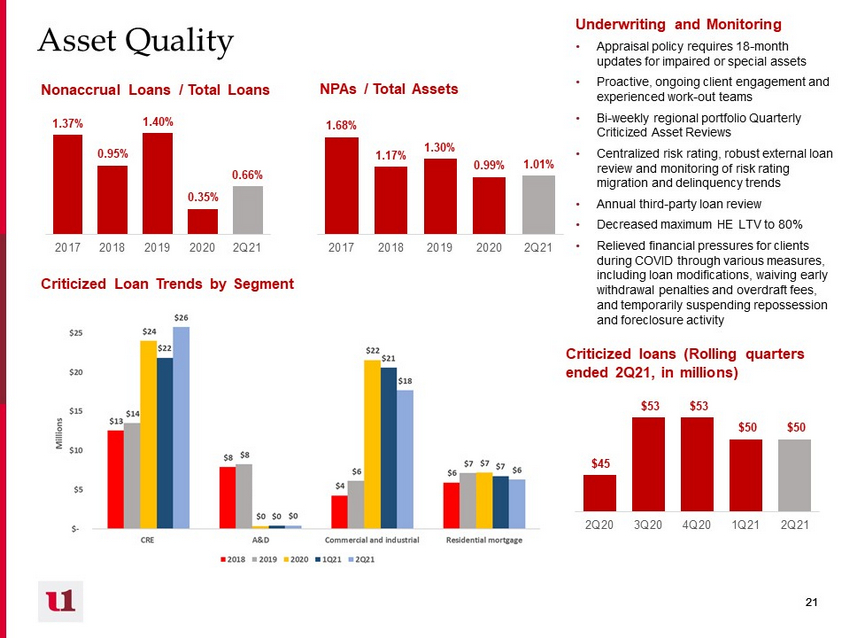
21 21 $45 $53 $53 $50 $50 2Q20 3Q20 4Q20 1Q21 2Q21 Asset Quality NPAs / Total Assets Criticized Loan Trends by Segment Criticized loans (Rolling quarters ended 2Q21, in millions) Nonaccrual Loans / Total Loans 1.37% 0.95% 1.40% 0.35% 0.66% 2017 2018 2019 2020 2Q21 Underwriting and Monitoring • Appraisal policy requires 18 - month updates for impaired or special assets • Proactive, ongoing client engagement and experienced work - out teams • Bi - weekly regional portfolio Quarterly Criticized Asset Reviews • Centralized risk rating, robust external loan review and monitoring of risk rating migration and delinquency trends • Annual third - party loan review • Decreased maximum HE LTV to 80% • Relieved financial pressures for clients during COVID through various measures, including loan modifications, waiving early withdrawal penalties and overdraft fees, and temporarily suspending repossession and foreclosure activity 1.68% 1.17% 1.30% 0.99% 1.01% 2017 2018 2019 2020 2Q21
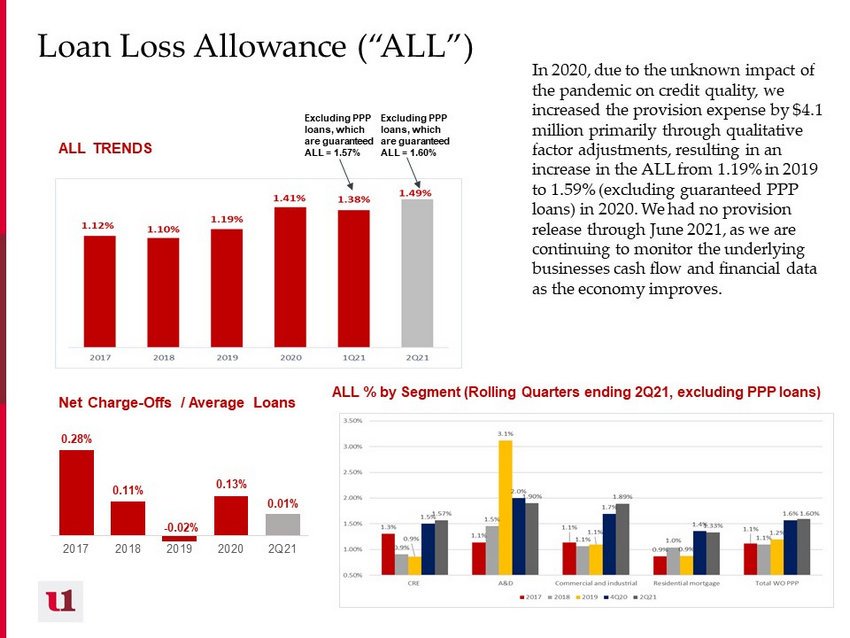
22 22 Loan Loss Allowance (“ALL”) ALL TRENDS ALL % by Segment (Rolling Quarters ending 2Q21, excluding PPP loans) 0.28% 0.11% - 0.02% 0.13% 0.01% 2017 2018 2019 2020 2Q21 Net Charge - Offs / Average Loans In 2020, due to the unknown impact of the pandemic on credit quality, we increased the provision expense by $4.1 million primarily through qualitative factor adjustments, resulting in an increase in the ALL from 1.19% in 2019 to 1.59% (excluding guaranteed PPP loans) in 2020. We had no provision release through June 2021, as we are continuing to monitor the underlying businesses cash flow and financial data as the economy improves. Excluding PPP loans, which are guaranteed ALL = 1.60% Excluding PPP loans, which are guaranteed ALL = 1.57%
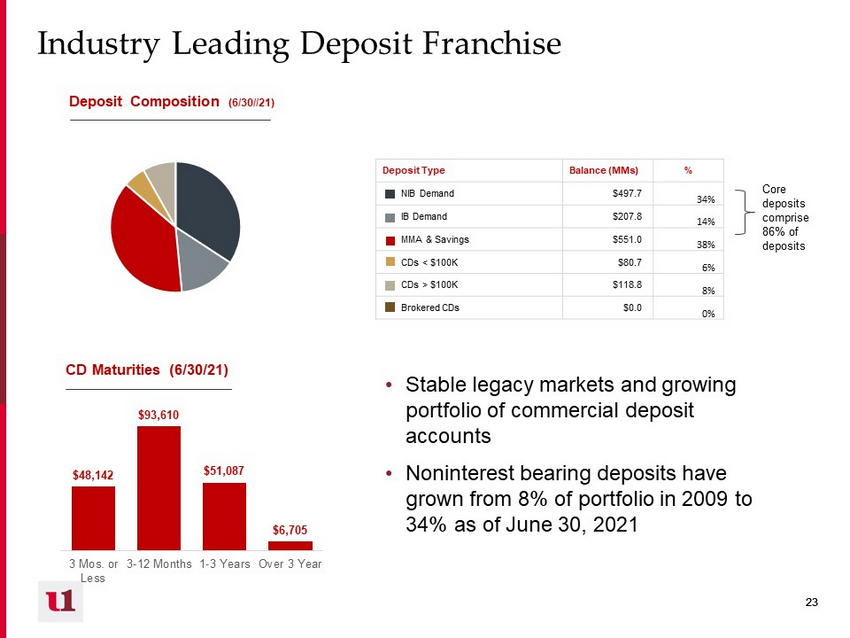
23 23 Industry Leading Deposit Franchise • Stable legacy markets and growing portfolio of commercial deposit accounts • Noninterest bearing deposits have grown from 8% of portfolio in 2009 to 34% as of June 30, 2021 Deposit Composition (6/30//21) Deposit Type Balance (MMs) % NIB Demand $497.7 34% IB Demand $207.8 14% MMA & Savings $551.0 38% CDs < $100K $80.7 6% CDs > $100K $118.8 8% Brokered CDs $0.0 0% Core deposits comprise 86% of deposits $48,142 $93,610 $51,087 $6,705 3 Mos. or Less 3-12 Months 1-3 Years Over 3 Year CD Maturities (6/30/21)
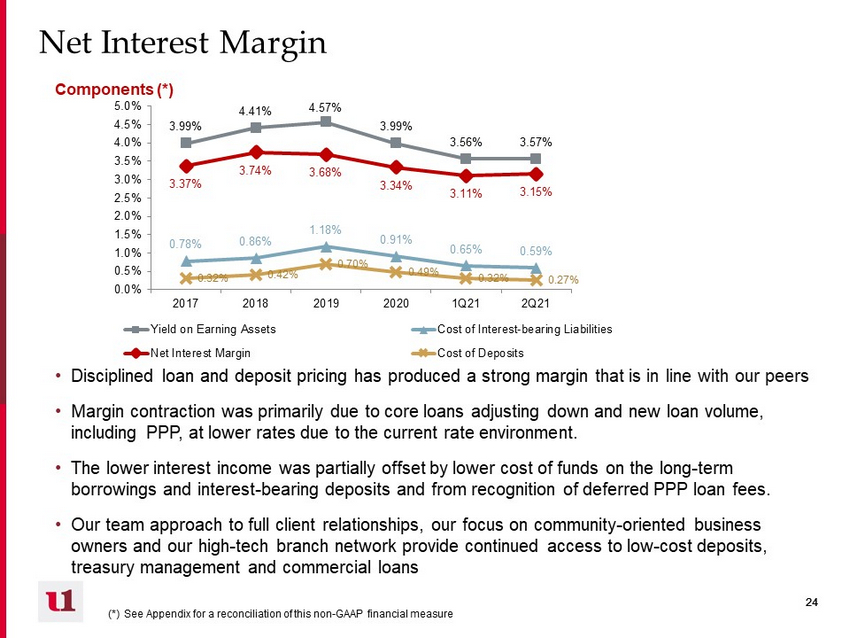
24 24 Net Interest Margin • Disciplined loan and deposit pricing has produced a strong margin that is in line with our peers • Margin contraction was primarily due to core loans adjusting down and new loan volume, including PPP, at lower rates due to the current rate environment. • The lower interest income was partially offset by lower cost of funds on the long - term borrowings and interest - bearing deposits and from recognition of deferred PPP loan fees. • Our team approach to full client relationships, our focus on community - oriented business owners and our high - tech branch network provide continued access to low - cost deposits, treasury management and commercial loans Components (*) (*) See Appendix for a reconciliation of this non - GAAP financial measure 3.99% 4.41% 4.57% 3.99% 3.56% 3.57% 0.78% 0.86% 1.18% 0.91% 0.65% 0.59% 3.37% 3.74% 3.68% 3.34% 3.11% 3.15% 0.32% 0.42% 0.70% 0.49% 0.32% 0.27% 0.0% 0.5% 1.0% 1.5% 2.0% 2.5% 3.0% 3.5% 4.0% 4.5% 5.0% 2017 2018 2019 2020 1Q21 2Q21 Yield on Earning Assets Cost of Interest-bearing Liabilities Net Interest Margin Cost of Deposits
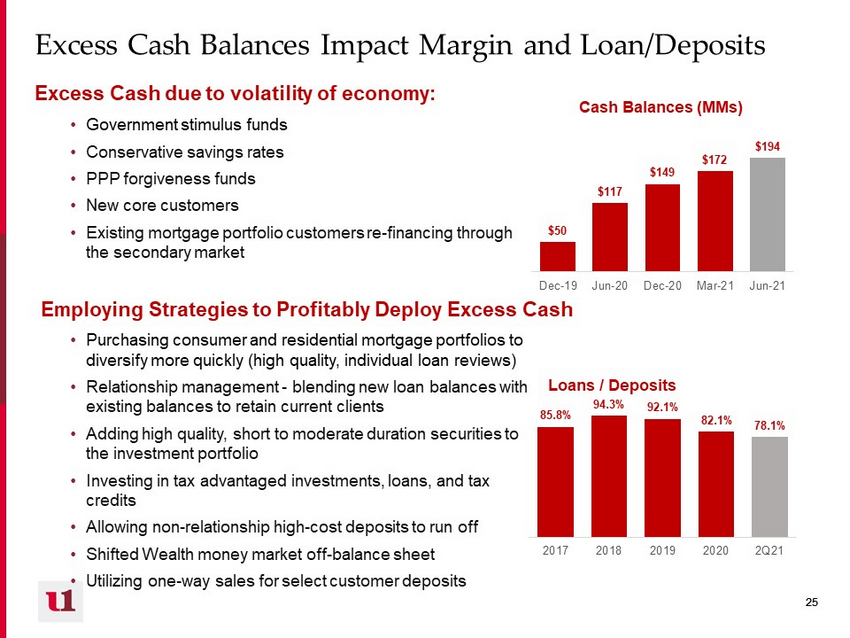
25 25 Excess Cash Balances Impact Margin and Loan/Deposits • Purchasing consumer and residential mortgage portfolios to diversify more quickly (high quality, individual loan reviews) • Relationship management - blending new loan balances with existing balances to retain current clients • Adding high quality, short to moderate duration securities to the investment portfolio • Investing in tax advantaged investments, loans, and tax credits • Allowing non - relationship high - cost deposits to run off • Shifted Wealth money market off - balance sheet • Utilizing one - way sales for select customer deposits Employing Strategies to Profitably Deploy Excess Cash $50 $117 $149 $172 $194 Dec-19 Jun-20 Dec-20 Mar-21 Jun-21 Cash Balances (MMs) Excess Cash due to volatility of economy: • Government stimulus funds • Conservative savings rates • PPP forgiveness funds • New core customers • Existing mortgage portfolio customers re - financing through the secondary market 85.8% 94.3% 92.1% 82.1% 78.1% 2017 2018 2019 2020 2Q21 Loans / Deposits
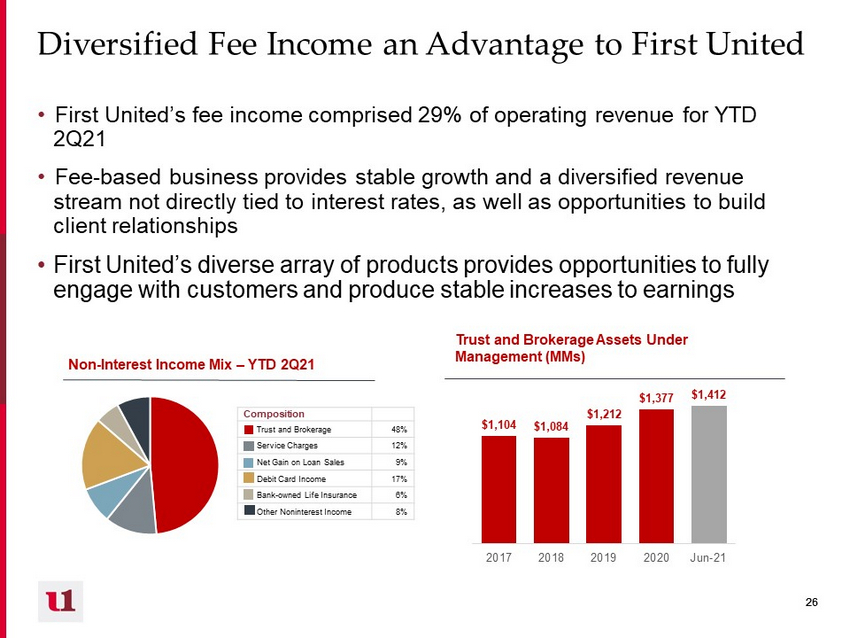
26 26 Diversified Fee Income an Advantage to First United • First United’s fee income comprised 29% of operating revenue for YTD 2Q21 • Fee - based business provides stable growth and a diversified revenue stream not directly tied to interest rates, as well as opportunities to build client relationships • First United’s diverse array of products provides opportunities to fully engage with customers and produce stable increases to earnings Trust and Brokerage Assets Under Management (MMs) Non - Interest Income Mix – YTD 2Q21 75% $1,104 $1,084 $1,212 $1,377 $1,412 2017 2018 2019 2020 Jun-21 Composition Trust and Brokerage 48% Service Charges 12% Net Gain on Loan Sales 9% Debit Card Income 17% Bank - owned Life Insurance 6% Other Noninterest Income 8%
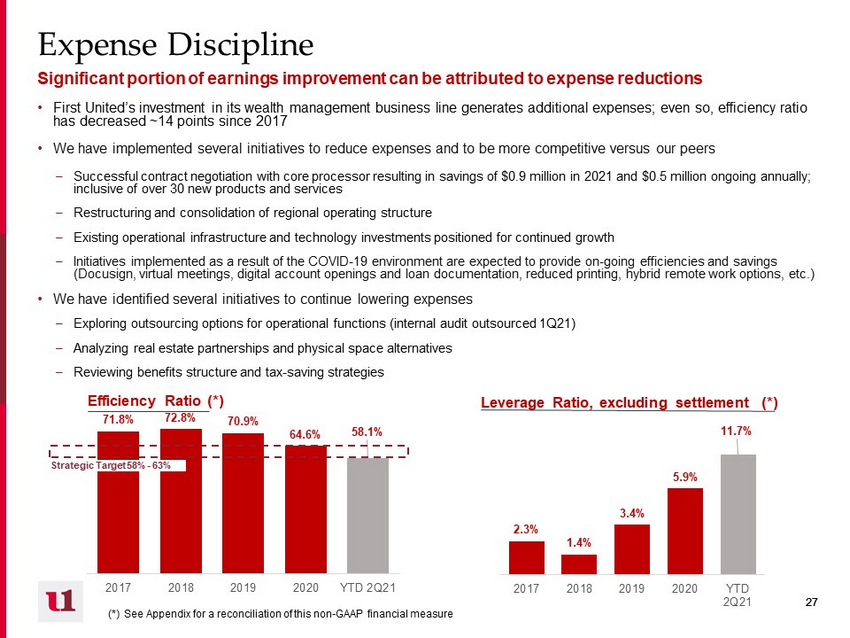
27 27 71.8% 72.8% 70.9% 64.6% 58.1% 2017 2018 2019 2020 YTD 2Q21 Expense Discipline Significant portion of earnings improvement can be attributed to expense reductions • First United’s investment in its wealth management business line generates additional expenses; even so, efficiency ratio has decreased ~14 points since 2017 • We have implemented several initiatives to reduce expenses and to be more competitive versus our peers – Successful contract negotiation with core processor resulting in savings of $0.9 million in 2021 and $0.5 million ongoing ann ual ly; inclusive of over 30 new products and services – Restructuring and consolidation of regional operating structure – Existing operational infrastructure and technology investments positioned for continued growth – Initiatives implemented as a result of the COVID - 19 environment are expected to provide on - going efficiencies and savings ( Docusign , virtual meetings, digital account openings and loan documentation, reduced printing, hybrid remote work options, etc.) • We have identified several initiatives to continue lowering expenses – Exploring outsourcing options for operational functions (internal audit outsourced 1Q21) – Analyzing real estate partnerships and physical space alternatives – Reviewing benefits structure and tax - saving strategies Efficiency Ratio (*) Strategic Target 58% - 63% (*) See Appendix for a reconciliation of this non - GAAP financial measure Leverage Ratio, excluding settlement (*) 2.3% 1.4% 3.4% 5.9% 11.7% 2017 2018 2019 2020 YTD 2Q21
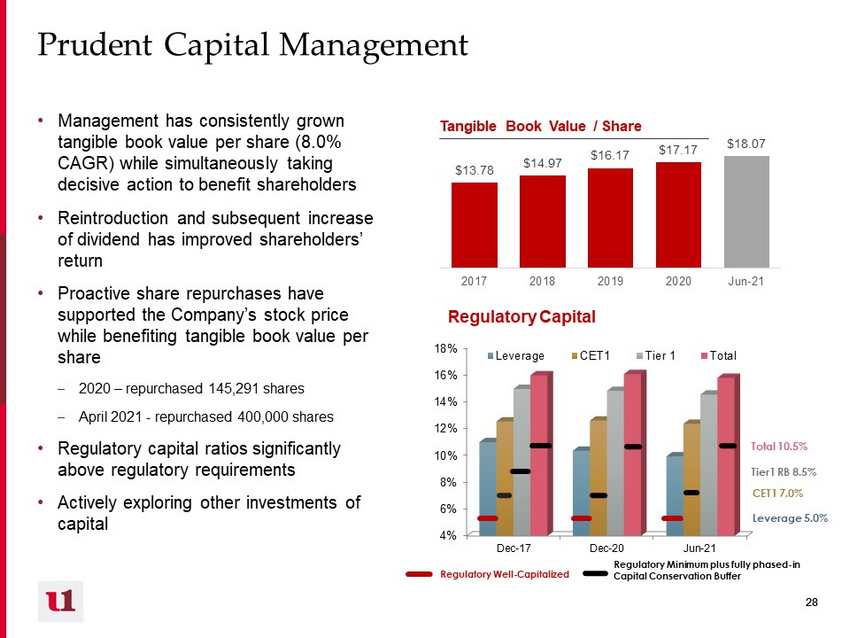
28 28 Prudent Capital Management $13.78 $14.97 $16.17 $17.17 $18.07 2017 2018 2019 2020 Jun-21 Tangible Book Value / Share • Management has consistently grown tangible book value per share (8.0% CAGR) while simultaneously taking decisive action to benefit shareholders • Reintroduction and subsequent increase of dividend has improved shareholders’ return • Proactive share repurchases have supported the Company’s stock price while benefiting tangible book value per share – 2020 – repurchased 145,291 shares – April 2021 - repurchased 400,000 shares • Regulatory capital ratios significantly above regulatory requirements • Actively exploring other investments of capital Regulatory Capital 4% 6% 8% 10% 12% 14% 16% 18% Dec-17 Dec-20 Jun-21 Leverage CET1 Tier 1 Total Regulatory Well - Capitalized Regulatory Minimum plus fully phased - in Capital Conservation Buffer Total 10.5% Tier1 RB 8.5% CET1 7.0% Leverage 5.0%

29 29 Strategic Targets Post - COVID - 19 Metric Actual 12/31/2019 Actual 12/31/2020 Long Term Strategic Target Range Strong Shareholder Return EPS Growth (YoY) 23% 7% 2% - 15% Dividend Payout Ratio 21.7% 26.3% 20% - 25% ROAA 0.93% 0.86% 1.00% - 1.25% ROAE 10.44% 10.89% 10% - 14% TCE Ratio 8.03% 6.97% 8% - 10% High Quality, Diversified Revenue Stream Revenue Growth (YoY) 6.3% 5.8% 2% - 7% NII / Revenue 26.5% 27.4% 24% - 28% N IM 3.68% 3.34% 3.3% - 3.7% Balance Sheet Growth % Loan Growth 4.4% 11.3% incl PPP 6% - 11% Loans / Assets 73% 67% 71% - 76% Loans / Deposits 92% 82% 87% - 90% Highly Efficient Operations Efficiency Ratio (adjusted for non - core items) 68.4% 64.3% 58% - 63% Positive Operating Leverage Operating Leverage Ratio 3.4% 5.9% 1% - 5% Robust Risk Enterprise Management NPLs / Loans 1.2% 0.35% 0.50% - 1.00% NCOs / Avg. Total Loans (0.02%) 0.13% 0.10% - 0.50%

30 30 III. Our Commitment to ESG
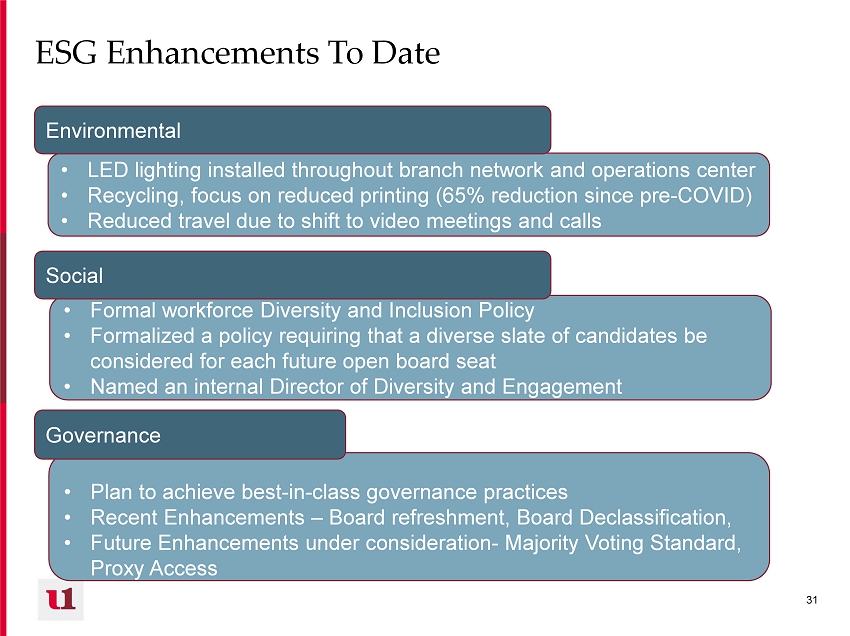
31 31 • LED lighting installed throughout branch network and operations center • Recycling, focus on reduced printing (65% reduction since pre - COVID) • Reduced travel due to shift to video meetings and calls ESG Enhancements To Date • Plan to achieve best - in - class governance practices • Recent Enhancements – Board refreshment, Board Declassification, • Future Enhancements under consideration - Majority Voting Standard, Proxy Access Governance • Formal workforce Diversity and Inclusion Policy • Formalized a policy requiring that a diverse slate of candidates be considered for each future open board seat • Named an internal Director of diversity and engagement Social Environmental
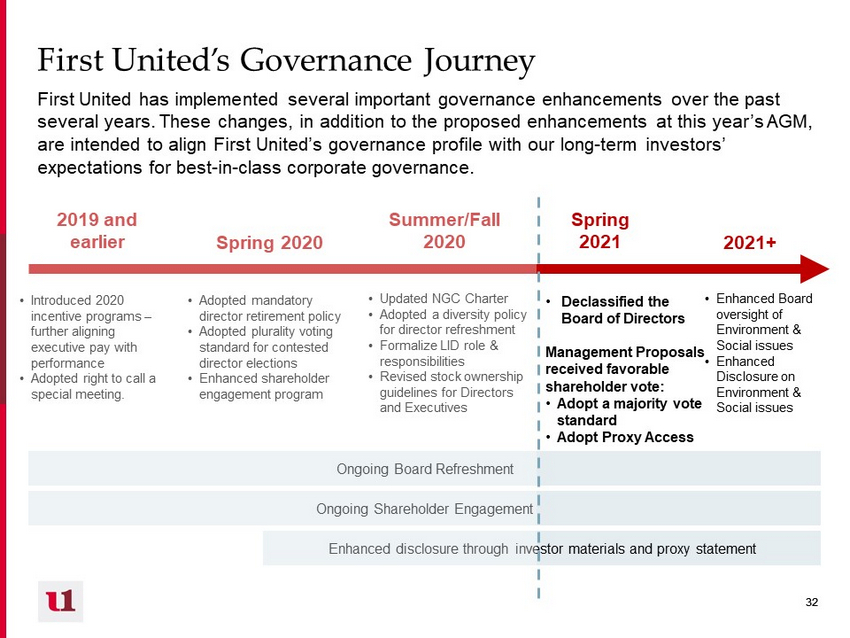
32 32 Ongoing Shareholder Engagement • Declassified the Board of Directors Management Proposals received favorable shareholder vote: • Adopt a majority vote standard • Adopt Proxy Access • Updated NGC Charter • Adopted a diversity policy for director refreshment • Formalize LID role & responsibilities • Revised stock ownership guidelines for Directors and Executives • Enhanced Board oversight of Environment & Social issues • Enhanced Disclosure on Environment & Social issues Ongoing Board Refreshment Enhanced disclosure through investor materials and proxy statement • Introduced 2020 incentive programs – further aligning executive pay with performance • Adopted right to call a special meeting. • Adopted mandatory director retirement policy • Adopted plurality voting standard for contested director elections • Enhanced shareholder engagement program Spring 2021 2021+ Summer/Fall 2020 Spring 2020 2019 and earlier First United’s Governance Journey First United has implemented several important governance enhancements over the past several years. These changes, in addition to the proposed enhancements at this year’s AGM, are intended to align First United’s governance profile with our long - term investors’ expectations for best - in - class corporate governance.
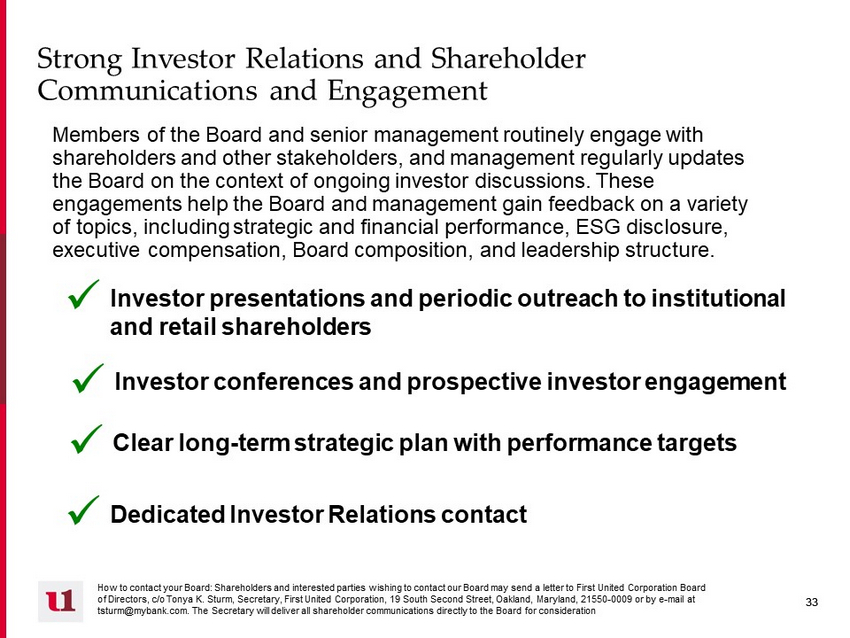
33 33 Strong Investor Relations and Shareholder Communications and Engagement Clear long - term strategic plan with performance targets x Dedicated Investor Relations contact x Investor conferences and prospective investor engagement x Members of the Board and senior management routinely engage with shareholders and other stakeholders, and management regularly updates the Board on the context of ongoing investor discussions. These engagements help the Board and management gain feedback on a variety of topics, including strategic and financial performance, ESG disclosure, executive compensation, Board composition, and leadership structure. Investor presentations and periodic outreach to institutional and retail shareholders x How to contact your Board: Shareholders and interested parties wishing to contact our Board may send a letter to First United Co rporation Board of Directors, c/o Tonya K. Sturm, Secretary, First United Corporation, 19 South Second Street, Oakland, Maryland, 21550 - 0009 or by e - mail at tsturm@mybank.com. The Secretary will deliver all shareholder communications directly to the Board for consideration
34 34 IV. Appendix

35 35 Our Dedicated Management Team Our management team has the right set of skills and experience to effectively execute on our strategy and continue driving shareholder returns Carissa Rodeheaver CEO & Chair • 29 - year career with First United with in depth industry, sales, wealth management, financial and operational experience • Holds leadership positions in the American & Maryland Bankers Associations as well as in Garrett County, one of our key markets Robert L. Fisher II SVP & Chief Revenue Officer • 25+years with in - depth industry, retail, commercial and mortgage banking experience • Serves a board member of the Salvation Army of Washington County Jason Rush SVP & Chief Operating Officer • 27 years with in - depth industry, retail, risk and compliance and operations experience • Serves on the Maryland Bankers Association’s Government Relations Committee • Involved in the Garrett County community as a board member for multiple organizations Keith Sanders SVP & Chief Wealth Officer • 28 years of experience specializing in Wealth management, estate planning, trust administration and financial planning • Serves on the Maryland Bankers Association’s Government Relations Committee and Trust Committee • Involved in the Garrett County community as a senior leader for several organizations Tonya Sturm SVP, CFO, Secretary & Treasurer • 35 years of extensive banking, audit, credit, retail, risk and compliance and financial experience • Serves on Advisory Councils for both the American & Maryland Bankers’ Associations • Involved in the Garrett County community as a board member for multiple organizations
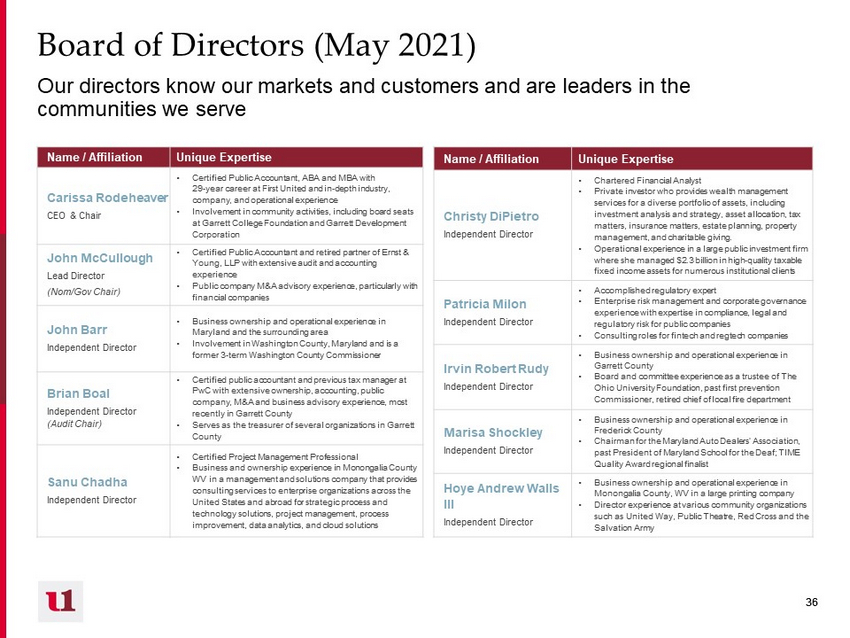
36 36 Board of Directors (May 2021) Our directors know our markets and customers and are leaders in the communities we serve Name / Affiliation Unique Expertise Carissa Rodeheaver CEO & Chair • Certified Public Accountant, ABA and MBA with 29 - year career at First United and in - depth industry, company, and operational experience • Involvement in community activities, including board seats at Garrett College Foundation and Garrett Development Corporation John McCullough Lead Director ( Nom/Gov Chair) • Certified Public Accountant and retired partner of Ernst & Young, LLP with extensive audit and accounting experience • Public company M&A advisory experience, particularly with financial companies John Barr Independent Director • Business ownership and operational experience in Maryland and the surrounding area • Involvement in Washington County, Maryland and is a former 3 - term Washington County Commissioner Brian Boal Independent Director (Audit Chair) • Certified public accountant and previous tax manager at PwC with extensive ownership, accounting, public company, M&A and business advisory experience, most recently in Garrett County • Serves as the treasurer of several organizations in Garrett County Sanu Chadha Independent Director • Certified Project Management Professional • Business and ownership experience in Monongalia County WV in a management and solutions company that provides consulting services to enterprise organizations across the United States and abroad for strategic process and technology solutions, project management, process improvement, data analytics, and cloud solutions Name / Affiliation Unique Expertise Christy DiPietro Independent Director • Chartered Financial Analyst • Private investor who provides wealth management services for a diverse portfolio of assets, including investment analysis and strategy, asset allocation, tax matters, insurance matters, estate planning, property management, and charitable giving. • Operational experience in a large public investment firm where she managed $2.3 billion in high - quality taxable fixed income assets for numerous institutional clients Patricia Milon Independent Director • Accomplished regulatory expert • Enterprise risk management and corporate governance experience with expertise in compliance, legal and regulatory risk for public companies • Consulting roles for fintech and regtech companies Irvin Robert Rudy Independent Director • Business ownership and operational experience in Garrett County • Board and committee experience as a trustee of The Ohio University Foundation, past first prevention Commissioner, retired chief of local fire department Marisa Shockley Independent Director • Business ownership and operational experience in Frederick County • Chairman for the Maryland Auto Dealers’ Association, past President of Maryland School for the Deaf; TIME Quality Award regional finalist Hoye Andrew Walls III Independent Director • Business ownership and operational experience in Monongalia County, WV in a large printing company • Director experience at various community organizations such as United Way, Public Theatre, Red Cross and the Salvation Army

37 37 Non - GAAP Reconciliation This presentation includes certain non - GAAP financial measures, including pre - provision net revenue, net income, earnings per share (basic and diluted), return on average assets, return on average tangible common equity, tangible common equity, tangible assets, the ratio of tangible common equity to tangible assets, tangible book value per share, net interest margin, and efficiency ratio. These non - GAAP finan cial measures and any other non - GAAP financial measures that are discussed in this presentation should not be considered in isolation, and should be considered as additions to, and not substitutes for or superior to, measures of financial performance prepared in accordance with GAAP. The re are a number of limitations related to the use of these non - GAAP financial measures versus their nearest GAAP equivalents. For example, other co mpanies may calculate non - GAAP financial measures differently or may use other measures to evaluate their performance, all of which could re duce the usefulness of the Company’s non - GAAP financial measures as tools for comparison. The following is a reconciliation of the non - GAAP financia l measures used in (or conveyed orally during) this presentation to their most directly comparable GAAP financial measures. ($000s, except where otherwise noted) YTD LTM 2017 2018 2019 2020 Q1 2020 Q2 2020 Q3 2020 Q4 2020 Q1 2021 Q2 2021 6/30/2021 6/30/2021 Pre-Provision Net Revenue ("PPNR") Pre-tax income, as reported 12,214$ 13,431$ 16,465$ 17,788$ 2,277$ 3,281$ 6,356$ 5,874$ 4,529$ 5,939$ 10,468$ 22,698$ Add back: Provision expense 2,534 2,111 1,320 5,401 2,654 2,167 160 420 110 555 665 1,245 Add back: Settlement expense, gross - - - - - - - - 3,300 - 3,300 3,300 Pre-Provision Net Revenue, as adjusted 14,748$ 15,542$ 17,785$ 23,189$ 4,931$ 5,448$ 6,516$ 6,294$ 7,939$ 6,494$ 14,433$ 27,243$ Net Income Net income, as reported 5,269$ 10,667$ 13,129$ 13,841$ 1,755$ 2,570$ 4,960$ 4,556$ 3,430$ 4,403$ 7,833$ 17,349$ Less: Preferred stock dividends (1,215) - - - - - - - - - - - Net income, available to common shareholders,as reported (a) 4,054$ 10,667$ 13,129$ 13,841$ 1,755$ 2,570$ 4,960$ 4,556$ 3,430$ 4,403$ 7,833$ 19,914$ Add Back: Impact of Tax Reform Act 3,226$ Add back: Settlement expense, net of tax - - - - - - - - 2,565 - 2,565 2,565 Net income, as adjusted (b) 7,280$ 10,667$ 13,129$ 13,841$ 1,755$ 2,570$ 4,960$ 4,556$ 5,995$ 4,403$ 10,398$ 22,479$ Weighted Average Common shares - basic (actual) (d) 6,931,889 7,078,644 7,110,022 7,003,955 6,966,898 6,973,595 6,987,583 6,991,607 6,995,798 6,609,275 6,802,537 6,911,572 Weighted Average Common shares - diluted (actual) (e) 6,931,889 7,078,644 7,110,022 7,013,164 6,991,902 6,991,954 6,992,653 6,996,677 7,000,305 6,615,117 6,807,711 6,919,341 Earnings Per Share - Basic Earnings Per Share - Basic, as reported (a)/(d) 0.58$ 1.51$ 1.85$ 1.98$ 0.25$ 0.37$ 0.71$ 0.65$ 0.49$ 0.66$ 1.15$ 2.88$ Add Back: Impact of Tax Reform Act 0.47 Add back: Settlement expense, net of tax - - - - - - - - 0.37 - 0.37 0.37 Earnings Per Share - Basic, as adjusted (b)/(d) 1.05$ 1.51$ 1.85$ 1.98$ 0.25$ 0.37$ 0.71$ 0.65$ 0.86$ 0.66$ 1.52$ 3.25$ Earnings Per Share - Diluted Earnings Per Share - Diluted, as reported (a)/(e) 0.58$ 1.51$ 1.85$ 1.97$ 0.25$ 0.37$ 0.71$ 0.65$ 0.49$ 0.66$ 1.15$ 2.88$ Add Back: Impact of Tax Reform Act 0.47 Add back: Settlement expense, net of tax - - - - - - - - 0.37 - 0.37 0.37 Earnings Per Share - Diluted, as adjusted (b)/(e) 1.05$ 1.51$ 1.85$ 1.97$ 0.25$ 0.37$ 0.71$ 0.65$ 0.86$ 0.66$ 1.52$ 3.25$ Return on Average Assets (quarter and YTD annualized) Average Assets ( c) 1,322,013$ 1,311,902$ 1,418,928$ 1,613,669$ 1,444,456$ 1,599,603$ 1,681,917$ 1,710,900$ 1,765,133$ 1,783,821$ 1,776,297$ 1,708,275$ Return on Average Assets, as reported (a)/(c) 0.31% 0.81% 0.93% 0.86% 0.49% 0.64% 1.18% 1.07% 0.78% 0.99% 0.88% 1.17% Add Back: Impact of Tax Reform Act 0.24% Add back: Settlement expense, net of tax - - - - - - - - 0.58% - 0.30% 0.15% Return on Average Assets, as adjusted (b)/(c) 0.55% 0.81% 0.93% 0.86% 0.49% 0.64% 1.18% 1.07% 1.36% 0.99% 1.18% 1.32%
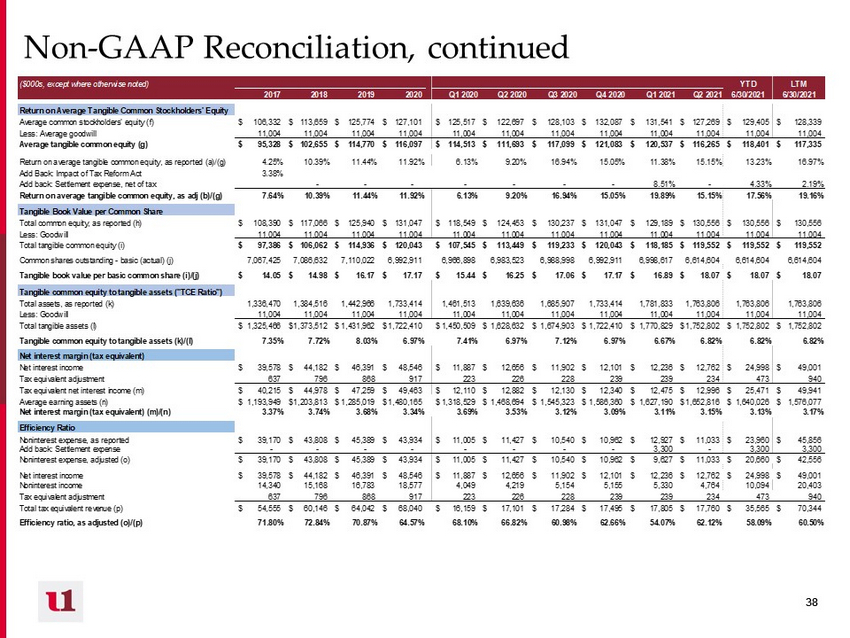
38 38 Non - GAAP Reconciliation, continued ($000s, except where otherwise noted) YTD LTM 2017 2018 2019 2020 Q1 2020 Q2 2020 Q3 2020 Q4 2020 Q1 2021 Q2 2021 6/30/2021 6/30/2021 Return on Average Tangible Common Stockholders' Equity Average common stockholders' equity (f) 106,332$ 113,659$ 125,774$ 127,101$ 125,517$ 122,697$ 128,103$ 132,087$ 131,541$ 127,269$ 129,405$ 128,339$ Less: Average goodwill 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 Average tangible common equity (g) 95,328$ 102,655$ 114,770$ 116,097$ 114,513$ 111,693$ 117,099$ 121,083$ 120,537$ 116,265$ 118,401$ 117,335$ Return on average tangible common equity, as reported (a)/(g) 4.25% 10.39% 11.44% 11.92% 6.13% 9.20% 16.94% 15.05% 11.38% 15.15% 13.23% 16.97% Add Back: Impact of Tax Reform Act 3.38% Add back: Settlement expense, net of tax - - - - - - - 8.51% - 4.33% 2.19% Return on average tangible common equity, as adj (b)/(g) 7.64% 10.39% 11.44% 11.92% 6.13% 9.20% 16.94% 15.05% 19.89% 15.15% 17.56% 19.16% Tangible Book Value per Common Share Total common equity, as reported (h) 108,390$ 117,066$ 125,940$ 131,047$ 118,549$ 124,453$ 130,237$ 131,047$ 129,189$ 130,556$ 130,556$ 130,556$ Less: Goodwill 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 Total tangible common equity (i) 97,386$ 106,062$ 114,936$ 120,043$ 107,545$ 113,449$ 119,233$ 120,043$ 118,185$ 119,552$ 119,552$ 119,552$ Common shares outstanding - basic (actual) (j) 7,067,425 7,086,632 7,110,022 6,992,911 6,966,898 6,983,523 6,988,998 6,992,911 6,998,617 6,614,604 6,614,604 6,614,604 Tangible book value per basic common share (i)/(j) 14.05$ 14.98$ 16.17$ 17.17$ 15.44$ 16.25$ 17.06$ 17.17$ 16.89$ 18.07$ 18.07$ 18.07$ Tangible common equity to tangible assets ("TCE Ratio") Total assets, as reported (k) 1,336,470 1,384,516 1,442,966 1,733,414 1,461,513 1,639,636 1,685,907 1,733,414 1,781,833 1,763,806 1,763,806 1,763,806 Less: Goodwill 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 11,004 Total tangible assets (l) 1,325,466$ 1,373,512$ 1,431,962$ 1,722,410$ 1,450,509$ 1,628,632$ 1,674,903$ 1,722,410$ 1,770,829$ 1,752,802$ 1,752,802$ 1,752,802$ Tangible common equity to tangible assets (k)/(l) 7.35% 7.72% 8.03% 6.97% 7.41% 6.97% 7.12% 6.97% 6.67% 6.82% 6.82% 6.82% Net interest margin (tax equivalent) Net interest income 39,578$ 44,182$ 46,391$ 48,546$ 11,887$ 12,656$ 11,902$ 12,101$ 12,236$ 12,762$ 24,998$ 49,001$ Tax equivalent adjustment 637 796 868 917 223 226 228 239 239 234 473 940 Tax equivalent net interest income (m) 40,215$ 44,978$ 47,259$ 49,463$ 12,110$ 12,882$ 12,130$ 12,340$ 12,475$ 12,996$ 25,471$ 49,941$ Average earning assets (n) 1,193,949$ 1,203,813$ 1,285,019$ 1,480,165$ 1,318,529$ 1,468,694$ 1,545,323$ 1,586,360$ 1,627,190$ 1,652,816$ 1,640,026$ 1,576,077$ Net interest margin (tax equivalent) (m)/(n) 3.37% 3.74% 3.68% 3.34% 3.69% 3.53% 3.12% 3.09% 3.11% 3.15% 3.13% 3.17% Efficiency Ratio Noninterest expense, as reported 39,170$ 43,808$ 45,389$ 43,934$ 11,005$ 11,427$ 10,540$ 10,962$ 12,927$ 11,033$ 23,960$ 45,856$ Add back: Settlement expense - - - - - - - - 3,300 - 3,300 3,300 Noninterest expense, adjusted (o) 39,170$ 43,808$ 45,389$ 43,934$ 11,005$ 11,427$ 10,540$ 10,962$ 9,627$ 11,033$ 20,660$ 42,556$ Net interest income 39,578$ 44,182$ 46,391$ 48,546$ 11,887$ 12,656$ 11,902$ 12,101$ 12,236$ 12,762$ 24,998$ 49,001$ Noninterest income 14,340 15,168 16,783 18,577 4,049 4,219 5,154 5,155 5,330 4,764 10,094 20,403 Tax equivalent adjustment 637 796 868 917 223 226 228 239 239 234 473 940 Total tax equivalent revenue (p) 54,555$ 60,146$ 64,042$ 68,040$ 16,159$ 17,101$ 17,284$ 17,495$ 17,805$ 17,760$ 35,565$ 70,344$ Efficiency ratio, as adjusted (o)/(p) 71.80% 72.84% 70.87% 64.57% 68.10% 66.82% 60.98% 62.66% 54.07% 62.12% 58.09% 60.50%