
Mfa Financial, Inc 8-K, filed Aug 5, 2026
Mfa Financial, Inc. (MFA)
8-K
2026-08-05
For: 2026-08-05
View Original
Added on
August 05, 2026
About this 8-K
Mfa Financial, Inc filed this 8-K on August 5, 2026.
Items reported
- Item 2.02: Financial results
- Item 7.01: Regulation FD disclosure
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported): August 5, 2026
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation or organization) | Commission File Number | (IRS Employer Identification No.) | |||||||||||||||
11th Floor - Suite 825 | |||||||||||||||||
| (Address of principal executive offices) | (Zip Code) | ||||||||||||||||
Registrant’s telephone number, including area code: (212 ) 207-6400
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class: | Trading Symbol(s): | Name of Each Exchange on Which Registered: | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
| Emerging growth company | ||||||||
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition and
Item 7.01 Regulation FD Disclosure
MFA Financial, Inc. (“MFA”) issued a press release, dated August 5, 2026, announcing its financial results for the quarter ended June 30, 2026, which is attached hereto as Exhibit 99.1 and is incorporated herein by reference. In addition, in conjunction with the announcement of its financial results, MFA issued additional information relating to its 2026 second quarter financial results. Such additional information is attached to this report as Exhibit 99.2 and is incorporated herein by reference.
The information referenced in this Current Report on Form 8-K (including Exhibits 99.1 and 99.2) is being “furnished” and, as such, shall not be deemed to be “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), or otherwise subject to the liabilities of that Section. The information set forth in this Current Report on Form 8-K (including Exhibits 99.1 and 99.2) is and will not be incorporated by reference into any registration statement or other document filed by MFA pursuant to the Securities Act of 1933, as amended (the “Securities Act”), except as may be expressly set forth by specific reference in such filing.
As discussed therein, the press release contains forward-looking statements within the meaning of the Securities Act and the Exchange Act and, as such, may involve known and unknown risks, uncertainties and assumptions. These forward-looking statements relate to MFA’s current expectations and are subject to the limitations and qualifications set forth in the press release as well as in MFA’s other documents filed with the SEC, including, without limitation, that actual events and/or results may differ materially from those projected in such forward-looking statements.
Exhibits
Exhibit Index
| Exhibit No. | Description | |||||||
| 104 | Cover Page Interactive Data File (formatted as Inline XBRL). | |||||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| MFA FINANCIAL, INC. | |||||||||||
| (REGISTRANT) | |||||||||||
| By: | /s/ Harold E. Schwartz | ||||||||||
| Name: | Harold E. Schwartz | ||||||||||
| Title: | Senior Vice President and General Counsel | ||||||||||
Date: August 5, 2026 | |||||||||||
Exhibit 99.1
| MFA | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FINANCIAL, INC. | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| PRESS RELEASE | FOR IMMEDIATE RELEASE | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
August 5, 2026 | NEW YORK METRO | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| INVESTOR CONTACT: | InvestorRelations@mfafinancial.com | NYSE: MFA | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 212-207-6488 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| www.mfafinancial.com | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| MEDIA CONTACT: | H/Advisors Abernathy | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Sydney Isaacs | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 713-343-0427 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
MFA Financial, Inc. Announces Second Quarter 2026 Financial Results
NEW YORK--(BUSINESS WIRE)--MFA Financial, Inc. (NYSE:MFA) today provided its financial results for the second quarter ended June 30, 2026:
Second Quarter 2026 Financial Results:
•MFA generated GAAP net income to common stockholders and participating securities for the second quarter of $36.2 million, or $0.35 per basic common share and $0.34 per diluted common share.
•Distributable earnings, a non-GAAP financial measure, were $12.2 million, or $0.12 per basic common share. Distributable earnings prior to realized credit losses, a non-GAAP financial measure, were $36.7 million, or $0.35 per basic common share.
•GAAP book value at June 30, 2026 was $12.71 per common share. Economic book value, a non-GAAP financial measure, was $13.20 per common share.
•Total economic return was 2.6% for the second quarter.
•MFA closed the quarter with $141.2 million of unrestricted cash and $294.1 million of unpledged Agency MBS.
•MFA paid a regular cash dividend of $0.36 per common share on July 31, 2026.
“We grew our investment portfolio, protected book value and made further progress on our strategic initiatives during the second quarter,” said Craig Knutson, MFA’s Chief Executive Officer. “Originations at Lima One grew by 44% to $316 million. We securitized or re-securitized over $800 million of loans. We resolved nearly $200 million of previously delinquent loans, driving our portfolio-wide default rate down to 7.0% from 7.8% at March 31. Although Distributable earnings were weighed down by realized losses incurred
1
on several legacy multifamily loans, DE prior to realized credit losses rose to 35 cents, which we believe better reflects the underlying earnings power of our portfolio.”
“We acquired over $1.6 billion of residential mortgage assets during the quarter,” added Bryan Wulfsohn, President and Chief Investment Officer. “We purchased $462 million of Non-QM loans and increased our Agency MBS position to $4.1 billion. We sold $94 million of newly-originated SFR loans to third-party investors, generating $2.3 million in gain-on-sale income. Finally, we again repurchased over 500,000 shares of our common stock, bringing cumulative repurchases to 2 million shares since last year.”
Q2 2026 Portfolio Activity
•MFA’s residential investment portfolio rose to $13.0 billion at June 30, 2026 from $12.5 billion at March 31, 2026.
•MFA purchased $714.4 million of Agency MBS during the quarter, bringing its Agency MBS position to $4.1 billion. MFA also entered into forward contracts in the “to-be-announced” (TBA) market with a notional amount of $178.0 million to acquire additional Agency MBS, bringing its TBA position to a notional amount of $478.0 million at June 30, 2026.
•Non-QM loan acquisitions totaled $462.3 million, bringing MFA’s Non-QM portfolio to $5.7 billion at June 30, 2026.
•Lima One funded $184.7 million of new business purpose loans with a maximum loan amount of $315.8 million. In addition, $84.9 million of draws were funded on previously originated Transitional loans. Lima One generated $8.4 million of mortgage banking income.
•Portfolio runoff was $781.0 million. Asset dispositions included $94.5 million of newly-originated single-family rental (SFR) loans. MFA also sold 76 REO properties in the second quarter for aggregate net proceeds of $30.7 million.
•60+ day delinquencies (measured as a percentage of UPB) for MFA’s residential loan portfolio decreased to 7.0% at June 30, 2026 from 7.8% at March 31, 2026.
•MFA completed two loan securitizations during the quarter collateralized by $817.4 million UPB of loans, bringing its total securitized debt to approximately $6.2 billion.
•MFA added a net $538.1 million of new interest rate hedges and estimates the net effective duration of its investment portfolio was 0.94 years.
•MFA’s Debt/Net Equity Ratio was 6.6x while recourse leverage was 3.0x at June 30, 2026.
2
Webcast
MFA Financial, Inc. plans to host a live audio webcast of its investor conference call on Wednesday, August 5, 2026, at 11:00 a.m. (Eastern Time) to discuss its second quarter 2026 financial results. The live audio webcast will be accessible to the general public over the internet at http://www.mfafinancial.com. Earnings presentation materials will be posted on the MFA website prior to the conference call and an audio replay will be available on the website following the call.
About MFA Financial, Inc.
MFA Financial, Inc. (NYSE: MFA) is a leading specialty finance company that invests in residential mortgage loans, residential mortgage-backed securities and other real estate assets. Through its wholly-owned subsidiary, Lima One Capital, MFA also originates and services business purpose loans for real estate investors. MFA has distributed over $5 billion in dividends to stockholders since its initial public offering in 1998. MFA is an internally-managed, publicly-traded real estate investment trust.
The following tables present MFA’s asset allocation as of June 30, 2026, and the yield on average interest-earning assets, average cost of funds, impact of net Swap carry and net interest rate spread for the various asset types.
Table 1 - Asset Allocation
| At June 30, 2026 | Non-QM loans | Single-family rental loans | Single-family transitional loans | Multifamily transitional loans | Seasoned RPL/NPL loans | Agency MBS | Other, net (1) | Total | ||||||||||||||||||||||||||||||||||||||||||
| (Dollars in Millions) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Asset Amount | $ | 5,671 | $ | 1,153 | $ | 654 | $ | 321 | $ | 920 | $ | 4,091 | $ | 619 | $ | 13,429 | ||||||||||||||||||||||||||||||||||
| Financing Agreements with Non-mark-to-market Collateral Provisions | — | (16) | (41) | (14) | — | — | — | (71) | ||||||||||||||||||||||||||||||||||||||||||
| Financing Agreements with Mark-to-market Collateral Provisions | (683) | (111) | (314) | (223) | (78) | (3,641) | (115) | (5,165) | ||||||||||||||||||||||||||||||||||||||||||
| Securitized Debt | (4,356) | (891) | (200) | — | (754) | — | (2) | (6,203) | ||||||||||||||||||||||||||||||||||||||||||
| Senior Notes and Other secured financing | — | — | — | — | — | — | (214) | (214) | ||||||||||||||||||||||||||||||||||||||||||
| Net Equity Allocated | $ | 632 | $ | 135 | $ | 99 | $ | 84 | $ | 88 | $ | 450 | $ | 288 | $ | 1,776 | ||||||||||||||||||||||||||||||||||
Debt/Net Equity Ratio (2) | 8.0x | 7.5x | 5.6x | 2.8x | 9.5x | 8.1x | 6.6x | |||||||||||||||||||||||||||||||||||||||||||
(1)Includes $141.2 million of cash and cash equivalents, $169.0 million of restricted cash, $56.0 million of other securities, $49.1 million of Other loans and $21.1 million of capital contributions made to loan origination partners, as well as other assets and other liabilities.
(2)Total Debt/Net Equity ratio represents the sum of borrowings under our financing agreements as a multiple of net equity allocated.
3
Table 2 - Net Interest Spread
| For the Three-Month Period Ended | ||||||||||||||||||||
| June 30, 2026 | March 31, 2026 | June 30, 2025 | ||||||||||||||||||
| Non-QM Loans | ||||||||||||||||||||
Net Yield (1) | 5.79 | % | 5.90 | % | 5.79 | % | ||||||||||||||
Cost of Funding (2) | (5.09) | % | (5.07) | % | (5.14) | % | ||||||||||||||
Impact of net Swap carry (3) | 0.28 | % | 0.36 | % | 0.70 | % | ||||||||||||||
| Net Interest Spread | 0.98 | % | 1.19 | % | 1.35 | % | ||||||||||||||
| Business Purpose Loans | ||||||||||||||||||||
Net Yield (1) | 7.12 | % | 7.12 | % | 7.99 | % | ||||||||||||||
Cost of Funding (2) | (5.42) | % | (5.54) | % | (6.07) | % | ||||||||||||||
Impact of net Swap carry (3) | 0.29 | % | 0.32 | % | 0.42 | % | ||||||||||||||
| Net Interest Spread | 1.99 | % | 1.90 | % | 2.34 | % | ||||||||||||||
| Seasoned RPL/NPL Loans | ||||||||||||||||||||
Net Yield (1) | 7.74 | % | 7.93 | % | 8.69 | % | ||||||||||||||
Cost of Funding (2) | (4.26) | % | (4.27) | % | (4.29) | % | ||||||||||||||
Impact of net Swap carry (3) | 0.36 | % | 0.36 | % | 0.40 | % | ||||||||||||||
| Net Interest Spread | 3.84 | % | 4.02 | % | 4.80 | % | ||||||||||||||
| Total Residential Whole Loans | ||||||||||||||||||||
Net Yield (1) | 6.30 | % | 6.42 | % | 6.85 | % | ||||||||||||||
Cost of Funding (2) | (5.08) | % | (5.09) | % | (5.35) | % | ||||||||||||||
Impact of net Swap carry (3) | 0.29 | % | 0.35 | % | 0.58 | % | ||||||||||||||
| Net Interest Spread | 1.51 | % | 1.68 | % | 2.08 | % | ||||||||||||||
Securities, at fair value | ||||||||||||||||||||
Net Yield (1) | 5.41 | % | 5.47 | % | 6.60 | % | ||||||||||||||
Cost of Funding (2) | (3.78) | % | (3.84) | % | (4.55) | % | ||||||||||||||
Impact of net Swap carry (3) | 0.57 | % | 0.56 | % | 1.05 | % | ||||||||||||||
| Net Interest Spread | 2.20 | % | 2.19 | % | 3.10 | % | ||||||||||||||
Total Balance Sheet | ||||||||||||||||||||
Net Yield (1) | 5.96 | % | 6.08 | % | 6.66 | % | ||||||||||||||
Cost of Funding (2) | (4.77) | % | (4.84) | % | (5.32) | % | ||||||||||||||
Impact of net Swap carry (3) | 0.37 | % | 0.40 | % | 0.64 | % | ||||||||||||||
| Net Interest Spread | 1.56 | % | 1.64 | % | 1.98 | % | ||||||||||||||
(1)Reflects annualized interest income divided by average amortized cost. Excludes servicing costs.
(2)Reflects annualized interest expense divided by average balance of agreements with mark-to-market collateral provisions (repurchase agreements), agreements with non-mark-to-market collateral provisions, and securitized debt.
(3)Reflects the difference between Swap interest income received and Swap interest expense paid on our Swaps. While we have not elected hedge accounting treatment for Swaps, and, accordingly, net Swap carry is not presented in interest expense in our consolidated statement of operations, we believe it is appropriate to allocate net Swap carry by asset class to reflect the economic impact of our Swaps on the net interest spread shown in the table above.
4
The following table presents the activity for our residential mortgage asset portfolio for the three months ended June 30, 2026:
Table 3 - Investment Portfolio Activity Q2 2026
| (In Millions) | March 31, 2026 | Runoff (1) | Acquisitions & Originations (2) | Other (3) | June 30, 2026 | Change | ||||||||||||||||||||||||||||||||
| Residential whole loans and REO | $ | 8,922 | $ | (632) | $ | 732 | $ | (126) | $ | 8,896 | $ | (26) | ||||||||||||||||||||||||||
| Securities, at fair value | 3,586 | (149) | 714 | (4) | 4,147 | 561 | ||||||||||||||||||||||||||||||||
| Total | $ | 12,508 | $ | (781) | $ | 1,446 | $ | (130) | $ | 13,043 | $ | 535 | ||||||||||||||||||||||||||
(1) Primarily includes principal repayments and sales of REO.
(2) Includes draws on previously originated Transitional loans.
(3) Primarily includes sales of residential whole loans and securities, changes in fair value and changes in the allowance for credit losses.
The following tables present information on our investments in residential whole loans:
Table 4 - Portfolio Composition/Residential Whole Loans
| Held at Carrying Value | Held at Fair Value | Total | ||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands) | June 30, 2026 | December 31, 2025 | June 30, 2026 | December 31, 2025 | June 30, 2026 | December 31, 2025 | ||||||||||||||||||||||||||||||||
| Non-QM loans | $ | 530,198 | $ | 593,213 | $ | 5,141,822 | $ | 4,753,480 | $ | 5,672,020 | $ | 5,346,693 | ||||||||||||||||||||||||||
| Business purpose loans: | ||||||||||||||||||||||||||||||||||||||
Single-family rental loans | $ | 78,747 | $ | 88,112 | $ | 1,075,637 | $ | 1,147,234 | $ | 1,154,384 | $ | 1,235,346 | ||||||||||||||||||||||||||
Single-family transitional loans (1) | 7,044 | 7,051 | 648,719 | 711,294 | 655,763 | 718,345 | ||||||||||||||||||||||||||||||||
| Multifamily transitional loans | — | — | 320,882 | 489,637 | 320,882 | 489,637 | ||||||||||||||||||||||||||||||||
| Total Business purpose loans | $ | 85,791 | $ | 95,163 | $ | 2,045,238 | $ | 2,348,165 | $ | 2,131,029 | $ | 2,443,328 | ||||||||||||||||||||||||||
| Seasoned RPL/NPL loans | 396,206 | 414,676 | 528,951 | 564,340 | 925,157 | 979,016 | ||||||||||||||||||||||||||||||||
| Other loans | — | — | 49,054 | 51,022 | 49,054 | 51,022 | ||||||||||||||||||||||||||||||||
| Allowance for Credit Losses | (9,393) | (9,705) | — | — | (9,393) | (9,705) | ||||||||||||||||||||||||||||||||
| Total Residential whole loans | $ | 1,002,802 | $ | 1,093,347 | $ | 7,765,065 | $ | 7,717,007 | $ | 8,767,867 | $ | 8,810,354 | ||||||||||||||||||||||||||
| Number of loans | 4,661 | 4,941 | 18,772 | 18,824 | 23,433 | 23,765 | ||||||||||||||||||||||||||||||||
(1)Includes $311.7 million and $300.2 million of loans collateralized by new construction projects at origination as of June 30, 2026 and December 31, 2025, respectively.
Table 5 - Yields and Average Balances/Residential Whole Loans
| For the Three-Month Period Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| June 30, 2026 | March 31, 2026 | June 30, 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in Thousands) | Interest | Average Balance | Average Yield | Interest | Average Balance | Average Yield | Interest | Average Balance | Average Yield | |||||||||||||||||||||||||||||||||||||||||||||||
| Non-QM loans | $ | 83,019 | $ | 5,735,430 | 5.79 | % | $ | 81,539 | $ | 5,526,191 | 5.90 | % | $ | 70,267 | $ | 4,852,559 | 5.79 | % | ||||||||||||||||||||||||||||||||||||||
| Business purpose loans: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Single-family rental loans | $ | 18,151 | $ | 1,199,977 | 6.05 | % | $ | 19,513 | $ | 1,237,745 | 6.31 | % | $ | 21,747 | $ | 1,349,448 | 6.45 | % | ||||||||||||||||||||||||||||||||||||||
| Single-family transitional loans | 15,817 | 683,649 | 9.25 | % | 15,554 | 702,710 | 8.85 | % | 23,726 | 969,259 | 9.79 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Multifamily transitional loans | 6,773 | 405,227 | 6.69 | % | 8,449 | 504,127 | 6.70 | % | 17,308 | 824,919 | 8.39 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total business purpose loans | $ | 40,741 | $ | 2,288,853 | 7.12 | % | $ | 43,516 | $ | 2,444,582 | 7.12 | % | $ | 62,781 | $ | 3,143,626 | 7.99 | % | ||||||||||||||||||||||||||||||||||||||
| Seasoned RPL/NPL loans | 16,748 | 865,419 | 7.74 | % | 17,573 | 886,001 | 7.93 | % | 21,076 | 969,699 | 8.69 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Other loans | 443 | 59,903 | 2.96 | % | 463 | 60,608 | 3.06 | % | 444 | 64,416 | 2.76 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Total Residential whole loans | $ | 140,951 | $ | 8,949,605 | 6.30 | % | $ | 143,091 | $ | 8,917,382 | 6.42 | % | $ | 154,568 | $ | 9,030,300 | 6.85 | % | ||||||||||||||||||||||||||||||||||||||
5
Table 6 - Credit-related Metrics/Residential Whole Loans
June 30, 2026
| Asset Amount | Fair Value | Unpaid Principal Balance (“UPB”) | Weighted Average Coupon (1) (2) | Weighted Average Term to Maturity (Months) | Weighted Average LTV Ratio (3) | Weighted Average Original FICO (4) | Aging by UPB | 60+ DQ % | 60+ LTV (5) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Past Due Days | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars In Thousands) | Current | 30-59 | 60-89 | 90+ | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-QM loans | $ | 5,670,728 | $ | 5,655,660 | $ | 5,684,786 | 6.70 | % | 336 | 64 | % | 740 | $ | 5,290,874 | $ | 153,057 | $ | 53,291 | $ | 187,564 | 4.2 | % | 66 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Business purpose loans: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Single-family rental | $ | 1,153,464 | $ | 1,155,689 | $ | 1,166,676 | 6.35 | % | 306 | 66 | % | 741 | $ | 1,113,690 | $ | 23,882 | $ | 1,644 | $ | 27,460 | 2.5 | % | 65 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Single-family transitional (5) | 654,221 | 654,585 | 671,699 | 10.09 | % | 6 | 68 | % | 754 | 559,111 | 20,782 | 13,167 | 78,639 | 13.7 | % | 85 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Multifamily transitional (5) | 320,882 | 320,882 | 360,373 | 10.09 | % | 2 | 90 | % | 750 | 269,854 | 2,439 | — | 88,080 | 24.4 | % | 160 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total business purpose loans | $ | 2,128,567 | $ | 2,131,156 | $ | 2,198,748 | 8.11 | % | 70 | % | $ | 1,942,655 | $ | 47,103 | $ | 14,811 | $ | 194,179 | 9.5 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Seasoned RPL/NPL loans | 919,518 | 934,422 | 1,042,205 | 5.07 | % | 241 | 53 | % | 646 | 756,263 | 105,823 | 35,606 | 144,513 | 17.3 | % | 60 | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other loans | 49,054 | 49,054 | 57,968 | 3.43 | % | 302 | 62 | % | 757 | 57,464 | 504 | — | — | — | % | — | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Residential whole loans, total or weighted average | $ | 8,767,867 | $ | 8,770,292 | $ | 8,983,707 | 6.85 | % | 64 | % | $ | 8,047,256 | $ | 306,487 | $ | 103,708 | $ | 526,256 | 7.0 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
(1)Weighted average is calculated based on the interest-bearing principal balance of each loan within the related category. For loans acquired with servicing rights released by the seller, interest rates included in the calculation do not reflect loan servicing fees. For loans acquired with servicing rights retained by the seller, interest rates included in the calculation are net of servicing fees. Certain Transitional Loans contain contractual features which increase the loan’s interest rate following an event of default. The weighted average coupon presented is calculated based on each loan’s coupon rate without regard to post-default rate adjustments.
(2)For the quarter ended June 30, 2026, the gross coupon was 6.82% for Non-QM loans, 6.37% for Single-family rental loans, 10.10% for Single-family transitional loans, 10.10% for Multifamily transitional loans, and 5.08% for Seasoned RPL/NPL loans.
(3)LTV represents the ratio of the total unpaid principal balance of the loan to the estimated value of the collateral securing the related loan as of the most recent date available, which may be the origination date. Excluded from the calculation of weighted average are certain low value loans secured by vacant lots, for which the LTV ratio is not meaningful.
(4)Excludes loans for which no Fair Isaac Corporation (“FICO”) score is available.
(5)For Single-family and Multifamily transitional loans that are less than 90 days delinquent, the LTV presented is generally the ratio of the maximum unpaid principal balance of the loan, including unfunded commitments, to the estimated “after repaired” value of the collateral securing the related loan, as of the most recent date available, which may be the origination date. For Single-family and Multifamily transitional loans that are 90 or more days delinquent, as well as certain performing loans for which an after repaired valuation was not available, the LTV presented is the ratio of the current unpaid principal balance of the loan to the estimated as-is value of the collateral securing the related loan as of the most recent date available, which may be the origination date.
Table 7 - Shock Table
The information presented in the following “Shock Table” projects the potential impact of sudden parallel changes in interest rates on our portfolio, including the impact of Swaps and securitized debt and other fixed rate debt, based on the assets in our investment portfolio as of June 30, 2026. All changes in value are measured as the percentage change from the projected portfolio value under the base interest rate scenario as of June 30, 2026.
| Change in Interest Rates | Percentage Change in Net Portfolio Value | Percentage Change in Total Stockholders' Equity | ||||||||||||
| +100 Basis Point Increase | (1.29) | % | (10.34) | % | ||||||||||
| + 50 Basis Point Increase | (0.56) | % | (4.48) | % | ||||||||||
| Actual as of June 30, 2026 | — | % | — | % | ||||||||||
| - 50 Basis Point Decrease | 0.39 | % | 3.09 | % | ||||||||||
| -100 Basis Point Decrease | 0.60 | % | 4.80 | % | ||||||||||
6
MFA FINANCIAL, INC.
CONSOLIDATED BALANCE SHEETS
| (In Thousands, Except Per Share Amounts) | June 30, 2026 | December 31, 2025 | ||||||||||||
(Unaudited) | ||||||||||||||
| Assets: | ||||||||||||||
Residential whole loans, net ($7,765,065 and $7,717,007 held at fair value, respectively) (1) | $ | 8,767,868 | $ | 8,810,354 | ||||||||||
| Securities, at fair value | 4,147,194 | 3,360,280 | ||||||||||||
| Cash and cash equivalents | 141,193 | 213,211 | ||||||||||||
| Restricted cash | 169,029 | 173,457 | ||||||||||||
| Other assets | 428,408 | 489,147 | ||||||||||||
| Total Assets | $ | 13,653,692 | $ | 13,046,449 | ||||||||||
| Liabilities: | ||||||||||||||
Financing agreements ($5,812,397 and $5,956,057 held at fair value, respectively) | $ | 11,653,885 | $ | 10,940,014 | ||||||||||
| Other liabilities | 223,719 | 278,740 | ||||||||||||
| Total Liabilities | $ | 11,877,604 | $ | 11,218,754 | ||||||||||
| Stockholders’ Equity: | ||||||||||||||
Preferred stock, $0.01 par value; 7.5% Series B cumulative redeemable; 12,050 and 12,050 shares authorized, respectively; 8,278 and 8,125 shares issued and outstanding, respectively ($206,960 and $203,132 aggregate liquidation preference, respectively) | $ | 83 | $ | 81 | ||||||||||
Preferred stock, $0.01 par value; 6.5% Series C fixed-to-floating rate cumulative redeemable; 16,650 and 16,650 shares authorized, respectively; 11,386 and 11,286 shares issued and outstanding, respectively ($284,648 and $282,148 aggregate liquidation preference, respectively) | 114 | 113 | ||||||||||||
Common stock, $0.01 par value; 866,300 and 866,300 shares authorized, respectively; 101,088 and 101,663 shares issued and outstanding, respectively | 1,011 | 1,017 | ||||||||||||
| Additional paid-in capital, in excess of par | 3,718,716 | 3,718,350 | ||||||||||||
| Accumulated deficit | (1,945,991) | (1,895,541) | ||||||||||||
| Accumulated other comprehensive income | 2,155 | 3,675 | ||||||||||||
| Total Stockholders’ Equity | $ | 1,776,088 | $ | 1,827,695 | ||||||||||
| Total Liabilities and Stockholders’ Equity | $ | 13,653,692 | $ | 13,046,449 | ||||||||||
(1)Includes approximately $7.2 billion and $7.6 billion of Residential whole loans transferred to consolidated variable interest entities (“VIEs”) at June 30, 2026 and December 31, 2025, respectively. Such assets can be used only to settle the obligations of each respective VIE.
7
MFA FINANCIAL, INC.
CONSOLIDATED STATEMENTS OF OPERATIONS
| Three Months Ended June 30, | Six Months Ended June 30, | |||||||||||||||||||||||||
| (In Thousands, Except Per Share Amounts) | 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||||
| (Unaudited) | (Unaudited) | (Unaudited) | (Unaudited) | |||||||||||||||||||||||
| Interest Income: | ||||||||||||||||||||||||||
| Residential whole loans | $ | 140,951 | $ | 154,568 | $ | 284,042 | $ | 305,878 | ||||||||||||||||||
| Securities, at fair value | 52,770 | 28,778 | 98,523 | 53,448 | ||||||||||||||||||||||
| Other interest-earning assets | 481 | 528 | 972 | 926 | ||||||||||||||||||||||
| Cash and cash equivalent investments | 2,572 | 4,470 | 5,163 | 8,597 | ||||||||||||||||||||||
| Interest Income | $ | 196,774 | $ | 188,344 | $ | 388,700 | $ | 368,849 | ||||||||||||||||||
| Interest Expense: | ||||||||||||||||||||||||||
| Asset-backed and other collateralized financing arrangements | $ | 133,234 | $ | 122,523 | $ | 261,045 | $ | 240,954 | ||||||||||||||||||
| Other interest expense | 4,969 | 4,545 | 9,894 | 9,082 | ||||||||||||||||||||||
| Interest Expense | $ | 138,203 | $ | 127,068 | $ | 270,939 | $ | 250,036 | ||||||||||||||||||
| Net Interest Income | $ | 58,571 | $ | 61,276 | $ | 117,761 | $ | 118,813 | ||||||||||||||||||
| Reversal/(Provision) for Credit Losses on Residential Whole Loans | $ | 62 | $ | (791) | $ | 304 | $ | (936) | ||||||||||||||||||
| Reversal/(Provision) for Credit Losses on Other Assets | — | — | — | — | ||||||||||||||||||||||
| Net Interest Income after Reversal/(Provision) for Credit Losses | $ | 58,633 | $ | 60,485 | $ | 118,065 | $ | 117,877 | ||||||||||||||||||
| Other Income/(Loss), net: | ||||||||||||||||||||||||||
| Net gain/(loss) on residential whole loans measured at fair value through earnings | $ | (45,480) | $ | 23,799 | $ | (84,613) | $ | 74,449 | ||||||||||||||||||
| Impairment and other net gain/(loss) on securities and other portfolio investments | (3,850) | 6,645 | (42,120) | 27,824 | ||||||||||||||||||||||
| Net gain/(loss) on real estate owned | (1,491) | (2,911) | (4,472) | (4,419) | ||||||||||||||||||||||
| Net gain/(loss) on derivatives | 44,625 | (18,251) | 76,686 | (49,306) | ||||||||||||||||||||||
| Net gain/(loss) on securitized debt measured at fair value through earnings | 25,268 | (7,105) | 45,113 | (29,036) | ||||||||||||||||||||||
| Lima One mortgage banking income | 8,367 | 6,087 | 16,027 | 11,524 | ||||||||||||||||||||||
| Net realized gain/(loss) on residential whole loans held at carrying value | — | (343) | — | (882) | ||||||||||||||||||||||
| Other, net | 2,246 | 4,329 | 7,179 | 6,608 | ||||||||||||||||||||||
| Other Income/(Loss), net | $ | 29,685 | $ | 12,250 | $ | 13,800 | $ | 36,762 | ||||||||||||||||||
| Operating and Other Expense: | ||||||||||||||||||||||||||
| Compensation and benefits | $ | 17,992 | $ | 19,308 | $ | 40,151 | $ | 42,565 | ||||||||||||||||||
| Other general and administrative expense | 13,162 | 10,621 | 25,316 | 20,912 | ||||||||||||||||||||||
| Loan servicing, financing and other related costs | 10,066 | 8,584 | 19,984 | 15,836 | ||||||||||||||||||||||
| Amortization of intangible assets | 300 | 800 | 600 | 1,600 | ||||||||||||||||||||||
| Operating and Other Expense | $ | 41,520 | $ | 39,313 | $ | 86,051 | $ | 80,913 | ||||||||||||||||||
| Income/(loss) before income taxes | $ | 46,798 | $ | 33,422 | $ | 45,814 | $ | 73,726 | ||||||||||||||||||
| Provision for/(benefit from) income taxes | $ | — | $ | 238 | $ | — | $ | (634) | ||||||||||||||||||
| Net Income/(Loss) | $ | 46,798 | $ | 33,184 | $ | 45,814 | $ | 74,360 | ||||||||||||||||||
| Less Preferred Stock Dividend Requirement | $ | 10,559 | $ | 10,560 | $ | 20,983 | $ | 18,779 | ||||||||||||||||||
| Net Income/(Loss) Available to Common Stock and Participating Securities | $ | 36,239 | $ | 22,624 | $ | 24,831 | $ | 55,581 | ||||||||||||||||||
| Basic Earnings/(Loss) per Common Share | $ | 0.35 | $ | 0.22 | $ | 0.23 | $ | 0.53 | ||||||||||||||||||
| Diluted Earnings/(Loss) per Common Share | $ | 0.34 | $ | 0.21 | $ | 0.23 | $ | 0.52 | ||||||||||||||||||
8
Segment Reporting
At June 30, 2026, the Company’s reportable segments include (i) mortgage-related assets and (ii) Lima One. The Corporate column in the table below primarily consists of corporate cash and related interest income, investments in loan originators and related economics, general and administrative expenses not directly attributable to Lima One, interest expense on unsecured senior notes, securitization issuance costs, and preferred stock dividends.
The following tables summarize segment financial information, which in total reconciles to the same data for the Company as a whole:
| (In Thousands) | Mortgage-Related Assets | Lima One | Corporate | Total | ||||||||||||||||||||||
| Three months ended June 30, 2026 | ||||||||||||||||||||||||||
| Interest Income | $ | 155,380 | $ | 39,909 | $ | 1,485 | $ | 196,774 | ||||||||||||||||||
| Interest Expense | 108,287 | 25,339 | 4,577 | 138,203 | ||||||||||||||||||||||
| Net Interest Income/(Expense) | $ | 47,093 | $ | 14,570 | $ | (3,092) | $ | 58,571 | ||||||||||||||||||
| Reversal/(Provision) for Credit Losses on Residential Whole Loans | 62 | — | — | 62 | ||||||||||||||||||||||
| Reversal/(Provision) for Credit Losses on Other Assets | — | — | — | — | ||||||||||||||||||||||
| Net Interest Income/(Expense) after Reversal/(Provision) for Credit Losses | $ | 47,155 | $ | 14,570 | $ | (3,092) | $ | 58,633 | ||||||||||||||||||
| Net gain/(loss) on residential whole loans measured at fair value through earnings | $ | (26,768) | $ | (18,712) | $ | — | $ | (45,480) | ||||||||||||||||||
| Impairment and other net gain/(loss) on securities and other portfolio investments | (4,362) | 11 | 501 | (3,850) | ||||||||||||||||||||||
Net gain on real estate owned | 534 | (2,025) | — | (1,491) | ||||||||||||||||||||||
| Net gain/(loss) on derivatives | 40,009 | 4,616 | — | 44,625 | ||||||||||||||||||||||
| Net gain/(loss) on securitized debt measured at fair value through earnings | 20,843 | 4,425 | — | 25,268 | ||||||||||||||||||||||
| Lima One mortgage banking income | — | 8,367 | — | 8,367 | ||||||||||||||||||||||
| Net realized gain/(loss) on residential whole loans held at carrying value | — | — | — | — | ||||||||||||||||||||||
| Other, net | (326) | 1,685 | 887 | 2,246 | ||||||||||||||||||||||
| Other Income/(Loss), net | $ | 29,930 | $ | (1,633) | $ | 1,388 | $ | 29,685 | ||||||||||||||||||
| Compensation and benefits | $ | — | $ | 8,926 | $ | 9,066 | $ | 17,992 | ||||||||||||||||||
| Other general and administrative expense | — | 4,086 | 9,076 | 13,162 | ||||||||||||||||||||||
| Loan servicing, financing and other related costs | 3,780 | 2,169 | 4,117 | 10,066 | ||||||||||||||||||||||
| Amortization of intangible assets | — | 300 | — | 300 | ||||||||||||||||||||||
| Income/(loss) before income taxes | $ | 73,305 | $ | (2,544) | $ | (23,963) | $ | 46,798 | ||||||||||||||||||
| Provision for/(benefit from) income taxes | — | — | — | — | ||||||||||||||||||||||
| Net Income/(Loss) | $ | 73,305 | $ | (2,544) | $ | (23,963) | $ | 46,798 | ||||||||||||||||||
| Less Preferred Stock Dividend Requirement | $ | — | $ | — | $ | 10,559 | $ | 10,559 | ||||||||||||||||||
| Net Income/(Loss) Available to Common Stock and Participating Securities | $ | 73,305 | $ | (2,544) | $ | (34,522) | $ | 36,239 | ||||||||||||||||||
| (Dollars in Thousands) | Mortgage-Related Assets | Lima One | Corporate | Total | ||||||||||||||||||||||
| June 30, 2026 | ||||||||||||||||||||||||||
| Total Assets | $ | 11,186,791 | $ | 2,299,954 | $ | 166,947 | $ | 13,653,692 | ||||||||||||||||||
| December 31, 2025 | ||||||||||||||||||||||||||
| Total Assets | $ | 10,128,088 | $ | 2,632,740 | $ | 285,621 | $ | 13,046,449 | ||||||||||||||||||
9
Reconciliation of GAAP Net Income to non-GAAP Distributable Earnings and non-GAAP Distributable Earnings Prior to Realized Credit Losses
“Distributable earnings” is a non-GAAP financial measure of our operating performance, within the meaning of Regulation G and Item 10(e) of Regulation S-K, as promulgated by the Securities and Exchange Commission. Distributable earnings is determined by adjusting GAAP net income/(loss) by removing certain unrealized gains and losses, primarily on residential mortgage investments, associated debt, and hedges that are, in each case, accounted for at fair value through earnings, certain realized gains and losses, as well as certain non-cash expenses and securitization-related transaction costs. Realized gains and losses arising from loans sold to third-parties by Lima One shortly after the origination of such loans are included in Distributable earnings. The transaction costs are primarily comprised of costs only incurred at the time of execution of our securitizations and include costs such as underwriting fees, legal fees, diligence fees, bank fees and other similar transaction related expenses. These costs are all incurred prior to or at the execution of our securitizations and do not recur. Beginning in the first quarter of 2026, losses/(gains) recognized in GAAP Net income/(loss) related to the extinguishment of debt were also included in the adjustments for Securitized debt held at fair value and Securitization-related transaction costs. Prior periods have been revised to reflect the current presentation. TBA dollar roll income, which represents the economic equivalent of interest income earned on Agency MBS, less an implied financing cost, is also included in Distributable Earnings. Recurring expenses, such as servicing fees, custodial fees, trustee fees and other similar ongoing fees are not excluded from Distributable earnings. Management believes that the adjustments made to GAAP earnings result in the removal of (i) income or expenses that are not reflective of the longer term performance of our investment portfolio, (ii) certain non-cash expenses, and (iii) expense items required to be recognized solely due to the election of the fair value option on certain related residential mortgage assets and associated liabilities. Distributable earnings is one of the factors that our Board of Directors considers when evaluating distributions to our shareholders. Accordingly, we believe that the adjustments to compute Distributable earnings specified below provide investors and analysts with additional information to evaluate our financial results.
Beginning in the first quarter of 2026, we have also reported a non-GAAP “Distributable earnings prior to realized credit losses” metric, whereby an adjustment is made to reported Distributable earnings to exclude realized credit losses, net of recoveries for all residential whole loans held at fair value. Prior periods have been revised to reflect the current presentation. Management believes Distributable earnings prior to realized credit losses provides users of our financial statements with meaningful information to consider in addition to Net income/(loss) and cash flows from operating activities in accordance with GAAP. Distributable earnings prior to realized credit losses is one of the factors that our Board of Directors considers when evaluating distributions to our shareholders. As the timing of a realized credit loss on a loan can differ significantly from when the initial fair value adjustment with respect to a loan is reflected in GAAP net income/(loss), management believes that adjusting Distributable earnings for the realized credit losses described above can help readers better understand the operating results of our business prior to the impact of realized credit losses, as well as evaluate and compare the performance of our Company and our peers.
Distributable earnings and Distributable earnings prior to realized credit losses should be used in conjunction with results presented in accordance with GAAP. Distributable earnings and Distributable earnings prior to realized credit losses do not represent and should not be considered as a substitute for net income or cash flows from operating activities, each as determined in accordance with GAAP, and our calculation of these measures may not be comparable to similarly titled measures reported by other companies.
10
The following table provides a reconciliation of our GAAP net income/(loss) used in the calculation of basic EPS to our non-GAAP Distributable earnings and non-GAAP Distributable Earnings Prior to Realized Credit Losses for the quarterly periods below:
| Quarter Ended | ||||||||||||||||||||||||||||||||
| (In Thousands, Except Per Share Amounts) | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | |||||||||||||||||||||||||||
| GAAP Net income/(loss) used in the calculation of basic EPS | $ | 35,930 | $ | (11,726) | $ | 43,402 | $ | 37,082 | $ | 22,424 | ||||||||||||||||||||||
| Adjustments: | ||||||||||||||||||||||||||||||||
| Unrealized and realized gains and losses on: | ||||||||||||||||||||||||||||||||
| Residential whole loans held at fair value | 21,016 | 34,761 | (4,405) | (41,293) | (33,612) | |||||||||||||||||||||||||||
| Securities held at fair value | 4,362 | 38,872 | (14,898) | (17,798) | (4,008) | |||||||||||||||||||||||||||
| Residential whole loans and securities at carrying value | — | — | (1,399) | (668) | 343 | |||||||||||||||||||||||||||
| Derivative instruments | (34,508) | (21,344) | 657 | 14,826 | 32,565 | |||||||||||||||||||||||||||
| Securitized debt held at fair value | (27,296) | (22,901) | (1,586) | 21,303 | 3,712 | |||||||||||||||||||||||||||
| Other portfolio investments | (512) | (601) | 582 | 462 | (2,637) | |||||||||||||||||||||||||||
| Other adjustments: | ||||||||||||||||||||||||||||||||
| TBA dollar roll income | 985 | — | — | — | — | |||||||||||||||||||||||||||
| Amortization of intangible assets | 300 | 300 | 300 | 300 | 800 | |||||||||||||||||||||||||||
| Equity based compensation | 2,214 | 6,329 | 1,880 | 1,861 | 2,274 | |||||||||||||||||||||||||||
| Securitization-related transaction costs | 4,100 | 3,926 | 2,584 | 3,712 | 1,890 | |||||||||||||||||||||||||||
Depreciation | 5,647 | 3,466 | 1,045 | 1,328 | 1,087 | |||||||||||||||||||||||||||
| Total adjustments | (23,692) | 42,808 | (15,240) | (15,967) | 2,414 | |||||||||||||||||||||||||||
| Distributable earnings | $ | 12,238 | $ | 31,082 | $ | 28,162 | $ | 21,115 | $ | 24,838 | ||||||||||||||||||||||
| Adjustment – realized credit losses on Residential whole loans at fair value, net of recoveries | 24,463 | 4,373 | 3,003 | 10,052 | 9,812 | |||||||||||||||||||||||||||
| Distributable earnings prior to realized credit losses | $ | 36,701 | $ | 35,455 | $ | 31,165 | $ | 31,167 | $ | 34,650 | ||||||||||||||||||||||
| GAAP earnings/(loss) per basic common share | $ | 0.35 | $ | (0.11) | $ | 0.42 | $ | 0.36 | $ | 0.22 | ||||||||||||||||||||||
| Distributable earnings per basic common share | $ | 0.12 | $ | 0.30 | $ | 0.27 | $ | 0.20 | $ | 0.24 | ||||||||||||||||||||||
| Distributable earnings prior to realized credit losses per basic common share | $ | 0.35 | $ | 0.34 | $ | 0.30 | $ | 0.30 | $ | 0.33 | ||||||||||||||||||||||
| Weighted average common shares for basic earnings per share | 103,674 | 104,253 | 103,061 | 103,683 | 103,705 | |||||||||||||||||||||||||||
11
Reconciliation of GAAP Book Value per Common Share to non-GAAP Economic Book Value per Common Share
“Economic book value” is a non-GAAP financial measure of our financial position. To calculate our Economic book value, our portfolios of Residential whole loans and securitized debt held at carrying value are adjusted to their fair value, rather than the carrying value that is required to be reported under the GAAP accounting model applied to these financial instruments. These adjustments are also reflected in the table below in our end of period stockholders’ equity. Management considers that Economic book value provides investors with a useful supplemental measure to evaluate our financial position as it reflects the impact of fair value changes for all of our investment activities, irrespective of the accounting model applied for GAAP reporting purposes. Economic book value does not represent and should not be considered as a substitute for Stockholders’ Equity, as determined in accordance with GAAP, and our calculation of this measure may not be comparable to similarly titled measures reported by other companies.
The following table provides a reconciliation of our GAAP book value per common share to our non-GAAP Economic book value per common share as of the quarterly periods below:
The following table provides a reconciliation of our GAAP book value per common share to our non-GAAP Economic book value per common share as of the quarterly periods below:
| Quarter Ended: | ||||||||||||||||||||||||||||||||||||||
| (In Millions, Except Per Share Amounts) | June 30, 2026 | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | |||||||||||||||||||||||||||||||||
| GAAP Total Stockholders’ Equity | $ | 1,776.1 | $ | 1,779.4 | $ | 1,827.7 | $ | 1,821.5 | $ | 1,822.1 | ||||||||||||||||||||||||||||
| Preferred Stock, liquidation preference | (491.6) | (489.3) | (485.3) | (479.9) | (475.0) | |||||||||||||||||||||||||||||||||
| GAAP Stockholders’ Equity for book value per common share | 1,284.5 | 1,290.1 | 1,342.4 | 1,341.6 | 1,347.1 | |||||||||||||||||||||||||||||||||
| Adjustments: | ||||||||||||||||||||||||||||||||||||||
| Fair value adjustment to Residential whole loans, at carrying value | 2.4 | 7.6 | 10.1 | 8.7 | 1.8 | |||||||||||||||||||||||||||||||||
| Fair value adjustment to Securitized debt, at carrying value | 47.5 | 45.2 | 45.7 | 48.5 | 57.1 | |||||||||||||||||||||||||||||||||
| Stockholders’ Equity including fair value adjustments to Residential whole loans and Securitized debt held at carrying value (Economic book value) | $ | 1,334.4 | $ | 1,342.9 | $ | 1,398.2 | $ | 1,398.8 | $ | 1,406.0 | ||||||||||||||||||||||||||||
| GAAP book value per common share | $ | 12.71 | $ | 12.70 | $ | 13.20 | $ | 13.13 | $ | 13.12 | ||||||||||||||||||||||||||||
| Economic book value per common share | $ | 13.20 | $ | 13.22 | $ | 13.75 | $ | 13.69 | $ | 13.69 | ||||||||||||||||||||||||||||
| Number of shares of common stock outstanding | 101.1 | 101.6 | 101.7 | 102.2 | 102.7 | |||||||||||||||||||||||||||||||||
12
Cautionary Note Regarding Forward-Looking Statements
When used in this press release or other written or oral communications, statements that are not historical in nature, including those containing words such as “will,” “believe,” “expect,” “anticipate,” “estimate,” “plan,” “continue,” “intend,” “should,” “could,” “would,” “may,” the negative of these words or similar expressions, are intended to identify “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, and, as such, may involve known and unknown risks, uncertainties and assumptions. These forward-looking statements include information about possible or assumed future results with respect to MFA’s business, financial condition, liquidity, results of operations, plans and objectives. Among the important factors that could cause our actual results to differ materially from those projected in any forward-looking statements that we make are: general economic developments and trends, including the current tensions in international trade and the performance of the labor, housing, real estate, mortgage finance and broader financial markets; inflation, increases in interest rates and changes in the market (i.e., fair) value of MFA’s residential whole loans, MBS, securitized debt and other assets, as well as changes in the value of MFA’s liabilities accounted for at fair value through earnings; the effectiveness of hedging transactions; changes in the prepayment rates on residential mortgage assets, an increase of which could result in a reduction of the yield on certain investments in its portfolio and could require MFA to reinvest the proceeds received by it as a result of such prepayments in investments with lower coupons, while a decrease in which could result in an increase in the interest rate duration of certain investments in MFA’s portfolio making their valuation more sensitive to changes in interest rates and could result in lower forecasted cash flows; credit risks underlying MFA’s assets, including changes in the default rates and management’s assumptions regarding default rates and loss severities on the mortgage loans in MFA’s residential whole loan portfolio; MFA’s ability to borrow to finance its assets and the terms, including the cost, maturity and other terms, of any such borrowings; implementation of or changes in government regulations or programs affecting MFA’s business (including as a result of the current U.S. administration); MFA’s estimates regarding taxable income, the actual amount of which is dependent on a number of factors, including, but not limited to, changes in the amount of interest income and financing costs, the method elected by MFA to accrete the market discount on residential whole loans and the extent of prepayments, realized losses and changes in the composition of MFA’s residential whole loan portfolios that may occur during the applicable tax period, including gain or loss on any MBS disposals or whole loan modifications, foreclosures and liquidations; the timing and amount of distributions to stockholders, which are declared and paid at the discretion of MFA’s Board of Directors and will depend on, among other things, MFA’s taxable income, its financial results and overall financial condition and liquidity, maintenance of its REIT qualification and such other factors as MFA’s Board of Directors deems relevant; MFA’s ability to maintain its qualification as a REIT for federal income tax purposes; MFA’s ability to maintain its exemption from registration under the Investment Company Act of 1940, as amended (or the Investment Company Act), including statements regarding the concept release issued by the Securities and Exchange Commission (“SEC”) relating to interpretive issues under the Investment Company Act with respect to the status under the Investment Company Act of certain companies that are engaged in the business of acquiring mortgages and mortgage-related interests; MFA’s ability to continue growing its residential whole loan portfolio, which is dependent on, among other things, the supply of loans offered for sale in the market; targeted or expected returns on our investments in recently-originated mortgage loans, the performance of which is, similar to our other mortgage loan investments, subject to, among other things, differences in prepayment risk, credit risk and financing costs associated with such investments; risks associated with the ongoing operation of Lima One Holdings, LLC (including, without limitation, industry competition, unanticipated expenditures relating to or liabilities arising from its operation (including, among other things, a failure to realize management’s assumptions regarding expected growth in business purpose loan (BPL) origination volumes and credit risks underlying BPLs, including changes in the default rates and management’s assumptions regarding default rates and loss severities on the BPLs originated by Lima One)); expected returns on MFA’s investments in nonperforming residential whole loans (“NPLs”), which are affected by, among other things, the length of time required to foreclose upon, sell, liquidate or otherwise reach a resolution of the property underlying the NPL, home price values, amounts advanced to carry the asset (e.g., taxes, insurance, maintenance expenses, etc. on the underlying property) and the amount ultimately realized upon resolution of the asset; risks associated with our investments in loan originators; risks associated with investing in real estate assets generally, including changes in business conditions and the general economy; and other risks, uncertainties and factors, including those described in the annual, quarterly and current reports that we file with the SEC. These forward-looking statements are based on beliefs, assumptions and expectations of MFA’s future performance, taking into account information currently available. Readers and listeners are cautioned not to place undue reliance on these forward-looking statements, which speak only as of the date on which they are made. New risks and uncertainties arise over time and it is not possible to predict those events or how they may affect MFA. Except as required by law, MFA is not obligated to, and does not intend to, update or revise any forward-looking statements, whether as a result of new information, future events or otherwise.
13
Earnings Presentation SECOND QUARTER 2026 MFA 2026 Earnings Call Q2 ex99-2
2 Q3 2022 Financial Snapshot Forward-looking statements When used in this presentation or other written or oral communications, statements that are not historical in nature, including those containing words such as “will,” “believe,” “expect,” “anticipate,” “estimate,” “plan,” “continue,” “intend,” “should,” “could,” “would,” “may,” the negative of these words or similar expressions, are intended to identify “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended, and, as such, may involve known and unknown risks, uncertainties and assumptions. These forward-looking statements include information about possible or assumed future results with respect to MFA’s business, financial condition, liquidity, results of operations, plans and objectives. Among the important factors that could cause our actual results to differ materially from those projected in any forward-looking statements that we make are: general economic developments and trends, including the current tensions in international trade and the performance of the labor, housing, real estate, mortgage finance and broader financial markets; inflation, increases in interest rates and changes in the market (i.e., fair) value of MFA’s residential whole loans, MBS, securitized debt and other assets, as well as changes in the value of MFA’s liabilities accounted for at fair value through earnings; the effectiveness of hedging transactions; changes in the prepayment rates on residential mortgage assets, an increase of which could result in a reduction of the yield on certain investments in its portfolio and could require MFA to reinvest the proceeds received by it as a result of such prepayments in investments with lower coupons, while a decrease in which could result in an increase in the interest rate duration of certain investments in MFA’s portfolio making their valuation more sensitive to changes in interest rates and could result in lower forecasted cash flows; credit risks underlying MFA’s assets, including changes in the default rates and management’s assumptions regarding default rates and loss severities on the mortgage loans in MFA’s residential whole loan portfolio; MFA’s ability to borrow to finance its assets and the terms, including the cost, maturity and other terms, of any such borrowings; implementation of or changes in government regulations or programs affecting MFA’s business (including as a result of the current U.S. administration); MFA’s estimates regarding taxable income, the actual amount of which is dependent on a number of factors, including, but not limited to, changes in the amount of interest income and financing costs, the method elected by MFA to accrete the market discount on residential whole loans and the extent of prepayments, realized losses and changes in the composition of MFA’s residential whole loan portfolios that may occur during the applicable tax period, including gain or loss on any MBS disposals or whole loan modifications, foreclosures and liquidations; the timing and amount of distributions to stockholders, which are declared and paid at the discretion of MFA’s Board of Directors and will depend on, among other things, MFA’s taxable income, its financial results and overall financial condition and liquidity, maintenance of its REIT qualification and such other factors as MFA’s Board of Directors deems relevant; MFA’s ability to maintain its qualification as a REIT for federal income tax purposes; MFA’s ability to maintain its exemption from registration under the Investment Company Act of 1940, as amended (or the “Investment Company Act”), including statements regarding the concept release issued by the Securities and Exchange Commission (“SEC”) relating to interpretive issues under the Investment Company Act with respect to the status under the Investment Company Act of certain companies that are engaged in the business of acquiring mortgages and mortgage-related interests; MFA’s ability to continue growing its residential whole loan portfolio, which is dependent on, among other things, the supply of loans offered for sale in the market; targeted or expected returns on our investments in recently-originated mortgage loans, the performance of which is, similar to our other mortgage loan investments, subject to, among other things, differences in prepayment risk, credit risk and financing costs associated with such investments; risks associated with the ongoing operation of Lima One Holdings, LLC (including, without limitation, industry competition, unanticipated expenditures relating to or liabilities arising from its operation (including, among other things, a failure to realize management’s assumptions regarding expected growth in business purpose loan (BPL) origination volumes and credit risks underlying BPLs, including changes in the default rates and management’s assumptions regarding default rates and loss severities on the BPLs originated by Lima One); expected returns on MFA’s investments in nonperforming residential whole loans (“NPLs”), which are affected by, among other things, the length of time required to foreclose upon, sell, liquidate or otherwise reach a resolution of the property underlying the NPL, home price values, amounts advanced to carry the asset (e.g., taxes, insurance, maintenance expenses, etc. on the underlying property) and the amount ultimately realized upon resolution of the asset; risks associated with our investments in loan originators; risks associated with investing in real estate assets generally, including changes in business conditions and the general economy; and other risks, uncertainties and factors, including those described in the annual, quarterly and current reports that we file with the SEC. These forward-looking statements are based on beliefs, assumptions and expectations of MFA’s future performance, taking into account information currently available. Readers and listeners are cautioned not to place undue reliance on these forward- looking statements, which speak only as of the date on which they are made. New risks and uncertainties arise over time and it is not possible to predict those events or how they may affect MFA. Except as required by law, MFA is not obligated to, and does not intend to, update or revise any forward-looking statements, whether as a result of new information, future events or otherwise.
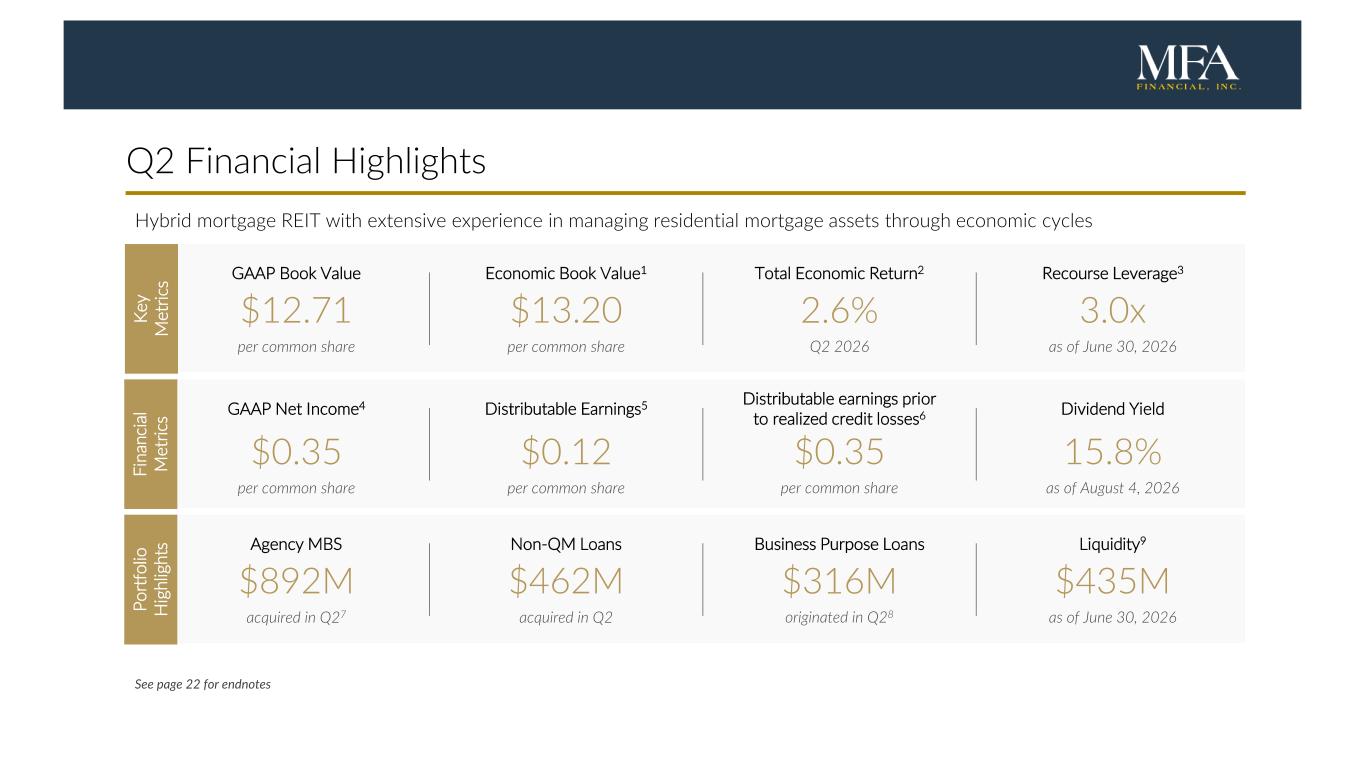
Q3 2022 Financial Snapshot Hybrid mortgage REIT with extensive experience in managing residential mortgage assets through economic cycles See page 22 for endnotes Q2 Financial Highlights GAAP Book Value $12.71 per common share Economic Book Value1 $13.20 per common share Total Economic Return2 2.6% Q2 2026 Recourse Leverage3 3.0x as of June 30, 2026 Ke y M et ric s GAAP Net Income4 $0.35 per common share Distributable Earnings5 $0.12 per common share Distributable earnings prior to realized credit losses6 $0.35 per common share Dividend Yield 15.8% as of August 4, 2026 Fi na nc ia l M et ric s Agency MBS $892M acquired in Q27 Non-QM Loans $462M acquired in Q2 Business Purpose Loans $316M originated in Q28 Liquidity9 $435M as of June 30, 2026 Po rt fo lio H ig hl ig ht s
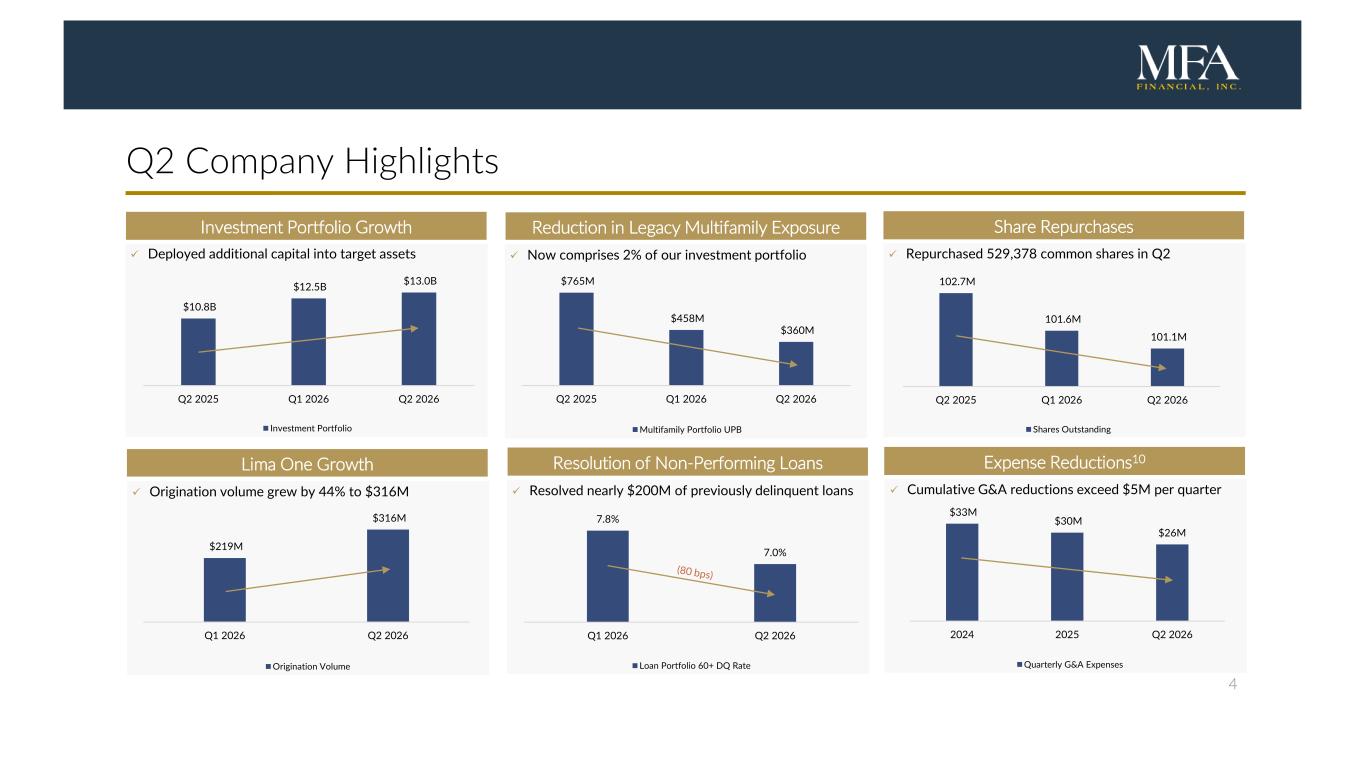
4 Q2 Company Highlights Reduction in Legacy Multifamily Exposure Repurchased 529,378 common shares in Q2 Share Repurchases Deployed additional capital into target assets Investment Portfolio Growth Resolution of Non-Performing LoansLima One Growth Expense Reductions10 Cumulative G&A reductions exceed $5M per quarter Now comprises 2% of our investment portfolio Resolved nearly $200M of previously delinquent loans 7.8% 7.0% Q1 2026 Q2 2026 Loan Portfolio 60+ DQ Rate Origination volume grew by 44% to $316M $765M $458M $360M Q2 2025 Q1 2026 Q2 2026 Multifamily Portfolio UPB 102.7M 101.6M 101.1M Q2 2025 Q1 2026 Q2 2026 Shares Outstanding $219M $316M Q1 2026 Q2 2026 Origination Volume $10.8B $12.5B $13.0B Q2 2025 Q1 2026 Q2 2026 Investment Portfolio $33M $30M $26M 2024 2025 Q2 2026 Quarterly G&A Expenses
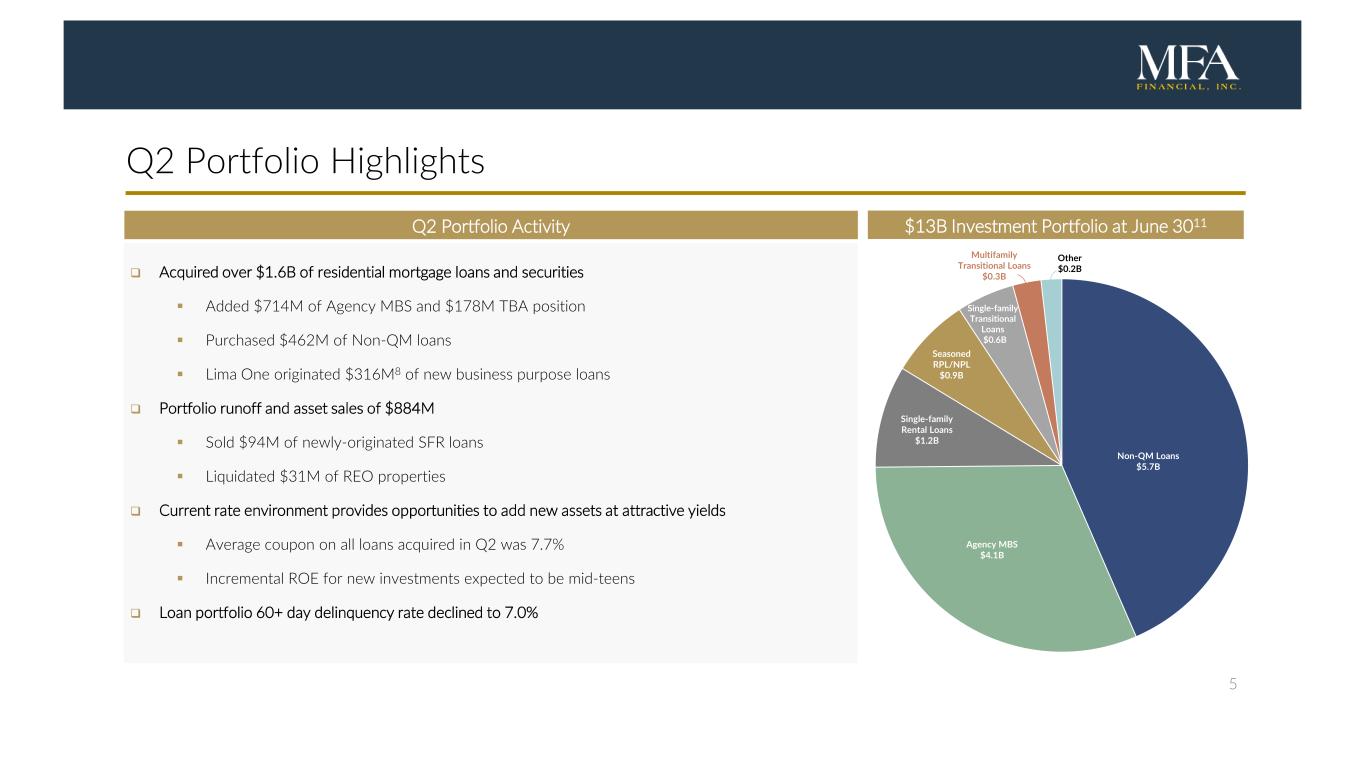
5 Acquired over $1.6B of residential mortgage loans and securities Added $714M of Agency MBS and $178M TBA position Purchased $462M of Non-QM loans Lima One originated $316M8 of new business purpose loans Portfolio runoff and asset sales of $884M Sold $94M of newly-originated SFR loans Liquidated $31M of REO properties Current rate environment provides opportunities to add new assets at attractive yields Average coupon on all loans acquired in Q2 was 7.7% Incremental ROE for new investments expected to be mid-teens Loan portfolio 60+ day delinquency rate declined to 7.0% Q Q2 Portfolio Highlights $13B Investment Portfolio at June 3011Q2 Portfolio Activity Non-QM Loans $5.7B Agency MBS $4.1B Multifamily Transitional Loans $0.3B Other $0.2B Seasoned RPL/NPL $0.9B Single-family Rental Loans $1.2B Single-family Transitional Loans $0.6B
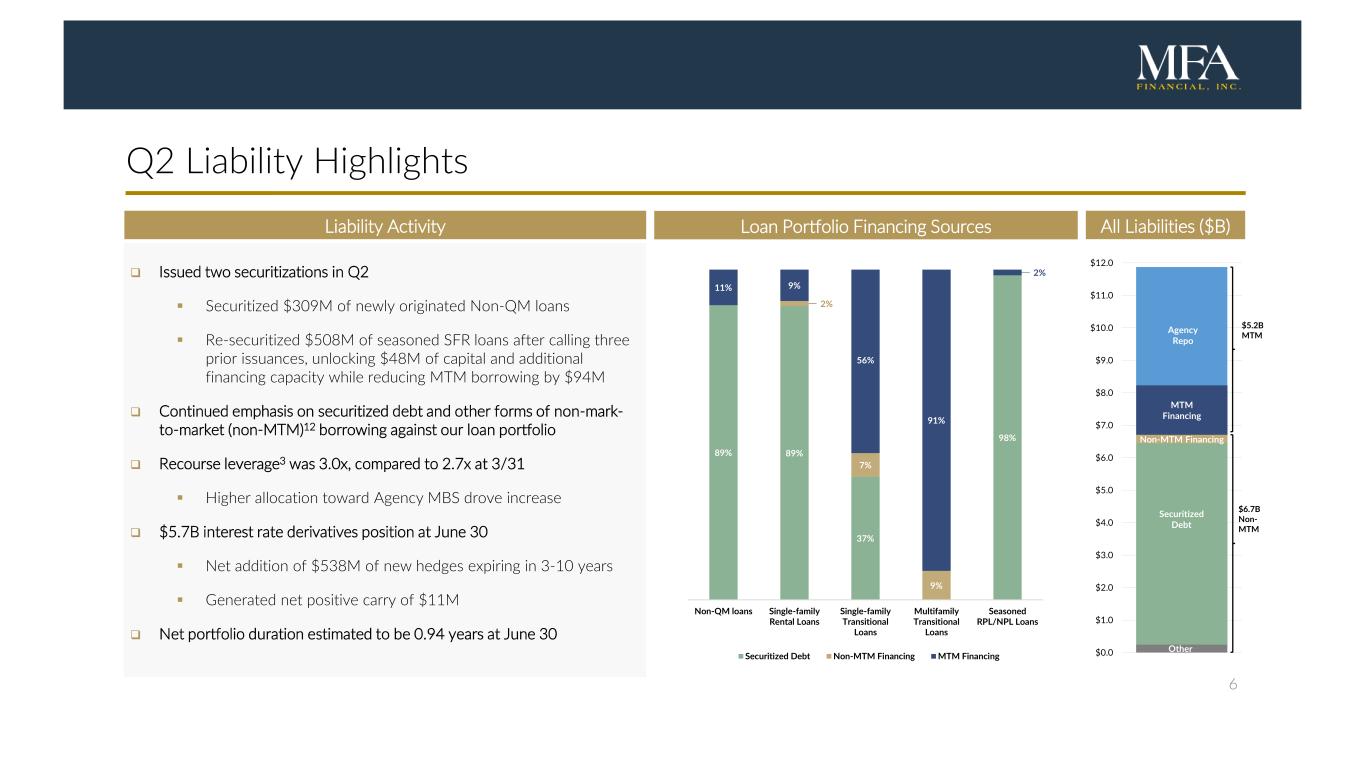
6 $0.0 $1.0 $2.0 $3.0 $4.0 $5.0 $6.0 $7.0 $8.0 $9.0 $10.0 $11.0 $12.0 Agency Repo MTM Financing Non-MTM Financing Securitized Debt Other 89% 89% 37% 98% 2% 7% 9% 11% 9% 56% 91% 2% Non-QM loans Single-family Rental Loans Single-family Transitional Loans Multifamily Transitional Loans Seasoned RPL/NPL Loans Securitized Debt Non-MTM Financing MTM Financing Issued two securitizations in Q2 Securitized $309M of newly originated Non-QM loans Re-securitized $508M of seasoned SFR loans after calling three prior issuances, unlocking $48M of capital and additional financing capacity while reducing MTM borrowing by $94M Continued emphasis on securitized debt and other forms of non-mark- to-market (non-MTM)12 borrowing against our loan portfolio Recourse leverage3 was 3.0x, compared to 2.7x at 3/31 Higher allocation toward Agency MBS drove increase $5.7B interest rate derivatives position at June 30 Net addition of $538M of new hedges expiring in 3-10 years Generated net positive carry of $11M Net portfolio duration estimated to be 0.94 years at June 30 Q2 Liability Highlights Loan Portfolio Financing SourcesLiability Activity $6.7B Non- MTM All Liabilities ($B) $5.2B MTM
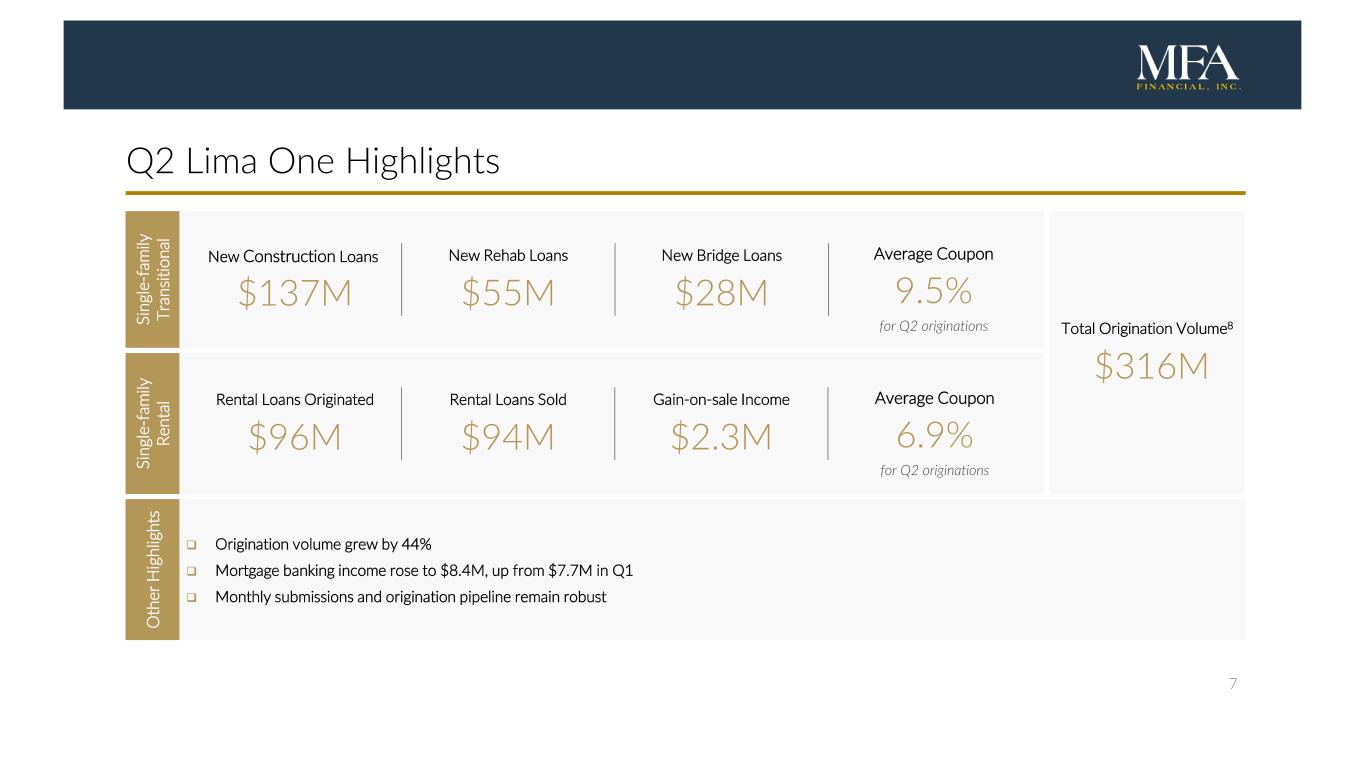
7 Si ng le -f am ily Re nt al Gain-on-sale Income $2.3M Si ng le -f am ily Tr an sit io na l New Bridge Loans $28M Q3 2022 Financial Snapshot Q2 Lima One Highlights New Rehab Loans $55M New Construction Loans $137M Total Origination Volume8 $316M Rental Loans Sold $94M Rental Loans Originated $96M Origination volume grew by 44% Mortgage banking income rose to $8.4M, up from $7.7M in Q1 Monthly submissions and origination pipeline remain robust O th er H ig hl ig ht s Average Coupon 9.5% for Q2 originations Average Coupon 6.9% for Q2 originations
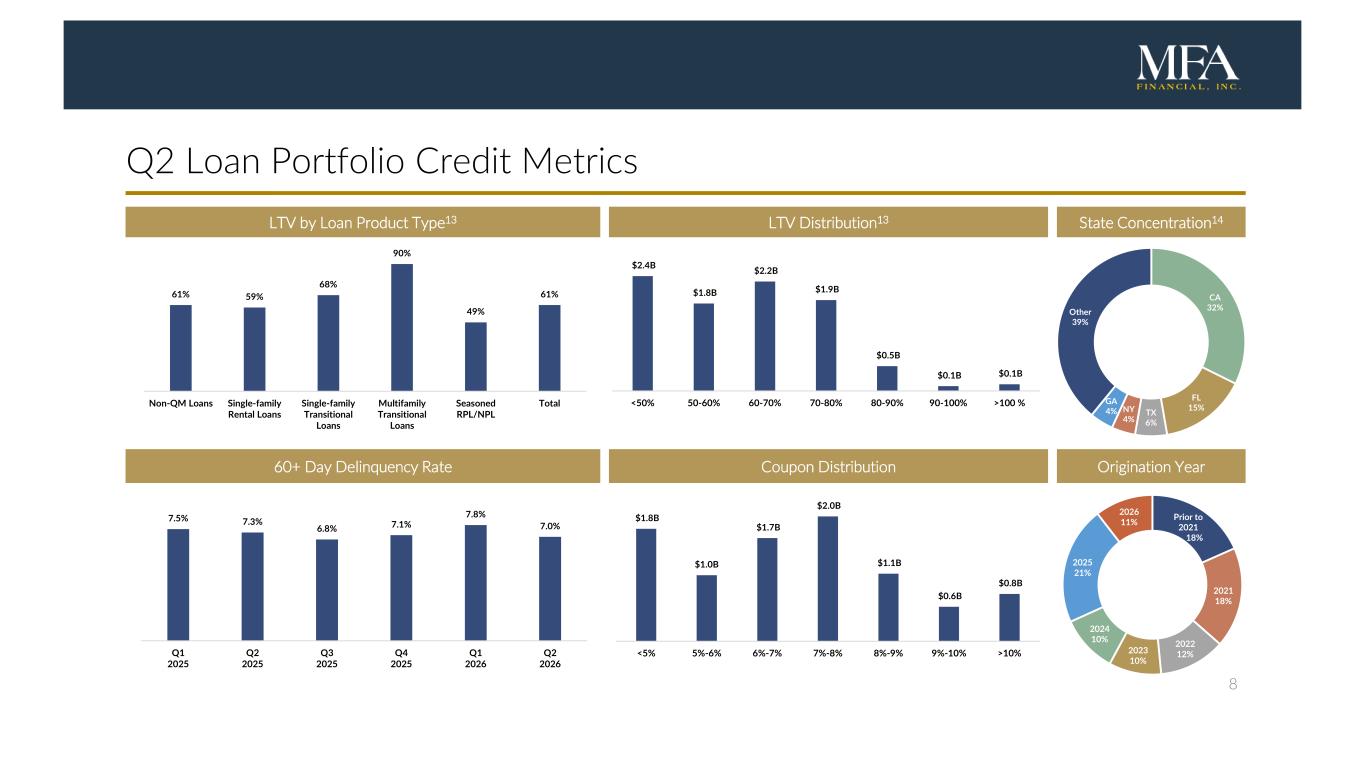
8 $2.4B $1.8B $2.2B $1.9B $0.5B $0.1B $0.1B <50% 50-60% 60-70% 70-80% 80-90% 90-100% >100 % CA 32% FL 15%TX 6% NY 4% GA 4% Other 39% Prior to 2021 18% 2021 18% 2022 12%2023 10% 2024 10% 2025 21% 2026 11% Q3 2022 Financial Snapshot Q2 Loan Portfolio Credit Metrics LTV by Loan Product Type13 LTV Distribution13 State Concentration14 60+ Day Delinquency Rate Coupon Distribution Origination Year 7.5% 7.3% 6.8% 7.1% 7.8% 7.0% Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Q2 2026 $1.8B $1.0B $1.7B $2.0B $1.1B $0.6B $0.8B <5% 5%-6% 6%-7% 7%-8% 8%-9% 9%-10% >10% 61% 59% 68% 90% 49% 61% Non-QM Loans Single-family Rental Loans Single-family Transitional Loans Multifamily Transitional Loans Seasoned RPL/NPL Total
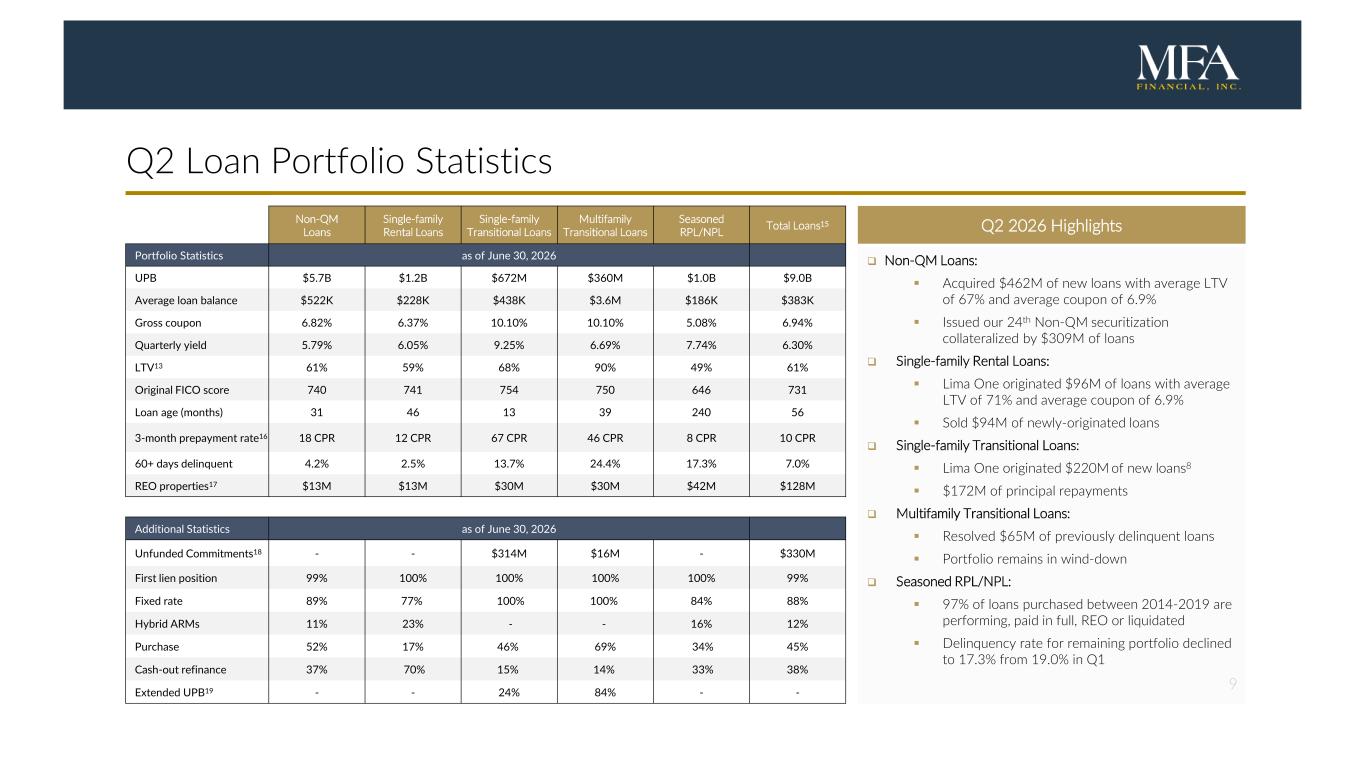
9 Q3 2022 Financial Snapshot Q2 Loan Portfolio Statistics Non-QM Loans Single-family Rental Loans Single-family Transitional Loans Multifamily Transitional Loans Seasoned RPL/NPL Total Loans15 Portfolio Statistics as of June 30, 2026 UPB $5.7B $1.2B $672M $360M $1.0B $9.0B Average loan balance $522K $228K $438K $3.6M $186K $383K Gross coupon 6.82% 6.37% 10.10% 10.10% 5.08% 6.94% Quarterly yield 5.79% 6.05% 9.25% 6.69% 7.74% 6.30% LTV13 61% 59% 68% 90% 49% 61% Original FICO score 740 741 754 750 646 731 Loan age (months) 31 46 13 39 240 56 3-month prepayment rate16 18 CPR 12 CPR 67 CPR 46 CPR 8 CPR 10 CPR 60+ days delinquent 4.2% 2.5% 13.7% 24.4% 17.3% 7.0% REO properties17 $13M $13M $30M $30M $42M $128M Additional Statistics as of June 30, 2026 Unfunded Commitments18 - - $314M $16M - $330M First lien position 99% 100% 100% 100% 100% 99% Fixed rate 89% 77% 100% 100% 84% 88% Hybrid ARMs 11% 23% - - 16% 12% Purchase 52% 17% 46% 69% 34% 45% Cash-out refinance 37% 70% 15% 14% 33% 38% Extended UPB19 - - 24% 84% - - Non-QM Loans: Acquired $462M of new loans with average LTV of 67% and average coupon of 6.9% Issued our 24th Non-QM securitization collateralized by $309M of loans Single-family Rental Loans: Lima One originated $96M of loans with average LTV of 71% and average coupon of 6.9% Sold $94M of newly-originated loans Single-family Transitional Loans: Lima One originated $220M of new loans8 $172M of principal repayments Multifamily Transitional Loans: Resolved $65M of previously delinquent loans Portfolio remains in wind-down Seasoned RPL/NPL: 97% of loans purchased between 2014-2019 are performing, paid in full, REO or liquidated Delinquency rate for remaining portfolio declined to 17.3% from 19.0% in Q1 Q2 2026 Highlights
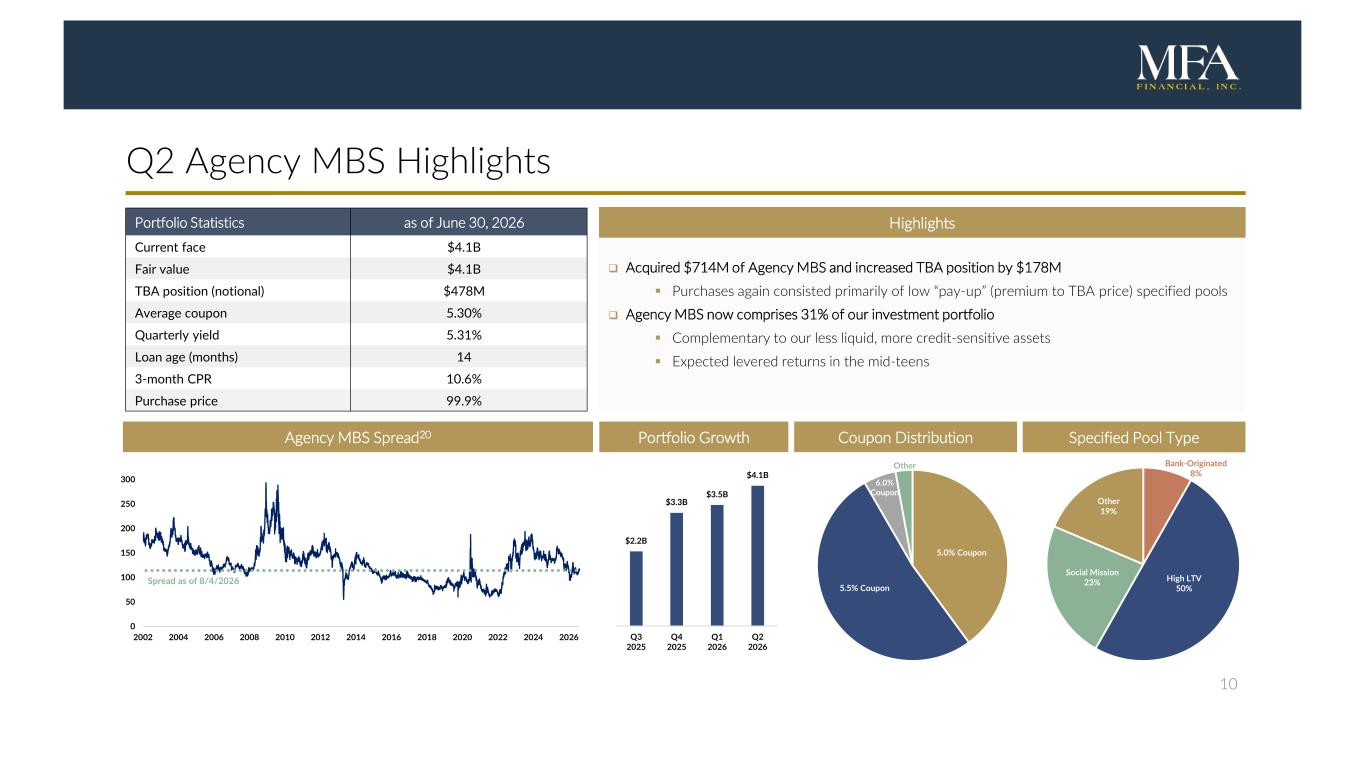
10 Q3 2022 Financial Snapshot Q2 Agency MBS Highlights Acquired $714M of Agency MBS and increased TBA position by $178M Purchases again consisted primarily of low “pay-up” (premium to TBA price) specified pools Agency MBS now comprises 31% of our investment portfolio Complementary to our less liquid, more credit-sensitive assets Expected levered returns in the mid-teens HighlightsPortfolio Statistics as of June 30, 2026 Current face $4.1B Fair value $4.1B TBA position (notional) $478M Average coupon 5.30% Quarterly yield 5.31% Loan age (months) 14 3-month CPR 10.6% Purchase price 99.9% Agency MBS Spread20 Portfolio Growth Coupon Distribution Specified Pool Type 0 50 100 150 200 250 300 2002 2004 2006 2008 2010 2012 2014 2016 2018 2020 2022 2024 2026 Spread as of 8/4/2026 5.0% Coupon 5.5% Coupon 6.0% Coupon Other Bank-Originated 8% High LTV 50% Social Mission 23% Other 19% $2.2B $3.3B $3.5B $4.1B Q3 2025 Q4 2025 Q1 2026 Q2 2026
11 Appendix James Casebere, Landscape with Houses (Dutchess County, NY) #2, 2010 (detail)
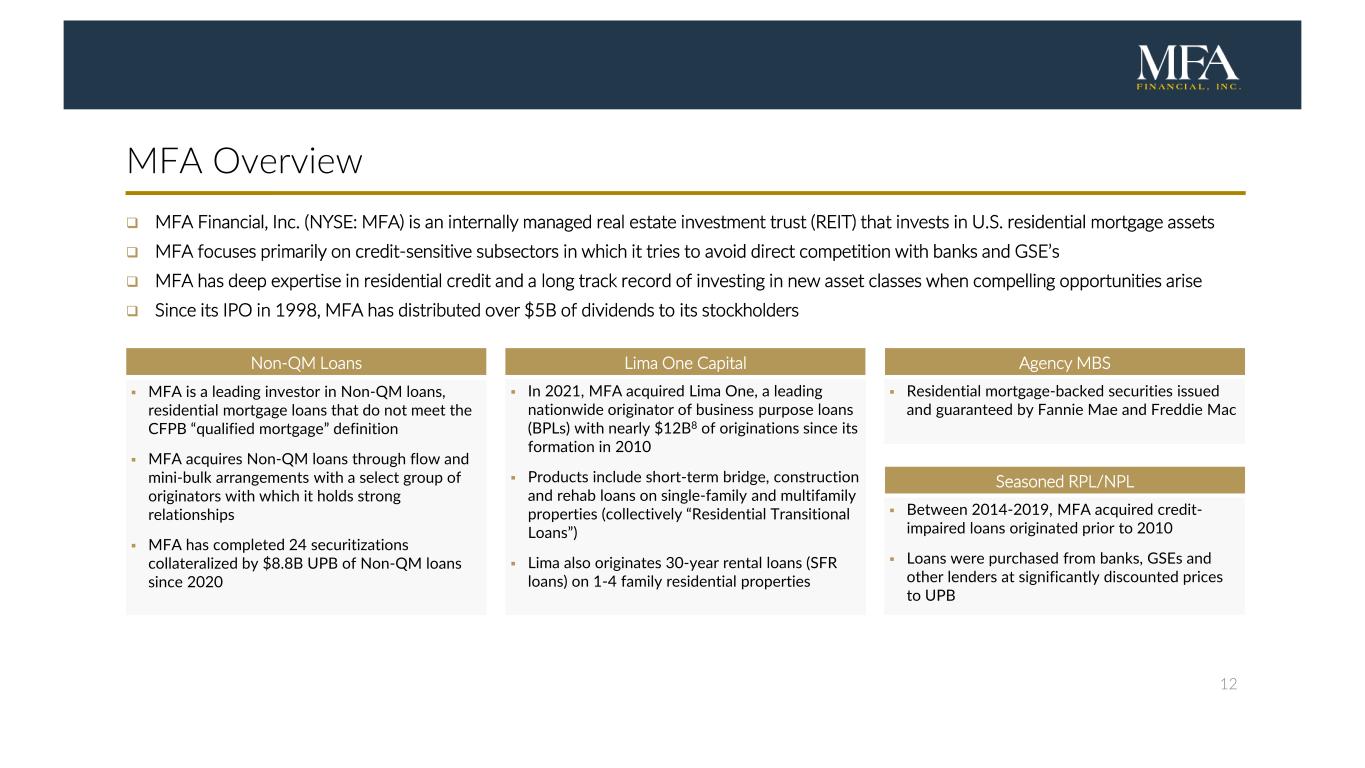
12 MFA Overview MFA Financial, Inc. (NYSE: MFA) is an internally managed real estate investment trust (REIT) that invests in U.S. residential mortgage assets MFA focuses primarily on credit-sensitive subsectors in which it tries to avoid direct competition with banks and GSE’s MFA has deep expertise in residential credit and a long track record of investing in new asset classes when compelling opportunities arise Since its IPO in 1998, MFA has distributed over $5B of dividends to its stockholders MFA is a leading investor in Non-QM loans, residential mortgage loans that do not meet the CFPB “qualified mortgage” definition MFA acquires Non-QM loans through flow and mini-bulk arrangements with a select group of originators with which it holds strong relationships MFA has completed 24 securitizations collateralized by $8.8B UPB of Non-QM loans since 2020 In 2021, MFA acquired Lima One, a leading nationwide originator of business purpose loans (BPLs) with nearly $12B8 of originations since its formation in 2010 Products include short-term bridge, construction and rehab loans on single-family and multifamily properties (collectively “Residential Transitional Loans”) Lima also originates 30-year rental loans (SFR loans) on 1-4 family residential properties Residential mortgage-backed securities issued and guaranteed by Fannie Mae and Freddie Mac Non-QM Loans Lima One Capital Agency MBS Between 2014-2019, MFA acquired credit- impaired loans originated prior to 2010 Loans were purchased from banks, GSEs and other lenders at significantly discounted prices to UPB Seasoned RPL/NPL
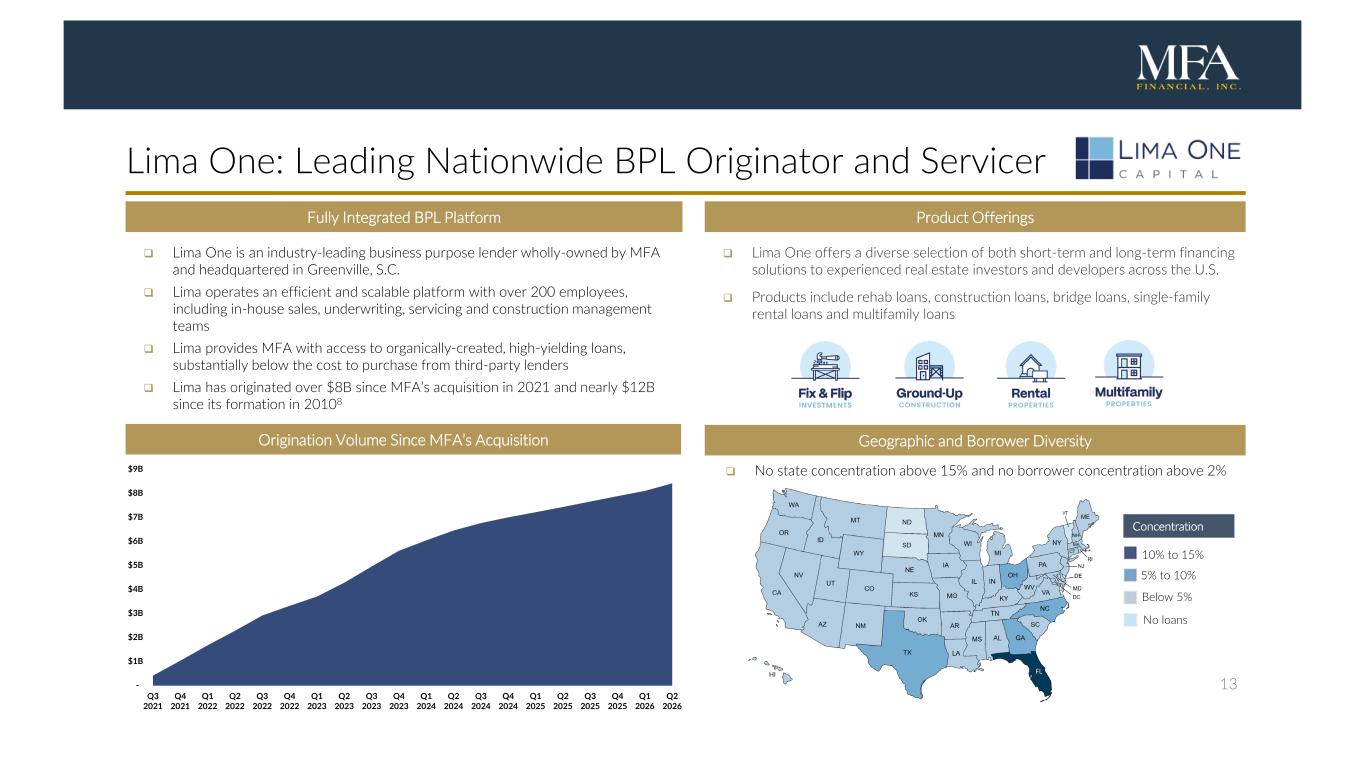
13 No state concentration above 15% and no borrower concentration above 2% Lima One is an industry-leading business purpose lender wholly-owned by MFA and headquartered in Greenville, S.C. Lima operates an efficient and scalable platform with over 200 employees, including in-house sales, underwriting, servicing and construction management teams Lima provides MFA with access to organically-created, high-yielding loans, substantially below the cost to purchase from third-party lenders Lima has originated over $8B since MFA’s acquisition in 2021 and nearly $12B since its formation in 20108 Lima One: Leading Nationwide BPL Originator and Servicer Fully Integrated BPL Platform Lima One offers a diverse selection of both short-term and long-term financing solutions to experienced real estate investors and developers across the U.S. Products include rehab loans, construction loans, bridge loans, single-family rental loans and multifamily loans Product Offerings Origination Volume Since MFA’s Acquisition Geographic and Borrower Diversity Concentration 10% to 15% 5% to 10% Below 5% No loans FL - $1B $2B $3B $4B $5B $6B $7B $8B $9B Q3 2021 Q4 2021 Q1 2022 Q2 2022 Q3 2022 Q4 2022 Q1 2023 Q2 2023 Q3 2023 Q4 2023 Q1 2024 Q2 2024 Q3 2024 Q4 2024 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Q2 2026
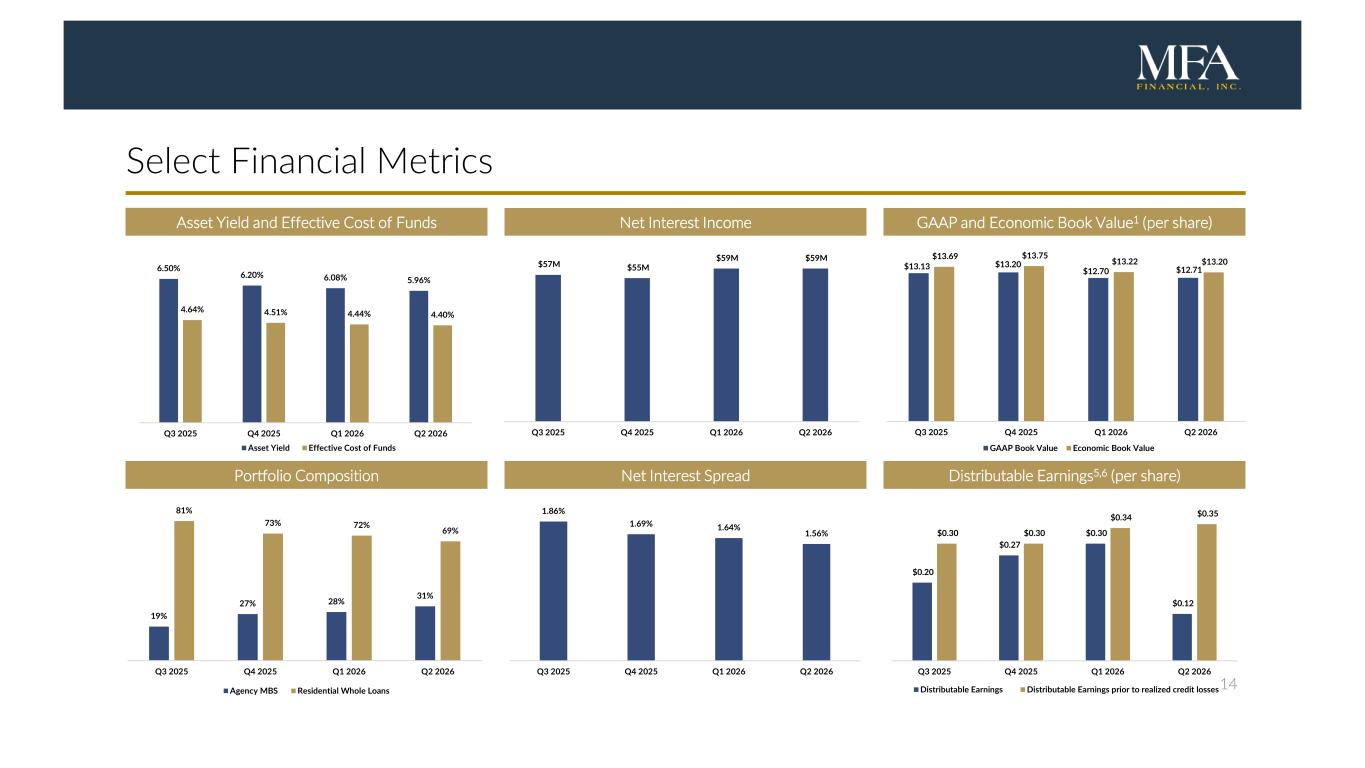
14 Select Financial Metrics Asset Yield and Effective Cost of Funds Net Interest Income GAAP and Economic Book Value1 (per share) Portfolio Composition Net Interest Spread Distributable Earnings5,6 (per share) 6.50% 6.20% 6.08% 5.96% 4.64% 4.51% 4.44% 4.40% Q3 2025 Q4 2025 Q1 2026 Q2 2026 Asset Yield Effective Cost of Funds $13.13 $13.20 $12.70 $12.71 $13.69 $13.75 $13.22 $13.20 Q3 2025 Q4 2025 Q1 2026 Q2 2026 GAAP Book Value Economic Book Value $57M $55M $59M $59M Q3 2025 Q4 2025 Q1 2026 Q2 2026 $0.20 $0.27 $0.30 $0.12 $0.30 $0.30 $0.34 $0.35 Q3 2025 Q4 2025 Q1 2026 Q2 2026 Distributable Earnings Distributable Earnings prior to realized credit losses 19% 27% 28% 31% 81% 73% 72% 69% Q3 2025 Q4 2025 Q1 2026 Q2 2026 Agency MBS Residential Whole Loans 1.86% 1.69% 1.64% 1.56% Q3 2025 Q4 2025 Q1 2026 Q2 2026
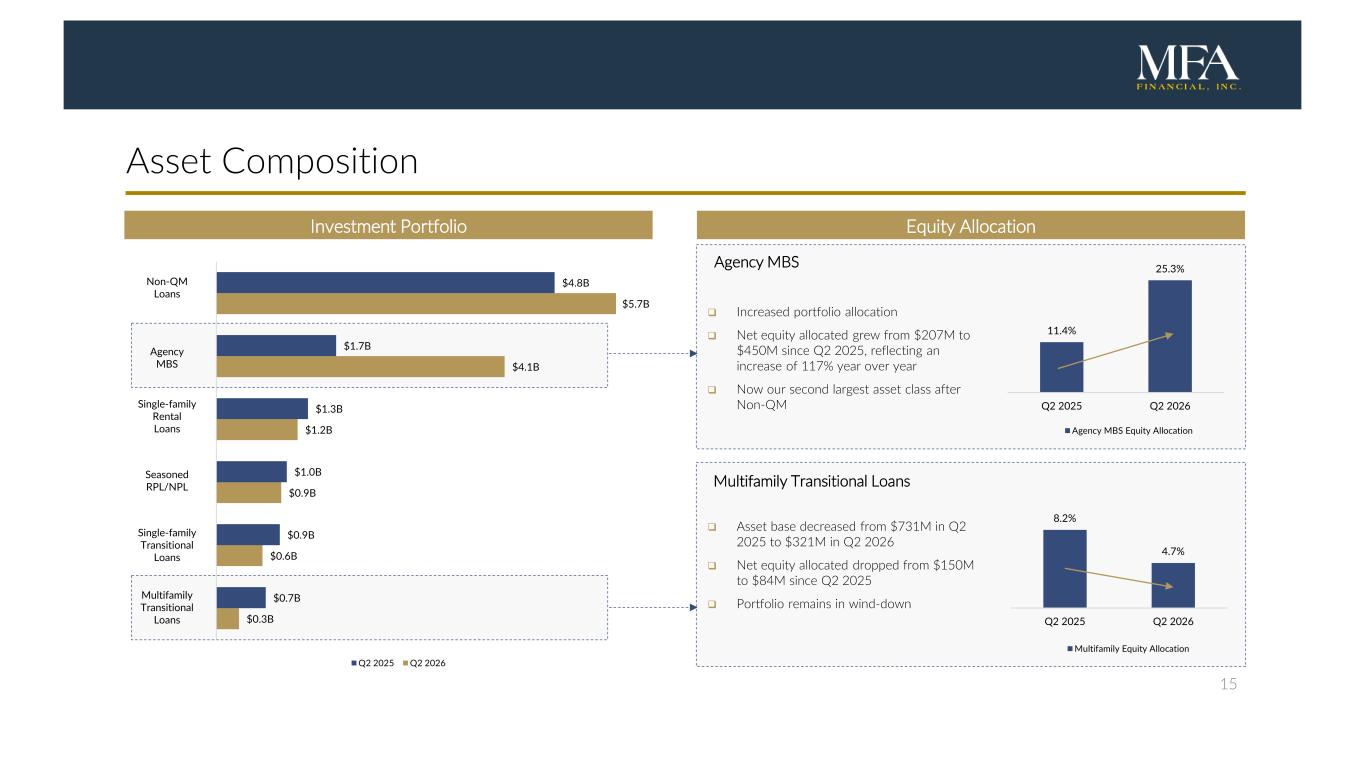
15 Asset Composition Investment Portfolio Equity Allocation Increased portfolio allocation Net equity allocated grew from $207M to $450M since Q2 2025, reflecting an increase of 117% year over year Now our second largest asset class after Non-QM Asset base decreased from $731M in Q2 2025 to $321M in Q2 2026 Net equity allocated dropped from $150M to $84M since Q2 2025 Portfolio remains in wind-down Non-QM Loans Agency MBS Single-family Rental Loans Seasoned RPL/NPL Single-family Transitional Loans Multifamily Transitional Loans Agency MBS Multifamily Transitional Loans 8.2% 4.7% Q2 2025 Q2 2026 Multifamily Equity Allocation $0.3B $0.6B $0.9B $1.2B $4.1B $5.7B $0.7B $0.9B $1.0B $1.3B $1.7B $4.8B Q2 2025 Q2 2026 11.4% 25.3% Q2 2025 Q2 2026 Agency MBS Equity Allocation
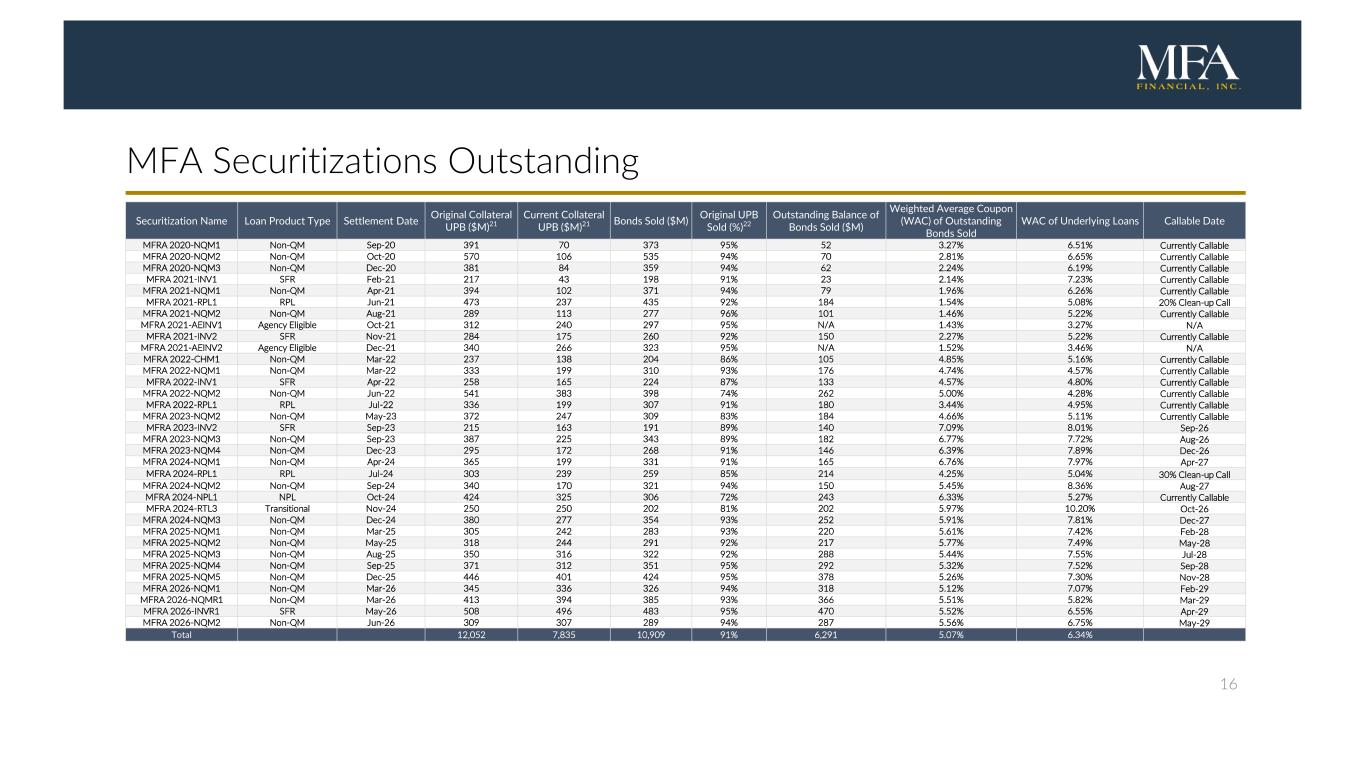
16 MFA Securitizations Outstanding Securitization Name Loan Product Type Settlement Date Original Collateral UPB ($M)21 Current Collateral UPB ($M)21 Bonds Sold ($M) Original UPB Sold (%)22 Outstanding Balance of Bonds Sold ($M) Weighted Average Coupon (WAC) of Outstanding Bonds Sold WAC of Underlying Loans Callable Date MFRA 2020-NQM1 Non-QM Sep-20 391 70 373 95% 52 3.27% 6.51% Currently Callable MFRA 2020-NQM2 Non-QM Oct-20 570 106 535 94% 70 2.81% 6.65% Currently Callable MFRA 2020-NQM3 Non-QM Dec-20 381 84 359 94% 62 2.24% 6.19% Currently Callable MFRA 2021-INV1 SFR Feb-21 217 43 198 91% 23 2.14% 7.23% Currently Callable MFRA 2021-NQM1 Non-QM Apr-21 394 102 371 94% 79 1.96% 6.26% Currently Callable MFRA 2021-RPL1 RPL Jun-21 473 237 435 92% 184 1.54% 5.08% 20% Clean-up Call MFRA 2021-NQM2 Non-QM Aug-21 289 113 277 96% 101 1.46% 5.22% Currently Callable MFRA 2021-AEINV1 Agency Eligible Oct-21 312 240 297 95% N/A 1.43% 3.27% N/A MFRA 2021-INV2 SFR Nov-21 284 175 260 92% 150 2.27% 5.22% Currently Callable MFRA 2021-AEINV2 Agency Eligible Dec-21 340 266 323 95% N/A 1.52% 3.46% N/A MFRA 2022-CHM1 Non-QM Mar-22 237 138 204 86% 105 4.85% 5.16% Currently Callable MFRA 2022-NQM1 Non-QM Mar-22 333 199 310 93% 176 4.74% 4.57% Currently Callable MFRA 2022-INV1 SFR Apr-22 258 165 224 87% 133 4.57% 4.80% Currently Callable MFRA 2022-NQM2 Non-QM Jun-22 541 383 398 74% 262 5.00% 4.28% Currently Callable MFRA 2022-RPL1 RPL Jul-22 336 199 307 91% 180 3.44% 4.95% Currently Callable MFRA 2023-NQM2 Non-QM May-23 372 247 309 83% 184 4.66% 5.11% Currently Callable MFRA 2023-INV2 SFR Sep-23 215 163 191 89% 140 7.09% 8.01% Sep-26 MFRA 2023-NQM3 Non-QM Sep-23 387 225 343 89% 182 6.77% 7.72% Aug-26 MFRA 2023-NQM4 Non-QM Dec-23 295 172 268 91% 146 6.39% 7.89% Dec-26 MFRA 2024-NQM1 Non-QM Apr-24 365 199 331 91% 165 6.76% 7.97% Apr-27 MFRA 2024-RPL1 RPL Jul-24 303 239 259 85% 214 4.25% 5.04% 30% Clean-up Call MFRA 2024-NQM2 Non-QM Sep-24 340 170 321 94% 150 5.45% 8.36% Aug-27 MFRA 2024-NPL1 NPL Oct-24 424 325 306 72% 243 6.33% 5.27% Currently Callable MFRA 2024-RTL3 Transitional Nov-24 250 250 202 81% 202 5.97% 10.20% Oct-26 MFRA 2024-NQM3 Non-QM Dec-24 380 277 354 93% 252 5.91% 7.81% Dec-27 MFRA 2025-NQM1 Non-QM Mar-25 305 242 283 93% 220 5.61% 7.42% Feb-28 MFRA 2025-NQM2 Non-QM May-25 318 244 291 92% 217 5.77% 7.49% May-28 MFRA 2025-NQM3 Non-QM Aug-25 350 316 322 92% 288 5.44% 7.55% Jul-28 MFRA 2025-NQM4 Non-QM Sep-25 371 312 351 95% 292 5.32% 7.52% Sep-28 MFRA 2025-NQM5 Non-QM Dec-25 446 401 424 95% 378 5.26% 7.30% Nov-28 MFRA 2026-NQM1 Non-QM Mar-26 345 336 326 94% 318 5.12% 7.07% Feb-29 MFRA 2026-NQMR1 Non-QM Mar-26 413 394 385 93% 366 5.51% 5.82% Mar-29 MFRA 2026-INVR1 SFR May-26 508 496 483 95% 470 5.52% 6.55% Apr-29 MFRA 2026-NQM2 Non-QM Jun-26 309 307 289 94% 287 5.56% 6.75% May-29 Total 12,052 7,835 10,909 91% 6,291 5.07% 6.34%
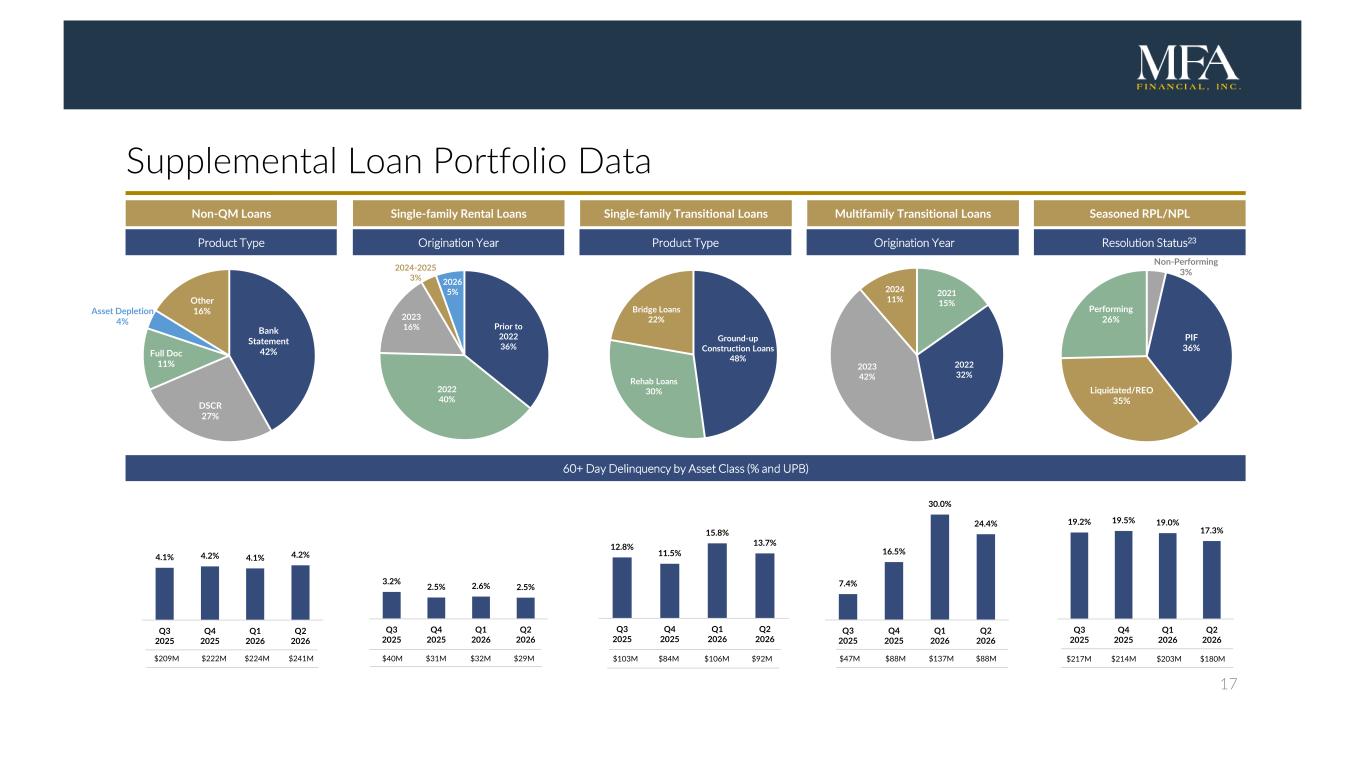
17 2021 15% 2022 32% 2023 42% 2024 11% Prior to 2022 36% 2022 40% 2023 16% 2024-2025 3% 2026 5% 3.2% 2.5% 2.6% 2.5% Q3 2025 Q4 2025 Q1 2026 Q2 2026 Q3 2022 Financial Snapshot Supplemental Loan Portfolio Data Product Type Origination Year Product Type Origination Year 60+ Day Delinquency by Asset Class (% and UPB) Resolution Status23 Non-QM Loans Single-family Rental Loans Single-family Transitional Loans Multifamily Transitional Loans Seasoned RPL/NPL $209M $222M $224M $241M $40M $31M $32M $29M $103M $84M $106M $92M $47M $88M $137M $88M $217M $214M $203M $180M PIF 36% Liquidated/REO 35% Performing 26% Non-Performing 3% Bank Statement 42% DSCR 27% Full Doc 11% Asset Depletion 4% Other 16% 4.1% 4.2% 4.1% 4.2% Q3 2025 Q4 2025 Q1 2026 Q2 2026 7.4% 16.5% 30.0% 24.4% Q3 2025 Q4 2025 Q1 2026 Q2 2026 12.8% 11.5% 15.8% 13.7% Q3 2025 Q4 2025 Q1 2026 Q2 2026 Ground-up Construction Loans 48% Rehab Loans 30% Bridge Loans 22% 19.2% 19.5% 19.0% 17.3% Q3 2025 Q4 2025 Q1 2026 Q2 2026
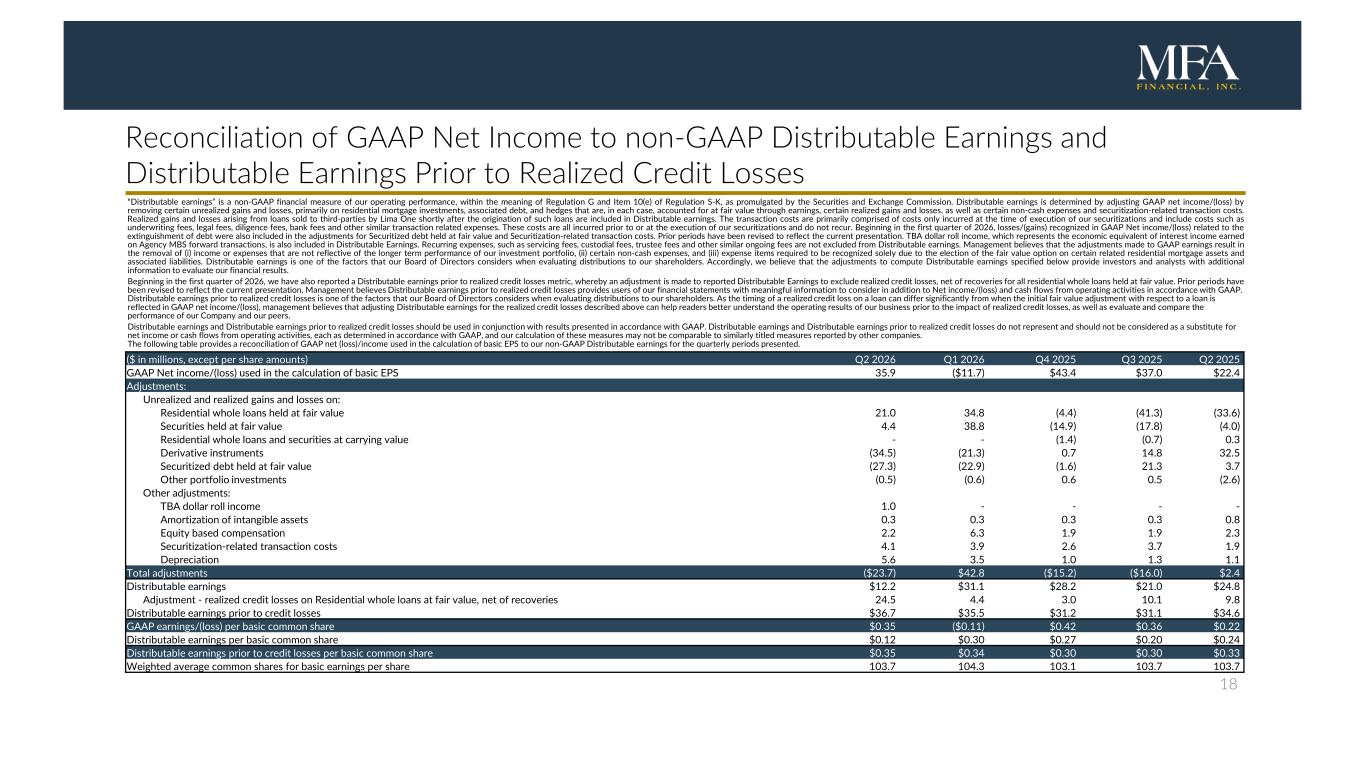
18 “Distributable earnings” is a non-GAAP financial measure of our operating performance, within the meaning of Regulation G and Item 10(e) of Regulation S-K, as promulgated by the Securities and Exchange Commission. Distributable earnings is determined by adjusting GAAP net income/(loss) by removing certain unrealized gains and losses, primarily on residential mortgage investments, associated debt, and hedges that are, in each case, accounted for at fair value through earnings, certain realized gains and losses, as well as certain non-cash expenses and securitization-related transaction costs. Realized gains and losses arising from loans sold to third-parties by Lima One shortly after the origination of such loans are included in Distributable earnings. The transaction costs are primarily comprised of costs only incurred at the time of execution of our securitizations and include costs such as underwriting fees, legal fees, diligence fees, bank fees and other similar transaction related expenses. These costs are all incurred prior to or at the execution of our securitizations and do not recur. Beginning in the first quarter of 2026, losses/(gains) recognized in GAAP Net income/(loss) related to the extinguishment of debt were also included in the adjustments for Securitized debt held at fair value and Securitization-related transaction costs. Prior periods have been revised to reflect the current presentation. TBA dollar roll income, which represents the economic equivalent of interest income earned on Agency MBS forward transactions, is also included in Distributable Earnings. Recurring expenses, such as servicing fees, custodial fees, trustee fees and other similar ongoing fees are not excluded from Distributable earnings. Management believes that the adjustments made to GAAP earnings result in the removal of (i) income or expenses that are not reflective of the longer term performance of our investment portfolio, (ii) certain non-cash expenses, and (iii) expense items required to be recognized solely due to the election of the fair value option on certain related residential mortgage assets and associated liabilities. Distributable earnings is one of the factors that our Board of Directors considers when evaluating distributions to our shareholders. Accordingly, we believe that the adjustments to compute Distributable earnings specified below provide investors and analysts with additional information to evaluate our financial results. Beginning in the first quarter of 2026, we have also reported a Distributable earnings prior to realized credit losses metric, whereby an adjustment is made to reported Distributable Earnings to exclude realized credit losses, net of recoveries for all residential whole loans held at fair value. Prior periods have been revised to reflect the current presentation. Management believes Distributable earnings prior to realized credit losses provides users of our financial statements with meaningful information to consider in addition to Net income/(loss) and cash flows from operating activities in accordance with GAAP. Distributable earnings prior to realized credit losses is one of the factors that our Board of Directors considers when evaluating distributions to our shareholders. As the timing of a realized credit loss on a loan can differ significantly from when the initial fair value adjustment with respect to a loan is reflected in GAAP net income/(loss), management believes that adjusting Distributable earnings for the realized credit losses described above can help readers better understand the operating results of our business prior to the impact of realized credit losses, as well as evaluate and compare the performance of our Company and our peers. Distributable earnings and Distributable earnings prior to realized credit losses should be used in conjunction with results presented in accordance with GAAP. Distributable earnings and Distributable earnings prior to realized credit losses do not represent and should not be considered as a substitute for net income or cash flows from operating activities, each as determined in accordance with GAAP, and our calculation of these measures may not be comparable to similarly titled measures reported by other companies. The following table provides a reconciliation of GAAP net (loss)/income used in the calculation of basic EPS to our non-GAAP Distributable earnings for the quarterly periods presented. Reconciliation of GAAP Net Income to non-GAAP Distributable Earnings and Distributable Earnings Prior to Realized Credit Losses ($ in millions, except per share amounts) Q2 2026 Q1 2026 Q4 2025 Q3 2025 Q2 2025 GAAP Net income/(loss) used in the calculation of basic EPS 35.9 ($11.7) $43.4 $37.0 $22.4 Adjustments: Unrealized and realized gains and losses on: Residential whole loans held at fair value 21.0 34.8 (4.4) (41.3) (33.6) Securities held at fair value 4.4 38.8 (14.9) (17.8) (4.0) Residential whole loans and securities at carrying value - - (1.4) (0.7) 0.3 Derivative instruments (34.5) (21.3) 0.7 14.8 32.5 Securitized debt held at fair value (27.3) (22.9) (1.6) 21.3 3.7 Other portfolio investments (0.5) (0.6) 0.6 0.5 (2.6) Other adjustments: TBA dollar roll income 1.0 - - - - Amortization of intangible assets 0.3 0.3 0.3 0.3 0.8 Equity based compensation 2.2 6.3 1.9 1.9 2.3 Securitization-related transaction costs 4.1 3.9 2.6 3.7 1.9 Depreciation 5.6 3.5 1.0 1.3 1.1 Total adjustments ($23.7) $42.8 ($15.2) ($16.0) $2.4 Distributable earnings $12.2 $31.1 $28.2 $21.0 $24.8 Adjustment - realized credit losses on Residential whole loans at fair value, net of recoveries 24.5 4.4 3.0 10.1 9.8 Distributable earnings prior to credit losses $36.7 $35.5 $31.2 $31.1 $34.6 GAAP earnings/(loss) per basic common share $0.35 ($0.11) $0.42 $0.36 $0.22 Distributable earnings per basic common share $0.12 $0.30 $0.27 $0.20 $0.24 Distributable earnings prior to credit losses per basic common share $0.35 $0.34 $0.30 $0.30 $0.33 Weighted average common shares for basic earnings per share 103.7 104.3 103.1 103.7 103.7
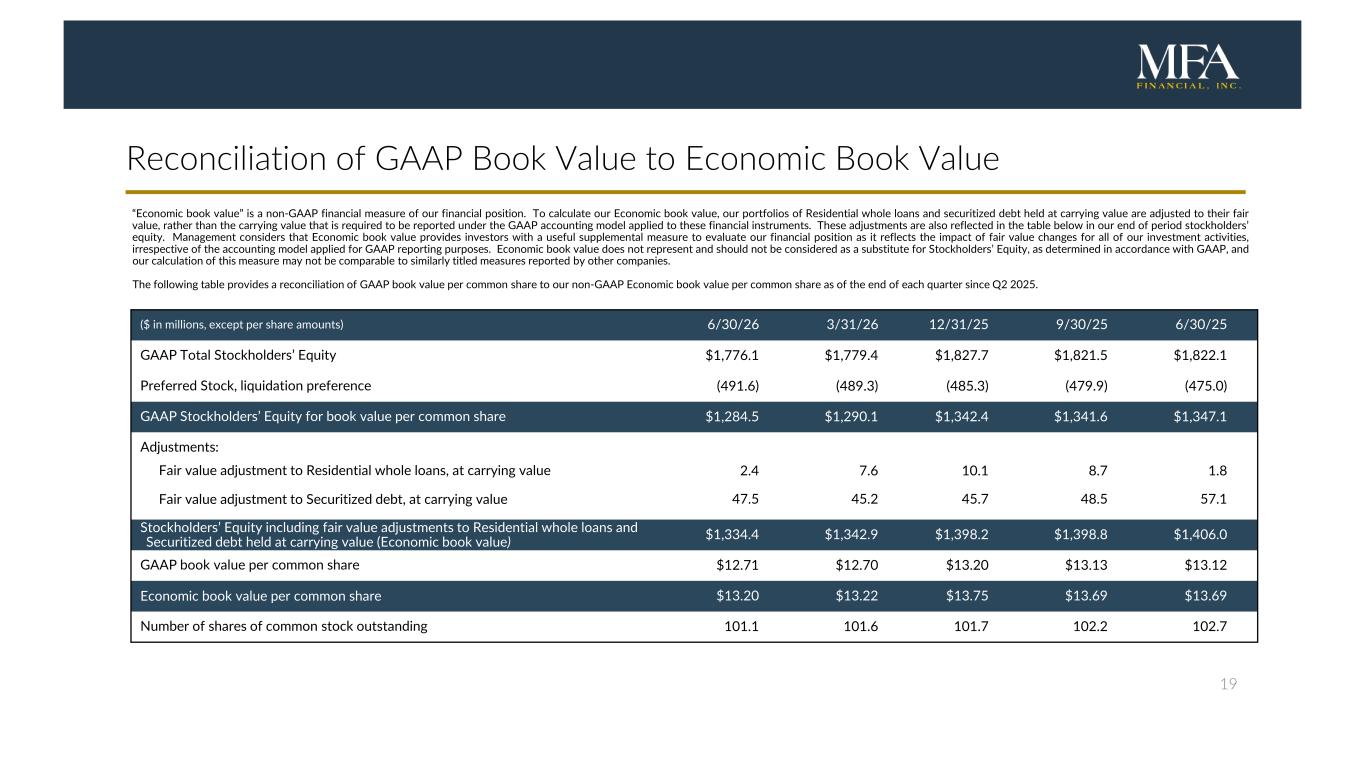
19 Reconciliation of GAAP Book Value to Economic Book Value “Economic book value” is a non-GAAP financial measure of our financial position. To calculate our Economic book value, our portfolios of Residential whole loans and securitized debt held at carrying value are adjusted to their fair value, rather than the carrying value that is required to be reported under the GAAP accounting model applied to these financial instruments. These adjustments are also reflected in the table below in our end of period stockholders’ equity. Management considers that Economic book value provides investors with a useful supplemental measure to evaluate our financial position as it reflects the impact of fair value changes for all of our investment activities, irrespective of the accounting model applied for GAAP reporting purposes. Economic book value does not represent and should not be considered as a substitute for Stockholders’ Equity, as determined in accordance with GAAP, and our calculation of this measure may not be comparable to similarly titled measures reported by other companies. The following table provides a reconciliation of GAAP book value per common share to our non-GAAP Economic book value per common share as of the end of each quarter since Q2 2025. ($ in millions, except per share amounts) 6/30/26 3/31/26 12/31/25 9/30/25 6/30/25 GAAP Total Stockholders’ Equity $1,776.1 $1,779.4 $1,827.7 $1,821.5 $1,822.1 Preferred Stock, liquidation preference (491.6) (489.3) (485.3) (479.9) (475.0) GAAP Stockholders’ Equity for book value per common share $1,284.5 $1,290.1 $1,342.4 $1,341.6 $1,347.1 Adjustments: Fair value adjustment to Residential whole loans, at carrying value 2.4 7.6 10.1 8.7 1.8 Fair value adjustment to Securitized debt, at carrying value 47.5 45.2 45.7 48.5 57.1 Stockholders’ Equity including fair value adjustments to Residential whole loans and Securitized debt held at carrying value (Economic book value) $1,334.4 $1,342.9 $1,398.2 $1,398.8 $1,406.0 GAAP book value per common share $12.71 $12.70 $13.20 $13.13 $13.12 Economic book value per common share $13.20 $13.22 $13.75 $13.69 $13.69 Number of shares of common stock outstanding 101.1 101.6 101.7 102.2 102.7
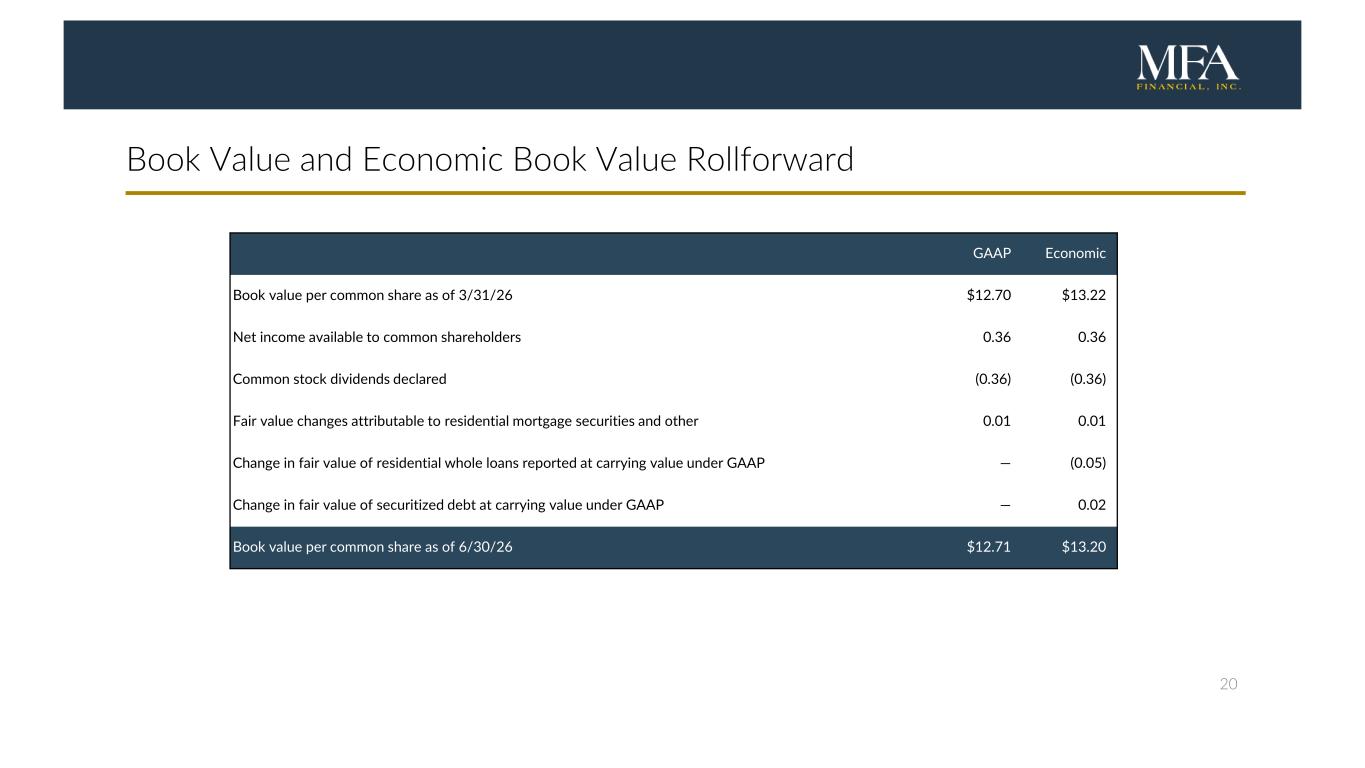
20 Book Value and Economic Book Value Rollforward GAAP Economic Book value per common share as of 3/31/26 $12.70 $13.22 Net income available to common shareholders 0.36 0.36 Common stock dividends declared (0.36) (0.36) Fair value changes attributable to residential mortgage securities and other 0.01 0.01 Change in fair value of residential whole loans reported at carrying value under GAAP — (0.05) Change in fair value of securitized debt at carrying value under GAAP — 0.02 Book value per common share as of 6/30/26 $12.71 $13.20
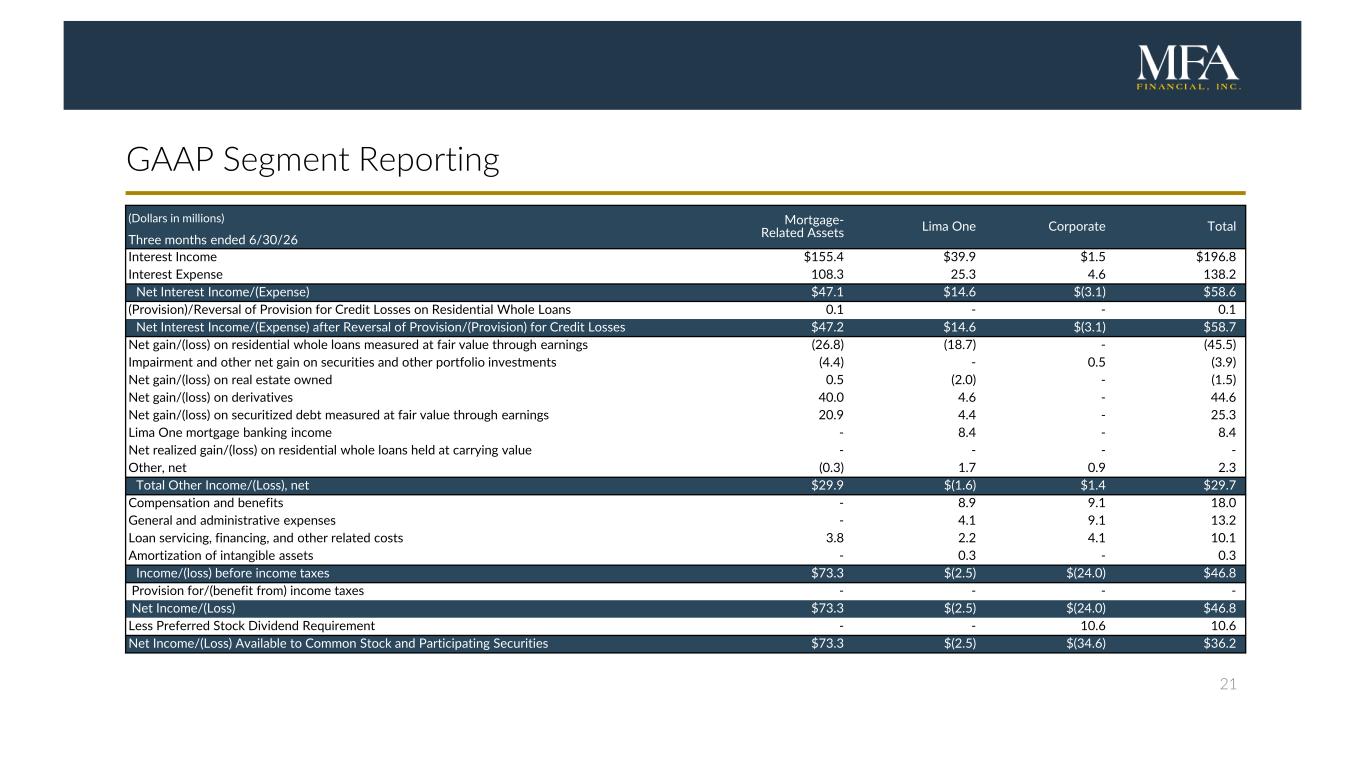
21 GAAP Segment Reporting (Dollars in millions) Mortgage- Related Assets Lima One Corporate Total Three months ended 6/30/26 Interest Income $155.4 $39.9 $1.5 $196.8 Interest Expense 108.3 25.3 4.6 138.2 Net Interest Income/(Expense) $47.1 $14.6 $(3.1) $58.6 (Provision)/Reversal of Provision for Credit Losses on Residential Whole Loans 0.1 - - 0.1 Net Interest Income/(Expense) after Reversal of Provision/(Provision) for Credit Losses $47.2 $14.6 $(3.1) $58.7 Net gain/(loss) on residential whole loans measured at fair value through earnings (26.8) (18.7) - (45.5) Impairment and other net gain on securities and other portfolio investments (4.4) - 0.5 (3.9) Net gain/(loss) on real estate owned 0.5 (2.0) - (1.5) Net gain/(loss) on derivatives 40.0 4.6 - 44.6 Net gain/(loss) on securitized debt measured at fair value through earnings 20.9 4.4 - 25.3 Lima One mortgage banking income - 8.4 - 8.4 Net realized gain/(loss) on residential whole loans held at carrying value - - - - Other, net (0.3) 1.7 0.9 2.3 Total Other Income/(Loss), net $29.9 $(1.6) $1.4 $29.7 Compensation and benefits - 8.9 9.1 18.0 General and administrative expenses - 4.1 9.1 13.2 Loan servicing, financing, and other related costs 3.8 2.2 4.1 10.1 Amortization of intangible assets - 0.3 - 0.3 Income/(loss) before income taxes $73.3 $(2.5) $(24.0) $46.8 Provision for/(benefit from) income taxes - - - - Net Income/(Loss) $73.3 $(2.5) $(24.0) $46.8 Less Preferred Stock Dividend Requirement - - 10.6 10.6 Net Income/(Loss) Available to Common Stock and Participating Securities $73.3 $(2.5) $(34.6) $36.2
22 Endnotes 1) Economic book value (EBV) is a non-GAAP financial measure. Refer to slide 19 for further information regarding the calculation of this measure and a reconciliation to GAAP book value. 2) Total economic return is calculated as the quarterly change in EBV plus common dividends declared during the quarter divided by EBV at the start of the quarter. 3) Recourse leverage is the ratio of MFA’s financing liabilities (excluding non-recourse debt) to net equity. Including securitized debt, MFA’s overall leverage ratio at June 30, 2026 was 6.6x. 4) GAAP net income is presented per basic and diluted common share. 5) Distributable earnings is a non-GAAP financial measure. Refer to slide 18 for further information regarding the calculation of this measure and a reconciliation to GAAP net income. Distributable earnings is presented per basic common share. 6) Distributable earnings prior to realized credit losses is a non-GAAP financial measure. Refer to slide 17 for further information regarding the calculation of this measure and a reconciliation to GAAP net income. 7) Includes $714M of Agency MBS plus forward contracts in the TBA securities market with a notional amount of $178M. 8) Origination amount is based on the maximum loan amount, which includes amounts initially funded plus any committed but undrawn amounts. $185M of funded originations occurred during Q2 2026 and $84M of draws were funded during Q2 2026 on previously originated Transitional loans. 9) Liquidity includes $141.2M of unrestricted cash and $294.1M of unpledged Agency MBS at June 30, 2026. 10) G&A figures for 2024 and 2025 represent quarterly averages during those years. $26M figure for Q2 2026 excludes $5M of one-time accelerated depreciation for FF&E at former corporate headquarters. Inclusive of that accelerated depreciation, G&A expense for Q2 2026 was $31M. 11) Amounts presented reflect the aggregation of fair value and carrying value amounts as presented in MFA’s consolidated balance sheet at June 30, 2026. 12) Non-MTM refers to financing arrangements not subject to margin calls based on changes in the fair value of the financed residential whole loans. Such agreements may experience changes in advance rates or collateral eligibility due to factors such as changes in the delinquency status of the financed residential whole loans. 13) Loan-to-value (LTV) ratio reflects principal amortization and estimated home price appreciation (or depreciation). Zillow Home Value Index (ZHVI) is utilized to estimate updated LTVs for Non-QM, SFR and Seasoned RPL/NPL assets. For Transitional loans, LTV reflects either the current unpaid principal balance (UPB) divided by the most recent as-is property valuation available, which may be at the time of origination, or the maximum UPB divided by the most recent after repaired value (ARV) available, which may be at the time of origination. 14) State concentration measured by loan balance. All states in “Other” category have concentrations below 4%. 15) Total also includes Agency-eligible investor loans, which had a fair value of $49M as of June 30, 2026. 16) CPR includes all principal repayments. 17) Balance sheet carrying value of real estate owned (REO) properties at June 30, 2026. 18) Undrawn construction funds for performing Transitional loans at June 30, 2026. Borrowers must be current in order to receive unfunded commitments. 19) Percentage of Transitional loan portfolios extended beyond original maturity date at June 30, 2026. 20) Current coupon Agency MBS spread over blended 5Y and 10Y Treasury yields. Data sourced from Bloomberg and presented in basis points. 21) Collateral UPB includes cash for Transitional loan securitizations. 22) Bonds sold relative to certificates issued. 23) Status at June 30, 2026 of all Seasoned RPL/NPL loans ever acquired. Non-performing status includes all active loans greater than 60 days delinquent. Liquidated/REO status includes both sold and active REO properties as well as short payoff liquidations and loans sold to third-parties.