Operator
Good day, and thank you for standing by. Welcome to the Bank of Hawaii Corporation's second quarter, 2026 earnings conference call. At this time, all participants are in a listen-only mode. After the speaker's presentation, there will be a question and answer session. To ask a question during the session, you will need to press star 11 on your telephone and wait for your name to be announced. To withdraw your question, press star 11 again. Please be advised that today's conference is being recorded. I would now like to hand the conference over to your speaker today, Chang Park, Executive Vice President, Executive Director of Financial Performance and Investor Relations. Please go ahead.
Good morning and good afternoon. Thank you for joining us today for our second quarter 2026 earnings conference call. Joining me today is our President and CEO, Jim Polk, CFO of Brad Sattenberg, Chief Risk Officer Brad Sherison, and Manager of Investor Relations, Patricia Lam. Before we get started, I want to remind you that today's conference call will contain some forward-looking statements. And while we believe our assumptions are reasonable, the actual results may differ materially from those projected. During the call today, we'll be referencing a slide presentation as well as the earnings release. Both of these are available on our website, boh.com, under the Investor Relations link. And now I would like to turn the call over to Jim.
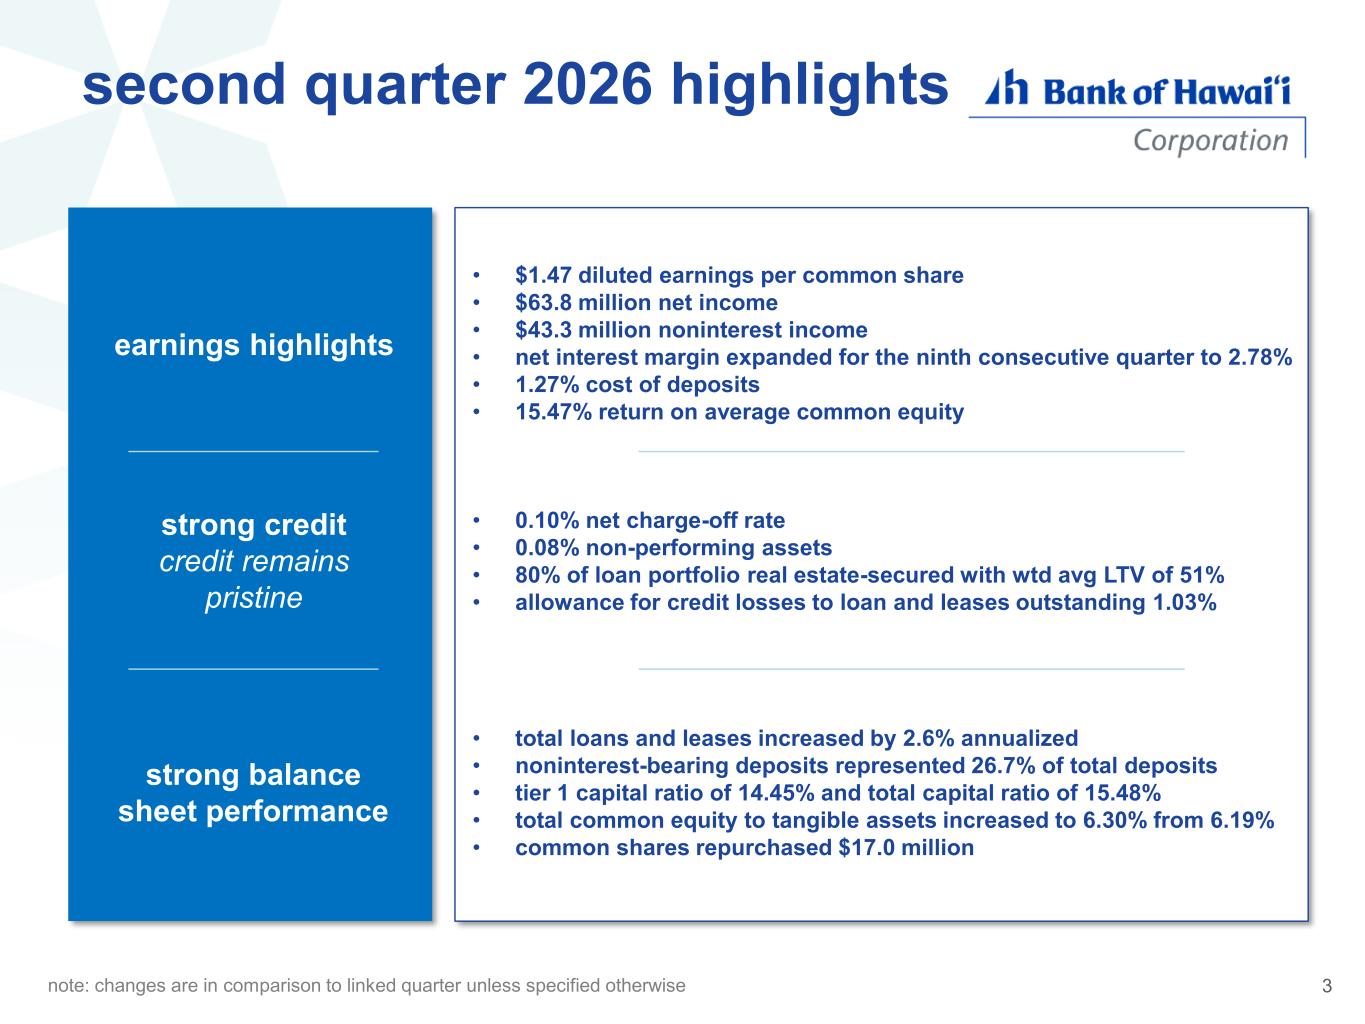
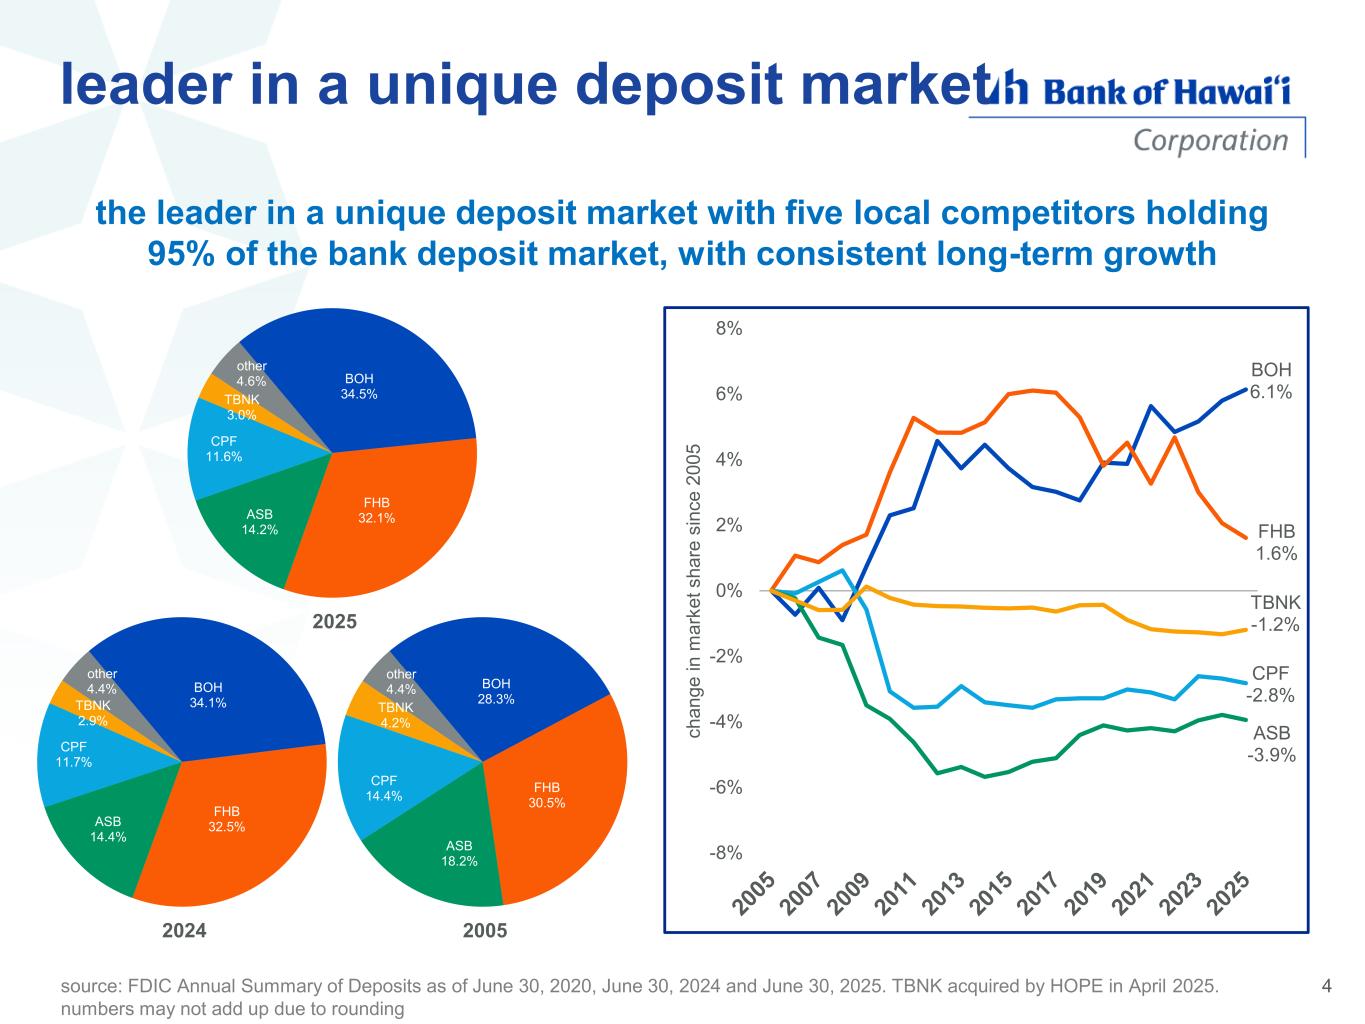
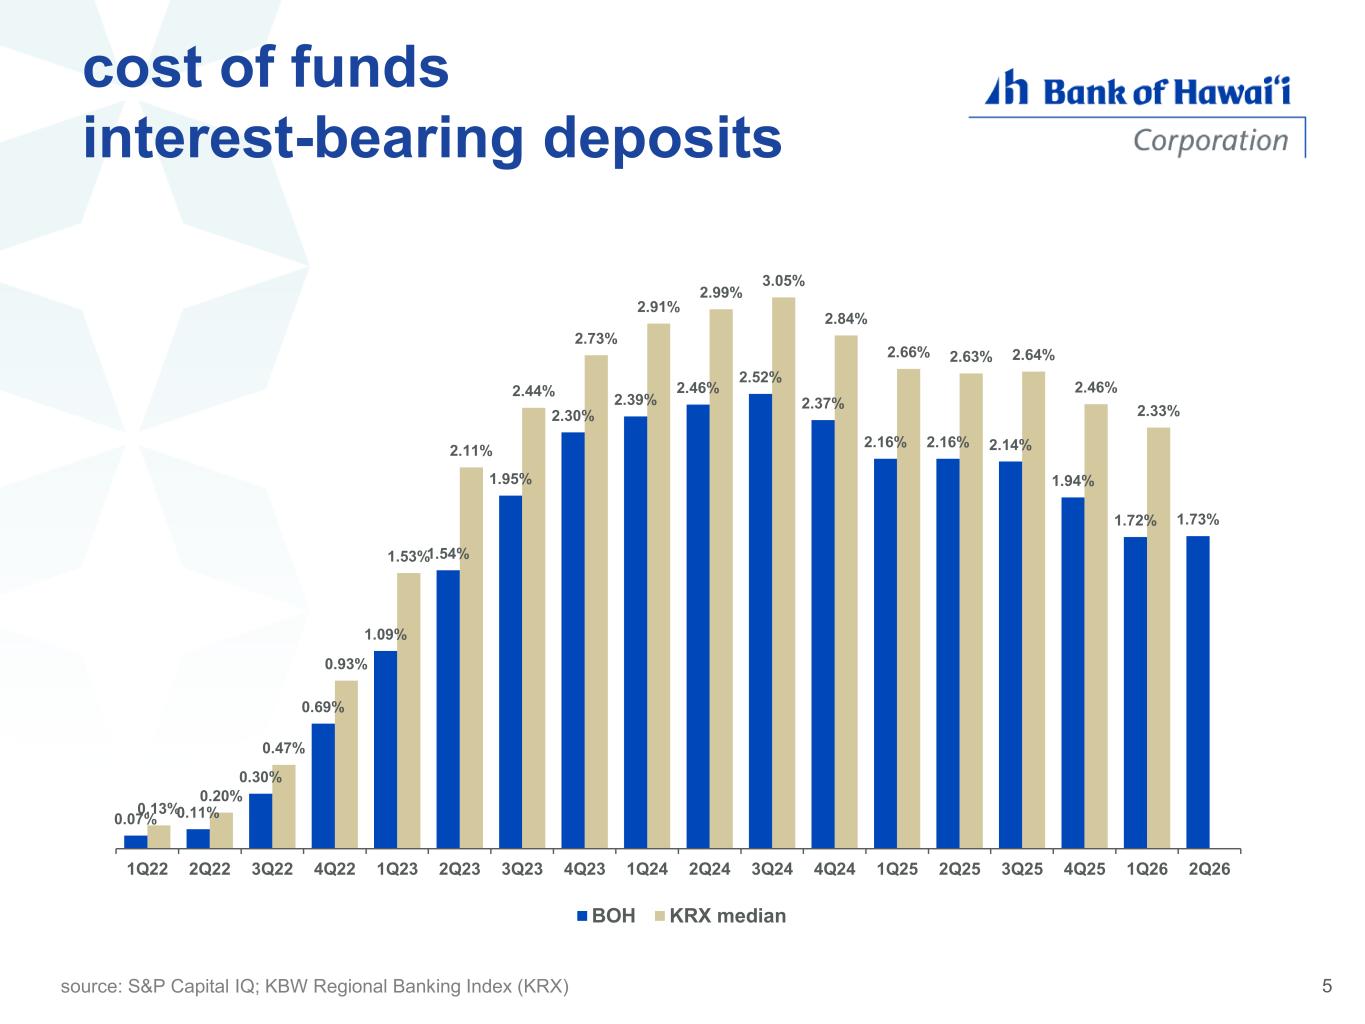
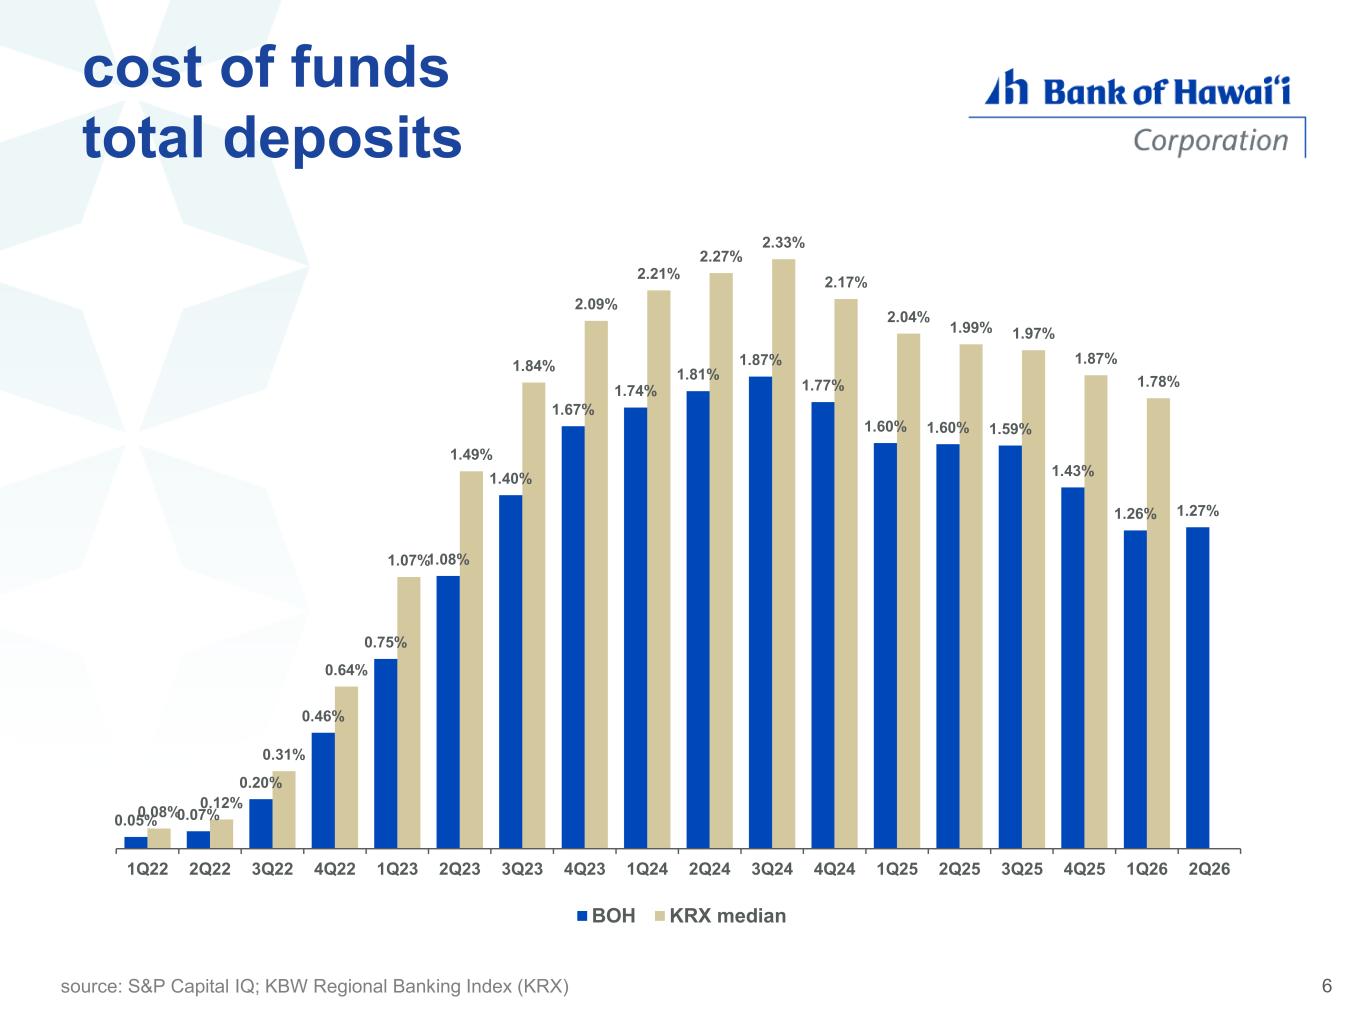
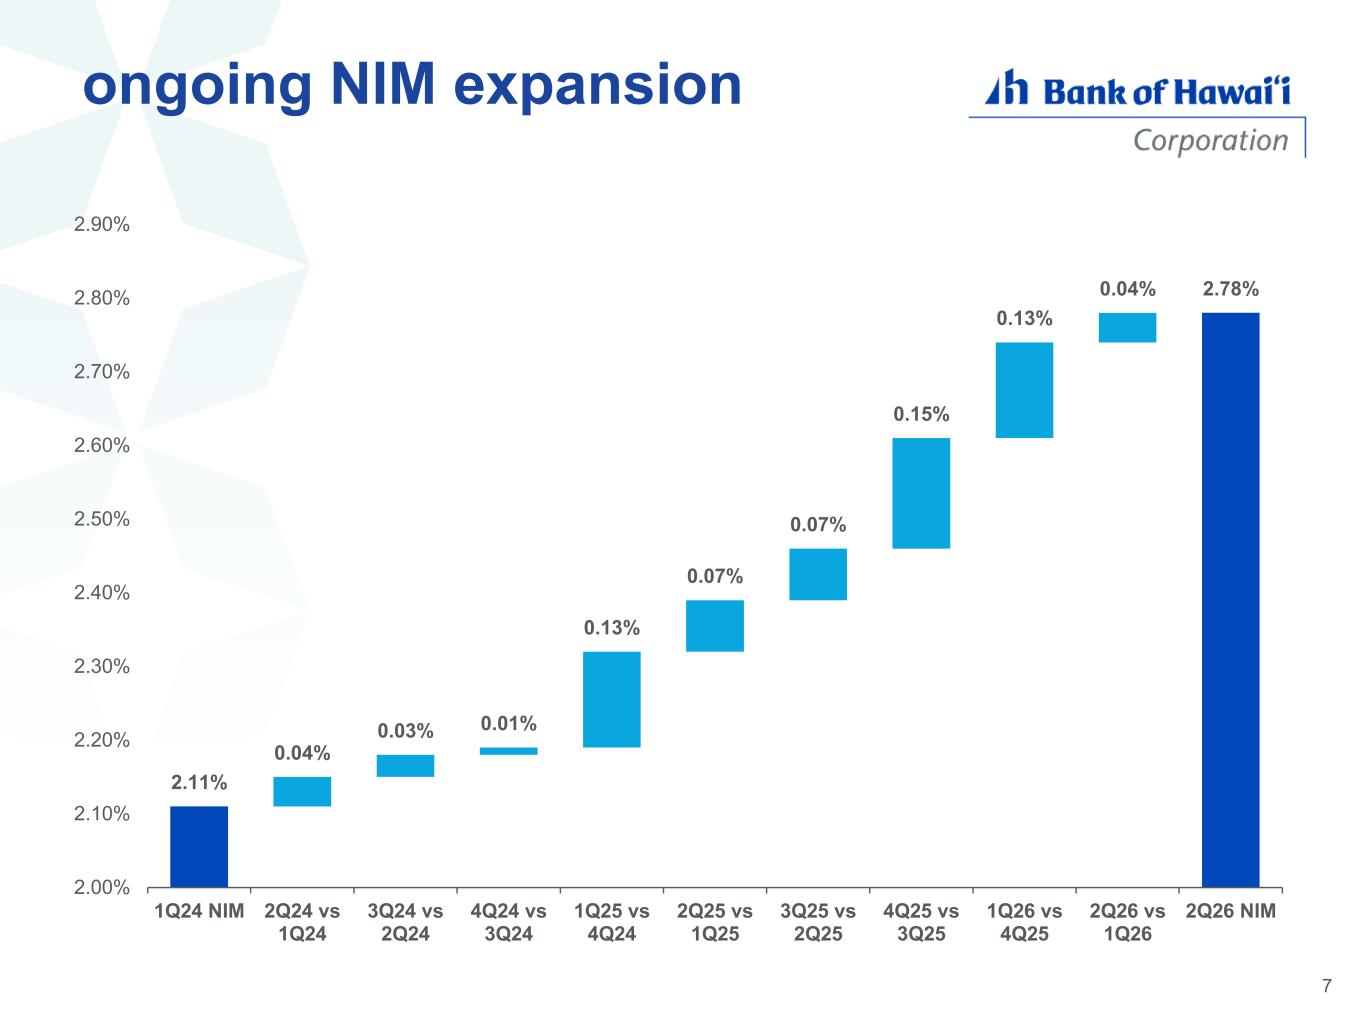
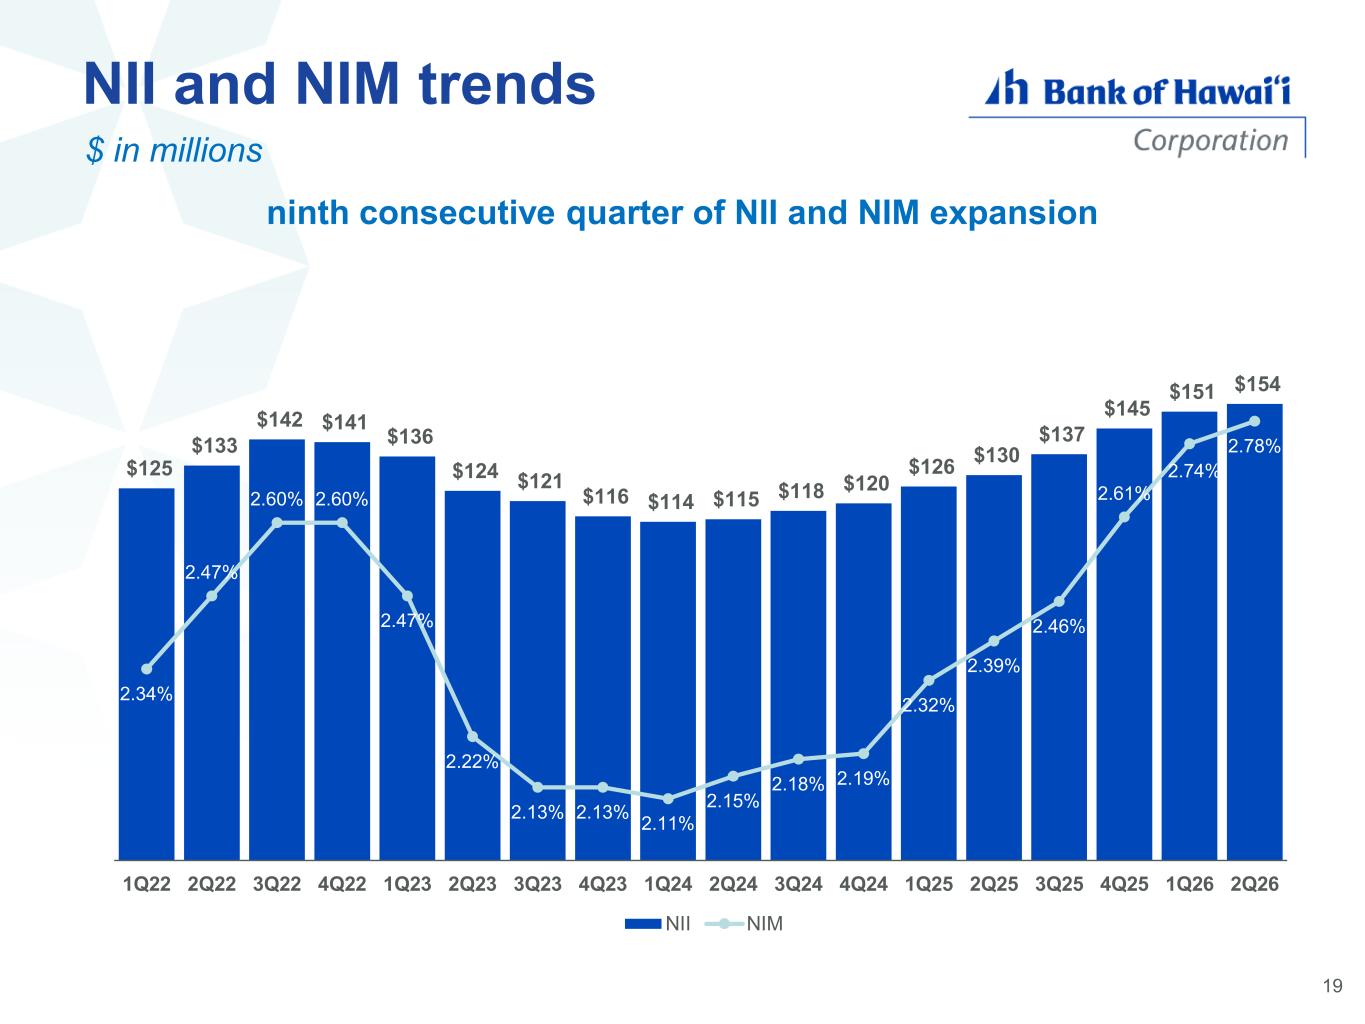
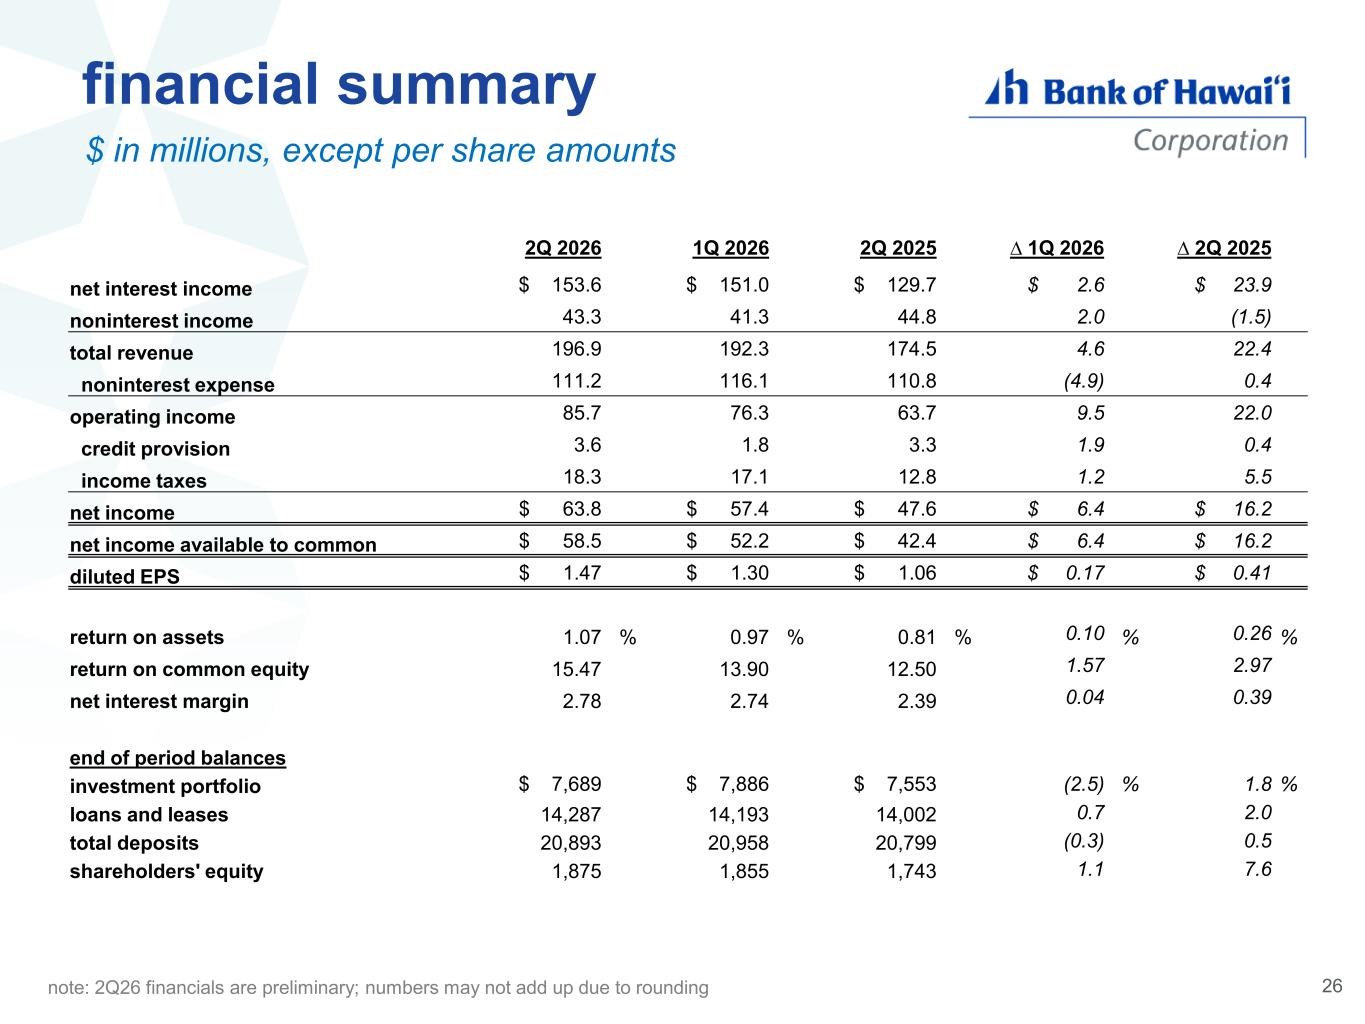
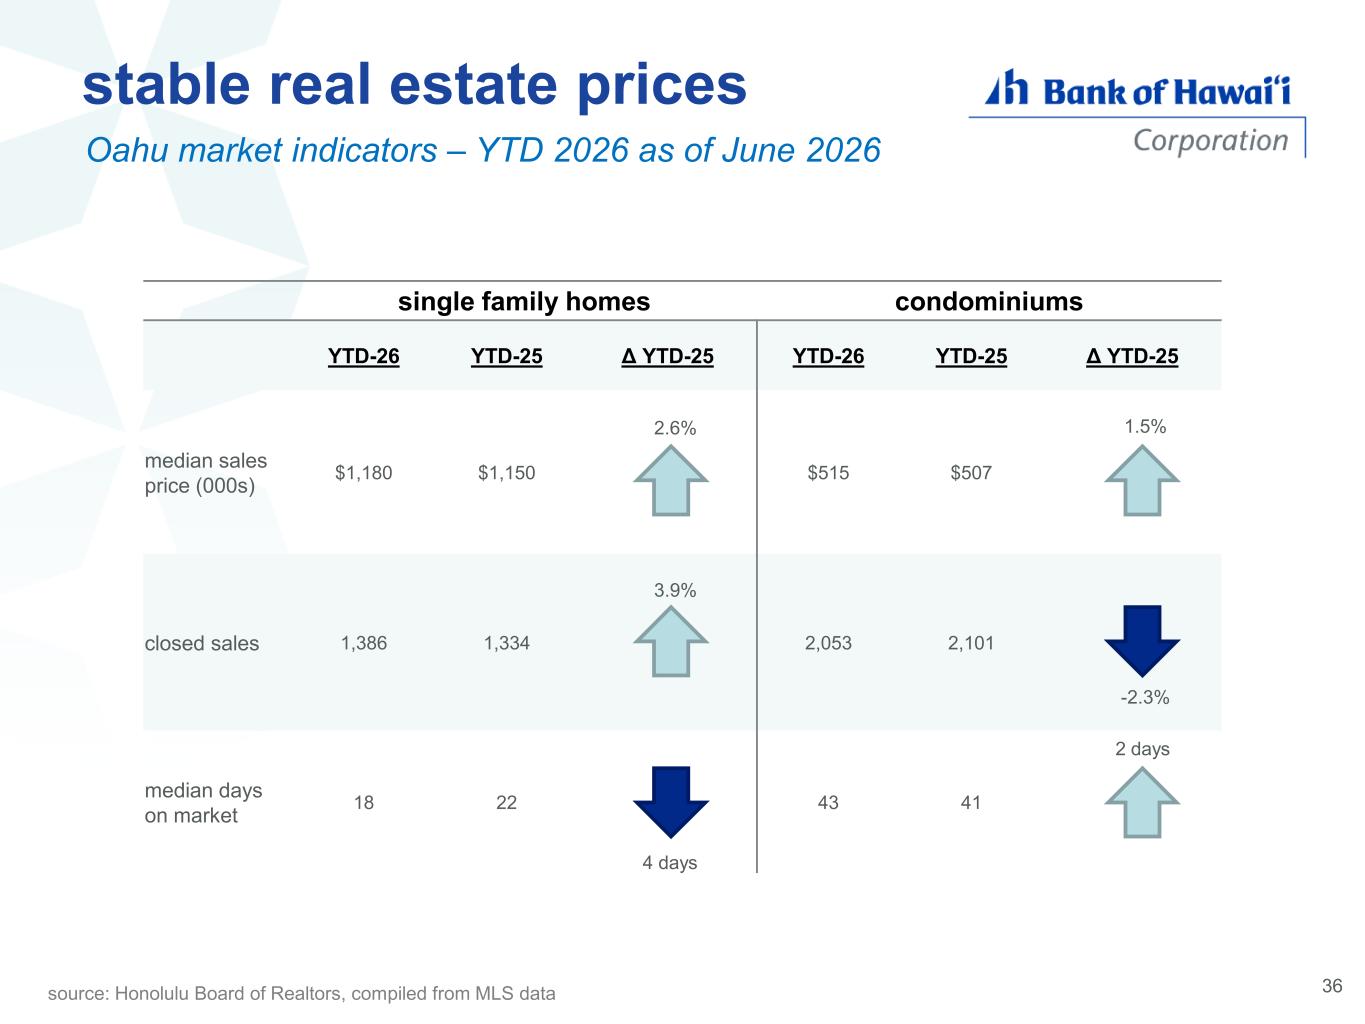
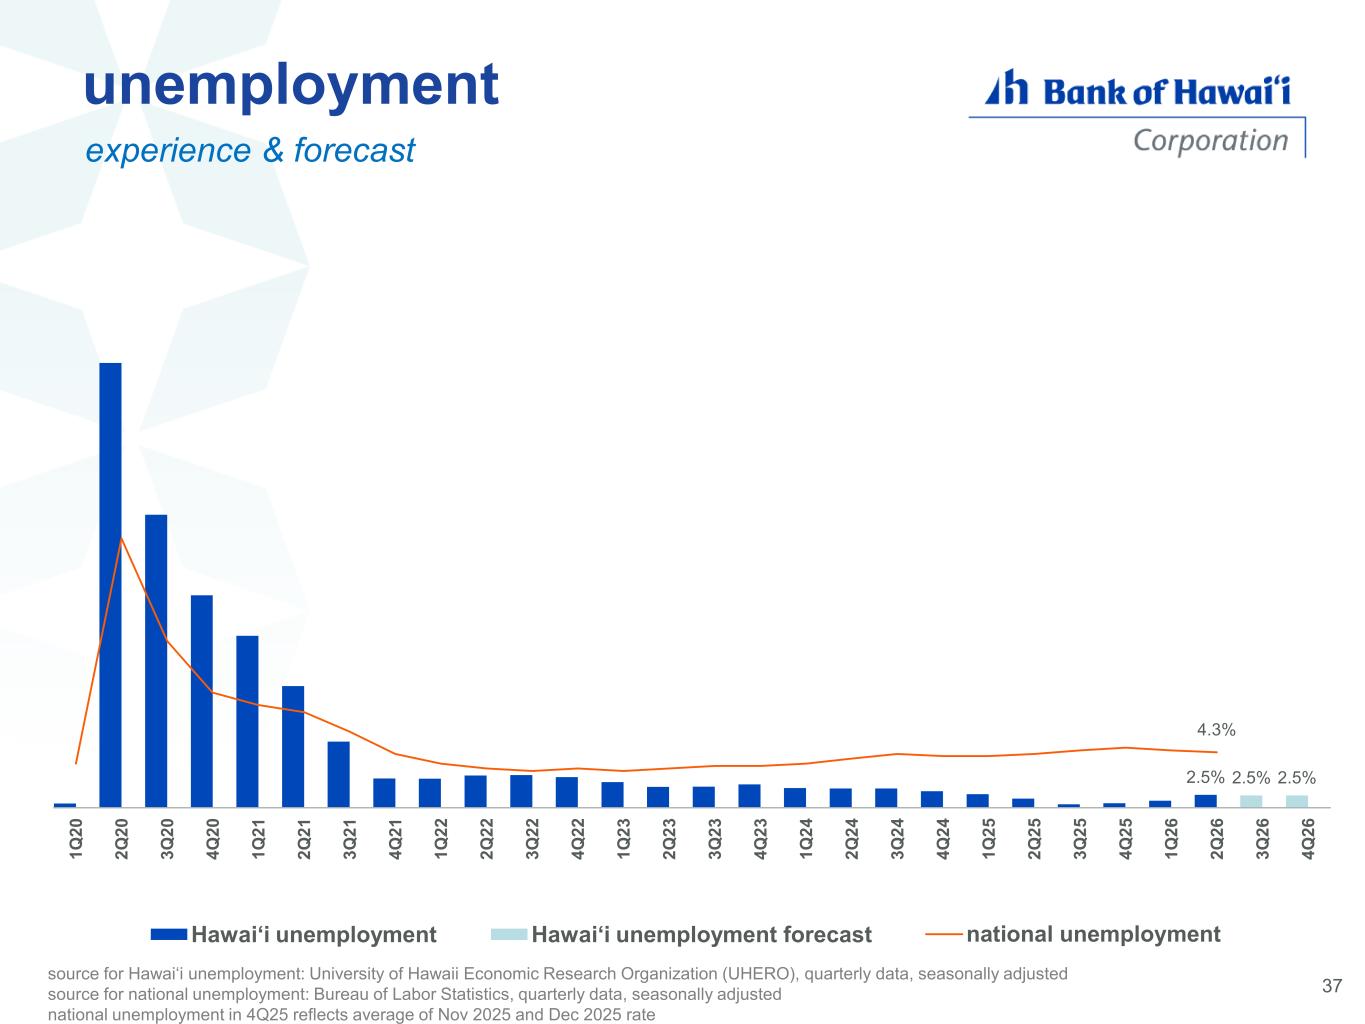
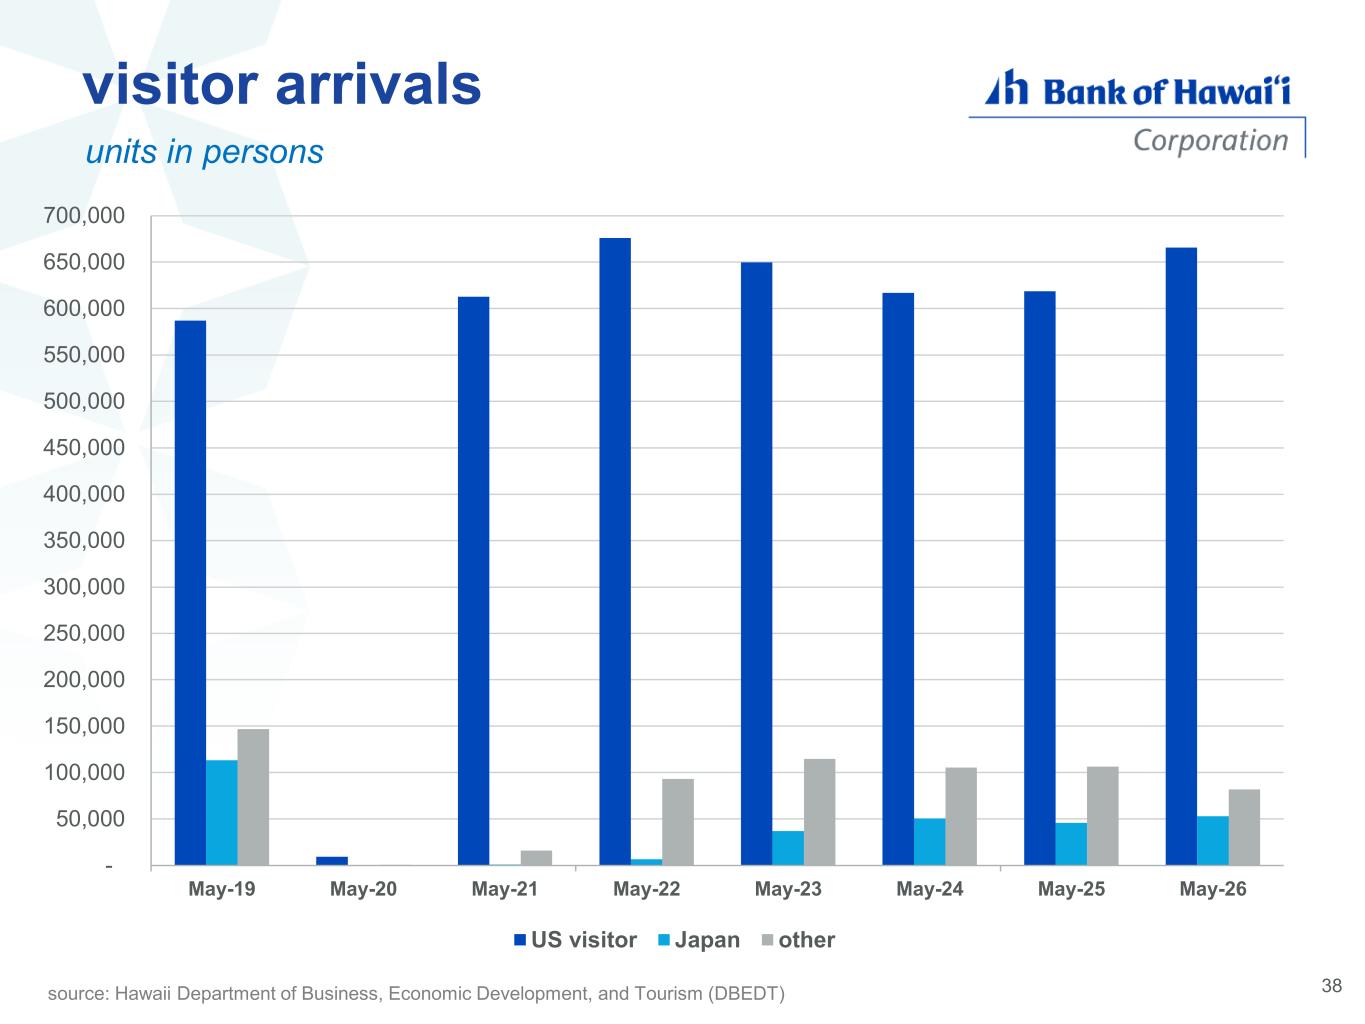
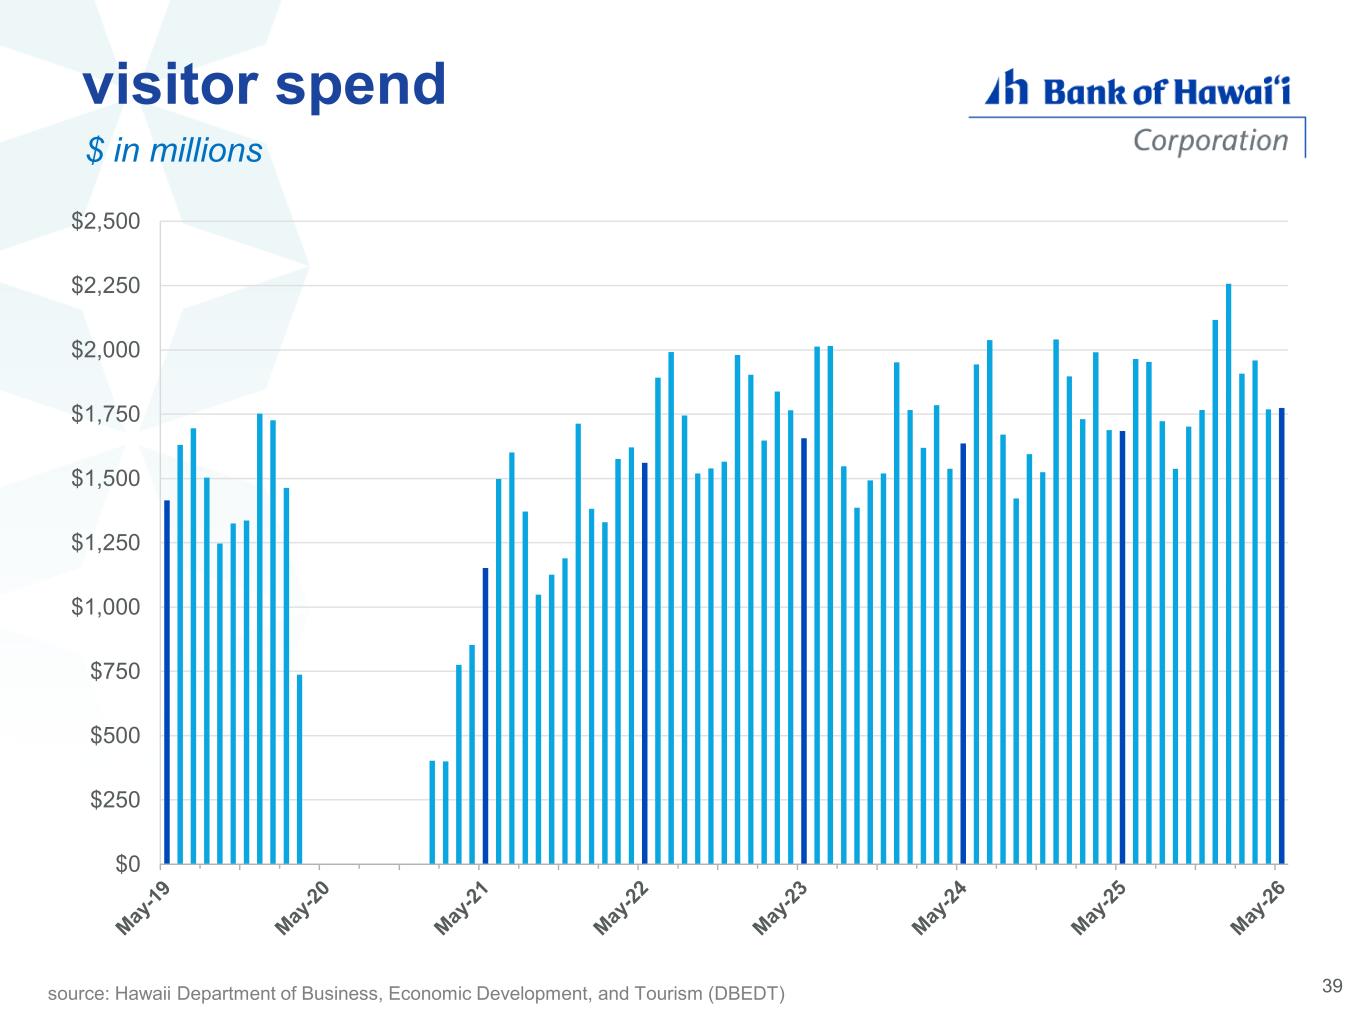
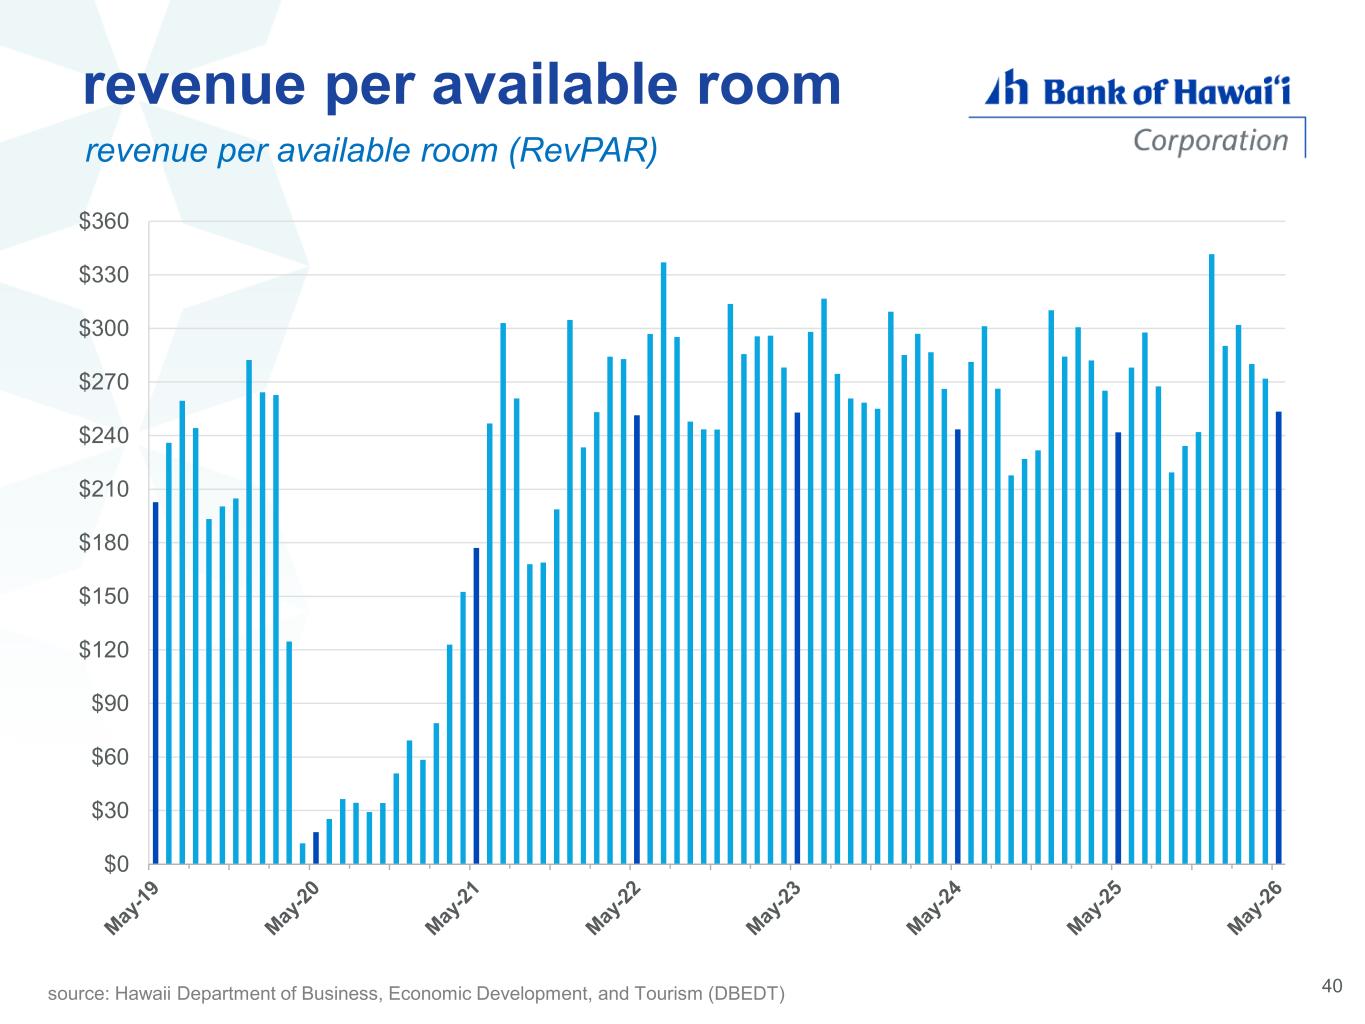
Thanks, Chang. Good morning and good afternoon, everyone, and thank you for joining us today. Bank of Hawaii delivered another solid quarter, reflecting continued progress in the underlying earnings power of the franchise. For the second quarter, we reported diluted earnings per share of $1.47 and net income of $63.8 million, up 13% and 11% respectively from the prior quarter. Return on average common equity improved to 15.5%. Net interest income increased to $153.6 million and our net interest margin expanded by four basis points to 2.78 percent. This marked our ninth consecutive quarter of margin expansion. The improvement reflected the continued repricing of our fixed rate assets along with disciplined deposit pricing. Our average cost of deposits remained essentially stable at 127 basis points. The interest rate environment continues to evolve with rates now expected to remain elevated for longer. We believe our balance sheet is well position for this environment as higher rates support earning asset yields and the continued repricing of our fixed rate portfolio. At the same time, the competitive environment for deposits remains elevated as customers continue to prioritize yield, which may limit opportunities for deposit cost improvement in the near term. As we have discussed previously, the second quarter is typically a seasonally lower period for deposits at Bank of Hawaii, and this quarter followed that pattern. Average deposits declined modestly from the prior quarter. At quarter-end, non-interest bearing deposits continued to represent approximately 27 percent of total deposits. Our deposit franchise remains one of Bank of Hawaii's most important structural advantages. Our leading market position, trusted brand, diversified customer base, and deep relationships across our markets provides a stable core funding base. These advantages allow us to manage pricing thoughtfully while continuing to meet our customers' needs. Based on our performance through the first half of the year and our current interest rate assumptions, we continue to trend toward a net interest margin approaching 2.9% by year end. While the composition of margin opportunity has shifted somewhat in the current rate environment, we remain confident in the earnings trajectory of the balance sheet. Turning to lending, total loans increased $94 million dollars during the quarter, representing annualized growth of approximately 2.6%. CNI and residential lending led the increase, while CRE growth was affected by payoff activity and the timing of deal closings. Residential mortgage growth benefited from the completion and closing of a large condominium project. Looking ahead, our commercial pipeline remains encouraging. On the consumer side, however, elevated interest rates and the absence of similar residential project closings are likely to moderate third-quarter growth in consumer. We continue to expect full-year loan growth in the lower, mid-single-digit range. Credit quality continues to be strong, and Brad will provide some additional details shortly. We also made progress on the strategic priorities we discussed last quarter. In wealth management, we are strengthening coordination across commercial banking, the private bank, Banco advisors, and our broader advisory capabilities. The Center for Family Business and Entrepreneurs, which opened in April, continues to develop its client pipeline around succession and estate planning, business valuation, merger and acquisitions, and other complex needs. Bank of Hawaii is uniquely positioned in our markets to bring together capabilities to help clients navigate these consequential financial and business decisions. Beyond these initiatives, our teams remain focused on disciplined execution, protecting our strong balance sheet, deepening customer relationships, investing in our people and technology, and supporting the communities we serve. And although the interest rate outlook continues to evolve, the fundamental strengths of Bank of Hawaii remain unchanged. A leading deposit franchise, a trusted brand, deep customer relationships, strong credit quality, and a conservatively positioned balance sheet. These strengths give us confidence in our ability to perform across a range of economic and interest rate environments. Turning to the economic outlook, Hawaii's economy remains resilient. Supported by low unemployment, healthy visitor spending, strong construction activity, and military investment, the Department of Business, Economic Development, and Tourism currently projects real economic growth of 1.6% in 2026. At the same time, we continue to monitor inflation, energy costs, consumer confidence, travel demand, and broader geopolitical and fiscal developments. With that said, I'll turn the call over to Brad Shearson to discuss credit. Brad Satenberg will then review our financial results in greater detail, after which we'll be pleased to take your questions.
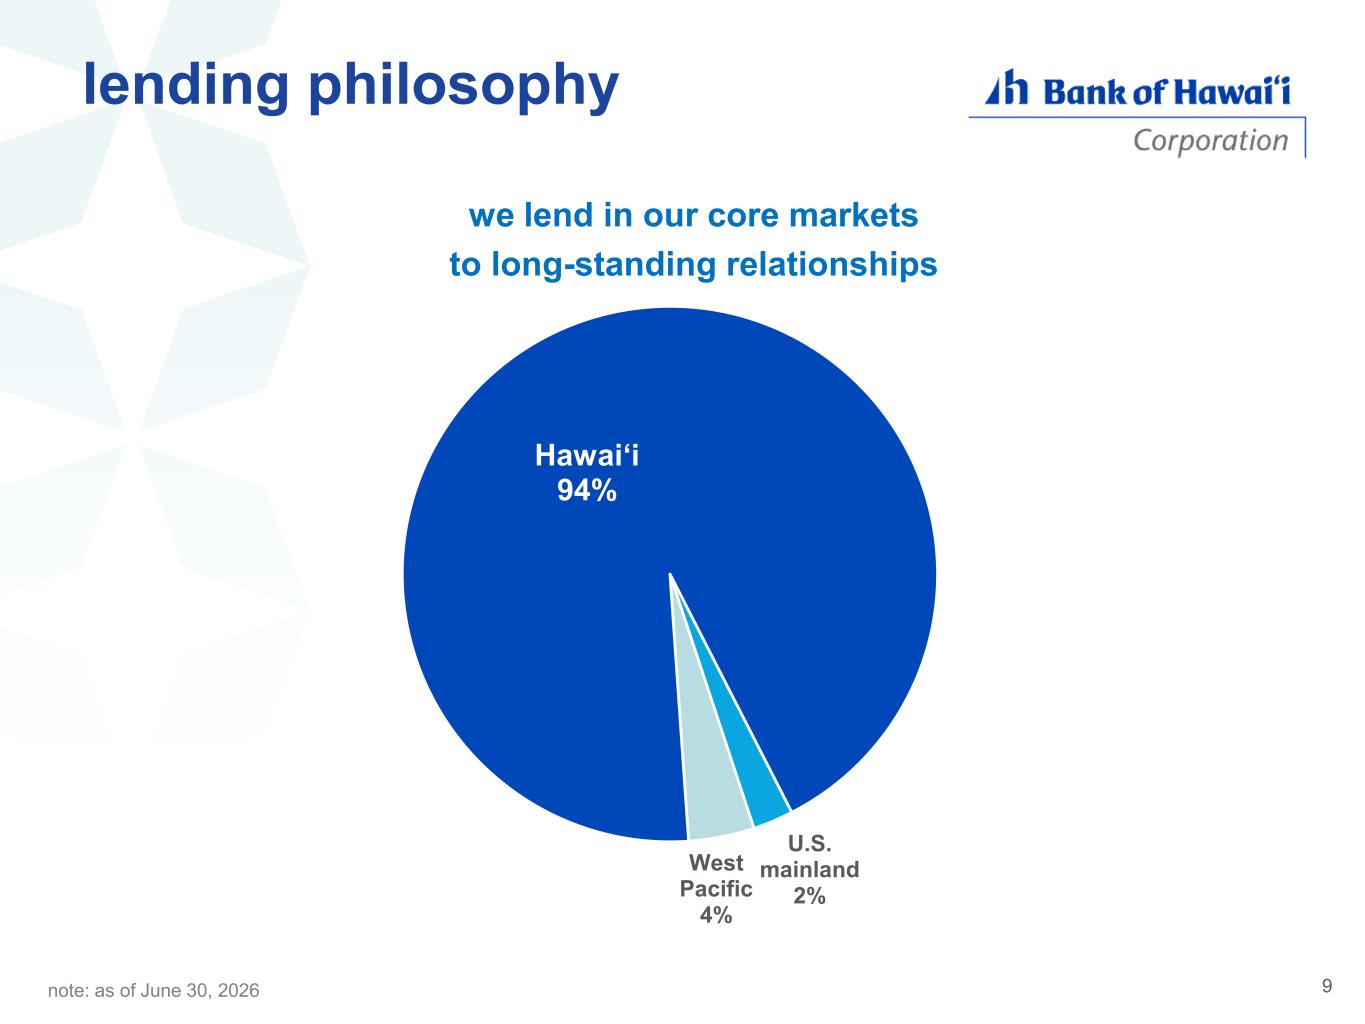
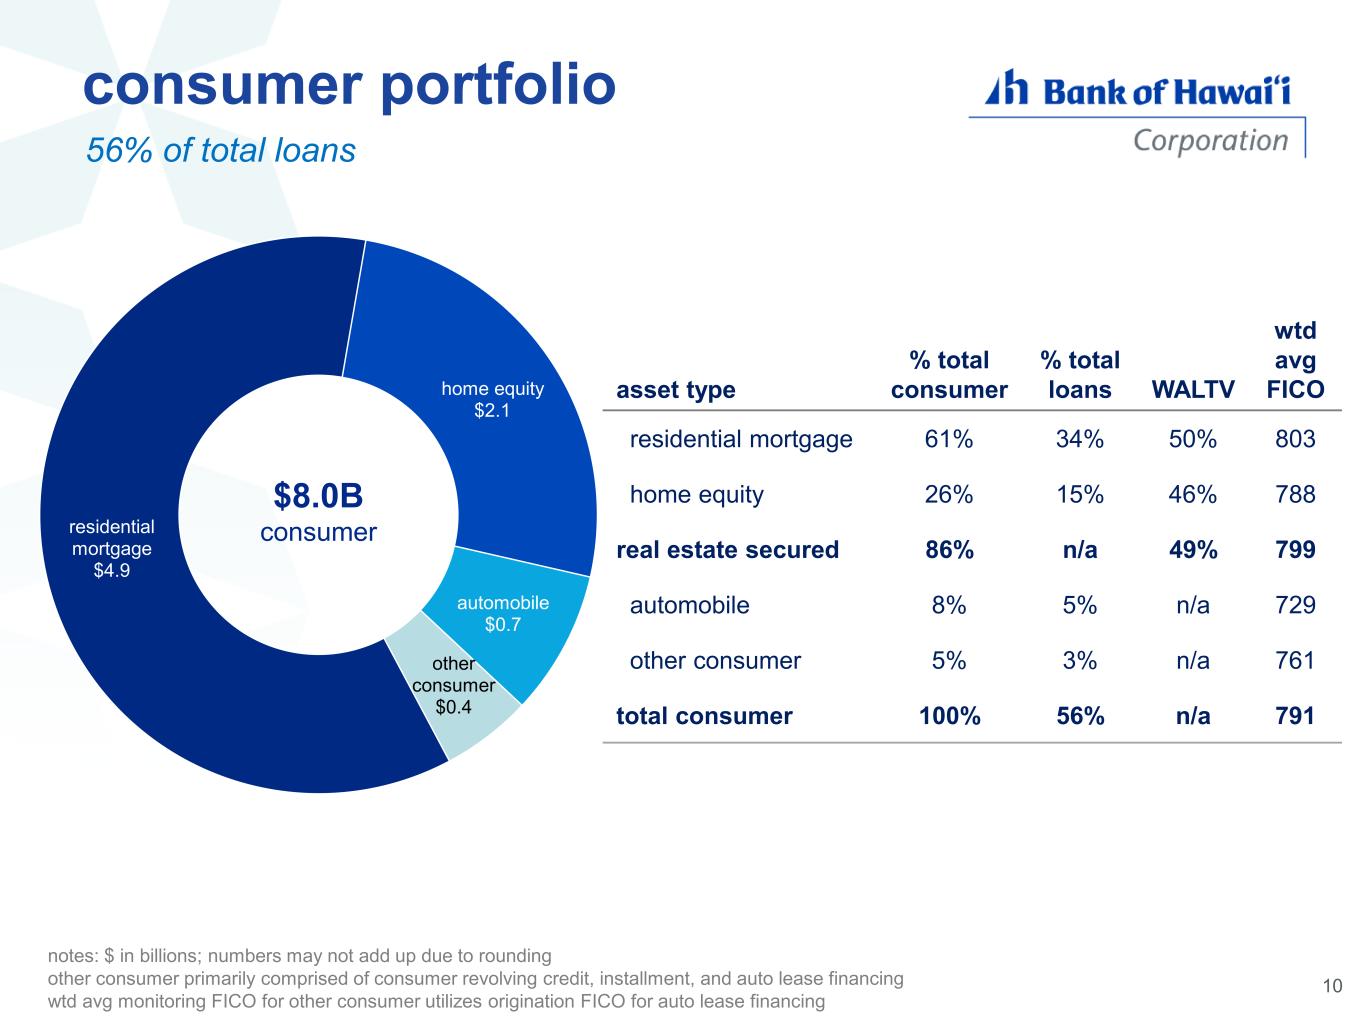
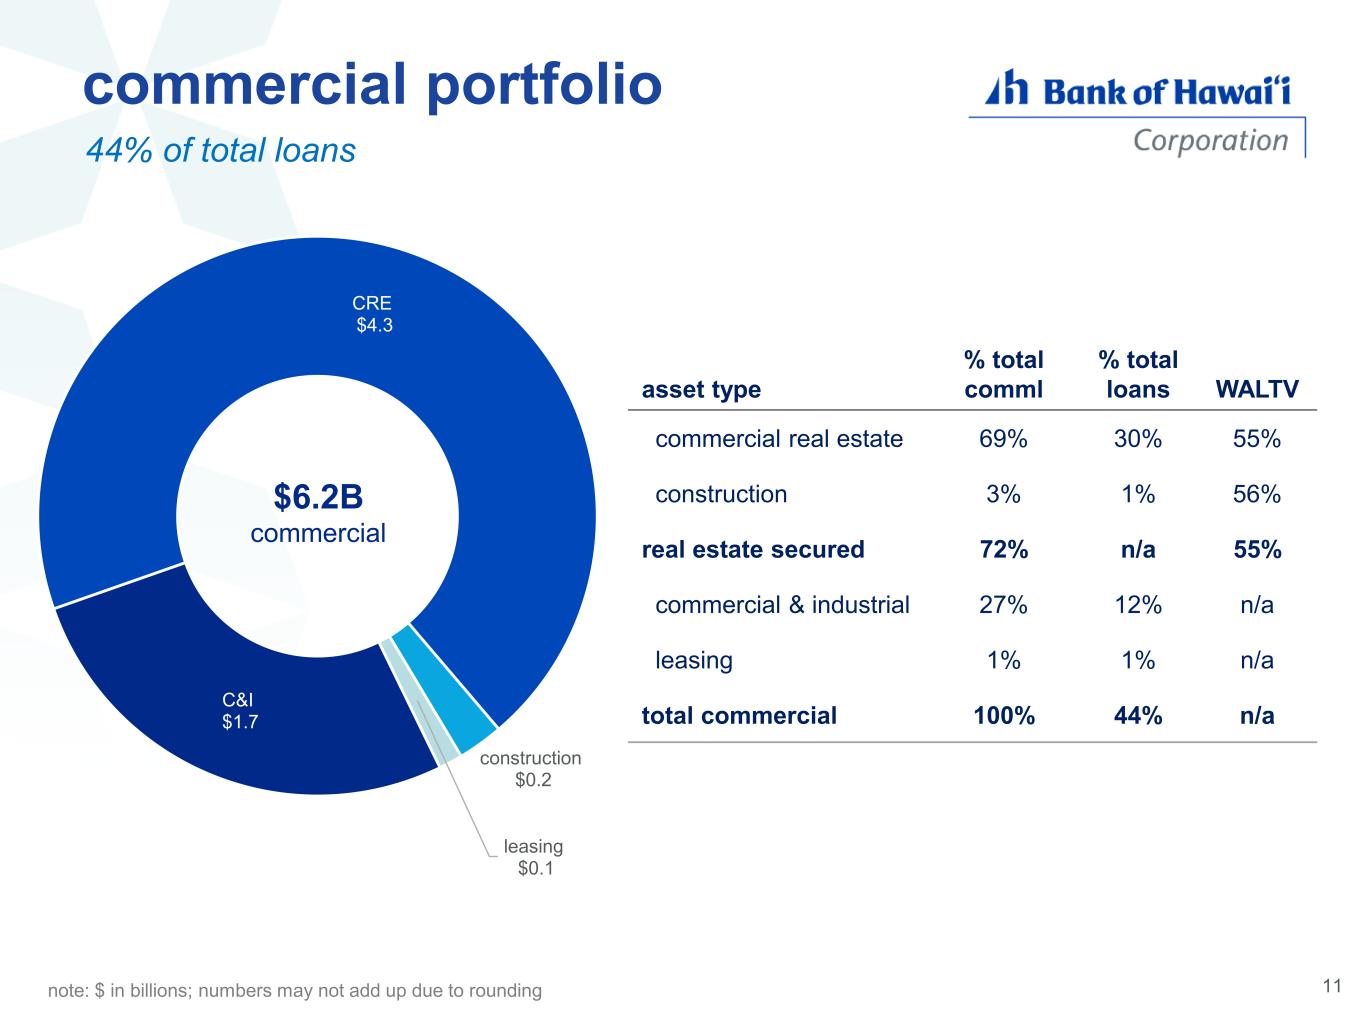
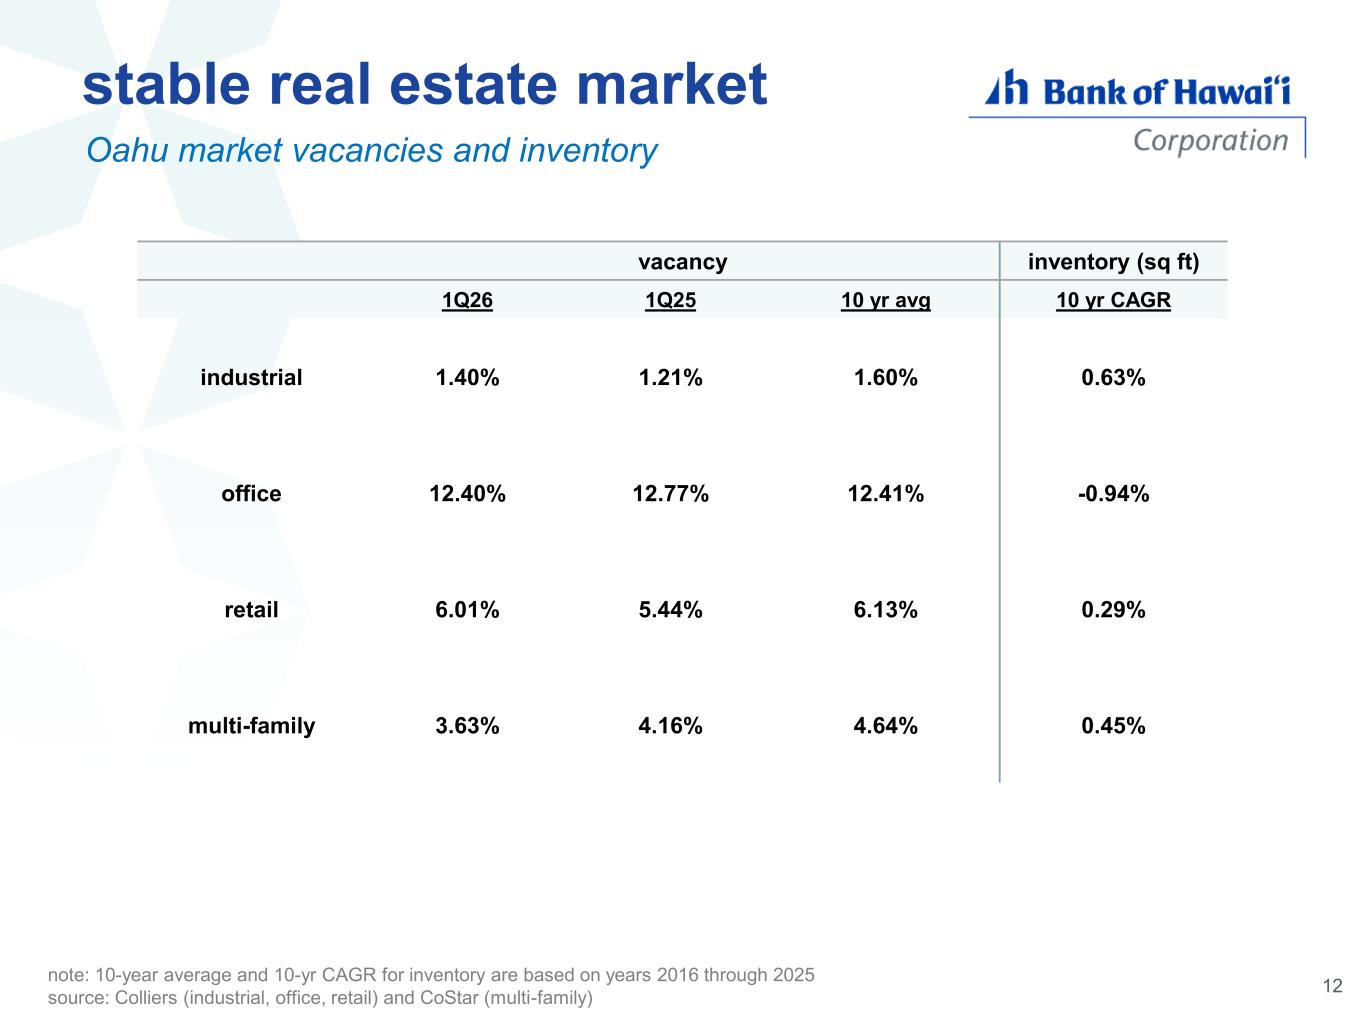
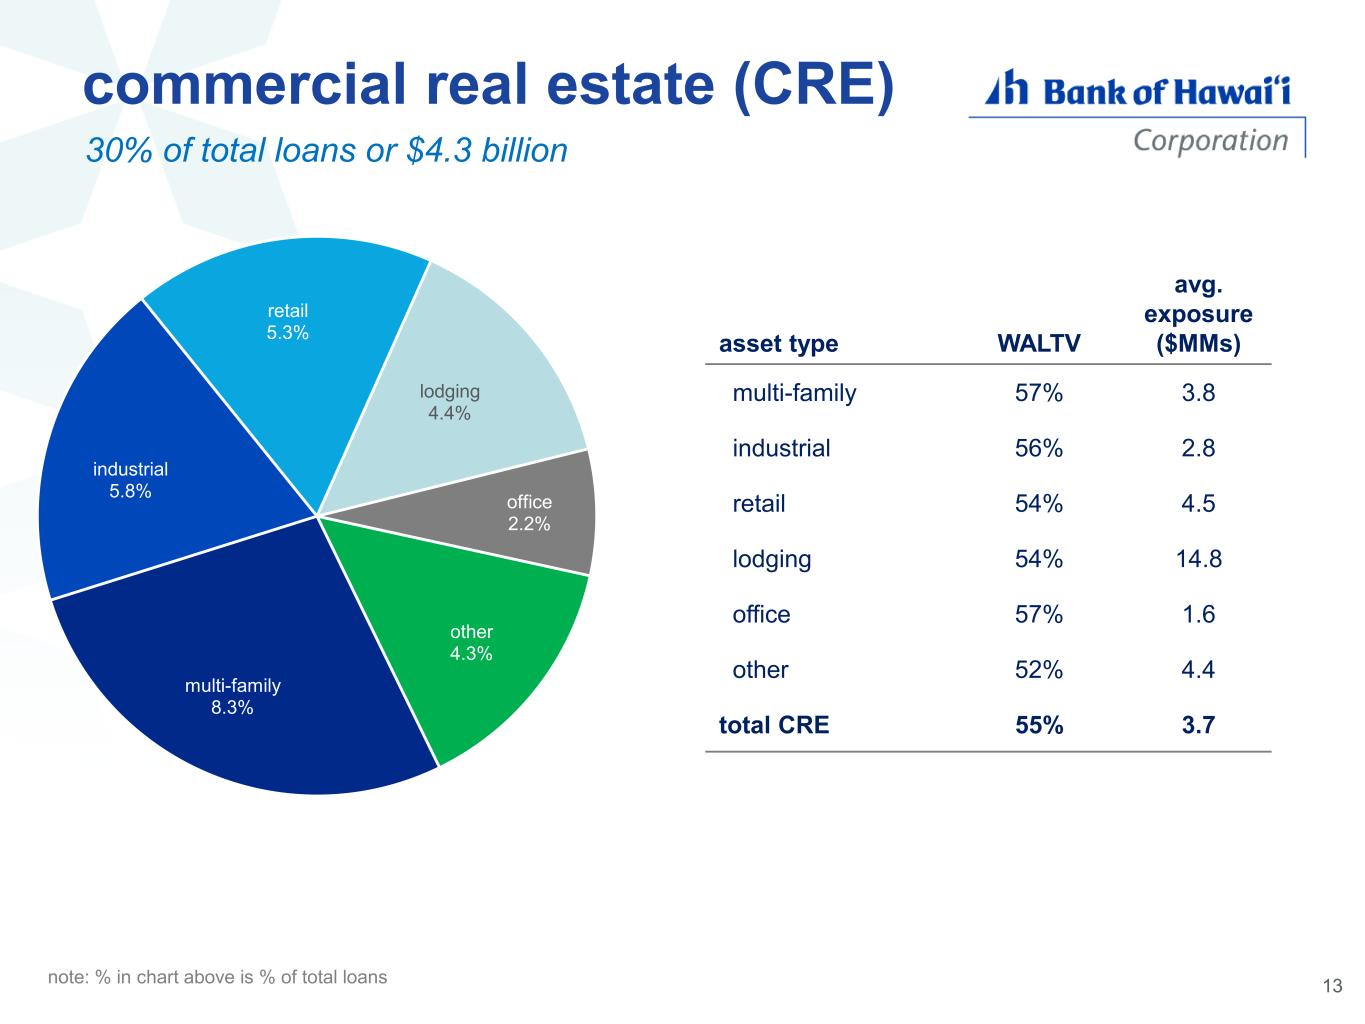
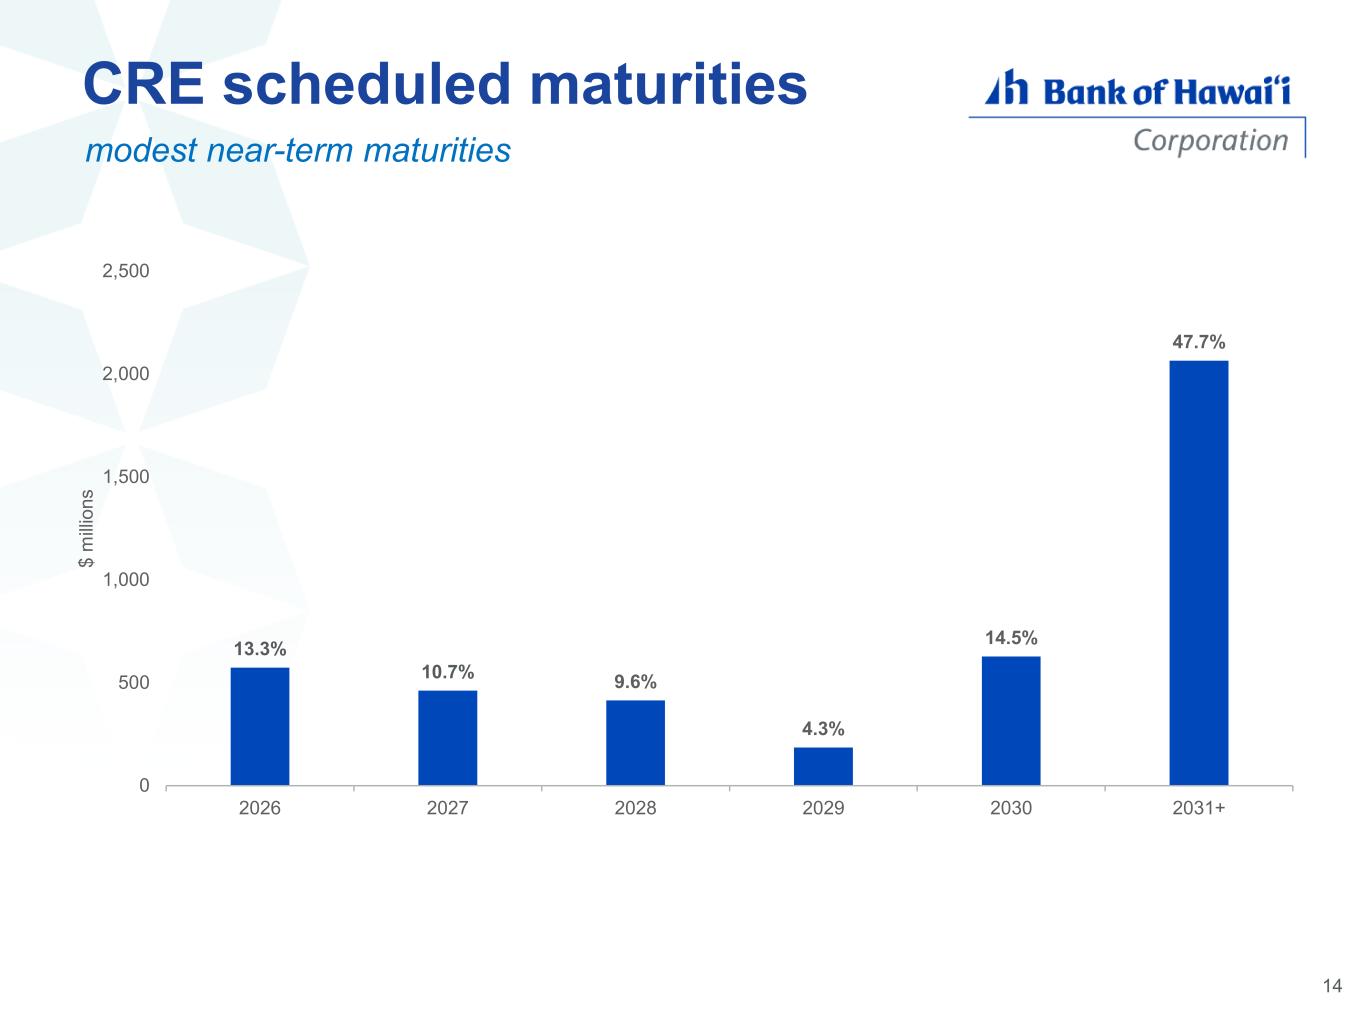
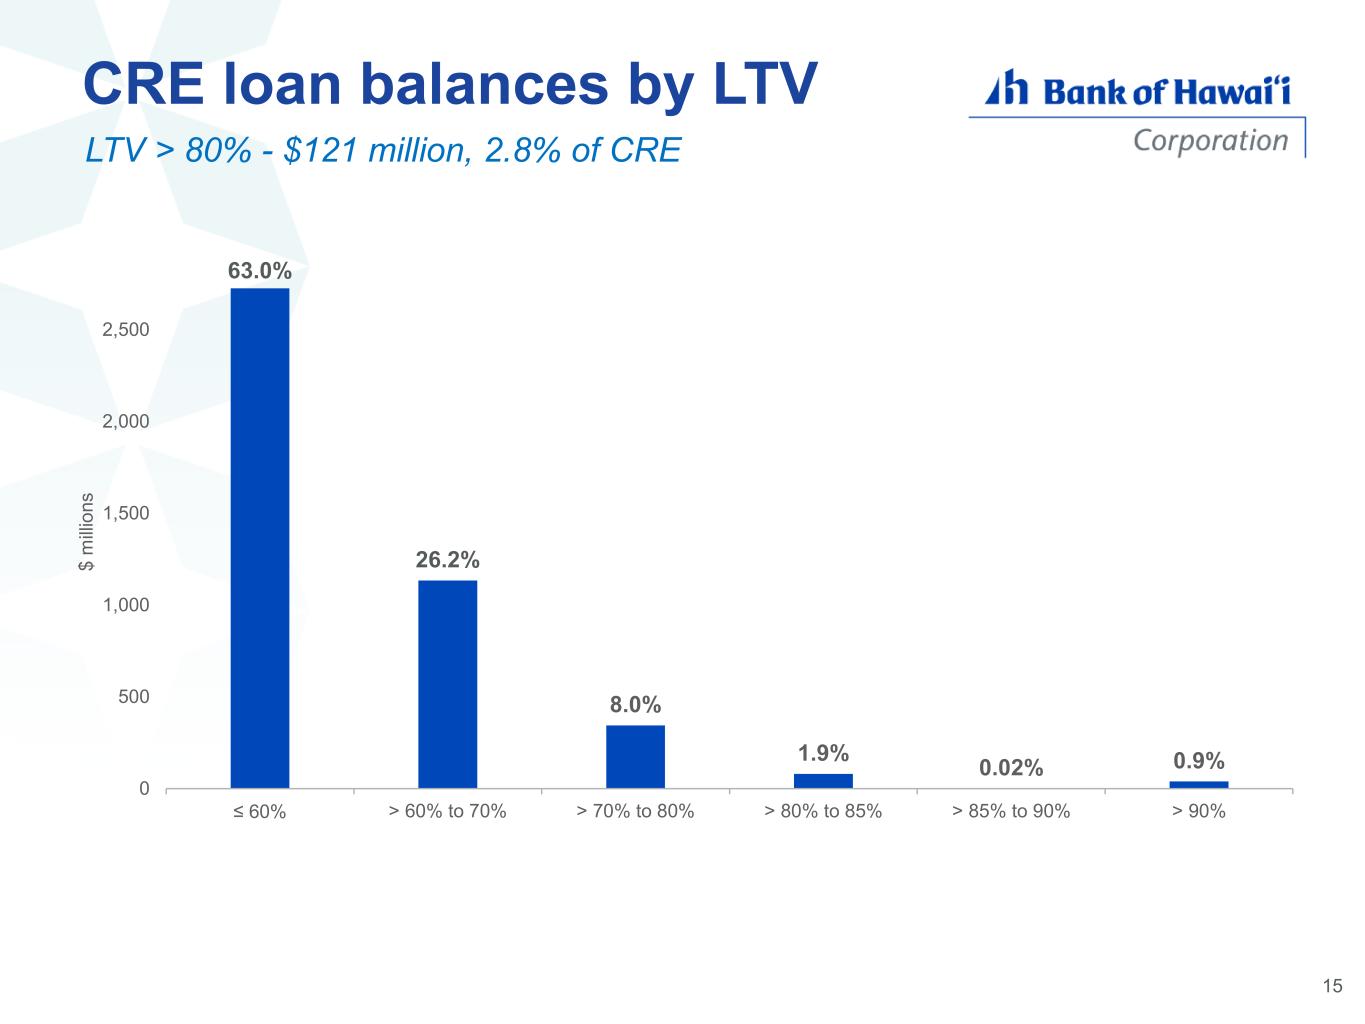
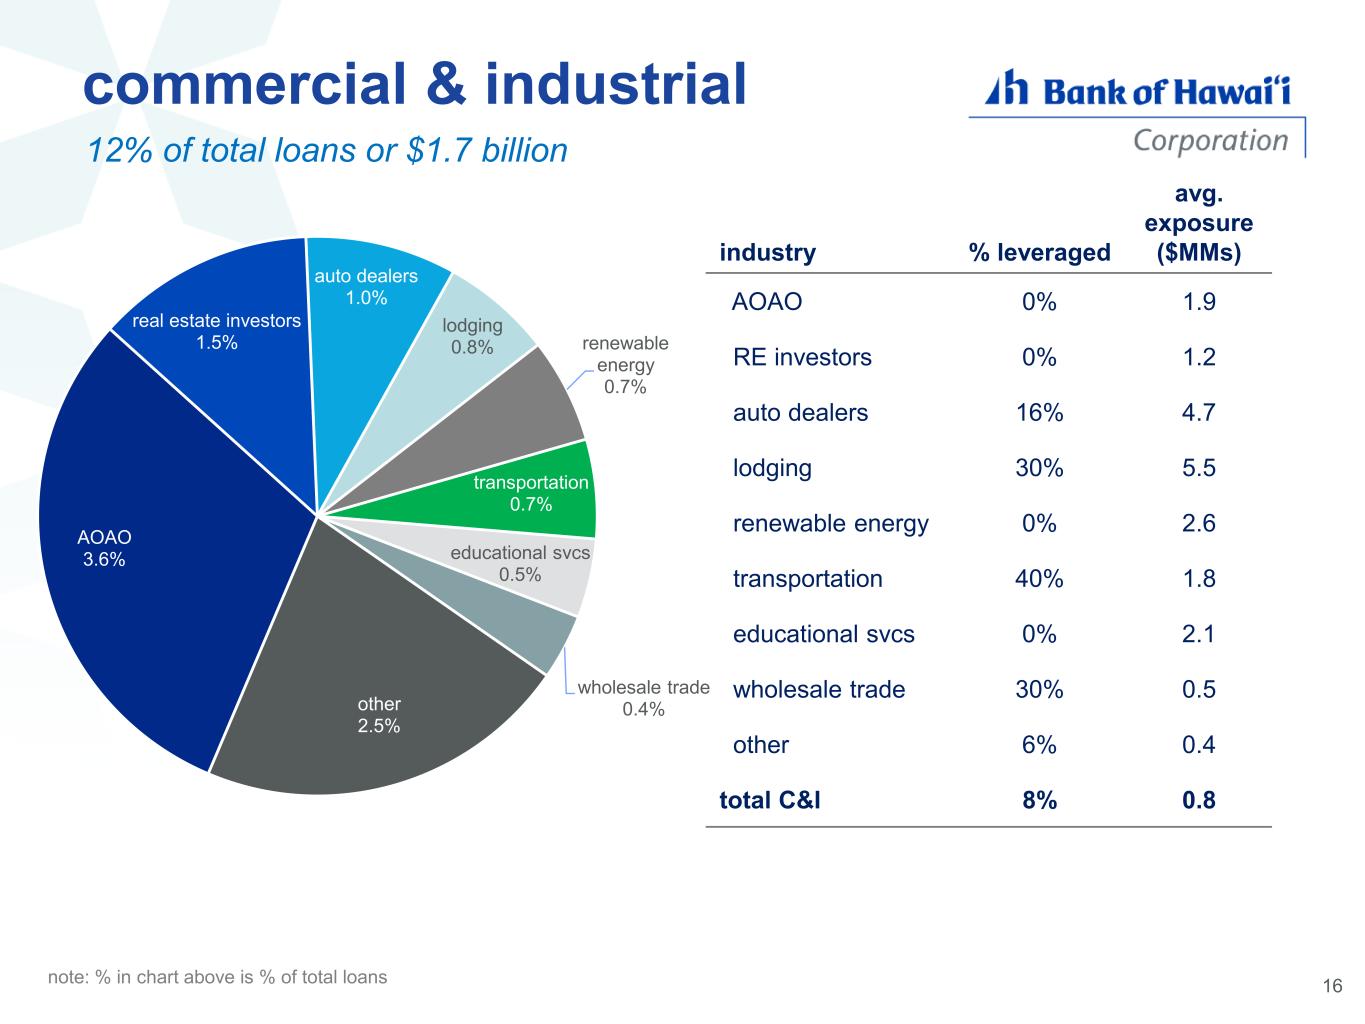
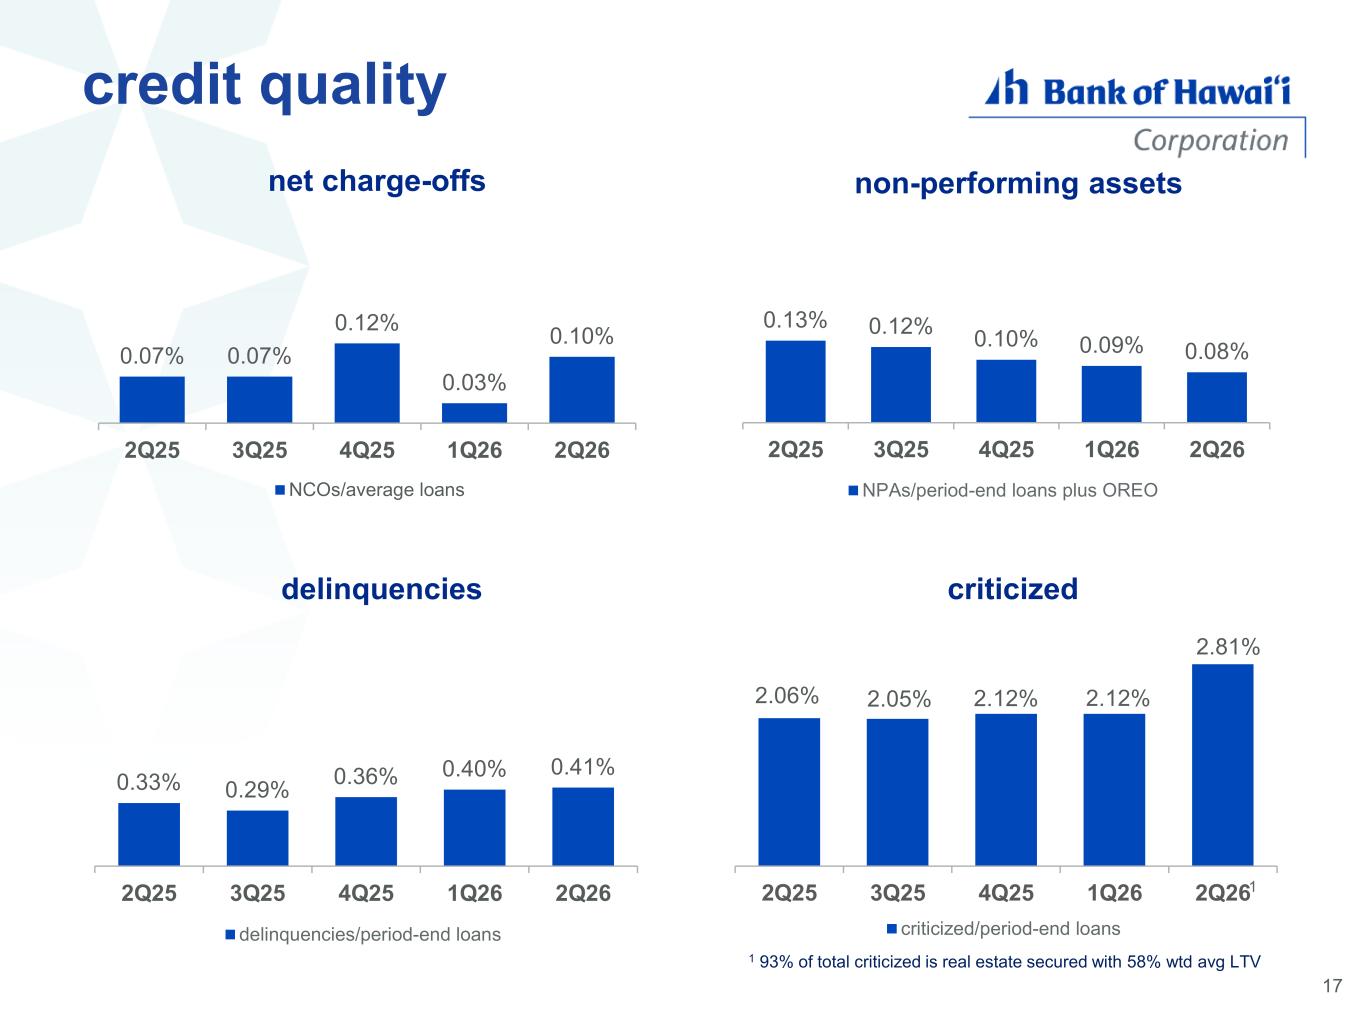
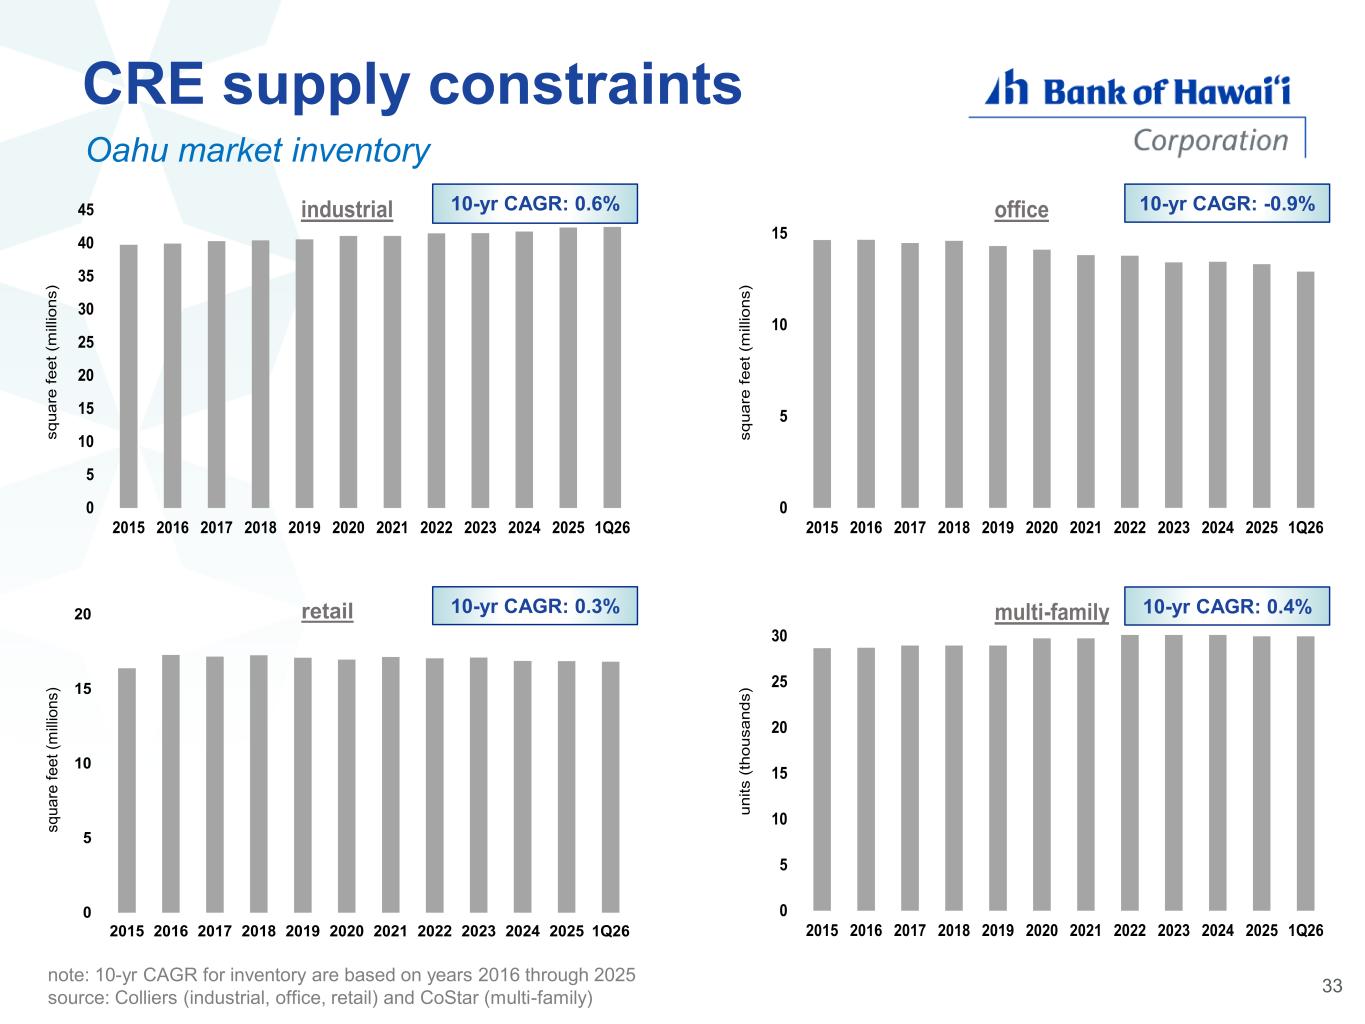
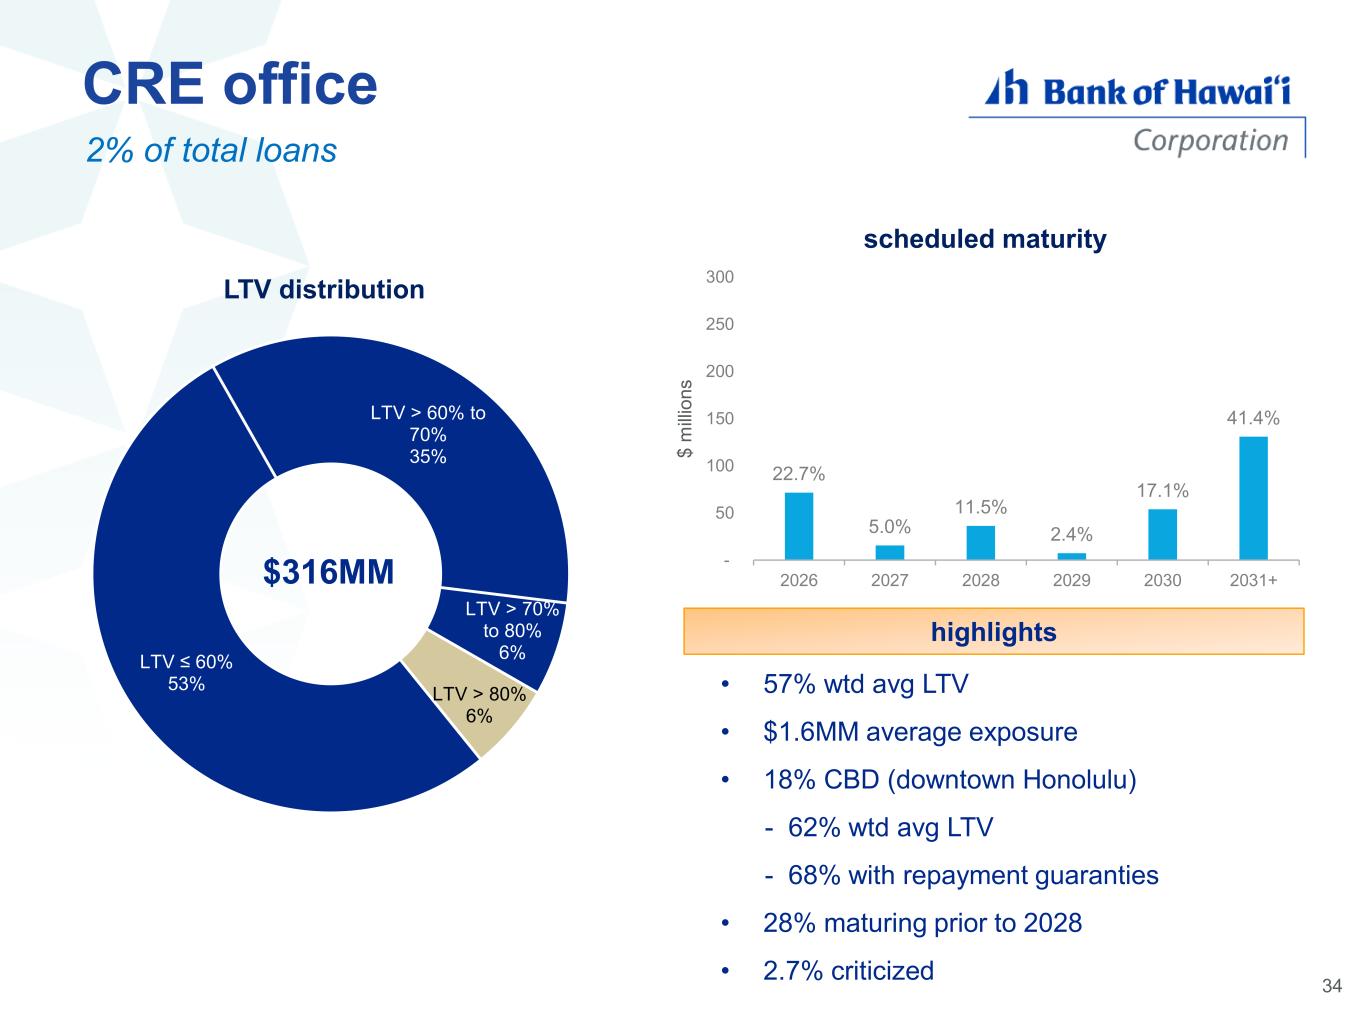
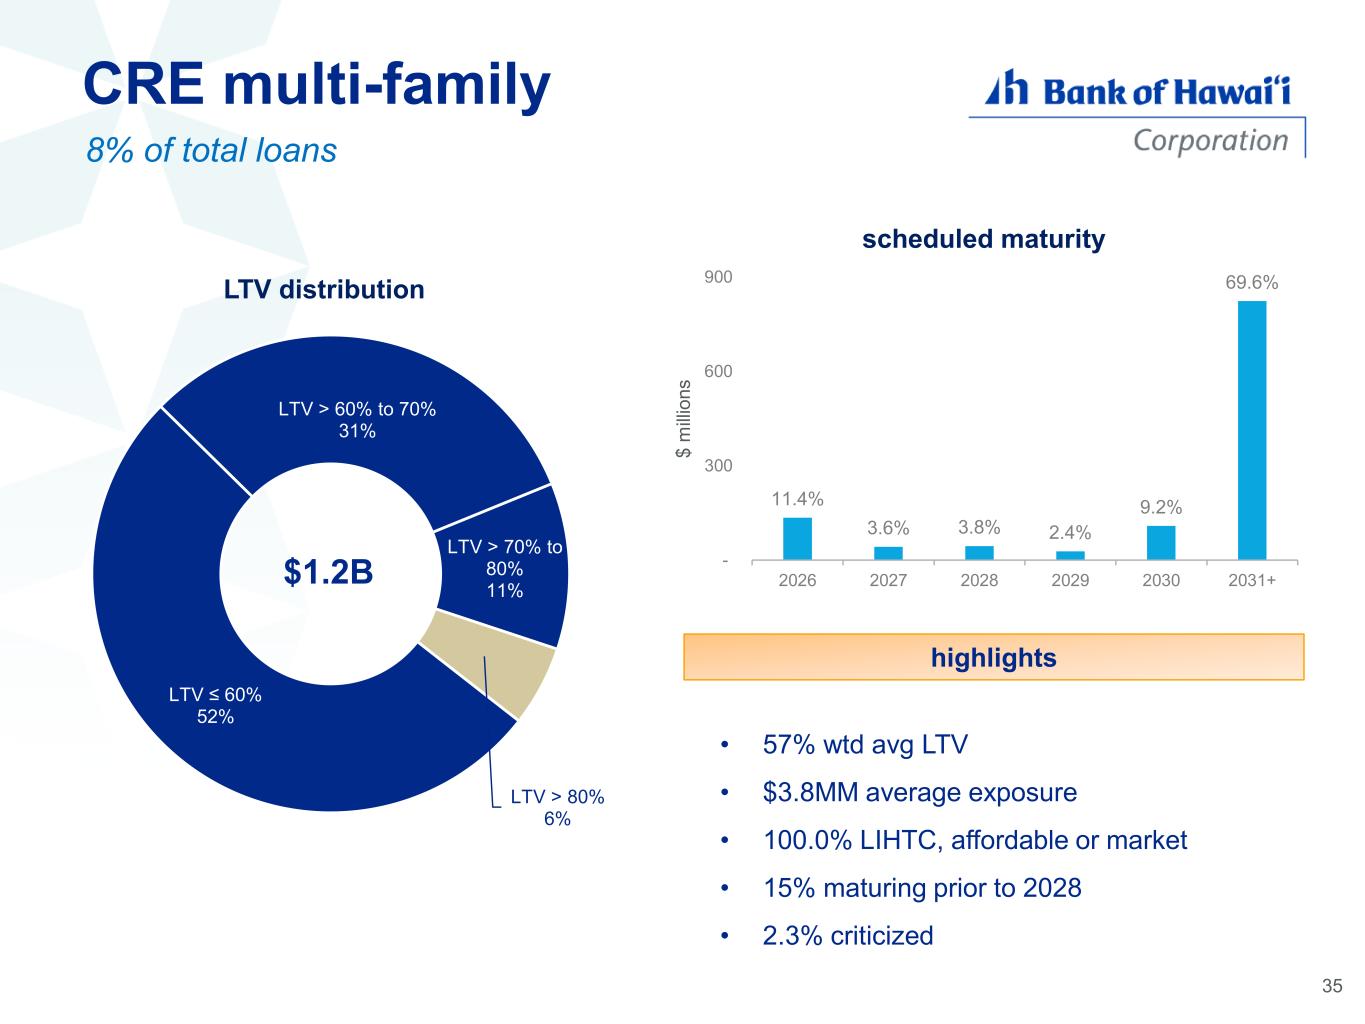
Thanks, Jim. I'll begin with an overview of our credit portfolio and conclude with asset quality metrics. And as you will see, our performance has remained strong consistent with prior quarters. Turning to our lending philosophy, the Bank of Hawaii is dedicated to serving our local communities, lending primarily within our core markets where our expertise allows us to make informed and disciplined credit decisions. Our portfolio is built on long tenured relationships with approximately 60% of both our commercial and consumer clients having been with the bank for more than 10 years. Geographically, our loan book is concentrated in markets we know well. Approximately 94% of loans are based in Hawaii, with 4% in the Western Pacific and just 2% on the mainland, primarily supporting existing clients who operate both locally and on the Our loan portfolio remains well-balanced between consumer and commercial exposure. Consumer loans represent 56% of total loans, or approximately $8 billion. Within the consumer portfolio, 86% consist of residential mortgage and home equity loans with a weighted average LTV of 49% and weighted average FICO score of 799. The remaining 14% of consumer loans are comprised of auto and personal lending. Credit quality in these segments also remains strong with FICO scores of 729 for auto loans and 761 for personal loans. Turning to commercial lending, the portfolio totals $6.2 billion, representing 44% of total loans. 72% is secured by real estate with a weighted average LTV of 55%. This reflects our ongoing emphasis on collateral protection. CRE remains our largest component of the commercial book totaling $4.3 billion, or 30% of total loans. And in Oahu, the state's largest CRE market, a combination of consistently low vacancy rates and flat inventory levels continues to support a stable real estate market. Across industrial, office, retail, and multifamily property types, vacancy rates remain below or close to their 10-year averages. Total office space on Oahu has declined by approximately 10% over the past decade, driven primarily by conversions to multifamily residential and lodging. This structural reduction in supply combined with the return to office trend has brought vacancy rates back down to the long-term average and well below national levels. Our CRE portfolio remains well diversified with no single property type exceeding 9% of total loans. conservative underwriting practices continue to be applied consistently with weighted average LTVs below 60% across all CRE categories. In addition, diversification within each segment remains strong supported by modest average loan sizes. Scheduled maturities are also well balanced with more than 60% of CRE loans maturing in 2030 or later, reducing near-term refinancing risk. Looking at the distribution of LTVs, there isn't much tail risk in our CRE portfolio. Less than 3% of CRE loans have greater than an 80% LTV. CNI accounts for 12% of total loans, totaling $1.7 billion. This portfolio is diversified across industries, characterized by modest average loan sizes, and there is very little leveraged lending. Turning to asset quality, overall credit performance remains strong and consistent with the trends we've seen over the past several quarters. Delinquencies, non-performing assets, and net charge-offs all remained at favorable levels during the quarter. Net charge-offs were just $3.4 million, or 10 basis points annualized, in line with the last several quarters, but up from the abnormally low three basis points last quarter that resulted from a large recovery. Non-performing assets declined a basis point to eight basis points, while delinquency levels increased a basis point to 41 basis points. The one notable change this quarter was an increase in the criticized asset ratio to 2.81% from 2.12%. That increase lease was driven by a single borrower relationship rather than broader weakness across the portfolio. The loans related to the borrower continue to perform and the exposure is well secured by real estate. More broadly, 93% of our criticized assets are secured by real estate with a weighted average LTV of 58%. And as an update on the allowance for credit losses on loans and leases, the ACL ended the quarter at $147 million flat to the linked quarter. The ratio of our ACL to outstandings ends down one basis point to 1.03%. This concludes my remarks. I will now turn the call over to Brad Sattenberg for a discussion on our financial performance.
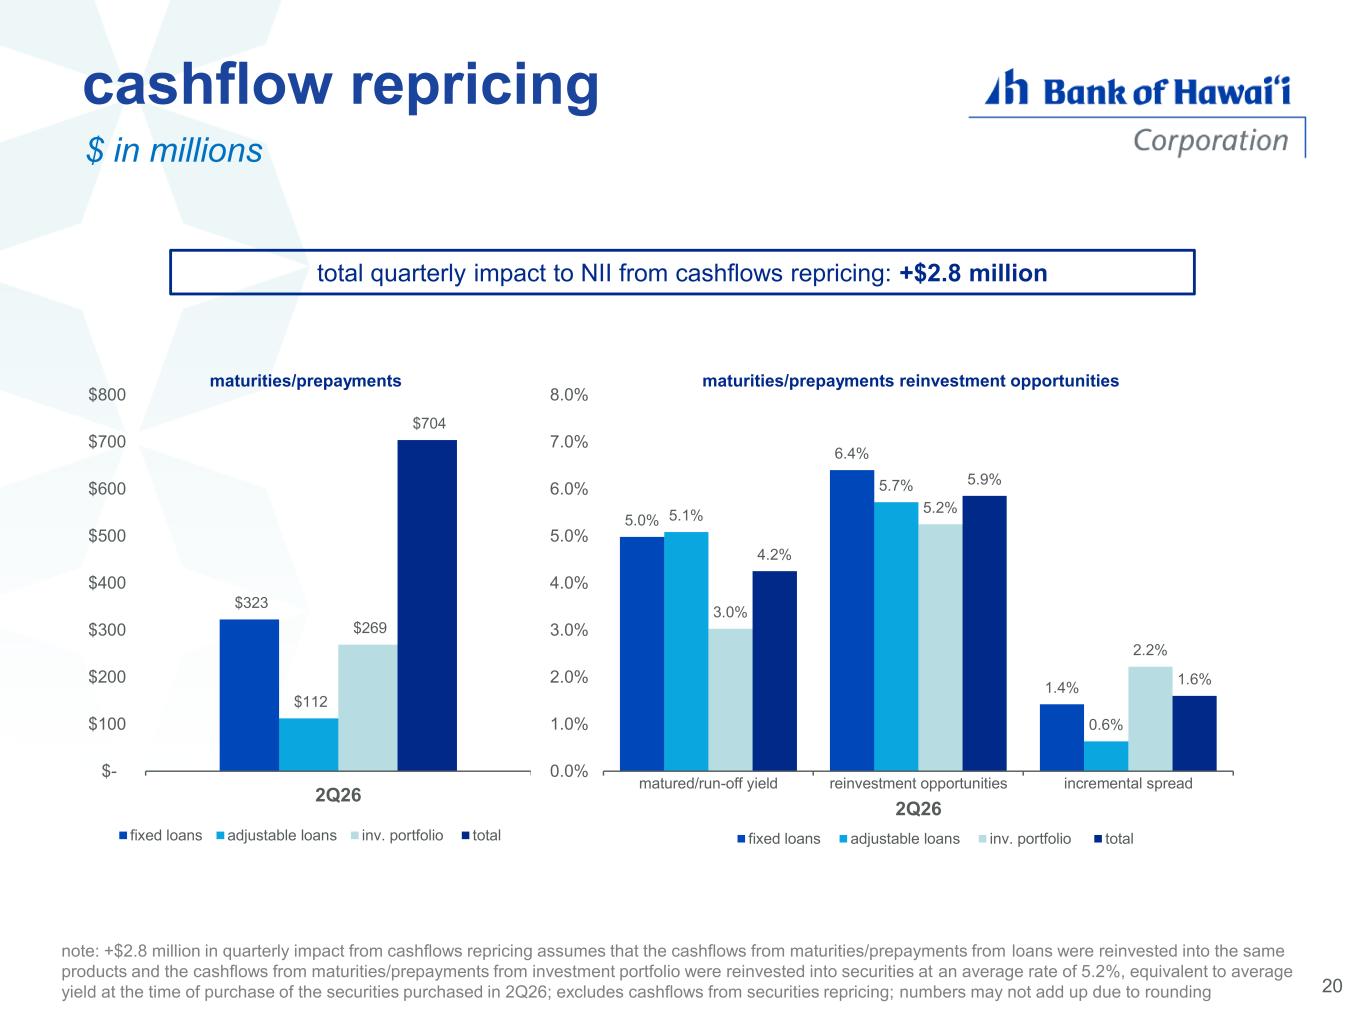
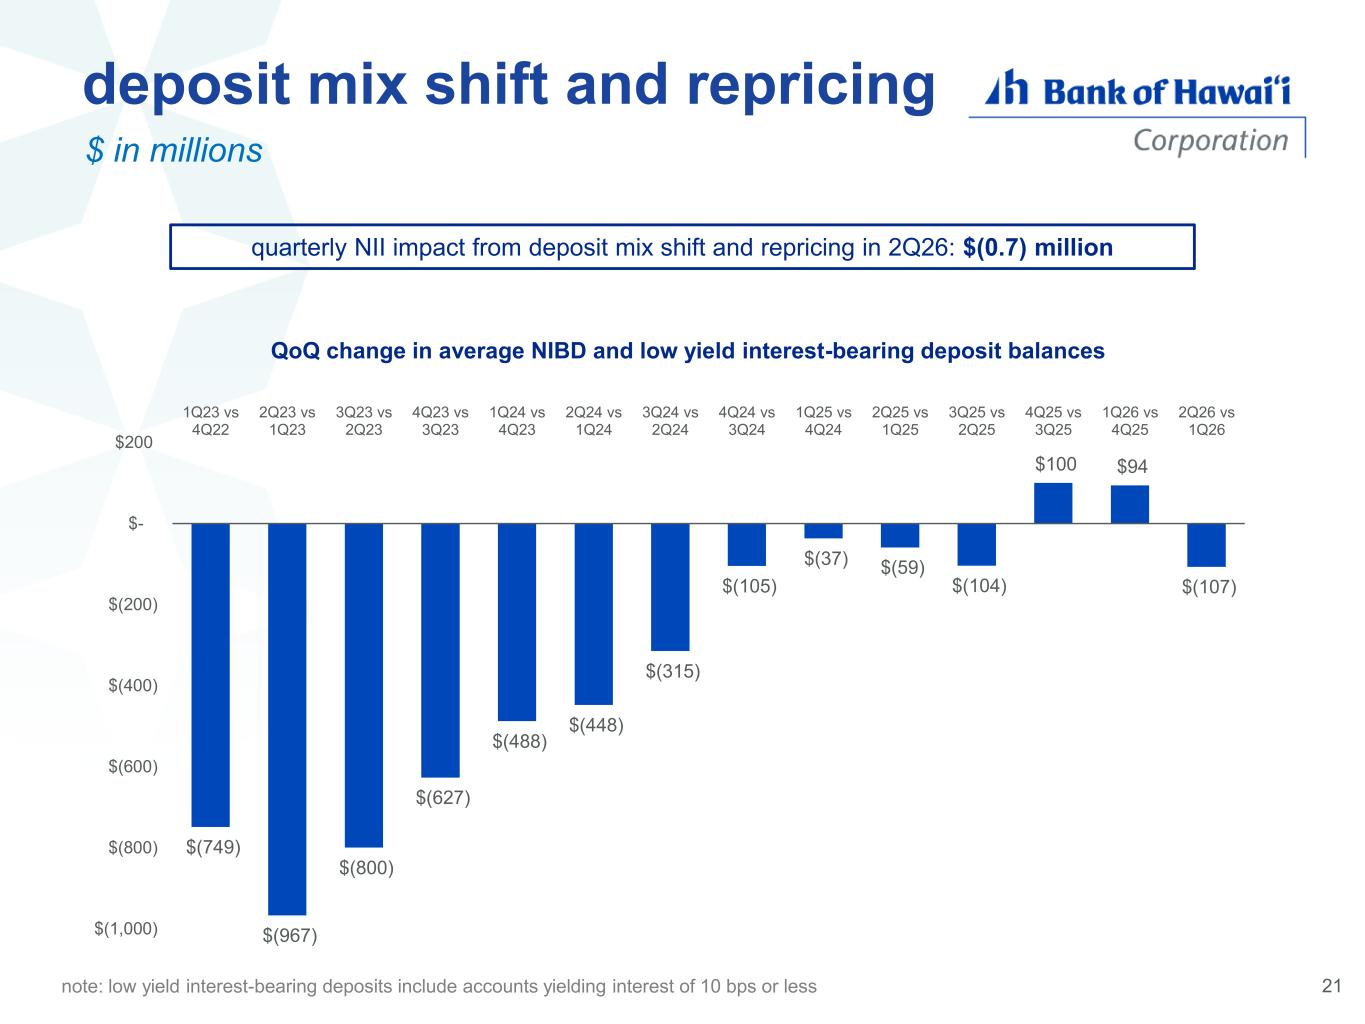
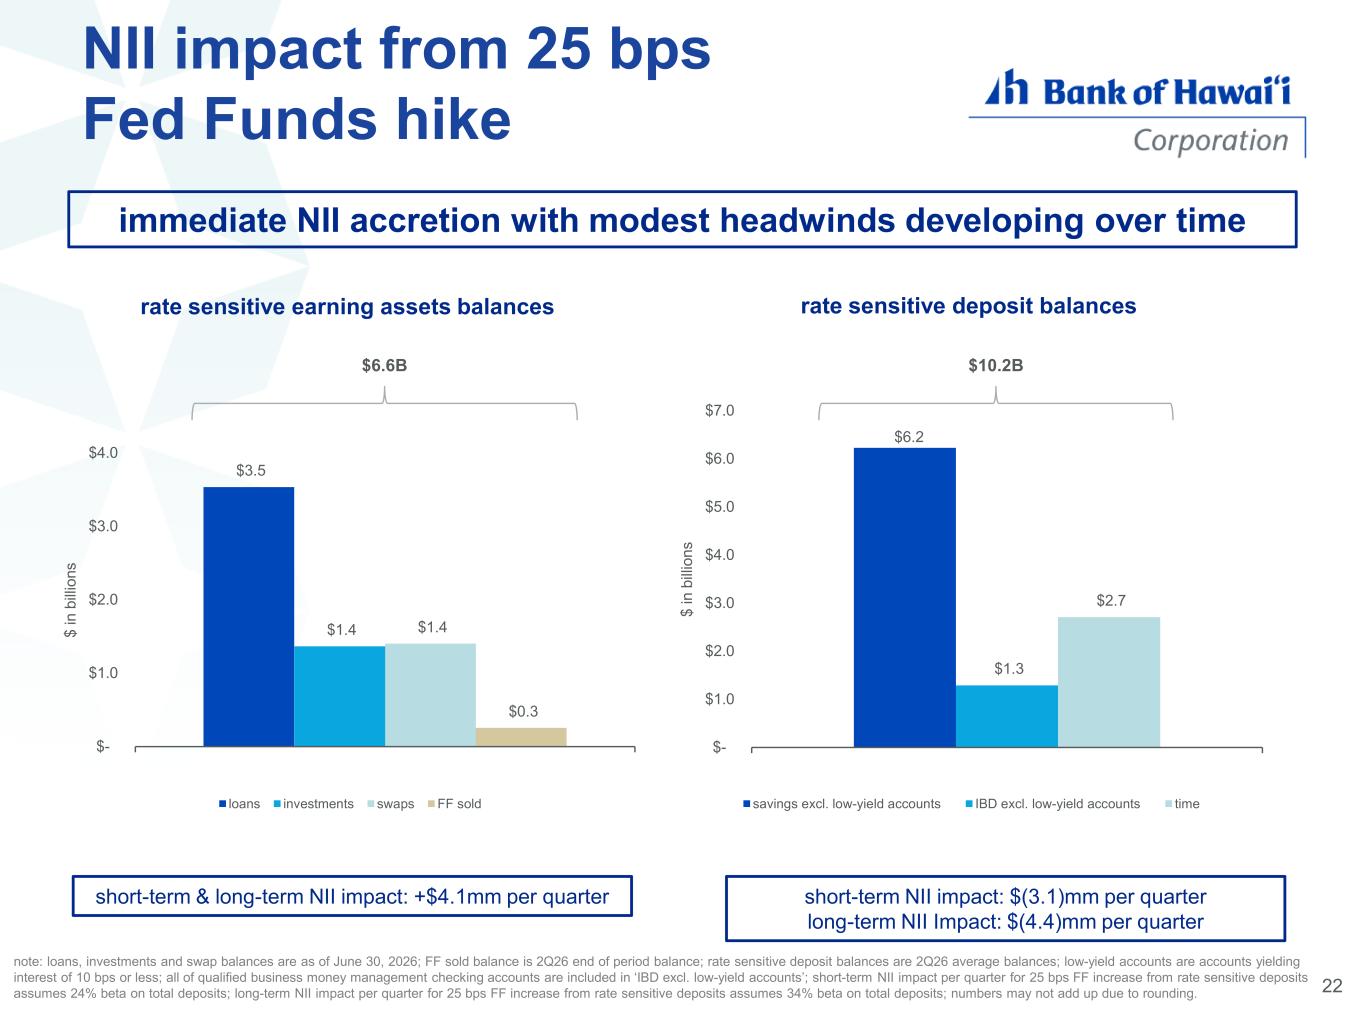
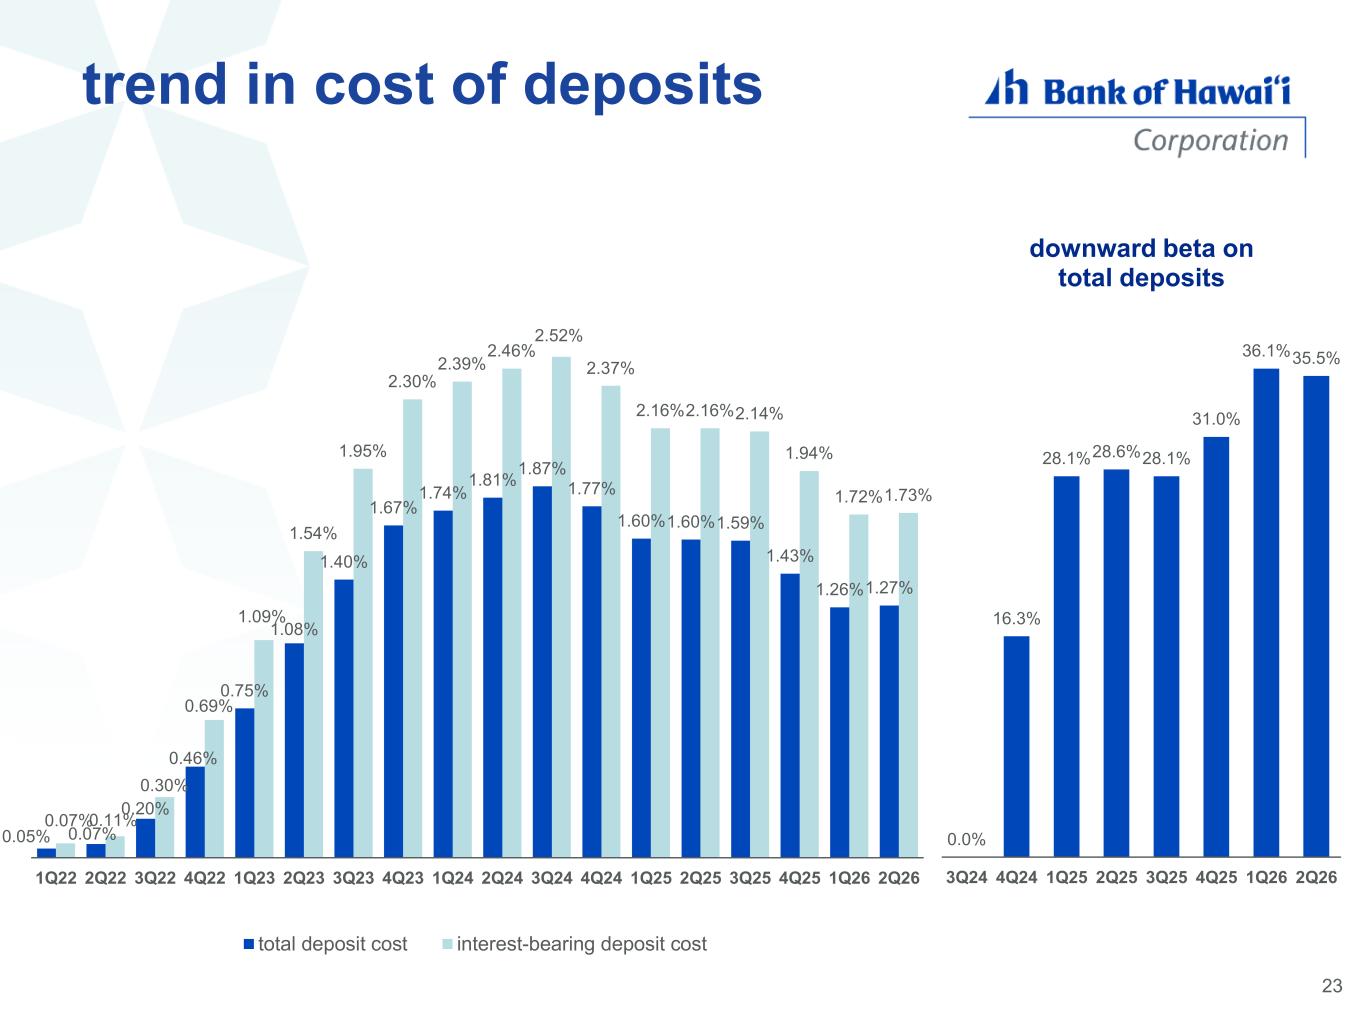
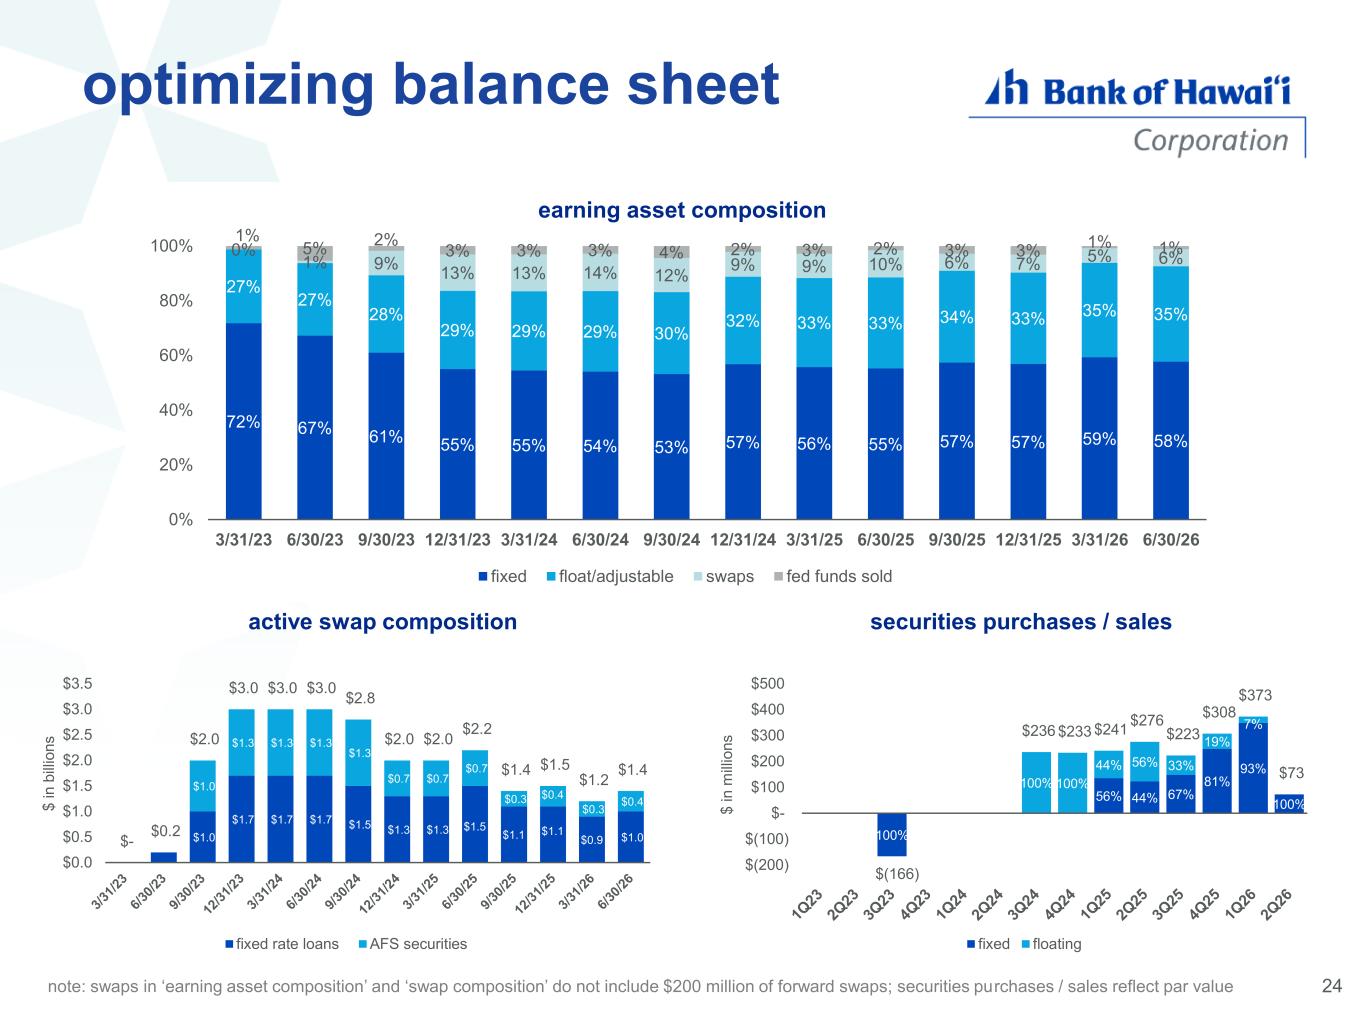
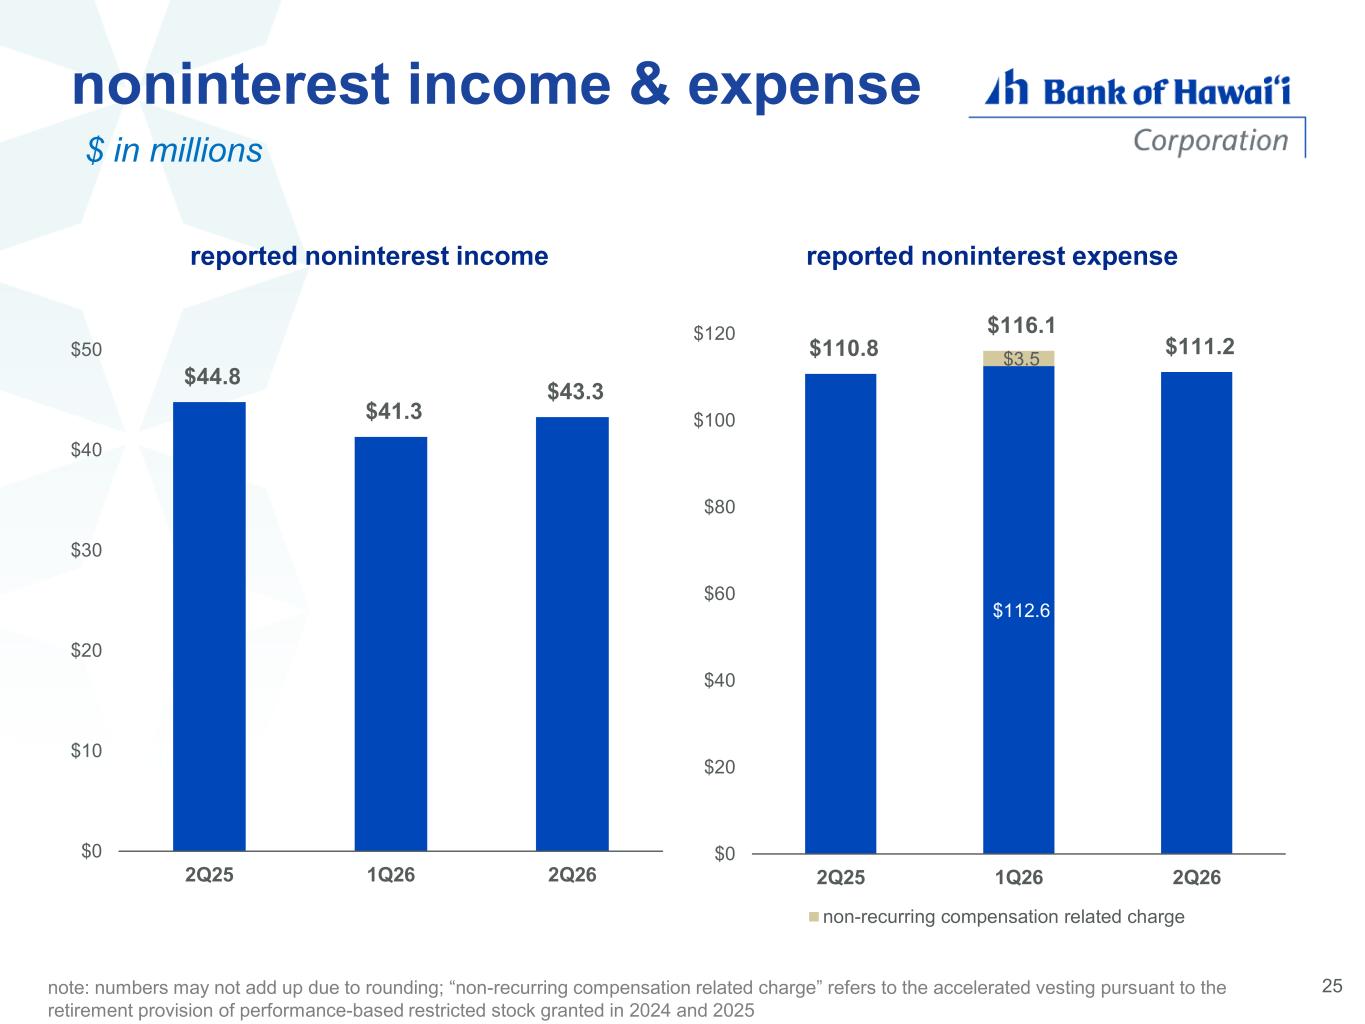
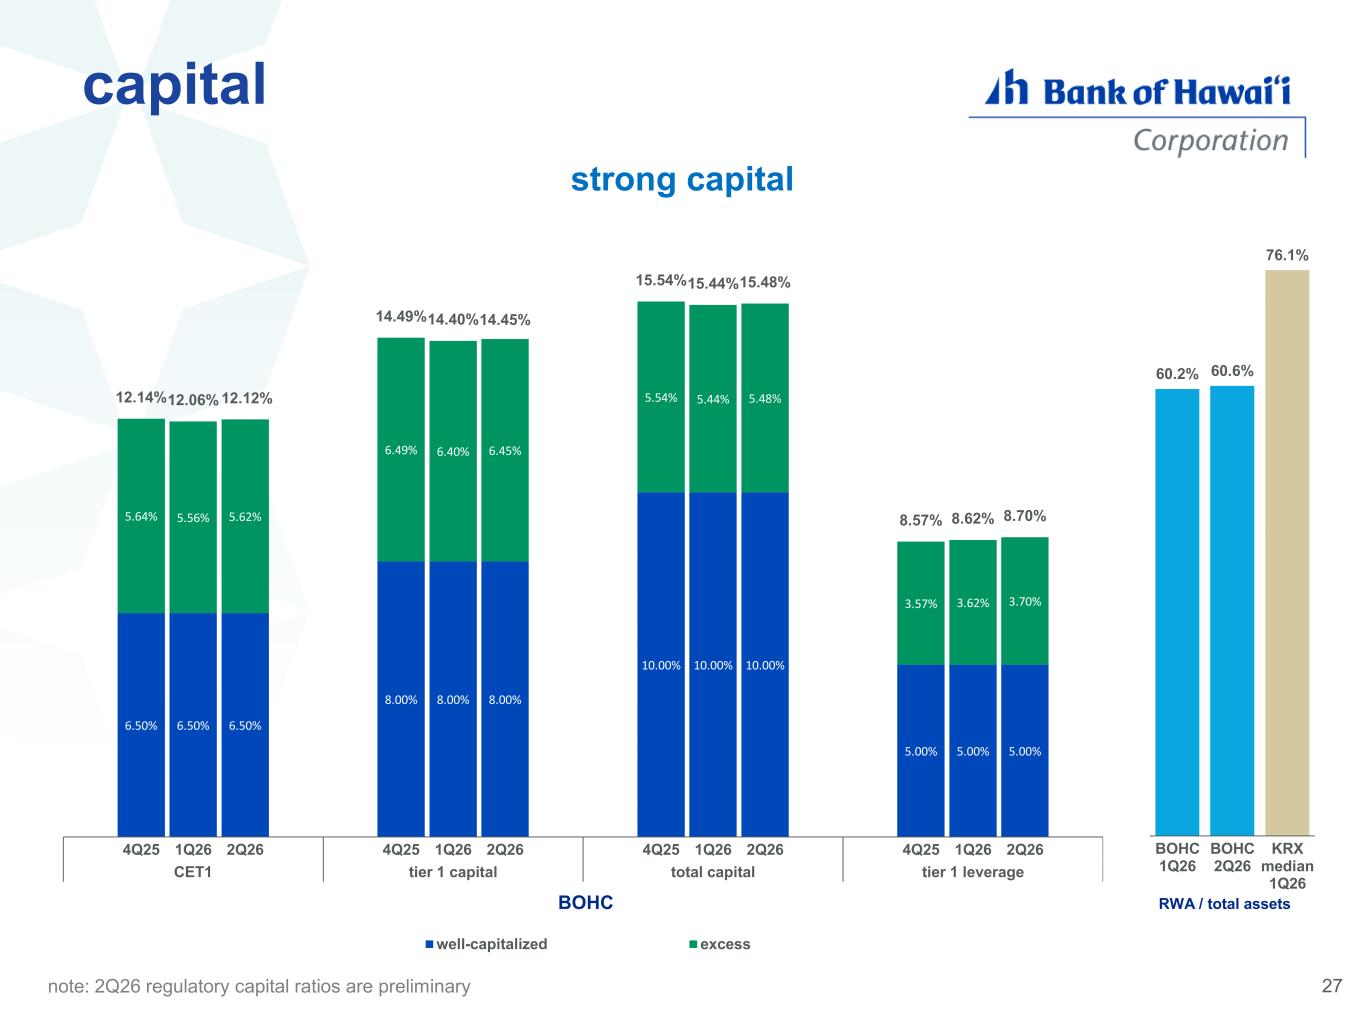
Thanks, Brad. For the quarter, we reported net income of $63.8 million and a diluted EPS of $1.47, up $6.4 million and 17 cents per share from the LING quarter, and as Jim mentioned, for the ninth consecutive quarter, both our NII and NIM expanded. Compared to the first quarter, NII increased $2.6 million, and NIM improved four basis points to 2.78%. The expansion was primarily driven by our fixed asset repart pricing, partially offset by the deposit mix shift, which accelerated for the first time in several quarters. Despite the increase this quarter, the broader trend remains positive, and over the past 12 months, the aggregate mix shift was only $17 million compared to $516 million during the same period a year ago. The yield on earning assets improved by five basis points during the quarter, which benefited from a $2.8 million contribution to our NII from the fixed asset repricing. Assuming that interest rates remain stable, I expect that the yield on our earning assets will continue to improve at a similar pace for the remainder of the year. The cost of interest-bearing liabilities increased by one basis points during the quarter, consistent with the rise in deposit costs. Deposit costs were 1.27%, and the deposit data declined slightly to 35.5%. As interest rate expectations have shifted, deposit pricing has become more competitive than earlier in the year, contributing to the higher deposit mix shift, along with the modest increase in deposit costs this quarter. In the current rain environment, I expect our cost of deposits to settle in the range of one and a quarter to 1.3% in the near term. I also expect public deposits to decline in the third quarter as we strategically allow certain higher-cost funds to run off. I'm forecasting that any interest rate hikes would initially benefit NII and NIM, but would ultimately become a modest headwind once our deposits fully repriced. The velocity of the impact from any change in rates will depend on the timing of deposit pricing adjustments and the terminal beta reached. I expect the deposit beta of any potential rate hikes to ultimately land at approximately 34%, which would mirror our beta from the last rate hike cycle. Regardless of any potential rate changes, I believe that we are well positioned to remain balanced from an interest rate sensitivity perspective. At quarter end, our fix-to-float ratio was 58%, down one percentage point from the prior quarter. We finished the quarter with an active pay-fixed, receive-float swap portfolio of $1.4 billion, with a weighted average fixed rate of 3.3% and an average life of 1.4 years. 1 billion of these swaps hedge our loan portfolio while 400 million hedge our securities. In addition, we have 200 million of forward starting swaps with a weighted average fixed rate of 3% and an average life of 2.1 years. These swaps will become effective during the third quarter. Non-interest income was $43.3 million during the quarter compared to $41.3 million during the linked quarter. This quarter included a $400,000 charge related to our Visa B conversion ratio change, while the first quarter included a similar $200,000 charge. Adjusting for these normalizing items, non-interest income was up $2.2 million. This improvement was primarily due to the strength of our wealth management division, which benefited from a strong market, as well as increased customer demand for annuity investments and other advisory-related fees. My forecast for the third quarter is that normalized non-interest income will be approximately $43 million. Non-interest expense was $111.2 million compared to $116.1 million during the link quarter. As a reminder, the first quarter included a seasonal payroll tax and benefits charge of $2.8 million, as well as non-recurring charges related to the accelerated investing or restricted stock awards of $3.5 million and an unrelated severance charge of $750,000. This quarter includes our annual merit increases of approximately $1.2 million and a $500,000 benefit in connection with the net forfeiture of unvested restricted stock. Excluding the impact of these items, expenses were up slightly compared to the first quarter. Third quarter normalized non-interest expense is expected to be approximately $112.5 million. During the quarter, we also recorded a provision for credit losses of $3.6 million, resulting in a coverage ratio of 1.03%. In addition, we reported a provision for taxes of $18.3 million during the quarter, resulting in an effective tax rate of 22.3%. The drop in the tax rate compared to the link quarter was primarily due to higher benefits from certain tax-advantaged investments. Our capital ratios remained above the well-capitalized regulatory capital thresholds during the quarter, with Tier 1 capital and total risk-based capital of 14.5 and 15.5 percent, respectively. And consistent with the linked quarter, we paid dividends of $28 million on our common stock and $5.3 million on our preferreds. During the second quarter, we repurchased $17 million of common shares at an average price of approximately $78 per share. I am currently planning to purchase an additional $20 million of stock during the third quarter, and $89 million remains available under the current repurchase plan. Finally, the Board declared a dividend of $0.70 per common share that we pay during the third quarter. Now, I'll turn the call back over to Jim.
Thanks, Brad. We'd now be happy to answer any questions that you might have.
Operator
Thank you. As a reminder, to ask a question, please press star 1-1 on your telephone and wait for your name to be announced. To withdraw your question, please press star 1-1 again. Please stand by while we compile the Q&A roster. Our first question comes from the line of Jeff Rulis with DA Davidson. Your line is now open.
Speaker 10
Hey, good morning, Jeff. Jim, you alluded to in your initial remarks on the wealth management momentum, and Brad kind of followed with the pieces of that strength. I just kind of want to see what is pretty solid for trust in asset management. What kind of growth do you see the rest of the year? I guess if you strip out, I guess the strong market is a variable, but I just wanted to see the outlook for that line item as you see it.
Yeah, I mean, it's always hard to judge these things with market conditions, but we feel really good about where we're at. Obviously, we've talked on several calls now just about the investments we've made in both Banco Advisors as well as the overall wealth platform. I would say that if you looked at the performance in Q3 on the wealth management side, you know, the increase in fees was driven probably half by market and half by production. And then we had some trust and testamentary fees that came in as well. So I would see that as sustainable without market change, you know, going forward. And then on the bank advisor side, the annuity income is really, I think you're really beginning to see sort of the partnership with Cetera, the greater efficiency that we've incorporated into the business, additional products that we've availed through the segment, and then the advisors that we're adding to the team just helping to drive overall sales.
Speaker 10
Appreciate it. And then one other one I had is just to check in on that margin. You mentioned the high 2% or approaching 2.9 by year-end. And it sounded like the composition of how you get there shifted a little bit. And just, I guess, if you couch this quarter's sequential increase in how you get there, if you could just provide a little more color through the back half of how you get there, it would be helpful.
Sure. Maybe I'll have Brad answer that question.
Yeah. Thanks, Jeff. That's a good question. So, our NIM for the quarter was 278. June was a 279. Now, we're forecasting one rate hike this year. Mid-September is what we have in our forecast. So all the components are still in place for, you know, the NIM to continue to grind higher. You know, we've got the fixed asset repricing, which we feel real good about, and the mixed shift, you know, has moderated, even though we took a step back this quarter. Really, if you look at over the longer-term trend, it's been positive. So with the rate hike and with the mixed shift and with the fixed asset repricing, I think we get to, you know, 290 by the end of the year. And that's, you know, I think we're looking at, you know, five basis points in NIM per quarter going, you know, forward.
Speaker 10
And Brad, just to clarify, that's a true exit, not the quarterly average in Q4 of 290.
Yeah, so I think it's going to be, yeah, my expectation is December would be just about 290.
Speaker 10
Sounds good. Thank you. Step back.
Operator
Our next question comes from the line of Matthew Clark with Piper Sandler. Your line is now open.
Hey, good morning, everyone. Good morning. Maybe just a little more on the margin, if you had the spot rate on deposits at the end of June, and how you're – and I was just going to – as a follow-on to that, just how you're, whether or not you're having to make any tweaks on, you know, exception pricing here, any upward pressure there, any changes to your promotional rates?
All right. So the spot, just to answer your first question, Matt, the spot rate was 126. So it was down one basis point from what our cost was for the quarter. And as far as exception pricing, obviously, I think competition has increased slightly. And I think there are some additional requests for some exception pricing, but it hasn't been, you know, material or significant. But we are looking at opportunities to grow deposits. And with that, you know, comes some additional pricing on our CDs. So we do think we're going to be pushing CD rates up slightly in the three and 12-month categories. But, you know, nothing material, but we do see that moving up.
Okay. And then just on the securities portfolios down this quarter, should we continue to assume that shrinks or are you going to start reinvesting there?
I mean, I wouldn't assume it's going to shrink, but I think this quarter, you know, between the loan growth that we experienced as well as, you know, we had some deposit runoff. So we used the excess cash flows from the investment portfolio to support those two. But, you know, we did take a step back in our investments and I think we'll just continue to, you know, reinvest at a pace, and it will only be dictated by, you know, what we see from the loan growth perspective, from the loan growth standpoint.
Operator
Thank you. Our next question comes from the line of Jared Shaw with Barclays. Your line is now open.
Speaker 8
Hey, Jared. Good morning. Good morning. I guess sticking with the deposits, was there anything unique about the DDA trends this quarter, maybe apart from some of the public funds and how are you thinking about sort of DDA as a component of growth going forward?
Yeah, I think the way I would characterize it is, you know, obviously the quarter was down, but if you look over the last several quarters, we've grown consistently. I just went back five quarters. We've had really nice growth going back to the beginning of 2025, and we had particularly strong growth in Q4 and in Q1 of 26. So I really look at, particularly on the NIBD side, is just sort of the normal ebbs and flows in the seasonality of Q2. There were some project-related funds that built up related to some of the condo stuff that moved out. But, you know, we're confident that the long-term sort of trend and sustainability of growth in the space still remains.
Speaker 8
All right. Thanks. And then on the buyback, thanks for the update on the $20 million expected for third quarter. Is that, you know, $20 million a quarter given capital and growth dynamics, and is that a good level to sort of assume for the next, you know, few quarters beyond third quarter?
Yeah, this is Brad. I would say, you know, obviously $20 million for the third quarter. I would expect $20 million for the fourth quarter is our forecast and our expectation, and then we're going to reevaluate it going into 2027.
Operator
Thank you. Our next question comes from the line of Andrew Terrell with Stephen. Your line is not open.
If I could go back to just the loan growth quickly, I think you mentioned in the prepared remarks kind of the low, mid-single-digit kind of goalposts was still where you were looking for kind of full-year loan growth. I heard some of the comments around just maybe some tougher consumer in the third quarter. I'm hoping you can just talk to maybe how the pipeline is building up overall, specifically on the commercial side, you know, what gives you confidence in, you know, growth that I think the guide implies, you know, stable to maybe improving growth in the back half of the year?
Yeah, so, you know, on the residential side or on the consumer side, you know, overall production was quite strong relative to our recent history. A component of that, maybe 25% of the total production was related to a condominium project that closed out this quarter. So, that gave us some extra juice on the residential side to maybe drive some I'll use the term outsized performance at least relative to our recent history so without any projects in the near horizon we'll kind of go down to a more organic level of growth in residential it'll still be positive but it's not going to be nearly the level it was for q2 and you know we continue to see challenges in indirect and home equity just given the rate environment and sort of the realities of cost of cars and financing of cars and so forth. But it'll be positive for the quarter, and it'll contribute to sort of the guide that I've already provided. The commercial side is looking pretty good. I mean, the pipeline, we really started to see the pipeline build out in the beginning part of the year. Q1 was a solid quarter. Q2, you know, we were expecting a little bit better performance, but we had some deals move out to the third quarter. We've seen those close already and the pipeline remains pretty good from my standpoint, healthy. So I feel pretty good about commercial growth. And I think the combination of those, what we see on the commercial side, as well as consumer will keep us in that low mid single digit range.
Great. And then just one on the margin, just to confirm the expectation for 290 exit rate of the year. That does include the assumption for the September rate hike of 25 basis points in there. And then I was hoping you could talk to, we heard, you know, some around the competitive dynamics, some of the deposit side, just competition for new loans today and your comfortability with, I think, your kind of blended reinvestment yield for the fixed and adjustable cash flows was still, you know, 160 basis points this quarter, same as last quarter. Your comfortability with that, you know, remaining relatively stable moving forward.
There was a lot in there. Can you repeat that again just to make sure we're answering your question correctly?
Yeah, I'm sorry. Does your guide include, does the 290 exit margin include the 25 base point September hike?
That's correct. Yeah, so we're expecting mid-September to have one hike, 25 bps.
Okay, and then competition for new loans today. Do you feel like there's any risk to that incremental spread on page 20 of the deck, you know, 160 basis point pickup for the maturity and adjustable, you know, cash flow reinvestment? Do you feel like there's any risk of spread compression there?
No, I don't see that at this point. I mean, spreads have been pretty stable for a while on the loan side. I mean, as we've said in previous quarters, there's always a one-off, but the market remains pretty rational.
Operator
Okay, thank you. Thank you. Our next question comes from the line of Andrew Leisch with Stonex Group. Your line is now open.
Speaker 9
Hey, good morning, Andrew. Just want to see, just kind of looking at the size of the average earning asset base here going forward. Have you seen deposits come back in seasonally this quarter? And it also sounds like you're going to have some other public funds outflows. I guess, how should we be thinking about where earning assets shake out?
Well, I'll start, and then Jim can chime in. This is Brad. Yeah, our earning assets, our average earning assets definitely took a step down from previous quarters, and I expect it to come in probably in the range of $100 million to $200 million this quarter, so relatively consistent where we ended this past quarter.
Speaker 9
All right, that's helpful. Yeah, go ahead, sorry.
No, I was just going to add, I think one of the things that we see out there, particularly in the deposit space, is sort of the higher-cost public deposits. So we're going to take a pretty strategic approach on how we look at those things, and that could have an impact on the ultimate earning asset base. Got it.
Speaker 9
Makes sense. Okay. And then just on the income, did I hear you're currently like $43 million for the third quarter?
Speaker 9
Okay. So if I take the 43.3 this last quarter, if I back out the securities loss there, I mean, you're kind of close to 44.3 million, I mean, or 44 million. I mean, I guess where does – I mean, what's going to cause the step down here, especially given the good commentary on the wealth side?
Well, it's really not a step down. I mean, if you think about those securities losses, really what those are, the Visa B conversion ratio. Right, yes. And so those are consistent quarter to quarter. And so the $43 million is really just consistent to where we finished the second quarter. so it's really a step up from the first quarter and sort of remaining relatively flat from the second quarter. Okay.
Speaker 9
Got it. That's a good way to think about it. Thanks so much. I'll step back. Thank you.
Operator
As a reminder, to ask a question at this time, please press star one one on your touchstone telephone. Our next question comes from the line of Kelly Mata with KBW. Your line is now open.
Speaker 2
Thank you so much for the question. It seems like based on Q2 results, as well as your expense guide of $112.5 million in Q3, that you're running below, or at least at the lower end, the 2.5% to 3% expense guide range you had previously given. Can you provide any color or context to the drivers of that, and if there's any updated color on how you see expenses coming in for the year? Thanks.
Yeah, I think the 2.5% to 3% is still consistent. And the way I look at it is our normalized non-interest expense going into the year was $435 million. So we're just adjusting for normalizing items. And so at 3%, it should come in about $448 for this year. And so I'm thinking on average, quarter by quarter, it's about $112 million. And so the first two quarters, we came in slightly below that. I'm expecting the third and fourth quarter to come in in that 112.5 range, which would land us at the end of the year right at about 3% from that normalized level I was just referencing.
Speaker 2
Got it. Okay. That's helpful. And then with the government deposits being strategic there, can you quantify how large that is in your deposit base and kind of what within that? I'm sure there's some operating accounts. What within that is the target for strategic reduction?
So our public deposits are about $2 billion of our total deposit base. And my expectation is this quarter for us, as far as running off public deposits, about 10% to 15% of those should run off, and those would be high cost deposits. So when I say high cost, I'm thinking somewhere in the range of, you know, three and a half to 4%.
Speaker 2
Okay. Got it. That's helpful. And then just if I could ask one more, when we step back and think about the margin longer term, I think, you know, you've reiterated that 290 by year end, which now includes the rate hike, which I understand is beneficial nearer term but maybe more more neutral longer term as we you think about a that 325 to 350 normalized margin any puts or takes in terms of the timeline of getting there is that still kind of how how we're thinking about it and kind of this change rate environment or um are there any other considerations to note i you know the way i look at it is we're still
on that trajectory, depending on what happens in interest rates, there's a lot of variability. This is, you know, still a couple years down the road, as we've talked about, but I don't see anything, you know, sort of at this point in time that would, you know, deviate, that would cause us to deviate materially from that.
Operator
Thank you. And I'm currently showing no further questions at this time. I now like to hand the call back over to Patricia Lam for closing remarks.
Speaker 2
Thank you everyone for joining us today and for your continued interest in Bank of Hawaii. As always, please feel free to reach out to us if you have any additional questions.
Operator
This concludes today's conference. Thank you for your participation. You may now disconnect.