
COMMERCIAL METALS Co 8-K, filed Oct 15, 2026
COMMERCIAL METALS Co (CMC)
8-K
2026-10-15
For: 2026-10-15
View Original
Added on
October 15, 2026
About this 8-K
COMMERCIAL METALS Co filed this 8-K on October 15, 2026.
Commercial Metals Company reported fiscal 2026 net earnings of $655.8 million and core EBITDA of $1.4 billion, a 14.5% core EBITDA margin. Net leverage adjusted for acquisitions ended at 1.9x, and the board declared a $0.20 quarterly dividend. AI summary
Items reported
- Item 2.02: Financial results
- Item 7.01: Regulation FD disclosure
- Item 9.01: Financial statements and exhibits
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, DC 20549
FORM 8-K
CURRENT REPORT PURSUANT
TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of report (Date of earliest event reported): October 15, 2026
(Exact Name of Registrant as Specified in Charter)
(State or Other Jurisdiction of Incorporation) | ||||||||||||||
(Commission File Number) | (IRS Employer Identification No.) | |||||||||||||
| (Address of Principal Executive Offices) | (Zip Code) | |||||||||||||
(214 ) 689-4300
(Registrant’s Telephone Number, Including Area Code)
Not Applicable
(Former Name or Former Address, if Changed Since Last Report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Trading Symbol(s) | Name of Each Exchange on Which Registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
| Emerging growth company | |||||
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
Item 2.02 Results of Operations and Financial Condition.
On October 15, 2026, CMC issued a press release announcing its financial results for the fourth quarter and the fiscal year ended August 31, 2026. A copy of the press release is attached hereto as Exhibit 99.1. The press release is incorporated by reference into this Item 2.02, and the foregoing description of the press release is qualified in its entirety by reference to Exhibit 99.1.
The information in this Item 2.02 of Form 8-K, including Exhibit 99.1, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), or otherwise subject to liabilities under that section and is not incorporated by reference into any filing of the Company under the Securities Act of 1933, as amended (the "Securities Act"), or the Exchange Act, whether made before or after the date hereof, regardless of any general incorporation language in such filing.
Item 7.01 Regulation FD Disclosure.
On October 15, 2026, CMC made available on its website a financial presentation regarding its financial results for the fourth quarter and the fiscal year ended August 31, 2026. A copy of the financial presentation is attached hereto as Exhibit 99.2. The financial presentation is incorporated by reference into this Item 7.01, and the foregoing description of the financial presentation is qualified in its entirety by reference to Exhibit 99.2.
The information in this Item 7.01 of Form 8-K, including Exhibit 99.2 shall not be deemed “filed” for purposes of Section 18 of the Exchange Act, or otherwise subject to liabilities under that section and is not incorporated by reference into any filing of CMC under the Securities Act or the Exchange Act, whether made before or after the date hereof, regardless of any general incorporation language in such filing.
| Item 9.01 Financial Statements and Exhibits. | |||||
| (d) | Exhibits | ||||
| The following exhibits are being furnished as part of this Current Report on Form 8-K: | |||||
| 99.1 | |||||
| 99.2 | |||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | ||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Commercial Metals Company | ||||||||
| Date: October 15, 2026 | By: /s/ Paul J. Lawrence | |||||||
| Name: Paul J. Lawrence | ||||||||
| Title: Senior Vice President and Chief Financial Officer | ||||||||
Exhibit No. 99.1
News Release 
CMC REPORTS FOURTH QUARTER AND FULL YEAR FISCAL 2026 RESULTS
•Fiscal 2026 net earnings of $655.8 million. Consolidated core EBITDA increased to $1.4 billion, from $837.3 million in fiscal 2025. Core EBITDA margin increased by 380 basis points to 14.5%.
•Fourth quarter net earnings of $212.5 million, or $1.91 per diluted share, and adjusted earnings of $233.6 million, or $2.09 per diluted share
•Fourth quarter consolidated core EBITDA increased 35.1% year-over-year to $393.7 million and core EBITDA margin increased by 100 basis points to 14.8%
•Improved results were driven by strong growth in the North America Steel Group, the inclusion of the acquired precast operations, and benefits from Transform, Advance, Grow (“TAG”) initiatives
•Precast integration on track
•Reduced net leverage adjusted for acquisitions1 to below 2x target
Irving, TX - October 15, 2026 - CMC (NYSE: CMC) (the "Company") today announced financial results for its fiscal fourth quarter and fiscal year ended August 31, 2026.
CEO Commentary
“Fiscal 2026 marked a transformational step forward for CMC. We continued to build organizational strength and enhance margin durability in our early-stage construction portfolio through our precast acquisitions, our successful TAG program, and our key growth investments, including our West Virginia micro mill. We also established a clear roadmap to fiscal 2029, setting ambitious and achievable targets with a focus on delivering long-term shareholder value,” said Peter Matt, President and Chief Executive Officer. "Our fourth quarter core EBITDA performance delivered solid year-over-year growth, driven by strong execution of our North American steel franchise and continued momentum of enterprise-wide TAG benefits. While broader demand conditions remain supportive, residential softness weighed on precast results in the period. With backlogs near record levels, a differentiated portfolio of solutions, and multiple value creation levers, we are well-positioned to deliver strong financial results and achieve our strategic goals in fiscal 2027."
1 Net leverage adjusted for acquisitions is a non-GAAP financial measure and is defined as net debt divided by modified consolidated EBITDA, both of which are also non-GAAP financial measures. Net debt is calculated as total debt minus cash and cash equivalents. Modified consolidated EBITDA is calculated as adjusted EBITDA for the trailing 12-month period, adjusted to (a) eliminate the impact of approximately $15.4 million of interest expense related to the judgment in the Pacific Steel Group litigation, (b) eliminate actual results from the precast business since the respective acquisition dates and (c) include $212 million of annualized EBITDA contribution from the precast business. Reconciliations to the most directly comparable measures prepared and presented in accordance with GAAP can be found in the financial tables that follow.
(CMC Fourth Quarter Fiscal 2026 - 2)
Fourth Quarter Operational and Financial Highlights
| Three Months Ended | ||||||||||||||||||||||||||||||||
| (in thousands, except per share data) | 8/31/2026 | 5/31/2026 | 8/31/2025 | QoQ Change | YoY Change | |||||||||||||||||||||||||||
| Net sales | $ | 2,658,334 | $ | 2,483,245 | $ | 2,114,518 | 7.1 | % | 25.7 | % | ||||||||||||||||||||||
| Net earnings | $ | 212,520 | $ | 173,015 | $ | 151,781 | 22.8 | % | 40.0 | % | ||||||||||||||||||||||
| Core EBITDA | $ | 393,658 | $ | 353,596 | $ | 291,441 | 11.3 | % | 35.1 | % | ||||||||||||||||||||||
| Core EBITDA margin | 14.8% | 14.2% | 13.8% | 60bps | 100bps | |||||||||||||||||||||||||||
| Net earnings per diluted share | $ | 1.91 | $ | 1.55 | $ | 1.35 | 23.2 | % | 41.5 | % | ||||||||||||||||||||||
| Adjusted earnings | $ | 233,590 | $ | 193,025 | $ | 154,965 | 21.0 | % | 50.7 | % | ||||||||||||||||||||||
| Adjusted earnings per diluted share | $ | 2.09 | $ | 1.73 | $ | 1.37 | 20.8 | % | 52.6 | % | ||||||||||||||||||||||
For the fourth quarter of fiscal 2026, the Company reported consolidated net earnings of $212.5 million or $1.91 per diluted share, up from $1.35 in the prior year period, due in part to a lower effective tax rate. Adjusted earnings were $233.6 million, or $2.09 per diluted share, an increase of 52.6% on a per-share basis versus the comparable prior year period.
Consolidated core EBITDA for the fiscal fourth quarter increased 35.1% year-over-year to $393.7 million, while core EBITDA margins expanded 100 basis points to 14.8%, driven by metal margin expansion and the inclusion of the higher-margin precast business. Relative to the fiscal third quarter, 11.3% core EBITDA growth was led by the North America Steel Group, where stronger margins and volume growth drove 60 basis points of core EBITDA margin expansion.
Business Segments - Fiscal Fourth Quarter 2026 Review
North America Steel Group
Fourth quarter North America Steel Group adjusted EBITDA increased 32.6% year-over-year to $317.5 million, while adjusted EBITDA margin increased to 16.4%, up from 14.8% in the prior year period. Segment performance reflects a combination of higher average selling price for steel products, merchant bar-led volume growth, and ongoing benefits from the Company’s TAG program.
Compared with the prior year period, metal margins increased $84 per ton to $652. Sequentially, metal margins improved by $42 per ton, driven primarily by a $32 per ton increase in average selling price while scrap costs declined $10 per ton. Sequential pricing growth reflects a balanced supply-demand environment, continued momentum in rebar and MBQ pricing, and ongoing commercial discipline.
Finished goods shipment volumes for the North America Steel Group increased 5.3% versus the prior year period. Merchant bar shipment volumes surged 27.5% year-over-year, and 16.0% sequentially, driven by continued strength in industrial applications, including data center-related activity, as well as our expanded merchant bar production capabilities at the Arizona 2 micro mill. Taken together, rebar and downstream product shipment volumes were essentially flat year-over-year and up 4.4% sequentially, reflecting our commercial discipline as well as our
(CMC Fourth Quarter Fiscal 2026 - 3)
differentiated capabilities that position us well to meet the complexity associated with large-scale megaproject demand.
Market conditions remain solid, with demand strength across the energy build-out, semiconductor manufacturing, industrial manufacturing, and key public infrastructure markets. These conditions have contributed to a healthy and growing backlog, with downstream backlog volumes increasing 5.0% sequentially and 15.5% year-over-year. Similarly, backlog pricing continues to trend higher, reflecting disciplined execution, healthy demand, and our differentiated market position across core end markets.
Construction Solutions Group
Construction Solutions Group ("CSG") fourth quarter net sales increased 94.5% to $431.4 million and adjusted EBITDA of $101.7 million was up 100.9% year-over-year. Adjusted EBITDA margin of 23.6% was up 80 basis points relative to the prior year period. In the period, precast sales and adjusted EBITDA were $190.8 million and $57.0 million, respectively. Precast adjusted EBITDA fell below management's prior expectations, primarily due to regional residential softness, which reduced volumes and created regional margin mix headwinds. Precast shipments decreased year-over-year with weakness in the Southeast that more than offset strong shipment growth in the Mid-Atlantic. Underlying precast demand remains healthy, with strong momentum in non-residential and infrastructure end markets. In the fourth quarter, bookings were up year-over-year and up 12.6% sequentially. Backlog increased roughly 3% from the prior year and nearly 4% from the fiscal third quarter, and average selling price continued to move higher, reflecting solid market fundamentals. These indicators reinforce our confidence in the outlook for the precast business and its ability to deliver higher growth, greater earnings stability, and stronger returns for CMC in 2027.
Tensar delivered results that were largely consistent with both the prior quarter and the year-ago period, capping off a strong fiscal 2026 in which profitability increased approximately 50%. Performance was driven by favorable construction activity across several key end markets, including data centers, energy, and infrastructure. Construction Services and Impact Metals also delivered strong revenue and adjusted EBITDA growth year on year. Performance Reinforcing Steel's results were lower due to a significant unplanned outage at Galvabar that impacted shipments during the quarter. Encouragingly, bookings, backlogs and pricing trends for that business remain strong, and the operational flexibility coming from the second Galvabar line, which will be commissioned later in calendar 2026, will further enhance our ability to serve demand and support future growth.
Europe Steel Group
For the fourth quarter, Europe Steel Group generated adjusted EBITDA of $15.6 million, versus $39.1 million in the prior year period, with the year-over-year comparison impacted by a $30.7 million CO₂ credit recognized in the prior year, while no credit was recognized in the current period. Metal margin expanded by $32 per ton year-over-year as average selling price increased $44 per ton and outpaced scrap costs, which increased $12 per ton over the same period. Finished goods shipment volumes for the Europe Steel Group increased 0.8% as lower rebar volumes were more than offset by strong growth in merchant bar and wire rod. Improved trade policies via the
(CMC Fourth Quarter Fiscal 2026 - 4)
EU Carbon Border Adjustment Mechanism ("CBAM") as well as the tariff-rate quota ("TRQ") system implemented July 1, 2026 are supporting a more constructive operating environment. Combined with gradually improving end-market demand trends, these developments reinforce our confidence in a return to mid-cycle performance levels.
Balance Sheet & Capital Allocation
As of August 31, 2026, cash, cash equivalents and restricted cash totaled $778.9 million and available liquidity was over $2.0 billion. Net leverage adjusted for acquisitions ended the quarter at 1.9x reflecting strong cash generation and balance sheet discipline.
During the quarter, CMC repurchased 383,333 shares of common stock valued at $26.7 million in the aggregate. As of August 31, 2026, $702.1 million remained available under the current share repurchase authorization.
On October 13, 2026, the board of directors declared a quarterly dividend of $0.20 per share of CMC common stock payable to stockholders of record on October 28, 2026. The dividend, to be paid on November 11, 2026, will mark the 248th consecutive quarterly payment by the Company.
Outlook
Mr. Matt added, “We expect fiscal 2027 will be another strong year for CMC, supported by a healthy and balanced market backdrop and the growing contribution from our value creation levers, including TAG, our growth investments, and an evolving early-stage construction portfolio. Our focus remains on delivering profitable growth, improving free cash flow generation, enhancing shareholder returns, and, above all, continuing to advance our strategic agenda for a stronger CMC."
For the first quarter of fiscal 2027, we continue to expect healthy operating performance across the portfolio with normal seasonal factors and input cost dynamics to impact results sequentially:
•For the North America Steel Group, improved pricing is expected to largely offset higher scrap costs, startup expenses, and a slight seasonal decline in shipments, resulting in adjusted EBITDA that is expected to be nearly flat in comparison to the fourth quarter.
•Within the Construction Solutions Group, adjusted EBITDA is expected to be down sequentially reflecting typical seasonal trends impacting the end market activity of this segment.
•Meaningful sequential growth in adjusted EBITDA is anticipated for the Europe Steel Group with the first quarter benefiting from improving operating conditions and a CO2 credit.
Conference Call
CMC invites you to listen to a live broadcast of its fourth quarter fiscal 2026 conference call today, Thursday, October 15, 2026 at 11:00 a.m. ET. Peter Matt, President and Chief Executive Officer, and Paul Lawrence, Senior Vice President and Chief Financial Officer, will host the call. The call is accessible via our website at www.cmc.com. In the event you are unable to listen to the live broadcast, the call will be archived and available
(CMC Fourth Quarter Fiscal 2026 - 5)
for replay on our website on the next business day. Financial and statistical information presented in the broadcast are located on CMC's website under "Investors."
About CMC
CMC is a Fortune 500 company headquartered in Irving, Texas, and a leading provider of early-stage construction solutions that support the foundational phases of modern infrastructure and building projects. Founded in 1915, CMC has grown from a single-site recycling operation to one of the largest U.S. manufacturers of steel reinforcing bar ("rebar"), a leading producer of subgrade soil stabilization and foundation enhancement solutions and a major supplier of concrete pipe and precast products.
Through an extensive manufacturing network primarily located in the United States and Central Europe, with strategic operations in the United Kingdom, Europe and Asia, CMC serves infrastructure, non-residential, residential, industrial and energy markets. While often unseen, CMC’s products are essential to highways, bridges, airports, commercial buildings and other critical structures that support everyday life.
(CMC Fourth Quarter Fiscal 2026 - 6)
Forward-Looking Statements
This news release contains forward-looking statements within the meaning of the federal securities laws with respect to the expected performance of our recently acquired precast platform, general economic conditions, key macro-economic drivers that impact our business, the effects of ongoing trade actions, the effects of continued pressure on the liquidity of our customers, potential synergies and growth provided by acquisitions and strategic investments, demand for our products, shipment volumes, metal margins, backlog volumes, the ability to operate our steel mills at full capacity, particularly during periods of domestic mill start-ups, the future availability and cost of supplies of raw materials and energy for our operations, growth rates in certain reportable segments, product margins within our Construction Solutions Group segment, share repurchases, legal proceedings, construction activity, international trade, the impact of geopolitical conditions, the effects of CBAM and other EU trade measures on European demand and pricing, capital expenditures, tax credits, the timing, amount and recurrence of CO2 or emissions-related credits, our liquidity and our ability to satisfy future liquidity requirements, our ability to achieve our stated deleveraging target within the anticipated timeframe, estimated contractual obligations, the expected capabilities and benefits of new facilities, the anticipated benefits and timeline for execution of our growth plan and initiatives, including our TAG operational and commercial excellence program, and our expectations or beliefs concerning future events. The statements in this release that are not historical statements are forward-looking statements. These forward-looking statements can generally be identified by phrases such as we or our management "expects," "anticipates," "believes," "estimates," "intends," "may," "plans to," "ought," "could," "will," "should," "likely," "appears," "projects," "forecasts," "outlook" or other similar words or phrases, as well as by discussions of strategy, plans or intentions.
The Company's forward-looking statements are based on management’s expectations and beliefs as of the date this news release. Although we believe that our expectations are reasonable, we can give no assurance that these expectations will prove to have been correct, and actual results may vary materially. Except as required by law, we undertake no obligation to update, amend or clarify any forward-looking statements to reflect changed assumptions, the occurrence of anticipated or unanticipated events, new information or circumstances or any other changes. Important factors that could cause actual results to differ materially from our expectations include those described in our filings with the U.S. Securities and Exchange Commission, including, but not limited to, in Part I, Item 1A, "Risk Factors" of our annual report on Form 10-K for the fiscal year ended August 31, 2025, as well as the following: changes in economic conditions which affect demand for our products or construction activity generally, and the impact of such changes on the highly cyclical steel industry; rapid and significant changes in the price of metals, potentially impairing our inventory values due to declines in commodity prices or reducing the profitability of downstream contracts within our vertically integrated steel operations due to rising commodity pricing; excess capacity in our industry, particularly in China, and product availability from competing steel mills and other steel suppliers including import quantities and pricing; the impact of additional steelmaking capacity expected to come online from a number of ongoing electric arc furnace projects in the U.S.; the impact of geopolitical conditions,
(CMC Fourth Quarter Fiscal 2026 - 7)
including political turmoil and volatility, regional conflicts, terrorism and war on the global economy, inflation, energy supplies and raw materials; global factors, such as trade measures, military conflicts and political uncertainties, including changes to current trade regulations, such as Section 232 trade tariffs and quotas, tax legislation and other regulations which might adversely impact our business; operating and startup risks, as well as market risks associated with the commissioning of new projects could prevent us from realizing anticipated benefits and could result in a loss of all or a substantial part of our investments; our ability to successfully execute our TAG operational and commercial excellence program and other transformation initiatives, including the realization of anticipated benefits within the expected timeframes; attention to environmental, social and governance ("ESG") matters, including any targets or other ESG, environmental justice or regulatory initiatives; impacts from global public health crises on the economy, demand for our products, global supply chain and on our operations; compliance with and changes in existing and future laws, regulations and other legal requirements and judicial decisions that govern our business, including increased environmental regulations associated with climate change and greenhouse gas emissions; involvement in various environmental matters that may result in fines, penalties or judgments; evolving remediation technology, changing regulations, possible third-party contributions, the inherent uncertainties of the estimation process and other factors that may impact amounts accrued for environmental liabilities; potential limitations in our or our customers' abilities to access credit and non-compliance with their contractual obligations, including payment obligations; activity in repurchasing shares of our common stock under our share repurchase program; financial and non-financial covenants and restrictions on the operation of our business contained in agreements governing our debt; our ability to successfully identify, consummate and integrate acquisitions and realize any or all of the anticipated synergies or other benefits of acquisitions; the effects that acquisitions may have on our financial leverage; risks associated with acquisitions generally, such as the inability to obtain, or delays in obtaining, required approvals under applicable antitrust legislation and other regulatory and third-party consents and approvals; lower than expected future levels of revenues and higher than expected future costs; failure or inability to implement growth strategies in a timely manner; the impact of goodwill or other indefinite-lived intangible asset impairment charges; the impact of long-lived asset impairment charges; currency fluctuations; availability and pricing of electricity, electrodes and natural gas for mill operations; our ability to hire and retain key executives and other employees; competition from other materials or from competitors that have a lower cost structure or access to greater financial resources; information technology interruptions and breaches in security; our ability to make necessary capital expenditures; availability and pricing of raw materials and other items over which we exert little influence, including scrap metal, energy and insurance; unexpected equipment failures; losses or limited potential gains due to hedging transactions; litigation claims and settlements, court decisions, regulatory rulings and legal compliance risks, including those related to the Pacific Steel Group litigation and other legal proceedings; risk of injury or death to employees, customers or other visitors to our operations; and civil unrest, protests and riots.
(CMC Fourth Quarter Fiscal 2026 - 8)
| COMMERCIAL METALS COMPANY AND SUBSIDIARIES FINANCIAL & OPERATING STATISTICS (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Year Ended | |||||||||||||||||||||||||||||||||||||||||||
| (in thousands, except per ton amounts) | 8/31/2026 | 5/31/2026 | 2/28/2026 | 11/30/2025 | 8/31/2025 | 8/31/2026 | 8/31/2025 | |||||||||||||||||||||||||||||||||||||
| North America Steel Group | ||||||||||||||||||||||||||||||||||||||||||||
| Net sales to external customers | $ | 1,939,404 | $ | 1,789,381 | $ | 1,608,321 | $ | 1,661,058 | $ | 1,616,078 | $ | 6,998,164 | $ | 6,083,849 | ||||||||||||||||||||||||||||||
| Adjusted EBITDA | 317,473 | 253,487 | 269,674 | 293,906 | 239,416 | 1,134,540 | 742,485 | |||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA margin | 16.4% | 14.2% | 16.8% | 17.7% | 14.8% | 16.2% | 12.2% | |||||||||||||||||||||||||||||||||||||
| External tons shipped | ||||||||||||||||||||||||||||||||||||||||||||
| Raw materials | 460 | 482 | 358 | 384 | 374 | 1,684 | 1,410 | |||||||||||||||||||||||||||||||||||||
| Rebar | 507 | 482 | 481 | 544 | 544 | 2,014 | 2,130 | |||||||||||||||||||||||||||||||||||||
| Merchant bar and other | 311 | 268 | 235 | 251 | 244 | 1,065 | 992 | |||||||||||||||||||||||||||||||||||||
| Steel products | 818 | 750 | 716 | 795 | 788 | 3,079 | 3,122 | |||||||||||||||||||||||||||||||||||||
| Downstream products | 397 | 384 | 335 | 350 | 366 | 1,466 | 1,375 | |||||||||||||||||||||||||||||||||||||
| Average selling price per ton | ||||||||||||||||||||||||||||||||||||||||||||
| Raw materials | $ | 981 | $ | 873 | $ | 985 | $ | 900 | $ | 881 | $ | 935 | $ | 876 | ||||||||||||||||||||||||||||||
| Steel products | 1,021 | 989 | 974 | 939 | 882 | 981 | 842 | |||||||||||||||||||||||||||||||||||||
| Downstream products | 1,288 | 1,260 | 1,242 | 1,236 | 1,214 | 1,258 | 1,226 | |||||||||||||||||||||||||||||||||||||
| Cost of raw materials per ton | $ | 754 | $ | 660 | $ | 741 | $ | 648 | $ | 649 | $ | 701 | $ | 661 | ||||||||||||||||||||||||||||||
| Cost of ferrous scrap utilized per ton | $ | 369 | $ | 379 | $ | 351 | $ | 318 | $ | 314 | $ | 354 | $ | 333 | ||||||||||||||||||||||||||||||
| Steel products metal margin per ton | $ | 652 | $ | 610 | $ | 623 | $ | 621 | $ | 568 | $ | 627 | $ | 509 | ||||||||||||||||||||||||||||||
| Construction Solutions Group | ||||||||||||||||||||||||||||||||||||||||||||
| Net sales to external customers | $ | 431,375 | $ | 394,574 | $ | 314,425 | $ | 198,277 | $ | 221,753 | $ | 1,338,651 | $ | 747,486 | ||||||||||||||||||||||||||||||
| Adjusted EBITDA | 101,725 | 97,411 | 53,420 | 39,581 | 50,630 | 292,137 | 137,721 | |||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA margin | 23.6% | 24.7% | 17.0% | 20.0% | 22.8% | 21.8% | 18.4% | |||||||||||||||||||||||||||||||||||||
| Europe Steel Group | ||||||||||||||||||||||||||||||||||||||||||||
| Net sales to external customers | $ | 281,222 | $ | 291,235 | $ | 200,014 | $ | 247,650 | $ | 263,294 | $ | 1,020,121 | $ | 918,320 | ||||||||||||||||||||||||||||||
| Adjusted EBITDA | 15,586 | 34,665 | (1,428) | 10,929 | 39,098 | 59,752 | 69,282 | |||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA margin | 5.5% | 11.9% | (0.7)% | 4.4% | 14.8% | 5.9% | 7.5% | |||||||||||||||||||||||||||||||||||||
| External tons shipped | ||||||||||||||||||||||||||||||||||||||||||||
| Rebar | 106 | 136 | 69 | 119 | 117 | 430 | 412 | |||||||||||||||||||||||||||||||||||||
| Merchant bar and other | 271 | 265 | 215 | 243 | 257 | 994 | 944 | |||||||||||||||||||||||||||||||||||||
| Steel products | 377 | 401 | 284 | 362 | 374 | 1,424 | 1,356 | |||||||||||||||||||||||||||||||||||||
| Average selling price per ton | ||||||||||||||||||||||||||||||||||||||||||||
| Steel products | $ | 712 | $ | 697 | $ | 672 | $ | 651 | $ | 668 | $ | 684 | $ | 647 | ||||||||||||||||||||||||||||||
| Cost of ferrous scrap utilized per ton | $ | 363 | $ | 367 | $ | 356 | $ | 345 | $ | 351 | $ | 359 | $ | 357 | ||||||||||||||||||||||||||||||
| Steel products metal margin per ton | $ | 349 | $ | 330 | $ | 316 | $ | 306 | $ | 317 | $ | 325 | $ | 290 | ||||||||||||||||||||||||||||||
(CMC Fourth Quarter Fiscal 2026 - 9)
| COMMERCIAL METALS COMPANY AND SUBSIDIARIES BUSINESS SEGMENTS (UNAUDITED) | ||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Year Ended | |||||||||||||||||||||||||||||||||||||||||||
| (in thousands) | 8/31/2026 | 5/31/2026 | 2/28/2026 | 11/30/2025 | 8/31/2025 | 8/31/2026 | 8/31/2025 | |||||||||||||||||||||||||||||||||||||
| Net sales to external customers | ||||||||||||||||||||||||||||||||||||||||||||
| North America Steel Group | $ | 1,939,404 | $ | 1,789,381 | $ | 1,608,321 | $ | 1,661,058 | $ | 1,616,078 | $ | 6,998,164 | $ | 6,083,849 | ||||||||||||||||||||||||||||||
| Construction Solutions Group | 431,375 | 394,574 | 314,425 | 198,277 | 221,753 | 1,338,651 | 747,486 | |||||||||||||||||||||||||||||||||||||
| Europe Steel Group | 281,222 | 291,235 | 200,014 | 247,650 | 263,294 | 1,020,121 | 918,320 | |||||||||||||||||||||||||||||||||||||
| Corporate and Other | 6,333 | 8,055 | 9,258 | 13,322 | 13,393 | 36,968 | 48,825 | |||||||||||||||||||||||||||||||||||||
| Total net sales to external customers | $ | 2,658,334 | $ | 2,483,245 | $ | 2,132,018 | $ | 2,120,307 | $ | 2,114,518 | $ | 9,393,904 | $ | 7,798,480 | ||||||||||||||||||||||||||||||
| Adjusted EBITDA | ||||||||||||||||||||||||||||||||||||||||||||
| North America Steel Group | $ | 317,473 | $ | 253,487 | $ | 269,674 | $ | 293,906 | $ | 239,416 | $ | 1,134,540 | $ | 742,485 | ||||||||||||||||||||||||||||||
| Construction Solutions Group | 101,725 | 97,411 | 53,420 | 39,581 | 50,630 | 292,137 | 137,721 | |||||||||||||||||||||||||||||||||||||
| Europe Steel Group | 15,586 | 34,665 | (1,428) | 10,929 | 39,098 | 59,752 | 69,282 | |||||||||||||||||||||||||||||||||||||
| Corporate and Other | (52,356) | (49,654) | (70,410) | (55,848) | (50,716) | (228,268) | (508,765) | |||||||||||||||||||||||||||||||||||||
| Total adjusted EBITDA | $ | 382,428 | $ | 335,909 | $ | 251,256 | $ | 288,568 | $ | 278,428 | $ | 1,258,161 | $ | 440,723 | ||||||||||||||||||||||||||||||
(CMC Fourth Quarter Fiscal 2026 - 10)
COMMERCIAL METALS COMPANY AND SUBSIDIARIES CONSOLIDATED STATEMENTS OF EARNINGS (UNAUDITED) | ||||||||||||||||||||||||||
| Three Months Ended August 31, | Year Ended August 31, | |||||||||||||||||||||||||
| (in thousands, except share and per share data) | 2026 | 2025 | 2026 | 2025 | ||||||||||||||||||||||
| Net sales | $ | 2,658,334 | $ | 2,114,518 | $ | 9,393,904 | $ | 7,798,480 | ||||||||||||||||||
| Costs and operating expenses: | ||||||||||||||||||||||||||
| Cost of goods sold | 2,156,827 | 1,721,710 | 7,642,218 | 6,578,324 | ||||||||||||||||||||||
| Selling, general and administrative expenses | 230,857 | 180,218 | 881,961 | 700,234 | ||||||||||||||||||||||
| Interest expense | 37,356 | 12,145 | 143,337 | 45,498 | ||||||||||||||||||||||
| Litigation expense | 3,776 | 3,776 | 15,356 | 362,272 | ||||||||||||||||||||||
| Asset impairments | 21 | 3,436 | 21 | 4,607 | ||||||||||||||||||||||
| Net costs and operating expenses | 2,428,837 | 1,921,285 | 8,682,893 | 7,690,935 | ||||||||||||||||||||||
| Earnings before income taxes | 229,497 | 193,233 | 711,011 | 107,545 | ||||||||||||||||||||||
| Income tax expense | 16,977 | 41,452 | 55,162 | 22,883 | ||||||||||||||||||||||
| Net earnings | $ | 212,520 | $ | 151,781 | $ | 655,849 | $ | 84,662 | ||||||||||||||||||
Earnings per share: | ||||||||||||||||||||||||||
| Basic | $ | 1.92 | $ | 1.36 | $ | 5.92 | $ | 0.75 | ||||||||||||||||||
| Diluted | 1.91 | 1.35 | 5.86 | 0.74 | ||||||||||||||||||||||
| Cash dividends per share | $ | 0.20 | $ | 0.18 | $ | 0.76 | $ | 0.72 | ||||||||||||||||||
| Average basic shares outstanding | 110,570,463 | 111,677,574 | 110,857,469 | 112,994,381 | ||||||||||||||||||||||
| Average diluted shares outstanding | 111,542,800 | 112,705,122 | 111,864,867 | 114,086,750 | ||||||||||||||||||||||
(CMC Fourth Quarter Fiscal 2026 - 11)
COMMERCIAL METALS COMPANY AND SUBSIDIARIES CONSOLIDATED BALANCE SHEETS (UNAUDITED) | ||||||||||||||
| (in thousands, except share and per share data) | August 31, 2026 | August 31, 2025 | ||||||||||||
| Assets | ||||||||||||||
| Current assets: | ||||||||||||||
| Cash and cash equivalents | $ | 775,676 | $ | 1,043,252 | ||||||||||
| Restricted cash | 3,174 | 2,652 | ||||||||||||
Accounts receivable (less allowance for doubtful accounts of $3,867 and $3,186) | 1,440,260 | 1,200,881 | ||||||||||||
| Income tax receivable | 131,557 | 799 | ||||||||||||
| Inventories | 1,104,719 | 934,310 | ||||||||||||
| Prepaid and other current assets | 352,441 | 312,924 | ||||||||||||
| Total current assets | 3,807,827 | 3,494,818 | ||||||||||||
| Property, plant and equipment: | ||||||||||||||
| Land | 246,300 | 170,823 | ||||||||||||
| Buildings and improvements | 1,626,950 | 1,206,672 | ||||||||||||
| Equipment | 4,172,111 | 3,477,813 | ||||||||||||
| Construction in process | 188,637 | 449,616 | ||||||||||||
| 6,233,998 | 5,304,924 | |||||||||||||
| Less accumulated depreciation and amortization | (2,780,284) | (2,562,151) | ||||||||||||
| Property, plant and equipment, net | 3,453,714 | 2,742,773 | ||||||||||||
| Intangible assets, net | 431,681 | 210,815 | ||||||||||||
| Goodwill | 2,138,616 | 386,846 | ||||||||||||
| Other noncurrent assets | 426,059 | 336,582 | ||||||||||||
| Total assets | $ | 10,257,897 | $ | 7,171,834 | ||||||||||
| Liabilities and stockholders' equity | ||||||||||||||
| Current liabilities: | ||||||||||||||
| Accounts payable | $ | 540,901 | $ | 358,373 | ||||||||||
| Accrued contingent litigation-related loss | 377,251 | 362,272 | ||||||||||||
| Other accrued expenses and payables | 642,946 | 493,879 | ||||||||||||
| Current maturities of long-term debt | 67,147 | 44,289 | ||||||||||||
| Total current liabilities | 1,628,245 | 1,258,813 | ||||||||||||
| Deferred income taxes | 354,298 | 184,645 | ||||||||||||
| Other noncurrent liabilities | 264,420 | 225,044 | ||||||||||||
| Long-term debt | 3,313,728 | 1,310,006 | ||||||||||||
| Total liabilities | 5,560,691 | 2,978,508 | ||||||||||||
| Stockholders' equity: | ||||||||||||||
Common stock, par value $0.01 per share; authorized 200,000,000 shares; issued 129,060,664 shares; outstanding 110,316,995 and 111,189,136 shares | 1,290 | 1,290 | ||||||||||||
| Additional paid-in capital | 423,334 | 406,916 | ||||||||||||
| Accumulated other comprehensive loss | (29,175) | (25,251) | ||||||||||||
| Retained earnings | 5,078,714 | 4,507,114 | ||||||||||||
Less treasury stock, 18,743,669 and 17,871,528 shares at cost | (777,231) | (697,003) | ||||||||||||
| Stockholders' equity | 4,696,932 | 4,193,066 | ||||||||||||
| Stockholders' equity attributable to non-controlling interests | 274 | 260 | ||||||||||||
| Total stockholders' equity | 4,697,206 | 4,193,326 | ||||||||||||
| Total liabilities and stockholders' equity | $ | 10,257,897 | $ | 7,171,834 | ||||||||||
(CMC Fourth Quarter Fiscal 2026 - 12)
COMMERCIAL METALS COMPANY AND SUBSIDIARIES CONSOLIDATED STATEMENTS OF CASH FLOWS (UNAUDITED) | ||||||||||||||||||||
| Year Ended August 31, | ||||||||||||||||||||
| (in thousands) | 2026 | 2025 | ||||||||||||||||||
| Cash flows from (used by) operating activities: | ||||||||||||||||||||
| Net earnings | $ | 655,849 | $ | 84,662 | ||||||||||||||||
Adjustments to reconcile net earnings to net cash flows from operating activities: | ||||||||||||||||||||
| Depreciation and amortization | 395,921 | 285,877 | ||||||||||||||||||
| Stock-based compensation | 43,932 | 37,053 | ||||||||||||||||||
| Write-off of committed financing fees | 11,563 | — | ||||||||||||||||||
| Deferred income taxes and other long-term taxes | 158,351 | (98,304) | ||||||||||||||||||
| Write-down of inventory | 333 | 2,473 | ||||||||||||||||||
| Unrealized loss (gain) on undesignated commodity hedges | 7,871 | (2,804) | ||||||||||||||||||
| Unrealized loss (gain) on undesignated foreign exchange hedges | 5,091 | (5,453) | ||||||||||||||||||
| Amortization of debt issuance costs | 4,812 | 1,529 | ||||||||||||||||||
| Asset impairments | 21 | 4,607 | ||||||||||||||||||
Net loss (gain) on sale of net assets | (741) | 1,827 | ||||||||||||||||||
| Litigation expense | 15,356 | 362,272 | ||||||||||||||||||
| Settlement of New Markets Tax Credit transaction | — | (2,786) | ||||||||||||||||||
| Other | 2,110 | 5,568 | ||||||||||||||||||
| Changes in operating assets and liabilities | (241,506) | 38,549 | ||||||||||||||||||
Net cash flows from operating activities | 1,058,963 | 715,070 | ||||||||||||||||||
| Cash flows from (used by) investing activities: | ||||||||||||||||||||
| Acquisitions, net of cash acquired | (2,516,424) | — | ||||||||||||||||||
| Capital expenditures | (579,844) | (402,821) | ||||||||||||||||||
| Proceeds from government assistance related to property, plant and equipment | 15,000 | 50,000 | ||||||||||||||||||
| Proceeds from the sale of property, plant and equipment | 11,250 | 5,758 | ||||||||||||||||||
| Proceeds from insurance | 9,602 | 2,237 | ||||||||||||||||||
| Other | (1,698) | (1,946) | ||||||||||||||||||
Net cash flows used by investing activities | (3,062,114) | (346,772) | ||||||||||||||||||
| Cash flows from (used by) financing activities: | ||||||||||||||||||||
| Proceeds from issuance of long-term debt, net | 1,985,000 | 147,724 | ||||||||||||||||||
| Repayments of long-term debt | (47,689) | (41,480) | ||||||||||||||||||
| Debt issuance costs | (8,489) | (622) | ||||||||||||||||||
| Committed financing fees | (11,563) | — | ||||||||||||||||||
| Proceeds from accounts receivable facilities | 173,257 | 35,979 | ||||||||||||||||||
| Repayments under accounts receivable facilities | (164,328) | (35,979) | ||||||||||||||||||
| Treasury stock acquired | (102,811) | (198,822) | ||||||||||||||||||
| Tax withholdings related to share settlements, net of purchase plans | (3,111) | (8,823) | ||||||||||||||||||
| Dividends | (84,249) | (81,433) | ||||||||||||||||||
| Contribution from non-controlling interest | 14 | 12 | ||||||||||||||||||
Net cash flows from (used by) financing activities | 1,736,031 | (183,444) | ||||||||||||||||||
| Effect of exchange rate changes on cash | 66 | 1,495 | ||||||||||||||||||
Increase (decrease) in cash and cash equivalents | (267,054) | 186,349 | ||||||||||||||||||
| Cash, restricted cash and cash equivalents at beginning of period | 1,045,904 | 859,555 | ||||||||||||||||||
| Cash, restricted cash and cash equivalents at end of period | $ | 778,850 | $ | 1,045,904 | ||||||||||||||||
(CMC Fourth Quarter Fiscal 2026 - 13)
COMMERCIAL METALS COMPANY
NON-GAAP FINANCIAL MEASURES (UNAUDITED)
This press release contains financial measures not derived in accordance with U.S. generally accepted accounting principles ("GAAP"). Reconciliations to the most comparable GAAP measure are provided below.
Adjusted EBITDA, core EBITDA, core EBITDA margin and adjusted earnings are non-GAAP financial measures. Adjusted earnings per diluted share is defined as adjusted earnings on a diluted per share basis. Core EBITDA margin is defined as core EBITDA divided by net sales. The adjustment "Settlement of New Markets Tax Credit transactions" represents the recognition of deferred revenue from 2016 and 2017 resulting from the Company’s participation in the New Markets Tax Credit program provided for in the Community Renewal Tax Relief Act of 2000 during the development of a micro mill, spooler and T-post shop located in eligible zones as determined by the Internal Revenue Service. The adjustment "Litigation expense" represents a provision recorded in the three months ended November 30, 2024 related to the judgment in the Pacific Steel Group litigation and, with respect to subsequent periods, primarily represents interest expense on the judgment amount. The adjustments “Acquisition and integration related costs” and "Acquisition, integration and financing related costs" represent nonrecurring fees associated with the Foley Products Company, LLC (“Foley”) and Concrete Pipe and Precast, LLC (“CP&P”) acquisitions. The adjustment "Purchase accounting effect on inventory" represents a one time fair value adjustment on inventory associated with the Foley and CP&P acquisitions. The adjustment "Amortization of acquired contract backlog" represents the amortization of the contract backlog intangible asset from the Foley and CP&P acquisitions.
Net leverage adjusted for acquisitions is a non-GAAP financial measure and is defined as net debt divided by modified consolidated EBITDA, both of which are also non-GAAP financial measures. Net debt is calculated as total debt minus cash and cash equivalents. Modified consolidated EBITDA is calculated as adjusted EBITDA for the trailing 12-month period, adjusted to (a) eliminate the impact of approximately $15.4 million of interest expense related to the judgment in the Pacific Steel Group litigation, (b) eliminate actual results from the precast business since the respective acquisition dates and (c) include $212 million of annualized EBITDA contribution from the precast business. The estimated annualized EBITDA contribution from the precast business was derived by annualizing the precast business’s actual results from the respective acquisition dates through August 31, 2026. The calculation also excludes the impact of the purchase accounting effect on inventory. The annualized figure assumes that the precast platform’s results for the post-acquisition period are representative of a full fiscal year. The figure does not reflect actual results the precast platform generated or will generate in any 12-month period, and it was not prepared in accordance with Article 11 of Regulation S-X. Results for future periods may differ materially.
Non-GAAP financial measures should be viewed in addition to, and not as alternatives to, the most directly comparable measures derived in accordance with GAAP and may not be comparable to similar measures presented by other companies. However, we believe that the non-GAAP financial measures provide relevant and useful information to management, investors, analysts, creditors and other interested parties in our industry as they allow: (i) comparison of our earnings to those of our competitors; (ii) a supplemental measure of our underlying business operational performance; and (iii) the assessment of period-to-period performance trends. Furthermore, management believes net leverage adjusted for acquisitions provide useful information to investors, analysts, creditors and other interested parties about the Company's financial condition. Management uses non-GAAP financial measures to evaluate financial performance and, more specifically, uses net leverage adjusted for acquisitions to monitor the Company's balance sheet and make capital allocation decisions. We have not reconciled the forward-looking estimates of TAG-related EBITDA benefits to comparable GAAP measures because applicable information for future periods, on which these reconciliations would be based, is not readily available due to uncertainty regarding, and the potential variability of metal margins, U.S. trade policy, cost levels of key production inputs, construction activity and related product demand and other factors. Accordingly, reconciliations of the forward-looking estimates of TAG-related EBITDA benefits to net earnings are not available at this time without unreasonable effort.
(CMC Fourth Quarter Fiscal 2026 - 14)
A reconciliation of net earnings to adjusted EBITDA and core EBITDA is provided below:
| Three Months Ended | Year Ended | |||||||||||||||||||||||||||||||||||||||||||
| (in thousands) | 8/31/2026 | 5/31/2026 | 2/28/2026 | 11/30/2025 | 8/31/2025 | 8/31/2026 | 8/31/2025 | |||||||||||||||||||||||||||||||||||||
| Net earnings | $ | 212,520 | $ | 173,015 | $ | 93,032 | $ | 177,282 | $ | 151,781 | $ | 655,849 | $ | 84,662 | ||||||||||||||||||||||||||||||
| Interest expense | 37,356 | 40,205 | 40,928 | 24,848 | 12,145 | 143,337 | 45,498 | |||||||||||||||||||||||||||||||||||||
| Income tax expense | 16,977 | 15,824 | 16,708 | 5,653 | 41,452 | 55,162 | 22,883 | |||||||||||||||||||||||||||||||||||||
| Depreciation and amortization | 113,210 | 107,422 | 102,567 | 72,722 | 72,480 | 395,921 | 285,877 | |||||||||||||||||||||||||||||||||||||
| Asset impairments | 21 | — | — | — | 3,436 | 21 | 4,607 | |||||||||||||||||||||||||||||||||||||
| Unrealized (gain) loss on undesignated commodity hedges | 2,344 | (557) | (1,979) | 8,063 | (2,866) | 7,871 | (2,804) | |||||||||||||||||||||||||||||||||||||
| Adjusted EBITDA | 382,428 | 335,909 | 251,256 | 288,568 | 278,428 | 1,258,161 | 440,723 | |||||||||||||||||||||||||||||||||||||
| Non-cash equity compensation | 6,506 | 11,384 | 14,806 | 11,236 | 9,237 | 43,932 | 37,053 | |||||||||||||||||||||||||||||||||||||
| Settlement of New Markets Tax Credit transactions | — | — | — | — | — | — | (2,786) | |||||||||||||||||||||||||||||||||||||
| Litigation expense | 3,776 | 3,778 | 4,067 | 3,735 | 3,776 | 15,356 | 362,272 | |||||||||||||||||||||||||||||||||||||
| Acquisition and integration related costs | 948 | 2,525 | 20,605 | 13,379 | — | 37,457 | — | |||||||||||||||||||||||||||||||||||||
| Purchase accounting effect on inventory | — | — | 6,739 | — | — | 6,739 | — | |||||||||||||||||||||||||||||||||||||
| Core EBITDA | $ | 393,658 | $ | 353,596 | $ | 297,473 | $ | 316,918 | $ | 291,441 | $ | 1,361,645 | $ | 837,262 | ||||||||||||||||||||||||||||||
| Net sales | $ | 2,658,334 | $ | 2,483,245 | $ | 2,132,018 | $ | 2,120,307 | $ | 2,114,518 | $ | 9,393,904 | $ | 7,798,480 | ||||||||||||||||||||||||||||||
| Core EBITDA margin | 14.8% | 14.2% | 14.0% | 14.9% | 13.8% | 14.5% | 10.7% | |||||||||||||||||||||||||||||||||||||
A reconciliation of net earnings to adjusted earnings is provided below:
| Three Months Ended | Year Ended | |||||||||||||||||||||||||||||||||||||||||||
| (in thousands, except per share data) | 8/31/2026 | 5/31/2026 | 2/28/2026 | 11/30/2025 | 8/31/2025 | 8/31/2026 | 8/31/2025 | |||||||||||||||||||||||||||||||||||||
| Net earnings | $ | 212,520 | $ | 173,015 | $ | 93,032 | $ | 177,282 | $ | 151,781 | $ | 655,849 | $ | 84,662 | ||||||||||||||||||||||||||||||
| Asset impairments | 21 | — | — | — | 3,436 | 21 | 4,607 | |||||||||||||||||||||||||||||||||||||
| Settlement of New Markets Tax Credit transactions | — | — | — | — | — | — | (2,786) | |||||||||||||||||||||||||||||||||||||
| Litigation expense | 3,776 | 3,778 | 4,067 | 3,735 | 3,776 | 15,356 | 362,272 | |||||||||||||||||||||||||||||||||||||
| Unrealized (gain) loss on undesignated commodity hedges | 2,344 | (557) | (1,979) | 8,063 | (2,866) | 7,871 | (2,804) | |||||||||||||||||||||||||||||||||||||
| Acquisition, integration and financing related costs | 948 | 2,525 | 20,605 | 24,942 | — | 49,020 | — | |||||||||||||||||||||||||||||||||||||
| Amortization of acquired contract backlog | 19,750 | 19,750 | 17,729 | — | — | 57,229 | — | |||||||||||||||||||||||||||||||||||||
| Purchase accounting effect on inventory | — | — | 6,739 | — | — | 6,739 | — | |||||||||||||||||||||||||||||||||||||
| Total adjustments (pre-tax) | $ | 26,839 | $ | 25,496 | $ | 47,161 | $ | 36,740 | $ | 4,346 | $ | 136,236 | $ | 361,289 | ||||||||||||||||||||||||||||||
| Related tax effects on adjustments | (5,769) | (5,486) | (10,046) | (7,846) | (1,162) | (29,147) | (88,668) | |||||||||||||||||||||||||||||||||||||
| Adjusted earnings | $ | 233,590 | $ | 193,025 | $ | 130,147 | $ | 206,176 | $ | 154,965 | $ | 762,938 | $ | 357,283 | ||||||||||||||||||||||||||||||
Net earnings per diluted share(1) | $ | 1.91 | $ | 1.55 | $ | 0.83 | $ | 1.58 | $ | 1.35 | $ | 5.86 | $ | 0.74 | ||||||||||||||||||||||||||||||
| Adjusted earnings per diluted share | $ | 2.09 | $ | 1.73 | $ | 1.16 | $ | 1.84 | $ | 1.37 | $ | 6.82 | $ | 3.13 | ||||||||||||||||||||||||||||||
__________________________________
(1) Net earnings per diluted share is calculated independently for each three month period and may not sum to the year to date period due to rounding.
(CMC Fourth Quarter Fiscal 2026 - 15)
As described above, net leverage adjusted for acquisitions represents net debt divided by modified consolidated EBITDA. Reconciliations of (i) net earnings to modified consolidated EBITDA and (ii) long-term debt to net debt are provided below:
| Modified Consolidated EBITDA (as used in the calculation of net leverage adjusted for acquisitions) | Year Ended | |||||||
| (in thousands) | 8/31/2026 | |||||||
| Net earnings | $ | 655,849 | ||||||
| Interest expense | 143,337 | |||||||
| Income tax expense | 55,162 | |||||||
| Depreciation and amortization | 395,921 | |||||||
| Asset impairments | 21 | |||||||
| Unrealized loss on undesignated commodity hedges | 7,871 | |||||||
| Adjusted EBITDA | 1,258,161 | |||||||
| Plus: Litigation expense | 15,356 | |||||||
| Less: Precast EBITDA contribution (actual) | 143,540 | |||||||
| Plus: Annualized precast EBITDA contribution | 212,159 | |||||||
| Modified consolidated EBITDA | $ | 1,342,136 | ||||||
| Net Debt (as used in the calculation of net leverage adjusted for acquisitions) | 8/31/2026 | |||||||
| Long-term debt | $ | 3,313,728 | ||||||
| Plus: Current maturities of long-term debt | 67,147 | |||||||
| Less: Short-term borrowings | 8,642 | |||||||
| Total debt | 3,372,233 | |||||||
| Less: Cash and cash equivalents | 775,676 | |||||||
| Net debt | $ | 2,596,557 | ||||||
| Net leverage adjusted for acquisitions | 1.9 | |||||||
Investor Relations Contact:
Andy Larkin
(720) 618-6013

O C T O B E R 2 0 2 6
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s This presentation contains forward-looking statements within the meaning of the federal securities laws with respect to the expected benefits of the recent acquisitions of Concrete Pipe & Precast (“CP&P”) and Foley Products Company (“Foley”), general economic conditions, key macro-economic drivers that impact our business, the effects of ongoing trade actions, the effects of continued pressure on the liquidity of our customers, potential synergies and growth provided by acquisitions and strategic investments, the performance of the precast business, demand for our products, shipment volumes, metal margins, backlog volumes, the ability to operate our steel mills at full capacity particularly during periods of domestic mill start-ups, future availability and cost of supplies of raw materials and energy for our operations, growth rates in certain reportable segments, product margins within our Construction Solutions Group segment, share repurchases, legal proceedings, construction activity, international trade, the impact of geopolitical conditions, the effects of CBAM and other EU trade measures on European demand and pricing, capital expenditures, tax credits, the timing, amount and recurrence of CO2 or emissions-related credits, our liquidity and our ability to satisfy future liquidity requirements, our ability to achieve our stated deleveraging target within the anticipated timeframe, estimated contractual obligations, the expected capabilities and benefits of new facilities, anticipated benefits and the timeline for execution of our growth plan and initiatives, including our Transform, Advance and Grow (“TAG”) operational and commercial excellence program, our long-term financial targets and expectations for future financial performance and our expectations or beliefs concerning future events. The statements in this presentation that are not historical statements, are forward-looking statements. These forward-looking statements can generally be identified by phrases such as we or our management “expects,” “anticipates,” “believes,” “estimates,” “intends,” “may,” “plans to,” “ought,” “could,” “will,” “should,” “likely,” “appears,” “projects,” “forecasts,” “outlook” or other similar words or phrases, as well as by discussions of strategy, plans or intentions. Our forward-looking statements are based on management’s expectations and beliefs as of the date of this presentation. Although we believe that our expectations are reasonable, we can give no assurance that these expectations will prove to have been correct, and actual results may vary materially. Except as required by law, we undertake no obligation to update, amend or clarify any forward-looking statements to reflect changed assumptions, the occurrence of anticipated or unanticipated events, new information or circumstances or any other changes. Important factors that could cause actual results to differ materially from our expectations include those described in our filings with the Securities and Exchange Commission, including, but not limited to, in Part I, Item 1A, “Risk Factors” of our annual report on Form 10-K for the fiscal year ended August 31, 2025, as well as the following: changes in economic conditions which affect demand for our products or construction activity generally, and the impact of such changes on the highly cyclical steel industry; rapid and significant changes in the price of metals, potentially impairing our inventory values due to declines in commodity prices or reducing the profitability of downstream contracts within our vertically integrated steel operations due to rising commodity pricing; excess capacity in our industry, particularly in China, and product availability from competing steel mills and other steel suppliers including import quantities and pricing; the impact of additional steelmaking capacity expected to come online from a number of electric arc furnace projects in the U.S.; the impact of geopolitical conditions, including political turmoil and volatility, regional conflicts, terrorism and war on the global economy, inflation, energy supplies and raw materials; global factors, such as trade measures, military conflicts and political uncertainties, including changes to current trade regulations, such as Section 232 trade tariffs and quotas, tax legislation and other regulations which might adversely impact our business; operating and startup risks, as well as market risks associated with the commissioning of new projects could prevent us from realizing anticipated benefits and could result in a loss of all or a substantial part of our investments; our ability to successfully execute our TAG operational and commercial excellence program and other transformation initiatives, including the realization of anticipated benefits within the expected timeframes; attention to environmental, social and governance (“ESG”) matters, including any targets or other ESG, environmental justice or regulatory initiatives; impacts from global public health crises on the economy, demand for our products, global supply chain and on our operations; compliance with and changes in existing and future laws, regulations and other legal requirements and judicial decisions that govern our business, including increased environmental regulations associated with climate change and greenhouse gas emissions; involvement in various environmental matters that may result in fines, penalties or judgments; evolving remediation technology, changing regulations, possible third-party contributions, the inherent uncertainties of the estimation process and other factors that may impact amounts accrued for environmental liabilities; potential limitations in our or our customers' abilities to access credit and non-compliance with their contractual obligations, including payment obligations; activity in repurchasing shares of our common stock under our share repurchase program; financial and non-financial covenants and restrictions on the operation of our business contained in agreements governing our debt; our ability to successfully identify, consummate and integrate acquisitions and realize any or all of the anticipated synergies or other benefits of acquisitions; the effects that acquisitions may have on our financial leverage; risks associated with acquisitions generally, such as the inability to obtain, or delays in obtaining, required approvals under applicable antitrust legislation and other regulatory and third-party consents and approvals; lower than expected future levels of revenues and higher than expected future costs; failure or inability to implement growth strategies in a timely manner; the impact of goodwill or other indefinite-lived intangible asset impairment charges; the impact of long-lived asset impairment charges; currency fluctuations; availability and pricing of electricity, electrodes and natural gas for mill operations; our ability to hire and retain key executives and other employees; competition from other materials or from competitors that have a lower cost structure or access to greater financial resources; information technology interruptions and breaches in security; our ability to make necessary capital expenditures; availability and pricing of raw materials and other items over which we exert little influence, including scrap metal, energy and insurance; unexpected equipment failures; losses or limited potential gains due to hedging transactions; litigation claims and settlements, court decisions, regulatory rulings and legal compliance risks, including risks related to the Pacific Steel Group (“PSG”) litigation; risk of injury or death to employees, customers or other visitors to our operations; and civil unrest, protests and riots. This presentation includes illustrative financial information with respect to the Company’s precast concrete and concrete pipe products business (together, the “precast platform”), which information is estimated based on historical results of CP&P and Foley. This information is presented for illustrative purposes only and is based on available information and certain assumptions and estimates that we believe are reasonable. The illustrative precast platform financial information presented herein has not been prepared and presented in accordance with the requirements of Regulation S-X. The assumptions and estimates underlying the precast platform financial information are inherently uncertain and are subject to a variety of significant business, economic and competitive risks and uncertainties that could cause actual results to differ materially from those contained in the illustrative financial information, including the risks and uncertainties described above. The illustrative precast platform financial information may not necessarily reflect what the precast platform’s results of operations and financial position will be in the future. The Company’s auditors have not audited, reviewed, compiled or performed any procedures with respect to the illustrative precast platform financial information. Forward-Looking Statements 2
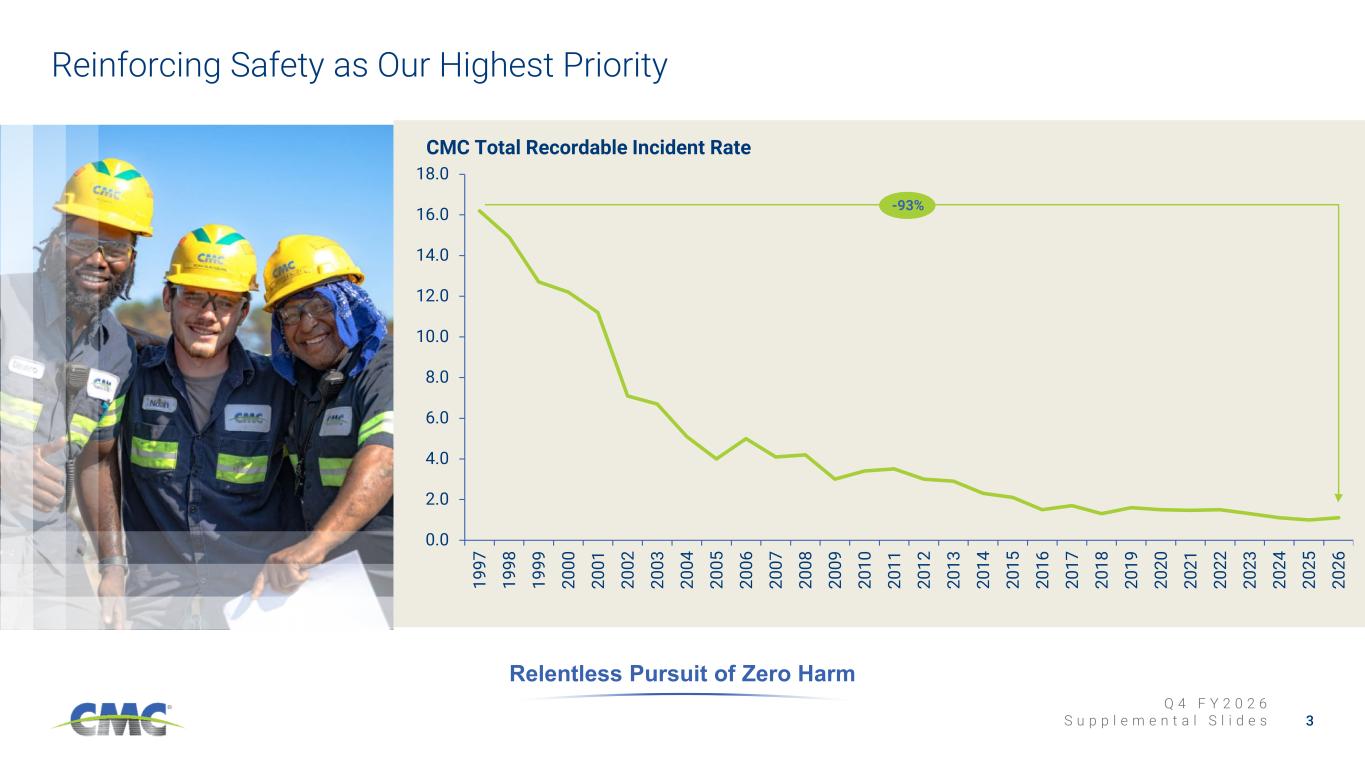
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s 0.0 2.0 4.0 6.0 8.0 10.0 12.0 14.0 16.0 18.0 19 97 19 98 19 99 20 00 20 01 20 02 20 03 20 04 20 05 20 06 20 07 20 08 20 09 20 10 20 11 20 12 20 13 20 14 20 15 20 16 20 17 20 18 20 19 20 20 20 21 20 22 20 23 20 24 20 25 20 26 Reinforcing Safety as Our Highest Priority 3 Relentless Pursuit of Zero Harm CMC Total Recordable Incident Rate -93%
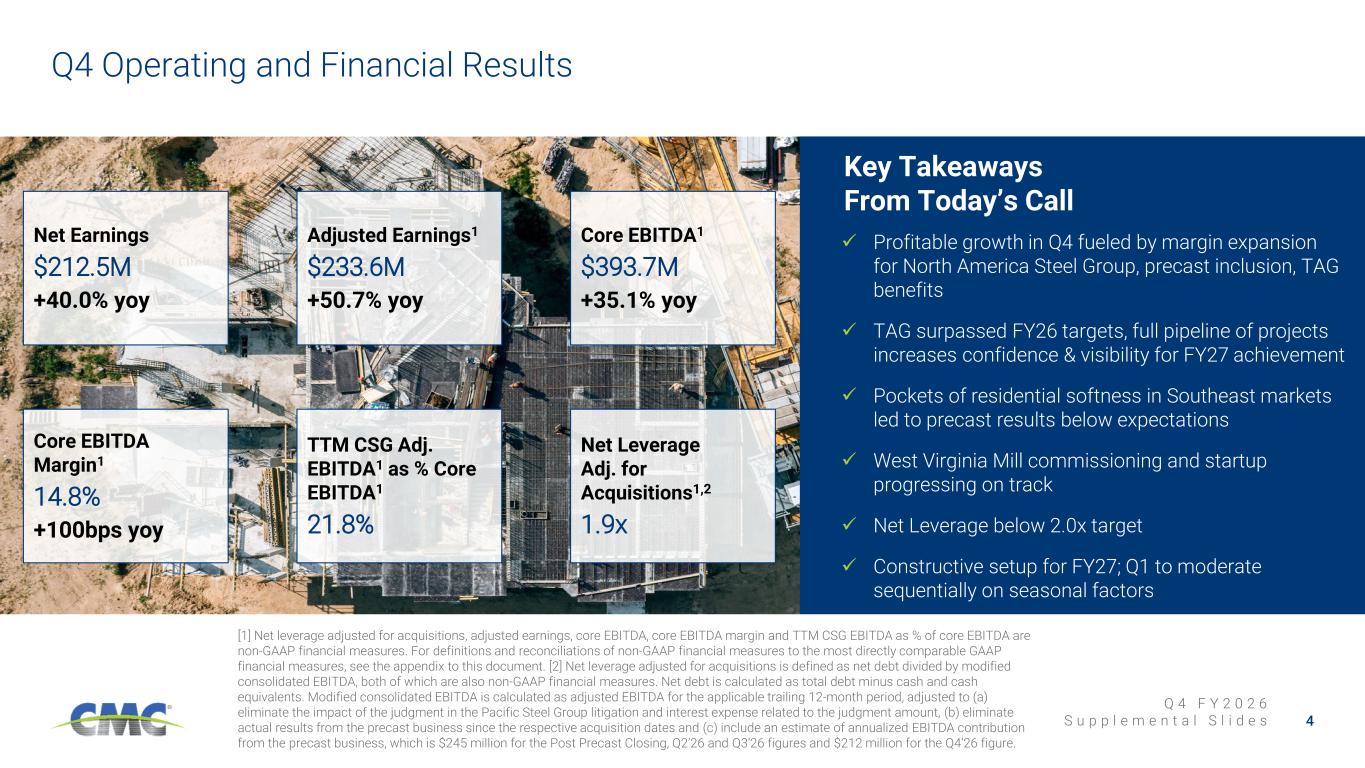
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s Core EBITDA Margin1 14.8% +100bps yoy Net Leverage Adj. for Acquisitions1,2 1.9x Q4 Operating and Financial Results 4 [1] Net leverage adjusted for acquisitions, adjusted earnings, core EBITDA, core EBITDA margin and TTM CSG EBITDA as % of core EBITDA are non-GAAP financial measures. For definitions and reconciliations of non-GAAP financial measures to the most directly comparable GAAP financial measures, see the appendix to this document. [2] Net leverage adjusted for acquisitions is defined as net debt divided by modified consolidated EBITDA, both of which are also non-GAAP financial measures. Net debt is calculated as total debt minus cash and cash equivalents. Modified consolidated EBITDA is calculated as adjusted EBITDA for the applicable trailing 12-month period, adjusted to (a) eliminate the impact of the judgment in the Pacific Steel Group litigation and interest expense related to the judgment amount, (b) eliminate actual results from the precast business since the respective acquisition dates and (c) include an estimate of annualized EBITDA contribution from the precast business, which is $245 million for the Post Precast Closing, Q2’26 and Q3’26 figures and $212 million for the Q4’26 figure. Key Takeaways From Today’s Call Profitable growth in Q4 fueled by margin expansion for North America Steel Group, precast inclusion, TAG benefits TAG surpassed FY26 targets, full pipeline of projects increases confidence & visibility for FY27 achievement Pockets of residential softness in Southeast markets led to precast results below expectations West Virginia Mill commissioning and startup progressing on track Net Leverage below 2.0x target Constructive setup for FY27; Q1 to moderate sequentially on seasonal factors Net Earnings $212.5M +40.0% yoy Adjusted Earnings1 $233.6M +50.7% yoy Core EBITDA1 $393.7M +35.1% yoy TTM CSG Adj. EBITDA1 as % Core EBITDA1 21.8%

Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s NASG Performance Reinforces Full Potential Opportunities 5 Driving excellence to deliver TAG benefits, MBQ growth from Arizona 2 Mill, and ramp Steel WV production Exercising commercial discipline to realize margin potential and generate growth Q4 2026 Financial Highlights 27.5% MBQ & Other Volume Growth YoY 8.5% Downstream Products Volume Growth YoY Improved Adj. EBITDA Contribution From Arizona 2 Q4 Record North American Steel Group Priorities Leveraging operational capabilities to be a critical partner on larger, more complex megaprojects

Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s Residential softness led to volume and Adj. EBITDA underperformance Mix shift towards Non-residential and Infrastructure end markets Stronger bookings & backlogs on both volume & price as compared to prior year Precast Integration on Track, Concentrated Volume Softness in Q4 6 Precast Thesis Firmly Intact Elevating safety across all precast facilities, substantially completed functional integration Opportunity to accelerate footprint optimization efforts Synergies are materializing as expected, or better Integration On Track Q4 Results

Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s Unleashing the Power of Our Portfolio through Three Clear Value Creation Levers Value Creation Levers Drive Durably Higher Margins and Growth with Lower Capital Intensity 1 Capturing Full Potential of Our Business 2 Harvesting Benefits of Growth Capital Deployed 3 Reshaping the Portfolio 7
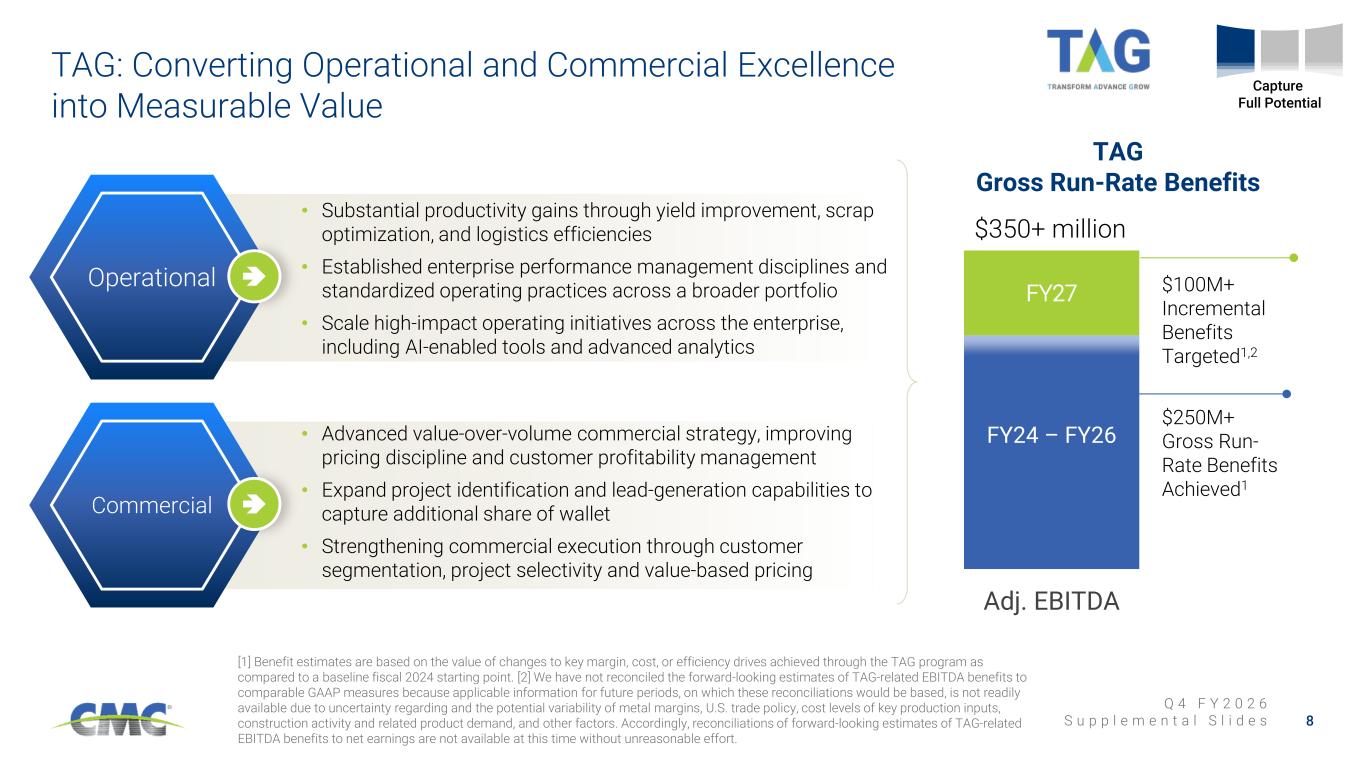
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s TAG: Converting Operational and Commercial Excellence into Measurable Value 8 [1] Benefit estimates are based on the value of changes to key margin, cost, or efficiency drives achieved through the TAG program as compared to a baseline fiscal 2024 starting point. [2] We have not reconciled the forward-looking estimates of TAG-related EBITDA benefits to comparable GAAP measures because applicable information for future periods, on which these reconciliations would be based, is not readily available due to uncertainty regarding and the potential variability of metal margins, U.S. trade policy, cost levels of key production inputs, construction activity and related product demand, and other factors. Accordingly, reconciliations of forward-looking estimates of TAG-related EBITDA benefits to net earnings are not available at this time without unreasonable effort. FY24 – FY26 FY27 $0 $50 $100 $150 $200 $250 $300 $350 $400 Adj. EBITDA Operational Commercial • Substantial productivity gains through yield improvement, scrap optimization, and logistics efficiencies • Established enterprise performance management disciplines and standardized operating practices across a broader portfolio • Scale high-impact operating initiatives across the enterprise, including AI-enabled tools and advanced analytics • Advanced value-over-volume commercial strategy, improving pricing discipline and customer profitability management • Expand project identification and lead-generation capabilities to capture additional share of wallet • Strengthening commercial execution through customer segmentation, project selectivity and value-based pricing TAG Gross Run-Rate Benefits Capture Full Potential $350+ million $100M+ Incremental Benefits Targeted1,2 $250M+ Gross Run- Rate Benefits Achieved1
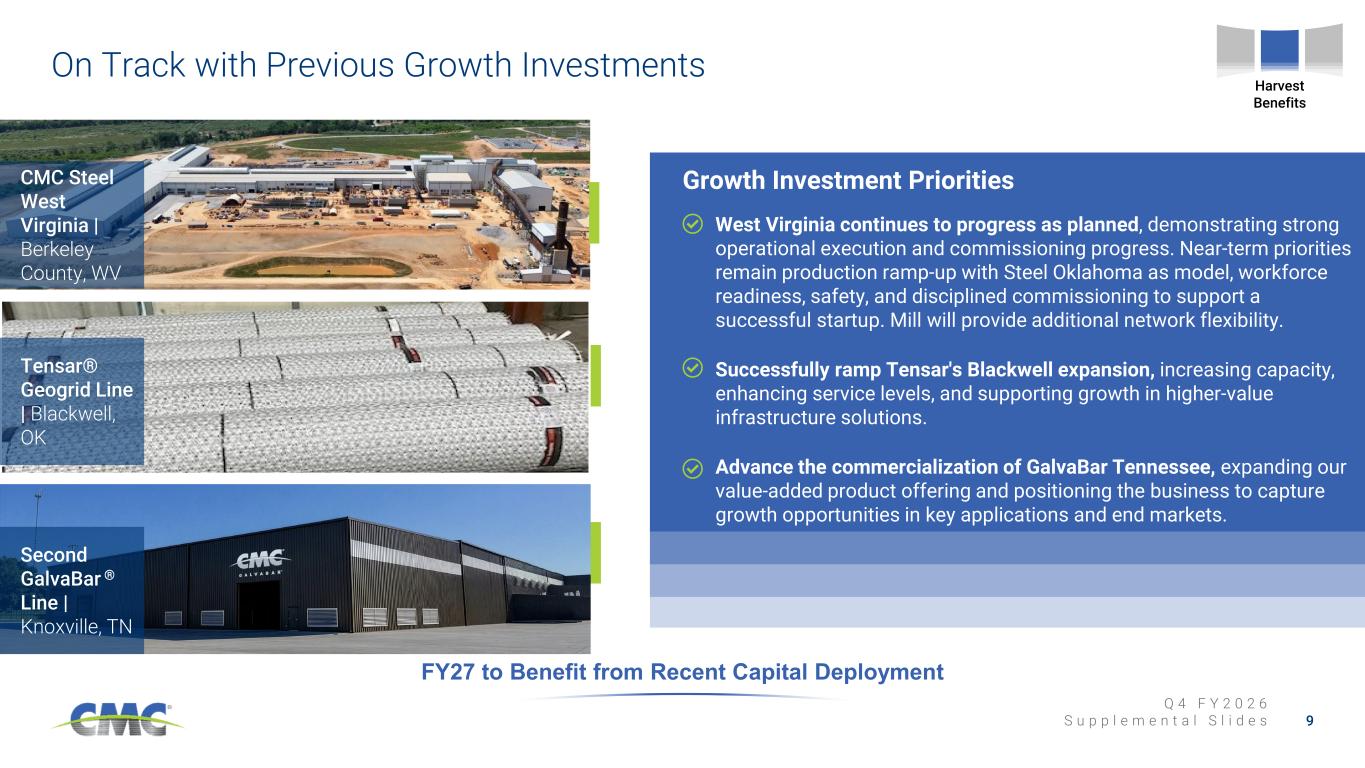
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s On Track with Previous Growth Investments 9 FY27 to Benefit from Recent Capital Deployment Harvest Benefits CMC Steel West Virginia | Berkeley County, WV Tensar® Geogrid Line | Blackwell, OK Growth Investment Priorities West Virginia continues to progress as planned, demonstrating strong operational execution and commissioning progress. Near-term priorities remain production ramp-up with Steel Oklahoma as model, workforce readiness, safety, and disciplined commissioning to support a successful startup. Mill will provide additional network flexibility. Successfully ramp Tensar's Blackwell expansion, increasing capacity, enhancing service levels, and supporting growth in higher-value infrastructure solutions. Advance the commercialization of GalvaBar Tennessee, expanding our value-added product offering and positioning the business to capture growth opportunities in key applications and end markets. Second GalvaBar ® Line | Knoxville, TN

Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s 50 100 150 200 250 Precast is Helping Transform CMC’s Financial Profile 10[1] Source: Federal Reserve Economic Data, Federal Reserve Bank of St. Louis Precast is Critical to Building a Stronger CMC Higher Growth Market leading position complements CMC’s Early-Stage Construction portfolio More Profitable Strengthening the margin profile of the enterprise More Consistent Proven track record of pricing and margin durability Jan 2006 July 2026 Precast PPI1 (Indexed to January 2006) Reshape Portfolio Footprint Leveraged to Population and Economic Growth Centers In-Focus Early-Stage Construction Applications Stormwater Dry Utility #1 In Core Geographies, including the Southeast avg. growth in quarterly PPI YoY since 20064.4% 16% 22% North America Steel Group Construction Solutions Group 10 Adjusted EBITDA Margin Fiscal 2026

Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s • Housing shortage is large and growing, providing for long-run opportunities • Multi-family outlook incrementally more positive • Within single-family construction, pockets of resiliency exist • Elevated interest rates and the mortgage lock-in effect continue to weigh on near-term demand and suppress builder confidence in the single-family residential market Portfolio is Positioned to Serve Healthy Demand Conditions 11 [1] Combined for North America Steel Group and Construction Solutions Group segment [2] Dodge Construction Network: August Construction Starts Infrastructure 35%-40% of Revenue1 Non-Residential 30%-35% of Revenue1 Residential 20%-25% of Revenue1 • Infrastructure demand remains elevated; successor spending bill will add visibility and extend public market tailwinds • Substantial IIJA dollars have yet to be spent, meaning a material "spending tail" will continue to flow into 2027 • Robust State DOT balance sheets provide multi-year demand visibility, particularly in key CMC markets. • Progress on Build 250 would add confidence to long-term infrastructure demand outlook • Dodge Momentum Index points to strong demand • Energy and utility infrastructure exhibiting signs of durable demand; construction starts up nearly 70% YTD, calendar year 20262. • New phase of semiconductor industry investment to support AI chips and memory needs • Data center construction remains a powerful demand driver, supporting activity in key CMC markets • CMC’s ability to serve large, complex projects is a differentiator

Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s Repositioning Our Steel Business through Deliberate Actions to Capitalize on Current Industry Structure LTPF = Leveling The Playing Field. EAF = Electric Arc Furnace. TAG = Transform, Advance, Grow. Conditions Are in Place to Fundamentally Change the Return Profile of Our Steel Franchise Industry Dynamics Support Improved Outcomes • Largely consolidated domestic rebar market • Materially better import landscape o Section 232 measures o Rebar imports showing signs of moderation as arbitrage opportunities diminish o Near- to long-term: more durable trade framework (e.g., trade cases, LTPF legislation, and Buy America) • Balanced supply / demand o Manageable additions to domestic supply CMC is Building a Stronger, More Resilient Steel Franchise • Taking advantage of our vertically integrated structure to more quickly respond to supply / demand changes • Capitalizing on flexible EAF network and TAG initiatives to be world class on cost and continually improving • Demonstrating commercial discipline – getting paid for value delivered and a return on capital invested • Restructuring our businesses to improve return profiles 12
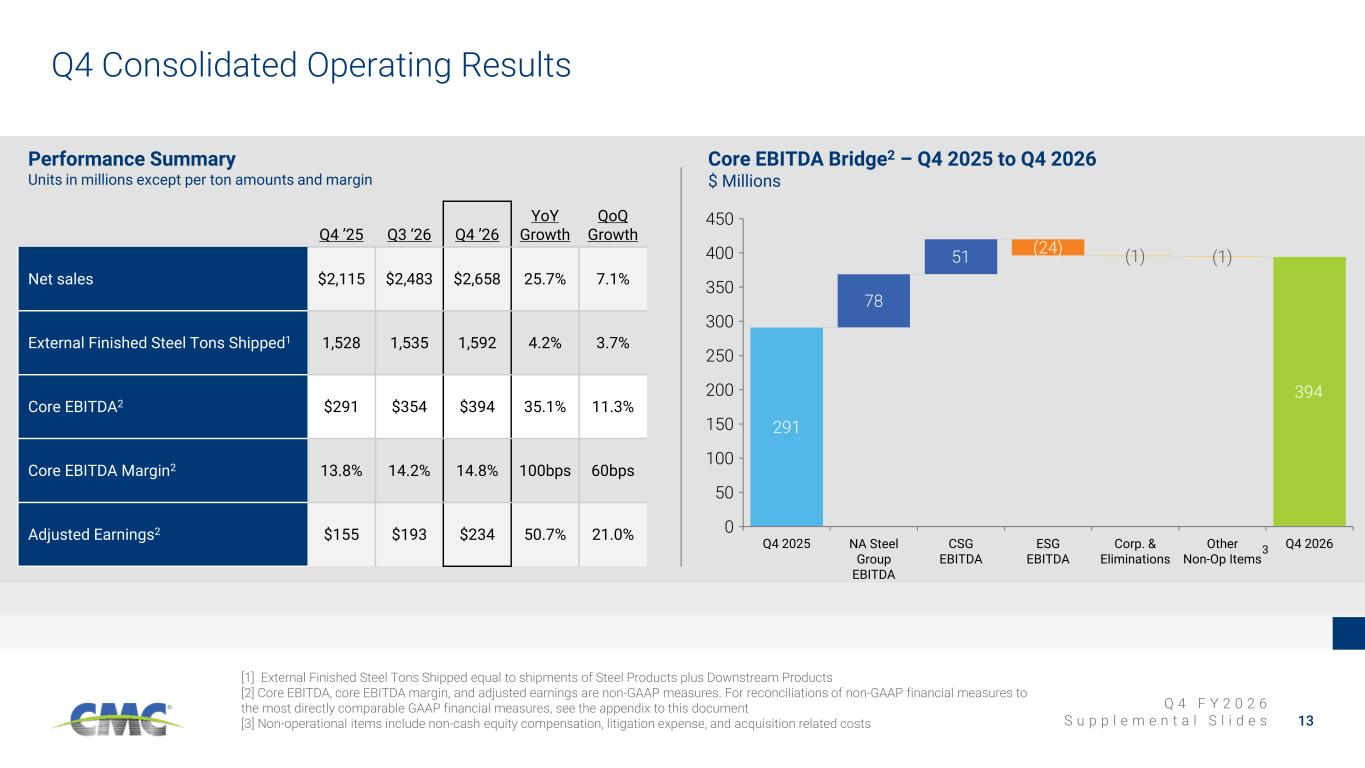
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s 291 78 51 (24) (1) (1) Q4 2025 NA Steel Group EBITDA CSG EBITDA ESG EBITDA Corp. & Eliminations Other Non-Op Items Q4 2026 0 50 100 150 200 250 300 350 400 450 Q4 Consolidated Operating Results 13 Q4 ’25 Q3 ‘26 Q4 ’26 YoY Growth QoQ Growth Net sales $2,115 $2,483 $2,658 25.7% 7.1% External Finished Steel Tons Shipped1 1,528 1,535 1,592 4.2% 3.7% Core EBITDA2 $291 $354 $394 35.1% 11.3% Core EBITDA Margin2 13.8% 14.2% 14.8% 100bps 60bps Adjusted Earnings2 $155 $193 $234 50.7% 21.0% [1] External Finished Steel Tons Shipped equal to shipments of Steel Products plus Downstream Products [2] Core EBITDA, core EBITDA margin, and adjusted earnings are non-GAAP measures. For reconciliations of non-GAAP financial measures to the most directly comparable GAAP financial measures, see the appendix to this document [3] Non-operational items include non-cash equity compensation, litigation expense, and acquisition related costs Performance Summary Units in millions except per ton amounts and margin Core EBITDA Bridge2 – Q4 2025 to Q4 2026 $ Millions 394 3

Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s Q4 North America Steel Group 14 [1] External Finished Steel Tons Shipped equal to shipments of Steel Products plus Downstream Products [2] Downstream Product Margin Over Scrap equals Average Selling Price minus cost of ferrous scrap utilized during the prior quarter [3] Steel Products Margin Over Scrap equals Average Selling Price minus cost of ferrous scrap utilized Q4 ’25 Q3 ‘26 Q4 ’26 YoY Growth QoQ Growth External Finished Steel Tons Shipped1 1,154 1,134 1,215 5.3% 7.1% Adjusted EBITDA $239 $253 $317 32.6% 25.2% Adjusted EBITDA per Ton of Finished Steel Shipped $207 $224 $261 25.9% 16.9% Adjusted EBITDA Margin 14.8% 14.2% 16.4% 160 bps 220 bps Performance Summary Units in millions except per ton amounts and margin Key Margins $ / ton 207 257 257 224 261 854 922 924 909 909 568 621 623 610 652 100 150 200 250 300 350 400 0 100 200 300 400 500 600 700 800 900 1,000 4Q'25 1Q'26 2Q'26 3Q'26 4Q'26 Adjusted EBITDA per Ton of Finished Steel Shipped Downstream Product Margin Over Scrap Steel Product Margin Over Scrap 2 3
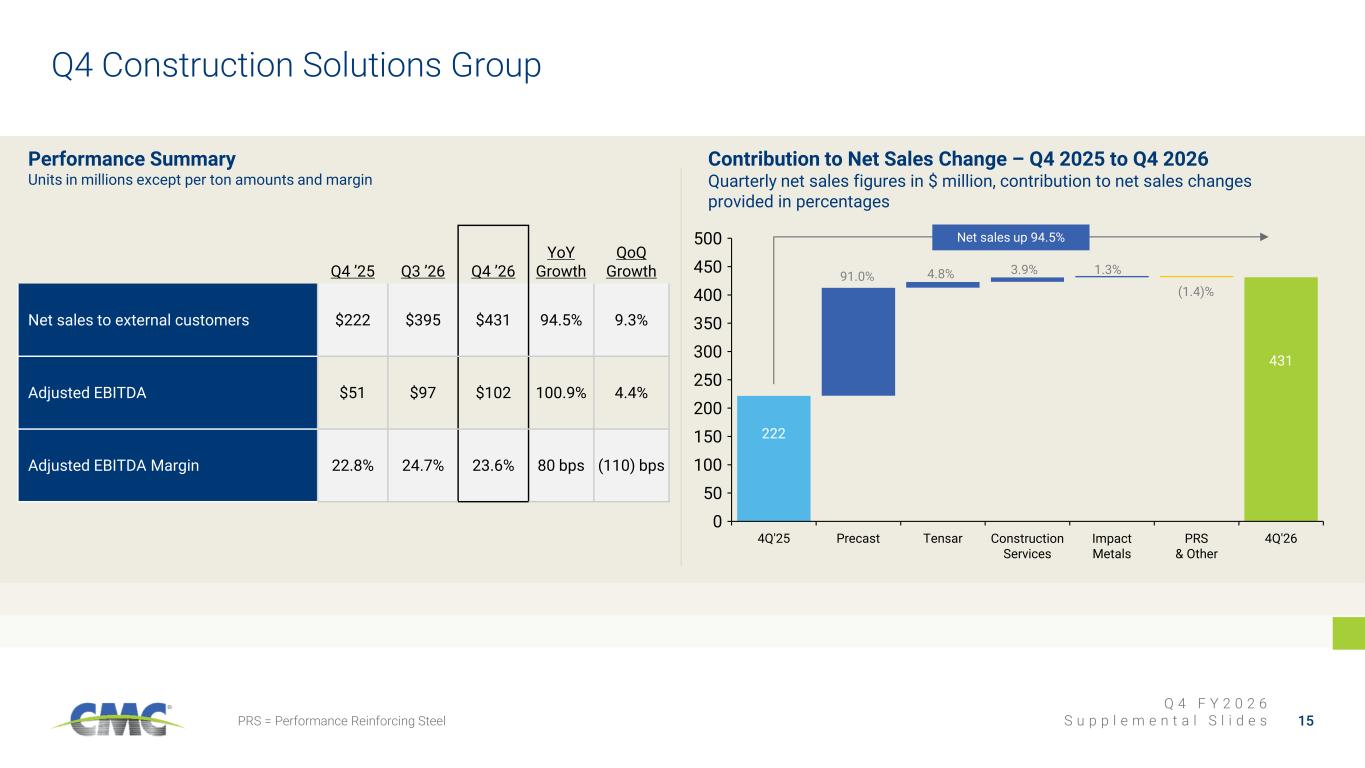
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s 4Q'25 Precast Tensar Construction Services Impact Metals PRS & Other 4Q'26 0 50 100 150 200 250 300 350 400 450 500 15PRS = Performance Reinforcing Steel Q4 ’25 Q3 ’26 Q4 ’26 YoY Growth QoQ Growth Net sales to external customers $222 $395 $431 94.5% 9.3% Adjusted EBITDA $51 $97 $102 100.9% 4.4% Adjusted EBITDA Margin 22.8% 24.7% 23.6% 80 bps (110) bps 91.0% 4.8% 3.9% 1.3% (1.4)% 222 Q4 Construction Solutions Group Performance Summary Units in millions except per ton amounts and margin Contribution to Net Sales Change – Q4 2025 to Q4 2026 Quarterly net sales figures in $ million, contribution to net sales changes provided in percentages 431 Net sales up 94.5%
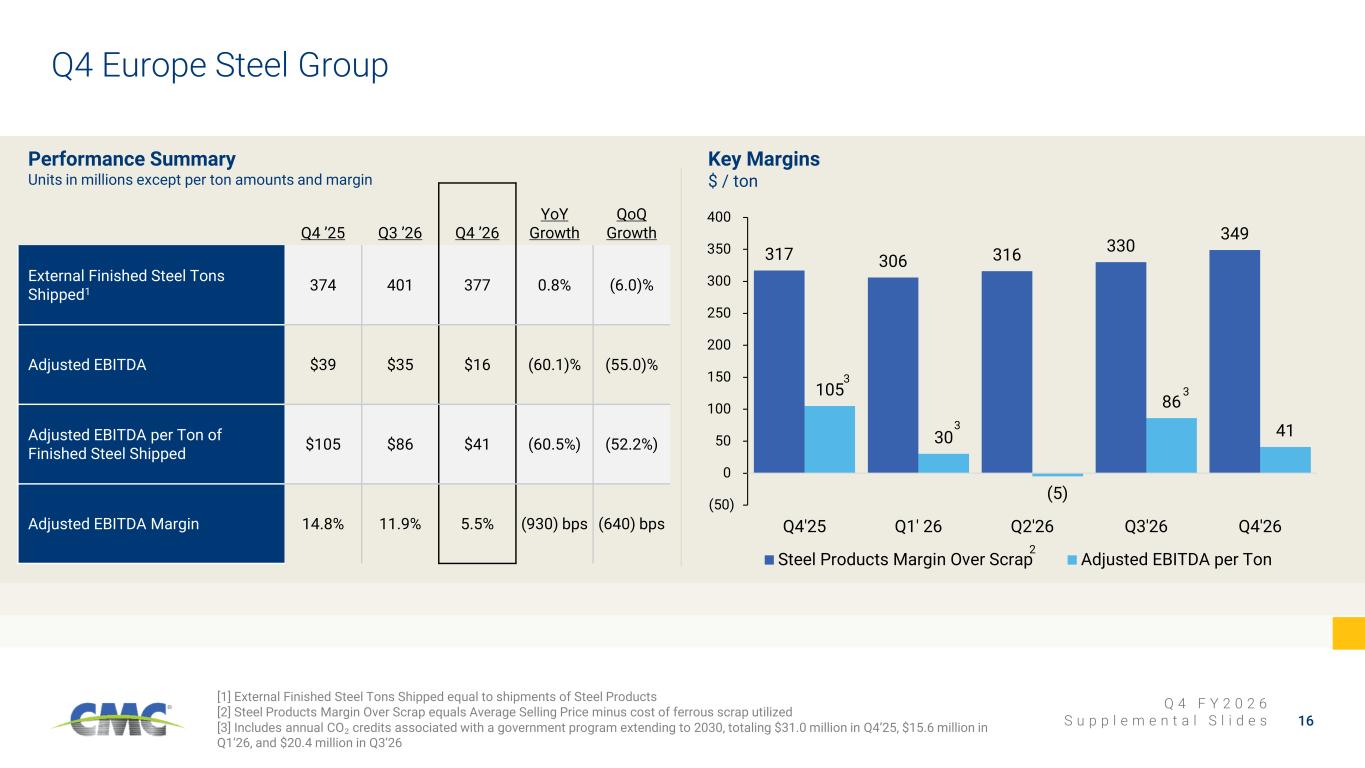
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s 317 306 316 330 349 105 30 (5) 86 41 (50) 0 50 100 150 200 250 300 350 400 Q4'25 Q1' 26 Q2'26 Q3'26 Q4'26 Steel Products Margin Over Scrap Adjusted EBITDA per Ton 16 [1] External Finished Steel Tons Shipped equal to shipments of Steel Products [2] Steel Products Margin Over Scrap equals Average Selling Price minus cost of ferrous scrap utilized [3] Includes annual CO₂ credits associated with a government program extending to 2030, totaling $31.0 million in Q4’25, $15.6 million in Q1’26, and $20.4 million in Q3’26 Q4 Europe Steel Group Q4 ’25 Q3 ’26 Q4 ’26 YoY Growth QoQ Growth External Finished Steel Tons Shipped1 374 401 377 0.8% (6.0)% Adjusted EBITDA $39 $35 $16 (60.1)% (55.0)% Adjusted EBITDA per Ton of Finished Steel Shipped $105 $86 $41 (60.5%) (52.2%) Adjusted EBITDA Margin 14.8% 11.9% 5.5% (930) bps (640) bps 3 3 3 2 Performance Summary Units in millions except per ton amounts and margin Key Margins $ / ton
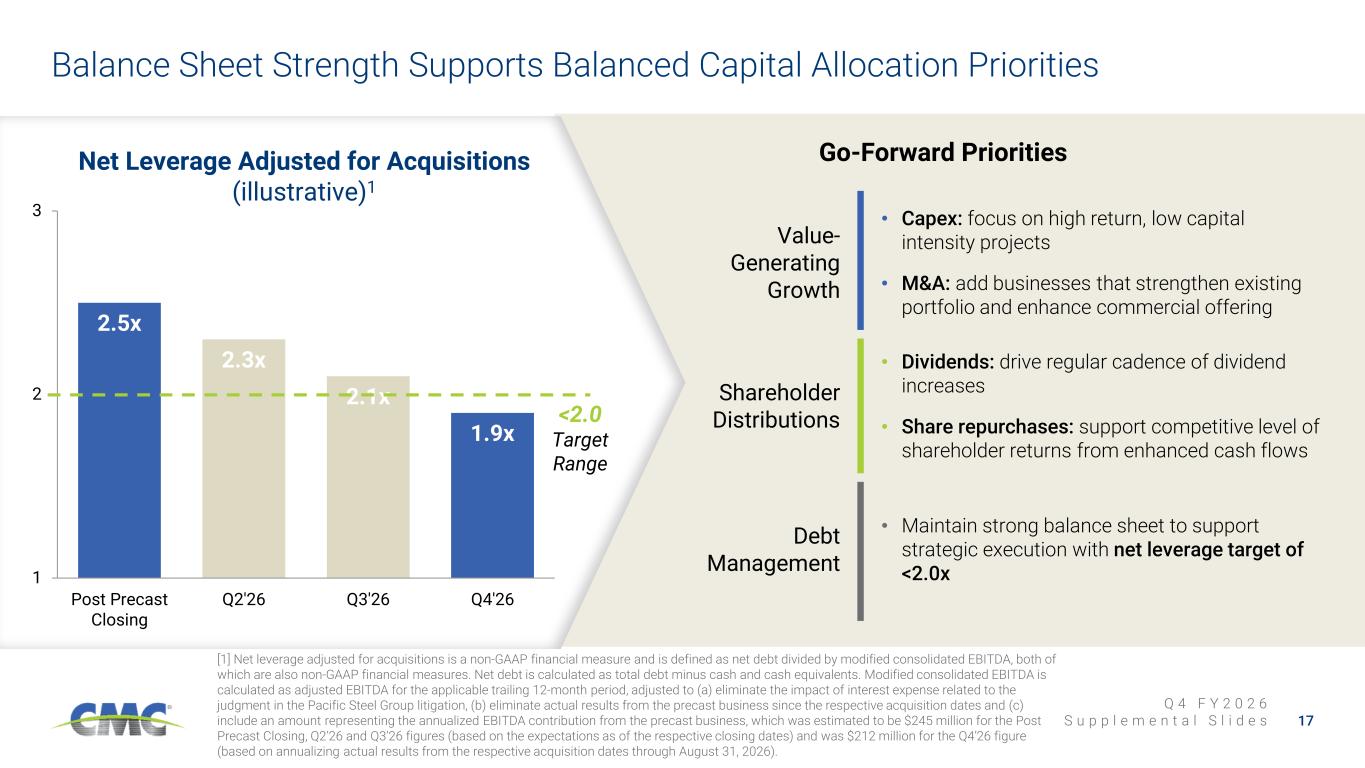
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s 2.5x 2.3x 2.1x 1.9x 1 2 3 Post Precast Closing Q2'26 Q3'26 Q4'26 Balance Sheet Strength Supports Balanced Capital Allocation Priorities 17 [1] Net leverage adjusted for acquisitions is a non-GAAP financial measure and is defined as net debt divided by modified consolidated EBITDA, both of which are also non-GAAP financial measures. Net debt is calculated as total debt minus cash and cash equivalents. Modified consolidated EBITDA is calculated as adjusted EBITDA for the applicable trailing 12-month period, adjusted to (a) eliminate the impact of interest expense related to the judgment in the Pacific Steel Group litigation, (b) eliminate actual results from the precast business since the respective acquisition dates and (c) include an amount representing the annualized EBITDA contribution from the precast business, which was estimated to be $245 million for the Post Precast Closing, Q2’26 and Q3’26 figures (based on the expectations as of the respective closing dates) and was $212 million for the Q4’26 figure (based on annualizing actual results from the respective acquisition dates through August 31, 2026). Go-Forward Priorities Value- Generating Growth • Capex: focus on high return, low capital intensity projects • M&A: add businesses that strengthen existing portfolio and enhance commercial offering Shareholder Distributions • Dividends: drive regular cadence of dividend increases • Share repurchases: support competitive level of shareholder returns from enhanced cash flows Debt Management • Maintain strong balance sheet to support strategic execution with net leverage target of <2.0x Net Leverage Adjusted for Acquisitions (illustrative)1 <2.0 Target Range
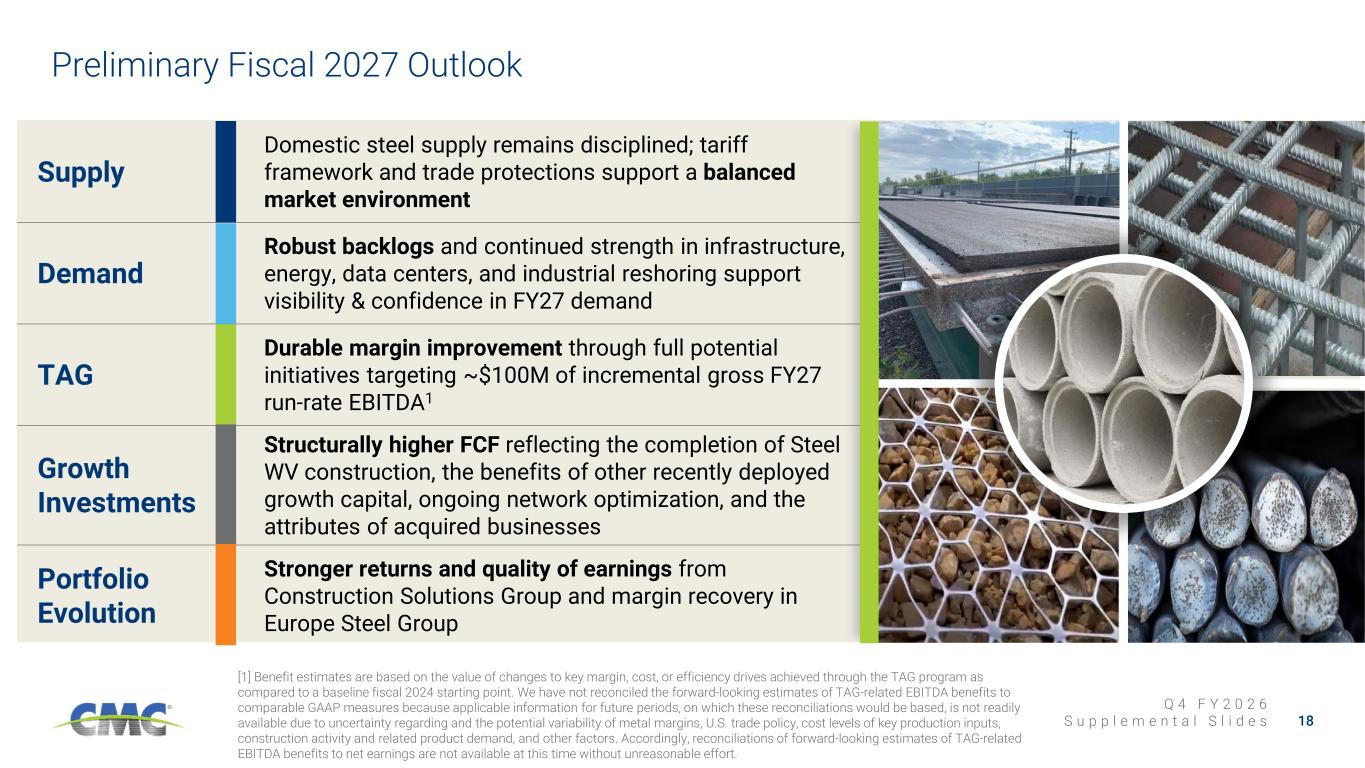
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s Preliminary Fiscal 2027 Outlook Supply Domestic steel supply remains disciplined; tariff framework and trade protections support a balanced market environment Demand Robust backlogs and continued strength in infrastructure, energy, data centers, and industrial reshoring support visibility & confidence in FY27 demand TAG Durable margin improvement through full potential initiatives targeting ~$100M of incremental gross FY27 run-rate EBITDA1 Growth Investments Structurally higher FCF reflecting the completion of Steel WV construction, the benefits of other recently deployed growth capital, ongoing network optimization, and the attributes of acquired businesses Portfolio Evolution Stronger returns and quality of earnings from Construction Solutions Group and margin recovery in Europe Steel Group 18 [1] Benefit estimates are based on the value of changes to key margin, cost, or efficiency drives achieved through the TAG program as compared to a baseline fiscal 2024 starting point. We have not reconciled the forward-looking estimates of TAG-related EBITDA benefits to comparable GAAP measures because applicable information for future periods, on which these reconciliations would be based, is not readily available due to uncertainty regarding and the potential variability of metal margins, U.S. trade policy, cost levels of key production inputs, construction activity and related product demand, and other factors. Accordingly, reconciliations of forward-looking estimates of TAG-related EBITDA benefits to net earnings are not available at this time without unreasonable effort.
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s Appendix Non-GAAP Financial Reconciliations
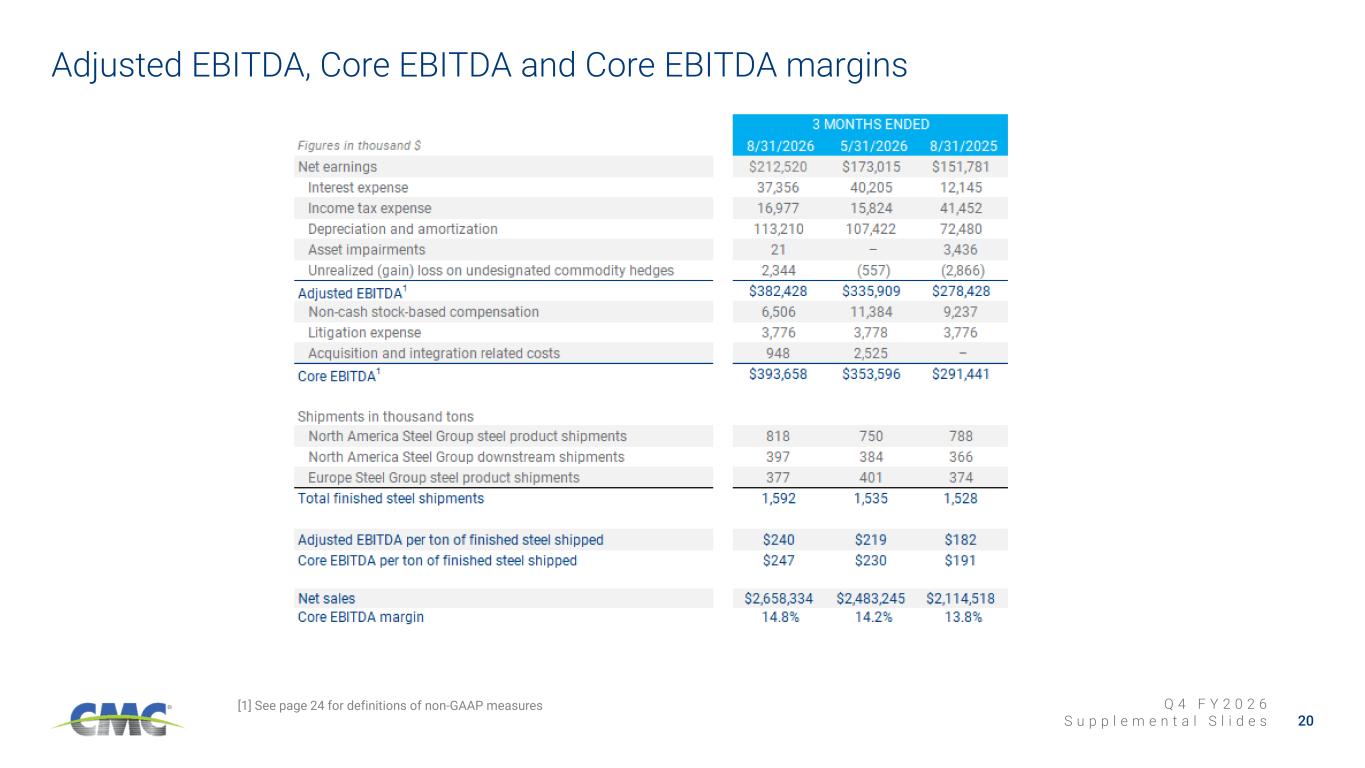
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s 20 Adjusted EBITDA, Core EBITDA and Core EBITDA margins [1] See page 24 for definitions of non-GAAP measures
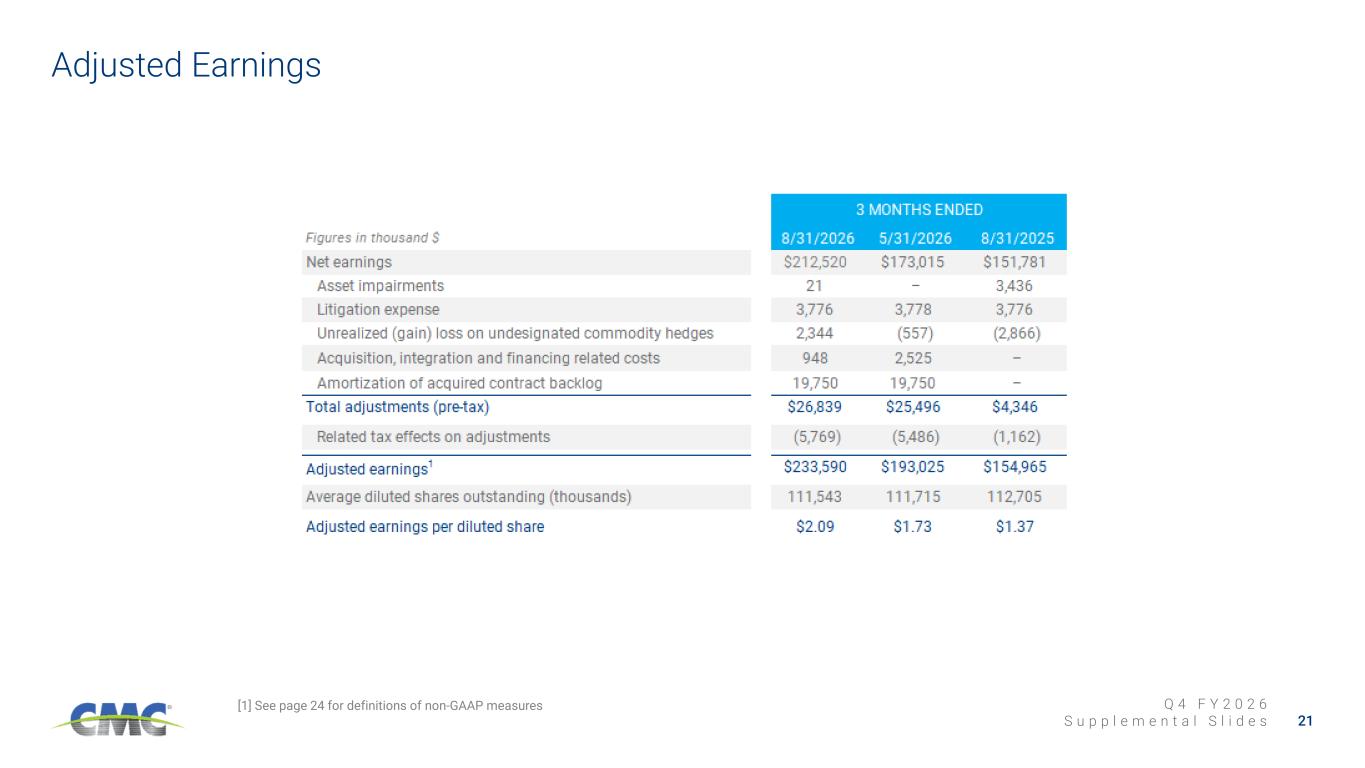
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s 21 Adjusted Earnings [1] See page 24 for definitions of non-GAAP measures
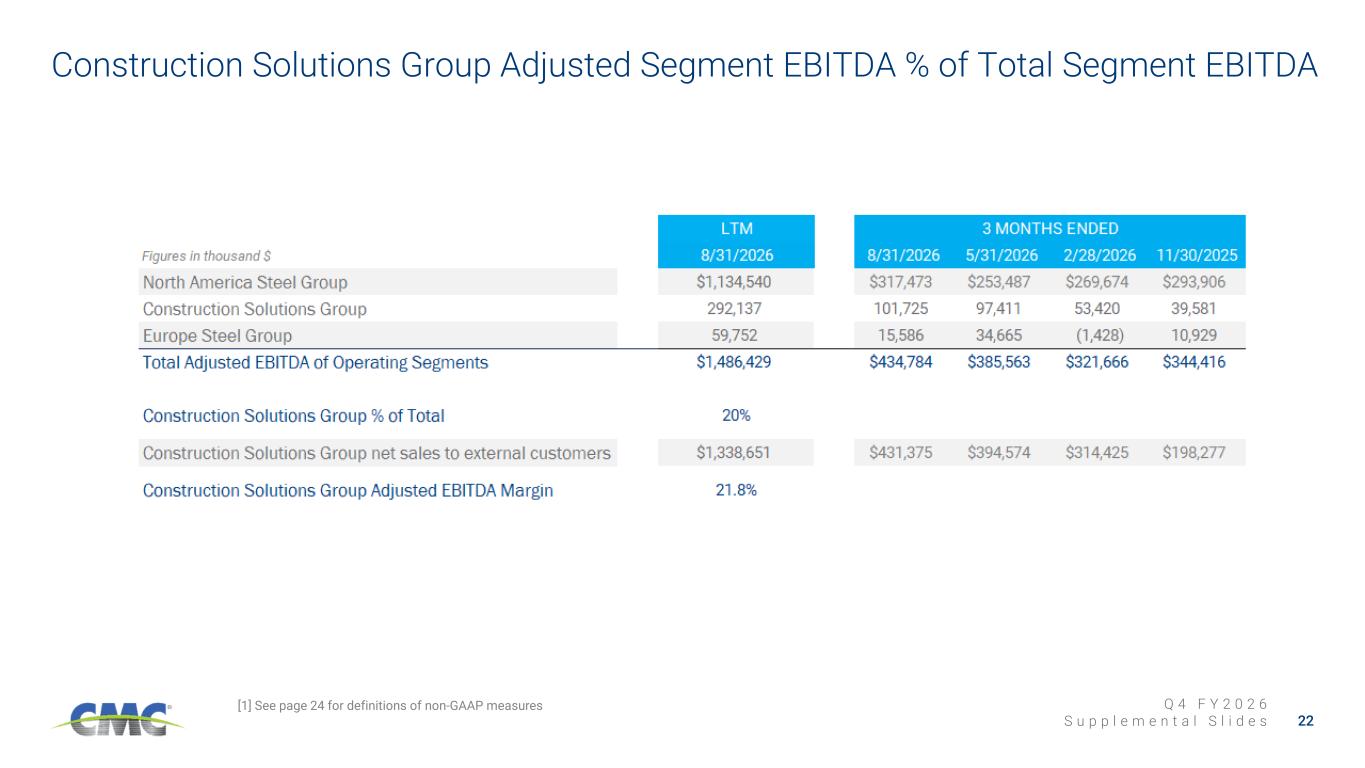
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s 22 Construction Solutions Group Adjusted Segment EBITDA % of Total Segment EBITDA [1] See page 24 for definitions of non-GAAP measures
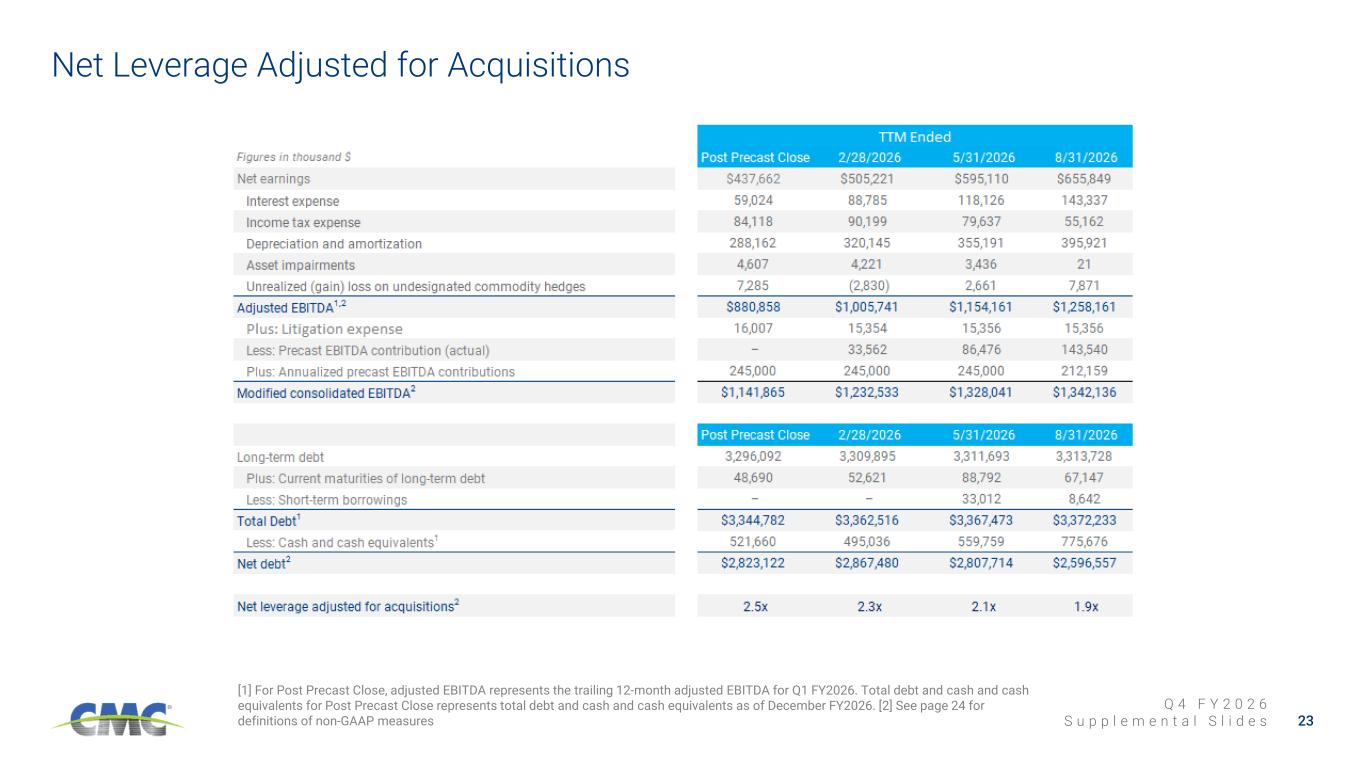
Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s 23 [1] For Post Precast Close, adjusted EBITDA represents the trailing 12-month adjusted EBITDA for Q1 FY2026. Total debt and cash and cash equivalents for Post Precast Close represents total debt and cash and cash equivalents as of December FY2026. [2] See page 24 for definitions of non-GAAP measures Net Leverage Adjusted for Acquisitions

Q 4 F Y 2 0 2 6 S u p p l e m e n t a l S l i d e s 24 Definitions for non-GAAP financial measures ADJUSTED EARNINGS Adjusted earnings is a non-GAAP financial measure that is equal to earnings (loss) before asset impairments and settlement for New Markets Tax Credit transactions, including the estimated income tax effects thereof. The adjustment “settlement for New Markets Tax Credit transaction” represents the recognition of deferred revenue from 2016 and 2017 resulting from the Company’s participation in the New Markets Tax Credit program provided for in the Community Renewal Tax Relief Act of 2000 during the development of a micro mill, spooler and T-post shop located in eligible zones as determined by the Internal Revenue Service. Adjusted earnings also excludes litigation expense, unrealized (gain) loss on undesignated commodity hedges and acquisition, integration and financing related costs, amortization of acquired contract backlog and purchase accounting effect on inventory. Adjusted earnings should not be considered as an alternative to net earnings (loss) or any other performance measure derived in accordance with GAAP. However, we believe that adjusted earnings provides relevant and useful information to investors as it allows: (i) a supplemental measure of our ongoing core performance and (ii) the assessment of period-to-period performance trends. Management uses adjusted earnings to evaluate our financial performance. Adjusted earnings may be inconsistent with similar measures presented by other companies. Adjusted earnings per diluted share (or adjusted EPS) is defined as adjusted earnings on a diluted per share basis. CORE EBITDA Core EBITDA is the sum of net earnings (loss) before interest expense and income taxes. It also excludes recurring non-cash charges for depreciation and amortization, asset impairments and unrealized (gain) loss on undesignated commodity hedges. Core EBITDA also excludes litigation expense, settlement for New Market Tax Credit transactions, non-cash stock-based compensation, loss on debt extinguishments, gains on sale of assets, acquisition settlements, acquisition and integration related costs, and purchase accounting effect on inventory. The adjustment “litigation expense” represents a provision recorded in the three months ended November 30, 2024 related to the judgment in the Pacific Steel Group litigation and, with respect to subsequent periods, interest expense on the judgment amount. The adjustment “settlement for New Markets Tax Credit transaction” represents the recognition of deferred revenue from 2016 and 2017 resulting from the Company’s participation in the New Markets Tax Credit program provided for in the Community Renewal Tax Relief Act of 2000 during the development of a micro mill, spooler and T-post shop located in eligible zones as determined by the Internal Revenue Service. Core EBITDA should not be considered an alternative to earnings (loss) from continuing operations or net earnings (loss), or as a better measure of liquidity than net cash flows from operating activities, as determined by GAAP. However, we believe that Core EBITDA provides relevant and useful information, which is often used by analysts, creditors and other interested parties in our industry as it allows: (i) comparison of our earnings to those of our competitors; (ii) a supplemental measure of our ongoing core performance; and (iii) the assessment of period-to-period performance trends. Additionally, Core EBITDA is the target benchmark for our annual and long-term cash incentive performance plans for management. Core EBITDA may be inconsistent with similar measures presented by other companies. CONSOLIDATED ADJUSTED EBITDA Adjusted EBITDA is a non-GAAP financial measure. Adjusted EBITDA is the sum of the Company’s net earnings (loss) before interest expense, income taxes, depreciation and amortization expense, asset impairments and unrealized (gain) loss on undesignated commodity hedges. Adjusted EBITDA should not be considered as an alternative to net earnings (loss), or any other performance measure derived in accordance with GAAP. However, we believe that adjusted EBITDA provides relevant and useful information to investors as it allows: (i) a supplemental measure of our ongoing performance and (ii) the assessment of period-to-period performance trends. Management uses adjusted EBITDA to evaluate our financial performance. Adjusted EBITDA may be inconsistent with similar measures presented by other companies. NET DEBT Net debt is defined as total long-term debt plus the current portion of long-term debt, less short-term borrowings (representing outstanding proceeds under the Poland accounts receivable facility), less cash and cash equivalents. NET LEVERAGE ADJUSTED FOR ACQUISITIONS Net leverage adjusted for acquisitions is a non-GAAP financial measure and is defined as net debt divided by modified consolidated EBITDA, both of which are also non-GAAP financial measures. Net debt is calculated as total debt minus cash and cash equivalents. Modified consolidated EBITDA is calculated as adjusted EBITDA for the trailing 12-month period, adjusted to (a) eliminate the impact of interest expense related to the judgment in the Pacific Steel Group litigation, which is $16 million for the Post Precast Closing and $15.4 million for each of Q2’26, Q3’26 and Q4’26, (b) eliminate actual results from the precast business since the respective acquisition dates and (c) include an estimate of annualized EBITDA contribution from the precast business, which is $245 million for the Post Precast Closing, Q2’26 and Q3’26 figures and $212 million for the Q4’26 figure. The annualized EBITDA contribution from the precast business used in the Q4’26 calculation was derived by annualizing the precast business’s actual results from the respective acquisition dates through August 31, 2026. The calculation also excludes the impact of the purchase accounting effect on inventory. The annualized figure used in the Q4’26 calculation assumes that the precast platform’s results for the post-acquisition period are representative of a full fiscal year. The figure does not reflect actual results the precast platform generated or will generate in any 12-month period, and it was not prepared in accordance with Article 11 of Regulation S-X. Results for future periods may differ materially. RETURN ON INVESTED CAPITAL Return on Invested Capital is defined as: 1) after-tax operating profit divided by 2) total assets less cash & cash equivalents less non-interest-bearing liabilities. For annual measures, trailing 5-quarter averages are used for balance sheet figures. During the fourth quarter of 2025, the Company modified its method of calculating adjusted EBITDA to exclude the impact of unrealized gains and losses from undesignated commodity derivatives. This change was primarily driven by heightened volatility in copper forward markets during 2025, which introduced significant non-cash fluctuations unrelated to core operations. By removing this volatility, the revised metric provides a more representative view of operating performance and cash-generating capability. Accordingly, the Company recast adjusted EBITDA, core EBITDA, core EBITDA margin, adjusted earnings and adjusted earnings per diluted share for all prior periods to conform to this presentation.