Operator
Good morning and welcome to the Hyatt first quarter 2025 earnings conference call. All lines have been placed on mute to prevent any background noise. After the speaker's remarks, we will have a question and answer session. To ask a question at that time, please press star followed by the number one on your telephone keypad. As a reminder, this conference call is being recorded. I would now like to turn the call over to Adam Roman, Senior Vice President of Investor Relations and Global FP&A. Thank you. Please go ahead.
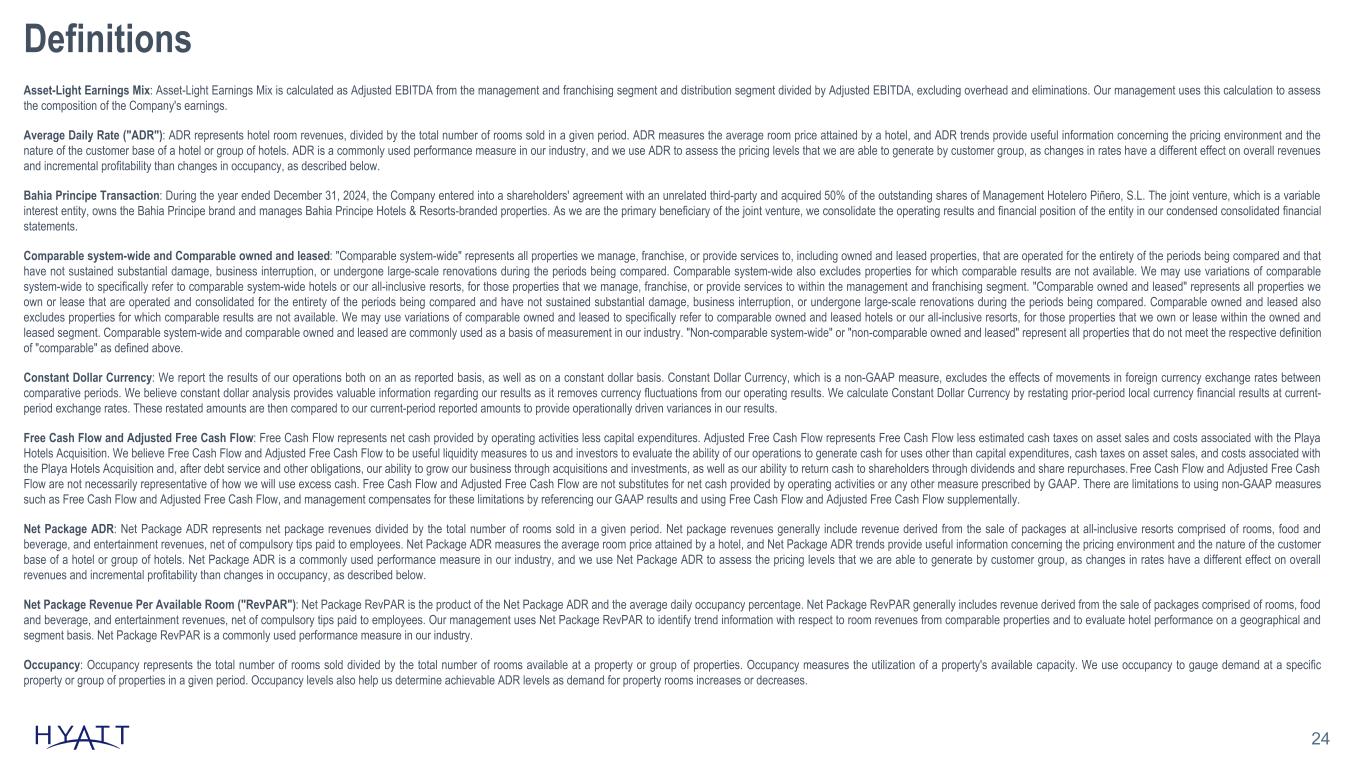
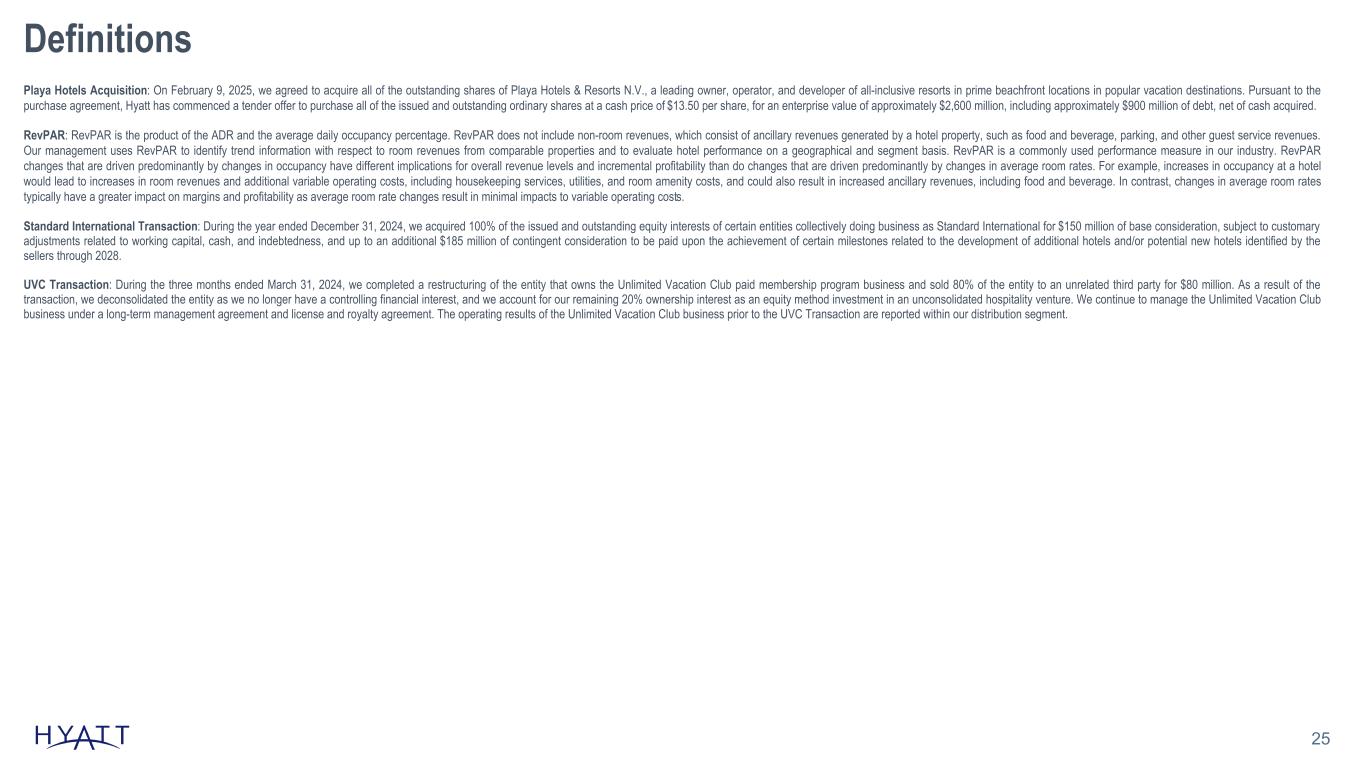
Thank you, and welcome to Hyatt's first quarter 2025 earnings conference call. Joining me on today's call are Mark Hoplamazian, Hyatt's President and Chief Executive Officer, and Joan Botterini. Hi, I start the call. I would like to remind everyone that our comments today will include forward-looking statements under federal securities laws. These statements are subject to numerous risks and uncertainties, as described in our annual report on Form 10 , 10 , and other SEC filings. These risks could cause our actual results to be materially different from those expressed in or implied by our comments. Forward-looking statements in the earnings release that we issue today, along with the comments on this call, are made only as of today and will not be updated as actual events unfold. In addition, you can find a reconciliation of non-GAAP financial measures referred to in today's remarks under the Financials section of our Investor Relations website and in this morning's earnings release. An archive of this call will be available on our website for 90 days. Additionally, we posted an investor presentation containing supplemental information on our Investor Relations website this morning. Please note that unless otherwise stated, references to occupancy, average daily rate, and RevPAR reflect comparable system-wide hotels on a constant currency basis. Percentage changes disclosed during the call are on a year-over-year basis. With that, I'll now turn the call over to Mark.
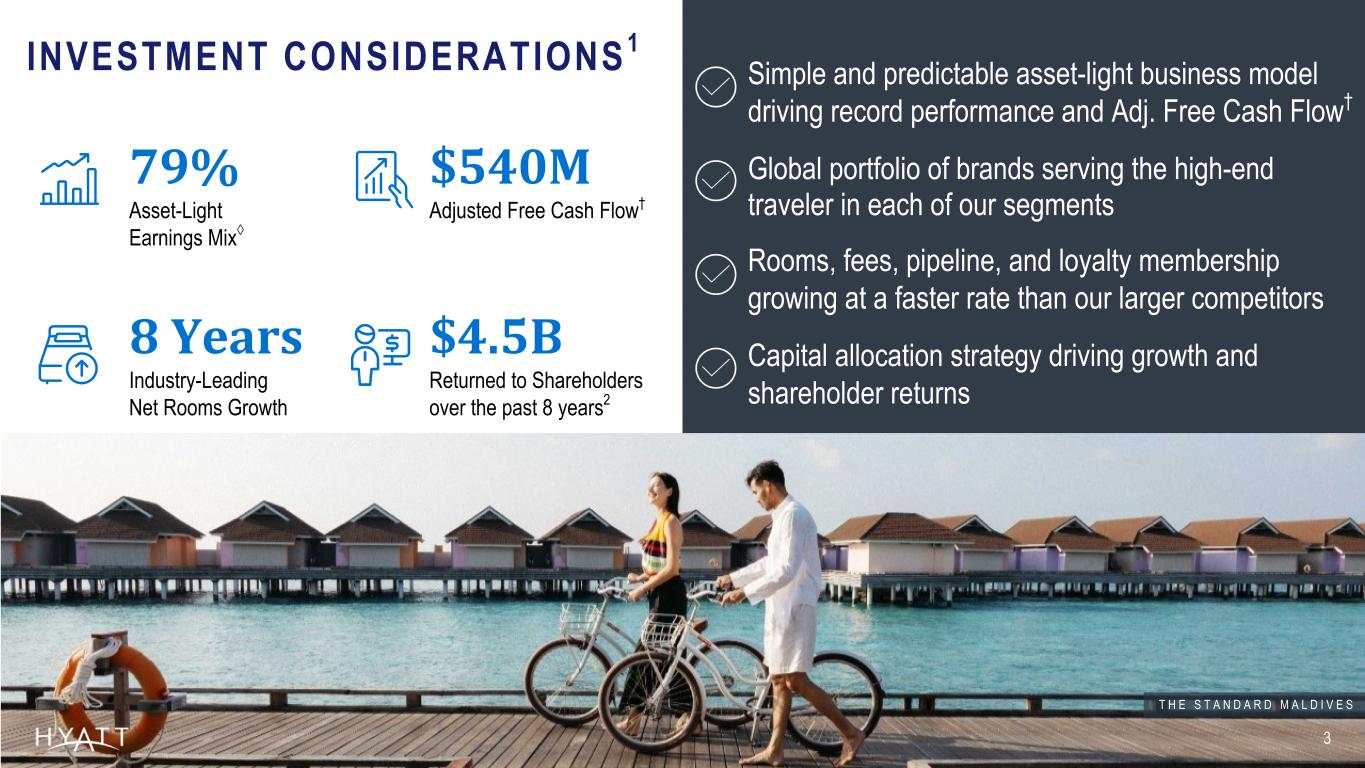
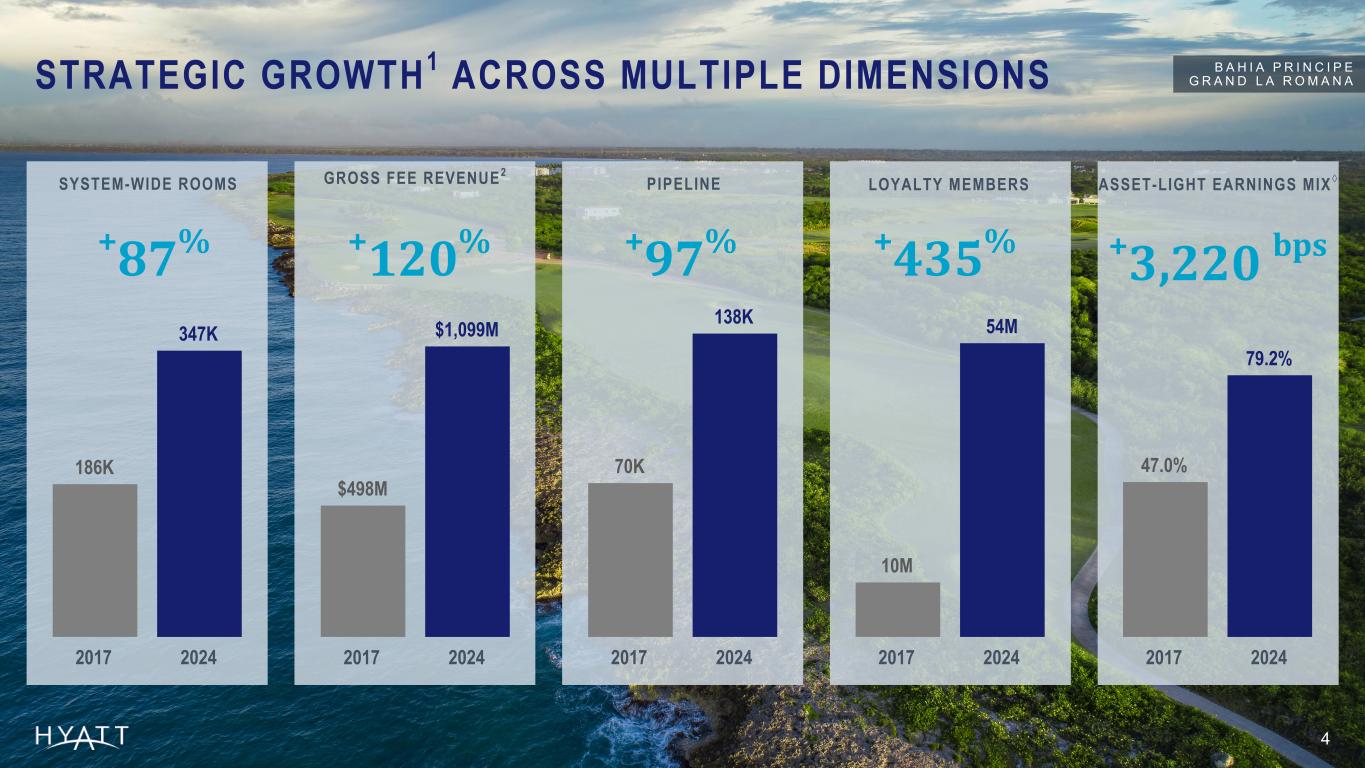
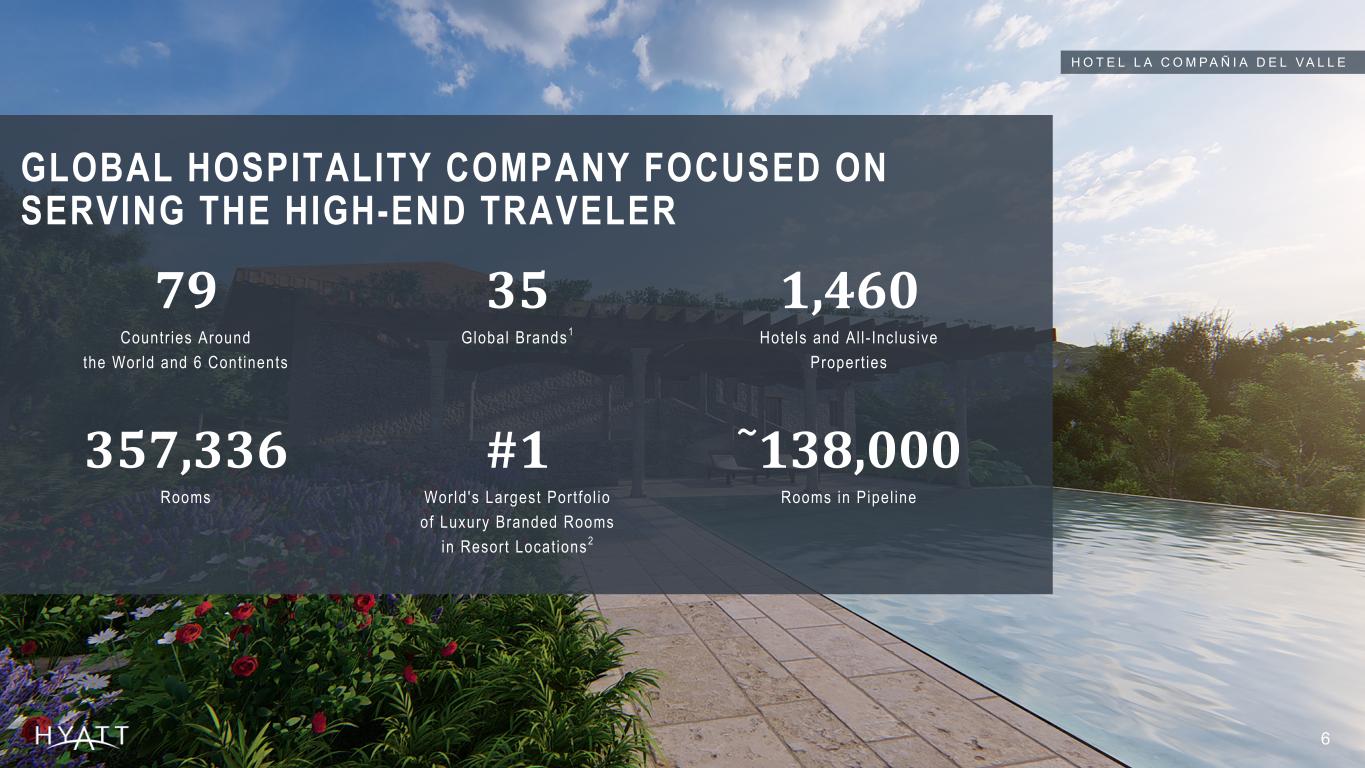
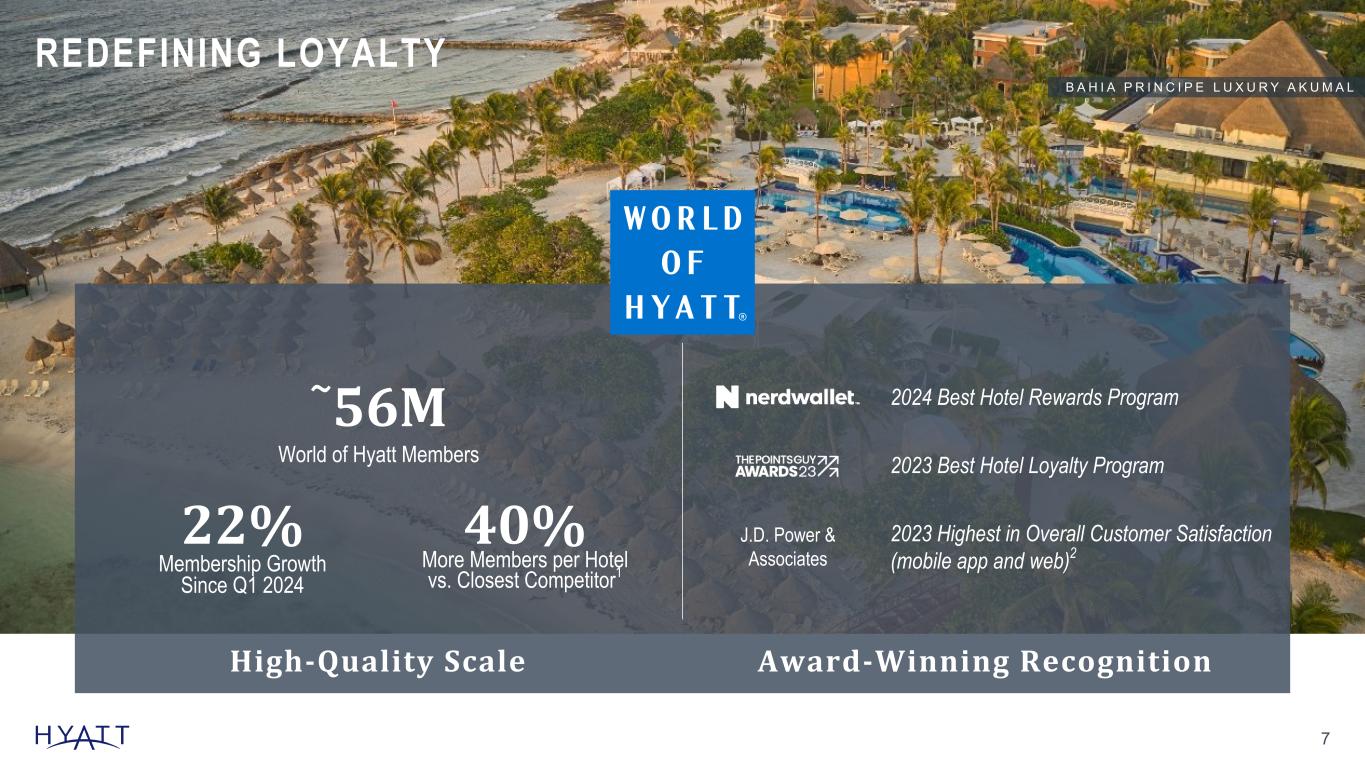
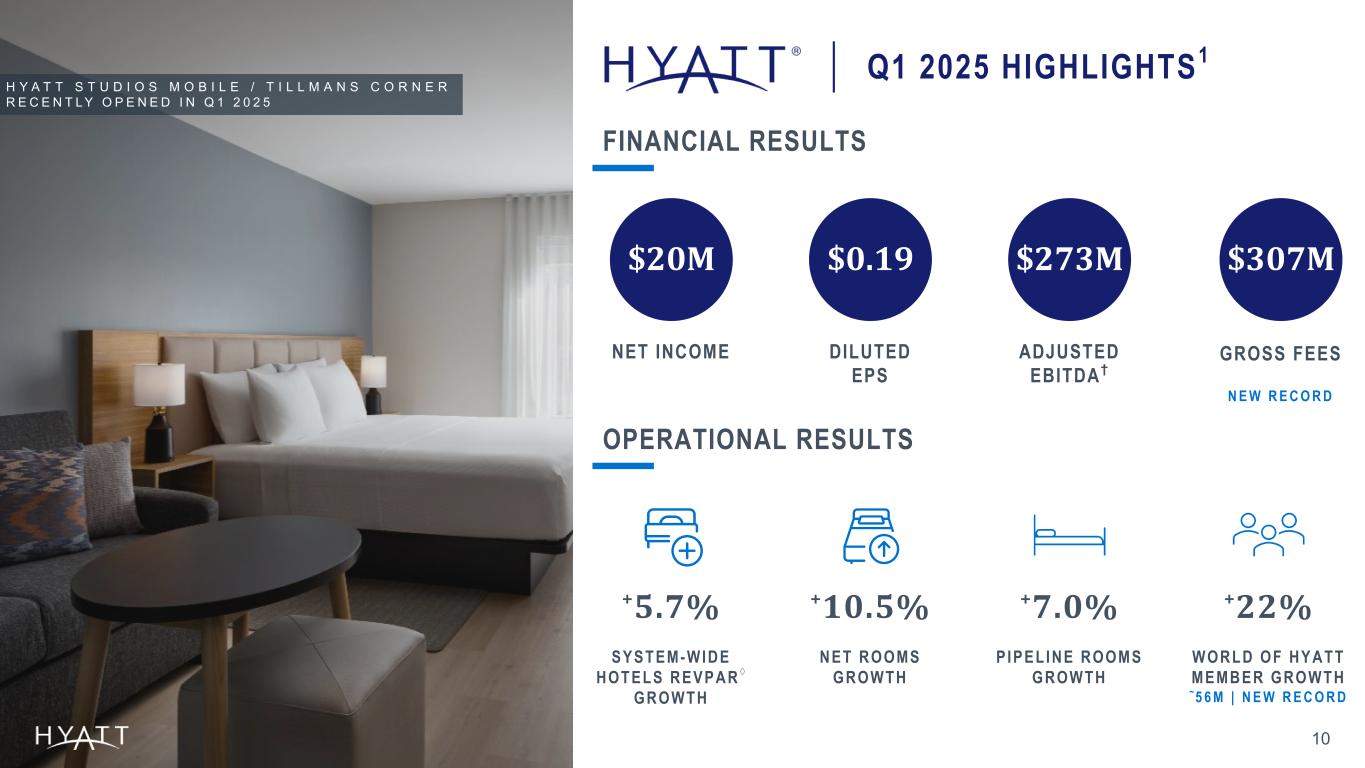
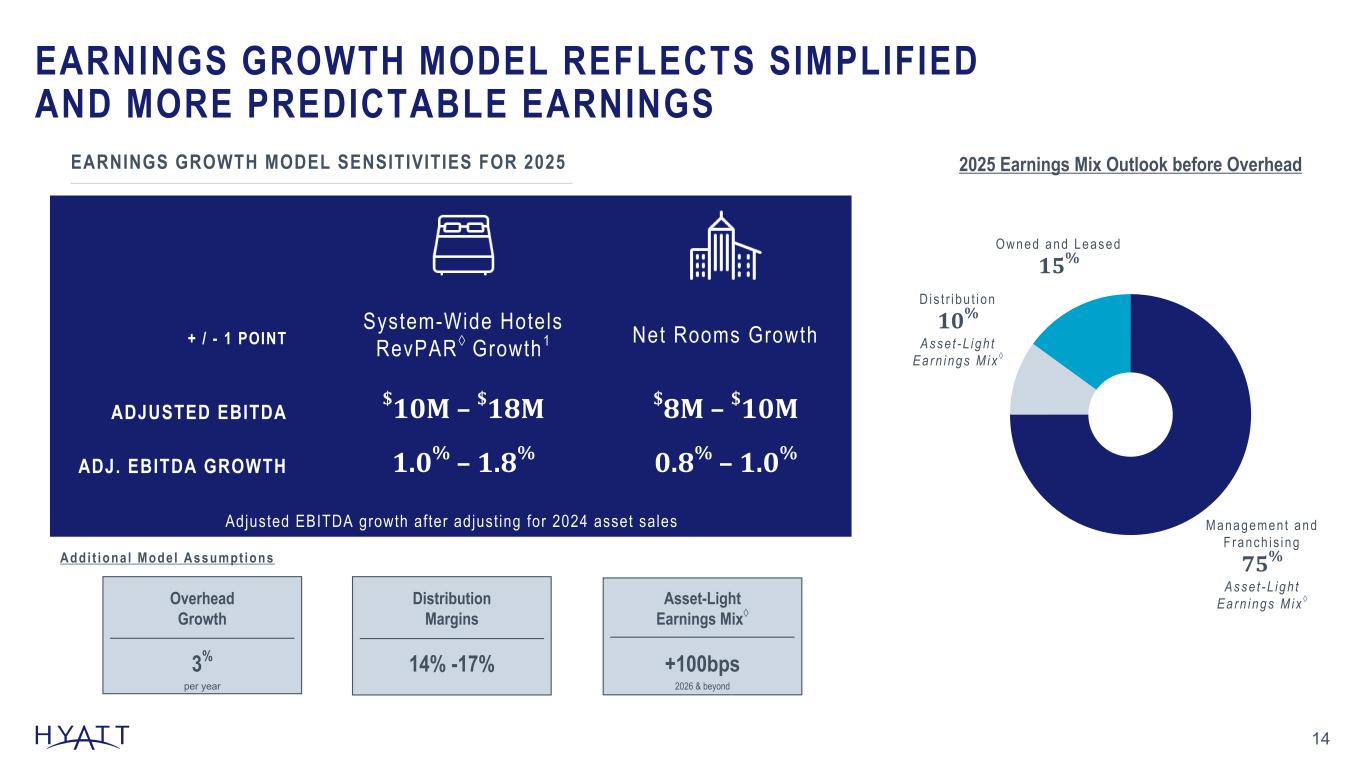
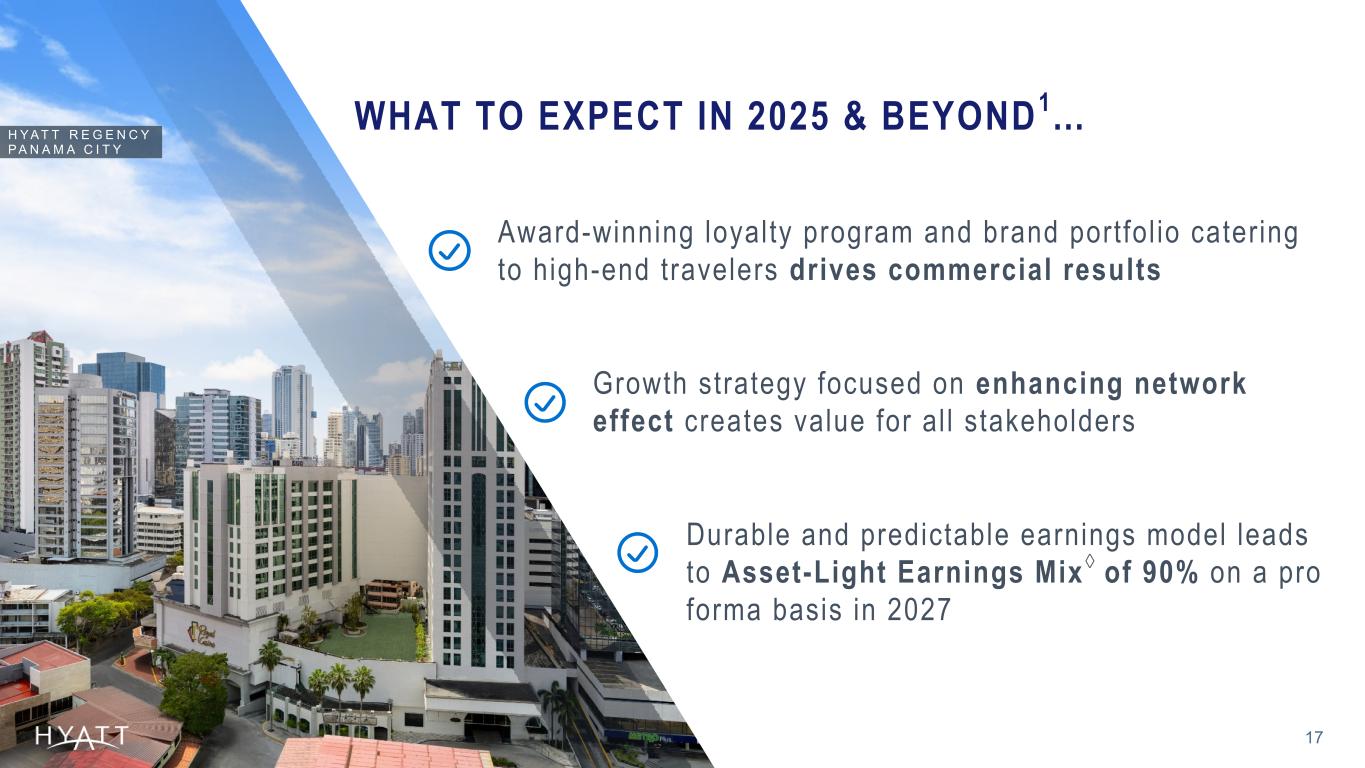
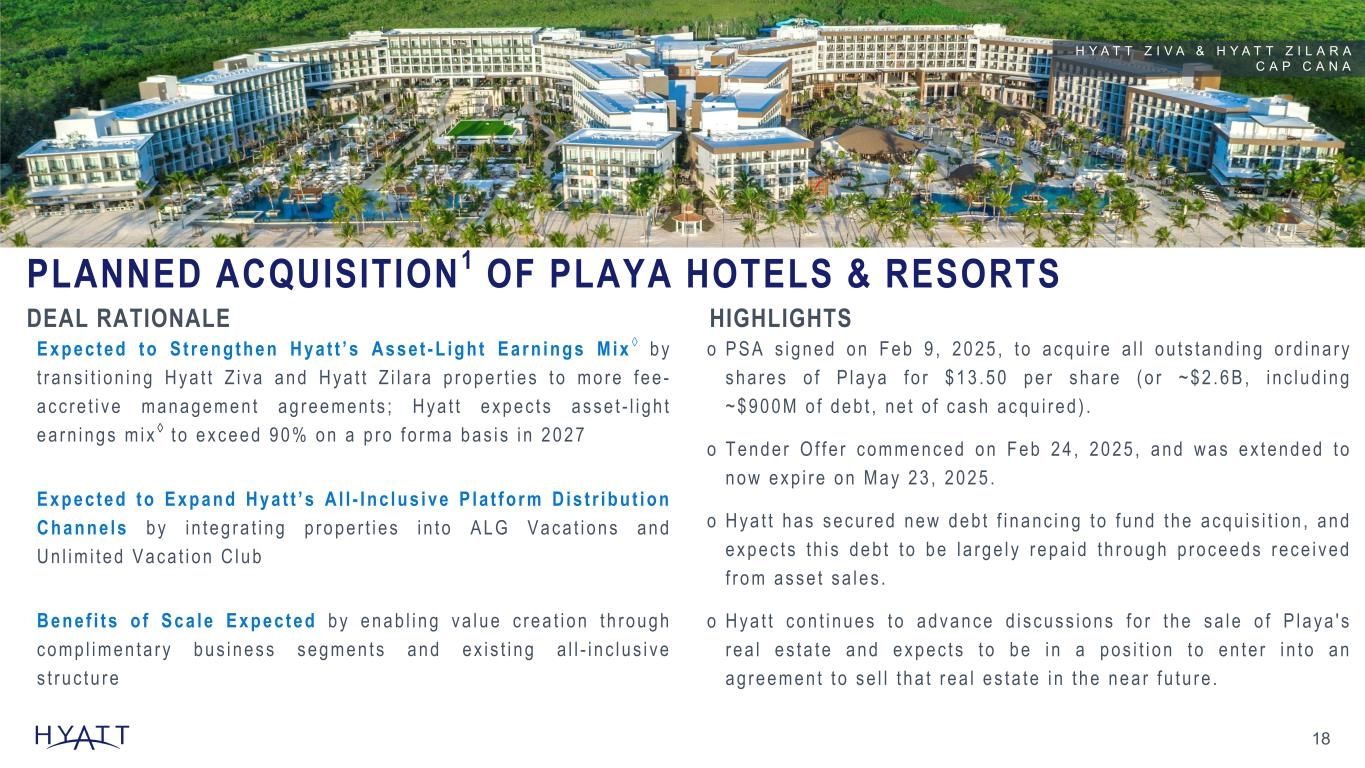
Thank you, Adam. Good morning, everyone, and thank you for joining us today. I'm very proud of our many accomplishments in the first quarter, including strong RevPAR and adjusted EBITDA growth, the introduction of the Hyatt Select brand, and being selected to the 100 best companies to work for annual list of U.S. companies according to Fortune and Great Places to Work for the 12th consecutive year. While we began to experience greater macro uncertainty during the first quarter, we delivered great results because of our durable asset light. Before I comment on our results, I'd like to provide a brief update on the playa. On April 28th, we extended the tender offer period until May 23rd, 2025, at which time we will evaluate if all closing conditions are met. We continue to advance discussions for the sale of Playa's real estate and expect to be in a position to enter into an agreement to sell the real estate in the near future. We will continue to provide updates on all aspects of the Playa transaction as we have additional information. we're also making progress to sell several of our owned properties including one that is under a signed psa two that are under a letter of intent and three hotels in a formal marketing process we remain under contract for the sales of and andas london liverpool street but do not expect either of those transactions to close this year we will continue to share additional updates as these transactions progress past statements expect that we will continue to reduce our Turning to growth, we were very busy on the approximately 138,000. New signings were placed, and development interest in our brands remained very strong. We signed several exciting projects during the quarter, including the Park Hyatt Tower Mina in Italy, the Grand Hyatt Shualak Hills in India, and a Hyatt-centric in downtown Cincinnati, to name a few. We are encouraged by the continued deal flow that we expect will translate to greater signings and expansion of our pipeline. We achieved net rooms growth of 10.5% during the quarter. We welcomed the Venetian Resort Las Vegas in January, and we are thrilled for our World of Hyatt members to experience these hotels on the Las Vegas Strip. Other notable full-service openings during the quarter included Andaz Doha and High Regency Bangkok Airport. In February, we opened the first Hyatt Studios Hotel in Mobile, Alabama. Hyatt Studios' Mobile Tillman's Corner is off to an impressive start, including strong bookings through Hyatt Direct Channels and great feedback from guests and developers. We are excited about the future growth of Hyatt Studios and the momentum we are building to expand our brand presence in the upper-mid-scale segment in the United States. To further accelerate our upper-mid-scale segment growth in the United States with the introduction of our newest brand, an upper mid-scale transient conversion brand, which we announced earlier this year. The brand expands Hyatt's offerings to travelers seeking shorter stays in secondary and tertiary markets, new builds, and active returns for owners, and offers an opportunity for us to expand our owner. As you will recall during our 2023 Investor Day, we discussed the opportunity to grow our domestic brand footprint, especially in suburban, interstate, and small metro markets, and we believe Hyatt Select, along with Hyatt Studios, are the perfect brands for growth in these markets. There are strong interests who are looking for conversion opportunities and access to Hyatt's powerful commercial platform, especially in markets where Hyatt has significant white space for growth. We are very excited about the potential of this brand and the opportunity to provide more options for our members and guests in new markets. Now turning to operating results, this morning we reported system-wide RevPAR growth of 5.7% for the quarter, which was positively impacted by the shift of EASTER from the first quarter in 2024 to the second quarter in 2025. RevPAR growth was strongest among our luxury brands, in line with the trends that we've seen over the last two years, as high-end consumers continued to prioritize travel. Leisure Transient RevPAR was flat to last year, reflecting the shift of Easter, and increased approximately 4% across our luxury brands. We also saw solid results across our all-inclusive resorts in the Americas, as net package RevPAR was up over 4% compared to the first quarter of 2024. Business Transient RevPAR grew 12% in the quarter, driven by our large corporate customers and group rep are increased nine percent in the quarter as the timing of Easter positively impacted both customer segments. Our strong brand portfolio and growth into new markets and customer segments is clearly resonating with guests driving the success of our award-winning world. We added over two million members during the first quarter ending the quarter with approximately 56 million members, a 22% increase over the past year. Loyalty room night penetration grew 170 basis points compared to last year as our members realized the benefits of our program, deepening their engagement with Hyatt and contribute to greater direct bookings. We also continue to see strong co-brand credit card spend, which increased significantly compared to as we look for mixed indicators as it relates to future booking activity. Based on what is currently on the books and recent booking trends, we expect red par growth in our international markets to outperform the United States, where pace is up approximately 7% in the second quarter for the Americas. In the United States, group pace for properties is up approximately 3% compared to 2024 for the last three quarters of the year. We expect group to positively contribute to REVPAR growth in the U.S. for the remainder of the year, but we do anticipate growth in the second quarter to be softer due to the timing of Easter. As we look further out, group production for 2026 and beyond increased by double digits in the quarter, driven by corporate bookings, and pace in 2026 is up over 10. We are seeing softer booking trends for near-term leisure and business transient bookings in the United States, which have been down in the high single digits in a few weeks, transient remains short-term. We believe that if visibility to macro could accelerate from what we have seen over the past, these trends informed our decision to adjust our full-year outlook, which Joan will review, call over to Joan, asset-like business model in the face of macroeconomic, and now have over 80% of our IPO in 2009. During the 2008 financial crisis, A 1% drop in REVPAR led to nearly 2.5% EBITDA due to our higher mix of owned and leased In REVPAR, it would lead to an approximate 1.4% change in adjusted EBITDA using the midpoint of our earnings model, which can be referenced on page 14 of our Supplemental Investor Deck. This sensitivity illustrates the positive benefits of our asset-like model, which is more durable and predictable through economic cycles. We have consistently invested in growth as a key part of our capital allocation strategy, which has enabled us to realize the benefits of scale. We believe our broader distribution across luxury, lifestyle, all-inclusive, and more recently upper-mid-scale segments positions us to meet our guests and customers in more places and engage them more frequently. As a result, our expanded reach and growing membership base have contributed to a pipeline that is now five times larger than it was in 2008, fueling the potential for continued fee growth well. We've sharpened our customer focus, reinforced our financial foundation, and significantly enhanced our organizational agility, enabling us to respond more swiftly and effectively as market dynamics evolve. Our teams closest to the customer are making more data-informed decisions, leveraging new tools that deliver tailored insights, results, resulting in quick, high-quality decision-making. We remain committed to investing in talent, systems, and processes that strengthen our agility and ensure we continue delivering exceptional value to all stakeholders regardless of the macroeconomic backdrop. I would like to close by expressing my gratitude to all Hyatt colleagues who live our purpose every day by caring for each of our stakeholders, especially in uncertain times. Joan will now provide more details on our operating results. Joan, over to you.
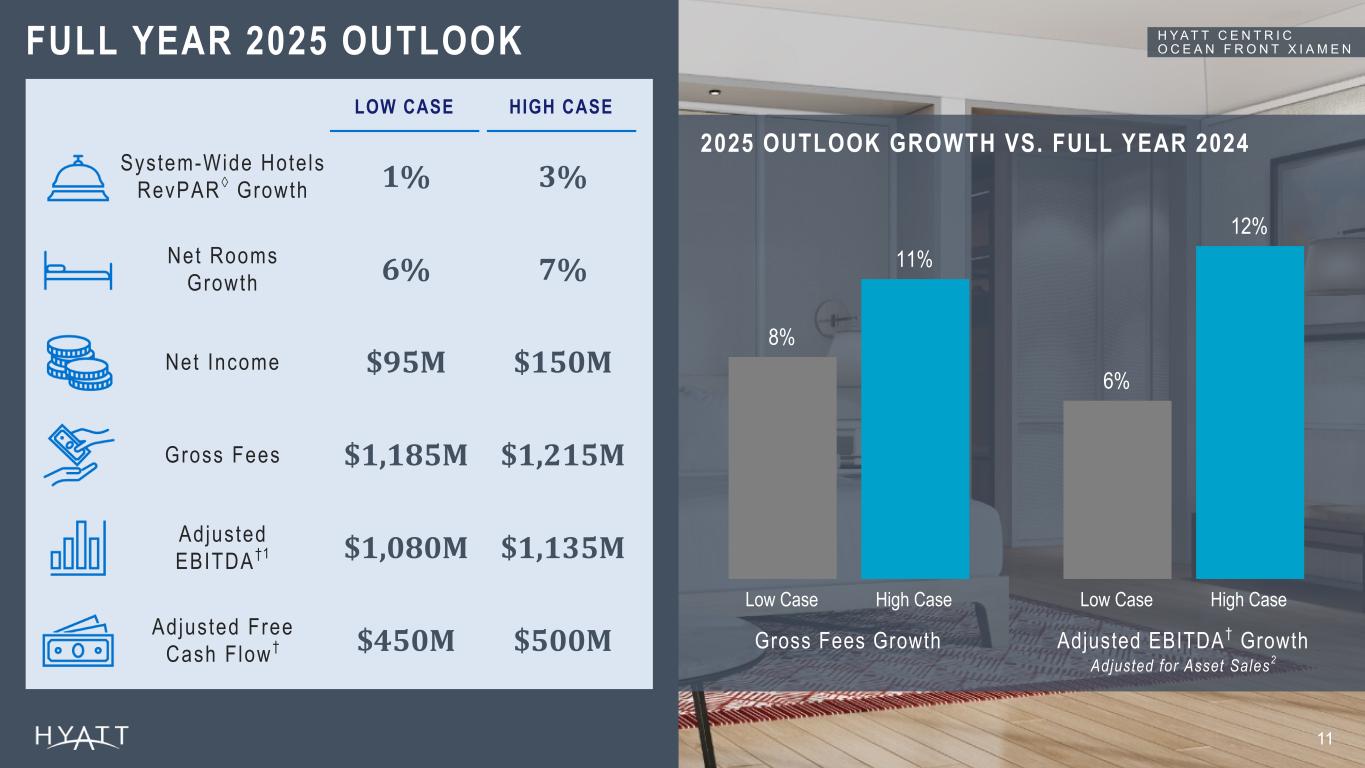
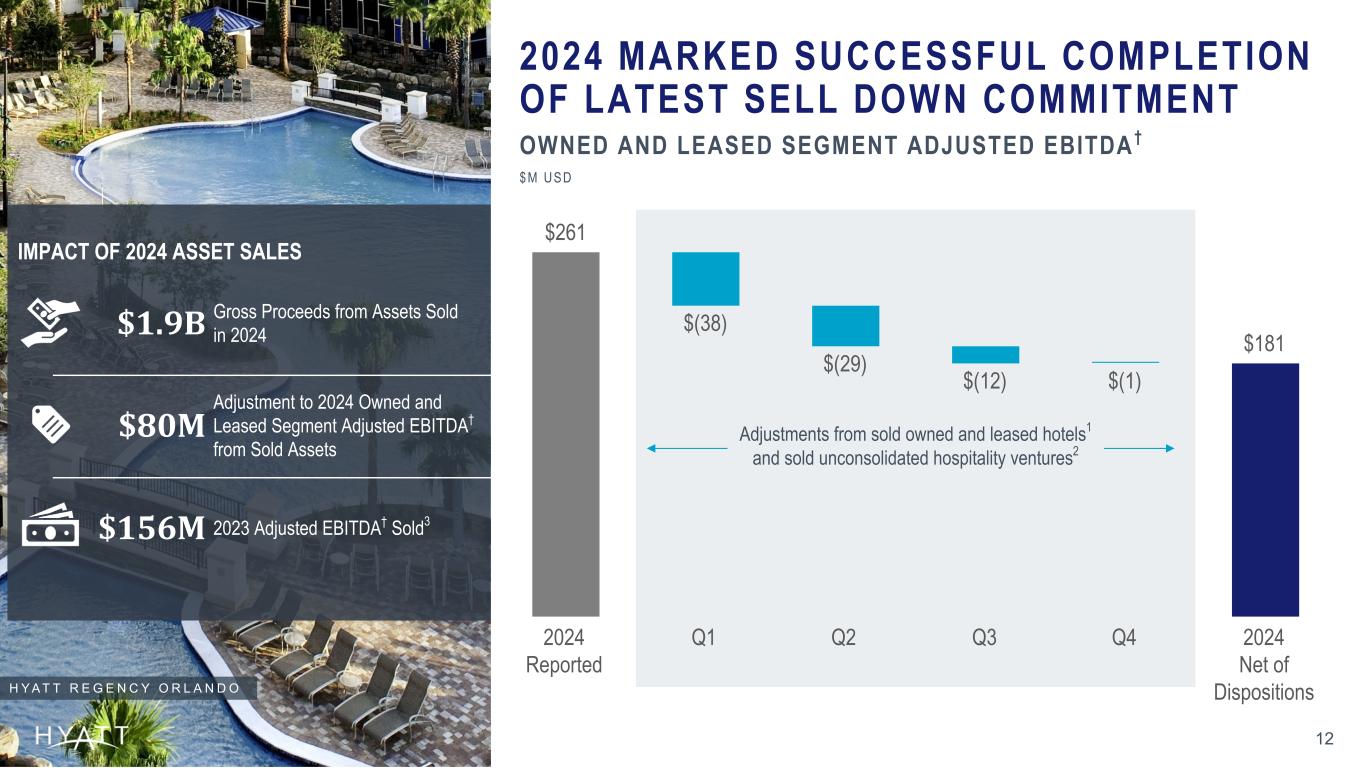
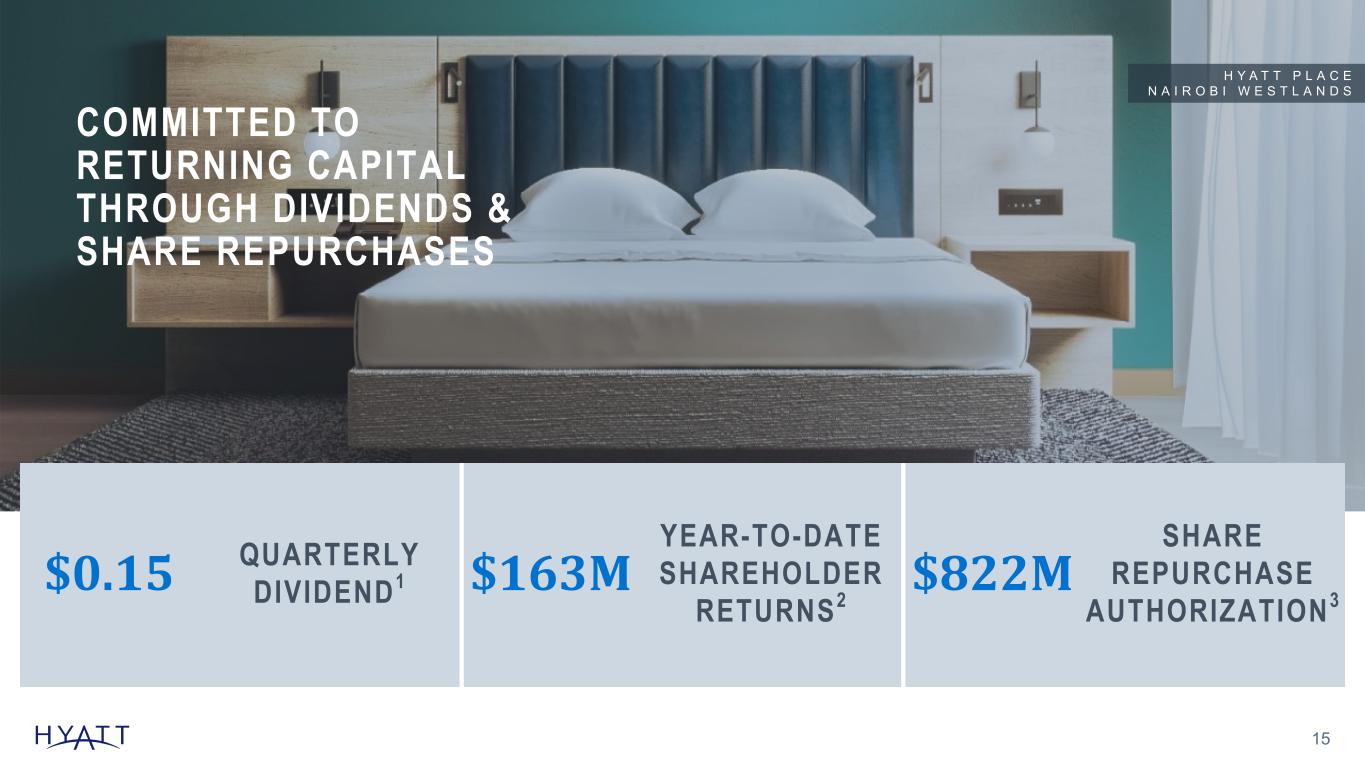
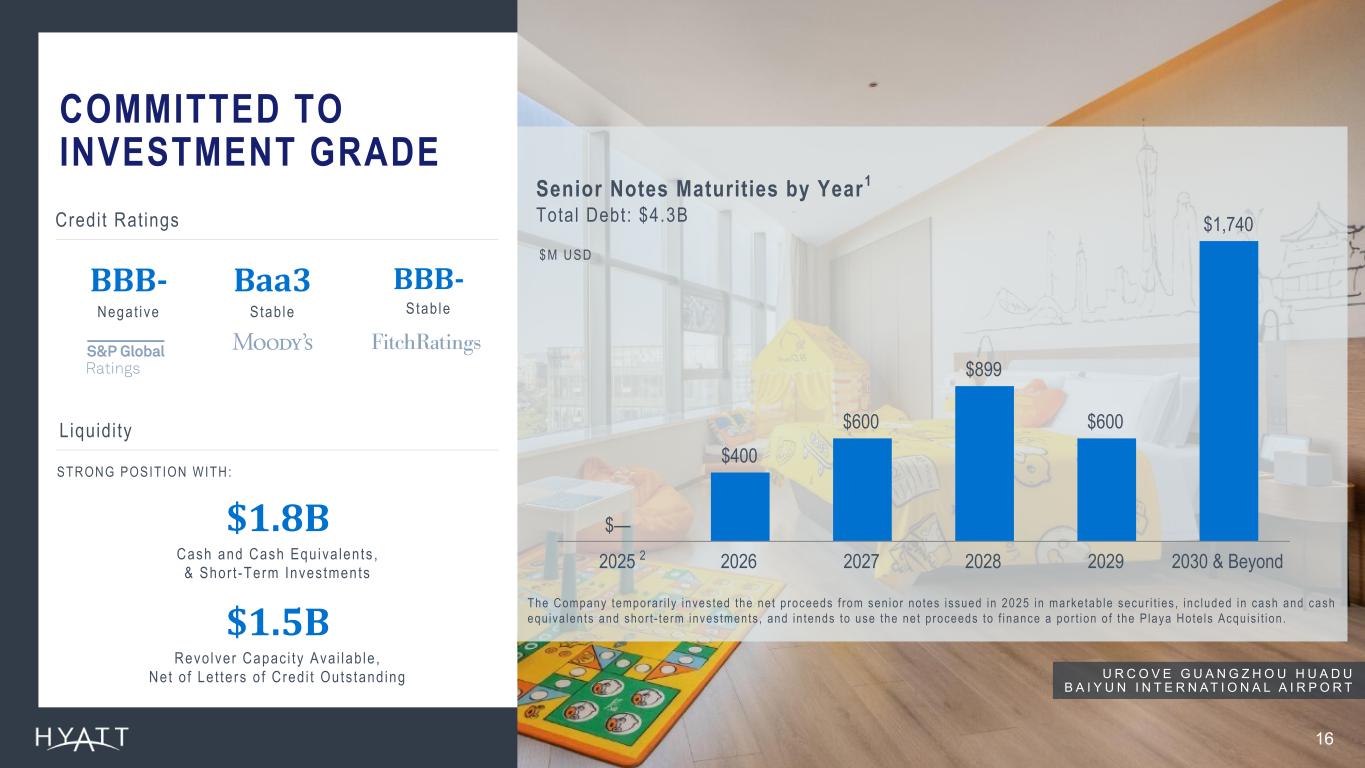
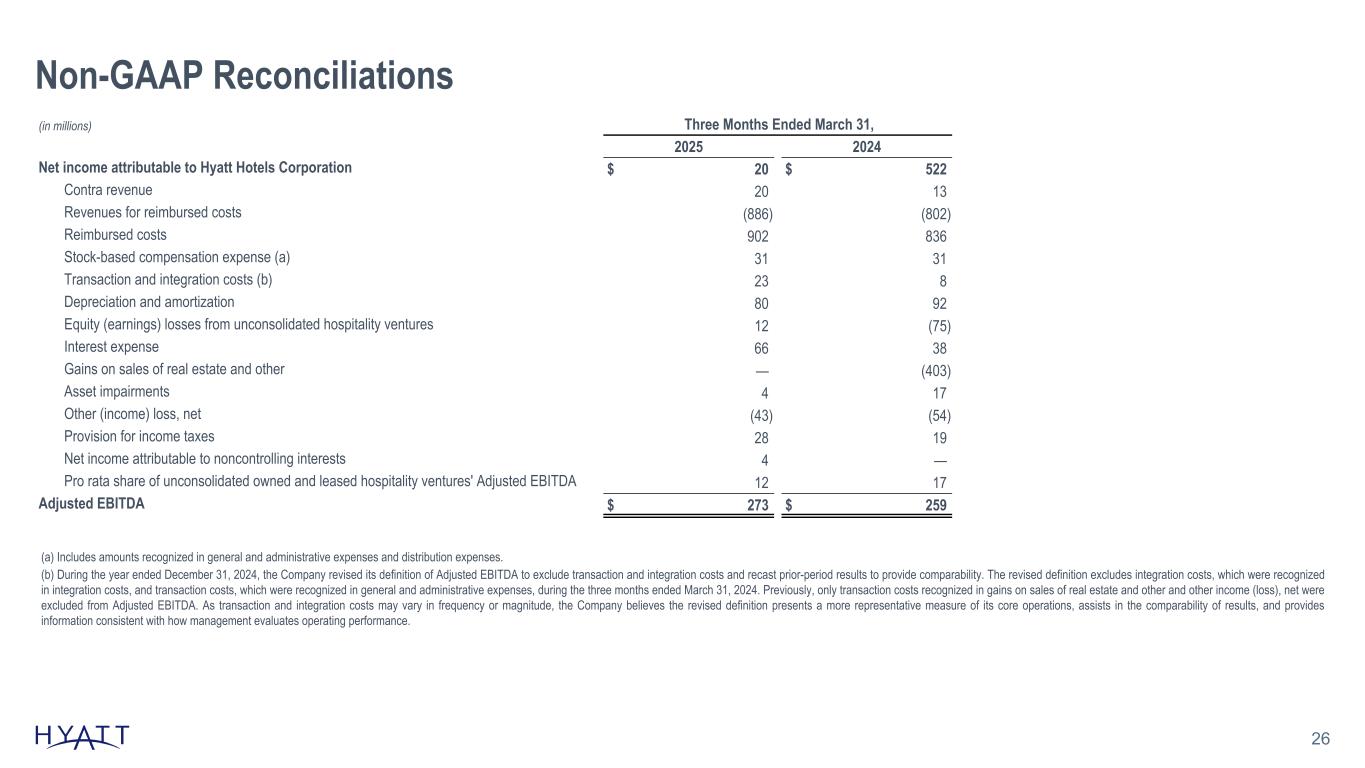
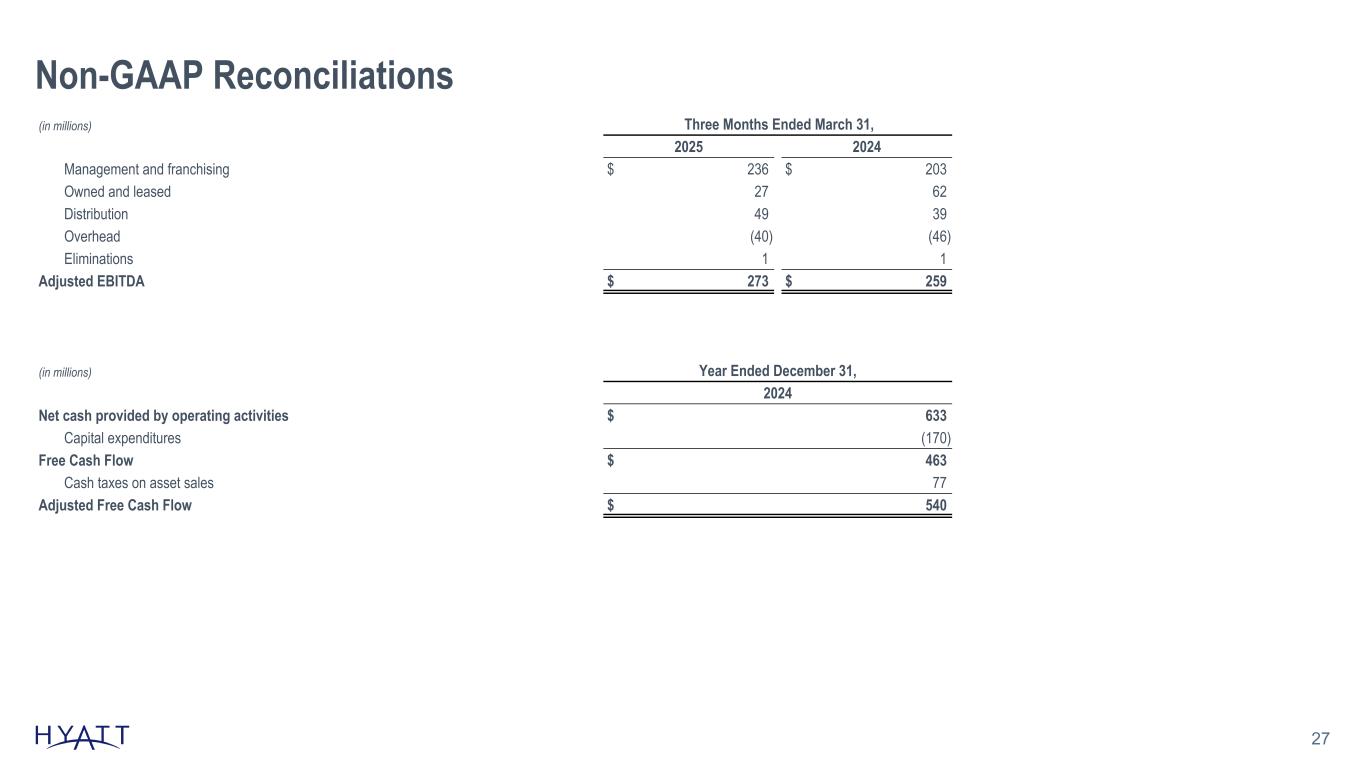
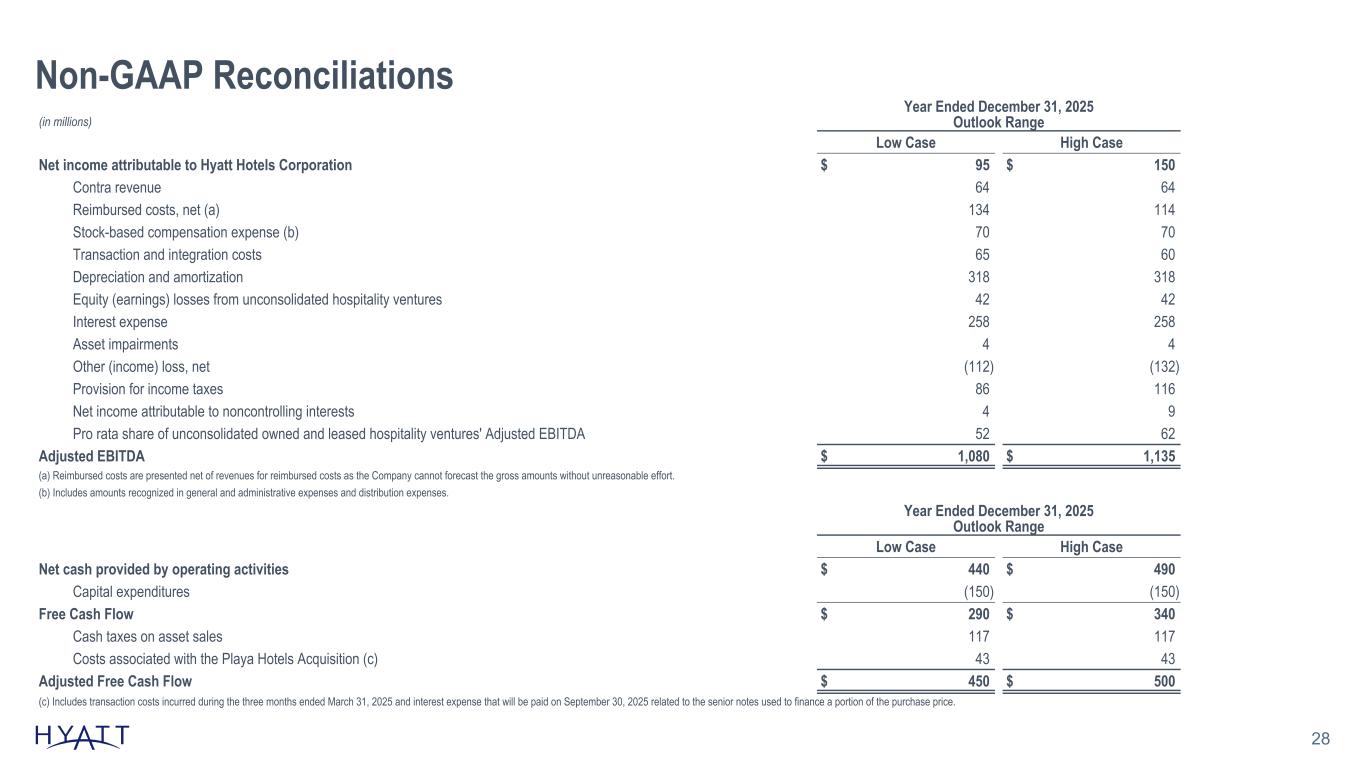
Thanks, Mark, and good morning, everyone. As we shared during our last earnings call, we expected first quarter REVPAR growth to exceed the high end of our full year range, and we were pleased with our exceptionally strong 5.7% REVPAR growth. As Mark mentioned, business transient, and group travel meaningfully contributed to REVPAR growth, and the highest end chain scales outperformed, with our luxury brand categories up over 8%, leading to over 2 percentage points of REVPAR index gains. In the United States, REVPAR increased 5.4%. The shift of Easter and the presidential inauguration in Washington, D.C., positively impacted growth by approximately 150 basis points, and group and business transient segments each delivered double-digit growth in the quarter. RevPAR in the Americas excluding the United States increased 2.3%, and net package RevPAR for our all-inclusive properties in the Americas increased 4.1%. In greater China, RevPAR was flat to last year as we lapped the strongest quarter of growth in 2024, but we increased our market share by approximately 1%. International inbound travel from the broader Asia-Pacific region increased 14% compared to last year. Asia-Pacific, excluding Greater China, had another great quarter, with REVPAR up 11.2%. REVPAR in Japan, India, Australia, and South Korea were up a combined 14%. percent. International inbound continues to be an important driver of results in the region. RevPAR in Europe grew by 8.5 percent compared to the same period last year. Leisure travel in the region grew by 8 percent from growth in both rate and demand. We reported growth fees in the quarter of 307 million dollars, up 16.9 percent. Our record level of fees was driven by strong RevPAR performance, new hotel openings, and growth in non-REVPAR fees. Owned in lease segment adjusted EBITDA increased by 18% when adjusted for the net impact of asset sales. Distribution segment adjusted EBITDA improved by 9.6% when excluding the impact of the UDC transaction. Performance in the quarter was driven by higher pricing, effective cost management, and favorable FX. In total, adjusted EBITDA was $273 million in the first quarter, an increase of approximately 24% after adjusting for assets sold in 2024. In the first quarter, we repurchased approximately $149 million of Class A common stock and have approximately $822 million remaining under our share repurchase authorization. During the quarter, we issued $1 billion of senior notes, and on April 11th, we closed on a $1.7 billion delayed draw term loan. We intend to use the net proceeds from our senior notes offering and the future proceeds to be drawn from the new term loan to finance the playa acquisitions. We remain committed to our investment grade profile, and as we've previously disclosed, we plan to use proceeds from the asset sales to pay down this incremental debt. On March 31, 2025, our balance sheet remains strong with total liquidity of approximately $3.3 billion, including approximately $1.5 billion in capacity on our revolving credit facility and approximately $1.8 billion of cash and cash equivalents and short-term investments. Again, $1 billion of our cash on hand is expected to fund a portion of the playa. I'll now cover our full-year outlook for 2025 with the full details to be found on page 3 of our earnings release. As a reminder, our outlook does not include acquisition or disposition activity beyond what we have completed as of today. We continue to monitor the dynamic macroeconomic environment, and while we had a very strong first quarter, the trends that Mark mentioned have led us to adjust our RevPAR expectations for the remainder of this year. We have seen signs of slowing customer booking behavior, particularly in short-term leisure and business transient demand. At this time, we anticipate RevPAR growth to moderate in the balance of the year. Our full year 2025 RevPAR range of 1% to 3% implies RevPAR growth for the balance of the year up between flat to up 2%. For the United States, after a strong first quarter with REVPAR up over 5% to last year, we expect REVPAR for the balance of the year to be around flat compared to last year. For greater China, visibility remains limited, but as we lap easier comparisons to last year, we believe REVPAR could be flat to slightly up for the balance of the year. We anticipate our properties in Asia-Pacific, excluding Greater China, will have the strongest growth in REVPAR of any geographic region as they continue to benefit from significant international inbound travel. We are maintaining our net rooms growth outlook range of 6% to 7% driven by organic growth. Growth fees are expected to be in the range of $1.185 to $1.215 billion, a 9% increase at the midpoint of our range compared to last year. Adjusted EBITDA is expected to be in the range of $1.08 to $1.135 billion, a 9% increase at the midpoint of our range compared to last year when adjusting for the impact of asset sales. As a reminder, owned assets sold in 2024 accounted for $80 million worth of owned and leased segment adjusted EBITDA last year. Adjusted free cash flow is expected to be in the range of $450 to $500 million, which excludes $117 million of deferred cash taxes expected to be paid in 2025 related to asset sales that took place in 2024, as well as approximately $43 million of costs related to the planned acquisition of PLIA. Our capital allocation strategy remains consistent. We are committed to our investment grade rating, identifying opportunities to invest in growth that create value for our shareholders, paying a quarterly dividend and returning excess cash in the form of share repurchases. We expect to return additional capital to shareholders in 2025 beyond quarterly dividends and our year-to-date share purchases. In closing, we're proud of our first quarter results, which highlight the strength of our asset light business model. We believe our commercial and growth strategy, the quality of our brand portfolio, and operational agility position us well to navigate this dynamic environment, and we remain committed to delivering against our long-term financial and strategic objectives. And this concludes our prepared remarks, and we're now happy to take your questions.
Operator
As a reminder to ask a question, please press star followed by the number one on your telephone keypad. In the interest of time, we ask that you please limit yourselves to one question and rejoin the queue for the additional questions. Our first question comes from Sean Kelly from Bank of America. Please go ahead. Your line is open.
Hi, good morning, everyone. Mark or Joan, just wondering if you could give us a little update on sort of how you expect some of your line items or business units to perform in, let's call it this choppier, you know, macro environment, specifically a little color on your expectations around distribution, given I think you called out, you know, some slower bookings, and then own and least and incentive management fees. is these are tough for a lot of people to model and understand the kind of sensitivity points given when RevPAR especially gets down to around the zero level, which I think you're implying for the balance of the year. Thanks.
Thanks, Sean. It's Mark. I'll start. It's obviously a choppy environment. The first quarter in the end of April is leisure. That is looking for 88% of the business book and q3's got 45 the leisure picture is um is much weaker in the u.s resorts than it is in the the non-us americas in canadian travelers into mexico and the caribbean on uh as we look at the it really is a tale of three in through the end of may now these are not huge part is in upscale and so BT is coming off uh in select I should say are actually positive uh in select service but the the overall business transient paces on the selects now we don't have any reason we'll yield a total year over the year it is we look at the um the GDP uh figures that
just came out are not encouraging you know I'm not an economist five opinions about that sure Sean, I'll just comment on the owned segment and distribution. So owned is a smaller portfolio now, less than 20% of our earnings mix, and there's a bit of a higher concentration to luxury. So the performance that we're seeing in those chain scales is obviously helping the portfolio in the quarter. And also because of the shift in Easter, New York had a really great quartiles there. As we look forward, this portfolio we expect to continue to be strong. We have a concentration in the U.S., so we're watching that closely as far as the short-term pickup. We have a Q3 difficult comp because of the European hotels and what we generated last year in Paris with the Olympics. But all in all, on balance, the own portfolio is performing strongly And margins are up in the quarter, up over last year, 70 basis points, which is really a result of our teams in the field and our asset management teams really pushing on productivity and costs that we can't control.
And, Joan, I would just add that that strength that you just described continued through April.
That's right. We had actually a very good April. Part of that was actually driven by New York, too, but continuing to be strong on the business side. For distribution, we had a good quarter in the first quarter, and it was a little bit better than expectations, actually, as our teams are being very, very disciplined about cost efficiencies. They are seeing some slowdown in booking activity at the lower chain scales, not into some of the five-star locations in Mexico and the Caribbean, but in lower chain scales. So they're working hard to make sure that we're very disciplined about the cost structure and driving pricing in those upper chain scales that they're delivering to. So that really helped results in the quarter, and we got a little boost from FX2 in that segment. As we look towards the remainder of the year, again, you know, we think we're watching the bookings closely. We do think that the $5 to $10 million upside to last year will probably be closer to around flat, which means, you know, a slight pullback in the last three quarters of the year relative to the first quarter. But nothing material. And, again, the teams have some levers at their disposal as they manage through the business into the coming weeks. That's where visibility is. It's really in the next couple of weeks.
Operator
Our next question comes from Michael Bellisario from Baird. Please go ahead. Your line is open.
Good morning, everyone. Just want to dig in a little bit more on the booking trends. Are you seeing cancellations, or is it all just less bookings at this point? and then group, what markets, what customer types are you seeing the hesitancy from and that 3% pace for the remainder of the year, where was that 90 days ago?
Yeah, I think, well, first of all, I guess a small percentage, a year that's so far transient in the group side, IT, this is on the BT side, the Q1. And so those are the key sectors that are the key that we're seeing at this moment is association pullback versus...
Yeah, I would just add, too, when we look globally, really the international markets are stronger, notably stronger when we look at the transient pacing, both on the business transient and the leisure transient side. So there really is, the U.S. is a little bit slower than in the last couple of weeks than international. So when you look on a global basis, Actually, business is up, and leisure on a global basis is slightly down, but that, again, is driven by the two different, very different dynamics we're seeing, international versus U.S.
Operator
Our next question comes from Ben Chaikin from Mizuho. Please go ahead. Your line is open.
Hey, good morning. Thanks for taking my question. I would love to give more color on the progress around Playa. Language in the release seems to suggest a little faster timeline than was indicated the last time we spoke, when i think you're referencing 2027 not sure if that read is fair and then any color on the number of uh potential buyers would be great thanks um yeah i i think as i mentioned um we expect to be in a position to be able to uh really beyond that it's we established um the end of 20 the aggregate
that we uh absolutely feel uh certain that we can accomplish we have actually beaten in terms of dollars and in terms of value.
Operator
The next question comes from Richard Clark from Bernstein. Please go ahead. Your line is open.
Hi, good morning. Thanks for taking my question. So just a question on the construction landscape. What level of cost inflation are your developers seeing, and is that having any impact on maybe your U.S. construction? And any update on the percentage of your pipeline that is under construction?
That was, I think, 25% the last quarter.
Thank you, Richard. A couple of things to be at the grand opening of the first time I spent all of my time talking to begin with. And to a person, they said that they are putting contingencies in their, in terms of the inspiring part of that conversation was that, well, in one case, they themselves stood up to these good manufacturers in the United States to limit any impact of ported case goods. A lot of the other, meaning ready-mixed concrete, not affected. I'm actually, I was really taken by the ingenuity and the creativity of the, we're going to see more, again, I think a lot of that has to do any impact from, by the way, with respect to the construction, it's actually about, excuse me, secondly, ported very vibrant, student of the industry for a long time, but for signings. So we're quite happy with that to see the activity that's underway in the system into the deals that we're currently making. I would say the activity on the pipeline are to me than it did a year ago.
Operator
Next question comes from Patrick Scholz from Truist Securities. Please go ahead. Your line is open.
Hey, good morning, everyone. Quick question for you on the PLEA transaction. What, if anything, at this point would make you not go forward with this deal. Thank you.
Well, we have a committed transaction and we're in the middle of a tender offer. There are conditions to the completion of that tender by any means an exhaustive list getting to an 80% tender, 80% of the shares would be clearance of all antitrust in order to the key condition.
Can I follow up? How confident at this Dr., do you feel about those key conditions being met or satisfied? Thank you.
We're confident that we'll get through this. I think the end of eight years have been maybe, I think we're just in a waiting period. I think we will get.
Operator
Understood. Thank you.
Operator
Our next question comes from Chad Bainan from Macquarie. Please go ahead. Your line is open.
Morning. Thanks for taking my question. With respect to the 2025 outlook, has anything changed with the non-hotel-related fees and with any softness that you've seen recently in the leisure traveler? Does that usually correlate with kind of what you see in that line?
No, Chad, on the non-hotel-related fees, in the first quarter, we had a very strong result up significantly in our franchise and other fees. Some of that was boosted by the UVC transaction, which closed in the last year in the middle of the quarter. So that did help us in the first quarter, but we're anticipating healthy growth in both franchise and other non rest of the year and then you know I don't know if this is behind your question but maybe just a little bit of color as we think about the other fee streams you know incentive management fees again strong in the in the quarter across all actually dimensions of our fee growth one thing that is important is the health of the US market and the China market which We've described China being flat in the quarter, and we anticipate as we look through the rest of the year that that could improve based on what we're seeing. In fact, April was a little bit better in China. And then for the U.S., the same comment I would make is that the short-term bookings being a little bit softer, with what we see evolves in the environment, we could see some pickup because the short the bookings are short term right now and again you know April was positive in the US so you know it's a it's a matter of watching this really closely and making sure that our teams are going to market where the demand is coming and that's what we're focused on in light of some booking activity that's a little bit softer than we would have anticipated a couple of months ago and And that should help us sustain these fee growth numbers through the rest of the year. We've posted 17% growth in the first quarter, and we anticipate the full year at the midpoint will be 9%. So still strong growth through the remaining three quarters of the year.
Operator
Our next question comes from Stephen Grambling from Morgan Stanley. Please go ahead. Your line is open.
I think last quarter we talked about this a little bit, but as we think about your COBRA credit card is there a path to this being potentially renegotiated early as some of your peers have and any to read reason to believe that your terms would be different than some of those recent renewals we don't have an update today to share and we will absolutely provide an update when we have more information we do believe we're going to achieve a very competitive new deal because of our brand portfolio our distribution the growth the options we provide so serving the high-end traveler helps us in this regard. And of course, the performance of the World of Hyatt program is also a key contributor to why we think we'll have a successful deal when we get to be able to share the negotiation.
Great. And then I think that you touched on this with Chad's question, but have you seen any big deviation in the spend on your existing co-brand credit card, whether it's shifting more towards goods versus services that may mirror some of what you're seeing on the other side from a RepPAR standpoint?
No, really strong results that we've seen personally and what we've heard from our issuer. So nothing that is concerning at all or materially different than that strong result.
Operator
Our next question comes from Dwayne Penigworth from Evercore ISI. Please go ahead. Your line is open.
Hey, thank you. On the favorable all-inclusive pacing, you briefly mentioned or alluded to Canadians overflying the U.S. I wondered if you had any stats on how the point-of-sale might be changing for all-inclusive. Is U.S. point-of-sale stable, or are you seeing other geographies meaningfully perk up?
So the percentage, but the U.S. is the, you know, for state business in the first quarter and the pacing is coming from the U.S. I would describe the is a bit of a cascade of some U.S. resorts, and the U.S. is.
Thank you for that. And then I just wonder, big picture, I know you have a longer-term goal, but how should we be thinking about dispositions this year excluding potential playa transaction? Thanks for taking the questions.
Yeah, I think it's a little less predictable in terms of chiming at this point. We'll see decisions, and that does create thinking about properties that we have for sale are actually in Europe. So the capital formation there is a little... So we absolutely have an expectation that we will quote enumerated early as we sit here at this moment.
Operator
The question comes from Smedes Rose from Citi. Please go ahead. Your line is open.
Hi. I just wanted to follow up a little bit on that, on the potential real estate dispositions. Maybe, you know, you've obviously been through a lot of cycles, you know, this space very well. You've been very successful at it. You mentioned sort of, you know, difficulties maybe around financing. And I'm just wondering, are you more inclined to offer seller financing in some circumstances? Have you gotten maybe pushback around pricing from potential buyers given increased uncertainty? Or are they kind of just looking through all of it? And any thoughts maybe just on more sort of institutional interest in the all-inclusive space, which I think you talked about a little bit on the last quarter, which we haven't seen so much of in terms of real estate ownership and just sort of any thoughts there?
Yeah. So, first of all, thanks, Meads. I appreciate the question. The fact is that you are, like we do, believe that medium to long-term value creation in the asset base. And so what you don't want to do is end up getting all that is the key from what you can read through valuations. This is all the balancing act. I mean, I've covered the whole waterfront now, but that's the way in which we are engaged in all of this.
Operator
Our next question comes from Connor Cunningham from Melius Research. Please go ahead. Your line is open.
Hi, everyone. Thank you. Sorry to get back to sort of the short-term question, but I'm just trying to understand what's going on on business transient and leisure in general. There's obviously a lot of noise from the calendar shifts and whatnot, but has demand end stabilized in April? Like if you exclude all the calendar stuff, is it now stable from where it was before all the uncertainty kind of crept into the market? And then just as you think about internationally, you talked about it outperforming the US, that all makes sense. But it seems like the entities are at much different spots. So if you could just talk about where you see the most upside and potential more muted outcomes, that would be helpful. Thank you.
So Connor, maybe I you touched on it and it's actually a way that we're sitting here as we're processing the numbers is that April was a unusual month because of the holiday the Easter holiday and the holiday being later in the month too so you have this you sort of have this spring break that existed for several weeks prior to the Easter holiday. we are looking at preliminary numbers for April and they're positive. So while we've been seeing some bookings flowing, April still has positive results and very strong continued momentum outside the U.S. in markets in Asia, outside of greater China, even though I also mentioned greater China was positive in the month. And in our all-inclusive business, you heard the pace numbers we were sharing at 7% in the Americas the all-inclusive segment so that's where the mixed comment comes and so we're watching it closely we will I think look at May and June as indicators of what you're suggesting with respect to a more quote normalized period in this uncertain environment where we can actually track what's landing because it is still short term and I mean the one the one call out that is probably you know a bit more of a as we look at the chain scales because luxury has been outperforming and the upscale segments have been underperforming they've been a bit weaker so So that's the area that, you know, we'll be watching that closely in particular in May and June when we have a little bit more of a clear calendar and a month that should be healthy from a business perspective on a normalized basis. So that'll give us, you know, next quarter's call, we'll be able to give you a really good insight into those two months.
Next question comes from Brant Montour from Barclays. please go ahead your line is open um good morning everybody um thanks for taking my question i was curious um if you give us an update on you know on the ground signing momentum um in china and specifically uh mark i was hoping you could kind of talk a little bit about the bigger a bigger picture uh question or idea that's been in the the news a lot lady lately of america inc and if seeing any sort of hesitation from local developers in China in terms of signing on with an American brand.
Thanks for that Grant. The signing activity in China started off as we expected. The continued activity in the upper mid-scale brand Yurko by Hyatt has been very strong. We have more than 70 hotels now, 130 hotels associated with it. These are hotels that are largely that we have, we don't see that.
Operator
Last question today will come from Kevin Koppelman from TD Cowan. Please go ahead, your line is open.
Thanks so much. I just had just a follow-up on the RevCar comments. First, could you clarify that the zero to two that you're thinking of for the rest of the year, is that also a good range for how you're thinking about the second quarter and on all-inclusive, could you help us translate the pacing numbers that you gave for how you get to that net package rev part in Q2, you know, understanding obviously that it's volatile right now. Thanks.
Sure, Kevin. The first question, and I'm going to ask you to repeat the second question, around the second quarter, the answer is yes. We expect around to be in that same range between zero to two percent I told you the numbers for April that are preliminary so you know we're tracking I would say to the higher end of the range in April and that's you know boosted by leisure because of because of Easter in the month and also boosted by the international markets Asia Pacific outside of Greater China and in Europe so the answer is yes and that's kind of a quarter to date.
Great, great. And on the all-inclusive, yeah, on the all-inclusive, just kind of the pacing, you shared the pacing data point, which looked really good. If you could just help translate that for us to how net package REVPAR might be looking for the second quarter compared to the first.
Yeah, you can expect, you know, a high single-digit pacing number is going to be about a mid-single-digit result on the net package REVPAR, similar to the first quarter. And, you know, that is strong. And actually, you know, on the books is healthy because we have a little bit more visibility into that business because it takes a little bit more time as travelers make the decisions about the second quarter.
Yeah, I would say we feel really good about it in Q2 because 88% of the businesses are so there's not a lot of... Yeah, there's not a lot of...
Well, thanks, everybody. I appreciate this morning, and we appreciate your interest in high...
Operator
This concludes today's conference call. Thank you for participating, and have a wonderful day. You may all disconnect.