Operator
Thank you for standing by. My name is Trevor and I will be your conference operator today. At this time, I would like to welcome everyone to the first Internet Bancorp Earnings Conference call for the second quarter, 2026. All lines have been placed on mute to prevent any background noise. After today's prepared remarks, we will host a question and answer session. If you would like to ask a question, please press star one to raise your hand. To withdraw your question, press star one again. Please note that this event is being recorded. It is now my pleasure to turn the call over to Julia Ferreira from ICR. You may begin your conference.
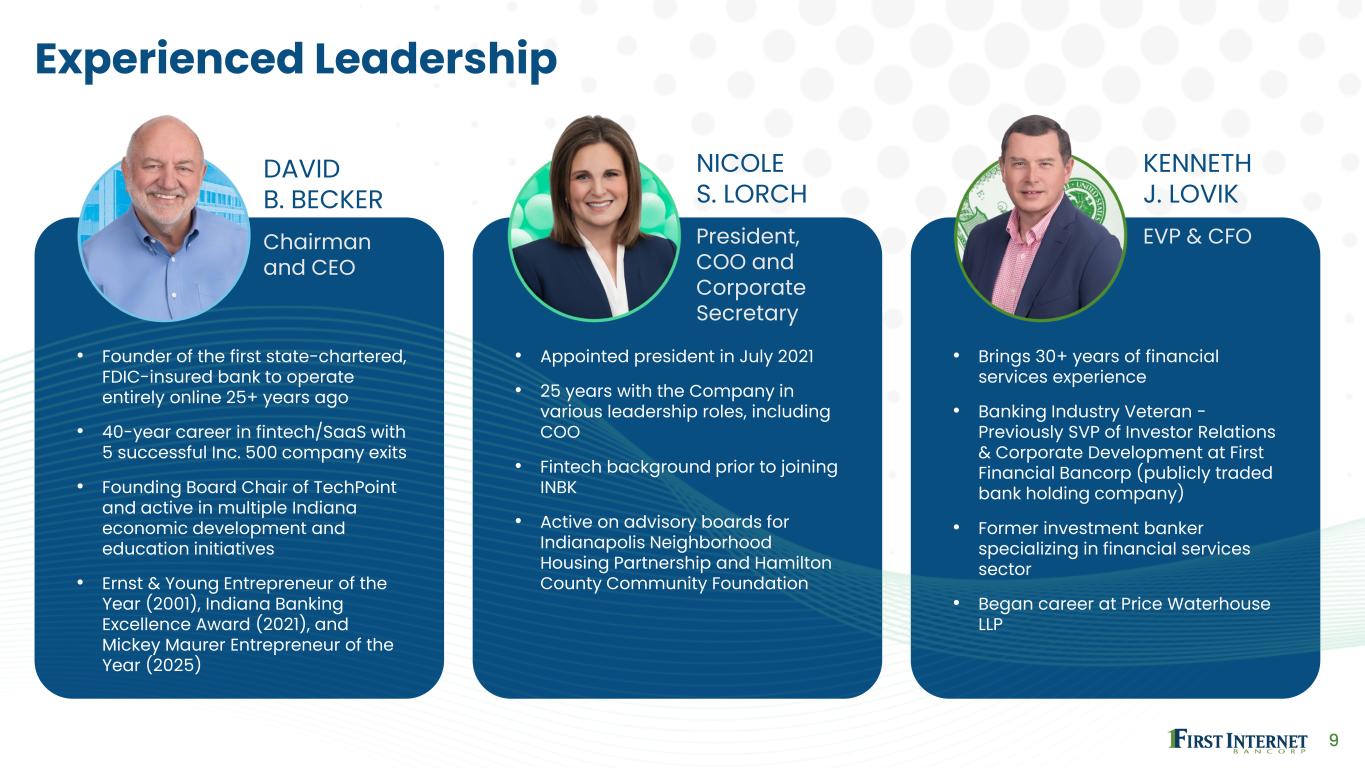
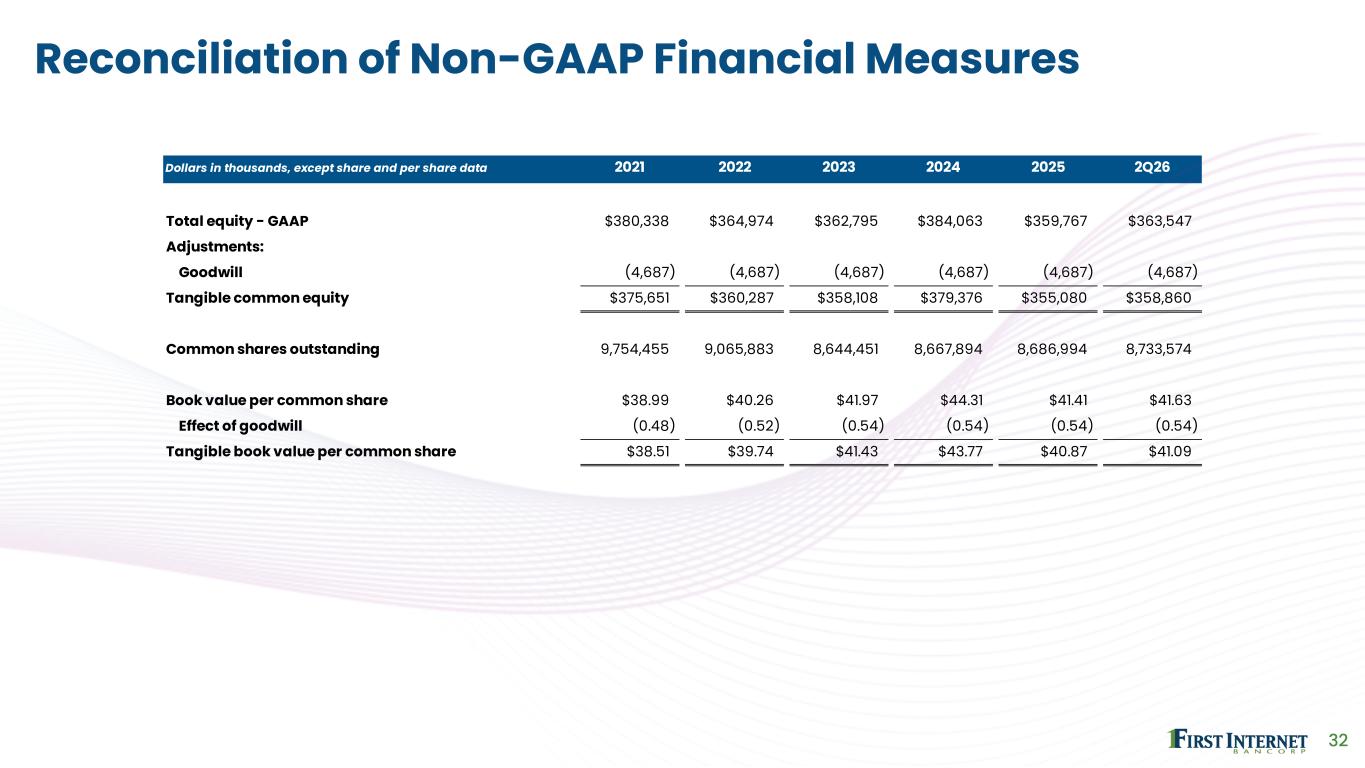
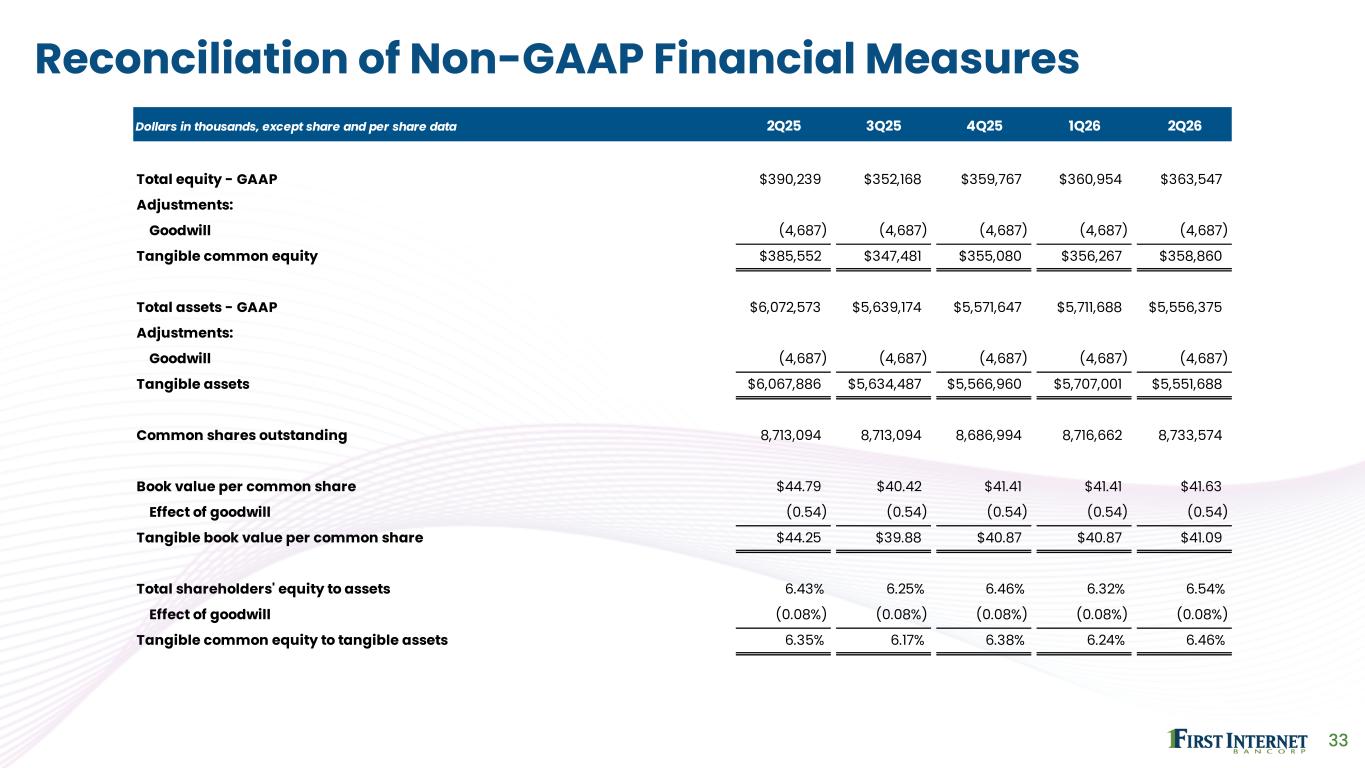
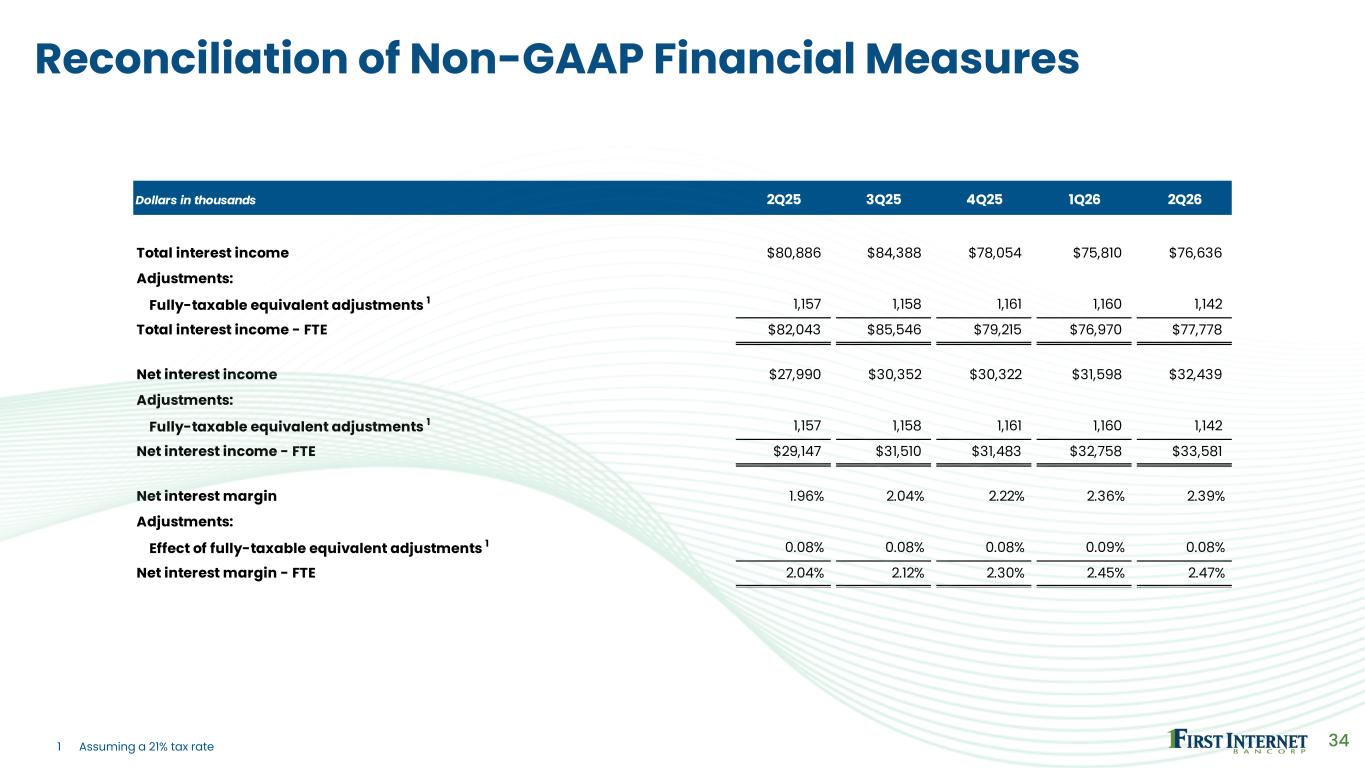
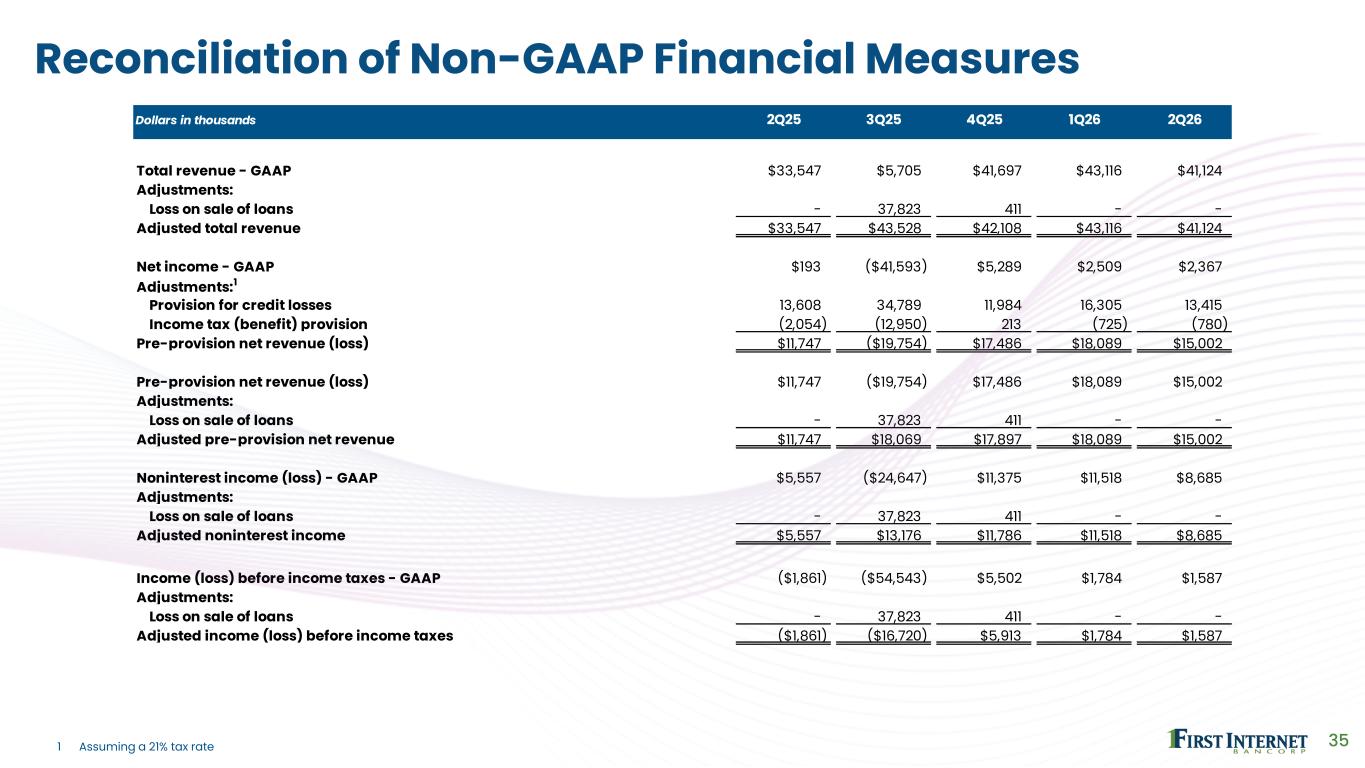
Thank you, Operator. Hello, everyone, and thank you for joining us to discuss First Internet Bank Corp's second quarter 2026 financial results. The company issued its earnings press release earlier this afternoon, and it is available on the company's website at www.firstinternetbancorp.com. In addition, the company has included a slide presentation that you can refer to during the call. You can also access these slides on the website. Joining us from the management team today are Chairman and CEO David Becker, President and COO Nicole Lorch, and Executive Vice President and CFO Ken Lovic. David and Nicole will provide an overview and Ken will discuss the financial results and then we'll open the call up for your questions. Before we begin, I'd like to remind you that this conference call contains forward-looking statements. With respect to the future performance and financial condition of First Internet Bank Corp. that involves recent uncertainties, various factors could cause actual results to be materially different from any future results expressed or implied by such forward-looking statements. These factors are discussed in the company's SEC filings, which are available on the company's website. The company claims any obligation to update any forward-looking statements during the call. Additionally, management may refer to non-GAAP measures, which are intended to supplement but not substitute for the most directly comparable GAAP measures. The press release available on the website contains the financial and other quantitative information to be discussed today, as well as the reconciliation of the GAAP to non-GAAP measures. At this time, I'd like to turn the call over to David.
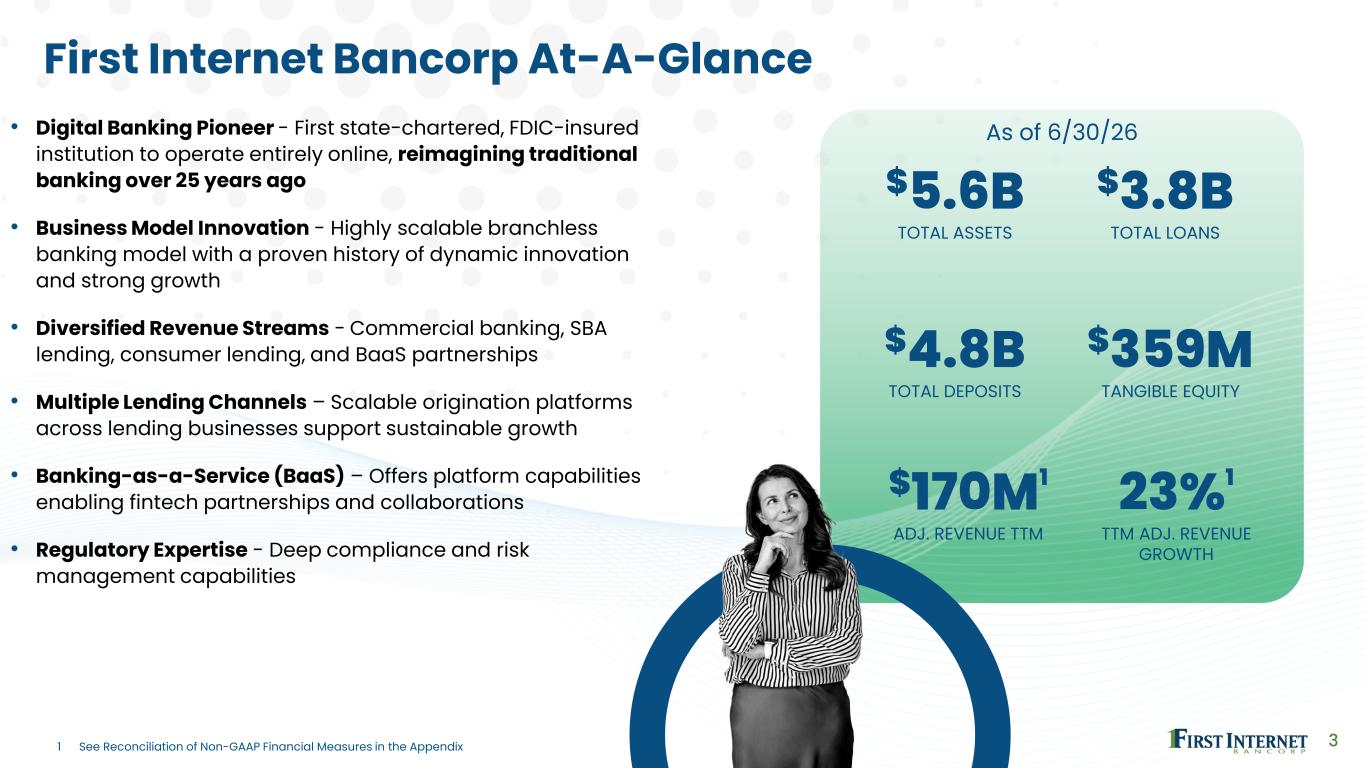
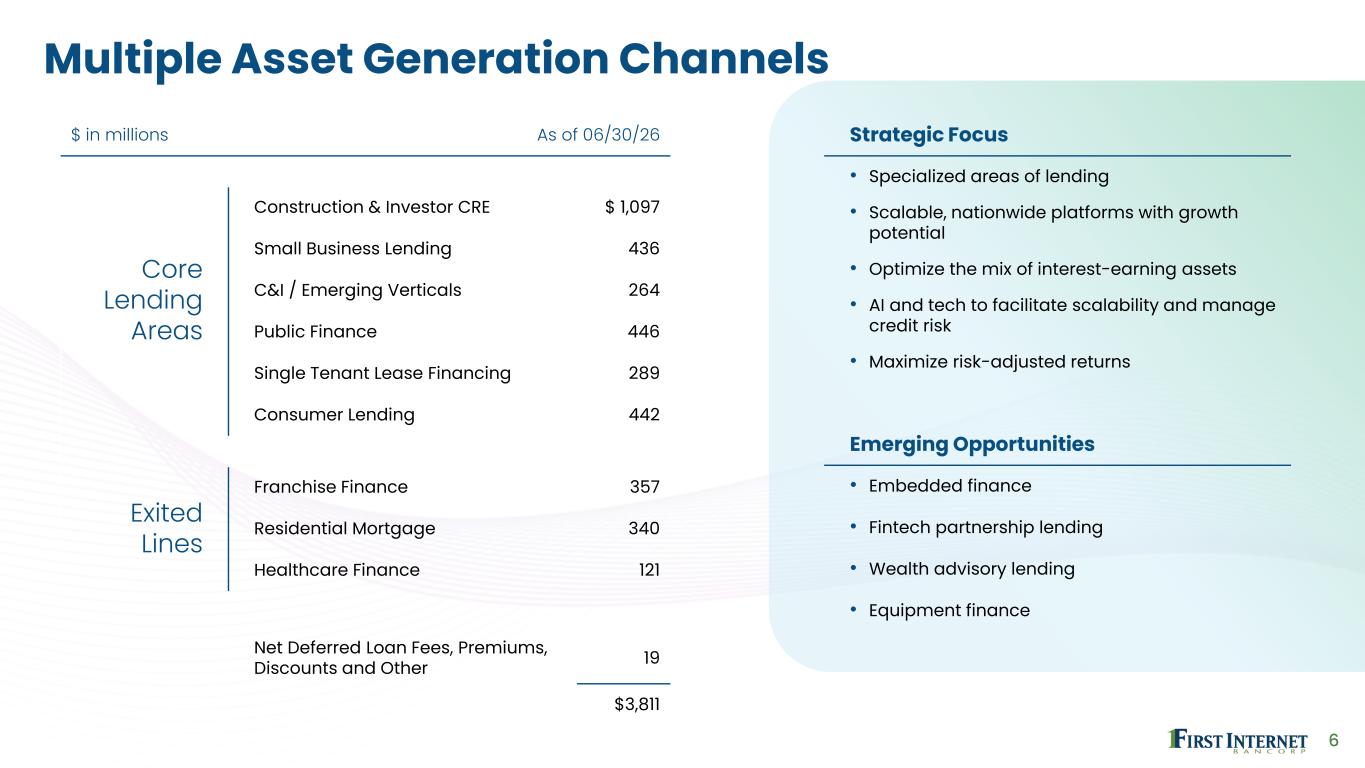
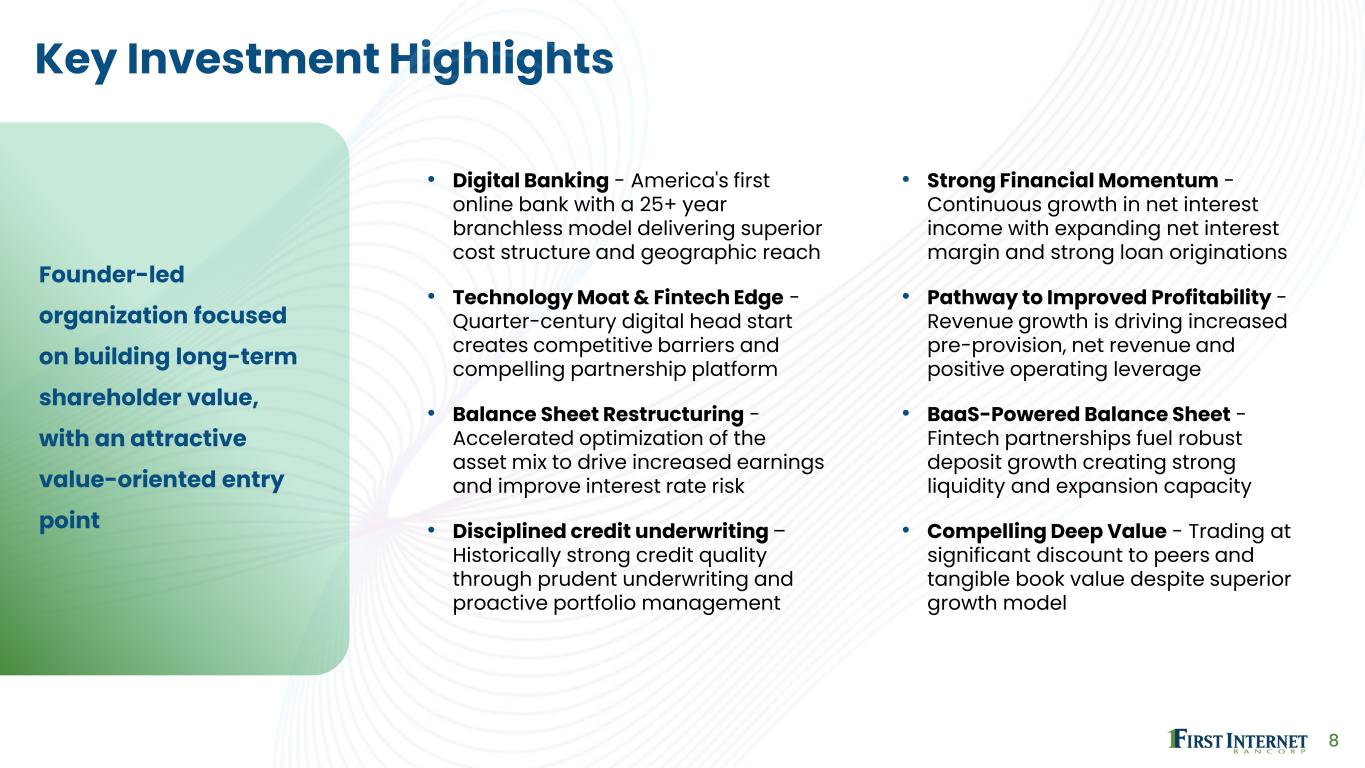
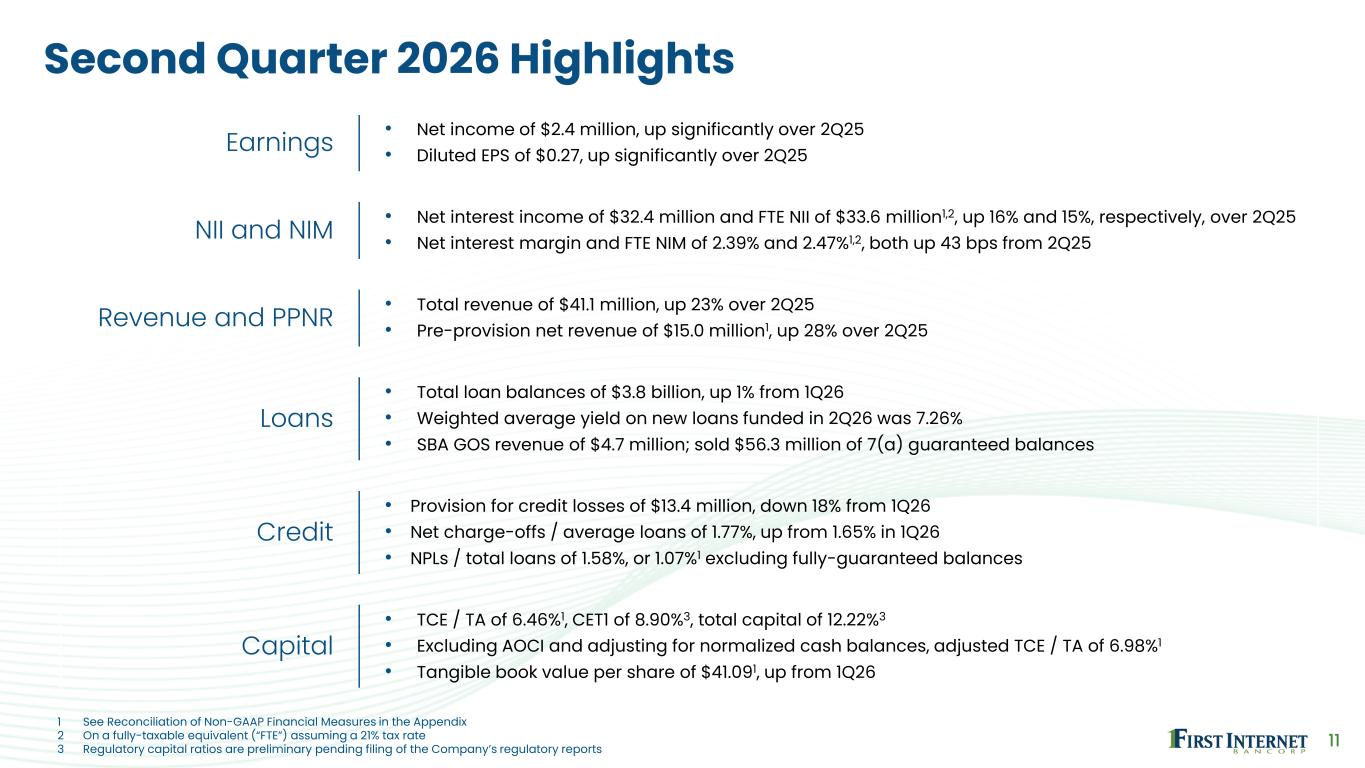
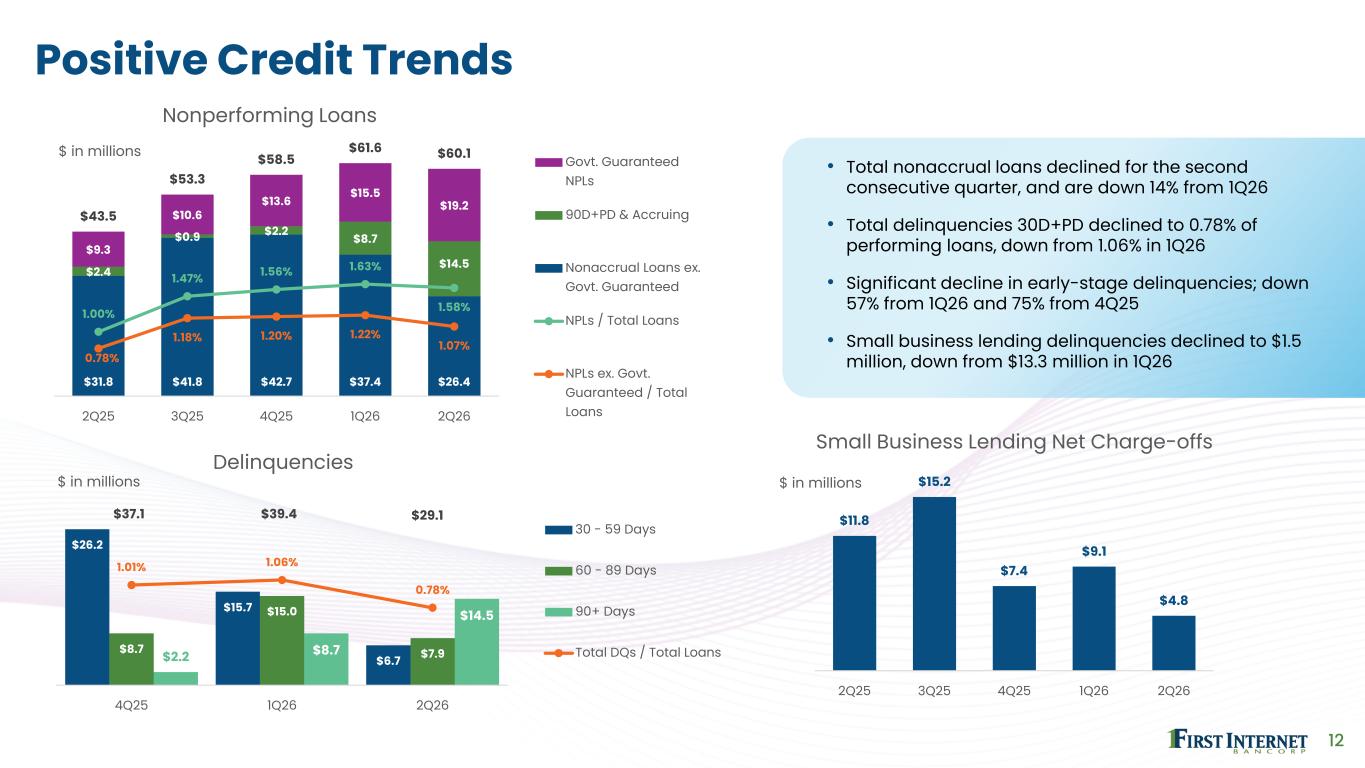
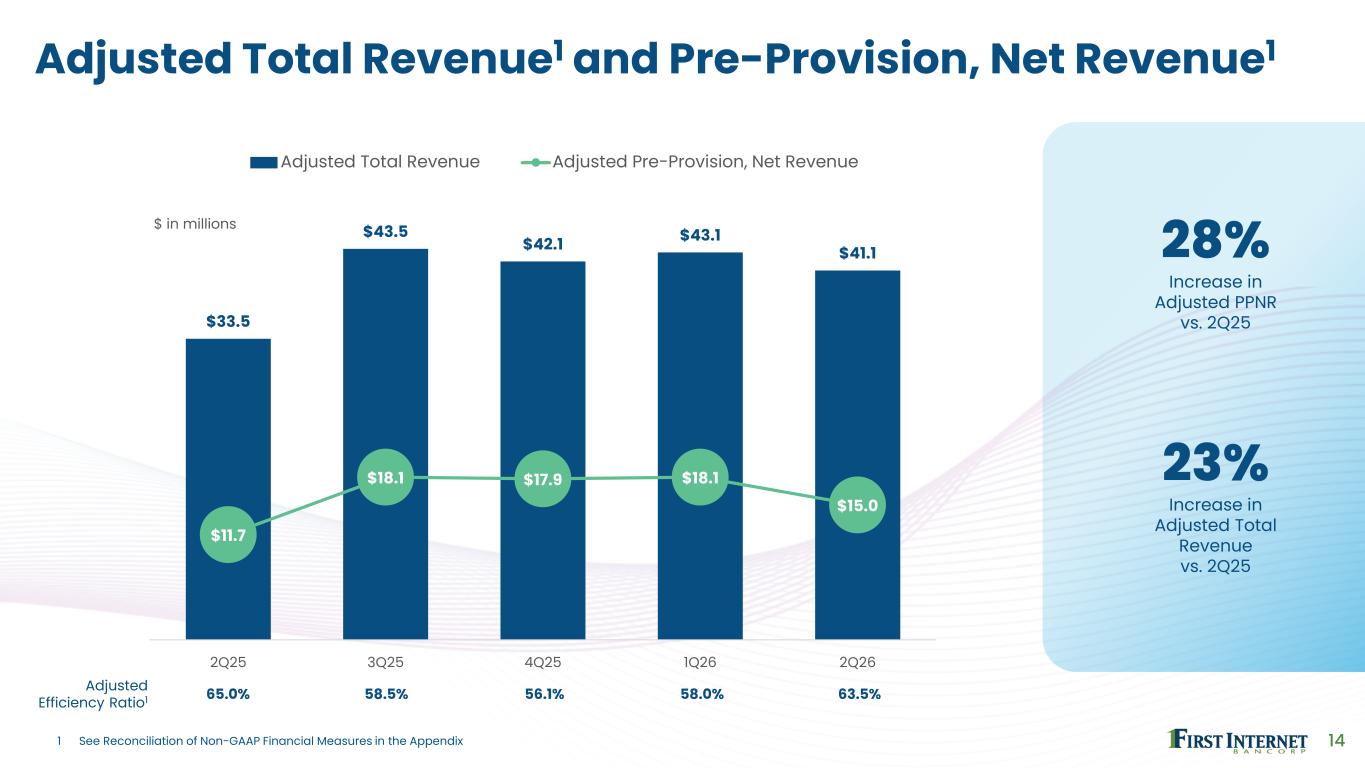
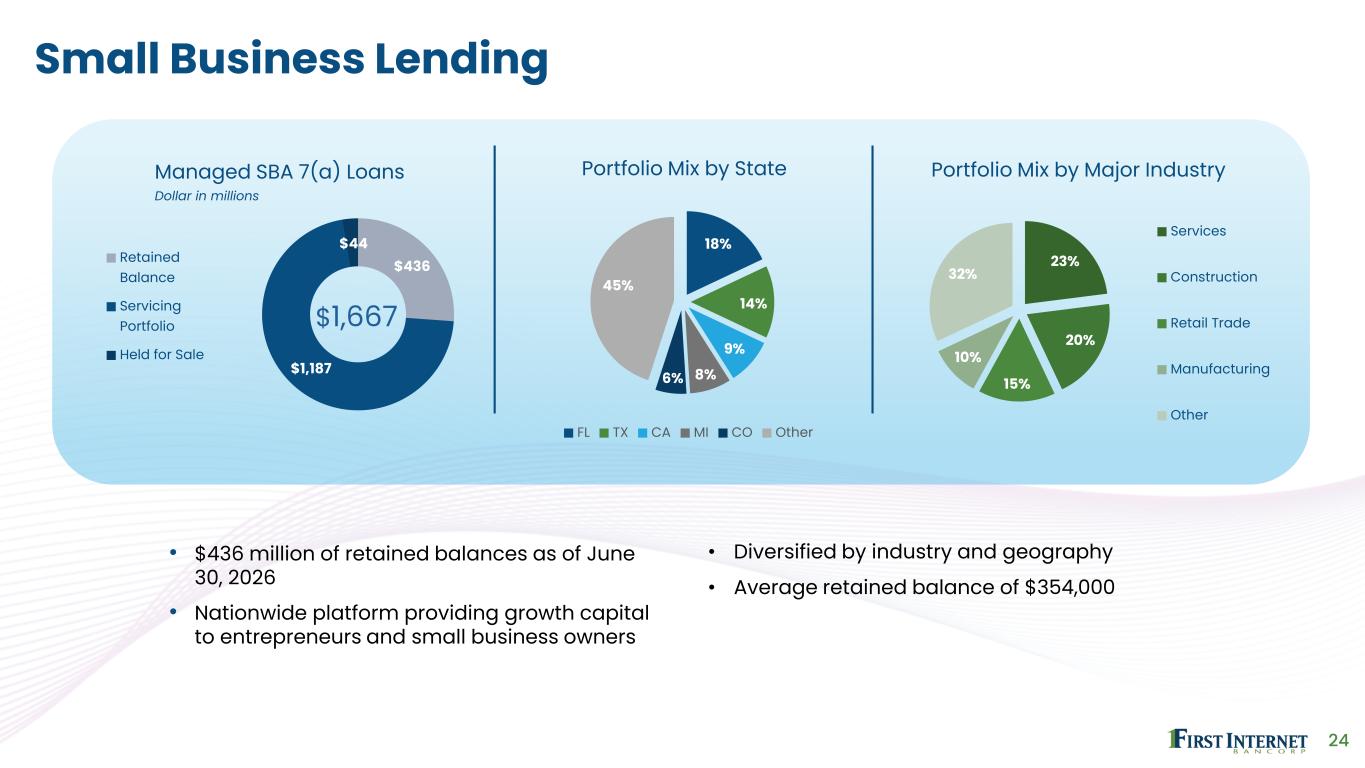
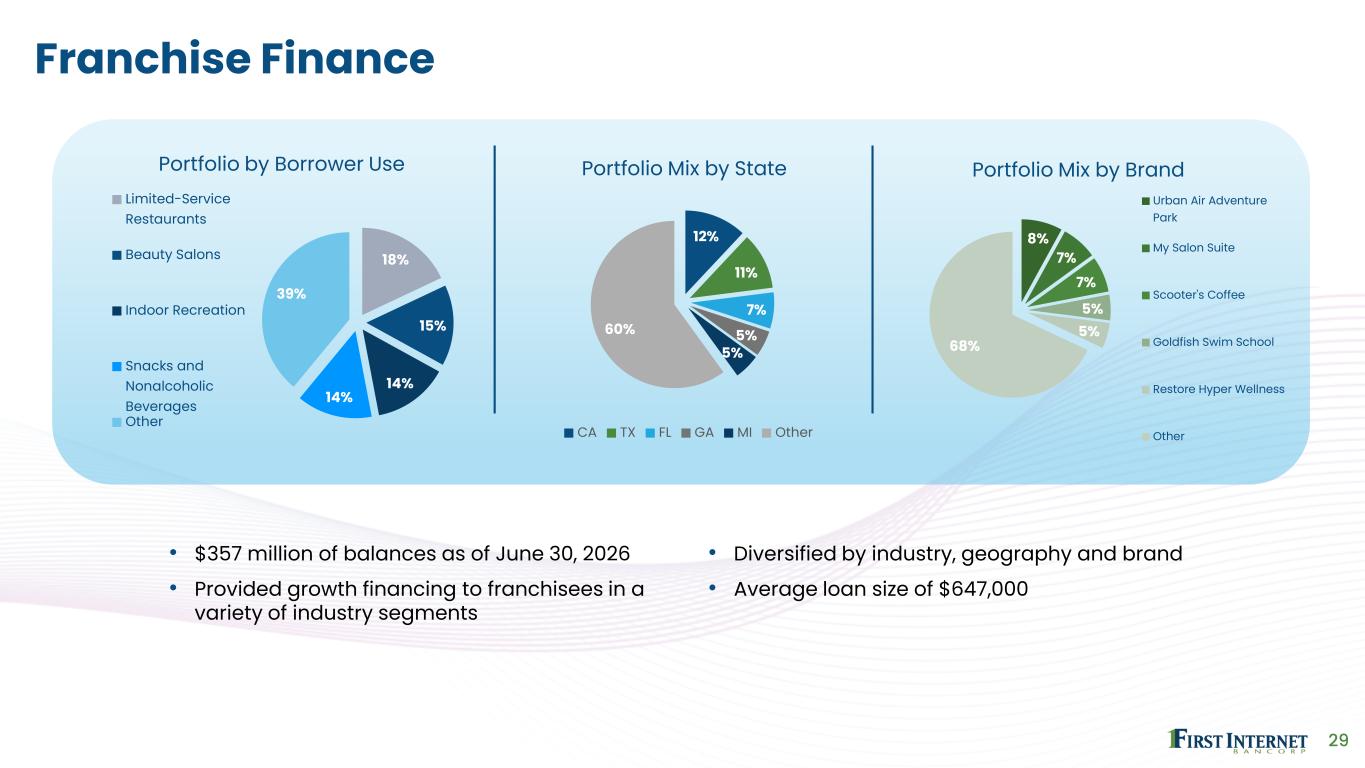
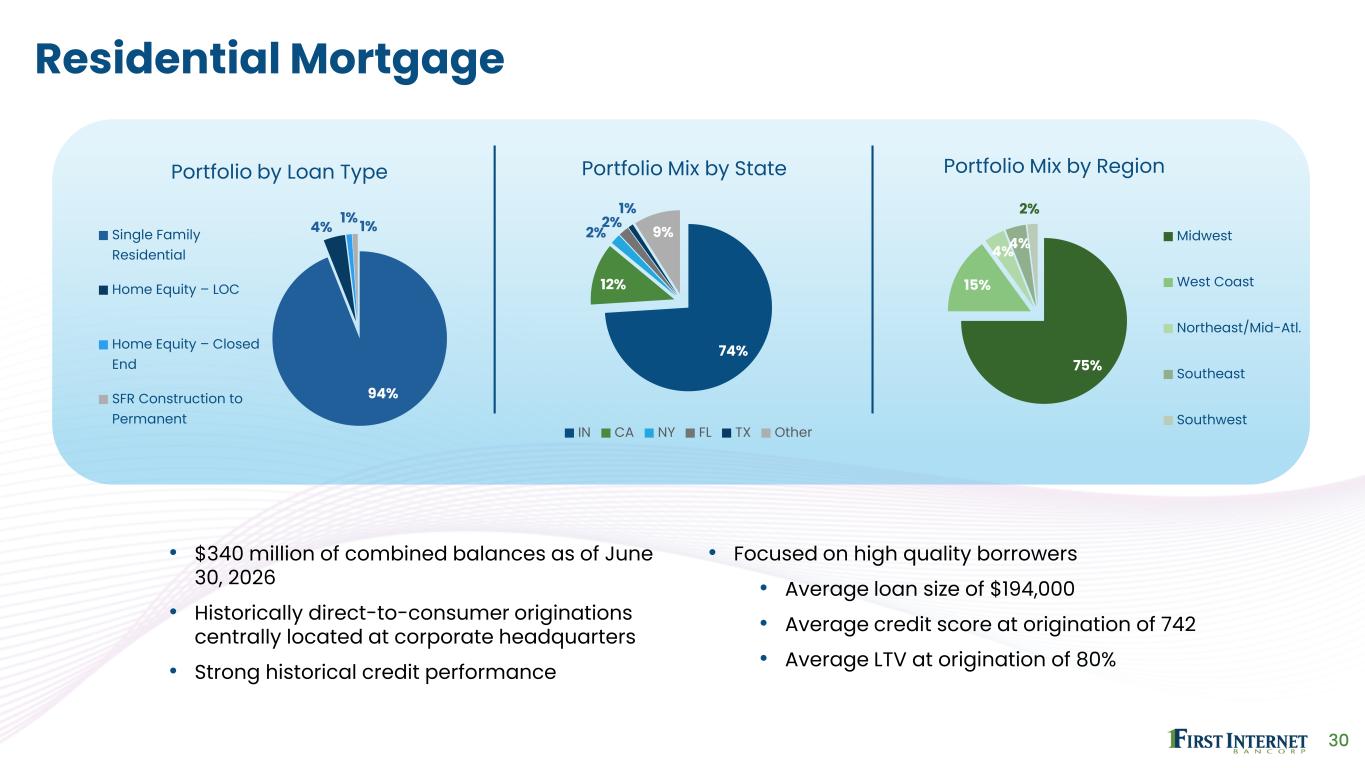
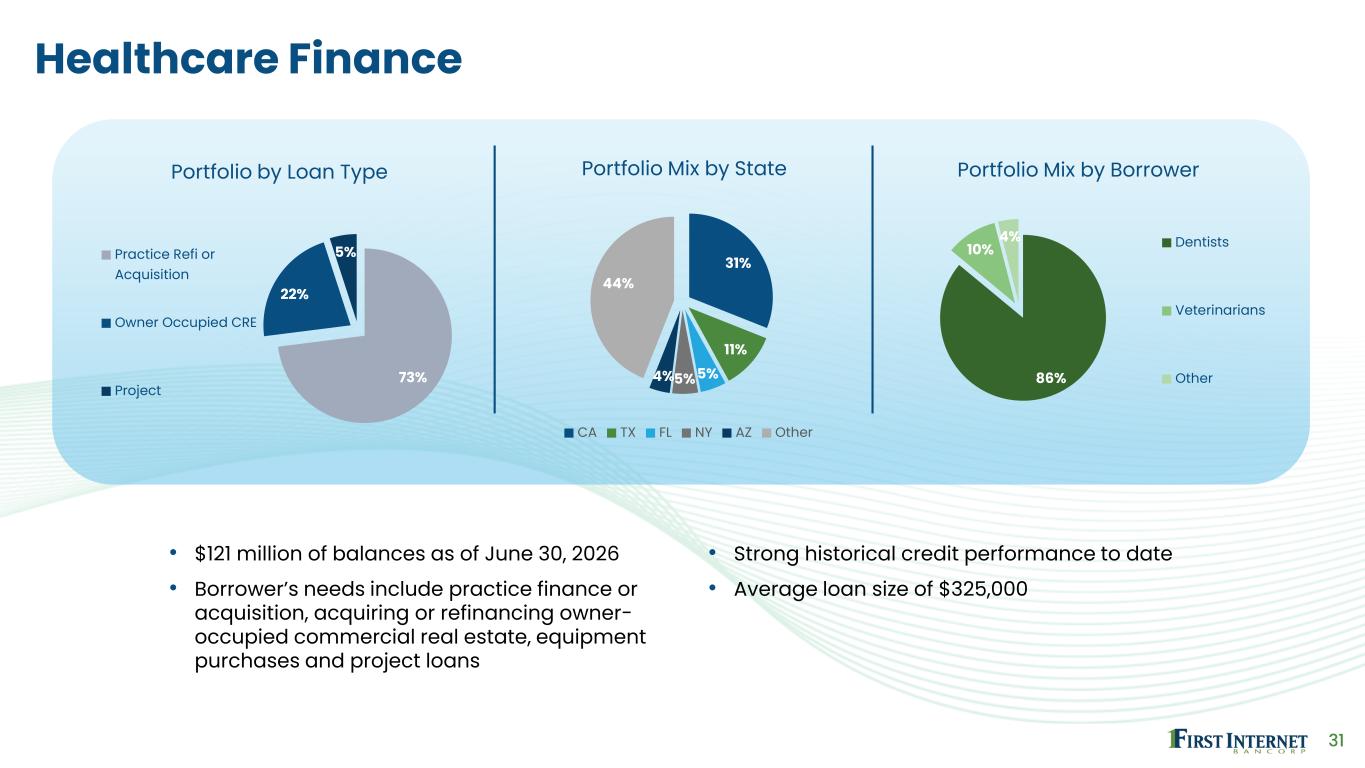
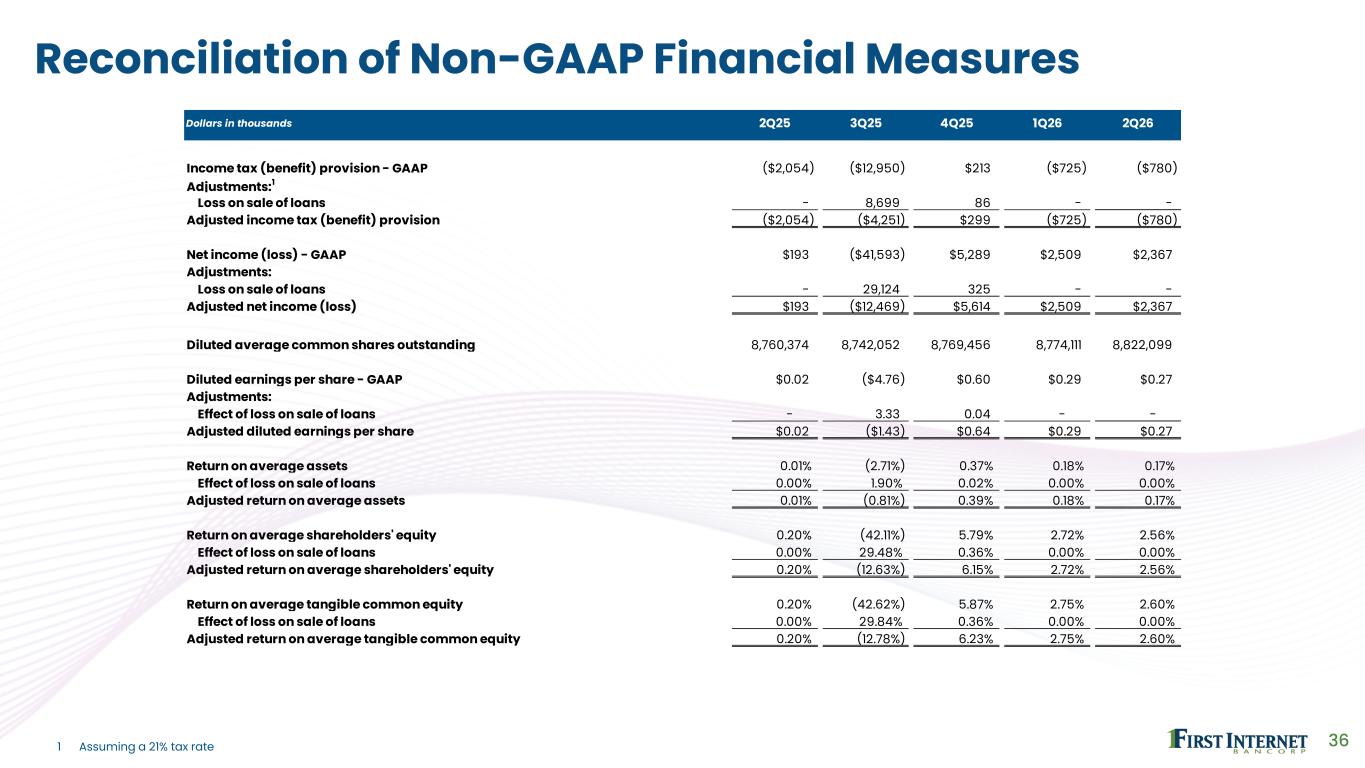
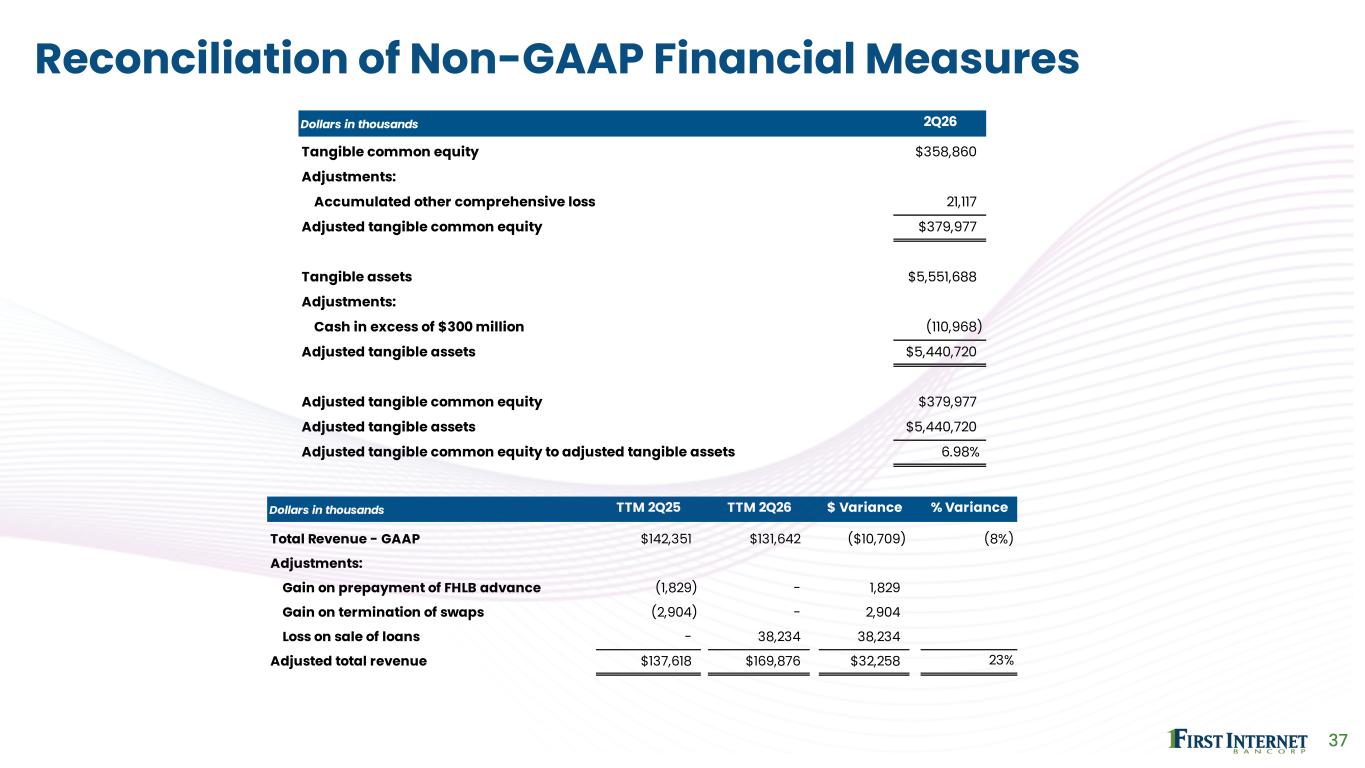
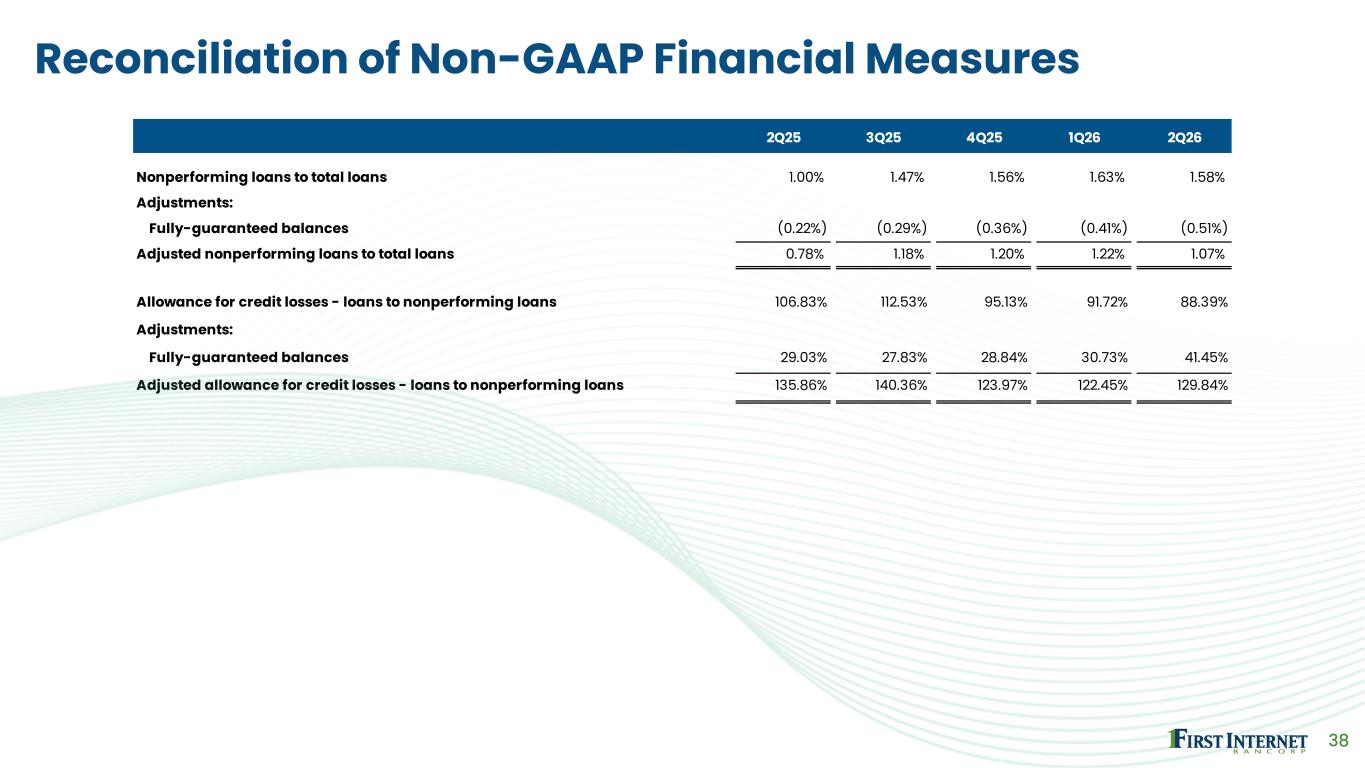
Thank you, Julia. Good afternoon, and thank you for joining us. We're excited to report solid second quarter results with total revenue growing 23% year-over-year, pre-provision net revenue up 28%, and earnings per share of 27 cents, up significantly from the prior year period. More importantly, this quarter marks a meaningful inflection point in our credit trajectory. For the past several quarters, credit has been the primary overhang on our results and on our stock this quarter that story began to turn over the past 18 months we took a hard look at the credit outcomes we experienced and made meaningful changes to our underwriting servicing portfolio management and resolution processes our disciplined actions are now translating into clear measurable improvement and we believe the credit trends we are seeing today mark a clear turning point in this cycle. Let me walk through why we feel confident in that conclusion. First, provision for credit losses, while still elevated on a historical basis, declined significantly from the prior quarter. Net charge-offs in our SBA portfolio were down almost 50 percent from the first quarter, reflecting the enhanced underwriting, servicing, and early warning capabilities we built over the past year. Second, non-performing loans declined from the first quarter, and total non-accrual loans declined for the second consecutive quarter, down 19 percent from year end. Furthermore, non-performing loans excluding government guaranteed balances declined to 1.07 percent of total loans, down from 1.22 percent in the prior quarter. And third, perhaps most encouraging of all, delinquencies fell significantly during the quarter. We experienced a sharp drop in early-stage delinquencies, and total small business lending delinquencies declined to $1.5 million from $13.3 million in the prior quarter. The reduction in provision expense demonstrates that our credit performance is improving today. The decline in non-performing loan formation and delinquency gives us conviction that credit costs will continue to moderate as we move through the second half of the year. At the same time, we continue to optimize the loan portfolio. Continued runoff in existing portfolios such as healthcare finance and residential mortgage, combined with elevated payoffs in franchise finance, is creating capacity that we are redeploying into construction, investor commercial real estate, single-tenant lease financing, small business lending, and emerging verticals such as wealth advisory lending and embedded finance, where we see better risk-adjusted returns and more efficient use of our balance sheet. A good example is the evolution of our relationship with JARUS, an embedded finance technology partner that helps payment processors and ISOs modernize their platforms through capabilities such as digital onboarding, instant payouts, and business financing solutions. Historically, we funded loans originated on JARUS's platform and retained a small portion of that production, selling the majority to a fund managed by JARUS. Beginning in June, we took that relationship a meaningful step further and are now retaining all originations going forward. The short duration high yielding assets should be accretive to net interest income and the expanded arrangement reflects the trust and depth of collaboration we have built with JARUS over time. Looking ahead, we are navigating the current macro and geopolitical environment with prudent strategy and appropriate discipline. Our credit trends and earnings are moving in the right direction while we continue to deepen in high value fintech partnerships and invest in the technology and talent that differentiate our platform. We believe this combination of improving credit, disciplined capital deployment, and expanding non-interest income positions as well to maximize growth and profitability in future periods. While the financial results speak for themselves, what gives us confidence in the future is the operational progress occurring throughout the company. I will now turn the call over to Nicole for additional perspective on the changes we've made and why we believe they position First Internet for continued improvement in the quarters ahead.
Thank you, David. One of the most encouraging takeaways from this quarter is that the improvement we're seeing across the business is the result of a sustained organizational effort over the last several quarters. We challenged longstanding processes, invested in new capabilities, and asked teams across the company to work differently. The numerical improvement in credit is evident in our results and the strength of the underlying processes producing those results lays the groundwork for improved performance in the future. Over the past 18 months, we've strengthened underwriting standards, enhanced portfolio monitoring, expanded special assets capabilities, and invested in predictive analytics and early warning tools that allow us to identify borrower stress sooner and engage customers earlier. We also created greater separation and specialization between portfolio management and problem loan resolution, allowing both teams to operate more effectively. In small business lending, net charge-offs declined significantly from the first quarter, delinquency trends improved meaningfully, and new delinquency formations slowed during the quarter. That reinforces our view that the portfolios we're originating today are performing in line with expectations and that our actions are producing durable improvements in credit quality. In franchise finance, our focus remains on disciplined execution and timely resolution of legacy problem credits. During the quarter, our special assets team took action on several relationships that drove elevated charge-off activity. However, the pace of loans moving to non-accrual status slowed dramatically, and early-stage delinquencies have declined over 85% since year-end. I want to thank our credit administration and portfolio management teams for their tireless execution. While work remains, the evidence suggests the remaining issues are manageable and increasingly concentrated. We've also become more deliberate about how and where we deploy capital. Over the last year, we evaluated major business lines through the lens of risk-adjusted returns, capital efficiency, and long-term growth potential. That process led us to lean more heavily into businesses where we believe we possess durable competitive advantages, including banking-as-a-service, embedded finance partnerships, and select commercial lending verticals. The expanded JARIS relationship is a good example of that approach in practice. We continue to see opportunities to deepen relationships with partners that value our compliance expertise, technical capabilities, and ability to operate at scale. In many cases, those opportunities allow us to generate attractive returns while using capital more efficiently than traditional balance sheet growth alone. Another area where we continue to invest is technology and automation. As pioneers in branchless banking, technology has been central to our business model from the beginning. But our technology strategy is grounded in business outcomes, not in chasing what is novel or interesting. Every investment is evaluated based on its ability to improve the customer experience, strengthen risk management, enhance efficiency, and generate an appropriate return on capital. Looking ahead, what excites me most is not any single business line or individual metric. It is that we are seeing progress across multiple dimensions of the company simultaneously. Credit trends are improving. Our funding profile continues to strengthen. FinTech and fee-based revenue streams are growing, and our teams are executing with discipline. There is no finish line when it comes to building a better bank, but the operational foundation we have built over the last several years positions us well for continued improvement in profitability and long-term shareholder value creation. And now I'll turn it over to Ken for additional insight into our second quarter performance and 2026 outlook.
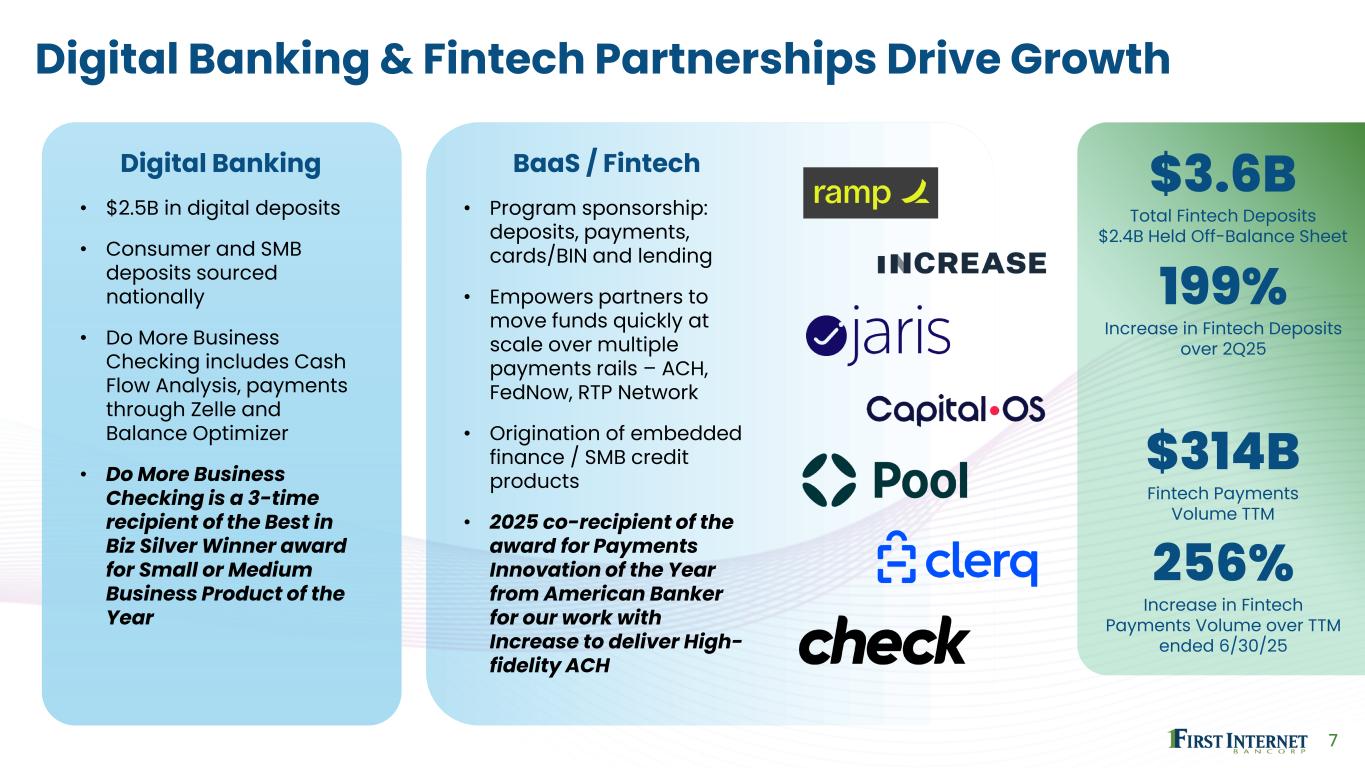
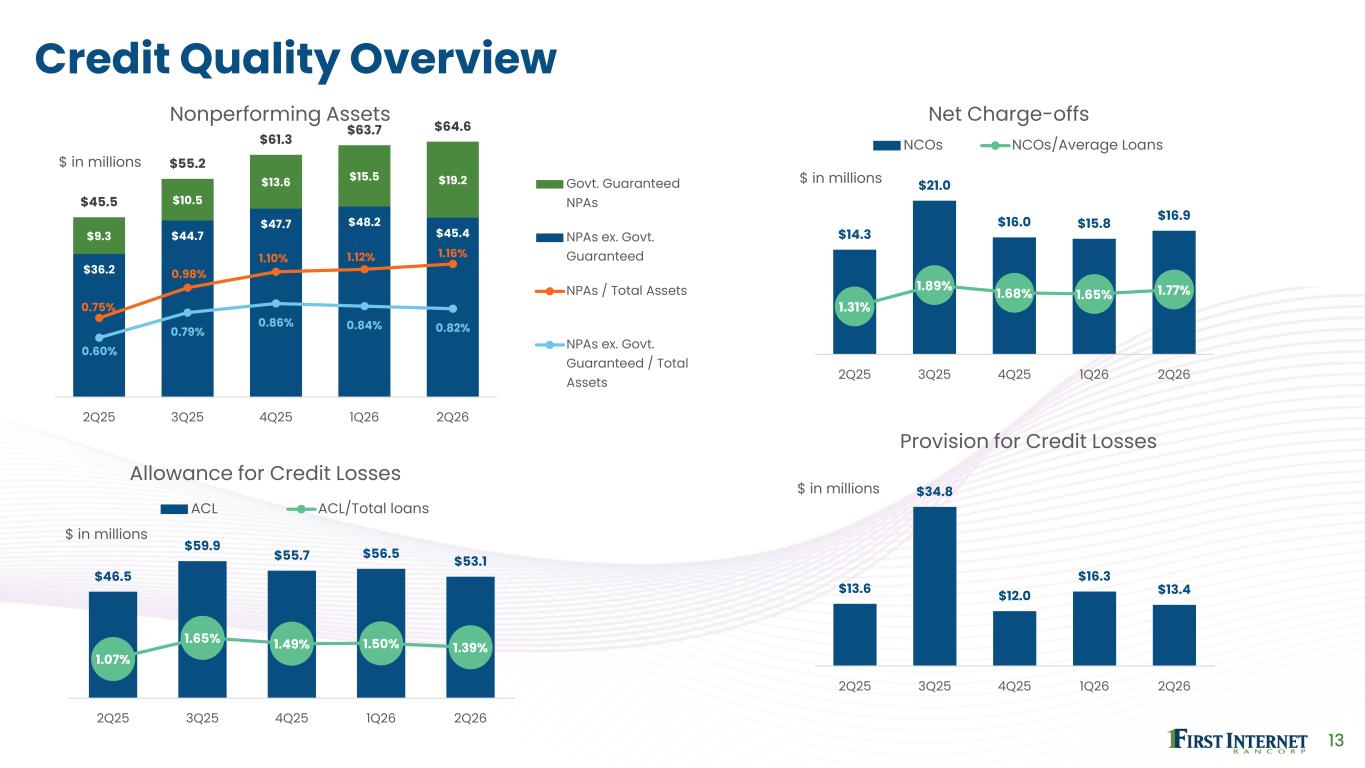
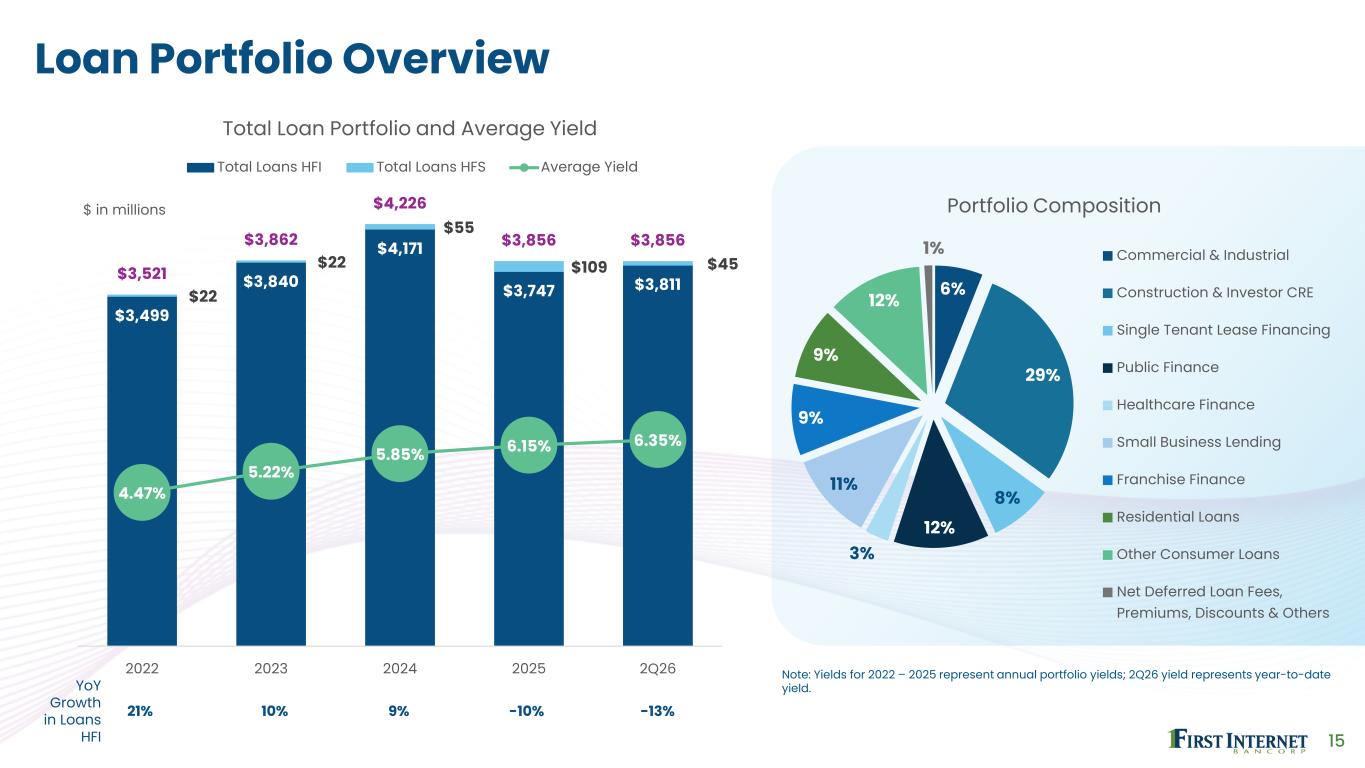
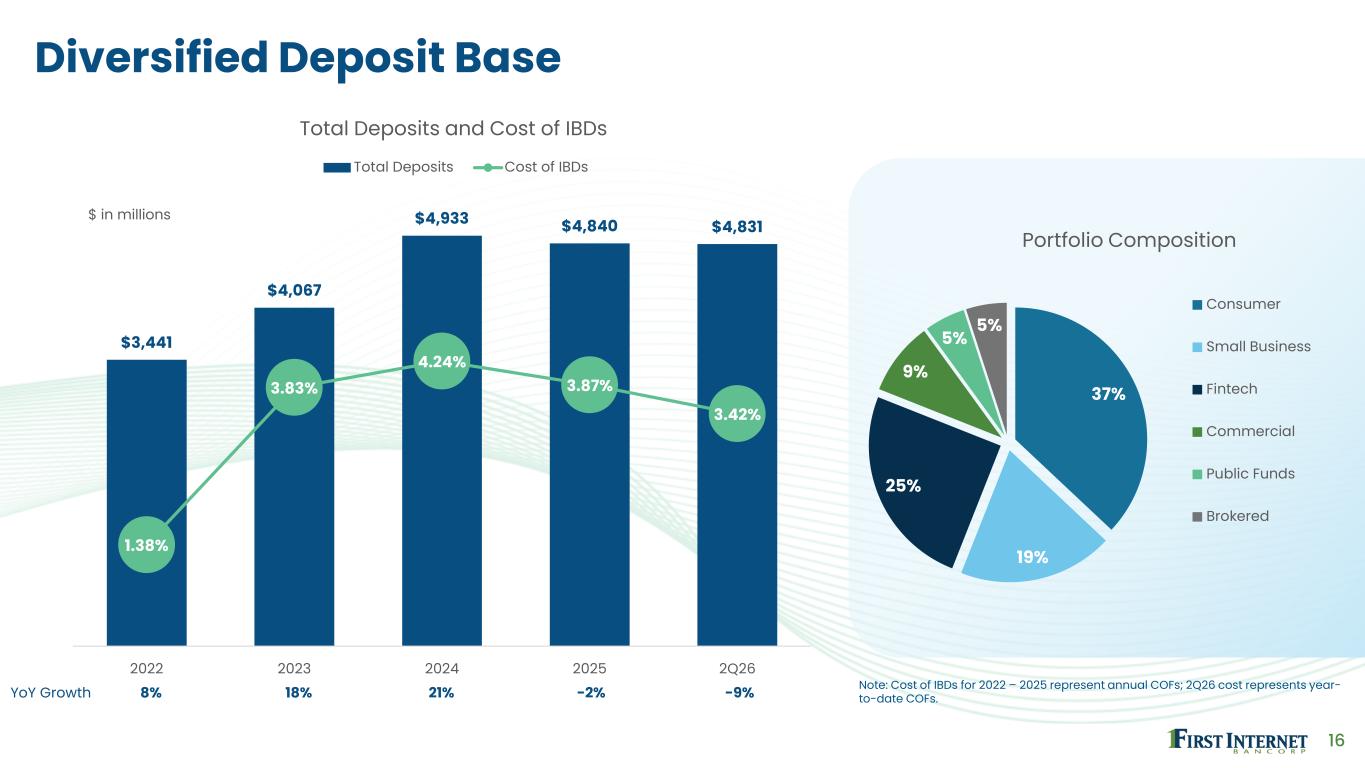
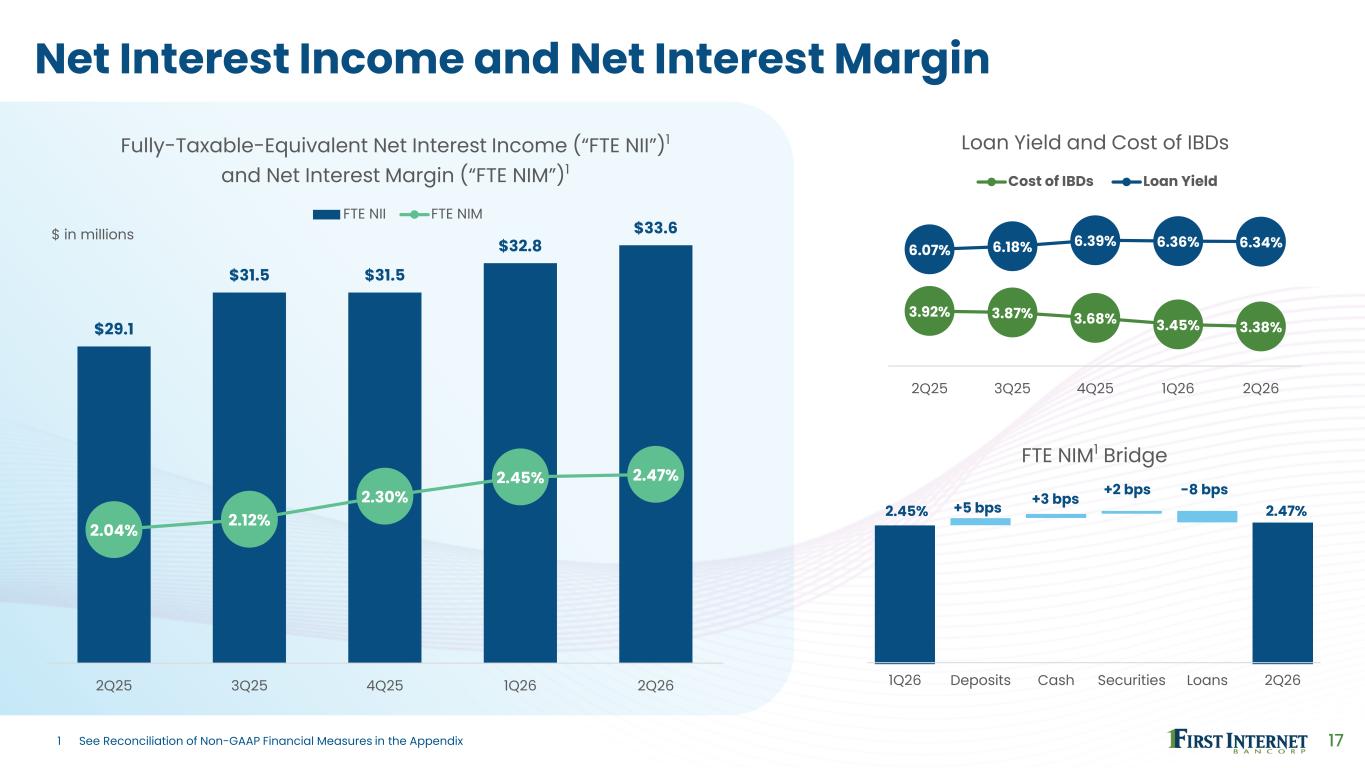
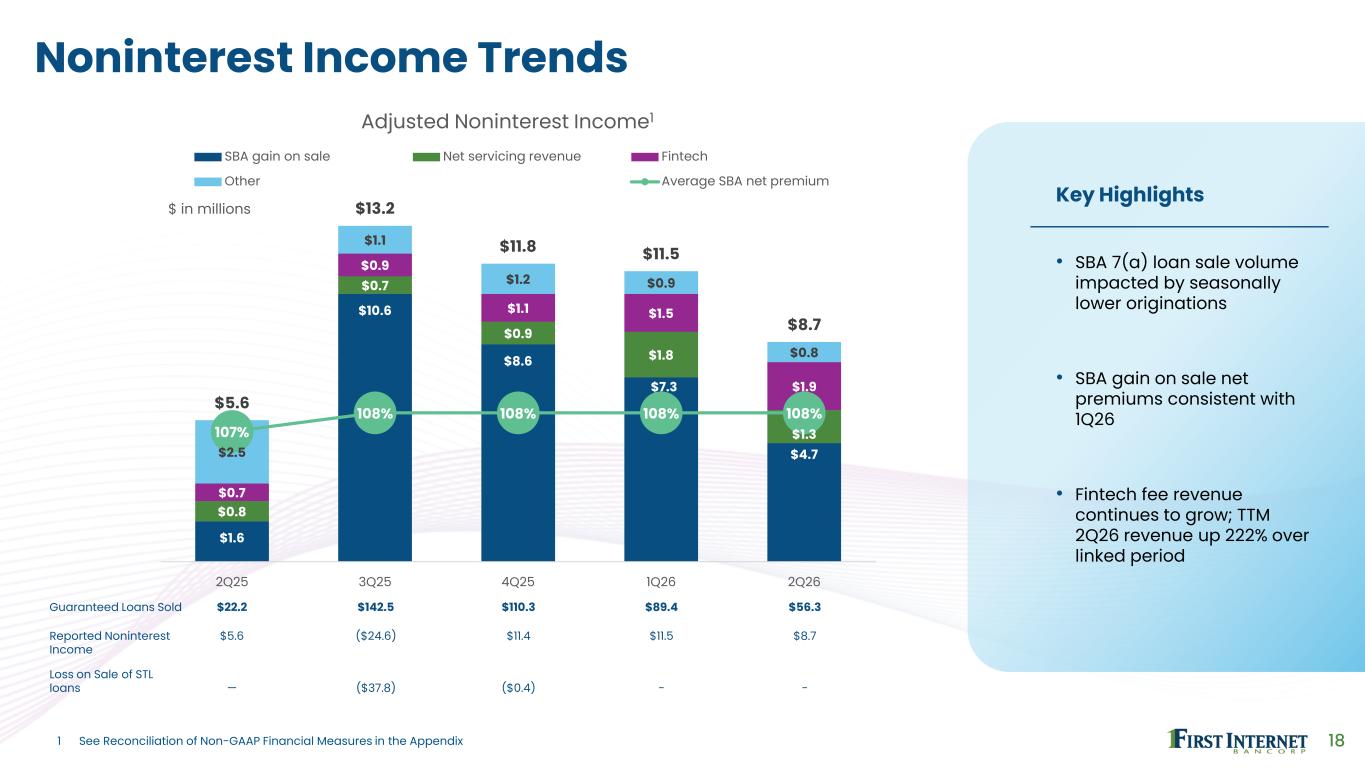
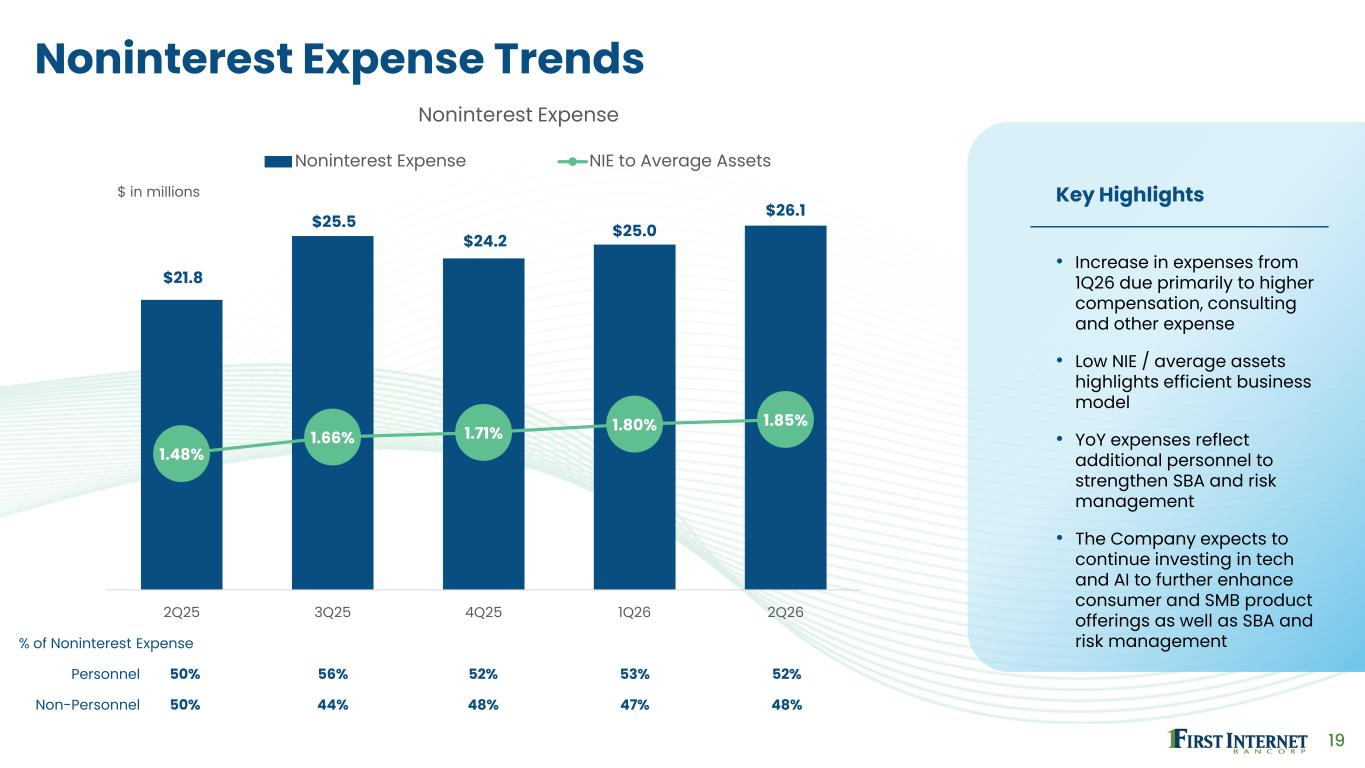
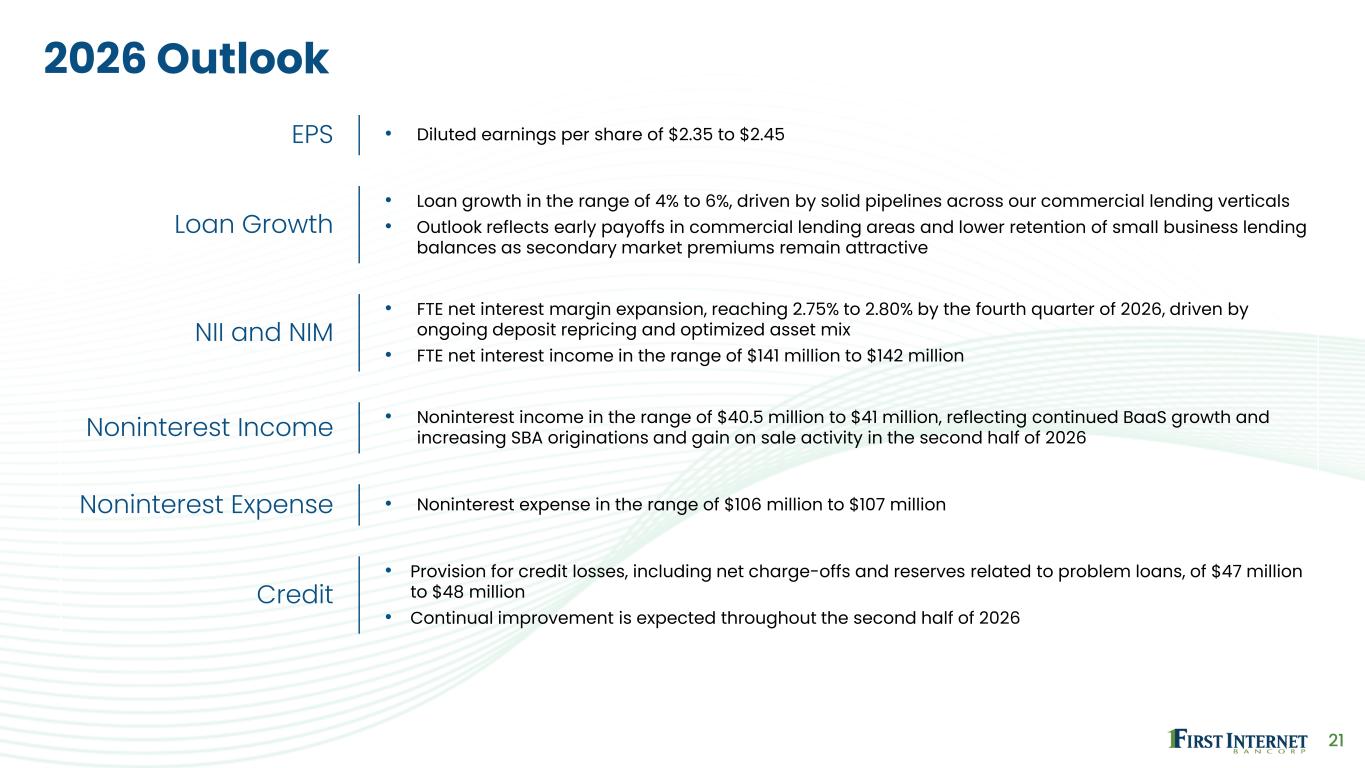
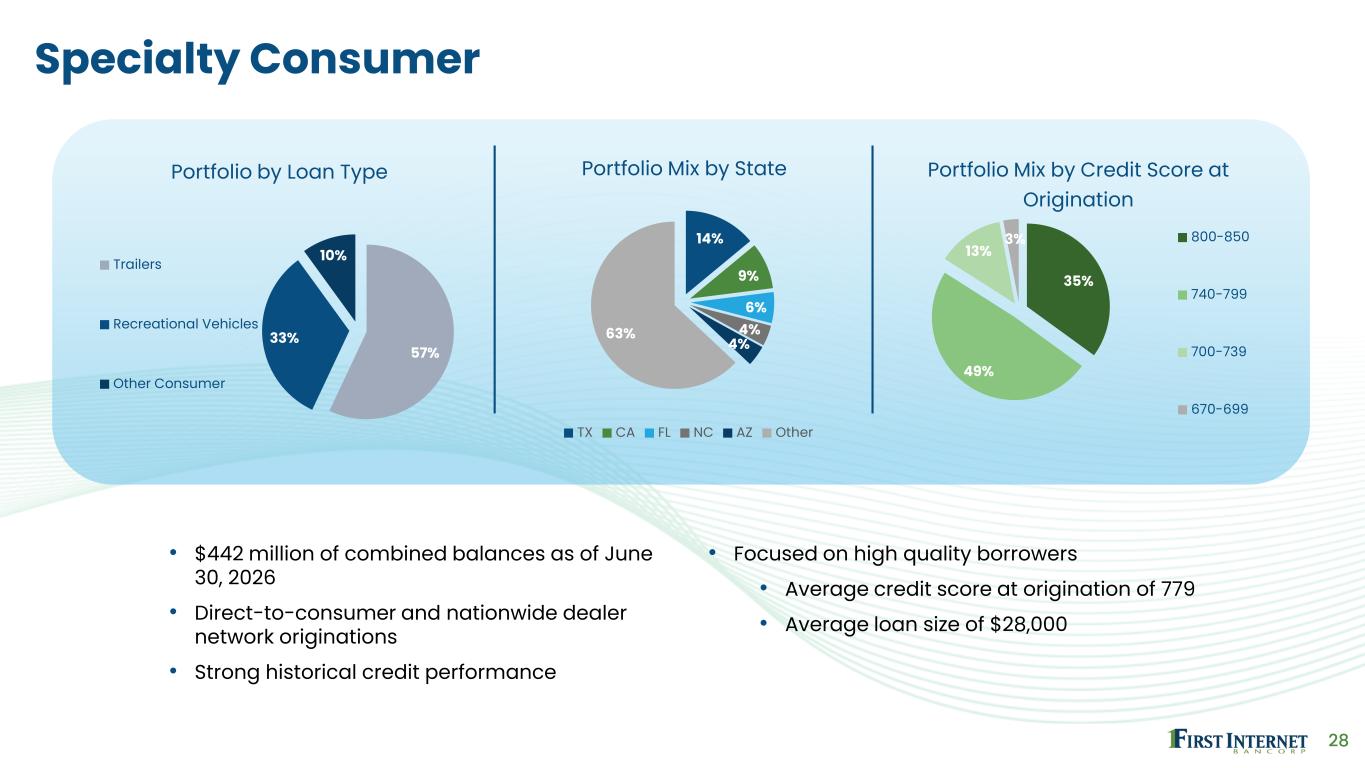
Thanks, Nicole. As David mentioned, we delivered solid second quarter results with net income of $2.4 million, or 27 cents per diluted share, both up significantly from the prior year period. Before discussing operating trends, I want to provide additional color on credit. Provision for credit losses was $13.4 million in the second quarter, down from $16.3 million in the first quarter. Net charge-offs totaled $16.9 million, up modestly from the prior quarter, but with important positive trends beneath the headline number. Net charge-offs in small business lending totaled $4.8 million, down significantly from $9.1 million in the first quarter. Franchise finance net charge-offs totaled $11.6 million, $6.7 million of which were covered under specific reserves previously applied to these loans. And as Nicole noted, the pace of franchise finance loans moving to non-accrual status slowed dramatically. Non-performing loans were $60.1 million, or 1.58% of total loans, down from $61.6 million, or 1.63%, in the linked quarter, the first sequential decline we have reported in several quarters. Total non-accrual loans declined for the second consecutive quarter, which was partially offset by an increase in franchise finance loans 90 days past due as certain loans work through the resolution process. We expect our efforts to ultimately result in the full collection of principal and interest related to these loans. The most encouraging data point was delinquencies, which declined to 78 basis points of total performing loans as of June 30th, down from 106 basis points at the end of first quarter and 101 basis points at year end. In dollars, total delinquencies declined 26% from the first quarter to $29.1 million and early stage delinquencies declined significantly. Taken together, lower provision for credit losses, the continued decline in non-accrual loans, and the significant drop in delinquencies support our expectation for continued improvement in credit costs throughout the remainder of 2026. Turning to operating trends, total revenue was $41.1 million, a 23 percent increase over the prior period. When combined with well-managed expenses, pre-provision net revenue totaled $15 million, up 28 percent year-over-year, driving continued positive operating leverage. Linked quarter revenue was down primarily due to lower gain-on-sale revenue from seasonally lighter SBA origination volumes and our more disciplined underwriting approach. As we think about what to expect in the third and fourth quarters, I would note that secondary market premiums remain strong, production levels picked up in the back half of the quarter, and we expect origination volumes to increase in the second half of the year. The decline in gain-on-sale revenue was partially offset by sustained growth in fee revenue from our fintech partnerships. Payments volume and fee revenue continued to build on a trailing 12-month basis, up 256% and 222%, respectively. Net interest income was $32.4 million, or $33.6 million, on a fully taxable equivalent basis, up 16% and 15% year-over-year, respectively. Net interest margin improved to 2.39 percent or 2.47 percent on a fully taxable equivalent basis, both up more than 40 basis points from a year ago. Margin expansion was driven primarily by continued improvement on the funding side of the balance sheet as the cost of interest-bearing deposits declined to 3.38 percent from 3.92 percent a year ago, benefiting from CD repricing and growth in lower-cost fintech deposits. On the other hand, earning asset yields were essentially stable. While period end loan balances were up from the prior quarter, average balances were down about 1%. Growth in construction and investor commercial real estate, single-tenant lease financing, trailers, and emerging verticals, such as wealth advisory lending and embedded finance, was more than offset by early paydowns and lighter small business lending originations earlier in the quarter. As a result, we carried higher cash balances which tempered the pace of margin expansion on a sequential basis. Looking forward, pipelines are strong across several commercial lending areas and small business lending production is expected to increase significantly in the second half of the year. In addition, the increased retention of embedded finance loans is expected to further enhance net interest income and margin. Deposit repricing remains a meaningful tailwind. CD and broker deposit balances declined more than $200 million from the prior quarter as we continued replacing higher-cost funding with lower-cost fintech deposits. The weighted average cost of CDs maturing during the second quarter was approximately 4.11%, while the average cost of on-balance sheet fintech deposits was 3.19%, and the cost of new and renewing CDs was 3.63%. The third quarter is a particularly large maturity quarter with more than $445 million of CDs coming due at a weighted average cost of 4.04%, and $700 million in total maturing in the second half of the year at a weighted average cost of 3.94%. With fintech deposit and CD replacement costs at significantly lower levels, we expect this dynamic to continue supporting net interest income and margin. To summarize our outlook on net interest income and net interest margin, lending pipelines are strong heading into the back end of the year. We continue to optimize the loan portfolio, with the composition now about 42% variable rate, providing the ability to maintain and increase yields on interest-earning assets. When combined with the ongoing ability to drive deposit costs lower, we expect to see sustained expansion of net interest income and margin throughout the remainder of the year. Regarding our outlook for the remainder of 2026, we remain comfortable with our full-year EPS forecast of $2.35 to $2.45. However, with a smaller balance sheet and continued opportunities to grow fee income, the mix between net interest income and non-interest income has shifted somewhat along with a revised outlook on operating expenses. We now expect full year loan growth of approximately 4% to 6%, reflecting elevated early payoffs, lighter first half small business production, and as secondary market premiums remain attractive, lower retention of guaranteed SBA balances with stronger pipelines expected to support growth in the second half of the year. Our fully taxable equivalent net interest margin outlook remains in the range of 2.75% to 2.80% by the fourth quarter based on the dynamics I mentioned earlier and excludes any interest rate cuts or increases. With a smaller balance sheet, we now expect full year fully taxable equivalent net interest income of $141 million to $142 million. This revision is partially offset by strength in gain-on-sale premiums and continued fintech fee income growth, enabling us to raise our non-interest income outlook to $40.5 million to $41 million. Additionally, we are lowering our non-interest expense outlook to $106 million to $107 million, reflecting lower compensation costs, while maintaining investment in technology and AI to support revenue and risk management initiatives. Finally, we expect provision for credit losses of $47 million to $48 million for the full year. Based on the improving trends in non-accrual loans and delinquencies, we expect provision expense to improve sequentially from the second quarter to the third quarter, and again from the third quarter to the fourth quarter. With that, I'll turn it back to the operator for questions.
Operator
Thank you. We will now begin the question and answer session. Please limit yourself to one question and one follow-up. If you would like to ask a question, please press star 1 to raise your hand. To withdraw your question, press star 1 again. We ask that you pick up your handset when asking a question to allow for optimum sound quality. If you are muted locally, please remember to unmute your device. Your first question comes from the line of Brett Rappitan with StoneX. Brett, your line is open.
Hey, good afternoon, everyone. Thanks for the questions. First, I wanted to talk about, hey, guys. First, I wanted to talk about the dynamic on the NII guide in the back half of the year, particularly kind of given where you're expecting the margin to be by the end of the year. And if I'm just doing kind of some rough math right, it basically implies kind of that your funding costs decline about 15 basis points and your earning asset yields are up about 25 to 30 basis points. Is that a fair way to think about it? And then maybe can you talk about how much JARUS and these other things, you know, might contribute to higher earning asset yields?
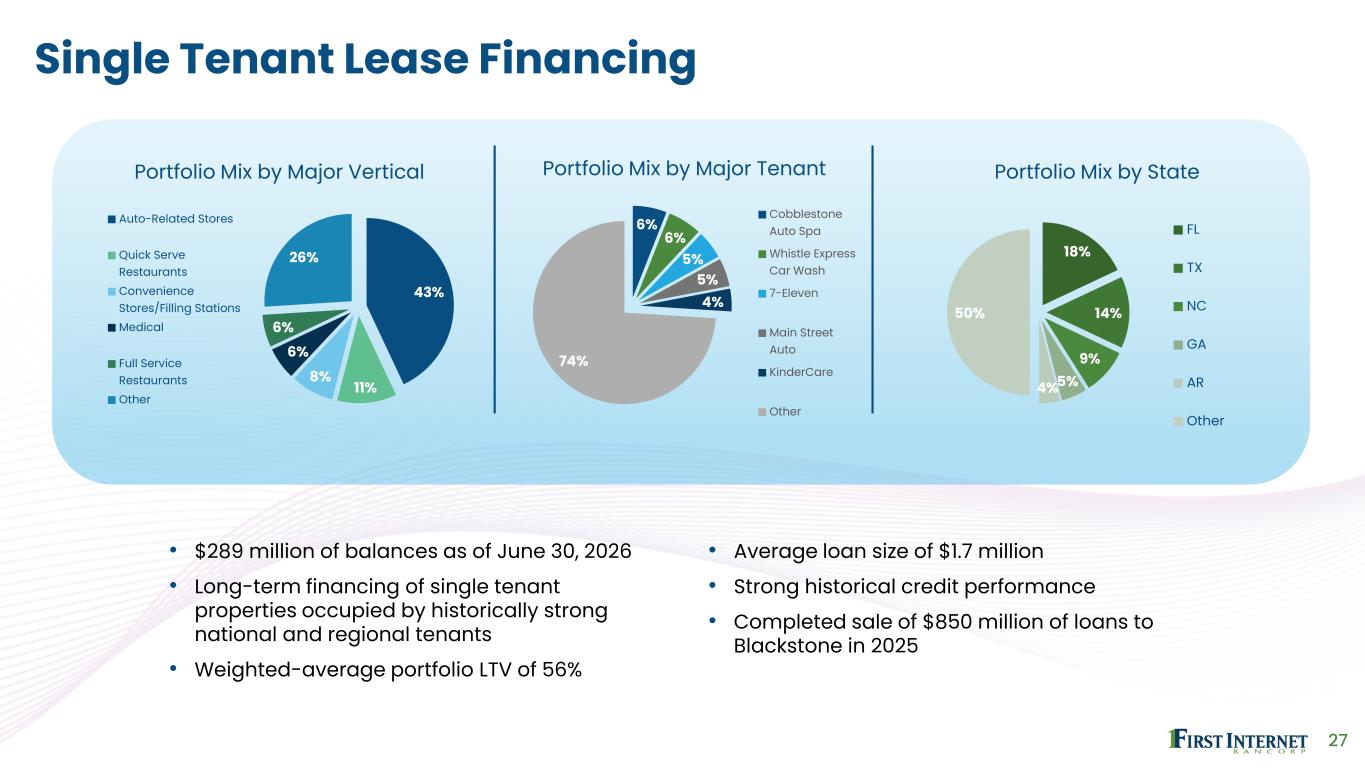
Yeah, I think you're in the ballpark, Brett. I mean, I think, you know, if you think about the deposit repricing opportunity, right, Right. As we mentioned in the prepared comments, we have a lot of CDs that are coming due here in the third quarter. And to be honest with you, right now in the CD market, we are not very competitively priced. What historically was a renewal rate in, call it anywhere from 60 to 70 percent, is now down in the 40 percent range. So we're just seeing a larger amount of these higher cost CDs rolling off and simply being replaced, you know, generally by fintech deposits that are somewhere in, you know, call it the 315 to 320 range, or small business checking. Those are much cheaper. But I think we continue to expect continued deposit leverage throughout the rest of the year. I think you're going to see more of it in the third quarter than the fourth quarter. but that's our expectation there. And quite, you know, to be honest with you, in the second quarter, our deposit kind of cost outlook, we were kind of right on top of that, kind of where we got, came up short a little bit in the second quarter was on the lending side. And we talked about average loan balances being down and some of the dynamics that drove that with lighter SBA originations in the front end of the year, or excuse me, in the front end of the quarter, but offset by strong growth, continued growth in construction and investor commercial real estate and single tenant lease financing. So as we kind of look forward into the third quarter and the fourth quarter, our pipelines in construction and ICRE are very strong. We expect a lot of draw activity in the third and fourth quarters. We have a lot of investor CRE projects that we expect the fund. Those are all kind of priced at a SOFR plus three range. The single tenant pipeline is very strong. And if you think about where long rates have gone here over the last, you know, you know, call it month, month and a half or so, we're pricing single tenant loans at kind of the highest yields that we have in quite some time. Those are priced at a 225 to 240 spread over the five-year treasury. You know, so those are, you know, those are coming on the books now, you know, anything that's pricing today is coming on at a 640 to 660 type yield. And then on the GERA side too, we're kind of really excited about that partnership because we, you know, historically we'd retained, call it 10 to 12% of their origination volumes. And if you think about it in terms of what we retained from say January through May, that was probably, least $4.5 to $5 million, so not very large balances. We were providing senior credit to their fund. That was probably a SOFR plus 3 or 4 type yield. But going forward, early part of this month, we did acquire some loans from JARIS as they wound down their funds. We kind of got a bulk of a pool of those, call it about $15 million or so earlier in July. And our expectation is we'll probably, combined with that with retained production, we'll probably have balances we'll acquire, kind of call it in the $45 to $50 million range. And those do have very nice, you know, kind of top-level gross yields. They're kind of, you know, they're, you know, usually a seven-month type turn on those. It's very structured, very similar to factoring. So the faster they pay, the higher yield there is. But the gross yield on those is very high. So, yeah, I mean, I think we expect. And then as we continue to see the lower yielding portfolios, some of the exited portfolios, health care, finance, mortgage that are 4% or lower continue to roll off. It's just the replacement dynamic combined with originations in some of our higher yield categories with SBA originations picking up significantly as well. The pathway to a higher yield on the overall loan portfolio is very visible when you put the pieces together.
That's all really helpful color, Ken. Appreciate that. And then just on the credit side, obviously, the SBA portfolio is having lower net charge-offs, delinquencies are down 20-plus basis points, link quarter, dealing with the franchise finance portfolio. I just wanted to hear, do you think you have your hands around all the issues that could be in those portfolios, or have you seen anything new come up here in the past quarter with some things that were originated in the 21 to 23 vintages, or do you feel like you have your hands around all those potential problems?
As it relates to SBA, Brett, we really do feel like the changes we implemented in underwriting as well as the changes that we have made to portfolio management that throughout the end of 2025 and into this year are really starting to show up. The vintages of 21 to 23, we believe we have worked through the worst of that. it's always possible of course with a small business for something to pop up but at this point we believe problems tend to show up in about the first 18 months um 18 to 24 months with small business especially when we're looking at business acquisition what we are seeing however is much better performance from the 2025 vintage and of course the 2026 year-to-date vintage so So we're feeling very confident that the changes we have made to underwriting guidelines, expectations of borrower strength, and then the changes that we've made as well within portfolio management are going to yield us much better results in the future.
Yeah. And I think kind of speaking on the franchise side of things, I think, you know, as we continue to work down, we talked about how we charged off, you know, a fair number of non-performing, non-accrual loans this quarter. We, you know, we referenced that the inflows to the non-accrual bucket was significantly reduced. So, net non-accrual franchise finance loans declined quite a bit. You know, we talked about the declines in SBA delinquencies, but even in early stage franchise delinquencies from the beginning of the year, that number is down over 75%. So similar to SBA, the non-performing loan formation has slowed dramatically. I mean, I think there's probably still some loans that we're keeping our eye on there, but the pool of loans where maybe a borrower is a habitual 30-day late payer or something like that. The pool of loans in franchising has certainly declined significantly, certainly from the beginning of the year.
In fact, just this afternoon, we were receiving a check on a loan that we had marked as doubtful. We had charged it down to, I think, $600,000 is all we had left on the book. got a check for $600,000. So I think that also speaks well to our ability to measure the recoverability of these loans. So that also gives us confidence going forward.
Okay. Really helpful. Thanks for all the color.
Operator
Our next question comes from the line of Emily Lee with KBW. Emily, your line is open.
Hi, Emily. Hey, everyone. This is stepping in for Tim Switzer. Thanks for taking my question. Yeah, so, yeah, end of period and average loan balances were impacted by early payoffs this quarter. What are your expectations for payoffs going forward?
You know what? We think, based upon what we've seen this year, we know that there are probably going to continue to have those pop up here and there. What we do like is when a borrower gives us notice. Like, for example, we got notice earlier this week that a construction loan or an ICRD loan that's going to mature in 27, that they're going to pay it down probably at the end of August. So it's nice when we get advance notice on that because we can certainly factor that into our models. And quite frankly, you know, it's enough lead time to, you know, get out there and replace the balance elsewhere. But I think we do expect there's probably going to be some. It's kind of hard to predict. We have seen elevated payoffs in the franchise finance portfolio on performing loans there. But we've kind of began to model that in because we've seen that for the past couple quarters. But I think, you know, I think it'll continue to happen. But I think we're trying to do our best to capture it in our modeling.
Understood. That's helpful. And then, you know, this quarter you increased the number of fintech partners. Just wondering if you could talk about expectations for growth from the BAS platform going forward and how the partner pipeline is looking now. You know, do you still look to kind of continue opportunistically adding more partners as you see fit or what are your plans there?
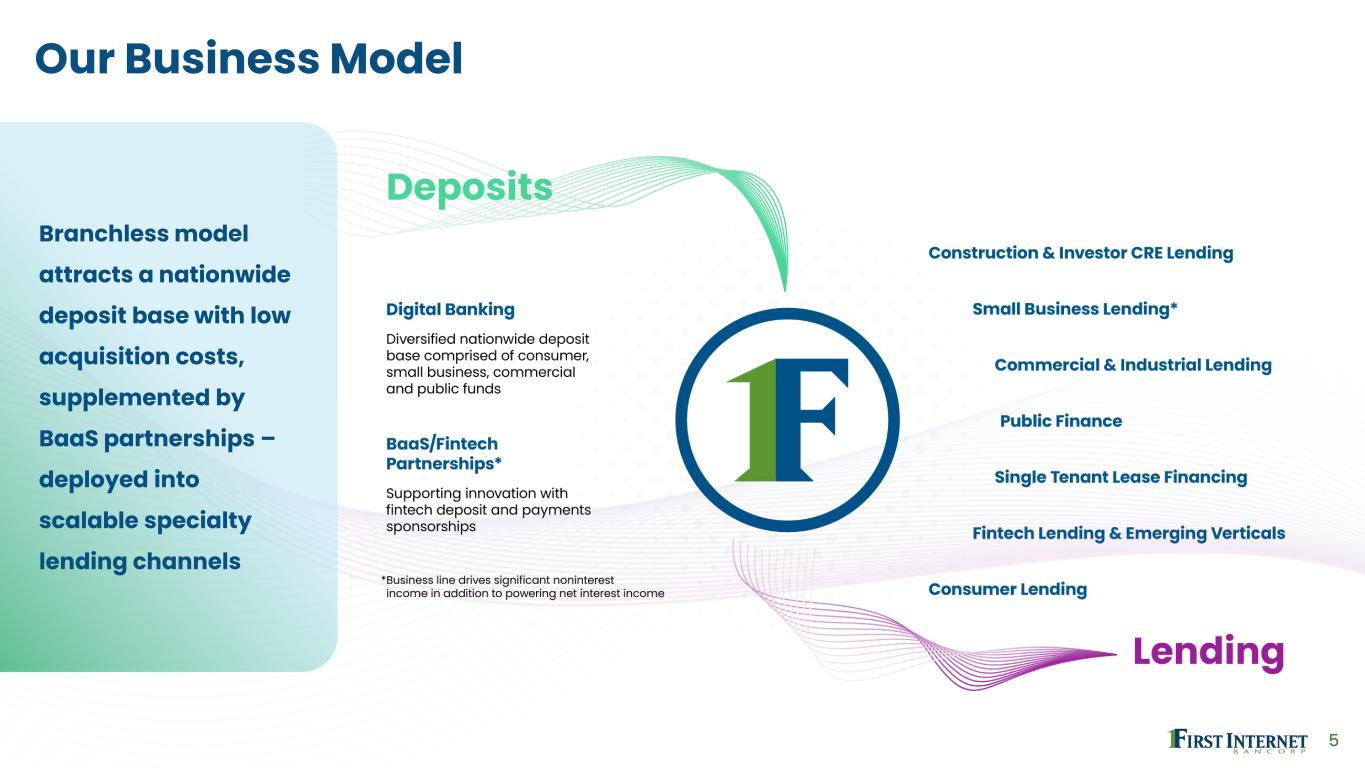
Sure. We have added three partners year to date and I think there are like, so we are now at 15 partners, 21 programs. We have two more programs that we expect to bring online before the end of 2026. And our pipeline of potential programs is healthy behind that. I don't expect us to grow into the triple digits by any means in the next year. We're very careful about how we curate our partnerships and we have some terrific partners in fact four of the 15 have expanded their relationship with us in the last year I think that speaks to the kind of relationships that we're forming and the capacity that we have to grow right alongside them so we believe that in terms of FinTech partnership revenue we're going to see growth from interest income on the lending program that we're doing. We also then will see a moderate increase from our fees that we collect, whether it's on transactions or on oversight fees. But, you know, our revenue has grown and our transactions have grown. I think our revenue is up 220 percent year over year. So, we do see a lot of runway there.
Great to hear. Thanks for taking my question.
Thanks. our next question comes from the line of nathan race with piper sandler nathan your line is open hi everyone good afternoon thanks for uh taking the question hey date how you doing i'm wondering if you could just good thanks dave david um just in terms of thinking about the reserve trajectory going forward i know it's difficult to predict in terms of you know what charge-offs are going to be underlying the provisioning assumptions for the back half of this year but was just curious you know if you could just shed some more light on in terms of how specific reserves are trending um particularly against the sd and franchise
finance portfolios and kind of what that suggests in terms of kind of lost content expectations over the next couple quarters um yeah i mean i think we we saw we you know we a lot of the you know as we mentioned in our comments right we you know we charged off about 11 and a half million of non-performing franchise loans that reduced our specific reserves by 6.7 million that came off. You know, when we think about like what the the the provision outlook looks like, you know, we do for some time for the provision sometimes it's kind of agnostic whether it's a charge off for a specific reserve. But I think we, again, we kind of continue to feel confident that with the enhancements that Nicole mentioned relative to SBA portfolio management, special assets, and where we see the number, potential number of franchise loans that could be a problem down the road, I think we just see continued decline there. And if you think about it in in terms of a net charge-off number. I think our expectation is that for net charge-offs to come down significantly from where they were in the first and second quarter, probably be a little bit, could be higher in the third quarter, could be less in the fourth. Like you said in your question, it's hard to predict the timing, but I think we believe the trajectory is certainly going down in the back half of the year.
And I think, too, to your question, Nate, with our enhanced portfolio management efforts and really being an ally to our borrowers, we're able to provide them more solutions when they get in touch with us earlier. So sometimes I've just seen over the last 18 months a night and day difference in the way we're better communicating, and that gives us more visibility into what the likelihood of loss would be. So the communication between portfolio management and finance is very, very strong, and that helps to prevent surprises.
The comment that Nicole made earlier about the $600,000 payment we got in today on a loan that we'd reserved against, we also have a significant franchisor that's got three units, a little over $6 million. We've already reserved a 30% reserve against that loan, and we think it's going to pay off in total. So we'll get a recovery of that 30% here this quarter, plus the full $6 million will fall out of the delinquency side and off the balance sheet in total. So that's kind of a wild card there, but the whole thing we've done with the special assets group has enabled us, as Nicole said, we've reached out and touched literally everybody in the SBA pool, everybody in the franchise pool, checking in with them, how things are going. With all the uncertainty and the economic factors out here right now, we're on a very strong offensive pull to try and reach everybody. So if things do start to go south, they'll call us. They won't run from us. And as she just pointed out, there's a lot of things we can do for them when we catch them early. When they're on their way to the bankruptcy court, it makes it tough for all of us.
So we're pretty positive that we've got the right people in the right seats doing the right things right now so it's a fun time indeed uh that's really helpful just going back to the margin discussion can i appreciate all the color around what you have maturing on the cd front in the back half of this year um the expectation that you know those cds will largely be replaced by some of the lower cost uh deposit gathering um programs you have going on with some of your partners or i mean what's kind of the incremental kind of replacement cost on some of those cds you know to the extent it's not back filled with some of those other
relationship deposits yeah i mean i i guess maybe the easiest way to think about it is is just simply replacing you know in the third quarter you know cds that are you know costing us you know, 404 on a weighted average basis being replaced with fintech at 320, 315 to 320. That's probably the easiest way to think about it. And as I mentioned, you know, why I think we'll probably get some more deposit cost savings in the back half of the year, certainly in the third quarter, is just the renewal rate on CDs. I mean, our renewal rate, we're, you know, if we're renewing CDs today, that rate is kind of around a 360. So you're still looking at a 40 basis point pickup, even if we just renewed everything or had new volume. But that renewal rate is going down, which when you're back filling more of it with fintech deposit growth, you're just going to capture more cost savings.
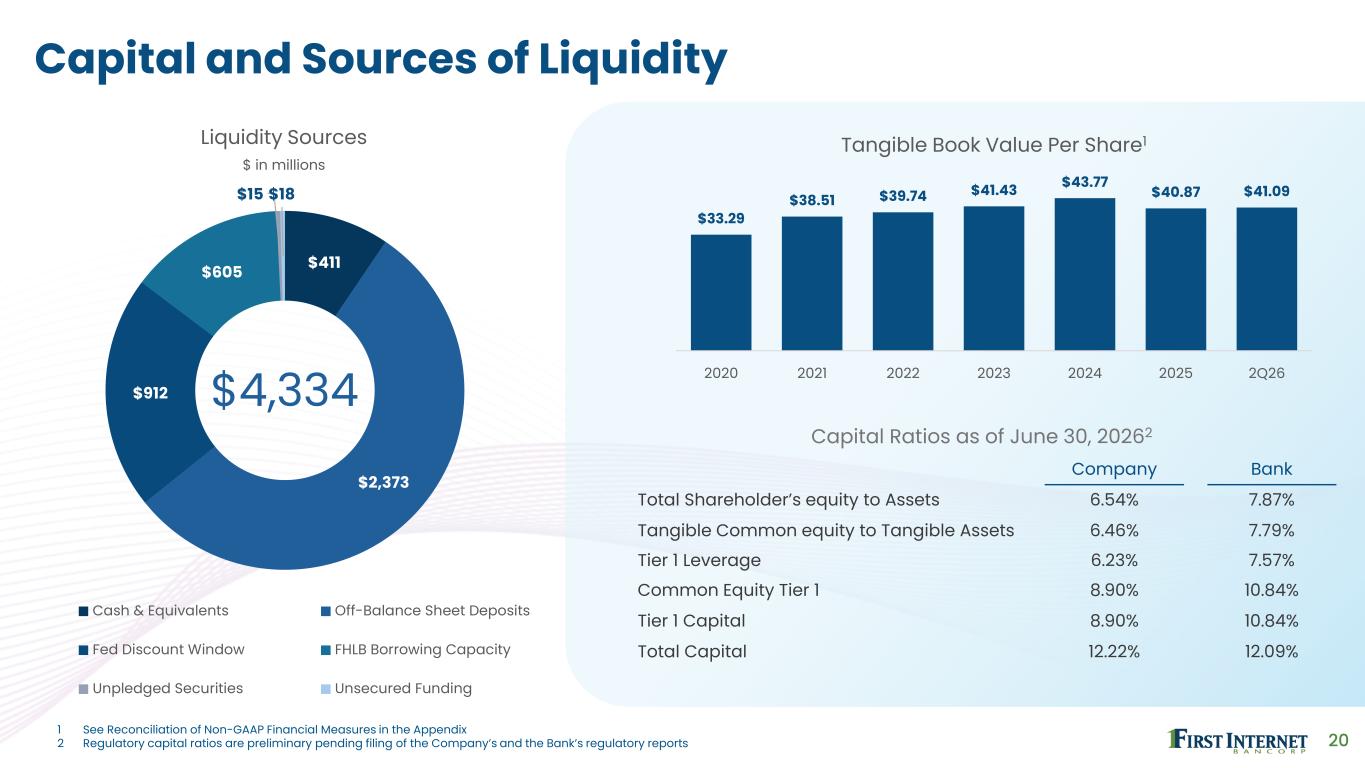
We're not feeling the pressure that a lot of our peers are on them because of the deposit market getting hot again and having to pay up for cds and or deposits with two and a half billion dollars off balance sheet in cash as ken said if half of those cds disappear we'll pull 200 million in at 318 versus the 420. so it's uh we're in a pretty enviable position right now with what's going on in the marketplace with the excess cash yep good stuff and then you know, if we were to get a rate hike later this year, can you just update us in terms of what that
kind of NI or margin sensitivity would be?
Sure. Yeah, Ana, and keep in mind that this is a static balance sheet, so it's not really factoring in growth. You know, obviously everything we've done over the last few years, we've moved ourselves much closer to a neutral position, but we still are a little bit liability sensitive so if we had a rate hike again static balance sheet it's probably about on an annual basis about 2.4 million dollar reduction to nii if it went the other way if we had a rate cut a 25 basis point rate reduction we would probably pick up about 2.2 million dollars uh in additional nii okay great and then just lastly ken what's the tax rate assumptions underpinning the uh eps guide for this year yeah i mean it's you know it's a little bit varying i'd say between the between the range i mean it's not a huge range but i'd say it's probably you know on the low end of the range call it a six to six and a quarter on the higher end of the range call it eight eight and a half i mean and this is full year um so you know i think with our expectations of you know stronger uh you know much stronger performance in uh um in the third quarter in the fourth quarter you could probably kind of math into you know if i'm giving you the tax rate for the year you can probably back into what it could be for the quarters uh yeah i think
that's something in the 15% range. Sounds like 15, 20%. Does that sound right?
Probably more 12 to 15-ish.
Okay. All right. Sounds good. I appreciate all the color. Thanks, everyone.
Operator
Our next question comes from the line of George Sutton with Craig Hallam. George, your line is open.
Thank you. You mentioned Wealth Advisory and Invented Finances are a new focus areas. I wondered if you could give us a little more picture on what the wealth advisory practice is lending to. And on the embedded finance side, I'm curious, is that broader than just JARIS or are you specifically focused on JARIS there?
I'll handle the wealth advisory piece. The wealth advisory lending is to RIAs generally, you know, for the purpose of, say, you know, ownership transition, succession issues. You may have, you know, what you see in the RIA, the registered investment advisor world today, is you see a lot of, you know, a lot of advisors are getting near retirement, and there's a lot of ownership transition, a senior partner selling to a junior partner. So, that's really what that is. It's financing acquisition or succession transition, ownership transition in the advisor space?
The average owner of an RIA today, George, is 66 years old, and so there's a lot of folks kind of saying enough's enough, and a little bit of volatility might be creating some of the issues, but we've been doing it for probably 18 to 24 months now, but the volume has really seemed to pick up over the last four to five months. I'll take on the embedded finance. Yeah, JARIS is by far the biggest opportunity for us in the short term. We have two others in the queue. One is wrapping up on their due diligence and final testing and should be going live, one of the ones that Nicole was talking about coming on between now and year end. But the big change for us in the second half of this year before the new guys come on board is JARIS. We had historically been buying about 10% of their production, and the rest was going to the fund. We actually bought out that fund, and it's going to jump. We did about $5 million with them in the first half of the year, and we're probably going to do $10 million to $15 million in the second half of the year. As Ken said, that tremendously helps them at the top end on the yield on it. At the short-term, as he said, factoring, it can be 35% to 40% depending upon the term and how quick they repay net yield to us at the bottom line, full reserves, processing, servicing, payment of fees, et cetera. It's still yielding in that 12% to 15% range for us. So that's doubled down anything else we have on the books today. So it's a great asset for us. and the other folks, the pricing will be similar for those that we're turning on here in the second half of the year.
You had historic fast growth. I'm just curious, how much of that would be ramp specific versus others?
We're spread out. Probably the biggest impact for ramp is on the deposit side of things, on the fee side of it. We're there with them, but we actually have some others that But the pure processing earnings are stronger. RAMP, we do their bill pay product, which has grown significantly. We started it with them square zero a little over two years ago. On June 30th and July 1, we literally cleared $1 billion plus per day in bill payments. But they're pennies of transactions. So the real growth that we've gotten out of RAMP in the last few months, obviously the numbers are going up, but they're pennies an item. is on the deposit side. That's been very, very strong for us. The others, we've adjusted fees almost across the board with all of our clients. Everybody's kind of in a nice growth spurt. As Nicole pointed out, we're not going after every Tom, Dick, and Harry that's out there. We're pretty judicious on who we work with and who we talk to. We've got a pretty good reputation in the business of being ahead of the regulators and not having compliance issues and we're viewed as a little bit painful to deal with. But at the end of the day, that's a win for us and the fintechs. So we've got good volume across the line. A few years back, we went from a million in revenue to two to four. We had forecasted eight. I think it's going to not pass 10 this year pretty easily. So it's all going up and to the right pretty quickly.
One quick one for Nicole, if I could, on SBA. Historically, you've kind of talked about your market ranking and goals for pretty material growth. Is that not necessarily the focus now?
Well, thanks for the question, George. Obviously, I mean, we want to put people in small business and help them achieve their dreams when we can and when it makes sense. We needed to retool our credit underwriting guidelines, we needed to build better portfolio management processes. So we didn't continue to add to the portfolio and then not have a way to keep up with our borrowers. So with those two things, you know, addressed, I think that we do have a good opportunity to ramp volume back up. But we're going to do that judiciously, not focus on quantity, but really focus on quality. It's painful to us when a business has to close its doors. And so we want to make sure that we're putting the right borrowers in the right business so that we can be a good partner to them. So I do think we have a good opportunity now that we have our processes in place and we have credit underwriting guidelines that we know work. We're feeling much better about our ability to scale volume again. I think we'll see some improvement in volume in the second half of this year. Our lending teams are growing slightly and we have with some good people with new contacts that they've made. Our referral sources, we're growing more loans that have some real estate behind them. So those command a better premium. So I think we did a lot of retooling that is going to help us in future periods.
The SBA industry as a whole, George, is down about 18% year-to-date on growth year-over-year compared to last year. So the industry as a whole was a little bit slower than it had been. We're still in the top 10 originators in the 7A world, and we'll probably stay there through the course of the year. As Nicole said, the pipelines are strong in volume. Second half will be a little better than it was in the first half.
Perfect. Okay. Thanks, guys.
Appreciate it. Thank you.
Operator
There are no further questions at this time. I will now turn the call back to David Becker for closing remarks.
Thanks Trevor and thanks everybody for joining us today and for your interest in First Internet Bancorp. This was the quarter we've been working towards for some time and we're proud of the progress our teams have made on credit as well as increasingly capital efficient fee generating direction of our business. We remain mindful of all the macro economic uncertainty in the world and things going on around us, but we are executing from a position of genuine momentum and we believe the hardest part of our credit cycle is truly behind us. We appreciate your support. Feel free to reach out to any of us if you have further questions. Thank you and have a good evening.
Operator
This concludes today's call. Thank you for attending. You may now disconnect.