
ABCB 8-K
Ameris Bancorp (ABCB)
8-K
2026-07-23
For: 2026-07-23
View Original
Added on
July 24, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
| Date of report (Date of earliest event reported): | |||||
| (Exact Name of Registrant as Specified in Charter) | ||
| (State or Other Jurisdiction of Incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||
| (Address of Principal Executive Offices) | (Zip Code) | |||||||
| Registrant’s telephone number, including area code: | ||||||||
(Former Name or Former Address, if Changed Since Last Report) | ||
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
Securities registered pursuant to Section 12(b) of the Act:
Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
Item 2.02 Results of Operations and Financial Condition.
On July 23, 2026 , Ameris Bancorp (the “Company”) issued a press release announcing its unaudited financial results for the quarter ended June 30, 2026. A copy of that press release is attached to this Current Report on Form 8-K (this “Report”) as Exhibit 99.1.
The information contained in this Item 2.02 and in Exhibit 99.1 attached to this Report is being furnished and shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of such section. Furthermore, such information shall not be deemed to be incorporated by reference into any registration statement or other document filed pursuant to the Securities Act of 1933, as amended.
Item 7.01 Regulation FD Disclosure.
A copy of the investor presentation material that the Company will present regarding its earnings during the teleconference beginning at 9:00 a.m. Eastern time on July 24, 2026 is attached to this Report as Exhibit 99.2. The investor presentation material is also available on the “Investor Relations” page of the Company’s website (http://www.amerisbank.com).
The information contained in this Item 7.01 and in Exhibit 99.2 attached to this Report is being furnished and shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of such section. Furthermore, such information shall not be deemed to be incorporated by reference into any registration statement or other document filed pursuant to the Securities Act of 1933, as amended.
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits.
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | ||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the registrant has duly caused this report to be signed on its behalf by the undersigned, hereunto duly authorized.
AMERIS BANCORP
| By: | /s/ Nicole S. Stokes | ||||
| Nicole S. Stokes | |||||
| Chief Financial Officer | |||||
Date: July 23, 2026
News Release
AMERIS BANCORP ANNOUNCES SECOND QUARTER 2026 FINANCIAL RESULTS
Highlights of Ameris’s results for the second quarter of 2026 include the following:
•Net income of $51.4 million, or $0.77 per diluted share
•Adjusted net income of $107.3 million, or $1.60 per diluted share
•Return on average assets ("ROA") of 0.73%; Adjusted ROA(1) of 1.53%
•Return on average tangible common equity(1) ("ROTCE") of 6.75%; Adjusted ROTCE of 14.08%
•Revenue growth of 14.9% annualized
•Stable net interest margin (TE) of 3.88%
•Efficiency ratio of 74.45% with adjusted efficiency ratio(1) lower at 50.42%
•Growth in average earning assets of $544.6 million, or 8.5% annualized
•Loan growth of $349.9 million, or 6.4% annualized
•Noninterest-bearing deposit mix improvement to 30.0% of total deposits
•Annualized net charge-off decline to 0.20% of average total loans
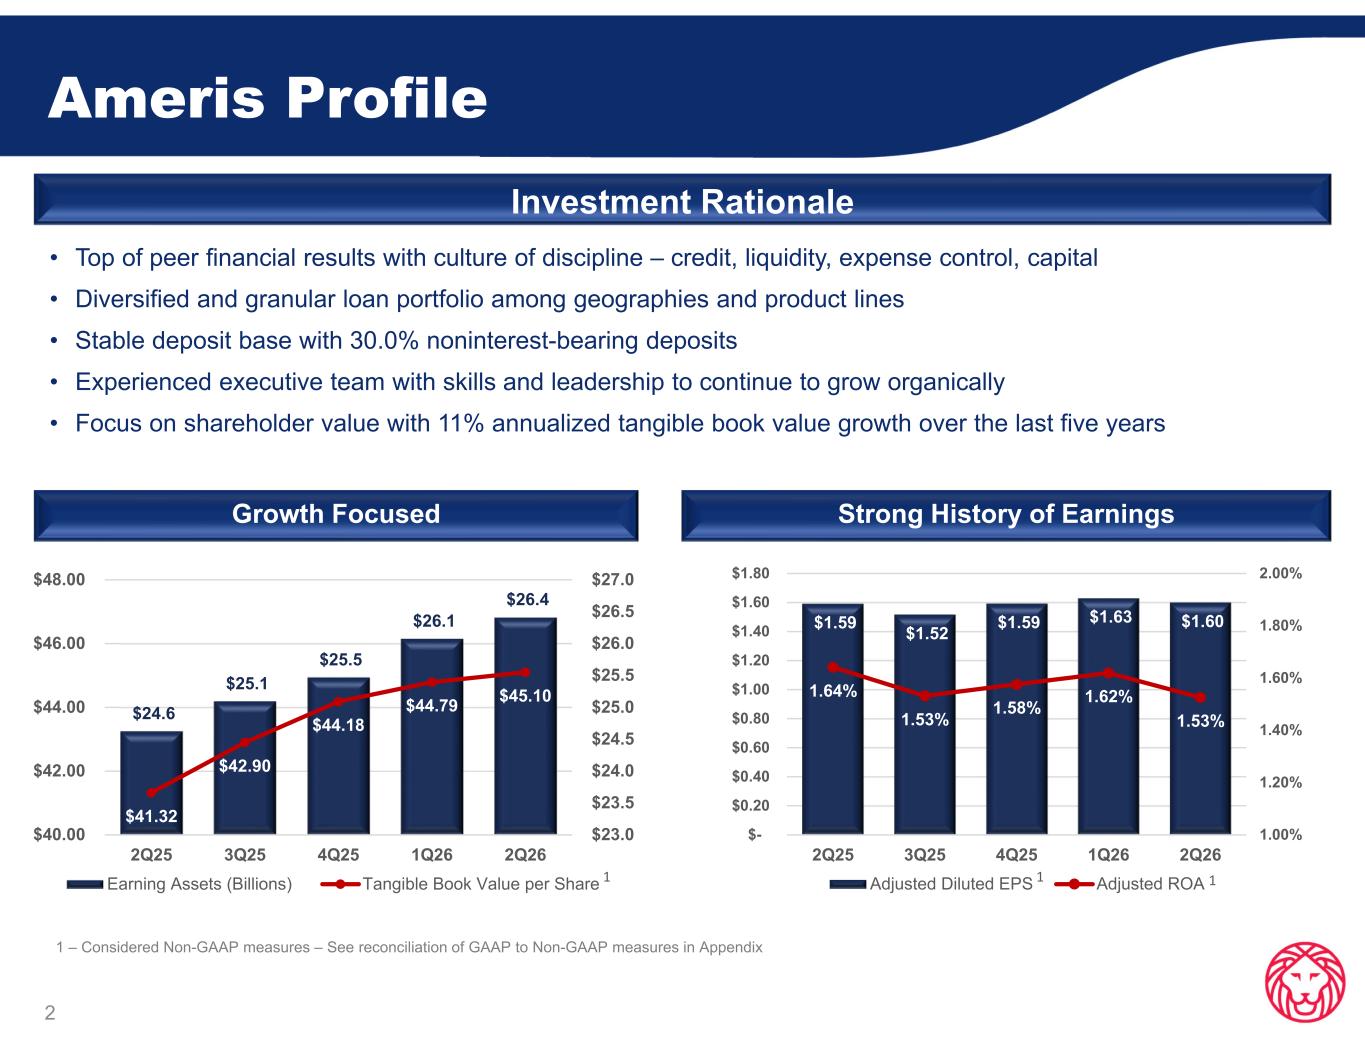
•Tangible book value(1) growth of $0.31 per share, or 2.8% annualized, to $45.10 at June 30, 2026
•Share repurchases totaling $19.0 million, or 226,600 shares, during the quarter
ATLANTA, GA, July 23, 2026 - Ameris Bancorp (NYSE: ABCB) (the “Company” or “Ameris”) today reported net income of $51.4 million, or $0.77 per diluted share, for the quarter ended June 30, 2026, compared with $109.8 million, or $1.60 per diluted share, for the quarter ended June 30, 2025. Excluding a litigation accrual and gain on the sale of securities, adjusted net income(1) was $107.3 million, or $1.60 per diluted share, for the quarter ended June 30, 2026, compared with $109.4 million, or $1.59 per diluted share, for the quarter ended June 30, 2025.
For the year-to-date period ending June 30, 2026, the Company reported net income of $161.9 million, or $2.40 per diluted share, compared with $197.8 million, or $2.87 per diluted share, for the same period in 2025. Adjusted net income(1) for the six months ended June 30, 2026 was $217.8 million, or $3.23 per diluted share, compared with $197.5 million, or $2.87 per diluted share, for the same period in 2025.
Commenting on the Company’s results, Palmer Proctor, the Company’s Chief Executive Officer, said, “Ameris delivered another quarter of strong underlying operating performance, underscoring the resilience of our franchise and the earning power of our business and reflecting the consistency of our long-term strategy and disciplined execution across the organization. We generated a return on assets of 1.53% on an adjusted basis, maintained a stable net interest margin of 3.88% and delivered annualized earning asset growth of 8.5%. We continued to build long-term shareholder value through a relentless focus on profitable growth and a high-quality balance sheet funded with 30% noninterest bearing deposits and tangible common equity exceeding 11%. During the quarter, we were pleased to announce our expansion into the Nashville market, another important step in extending our high-performing Southeast franchise and creating additional opportunities for profitable growth.”
Net Interest Income and Net Interest Margin
Net interest income on a tax-equivalent basis (TE) was $253.4 million in the second quarter of 2026, an increase of $8.1 million, or 3.3%, from last quarter and $20.7 million, or 8.9%, compared with the second quarter of 2025. The Company's average earning assets increased during the quarter by $544.6 million, or 8.5% annualized, primarily due to an increase of $356.9 million in average portfolio loans outstanding and an increase of $170.9 million in the average balance of investment securities.
The Company's net interest margin was stable at 3.88% for the second quarter of 2026, unchanged from the first quarter of 2026 and an 11 basis point improvement from the 3.77% reported for the second quarter of 2025.
Yields on earning assets increased four basis points during the quarter to 5.61%, compared with 5.57% in the first quarter of 2026. This increase is primarily related to a 40 basis point increase in yield on taxable investment securities and a 12 basis point increase in yield on loans held for sale, partially offset by a one-basis point decrease in yield on portfolio loans outstanding during the second quarter of 2026.
The Company’s total cost of funds increased three basis points to 1.91% in the second quarter of 2026, compared with 1.88% in the first quarter of 2026, and improved 15 basis points compared with the second quarter of 2025. Deposit costs increased one-basis point during the second quarter of 2026 to 1.77%, compared with 1.76% in the first quarter of 2026. Costs of interest-bearing deposits during the quarter were 2.52%, an increase of two-basis points compared with the first quarter of 2026.
Noninterest Income
Noninterest income increased $3.6 million, or 5.2%, in the second quarter of 2026 to $73.5 million, compared with $69.9 million for the first quarter of 2026, driven primarily by a $7.4 million securities gain. Mortgage banking activity decreased $4.5 million, or 12.1%, to $32.5 million in the second quarter of 2026, compared with $37.0 million for the first quarter of 2026. Total production in the retail mortgage division increased $65.2 million, or 6.0%, to $1.15 billion in the second quarter of 2026, compared with $1.09 billion for the first quarter of 2026. The retail mortgage open pipeline was $609.3 million at the end of the second quarter of 2026, compared with $632.7 million at the end of the first quarter of 2026. Gain on sale spreads decreased to 2.04% in the second quarter of 2026 from 2.08% for the first quarter of 2026. Gain on securities was $7.4 million for the second quarter of 2026, primarily resulting from a gain on the conversion of Visa Class B-2 shares during the quarter and related gain on sale and mark-to-market adjustments. Other noninterest income increased $437,000, or 4.8%, in the second quarter of 2026 to $9.6 million, compared with $9.1 million for the first quarter of 2026.
Noninterest Expense
Noninterest expense increased $85.6 million, or 54.5%, to $242.7 million during the second quarter of 2026, compared with $157.1 million for the first quarter of 2026. The increase was driven by a litigation expense accrual of $82.5 million related to a jury verdict in an employment case in California. Adjusted noninterest expense(1) increased $3.1 million, or 2.0%, compared with the first quarter of 2026, primarily due to increased legal expenses and charitable donations. Management continues to focus on delivering high performing operating efficiency, with an adjusted efficiency ratio(1) of 50.42% in the second quarter of 2026, compared with 49.97% in the first quarter of 2026 and 51.74% in the second quarter of 2025.
Income Tax Expense
The Company's effective tax rate for the second quarter of 2026 was 22.1%, compared with 21.5% for the first quarter of 2026. The increased rate resulted primarily from a decline in the excess benefit from share-based compensation awards compared with the first quarter of 2026.
Balance Sheet Trends
Total assets at June 30, 2026 were $28.49 billion, compared with $28.11 billion at March 31, 2026 and $27.52 billion at December 31, 2025. During the second quarter of 2026, loans, net of unearned income, increased by $349.9 million, or 6.4% annualized. Loans held for sale decreased to $482.2 million at June 30, 2026 from $623.2 million at December 31, 2025. Debt securities available-for-sale amounted to $2.46 billion, compared with $2.35 billion at March 31, 2026 and $2.21 billion at December 31, 2025.
At June 30, 2026, total deposits amounted to $22.59 billion, compared with $22.38 billion at December 31, 2025. Average deposits in the second quarter of 2026 increased $243.4 million, or 4.4% annualized; however, end of period balances decreased $49.2 million, with noninterest bearing deposits increasing $33.9 million and interest bearing decreasing $83.1 million. Non-brokered, non-public fund deposits decreased $112.2 million, seasonal outflows of public funds totaled $111.0 million and brokered CDs increased $174.0 million. Noninterest-bearing accounts as a percentage of total deposits increased, such that at June 30, 2026, noninterest-bearing deposit accounts represented $6.78 billion, or 30.0% of total deposits, compared with $6.43 billion, or 28.7% of total deposits, at December 31, 2025.
Shareholders’ equity at June 30, 2026 totaled $4.09 billion, an increase of $14.5 million, or 0.4%, from December 31, 2025. The increase in shareholders’ equity was primarily the result of earnings of $161.9 million during the first six months of 2026, largely offset by share repurchases, dividends declared and a decrease in accumulated other comprehensive income of $24.8 million resulting from changes in interest rates on the Company's investment portfolio. Tangible book value per share(1) increased $0.92 per share, or 4.2% annualized, during the first six months of 2026 to $45.10 at June 30, 2026. Tangible common equity as a percentage of tangible assets was 11.04% at June 30, 2026, compared with 11.37% at the end of 2025. The Company repurchased 226,600 shares of its common stock during the quarter ending June 30, 2026.
Credit Quality
During the second quarter of 2026, the Company recorded a provision for credit losses of $17.3 million, compared with a provision of $16.6 million in the first quarter of 2026. The allowance for credit losses on loans was 1.62% of loans at June 30, 2026, unchanged from the end of 2025. Nonperforming assets as a percentage of total assets increased two basis points to 0.47% during the quarter. Approximately $33.7 million, or 25.4%, of the nonperforming assets at June 30, 2026 were GNMA-guaranteed mortgage loans, which present minimal loss exposure for the Company. Excluding these government-guaranteed loans, nonperforming assets as a percentage of total assets increased two basis points to 0.35% at June 30, 2026, compared with 0.33% at the end of the first quarter of 2026. The net charge-off ratio was 20 basis points for the second quarter of 2026, compared with 21 basis points for the first quarter of 2026.
Conference Call
The Company will host a teleconference at 9:00 a.m. Eastern time on Friday, July 24, 2026, to discuss the Company's results and answer appropriate questions. The conference call can be accessed by dialing 1-844-481-2939. The conference call ID is Ameris Bancorp. A replay of the call will be available beginning one hour after the end of the conference call until July 31, 2026. To listen to the replay, dial 1-855-669-9658. The conference replay access code is 7503680. The financial information discussed will be available on the Investor Relations page of the Ameris Bank website at ir.amerisbank.com. Participants also may listen to a live webcast of the presentation by visiting the link on the Investor Relations page of the Ameris Bank website.
About Ameris Bancorp
Ameris Bancorp is the parent of Ameris Bank, a state-chartered bank headquartered in Atlanta, Georgia. Ameris operates financial centers in five southeastern states and also serves consumer and business customers nationwide through select lending channels. Ameris manages $28.5 billion in assets as of June 30, 2026, and provides a full range of traditional banking and lending products, treasury and cash management, insurance premium financing, and mortgage and refinancing services. Learn more about Ameris at www.amerisbank.com.
(1) Considered non-GAAP financial measure - See reconciliation of GAAP to non-GAAP financial measures in tables 9A - 9D.
This news release contains certain performance measures determined by methods other than in accordance with accounting principles generally accepted in the United States of America (“GAAP”). The Company’s management uses these non-GAAP financial measures in its analysis of the Company’s performance. These measures are useful when evaluating the underlying performance and efficiency of the Company’s operations and balance sheet. The Company’s management believes that these non-GAAP financial measures provide a greater understanding of ongoing operations, enhance comparability of results with prior periods and demonstrate the effects of significant gains and charges in the current period. The Company’s management believes that investors may use these non-GAAP financial measures to evaluate the Company’s financial performance without the impact of unusual items that may obscure trends in the Company’s underlying performance. These disclosures should not be
viewed as a substitute for financial measures determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP financial measures that may be presented by other companies.
This news release contains forward-looking statements, as defined by federal securities laws, including, among other forward-looking statements, certain plans, expectations and goals. Words such as “may,” “believe,” “expect,” “anticipate,” “intend,” “will,” “should,” “plan,” “estimate,” “predict,” “continue” and “potential” or the negative of these terms or other comparable terminology, as well as similar expressions, are meant to identify forward-looking statements. The forward-looking statements in this news release are based on management's opinions only as of the date hereof and are provided to assist in the understanding of potential future performance. Such forward-looking statements involve numerous assumptions, risks and uncertainties that may cause actual results to differ materially from those expressed or implied in any such statements, including, without limitation, the following: general competitive, economic, unemployment, political and market conditions and fluctuations, including real estate market conditions, and the effects of such conditions and fluctuations on the creditworthiness and payment behavior of borrowers, collateral values, asset recovery values and the value of investment securities; movements in interest rates and their impacts on net interest margin, investment security valuations and other performance measures; expectations on credit quality and performance; legislative and regulatory changes; changes in U.S. government trade, monetary and fiscal policies, including tariffs; competitive pressures on product pricing and services; fraud, theft or other misconduct impacting our customers or operations; cybersecurity risks, including data breaches, malware, ransomware and account takeover; the success and timing of our business strategies and plans; our outlook and long-term goals for future growth; and natural disasters, geopolitical events, acts of war or terrorism or other hostilities, public health crises and other catastrophic events beyond our control. For a discussion of some of the other risks and other factors that may cause such forward-looking statements to differ materially from actual results, please refer to the Company’s filings with the Securities and Exchange Commission, including the Company’s Annual Report on Form 10-K for the year ended December 31, 2025 and the Company's subsequently filed periodic reports and other filings. Forward-looking statements speak only as of the date they are made, and the Company undertakes no obligation to update or revise forward-looking statements except as required by law.
For more information, contact:
Brady Gailey
Executive Director of Corporate Development
(404) 240-1517
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Financial Highlights | Table 1 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||||||||
| EARNINGS | |||||||||||||||||||||||||||||||||||||||||
| Net income | $ | 51,446 | $ | 110,492 | $ | 108,356 | $ | 106,029 | $ | 109,834 | $ | 161,938 | $ | 197,769 | |||||||||||||||||||||||||||
Adjusted net income(1) | $ | 107,309 | $ | 110,492 | $ | 108,838 | $ | 104,040 | $ | 109,444 | $ | 217,801 | $ | 197,470 | |||||||||||||||||||||||||||
| COMMON SHARE DATA | |||||||||||||||||||||||||||||||||||||||||
| Earnings per share available to common shareholders | |||||||||||||||||||||||||||||||||||||||||
| Basic | $ | 0.77 | $ | 1.64 | $ | 1.59 | $ | 1.55 | $ | 1.60 | $ | 2.41 | $ | 2.88 | |||||||||||||||||||||||||||
| Diluted | $ | 0.77 | $ | 1.63 | $ | 1.59 | $ | 1.54 | $ | 1.60 | $ | 2.40 | $ | 2.87 | |||||||||||||||||||||||||||
Adjusted diluted EPS(1) | $ | 1.60 | $ | 1.63 | $ | 1.59 | $ | 1.52 | $ | 1.59 | $ | 3.23 | $ | 2.87 | |||||||||||||||||||||||||||
| Cash dividends per share | $ | 0.20 | $ | 0.20 | $ | 0.20 | $ | 0.20 | $ | 0.20 | $ | 0.40 | $ | 0.40 | |||||||||||||||||||||||||||
| Book value per share (period end) | $ | 60.96 | $ | 60.64 | $ | 59.92 | $ | 58.56 | $ | 57.02 | $ | 60.96 | $ | 57.02 | |||||||||||||||||||||||||||
Tangible book value per share (period end)(1) | $ | 45.10 | $ | 44.79 | $ | 44.18 | $ | 42.90 | $ | 41.32 | $ | 45.10 | $ | 41.32 | |||||||||||||||||||||||||||
| Weighted average number of shares | |||||||||||||||||||||||||||||||||||||||||
| Basic | 66,883,935 | 67,540,444 | 68,022,346 | 68,401,737 | 68,594,608 | 67,210,376 | 68,689,506 | ||||||||||||||||||||||||||||||||||
| Diluted | 67,099,941 | 67,766,997 | 68,328,365 | 68,665,669 | 68,796,577 | 67,430,193 | 68,912,750 | ||||||||||||||||||||||||||||||||||
| Period end number of shares | 67,106,587 | 67,320,298 | 68,022,316 | 68,587,742 | 68,711,043 | 67,106,587 | 68,711,043 | ||||||||||||||||||||||||||||||||||
| Market data | |||||||||||||||||||||||||||||||||||||||||
| High intraday price | $ | 91.41 | $ | 87.98 | $ | 78.99 | $ | 76.58 | $ | 65.43 | $ | 91.41 | $ | 68.85 | |||||||||||||||||||||||||||
| Low intraday price | $ | 77.01 | $ | 73.20 | $ | 68.80 | $ | 64.30 | $ | 48.27 | $ | 73.20 | $ | 48.27 | |||||||||||||||||||||||||||
| Period end closing price | $ | 90.26 | $ | 77.99 | $ | 74.27 | $ | 73.31 | $ | 64.70 | $ | 90.26 | $ | 64.70 | |||||||||||||||||||||||||||
| Average daily volume | 531,184 | 558,814 | 448,341 | 435,766 | 416,355 | 544,887 | 423,428 | ||||||||||||||||||||||||||||||||||
| PERFORMANCE RATIOS | |||||||||||||||||||||||||||||||||||||||||
| Return on average assets | 0.73 | % | 1.62 | % | 1.57 | % | 1.56 | % | 1.65 | % | 1.17 | % | 1.51 | % | |||||||||||||||||||||||||||
Adjusted return on average assets(1) | 1.53 | % | 1.62 | % | 1.58 | % | 1.53 | % | 1.64 | % | 1.57 | % | 1.50 | % | |||||||||||||||||||||||||||
| Return on average common equity | 5.00 | % | 10.91 | % | 10.63 | % | 10.61 | % | 11.40 | % | 7.94 | % | 10.41 | % | |||||||||||||||||||||||||||
Adjusted return on average tangible common equity(1) | 14.08 | % | 14.75 | % | 14.53 | % | 14.29 | % | 15.76 | % | 14.41 | % | 14.48 | % | |||||||||||||||||||||||||||
| Earning asset yield (TE) | 5.61 | % | 5.57 | % | 5.61 | % | 5.66 | % | 5.64 | % | 5.59 | % | 5.63 | % | |||||||||||||||||||||||||||
| Total cost of funds | 1.91 | % | 1.88 | % | 1.95 | % | 2.05 | % | 2.06 | % | 1.89 | % | 2.06 | % | |||||||||||||||||||||||||||
| Net interest margin (TE) | 3.88 | % | 3.88 | % | 3.85 | % | 3.80 | % | 3.77 | % | 3.88 | % | 3.75 | % | |||||||||||||||||||||||||||
| Efficiency ratio | 74.45 | % | 49.97 | % | 46.59 | % | 49.19 | % | 51.63 | % | 62.43 | % | 52.22 | % | |||||||||||||||||||||||||||
Adjusted efficiency ratio(1) | 50.42 | % | 49.97 | % | 46.68 | % | 49.62 | % | 51.74 | % | 50.19 | % | 52.25 | % | |||||||||||||||||||||||||||
| CAPITAL ADEQUACY (period end) | |||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity to assets | 14.36 | % | 14.52 | % | 14.81 | % | 14.82 | % | 14.68 | % | 14.36 | % | 14.68 | % | |||||||||||||||||||||||||||
Tangible common equity to tangible assets(1) | 11.04 | % | 11.15 | % | 11.37 | % | 11.31 | % | 11.09 | % | 11.04 | % | 11.09 | % | |||||||||||||||||||||||||||
| OTHER DATA (period end) | |||||||||||||||||||||||||||||||||||||||||
| Full time equivalent employees | |||||||||||||||||||||||||||||||||||||||||
| Banking Division | 2,039 | 2,023 | 2,043 | 2,068 | 2,036 | 2,039 | 2,036 | ||||||||||||||||||||||||||||||||||
| Retail Mortgage Division | 516 | 528 | 538 | 546 | 550 | 516 | 550 | ||||||||||||||||||||||||||||||||||
| Warehouse Lending Division | 7 | 7 | 7 | 8 | 8 | 7 | 8 | ||||||||||||||||||||||||||||||||||
| Premium Finance Division | 88 | 84 | 85 | 78 | 78 | 88 | 78 | ||||||||||||||||||||||||||||||||||
| Total Ameris Bancorp FTE headcount | 2,650 | 2,642 | 2,673 | 2,700 | 2,672 | 2,650 | 2,672 | ||||||||||||||||||||||||||||||||||
| Branch locations | 163 | 163 | 163 | 164 | 164 | 163 | 164 | ||||||||||||||||||||||||||||||||||
| Deposits per branch location | $ | 138,574 | $ | 138,876 | $ | 137,276 | $ | 135,537 | $ | 133,736 | $ | 138,574 | $ | 133,736 | |||||||||||||||||||||||||||
(1)Considered non-GAAP financial measure - See reconciliation of GAAP to non-GAAP financial measures in tables 9A - 9D | |||||||||||||||||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Income Statement | Table 2 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||||||||
| Interest income | |||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 326,705 | $ | 317,883 | $ | 323,833 | $ | 321,457 | $ | 315,893 | $ | 644,588 | $ | 620,061 | |||||||||||||||||||||||||||
| Interest on taxable securities | 30,217 | 25,474 | 24,886 | 23,253 | 20,696 | 55,691 | 39,188 | ||||||||||||||||||||||||||||||||||
| Interest on nontaxable securities | 383 | 374 | 422 | 343 | 334 | 757 | 663 | ||||||||||||||||||||||||||||||||||
| Interest on deposits in other banks | 8,270 | 8,040 | 8,922 | 9,993 | 10,715 | 16,310 | 21,504 | ||||||||||||||||||||||||||||||||||
| Total interest income | 365,575 | 351,771 | 358,063 | 355,046 | 347,638 | 717,346 | 681,416 | ||||||||||||||||||||||||||||||||||
| Interest expense | |||||||||||||||||||||||||||||||||||||||||
| Interest on deposits | 98,995 | 96,227 | 105,314 | 106,851 | 106,796 | 195,222 | 212,011 | ||||||||||||||||||||||||||||||||||
| Interest on other borrowings | 14,096 | 11,108 | 7,442 | 10,231 | 9,029 | 25,204 | 15,753 | ||||||||||||||||||||||||||||||||||
| Total interest expense | 113,091 | 107,335 | 112,756 | 117,082 | 115,825 | 220,426 | 227,764 | ||||||||||||||||||||||||||||||||||
| Net interest income | 252,484 | 244,436 | 245,307 | 237,964 | 231,813 | 496,920 | 453,652 | ||||||||||||||||||||||||||||||||||
| Provision for loan losses | 15,894 | 17,895 | 16,601 | 11,176 | 3,110 | 33,789 | 19,629 | ||||||||||||||||||||||||||||||||||
| Provision for unfunded commitments | 1,360 | (1,338) | 6,348 | 11,446 | (335) | 22 | 5,038 | ||||||||||||||||||||||||||||||||||
| Provision for other credit losses | (1) | (6) | 1 | 8 | (3) | (7) | (3) | ||||||||||||||||||||||||||||||||||
| Provision for credit losses | 17,253 | 16,551 | 22,950 | 22,630 | 2,772 | 33,804 | 24,664 | ||||||||||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 235,231 | 227,885 | 222,357 | 215,334 | 229,041 | 463,116 | 428,988 | ||||||||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||
| Service charges on deposit accounts | 14,044 | 13,679 | 14,088 | 13,931 | 13,493 | 27,723 | 26,626 | ||||||||||||||||||||||||||||||||||
| Mortgage banking activity | 32,526 | 37,008 | 31,874 | 40,666 | 39,221 | 69,534 | 74,475 | ||||||||||||||||||||||||||||||||||
| Other service charges, commissions and fees | 1,065 | 1,027 | 1,102 | 1,124 | 1,158 | 2,092 | 2,267 | ||||||||||||||||||||||||||||||||||
| Gain on securities | 7,392 | — | 12 | 1,581 | — | 7,392 | 40 | ||||||||||||||||||||||||||||||||||
| Equipment finance activity | 8,948 | 9,086 | 8,434 | 8,858 | 6,572 | 18,034 | 13,270 | ||||||||||||||||||||||||||||||||||
| Other noninterest income | 9,557 | 9,120 | 6,317 | 10,114 | 8,467 | 18,677 | 16,256 | ||||||||||||||||||||||||||||||||||
| Total noninterest income | 73,532 | 69,920 | 61,827 | 76,274 | 68,911 | 143,452 | 132,934 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 91,494 | 91,366 | 81,997 | 90,948 | 89,308 | 182,860 | 175,923 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment | 12,555 | 11,625 | 11,321 | 11,524 | 11,401 | 24,180 | 22,078 | ||||||||||||||||||||||||||||||||||
| Data processing and communications expenses | 15,571 | 16,793 | 16,236 | 16,058 | 15,366 | 32,364 | 30,221 | ||||||||||||||||||||||||||||||||||
Credit resolution-related expenses(1) | 798 | 509 | 953 | 770 | 657 | 1,307 | 1,422 | ||||||||||||||||||||||||||||||||||
| Advertising and marketing | 3,452 | 3,296 | 1,984 | 3,377 | 3,745 | 6,748 | 6,628 | ||||||||||||||||||||||||||||||||||
| Amortization of intangible assets | 3,114 | 3,393 | 3,879 | 3,879 | 4,076 | 6,507 | 8,179 | ||||||||||||||||||||||||||||||||||
| Loan servicing expenses | 7,205 | 7,380 | 7,267 | 8,142 | 7,897 | 14,585 | 15,720 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 108,525 | 22,718 | 19,453 | 19,868 | 22,810 | 131,243 | 46,123 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 242,714 | 157,080 | 143,090 | 154,566 | 155,260 | 399,794 | 306,294 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 66,049 | 140,725 | 141,094 | 137,042 | 142,692 | 206,774 | 255,628 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 14,603 | 30,233 | 32,738 | 31,013 | 32,858 | 44,836 | 57,859 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 51,446 | $ | 110,492 | $ | 108,356 | $ | 106,029 | $ | 109,834 | $ | 161,938 | $ | 197,769 | |||||||||||||||||||||||||||
| Diluted earnings per common share | $ | 0.77 | $ | 1.63 | $ | 1.59 | $ | 1.54 | $ | 1.60 | $ | 2.40 | $ | 2.87 | |||||||||||||||||||||||||||
| (1) Includes expenses associated with problem loans and OREO, as well as OREO losses and writedowns. | |||||||||||||||||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||
| Period End Balance Sheet | Table 3 | ||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | |||||||||||||||||||||||||
| (dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Cash and due from banks | $ | 237,431 | $ | 235,114 | $ | 253,807 | $ | 216,927 | $ | 249,676 | |||||||||||||||||||
| Interest-bearing deposits in banks | 959,682 | 1,094,185 | 835,113 | 826,237 | 920,594 | ||||||||||||||||||||||||
| Debt securities available-for-sale, at fair value | 2,460,623 | 2,353,396 | 2,207,173 | 2,131,671 | 1,871,298 | ||||||||||||||||||||||||
| Debt securities held-to-maturity, at amortized cost | 208,155 | 202,550 | 203,242 | 202,581 | 176,487 | ||||||||||||||||||||||||
| Other investments | 123,871 | 100,718 | 85,443 | 70,644 | 69,910 | ||||||||||||||||||||||||
| Loans held for sale | 482,220 | 496,629 | 623,152 | 604,136 | 544,091 | ||||||||||||||||||||||||
| Loans, net of unearned income | 22,177,865 | 21,827,980 | 21,513,522 | 21,258,374 | 21,041,497 | ||||||||||||||||||||||||
| Allowance for credit losses | (359,513) | (354,682) | (348,141) | (345,294) | (341,567) | ||||||||||||||||||||||||
| Loans, net | 21,818,352 | 21,473,298 | 21,165,381 | 20,913,080 | 20,699,930 | ||||||||||||||||||||||||
| Other real estate owned | 4,043 | 3,091 | 2,918 | 3,137 | 1,825 | ||||||||||||||||||||||||
| Premises and equipment, net | 220,500 | 216,397 | 213,097 | 211,567 | 211,434 | ||||||||||||||||||||||||
| Goodwill | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | ||||||||||||||||||||||||
| Other intangible assets, net | 48,317 | 51,430 | 54,824 | 58,703 | 62,582 | ||||||||||||||||||||||||
| Cash value of bank owned life insurance | 427,789 | 424,164 | 420,583 | 417,096 | 414,381 | ||||||||||||||||||||||||
| Deferred income taxes, net | — | ||||||||||||||||||||||||||||
| Other assets | 482,214 | 443,317 | 435,500 | 428,404 | 442,299 | ||||||||||||||||||||||||
| Total assets | $ | 28,488,843 | $ | 28,109,935 | $ | 27,515,879 | $ | 27,099,829 | $ | 26,680,153 | |||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||
| Noninterest-bearing | $ | 6,782,882 | $ | 6,748,976 | $ | 6,426,145 | $ | 6,757,233 | $ | 6,800,519 | |||||||||||||||||||
| Interest-bearing | 15,804,691 | 15,887,764 | 15,949,850 | 15,470,845 | 15,132,156 | ||||||||||||||||||||||||
| Total deposits | 22,587,573 | 22,636,740 | 22,375,995 | 22,228,078 | 21,932,675 | ||||||||||||||||||||||||
| Other borrowings | 1,250,049 | 887,974 | 558,039 | 337,094 | 376,700 | ||||||||||||||||||||||||
| Subordinated deferrable interest debentures | 135,299 | 134,801 | 134,302 | 133,804 | 133,306 | ||||||||||||||||||||||||
| Other liabilities | 425,345 | 368,293 | 371,515 | 384,152 | 319,794 | ||||||||||||||||||||||||
| Total liabilities | 24,398,266 | 24,027,808 | 23,439,851 | 23,083,128 | 22,762,475 | ||||||||||||||||||||||||
| Shareholders' Equity | |||||||||||||||||||||||||||||
| Preferred stock | — | — | — | — | — | ||||||||||||||||||||||||
| Common stock | 73,265 | 73,252 | 72,898 | 72,900 | 72,897 | ||||||||||||||||||||||||
| Capital stock | 1,978,573 | 1,973,881 | 1,971,131 | 1,968,124 | 1,964,896 | ||||||||||||||||||||||||
| Retained earnings | 2,345,292 | 2,307,358 | 2,210,385 | 2,115,712 | 2,023,493 | ||||||||||||||||||||||||
| Accumulated other comprehensive income (loss), net of tax | (16,508) | (1,476) | 8,312 | 5,171 | (6,886) | ||||||||||||||||||||||||
| Treasury stock | (290,045) | (270,888) | (186,698) | (145,206) | (136,722) | ||||||||||||||||||||||||
| Total shareholders' equity | 4,090,577 | 4,082,127 | 4,076,028 | 4,016,701 | 3,917,678 | ||||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 28,488,843 | $ | 28,109,935 | $ | 27,515,879 | $ | 27,099,829 | $ | 26,680,153 | |||||||||||||||||||
| Other Data | |||||||||||||||||||||||||||||
| Earning assets | $ | 26,412,416 | $ | 26,075,458 | $ | 25,467,645 | $ | 25,093,643 | $ | 24,623,877 | |||||||||||||||||||
| Intangible assets | 1,063,963 | 1,067,076 | 1,070,470 | 1,074,349 | 1,078,228 | ||||||||||||||||||||||||
| Interest-bearing liabilities | 17,190,039 | 16,910,539 | 16,642,191 | 15,941,743 | 15,642,162 | ||||||||||||||||||||||||
| Average assets | 28,210,184 | 27,672,313 | 27,394,953 | 26,972,134 | 26,757,322 | ||||||||||||||||||||||||
| Average common shareholders' equity | 4,122,923 | 4,107,670 | 4,044,338 | 3,964,207 | 3,865,031 | ||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Asset Quality Information | Table 4 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||||||||
| Allowance for Credit Losses | |||||||||||||||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 406,755 | $ | 401,558 | $ | 392,362 | $ | 377,181 | $ | 381,507 | $ | 401,558 | $ | 368,663 | |||||||||||||||||||||||||||
| Provision for loan losses | 15,894 | 17,895 | 16,601 | 11,176 | 3,110 | 33,789 | 19,629 | ||||||||||||||||||||||||||||||||||
| Provision for unfunded commitments | 1,360 | (1,338) | 6,348 | 11,446 | (335) | 22 | 5,038 | ||||||||||||||||||||||||||||||||||
| Provision for other credit losses | (1) | (6) | 1 | 8 | (3) | (7) | (3) | ||||||||||||||||||||||||||||||||||
| Provision for credit losses | 17,253 | 16,551 | 22,950 | 22,630 | 2,772 | 33,804 | 24,664 | ||||||||||||||||||||||||||||||||||
| Charge-offs | 16,616 | 17,527 | 19,575 | 13,631 | 14,227 | 34,143 | 29,610 | ||||||||||||||||||||||||||||||||||
| Recoveries | 5,553 | 6,173 | 5,821 | 6,182 | 7,129 | 11,726 | 13,464 | ||||||||||||||||||||||||||||||||||
| Net charge-offs (recoveries) | 11,063 | 11,354 | 13,754 | 7,449 | 7,098 | 22,417 | 16,146 | ||||||||||||||||||||||||||||||||||
| Ending balance | $ | 412,945 | $ | 406,755 | $ | 401,558 | $ | 392,362 | $ | 377,181 | $ | 412,945 | $ | 377,181 | |||||||||||||||||||||||||||
| Allowance for loan losses | $ | 359,513 | $ | 354,682 | $ | 348,141 | $ | 345,294 | $ | 341,567 | $ | 359,513 | $ | 341,567 | |||||||||||||||||||||||||||
| Allowance for unfunded commitments | 53,364 | 52,004 | 53,342 | 46,994 | 35,548 | 53,364 | 35,548 | ||||||||||||||||||||||||||||||||||
| Allowance for other credit losses | 68 | 69 | 75 | 74 | 66 | 68 | 66 | ||||||||||||||||||||||||||||||||||
| Total allowance for credit losses | $ | 412,945 | $ | 406,755 | $ | 401,558 | $ | 392,362 | $ | 377,181 | $ | 412,945 | $ | 377,181 | |||||||||||||||||||||||||||
| Non-Performing Assets | |||||||||||||||||||||||||||||||||||||||||
| Nonaccrual portfolio loans | $ | 86,819 | $ | 81,969 | $ | 84,711 | $ | 77,257 | $ | 75,286 | $ | 86,819 | $ | 75,286 | |||||||||||||||||||||||||||
| Other real estate owned | 4,043 | 3,091 | 2,918 | 3,137 | 1,825 | 4,043 | 1,825 | ||||||||||||||||||||||||||||||||||
| Repossessed assets | — | 4 | 4 | 3 | 2 | — | 2 | ||||||||||||||||||||||||||||||||||
| Accruing loans delinquent 90 days or more | 8,364 | 8,230 | 8,492 | 9,325 | 8,415 | 8,364 | 8,415 | ||||||||||||||||||||||||||||||||||
| Non-performing portfolio assets | $ | 99,226 | $ | 93,294 | $ | 96,125 | $ | 89,722 | $ | 85,528 | $ | 99,226 | $ | 85,528 | |||||||||||||||||||||||||||
| Serviced GNMA-guaranteed mortgage nonaccrual loans | 33,707 | 34,489 | 24,347 | 19,706 | 11,733 | 33,707 | 11,733 | ||||||||||||||||||||||||||||||||||
| Total non-performing assets | $ | 132,933 | $ | 127,783 | $ | 120,472 | $ | 109,428 | $ | 97,261 | $ | 132,933 | $ | 97,261 | |||||||||||||||||||||||||||
| Asset Quality Ratios | |||||||||||||||||||||||||||||||||||||||||
| Non-performing portfolio assets as a percent of total assets | 0.35 | % | 0.33 | % | 0.35 | % | 0.33 | % | 0.32 | % | 0.35 | % | 0.32 | % | |||||||||||||||||||||||||||
| Total non-performing assets as a percent of total assets | 0.47 | % | 0.45 | % | 0.44 | % | 0.40 | % | 0.36 | % | 0.47 | % | 0.36 | % | |||||||||||||||||||||||||||
| Net charge-offs as a percent of average loans (annualized) | 0.20 | % | 0.21 | % | 0.26 | % | 0.14 | % | 0.14 | % | 0.21 | % | 0.16 | % | |||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||
| Loan Information | Table 5 | ||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | |||||||||||||||||||||||||
| (dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||
| Loans by Type | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 3,453,501 | $ | 3,400,837 | $ | 3,288,505 | $ | 3,299,269 | $ | 3,184,211 | |||||||||||||||||||
| Consumer | 157,252 | 166,652 | 180,010 | 202,688 | 209,990 | ||||||||||||||||||||||||
| Mortgage warehouse | 1,345,808 | 1,232,103 | 1,150,782 | 1,083,941 | 1,092,475 | ||||||||||||||||||||||||
| Municipal | 415,396 | 420,775 | 434,234 | 437,823 | 436,759 | ||||||||||||||||||||||||
| Premium Finance | 1,534,445 | 1,365,018 | 1,306,267 | 1,358,259 | 1,294,293 | ||||||||||||||||||||||||
| Real estate - construction and development | 1,702,983 | 1,564,242 | 1,469,250 | 1,411,178 | 1,485,842 | ||||||||||||||||||||||||
| Real estate - commercial and farmland | 9,243,359 | 9,364,885 | 9,311,405 | 9,054,927 | 8,877,750 | ||||||||||||||||||||||||
| Real estate - residential | 4,325,121 | 4,313,468 | 4,373,069 | 4,410,289 | 4,460,177 | ||||||||||||||||||||||||
| Total loans | $ | 22,177,865 | $ | 21,827,980 | $ | 21,513,522 | $ | 21,258,374 | $ | 21,041,497 | |||||||||||||||||||
| Loans by Risk Grade | |||||||||||||||||||||||||||||
| Pass | $ | 21,942,518 | $ | 21,598,675 | $ | 21,305,745 | $ | 21,058,458 | $ | 20,820,888 | |||||||||||||||||||
| Other assets especially mentioned | 61,021 | 49,359 | 39,709 | 37,236 | 66,677 | ||||||||||||||||||||||||
| Substandard | 174,326 | 179,946 | 168,068 | 162,680 | 153,932 | ||||||||||||||||||||||||
| Total loans | $ | 22,177,865 | $ | 21,827,980 | $ | 21,513,522 | $ | 21,258,374 | $ | 21,041,497 | |||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Average Balances | Table 6 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||||||||
| Earning Assets | |||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in banks | $ | 883,521 | $ | 879,724 | $ | 884,149 | $ | 883,976 | $ | 951,851 | $ | 881,633 | $ | 965,930 | |||||||||||||||||||||||||||
| Debt securities - taxable | 2,703,887 | 2,532,669 | 2,432,934 | 2,282,470 | 2,117,596 | 2,618,751 | 2,058,241 | ||||||||||||||||||||||||||||||||||
| Debt securities - nontaxable | 44,914 | 45,241 | 45,237 | 44,823 | 41,299 | 45,077 | 41,344 | ||||||||||||||||||||||||||||||||||
| Loans held for sale | 629,469 | 616,530 | 758,588 | 706,679 | 730,770 | 623,035 | 648,607 | ||||||||||||||||||||||||||||||||||
| Loans | 21,947,729 | 21,590,793 | 21,278,859 | 21,038,350 | 20,928,825 | 21,770,247 | 20,775,652 | ||||||||||||||||||||||||||||||||||
| Total Earning Assets | $ | 26,209,520 | $ | 25,664,957 | $ | 25,399,767 | $ | 24,956,298 | $ | 24,770,341 | $ | 25,938,743 | $ | 24,489,774 | |||||||||||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | $ | 6,695,490 | $ | 6,547,843 | $ | 6,668,120 | $ | 6,849,129 | $ | 6,766,557 | $ | 6,622,075 | $ | 6,645,340 | |||||||||||||||||||||||||||
| NOW accounts | 4,212,047 | 4,195,369 | 4,052,397 | 3,900,999 | 3,939,802 | 4,203,754 | 3,963,995 | ||||||||||||||||||||||||||||||||||
| MMDA | 7,072,892 | 7,189,981 | 7,347,897 | 6,977,134 | 6,918,382 | 7,131,112 | 6,914,988 | ||||||||||||||||||||||||||||||||||
| Savings accounts | 774,903 | 760,258 | 754,439 | 756,383 | 766,331 | 767,621 | 766,738 | ||||||||||||||||||||||||||||||||||
| Retail CDs | 2,250,844 | 2,268,935 | 2,325,456 | 2,344,084 | 2,393,402 | 2,259,840 | 2,415,067 | ||||||||||||||||||||||||||||||||||
| Brokered CDs | 1,420,811 | 1,221,181 | 1,249,020 | 1,070,735 | 1,145,043 | 1,321,548 | 1,054,409 | ||||||||||||||||||||||||||||||||||
| Total Deposits | 22,426,987 | 22,183,567 | 22,397,329 | 21,898,464 | 21,929,517 | 22,305,950 | 21,760,537 | ||||||||||||||||||||||||||||||||||
| Non-Deposit Funding | |||||||||||||||||||||||||||||||||||||||||
| Federal funds purchased and securities sold under agreements to repurchase | — | 1 | — | 1 | — | 1 | — | ||||||||||||||||||||||||||||||||||
| FHLB advances | 1,171,702 | 871,128 | 423,669 | 443,243 | 326,054 | 1,022,245 | 238,283 | ||||||||||||||||||||||||||||||||||
| Other borrowings | 9,768 | 9,899 | 9,920 | 169,994 | 193,492 | 9,833 | 193,493 | ||||||||||||||||||||||||||||||||||
| Subordinated deferrable interest debentures | 135,037 | 134,537 | 134,041 | 133,541 | 133,043 | 134,789 | 132,795 | ||||||||||||||||||||||||||||||||||
| Total Non-Deposit Funding | 1,316,507 | 1,015,565 | 567,630 | 746,779 | 652,589 | 1,166,868 | 564,571 | ||||||||||||||||||||||||||||||||||
| Total Funding | $ | 23,743,494 | $ | 23,199,132 | $ | 22,964,959 | $ | 22,645,243 | $ | 22,582,106 | $ | 23,472,818 | $ | 22,325,108 | |||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Interest Income and Interest Expense (TE) | Table 7 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||||||||
| Interest Income | |||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in banks | $ | 8,270 | $ | 8,040 | $ | 8,922 | $ | 9,993 | $ | 10,715 | $ | 16,310 | $ | 21,504 | |||||||||||||||||||||||||||
| Debt securities - taxable | 30,217 | 25,474 | 24,886 | 23,253 | 20,696 | 55,691 | 39,188 | ||||||||||||||||||||||||||||||||||
| Debt securities - nontaxable (TE) | 485 | 473 | 535 | 434 | 423 | 958 | 839 | ||||||||||||||||||||||||||||||||||
| Loans held for sale | 9,478 | 9,000 | 11,233 | 11,237 | 11,578 | 18,478 | 20,623 | ||||||||||||||||||||||||||||||||||
| Loans (TE) | 318,079 | 309,732 | 313,467 | 311,082 | 305,154 | 627,811 | 601,118 | ||||||||||||||||||||||||||||||||||
| Total Earning Assets | $ | 366,529 | $ | 352,719 | $ | 359,043 | $ | 355,999 | $ | 348,566 | $ | 719,248 | $ | 683,272 | |||||||||||||||||||||||||||
| Interest Expense | |||||||||||||||||||||||||||||||||||||||||
| Interest-Bearing Deposits | |||||||||||||||||||||||||||||||||||||||||
| NOW accounts | $ | 18,925 | $ | 18,106 | $ | 18,508 | $ | 18,230 | $ | 18,144 | $ | 37,031 | $ | 36,450 | |||||||||||||||||||||||||||
| MMDA | 47,070 | 46,737 | 52,455 | 54,657 | 53,469 | 93,807 | 105,730 | ||||||||||||||||||||||||||||||||||
| Savings accounts | 688 | 679 | 734 | 813 | 826 | 1,367 | 1,656 | ||||||||||||||||||||||||||||||||||
| Retail CDs | 18,531 | 18,958 | 20,567 | 21,253 | 21,852 | 37,489 | 45,097 | ||||||||||||||||||||||||||||||||||
| Brokered CDs | 13,781 | 11,747 | 13,050 | 11,898 | 12,505 | 25,528 | 23,078 | ||||||||||||||||||||||||||||||||||
| Total Interest-Bearing Deposits | 98,995 | 96,227 | 105,314 | 106,851 | 106,796 | 195,222 | 212,011 | ||||||||||||||||||||||||||||||||||
| Non-Deposit Funding | |||||||||||||||||||||||||||||||||||||||||
| FHLB advances | 11,182 | 8,179 | 4,347 | 4,863 | 3,508 | 19,361 | 4,870 | ||||||||||||||||||||||||||||||||||
| Other borrowings | 129 | 159 | 169 | 2,328 | 2,499 | 288 | 4,849 | ||||||||||||||||||||||||||||||||||
| Subordinated deferrable interest debentures | 2,785 | 2,770 | 2,926 | 3,040 | 3,022 | 5,555 | 6,034 | ||||||||||||||||||||||||||||||||||
| Total Non-Deposit Funding | 14,096 | 11,108 | 7,442 | 10,231 | 9,029 | 25,204 | 15,753 | ||||||||||||||||||||||||||||||||||
| Total Interest-Bearing Funding | $ | 113,091 | $ | 107,335 | $ | 112,756 | $ | 117,082 | $ | 115,825 | $ | 220,426 | $ | 227,764 | |||||||||||||||||||||||||||
| Net Interest Income (TE) | $ | 253,438 | $ | 245,384 | $ | 246,287 | $ | 238,917 | $ | 232,741 | $ | 498,822 | $ | 455,508 | |||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
Yields(1) | Table 8 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | |||||||||||||||||||||||||||||||||||
| Earning Assets | |||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in banks | 3.75 | % | 3.71 | % | 4.00 | % | 4.48 | % | 4.52 | % | 3.73 | % | 4.49 | % | |||||||||||||||||||||||||||
| Debt securities - taxable | 4.48 | % | 4.08 | % | 4.06 | % | 4.04 | % | 3.92 | % | 4.29 | % | 3.84 | % | |||||||||||||||||||||||||||
| Debt securities - nontaxable (TE) | 4.33 | % | 4.24 | % | 4.69 | % | 3.84 | % | 4.11 | % | 4.29 | % | 4.09 | % | |||||||||||||||||||||||||||
| Loans held for sale | 6.04 | % | 5.92 | % | 5.87 | % | 6.31 | % | 6.35 | % | 5.98 | % | 6.41 | % | |||||||||||||||||||||||||||
| Loans (TE) | 5.81 | % | 5.82 | % | 5.84 | % | 5.87 | % | 5.85 | % | 5.82 | % | 5.83 | % | |||||||||||||||||||||||||||
| Total Earning Assets | 5.61 | % | 5.57 | % | 5.61 | % | 5.66 | % | 5.64 | % | 5.59 | % | 5.63 | % | |||||||||||||||||||||||||||
| Interest-Bearing Deposits | |||||||||||||||||||||||||||||||||||||||||
| NOW accounts | 1.80 | % | 1.75 | % | 1.81 | % | 1.85 | % | 1.85 | % | 1.78 | % | 1.85 | % | |||||||||||||||||||||||||||
| MMDA | 2.67 | % | 2.64 | % | 2.83 | % | 3.11 | % | 3.10 | % | 2.65 | % | 3.08 | % | |||||||||||||||||||||||||||
| Savings accounts | 0.36 | % | 0.36 | % | 0.39 | % | 0.43 | % | 0.43 | % | 0.36 | % | 0.44 | % | |||||||||||||||||||||||||||
| Retail CDs | 3.30 | % | 3.39 | % | 3.51 | % | 3.60 | % | 3.66 | % | 3.35 | % | 3.77 | % | |||||||||||||||||||||||||||
| Brokered CDs | 3.89 | % | 3.90 | % | 4.15 | % | 4.41 | % | 4.38 | % | 3.90 | % | 4.41 | % | |||||||||||||||||||||||||||
| Total Interest-Bearing Deposits | 2.52 | % | 2.50 | % | 2.66 | % | 2.82 | % | 2.83 | % | 2.51 | % | 2.83 | % | |||||||||||||||||||||||||||
| Non-Deposit Funding | |||||||||||||||||||||||||||||||||||||||||
| Federal funds purchased and securities sold under agreements to repurchase | — | % | — | % | — | % | — | % | — | % | — | % | — | % | |||||||||||||||||||||||||||
| FHLB advances | 3.83 | % | 3.81 | % | 4.07 | % | 4.35 | % | 4.32 | % | 3.82 | % | 4.12 | % | |||||||||||||||||||||||||||
| Other borrowings | 5.30 | % | 6.51 | % | 6.76 | % | 5.43 | % | 5.18 | % | 5.91 | % | 5.05 | % | |||||||||||||||||||||||||||
| Subordinated deferrable interest debentures | 8.27 | % | 8.35 | % | 8.66 | % | 9.03 | % | 9.11 | % | 8.31 | % | 9.16 | % | |||||||||||||||||||||||||||
| Total Non-Deposit Funding | 4.29 | % | 4.44 | % | 5.20 | % | 5.44 | % | 5.55 | % | 4.36 | % | 5.63 | % | |||||||||||||||||||||||||||
Total Interest-Bearing Liabilities | 2.66 | % | 2.61 | % | 2.74 | % | 2.94 | % | 2.94 | % | 2.64 | % | 2.93 | % | |||||||||||||||||||||||||||
| Net Interest Spread | 2.95 | % | 2.96 | % | 2.87 | % | 2.72 | % | 2.70 | % | 2.95 | % | 2.70 | % | |||||||||||||||||||||||||||
Net Interest Margin(2) | 3.88 | % | 3.88 | % | 3.85 | % | 3.80 | % | 3.77 | % | 3.88 | % | 3.75 | % | |||||||||||||||||||||||||||
Total Cost of Funds(3) | 1.91 | % | 1.88 | % | 1.95 | % | 2.05 | % | 2.06 | % | 1.89 | % | 2.06 | % | |||||||||||||||||||||||||||
| (1) Interest and average rates are calculated on a tax-equivalent basis using an effective tax rate of 21%. | |||||||||||||||||||||||||||||||||||||||||
| (2) Rate calculated based on average earning assets. | |||||||||||||||||||||||||||||||||||||||||
| (3) Rate calculated based on total average funding including noninterest-bearing deposits. | |||||||||||||||||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Non-GAAP Reconciliations | |||||||||||||||||||||||||||||||||||||||||
| Adjusted Net Income | Table 9A | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $ | 51,446 | $ | 110,492 | $ | 108,356 | $ | 106,029 | $ | 109,834 | $ | 161,938 | $ | 197,769 | |||||||||||||||||||||||||||
| Adjustment items: | |||||||||||||||||||||||||||||||||||||||||
| Litigation accrual | 82,503 | — | — | — | — | 82,503 | — | ||||||||||||||||||||||||||||||||||
| Loss (gain) on sale of MSR | — | — | 1,127 | (125) | (356) | — | (342) | ||||||||||||||||||||||||||||||||||
| Gain on securities | (7,392) | — | (12) | (1,581) | — | (7,392) | (40) | ||||||||||||||||||||||||||||||||||
| Servicing right impairment (recovery) | — | — | 910 | — | — | — | — | ||||||||||||||||||||||||||||||||||
| Gain on BOLI proceeds | (846) | — | (220) | (390) | — | (846) | (11) | ||||||||||||||||||||||||||||||||||
| FDIC special assessment | — | — | (1,136) | (318) | (138) | — | — | ||||||||||||||||||||||||||||||||||
Tax effect of adjustment items (Note 1) | (18,402) | — | (217) | 495 | 121 | (18,402) | 94 | ||||||||||||||||||||||||||||||||||
| After tax adjustment items | 55,863 | — | 452 | (1,919) | (373) | 55,863 | (299) | ||||||||||||||||||||||||||||||||||
| Adjusted net income | $ | 107,309 | $ | 110,492 | $ | 108,808 | $ | 104,110 | $ | 109,461 | $ | 217,801 | $ | 197,470 | |||||||||||||||||||||||||||
| Weighted average number of shares - diluted | 67,099,941 | 67,766,997 | 68,328,365 | 68,665,669 | 68,796,577 | 67,430,193 | 68,912,750 | ||||||||||||||||||||||||||||||||||
| Net income per diluted share | $ | 0.77 | $ | 1.63 | $ | 1.59 | $ | 1.54 | $ | 1.60 | $ | 2.40 | $ | 2.87 | |||||||||||||||||||||||||||
| Adjusted net income per diluted share | $ | 1.60 | $ | 1.63 | $ | 1.59 | $ | 1.52 | $ | 1.59 | $ | 3.23 | $ | 2.87 | |||||||||||||||||||||||||||
| Average assets | $ | 28,210,184 | $ | 27,672,313 | $ | 27,394,953 | $ | 26,972,134 | $ | 26,757,322 | $ | 27,946,326 | $ | 26,494,831 | |||||||||||||||||||||||||||
| Return on average assets | 0.73 | % | 1.62 | % | 1.57 | % | 1.56 | % | 1.65 | % | 1.17 | % | 1.51 | % | |||||||||||||||||||||||||||
| Adjusted return on average assets | 1.53 | % | 1.62 | % | 1.58 | % | 1.53 | % | 1.64 | % | 1.57 | % | 1.50 | % | |||||||||||||||||||||||||||
| Average common equity | $ | 4,122,923 | $ | 4,107,670 | $ | 4,044,338 | $ | 3,964,207 | $ | 3,865,031 | $ | 4,115,344 | $ | 3,831,775 | |||||||||||||||||||||||||||
| Average tangible common equity | $ | 3,057,445 | $ | 3,039,019 | $ | 2,971,985 | $ | 2,887,961 | $ | 2,784,819 | $ | 3,048,288 | $ | 2,749,529 | |||||||||||||||||||||||||||
| Return on average common equity | 5.00 | % | 10.91 | % | 10.63 | % | 10.61 | % | 11.40 | % | 7.94 | % | 10.41 | % | |||||||||||||||||||||||||||
| Return on average tangible common equity | 6.75 | % | 14.75 | % | 14.46 | % | 14.57 | % | 15.82 | % | 10.71 | % | 14.50 | % | |||||||||||||||||||||||||||
| Adjusted return on average tangible common equity | 14.08 | % | 14.75 | % | 14.53 | % | 14.29 | % | 15.76 | % | 14.41 | % | 14.48 | % | |||||||||||||||||||||||||||
| Note 1: Tax effect is calculated utilizing a 24.5% rate for taxable adjustments. Gain on BOLI proceeds is non-taxable and no tax effect is included. | |||||||||||||||||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Non-GAAP Reconciliations (continued) | |||||||||||||||||||||||||||||||||||||||||
| Adjusted Efficiency Ratio | Table 9B | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||||||||
| Adjusted Noninterest Expense | |||||||||||||||||||||||||||||||||||||||||
| Total noninterest expense | $ | 242,714 | $ | 157,080 | $ | 143,090 | $ | 154,566 | $ | 155,260 | $ | 399,794 | $ | 306,294 | |||||||||||||||||||||||||||
| Adjustment items: | |||||||||||||||||||||||||||||||||||||||||
| Litigation accrual | (82,503) | — | — | — | — | (82,503) | — | ||||||||||||||||||||||||||||||||||
| FDIC special assessment | — | — | 1,136 | 318 | 138 | — | — | ||||||||||||||||||||||||||||||||||
| Adjusted noninterest expense | $ | 160,211 | $ | 157,080 | $ | 144,226 | $ | 154,884 | $ | 155,398 | $ | 317,291 | $ | 306,294 | |||||||||||||||||||||||||||
| Adjusted Total Revenue | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 252,484 | $ | 244,436 | $ | 245,307 | $ | 237,964 | $ | 231,813 | $ | 496,920 | $ | 453,652 | |||||||||||||||||||||||||||
| Noninterest income | 73,532 | 69,920 | 61,827 | 76,274 | 68,911 | 143,452 | 132,934 | ||||||||||||||||||||||||||||||||||
| Total revenue | 326,016 | 314,356 | 307,134 | 314,238 | 300,724 | $ | 640,372 | $ | 586,586 | ||||||||||||||||||||||||||||||||
| Adjustment items: | |||||||||||||||||||||||||||||||||||||||||
| Gain on securities | (7,392) | — | (12) | (1,581) | — | (7,392) | (40) | ||||||||||||||||||||||||||||||||||
| (Gain)/loss on sale of MSR | — | — | 1,127 | (125) | (356) | — | (342) | ||||||||||||||||||||||||||||||||||
| Gain on BOLI proceeds | (846) | — | (220) | (390) | — | (846) | (11) | ||||||||||||||||||||||||||||||||||
| Servicing right impairment (recovery) | — | — | 910 | — | — | — | — | ||||||||||||||||||||||||||||||||||
| Adjusted total revenue | $ | 317,778 | $ | 314,356 | $ | 308,939 | $ | 312,142 | $ | 300,368 | $ | 632,134 | $ | 586,193 | |||||||||||||||||||||||||||
| Efficiency ratio | 74.45 | % | 49.97 | % | 46.59 | % | 49.19 | % | 51.63 | % | 62.43 | % | 52.22 | % | |||||||||||||||||||||||||||
| Adjusted efficiency ratio | 50.42 | % | 49.97 | % | 46.68 | % | 49.62 | % | 51.74 | % | 50.19 | % | 52.25 | % | |||||||||||||||||||||||||||
| Tangible Book Value Per Share | Table 9C | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands except per share data) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||||||||
| Total shareholders' equity | $ | 4,090,577 | $ | 4,082,127 | $ | 4,076,028 | $ | 4,016,701 | $ | 3,917,678 | $ | 4,090,577 | $ | 3,917,678 | |||||||||||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||||||||||||||
| Goodwill | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | ||||||||||||||||||||||||||||||||||
| Other intangibles, net | 48,317 | 51,430 | 54,824 | 58,703 | 62,582 | 48,317 | 62,582 | ||||||||||||||||||||||||||||||||||
| Total tangible shareholders' equity | $ | 3,026,614 | $ | 3,015,051 | $ | 3,005,558 | $ | 2,942,352 | $ | 2,839,450 | $ | 3,026,614 | $ | 2,839,450 | |||||||||||||||||||||||||||
| Period end number of shares | 67,106,587 | 67,320,298 | 68,022,316 | 68,587,742 | 68,711,043 | 67,106,587 | 68,711,043 | ||||||||||||||||||||||||||||||||||
| Book value per share (period end) | $ | 60.96 | $ | 60.64 | $ | 59.92 | $ | 58.56 | $ | 57.02 | $ | 60.96 | $ | 57.02 | |||||||||||||||||||||||||||
| Tangible book value per share (period end) | $ | 45.10 | $ | 44.79 | $ | 44.18 | $ | 42.90 | $ | 41.32 | $ | 45.10 | $ | 41.32 | |||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||
| Non-GAAP Reconciliations (continued) | |||||||||||||||||||||||||||||
| Tangible Common Equity to Tangible Assets ("TCE Ratio") | Table 9D | ||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | |||||||||||||||||||||||||
| (dollars in thousands except per share data) | 2026 | 2026 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||
| Total shareholders' equity | $ | 4,090,577 | $ | 4,082,127 | $ | 4,076,028 | $ | 4,016,701 | $ | 3,917,678 | |||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||
| Goodwill | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | ||||||||||||||||||||||||
| Other intangibles, net | 48,317 | 51,430 | 54,824 | 58,703 | 62,582 | ||||||||||||||||||||||||
| Total tangible shareholders' equity | $ | 3,026,614 | $ | 3,015,051 | $ | 3,005,558 | $ | 2,942,352 | $ | 2,839,450 | |||||||||||||||||||
| Total assets | $ | 28,488,843 | $ | 28,109,935 | $ | 27,515,879 | $ | 27,099,829 | $ | 26,680,153 | |||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||
| Goodwill | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | 1,015,646 | ||||||||||||||||||||||||
| Other intangibles, net | 48,317 | 51,430 | 54,824 | 58,703 | 62,582 | ||||||||||||||||||||||||
| Total tangible assets | $ | 27,424,880 | $ | 27,042,859 | $ | 26,445,409 | $ | 26,025,480 | $ | 25,601,925 | |||||||||||||||||||
| Equity to Assets | 14.36 | % | 14.52 | % | 14.81 | % | 14.82 | % | 14.68 | % | |||||||||||||||||||
| Tangible Common Equity to Tangible Assets | 11.04 | % | 11.15 | % | 11.37 | % | 11.31 | % | 11.09 | % | |||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Segment Reporting | Table 10 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||||||||
| Retail Mortgage Division | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 15,844 | $ | 16,828 | $ | 19,312 | $ | 20,179 | $ | 22,031 | $ | 32,672 | $ | 43,875 | |||||||||||||||||||||||||||
| Provision for credit losses | (3,346) | 3,074 | (3,142) | 529 | 1,010 | (272) | 6,201 | ||||||||||||||||||||||||||||||||||
| Noninterest income | 32,151 | 36,316 | 30,056 | 40,081 | 37,726 | 68,467 | 72,455 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 21,493 | 21,912 | 21,413 | 21,589 | 24,358 | 43,405 | 45,353 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment expenses | 685 | 649 | 754 | 760 | 811 | 1,334 | 1,640 | ||||||||||||||||||||||||||||||||||
| Data processing and telecommunications expenses | 1,302 | 1,224 | 1,315 | 1,232 | 1,391 | 2,526 | 2,688 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 11,587 | 12,532 | 11,547 | 12,480 | 12,496 | 24,119 | 24,459 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 35,067 | 36,317 | 35,029 | 36,061 | 39,056 | 71,384 | 74,140 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 16,274 | 13,753 | 17,481 | 23,670 | 19,691 | 30,027 | 35,989 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 3,417 | 2,888 | 3,671 | 4,970 | 4,135 | 6,305 | 7,558 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 12,857 | $ | 10,865 | $ | 13,810 | $ | 18,700 | $ | 15,556 | $ | 23,722 | $ | 28,431 | |||||||||||||||||||||||||||
| Warehouse Lending Division | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 8,825 | $ | 7,594 | $ | 7,430 | $ | 7,474 | $ | 7,091 | $ | 16,419 | $ | 12,993 | |||||||||||||||||||||||||||
| Provision for credit losses | 184 | 177 | 129 | 23 | 369 | 361 | 194 | ||||||||||||||||||||||||||||||||||
| Noninterest income | 794 | 796 | 736 | 756 | 1,893 | 1,590 | 2,447 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 468 | 544 | 556 | 566 | 618 | 1,012 | 1,170 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment expenses | 7 | 8 | 7 | 7 | 7 | 15 | 14 | ||||||||||||||||||||||||||||||||||
| Data processing and telecommunications expenses | 59 | 35 | 54 | 57 | 59 | 94 | 97 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 184 | 179 | 195 | 195 | 96 | 363 | 366 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 718 | 766 | 812 | 825 | 780 | 1,484 | 1,647 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 8,717 | 7,447 | 7,225 | 7,382 | 7,835 | 16,164 | 13,599 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 1,831 | 1,564 | 1,517 | 1,550 | 1,646 | 3,395 | 2,856 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 6,886 | $ | 5,883 | $ | 5,708 | $ | 5,832 | $ | 6,189 | $ | 12,769 | $ | 10,743 | |||||||||||||||||||||||||||
| Premium Finance Division | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 12,515 | $ | 11,647 | $ | 11,802 | $ | 12,251 | $ | 11,190 | $ | 24,162 | $ | 21,070 | |||||||||||||||||||||||||||
| Provision for credit losses | 417 | 1,447 | 926 | 461 | 716 | 1,864 | 1,172 | ||||||||||||||||||||||||||||||||||
| Noninterest income | 18 | 17 | 17 | 18 | 17 | 35 | 33 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 2,865 | 2,664 | 2,446 | 2,492 | 2,331 | 5,529 | 4,683 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment expenses | 40 | 38 | 37 | 39 | 36 | 78 | 73 | ||||||||||||||||||||||||||||||||||
| Data processing and telecommunications expenses | 169 | 186 | 106 | 101 | 91 | 355 | 220 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 390 | 687 | 1,240 | 1,075 | 1,115 | 1,077 | 2,084 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 3,464 | 3,575 | 3,829 | 3,707 | 3,573 | 7,039 | 7,060 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 8,652 | 6,642 | 7,064 | 8,101 | 6,918 | 15,294 | 12,871 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 1,817 | 1,384 | 1,450 | 1,669 | 1,410 | 3,201 | 2,624 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 6,835 | $ | 5,258 | $ | 5,614 | $ | 6,432 | $ | 5,508 | $ | 12,093 | $ | 10,247 | |||||||||||||||||||||||||||
| AMERIS BANCORP AND SUBSIDIARIES | |||||||||||||||||||||||||||||||||||||||||
| FINANCIAL TABLES | |||||||||||||||||||||||||||||||||||||||||
| Segment Reporting (continued) | Table 10 | ||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | Six Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Jun | Mar | Dec | Sep | Jun | Jun | Jun | |||||||||||||||||||||||||||||||||||
| (dollars in thousands) | 2026 | 2026 | 2025 | 2025 | 2025 | 2026 | 2025 | ||||||||||||||||||||||||||||||||||
| Banking Division | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 215,300 | $ | 208,367 | $ | 206,763 | $ | 198,060 | $ | 191,501 | $ | 423,667 | $ | 375,714 | |||||||||||||||||||||||||||
| Provision for credit losses | 19,998 | 11,853 | 25,037 | 21,617 | 677 | 31,851 | 17,097 | ||||||||||||||||||||||||||||||||||
| Noninterest income | 40,569 | 32,791 | 31,018 | 35,419 | 29,275 | 73,360 | 57,999 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 66,668 | 66,246 | 57,582 | 66,301 | 62,001 | 132,914 | 124,717 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment expenses | 11,823 | 10,930 | 10,523 | 10,718 | 10,547 | 22,753 | 20,351 | ||||||||||||||||||||||||||||||||||
| Data processing and telecommunications expenses | 14,041 | 15,348 | 14,761 | 14,668 | 13,825 | 29,389 | 27,216 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 110,933 | 23,898 | 20,554 | 22,286 | 25,478 | 134,831 | 51,163 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 203,465 | 116,422 | 103,420 | 113,973 | 111,851 | 319,887 | 223,447 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 32,406 | 112,883 | 109,324 | 97,889 | 108,248 | 145,289 | 193,169 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 7,538 | 24,397 | 26,100 | 22,824 | 25,667 | 31,935 | 44,821 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 24,868 | $ | 88,486 | $ | 83,224 | $ | 75,065 | $ | 82,581 | $ | 113,354 | $ | 148,348 | |||||||||||||||||||||||||||
| Total Consolidated | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 252,484 | $ | 244,436 | $ | 245,307 | $ | 237,964 | $ | 231,813 | $ | 496,920 | $ | 453,652 | |||||||||||||||||||||||||||
| Provision for credit losses | 17,253 | 16,551 | 22,950 | 22,630 | 2,772 | 33,804 | 24,664 | ||||||||||||||||||||||||||||||||||
| Noninterest income | 73,532 | 69,920 | 61,827 | 76,274 | 68,911 | 143,452 | 132,934 | ||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 91,494 | 91,366 | 81,997 | 90,948 | 89,308 | 182,860 | 175,923 | ||||||||||||||||||||||||||||||||||
| Occupancy and equipment expenses | 12,555 | 11,625 | 11,321 | 11,524 | 11,401 | 24,180 | 22,078 | ||||||||||||||||||||||||||||||||||
| Data processing and telecommunications expenses | 15,571 | 16,793 | 16,236 | 16,058 | 15,366 | 32,364 | 30,221 | ||||||||||||||||||||||||||||||||||
| Other noninterest expenses | 123,094 | 37,296 | 33,536 | 36,036 | 39,185 | 160,390 | 78,072 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 242,714 | 157,080 | 143,090 | 154,566 | 155,260 | 399,794 | 306,294 | ||||||||||||||||||||||||||||||||||
| Income before income tax expense | 66,049 | 140,725 | 141,094 | 137,042 | 142,692 | 206,774 | 255,628 | ||||||||||||||||||||||||||||||||||
| Income tax expense | 14,603 | 30,233 | 32,738 | 31,013 | 32,858 | 44,836 | 57,859 | ||||||||||||||||||||||||||||||||||
| Net income | $ | 51,446 | $ | 110,492 | $ | 108,356 | $ | 106,029 | $ | 109,834 | $ | 161,938 | $ | 197,769 | |||||||||||||||||||||||||||
2nd Quarter 2026 Results Investor Presentation
Cautionary Statements 1 This presentation contains forward-looking statements, as defined by federal securities laws, including, among other forward- looking statements, certain plans, expectations and goals. Words such as “may,” “believe,” “expect,” “anticipate,” “intend,” “will,” “should,” “plan,” “estimate,” “predict,” “continue” and “potential” or the negative of these terms or other comparable terminology, as well as similar expressions, are meant to identify forward-looking statements. The forward-looking statements in this presentation are based on management’s opinions only as of the date hereof and are provided to assist in the understanding of potential future performance. Such forward-looking statements involve numerous assumptions, risks and uncertainties that may cause actual results to differ materially from those expressed or implied in any such statements, including, without limitation, the following: general competitive, economic, unemployment, political and market conditions and fluctuations, including real estate market conditions, and the effects of such conditions and fluctuations on the creditworthiness and payment behaviors of borrowers, collateral values, asset recovery values and the value of investment securities; movements in interest rates and their impacts on net interest margin, investment security valuations and other performance measures; expectations and assumptions regarding credit quality and performance; legislative and regulatory changes; changes in U.S. government trade, monetary and fiscal policies, including tariffs; competitive pressures on product pricing and services; fraud, theft or other misconduct impacting our customers or operations; cybersecurity risks, including data breaches, malware, ransomware and account takeovers; the success and timing of our business strategies and plans; our outlook and long-term goals for future growth; and natural disasters, geopolitical events, acts of war or terrorism or other hostilities, public health crises and other catastrophic events beyond our control. For a discussion of some of the other risks and other factors that may cause such forward-looking statements to differ materially from actual results, please refer to the Company’s filings with the Securities and Exchange Commission, including the Company’s Annual Report on Form 10-K for the year ended December 31, 2025, and the Company’s subsequently filed periodic reports and other filings. Forward-looking statements speak only as of the date they are made, and, except as required by law, the Company undertakes no obligation to update or revise forward-looking statements except as required by law.
Ameris Profile Investment Rationale • Top of peer financial results with culture of discipline – credit, liquidity, expense control, capital • Diversified and granular loan portfolio among geographies and product lines • Stable deposit base with 30.0% noninterest-bearing deposits • Experienced executive team with skills and leadership to continue to grow organically • Focus on shareholder value with 11% annualized tangible book value growth over the last five years Strong History of Earnings 2 Growth Focused $24.6 $25.1 $25.5 $26.1 $26.4 $41.32 $42.90 $44.18 $44.79 $45.10 $23.0 $23.5 $24.0 $24.5 $25.0 $25.5 $26.0 $26.5 $27.0 $40.00 $42.00 $44.00 $46.00 $48.00 2Q25 3Q25 4Q25 1Q26 2Q26 Earning Assets (Billions) Tangible Book Value per Share 1 – Considered Non-GAAP measures – See reconciliation of GAAP to Non-GAAP measures in Appendix 111 $1.59 $1.52 $1.59 $1.63 $1.60 1.64% 1.53% 1.58% 1.62% 1.53% 1.00% 1.20% 1.40% 1.60% 1.80% 2.00% $- $0.20 $0.40 $0.60 $0.80 $1.00 $1.20 $1.40 $1.60 $1.80 2Q25 3Q25 4Q25 1Q26 2Q26 Adjusted Diluted EPS Adjusted ROA
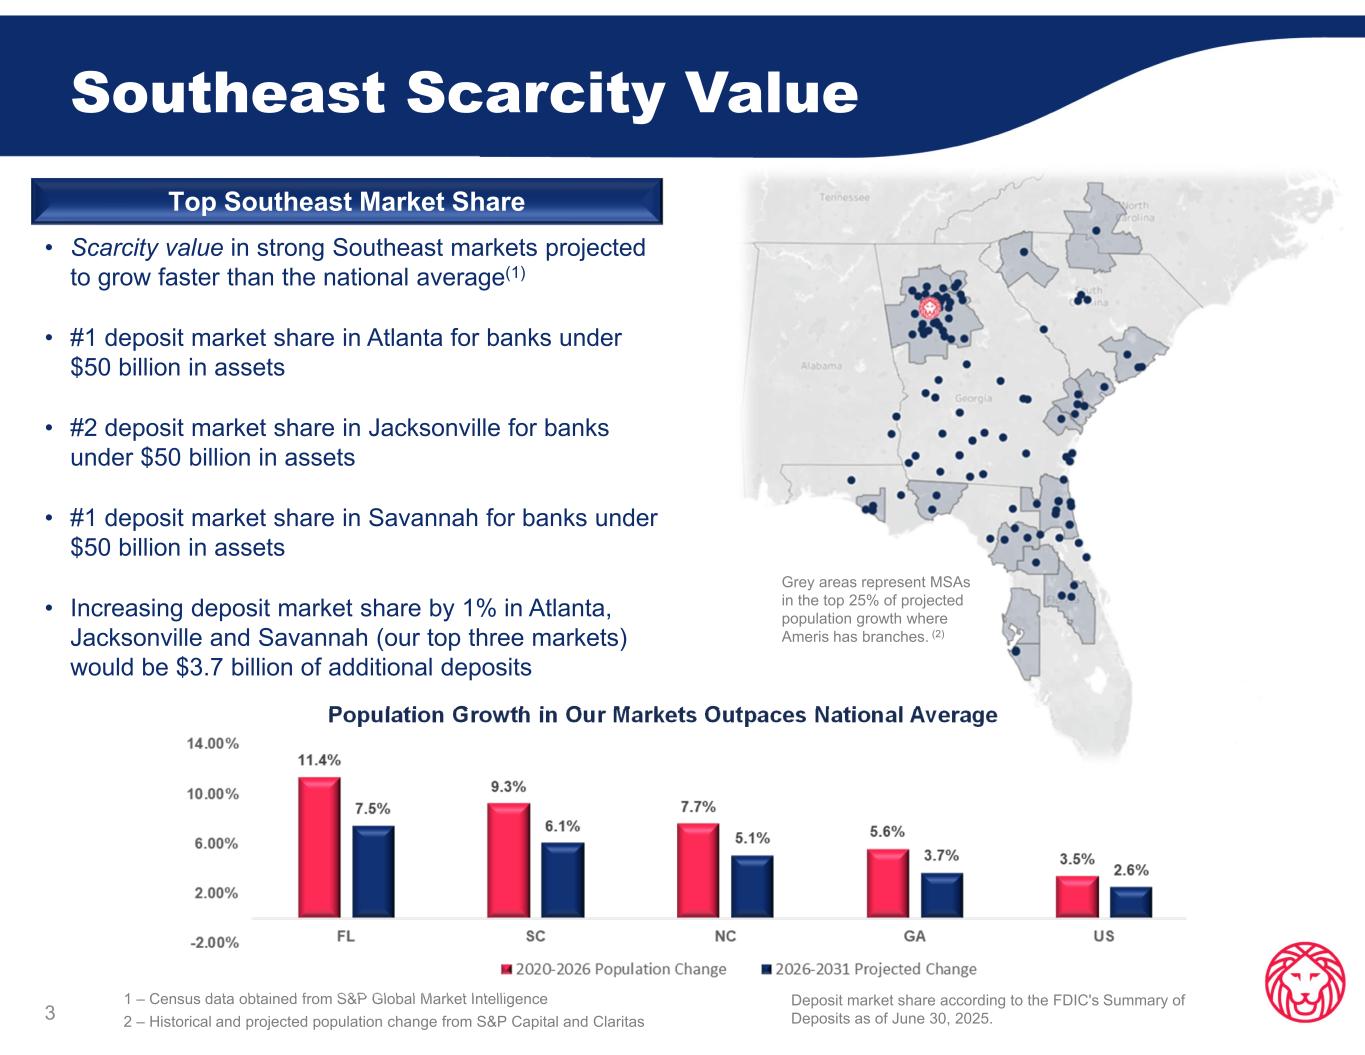
Southeast Scarcity Value 3 1 – Census data obtained from S&P Global Market Intelligence 2 – Historical and projected population change from S&P Capital and Claritas Grey areas represent MSAs in the top 25% of projected population growth where Ameris has branches. (2) Top Southeast Market Share • Scarcity value in strong Southeast markets projected to grow faster than the national average(1) • #1 deposit market share in Atlanta for banks under $50 billion in assets • #2 deposit market share in Jacksonville for banks under $50 billion in assets • #1 deposit market share in Savannah for banks under $50 billion in assets • Increasing deposit market share by 1% in Atlanta, Jacksonville and Savannah (our top three markets) would be $3.7 billion of additional deposits Population Growth in Our Markets Outpaces National Average Deposit market share according to the FDIC's Summary of Deposits as of June 30, 2025.
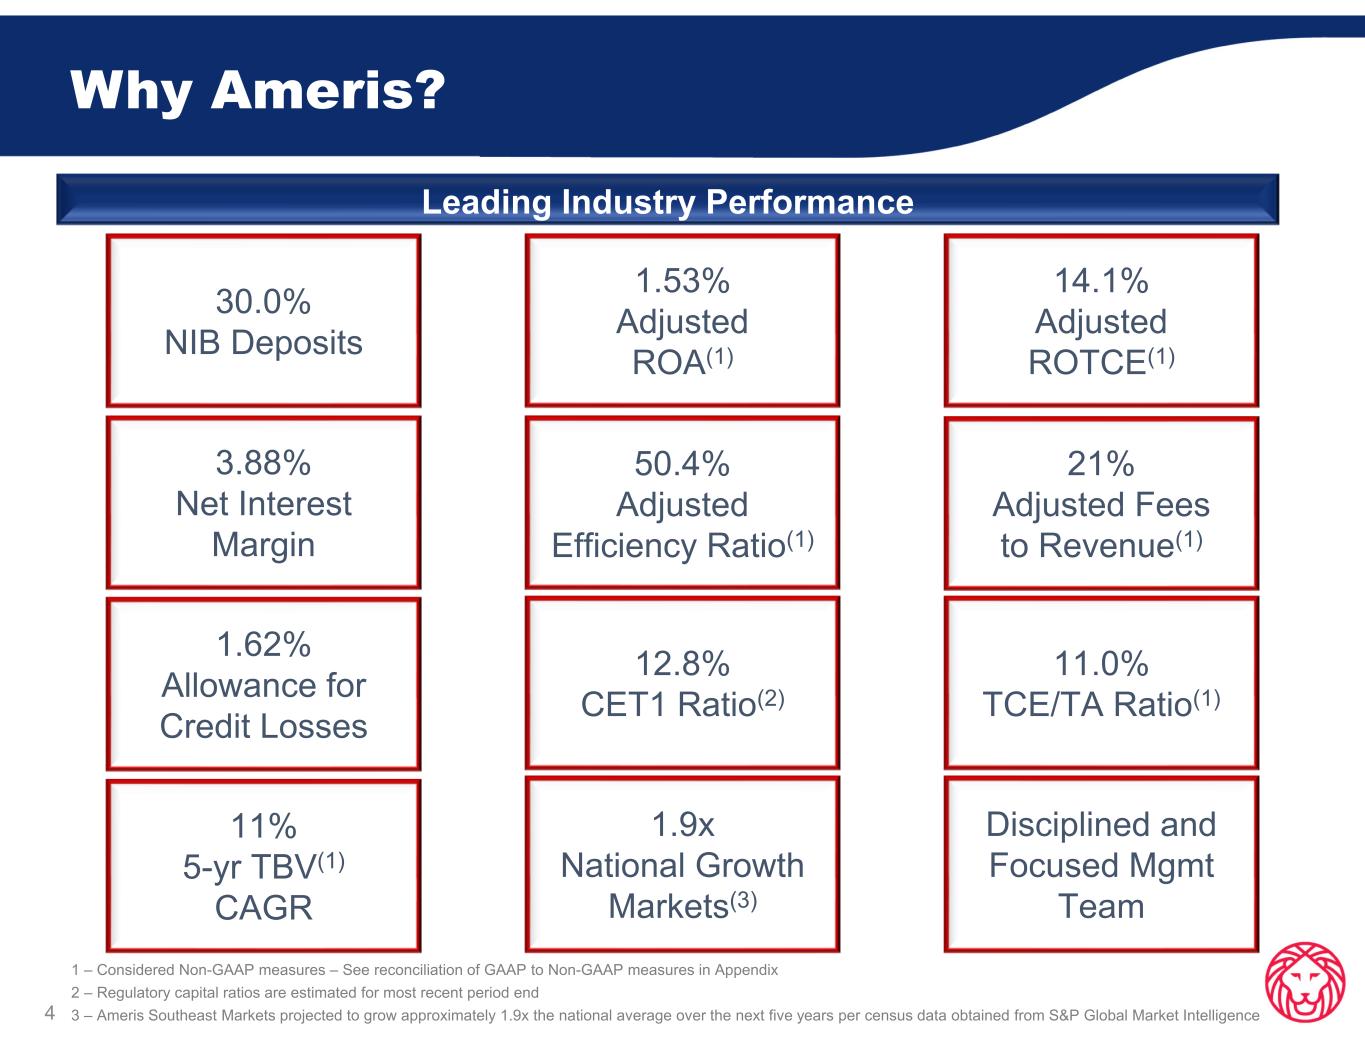
50.4% Adjusted Efficiency Ratio(1) 1.9x National Growth Markets(3) 1.62% Allowance for Credit Losses 12.8% CET1 Ratio(2) 11% 5-yr TBV(1) CAGR 14.1% Adjusted ROTCE(1) 21% Adjusted Fees to Revenue(1) Disciplined and Focused Mgmt Team 11.0% TCE/TA Ratio(1) 30.0% NIB Deposits 3.88% Net Interest Margin 1.53% Adjusted ROA(1) 1 – Considered Non-GAAP measures – See reconciliation of GAAP to Non-GAAP measures in Appendix 2 – Regulatory capital ratios are estimated for most recent period end 3 – Ameris Southeast Markets projected to grow approximately 1.9x the national average over the next five years per census data obtained from S&P Global Market Intelligence4 Why Ameris? Leading Industry Performance
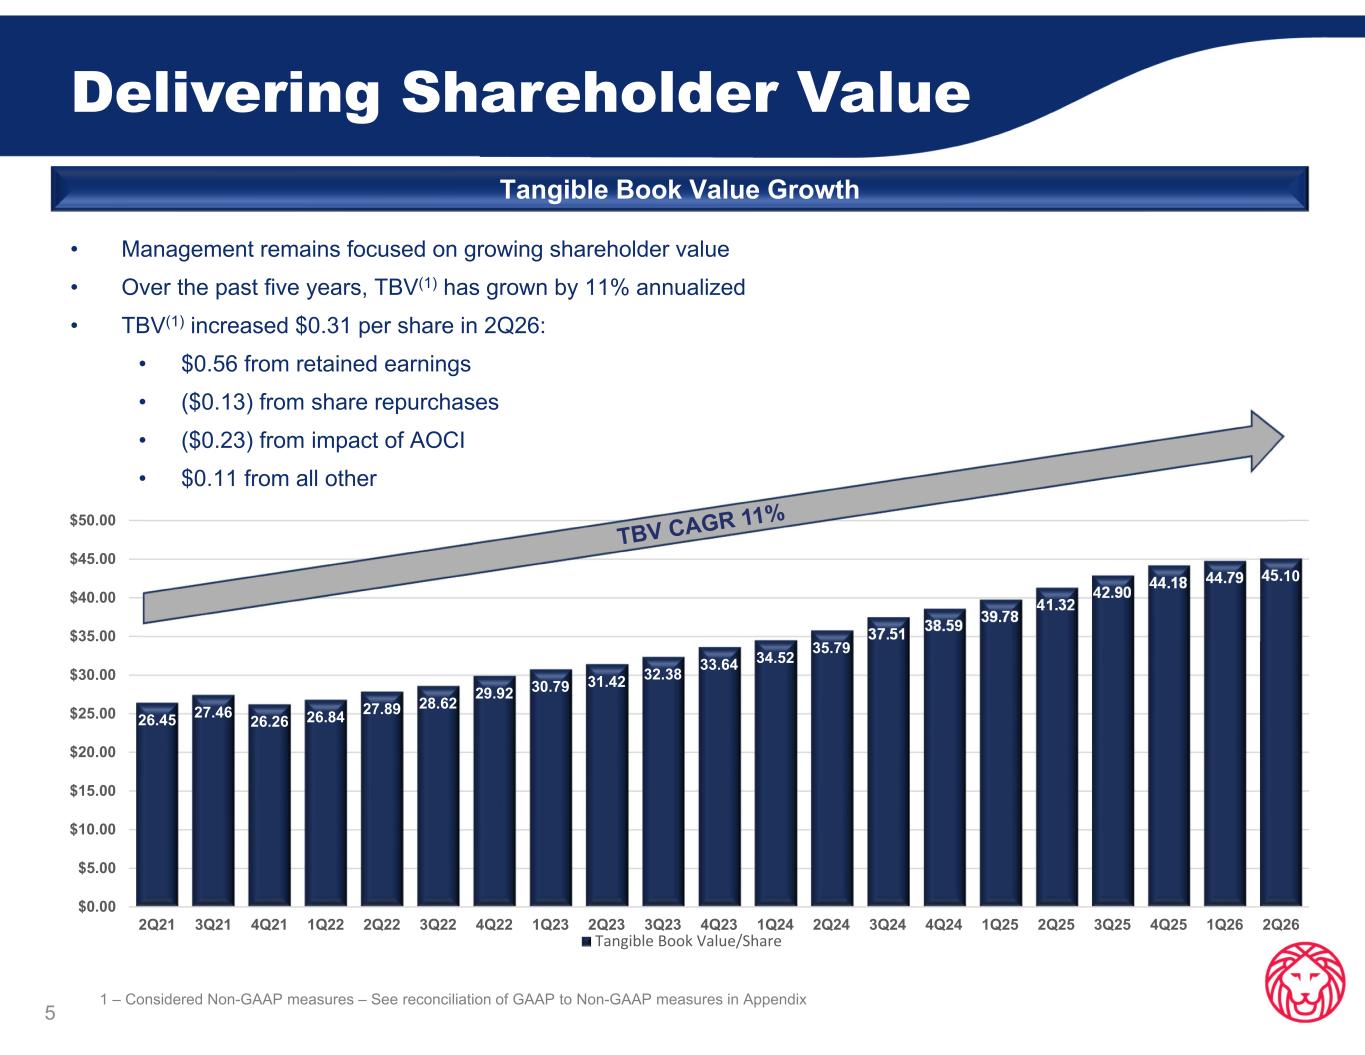
26.45 27.46 26.26 26.84 27.89 28.62 29.92 30.79 31.42 32.38 33.64 34.52 35.79 37.51 38.59 39.78 41.32 42.90 44.18 44.79 45.10 $0.00 $5.00 $10.00 $15.00 $20.00 $25.00 $30.00 $35.00 $40.00 $45.00 $50.00 2Q21 3Q21 4Q21 1Q22 2Q22 3Q22 4Q22 1Q23 2Q23 3Q23 4Q23 1Q24 2Q24 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Tangible Book Value/Share Delivering Shareholder Value Tangible Book Value Growth 5 • Management remains focused on growing shareholder value • Over the past five years, TBV(1) has grown by 11% annualized • TBV(1) increased $0.31 per share in 2Q26: • $0.56 from retained earnings • ($0.13) from share repurchases • ($0.23) from impact of AOCI • $0.11 from all other 1 – Considered Non-GAAP measures – See reconciliation of GAAP to Non-GAAP measures in Appendix
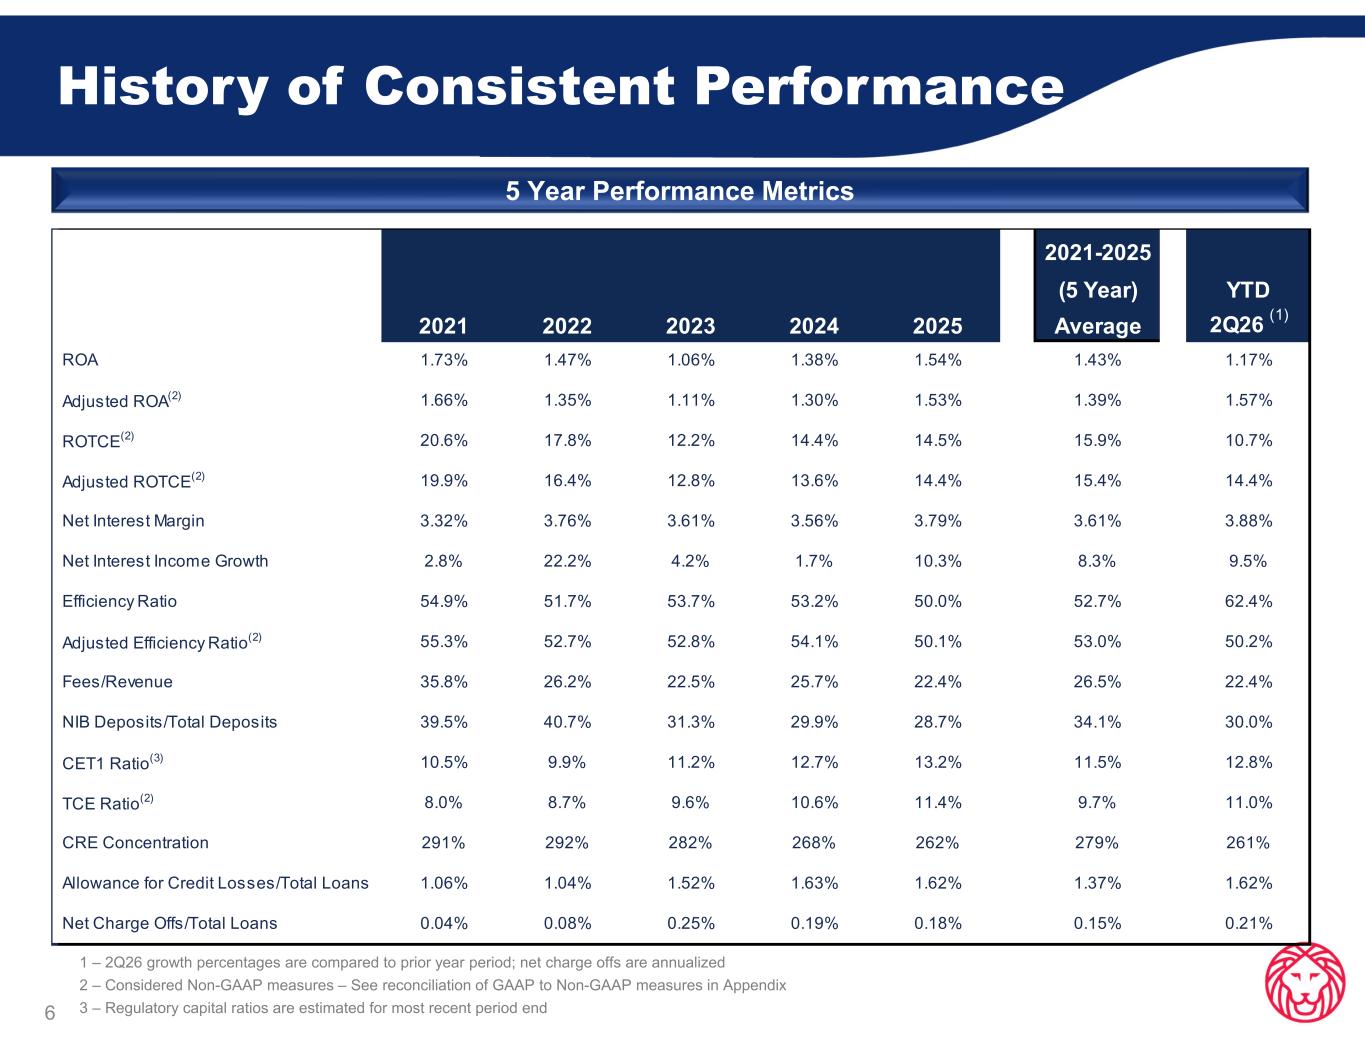
1 – 2Q26 growth percentages are compared to prior year period; net charge offs are annualized 2 – Considered Non-GAAP measures – See reconciliation of GAAP to Non-GAAP measures in Appendix 3 – Regulatory capital ratios are estimated for most recent period end6 History of Consistent Performance 5 Year Performance Metrics 2021-2025 (5 Year) YTD 2021 2022 2023 2024 2025 Average 2Q26 (1) ROA 1.73% 1.47% 1.06% 1.38% 1.54% 1.43% 1.17% Adjusted ROA(2) 1.66% 1.35% 1.11% 1.30% 1.53% 1.39% 1.57% ROTCE(2) 20.6% 17.8% 12.2% 14.4% 14.5% 15.9% 10.7% Adjusted ROTCE(2) 19.9% 16.4% 12.8% 13.6% 14.4% 15.4% 14.4% Net Interest Margin 3.32% 3.76% 3.61% 3.56% 3.79% 3.61% 3.88% Net Interest Income Growth 2.8% 22.2% 4.2% 1.7% 10.3% 8.3% 9.5% Efficiency Ratio 54.9% 51.7% 53.7% 53.2% 50.0% 52.7% 62.4% Adjusted Efficiency Ratio(2) 55.3% 52.7% 52.8% 54.1% 50.1% 53.0% 50.2% Fees/Revenue 35.8% 26.2% 22.5% 25.7% 22.4% 26.5% 22.4% NIB Deposits/Total Deposits 39.5% 40.7% 31.3% 29.9% 28.7% 34.1% 30.0% CET1 Ratio(3) 10.5% 9.9% 11.2% 12.7% 13.2% 11.5% 12.8% TCE Ratio(2) 8.0% 8.7% 9.6% 10.6% 11.4% 9.7% 11.0% CRE Concentration 291% 292% 282% 268% 262% 279% 261% Allowance for Credit Losses/Total Loans 1.06% 1.04% 1.52% 1.63% 1.62% 1.37% 1.62% Net Charge Offs/Total Loans 0.04% 0.08% 0.25% 0.19% 0.18% 0.15% 0.21%
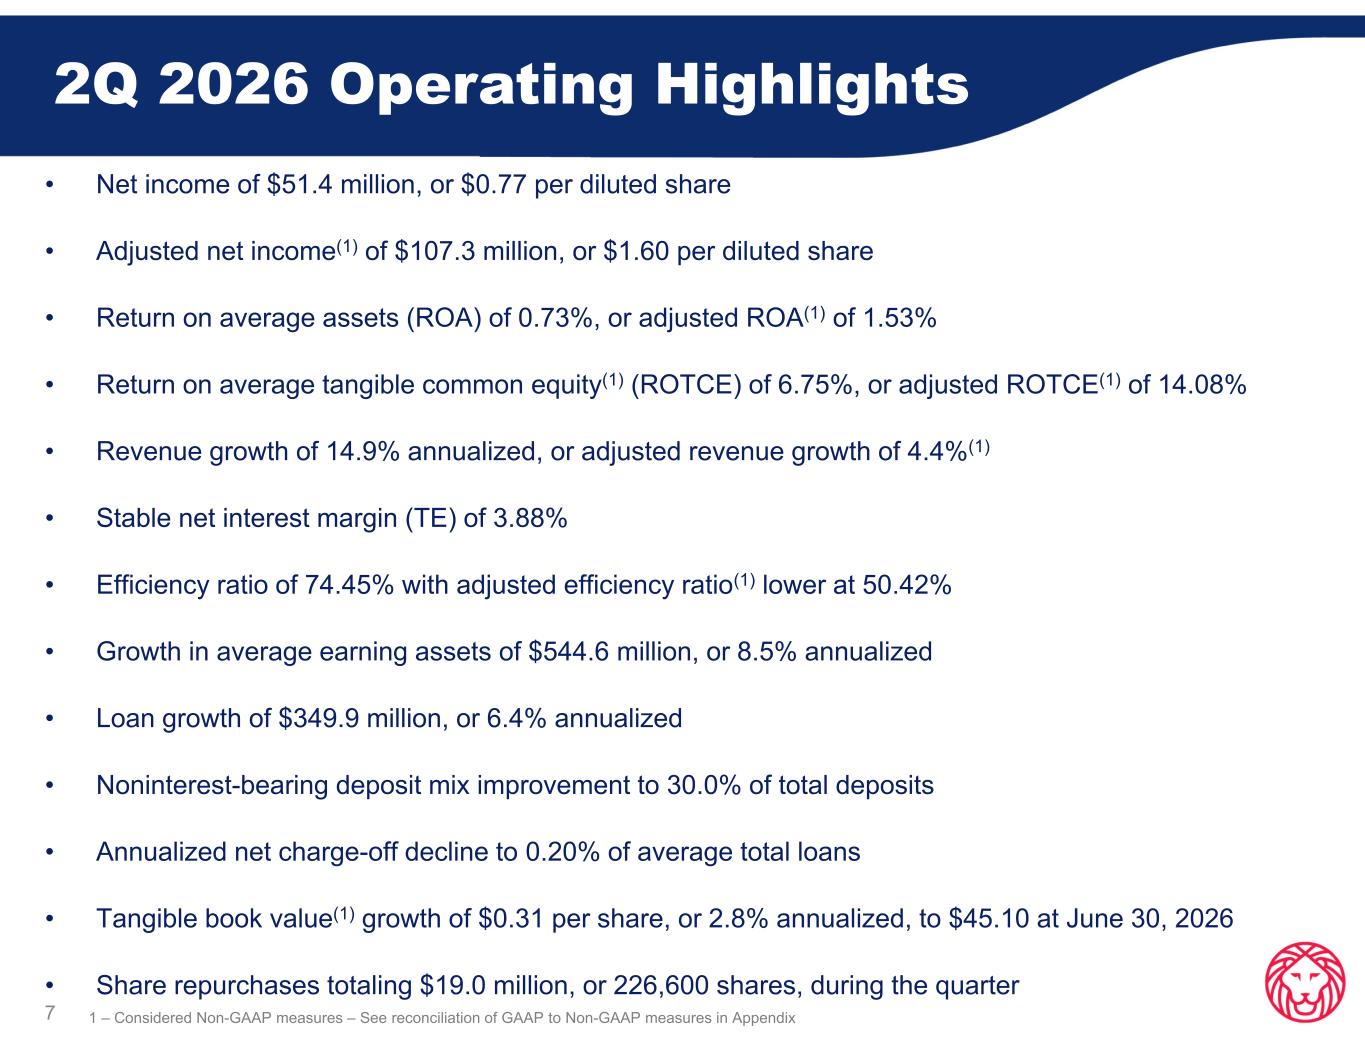
2Q 2026 Operating Highlights 7 • Net income of $51.4 million, or $0.77 per diluted share • Adjusted net income(1) of $107.3 million, or $1.60 per diluted share • Return on average assets (ROA) of 0.73%, or adjusted ROA(1) of 1.53% • Return on average tangible common equity(1) (ROTCE) of 6.75%, or adjusted ROTCE(1) of 14.08% • Revenue growth of 14.9% annualized, or adjusted revenue growth of 4.4%(1) • Stable net interest margin (TE) of 3.88% • Efficiency ratio of 74.45% with adjusted efficiency ratio(1) lower at 50.42% • Growth in average earning assets of $544.6 million, or 8.5% annualized • Loan growth of $349.9 million, or 6.4% annualized • Noninterest-bearing deposit mix improvement to 30.0% of total deposits • Annualized net charge-off decline to 0.20% of average total loans • Tangible book value(1) growth of $0.31 per share, or 2.8% annualized, to $45.10 at June 30, 2026 • Share repurchases totaling $19.0 million, or 226,600 shares, during the quarter 1 – Considered Non-GAAP measures – See reconciliation of GAAP to Non-GAAP measures in Appendix
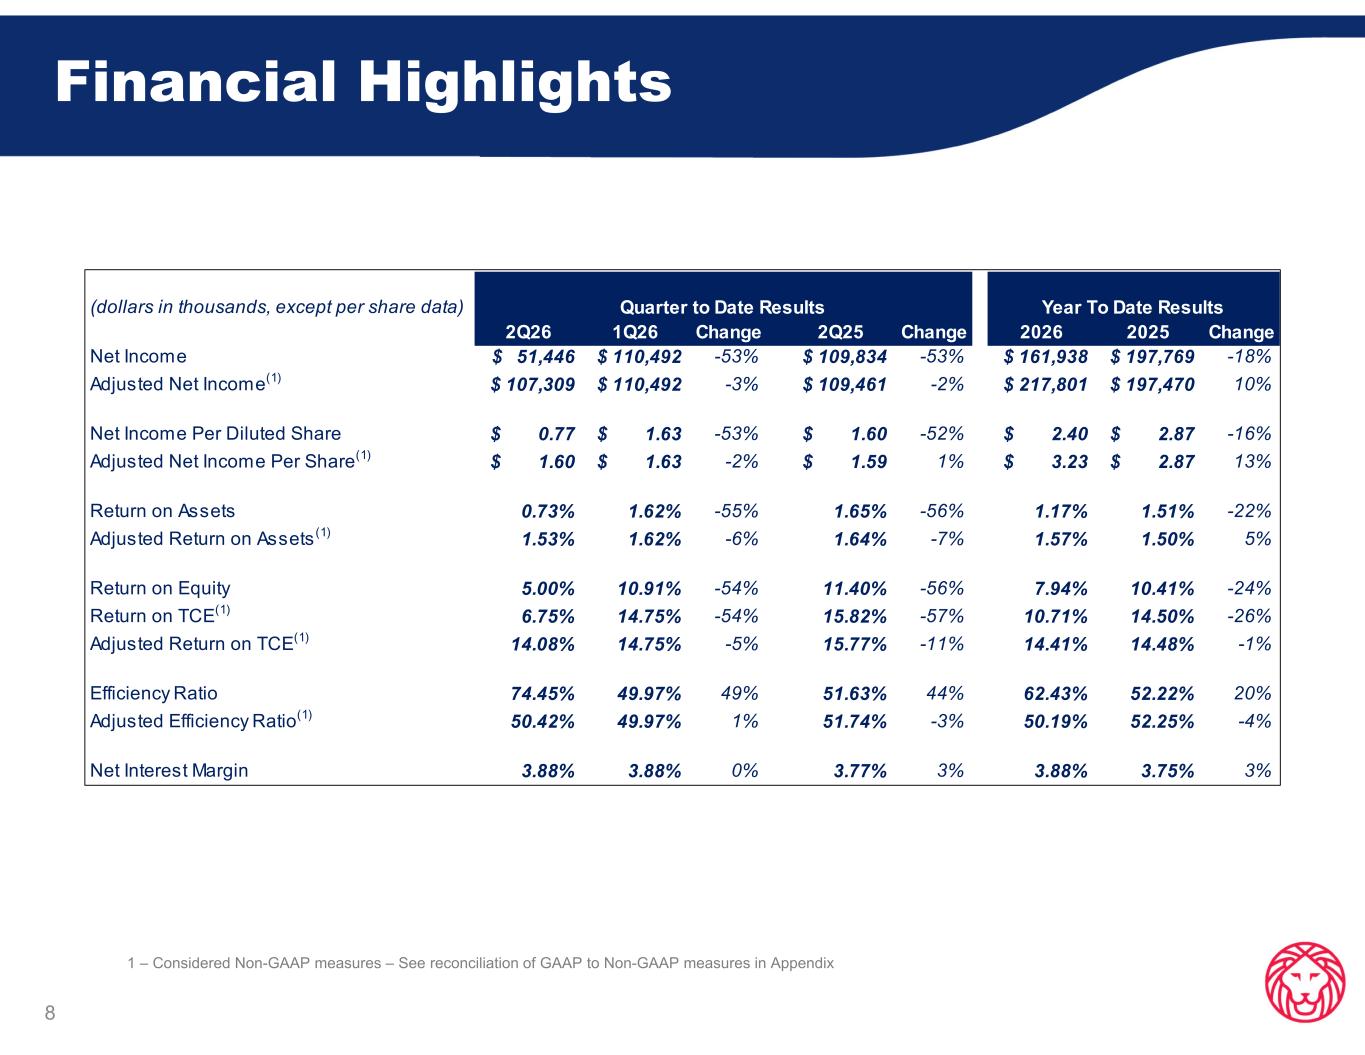
Financial Highlights 8 1 – Considered Non-GAAP measures – See reconciliation of GAAP to Non-GAAP measures in Appendix (dollars in thousands, except per share data) 2Q26 1Q26 Change 2Q25 Change 2026 2025 Change Net Income $ 51,446 $ 110,492 -53% $ 109,834 -53% $ 161,938 $ 197,769 -18% Adjusted Net Income(1) $ 107,309 $ 110,492 -3% $ 109,461 -2% $ 217,801 $ 197,470 10% Net Income Per Diluted Share $ 0.77 $ 1.63 -53% $ 1.60 -52% $ 2.40 $ 2.87 -16% Adjusted Net Income Per Share(1) $ 1.60 $ 1.63 -2% $ 1.59 1% $ 3.23 $ 2.87 13% Return on Assets 0.73% 1.62% -55% 1.65% -56% 1.17% 1.51% -22% Adjusted Return on Assets(1) 1.53% 1.62% -6% 1.64% -7% 1.57% 1.50% 5% Return on Equity 5.00% 10.91% -54% 11.40% -56% 7.94% 10.41% -24% Return on TCE(1) 6.75% 14.75% -54% 15.82% -57% 10.71% 14.50% -26% Adjusted Return on TCE(1) 14.08% 14.75% -5% 15.77% -11% 14.41% 14.48% -1% Efficiency Ratio 74.45% 49.97% 49% 51.63% 44% 62.43% 52.22% 20% Adjusted Efficiency Ratio(1) 50.42% 49.97% 1% 51.74% -3% 50.19% 52.25% -4% Net Interest Margin 3.88% 3.88% 0% 3.77% 3% 3.88% 3.75% 3% Quarter to Date Results Year To Date Results
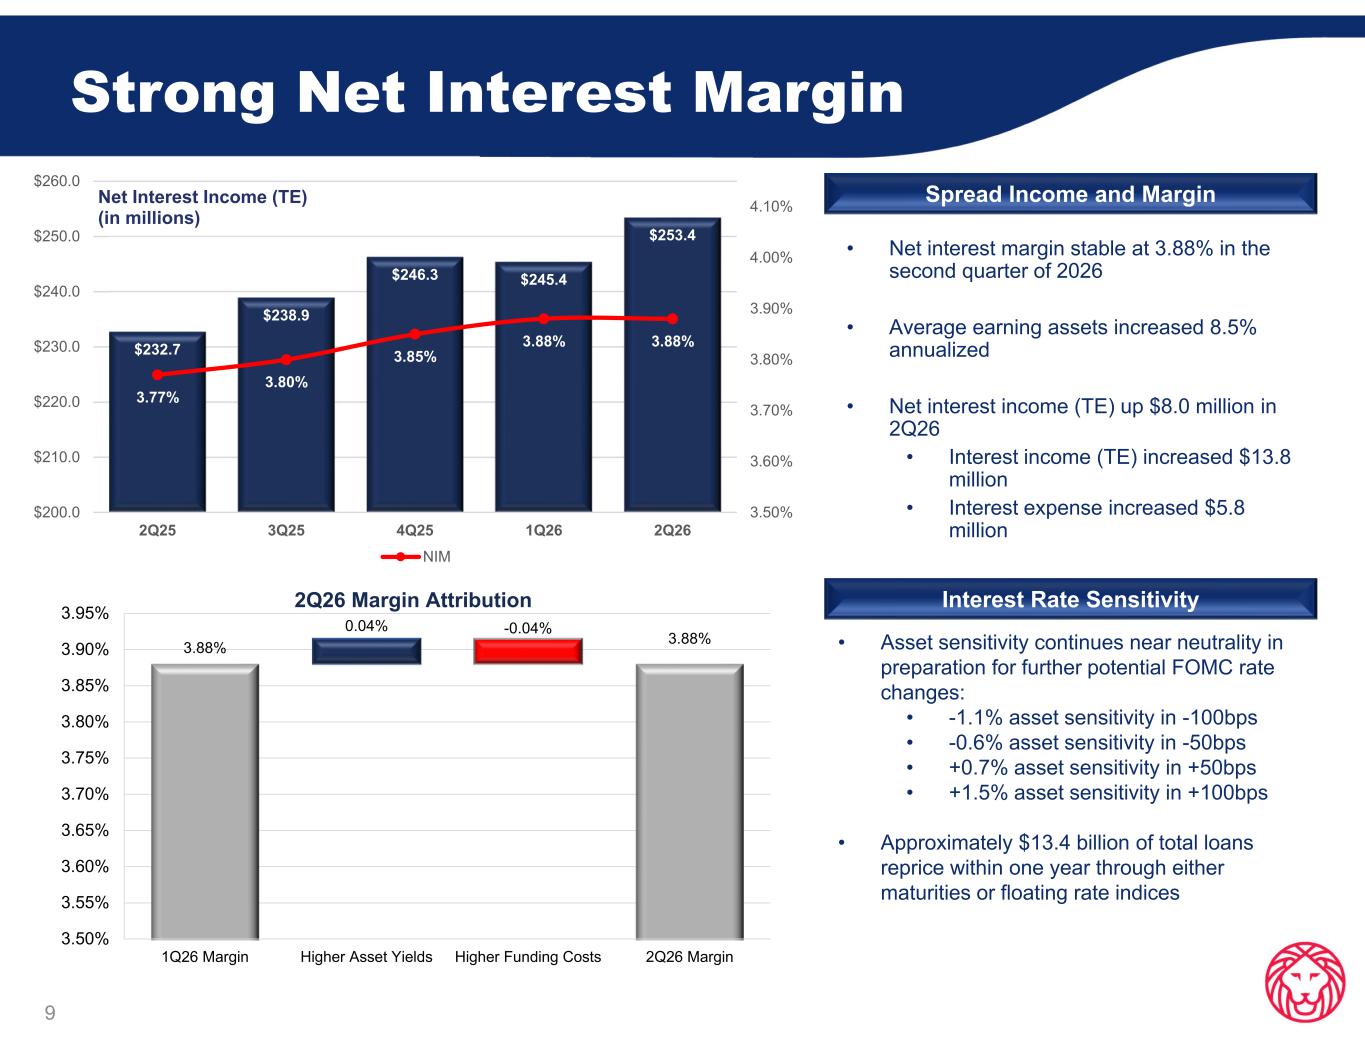
Strong Net Interest Margin 9 • Net interest margin stable at 3.88% in the second quarter of 2026 • Average earning assets increased 8.5% annualized • Net interest income (TE) up $8.0 million in 2Q26 • Interest income (TE) increased $13.8 million • Interest expense increased $5.8 million Spread Income and Margin Interest Rate Sensitivity • Asset sensitivity continues near neutrality in preparation for further potential FOMC rate changes: • -1.1% asset sensitivity in -100bps • -0.6% asset sensitivity in -50bps • +0.7% asset sensitivity in +50bps • +1.5% asset sensitivity in +100bps • Approximately $13.4 billion of total loans reprice within one year through either maturities or floating rate indices $232.7 $238.9 $246.3 $245.4 $253.4 3.77% 3.80% 3.85% 3.88% 3.88% 3.50% 3.60% 3.70% 3.80% 3.90% 4.00% 4.10% $200.0 $210.0 $220.0 $230.0 $240.0 $250.0 $260.0 2Q25 3Q25 4Q25 1Q26 2Q26 Net Interest Income (TE) (in millions) NIM 0.04% -0.04% 3.88% 3.88% 3.50% 3.55% 3.60% 3.65% 3.70% 3.75% 3.80% 3.85% 3.90% 3.95% 1Q26 Margin Higher Asset Yields Higher Funding Costs 2Q26 Margin 2Q26 Margin Attribution
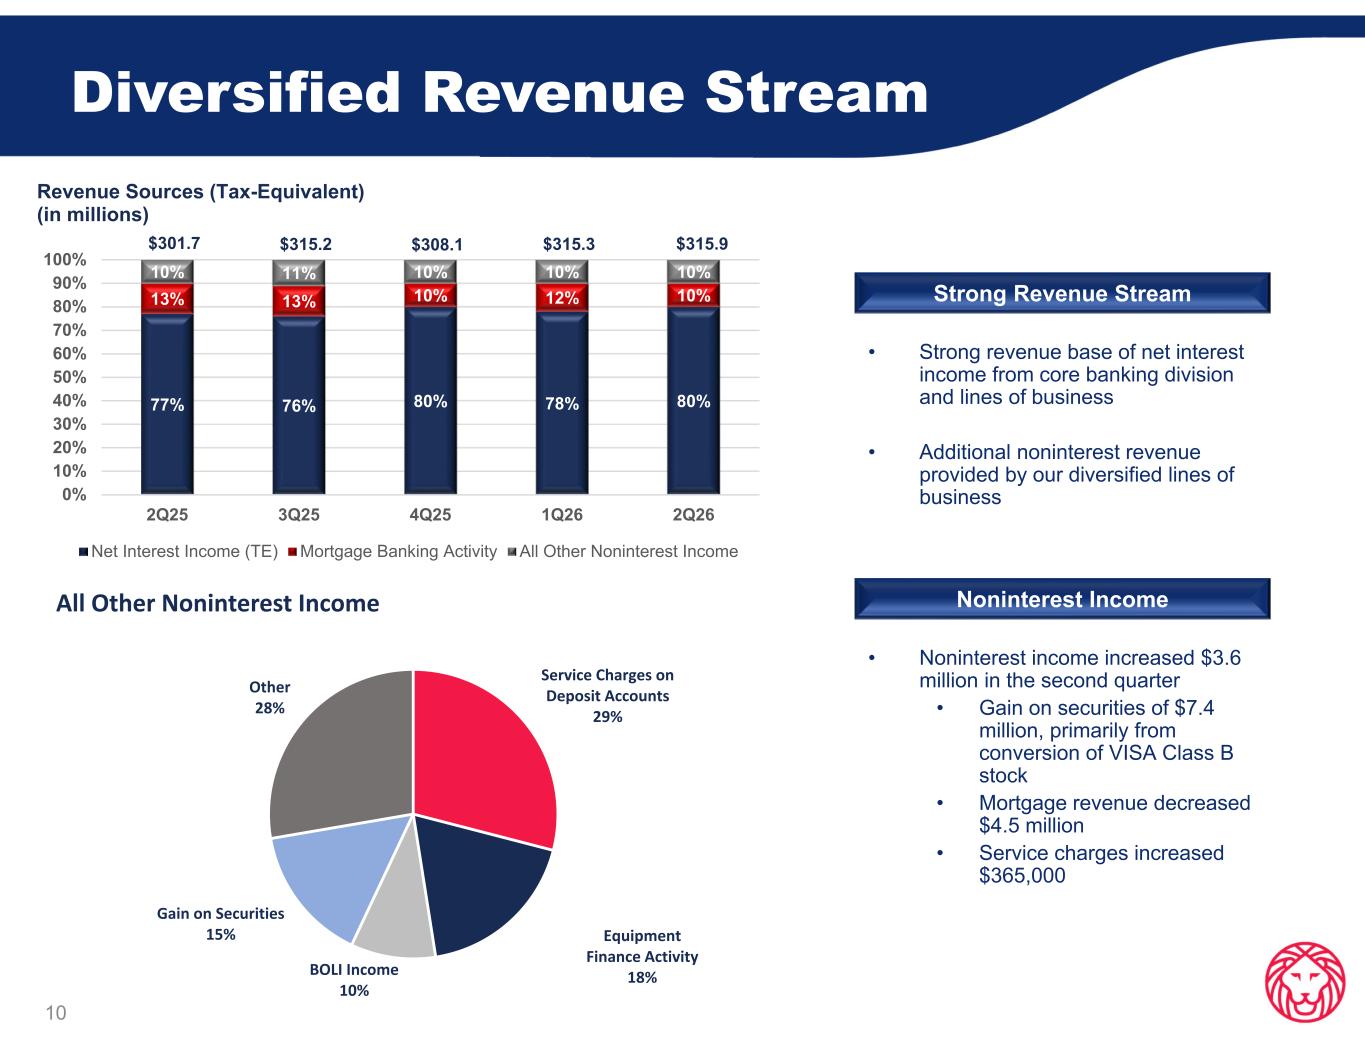
Diversified Revenue Stream 10 • Strong revenue base of net interest income from core banking division and lines of business • Additional noninterest revenue provided by our diversified lines of business Noninterest Income • Noninterest income increased $3.6 million in the second quarter • Gain on securities of $7.4 million, primarily from conversion of VISA Class B stock • Mortgage revenue decreased $4.5 million • Service charges increased $365,000 Strong Revenue Stream 77% 76% 80% 78% 80% 13% 13% 10% 12% 10% 10% 11% 10% 10% 10% $301.7 $315.2 $308.1 $315.3 $315.9 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% 2Q25 3Q25 4Q25 1Q26 2Q26 Revenue Sources (Tax-Equivalent) (in millions) Net Interest Income (TE) Mortgage Banking Activity All Other Noninterest Income Service Charges on Deposit Accounts 29% Equipment Finance Activity 18%BOLI Income 10% Gain on Securities 15% Other 28% All Other Noninterest Income
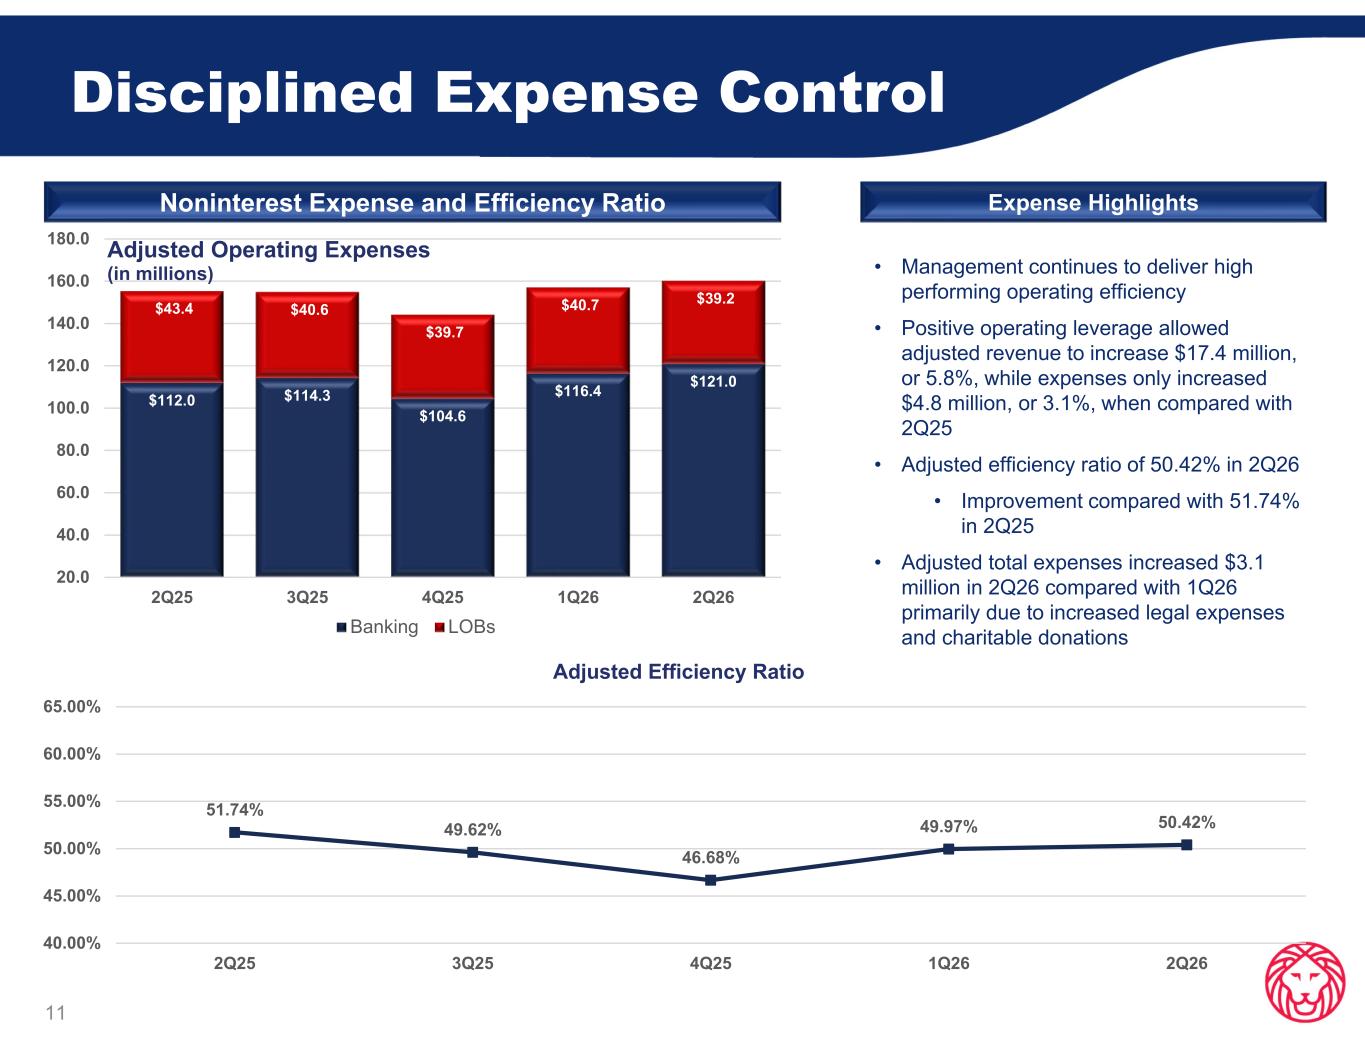
Disciplined Expense Control Noninterest Expense and Efficiency Ratio Expense Highlights 11 • Management continues to deliver high performing operating efficiency • Positive operating leverage allowed adjusted revenue to increase $17.4 million, or 5.8%, while expenses only increased $4.8 million, or 3.1%, when compared with 2Q25 • Adjusted efficiency ratio of 50.42% in 2Q26 • Improvement compared with 51.74% in 2Q25 • Adjusted total expenses increased $3.1 million in 2Q26 compared with 1Q26 primarily due to increased legal expenses and charitable donations $112.0 $114.3 $104.6 $116.4 $121.0 $43.4 $40.6 $39.7 $40.7 $39.2 20.0 40.0 60.0 80.0 100.0 120.0 140.0 160.0 180.0 2Q25 3Q25 4Q25 1Q26 2Q26 Adjusted Operating Expenses (in millions) Banking LOBs 51.74% 49.62% 46.68% 49.97% 50.42% 40.00% 45.00% 50.00% 55.00% 60.00% 65.00% 2Q25 3Q25 4Q25 1Q26 2Q26 Adjusted Efficiency Ratio
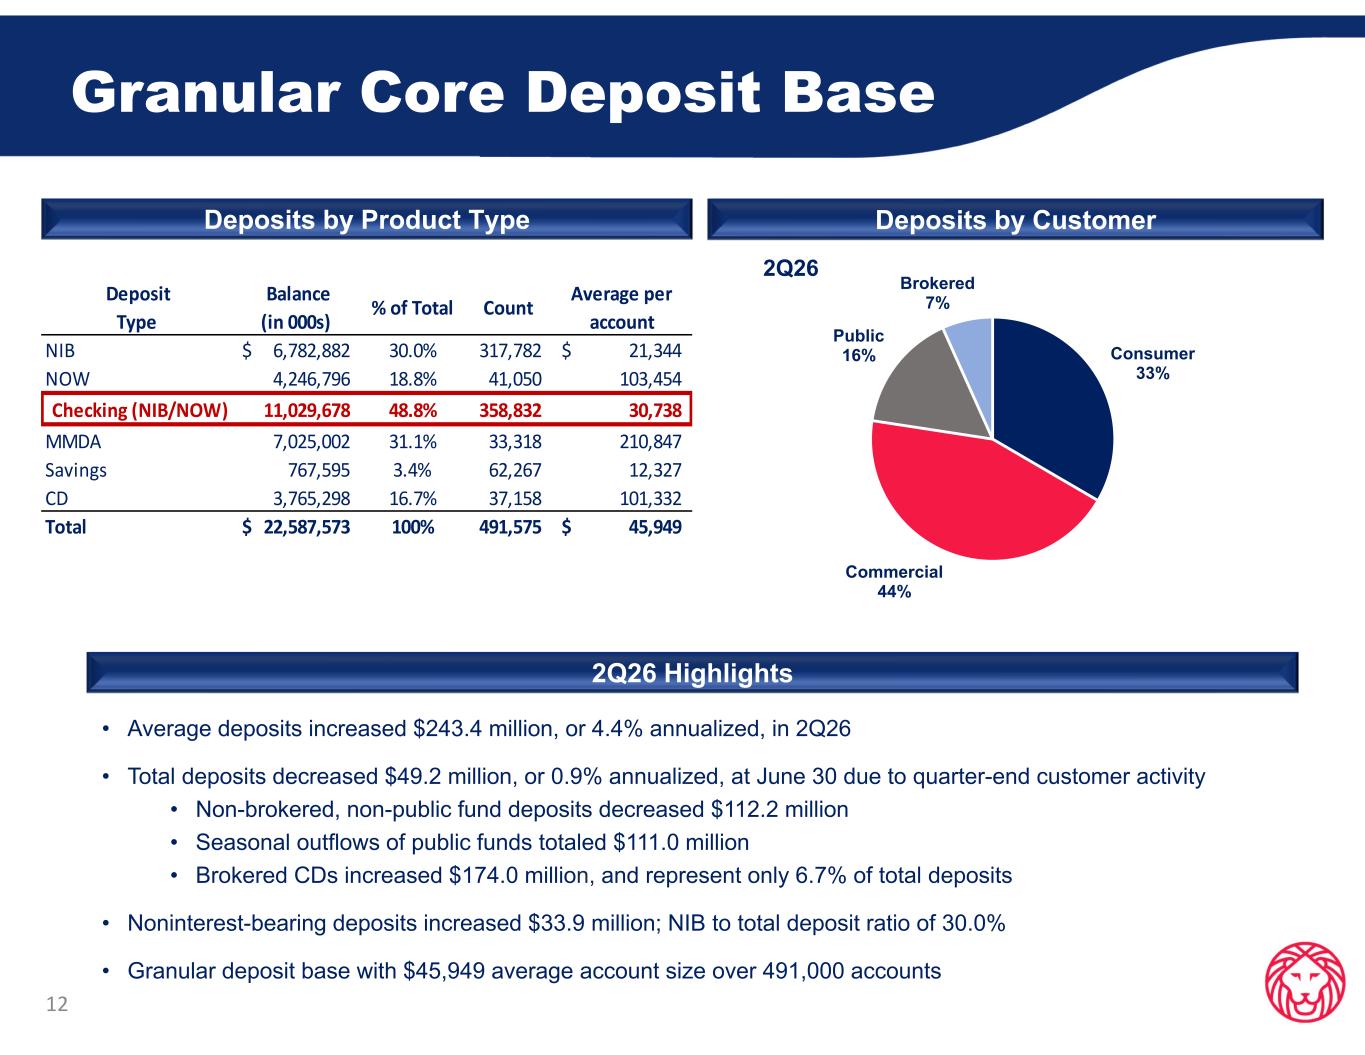
Granular Core Deposit Base 12 Deposits by Product Type • Average deposits increased $243.4 million, or 4.4% annualized, in 2Q26 • Total deposits decreased $49.2 million, or 0.9% annualized, at June 30 due to quarter-end customer activity • Non-brokered, non-public fund deposits decreased $112.2 million • Seasonal outflows of public funds totaled $111.0 million • Brokered CDs increased $174.0 million, and represent only 6.7% of total deposits • Noninterest-bearing deposits increased $33.9 million; NIB to total deposit ratio of 30.0% • Granular deposit base with $45,949 average account size over 491,000 accounts 2Q26 Highlights Deposits by Customer Deposit Type Balance (in 000s) % of Total Count Average per account NIB 6,782,882$ 30.0% 317,782 21,344$ NOW 4,246,796 18.8% 41,050 103,454 Checking (NIB/NOW) 11,029,678 48.8% 358,832 30,738 MMDA 7,025,002 31.1% 33,318 210,847 Savings 767,595 3.4% 62,267 12,327 CD 3,765,298 16.7% 37,158 101,332 Total 22,587,573$ 100% 491,575 45,949$ Consumer 33% Commercial 44% Public 16% Brokered 7% 2Q26
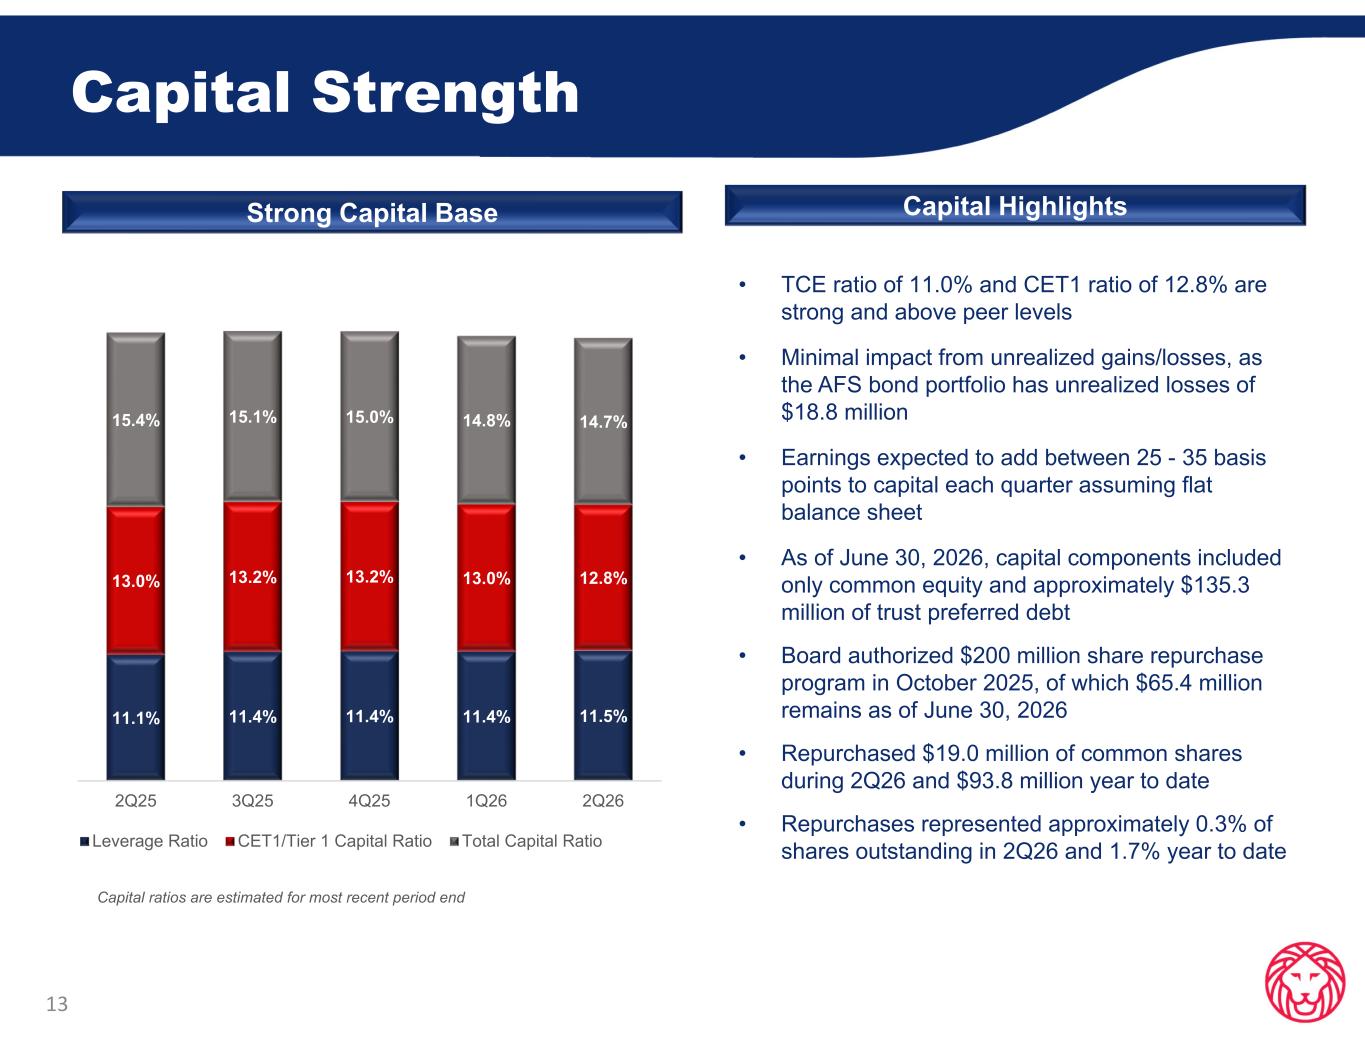
Capital Strength 13 • TCE ratio of 11.0% and CET1 ratio of 12.8% are strong and above peer levels • Minimal impact from unrealized gains/losses, as the AFS bond portfolio has unrealized losses of $18.8 million • Earnings expected to add between 25 - 35 basis points to capital each quarter assuming flat balance sheet • As of June 30, 2026, capital components included only common equity and approximately $135.3 million of trust preferred debt • Board authorized $200 million share repurchase program in October 2025, of which $65.4 million remains as of June 30, 2026 • Repurchased $19.0 million of common shares during 2Q26 and $93.8 million year to date • Repurchases represented approximately 0.3% of shares outstanding in 2Q26 and 1.7% year to date Capital ratios are estimated for most recent period end Strong Capital Base Capital Highlights 11.1% 11.4% 11.4% 11.4% 11.5% 13.0% 13.2% 13.2% 13.0% 12.8% 15.4% 15.1% 15.0% 14.8% 14.7% 2Q25 3Q25 4Q25 1Q26 2Q26 Leverage Ratio CET1/Tier 1 Capital Ratio Total Capital Ratio
Loan Diversification and Credit Quality
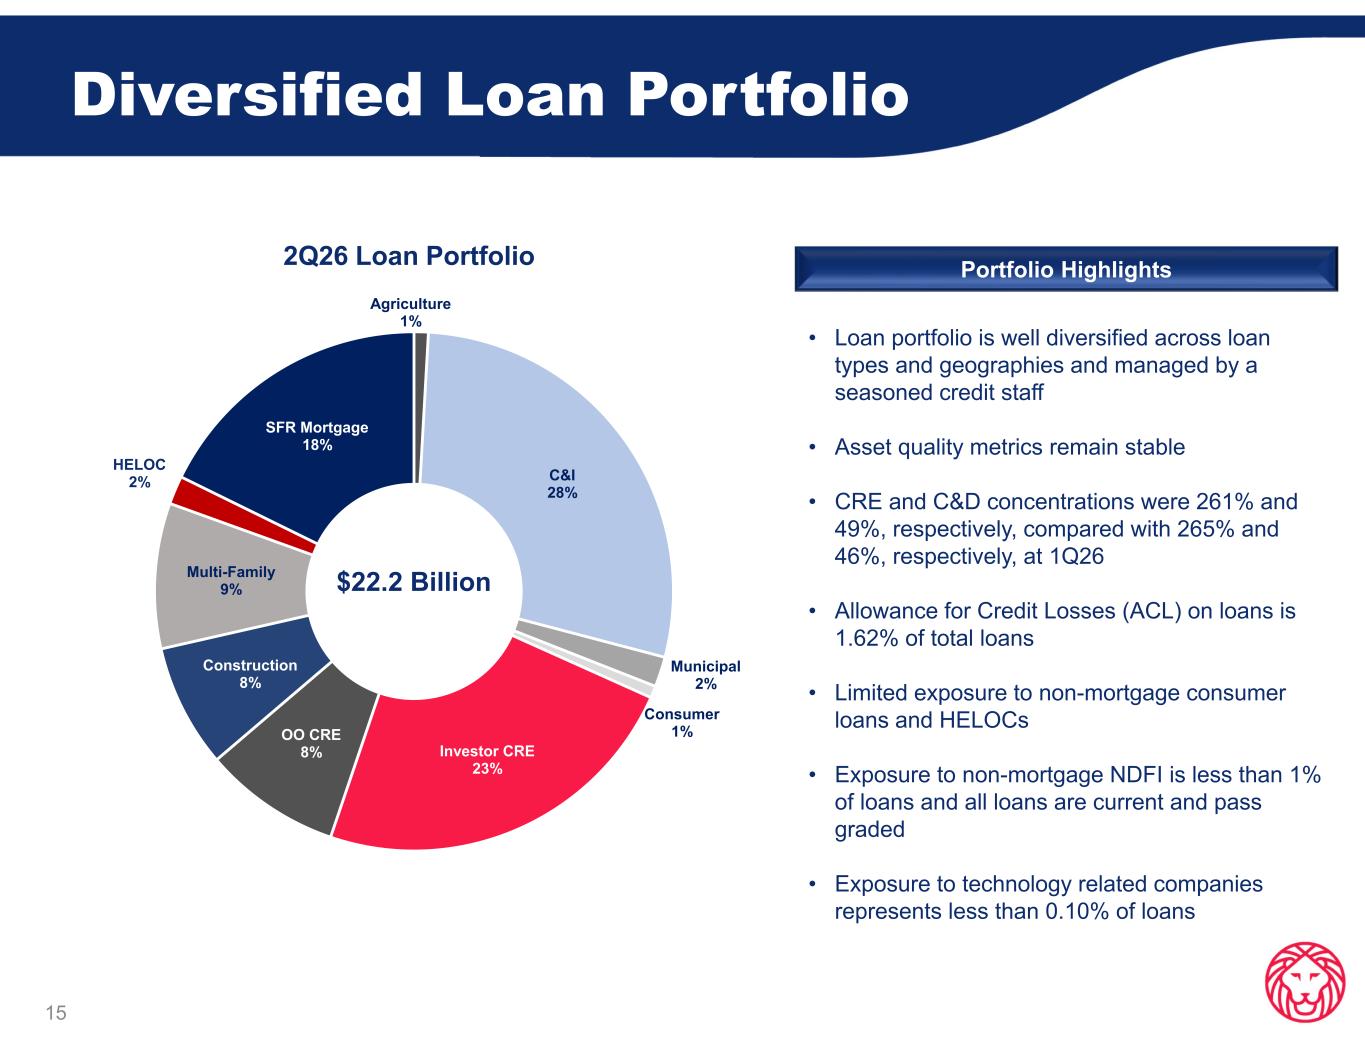
Diversified Loan Portfolio 2Q26 Loan Portfolio 15 • Loan portfolio is well diversified across loan types and geographies and managed by a seasoned credit staff • Asset quality metrics remain stable • CRE and C&D concentrations were 261% and 49%, respectively, compared with 265% and 46%, respectively, at 1Q26 • Allowance for Credit Losses (ACL) on loans is 1.62% of total loans • Limited exposure to non-mortgage consumer loans and HELOCs • Exposure to non-mortgage NDFI is less than 1% of loans and all loans are current and pass graded • Exposure to technology related companies represents less than 0.10% of loans Portfolio Highlights Agriculture 1% C&I 28% Municipal 2% Consumer 1% Investor CRE 23% OO CRE 8% Construction 8% Multi-Family 9% HELOC 2% SFR Mortgage 18% $22.2 Billion
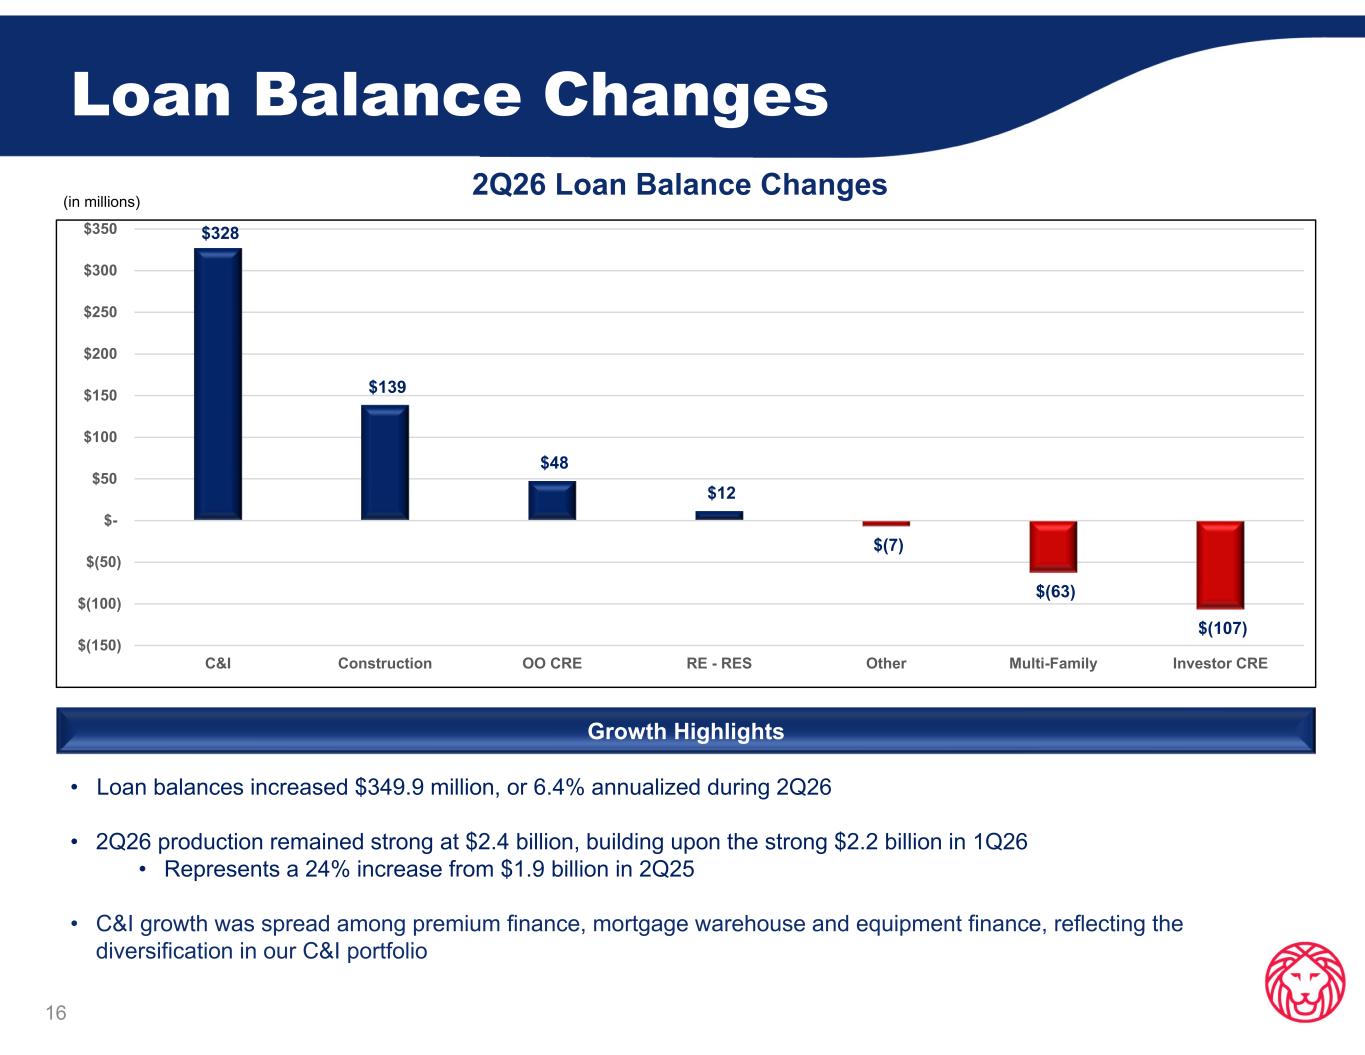
Loan Balance Changes 2Q26 Loan Balance Changes 16 • Loan balances increased $349.9 million, or 6.4% annualized during 2Q26 • 2Q26 production remained strong at $2.4 billion, building upon the strong $2.2 billion in 1Q26 • Represents a 24% increase from $1.9 billion in 2Q25 • C&I growth was spread among premium finance, mortgage warehouse and equipment finance, reflecting the diversification in our C&I portfolio (in millions) Growth Highlights $328 $139 $48 $12 $(7) $(63) $(107) $(150) $(100) $(50) $- $50 $100 $150 $200 $250 $300 $350 C&I Construction OO CRE RE - RES Other Multi-Family Investor CRE
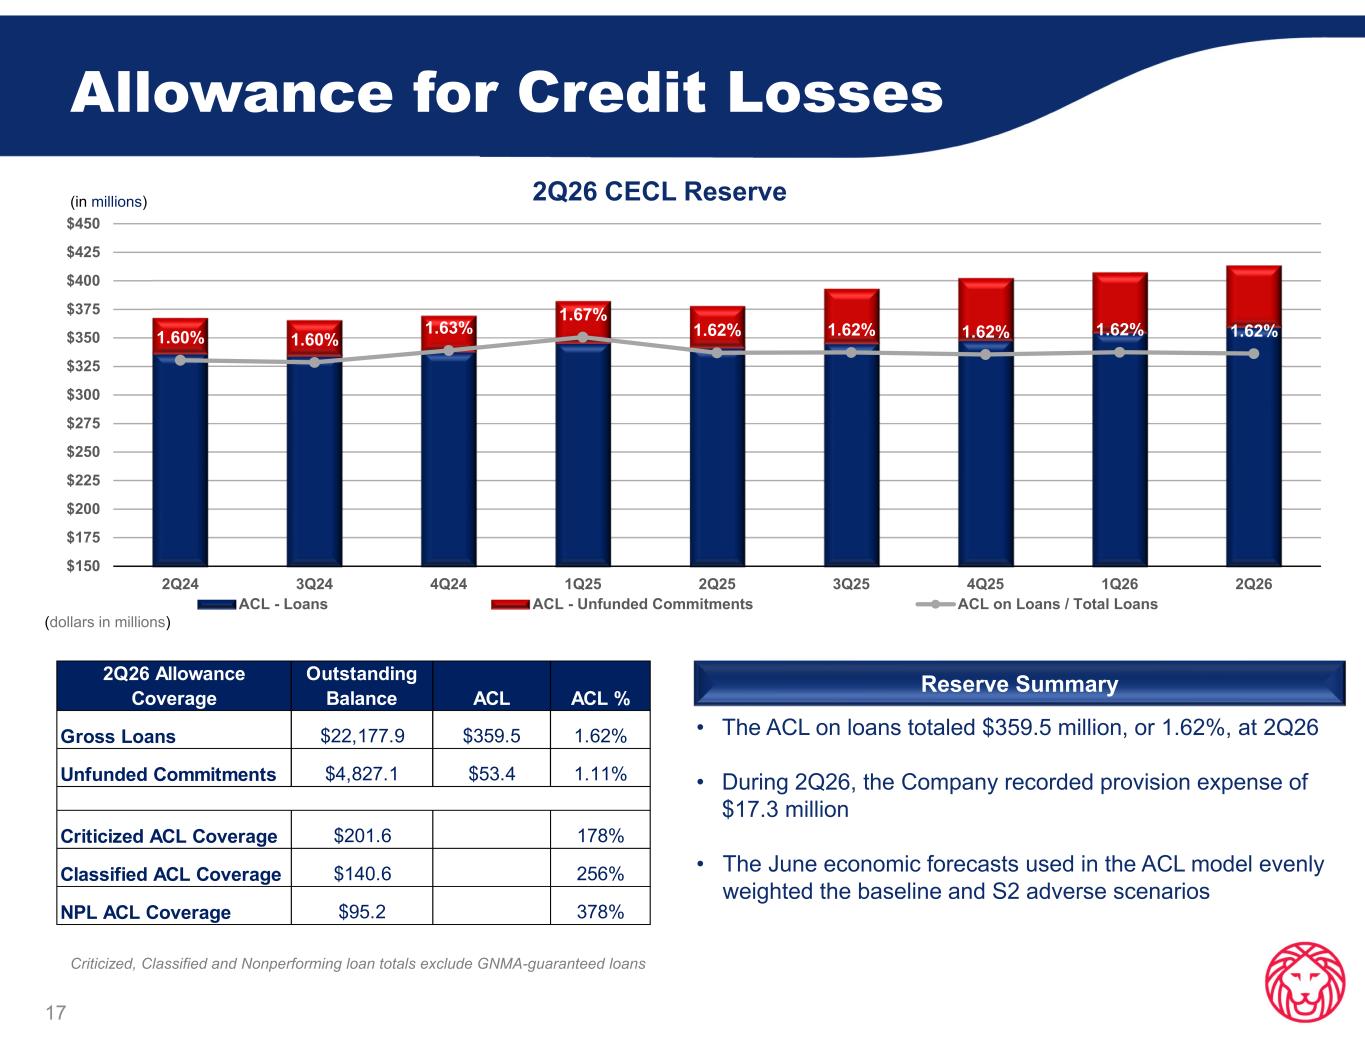
Allowance for Credit Losses 17 • The ACL on loans totaled $359.5 million, or 1.62%, at 2Q26 • During 2Q26, the Company recorded provision expense of $17.3 million • The June economic forecasts used in the ACL model evenly weighted the baseline and S2 adverse scenarios 2Q26 CECL Reserve Reserve Summary (in millions) (dollars in millions) 1.60% 1.60% 1.63% 1.67% 1.62% 1.62% 1.62% 1.62% 1.62% 1.00% 1.20% 1.40% 1.60% 1.80% 2.00% $150 $175 $200 $225 $250 $275 $300 $325 $350 $375 $400 $425 $450 2Q24 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 ACL - Loans ACL - Unfunded Commitments ACL on Loans / Total Loans 2Q26 Allowance Coverage Outstanding Balance ACL ACL % Gross Loans $22,177.9 $359.5 1.62% Unfunded Commitments $4,827.1 $53.4 1.11% Criticized ACL Coverage $201.6 178% Classified ACL Coverage $140.6 256% NPL ACL Coverage $95.2 378% Criticized, Classified and Nonperforming loan totals exclude GNMA-guaranteed loans
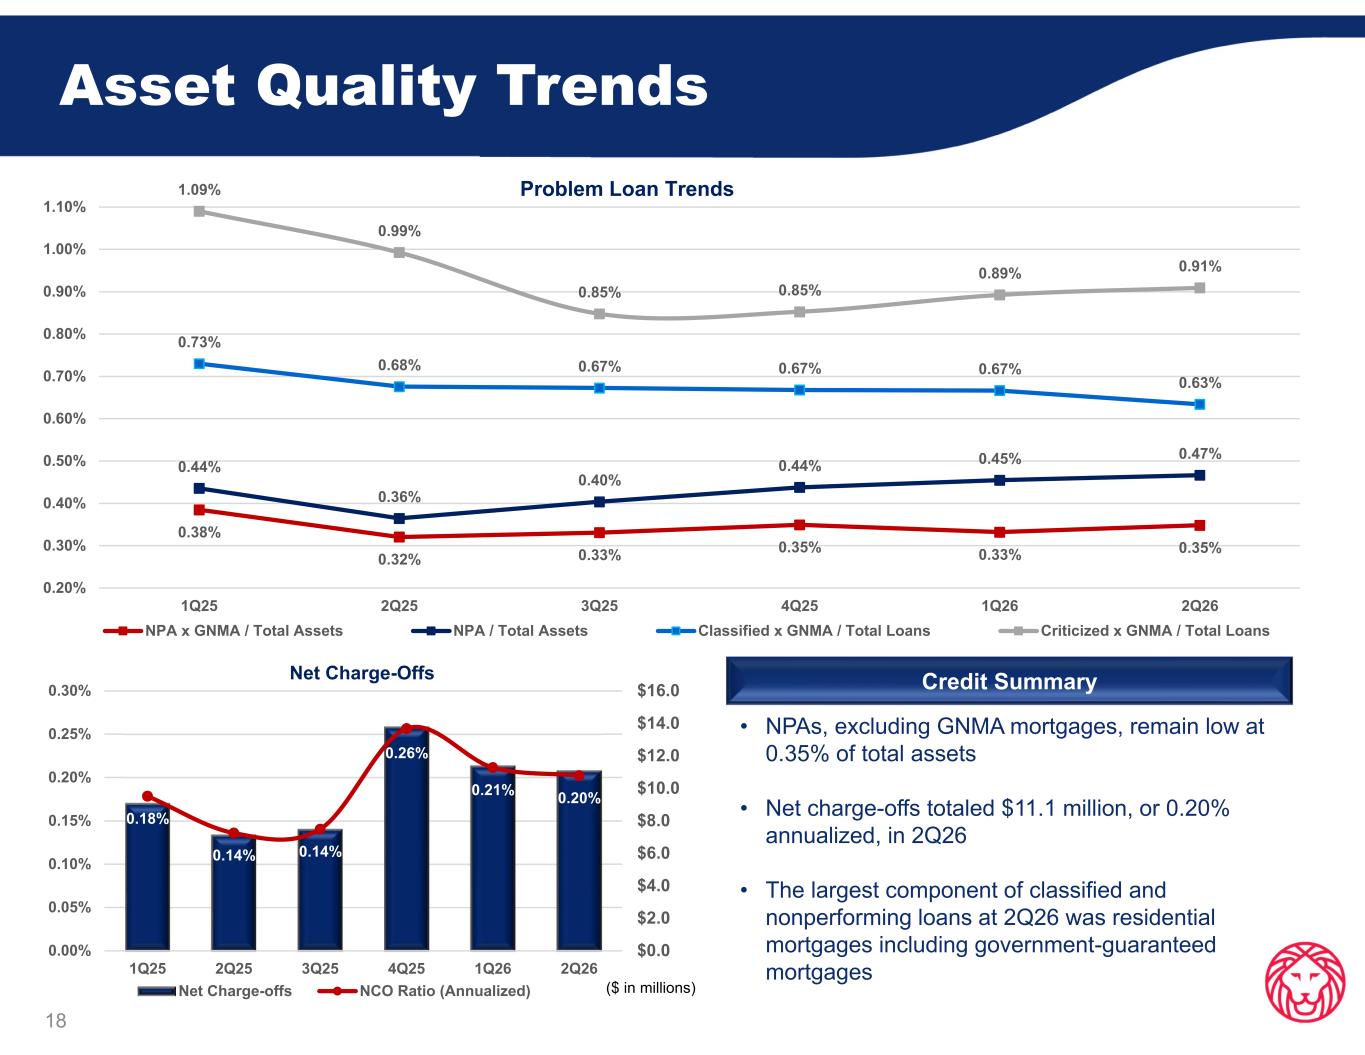
Asset Quality Trends 18 • NPAs, excluding GNMA mortgages, remain low at 0.35% of total assets • Net charge-offs totaled $11.1 million, or 0.20% annualized, in 2Q26 • The largest component of classified and nonperforming loans at 2Q26 was residential mortgages including government-guaranteed mortgages Credit Summary ($ in millions) 0.18% 0.14% 0.14% 0.26% 0.21% 0.20% $0.0 $2.0 $4.0 $6.0 $8.0 $10.0 $12.0 $14.0 $16.0 0.00% 0.05% 0.10% 0.15% 0.20% 0.25% 0.30% 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Net Charge-Offs Net Charge-offs NCO Ratio (Annualized) 0.38% 0.32% 0.33% 0.35% 0.33% 0.35% 0.44% 0.36% 0.40% 0.44% 0.45% 0.47% 0.73% 0.68% 0.67% 0.67% 0.67% 0.63% 1.09% 0.99% 0.85% 0.85% 0.89% 0.91% 0.20% 0.30% 0.40% 0.50% 0.60% 0.70% 0.80% 0.90% 1.00% 1.10% 1Q25 2Q25 3Q25 4Q25 1Q26 2Q26 Problem Loan Trends NPA x GNMA / Total Assets NPA / Total Assets Classified x GNMA / Total Loans Criticized x GNMA / Total Loans
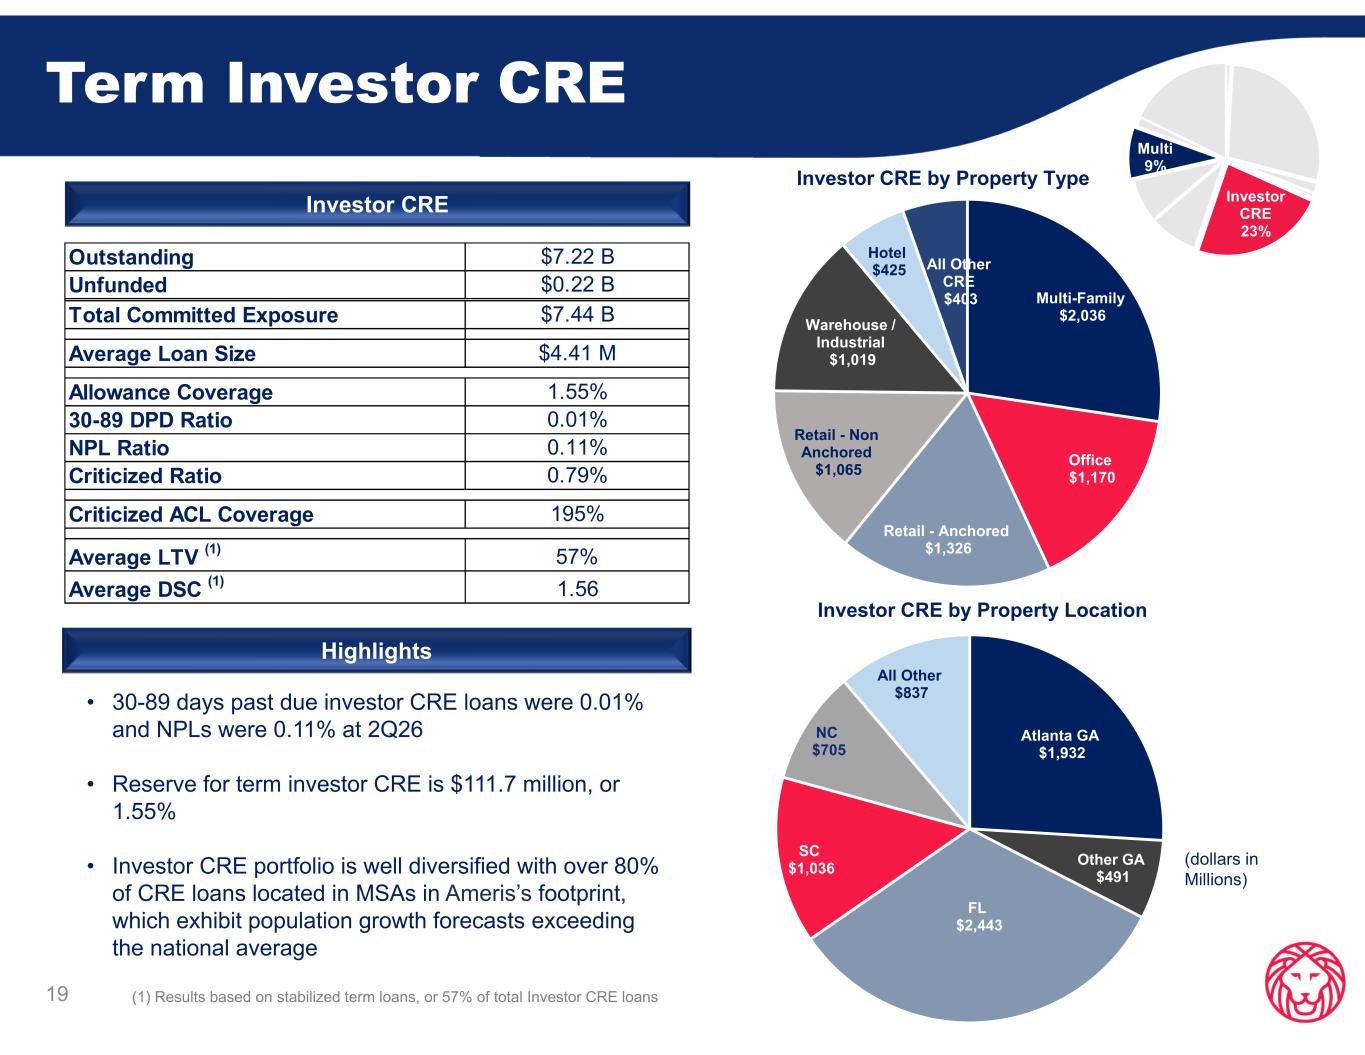
Term Investor CRE • 30-89 days past due investor CRE loans were 0.01% and NPLs were 0.11% at 2Q26 • Reserve for term investor CRE is $111.7 million, or 1.55% • Investor CRE portfolio is well diversified with over 80% of CRE loans located in MSAs in Ameris’s footprint, which exhibit population growth forecasts exceeding the national average 19 Highlights (1) Results based on stabilized term loans, or 57% of total Investor CRE loans Investor CRE (dollars in Millions) Outstanding $7.22 B Unfunded $0.22 B Total Committed Exposure $7.44 B Average Loan Size $4.41 M Allowance Coverage 1.55% 30-89 DPD Ratio 0.01% NPL Ratio 0.11% Criticized Ratio 0.79% Criticized ACL Coverage 195% Average LTV (1) 57% Average DSC (1) 1.56 Atlanta GA $1,932 Other GA $491 FL $2,443 SC $1,036 NC $705 All Other $837 Investor CRE by Property Location Multi-Family $2,036 Office $1,170 Retail - Anchored $1,326 Retail - Non Anchored $1,065 Warehouse / Industrial $1,019 Hotel $425 All Other CRE $403 Investor CRE by Property Type Investor CRE 23% Multi 9%
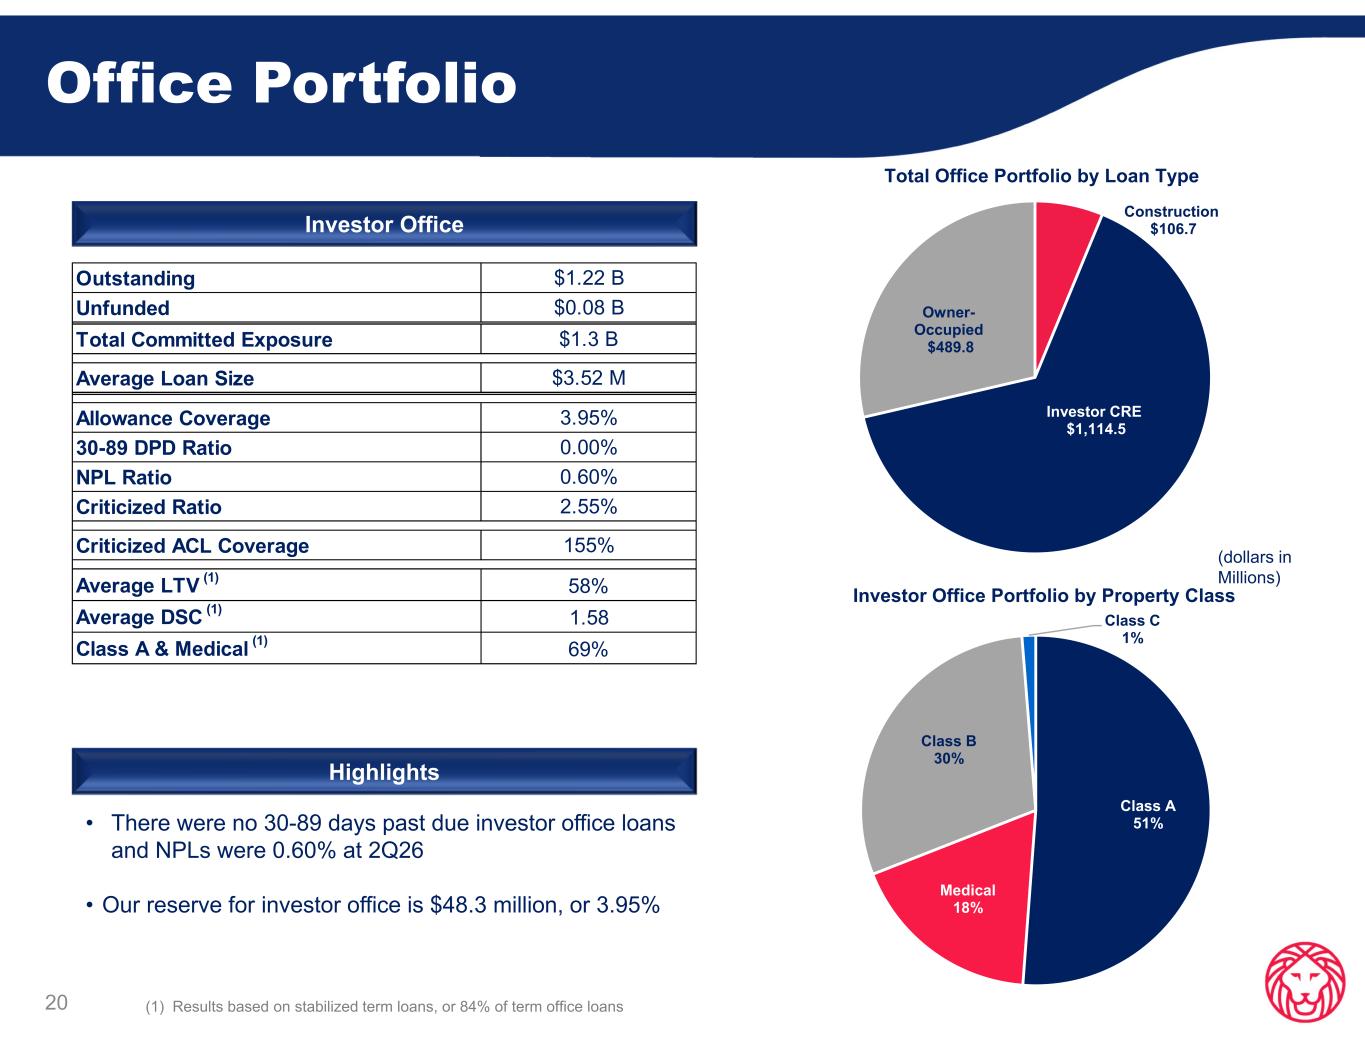
Office Portfolio • There were no 30-89 days past due investor office loans and NPLs were 0.60% at 2Q26 • Our reserve for investor office is $48.3 million, or 3.95% 20 Highlights (1) Results based on stabilized term loans, or 84% of term office loans Investor Office (dollars in Millions) Construction $106.7 Investor CRE $1,114.5 Owner- Occupied $489.8 Total Office Portfolio by Loan Type Class A 51% Medical 18% Class B 30% Class C 1% Investor Office Portfolio by Property Class Outstanding $1.22 B Unfunded $0.08 B Total Committed Exposure $1.3 B Average Loan Size $3.52 M Allowance Coverage 3.95% 30-89 DPD Ratio 0.00% NPL Ratio 0.60% Criticized Ratio 2.55% Criticized ACL Coverage 155% Average LTV (1) 58% Average DSC (1) 1.58 Class A & Medical (1) 69%
Appendix
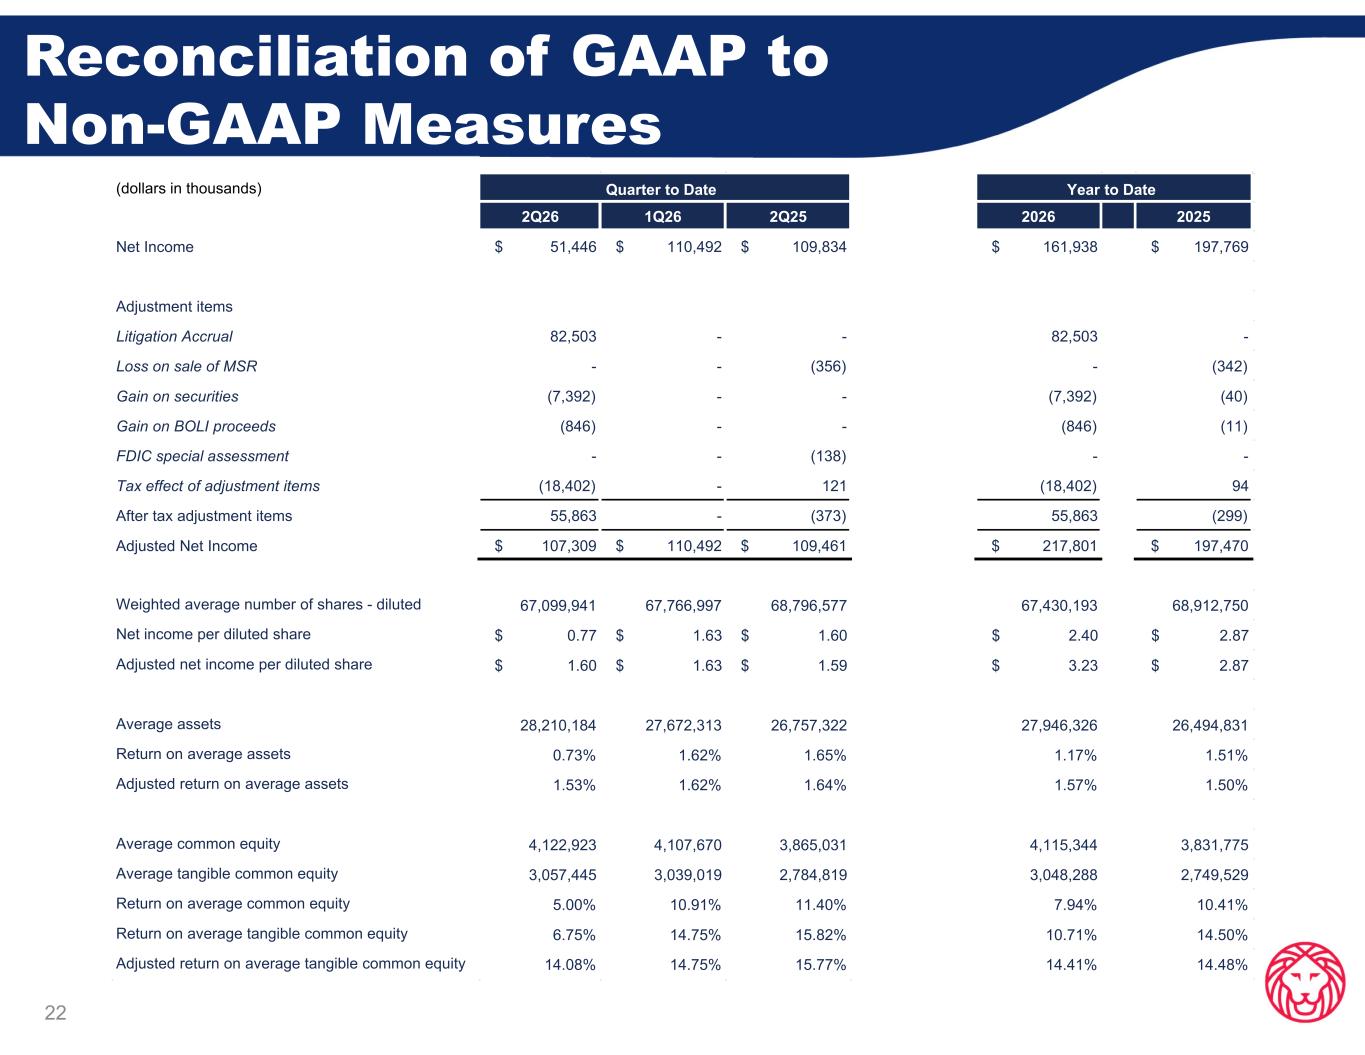
22 Reconciliation of GAAP to Non-GAAP Measures (dollars in thousands) 2Q26 1Q26 2Q25 2026 2025 Net Income $ 51,446 $ 110,492 $ 109,834 $ 161,938 $ 197,769 Adjustment items Litigation Accrual 82,503 - - 82,503 - Loss on sale of MSR - - (356) - (342) Gain on securities (7,392) - - (7,392) (40) Gain on BOLI proceeds (846) - - (846) (11) FDIC special assessment - - (138) - - Tax effect of adjustment items (18,402) - 121 (18,402) 94 After tax adjustment items 55,863 - (373) 55,863 (299) Adjusted Net Income $ 107,309 $ 110,492 $ 109,461 $ 217,801 $ 197,470 Weighted average number of shares - diluted 67,099,941 67,766,997 68,796,577 67,430,193 68,912,750 Net income per diluted share $ 0.77 $ 1.63 $ 1.60 $ 2.40 $ 2.87 Adjusted net income per diluted share $ 1.60 $ 1.63 $ 1.59 $ 3.23 $ 2.87 Average assets 28,210,184 27,672,313 26,757,322 27,946,326 26,494,831 Return on average assets 0.73% 1.62% 1.65% 1.17% 1.51% Adjusted return on average assets 1.53% 1.62% 1.64% 1.57% 1.50% Average common equity 4,122,923 4,107,670 3,865,031 4,115,344 3,831,775 Average tangible common equity 3,057,445 3,039,019 2,784,819 3,048,288 2,749,529 Return on average common equity 5.00% 10.91% 11.40% 7.94% 10.41% Return on average tangible common equity 6.75% 14.75% 15.82% 10.71% 14.50% Adjusted return on average tangible common equity 14.08% 14.75% 15.77% 14.41% 14.48% Quarter to Date Year to Date
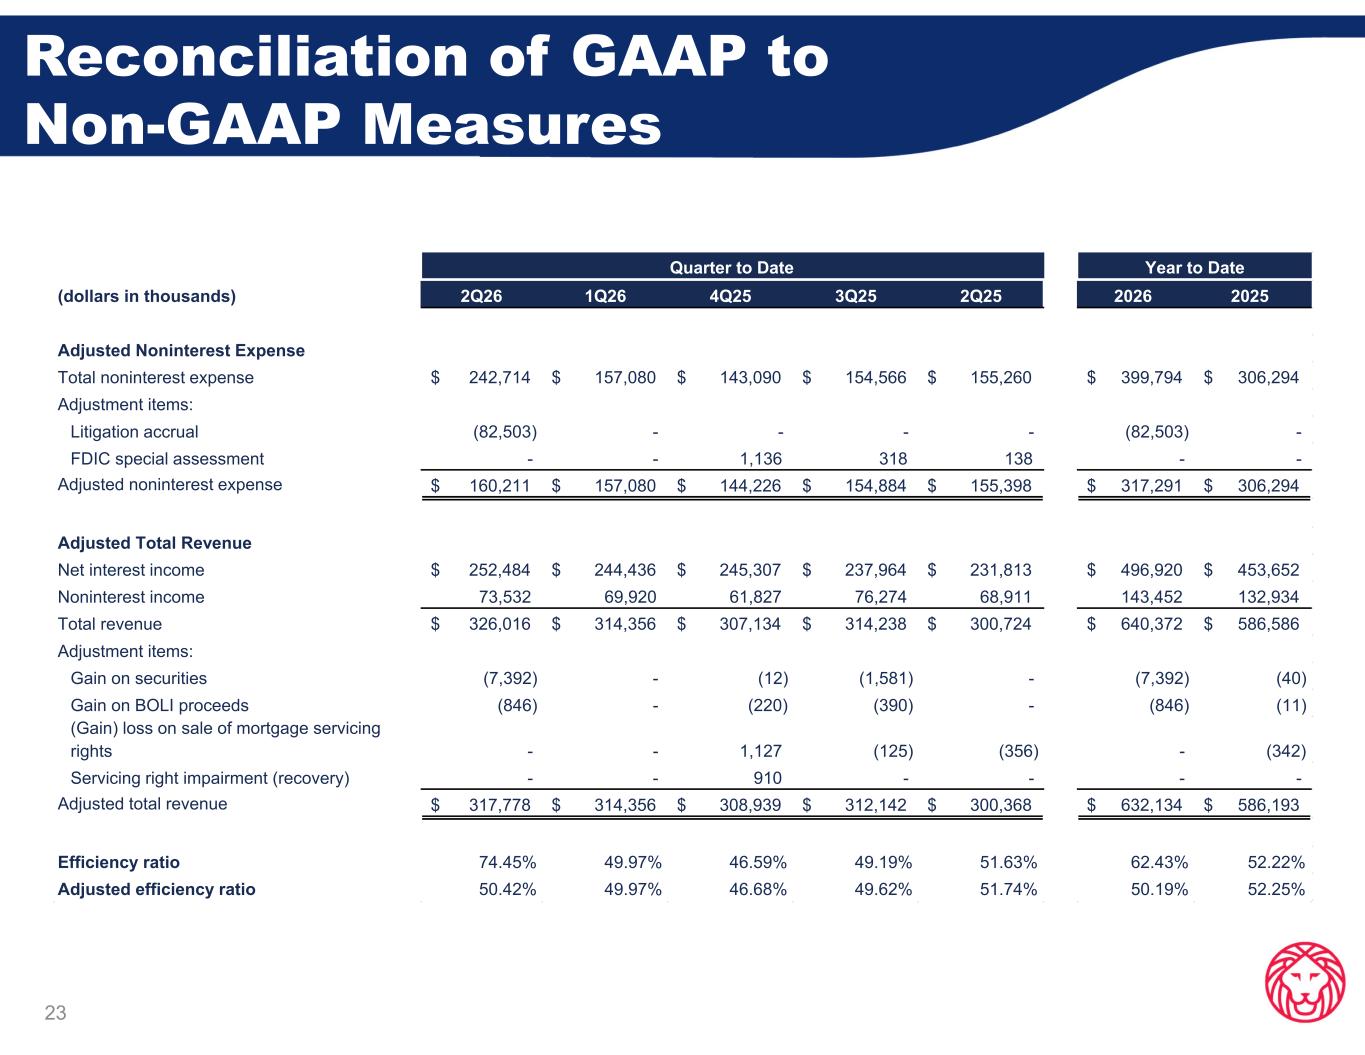
23 Reconciliation of GAAP to Non-GAAP Measures (dollars in thousands) 2Q26 1Q26 4Q25 3Q25 2Q25 2026 2025 Adjusted Noninterest Expense Total noninterest expense 242,714$ 157,080$ 143,090$ 154,566$ 155,260$ 399,794$ 306,294$ Adjustment items: Litigation accrual (82,503) - - - - (82,503) - FDIC special assessment - - 1,136 318 138 - - Adjusted noninterest expense 160,211$ 157,080$ 144,226$ 154,884$ 155,398$ 317,291$ 306,294$ Adjusted Total Revenue Net interest income 252,484$ 244,436$ 245,307$ 237,964$ 231,813$ 496,920$ 453,652$ Noninterest income 73,532 69,920 61,827 76,274 68,911 143,452 132,934 Total revenue 326,016$ 314,356$ 307,134$ 314,238$ 300,724$ 640,372$ 586,586$ Adjustment items: Gain on securities (7,392) - (12) (1,581) - (7,392) (40) Gain on BOLI proceeds (846) - (220) (390) - (846) (11) (Gain) loss on sale of mortgage servicing rights - - 1,127 (125) (356) - (342) Servicing right impairment (recovery) - - 910 - - - - Adjusted total revenue 317,778$ 314,356$ 308,939$ 312,142$ 300,368$ 632,134$ 586,193$ Efficiency ratio 74.45% 49.97% 46.59% 49.19% 51.63% 62.43% 52.22% Adjusted efficiency ratio 50.42% 49.97% 46.68% 49.62% 51.74% 50.19% 52.25% Year to DateQuarter to Date
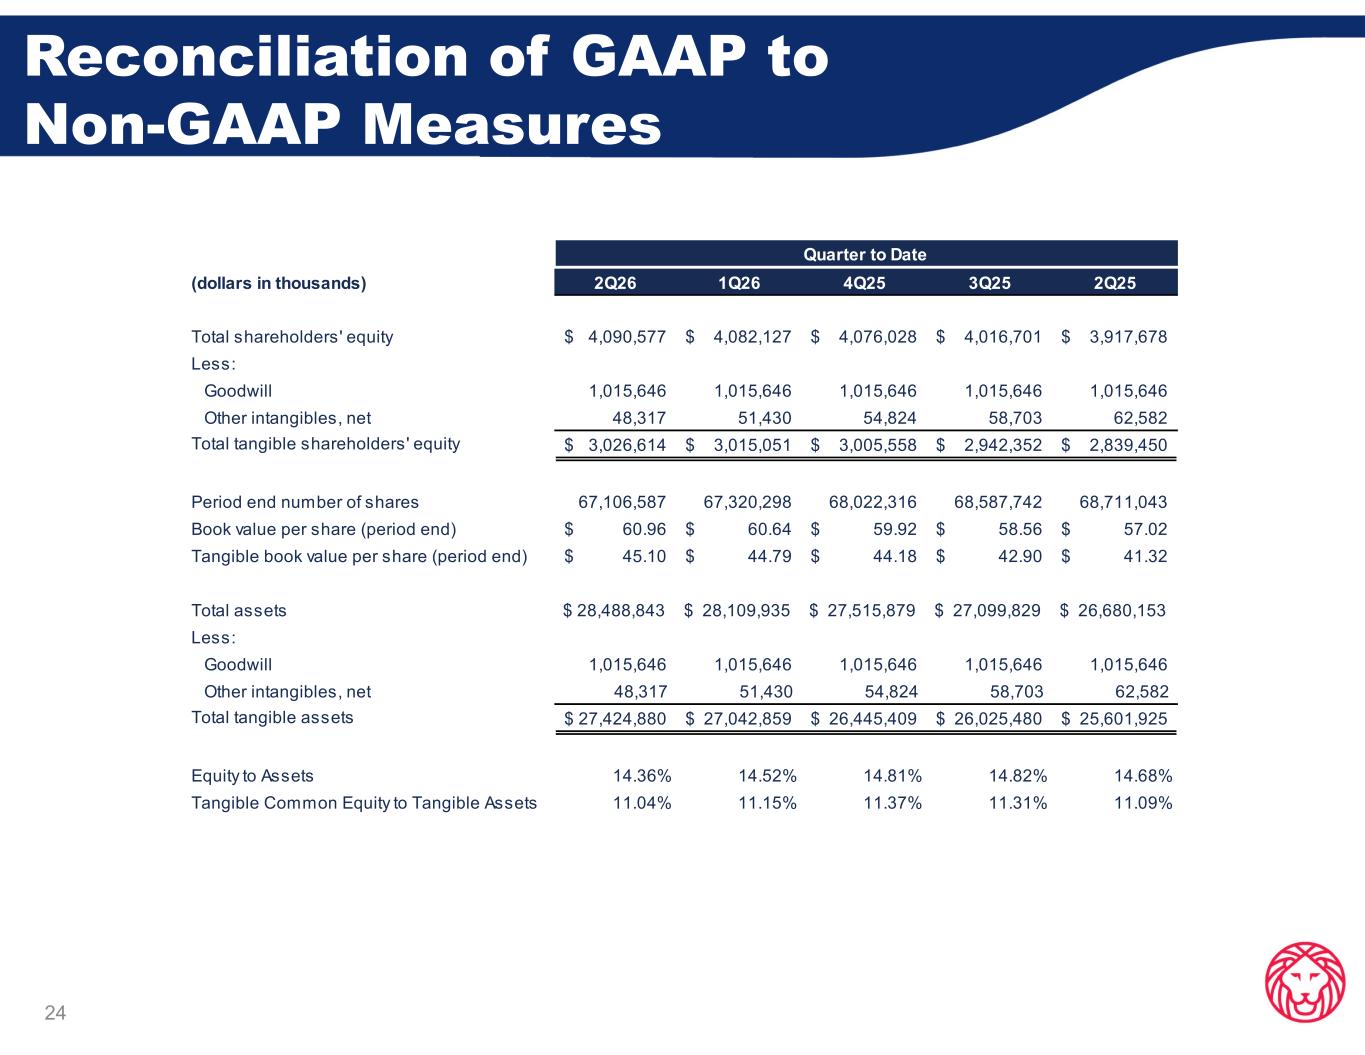
24 Reconciliation of GAAP to Non-GAAP Measures (dollars in thousands) 2Q26 1Q26 4Q25 3Q25 2Q25 Total shareholders' equity 4,090,577$ 4,082,127$ 4,076,028$ 4,016,701$ 3,917,678$ Less: Goodwill 1,015,646 1,015,646 1,015,646 1,015,646 1,015,646 Other intangibles, net 48,317 51,430 54,824 58,703 62,582 Total tangible shareholders' equity 3,026,614$ 3,015,051$ 3,005,558$ 2,942,352$ 2,839,450$ Period end number of shares 67,106,587 67,320,298 68,022,316 68,587,742 68,711,043 Book value per share (period end) 60.96$ 60.64$ 59.92$ 58.56$ 57.02$ Tangible book value per share (period end) 45.10$ 44.79$ 44.18$ 42.90$ 41.32$ Total assets $ 28,488,843 $ 28,109,935 $ 27,515,879 $ 27,099,829 $ 26,680,153 Less: Goodwill 1,015,646 1,015,646 1,015,646 1,015,646 1,015,646 Other intangibles, net 48,317 51,430 54,824 58,703 62,582 Total tangible assets 27,424,880$ 27,042,859$ 26,445,409$ 26,025,480$ 25,601,925$ Equity to Assets 14.36% 14.52% 14.81% 14.82% 14.68% Tangible Common Equity to Tangible Assets 11.04% 11.15% 11.37% 11.31% 11.09% Quarter to Date
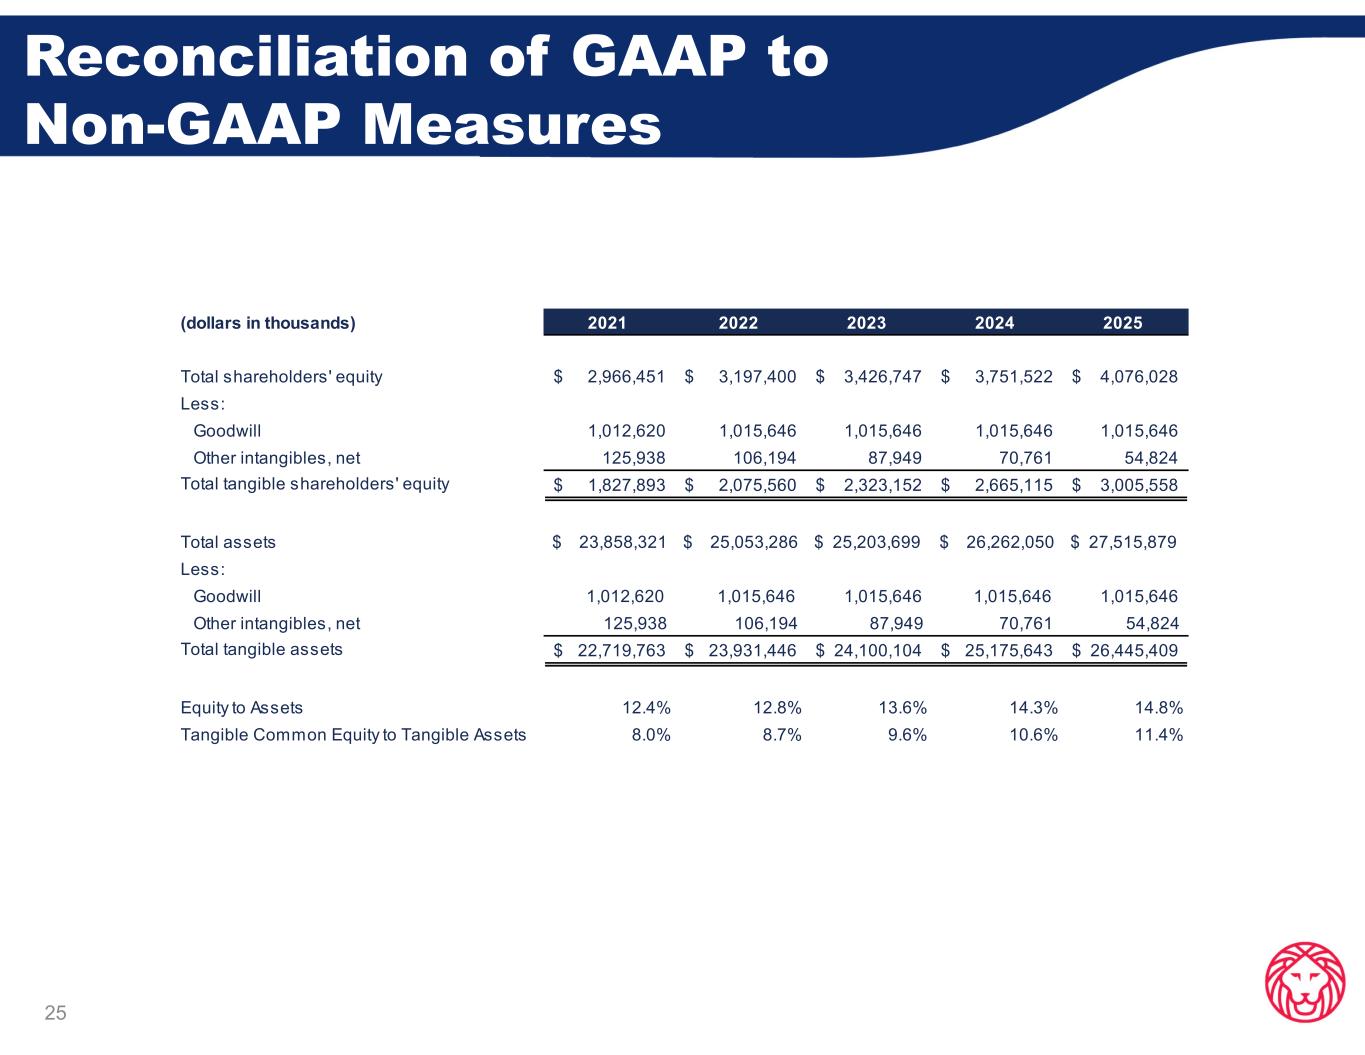
25 Reconciliation of GAAP to Non-GAAP Measures (dollars in thousands) 2021 2022 2023 2024 2025 Total shareholders' equity 2,966,451$ 3,197,400$ 3,426,747$ 3,751,522$ 4,076,028$ Less: Goodwill 1,012,620 1,015,646 1,015,646 1,015,646 1,015,646 Other intangibles, net 125,938 106,194 87,949 70,761 54,824 Total tangible shareholders' equity 1,827,893$ 2,075,560$ 2,323,152$ 2,665,115$ 3,005,558$ Total assets $ 23,858,321 $ 25,053,286 $ 25,203,699 $ 26,262,050 $ 27,515,879 Less: Goodwill 1,012,620 1,015,646 1,015,646 1,015,646 1,015,646 Other intangibles, net 125,938 106,194 87,949 70,761 54,824 Total tangible assets 22,719,763$ 23,931,446$ 24,100,104$ 25,175,643$ 26,445,409$ Equity to Assets 12.4% 12.8% 13.6% 14.3% 14.8% Tangible Common Equity to Tangible Assets 8.0% 8.7% 9.6% 10.6% 11.4%
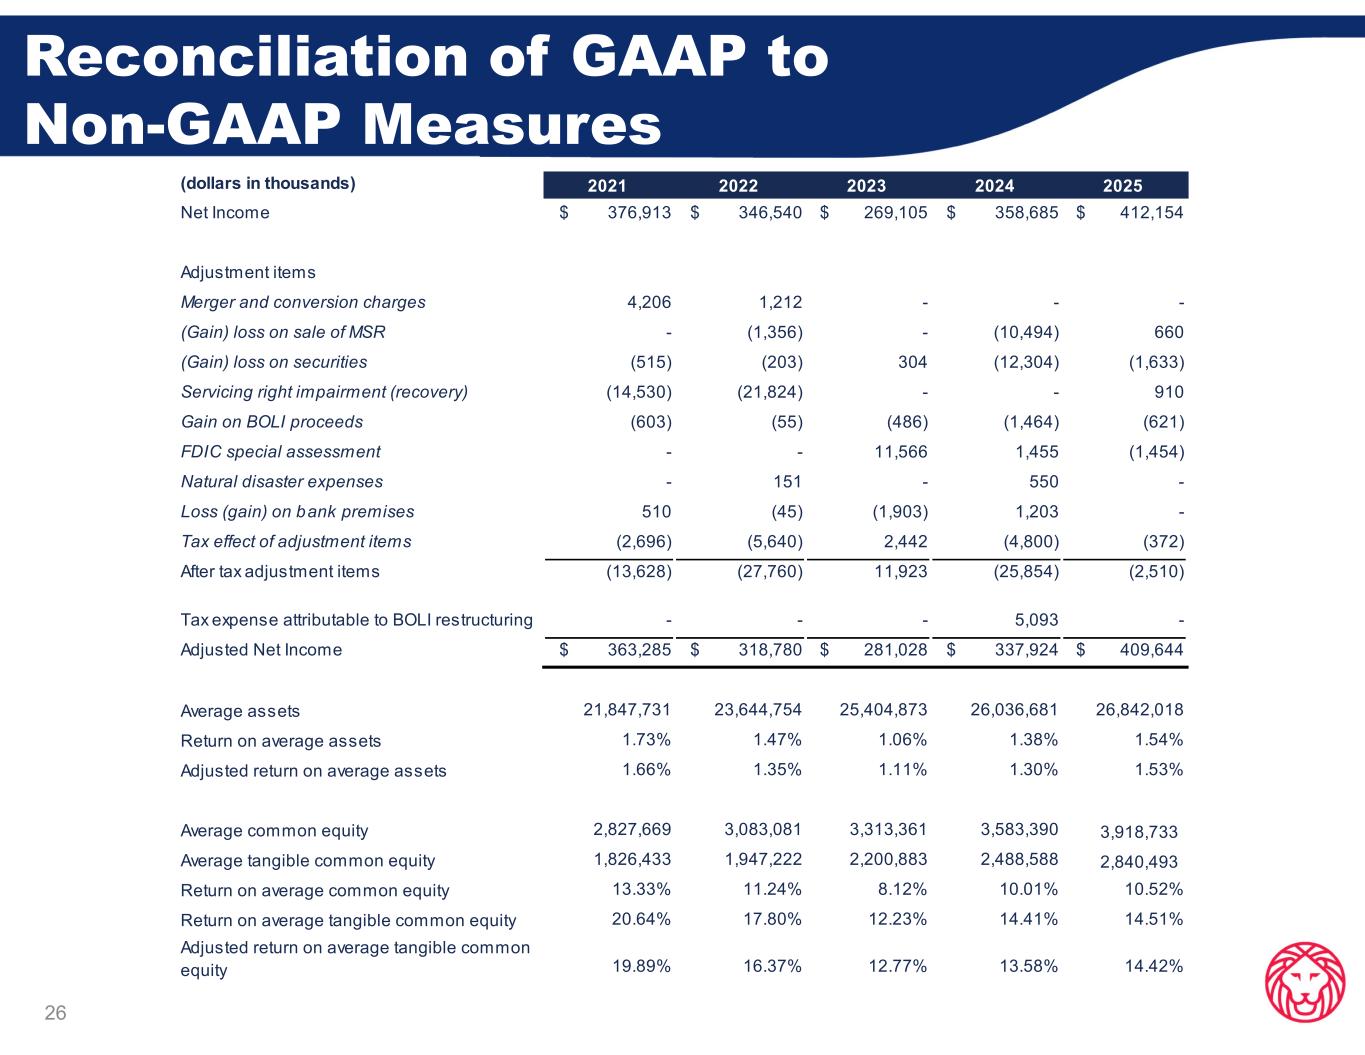
26 Reconciliation of GAAP to Non-GAAP Measures (dollars in thousands) 2021 2022 2023 2024 2025 Net Income $ 376,913 $ 346,540 $ 269,105 $ 358,685 $ 412,154 Adjustment items Merger and conversion charges 4,206 1,212 - - - (Gain) loss on sale of MSR - (1,356) - (10,494) 660 (Gain) loss on securities (515) (203) 304 (12,304) (1,633) Servicing right impairment (recovery) (14,530) (21,824) - - 910 Gain on BOLI proceeds (603) (55) (486) (1,464) (621) FDIC special assessment - - 11,566 1,455 (1,454) Natural disaster expenses - 151 - 550 - Loss (gain) on bank premises 510 (45) (1,903) 1,203 - Tax effect of adjustment items (2,696) (5,640) 2,442 (4,800) (372) After tax adjustment items (13,628) (27,760) 11,923 (25,854) (2,510) Tax expense attributable to BOLI restructuring - - - 5,093 - Adjusted Net Income $ 363,285 $ 318,780 $ 281,028 $ 337,924 $ 409,644 Average assets 21,847,731 23,644,754 25,404,873 26,036,681 26,842,018 Return on average assets 1.73% 1.47% 1.06% 1.38% 1.54% Adjusted return on average assets 1.66% 1.35% 1.11% 1.30% 1.53% Average common equity 2,827,669 3,083,081 3,313,361 3,583,390 3,918,733 Average tangible common equity 1,826,433 1,947,222 2,200,883 2,488,588 2,840,493 Return on average common equity 13.33% 11.24% 8.12% 10.01% 10.52% Return on average tangible common equity 20.64% 17.80% 12.23% 14.41% 14.51% Adjusted return on average tangible common equity 19.89% 16.37% 12.77% 13.58% 14.42%
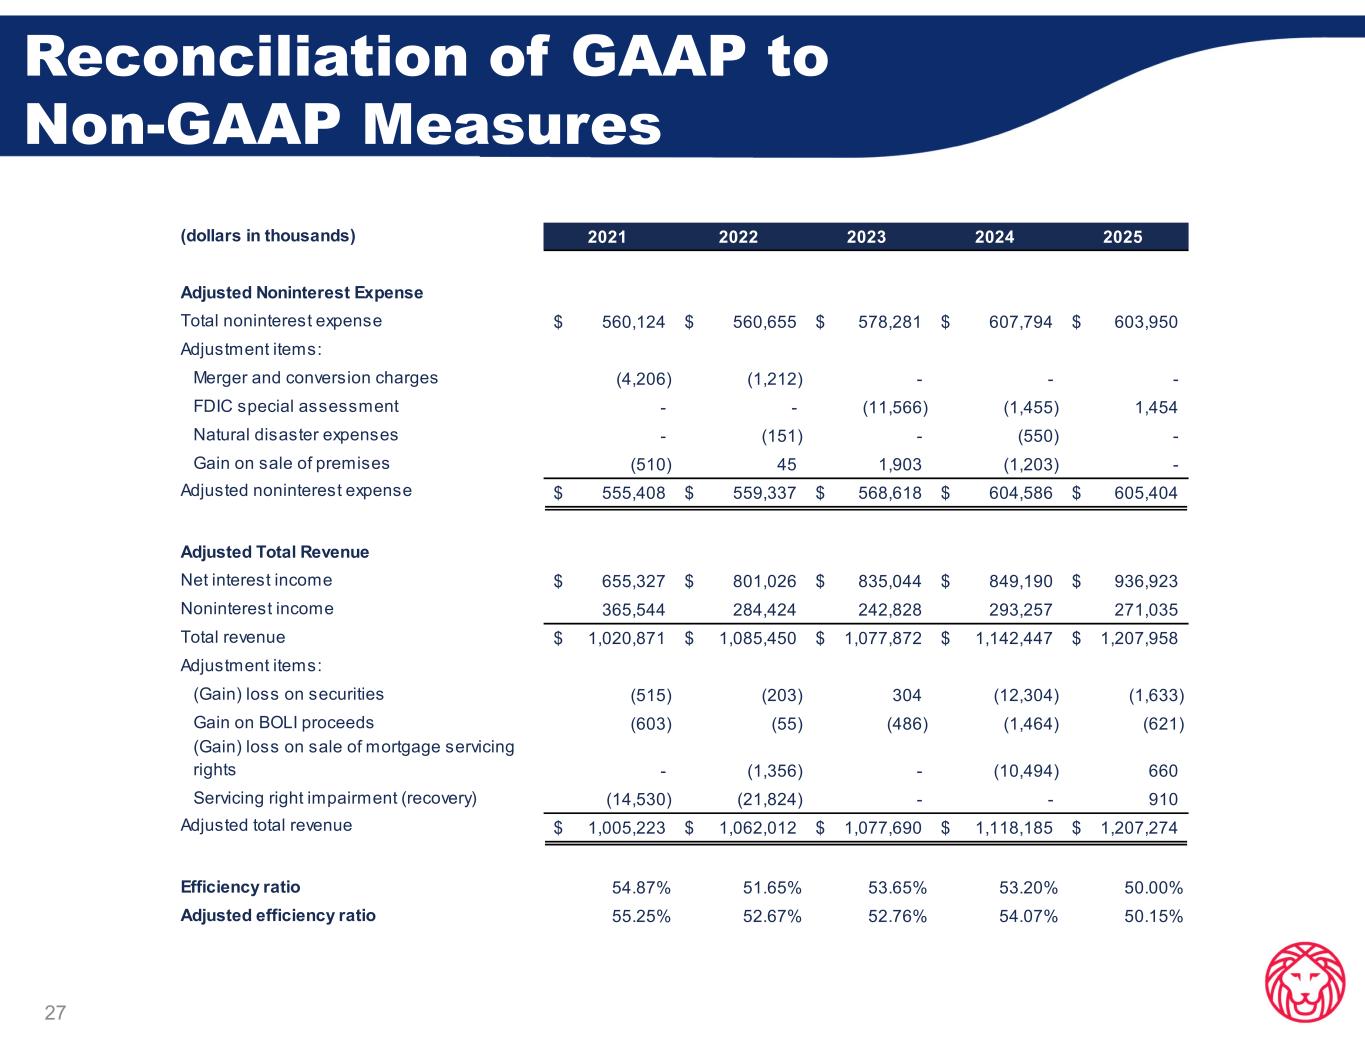
27 Reconciliation of GAAP to Non-GAAP Measures (dollars in thousands) 2021 2022 2023 2024 2025 Adjusted Noninterest Expense Total noninterest expense 560,124$ 560,655$ 578,281$ 607,794$ 603,950$ Adjustment items: Merger and conversion charges (4,206) (1,212) - - - FDIC special assessment - - (11,566) (1,455) 1,454 Natural disaster expenses - (151) - (550) - Gain on sale of premises (510) 45 1,903 (1,203) - Adjusted noninterest expense 555,408$ 559,337$ 568,618$ 604,586$ 605,404$ Adjusted Total Revenue Net interest income 655,327$ 801,026$ 835,044$ 849,190$ 936,923$ Noninterest income 365,544 284,424 242,828 293,257 271,035 Total revenue 1,020,871$ 1,085,450$ 1,077,872$ 1,142,447$ 1,207,958$ Adjustment items: (Gain) loss on securities (515) (203) 304 (12,304) (1,633) Gain on BOLI proceeds (603) (55) (486) (1,464) (621) (Gain) loss on sale of mortgage servicing rights - (1,356) - (10,494) 660 Servicing right impairment (recovery) (14,530) (21,824) - - 910 Adjusted total revenue 1,005,223$ 1,062,012$ 1,077,690$ 1,118,185$ 1,207,274$ Efficiency ratio 54.87% 51.65% 53.65% 53.20% 50.00% Adjusted efficiency ratio 55.25% 52.67% 52.76% 54.07% 50.15%