
ASB 8-K
Associated Banc-Corp (ASB)
8-K
2021-01-21
For: 2021-01-21
View Original
Added on
April 06, 2026
| UNITED STATES SECURITIES AND EXCHANGE COMMISSION WASHINGTON, DC 20549 | |||||
| FORM | |||||
| CURRENT REPORT | |||||
| Pursuant to Section 13 OR 15(d) of the Securities Exchange Act of 1934 | |||||
| Date of Report (Date of earliest event reported) | |||||
| | ||
| (Exact name of registrant as specified in its chapter) | ||
(State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||
| (Address of principal executive offices) | (Zip code) | ||||||||||
| Registrant’s telephone number, including area code | ||||||||
| (Former name or former address, if changed since last report) | |||||
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below): | |||||
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities Registered Pursuant to Section 12(b) of the act:
| Title of each class | Trading symbol | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). | |||||
Emerging growth company | |||||
☐ | If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. | ||||
| Item 2.02 Results of Operations and Financial Condition. | ||
| On January 21, 2021, Associated Banc-Corp announced its earnings for the quarter ended December 31, 2020. A copy of the registrant’s press release containing this information and the slide presentation discussed on the conference call for investors and analysts on January 21, 2021, are being furnished as Exhibit 99.1 and Exhibit 99.2, respectively, to this Report on Form 8-K and are incorporated herein by reference. | ||
| Item 9.01 Financial Statements and Exhibits. | ||
(d) Exhibits. | ||
The following exhibits are furnished as part of this Report on Form 8-K: | ||
| SIGNATURES | ||||||||
| Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized. | ||||||||
| Associated Banc-Corp | ||||||||
| (Registrant) | ||||||||
| Date: January 21, 2021 | By: /s/ Christopher J. Del Moral-Niles | |||||||
| Christopher J. Del Moral-Niles | ||||||||
| Chief Financial Officer | ||||||||
Exhibit 99.1
 | NEWS RELEASE Investor Contact: Ben McCarville, Vice President, Director of Investor Relations 920-491-7059 Media Contact: Jennifer Kaminski, Vice President, Public Relations Senior Manager 920-491-7576 | ||||
Associated Banc-Corp Reports Fourth Quarter 2020 Earnings of $0.40 Per Common Share and $1.86 Per Common Share for the Full Year 2020.
GREEN BAY, Wis. -- January 21, 2021 -- Associated Banc-Corp (NYSE: ASB) ("Associated" or "Company") today reported net income available to common equity ("earnings") of $62 million, or $0.40 per common share, for the quarter ended December 31, 2020. These amounts compare to earnings of $40 million, or $0.26 per common share for the quarter ended September 30, 2020. For the year ended December 31, 2020, the Company reported earnings of $288 million, or $1.86 per common share; or $1.19 per common share excluding the gain on sale of Associated Benefits and Risk Consulting1. These amounts compare to earnings of $312 million, or $1.91 per common share, for the year ended December 31, 2019.
“In the face of an extraordinarily challenging environment,” said President and CEO Philip B. Flynn, “We reimagined and reengineered the way we service our customers while driving higher engagement and satisfaction; we grew loans, customer deposits, and capital to record levels; and we adopted our service models while also streamlining our branch network and back office functions. Our strategies to grow low-cost deposits and widen commercial loan margins took hold in the fourth quarter. In addition, we exited several lower-margin businesses and geographies. Our agility and approach have positioned us well to participate in the economic recovery we expect to see in 2021.”
The Company also announced today that Mr. Flynn has informed its Board of Directors of his plans to retire at the end of 2021. The Board has commenced a search for a permanent successor which will consider our internal as well as external candidates. Mr. Flynn will continue as president and CEO until a successor is in place, at which time he will step down from both roles and from the board of directors. Mr. Flynn will then be available to the new CEO in an advisory capacity. Additional details can be found in the press release available at http://investor.associatedbank.com.
2020 SUMMARY (all comparisons to 2019)
•Average loans of $24.5 billion were up 6%, or $1.4 billion
•Average deposits of $26.0 billion were up 5%, or $1.3 billion
•Net interest income of $763 million decreased 9%, or $73 million
•Net interest margin of 2.53%, declined 33 basis points from 2.86%
•Provision for credit losses was $174 million, compared to $16 million
•Noninterest income of $514 million increased 35%, or $133 million
•Noninterest expense of $776 million decreased 2%, or $18 million
•Tangible book value per share was $16.67, up 9% from $15.28
1This is a non-GAAP financial measure. Management believes these measures are meaningful because they reflect adjustments commonly made by management, investors, regulators, and analysts to evaluate the adequacy of earnings per common share, provide greater understanding of ongoing operations and enhance comparability of results with prior periods. See pages 10 and 11 of the attached tables for a reconciliation of non-GAAP financial measures to GAAP financial measures.
Loans
Full year 2020 average loans of $24.5 billion were up 6%, or $1.4 billion from 2019, driven by Paycheck Protection Program (PPP) and commercial real estate lending. With respect to full year 2020 average balances by loan category compared to 2019:
•Commercial and business lending increased $983 million, or 12%, to $9.4 billion, primarily due to growth in PPP.
•Commercial real estate lending increased $661 million, or 13%, to $5.8 billion, driven primarily by the funding of existing loan commitments throughout the year.
•Consumer lending decreased $230 million, or 2%, to $9.3 billion as residential mortgages refinanced and home equity loans paid down.
Fourth quarter 2020 average loans of $24.7 billion were down 1%, or $281 million from the third quarter 2020 and were up 8%, or $1.9 billion from the same period last year. With respect to fourth quarter average balances by loan category:
•Commercial real estate lending increased $125 million from the third quarter 2020 and $963 million from the same period last year to $6.2 billion.
•Consumer lending was $9.1 billion, down $79 million from the third quarter 2020 and down $300 million from the same period last year.
•Commercial and business lending decreased $327 million from third quarter 2020, driven by PPP forgiveness, and increased $1.2 billion compared to the same period last year to $9.4 billion.
We expect full-year commercial loan growth of 2%-4% in 2021, driven by a 4%-6% increase in CRE balances and a 1%-2% increase in C&I outstandings, excluding PPP.
Deposits
Full year 2020 average deposits of $26.0 billion increased 5%, or $1.3 billion from 2019.
With respect to full year 2020 average balances by deposit category as compared to 2019:
•Noninterest-bearing demand deposits increased $1.7 billion, or 32% to $6.9 billion.
•Savings increased $867 million, or 36% to $3.3 billion.
•Interest-bearing demand deposits increased $502 million, or 10% to $5.6 billion.
•Network transaction deposits decreased $418 million, or 22% to $1.4 billion.
•Money market deposits decreased $495 million, or 7% to $6.5 billion.
•Time deposits decreased $848 million, or 27% to $2.3 billion.
Fourth quarter 2020 average deposits of $26.7 billion were down $101 million compared to the third quarter 2020 and were up $2.6 billion, or 11%, from the same period last year.
With respect to fourth quarter 2020 average balances by deposit category:
•Noninterest-bearing demand deposits increased $265 million from the prior quarter and $2.2 billion from the same period last year to $7.7 billion.
•Savings increased $166 million from the prior quarter and $914 million from the same period last year to $3.6 billion.
•Interest-bearing demand deposits decreased $96 million from the prior quarter and increased $602 million from the same period last year to $5.7 billion.
•Money market deposits increased $75 million from the prior quarter and decreased $55 million from the same period last year to $6.5 billion.
•Time deposits decreased $248 million from the prior quarter and $859 million from the same period last year to $1.9 billion.
•Network transaction deposits decreased $262 million from the prior quarter and $173 million from the same period last year to $1.3 billion.
Net Interest Income and Net Interest Margin
Full year 2020 net interest income of $763 million was down 9%, or $73 million from 2019. Net interest margin of
2.53% was down 33 basis points from the prior year. The decreases in net interest income and margin were driven
by record low levels of interest rates and significant increases in liquidity during 2020.
•The average yield on total earning assets decreased 98 basis points from the prior year to 3.01%
•The average cost of interest-bearing liabilities decreased 78 basis points from the prior year to 0.65%.
•The net free funds benefit compressed 13 basis points from the prior year.
Fourth quarter 2020 net interest income of $188 million was up 3%, or $6 million from the prior quarter and the net interest margin increased 18 basis points, from the prior quarter to 2.49%. Compared to the same period last year, net interest income decreased 6%, or $12 million, and the net interest margin decreased 34 basis points.
•The average yield on total earning assets for the fourth quarter of 2020 increased 10 basis points from the prior quarter and decreased 98 basis points from the same period last year to 2.80%.
•The average cost of total interest-bearing liabilities for the fourth quarter of 2020 decreased 9 basis points from the prior quarter and decreased 80 basis points from the same period last year to 0.43%.
•The net free funds benefit for the fourth quarter of 2020 compressed one basis point from the prior quarter and compressed 16 basis points compared to the same period last year.
We would expect the full year’s margin to be between 2.55% and 2.65% in 2021.
Noninterest Income
Full year 2020 noninterest income of $514 million increased $133 million from the prior year.
•Net mortgage banking income increased $14 million from the prior year, driven by higher refinance activity.
•Gains on sales of assets increased $153 million from the prior year, due to the sale of Associated Benefits and Risk Consulting (ABRC). The sale of ABRC also drove the reduction in insurance revenue.
•Service charges and deposit account fees were down $7 million primarily driven by higher deposit account balances and reduced customer activity.
Fourth quarter 2020 total noninterest income of $86 million increased $10 million from the prior quarter and decreased $7 million from the same period last year.
With respect to fourth quarter 2020 noninterest income line items:
•Gains on previously disclosed sale of branches were $7 million.
•Mortgage Banking, net was $15 million for the fourth quarter, up $2 million from the previous quarter and up $8 million from the same period last year.
•Service charges and deposit account fees were $15 million for the fourth quarter, up $1 million from the previous quarter and down $1 million from the same period last year.
We expect noninterest income of $280 million to $300 million in 2021.
Noninterest Expense
Full year 2020 noninterest expense of $776 million decreased 2%, or $18 million from the prior year. Included in
noninterest expense figures is the loss on prepayments of FHLB advances of $45 million in 2020.
With respect to full year 2020 noninterest expense line items:
•Personnel costs decreased $55 million from the prior year, largely driven by reduced management incentive plan expense.
•Business development and advertising decreased $11 million from the prior year as there was less travel and entertainment expense.
•Acquisition costs decreased $5 million from the prior year due to less acquisition activity.
Fourth quarter 2020 total noninterest expense of $173 million decreased $55 million from the prior quarter and decreased $31 million compared to the same period last year.
With respect to fourth quarter 2020 noninterest expense line items:
•Loss on prepayments of FHLB advances stepped down $45 million from the prior quarter.
•Personnel expense decreased $11 million from the prior quarter and $23 million from the same period last year, primarily driven by lower severance costs related to the restructuring in 3Q 2020 and the sale of ABRC.
•Other expense decreased $3 million from the prior quarter and $1 million from the same period last year.
•Occupancy expense decreased $2 million from the prior quarter and $1 million from the same period last year.
We expect 2021 noninterest expense to be approximately $675 million.
Taxes
The fourth quarter 2020 tax expense was $17 million compared to $58 million of tax benefit in the prior quarter and $17 million of tax expense in the same period last year. The tax benefit recognized in the third quarter was driven by capital losses from the reorganization of our securities and real estate lending subsidiaries.
We expect the annual 2021 tax rate to be between 18% to 21%.
Credit
Full year 2020 provision for credit losses was $174 million, up from $16 million in the prior year.
The fourth quarter 2020 provision for credit losses was $17 million, down from $43 million in the prior quarter and up from zero in the same period last year.
With respect to fourth quarter 2020 credit quality:
•Potential problem loans of $282 million were down $11 million, or 4%, from the prior quarter and up $121 million, or 75%, from the same period last year.
•Nonaccrual loans of $211 million were down $21 million from the prior quarter and up $92 million from the same period last year. The nonaccrual loans to total loans ratio was 0.86% in the fourth quarter, down from 0.93% in the prior quarter and up from 0.52% in the same period last year.
•Net charge offs of $28 million were down $2 million from the prior quarter and up $13 million from the same period last year.
•The allowance for credit losses on loans (ACLL) of $431 million was down $11 million from the prior quarter and up $208 million compared to the same period last year. The ACLL to total loans ratio was 1.76% in the fourth quarter, down from 1.77% in the prior quarter and up from 0.98% in the same period last year.
We expect our full year 2021 provision to be no more than $70 million, with some quarterly variability.
Capital
The Company’s capital position remains strong, with a CET1 capital ratio of 10.4% at December 31, 2020. The Company’s capital ratios continue to be in excess of the Basel III “well-capitalized” regulatory benchmarks on a fully phased in basis.
FOURTH QUARTER 2020 EARNINGS RELEASE CONFERENCE CALL
The Company will host a conference call for investors and analysts at 4:00 p.m. Central Time (CT) today, January 21, 2021. Interested parties can access the live webcast of the call through the Investor Relations section of the Company's website, http://investor.associatedbank.com. Parties may also dial into the call at 877-407-8037 (domestic) or 201-689-8037 (international) and request the Associated Banc-Corp fourth quarter 2020 earnings call. The fourth quarter 2020 financial tables with an accompanying slide presentation will be available on the Company's website just prior to the call. An audio archive of the webcast will be available on the Company's website approximately fifteen minutes after the call is over.
ABOUT ASSOCIATED BANC-CORP
Associated Banc-Corp (NYSE: ASB) has total assets of $33 billion and is one of the top 50 publicly traded U.S. bank holding companies. Headquartered in Green Bay, Wisconsin, Associated is a leading Midwest banking franchise, offering a full range of financial products and services from more than 220 banking locations serving more than 120 communities throughout Wisconsin, Illinois and Minnesota, and commercial financial services in Indiana, Michigan, Missouri, Ohio and Texas. Associated Bank, N.A. is an Equal Housing Lender, Equal Opportunity Lender and Member FDIC. More information about Associated Banc-Corp is available at www.associatedbank.com.
FORWARD-LOOKING STATEMENTS
Statements made in this document which are not purely historical are forward-looking statements, as defined in the Private Securities Litigation Reform Act of 1995. This includes any statements regarding management’s plans, objectives, or goals for future operations, products or services, and forecasts of its revenues, earnings, or other measures of performance. Such forward-looking statements may be identified by the use of words such as “believe,” “expect,” “anticipate,” “plan,” “estimate,” “should,” “will,” “intend,” "target," “outlook,” or similar expressions. Forward-looking statements are based on current management expectations and, by their nature, are subject to risks and uncertainties. Actual results may differ materially from those contained in the forward-looking statements. Factors which may cause actual results to differ materially from those contained in such forward-looking statements include those identified in the Company’s most recent Form 10-K and subsequent SEC filings. Such factors are incorporated herein by reference.
NON-GAAP FINANCIAL MEASURES
This press release and related materials may contain references to measures which are not defined in generally accepted accounting principles (“GAAP”). Information concerning these non-GAAP financial measures can be found in the financial tables. Management believes these measures are meaningful because they reflect adjustments commonly made by management, investors, regulators, and analysts to evaluate the adequacy of earnings per common share, provide a greater understanding of ongoing operations and enhance comparability of results with prior periods.
# # #
| Associated Banc-Corp Consolidated Balance Sheets (Unaudited) | |||||||||||||||||||||||
| ($ in thousands) | December 31, 2020 | September 30, 2020 | Seql Qtr $ Change | June 30, 2020 | March 31, 2020 | December 31, 2019 | Comp Qtr $ Change | ||||||||||||||||
| Assets | |||||||||||||||||||||||
| Cash and due from banks | $ | 416,154 | $ | 401,151 | $ | 15,003 | $ | 443,500 | $ | 480,337 | $ | 373,380 | $ | 42,774 | |||||||||
| Interest-bearing deposits in other financial institutions | 298,759 | 712,416 | (413,657) | 1,569,006 | 176,440 | 207,624 | 91,135 | ||||||||||||||||
| Federal funds sold and securities purchased under agreements to resell | 1,135 | 95 | 1,040 | 185 | 22,455 | 7,740 | (6,605) | ||||||||||||||||
| Investment securities available for sale, at fair value | 3,085,441 | 3,258,360 | (172,919) | 3,149,773 | 2,928,787 | 3,262,586 | (177,145) | ||||||||||||||||
Investment securities held to maturity, net, at amortized cost(a) | 1,878,938 | 1,990,870 | (111,932) | 2,077,225 | 2,149,373 | 2,205,083 | (326,145) | ||||||||||||||||
| Equity securities | 15,106 | 15,090 | 16 | 15,091 | 15,063 | 15,090 | 16 | ||||||||||||||||
| Federal Home Loan Bank and Federal Reserve Bank stocks, at cost | 168,280 | 168,280 | — | 206,281 | 222,922 | 227,347 | (59,067) | ||||||||||||||||
| Residential loans held for sale | 129,158 | 130,139 | (981) | 196,673 | 366,330 | 136,280 | (7,122) | ||||||||||||||||
| Commercial loans held for sale | — | 19,360 | (19,360) | 3,565 | — | 15,000 | (15,000) | ||||||||||||||||
| Loans | 24,451,724 | 25,003,753 | (552,029) | 24,832,671 | 24,365,633 | 22,821,440 | 1,630,284 | ||||||||||||||||
Allowance for loan losses(b) | (383,702) | (384,711) | 1,009 | (363,803) | (337,793) | (201,371) | (182,331) | ||||||||||||||||
| Loans, net | 24,068,022 | 24,619,041 | (551,019) | 24,468,868 | 24,027,841 | 22,620,068 | 1,447,954 | ||||||||||||||||
| Tax credit and other investments | 297,232 | 314,066 | (16,834) | 303,132 | 315,909 | 279,969 | 17,263 | ||||||||||||||||
| Premises and equipment, net | 418,914 | 422,222 | (3,308) | 434,042 | 438,469 | 435,284 | (16,370) | ||||||||||||||||
| Bank and corporate owned life insurance | 679,647 | 679,257 | 390 | 676,196 | 674,026 | 671,948 | 7,699 | ||||||||||||||||
| Goodwill | 1,109,300 | 1,107,902 | 1,398 | 1,107,902 | 1,191,388 | 1,176,230 | (66,930) | ||||||||||||||||
| Other intangible assets, net | 68,254 | 70,507 | (2,253) | 72,759 | 92,723 | 88,301 | (20,047) | ||||||||||||||||
| Mortgage servicing rights, net | 41,961 | 45,261 | (3,300) | 49,403 | 58,289 | 67,306 | (25,345) | ||||||||||||||||
| Interest receivable | 90,263 | 91,612 | (1,349) | 87,097 | 92,377 | 91,196 | (933) | ||||||||||||||||
| Other assets | 653,219 | 653,117 | 102 | 640,765 | 655,328 | 506,046 | 147,173 | ||||||||||||||||
| Total assets | $ | 33,419,783 | $ | 34,698,746 | $ | (1,278,963) | $ | 35,501,464 | $ | 33,908,056 | $ | 32,386,478 | $ | 1,033,305 | |||||||||
| Liabilities and stockholders’ equity | |||||||||||||||||||||||
| Noninterest-bearing demand deposits | $ | 7,661,728 | $ | 7,489,048 | $ | 172,680 | $ | 7,573,942 | $ | 6,107,386 | $ | 5,450,709 | $ | 2,211,019 | |||||||||
| Interest-bearing deposits | 18,820,753 | 19,223,500 | (402,747) | 18,977,502 | 19,554,194 | 18,328,355 | 492,398 | ||||||||||||||||
| Total deposits | 26,482,481 | 26,712,547 | (230,066) | 26,551,444 | 25,661,580 | 23,779,064 | 2,703,417 | ||||||||||||||||
| Federal funds purchased and securities sold under agreements to repurchase | 192,971 | 155,329 | 37,642 | 142,293 | 133,007 | 433,097 | (240,126) | ||||||||||||||||
| Commercial paper | 59,346 | 50,987 | 8,359 | 39,535 | 33,647 | 32,016 | 27,330 | ||||||||||||||||
| PPPLF | — | 1,022,217 | (1,022,217) | 1,009,760 | — | — | — | ||||||||||||||||
| FHLB advances | 1,632,723 | 1,706,763 | (74,040) | 2,657,016 | 3,214,194 | 3,180,967 | (1,548,244) | ||||||||||||||||
| Other long-term funding | 549,465 | 549,201 | 264 | 548,937 | 549,644 | 549,343 | 122 | ||||||||||||||||
Allowance for unfunded commitments(b) | 47,776 | 57,276 | (9,500) | 64,776 | 56,276 | 21,907 | 25,869 | ||||||||||||||||
Accrued expenses and other liabilities(b) | 364,088 | 398,991 | (34,903) | 463,245 | 469,236 | 467,961 | (103,873) | ||||||||||||||||
| Total liabilities | 29,328,850 | 30,653,313 | (1,324,463) | 31,477,007 | 30,117,584 | 28,464,355 | 864,495 | ||||||||||||||||
| Stockholders’ equity | |||||||||||||||||||||||
| Preferred equity | 353,512 | 353,637 | (125) | 353,846 | 256,716 | 256,716 | 96,796 | ||||||||||||||||
Common equity(b) | 3,737,421 | 3,691,796 | 45,625 | 3,670,612 | 3,533,755 | 3,665,407 | 72,014 | ||||||||||||||||
| Total stockholders’ equity | 4,090,933 | 4,045,433 | 45,500 | 4,024,457 | 3,790,471 | 3,922,124 | 168,809 | ||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 33,419,783 | $ | 34,698,746 | $ | (1,278,963) | $ | 35,501,464 | $ | 33,908,056 | $ | 32,386,478 | $ | 1,033,305 | |||||||||
Numbers may not sum due to rounding.
(a) Beginning in 2020, the investment securities held to maturity are reported net of the related allowance for credit losses. Prior periods were unadjusted due to the modified retrospective application of ASU 2016-13.
(b) At January 1, 2020, the adoption of ASU 2016-13 resulted in an increase to the allowance for loan losses of $112 million and an increase to the allowance for unfunded commitments of $19 million for a total increase to the allowance for credit losses on loans of $131 million. A corresponding after tax decrease to common equity of $98 million was recorded along with a deferred tax asset of $33 million resulting in a decrease to accrued expenses and other liabilities. Prior periods were unadjusted due to the modified retrospective application of ASU 2016-13.
1
| Associated Banc-Corp Consolidated Statements of Income (Unaudited) | Comp Qtr | YTD | YTD | Comp YTD | |||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands, except per share data) | 4Q20 | 4Q19 | $ Change | % Change | Dec 2020 | Dec 2019 | $ Change | % Change | |||||||||||||||||||||||||||||||||||||||
| Interest income | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 185,934 | $ | 229,883 | $ | (43,949) | (19) | % | $ | 785,241 | $ | 998,099 | $ | (212,858) | (21) | % | |||||||||||||||||||||||||||||||
| Interest and dividends on investment securities | |||||||||||||||||||||||||||||||||||||||||||||||
| Taxable | 9,746 | 21,056 | (11,310) | (54) | % | 59,806 | 100,304 | (40,498) | (40) | % | |||||||||||||||||||||||||||||||||||||
| Tax-exempt | 14,296 | 14,615 | (319) | (2) | % | 58,320 | 57,565 | 755 | 1 | % | |||||||||||||||||||||||||||||||||||||
| Other interest | 1,699 | 3,556 | (1,857) | (52) | % | 9,473 | 16,643 | (7,170) | (43) | % | |||||||||||||||||||||||||||||||||||||
| Total interest income | 211,675 | 269,110 | (57,435) | (21) | % | 912,840 | 1,172,610 | (259,770) | (22) | % | |||||||||||||||||||||||||||||||||||||
| Interest expense | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest on deposits | 7,762 | 45,877 | (38,115) | (83) | % | 67,639 | 237,286 | (169,647) | (71) | % | |||||||||||||||||||||||||||||||||||||
| Interest on federal funds purchased and securities sold under agreements to repurchase | 32 | 521 | (489) | (94) | % | 485 | 1,579 | (1,094) | (69) | % | |||||||||||||||||||||||||||||||||||||
| Interest on other short-term funding | 5 | 25 | (20) | (80) | % | 51 | 138 | (87) | (63) | % | |||||||||||||||||||||||||||||||||||||
| Interest on PPPLF | 410 | — | 410 | N/M | 1,984 | — | 1,984 | N/M | |||||||||||||||||||||||||||||||||||||||
| Interest on FHLB Advances | 9,888 | 16,623 | (6,735) | (41) | % | 57,359 | 69,816 | (12,457) | (18) | % | |||||||||||||||||||||||||||||||||||||
| Interest on long-term funding | 5,585 | 5,921 | (336) | (6) | % | 22,365 | 28,116 | (5,751) | (20) | % | |||||||||||||||||||||||||||||||||||||
| Total interest expense | 23,682 | 68,967 | (45,285) | (66) | % | 149,883 | 336,936 | (187,053) | (56) | % | |||||||||||||||||||||||||||||||||||||
| Net interest income | 187,993 | 200,142 | (12,149) | (6) | % | 762,957 | 835,674 | (72,717) | (9) | % | |||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 16,997 | — | 16,997 | N/M | 174,006 | 16,000 | 158,006 | N/M | |||||||||||||||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 170,996 | 200,142 | (29,146) | (15) | % | 588,950 | 819,674 | (230,724) | (28) | % | |||||||||||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||||||||
Wealth management fees(a) | 22,073 | 21,582 | 491 | 2 | % | 84,957 | 83,467 | 1,490 | 2 | % | |||||||||||||||||||||||||||||||||||||
| Service charges and deposit account fees | 15,318 | 16,032 | (714) | (4) | % | 56,307 | 63,135 | (6,828) | (11) | % | |||||||||||||||||||||||||||||||||||||
| Card-based fees | 9,848 | 9,906 | (58) | (1) | % | 38,534 | 39,755 | (1,221) | (3) | % | |||||||||||||||||||||||||||||||||||||
| Other fee-based revenue | 4,998 | 4,696 | 302 | 6 | % | 19,238 | 18,942 | 296 | 2 | % | |||||||||||||||||||||||||||||||||||||
Capital markets, net | 5,898 | 7,647 | (1,749) | (23) | % | 27,966 | 19,862 | 8,104 | 41 | % | |||||||||||||||||||||||||||||||||||||
| Mortgage banking, net | 14,537 | 6,760 | 7,777 | 115 | % | 45,580 | 31,878 | 13,702 | 43 | % | |||||||||||||||||||||||||||||||||||||
| Bank and corporate owned life insurance | 3,978 | 3,364 | 614 | 18 | % | 13,771 | 14,845 | (1,074) | (7) | % | |||||||||||||||||||||||||||||||||||||
| Insurance commissions and fees | 92 | 19,701 | (19,609) | (100) | % | 45,245 | 89,104 | (43,859) | (49) | % | |||||||||||||||||||||||||||||||||||||
Asset gains (losses), net(b) | (1,356) | 398 | (1,754) | N/M | 155,589 | 2,713 | 152,876 | N/M | |||||||||||||||||||||||||||||||||||||||
| Investment securities gains (losses), net | — | 26 | (26) | (100) | % | 9,222 | 5,957 | 3,265 | 55 | % | |||||||||||||||||||||||||||||||||||||
| Gains (losses) on sale of branches, net | 7,449 | — | 7,449 | N/M | 7,449 | — | 7,449 | N/M | |||||||||||||||||||||||||||||||||||||||
Other | 2,879 | 2,822 | 57 | 2 | % | 10,200 | 11,165 | (965) | (9) | % | |||||||||||||||||||||||||||||||||||||
| Total noninterest income | 85,714 | 92,934 | (7,220) | (8) | % | 514,056 | 380,824 | 133,232 | 35 | % | |||||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||||||||
| Personnel | 98,033 | 120,614 | (22,581) | (19) | % | 432,151 | 487,063 | (54,912) | (11) | % | |||||||||||||||||||||||||||||||||||||
| Technology | 19,574 | 22,731 | (3,157) | (14) | % | 81,214 | 82,429 | (1,215) | (1) | % | |||||||||||||||||||||||||||||||||||||
| Occupancy | 15,678 | 16,933 | (1,255) | (7) | % | 64,064 | 62,399 | 1,665 | 3 | % | |||||||||||||||||||||||||||||||||||||
| Business development and advertising | 5,421 | 8,316 | (2,895) | (35) | % | 18,428 | 29,600 | (11,172) | (38) | % | |||||||||||||||||||||||||||||||||||||
| Equipment | 5,555 | 5,970 | (415) | (7) | % | 21,705 | 23,550 | (1,845) | (8) | % | |||||||||||||||||||||||||||||||||||||
| Legal and professional | 5,737 | 5,559 | 178 | 3 | % | 21,546 | 19,901 | 1,645 | 8 | % | |||||||||||||||||||||||||||||||||||||
| Loan and foreclosure costs | 3,758 | 3,262 | 496 | 15 | % | 12,600 | 8,861 | 3,739 | 42 | % | |||||||||||||||||||||||||||||||||||||
| FDIC assessment | 5,700 | 4,000 | 1,700 | 43 | % | 20,350 | 16,250 | 4,100 | 25 | % | |||||||||||||||||||||||||||||||||||||
| Other intangible amortization | 2,253 | 2,712 | (459) | (17) | % | 10,192 | 9,948 | 244 | 2 | % | |||||||||||||||||||||||||||||||||||||
Acquisition related costs(c) | (10) | 1,325 | (1,335) | N/M | 2,447 | 7,320 | (4,873) | (67) | % | ||||||||||||||||||||||||||||||||||||||
| Loss on prepayments of FHLB advances | — | — | — | N/M | 44,650 | — | 44,650 | N/M | |||||||||||||||||||||||||||||||||||||||
| Other | 11,151 | 12,187 | (1,036) | (9) | % | 46,688 | 46,666 | 22 | — | % | |||||||||||||||||||||||||||||||||||||
| Total noninterest expense | 172,850 | 203,609 | (30,759) | (15) | % | 776,034 | 793,988 | (17,954) | (2) | % | |||||||||||||||||||||||||||||||||||||
| Income (loss) before income taxes | 83,860 | 89,467 | (5,607) | (6) | % | 326,972 | 406,509 | (79,537) | (20) | % | |||||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | 16,858 | 17,364 | (506) | (3) | % | 20,200 | 79,720 | (59,520) | (75) | % | |||||||||||||||||||||||||||||||||||||
| Net income | 67,002 | 72,103 | (5,101) | (7) | % | 306,771 | 326,790 | (20,019) | (6) | % | |||||||||||||||||||||||||||||||||||||
| Preferred stock dividends | 5,207 | 3,801 | 1,406 | 37 | % | 18,358 | 15,202 | 3,156 | 21 | % | |||||||||||||||||||||||||||||||||||||
| Net income available to common equity | $ | 61,795 | $ | 68,303 | $ | (6,508) | (10) | % | $ | 288,413 | $ | 311,587 | $ | (23,174) | (7) | % | |||||||||||||||||||||||||||||||
| Earnings per common share | |||||||||||||||||||||||||||||||||||||||||||||||
| Basic | $ | 0.40 | $ | 0.43 | $ | (0.03) | (7) | % | $ | 1.87 | $ | 1.93 | $ | (0.06) | (3) | % | |||||||||||||||||||||||||||||||
| Diluted | $ | 0.40 | $ | 0.43 | $ | (0.03) | (7) | % | $ | 1.86 | $ | 1.91 | $ | (0.05) | (3) | % | |||||||||||||||||||||||||||||||
| Average common shares outstanding | |||||||||||||||||||||||||||||||||||||||||||||||
| Basic | 152,497 | 156,994 | (4,497) | (3) | % | 153,005 | 160,534 | (7,529) | (5) | % | |||||||||||||||||||||||||||||||||||||
| Diluted | 153,262 | 158,472 | (5,210) | (3) | % | 153,642 | 161,932 | (8,290) | (5) | % | |||||||||||||||||||||||||||||||||||||
N/M = Not meaningful
Numbers may not sum due to rounding.
(a) Includes trust, asset management, brokerage, and annuity fees.
(b) YTD 2020 include a gain of $163 million from the sale of Associated Benefits & Risk Consulting. YTD 2019 include less than $1 million of Huntington related asset losses.
(c) Includes Huntington branch and First Staunton acquisition related costs only.
2
| Associated Banc-Corp Consolidated Statements of Income (Unaudited) - Quarterly Trend | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands, except per share data) | Seql Qtr | Comp Qtr | |||||||||||||||||||||||||||||||||||||||||||||||||||
| 4Q20 | 3Q20 | $ Change | % Change | 2Q20 | 1Q20 | 4Q19 | $ Change | % Change | |||||||||||||||||||||||||||||||||||||||||||||
| Interest income | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 185,934 | $ | 182,625 | $ | 3,309 | 2 | % | $ | 191,895 | $ | 224,786 | $ | 229,883 | $ | (43,949) | (19) | % | |||||||||||||||||||||||||||||||||||
| Interest and dividends on investment securities | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Taxable | 9,746 | 13,689 | (3,943) | (29) | % | 16,103 | 20,272 | 21,056 | (11,310) | (54) | % | ||||||||||||||||||||||||||||||||||||||||||
| Tax-exempt | 14,296 | 14,523 | (227) | (2) | % | 14,616 | 14,882 | 14,615 | (319) | (2) | % | ||||||||||||||||||||||||||||||||||||||||||
| Other interest | 1,699 | 2,238 | (539) | (24) | % | 2,231 | 3,304 | 3,556 | (1,857) | (52) | % | ||||||||||||||||||||||||||||||||||||||||||
| Total interest income | 211,675 | 213,075 | (1,400) | (1) | % | 224,845 | 263,244 | 269,110 | (57,435) | (21) | % | ||||||||||||||||||||||||||||||||||||||||||
| Interest expense | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest on deposits | 7,762 | 10,033 | (2,271) | (23) | % | 13,178 | 36,666 | 45,877 | (38,115) | (83) | % | ||||||||||||||||||||||||||||||||||||||||||
| Interest on federal funds purchased and securities sold under agreements to repurchase | 32 | 34 | (2) | (6) | % | 51 | 368 | 521 | (489) | (94) | % | ||||||||||||||||||||||||||||||||||||||||||
| Interest on other short-term funding | 5 | 5 | — | — | % | 5 | 36 | 25 | (20) | (80) | % | ||||||||||||||||||||||||||||||||||||||||||
| Interest on PPPLF | 410 | 899 | (489) | (54) | % | 676 | — | — | 410 | N/M | |||||||||||||||||||||||||||||||||||||||||||
| Interest on FHLB Advances | 9,888 | 14,375 | (4,487) | (31) | % | 15,470 | 17,626 | 16,623 | (6,735) | (41) | % | ||||||||||||||||||||||||||||||||||||||||||
| Interest on long-term funding | 5,585 | 5,580 | 5 | — | % | 5,593 | 5,607 | 5,921 | (336) | (6) | % | ||||||||||||||||||||||||||||||||||||||||||
| Total interest expense | 23,682 | 30,925 | (7,243) | (23) | % | 34,973 | 60,303 | 68,967 | (45,285) | (66) | % | ||||||||||||||||||||||||||||||||||||||||||
| Net interest income | 187,993 | 182,150 | 5,843 | 3 | % | 189,872 | 202,942 | 200,142 | (12,149) | (6) | % | ||||||||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 16,997 | 43,009 | (26,012) | (60) | % | 61,000 | 53,001 | — | 16,997 | N/M | |||||||||||||||||||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 170,996 | 139,141 | 31,855 | 23 | % | 128,872 | 149,941 | 200,142 | (29,146) | (15) | % | ||||||||||||||||||||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Wealth management fees(a) | 22,073 | 21,152 | 921 | 4 | % | 20,916 | 20,816 | 21,582 | 491 | 2 | % | ||||||||||||||||||||||||||||||||||||||||||
| Service charges and deposit account fees | 15,318 | 14,283 | 1,035 | 7 | % | 11,484 | 15,222 | 16,032 | (714) | (4) | % | ||||||||||||||||||||||||||||||||||||||||||
| Card-based fees | 9,848 | 10,195 | (347) | (3) | % | 8,893 | 9,597 | 9,906 | (58) | (1) | % | ||||||||||||||||||||||||||||||||||||||||||
| Other fee-based revenue | 4,998 | 4,968 | 30 | 1 | % | 4,774 | 4,497 | 4,696 | 302 | 6 | % | ||||||||||||||||||||||||||||||||||||||||||
| Capital markets, net | 5,898 | 7,222 | (1,324) | (18) | % | 6,910 | 7,935 | 7,647 | (1,749) | (23) | % | ||||||||||||||||||||||||||||||||||||||||||
| Mortgage banking, net | 14,537 | 12,636 | 1,901 | 15 | % | 12,263 | 6,143 | 6,760 | 7,777 | 115 | % | ||||||||||||||||||||||||||||||||||||||||||
| Bank and corporate owned life insurance | 3,978 | 3,074 | 904 | 29 | % | 3,625 | 3,094 | 3,364 | 614 | 18 | % | ||||||||||||||||||||||||||||||||||||||||||
| Insurance commissions and fees | 92 | 114 | (22) | (19) | % | 22,430 | 22,608 | 19,701 | (19,609) | (100) | % | ||||||||||||||||||||||||||||||||||||||||||
Asset gains (losses), net(b) | (1,356) | (339) | (1,017) | N/M | 157,361 | (77) | 398 | (1,754) | N/M | ||||||||||||||||||||||||||||||||||||||||||||
| Investment securities gains (losses), net | — | 7 | (7) | (100) | % | 3,096 | 6,118 | 26 | (26) | (100) | % | ||||||||||||||||||||||||||||||||||||||||||
| Gains (losses) on sale of branches, net | 7,449 | — | 7,449 | N/M | — | — | — | 7,449 | N/M | ||||||||||||||||||||||||||||||||||||||||||||
| Other | 2,879 | 2,232 | 647 | 29 | % | 2,737 | 2,352 | 2,822 | 57 | 2 | % | ||||||||||||||||||||||||||||||||||||||||||
| Total noninterest income | 85,714 | 75,545 | 10,169 | 13 | % | 254,490 | 98,306 | 92,934 | (7,220) | (8) | % | ||||||||||||||||||||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Personnel | 98,033 | 108,567 | (10,534) | (10) | % | 111,350 | 114,200 | 120,614 | (22,581) | (19) | % | ||||||||||||||||||||||||||||||||||||||||||
| Technology | 19,574 | 19,666 | (92) | — | % | 21,174 | 20,799 | 22,731 | (3,157) | (14) | % | ||||||||||||||||||||||||||||||||||||||||||
| Occupancy | 15,678 | 17,854 | (2,176) | (12) | % | 14,464 | 16,069 | 16,933 | (1,255) | (7) | % | ||||||||||||||||||||||||||||||||||||||||||
| Business development and advertising | 5,421 | 3,626 | 1,795 | 50 | % | 3,556 | 5,826 | 8,316 | (2,895) | (35) | % | ||||||||||||||||||||||||||||||||||||||||||
| Equipment | 5,555 | 5,399 | 156 | 3 | % | 5,312 | 5,439 | 5,970 | (415) | (7) | % | ||||||||||||||||||||||||||||||||||||||||||
| Legal and professional | 5,737 | 5,591 | 146 | 3 | % | 5,058 | 5,160 | 5,559 | 178 | 3 | % | ||||||||||||||||||||||||||||||||||||||||||
| Loan and foreclosure costs | 3,758 | 2,118 | 1,640 | 77 | % | 3,605 | 3,120 | 3,262 | 496 | 15 | % | ||||||||||||||||||||||||||||||||||||||||||
| FDIC assessment | 5,700 | 3,900 | 1,800 | 46 | % | 5,250 | 5,500 | 4,000 | 1,700 | 43 | % | ||||||||||||||||||||||||||||||||||||||||||
| Other intangible amortization | 2,253 | 2,253 | — | — | % | 2,872 | 2,814 | 2,712 | (459) | (17) | % | ||||||||||||||||||||||||||||||||||||||||||
Acquisition related costs(c) | (10) | 218 | (228) | N/M | 518 | 1,721 | 1,325 | (1,335) | N/M | ||||||||||||||||||||||||||||||||||||||||||||
| Loss on prepayments of FHLB advances | — | 44,650 | (44,650) | (100) | % | — | — | — | — | N/M | |||||||||||||||||||||||||||||||||||||||||||
| Other | 11,151 | 13,745 | (2,594) | (19) | % | 10,249 | 11,543 | 12,187 | (1,036) | (9) | % | ||||||||||||||||||||||||||||||||||||||||||
| Total noninterest expense | 172,850 | 227,587 | (54,737) | (24) | % | 183,407 | 192,191 | 203,609 | (30,759) | (15) | % | ||||||||||||||||||||||||||||||||||||||||||
| Income (loss) before income taxes | 83,860 | (12,900) | 96,760 | N/M | 199,955 | 56,056 | 89,467 | (5,607) | (6) | % | |||||||||||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | 16,858 | (58,114) | 74,972 | (129) | % | 51,238 | 10,219 | 17,364 | (506) | (3) | % | ||||||||||||||||||||||||||||||||||||||||||
| Net income | 67,002 | 45,214 | 21,788 | 48 | % | 148,718 | 45,838 | 72,103 | (5,101) | (7) | % | ||||||||||||||||||||||||||||||||||||||||||
| Preferred stock dividends | 5,207 | 5,207 | — | — | % | 4,144 | 3,801 | 3,801 | 1,406 | 37 | % | ||||||||||||||||||||||||||||||||||||||||||
| Net income available to common equity | $ | 61,795 | $ | 40,007 | $ | 21,788 | 54 | % | $ | 144,573 | $ | 42,037 | $ | 68,303 | $ | (6,508) | (10) | % | |||||||||||||||||||||||||||||||||||
| Earnings per common share | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Basic | $ | 0.40 | $ | 0.26 | $ | 0.14 | 54 | % | $ | 0.94 | $ | 0.27 | $ | 0.43 | $ | (0.03) | (7) | % | |||||||||||||||||||||||||||||||||||
| Diluted | $ | 0.40 | $ | 0.26 | $ | 0.14 | 54 | % | $ | 0.94 | $ | 0.27 | $ | 0.43 | $ | (0.03) | (7) | % | |||||||||||||||||||||||||||||||||||
| Average common shares outstanding | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Basic | 152,497 | 152,440 | 57 | — | % | 152,393 | 154,701 | 156,994 | (4,497) | (3) | % | ||||||||||||||||||||||||||||||||||||||||||
| Diluted | 153,262 | 153,194 | 68 | — | % | 153,150 | 155,619 | 158,472 | (5,210) | (3) | % | ||||||||||||||||||||||||||||||||||||||||||
N/M = Not meaningful
Numbers may not sum due to rounding.
(a) Includes trust, asset management, brokerage, and annuity fees.
(b) 2Q20 includes a gain of $163 million from the sale of Associated Benefits & Risk Consulting.
(c) Includes Huntington branch and First Staunton acquisition related costs only.
3
| Associated Banc-Corp Selected Quarterly Information | |||||||||||||||||||||||
| ($ in millions except per share data and COVID-19 loan modifications; shares repurchased and outstanding in thousands) | YTD Dec 2020 | YTD Dec 2019 | 4Q20 | 3Q20 | 2Q20 | 1Q20 | 4Q19 | ||||||||||||||||
| Per common share data | |||||||||||||||||||||||
| Dividends | $ | 0.72 | $ | 0.69 | $ | 0.18 | $ | 0.18 | $ | 0.18 | $ | 0.18 | $ | 0.18 | |||||||||
| Market value: | |||||||||||||||||||||||
| High | 21.94 | 23.67 | 17.17 | 14.25 | 17.03 | 21.94 | 22.51 | ||||||||||||||||
| Low | 10.85 | 18.64 | 12.68 | 11.86 | 11.48 | 10.85 | 18.96 | ||||||||||||||||
| Close | 17.05 | 22.04 | 17.05 | 12.62 | 13.68 | 12.79 | 22.04 | ||||||||||||||||
| Book value | 24.34 | 23.32 | 24.34 | 24.04 | 23.89 | 22.99 | 23.32 | ||||||||||||||||
| Tangible book value / share | 16.67 | 15.28 | 16.67 | 16.37 | 16.21 | 14.64 | 15.28 | ||||||||||||||||
| Performance ratios (annualized) | |||||||||||||||||||||||
| Return on average assets | 0.90 | % | 0.99 | % | 0.78 | % | 0.51 | % | 1.72 | % | 0.57 | % | 0.89 | % | |||||||||
| Noninterest expense / average assets | 2.26 | % | 2.40 | % | 2.02 | % | 2.55 | % | 2.12 | % | 2.37 | % | 2.51 | % | |||||||||
| Effective tax rate | 6.18 | % | 19.61 | % | 20.10 | % | N/M | 25.62 | % | 18.23 | % | 19.41 | % | ||||||||||
Dividend payout ratio(a) | 38.50 | % | 35.75 | % | 45.00 | % | 69.23 | % | 19.15 | % | 66.67 | % | 41.86 | % | |||||||||
| Net interest margin | 2.53 | % | 2.86 | % | 2.49 | % | 2.31 | % | 2.49 | % | 2.84 | % | 2.83 | % | |||||||||
| Selected trend information | |||||||||||||||||||||||
Average full time equivalent employees(b) | 4,459 | 4,702 | 4,134 | 4,374 | 4,701 | 4,631 | 4,696 | ||||||||||||||||
| Branch count | 228 | 249 | 249 | 249 | 248 | ||||||||||||||||||
Assets under management, at market value(c) | $ | 13,314 | $ | 12,195 | $ | 11,755 | $ | 10,454 | $ | 12,104 | |||||||||||||
| Mortgage loans originated for sale during period | $ | 1,642 | $ | 1,091 | $ | 323 | $ | 458 | $ | 550 | $ | 310 | $ | 267 | |||||||||
| Mortgage loan settlements during period | $ | 1,960 | $ | 1,317 | $ | 339 | $ | 599 | $ | 725 | $ | 297 | $ | 268 | |||||||||
| Mortgage portfolio loans transferred to held for sale during period | $ | 269 | $ | 242 | $ | — | $ | 70 | $ | — | $ | 200 | $ | — | |||||||||
| Mortgage portfolio serviced for others | $ | 7,744 | $ | 8,219 | $ | 8,454 | $ | 8,549 | $ | 8,489 | |||||||||||||
| Mortgage servicing rights, net / mortgage portfolio serviced for others | 0.54 | % | 0.55 | % | 0.58 | % | 0.68 | % | 0.79 | % | |||||||||||||
Shares repurchased during period(d) | 4,264 | 8,211 | — | — | — | 4,264 | 2,256 | ||||||||||||||||
| Shares outstanding, end of period | 153,540 | 157,171 | 153,540 | 153,552 | 153,616 | 153,690 | 157,171 | ||||||||||||||||
| Paycheck Protection Program fees, net | |||||||||||||||||||||||
| Fees, beginning of period | $ | 27 | N/A | $ | 21 | $ | 24 | $ | 27 | N/A | N/A | ||||||||||||
| Fees recognized | (15) | N/A | (9) | (4) | (3) | N/A | N/A | ||||||||||||||||
| Fees, end of period | $ | 12 | N/A | $ | 12 | $ | 21 | $ | 24 | N/A | N/A | ||||||||||||
| COVID-19 Impacted Loans in Forbearances ($ in thousands) | |||||||||||||||||||||||
| Commercial and industrial | $ | 5,640 | $ | 19,414 | $ | 45,415 | $ | 345 | N/A | ||||||||||||||
| Commercial real estate—owner occupied | 6,737 | 42,121 | 142,293 | — | N/A | ||||||||||||||||||
| Commercial and business lending | 12,377 | 61,535 | 187,708 | 345 | N/A | ||||||||||||||||||
| Commercial real estate—investor | 18,345 | 246,833 | 643,168 | 595 | N/A | ||||||||||||||||||
| Real estate construction | 22 | 2,009 | 32,214 | — | N/A | ||||||||||||||||||
| Commercial real estate lending | 18,368 | 248,842 | 675,382 | 595 | N/A | ||||||||||||||||||
| Total commercial | 30,744 | 310,377 | 863,090 | 940 | N/A | ||||||||||||||||||
| Residential mortgage | 45,851 | 364,593 | 692,307 | 428 | N/A | ||||||||||||||||||
| Home equity | 1,762 | 10,068 | 30,554 | — | N/A | ||||||||||||||||||
| Other consumer | 222 | 1,132 | 2,060 | — | N/A | ||||||||||||||||||
| Total consumer | 47,835 | 375,794 | 724,921 | 428 | N/A | ||||||||||||||||||
| Total COVID-19 impacted loans in forbearance | $ | 78,579 | $ | 686,171 | $ | 1,588,011 | $ | 1,368 | N/A | ||||||||||||||
| Selected quarterly ratios | |||||||||||||||||||||||
| Loans / deposits | 92.33 | % | 93.60 | % | 93.53 | % | 94.95 | % | 95.97 | % | |||||||||||||
| Stockholders’ equity / assets | 12.24 | % | 11.66 | % | 11.34 | % | 11.18 | % | 12.11 | % | |||||||||||||
Risk-based capital(e)(f) | |||||||||||||||||||||||
| Total risk-weighted assets | $ | 25,903 | $ | 26,142 | $ | 25,864 | $ | 25,866 | $ | 24,296 | |||||||||||||
| Common equity Tier 1 | $ | 2,706 | $ | 2,672 | $ | 2,651 | $ | 2,421 | $ | 2,481 | |||||||||||||
| Common equity Tier 1 capital ratio | 10.45 | % | 10.22 | % | 10.25 | % | 9.36 | % | 10.21 | % | |||||||||||||
| Tier 1 capital ratio | 11.81 | % | 11.57 | % | 11.62 | % | 10.35 | % | 11.26 | % | |||||||||||||
| Total capital ratio | 14.02 | % | 13.78 | % | 13.83 | % | 12.56 | % | 13.21 | % | |||||||||||||
| Tier 1 leverage ratio | 9.37 | % | 9.02 | % | 9.08 | % | 8.50 | % | 8.83 | % | |||||||||||||
| Mortgage banking, net | |||||||||||||||||||||||
Mortgage servicing fees, net(g) | $ | (1) | $ | 10 | $ | (1) | $ | (1) | $ | (1) | $ | 2 | $ | 2 | |||||||||
| Gains (losses) and fair value adjustments on loans held for sale | 60 | 17 | 15 | 14 | 21 | 10 | 5 | ||||||||||||||||
| Fair value adjustment on portfolio loans transferred to held for sale | 4 | 4 | — | 1 | — | 3 | — | ||||||||||||||||
| Mortgage servicing rights (impairment) recovery | (18) | — | 1 | (1) | (8) | (9) | — | ||||||||||||||||
| Mortgage banking, net | $ | 46 | $ | 32 | $ | 15 | $ | 13 | $ | 12 | $ | 6 | $ | 7 | |||||||||
N/M = Not meaningful
Numbers may not sum due to rounding.
(a)Ratio is based upon basic earnings per common share.
(b)Average full time equivalent employees without overtime.
(c)Excludes assets held in brokerage accounts.
(d)Does not include repurchases related to tax withholding on equity compensation.
(e)The Federal Reserve establishes regulatory capital requirements, including well-capitalized standards for the Corporation. The regulatory capital requirements effective for the Corporation follow Basel III, subject to certain transition provisions.
(f)December 31, 2020 data is estimated.
(g)Includes mortgage origination and servicing fees, net of mortgage servicing rights amortization.
4
| Associated Banc-Corp Selected Asset Quality Information | |||||||||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2020 | Sep 30, 2020 | Seql Qtr % Change | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Comp Qtr % Change | ||||||||||||||||||||||
| Allowance for loan losses | |||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 384,711 | $ | 363,803 | 6 | % | $ | 337,793 | $ | 201,371 | $214,425 | 79 | % | ||||||||||||||||
| Cumulative effect of ASU 2016-13 adoption (CECL) | N/A | N/A | N/A | 112,457 | N/A | ||||||||||||||||||||||||
| January 1, 2020 | N/A | N/A | N/A | 313,828 | N/A | ||||||||||||||||||||||||
| Provision for loan losses | 26,500 | 50,500 | (48) | % | 52,500 | 37,500 | 1,000 | N/M | |||||||||||||||||||||
| Allowance for PCD loans for bank acquisition | N/A | N/A | N/A | 3,504 | N/A | ||||||||||||||||||||||||
| Charge offs | (30,315) | (34,079) | (11) | % | (28,351) | (19,308) | (16,752) | 81 | % | ||||||||||||||||||||
| Recoveries | 2,805 | 4,488 | (38) | % | 1,861 | 2,268 | 2,699 | 4 | % | ||||||||||||||||||||
| Net charge offs | (27,510) | (29,592) | (7) | % | (26,490) | (17,040) | (14,054) | 96 | % | ||||||||||||||||||||
| Balance at end of period | $ | 383,702 | $ | 384,711 | — | % | $ | 363,803 | $ | 337,793 | $ | 201,371 | 91 | % | |||||||||||||||
| Allowance for unfunded commitments | |||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 57,276 | $ | 64,776 | (12) | % | $ | 56,276 | $ | 21,907 | $ | 22,907 | 150 | % | |||||||||||||||
| Cumulative effect of ASU 2016-13 adoption (CECL) | N/A | N/A | N/A | 18,690 | N/A | ||||||||||||||||||||||||
| January 1, 2020 | N/A | N/A | N/A | 40,597 | N/A | ||||||||||||||||||||||||
| Provision for unfunded commitments | (9,500) | (7,500) | 27 | % | 8,500 | 15,500 | (1,000) | N/M | |||||||||||||||||||||
| Amount recorded at acquisition | — | — | N/M | — | 179 | — | N/M | ||||||||||||||||||||||
| Balance at end of period | $ | 47,776 | $ | 57,276 | (17) | % | $ | 64,776 | $ | 56,276 | $ | 21,907 | 118 | % | |||||||||||||||
Allowance for credit losses on loans (ACLL)(a) | $ | 431,478 | $ | 441,988 | (2) | % | $ | 428,579 | $ | 394,069 | $ | 223,278 | 93 | % | |||||||||||||||
Provision for credit losses on loans(b) | $ | 17,000 | $ | 43,000 | (60) | % | $ | 61,000 | $ | 53,000 | $ | — | N/M | ||||||||||||||||
| ($ in thousands) | Dec 31, 2020 | Sep 30, 2020 | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | ||||||||||||||||||||||||
| Net (charge offs) recoveries | |||||||||||||||||||||||||||||
| PPP Loans | $ | — | $ | — | N/M | $ | — | $ | — | $ | — | N/M | |||||||||||||||||
| Commercial and industrial | (8,514) | (24,834) | (66) | % | (24,919) | (15,049) | (11,917) | (29) | % | ||||||||||||||||||||
| Commercial real estate—owner occupied | 143 | (416) | (134) | % | 1 | — | — | N/M | |||||||||||||||||||||
| Commercial and business lending | (8,371) | (25,249) | (67) | % | (24,919) | (15,048) | (11,917) | (30) | % | ||||||||||||||||||||
| Commercial real estate—investor | (18,696) | (3,609) | N/M | 28 | — | — | N/M | ||||||||||||||||||||||
| Real estate construction | 43 | (21) | N/M | (3) | 11 | 72 | (40) | % | |||||||||||||||||||||
| Commercial real estate lending | (18,653) | (3,630) | N/M | 25 | 11 | 72 | N/M | ||||||||||||||||||||||
| Total commercial | (27,024) | (28,879) | (6) | % | (24,893) | (15,037) | (11,845) | 128 | % | ||||||||||||||||||||
| Residential mortgage | (162) | (79) | 105 | % | (215) | (912) | (1,415) | (89) | % | ||||||||||||||||||||
| Home equity | 335 | 156 | 115 | % | (303) | 71 | 480 | (30) | % | ||||||||||||||||||||
| Other consumer | (659) | (790) | (17) | % | (1,078) | (1,162) | (1,274) | (48) | % | ||||||||||||||||||||
| Total consumer | (486) | (712) | (32) | % | (1,596) | (2,003) | (2,208) | (78) | % | ||||||||||||||||||||
| Total net (charge offs) recoveries | $ | (27,510) | $ | (29,592) | (7) | % | $ | (26,490) | $ | (17,040) | $ | (14,054) | 96 | % | |||||||||||||||
| (In basis points) | Dec 31, 2020 | Sep 30, 2020 | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | ||||||||||||||||||||||||
| Net charge offs to average loans (annualized) | |||||||||||||||||||||||||||||
| PPP Loans | — | — | — | — | — | ||||||||||||||||||||||||
| Commercial and industrial | (45) | (126) | (121) | (81) | (65) | ||||||||||||||||||||||||
| Commercial real estate—owner occupied | 6 | (18) | — | — | — | ||||||||||||||||||||||||
| Commercial and business lending | (35) | (103) | (100) | (72) | (58) | ||||||||||||||||||||||||
| Commercial real estate—investor | (173) | (34) | — | — | — | ||||||||||||||||||||||||
| Real estate construction | 1 | — | — | — | 2 | ||||||||||||||||||||||||
| Commercial real estate lending | (121) | (24) | — | — | 1 | ||||||||||||||||||||||||
| Total commercial | (69) | (73) | (64) | (44) | (35) | ||||||||||||||||||||||||
| Residential mortgage | (1) | — | (1) | (4) | (7) | ||||||||||||||||||||||||
| Home equity | 18 | 8 | (15) | 3 | 22 | ||||||||||||||||||||||||
| Other consumer | (83) | (98) | (128) | (134) | (145) | ||||||||||||||||||||||||
| Total consumer | (2) | (3) | (7) | (8) | (9) | ||||||||||||||||||||||||
| Total net charge offs | (44) | (47) | (42) | (29) | (24) | ||||||||||||||||||||||||
| ($ in thousands) | Dec 31, 2020 | Sep 30, 2020 | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | ||||||||||||||||||||||||
| Credit Quality | |||||||||||||||||||||||||||||
| Nonaccrual loans | $ | 210,854 | $ | 231,590 | (9) | % | $ | 171,607 | $ | 136,717 | $ | 118,380 | 78 | % | |||||||||||||||
| Other real estate owned (OREO) | 14,269 | 18,983 | (25) | % | 20,264 | 22,530 | 21,101 | (32) | % | ||||||||||||||||||||
| Other nonperforming assets | — | 909 | (100) | % | 909 | 6,004 | 6,004 | (100) | % | ||||||||||||||||||||
| Total nonperforming assets | $ | 225,123 | $ | 251,481 | (10) | % | $ | 192,780 | $ | 165,251 | $ | 145,485 | 55 | % | |||||||||||||||
| Loans 90 or more days past due and still accruing | $ | 1,598 | $ | 1,854 | (14) | % | $ | 1,466 | $ | 2,255 | $ | 2,259 | (29) | % | |||||||||||||||
| Allowance for credit losses to loans | 1.76 | % | 1.77 | % | 1.73 | % | 1.62 | % | 0.98 | % | |||||||||||||||||||
| Allowance for credit losses to nonaccrual loans | 204.63 | % | 190.85 | % | 249.74 | % | 288.24 | % | 188.61 | % | |||||||||||||||||||
| Nonaccrual loans to total loans | 0.86 | % | 0.93 | % | 0.69 | % | 0.56 | % | 0.52 | % | |||||||||||||||||||
| Nonperforming assets to total loans plus OREO | 0.92 | % | 1.01 | % | 0.78 | % | 0.68 | % | 0.64 | % | |||||||||||||||||||
| Nonperforming assets to total assets | 0.67 | % | 0.72 | % | 0.54 | % | 0.49 | % | 0.45 | % | |||||||||||||||||||
| Year-to-date net charge offs to year-to-date average loans (annualized) | 0.41 | % | 0.40 | % | 0.36 | % | 0.29 | % | 0.24 | % | |||||||||||||||||||
(a) Excludes approximately $67,000 of allowance for held to maturity investment securities
(b) Excludes provision for held to maturity investment securities.
5
| Associated Banc-Corp Selected Asset Quality Information (continued) | |||||||||||||||||||||||||||||
| (In thousands) | Dec 31, 2020 | Sep 30, 2020 | Seql Qtr % Change | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Comp Qtr % Change | ||||||||||||||||||||||
| Nonaccrual loans | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 61,859 | $ | 105,899 | (42) | % | $ | 80,239 | $ | 58,854 | $ | 46,312 | 34 | % | |||||||||||||||
| Commercial real estate—owner occupied | 1,058 | 2,043 | (48) | % | 1,932 | 1,838 | 67 | N/M | |||||||||||||||||||||
| Commercial and business lending | 62,917 | 107,941 | (42) | % | 82,171 | 60,692 | 46,380 | 36 | % | ||||||||||||||||||||
| Commercial real estate—investor | 78,220 | 50,458 | 55 | % | 11,172 | 1,091 | 4,409 | N/M | |||||||||||||||||||||
| Real estate construction | 353 | 392 | (10) | % | 503 | 486 | 493 | (28) | % | ||||||||||||||||||||
| Commercial real estate lending | 78,573 | 50,850 | 55 | % | 11,675 | 1,577 | 4,902 | N/M | |||||||||||||||||||||
| Total commercial | 141,490 | 158,792 | (11) | % | 93,846 | 62,269 | 51,282 | 176 | % | ||||||||||||||||||||
| Residential mortgage | 59,337 | 62,331 | (5) | % | 66,656 | 64,855 | 57,844 | 3 | % | ||||||||||||||||||||
| Home equity | 9,888 | 10,277 | (4) | % | 10,829 | 9,378 | 9,104 | 9 | % | ||||||||||||||||||||
| Other consumer | 140 | 190 | (26) | % | 276 | 215 | 152 | (8) | % | ||||||||||||||||||||
| Total consumer | 69,364 | 72,798 | (5) | % | 77,761 | 74,448 | 67,099 | 3 | % | ||||||||||||||||||||
| Total nonaccrual loans | $ | 210,854 | $ | 231,590 | (9) | % | $ | 171,607 | $ | 136,717 | $ | 118,380 | 78 | % | |||||||||||||||
| Dec 31, 2020 | Sep 30, 2020 | Seql Qtr % Change | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Comp Qtr % Change | |||||||||||||||||||||||
Restructured loans (accruing)(a) | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 12,713 | $ | 16,002 | (21) | % | $ | 16,321 | $ | 16,056 | $ | 16,678 | (24) | % | |||||||||||||||
| Commercial real estate—owner occupied | 1,711 | 1,389 | 23 | % | 1,441 | 2,091 | 1,676 | 2 | % | ||||||||||||||||||||
| Commercial and business lending | 14,424 | 17,391 | (17) | % | 17,762 | 18,146 | 18,353 | (21) | % | ||||||||||||||||||||
| Commercial real estate—investor | 26,435 | 635 | N/M | 114 | 281 | 293 | N/M | ||||||||||||||||||||||
| Real estate construction | 260 | 382 | (32) | % | 313 | 339 | 298 | (13) | % | ||||||||||||||||||||
| Commercial real estate lending | 26,695 | 1,016 | N/M | 427 | 620 | 591 | N/M | ||||||||||||||||||||||
| Total commercial | 41,119 | 18,407 | 123 | % | 18,189 | 18,767 | 18,944 | 117 | % | ||||||||||||||||||||
| Residential mortgage | 7,825 | 5,378 | 46 | % | 4,178 | 4,654 | 3,955 | 98 | % | ||||||||||||||||||||
| Home equity | 1,957 | 1,889 | 4 | % | 1,717 | 1,719 | 1,896 | 3 | % | ||||||||||||||||||||
| Other consumer | 1,191 | 1,218 | (2) | % | 1,219 | 1,245 | 1,246 | (4) | % | ||||||||||||||||||||
| Total consumer | 10,973 | 8,485 | 29 | % | 7,114 | 7,618 | 7,097 | 55 | % | ||||||||||||||||||||
| Total restructured loans (accruing) | $ | 52,092 | $ | 26,891 | 94 | % | $ | 25,303 | $ | 26,384 | $ | 26,041 | 100 | % | |||||||||||||||
| Nonaccrual restructured loans (included in nonaccrual loans) | $ | 20,190 | $ | 23,844 | (15) | % | $ | 25,362 | $ | 24,204 | $ | 22,494 | (10) | % | |||||||||||||||
| Dec 31, 2020 | Sep 30, 2020 | Seql Qtr % Change | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Comp Qtr % Change | |||||||||||||||||||||||
| Accruing Loans 30-89 Days Past Due | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 6,119 | $ | 298 | N/M | $ | 716 | $ | 976 | $ | 821 | N/M | |||||||||||||||||
| Commercial real estate—owner occupied | 373 | 870 | (57) | % | 199 | 51 | 1,369 | (73) | % | ||||||||||||||||||||
| Commercial and business lending | 6,492 | 1,167 | N/M | 916 | 1,027 | 2,190 | 196 | % | |||||||||||||||||||||
| Commercial real estate—investor | 12,793 | 409 | N/M | 13,874 | 14,462 | 1,812 | N/M | ||||||||||||||||||||||
| Real estate construction | 991 | 111 | N/M | 385 | 179 | 97 | N/M | ||||||||||||||||||||||
| Commercial real estate lending | 13,784 | 520 | N/M | 14,260 | 14,641 | 1,909 | N/M | ||||||||||||||||||||||
| Total commercial | 20,276 | 1,687 | N/M | 15,175 | 15,668 | 4,099 | N/M | ||||||||||||||||||||||
| Residential mortgage | 10,385 | 6,185 | 68 | % | 3,023 | 10,102 | 9,274 | 12 | % | ||||||||||||||||||||
| Home equity | 4,802 | 5,609 | (14) | % | 3,108 | 7,001 | 5,647 | (15) | % | ||||||||||||||||||||
| Other consumer | 1,599 | 1,351 | 18 | % | 1,482 | 1,777 | 2,083 | (23) | % | ||||||||||||||||||||
| Total consumer | 16,786 | 13,144 | 28 | % | 7,613 | 18,879 | 17,005 | (1) | % | ||||||||||||||||||||
| Total accruing loans 30-89 days past due | $ | 37,062 | $ | 14,831 | 150 | % | $ | 22,788 | $ | 34,547 | $ | 21,104 | 76 | % | |||||||||||||||
| Dec 31, 2020 | Sep 30, 2020 | Seql Qtr % Change | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Comp Qtr % Change | |||||||||||||||||||||||
| Potential Problem Loans | |||||||||||||||||||||||||||||
| PPP Loans | $ | 18,002 | $ | 19,161 | (6) | % | $ | 19,161 | $ | — | $ | — | N/M | ||||||||||||||||
| Commercial and industrial | 121,487 | 144,159 | (16) | % | 176,270 | 149,747 | 110,308 | 10 | % | ||||||||||||||||||||
| Commercial real estate—owner occupied | 26,179 | 22,808 | 15 | % | 15,919 | 15,802 | 19,889 | 32 | % | ||||||||||||||||||||
| Commercial and business lending | 165,668 | 186,129 | (11) | % | 211,350 | 165,550 | 130,197 | 27 | % | ||||||||||||||||||||
| Commercial real estate—investor | 91,396 | 100,459 | (9) | % | 88,237 | 61,030 | 29,449 | N/M | |||||||||||||||||||||
| Real estate construction | 19,046 | 2,178 | N/M | 2,170 | 1,753 | — | N/M | ||||||||||||||||||||||
| Commercial real estate lending | 110,442 | 102,637 | 8 | % | 90,407 | 62,783 | 29,449 | N/M | |||||||||||||||||||||
| Total commercial | 276,111 | 288,766 | (4) | % | 301,758 | 228,333 | 159,646 | 73 | % | ||||||||||||||||||||
| Residential mortgage | 3,749 | 2,396 | 56 | % | 3,157 | 3,322 | 1,451 | 158 | % | ||||||||||||||||||||
| Home equity | 2,068 | 1,632 | 27 | % | 1,921 | 2,238 | — | N/M | |||||||||||||||||||||
| Total consumer | 5,817 | 4,028 | 44 | % | 5,078 | 5,559 | 1,451 | N/M | |||||||||||||||||||||
| Total potential problem loans | $ | 281,928 | $ | 292,794 | (4) | % | $ | 306,836 | $ | 233,892 | $ | 161,097 | 75 | % | |||||||||||||||
N/M = Not meaningful
N/A = Not applicable
Numbers may not sum due to rounding.
(a) Does not include any restructured loans related to COVID-19 in accordance with regulatory guidance
6
| Associated Banc-Corp Net Interest Income Analysis - Fully Tax-Equivalent Basis - Sequential and Comparable Quarter | |||||||||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||||||||
| December 31, 2020 | September 30, 2020 | December 31, 2019 | |||||||||||||||||||||||||||||||||
| ($ in thousands) | Average Balance | Interest Income /Expense | Average Yield /Rate | Average Balance | Interest Income /Expense | Average Yield /Rate | Average Balance | Interest Income /Expense | Average Yield /Rate | ||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||
| Earning assets | |||||||||||||||||||||||||||||||||||
Loans (a) (b) (c) | |||||||||||||||||||||||||||||||||||
| Commercial PPP lending | $ | 929,859 | $ | 10,854 | 4.64 | % | $ | 1,019,808 | $ | 6,172 | 2.41 | % | $ | — | $ | — | — | % | |||||||||||||||||
| Commercial and business lending (excl PPP loans) | 8,513,750 | 57,473 | 2.69 | % | 8,751,083 | 56,951 | 2.59 | % | 8,208,076 | 85,418 | 4.13 | % | |||||||||||||||||||||||
| Commercial real estate lending | 6,157,622 | 44,636 | 2.88 | % | 6,032,308 | 44,354 | 2.93 | % | 5,195,025 | 59,490 | 4.55 | % | |||||||||||||||||||||||
| Total commercial | 15,601,230 | 112,963 | 2.88 | % | 15,803,199 | 107,476 | 2.71 | % | 13,403,101 | 144,908 | 4.29 | % | |||||||||||||||||||||||
| Residential mortgage | 8,029,585 | 60,292 | 3.00 | % | 8,058,283 | 61,701 | 3.06 | % | 8,167,795 | 66,805 | 3.27 | % | |||||||||||||||||||||||
| Retail | 1,051,022 | 13,035 | 4.95 | % | 1,101,589 | 13,780 | 4.99 | % | 1,212,438 | 18,422 | 6.06 | % | |||||||||||||||||||||||
| Total loans | 24,681,837 | 186,290 | 3.01 | % | 24,963,071 | 182,957 | 2.92 | % | 22,783,334 | 230,135 | 4.02 | % | |||||||||||||||||||||||
| Investment securities | |||||||||||||||||||||||||||||||||||
| Taxable | 3,155,508 | 9,746 | 1.24 | % | 3,438,858 | 13,689 | 1.59 | % | 3,624,465 | 21,056 | 2.32 | % | |||||||||||||||||||||||
Tax-exempt(a) | 1,909,512 | 17,870 | 3.74 | % | 1,923,445 | 18,154 | 3.78 | % | 1,929,374 | 18,269 | 3.79 | % | |||||||||||||||||||||||
| Other short-term investments | 985,091 | 1,699 | 0.69 | % | 1,788,471 | 2,238 | 0.50 | % | 445,869 | 3,556 | 3.17 | % | |||||||||||||||||||||||
| Investments and other | 6,050,111 | 29,315 | 1.94 | % | 7,150,775 | 34,081 | 1.90 | % | 5,999,708 | 42,881 | 2.86 | % | |||||||||||||||||||||||
| Total earning assets | 30,731,948 | $ | 215,605 | 2.80 | % | 32,113,847 | $ | 217,038 | 2.70 | % | 28,783,042 | $ | 273,015 | 3.78 | % | ||||||||||||||||||||
| Other assets, net | 3,343,844 | 3,436,512 | 3,399,141 | ||||||||||||||||||||||||||||||||
| Total assets | $ | 34,075,792 | $ | 35,550,359 | $ | 32,182,183 | |||||||||||||||||||||||||||||
| Liabilities and stockholders' equity | |||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities | |||||||||||||||||||||||||||||||||||
| Interest-bearing deposits | |||||||||||||||||||||||||||||||||||
| Savings | $ | 3,628,458 | $ | 356 | 0.04 | % | $ | 3,462,942 | $ | 382 | 0.04 | % | $ | 2,714,191 | $ | 2,086 | 0.30 | % | |||||||||||||||||
| Interest-bearing demand | 5,739,983 | 1,215 | 0.08 | % | 5,835,597 | 1,085 | 0.07 | % | 5,138,116 | 11,458 | 0.88 | % | |||||||||||||||||||||||
| Money market | 6,539,583 | 1,121 | 0.07 | % | 6,464,784 | 1,444 | 0.09 | % | 6,594,681 | 13,959 | 0.84 | % | |||||||||||||||||||||||
| Network transaction deposits | 1,265,748 | 468 | 0.15 | % | 1,528,199 | 609 | 0.16 | % | 1,438,908 | 6,295 | 1.74 | % | |||||||||||||||||||||||
| Time deposits | 1,888,074 | 4,602 | 0.97 | % | 2,135,870 | 6,513 | 1.21 | % | 2,746,978 | 12,080 | 1.74 | % | |||||||||||||||||||||||
| Total interest-bearing deposits | 19,061,847 | 7,762 | 0.16 | % | 19,427,392 | 10,033 | 0.21 | % | 18,632,874 | 45,877 | 0.98 | % | |||||||||||||||||||||||
| Federal funds purchased and securities sold under agreements to repurchase | 164,091 | 32 | 0.08 | % | 140,321 | 34 | 0.10 | % | 176,999 | 521 | 1.17 | % | |||||||||||||||||||||||
| Commercial Paper | 40,128 | 5 | 0.05 | % | 42,338 | 5 | 0.05 | % | 27,708 | 25 | 0.36 | % | |||||||||||||||||||||||
| PPPLF | 464,119 | 410 | 0.35 | % | 1,018,994 | 899 | 0.35 | % | — | — | — | % | |||||||||||||||||||||||
| FHLB advances | 1,660,274 | 9,888 | 2.37 | % | 2,450,344 | 14,375 | 2.33 | % | 2,909,462 | 16,623 | 2.27 | % | |||||||||||||||||||||||
| Long-term funding | 549,307 | 5,585 | 4.07 | % | 549,042 | 5,580 | 4.06 | % | 585,024 | 5,921 | 4.05 | % | |||||||||||||||||||||||
| Total short and long-term funding | 2,877,919 | 15,920 | 2.20 | % | 4,201,039 | 20,892 | 1.98 | % | 3,699,192 | 23,090 | 2.48 | % | |||||||||||||||||||||||
| Total interest-bearing liabilities | 21,939,766 | $ | 23,682 | 0.43 | % | 23,628,431 | $ | 30,925 | 0.52 | % | 22,332,066 | $ | 68,967 | 1.23 | % | ||||||||||||||||||||
| Noninterest-bearing demand deposits | 7,677,003 | 7,412,186 | 5,470,496 | ||||||||||||||||||||||||||||||||
| Other liabilities | 405,430 | 475,310 | 465,081 | ||||||||||||||||||||||||||||||||
| Stockholders’ equity | 4,053,593 | 4,034,432 | 3,914,539 | ||||||||||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 34,075,792 | $ | 35,550,359 | $ | 32,182,183 | |||||||||||||||||||||||||||||
| Interest rate spread | 2.37 | % | 2.18 | % | 2.55 | % | |||||||||||||||||||||||||||||
| Net free funds | 0.12 | % | 0.13 | % | 0.28 | % | |||||||||||||||||||||||||||||
| Fully tax-equivalent net interest income and net interest margin ("NIM") | $ | 191,923 | 2.49 | % | $ | 186,112 | 2.31 | % | $ | 204,048 | 2.83 | % | |||||||||||||||||||||||
| Fully tax-equivalent adjustment | 3,930 | 3,963 | 3,906 | ||||||||||||||||||||||||||||||||
| Net interest income | $ | 187,993 | $ | 182,150 | $ | 200,142 | |||||||||||||||||||||||||||||
Numbers may not sum due to rounding.
(a)The yield on tax-exempt loans and securities is computed on a fully tax-equivalent basis using a tax rate of 21% and is net of the effects of certain disallowed interest deductions.
(b)Nonaccrual loans and loans held for sale have been included in the average balances.
(c)Interest income includes amortization of net deferred loan origination costs and net accreted purchase loan discount.
7
| Associated Banc-Corp Net Interest Income Analysis - Fully Tax-Equivalent Basis - Year Over Year | ||||||||||||||||||||||||||||||||||||||
| Year Ended December 31, | ||||||||||||||||||||||||||||||||||||||
| 2020 | 2019 | |||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Average Balance | Interest Income /Expense | Average Yield / Rate | Average Balance | Interest Income /Expense | Average Yield / Rate | ||||||||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||||||||
| Earning assets | ||||||||||||||||||||||||||||||||||||||
Loans (a) (b) (c) | ||||||||||||||||||||||||||||||||||||||
| Commercial PPP lending | $ | 701,111 | $ | 21,867 | 3.12 | % | $ | — | $ | — | — | % | ||||||||||||||||||||||||||
| Commercial and business lending (excl PPP loans) | 8,709,043 | 258,738 | 2.97 | % | 8,426,774 | 385,072 | 4.57 | % | ||||||||||||||||||||||||||||||
| Commercial real estate lending | 5,811,498 | 192,545 | 3.31 | % | 5,150,464 | 255,582 | 4.96 | % | ||||||||||||||||||||||||||||||
| Total commercial | 15,221,651 | 473,150 | 3.11 | % | 13,577,238 | 640,655 | 4.72 | % | ||||||||||||||||||||||||||||||
Residential mortgage | 8,190,190 | 254,814 | 3.11 | % | 8,311,914 | 282,134 | 3.39 | % | ||||||||||||||||||||||||||||||
| Retail | 1,125,806 | 58,655 | 5.21 | % | 1,233,646 | 76,939 | 6.24 | % | ||||||||||||||||||||||||||||||
| Total loans | 24,537,648 | 786,619 | 3.21 | % | 23,122,797 | 999,727 | 4.32 | % | ||||||||||||||||||||||||||||||
| Investment securities | ||||||||||||||||||||||||||||||||||||||
| Taxable | 3,295,718 | 59,806 | 1.81 | % | 4,284,991 | 100,304 | 2.34 | % | ||||||||||||||||||||||||||||||
Tax-exempt (a) | 1,930,853 | 72,901 | 3.78 | % | 1,909,474 | 71,956 | 3.77 | % | ||||||||||||||||||||||||||||||
| Other short-term investments | 1,067,788 | 9,473 | 0.89 | % | 503,566 | 16,643 | 3.30 | % | ||||||||||||||||||||||||||||||
| Investments and other | 6,294,359 | 142,179 | 2.26 | % | 6,698,032 | 188,903 | 2.82 | % | ||||||||||||||||||||||||||||||
| Total earning assets | 30,832,007 | $ | 928,799 | 3.01 | % | 29,820,829 | $ | 1,188,630 | 3.99 | % | ||||||||||||||||||||||||||||
| Other assets, net | 3,433,200 | 3,225,775 | ||||||||||||||||||||||||||||||||||||
| Total assets | $ | 34,265,207 | $ | 33,046,604 | ||||||||||||||||||||||||||||||||||
| Liabilities and stockholders' equity | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits | ||||||||||||||||||||||||||||||||||||||
| Savings | $ | 3,306,385 | $ | 2,966 | 0.09 | % | $ | 2,439,872 | $ | 7,086 | 0.29 | % | ||||||||||||||||||||||||||
| Interest-bearing demand | 5,583,144 | 12,496 | 0.22 | % | 5,080,857 | 56,742 | 1.12 | % | ||||||||||||||||||||||||||||||
| Money market | 6,509,924 | 15,273 | 0.23 | % | 7,005,265 | 74,467 | 1.06 | % | ||||||||||||||||||||||||||||||
| Network transaction deposits | 1,442,951 | 6,219 | 0.43 | % | 1,860,951 | 42,523 | 2.29 | % | ||||||||||||||||||||||||||||||
| Time deposits | 2,281,040 | 30,685 | 1.35 | % | 3,129,142 | 56,468 | 1.80 | % | ||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 19,123,444 | 67,639 | 0.35 | % | 19,516,088 | 237,286 | 1.22 | % | ||||||||||||||||||||||||||||||
| Federal funds purchased and securities sold under agreements to repurchase | 175,713 | 485 | 0.28 | % | 137,679 | 1,579 | 1.15 | % | ||||||||||||||||||||||||||||||
| Commercial Paper | 38,583 | 41 | 0.11 | % | 32,123 | 138 | 0.43 | % | ||||||||||||||||||||||||||||||
| PPPLF | 565,371 | 1,984 | 0.35 | % | — | — | — | % | ||||||||||||||||||||||||||||||
| Other short-term funding | 4,226 | 11 | 0.25 | % | — | — | — | % | ||||||||||||||||||||||||||||||
| FHLB advances | 2,535,731 | 57,359 | 2.26 | % | 3,106,279 | 69,816 | 2.25 | % | ||||||||||||||||||||||||||||||
| Long-term funding | 549,143 | 22,365 | 4.07 | % | 742,946 | 28,116 | 3.78 | % | ||||||||||||||||||||||||||||||
| Total short and long-term funding | 3,868,767 | 82,245 | 2.13 | % | 4,019,027 | 99,651 | 2.48 | % | ||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 22,992,211 | $ | 149,883 | 0.65 | % | 23,535,115 | $ | 336,936 | 1.43 | % | ||||||||||||||||||||||||||||
| Noninterest-bearing demand deposits | 6,884,241 | 5,219,520 | ||||||||||||||||||||||||||||||||||||
| Other liabilities | 444,183 | 420,100 | ||||||||||||||||||||||||||||||||||||
| Stockholders’ equity | 3,944,572 | 3,871,869 | ||||||||||||||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 34,265,207 | $ | 33,046,604 | ||||||||||||||||||||||||||||||||||
| Interest rate spread | 2.36 | % | 2.56 | % | ||||||||||||||||||||||||||||||||||
| Net free funds | 0.17 | % | 0.30 | % | ||||||||||||||||||||||||||||||||||
| Fully tax-equivalent net interest income and net interest margin ("NIM") | $ | 778,915 | 2.53 | % | $ | 851,693 | 2.86 | % | ||||||||||||||||||||||||||||||
| Fully tax-equivalent adjustment | 15,959 | 16,020 | ||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 762,957 | $ | 835,674 | ||||||||||||||||||||||||||||||||||
Numbers may not sum due to rounding.
(a)The yield on tax-exempt loans and securities is computed on a fully tax-equivalent basis using a tax rate of 21% and is net of the effects of certain disallowed interest deductions.
(b)Nonaccrual loans and loans held for sale have been included in the average balances.
(c)Interest income includes amortization of net deferred loan origination costs and net accreted purchase loan discount.
8
| Associated Banc-Corp Loan and Deposit Composition | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | ||||||||||||||||||||||||||||||||||||||||||||
| Period end loan composition | Dec 31, 2020 | Sep 30, 2020 | Seql Qtr % Change | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Comp Qtr % Change | |||||||||||||||||||||||||||||||||||||
| PPP Loans | $ | 767,757 | $ | 1,022,217 | (25) | % | $ | 1,012,033 | $ | — | $ | — | N/M | |||||||||||||||||||||||||||||||
| Commercial and industrial | 7,701,422 | 7,933,404 | (3) | % | 7,968,709 | 8,517,974 | 7,354,594 | 5 | % | |||||||||||||||||||||||||||||||||||
| Commercial real estate—owner occupied | 900,912 | 904,997 | — | % | 914,385 | 940,687 | 911,265 | (1) | % | |||||||||||||||||||||||||||||||||||
| Commercial and business lending | 9,370,091 | 9,860,618 | (5) | % | 9,895,127 | 9,458,661 | 8,265,858 | 13 | % | |||||||||||||||||||||||||||||||||||
| Commercial real estate—investor | 4,342,584 | 4,320,926 | 1 | % | 4,174,125 | 4,038,036 | 3,794,517 | 14 | % | |||||||||||||||||||||||||||||||||||
| Real estate construction | 1,840,417 | 1,859,609 | (1) | % | 1,708,189 | 1,544,858 | 1,420,900 | 30 | % | |||||||||||||||||||||||||||||||||||
| Commercial real estate lending | 6,183,001 | 6,180,536 | — | % | 5,882,314 | 5,582,894 | 5,215,417 | 19 | % | |||||||||||||||||||||||||||||||||||
| Total commercial | 15,553,091 | 16,041,154 | (3) | % | 15,777,441 | 15,041,555 | 13,481,275 | 15 | % | |||||||||||||||||||||||||||||||||||
| Residential mortgage | 7,878,324 | 7,885,523 | — | % | 7,933,518 | 8,132,417 | 8,136,980 | (3) | % | |||||||||||||||||||||||||||||||||||
| Home equity | 707,255 | 761,593 | (7) | % | 795,671 | 844,901 | 852,025 | (17) | % | |||||||||||||||||||||||||||||||||||
| Other consumer | 313,054 | 315,483 | (1) | % | 326,040 | 346,761 | 351,159 | (11) | % | |||||||||||||||||||||||||||||||||||
| Total consumer | 8,898,632 | 8,962,599 | (1) | % | 9,055,230 | 9,324,079 | 9,340,164 | (5) | % | |||||||||||||||||||||||||||||||||||
| Total loans | $ | 24,451,724 | $ | 25,003,753 | (2) | % | $ | 24,832,671 | $ | 24,365,633 | $ | 22,821,440 | 7 | % | ||||||||||||||||||||||||||||||
| Period end deposit and customer funding composition | Dec 31, 2020 | Sep 30, 2020 | Seql Qtr % Change | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Comp Qtr % Change | |||||||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 7,661,728 | $ | 7,489,048 | 2 | % | $ | 7,573,942 | $ | 6,107,386 | $ | 5,450,709 | 41 | % | ||||||||||||||||||||||||||||||
| Savings | 3,650,085 | 3,529,423 | 3 | % | 3,394,930 | 3,033,039 | 2,735,036 | 33 | % | |||||||||||||||||||||||||||||||||||
| Interest-bearing demand | 6,090,869 | 5,979,449 | 2 | % | 5,847,349 | 6,170,071 | 5,329,717 | 14 | % | |||||||||||||||||||||||||||||||||||
| Money market | 7,322,769 | 7,687,775 | (5) | % | 7,486,319 | 7,717,739 | 7,640,798 | (4) | % | |||||||||||||||||||||||||||||||||||
| Brokered CDs | — | — | N/M | 4,225 | 65,000 | 5,964 | (100) | % | ||||||||||||||||||||||||||||||||||||
| Other time | 1,757,030 | 2,026,852 | (13) | % | 2,244,680 | 2,568,345 | 2,616,839 | (33) | % | |||||||||||||||||||||||||||||||||||
| Total deposits | 26,482,481 | 26,712,547 | (1) | % | 26,551,444 | 25,661,580 | 23,779,064 | 11 | % | |||||||||||||||||||||||||||||||||||
Customer funding(a) | 245,247 | 198,741 | 23 | % | 178,398 | 142,174 | 103,113 | 138 | % | |||||||||||||||||||||||||||||||||||
| Total deposits and customer funding | $ | 26,727,727 | $ | 26,911,289 | (1) | % | $ | 26,729,842 | $ | 25,803,754 | $ | 23,882,177 | 12 | % | ||||||||||||||||||||||||||||||
Network transaction deposits(b) | $ | 1,197,093 | $ | 1,390,778 | (14) | % | $ | 1,496,958 | $ | 1,731,996 | $ | 1,336,286 | (10) | % | ||||||||||||||||||||||||||||||
| Net deposits and customer funding (Total deposits and customer funding, excluding Brokered CDs and network transaction deposits) | $ | 25,530,634 | $ | 25,520,511 | — | % | $ | 25,228,660 | $ | 24,006,758 | $ | 22,539,927 | 13 | % | ||||||||||||||||||||||||||||||
| Quarter average loan composition | Dec 31, 2020 | Sep 30, 2020 | Seql Qtr % Change | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Comp Qtr % Change | |||||||||||||||||||||||||||||||||||||
| PPP Loans | $ | 929,859 | $ | 1,019,808 | (9) | % | $ | 848,761 | $ | — | $ | — | N/M | |||||||||||||||||||||||||||||||
| Commercial and industrial | 7,609,185 | 7,844,209 | (3) | % | 8,263,270 | 7,455,528 | 7,291,592 | 4 | % | |||||||||||||||||||||||||||||||||||
| Commercial real estate—owner occupied | 904,565 | 906,874 | — | % | 929,640 | 924,585 | 916,484 | (1) | % | |||||||||||||||||||||||||||||||||||
| Commercial and business lending | 9,443,609 | 9,770,891 | (3) | % | 10,041,671 | 8,380,113 | 8,208,076 | 15 | % | |||||||||||||||||||||||||||||||||||
| Commercial real estate—investor | 4,289,703 | 4,255,473 | 1 | % | 4,113,895 | 3,857,277 | 3,806,168 | 13 | % | |||||||||||||||||||||||||||||||||||
| Real estate construction | 1,867,919 | 1,776,835 | 5 | % | 1,606,367 | 1,472,292 | 1,388,857 | 34 | % | |||||||||||||||||||||||||||||||||||
| Commercial real estate lending | 6,157,622 | 6,032,308 | 2 | % | 5,720,262 | 5,329,568 | 5,195,025 | 19 | % | |||||||||||||||||||||||||||||||||||
| Total commercial | 15,601,230 | 15,803,199 | (1) | % | 15,761,933 | 13,709,681 | 13,403,101 | 16 | % | |||||||||||||||||||||||||||||||||||
| Residential mortgage | 8,029,585 | 8,058,283 | — | % | 8,271,757 | 8,404,351 | 8,167,795 | (2) | % | |||||||||||||||||||||||||||||||||||
| Home equity | 736,059 | 780,202 | (6) | % | 819,680 | 845,422 | 864,144 | (15) | % | |||||||||||||||||||||||||||||||||||
| Other consumer | 314,963 | 321,387 | (2) | % | 337,436 | 349,164 | 348,295 | (10) | % | |||||||||||||||||||||||||||||||||||
| Total consumer | 9,080,607 | 9,159,872 | (1) | % | 9,428,873 | 9,598,937 | 9,380,233 | (3) | % | |||||||||||||||||||||||||||||||||||
Total loans(c) | $ | 24,681,837 | $ | 24,963,071 | (1) | % | $ | 25,190,806 | $ | 23,308,618 | $ | 22,783,334 | 8 | % | ||||||||||||||||||||||||||||||
| Quarter average deposit composition | Dec 31, 2020 | Sep 30, 2020 | Seql Qtr % Change | Jun 30, 2020 | Mar 31, 2020 | Dec 31, 2019 | Comp Qtr % Change | |||||||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 7,677,003 | $ | 7,412,186 | 4 | % | $ | 6,926,401 | $ | 5,506,861 | $ | 5,470,496 | 40 | % | ||||||||||||||||||||||||||||||
| Savings | 3,628,458 | 3,462,942 | 5 | % | 3,260,040 | 2,868,840 | 2,714,191 | 34 | % | |||||||||||||||||||||||||||||||||||
| Interest-bearing demand | 5,739,983 | 5,835,597 | (2) | % | 5,445,267 | 5,307,230 | 5,138,116 | 12 | % | |||||||||||||||||||||||||||||||||||
| Money market | 6,539,583 | 6,464,784 | 1 | % | 6,496,841 | 6,538,658 | 6,594,681 | (1) | % | |||||||||||||||||||||||||||||||||||
| Network transaction deposits | 1,265,748 | 1,528,199 | (17) | % | 1,544,737 | 1,434,128 | 1,438,908 | (12) | % | |||||||||||||||||||||||||||||||||||
| Time deposits | 1,888,074 | 2,135,870 | (12) | % | 2,469,899 | 2,636,231 | 2,746,978 | (31) | % | |||||||||||||||||||||||||||||||||||
| Total deposits | $ | 26,738,850 | $ | 26,839,578 | — | % | $ | 26,143,186 | $ | 24,291,949 | $ | 24,103,371 | 11 | % | ||||||||||||||||||||||||||||||
N/M = Not meaningful
Numbers may not sum due to rounding.
(a)Includes repurchase agreements and commercial paper.
(b)Included above in interest-bearing demand and money market.
(c)Nonaccrual loans and loans held for sale have been included in the average balances.
9
| Associated Banc-Corp Non-GAAP Financial Measures Reconciliation | YTD | YTD | |||||||||||||||||||||
| ($ in millions, except per share data) | Dec 2020 | Dec 2019 | 4Q20 | 3Q20 | 2Q20 | 1Q20 | 4Q19 | ||||||||||||||||
Tangible common equity reconciliation(a) | |||||||||||||||||||||||
| Common equity | $ | 3,737 | $ | 3,692 | $ | 3,671 | $ | 3,534 | $ | 3,665 | |||||||||||||
| Goodwill and other intangible assets, net | (1,178) | (1,178) | (1,181) | (1,284) | (1,265) | ||||||||||||||||||
| Tangible common equity | $ | 2,560 | $ | 2,513 | $ | 2,490 | $ | 2,250 | $ | 2,401 | |||||||||||||
Tangible assets reconciliation(a) | |||||||||||||||||||||||
| Total assets | $ | 33,420 | $ | 34,699 | $ | 35,501 | $ | 33,908 | $ | 32,386 | |||||||||||||
| Goodwill and other intangible assets, net | (1,178) | (1,178) | (1,181) | (1,284) | (1,265) | ||||||||||||||||||
| Tangible assets | $ | 32,242 | $ | 33,520 | $ | 34,321 | $ | 32,624 | $ | 31,122 | |||||||||||||
Average tangible common equity and average common equity tier 1 reconciliation(a) | |||||||||||||||||||||||
| Common equity | $ | 3,633 | $ | 3,615 | $ | 3,700 | $ | 3,681 | $ | 3,566 | $ | 3,585 | $ | 3,658 | |||||||||
| Goodwill and other intangible assets, net | (1,228) | (1,257) | (1,178) | (1,180) | (1,281) | (1,272) | (1,266) | ||||||||||||||||
| Tangible common equity | 2,406 | 2,358 | 2,522 | 2,501 | 2,285 | 2,313 | 2,392 | ||||||||||||||||
| Modified CECL transitional amount | 115 | N/A | 123 | 120 | 115 | 101 | N/A | ||||||||||||||||
| Accumulated other comprehensive loss (income) | 3 | 69 | (4) | (4) | 8 | 10 | 37 | ||||||||||||||||
| Deferred tax assets (liabilities), net | 44 | 47 | 42 | 42 | 45 | 47 | 48 | ||||||||||||||||
| Average common equity Tier 1 | $ | 2,567 | $ | 2,474 | $ | 2,683 | $ | 2,660 | $ | 2,453 | $ | 2,471 | $ | 2,476 | |||||||||
Average tangible assets reconciliation(a) | |||||||||||||||||||||||
| Total assets | $ | 34,265 | $ | 33,047 | $ | 34,076 | $ | 35,550 | $ | 34,846 | $ | 32,577 | $ | 32,182 | |||||||||
| Goodwill and other intangible assets, net | (1,228) | (1,257) | (1,178) | (1,180) | (1,281) | (1,272) | (1,266) | ||||||||||||||||
| Tangible assets | $ | 33,038 | $ | 31,790 | $ | 32,898 | $ | 34,371 | $ | 33,565 | $ | 31,305 | $ | 30,916 | |||||||||
Selected trend information(b) | |||||||||||||||||||||||
Wealth management fees(c) | 85 | 83 | 22 | 21 | 21 | 21 | 22 | ||||||||||||||||
| Service charges and deposit account fees | 56 | 63 | 15 | 14 | 11 | 15 | 16 | ||||||||||||||||
| Card-based fees | 39 | 40 | 10 | 10 | 9 | 10 | 10 | ||||||||||||||||
| Other fee-based revenue | 19 | 19 | 5 | 5 | 5 | 4 | 5 | ||||||||||||||||
| Fee-based revenue | 199 | 205 | 52 | 51 | 46 | 50 | 52 | ||||||||||||||||
| Other | 315 | 176 | 33 | 25 | 208 | 48 | 41 | ||||||||||||||||
| Total noninterest income | $ | 514 | $ | 381 | $ | 86 | $ | 76 | $ | 254 | $ | 98 | $ | 93 | |||||||||
Selected equity and performance ratios(a)(d) | |||||||||||||||||||||||
| Tangible common equity / tangible assets | 7.94 | % | 7.50 | % | 7.25 | % | 6.90 | % | 7.71 | % | |||||||||||||
| Return on average equity | 7.78 | % | 8.44 | % | 6.58 | % | 4.46 | % | 15.55 | % | 4.80 | % | 7.31 | % | |||||||||
| Return on average tangible common equity | 11.99 | % | 13.21 | % | 9.75 | % | 6.36 | % | 25.45 | % | 7.31 | % | 11.33 | % | |||||||||
| Return on average common equity Tier 1 | 11.23 | % | 12.59 | % | 9.16 | % | 5.98 | % | 23.71 | % | 6.84 | % | 10.94 | % | |||||||||
| Return on average tangible assets | 0.93 | % | 1.03 | % | 0.81 | % | 0.52 | % | 1.78 | % | 0.59 | % | 0.93 | % | |||||||||
Efficiency ratio reconciliation(e) | |||||||||||||||||||||||
| Federal Reserve efficiency ratio | 61.76 | % | 65.38 | % | 59.68 | % | 85.41 | % | 43.49 | % | 70.37 | % | 69.14 | % | |||||||||
| Fully tax-equivalent adjustment | (0.77) | % | (0.85) | % | (0.84) | % | (1.29) | % | (0.39) | % | (0.96) | % | (0.91) | % | |||||||||
| Other intangible amortization | (0.80) | % | (0.82) | % | (0.82) | % | (0.87) | % | (0.65) | % | (0.95) | % | (0.93) | % | |||||||||
| Fully tax-equivalent efficiency ratio | 60.20 | % | 63.72 | % | 58.02 | % | 83.25 | % | 42.46 | % | 68.47 | % | 67.32 | % | |||||||||
| Acquisition related costs adjustment | (0.19) | % | (0.60) | % | — | % | (0.08) | % | (0.12) | % | (0.58) | % | (0.45) | % | |||||||||
| Provision for unfunded commitments adjustment | (0.55) | % | 0.20 | % | 3.42 | % | 2.87 | % | (1.91) | % | (5.18) | % | 0.34 | % | |||||||||
| Asset gains (losses), net adjustment | 8.20 | % | 0.14 | % | (0.30) | % | (0.11) | % | 22.10 | % | (0.02) | % | 0.09 | % | |||||||||
| Branch Sales | 0.41 | % | — | % | 1.68 | % | — | % | — | % | — | % | — | % | |||||||||
| 3Q 2020 Initiatives | (5.32) | % | — | % | — | % | (22.90) | % | — | % | — | % | — | % | |||||||||
| Adjusted efficiency ratio | 62.76 | % | 63.47 | % | 62.83 | % | 63.02 | % | 62.53 | % | 62.70 | % | 67.30 | % | |||||||||
Numbers may not sum due to rounding.
(a)The ratio tangible common equity to tangible assets excludes goodwill and other intangible assets, net. This financial measure has been included as it is considered to be a critical metric with which to analyze and evaluate financial condition and capital strength.
(b)These financial measures have been included as they provide meaningful supplemental information to assess trends in the Corporation’s results of operations.
(c)Includes trust, asset management, brokerage, and annuity fees.
(d)These capital measurements are used by management, regulators, investors, and analysts to assess, monitor and compare the quality and composition of our capital with the capital of other financial services companies.
(e)The efficiency ratio as defined by the Federal Reserve guidance is noninterest expense (which includes the provision for unfunded commitments) divided by the sum of net interest income plus noninterest income, excluding investment securities gains / losses, net. The fully tax-equivalent efficiency ratio is noninterest expense (which includes the provision for unfunded commitments), excluding other intangible amortization, divided by the sum of fully tax-equivalent net interest income plus noninterest income, excluding investment securities gains / losses, net. The adjusted efficiency ratio is noninterest expense, which excludes the provision for unfunded commitments, other intangible amortization, acquisition related costs, and 3Q20 initiatives, divided by the sum of fully tax-equivalent net interest income plus noninterest income, excluding investment securities gains (losses), net, acquisition related costs, asset gains (losses), net and gain on sale of branches. Management believes the adjusted efficiency ratio is a meaningful measure as it enhances the comparability of net interest income arising from taxable and tax-exempt sources and provides a better measure as to how the Corporation is managing its expenses by adjusting for acquisition related costs, provision for unfunded commitments, asset gains (losses), net, branch sales, and 3Q 2020 initiatives.
10
| Associated Banc-Corp Non-GAAP Financial Measures Reconciliation | |||||||||||
| ($ in millions, except per share data) | |||||||||||
Gain on Sale of ABRC (net of tax) (a) | YTD 2020 | YTD per share data (b) | |||||||||
| GAAP earnings: | $ | 288 | $ | 1.86 | |||||||
| Gain on sale of ABRC (asset gains, net) | (104) | (0.68) | |||||||||
| Earnings, excluding above items: | $ | 184 | $ | 1.19 | |||||||
YTD 2020 Pre-tax Pre-Provision income, excluding 2020 Initiatives(a) | YTD 2020 | 4Q 2020 | |||||||||
| Pre-tax pre-provision income | |||||||||||
| Income before income taxes | $ | 327 | $ | 84 | |||||||
| Provision for credit losses | 174 | 17 | |||||||||
| Pre-tax pre-provision income | $ | 501 | $ | 101 | |||||||
| 2020 Acquisitions, dispositions, and announced initiatives | |||||||||||
| Sale of ABRC | $ | (163) | $ | — | |||||||
| Gain on sale of branches | (7) | (7) | |||||||||
| Acquisitions related costs (noninterest expense) | 2 | — | |||||||||
| Loss on prepayments of FHLB Advances | 45 | — | |||||||||
| Severance | 10 | — | |||||||||
| Branch sales & consolidations | 6 | — | |||||||||
| 3Q 2020 Initiatives | 60 | — | |||||||||
| 2020 Acquisitions, dispositions, and announced initiatives | $ | (108) | $ | (7) | |||||||
| Pre-tax pre-provision income, excluding 2020 initiatives | $ | 393 | $ | 94 | |||||||
Numbers may not sum due to rounding.
(a) Management believes these measures are meaningful because they reflect adjustments commonly made by management, investors, regulators, and analysts to evaluate the adequacy of earnings per common share and provide greater understanding of ongoing operations and enhanced comparability of results with prior periods.
(b) Diluted earnings and per share data presented after-tax.
11
FOURTH QUARTER 2020 EARNINGS PRESENTATION JANUARY 21, 2021 Exhibit 99.2
1 Forward-looking Statements Important note regarding forward-looking statements: Statements made in this presentation which are not purely historical are forward-looking statements, as defined in the Private Securities Litigation Reform Act of 1995. This includes any statements regarding management’s plans, objectives, or goals for future operations, products or services, and forecasts of its revenues, earnings, or other measures of performance. Such forward-looking statements may be identified by the use of words such as “believe,” “expect,” “anticipate,” “plan,” “estimate,” “should,” “will,” “intend,” "target," “outlook” or similar expressions. Forward-looking statements are based on current management expectations and, by their nature, are subject to risks and uncertainties. Actual results may differ materially from those contained in the forward-looking statements. These forward-looking statements include: management plans relating to the pending sale of Whitnell & Co. and formation of a strategic partnership with Rockefeller (the “transaction”); the expected timing of the completion of the transaction; the ability to complete the transaction; the ability to obtain any required regulatory approvals; any statements of the plans and objectives of management for future operations, products or services; any statements of expectation or belief; projections related to certain financial results or other benefits of the transaction; and any statements of assumptions underlying any of the foregoing. Factors which may cause actual results to differ materially from those contained in such forward-looking statements include those identified in the Company’s most recent Form 10-K and subsequent Form 10-Qs and other SEC filings, and such factors are incorporated herein by reference. Additional factors which may cause actual results of the transaction to differ materially from those contained in forward-looking statements are the possibility that expected benefits of the transaction may not materialize in the timeframe expected or at all, or may be more costly to achieve; the transaction may not be timely completed, if at all; that required regulatory approvals are not obtained or other customary closing conditions are not satisfied in a timely manner or at all; reputational risks and the reaction of shareholders, customers, employees or other constituents to the transaction; and diversion of management time on acquisition-related matters. Trademarks: All trademarks, service marks, and trade names referenced in this material are official trademarks and the property of their respective owners. Presentation: Within the charts and tables presented, certain segments, columns and rows may not sum to totals shown due to rounding. Non-GAAP Measures: This presentation includes certain non-GAAP financial measures. These non-GAAP measures are provided in addition to, and not as substitutes for, measures of our financial performance determined in accordance with GAAP. Our calculation of these non-GAAP measures may not be comparable to similarly titled measures of other companies due to potential differences between companies in the method of calculation. As a result, the use of these non-GAAP measures has limitations and should not be considered superior to, in isolation from, or as a substitute for, related GAAP measures. Reconciliations of these non-GAAP financial measures to the most directly comparable GAAP financial measures can be found at the end of this presentation.
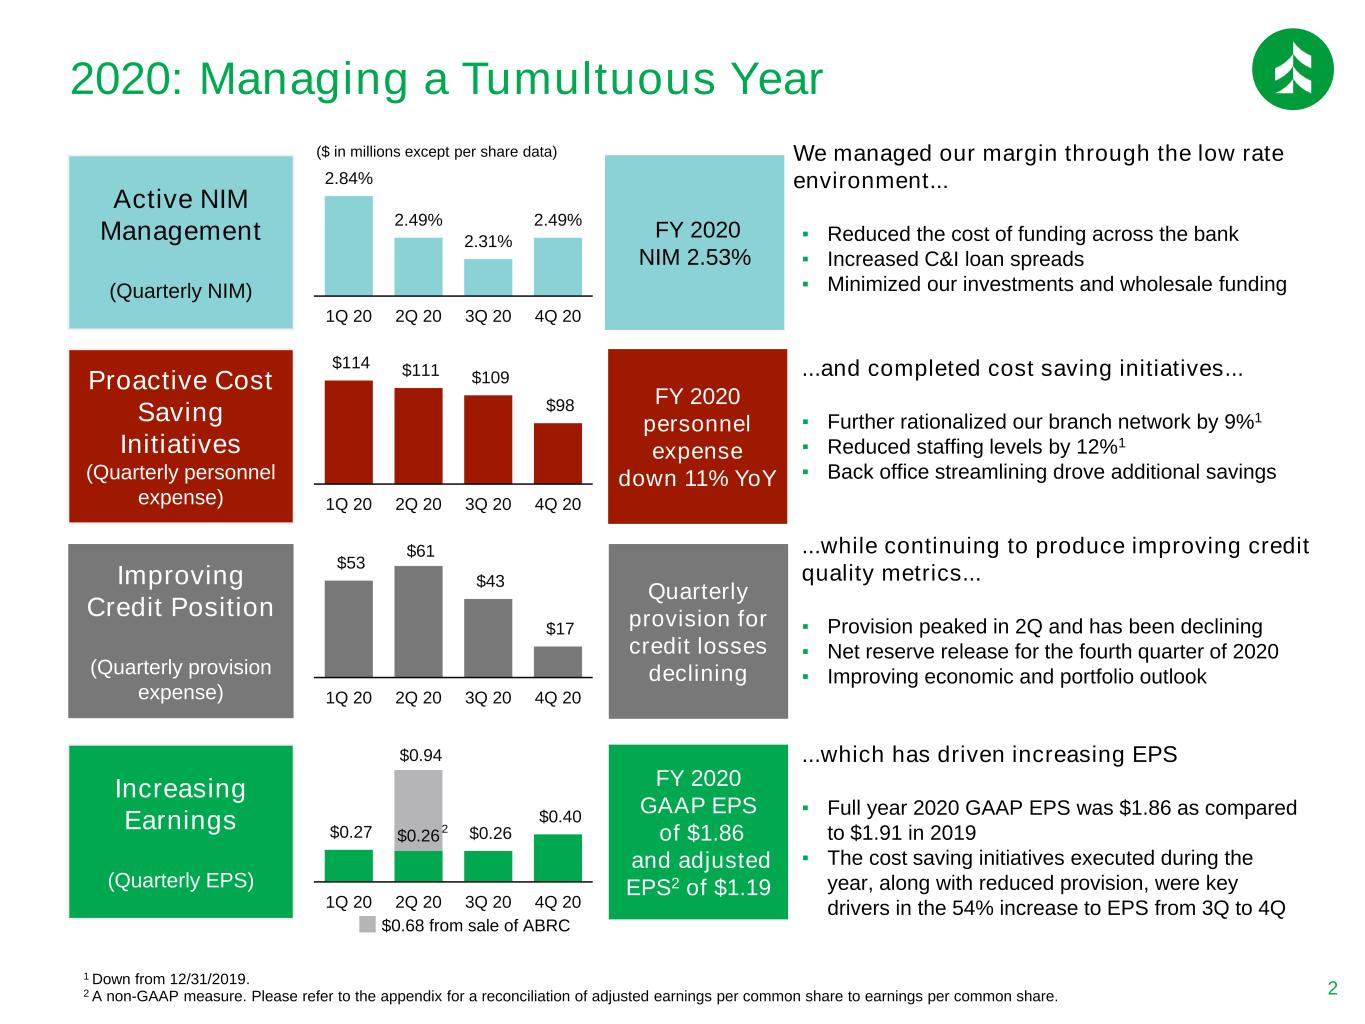
2 Improving Credit Position (Quarterly provision expense) Increasing Earnings (Quarterly EPS) Active NIM Management (Quarterly NIM) ...and completed cost saving initiatives... ▪ Further rationalized our branch network by 9%1 ▪ Reduced staffing levels by 12%1 ▪ Back office streamlining drove additional savings ...while continuing to produce improving credit quality metrics... ▪ Provision peaked in 2Q and has been declining ▪ Net reserve release for the fourth quarter of 2020 ▪ Improving economic and portfolio outlook ...which has driven increasing EPS ▪ Full year 2020 GAAP EPS was $1.86 as compared to $1.91 in 2019 ▪ The cost saving initiatives executed during the year, along with reduced provision, were key drivers in the 54% increase to EPS from 3Q to 4Q Proactive Cost Saving Initiatives (Quarterly personnel expense) We managed our margin through the low rate environment... ▪ Reduced the cost of funding across the bank ▪ Increased C&I loan spreads ▪ Minimized our investments and wholesale funding FY 2020 personnel expense down 11% YoY FY 2020 GAAP EPS of $1.86 and adjusted EPS2 of $1.19 Quarterly provision for credit losses declining 2.84% 2.49% 2.31% 2.49% 1Q 20 2Q 20 3Q 20 4Q 20 $114 $111 $109 $98 1Q 20 2Q 20 3Q 20 4Q 20 $53 $61 $43 $17 1Q 20 2Q 20 3Q 20 4Q 20 $0.26$0.27 $0.94 $0.26 $0.40 1Q 20 2Q 20 3Q 20 4Q 20 FY 2020 NIM 2.53% $0.68 from sale of ABRC ($ in millions except per share data) 2020: Managing a Tumultuous Year 1 Down from 12/31/2019. 2 A non-GAAP measure. Please refer to the appendix for a reconciliation of adjusted earnings per common share to earnings per common share. 2
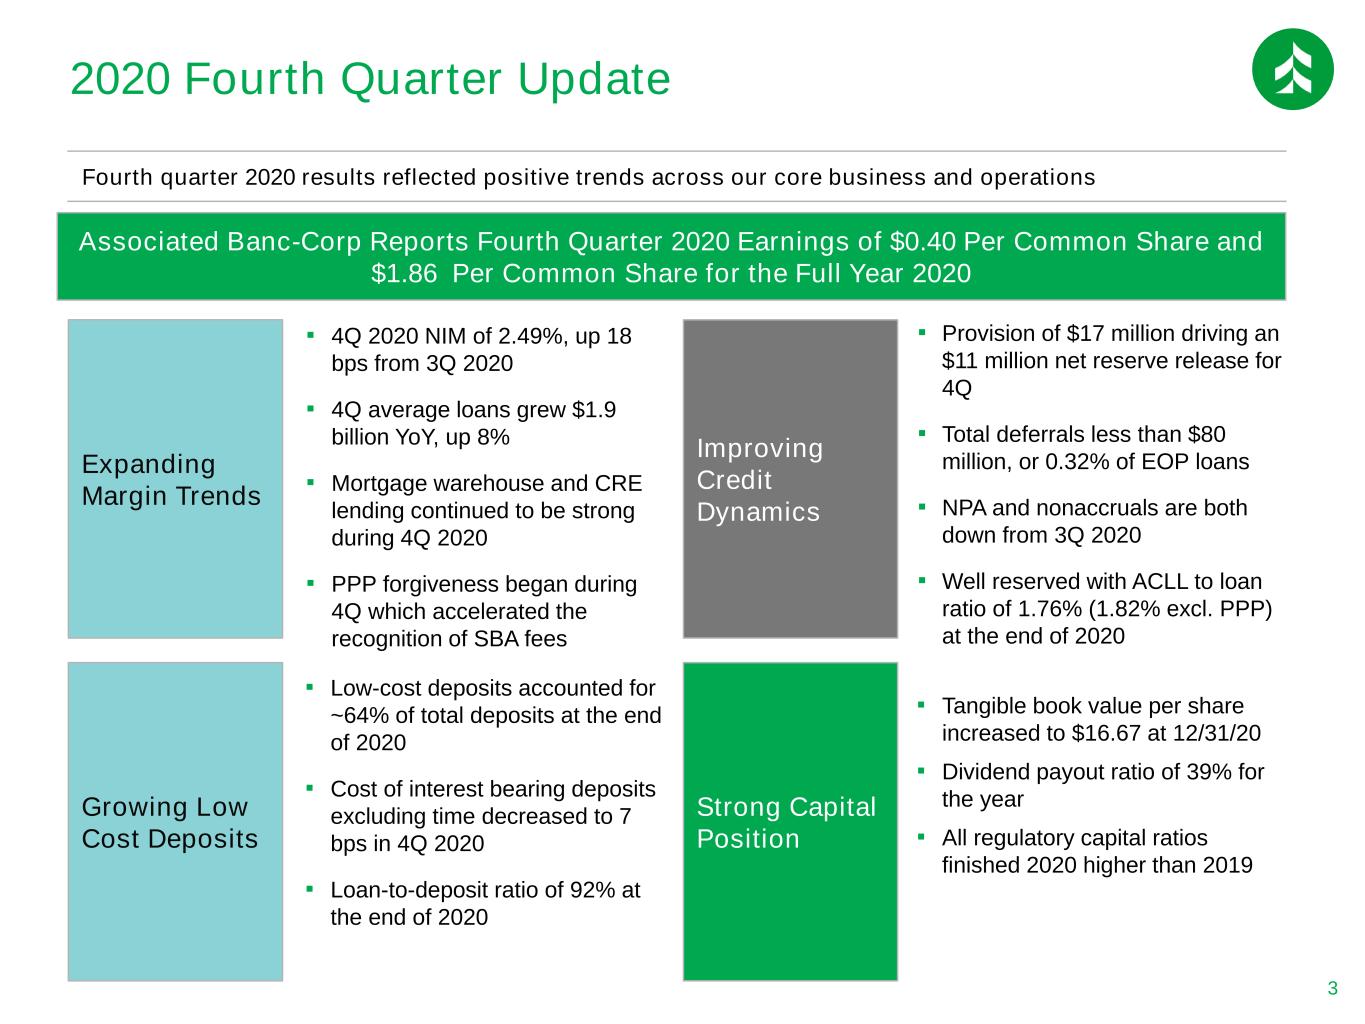
3 Expanding Margin Trends ▪ 4Q 2020 NIM of 2.49%, up 18 bps from 3Q 2020 ▪ 4Q average loans grew $1.9 billion YoY, up 8% ▪ Mortgage warehouse and CRE lending continued to be strong during 4Q 2020 ▪ PPP forgiveness began during 4Q which accelerated the recognition of SBA fees Strong Capital Position ▪ Tangible book value per share increased to $16.67 at 12/31/20 ▪ Dividend payout ratio of 39% for the year ▪ All regulatory capital ratios finished 2020 higher than 2019 Improving Credit Dynamics ▪ Provision of $17 million driving an $11 million net reserve release for 4Q ▪ Total deferrals less than $80 million, or 0.32% of EOP loans ▪ NPA and nonaccruals are both down from 3Q 2020 ▪ Well reserved with ACLL to loan ratio of 1.76% (1.82% excl. PPP) at the end of 2020 Growing Low Cost Deposits ▪ Low-cost deposits accounted for ~64% of total deposits at the end of 2020 ▪ Cost of interest bearing deposits excluding time decreased to 7 bps in 4Q 2020 ▪ Loan-to-deposit ratio of 92% at the end of 2020 Fourth quarter 2020 results reflected positive trends across our core business and operations Associated Banc-Corp Reports Fourth Quarter 2020 Earnings of $0.40 Per Common Share and $1.86 Per Common Share for the Full Year 2020 2020 Fourth Quarter Update
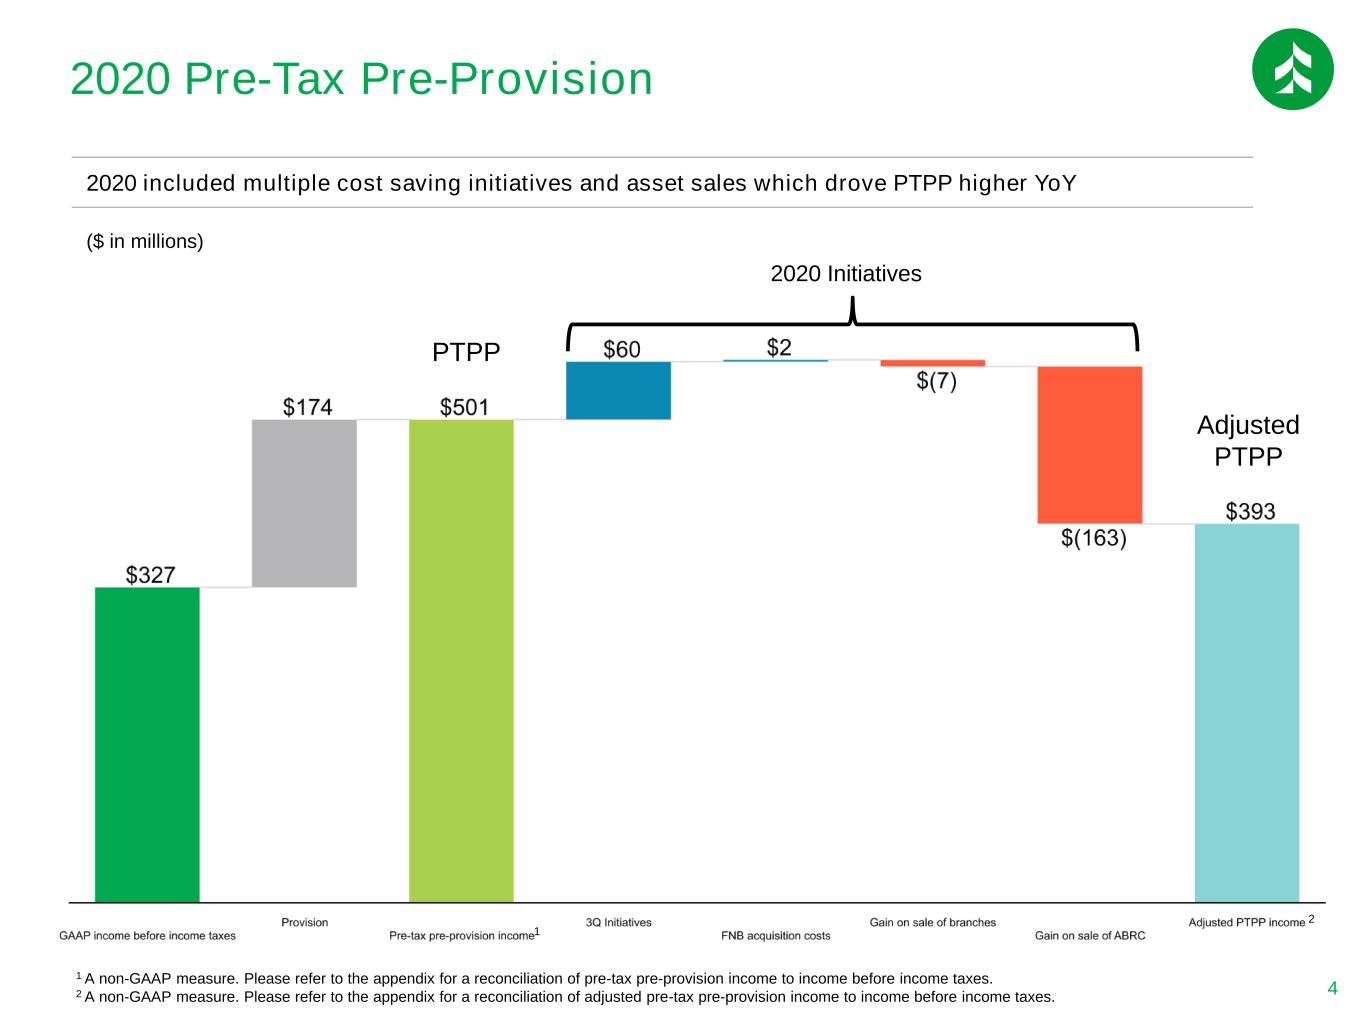
4 2020 included multiple cost saving initiatives and asset sales which drove PTPP higher YoY ($ in millions) 1 A non-GAAP measure. Please refer to the appendix for a reconciliation of pre-tax pre-provision income to income before income taxes. 2 A non-GAAP measure. Please refer to the appendix for a reconciliation of adjusted pre-tax pre-provision income to income before income taxes. 1 2 2020 Pre-Tax Pre-Provision PTPP 2020 Initiatives Adjusted PTPP
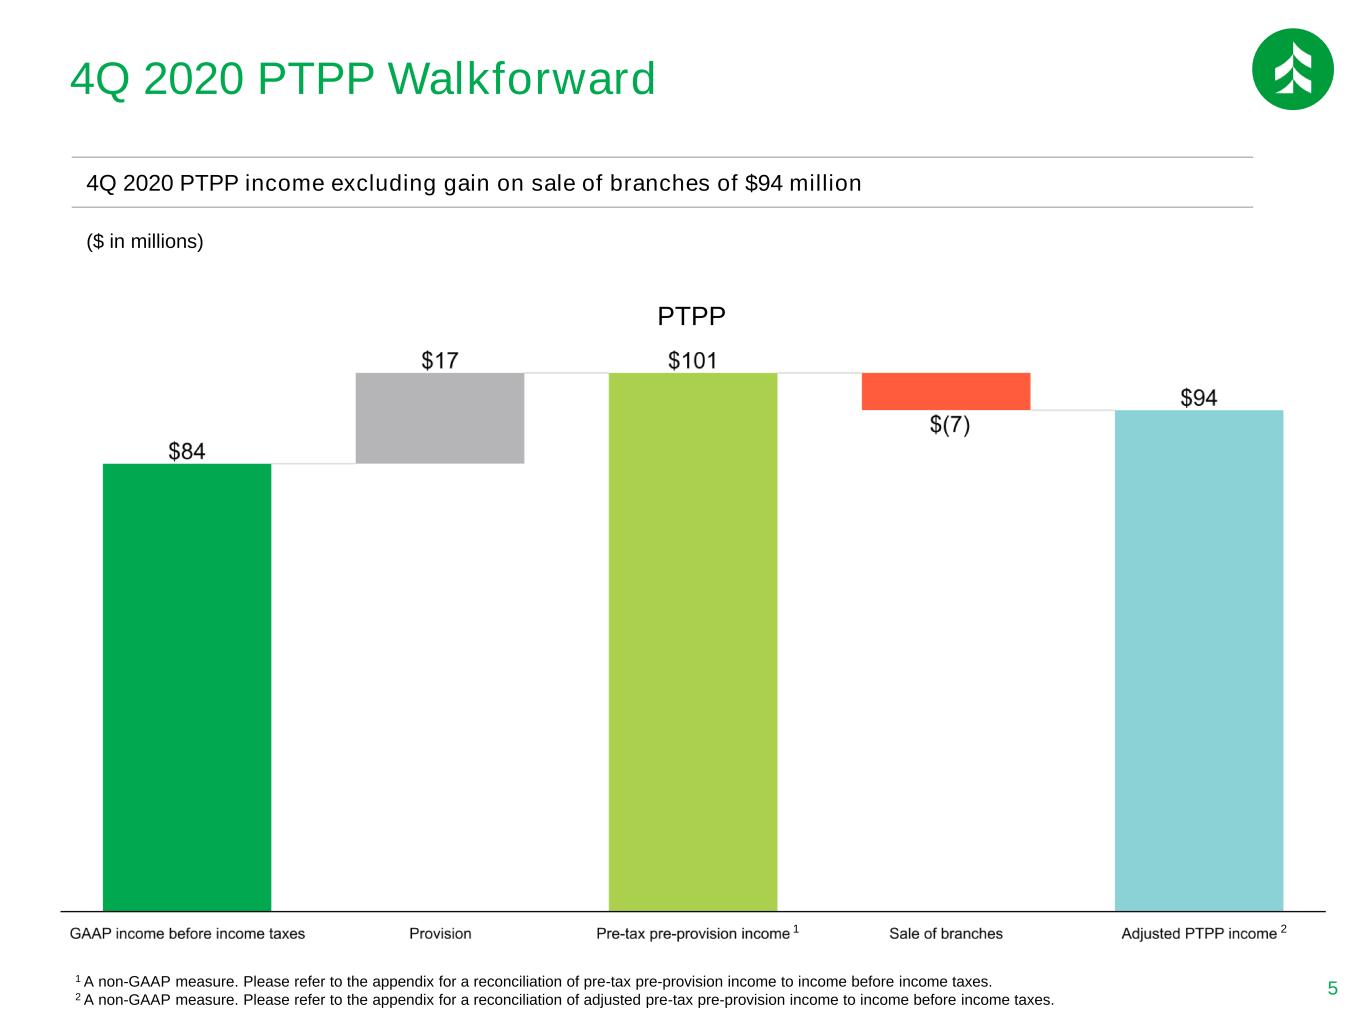
5 4Q 2020 PTPP income excluding gain on sale of branches of $94 million ($ in millions) 1 A non-GAAP measure. Please refer to the appendix for a reconciliation of pre-tax pre-provision income to income before income taxes. 2 A non-GAAP measure. Please refer to the appendix for a reconciliation of adjusted pre-tax pre-provision income to income before income taxes. 1 2 4Q 2020 PTPP Walkforward PTPP
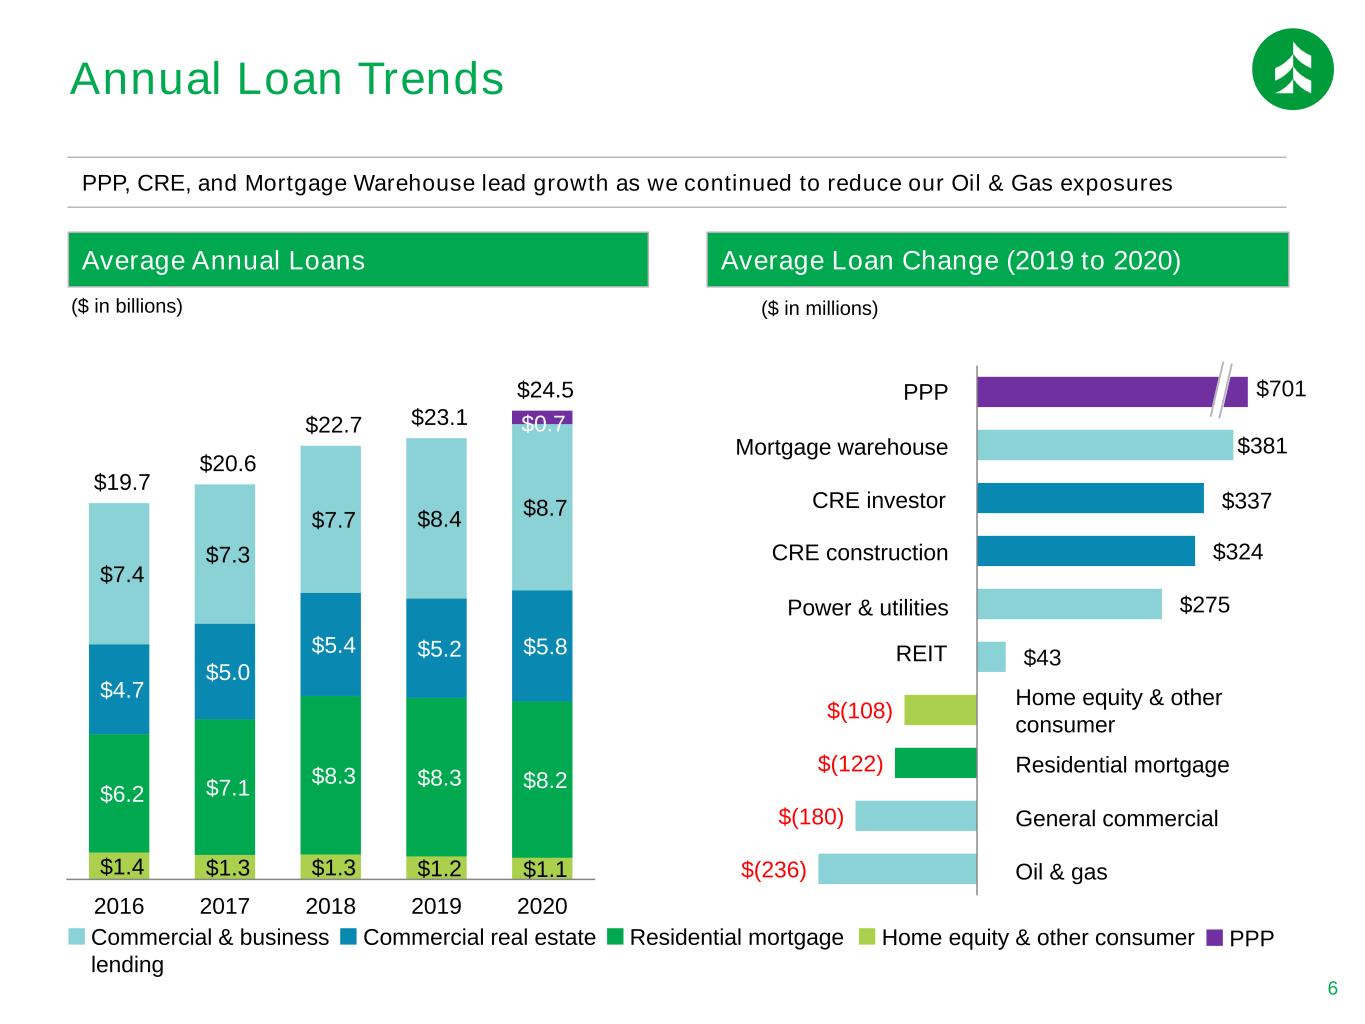
6 $1.4 $1.3 $1.3 $1.2 $1.1 $6.2 $7.1 $8.3 $8.3 $8.2 $4.7 $5.0 $5.4 $5.2 $5.8 $7.4 $7.3 $7.7 $8.4 $8.7 $0.7 $19.7 $20.6 $22.7 $23.1 $24.5 2016 2017 2018 2019 2020 $(236) $(180) $(122) $(108) $43 $275 $324 $337 $381 Annual Loan Trends CRE investor Residential mortgage Home equity & other consumer General commercial REIT Mortgage warehouse Power & utilities ($ in millions) Oil & gas PPP, CRE, and Mortgage Warehouse lead growth as we continued to reduce our Oil & Gas exposures CRE construction PPP $701 Average Annual Loans ($ in billions) Average Loan Change (2019 to 2020) Commercial & business lending Commercial real estate Residential mortgage Home equity & other consumer PPP
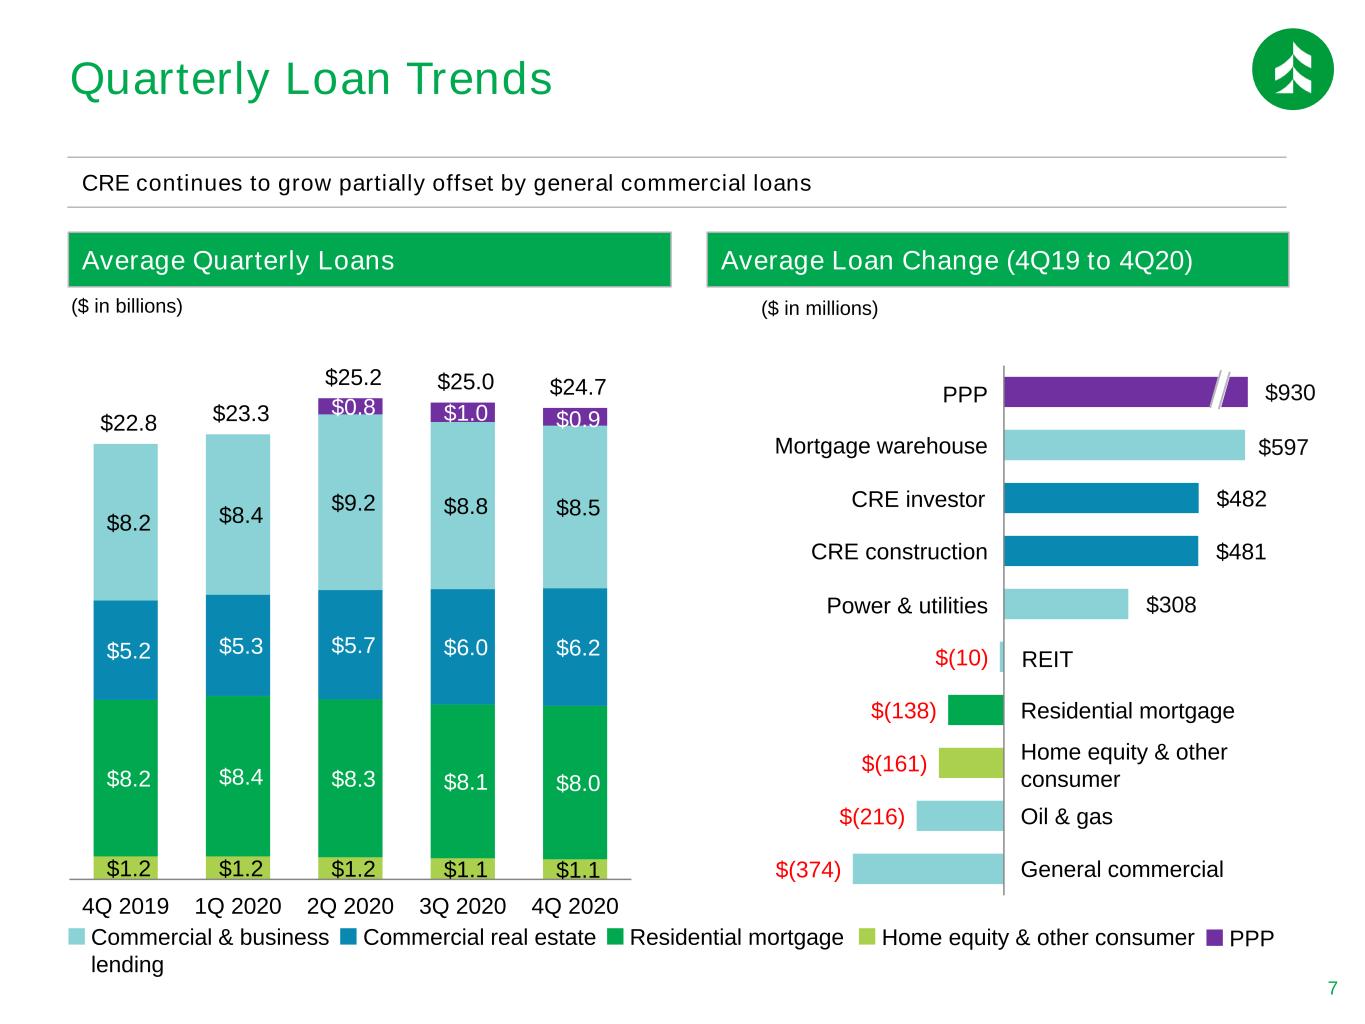
7 $1.2 $1.2 $1.2 $1.1 $1.1 $8.2 $8.4 $8.3 $8.1 $8.0 $5.2 $5.3 $5.7 $6.0 $6.2 $8.2 $8.4 $9.2 $8.8 $8.5 $0.8 $1.0 $0.9 $22.8 $23.3 $25.2 $25.0 $24.7 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 $(374) $(216) $(161) $(138) $(10) $308 $481 $482 Quarterly Loan Trends CRE investor Residential mortgage Home equity & other consumer General commercial REIT Mortgage warehouse Power & utilities ($ in millions) Oil & gas CRE continues to grow partially offset by general commercial loans CRE construction PPP Average Quarterly Loans ($ in billions) Average Loan Change (4Q19 to 4Q20) Commercial & business lending Commercial real estate Residential mortgage Home equity & other consumer PPP $930 $597
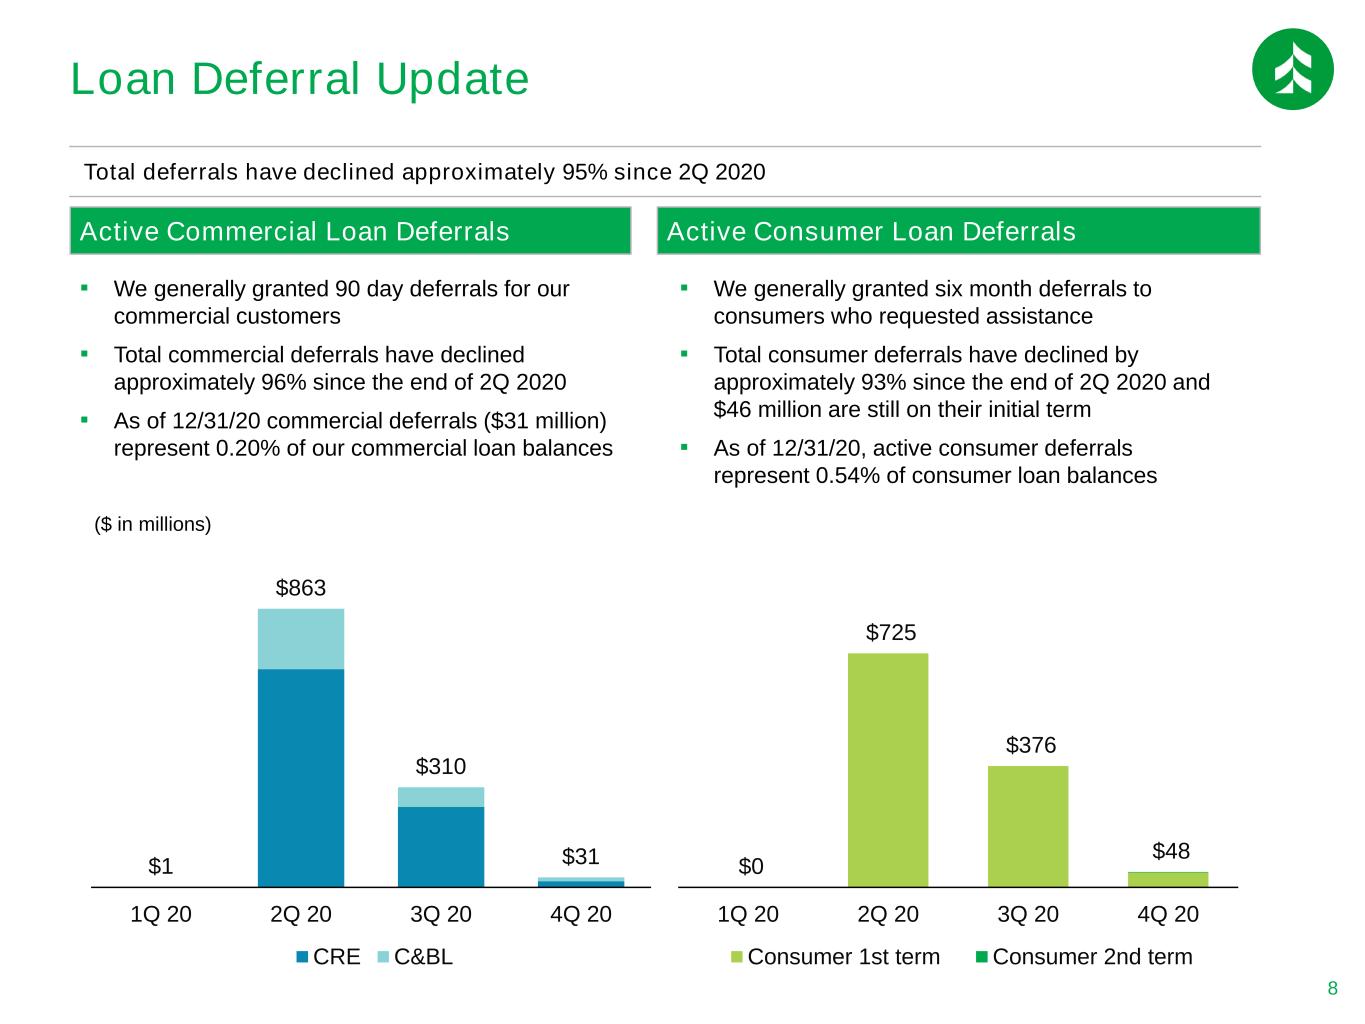
8 ▪ We generally granted 90 day deferrals for our commercial customers ▪ Total commercial deferrals have declined approximately 96% since the end of 2Q 2020 ▪ As of 12/31/20 commercial deferrals ($31 million) represent 0.20% of our commercial loan balances Active Commercial Loan Deferrals Active Consumer Loan Deferrals Total deferrals have declined approximately 95% since 2Q 2020 $1 $863 $310 $31 1Q 20 2Q 20 3Q 20 4Q 20 CRE C&BL ($ in millions) $0 $725 $376 $48 1Q 20 2Q 20 3Q 20 4Q 20 Consumer 1st term Consumer 2nd term ▪ We generally granted six month deferrals to consumers who requested assistance ▪ Total consumer deferrals have declined by approximately 93% since the end of 2Q 2020 and $46 million are still on their initial term ▪ As of 12/31/20, active consumer deferrals represent 0.54% of consumer loan balances Loan Deferral Update
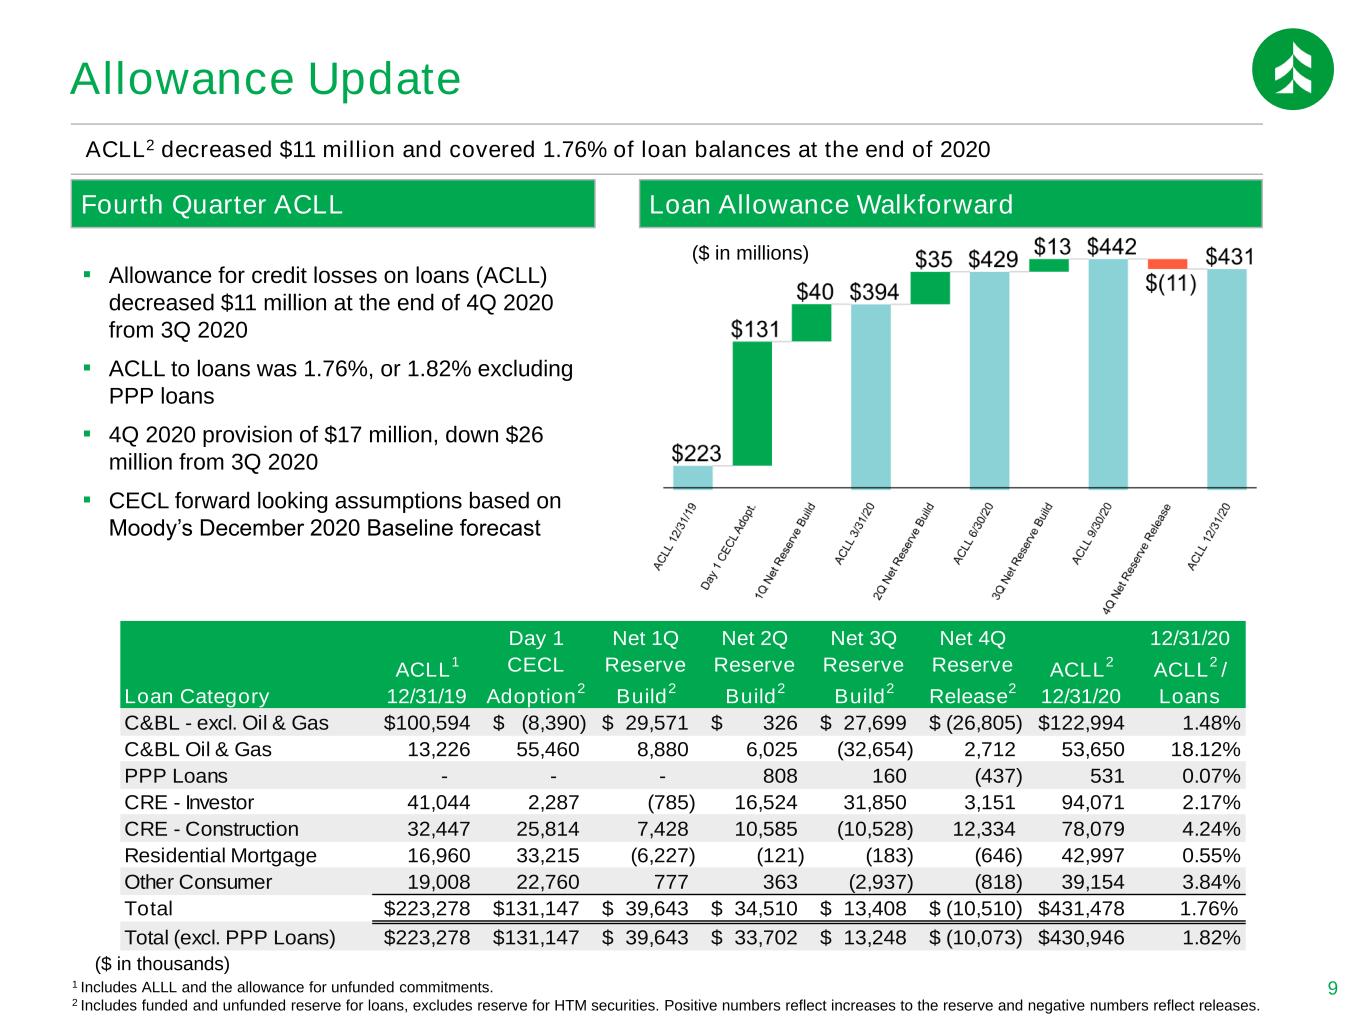
9 Fourth Quarter ACLL ▪ Allowance for credit losses on loans (ACLL) decreased $11 million at the end of 4Q 2020 from 3Q 2020 ▪ ACLL to loans was 1.76%, or 1.82% excluding PPP loans ▪ 4Q 2020 provision of $17 million, down $26 million from 3Q 2020 ▪ CECL forward looking assumptions based on Moody’s December 2020 Baseline forecast 1 Includes ALLL and the allowance for unfunded commitments. 2 Includes funded and unfunded reserve for loans, excludes reserve for HTM securities. Positive numbers reflect increases to the reserve and negative numbers reflect releases. ($ in thousands) Loan Allowance Walkforward ACLL2 decreased $11 million and covered 1.76% of loan balances at the end of 2020 ($ in millions) Allowance Update Loan Category ACLL 1 12/31/19 Day 1 CECL Adoption 2 Net 1Q Reserve Build 2 Net 2Q Reserve Build 2 Net 3Q Reserve Build 2 Net 4Q Reserve Release 2 ACLL 2 12/31/20 12/31/20 ACLL 2 / Loans C&BL - excl. Oil & Gas 100,594$ (8,390)$ 29,571$ 326$ 27,699$ (26,805)$ 122,994$ 1.48% C&BL Oil & Gas 13,226 55,460 8,880 6,025 (32,654) 2,712 53,650 18.12% PPP Loans - - - 808 160 (437) 531 0.07% CRE - Investor 41,044 2,287 (785) 16,524 31,850 3,151 94,071 2.17% CRE - Construction 32,447 25,814 7,428 10,585 (10,528) 12,334 78,079 4.24% Residential Mortgage 16,960 33,215 (6,227) (121) (183) (646) 42,997 0.55% Other Consumer 19,008 22,760 777 363 (2,937) (818) 39,154 3.84% Total 223,278$ 131,147$ 39,643$ 34,510$ 13,408$ (10,510)$ 431,478$ 1.76% Total (excl. PPP Loans) 223,278$ 131,147$ 39,643$ 33,702$ 13,248$ (10,073)$ 430,946$ 1.82%
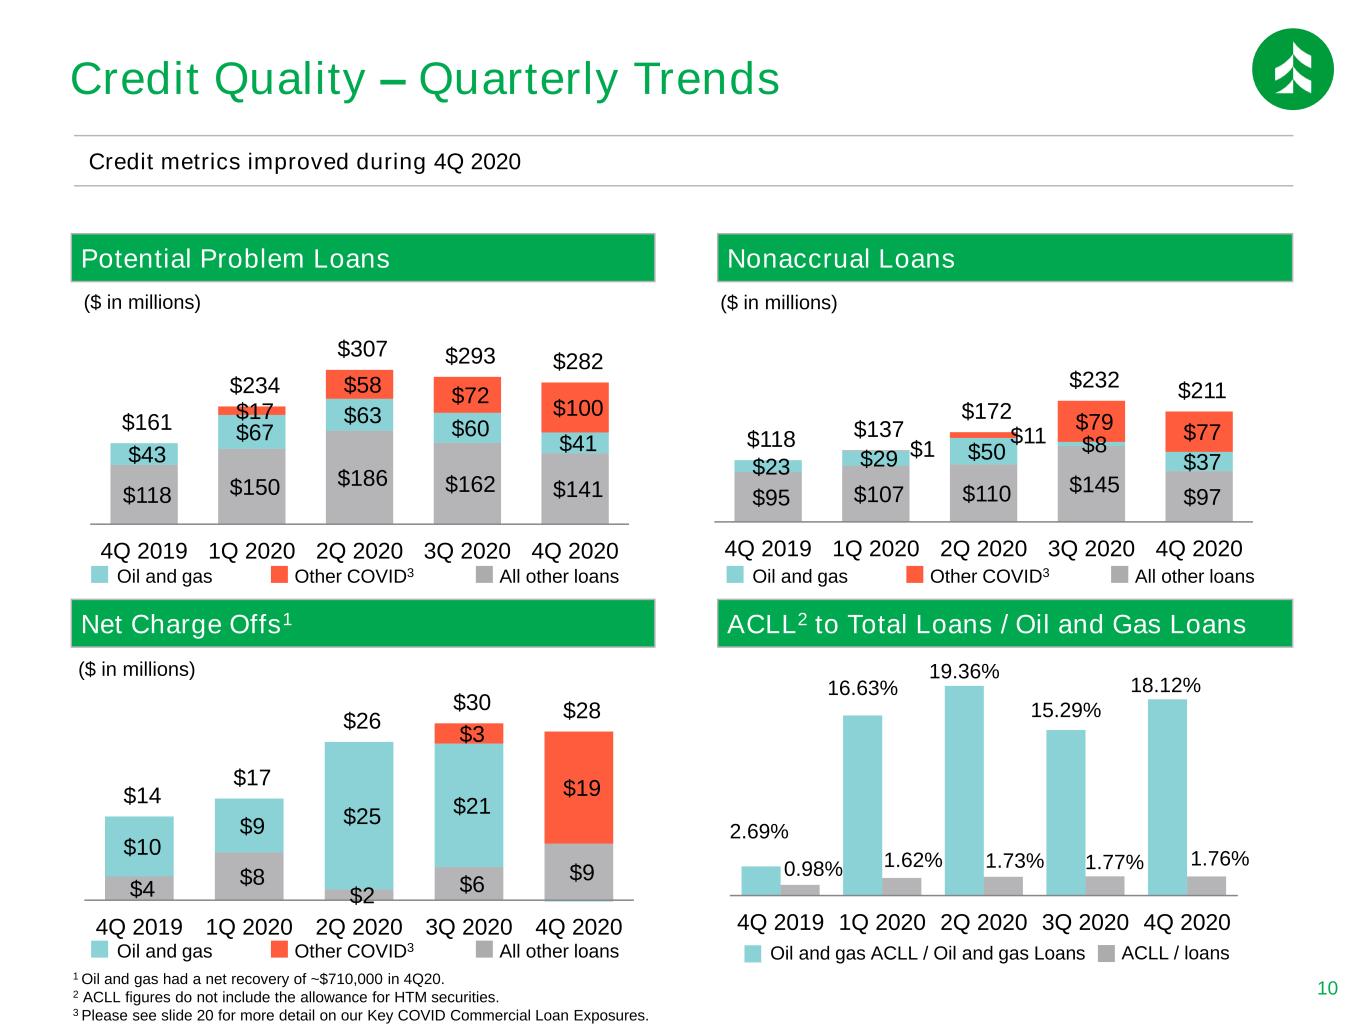
10 2.69% 16.63% 19.36% 15.29% 18.12% 0.98% 1.62% 1.73% 1.77% 1.76% 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 $4 $8 $2 $6 $9 $10 $9 $25 $21 $3 $19 $14 $17 $26 $30 $28 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 Credit Quality – Quarterly Trends $95 $107 $110 $145 $97 $23 $29 $50 $8 $37 $1 $11 $79 $77 $118 $137 $172 $232 $211 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 $118 $150 $186 $162 $141 $43 $67 $63 $60 $41 $17 $58 $72 $100 $161 $234 $307 $293 $282 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 Credit metrics improved during 4Q 2020 ($ in millions) ($ in millions) ($ in millions) 1 Oil and gas had a net recovery of ~$710,000 in 4Q20. 2 ACLL figures do not include the allowance for HTM securities. 3 Please see slide 20 for more detail on our Key COVID Commercial Loan Exposures. Oil and gas ACLL / Oil and gas Loans ACLL / loans Potential Problem Loans Nonaccrual Loans ACLL2 to Total Loans / Oil and Gas LoansNet Charge Offs1 Oil and gas All other loansOther COVID3 Oil and gas All other loansOther COVID3 Oil and gas All other loansOther COVID3
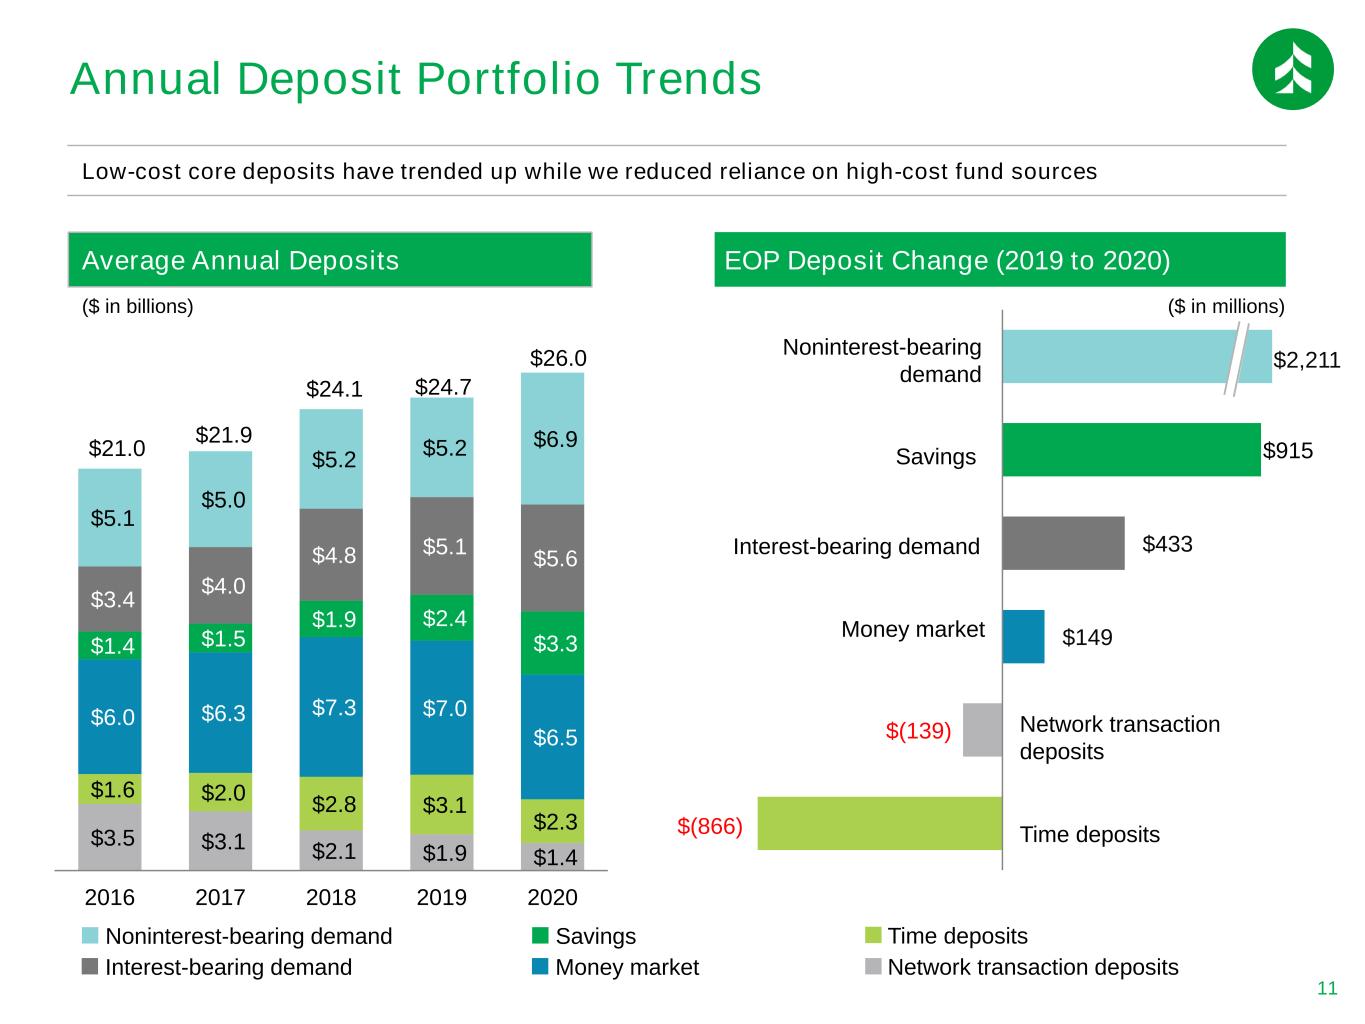
11 $3.5 $3.1 $2.1 $1.9 $1.4 $1.6 $2.0 $2.8 $3.1 $2.3 $6.0 $6.3 $7.3 $7.0 $6.5 $1.4 $1.5 $1.9 $2.4 $3.3 $3.4 $4.0 $4.8 $5.1 $5.6 $5.1 $5.0 $5.2 $5.2 $6.9 $21.0 $21.9 $24.1 $24.7 $26.0 2016 2017 2018 2019 2020 Annual Deposit Portfolio Trends ($ in billions) Average Annual Deposits Time depositsSavings Money market EOP Deposit Change (2019 to 2020) Network transaction deposits Low-cost core deposits have trended up while we reduced reliance on high-cost fund sources Noninterest-bearing demand Interest-bearing demand $(139) $149 $433 $915 Interest-bearing demand Savings Noninterest-bearing demand Money market Network transaction deposits Time deposits ($ in millions) $2,211 $(866)
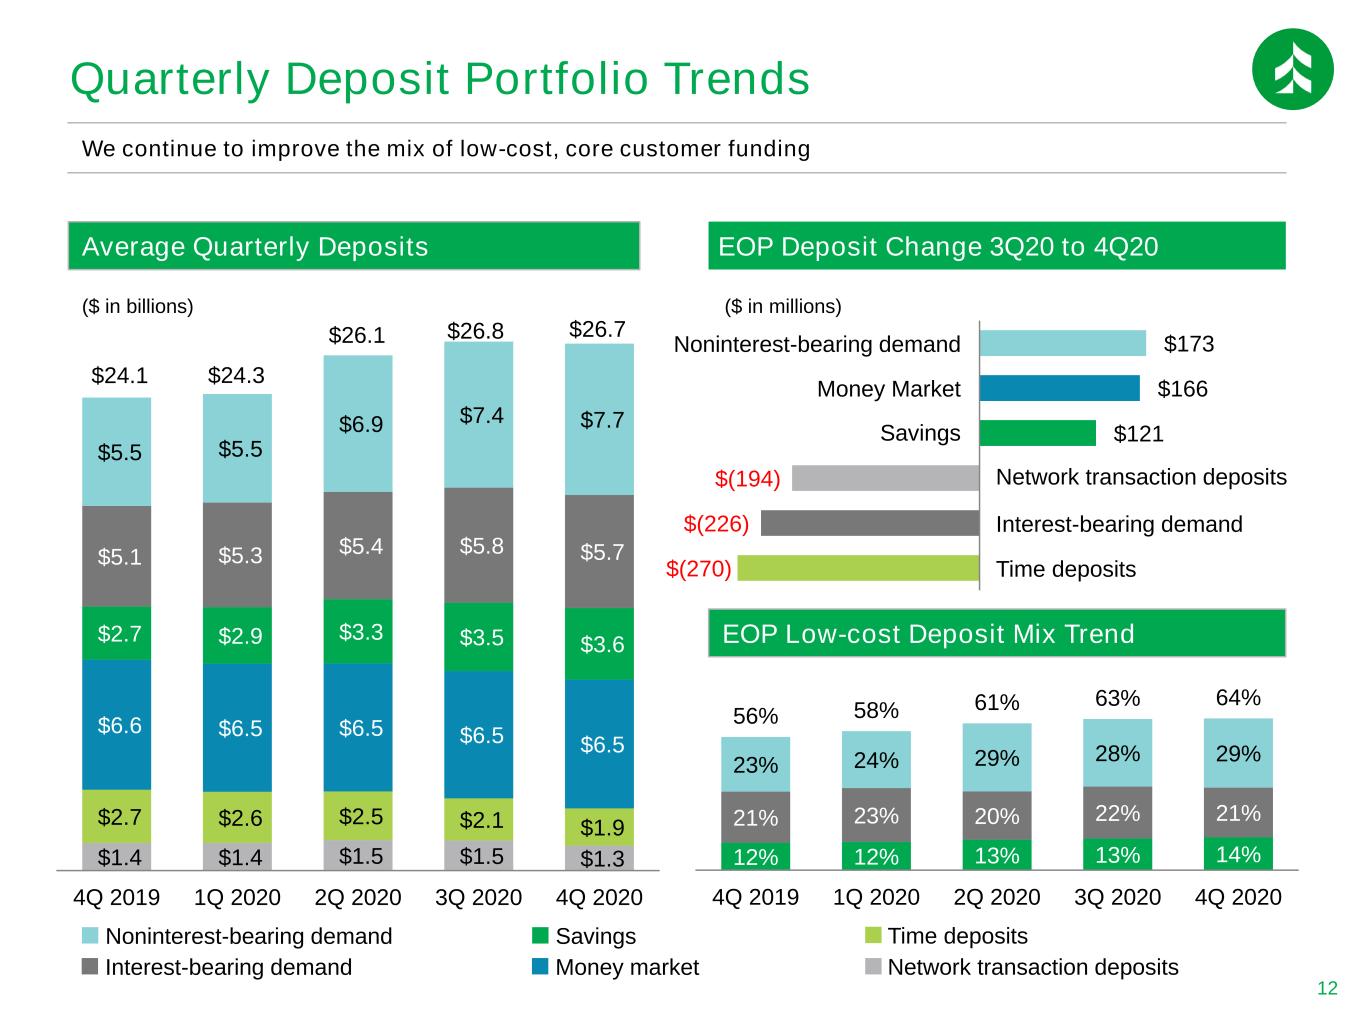
12 $1.4 $1.4 $1.5 $1.5 $1.3 $2.7 $2.6 $2.5 $2.1 $1.9 $6.6 $6.5 $6.5 $6.5 $6.5 $2.7 $2.9 $3.3 $3.5 $3.6 $5.1 $5.3 $5.4 $5.8 $5.7 $5.5 $5.5 $6.9 $7.4 $7.7 $24.1 $24.3 $26.1 $26.8 $26.7 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 Quarterly Deposit Portfolio Trends ($ in billions) Average Quarterly Deposits Time depositsSavings Money market EOP Deposit Change 3Q20 to 4Q20 Network transaction deposits We continue to improve the mix of low-cost, core customer funding Noninterest-bearing demand Interest-bearing demand $(270) $(226) $(194) $121 $166 $173 ($ in millions) EOP Low-cost Deposit Mix Trend 12% 12% 13% 13% 14% 21% 23% 20% 22% 21% 23% 24% 29% 28% 29% 56% 58% 61% 63% 64% 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 Noninterest-bearing demand Savings Money Market Network transaction deposits Time deposits Interest-bearing demand
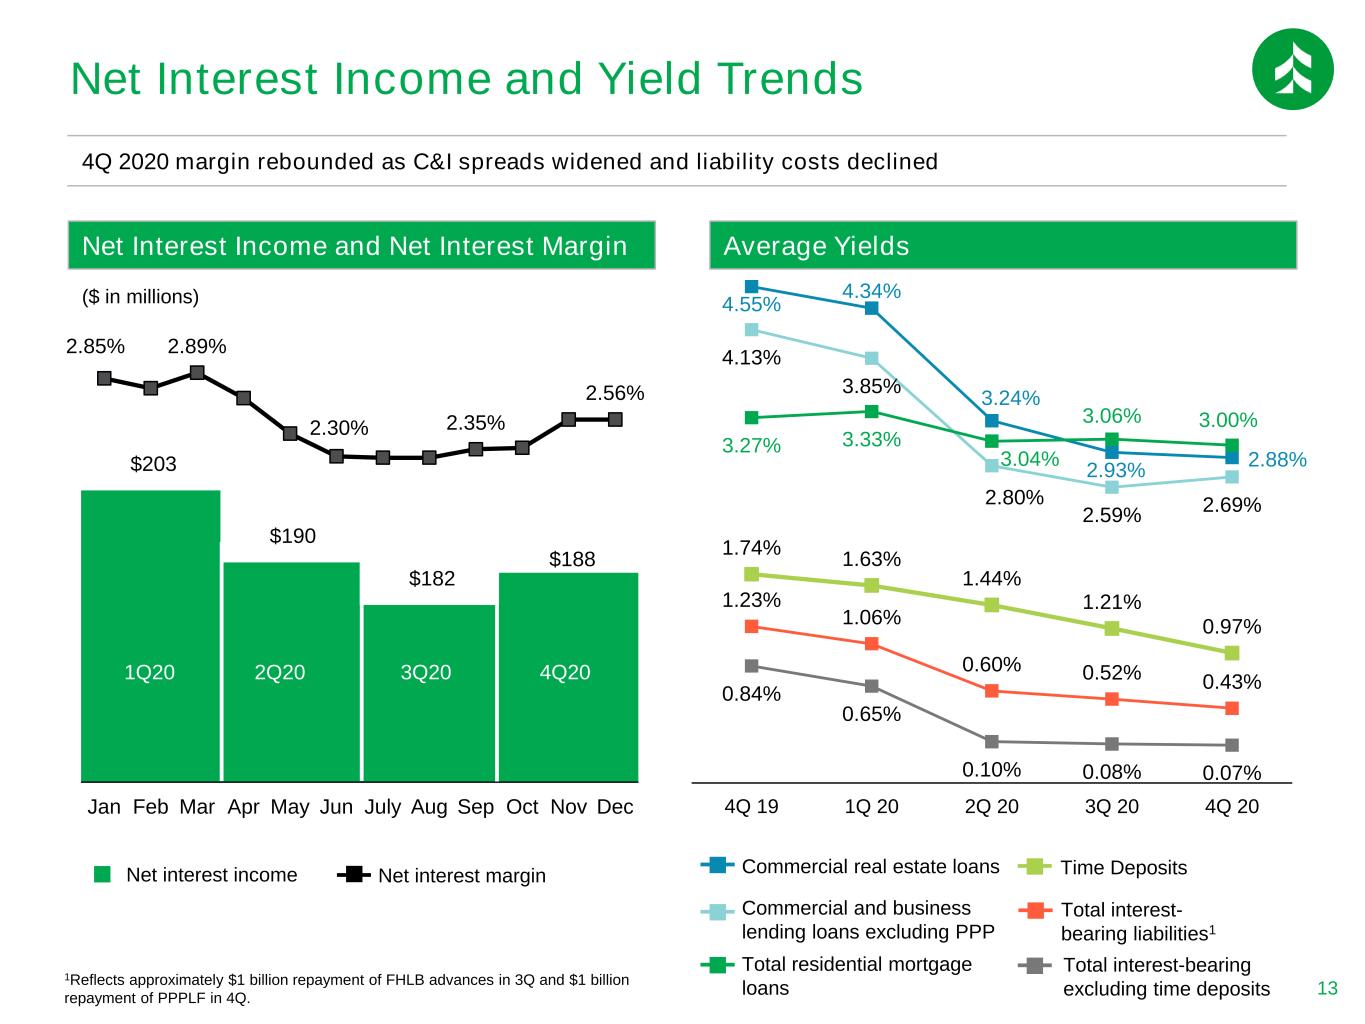
13 Net Interest Income and Yield Trends Net Interest Income and Net Interest Margin 4.55% 4.34% 3.24% 2.93% 2.88% 4.13% 3.85% 2.80% 2.59% 2.69% 3.27% 3.33% 3.04% 3.06% 3.00% 1.23% 1.06% 0.60% 0.52% 0.43% 0.84% 0.65% 0.10% 0.08% 0.07% 1.74% 1.63% 1.44% 1.21% 0.97% 4Q 19 1Q 20 2Q 20 3Q 20 4Q 20 $203 $190 $182 $188 2.85% 2.89% 2.30% 2.35% 2.56% Jan Feb Mar Apr May Jun July Aug Sep Oct Nov Dec Average Yields ($ in millions) 4Q 2020 margin rebounded as C&I spreads widened and liability costs declined Total residential mortgage loans Commercial and business lending loans excluding PPP Commercial real estate loans Total interest- bearing liabilities1 Time DepositsNet interest income Net interest margin Total interest-bearing excluding time deposits 1Q20 2Q20 3Q20 4Q20 1Reflects approximately $1 billion repayment of FHLB advances in 3Q and $1 billion repayment of PPPLF in 4Q.
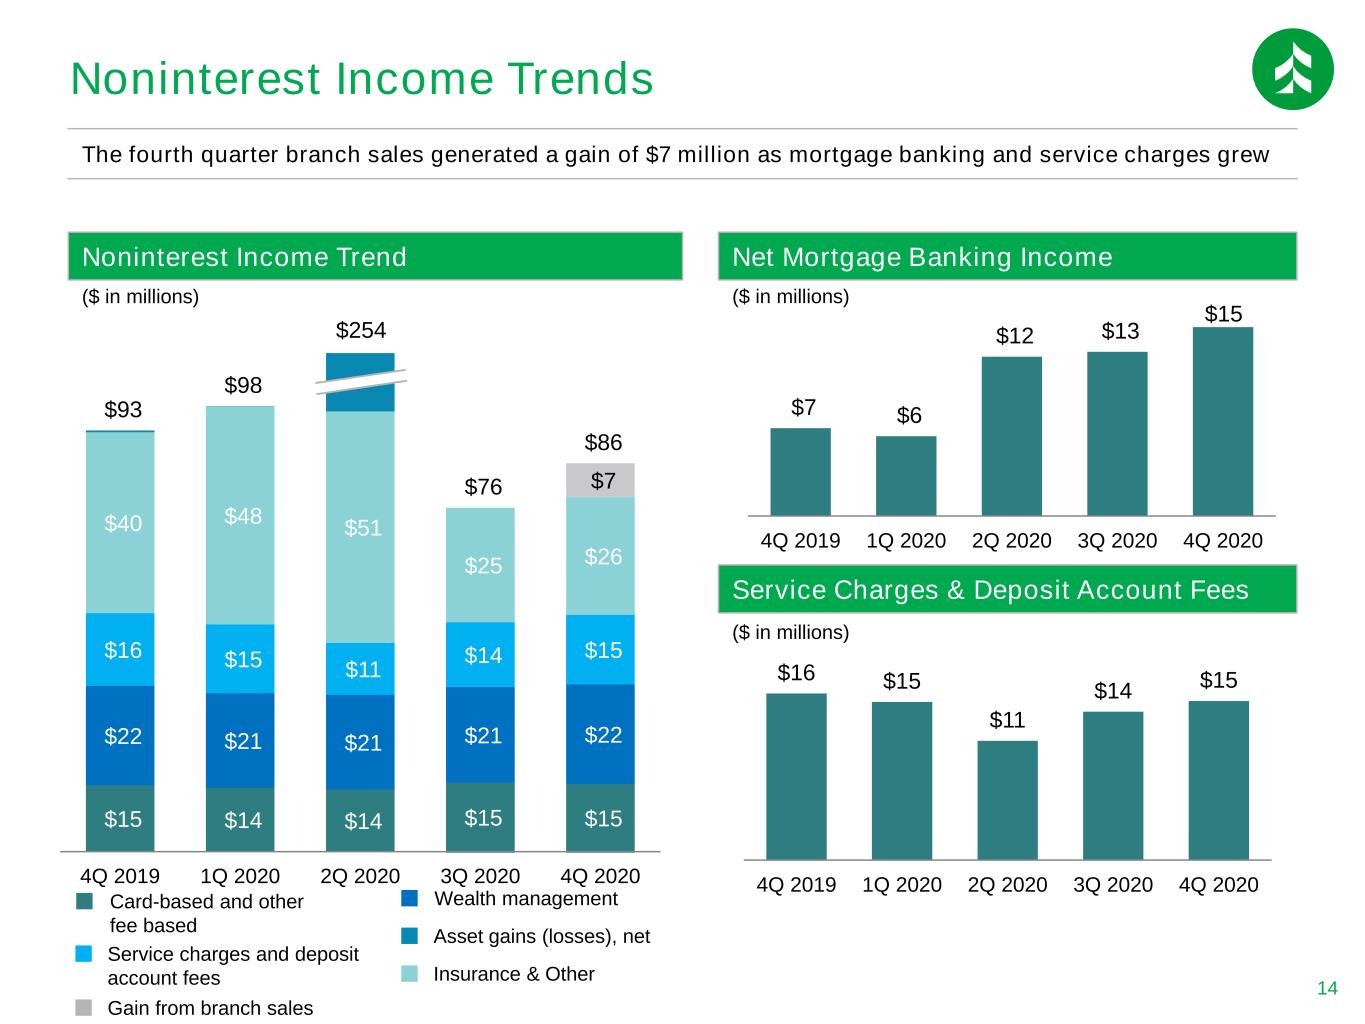
14 $15 $14 $14 $15 $15 $22 $21 $21 $21 $22 $16 $15 $11 $14 $15 $40 $48 $51 $25 $26 $7 $93 $98 $76 $86 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 $254 Noninterest Income Trends Net Mortgage Banking IncomeNoninterest Income Trend $7 $6 $12 $13 $15 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 $16 $15 $11 $14 $15 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 ($ in millions) ($ in millions) ($ in millions) Service Charges & Deposit Account Fees The fourth quarter branch sales generated a gain of $7 million as mortgage banking and service charges grew Card-based and other fee based Service charges and deposit account fees Wealth management Insurance & Other Asset gains (losses), net Gain from branch sales
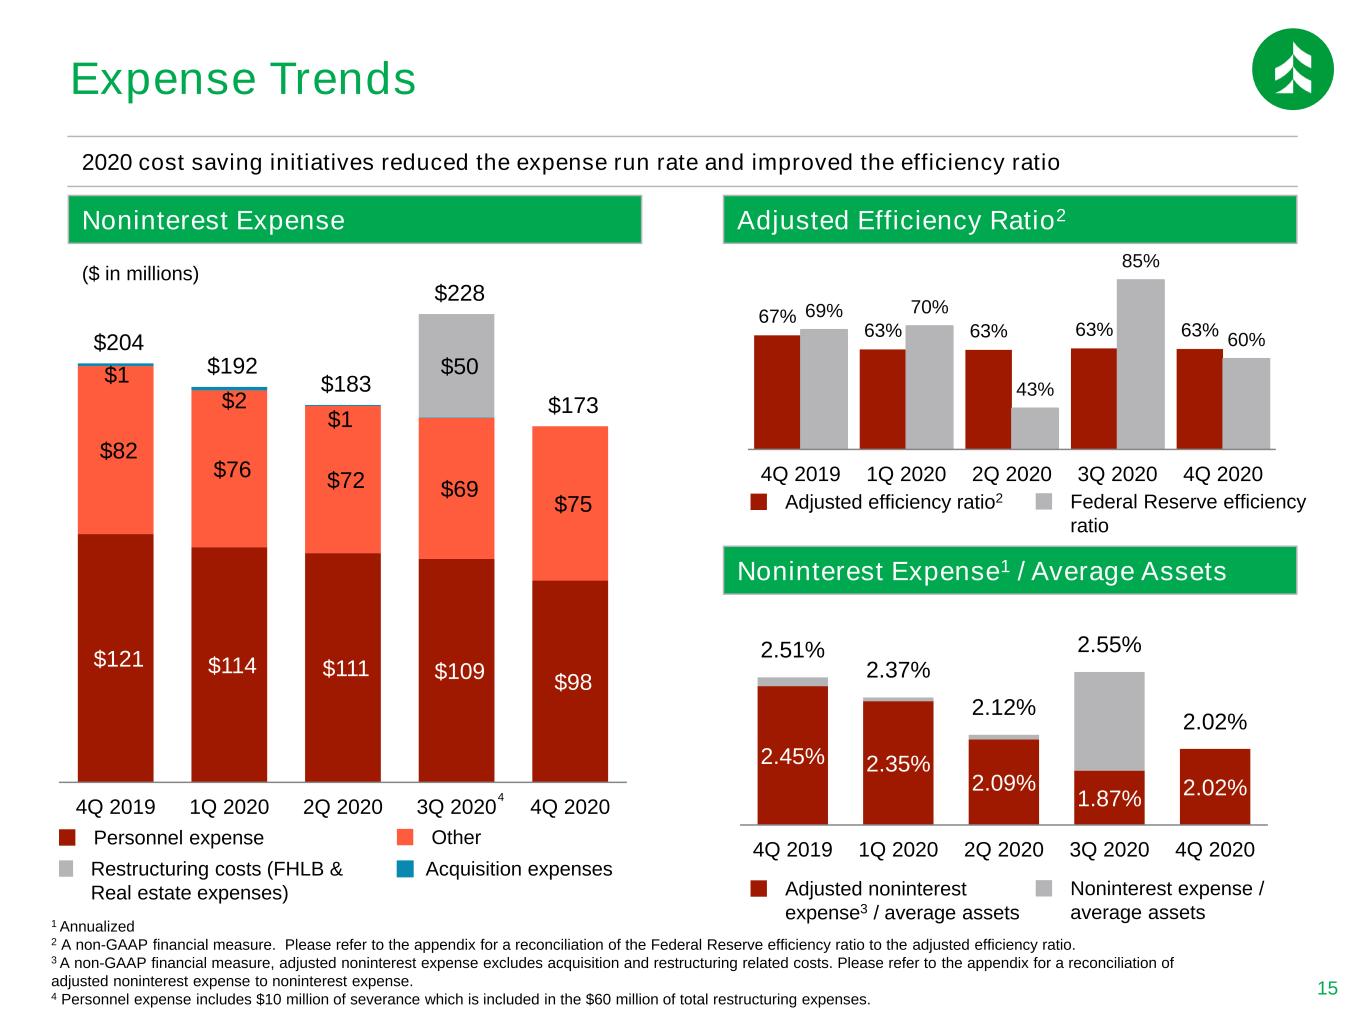
15 $121 $114 $111 $109 $98 $82 $76 $72 $69 $75 $1 $2 $1 $50 $204 $192 $183 $228 $173 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 Expense Trends Adjusted Efficiency Ratio2Noninterest Expense 67% 63% 63% 63% 63% 69% 70% 43% 85% 60% 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 2.45% 2.35% 2.09% 1.87% 2.02% 2.51% 2.37% 2.12% 2.55% 2.02% 4Q 2019 1Q 2020 2Q 2020 3Q 2020 4Q 2020 1 Annualized 2 A non-GAAP financial measure. Please refer to the appendix for a reconciliation of the Federal Reserve efficiency ratio to the adjusted efficiency ratio. 3 A non-GAAP financial measure, adjusted noninterest expense excludes acquisition and restructuring related costs. Please refer to the appendix for a reconciliation of adjusted noninterest expense to noninterest expense. 4 Personnel expense includes $10 million of severance which is included in the $60 million of total restructuring expenses. ($ in millions) Noninterest Expense1 / Average Assets 2020 cost saving initiatives reduced the expense run rate and improved the efficiency ratio Personnel expense Other Acquisition expenses Adjusted noninterest expense3 / average assets Noninterest expense / average assets Restructuring costs (FHLB & Real estate expenses) 4 Adjusted efficiency ratio2 Federal Reserve efficiency ratio
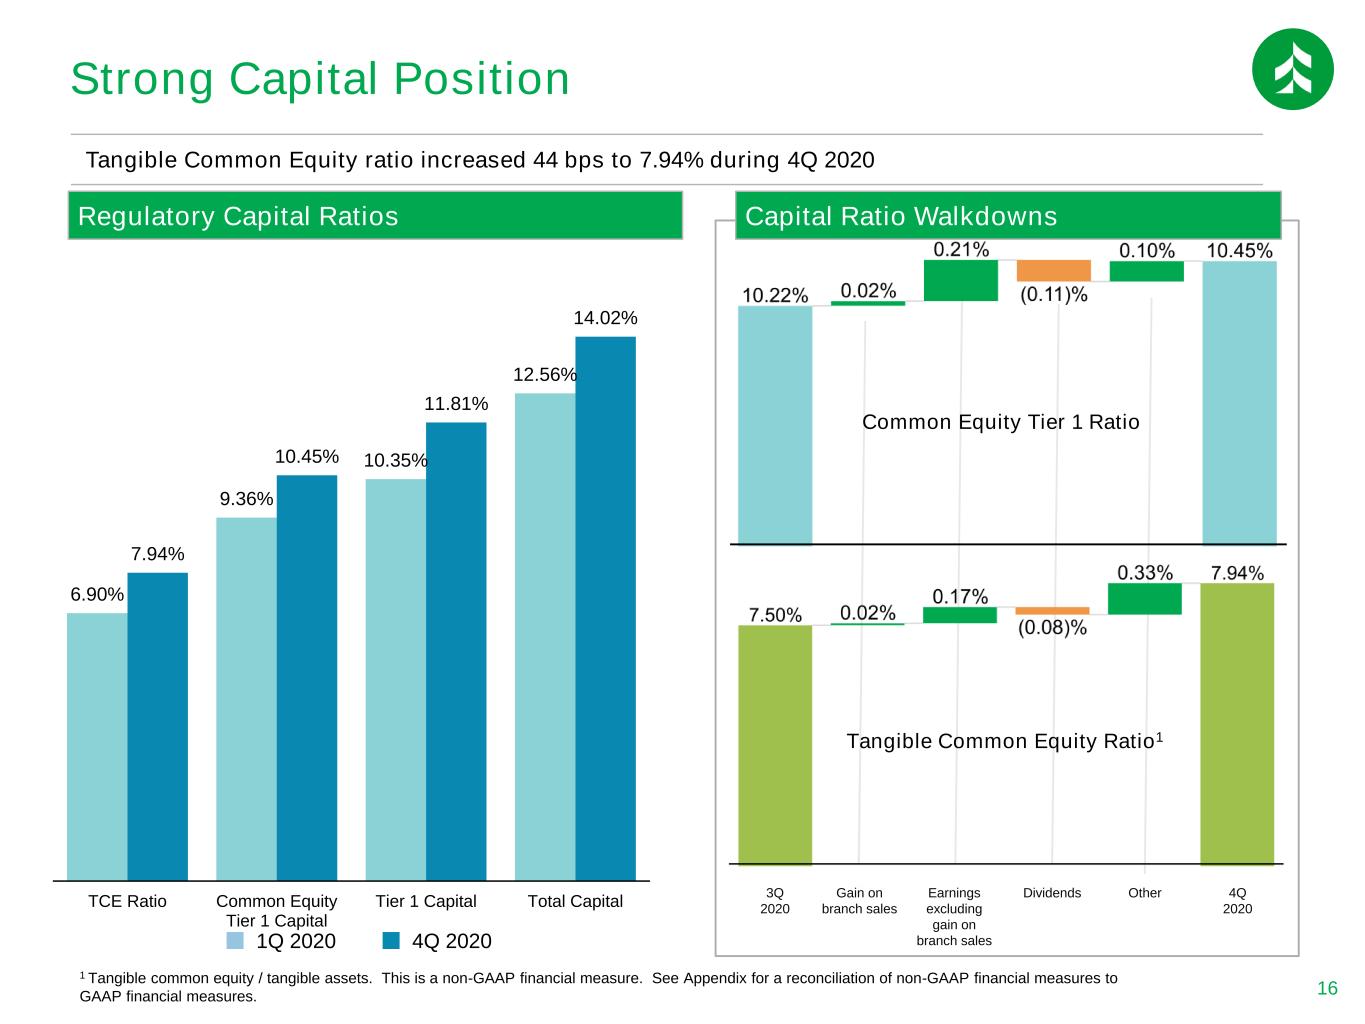
16 6.90% 9.36% 10.35% 12.56% 7.94% 10.45% 11.81% 14.02% TCE Ratio Common Equity Tier 1 Capital Tier 1 Capital Total Capital 1 Tangible common equity / tangible assets. This is a non-GAAP financial measure. See Appendix for a reconciliation of non-GAAP financial measures to GAAP financial measures. Regulatory Capital Ratios 1Q 2020 Tangible Common Equity Ratio1 Common Equity Tier 1 Ratio Tangible Common Equity ratio increased 44 bps to 7.94% during 4Q 2020 4Q 2020 Capital Ratio Walkdowns 3Q 2020 Gain on branch sales Dividends Other 4Q 2020 Earnings excluding gain on branch sales Strong Capital Position
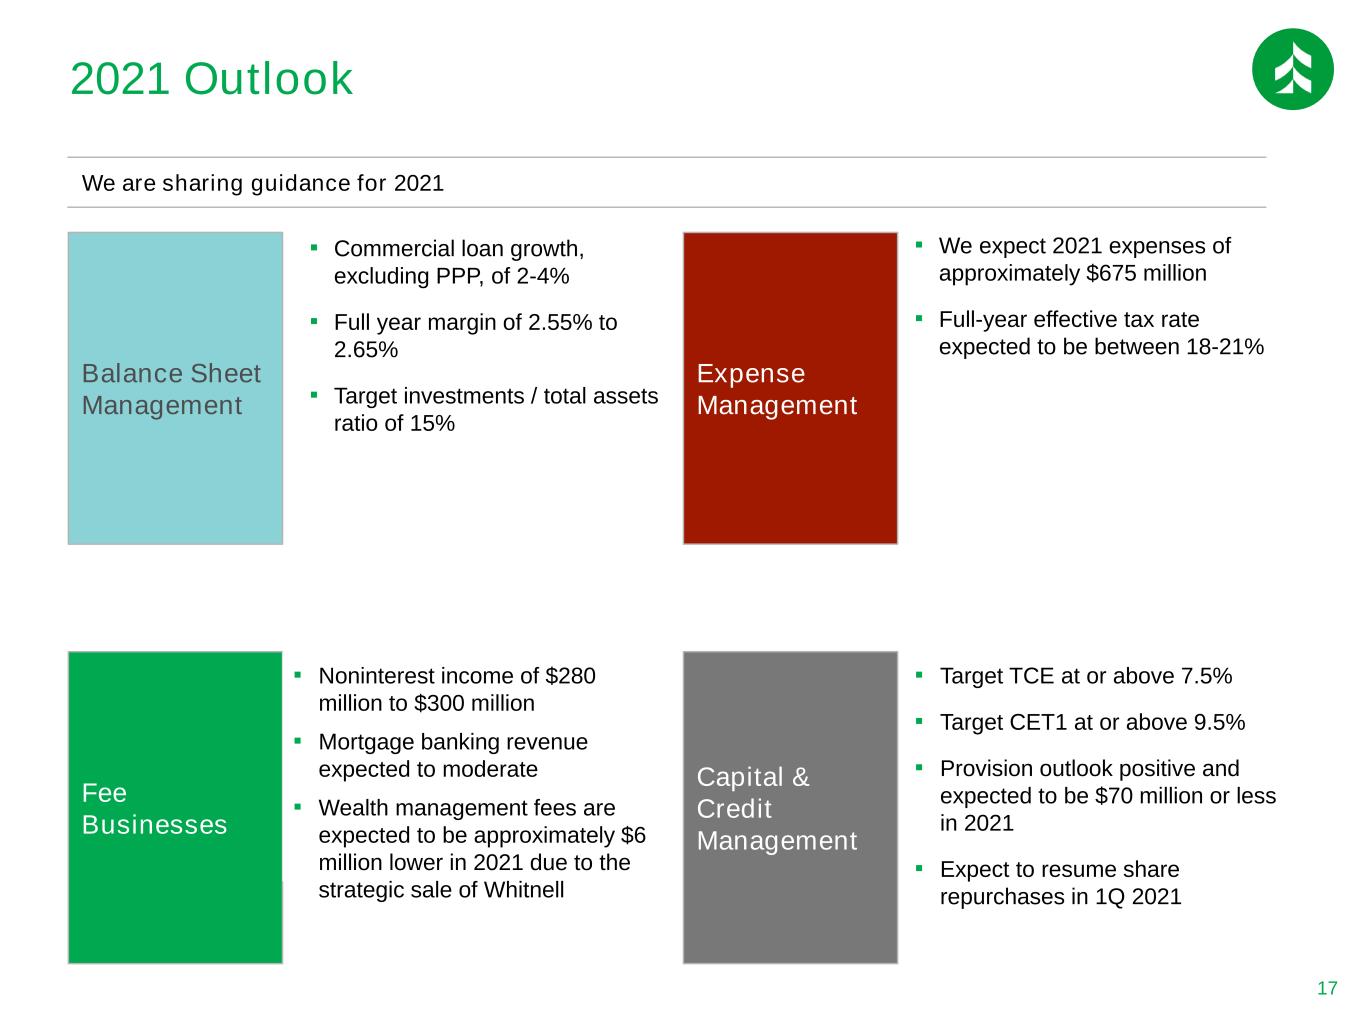
17 Balance Sheet Management ▪ Commercial loan growth, excluding PPP, of 2-4% ▪ Full year margin of 2.55% to 2.65% ▪ Target investments / total assets ratio of 15% Fee Businesses ▪ Noninterest income of $280 million to $300 million ▪ Mortgage banking revenue expected to moderate ▪ Wealth management fees are expected to be approximately $6 million lower in 2021 due to the strategic sale of Whitnell Expense Management ▪ We expect 2021 expenses of approximately $675 million ▪ Full-year effective tax rate expected to be between 18-21% Capital & Credit Management ▪ Target TCE at or above 7.5% ▪ Target CET1 at or above 9.5% ▪ Provision outlook positive and expected to be $70 million or less in 2021 ▪ Expect to resume share repurchases in 1Q 2021 We are sharing guidance for 2021 2021 Outlook
APPENDIX
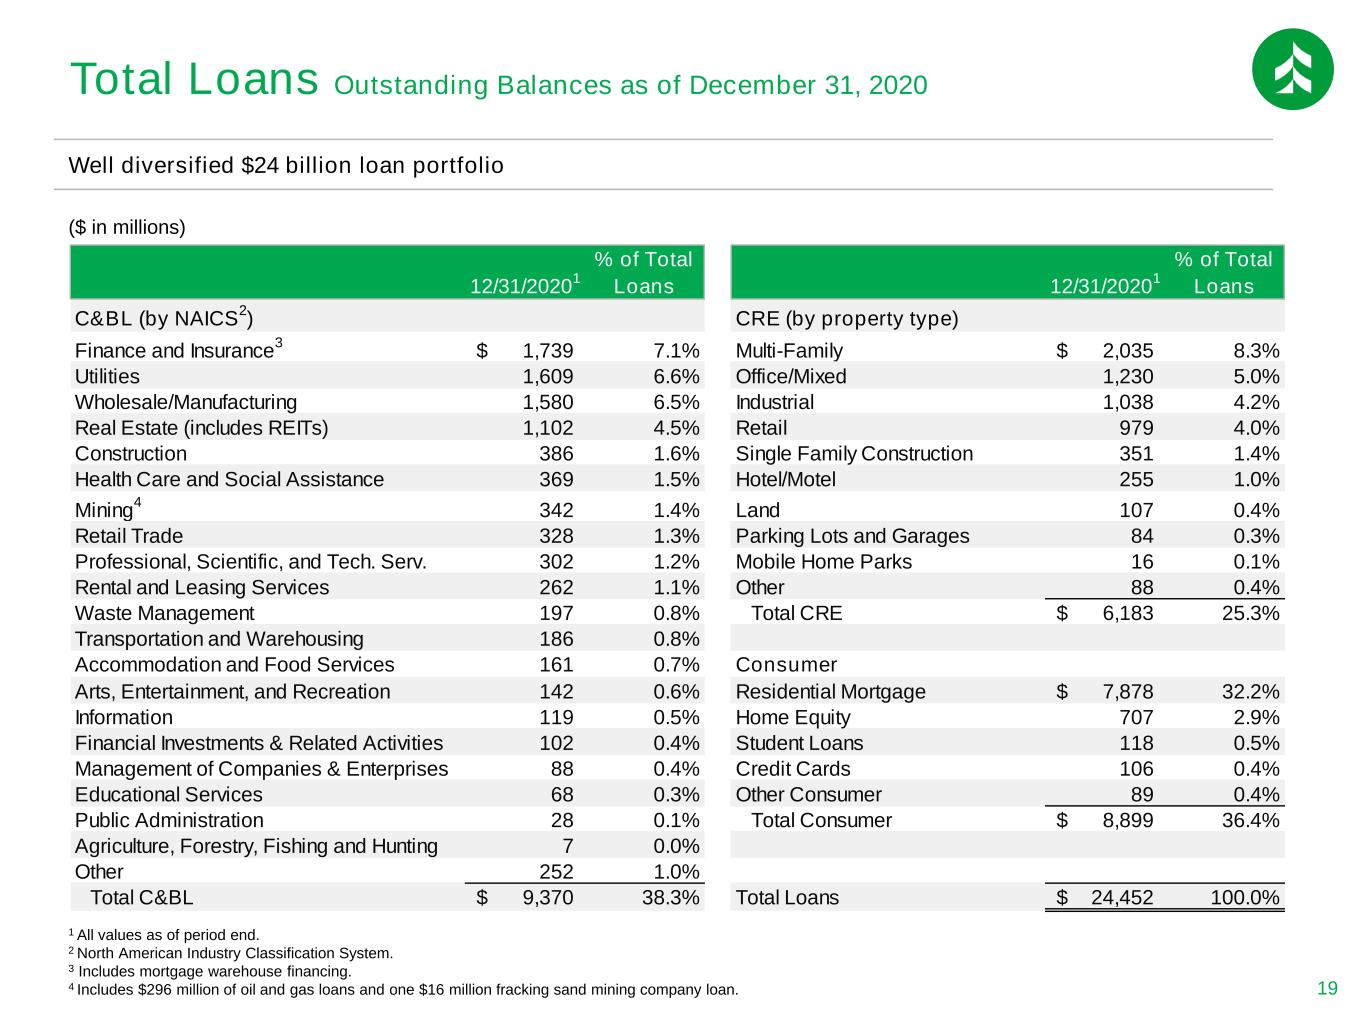
19 Total Loans Outstanding Balances as of December 31, 2020 1 All values as of period end. 2 North American Industry Classification System. 3 Includes mortgage warehouse financing. 4 Includes $296 million of oil and gas loans and one $16 million fracking sand mining company loan. Well diversified $24 billion loan portfolio ($ in millions) 12/31/2020 1 % of Total Loans 12/31/2020 1 % of Total Loans C&BL (by NAICS 2 ) CRE (by property type) Finance and Insurance 3 1,739$ 7.1% Multi-Family 2,035$ 8.3% Utilities 1,609 6.6% Office/Mixed 1,230 5.0% Wholesale/Manufacturing 1,580 6.5% Industrial 1,038 4.2% Real Estate (includes REITs) 1,102 4.5% Retail 979 4.0% Construction 386 1.6% Single Family Construction 351 1.4% Health Care and Social Assistance 369 1.5% Hotel/Motel 255 1.0% Mining 4 342 1.4% Land 107 0.4% Retail Trade 328 1.3% Parking Lots and Garages 84 0.3% Professional, Scientific, and Tech. Serv. 302 1.2% Mobile Home Parks 16 0.1% Rental and Leasing Services 262 1.1% Other 88 0.4% Waste Management 197 0.8% Total CRE 6,183$ 25.3% Transportation and Warehousing 186 0.8% Accommodation and Food Services 161 0.7% Consumer Arts, Entertainment, and Recreation 142 0.6% Residential Mortgage 7,878$ 32.2% Information 119 0.5% Home Equity 707 2.9% Financial Investments & Related Activities 102 0.4% Student Loans 118 0.5% Management of Companies & Enterprises 88 0.4% Credit Cards 106 0.4% Educational Services 68 0.3% Other Consumer 89 0.4% Public Administration 28 0.1% Total Consumer 8,899$ 36.4% Agriculture, Forestry, Fishing and Hunting 7 0.0% Other 252 1.0% Total C&BL 9,370$ 38.3% Total Loans 24,452$ 100.0%
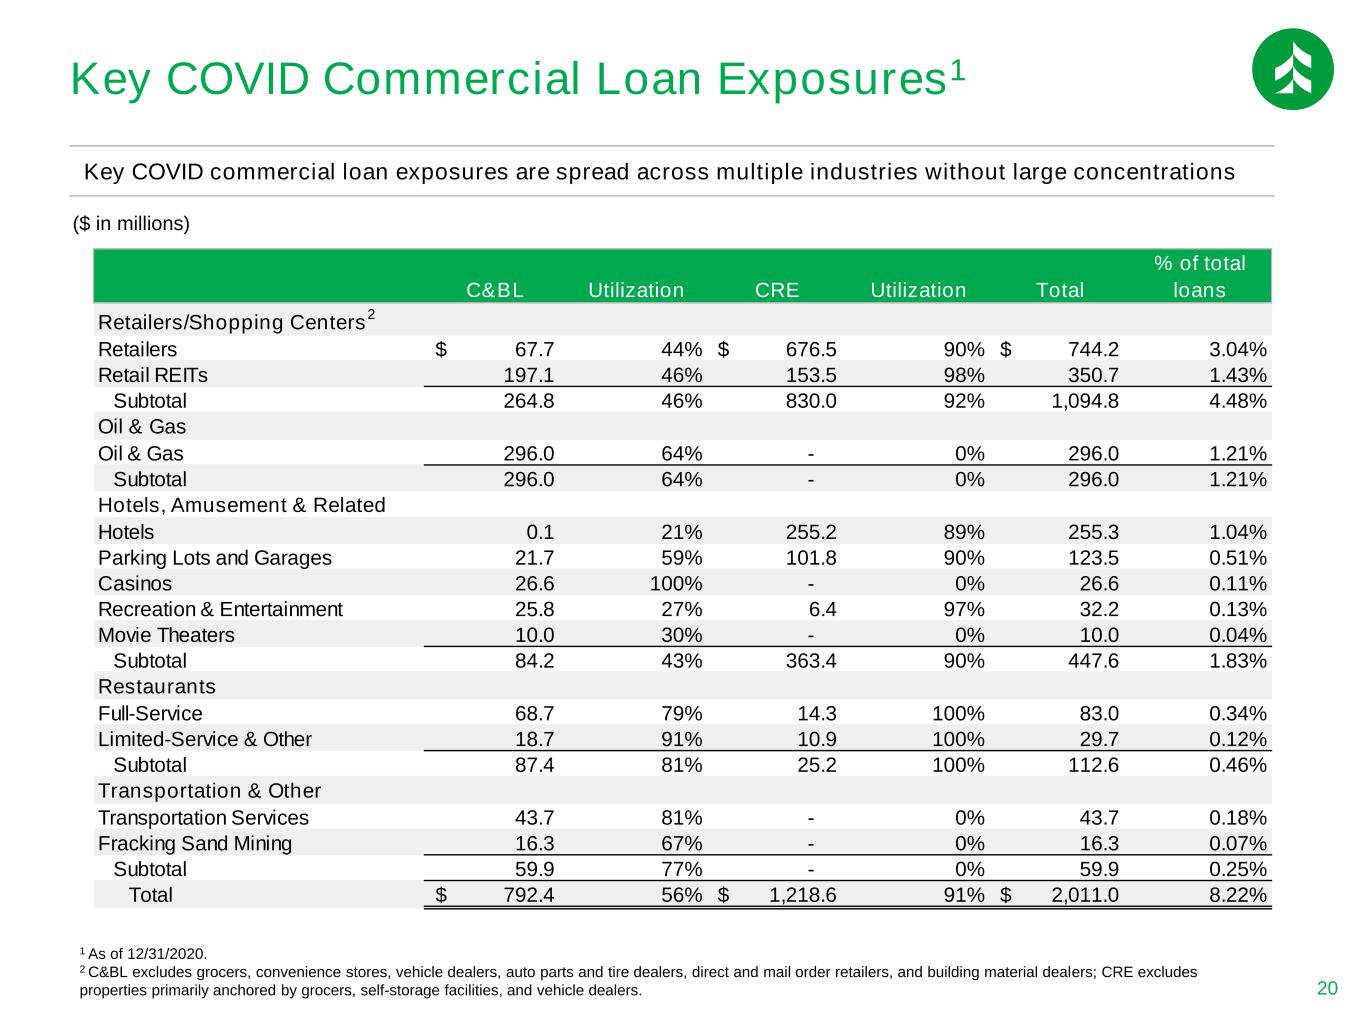
20 1 As of 12/31/2020. 2 C&BL excludes grocers, convenience stores, vehicle dealers, auto parts and tire dealers, direct and mail order retailers, and building material dealers; CRE excludes properties primarily anchored by grocers, self-storage facilities, and vehicle dealers. Key COVID commercial loan exposures are spread across multiple industries without large concentrations ($ in millions) Key COVID Commercial Loan Exposures1 C&BL Utilization CRE Utilization Total % of total loans Retailers/Shopping Centers 2 Retailers 67.7$ 44% 676.5$ 90% 744.2$ 3.04% Retail REITs 197.1 46% 153.5 98% 350.7 1.43% Subtotal 264.8 46% 830.0 92% 1,094.8 4.48% Oil & Gas Oil & Gas 296.0 64% - 0% 296.0 1.21% Subtotal 296.0 64% - 0% 296.0 1.21% Hotels, Amusement & Related Hotels 0.1 21% 255.2 89% 255.3 1.04% Parking Lots and Garages 21.7 59% 101.8 90% 123.5 0.51% Casinos 26.6 100% - 0% 26.6 0.11% Recreation & Entertainment 25.8 27% 6.4 97% 32.2 0.13% Movie Theaters 10.0 30% - 0% 10.0 0.04% Subtotal 84.2 43% 363.4 90% 447.6 1.83% Restaurants Full-Service 68.7 79% 14.3 100% 83.0 0.34% Limited-Service & Other 18.7 91% 10.9 100% 29.7 0.12% Subtotal 87.4 81% 25.2 100% 112.6 0.46% Transportation & Other Transportation Services 43.7 81% - 0% 43.7 0.18% Fracking Sand Mining 16.3 67% - 0% 16.3 0.07% Subtotal 59.9 77% - 0% 59.9 0.25% Total 792.4$ 56% 1,218.6$ 91% 2,011.0$ 8.22%
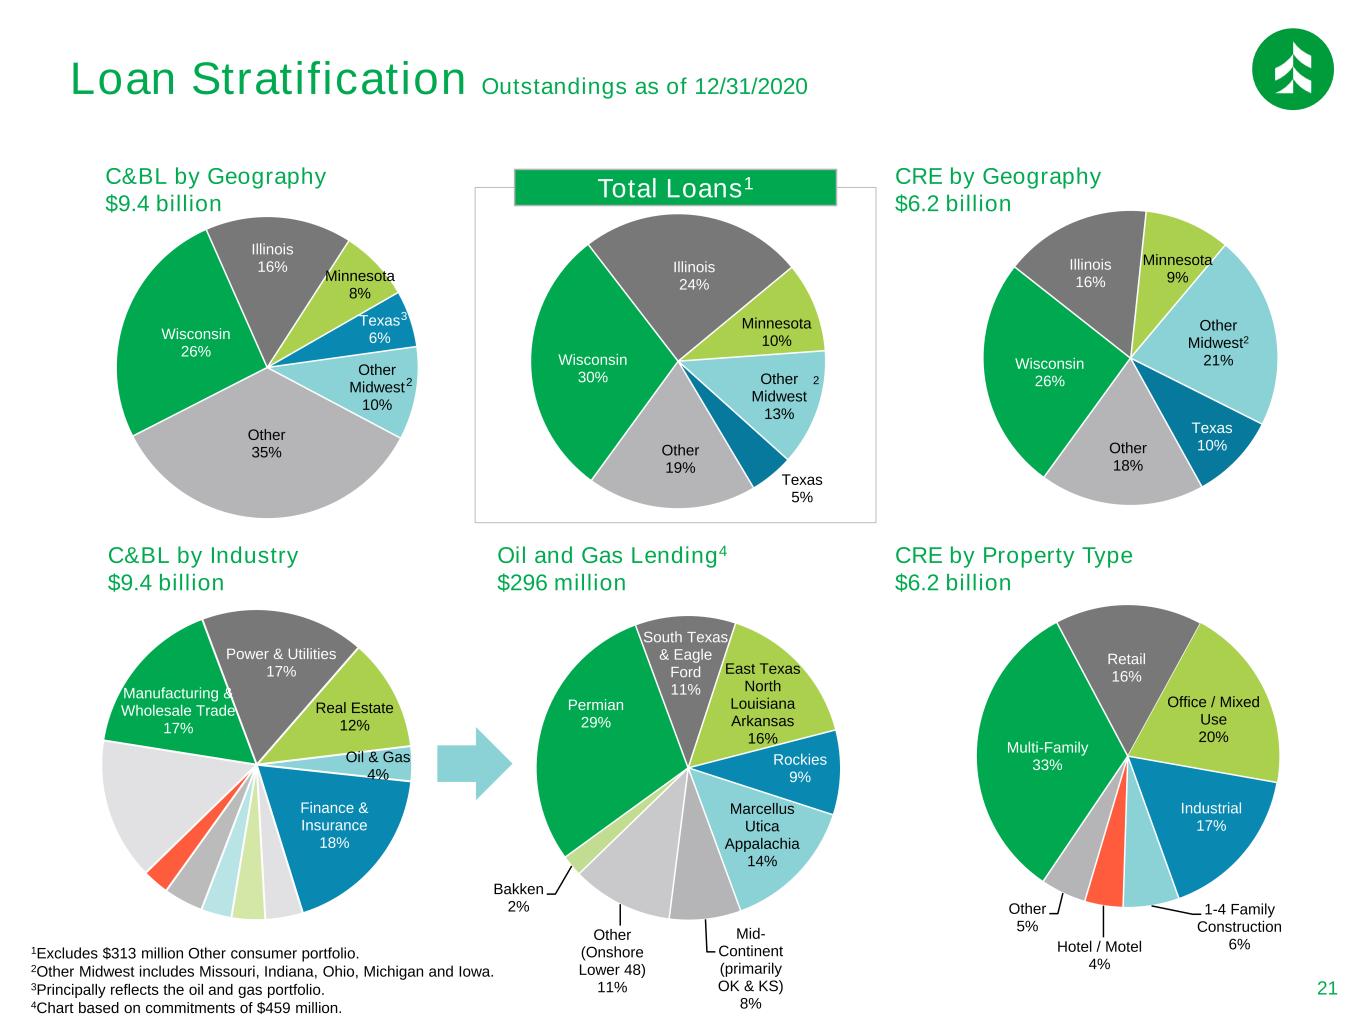
21 Manufacturing & Wholesale Trade 17% Power & Utilities 17% Real Estate 12% Oil & Gas 4% Finance & Insurance 18% 1Excludes $313 million Other consumer portfolio. 2Other Midwest includes Missouri, Indiana, Ohio, Michigan and Iowa. 3Principally reflects the oil and gas portfolio. 4Chart based on commitments of $459 million. C&BL by Geography $9.4 billion CRE by Geography $6.2 billion Multi-Family 33% Retail 16% Office / Mixed Use 20% Industrial 17% 1-4 Family Construction 6%Hotel / Motel 4% Other 5% Permian 29% South Texas & Eagle Ford 11% East Texas North Louisiana Arkansas 16% Rockies 9% Marcellus Utica Appalachia 14% Mid- Continent (primarily OK & KS) 8% Other (Onshore Lower 48) 11% Bakken 2% Wisconsin 26% Illinois 16% Minnesota 8% Texas 6% Other Midwest 10% Other 35% Wisconsin 26% Illinois 16% Minnesota 9% Other Midwest2 21% Texas 10%Other 18% Total Loans1 Wisconsin 30% Illinois 24% Minnesota 10% Other Midwest 13% Texas 5% Other 19% C&BL by Industry $9.4 billion Oil and Gas Lending4 $296 million CRE by Property Type $6.2 billion 3 2 2 Loan Stratification Outstandings as of 12/31/2020
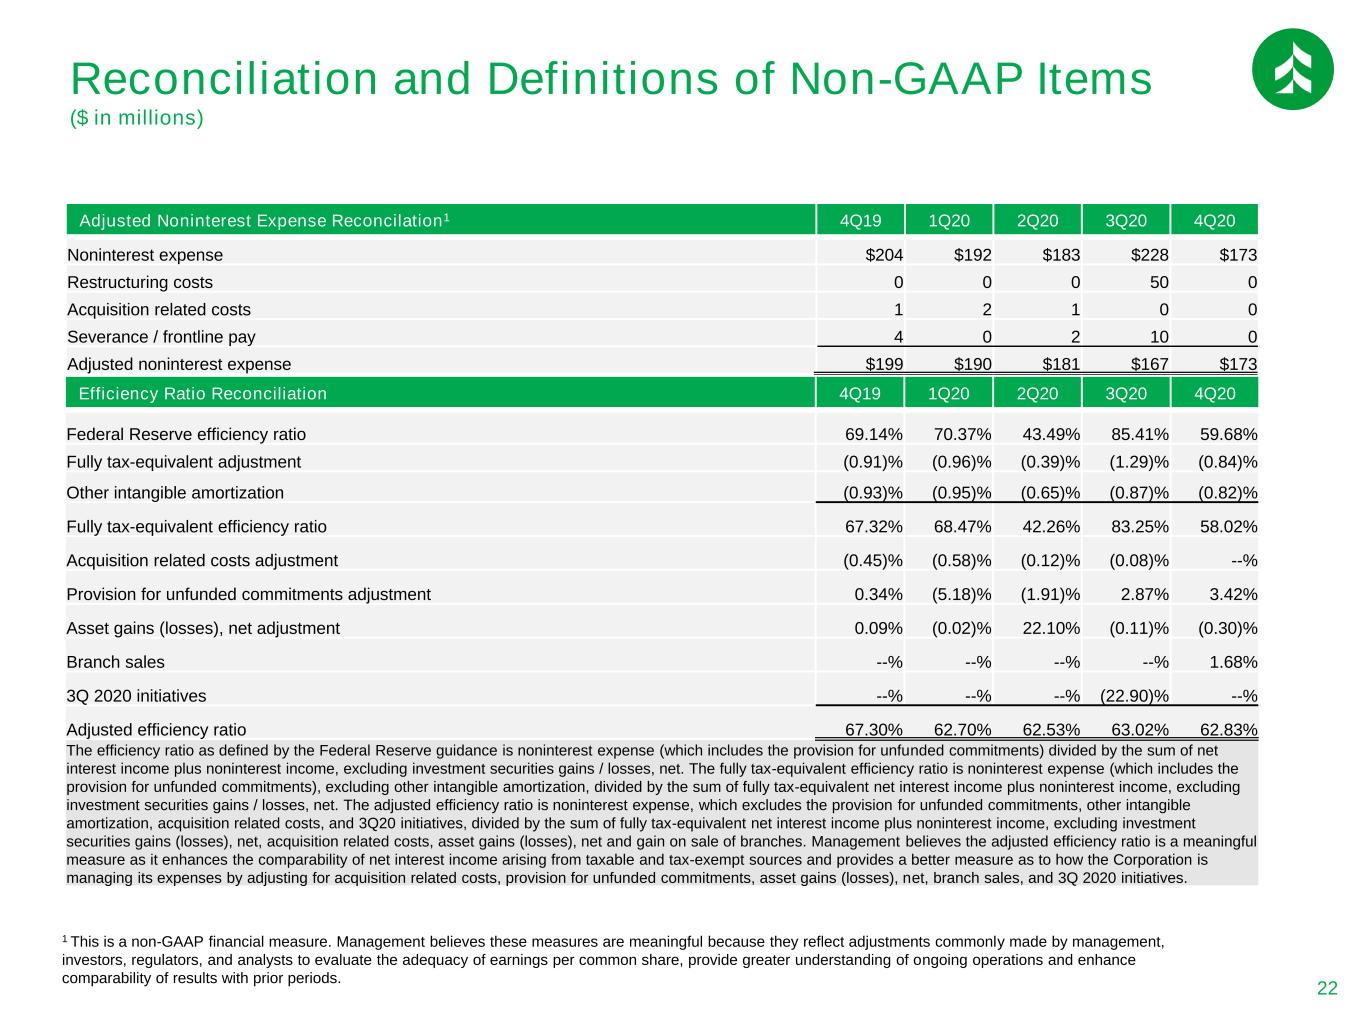
22 Reconciliation and Definitions of Non-GAAP Items ($ in millions) Adjusted Noninterest Expense Reconcilation1 4Q19 1Q20 2Q20 3Q20 4Q20 Noninterest expense $204 $192 $183 $228 $173 Restructuring costs 0 0 0 50 0 Acquisition related costs 1 2 1 0 0 Severance / frontline pay 4 0 2 10 0 Adjusted noninterest expense $199 $190 $181 $167 $173 1 This is a non-GAAP financial measure. Management believes these measures are meaningful because they reflect adjustments commonly made by management, investors, regulators, and analysts to evaluate the adequacy of earnings per common share, provide greater understanding of ongoing operations and enhance comparability of results with prior periods. Efficiency Ratio Reconciliation 4Q19 1Q20 2Q20 3Q20 4Q20 Federal Reserve efficiency ratio 69.14% 70.37% 43.49% 85.41% 59.68% Fully tax-equivalent adjustment (0.91)% (0.96)% (0.39)% (1.29)% (0.84)% Other intangible amortization (0.93)% (0.95)% (0.65)% (0.87)% (0.82)% Fully tax-equivalent efficiency ratio 67.32% 68.47% 42.26% 83.25% 58.02% Acquisition related costs adjustment (0.45)% (0.58)% (0.12)% (0.08)% --% Provision for unfunded commitments adjustment 0.34% (5.18)% (1.91)% 2.87% 3.42% Asset gains (losses), net adjustment 0.09% (0.02)% 22.10% (0.11)% (0.30)% Branch sales --% --% --% --% 1.68% 3Q 2020 initiatives --% --% --% (22.90)% --% Adjusted efficiency ratio 67.30% 62.70% 62.53% 63.02% 62.83% The efficiency ratio as defined by the Federal Reserve guidance is noninterest expense (which includes the provision for unfunded commitments) divided by the sum of net interest income plus noninterest income, excluding investment securities gains / losses, net. The fully tax-equivalent efficiency ratio is noninterest expense (which includes the provision for unfunded commitments), excluding other intangible amortization, divided by the sum of fully tax-equivalent net interest income plus noninterest income, excluding investment securities gains / losses, net. The adjusted efficiency ratio is noninterest expense, which excludes the provision for unfunded commitments, other intangible amortization, acquisition related costs, and 3Q20 initiatives, divided by the sum of fully tax-equivalent net interest income plus noninterest income, excluding investment securities gains (losses), net, acquisition related costs, asset gains (losses), net and gain on sale of branches. Management believes the adjusted efficiency ratio is a meaningful measure as it enhances the comparability of net interest income arising from taxable and tax-exempt sources and provides a better measure as to how the Corporation is managing its expenses by adjusting for acquisition related costs, provision for unfunded commitments, asset gains (losses), net, branch sales, and 3Q 2020 initiatives.

23 Reconciliation and Definitions of Non-GAAP Items ($ in millions) 1 This is a non-GAAP financial measure. Management believes these measures are meaningful because they reflect adjustments commonly made by management, investors, regulators, and analysts to evaluate the adequacy of earnings per common share, provide greater understanding of ongoing operations and enhance comparability of results with prior periods. 2 The ratio tangible common equity to tangible assets excludes goodwill and other intangible assets, net. This financial measure has been included as it is considered to be a critical metric with which to analyze and evaluate financial condition and capital strength. YTD 2020 Adjusted Pre-tax Pre-Provision Income Reconciliation1 YTD 2020 4Q 2020 Pre-tax pre-provision income Income before income taxes $327 $84 Provision for credit losses 174 17 Pre-tax pre-provision income 501 101 2020 Acquisitions, dispositions, and announced initiatives Sale of ABRC $(163) 0 Gain on sale of branches (7) (7) Acquisitions related to costs (noninterest expense) 2 0 Loss on prepayment of FHLB advances 45 0 Severance 10 0 Branch sales & consolidations 6 0 3Q 2020 initiatives 60 0 2020 Acquisitions, dispositions, and announced initiatives $(108) $(7) Pre-tax pre-provision income excluding 2020 initiatives $393 $94 Tangible Common Equity and Tangible Assets Reconciliation2 3Q20 4Q20 Common equity $3,692 $3,737 Goodwill and other intangible assets, net (1,178) (1,178) Tangible common equity $2,513 $2,560 Total assets $34,699 $33,420 Goodwill and other intangible assets, net (1,178) (1,178) Tangible assets $33,520 $32,242