ACIC 8-K
AMERICAN COASTAL INSURANCE Corp (ACIC)
8-K
2022-08-08
For: 2022-08-08
View Original
Added on
April 12, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of report (Date of earliest event reported): August 8, 2022
| (Exact name of registrant as specified in its charter) | ||||||||||||||||||||
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||||||||||||||
| (Address of principal executive offices) | (Zip Code) | |||||||||||||||||||
| (Registrant's telephone number, including area code) | ||||||||||||||||||||
| (Former name or former address, if changed since last report.) | ||||||||||||||||||||
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Trading Symbol(s) | Name of Each Exchange on Which Registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition
On August 8, 2022 , United Insurance Holdings Corp. (the Company, we, our) issued a press release relating to our earnings for the second quarter ended June 30, 2022 (the Earnings Release). We have attached a copy of the Earnings Release as Exhibit 99.1.
Item 7.01: Regulation FD Disclosure.
The executive officers of the Company intend to use the materials filed herewith, in whole or in part, in one or more meetings with investors and analysts, beginning on August 8, 2022. A copy of the investor presentation is attached hereto as Exhibit 99.2.
The information furnished under this Item 2.02 and 7.01, including Exhibit 99.1 and Exhibit 99.2 attached hereto, shall not be deemed “filed” for purposes of Section 18 of the Securities Act of 1934, nor shall it be deemed incorporated by reference in any filing under the Securities Act of 1933, except as shall be expressly set forth by specific reference to such filing.
Item 9.01. Financial Statements and Exhibits
| Exhibit No. | Description | |||||||
| Earnings release issued by the Company on August 8, 2022 | ||||||||
| Investor presentation issued by the Company on August 8, 2022 | ||||||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | |||||||
Signature
Pursuant to the requirements of the Securities Exchange Act of 1934, the Company has duly caused this report to be signed on its behalf by the undersigned thereunder duly authorized.
| UNITED INSURANCE HOLDINGS CORP. | ||||||||
| August 8, 2022 | By: | /s/ B. Bradford Martz | ||||||
| B. Bradford Martz, President and Chief Financial Officer (principal financial officer and principal accounting officer) | ||||||||
Exhibit 99.1
FOR IMMEDIATE RELEASE
UNITED INSURANCE HOLDINGS CORP. REPORTS FINANCIAL RESULTS
FOR ITS SECOND QUARTER ENDED JUNE 30, 2022
Company to Host Quarterly Conference Call at 5:00 P.M. ET on August 8, 2022
The information in this press release should be read in conjunction with an investor presentation that is available on the Company's website at investors.upcinsurance.com/Presentations.
St. Petersburg, FL - August 8, 2022: United Insurance Holdings Corp. (Nasdaq: UIHC) (UPC Insurance or the Company), a property and casualty insurance holding company, today reported its financial results for the second quarter ended June 30, 2022.
| ($ in thousands, except for per share data) | Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||
| June 30, | June 30, | ||||||||||||||||||||||||||||||||||
| 2022 | 2021 | Change | 2022 | 2021 | Change | ||||||||||||||||||||||||||||||
| Gross premiums written | $ | 360,146 | $ | 426,424 | (15.5) | % | $ | 639,621 | $ | 738,062 | (13.3) | % | |||||||||||||||||||||||
| Gross premiums earned | $ | 305,758 | $ | 356,433 | (14.2) | % | $ | 624,964 | $ | 713,096 | (12.4) | % | |||||||||||||||||||||||
| Net premiums earned | $ | 111,405 | $ | 145,460 | (23.4) | % | $ | 212,262 | $ | 291,409 | (27.2) | % | |||||||||||||||||||||||
| Total revenues | $ | 115,793 | $ | 155,454 | (25.5) | % | $ | 218,159 | $ | 317,243 | (31.2) | % | |||||||||||||||||||||||
| Loss before income tax | $ | (32,905) | $ | (32,773) | (0.4) | % | $ | (77,212) | $ | (59,055) | (30.7) | % | |||||||||||||||||||||||
| Net loss attributable to UIHC | $ | (69,029) | $ | (23,510) | NM | $ | (102,201) | $ | (41,281) | NM | |||||||||||||||||||||||||
Net loss available to UIHC common stockholders per diluted share | $ | (1.60) | $ | (0.55) | NM | $ | (2.38) | $ | (0.96) | NM | |||||||||||||||||||||||||
| Reconciliation of net loss to core loss: | |||||||||||||||||||||||||||||||||||
| Plus: Non-cash amortization of intangible assets | $ | 812 | $ | 889 | (8.7) | % | $ | 1,624 | $ | 1,932 | (15.9) | % | |||||||||||||||||||||||
| Less: Net realized gains (losses) on investment portfolio | $ | (78) | $ | (124) | 37.1 | % | $ | (1,847) | $ | 379 | NM | ||||||||||||||||||||||||
| Less: Unrealized gains (losses) on equity securities | $ | (5,084) | $ | 2,438 | NM | $ | (7,352) | $ | 5,002 | NM | |||||||||||||||||||||||||
Less: Net tax impact (1) | $ | 1,255 | $ | (299) | NM | $ | 2,273 | $ | (724) | NM | |||||||||||||||||||||||||
Core loss (2) (3) | $ | (64,310) | $ | (24,636) | NM | $ | (93,651) | $ | (44,006) | NM | |||||||||||||||||||||||||
Core loss per diluted share (2) (3) | $ | (1.49) | $ | (0.57) | NM | $ | (2.18) | $ | (1.03) | NM | |||||||||||||||||||||||||
| Book value per share | $ | 3.85 | $ | 7.85 | (51.0) | % | |||||||||||||||||||||||||||||
NM = Not Meaningful
(1) In order to reconcile net loss to the core loss measures, the Company included the tax impact of all adjustments using the 21% corporate federal tax rate.
(2) For both the three and six months ended June 30, 2022, core loss includes $43.7 million in tax expense related to the Company's recognition of a valuation allowance.
(3) Core loss, and core loss per diluted share, both of which are measures that are not based on GAAP, are reconciled above to net loss and net loss per diluted share, respectively, the most directly comparable GAAP measures. Additional information regarding non-GAAP financial measures presented in this press release can be found in the "Definitions of Non-GAAP Measures" section, below.
“During the second quarter, we reached a milestone in our plan to transition towards a specialty commercial lines writer,” said Dan Peed, CEO of UPC Insurance. “For the first time, commercial lines direct written premium of $181.1 million exceeded personal lines direct written premium of $179.1 million. Results support continuation of this plan, with a commercial lines combined ratio of 61.5% and an $18.8 million pre-tax profit. On a consolidated basis, second quarter net loss attributable to the Company was $69.0 million, which included recognition of a valuation allowance against our deferred tax asset of $43.7 million.”
1
Exhibit 99.1
Return on Equity and Core Return on Equity
The calculations of the Company's return on equity and core return on equity are shown below.
| ($ in thousands) | Three Months Ended | Six Months Ended | |||||||||||||||||||||
| June 30, | June 30, | ||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||
| Net loss attributable to UIHC | $ | (69,029) | $ | (23,510) | $ | (102,201) | $ | (41,281) | |||||||||||||||
Return on equity based on GAAP net loss attributable to UIHC (1) | (97.5) | % | (23.3) | % | (72.2) | % | (20.5) | % | |||||||||||||||
| Core loss | $ | (64,310) | $ | (24,636) | $ | (93,651) | $ | (44,006) | |||||||||||||||
Core return on equity (1)(2) | (90.9) | % | (24.4) | % | (66.2) | % | (21.8) | % | |||||||||||||||
(1) Return on equity for the three and six months ended June 30, 2022 and 2021 is calculated on an annualized basis by dividing the net loss or core loss for the period by the average stockholders' equity for the trailing twelve months.
(2) Core return on equity, a measure that is not based on GAAP, is calculated based on core loss, which is reconciled on the first page of this press release to net loss, the most directly comparable GAAP measure. Additional information regarding non-GAAP financial measures presented in this press release can be found in the "Definitions of Non-GAAP Measures" section, below.
2
Exhibit 99.1
Combined Ratio and Underlying Ratio
The calculations of the Company's combined ratio and underlying combined ratio on a consolidated basis and attributable to both our personal residential property and casualty insurance policies (personal lines) and commercial residential property and casualty insurance policies (commercial lines) operating segments are shown below.
| ($ in thousands) | Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||
| June 30, | June 30, | ||||||||||||||||||||||||||||||||||
| 2022 | 2021 | Change | 2022 | 2021 | Change | ||||||||||||||||||||||||||||||
| Consolidated | |||||||||||||||||||||||||||||||||||
Loss ratio, net(1) | 80.9 | % | 81.2 | % | (0.3) | pts | 85.5 | % | 80.2 | % | 5.3 | pts | |||||||||||||||||||||||
Expense ratio, net(2) | 50.7 | % | 46.7 | % | 4.0 | pts | 52.2 | % | 47.3 | % | 4.9 | pts | |||||||||||||||||||||||
Combined ratio (CR)(3) | 131.6 | % | 127.9 | % | 3.7 | pts | 137.7 | % | 127.5 | % | 10.2 | pts | |||||||||||||||||||||||
| Effect of current year catastrophe losses on CR | 18.4 | % | 27.7 | % | (9.3) | pts | 23.2 | % | 22.0 | % | 1.2 | pts | |||||||||||||||||||||||
| Effect of prior year unfavorable (favorable) development on CR | 7.0 | % | (0.3) | % | 7.3 | pts | 4.3 | % | 10.1 | % | (5.8) | pts | |||||||||||||||||||||||
Underlying combined ratio(4) | 106.2 | % | 100.5 | % | 5.7 | pts | 110.2 | % | 95.4 | % | 14.8 | pts | |||||||||||||||||||||||
| Personal Lines | |||||||||||||||||||||||||||||||||||
Loss ratio, net(1) | 136.6 | % | 97.1 | % | 39.5 | pts | 137.9 | % | 97.6 | % | 40.3 | pts | |||||||||||||||||||||||
Expense ratio, net(2) | 54.1 | % | 46.0 | % | 8.1 | pts | 57.3 | % | 46.0 | % | 11.3 | pts | |||||||||||||||||||||||
Combined ratio (CR)(3) | 190.7 | % | 143.1 | % | 47.6 | pts | 195.2 | % | 143.6 | % | 51.6 | pts | |||||||||||||||||||||||
| Effect of current year catastrophe losses on CR | 38.6 | % | 36.8 | % | 1.8 | pts | 42.2 | % | 27.8 | % | 14.4 | pts | |||||||||||||||||||||||
| Effect of prior year unfavorable (favorable) development on CR | 16.1 | % | 0.2 | % | 15.9 | pts | 11.2 | % | 14.6 | % | (3.4) | pts | |||||||||||||||||||||||
Underlying combined ratio(4) | 136.0 | % | 106.1 | % | 29.9 | pts | 141.8 | % | 101.2 | % | 40.6 | pts | |||||||||||||||||||||||
| Commercial Lines | |||||||||||||||||||||||||||||||||||
Loss ratio, net(1) | 15.9 | % | 42.9 | % | (27.0) | pts | 23.0 | % | 38.0 | % | (15.0) | pts | |||||||||||||||||||||||
Expense ratio, net(2) | 45.6 | % | 47.3 | % | (1.7) | pts | 45.0 | % | 49.2 | % | (4.2) | pts | |||||||||||||||||||||||
Combined ratio (CR)(3) | 61.5 | % | 0 | 90.2 | % | (28.7) | pts | 68.0 | % | 87.2 | % | (19.2) | pts | ||||||||||||||||||||||
| Effect of current year catastrophe losses on CR | (5.0) | % | 5.7 | % | (10.7) | pts | 0.5 | % | 8.0 | % | (7.5) | pts | |||||||||||||||||||||||
| Effect of prior year favorable development on CR | (3.7) | % | (1.4) | % | (2.3) | pts | (3.8) | % | (1.0) | % | (2.8) | pts | |||||||||||||||||||||||
Underlying combined ratio(4) | 70.2 | % | 85.9 | % | (15.7) | pts | 71.3 | % | 80.2 | % | (8.9) | pts | |||||||||||||||||||||||
(1) Loss ratio, net is calculated as losses and loss adjustment expenses (LAE), net of losses ceded to reinsurers, relative to net premiums earned.
(2) Expense ratio, net is calculated as the sum of all operating expenses less interest expense relative to net premiums earned.
(3) Combined ratio is the sum of the loss ratio, net and expense ratio, net.
(4) Underlying combined ratio, a measure that is not based on GAAP, is reconciled above to the combined ratio, the most directly comparable GAAP measure. Additional information regarding non-GAAP financial measures presented in this press release can be found in the "Definitions of Non-GAAP Measures" section, below.
3
Exhibit 99.1
Combined Ratio Analysis
The calculations of the Company's loss ratios and underlying loss ratios are shown below.
| ($ in thousands) | Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||
| June 30, | June 30, | ||||||||||||||||||||||||||||||||||
| 2022 | 2021 | Change | 2022 | 2021 | Change | ||||||||||||||||||||||||||||||
| Loss and LAE | $ | 90,074 | $ | 118,064 | $ | (27,990) | $ | 181,442 | $ | 233,845 | $ | (52,403) | |||||||||||||||||||||||
| % of Gross earned premiums | 29.5 | % | 33.1 | % | (3.6) | pts | 29.0 | % | 32.8 | % | (3.8) | pts | |||||||||||||||||||||||
| % of Net earned premiums | 80.9 | % | 81.2 | % | (0.3) | pts | 85.5 | % | 80.2 | % | 5.3 | pts | |||||||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||||||||
| Current year catastrophe losses | $ | 20,553 | $ | 40,257 | $ | (19,704) | $ | 49,169 | $ | 64,222 | $ | (15,053) | |||||||||||||||||||||||
| Prior year reserve unfavorable (favorable) development | 7,766 | (372) | 8,138 | 9,199 | 29,397 | (20,198) | |||||||||||||||||||||||||||||
Underlying loss and LAE (1) | $ | 61,755 | $ | 78,179 | $ | (16,424) | $ | 123,074 | $ | 140,226 | $ | (17,152) | |||||||||||||||||||||||
| % of Gross earned premiums | 20.2 | % | 21.9 | % | (1.7) | pts | 19.7 | % | 19.7 | % | — | pts | |||||||||||||||||||||||
| % of Net earned premiums | 55.5 | % | 53.7 | % | 1.8 | pts | 58.0 | % | 48.1 | % | 9.9 | pts | |||||||||||||||||||||||
(1) Underlying loss and LAE is a non-GAAP financial measure and is reconciled above to loss and LAE, the most directly comparable GAAP measure. Additional information regarding non-GAAP financial measures presented in this press release can be found in the "Definitions of Non-GAAP Measures" section, below.
The calculations of the Company's expense ratios are shown below.
| ($ in thousands) | Three Months Ended | Six Months Ended | |||||||||||||||||||||||||||||||||
| June 30, | June 30, | ||||||||||||||||||||||||||||||||||
| 2022 | 2021 | Change | 2022 | 2021 | Change | ||||||||||||||||||||||||||||||
| Policy acquisition costs | $ | 28,988 | $ | 41,327 | $ | (12,339) | $ | 55,004 | $ | 82,148 | $ | (27,144) | |||||||||||||||||||||||
| Operating and underwriting | 13,019 | 13,482 | (463) | 25,267 | 26,704 | (1,437) | |||||||||||||||||||||||||||||
| General and administrative | 14,494 | 13,112 | 1,382 | 30,499 | 28,994 | 1,505 | |||||||||||||||||||||||||||||
| Total Operating Expenses | $ | 56,501 | $ | 67,921 | $ | (11,420) | $ | 110,770 | $ | 137,846 | $ | (27,076) | |||||||||||||||||||||||
% of Gross earned premiums | 18.5 | % | 19.1 | % | (0.6) | pts | 17.7 | % | 19.3 | % | (1.6) | pts | |||||||||||||||||||||||
% of Net earned premiums | 50.7 | % | 46.7 | % | 4.0 | pts | 52.2 | % | 47.3 | % | 4.9 | pts | |||||||||||||||||||||||
4
Exhibit 99.1
Quarterly Financial Results
Net loss attributable to the Company for the second quarter of 2022 was $69.0 million, or $1.60 per diluted share, compared to $23.5 million, or $0.55 per diluted share, for the second quarter of 2021. The increase in net loss was primarily due to an increase in our provision for income taxes from the recognition of a valuation allowance against our deferred tax asset during the quarter of $43.7 million. Total revenue also decreased as the result of decreased gross written premiums, partially offset by decreased ceded premiums earned. On the expense side, policy acquisition costs also decreased quarter-over-quarter. The details of these changes are described below. In addition, loss and LAE incurred by the Company decreased for the period, driven by lower current year catastrophe losses in 2022.
The Company's total gross written premium decreased by $66.3 million, or 15.5%, to $360.1 million for the second quarter of 2022, from $426.4 million for the second quarter of 2021. This decrease was driven primarily by the transition of the Northeast business to Homeowners Choice Property & Casualty Insurance Company, Inc. (HCPCI) in the fourth quarter of 2021 and the first half of 2022. In addition, the Company experienced a decline in written premiums across the personal lines business, due to underwriting actions taken by the Company throughout 2021 and in the first half of 2022. The breakdown of the quarter-over-quarter changes in both direct written and assumed premiums by region and gross written premium by line of business are shown in the table below.
| ($ in thousands) | Three Months Ended June 30, | |||||||||||||||||||||||||
| 2022 | 2021 | Change $ | Change % | |||||||||||||||||||||||
Direct Written and Assumed Premium by Region (1) | ||||||||||||||||||||||||||
| Florida | $ | 289,551 | $ | 281,728 | $ | 7,823 | 2.8 | % | ||||||||||||||||||
| Gulf | 56,739 | 67,290 | (10,551) | (15.7) | ||||||||||||||||||||||
| Southeast | 16,719 | 27,483 | (10,764) | (39.2) | ||||||||||||||||||||||
| Northeast | (3,018) | 49,879 | (52,897) | (106.1) | ||||||||||||||||||||||
| Total direct written premium by region | 359,991 | 426,380 | (66,389) | (15.6) | ||||||||||||||||||||||
Assumed premium (2) | 155 | 44 | 111 | 252.3 | ||||||||||||||||||||||
| Total gross written premium by region | $ | 360,146 | $ | 426,424 | $ | (66,278) | (15.5) | % | ||||||||||||||||||
| Gross Written Premium by Line of Business | ||||||||||||||||||||||||||
| Commercial property | $ | 181,067 | $ | 155,982 | $ | 25,085 | 16.1 | % | ||||||||||||||||||
| Personal property | 179,079 | 270,442 | (91,363) | (33.8) | ||||||||||||||||||||||
| Total gross written premium by line of business | $ | 360,146 | $ | 426,424 | $ | (66,278) | (15.5) | % | ||||||||||||||||||
(1) "Gulf" is comprised of Louisiana and Texas; "Northeast" is comprised of Massachusetts, New Jersey and New York in 2022 and Connecticut, Massachusetts, New Jersey, New York and Rhode Island in 2021; and "Southeast" is comprised of Georgia, North Carolina and South Carolina. The Company is no longer writing in New Jersey as of January 15, 2022, Massachusetts as of April 1, 2022, and South Carolina as of June 1, 2022 as the policies have transitioned to HCPCI.
(2) Assumed premium written for 2022 and 2021 primarily included commercial property business assumed from unaffiliated insurers.
Loss and LAE decreased by $28.0 million, or 23.7%, to $90.1 million for the second quarter of 2022, from $118.1 million for the second quarter of 2021. Loss and LAE expense as a percentage of net earned premiums decreased 0.3 points to 80.9% for the second quarter of 2022, compared to 81.2% for the second quarter of 2021. Excluding catastrophe losses and reserve development, the Company's gross underlying loss and LAE ratio for the second quarter of 2022 would have been 20.2%, a decrease of 1.7 points from 21.9% during the second quarter of 2021.
Policy acquisition costs decreased by $12.3 million, or 29.8%, to $29.0 million for the second quarter of 2022, from $41.3 million for the second quarter of 2021, primarily due to a decrease in expenses such as premium taxes, policy administration fees and agent commissions, which fluctuate in conjunction with the quarter-over-quarter decrease in personal lines gross written premium. This was partially offset by increased external management fees incurred during the second quarter of 2022, as a result of an increased volume of commercial lines gross written premium and ceding commission income decreased due to changes in terms of the Company's quota share reinsurance agreements.
Operating and underwriting expenses remained relatively flat, decreasing by $0.5 million, or 3.7%, to $13.0 million for the second quarter of 2022, from $13.5 million for the second quarter of 2021.
5
Exhibit 99.1
General and administrative expenses increased by $1.4 million, or 10.7%, to $14.5 million for the second quarter of 2022, from $13.1 million for the second quarter of 2021, driven by increased external fees related to legal, audit, actuarial and tax services provided during the quarter.
Personal Lines Operating Segment Highlights
Pretax losses attributable to the Company's personal lines operating segment totaled $48.8 million for the second quarter of 2022 compared to $35.6 million for the second quarter of 2021. This increase can be attributed to decreased net premiums earned of $42.6 million from decreased gross written premiums quarter-over-quarter as described above.
This decrease in revenues was partially offset by a $32.6 million or 22.2% decrease in expenses, driven by a $17.8 million decrease in loss and LAE incurred and a $14.6 million decrease in policy acquisition costs. The decrease in loss and LAE incurred can be attributed to decreased current year catastrophe losses. The decrease in policy acquisition costs can be attributed to the decrease in gross written premiums quarter-over-quarter as well as decreased ceding commission income related to changes in the terms of the Company's quota share reinsurance agreements.
Commercial Lines Operating Segment Highlights
Pretax earnings attributable to the Company's commercial lines operating segment totaled $18.8 million for the second quarter of 2022 compared to $5.6 million for the second quarter of 2021. This increase can be attributed to decreased expenses of $6.9 million or 17.9%, driven by a $10.2 million decrease in loss and LAE incurred, partially offset by a $2.3 million increase in policy acquisition costs. The decrease in loss and LAE incurred can be attributed to decreased catastrophe losses quarter-over-quarter, while the increase in policy acquisition costs can be attributed to external management fees driven by increased gross written premiums for the period.
In addition, revenues increased $6.3 million or 14.3%, driven by an $8.7 million increase in net premiums earned. This increase can be attributed to increased gross written premiums quarter-over-quarter as the Company looks to balance its commercial lines and personal lines business.
Reinsurance Costs as a Percentage of Gross Earned Premium
Reinsurance costs as a percentage of gross earned premium in the second quarter of 2022 and 2021 were as follows:
| 2022 | 2021 | ||||||||||
| Non-at-Risk | (2.3) | % | (2.0) | % | |||||||
| Quota Share | (25.7) | % | (25.6) | % | |||||||
| All Other | (35.6) | % | (31.6) | % | |||||||
| Total Ceding Ratio | (63.6) | % | (59.2) | % | |||||||
While ceded premiums earned decreased quarter-over-quarter, the Company's ceding ratio on a consolidated basis increased, driven by the Company's decrease in gross premiums earned quarter-over-quarter.
Ceded premiums earned related to the Company's quota share reinsurance contracts decreased quarter-over-quarter driven by a decrease in the cession rate for one of the Company's external quota shares and changes to the geographic footprint and exposure covered by the external quota share contracts.
Ceded premiums earned related to the Company's catastrophe program also decreased, driven by the need for less coverage for the 2022-2023 treaty year for the reduction in the geographic footprint and exposure, as well as the change from a cascading aggregate structure to an occurrence-based structure for the Company's 2022-2023 program.
6
Exhibit 99.1
Reinsurance costs as a percentage of gross earned premium in the second quarter of 2022 and 2021 for our personal lines and commercial lines operating segments were as follows:
| Personal | Commercial | ||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | ||||||||||||||||||||
| Non-at-Risk | (3.4) | % | (2.6) | % | (0.5) | % | (0.5) | % | |||||||||||||||
| Quota Share | (31.2) | % | (30.4) | % | (16.3) | % | (13.5) | % | |||||||||||||||
| All Other | (34.3) | % | (26.7) | % | (37.8) | % | (43.8) | % | |||||||||||||||
| Total Ceding Ratio | (68.9) | % | (59.7) | % | (54.6) | % | (57.8) | % | |||||||||||||||
Investment Portfolio Highlights
The Company's cash, restricted cash and investment holdings decreased from $964.8 million at December 31, 2021 to $898.4 million at June 30, 2022. The Company's cash and investment holdings consist of investments in U.S. government and agency securities, corporate debt and 100% investment grade money market instruments. Fixed maturities represented approximately 90.7% of total investments at June 30, 2022, compared to 92.2% at December 31, 2021. At June 30, 2022, the Company's fixed maturity investments had a modified duration of 3.8 years, compared to 4.0 years at December 31, 2021.
At June 30, 2022, the Company's fixed maturity investment holdings decreased by $136.5 million, or 20.6% from December 31, 2021, through the sale of securities in order to satisfy the Company's liquidity requirements during 2022 and due to unrealized losses recognized on the portfolio.
Book Value Analysis
Book value per common share decreased 46.5% from $7.20 at December 31, 2021, to $3.85 at June 30, 2022. Underlying book value per common share decreased 32.2% from $7.35 at December 31, 2021 to $4.98 at June 30, 2022. A decrease in the Company's retained earnings as the result of a net loss in the first half of 2022 drove the decrease in the Company's book value per share. As shown in the table below, removing the effect of AOCI increases the Company's book value per common share, as the Company experienced unfavorable market conditions for the six months ended June 30, 2022.
| ($ in thousands, except for share and per share data) | June 30, 2022 | December 31, 2021 | ||||||||||||
| Book Value per Share | ||||||||||||||
| Numerator: | ||||||||||||||
| Common stockholders' equity attributable to UIHC | $ | 166,972 | $ | 312,406 | ||||||||||
| Denominator: | ||||||||||||||
| Total Shares Outstanding | 43,313,166 | 43,370,442 | ||||||||||||
| Book Value Per Common Share | $ | 3.85 | $ | 7.20 | ||||||||||
| Book Value per Share, Excluding the Impact of Accumulated Other Comprehensive Income (AOCI) | ||||||||||||||
| Numerator: | ||||||||||||||
| Common stockholders' equity attributable to UIHC | $ | 166,972 | $ | 312,406 | ||||||||||
| Less: Accumulated other comprehensive loss | (48,861) | (6,531) | ||||||||||||
| Stockholders' Equity, excluding AOCI | $ | 215,833 | $ | 318,937 | ||||||||||
| Denominator: | ||||||||||||||
| Total Shares Outstanding | 43,313,166 | 43,370,442 | ||||||||||||
Underlying Book Value Per Common Share(1) | $ | 4.98 | $ | 7.35 | ||||||||||
(1) Underlying book value per common share is a non-GAAP financial measure and is reconciled above to book value per common share, the most directly comparable GAAP measure. Additional information regarding non-GAAP financial measures presented in this press release can be found in the "Definitions of Non-GAAP Measures" section, below.
7
Exhibit 99.1
Definitions of Non-GAAP Measures
The Company believes that investors' understanding of UPC Insurance's performance is enhanced by the Company's disclosure of the following non-GAAP measures. The Company's methods for calculating these measures may differ from those used by other companies and therefore comparability may be limited.
Net loss excluding the effects of amortization of intangible assets, realized gains (losses) and unrealized gains (losses) on equity securities, net of tax (core loss) is a non-GAAP measure that is computed by adding amortization, net of tax, to net income and subtracting realized gains (losses) on the Company's investment portfolio, net of tax, and unrealized gains (losses) on the Company's equity securities, net of tax, from net loss. Amortization expense is related to the amortization of intangible assets acquired through mergers and, therefore, the expense does not arise through normal operations. Investment portfolio gains (losses) and unrealized equity security gains (losses) vary independent of the Company's operations. The Company believes it is useful for investors to evaluate these components both separately and in the aggregate when reviewing the Company's performance. The most directly comparable GAAP measure is net loss. The core loss measure should not be considered a substitute for net loss and does not reflect the overall profitability of the Company's business.
Core return on equity is a non-GAAP ratio calculated using non-GAAP measures. It is calculated by dividing the core loss for the period by the average stockholders’ equity for the trailing twelve months (or one quarter of such average, in the case of quarterly periods). Core loss is an after-tax non-GAAP measure that is calculated by excluding from net loss the effect of non-cash amortization of intangible assets, unrealized gains or losses on the Company's equity security investments and net realized gains or losses on the Company's investment portfolio. In the opinion of the Company’s management, core loss, core loss per share and core return on equity are meaningful indicators to investors of the Company's underwriting and operating results, since the excluded items are not necessarily indicative of operating trends. Internally, the Company’s management uses core loss, core loss per share and core return on equity to evaluate performance against historical results and establish financial targets on a consolidated basis. The most directly comparable GAAP measure is return on equity. The core return on equity measure should not be considered a substitute for return on equity and does not reflect the overall profitability of the Company's business.
Combined ratio excluding the effects of current year catastrophe losses and prior year reserve development (underlying combined ratio) is a non-GAAP measure, that is computed by subtracting the effect of current year catastrophe losses and prior year development from the combined ratio. The Company believes that this ratio is useful to investors, and it is used by management to highlight the trends in the Company's business that may be obscured by current year catastrophe losses and prior year development. Current year catastrophe losses cause the Company's loss trends to vary significantly between periods as a result of their frequency of occurrence and severity and can have a significant impact on the combined ratio. Prior year development is caused by unexpected loss development on historical reserves. The Company believes it is useful for investors to evaluate these components both separately and in the aggregate when reviewing the Company's performance. The most directly comparable GAAP measure is the combined ratio. The underlying combined ratio should not be considered as a substitute for the combined ratio and does not reflect the overall profitability of the Company's business.
Net loss and LAE excluding the effects of current year catastrophe losses and prior year reserve development (underlying loss and LAE) is a non-GAAP measure that is computed by subtracting the effect of current year catastrophe losses and prior year reserve development from net loss and LAE. The Company uses underlying loss and LAE figures to analyze the Company's loss trends that may be impacted by current year catastrophe losses and prior year development on the Company's reserves. As discussed previously, these two items can have a significant impact on the Company's loss trends in a given period. The Company believes it is useful for investors to evaluate these components both separately and in the aggregate when reviewing the Company's performance. The most directly comparable GAAP measure is net loss and LAE. The underlying loss and LAE measure should not be considered a substitute for net loss and LAE and does not reflect the overall profitability of the Company's business.
Book value per common share, excluding the impact of accumulated other comprehensive loss (underlying book value per common share), is a non-GAAP measure that is computed by dividing common stockholders' equity after excluding accumulated other comprehensive loss, by total common shares outstanding plus dilutive potential common shares outstanding. The Company uses the trend in book value per common share, excluding the impact of accumulated other comprehensive loss, in conjunction with book value per common share to identify and analyze the change in net worth attributable to management efforts between periods. The Company believes this
8
Exhibit 99.1
non-GAAP measure is useful to investors because it eliminates the effect of interest rates that can fluctuate significantly from period to period and are generally driven by economic and financial factors that are not influenced by management. Book value per common share is the most directly comparable GAAP measure. Book value per common share, excluding the impact of accumulated other comprehensive loss, should not be considered a substitute for book value per common share and does not reflect the recorded net worth of the Company's business.
9
Exhibit 99.1
Conference Call Details
Date and Time: August 8, 2022 - 5:00 P.M. ET
Participant Dial-In: (United States): 877-445-9755
(International): 201-493-6744
Webcast: To listen to the live webcast, please go to http://investors.upcinsurance.com and click on the conference call link at the top of the page or go to: https://event.webcasts.com/starthere.jsp?ei=1558133&tp_key=d91498dcef
An archive of the webcast will be available for a limited period of time thereafter.
Presentation: The information in this press release should be read in conjunction with an investor presentation that is available on the Company's website at investors.upcinsurance.com/Presentations.
About UPC Insurance
Founded in 1999, UPC Insurance is an insurance holding company that sources, writes and services personal and commercial residential property and casualty insurance policies using a group of wholly owned insurance subsidiaries and one majority owned insurance subsidiary through a variety of distribution channels. The Company currently writes policies in Florida, Louisiana, New York, and Texas. The Company also writes policies in Georgia, South Carolina and North Carolina, where renewal rights have been sold and all premiums and losses are ceded. From its headquarters in St. Petersburg, UPC Insurance's team of dedicated professionals manages a completely integrated insurance company, including sales, underwriting, customer service and claims.
Forward-Looking Statements
Statements made in this press release, or on the conference call identified above, and otherwise, that are not historical facts are “forward-looking statements”. The Company believes these statements are based on reasonable estimates, assumptions and plans. However, if the estimates, assumptions, or plans underlying the forward-looking statements prove inaccurate or if other risks or uncertainties arise, actual results could differ materially from those expressed in, or implied by, the forward-looking statements. These statements are made subject to the safe-harbor provisions of the Private Securities Litigation Reform Act of 1995. These forward-looking statements do not relate strictly to historical or current facts and may be identified by their use of words such as “may,” “will,” “expect,” "endeavor," "project," “believe,” "plan," “anticipate,” “intend,” “could,” “would,” “estimate” or “continue” or the negative variations thereof or comparable terminology. Factors that could cause actual results to differ materially may be found in the Company's filings with the U.S. Securities and Exchange Commission, in the “Risk Factors” section in the Company's most recent Annual Report on Form 10-K and subsequent Quarterly Reports on Form 10-Q. Forward-looking statements speak only as of the date on which they are made, and, except as required by applicable law, the Company undertakes no obligation to update or revise any forward-looking statements.
### #### ###
| CONTACT: | OR | INVESTOR RELATIONS: | ||||||||||||
| United Insurance Holdings Corp. | The Equity Group | |||||||||||||
| Jessica Barclay | Karin Daly | |||||||||||||
| Deputy CFO | Vice President | |||||||||||||
| (727) 895-7737 / [email protected] | (212) 836-9623 / [email protected] | |||||||||||||
10
Exhibit 99.1
Consolidated Statements of Comprehensive Loss
In thousands, except share and per share amounts
| Three Months Ended | Six Months Ended | |||||||||||||||||||||||||
| June 30, | June 30, | |||||||||||||||||||||||||
| 2022 | 2021 | 2022 | 2021 | |||||||||||||||||||||||
| REVENUE: | ||||||||||||||||||||||||||
| Gross premiums written | $ | 360,146 | $ | 426,424 | $ | 639,621 | $ | 738,062 | ||||||||||||||||||
| Change in gross unearned premiums | (54,388) | (69,991) | (14,657) | (24,966) | ||||||||||||||||||||||
| Gross premiums earned | 305,758 | 356,433 | 624,964 | 713,096 | ||||||||||||||||||||||
| Ceded premiums earned | (194,353) | (210,973) | (412,702) | (421,687) | ||||||||||||||||||||||
| Net premiums earned | 111,405 | 145,460 | 212,262 | 291,409 | ||||||||||||||||||||||
| Net investment income | 3,140 | 3,683 | 5,618 | 7,266 | ||||||||||||||||||||||
| Net realized investment gains (losses) | (78) | (124) | (1,847) | 379 | ||||||||||||||||||||||
| Net unrealized gains (losses) on equity securities | (5,084) | 2,438 | (7,352) | 5,002 | ||||||||||||||||||||||
| Other revenue | 6,410 | 3,997 | 9,478 | 13,187 | ||||||||||||||||||||||
| Total revenues | $ | 115,793 | $ | 155,454 | $ | 218,159 | $ | 317,243 | ||||||||||||||||||
| EXPENSES: | ||||||||||||||||||||||||||
| Losses and loss adjustment expenses | 90,074 | 118,064 | 181,442 | 233,845 | ||||||||||||||||||||||
| Policy acquisition costs | 28,988 | 41,327 | 55,004 | 82,148 | ||||||||||||||||||||||
| Operating expenses | 13,019 | 13,482 | 25,267 | 26,704 | ||||||||||||||||||||||
| General and administrative expenses | 14,494 | 13,112 | 30,499 | 28,994 | ||||||||||||||||||||||
| Interest expense | 2,394 | 2,257 | 4,773 | 4,632 | ||||||||||||||||||||||
| Total expenses | 148,969 | 188,242 | 296,985 | 376,323 | ||||||||||||||||||||||
| Loss before other income | (33,176) | (32,788) | (78,826) | (59,080) | ||||||||||||||||||||||
| Other income | 271 | 15 | 1,614 | 25 | ||||||||||||||||||||||
| Loss before income taxes | (32,905) | (32,773) | (77,212) | (59,055) | ||||||||||||||||||||||
| Provision (benefit) for income taxes | 36,150 | (9,352) | 25,100 | (17,174) | ||||||||||||||||||||||
| Net Loss | $ | (69,055) | $ | (23,421) | $ | (102,312) | $ | (41,881) | ||||||||||||||||||
| Less: Net income (loss) attributable to noncontrolling interests | (26) | 89 | (111) | (600) | ||||||||||||||||||||||
| Net loss attributable to UIHC | $ | (69,029) | $ | (23,510) | $ | (102,201) | $ | (41,281) | ||||||||||||||||||
| OTHER COMPREHENSIVE INCOME (LOSS): | ||||||||||||||||||||||||||
| Change in net unrealized gains (losses) on investments | (16,590) | 8,242 | (44,279) | (13,497) | ||||||||||||||||||||||
| Reclassification adjustment for net realized investment losses (gains) | 78 | 124 | 1,847 | (379) | ||||||||||||||||||||||
| Income tax benefit (expense) related to items of other comprehensive income (loss) | (6,187) | (2,012) | 49 | 3,364 | ||||||||||||||||||||||
| Total comprehensive loss | $ | (91,754) | $ | (17,067) | $ | (144,695) | $ | (52,393) | ||||||||||||||||||
| Less: Comprehensive income (loss) attributable to noncontrolling interests | 479 | 160 | (164) | (757) | ||||||||||||||||||||||
| Comprehensive loss attributable to UIHC | $ | (92,233) | $ | (17,227) | $ | (144,531) | $ | (51,636) | ||||||||||||||||||
| Weighted average shares outstanding | ||||||||||||||||||||||||||
| Basic | 43,049,227 | 42,950,666 | 43,015,114 | 42,924,662 | ||||||||||||||||||||||
| Diluted | 43,049,227 | 42,950,666 | 43,015,114 | 42,924,662 | ||||||||||||||||||||||
| Earnings available to UIHC common stockholders per share | ||||||||||||||||||||||||||
| Basic | $ | (1.60) | $ | (0.55) | $ | (2.38) | $ | (0.96) | ||||||||||||||||||
| Diluted | $ | (1.60) | $ | (0.55) | $ | (2.38) | $ | (0.96) | ||||||||||||||||||
| Dividends declared per share | $ | — | $ | 0.06 | $ | 0.06 | $ | 0.12 | ||||||||||||||||||
11
Exhibit 99.1
Consolidated Balance Sheets
In thousands, except share amounts
| June 30, 2022 | December 31, 2021 | |||||||||||||
| ASSETS | ||||||||||||||
| Investments, at fair value: | ||||||||||||||
| Fixed maturities, available-for-sale | $ | 527,091 | $ | 663,602 | ||||||||||
| Equity securities | 37,552 | 37,958 | ||||||||||||
| Other investments | 16,590 | 18,006 | ||||||||||||
| Total investments | $ | 581,233 | $ | 719,566 | ||||||||||
| Cash and cash equivalents | 283,785 | 212,024 | ||||||||||||
| Restricted cash | 33,361 | 33,254 | ||||||||||||
| Accrued investment income | 3,096 | 3,296 | ||||||||||||
| Property and equipment, net | 27,890 | 31,561 | ||||||||||||
| Premiums receivable, net | 101,546 | 79,166 | ||||||||||||
| Reinsurance recoverable on paid and unpaid losses | 757,511 | 997,120 | ||||||||||||
| Ceded unearned premiums | 502,664 | 430,631 | ||||||||||||
| Goodwill | 73,045 | 73,045 | ||||||||||||
| Deferred policy acquisition costs | 77,191 | 38,520 | ||||||||||||
| Intangible assets, net | 16,751 | 18,375 | ||||||||||||
| Other assets | 35,981 | 62,015 | ||||||||||||
| Total Assets | $ | 2,494,054 | $ | 2,698,573 | ||||||||||
| LIABILITIES AND STOCKHOLDERS' EQUITY | ||||||||||||||
| Liabilities: | ||||||||||||||
| Unpaid losses and loss adjustment expenses | $ | 849,994 | $ | 1,084,450 | ||||||||||
| Unearned premiums | 659,597 | 644,940 | ||||||||||||
| Reinsurance payable on premiums | 437,684 | 248,625 | ||||||||||||
| Payments outstanding | 108,963 | 114,524 | ||||||||||||
| Accounts payable and accrued expenses | 68,565 | 76,258 | ||||||||||||
| Operating lease liability | 1,600 | 1,934 | ||||||||||||
| Other liabilities | 44,711 | 39,324 | ||||||||||||
| Notes payable, net | 155,968 | 156,561 | ||||||||||||
| Total Liabilities | $ | 2,327,082 | $ | 2,366,616 | ||||||||||
| Commitments and contingencies | ||||||||||||||
| Stockholders' Equity: | ||||||||||||||
| Preferred stock, $0.0001 par value; 1,000,000 authorized; none issued or outstanding | — | — | ||||||||||||
Common stock, $0.0001 par value; 100,000,000 shares authorized; 43,525,249 and 43,360,429 issued, respectively; 43,313,166 and 43,370,442 outstanding, respectively | 4 | 4 | ||||||||||||
| Additional paid-in capital | 394,902 | 394,268 | ||||||||||||
| Treasury shares, at cost; 212,083 shares | (431) | (431) | ||||||||||||
| Accumulated other comprehensive loss | (48,861) | (6,531) | ||||||||||||
| Retained earnings (deficit) | (178,642) | (74,904) | ||||||||||||
| Total stockholders' equity attributable to UIHC stockholders | $ | 166,972 | $ | 312,406 | ||||||||||
| Noncontrolling interests | — | 19,551 | ||||||||||||
| Total Stockholders' Equity | $ | 166,972 | $ | 331,957 | ||||||||||
| Total Liabilities and Stockholders' Equity | $ | 2,494,054 | $ | 2,698,573 | ||||||||||
12
United Insurance Holdings Corporation (Nasdaq: UIHC) Investor Presentation August 8th, 2022
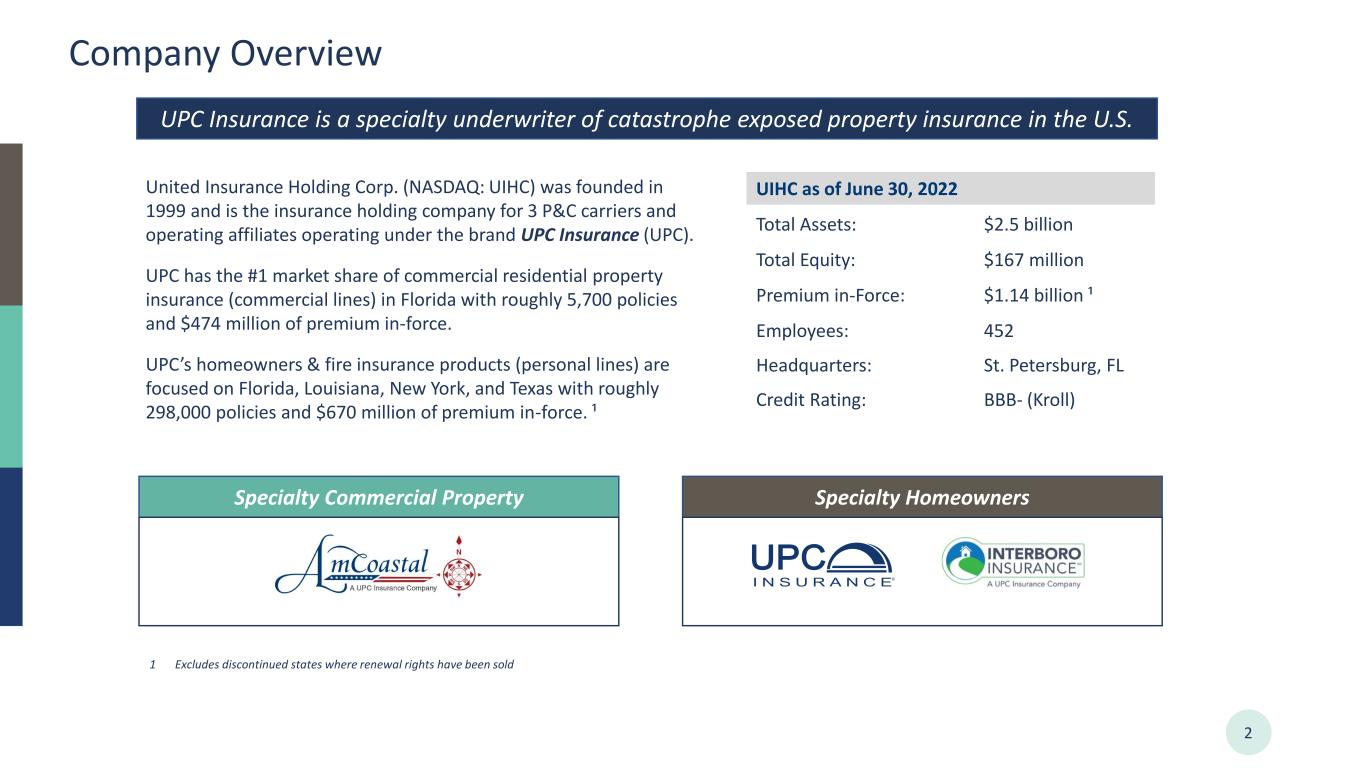
Company Overview 2 UPC Insurance is a specialty underwriter of catastrophe exposed property insurance in the U.S. United Insurance Holding Corp. (NASDAQ: UIHC) was founded in 1999 and is the insurance holding company for 3 P&C carriers and operating affiliates operating under the brand UPC Insurance (UPC). UPC has the #1 market share of commercial residential property insurance (commercial lines) in Florida with roughly 5,700 policies and $474 million of premium in-force. UPC’s homeowners & fire insurance products (personal lines) are focused on Florida, Louisiana, New York, and Texas with roughly 298,000 policies and $670 million of premium in-force. ¹ UIHC as of June 30, 2022 Total Assets: $2.5 billion Total Equity: $167 million Premium in-Force: $1.14 billion ¹ Employees: 452 Headquarters: St. Petersburg, FL Credit Rating: BBB- (Kroll) 1 Excludes discontinued states where renewal rights have been sold Specialty Commercial Property Specialty Homeowners
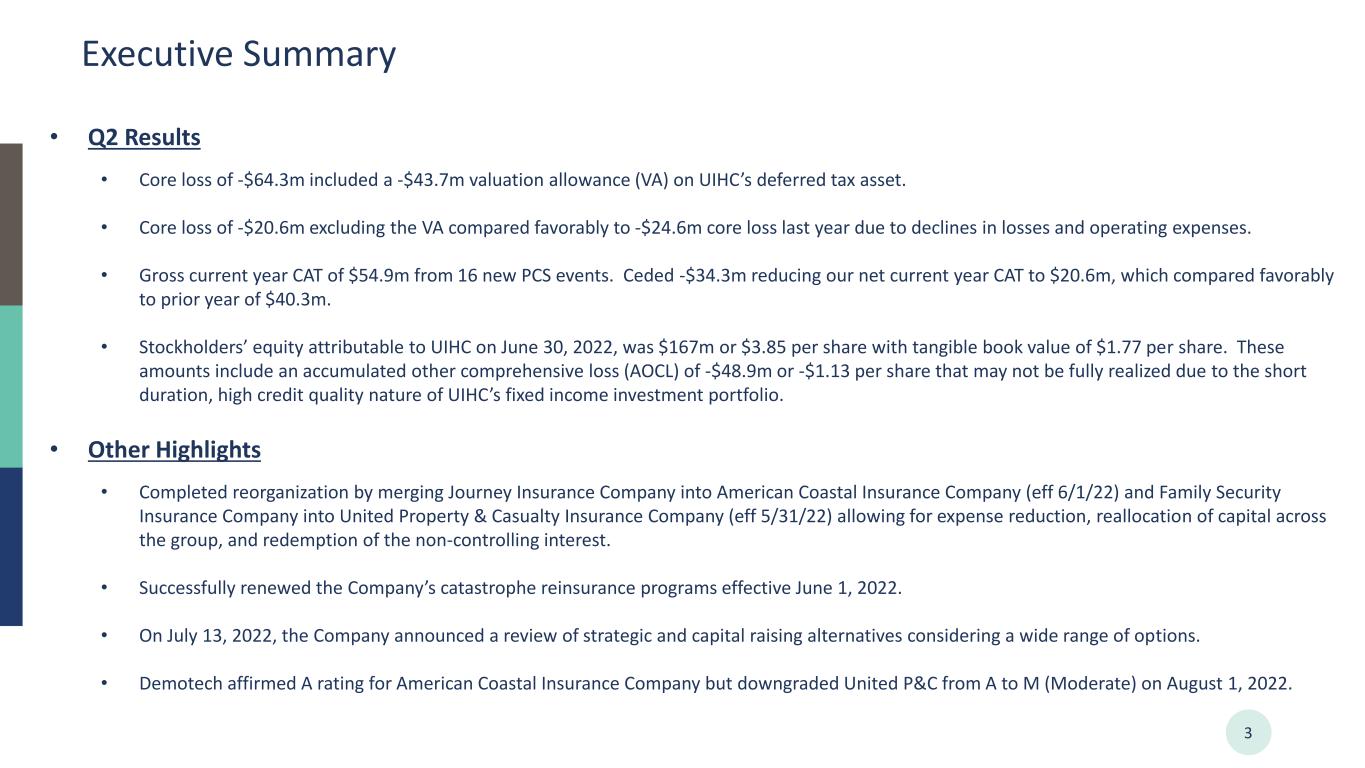
3 Executive Summary • Q2 Results • Core loss of -$64.3m included a -$43.7m valuation allowance (VA) on UIHC’s deferred tax asset. • Core loss of -$20.6m excluding the VA compared favorably to -$24.6m core loss last year due to declines in losses and operating expenses. • Gross current year CAT of $54.9m from 16 new PCS events. Ceded -$34.3m reducing our net current year CAT to $20.6m, which compared favorably to prior year of $40.3m. • Stockholders’ equity attributable to UIHC on June 30, 2022, was $167m or $3.85 per share with tangible book value of $1.77 per share. These amounts include an accumulated other comprehensive loss (AOCL) of -$48.9m or -$1.13 per share that may not be fully realized due to the short duration, high credit quality nature of UIHC’s fixed income investment portfolio. • Other Highlights • Completed reorganization by merging Journey Insurance Company into American Coastal Insurance Company (eff 6/1/22) and Family Security Insurance Company into United Property & Casualty Insurance Company (eff 5/31/22) allowing for expense reduction, reallocation of capital across the group, and redemption of the non-controlling interest. • Successfully renewed the Company’s catastrophe reinsurance programs effective June 1, 2022. • On July 13, 2022, the Company announced a review of strategic and capital raising alternatives considering a wide range of options. • Demotech affirmed A rating for American Coastal Insurance Company but downgraded United P&C from A to M (Moderate) on August 1, 2022.
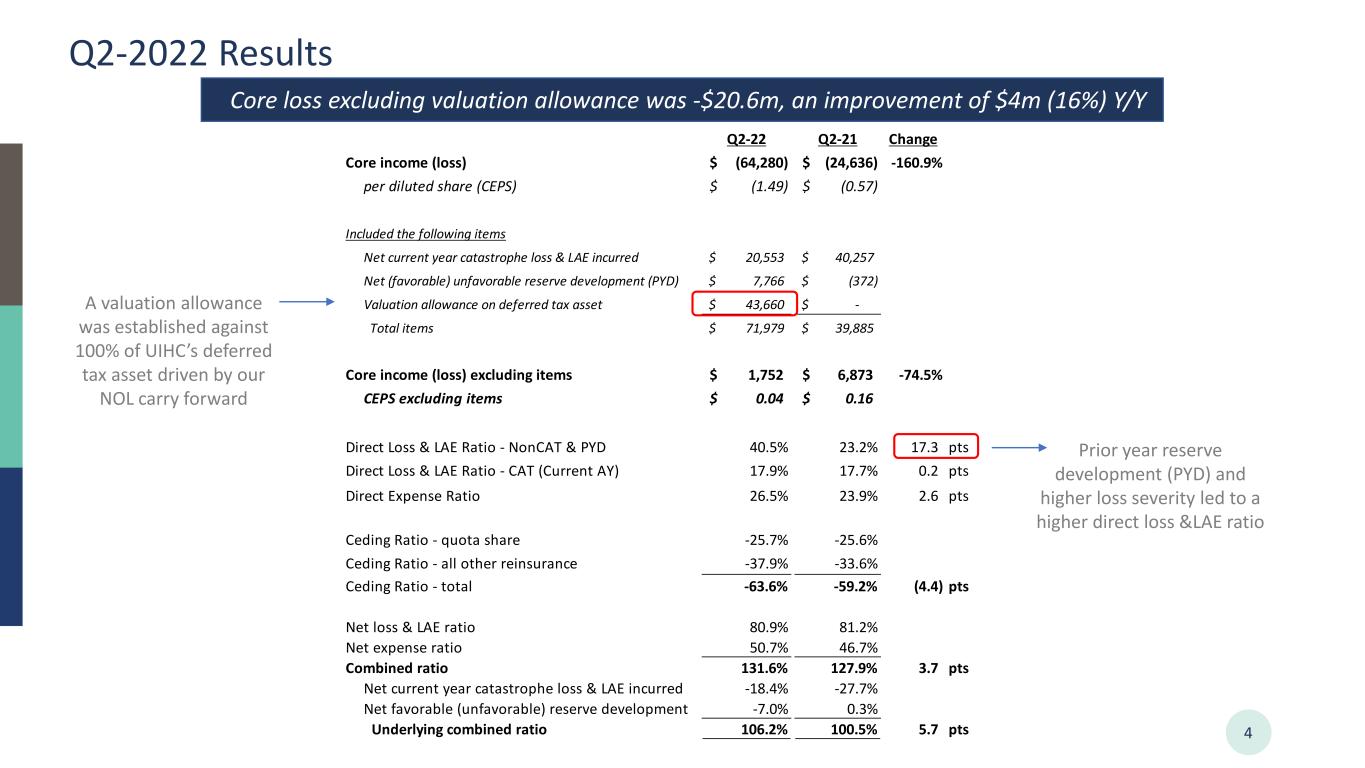
Q2-2022 Results 4 Core loss excluding valuation allowance was -$20.6m, an improvement of $4m (16%) Y/Y A valuation allowance was established against 100% of UIHC’s deferred tax asset driven by our NOL carry forward Prior year reserve development (PYD) and higher loss severity led to a higher direct loss &LAE ratio Q2-22 Q2-21 Change Core income (loss) (64,280)$ (24,636)$ -160.9% per diluted share (CEPS) (1.49)$ (0.57)$ Included the following items Net current year catastrophe loss & LAE incurred 20,553$ 40,257$ Net (favorable) unfavorable reserve development (PYD) 7,766$ (372)$ Valuation allowance on deferred tax asset 43,660$ -$ Total items 71,979$ 39,885$ Core income (loss) excluding items 1,752$ 6,873$ -74.5% CEPS excluding items 0.04$ 0.16$ Direct Loss & LAE Ratio - NonCAT & PYD 40.5% 23.2% 17.3 pts Direct Loss & LAE Ratio - CAT (Current AY) 17.9% 17.7% 0.2 pts Direct Expense Ratio 26.5% 23.9% 2.6 pts Ceding Ratio - quota share -25.7% -25.6% Ceding Ratio - all other reinsurance -37.9% -33.6% Ceding Ratio - total -63.6% -59.2% (4.4) pts Net loss & LAE ratio 80.9% 81.2% Net expense ratio 50.7% 46.7% Combined ratio 131.6% 127.9% 3.7 pts Net current year catastrophe loss & LAE incurred -18.4% -27.7% Net favorable (unfavorable) reserve development -7.0% 0.3% Underlying combined ratio 106.2% 100.5% 5.7 pts
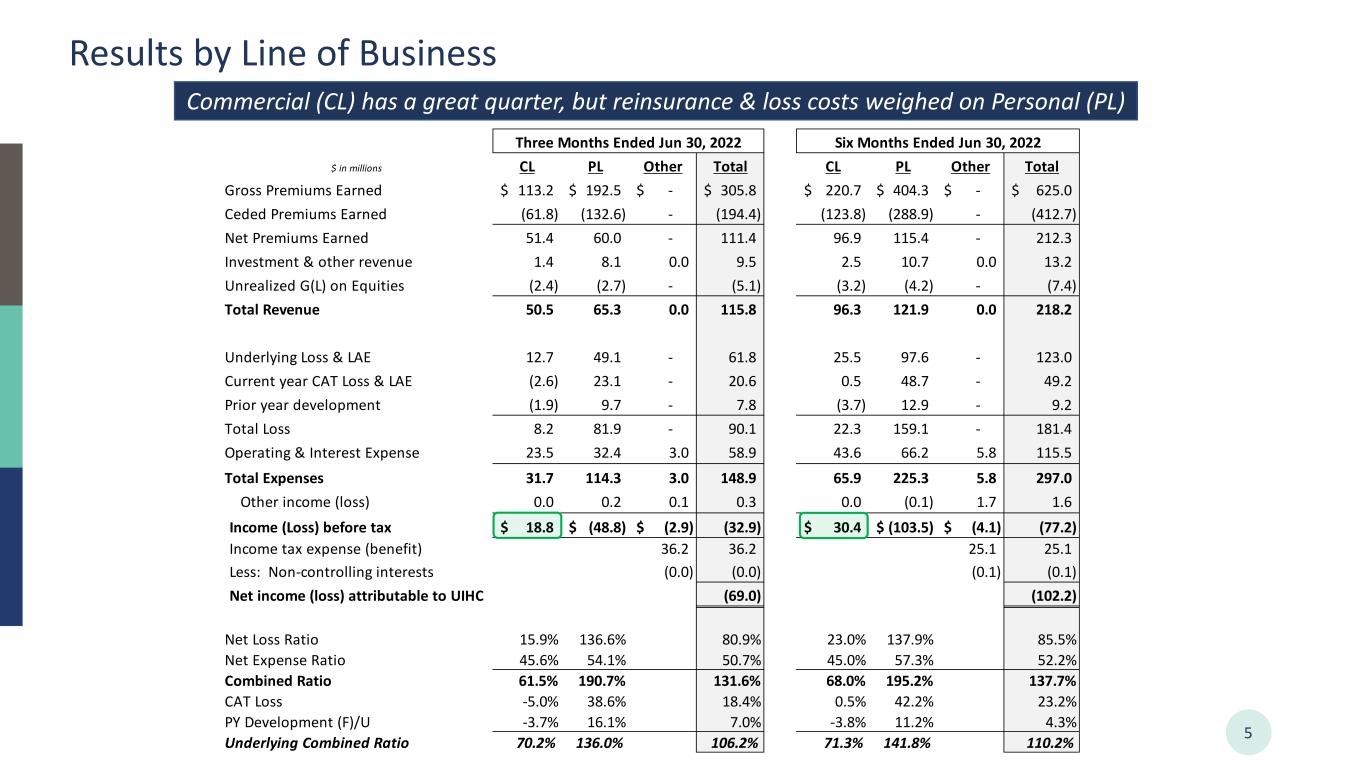
Results by Line of Business 5 Commercial (CL) has a great quarter, but reinsurance & loss costs weighed on Personal (PL) $ in millions CL PL Other Total CL PL Other Total Gross Premiums Earned 113.2$ 192.5$ -$ 305.8$ 220.7$ 404.3$ -$ 625.0$ Ceded Premiums Earned (61.8) (132.6) - (194.4) (123.8) (288.9) - (412.7) Net Premiums Earned 51.4 60.0 - 111.4 96.9 115.4 - 212.3 Investment & other revenue 1.4 8.1 0.0 9.5 2.5 10.7 0.0 13.2 Unrealized G(L) on Equities (2.4) (2.7) - (5.1) (3.2) (4.2) - (7.4) Total Revenue 50.5 65.3 0.0 115.8 96.3 121.9 0.0 218.2 Underlying Loss & LAE 12.7 49.1 - 61.8 25.5 97.6 - 123.0 Current year CAT Loss & LAE (2.6) 23.1 - 20.6 0.5 48.7 - 49.2 Prior year development (1.9) 9.7 - 7.8 (3.7) 12.9 - 9.2 Total Loss 8.2 81.9 - 90.1 22.3 159.1 - 181.4 Operating & Interest Expense 23.5 32.4 3.0 58.9 43.6 66.2 5.8 115.5 Total Expenses 31.7 114.3 3.0 148.9 65.9 225.3 5.8 297.0 Other income (loss) 0.0 0.2 0.1 0.3 0.0 (0.1) 1.7 1.6 Income (Loss) before tax 18.8$ (48.8)$ (2.9)$ (32.9) 30.4$ (103.5)$ (4.1)$ (77.2) Income tax expense (benefit) 36.2 36.2 25.1 25.1 Less: Non-controlling interests (0.0) (0.0) (0.1) (0.1) Net income (loss) attributable to UIHC (69.0) (102.2) Net Loss Ratio 15.9% 136.6% 80.9% 23.0% 137.9% 85.5% Net Expense Ratio 45.6% 54.1% 50.7% 45.0% 57.3% 52.2% Combined Ratio 61.5% 190.7% 131.6% 68.0% 195.2% 137.7% CAT Loss -5.0% 38.6% 18.4% 0.5% 42.2% 23.2% PY Development (F)/U -3.7% 16.1% 7.0% -3.8% 11.2% 4.3% Underlying Combined Ratio 70.2% 136.0% 106.2% 71.3% 141.8% 110.2% Three Months Ended Jun 30, 2022 Six Months Ended Jun 30, 2022
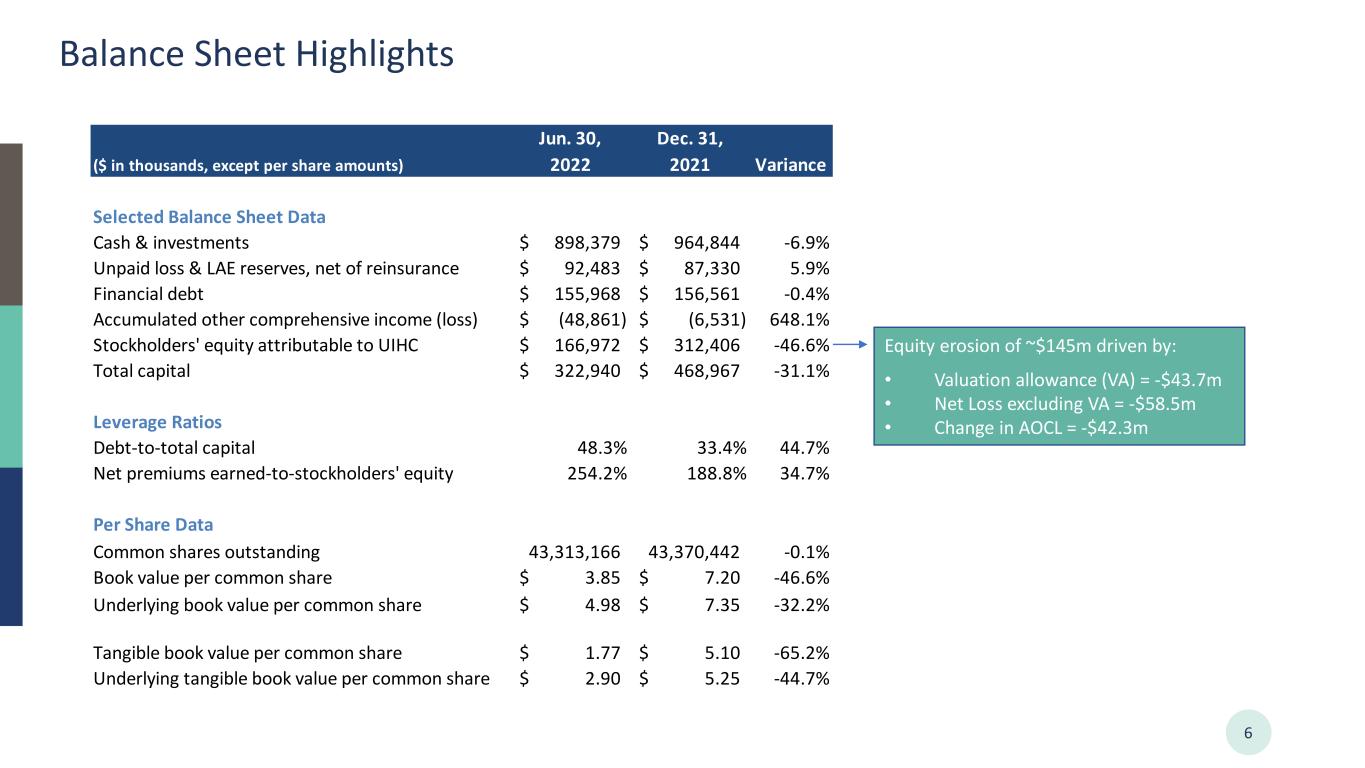
Balance Sheet Highlights 6 Equity erosion of ~$145m driven by: • Valuation allowance (VA) = -$43.7m • Net Loss excluding VA = -$58.5m • Change in AOCL = -$42.3m Jun. 30, Dec. 31, ($ in thousands, except per share amounts) 2022 2021 Variance Selected Balance Sheet Data Cash & investments 898,379$ 964,844$ -6.9% Unpaid loss & LAE reserves, net of reinsurance 92,483$ 87,330$ 5.9% Financial debt 155,968$ 156,561$ -0.4% Accumulated other comprehensive income (loss) (48,861)$ (6,531)$ 648.1% Stockholders' equity attributable to UIHC 166,972$ 312,406$ -46.6% Total capital 322,940$ 468,967$ -31.1% Leverage Ratios Debt-to-total capital 48.3% 33.4% 44.7% Net premiums earned-to-stockholders' equity 254.2% 188.8% 34.7% Per Share Data Common shares outstanding 43,313,166 43,370,442 -0.1% Book value per common share 3.85$ 7.20$ -46.6% Underlying book value per common share 4.98$ 7.35$ -32.2% Tangible book value per common share 1.77$ 5.10$ -65.2% Underlying tangible book value per common share 2.90$ 5.25$ -44.7%
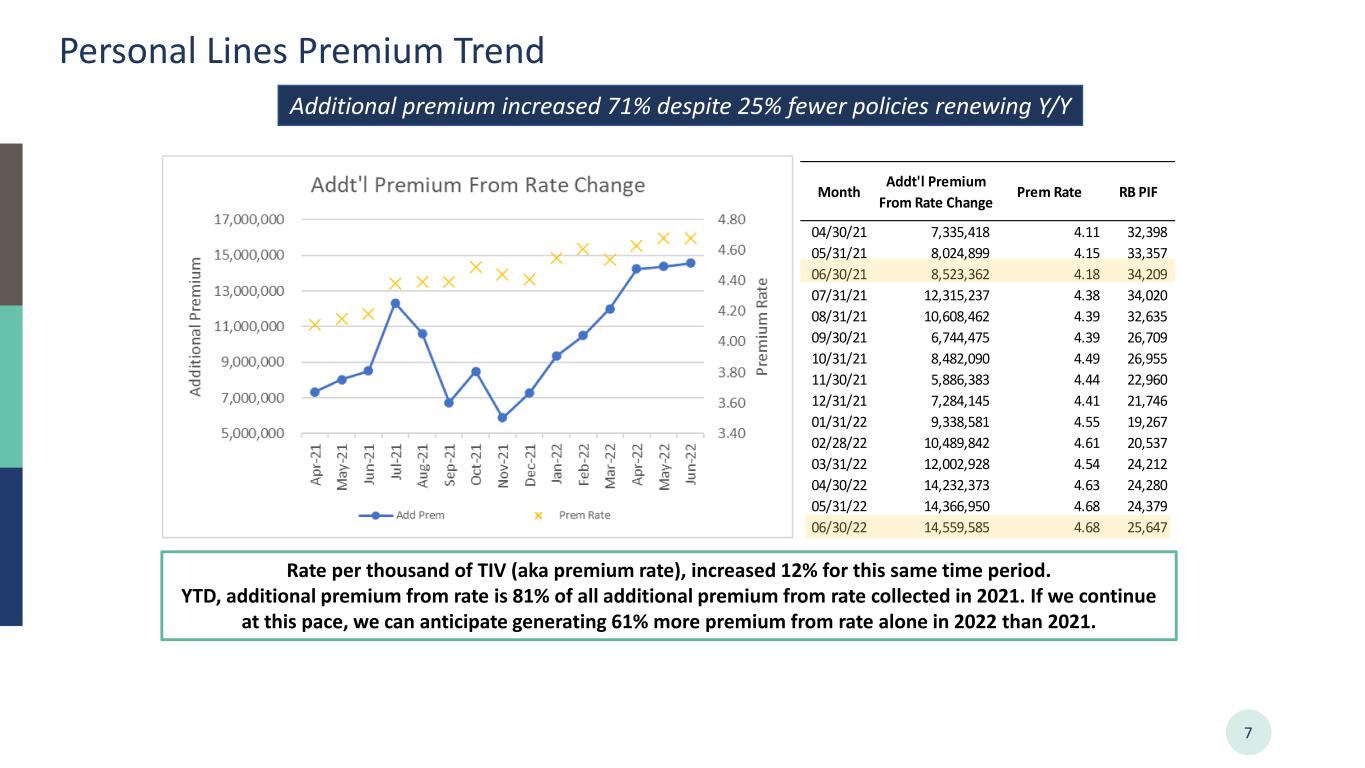
Personal Lines Premium Trend 7 Additional premium increased 71% despite 25% fewer policies renewing Y/Y Month Addt'l Premium From Rate Change Prem Rate RB PIF 04/30/21 7,335,418 4.11 32,398 05/31/21 8,024,899 4.15 33,357 06/30/21 8,523,362 4.18 34,209 07/31/21 12,315,237 4.38 34,020 08/31/21 10,608,462 4.39 32,635 09/30/21 6,744,475 4.39 26,709 10/31/21 8,482,090 4.49 26,955 11/30/21 5,886,383 4.44 22,960 12/31/21 7,284,145 4.41 21,746 01/31/22 9,338,581 4.55 19,267 02/28/22 10,489,842 4.61 20,537 03/31/22 12,002,928 4.54 24,212 04/30/22 14,232,373 4.63 24,280 05/31/22 14,366,950 4.68 24,379 06/30/22 14,559,585 4.68 25,647 Rate per thousand of TIV (aka premium rate), increased 12% for this same time period. YTD, additional premium from rate is 81% of all additional premium from rate collected in 2021. If we continue at this pace, we can anticipate generating 61% more premium from rate alone in 2022 than 2021.
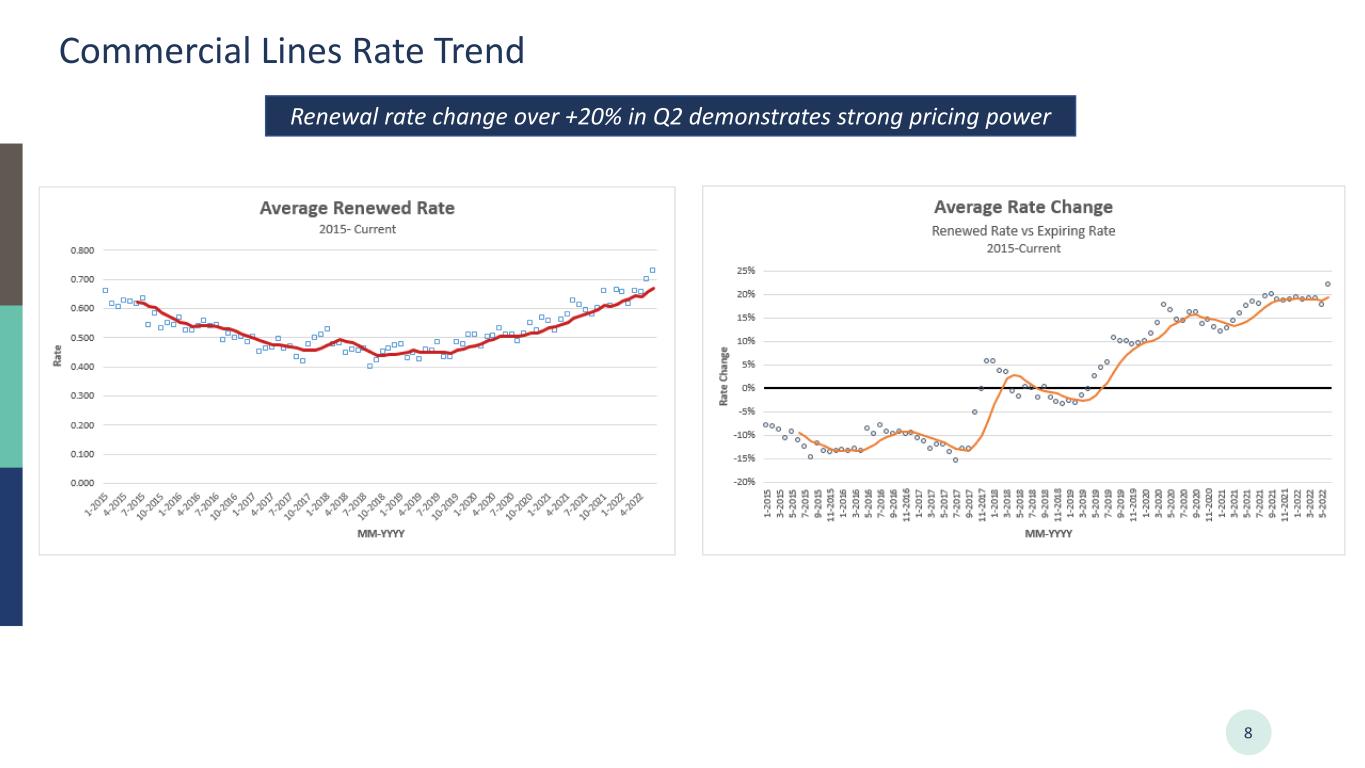
Commercial Lines Rate Trend 8 Renewal rate change over +20% in Q2 demonstrates strong pricing power
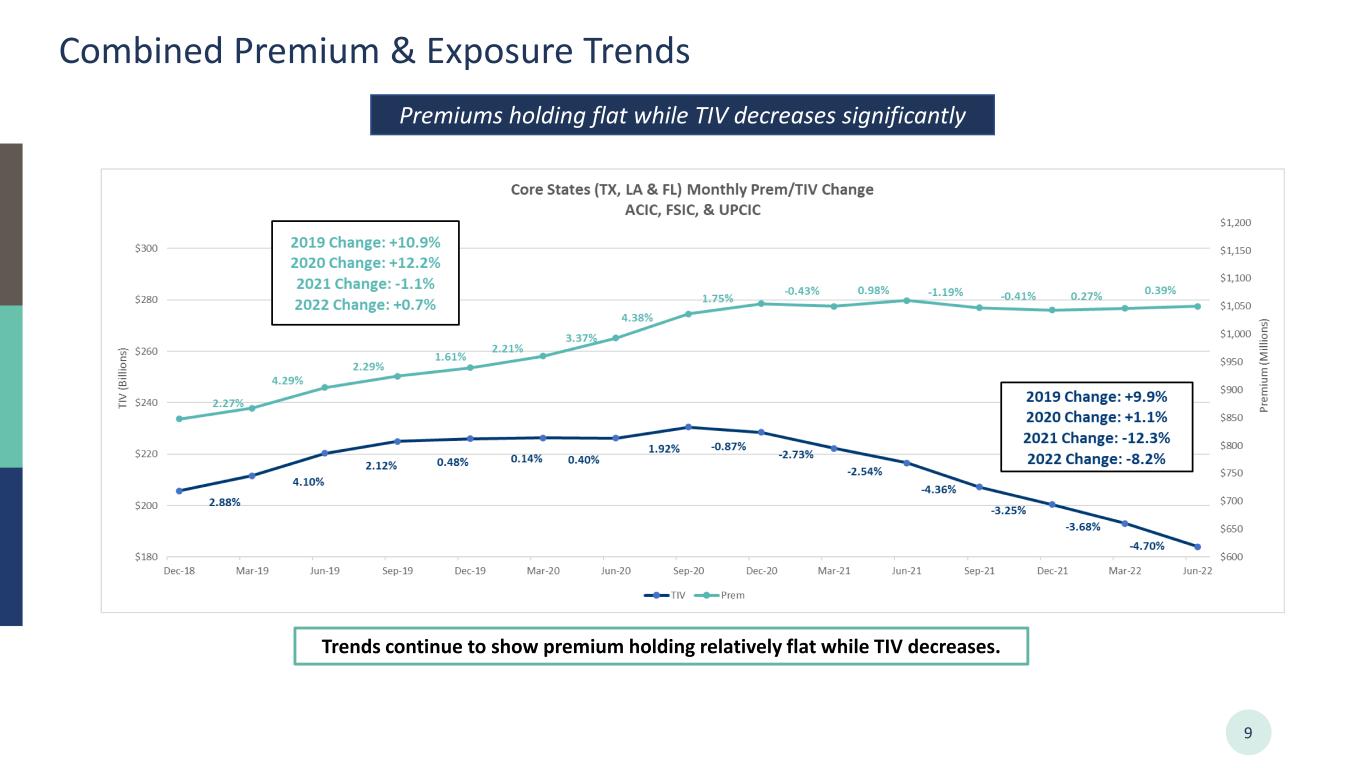
Combined Premium & Exposure Trends 9 Premiums holding flat while TIV decreases significantly Trends continue to show premium holding relatively flat while TIV decreases.
Cautionary Statements 10 This presentation contains "forward-looking statements" within the meaning of the Private Securities Litigation Reform Act of 1995. These forward looking statements include expectations regarding our diversification, growth opportunities, retention rates, liquidity, investment returns and our ability to meet our investment objectives and to manage and mitigate market risk with respect to our investments. These statements are based on current expectations, estimates and projections about the industry and market in which we operate, and management's beliefs and assumptions. Without limiting the generality of the foregoing, words such as "may," "will," "expect," "endeavor," "project," "believe," "anticipate," "intend," "could," "would," "estimate," or "continue" or the negative variations thereof, or comparable terminology, are intended to identify forward-looking statements. Forward-looking statements are not guarantees of future performance and involve certain known and unknown risks and uncertainties that could cause actual results to differ materially from those expressed or implied by such statements. The risks and uncertainties include, without limitation: the regulatory, economic and weather conditions in the states in which we operate; the impact of new federal or state regulations that affect the property and casualty insurance market; the cost, variability and availability of reinsurance; assessments charged by various governmental agencies; pricing competition and other initiatives by competitors; our ability to attract and retain the services of senior management; the outcome of litigation pending against us, including the terms of any settlements; dependence on investment income and the composition of our investment portfolio and related market risks; our exposure to catastrophic events and severe weather conditions; downgrades in our financial strength ratings; risks and uncertainties relating to our acquisitions including our ability to successfully integrate the acquired companies; and other risks and uncertainties described in the section entitled "Risk Factors" and elsewhere in our filings with the Securities and Exchange Commission (the "SEC"), including our Annual Report in Form 10-K for the year ended December 31, 2020 and 2021 and our Form 10-Q for the periods ending March 31, 2021, June 30, 2021, September 30, 2021, March 31, 2022, and June 30, 2022 once available. We caution you not to place undue reliance on these forward looking statements, which are valid only as of the date they were made. Except as may be required by applicable law, we undertake no obligation to update or revise any forward-looking statements to reflect new information, the occurrence of unanticipated events, or otherwise. This presentation contains certain non-GAAP financial measures. See our earnings release, Form 10-K ,and Form 10-Q for further information regarding these non-GAAP financial measures. The information in this presentation is confidential. Any photocopying, disclosure, reproduction or alteration of the contents of this presentation and any forwarding of a copy of this presentation or any portion of this presentation to any person is prohibited.