
CFG 8-K
Citizens Financial Group Inc/Ri (CFG)
8-K
2026-04-16
For: 2026-04-16
View Original
Added on
April 16, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d)
OF THE SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported): April 16, 2026
(Exact name of the registrant as specified in its charter)
| (State or Other Jurisdiction of Incorporation) | (Commission File Number) | (I.R.S. Employer Identification Number) | |||||||||
| (Address of principal executive offices) | (Zip Code) | ||||||||||
Registrant’s telephone number, including area code: (203 ) 900-6715
Not Applicable
(Former name or former address, if changed since last report.)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 under the Securities Act (17 CFR 230.405) or Rule 12b-2 under the Exchange Act (17 CFR 240.12b-2).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition.
On April 16, 2026, Citizens Financial Group, Inc. (the “Company”) issued a press release announcing its first quarter 2026 earnings and posted on its website the press release and a financial supplement. Copies of the press release and financial supplement are being furnished as Exhibits 99.1 and 99.3, respectively.
Item 7.01 Regulation FD Disclosure.
For the benefit of investors, the Company has posted on its website an investor presentation in connection with its earnings conference call. A copy of the investor presentation is being furnished as Exhibit 99.2.
The information in this Form 8-K and Exhibits attached hereto are being furnished pursuant to Items 2.02 and 7.01, respectively, and shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, nor shall this information be deemed incorporated by reference into any filings under the Securities Act of 1933, as amended.
Item 9.01 Financial Statements and Exhibits.
| Exhibit Number | Description | ||||||||||
| (d) | Exhibit 99.1 | ||||||||||
| Exhibit 99.2 | |||||||||||
| Exhibit 99.3 | |||||||||||
| Exhibit 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | ||||||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| CITIZENS FINANCIAL GROUP, INC. | ||||||||
| By: | /s/ Aunoy Banerjee | |||||||
| Aunoy Banerjee | ||||||||
| Executive Vice President and Chief Financial Officer | ||||||||
Date: April 16, 2026
Citizens Financial Group, Inc. Reports First Quarter 2026 Net Income of
$517 million, up 39% YoY, and EPS of $1.13, up 47% YoY
Positive Operating Leverage of 7.2% YoY
| Key Financial Data | 1Q26 | 4Q25 | 1Q25 | First Quarter 2026 Highlights | ||||||||||||||||||||||
| Income Statement | ($s in millions) | ■EPS of $1.13; ROTCE of 12.2% –Continued strong Private Bank progress, contributing $0.11 to EPS ■PPNR of $790 million, down 3% QoQ, up 27% YoY –NII up 1.6% QoQ as NIM continues to expand, up 7 bps to 3.14%; NII up 12%, NIM up 24 bps YoY –Fees up 11% YoY driven by Capital Markets and Wealth; down 2% QoQ, reflecting seasonality and market dynamics –Positive operating leverage of 7.2% YoY ■Loans up 1% QoQ on a spot and average basis with growth led by Commercial and Private Bank –Lower Non-Core runoff and balance sheet optimization impacts ■Continuing favorable credit trends; net charge-offs of 39 bps, down 4 bps QoQ ■Strong ACL coverage of 1.52% ■Average deposits up 1% QoQ driven by growth in Private Bank –Private Bank spot deposits of $16.6 billion –Interest-bearing deposit costs down 16 bps QoQ ■Strong liquidity profile; spot LDR of 78.1% ■Strong CET1 ratio of 10.5%; 9.3% adjusted for AOCI opt-out removal ■TBV/share of $37.94 broadly stable QoQ | ||||||||||||||||||||||||
| Total revenue | $ | 2,168 | $ | 2,157 | $ | 1,935 | ||||||||||||||||||||
| Pre-provision profit | 790 | 814 | 621 | |||||||||||||||||||||||
| Provision for credit losses | 140 | 137 | 153 | |||||||||||||||||||||||
| Net income | 517 | 528 | 373 | |||||||||||||||||||||||
| Balance Sheet & Credit Quality | ($s in billions) | |||||||||||||||||||||||||
| Period-end loans and leases | $ | 143.7 | $ | 142.7 | $ | 137.6 | ||||||||||||||||||||
| Average loans and leases | 143.4 | 141.8 | 139.7 | |||||||||||||||||||||||
| Period-end deposits | 184.0 | 183.3 | 177.6 | |||||||||||||||||||||||
| Average deposits | 181.3 | 179.9 | 172.7 | |||||||||||||||||||||||
| Loan-to-deposit ratio (spot) | 78.1 | % | 77.8 | % | 77.5 | % | ||||||||||||||||||||
| NCO ratio | 0.39 | % | 0.43 | % | 0.58 | % | ||||||||||||||||||||
| Financial Metrics | Diluted EPS | $ | 1.13 | $ | 1.13 | $ | 0.77 | |||||||||||||||||||
| ROTCE | 12.2 | % | 12.2 | % | 9.6 | % | ||||||||||||||||||||
| Net interest margin, FTE | 3.14 | 3.07 | 2.90 | |||||||||||||||||||||||
| Efficiency ratio | 63.6 | 62.2 | 67.9 | |||||||||||||||||||||||
| CET1 | 10.5 | % | 10.6 | % | 10.6 | % | ||||||||||||||||||||
| TBV/Share | $ | 37.94 | $ | 38.07 | $ | 33.97 | ||||||||||||||||||||
| Comments from Chairman and CEO Bruce Van Saun | ||||||||
“We are pleased to get off to a strong start in 2026 notwithstanding heightened geopolitical tensions and uncertainty in the macro environment,” said Chairman and CEO Bruce Van Saun. “Our financial results in a seasonally soft quarter were good, with year-over-year EPS growth of 47%, positive operating leverage of 7%, NIM expansion of 7 bps sequentially and 24 bps versus a year ago, and a robust balance sheet position. Credit is trending favorably, the Private Bank continues to grow nicely, and Reimagine the Bank is off to a great start. We continue to be well-positioned to deliver a strong year and reach our medium-term targets.”
Citizens also announced today that its board of directors declared a quarterly common stock dividend of $0.46 per share. The dividend is payable on May 14, 2026 to shareholders of record at the close of business on April 30, 2026.
Citizens Financial Group, Inc.
Earnings highlights(1):
| Quarterly Trends | ||||||||||||||||||||||||||||||||
| 1Q26 change from | ||||||||||||||||||||||||||||||||
| ($s in millions, except per share data) | 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | |||||||||||||||||||||||||||
| Earnings | $/bps/% | % | $/bps/% | % | ||||||||||||||||||||||||||||
| Net interest income | $ | 1,562 | $ | 1,537 | $ | 1,391 | $ | 25 | 2 | % | $ | 171 | 12 | % | ||||||||||||||||||
| Noninterest income | 606 | 620 | 544 | (14) | (2) | 62 | 11 | |||||||||||||||||||||||||
| Total revenue | 2,168 | 2,157 | 1,935 | 11 | 1 | 233 | 12 | |||||||||||||||||||||||||
| Noninterest expense | 1,378 | 1,343 | 1,314 | 35 | 3 | 64 | 5 | |||||||||||||||||||||||||
| Pre-provision profit | 790 | 814 | 621 | (24) | (3) | 169 | 27 | |||||||||||||||||||||||||
| Provision for credit losses | 140 | 137 | 153 | 3 | 2 | (13) | (8) | |||||||||||||||||||||||||
| Net income | 517 | 528 | 373 | (11) | (2) | 144 | 39 | |||||||||||||||||||||||||
| Preferred dividends/other | 33 | 39 | 33 | (6) | (15) | — | — | |||||||||||||||||||||||||
| Net income available to common stockholders | $ | 484 | $ | 489 | $ | 340 | $ | (5) | (1) | % | $ | 144 | 42 | % | ||||||||||||||||||
| Average common shares outstanding | ||||||||||||||||||||||||||||||||
| Basic (in millions) | 425.3 | 429.5 | 438.3 | (4.1) | (1) | (13.0) | (3) | |||||||||||||||||||||||||
| Diluted (in millions) | 429.9 | 434.1 | 442.2 | (4.2) | (1) | (12.3) | (3) | |||||||||||||||||||||||||
| Diluted earnings per share | 1.13 | 1.13 | 0.77 | — | — | 0.36 | 47 | |||||||||||||||||||||||||
| Performance metrics | ||||||||||||||||||||||||||||||||
| Net interest margin | 3.14 | % | 3.06 | % | 2.89 | % | 8 | bps | 25 | bps | ||||||||||||||||||||||
| Net interest margin, FTE | 3.14 | 3.07 | 2.90 | 7 | 24 | |||||||||||||||||||||||||||
| Effective income tax rate | 20.5 | 22.0 | 20.3 | (157) | 20 | |||||||||||||||||||||||||||
| Efficiency ratio | 63.6 | 62.2 | 67.9 | 131 | (436) | |||||||||||||||||||||||||||
| Return on average tangible common equity | 12.2 | 12.2 | 9.6 | 1 | 255 | |||||||||||||||||||||||||||
| Return on average total tangible assets | 0.97 | % | 0.98 | % | 0.73 | % | (1) | bp | 24 | bps | ||||||||||||||||||||||
Capital adequacy(2,3) | ||||||||||||||||||||||||||||||||
| Common equity tier 1 capital ratio | 10.5 | % | 10.6 | % | 10.6 | % | ||||||||||||||||||||||||||
| Total capital ratio | 13.7 | 13.8 | 13.9 | |||||||||||||||||||||||||||||
| Tier 1 leverage ratio | 9.3 | 9.5 | 9.4 | |||||||||||||||||||||||||||||
| Tangible common equity ratio | 7.3 | 7.5 | 7.0 | |||||||||||||||||||||||||||||
| Allowance for credit losses to loans and leases | 1.52 | % | 1.53 | % | 1.61 | % | (1) | bp | (9) | bps | ||||||||||||||||||||||
Asset quality(3) | ||||||||||||||||||||||||||||||||
| Nonaccrual loans and leases to loans and leases | 1.04 | % | 1.05 | % | 1.15 | % | (1) | bp | (11) | bps | ||||||||||||||||||||||
| Allowance for credit losses to nonaccrual loans and leases | 146 | 145 | 140 | 1 | % | 6 | % | |||||||||||||||||||||||||
| Net charge-offs as a % of average loans and leases | 0.39 | % | 0.43 | % | 0.58 | % | (4) | bps | (19) | bps | ||||||||||||||||||||||
(1) Unless otherwise noted, references to balance sheet items are on an average basis, loans exclude loans held for sale, earnings per share
represent fully diluted per common share and references to NIM are on a FTE basis.
(2) Current reporting-period regulatory capital ratios are preliminary.
(3) Capital adequacy and asset-quality ratios calculated on a period-end basis, except net charge-offs.
2
Citizens Financial Group, Inc.
Consolidated balance sheet summary(1):
| 1Q26 change from | ||||||||||||||||||||||||||||||||||||||
| ($s in millions) | 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | |||||||||||||||||||||||||||||||||
| $/bps | % | $/bps | % | |||||||||||||||||||||||||||||||||||
| Total assets | $ | 227,918 | $ | 226,351 | $ | 220,148 | $ | 1,567 | 1 | % | $ | 7,770 | 4 | % | ||||||||||||||||||||||||
| Total loans and leases | 143,667 | 142,692 | 137,635 | 975 | 1 | 6,032 | 4 | |||||||||||||||||||||||||||||||
| Total loans held for sale | 1,537 | 1,198 | 2,820 | 339 | 28 | (1,283) | (45) | |||||||||||||||||||||||||||||||
| Deposits | 184,035 | 183,313 | 177,576 | 722 | — | 6,459 | 4 | |||||||||||||||||||||||||||||||
| Stockholders' equity | 26,172 | 26,317 | 24,866 | (145) | (1) | 1,306 | 5 | |||||||||||||||||||||||||||||||
| Stockholders' common equity | 24,061 | 24,206 | 22,753 | (145) | (1) | 1,308 | 6 | |||||||||||||||||||||||||||||||
| Tangible common equity | $ | 16,165 | $ | 16,341 | $ | 14,867 | $ | (176) | (1) | % | $ | 1,298 | 9 | % | ||||||||||||||||||||||||
Loan-to-deposit ratio (period-end)(2) | 78.1 | % | 77.8 | % | 77.5 | % | 23 | bps | 56 | bps | ||||||||||||||||||||||||||||
Loan-to-deposit ratio (average)(2) | 79.1 | % | 78.8 | % | 80.9 | % | 27 | bps | (180) | bps | ||||||||||||||||||||||||||||
| (1) Represents period-end unless otherwise noted. | ||||||||||||||||||||||||||||||||||||||
| (2) Excludes loans held for sale. | ||||||||||||||||||||||||||||||||||||||
3
Citizens Financial Group, Inc.
Discussion of results:
| Net interest income | 1Q26 change from | |||||||||||||||||||||||||||||||||||||||||||
| ($s in millions) | 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | |||||||||||||||||||||||||||||||||||||||
| $/bps | % | $/bps | % | |||||||||||||||||||||||||||||||||||||||||
| Interest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans and leases and loans held for sale | $ | 1,905 | $ | 1,923 | $ | 1,845 | $ | (18) | (1) | % | $ | 60 | 3 | % | ||||||||||||||||||||||||||||||
| Investment securities | 424 | 434 | 418 | (10) | (2) | 6 | 1 | |||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in banks | 91 | 89 | 89 | 2 | 2 | 2 | 2 | |||||||||||||||||||||||||||||||||||||
| Total interest income | $ | 2,420 | $ | 2,446 | $ | 2,352 | $ | (26) | (1) | % | $ | 68 | 3 | % | ||||||||||||||||||||||||||||||
| Interest expense: | ||||||||||||||||||||||||||||||||||||||||||||
| Deposits | $ | 715 | $ | 781 | $ | 795 | $ | (66) | (8) | % | $ | (80) | (10) | % | ||||||||||||||||||||||||||||||
| Short-term borrowed funds | 4 | — | 8 | 4 | 100 | (4) | (50) | |||||||||||||||||||||||||||||||||||||
| Long-term borrowed funds | 139 | 128 | 158 | 11 | 9 | (19) | (12) | |||||||||||||||||||||||||||||||||||||
| Total interest expense | $ | 858 | $ | 909 | $ | 961 | $ | (51) | (6) | % | $ | (103) | (11) | % | ||||||||||||||||||||||||||||||
| Net interest income | $ | 1,562 | $ | 1,537 | $ | 1,391 | $ | 25 | 2 | % | $ | 171 | 12 | % | ||||||||||||||||||||||||||||||
| Net interest margin, FTE | 3.14 | % | 3.07 | % | 2.90 | % | 7 | bps | 24 | bps | ||||||||||||||||||||||||||||||||||
| First quarter 2026 | vs. | fourth quarter 2025 | ||||||
Net interest income of $1.6 billion increased 1.6%, reflecting a higher net interest margin along with a 1% increase in average interest-earning assets, partially offset by the day count impact of $22 million.
•Net interest margin of 3.14% increased 7 basis points, reflecting the benefit of lower terminated swap impacts and Non-Core runoff, fixed-rate asset repricing and improved funding costs, partially offset by lower asset yields.
•Interest-bearing deposit costs decreased 16 basis points to 2.04%; total deposit costs decreased 12 basis points to 1.60%; total cost of funds decreased 10 basis points to 1.80%.
| First quarter 2026 | vs. | first quarter 2025 | ||||||
Net interest income of $1.6 billion increased 12%, primarily reflecting a higher net interest margin, as well as a 4% increase in interest-earning assets.
•Net interest margin of 3.14% increased 24 basis points, largely driven by the benefit of Non-Core runoff and terminated swap impacts, fixed-rate asset repricing and improved funding costs, partially offset by lower asset yields.
4
Citizens Financial Group, Inc.
| Noninterest Income | 1Q26 change from | |||||||||||||||||||||||||||||||||||||||||||
| ($s in millions) | 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | |||||||||||||||||||||||||||||||||||||||
| $ | % | $ | % | |||||||||||||||||||||||||||||||||||||||||
| Service charges and fees | $ | 112 | $ | 112 | $ | 109 | $ | — | — | % | $ | 3 | 3 | % | ||||||||||||||||||||||||||||||
| Capital markets fees | 134 | 140 | 100 | (6) | (4) | 34 | 34 | |||||||||||||||||||||||||||||||||||||
| Wealth fees | 100 | 98 | 81 | 2 | 2 | 19 | 23 | |||||||||||||||||||||||||||||||||||||
| Card fees | 83 | 86 | 83 | (3) | (3) | — | — | |||||||||||||||||||||||||||||||||||||
| Mortgage banking fees | 42 | 52 | 59 | (10) | (19) | (17) | (29) | |||||||||||||||||||||||||||||||||||||
| Foreign exchange and derivative products | 44 | 34 | 39 | 10 | 29 | 5 | 13 | |||||||||||||||||||||||||||||||||||||
| Letter of credit and loan fees | 50 | 49 | 44 | 1 | 2 | 6 | 14 | |||||||||||||||||||||||||||||||||||||
Securities gains, net | 7 | 7 | 7 | — | — | — | — | |||||||||||||||||||||||||||||||||||||
Other income(1) | 34 | 42 | 22 | (8) | (19) | 12 | 55 | |||||||||||||||||||||||||||||||||||||
| Noninterest income | $ | 606 | $ | 620 | $ | 544 | $ | (14) | (2) | % | $ | 62 | 11 | % | ||||||||||||||||||||||||||||||
| (1) Includes bank-owned life insurance income and other miscellaneous income for all periods presented. | ||||||||||||||||||||||||||||||||||||||||||||
| First quarter 2026 | vs. | fourth quarter 2025 | ||||||
Noninterest income of $606 million decreased $14 million, or 2%.
•Capital markets fees decreased $6 million relative to a seasonally strong fourth quarter. Notwithstanding heightened geopolitical tensions and uncertainty in the macro environment, fees posted a record first quarter. Results reflect lower loan syndication fees, partially offset by higher M&A and bond underwriting fees.
•Wealth fees increased $2 million, reflecting higher advisory fees.
•Card fees decreased $3 million, given seasonal impacts.
•Mortgage banking fees decreased $10 million, reflecting lower MSR valuation results, net of hedge impact, partially offset by slightly higher servicing and production revenue.
•FX and derivative products increased $10 million, reflecting higher client commodities and interest rate hedging activity.
•Other income decreased $8 million, given higher small revenue items in the prior quarter.
| First quarter 2026 | vs. | first quarter 2025 | ||||||
Noninterest income of $606 million increased $62 million, or 11%.
•Capital markets fees increased $34 million, driven by higher M&A, loan syndication and equity underwriting fees.
•Wealth fees increased $19 million, primarily reflecting growth in AUM, largely from net inflows.
•Mortgage banking fees decreased $17 million, reflecting lower MSR valuation results, net of hedge impact, and lower servicing revenue, partially offset by higher production revenue.
•Other income increased $12 million, given favorable performance across several small revenue items.
5
Citizens Financial Group, Inc.
| Noninterest Expense | 1Q26 change from | |||||||||||||||||||||||||||||||||||||
| ($s in millions) | 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | |||||||||||||||||||||||||||||||||
| $ | % | $ | % | |||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | $ | 758 | $ | 716 | $ | 696 | $ | 42 | 6 | % | $ | 62 | 9 | % | ||||||||||||||||||||||||
| Equipment and software | 197 | 199 | 194 | (2) | (1) | 3 | 2 | |||||||||||||||||||||||||||||||
| Outside services | 162 | 148 | 155 | 14 | 9 | 7 | 5 | |||||||||||||||||||||||||||||||
| Occupancy | 114 | 109 | 112 | 5 | 5 | 2 | 2 | |||||||||||||||||||||||||||||||
| Other operating expense | 147 | 171 | 157 | (24) | (14) | (10) | (6) | |||||||||||||||||||||||||||||||
| Noninterest expense | $ | 1,378 | $ | 1,343 | $ | 1,314 | $ | 35 | 3 | % | $ | 64 | 5 | % | ||||||||||||||||||||||||
| First quarter 2026 | vs. | fourth quarter 2025 | ||||||
Noninterest expense of $1.4 billion increased 2.6%.
•Salaries and employee benefits increased $42 million, primarily reflecting a seasonal increase in payroll taxes.
•Outside services increased $14 million, primarily driven by higher technology-related costs and costs to implement the Reimagine the Bank program.
•Other operating expense decreased $24 million, reflecting lower fraud losses and seasonal factors.
The effective tax rate was 20.5% in first quarter 2026 compared with 22.0% in fourth quarter 2025, primarily driven by discrete tax benefits recognized in the first quarter.
| First quarter 2026 | vs. | first quarter 2025 | ||||||
Noninterest expense of $1.4 billion increased 5%.
•Salaries and employee benefits increased $62 million, reflecting hiring related to the Private Bank and Private Wealth buildout, and strong Capital Markets fee performance.
•Equipment and software increased $3 million, reflecting technology investments.
•Outside services increased $7 million, primarily driven by costs to implement the Reimagine the Bank program.
•Other operating expense decreased $10 million, reflecting the impact of various favorable sundry items.
The effective tax rate was 20.5% in first quarter 2026 compared with 20.3% in first quarter 2025.
6
Citizens Financial Group, Inc.
| Interest-earning assets | 1Q26 change from | ||||||||||||||||||||||||||||||||||
| ($s in millions) | 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||
| Period-end interest-earning assets | $ | % | $ | % | |||||||||||||||||||||||||||||||
| Investments | $ | 45,218 | $ | 44,650 | $ | 43,544 | $ | 568 | 1 | % | $ | 1,674 | 4 | % | |||||||||||||||||||||
| Interest-bearing deposits in banks | 12,076 | 12,224 | 11,144 | (148) | (1) | 932 | 8 | ||||||||||||||||||||||||||||
| Commercial loans and leases | 74,589 | 73,812 | 70,508 | 777 | 1 | 4,081 | 6 | ||||||||||||||||||||||||||||
| Retail loans | 69,078 | 68,880 | 67,127 | 198 | — | 1,951 | 3 | ||||||||||||||||||||||||||||
| Total loans and leases | 143,667 | 142,692 | 137,635 | 975 | 1 | 6,032 | 4 | ||||||||||||||||||||||||||||
Loans held for sale | 1,537 | 1,198 | 2,820 | 339 | 28 | (1,283) | (45) | ||||||||||||||||||||||||||||
| Total loans and leases and loans held for sale | 145,204 | 143,890 | 140,455 | 1,314 | 1 | 4,749 | 3 | ||||||||||||||||||||||||||||
| Total period-end interest-earning assets | $ | 202,498 | $ | 200,764 | $ | 195,143 | $ | 1,734 | 1 | % | $ | 7,355 | 4 | % | |||||||||||||||||||||
Average interest-earning assets(1) | |||||||||||||||||||||||||||||||||||
Investments | $ | 46,929 | $ | 46,731 | $ | 46,069 | $ | 198 | — | % | $ | 860 | 2 | % | |||||||||||||||||||||
| Interest-bearing deposits in banks | 10,079 | 9,156 | 8,092 | 923 | 10 | 1,987 | 25 | ||||||||||||||||||||||||||||
| Commercial loans and leases | 74,541 | 73,151 | 70,612 | 1,390 | 2 | 3,929 | 6 | ||||||||||||||||||||||||||||
| Retail loans | 68,869 | 68,606 | 69,098 | 263 | — | (229) | — | ||||||||||||||||||||||||||||
| Total loans and leases | 143,410 | 141,757 | 139,710 | 1,653 | 1 | 3,700 | 3 | ||||||||||||||||||||||||||||
Loans held for sale | 1,511 | 1,523 | 1,187 | (12) | (1) | 324 | 27 | ||||||||||||||||||||||||||||
| Total loans and leases and loans held for sale | 144,921 | 143,280 | 140,897 | 1,641 | 1 | 4,024 | 3 | ||||||||||||||||||||||||||||
| Total average interest-earning assets | $ | 201,929 | $ | 199,167 | $ | 195,058 | $ | 2,762 | 1 | % | $ | 6,871 | 4 | % | |||||||||||||||||||||
(1) Total average interest-earning assets excludes the mark-to-market on investment securities and unsettled purchases or sales of loans and investments. | |||||||||||||||||||||||||||||||||||
| First quarter 2026 | vs. | fourth quarter 2025 | ||||||
Period-end interest-earning assets of $202.5 billion increased $1.7 billion, or 1%, reflecting a $568 million increase in investments in securities and 1% growth in loans and leases. Total loans and leases increased $975 million, as growth in the Private Bank, net new money originations in corporate banking and higher commercial line utilization, as well as growth in home equity and mortgage, were partially offset by commercial real estate paydowns and the runoff of Non-Core loans.
Average interest-earning assets of $201.9 billion increased $2.8 billion, or 1%, reflecting a $1.7 billion increase in total loans and leases and a $923 million increase in cash held in interest-bearing deposits.
The average effective duration of the securities portfolio was 4.0 years, compared with 3.8 years at December 31, 2025 and 3.6 years at March 31, 2025.
| First quarter 2026 | vs. | first quarter 2025 | ||||||
Period-end interest-earning assets of $202.5 billion increased $7.4 billion, or 4%, reflecting a $1.7 billion increase in investments in securities, a $932 million increase in cash held in interest-bearing deposits and a $4.7 billion increase in total loans and leases and loans held for sale. The increase in total loans and leases and loans held for sale was largely driven by $4.1 billion of growth in commercial given net new money originations in corporate banking and higher commercial line utilization, as well as growth in the Private Bank, partially offset by commercial real estate paydowns. Retail also grew $2.0 billion, reflecting growth in home equity and mortgage, partially offset by Non-Core portfolio runoff.
Average interest-earning assets of $201.9 billion increased $6.9 billion, primarily reflecting a $4.0 billion increase in total loans and leases and loans held for sale, as well as $2.0 billion increase in cash held as interest-bearing deposits and a $860 million increase in investments in securities.
7
Citizens Financial Group, Inc.
| Deposits | 1Q26 change from | ||||||||||||||||||||||||||||||||||
| ($s in millions) | 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||
| Period-end deposits | $ | % | $ | % | |||||||||||||||||||||||||||||||
Noninterest-bearing demand | $ | 41,672 | $ | 40,417 | $ | 37,556 | $ | 1,255 | 3 | % | $ | 4,116 | 11 | % | |||||||||||||||||||||
| Checking with interest | 37,675 | 37,428 | 34,456 | 247 | 1 | 3,219 | 9 | ||||||||||||||||||||||||||||
| Savings | 24,114 | 24,353 | 25,765 | (239) | (1) | (1,651) | (6) | ||||||||||||||||||||||||||||
| Money market | 59,611 | 60,062 | 55,996 | (451) | (1) | 3,615 | 6 | ||||||||||||||||||||||||||||
| Time | 20,963 | 21,053 | 23,803 | (90) | — | (2,840) | (12) | ||||||||||||||||||||||||||||
| Total period-end deposits | $ | 184,035 | $ | 183,313 | $ | 177,576 | $ | 722 | — | % | $ | 6,459 | 4 | % | |||||||||||||||||||||
| Average deposits | |||||||||||||||||||||||||||||||||||
Noninterest-bearing demand | $ | 39,286 | $ | 38,993 | $ | 36,543 | $ | 293 | 1 | % | $ | 2,743 | 8 | % | |||||||||||||||||||||
| Checking with interest | 37,027 | 36,257 | 32,693 | 770 | 2 | 4,334 | 13 | ||||||||||||||||||||||||||||
| Savings | 24,095 | 24,477 | 25,760 | (382) | (2) | (1,665) | (6) | ||||||||||||||||||||||||||||
| Money market | 60,141 | 58,904 | 54,432 | 1,237 | 2 | 5,709 | 10 | ||||||||||||||||||||||||||||
| Time | 20,766 | 21,226 | 23,277 | (460) | (2) | (2,511) | (11) | ||||||||||||||||||||||||||||
| Total average deposits | $ | 181,315 | $ | 179,857 | $ | 172,705 | $ | 1,458 | 1 | % | $ | 8,610 | 5 | % | |||||||||||||||||||||
| First quarter 2026 | vs. | fourth quarter 2025 | ||||||
Total period-end deposits of $184.0 billion are broadly stable, with growth in Private Bank and retail partially offset by lower commercial deposits given seasonality. Private Bank deposits reached $16.6 billion at the end of first quarter 2026.
Average deposits of $181.3 billion increased 1%, primarily driven by growth in Private Bank.
| First quarter 2026 | vs. | first quarter 2025 | ||||||
Total period-end deposits of $184.0 billion increased 4%, primarily reflecting growth in Private Bank of $7.9 billion, and $1.9 billion in Commercial, partially offset by a $2.4 billion reduction in higher-cost Treasury brokered deposits.
Average deposits of $181.3 billion were up 5%.
8
Citizens Financial Group, Inc.
| Borrowed Funds | 1Q26 change from | ||||||||||||||||||||||||||||||||||
| ($s in millions) | 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||
| Period-end borrowed funds | $ | % | $ | % | |||||||||||||||||||||||||||||||
| Short-term borrowed funds | $ | 54 | $ | 58 | $ | 47 | $ | (4) | (7) % | $ | 7 | 15 | % | ||||||||||||||||||||||
| Long-term borrowed funds | |||||||||||||||||||||||||||||||||||
| FHLB advances | 2,513 | 2,014 | 42 | 499 | 25 | 2,471 | NM | ||||||||||||||||||||||||||||
| Senior debt | 7,076 | 6,328 | 7,568 | 748 | 12 | (492) | (7) | ||||||||||||||||||||||||||||
| Subordinated debt and other debt | 1,419 | 1,284 | 1,772 | 135 | 11 | (353) | (20) | ||||||||||||||||||||||||||||
| Auto collateralized borrowings | 1,252 | 1,598 | 2,885 | (346) | (22) | (1,633) | (57) | ||||||||||||||||||||||||||||
| Total borrowed funds | $ | 12,314 | $ | 11,282 | $ | 12,314 | $ | 1,032 | 9 | % | $ | — | — | % | |||||||||||||||||||||
| Average borrowed funds | |||||||||||||||||||||||||||||||||||
| Short-term borrowed funds | $ | 454 | $ | 221 | $ | 675 | $ | 233 | 105 % | $ | (221) | (33) | % | ||||||||||||||||||||||
| Long-term borrowed funds | |||||||||||||||||||||||||||||||||||
| FHLB advances | 1,408 | 35 | 595 | 1,373 | NM | 813 | 137 | ||||||||||||||||||||||||||||
| Senior debt | 6,843 | 6,642 | 7,133 | 201 | 3 | (290) | (4) | ||||||||||||||||||||||||||||
| Subordinated debt and other debt | 1,415 | 1,405 | 1,809 | 10 | 1 | (394) | (22) | ||||||||||||||||||||||||||||
| Auto collateralized borrowings | 1,409 | 1,774 | 3,120 | (365) | (21) | (1,711) | (55) | ||||||||||||||||||||||||||||
| Total average borrowed funds | $ | 11,529 | $ | 10,077 | $ | 13,332 | $ | 1,452 | 14 | % | $ | (1,803) | (14) | % | |||||||||||||||||||||
| First quarter 2026 | vs. | fourth quarter 2025 | ||||||
Period-end borrowed funds increased $1.0 billion, reflecting an increase in senior debt and subordinated debt of $748 million and $135 million, respectively, given net issuances, and an increase of FHLB advances of $499 million, partially offset by a $346 million decrease in collateralized borrowings on auto loans as the associated portfolio runs down.
Average borrowed funds increased $1.5 billion, driven primarily by an increase in FHLB advances and short-term borrowed funds of $1.4 billion and $233 million, respectively, as well as an increase in senior debt of $201 million, partially offset by a $365 million decrease in auto collateralized borrowings.
| First quarter 2026 | vs. | first quarter 2025 | ||||||
Period-end borrowed funds were stable, reflecting an increase in FHLB advances of $2.5 billion, offset by a decrease of $1.6 billion in auto collateralized borrowings, given runoff of the associated portfolio, and decreases of $492 million and $353 million in senior debt and subordinated debt, respectively, given the impact of redemptions.
Average borrowed funds decreased by $1.8 billion, given a $1.7 billion decrease in auto collateralized borrowings, and decreases in senior and subordinated debt of $290 million and $394 million respectively, given the impact of redemptions. These results were partially offset by an increase in FHLB advances of $813 million.
9
Citizens Financial Group, Inc.
| Capital | 1Q26 change from | ||||||||||||||||||||||||||||||||||
| ($s and shares in millions, except per share data) | 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||
| Period-end capital | $ | % | $ | % | |||||||||||||||||||||||||||||||
| Stockholders' equity | $ | 26,172 | $ | 26,317 | $ | 24,866 | $ | (145) | (1) | % | $ | 1,306 | 5 | % | |||||||||||||||||||||
| Stockholders' common equity | 24,061 | 24,206 | 22,753 | (145) | (1) | 1,308 | 6 | ||||||||||||||||||||||||||||
| Tangible common equity | 16,165 | 16,341 | 14,867 | (176) | (1) | 1,298 | 9 | ||||||||||||||||||||||||||||
| Tangible book value per common share | $ | 37.94 | $ | 38.07 | $ | 33.97 | $ | (0.13) | — | % | $ | 3.97 | 12 | % | |||||||||||||||||||||
| Common shares - at end of period | 426.0 | 429.2 | 437.7 | (3.2) | (1) | (11.6) | (3) | ||||||||||||||||||||||||||||
| Common shares - average (diluted) | 429.9 | 434.1 | 442.2 | (4.2) | (1) | % | (12.3) | (3) | % | ||||||||||||||||||||||||||
Common equity tier 1 capital ratio(1) | 10.5 | % | 10.6 | % | 10.6 | % | |||||||||||||||||||||||||||||
Total capital ratio(1) | 13.7 | 13.8 | 13.9 | ||||||||||||||||||||||||||||||||
| Tangible common equity ratio | 7.3 | 7.5 | 7.0 | ||||||||||||||||||||||||||||||||
Tier 1 leverage ratio(1) | 9.3 | 9.5 | 9.4 | ||||||||||||||||||||||||||||||||
| (1) Current reporting-period regulatory capital ratios are preliminary. | |||||||||||||||||||||||||||||||||||
| First quarter 2026 | ||
•The CET1 capital ratio of 10.5% as of March 31, 2026 compares with 10.6% at December 31, 2025 and March 31, 2025.
•Total capital ratio of 13.7% compares with 13.8% at December 31, 2025 and 13.9% as of March 31, 2025.
•Tangible common equity ratio of 7.3% compares with 7.5% at December 31, 2025 and 7.0% as of March 31, 2025.
•Tangible book value per common share of $37.94 was broadly stable with fourth quarter 2025.
•Paid $198 million in common dividends to shareholders during first quarter 2026. This compares with $201 million in common dividends during fourth quarter 2025 and $186 million during first quarter 2025.
•Repurchased $300 million of common shares during first quarter 2026, compared with $125 million in fourth quarter 2025 and $200 million in first quarter 2025.
10
Citizens Financial Group, Inc.
| Credit quality review | 1Q26 change from | |||||||||||||||||||||||||||||||||||||||||||
| ($s in millions) | 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | |||||||||||||||||||||||||||||||||||||||
| $/bps/% | % | $/bps/% | % | |||||||||||||||||||||||||||||||||||||||||
Nonaccrual loans and leases(1) | $ | 1,497 | $ | 1,504 | $ | 1,582 | $ | (7) | — | % | $ | (85) | (5) | % | ||||||||||||||||||||||||||||||
90+ days past due and accruing(2) | 208 | 169 | 155 | 39 | 23 | 53 | 34 | |||||||||||||||||||||||||||||||||||||
| Net charge-offs | 138 | 155 | 200 | (17) | (11) | (62) | (31) | |||||||||||||||||||||||||||||||||||||
| Provision for credit losses | 140 | 137 | 153 | 3 | 2 | (13) | (8) | |||||||||||||||||||||||||||||||||||||
| Allowance for credit losses | $ | 2,185 | $ | 2,183 | $ | 2,212 | $ | 2 | — | % | $ | (27) | (1) | % | ||||||||||||||||||||||||||||||
| Nonaccrual loans and leases to loans and leases | 1.04 | % | 1.05 | % | 1.15 | % | (1) | bp | (11) | bps | ||||||||||||||||||||||||||||||||||
| Net charge-offs as a % of total loans and leases | 0.39 | 0.43 | 0.58 | (4) | (19) | |||||||||||||||||||||||||||||||||||||||
| Allowance for credit losses to loans and leases | 1.52 | 1.53 | 1.61 | (1) | (9) | |||||||||||||||||||||||||||||||||||||||
| Allowance for credit losses to nonaccrual loans and leases | 146 | % | 145 | % | 140 | % | 1 | % | 6 | % | ||||||||||||||||||||||||||||||||||
(1) Loans fully or partially guaranteed by the FHA, VA and USDA are classified as accruing. | ||||||||||||||||||||||||||||||||||||||||||||
(2) 90+ days past due and accruing includes $179 million, $141 million, and $137 million of loans fully or partially guaranteed by the FHA, VA, and USDA for March 31, 2026, December 31, 2025, and March 31, 2025, respectively. | ||||||||||||||||||||||||||||||||||||||||||||
| First quarter 2026 | vs. | fourth quarter 2025 | ||||||
•Nonaccrual loans of $1.5 billion decreased modestly. The nonaccrual loans to total loans ratio of 1.04% compares with 1.05% at December 31, 2025.
•Net charge-offs of $138 million, or 39 basis points of average loans and leases, compares with 43 basis points in the prior quarter, with the decrease driven by retail and commercial real estate.
•The first quarter 2026 provision for credit losses of $140 million compares with $137 million for fourth quarter 2025.
•The ratio of allowance for credit losses to total loans of 1.52% was slightly down compared with 1.53% as of December 31, 2025 reflecting improved loan mix given the continued reduction in the Non-Core portfolio and a decrease in commercial real estate balances, with originations primarily in C&I and retail real estate secured that have a lower loss content profile.
•The allowance for credit losses to nonaccrual loans and leases ratio of 146% is stable with December 31, 2025.
| First quarter 2026 | vs. | first quarter 2025 | ||||||
•Nonaccrual loans decreased 5% driven largely by a 12% decrease in commercial. The nonaccrual loans to total loans ratio of 1.04% compares with 1.15% at March 31, 2025.
•Net charge-offs of $138 million, or 39 basis points of average loans and leases compares with 58 basis points for first quarter 2025. This reflects a decrease in retail, given charge-offs associated with a loan sale in first quarter 2025, and a decrease in commercial real estate.
•Provision for credit losses of $140 million decreased compared with a $153 million provision in first quarter 2025 reflecting the runoff of the Non-Core portfolio and improving credit trends and loan mix.
•Allowance for credit losses of $2.2 billion decreased $27 million compared with March 31, 2025 given the benefit of the sale of Non-Core education loans, continued Non-Core runoff and other improvements in loan mix. Allowance for credit losses ratio of 1.52% as of March 31, 2026 compares with 1.61% as of March 31, 2025.
•The allowance for credit losses to nonaccrual loans and leases ratio of 146% compares with 140% as of March 31, 2025.
11
Citizens Financial Group, Inc.
Corresponding Financial Tables and Information
Investors are encouraged to review the foregoing summary and discussion of Citizens’ earnings and financial condition in conjunction with the detailed financial tables and other information available on the Investor Relations portion of the company’s website at www.citizensbank.com/about-us.
Media: Peter Lucht - (781) 655-2289
Investors: Kristin Silberberg - (203) 900-6854
Conference Call
CFG management will host a live conference call today with details as follows:
Time: 9:00 am ET
Dial-in: (800) 369-1703, conference ID 1679767
Webcast/Presentation: The live webcast will be available at http://investor.citizensbank.com under Events & Presentations.
Replay Information: A replay of the conference call will be available beginning at 12:00 pm ET on April 16, 2026 through May 16, 2026. The webcast replay will be available at http://investor.citizensbank.com under Events & Presentations.
About Citizens Financial Group, Inc.
Citizens Financial Group, Inc. is one of the nation’s oldest and largest financial institutions, with $227.9 billion in assets as of March 31, 2026. Headquartered in Providence, Rhode Island, Citizens offers a broad range of retail, private banking, wealth management and commercial banking products and services to individuals, small businesses, middle-market companies, large corporations and institutions. Citizens helps its customers reach their potential by listening to them and by understanding their needs in order to offer tailored advice, ideas and solutions. In Consumer Banking, Citizens provides an integrated experience that includes mobile and online banking, a full-service customer contact center and the convenience of approximately 3,000 ATMs and approximately 1,000 branches in 14 states and the District of Columbia. Consumer Banking products and services include a full range of banking, lending, savings, wealth management and small business offerings. Consumer Banking includes Citizens Private Bank and Private Wealth, which integrate banking services and wealth management solutions to serve high- and ultra-high-net-worth individuals and families, as well as investors, entrepreneurs and businesses. In Commercial Banking, Citizens offers a broad complement of financial products and solutions, including lending and leasing, deposit and treasury management services, foreign exchange, interest rate and commodity risk management solutions, as well as loan syndication, corporate finance, merger and acquisition, and debt and equity capital markets capabilities. More information is available at www.citizensbank.com or visit us on X, LinkedIn or Facebook.
12
Citizens Financial Group, Inc.
Non-GAAP Financial Measures and Reconciliations
Non-GAAP Financial Measures:
This document contains non-GAAP financial measures that we believe provide useful information to investors to understand our results of operations or financial condition. We caution investors not to place undue reliance on such non-GAAP financial measures, but to consider them with the most directly comparable GAAP financial measures. Non-GAAP financial measures have limitations as analytical tools and should not be considered in isolation or as a substitute for our results reported under GAAP. See the following pages for reconciliations of our non-GAAP measures to the most directly comparable GAAP financial measures.
13
Citizens Financial Group, Inc.
Non-GAAP financial measures and reconciliations
(in millions, except share, per-share and ratio data)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 Change | ||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||
| $/bps | % | $/bps | % | |||||||||||||||||||||||||||||||||||||||||
| Pre-provision profit: | ||||||||||||||||||||||||||||||||||||||||||||
| Total revenue (GAAP) | A | $2,168 | $2,157 | $1,935 | $11 | 1 | % | $233 | 12 | % | ||||||||||||||||||||||||||||||||||
| Less: Noninterest expense (GAAP) | B | 1,378 | 1,343 | 1,314 | 35 | 3 | 64 | 5 | ||||||||||||||||||||||||||||||||||||
| Pre-provision profit (non-GAAP) | $790 | $814 | $621 | ($24) | (3 | %) | $169 | 27 | % | |||||||||||||||||||||||||||||||||||
| Operating leverage: | ||||||||||||||||||||||||||||||||||||||||||||
| Total revenue (GAAP) | A | $2,168 | $2,157 | $1,935 | $11 | 0.53 | % | $233 | 12.11 | % | ||||||||||||||||||||||||||||||||||
| Less: Noninterest expense (GAAP) | B | 1,378 | 1,343 | 1,314 | 35 | 2.65 | 64 | 4.91 | ||||||||||||||||||||||||||||||||||||
| Operating leverage | (2.12 | %) | 7.20 | % | ||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio: | ||||||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | B/A | 63.55 | % | 62.24 | % | 67.91 | % | 131 | bps | (436) | bps | |||||||||||||||||||||||||||||||||
| Book value per common share and tangible book value per common share: | ||||||||||||||||||||||||||||||||||||||||||||
| Common shares - at period-end (GAAP) | C | 426,023,578 | 429,242,174 | 437,668,127 | (3,218,596) | (1 | %) | (11,644,549) | (3 | %) | ||||||||||||||||||||||||||||||||||
| Common stockholders' equity (GAAP) | D | $24,061 | $24,206 | $22,753 | ($145) | (1) | $1,308 | 6 | ||||||||||||||||||||||||||||||||||||
| Less: Goodwill (GAAP) | 8,221 | 8,187 | 8,187 | 34 | — | 34 | — | |||||||||||||||||||||||||||||||||||||
| Less: Other intangible assets (GAAP) | 112 | 115 | 137 | (3) | (3) | (25) | (18) | |||||||||||||||||||||||||||||||||||||
| Add: Deferred tax liabilities related to goodwill and other intangible assets (GAAP) | 437 | 437 | 438 | — | — | (1) | — | |||||||||||||||||||||||||||||||||||||
| Tangible common equity (non-GAAP) | E | $16,165 | $16,341 | $14,867 | ($176) | (1 | %) | $1,298 | 9 | % | ||||||||||||||||||||||||||||||||||
| Book value per common share (GAAP) | D/C | $56.48 | $56.39 | $51.99 | $0.09 | — | % | $4.49 | 9 | % | ||||||||||||||||||||||||||||||||||
| Tangible book value per common share (non-GAAP) | E/C | 37.94 | 38.07 | 33.97 | (0.13) | — | 3.97 | 12 | ||||||||||||||||||||||||||||||||||||
| Net interest income and net interest margin on an FTE basis: | ||||||||||||||||||||||||||||||||||||||||||||
| Net interest income (annualized) (GAAP) | F | $6,337 | $6,098 | $5,637 | $239 | 4 | % | $700 | 12 | % | ||||||||||||||||||||||||||||||||||
| Average interest-earning assets (GAAP) | G | 201,929 | 199,167 | 195,058 | 2,762 | 1 | 6,871 | 4 | ||||||||||||||||||||||||||||||||||||
| Net interest margin (GAAP) | F/G | 3.14 | % | 3.06 | % | 2.89 | % | 8 | bps | 25 | bps | |||||||||||||||||||||||||||||||||
| Net interest income (GAAP) | $1,562 | $1,537 | $1,391 | $25 | 2 | % | $171 | 12 | % | |||||||||||||||||||||||||||||||||||
| FTE adjustment | 3 | 4 | 4 | (1) | (25) | (1) | (25) | |||||||||||||||||||||||||||||||||||||
| Net interest income on an FTE basis (non-GAAP) | 1,565 | 1,541 | 1,395 | 24 | 2 | 170 | 12 | |||||||||||||||||||||||||||||||||||||
| Net interest income on an FTE basis (annualized) (non-GAAP) | H | 6,350 | 6,112 | 5,653 | 238 | 4 | 697 | 12 | ||||||||||||||||||||||||||||||||||||
| Net interest margin on an FTE basis (non-GAAP) | H/G | 3.14 | % | 3.07 | % | 2.90 | % | 7 | bps | 24 | bps | |||||||||||||||||||||||||||||||||
| Return on average common equity and return on average tangible common equity: | ||||||||||||||||||||||||||||||||||||||||||||
| Net income available to common stockholders (GAAP) | I | $484 | $489 | $340 | ($5) | (1 | %) | $144 | 42 | % | ||||||||||||||||||||||||||||||||||
| Average common equity (GAAP) | J | $23,995 | $23,823 | $22,188 | $172 | 1 | $1,807 | 8 | ||||||||||||||||||||||||||||||||||||
| Less: Average goodwill (GAAP) | 8,198 | 8,187 | 8,187 | 11 | — | 11 | — | |||||||||||||||||||||||||||||||||||||
| Less: Average other intangibles (GAAP) | 114 | 120 | 142 | (6) | (5) | (28) | (20) | |||||||||||||||||||||||||||||||||||||
| Add: Average deferred tax liabilities related to goodwill and other intangible assets (GAAP) | 437 | 440 | 438 | (3) | (1) | (1) | — | |||||||||||||||||||||||||||||||||||||
| Average tangible common equity (non-GAAP) | K | $16,120 | $15,956 | $14,297 | $164 | 1 | % | $1,823 | 13 | % | ||||||||||||||||||||||||||||||||||
| Return on average common equity (GAAP) | I/J | 8.19 | % | 8.16 | % | 6.21 | % | 3 | bps | 198 | bps | |||||||||||||||||||||||||||||||||
| Return on average tangible common equity (non-GAAP) | I/K | 12.19 | % | 12.18 | % | 9.64 | % | 1 | bps | 255 | bps | |||||||||||||||||||||||||||||||||
| Return on average total assets and return on average total tangible assets: | ||||||||||||||||||||||||||||||||||||||||||||
| Net income (GAAP) | L | $517 | $528 | $373 | ($11) | (2 | %) | $144 | 39 | % | ||||||||||||||||||||||||||||||||||
| Average total assets (GAAP) | M | $224,224 | $221,242 | $216,309 | $2,982 | 1 | $7,915 | 4 | ||||||||||||||||||||||||||||||||||||
| Less: Average goodwill (GAAP) | 8,198 | 8,187 | 8,187 | 11 | — | 11 | — | |||||||||||||||||||||||||||||||||||||
| Less: Average other intangibles (GAAP) | 114 | 120 | 142 | (6) | (5) | (28) | (20) | |||||||||||||||||||||||||||||||||||||
| Add: Average deferred tax liabilities related to goodwill and other intangible assets (GAAP) | 437 | 440 | 438 | (3) | (1) | (1) | — | |||||||||||||||||||||||||||||||||||||
| Average tangible assets (non-GAAP) | N | $216,349 | $213,375 | $208,418 | $2,974 | 1 | % | $7,931 | 4 | % | ||||||||||||||||||||||||||||||||||
| Return on average total assets (GAAP) | L/M | 0.94 | % | 0.95 | % | 0.70 | % | (1) | bps | 24 | bps | |||||||||||||||||||||||||||||||||
| Return on average total tangible assets (non-GAAP) | L/N | 0.97 | % | 0.98 | % | 0.73 | % | (1) | bps | 24 | bps | |||||||||||||||||||||||||||||||||
14
Citizens Financial Group, Inc.
Non-GAAP financial measures and reconciliations (continued)
(in millions, except share, per-share and ratio data)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 Change | ||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||
| $/bps | % | $/bps | % | |||||||||||||||||||||||||||||||||||||||||
| Common equity ratio and tangible common equity ratio: | ||||||||||||||||||||||||||||||||||||||||||||
| Total assets (GAAP) | O | $227,918 | $226,351 | $220,148 | $1,567 | 1 | % | $7,770 | 4 | % | ||||||||||||||||||||||||||||||||||
| Less: Goodwill (GAAP) | 8,221 | 8,187 | 8,187 | 34 | — | 34 | — | |||||||||||||||||||||||||||||||||||||
| Less: Other intangible assets (GAAP) | 112 | 115 | 137 | (3) | (3) | (25) | (18) | |||||||||||||||||||||||||||||||||||||
| Add: Deferred tax liabilities related to goodwill and other intangible assets (GAAP) | 437 | 437 | 438 | — | — | (1) | — | |||||||||||||||||||||||||||||||||||||
| Tangible assets (non-GAAP) | P | $220,022 | $218,486 | $212,262 | $1,536 | 1 | % | $7,760 | 4 | % | ||||||||||||||||||||||||||||||||||
| Common equity ratio (GAAP) | D/O | 10.6 | % | 10.7 | % | 10.3 | % | (13) bps | 22 bps | |||||||||||||||||||||||||||||||||||
| Tangible common equity ratio (non-GAAP) | E/P | 7.3 | 7.5 | 7.0 | (20) bps | 30 bps | ||||||||||||||||||||||||||||||||||||||
15
Citizens Financial Group, Inc.
Non-GAAP financial measures and reconciliations (continued)
(in millions, except share, per-share and ratio data)
| 1Q26 | ||||||||
CET1 Ratio adjusted for AOCI opt-out removal | ||||||||
| CET1 capital | $ | 18,178 | ||||||
| Less: AFS securities - AOCI | 1,027 | |||||||
HTM securities - AOCI(1) | 657 | |||||||
| DTA for AFS/HTM securities | 35 | |||||||
| Pension | 245 | |||||||
| DTA for Pension | 3 | |||||||
| CET 1 capital adjusted for AOCI opt-out removal | A | $16,211 | ||||||
| Risk-weighted assets | 173,268 | |||||||
| Less: HTM securities - AOCI | 113 | |||||||
| AFS securities - AOCI | 167 | |||||||
| DTA for AFS/HTM securities | (1,471) | |||||||
| Pension | 245 | |||||||
| DTA for Pension | (216) | |||||||
| Risk-weighted assets adjusted for AOCI opt-out removal | B | $174,430 | ||||||
CET1 Ratio adjusted for AOCI opt-out removal | A/B | 9.3 | % | |||||
(1) HTM securities - AOCI refers to unrealized losses recognized on securities before transfer to HTM | ||||||||
16
Citizens Financial Group, Inc.
Forward-Looking Statements
This document contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Any statement that does not describe historical or current facts is a forward-looking statement. These statements often include the words "believes," "expects," "anticipates," "estimates," "intends," "plans," "goals," "targets," "initiatives," "potentially," "probably," "projects," "outlook," "guidance" or similar expressions or future conditional verbs such as "may," "will," "likely," "should," "would," and "could."
Forward-looking statements are based upon the current beliefs and expectations of management, and on information currently available to management. Our statements speak as of the date hereof, and we do not assume any obligation to update these statements or to update the reasons why actual results could differ from those contained in such statements in light of new information or future events. We caution you, therefore, against relying on any of these forward-looking statements. They are neither statements of historical fact nor guarantees or assurances of future performance. While there is no assurance that any list of risks and uncertainties or risk factors is complete, important factors that could cause actual results to differ materially from those in the forward-looking statements include the following, without limitation:
•Negative economic, business and political conditions, including as a result of the interest rate environment, supply chain disruptions, tariffs, inflationary pressures, and labor shortages that adversely affect the general economy, housing prices, the job market, consumer confidence, and spending habits;
•The general state of the economy and employment, as well as general business and economic conditions, and changes in the competitive environment;
•Our capital and liquidity requirements under regulatory standards and our ability to generate capital and liquidity on favorable terms;
•The effect of changes in our credit ratings on our cost of funding, access to capital markets, ability to market our securities, and overall liquidity position;
•The effect of changes in the level of commercial and consumer deposits on our funding costs and net interest margin;
•Our ability to achieve our financial performance goals and execute on our strategic business initiatives, including the continued expansion of Private Bank and Private Wealth, and our aim to position us as a more innovative, modern, and customer-centric bank;
•The effects of geopolitical instability, including the war in Ukraine and the conflict in the Middle East, on economic and market conditions, inflationary pressures and the interest rate environment, commodity price and foreign exchange rate volatility, and heightened cybersecurity risks;
•Our ability to comply with supervisory requirements and expectations as well as new or amended regulations;
•Liabilities and business restrictions resulting from litigation and regulatory investigations;
•The impact of changes in interest rates on our net interest income, net interest margin, mortgage originations, and mortgage servicing rights, as well as on market liquidity, which could affect our funding sources and ability to originate and distribute financial products in the primary and secondary markets;
•Financial services reform and other current, pending, or future legislation or regulation that could have a negative effect on our revenue and businesses;
•Environmental risks, such as physical or transition risks associated with climate change, and social and governance risks that could adversely affect our reputation, operations, business, and customers;
•A failure in, or breach of, our compliance with laws, as well as operational or security systems or infrastructure, or those of our third-party vendors or other service providers, including as a result of cyberattacks; and
•Management’s ability to identify and manage these and other risks.
In addition to the above factors, we also caution that the actual amounts and timing of any future common stock dividends or share repurchases will be subject to various factors, including our capital position, financial performance, balance sheet growth, market conditions, and regulatory considerations, as well as any other factors that our Board of Directors deems relevant in making such a determination. Therefore, there can be no assurance that we will repurchase shares from, or pay any dividends to, holders of our common stock, or as to the amount of any such repurchases or dividends.
More information about factors that could cause actual results to differ materially from those described in the forward-looking statements can be found in the “Risk Factors” section in Part I, Item 1A of our Annual Report on Form 10-K for the fiscal year ended December 31, 2025 as filed with the Securities and Exchange Commission.
Note: Per share amounts and ratios presented in this document are calculated using whole dollars.
17
Citizens Financial Group, Inc.
CFG-IR
18
1Q26 Financial Results April 16, 2026
2 Forward-looking statements and use of non-GAAP financial measures This document contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Any statement that does not describe historical or current facts is a forward- looking statement. These statements often include the words "believes," "expects," "anticipates," "estimates," "intends," "plans," "goals," "targets," "initiatives," "potentially," "probably," "projects," "outlook," "guidance" or similar expressions or future conditional verbs such as "may," "will," "likely," "should," "would," and "could." Forward-looking statements are based upon the current beliefs and expectations of management, and on information currently available to management. Our statements speak as of the date hereof, and we do not assume any obligation to update these statements or to update the reasons why actual results could differ from those contained in such statements in light of new information or future events. We caution you, therefore, against relying on any of these forward-looking statements. They are neither statements of historical fact nor guarantees or assurances of future performance. While there is no assurance that any list of risks and uncertainties or risk factors is complete, important factors that could cause actual results to differ materially from those in the forward-looking statements include the following, without limitation: • Negative economic, business and political conditions, including as a result of the interest rate environment, supply chain disruptions, tariffs, inflationary pressures, and labor shortages that adversely affect the general economy, housing prices, the job market, consumer confidence, and spending habits; • The general state of the economy and employment, as well as general business and economic conditions, and changes in the competitive environment; • Our capital and liquidity requirements under regulatory standards and our ability to generate capital and liquidity on favorable terms; • The effect of changes in our credit ratings on our cost of funding, access to capital markets, ability to market our securities, and overall liquidity position; • The effect of changes in the level of commercial and consumer deposits on our funding costs and net interest margin; • Our ability to achieve our financial performance goals and execute on our strategic business initiatives, including the continued expansion of Private Bank and Private Wealth, and our aim to position us as a more innovative, modern, and customer-centric bank; • The effects of geopolitical instability, including the war in Ukraine and the conflict in the Middle East, on economic and market conditions, inflationary pressures and the interest rate environment, commodity price and foreign exchange rate volatility, and heightened cybersecurity risks; • Our ability to comply with supervisory requirements and expectations as well as new or amended regulations; • Liabilities and business restrictions resulting from litigation and regulatory investigations; • The impact of changes in interest rates on our net interest income, net interest margin, mortgage originations, and mortgage servicing rights, as well as on market liquidity, which could affect our funding sources and ability to originate and distribute financial products in the primary and secondary markets; • Financial services reform and other current, pending, or future legislation or regulation that could have a negative effect on our revenue and businesses; • Environmental risks, such as physical or transition risks associated with climate change, and social and governance risks that could adversely affect our reputation, operations, business, and customers; • A failure in, or breach of, our compliance with laws, as well as operational or security systems or infrastructure, or those of our third-party vendors or other service providers, including as a result of cyberattacks; and • Management’s ability to identify and manage these and other risks. In addition to the above factors, we also caution that the actual amounts and timing of any future common stock dividends or share repurchases will be subject to various factors, including our capital position, financial performance, balance sheet growth, market conditions, and regulatory considerations, as well as any other factors that our Board of Directors deems relevant in making such a determination. Therefore, there can be no assurance that we will repurchase shares from, or pay any dividends to, holders of our common stock, or as to the amount of any such repurchases or dividends. More information about factors that could cause actual results to differ materially from those described in the forward-looking statements can be found in the “Risk Factors” section in Part I, Item 1A of our Annual Report on Form 10-K for the fiscal year ended December 31, 2025 as filed with the Securities and Exchange Commission. Non-GAAP Financial Measures: This document contains non-GAAP financial measures that we believe provide useful information to investors to understand our results of operations or financial condition. We caution investors not to place undue reliance on such non-GAAP financial measures, but to consider them with the most directly comparable GAAP financial measures. Non-GAAP financial measures have limitations as analytical tools and should not be considered in isolation or as a substitute for our results reported under GAAP. The Appendix presents reconciliations of our non-GAAP measures to the most directly comparable GAAP financial measures.
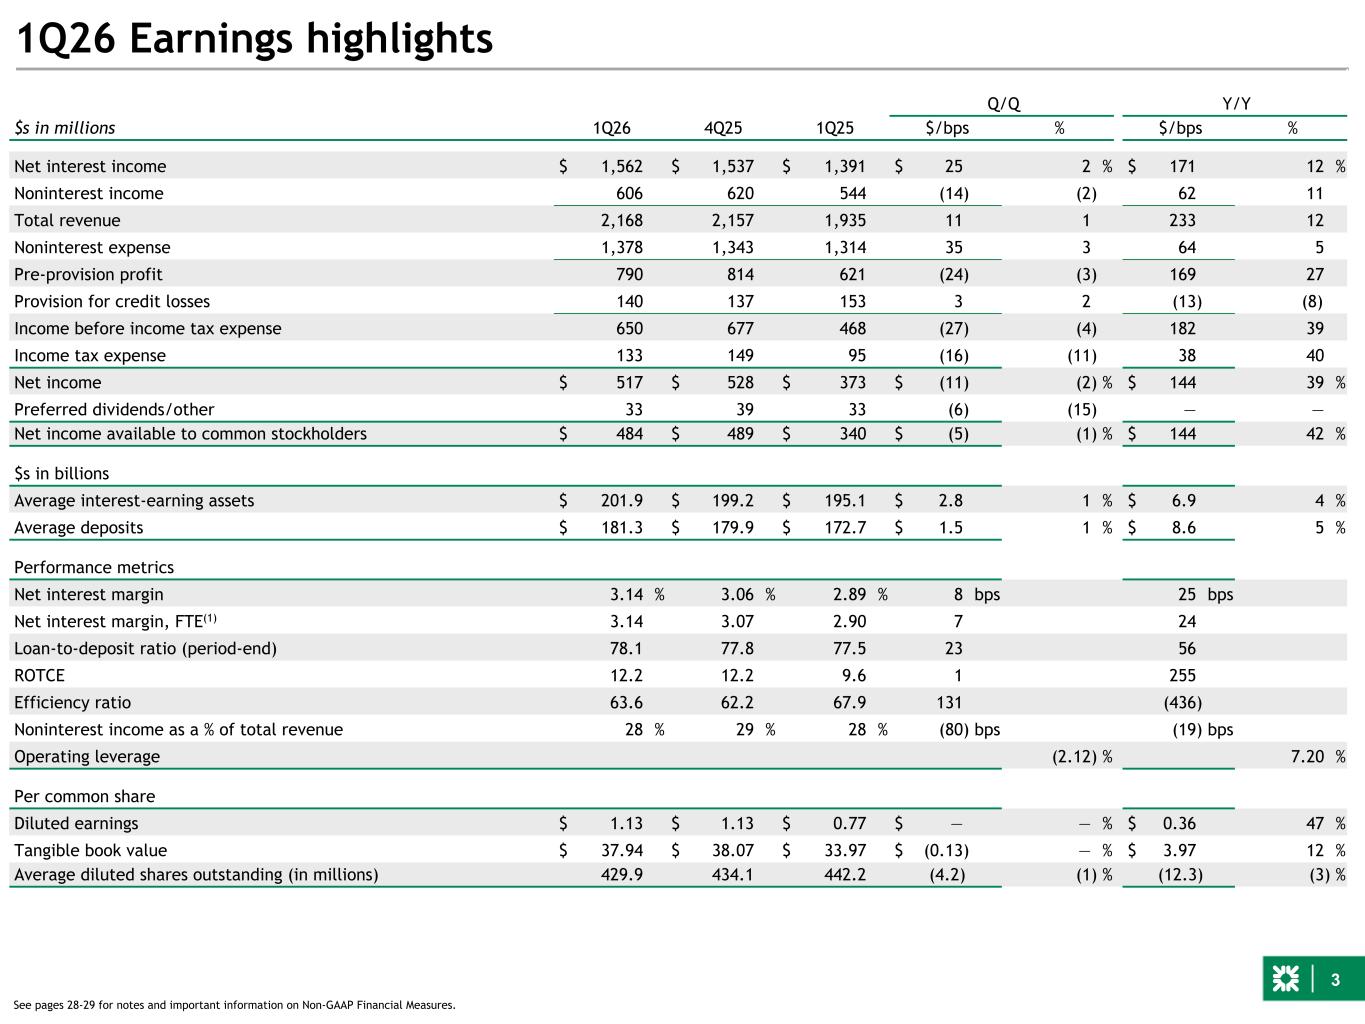
3 1Q26 Earnings highlights 1Q26 4Q25 1Q25 Q/Q Y/Y $s in millions $/bps % $/bps % Net interest income $ 1,562 $ 1,537 $ 1,391 $ 25 2 % $ 171 12 % Noninterest income 606 620 544 (14) (2) 62 11 Total revenue 2,168 2,157 1,935 11 1 233 12 Noninterest expense 1,378 1,343 1,314 35 3 64 5 Pre-provision profit 790 814 621 (24) (3) 169 27 Provision for credit losses 140 137 153 3 2 (13) (8) Income before income tax expense 650 677 468 (27) (4) 182 39 Income tax expense 133 149 95 (16) (11) 38 40 Net income $ 517 $ 528 $ 373 $ (11) (2) % $ 144 39 % Preferred dividends/other 33 39 33 (6) (15) — — Net income available to common stockholders $ 484 $ 489 $ 340 $ (5) (1) % $ 144 42 % $s in billions Average interest-earning assets $ 201.9 $ 199.2 $ 195.1 $ 2.8 1 % $ 6.9 4 % Average deposits $ 181.3 $ 179.9 $ 172.7 $ 1.5 1 % $ 8.6 5 % Performance metrics Net interest margin 3.14 % 3.06 % 2.89 % 8 bps 25 bps Net interest margin, FTE(1) 3.14 3.07 2.90 7 24 Loan-to-deposit ratio (period-end) 78.1 77.8 77.5 23 56 ROTCE 12.2 12.2 9.6 1 255 Efficiency ratio 63.6 62.2 67.9 131 (436) Noninterest income as a % of total revenue 28 % 29 % 28 % (80) bps (19) bps Operating leverage (2.12) % 7.20 % Per common share Diluted earnings $ 1.13 $ 1.13 $ 0.77 $ — — % $ 0.36 47 % Tangible book value $ 37.94 $ 38.07 $ 33.97 $ (0.13) — % $ 3.97 12 % Average diluted shares outstanding (in millions) 429.9 434.1 442.2 (4.2) (1) % (12.3) (3) % See pages 28-29 for notes and important information on Non-GAAP Financial Measures.
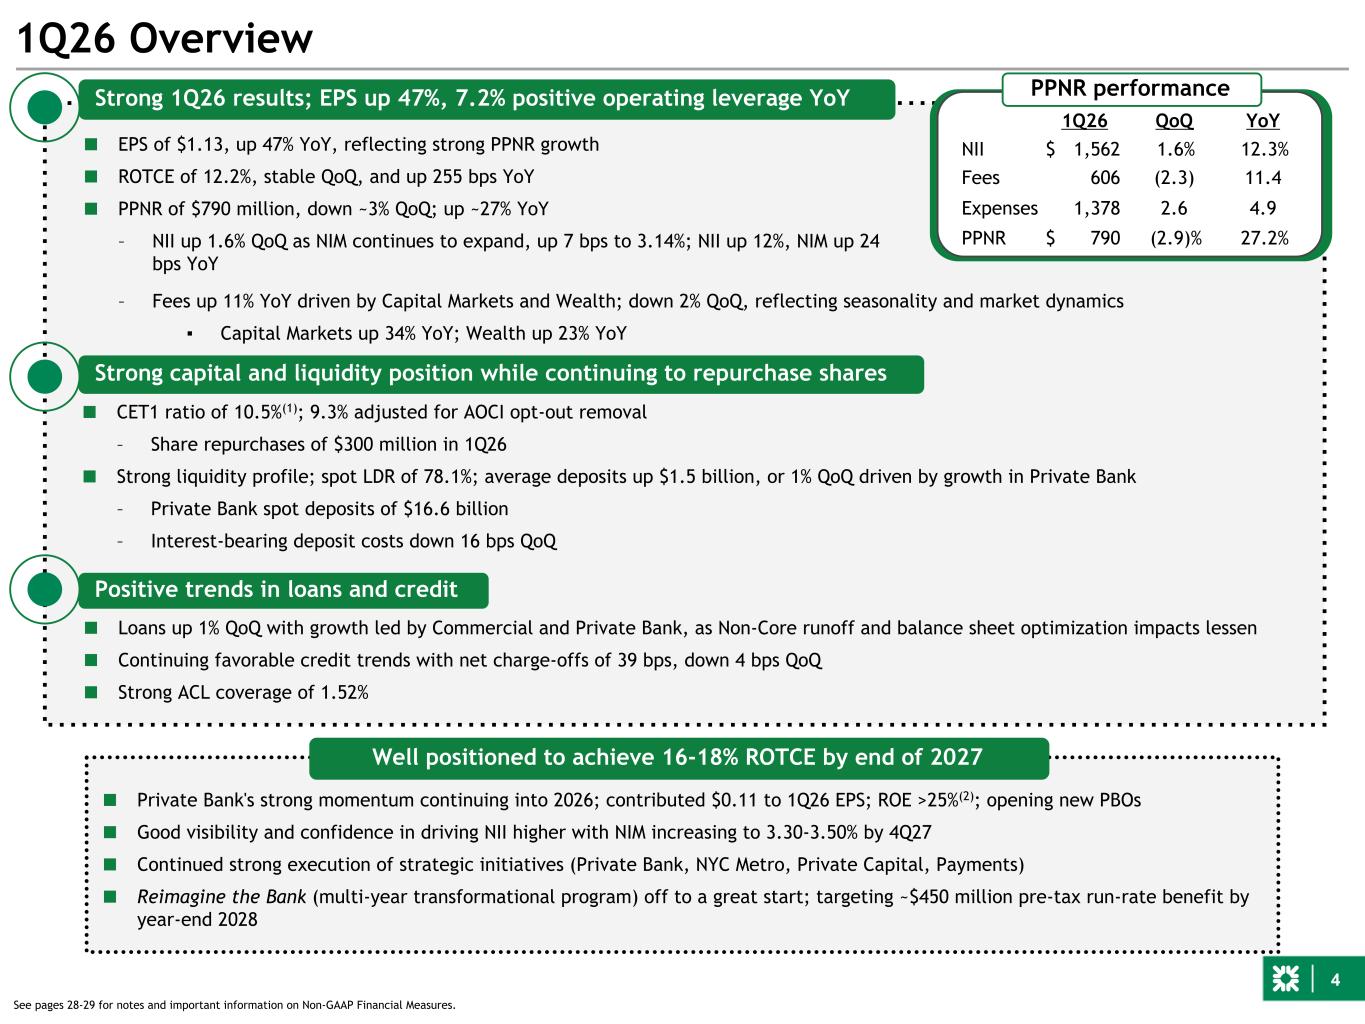
4 ■ CET1 ratio of 10.5%(1); 9.3% adjusted for AOCI opt-out removal – Share repurchases of $300 million in 1Q26 ■ Strong liquidity profile; spot LDR of 78.1%; average deposits up $1.5 billion, or 1% QoQ driven by growth in Private Bank – Private Bank spot deposits of $16.6 billion – Interest-bearing deposit costs down 16 bps QoQ ■ Loans up 1% QoQ with growth led by Commercial and Private Bank, as Non-Core runoff and balance sheet optimization impacts lessen ■ Continuing favorable credit trends with net charge-offs of 39 bps, down 4 bps QoQ ■ Strong ACL coverage of 1.52% ■ EPS of $1.13, up 47% YoY, reflecting strong PPNR growth ■ ROTCE of 12.2%, stable QoQ, and up 255 bps YoY ■ PPNR of $790 million, down ~3% QoQ; up ~27% YoY – NII up 1.6% QoQ as NIM continues to expand, up 7 bps to 3.14%; NII up 12%, NIM up 24 bps YoY Strong 1Q26 results; EPS up 47%, 7.2% positive operating leverage YoY Strong capital and liquidity position while continuing to repurchase shares Positive trends in loans and credit 1Q26 Overview ■ Private Bank's strong momentum continuing into 2026; contributed $0.11 to 1Q26 EPS; ROE >25%(2); opening new PBOs ■ Good visibility and confidence in driving NII higher with NIM increasing to 3.30-3.50% by 4Q27 ■ Continued strong execution of strategic initiatives (Private Bank, NYC Metro, Private Capital, Payments) ■ Reimagine the Bank (multi-year transformational program) off to a great start; targeting ~$450 million pre-tax run-rate benefit by year-end 2028 Well positioned to achieve 16-18% ROTCE by end of 2027 PPNR performance 1Q26 QoQ YoY NII $ 1,562 1.6% 12.3% Fees 606 (2.3) 11.4 Expenses 1,378 2.6 4.9 PPNR $ 790 (2.9)% 27.2% See pages 28-29 for notes and important information on Non-GAAP Financial Measures. – Fees up 11% YoY driven by Capital Markets and Wealth; down 2% QoQ, reflecting seasonality and market dynamics ▪ Capital Markets up 34% YoY; Wealth up 23% YoY
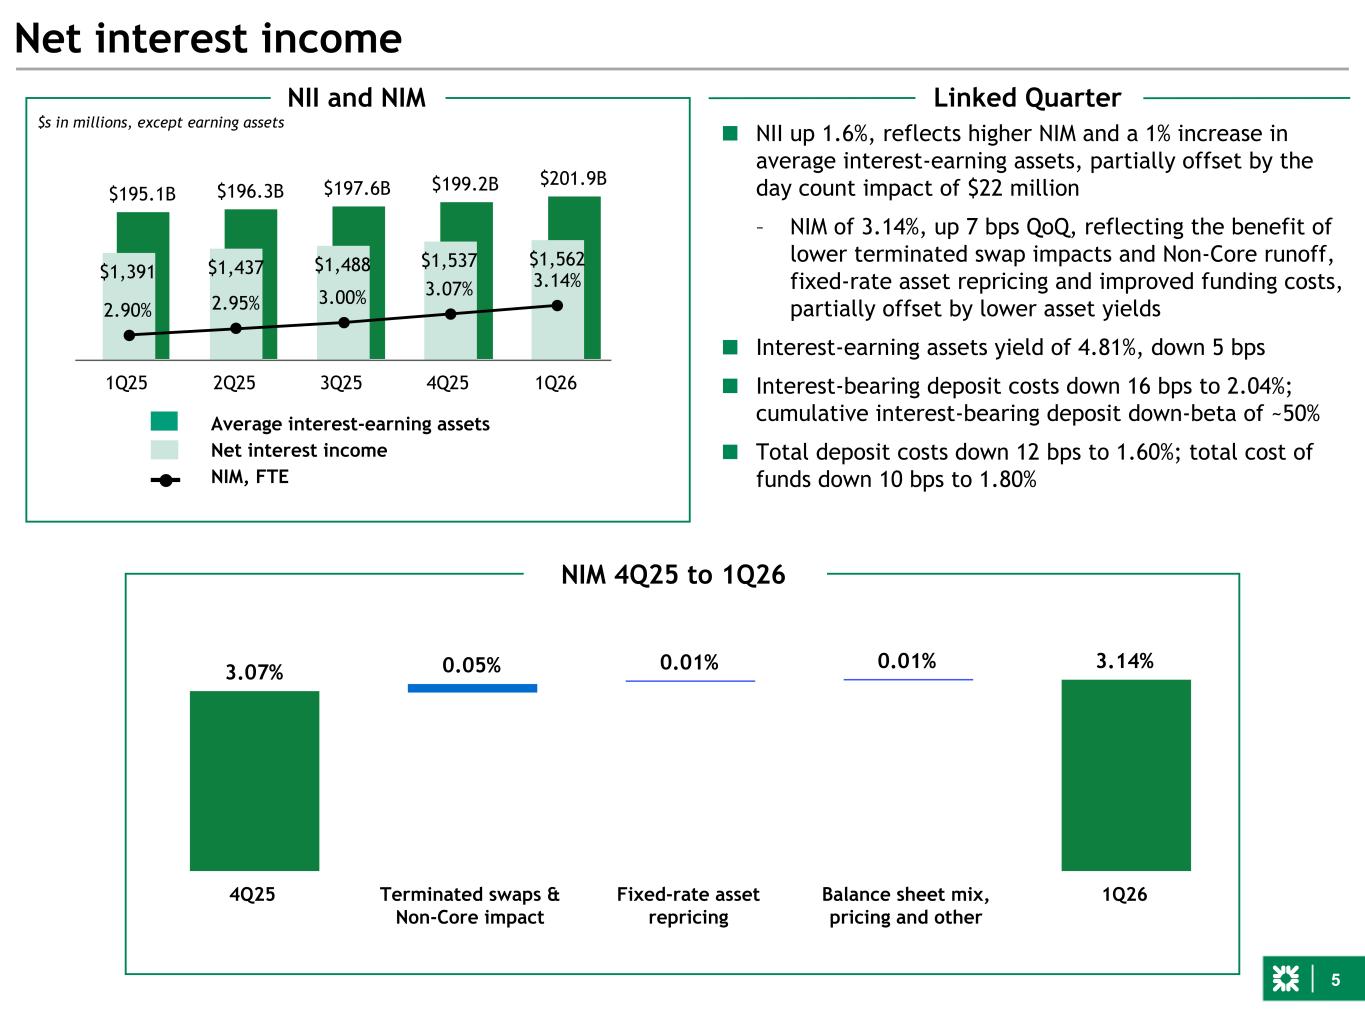
5 3.07% 0.05% 0.01% 0.01% 3.14% 4Q25 Terminated swaps & Non-Core impact Fixed-rate asset repricing Balance sheet mix, pricing and other 1Q26 $195.1B $196.3B $197.6B $199.2B $201.9B $1,391 $1,437 $1,488 $1,537 $1,562 2.90% 2.95% 3.00% 3.07% 3.14% 1Q25 2Q25 3Q25 4Q25 1Q26 ■ NII up 1.6%, reflects higher NIM and a 1% increase in average interest-earning assets, partially offset by the day count impact of $22 million – NIM of 3.14%, up 7 bps QoQ, reflecting the benefit of lower terminated swap impacts and Non-Core runoff, fixed-rate asset repricing and improved funding costs, partially offset by lower asset yields ■ Interest-earning assets yield of 4.81%, down 5 bps ■ Interest-bearing deposit costs down 16 bps to 2.04%; cumulative interest-bearing deposit down-beta of ~50% ■ Total deposit costs down 12 bps to 1.60%; total cost of funds down 10 bps to 1.80% Net interest income NII and NIM Average interest-earning assets Net interest income NIM, FTE Linked Quarter NIM 4Q25 to 1Q26 $s in millions, except earning assets *
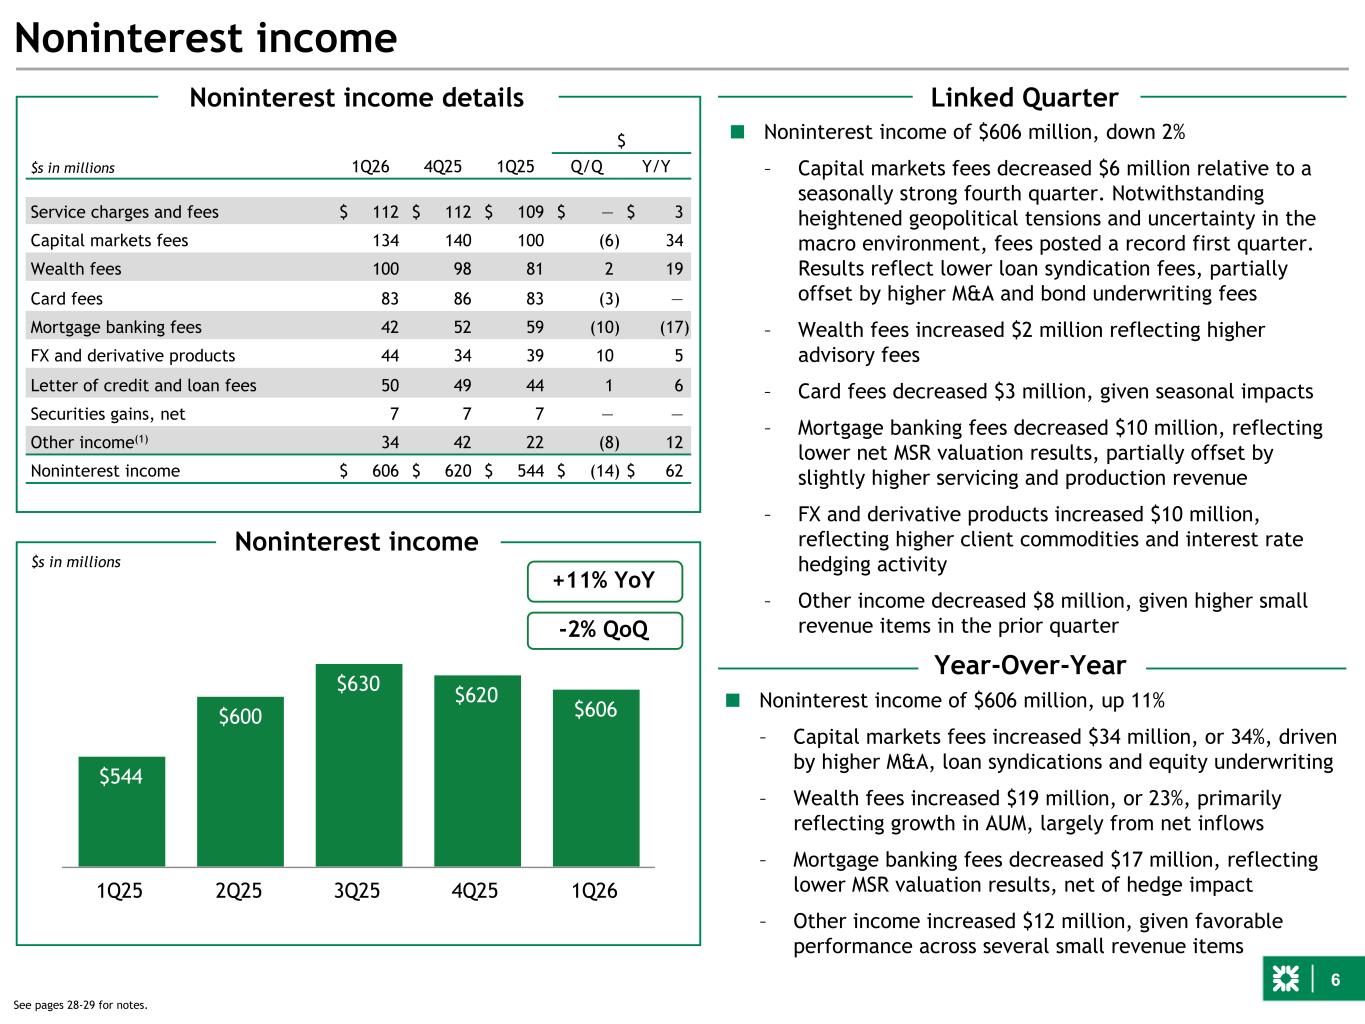
6 $544 $600 $630 $620 $606 1Q25 2Q25 3Q25 4Q25 1Q26 Noninterest income $s in millions Linked Quarter Year-Over-Year Noninterest income $s in millions 1Q26 4Q25 1Q25 $ Q/Q Y/Y Service charges and fees $ 112 $ 112 $ 109 $ — $ 3 Capital markets fees 134 140 100 (6) 34 Wealth fees 100 98 81 2 19 Card fees 83 86 83 (3) — Mortgage banking fees 42 52 59 (10) (17) FX and derivative products 44 34 39 10 5 Letter of credit and loan fees 50 49 44 1 6 Securities gains, net 7 7 7 — — Other income(1) 34 42 22 (8) 12 Noninterest income $ 606 $ 620 $ 544 $ (14) $ 62 Noninterest income details ■ Noninterest income of $606 million, up 11% – Capital markets fees increased $34 million, or 34%, driven by higher M&A, loan syndications and equity underwriting – Wealth fees increased $19 million, or 23%, primarily reflecting growth in AUM, largely from net inflows – Mortgage banking fees decreased $17 million, reflecting lower MSR valuation results, net of hedge impact – Other income increased $12 million, given favorable performance across several small revenue items +11% YoY -2% QoQ ■ Noninterest income of $606 million, down 2% – Capital markets fees decreased $6 million relative to a seasonally strong fourth quarter. Notwithstanding heightened geopolitical tensions and uncertainty in the macro environment, fees posted a record first quarter. Results reflect lower loan syndication fees, partially offset by higher M&A and bond underwriting fees – Wealth fees increased $2 million reflecting higher advisory fees – Card fees decreased $3 million, given seasonal impacts – Mortgage banking fees decreased $10 million, reflecting lower net MSR valuation results, partially offset by slightly higher servicing and production revenue – FX and derivative products increased $10 million, reflecting higher client commodities and interest rate hedging activity – Other income decreased $8 million, given higher small revenue items in the prior quarter See pages 28-29 for notes.
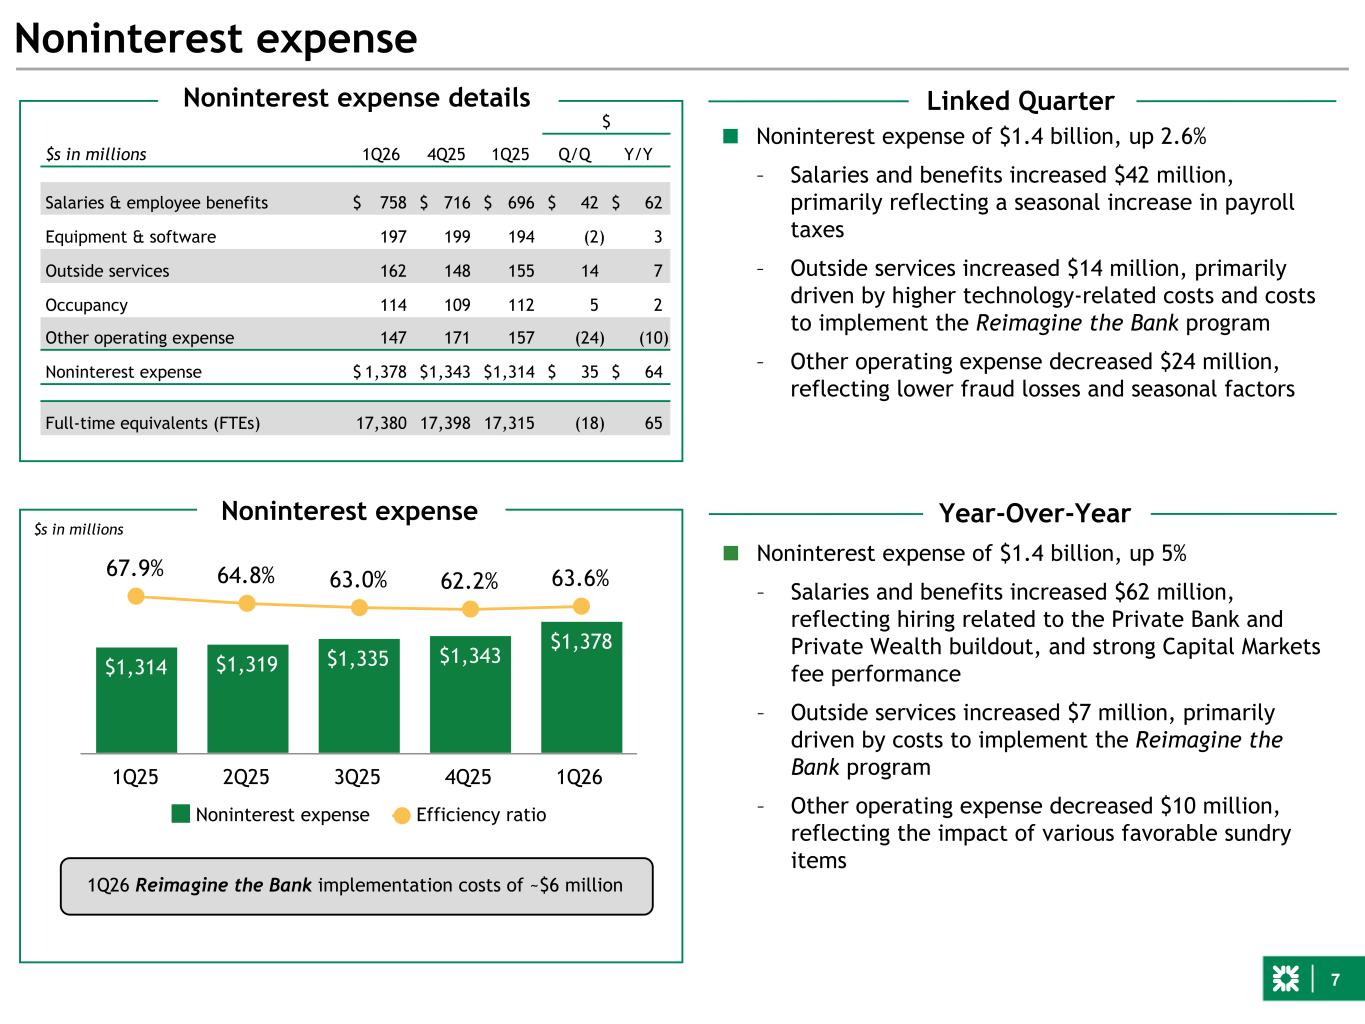
7 Noninterest expense Linked Quarter Year-Over-Year 1Q26 4Q25 1Q25 $ $s in millions Q/Q Y/Y Salaries & employee benefits $ 758 $ 716 $ 696 $ 42 $ 62 Equipment & software 197 199 194 (2) 3 Outside services 162 148 155 14 7 Occupancy 114 109 112 5 2 Other operating expense 147 171 157 (24) (10) Noninterest expense $ 1,378 $ 1,343 $ 1,314 $ 35 $ 64 Full-time equivalents (FTEs) 17,380 17,398 17,315 (18) 65 Noninterest expense details $1,314 $1,319 $1,335 $1,343 $1,378 67.9% 64.8% 63.0% 62.2% 63.6% Noninterest expense Efficiency ratio 1Q25 2Q25 3Q25 4Q25 1Q26 ■ Noninterest expense of $1.4 billion, up 2.6% – Salaries and benefits increased $42 million, primarily reflecting a seasonal increase in payroll taxes – Outside services increased $14 million, primarily driven by higher technology-related costs and costs to implement the Reimagine the Bank program – Other operating expense decreased $24 million, reflecting lower fraud losses and seasonal factors ■ Noninterest expense of $1.4 billion, up 5% – Salaries and benefits increased $62 million, reflecting hiring related to the Private Bank and Private Wealth buildout, and strong Capital Markets fee performance – Outside services increased $7 million, primarily driven by costs to implement the Reimagine the Bank program – Other operating expense decreased $10 million, reflecting the impact of various favorable sundry items $s in millions Noninterest expense 1Q26 Reimagine the Bank implementation costs of ~$6 million
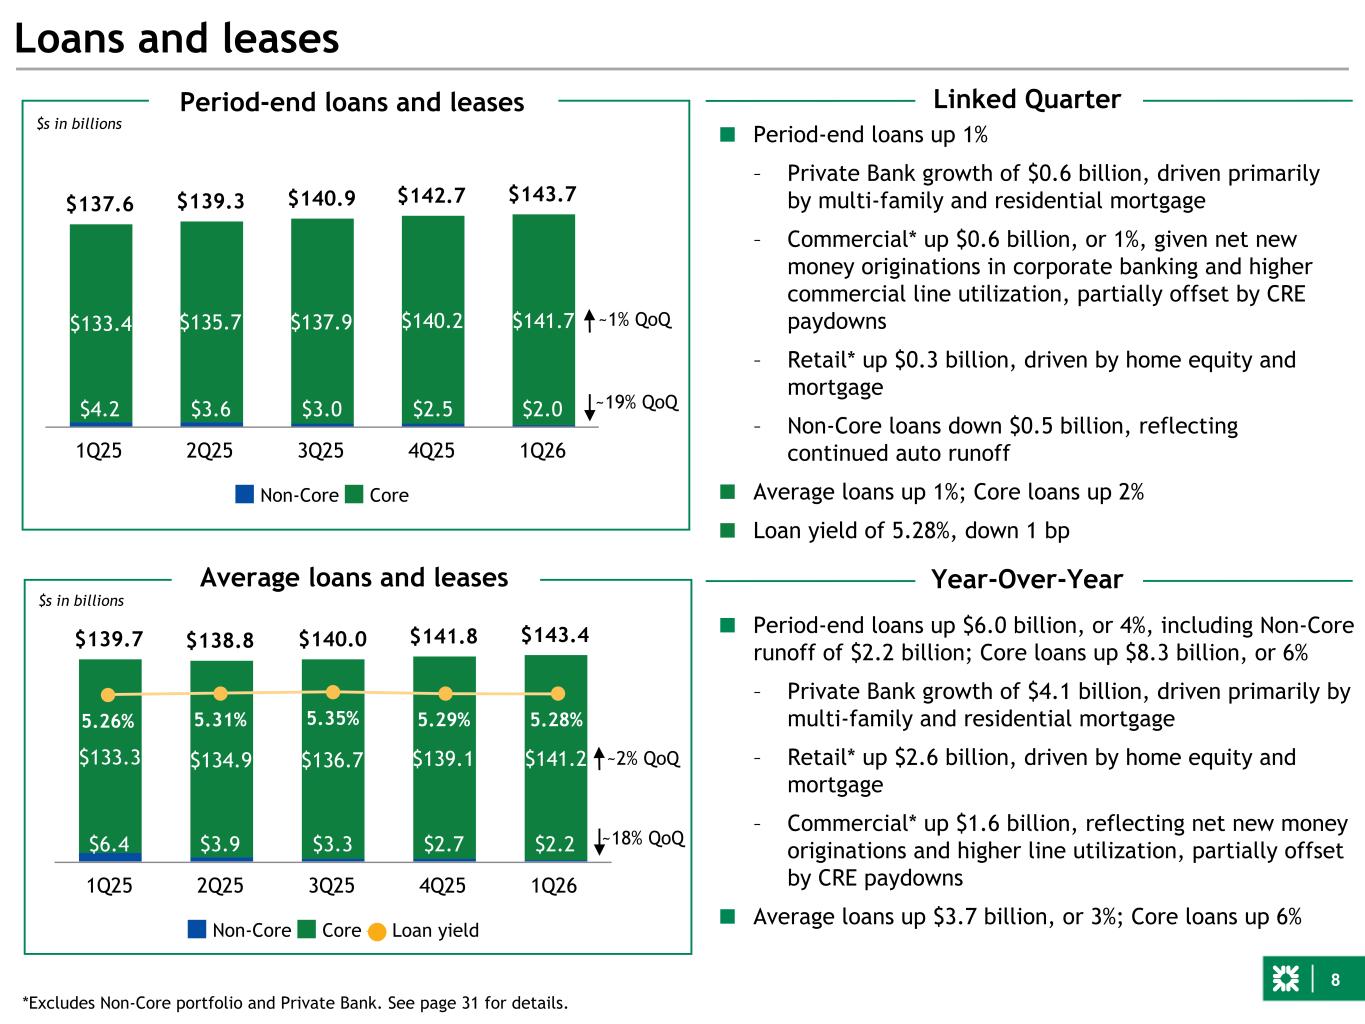
8 $139.7 $138.8 $140.0 $141.8 $143.4 $6.4 $3.9 $3.3 $2.7 $2.2 $133.3 $134.9 $136.7 $139.1 $141.2 Non-Core Core Loan yield 1Q25 2Q25 3Q25 4Q25 1Q26 ~18% QoQ ■ Period-end loans up 1% – Private Bank growth of $0.6 billion, driven primarily by multi-family and residential mortgage – Commercial* up $0.6 billion, or 1%, given net new money originations in corporate banking and higher commercial line utilization, partially offset by CRE paydowns – Retail* up $0.3 billion, driven by home equity and mortgage – Non-Core loans down $0.5 billion, reflecting continued auto runoff ■ Average loans up 1%; Core loans up 2% ■ Loan yield of 5.28%, down 1 bp Loans and leases $s in billions Average loans and leases $137.6 $139.3 $140.9 $142.7 $143.7 $4.2 $3.6 $3.0 $2.5 $2.0 $133.4 $135.7 $137.9 $140.2 $141.7 Non-Core Core 1Q25 2Q25 3Q25 4Q25 1Q26 $s in billions Period-end loans and leases 5.26% 5.31% 5.35% 5.29% 5.28% Linked Quarter Year-Over-Year ~19% QoQ ~1% QoQ ~2% QoQ *Excludes Non-Core portfolio and Private Bank. See page 31 for details. ■ Period-end loans up $6.0 billion, or 4%, including Non-Core runoff of $2.2 billion; Core loans up $8.3 billion, or 6% – Private Bank growth of $4.1 billion, driven primarily by multi-family and residential mortgage – Retail* up $2.6 billion, driven by home equity and mortgage – Commercial* up $1.6 billion, reflecting net new money originations and higher line utilization, partially offset by CRE paydowns ■ Average loans up $3.7 billion, or 3%; Core loans up 6%
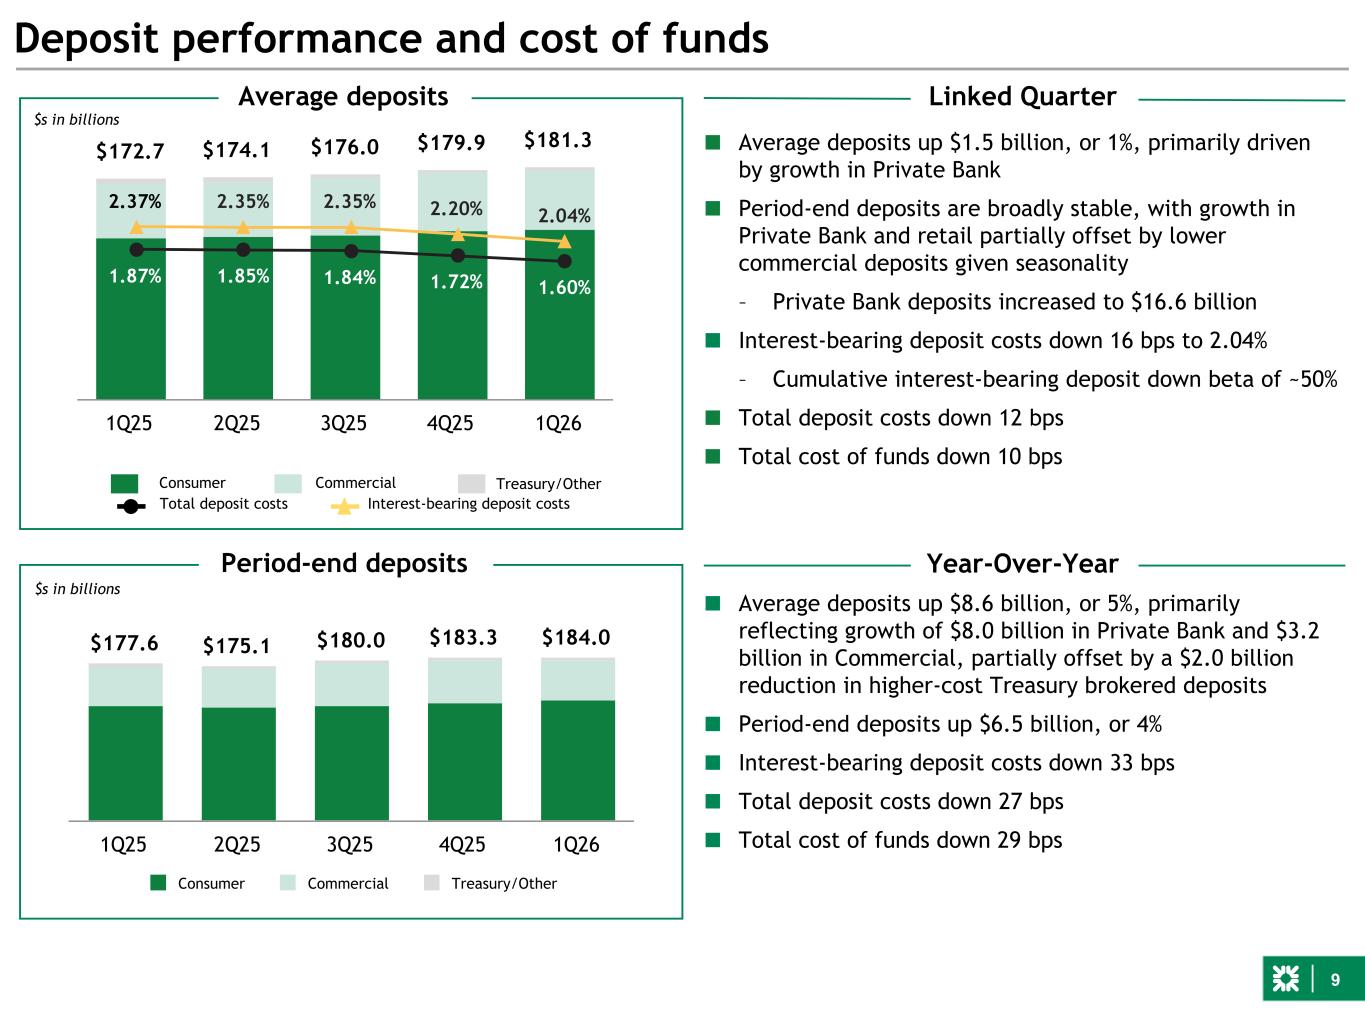
9 $172.7 $174.1 $176.0 $179.9 $181.3 1Q25 2Q25 3Q25 4Q25 1Q26 Deposit performance and cost of funds $s in billions Average deposits 1.87% 1.85% 1.84% 1.72% 1.60% 2.37% 2.35% 2.35% 2.20% 2.04% Total deposit costs Interest-bearing deposit costs CommercialConsumer Treasury/Other Year-Over-YearPeriod-end deposits Linked Quarter ■ Average deposits up $1.5 billion, or 1%, primarily driven by growth in Private Bank ■ Period-end deposits are broadly stable, with growth in Private Bank and retail partially offset by lower commercial deposits given seasonality – Private Bank deposits increased to $16.6 billion ■ Interest-bearing deposit costs down 16 bps to 2.04% – Cumulative interest-bearing deposit down beta of ~50% ■ Total deposit costs down 12 bps ■ Total cost of funds down 10 bps $s in billions ■ Average deposits up $8.6 billion, or 5%, primarily reflecting growth of $8.0 billion in Private Bank and $3.2 billion in Commercial, partially offset by a $2.0 billion reduction in higher-cost Treasury brokered deposits ■ Period-end deposits up $6.5 billion, or 4% ■ Interest-bearing deposit costs down 33 bps ■ Total deposit costs down 27 bps ■ Total cost of funds down 29 bps $177.6 $175.1 $180.0 $183.3 $184.0 Consumer Commercial Treasury/Other 1Q25 2Q25 3Q25 4Q25 1Q26
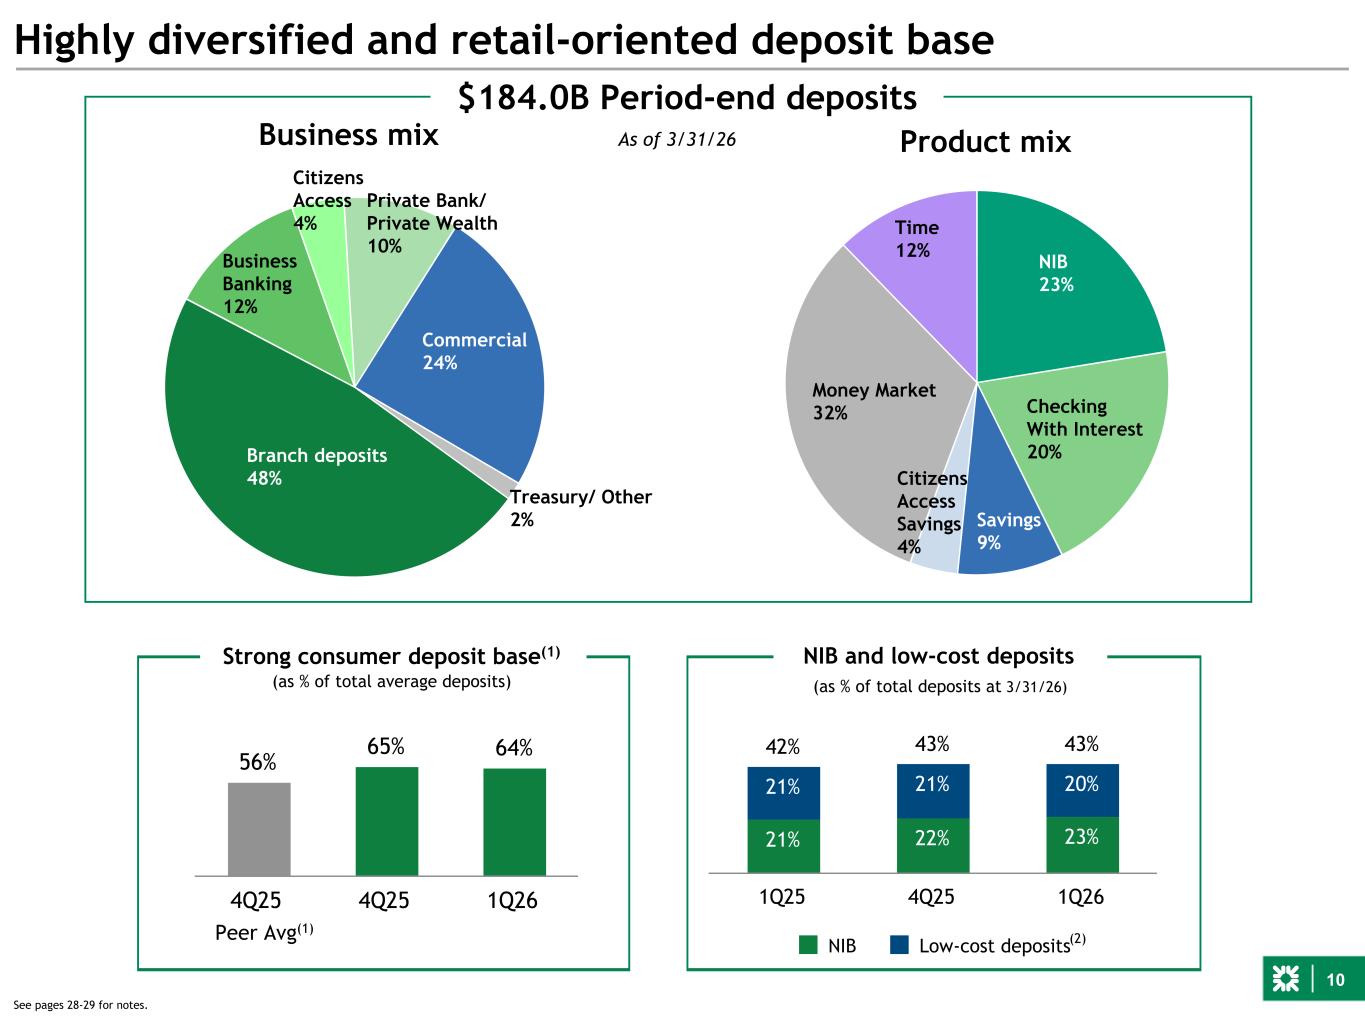
10 Branch deposits 48% Business Banking 12% Citizens Access 4% Private Bank/ Private Wealth 10% Commercial 24% Treasury/ Other 2% As of 3/31/26 Highly diversified and retail-oriented deposit base $184.0B Period-end deposits Peer Avg(1) Business mix Product mix Strong consumer deposit base(1) (as % of total average deposits) 42% 43% 43% 21% 22% 23% 21% 21% 20% NIB Low-cost deposits 1Q25 4Q25 1Q26 NIB and low-cost deposits (2) 56% 65% 64% 4Q25 4Q25 1Q26 See pages 28-29 for notes. NIB 23% Checking With Interest 20% Savings 9% Citizens Access Savings 4% Money Market 32% Time 12% (as % of total deposits at 3/31/26)
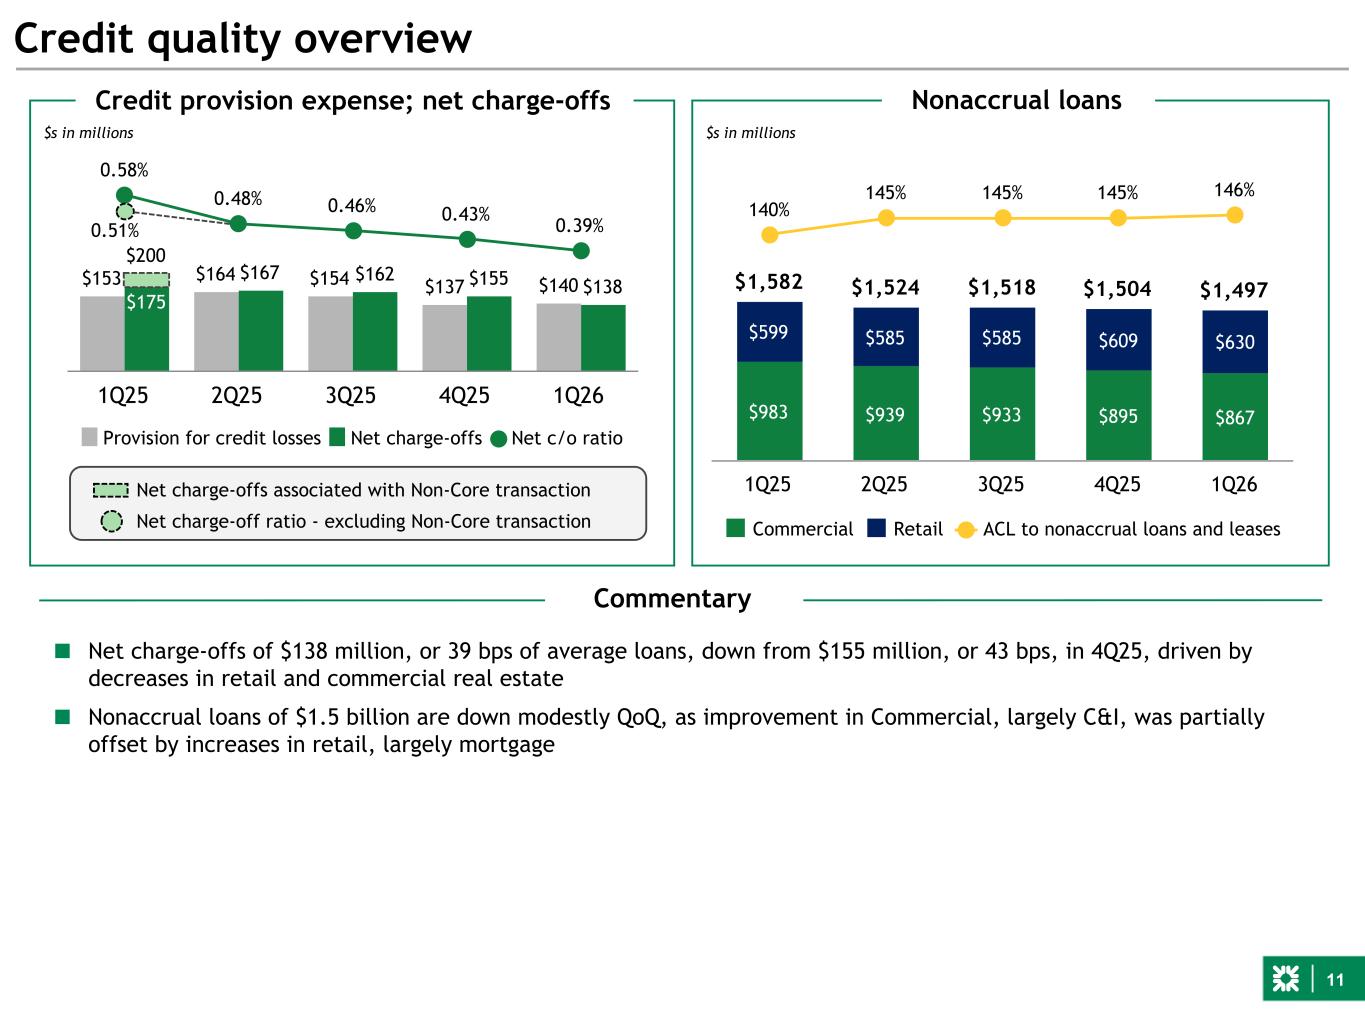
11 $153 $164 $154 $137 $140 $200 $167 $162 $155 $138 0.58% 0.48% 0.46% 0.43% 0.39% Provision for credit losses Net charge-offs Net c/o ratio 1Q25 2Q25 3Q25 4Q25 1Q26 0.51% Credit quality overview $s in millions $s in millions Credit provision expense; net charge-offs $1,582 $1,524 $1,518 $1,504 $1,497 $983 $939 $933 $895 $867 $599 $585 $585 $609 $630 140% 145% 145% 145% 146% Commercial Retail ACL to nonaccrual loans and leases 1Q25 2Q25 3Q25 4Q25 1Q26 Nonaccrual loans Net charge-offs associated with Non-Core transaction $175 Net charge-off ratio - excluding Non-Core transaction Commentary ■ Net charge-offs of $138 million, or 39 bps of average loans, down from $155 million, or 43 bps, in 4Q25, driven by decreases in retail and commercial real estate ■ Nonaccrual loans of $1.5 billion are down modestly QoQ, as improvement in Commercial, largely C&I, was partially offset by increases in retail, largely mortgage
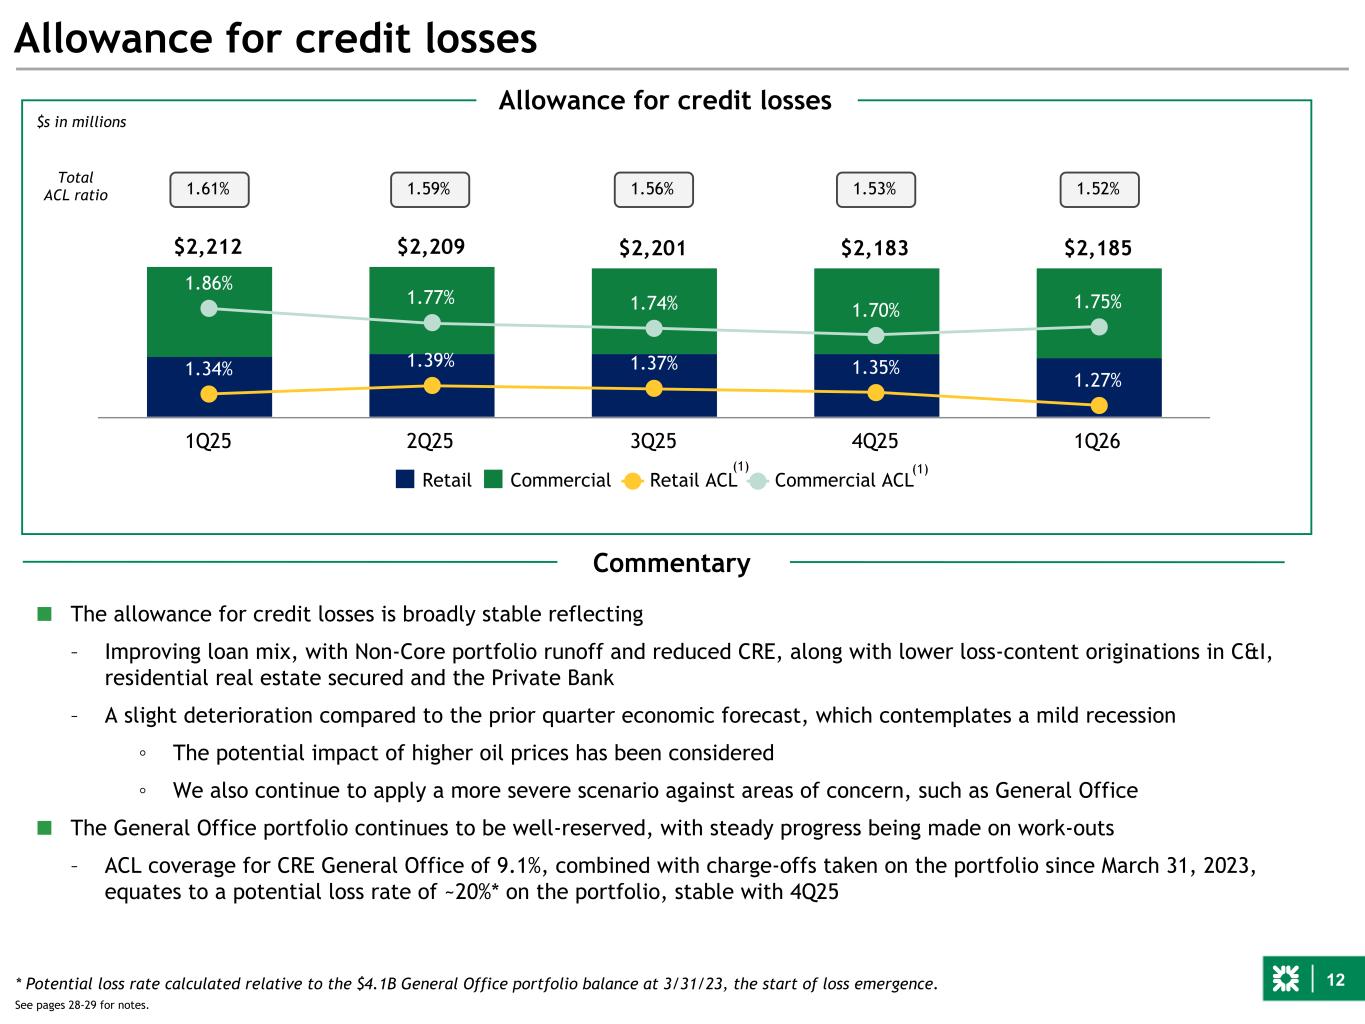
12 ■ The allowance for credit losses is broadly stable reflecting – Improving loan mix, with Non-Core portfolio runoff and reduced CRE, along with lower loss-content originations in C&I, residential real estate secured and the Private Bank – A slight deterioration compared to the prior quarter economic forecast, which contemplates a mild recession ◦ The potential impact of higher oil prices has been considered ◦ We also continue to apply a more severe scenario against areas of concern, such as General Office ■ The General Office portfolio continues to be well-reserved, with steady progress being made on work-outs – ACL coverage for CRE General Office of 9.1%, combined with charge-offs taken on the portfolio since March 31, 2023, equates to a potential loss rate of ~20%* on the portfolio, stable with 4Q25 Allowance for credit losses $2,212 $2,209 $2,201 $2,183 $2,185 1.34% 1.39% 1.37% 1.35% 1.27% 1.86% 1.77% 1.74% 1.70% 1.75% Retail Commercial Retail ACL Commercial ACL 1Q25 2Q25 3Q25 4Q25 1Q26 $s in millions Allowance for credit losses (1) * Potential loss rate calculated relative to the $4.1B General Office portfolio balance at 3/31/23, the start of loss emergence. Commentary 1.61% 1.59% 1.56% 1.53% 1.52% Total ACL ratio See pages 28-29 for notes. (1)
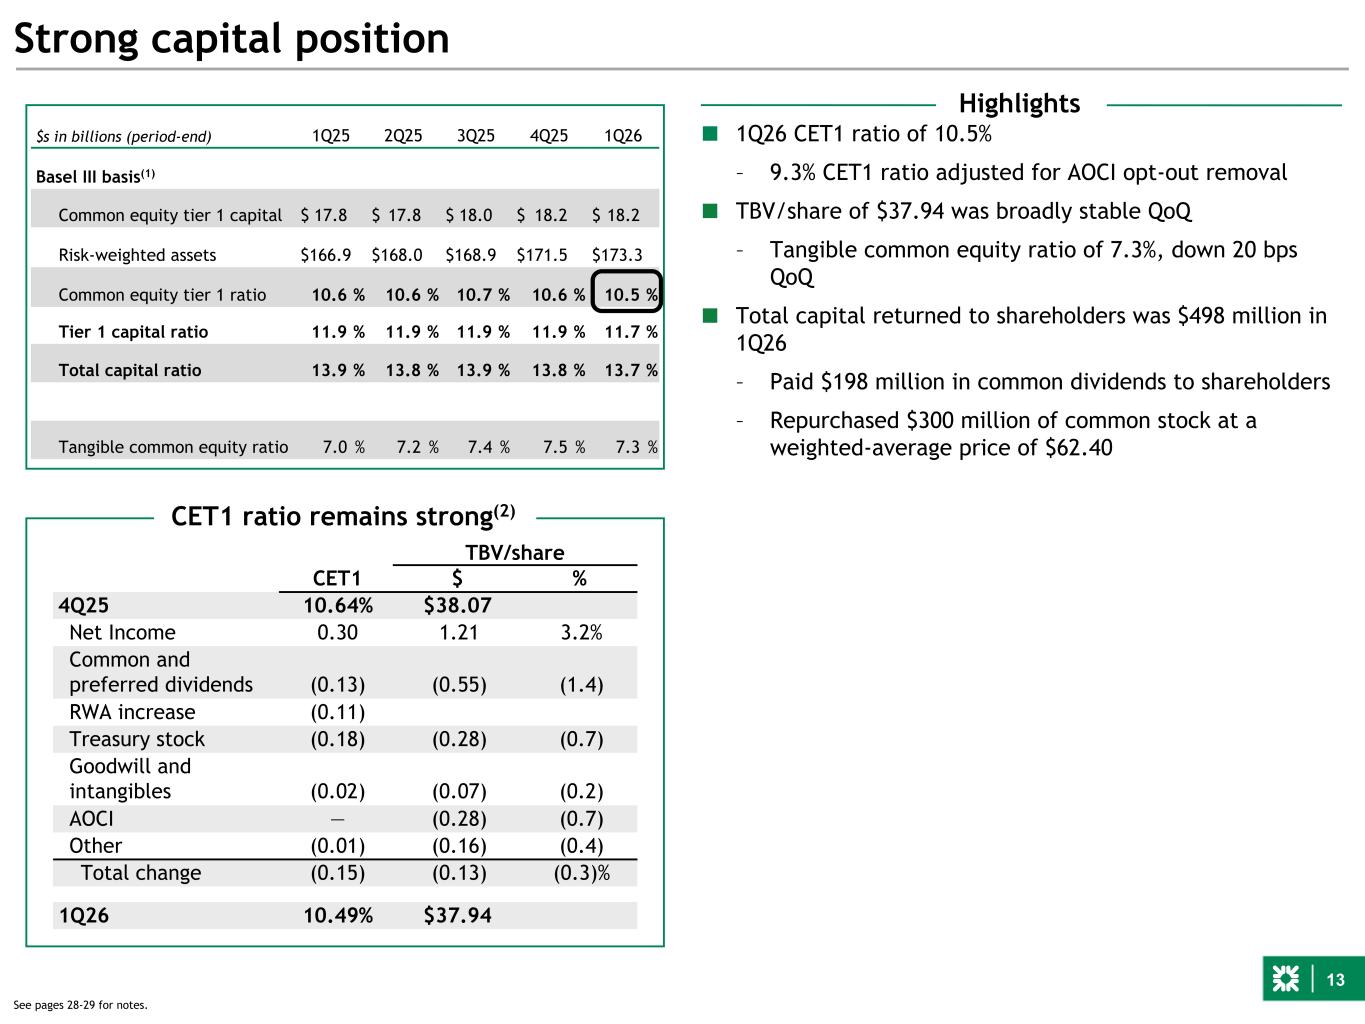
13 Strong capital position $s in billions (period-end) 1Q25 2Q25 3Q25 4Q25 1Q26 Basel III basis(1) Common equity tier 1 capital $ 17.8 $ 17.8 $ 18.0 $ 18.2 $ 18.2 Risk-weighted assets $ 166.9 $ 168.0 $ 168.9 $ 171.5 $ 173.3 Common equity tier 1 ratio 10.6 % 10.6 % 10.7 % 10.6 % 10.5 % Tier 1 capital ratio 11.9 % 11.9 % 11.9 % 11.9 % 11.7 % Total capital ratio 13.9 % 13.8 % 13.9 % 13.8 % 13.7 % Tangible common equity ratio 7.0 % 7.2 % 7.4 % 7.5 % 7.3 % TBV/share CET1 $ % 4Q25 10.64% $38.07 Net Income 0.30 1.21 3.2% Common and preferred dividends (0.13) (0.55) (1.4) RWA increase (0.11) Treasury stock (0.18) (0.28) (0.7) Goodwill and intangibles (0.02) (0.07) (0.2) AOCI — (0.28) (0.7) Other (0.01) (0.16) (0.4) Total change (0.15) (0.13) (0.3)% 1Q26 10.49% $37.94 CET1 ratio remains strong(2) Highlights ■ 1Q26 CET1 ratio of 10.5% – 9.3% CET1 ratio adjusted for AOCI opt-out removal ■ TBV/share of $37.94 was broadly stable QoQ – Tangible common equity ratio of 7.3%, down 20 bps QoQ ■ Total capital returned to shareholders was $498 million in 1Q26 – Paid $198 million in common dividends to shareholders – Repurchased $300 million of common stock at a weighted-average price of $62.40 See pages 28-29 for notes.
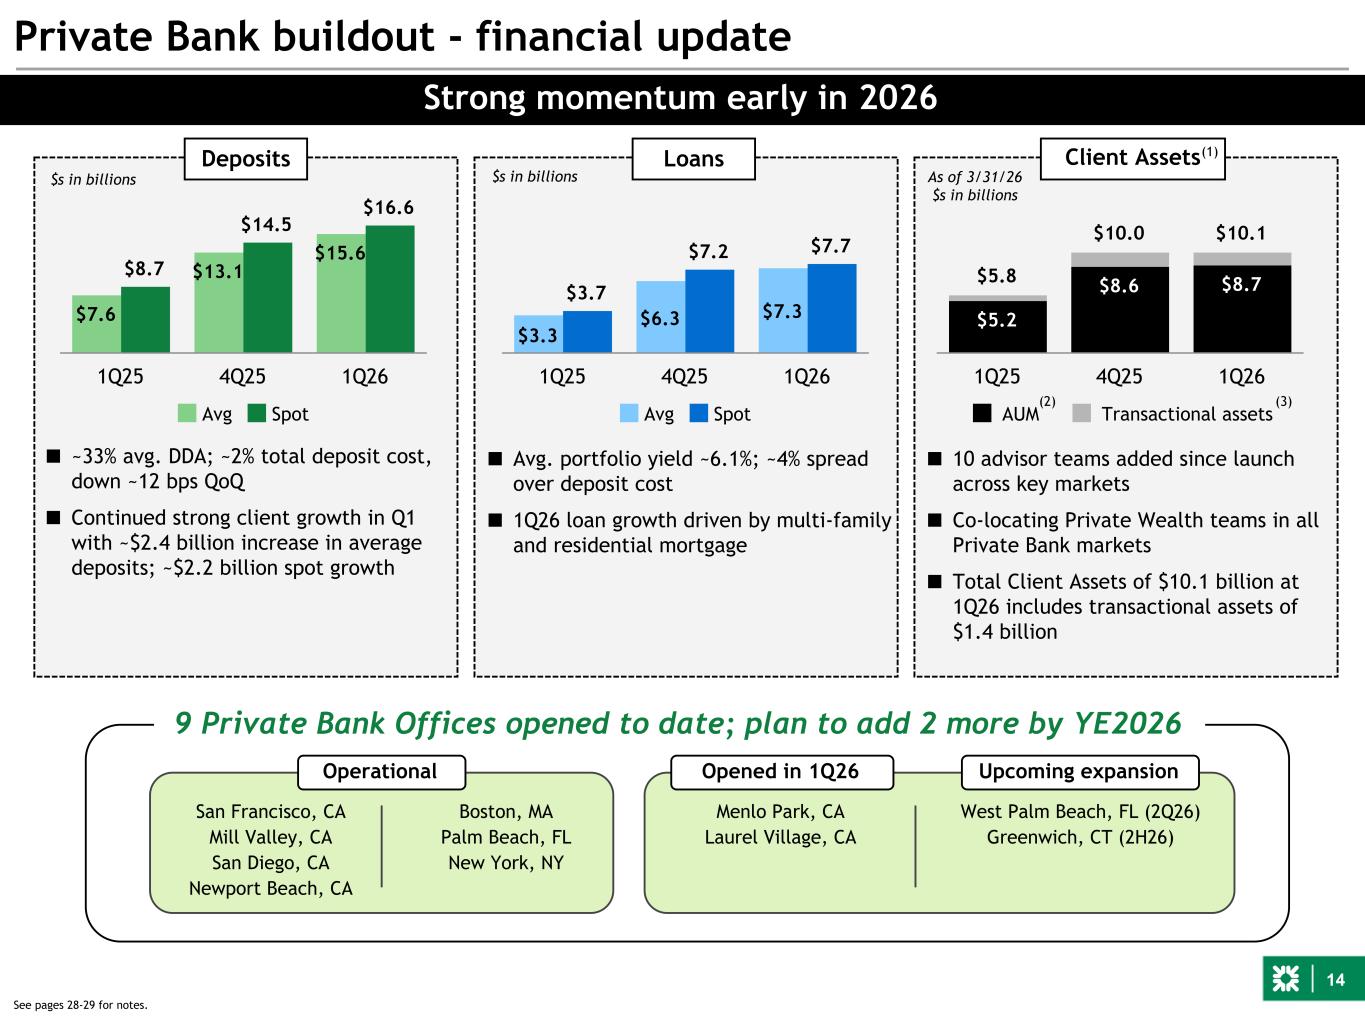
14 ■ ~33% avg. DDA; ~2% total deposit cost, down ~12 bps QoQ ■ Continued strong client growth in Q1 with ~$2.4 billion increase in average deposits; ~$2.2 billion spot growth Deposits $3.3 $6.3 $7.3 $3.7 $7.2 $7.7 Avg Spot 1Q25 4Q25 1Q26 $7.6 $13.1 $15.6 $8.7 $14.5 $16.6 Avg Spot 1Q25 4Q25 1Q26 Loans Private Bank buildout - financial update Strong momentum early in 2026 $s in billions $5.8 $10.0 $10.1 $5.2 $8.6 $8.7 AUM Transactional assets 1Q25 4Q25 1Q26 As of 3/31/26 $s in billions Client Assets ■ Avg. portfolio yield ~6.1%; ~4% spread over deposit cost ■ 1Q26 loan growth driven by multi-family and residential mortgage (2) (1) (3) 9 Private Bank Offices opened to date; plan to add 2 more by YE2026 $s in billions ■ 10 advisor teams added since launch across key markets ■ Co-locating Private Wealth teams in all Private Bank markets ■ Total Client Assets of $10.1 billion at 1Q26 includes transactional assets of $1.4 billion Operational San Francisco, CA Boston, MA Menlo Park, CA West Palm Beach, FL (2Q26) Mill Valley, CA Palm Beach, FL Laurel Village, CA Greenwich, CT (2H26) San Diego, CA New York, NY Newport Beach, CA Opened in 1Q26 Upcoming expansion See pages 28-29 for notes.
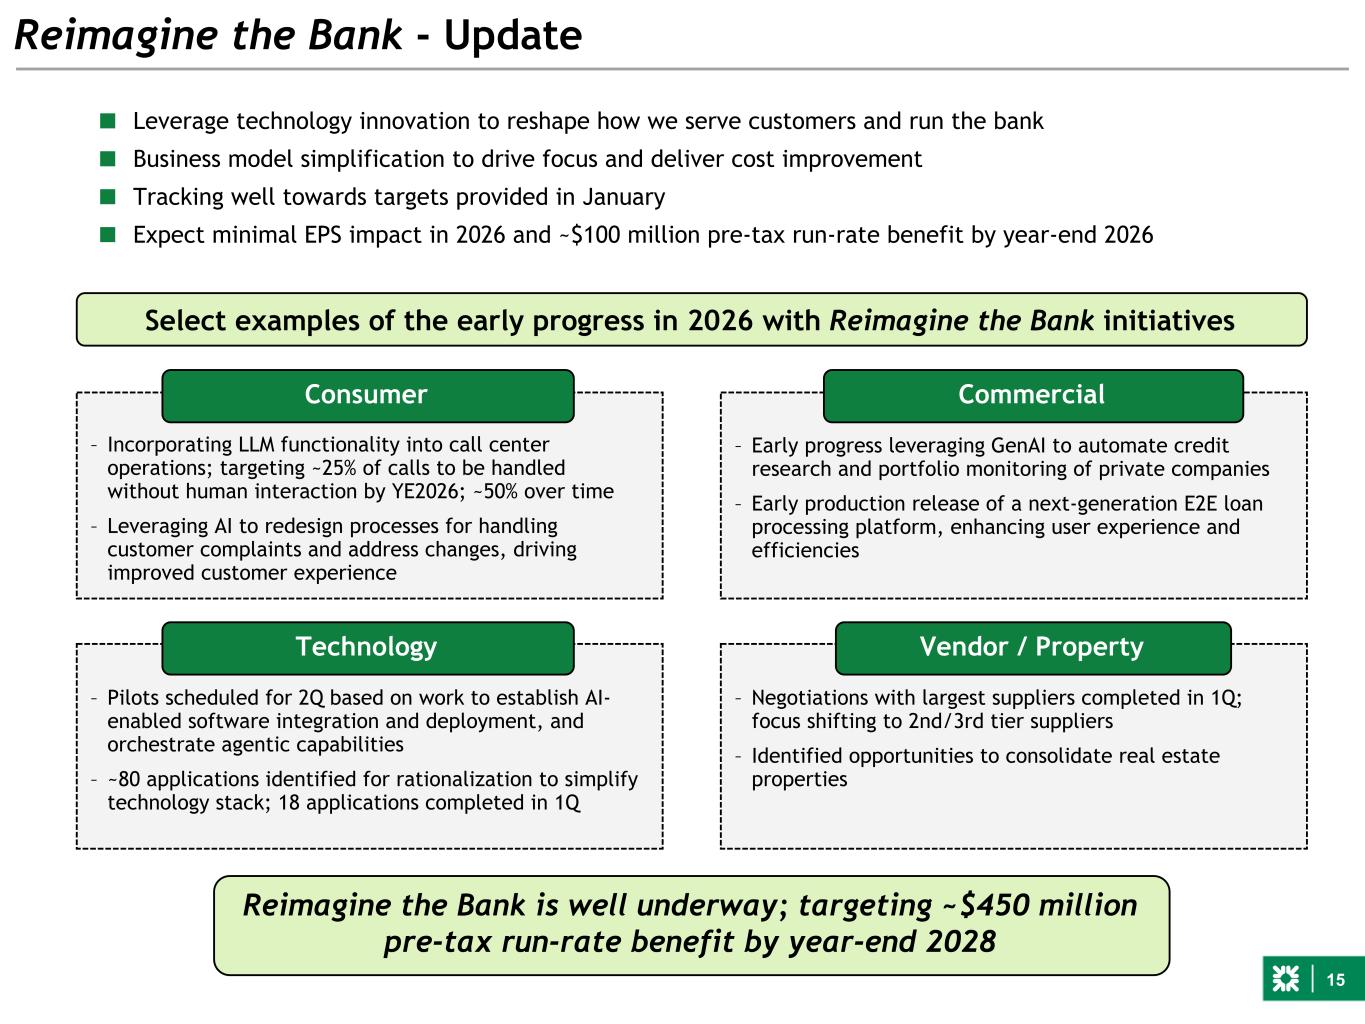
15 Reimagine the Bank - Update ■ Leverage technology innovation to reshape how we serve customers and run the bank ■ Business model simplification to drive focus and deliver cost improvement ■ Tracking well towards targets provided in January ■ Expect minimal EPS impact in 2026 and ~$100 million pre-tax run-rate benefit by year-end 2026 Consumer Commercial Technology Vendor / Property Select examples of the early progress in 2026 with Reimagine the Bank initiatives – Incorporating LLM functionality into call center operations; targeting ~25% of calls to be handled without human interaction by YE2026; ~50% over time – Leveraging AI to redesign processes for handling customer complaints and address changes, driving improved customer experience – Early progress leveraging GenAI to automate credit research and portfolio monitoring of private companies – Early production release of a next-generation E2E loan processing platform, enhancing user experience and efficiencies – Pilots scheduled for 2Q based on work to establish AI- enabled software integration and deployment, and orchestrate agentic capabilities – ~80 applications identified for rationalization to simplify technology stack; 18 applications completed in 1Q – Negotiations with largest suppliers completed in 1Q; focus shifting to 2nd/3rd tier suppliers – Identified opportunities to consolidate real estate properties Reimagine the Bank is well underway; targeting ~$450 million pre-tax run-rate benefit by year-end 2028
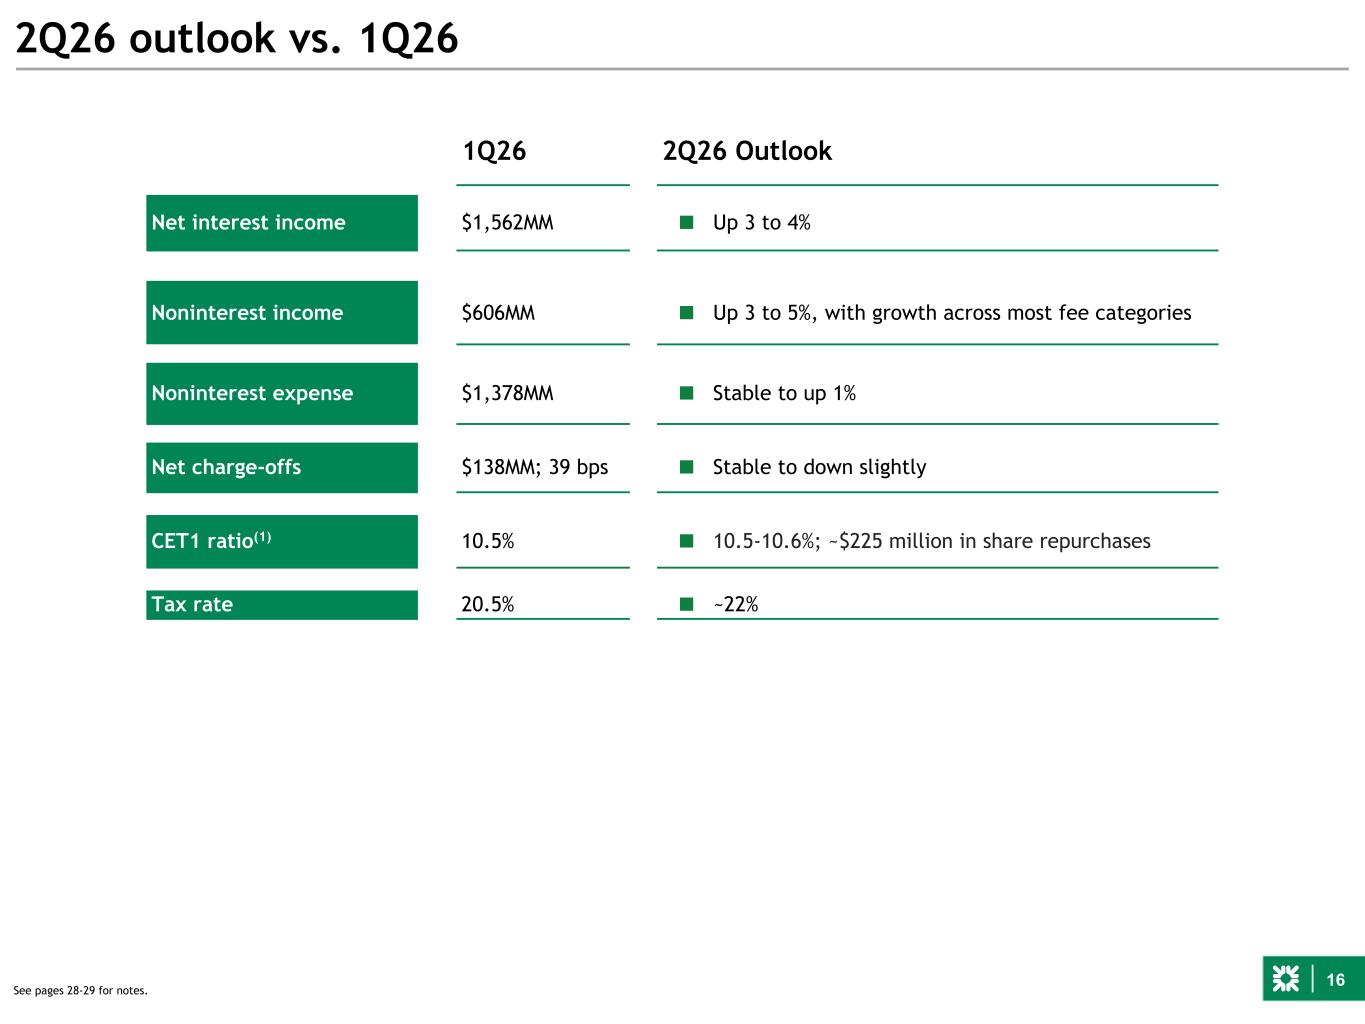
16 2Q26 outlook vs. 1Q26 See pages 28-29 for notes. 1Q26 2Q26 Outlook Net interest income $1,562MM ■ Up 3 to 4% Noninterest income $606MM ■ Up 3 to 5%, with growth across most fee categories Noninterest expense $1,378MM ■ Stable to up 1% Net charge-offs $138MM; 39 bps ■ Stable to down slightly CET1 ratio(1) 10.5% ■ 10.5-10.6%; ~$225 million in share repurchases Tax rate 20.5% ■ ~22%
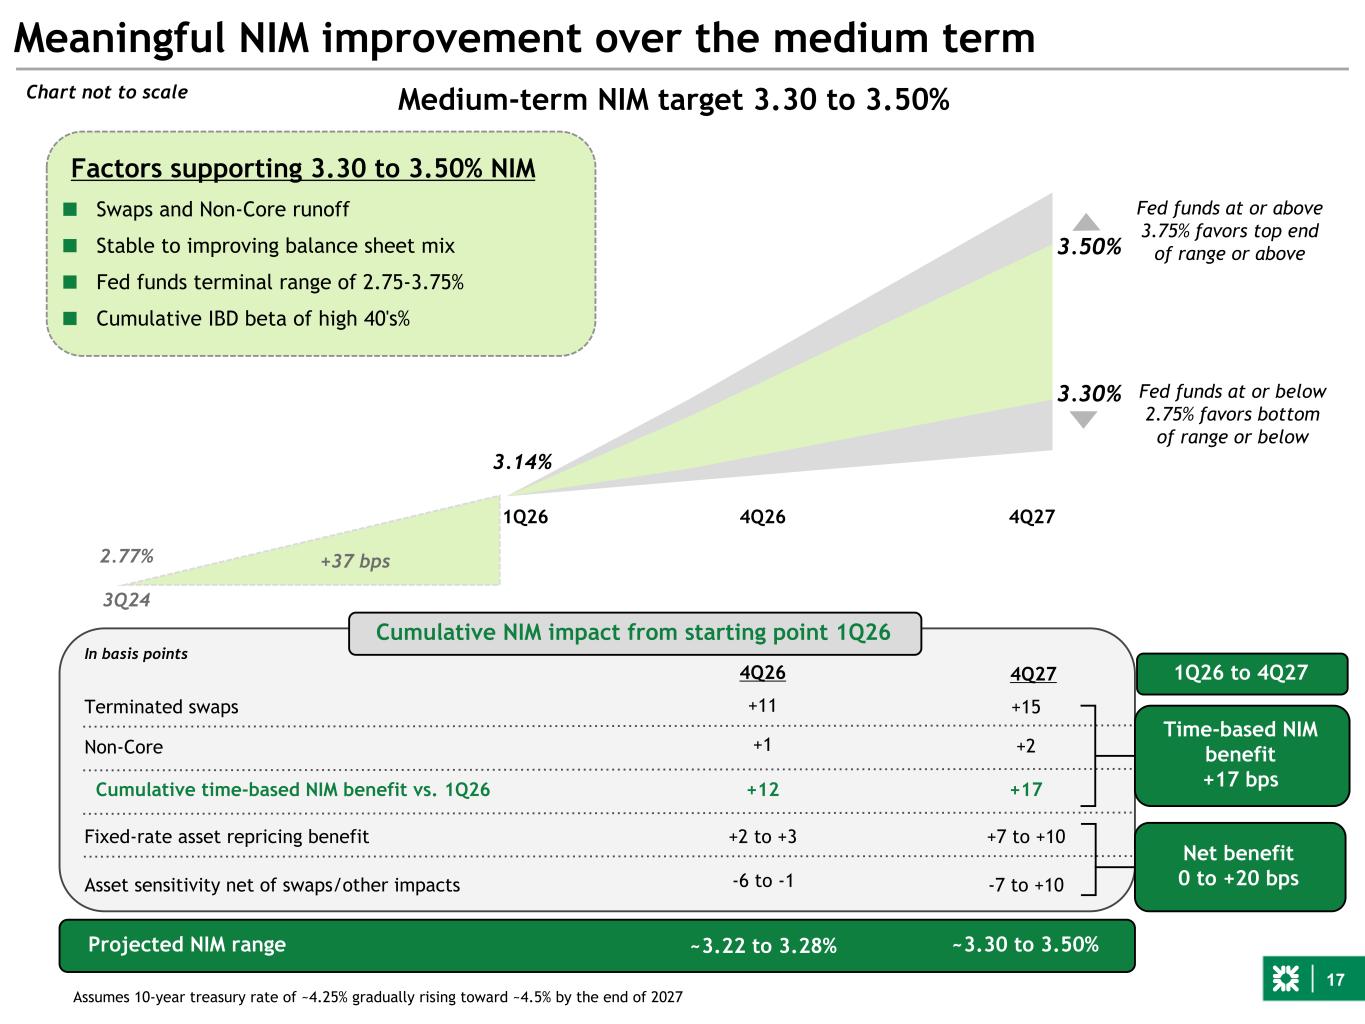
17 Meaningful NIM improvement over the medium term Medium-term NIM target 3.30 to 3.50% Terminated swaps Non-Core Asset sensitivity net of swaps/other impacts Projected NIM range Fixed-rate asset repricing benefit Cumulative time-based NIM benefit vs. 1Q26 4Q26 4Q27 In basis points +11 +1 +12 +15 +2 +17 +7 to +10 -7 to +10 ~3.30 to 3.50% Chart not to scale Net benefit 0 to +20 bps 3.30% 3.50% Fed funds at or above 3.75% favors top end of range or above Fed funds at or below 2.75% favors bottom of range or below Factors supporting 3.30 to 3.50% NIM ■ Swaps and Non-Core runoff ■ Stable to improving balance sheet mix ■ Fed funds terminal range of 2.75-3.75% ■ Cumulative IBD beta of high 40's% Time-based NIM benefit +17 bps Assumes 10-year treasury rate of ~4.25% gradually rising toward ~4.5% by the end of 2027 +2 to +3 Cumulative NIM impact from starting point 1Q26 3Q24 2.77% 1Q26 3.14% 4Q26 4Q27 +37 bps -6 to -1 ~3.22 to 3.28% 1Q26 to 4Q27
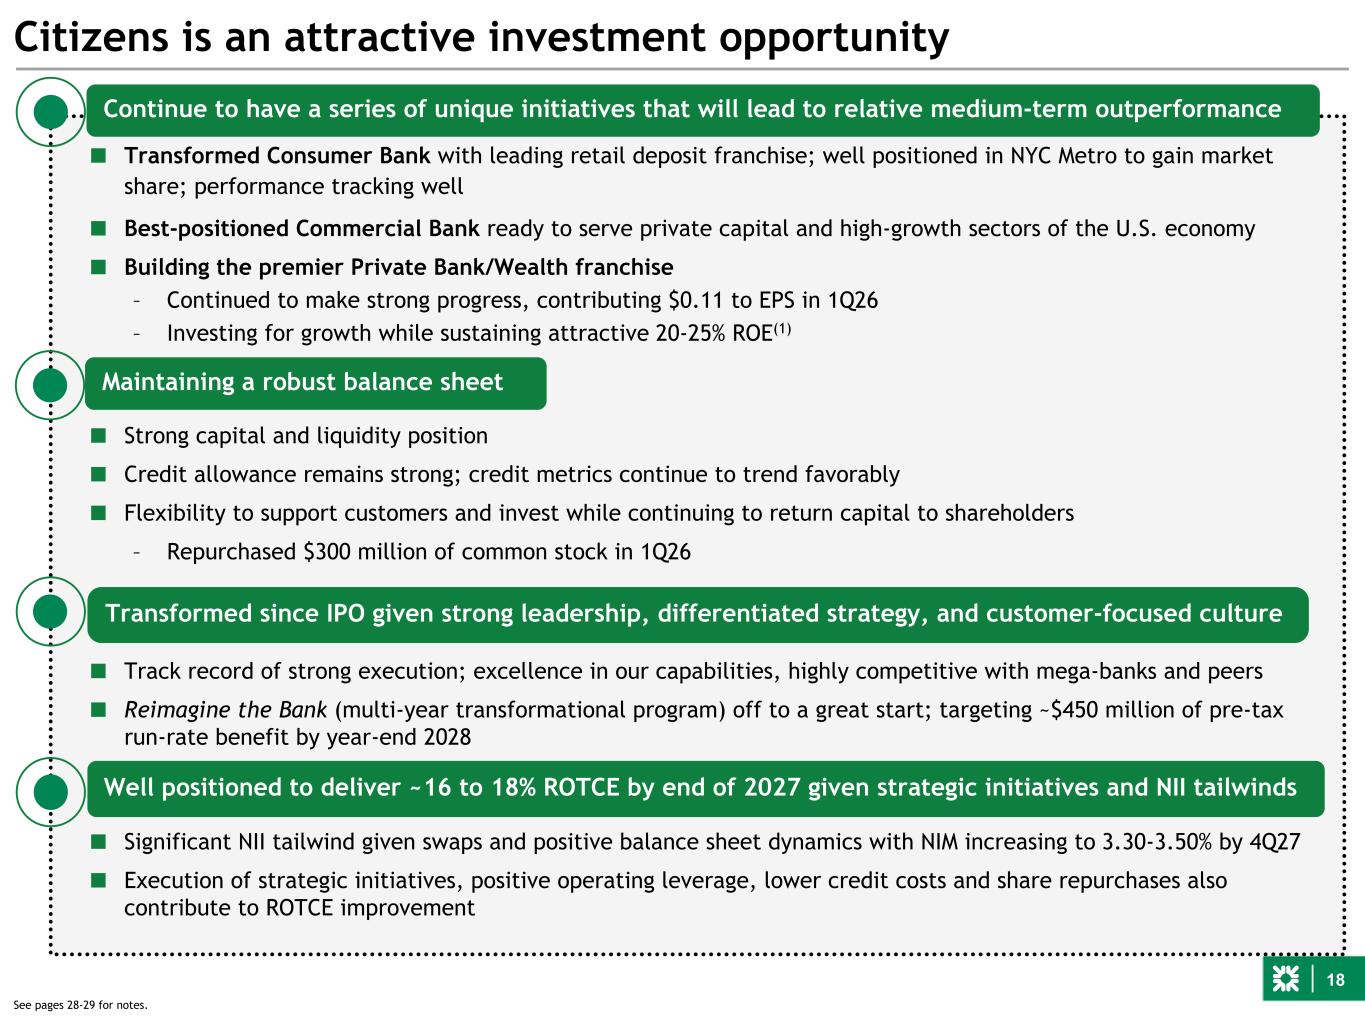
18 ■ Track record of strong execution; excellence in our capabilities, highly competitive with mega-banks and peers ■ Reimagine the Bank (multi-year transformational program) off to a great start; targeting ~$450 million of pre-tax run-rate benefit by year-end 2028 ■ Strong capital and liquidity position ■ Credit allowance remains strong; credit metrics continue to trend favorably ■ Flexibility to support customers and invest while continuing to return capital to shareholders – Repurchased $300 million of common stock in 1Q26 Citizens is an attractive investment opportunity Maintaining a robust balance sheet Transformed since IPO given strong leadership, differentiated strategy, and customer-focused culture Well positioned to deliver ~16 to 18% ROTCE by end of 2027 given strategic initiatives and NII tailwinds ■ Transformed Consumer Bank with leading retail deposit franchise; well positioned in NYC Metro to gain market share; performance tracking well ■ Best-positioned Commercial Bank ready to serve private capital and high-growth sectors of the U.S. economy ■ Building the premier Private Bank/Wealth franchise – Continued to make strong progress, contributing $0.11 to EPS in 1Q26 – Investing for growth while sustaining attractive 20-25% ROE(1) ■ Significant NII tailwind given swaps and positive balance sheet dynamics with NIM increasing to 3.30-3.50% by 4Q27 ■ Execution of strategic initiatives, positive operating leverage, lower credit costs and share repurchases also contribute to ROTCE improvement Continue to have a series of unique initiatives that will lead to relative medium-term outperformance See pages 28-29 for notes.
Appendix ■ Private Bank financial performance ■ Interest rate risk management ■ Non-Core portfolio ■ Credit
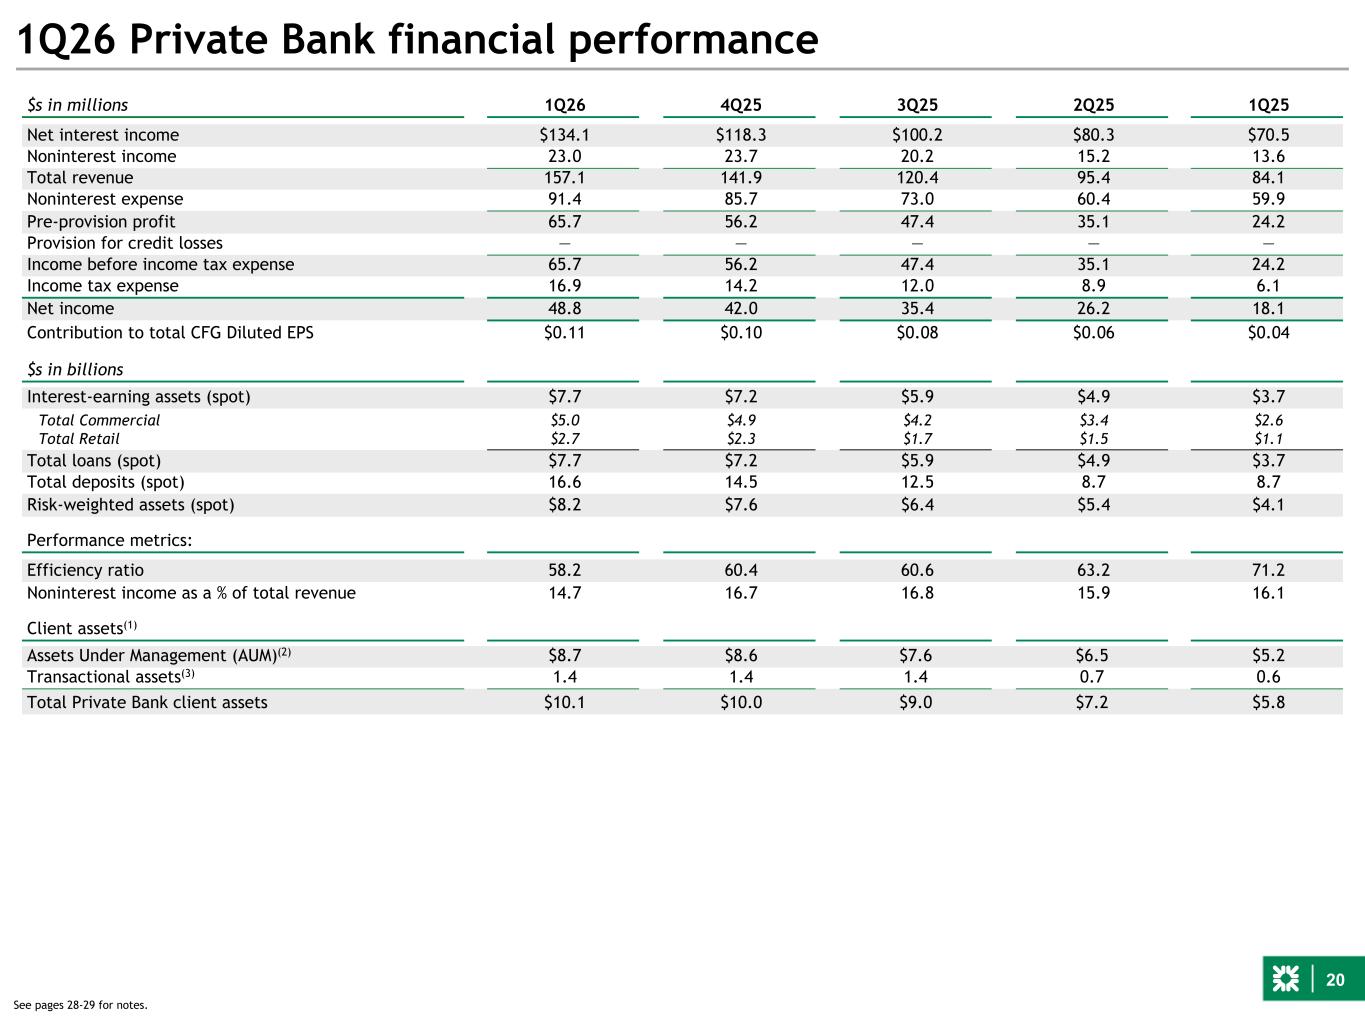
20 1Q26 Private Bank financial performance $s in millions 1Q26 4Q25 3Q25 2Q25 1Q25 Net interest income $134.1 $118.3 $100.2 $80.3 $70.5 Noninterest income 23.0 23.7 20.2 15.2 13.6 Total revenue 157.1 141.9 120.4 95.4 84.1 Noninterest expense 91.4 85.7 73.0 60.4 59.9 Pre-provision profit 65.7 56.2 47.4 35.1 24.2 Provision for credit losses — — — — — Income before income tax expense 65.7 56.2 47.4 35.1 24.2 Income tax expense 16.9 14.2 12.0 8.9 6.1 Net income 48.8 42.0 35.4 26.2 18.1 Contribution to total CFG Diluted EPS $0.11 $0.10 $0.08 $0.06 $0.04 $s in billions Interest-earning assets (spot) $7.7 $7.2 $5.9 $4.9 $3.7 Total Commercial $5.0 $4.9 $4.2 $3.4 $2.6 Total Retail $2.7 $2.3 $1.7 $1.5 $1.1 Total loans (spot) $7.7 $7.2 $5.9 $4.9 $3.7 Total deposits (spot) 16.6 14.5 12.5 8.7 8.7 Risk-weighted assets (spot) $8.2 $7.6 $6.4 $5.4 $4.1 Performance metrics: Efficiency ratio 58.2 60.4 60.6 63.2 71.2 Noninterest income as a % of total revenue 14.7 16.7 16.8 15.9 16.1 Client assets(1) Assets Under Management (AUM)(2) $8.7 $8.6 $7.6 $6.5 $5.2 Transactional assets(3) 1.4 1.4 1.4 0.7 0.6 Total Private Bank client assets $10.1 $10.0 $9.0 $7.2 $5.8 See pages 28-29 for notes.
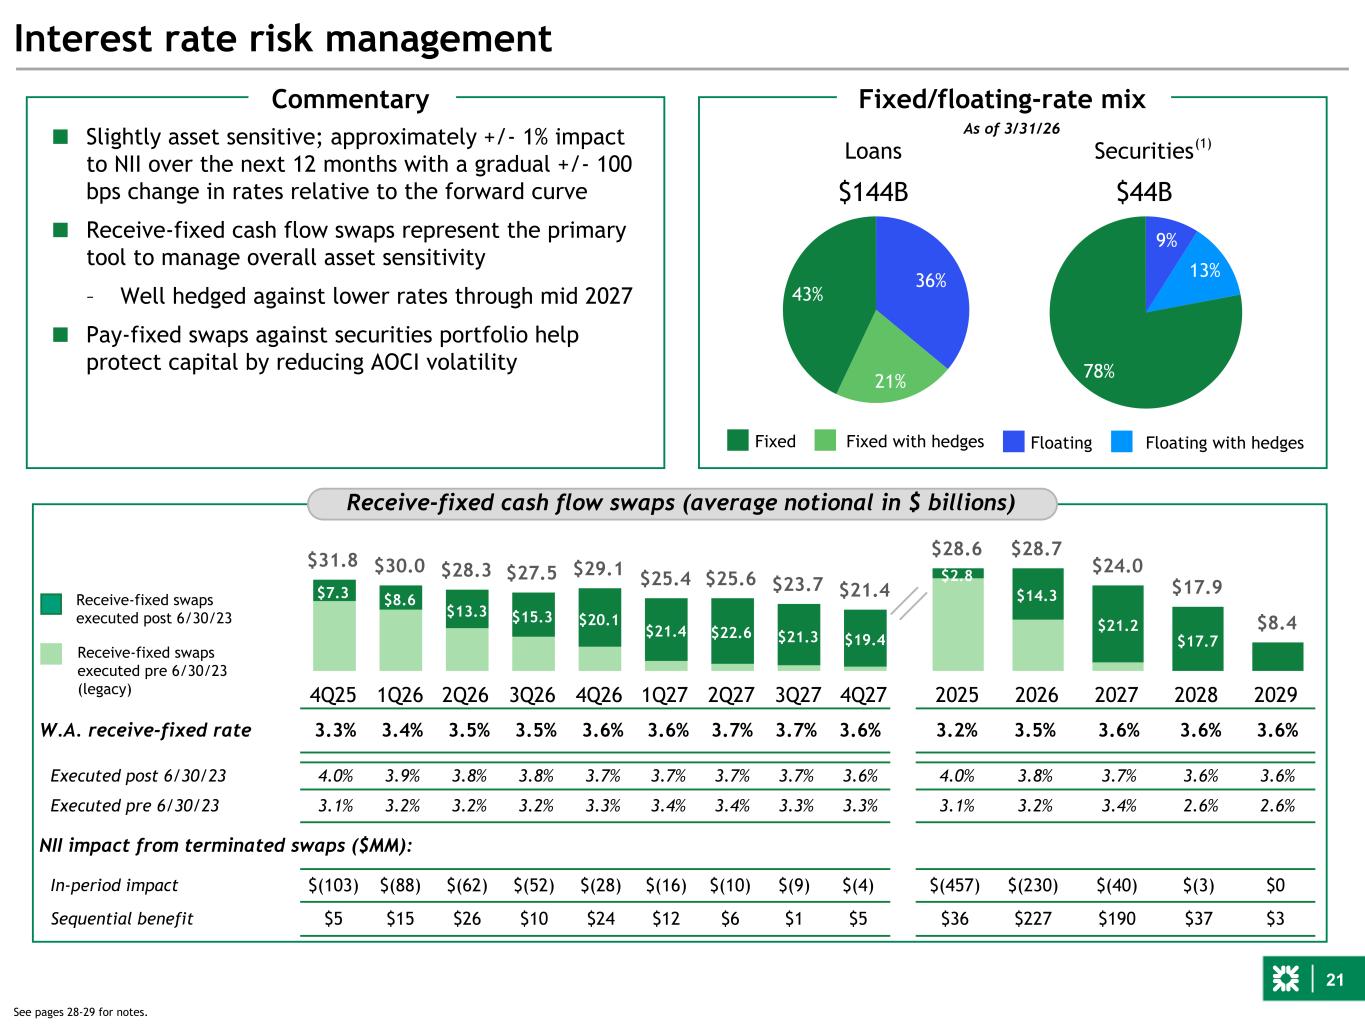
21 $31.8 $30.0 $28.3 $27.5 $29.1 $25.4 $25.6 $23.7 $21.4$7.3 $8.6 $13.3 $15.3 $20.1 $21.4 $22.6 $21.3 $19.4 4Q25 1Q26 2Q26 3Q26 4Q26 1Q27 2Q27 3Q27 4Q27 $28.6 $28.7 $24.0 $17.9 $8.4 $2.8 $14.3 $21.2 $17.7 2025 2026 2027 2028 2029 Interest rate risk management W.A. receive-fixed rate 3.3% 3.4% 3.5% 3.5% 3.6% 3.6% 3.7% 3.7% 3.6% 3.2% 3.5% 3.6% 3.6% 3.6% Executed post 6/30/23 4.0% 3.9% 3.8% 3.8% 3.7% 3.7% 3.7% 3.7% 3.6% 4.0% 3.8% 3.7% 3.6% 3.6% Executed pre 6/30/23 3.1% 3.2% 3.2% 3.2% 3.3% 3.4% 3.4% 3.3% 3.3% 3.1% 3.2% 3.4% 2.6% 2.6% NII impact from terminated swaps ($MM): In-period impact $(103) $(88) $(62) $(52) $(28) $(16) $(10) $(9) $(4) $(457) $(230) $(40) $(3) $0 Sequential benefit $5 $15 $26 $10 $24 $12 $6 $1 $5 $36 $227 $190 $37 $3 Receive-fixed cash flow swaps (average notional in $ billions) ■ Slightly asset sensitive; approximately +/- 1% impact to NII over the next 12 months with a gradual +/- 100 bps change in rates relative to the forward curve ■ Receive-fixed cash flow swaps represent the primary tool to manage overall asset sensitivity – Well hedged against lower rates through mid 2027 ■ Pay-fixed swaps against securities portfolio help protect capital by reducing AOCI volatility Receive-fixed swaps executed post 6/30/23 Receive-fixed swaps executed pre 6/30/23 (legacy) Fixed/floating-rate mix 9% 13% 78% Securities $44B 36% 21% 43% Loans $144B Fixed Fixed with hedges Floating Floating with hedges Commentary 15% 15% 70% As of 3/31/26 (1) See pages 28-29 for notes.
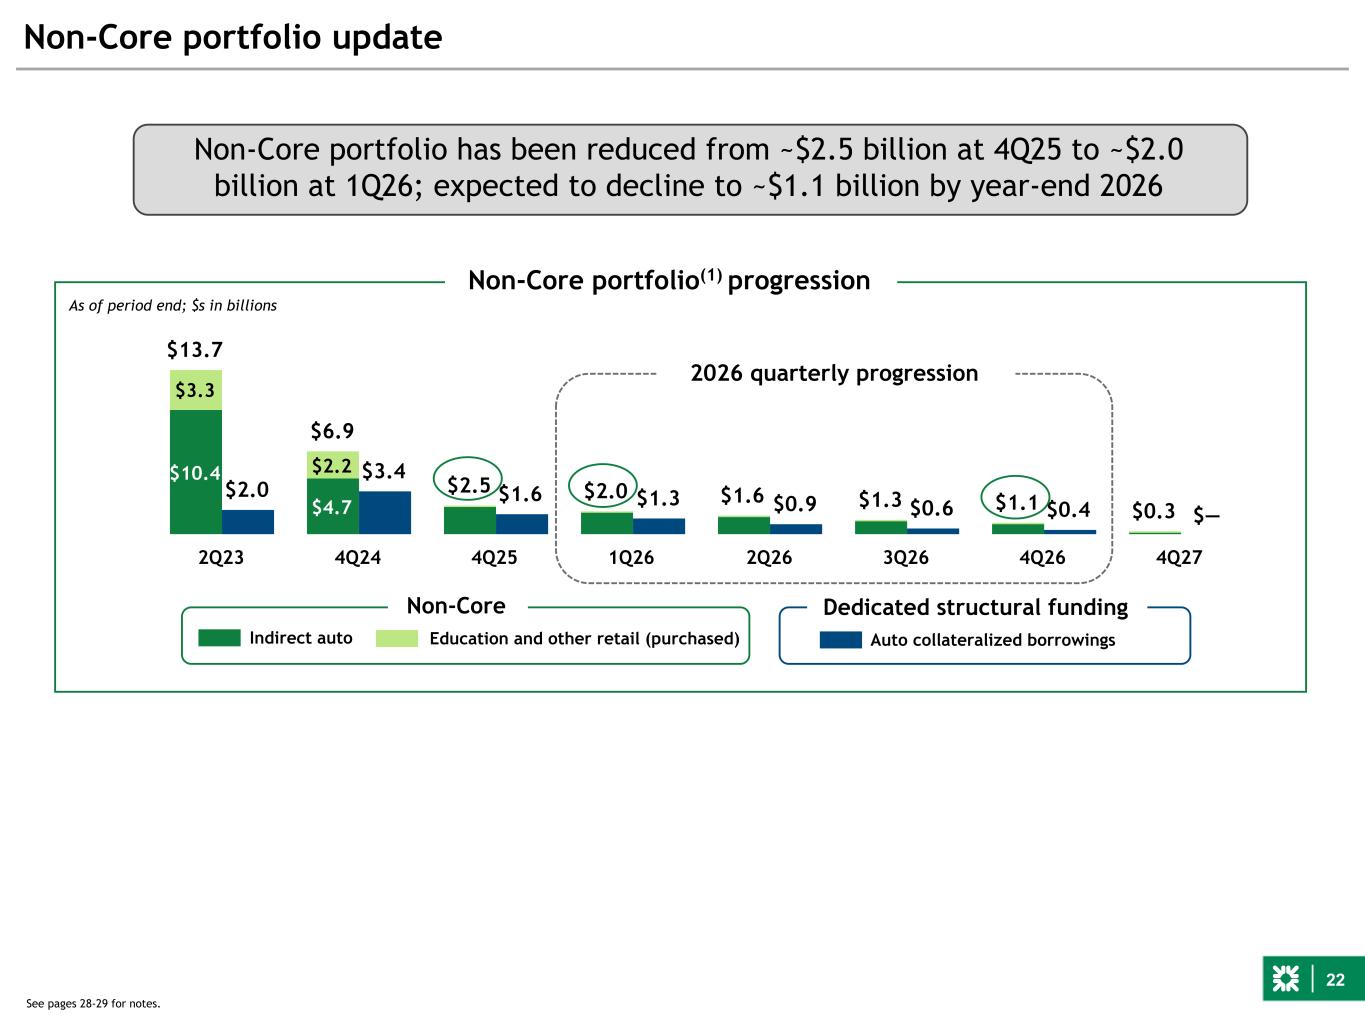
22 $13.7 $6.9 $2.5 $2.0 $1.6 $1.3 $1.1 $0.3 $2.0 $3.4 $1.6 $1.3 $0.9 $0.6 $0.4 $— $10.4 $4.7 $3.3 $2.2 2Q23 4Q24 4Q25 1Q26 2Q26 3Q26 4Q26 4Q27 Non-Core portfolio update Non-Core Dedicated structural funding Indirect auto Auto collateralized borrowings As of period end; $s in billions See pages 28-29 for notes. Non-Core portfolio(1) progression Education and other retail (purchased) Non-Core portfolio has been reduced from ~$2.5 billion at 4Q25 to ~$2.0 billion at 1Q26; expected to decline to ~$1.1 billion by year-end 2026 2026 quarterly progression
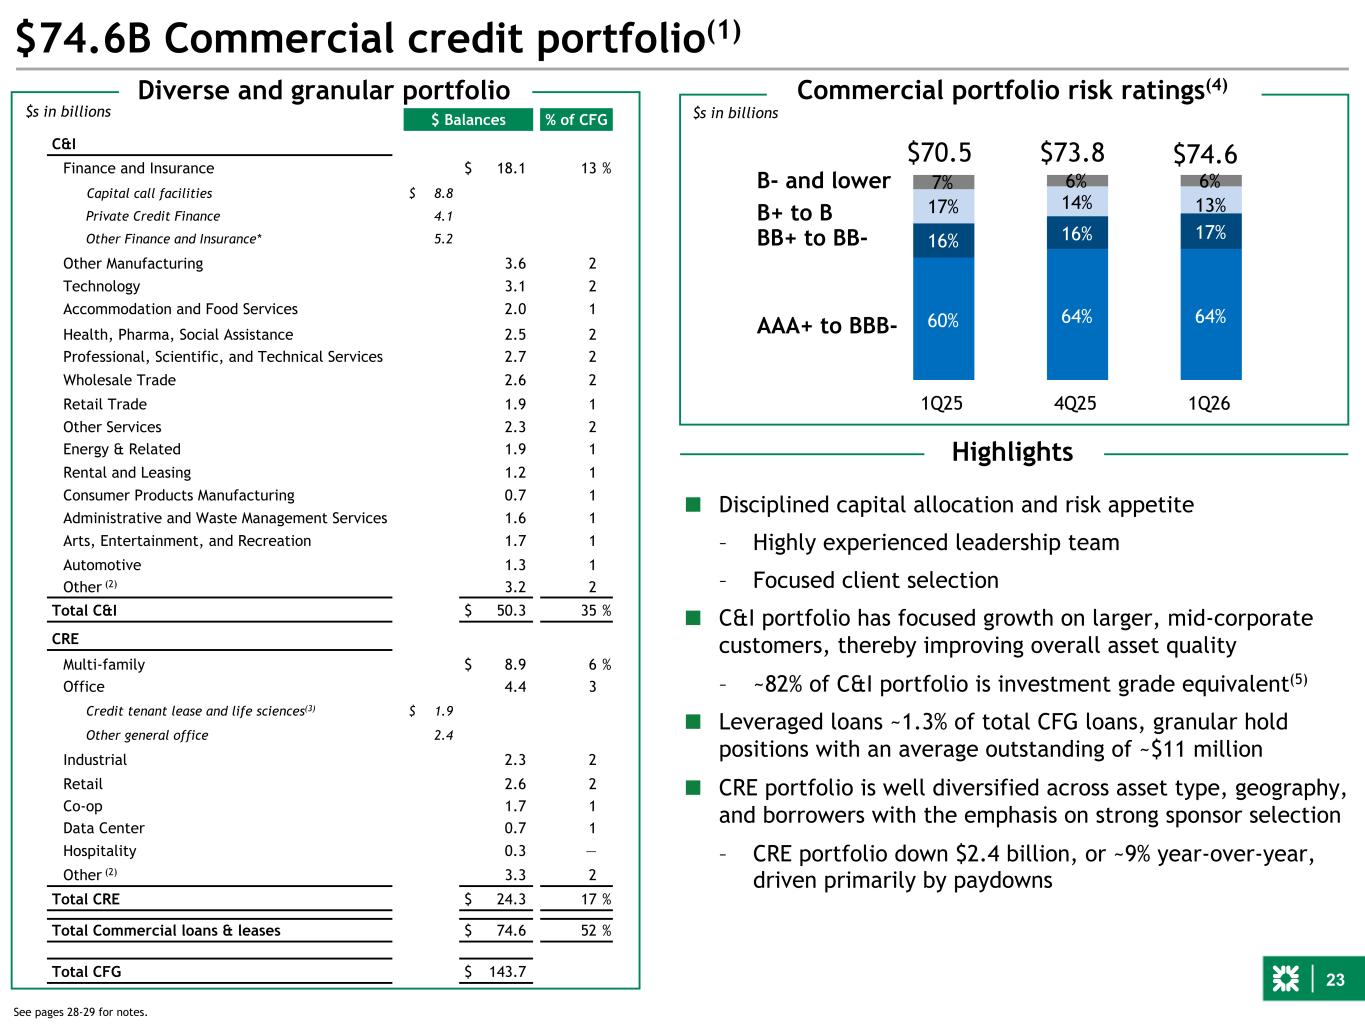
23 $74.6B Commercial credit portfolio(1) Commercial portfolio risk ratings(4) $s in billions 60% 64% 64% 16% 16% 17% 17% 14% 13% 7% 6% 6% 1Q25 4Q25 1Q26 B- and lower B+ to B BB+ to BB- AAA+ to BBB- $74.6 Highlights $73.8 $ Balances % of CFG C&I Finance and Insurance $ 18.1 13 % Capital call facilities $ 8.8 Private Credit Finance 4.1 Other Finance and Insurance* 5.2 Other Manufacturing 3.6 2 Technology 3.1 2 Accommodation and Food Services 2.0 1 Health, Pharma, Social Assistance 2.5 2 Professional, Scientific, and Technical Services 2.7 2 Wholesale Trade 2.6 2 Retail Trade 1.9 1 Other Services 2.3 2 Energy & Related 1.9 1 Rental and Leasing 1.2 1 Consumer Products Manufacturing 0.7 1 Administrative and Waste Management Services 1.6 1 Arts, Entertainment, and Recreation 1.7 1 Automotive 1.3 1 Other (2) 3.2 2 Total C&I $ 50.3 35 % CRE Multi-family $ 8.9 6 % Office 4.4 3 Credit tenant lease and life sciences(3) $ 1.9 Other general office 2.4 Industrial 2.3 2 Retail 2.6 2 Co-op 1.7 1 Data Center 0.7 1 Hospitality 0.3 — Other (2) 3.3 2 Total CRE $ 24.3 17 % Total Commercial loans & leases $ 74.6 52 % Total CFG $ 143.7 Diverse and granular portfolio ■ Disciplined capital allocation and risk appetite – Highly experienced leadership team – Focused client selection ■ C&I portfolio has focused growth on larger, mid-corporate customers, thereby improving overall asset quality – ~82% of C&I portfolio is investment grade equivalent(5) ■ Leveraged loans ~1.3% of total CFG loans, granular hold positions with an average outstanding of ~$11 million ■ CRE portfolio is well diversified across asset type, geography, and borrowers with the emphasis on strong sponsor selection – CRE portfolio down $2.4 billion, or ~9% year-over-year, driven primarily by paydowns $70.5 See pages 28-29 for notes. $s in billions
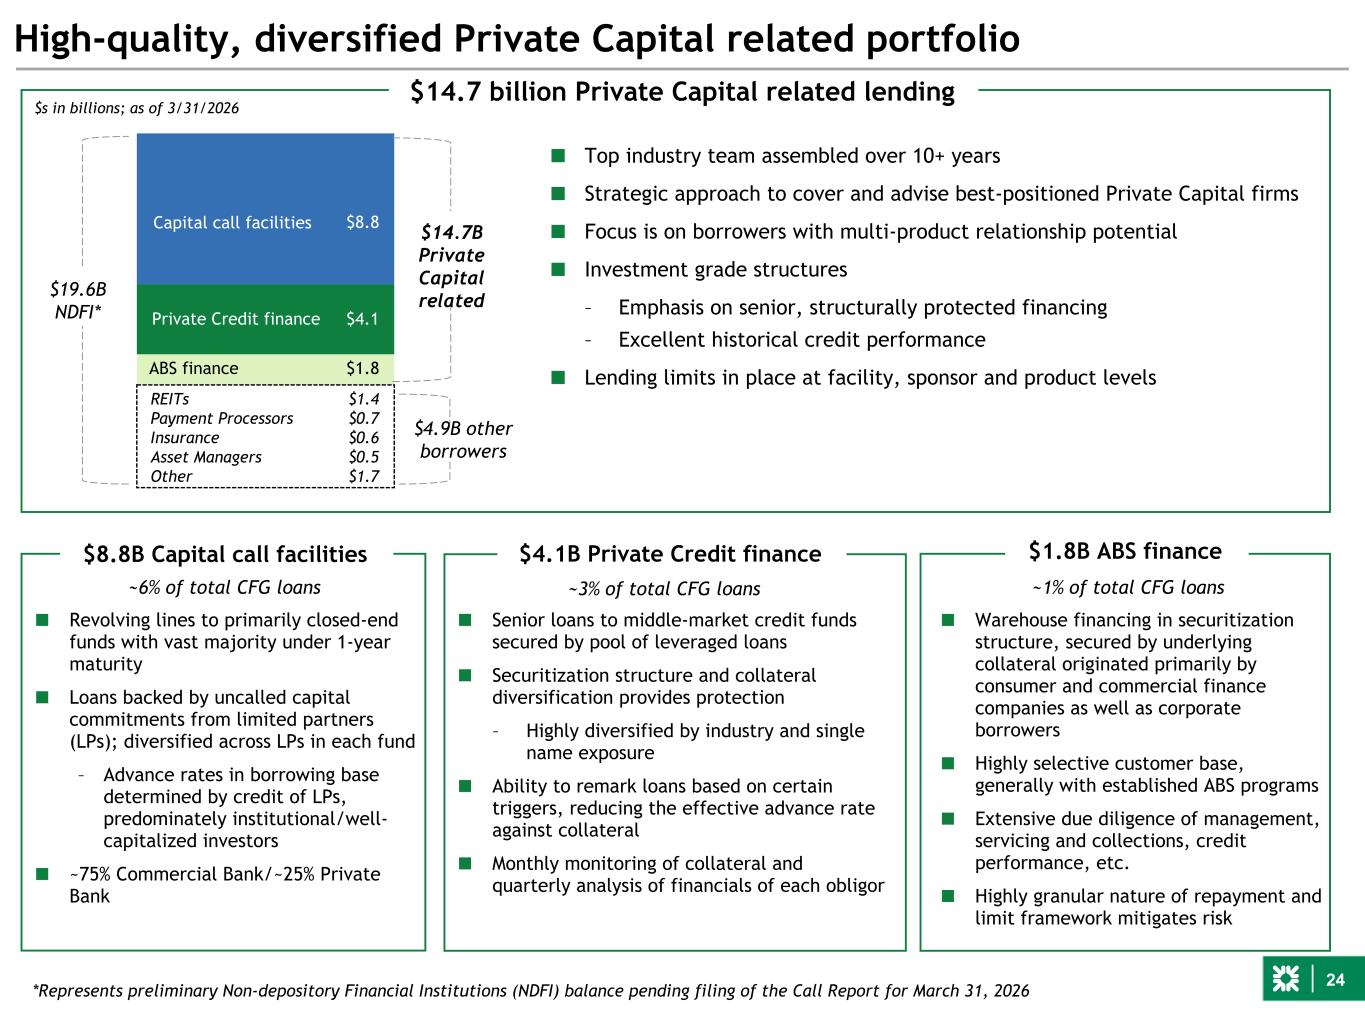
24 High-quality, diversified Private Capital related portfolio Capital call facilities Private Credit finance $8.6 $4.1 $s in billions; as of 3/31/2026 $8.8B Capital call facilities $1.8B ABS finance ■ Senior loans to middle-market credit funds secured by pool of leveraged loans ■ Securitization structure and collateral diversification provides protection – Highly diversified by industry and single name exposure ■ Ability to remark loans based on certain triggers, reducing the effective advance rate against collateral ■ Monthly monitoring of collateral and quarterly analysis of financials of each obligor ■ Warehouse financing in securitization structure, secured by underlying collateral originated primarily by consumer and commercial finance companies as well as corporate borrowers ■ Highly selective customer base, generally with established ABS programs ■ Extensive due diligence of management, servicing and collections, credit performance, etc. ■ Highly granular nature of repayment and limit framework mitigates risk ■ Revolving lines to primarily closed-end funds with vast majority under 1-year maturity ■ Loans backed by uncalled capital commitments from limited partners (LPs); diversified across LPs in each fund – Advance rates in borrowing base determined by credit of LPs, predominately institutional/well- capitalized investors ■ ~75% Commercial Bank/~25% Private Bank $4.1B Private Credit finance $19.6B NDFI* ABS finance $1.8 REITs Payment Processors Insurance Asset Managers Other $14.7B Private Capital related Capital call facilities $8.8 $14.7 billion Private Capital related lending ~6% of total CFG loans ~3% of total CFG loans ~1% of total CFG loans *Represents preliminary Non-depository Financial Institutions (NDFI) balance pending filing of the Call Report for March 31, 2026 $1.4 $0.7 $0.6 $0.5 $1.7 ■ Top industry team assembled over 10+ years ■ Strategic approach to cover and advise best-positioned Private Capital firms ■ Focus is on borrowers with multi-product relationship potential ■ Investment grade structures – Emphasis on senior, structurally protected financing – Excellent historical credit performance ■ Lending limits in place at facility, sponsor and product levels $4.9B other borrowers
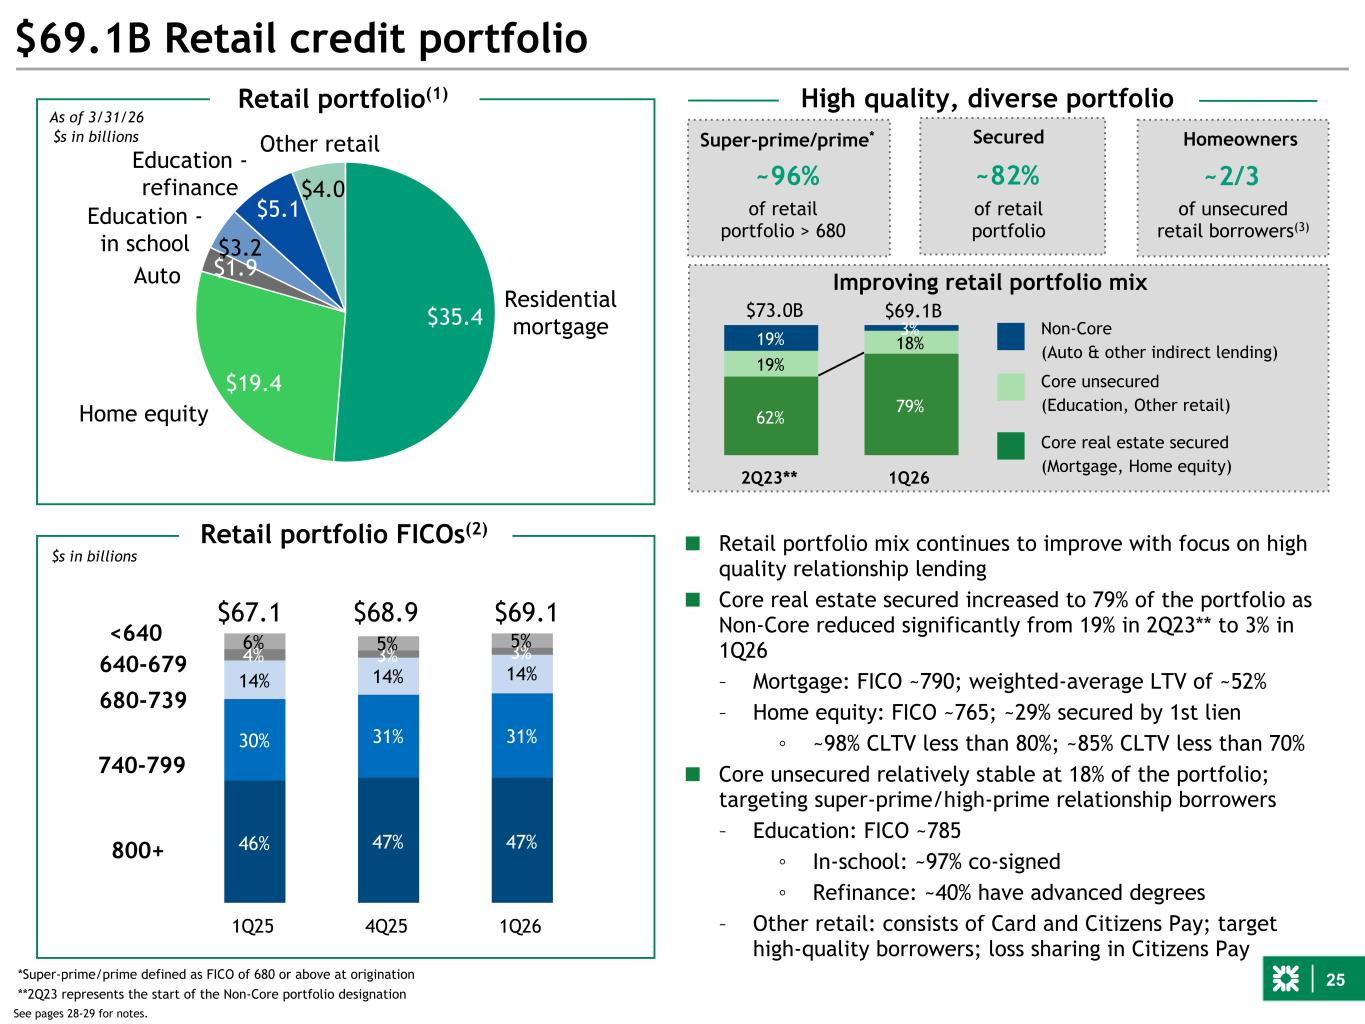
25 46% 47% 47% 30% 31% 31% 14% 14% 14% 4% 3% 3%6% 5% 5% 1Q25 4Q25 1Q26 $35.4 $19.4 $1.9 $3.2 $5.1 $4.0 $69.1B Retail credit portfolio 800+ 740-799 680-739 640-679 <640 $69.1 $s in billions $68.9 Home equity Retail portfolio(1) Residential mortgage Auto Education - in school Education - refinance Other retail ~96% Super-prime/prime* ~82% Secured ■ Retail portfolio mix continues to improve with focus on high quality relationship lending ■ Core real estate secured increased to 79% of the portfolio as Non-Core reduced significantly from 19% in 2Q23** to 3% in 1Q26 – Mortgage: FICO ~790; weighted-average LTV of ~52% – Home equity: FICO ~765; ~29% secured by 1st lien ◦ ~98% CLTV less than 80%; ~85% CLTV less than 70% ■ Core unsecured relatively stable at 18% of the portfolio; targeting super-prime/high-prime relationship borrowers – Education: FICO ~785 ◦ In-school: ~97% co-signed ◦ Refinance: ~40% have advanced degrees – Other retail: consists of Card and Citizens Pay; target high-quality borrowers; loss sharing in Citizens Pay High quality, diverse portfolio *Super-prime/prime defined as FICO of 680 or above at origination Retail portfolio FICOs(2) $67.1 Homeowners ~2/3 See pages 28-29 for notes. As of 3/31/26 62% 79% 19% 18%19% 3% 2Q23** 1Q26 Non-Core (Auto & other indirect lending) Core unsecured (Education, Other retail) Core real estate secured (Mortgage, Home equity) of unsecured retail borrowers(3) of retail portfolio > 680 Improving retail portfolio mix of retail portfolio **2Q23 represents the start of the Non-Core portfolio designation $69.1B$73.0B $s in billions To discuss: provide LTV stratification of 1st mortgages in light of B3E?
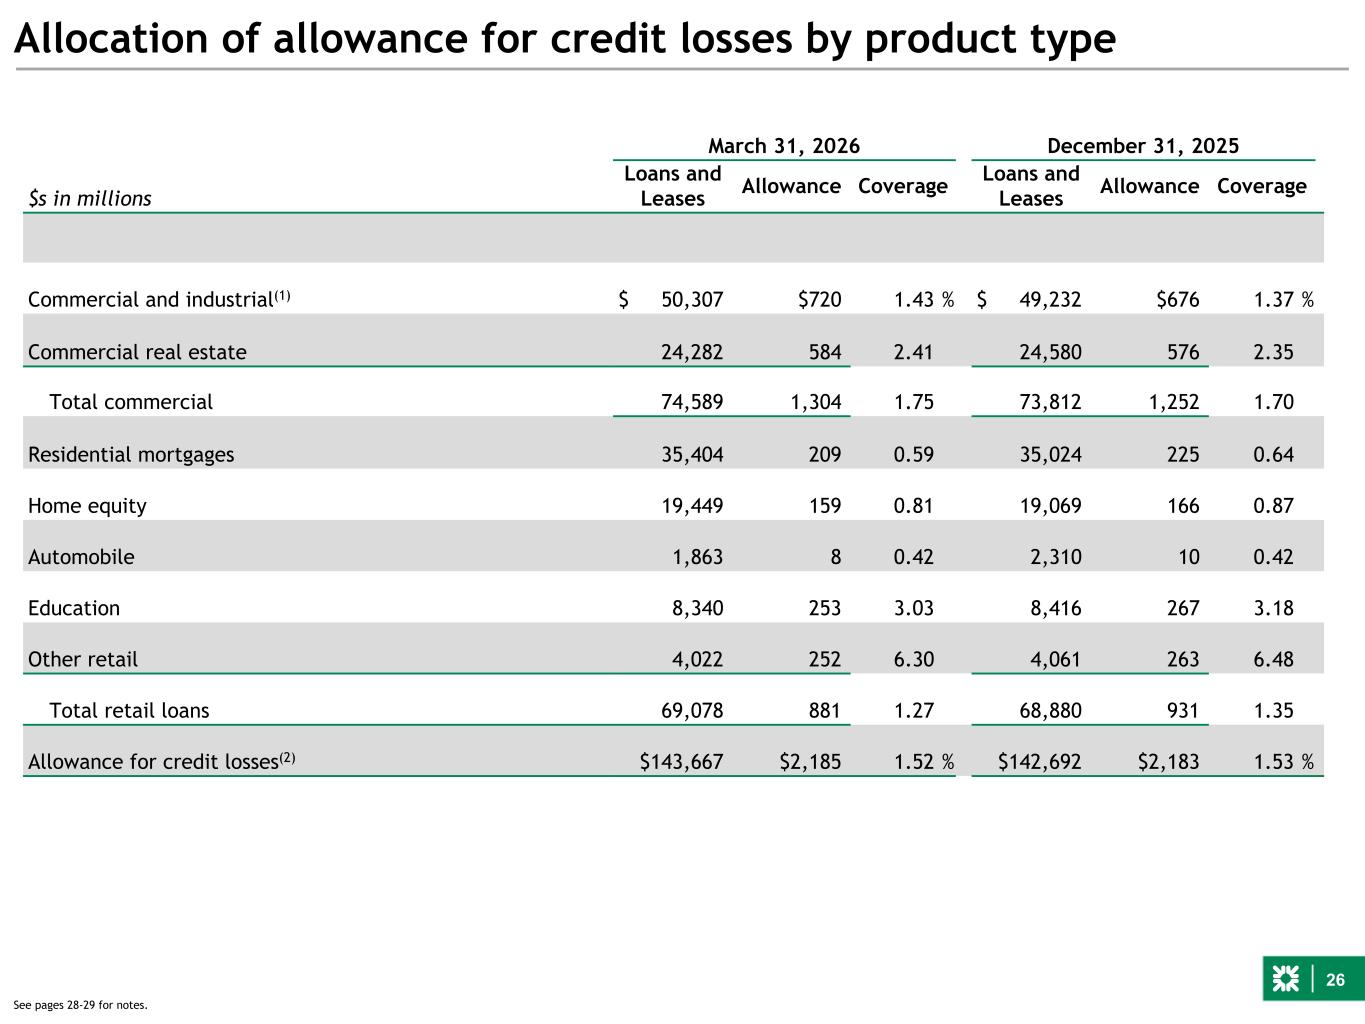
26 Allocation of allowance for credit losses by product type March 31, 2026 December 31, 2025 $s in millions Loans and Leases Allowance Coverage Loans and Leases Allowance Coverage Commercial and industrial(1) $ 50,307 $720 1.43 % $ 49,232 $676 1.37 % Commercial real estate 24,282 584 2.41 24,580 576 2.35 Total commercial 74,589 1,304 1.75 73,812 1,252 1.70 Residential mortgages 35,404 209 0.59 35,024 225 0.64 Home equity 19,449 159 0.81 19,069 166 0.87 Automobile 1,863 8 0.42 2,310 10 0.42 Education 8,340 253 3.03 8,416 267 3.18 Other retail 4,022 252 6.30 4,061 263 6.48 Total retail loans 69,078 881 1.27 68,880 931 1.35 Allowance for credit losses(2) $143,667 $2,185 1.52 % $142,692 $2,183 1.53 % See pages 28-29 for notes.
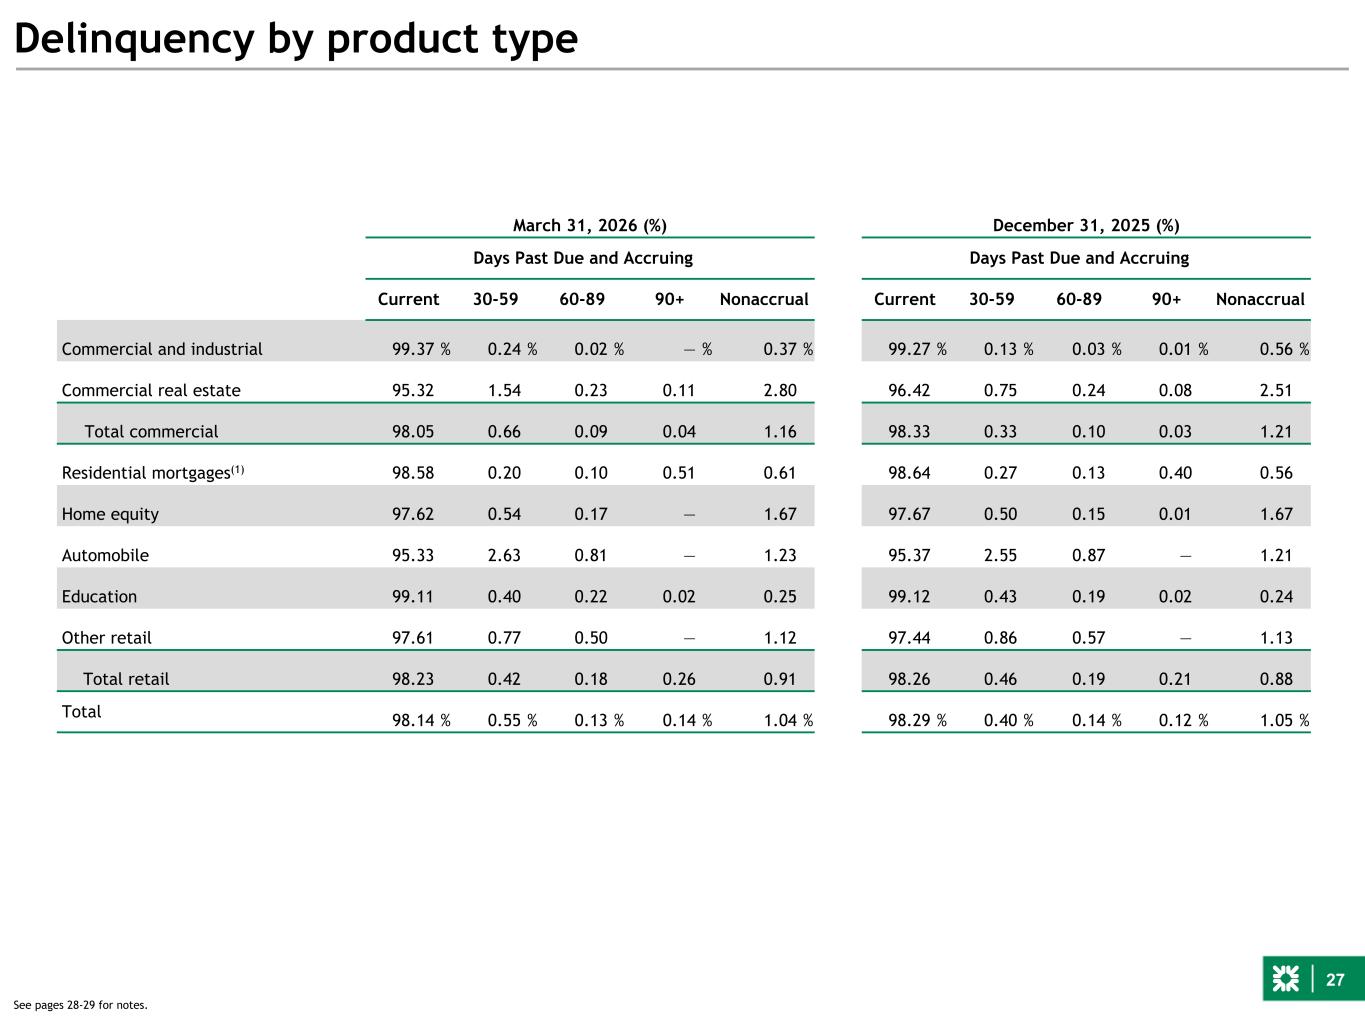
27 Delinquency by product type March 31, 2026 (%) December 31, 2025 (%) Days Past Due and Accruing Days Past Due and Accruing Current 30-59 60-89 90+ Nonaccrual Current 30-59 60-89 90+ Nonaccrual Commercial and industrial 99.37 % 0.24 % 0.02 % — % 0.37 % 99.27 % 0.13 % 0.03 % 0.01 % 0.56 % Commercial real estate 95.32 1.54 0.23 0.11 2.80 96.42 0.75 0.24 0.08 2.51 Total commercial 98.05 0.66 0.09 0.04 1.16 98.33 0.33 0.10 0.03 1.21 Residential mortgages(1) 98.58 0.20 0.10 0.51 0.61 98.64 0.27 0.13 0.40 0.56 Home equity 97.62 0.54 0.17 — 1.67 97.67 0.50 0.15 0.01 1.67 Automobile 95.33 2.63 0.81 — 1.23 95.37 2.55 0.87 — 1.21 Education 99.11 0.40 0.22 0.02 0.25 99.12 0.43 0.19 0.02 0.24 Other retail 97.61 0.77 0.50 — 1.12 97.44 0.86 0.57 — 1.13 Total retail 98.23 0.42 0.18 0.26 0.91 98.26 0.46 0.19 0.21 0.88 Total 98.14 % 0.55 % 0.13 % 0.14 % 1.04 % 98.29 % 0.40 % 0.14 % 0.12 % 1.05 % See pages 28-29 for notes.
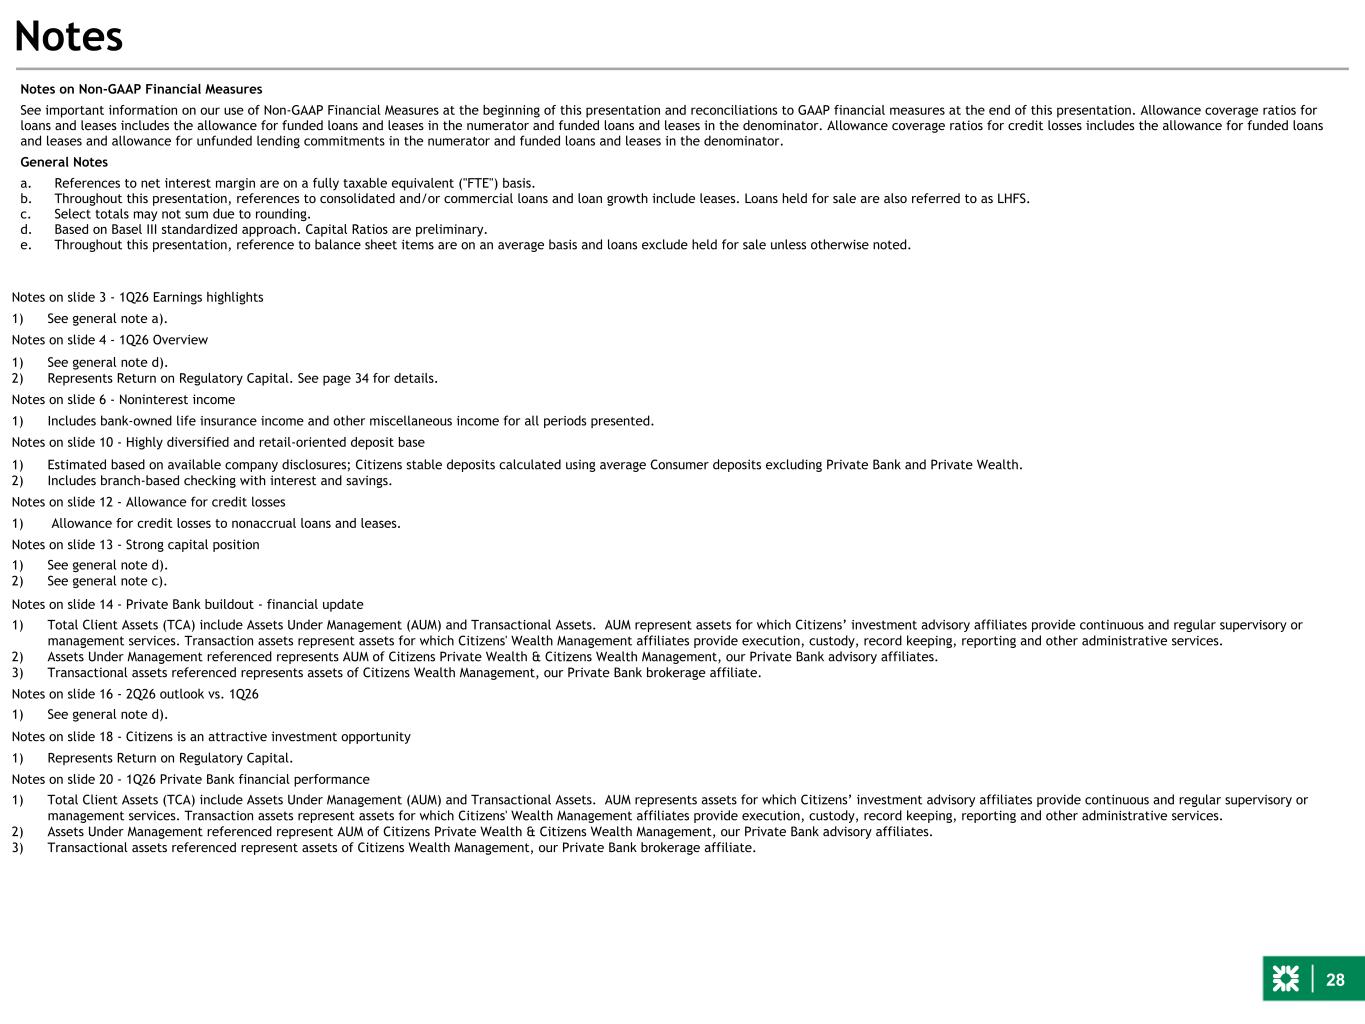
28 Notes on Non-GAAP Financial Measures See important information on our use of Non-GAAP Financial Measures at the beginning of this presentation and reconciliations to GAAP financial measures at the end of this presentation. Allowance coverage ratios for loans and leases includes the allowance for funded loans and leases in the numerator and funded loans and leases in the denominator. Allowance coverage ratios for credit losses includes the allowance for funded loans and leases and allowance for unfunded lending commitments in the numerator and funded loans and leases in the denominator. General Notes a. References to net interest margin are on a fully taxable equivalent ("FTE") basis. b. Throughout this presentation, references to consolidated and/or commercial loans and loan growth include leases. Loans held for sale are also referred to as LHFS. c. Select totals may not sum due to rounding. d. Based on Basel III standardized approach. Capital Ratios are preliminary. e. Throughout this presentation, reference to balance sheet items are on an average basis and loans exclude held for sale unless otherwise noted. Notes Notes on slide 3 - 1Q26 Earnings highlights 1) See general note a). Notes on slide 4 - 1Q26 Overview 1) See general note d). 2) Represents Return on Regulatory Capital. See page 34 for details. Notes on slide 6 - Noninterest income 1) Includes bank-owned life insurance income and other miscellaneous income for all periods presented. Notes on slide 10 - Highly diversified and retail-oriented deposit base 1) Estimated based on available company disclosures; Citizens stable deposits calculated using average Consumer deposits excluding Private Bank and Private Wealth. 2) Includes branch-based checking with interest and savings. Notes on slide 12 - Allowance for credit losses 1) Allowance for credit losses to nonaccrual loans and leases. Notes on slide 13 - Strong capital position 1) See general note d). 2) See general note c). Notes on slide 14 - Private Bank buildout - financial update 1) Total Client Assets (TCA) include Assets Under Management (AUM) and Transactional Assets. AUM represent assets for which Citizens’ investment advisory affiliates provide continuous and regular supervisory or management services. Transaction assets represent assets for which Citizens' Wealth Management affiliates provide execution, custody, record keeping, reporting and other administrative services. 2) Assets Under Management referenced represents AUM of Citizens Private Wealth & Citizens Wealth Management, our Private Bank advisory affiliates. 3) Transactional assets referenced represents assets of Citizens Wealth Management, our Private Bank brokerage affiliate. Notes on slide 16 - 2Q26 outlook vs. 1Q26 1) See general note d). Notes on slide 18 - Citizens is an attractive investment opportunity 1) Represents Return on Regulatory Capital. Notes on slide 20 - 1Q26 Private Bank financial performance 1) Total Client Assets (TCA) include Assets Under Management (AUM) and Transactional Assets. AUM represents assets for which Citizens’ investment advisory affiliates provide continuous and regular supervisory or management services. Transaction assets represent assets for which Citizens' Wealth Management affiliates provide execution, custody, record keeping, reporting and other administrative services. 2) Assets Under Management referenced represent AUM of Citizens Private Wealth & Citizens Wealth Management, our Private Bank advisory affiliates. 3) Transactional assets referenced represent assets of Citizens Wealth Management, our Private Bank brokerage affiliate.
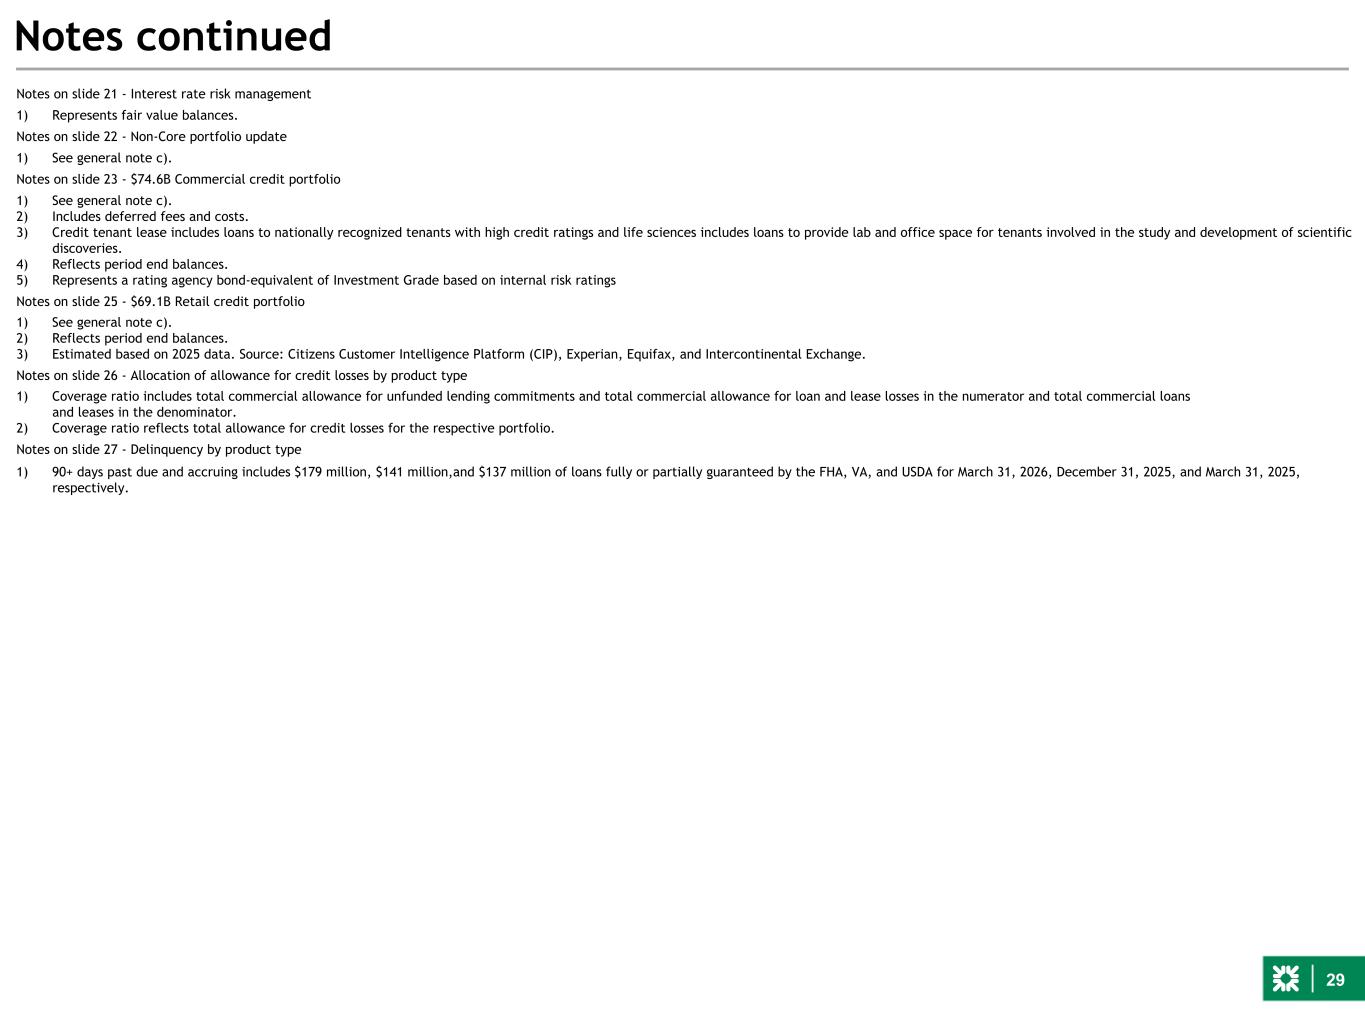
29 Notes continued Notes on slide 21 - Interest rate risk management 1) Represents fair value balances. Notes on slide 22 - Non-Core portfolio update 1) See general note c). Notes on slide 23 - $74.6B Commercial credit portfolio 1) See general note c). 2) Includes deferred fees and costs. 3) Credit tenant lease includes loans to nationally recognized tenants with high credit ratings and life sciences includes loans to provide lab and office space for tenants involved in the study and development of scientific discoveries. 4) Reflects period end balances. 5) Represents a rating agency bond-equivalent of Investment Grade based on internal risk ratings Notes on slide 25 - $69.1B Retail credit portfolio 1) See general note c). 2) Reflects period end balances. 3) Estimated based on 2025 data. Source: Citizens Customer Intelligence Platform (CIP), Experian, Equifax, and Intercontinental Exchange. Notes on slide 26 - Allocation of allowance for credit losses by product type 1) Coverage ratio includes total commercial allowance for unfunded lending commitments and total commercial allowance for loan and lease losses in the numerator and total commercial loans and leases in the denominator. 2) Coverage ratio reflects total allowance for credit losses for the respective portfolio. Notes on slide 27 - Delinquency by product type 1) 90+ days past due and accruing includes $179 million, $141 million,and $137 million of loans fully or partially guaranteed by the FHA, VA, and USDA for March 31, 2026, December 31, 2025, and March 31, 2025, respectively.
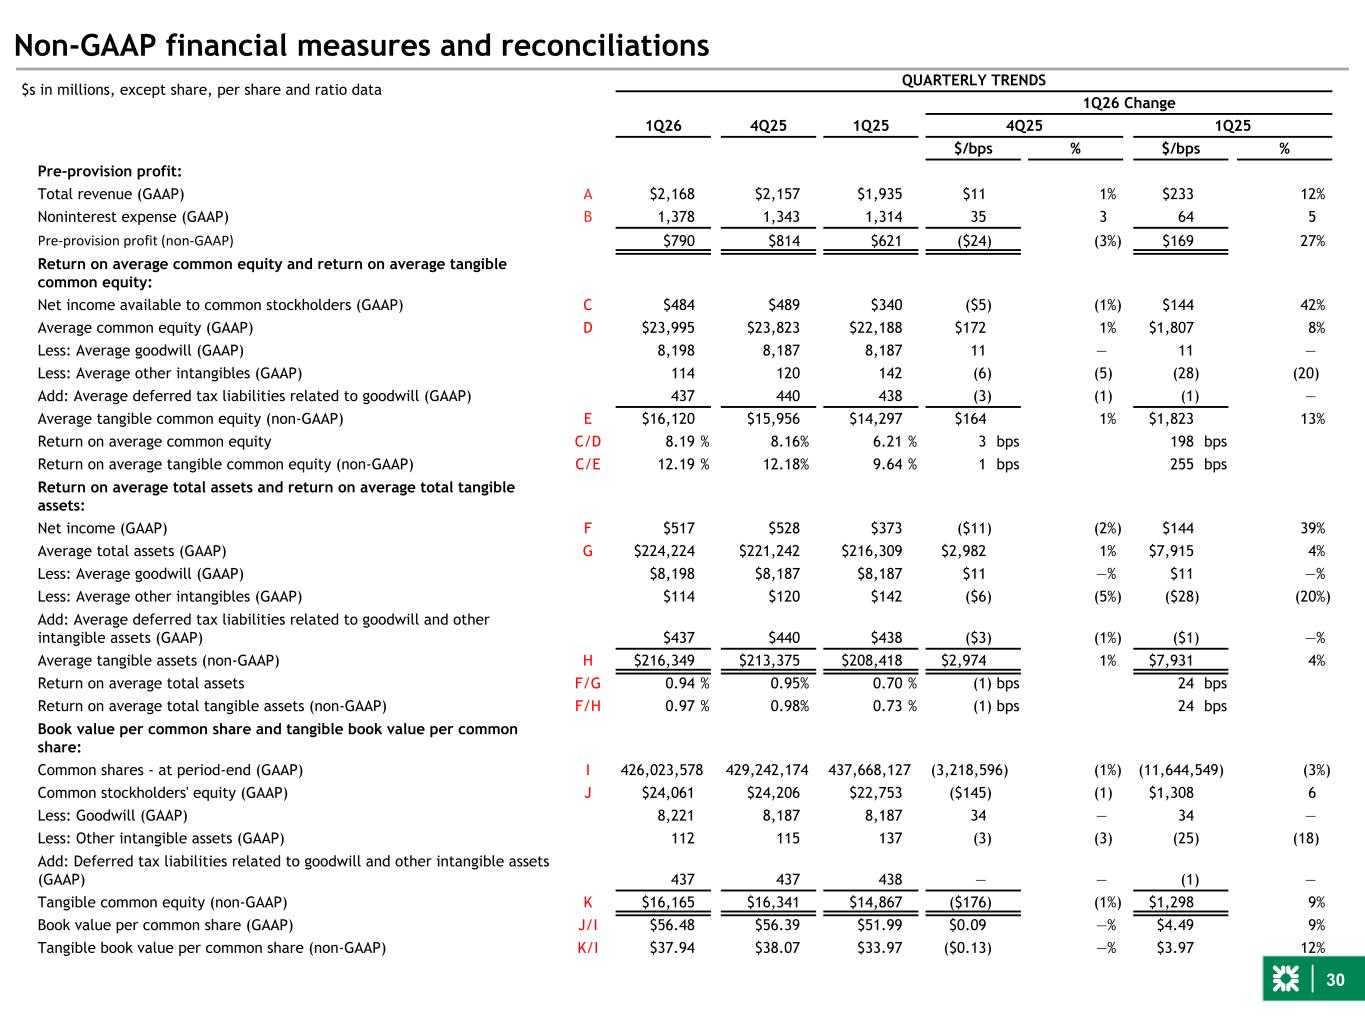
30 Non-GAAP financial measures and reconciliations $s in millions, except share, per share and ratio data QUARTERLY TRENDS 1Q26 Change 1Q26 4Q25 1Q25 4Q25 1Q25 $/bps % $/bps % Pre-provision profit: Total revenue (GAAP) A $2,168 $2,157 $1,935 $11 1% $233 12% Noninterest expense (GAAP) B 1,378 1,343 1,314 35 3 64 5 Pre-provision profit (non-GAAP) $790 $814 $621 ($24) (3%) $169 27% Return on average common equity and return on average tangible common equity: Net income available to common stockholders (GAAP) C $484 $489 $340 ($5) (1%) $144 42% Average common equity (GAAP) D $23,995 $23,823 $22,188 $172 1% $1,807 8% Less: Average goodwill (GAAP) 8,198 8,187 8,187 11 — 11 — Less: Average other intangibles (GAAP) 114 120 142 (6) (5) (28) (20) Add: Average deferred tax liabilities related to goodwill (GAAP) 437 440 438 (3) (1) (1) — Average tangible common equity (non-GAAP) E $16,120 $15,956 $14,297 $164 1% $1,823 13% Return on average common equity C/D 8.19 % 8.16% 6.21 % 3 bps 198 bps Return on average tangible common equity (non-GAAP) C/E 12.19 % 12.18% 9.64 % 1 bps 255 bps Return on average total assets and return on average total tangible assets: Net income (GAAP) F $517 $528 $373 ($11) (2%) $144 39% Average total assets (GAAP) G $224,224 $221,242 $216,309 $2,982 1% $7,915 4% Less: Average goodwill (GAAP) $8,198 $8,187 $8,187 $11 —% $11 —% Less: Average other intangibles (GAAP) $114 $120 $142 ($6) (5%) ($28) (20%) Add: Average deferred tax liabilities related to goodwill and other intangible assets (GAAP) $437 $440 $438 ($3) (1%) ($1) —% Average tangible assets (non-GAAP) H $216,349 $213,375 $208,418 $2,974 1% $7,931 4% Return on average total assets F/G 0.94 % 0.95% 0.70 % (1) bps 24 bps Return on average total tangible assets (non-GAAP) F/H 0.97 % 0.98% 0.73 % (1) bps 24 bps Book value per common share and tangible book value per common share: Common shares - at period-end (GAAP) I 426,023,578 429,242,174 437,668,127 (3,218,596) (1%) (11,644,549) (3%) Common stockholders' equity (GAAP) J $24,061 $24,206 $22,753 ($145) (1) $1,308 6 Less: Goodwill (GAAP) 8,221 8,187 8,187 34 — 34 — Less: Other intangible assets (GAAP) 112 115 137 (3) (3) (25) (18) Add: Deferred tax liabilities related to goodwill and other intangible assets (GAAP) 437 437 438 — — (1) — Tangible common equity (non-GAAP) K $16,165 $16,341 $14,867 ($176) (1%) $1,298 9% Book value per common share (GAAP) J/I $56.48 $56.39 $51.99 $0.09 —% $4.49 9% Tangible book value per common share (non-GAAP) K/I $37.94 $38.07 $33.97 ($0.13) —% $3.97 12%
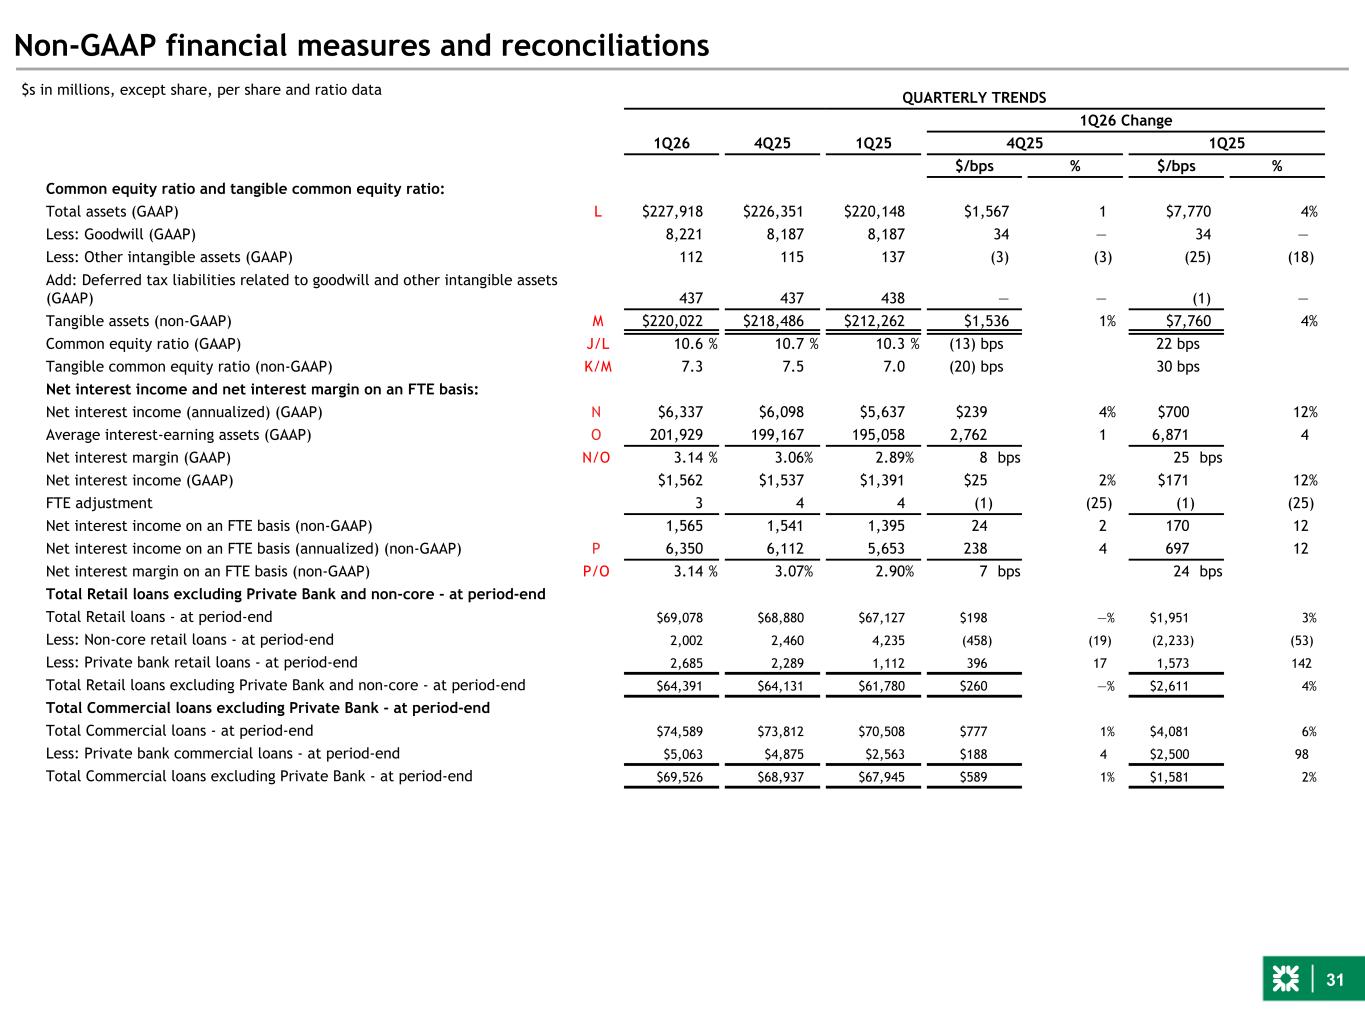
31 Non-GAAP financial measures and reconciliations QUARTERLY TRENDS 1Q26 Change 1Q26 4Q25 1Q25 4Q25 1Q25 $/bps % $/bps % Common equity ratio and tangible common equity ratio: Total assets (GAAP) L $227,918 $226,351 $220,148 $1,567 1 $7,770 4% Less: Goodwill (GAAP) 8,221 8,187 8,187 34 — 34 — Less: Other intangible assets (GAAP) 112 115 137 (3) (3) (25) (18) Add: Deferred tax liabilities related to goodwill and other intangible assets (GAAP) 437 437 438 — — (1) — Tangible assets (non-GAAP) M $220,022 $218,486 $212,262 $1,536 1% $7,760 4% Common equity ratio (GAAP) J/L 10.6 % 10.7 % 10.3 % (13) bps 22 bps Tangible common equity ratio (non-GAAP) K/M 7.3 7.5 7.0 (20) bps 30 bps Net interest income and net interest margin on an FTE basis: Net interest income (annualized) (GAAP) N $6,337 $6,098 $5,637 $239 4% $700 12% Average interest-earning assets (GAAP) O 201,929 199,167 195,058 2,762 1 6,871 4 Net interest margin (GAAP) N/O 3.14 % 3.06% 2.89% 8 bps 25 bps Net interest income (GAAP) $1,562 $1,537 $1,391 $25 2% $171 12% FTE adjustment 3 4 4 (1) (25) (1) (25) Net interest income on an FTE basis (non-GAAP) 1,565 1,541 1,395 24 2 170 12 Net interest income on an FTE basis (annualized) (non-GAAP) P 6,350 6,112 5,653 238 4 697 12 Net interest margin on an FTE basis (non-GAAP) P/O 3.14 % 3.07% 2.90% 7 bps 24 bps Total Retail loans excluding Private Bank and non-core - at period-end Total Retail loans - at period-end $69,078 $68,880 $67,127 $198 —% $1,951 3% Less: Non-core retail loans - at period-end 2,002 2,460 4,235 (458) (19) (2,233) (53) Less: Private bank retail loans - at period-end 2,685 2,289 1,112 396 17 1,573 142 Total Retail loans excluding Private Bank and non-core - at period-end $64,391 $64,131 $61,780 $260 —% $2,611 4% Total Commercial loans excluding Private Bank - at period-end Total Commercial loans - at period-end $74,589 $73,812 $70,508 $777 1% $4,081 6% Less: Private bank commercial loans - at period-end $5,063 $4,875 $2,563 $188 4 $2,500 98 Total Commercial loans excluding Private Bank - at period-end $69,526 $68,937 $67,945 $589 1% $1,581 2% $s in millions, except share, per share and ratio data
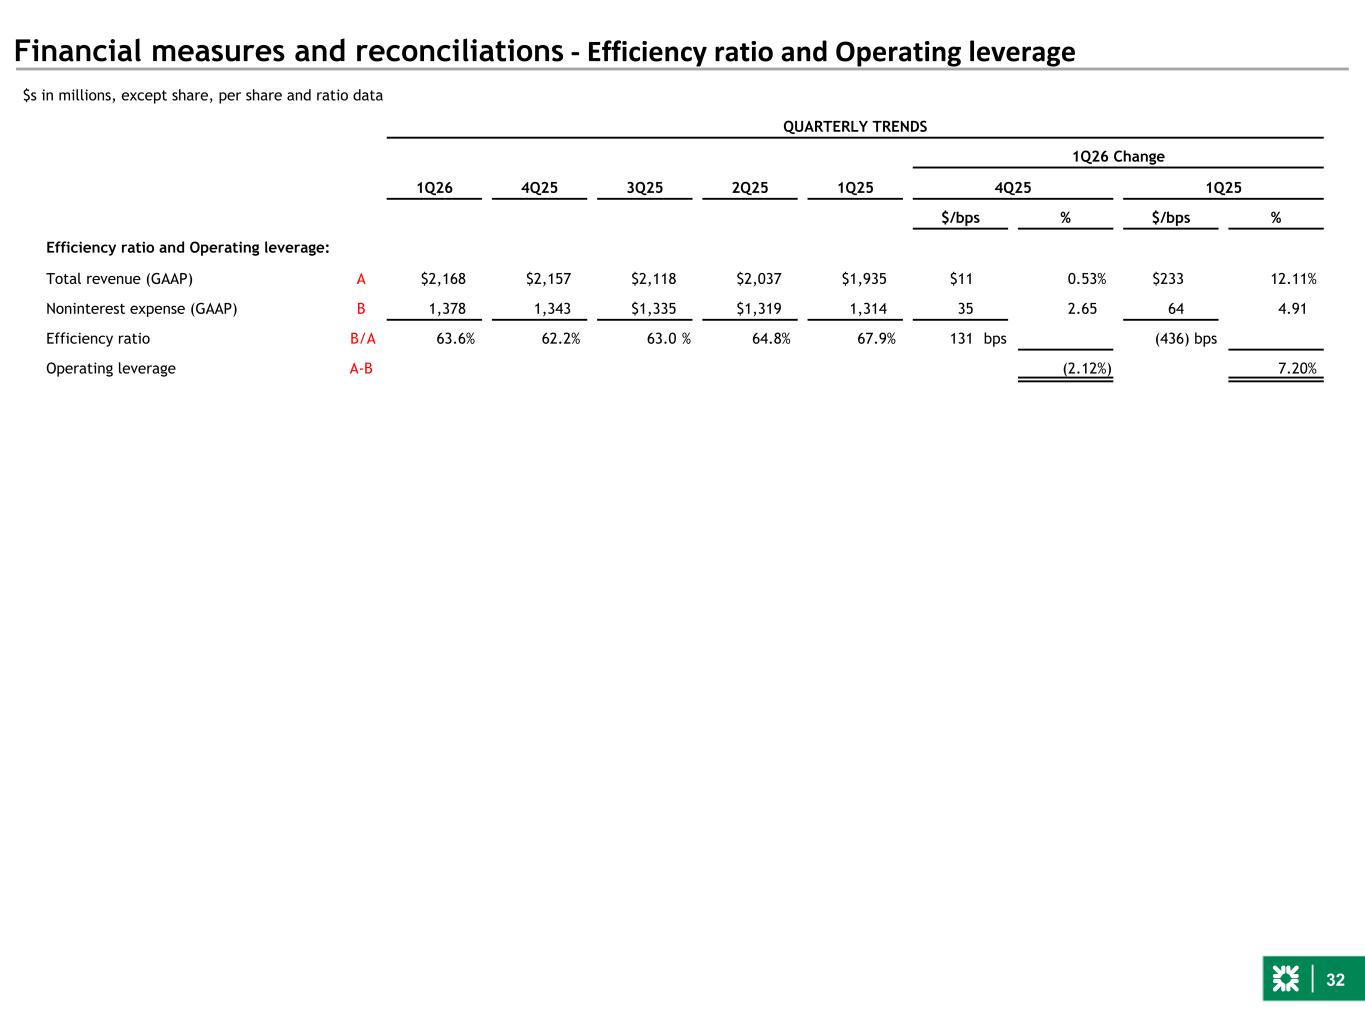
32 Financial measures and reconciliations - Efficiency ratio and Operating leverage $s in millions, except share, per share and ratio data QUARTERLY TRENDS 1Q26 Change 1Q26 4Q25 3Q25 2Q25 1Q25 4Q25 1Q25 $/bps % $/bps % Efficiency ratio and Operating leverage: Total revenue (GAAP) A $2,168 $2,157 $2,118 $2,037 $1,935 $11 0.53% $233 12.11% Noninterest expense (GAAP) B 1,378 1,343 $1,335 $1,319 1,314 35 2.65 64 4.91 Efficiency ratio B/A 63.6% 62.2% 63.0 % 64.8% 67.9% 131 bps (436) bps Operating leverage A-B (2.12%) 7.20%
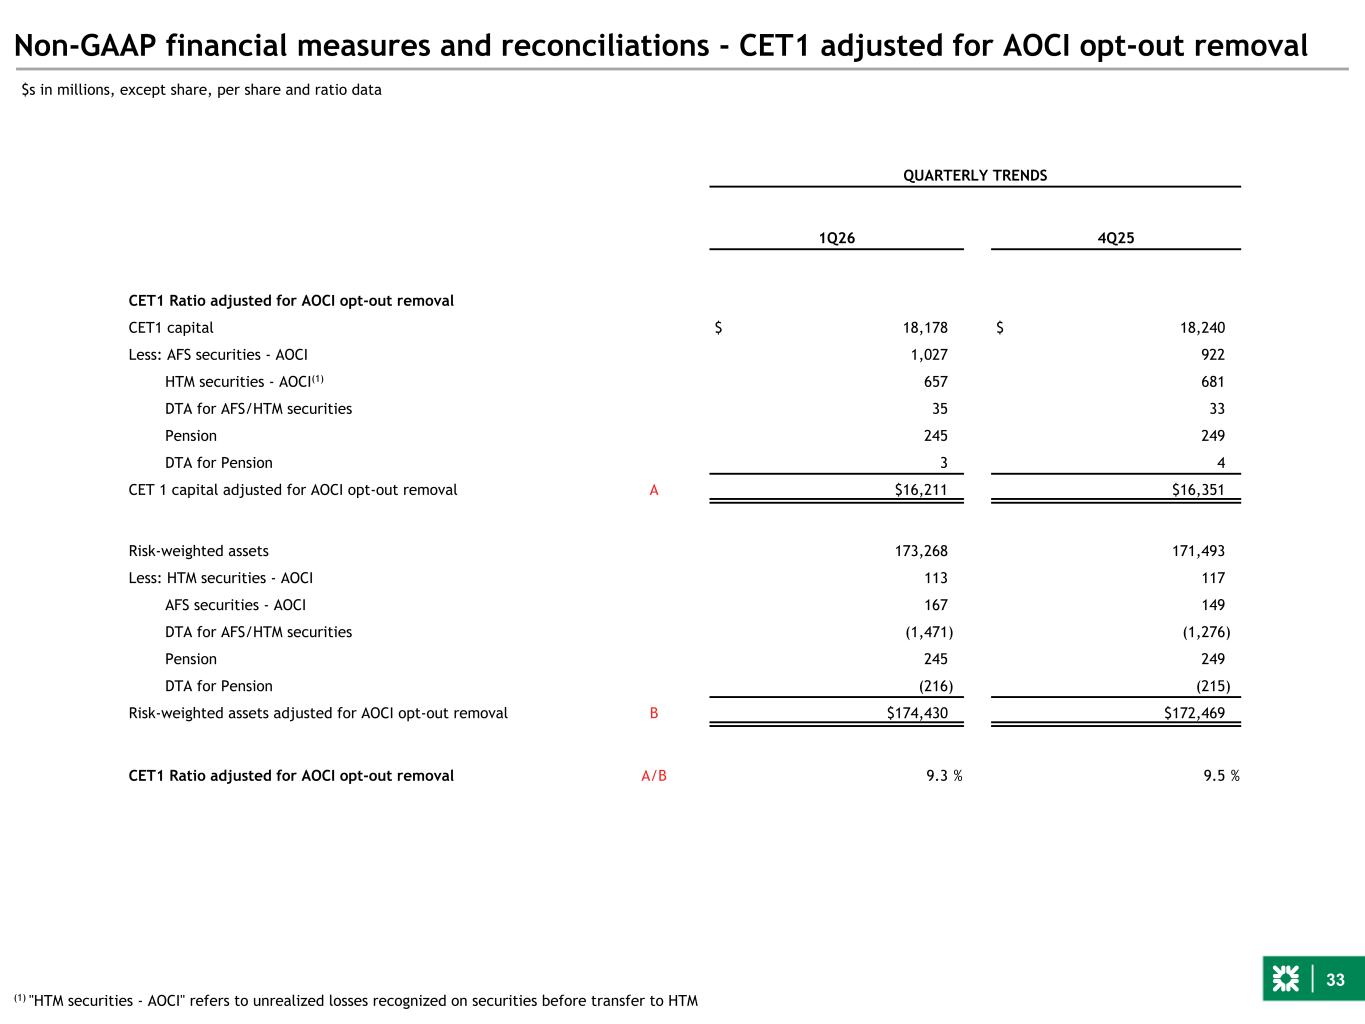
33 Non-GAAP financial measures and reconciliations - CET1 adjusted for AOCI opt-out removal QUARTERLY TRENDS 1Q26 4Q25 CET1 Ratio adjusted for AOCI opt-out removal CET1 capital $ 18,178 $ 18,240 Less: AFS securities - AOCI 1,027 922 HTM securities - AOCI(1) 657 681 DTA for AFS/HTM securities 35 33 Pension 245 249 DTA for Pension 3 4 CET 1 capital adjusted for AOCI opt-out removal A $16,211 $16,351 Risk-weighted assets 173,268 171,493 Less: HTM securities - AOCI 113 117 AFS securities - AOCI 167 149 DTA for AFS/HTM securities (1,471) (1,276) Pension 245 249 DTA for Pension (216) (215) Risk-weighted assets adjusted for AOCI opt-out removal B $174,430 $172,469 CET1 Ratio adjusted for AOCI opt-out removal A/B 9.3 % 9.5 % $s in millions, except share, per share and ratio data (1) "HTM securities - AOCI" refers to unrealized losses recognized on securities before transfer to HTM
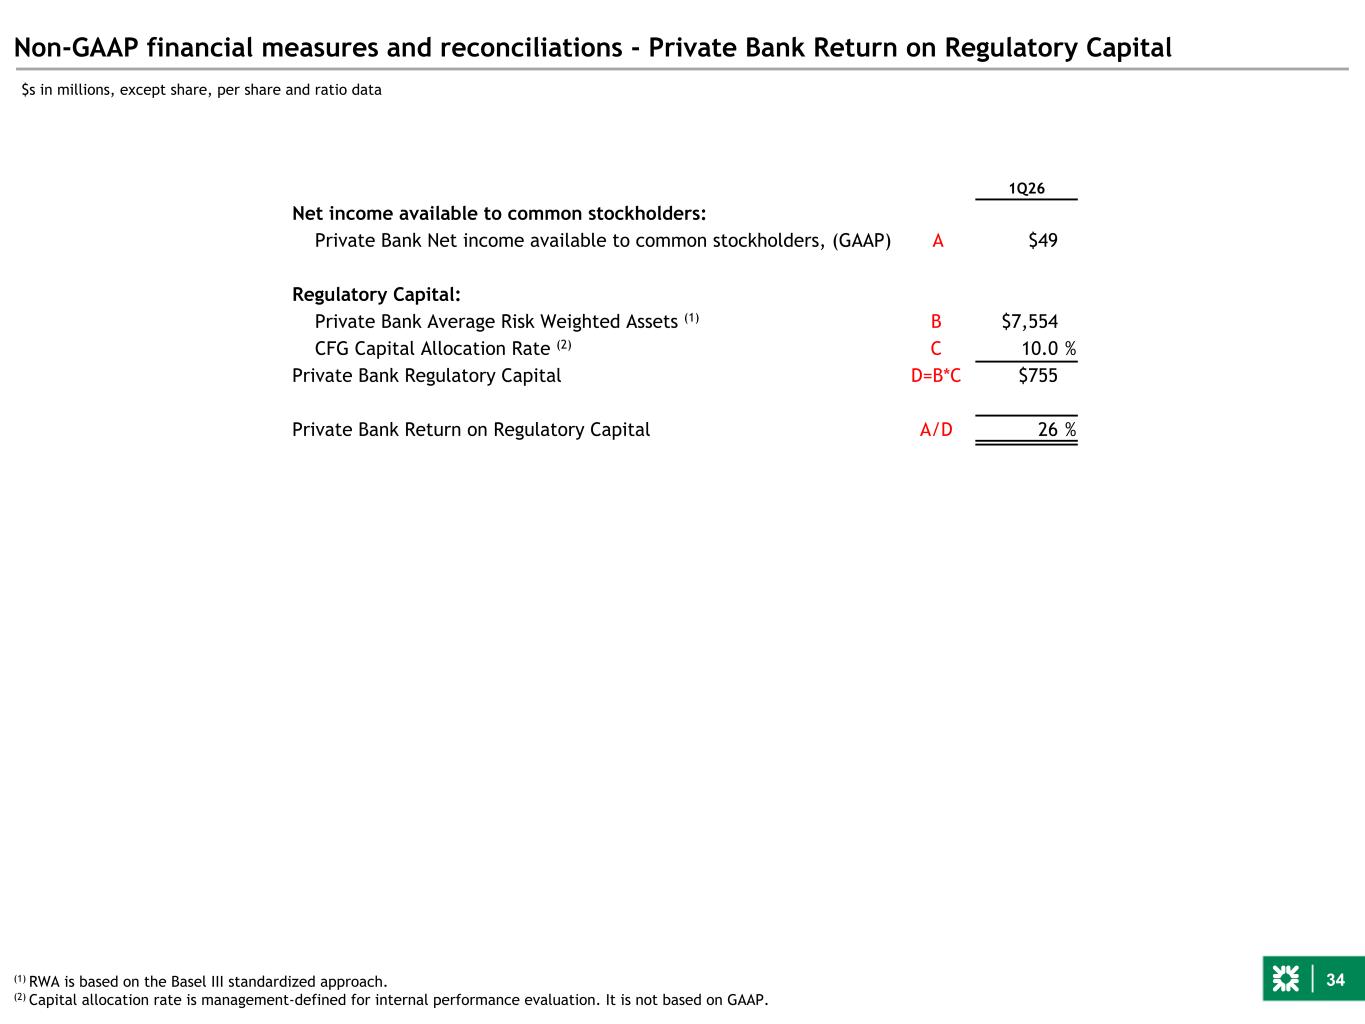
34 Non-GAAP financial measures and reconciliations - Private Bank Return on Regulatory Capital $s in millions, except share, per share and ratio data 1Q26 Net income available to common stockholders: Private Bank Net income available to common stockholders, (GAAP) A $49 Regulatory Capital: Private Bank Average Risk Weighted Assets (1) B $7,554 CFG Capital Allocation Rate (2) C 10.0 % Private Bank Regulatory Capital D=B*C $755 Private Bank Return on Regulatory Capital A/D 26 % (1) RWA is based on the Basel III standardized approach. (2) Capital allocation rate is management-defined for internal performance evaluation. It is not based on GAAP.
Financial Supplement
First Quarter 2026
1
| Table of Contents | Page | |||||||
Credit-Related Information: | ||||||||
The information in this Financial Supplement is preliminary and based on company data available at the time of the earnings presentation. It speaks only as of the particular date or dates included in the accompanying pages. The Company does not undertake an obligation to, and disclaims any duty to, update any of the information provided. Any forward-looking statements in this Financial Supplement are subject to the forward-looking statements language contained in the Company’s reports filed with the SEC pursuant to the Securities Exchange Act of 1934, which can be found on the SEC’s website (www.sec.gov) or on the Company’s website (www.citizensbank.com). The Company’s future financial performance is subject to the risks and uncertainties described in its SEC filings. | ||||||||
2
CONSOLIDATED FINANCIAL HIGHLIGHTS
(dollars in millions, except per share data)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 3Q25 | 2Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $/bps | % | $/bps | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| SELECTED OPERATING DATA | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total revenue | A | $2,168 | $2,157 | $2,118 | $2,037 | $1,935 | $11 | 1 | % | $233 | 12 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest expense | B | 1,378 | 1,343 | 1,335 | 1,319 | 1,314 | 35 | 3 | 64 | 5 | ||||||||||||||||||||||||||||||||||||||||||||||
Pre-provision profit1 | 790 | 814 | 783 | 718 | 621 | (24) | (3) | 169 | 27 | |||||||||||||||||||||||||||||||||||||||||||||||
| Provision (benefit) for credit losses | 140 | 137 | 154 | 164 | 153 | 3 | 2 | (13) | (8) | |||||||||||||||||||||||||||||||||||||||||||||||
| NET INCOME | 517 | 528 | 494 | 436 | 373 | (11) | (2) | 144 | 39 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net income available to common stockholders | 484 | 489 | 457 | 402 | 340 | (5) | (1) | 144 | 42 | |||||||||||||||||||||||||||||||||||||||||||||||
| PER COMMON SHARE DATA | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Basic earnings | $1.14 | $1.14 | $1.06 | $0.93 | $0.78 | $— | — | % | $0.36 | 46 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Diluted earnings | 1.13 | 1.13 | 1.05 | 0.92 | 0.77 | — | — | 0.36 | 47 | |||||||||||||||||||||||||||||||||||||||||||||||
| Cash dividends declared and paid per common share | 0.46 | 0.46 | 0.42 | 0.42 | 0.42 | — | — | 0.04 | 10 | |||||||||||||||||||||||||||||||||||||||||||||||
| Book value per common share | 56.48 | 56.39 | 54.97 | 53.43 | 51.99 | 0.09 | — | 4.49 | 9 | |||||||||||||||||||||||||||||||||||||||||||||||
Tangible book value per common share1 | 37.94 | 38.07 | 36.73 | 35.23 | 33.97 | (0.13) | — | 3.97 | 12 | |||||||||||||||||||||||||||||||||||||||||||||||
| Dividend payout ratio | 40 | % | 40 | % | 40 | % | 45 | % | 54 | % | — | bps | (1,350) | bps | ||||||||||||||||||||||||||||||||||||||||||
| COMMON SHARES OUTSTANDING | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average: Basic | 425,344,491 | 429,483,110 | 431,365,552 | 433,640,210 | 438,320,757 | (4,138,619) | (1 | %) | (12,976,266) | (3 | %) | |||||||||||||||||||||||||||||||||||||||||||||
Diluted | 429,894,837 | 434,077,960 | 435,472,350 | 436,539,774 | 442,200,180 | (4,183,123) | (1) | (12,305,343) | (3) | |||||||||||||||||||||||||||||||||||||||||||||||
| Common shares at period-end | 426,023,578 | 429,242,174 | 431,453,142 | 432,768,811 | 437,668,127 | (3,218,596) | (1) | (11,644,549) | (3) | |||||||||||||||||||||||||||||||||||||||||||||||
| FINANCIAL RATIOS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin | 3.14 | % | 3.06 | % | 2.99 | % | 2.94 | % | 2.89 | % | 8 bps | 25 bps | ||||||||||||||||||||||||||||||||||||||||||||
Net interest margin, FTE1,2 | 3.14 | 3.07 | 3.00 | 2.95 | 2.90 | 7 | 24 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Return on average common equity | 8.19 | 8.16 | 7.77 | 7.18 | 6.21 | 3 | 198 | |||||||||||||||||||||||||||||||||||||||||||||||||
Return on average tangible common equity1 | 12.19 | 12.18 | 11.75 | 11.05 | 9.64 | 1 | 255 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Return on average total assets | 0.94 | 0.95 | 0.90 | 0.80 | 0.70 | (1) | 24 | |||||||||||||||||||||||||||||||||||||||||||||||||
Return on average total tangible assets1 | 0.97 | 0.98 | 0.93 | 0.83 | 0.73 | (1) | 24 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Effective income tax rate | 20.46 | 22.03 | 21.38 | 21.37 | 20.26 | (157) | 20 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | B/A | 63.55 | 62.24 | 63.03 | 64.76 | 67.91 | 131 | (436) | ||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest income as a % of total revenue | 27.95 | 28.75 | 29.75 | 29.41 | 28.14 | (80) | (19) | |||||||||||||||||||||||||||||||||||||||||||||||||
Operating leverage: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total revenue | $2,168 | $2,157 | $1,935 | $11 | 0.53 | % | $233 | 12.11 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Less: Noninterest expense | 1,378 | 1,343 | 1,314 | 35 | 2.65 | 64 | 4.91 | |||||||||||||||||||||||||||||||||||||||||||||||||
Operating leverage | (2.12 | %) | 7.20 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||||
CAPITAL RATIOS - PERIOD-END (PRELIMINARY) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| CET1 capital ratio | 10.5 | % | 10.6 | % | 10.7 | % | 10.6 | % | 10.6 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Tier 1 capital ratio | 11.7 | 11.9 | 11.9 | 11.9 | 11.9 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Total capital ratio | 13.7 | 13.8 | 13.9 | 13.8 | 13.9 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Tier 1 leverage ratio | 9.3 | 9.5 | 9.4 | 9.4 | 9.4 | |||||||||||||||||||||||||||||||||||||||||||||||||||
Common equity ratio | 10.6 | 10.7 | 10.6 | 10.6 | 10.3 | |||||||||||||||||||||||||||||||||||||||||||||||||||
Tangible common equity ratio1 | 7.3 | 7.5 | 7.4 | 7.2 | 7.0 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| SELECTED BALANCE SHEET DATA | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loan-to-deposit ratio (period-end balances) | 78.07 | % | 77.84 | % | 78.26 | % | 79.56 | % | 77.51 | % | 23 | bps | 56 | bps | ||||||||||||||||||||||||||||||||||||||||||
| Loan-to-deposit ratio (average balances) | 79.09 | 78.82 | 79.57 | 79.72 | 80.89 | 27 | bps | (180) | bps | |||||||||||||||||||||||||||||||||||||||||||||||
| Full-time equivalent colleagues (period-end) | 17,380 | 17,398 | 17,496 | 17,677 | 17,315 | (18) | — | 65 | — | |||||||||||||||||||||||||||||||||||||||||||||||
1 These are non-GAAP financial measures. For further information on these measures, refer to "Non-GAAP Financial Measures and Reconciliations."
2 Net interest margin is presented on a fully taxable-equivalent ("FTE") basis using the federal statutory tax rate of 21% to adjust for the tax-exempt status of income from certain assets held by the Company.
3
CONSOLIDATED STATEMENTS OF OPERATIONS (unaudited)
(dollars in millions)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 3Q25 | 2Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | % | $ | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| INTEREST INCOME | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans and leases | $1,884 | $1,901 | $1,897 | $1,851 | $1,829 | ($17) | (1 | %) | $55 | 3 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans held for sale | 21 | 22 | 31 | 36 | 16 | (1) | (5) | 5 | 31 | |||||||||||||||||||||||||||||||||||||||||||||||
| Investment securities | 424 | 434 | 433 | 428 | 418 | (10) | (2) | 6 | 1 | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in banks | 91 | 89 | 97 | 92 | 89 | 2 | 2 | 2 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest income | 2,420 | 2,446 | 2,458 | 2,407 | 2,352 | (26) | (1) | 68 | 3 | |||||||||||||||||||||||||||||||||||||||||||||||
| INTEREST EXPENSE | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Deposits | 715 | 781 | 816 | 802 | 795 | (66) | (8) | (80) | (10) | |||||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowed funds | 4 | — | 5 | 9 | 8 | 4 | 100 | (4) | (50) | |||||||||||||||||||||||||||||||||||||||||||||||
| Long-term borrowed funds | 139 | 128 | 149 | 159 | 158 | 11 | 9 | (19) | (12) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest expense | 858 | 909 | 970 | 970 | 961 | (51) | (6) | (103) | (11) | |||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | 1,562 | 1,537 | 1,488 | 1,437 | 1,391 | 25 | 2 | 171 | 12 | |||||||||||||||||||||||||||||||||||||||||||||||
| NONINTEREST INCOME | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Service charges and fees | 112 | 112 | 112 | 111 | 109 | — | — | 3 | 3 | |||||||||||||||||||||||||||||||||||||||||||||||
| Capital markets fees | 134 | 140 | 166 | 105 | 100 | (6) | (4) | 34 | 34 | |||||||||||||||||||||||||||||||||||||||||||||||
Wealth fees | 100 | 98 | 93 | 88 | 81 | 2 | 2 | 19 | 23 | |||||||||||||||||||||||||||||||||||||||||||||||
| Card fees | 83 | 86 | 87 | 90 | 83 | (3) | (3) | — | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Mortgage banking fees | 42 | 52 | 49 | 73 | 59 | (10) | (19) | (17) | (29) | |||||||||||||||||||||||||||||||||||||||||||||||
| Foreign exchange and derivative products | 44 | 34 | 42 | 41 | 39 | 10 | 29 | 5 | 13 | |||||||||||||||||||||||||||||||||||||||||||||||
| Letter of credit and loan fees | 50 | 49 | 48 | 45 | 44 | 1 | 2 | 6 | 14 | |||||||||||||||||||||||||||||||||||||||||||||||
| Securities gains, net | 7 | 7 | 2 | 5 | 7 | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Other income | 34 | 42 | 31 | 42 | 22 | (8) | (19) | 12 | 55 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total noninterest income | 606 | 620 | 630 | 600 | 544 | (14) | (2) | 62 | 11 | |||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL REVENUE | 2,168 | 2,157 | 2,118 | 2,037 | 1,935 | 11 | 1 | 233 | 12 | |||||||||||||||||||||||||||||||||||||||||||||||
| Provision (benefit) for credit losses | 140 | 137 | 154 | 164 | 153 | 3 | 2 | (13) | (8) | |||||||||||||||||||||||||||||||||||||||||||||||
| NONINTEREST EXPENSE | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 758 | 716 | 705 | 681 | 696 | 42 | 6 | 62 | 9 | |||||||||||||||||||||||||||||||||||||||||||||||
| Equipment and software | 197 | 199 | 197 | 193 | 194 | (2) | (1) | 3 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||
| Outside services | 162 | 148 | 161 | 169 | 155 | 14 | 9 | 7 | 5 | |||||||||||||||||||||||||||||||||||||||||||||||
| Occupancy | 114 | 109 | 106 | 108 | 112 | 5 | 5 | 2 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||
| Other operating expense | 147 | 171 | 166 | 168 | 157 | (24) | (14) | (10) | (6) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total noninterest expense | 1,378 | 1,343 | 1,335 | 1,319 | 1,314 | 35 | 3 | 64 | 5 | |||||||||||||||||||||||||||||||||||||||||||||||
| Income before income tax expense | 650 | 677 | 629 | 554 | 468 | (27) | (4) | 182 | 39 | |||||||||||||||||||||||||||||||||||||||||||||||
| Income tax expense | 133 | 149 | 135 | 118 | 95 | (16) | (11) | 38 | 40 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net income | $517 | $528 | $494 | $436 | $373 | ($11) | (2 | %) | $144 | 39 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Net income available to common stockholders | $484 | $489 | $457 | $402 | $340 | ($5) | (1 | %) | $144 | 42 | % | |||||||||||||||||||||||||||||||||||||||||||||
4
CONSOLIDATED BALANCE SHEETS (unaudited)
(dollars in millions, except par value)
| PERIOD-END BALANCES | AS OF | MARCH 31, 2026 CHANGE | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Sept 30, 2025 | June 30, 2025 | Mar 31, 2025 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | % | $ | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | $1,084 | $1,464 | $1,254 | $1,107 | $1,082 | ($380) | (26 | %) | $2 | — | % | |||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing cash and due from banks | 11,246 | 11,263 | 10,396 | 7,441 | 10,459 | (17) | — | 787 | 8 | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in banks | 830 | 961 | 694 | 680 | 685 | (131) | (14) | 145 | 21 | |||||||||||||||||||||||||||||||||||||||||||||||
| Debt securities available for sale, at fair value | 36,361 | 35,697 | 35,419 | 34,658 | 34,208 | 664 | 2 | 2,153 | 6 | |||||||||||||||||||||||||||||||||||||||||||||||
| Debt securities held to maturity | 7,800 | 7,933 | 8,124 | 8,293 | 8,469 | (133) | (2) | (669) | (8) | |||||||||||||||||||||||||||||||||||||||||||||||
Loans held for sale | 1,537 | 1,198 | 1,334 | 2,093 | 2,820 | 339 | 28 | (1,283) | (45) | |||||||||||||||||||||||||||||||||||||||||||||||
| Loans and leases | 143,667 | 142,692 | 140,870 | 139,304 | 137,635 | 975 | 1 | 6,032 | 4 | |||||||||||||||||||||||||||||||||||||||||||||||
| Less: Allowance for loan and lease losses | (1,958) | (1,943) | (1,972) | (2,008) | (2,014) | (15) | 1 | 56 | (3) | |||||||||||||||||||||||||||||||||||||||||||||||
| Net loans and leases | 141,709 | 140,749 | 138,898 | 137,296 | 135,621 | 960 | 1 | 6,088 | 4 | |||||||||||||||||||||||||||||||||||||||||||||||
| Premises and equipment | 874 | 915 | 857 | 855 | 855 | (41) | (4) | 19 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||
| Bank-owned life insurance | 3,464 | 3,441 | 3,422 | 3,408 | 3,386 | 23 | 1 | 78 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||
| Goodwill | 8,221 | 8,187 | 8,187 | 8,187 | 8,187 | 34 | — | 34 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Other intangible assets | 112 | 115 | 123 | 129 | 137 | (3) | (3) | (25) | (18) | |||||||||||||||||||||||||||||||||||||||||||||||
Other assets | 14,680 | 14,428 | 14,039 | 14,163 | 14,239 | 252 | 2 | 441 | 3 | |||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL ASSETS | $227,918 | $226,351 | $222,747 | $218,310 | $220,148 | $1,567 | 1 | % | $7,770 | 4 | % | |||||||||||||||||||||||||||||||||||||||||||||
| LIABILITIES AND STOCKHOLDERS' EQUITY | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| LIABILITIES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Deposits: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing | $41,672 | $40,417 | $39,472 | $38,001 | $37,556 | $1,255 | 3 | % | $4,116 | 11 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing | 142,363 | 142,896 | 140,539 | 137,085 | 140,020 | (533) | — | 2,343 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total deposits | 184,035 | 183,313 | 180,011 | 175,086 | 177,576 | 722 | — | 6,459 | 4 | |||||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowed funds | 54 | 58 | 214 | 249 | 47 | (4) | (7) | 7 | 15 | |||||||||||||||||||||||||||||||||||||||||||||||
| Long-term borrowed funds: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FHLB advances | 2,513 | 2,014 | 14 | 1,542 | 42 | 499 | 25 | 2,471 | NM | |||||||||||||||||||||||||||||||||||||||||||||||
| Senior debt | 7,076 | 6,328 | 6,825 | 6,821 | 7,568 | 748 | 12 | (492) | (7) | |||||||||||||||||||||||||||||||||||||||||||||||
| Subordinated debt and other debt | 2,671 | 2,882 | 3,602 | 4,163 | 4,657 | (211) | (7) | (1,986) | (43) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total long-term borrowed funds | 12,260 | 11,224 | 10,441 | 12,526 | 12,267 | 1,036 | 9 | (7) | — | |||||||||||||||||||||||||||||||||||||||||||||||
Other liabilities | 5,397 | 5,439 | 6,252 | 5,215 | 5,392 | (42) | (1) | 5 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL LIABILITIES | 201,746 | 200,034 | 196,918 | 193,076 | 195,282 | 1,712 | 1 | 6,464 | 3 | |||||||||||||||||||||||||||||||||||||||||||||||
| STOCKHOLDERS' EQUITY | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Preferred stock: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| $25.00 par value, 100,000,000 shares authorized for each of the periods presented | 2,111 | 2,111 | 2,111 | 2,113 | 2,113 | — | — | (2) | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Common stock: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| $0.01 par value, 1,000,000,000 shares authorized for each of the periods presented | 7 | 7 | 7 | 7 | 7 | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Additional paid-in capital | 22,466 | 22,476 | 22,448 | 22,420 | 22,370 | (10) | — | 96 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Retained earnings | 11,631 | 11,345 | 11,056 | 10,783 | 10,566 | 286 | 3 | 1,065 | 10 | |||||||||||||||||||||||||||||||||||||||||||||||
| Treasury stock, at cost | (7,955) | (7,652) | (7,526) | (7,450) | (7,249) | (303) | (4) | (706) | (10) | |||||||||||||||||||||||||||||||||||||||||||||||
| Accumulated other comprehensive income (loss) | (2,088) | (1,970) | (2,267) | (2,639) | (2,941) | (118) | (6) | 853 | 29 | |||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL STOCKHOLDERS' EQUITY | 26,172 | 26,317 | 25,829 | 25,234 | 24,866 | (145) | (1) | 1,306 | 5 | |||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL LIABILITIES AND STOCKHOLDERS' EQUITY | $227,918 | $226,351 | $222,747 | $218,310 | $220,148 | $1,567 | 1 | % | $7,770 | 4 | % | |||||||||||||||||||||||||||||||||||||||||||||
Memo: Total tangible common equity1 | $16,165 | $16,341 | $15,848 | $15,246 | $14,867 | ($176) | (1 | %) | $1,298 | 9 | % | |||||||||||||||||||||||||||||||||||||||||||||
1 Represents a non-GAAP financial measure. For further information on this measure, refer to "Non-GAAP Financial Measures and Reconciliations."
5
LOANS AND DEPOSITS
(dollars in millions)
| PERIOD-END BALANCES | AS OF | MARCH 31, 2026 CHANGE | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Sept 30, 2025 | June 30, 2025 | Mar 31, 2025 | Dec 31, 2025 | March 31, 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | % | $ | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| LOANS AND LEASES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial and industrial | $50,307 | $49,232 | $46,953 | $45,412 | $43,781 | $1,075 | 2 | % | $6,526 | 15 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 24,282 | 24,580 | 25,540 | 26,230 | 26,727 | (298) | (1) | (2,445) | (9) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 74,589 | 73,812 | 72,493 | 71,642 | 70,508 | 777 | 1 | 4,081 | 6 | |||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgages | 35,404 | 35,024 | 34,477 | 33,823 | 33,114 | 380 | 1 | 2,290 | 7 | |||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 19,449 | 19,069 | 18,415 | 17,711 | 16,853 | 380 | 2 | 2,596 | 15 | |||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | 1,863 | 2,310 | 2,816 | 3,407 | 4,044 | (447) | (19) | (2,181) | (54) | |||||||||||||||||||||||||||||||||||||||||||||||
| Education | 8,340 | 8,416 | 8,556 | 8,550 | 8,779 | (76) | (1) | (439) | (5) | |||||||||||||||||||||||||||||||||||||||||||||||
| Other retail | 4,022 | 4,061 | 4,113 | 4,171 | 4,337 | (39) | (1) | (315) | (7) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total retail | 69,078 | 68,880 | 68,377 | 67,662 | 67,127 | 198 | — | 1,951 | 3 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $143,667 | $142,692 | $140,870 | $139,304 | $137,635 | $975 | 1 | % | $6,032 | 4 | % | |||||||||||||||||||||||||||||||||||||||||||||
Loans held for sale | 1,537 | 1,198 | 1,334 | 2,093 | 2,820 | 339 | 28 | (1,283) | (45) | |||||||||||||||||||||||||||||||||||||||||||||||
| Loans and leases and loans held for sale | $145,204 | $143,890 | $142,204 | $141,397 | $140,455 | $1,314 | 1 | % | $4,749 | 3 | % | |||||||||||||||||||||||||||||||||||||||||||||
| DEPOSITS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Noninterest-bearing demand | $41,672 | $40,417 | $39,472 | $38,001 | $37,556 | $1,255 | 3 | % | $4,116 | 11 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Checking with interest | 37,675 | 37,428 | 35,219 | 34,918 | 34,456 | 247 | 1 | 3,219 | 9 | |||||||||||||||||||||||||||||||||||||||||||||||
| Savings | 24,114 | 24,353 | 24,759 | 25,400 | 25,765 | (239) | (1) | (1,651) | (6) | |||||||||||||||||||||||||||||||||||||||||||||||
| Money market | 59,611 | 60,062 | 59,709 | 55,638 | 55,996 | (451) | (1) | 3,615 | 6 | |||||||||||||||||||||||||||||||||||||||||||||||
Time | 20,963 | 21,053 | 20,852 | 21,129 | 23,803 | (90) | — | (2,840) | (12) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total deposits | $184,035 | $183,313 | $180,011 | $175,086 | $177,576 | $722 | — | % | $6,459 | 4 | % | |||||||||||||||||||||||||||||||||||||||||||||
6
| AVERAGE BALANCE SHEETS, ANNUALIZED YIELDS AND RATES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| QUARTERLY TRENDS | 1Q26 Change | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Average Balance | Interest | Rate | Average Balance | Interest | Rate | Average Balance | Interest | Rate | Average Balance | Interest | Rate | Average Balance | Interest | Rate | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| INTEREST-EARNING ASSETS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing cash and due from banks and deposits in banks | $10,079 | $91 | 3.60 | % | $9,156 | $89 | 3.80 | % | $8,092 | $89 | 4.42 | % | $923 | $2 | (20) bps | $1,987 | $2 | (82) bps | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Taxable investment securities | 46,928 | 424 | 3.62 | 46,730 | 434 | 3.71 | 46,068 | 418 | 3.63 | 198 | (10) | (9) | 860 | 6 | (1) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-taxable investment securities | 1 | — | 2.60 | 1 | — | 2.60 | 1 | — | 2.60 | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total investment securities | 46,929 | 424 | 3.62 | 46,731 | 434 | 3.71 | 46,069 | 418 | 3.63 | 198 | (10) | (9) | 860 | 6 | (1) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial and industrial | 50,140 | 644 | 5.14 | 48,108 | 605 | 4.92 | 43,599 | 515 | 4.72 | 2,032 | 39 | 22 | 6,541 | 129 | 42 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 24,401 | 328 | 5.38 | 25,043 | 358 | 5.59 | 27,013 | 387 | 5.74 | (642) | (30) | (21) | (2,612) | (59) | (36) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 74,541 | 972 | 5.22 | 73,151 | 963 | 5.15 | 70,612 | 902 | 5.11 | 1,390 | 9 | 7 | 3,929 | 70 | 11 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgages | 35,090 | 353 | 4.03 | 34,752 | 350 | 4.03 | 32,872 | 318 | 3.86 | 338 | 3 | — | 2,218 | 35 | 17 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 19,230 | 307 | 6.47 | 18,754 | 323 | 6.84 | 16,647 | 293 | 7.13 | 476 | (16) | (37) | 2,583 | 14 | (66) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | 2,090 | 24 | 4.68 | 2,557 | 30 | 4.60 | 4,394 | 47 | 4.38 | (467) | (6) | 8 | (2,304) | (23) | 30 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Education | 8,442 | 127 | 6.08 | 8,469 | 128 | 6.00 | 10,690 | 148 | 5.61 | (27) | (1) | 8 | (2,248) | (21) | 47 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other retail | 4,017 | 101 | 10.22 | 4,074 | 107 | 10.34 | 4,495 | 121 | 10.91 | (57) | (6) | (12) | (478) | (20) | (69) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total retail | 68,869 | 912 | 5.34 | 68,606 | 938 | 5.44 | 69,098 | 927 | 5.41 | 263 | (26) | (10) | (229) | (15) | (7) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | 143,410 | 1,884 | 5.28 | 141,757 | 1,901 | 5.29 | 139,710 | 1,829 | 5.26 | 1,653 | (17) | (1) | 3,700 | 55 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Loans held for sale | 1,511 | 21 | 5.65 | 1,523 | 22 | 5.95 | 1,187 | 16 | 5.34 | (12) | (1) | (30) | 324 | 5 | 31 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 201,929 | 2,420 | 4.81 | 199,167 | 2,446 | 4.86 | 195,058 | 2,352 | 4.84 | 2,762 | (26) | (5) | 6,871 | 68 | (3) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-earning assets | 22,295 | 22,075 | 21,251 | 220 | 1,044 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL ASSETS | $224,224 | $221,242 | $216,309 | $2,982 | $7,915 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| INTEREST-BEARING LIABILITIES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Checking with interest | $37,027 | $122 | 1.33 | % | $36,257 | $135 | 1.48 | % | $32,693 | $110 | 1.36 | % | $770 | ($13) | (15) | $4,334 | $12 | (3) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Savings | 24,095 | 65 | 1.10 | 24,477 | 77 | 1.26 | 25,760 | 89 | 1.39 | (382) | (12) | (16) | (1,665) | (24) | (29) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Money market | 60,141 | 350 | 2.36 | 58,904 | 377 | 2.54 | 54,432 | 357 | 2.66 | 1,237 | (27) | (18) | 5,709 | (7) | (30) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Time | 20,766 | 178 | 3.46 | 21,226 | 192 | 3.57 | 23,277 | 239 | 4.17 | (460) | (14) | (11) | (2,511) | (61) | (71) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 142,029 | 715 | 2.04 | 140,864 | 781 | 2.20 | 136,162 | 795 | 2.37 | 1,165 | (66) | (16) | 5,867 | (80) | (33) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowed funds | 454 | 4 | 3.74 | 221 | — | 1.34 | 675 | 8 | 4.53 | 233 | 4 | 240 | (221) | (4) | (79) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| FHLB advances | 1,408 | 14 | 4.02 | 35 | 1 | 3.31 | 595 | 7 | 4.57 | 1,373 | 13 | 71 | 813 | 7 | (55) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Senior debt | 6,843 | 86 | 5.04 | 6,642 | 84 | 5.11 | 7,133 | 86 | 4.85 | 201 | 2 | (7) | (290) | — | 19 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Subordinated debt and other debt | 2,824 | 39 | 5.50 | 3,179 | 43 | 5.32 | 4,929 | 65 | 5.30 | (355) | (4) | 18 | (2,105) | (26) | 20 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total long-term borrowed funds | 11,075 | 139 | 5.03 | 9,856 | 128 | 5.17 | 12,657 | 158 | 5.01 | 1,219 | 11 | (14) | (1,582) | (19) | 2 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total borrowed funds | 11,529 | 143 | 4.98 | 10,077 | 128 | 5.09 | 13,332 | 166 | 4.99 | 1,452 | 15 | (11) | (1,803) | (23) | (1) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 153,558 | 858 | 2.26 | 150,941 | 909 | 2.39 | 149,494 | 961 | 2.60 | 2,617 | (51) | (13) | 4,064 | (103) | (34) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Noninterest-bearing demand deposits | 39,286 | 38,993 | 36,543 | 293 | 2,743 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other noninterest-bearing liabilities | 5,274 | 5,374 | 5,971 | (100) | (697) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL LIABILITIES | 198,118 | 195,308 | 192,008 | 2,810 | 6,110 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| STOCKHOLDERS' EQUITY | 26,106 | 25,934 | 24,301 | 172 | 1,805 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| TOTAL LIABILITIES AND STOCKHOLDERS' EQUITY | $224,224 | $221,242 | $216,309 | $2,982 | $7,915 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| INTEREST RATE SPREAD | 2.55 | % | 2.47 | % | 2.24 | % | 8 | 31 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
NET INTEREST INCOME AND NET INTEREST MARGIN | $1,562 | 3.14 | % | $1,537 | 3.06 | % | $1,391 | 2.89 | % | $25 | 8 | $171 | 25 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
NET INTEREST INCOME AND NET INTEREST MARGIN, FTE1 | $1,565 | 3.14 | % | $1,541 | 3.07 | % | $1,395 | 2.90 | % | $24 | 7 | $170 | 24 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Memo: Total deposits (interest-bearing and noninterest-bearing demand) | $181,315 | $715 | 1.60 | % | $179,857 | $781 | 1.72 | % | $172,705 | $795 | 1.87 | % | $1,458 | ($66) | (12) bps | $8,610 | ($80) | (27) bps | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
1Net interest income and net interest margin are presented on a fully taxable-equivalent ("FTE") basis using the federal statutory tax rate of 21% to adjust for the tax-exempt status of income from certain assets held by the Company and are considered non-GAAP financial measures. For further information on these measures, refer to "Non-GAAP Financial Measures and Reconciliations."
7
MORTGAGE BANKING FEES SUMMARY
(dollars in millions)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 3Q25 | 2Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $/bps | % | $/bps | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| MORTGAGE BANKING FEES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Production revenue | $21 | $19 | $18 | $19 | $15 | $2 | 11 | % | $6 | 40 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Mortgage servicing revenue | 24 | 21 | 29 | 28 | 32 | 3 | 14 | (8) | (25) | |||||||||||||||||||||||||||||||||||||||||||||||
| MSR valuation changes, net of hedge impact | (3) | 12 | 2 | 26 | 12 | (15) | NM | (15) | NM | |||||||||||||||||||||||||||||||||||||||||||||||
| Total mortgage banking fees | $42 | $52 | $49 | $73 | $59 | ($10) | (19 | %) | ($17) | (29 | %) | |||||||||||||||||||||||||||||||||||||||||||||
| Pull-through adjusted locks | $2,299 | $2,486 | $2,150 | $2,458 | $2,112 | ($187) | (8 | %) | $187 | 9 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Production revenue as a percentage of Pull-through adjusted locks | 0.90 | % | 0.78 | % | 0.81 | % | 0.78 | % | 0.71 | % | 12 | bps | 19 | bps | ||||||||||||||||||||||||||||||||||||||||||
| RESIDENTIAL REAL ESTATE ORIGINATIONS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Retail | $1,944 | $2,175 | $2,019 | $2,189 | $1,444 | ($231) | (11 | %) | $500 | 35 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Third Party | 1,854 | 2,179 | 1,837 | 1,916 | 1,474 | (325) | (15) | 380 | 26 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total | $3,798 | $4,354 | $3,856 | $4,105 | $2,918 | ($556) | (13 | %) | $880 | 30 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Originated for sale | $2,415 | $2,748 | $2,379 | $2,486 | $1,916 | ($333) | (12 | %) | $499 | 26 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Originated for investment | 1,383 | 1,606 | 1,477 | 1,619 | 1,002 | (223) | (14) | 381 | 38 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total | $3,798 | $4,354 | $3,856 | $4,105 | $2,918 | ($556) | (13 | %) | $880 | 30 | % | |||||||||||||||||||||||||||||||||||||||||||||
| MORTGAGE SERVICING INFORMATION (UPB) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans serviced for others | $94,794 | $94,877 | $95,244 | $95,422 | $95,203 | ($83) | — | % | ($409) | — | % | |||||||||||||||||||||||||||||||||||||||||||||
| Owned loans serviced | 35,888 | 35,599 | 34,760 | 34,284 | 33,737 | 289 | 1 | 2,151 | 6 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total | $130,682 | $130,476 | $130,004 | $129,706 | $128,940 | $206 | — | % | $1,742 | 1 | % | |||||||||||||||||||||||||||||||||||||||||||||
| MSR at fair value | $1,462 | $1,455 | $1,430 | $1,426 | $1,397 | $7 | — | % | $65 | 5 | % | |||||||||||||||||||||||||||||||||||||||||||||
8
SEGMENT FINANCIAL HIGHLIGHTS - CONSUMER BANKING
(dollars in millions)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
CONSUMER BANKING | 1Q26 Change | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 3Q25 | 2Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $/bps | % | $/bps | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $1,309 | $1,299 | $1,262 | $1,218 | $1,193 | $10 | 1 | % | $116 | 10 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Noninterest income | 299 | 315 | 311 | 329 | 297 | (16) | (5) | 2 | 1 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total revenue | 1,608 | 1,614 | 1,573 | 1,547 | 1,490 | (6) | — | 118 | 8 | |||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 1,028 | 984 | 979 | 963 | 954 | 44 | 4 | 74 | 8 | |||||||||||||||||||||||||||||||||||||||||||||||
| Profit (loss) before credit losses | 580 | 630 | 594 | 584 | 536 | (50) | (8) | 44 | 8 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net charge-offs | 71 | 80 | 81 | 81 | 86 | (9) | (11) | (15) | (17) | |||||||||||||||||||||||||||||||||||||||||||||||
| Income (loss) before income tax expense (benefit) | 509 | 550 | 513 | 503 | 450 | (41) | (7) | 59 | 13 | |||||||||||||||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | 131 | 139 | 130 | 127 | 114 | (8) | (6) | 17 | 15 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net income (loss) | $378 | $411 | $383 | $376 | $336 | ($33) | (8 | %) | $42 | 13 | % | |||||||||||||||||||||||||||||||||||||||||||||
| AVERAGE BALANCES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $83,870 | $82,552 | $80,729 | $78,822 | $77,534 | $1,318 | 2 | % | $6,336 | 8 | % | |||||||||||||||||||||||||||||||||||||||||||||
Total loans and leases1 | 77,089 | 75,980 | 74,274 | 72,402 | 71,054 | 1,109 | 1 | 6,035 | 8 | |||||||||||||||||||||||||||||||||||||||||||||||
| Deposits | 133,126 | 131,488 | 128,547 | 127,271 | 125,728 | 1,638 | 1 | 7,398 | 6 | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets | 77,695 | 76,583 | 74,870 | 72,988 | 71,635 | 1,112 | 1 | 6,060 | 8 | |||||||||||||||||||||||||||||||||||||||||||||||
| KEY METRICS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin | 6.83 | % | 6.73 | % | 6.69 | % | 6.69 | % | 6.76 | % | 10 | bps | 7 | bps | ||||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 63.94 | 60.98 | 62.22 | 62.24 | 64.06 | 296 | bps | (12) | bps | |||||||||||||||||||||||||||||||||||||||||||||||
| Loan-to-deposit ratio (period-end balances) | 56.55 | 57.28 | 57.40 | 57.24 | 54.97 | (73) | bps | 158 | bps | |||||||||||||||||||||||||||||||||||||||||||||||
| Loan-to-deposit ratio (average balances) | 57.36 | 57.19 | 57.16 | 56.26 | 56.04 | 17 | bps | 132 | bps | |||||||||||||||||||||||||||||||||||||||||||||||
1 Includes loans held for sale.
9
SEGMENT FINANCIAL HIGHLIGHTS - COMMERCIAL BANKING
(dollars in millions)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
COMMERCIAL BANKING | 1Q26 Change | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 3Q25 | 2Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $/bps | % | $/bps | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $456 | $450 | $448 | $439 | $441 | $6 | 1 | % | $15 | 3 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Noninterest income | 263 | 262 | 286 | 232 | 215 | 1 | — | 48 | 22 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total revenue | 719 | 712 | 734 | 671 | 656 | 7 | 1 | 63 | 10 | |||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 334 | 357 | 333 | 317 | 327 | (23) | (6) | 7 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||
| Profit (loss) before credit losses | 385 | 355 | 401 | 354 | 329 | 30 | 8 | 56 | 17 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net charge-offs | 64 | 70 | 78 | 84 | 77 | (6) | (9) | (13) | (17) | |||||||||||||||||||||||||||||||||||||||||||||||
| Income (loss) before income tax expense (benefit) | 321 | 285 | 323 | 270 | 252 | 36 | 13 | 69 | 27 | |||||||||||||||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | 78 | 70 | 75 | 64 | 56 | 8 | 11 | 22 | 39 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net income (loss) | $243 | $215 | $248 | $206 | $196 | $28 | 13 | % | $47 | 24 | % | |||||||||||||||||||||||||||||||||||||||||||||
| AVERAGE BALANCES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $67,737 | $66,750 | $66,134 | $66,284 | $65,366 | $987 | 1 | % | $2,371 | 4 | % | |||||||||||||||||||||||||||||||||||||||||||||
Total loans and leases1 | 64,574 | 63,356 | 62,905 | 63,057 | 62,437 | 1,218 | 2 | 2,137 | 3 | |||||||||||||||||||||||||||||||||||||||||||||||
| Deposits | 45,354 | 45,443 | 44,482 | 42,481 | 42,178 | (89) | — | 3,176 | 8 | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets | 65,345 | 64,248 | 63,719 | 63,710 | 63,018 | 1,097 | 2 | 2,327 | 4 | |||||||||||||||||||||||||||||||||||||||||||||||
| KEY METRICS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin | 2.84 | % | 2.78 | % | 2.78 | % | 2.78 | % | 2.83 | % | 6 | bps | 1 | bps | ||||||||||||||||||||||||||||||||||||||||||
| Efficiency ratio | 46.66 | 50.09 | 45.15 | 47.47 | 49.77 | (343) | bps | (311) | bps | |||||||||||||||||||||||||||||||||||||||||||||||
| Loan-to-deposit ratio (period-end balances) | 141.03 | 132.96 | 132.70 | 139.59 | 142.21 | 807 | bps | (118) | bps | |||||||||||||||||||||||||||||||||||||||||||||||
| Loan-to-deposit ratio (average balances) | 140.64 | 138.26 | 140.06 | 146.90 | 146.86 | 238 | bps | (622) | bps | |||||||||||||||||||||||||||||||||||||||||||||||
1 Includes loans held for sale.
10
SEGMENT FINANCIAL HIGHLIGHTS - OTHER
(dollars in millions)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
OTHER1 | 1Q26 Change | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 3Q25 | 2Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | % | $ | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | ($203) | ($212) | ($222) | ($220) | ($243) | $9 | 4 | % | $40 | 16 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Noninterest income | 44 | 43 | 33 | 39 | 32 | 1 | 2 | 12 | 38 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total revenue | (159) | (169) | (189) | (181) | (211) | 10 | 6 | 52 | 25 | |||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 16 | 2 | 23 | 39 | 33 | 14 | NM | (17) | (52) | |||||||||||||||||||||||||||||||||||||||||||||||
| Profit (loss) before provision (benefit) for credit losses | (175) | (171) | (212) | (220) | (244) | (4) | (2) | 69 | 28 | |||||||||||||||||||||||||||||||||||||||||||||||
| Provision (benefit) for credit losses | 5 | (13) | (5) | (1) | (10) | 18 | NM | 15 | NM | |||||||||||||||||||||||||||||||||||||||||||||||
| Income (loss) before income tax expense (benefit) | (180) | (158) | (207) | (219) | (234) | (22) | (14) | 54 | 23 | |||||||||||||||||||||||||||||||||||||||||||||||
| Income tax expense (benefit) | (76) | (60) | (70) | (73) | (75) | (16) | (27) | (1) | (1) | |||||||||||||||||||||||||||||||||||||||||||||||
| Net income (loss) | ($104) | ($98) | ($137) | ($146) | ($159) | ($6) | (6 | %) | $55 | 35 | % | |||||||||||||||||||||||||||||||||||||||||||||
| AVERAGE BALANCES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $72,617 | $71,940 | $72,254 | $72,555 | $73,409 | $677 | 1 | % | ($792) | (1 | %) | |||||||||||||||||||||||||||||||||||||||||||||
Total loans and leases2 | 3,258 | 3,944 | 4,950 | 6,104 | 7,406 | (686) | (17) | (4,148) | (56) | |||||||||||||||||||||||||||||||||||||||||||||||
| Deposits | 2,835 | 2,926 | 2,928 | 4,376 | 4,799 | (91) | (3) | (1,964) | (41) | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets | 58,889 | 58,336 | 59,009 | 59,620 | 60,406 | 553 | 1 | (1,517) | (3) | |||||||||||||||||||||||||||||||||||||||||||||||
1 Consists primarily of treasury and community development, and includes assets, liabilities, capital, revenues, provision (benefit) for credit losses, expenses, and income tax expense (benefit) not attributed to our Consumer Banking or Commercial Banking segments.
2 Includes loans held for sale.
11
CREDIT-RELATED INFORMATION
(dollars in millions)
| AS OF | MARCH 31, 2026 CHANGE | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Sept 30, 2025 | June 30, 2025 | Mar 31, 2025 | Dec 31, 2025 | March 31, 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $/bps/% | % | $/bps/% | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| NONACCRUAL LOANS AND LEASES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial and industrial | $188 | $277 | $230 | $233 | $283 | ($89) | (32 | %) | ($95) | (34 | %) | |||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 679 | 618 | 703 | 706 | 700 | 61 | 10 | (21) | (3) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 867 | 895 | 933 | 939 | 983 | (28) | (3) | (116) | (12) | |||||||||||||||||||||||||||||||||||||||||||||||
Residential mortgages1 | 217 | 196 | 188 | 198 | 198 | 21 | 11 | 19 | 10 | |||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 324 | 319 | 297 | 282 | 282 | 5 | 2 | 42 | 15 | |||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | 23 | 28 | 31 | 34 | 39 | (5) | (18) | (16) | (41) | |||||||||||||||||||||||||||||||||||||||||||||||
| Education | 21 | 20 | 20 | 19 | 20 | 1 | 5 | 1 | 5 | |||||||||||||||||||||||||||||||||||||||||||||||
| Other retail | 45 | 46 | 49 | 52 | 60 | (1) | (2) | (15) | (25) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total retail | 630 | 609 | 585 | 585 | 599 | 21 | 3 | 31 | 5 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total nonaccrual loans and leases | 1,497 | 1,504 | 1,518 | 1,524 | 1,582 | (7) | — | (85) | (5) | |||||||||||||||||||||||||||||||||||||||||||||||
| ASSET QUALITY RATIOS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses to loans and leases | 1.36 | % | 1.36 | % | 1.40 | % | 1.44 | % | 1.46 | % | — | bps | (10) | bps | ||||||||||||||||||||||||||||||||||||||||||
| Allowance for credit losses to loans and leases | 1.52 | 1.53 | 1.56 | 1.59 | 1.61 | (1) | bps | (9) | bps | |||||||||||||||||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses to nonaccrual loans and leases | 131 | 129 | 130 | 132 | 127 | 2 | % | 4 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Allowance for credit losses to nonaccrual loans and leases | 146 | 145 | 145 | 145 | 140 | 1 | % | 6 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Nonaccrual loans and leases to loans and leases | 1.04 | 1.05 | 1.08 | 1.09 | 1.15 | (1) | bps | (11) | bps | |||||||||||||||||||||||||||||||||||||||||||||||
1 Loans fully or partially guaranteed by the FHA, VA and USDA are classified as accruing.
12
CREDIT-RELATED INFORMATION, CONTINUED
(dollars in millions)
| AS OF | MARCH 31, 2026 CHANGE | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Sept 30, 2025 | June 30, 2025 | Mar 31, 2025 | Dec 31, 2025 | March 31, 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $/bps | % | $/bps | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| LOANS AND LEASES 90 DAYS OR MORE PAST DUE AND ACCRUING | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial and industrial | $1 | $5 | $39 | $3 | $9 | ($4) | (80 | %) | ($8) | (89 | %) | |||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 26 | 20 | 7 | 60 | 4 | 6 | 30 | 22 | NM | |||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 27 | 25 | 46 | 63 | 13 | 2 | 8 | 14 | 108 | |||||||||||||||||||||||||||||||||||||||||||||||
Residential mortgages1 | 179 | 141 | 114 | 128 | 138 | 38 | 27 | 41 | 30 | |||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | — | 1 | — | — | — | (1) | (100) | — | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | — | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Education | 2 | 2 | 2 | 2 | 3 | — | — | (1) | (33) | |||||||||||||||||||||||||||||||||||||||||||||||
| Other retail | — | — | — | 1 | 1 | — | — | (1) | (100) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total retail | 181 | 144 | 116 | 131 | 142 | 37 | 26 | 39 | 27 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $208 | $169 | $162 | $194 | $155 | $39 | 23 | % | $53 | 34 | % | |||||||||||||||||||||||||||||||||||||||||||||
1 90+ days past due and accruing includes $179 million, $141 million, $114 million, $128 million, and $137 million of loans fully or partially guaranteed by the FHA, VA, and USDA for March 31, 2026, December 31, 2025, September 30, 2025, June 30, 2025 and March 31, 2025, respectively.
13
CREDIT-RELATED INFORMATION, CONTINUED
(dollars in millions)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 3Q25 | 2Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | % | $ | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| CHARGE-OFFS, RECOVERIES AND RELATED RATIOS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| GROSS CHARGE-OFFS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial and industrial | $50 | $40 | $33 | $39 | $34 | $10 | 25 | % | $16 | 47 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 41 | 42 | 58 | 54 | 51 | (1) | (2) | (10) | (20) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 91 | 82 | 91 | 93 | 85 | 9 | 11 | 6 | 7 | |||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgages | 1 | 5 | 1 | — | 1 | (4) | (80) | — | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 6 | 5 | 3 | 4 | 5 | 1 | 20 | 1 | 20 | |||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | 9 | 12 | 13 | 14 | 20 | (3) | (25) | (11) | (55) | |||||||||||||||||||||||||||||||||||||||||||||||
| Education | 22 | 26 | 25 | 26 | 56 | (4) | (15) | (34) | (61) | |||||||||||||||||||||||||||||||||||||||||||||||
| Other retail | 54 | 57 | 62 | 64 | 67 | (3) | (5) | (13) | (19) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total retail | 92 | 105 | 104 | 108 | 149 | (13) | (12) | (57) | (38) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total gross charge-offs | $183 | $187 | $195 | $201 | $234 | ($4) | (2 | %) | ($51) | (22 | %) | |||||||||||||||||||||||||||||||||||||||||||||
| GROSS RECOVERIES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial and industrial | $15 | $6 | $3 | $— | $4 | $9 | 150 | % | $11 | NM | ||||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 3 | 1 | 3 | 1 | — | 2 | 200 | 3 | 100 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 18 | 7 | 6 | 1 | 4 | 11 | 157 | 14 | NM | |||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgages | 3 | — | 1 | — | 1 | 3 | 100 | 2 | 200 | |||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 4 | 5 | 6 | 6 | 5 | (1) | (20) | (1) | (20) | |||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | 7 | 9 | 9 | 11 | 12 | (2) | (22) | (5) | (42) | |||||||||||||||||||||||||||||||||||||||||||||||
| Education | 6 | 6 | 5 | 8 | 5 | — | — | 1 | 20 | |||||||||||||||||||||||||||||||||||||||||||||||
| Other retail | 7 | 5 | 6 | 8 | 7 | 2 | 40 | — | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Total retail | 27 | 25 | 27 | 33 | 30 | 2 | 8 | (3) | (10) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total gross recoveries | $45 | $32 | $33 | $34 | $34 | $13 | 41 | % | $11 | 32 | % | |||||||||||||||||||||||||||||||||||||||||||||
| NET CHARGE-OFFS (RECOVERIES) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial and industrial | $35 | $34 | $30 | $39 | $30 | $1 | 3 | % | $5 | 17 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 38 | 41 | 55 | 53 | 51 | (3) | (7) | (13) | (25) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 73 | 75 | 85 | 92 | 81 | (2) | (3) | (8) | (10) | |||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgages | (2) | 5 | — | — | — | (7) | NM | (2) | (100) | |||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 2 | — | (3) | (2) | — | 2 | 100 | 2 | 100 | |||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | 2 | 3 | 4 | 3 | 8 | (1) | (33) | (6) | (75) | |||||||||||||||||||||||||||||||||||||||||||||||
| Education | 16 | 20 | 20 | 18 | 51 | (4) | (20) | (35) | (69) | |||||||||||||||||||||||||||||||||||||||||||||||
| Other retail | 47 | 52 | 56 | 56 | 60 | (5) | (10) | (13) | (22) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total retail | 65 | 80 | 77 | 75 | 119 | (15) | (19) | (54) | (45) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total net charge-offs | $138 | $155 | $162 | $167 | $200 | ($17) | (11 | %) | ($62) | (31 | %) | |||||||||||||||||||||||||||||||||||||||||||||
14
CREDIT-RELATED INFORMATION, CONTINUED
(dollars in millions)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 3Q25 | 2Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $/bps | % | $/bps | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| ANNUALIZED NET CHARGE-OFF (RECOVERY) RATES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial and industrial | 0.28 | % | 0.28 | % | 0.26 | % | 0.35 | % | 0.28 | % | — | bps | — | bps | ||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 0.64 | 0.64 | 0.85 | 0.80 | 0.77 | — | (13) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 0.40 | 0.40 | 0.47 | 0.51 | 0.47 | — | (7) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgages | (0.02) | 0.05 | — | — | 0.01 | (7) | (3) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 0.04 | — | (0.06) | (0.05) | (0.01) | 4 | 5 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | 0.35 | 0.60 | 0.43 | 0.36 | 0.73 | (25) | (38) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Education | 0.80 | 0.94 | 0.92 | 0.86 | 1.92 | (14) | (112) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Other retail | 4.74 | 5.02 | 5.45 | 5.23 | 5.46 | (28) | (72) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total retail | 0.38 | 0.46 | 0.45 | 0.45 | 0.70 | (8) | (32) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | 0.39 | % | 0.43 | % | 0.46 | % | 0.48 | % | 0.58 | % | (4) | bps | (19) | bps | ||||||||||||||||||||||||||||||||||||||||||
| Memo: Average loans | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Commercial and industrial | $50,140 | $48,108 | $46,351 | $44,936 | $43,599 | $2,032 | 4 | % | $6,541 | 15 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 24,401 | 25,043 | 25,799 | 26,487 | 27,013 | (642) | (3) | (2,612) | (10) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total commercial | 74,541 | 73,151 | 72,150 | 71,423 | 70,612 | 1,390 | 2 | 3,929 | 6 | |||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgages | 35,090 | 34,752 | 34,134 | 33,420 | 32,872 | 338 | 1 | 2,218 | 7 | |||||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 19,230 | 18,754 | 18,027 | 17,324 | 16,647 | 476 | 3 | 2,583 | 16 | |||||||||||||||||||||||||||||||||||||||||||||||
| Automobile | 2,090 | 2,557 | 3,096 | 3,705 | 4,394 | (467) | (18) | (2,304) | (52) | |||||||||||||||||||||||||||||||||||||||||||||||
| Education | 8,442 | 8,469 | 8,513 | 8,660 | 10,690 | (27) | — | (2,248) | (21) | |||||||||||||||||||||||||||||||||||||||||||||||
| Other retail | 4,017 | 4,074 | 4,091 | 4,277 | 4,495 | (57) | (1) | (478) | (11) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total retail | 68,869 | 68,606 | 67,861 | 67,386 | 69,098 | 263 | — | (229) | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | $143,410 | $141,757 | $140,011 | $138,809 | $139,710 | $1,653 | 1 | % | $3,700 | 3 | % | |||||||||||||||||||||||||||||||||||||||||||||
15
CREDIT-RELATED INFORMATION, CONTINUED
(dollars in millions)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 3Q25 | 2Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | % | $ | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| SUMMARY OF CHANGES IN THE COMPONENTS OF THE ALLOWANCE FOR CREDIT LOSSES | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses - beginning | $1,943 | $1,972 | $2,008 | $2,014 | $2,061 | ($29) | (1 | %) | ($118) | (6 | %) | |||||||||||||||||||||||||||||||||||||||||||||
| Charge-offs: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial | 91 | 82 | 91 | 93 | 85 | 9 | 11 | 6 | 7 | |||||||||||||||||||||||||||||||||||||||||||||||
| Retail | 92 | 105 | 104 | 108 | 149 | (13) | (12) | (57) | (38) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total charge-offs | 183 | 187 | 195 | 201 | 234 | (4) | (2) | (51) | (22) | |||||||||||||||||||||||||||||||||||||||||||||||
| Recoveries: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial | 18 | 7 | 6 | 1 | 4 | 11 | 157 | 14 | NM | |||||||||||||||||||||||||||||||||||||||||||||||
| Retail | 27 | 25 | 27 | 33 | 30 | 2 | 8 | (3) | (10) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total recoveries | 45 | 32 | 33 | 34 | 34 | 13 | 41 | 11 | 32 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net charge-offs | 138 | 155 | 162 | 167 | 200 | (17) | (11) | (62) | (31) | |||||||||||||||||||||||||||||||||||||||||||||||
| Provision (benefit) for loan and lease losses: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial | 130 | 50 | 62 | 50 | 89 | 80 | 160 | 41 | 46 | |||||||||||||||||||||||||||||||||||||||||||||||
| Retail | 23 | 76 | 64 | 111 | 64 | (53) | (70) | (41) | (64) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total provision (benefit) for loan and lease losses | 153 | 126 | 126 | 161 | 153 | 27 | 21 | — | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses - ending | $1,958 | $1,943 | $1,972 | $2,008 | $2,014 | $15 | 1 | % | ($56) | (3 | %) | |||||||||||||||||||||||||||||||||||||||||||||
| Allowance for unfunded lending commitments - beginning | $240 | $229 | $201 | $198 | $198 | $11 | 5 | % | $42 | 21 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Provision (benefit) for unfunded lending commitments | (13) | 11 | 28 | 3 | — | (24) | NM | (13) | (100) | |||||||||||||||||||||||||||||||||||||||||||||||
| Allowance for unfunded lending commitments - ending | $227 | $240 | $229 | $201 | $198 | ($13) | (5 | %) | $29 | 15 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Total allowance for credit losses - ending | $2,185 | $2,183 | $2,201 | $2,209 | $2,212 | $2 | — | % | ($27) | (1 | %) | |||||||||||||||||||||||||||||||||||||||||||||
| Memo: Total allowance for credit losses by product | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial | $1,304 | $1,252 | $1,265 | $1,269 | $1,312 | $52 | 4 | % | ($8) | (1 | %) | |||||||||||||||||||||||||||||||||||||||||||||
| Retail | 881 | 931 | 936 | 940 | 900 | (50) | (5) | (19) | (2) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total allowance for credit losses | $2,185 | $2,183 | $2,201 | $2,209 | $2,212 | $2 | — | % | ($27) | (1 | %) | |||||||||||||||||||||||||||||||||||||||||||||
16
CAPITAL AND RATIOS
(dollars in millions)
| AS OF | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| MARCH 31, 2026 CHANGE | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Mar 31, 2026 | Dec 31, 2025 | Sept 30, 2025 | June 30, 2025 | Mar 31, 2025 | Dec 31, 2025 | March 31, 2025 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | % | $ | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| CAPITAL RATIOS AND COMPONENTS (PRELIMINARY) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| CET1 capital | $18,178 | $18,240 | $18,046 | $17,812 | $17,751 | ($62) | — | % | $427 | 2 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Tier 1 capital | 20,289 | 20,351 | 20,157 | 19,925 | 19,864 | (62) | — | 425 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total capital | 23,751 | 23,654 | 23,455 | 23,221 | 23,156 | 97 | — | 595 | 3 | |||||||||||||||||||||||||||||||||||||||||||||||
| Risk-weighted assets | 173,268 | 171,493 | 168,932 | 168,017 | 166,908 | 1,775 | 1 | 6,360 | 4 | |||||||||||||||||||||||||||||||||||||||||||||||
Adjusted average assets1 | 218,192 | 215,321 | 213,536 | 212,450 | 211,119 | 2,871 | 1 | 7,073 | 3 | |||||||||||||||||||||||||||||||||||||||||||||||
| CET1 capital ratio | 10.5 | % | 10.6 | % | 10.7 | % | 10.6 | % | 10.6 | % | ||||||||||||||||||||||||||||||||||||||||||||||
| Tier 1 capital ratio | 11.7 | 11.9 | 11.9 | 11.9 | 11.9 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Total capital ratio | 13.7 | 13.8 | 13.9 | 13.8 | 13.9 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Tier 1 leverage ratio | 9.3 | 9.5 | 9.4 | 9.4 | 9.4 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| TANGIBLE COMMON EQUITY (PERIOD-END) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Common stockholders' equity | $24,061 | $24,206 | $23,718 | $23,121 | $22,753 | ($145) | (1 | %) | $1,308 | 6 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Goodwill | 8,221 | 8,187 | 8,187 | 8,187 | 8,187 | 34 | — | 34 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Less: Other intangible assets | 112 | 115 | 123 | 128 | 137 | (3) | (3) | (25) | (18) | |||||||||||||||||||||||||||||||||||||||||||||||
Add: Deferred tax liabilities2 | 437 | 437 | 440 | 440 | 438 | — | — | (1) | — | |||||||||||||||||||||||||||||||||||||||||||||||
Total tangible common equity3 | $16,165 | $16,341 | $15,848 | $15,246 | $14,867 | ($176) | (1 | %) | $1,298 | 9 | % | |||||||||||||||||||||||||||||||||||||||||||||
| TANGIBLE COMMON EQUITY (AVERAGE) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Common stockholders' equity | $23,995 | $23,823 | $23,288 | $22,494 | $22,188 | $172 | 1 | % | $1,807 | 8 | % | |||||||||||||||||||||||||||||||||||||||||||||
| Less: Goodwill | 8,198 | 8,187 | 8,187 | 8,187 | 8,187 | 11 | — | 11 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Less: Other intangible assets | 114 | 120 | 126 | 134 | 142 | (6) | (5) | (28) | (20) | |||||||||||||||||||||||||||||||||||||||||||||||
Add: Deferred tax liabilities2 | 437 | 440 | 440 | 438 | 438 | (3) | (1) | (1) | — | |||||||||||||||||||||||||||||||||||||||||||||||
Total tangible common equity3 | $16,120 | $15,956 | $15,415 | $14,611 | $14,297 | $164 | 1 | % | $1,823 | 13 | % | |||||||||||||||||||||||||||||||||||||||||||||
| INTANGIBLE ASSETS (PERIOD-END) | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Goodwill | $8,221 | $8,187 | $8,187 | $8,187 | $8,187 | $34 | — | % | $34 | — | % | |||||||||||||||||||||||||||||||||||||||||||||
| Other intangible assets | 112 | 115 | 123 | 128 | 137 | (3) | (3) | (25) | (18) | |||||||||||||||||||||||||||||||||||||||||||||||
| Total intangible assets | $8,333 | $8,302 | $8,310 | $8,315 | $8,324 | $31 | — | % | $9 | — | % | |||||||||||||||||||||||||||||||||||||||||||||
1 Adjusted average assets include quarterly average assets, less deductions for disallowed goodwill and other intangible assets, net of deferred taxes, and the accumulated other comprehensive
income impact related to the adoption of post-retirement benefit plan guidance under GAAP.
income impact related to the adoption of post-retirement benefit plan guidance under GAAP.
2 Deferred tax liabilities relate to tax-deductible goodwill and other intangible assets.
3 These are non-GAAP financial measures. For further information on these measures, refer to "Non-GAAP Financial Measures and Reconciliations."
17
NON-GAAP FINANCIAL MEASURES AND RECONCILIATIONS
(dollars in millions, except per share data)
Non-GAAP Financial Measures
This document contains non-GAAP financial measures that we believe provide useful information to investors to understand our results of operations or financial condition. We caution investors not to place undue reliance on such non-GAAP financial measures, but to consider them with the most directly comparable GAAP financial measures. Non-GAAP financial measures have limitations as analytical tools and should not be considered in isolation or as a substitute for our results reported under GAAP. The following tables present reconciliations of our non-GAAP financial measures to the most directly comparable GAAP financial measures.
18
NON-GAAP FINANCIAL MEASURES AND RECONCILIATIONS, CONTINUED
(dollars in millions, except per share data)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 3Q25 | 2Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| $ | % | $ | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Pre-provision profit: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total revenue (GAAP) | A | $2,168 | $2,157 | $2,118 | $2,037 | $1,935 | $11 | 1 | % | $233 | 12 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Less: Noninterest expense (GAAP) | B | 1,378 | 1,343 | 1,335 | 1,319 | 1,314 | 35 | 3 | 64 | 5 | ||||||||||||||||||||||||||||||||||||||||||||||
Pre-provision profit (non-GAAP) | $790 | $814 | $783 | $718 | $621 | ($24) | (3 | %) | $169 | 27 | % | |||||||||||||||||||||||||||||||||||||||||||||
Book value per common share and tangible book value per common share: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Common shares - at period-end (GAAP) | C | 426,023,578 | 429,242,174 | 431,453,142 | 432,768,811 | 437,668,127 | (3,218,596) | (1 | %) | (11,644,549) | (3 | %) | ||||||||||||||||||||||||||||||||||||||||||||
| Common stockholders' equity (GAAP) | D | $24,061 | $24,206 | $23,718 | $23,121 | $22,753 | ($145) | (1) | $1,308 | 6 | ||||||||||||||||||||||||||||||||||||||||||||||
| Less: Goodwill (GAAP) | 8,221 | 8,187 | 8,187 | 8,187 | 8,187 | 34 | — | 34 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Less: Other intangible assets (GAAP) | 112 | 115 | 123 | 128 | 137 | (3) | (3) | (25) | (18) | |||||||||||||||||||||||||||||||||||||||||||||||
| Add: Deferred tax liabilities related to goodwill and other intangible assets (GAAP) | 437 | 437 | 440 | 440 | 438 | — | — | (1) | — | |||||||||||||||||||||||||||||||||||||||||||||||
Tangible common equity (non-GAAP) | E | $16,165 | $16,341 | $15,848 | $15,246 | $14,867 | ($176) | (1 | %) | $1,298 | 9 | % | ||||||||||||||||||||||||||||||||||||||||||||
Book value per common share (GAAP) | D/C | $56.48 | $56.39 | $54.97 | $53.43 | $51.99 | $0.09 | — | % | $4.49 | 9 | % | ||||||||||||||||||||||||||||||||||||||||||||
Tangible book value per common share (non-GAAP) | E/C | 37.94 | 38.07 | 36.73 | 35.23 | 33.97 | (0.13) | — | 3.97 | 12 | ||||||||||||||||||||||||||||||||||||||||||||||
Net interest income and net interest margin on an FTE basis: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income (annualized) (GAAP) | F | $6,337 | $6,098 | $5,902 | $5,770 | $5,637 | $239 | 4 | % | $700 | 12 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Average interest-earning assets (GAAP) | G | 201,929 | 199,167 | 197,598 | 196,318 | 195,058 | 2,762 | 1 | 6,871 | 4 | ||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin (GAAP) | F/G | 3.14 | % | 3.06 | % | 2.99 | % | 2.94 | % | 2.89 | % | 8 | bps | 25 | bps | |||||||||||||||||||||||||||||||||||||||||
| Net interest income (GAAP) | $1,562 | $1,537 | $1,488 | $1,437 | $1,391 | $25 | 2 | % | $171 | 12 | % | |||||||||||||||||||||||||||||||||||||||||||||
| FTE adjustment | 3 | 4 | 4 | 4 | 4 | (1) | (25) | (1) | (25) | |||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income on an FTE basis (non-GAAP) | 1,565 | 1,541 | 1,492 | 1,441 | 1,395 | 24 | 2 | 170 | 12 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income on an FTE basis (annualized) (non-GAAP) | H | 6,350 | 6,112 | 5,919 | 5,786 | 5,653 | 238 | 4 | 697 | 12 | ||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin on an FTE basis (non-GAAP) | H/G | 3.14 | % | 3.07 | % | 3.00 | % | 2.95 | % | 2.90 | % | 7 | bps | 24 | bps | |||||||||||||||||||||||||||||||||||||||||
Return on average common equity and return on average tangible common equity: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net income available to common stockholders (GAAP) | I | $484 | $489 | $457 | $402 | $340 | ($5) | (1 | %) | $144 | 42 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Average common equity (GAAP) | J | $23,995 | $23,823 | $23,288 | $22,494 | $22,188 | $172 | 1 | $1,807 | 8 | ||||||||||||||||||||||||||||||||||||||||||||||
| Less: Average goodwill (GAAP) | 8,198 | 8,187 | 8,187 | 8,187 | 8,187 | 11 | — | 11 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Less: Average other intangibles (GAAP) | 114 | 120 | 126 | 134 | 142 | (6) | (5) | (28) | (20) | |||||||||||||||||||||||||||||||||||||||||||||||
| Add: Average deferred tax liabilities related to goodwill and other intangible assets (GAAP) | 437 | 440 | 440 | 438 | 438 | (3) | (1) | (1) | — | |||||||||||||||||||||||||||||||||||||||||||||||
Average tangible common equity (non-GAAP) | K | $16,120 | $15,956 | $15,415 | $14,611 | $14,297 | $164 | 1 | % | $1,823 | 13 | % | ||||||||||||||||||||||||||||||||||||||||||||
Return on average common equity (GAAP) | I/J | 8.19 | % | 8.16 | % | 7.77 | % | 7.18 | % | 6.21 | % | 3 | bps | 198 | bps | |||||||||||||||||||||||||||||||||||||||||
| Return on average tangible common equity (non-GAAP) | I/K | 12.19 | % | 12.18 | % | 11.75 | % | 11.05 | % | 9.64 | % | 1 | bps | 255 | bps | |||||||||||||||||||||||||||||||||||||||||
Return on average total assets and return on average total tangible assets: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net income (GAAP) | L | $517 | $528 | $494 | $436 | $373 | ($11) | (2 | %) | $144 | 39 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Average total assets (GAAP) | M | $224,224 | $221,242 | $219,117 | $217,661 | $216,309 | $2,982 | 1 | $7,915 | 4 | ||||||||||||||||||||||||||||||||||||||||||||||
| Less: Average goodwill (GAAP) | 8,198 | 8,187 | 8,187 | 8,187 | 8,187 | 11 | — | 11 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Less: Average other intangibles (GAAP) | 114 | 120 | 126 | 134 | 142 | (6) | (5) | (28) | (20) | |||||||||||||||||||||||||||||||||||||||||||||||
| Add: Average deferred tax liabilities related to goodwill and other intangible assets (GAAP) | 437 | 440 | 440 | 438 | 438 | (3) | (1) | (1) | — | |||||||||||||||||||||||||||||||||||||||||||||||
Average tangible assets (non-GAAP) | N | $216,349 | $213,375 | $211,244 | $209,778 | $208,418 | $2,974 | 1 | % | $7,931 | 4 | % | ||||||||||||||||||||||||||||||||||||||||||||
Return on average total assets (GAAP) | L/M | 0.94 | % | 0.95 | % | 0.90 | % | 0.80 | % | 0.70 | % | (1) | bps | 24 | bps | |||||||||||||||||||||||||||||||||||||||||
Return on average total tangible assets (non-GAAP) | L/N | 0.97 | % | 0.98 | % | 0.93 | % | 0.83 | % | 0.73 | % | (1) | bps | 24 | bps | |||||||||||||||||||||||||||||||||||||||||
19
NON-GAAP FINANCIAL MEASURES AND RECONCILIATIONS, CONTINUED
(dollars in millions, except per share data)
| QUARTERLY TRENDS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 Change | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| 1Q26 | 4Q25 | 3Q25 | 2Q25 | 1Q25 | 4Q25 | 1Q25 | ||||||||||||||||||||||||||||||||||||||||||||||||||
$/bps | % | $/bps | % | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Common equity ratio and tangible common equity ratio: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
Total assets (GAAP) | O | $227,918 | $226,351 | $222,747 | $218,310 | $220,148 | $1,567 | 1 | % | $7,770 | 4 | % | ||||||||||||||||||||||||||||||||||||||||||||
| Less: Goodwill (GAAP) | 8,221 | 8,187 | 8,187 | 8,187 | 8,187 | 34 | — | 34 | — | |||||||||||||||||||||||||||||||||||||||||||||||
| Less: Other intangible assets (GAAP) | 112 | 115 | 123 | 128 | 137 | (3) | (3) | (25) | (18) | |||||||||||||||||||||||||||||||||||||||||||||||
| Add: Deferred tax liabilities related to goodwill and other intangible assets (GAAP) | 437 | 437 | 440 | 440 | 438 | — | — | (1) | — | |||||||||||||||||||||||||||||||||||||||||||||||
Tangible assets (non-GAAP) | P | $220,022 | $218,486 | $214,877 | $210,435 | $212,262 | $1,536 | 1 | % | $7,760 | 4 | % | ||||||||||||||||||||||||||||||||||||||||||||
Common equity ratio (GAAP) | D/O | 10.6 | % | 10.7 | % | 10.6 | % | 10.6 | % | 10.3 | % | (13) bps | 22 bps | |||||||||||||||||||||||||||||||||||||||||||
Tangible common equity ratio (non-GAAP) | E/P | 7.3 | 7.5 | 7.4 | 7.2 | 7.0 | (20) bps | 30 bps | ||||||||||||||||||||||||||||||||||||||||||||||||
20