
FITB 8-K
Fifth Third Bancorp (FITB)
8-K
2022-04-19
For: 2022-04-19
View Original
Added on
April 10, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, DC 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(D)
OF THE SECURITIES EXCHANGE ACT OF 1934
Date of report (Date of earliest event reported): April 19, 2022

(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||||||||
| , | , | |||||||||||||||||||
| (Address of Principal Executive Offices) | (Zip Code) | |||||||||||||||||||
(800 ) 972-3030
(Registrant's telephone number, including area code)
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below)
| Securities registered pursuant to Section 12(b) of the Act: | ||||||||||||||||||||
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||||||||
| The | Stock Market LLC | |||||||||||||||||||
| Depositary Shares Representing a 1/1000th Ownership Interest in a Share of 6.625% Fixed-to-Floating Rate Non-Cumulative Perpetual Preferred Stock, Series I | The | Stock Market LLC | ||||||||||||||||||
| The | Stock Market LLC | |||||||||||||||||||
| The | Stock Market LLC | |||||||||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition.
On April 19, 2022, Fifth Third Bancorp issued a press release announcing its earnings release for the first quarter of 2022. A copy of this press release is attached as Exhibit 99.1. This information is furnished under both Item 2.02 Results of Operations and Financial Condition and Item 7.01 Regulation FD Disclosure.
The information in this Item 2.02 of Form 8-K and Exhibits attached hereto shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934, nor shall they be deemed incorporated by reference in any filing under the Securities Exchange Act of 1934 or the Securities Act of 1933, except as shall be expressly set forth by specific reference.
Item 7.01 Regulation FD Disclosure.
On April 19, 2022, Fifth Third Bancorp issued a press release announcing its earnings release for the first quarter of 2022. A copy of this press release is attached as Exhibit 99.1. This information is furnished under both Item 2.02 Results of Operations and Financial Condition and Item 7.01 Regulation FD Disclosure.
For the benefit of its investors, Fifth Third Bancorp is also furnishing a presentation regarding its earnings conference call. A copy of this item is attached as Exhibit 99.2.
The information in this Item 7.01 of Form 8-K and Exhibits attached hereto shall not be deemed filed for purposes of Section 18 of the Securities Exchange Act of 1934, nor shall they be deemed incorporated by reference in any filing under the Securities Exchange Act of 1934 or the Securities Act of 1933, except as shall be expressly set forth by specific reference.
Item 9.01 Financial Statements and Exhibits
Exhibit 99.1 – Press release dated April 19, 2022
Exhibit 99.2 – First Quarter 2022 Earnings Presentation
Exhibit 104 – Cover Page Interactive Data File (embedded within the Inline XBRL document)
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| FIFTH THIRD BANCORP | ||||||||
| (Registrant) | ||||||||
Date: April 19, 2022 | /s/ James C. Leonard | |||||||
| James C. Leonard | ||||||||
| Executive Vice President and Chief Financial Officer | ||||||||
Fifth Third Announces First Quarter 2022 Results
Reported diluted earnings per share of $0.68
Reported results included a negative $0.01 impact from certain item(s) on page 2
| Key Financial Data | Key Highlights | |||||||||||||||||||||||||
| $ millions for all balance sheet and income statement items | ||||||||||||||||||||||||||
1Q22 | 4Q21 | 1Q21 | Select Business Highlights: •Named one of the "World's Most Ethical Companies" by Ethisphere in March 2022 for the third time •Generated consumer household growth of 3% compared to 1Q21 •Announced $20/hour minimum wage for eligible employees effective July 2022 Select Financial Highlights: •ROTCE(a) of 13.4%; adjusted ROTCE(a) of 13.7% excl. AOCI •Net interest income(a) stable compared to 4Q21, or up 1% excluding the impact of PPP; NIM(a) up 4 basis points compared to 4Q21 •Average C&I loan growth ex. PPP of 8% compared to 4Q21 •Average securities balances increased $5 billion compared to 4Q21 •Core deposits increased 1% compared to 4Q21; Interest bearing deposit costs flat •Benign credit quality continued, including near-record low NCO ratio, stable non-performing loans and lower commercial criticized assets | |||||||||||||||||||||||
| Income Statement Data | ||||||||||||||||||||||||||
| Net income available to common shareholders | $474 | $627 | $674 | |||||||||||||||||||||||
| Net interest income (U.S. GAAP) | 1,195 | 1,197 | 1,176 | |||||||||||||||||||||||
Net interest income (FTE)(a) | 1,198 | 1,200 | 1,179 | |||||||||||||||||||||||
| Noninterest income | 684 | 791 | 749 | |||||||||||||||||||||||
| Noninterest expense | 1,222 | 1,206 | 1,215 | |||||||||||||||||||||||
| Per Share Data | ||||||||||||||||||||||||||
| Earnings per share, basic | $0.69 | $0.91 | $0.94 | |||||||||||||||||||||||
| Earnings per share, diluted | 0.68 | 0.90 | 0.93 | |||||||||||||||||||||||
| Book value per share | 26.33 | 29.43 | 28.78 | |||||||||||||||||||||||
Tangible book value per share(a) | 19.54 | 22.58 | 22.60 | |||||||||||||||||||||||
| Balance Sheet & Credit Quality | ||||||||||||||||||||||||||
| Average portfolio loans and leases | $113,467 | $109,487 | $108,956 | |||||||||||||||||||||||
| Average deposits | 168,662 | 167,541 | 158,888 | |||||||||||||||||||||||
Net charge-off ratio(b) | 0.12 | % | 0.14 | % | 0.27 | % | ||||||||||||||||||||
Nonperforming asset ratio(c) | 0.47 | 0.47 | 0.72 | |||||||||||||||||||||||
| Financial Ratios | ||||||||||||||||||||||||||
| Return on average assets | 0.96 | % | 1.25 | % | 1.38 | % | ||||||||||||||||||||
| Return on average common equity | 10.0 | 12.2 | 13.1 | |||||||||||||||||||||||
Return on average tangible common equity(a) | 13.4 | 16.1 | 16.8 | |||||||||||||||||||||||
CET1 capital(d)(e) | 9.28 | 9.54 | 10.46 | |||||||||||||||||||||||
Net interest margin(a) | 2.59 | 2.55 | 2.62 | |||||||||||||||||||||||
Efficiency(a) | 64.9 | 60.6 | 63.0 | |||||||||||||||||||||||
Other than the Quarterly Financial Review tables beginning on page 14, commentary is on a fully taxable-equivalent (FTE) basis unless otherwise noted. Consistent with SEC guidance in Regulation S-K that contemplates the calculation of tax-exempt income on a taxable-equivalent basis, net interest income, net interest margin, net interest rate spread, total revenue and the efficiency ratio are provided on an FTE basis. | ||||||||||||||||||||||||||
| CEO Commentary | ||||||||||||||
Fifth Third continued to produce solid financial results in a volatile first quarter of 2022 while fully supporting customers, communities, and employees. We continue to navigate the economic environment with a disciplined approach focused on long-term through-the-cycle outperformance, and remain extremely well positioned to benefit from higher short-term interest rates. We generated strong loan growth during the quarter, including average C&I growth of 8% excluding PPP. Also excluding PPP, net interest income increased 1% sequentially, reflecting the partial impact of our decision to begin growing the securities portfolio.
We had yet another quarter of benign credit quality reflecting our disciplined approach to client selection and underwriting, which resulted in near-record low charge-offs of just 12 basis points. Additionally, commercial criticized assets continued to improve.
Last week, I announced my plans to retire as CEO and transition to Executive Chairman, effective July 5, 2022. As part of our thorough succession planning process, I am excited and proud to announce the Board of Directors has appointed Tim Spence to succeed me as our next CEO. I believe this is the right time for a transition, given Fifth Third’s tremendous financial health and performance. Being the CEO of Fifth Third has been an honor of a lifetime. I am grateful for the hard work, dedication, and support of all our employees over the years. I am also grateful for the confidence the Board and shareholders have had in me throughout my tenure.
Investor contact: Chris Doll (513) 534-2345 | Media contact: Ed Loyd (513) 534-6397 April 19, 2022
(Continued)
Tim is an outstanding and visionary leader. He has been an integral part of Fifth Third's leadership team since 2015, helping develop the strategies and vision that we continue to execute with excellence through innovation and technology. I have no doubt that Tim’s focus on operational discipline will extend our track record for delivering on our commitments to continue generating sustainable, top quartile results among regional banks.
-Greg D. Carmichael, Chairman and CEO
| Income Statement Highlights | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions, except per share data) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| March | December | March | ||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2021 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Condensed Statements of Income | ||||||||||||||||||||||||||||||||||||||||||||
Net interest income (NII)(a) | $1,198 | $1,200 | $1,179 | — | 2% | |||||||||||||||||||||||||||||||||||||||
| Provision for (benefit from) credit losses | 45 | (47) | (173) | NM | NM | |||||||||||||||||||||||||||||||||||||||
| Noninterest income | 684 | 791 | 749 | (14)% | (9)% | |||||||||||||||||||||||||||||||||||||||
| Noninterest expense | 1,222 | 1,206 | 1,215 | 1% | 1% | |||||||||||||||||||||||||||||||||||||||
Income before income taxes(a) | $615 | $832 | $886 | (26)% | (31)% | |||||||||||||||||||||||||||||||||||||||
| Taxable equivalent adjustment | $3 | $3 | $3 | — | — | |||||||||||||||||||||||||||||||||||||||
| Applicable income tax expense | 118 | 167 | 189 | (29)% | (38)% | |||||||||||||||||||||||||||||||||||||||
| Net income | $494 | $662 | $694 | (25)% | (29)% | |||||||||||||||||||||||||||||||||||||||
| Dividends on preferred stock | 20 | 35 | 20 | (43)% | — | |||||||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $474 | $627 | $674 | (24)% | (30)% | |||||||||||||||||||||||||||||||||||||||
| Earnings per share, diluted | $0.68 | $0.90 | $0.93 | (24)% | (27)% | |||||||||||||||||||||||||||||||||||||||
Fifth Third Bancorp (NASDAQ®: FITB) today reported first quarter 2022 net income of $494 million compared to net income of $662 million in the prior quarter and $694 million in the year-ago quarter. Net income available to common shareholders in the current quarter was $474 million, or $0.68 per diluted share, compared to $627 million, or $0.90 per diluted share, in the prior quarter and $674 million, or $0.93 per diluted share, in the year-ago quarter.
Diluted earnings per share impact of certain item(s) - 1Q22 | |||||||||||||||||
(after-tax impact(f); $ in millions, except per share data) | |||||||||||||||||
| Valuation of Visa total return swap (noninterest income) | $(8) | ||||||||||||||||
Diluted earnings per share impact of certain item(s)1 | $(0.01) | ||||||||||||||||
1Diluted earnings per share impact reflects 696.242 million average diluted shares outstanding | |||||||||||||||||
2
| Net Interest Income | ||||||||||||||||||||||||||||||||||||||||||||
(FTE; $ in millions)(a) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| March | December | March | ||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2021 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Interest Income | ||||||||||||||||||||||||||||||||||||||||||||
| Interest income | $1,292 | $1,297 | $1,305 | — | (1)% | |||||||||||||||||||||||||||||||||||||||
| Interest expense | 94 | 97 | 126 | (3)% | (25)% | |||||||||||||||||||||||||||||||||||||||
| Net interest income (NII) | $1,198 | $1,200 | $1,179 | — | 2% | |||||||||||||||||||||||||||||||||||||||
| Average Yield/Rate Analysis | bps Change | |||||||||||||||||||||||||||||||||||||||||||
| Yield on interest-earning assets | 2.79 | % | 2.75 | % | 2.90 | % | 4 | (11) | ||||||||||||||||||||||||||||||||||||
| Rate paid on interest-bearing liabilities | 0.33 | % | 0.33 | % | 0.44 | % | — | (11) | ||||||||||||||||||||||||||||||||||||
| Ratios | ||||||||||||||||||||||||||||||||||||||||||||
| Net interest rate spread | 2.46 | % | 2.42 | % | 2.46 | % | 4 | — | ||||||||||||||||||||||||||||||||||||
| Net interest margin (NIM) | 2.59 | % | 2.55 | % | 2.62 | % | 4 | (3) | ||||||||||||||||||||||||||||||||||||
Compared to the prior quarter, NII was stable, as the impacts of lower day count, lower PPP-related income, and a decline in residential mortgage balances (primarily from previous purchases of government guaranteed loan buyouts from a third party) were partially offset by higher commercial & industrial (C&I) loan balances, higher investment portfolio balances, and the impact of higher market rates. PPP-related income was $20 million in the current quarter compared to $36 million in the prior quarter. Excluding the impact of PPP-related income, NII increased $14 million, or 1%, sequentially. Compared to the prior quarter, reported NIM increased 4 bps, primarily due to a decrease in other short-term investments (primarily interest-bearing cash), the impact of lower day count, and higher market rates.
Compared to the year-ago quarter, NII increased $19 million, or 2%, primarily reflecting higher C&I and indirect secured consumer loan balances, higher investment portfolio balances, and a reduction in long-term debt, partially offset by lower PPP-related income and lower home equity balances. Excluding the impact of PPP-related income, NII increased $52 million, or 5%, year-over-year. Compared to the year-ago quarter, reported NIM decreased 3 bps, primarily reflecting loan spread compression, partially offset by lower other short-term investments (primarily interest-bearing cash) and lower long-term debt and deposit costs.
3
| Noninterest Income | |||||||||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | |||||||||||||||||||||||||||||||||
| March | December | March | |||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2021 | Seq | Yr/Yr | |||||||||||||||||||||||||||||||
| Noninterest Income | |||||||||||||||||||||||||||||||||||
| Service charges on deposits | $152 | $156 | $144 | (3)% | 6% | ||||||||||||||||||||||||||||||
| Commercial banking revenue | 135 | 171 | 153 | (21)% | (12)% | ||||||||||||||||||||||||||||||
| Mortgage banking net revenue | 52 | 35 | 85 | 49% | (39)% | ||||||||||||||||||||||||||||||
| Wealth and asset management revenue | 149 | 150 | 143 | (1)% | 4% | ||||||||||||||||||||||||||||||
| Card and processing revenue | 97 | 104 | 94 | (7)% | 3% | ||||||||||||||||||||||||||||||
| Leasing business revenue | 62 | 74 | 87 | (16)% | (29)% | ||||||||||||||||||||||||||||||
| Other noninterest income | 52 | 120 | 42 | (57)% | 24% | ||||||||||||||||||||||||||||||
| Securities (losses) gains, net | (14) | (19) | 3 | (26)% | NM | ||||||||||||||||||||||||||||||
| Securities losses, net - non-qualifying hedges | |||||||||||||||||||||||||||||||||||
| on mortgage servicing rights | (1) | — | (2) | NM | (50)% | ||||||||||||||||||||||||||||||
| Total noninterest income | $684 | $791 | $749 | (14)% | (9)% | ||||||||||||||||||||||||||||||
Reported noninterest income decreased $107 million, or 14%, from the prior quarter, and decreased $65 million, or 9%, from the year-ago quarter. The reported results reflect the impact of certain items in the table below. Reported current quarter results included $14 million of net securities losses, which comprised of $14 million in net losses attributable to mark-to-market impacts related to non-qualified deferred compensation assets and a $12 million loss attributable to market value changes on Fifth Third's shares of AvidXchange Holdings, Inc., partially offset by $12 million in net gains related to investment portfolio activity.
| Noninterest Income excluding certain items | |||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | ||||||||||||||||||||||||||||
| March | December | March | |||||||||||||||||||||||||||
| 2022 | 2021 | 2021 | |||||||||||||||||||||||||||
| Noninterest Income excluding certain items | |||||||||||||||||||||||||||||
| Noninterest income (U.S. GAAP) | $684 | $791 | $749 | ||||||||||||||||||||||||||
| Valuation of Visa total return swap | 11 | 19 | 13 | ||||||||||||||||||||||||||
| Securities losses/(gains), net | 14 | 19 | (3) | ||||||||||||||||||||||||||
Noninterest income excluding certain items(a) | $709 | $829 | $759 | ||||||||||||||||||||||||||
Compared to the prior quarter, noninterest income excluding certain items decreased $120 million, or 14%. Compared to the year-ago quarter, noninterest income excluding certain items decreased $50 million, or 7%.
Compared to the prior quarter, service charges on deposits decreased $4 million, or 3%, primarily reflecting a decrease in consumer deposit fees. Commercial banking revenue decreased $36 million, or 21%, primarily driven by lower M&A advisory revenue and loan syndication revenue, partially offset by higher customer financial risk management revenue. Mortgage banking net revenue increased $17 million, or 49%, reflecting a $14 million increase from MSR net valuation adjustments and an $11 million decrease in MSR asset decay reflecting slower prepayment speeds, partially offset by a $12 million decrease in origination fees and gains on loan sales. Wealth and asset management revenue decreased $1 million, or 1%, as the impact of lower market values was mostly offset by seasonally strong tax-related private client service revenue combined with continued asset inflows. Card and processing revenue decreased $7 million, or 7%, primarily driven by seasonally lower spend volume. Leasing business revenue decreased $12 million, or 16%, primarily driven by a decrease in lease remarketing revenue. The decline in other noninterest income was primarily attributable to the prior quarter recognition of tax receivable agreement revenue as well as lower private equity income.
4
Compared to the year-ago quarter, service charges on deposits increased $8 million, or 6%, reflecting an increase in commercial treasury management fees. Commercial banking revenue decreased $18 million, or 12%, primarily driven by decreases in corporate bond fees, partially offset by an increase in customer financial risk management revenue. Mortgage banking net revenue decreased $33 million, or 39%, reflecting a $64 million decrease in origination fees and gains on loan sales and a $9 million reduction from MSR net valuation adjustments, partially offset by a $28 million decrease in MSR asset decay reflecting slower prepayment speeds. Wealth and asset management revenue increased $6 million, or 4%, primarily driven by higher personal asset management revenue. Card and processing revenue increased $3 million, or 3%, primarily driven by higher spend volumes, partially offset by higher rewards. Leasing business revenue decreased $25 million, or 29%, primarily reflecting a decrease in lease syndication revenue.
| Noninterest Expense | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| March | December | March | ||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2021 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Noninterest Expense | ||||||||||||||||||||||||||||||||||||||||||||
| Compensation and benefits | $711 | $655 | $706 | 9% | 1% | |||||||||||||||||||||||||||||||||||||||
| Net occupancy expense | 77 | 77 | 79 | — | (3)% | |||||||||||||||||||||||||||||||||||||||
| Technology and communications | 101 | 103 | 93 | (2)% | 9% | |||||||||||||||||||||||||||||||||||||||
| Equipment expense | 36 | 36 | 34 | — | 6% | |||||||||||||||||||||||||||||||||||||||
| Card and processing expense | 19 | 19 | 30 | — | (37)% | |||||||||||||||||||||||||||||||||||||||
| Leasing business expense | 32 | 36 | 35 | (11)% | (9)% | |||||||||||||||||||||||||||||||||||||||
| Marketing expense | 24 | 35 | 23 | (31)% | 4% | |||||||||||||||||||||||||||||||||||||||
| Other noninterest expense | 222 | 245 | 215 | (9)% | 3% | |||||||||||||||||||||||||||||||||||||||
| Total noninterest expense | $1,222 | $1,206 | $1,215 | 1% | 1% | |||||||||||||||||||||||||||||||||||||||
Reported noninterest expense increased $16 million, or 1%, from the prior quarter. The results in the prior period were impacted by the item shown in the table below.
| Noninterest Expense excluding certain item(s) | |||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | ||||||||||||||||||||||||||||
| March | December | March | |||||||||||||||||||||||||||
| 2022 | 2021 | 2021 | |||||||||||||||||||||||||||
| Noninterest Expense excluding certain item(s) | |||||||||||||||||||||||||||||
| Noninterest expense (U.S. GAAP) | $1,222 | $1,206 | $1,215 | ||||||||||||||||||||||||||
| Special COVID staffing bonus to front-line employees | — | (10) | — | ||||||||||||||||||||||||||
Noninterest expense excluding certain item(s)(a) | $1,222 | $1,196 | $1,215 | ||||||||||||||||||||||||||
Compared to the prior quarter, noninterest expense excluding certain items increased $26 million, or 2%, primarily reflecting a seasonal increase in compensation and benefits expense and a $21 million impact from the previously communicated special broad-based compensation bonus, partially offset by a decrease in incentive compensation and marketing expense. Noninterest expense in the current quarter included a $12 million benefit related to the impact of non-qualified deferred compensation mark-to-market (compared to $10 million expense in the prior quarter).
Compared to the year-ago quarter, noninterest expense increased $7 million, or 1%, reflecting an increase in technology and communications expense related to continued modernization investments, and an increase in compensation and benefits expense. These items were partially offset by lower card and processing expense due to contract renegotiations.
5
| Average Interest-Earning Assets | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| March | December | March | ||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2021 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Average Portfolio Loans and Leases | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans and leases: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial loans | $52,554 | $49,566 | $49,629 | 6% | 6% | |||||||||||||||||||||||||||||||||||||||
| Commercial mortgage loans | 10,521 | 10,247 | 10,532 | 3% | — | |||||||||||||||||||||||||||||||||||||||
| Commercial construction loans | 5,371 | 5,329 | 6,039 | 1% | (11)% | |||||||||||||||||||||||||||||||||||||||
| Commercial leases | 2,942 | 3,057 | 3,114 | (4)% | (6)% | |||||||||||||||||||||||||||||||||||||||
| Total commercial loans and leases | $71,388 | $68,199 | $69,314 | 5% | 3% | |||||||||||||||||||||||||||||||||||||||
| Consumer loans: | ||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage loans | $16,501 | $16,188 | $15,803 | 2% | 4% | |||||||||||||||||||||||||||||||||||||||
| Home equity | 4,009 | 4,179 | 5,009 | (4)% | (20)% | |||||||||||||||||||||||||||||||||||||||
| Indirect secured consumer loans | 17,136 | 16,345 | 13,955 | 5% | 23% | |||||||||||||||||||||||||||||||||||||||
| Credit card | 1,691 | 1,739 | 1,879 | (3)% | (10)% | |||||||||||||||||||||||||||||||||||||||
| Other consumer loans | 2,742 | 2,837 | 2,996 | (3)% | (8)% | |||||||||||||||||||||||||||||||||||||||
| Total consumer loans | $42,079 | $41,288 | $39,642 | 2% | 6% | |||||||||||||||||||||||||||||||||||||||
| Total average portfolio loans and leases | $113,467 | $109,487 | $108,956 | 4% | 4% | |||||||||||||||||||||||||||||||||||||||
| Memo: | ||||||||||||||||||||||||||||||||||||||||||||
| Average PPP loans | $1,012 | $1,756 | $5,200 | (42)% | (81)% | |||||||||||||||||||||||||||||||||||||||
| Average portfolio commercial and industrial loans - excl. PPP loans | $51,542 | $47,810 | $44,429 | 8% | 16% | |||||||||||||||||||||||||||||||||||||||
| Average Loans and Leases Held for Sale | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial loans and leases held for sale | $18 | $5 | $104 | 260% | (83)% | |||||||||||||||||||||||||||||||||||||||
| Consumer loans held for sale | 3,677 | 5,298 | 4,641 | (31)% | (21)% | |||||||||||||||||||||||||||||||||||||||
| Total average loans and leases held for sale | $3,695 | $5,303 | $4,745 | (30)% | (22)% | |||||||||||||||||||||||||||||||||||||||
| Securities (taxable and tax-exempt) | $42,422 | $37,631 | $36,297 | 13% | 17% | |||||||||||||||||||||||||||||||||||||||
| Other short-term investments | 28,310 | 34,624 | 32,717 | (18)% | (13)% | |||||||||||||||||||||||||||||||||||||||
| Total average interest-earning assets | $187,894 | $187,045 | $182,715 | — | 3% | |||||||||||||||||||||||||||||||||||||||
Compared to the prior quarter, total average portfolio loans and leases increased 4%, reflecting an increase in both commercial loan and lease balances and consumer loans. Average commercial portfolio loans and leases increased 5%, primarily reflecting of 8% in C&I loans excluding PPP. Average consumer portfolio loans increased 2%, reflecting higher indirect secured consumer and residential mortgage loans, partially offset by lower home equity and other consumer loan balances.
Compared to the year-ago quarter, total average portfolio loans and leases increased 4%, reflecting an increase in both consumer loans and commercial loans and leases. Average commercial portfolio loans and leases increased 3%, primarily reflecting growth of 16% in C&I loans excluding PPP, partially offset by PPP forgiveness and lower commercial construction loans. Average consumer portfolio loans increased 6%, as higher indirect secured consumer and residential mortgage loans were partially offset by lower home equity and other consumer loan balances.
Average loans and leases held for sale were $4 billion in the current quarter compared to $5 billion in the prior quarter and $5 billion in the year-ago quarter. Current quarter average loans and leases held for sale were impacted by a decline in residential mortgage balances (primarily from a decline in government loan buyouts purchased from a third party).
Average securities (taxable and tax-exempt) of $42 billion in the current quarter increased $5 billion, or 13%, compared to the prior quarter and increased $6 billion, or 17%, compared to the year-ago quarter. Average other short-term investments (including interest-bearing cash) of $28 billion in the current quarter decreased $6 billion, or 18%, compared to the prior quarter and decreased $4 billion, or 13%, compared to the year-ago quarter.
6
Total period-end commercial portfolio loans and leases of $73 billion increased 4% compared to the prior quarter, primarily reflecting growth of 6% in C&I loans excluding PPP, partially offset by PPP forgiveness. Compared to the year-ago quarter, total period-end commercial portfolio loans increased $4 billion, or 6%, primarily reflecting growth of 22% in C&I loans excluding PPP, partially offset by PPP forgiveness and lower construction loan balances. Period-end commercial revolving line utilization was 36%, compared to 33% in the prior quarter and 31% in the year-ago quarter.
Period-end consumer portfolio loans of $43 billion increased 3% compared to the prior quarter, primarily reflecting higher residential mortgage and indirect secured consumer loan balances, partially offset by a decline in home equity balances. Compared to the year-ago quarter, total period-end consumer portfolio loans increased $3 billion, or 8%, reflecting an increase in indirect secured consumer loans and residential mortgage balances, partially offset by lower home equity and other consumer loan balances.
Total period-end securities (taxable and tax-exempt; amortized cost) of $51 billion in the current quarter increased $13 billion, or 34%, compared to the prior quarter and increased $14 billion, or 38%, compared to the year-ago quarter. Period-end other short term investments of $21 billion in the current quarter decreased $14 billion, or 41%, compared to the prior quarter and decreased $14 billion, or 40%, compared to the year-ago quarter.
| Average Deposits | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| March | December | March | ||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2021 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Average Deposits | ||||||||||||||||||||||||||||||||||||||||||||
| Demand | $64,212 | $64,828 | $58,586 | (1)% | 10% | |||||||||||||||||||||||||||||||||||||||
| Interest checking | 48,659 | 47,384 | 45,568 | 3% | 7% | |||||||||||||||||||||||||||||||||||||||
| Savings | 22,772 | 21,702 | 18,951 | 5% | 20% | |||||||||||||||||||||||||||||||||||||||
| Money market | 30,263 | 30,566 | 30,601 | (1)% | (1)% | |||||||||||||||||||||||||||||||||||||||
Foreign office(g) | 126 | 193 | 128 | (35)% | (2)% | |||||||||||||||||||||||||||||||||||||||
| Total transaction deposits | $166,032 | $164,673 | $153,834 | 1% | 8% | |||||||||||||||||||||||||||||||||||||||
| CDs $250,000 or less | 2,376 | 2,604 | 3,828 | (9)% | (38)% | |||||||||||||||||||||||||||||||||||||||
| Total core deposits | $168,408 | $167,277 | $157,662 | 1% | 7% | |||||||||||||||||||||||||||||||||||||||
| CDs over $250,000 | 254 | 264 | 1,226 | (4)% | (79)% | |||||||||||||||||||||||||||||||||||||||
| Total average deposits | $168,662 | $167,541 | $158,888 | 1% | 6% | |||||||||||||||||||||||||||||||||||||||
Compared to the prior quarter, average core deposits increased 1%, as increases in interest checking and savings deposit balances (led by consumer and wealth customer balance growth) were partially offset by decreases in demand and money market balances from commercial customer seasonal impacts. Average demand deposits represented 38% of total core deposits in the current quarter, relatively stable with the prior quarter. Average commercial transaction deposits decreased 2% and average consumer transaction deposits increased 4%.
Compared to the year-ago quarter, average core deposits increased 7%, reflecting ongoing success in generating consumer household growth. Average commercial transaction deposits increased 5% and average consumer transaction deposits increased 11%.
The period end portfolio loan-to-core deposit ratio was 68% in the current quarter, compared to 66% in the prior quarter and 68% in the year-ago quarter.
7
| Average Wholesale Funding | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | For the Three Months Ended | % Change | ||||||||||||||||||||||||||||||||||||||||||
| March | December | March | ||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2021 | Seq | Yr/Yr | ||||||||||||||||||||||||||||||||||||||||
| Average Wholesale Funding | ||||||||||||||||||||||||||||||||||||||||||||
| CDs over $250,000 | $254 | $264 | $1,226 | (4)% | (79)% | |||||||||||||||||||||||||||||||||||||||
| Federal funds purchased | 259 | 315 | 324 | (18)% | (20)% | |||||||||||||||||||||||||||||||||||||||
| Other short-term borrowings | 890 | 1,000 | 1,209 | (11)% | (26)% | |||||||||||||||||||||||||||||||||||||||
| Long-term debt | 11,165 | 11,697 | 14,849 | (5)% | (25)% | |||||||||||||||||||||||||||||||||||||||
| Total average wholesale funding | $12,568 | $13,276 | $17,608 | (5)% | (29)% | |||||||||||||||||||||||||||||||||||||||
Compared to the prior quarter, average wholesale funding decreased 5%, reflecting the impact of reductions in long-term debt over the past two quarters (including the retirement of $800 million in long-term debt during the first quarter of 2022), as well as continued runoff in other short-term borrowings and jumbo CD balances. Compared to the year-ago quarter, average wholesale funding decreased 29%, reflecting decreases in long-term debt, jumbo CD balances, and other short-term borrowings.
8
| Credit Quality Summary | ||||||||||||||||||||||||||||||||||||||||||||
| ($ in millions) | As of and For the Three Months Ended | |||||||||||||||||||||||||||||||||||||||||||
| March | December | September | June | March | ||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2021 | 2021 | 2021 | ||||||||||||||||||||||||||||||||||||||||
| Total nonaccrual portfolio loans and leases (NPLs) | $508 | $498 | $528 | $621 | $741 | |||||||||||||||||||||||||||||||||||||||
| Repossessed property | 5 | 5 | 4 | 5 | 7 | |||||||||||||||||||||||||||||||||||||||
| OREO | 27 | 24 | 27 | 31 | 35 | |||||||||||||||||||||||||||||||||||||||
| Total nonperforming portfolio loans and leases and OREO (NPAs) | $540 | $527 | $559 | $657 | $783 | |||||||||||||||||||||||||||||||||||||||
NPL ratio(h) | 0.44 | % | 0.44 | % | 0.49 | % | 0.58 | % | 0.68 | % | ||||||||||||||||||||||||||||||||||
NPA ratio(c) | 0.47 | % | 0.47 | % | 0.52 | % | 0.61 | % | 0.72 | % | ||||||||||||||||||||||||||||||||||
| Total loans and leases 30-89 days past due (accrual) | $288 | $254 | $267 | $281 | $305 | |||||||||||||||||||||||||||||||||||||||
| Total loans and leases 90 days past due (accrual) | 76 | 117 | 92 | 83 | 124 | |||||||||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses (ALLL), beginning | $1,892 | $1,954 | $2,033 | $2,208 | $2,453 | |||||||||||||||||||||||||||||||||||||||
| Total net losses charged-off | (34) | (38) | (21) | (44) | (71) | |||||||||||||||||||||||||||||||||||||||
| Provision for (benefit from) loan and lease losses | 50 | (24) | (58) | (131) | (174) | |||||||||||||||||||||||||||||||||||||||
| ALLL, ending | $1,908 | $1,892 | $1,954 | $2,033 | $2,208 | |||||||||||||||||||||||||||||||||||||||
| Reserve for unfunded commitments, beginning | $182 | $205 | $189 | $173 | $172 | |||||||||||||||||||||||||||||||||||||||
| (Benefit from) provision for the reserve for unfunded commitments | (5) | (23) | 16 | 16 | 1 | |||||||||||||||||||||||||||||||||||||||
| Reserve for unfunded commitments, ending | $177 | $182 | $205 | $189 | $173 | |||||||||||||||||||||||||||||||||||||||
| Total allowance for credit losses (ACL) | $2,085 | $2,074 | $2,159 | $2,222 | $2,381 | |||||||||||||||||||||||||||||||||||||||
| ACL ratios: | ||||||||||||||||||||||||||||||||||||||||||||
| As a % of portfolio loans and leases | 1.80 | % | 1.85 | % | 2.00 | % | 2.06 | % | 2.19 | % | ||||||||||||||||||||||||||||||||||
| As a % of nonperforming portfolio loans and leases | 411 | % | 416 | % | 409 | % | 358 | % | 321 | % | ||||||||||||||||||||||||||||||||||
| As a % of nonperforming portfolio assets | 386 | % | 394 | % | 386 | % | 338 | % | 304 | % | ||||||||||||||||||||||||||||||||||
| ALLL as a % of portfolio loans and leases | 1.65 | % | 1.69 | % | 1.81 | % | 1.89 | % | 2.03 | % | ||||||||||||||||||||||||||||||||||
| Total losses charged-off | $(64) | $(77) | $(56) | $(103) | $(109) | |||||||||||||||||||||||||||||||||||||||
| Total recoveries of losses previously charged-off | 30 | 39 | 35 | 59 | 38 | |||||||||||||||||||||||||||||||||||||||
| Total net losses charged-off | $(34) | $(38) | $(21) | $(44) | $(71) | |||||||||||||||||||||||||||||||||||||||
Net charge-off ratio (NCO ratio)(b) | 0.12 | % | 0.14 | % | 0.08 | % | 0.16 | % | 0.27 | % | ||||||||||||||||||||||||||||||||||
| Commercial NCO ratio | 0.05 | % | 0.10 | % | 0.03 | % | 0.10 | % | 0.17 | % | ||||||||||||||||||||||||||||||||||
| Consumer NCO ratio | 0.25 | % | 0.21 | % | 0.16 | % | 0.26 | % | 0.43 | % | ||||||||||||||||||||||||||||||||||
Nonperforming portfolio loans and leases were $508 million in the current quarter, with the resulting NPL ratio of 0.44%. Compared to the prior quarter, NPLs increased $10 million. Compared to the year-ago quarter, NPLs decreased $233 million with the NPL ratio decreasing 24 bps.
Nonperforming portfolio assets were $540 million in the current quarter, with the resulting NPA ratio of 0.47%. Compared to the prior quarter, NPAs increased $13 million. Compared to the year-ago quarter, NPAs decreased $243 million with the NPA ratio decreasing 25 bps.
The provision for credit losses totaled $45 million in the current quarter. The allowance for credit loss ratio represented 1.80% of total portfolio loans and leases at quarter end, compared with 1.85% for the prior quarter end and 2.19% for the year-ago quarter end. In the current quarter, the allowance for credit losses represented 411% of nonperforming portfolio loans and leases and 386% of nonperforming portfolio assets.
9
Net charge-offs were $34 million in the current quarter, with the resulting NCO ratio of 0.12%. Compared to the prior quarter, net charge-offs decreased $4 million and the NCO ratio decreased 2 bps, reflecting lower charge-offs in the commercial portfolio. Compared to the year-ago quarter, net charge-offs decreased $37 million and the NCO ratio decreased 15 bps, reflecting improvement in both commercial and consumer portfolios.
| Capital Position | ||||||||||||||||||||||||||||||||||||||||||||||||||
| As of and For the Three Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||
| March | December | September | June | March | ||||||||||||||||||||||||||||||||||||||||||||||
| 2022 | 2021 | 2021 | 2021 | 2021 | ||||||||||||||||||||||||||||||||||||||||||||||
| Capital Position | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Average total Bancorp shareholders' equity as a % of average assets | 10.23 | % | 10.71 | % | 11.16% | 11.11% | 11.26 | % | ||||||||||||||||||||||||||||||||||||||||||
Tangible equity(a) | 7.98 | % | 7.97 | % | 8.06% | 8.35% | 8.20 | % | ||||||||||||||||||||||||||||||||||||||||||
Tangible common equity (excluding AOCI)(a) | 6.96 | % | 6.94 | % | 7.01% | 7.28% | 7.14 | % | ||||||||||||||||||||||||||||||||||||||||||
Tangible common equity (including AOCI)(a) | 6.48 | % | 7.47 | % | 7.74% | 8.18% | 7.95 | % | ||||||||||||||||||||||||||||||||||||||||||
Regulatory Capital Ratios(d)(e) | ||||||||||||||||||||||||||||||||||||||||||||||||||
CET1 capital | 9.28 | % | 9.54 | % | 9.86% | 10.37% | 10.46 | % | ||||||||||||||||||||||||||||||||||||||||||
Tier I risk-based capital | 10.60 | % | 10.91 | % | 11.28% | 11.83% | 11.94 | % | ||||||||||||||||||||||||||||||||||||||||||
Total risk-based capital | 12.88 | % | 13.42 | % | 13.94% | 14.60% | 14.80 | % | ||||||||||||||||||||||||||||||||||||||||||
| Tier I leverage | 8.32 | % | 8.27 | % | 8.41% | 8.55% | 8.61 | % | ||||||||||||||||||||||||||||||||||||||||||
The CET1 capital ratio was 9.28%, the tangible common equity to tangible assets ratio was 6.96% excluding AOCI, and 6.48% including AOCI. The Tier I risk-based capital ratio was 10.60%, the Total risk-based capital ratio was 12.88%, and the Tier I leverage ratio was 8.32%. Certain capital ratios, including the Tier I leverage ratio, continued to be impacted by the increase in assets since the onset of the pandemic, predominantly from 0% risk-weighted assets resulting from interest-bearing cash as well as PPP loans.
10
Tax Rate
The effective tax rate was 19.2% compared with 20.1% in the prior quarter and 21.4% in the year-ago quarter.
Conference Call
Fifth Third will host a conference call to discuss these financial results at 10:00 a.m. (Eastern Time) today. This conference call will be webcast live and may be accessed through the Fifth Third Investor Relations website at www.53.com (click on “About Us” then “Investor Relations”). Those unable to listen to the live webcast may access a webcast replay through the Fifth Third Investor Relations website at the same web address, which will be available for 30 days.
Corporate Profile
Fifth Third Bancorp is a diversified financial services company headquartered in Cincinnati, Ohio, and the indirect parent company of Fifth Third Bank, National Association, a federally chartered institution. As of March 31, 2022, the Company had $211 billion in assets and operates 1,079 full-service Banking Centers, and 2,201 Fifth Third branded ATMs in Ohio, Kentucky, Indiana, Michigan, Illinois, Florida, Tennessee, West Virginia, Georgia, North Carolina and South Carolina. In total, Fifth Third provides its customers with access to approximately 54,000 fee-free ATMs across the United States. Fifth Third operates four main businesses: Commercial Banking, Branch Banking, Consumer Lending, and Wealth & Asset Management. Fifth Third is among the largest money managers in the Midwest and, as of March 31, 2022, had $549 billion in assets under care, of which it managed $61 billion for individuals, corporations and not-for-profit organizations through its Trust and Registered Investment Advisory businesses. Investor information and press releases can be viewed at www.53.com. Fifth Third’s common stock is traded on the NASDAQ® Global Select Market under the symbol “FITB.”
Earnings Release End Notes
(a)Non-GAAP measure; see discussion of non-GAAP reconciliation beginning on page 26.
(b)Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis.
(c)Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO.
(d)Regulatory capital ratios are calculated pursuant to the five-year transition provision option to phase in the effects of CECL on regulatory capital after its adoption on January 1, 2020.
(e)Current period regulatory capital ratios are estimated.
(f)Assumes a 23% tax rate.
(g)Includes commercial customer Eurodollar sweep balances for which the Bank pays rates comparable to other commercial deposit accounts.
(h)Nonperforming portfolio loans and leases as a percent of portfolio loans and leases.
11
FORWARD-LOOKING STATEMENTS
This release contains statements that we believe are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Rule 175 promulgated thereunder, and Section 21E of the Securities Exchange Act of 1934, as amended, and Rule 3b-6 promulgated thereunder. All statements other than statements of historical fact are forward-looking statements. These statements relate to our financial condition, results of operations, plans, objectives, future performance, capital actions or business. They usually can be identified by the use of forward-looking language such as “will likely result,” “may,” “are expected to,” “is anticipated,” “potential,” “estimate,” “forecast,” “projected,” “intends to,” or may include other similar words or phrases such as “believes,” “plans,” “trend,” “objective,” “continue,” “remain,” or similar expressions, or future or conditional verbs such as “will,” “would,” “should,” “could,” “might,” “can,” or similar verbs. You should not place undue reliance on these statements, as they are subject to risks and uncertainties, including but not limited to the risk factors set forth in our most recent Annual Report on Form 10-K as updated by our filings with the U.S. Securities and Exchange Commission (“SEC”).
There are a number of important factors that could cause future results to differ materially from historical performance and these forward-looking statements. Factors that might cause such a difference include, but are not limited to: (1) effects of the global COVID-19 pandemic; (2) deteriorating credit quality; (3) loan concentration by location or industry of borrowers or collateral; (4) problems encountered by other financial institutions; (5) inadequate sources of funding or liquidity; (6) unfavorable actions of rating agencies; (7) inability to maintain or grow deposits; (8) limitations on the ability to receive dividends from subsidiaries; (9) cyber-security risks; (10) Fifth Third’s ability to secure confidential information and deliver products and services through the use of computer systems and telecommunications networks; (11) failures by third-party service providers; (12) inability to manage strategic initiatives and/or organizational changes; (13) inability to implement technology system enhancements; (14) failure of internal controls and other risk management systems; (15) losses related to fraud, theft, misappropriation or violence; (16) inability to attract and retain skilled personnel; (17) adverse impacts of government regulation; (18) governmental or regulatory changes or other actions; (19) failures to meet applicable capital requirements; (20) regulatory objections to Fifth Third’s capital plan; (21) regulation of Fifth Third’s derivatives activities; (22) deposit insurance premiums; (23) assessments for the orderly liquidation fund; (24) replacement of LIBOR; (25) weakness in the national or local economies; (26) global political and economic uncertainty or negative actions; (27) changes in interest rates; (28) changes and trends in capital markets; (29) fluctuation of Fifth Third’s stock price; (30) volatility in mortgage banking revenue; (31) litigation, investigations, and enforcement proceedings by governmental authorities; (32) breaches of contractual covenants, representations and warranties; (33) competition and changes in the financial services industry; (34) changing retail distribution strategies, customer preferences and behavior; (35) difficulties in identifying, acquiring or integrating suitable strategic partnerships, investments or acquisitions; (36) potential dilution from future acquisitions; (37) loss of income and/or difficulties encountered in the sale and separation of businesses, investments or other assets; (38) results of investments or acquired entities; (39) changes in accounting standards or interpretation or declines in the value of Fifth Third’s goodwill or other intangible assets; (40) inaccuracies or other failures from the use of models; (41) effects of critical accounting policies and judgments or the use of inaccurate estimates; (42) weather-related events, other natural disasters, or health emergencies (including pandemics); (43) the impact of reputational risk created by these or other developments on such matters as business generation and retention, funding and liquidity; (44) changes in law or requirements imposed by Fifth Third’s regulators impacting our capital actions, including dividend payments and stock repurchases; and (45) Fifth Third's ability to meet its sustainability targets, goals and commitments.
You should refer to our periodic and current reports filed with the Securities and Exchange Commission, or “SEC,” for further information on other factors, which could cause actual results to be significantly different from those expressed or implied by these forward-looking statements. Moreover, you should treat these statements as speaking only as of the date they are made and based only on information then actually known to us. We expressly disclaim any obligation or undertaking to release publicly any updates or revisions to any forward-looking statements contained herein to reflect any change in our expectations or any changes in events, conditions or circumstances on which any such statement is based, except as may be required by law, and we claim the protection of the safe harbor for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. The information contained herein is intended to be reviewed in its totality, and any stipulations, conditions or provisos that apply to a given piece of information in one part of this press release should be read as applying mutatis mutandis to every other instance of such information appearing herein.
# # #
12
Quarterly Financial Review for March 31, 2022
Table of Contents
| Financial Highlights | 14-15 | ||||||||||
| Consolidated Statements of Income | 16-17 | ||||||||||
| Consolidated Balance Sheets | 18-19 | ||||||||||
| Consolidated Statements of Changes in Equity | 20 | ||||||||||
| Average Balance Sheet and Yield Analysis | 21 | ||||||||||
| Summary of Loans and Leases | 22 | ||||||||||
| Regulatory Capital | 23 | ||||||||||
| Summary of Credit Loss Experience | 24 | ||||||||||
| Asset Quality | 25 | ||||||||||
| Non-GAAP Reconciliation | 26-28 | ||||||||||
| Segment Presentation | 29 | ||||||||||
13
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||||||||
| Financial Highlights | % / bps | |||||||||||||||||||
| $ in millions, except per share data | For the Three Months Ended | Change | ||||||||||||||||||
| (unaudited) | March | December | March | |||||||||||||||||
| 2022 | 2021 | 2021 | Seq | Yr/Yr | ||||||||||||||||
| Income Statement Data | ||||||||||||||||||||
| Net interest income | $1,195 | $1,197 | $1,176 | — | 2% | |||||||||||||||
Net interest income (FTE)(a) | 1,198 | 1,200 | 1,179 | — | 2% | |||||||||||||||
| Noninterest income | 684 | 791 | 749 | (14%) | (9%) | |||||||||||||||
Total revenue (FTE)(a) | 1,882 | 1,991 | 1,928 | (5%) | (2%) | |||||||||||||||
| Provision for (benefit from) credit losses | 45 | (47) | (173) | NM | NM | |||||||||||||||
| Noninterest expense | 1,222 | 1,206 | 1,215 | 1% | 1% | |||||||||||||||
| Net income | 494 | 662 | 694 | (25%) | (29%) | |||||||||||||||
| Net income available to common shareholders | 474 | 627 | 674 | (24%) | (30%) | |||||||||||||||
| Earnings Per Share Data | ||||||||||||||||||||
| Net income allocated to common shareholders | $473 | $625 | $672 | (24%) | (30%) | |||||||||||||||
| Average common shares outstanding (in thousands): | ||||||||||||||||||||
| Basic | 687,538 | 688,370 | 714,433 | — | (4%) | |||||||||||||||
| Diluted | 696,242 | 697,532 | 723,425 | — | (4%) | |||||||||||||||
| Earnings per share, basic | $0.69 | $0.91 | $0.94 | (24%) | (27%) | |||||||||||||||
| Earnings per share, diluted | 0.68 | 0.90 | 0.93 | (24%) | (27%) | |||||||||||||||
| Common Share Data | ||||||||||||||||||||
| Cash dividends per common share | $0.30 | $0.30 | $0.27 | — | 11% | |||||||||||||||
| Book value per share | 26.33 | 29.43 | 28.78 | (11%) | (9%) | |||||||||||||||
| Market value per share | 43.04 | 43.55 | 37.45 | (1%) | 15% | |||||||||||||||
| Common shares outstanding (in thousands) | 685,905 | 682,778 | 711,596 | — | (4%) | |||||||||||||||
| Market capitalization | $29,521 | $29,735 | $26,649 | (1%) | 11% | |||||||||||||||
| Financial Ratios | ||||||||||||||||||||
| Return on average assets | 0.96 | % | 1.25 | % | 1.38 | % | (29) | (42) | ||||||||||||
| Return on average common equity | 10.0 | % | 12.2 | % | 13.1 | % | (220) | (310) | ||||||||||||
Return on average tangible common equity(a) | 13.4 | % | 16.1 | % | 16.8 | % | (270) | (340) | ||||||||||||
Noninterest income as a percent of total revenue(a) | 36 | % | 40 | % | 39 | % | (400) | (300) | ||||||||||||
| Dividend payout | 43.5 | % | 33.0 | % | 28.7 | % | 1,050 | 1,480 | ||||||||||||
| Average total Bancorp shareholders' equity as a percent of average assets | 10.23 | % | 10.71 | % | 11.26 | % | (48) | (103) | ||||||||||||
Tangible common equity(a) | 6.96 | % | 6.94 | % | 7.14 | % | 2 | (18) | ||||||||||||
Net interest margin (FTE)(a) | 2.59 | % | 2.55 | % | 2.62 | % | 4 | (3) | ||||||||||||
Efficiency (FTE)(a) | 64.9 | % | 60.6 | % | 63.0 | % | 430 | 190 | ||||||||||||
| Effective tax rate | 19.2 | % | 20.1 | % | 21.4 | % | (90) | (220) | ||||||||||||
| Credit Quality | ||||||||||||||||||||
| Net losses charged-off | $34 | $38 | $71 | (11 | %) | (52 | %) | |||||||||||||
| Net losses charged-off as a percent of average portfolio loans and leases (annualized) | 0.12 | % | 0.14 | % | 0.27 | % | (2) | (15) | ||||||||||||
| ALLL as a percent of portfolio loans and leases | 1.65 | % | 1.69 | % | 2.03 | % | (4) | (38) | ||||||||||||
ACL as a percent of portfolio loans and leases(g) | 1.80 | % | 1.85 | % | 2.19 | % | (5) | (39) | ||||||||||||
| Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO | 0.47 | % | 0.47 | % | 0.72 | % | — | (25) | ||||||||||||
| Average Balances | ||||||||||||||||||||
| Loans and leases, including held for sale | $117,162 | $114,790 | $113,701 | 2% | 3% | |||||||||||||||
| Securities and other short-term investments | 70,732 | 72,255 | 69,014 | (2%) | 2% | |||||||||||||||
| Assets | 209,150 | 209,604 | 203,836 | — | 3% | |||||||||||||||
Transaction deposits(b) | 166,032 | 164,673 | 153,834 | 1% | 8% | |||||||||||||||
Core deposits(c) | 168,408 | 167,277 | 157,662 | 1% | 7% | |||||||||||||||
Wholesale funding(d) | 12,568 | 13,276 | 17,608 | (5%) | (29%) | |||||||||||||||
| Bancorp shareholders' equity | 21,402 | 22,449 | 22,952 | (5%) | (7%) | |||||||||||||||
Regulatory Capital Ratios(e)(f) | ||||||||||||||||||||
CET1 capital | 9.28 | % | 9.54 | % | 10.46 | % | (26) | (118) | ||||||||||||
Tier I risk-based capital | 10.60 | % | 10.91 | % | 11.94 | % | (31) | (134) | ||||||||||||
Total risk-based capital | 12.88 | % | 13.42 | % | 14.80 | % | (54) | (192) | ||||||||||||
| Tier I leverage | 8.32 | % | 8.27 | % | 8.61 | % | 5 | (29) | ||||||||||||
| Operations | ||||||||||||||||||||
| Banking centers | 1,079 | 1,117 | 1,098 | (3%) | (2%) | |||||||||||||||
| ATMs | 2,201 | 2,322 | 2,383 | (5%) | (8%) | |||||||||||||||
| Full-time equivalent employees | 19,247 | 19,112 | 19,819 | 1% | (3%) | |||||||||||||||
(a)Non-GAAP measure; see discussion and reconciliation of non-GAAP measures beginning on page 26.
(b)Includes demand, interest checking, savings, money market and foreign office deposits of commercial customers.
(c)Includes transaction deposits plus CDs $250,000 or less.
(d)Includes CDs over $250,000, other deposits, federal funds purchased, other short-term borrowings and long-term debt.
(e)Current period regulatory capital ratios are estimates.
(f)Regulatory capital ratios are calculated pursuant to the five-year transition provision option to phase in the effects of CECL on regulatory capital after its adoption on January 1, 2020.
(g)The allowance for credit losses is the sum of the ALLL and the reserve for unfunded commitments.
14
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||||||||
| Financial Highlights | ||||||||||||||||||||
| $ in millions, except per share data | For the Three Months Ended | |||||||||||||||||||
| (unaudited) | March | December | September | June | March | |||||||||||||||
| 2022 | 2021 | 2021 | 2021 | 2021 | ||||||||||||||||
| Income Statement Data | ||||||||||||||||||||
| Net interest income | $1,195 | $1,197 | $1,189 | $1,208 | $1,176 | |||||||||||||||
Net interest income (FTE)(a) | 1,198 | 1,200 | 1,192 | 1,211 | 1,179 | |||||||||||||||
| Noninterest income | 684 | 791 | 836 | 741 | 749 | |||||||||||||||
Total revenue (FTE)(a) | 1,882 | 1,991 | 2,028 | 1,952 | 1,928 | |||||||||||||||
| Provision for (benefit from) credit losses | 45 | (47) | (42) | (115) | (173) | |||||||||||||||
| Noninterest expense | 1,222 | 1,206 | 1,172 | 1,153 | 1,215 | |||||||||||||||
| Net income | 494 | 662 | 704 | 709 | 694 | |||||||||||||||
| Net income available to common shareholders | 474 | 627 | 684 | 674 | 674 | |||||||||||||||
| Earnings Per Share Data | ||||||||||||||||||||
| Net income allocated to common shareholders | $473 | $625 | $683 | $673 | $672 | |||||||||||||||
| Average common shares outstanding (in thousands): | ||||||||||||||||||||
| Basic | 687,538 | 688,370 | 697,457 | 708,833 | 714,433 | |||||||||||||||
| Diluted | 696,242 | 697,532 | 706,090 | 718,085 | 723,425 | |||||||||||||||
| Earnings per share, basic | $0.69 | $0.91 | $0.98 | $0.95 | $0.94 | |||||||||||||||
| Earnings per share, diluted | 0.68 | 0.90 | 0.97 | 0.94 | 0.93 | |||||||||||||||
| Common Share Data | ||||||||||||||||||||
| Cash dividends per common share | $0.30 | $0.30 | $0.30 | $0.27 | $0.27 | |||||||||||||||
| Book value per share | 26.33 | 29.43 | 29.59 | 29.57 | 28.78 | |||||||||||||||
| Market value per share | 43.04 | 43.55 | 42.44 | 38.23 | 37.45 | |||||||||||||||
| Common shares outstanding (in thousands) | 685,905 | 682,778 | 689,790 | 703,740 | 711,596 | |||||||||||||||
| Market capitalization | $29,521 | $29,735 | $29,275 | $26,904 | $26,649 | |||||||||||||||
| Financial Ratios | ||||||||||||||||||||
| Return on average assets | 0.96 | % | 1.25 | % | 1.36 | % | 1.38 | % | 1.38 | % | ||||||||||
| Return on average common equity | 10.0 | % | 12.2 | % | 13.0 | % | 13.0 | % | 13.1 | % | ||||||||||
Return on average tangible common equity(a) | 13.4 | % | 16.1 | % | 16.9 | % | 16.6 | % | 16.8 | % | ||||||||||
Noninterest income as a percent of total revenue(a) | 36 | % | 40 | % | 41 | % | 38 | % | 39 | % | ||||||||||
| Dividend payout | 43.5 | % | 33.0 | % | 30.6 | % | 28.4 | % | 28.7 | % | ||||||||||
| Average total Bancorp shareholders' equity as a percent of average assets | 10.23 | % | 10.71 | % | 11.16 | % | 11.11 | % | 11.26 | % | ||||||||||
Tangible common equity(a) | 6.96 | % | 6.94 | % | 7.01 | % | 7.28 | % | 7.14 | % | ||||||||||
Net interest margin (FTE)(a) | 2.59 | % | 2.55 | % | 2.59 | % | 2.63 | % | 2.62 | % | ||||||||||
Efficiency (FTE)(a) | 64.9 | % | 60.6 | % | 57.8 | % | 59.1 | % | 63.0 | % | ||||||||||
| Effective tax rate | 19.2 | % | 20.1 | % | 21.3 | % | 22.1 | % | 21.4 | % | ||||||||||
| Credit Quality | ||||||||||||||||||||
| Net losses charged-off | $34 | $38 | $21 | $44 | $71 | |||||||||||||||
| Net losses charged-off as a percent of average portfolio loans and leases (annualized) | 0.12 | % | 0.14 | % | 0.08 | % | 0.16 | % | 0.27 | % | ||||||||||
| ALLL as a percent of portfolio loans and leases | 1.65 | % | 1.69 | % | 1.81 | % | 1.89 | % | 2.03 | % | ||||||||||
ACL as a percent of portfolio loans and leases(g) | 1.80 | % | 1.85 | % | 2.00 | % | 2.06 | % | 2.19 | % | ||||||||||
| Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO | 0.47 | % | 0.47 | % | 0.52 | % | 0.61 | % | 0.72 | % | ||||||||||
| Average Balances | ||||||||||||||||||||
| Loans and leases, including held for sale | $117,162 | $114,790 | $113,528 | $114,443 | $113,701 | |||||||||||||||
| Securities and other short-term investments | 70,732 | 72,255 | 69,273 | 70,475 | 69,014 | |||||||||||||||
| Assets | 209,150 | 209,604 | 205,449 | 206,353 | 203,836 | |||||||||||||||
Transaction deposits(b) | 166,032 | 164,673 | 159,404 | 158,779 | 153,834 | |||||||||||||||
Core deposits(c) | 168,408 | 167,277 | 162,341 | 162,294 | 157,662 | |||||||||||||||
Wholesale funding(d) | 12,568 | 13,276 | 13,833 | 15,651 | 17,608 | |||||||||||||||
| Bancorp shareholders' equity | 21,402 | 22,449 | 22,927 | 22,927 | 22,952 | |||||||||||||||
Regulatory Capital Ratios(e)(f) | ||||||||||||||||||||
CET1 capital | 9.28 | % | 9.54 | % | 9.86 | % | 10.37 | % | 10.46 | % | ||||||||||
Tier I risk-based capital | 10.60 | % | 10.91 | % | 11.28 | % | 11.83 | % | 11.94 | % | ||||||||||
Total risk-based capital | 12.88 | % | 13.42 | % | 13.94 | % | 14.60 | % | 14.80 | % | ||||||||||
| Tier I leverage | 8.32 | % | 8.27 | % | 8.41 | % | 8.55 | % | 8.61 | % | ||||||||||
| Operations | ||||||||||||||||||||
| Banking centers | 1,079 | 1,117 | 1,100 | 1,096 | 1,098 | |||||||||||||||
| ATMs | 2,201 | 2,322 | 2,336 | 2,369 | 2,383 | |||||||||||||||
| Full-time equivalent employees | 19,247 | 19,112 | 19,171 | 19,402 | 19,819 | |||||||||||||||
(a)Non-GAAP measure; see discussion and reconciliation of non-GAAP measures beginning on page 26.
(b)Includes demand, interest checking, savings, money market and foreign office deposits of commercial customers.
(c)Includes transaction deposits plus CDs $250,000 or less.
(d)Includes CDs over $250,000, other deposits, federal funds purchased, other short-term borrowings and long-term debt.
(e)Current period regulatory capital ratios are estimates.
(f)Regulatory capital ratios are calculated pursuant to the five-year transition provision option to phase in the effects of CECL on regulatory capital after its adoption on January 1, 2020.
(g)The allowance for credit losses is the sum of the ALLL and the reserve for unfunded commitments.
15
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Consolidated Statements of Income | |||||||||||||||||
| $ in millions | For the Three Months Ended | % Change | |||||||||||||||
| (unaudited) | March | December | March | ||||||||||||||
| 2022 | 2021 | 2021 | Seq | Yr/Yr | |||||||||||||
| Interest Income | |||||||||||||||||
| Interest and fees on loans and leases | $983 | $1,000 | $1,030 | (2%) | (5%) | ||||||||||||
| Interest on securities | 294 | 281 | 264 | 5% | 11% | ||||||||||||
| Interest on other short-term investments | 12 | 13 | 8 | (8%) | 50% | ||||||||||||
| Total interest income | 1,289 | 1,294 | 1,302 | — | (1%) | ||||||||||||
| Interest Expense | |||||||||||||||||
| Interest on deposits | 11 | 11 | 21 | — | (48%) | ||||||||||||
| Interest on other short-term borrowings | — | — | 1 | NM | (100%) | ||||||||||||
| Interest on long-term debt | 83 | 86 | 104 | (3%) | (20%) | ||||||||||||
| Total interest expense | 94 | 97 | 126 | (3%) | (25%) | ||||||||||||
| Net Interest Income | 1,195 | 1,197 | 1,176 | — | 2% | ||||||||||||
| Provision for (benefit from) credit losses | 45 | (47) | (173) | NM | NM | ||||||||||||
| Net Interest Income After Provision for (Benefit from) Credit Losses | 1,150 | 1,244 | 1,349 | (8%) | (15%) | ||||||||||||
| Noninterest Income | |||||||||||||||||
| Service charges on deposits | 152 | 156 | 144 | (3%) | 6% | ||||||||||||
| Commercial banking revenue | 135 | 171 | 153 | (21%) | (12%) | ||||||||||||
| Mortgage banking net revenue | 52 | 35 | 85 | 49% | (39%) | ||||||||||||
| Wealth and asset management revenue | 149 | 150 | 143 | (1%) | 4% | ||||||||||||
| Card and processing revenue | 97 | 104 | 94 | (7%) | 3% | ||||||||||||
| Leasing business revenue | 62 | 74 | 87 | (16%) | (29%) | ||||||||||||
| Other noninterest income | 52 | 120 | 42 | (57%) | 24% | ||||||||||||
| Securities (losses) gains, net | (14) | (19) | 3 | (26%) | NM | ||||||||||||
| Securities losses, net - non-qualifying hedges on mortgage servicing rights | (1) | — | (2) | NM | (50%) | ||||||||||||
| Total noninterest income | 684 | 791 | 749 | (14%) | (9%) | ||||||||||||
| Noninterest Expense | |||||||||||||||||
| Compensation and benefits | 711 | 655 | 706 | 9% | 1% | ||||||||||||
| Net occupancy expense | 77 | 77 | 79 | — | (3%) | ||||||||||||
| Technology and communications | 101 | 103 | 93 | (2%) | 9% | ||||||||||||
| Equipment expense | 36 | 36 | 34 | — | 6% | ||||||||||||
| Card and processing expense | 19 | 19 | 30 | — | (37%) | ||||||||||||
| Leasing business expense | 32 | 36 | 35 | (11%) | (9%) | ||||||||||||
| Marketing expense | 24 | 35 | 23 | (31%) | 4% | ||||||||||||
| Other noninterest expense | 222 | 245 | 215 | (9%) | 3% | ||||||||||||
| Total noninterest expense | 1,222 | 1,206 | 1,215 | 1% | 1% | ||||||||||||
| Income Before Income Taxes | 612 | 829 | 883 | (26%) | (31%) | ||||||||||||
| Applicable income tax expense | 118 | 167 | 189 | (29%) | (38%) | ||||||||||||
| Net Income | 494 | 662 | 694 | (25%) | (29%) | ||||||||||||
| Dividends on preferred stock | 20 | 35 | 20 | (43%) | — | ||||||||||||
| Net Income Available to Common Shareholders | $474 | $627 | $674 | (24%) | (30%) | ||||||||||||
16
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Consolidated Statements of Income | |||||||||||||||||
| $ in millions | For the Three Months Ended | ||||||||||||||||
| (unaudited) | March | December | September | June | March | ||||||||||||
| 2022 | 2021 | 2021 | 2021 | 2021 | |||||||||||||
| Interest Income | |||||||||||||||||
| Interest and fees on loans and leases | $983 | $1,000 | $1,014 | $1,035 | $1,030 | ||||||||||||
| Interest on securities | 294 | 281 | 266 | 279 | 264 | ||||||||||||
| Interest on other short-term investments | 12 | 13 | 12 | 9 | 8 | ||||||||||||
| Total interest income | 1,289 | 1,294 | 1,292 | 1,323 | 1,302 | ||||||||||||
| Interest Expense | |||||||||||||||||
| Interest on deposits | 11 | 11 | 12 | 15 | 21 | ||||||||||||
| Interest on other short-term borrowings | — | — | — | — | 1 | ||||||||||||
| Interest on long-term debt | 83 | 86 | 91 | 100 | 104 | ||||||||||||
| Total interest expense | 94 | 97 | 103 | 115 | 126 | ||||||||||||
| Net Interest Income | 1,195 | 1,197 | 1,189 | 1,208 | 1,176 | ||||||||||||
| Provision for (benefit from) credit losses | 45 | (47) | (42) | (115) | (173) | ||||||||||||
| Net Interest Income After Provision for (Benefit from) Credit Losses | 1,150 | 1,244 | 1,231 | 1,323 | 1,349 | ||||||||||||
| Noninterest Income | |||||||||||||||||
| Service charges on deposits | 152 | 156 | 152 | 149 | 144 | ||||||||||||
| Commercial banking revenue | 135 | 171 | 152 | 160 | 153 | ||||||||||||
| Mortgage banking net revenue | 52 | 35 | 86 | 64 | 85 | ||||||||||||
| Wealth and asset management revenue | 149 | 150 | 147 | 145 | 143 | ||||||||||||
| Card and processing revenue | 97 | 104 | 102 | 102 | 94 | ||||||||||||
| Leasing business revenue | 62 | 74 | 78 | 61 | 87 | ||||||||||||
| Other noninterest income | 52 | 120 | 120 | 49 | 42 | ||||||||||||
| Securities (losses) gains, net | (14) | (19) | (1) | 10 | 3 | ||||||||||||
| Securities (losses) gains, net - non-qualifying hedges on mortgage servicing rights | (1) | — | — | 1 | (2) | ||||||||||||
| Total noninterest income | 684 | 791 | 836 | 741 | 749 | ||||||||||||
| Noninterest Expense | |||||||||||||||||
| Compensation and benefits | 711 | 655 | 627 | 638 | 706 | ||||||||||||
| Net occupancy expense | 77 | 77 | 79 | 77 | 79 | ||||||||||||
| Technology and communications | 101 | 103 | 98 | 94 | 93 | ||||||||||||
| Equipment expense | 36 | 36 | 34 | 34 | 34 | ||||||||||||
| Card and processing expense | 19 | 19 | 19 | 20 | 30 | ||||||||||||
| Leasing business expense | 32 | 36 | 33 | 33 | 35 | ||||||||||||
| Marketing expense | 24 | 35 | 29 | 20 | 23 | ||||||||||||
| Other noninterest expense | 222 | 245 | 253 | 237 | 215 | ||||||||||||
| Total noninterest expense | 1,222 | 1,206 | 1,172 | 1,153 | 1,215 | ||||||||||||
| Income Before Income Taxes | 612 | 829 | 895 | 911 | 883 | ||||||||||||
| Applicable income tax expense | 118 | 167 | 191 | 202 | 189 | ||||||||||||
| Net Income | 494 | 662 | 704 | 709 | 694 | ||||||||||||
| Dividends on preferred stock | 20 | 35 | 20 | 35 | 20 | ||||||||||||
| Net Income Available to Common Shareholders | $474 | $627 | $684 | $674 | $674 | ||||||||||||
17
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Consolidated Balance Sheets | |||||||||||||||||
| $ in millions, except per share data | As of | % Change | |||||||||||||||
| (unaudited) | March | December | March | ||||||||||||||
| 2022 | 2021 | 2021 | Seq | Yr/Yr | |||||||||||||
| Assets | |||||||||||||||||
| Cash and due from banks | $3,049 | $2,994 | $3,122 | 2% | (2%) | ||||||||||||
| Other short-term investments | 20,529 | 34,572 | 34,187 | (41%) | (40%) | ||||||||||||
Available-for-sale debt and other securities(a) | 48,832 | 38,110 | 37,595 | 28% | 30% | ||||||||||||
Held-to-maturity securities(b) | 6 | 8 | 10 | (25%) | (40%) | ||||||||||||
| Trading debt securities | 324 | 512 | 728 | (37%) | (55%) | ||||||||||||
| Equity securities | 358 | 376 | 315 | (5%) | 14% | ||||||||||||
| Loans and leases held for sale | 2,616 | 4,415 | 5,477 | (41%) | (52%) | ||||||||||||
| Portfolio loans and leases: | |||||||||||||||||
| Commercial and industrial loans | 53,909 | 51,659 | 49,094 | 4% | 10% | ||||||||||||
| Commercial mortgage loans | 10,694 | 10,316 | 10,481 | 4% | 2% | ||||||||||||
| Commercial construction loans | 5,420 | 5,241 | 6,198 | 3% | (13%) | ||||||||||||
| Commercial leases | 2,915 | 3,052 | 3,255 | (4%) | (10%) | ||||||||||||
| Total commercial loans and leases | 72,938 | 70,268 | 69,028 | 4% | 6% | ||||||||||||
| Residential mortgage loans | 17,144 | 16,397 | 15,776 | 5% | 9% | ||||||||||||
| Home equity | 3,916 | 4,084 | 4,815 | (4%) | (19%) | ||||||||||||
| Indirect secured consumer loans | 17,424 | 16,783 | 14,336 | 4% | 22% | ||||||||||||
| Credit card | 1,690 | 1,766 | 1,810 | (4%) | (7%) | ||||||||||||
| Other consumer loans | 2,753 | 2,752 | 3,090 | — | (11%) | ||||||||||||
| Total consumer loans | 42,927 | 41,782 | 39,827 | 3% | 8% | ||||||||||||
| Portfolio loans and leases | 115,865 | 112,050 | 108,855 | 3% | 6% | ||||||||||||
| Allowance for loan and lease losses | (1,908) | (1,892) | (2,208) | 1% | (14%) | ||||||||||||
| Portfolio loans and leases, net | 113,957 | 110,158 | 106,647 | 3% | 7% | ||||||||||||
| Bank premises and equipment | 2,102 | 2,120 | 2,072 | (1%) | 1% | ||||||||||||
| Operating lease equipment | 622 | 616 | 718 | 1% | (13%) | ||||||||||||
| Goodwill | 4,514 | 4,514 | 4,259 | — | 6% | ||||||||||||
| Intangible assets | 145 | 156 | 127 | (7%) | 14% | ||||||||||||
| Servicing rights | 1,444 | 1,121 | 784 | 29% | 84% | ||||||||||||
| Other assets | 12,961 | 11,444 | 10,858 | 13% | 19% | ||||||||||||
| Total Assets | $211,459 | $211,116 | $206,899 | — | 2% | ||||||||||||
| Liabilities | |||||||||||||||||
| Deposits: | |||||||||||||||||
| Demand | $65,590 | $65,088 | $61,363 | 1% | 7% | ||||||||||||
| Interest checking | 48,836 | 48,870 | 45,582 | — | 7% | ||||||||||||
| Savings | 23,622 | 22,227 | 20,162 | 6% | 17% | ||||||||||||
| Money market | 29,947 | 30,263 | 30,630 | (1%) | (2%) | ||||||||||||
| Foreign office | 115 | 121 | 113 | (5%) | 2% | ||||||||||||
| CDs $250,000 or less | 2,267 | 2,486 | 3,404 | (9%) | (33%) | ||||||||||||
| CDs over $250,000 | 234 | 269 | 1,139 | (13%) | (79%) | ||||||||||||
| Total deposits | 170,611 | 169,324 | 162,393 | 1% | 5% | ||||||||||||
| Federal funds purchased | 250 | 281 | 302 | (11%) | (17%) | ||||||||||||
| Other short-term borrowings | 872 | 980 | 1,106 | (11%) | (21%) | ||||||||||||
| Accrued taxes, interest and expenses | 1,471 | 2,233 | 1,879 | (34%) | (22%) | ||||||||||||
| Other liabilities | 7,263 | 4,267 | 3,881 | 70% | 87% | ||||||||||||
| Long-term debt | 10,815 | 11,821 | 14,743 | (9%) | (27%) | ||||||||||||
| Total Liabilities | 191,282 | 188,906 | 184,304 | 1% | 4% | ||||||||||||
| Equity | |||||||||||||||||
Common stock(c) | 2,051 | 2,051 | 2,051 | — | — | ||||||||||||
| Preferred stock | 2,116 | 2,116 | 2,116 | — | — | ||||||||||||
| Capital surplus | 3,615 | 3,624 | 3,592 | — | 1% | ||||||||||||
| Retained earnings | 20,501 | 20,236 | 18,863 | 1% | 9% | ||||||||||||
| Accumulated other comprehensive (loss) income | (1,096) | 1,207 | 1,792 | NM | NM | ||||||||||||
| Treasury stock | (7,010) | (7,024) | (5,819) | — | 20% | ||||||||||||
| Total Equity | 20,177 | 22,210 | 22,595 | (9%) | (11%) | ||||||||||||
| Total Liabilities and Equity | $211,459 | $211,116 | $206,899 | — | 2% | ||||||||||||
| (a) Amortized cost | $50,171 | $36,941 | $35,963 | 36% | 40% | ||||||||||||
| (b) Market values | 6 | 8 | 10 | (25%) | (40%) | ||||||||||||
| (c) Common shares, stated value $2.22 per share (in thousands): | |||||||||||||||||
| Authorized | 2,000,000 | 2,000,000 | 2,000,000 | — | — | ||||||||||||
| Outstanding, excluding treasury | 685,905 | 682,778 | 711,596 | — | (4 | %) | |||||||||||
| Treasury | 237,987 | 241,115 | 212,297 | (1 | %) | 12 | % | ||||||||||
18
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Consolidated Balance Sheets | |||||||||||||||||
| $ in millions, except per share data | As of | ||||||||||||||||
| (unaudited) | March | December | September | June | March | ||||||||||||
| 2022 | 2021 | 2021 | 2021 | 2021 | |||||||||||||
| Assets | |||||||||||||||||
| Cash and due from banks | $3,049 | $2,994 | $3,213 | $3,285 | $3,122 | ||||||||||||
| Other short-term investments | 20,529 | 34,572 | 34,203 | 32,409 | 34,187 | ||||||||||||
Available-for-sale debt and other securities(a) | 48,832 | 38,110 | 37,870 | 38,012 | 37,595 | ||||||||||||
Held-to-maturity securities(b) | 6 | 8 | 8 | 10 | 10 | ||||||||||||
| Trading debt securities | 324 | 512 | 685 | 711 | 728 | ||||||||||||
| Equity securities | 358 | 376 | 329 | 341 | 315 | ||||||||||||
| Loans and leases held for sale | 2,616 | 4,415 | 5,203 | 5,730 | 5,477 | ||||||||||||
| Portfolio loans and leases: | |||||||||||||||||
| Commercial and industrial loans | 53,909 | 51,659 | 47,834 | 47,564 | 49,094 | ||||||||||||
| Commercial mortgage loans | 10,694 | 10,316 | 10,300 | 10,347 | 10,481 | ||||||||||||
| Commercial construction loans | 5,420 | 5,241 | 5,456 | 5,871 | 6,198 | ||||||||||||
| Commercial leases | 2,915 | 3,052 | 3,130 | 3,238 | 3,255 | ||||||||||||
| Total commercial loans and leases | 72,938 | 70,268 | 66,720 | 67,020 | 69,028 | ||||||||||||
| Residential mortgage loans | 17,144 | 16,397 | 16,158 | 16,131 | 15,776 | ||||||||||||
| Home equity | 3,916 | 4,084 | 4,276 | 4,545 | 4,815 | ||||||||||||
| Indirect secured consumer loans | 17,424 | 16,783 | 16,004 | 15,192 | 14,336 | ||||||||||||
| Credit card | 1,690 | 1,766 | 1,744 | 1,793 | 1,810 | ||||||||||||
| Other consumer loans | 2,753 | 2,752 | 3,009 | 3,052 | 3,090 | ||||||||||||
| Total consumer loans | 42,927 | 41,782 | 41,191 | 40,713 | 39,827 | ||||||||||||
| Portfolio loans and leases | 115,865 | 112,050 | 107,911 | 107,733 | 108,855 | ||||||||||||
| Allowance for loan and lease losses | (1,908) | (1,892) | (1,954) | (2,033) | (2,208) | ||||||||||||
| Portfolio loans and leases, net | 113,957 | 110,158 | 105,957 | 105,700 | 106,647 | ||||||||||||
| Bank premises and equipment | 2,102 | 2,120 | 2,101 | 2,073 | 2,072 | ||||||||||||
| Operating lease equipment | 622 | 616 | 647 | 715 | 718 | ||||||||||||
| Goodwill | 4,514 | 4,514 | 4,514 | 4,259 | 4,259 | ||||||||||||
| Intangible assets | 145 | 156 | 169 | 117 | 127 | ||||||||||||
| Servicing rights | 1,444 | 1,121 | 943 | 818 | 784 | ||||||||||||
| Other assets | 12,961 | 11,444 | 11,889 | 11,210 | 10,858 | ||||||||||||
| Total Assets | $211,459 | $211,116 | $207,731 | $205,390 | $206,899 | ||||||||||||
| Liabilities | |||||||||||||||||
| Deposits: | |||||||||||||||||
| Demand | $65,590 | $65,088 | $63,879 | $62,760 | $61,363 | ||||||||||||
| Interest checking | 48,836 | 48,870 | 45,964 | 44,872 | 45,582 | ||||||||||||
| Savings | 23,622 | 22,227 | 21,423 | 20,667 | 20,162 | ||||||||||||
| Money market | 29,947 | 30,263 | 30,652 | 30,564 | 30,630 | ||||||||||||
| Foreign office | 115 | 121 | 202 | 152 | 113 | ||||||||||||
| CDs $250,000 or less | 2,267 | 2,486 | 2,691 | 2,958 | 3,404 | ||||||||||||
| CDs over $250,000 | 234 | 269 | 297 | 310 | 1,139 | ||||||||||||
| Total deposits | 170,611 | 169,324 | 165,108 | 162,283 | 162,393 | ||||||||||||
| Federal funds purchased | 250 | 281 | 309 | 338 | 302 | ||||||||||||
| Other short-term borrowings | 872 | 980 | 949 | 1,130 | 1,106 | ||||||||||||
| Accrued taxes, interest and expenses | 1,471 | 2,233 | 2,083 | 2,045 | 1,879 | ||||||||||||
| Other liabilities | 7,263 | 4,267 | 5,339 | 4,304 | 3,881 | ||||||||||||
| Long-term debt | 10,815 | 11,821 | 11,419 | 12,364 | 14,743 | ||||||||||||
| Total Liabilities | 191,282 | 188,906 | 185,207 | 182,464 | 184,304 | ||||||||||||
| Equity | |||||||||||||||||
Common stock(c) | 2,051 | 2,051 | 2,051 | 2,051 | 2,051 | ||||||||||||
| Preferred stock | 2,116 | 2,116 | 2,116 | 2,116 | 2,116 | ||||||||||||
| Capital surplus | 3,615 | 3,624 | 3,611 | 3,602 | 3,592 | ||||||||||||
| Retained earnings | 20,501 | 20,236 | 19,817 | 19,343 | 18,863 | ||||||||||||
| Accumulated other comprehensive (loss) income | (1,096) | 1,207 | 1,637 | 1,974 | 1,792 | ||||||||||||
| Treasury stock | (7,010) | (7,024) | (6,708) | (6,160) | (5,819) | ||||||||||||
| Total Equity | 20,177 | 22,210 | 22,524 | 22,926 | 22,595 | ||||||||||||
| Total Liabilities and Equity | $211,459 | $211,116 | $207,731 | $205,390 | $206,899 | ||||||||||||
| (a) Amortized cost | $50,171 | $36,941 | $36,308 | $36,081 | $35,963 | ||||||||||||
| (b) Market values | 6 | 8 | 8 | 10 | 10 | ||||||||||||
| (c) Common shares, stated value $2.22 per share (in thousands): | |||||||||||||||||
| Authorized | 2,000,000 | 2,000,000 | 2,000,000 | 2,000,000 | 2,000,000 | ||||||||||||
| Outstanding, excluding treasury | 685,905 | 682,778 | 689,790 | 703,740 | 711,596 | ||||||||||||
| Treasury | 237,987 | 241,115 | 234,102 | 220,153 | 212,297 | ||||||||||||
19
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||
| Consolidated Statements of Changes in Equity | ||||||||||||||
| $ in millions | ||||||||||||||
| (unaudited) | ||||||||||||||
| For the Three Months Ended | ||||||||||||||
| March | March | |||||||||||||
| 2022 | 2021 | |||||||||||||
| Total Equity, Beginning | $22,210 | $23,111 | ||||||||||||
| Net income | 494 | 694 | ||||||||||||
| Other comprehensive loss, net of tax: | ||||||||||||||
| Change in unrealized (losses) gains: | ||||||||||||||
| Available-for-sale debt securities | (1,931) | (689) | ||||||||||||
| Qualifying cash flow hedges | (373) | (121) | ||||||||||||
| Change in accumulated other comprehensive income related to employee benefit plans | 1 | 1 | ||||||||||||
| Comprehensive income | (1,809) | (115) | ||||||||||||
| Cash dividends declared: | ||||||||||||||
| Common stock | (209) | (195) | ||||||||||||
| Preferred stock | (20) | (20) | ||||||||||||
| Impact of stock transactions under stock compensation plans, net | 5 | (6) | ||||||||||||
| Shares acquired for treasury | — | (180) | ||||||||||||
| Total Equity, Ending | $20,177 | $22,595 | ||||||||||||
20
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||||||||||||||
| Average Balance Sheet and Yield/Rate Analysis | For the Three Months Ended | |||||||||||||||||||||||||
| $ in millions | March | December | March | |||||||||||||||||||||||
| (unaudited) | 2022 | 2021 | 2021 | |||||||||||||||||||||||
| Average | Average | Average | Average | Average | Average | |||||||||||||||||||||
| Balance | Yield/Rate | Balance | Yield/Rate | Balance | Yield/Rate | |||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||
| Loans and leases: | ||||||||||||||||||||||||||
Commercial and industrial loans(a) | $52,562 | 3.29 | % | $49,571 | 3.42 | % | $49,715 | 3.60 | % | |||||||||||||||||
Commercial mortgage loans(a) | 10,529 | 3.00 | % | 10,247 | 2.86 | % | 10,534 | 3.06 | % | |||||||||||||||||
Commercial construction loans(a) | 5,371 | 3.29 | % | 5,329 | 3.10 | % | 6,039 | 3.20 | % | |||||||||||||||||
Commercial leases(a) | 2,943 | 2.85 | % | 3,057 | 2.81 | % | 3,130 | 3.17 | % | |||||||||||||||||
| Total commercial loans and leases | 71,405 | 3.23 | % | 68,204 | 3.28 | % | 69,418 | 3.46 | % | |||||||||||||||||
| Residential mortgage loans | 20,179 | 3.17 | % | 21,486 | 3.17 | % | 20,444 | 3.36 | % | |||||||||||||||||
| Home equity | 4,010 | 3.52 | % | 4,179 | 3.60 | % | 5,009 | 3.58 | % | |||||||||||||||||
| Indirect secured consumer loans | 17,136 | 3.08 | % | 16,345 | 3.18 | % | 13,955 | 3.58 | % | |||||||||||||||||
| Credit card | 1,691 | 12.31 | % | 1,739 | 12.24 | % | 1,879 | 12.36 | % | |||||||||||||||||
| Other consumer loans | 2,741 | 6.08 | % | 2,837 | 6.15 | % | 2,996 | 6.12 | % | |||||||||||||||||
| Total consumer loans | 45,757 | 3.68 | % | 46,586 | 3.73 | % | 44,283 | 4.02 | % | |||||||||||||||||
| Total loans and leases | 117,162 | 3.41 | % | 114,790 | 3.46 | % | 113,701 | 3.68 | % | |||||||||||||||||
| Securities: | ||||||||||||||||||||||||||
| Taxable securities | 41,412 | 2.84 | % | 36,607 | 3.00 | % | 35,764 | 2.97 | % | |||||||||||||||||
Tax exempt securities(a) | 1,010 | 2.40 | % | 1,024 | 2.38 | % | 533 | 2.26 | % | |||||||||||||||||
| Other short-term investments | 28,310 | 0.18 | % | 34,624 | 0.15 | % | 32,717 | 0.10 | % | |||||||||||||||||
| Total interest-earning assets | 187,894 | 2.79 | % | 187,045 | 2.75 | % | 182,715 | 2.90 | % | |||||||||||||||||
| Cash and due from banks | 2,962 | 3,079 | 2,991 | |||||||||||||||||||||||
| Other assets | 20,186 | 21,433 | 20,580 | |||||||||||||||||||||||
| Allowance for loan and lease losses | (1,892) | (1,953) | (2,450) | |||||||||||||||||||||||
| Total Assets | $209,150 | $209,604 | $203,836 | |||||||||||||||||||||||
| Liabilities | ||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||
| Interest checking deposits | $48,659 | 0.05 | % | $47,384 | 0.05 | % | $45,568 | 0.07 | % | |||||||||||||||||
| Savings deposits | 22,772 | 0.02 | % | 21,702 | 0.02 | % | 18,951 | 0.03 | % | |||||||||||||||||
| Money market deposits | 30,263 | 0.03 | % | 30,566 | 0.03 | % | 30,601 | 0.05 | % | |||||||||||||||||
| Foreign office deposits | 126 | 0.04 | % | 193 | 0.04 | % | 128 | 0.05 | % | |||||||||||||||||
| CDs $250,000 or less | 2,376 | 0.12 | % | 2,604 | 0.16 | % | 3,828 | 0.50 | % | |||||||||||||||||
| Total interest-bearing core deposits | 104,196 | 0.04 | % | 102,449 | 0.04 | % | 99,076 | 0.07 | % | |||||||||||||||||
| CDs over $250,000 | 254 | 0.85 | % | 264 | 0.94 | % | 1,226 | 1.31 | % | |||||||||||||||||
| Federal funds purchased | 259 | 0.15 | % | 315 | 0.13 | % | 324 | 0.13 | % | |||||||||||||||||
| Securities sold under repurchase agreements | 491 | 0.01 | % | 578 | 0.01 | % | 663 | 0.04 | % | |||||||||||||||||
| Derivative collateral and other secured borrowings | 399 | 0.31 | % | 422 | 0.26 | % | 546 | 0.48 | % | |||||||||||||||||
| Long-term debt | 11,165 | 3.02 | % | 11,697 | 2.92 | % | 14,849 | 2.83 | % | |||||||||||||||||
| Total interest-bearing liabilities | 116,764 | 0.33 | % | 115,725 | 0.33 | % | 116,684 | 0.44 | % | |||||||||||||||||
| Demand deposits | 64,212 | 64,828 | 58,586 | |||||||||||||||||||||||
| Other liabilities | 6,772 | 6,602 | 5,614 | |||||||||||||||||||||||
| Total Liabilities | 187,748 | 187,155 | 180,884 | |||||||||||||||||||||||
| Total Equity | 21,402 | 22,449 | 22,952 | |||||||||||||||||||||||
| Total Liabilities and Equity | $209,150 | $209,604 | $203,836 | |||||||||||||||||||||||
| Ratios: | ||||||||||||||||||||||||||
Net interest margin (FTE)(b) | 2.59 | % | 2.55 | % | 2.62 | % | ||||||||||||||||||||
Net interest rate spread (FTE)(b) | 2.46 | % | 2.42 | % | 2.46 | % | ||||||||||||||||||||
| Interest-bearing liabilities to interest-earning assets | 62.14 | % | 61.87 | % | 63.86 | % | ||||||||||||||||||||
| (a) Average Yield/Rate of these assets are presented on an FTE basis. | ||||||||||||||||||||||||||
| (b) Non-GAAP measure; see discussion and reconciliation of non-GAAP measures beginning on page 26. | ||||||||||||||||||||||||||
21
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Summary of Loans and Leases | |||||||||||||||||
| $ in millions | For the Three Months Ended | ||||||||||||||||
| (unaudited) | March | December | September | June | March | ||||||||||||
| 2022 | 2021 | 2021 | 2021 | 2021 | |||||||||||||
| Average Portfolio Loans and Leases | |||||||||||||||||
| Commercial loans and leases: | |||||||||||||||||
| Commercial and industrial loans | $52,554 | $49,566 | $47,766 | $48,773 | $49,629 | ||||||||||||
| Commercial mortgage loans | 10,521 | 10,247 | 10,317 | 10,459 | 10,532 | ||||||||||||
| Commercial construction loans | 5,371 | 5,329 | 5,728 | 6,043 | 6,039 | ||||||||||||
| Commercial leases | 2,942 | 3,057 | 3,158 | 3,174 | 3,114 | ||||||||||||
| Total commercial loans and leases | 71,388 | 68,199 | 66,969 | 68,449 | 69,314 | ||||||||||||
| Consumer loans: | |||||||||||||||||
| Residential mortgage loans | 16,501 | 16,188 | 16,223 | 15,883 | 15,803 | ||||||||||||
| Home equity | 4,009 | 4,179 | 4,409 | 4,674 | 5,009 | ||||||||||||
| Indirect secured consumer loans | 17,136 | 16,345 | 15,590 | 14,702 | 13,955 | ||||||||||||
| Credit card | 1,691 | 1,739 | 1,748 | 1,770 | 1,879 | ||||||||||||
| Other consumer loans | 2,742 | 2,837 | 3,031 | 3,056 | 2,996 | ||||||||||||
| Total consumer loans | 42,079 | 41,288 | 41,001 | 40,085 | 39,642 | ||||||||||||
| Total average portfolio loans and leases | $113,467 | $109,487 | $107,970 | $108,534 | $108,956 | ||||||||||||
| Average Loans and Leases Held for Sale | |||||||||||||||||
| Commercial loans and leases held for sale | $18 | $5 | $31 | $52 | $104 | ||||||||||||
| Consumer loans held for sale | 3,677 | 5,298 | 5,527 | 5,857 | 4,641 | ||||||||||||
| Average loans and leases held for sale | $3,695 | $5,303 | $5,558 | $5,909 | $4,745 | ||||||||||||
Average PPP loans(a) | $1,012 | $1,756 | $3,071 | $4,810 | $5,200 | ||||||||||||
| Average portfolio commercial and industrial loans - excluding PPP loans | 51,542 | 47,810 | 44,695 | 43,963 | 44,429 | ||||||||||||
| Total average portfolio commercial and industrial loans | $52,554 | $49,566 | $47,766 | $48,773 | $49,629 | ||||||||||||
| End of Period Portfolio Loans and Leases | |||||||||||||||||
| Commercial loans and leases: | |||||||||||||||||
| Commercial and industrial loans | $53,909 | $51,659 | $47,834 | $47,564 | $49,094 | ||||||||||||
| Commercial mortgage loans | 10,694 | 10,316 | 10,300 | 10,347 | 10,481 | ||||||||||||
| Commercial construction loans | 5,420 | 5,241 | 5,456 | 5,871 | 6,198 | ||||||||||||
| Commercial leases | 2,915 | 3,052 | 3,130 | 3,238 | 3,255 | ||||||||||||
| Total commercial loans and leases | 72,938 | 70,268 | 66,720 | 67,020 | 69,028 | ||||||||||||
| Consumer loans: | |||||||||||||||||
| Residential mortgage loans | 17,144 | 16,397 | 16,158 | 16,131 | 15,776 | ||||||||||||
| Home equity | 3,916 | 4,084 | 4,276 | 4,545 | 4,815 | ||||||||||||
| Indirect secured consumer loans | 17,424 | 16,783 | 16,004 | 15,192 | 14,336 | ||||||||||||
| Credit card | 1,690 | 1,766 | 1,744 | 1,793 | 1,810 | ||||||||||||
| Other consumer loans | 2,753 | 2,752 | 3,009 | 3,052 | 3,090 | ||||||||||||
| Total consumer loans | 42,927 | 41,782 | 41,191 | 40,713 | 39,827 | ||||||||||||
| Total portfolio loans and leases | $115,865 | $112,050 | $107,911 | $107,733 | $108,855 | ||||||||||||
End of Period Loans and Leases Held for Sale | |||||||||||||||||
| Commercial loans and leases held for sale | $23 | $21 | $2 | $46 | $80 | ||||||||||||
| Consumer loans held for sale | 2,593 | 4,394 | 5,201 | 5,684 | 5,397 | ||||||||||||
| Loans and leases held for sale | $2,616 | $4,415 | $5,203 | $5,730 | $5,477 | ||||||||||||
| Operating lease equipment | $622 | $616 | $647 | $715 | $718 | ||||||||||||
Loans and Leases Serviced for Others(b) | |||||||||||||||||
| Commercial and industrial loans | $993 | $923 | $879 | $919 | $1,011 | ||||||||||||
| Commercial mortgage loans | 592 | 610 | 620 | 623 | 639 | ||||||||||||
| Commercial construction loans | 502 | 474 | 487 | 528 | 592 | ||||||||||||
| Commercial leases | 571 | 589 | 555 | 536 | 547 | ||||||||||||
| Residential mortgage loans | 97,736 | 89,234 | 77,929 | 71,496 | 65,922 | ||||||||||||
| Other consumer loans | — | — | 50 | 50 | 50 | ||||||||||||
| Total loans and leases serviced for others | 100,394 | 91,830 | 80,520 | 74,152 | 68,761 | ||||||||||||
| Total loans and leases owned or serviced | $219,497 | $208,911 | $194,281 | $188,330 | $183,811 | ||||||||||||
End of period PPP loans(a) | $737 | $1,305 | $2,344 | $3,685 | $5,381 | ||||||||||||
| End of period portfolio commercial and industrial loans - excluding PPP loans | 53,172 | 50,354 | 45,490 | 43,879 | 43,713 | ||||||||||||
| Total end of period portfolio commercial and industrial loans | $53,909 | $51,659 | $47,834 | $47,564 | $49,094 | ||||||||||||
(a)Paycheck Protection Program loans are included in commercial and industrial loans in the Condensed Consolidated Balance Sheets.
(b)Fifth Third sells certain loans and leases and obtains servicing responsibilities.
22
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||||||||
| Regulatory Capital | |||||||||||||||||||||||
| $ in millions | As of | ||||||||||||||||||||||
| (unaudited) | March | December | September | June | March | ||||||||||||||||||
2021(a) | 2021 | 2021 | 2021 | 2021 | |||||||||||||||||||
Regulatory Capital(b) | |||||||||||||||||||||||
| CET1 capital | $14,937 | $14,781 | $14,673 | $15,050 | $14,931 | ||||||||||||||||||
| Additional tier I capital | 2,116 | 2,116 | 2,116 | 2,116 | 2,117 | ||||||||||||||||||
| Tier I capital | 17,053 | 16,897 | 16,789 | 17,166 | 17,048 | ||||||||||||||||||
| Tier II capital | 3,673 | 3,892 | 3,953 | 4,018 | 4,083 | ||||||||||||||||||
| Total regulatory capital | $20,726 | $20,789 | $20,742 | $21,184 | $21,131 | ||||||||||||||||||
Risk-weighted assets | $160,907 | $154,860 | $148,827 | $145,084 | $142,799 | ||||||||||||||||||
| Ratios | |||||||||||||||||||||||
| Average total Bancorp shareholders' equity as a percent of average assets | 10.23 | % | 10.71 | % | 11.16 | % | 11.11 | % | 11.26 | % | |||||||||||||
Regulatory Capital Ratios(b) | |||||||||||||||||||||||
| Fifth Third Bancorp | |||||||||||||||||||||||
CET1 capital | 9.28 | % | 9.54 | % | 9.86 | % | 10.37 | % | 10.46 | % | |||||||||||||
Tier I risk-based capital | 10.60 | % | 10.91 | % | 11.28 | % | 11.83 | % | 11.94 | % | |||||||||||||
Total risk-based capital | 12.88 | % | 13.42 | % | 13.94 | % | 14.60 | % | 14.80 | % | |||||||||||||
| Tier I leverage | 8.32 | % | 8.27 | % | 8.41 | % | 8.55 | % | 8.61 | % | |||||||||||||
| Fifth Third Bank, National Association | |||||||||||||||||||||||
Tier I risk-based capital | 10.80 | % | 10.90 | % | 11.25 | % | 11.67 | % | 12.70 | % | |||||||||||||
Total risk-based capital | 12.19 | % | 12.33 | % | 12.79 | % | 13.27 | % | 14.41 | % | |||||||||||||
| Tier I leverage | 8.49 | % | 8.29 | % | 8.43 | % | 8.46 | % | 9.19 | % | |||||||||||||
(a)Current period regulatory capital data and ratios are estimated.
(b)Regulatory capital ratios are calculated pursuant to the five-year transition provision option to phase in the effects of CECL on regulatory capital after its adoption on January 1, 2020.
23
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||
| Summary of Credit Loss Experience | |||||||||||||||||
| $ in millions | For the Three Months Ended | ||||||||||||||||
| (unaudited) | March | December | September | June | March | ||||||||||||
| 2022 | 2021 | 2021 | 2021 | 2021 | |||||||||||||
| Average portfolio loans and leases: | |||||||||||||||||
| Commercial and industrial loans | $52,554 | $49,566 | $47,766 | $48,773 | $49,629 | ||||||||||||
| Commercial mortgage loans | 10,521 | 10,247 | 10,317 | 10,459 | 10,532 | ||||||||||||
| Commercial construction loans | 5,371 | 5,329 | 5,728 | 6,043 | 6,039 | ||||||||||||
| Commercial leases | 2,942 | 3,057 | 3,158 | 3,174 | 3,114 | ||||||||||||
| Total commercial loans and leases | 71,388 | 68,199 | 66,969 | 68,449 | 69,314 | ||||||||||||
| Residential mortgage loans | 16,501 | 16,188 | 16,223 | 15,883 | 15,803 | ||||||||||||
| Home equity | 4,009 | 4,179 | 4,409 | 4,674 | 5,009 | ||||||||||||
| Indirect secured consumer loans | 17,136 | 16,345 | 15,590 | 14,702 | 13,955 | ||||||||||||
| Credit card | 1,691 | 1,739 | 1,748 | 1,770 | 1,879 | ||||||||||||
| Other consumer loans | 2,742 | 2,837 | 3,031 | 3,056 | 2,996 | ||||||||||||
| Total consumer loans | 42,079 | 41,288 | 41,001 | 40,085 | 39,642 | ||||||||||||
| Total average portfolio loans and leases | $113,467 | $109,487 | $107,970 | $108,534 | $108,956 | ||||||||||||
| Losses charged-off: | |||||||||||||||||
| Commercial and industrial loans | ($11) | ($25) | ($10) | ($36) | ($32) | ||||||||||||
| Commercial mortgage loans | — | (1) | — | (8) | (3) | ||||||||||||
| Commercial leases | — | (2) | — | (1) | — | ||||||||||||
| Total commercial loans and leases | (11) | (28) | (10) | (45) | (35) | ||||||||||||
| Residential mortgage loans | (1) | — | (1) | (1) | (1) | ||||||||||||
| Home equity | (2) | (2) | (2) | (2) | (3) | ||||||||||||
| Indirect secured consumer loans | (16) | (13) | (9) | (11) | (18) | ||||||||||||
| Credit card | (17) | (17) | (17) | (26) | (31) | ||||||||||||
| Other consumer loans | (17) | (17) | (17) | (18) | (21) | ||||||||||||
| Total consumer loans | (53) | (49) | (46) | (58) | (74) | ||||||||||||
| Total losses charged-off | ($64) | ($77) | ($56) | ($103) | ($109) | ||||||||||||
| Recoveries of losses previously charged-off: | |||||||||||||||||
| Commercial and industrial loans | $2 | $11 | $5 | $23 | $5 | ||||||||||||
| Commercial mortgage loans | 1 | — | 1 | 2 | 1 | ||||||||||||
| Commercial leases | — | — | — | 3 | 1 | ||||||||||||
| Total commercial loans and leases | 3 | 11 | 6 | 28 | 7 | ||||||||||||
| Residential mortgage loans | 2 | 3 | 2 | 1 | 1 | ||||||||||||
| Home equity | 3 | 4 | 3 | 3 | 3 | ||||||||||||
| Indirect secured consumer loans | 9 | 7 | 10 | 11 | 9 | ||||||||||||
| Credit card | 4 | 4 | 5 | 6 | 6 | ||||||||||||
| Other consumer loans | 9 | 10 | 9 | 10 | 12 | ||||||||||||
| Total consumer loans | 27 | 28 | 29 | 31 | 31 | ||||||||||||
| Total recoveries of losses previously charged-off | $30 | $39 | $35 | $59 | $38 | ||||||||||||
| Net losses charged-off: | |||||||||||||||||
| Commercial and industrial loans | ($9) | ($14) | ($5) | ($13) | ($27) | ||||||||||||
| Commercial mortgage loans | 1 | (1) | 1 | (6) | (2) | ||||||||||||
| Commercial leases | — | (2) | — | 2 | 1 | ||||||||||||
| Total commercial loans and leases | (8) | (17) | (4) | (17) | (28) | ||||||||||||
| Residential mortgage loans | 1 | 3 | 1 | — | — | ||||||||||||
| Home equity | 1 | 2 | 1 | 1 | — | ||||||||||||
| Indirect secured consumer loans | (7) | (6) | 1 | — | (9) | ||||||||||||
| Credit card | (13) | (13) | (12) | (20) | (25) | ||||||||||||
| Other consumer loans | (8) | (7) | (8) | (8) | (9) | ||||||||||||
| Total consumer loans | (26) | (21) | (17) | (27) | (43) | ||||||||||||
| Total net losses charged-off | ($34) | ($38) | ($21) | ($44) | ($71) | ||||||||||||
| Net losses charged-off as a percent of average portfolio loans and leases (annualized): | |||||||||||||||||
| Commercial and industrial loans | 0.07 | % | 0.11 | % | 0.04 | % | 0.11 | % | 0.22 | % | |||||||
| Commercial mortgage loans | (0.03 | %) | 0.03 | % | (0.03 | %) | 0.22 | % | 0.09 | % | |||||||
| Commercial leases | (0.02 | %) | 0.24 | % | — | (0.21 | %) | (0.09 | %) | ||||||||
| Total commercial loans and leases | 0.05 | % | 0.10 | % | 0.03 | % | 0.10 | % | 0.17 | % | |||||||
| Residential mortgage loans | (0.02 | %) | (0.06 | %) | (0.02 | %) | (0.01 | %) | (0.01 | %) | |||||||
| Home equity | (0.07 | %) | (0.18 | %) | (0.13 | %) | (0.09 | %) | 0.01 | % | |||||||
| Indirect secured consumer loans | 0.17 | % | 0.14 | % | (0.02 | %) | 0.01 | % | 0.25 | % | |||||||
| Credit card | 3.13 | % | 2.90 | % | 2.70 | % | 4.52 | % | 5.50 | % | |||||||
| Other consumer loans | 1.07 | % | 1.12 | % | 1.05 | % | 0.91 | % | 1.17 | % | |||||||
| Total consumer loans | 0.25 | % | 0.21 | % | 0.16 | % | 0.26 | % | 0.43 | % | |||||||
| Total net losses charged-off as a percent of average portfolio loans and leases (annualized) | 0.12 | % | 0.14 | % | 0.08 | % | 0.16 | % | 0.27 | % | |||||||
24
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||||||||
| Asset Quality | ||||||||||||||||||||
| $ in millions | For the Three Months Ended | |||||||||||||||||||
| (unaudited) | March | December | September | June | March | |||||||||||||||
| 2022 | 2021 | 2021 | 2021 | 2021 | ||||||||||||||||
| Allowance for Credit Losses | ||||||||||||||||||||
| Allowance for loan and lease losses, beginning | $1,892 | $1,954 | $2,033 | $2,208 | $2,453 | |||||||||||||||
| Total net losses charged-off | (34) | (38) | (21) | (44) | (71) | |||||||||||||||
| Provision for (benefit from) loan and lease losses | 50 | (24) | (58) | (131) | (174) | |||||||||||||||
| Allowance for loan and lease losses, ending | $1,908 | $1,892 | $1,954 | $2,033 | $2,208 | |||||||||||||||
| Reserve for unfunded commitments, beginning | $182 | $205 | $189 | $173 | $172 | |||||||||||||||
| (Benefit from) provision for the reserve for unfunded commitments | (5) | (23) | 16 | 16 | 1 | |||||||||||||||
| Reserve for unfunded commitments, ending | $177 | $182 | $205 | $189 | $173 | |||||||||||||||
| Components of allowance for credit losses: | ||||||||||||||||||||
| Allowance for loan and lease losses | $1,908 | $1,892 | $1,954 | $2,033 | $2,208 | |||||||||||||||
| Reserve for unfunded commitments | 177 | 182 | 205 | 189 | 173 | |||||||||||||||
| Total allowance for credit losses | $2,085 | $2,074 | $2,159 | $2,222 | $2,381 | |||||||||||||||
| As of | ||||||||||||||||||||
| March | December | September | June | March | ||||||||||||||||
| 2022 | 2021 | 2021 | 2021 | 2021 | ||||||||||||||||
| Nonperforming Assets and Delinquent Loans | ||||||||||||||||||||
| Nonaccrual portfolio loans and leases: | ||||||||||||||||||||
| Commercial and industrial loans | $105 | $116 | $172 | $193 | $197 | |||||||||||||||
| Commercial mortgage loans | 32 | 42 | 43 | 43 | 50 | |||||||||||||||
| Commercial construction loans | 6 | 6 | — | — | 1 | |||||||||||||||
| Commercial leases | 3 | 4 | 6 | 9 | 6 | |||||||||||||||
| Residential mortgage loans | 24 | 10 | 13 | 17 | 22 | |||||||||||||||
| Home equity | 49 | 47 | 48 | 53 | 55 | |||||||||||||||
| Indirect secured consumer loans | 5 | 5 | 5 | 6 | 6 | |||||||||||||||
| Other consumer loans | 1 | 1 | 1 | 1 | 2 | |||||||||||||||
| Total nonaccrual portfolio loans and leases (excludes restructured loans) | 225 | 231 | 288 | 322 | 339 | |||||||||||||||
| Nonaccrual restructured portfolio commercial loans | 177 | 169 | 128 | 164 | 255 | |||||||||||||||
Nonaccrual restructured portfolio consumer loans(c) | 106 | 98 | 112 | 135 | 147 | |||||||||||||||
| Total nonaccrual portfolio loans and leases | 508 | 498 | 528 | 621 | 741 | |||||||||||||||
| Repossessed property | 5 | 5 | 4 | 5 | 7 | |||||||||||||||
| OREO | 27 | 24 | 27 | 31 | 35 | |||||||||||||||
| Total nonperforming portfolio loans and leases and OREO | 540 | 527 | 559 | 657 | 783 | |||||||||||||||
| Nonaccrual loans held for sale | — | 15 | — | 13 | 2 | |||||||||||||||
| Nonaccrual restructured loans held for sale | 4 | — | 1 | 27 | 20 | |||||||||||||||
| Total nonperforming assets | $544 | $542 | $560 | $697 | $805 | |||||||||||||||
| Loans and leases 90 days past due (accrual): | ||||||||||||||||||||
| Commercial and industrial loans | $9 | $17 | $4 | $2 | $8 | |||||||||||||||
| Commercial mortgage loans | 2 | 1 | 2 | 4 | 7 | |||||||||||||||
| Commercial construction loans | — | 1 | — | — | 1 | |||||||||||||||
| Commercial leases | — | — | 1 | — | — | |||||||||||||||
| Total commercial loans and leases | 11 | 19 | 7 | 6 | 16 | |||||||||||||||
Residential mortgage loans(c) | 40 | 72 | 61 | 57 | 73 | |||||||||||||||
| Home equity | 1 | 1 | 1 | 1 | 1 | |||||||||||||||
| Indirect secured consumer loans | 9 | 9 | 8 | 4 | 8 | |||||||||||||||
| Credit card | 14 | 15 | 14 | 14 | 25 | |||||||||||||||
| Other consumer loans | 1 | 1 | 1 | 1 | 1 | |||||||||||||||
| Total consumer loans | 65 | 98 | 85 | 77 | 108 | |||||||||||||||
Total loans and leases 90 days past due (accrual)(b) | $76 | $117 | $92 | $83 | $124 | |||||||||||||||
| Ratios | ||||||||||||||||||||
| Net losses charged-off as a percent of average portfolio loans and leases (annualized) | 0.12 | % | 0.14 | % | 0.08 | % | 0.16 | % | 0.27 | % | ||||||||||
| Allowance for credit losses: | ||||||||||||||||||||
| As a percent of portfolio loans and leases | 1.80 | % | 1.85 | % | 2.00 | % | 2.06 | % | 2.19 | % | ||||||||||
As a percent of nonperforming portfolio loans and leases(a) | 411 | % | 416 | % | 409 | % | 358 | % | 321 | % | ||||||||||
As a percent of nonperforming portfolio assets(a) | 386 | % | 394 | % | 386 | % | 338 | % | 304 | % | ||||||||||
Nonperforming portfolio loans and leases as a percent of portfolio loans and leases(a) | 0.44 | % | 0.44 | % | 0.49 | % | 0.58 | % | 0.68 | % | ||||||||||
Nonperforming portfolio assets as a percent of portfolio loans and leases and OREO(a) | 0.47 | % | 0.47 | % | 0.52 | % | 0.61 | % | 0.72 | % | ||||||||||
| Nonperforming assets as a percent of total loans and leases, OREO, and repossessed property | 0.46 | % | 0.47 | % | 0.49 | % | 0.61 | % | 0.70 | % | ||||||||||
| (a) Excludes nonaccrual loans held for sale. | ||||||||||||||||||||
| (b) Excludes loans held for sale. | ||||||||||||||||||||
| (c) Excludes government guaranteed residential mortgage loans. | ||||||||||||||||||||
25
Use of Non-GAAP Financial Measures
In addition to GAAP measures, management considers various non-GAAP measures when evaluating the performance of the business, including: “net interest income (FTE),” “interest income (FTE),” “net interest margin (FTE),” “net interest rate spread (FTE),” “income before income taxes (FTE),” “tangible net income available to common shareholders,” “average tangible common equity,” “return on average tangible common equity,” “tangible common equity (excluding AOCI),” “tangible common equity (including AOCI),” “tangible equity,” “tangible book value per share,” “tangible book value per share (excluding AOCI),” “adjusted noninterest income,” “noninterest income excluding certain items,” “adjusted noninterest expense,” “noninterest expense excluding certain items,” “pre-provision net revenue,” “adjusted efficiency ratio,” “adjusted return on average common equity,” “adjusted return on average tangible common equity,” “adjusted return on average tangible common equity, excluding accumulated other comprehensive income", “adjusted pre-provision net revenue,” “adjusted return on average assets,” “efficiency ratio (FTE),” “total revenue (FTE),” “noninterest income as a percent of total revenue”, and certain ratios derived from these measures. The Bancorp believes these non-GAAP measures provide useful information to investors because these are among the measures used by the Fifth Third management team to evaluate operating performance and to make day-to-day operating decisions.
The FTE basis adjusts for the tax-favored status of income from certain loans and securities held by the Bancorp that are not taxable for federal income tax purposes. The Bancorp believes this presentation to be the preferred industry measurement of net interest income and net interest margin as it provides a relevant comparison between taxable and non-taxable amounts.
The Bancorp believes tangible net income available to common shareholders, average tangible common equity, tangible common equity (excluding AOCI), tangible common equity (including AOCI), tangible equity, tangible book value per share and return on average tangible common equity are important measures for evaluating the performance of the business without the impacts of intangible items, whether acquired or created internally, in a manner comparable to other companies in the industry who present similar measures.
The Bancorp believes noninterest income, noninterest expense, net interest income, net interest margin, pre-provision net revenue, efficiency ratio, noninterest income as a percent of total revenue, return on average common equity, return on average tangible common equity, and return on average assets are important measures that adjust for significant, unusual, or large transactions that may occur in a reporting period which management does not consider indicative of ongoing financial performance and enhances comparability of results with prior periods.
The Bancorp believes noninterest income excluding certain items and noninterest expense excluding certain items are important measures that adjust for certain components that are prone to significant period-to-period changes in order to facilitate the explanation of variances in the noninterest income and noninterest expense line items.
Management considers various measures when evaluating capital utilization and adequacy, including the tangible equity and tangible common equity (including and excluding AOCI), in addition to capital ratios defined by U.S. banking agencies. These calculations are intended to complement the capital ratios defined by U.S. banking agencies for both absolute and comparative purposes. These ratios are not formally defined by U.S. GAAP or codified in the federal banking regulations and, therefore, are considered to be non-GAAP financial measures. Management believes that providing the tangible common equity ratio excluding AOCI on certain assets and liabilities enables investors and others to assess the Bancorp’s use of equity without the effects of changes in AOCI, some of which are uncertain; providing the tangible common equity ratio including AOCI enables investors and others to assess the Bancorp’s use of equity if components of AOCI, such as unrealized gains or losses, were to be monetized.
Please note that although non-GAAP financial measures provide useful insight, they should not be considered in isolation or relied upon as a substitute for analysis using GAAP measures.
Please see reconciliations of all historical non-GAAP measures used in this release to the most directly comparable GAAP measures, beginning on the following page.
26
| Fifth Third Bancorp and Subsidiaries | ||||||||||||||||||||||||||
| Non-GAAP Reconciliation | ||||||||||||||||||||||||||
| $ and shares in millions | As of and For the Three Months Ended | |||||||||||||||||||||||||
| (unaudited) | March | December | September | June | March | |||||||||||||||||||||
| 2022 | 2021 | 2021 | 2021 | 2021 | ||||||||||||||||||||||
| Net interest income | $1,195 | $1,197 | $1,189 | $1,208 | $1,176 | |||||||||||||||||||||
| Add: Taxable equivalent adjustment | 3 | 3 | 3 | 3 | 3 | |||||||||||||||||||||
| Net interest income (FTE) (a) | 1,198 | 1,200 | 1,192 | 1,211 | 1,179 | |||||||||||||||||||||
| Net interest income (annualized) (b) | 4,846 | 4,749 | 4,717 | 4,845 | 4,769 | |||||||||||||||||||||
| Net interest income (FTE) (annualized) (c) | 4,859 | 4,761 | 4,729 | 4,857 | 4,782 | |||||||||||||||||||||
| Interest income | 1,289 | 1,294 | 1,292 | 1,323 | 1,302 | |||||||||||||||||||||
| Add: Taxable equivalent adjustment | 3 | 3 | 3 | 3 | 3 | |||||||||||||||||||||
| Interest income (FTE) | 1,292 | 1,297 | 1,295 | 1,326 | 1,305 | |||||||||||||||||||||
| Interest income (FTE) (annualized) (d) | 5,240 | 5,146 | 5,138 | 5,319 | 5,293 | |||||||||||||||||||||
| Interest expense (annualized) (e) | 381 | 385 | 409 | 461 | 511 | |||||||||||||||||||||
| Average interest-earning assets (f) | 187,894 | 187,045 | 182,801 | 184,918 | 182,715 | |||||||||||||||||||||
| Average interest-bearing liabilities (g) | 116,764 | 115,725 | 113,548 | 115,951 | 116,684 | |||||||||||||||||||||
| Net interest margin (b) / (f) | 2.58 | % | 2.54 | % | 2.58 | % | 2.62 | % | 2.61 | % | ||||||||||||||||
| Net interest margin (FTE) (c) / (f) | 2.59 | % | 2.55 | % | 2.59 | % | 2.63 | % | 2.62 | % | ||||||||||||||||
| Net interest rate spread (FTE) (d) / (f) - (e) / (g) | 2.46 | % | 2.42 | % | 2.45 | % | 2.48 | % | 2.46 | % | ||||||||||||||||
| Income before income taxes | $612 | $829 | $895 | $911 | $883 | |||||||||||||||||||||
| Add: Taxable equivalent adjustment | 3 | 3 | 3 | 3 | 3 | |||||||||||||||||||||
| Income before income taxes (FTE) | $615 | $832 | $898 | $914 | $886 | |||||||||||||||||||||
| Net income available to common shareholders | $474 | $627 | $684 | $674 | $674 | |||||||||||||||||||||
| Add: Intangible amortization, net of tax | 9 | 9 | 9 | 8 | 9 | |||||||||||||||||||||
| Tangible net income available to common shareholders (h) | 483 | 636 | 693 | 682 | 683 | |||||||||||||||||||||
| Tangible net income available to common shareholders (annualized) (i) | 1,959 | 2,523 | 2,749 | 2,735 | 2,770 | |||||||||||||||||||||
| Average Bancorp shareholders' equity | 21,402 | 22,449 | 22,927 | 22,927 | 22,952 | |||||||||||||||||||||
| Less: | Average preferred stock | (2,116) | (2,116) | (2,116) | (2,116) | (2,116) | ||||||||||||||||||||
| Average goodwill | (4,514) | (4,514) | (4,430) | (4,259) | (4,259) | |||||||||||||||||||||
| Average intangible assets | (150) | (162) | (149) | (122) | (133) | |||||||||||||||||||||
| Average tangible common equity, including AOCI (j) | 14,622 | 15,657 | 16,232 | 16,430 | 16,444 | |||||||||||||||||||||
| Less: | Average AOCI | (129) | (1,382) | (1,980) | (1,968) | (2,231) | ||||||||||||||||||||
| Average tangible common equity, excluding AOCI (k) | 14,493 | 14,275 | 14,252 | 14,462 | 14,213 | |||||||||||||||||||||
| Total Bancorp shareholders' equity | 20,177 | 22,210 | 22,524 | 22,926 | 22,595 | |||||||||||||||||||||
| Less: | Preferred stock | (2,116) | (2,116) | (2,116) | (2,116) | (2,116) | ||||||||||||||||||||
| Goodwill | (4,514) | (4,514) | (4,514) | (4,259) | (4,259) | |||||||||||||||||||||
| Intangible assets | (145) | (156) | (169) | (117) | (127) | |||||||||||||||||||||
| Tangible common equity, including AOCI (l) | 13,402 | 15,424 | 15,725 | 16,434 | 16,093 | |||||||||||||||||||||
| Less: | AOCI | 1,096 | (1,207) | (1,637) | (1,974) | (1,792) | ||||||||||||||||||||
| Tangible common equity, excluding AOCI (m) | 14,498 | 14,217 | 14,088 | 14,460 | 14,301 | |||||||||||||||||||||
| Add: | Preferred stock | 2,116 | 2,116 | 2,116 | 2,116 | 2,116 | ||||||||||||||||||||
| Tangible equity (n) | 16,614 | 16,333 | 16,204 | 16,576 | 16,417 | |||||||||||||||||||||
| Total assets | 211,459 | 211,116 | 207,731 | 205,390 | 206,899 | |||||||||||||||||||||
| Less: | Goodwill | (4,514) | (4,514) | (4,514) | (4,259) | (4,259) | ||||||||||||||||||||
| Intangible assets | (145) | (156) | (169) | (117) | (127) | |||||||||||||||||||||
| Tangible assets, including AOCI (o) | 206,800 | 206,446 | 203,048 | 201,014 | 202,513 | |||||||||||||||||||||
| Less: | AOCI, before tax | 1,387 | (1,528) | (2,072) | (2,499) | (2,268) | ||||||||||||||||||||
| Tangible assets, excluding AOCI (p) | $208,187 | $204,918 | $200,976 | $198,515 | $200,245 | |||||||||||||||||||||
| Common shares outstanding (q) | 686 | 683 | 690 | 704 | 712 | |||||||||||||||||||||
| Tangible equity (n) / (p) | 7.98 | % | 7.97 | % | 8.06 | % | 8.35 | % | 8.20 | % | ||||||||||||||||
| Tangible common equity (excluding AOCI) (m) / (p) | 6.96 | % | 6.94 | % | 7.01 | % | 7.28 | % | 7.14 | % | ||||||||||||||||
| Tangible common equity (including AOCI) (l) / (o) | 6.48 | % | 7.47 | % | 7.74 | % | 8.18 | % | 7.95 | % | ||||||||||||||||
| Tangible book value per share (including AOCI) (l) / (q) | $19.54 | $22.58 | $22.79 | $23.34 | $22.60 | |||||||||||||||||||||
| Tangible book value per share (excluding AOCI) (m) / (q) | $21.13 | $20.82 | $20.42 | $20.54 | $20.09 | |||||||||||||||||||||
27
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||||||||
| Non-GAAP Reconciliation | |||||||||||||||||||||||
| $ in millions | For the Three Months Ended | ||||||||||||||||||||||
| (unaudited) | March | December | March | ||||||||||||||||||||
| 2022 | 2021 | 2021 | |||||||||||||||||||||
| Net income (r) | $494 | $662 | $694 | ||||||||||||||||||||
| Net income (annualized) (s) | 2,003 | 2,626 | 2,815 | ||||||||||||||||||||
| Adjustments (pre-tax items) | |||||||||||||||||||||||
| Valuation of Visa total return swap | 11 | 19 | 13 | ||||||||||||||||||||
| Special COVID staffing bonus to front-line employees | - | 10 | - | ||||||||||||||||||||
Adjustments, after-tax (t)(a) | 8 | 22 | 10 | ||||||||||||||||||||
| Noninterest income (u) | 684 | 791 | 749 | ||||||||||||||||||||
| Valuation of Visa total return swap | 11 | 19 | 13 | ||||||||||||||||||||
| Adjusted noninterest income (v) | 695 | 810 | 762 | ||||||||||||||||||||
| Noninterest expense (w) | 1,222 | 1,206 | 1,215 | ||||||||||||||||||||
| Special COVID staffing bonus to front-line employees | - | (10) | - | ||||||||||||||||||||
| Adjusted noninterest expense (x) | 1,222 | 1,196 | 1,215 | ||||||||||||||||||||
| Adjusted net income (r) + (t) | 502 | 684 | 704 | ||||||||||||||||||||
| Adjusted net income (annualized) (y) | 2,036 | 2,714 | 2,855 | ||||||||||||||||||||
| Adjusted tangible net income available to common shareholders (h) + (t) | 491 | 658 | 693 | ||||||||||||||||||||
| Adjusted tangible net income available to common shareholders (annualized) (z) | 1,991 | 2,611 | 2,811 | ||||||||||||||||||||
| Average assets (aa) | $209,150 | $209,604 | $203,836 | ||||||||||||||||||||
| Return on average tangible common equity (i) / (j) | 13.4 | % | 16.1 | % | 16.8 | % | |||||||||||||||||
| Return on average tangible common equity excluding AOCI (i) / (k) | 13.5 | % | 17.7 | % | 19.5 | % | |||||||||||||||||
| Adjusted return on average tangible common equity, including AOCI (z) / (j) | 13.6 | % | 16.7 | % | 17.1 | % | |||||||||||||||||
| Adjusted return on average tangible common equity, excluding AOCI (z) / (k) | 13.7 | % | 18.3 | % | 19.8 | % | |||||||||||||||||
| Return on average assets (s) / (aa) | 0.96 | % | 1.25 | % | 1.38 | % | |||||||||||||||||
| Adjusted return on average assets (y) / (aa) | 0.97 | % | 1.29 | % | 1.40 | % | |||||||||||||||||
| Efficiency ratio (FTE) (w) / [(a) + (u)] | 64.9 | % | 60.6 | % | 63.0 | % | |||||||||||||||||
| Adjusted efficiency ratio (x) / [(a) + (v)] | 64.6 | % | 59.5 | % | 62.6 | % | |||||||||||||||||
| Total revenue (FTE) (a) + (u) | $1,882 | $1,991 | $1,928 | ||||||||||||||||||||
| Pre-provision net revenue (PPNR) (a) + (u) - (w) | $660 | $785 | $713 | ||||||||||||||||||||
| Adjusted pre-provision net revenue (PPNR) (a) + (v) - (x) | $671 | $814 | $726 | ||||||||||||||||||||
| Totals may not foot due to rounding; (a) Assumes a 23% tax rate | |||||||||||||||||||||||
28
| Fifth Third Bancorp and Subsidiaries | |||||||||||||||||||||||
| Segment Presentation | |||||||||||||||||||||||
| $ in millions | |||||||||||||||||||||||
| (unaudited) | |||||||||||||||||||||||
For the three months ended March 31, 2022 | Commercial Banking | Branch Banking(b) | Consumer Lending(c) | Wealth and Asset Management | Other/ Eliminations | Total | |||||||||||||||||
Net interest income (FTE)(a) | $481 | $430 | $131 | $35 | $121 | $1,198 | |||||||||||||||||
| (Provision for) benefit from credit losses | 28 | (17) | (6) | — | (50) | (45) | |||||||||||||||||
| Net interest income after (provision for) benefit from credit losses | 509 | 413 | 125 | 35 | 71 | 1,153 | |||||||||||||||||
| Noninterest income | 327 | 216 | 52 | 144 | (55) | 684 | |||||||||||||||||
| Noninterest expense | (446) | (490) | (144) | (142) | — | (1,222) | |||||||||||||||||
| Income before income taxes | 390 | 139 | 33 | 37 | 16 | 615 | |||||||||||||||||
Applicable income tax expense(a) | (72) | (30) | (7) | (8) | (4) | (121) | |||||||||||||||||
| Net income | $318 | $109 | $26 | $29 | $12 | $494 | |||||||||||||||||
For the three months ended December 31, 2021 | Commercial Banking | Branch Banking(b) | Consumer Lending(c) | Wealth and Asset Management | Other/ Eliminations | Total | |||||||||||||||||
Net interest income (FTE)(a) | $390 | $316 | $147 | $24 | $323 | $1,200 | |||||||||||||||||
| Benefit from (provision for) credit losses | 114 | (18) | (3) | — | (46) | 47 | |||||||||||||||||
| Net interest income after benefit from (provision for) credit losses | 504 | 298 | 144 | 24 | 277 | 1,247 | |||||||||||||||||
| Noninterest income | 372 | 235 | 35 | 145 | 4 | 791 | |||||||||||||||||
| Noninterest expense | (431) | (471) | (157) | (139) | (8) | (1,206) | |||||||||||||||||
| Income before income taxes | 445 | 62 | 22 | 30 | 273 | 832 | |||||||||||||||||
Applicable income tax expense(a) | (86) | (12) | (5) | (7) | (60) | (170) | |||||||||||||||||
| Net income | $359 | $50 | $17 | $23 | $213 | $662 | |||||||||||||||||
For the three months ended September 30, 2021 | Commercial Banking | Branch Banking(b) | Consumer Lending(c) | Wealth and Asset Management | Other/ Eliminations | Total | |||||||||||||||||
Net interest income (FTE)(a) | $371 | $309 | $145 | $22 | $345 | $1,192 | |||||||||||||||||
| Benefit from (provision for) credit losses | 242 | (13) | 2 | — | (189) | 42 | |||||||||||||||||
| Net interest income after benefit from (provision for) credit losses | 613 | 296 | 147 | 22 | 156 | 1,234 | |||||||||||||||||
| Noninterest income | 362 | 229 | 84 | 143 | 18 | 836 | |||||||||||||||||
| Noninterest expense | (406) | (463) | (158) | (134) | (11) | (1,172) | |||||||||||||||||
| Income before income taxes | 569 | 62 | 73 | 31 | 163 | 898 | |||||||||||||||||
Applicable income tax expense(a) | (112) | (14) | (15) | (7) | (46) | (194) | |||||||||||||||||
| Net income | $457 | $48 | $58 | $24 | $117 | $704 | |||||||||||||||||
For the three months ended June 30, 2021 | Commercial Banking | Branch Banking(b) | Consumer Lending(c) | Wealth and Asset Management | Other/ Eliminations | Total | |||||||||||||||||
Net interest income (FTE)(a) | $378 | $301 | $142 | $21 | $369 | $1,211 | |||||||||||||||||
| Benefit from (provision for) credit losses | 151 | (25) | — | — | (11) | 115 | |||||||||||||||||
| Net interest income after benefit from (provision for) credit losses | 529 | 276 | 142 | 21 | 358 | 1,326 | |||||||||||||||||
| Noninterest income | 355 | 224 | 63 | 143 | (44) | 741 | |||||||||||||||||
| Noninterest expense | (399) | (450) | (163) | (131) | (10) | (1,153) | |||||||||||||||||
| Income before income taxes | 485 | 50 | 42 | 33 | 304 | 914 | |||||||||||||||||
Applicable income tax expense(a) | (92) | (10) | (9) | (7) | (87) | (205) | |||||||||||||||||
| Net income | $393 | $40 | $33 | $26 | $217 | $709 | |||||||||||||||||
For the three months ended March 31, 2021 | Commercial Banking | Branch Banking(b) | Consumer Lending(c) | Wealth and Asset Management | Other/ Eliminations | Total | |||||||||||||||||
Net interest income (FTE)(a) | $367 | $295 | $128 | $21 | $368 | $1,179 | |||||||||||||||||
| Benefit from (provision for) credit losses | 76 | (41) | (8) | 1 | 145 | 173 | |||||||||||||||||
| Net interest income after benefit from (provision for) credit losses | 443 | 254 | 120 | 22 | 513 | 1,352 | |||||||||||||||||
| Noninterest income | 361 | 204 | 82 | 138 | (36) | 749 | |||||||||||||||||
| Noninterest expense | (420) | (489) | (161) | (135) | (10) | (1,215) | |||||||||||||||||
| Income (loss) before income taxes | 384 | (31) | 41 | 25 | 467 | 886 | |||||||||||||||||
Applicable income tax (expense) benefit(a) | (72) | 7 | (9) | (5) | (113) | (192) | |||||||||||||||||
| Net income (loss) | $312 | $(24) | $32 | $20 | $354 | $694 | |||||||||||||||||
(a) Includes taxable equivalent adjustments of $3 million for the three months ended March 31, 2022, December 31, 2021, September 30, 2021, June 30, 2021 and March 31, 2021. | |||||||||||||||||||||||
| (b) Branch Banking provides a full range of deposit and loan and lease products to individuals and small businesses through full-service banking centers. | |||||||||||||||||||||||
| (c) Consumer Lending includes the Bancorp's residential mortgage, home equity, automobile and other indirect lending activities. | |||||||||||||||||||||||
29
1 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Fifth Third Bancorp 1Q22 Earnings Presentation April 19th, 2022 Refer to earnings release dated April 19, 2022 for further information.
2 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Cautionary statement This presentation contains statements that we believe are “forward-looking statements” within the meaning of Section 27A of the Securities Act of 1933, as amended, and Rule 175 promulgated thereunder, and Section 21E of the Securities Exchange Act of 1934, as amended, and Rule 3b-6 promulgated thereunder. All statements other than statements of historical fact are forward-looking statements. These statements relate to our financial condition, results of operations, plans, objectives, future performance, capital actions or business. They usually can be identified by the use of forward-looking language such as “will likely result,” “may,” “are expected to,” “is anticipated,” “potential,” “estimate,” “forecast,” “projected,” “intends to,” or may include other similar words or phrases such as “believes,” “plans,” “trend,” “objective,” “continue,” “remain,” or similar expressions, or future or conditional verbs such as “will,” “would,” “should,” “could,” “might,” “can,” or similar verbs. You should not place undue reliance on these statements, as they are subject to risks and uncertainties, including but not limited to the risk factors set forth in our most recent Annual Report on Form 10-K as updated by our filings with the U.S. Securities and Exchange Commission (“SEC”). There are a number of important factors that could cause future results to differ materially from historical performance and these forward-looking statements. Factors that might cause such a difference include, but are not limited to: (1) effects of the global COVID-19 pandemic; (2) deteriorating credit quality; (3) loan concentration by location or industry of borrowers or collateral; (4) problems encountered by other financial institutions; (5) inadequate sources of funding or liquidity; (6) unfavorable actions of rating agencies; (7) inability to maintain or grow deposits; (8) limitations on the ability to receive dividends from subsidiaries; (9) cyber-security risks; (10) Fifth Third’s ability to secure confidential information and deliver products and services through the use of computer systems and telecommunications networks; (11) failures by third-party service providers; (12) inability to manage strategic initiatives and/or organizational changes; (13) inability to implement technology system enhancements; (14) failure of internal controls and other risk management systems; (15) losses related to fraud, theft, misappropriation or violence; (16) inability to attract and retain skilled personnel; (17) adverse impacts of government regulation; (18) governmental or regulatory changes or other actions; (19) failures to meet applicable capital requirements; (20) regulatory objections to Fifth Third’s capital plan; (21) regulation of Fifth Third’s derivatives activities; (22) deposit insurance premiums; (23) assessments for the orderly liquidation fund; (24) replacement of LIBOR; (25) weakness in the national or local economies; (26) global political and economic uncertainty or negative actions; (27) changes in interest rates; (28) changes and trends in capital markets; (29) fluctuation of Fifth Third’s stock price; (30) volatility in mortgage banking revenue; (31) litigation, investigations, and enforcement proceedings by governmental authorities; (32) breaches of contractual covenants, representations and warranties; (33) competition and changes in the financial services industry; (34) changing retail distribution strategies, customer preferences and behavior; (35) difficulties in identifying, acquiring or integrating suitable strategic partnerships, investments or acquisitions; (36) potential dilution from future acquisitions; (37) loss of income and/or difficulties encountered in the sale and separation of businesses, investments or other assets; (38) results of investments or acquired entities; (39) changes in accounting standards or interpretation or declines in the value of Fifth Third’s goodwill or other intangible assets; (40) inaccuracies or other failures from the use of models; (41) effects of critical accounting policies and judgments or the use of inaccurate estimates; (42) weather-related events, other natural disasters, or health emergencies (including pandemics); (43) the impact of reputational risk created by these or other developments on such matters as business generation and retention, funding and liquidity; (44) changes in law or requirements imposed by Fifth Third’s regulators impacting our capital actions, including dividend payments and stock repurchases; and (45) Fifth Third's ability to meet its sustainability targets, goals and commitments. You should refer to our periodic and current reports filed with the SEC for further information on other factors, which could cause actual results to be significantly different from those expressed or implied by these forward-looking statements. Moreover, you should treat these statements as speaking only as of the date they are made and based only on information then actually known to us. We expressly disclaim any obligation or undertaking to release publicly any updates or revisions to any forward-looking statements contained herein to reflect any change in our expectations or any changes in events, conditions or circumstances on which any such statement is based, except as may be required by law, and we claim the protection of the safe harbor for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. The information contained herein is intended to be reviewed in its totality, and any stipulations, conditions or provisos that apply to a given piece of information in one part of this press release should be read as applying mutatis mutandis to every other instance of such information appearing herein. Copies of those filings are available at no cost on the SEC’s website at www.sec.gov or on our website at www.53.com. Annualized, pro forma, projected and estimated numbers are used for illustrative purpose only, are not forecasts and may not reflect actual results. In this presentation, we may sometimes provide non-GAAP financial information. Please note that although non-GAAP financial measures provide useful insight to analysts, investors and regulators, they should not be considered in isolation or relied upon as a substitute for analysis using GAAP measures. We provide a discussion of non-GAAP measures and reconciliations to the most directly comparable GAAP measures in later slides in this presentation, as well as on pages 26 through 28 of our 1Q22 earnings release. Management does not provide a reconciliation for forward-looking non-GAAP financial measures where it is unable to provide a meaningful or accurate calculation or estimation of reconciling items and the information is not available without unreasonable effort. This is due to the inherent difficulty of forecasting the occurrence and the financial impact of various items that have not yet occurred, are out of the Bancorp's control or cannot be reasonably predicted. For the same reasons, Bancorp's management is unable to address the probable significance of the unavailable information. Forward-looking non-GAAP financial measures provided without the most directly comparable GAAP financial measures may vary materially from the corresponding GAAP financial measures.
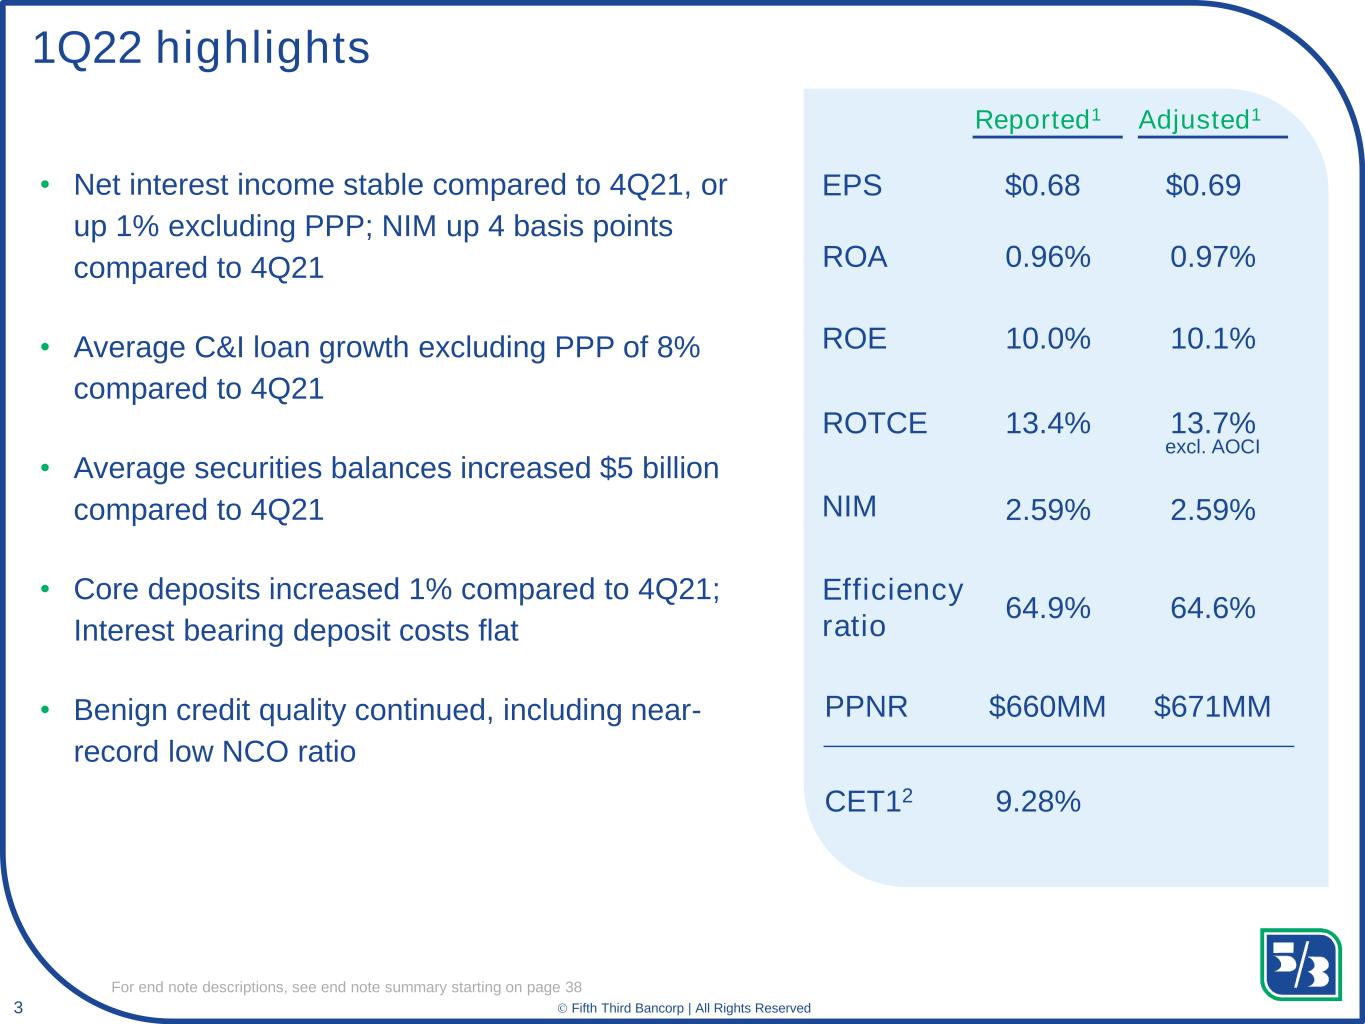
3 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved • Net interest income stable compared to 4Q21, or up 1% excluding PPP; NIM up 4 basis points compared to 4Q21 • Average C&I loan growth excluding PPP of 8% compared to 4Q21 • Average securities balances increased $5 billion compared to 4Q21 • Core deposits increased 1% compared to 4Q21; Interest bearing deposit costs flat • Benign credit quality continued, including near- record low NCO ratio 1Q22 highlights Reported1 Adjusted1 ROA Efficiency ratio ROTCE 0.97% 13.7% NIM 2.59%2.59% 0.96% 13.4% 64.6%64.9% ROE 10.1%10.0% excl. AOCI PPNR $671MM$660MM EPS $0.69$0.68 CET12 9.28% For end note descriptions, see end note summary starting on page 38
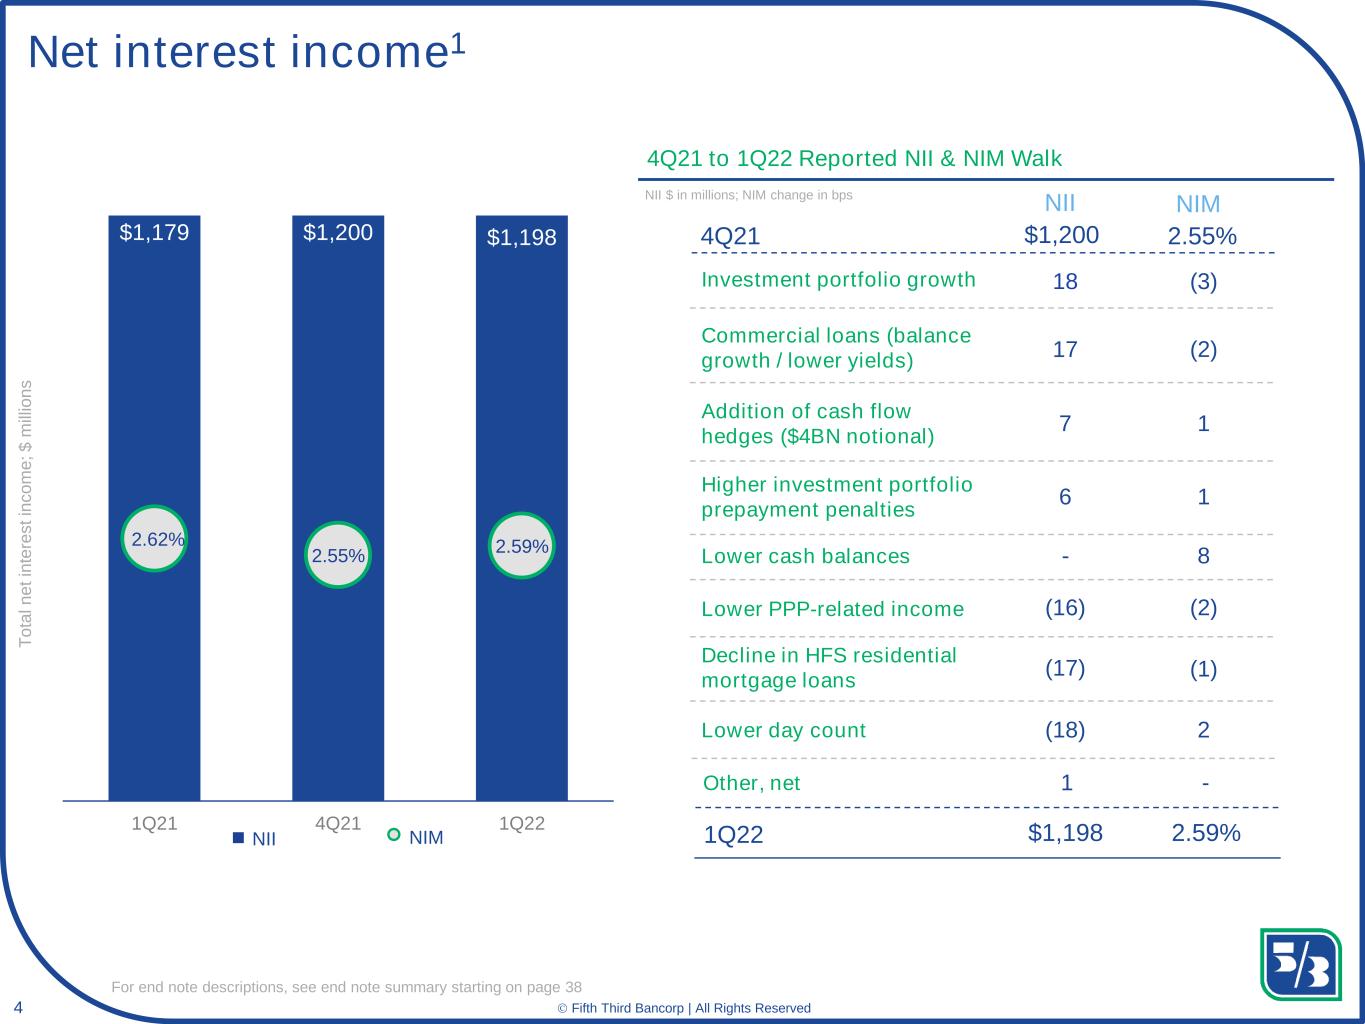
4 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Net interest income1 T o ta l n e t in te re s t in c o m e ; $ m ill io n s NII NII $ in millions; NIM change in bps $1,2004Q21 2.55% 4Q21 to 1Q22 Reported NII & NIM Walk NIM $1,198 2.59%1Q22 Addition of cash flow hedges ($4BN notional) Investment portfolio growth 7 1 18 (3) 17 (2) T o ta l n e t in te re s t in c o m e ; $ m ill io n s NII NIM Higher investment portfolio prepayment penalties 6 1 (16) (2) Decline in HFS residential mortgage loans (17) (1) Lower cash balances - 8 $1,179 $1,200 $1,198 2.62% 2.55% 2.59% 1Q21 4Q21 1Q22 Lower day count (18) 2 Commercial loans (balance growth / lower yields) Lower PPP-related income For end note descriptions, see end note summary starting on page 38 Other, net 1 -

5 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Adjusted noninterest income (excl. securities (gains)/losses)1 Noninterest income • Adjusted noninterest income1 down $120 million, or 14% • Primary drivers: ‒ Other noninterest income (down 55%) ‒ Commercial banking revenue (down 21%) ‒ Leasing business revenue (down 16%) ‒ Partially offset by mortgage banking net revenue (up 49%) T o ta l n o n in te re s t in c o m e ; $ m ill io n s Noninterest income • Adjusted noninterest income1 down $50 million, or 7% • Primary drivers: ‒ Mortgage banking revenue (down 39%) ‒ Leasing business revenue (down 29%) ‒ Commercial banking revenue (down 12%) ‒ Partially offset by other noninterest income (up 15%) 1Q22 vs. 1Q21 1Q22 vs. 4Q21 $749 $791 $684 $759 $829 $709 1Q21 4Q21 1Q22 For end note descriptions, see end note summary starting on page 38
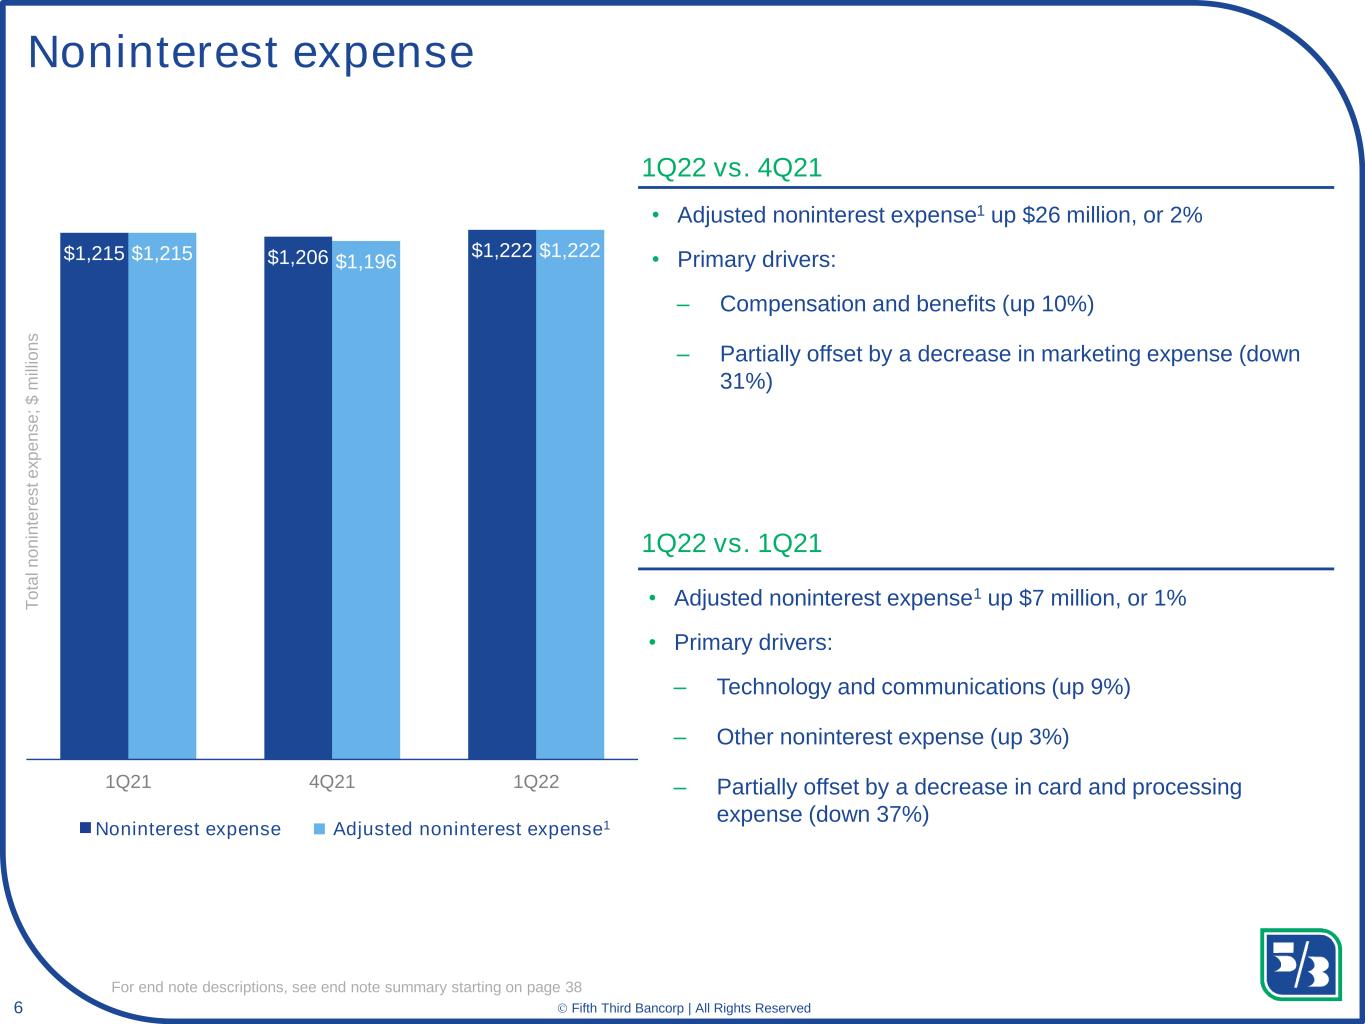
6 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $1,215 $1,206 $1,222$1,215 $1,196 $1,222 1Q21 4Q21 1Q22 Adjusted noninterest expense1 Noninterest expense • Adjusted noninterest expense1 up $26 million, or 2% • Primary drivers: ‒ Compensation and benefits (up 10%) ‒ Partially offset by a decrease in marketing expense (down 31%) T o ta l n o n in te re s t e x p e n s e ; $ m ill io n s • Adjusted noninterest expense1 up $7 million, or 1% • Primary drivers: ‒ Technology and communications (up 9%) ‒ Other noninterest expense (up 3%) ‒ Partially offset by a decrease in card and processing expense (down 37%) Noninterest expense 1Q22 vs. 1Q21 1Q22 vs. 4Q21 For end note descriptions, see end note summary starting on page 38
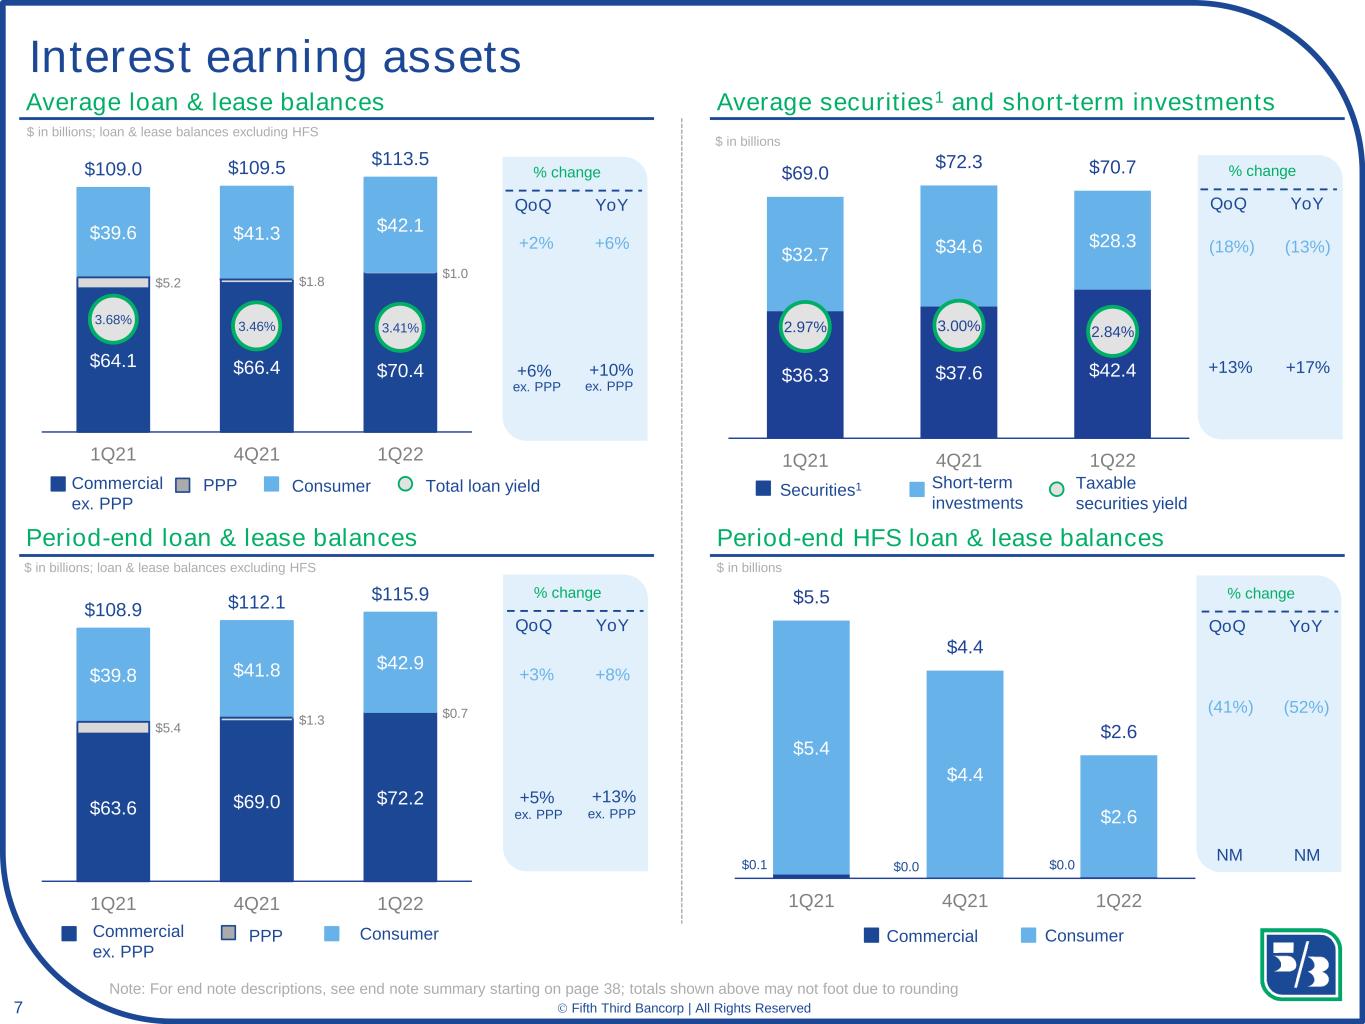
7 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $63.6 $69.0 $72.2 $5.4 $1.3 $0.7 $39.8 $41.8 $42.9 $108.9 $112.1 $115.9 $0.0 $20.0 $40.0 $60.0 $80.0 $100.0 1Q21 4Q21 1Q22 $36.3 $37.6 $42.4 $32.7 $34.6 $28.3 $69.0 $72.3 $70.7 2.97% 3.00% 2.84% $0.0 $10.0 $20.0 $30.0 $40.0 $50.0 $60.0 $70.0 $80.0 1Q21 4Q21 1Q22 $0.1 $0.0 $0.0 $5.4 $4.4 $2.6 $5.5 $4.4 $2.6 1Q21 4Q21 1Q22 $64.1 $66.4 $70.4 $5.2 $1.8 $1.0 $39.6 $41.3 $42.1 $109.0 $109.5 $113.5 3.68% 3.46% 3.41% 0.00% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% 7.00% 8.00% 9.00% $0.0 $20.0 $40.0 $60.0 $80.0 $100.0 $120.0 1Q21 4Q21 1Q22 Commercial ex. PPP Securities1Commercial ex. PPP Interest earning assets Average securities1 and short-term investmentsAverage loan & lease balances Consumer Total loan yield $ in billions; loan & lease balances excluding HFS Short-term investments Taxable securities yield Consumer Period-end loan & lease balances Period-end HFS loan & lease balances Commercial Consumer $ in billions Note: For end note descriptions, see end note summary starting on page 38; totals shown above may not foot due to rounding +2% +6% QoQ YoY % change (41%) (52%) NM NM QoQ YoY % change (18%) (13%) +13% +17% QoQ YoY % change +3% +8% QoQ YoY % change +6% +10% ex. PPP ex. PPP +5% +13% ex. PPP ex. PPP PPP PPP $ in billions; loan & lease balances excluding HFS $ in billions
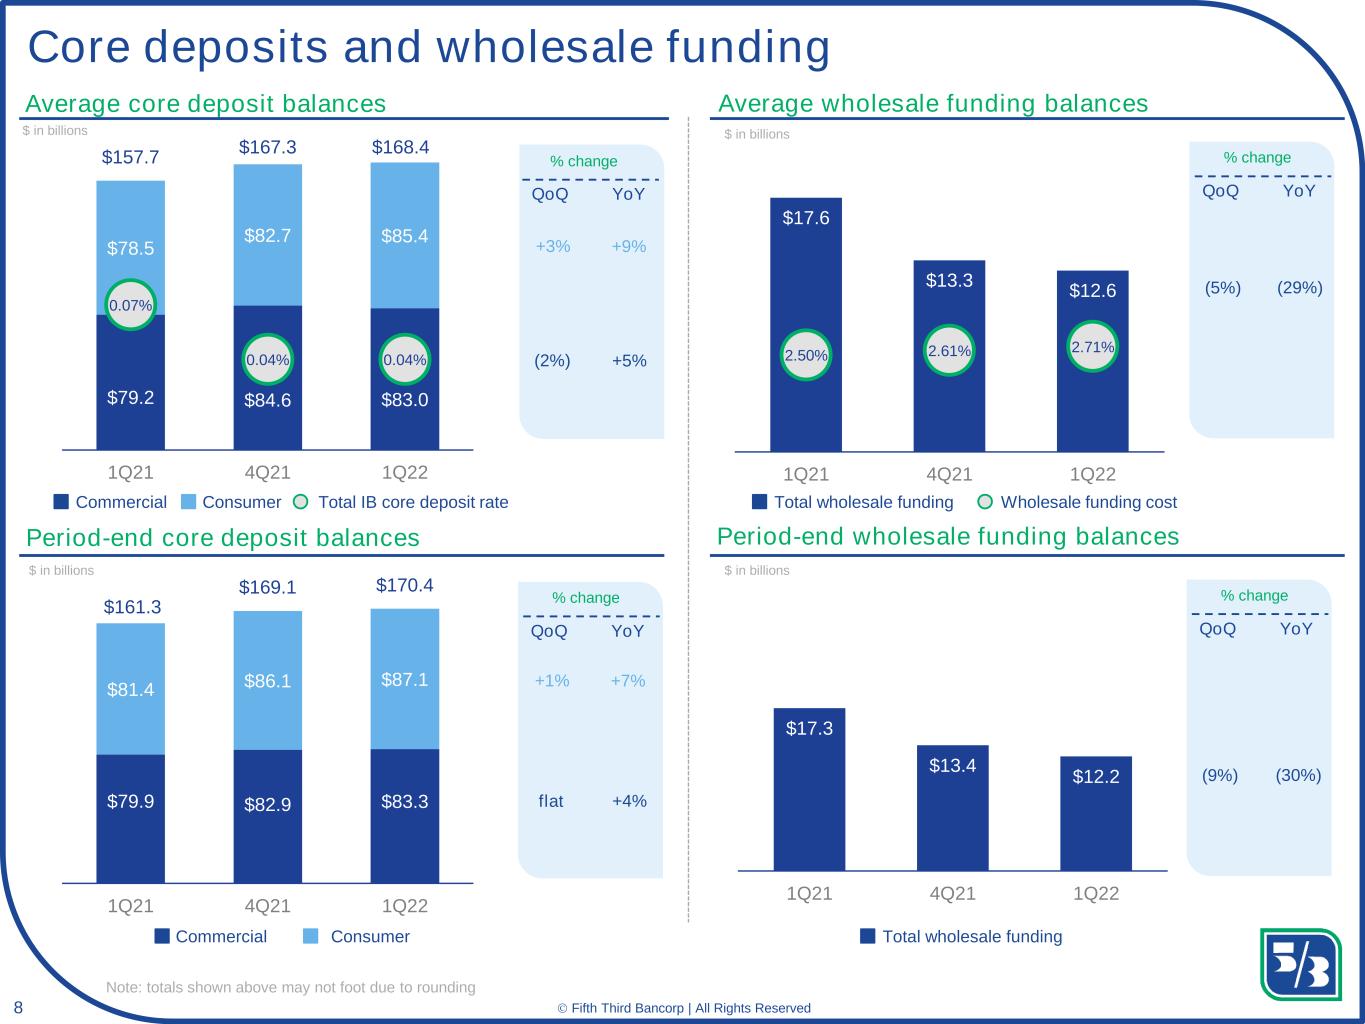
8 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $17.3 $13.4 $12.2 1Q21 4Q21 1Q22 $17.6 $13.3 $12.6 2.50% 2.61% 2.71% $0.0 $2.0 $4.0 $6.0 $8.0 $10.0 $12.0 $14.0 $16.0 $18.0 $20.0 1Q21 4Q21 1Q22 $79.9 $82.9 $83.3 $81.4 $86.1 $87.1 $161.3 $169.1 $170.4 $0.0 $20.0 $40.0 $60.0 $80.0 $100.0 $120.0 $140.0 $160.0 $180.0 1Q21 4Q21 1Q22 $79.2 $84.6 $83.0 $78.5 $82.7 $85.4 $157.7 $167.3 $168.4 0.07% 0.04% 0.04% -0.01% 0.01% 0.03% 0.05% 0.07% 0.09% 0.11% 0.13% 0.15% 1Q21 4Q21 1Q22 Core deposits and wholesale funding Average wholesale funding balancesAverage core deposit balances Commercial Consumer Total IB core deposit rate $ in billions $ in billions Period-end core deposit balances Period-end wholesale funding balances Total wholesale funding Wholesale funding cost Total wholesale fundingCommercial Consumer $ in billions $ in billions Note: totals shown above may not foot due to rounding +3% +9% (2%) +5% QoQ YoY % change +1% +7% flat +4% QoQ YoY % change (9%) (30%) QoQ YoY % change (5%) (29%) QoQ YoY % change

9 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved 0.11% 0.13% 0.18% 0.20% 0.32% 0.40% 0.33% 0.40% 0.17%0.10% 0.03% 0.10% 0.05% 0.68% 0.59% 0.68% 0.78% 0.66% 0.52% 0.40% 0.47% 0.43% 0.26% 0.16% 0.21% 0.25% 0.32% 0.29% 0.36% 0.41% 0.44% 0.44% 0.35% 0.43% 0.27% 0.16% 0.08% 0.14% 0.12% -0.10% 0.10% 0.30% 0.50% 0.70% 0.90% 1.10% 1.30% 1Q19 1Q20 1Q21 1Q22 Commercial NCO ratio Consumer NCO ratio Total NCO Ratio 0.45% 0.51% 0.47% 0.62% 0.60% 0.65% 0.84% 0.79% 0.72% 0.61% 0.52% 0.47% 0.47% 0.29% 0.35% 0.37% 0.33% 0.35% 0.33% 0.29% 0.33% 0.28% 0.26% 0.25% 0.23% 0.25% 0.00% 0.20% 0.40% 0.60% 0.80% 1.00% 1.20% 1Q19 1Q20 1Q21 1Q22 NPA ratio(c) 30-89 days past due as a % of Portfolio loans 2.19% 2.06% 2.00% 1.85% 1.80% 0.00% 0.50% 1.00% 1.50% 2.00% 2.50% 1Q21 2Q21 3Q21 4Q21 1Q22 1.81% 2.30% 2.05% Credit quality overview Early stage delinquencies and NPAs Net charge-offs (NCOs) ACL as % of portfolio loans and leases Ex. PPP • ACL ratio of 1.80% decreased 5 bps (ACL increased $11MM) sequentially • NCO ratio of 0.12%, down 2 bps from the prior quarter and down 15 bps from the year-ago quarter • NPA ratio of 0.47%, flat from the prior quarter • ACL represents 411% of NPLs and 386% of NPAs 2.14% 1.87% 4Q21 1 4Q21 1 For end note descriptions, see end note summary starting on page 38
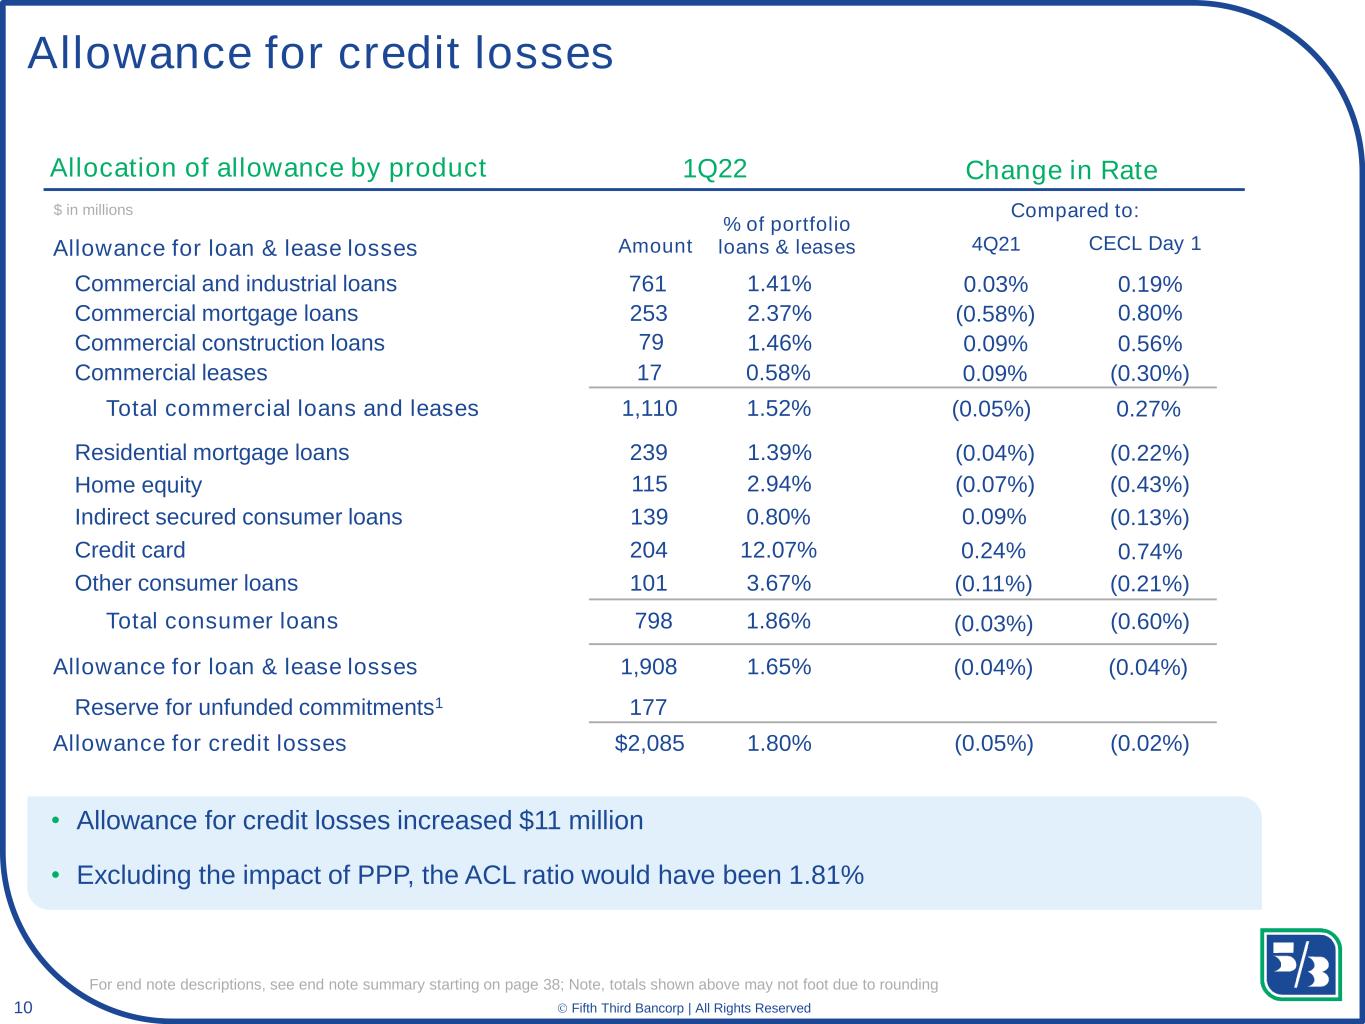
10 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Allowance for credit losses Allowance for loan & lease losses Commercial and industrial loans Commercial mortgage loans Commercial construction loans Commercial leases Total commercial loans and leases Residential mortgage loans Home equity Indirect secured consumer loans Credit card Other consumer loans Total consumer loans Allowance for loan & lease losses Reserve for unfunded commitments1 Allowance for credit losses 79 17 1,110 239 115 139 204 101 798 1,908 177 $2,085 253 761 1.46% 0.58% 1.52% 1.39% 2.94% 0.80% 12.07% 3.67% 1.86% 1.65% 1.80% 1.41% 2.37% Allocation of allowance by product $ in millions 1Q22 • Allowance for credit losses increased $11 million • Excluding the impact of PPP, the ACL ratio would have been 1.81% Amount % of portfolio loans & leases For end note descriptions, see end note summary starting on page 38; Note, totals shown above may not foot due to rounding Change in Rate 0.56% (0.30%) 0.27% (0.22%) (0.43%) (0.13%) 0.74% (0.21%) (0.60%) (0.04%) (0.05%) 0.80% 0.19% 0.09% 0.09% (0.05%) (0.04%) (0.07%) 0.09% 0.24% (0.11%) (0.04%) 0.03% (0.58%) Compared to: 4Q21 CECL Day 1 (0.02%) (0.03%)
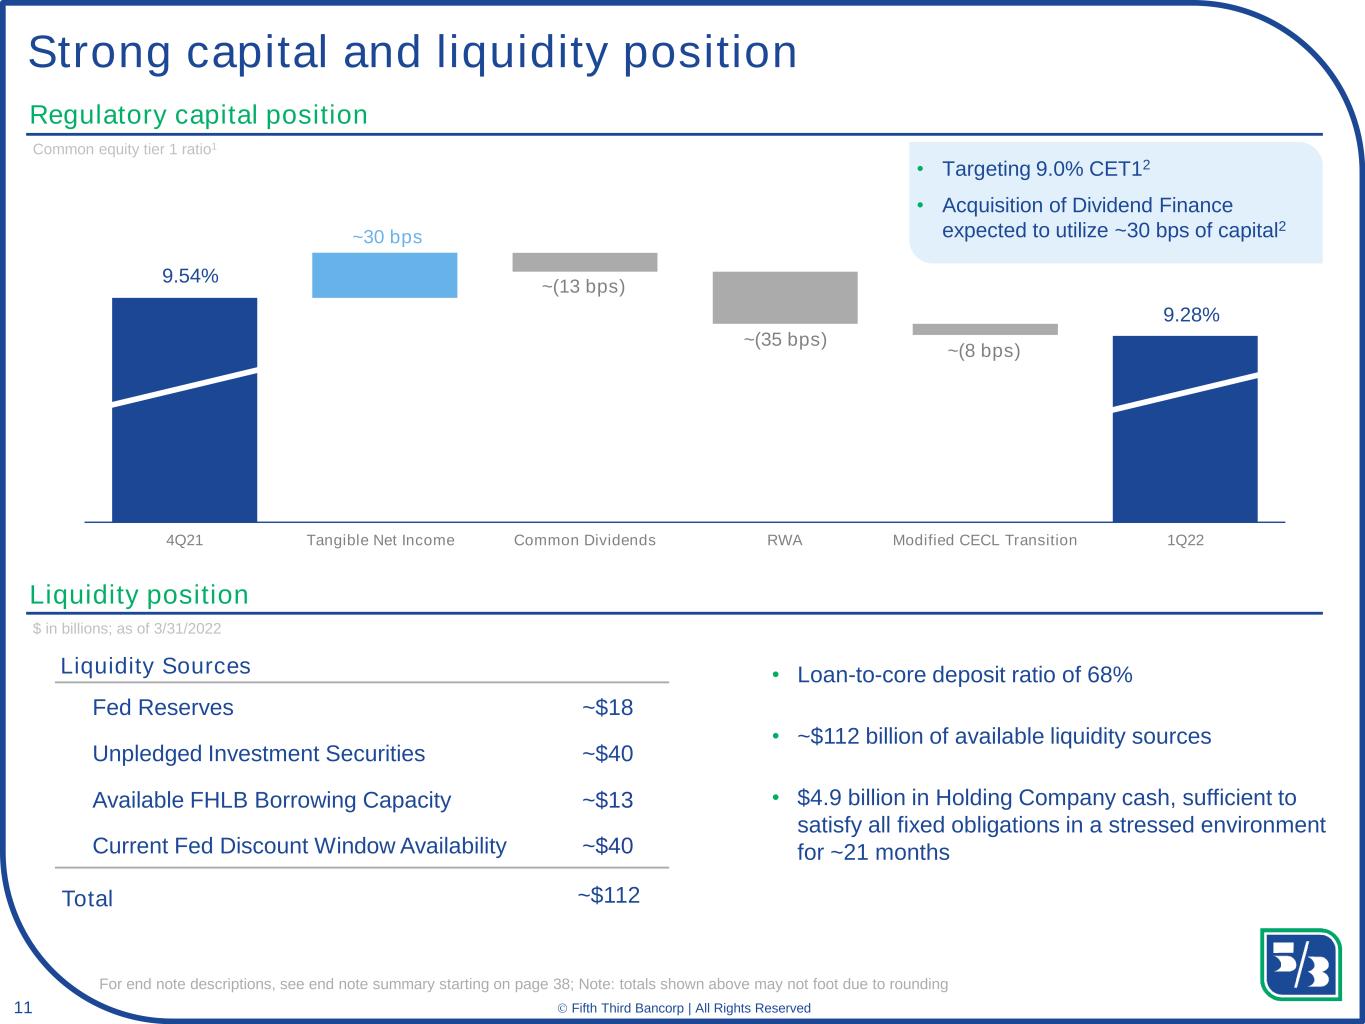
11 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved 4Q21 Tangible Net Income Common Dividends RWA Modified CECL Transition 1Q22 ~30 bps 9.28% 9.54% ~(8 bps) ~(13 bps) ~(35 bps) • Loan-to-core deposit ratio of 68% • ~$112 billion of available liquidity sources • $4.9 billion in Holding Company cash, sufficient to satisfy all fixed obligations in a stressed environment for ~21 months Strong capital and liquidity position Regulatory capital position Fed Reserves Unpledged Investment Securities Available FHLB Borrowing Capacity Current Fed Discount Window Availability Total ~$18 ~$40 ~$13 ~$40 ~$112 Liquidity Sources Liquidity position $ in billions; as of 3/31/2022 Common equity tier 1 ratio1 For end note descriptions, see end note summary starting on page 38; Note: totals shown above may not foot due to rounding • Targeting 9.0% CET12 • Acquisition of Dividend Finance expected to utilize ~30 bps of capital2
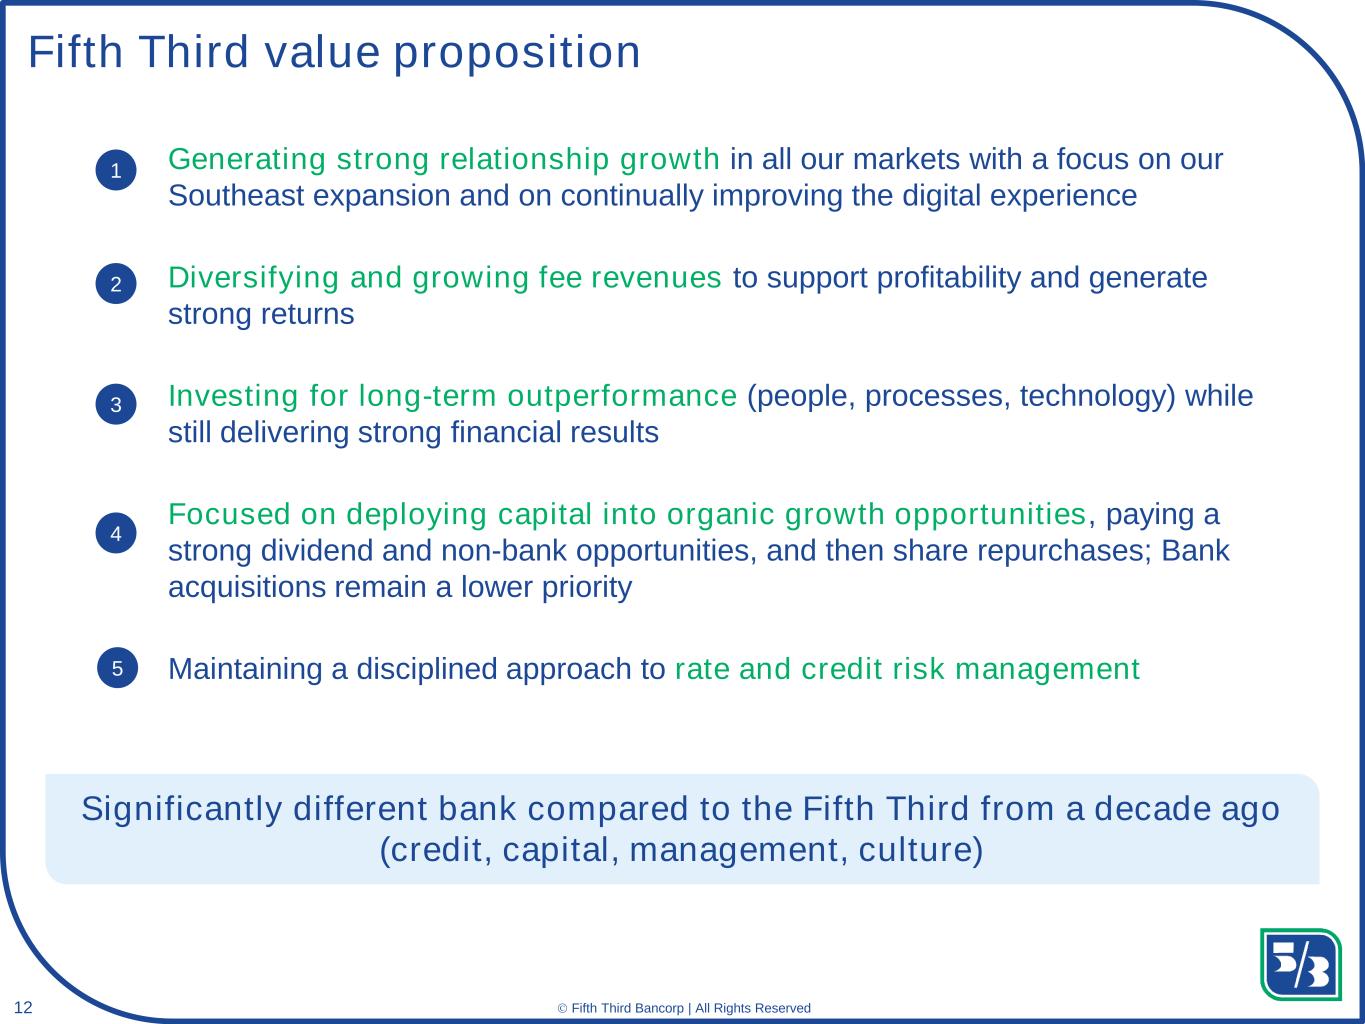
12 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Fifth Third value proposition Generating strong relationship growth in all our markets with a focus on our Southeast expansion and on continually improving the digital experience Diversifying and growing fee revenues to support profitability and generate strong returns Investing for long-term outperformance (people, processes, technology) while still delivering strong financial results Focused on deploying capital into organic growth opportunities, paying a strong dividend and non-bank opportunities, and then share repurchases; Bank acquisitions remain a lower priority Maintaining a disciplined approach to rate and credit risk management Significantly different bank compared to the Fifth Third from a decade ago (credit, capital, management, culture) 1 2 3 4 5
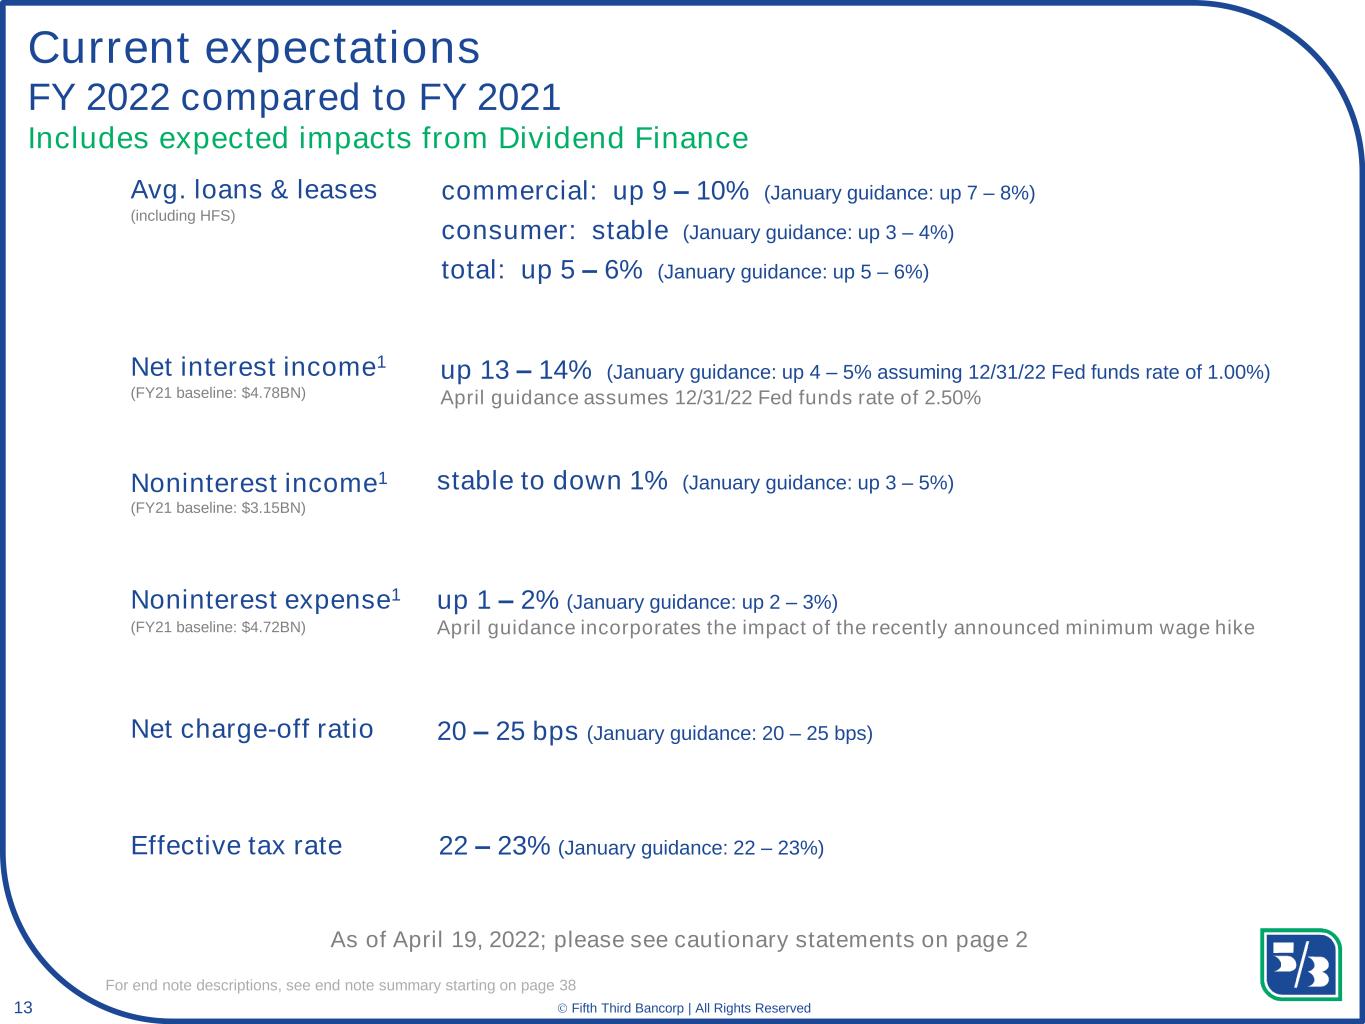
13 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Current expectations FY 2022 compared to FY 2021 Includes expected impacts from Dividend Finance (including HFS) Avg. loans & leases commercial: up 9 – 10% (January guidance: up 7 – 8%) consumer: stable (January guidance: up 3 – 4%) total: up 5 – 6% (January guidance: up 5 – 6%) Net interest income1 Noninterest income1 stable to down 1% (January guidance: up 3 – 5%) Noninterest expense1 up 1 – 2% (January guidance: up 2 – 3%) April guidance incorporates the impact of the recently announced minimum wage hike up 13 – 14% (January guidance: up 4 – 5% assuming 12/31/22 Fed funds rate of 1.00%) April guidance assumes 12/31/22 Fed funds rate of 2.50%(FY21 baseline: $4.78BN) (FY21 baseline: $3.15BN) (FY21 baseline: $4.72BN) Net charge-off ratio 20 – 25 bps (January guidance: 20 – 25 bps) Effective tax rate 22 – 23% (January guidance: 22 – 23%) For end note descriptions, see end note summary starting on page 38 As of April 19, 2022; please see cautionary statements on page 2
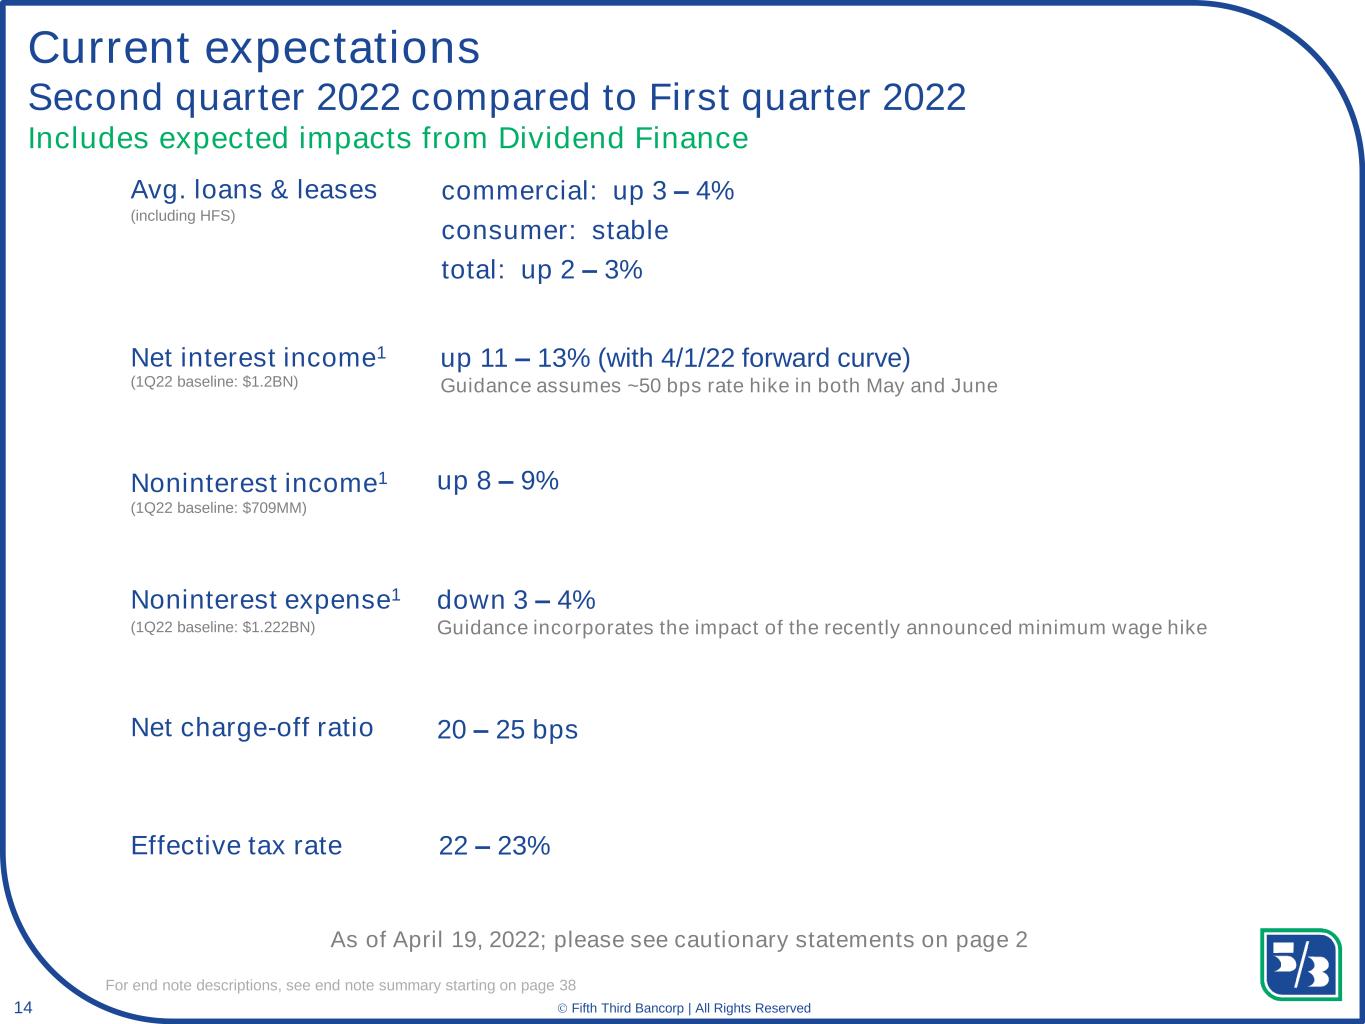
14 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Current expectations As of April 19, 2022; please see cautionary statements on page 2 (including HFS) Avg. loans & leases commercial: up 3 – 4% consumer: stable total: up 2 – 3% Net interest income1 Noninterest income1 up 8 – 9% Noninterest expense1 down 3 – 4% Guidance incorporates the impact of the recently announced minimum wage hike up 11 – 13% (with 4/1/22 forward curve) Guidance assumes ~50 bps rate hike in both May and June(1Q22 baseline: $1.2BN) (1Q22 baseline: $709MM) (1Q22 baseline: $1.222BN) Net charge-off ratio 20 – 25 bps Effective tax rate 22 – 23% Second quarter 2022 compared to First quarter 2022 Includes expected impacts from Dividend Finance For end note descriptions, see end note summary starting on page 38
15 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Appendix
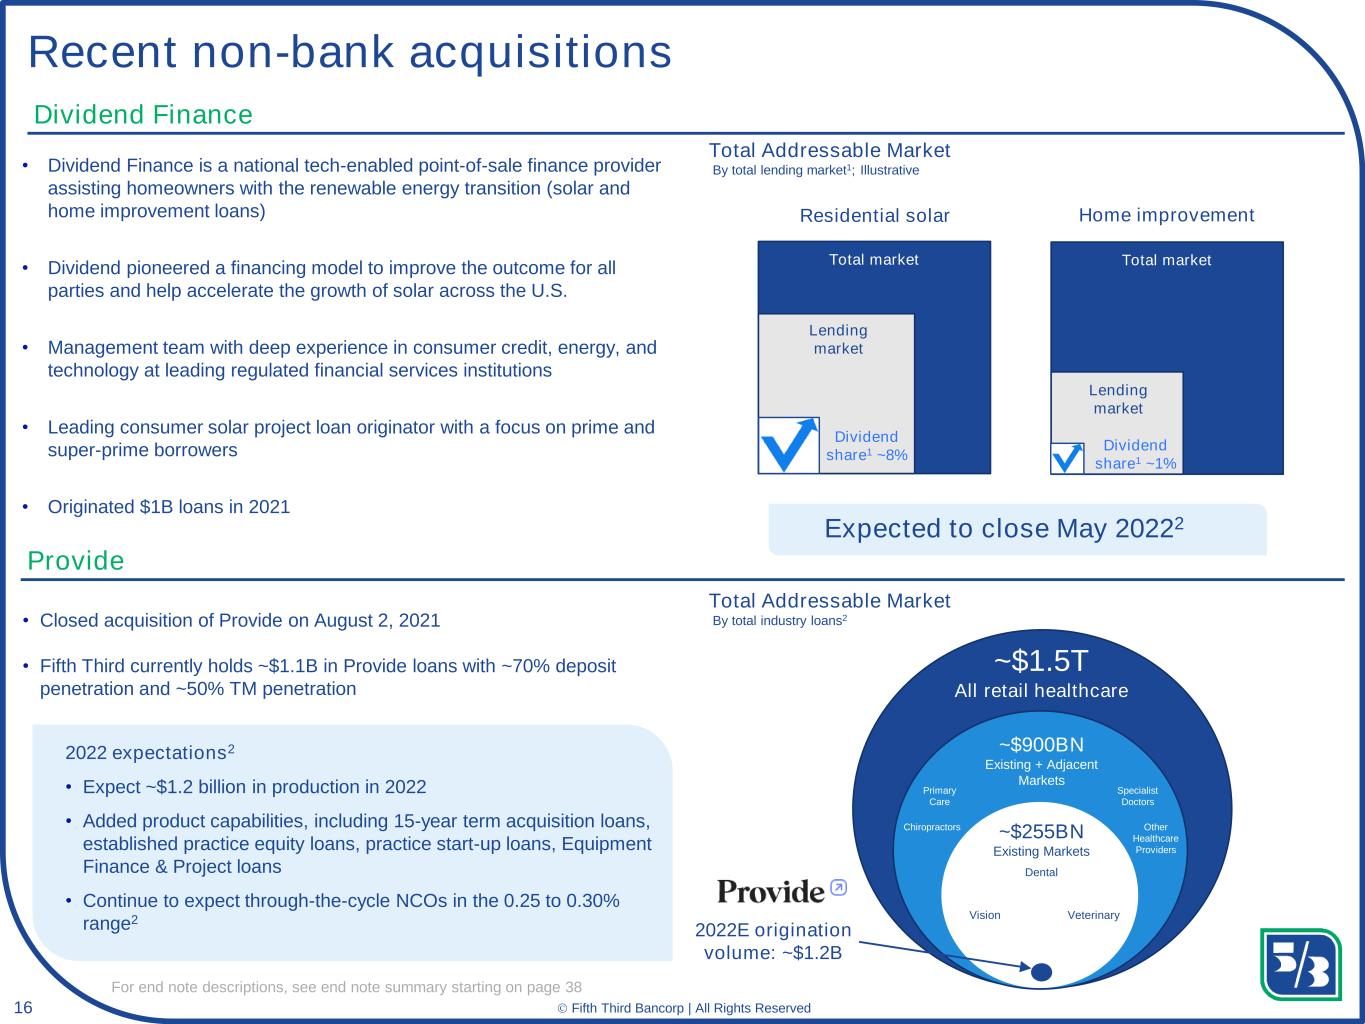
16 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved 2022 expectations2 • Expect ~$1.2 billion in production in 2022 • Added product capabilities, including 15-year term acquisition loans, established practice equity loans, practice start-up loans, Equipment Finance & Project loans • Continue to expect through-the-cycle NCOs in the 0.25 to 0.30% range2 Recent non-bank acquisitions • Dividend Finance is a national tech-enabled point-of-sale finance provider assisting homeowners with the renewable energy transition (solar and home improvement loans) • Dividend pioneered a financing model to improve the outcome for all parties and help accelerate the growth of solar across the U.S. • Management team with deep experience in consumer credit, energy, and technology at leading regulated financial services institutions • Leading consumer solar project loan originator with a focus on prime and super-prime borrowers • Originated $1B loans in 2021 Dividend Finance Provide • Closed acquisition of Provide on August 2, 2021 • Fifth Third currently holds ~$1.1B in Provide loans with ~70% deposit penetration and ~50% TM penetration Expected to close May 20222 Total Addressable Market By total industry loans2 Dental Vision Veterinary ~$255BN Existing Markets ~$900BN Existing + Adjacent Markets Specialist Doctors Chiropractors Primary Care ~$1.5T Other Healthcare Providers All retail healthcare 2022E origination volume: ~$1.2B Residential solar Home improvement Total market Lending market Dividend share1 ~8% Total market Dividend share1 ~1% Lending market Total Addressable Market By total lending market1; Illustrative For end note descriptions, see end note summary starting on page 38
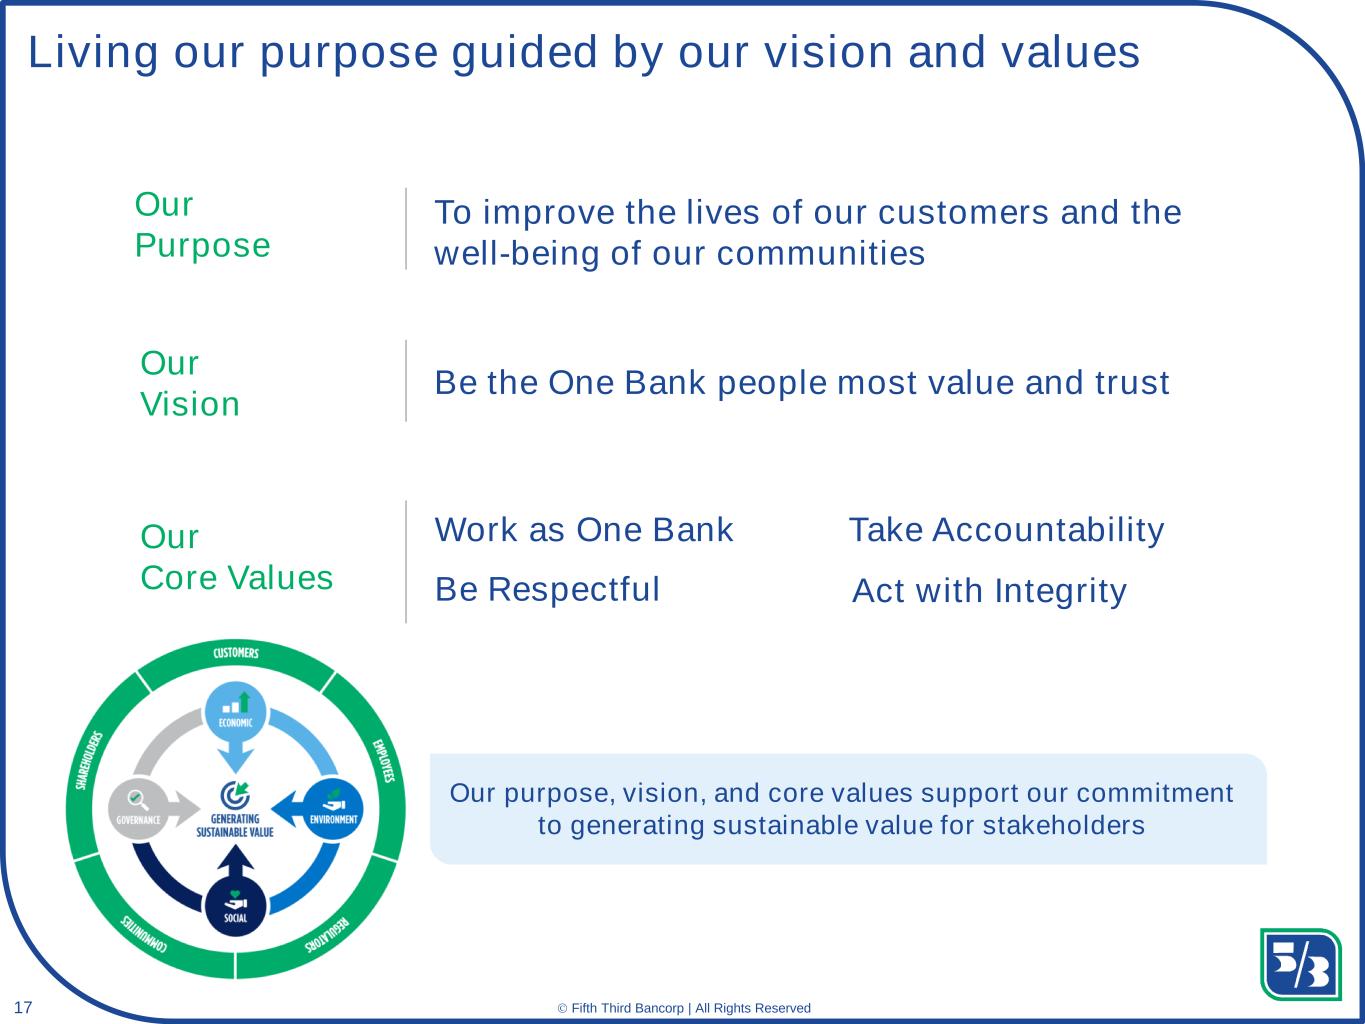
17 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Living our purpose guided by our vision and values Our Vision Be the One Bank people most value and trust Our Core Values Our Purpose To improve the lives of our customers and the well-being of our communities Work as One Bank Take Accountability Be Respectful Act with Integrity Our purpose, vision, and core values support our commitment to generating sustainable value for stakeholders
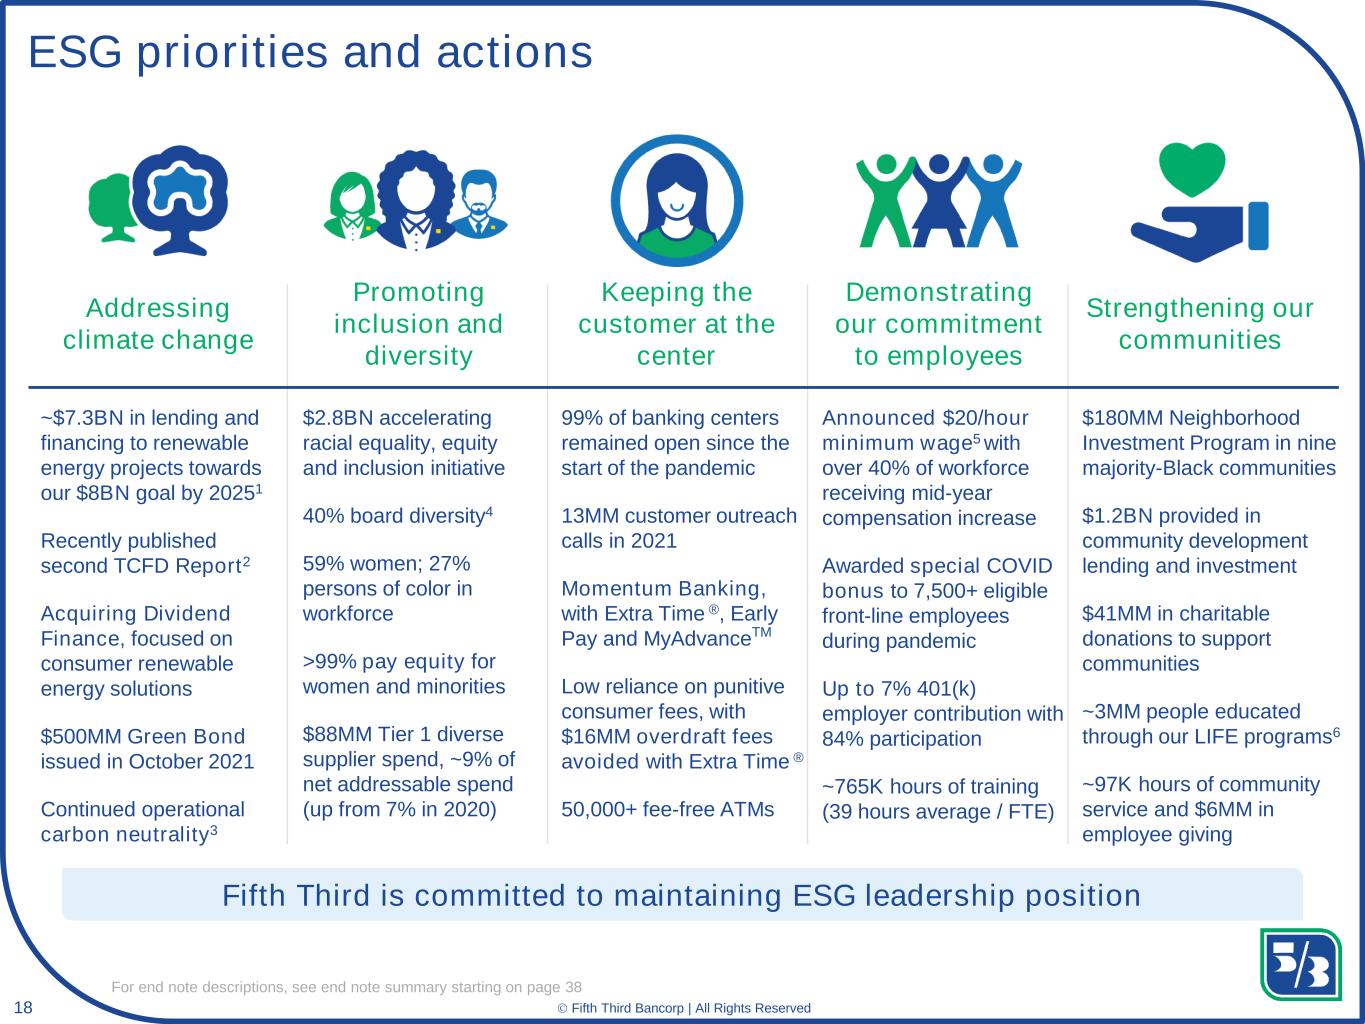
18 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved ESG priorities and actions Addressing climate change Promoting inclusion and diversity Demonstrating our commitment to employees Strengthening our communities Keeping the customer at the center $180MM Neighborhood Investment Program in nine majority-Black communities $1.2BN provided in community development lending and investment $41MM in charitable donations to support communities ~3MM people educated through our LIFE programs6 ~97K hours of community service and $6MM in employee giving Announced $20/hour minimum wage5 with over 40% of workforce receiving mid-year compensation increase Awarded special COVID bonus to 7,500+ eligible front-line employees during pandemic Up to 7% 401(k) employer contribution with 84% participation ~765K hours of training (39 hours average / FTE) 99% of banking centers remained open since the start of the pandemic 13MM customer outreach calls in 2021 Momentum Banking, with Extra Time ®, Early Pay and MyAdvanceTM Low reliance on punitive consumer fees, with $16MM overdraft fees avoided with Extra Time ® 50,000+ fee-free ATMs $2.8BN accelerating racial equality, equity and inclusion initiative 40% board diversity4 59% women; 27% persons of color in workforce >99% pay equity for women and minorities $88MM Tier 1 diverse supplier spend, ~9% of net addressable spend (up from 7% in 2020) ~$7.3BN in lending and financing to renewable energy projects towards our $8BN goal by 20251 Recently published second TCFD Report2 Acquiring Dividend Finance, focused on consumer renewable energy solutions $500MM Green Bond issued in October 2021 Continued operational carbon neutrality3 Fifth Third is committed to maintaining ESG leadership position For end note descriptions, see end note summary starting on page 38
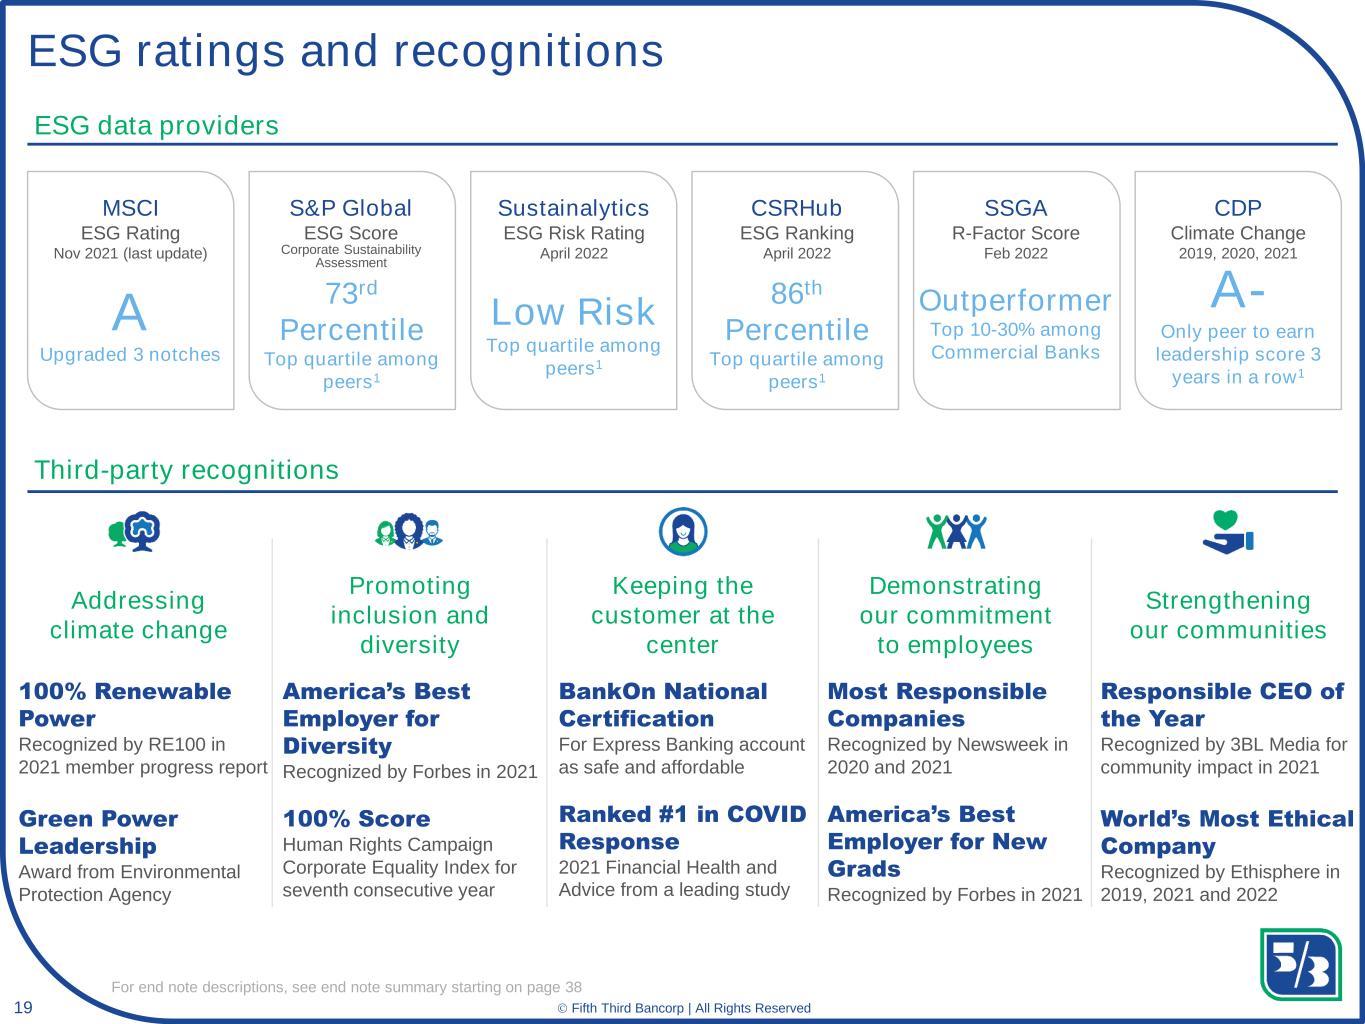
19 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved ESG ratings and recognitions ESG data providers SSGA R-Factor Score Feb 2022 Outperformer Top 10-30% among Commercial Banks S&P Global ESG Score Corporate Sustainability Assessment 73rd Percentile Top quartile among peers1 MSCI ESG Rating Nov 2021 (last update) A Upgraded 3 notches CSRHub ESG Ranking April 2022 86th Percentile Top quartile among peers1 CDP Climate Change 2019, 2020, 2021 A- Only peer to earn leadership score 3 years in a row1 Sustainalytics ESG Risk Rating April 2022 Low Risk Top quartile among peers1 Third-party recognitions Addressing climate change Promoting inclusion and diversity Demonstrating our commitment to employees Strengthening our communities Keeping the customer at the center 100% Renewable Power Recognized by RE100 in 2021 member progress report Green Power Leadership Award from Environmental Protection Agency BankOn National Certification For Express Banking account as safe and affordable Ranked #1 in COVID Response 2021 Financial Health and Advice from a leading study America’s Best Employer for Diversity Recognized by Forbes in 2021 100% Score Human Rights Campaign Corporate Equality Index for seventh consecutive year Most Responsible Companies Recognized by Newsweek in 2020 and 2021 America’s Best Employer for New Grads Recognized by Forbes in 2021 Responsible CEO of the Year Recognized by 3BL Media for community impact in 2021 World’s Most Ethical Company Recognized by Ethisphere in 2019, 2021 and 2022 For end note descriptions, see end note summary starting on page 38
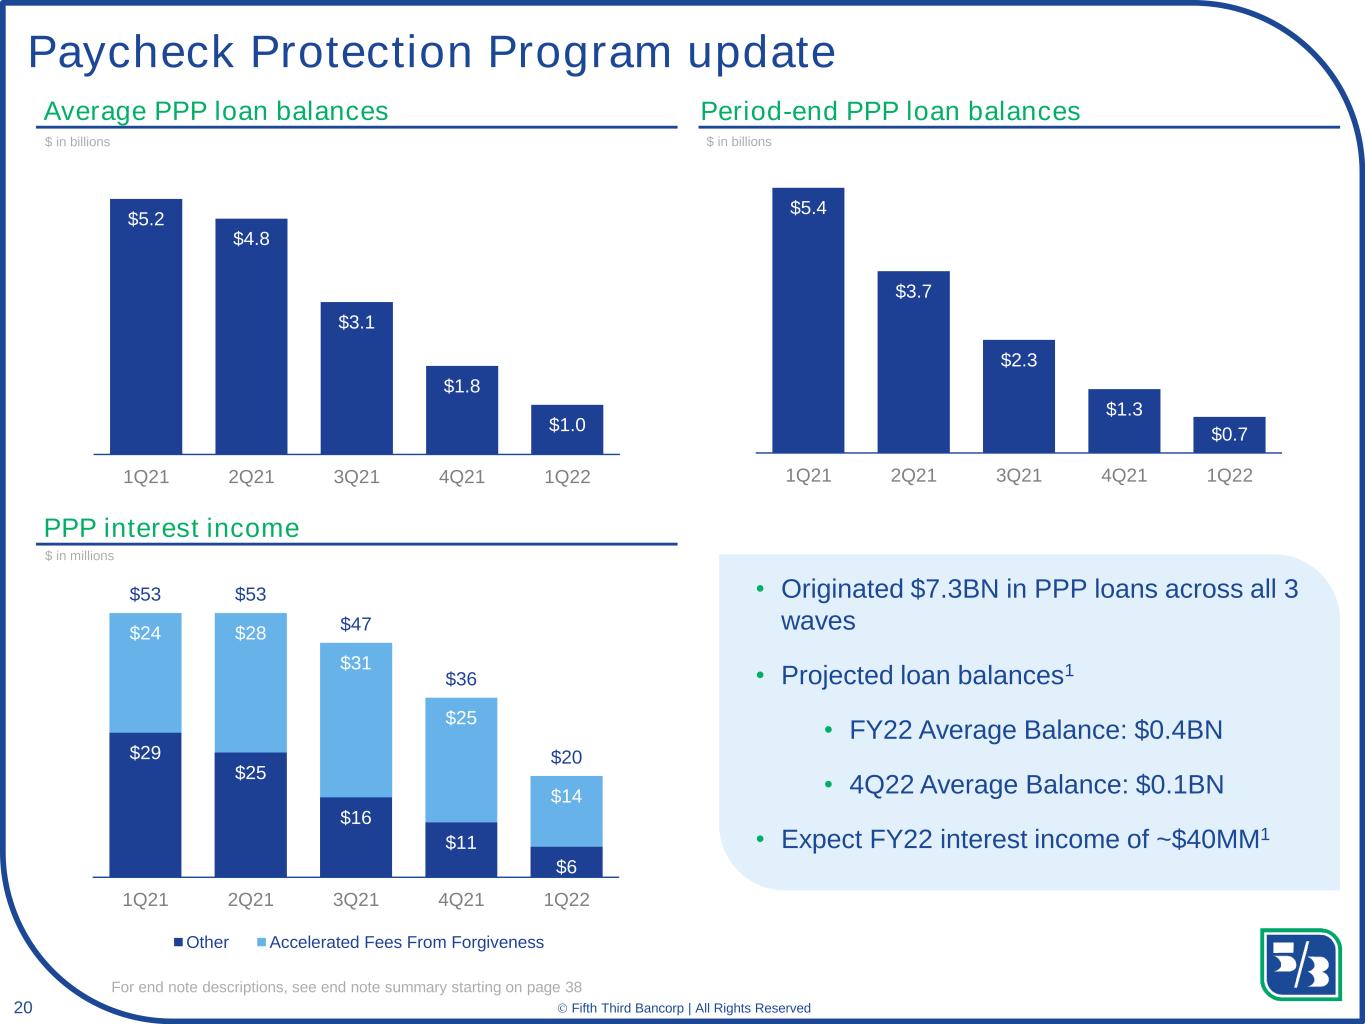
20 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $29 $25 $16 $11 $6 $24 $28 $31 $25 $14 $53 $53 $47 $36 $20 1Q21 2Q21 3Q21 4Q21 1Q22 Other Accelerated Fees From Forgiveness $5.4 $3.7 $2.3 $1.3 $0.7 1Q21 2Q21 3Q21 4Q21 1Q22 $5.2 $4.8 $3.1 $1.8 $1.0 1Q21 2Q21 3Q21 4Q21 1Q22 Average PPP loan balances Period-end PPP loan balances PPP interest income • Originated $7.3BN in PPP loans across all 3 waves • Projected loan balances1 • FY22 Average Balance: $0.4BN • 4Q22 Average Balance: $0.1BN • Expect FY22 interest income of ~$40MM1 $ in millions $ in billions $ in billions Paycheck Protection Program update For end note descriptions, see end note summary starting on page 38
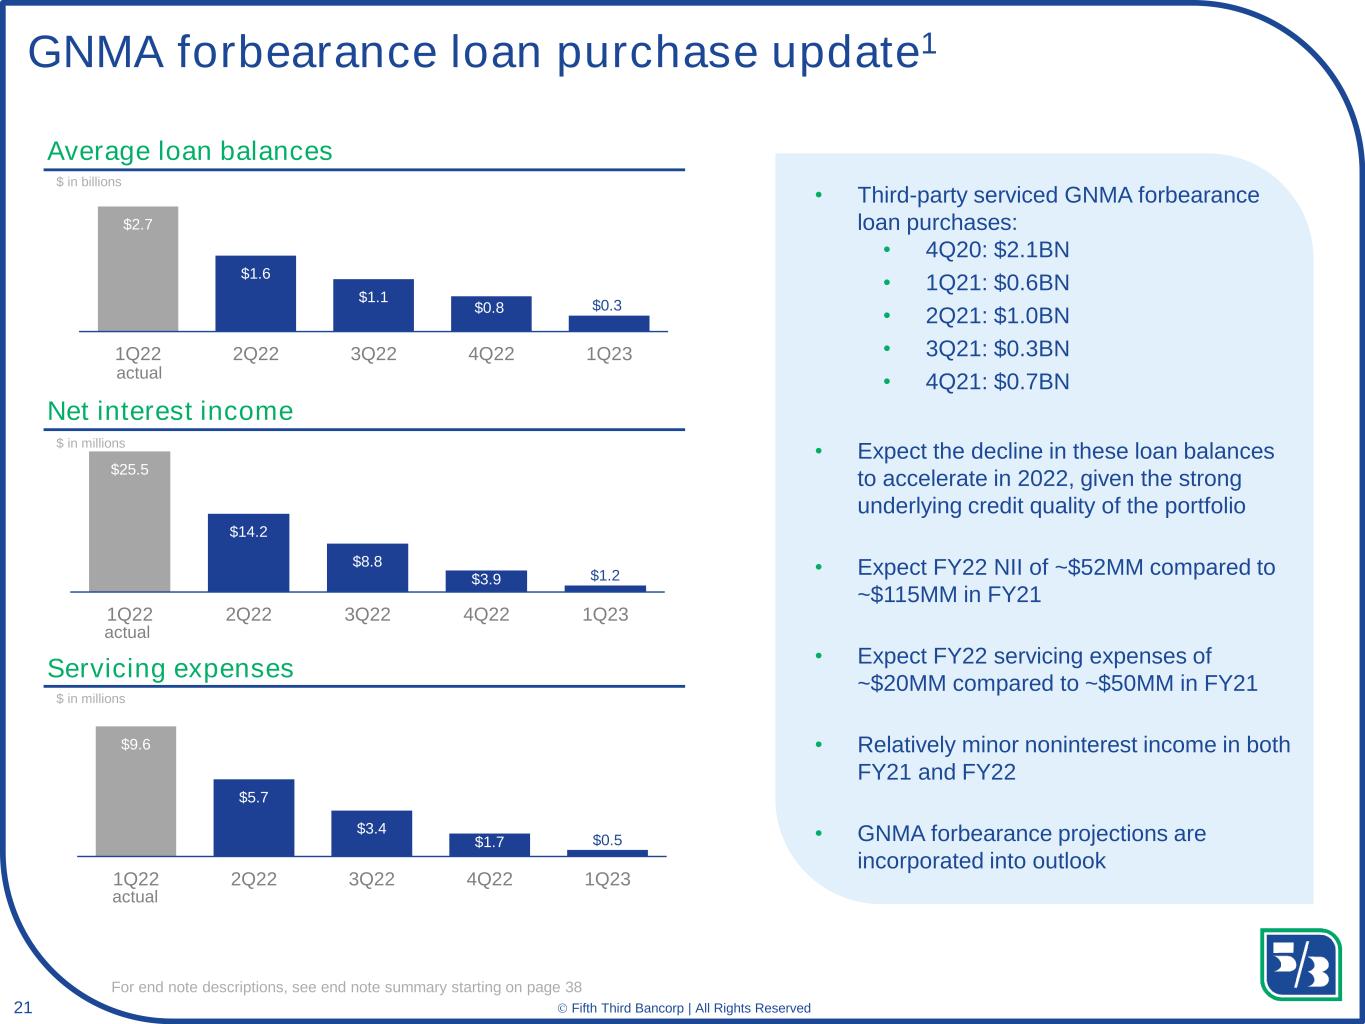
21 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $9.6 $5.7 $3.4 $1.7 $0.5 0.00 2.00 4.00 6.00 8.00 10.00 12.00 1Q22 2Q22 3Q22 4Q22 1Q23 $25.5 $14.2 $8.8 $3.9 $1.2 0.00 5.00 10.00 15.00 20.00 25.00 30.00 1Q22 2Q22 3Q22 4Q22 1Q23 $2.7 $1.6 $1.1 $0.8 $0.3 1Q22 2Q22 3Q22 4Q22 1Q23 Average loan balances • Third-party serviced GNMA forbearance loan purchases: • 4Q20: $2.1BN • 1Q21: $0.6BN • 2Q21: $1.0BN • 3Q21: $0.3BN • 4Q21: $0.7BN • Expect the decline in these loan balances to accelerate in 2022, given the strong underlying credit quality of the portfolio • Expect FY22 NII of ~$52MM compared to ~$115MM in FY21 • Expect FY22 servicing expenses of ~$20MM compared to ~$50MM in FY21 • Relatively minor noninterest income in both FY21 and FY22 • GNMA forbearance projections are incorporated into outlook $ in billions GNMA forbearance loan purchase update1 Net interest income $ in millions Servicing expenses $ in millions actual actual actual For end note descriptions, see end note summary starting on page 38
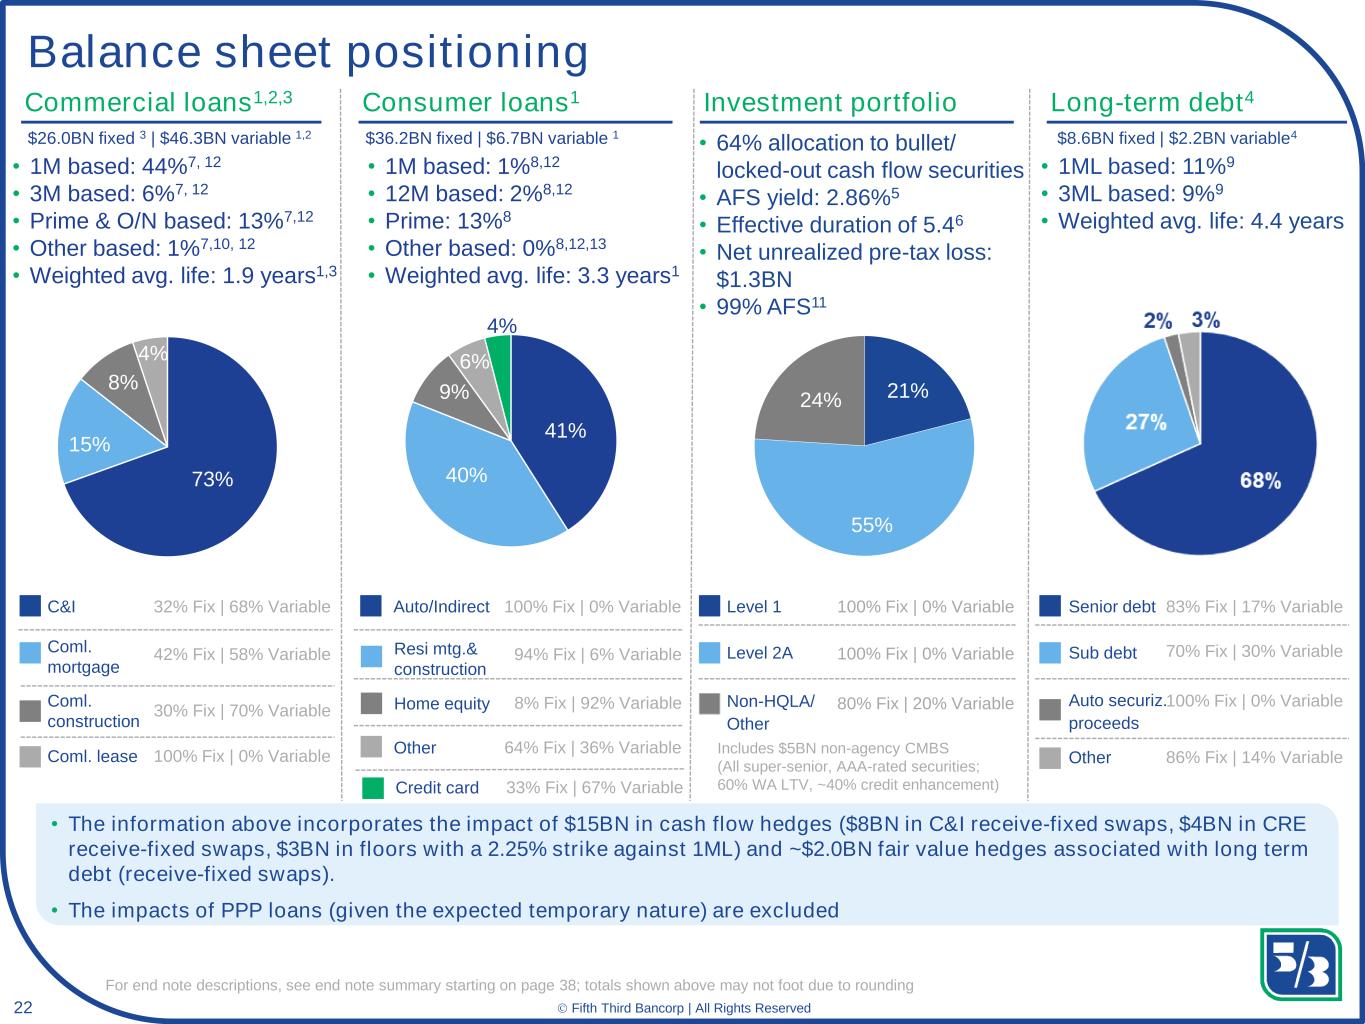
22 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved 0% 100% Fix | 0% Variable 80% Fix | 20% Variable Balance sheet positioning Investment portfolio $26.0BN fixed 3 | $46.3BN variable 1,2 Commercial loans1,2,3 Consumer loans1 Long-term debt4 $36.2BN fixed | $6.7BN variable 1 $8.6BN fixed | $2.2BN variable4 • 1M based: 44%7, 12 • 3M based: 6%7, 12 • Prime & O/N based: 13%7,12 • Other based: 1%7,10, 12 • Weighted avg. life: 1.9 years1,3 • 1M based: 1%8,12 • 12M based: 2%8,12 • Prime: 13%8 • Other based: 0%8,12,13 • Weighted avg. life: 3.3 years1 • 1ML based: 11%9 • 3ML based: 9%9 • Weighted avg. life: 4.4 years C&I 32% Fix | 68% Variable Coml. mortgage 42% Fix | 58% Variable Coml. lease 100% Fix | 0% Variable Resi mtg.& construction 94% Fix | 6% Variable Home equity 8% Fix | 92% Variable Senior debt 83% Fix | 17% Variable Sub debt 70% Fix | 30% Variable Auto securiz. proceeds 100% Fix | 0% VariableComl. construction 30% Fix | 70% Variable Credit card 33% Fix | 67% Variable Other 64% Fix | 36% Variable Other 86% Fix | 14% Variable • 64% allocation to bullet/ locked-out cash flow securities • AFS yield: 2.86%5 • Effective duration of 5.46 • Net unrealized pre-tax loss: $1.3BN • 99% AFS11 Level 1 100% Fix | 0% Variable Level 2A Non-HQLA/ Other • The information above incorporates the impact of $15BN in cash flow hedges ($8BN in C&I receive-fixed swaps, $4BN in CRE receive-fixed swaps, $3BN in floors with a 2.25% strike against 1ML) and ~$2.0BN fair value hedges associated with long term debt (receive-fixed swaps). • The impacts of PPP loans (given the expected temporary nature) are excluded Includes $5BN non-agency CMBS (All super-senior, AAA-rated securities; 60% WA LTV, ~40% credit enhancement) For end note descriptions, see end note summary starting on page 38; totals shown above may not foot due to rounding 73% 15% 8% 4% 21% 55% 24% Auto/Indirect 100% Fix | 0% Variable 41% 40% 9% 6% 4%
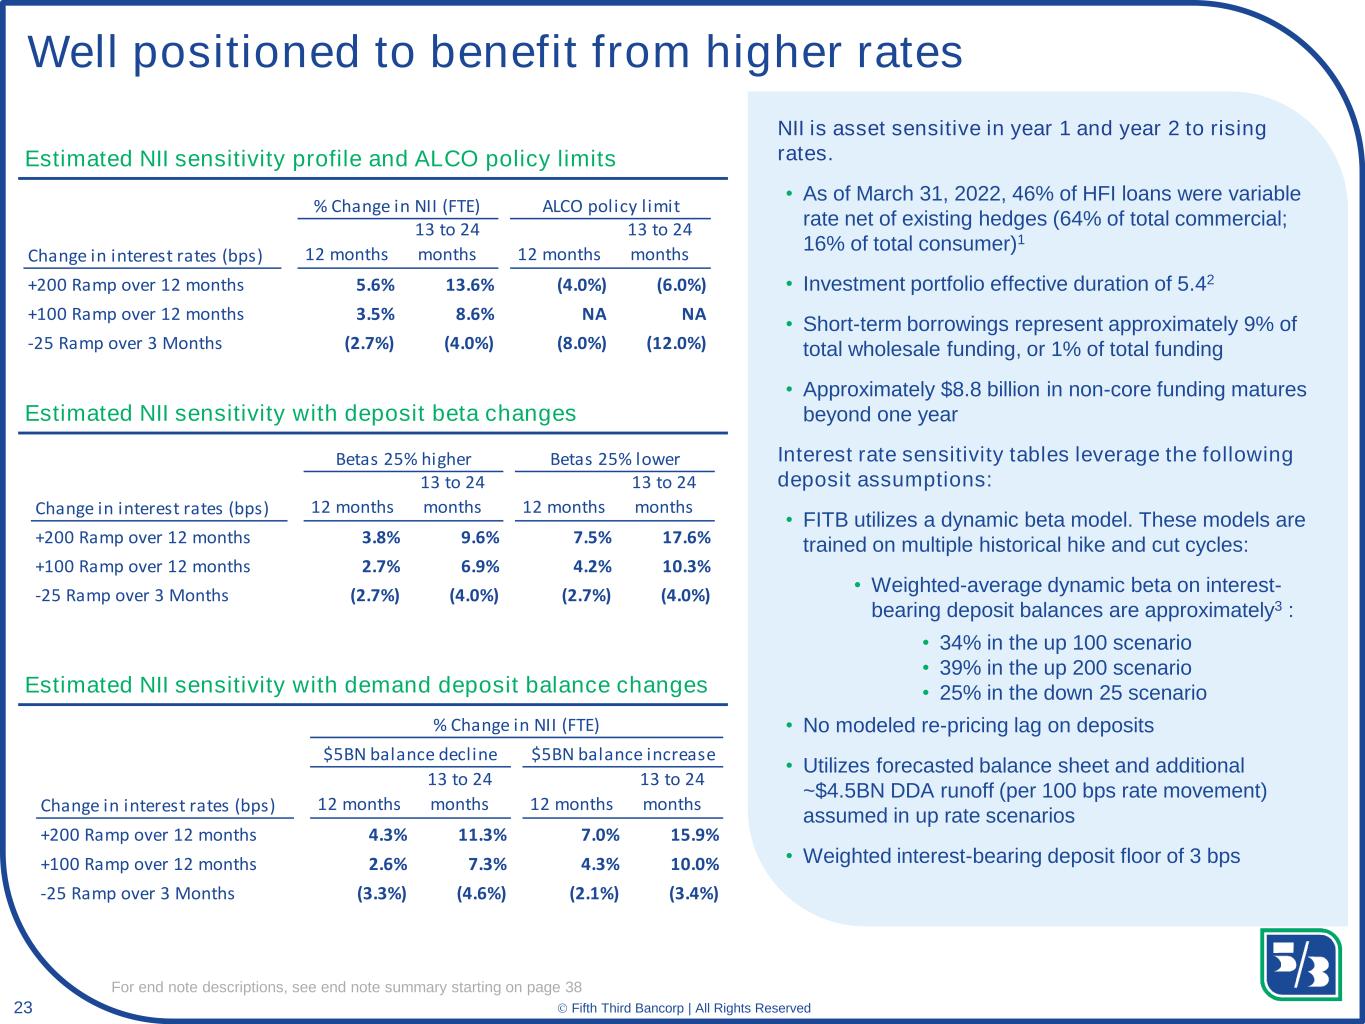
23 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Well positioned to benefit from higher rates Estimated NII sensitivity profile and ALCO policy limits Estimated NII sensitivity with demand deposit balance changes Estimated NII sensitivity with deposit beta changes NII is asset sensitive in year 1 and year 2 to rising rates. • As of March 31, 2022, 46% of HFI loans were variable rate net of existing hedges (64% of total commercial; 16% of total consumer)1 • Investment portfolio effective duration of 5.42 • Short-term borrowings represent approximately 9% of total wholesale funding, or 1% of total funding • Approximately $8.8 billion in non-core funding matures beyond one year Interest rate sensitivity tables leverage the following deposit assumptions: • FITB utilizes a dynamic beta model. These models are trained on multiple historical hike and cut cycles: • Weighted-average dynamic beta on interest- bearing deposit balances are approximately3 : • 34% in the up 100 scenario • 39% in the up 200 scenario • 25% in the down 25 scenario • No modeled re-pricing lag on deposits • Utilizes forecasted balance sheet and additional ~$4.5BN DDA runoff (per 100 bps rate movement) assumed in up rate scenarios • Weighted interest-bearing deposit floor of 3 bps ALCO policy limit Change in interest rates (bps) 12 months 13 to 24 months 12 months 13 to 24 months +200 Ramp over 12 months 5.6% 13.6% (4.0%) (6.0%) +100 Ramp over 12 months 3.5% 8.6% NA NA -25 Ramp over 3 Months (2.7%) (4.0%) (8.0%) (12.0%) % Change in NII (FTE) Betas 25% higher Betas 25% lower Change in interest rates (bps) 12 months 13 to 24 months 12 months 13 to 24 months +200 Ramp over 12 months 3.8% 9.6% 7.5% 17.6% +100 Ramp over 12 months 2.7% 6.9% 4.2% 10.3% -25 Ramp over 3 Months (2.7%) (4.0%) (2.7%) (4.0%) $5BN balance decline $5BN balance increase Change in interest rates (bps) 12 months 13 to 24 months 12 months 13 to 24 months +200 Ramp over 12 months 4.3% 11.3% 7.0% 15.9% +100 Ramp over 12 months 2.6% 7.3% 4.3% 10.0% -25 Ramp over 3 Months (3.3%) (4.6%) (2.1%) (3.4%) % Change in NII (FTE) For end note descriptions, see end note summary starting on page 38

24 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $12 $12 $12 $12 $11 $11 $11 $7 $7 $6 $5 $5 $3 $3 $3 $3 $3 $3 $3 $3 $3 $3 $3 $15 $15 $15 $15 $14 $14 $14 $10 $10 $9 $8 $5 1Q22 2Q22 3Q22 4Q22 1Q23 2Q23 3Q23 4Q23 1Q24 2Q24 3Q24 4Q24 Floors Swaps ($3BN @ 2.25% 1-month LIBOR strike) Cash flow hedges continue to protect NIM1 EOP notional value of cash flow hedges ($ in billions) Cash flow hedges Actual Gross receive fixed rate of swaps: • 1Q22-4Q22: 2.35% • 1Q23-3Q23: 2.32% • 4Q23-1Q24: 1.89% • 2Q24: 1.71% • 3Q24-4Q24: 1.44% 2 For end note descriptions, see end note summary starting on page 38
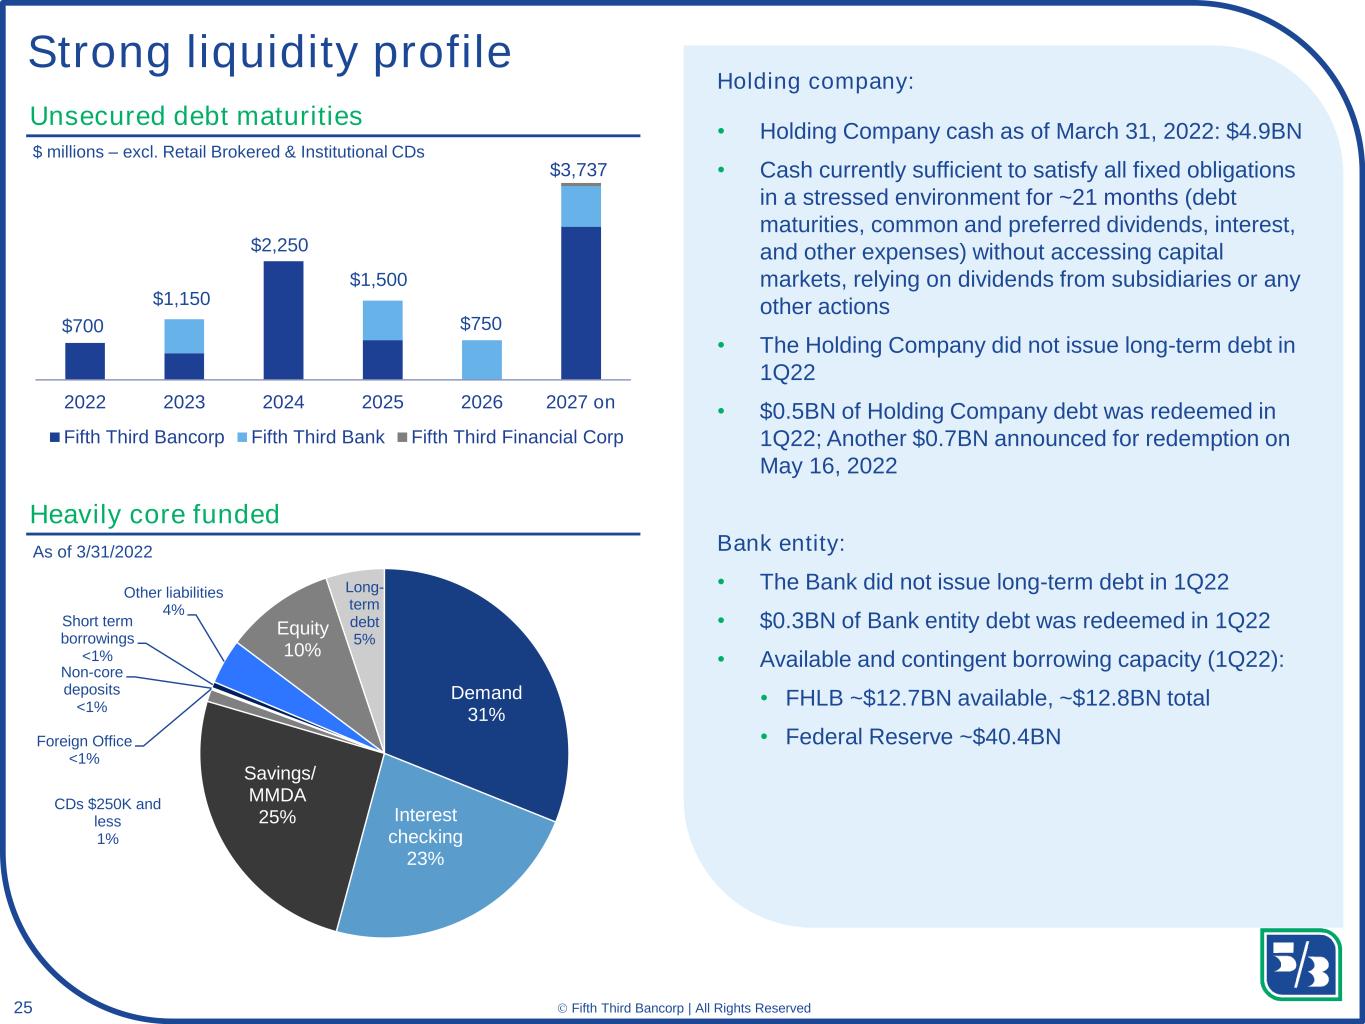
25 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Strong liquidity profile $ millions – excl. Retail Brokered & Institutional CDs Unsecured debt maturities Heavily core funded Demand 31% Interest checking 23% Savings/ MMDA 25% CDs $250K and less 1% Foreign Office <1% Non-core deposits <1% Short term borrowings <1% Other liabilities 4% Equity 10% Long- term debt 5% Holding company: • Holding Company cash as of March 31, 2022: $4.9BN • Cash currently sufficient to satisfy all fixed obligations in a stressed environment for ~21 months (debt maturities, common and preferred dividends, interest, and other expenses) without accessing capital markets, relying on dividends from subsidiaries or any other actions • The Holding Company did not issue long-term debt in 1Q22 • $0.5BN of Holding Company debt was redeemed in 1Q22; Another $0.7BN announced for redemption on May 16, 2022 Bank entity: • The Bank did not issue long-term debt in 1Q22 • $0.3BN of Bank entity debt was redeemed in 1Q22 • Available and contingent borrowing capacity (1Q22): • FHLB ~$12.7BN available, ~$12.8BN total • Federal Reserve ~$40.4BN As of 3/31/2022 2022 2023 2024 2025 2026 2027 on Fifth Third Bancorp Fifth Third Bank Fifth Third Financial Corp $2,250 $3,737 $750$700 $1,150 $1,500
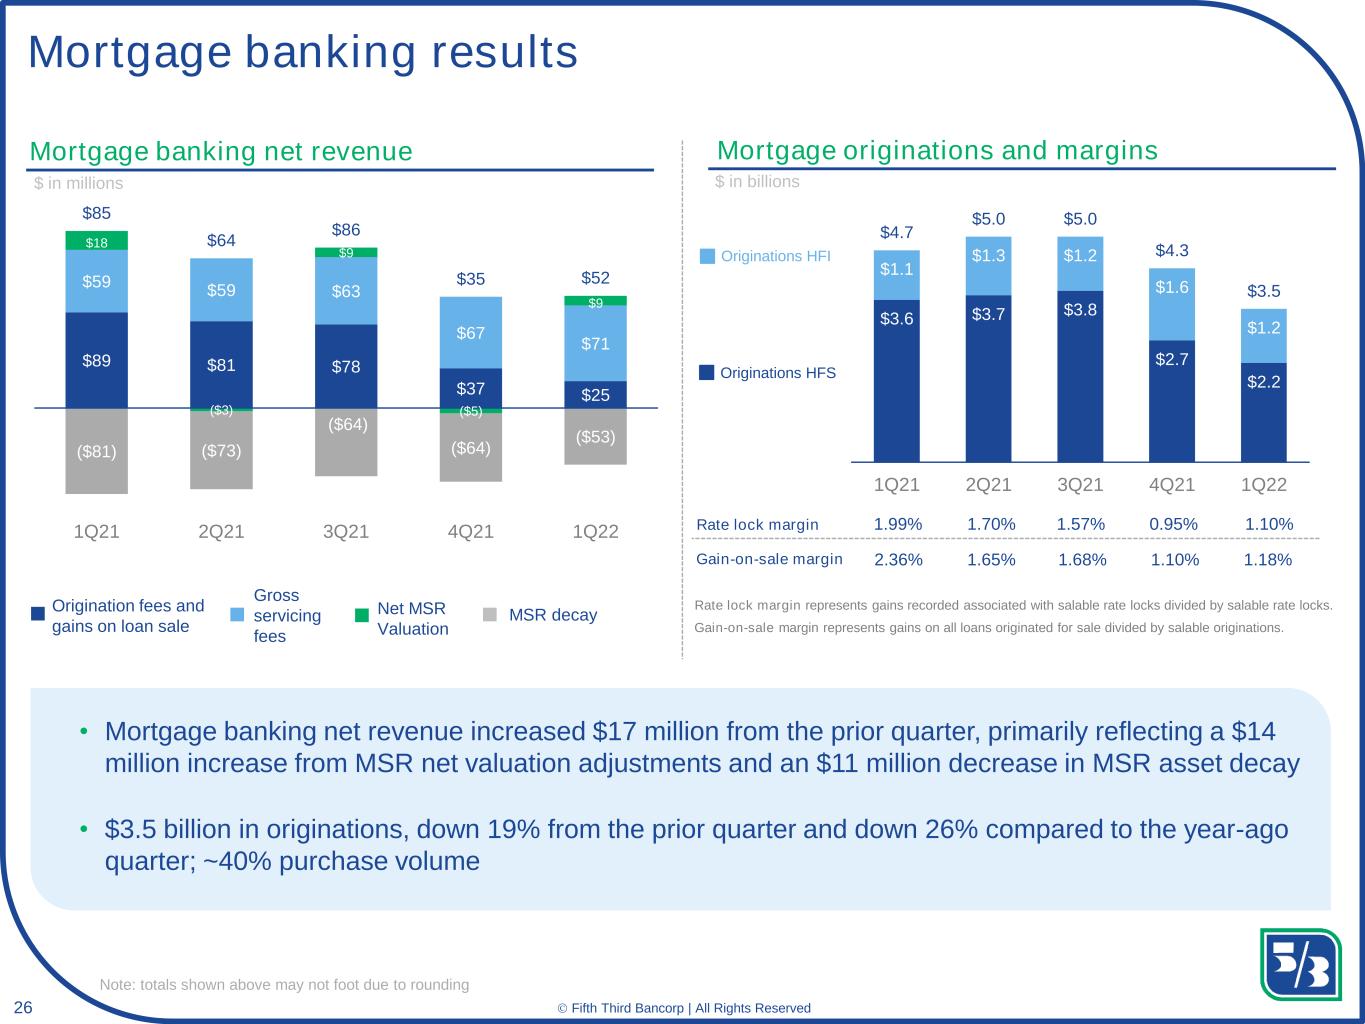
26 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $89 $81 $78 $37 $25 $59 $59 $63 $67 $71 $18 ($3) $9 ($5) $9 ($81) ($73) ($64) ($64) ($53) $85 $64 $86 $35 $52 -$100 -$75 -$50 -$25 $0 $25 $50 $75 $100 $125 $150 $175 $200 $225 $250 1Q21 2Q21 3Q21 4Q21 1Q22 $3.6 $3.7 $3.8 $2.7 $2.2 $1.1 $1.3 $1.2 $1.6 $1.2 $4.7 $5.0 $5.0 $4.3 $3.5 1Q21 2Q21 3Q21 4Q21 1Q22 Gross servicing fees Mortgage banking results $ in millions Mortgage banking net revenue Mortgage originations and margins • Mortgage banking net revenue increased $17 million from the prior quarter, primarily reflecting a $14 million increase from MSR net valuation adjustments and an $11 million decrease in MSR asset decay • $3.5 billion in originations, down 19% from the prior quarter and down 26% compared to the year-ago quarter; ~40% purchase volume Origination fees and gains on loan sale MSR decayNet MSR Valuation Note: totals shown above may not foot due to rounding $ in billions Originations HFS Originations HFI 1.99% 2.36% 1.70% 1.65% 1.57% 1.68% 0.95% 1.10%Gain-on-sale margin Gain-on-sale margin represents gains on all loans originated for sale divided by salable originations. Rate lock margin Rate lock margin represents gains recorded associated with salable rate locks divided by salable rate locks. 1.10% 1.18%
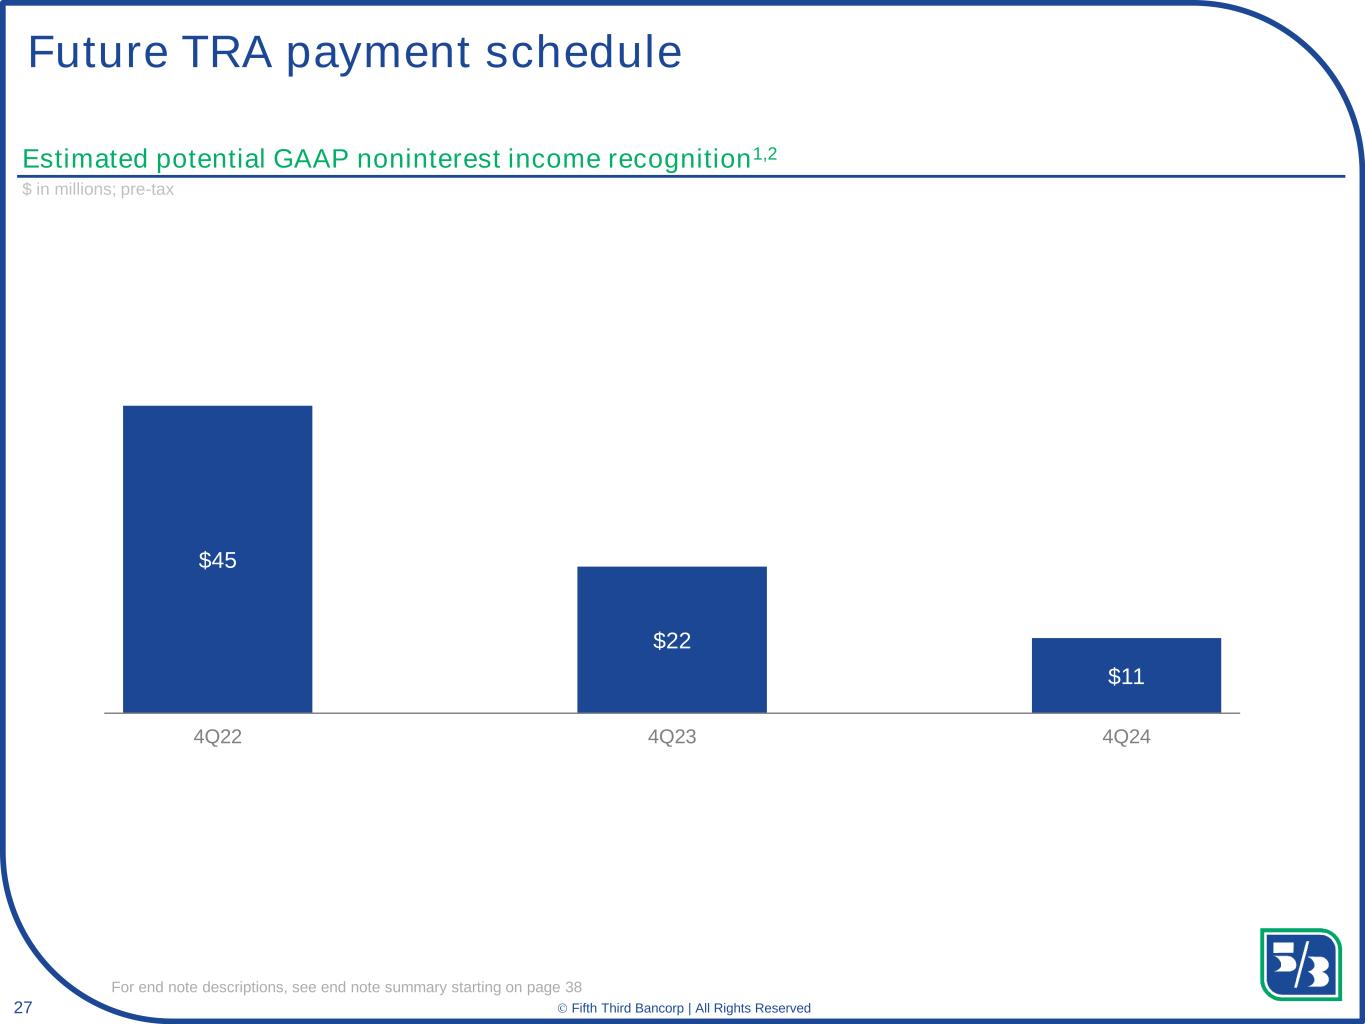
27 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $45 $22 $11 4Q22 4Q23 4Q24 Estimated potential GAAP noninterest income recognition1,2 Future TRA payment schedule $ in millions; pre-tax For end note descriptions, see end note summary starting on page 38
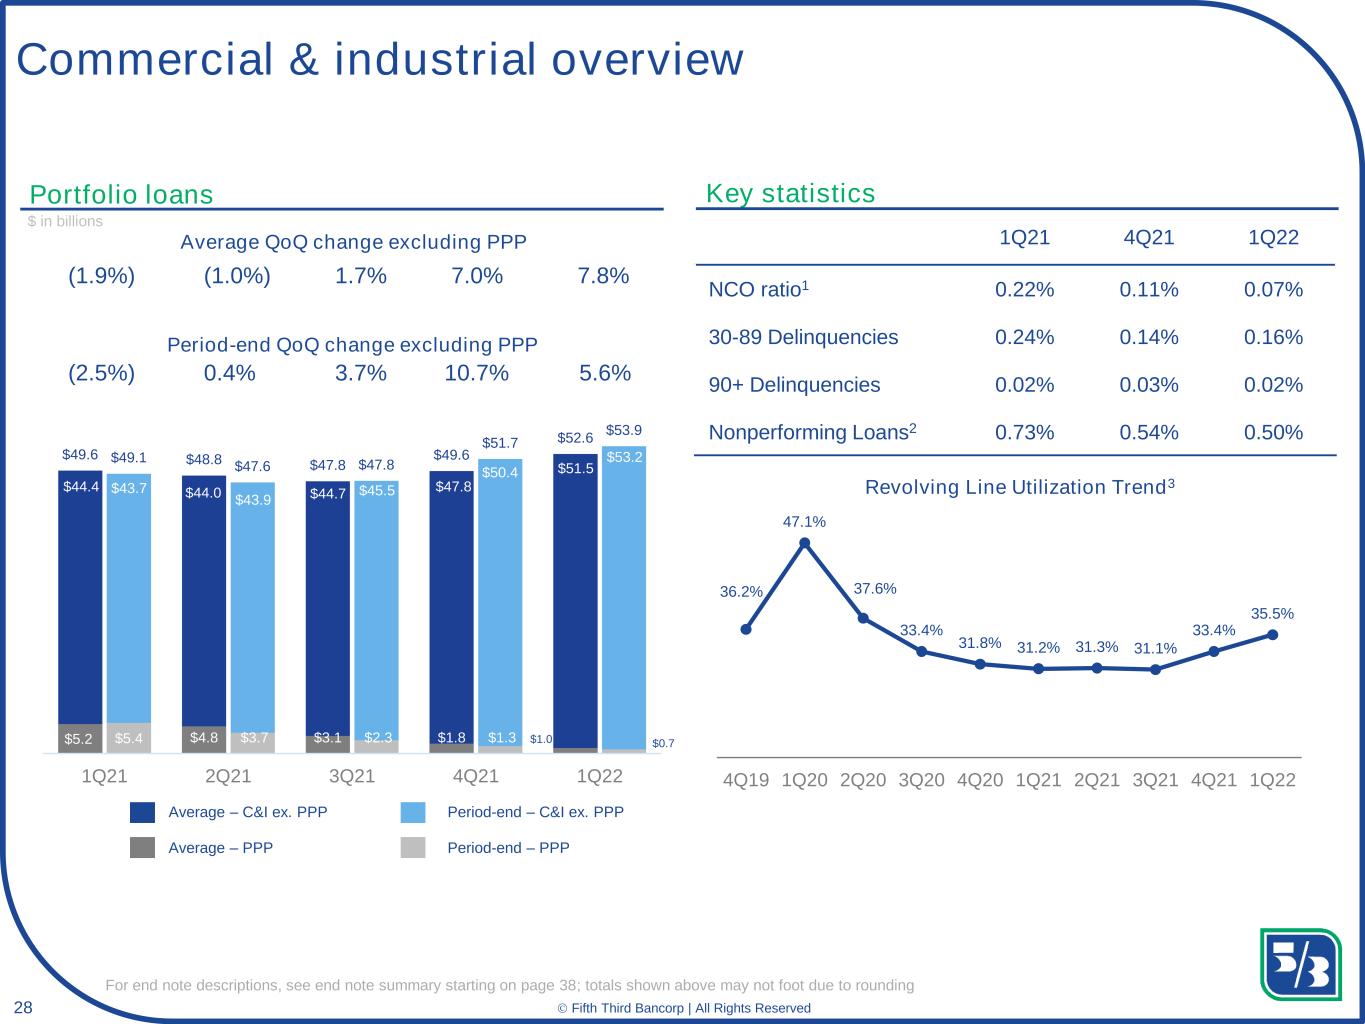
28 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved 36.2% 47.1% 37.6% 33.4% 31.8% 31.2% 31.3% 31.1% 33.4% 35.5% 4Q19 1Q20 2Q20 3Q20 4Q20 1Q21 2Q21 3Q21 4Q21 1Q22 $49.6 $48.8 $47.8 $49.6 $52.6 $49.1 $47.6 $47.8 $51.7 $53.9 $5.2 $4.8 $3.1 $1.8 $1.0$5.4 $3.7 $2.3 $1.3 $0.7 $0.0 $10.0 $20.0 $30.0 $40.0 $50.0 $60.0 $0.0 $10.0 $20.0 $30.0 $40.0 $50.0 $60.0 1Q21 2Q21 3Q21 4Q21 1Q22 Commercial & industrial overview Portfolio loans Key statistics 1Q21 4Q21 1Q22 NCO ratio1 0.22% 0.11% 0.07% 30-89 Delinquencies 0.24% 0.14% 0.16% 90+ Delinquencies 0.02% 0.03% 0.02% Nonperforming Loans2 0.73% 0.54% 0.50% $ in billions Revolving Line Utilization Trend3 (2.5%) 0.4% 3.7% 10.7% 5.6% Period-end QoQ change excluding PPP Average QoQ change excluding PPP (1.9%) (1.0%) 1.7% 7.0% 7.8% Average – C&I ex. PPP Average – PPP Period-end – C&I ex. PPP Period-end – PPP $44.4 $43.7 $44.0 $43.9 $44.7 $45.5 $47.8 $50.4 $51.5 For end note descriptions, see end note summary starting on page 38; totals shown above may not foot due to rounding $53.2
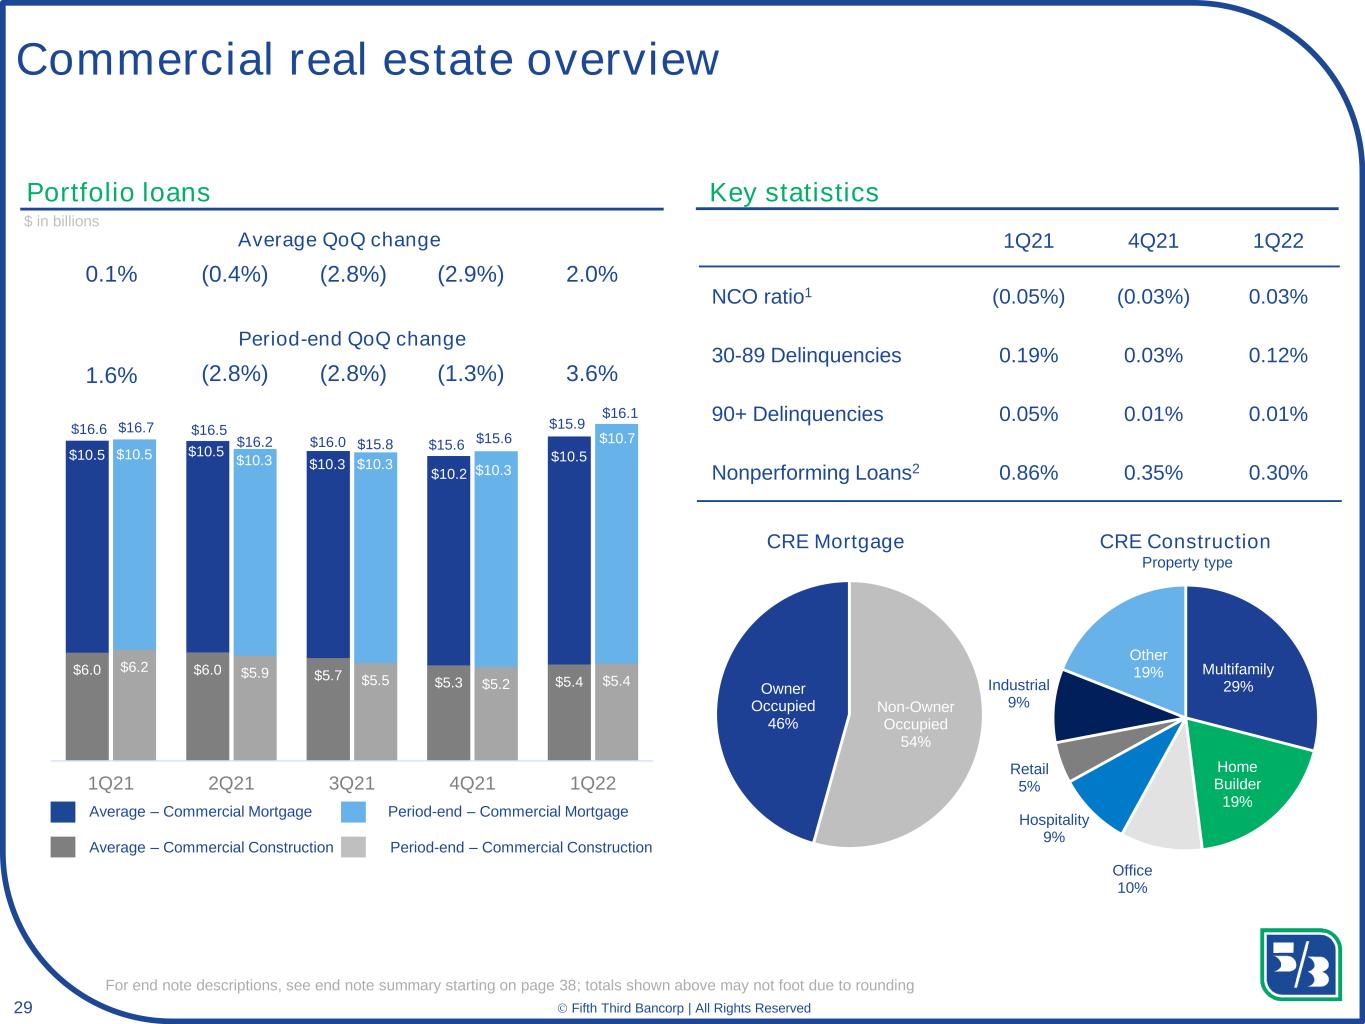
29 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Non-Owner Occupied 54% Owner Occupied 46% Multifamily 29% Home Builder 19% Office 10% Hospitality 9% Retail 5% Industrial 9% Other 19% $10.5 $10.5 $10.3 $10.2 $10.5$10.5 $10.3 $10.3 $10.3 $10.7 $6.0 $6.0 $5.7 $5.3 $5.4 $6.2 $5.9 $5.5 $5.2 $5.4 $16.7 $16.2 $15.8 $15.6 $16.1 $16.6 $16.5 $16.0 $15.6 $15.9 $0.0 $2.0 $4.0 $6.0 $8.0 $10.0 $12.0 $14.0 $16.0 $18.0 $20.0 $6.0 $6.5 $7.0 $7.5 $8.0 $8.5 $9.0 $9.5 $10.0 $10.5 $11.0 1Q21 2Q21 3Q21 4Q21 1Q22 Commercial real estate overview Portfolio loans Key statistics 1Q21 4Q21 1Q22 NCO ratio1 (0.05%) (0.03%) 0.03% 30-89 Delinquencies 0.19% 0.03% 0.12% 90+ Delinquencies 0.05% 0.01% 0.01% Nonperforming Loans2 0.86% 0.35% 0.30% $ in billions 0.1% (0.4%) (2.8%) (2.9%) 2.0% Average QoQ change CRE Mortgage CRE Construction Property type 1.6% (2.8%) (2.8%) (1.3%) 3.6% Period-end QoQ change $10.5 $10.5 $10.5 $10.3 $10.3 $10.3 $10.2 $10.3 $10.5 $10.7 Average – Commercial Mortgage Average – Commercial Construction Period-end – Commercial Mortgage Period-end – Commercial Construction For end note descriptions, see end note summary starting on page 38; totals shown above may not foot due to rounding
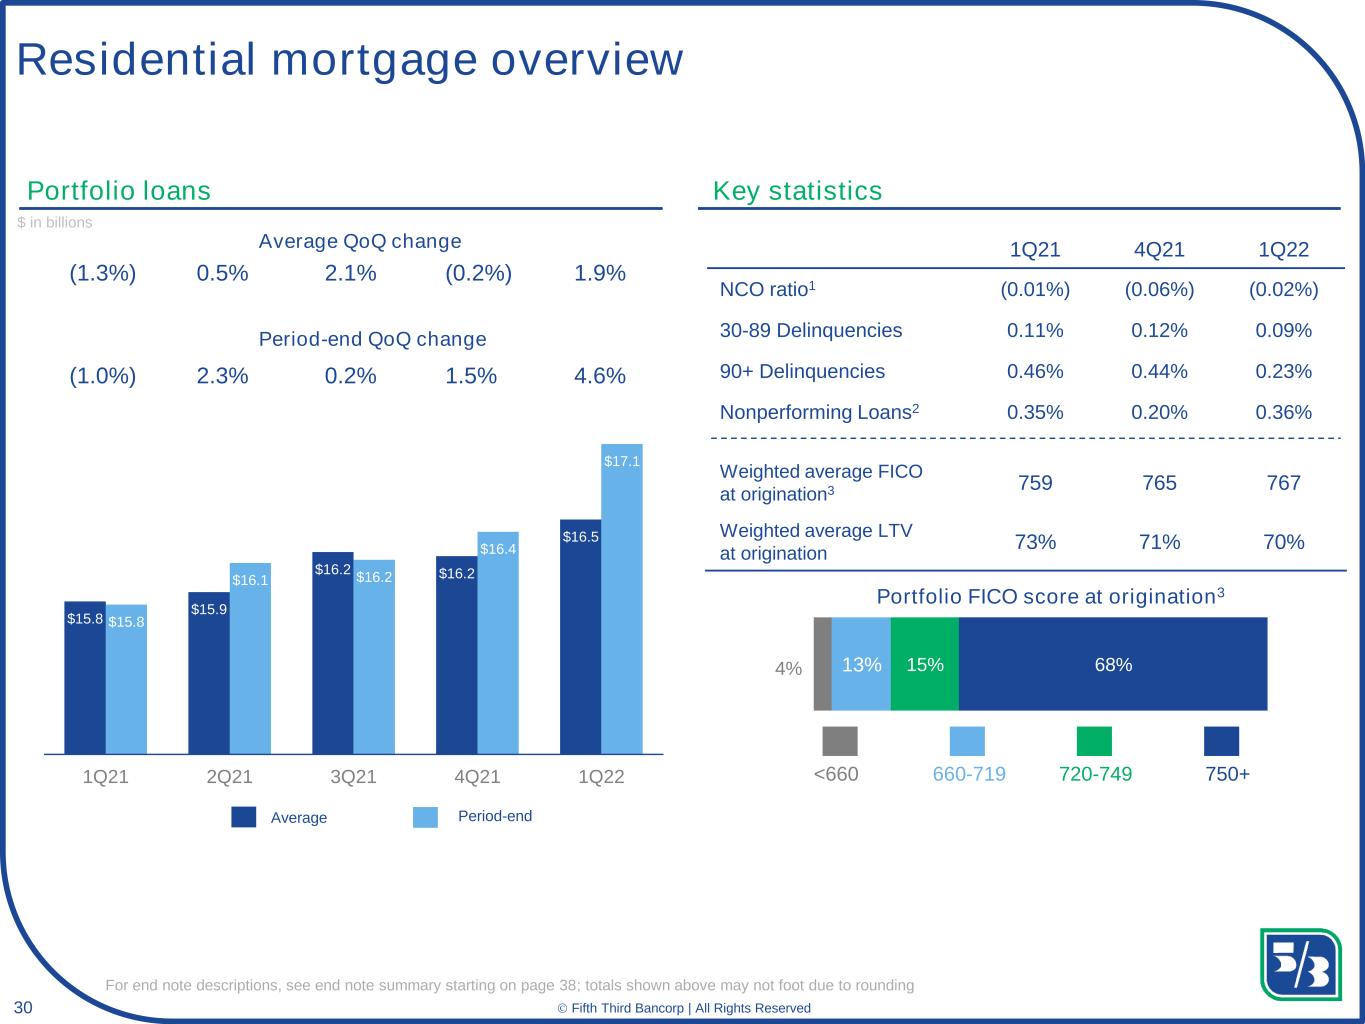
30 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $15.8 $15.9 $16.2 $16.2 $16.5 $15.8 $16.1 $16.2 $16.4 $17.1 1Q21 2Q21 3Q21 4Q21 1Q22 1Q21 4Q21 1Q22 NCO ratio1 (0.01%) (0.06%) (0.02%) 30-89 Delinquencies 0.11% 0.12% 0.09% 90+ Delinquencies 0.46% 0.44% 0.23% Nonperforming Loans2 0.35% 0.20% 0.36% Weighted average FICO at origination3 759 765 767 Weighted average LTV at origination 73% 71% 70% Residential mortgage overview Portfolio loans $ in billions (1.3%) 0.5% 2.1% (0.2%) 1.9% Average QoQ change 4% 13% 15% 68% Key statistics Portfolio FICO score at origination3 750+720-749<660 660-719 (1.0%) 2.3% 0.2% 1.5% 4.6% Period-end QoQ change Average Period-end For end note descriptions, see end note summary starting on page 38; totals shown above may not foot due to rounding
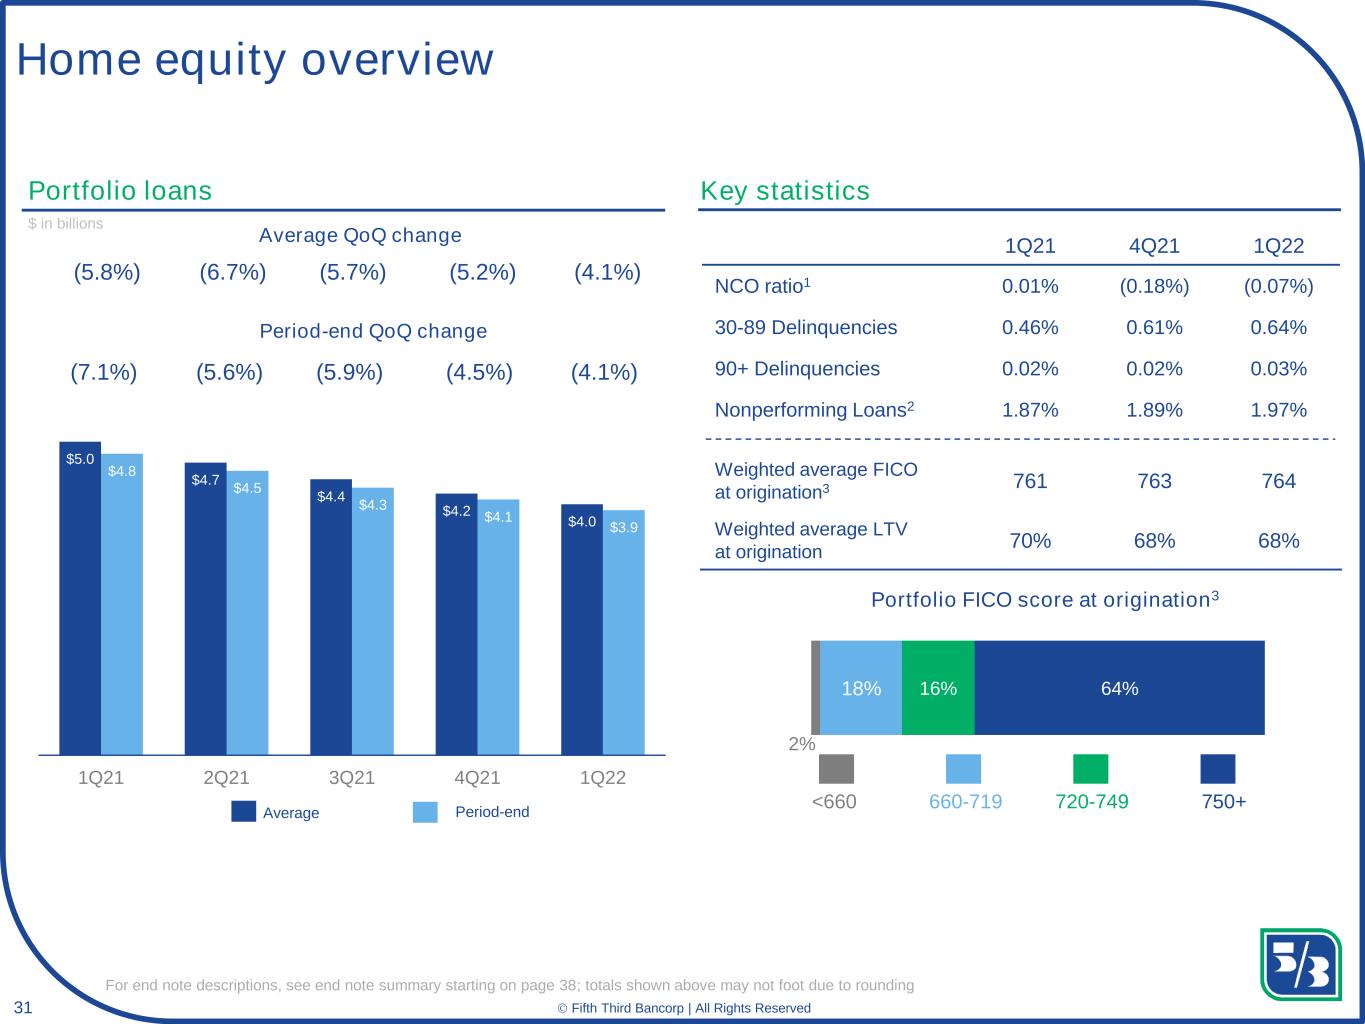
31 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $5.0 $4.7 $4.4 $4.2 $4.0 $4.8 $4.5 $4.3 $4.1 $3.9 1Q21 2Q21 3Q21 4Q21 1Q22 2% 18% 16% 64% Home equity overview Portfolio loans Key statistics 1Q21 4Q21 1Q22 NCO ratio1 0.01% (0.18%) (0.07%) 30-89 Delinquencies 0.46% 0.61% 0.64% 90+ Delinquencies 0.02% 0.02% 0.03% Nonperforming Loans2 1.87% 1.89% 1.97% Weighted average FICO at origination3 761 763 764 Weighted average LTV at origination 70% 68% 68% $ in billions Portfolio FICO score at origination3 (5.8%) (6.7%) (5.7%) (5.2%) (4.1%) Average QoQ change (7.1%) (5.6%) (5.9%) (4.5%) (4.1%) Period-end QoQ change Average Period-end 750+720-749<660 660-719 For end note descriptions, see end note summary starting on page 38; totals shown above may not foot due to rounding
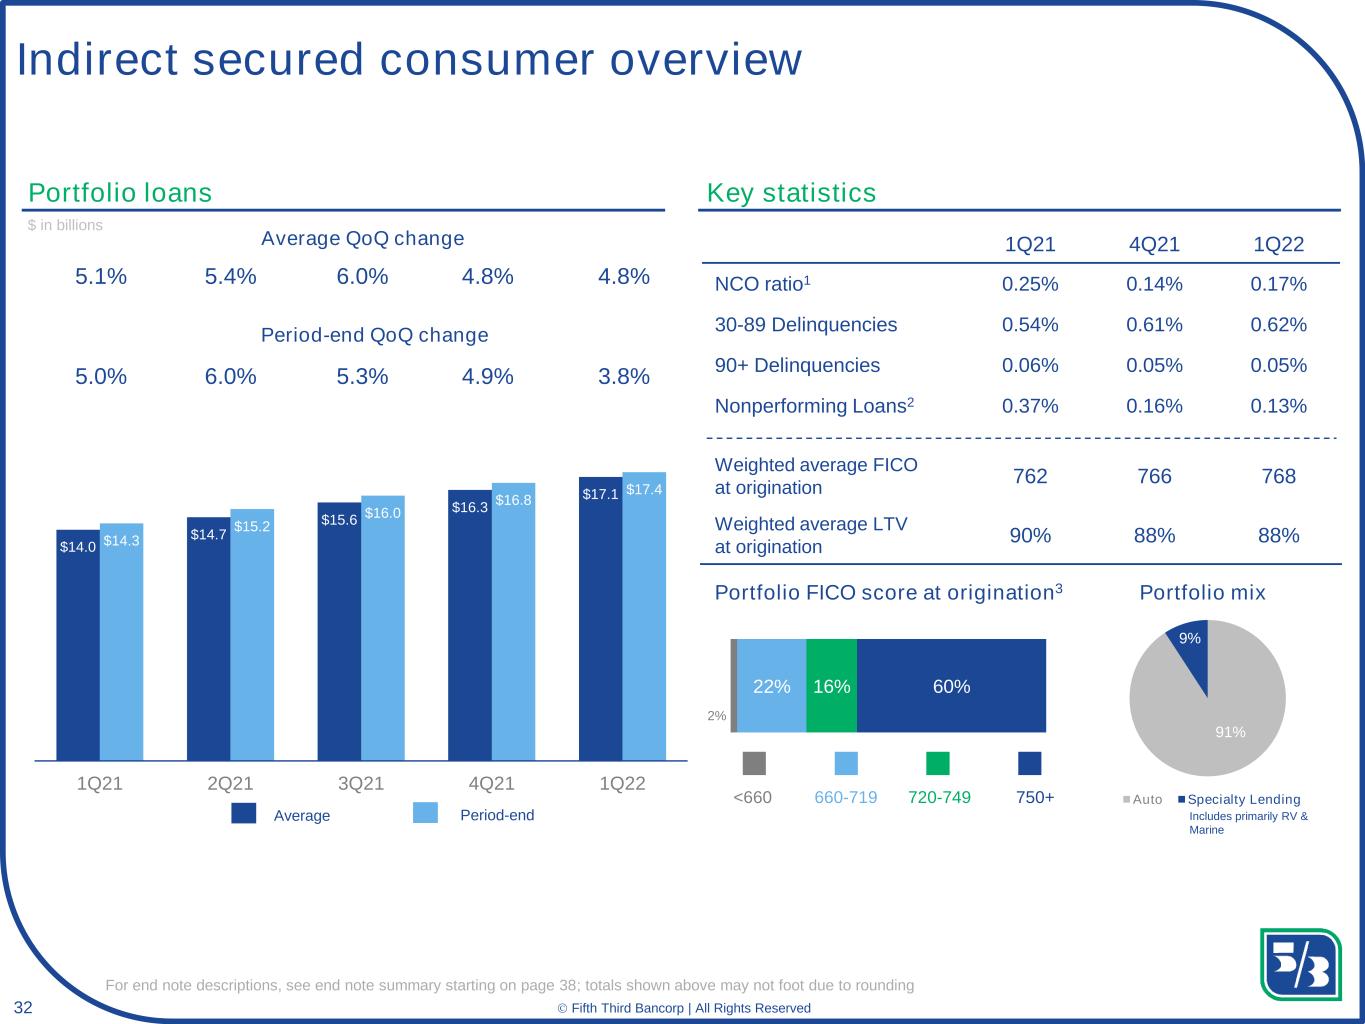
32 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $14.0 $14.7 $15.6 $16.3 $17.1 $14.3 $15.2 $16.0 $16.8 $17.4 1Q21 2Q21 3Q21 4Q21 1Q22 Indirect secured consumer overview Portfolio loans $ in billions 5.1% 5.4% 6.0% 4.8% 4.8% Average QoQ change 2% 22% 16% 60% 1Q21 4Q21 1Q22 NCO ratio1 0.25% 0.14% 0.17% 30-89 Delinquencies 0.54% 0.61% 0.62% 90+ Delinquencies 0.06% 0.05% 0.05% Nonperforming Loans2 0.37% 0.16% 0.13% Weighted average FICO at origination 762 766 768 Weighted average LTV at origination 90% 88% 88% Portfolio FICO score at origination3 750+720-749<660 660-719 91% 9% Auto Specialty Lending Includes primarily RV & Marine Portfolio mix Key statistics 5.0% 6.0% 5.3% 4.9% 3.8% Period-end QoQ change Average Period-end For end note descriptions, see end note summary starting on page 38; totals shown above may not foot due to rounding

33 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved $1.9 $1.8 $1.7 $1.7 $1.7 $1.8 $1.8 $1.7 $1.8 $1.7 1Q21 2Q21 3Q21 4Q21 1Q22 Credit card overview Portfolio loans $ in billions (8.0%) (5.8%) (1.2%) (0.5%) (2.8%) Average QoQ change 5% 29% 20% 46% Key statistics 1Q21 4Q21 1Q22 NCO ratio1 5.50% 2.90% 3.13% 30-89 Delinquencies 0.99% 1.02% 1.01% 90+ Delinquencies 1.38% 0.85% 0.83% Nonperforming Loans2 1.66% 1.30% 1.36% Weighted average FICO at origination3 738 741 741 Portfolio FICO score at origination3 750+720-749<660 660-719 (9.8%) (0.9%) (2.7%) 1.3% (4.3%) Period-end QoQ change Average Period-End For end note descriptions, see end note summary starting on page 38; totals shown above may not foot due to rounding

34 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved 1Q21 2Q21 3Q21 4Q21 1Q22 196$ 232$ 212$ 179$ 161$ Transfers to nonaccrual status 103 40 33 30 71 Transfers to accrual status (44) (37) (45) (30) (40) Transfers to held for sale - - - - - Loan paydowns/payoffs (13) (15) (14) (13) (6) Transfers to OREO (1) (1) - - (1) Charge-offs (11) (7) (7) (5) - Draws/other extensions of credit 2 - - - - 232$ 212$ 179$ 161$ 185$ Balance, beginning of period Balance, end of period NPL rollforward1 Commercial Consumer Total NPL $ in millions $ in millions $ in millions Total NPL 741$ 621$ 528$ 498$ 508$ Total new nonaccrual loans - HFI 132$ 140$ 80$ 92$ 125$ For end note descriptions, see end note summary starting on page 38 1Q21 2Q21 3Q21 4Q21 1Q22 638$ 509$ 409$ 349$ 337$ Transfers to nonaccrual status 29 100 47 62 54 Transfers to accrual status (1) - - (26) (2) Transfers to held for sale (42) (45) (1) (2) (4) Loan paydowns/payoffs (99) (116) (97) (21) (52) Transfers to OREO (1) - - - - Charge-offs (35) (45) (10) (28) (11) Draws/other extensions of credit 20 6 1 3 1 509$ 409$ 349$ 337$ 323$ Balance, beginning of period Balance, end of period
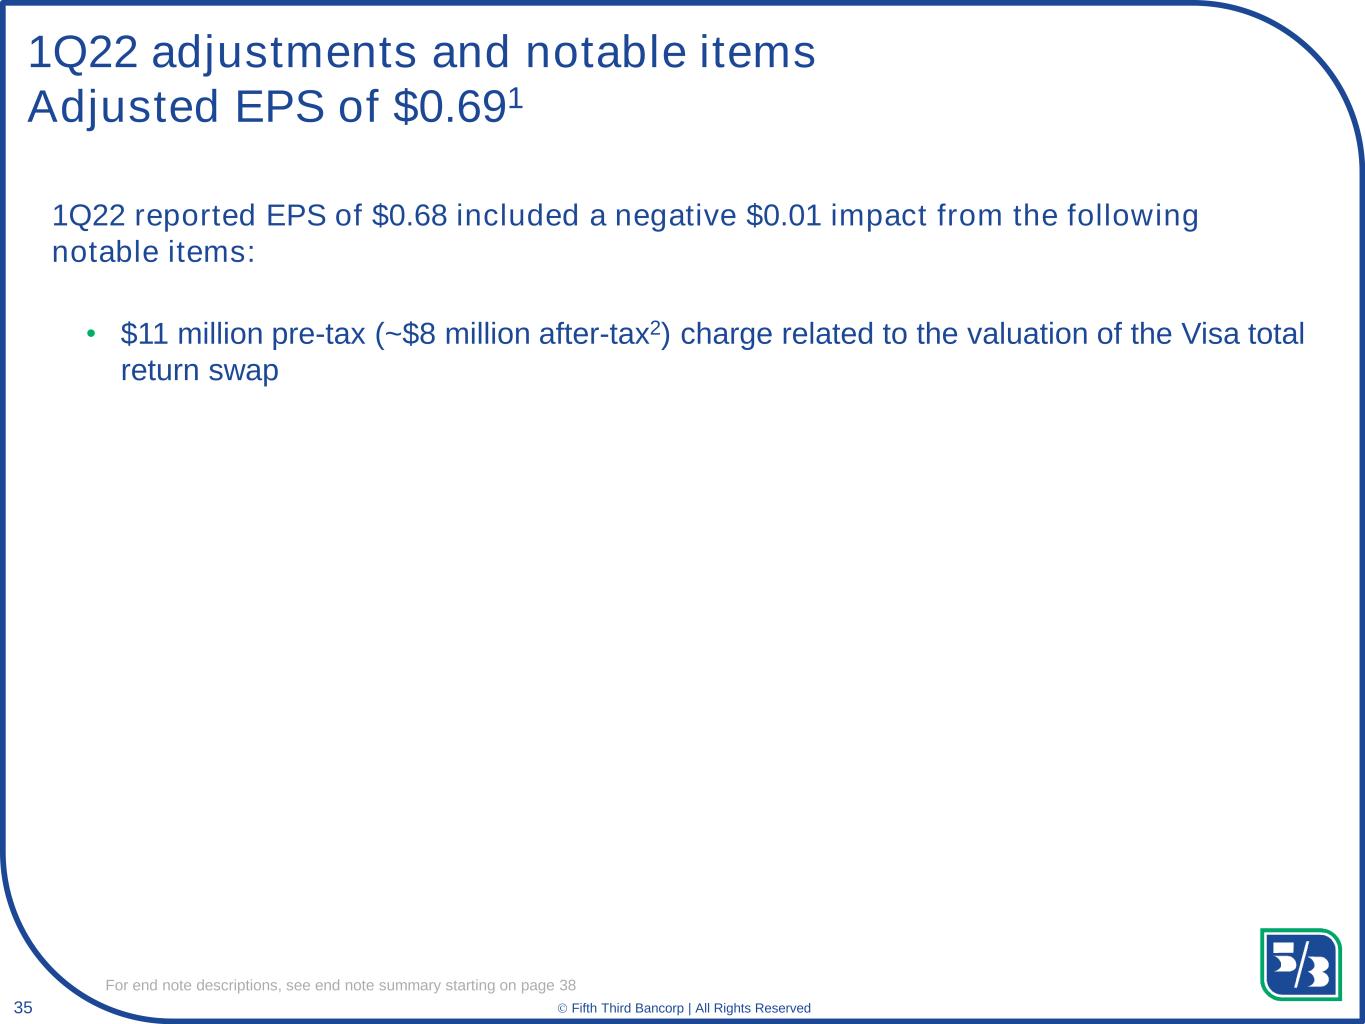
35 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved 1Q22 adjustments and notable items Adjusted EPS of $0.691 1Q22 reported EPS of $0.68 included a negative $0.01 impact from the following notable items: • $11 million pre-tax (~$8 million after-tax2) charge related to the valuation of the Visa total return swap For end note descriptions, see end note summary starting on page 38
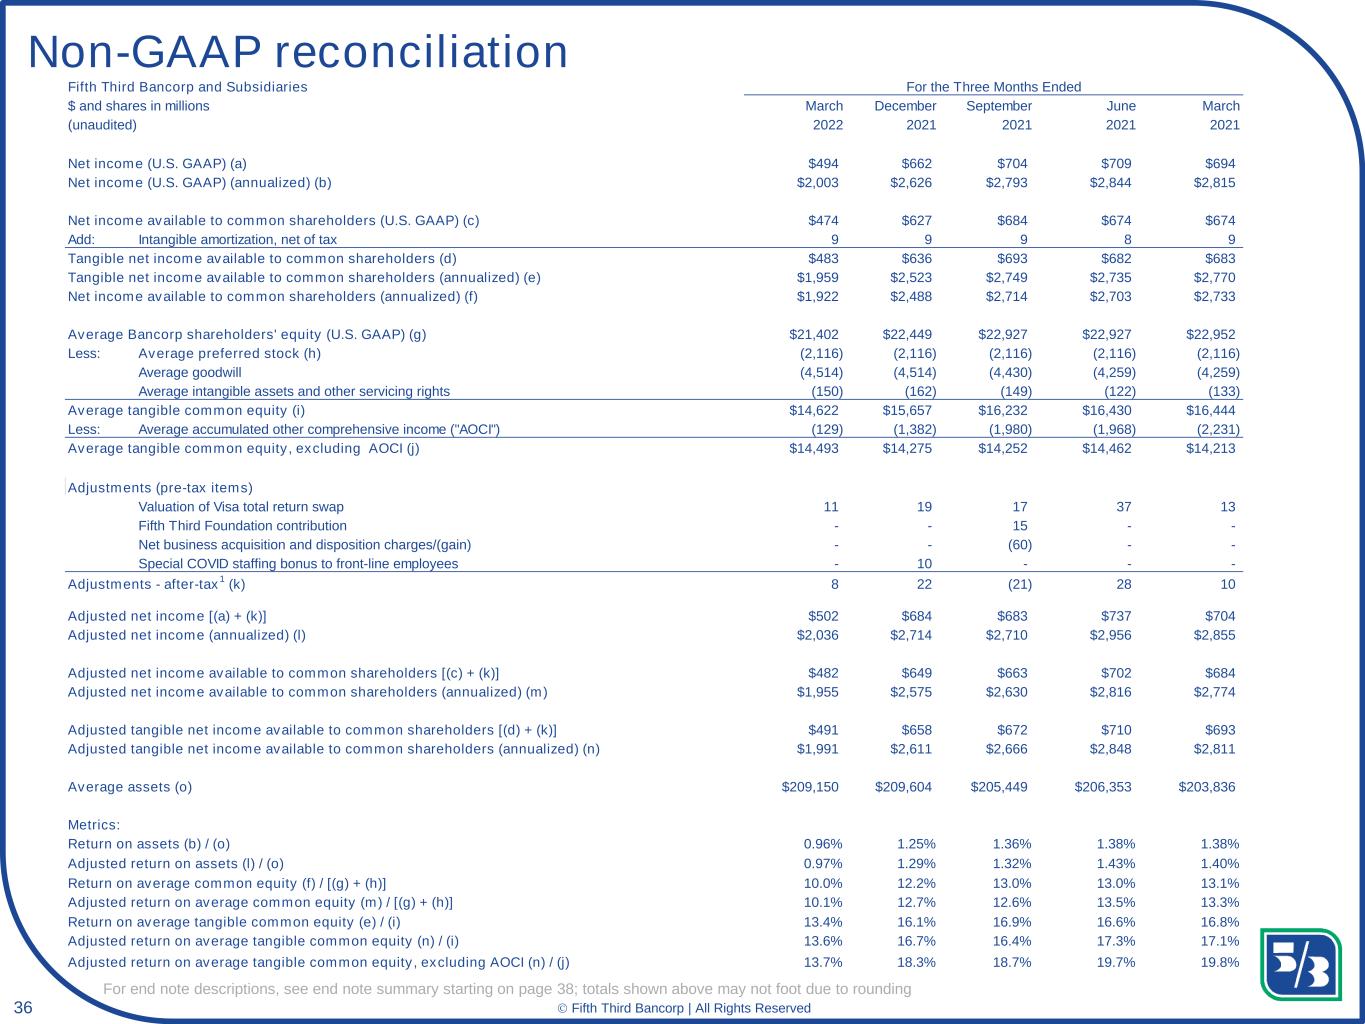
36 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Non-GAAP reconciliation For end note descriptions, see end note summary starting on page 38; totals shown above may not foot due to rounding Fifth Third Bancorp and Subsidiaries $ and shares in millions March December September June March (unaudited) 2022 2021 2021 2021 2021 Net income (U.S. GAAP) (a) $494 $662 $704 $709 $694 Net income (U.S. GAAP) (annualized) (b) $2,003 $2,626 $2,793 $2,844 $2,815 Net income available to common shareholders (U.S. GAAP) (c) $474 $627 $684 $674 $674 Add: Intangible amortization, net of tax 9 9 9 8 9 Tangible net income available to common shareholders (d) $483 $636 $693 $682 $683 Tangible net income available to common shareholders (annualized) (e) $1,959 $2,523 $2,749 $2,735 $2,770 Net income available to common shareholders (annualized) (f) $1,922 $2,488 $2,714 $2,703 $2,733 Average Bancorp shareholders' equity (U.S. GAAP) (g) $21,402 $22,449 $22,927 $22,927 $22,952 Less: Average preferred stock (h) (2,116) (2,116) (2,116) (2,116) (2,116) Average goodwill (4,514) (4,514) (4,430) (4,259) (4,259) Average intangible assets and other servicing rights (150) (162) (149) (122) (133) Average tangible common equity (i) $14,622 $15,657 $16,232 $16,430 $16,444 Less: Average accumulated other comprehensive income ("AOCI") (129) (1,382) (1,980) (1,968) (2,231) Average tangible common equity, excluding AOCI (j) $14,493 $14,275 $14,252 $14,462 $14,213 Adjustments (pre-tax items) Valuation of Visa total return swap 11 19 17 37 13 Fifth Third Foundation contribution - - 15 - - Net business acquisition and disposition charges/(gain) - - (60) - - Special COVID staffing bonus to front-line employees - 10 - - - Adjustments - after-tax 1 (k) 8 22 (21) 28 10 Adjusted net income [(a) + (k)] $502 $684 $683 $737 $704 Adjusted net income (annualized) (l) $2,036 $2,714 $2,710 $2,956 $2,855 Adjusted net income available to common shareholders [(c) + (k)] $482 $649 $663 $702 $684 Adjusted net income available to common shareholders (annualized) (m) $1,955 $2,575 $2,630 $2,816 $2,774 Adjusted tangible net income available to common shareholders [(d) + (k)] $491 $658 $672 $710 $693 Adjusted tangible net income available to common shareholders (annualized) (n) $1,991 $2,611 $2,666 $2,848 $2,811 Average assets (o) $209,150 $209,604 $205,449 $206,353 $203,836 Metrics: Return on assets (b) / (o) 0.96% 1.25% 1.36% 1.38% 1.38% Adjusted return on assets (l) / (o) 0.97% 1.29% 1.32% 1.43% 1.40% Return on average common equity (f) / [(g) + (h)] 10.0% 12.2% 13.0% 13.0% 13.1% Adjusted return on average common equity (m) / [(g) + (h)] 10.1% 12.7% 12.6% 13.5% 13.3% Return on average tangible common equity (e) / (i) 13.4% 16.1% 16.9% 16.6% 16.8% Adjusted return on average tangible common equity (n) / (i) 13.6% 16.7% 16.4% 17.3% 17.1% Adjusted return on average tangible common equity, excluding AOCI (n) / (j) 13.7% 18.3% 18.7% 19.7% 19.8% For the Three Months Ended
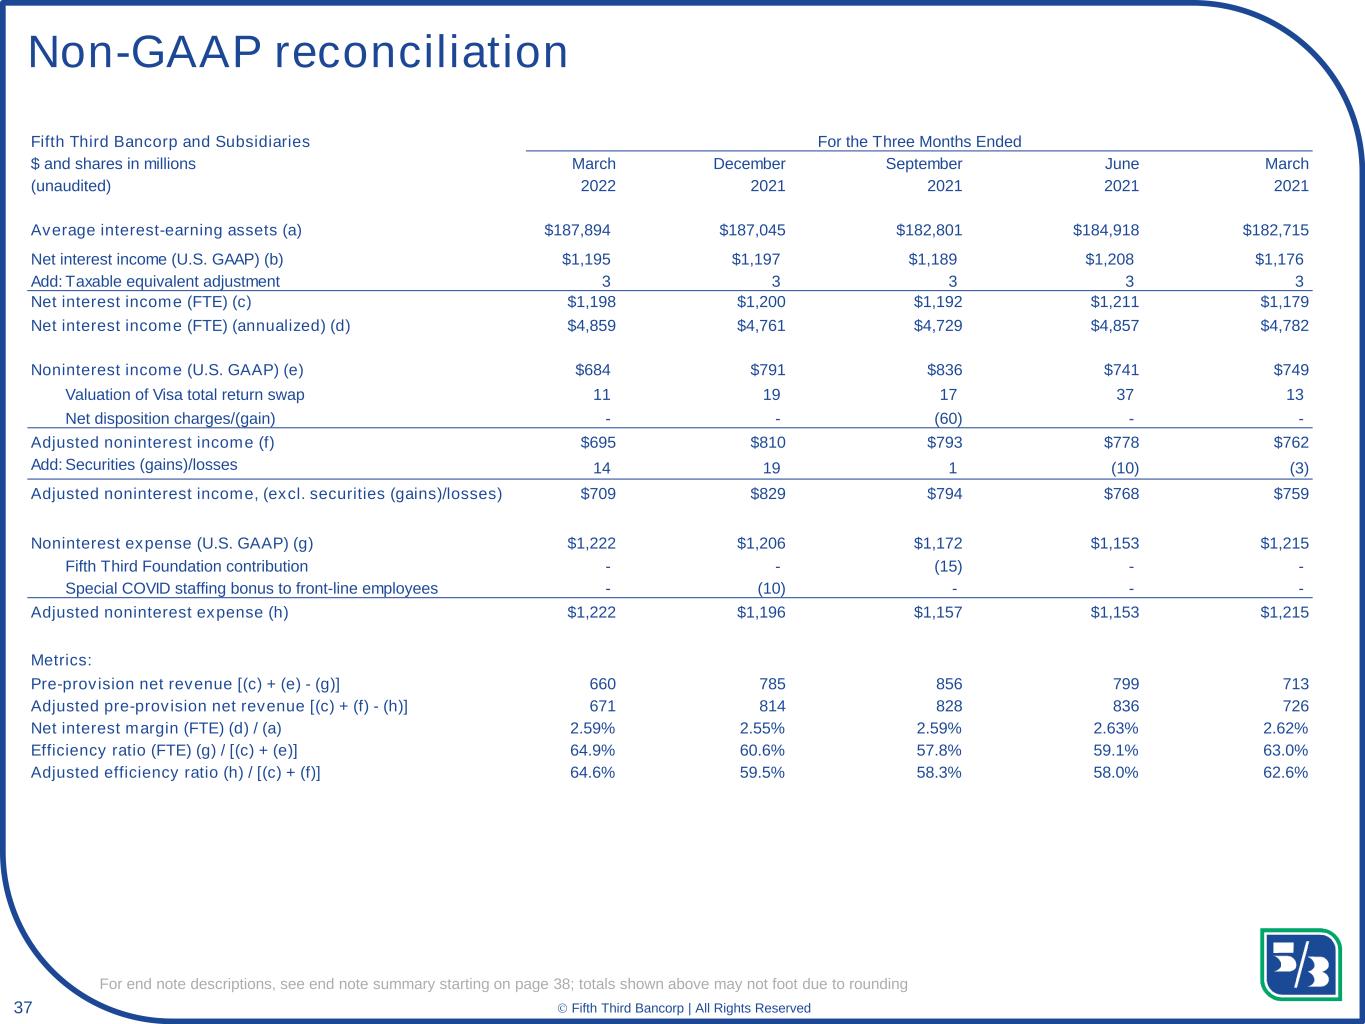
37 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Non-GAAP reconciliation For end note descriptions, see end note summary starting on page 38; totals shown above may not foot due to rounding Fifth Third Bancorp and Subsidiaries For the Three Months Ended $ and shares in millions March December September June March (unaudited) 2022 2021 2021 2021 2021 Average interest-earning assets (a) $187,894 $187,045 $182,801 $184,918 $182,715 Net interest income (U.S. GAAP) (b) $1,195 $1,197 $1,189 $1,208 $1,176 Add: Taxable equivalent adjustment 3 3 3 3 3 Net interest income (FTE) (c) $1,198 $1,200 $1,192 $1,211 $1,179 Net interest income (FTE) (annualized) (d) $4,859 $4,761 $4,729 $4,857 $4,782 Noninterest income (U.S. GAAP) (e) $684 $791 $836 $741 $749 Valuation of Visa total return swap 11 19 17 37 13 Net disposition charges/(gain) - - (60) - - Adjusted noninterest income (f) $695 $810 $793 $778 $762 Add: Securities (gains)/losses 14 19 1 (10) (3) Adjusted noninterest income, (excl. securities (gains)/losses) $709 $829 $794 $768 $759 Noninterest expense (U.S. GAAP) (g) $1,222 $1,206 $1,172 $1,153 $1,215 Fifth Third Foundation contribution - - (15) - - Special COVID staffing bonus to front-line employees - (10) - - - Adjusted noninterest expense (h) $1,222 $1,196 $1,157 $1,153 $1,215 Metrics: Pre-provision net revenue [(c) + (e) - (g)] 660 785 856 799 713 Adjusted pre-provision net revenue [(c) + (f) - (h)] 671 814 828 836 726 Net interest margin (FTE) (d) / (a) 2.59% 2.55% 2.59% 2.63% 2.62% Efficiency ratio (FTE) (g) / [(c) + (e)] 64.9% 60.6% 57.8% 59.1% 63.0% Adjusted efficiency ratio (h) / [(c) + (f)] 64.6% 59.5% 58.3% 58.0% 62.6%
38 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Earnings presentation end notes Slide 3 end notes 1. Reported ROTCE, NIM, pre-provision net revenue, and efficiency ratio are non-GAAP measures: all adjusted figures are non-GAAP measures; see reconciliation on pages 36 and 37 of this presentation and the use of non-GAAP measures on pages 26-28 of the earnings release. 2. Current period regulatory capital ratios are estimated. Slide 4 end notes 1. Results are on a fully-taxable equivalent basis; non-GAAP measure: see reconciliation on pages 36 and 37 of this presentation and use of non-GAAP measures on pages 26-28 of the earnings release. Slide 5 end notes 1. Non-GAAP measure: see reconciliation on pages 36 and 37 of this presentation and use of non-GAAP measures on pages 26-28 of the earnings release. Slide 6 end notes 1. Non-GAAP measure: see reconciliation on pages 36 and 37 of this presentation and use of non-GAAP measures on pages 26-28 of the earnings release. Slide 7 end notes 1. Includes taxable and tax-exempt securities. Slide 9 end notes 1. Excludes HFS loans. Slide 10 end notes 1. 1Q22 commercial and consumer portfolio make up $143M and $34M, respectively, of the total reserve for unfunded commitment. Slide 11 end notes 1. Current period regulatory capital ratios are estimated. 2. See forward-looking statements on page 2 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 26-28 of the earnings release. Slide 13 end notes 1. Non-GAAP measure: see forward-looking statements on page 2 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 26-28 of the earnings release. Slide 14 end notes 1. Non-GAAP measure: see forward-looking statements on page 2 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 26-28 of the earnings release. Slide 16 end notes 1. Dividend share shown as a percentage of lending market. 2. See forward-looking statements on page 2 of this presentation.
39 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Earnings presentation end notes Slide 18 end notes Data is for fiscal year 2021, unless otherwise noted 1. 1/1/2012-12/31/2021. 2. Refer to press release. 3. For Scope 1, Scope 2 and business travel under Scope 3 emissions. Projected full year 2021 CO2e emissions are based on 2021 year-to-date data as well as historical company data from 2014-2020. Final CO2e emissions will be made available in 2022 following independent verification. 4. In terms of ethnicity or gender. 5. $20 per hour minimum wage is effective on July 4, 2022. For additional details, refer to press release. 6. Since 2004. Slide 19 end notes 1. Peer group comprises of Fifth Third’s board approved peers. Slide 20 end notes 1. See forward-looking statements on page 2 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 26-28 of the earnings release. Slide 21 end notes 1. See forward-looking statements on page 2 of this presentation regarding forward-looking non-GAAP measures and use of non-GAAP measures on pages 26-28 of the earnings release. Slide 22 end notes Note: Data as of 3/31/22. 1. Excludes HFS Loans & Leases. 2. Fifth Third had $15B of commercial variable loans classified as fixed given the impacts of $3BN in floors with a 2.25% 1ML strike, $8BN in C&I receive-fix swaps, and $4BN in CRE receive-fix swaps 3. Excludes ~$0.7BN in Small Business Administration Paycheck Protection Program (PPP) loans. 4. Fifth Third had $705MM 3ML receive-fix swaps and $1.25BN 1ML receive-fix swaps outstanding against long-term debt, which are being included in floating long-term debt. 5. Yield of the 1Q22 weighted average taxable and non-taxable (tax equivalent) available for sale portfolio. 6. Effective duration taxable and non-taxable available for sale portfolio. 7. As a percent of total commercial, excluding PPP loans. 8. As a percent of total consumer. 9. As a percent of par. 10. Includes 12M term, 6M term, and Fed Funds based loans. 11. Excludes equity securities. 12. Term points include LIBOR, SOFR, BSBY, AMERIBOR, Treasuries & FX curves. 13. Includes overnight term, 3M term, 6M term, 12M term and Fed Funds. Slide 23 end notes Note: Data as of 03/31/22; actual results may vary from these simulated results due to differences between forecasted and actual balance sheet composition, timing, magnitude, and frequency of interest rate changes, as well as other changes in market conditions and management strategies. 1. Excludes ~$0.7BN in Small Business Administration Paycheck Protection Program (PPP) loans. 2. Effective duration taxable and non-taxable available for sale portfolio. 3. Re-pricing percentage or “beta” is the estimated change in yield after the 12-month ramp scenarios are fully realized and therefore reflects year-2. Slide 24 end notes 1. Represents forward looking statement, please refer to page 2 of this presentation regarding forward-looking non-GAAP measures; All swaps are receive fixed / pay 1-month LIBOR. 2. $3BN floors mature on 12/16/2024.
40 Classification: Internal Use© Fifth Third Banc rp | All Rights Reserved Earnings presentation end notes Slide 27 end notes 1. Assumes FIS will have sufficient taxable income to utilize TRA related deductions and have a marginal tax rate of 25%. 2. See forward-looking statements on page 2. Slide 28 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. 3. Total commercial portfolio line utilization. Slide 29 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. Slide 30 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. 3. FICO distributions at origination exclude certain acquired mortgage loans. Slide 31 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. 3. FICO distributions at origination exclude certain acquired home equity loans. Slide 32 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. 3. Reflects a FICO band reclassification from 4Q21 of certain auto loans. Slide 33 end notes 1. Net losses charged-off as a percent of average portfolio loans and leases presented on an annualized basis. 2. Nonperforming portfolio loans and leases as a percent of portfolio loans and leases. 3. FICO distributions at origination exclude ~$80 million from credit loans on book primarily ~15+ years. Slide 34 end notes 1. Loan balances exclude nonaccrual loans HFS. Slide 35 end notes 1. Average diluted common shares outstanding (thousands); 696,242; all adjusted figures are non-GAAP measures; see reconciliation on pages 36 and 37 of this presentation and the use of non-GAAP measures on pages 26-28 of the earnings release. 2. Assumes a 23% tax rate. Slide 36 end notes Note: See pages 26-28 of the earnings release for a discussion on the use of non-GAAP financial measures. 1. Assumes a 23% tax rate. Slide 37 end notes Note: See pages 26-28 of the earnings release for a discussion on the use of non-GAAP financial measures.