
Medallion Financial Corp 8-K/A, filed Mar 30, 2020
Medallion Financial Corp (MFIN)
About this 8-K/A
Medallion Financial Corp filed this 8-K/A on March 30, 2020, reporting on events of February 20, 2020.
Items reported
- Item 2.02: Financial results
- Item 9.01: Financial statements and exhibits
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K/A
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): February 20, 2020
MEDALLION FINANCIAL CORP.
(Exact name of Registrant as Specified in Its Charter)
|
Delaware |
001-37747 |
04-3291176 |
|
(State or Other Jurisdiction of Incorporation) |
(Commission File Number) |
(IRS Employer Identification No.) |
|
|
|
|
|
437 Madison Ave New York, New York |
|
10022 |
|
(Address of Principal Executive Offices) |
|
(Zip Code) |
Registrant’s Telephone Number, Including Area Code: (212) 328-2100
Not Applicable
(Former Name or Former Address, if Changed Since Last Report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
|
☐ |
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) |
|
☐ |
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) |
|
☐ |
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) |
|
☐ |
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) |
Securities registered pursuant to Section 12(b) of the Act:
|
Title of each class |
|
Trading Symbol(s) |
|
Name of each exchange on which registered |
|
Common Stock, par value $0.01 per share |
|
MFIN |
|
NASDAQ Global Select Market |
|
9.000% Senior Notes due 2021 |
|
MFINL |
|
NASDAQ Global Select Market |
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§ 230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§ 240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition.
This Amendment No. 1 to Current Report on Form 8-K is being furnished to reflect changes in the financial results of Medallion Financial Corp. (the “Company”) as of, and for the quarter and year ended, December 31, 2019 contained in the press release previously filed as Exhibit 99.1 to the Company’s Current Report on Form 8-K furnished to the U.S. Securities and Exchange Commission on February 20, 2020 (the “Initial Form 8-K”).
Just prior to the anticipated filing of the Company’s 2019 audited financial statements, the Company reviewed three borrower relationships, representing 61 medallion loans with $27.5 million aggregate principal amount, including consideration of additional information identified since the filing of the Initial Form 8-K. These loans were categorized as performing loans at the time the Company filed the Initial Form 8-K, and therefore had a general allowance for credit losses reserve allocation of $5.6 million, as of year-end. The Company’s financial results as of, and for the periods ended, December 31, 2019 were reported in the Initial Form 8-K on that basis. However, upon consideration of the additional information about these loans, the Company determined to categorize these loans as impaired loans and classified these loans as troubled debt restructurings (“TDR”). The Company also applied the same impairment calculation methodology to 18 medallion loans already classified as TDRs. The net effect of these adjustments was an increase in the total TDR amount of $27.5 million and an additional $4.3 million provision for credit losses, resulting in a reduction of after tax net income of $3.2 million, for the quarter and year ended December 31, 2019.
The below tables summarize the significant revisions, including the impact of the change in the allowance and provision for credit losses, charge-offs and related reductions to other assets, other liabilities, non-interest expense and income tax expense.
A revised version of the press release previously filed as Exhibit 99.1 to the Initial Form 8-K is attached hereto as Exhibit 99.1 and is incorporated herein by reference. The information in the press release is being furnished, not filed, pursuant to Item 2.02. Accordingly, the information in the press release will not be incorporated by reference into any registration statement filed by the Company under the Securities Act of 1933, as amended, unless specifically identified therein as being incorporated therein by reference.

Item 9.01 Financial Statements and Exhibits
|
(d) |
Exhibits |
The following exhibits are being filed with this Current Report on Form 8-K:
|
|
|
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
Dated: March 30, 2020
|
|
|
|
|
MEDALLION FINANCIAL CORP. |
||
|
|
|
|
|
By: |
|
/s/ Larry D. Hall |
|
|
|
Name: Larry D. Hall |
|
|
|
Title: Chief Financial Officer |
EXHIBIT 99.1

FOR IMMEDIATE RELEASE:
MEDALLION FINANCIAL CORP. REPORTS REVISED 2019 FOURTH QUARTER
AND FULL YEAR RESULTS
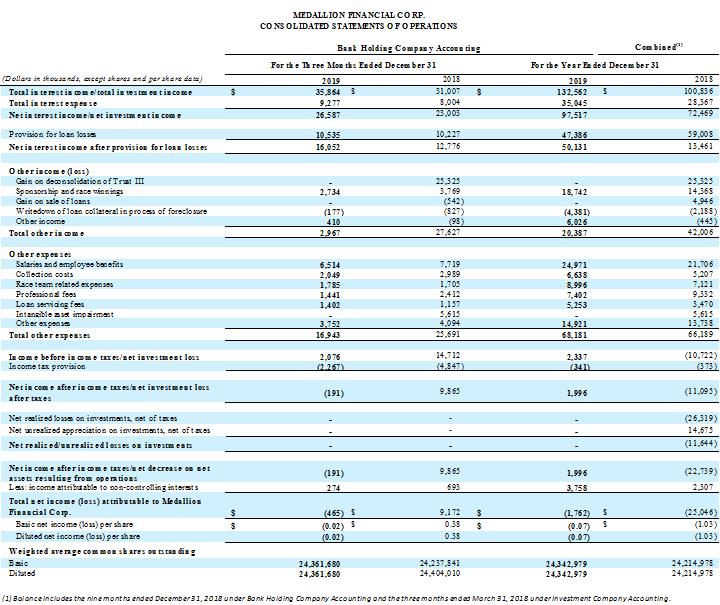
NEW YORK, NY – March 30, 2020 – Medallion Financial Corp. (Nasdaq: MFIN, Medallion or the Company), a finance company that originates and services loans in various consumer and commercial niche industries, initially reported results for the quarter and year ended December 31, 2019 on February 18, 2020. Just prior to the anticipated filing of the Company’s 2019 audited financial statements, the Company reviewed three borrower relationships, representing 61 medallion loans with $27.5 million aggregate principal amount, including consideration of additional information identified since the Company initially reported results. These loans were categorized as performing loans at the time the Company initially reported results, and therefore had a general allowance for credit losses reserve allocation of $5.6 million, as of year-end. The Company’s financial results as of, and for the periods ended, December 31, 2019 were reported on that basis at the time the Company initially reported results. However, upon consideration of the additional information about these loans, the Company determined to categorize these loans as impaired loans and classified these loans as troubled debt restructurings (“TDR”). The Company also applied the same impairment calculation methodology to 18 medallion loans already classified as TDRs. The net effect of these adjustments was an increase in the total TDR amount of $27.5 million and an additional $4.3 million provision for credit losses, resulting in a reduction of after tax net income of $3.2 million for the quarter and year ended December 31, 2019. The remainder of this release and the tables at the end of this release have been updated to reflect these changes.
2019 Fourth Quarter Highlights
|
|
• |
Net loss was $0.5 million, or $0.02 per share, compared to net income of $9.2 million, or $0.38 per share, in the prior year period, which included a gain of $25.3 million as a result of the Company successfully deconsolidating Trust III in the 2018 fourth quarter |
|
|
• |
Net interest income was $26.6 million, primarily reflective of the contributions of the consumer lending segments |
|
|
• |
Net interest margin was 8.83%, up from 8.07% in the year ago quarter, reflecting the greater contribution of the higher yielding consumer and commercial segments |
|
|
• |
Net interest margins for the recreation and home improvement segments were 12.98% and 7.13% |
|
|
• |
Net income from the consumer and commercial segments totaled $7.2 million in the quarter |
|
|
• |
The total interest yield on the Company’s loan portfolio was 12.70% in the 2019 fourth quarter |
|
|
• |
Medallion loan exposure continued to be reduced, with the net portfolio at $105.0 million at quarter-end which represented 7% of total assets |
|
|
• |
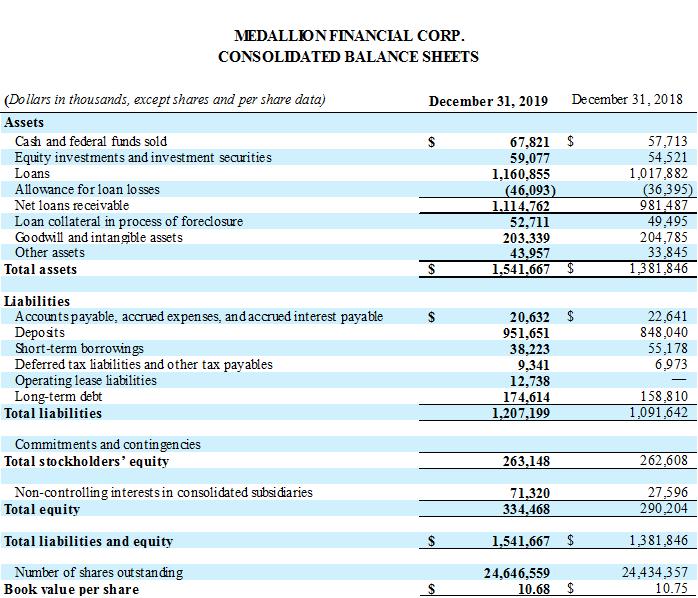
Total assets were $1.54 billion as of December 31, 2019 |
2019 Full Year Highlights
|
|
• |
2019 total net loss was $1.8 million compared to a loss of $25.0 million in 2018 |
|
|
• |
2019 net income from Medallion’s consumer and commercial segments was $31.9 million |
|
|
• |
Net consumer loans grew 23% year over year |
|
|
• |
Consumer originations were $443.5 million for the year, up from $408.4 million in 2018 |
|
|
• |
2019 net interest margin was 8.64% |
|
|
• |
Net cash flow from operations was $64.9 million |
|
|
• |
Total medallion loans 90 days or more past due were $2.6 million, or 2.0% of total medallion loans at the end of 2019 |
|
|
• |
Net medallion loans dropped 33% from $155.9 million to $105.0 million at year end |
Andrew Murstein, President of Medallion, stated, “2019 was a significant year for us as we turned the corner, moved forward, and delivered on the strategy we have laid out. We continued to reduce the Company’s medallion losses and portfolio, raised capital, and began the process to provide loan origination services to the fintech industry. Losses from our medallion exposure, in particular in the second half of the year, have been lower than in recent years. We completed both a private placement at Medallion Financial of investment grade debt, and an initial public offering of perpetual preferred stock at Medallion Bank, raising over $82 million in total during 2019.
This past July, we hired an experienced executive at Medallion Bank to build-out its Strategic Partnership Program with financial technology companies. We are pleased to announce that Medallion Bank has entered into a strategic partnership with Choice Payment Services. The partnership will leverage Medallion Bank’s compliance, lending operations, and management expertise and Choice Payment Services’ comprehensive lending platform to provide consumer lending solutions to merchants and healthcare providers seeking to more efficiently and effectively serve their customers. We will be providing updates on our progress in building out this program in our future quarterly earnings reports.
Our consumer and commercial segments had a solid year after coming off a strong 2018, as net income before taxes from our mezzanine, home improvement, and recreation lending divisions totaled $43 million in 2019. At the end of the year, Medallion Capital, the lead driver in our commercial lending segment, had $40 million in capital, and Medallion Bank had $227 million in capital.”
Mr. Murstein continued: “The medallion loan portfolio remains at the lowest level since going public in 1996. We continue to monitor industry news, both from a legislative and regulatory standpoint.”
Larry Hall, Chief Financial Officer, stated, “We recorded a net interest margin of 8.83% in the 2019 fourth quarter, the highest in 12 years, which resulted in the Company being able to end the year with a net interest margin of 8.64%. The total interest yield on the Company’s loan portfolio was 12.69% in the 2019 fourth quarter, the highest it has been since we withdrew our BDC election and consolidated Medallion Bank. As a result of the Bank’s public offering of preferred shares, the Bank ended 2019 with a Tier 1 leverage ratio of 19.35%. The fourth quarter income tax provision included a charge of $1.5 million or $0.06 per share, attributable to the change in the Company’s effective state income tax rate and its impact on the deferred tax liability.”
Consumer Lending Segments
Medallion’s net consumer lending portfolio as of December 31, 2019 was $940.0 million, compared to $761.5 million at the end of 2018. Net interest income for the 2019 fourth quarter was $27.0 million, compared to $23.6 million in the prior year period. The average interest rate on the portfolio was 14.54% at December 31, 2019, compared to 15.06% at the end of 2018. Consumer loan delinquencies 90 days or more past due as of December 31, 2019 were 0.64%, compared to 0.57% a year ago.
Commercial Lending Segment
The Company’s net commercial lending portfolio as of December 31, 2019 was $66.4 million, compared to $60.0 million at the end of the prior year period. The yield on the portfolio was 10.74% in the 2019 fourth quarter, compared to 14.33% in the 2018 fourth quarter. Net income for the 2019 fourth quarter was $0.366 million.
Medallion Lending Segment
The Company’s net medallion lending portfolio as of December 31, 2019 was $105.0 million, compared to $155.9 million at the end of 2018. The average interest rate on the medallion portfolio was 4.17%, compared to 4.43% a year ago. Total medallion loan delinquencies 90 days or more past due were $2.6 million, or 2.0% of the total portfolio, as of December 31, 2019, compared to $16.7 million or 9.4% of the total portfolio at the end of 2018. Total medallion loan delinquencies 30 days or more past due were $17.2 million as of December 31, 2019, or 13.6% of the total portfolio, compared to $28.1 million, or 15.9% of the total portfolio, at December 31, 2018. Medallion loans comprised 10% of the Company’s net loans receivable as of December 31, 2019, compared to 16% at the end of 2018.
* * *
2
About Medallion Financial Corp.
Medallion Financial Corp. is a finance company that originates and services loans in various industries, and its wholly-owned subsidiary, Medallion Bank, also originates and services consumer loans. Medallion Financial Corp. has lent more than $8.8 billion since its initial public offering in 1996.
Please note that this press release contains forward-looking statements that involve risks and uncertainties relating to business performance, cash flow, costs, sales, net investment income, earnings, and growth. Medallion’s actual results may differ significantly from the results discussed in such forward-looking statements. Factors that might cause such a difference include, but are not limited to, risks related to the ongoing COVID-19 pandemic and the factors discussed under the heading “Risk Factors,” in Medallion’s 2018 Annual Report on Form 10-K, Medallion’s 2019 Annual Report on Form 10-K that will be filed later on today and its other filings with the SEC.
Company Contact:
Alex E. Arzeno
Investor Relations
212-328-2176
InvestorRelations@medallion.com
3
5