
OBK 8-K
Origin Bancorp, Inc. (OBK)
8-K
2025-04-23
For: 2025-04-23
View Original
Added on
April 09, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the
Securities Exchange Act of 1934
Date of Report (Date of earliest event reported)
(Exact name of Registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File No.) | (I.R.S. Employer Identification No.) | ||||||||||||
| (Address of principal executive offices including zip code) | ||
(318 ) 255-2222
| (Registrant's telephone number, including area code) | ||
| (Former name or former address, if changed since last report) | ||
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
| Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). | |||||
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨ | |||||
| ITEM 2.02 | Results of Operations and Financial Condition | ||||
On April 23, 2025, Origin Bancorp, Inc. (the "Company" or the "Registrant") issued a press release announcing its first quarter 2025 results of operations. A copy of the press release is attached hereto as Exhibit 99.1, which is incorporated herein by reference.
On Thursday, April 24, 2025, at 8:00 a.m. Central Time, the Company will host an investor conference call and webcast to review its first quarter 2025 financial results. The webcast will include presentation materials, which consist of information regarding the Company's results of operations and financial performance. The presentation materials will be posted on the Company's website on April 23, 2025. The presentation materials are attached hereto as Exhibit 99.2, which is incorporated herein by reference.
As provided in General Instructions B.2 to Form 8-K, the information furnished in Item 2.02, Exhibit 99.1 and Exhibit 99.2 of this Current Report on Form 8-K shall not be deemed "filed" for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the "Exchange Act"), or otherwise subject to the liabilities of that section, and such information shall not be deemed incorporated by reference in any filing under the Securities Act of 1933, as amended, or the Exchange Act, except as shall be expressly set forth by specific reference in such filing.
| ITEM 8.01 | Other Events | ||||
On April 23, 2025, the Company issued a press release announcing that the board of directors of the Company declared a quarterly cash dividend of $0.15 per share of its common stock. The cash dividend will be paid on May 30, 2025, to stockholders of record as of the close of business on May 15, 2025. The press release is attached hereto as Exhibit 99.3, and incorporated herein by reference.
| ITEM 9.01 | Financial Statements and Exhibits | ||||
| (d) | Exhibits. | ||||
| Exhibit 99.1 | |||||
| Exhibit 99.2 | |||||
| Exhibit 99.3 | |||||
| Exhibit 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | ||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the Registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized.
Dated: April 23, 2025 | ORIGIN BANCORP, INC. | |||||||
By: /s/ William J. Wallace, IV | ||||||||
| William J. Wallace, IV | ||||||||
| Senior Executive Officer and Chief Financial Officer | ||||||||
`
Exhibit 99.1
For Immediate Release
ORIGIN BANCORP, INC. REPORTS EARNINGS FOR FIRST QUARTER 2025
RUSTON, Louisiana (April 23, 2025) - Origin Bancorp, Inc. (NYSE: OBK) (“Origin,” “we,” “our” or the “Company”), the holding company for Origin Bank (the “Bank”), today announced net income of $22.4 million, or $0.71 diluted earnings per share (“EPS”) for the quarter ended March 31, 2025, compared to net income of $14.3 million, or $0.46 diluted earnings per share, for the quarter ended December 31, 2024. Pre-tax, pre-provision (“PTPP”)(1) earnings were $32.0 million for the quarter ended March 31, 2025, compared to $12.6 million for the linked quarter.
“Origin reported solid results for the quarter, and I am proud of how our bankers remain responsive to our customers and communities,” said Drake Mills, chairman, president and CEO of Origin Bancorp, Inc. “During last quarter’s earnings call, we introduced Optimize Origin, which is our plan to deliver sustainable elite-level financial performance. I am pleased with the overwhelming focus and commitment our employees have on accomplishing this goal and the progress we have made since launch.”
(1) PTPP earnings is a non-GAAP financial measure, please see the last few pages of this document for a reconciliation of this alternative financial measure to its most directly comparable GAAP measure.
Optimize Origin
•In January 2025, we announced our initiative to drive elite financial performance and enhance our award-winning culture.
•Built on three primary pillars:
◦Productivity, Delivery & Efficiency
◦Balance Sheet Optimization
◦Culture & Employee Engagement
•Established near term target of greater than a 1% ROAA run rate by 4Q25 and an ultimate target of top quartile ROAA.
•Near term target is being achieved in part by branch consolidation, headcount reduction, securities optimization, capital optimization, cash/liquidity management, mortgage restructuring, as well as other opportunistic efficiency optimizations throughout the organization.
•We believe the actions we have taken will drive earnings improvement of approximately $23.4 million annually on a pre-tax pre-provision basis.
Financial Highlights
•Net interest income was $78.5 million for the quarter ended March 31, 2025, reflecting an increase of $110,000, or 0.1%, compared to the linked quarter and is at its highest level in eight quarters.
•Net income was $22.4 million for the quarter ended March 31, 2025, reflecting an increase of $8.1 million, or 57.0% compared to the linked quarter.
•Our fully tax equivalent net interest margin (“NIM-FTE”) expanded 11 basis points for the quarter ended March 31, 2025, compared to the quarter ended December 31, 2024. This expansion was driven primarily by a 34 basis point
1
`
reduction in rates paid on interest-bearing liabilities, offset by a 12 basis point decline in our yield earned on interest-earning assets.
•Return on average assets (“ROAA”), annualized, was 0.93% for the quarter ended March 31, 2025, a 63.2% increase when compared to 0.57% in the linked quarter. PTPP ROAA(1), annualized, was 1.32% for the quarter ended March 31, 2025, reflecting an increase of 164.0% compared to 0.50% in the linked quarter.
•Total loans held for investment (“LHFI”) were $7.59 billion at March 31, 2025, reflecting an increase of $11.8 million, or 0.2%, compared to December 31, 2024. Average LHFI were $7.50 billion for the quarter ended March 31, 2025, reflecting a decrease of $298.2 million, or 3.83%, compared to the quarter ended December 31, 2024.
•Total deposits were $8.34 billion at March 31, 2025, reflecting an increase of $115.3 million, or 1.4%, compared to December 31, 2024. Deposits, excluding brokered deposits, were $8.29 billion at March 31, 2025, reflecting an increase of $145.5 million, or 1.8%, compared to December 31, 2024.
(1) PTPP ROAA is a non-GAAP financial measure, please see the last few pages of this document for a reconciliation of this alternative financial measure to its most directly comparable GAAP measure.
Results of Operations for the Quarter Ended March 31, 2025
Net Interest Income and Net Interest Margin
Net interest income for the quarter ended March 31, 2025, was $78.5 million, an increase of $110,000, or 0.1%, compared to the quarter ended December 31, 2024. The increase was primarily driven by a $7.7 million decrease in interest expense paid on interest-bearing deposits and increases of $1.4 million and $1.3 million in interest income earned on investment securities and average interest-earning balances due from banks, partially offset by a decrease of $9.9 million in interest income earned on LHFI.
The decrease in average rates of interest-bearing deposits during the quarter ended March 31, 2025, and two fewer days in the current quarter, reduced interest expense by $5.8 million and $1.2 million, respectively, when compared to the quarter ended December 31, 2024. The average rate on interest-bearing deposits was 3.23% for the quarter ended March 31, 2025, a decrease of 38 basis points, from 3.61% for the quarter ended December 31, 2024.
The $1.4 million increase in interest income earned on investment securities was primarily driven by the bond portfolio optimization strategy we executed during the quarter ended December 31, 2024, in which we replaced securities with a total book value of $188.2 million and a weighted average yield of 1.51% with new securities totaling $173.7 million with a weighted average yield of 5.22%.
The $1.3 million increase in interest income earned on average interest-earning balances due from banks was primarily driven by a $149.0 million increase in average interest-earning balances due from banks which led to a $1.8 million increase in interest income, partially offset by a reduction in average yield.
The decrease in average LHFI principal balance, the impact of two fewer calendar days and a decline in average rates during the quarter ended March 31, 2025, resulted in decreases to interest income of $5.5 million, $2.6 million and $1.8 million, respectively, when compared to the quarter ended December 31, 2024. The decrease in average LHFI principal balance was primarily driven by decreases of $170.2 million and $114.4 million in mortgage warehouse lines of credit (“MW LOC”) and average construction/land/land development loan balances. The average rate on LHFI was 6.33% for the quarter ended March 31, 2025, a decrease of 14 basis points, compared to 6.47% for the quarter ended December 31, 2024.
The Federal Reserve Board sets various benchmark rates, including the federal funds rate, and thereby influences the general market rates of interest, including the loan and deposit rates offered by financial institutions. On September 18, 2024, the Federal Reserve reduced the federal funds target rate range by 50 basis points, to a range of 4.75% to 5.00%, marking the first rate reduction since early 2020. Subsequently, it implemented two additional reductions, with the current federal funds target range set to 4.25% to 4.50% on December 18, 2024. The Federal Reserve maintained this target range throughout the first quarter of 2025. In total, the federal funds target range has decreased 100 basis points from its recent cycle high.
2
`
Our NIM-FTE was 3.44% for the quarter ended March 31, 2025, representing 11- and 25-basis-point increases compared to the linked quarter and the prior year same quarter, respectively. The yield earned on interest-earning assets for the quarter ended March 31, 2025, was 5.79%, a decrease of 12 and 20 basis points compared to the linked quarter and the quarter ended March 31, 2024. The average rate paid on total interest-bearing liabilities for the quarter ended March 31, 2025, was 3.30%, representing 34- and 58-basis point decreases compared to the linked quarter and the quarter ended March 31, 2024, respectively.
Credit Quality
The table below includes key credit quality information:
| At and For the Three Months Ended | Change | % Change | |||||||||||||||||||||||||||
| (Dollars in thousands, unaudited) | March 31, 2025 | December 31, 2024 | March 31, 2024 | Linked Quarter | Linked Quarter | ||||||||||||||||||||||||
| Past due LHFI | $ | 72,774 | $ | 42,437 | $ | 32,835 | $ | 30,337 | 71.5 | % | |||||||||||||||||||
Allowance for loan credit losses (“ALCL”) | 92,011 | 91,060 | 98,375 | 951 | 1.0 | ||||||||||||||||||||||||
| Classified loans | 127,676 | 118,782 | 84,217 | 8,894 | 7.5 | ||||||||||||||||||||||||
| Total nonperforming LHFI | 81,368 | 75,002 | 40,439 | 6,366 | 8.5 | ||||||||||||||||||||||||
| Provision (benefit) for credit losses | 3,444 | (5,398) | 3,012 | 8,842 | N/M | ||||||||||||||||||||||||
| Net charge-offs (recoveries) | 2,728 | (560) | 2,582 | 3,288 | N/M | ||||||||||||||||||||||||
Credit quality ratios(1): | |||||||||||||||||||||||||||||
| ALCL to nonperforming LHFI | 113.08 | % | 121.41 | % | 243.27 | % | (8.33) | % | N/A | ||||||||||||||||||||
| ALCL to total LHFI | 1.21 | 1.20 | 1.25 | 0.01 | N/A | ||||||||||||||||||||||||
ALCL to total LHFI, adjusted(2) | 1.28 | 1.25 | 1.30 | 0.03 | N/A | ||||||||||||||||||||||||
| Classified loans to total LHFI | 1.68 | 1.57 | 1.07 | 0.11 | N/A | ||||||||||||||||||||||||
| Nonperforming LHFI to LHFI | 1.07 | 0.99 | 0.51 | 0.08 | N/A | ||||||||||||||||||||||||
| Net charge-offs to total average LHFI (annualized) | 0.15 | (0.03) | 0.13 | 0.18 | N/A | ||||||||||||||||||||||||
N/M = Not meaningful.
N/A = Not applicable.
(1)Please see the Loan Data schedule at the back of this document for additional information.
(2)The ALCL to total LHFI, adjusted, is calculated by excluding the ALCL for MW LOC loans from the total LHFI ALCL in the numerator and excluding the MW LOC loans from the LHFI in the denominator. Due to their low-risk profile, MW LOC loans require a disproportionately low allocation of the ALCL.
Past due loans increased $30.3 million for the current quarter compared to the linked quarter. The increase was primarily due to 11 relationships totaling $39.8 million. The increase in past due loan relationships primarily consisted of residential real estate totaling $18.0 million, commercial real estate totaling $8.3 million, commercial and industrial totaling $9.7 million and construction/land/land development totaling $3.9 million. These increases were partially offset by a $4.5 million decrease in three previously past due residential real estate relationships, one of which paid off during the current quarter.
Nonperforming LHFI increased $6.4 million for the current quarter compared to the linked quarter, evidenced by an increase in the percentage of nonperforming LHFI to LHFI to 1.07% compared to 0.99% for the linked quarter. The increase in nonperforming loans was primarily driven by two loan relationships totaling $8.2 million at March 31, 2025, with residential real estate loans totaling $5.1 million of the increase. The increase in nonperforming loans was partially offset by one residential real estate loan relationship totaling $2.1 million that paid off during the current quarter, but was considered nonperforming at December 31, 2024.
Classified loans increased $8.9 million to $127.7 million at March 31, 2025, compared to $118.8 million at December 31, 2024. As discussed in previous filings, our classified and nonperforming LHFI were negatively impacted beginning in the second quarter of 2024 as a result of litigation against the bank brought in response to certain questioned activity involving a former banker in our East Texas market. We continue to work toward a resolution in this matter.
Our results included a credit loss provision expense of $3.4 million during the quarter ended March 31, 2025, which includes a $3.7 million provision for loan credit losses, compared to provision release of $5.5 million for the linked quarter. Our allowance for credit losses increased $1.0 million during the current quarter, primarily driven by the $1.4 million increase in the individually evaluated portion of the reserve as a result of the increase in nonperforming loans.
3
`
Net charge-offs increased $3.3 million for the quarter ended March 31, 2025, when compared to the quarter ended December 31, 2024, primarily due to total charge-offs of $4.8 million in the current quarter, consisting primarily of two commercial and industrial loan relationships with charge-offs totaling $2.6 million.
Noninterest Income
Noninterest income for the quarter ended March 31, 2025, was $15.6 million, an increase of $15.9 million from the linked quarter, primarily driven by the $14.6 million loss on sales of securities, net, in the linked quarter and the $2.5 million increase in insurance commission and fee income in the current quarter. These increases were offset by a decrease of $1.6 million in limited partnership investment (loss) income.
The loss on sales of securities, net, during the linked quarter was due to the execution of the bond portfolio optimization strategy security sale, with no such sale in the current quarter.
The increase in insurance commission and fee income was primarily driven by a seasonal increase in annual contingency fee income recognized in the first quarter.
The decrease in limited partnership investment income (loss) was due to $1.6 million in fair value adjustments on multiple limited partnership investments.
Noninterest Expense
Noninterest expense for the quarter ended March 31, 2025, was $62.1 million, a decrease of $3.4 million, or 5.1% from the linked quarter. The decrease was primarily driven by decreases of $3.1 million, $814,000 and $796,000 in other noninterest expense, professional services and advertising and marketing expense, respectively, that was partially offset by an increase of $1.3 million in salaries and employee benefit expense.
The decrease in other noninterest expense was primarily due to $3.1 million in contingency expense recorded during the linked quarter. There was no such contingency reserve recorded in the current quarter.
The $814,000 decrease in professional services was primarily due to a decrease of $668,000 in forensic accounting fees compared to the linked quarter.
The $796,000 decrease in advertising and marketing was primarily due to a decrease in targeted marketing efforts in the current quarter compared to the prior quarter.
The $1.3 million increase in salaries and employee benefit expense was primarily due to an Employee Retention Credit (“ERC”) of $1.7 million that was recorded in the linked quarter and related to the operations of BTH Bank, N.A., which we acquired in 2022. The ERC is a refundable tax credit for certain eligible businesses that had employees affected during the COVID-19 pandemic. This was partially offset by a decrease in incentive compensation due to the adjustment of the incentive compensation accrual during the current quarter.
Financial Condition
Loans
•Total LHFI at March 31, 2025, were $7.59 billion, an increase of $11.8 million, or 0.2%, from $7.57 billion at December 31, 2024, and a decrease of $314.5 million, or 4.0%, compared to March 31, 2024.
•The primary driver of the increase during the quarter ended March 31, 2025, compared to the linked quarter, were increases in multi-family real estate, MW LOC, residential real estate - single family and commercial and industrial loans of $64.3 million, $55.1 million, $33.1 million and $19.5 million, respectively. These increases were partially offset by decreases of $93.6 million and $65.4 million in total commercial real estate and construction/land/land development loans, respectively.
4
`
Securities
•Total securities at March 31, 2025 were $1.18 billion, an increase of $58.8 million, or 5.3%, from $1.12 billion at December 31, 2024, and a decrease of $30.4 million, or 2.5%, compared to March 31, 2024.
•The increase in securities was due to purchases of $73.1 million in the current quarter. This was partially offset by maturities, scheduled principal payments and calls.
•Accumulated other comprehensive loss, net of taxes, primarily associated with unrealized losses within the available for sale portfolio, was $90.4 million at March 31, 2025, a decrease of $15.6 million, or 14.7% , from the linked quarter.
•The weighted average effective duration for the total securities portfolio was 4.10 years as of March 31, 2025, compared to 4.46 years as of December 31, 2024.
Deposits
•Total deposits at March 31, 2025, were $8.34 billion, an increase of $115.3 million, or 1.4%, compared to the linked quarter, and a decrease of $167.1 million, or 2.0%, from March 31, 2024. The increase in the current quarter compared to the linked quarter was primarily due to an increase of $278.9 million in money market deposits. The increase was partially offset by decreases of $78.0 million and $67.1 million in time deposits (excluding brokered time deposits) and interest-bearing demand deposits, respectively.
•At March 31, 2025, noninterest-bearing deposits as a percentage of total deposits were 22.7%, compared to 23.1% and 22.2% at December 31, 2024, and March 31, 2024, respectively. Excluding brokered deposits, noninterest-bearing deposits as a percentage of total deposits were 22.8%, compared to 23.3% and 23.9% at December 31, 2024, and March 31, 2024, respectively.
Subordinate debentures
•Total subordinated debentures at March 31, 2025, were $89.6 million, a decrease of $70.3 million, or 44.0%, from $159.9 million at December 31, 2024, and a decrease of $71.1 million, or 44.2%, compared to March 31, 2024.
•The decrease was due to the redemption of $70.0 million in subordinated debentures in conjunction with our Optimize Origin initiative, as forecasted in our fourth quarter 2024 investor presentation. We recognized $681,000 in original issue discount amortization related to the redemption during the current quarter. Based upon our forecast, the redemption is expected to result in approximately $2.1 million in annualized future interest expense savings.
Conference Call
Origin will hold a conference call to discuss its first quarter 2025 results on Thursday, April 24, 2025, at 8:00 a.m. Central Time (9:00 a.m. Eastern Time). To participate in the live conference call, please dial +1 (929) 272-1574 (U.S. Local / International 1); +1 (857) 999-3259 (U.S. Local / International 2); +1 (888) 700-7550 (U.S. Toll Free), enter Conference ID: 66134 and request to be joined into the Origin Bancorp, Inc. (OBK) call. A simultaneous audio-only webcast may be accessed via Origin’s website at www.origin.bank under the investor relations, News & Events, Events & Presentations link or directly by visiting https://dealroadshow.com/e/ORIGINQ125.
If you are unable to participate during the live webcast, the webcast will be archived on the Investor Relations section of Origin’s website at www.origin.bank, under Investor Relations, News & Events, Events & Presentations.
About Origin
Origin Bancorp, Inc. is a financial holding company headquartered in Ruston, Louisiana. Origin’s wholly owned bank subsidiary, Origin Bank, was founded in 1912 in Choudrant, Louisiana. Deeply rooted in Origin’s history is a culture committed to providing personalized relationship banking to businesses, municipalities, and personal clients to enrich the lives of the people in the communities it serves. Origin provides a broad range of financial services and currently operates more than 55 locations in Dallas/Fort Worth, East Texas, Houston, North Louisiana, Mississippi, South Alabama and the Florida Panhandle. For more information, visit www.origin.bank.
5
`
Non-GAAP Financial Measures
Origin reports its results in accordance with generally accepted accounting principles in the United States of America ("GAAP"). However, management believes that certain supplemental non-GAAP financial measures may provide meaningful information to investors that is useful in understanding Origin's results of operations and underlying trends in its business. However, non-GAAP financial measures are supplemental and should be viewed in addition to, and not as an alternative for, Origin's reported results prepared in accordance with GAAP. The following are the non-GAAP measures used in this release: PTPP earnings, PTPP ROAA, tangible book value per common share, adjusted tangible book value per common share, ROATCE, and core efficiency ratio.
Please see the last few pages of this release for reconciliations of non-GAAP measures to the most directly comparable financial measures calculated in accordance with GAAP.
6
`
Forward-Looking Statements
This press release contains certain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Forward-looking statements include information regarding Origin Bancorp, Inc’s (“Origin”, “we”, “our” or the “Company”) future financial performance, business and growth strategies, projected plans and objectives, and any expected purchases of its outstanding common stock, and related transactions and other projections based on macroeconomic and industry trends, including changes to interest rates by the Federal Reserve and the resulting impact on Origin’s results of operations, estimated forbearance amounts and expectations regarding the Company’s liquidity, including in connection with advances obtained from the FHLB, which are all subject to change and may be inherently unreliable due to the multiple factors that impact broader economic and industry trends, and any such changes may be material. Such forward-looking statements are based on various facts and derived utilizing important assumptions and current expectations, estimates and projections about Origin and its subsidiaries, any of which may change over time and some of which may be beyond Origin’s control. Statements or statistics preceded by, followed by or that otherwise include the words “assumes,” “anticipates,” “believes,” “estimates,” “expects,” “foresees,” “intends,” “plans,” “projects,” and similar expressions or future or conditional verbs such as “could,” “may,” “might,” “should,” “will,” and “would” and variations of such terms are generally forward-looking in nature and not historical facts, although not all forward-looking statements include the foregoing words. Further, certain factors that could affect Origin’s future results and cause actual results to differ materially from those expressed in the forward-looking statements include, but are not limited to: (1) the impact of current and future economic conditions generally and in the financial services industry, nationally and within Origin’s primary market areas, including the impact of tariffs, as well as the financial stress on borrowers and changes to customer and client behavior as a result of the foregoing; (2) changes in benchmark interest rates and the resulting impacts on net interest income; (3) deterioration of Origin’s asset quality; (4) factors that can impact the performance of Origin’s loan portfolio, including real estate values and liquidity in Origin’s primary market areas; (5) the financial health of Origin’s commercial borrowers and the success of construction projects that Origin finances; (6) changes in the value of collateral securing Origin’s loans; (7) the impact of generative artificial intelligence; (8) Origin’s ability to anticipate interest rate changes and manage interest rate risk; (9) the impact of heightened regulatory requirements, reduced debit interchange and overdraft income and the possibility of facing related adverse business consequences if our total assets grow in excess of $10 billion as of December 31 of any calendar year; (10) the effectiveness of Origin’s risk management framework and quantitative models; (11) Origin’s inability to receive dividends from Origin Bank and to service debt, pay dividends to Origin’s common stockholders, repurchase Origin’s shares of common stock and satisfy obligations as they become due; (12) the impact of labor pressures; (13) changes in Origin’s operation or expansion strategy or Origin’s ability to prudently manage its growth and execute its strategy; (14) changes in management personnel; (15) Origin’s ability to maintain important customer relationships, reputation or otherwise avoid liquidity risks; (16) increasing costs as Origin grows deposits; (17) operational risks associated with Origin’s business; (18) significant turbulence or a disruption in the capital or financial markets and the effect of market disruption and interest rate volatility on our investment securities; (19) increased competition in the financial services industry, particularly from regional and national institutions, as well as from fintech companies; (20) compliance with governmental and regulatory requirements and changes in laws, rules, regulations, interpretations or policies relating to financial institutions; (21) periodic changes to the extensive body of accounting rules and best practices; (22) further government intervention in the U.S. financial system; (23) a deterioration of the credit rating for U.S. long-term sovereign debt; (24) Origin’s ability to comply with applicable capital and liquidity requirements, including its ability to generate liquidity internally or raise capital on favorable terms, including continued access to the debt and equity capital markets; (25) natural disasters and other adverse weather events, pandemics, acts of terrorism, war, and other matters beyond Origin’s control; (26) developments in our mortgage banking business, including loan modifications, general demand, and the effects of judicial or regulatory requirements or guidance; (27) fraud or misconduct by internal or external actors (including Origin employees); (28) cybersecurity threats or security breaches and the cost of defending against them; (29) Origin’s ability to maintain adequate internal controls over financial and non-financial reporting; and (30) potential claims, damages, penalties, fines, costs and reputational damage resulting from pending or future litigation, regulatory proceedings and enforcement actions. For a discussion of these and other risks that may cause actual results to differ from expectations, please refer to the sections titled “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors” in Origin’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any updates to those sections set forth in Origin’s subsequent Quarterly Reports on Form 10-Q and Current Reports on Form 8-K. If one or more events related to these or other risks or uncertainties materialize, or if Origin’s underlying assumptions prove to be incorrect, actual results may differ materially from what Origin anticipates. Accordingly, you should not place undue reliance on any forward-looking statements. Any forward-looking statement speaks only as of the date on which it is made, and Origin does not undertake any obligation to publicly update or review any forward-looking statement, whether as a result of new information, future developments or otherwise.
7
`
New risks and uncertainties arise from time to time, and it is not possible for Origin to predict those events or how they may affect Origin. In addition, Origin cannot assess the impact of each factor on Origin’s business or the extent to which any factor, or combination of factors, may cause actual results to differ materially from those contained in any forward-looking statements. All forward-looking statements, expressed or implied, included in this communication are expressly qualified in their entirety by this cautionary statement. This cautionary statement should also be considered in connection with any subsequent written or oral forward-looking statements that Origin or persons acting on Origin’s behalf may issue. Annualized, pro forma, adjusted, projected, and estimated numbers are used for illustrative purposes only, are not forecasts, and may not reflect actual results.
This press release contains projected financial information with respect to Origin, including with respect to certain goals and strategic initiatives of Origin and the anticipated benefits thereof. This projected financial information constitutes forward-looking information and is for illustrative purposes only and should not be relied upon as necessarily being indicative of future results. The assumptions and estimates underlying such projected financial information are inherently uncertain and are subject to significant business, economic (including interest rate), competitive, and other risks and uncertainties. Actual results may differ materially from the results contemplated by the projected financial information contained herein and the inclusion of such projected financial information in this release should not be regarded as a representation by any person that such actions will be taken or accomplished or that the results reflected in such projected financial information with respect thereto will be achieved.
Contact:
Investor Relations
Chris Reigelman
318-497-3177
Media Contact
Ryan Kilpatrick
318-232-7472
8
Origin Bancorp, Inc.
Selected Quarterly Financial Data
(Unaudited)
| Three Months Ended | |||||||||||||||||||||||||||||
| March 31, 2025 | December 31, 2024 | September 30, 2024 | June 30, 2024 | March 31, 2024 | |||||||||||||||||||||||||
| Income statement and share amounts | (Dollars in thousands, except per share amounts) | ||||||||||||||||||||||||||||
Net interest income | $ | 78,459 | $ | 78,349 | $ | 74,804 | $ | 73,890 | $ | 73,323 | |||||||||||||||||||
| Provision (benefit) for credit losses | 3,444 | (5,398) | 4,603 | 5,231 | 3,012 | ||||||||||||||||||||||||
Noninterest income | 15,602 | (330) | 15,989 | 22,465 | 17,255 | ||||||||||||||||||||||||
| Noninterest expense | 62,068 | 65,422 | 62,521 | 64,388 | 58,707 | ||||||||||||||||||||||||
Income before income tax expense | 28,549 | 17,995 | 23,669 | 26,736 | 28,859 | ||||||||||||||||||||||||
| Income tax expense | 6,138 | 3,725 | 5,068 | 5,747 | 6,227 | ||||||||||||||||||||||||
Net income | $ | 22,411 | $ | 14,270 | $ | 18,601 | $ | 20,989 | $ | 22,632 | |||||||||||||||||||
PTPP earnings(1) | $ | 31,993 | $ | 12,597 | $ | 28,272 | $ | 31,967 | $ | 31,871 | |||||||||||||||||||
Basic earnings per common share | 0.72 | 0.46 | 0.60 | 0.68 | 0.73 | ||||||||||||||||||||||||
| Diluted earnings per common share | 0.71 | 0.46 | 0.60 | 0.67 | 0.73 | ||||||||||||||||||||||||
| Dividends declared per common share | 0.15 | 0.15 | 0.15 | 0.15 | 0.15 | ||||||||||||||||||||||||
Weighted average common shares outstanding - basic | 31,205,752 | 31,155,486 | 31,130,293 | 31,042,527 | 30,981,333 | ||||||||||||||||||||||||
Weighted average common shares outstanding - diluted | 31,412,010 | 31,308,805 | 31,239,877 | 31,131,829 | 31,078,910 | ||||||||||||||||||||||||
Balance sheet data | |||||||||||||||||||||||||||||
Total LHFI | $ | 7,585,526 | $ | 7,573,713 | $ | 7,956,790 | $ | 7,959,171 | $ | 7,900,027 | |||||||||||||||||||
| Total LHFI excluding MW LOC | 7,181,395 | 7,224,632 | 7,461,602 | 7,452,666 | 7,499,032 | ||||||||||||||||||||||||
Total assets | 9,750,372 | 9,678,702 | 9,965,986 | 9,947,182 | 9,892,379 | ||||||||||||||||||||||||
| Total deposits | 8,338,412 | 8,223,120 | 8,486,568 | 8,510,842 | 8,505,464 | ||||||||||||||||||||||||
| Total stockholders’ equity | 1,180,177 | 1,145,245 | 1,145,673 | 1,095,894 | 1,078,853 | ||||||||||||||||||||||||
| Performance metrics and capital ratios | |||||||||||||||||||||||||||||
| Yield on LHFI | 6.33 | % | 6.47 | % | 6.67 | % | 6.58 | % | 6.58 | % | |||||||||||||||||||
| Yield on interest-earnings assets | 5.79 | 5.91 | 6.09 | 6.04 | 5.99 | ||||||||||||||||||||||||
| Cost of interest-bearing deposits | 3.23 | 3.61 | 4.01 | 3.95 | 3.85 | ||||||||||||||||||||||||
| Cost of total deposits | 2.52 | 2.79 | 3.14 | 3.08 | 2.99 | ||||||||||||||||||||||||
| NIM - fully tax equivalent ("FTE") | 3.44 | 3.33 | 3.18 | 3.17 | 3.19 | ||||||||||||||||||||||||
| Return on average assets (annualized) ("ROAA") | 0.93 | 0.57 | 0.74 | 0.84 | 0.92 | ||||||||||||||||||||||||
PTPP ROAA (annualized)(1) | 1.32 | 0.50 | 1.13 | 1.28 | 1.30 | ||||||||||||||||||||||||
| Return on average stockholders’ equity (annualized) ("ROAE") | 7.79 | 4.94 | 6.57 | 7.79 | 8.57 | ||||||||||||||||||||||||
| Book value per common share | $ | 37.77 | $ | 36.71 | $ | 36.76 | $ | 35.23 | $ | 34.79 | |||||||||||||||||||
Tangible book value per common share (1) | 32.43 | 31.38 | 31.37 | 29.77 | 29.24 | ||||||||||||||||||||||||
Adjusted tangible book value per common share(1) | 35.33 | 34.78 | 34.39 | 33.86 | 33.27 | ||||||||||||||||||||||||
Return on average tangible common equity (annualized) ("ROATCE")(1) | 9.09 | % | 5.78 | % | 7.74 | % | 9.25 | % | 10.24 | % | |||||||||||||||||||
Efficiency ratio(2) | 65.99 | 83.85 | 68.86 | 66.82 | 64.81 | ||||||||||||||||||||||||
Core efficiency ratio(1) | 65.33 | 82.79 | 67.48 | 65.55 | 65.24 | ||||||||||||||||||||||||
Common equity tier 1 to risk-weighted assets(3) | 13.57 | 13.32 | 12.46 | 12.15 | 11.97 | ||||||||||||||||||||||||
Tier 1 capital to risk-weighted assets(3) | 13.76 | 13.52 | 12.64 | 12.33 | 12.15 | ||||||||||||||||||||||||
Total capital to risk-weighted assets(3) | 15.81 | 16.44 | 15.45 | 15.16 | 14.98 | ||||||||||||||||||||||||
Tier 1 leverage ratio(3) | 11.47 | 11.08 | 10.93 | 10.70 | 10.66 | ||||||||||||||||||||||||
__________________________
(1)PTPP earnings, PTPP ROAA, tangible book value per common share, adjusted tangible book value per common share, ROATCE, and core efficiency ratio are either non-GAAP financial measures or use a non-GAAP contributor in the formula. For a reconciliation of these alternative financial measures to their most directly comparable GAAP measures, please see the last few pages of this release.
(2)Calculated by dividing noninterest expense by the sum of net interest income plus noninterest income.
(3)March 31, 2025, ratios are estimated and calculated at the Company level, which is subject to the capital adequacy requirements of the Federal Reserve Board.
9
Origin Bancorp, Inc.
Consolidated Quarterly Statements of Income
(Unaudited)
| Three Months Ended | |||||||||||||||||||||||||||||
| March 31, 2025 | December 31, 2024 | September 30, 2024 | June 30, 2024 | March 31, 2024 | |||||||||||||||||||||||||
| Interest and dividend income | (Dollars in thousands, except per share amounts) | ||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 117,075 | $ | 127,021 | $ | 133,195 | $ | 129,879 | $ | 127,186 | |||||||||||||||||||
| Investment securities-taxable | 8,076 | 6,651 | 6,536 | 6,606 | 6,849 | ||||||||||||||||||||||||
| Investment securities-nontaxable | 968 | 964 | 905 | 893 | 910 | ||||||||||||||||||||||||
| Interest and dividend income on assets held in other financial institutions | 6,424 | 5,197 | 3,621 | 4,416 | 3,756 | ||||||||||||||||||||||||
| Total interest and dividend income | 132,543 | 139,833 | 144,257 | 141,794 | 138,701 | ||||||||||||||||||||||||
| Interest expense | |||||||||||||||||||||||||||||
| Interest-bearing deposits | 51,779 | 59,511 | 67,051 | 65,469 | 62,842 | ||||||||||||||||||||||||
| FHLB advances and other borrowings | 96 | 88 | 482 | 514 | 518 | ||||||||||||||||||||||||
| Subordinated indebtedness | 2,209 | 1,885 | 1,920 | 1,921 | 2,018 | ||||||||||||||||||||||||
| Total interest expense | 54,084 | 61,484 | 69,453 | 67,904 | 65,378 | ||||||||||||||||||||||||
Net interest income | 78,459 | 78,349 | 74,804 | 73,890 | 73,323 | ||||||||||||||||||||||||
| Provision (benefit) for credit losses | 3,444 | (5,398) | 4,603 | 5,231 | 3,012 | ||||||||||||||||||||||||
| Net interest income after provision for credit losses | 75,015 | 83,747 | 70,201 | 68,659 | 70,311 | ||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||
| Insurance commission and fee income | 7,927 | 5,441 | 6,928 | 6,665 | 7,725 | ||||||||||||||||||||||||
| Service charges and fees | 4,716 | 4,801 | 4,664 | 4,862 | 4,688 | ||||||||||||||||||||||||
| Other fee income | 2,301 | 2,152 | 2,114 | 2,404 | 2,247 | ||||||||||||||||||||||||
| Mortgage banking revenue | 915 | 1,151 | 1,153 | 1,878 | 2,398 | ||||||||||||||||||||||||
| Swap fee income | 533 | 116 | 106 | 44 | 57 | ||||||||||||||||||||||||
| (Loss) gain on sales of securities, net | — | (14,617) | 221 | — | (403) | ||||||||||||||||||||||||
| Limited partnership investment (loss) income | (1,692) | (62) | 375 | 68 | 138 | ||||||||||||||||||||||||
| Change in fair value of equity investments | — | — | — | 5,188 | — | ||||||||||||||||||||||||
| Other income | 902 | 688 | 428 | 1,356 | 405 | ||||||||||||||||||||||||
| Total noninterest income (loss) | 15,602 | (330) | 15,989 | 22,465 | 17,255 | ||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||
| Salaries and employee benefits | 37,731 | 36,405 | 38,491 | 38,109 | 35,818 | ||||||||||||||||||||||||
| Occupancy and equipment, net | 8,544 | 7,913 | 6,298 | 7,009 | 6,645 | ||||||||||||||||||||||||
| Data processing | 2,957 | 3,414 | 3,470 | 3,468 | 3,145 | ||||||||||||||||||||||||
| Office and operations | 2,972 | 2,883 | 2,984 | 3,072 | 2,502 | ||||||||||||||||||||||||
| Intangible asset amortization | 1,761 | 1,800 | 1,905 | 2,137 | 2,137 | ||||||||||||||||||||||||
| Regulatory assessments | 1,392 | 1,535 | 1,791 | 1,842 | 1,734 | ||||||||||||||||||||||||
| Advertising and marketing | 1,133 | 1,929 | 1,449 | 1,328 | 1,444 | ||||||||||||||||||||||||
| Professional services | 1,250 | 2,064 | 2,012 | 1,303 | 1,231 | ||||||||||||||||||||||||
| Electronic banking | 1,354 | 1,377 | 1,308 | 1,238 | 1,239 | ||||||||||||||||||||||||
| Loan-related expenses | 599 | 431 | 751 | 1,077 | 905 | ||||||||||||||||||||||||
| Franchise tax expense | 675 | 884 | 721 | 815 | 477 | ||||||||||||||||||||||||
| Other expenses | 1,700 | 4,787 | 1,341 | 2,990 | 1,430 | ||||||||||||||||||||||||
| Total noninterest expense | 62,068 | 65,422 | 62,521 | 64,388 | 58,707 | ||||||||||||||||||||||||
| Income before income tax expense | 28,549 | 17,995 | 23,669 | 26,736 | 28,859 | ||||||||||||||||||||||||
| Income tax expense | 6,138 | 3,725 | 5,068 | 5,747 | 6,227 | ||||||||||||||||||||||||
| Net income | $ | 22,411 | $ | 14,270 | $ | 18,601 | $ | 20,989 | $ | 22,632 | |||||||||||||||||||
10
Origin Bancorp, Inc.
Consolidated Balance Sheets
(Unaudited)
| (Dollars in thousands) | March 31, 2025 | December 31, 2024 | September 30, 2024 | June 30, 2024 | March 31, 2024 | ||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Cash and due from banks | $ | 112,888 | $ | 132,991 | $ | 159,337 | $ | 137,615 | $ | 98,147 | |||||||||||||||||||
| Interest-bearing deposits in banks | 373,314 | 337,258 | 161,854 | 150,435 | 193,365 | ||||||||||||||||||||||||
| Total cash and cash equivalents | 486,202 | 470,249 | 321,191 | 288,050 | 291,512 | ||||||||||||||||||||||||
| Securities: | |||||||||||||||||||||||||||||
| AFS | 1,161,368 | 1,102,528 | 1,160,965 | 1,160,048 | 1,190,922 | ||||||||||||||||||||||||
| Held to maturity, net of allowance for credit losses | 11,094 | 11,095 | 11,096 | 11,616 | 11,651 | ||||||||||||||||||||||||
| Securities carried at fair value through income | 6,512 | 6,512 | 6,533 | 6,499 | 6,755 | ||||||||||||||||||||||||
| Total securities | 1,178,974 | 1,120,135 | 1,178,594 | 1,178,163 | 1,209,328 | ||||||||||||||||||||||||
| Non-marketable equity securities held in other financial institutions | 71,754 | 71,643 | 67,068 | 64,010 | 53,870 | ||||||||||||||||||||||||
| Loans held for sale | 10,191 | 10,494 | 7,631 | 18,291 | 14,975 | ||||||||||||||||||||||||
| LHFI | 7,585,526 | 7,573,713 | 7,956,790 | 7,959,171 | 7,900,027 | ||||||||||||||||||||||||
| Less: ALCL | 92,011 | 91,060 | 95,989 | 100,865 | 98,375 | ||||||||||||||||||||||||
| LHFI, net of ALCL | 7,493,515 | 7,482,653 | 7,860,801 | 7,858,306 | 7,801,652 | ||||||||||||||||||||||||
| Premises and equipment, net | 123,847 | 126,620 | 126,751 | 121,562 | 120,931 | ||||||||||||||||||||||||
| Cash surrender value of bank-owned life insurance | 41,021 | 40,840 | 40,602 | 40,365 | 40,134 | ||||||||||||||||||||||||
| Goodwill | 128,679 | 128,679 | 128,679 | 128,679 | 128,679 | ||||||||||||||||||||||||
| Other intangible assets, net | 38,212 | 37,473 | 39,272 | 41,177 | 43,314 | ||||||||||||||||||||||||
| Accrued interest receivable and other assets | 177,977 | 189,916 | 195,397 | 208,579 | 187,984 | ||||||||||||||||||||||||
| Total assets | $ | 9,750,372 | $ | 9,678,702 | $ | 9,965,986 | $ | 9,947,182 | $ | 9,892,379 | |||||||||||||||||||
| Liabilities and Stockholders’ Equity | |||||||||||||||||||||||||||||
| Noninterest-bearing deposits | $ | 1,888,808 | $ | 1,900,651 | $ | 1,893,767 | $ | 1,866,622 | $ | 1,887,066 | |||||||||||||||||||
| Interest-bearing deposits excluding brokered interest-bearing deposits, if any | 5,536,636 | 5,301,243 | 5,137,940 | 4,984,817 | 4,990,632 | ||||||||||||||||||||||||
| Time deposits | 862,968 | 941,000 | 1,023,252 | 1,022,589 | 1,030,656 | ||||||||||||||||||||||||
| Brokered deposits | 50,000 | 80,226 | 431,609 | 636,814 | 597,110 | ||||||||||||||||||||||||
| Total deposits | 8,338,412 | 8,223,120 | 8,486,568 | 8,510,842 | 8,505,464 | ||||||||||||||||||||||||
| FHLB advances and other borrowings | 12,488 | 12,460 | 30,446 | 40,737 | 13,158 | ||||||||||||||||||||||||
| Subordinated indebtedness | 89,599 | 159,943 | 159,861 | 159,779 | 160,684 | ||||||||||||||||||||||||
| Accrued expenses and other liabilities | 129,696 | 137,934 | 143,438 | 139,930 | 134,220 | ||||||||||||||||||||||||
| Total liabilities | 8,570,195 | 8,533,457 | 8,820,313 | 8,851,288 | 8,813,526 | ||||||||||||||||||||||||
| Stockholders’ equity: | |||||||||||||||||||||||||||||
Common stock | 156,220 | 155,988 | 155,837 | 155,543 | 155,057 | ||||||||||||||||||||||||
| Additional paid-in capital | 538,790 | 537,366 | 535,662 | 532,950 | 530,380 | ||||||||||||||||||||||||
| Retained earnings | 575,578 | 557,920 | 548,419 | 534,585 | 518,325 | ||||||||||||||||||||||||
| Accumulated other comprehensive loss | (90,411) | (106,029) | (94,245) | (127,184) | (124,909) | ||||||||||||||||||||||||
| Total stockholders’ equity | 1,180,177 | 1,145,245 | 1,145,673 | 1,095,894 | 1,078,853 | ||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 9,750,372 | $ | 9,678,702 | $ | 9,965,986 | $ | 9,947,182 | $ | 9,892,379 | |||||||||||||||||||
11
Origin Bancorp, Inc.
Loan Data
(Unaudited)
| At and For the Three Months Ended | |||||||||||||||||||||||||||||
| March 31, 2025 | December 31, 2024 | September 30, 2024 | June 30, 2024 | March 31, 2024 | |||||||||||||||||||||||||
| LHFI | (Dollars in thousands) | ||||||||||||||||||||||||||||
| Owner occupied commercial real estate | $ | 937,985 | $ | 975,947 | $ | 991,671 | $ | 959,850 | $ | 948,624 | |||||||||||||||||||
| Non-owner occupied commercial real estate | 1,445,864 | 1,501,484 | 1,533,093 | 1,563,152 | 1,472,164 | ||||||||||||||||||||||||
| Construction/land/land development | 798,609 | 864,011 | 991,545 | 1,017,389 | 1,168,597 | ||||||||||||||||||||||||
| Residential real estate - single family | 1,465,192 | 1,432,129 | 1,414,013 | 1,421,027 | 1,373,532 | ||||||||||||||||||||||||
| Multi-family real estate | 489,765 | 425,460 | 434,317 | 398,202 | 359,765 | ||||||||||||||||||||||||
| Total real estate loans | 5,137,415 | 5,199,031 | 5,364,639 | 5,359,620 | 5,322,682 | ||||||||||||||||||||||||
| Commercial and industrial | 2,022,085 | 2,002,634 | 2,074,037 | 2,070,947 | 2,154,151 | ||||||||||||||||||||||||
| MW LOC | 404,131 | 349,081 | 495,188 | 506,505 | 400,995 | ||||||||||||||||||||||||
| Consumer | 21,895 | 22,967 | 22,926 | 22,099 | 22,199 | ||||||||||||||||||||||||
| Total LHFI | 7,585,526 | 7,573,713 | 7,956,790 | 7,959,171 | 7,900,027 | ||||||||||||||||||||||||
| Less: ALCL | 92,011 | 91,060 | 95,989 | 100,865 | 98,375 | ||||||||||||||||||||||||
| LHFI, net | $ | 7,493,515 | $ | 7,482,653 | $ | 7,860,801 | $ | 7,858,306 | $ | 7,801,652 | |||||||||||||||||||
Nonperforming assets(1) | |||||||||||||||||||||||||||||
| Nonperforming LHFI | |||||||||||||||||||||||||||||
| Commercial real estate | $ | 5,465 | $ | 4,974 | $ | 2,776 | $ | 2,196 | $ | 4,474 | |||||||||||||||||||
| Construction/land/land development | 17,694 | 18,505 | 26,291 | 26,336 | 383 | ||||||||||||||||||||||||
Residential real estate(2) | 40,749 | 36,221 | 14,313 | 13,493 | 14,918 | ||||||||||||||||||||||||
| Commercial and industrial | 17,325 | 15,120 | 20,486 | 33,608 | 20,560 | ||||||||||||||||||||||||
| Consumer | 135 | 182 | 407 | 179 | 104 | ||||||||||||||||||||||||
| Total nonperforming LHFI | 81,368 | 75,002 | 64,273 | 75,812 | 40,439 | ||||||||||||||||||||||||
| Other real estate owned/repossessed assets | 1,990 | 3,635 | 6,043 | 6,827 | 3,935 | ||||||||||||||||||||||||
| Total nonperforming assets | $ | 83,358 | $ | 78,637 | $ | 70,316 | $ | 82,639 | $ | 44,374 | |||||||||||||||||||
| Classified assets | $ | 129,666 | $ | 122,417 | $ | 113,529 | $ | 125,081 | $ | 88,152 | |||||||||||||||||||
Past due LHFI(3) | 72,774 | 42,437 | 38,838 | 66,276 | 32,835 | ||||||||||||||||||||||||
| Allowance for loan credit losses | |||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 91,060 | $ | 95,989 | $ | 100,865 | $ | 98,375 | $ | 96,868 | |||||||||||||||||||
| Provision (benefit) for loan credit losses | 3,679 | (5,489) | 4,644 | 5,436 | 4,089 | ||||||||||||||||||||||||
| Loans charged off | 4,848 | 2,025 | 11,226 | 3,706 | 6,683 | ||||||||||||||||||||||||
| Loan recoveries | 2,120 | 2,585 | 1,706 | 760 | 4,101 | ||||||||||||||||||||||||
| Net charge-offs (recoveries) | 2,728 | (560) | 9,520 | 2,946 | 2,582 | ||||||||||||||||||||||||
| Balance at end of period | $ | 92,011 | $ | 91,060 | $ | 95,989 | $ | 100,865 | $ | 98,375 | |||||||||||||||||||
| Credit quality ratios | |||||||||||||||||||||||||||||
| Total nonperforming assets to total assets | 0.85 | % | 0.81 | % | 0.71 | % | 0.83 | % | 0.45 | % | |||||||||||||||||||
| Nonperforming LHFI to LHFI | 1.07 | 0.99 | 0.81 | 0.95 | 0.51 | ||||||||||||||||||||||||
| Past due LHFI to LHFI | 0.96 | 0.56 | 0.49 | 0.83 | 0.42 | ||||||||||||||||||||||||
| ALCL to nonperforming LHFI | 113.08 | 121.41 | 149.35 | 133.05 | 243.27 | ||||||||||||||||||||||||
| ALCL to total LHFI | 1.21 | 1.20 | 1.21 | 1.27 | 1.25 | ||||||||||||||||||||||||
ALCL to total LHFI, adjusted(4) | 1.28 | 1.25 | 1.28 | 1.34 | 1.30 | ||||||||||||||||||||||||
| Net charge-offs (recoveries) to total average LHFI (annualized) | 0.15 | (0.03) | 0.48 | 0.15 | 0.13 | ||||||||||||||||||||||||
____________________________
(1)Nonperforming assets consist of nonperforming/nonaccrual loans and property acquired through foreclosures or repossession, as well as bank-owned property not in use and listed for sale, if any.
(2)Includes multi-family real estate.
(3)Past due LHFI are defined as loans 30 days or more past due.
(4)The ALCL to total LHFI, adjusted is calculated by excluding the ALCL for MW LOC loans from the total LHFI ALCL in the numerator and excluding the MW LOC loans from the LHFI in the denominator. Due to their low-risk profile, MW LOC loans require a disproportionately low allocation of the ALCL.
12
Origin Bancorp, Inc.
Average Balances and Yields/Rates
(Unaudited)
| Three Months Ended | |||||||||||||||||||||||||||||||||||
| March 31, 2025 | December 31, 2024 | March 31, 2024 | |||||||||||||||||||||||||||||||||
| Average Balance | Yield/Rate | Average Balance | Yield/Rate | Average Balance | Yield/Rate | ||||||||||||||||||||||||||||||
| Assets | (Dollars in thousands) | ||||||||||||||||||||||||||||||||||
| Commercial real estate | $ | 2,448,099 | 5.82 | % | $ | 2,499,279 | 5.89 | % | $ | 2,438,476 | 5.84 | % | |||||||||||||||||||||||
| Construction/land/land development | 821,754 | 6.87 | 936,134 | 6.92 | 1,130,355 | 7.25 | |||||||||||||||||||||||||||||
Residential real estate(1) | 1,909,922 | 5.53 | 1,847,399 | 5.50 | 1,739,105 | 5.40 | |||||||||||||||||||||||||||||
| Commercial and industrial ("C&I") | 2,004,034 | 7.37 | 2,028,290 | 7.68 | 2,121,502 | 7.89 | |||||||||||||||||||||||||||||
| MW LOC | 289,521 | 7.07 | 459,716 | 7.26 | 306,248 | 7.59 | |||||||||||||||||||||||||||||
| Consumer | 22,709 | 7.45 | 23,393 | 7.64 | 23,319 | 8.07 | |||||||||||||||||||||||||||||
| LHFI | 7,496,039 | 6.33 | 7,794,211 | 6.47 | 7,759,005 | 6.58 | |||||||||||||||||||||||||||||
| Loans held for sale | 8,590 | 6.18 | 10,981 | 6.81 | 12,906 | 5.86 | |||||||||||||||||||||||||||||
| Loans receivable | 7,504,629 | 6.33 | 7,805,192 | 6.47 | 7,771,911 | 6.58 | |||||||||||||||||||||||||||||
| Investment securities-taxable | 1,021,904 | 3.21 | 1,002,216 | 2.64 | 1,095,480 | 2.51 | |||||||||||||||||||||||||||||
| Investment securities-nontaxable | 140,875 | 2.79 | 149,307 | 2.57 | 148,077 | 2.47 | |||||||||||||||||||||||||||||
| Non-marketable equity securities held in other financial institutions | 71,669 | 2.35 | 69,070 | 2.78 | 58,455 | 3.77 | |||||||||||||||||||||||||||||
| Interest-earning balances due from banks | 543,821 | 4.48 | 394,790 | 4.75 | 240,432 | 5.37 | |||||||||||||||||||||||||||||
| Total interest-earning assets | 9,282,898 | 5.79 | 9,420,575 | 5.91 | 9,314,355 | 5.99 | |||||||||||||||||||||||||||||
| Noninterest-earning assets | 525,317 | 557,968 | 546,881 | ||||||||||||||||||||||||||||||||
| Total assets | $ | 9,808,215 | $ | 9,978,543 | $ | 9,861,236 | |||||||||||||||||||||||||||||
| Liabilities and Stockholders’ Equity | |||||||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities | |||||||||||||||||||||||||||||||||||
| Savings and interest-bearing transaction accounts | $ | 5,538,710 | 3.14 | % | $ | 5,341,028 | 3.48 | % | $ | 5,009,117 | 3.69 | % | |||||||||||||||||||||||
| Time deposits | 972,176 | 3.69 | 1,213,565 | 4.20 | 1,563,992 | 4.35 | |||||||||||||||||||||||||||||
| Total interest-bearing deposits | 6,510,886 | 3.23 | 6,554,593 | 3.61 | 6,573,109 | 3.85 | |||||||||||||||||||||||||||||
| FHLB advances and other borrowings | 14,148 | 2.75 | 12,698 | 2.76 | 42,284 | 4.92 | |||||||||||||||||||||||||||||
| Subordinated indebtedness | 124,133 | 7.22 | 159,910 | 4.69 | 165,252 | 4.91 | |||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 6,649,167 | 3.30 | 6,727,201 | 3.64 | 6,780,645 | 3.88 | |||||||||||||||||||||||||||||
| Noninterest-bearing liabilities | |||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 1,837,365 | 1,940,689 | 1,866,496 | ||||||||||||||||||||||||||||||||
| Other liabilities | 154,934 | 161,425 | 151,390 | ||||||||||||||||||||||||||||||||
| Total liabilities | 8,641,466 | 8,829,315 | 8,798,531 | ||||||||||||||||||||||||||||||||
| Stockholders’ Equity | 1,166,749 | 1,149,228 | 1,062,705 | ||||||||||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 9,808,215 | $ | 9,978,543 | $ | 9,861,236 | |||||||||||||||||||||||||||||
| Net interest spread | 2.49 | % | 2.27 | % | 2.11 | % | |||||||||||||||||||||||||||||
| NIM | 3.43 | 3.31 | 3.17 | ||||||||||||||||||||||||||||||||
NIM-FTE(2) | 3.44 | 3.33 | 3.19 | ||||||||||||||||||||||||||||||||
____________________________
(1)Includes multi-family real estate.
(2)In order to present pre-tax income and resulting yields on tax-exempt investments comparable to those on taxable investments, a tax-equivalent adjustment has been computed. This adjustment also includes income tax credits received on Qualified School Construction Bonds.
13
Origin Bancorp, Inc.
Notable Items
(Unaudited)
| At and For the Three Months Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, 2025 | December 31, 2024 | September 30, 2024 | June 30, 2024 | March 31, 2024 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| $ Impact | EPS Impact(1) | $ Impact | EPS Impact(1) | $ Impact | EPS Impact(1) | $ Impact | EPS Impact(1) | $ Impact | EPS Impact(1) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share amounts) | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Notable interest income items: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest income reversal on relationships impacted by questioned banker activity | $ | — | $ | — | $ | — | $ | — | $ | — | $ | — | $ | (1,206) | $ | (0.03) | $ | — | $ | — | |||||||||||||||||||||||||||||||||||||||
| Notable interest expense items: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| OID amortization - subordinated debenture redemption | (681) | (0.02) | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Notable provision expense items: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Provision release (expense) related to questioned banker activity | — | — | 3,212 | 0.08 | — | — | (3,212) | (0.08) | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Provision release (expense) on relationships impacted by questioned banker activity | 375 | 0.01 | — | — | — | — | (4,131) | (0.11) | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
Notable noninterest income items(2): | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| MSR gain (impairment) | — | — | — | — | — | — | — | — | 410 | 0.01 | |||||||||||||||||||||||||||||||||||||||||||||||||
| (Loss) gain on sales of securities, net | — | — | (14,617) | (0.37) | 221 | 0.01 | — | — | (403) | (0.01) | |||||||||||||||||||||||||||||||||||||||||||||||||
| Gain on sub-debt repurchase | — | — | — | — | — | — | 81 | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Positive valuation adjustment on non-marketable equity securities | — | — | — | — | — | — | 5,188 | 0.13 | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
Net (loss) gain on OREO properties(2) | (212) | (0.01) | 198 | — | — | — | 800 | 0.02 | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| BOLI payout | 208 | 0.01 | — | — | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Notable noninterest expense items: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Operating expense related to questioned banker activity | (543) | (0.01) | (4,069) | (0.10) | (848) | (0.02) | (1,452) | (0.04) | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
Operating expense related to strategic Optimize Origin initiatives | (1,615) | (0.04) | (1,121) | (0.03) | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Employee Retention Credit | 213 | 0.01 | 1,651 | 0.04 | — | — | — | — | — | — | |||||||||||||||||||||||||||||||||||||||||||||||||
| Total notable items | $ | (2,255) | (0.06) | $ | (14,746) | (0.37) | $ | (627) | (0.02) | $ | (3,932) | (0.10) | $ | 7 | — | ||||||||||||||||||||||||||||||||||||||||||||
____________________________
(1)The diluted EPS impact is calculated using a 21% effective tax rate. The total of the diluted EPS impact of each individual line item may not equal the calculated diluted EPS impact on the total notable items due to rounding.
(2)The $212,000 net (loss) gain on OREO properties for the quarter ended March 31, 2025, includes a $444,000 expected insurance settlement recovery that was included in noninterest income on the face of the income statement and a $148,000 repair cost that was included in noninterest expense.
14
Origin Bancorp, Inc.
Non-GAAP Financial Measures
(Unaudited)
| At and For the Three Months Ended | |||||||||||||||||||||||||||||
| March 31, 2025 | December 31, 2024 | September 30, 2024 | June 30, 2024 | March 31, 2024 | |||||||||||||||||||||||||
| (Dollars in thousands, except per share amounts) | |||||||||||||||||||||||||||||
| Calculation of PTPP earnings: | |||||||||||||||||||||||||||||
| Net income | $ | 22,411 | $ | 14,270 | $ | 18,601 | $ | 20,989 | $ | 22,632 | |||||||||||||||||||
| Provision (benefit) for credit losses | 3,444 | (5,398) | 4,603 | 5,231 | 3,012 | ||||||||||||||||||||||||
| Income tax expense | 6,138 | 3,725 | 5,068 | 5,747 | 6,227 | ||||||||||||||||||||||||
| PTPP earnings (non-GAAP) | $ | 31,993 | $ | 12,597 | $ | 28,272 | $ | 31,967 | $ | 31,871 | |||||||||||||||||||
| Calculation of PTPP ROAA: | |||||||||||||||||||||||||||||
| PTPP earnings | $ | 31,993 | $ | 12,597 | $ | 28,272 | $ | 31,967 | $ | 31,871 | |||||||||||||||||||
| Divided by number of days in the quarter | 90 | 92 | 92 | 91 | 91 | ||||||||||||||||||||||||
| Multiplied by the number of days in the year | 365 | 366 | 366 | 366 | 366 | ||||||||||||||||||||||||
| PTPP earnings, annualized | $ | 129,749 | $ | 50,114 | $ | 112,473 | $ | 128,571 | $ | 128,184 | |||||||||||||||||||
| Divided by total average assets | $ | 9,808,215 | $ | 9,978,543 | $ | 9,985,836 | $ | 10,008,225 | $ | 9,861,236 | |||||||||||||||||||
| ROAA (annualized) (GAAP) | 0.93 | % | 0.57 | % | 0.74 | % | 0.84 | % | 0.92 | % | |||||||||||||||||||
| PTPP ROAA (annualized) (non-GAAP) | 1.32 | 0.50 | 1.13 | 1.28 | 1.30 | ||||||||||||||||||||||||
| Calculation of tangible book value per common share and adjusted tangible book value per common share: | |||||||||||||||||||||||||||||
| Total common stockholders’ equity | $ | 1,180,177 | $ | 1,145,245 | $ | 1,145,673 | $ | 1,095,894 | $ | 1,078,853 | |||||||||||||||||||
| Goodwill | (128,679) | (128,679) | (128,679) | (128,679) | (128,679) | ||||||||||||||||||||||||
| Other intangible assets, net | (38,212) | (37,473) | (39,272) | (41,177) | (43,314) | ||||||||||||||||||||||||
| Tangible common equity | 1,013,286 | 979,093 | 977,722 | 926,038 | 906,860 | ||||||||||||||||||||||||
| Accumulated other comprehensive loss | 90,411 | 106,029 | 94,245 | 127,184 | 124,909 | ||||||||||||||||||||||||
| Adjusted tangible common equity | 1,103,697 | 1,085,122 | 1,071,967 | 1,053,222 | 1,031,769 | ||||||||||||||||||||||||
| Divided by common shares outstanding at the end of the period | 31,244,006 | 31,197,574 | 31,167,410 | 31,108,667 | 31,011,304 | ||||||||||||||||||||||||
| Book value per common share (GAAP) | $ | 37.77 | $ | 36.71 | $ | 36.76 | $ | 35.23 | $ | 34.79 | |||||||||||||||||||
| Tangible book value per common share (non-GAAP) | 32.43 | 31.38 | 31.37 | 29.77 | 29.24 | ||||||||||||||||||||||||
| Adjusted tangible book value per common share (non-GAAP) | 35.33 | 34.78 | 34.39 | 33.86 | 33.27 | ||||||||||||||||||||||||
| Calculation of ROATCE: | |||||||||||||||||||||||||||||
| Net income | $ | 22,411 | $ | 14,270 | $ | 18,601 | $ | 20,989 | $ | 22,632 | |||||||||||||||||||
| Divided by number of days in the quarter | 90 | 92 | 92 | 91 | 91 | ||||||||||||||||||||||||
| Multiplied by number of days in the year | 365 | 366 | 366 | 366 | 366 | ||||||||||||||||||||||||
| Annualized net income | $ | 90,889 | $ | 56,770 | $ | 74,000 | $ | 84,417 | $ | 91,025 | |||||||||||||||||||
| Total average common stockholders’ equity | $ | 1,166,749 | $ | 1,149,228 | $ | 1,125,697 | $ | 1,084,269 | $ | 1,062,705 | |||||||||||||||||||
| Average goodwill | (128,679) | (128,679) | (128,679) | (128,679) | (128,679) | ||||||||||||||||||||||||
| Average other intangible assets, net | (38,254) | (38,646) | (40,487) | (42,563) | (44,700) | ||||||||||||||||||||||||
| Average tangible common equity | 999,816 | 981,903 | 956,531 | 913,027 | 889,326 | ||||||||||||||||||||||||
| ROATCE (non-GAAP) | 9.09 | % | 5.78 | % | 7.74 | % | 9.25 | % | 10.24 | % | |||||||||||||||||||
15
Origin Bancorp, Inc.
Non-GAAP Financial Measures- Continued
(Unaudited)
| At and For the Three Months Ended | |||||||||||||||||||||||||||||
| March 31, 2025 | December 31, 2024 | September 30, 2024 | June 30, 2024 | March 31, 2024 | |||||||||||||||||||||||||
| (Dollars in thousands, except per share amounts) | |||||||||||||||||||||||||||||
| Calculation of core efficiency ratio: | |||||||||||||||||||||||||||||
| Total noninterest expense | $ | 62,068 | $ | 65,422 | $ | 62,521 | $ | 64,388 | $ | 58,707 | |||||||||||||||||||
| Insurance and mortgage noninterest expense | (8,230) | (8,497) | (8,448) | (8,402) | (8,045) | ||||||||||||||||||||||||
| Adjusted total noninterest expense | 53,838 | 56,925 | 54,073 | 55,986 | 50,662 | ||||||||||||||||||||||||
| Net interest income | $ | 78,459 | $ | 78,349 | $ | 74,804 | $ | 73,890 | $ | 73,323 | |||||||||||||||||||
| Insurance and mortgage net interest income | (2,815) | (2,666) | (2,578) | (2,407) | (2,795) | ||||||||||||||||||||||||
| Total noninterest income | 15,602 | (330) | 15,989 | 22,465 | 17,255 | ||||||||||||||||||||||||
| Insurance and mortgage noninterest income | (8,842) | (6,592) | (8,081) | (8,543) | (10,123) | ||||||||||||||||||||||||
| Adjusted total revenue | 82,404 | 68,761 | 80,134 | 85,405 | 77,660 | ||||||||||||||||||||||||
| Efficiency ratio (GAAP) | 65.99 | % | 83.85 | % | 68.86 | % | 66.82 | % | 64.81 | % | |||||||||||||||||||
| Core efficiency ratio (non-GAAP) | 65.33 | 82.79 | 67.48 | 65.55 | 65.24 | ||||||||||||||||||||||||
16
1Q TWENTY25 INVESTOR PRESENTATION ORIGIN BANCORP, INC.
2 FORWARD-LOOKING STATEMENTS AND NON-GAAP MEASURES This presentation contains certain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Forward-looking statements include information regarding Origin Bancorp, Inc’s (“Origin”, “we”, “our” or the “Company”) future financial performance, business and growth strategies, projected plans and objectives, and any expected purchases of its outstanding common stock, and related transactions and other projections based on macroeconomic and industry trends, including changes to interest rates by the Federal Reserve and the resulting impact on Origin’s results of operations, estimated forbearance amounts and expectations regarding the Company’s liquidity, including in connection with advances obtained from the FHLB, which are all subject to change and may be inherently unreliable due to the multiple factors that impact broader economic and industry trends, and any such changes may be material. Such forward-looking statements are based on various facts and derived utilizing important assumptions and current expectations, estimates and projections about Origin and its subsidiaries, any of which may change over time and some of which may be beyond Origin’s control. Statements or statistics preceded by, followed by or that otherwise include the words “assumes,” “anticipates,” “believes,” “estimates,” “expects,” “foresees,” “intends,” “plans,” “projects,” and similar expressions or future or conditional verbs such as “could,” “may,” “might,” “should,” “will,” and “would” and variations of such terms are generally forward-looking in nature and not historical facts, although not all forward-looking statements include the foregoing words. Further, certain factors that could affect Origin’s future results and cause actual results to differ materially from those expressed in the forward- looking statements include, but are not limited to: (1) the impact of current and future economic conditions generally and in the financial services industry, nationally and within Origin’s primary market areas, including the impact of tariffs, as well as the financial stress on borrowers and changes to customer and client behavior as a result of the foregoing; (2) changes in benchmark interest rates and the resulting impacts on net interest income; (3) deterioration of Origin’s asset quality; (4) factors that can impact the performance of Origin’s loan portfolio, including real estate values and liquidity in Origin’s primary market areas; (5) the financial health of Origin’s commercial borrowers and the success of construction projects that Origin finances; (6) changes in the value of collateral securing Origin’s loans; (7) the impact of generative artificial intelligence; (8) Origin’s ability to anticipate interest rate changes and manage interest rate risk; (9) the impact of heightened regulatory requirements, reduced debit interchange and overdraft income and the possibility of facing related adverse business consequences if our total assets grow in excess of $10 billion as of December 31 of any calendar year; (10) the effectiveness of Origin’s risk management framework and quantitative models; (11) Origin’s inability to receive dividends from Origin Bank and to service debt, pay dividends to Origin’s common stockholders, repurchase Origin’s shares of common stock and satisfy obligations as they become due; (12) the impact of labor pressures; (13) changes in Origin’s operation or expansion strategy or Origin’s ability to prudently manage its growth and execute its strategy; (14) changes in management personnel; (15) Origin’s ability to maintain important customer relationships, reputation or otherwise avoid liquidity risks; (16) increasing costs as Origin grows deposits; (17) operational risks associated with Origin’s business; (18) significant turbulence or a disruption in the capital or financial markets and the effect of market disruption and interest rate volatility on our investment securities; (19) increased competition in the financial services industry, particularly from regional and national institutions, as well as from fintech companies; (20) compliance with governmental and regulatory requirements and changes in laws, rules, regulations, interpretations or policies relating to financial institutions; (21) periodic changes to the extensive body of accounting rules and best practices; (22) further government intervention in the U.S. financial system; (23) a deterioration of the credit rating for U.S. long-term sovereign debt; (24) Origin’s ability to comply with applicable capital and liquidity requirements, including its ability to generate liquidity internally or raise capital on favorable terms, including continued access to the debt and equity capital markets; (25) natural disasters and other adverse weather events, pandemics, acts of terrorism, war, and other matters beyond Origin’s control; (26) developments in our mortgage banking business, including loan modifications, general demand, and the effects of judicial or regulatory requirements or guidance; (27) fraud or misconduct by internal or external actors (including Origin employees); (28) cybersecurity threats or security breaches and the cost of defending against them; (29) Origin’s ability to maintain adequate internal controls over financial and non-financial reporting; and (30) potential claims, damages, penalties, fines, costs and reputational damage resulting from pending or future litigation, regulatory proceedings and enforcement actions. For a discussion of these and other risks that may cause actual results to differ from expectations, please refer to the sections titled “Cautionary Note Regarding Forward-Looking Statements” and “Risk Factors” in Origin’s most recent Annual Report on Form 10-K filed with the Securities and Exchange Commission and any updates to those sections set forth in Origin’s subsequent Quarterly Reports on Form 10-Q and Current Reports on Form 8-K. If one or more events related to these or other risks or uncertainties materialize, or if Origin’s underlying assumptions prove to be incorrect, actual results may differ materially from what Origin anticipates. Accordingly, you should not place undue reliance on any forward-looking statements. Any forward-looking statement speaks only as of the date on which it is made, and Origin does not undertake any obligation to publicly update or review any forward-looking statement, whether as a result of new information, future developments or otherwise. New risks and uncertainties arise from time to time, and it is not possible for Origin to predict those events or how they may affect Origin. In addition, Origin cannot assess the impact of each factor on Origin’s business or the extent to which any factor, or combination of factors, may cause actual results to differ materially from those contained in any forward-looking statements. All forward-looking statements, expressed or implied, included in this communication are expressly qualified in their entirety by this cautionary statement. This cautionary statement should also be considered in connection with any subsequent written or oral forward-looking statements that Origin or persons acting on Origin’s behalf may issue. Annualized, pro forma, adjusted, projected, and estimated numbers are used for illustrative purposes only, are not forecasts, and may not reflect actual results. This presentation contains projected financial information with respect to Origin, including with respect to certain goals and strategic initiatives of Origin and the anticipated benefits thereof. This projected financial information constitutes forward-looking information and is for illustrative purposes only and should not be relied upon as necessarily being indicative of future results. The assumptions and estimates underlying such projected financial information are inherently uncertain and are subject to significant business, economic (including interest rate), competitive, and other risks and uncertainties. Actual results may differ materially from the results contemplated by the projected financial information contained herein and the inclusion of such projected financial information in this presentation should not be regarded as a representation by any person that such actions will be taken or accomplished or that the results reflected in such projected financial information with respect thereto will be achieved. Origin reports its results in accordance with generally accepted accounting principles in the United States ("GAAP"). However, management believes that certain supplemental non-GAAP financial measures may provide meaningful information to investors that is useful in understanding Origin's results of operations and underlying trends in its business. However, non-GAAP financial measures are supplemental and should be viewed in addition to, and not as an alternative for, Origin's reported results prepared in accordance with GAAP. The following are the non-GAAP measures used in this presentation: Pre-tax, pre-provision (“PTPP”) earnings, PTPP ROAA, tangible book value per common share, adjusted tangible book value per common share, tangible common equity to tangible assets, return on average tangible common equity (“ROATCE”) and core efficiency ratio. Please see “Reconciliation of Non-GAAP Financial Measures” at the end of this presentation for reconciliations of non-GAAP measures to the most directly comparable financial measures calculated in accordance with GAAP. ORIGIN BANCORP, INC. _______
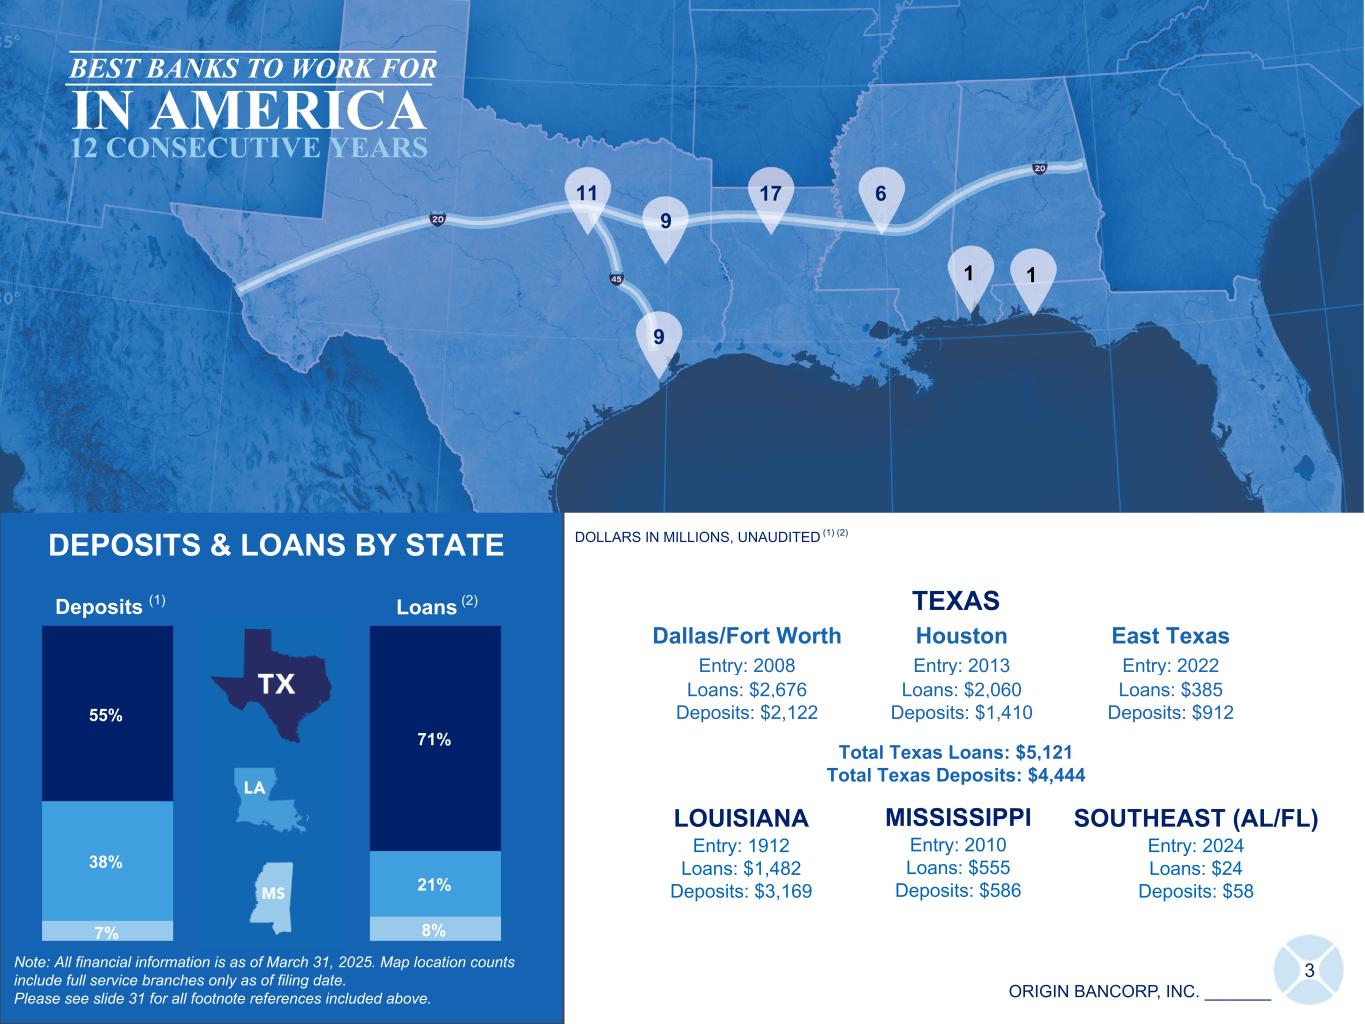
ORIGIN BANCORP, INC. _______ LOUISIANA Entry: 1912 Loans: $1,482 Deposits: $3,169 DOLLARS IN MILLIONS, UNAUDITED (1) (2) 3 DEPOSITS & LOANS BY STATE Note: All financial information is as of March 31, 2025. Map location counts include full service branches only as of filing date. Please see slide 31 for all footnote references included above. MISSISSIPPI Entry: 2010 Loans: $555 Deposits: $586 7% 8% 38% 21% 55% 71% Loans (2)Deposits (1) ICS ICS TEXAS Dallas/Fort Worth Houston East Texas Entry: 2008 Entry: 2013 Entry: 2022 Loans: $2,676 Loans: $2,060 Loans: $385 Deposits: $2,122 Deposits: $1,410 Deposits: $912 Total Texas Loans: $5,121 Total Texas Deposits: $4,444 SOUTHEAST (AL/FL) Entry: 2024 Loans: $24 Deposits: $58 11 9 9 17 6 11 BEST BANKS TO WORK FOR IN AMERICA 12 CONSECUTIVE YEARS
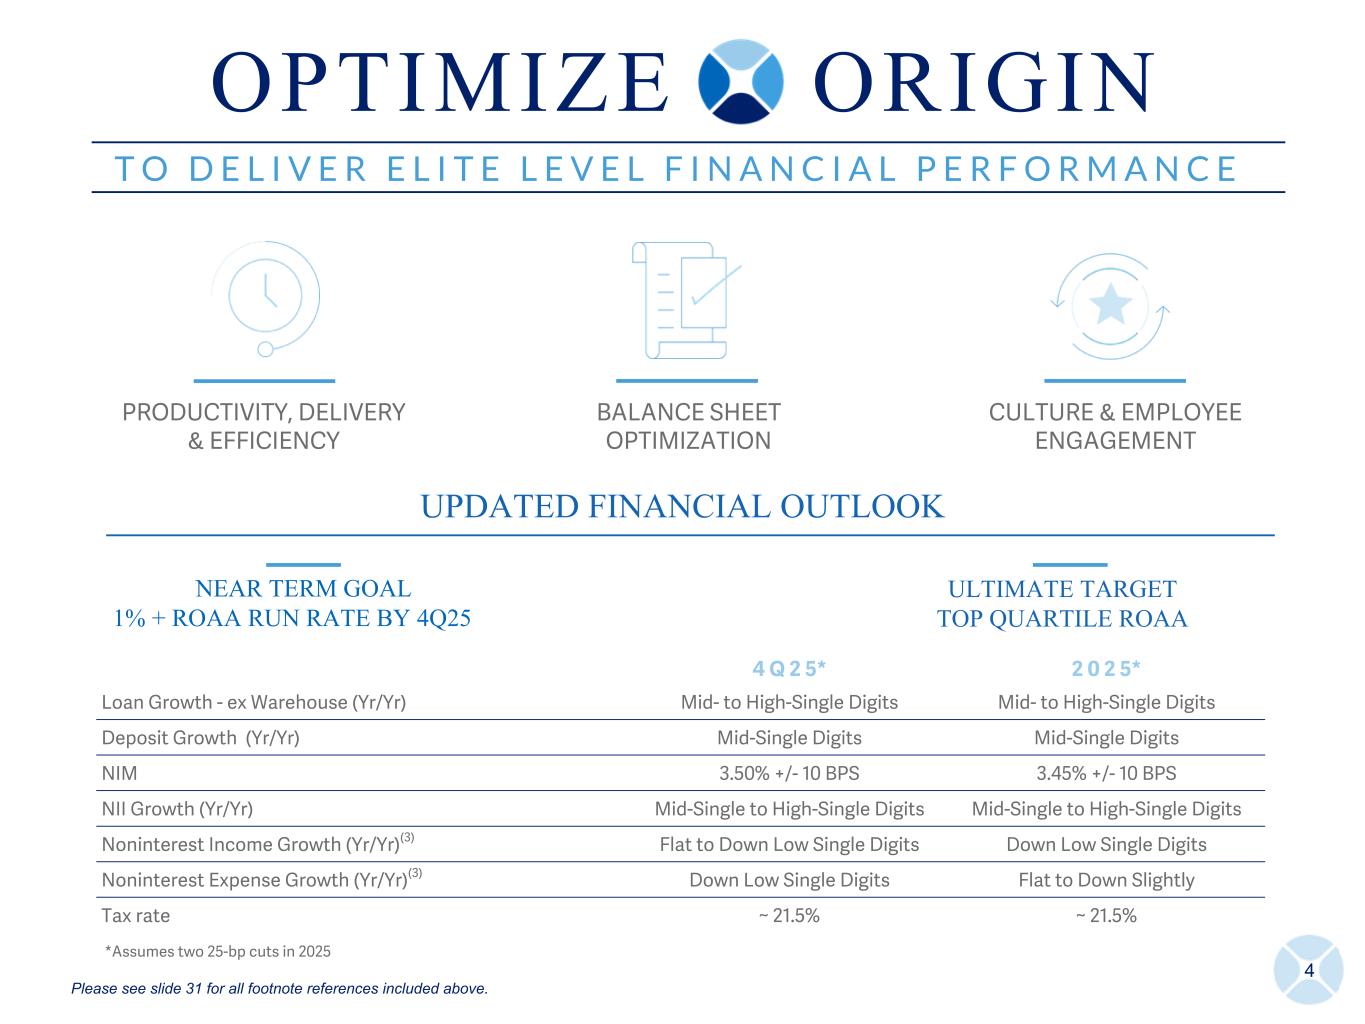
4 T O D E L I V E R E L I T E L E V E L F I N A N C I A L P E R F O R M A N C E T O D E L I V E R E L I T E L E V E L F I N A N C I A L P E R F O R M A N C E PRODUCTIVITY, DELIVERY & EFFICIENCY BALANCE SHEET OPTIMIZATION CULTURE & EMPLOYEE ENGAGEMENT UPDATED FINANCIAL OUTLOOK 4 Q 2 5* 2 0 2 5* Loan Growth - ex Warehouse (Yr/Yr) Mid- to High-Single Digits Mid- to High-Single Digits Deposit Growth (Yr/Yr) Mid-Single Digits Mid-Single Digits NIM 3.50% +/- 10 BPS 3.45% +/- 10 BPS NII Growth (Yr/Yr) Mid-Single to High-Single Digits Mid-Single to High-Single Digits Noninterest Income Growth (Yr/Yr)(3) Flat to Down Low Single Digits Down Low Single Digits Noninterest Expense Growth (Yr/Yr)(3) Down Low Single Digits Flat to Down Slightly Tax rate ~ 21.5% ~ 21.5% *Assumes two 25-bp cuts in 2025 NEAR TERM GOAL 1% + ROAA RUN RATE BY 4Q25 ULTIMATE TARGET TOP QUARTILE ROAA O P T I M I Z E O R I G I N Please see slide 31 for all footnote references included above.
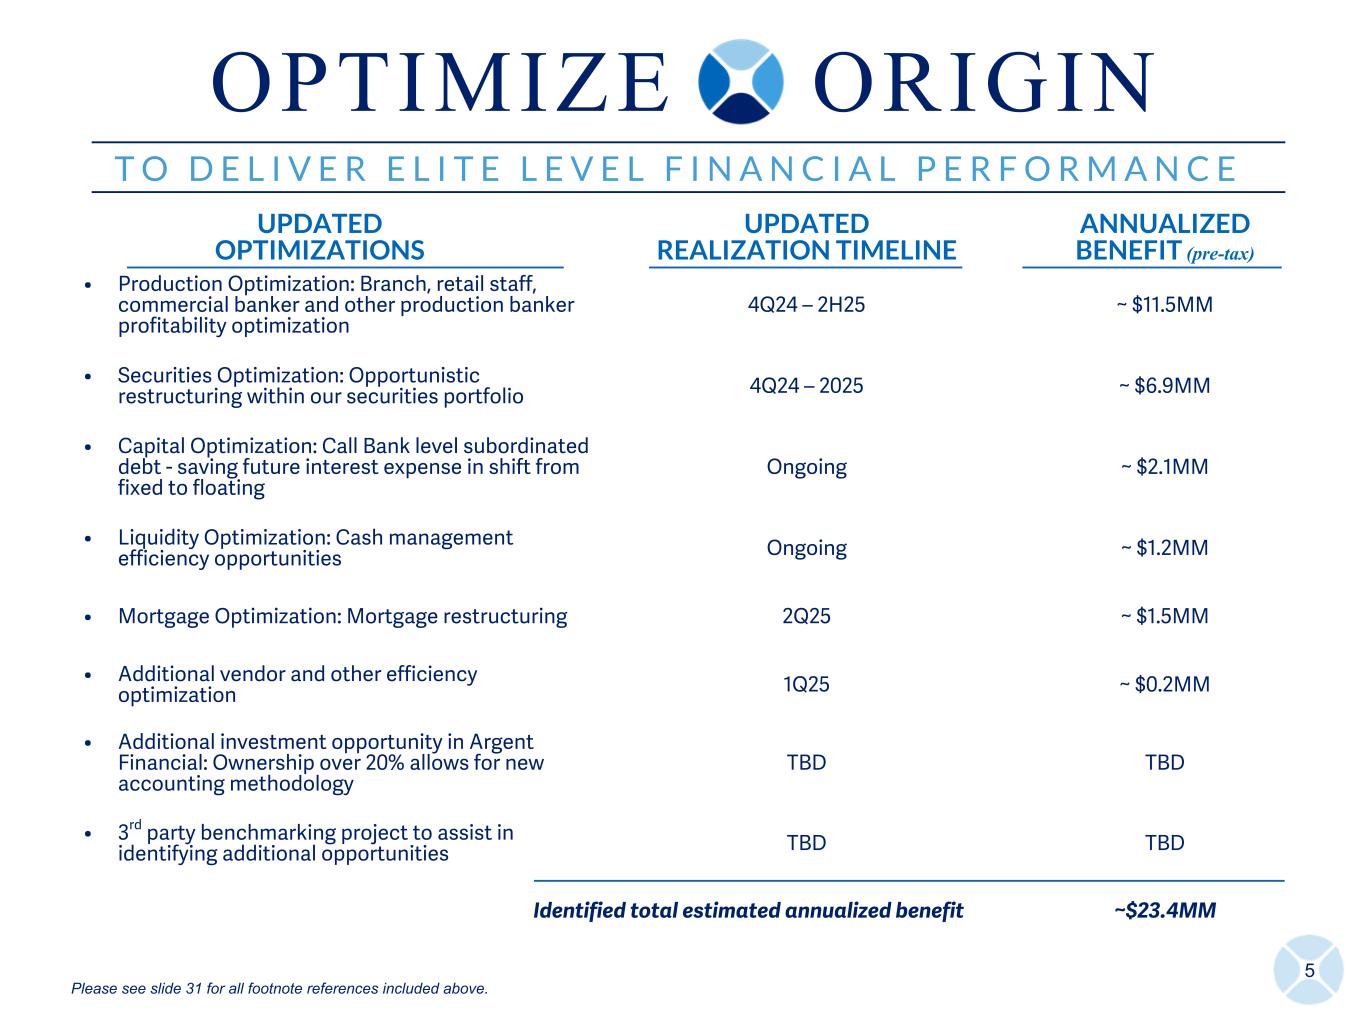
UPDATED OPTIMIZATIONS UPDATED REALIZATION TIMELINE ANNUALIZED BENEFIT (pre-tax) • Production Optimization: Branch, retail staff, commercial banker and other production banker profitability optimization 4Q24 – 2H25 ~ $11.5MM • Securities Optimization: Opportunistic restructuring within our securities portfolio 4Q24 – 2025 ~ $6.9MM • Capital Optimization: Call Bank level subordinated debt - saving future interest expense in shift from fixed to floating Ongoing ~ $2.1MM • Liquidity Optimization: Cash management efficiency opportunities Ongoing ~ $1.2MM • Mortgage Optimization: Mortgage restructuring 2Q25 ~ $1.5MM • Additional vendor and other efficiency optimization 1Q25 ~ $0.2MM • Additional investment opportunity in Argent Financial: Ownership over 20% allows for new accounting methodology TBD TBD • 3rd party benchmarking project to assist in identifying additional opportunities TBD TBD Identified total estimated annualized benefit ~$23.4MM 5 T O D E L I V E R E L I T E L E V E L F I N A N C I A L P E R F O R M A N C E O P T I M I Z E O R I G I N Please see slide 31 for all footnote references included above.
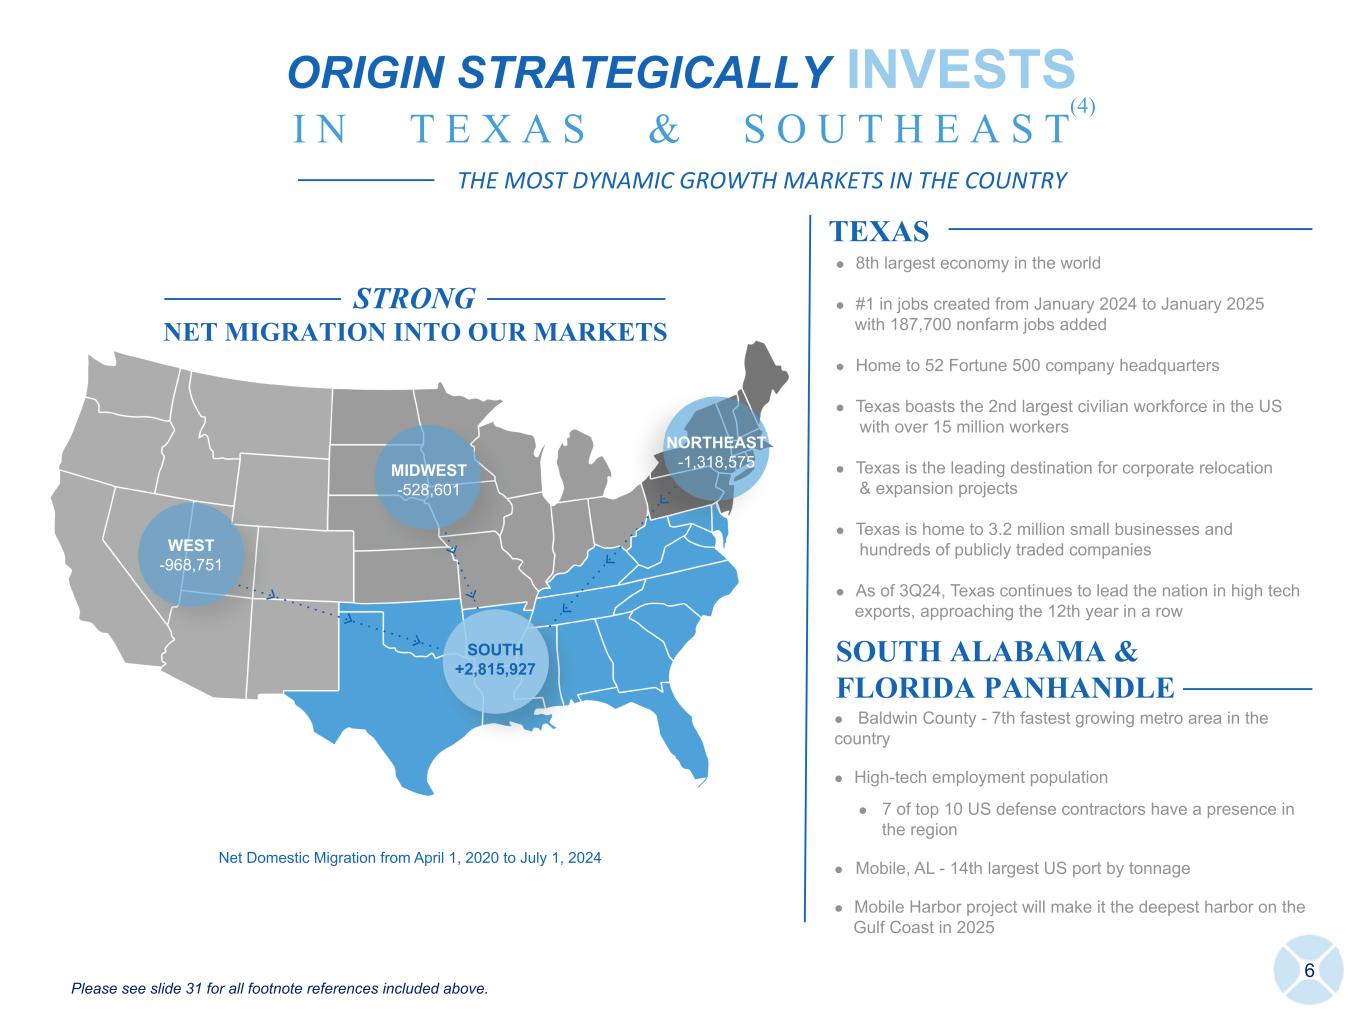
Net Domestic Migration from April 1, 2020 to July 1, 2024 STRONG NET MIGRATION INTO OUR MARKETS WEST -968,751 MIDWEST -528,601 NORTHEAST -1,318,575 SOUTH +2,815,927 6 TEXAS SOUTH ALABAMA & FLORIDA PANHANDLE l Baldwin County - 7th fastest growing metro area in the country l High-tech employment population l 7 of top 10 US defense contractors have a presence in the region l Mobile, AL - 14th largest US port by tonnage l Mobile Harbor project will make it the deepest harbor on the Gulf Coast in 2025 l 8th largest economy in the world l #1 in jobs created from January 2024 to January 2025 with 187,700 nonfarm jobs added l Home to 52 Fortune 500 company headquarters l Texas boasts the 2nd largest civilian workforce in the US with over 15 million workers l Texas is the leading destination for corporate relocation & expansion projects l Texas is home to 3.2 million small businesses and hundreds of publicly traded companies l As of 3Q24, Texas continues to lead the nation in high tech exports, approaching the 12th year in a row ORIGIN STRATEGICALLY INVESTS I N T E X A S & S O U T H E A S T THE MOST DYNAMIC GROWTH MARKETS IN THE COUNTRY (4) Please see slide 31 for all footnote references included above.
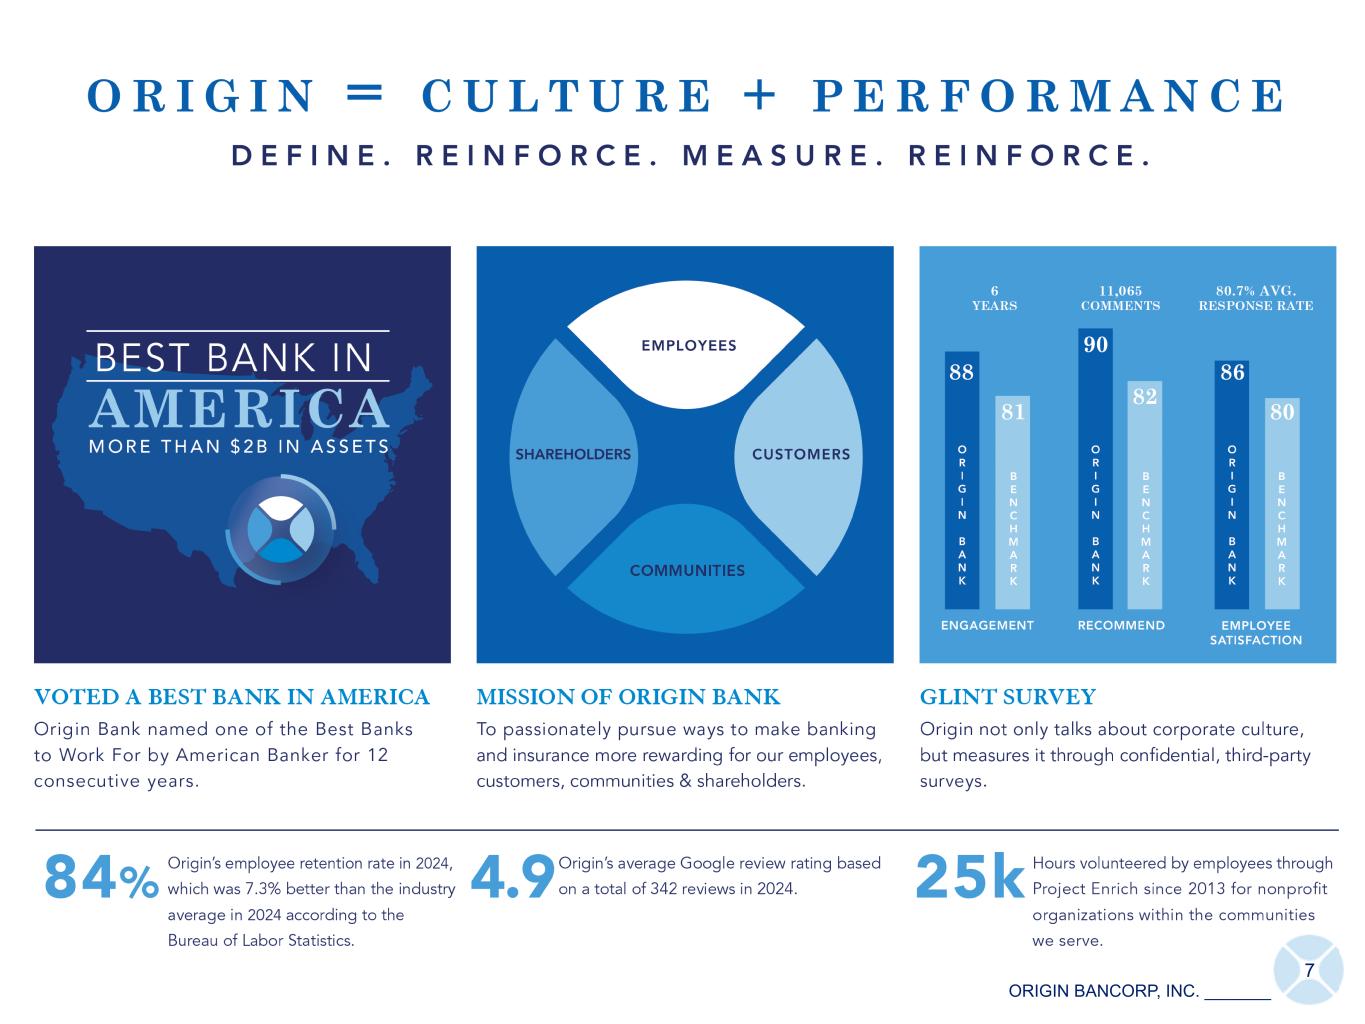
7 ORIGIN BANCORP, INC. _______
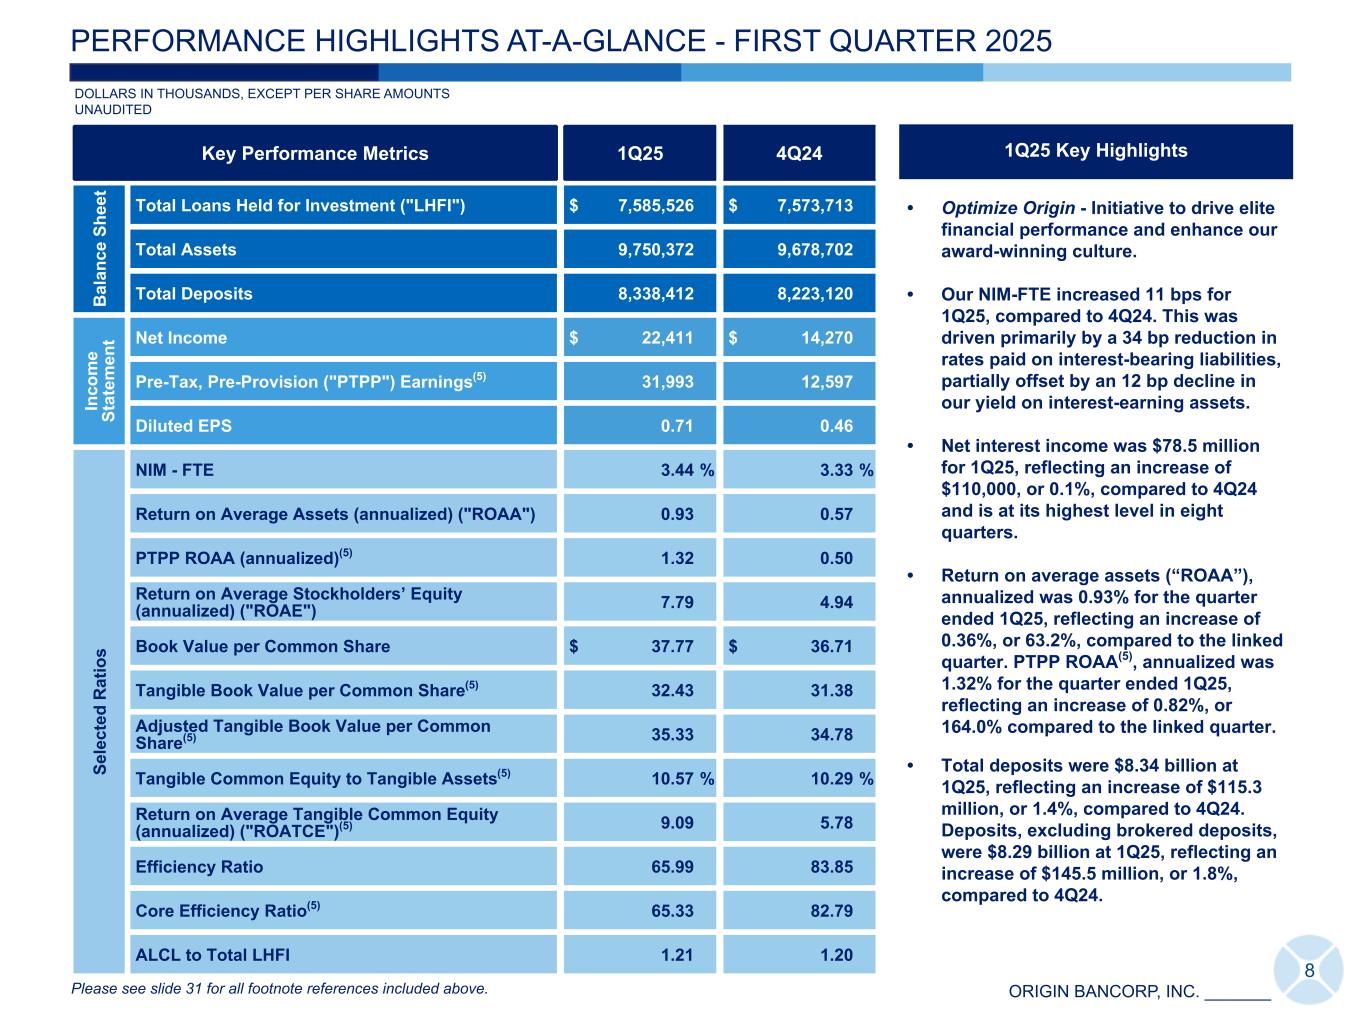
ORIGIN BANCORP, INC. _______ • Optimize Origin - Initiative to drive elite financial performance and enhance our award-winning culture. • Our NIM-FTE increased 11 bps for 1Q25, compared to 4Q24. This was driven primarily by a 34 bp reduction in rates paid on interest-bearing liabilities, partially offset by an 12 bp decline in our yield on interest-earning assets. • Net interest income was $78.5 million for 1Q25, reflecting an increase of $110,000, or 0.1%, compared to 4Q24 and is at its highest level in eight quarters. • Return on average assets (“ROAA”), annualized was 0.93% for the quarter ended 1Q25, reflecting an increase of 0.36%, or 63.2%, compared to the linked quarter. PTPP ROAA(5), annualized was 1.32% for the quarter ended 1Q25, reflecting an increase of 0.82%, or 164.0% compared to the linked quarter. • Total deposits were $8.34 billion at 1Q25, reflecting an increase of $115.3 million, or 1.4%, compared to 4Q24. Deposits, excluding brokered deposits, were $8.29 billion at 1Q25, reflecting an increase of $145.5 million, or 1.8%, compared to 4Q24. Key Performance Metrics 1Q25 4Q24 B al an ce S he et Total Loans Held for Investment ("LHFI") $ 7,585,526 $ 7,573,713 Total Assets 9,750,372 9,678,702 Total Deposits 8,338,412 8,223,120 In co m e St at em en t Net Income $ 22,411 $ 14,270 Pre-Tax, Pre-Provision ("PTPP") Earnings(5) 31,993 12,597 Diluted EPS 0.71 0.46 Se le ct ed R at io s NIM - FTE 3.44 % 3.33 % Return on Average Assets (annualized) ("ROAA") 0.93 0.57 PTPP ROAA (annualized)(5) 1.32 0.50 Return on Average Stockholders’ Equity (annualized) ("ROAE") 7.79 4.94 Book Value per Common Share $ 37.77 $ 36.71 Tangible Book Value per Common Share(5) 32.43 31.38 Adjusted Tangible Book Value per Common Share(5) 35.33 34.78 Tangible Common Equity to Tangible Assets(5) 10.57 % 10.29 % Return on Average Tangible Common Equity (annualized) ("ROATCE")(5) 9.09 5.78 Efficiency Ratio 65.99 83.85 Core Efficiency Ratio(5) 65.33 82.79 ALCL to Total LHFI 1.21 1.20 DOLLARS IN THOUSANDS, EXCEPT PER SHARE AMOUNTS UNAUDITED 8 PERFORMANCE HIGHLIGHTS AT-A-GLANCE - FIRST QUARTER 2025 1Q25 Key Highlights Please see slide 31 for all footnote references included above.
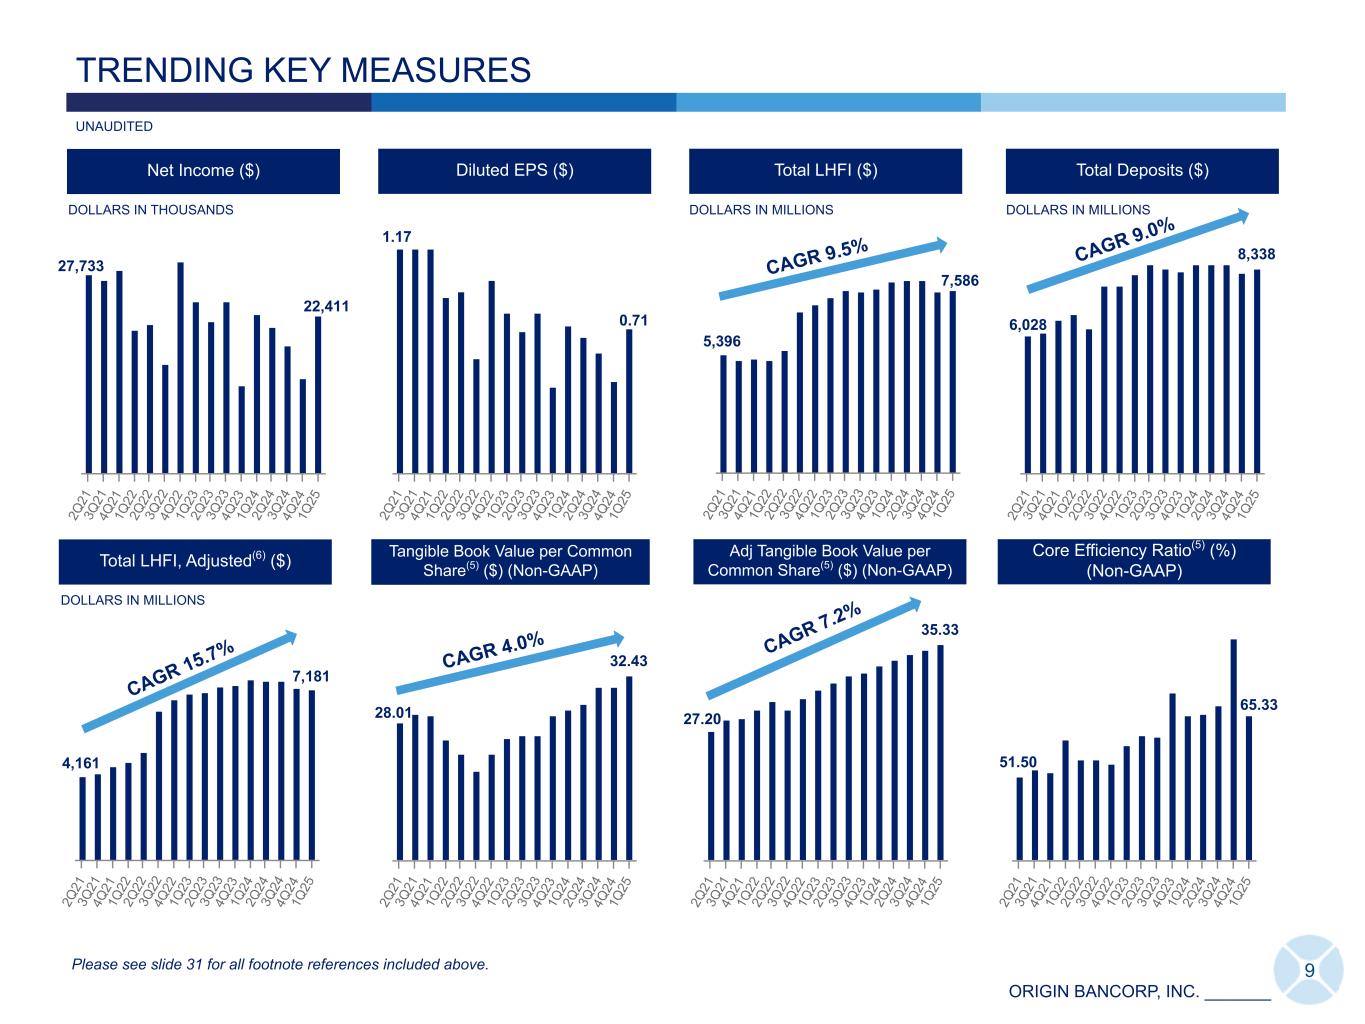
ORIGIN BANCORP, INC. _______ TRENDING KEY MEASURES UNAUDITED Diluted EPS ($)Net Income ($) Total LHFI, Adjusted(6) ($) Total Deposits ($) 2Q 21 3Q 21 4Q 21 1Q 22 2Q 22 3Q 22 4Q 22 1Q 23 2Q 23 3Q 23 4Q 23 1Q 24 2Q 24 3Q 24 4Q 24 1Q 25 2Q 21 3Q 21 4Q 21 1Q 22 2Q 22 3Q 22 4Q 22 1Q 23 2Q 23 3Q 23 4Q 23 1Q 24 2Q 24 3Q 24 4Q 24 1Q 25 8,338 2Q 21 3Q 21 4Q 21 1Q 22 2Q 22 3Q 22 4Q 22 1Q 23 2Q 23 3Q 23 4Q 23 1Q 24 2Q 24 3Q 24 4Q 24 1Q 25 4,161 7,181 2Q 21 3Q 21 4Q 21 1Q 22 2Q 22 3Q 22 4Q 22 1Q 23 2Q 23 3Q 23 4Q 23 1Q 24 2Q 24 3Q 24 4Q 24 1Q 25 DOLLARS IN THOUSANDS 9 Total LHFI ($) DOLLARS IN MILLIONS 5,396 2Q 21 3Q 21 4Q 21 1Q 22 2Q 22 3Q 22 4Q 22 1Q 23 2Q 23 3Q 23 4Q 23 1Q 24 2Q 24 3Q 24 4Q 24 1Q 25 DOLLARS IN MILLIONS DOLLARS IN MILLIONS Please see slide 31 for all footnote references included above. CAGR 9.5% CAGR 15.7% CAGR 9.0% 6,028 27,733 22,411 Core Efficiency Ratio(5) (%) (Non-GAAP) 51.50 2Q 21 3Q 21 4Q 21 1Q 22 2Q 22 3Q 22 4Q 22 1Q 23 2Q 23 3Q 23 4Q 23 1Q 24 2Q 24 3Q 24 4Q 24 1Q 25 32.43 2Q 21 3Q 21 4Q 21 1Q 22 2Q 22 3Q 22 4Q 22 1Q 23 2Q 23 3Q 23 4Q 23 1Q 24 2Q 24 3Q 24 4Q 24 1Q 25 Tangible Book Value per Common Share(5) ($) (Non-GAAP) 35.33 2Q 21 3Q 21 4Q 21 1Q 22 2Q 22 3Q 22 4Q 22 1Q 23 2Q 23 3Q 23 4Q 23 1Q 24 2Q 24 3Q 24 4Q 24 1Q 25 Adj Tangible Book Value per Common Share(5) ($) (Non-GAAP) CAGR 4.0% CAGR 7.2% 1.17 0.71 28.01 27.20 7,586 65.33
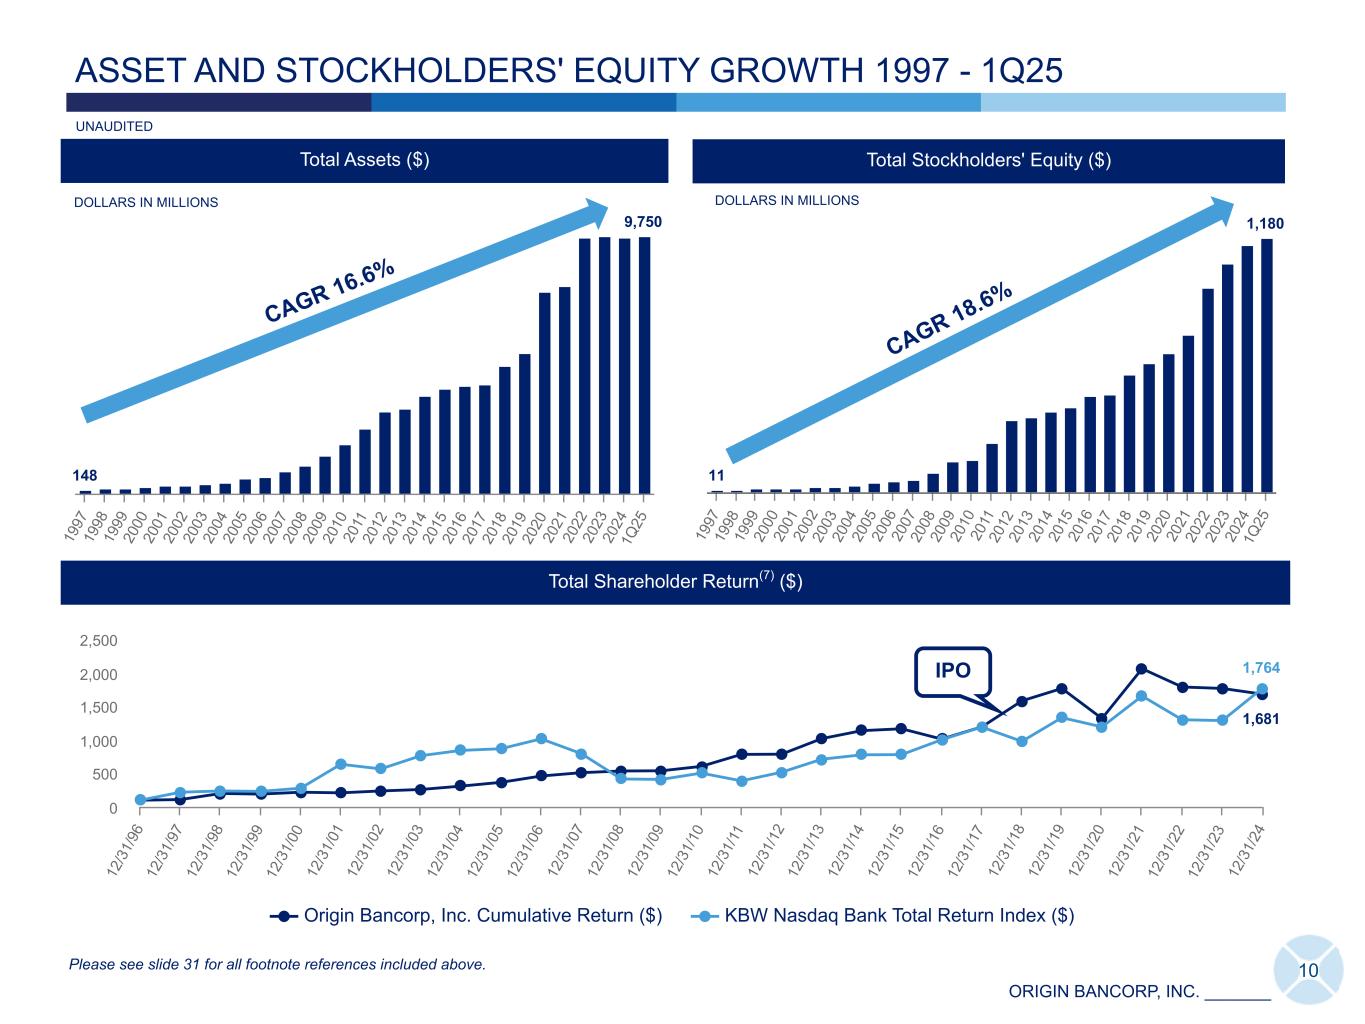
ORIGIN BANCORP, INC. _______ ASSET AND STOCKHOLDERS' EQUITY GROWTH 1997 - 1Q25 DOLLARS IN MILLIONS Total Assets ($) 148 9,750 19 97 19 98 19 99 20 00 20 01 20 02 20 03 20 04 20 05 20 06 20 07 20 08 20 09 20 10 20 11 20 12 20 13 20 14 20 15 20 16 20 17 20 18 20 19 20 20 20 21 20 22 20 23 20 24 1Q 25 Total Stockholders' Equity ($) 11 1,180 19 97 19 98 19 99 20 00 20 01 20 02 20 03 20 04 20 05 20 06 20 07 20 08 20 09 20 10 20 11 20 12 20 13 20 14 20 15 20 16 20 17 20 18 20 19 20 20 20 21 20 22 20 23 20 24 1Q 25 CAGR 16.6% CAGR 18.6% 10 1,681 1,764 Origin Bancorp, Inc. Cumulative Return ($) KBW Nasdaq Bank Total Return Index ($) 12 /3 1/ 96 12 /3 1/ 97 12 /3 1/ 98 12 /3 1/ 99 12 /3 1/ 00 12 /3 1/ 01 12 /3 1/ 02 12 /3 1/ 03 12 /3 1/ 04 12 /3 1/ 05 12 /3 1/ 06 12 /3 1/ 07 12 /3 1/ 08 12 /3 1/ 09 12 /3 1/ 10 12 /3 1/ 11 12 /3 1/ 12 12 /3 1/ 13 12 /3 1/ 14 12 /3 1/ 15 12 /3 1/ 16 12 /3 1/ 17 12 /3 1/ 18 12 /3 1/ 19 12 /3 1/ 20 12 /3 1/ 21 12 /3 1/ 22 12 /3 1/ 23 12 /3 1/ 24 0 500 1,000 1,500 2,000 2,500 Total Shareholder Return(7) ($) IPO Please see slide 31 for all footnote references included above. DOLLARS IN MILLIONS UNAUDITED
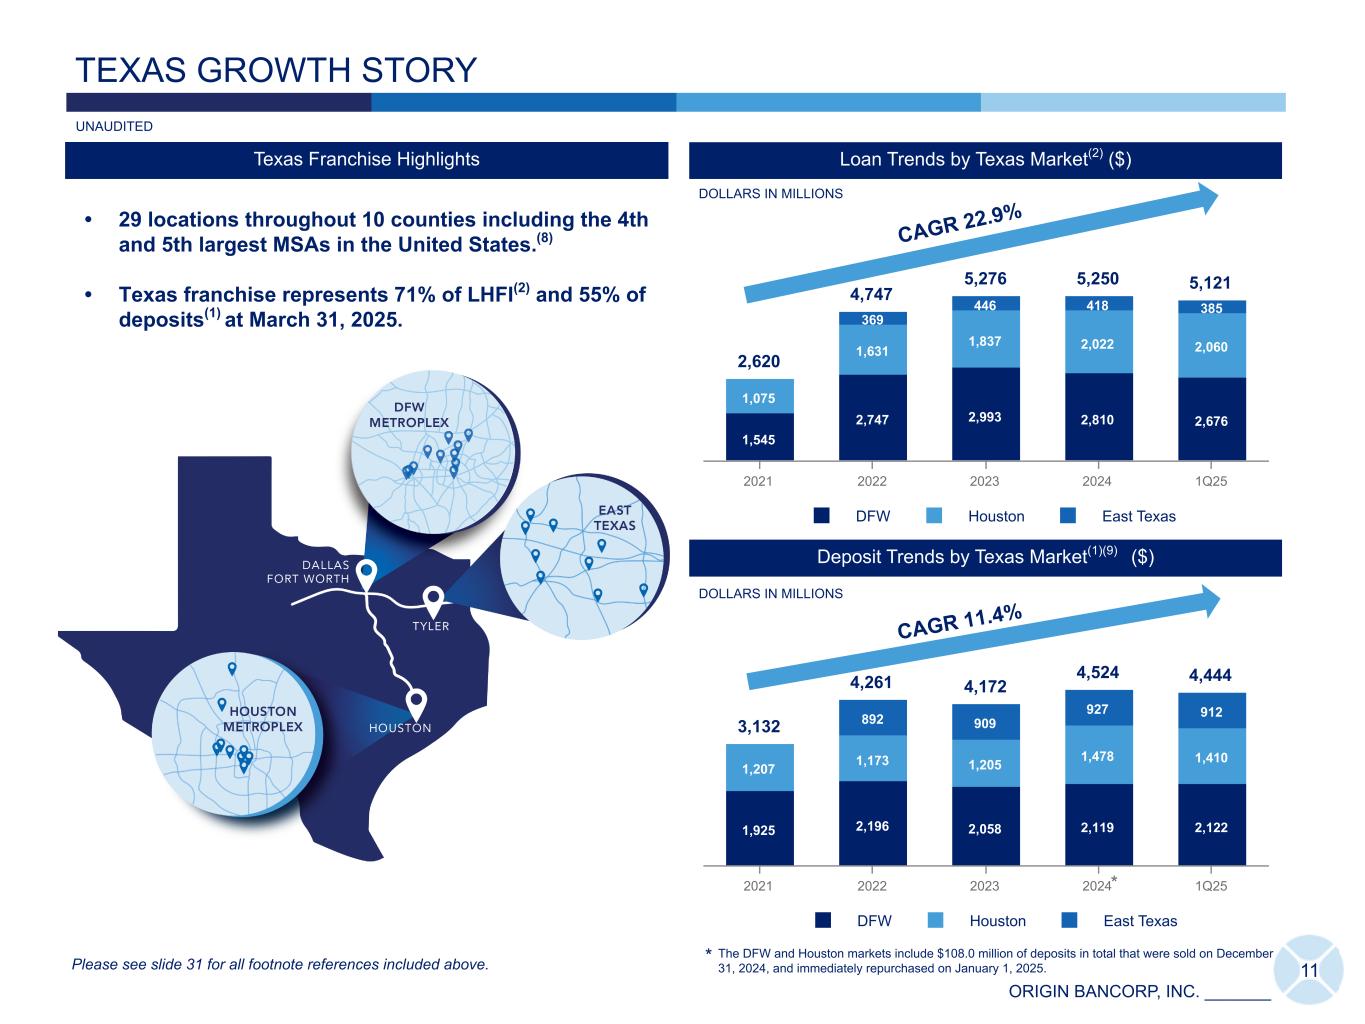
ORIGIN BANCORP, INC. _______ 11 2,620 4,747 5,276 5,250 5,121 1,545 2,747 2,993 2,810 2,676 1,075 1,631 1,837 2,022 2,060 369 446 418 385 DFW Houston East Texas 2021 2022 2023 2024 1Q25 Deposit Trends by Texas Market(1)(9) ($) Loan Trends by Texas Market(2) ($) TEXAS GROWTH STORY Texas Franchise Highlights DOLLARS IN MILLIONS • 29 locations throughout 10 counties including the 4th and 5th largest MSAs in the United States.(8) • Texas franchise represents 71% of LHFI(2) and 55% of deposits(1) at March 31, 2025. 3,132 4,261 4,172 4,524 4,444 1,925 2,196 2,058 2,119 2,122 1,207 1,173 1,205 1,478 1,410 892 909 927 912 DFW Houston East Texas 2021 2022 2023 2024 1Q25 CAGR 22.9% CAGR 11.4% Please see slide 31 for all footnote references included above. DOLLARS IN MILLIONS UNAUDITED * The DFW and Houston markets include $108.0 million of deposits in total that were sold on December 31, 2024, and immediately repurchased on January 1, 2025. *
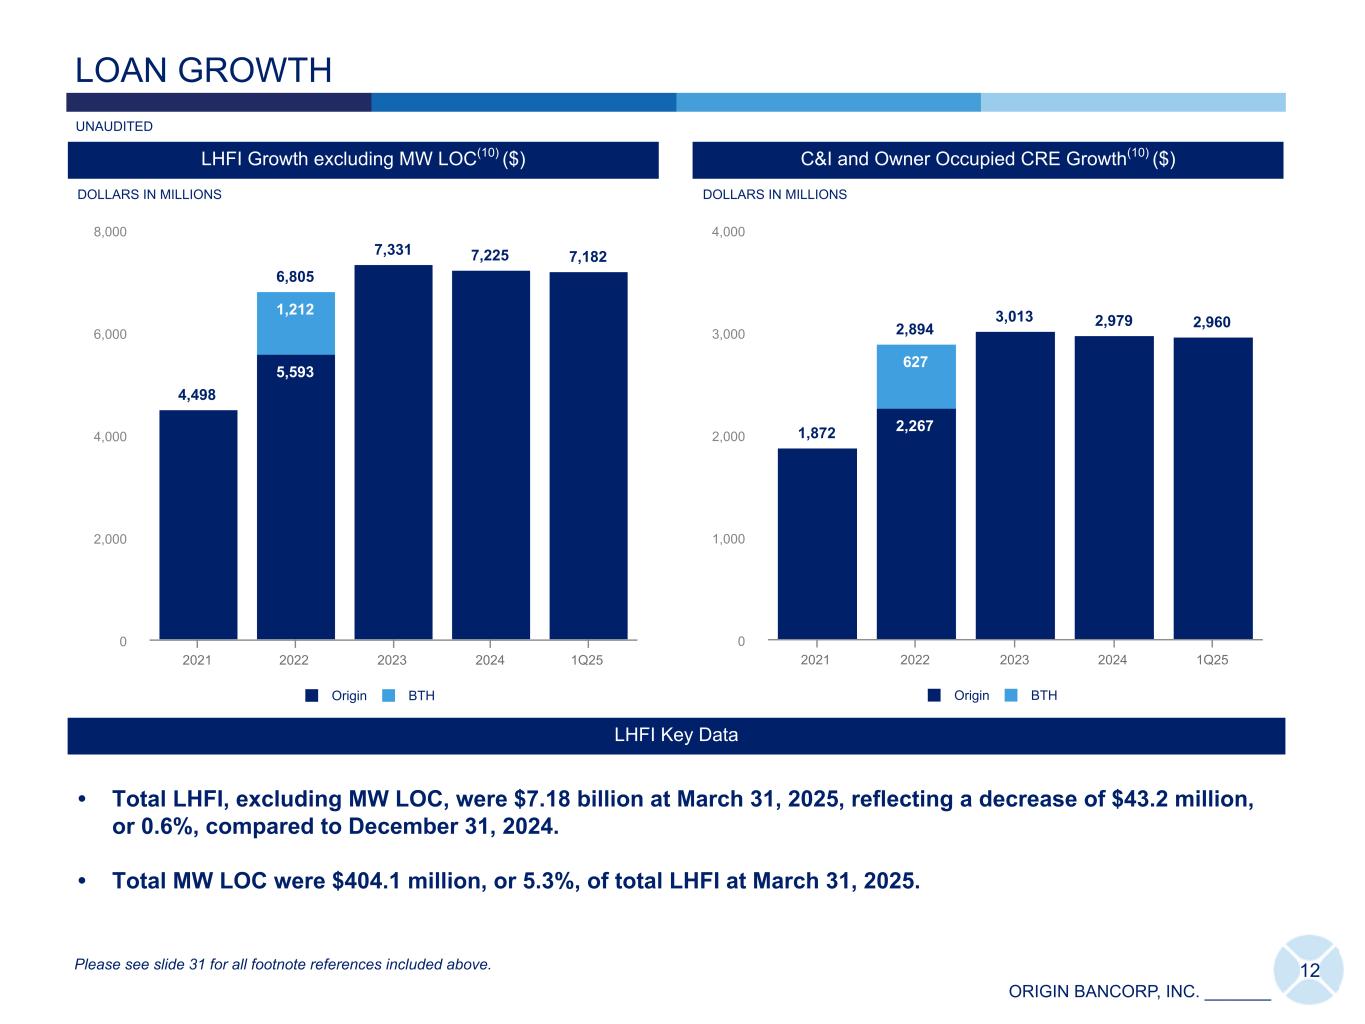
ORIGIN BANCORP, INC. _______ 12 LOAN GROWTH 4,498 6,805 7,331 7,225 7,182 4,498 5,593 7,225 7,182 1,212 Origin BTH 2021 2022 2023 2024 1Q25 0 2,000 4,000 6,000 8,000 LHFI Key Data DOLLARS IN MILLIONS IDT • Total LHFI, excluding MW LOC, were $7.18 billion at March 31, 2025, reflecting a decrease of $43.2 million, or 0.6%, compared to December 31, 2024. • Total MW LOC were $404.1 million, or 5.3%, of total LHFI at March 31, 2025. LHFI Growth excluding MW LOC(10) ($) 1,872 2,894 3,013 2,979 2,960 1,872 2,267 2,979 2,960627 Origin BTH 2021 2022 2023 2024 1Q25 0 1,000 2,000 3,000 4,000 C&I and Owner Occupied CRE Growth(10) ($) Please see slide 31 for all footnote references included above. DOLLARS IN MILLIONS UNAUDITED
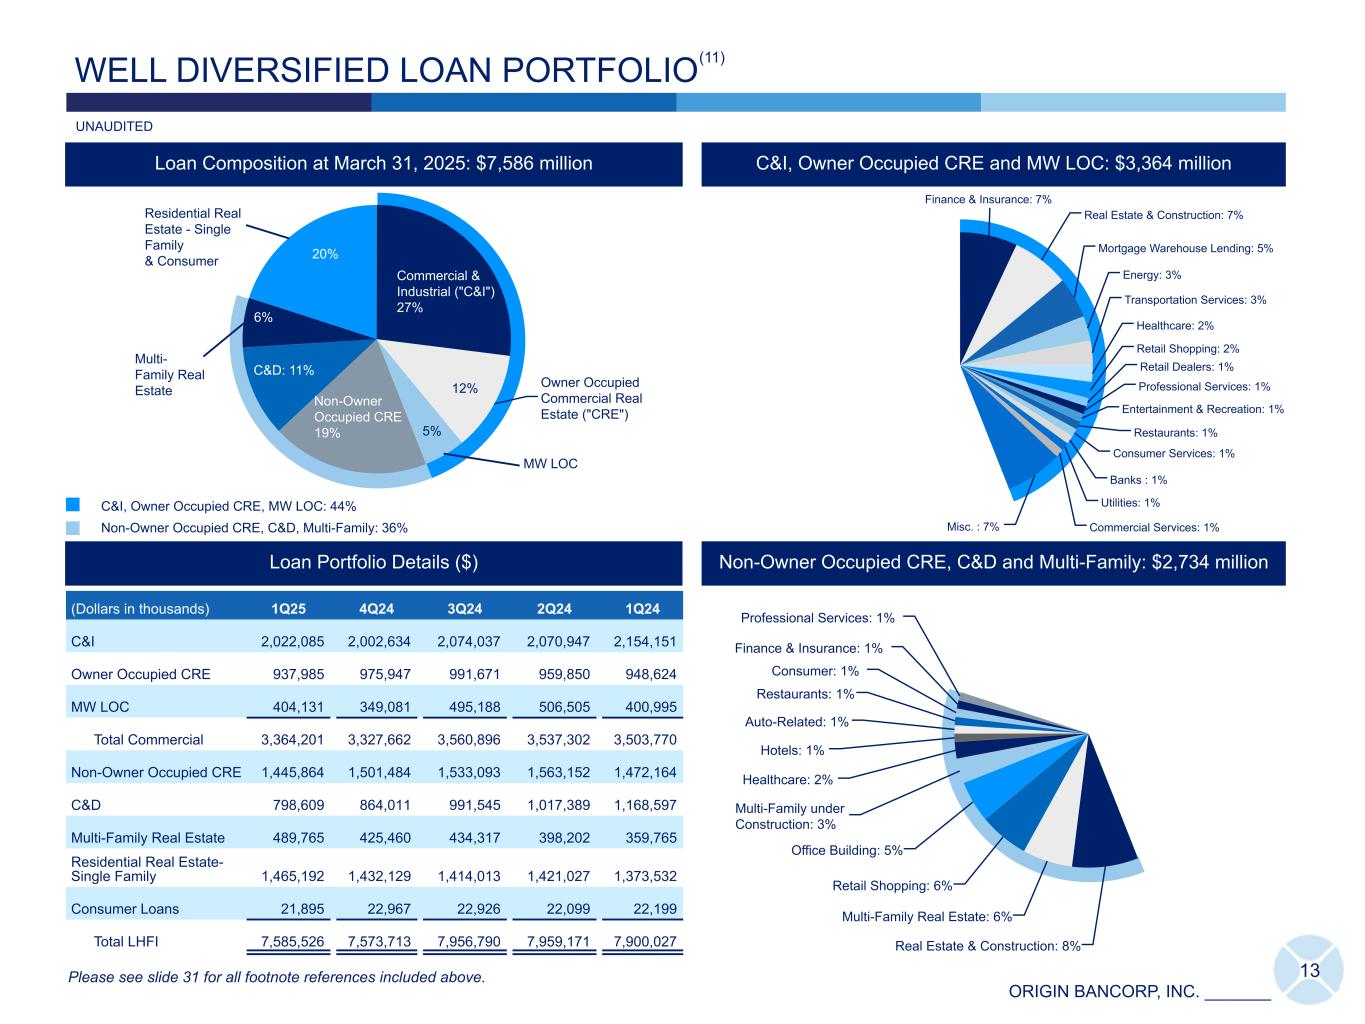
ORIGIN BANCORP, INC. _______ Commercial & Industrial ("C&I") 27% Owner Occupied Commercial Real Estate ("CRE") Non-Owner Occupied CRE 19% C&D: 11% Multi- Family Real Estate Residential Real Estate - Single Family & Consumer 13 WELL DIVERSIFIED LOAN PORTFOLIO (Dollars in thousands) 1Q25 4Q24 3Q24 2Q24 1Q24 C&I 2,022,085 2,002,634 2,074,037 2,070,947 2,154,151 Owner Occupied CRE 937,985 975,947 991,671 959,850 948,624 MW LOC 404,131 349,081 495,188 506,505 400,995 Total Commercial 3,364,201 3,327,662 3,560,896 3,537,302 3,503,770 Non-Owner Occupied CRE 1,445,864 1,501,484 1,533,093 1,563,152 1,472,164 C&D 798,609 864,011 991,545 1,017,389 1,168,597 Multi-Family Real Estate 489,765 425,460 434,317 398,202 359,765 Residential Real Estate- Single Family 1,465,192 1,432,129 1,414,013 1,421,027 1,373,532 Consumer Loans 21,895 22,967 22,926 22,099 22,199 Total LHFI 7,585,526 7,573,713 7,956,790 7,959,171 7,900,027 Loan Portfolio Details ($) Non-Owner Occupied CRE, C&D and Multi-Family: $2,734 million C&I, Owner Occupied CRE and MW LOC: $3,364 million C&I, Owner Occupied CRE, MW LOC: 44% Non-Owner Occupied CRE, C&D, Multi-Family: 36% Loan Composition at March 31, 2025: $7,586 million Please see slide 31 for all footnote references included above. UNAUDITED (11) MW LOC 6% 20% 12% 5% Real Estate & Construction: 8% Multi-Family Real Estate: 6% Retail Shopping: 6% Office Building: 5% Multi-Family under Construction: 3% Healthcare: 2% Hotels: 1% Auto-Related: 1% Restaurants: 1% Consumer: 1% Finance & Insurance: 1% Professional Services: 1% Finance & Insurance: 7% Real Estate & Construction: 7% Mortgage Warehouse Lending: 5% Energy: 3% Transportation Services: 3% Healthcare: 2% Retail Shopping: 2% Retail Dealers: 1% Professional Services: 1% Entertainment & Recreation: 1% Restaurants: 1% Consumer Services: 1% Banks : 1% Utilities: 1% Commercial Services: 1%Misc. : 7%
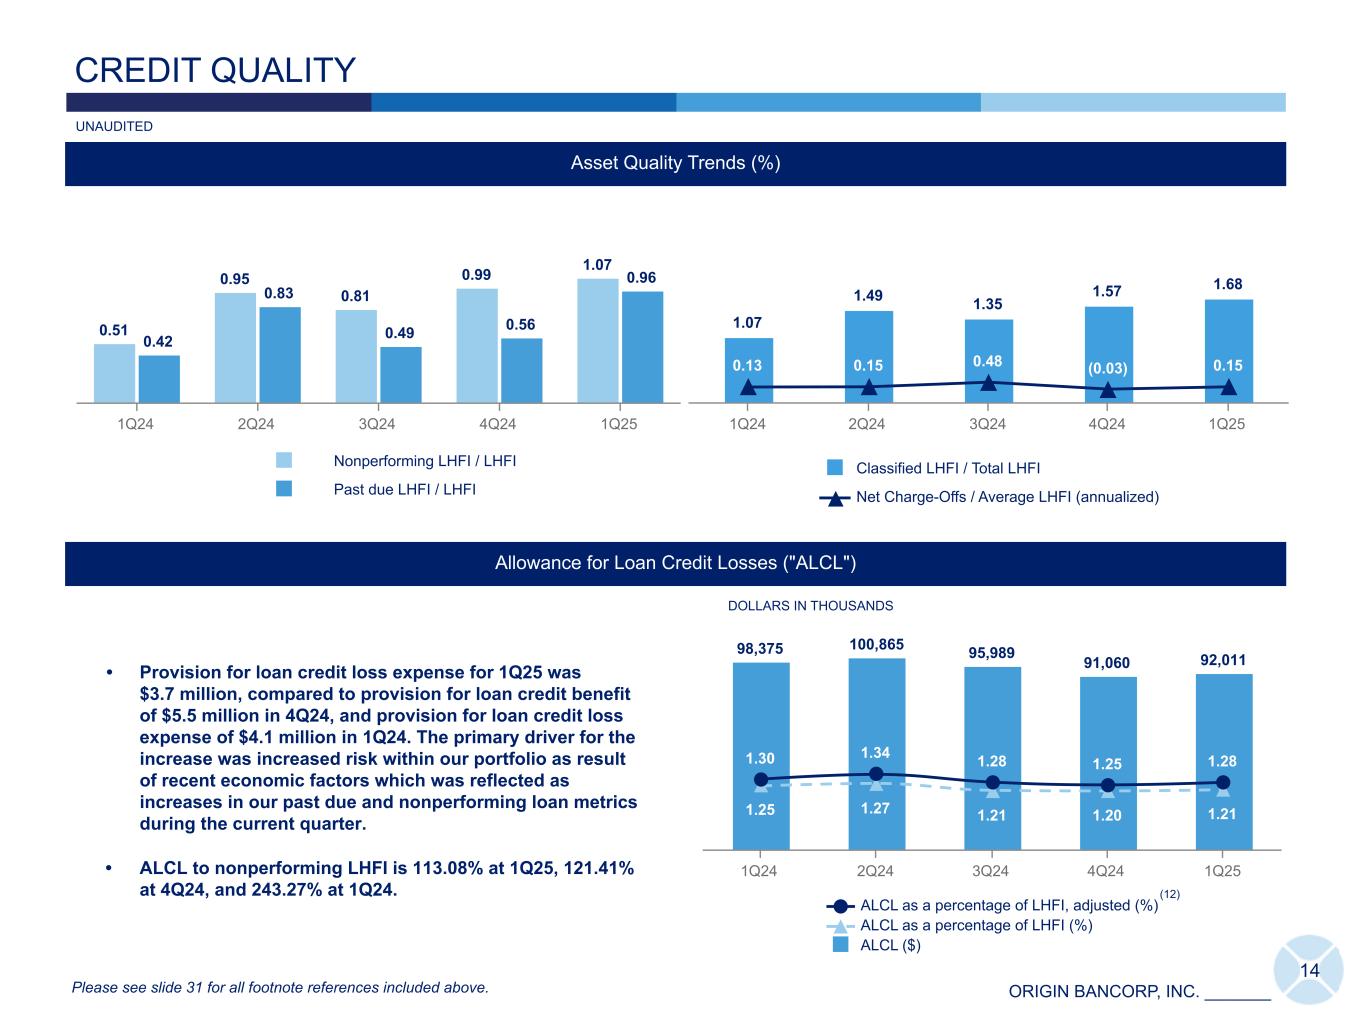
ORIGIN BANCORP, INC. _______ 1.07 1.49 1.35 1.57 1.68 0.13 0.15 0.48 (0.03) 0.15 Classified LHFI / Total LHFI Net Charge-Offs / Average LHFI (annualized) 1Q24 2Q24 3Q24 4Q24 1Q25 0.51 0.95 0.81 0.99 1.07 0.42 0.83 0.49 0.56 0.96 Nonperforming LHFI / LHFI Past due LHFI / LHFI 1Q24 2Q24 3Q24 4Q24 1Q25 14 CREDIT QUALITY Asset Quality Trends (%) Allowance for Loan Credit Losses ("ALCL") 98,375 100,865 95,989 91,060 92,011 1.25 1.27 1.21 1.20 1.21 1.30 1.34 1.28 1.25 1.28 ALCL as a percentage of LHFI, adjusted (%) ALCL as a percentage of LHFI (%) ALCL ($) 1Q24 2Q24 3Q24 4Q24 1Q25 • Provision for loan credit loss expense for 1Q25 was $3.7 million, compared to provision for loan credit benefit of $5.5 million in 4Q24, and provision for loan credit loss expense of $4.1 million in 1Q24. The primary driver for the increase was increased risk within our portfolio as result of recent economic factors which was reflected as increases in our past due and nonperforming loan metrics during the current quarter. • ALCL to nonperforming LHFI is 113.08% at 1Q25, 121.41% at 4Q24, and 243.27% at 1Q24. DOLLARS IN THOUSANDS (12) Please see slide 31 for all footnote references included above. UNAUDITED
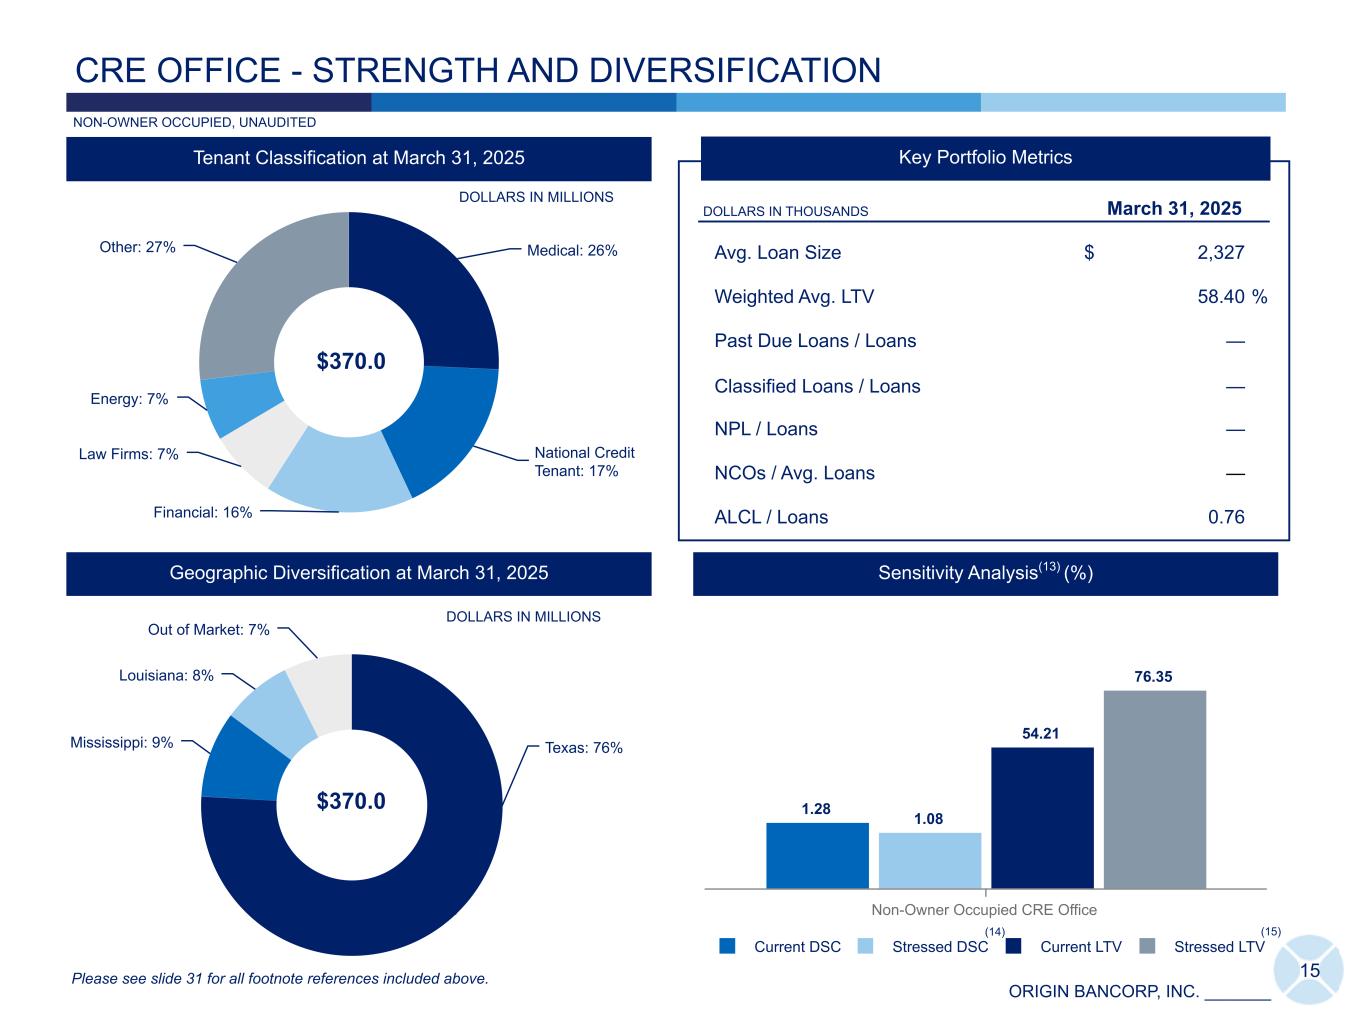
ORIGIN BANCORP, INC. _______ Texas: 76%Mississippi: 9% Louisiana: 8% Out of Market: 7% 15 Medical: 26% National Credit Tenant: 17% Financial: 16% Law Firms: 7% Energy: 7% Other: 27% CRE OFFICE - STRENGTH AND DIVERSIFICATION Tenant Classification at March 31, 2025 $370.0 $370.0 Geographic Diversification at March 31, 2025 DOLLARS IN THOUSANDS March 31, 2025 Avg. Loan Size $ 2,327 Weighted Avg. LTV 58.40 % Past Due Loans / Loans — Classified Loans / Loans — NPL / Loans — NCOs / Avg. Loans — ALCL / Loans 0.76 Key Portfolio Metrics DOLLARS IN MILLIONS DOLLARS IN MILLIONS NON-OWNER OCCUPIED, UNAUDITED Sensitivity Analysis(13) (%) 1.28 1.08 54.21 76.35 Current DSC Stressed DSC Current LTV Stressed LTV Non-Owner Occupied CRE Office (14) Please see slide 31 for all footnote references included above. (15)
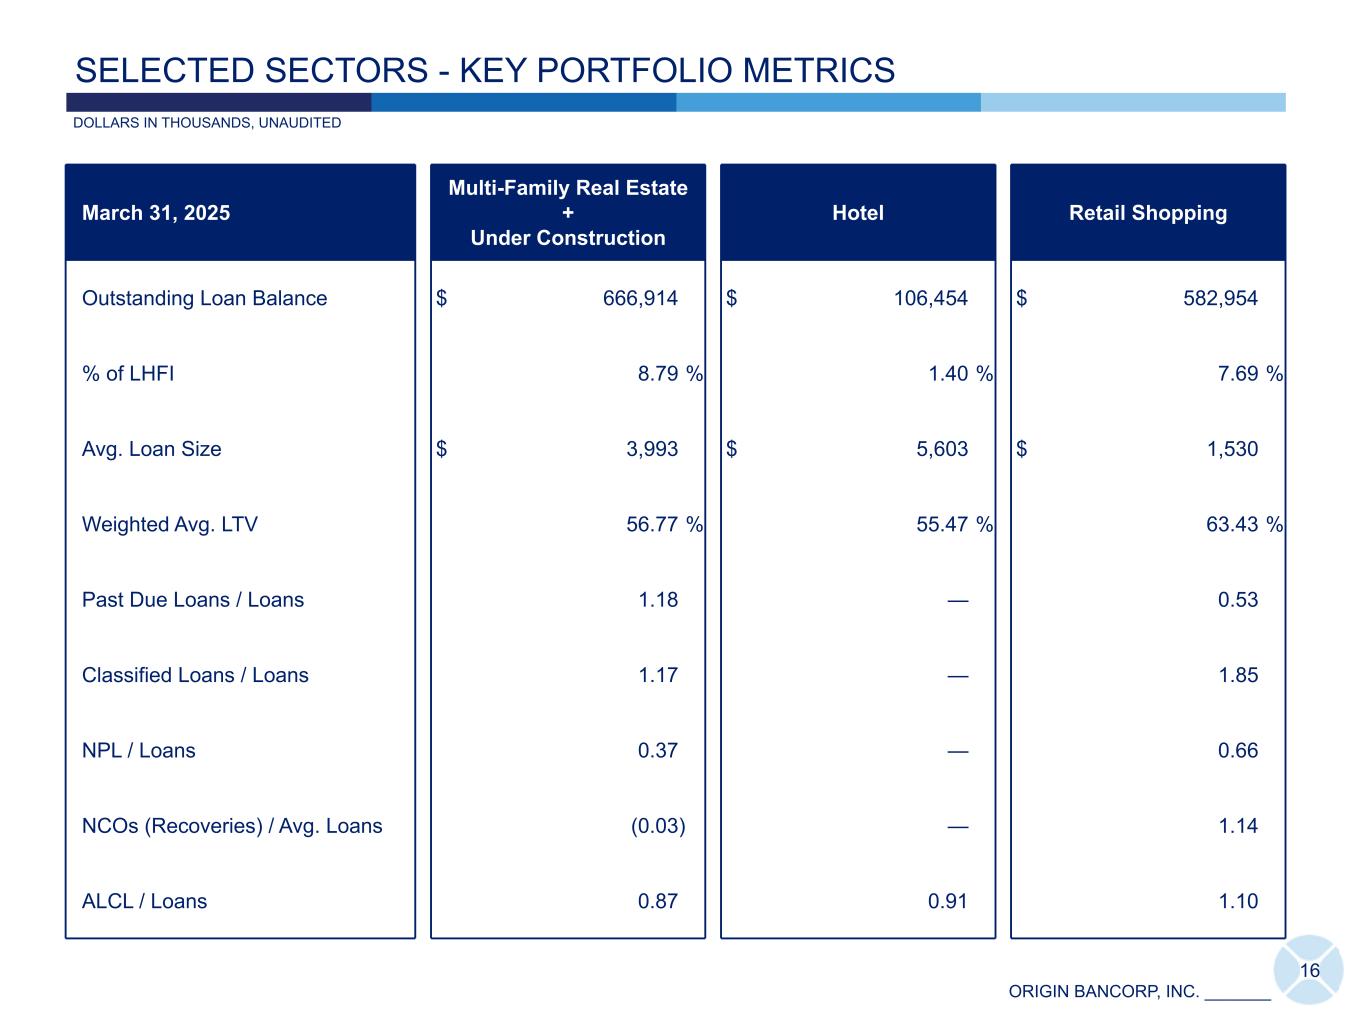
ORIGIN BANCORP, INC. _______ 16 SELECTED SECTORS - KEY PORTFOLIO METRICS March 31, 2025 Multi-Family Real Estate + Under Construction Hotel Retail Shopping Outstanding Loan Balance $ 666,914 $ 106,454 $ 582,954 % of LHFI 8.79 % 1.40 % 7.69 % Avg. Loan Size $ 3,993 $ 5,603 $ 1,530 Weighted Avg. LTV 56.77 % 55.47 % 63.43 % Past Due Loans / Loans 1.18 — 0.53 Classified Loans / Loans 1.17 — 1.85 NPL / Loans 0.37 — 0.66 NCOs (Recoveries) / Avg. Loans (0.03) — 1.14 ALCL / Loans 0.87 0.91 1.10 DOLLARS IN THOUSANDS, UNAUDITED
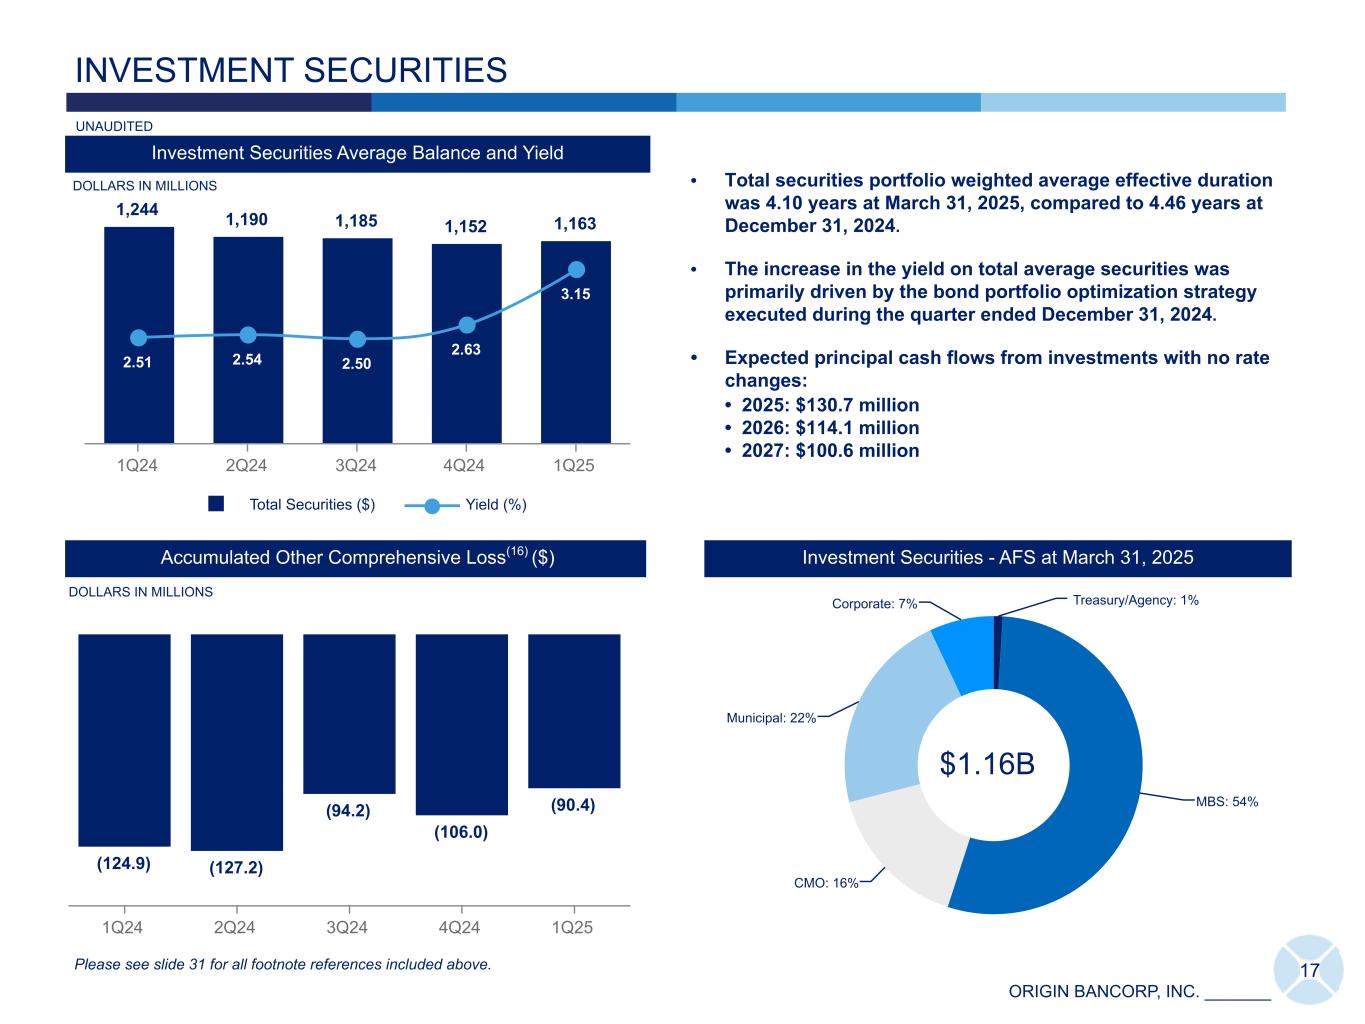
ORIGIN BANCORP, INC. _______ Treasury/Agency: 1% MBS: 54% CMO: 16% Municipal: 22% Corporate: 7% 1,244 1,190 1,185 1,152 1,163 2.51 2.54 2.50 2.63 3.15 Total Securities ($) Yield (%) 1Q24 2Q24 3Q24 4Q24 1Q25 Investment Securities Average Balance and Yield INVESTMENT SECURITIES DOLLARS IN MILLIONS • Total securities portfolio weighted average effective duration was 4.10 years at March 31, 2025, compared to 4.46 years at December 31, 2024. • The increase in the yield on total average securities was primarily driven by the bond portfolio optimization strategy executed during the quarter ended December 31, 2024. • Expected principal cash flows from investments with no rate changes: • 2025: $130.7 million • 2026: $114.1 million • 2027: $100.6 million 17 (124.9) (127.2) (94.2) (106.0) (90.4) 1Q24 2Q24 3Q24 4Q24 1Q25 Accumulated Other Comprehensive Loss(16) ($) Investment Securities - AFS at March 31, 2025 Please see slide 31 for all footnote references included above. $1.16B DOLLARS IN MILLIONS UNAUDITED
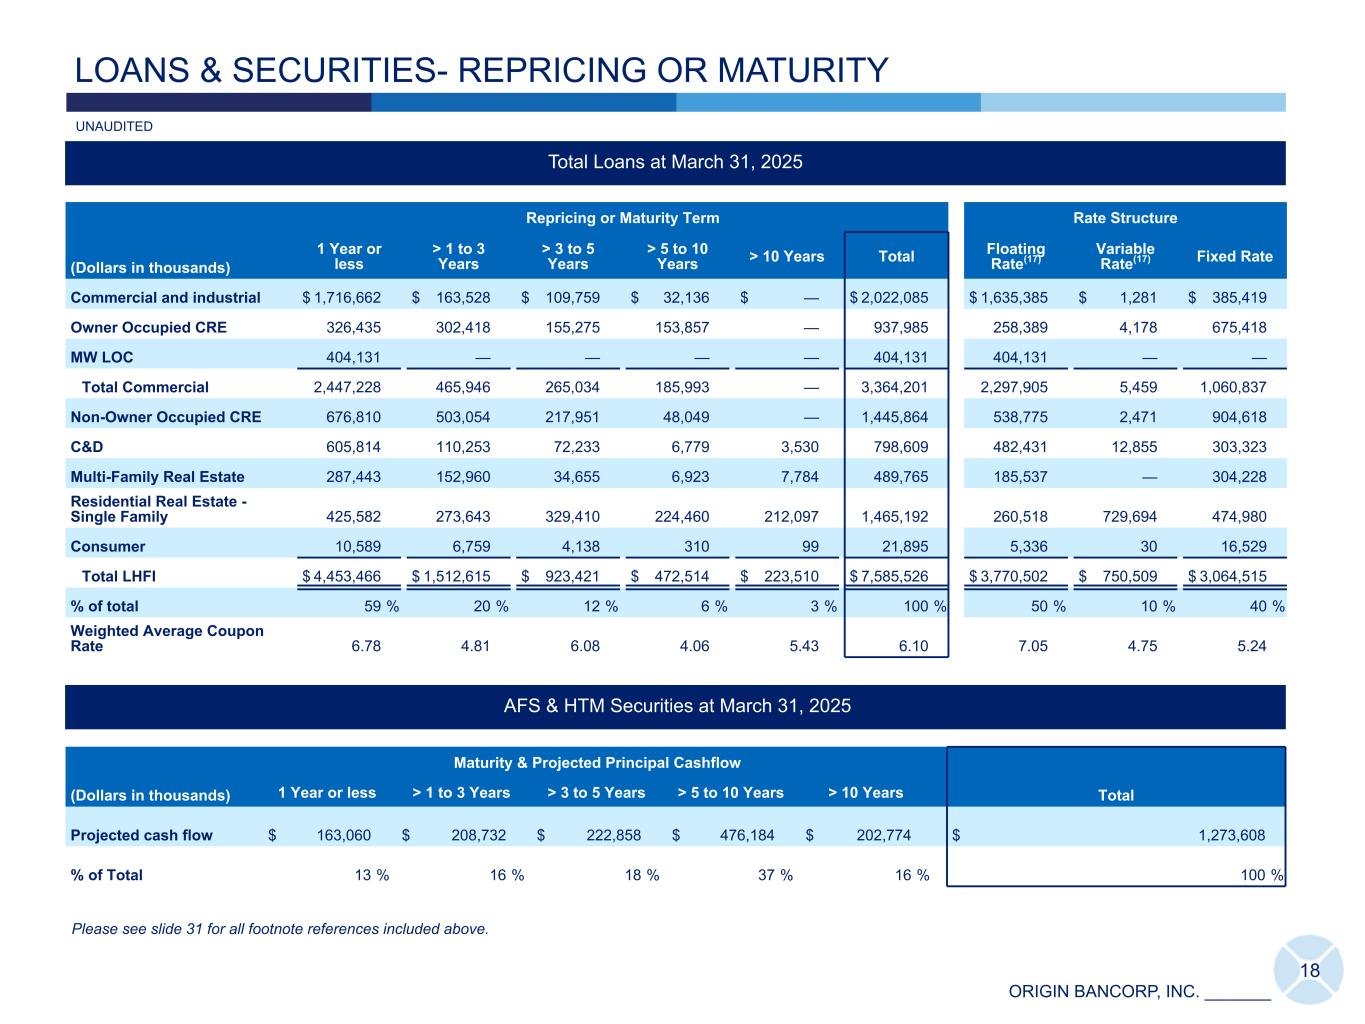
ORIGIN BANCORP, INC. _______ Total Loans at March 31, 2025 (Dollars in thousands) Repricing or Maturity Term Rate Structure 1 Year or less > 1 to 3 Years > 3 to 5 Years > 5 to 10 Years > 10 Years Total Floating Rate(17) Variable Rate(17) Fixed Rate Commercial and industrial $ 1,716,662 $ 163,528 $ 109,759 $ 32,136 $ — $ 2,022,085 $ 1,635,385 $ 1,281 $ 385,419 Owner Occupied CRE 326,435 302,418 155,275 153,857 — 937,985 258,389 4,178 675,418 MW LOC 404,131 — — — — 404,131 404,131 — — Total Commercial 2,447,228 465,946 265,034 185,993 — 3,364,201 2,297,905 5,459 1,060,837 Non-Owner Occupied CRE 676,810 503,054 217,951 48,049 — 1,445,864 538,775 2,471 904,618 C&D 605,814 110,253 72,233 6,779 3,530 798,609 482,431 12,855 303,323 Multi-Family Real Estate 287,443 152,960 34,655 6,923 7,784 489,765 185,537 — 304,228 Residential Real Estate - Single Family 425,582 273,643 329,410 224,460 212,097 1,465,192 260,518 729,694 474,980 Consumer 10,589 6,759 4,138 310 99 21,895 5,336 30 16,529 Total LHFI $ 4,453,466 $ 1,512,615 $ 923,421 $ 472,514 $ 223,510 $ 7,585,526 $ 3,770,502 $ 750,509 $ 3,064,515 % of total 59 % 20 % 12 % 6 % 3 % 100 % 50 % 10 % 40 % Weighted Average Coupon Rate 6.78 4.81 6.08 4.06 5.43 6.10 7.05 4.75 5.24 AFS & HTM Securities at March 31, 2025 (Dollars in thousands) Maturity & Projected Principal Cashflow Total1 Year or less > 1 to 3 Years > 3 to 5 Years > 5 to 10 Years > 10 Years Projected cash flow $ 163,060 $ 208,732 $ 222,858 $ 476,184 $ 202,774 $ 1,273,608 % of Total 13 % 16 % 18 % 37 % 16 % 100 % LOANS & SECURITIES- REPRICING OR MATURITY 18 UNAUDITED Please see slide 31 for all footnote references included above.
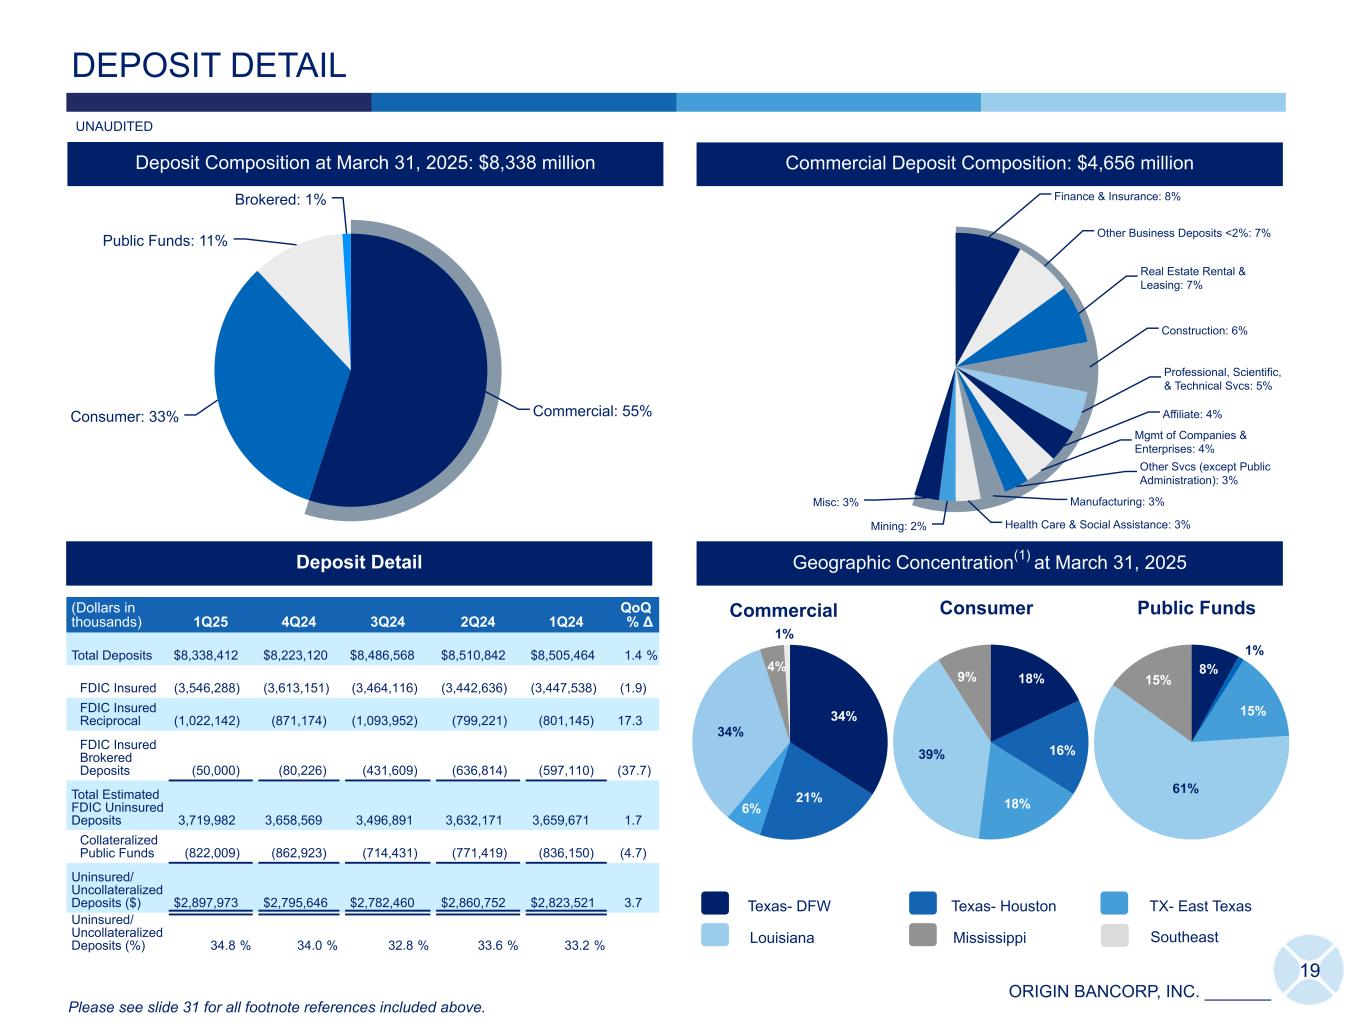
ORIGIN BANCORP, INC. _______ Commercial: 55%Consumer: 33% Public Funds: 11% Brokered: 1% 34% 21% 6% 34% 4% 1% 8% 1% 15% 61% 15% Finance & Insurance: 8% Other Business Deposits <2%: 7% Real Estate Rental & Leasing: 7% Construction: 6% Professional, Scientific, & Technical Svcs: 5% Affiliate: 4% Mgmt of Companies & Enterprises: 4% Other Svcs (except Public Administration): 3% Manufacturing: 3% Health Care & Social Assistance: 3%Mining: 2% Misc: 3% 19 DEPOSIT DETAIL (Dollars in thousands) 1Q25 4Q24 3Q24 2Q24 1Q24 QoQ % Δ Total Deposits $ 8,338,412 $ 8,486,568 $ 8,510,842 $ 8,505,464 $ 8,251,125 (1.7) % FDIC Insured (3,464,116) (3,464,116) (3,442,636) (3,447,538) (3,425,268) — FDIC Insured Reciprocal (1,093,952) (1,093,952) (799,221) (801,145) (801,699) — FDIC Insured Brokered Deposits (431,609) (431,609) (636,814) (597,110) (444,989) — Total Estimated FDIC Uninsured Deposits 3,348,735 3,496,891 3,632,171 3,659,671 3,579,169 (4.2) Collateralized Public Funds (714,431) (714,431) (771,419) (836,150) (849,603) — Uninsured/ Uncollateralized Deposits ($) $ 2,634,304 $ 2,782,460 $ 2,860,752 $ 2,823,521 $ 2,729,566 (5.3) Uninsured/ Uncollateralized Deposits (%) 31.6 % 32.8 % 33.6 % 33.2 % 33.1 % Deposit Detail Geographic Concentration(1) at March 31, 2025 Commercial Deposit Composition: $4,656 million Deposit Composition at March 31, 2025: $8,338 million Commercial Public FundsConsumer MississippiLouisiana Texas- DFW TX- East TexasTexas- Houston Please see slide 31 for all footnote references included above. UNAUDITED Southeast 18% 16% 18% 39% 9% (Dollars in thousands) 1Q25 4Q24 3Q24 2Q24 1Q24 QoQ % Δ Total Deposits $ 8,338,412 $ 8,223,120 $ 8,486,568 $ 8,510,842 $ 8,505,464 1.4 % FDIC Insured (3,546,288) (3,613,151) (3,464,116) (3,442,636) (3,447,538) (1.9) FDIC Insured Reciprocal (1,022,142) (871,174) (1,093,952) (799,221) (801,145) 17.3 FDIC Insured Brokered Deposits (50,000) (80,226) (431,609) (636,814) (597,110) (37.7) Total Estimated FDIC Uninsured Deposits 3,719,982 3,658,569 3,496,891 3,632,171 3,659,671 1.7 Collateralized Public Funds (822,009) (862,923) (714,431) (771,419) (836,150) (4.7) Uninsured/ Uncollateralized Deposits ($) $ 2,897,973 $ 2,795,646 $ 2,782,460 $ 2,860,752 $ 2,823,521 3.7 Uninsured/ Uncollateralized Deposits (%) 34.8 % 34.0 % 32.8 % 33.6 % 33.2 % Deposit Detail
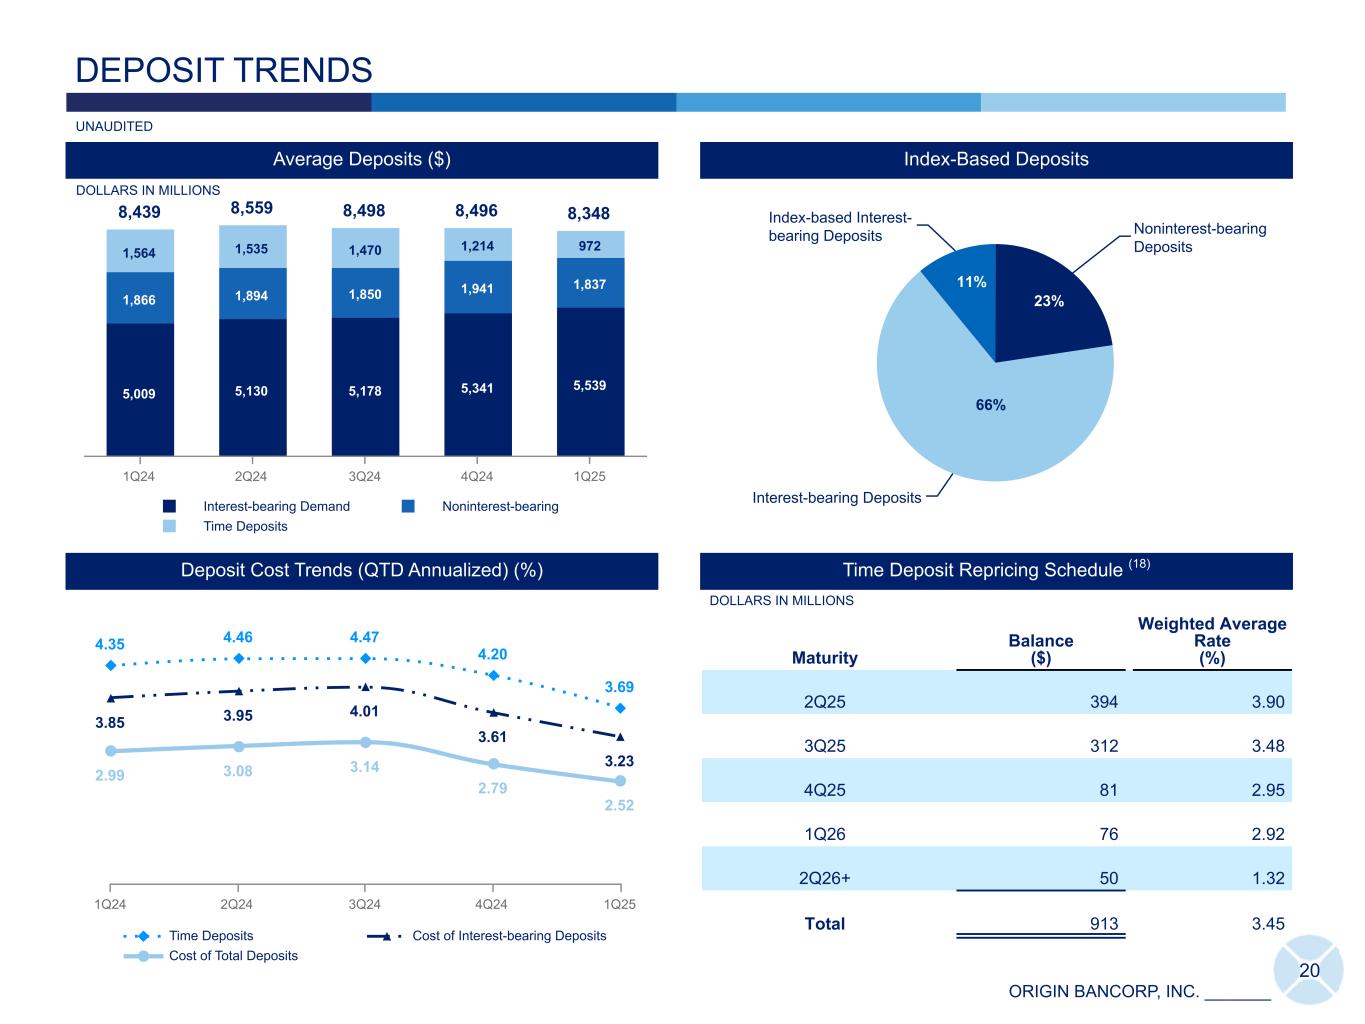
ORIGIN BANCORP, INC. _______ 20 8,439 8,559 8,498 8,496 8,348 5,009 5,130 5,178 5,341 5,539 1,866 1,894 1,850 1,941 1,837 1,564 1,535 1,470 1,214 972 Interest-bearing Demand Noninterest-bearing Time Deposits 1Q24 2Q24 3Q24 4Q24 1Q25 Average Deposits ($) DEPOSIT TRENDS IDT Index-Based Deposits DOLLARS IN MILLIONS UNAUDITED Deposit Cost Trends (QTD Annualized) (%) 4.35 4.46 4.47 4.20 3.69 3.85 3.95 4.01 3.61 3.23 2.99 3.08 3.14 2.79 2.52 Time Deposits Cost of Interest-bearing Deposits Cost of Total Deposits 1Q24 2Q24 3Q24 4Q24 1Q25 Time Deposit Repricing Schedule (18) Maturity Balance ($) Weighted Average Rate (%) 2Q25 394 3.90 3Q25 312 3.48 4Q25 81 2.95 1Q26 76 2.92 2Q26+ 50 1.32 Total 913 3.45 DOLLARS IN MILLIONS Noninterest-bearing Deposits Interest-bearing Deposits Index-based Interest- bearing Deposits 11% 66% 23%
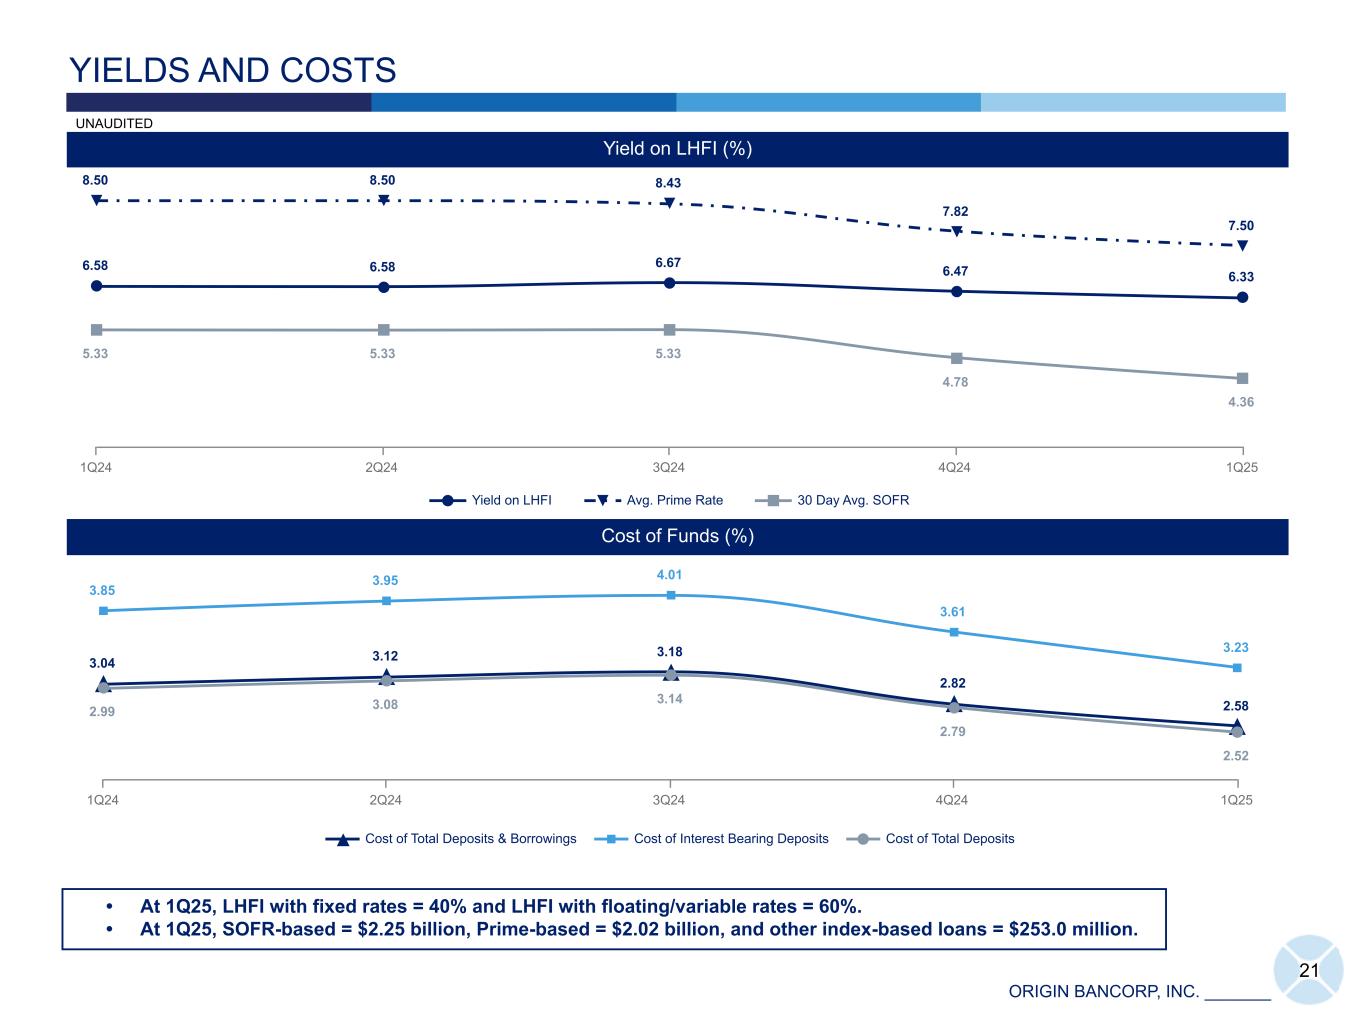
ORIGIN BANCORP, INC. _______ 21 YIELDS AND COSTS Yield on LHFI (%) Cost of Funds (%) • At 1Q25, LHFI with fixed rates = 40% and LHFI with floating/variable rates = 60%. • At 1Q25, SOFR-based = $2.25 billion, Prime-based = $2.02 billion, and other index-based loans = $253.0 million. UNAUDITED 6.58 6.58 6.67 6.47 6.33 8.50 8.50 8.43 7.82 7.50 5.33 5.33 5.33 4.78 4.36 Yield on LHFI Avg. Prime Rate 30 Day Avg. SOFR 1Q24 2Q24 3Q24 4Q24 1Q25 3.04 3.12 3.18 2.82 2.58 3.85 3.95 4.01 3.61 3.23 2.99 3.08 3.14 2.79 2.52 Cost of Total Deposits & Borrowings Cost of Interest Bearing Deposits Cost of Total Deposits 1Q24 2Q24 3Q24 4Q24 1Q25
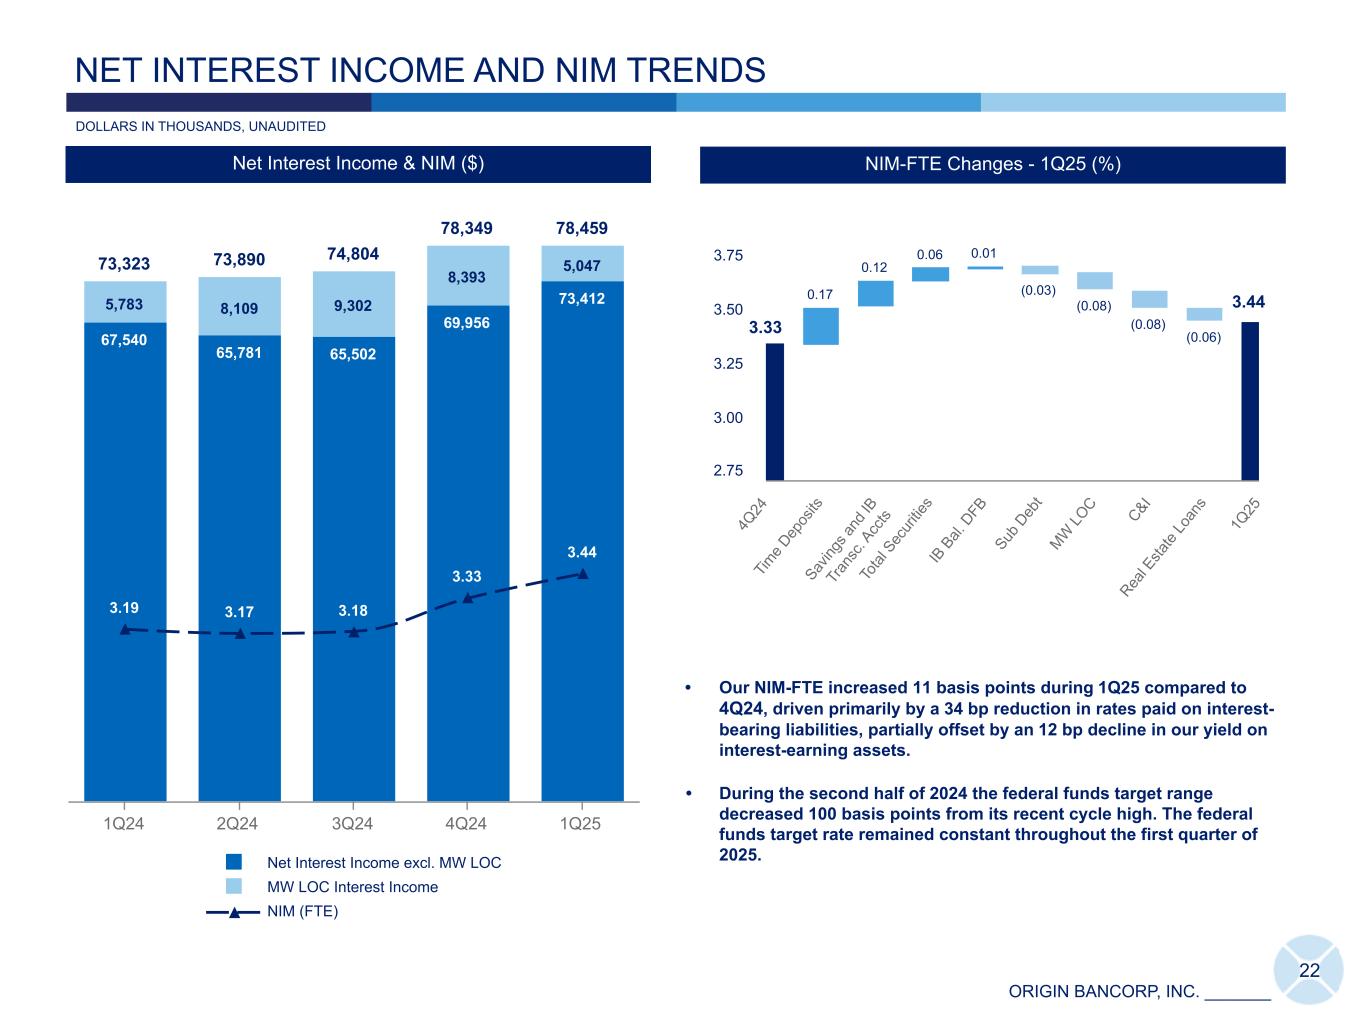
ORIGIN BANCORP, INC. _______ 73,323 73,890 74,804 78,349 78,459 67,540 65,781 65,502 69,956 73,4125,783 8,109 9,302 8,393 5,047 3.19 3.17 3.18 3.33 3.44 Net Interest Income excl. MW LOC MW LOC Interest Income NIM (FTE) 1Q24 2Q24 3Q24 4Q24 1Q25 22 DOLLARS IN THOUSANDS, UNAUDITED NET INTEREST INCOME AND NIM TRENDS 3.33 0.17 0.12 0.06 0.01 (0.03) (0.08) (0.08) (0.06) 4Q 24 Tim e D ep os its Sav ing s a nd IB Tr an sc . A cc ts To tal S ec ur itie s IB B al. D FB Sub D eb t MW LO C C&I Rea l E sta te Lo an s 1Q 25 2.75 3.00 3.25 3.50 3.75 24.64 29.52 21.01 8.58 2.04 2.480.12 0.77 2.18 3.65 4.99 5.26 5.33 4.65 Cumulative NIM-FTE Beta Average Quarterly Fed Funds Rate 2Q22 3Q22 4Q22 1Q23 3Q23 4Q23 1Q24 2Q24 1Q25 NIM Beta - 1Q25 (%) 1.54 2.48 4.51 NIM-FTE Changes - 1Q25 (%) NIM-FTE Changes - 1Q25 (%) 73,32372,989 1,362 1,537 568 432 (298) (3,267) 4Q 23 RE Lo an s C&I MW LO C Othe r FH LB & O the r Bor ro wing s Sav ing s & IB Tr an sa c. Acc ts. 1Q 24 40,000 60,000 80,000 • Our NIM-FTE increased 11 basis points during 1Q25 compared to 4Q24, driven primarily by a 34 bp reduction in rates paid on interest- bearing liabilities, partially offset by an 12 bp decline in our yield on interest-earning assets. • During the second half of 2024 the federal funds target range decreased 100 basis points from its recent cycle high. The federal funds target rate remained constant throughout the first quarter of 2025. Net Interest Income & NIM ($) 3.44
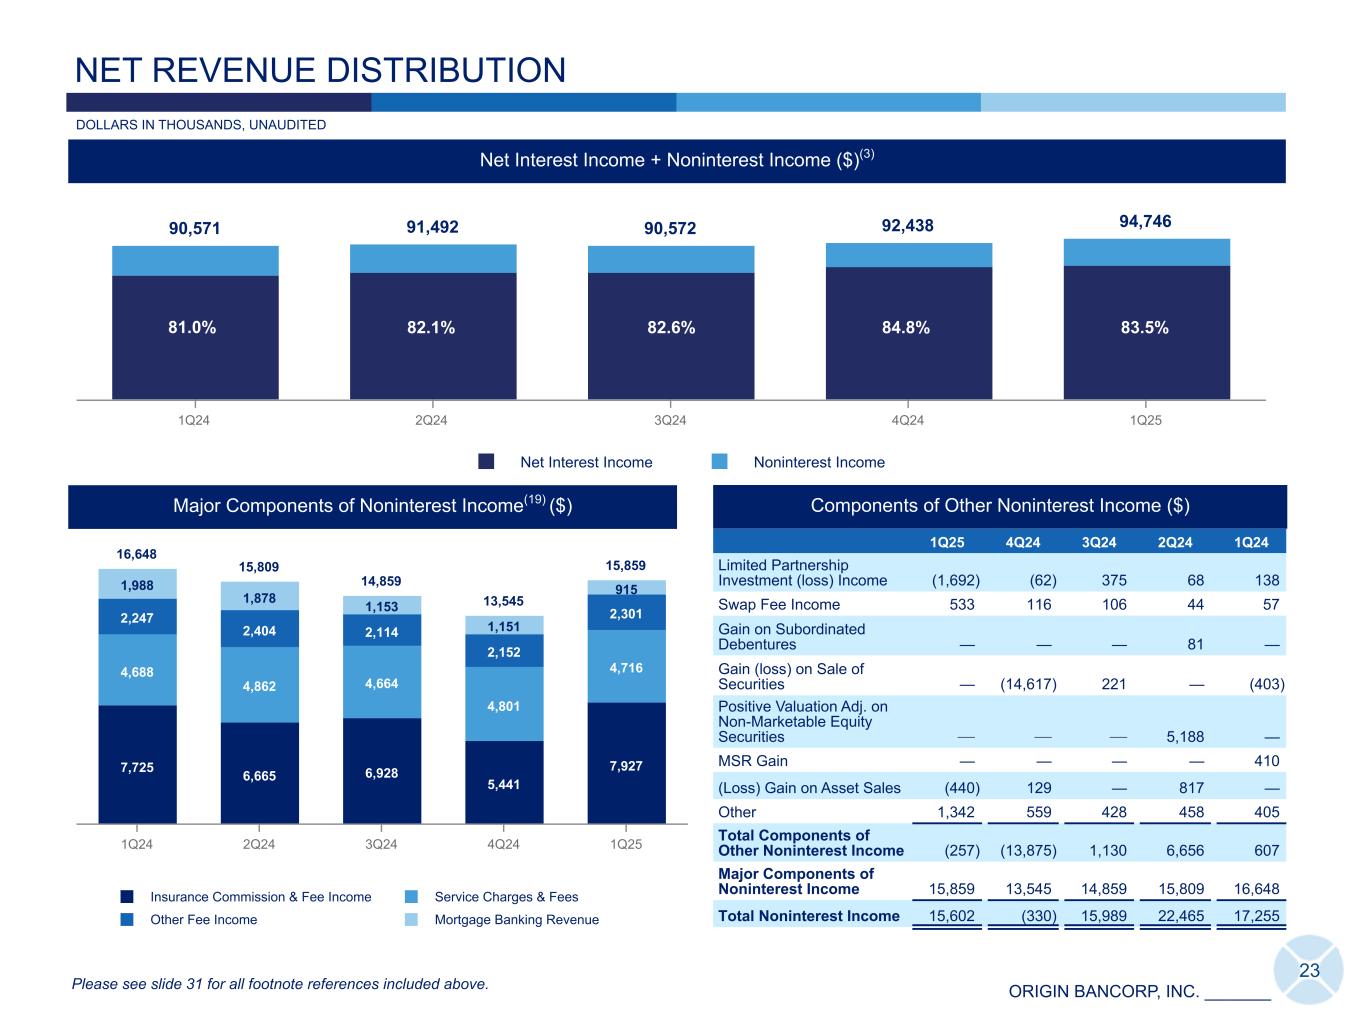
ORIGIN BANCORP, INC. _______ 90,571 91,492 90,572 92,438 94,746 Net Interest Income Noninterest Income 1Q24 2Q24 3Q24 4Q24 1Q25 16,648 15,809 14,859 13,545 15,859 7,725 6,665 6,928 5,441 7,927 4,688 4,862 4,664 4,801 4,716 2,247 2,404 2,114 2,152 2,301 1,988 1,878 1,153 1,151 915 Insurance Commission & Fee Income Service Charges & Fees Other Fee Income Mortgage Banking Revenue 1Q24 2Q24 3Q24 4Q24 1Q25 23 Major Components of Noninterest Income(19) ($) Net Interest Income + Noninterest Income ($)(3) NET REVENUE DISTRIBUTION Components of Other Noninterest Income ($) 1Q25 4Q24 3Q24 2Q24 1Q24 Limited Partnership Investment (loss) Income (1,692) (62) 375 68 138 Swap Fee Income 533 116 106 44 57 Gain on Subordinated Debentures — — — 81 — Gain (loss) on Sale of Securities — (14,617) 221 — (403) Positive Valuation Adj. on Non-Marketable Equity Securities — — — 5,188 — MSR Gain — — — — 410 (Loss) Gain on Asset Sales (440) 129 — 817 — Other 1,342 559 428 458 405 Total Components of Other Noninterest Income (257) (13,875) 1,130 6,656 607 Major Components of Noninterest Income 15,859 13,545 14,859 15,809 16,648 Total Noninterest Income 15,602 (330) 15,989 22,465 17,255 81.0% 83.5% Please see slide 31 for all footnote references included above. DOLLARS IN THOUSANDS, UNAUDITED 84.8%82.6%82.1%
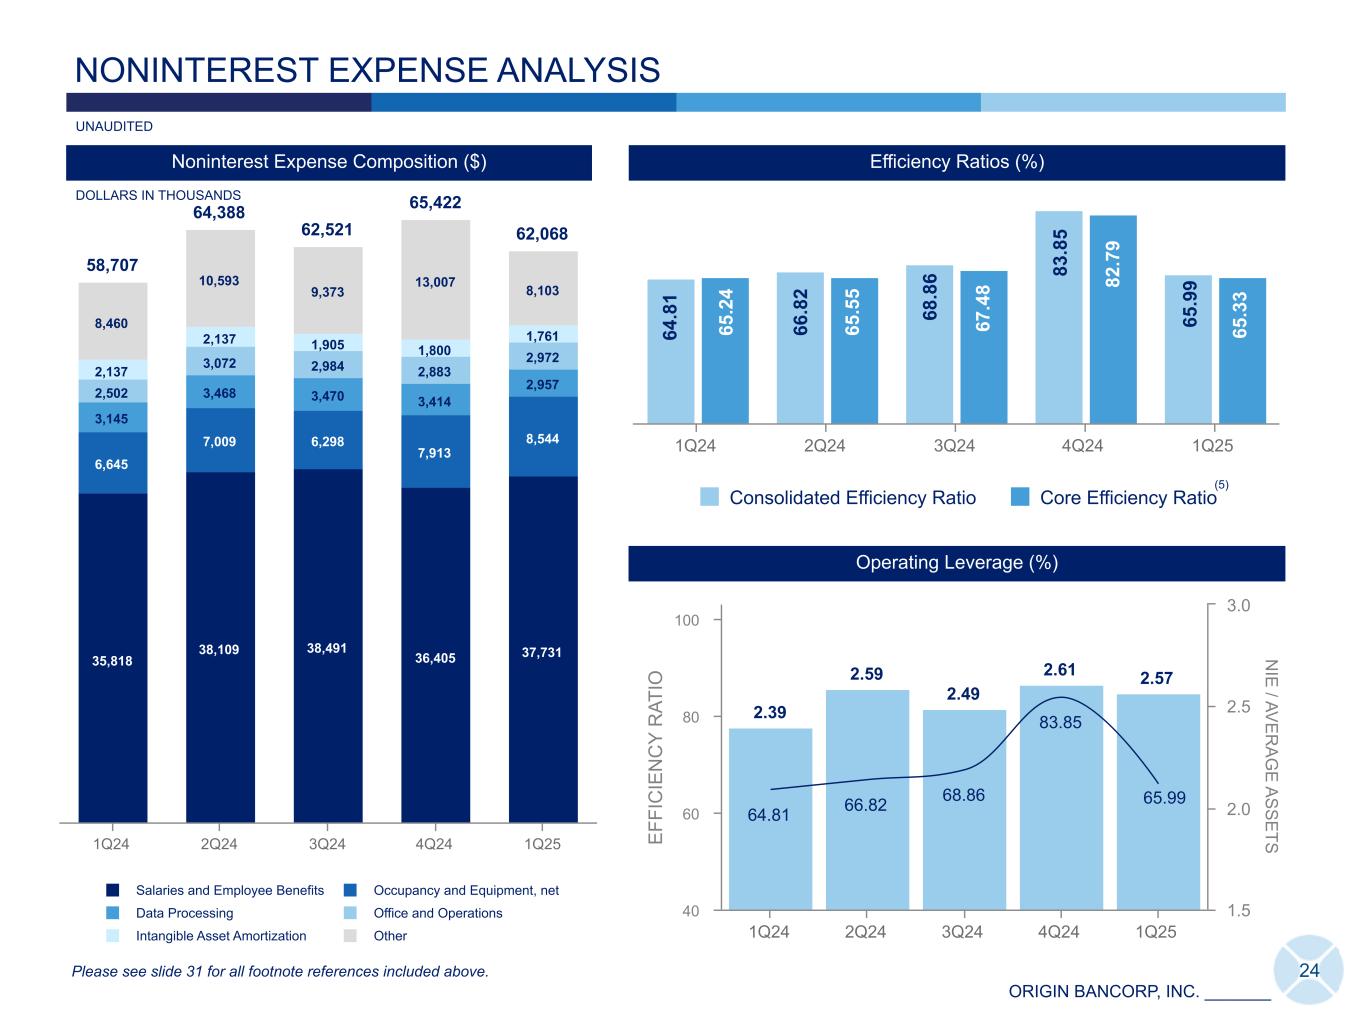
ORIGIN BANCORP, INC. _______ 24 Efficiency Ratios (%) NONINTEREST EXPENSE ANALYSIS DOLLARS IN THOUSANDS Noninterest Expense Composition ($) Consolidated Efficiency Ratio Core Efficiency Ratio 1Q24 2Q24 3Q24 4Q24 1Q25 Operating Leverage (%) E FF IC IE N C Y R AT IO N IE / AV E R A G E A S S E TS 2.39 2.59 2.49 2.61 2.57 64.81 66.82 68.86 83.85 1Q24 2Q24 3Q24 4Q24 1Q25 40 60 80 100 1.5 2.0 2.5 3.0 64 .8 1 65 .2 4 65 .5 5 66 .8 2 Please see slide 31 for all footnote references included above. 67 .4 8 65 .9 9 (5) UNAUDITED 65 .3 3 68 .8 6 83 .8 5 82 .7 9 58,707 64,388 62,521 65,422 62,068 35,818 38,109 38,491 36,405 37,731 6,645 7,009 6,298 7,913 8,544 3,145 3,468 3,470 3,414 2,9572,502 3,072 2,984 2,883 2,972 2,137 2,137 1,905 1,800 1,761 8,460 10,593 9,373 13,007 8,103 Salaries and Employee Benefits Occupancy and Equipment, net Data Processing Office and Operations Intangible Asset Amortization Other 1Q24 2Q24 3Q24 4Q24 1Q25 65.99
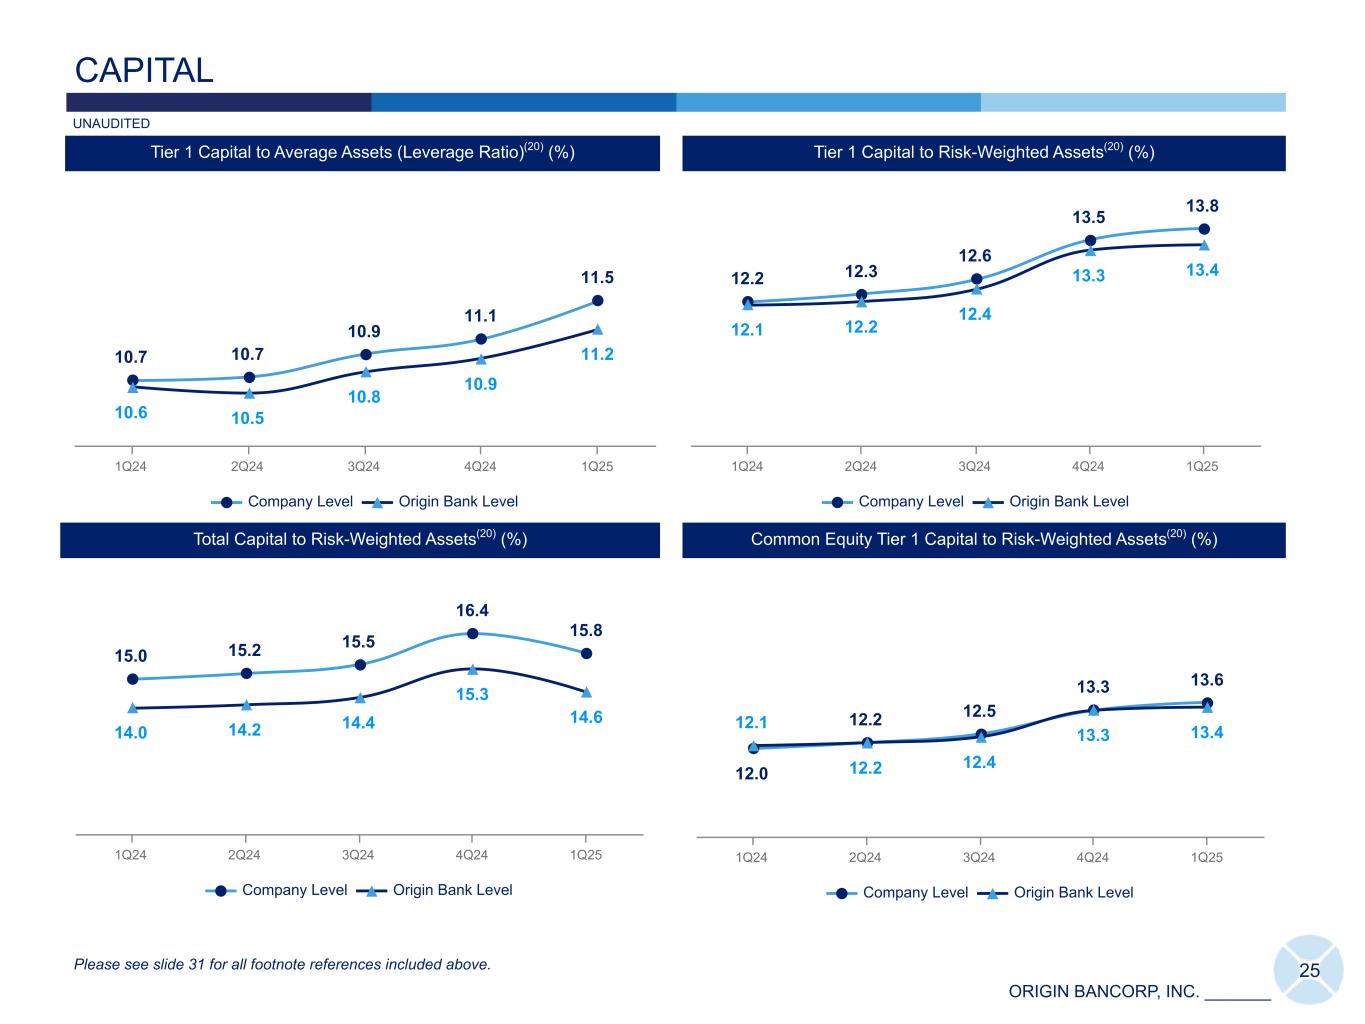
ORIGIN BANCORP, INC. _______ 10.7 10.7 10.9 11.1 11.5 10.6 10.5 10.8 10.9 11.2 Company Level Origin Bank Level 1Q24 2Q24 3Q24 4Q24 1Q25 12.2 12.3 12.6 13.5 13.8 12.1 12.2 12.4 13.3 13.4 Company Level Origin Bank Level 1Q24 2Q24 3Q24 4Q24 1Q25 25 CAPITAL 15.0 15.2 15.5 16.4 15.8 14.0 14.2 14.4 15.3 14.6 Company Level Origin Bank Level 1Q24 2Q24 3Q24 4Q24 1Q25 Common Equity Tier 1 Capital to Risk-Weighted Assets(20) (%) ICap ICap Total Capital to Risk-Weighted Assets(20) (%) Tier 1 Capital to Risk-Weighted Assets(20) (%)Tier 1 Capital to Average Assets (Leverage Ratio)(20) (%) Please see slide 31 for all footnote references included above. UNAUDITED 12.0 12.2 12.5 13.3 13.6 12.1 12.2 12.4 13.3 13.4 Company Level Origin Bank Level 1Q24 2Q24 3Q24 4Q24 1Q25
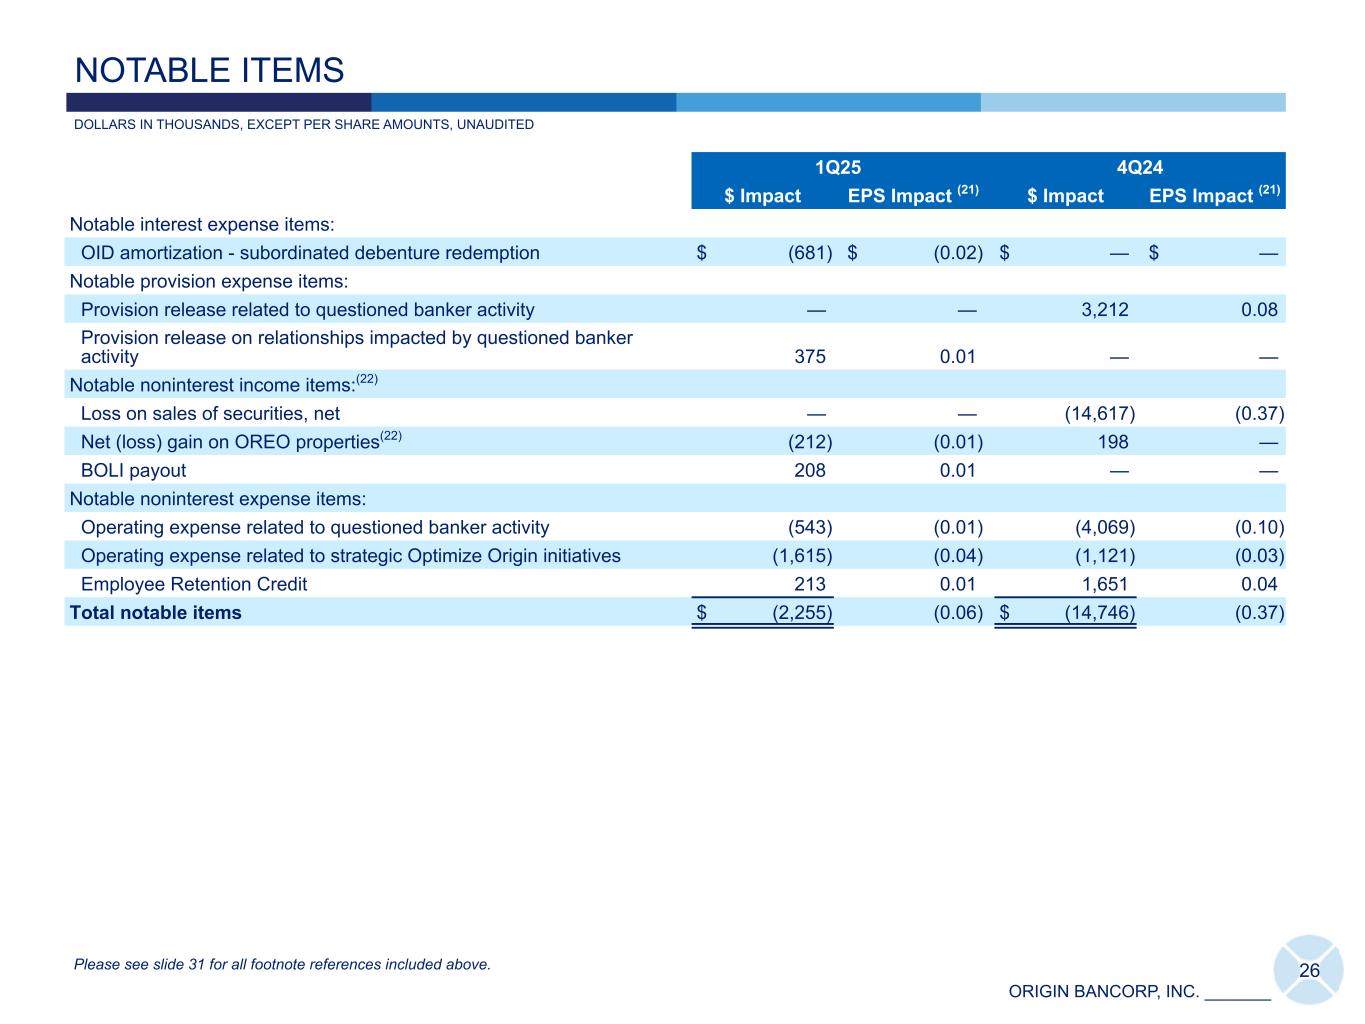
ORIGIN BANCORP, INC. _______ 1Q25 4Q24 $ Impact EPS Impact (21) $ Impact EPS Impact (21) Notable interest expense items: OID amortization - subordinated debenture redemption $ (681) $ (0.02) $ — $ — Notable provision expense items: Provision release related to questioned banker activity — — 3,212 0.08 Provision release on relationships impacted by questioned banker activity 375 0.01 — — Notable noninterest income items:(22) Loss on sales of securities, net — — (14,617) (0.37) Net (loss) gain on OREO properties(22) (212) (0.01) 198 — BOLI payout 208 0.01 — — Notable noninterest expense items: Operating expense related to questioned banker activity (543) (0.01) (4,069) (0.10) Operating expense related to strategic Optimize Origin initiatives (1,615) (0.04) (1,121) (0.03) Employee Retention Credit 213 0.01 1,651 0.04 Total notable items $ (2,255) (0.06) $ (14,746) (0.37) 26 DOLLARS IN THOUSANDS, EXCEPT PER SHARE AMOUNTS, UNAUDITED NOTABLE ITEMS Please see slide 31 for all footnote references included above.
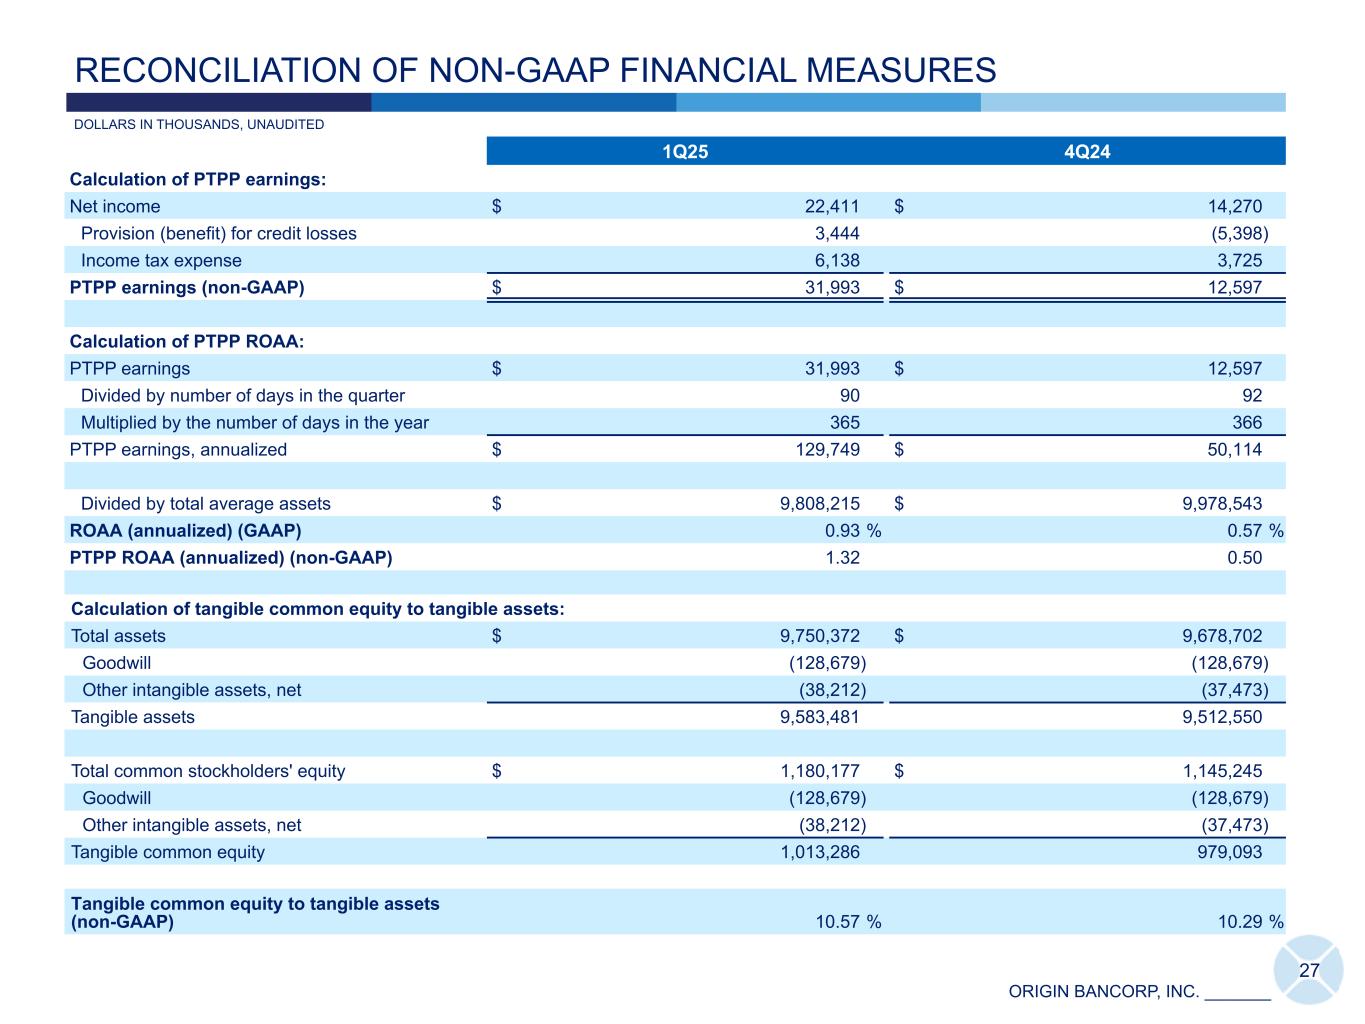
ORIGIN BANCORP, INC. _______ 1Q25 4Q24 Calculation of PTPP earnings: Net income $ 22,411 $ 14,270 Provision (benefit) for credit losses 3,444 (5,398) Income tax expense 6,138 3,725 PTPP earnings (non-GAAP) $ 31,993 $ 12,597 Calculation of PTPP ROAA: PTPP earnings $ 31,993 $ 12,597 Divided by number of days in the quarter 90 92 Multiplied by the number of days in the year 365 366 PTPP earnings, annualized $ 129,749 $ 50,114 Divided by total average assets $ 9,808,215 $ 9,978,543 ROAA (annualized) (GAAP) 0.93 % 0.57 % PTPP ROAA (annualized) (non-GAAP) 1.32 0.50 Calculation of tangible common equity to tangible assets: Total assets $ 9,750,372 $ 9,678,702 Goodwill (128,679) (128,679) Other intangible assets, net (38,212) (37,473) Tangible assets 9,583,481 9,512,550 Total common stockholders' equity $ 1,180,177 $ 1,145,245 Goodwill (128,679) (128,679) Other intangible assets, net (38,212) (37,473) Tangible common equity 1,013,286 979,093 Tangible common equity to tangible assets (non-GAAP) 10.57 % 10.29 % 27 DOLLARS IN THOUSANDS, UNAUDITED RECONCILIATION OF NON-GAAP FINANCIAL MEASURES
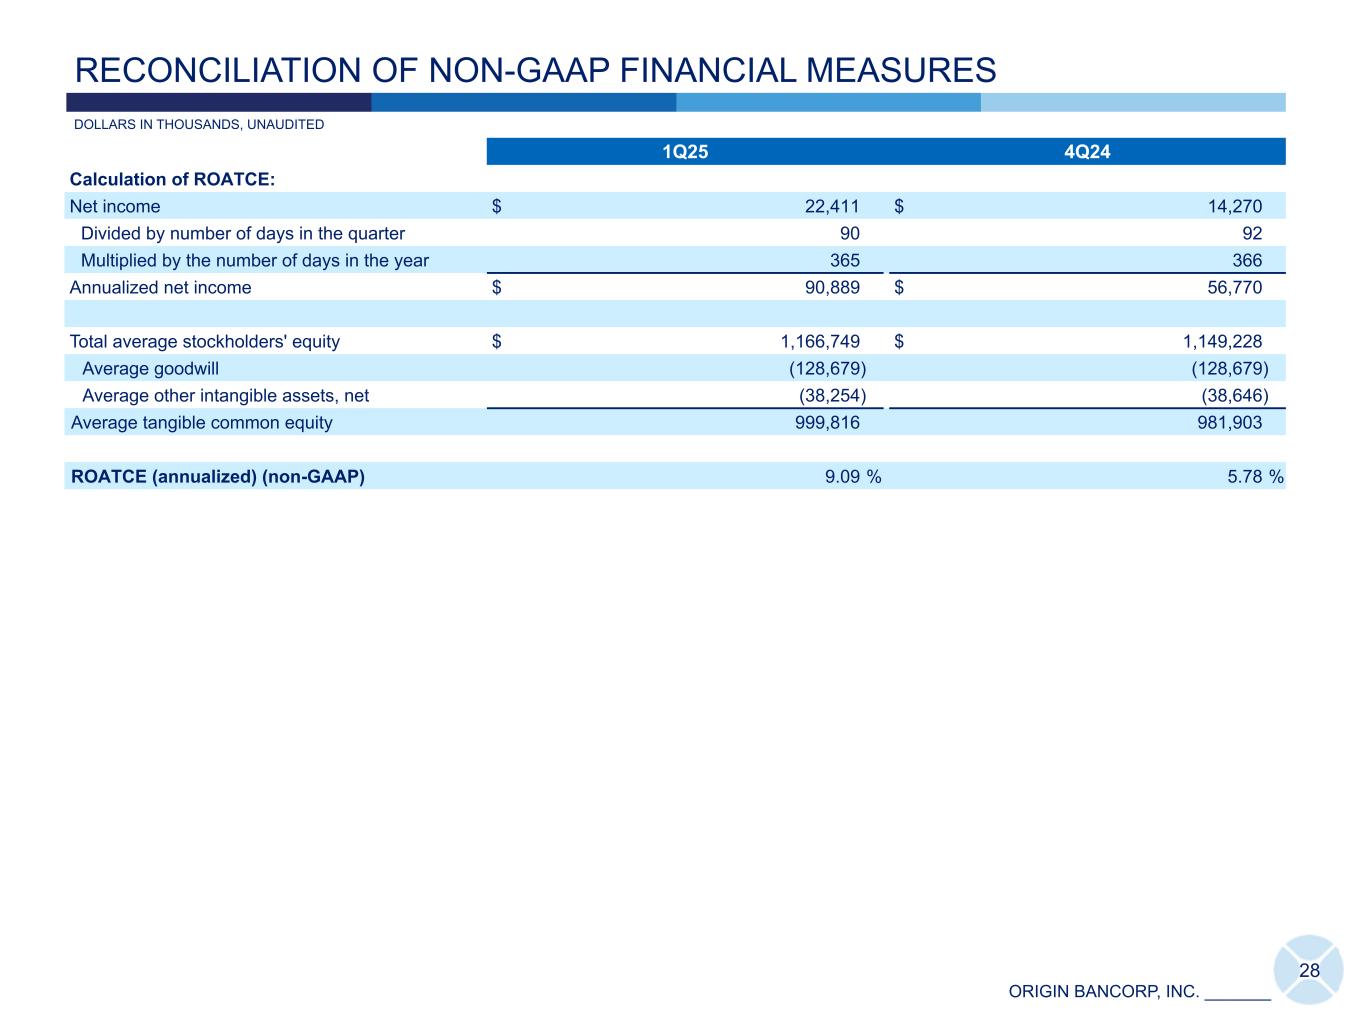
ORIGIN BANCORP, INC. _______ 1Q25 4Q24 Calculation of ROATCE: Net income $ 22,411 $ 14,270 Divided by number of days in the quarter 90 92 Multiplied by the number of days in the year 365 366 Annualized net income $ 90,889 $ 56,770 Total average stockholders' equity $ 1,166,749 $ 1,149,228 Average goodwill (128,679) (128,679) Average other intangible assets, net (38,254) (38,646) Average tangible common equity 999,816 981,903 ROATCE (annualized) (non-GAAP) 9.09 % 5.78 % 28 DOLLARS IN THOUSANDS, UNAUDITED RECONCILIATION OF NON-GAAP FINANCIAL MEASURES
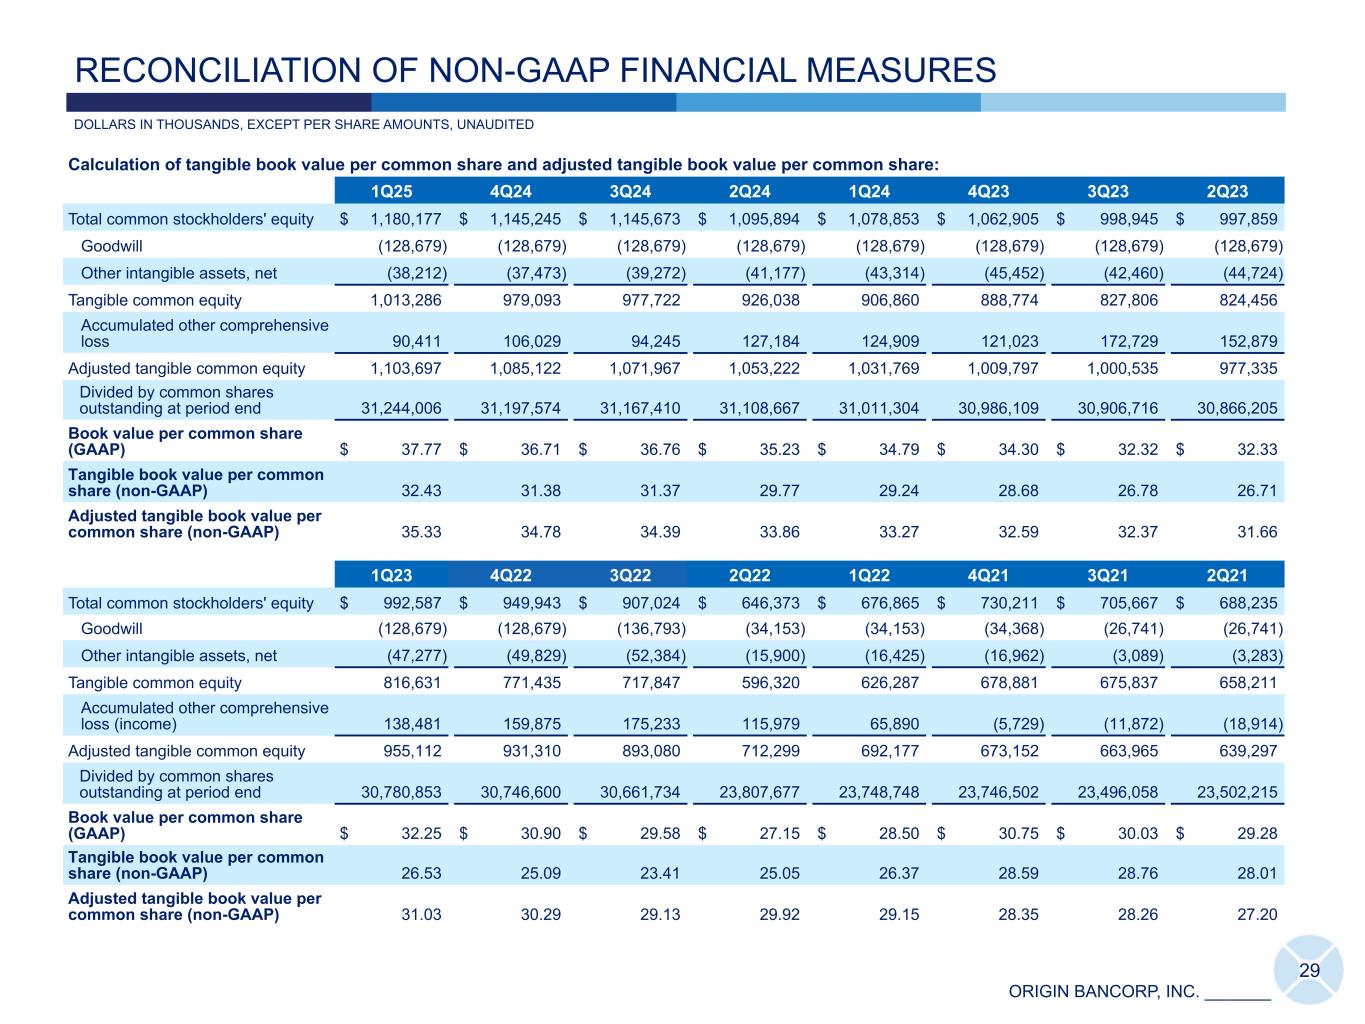
ORIGIN BANCORP, INC. _______ Calculation of tangible book value per common share and adjusted tangible book value per common share: 1Q25 4Q24 3Q24 2Q24 1Q24 4Q23 3Q23 2Q23 Total common stockholders' equity $ 1,180,177 $ 1,145,245 $ 1,145,673 $ 1,095,894 $ 1,078,853 $ 1,062,905 $ 998,945 $ 997,859 Goodwill (128,679) (128,679) (128,679) (128,679) (128,679) (128,679) (128,679) (128,679) Other intangible assets, net (38,212) (37,473) (39,272) (41,177) (43,314) (45,452) (42,460) (44,724) Tangible common equity 1,013,286 979,093 977,722 926,038 906,860 888,774 827,806 824,456 Accumulated other comprehensive loss 90,411 106,029 94,245 127,184 124,909 121,023 172,729 152,879 Adjusted tangible common equity 1,103,697 1,085,122 1,071,967 1,053,222 1,031,769 1,009,797 1,000,535 977,335 Divided by common shares outstanding at period end 31,244,006 31,197,574 31,167,410 31,108,667 31,011,304 30,986,109 30,906,716 30,866,205 Book value per common share (GAAP) $ 37.77 $ 36.71 $ 36.76 $ 35.23 $ 34.79 $ 34.30 $ 32.32 $ 32.33 Tangible book value per common share (non-GAAP) 32.43 31.38 31.37 29.77 29.24 28.68 26.78 26.71 Adjusted tangible book value per common share (non-GAAP) 35.33 34.78 34.39 33.86 33.27 32.59 32.37 31.66 1Q23 4Q22 3Q22 2Q22 1Q22 4Q21 3Q21 2Q21 Total common stockholders' equity $ 992,587 $ 949,943 $ 907,024 $ 646,373 $ 676,865 $ 730,211 $ 705,667 $ 688,235 Goodwill (128,679) (128,679) (136,793) (34,153) (34,153) (34,368) (26,741) (26,741) Other intangible assets, net (47,277) (49,829) (52,384) (15,900) (16,425) (16,962) (3,089) (3,283) Tangible common equity 816,631 771,435 717,847 596,320 626,287 678,881 675,837 658,211 Accumulated other comprehensive loss (income) 138,481 159,875 175,233 115,979 65,890 (5,729) (11,872) (18,914) Adjusted tangible common equity 955,112 931,310 893,080 712,299 692,177 673,152 663,965 639,297 Divided by common shares outstanding at period end 30,780,853 30,746,600 30,661,734 23,807,677 23,748,748 23,746,502 23,496,058 23,502,215 Book value per common share (GAAP) $ 32.25 $ 30.90 $ 29.58 $ 27.15 $ 28.50 $ 30.75 $ 30.03 $ 29.28 Tangible book value per common share (non-GAAP) 26.53 25.09 23.41 25.05 26.37 28.59 28.76 28.01 Adjusted tangible book value per common share (non-GAAP) 31.03 30.29 29.13 29.92 29.15 28.35 28.26 27.20 29 RECONCILIATION OF NON-GAAP FINANCIAL MEASURES DOLLARS IN THOUSANDS, EXCEPT PER SHARE AMOUNTS, UNAUDITED
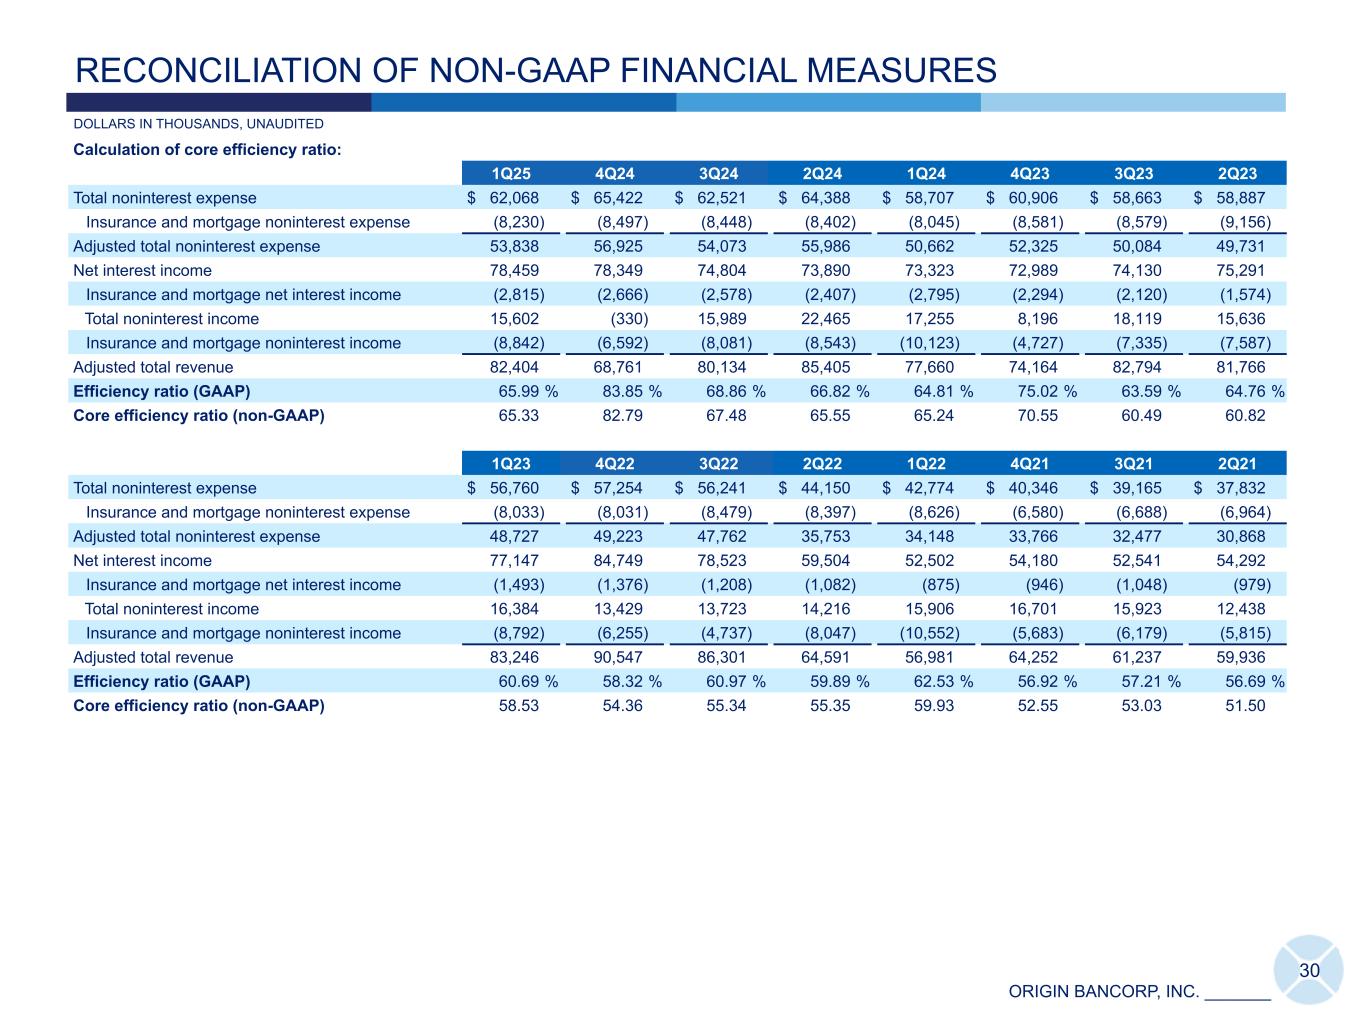
ORIGIN BANCORP, INC. _______ RECONCILIATION OF NON-GAAP FINANCIAL MEASURES DOLLARS IN THOUSANDS, UNAUDITED Calculation of core efficiency ratio: 1Q25 4Q24 3Q24 2Q24 1Q24 4Q23 3Q23 2Q23 Total noninterest expense $ 62,068 $ 65,422 $ 62,521 $ 64,388 $ 58,707 $ 60,906 $ 58,663 $ 58,887 Insurance and mortgage noninterest expense (8,230) (8,497) (8,448) (8,402) (8,045) (8,581) (8,579) (9,156) Adjusted total noninterest expense 53,838 56,925 54,073 55,986 50,662 52,325 50,084 49,731 Net interest income 78,459 78,349 74,804 73,890 73,323 72,989 74,130 75,291 Insurance and mortgage net interest income (2,815) (2,666) (2,578) (2,407) (2,795) (2,294) (2,120) (1,574) Total noninterest income 15,602 (330) 15,989 22,465 17,255 8,196 18,119 15,636 Insurance and mortgage noninterest income (8,842) (6,592) (8,081) (8,543) (10,123) (4,727) (7,335) (7,587) Adjusted total revenue 82,404 68,761 80,134 85,405 77,660 74,164 82,794 81,766 Efficiency ratio (GAAP) 65.99 % 83.85 % 68.86 % 66.82 % 64.81 % 75.02 % 63.59 % 64.76 % Core efficiency ratio (non-GAAP) 65.33 82.79 67.48 65.55 65.24 70.55 60.49 60.82 1Q23 4Q22 3Q22 2Q22 1Q22 4Q21 3Q21 2Q21 Total noninterest expense $ 56,760 $ 57,254 $ 56,241 $ 44,150 $ 42,774 $ 40,346 $ 39,165 $ 37,832 Insurance and mortgage noninterest expense (8,033) (8,031) (8,479) (8,397) (8,626) (6,580) (6,688) (6,964) Adjusted total noninterest expense 48,727 49,223 47,762 35,753 34,148 33,766 32,477 30,868 Net interest income 77,147 84,749 78,523 59,504 52,502 54,180 52,541 54,292 Insurance and mortgage net interest income (1,493) (1,376) (1,208) (1,082) (875) (946) (1,048) (979) Total noninterest income 16,384 13,429 13,723 14,216 15,906 16,701 15,923 12,438 Insurance and mortgage noninterest income (8,792) (6,255) (4,737) (8,047) (10,552) (5,683) (6,179) (5,815) Adjusted total revenue 83,246 90,547 86,301 64,591 56,981 64,252 61,237 59,936 Efficiency ratio (GAAP) 60.69 % 58.32 % 60.97 % 59.89 % 62.53 % 56.92 % 57.21 % 56.69 % Core efficiency ratio (non-GAAP) 58.53 54.36 55.34 55.35 59.93 52.55 53.03 51.50 30
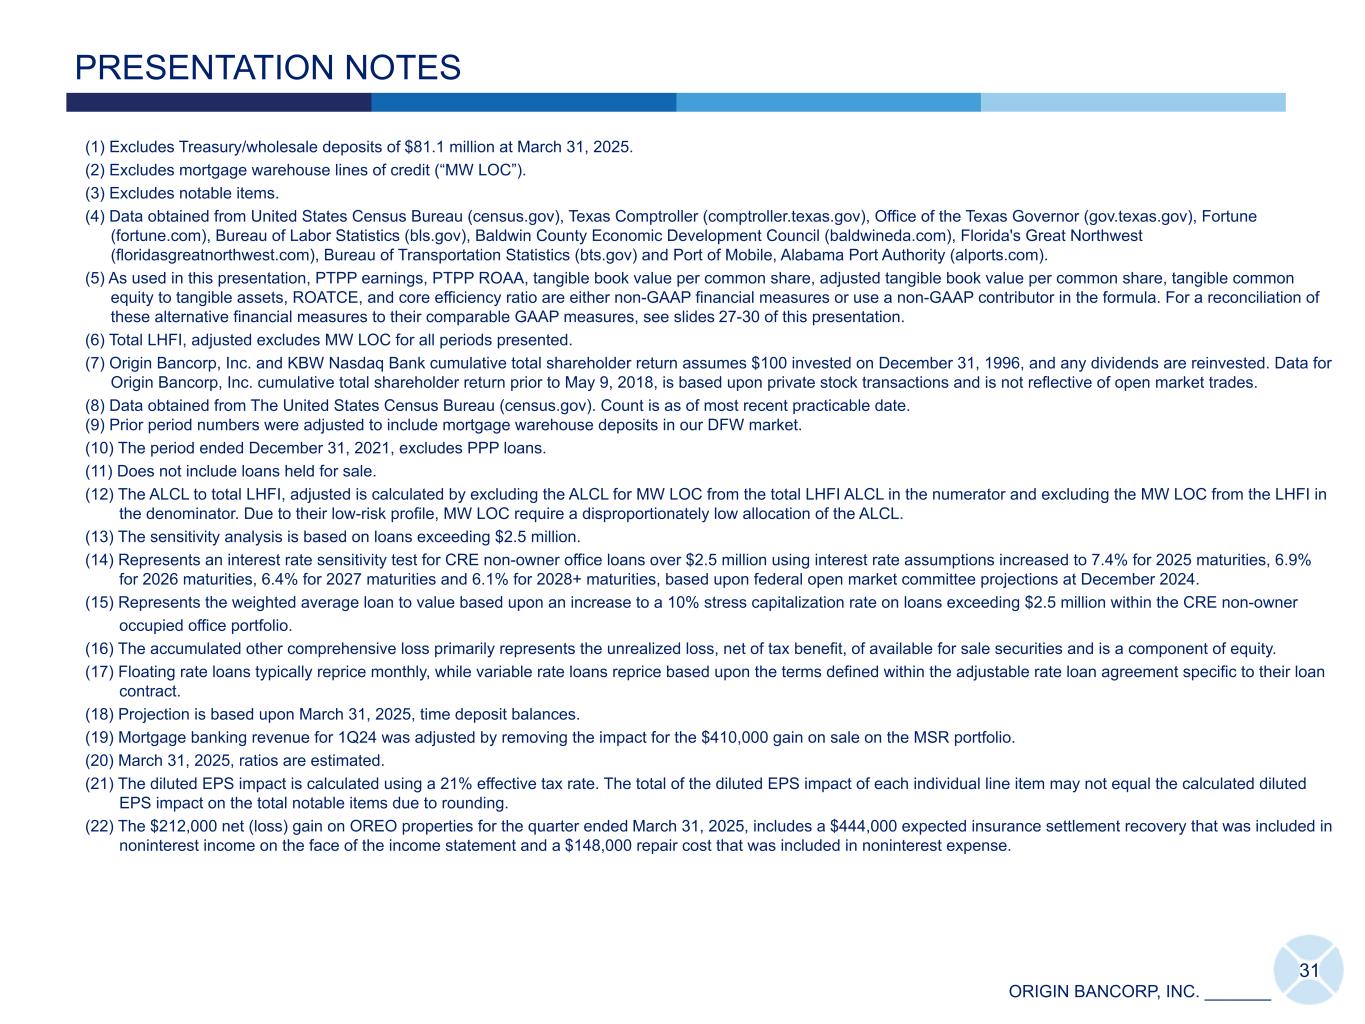
ORIGIN BANCORP, INC. _______ 31 PRESENTATION NOTES (1) Excludes Treasury/wholesale deposits of $81.1 million at March 31, 2025. (2) Excludes mortgage warehouse lines of credit (“MW LOC”). (3) Excludes notable items. (4) Data obtained from United States Census Bureau (census.gov), Texas Comptroller (comptroller.texas.gov), Office of the Texas Governor (gov.texas.gov), Fortune (fortune.com), Bureau of Labor Statistics (bls.gov), Baldwin County Economic Development Council (baldwineda.com), Florida's Great Northwest (floridasgreatnorthwest.com), Bureau of Transportation Statistics (bts.gov) and Port of Mobile, Alabama Port Authority (alports.com). (5) As used in this presentation, PTPP earnings, PTPP ROAA, tangible book value per common share, adjusted tangible book value per common share, tangible common equity to tangible assets, ROATCE, and core efficiency ratio are either non-GAAP financial measures or use a non-GAAP contributor in the formula. For a reconciliation of these alternative financial measures to their comparable GAAP measures, see slides 27-30 of this presentation. (6) Total LHFI, adjusted excludes MW LOC for all periods presented. (7) Origin Bancorp, Inc. and KBW Nasdaq Bank cumulative total shareholder return assumes $100 invested on December 31, 1996, and any dividends are reinvested. Data for Origin Bancorp, Inc. cumulative total shareholder return prior to May 9, 2018, is based upon private stock transactions and is not reflective of open market trades. (8) Data obtained from The United States Census Bureau (census.gov). Count is as of most recent practicable date. (9) Prior period numbers were adjusted to include mortgage warehouse deposits in our DFW market. (10) The period ended December 31, 2021, excludes PPP loans. (11) Does not include loans held for sale. (12) The ALCL to total LHFI, adjusted is calculated by excluding the ALCL for MW LOC from the total LHFI ALCL in the numerator and excluding the MW LOC from the LHFI in the denominator. Due to their low-risk profile, MW LOC require a disproportionately low allocation of the ALCL. (13) The sensitivity analysis is based on loans exceeding $2.5 million. (14) Represents an interest rate sensitivity test for CRE non-owner office loans over $2.5 million using interest rate assumptions increased to 7.4% for 2025 maturities, 6.9% for 2026 maturities, 6.4% for 2027 maturities and 6.1% for 2028+ maturities, based upon federal open market committee projections at December 2024. (15) Represents the weighted average loan to value based upon an increase to a 10% stress capitalization rate on loans exceeding $2.5 million within the CRE non-owner occupied office portfolio. (16) The accumulated other comprehensive loss primarily represents the unrealized loss, net of tax benefit, of available for sale securities and is a component of equity. (17) Floating rate loans typically reprice monthly, while variable rate loans reprice based upon the terms defined within the adjustable rate loan agreement specific to their loan contract. (18) Projection is based upon March 31, 2025, time deposit balances. (19) Mortgage banking revenue for 1Q24 was adjusted by removing the impact for the $410,000 gain on sale on the MSR portfolio. (20) March 31, 2025, ratios are estimated. (21) The diluted EPS impact is calculated using a 21% effective tax rate. The total of the diluted EPS impact of each individual line item may not equal the calculated diluted EPS impact on the total notable items due to rounding. (22) The $212,000 net (loss) gain on OREO properties for the quarter ended March 31, 2025, includes a $444,000 expected insurance settlement recovery that was included in noninterest income on the face of the income statement and a $148,000 repair cost that was included in noninterest expense.
Exhibit 99.3
FOR IMMEDIATE RELEASE
April 23, 2025
Origin Bancorp, Inc. Announces Declaration of Quarterly Cash Dividend
RUSTON, LOUISIANA (April 23, 2025) - Origin Bancorp, Inc. (NYSE: OBK) ("Origin"), the holding company for Origin Bank, today announced that on April 23, 2025, its board of directors declared a quarterly cash dividend of $0.15 per share of its common stock. The cash dividend will be paid on May 30, 2025, to stockholders of record as of the close of business on May 15, 2025.
About Origin Bancorp, Inc.
Origin Bancorp, Inc. is a financial holding company headquartered in Ruston, Louisiana. Origin’s wholly owned bank subsidiary, Origin Bank, was founded in 1912 in Choudrant, Louisiana. Deeply rooted in Origin’s history is a culture committed to providing personalized relationship banking to businesses, municipalities, and personal clients to enrich the lives of the people in the communities it serves. Origin provides a broad range of financial services and currently operates more than 55 locations in Dallas/Fort Worth, East Texas, Houston, North Louisiana, Mississippi, South Alabama and the Florida Panhandle. For more information, visit www.origin.bank.
Forward-Looking Statements
When used in filings by Origin Bancorp, Inc. (the "Company") with the Securities and Exchange Commission (the "SEC"), in the Company's press releases or other public or stockholder communications, and in oral statements made with the approval of an authorized executive officer, the words or phrases "anticipates," "believes," "estimates," "expects," “foresees,” "intends," "plans," "projects," and similar expressions or future or conditional verbs such as "could," "may," “might,” "should," "will," and "would" or variations of such terms" are intended to identify "forward-looking statements" within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements are subject to certain risks and uncertainties that could cause actual results to differ materially from historical earnings and those presently anticipated or projected. Factors that might cause such a difference include among other things: the expected payment date of its quarterly cash dividend; changes in economic conditions; other legislative changes generally; changes in policies by regulatory agencies; fluctuations in interest rates; the risks of lending and investing activities, including changes in the level and direction of loan delinquencies and write-offs and changes in estimates of the adequacy of the allowance for loan losses; the Company's ability to access cost-effective funding; fluctuations in real estate values and both residential and commercial real estate market conditions; demand for loans and deposits in the Company's market area; competition; and changes in management’s business strategies and other factors set forth in the Company's filings with the SEC.
The Company does not undertake and specifically declines any obligation - to update or revise any forward-looking statements to reflect events or circumstances that occur after the date of such statements or to reflect the occurrence of anticipated or unanticipated events.
Contact Information
Investor Relations
Chris Reigelman
318-497-3177
Media Contact
Ryan Kilpatrick
318-232-7472