
PATK 8-K
Patrick Industries Inc (PATK)
8-K
2020-10-29
For: 2020-10-29
View Original
Added on
April 10, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM
CURRENT REPORT
Pursuant To Section 13 OR 15(d) Of The Securities Exchange Act Of 1934
Date of report (Date of earliest event reported) | |||||
| (Exact name of registrant as specified in its charter) | |||||
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification Number) | ||||||
| (Address of Principal Executive Offices) | (Zip Code) | ||||||||||
| Registrant’s Telephone Number, including area code | ||||||||
| (Former name or former address if changed since last report) | ||||||||
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol | Name of each exchange on which registered | ||||||
| | | |||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter). Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
Item 2.02 Results of Operations and Financial Condition.
On October 29, 2020, the Company issued a press release announcing operating results for the third quarter ended September 27, 2020. A copy of the press release is furnished herewith as Exhibit 99.1 and incorporated herein by reference.
Item 7.01 Regulation FD Disclosure
The information referenced in this Form 8-K is furnished pursuant to Item 7.01, “Regulation FD Disclosure.” Such information, including the Exhibit attached hereto, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, nor shall it be deemed incorporated by reference in any filing under the Securities Act of 1933, except as shall be expressly set forth by specific reference in such filing.
(a) Slides for Earnings Presentation as contained in Exhibit 99.2
Item 9.01 Financial Statements and Exhibits
(d) Exhibits
Exhibit 99.1 - Press Release issued October 29, 2020
Exhibit 99.2 - Slides for Earnings Presentation
Exhibit 104 - Cover Page Interactive Date File (embedded within the Inline XBRL document)
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| PATRICK INDUSTRIES, INC. | ||||||||
| (Registrant) | ||||||||
| Date: October 29, 2020 | By: | /s/ John A. Forbes | ||||||
| John A. Forbes | ||||||||
| Interim Chief Financial Officer | ||||||||
Patrick Industries, Inc. Reports Third Quarter 2020 Financial Results
Third Quarter 2020 Highlights (all metrics compared to Third Quarter 2019 unless otherwise noted)
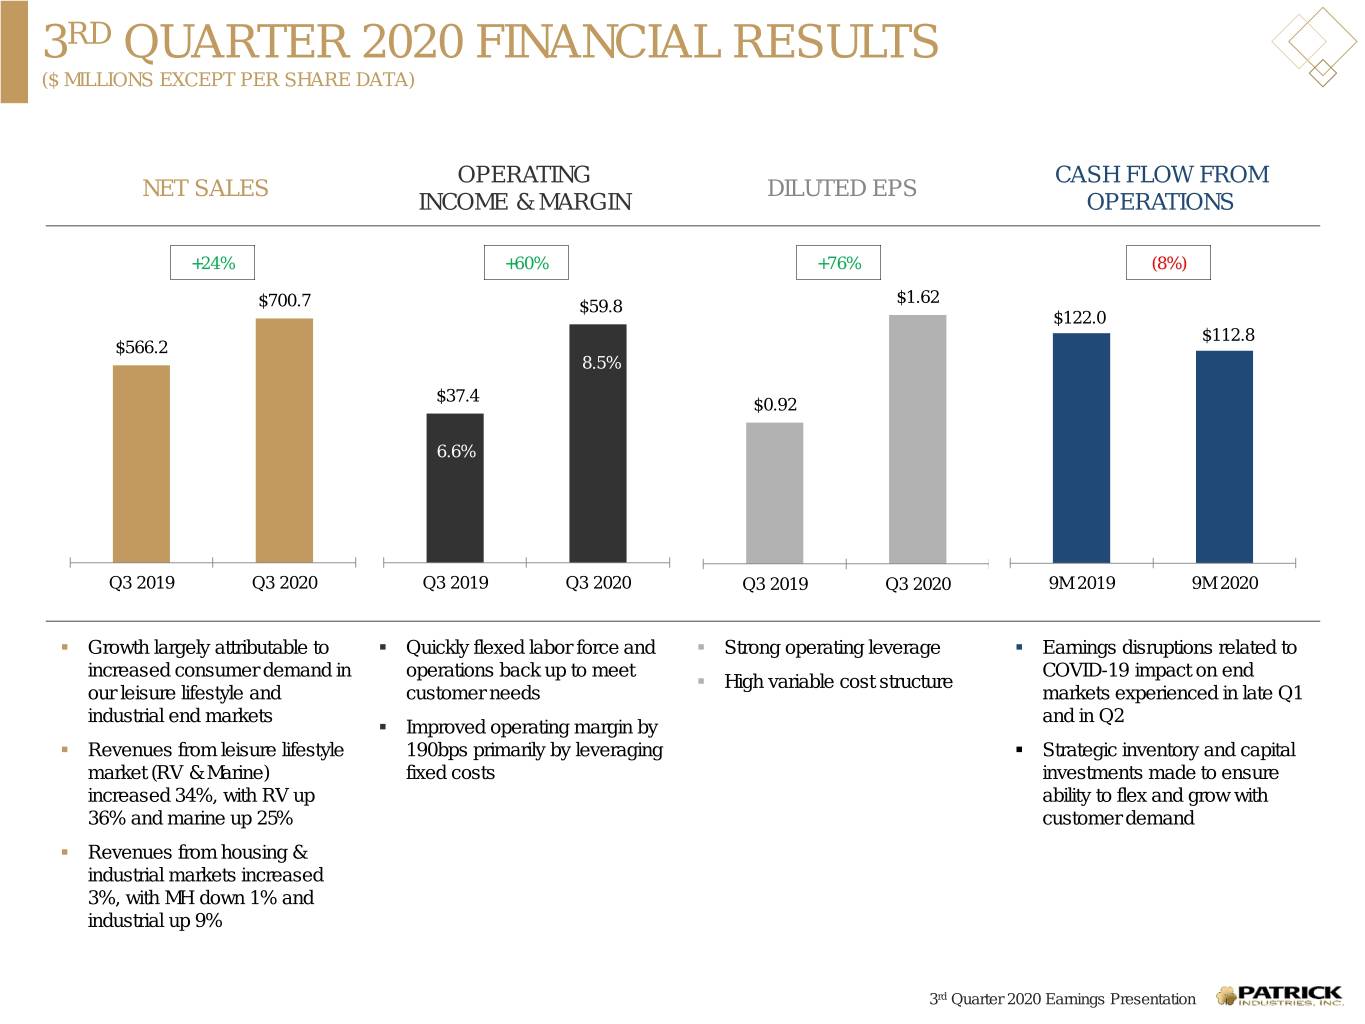
•Net sales of $700.7 million increased 24% with strong demand in RV, marine and industrial markets
•Operating income of $59.8 million increased 60%
•Net income of $37.3 million increased 75%
•Diluted EPS of $1.62 increased 76%
•Strategic acquisitions of Inland Plywood, Synergy RV Transport and Front Range Stone
ELKHART, IN - October 29, 2020 - Patrick Industries, Inc. (NASDAQ: PATK), a major manufacturer and distributor of component and building products for the recreational vehicle (“RV”), marine, manufactured housing (“MH”), and industrial markets, today reported financial results for the third quarter ended September 27, 2020.
Net sales in the third quarter of 2020 increased $134.5 million, or 24%, to $700.7 million from $566.2 million in the third quarter of 2019. The consolidated net sales increase in the third quarter of 2020 was attributed to sales increases in our RV, marine and industrial markets.
Operating income increased $22.4 million, or 60%, to $59.8 million in the third quarter of 2020 from $37.4 million in 2019. As a percentage of net sales, operating income was 8.5% in the third quarter of 2020 versus 6.6% in the same period in 2019.
Net income increased $16.0 million, or 75%, to $37.3 million in the third quarter of 2020 compared to $21.3 million in the third quarter of 2019. Net income per diluted share increased $0.70, or 76%, to $1.62 for the third quarter of 2020 compared to $0.92 for the third quarter of 2019.
Net sales in the first nine months of 2020 decreased $73.6 million, or 4%, to $1,714.0 million from $1,787.6 million in the first nine months of 2019. Operating income decreased $7.3 million, or 6%, to $111.2 million in the first nine months of 2020 from $118.5 million in 2019. As a percentage of net sales, operating income was 6.5% in the first nine months of 2020 versus 6.6% in the same period in 2019. Net income for the first nine months of 2020 was $59.2 million compared to net income of $69.6 million for the first nine months of 2019, and net income per diluted share for the first nine months of 2020 was $2.57 compared to $2.99 for the first nine months of 2019. Year-to-date operating results include the impact of industry and statewide shutdowns implemented in response to COVID-19 late in the first quarter of 2020 and through early May 2020.
"Our leisure lifestyle markets continued to rebound in the third quarter with a continuation of positive secular trends and tailwinds in on-the-road domestic travel and outdoor activities," said Andy Nemeth, President and Chief Executive Officer. "Strong demand in our RV, marine and industrial markets resulted in improved profitability as we leveraged our fixed cost structure, despite direct labor inefficiencies due to the significant snap back in production levels which have exceeded pre-pandemic levels. The strategic acquisitions we completed in the third quarter of Inland Plywood, Synergy RV Transport and Front Range Stone capitalize on recent momentum, support customer growth and expand our product offerings in our end markets."
Third Quarter 2020 Revenue by Market Sector (all metrics compared to Third Quarter 2019 unless otherwise noted)
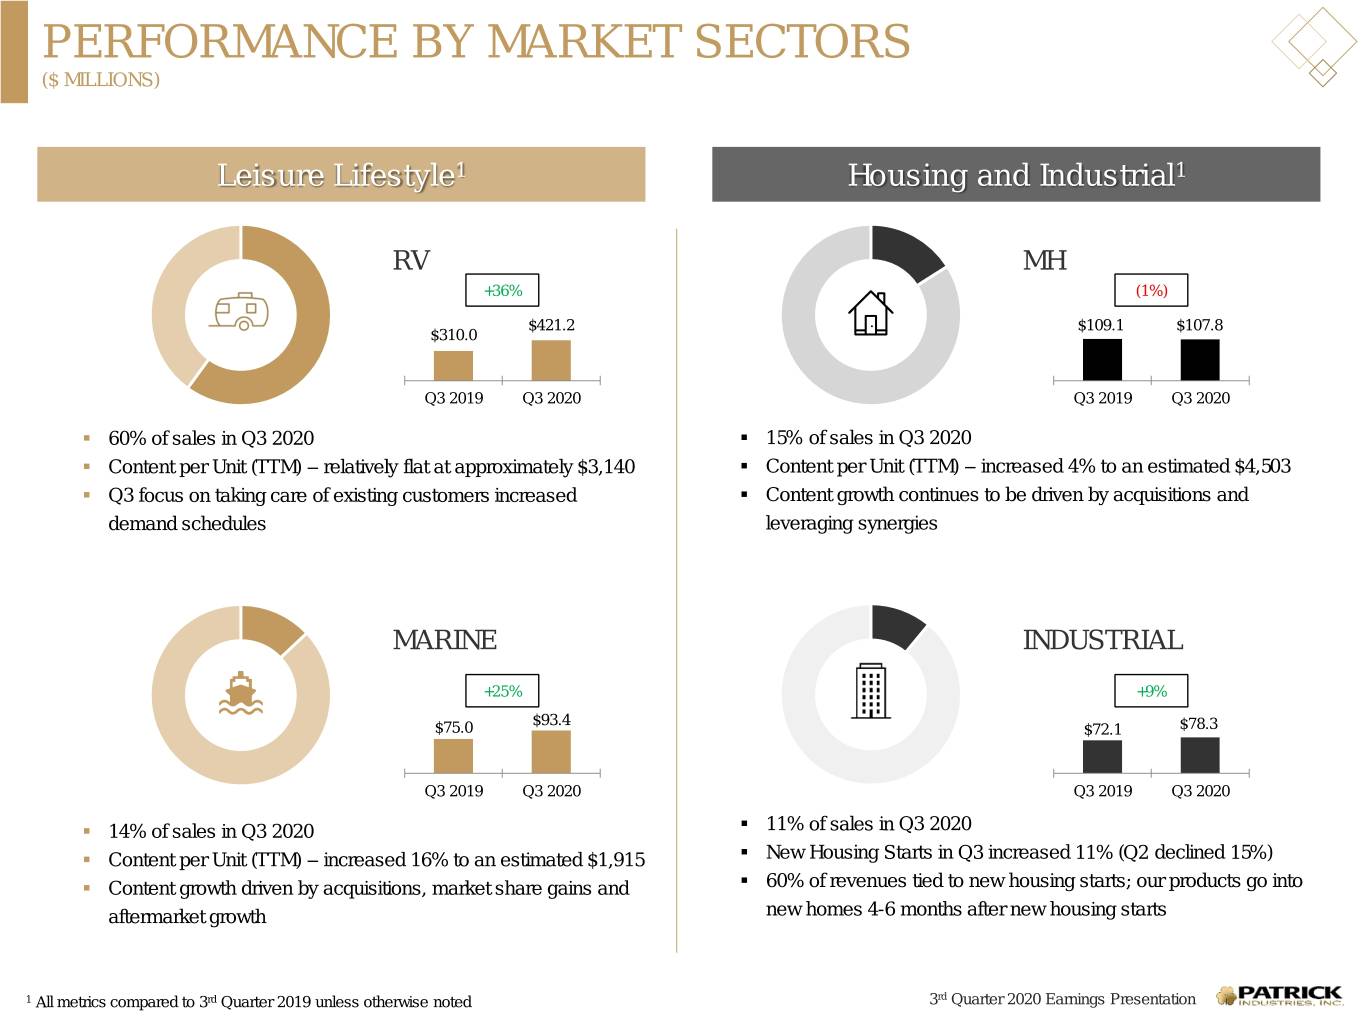
RV (60% Revenue)
•Revenue of $421.2 million increased 36% while wholesale RV unit shipments increased 33%
•Content per wholesale RV unit (on a trailing twelve-month basis) was relatively flat at approximately $3,140
Marine (14% Revenue)
•Revenue of $93.4 million increased 25% while estimated wholesale powerboat shipments decreased 4%
•Estimated content per wholesale powerboat unit (on a trailing twelve-month basis) increased 16% to $1,915
MH (15% Revenue)
•Revenue of $107.8 million decreased 1% while estimated wholesale MH unit shipments decreased 2%
•Estimated content per wholesale MH unit (on a trailing twelve-month basis) increased 4% to $4,503
Industrial (11% Revenue)
•Revenue of $78.3 million increased 9% while housing starts increased 11%
"Outdoor recreation has and continues to see, a significant increase in popularity as a result of the COVID-19 environment," said Mr. Nemeth. "Our leisure lifestyle markets–RV and marine–provide ideal outlets for multiple generations of friends and family to spend quality time together in both the COVID-19 and post COVID-19 environment. Our industrial market has benefited from an increase in housing starts and home improvement activity, and our MH market, while affected by short-term labor constraints, has recovered from COVID-19 disruptions with increasing backlogs."
COVID-19 Business Impact
As previously disclosed, the Company suspended operations at certain of its facilities from late March 2020 through early May 2020 as a result of production shutdowns by certain OEM customers in response to the COVID-19 pandemic. The Company successfully implemented CDC, state and local safety best practices at its facilities as we began to increase production levels in early May, and we continue to provide a healthy and safe environment for our team members as they work to safely accommodate increased demand in our end markets.
Balance Sheet, Cash Flow and Capital Allocation
Operating cash flow for the third quarter of 2020 was $73.4 million, an increase of 160%, from $28.2 million in the third quarter of 2019. Operating cash flows of $112.8 million for the nine months ended September 27, 2020 decreased 8% compared to the prior year, primarily reflecting the impact to net income related to COVID-19 business disruptions that largely affected second quarter 2020 operating results. The Company invested $99.2 million in business acquisitions in the third quarter of 2020 to expand its product offerings and geographic presence in the RV, marine and industrial end markets, with year-to-date investments in business acquisitions totaling $124.0 million. Capital expenditures in the third quarter of 2020 totaled $10.9 million, an increase of 168%, compared to $4.0 million in the third quarter of 2019. The increase in capital spending is facilitating strategic capacity expansion in certain of our facilities in response to, and in anticipation of, increased demand in our end markets that began in the latter half of the second quarter of 2020, and is
2
currently expected to continue into and through 2021. The Company currently expects capital expenditures to total approximately $35 million for full year 2020.
In alignment with our dividend policy and capital allocation strategy, the Company returned $5.7 million to shareholders in the third quarter of 2020 in the form of dividends, with year-to-date dividends totaling $17.3 million, and resumed share repurchases with 88,950 shares repurchased in the amount of $4.7 million during the third quarter of 2020 and 545,105 shares repurchased year-to-date in the amount of $20.3 million.
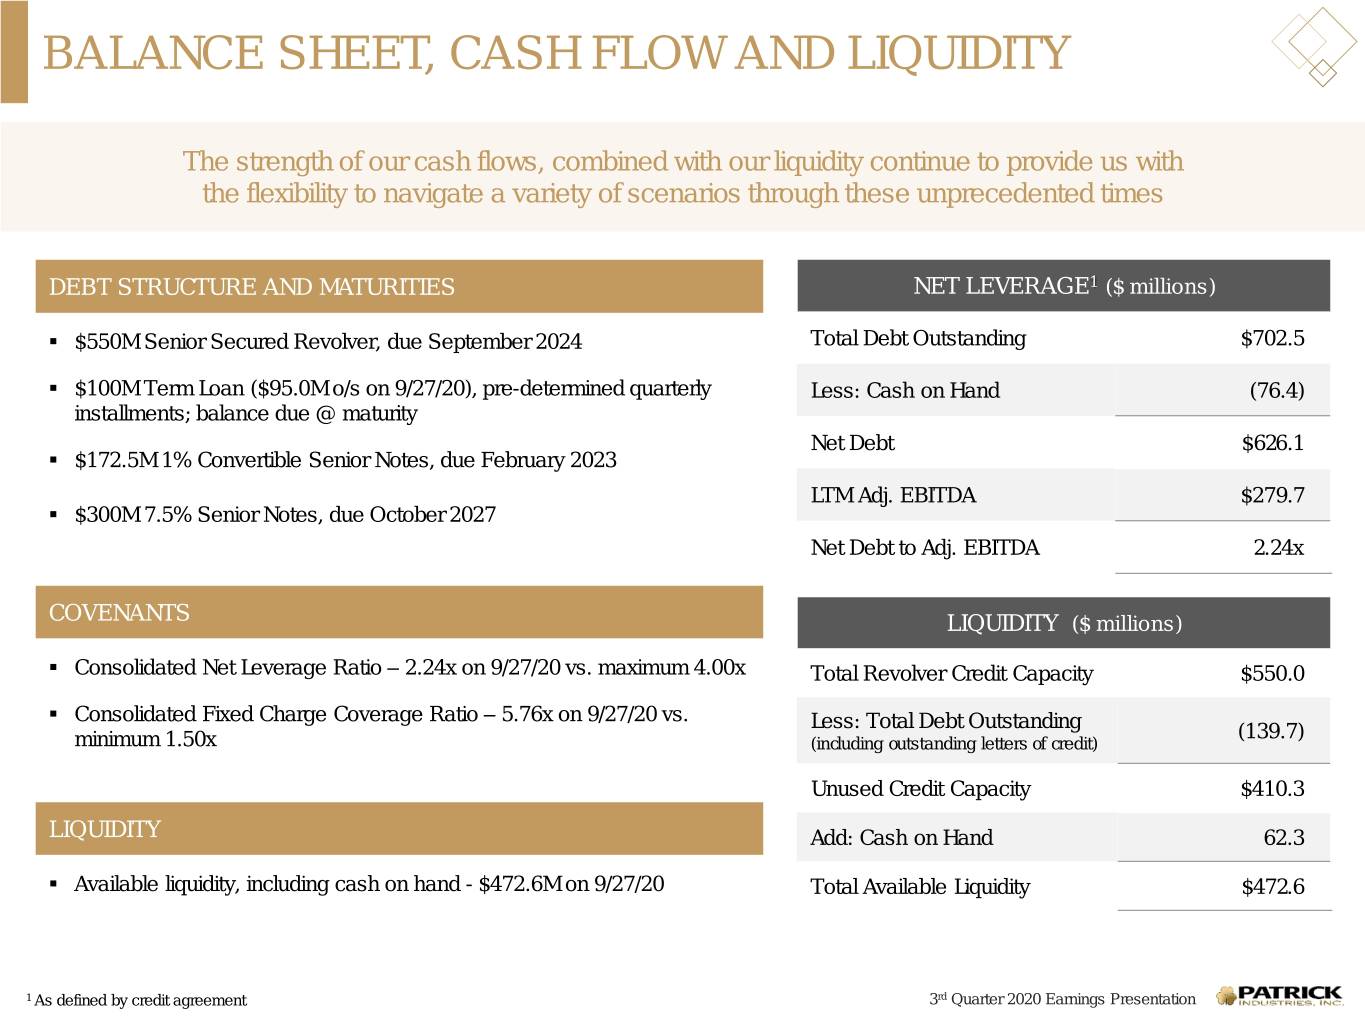
The Company’s net debt at the end of the quarter was approximately $640 million, resulting in a net leverage ratio of 2.2x (as calculated in accordance with our credit agreement). Available liquidity, comprised of borrowing availability under the Company’s credit facility and $62.3 million of cash on hand, was approximately $473 million, with no major debt maturities until 2023.
Business Outlook
"Momentum in our RV and marine sectors is expected to remain strong, and our housing and industrial markets are experiencing tailwinds with low interest rates, an increase in home improvement activity, and urban to suburban and rural relocation trends," said Mr. Nemeth. “We have strategically and aggressively pulled forward certain capital expenditure initiatives to ensure that we are in the best position possible with continued available capacity to support and grow with our customers for the 2021 model season and beyond. Our strong cash flows and liquidity allow us to invest in our businesses, continue to deploy strategic capital, and capitalize on growth opportunities as they arise in support of expansion necessary to serve our primary end markets over the long-term."
Conference Call Webcast
As previously announced, Patrick Industries will host an online webcast of its third quarter 2020 earnings conference call that can be accessed on the Company’s website, www.patrickind.com, under “Investor Relations,” on Thursday, October 29, 2020 at 10:00 a.m. Eastern time. In addition, a supplemental earnings presentation can be accessed on the Company’s website, www.patrickind.com under “Investor Relations - Presentations.”
About Patrick Industries, Inc.
Patrick Industries, Inc. is a major manufacturer and distributor of component products and building products serving the recreational vehicle, marine, manufactured housing, residential housing, high-rise, hospitality, kitchen cabinet, office and household furniture, fixtures and commercial furnishings, and other industrial markets and operates coast-to-coast in various locations throughout the United States and in Canada, China and the Netherlands. Patrick’s major manufactured products include decorative vinyl and paper laminated panels, countertops, fabricated aluminum products, wrapped profile mouldings, slide-out trim and fascia, cabinet doors and components, hardwood furniture, fiberglass bath fixtures and tile systems, thermoformed shower surrounds, specialty bath and closet building products, fiberglass and plastic helm systems and component products, wiring and wire harnesses, boat covers, towers, tops and frames, electrical systems components including instrument and dash panels, softwoods lumber, interior passage doors, air handling products, RV painting, slotwall panels and components, aluminum fuel tanks, and CNC molds and composite parts and other products. The Company also distributes drywall and drywall finishing products, electronics and audio systems components, wiring, electrical and plumbing products, appliances, cement siding, raw and processed lumber, FRP products, interior passage doors, roofing products, tile, laminate and ceramic flooring, shower doors, furniture, fireplaces and surrounds, interior and exterior lighting products, and other miscellaneous products, in addition to providing transportation and logistics services.
3
Use of Financial Metrics
In addition to reporting financial results in accordance with U.S. GAAP, the Company also provides financial metrics, such as net leverage ratio, RV content per unit, estimated marine and MH content per unit, net debt and available liquidity, which we believe are important measures of the Company's business performance. These metrics should not be considered alternatives to U.S. GAAP. Our computations of net leverage ratio, content per unit, net debt and available liquidity may differ from similarly titled measures used by others. You should not consider these metrics in isolation or as substitutes for an analysis of our results as reported under U.S. GAAP. Beginning in the third quarter of 2020, we calculate marine content per unit based on estimated wholesale powerboat unit shipments, which we believe better represents the relationship between our sales and marine OEM production, rather than based on estimated retail powerboat unit sales.
Cautionary Statement Regarding Forward-Looking Statements
This press release contains certain statements related to future results, our intentions, beliefs and expectations or predictions for the future, which are forward-looking statements as that term is defined in the Private Securities Litigation Reform Act of 1995. These forward-looking statements involve a number of risks and uncertainties that could cause actual results to differ materially from either historical or anticipated results depending on a variety of factors. Potential factors that could impact results include: the impact of the continuing financial and operational uncertainty due to the COVID-19 pandemic, including its impact on the overall economy, our sales, customers, operations, team members, suppliers, and the countries where we have operations or from which we source products and raw materials, such as China; adverse economic and business conditions, including cyclicality and seasonality in the industries we sell our products; the deterioration of the financial condition of our customers or suppliers; the ability to adjust our production schedules up or down quickly in response to rapid changes in demand; the loss of a significant customer; changes in consumer preferences; pricing pressures due to competition; conditions in the credit market limiting the ability of consumers and wholesale customers to obtain retail and wholesale financing for RVs, manufactured homes, and marine products; the imposition of restrictions and taxes on imports of raw materials and components used in our products; information technology performance and security; any increased cost or limited availability of certain raw materials; the impact of governmental and environmental regulations, and our inability to comply with them; our level of indebtedness; the ability to remain in compliance with our credit agreement covenants; the availability and costs of labor and production facilities and the impact of labor shortages; inventory levels of retailers and manufacturers; the ability to generate cash flow or obtain financing to fund growth; future growth rates in the Company's core businesses; realization and impact of efficiency improvements and cost reductions; the successful integration of acquisitions and other growth initiatives; increases in interest rates and oil and gasoline prices; the ability to retain key executive and management personnel; the disruption of business resulting from natural disasters or other unforeseen events, and adverse weather conditions impacting retail sales.
There can be no assurance that any forward-looking statement will be realized or that actual results will not be significantly different from that set forth in such forward-looking statement. Information about certain risks that could affect our business and cause actual results to differ from those expressed or implied in the forward-looking statements are contained in the section entitled “Risk Factors” in the Company’s Annual Report on Form 10-K for the year ended December 31, 2019, and in the Company's Forms 10-Q for subsequent quarterly periods, which are filed with the Securities and Exchange Commission (“SEC”) and are available on the SEC’s website at www.sec.gov. Each forward-looking statement speaks only as of the date of this press release, and we undertake no obligation to update any forward-looking statement to reflect events or circumstances occurring after the date on which it is made.
Contact:
Julie Ann Kotowski
Investor Relations
574.294.7511
4
| PATRICK INDUSTRIES, INC. | |||||||||||||||||||||||
| CONDENSED CONSOLIDATED STATEMENTS OF INCOME (Unaudited) | |||||||||||||||||||||||
| Third Quarter Ended | Nine Months Ended | ||||||||||||||||||||||
| (thousands except per share data) | September 27, 2020 | September 29, 2019 | September 27, 2020 | September 29, 2019 | |||||||||||||||||||
| NET SALES | $ | 700,707 | $ | 566,186 | $ | 1,713,984 | $ | 1,787,622 | |||||||||||||||
| Cost of goods sold | 567,210 | 461,851 | 1,397,285 | 1,464,078 | |||||||||||||||||||
| GROSS PROFIT | 133,497 | 104,335 | 316,699 | 323,544 | |||||||||||||||||||
| Operating Expenses: | |||||||||||||||||||||||
| Warehouse and delivery | 25,263 | 23,917 | 70,204 | 74,228 | |||||||||||||||||||
| Selling, general and administrative | 38,184 | 33,817 | 105,681 | 104,403 | |||||||||||||||||||
| Amortization of intangible assets | 10,221 | 9,191 | 29,600 | 26,448 | |||||||||||||||||||
| Total operating expenses | 73,668 | 66,925 | 205,485 | 205,079 | |||||||||||||||||||
| OPERATING INCOME | 59,829 | 37,410 | 111,214 | 118,465 | |||||||||||||||||||
| Interest expense, net | 10,507 | 8,603 | 31,820 | 26,222 | |||||||||||||||||||
| Income before income taxes | 49,322 | 28,807 | 79,394 | 92,243 | |||||||||||||||||||
| Income taxes | 11,986 | 7,490 | 20,157 | 22,661 | |||||||||||||||||||
| NET INCOME | $ | 37,336 | $ | 21,317 | $ | 59,237 | $ | 69,582 | |||||||||||||||
| BASIC NET INCOME PER COMMON SHARE | $ | 1.65 | $ | 0.92 | $ | 2.60 | $ | 3.02 | |||||||||||||||
| DILUTED NET INCOME PER COMMON SHARE | $ | 1.62 | $ | 0.92 | $ | 2.57 | $ | 2.99 | |||||||||||||||
| Weighted average shares outstanding - Basic | 22,674 | 23,076 | 22,784 | 23,073 | |||||||||||||||||||
| Weighted average shares outstanding - Diluted | 23,072 | 23,273 | 23,088 | 23,279 | |||||||||||||||||||
5
| PATRICK INDUSTRIES, INC. | |||||||||||
| CONDENSED CONSOLIDATED STATEMENTS OF FINANCIAL POSITION (Unaudited) | |||||||||||
| As of | |||||||||||
| (thousands) | September 27, 2020 | December 31, 2019 | |||||||||
| ASSETS | |||||||||||
| Current Assets | |||||||||||
| Cash and cash equivalents | $ | 62,347 | $ | 139,390 | |||||||
| Trade receivables, net | 175,533 | 87,536 | |||||||||
| Inventories | 281,374 | 253,870 | |||||||||
| Prepaid expenses and other | 12,580 | 36,038 | |||||||||
| Total current assets | 531,834 | 516,834 | |||||||||
| Property, plant and equipment, net | 197,415 | 180,849 | |||||||||
| Operating lease right-of-use assets | 105,410 | 93,546 | |||||||||
| Goodwill and intangible assets, net | 737,352 | 676,363 | |||||||||
| Deferred financing costs, net | 2,544 | 2,978 | |||||||||
| Other non-current assets | 384 | 423 | |||||||||
| TOTAL ASSETS | $ | 1,574,939 | $ | 1,470,993 | |||||||
| LIABILITIES AND SHAREHOLDERS’ EQUITY | |||||||||||
| Current Liabilities | |||||||||||
| Current maturities of long-term debt | $ | 5,000 | $ | 5,000 | |||||||
| Current operating lease liabilities | 29,565 | 27,694 | |||||||||
| Accounts payable | 117,088 | 96,208 | |||||||||
| Accrued liabilities | 101,296 | 58,033 | |||||||||
| Total current liabilities | 252,949 | 186,935 | |||||||||
| Long-term debt, less current maturities, net | 673,852 | 670,354 | |||||||||
| Long-term operating lease liabilities | 76,873 | 66,467 | |||||||||
| Deferred tax liabilities, net | 26,100 | 27,284 | |||||||||
| Other long-term liabilities | 19,336 | 22,472 | |||||||||
| TOTAL LIABILITIES | 1,049,110 | 973,512 | |||||||||
| SHAREHOLDERS’ EQUITY | |||||||||||
| Common stock | 177,308 | 172,662 | |||||||||
| Additional paid-in-capital | 24,440 | 25,014 | |||||||||
| Accumulated other comprehensive loss | (7,243) | (5,698) | |||||||||
| Retained earnings | 331,324 | 305,503 | |||||||||
| TOTAL SHAREHOLDERS’ EQUITY | 525,829 | 497,481 | |||||||||
| TOTAL LIABILITIES AND SHAREHOLDERS’ EQUITY | $ | 1,574,939 | $ | 1,470,993 | |||||||
6
PATRICK INDUSTRIES, INC.
CONDENSED CONSOLIDATED STATEMENTS OF CASH FLOWS (Unaudited)
| Nine Months Ended | |||||||||||
| (thousands) | September 27, | September 29, | |||||||||
| 2020 | 2019 | ||||||||||
| CASH FLOWS FROM OPERATING ACTIVITIES | |||||||||||
Net income | $ | 59,237 | $ | 69,582 | |||||||
Depreciation and amortization | 52,955 | 46,449 | |||||||||
Stock-based compensation expense | 11,177 | 12,039 | |||||||||
Amortization of convertible notes debt discount | 5,302 | 5,123 | |||||||||
Other adjustments to reconcile net income to net cash provided by operating activities | (536) | (559) | |||||||||
| Change in operating assets and liabilities, net of acquisitions of businesses | (15,377) | (10,601) | |||||||||
Net cash provided by operating activities | 112,758 | 122,033 | |||||||||
| CASH FLOWS FROM INVESTING ACTIVITIES | |||||||||||
Capital expenditures | (22,159) | (22,227) | |||||||||
| Business acquisitions and other investing activities | (123,265) | (17,841) | |||||||||
Net cash used in investing activities | (145,424) | (40,068) | |||||||||
| NET CASH FLOWS (USED IN) PROVIDED BY FINANCING ACTIVITIES | (44,377) | 27,852 | |||||||||
Increase (decrease) in cash and cash equivalents | (77,043) | 109,817 | |||||||||
| Cash and cash equivalents at beginning of period | 139,390 | 6,895 | |||||||||
| Cash and cash equivalents at end of period | $ | 62,347 | $ | 116,712 | |||||||
7
3RD QUARTER 2020 EARNINGS PRESENTATION October 29, 2020
FORWARD-LOOKING STATEMENTS This presentation contains certain statements related to future results, our intentions, beliefs and expectations or predictions for the future which are forward-looking statements as that term is defined in the Private Securities Litigation Reform Act of 1995. These forward-looking statements involve a number of risks and uncertainties that could cause actual results to differ materially from either historical or anticipated results depending on a variety of factors. These risks and uncertainties include, but are not limited to, the impact of the continuing financial and operational uncertainty due to the COVID-19 pandemic, including its impact on the overall economy, our sales, customers, operations, team members and suppliers. Further information concerning the Company and its business, including factors that potentially could materially affect the Company’s financial results, is contained in the Company’s filings with the Securities and Exchange Commission. This presentation includes market and industry data, forecasts and valuations that have been obtained from independent consultant reports, publicly available information, various industry publications and other published industry sources. Although we believe these sources are reliable, we have not independently verified the information and cannot make any representation as to the accuracy or completeness of such information. We disclaim any obligation or undertaking to disseminate any updates or revisions to any forward- looking statements contained in this presentation or to reflect any change in our expectations after the date of this presentation or any change in events, conditions or circumstances on which any statement is based. Use of Non-GAAP Financial Measures This presentation contains non-GAAP financial measures. These measures, the purposes for which management uses them, why management believes they are useful to investors, and a reconciliation to the most directly comparable GAAP financial measures can be found in the Appendix of this presentation. All references to profit measures and earnings per share on a comparable basis exclude items that affect comparability. 3rd Quarter 2020 Earnings Presentation
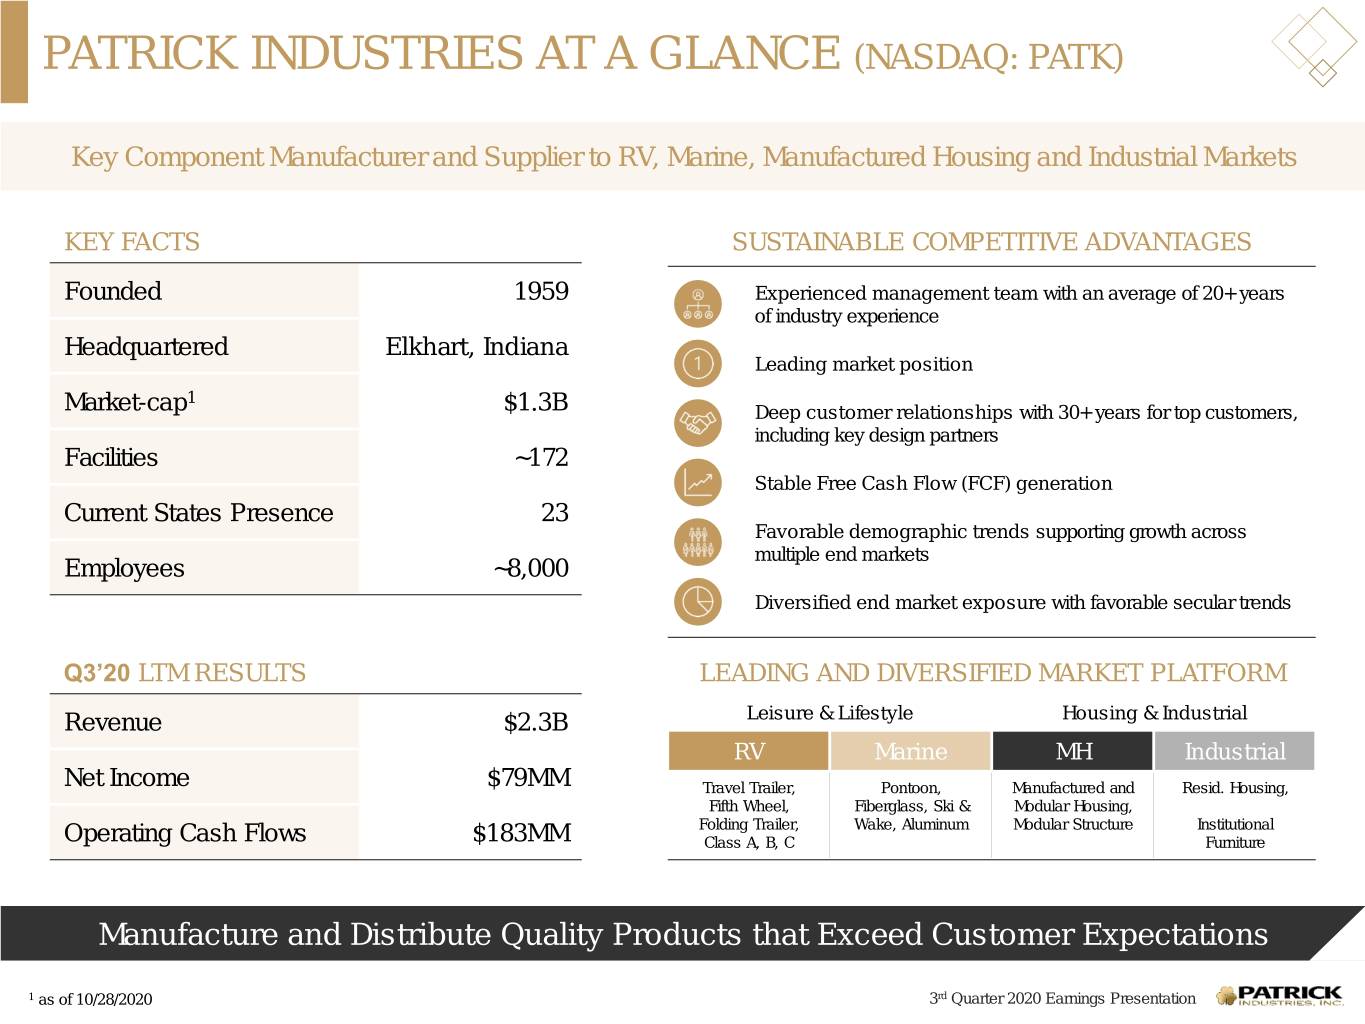
PATRICK INDUSTRIES AT A GLANCE (NASDAQ: PATK) Key Component Manufacturer and Supplier to RV, Marine, Manufactured Housing and Industrial Markets KEY FACTS SUSTAINABLE COMPETITIVE ADVANTAGES Founded 1959 Experienced management team with an average of 20+ years of industry experience Headquartered Elkhart, Indiana Leading market position 1 Market-cap $1.3B Deep customer relationships with 30+ years for top customers, including key design partners Facilities ~172 Stable Free Cash Flow (FCF) generation Current States Presence 23 Favorable demographic trends supporting growth across multiple end markets Employees ~8,000 Diversified end market exposure with favorable secular trends Q3’20 LTM RESULTS LEADING AND DIVERSIFIED MARKET PLATFORM Revenue $2.3B Leisure & Lifestyle Housing & Industrial RV Marine MH Industrial Net Income $79MM Travel Trailer, Pontoon, Manufactured and Resid. Housing, Fifth Wheel, Fiberglass, Ski & Modular Housing, Folding Trailer, Wake, Aluminum Modular Structure Institutional Operating Cash Flows $183MM Class A, B, C Furniture Manufacture and Distribute Quality Products that Exceed Customer Expectations 1 as of 10/28/2020 3rd Quarter 2020 Earnings Presentation
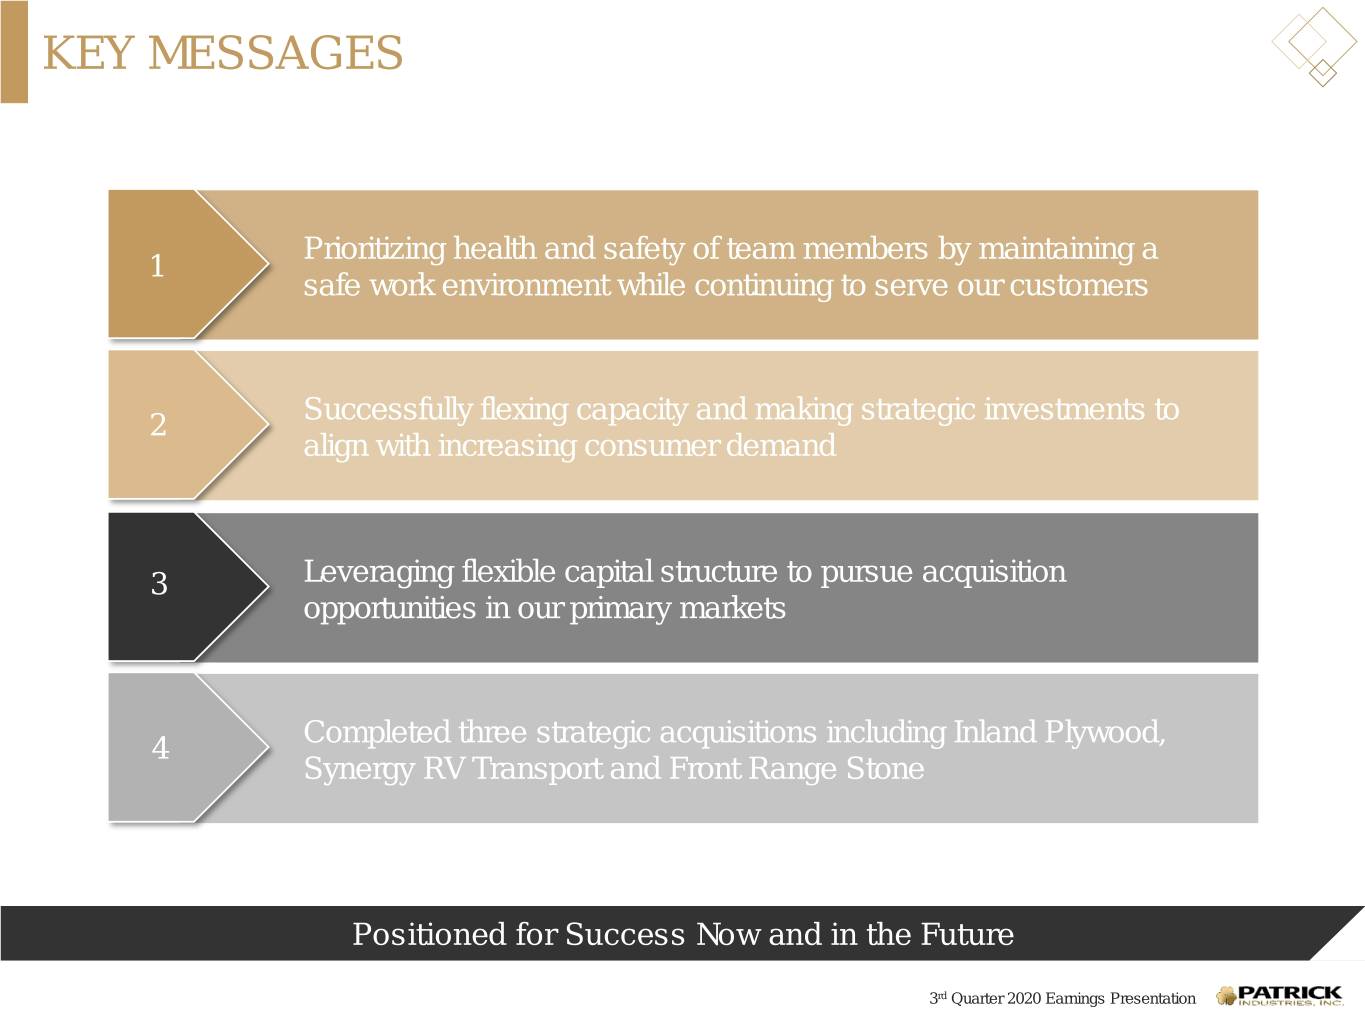
KEY MESSAGES Prioritizing health and safety of team members by maintaining a 1 safe work environment while continuing to serve our customers Successfully flexing capacity and making strategic investments to 2 align with increasing consumer demand 3 Leveraging flexible capital structure to pursue acquisition opportunities in our primary markets Completed three strategic acquisitions including Inland Plywood, 4 Synergy RV Transport and Front Range Stone Positioned for Success Now and in the Future 3rd Quarter 2020 Earnings Presentation
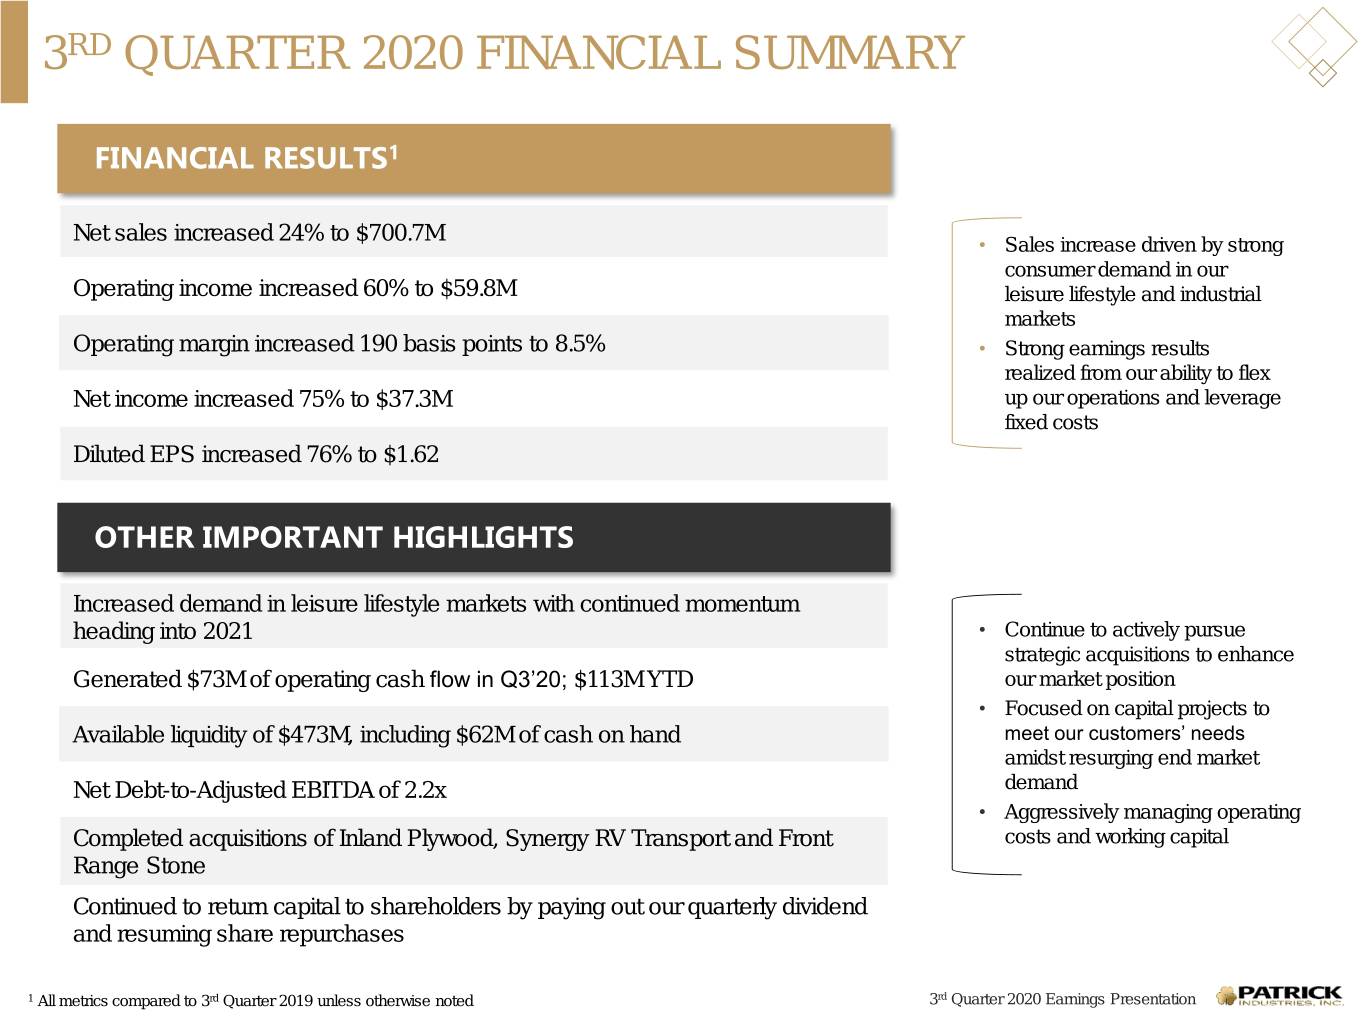
3RD QUARTER 2020 FINANCIAL SUMMARY FINANCIAL RESULTS1 Net sales increased 24% to $700.7M • Sales increase driven by strong consumer demand in our Operating income increased 60% to $59.8M leisure lifestyle and industrial markets Operating margin increased 190 basis points to 8.5% • Strong earnings results realized from our ability to flex Net income increased 75% to $37.3M up our operations and leverage fixed costs Diluted EPS increased 76% to $1.62 OTHER IMPORTANT HIGHLIGHTS Increased demand in leisure lifestyle markets with continued momentum heading into 2021 • Continue to actively pursue strategic acquisitions to enhance Generated $73M of operating cash flow in Q3’20; $113M YTD our market position • Focused on capital projects to Available liquidity of $473M, including $62M of cash on hand meet our customers’ needs amidst resurging end market Net Debt-to-Adjusted EBITDA of 2.2x demand • Aggressively managing operating Completed acquisitions of Inland Plywood, Synergy RV Transport and Front costs and working capital Range Stone Continued to return capital to shareholders by paying out our quarterly dividend and resuming share repurchases 1 All metrics compared to 3rd Quarter 2019 unless otherwise noted 3rd Quarter 2020 Earnings Presentation
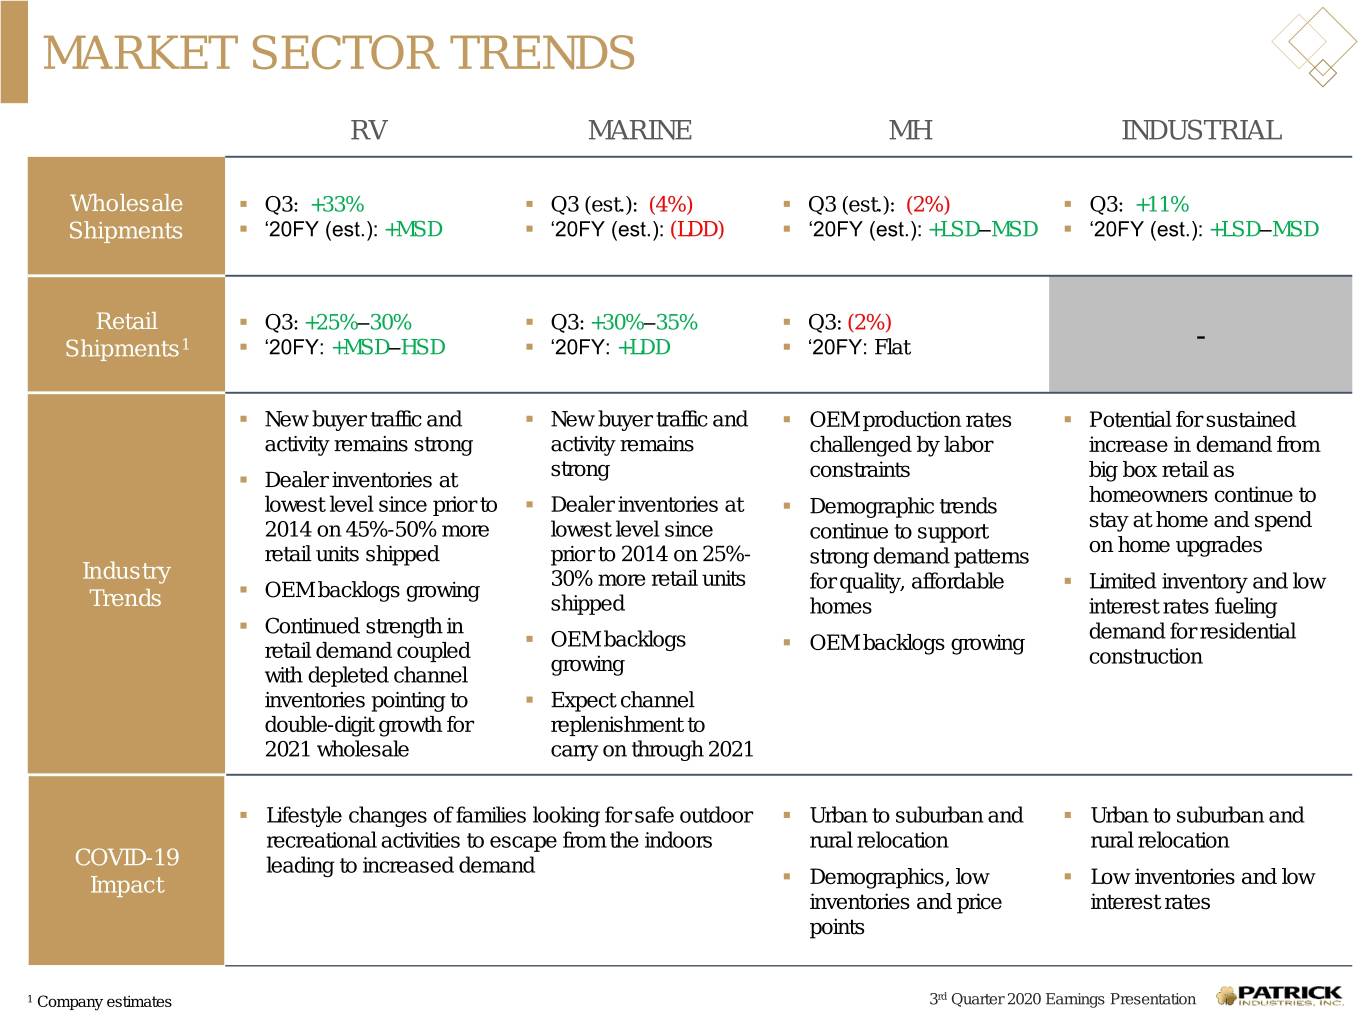
MARKET SECTOR TRENDS RV MARINE MH INDUSTRIAL Wholesale . Q3: +33% . Q3 (est.): (4%) . Q3 (est.): (2%) . Q3: +11% Shipments . ‘20FY (est.): +MSD . ‘20FY (est.): (LDD) . ‘20FY (est.): +LSD–MSD . ‘20FY (est.): +LSD–MSD Retail . Q3: +25%–30% . Q3: +30%–35% . Q3: (2%) Shipments1 . ‘20FY: +MSD–HSD . ‘20FY: +LDD . ‘20FY: Flat - . New buyer traffic and . New buyer traffic and . OEM production rates . Potential for sustained activity remains strong activity remains challenged by labor increase in demand from strong . Dealer inventories at constraints big box retail as homeowners continue to lowest level since prior to . Dealer inventories at . Demographic trends stay at home and spend 2014 on 45%-50% more lowest level since continue to support on home upgrades retail units shipped prior to 2014 on 25%- strong demand patterns Industry 30% more retail units . OEM backlogs growing for quality, affordable . Limited inventory and low Trends shipped homes interest rates fueling . Continued strength in . OEM backlogs demand for residential retail demand coupled . OEM backlogs growing growing construction with depleted channel inventories pointing to . Expect channel double-digit growth for replenishment to 2021 wholesale carry on through 2021 . Lifestyle changes of families looking for safe outdoor . Urban to suburban and . Urban to suburban and recreational activities to escape from the indoors rural relocation rural relocation COVID-19 leading to increased demand Impact . Demographics, low . Low inventories and low inventories and price interest rates points 1 Company estimates 3rd Quarter 2020 Earnings Presentation
3RD QUARTER 2020 FINANCIAL RESULTS ($ MILLIONS EXCEPT PER SHARE DATA) OPERATING CASH FLOW FROM NET SALES DILUTED EPS INCOME & MARGIN OPERATIONS +24% +60% +76% (8%) $1.62 $700.7 $59.8 $122.0 $112.8 $566.2 8.5% $37.4 $0.92 6.6% Q3 2019 Q3 2020 Q3 2019 Q3 2020 Q3 2019 Q3 2020 9M 2019 9M 2020 . Growth largely attributable to . Quickly flexed labor force and . Strong operating leverage . Earnings disruptions related to increased consumer demand in operations back up to meet COVID-19 impact on end . High variable cost structure our leisure lifestyle and customer needs markets experienced in late Q1 industrial end markets and in Q2 . Improved operating margin by . Revenues from leisure lifestyle 190bps primarily by leveraging . Strategic inventory and capital market (RV & Marine) fixed costs investments made to ensure increased 34%, with RV up ability to flex and grow with 36% and marine up 25% customer demand . Revenues from housing & industrial markets increased 3%, with MH down 1% and industrial up 9% 3rd Quarter 2020 Earnings Presentation
PERFORMANCE BY MARKET SECTORS ($ MILLIONS) Leisure Lifestyle1 Housing and Industrial1 RV MH +36% (1%) $421.2 $109.1 $107.8 $310.0 Q3 2019 Q3 2020 Q3 2019 Q3 2020 . 60% of sales in Q3 2020 . 15% of sales in Q3 2020 . Content per Unit (TTM) – relatively flat at approximately $3,140 . Content per Unit (TTM) – increased 4% to an estimated $4,503 . Q3 focus on taking care of existing customers increased . Content growth continues to be driven by acquisitions and demand schedules leveraging synergies MARINE INDUSTRIAL +25% +9% $93.4 $75.0 $72.1 $78.3 Q3 2019 Q3 2020 Q3 2019 Q3 2020 . 14% of sales in Q3 2020 . 11% of sales in Q3 2020 . Content per Unit (TTM) – increased 16% to an estimated $1,915 . New Housing Starts in Q3 increased 11% (Q2 declined 15%) . Content growth driven by acquisitions, market share gains and . 60% of revenues tied to new housing starts; our products go into aftermarket growth new homes 4-6 months after new housing starts 1 All metrics compared to 3rd Quarter 2019 unless otherwise noted 3rd Quarter 2020 Earnings Presentation
BALANCE SHEET, CASH FLOW AND LIQUIDITY The strength of our cash flows, combined with our liquidity continue to provide us with the flexibility to navigate a variety of scenarios through these unprecedented times DEBT STRUCTURE AND MATURITIES NET LEVERAGE1 ($ millions) . $550M Senior Secured Revolver, due September 2024 Total Debt Outstanding $702.5 . $100M Term Loan ($95.0M o/s on 9/27/20), pre-determined quarterly Less: Cash on Hand (76.4) installments; balance due @ maturity Net Debt $626.1 . $172.5M 1% Convertible Senior Notes, due February 2023 LTM Adj. EBITDA $279.7 . $300M 7.5% Senior Notes, due October 2027 Net Debt to Adj. EBITDA 2.24x COVENANTS LIQUIDITY ($ millions) . Consolidated Net Leverage Ratio – 2.24x on 9/27/20 vs. maximum 4.00x Total Revolver Credit Capacity $550.0 . Consolidated Fixed Charge Coverage Ratio – 5.76x on 9/27/20 vs. Less: Total Debt Outstanding (139.7) minimum 1.50x (including outstanding letters of credit) Unused Credit Capacity $410.3 LIQUIDITY Add: Cash on Hand 62.3 . Available liquidity, including cash on hand - $472.6M on 9/27/20 Total Available Liquidity $472.6 1 As defined by credit agreement 3rd Quarter 2020 Earnings Presentation
CONCLUSION / TAKEAWAYS MARKET BUSINESS LEADERSHIP STRATEGIC LIQUIDITY POSITION MODEL Market leader in our Deep industry Flexible, high Disciplined cost Strong balance primary market experience and variable cost management sheet with no near- sectors; uniquely proven track record business model to balanced with term debt positioned for near- of successfully drive operational strategic growth maturities, ample and long-term shift navigating efficiency and investment liquidity and an toward outdoor economic cycles navigate through all opportunities enhanced capital activities economic structure conditions Long-Term Shareholder Value Creation 3rd Quarter 2020 Earnings Presentation
Appendix 3rd Quarter 2020 Earnings Presentation
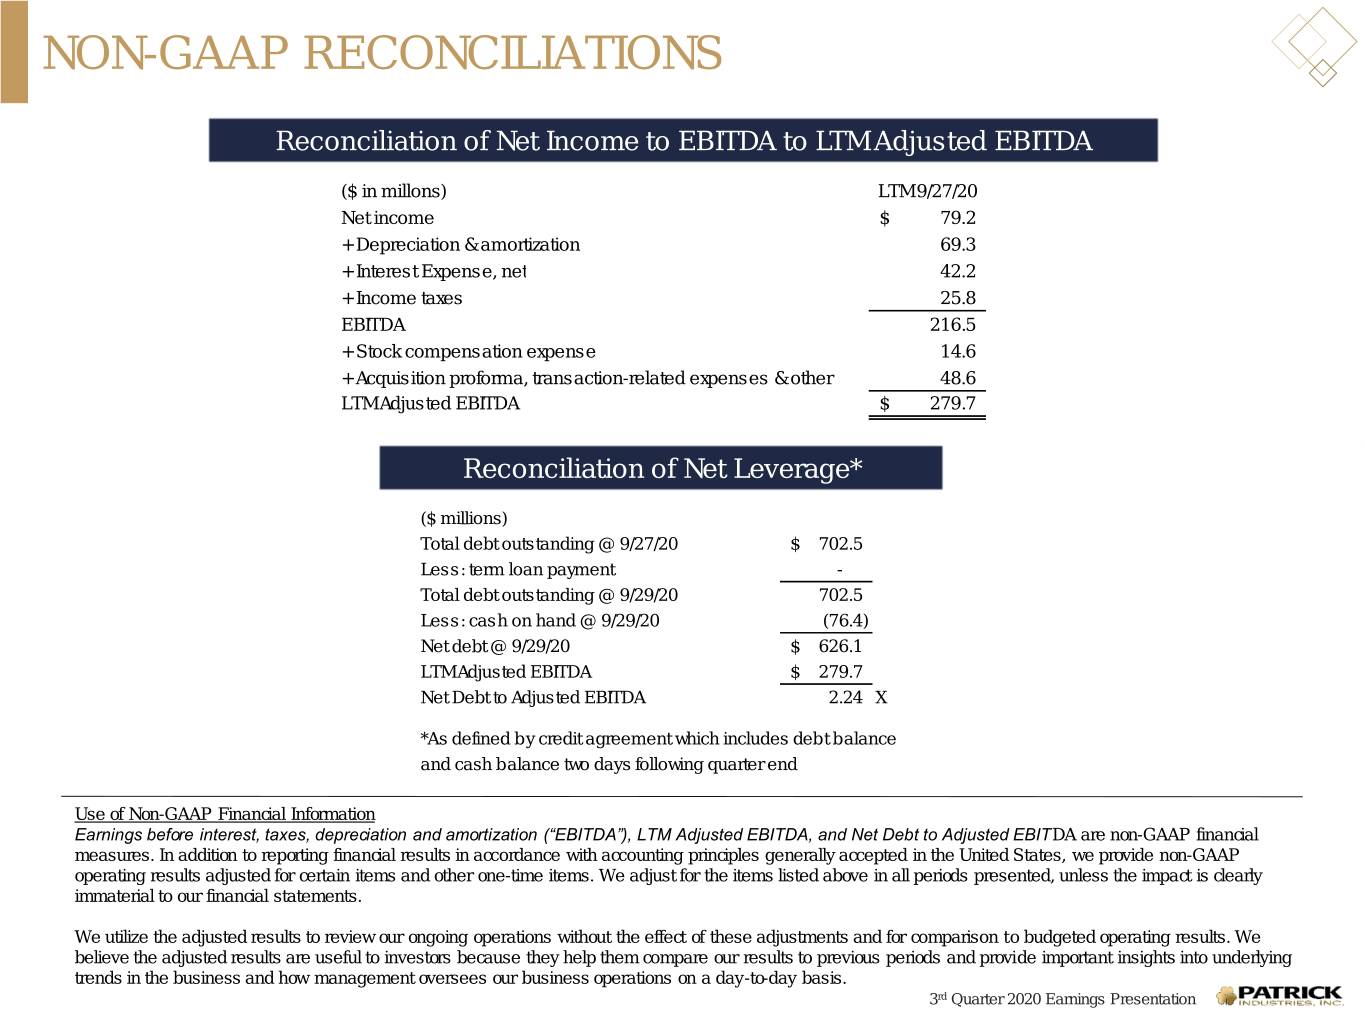
NON-GAAP RECONCILIATIONS Reconciliation of Net Income to EBITDA to LTM Adjusted EBITDA ($ in millons) LTM 9/27/20 Net income $ 79.2 + Depreciation & amortization 69.3 + Interest Expense, net 42.2 + Income taxes 25.8 EBITDA 216.5 + Stock compensation expense 14.6 + Acquisition proforma, transaction-related expenses & other 48.6 LTM Adjusted EBITDA $ 279.7 Reconciliation of Net Leverage* ($ millions) Total debt outstanding @ 9/27/20 $ 702.5 Less: term loan payment - Total debt outstanding @ 9/29/20 702.5 Less: cash on hand @ 9/29/20 (76.4) Net debt @ 9/29/20 $ 626.1 LTM Adjusted EBITDA $ 279.7 Net Debt to Adjusted EBITDA 2.24 X *As defined by credit agreement which includes debt balance and cash balance two days following quarter end Use of Non-GAAP Financial Information Earnings before interest, taxes, depreciation and amortization (“EBITDA”), LTM Adjusted EBITDA, and Net Debt to Adjusted EBITDA are non-GAAP financial measures. In addition to reporting financial results in accordance with accounting principles generally accepted in the United States, we provide non-GAAP operating results adjusted for certain items and other one-time items. We adjust for the items listed above in all periods presented, unless the impact is clearly immaterial to our financial statements. We utilize the adjusted results to review our ongoing operations without the effect of these adjustments and for comparison to budgeted operating results. We believe the adjusted results are useful to investors because they help them compare our results to previous periods and provide important insights into underlying trends in the business and how management oversees our business operations on a day-to-day basis. 3rd Quarter 2020 Earnings Presentation