
TFC 8-K
Truist Financial Corp (TFC)
8-K
2025-07-18
For: 2025-07-18
View Original
Added on
April 05, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
_____________________________________________
Form 8-K
Current Report
_____________________________________________
Pursuant to Section 13 or 15(d)
of the Securities Exchange Act of 1934
Date of Report (Date of earliest event reported)
(Exact name of registrant as specified in its charter)
_____________________________________________
(State or other jurisdiction of incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) | ||||||
(Address of principal executive offices) | (Zip Code) | |||||||
(844 ) 487-8478
(Registrant’s telephone number, including area code)
_____________________________________________
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
ITEM 2.02 Results of Operations and Financial Condition.
On July 18, 2025, Truist Financial Corporation (“Truist”) issued a press release announcing its reporting of second quarter 2025 results and posted on its website its second quarter 2025 Earnings Release, Quarterly Performance Summary, and Earnings Release Presentation. The materials contain forward-looking statements regarding Truist and include cautionary language identifying important factors that could cause actual results to differ materially from those anticipated. The Earnings Release, Quarterly Performance Summary, and Earnings Release Presentation are furnished as Exhibits 99.1, 99.2, and 99.3, respectively. Consequently, they are not deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934 or otherwise subject to the liabilities of that section. Such materials may only be incorporated by reference into another filing under the Exchange Act or Securities Act of 1933 if such subsequent filing specifically references this Form 8-K. All information in the Earnings Release, Quarterly Performance Summary, and Earnings Release Presentation speaks as of the date thereof, and Truist does not assume any obligation to update such information in the future.
ITEM 9.01 Financial Statements and Exhibits.
(d) Exhibits.
| Exhibit No. | Description of Exhibit | |||||||
| Earnings Release issued July 18, 2025. | ||||||||
| Quarterly Performance Summary issued July 18, 2025. | ||||||||
| Earnings Release Presentation issued July 18, 2025. | ||||||||
| 104 | The cover page from this Current Report on Form 8-K, formatted in Inline XBRL | |||||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
TRUIST FINANCIAL CORPORATION | ||||||||
(Registrant) | ||||||||
| By: | /s/ Cynthia B. Powell | |||||||
Cynthia B. Powell | ||||||||
Executive Vice President and Corporate Controller | ||||||||
(Principal Accounting Officer) | ||||||||
Date: July 18, 2025
`
 | News Release | ||||||||||
Truist reports second quarter 2025 results | |||||||||||
Net income available to common shareholders of $1.2 billion, or $0.90 per share | Average loans increased $6.2 billion, or 2.0% | Repurchased $750 million in common shares; Dividend and total payout ratios of 57% and 121% | |||||||||
2Q25 Key Financial Data | 2Q25 Performance Highlights(4) | ||||||||||
| (Dollars in billions, except per share data) | 2Q25 | 1Q25 | 2Q24 | ||||||||
| Summary Income Statement | |||||||||||
| Net interest income | $ | 3.59 | $ | 3.51 | $ | 3.53 | |||||
Net interest income - TE(1) | 3.64 | 3.56 | 3.58 | ||||||||
| Noninterest income | 1.40 | 1.39 | (5.21) | ||||||||
| Total revenue | 4.99 | 4.90 | (1.68) | ||||||||
Total revenue - TE(1) | 5.04 | 4.95 | (1.63) | ||||||||
| Noninterest expense | 2.99 | 2.91 | 3.09 | ||||||||
| Net income (loss) from continuing operations | 1.24 | 1.26 | (3.91) | ||||||||
| Net income from discontinued operations | – | – | 4.83 | ||||||||
| Net income | 1.24 | 1.26 | 0.92 | ||||||||
| Net income available to common shareholders | 1.18 | 1.16 | 0.83 | ||||||||
Adjusted net income available to common shareholders(1) | 1.19 | 1.16 | 1.24 | ||||||||
PPNR - unadjusted(1)(2) | 2.05 | 2.04 | NM | ||||||||
PPNR - adjusted(1)(2) | 2.10 | 2.08 | 2.12 | ||||||||
| Key Metrics | |||||||||||
| Diluted EPS | $ | 0.90 | $ | 0.87 | $ | 0.62 | |||||
Adjusted diluted EPS(1) | 0.91 | 0.87 | 0.91 | ||||||||
| BVPS | 45.70 | 44.85 | 42.71 | ||||||||
TBVPS(1) | 31.63 | 30.95 | 28.91 | ||||||||
| ROCE | 8.1 | % | 8.1 | % | 6.1 | % | |||||
ROTCE(1) | 12.3 | 12.3 | 10.4 | ||||||||
Efficiency ratio - unadjusted(2) | 59.9 | 59.3 | NM | ||||||||
Efficiency ratio - adjusted(1)(2) | 57.1 | 56.4 | 56.0 | ||||||||
Fee income ratio - unadjusted(2) | 28.1 | 28.4 | NM | ||||||||
Fee income ratio - adjusted(1)(2) | 28.1 | 28.2 | 28.7 | ||||||||
NIM - TE(1) | 3.02 | 3.01 | 3.02 | ||||||||
| NCO ratio | 0.51 | 0.60 | 0.58 | ||||||||
| ALLL ratio | 1.54 | 1.58 | 1.57 | ||||||||
CET1 ratio(3) | 11.0 | 11.3 | 11.6 | ||||||||
| Average Balances | |||||||||||
| Assets | $ | 537 | $ | 532 | $ | 527 | |||||
| Securities | 122 | 124 | 122 | ||||||||
| Loans and leases | 314 | 308 | 308 | ||||||||
| Deposits | 400 | 392 | 388 | ||||||||
•Net income available to common shareholders was $1.2 billion, or $0.90 per diluted share
•Total TE revenues were up 1.8%, or 2.1% adjusted for securities losses
◦TE net interest income increased 2.3%; net interest margin was up one basis point
◦Noninterest income was up 0.6% primarily due to higher other income, offset by lower investment banking and trading income
•Noninterest expense was up 2.8%. Adjusted noninterest expense(1) was up 3.1%, primarily reflecting higher personnel expense
•Average loans and leases HFI were up 2.0% due to increases in the commercial and industrial, residential mortgage, other consumer, and indirect auto portfolios
◦End of period loans and leases HFI were $318.8 billion, up $10.2 billion, or 3.3%
•Average deposits increased 2.1% due to increases in interest checking and time deposits, partially offset by a decline in money market and savings accounts
•Asset quality remained strong
◦Nonperforming loans to total loans HFI were down nine basis points due to declines in the CRE, commercial and industrial, and LHFS portfolios
◦Loans 90 days or more past due to total loans HFI were down three basis points, or down one basis point excluding government guaranteed loans
◦ALLL ratio decreased four basis points
◦Net charge-off ratio of 51 basis points, down nine basis points
•Capital levels remained strong
◦Repurchased $750 million in common shares, resulting in a dividend and total payout ratio of 57% and 121%, respectively
◦CET1 ratio(3) was 11.0%
◦Received the preliminary SCB requirement of 2.5%, down 30 basis points from the SCB received in 2024
Amounts may not foot due to rounding.
(1)Represents a non-GAAP measure. A reconciliation of each of these non-GAAP measures to the most directly comparable GAAP measure is included in this release or the appendix to Truist’s Second Quarter 2025 Earnings Presentation.
(2)This metric is calculated based on continuing operations.
(3)Current quarter capital ratios are preliminary.
(4)Comparisons noted in this section summarize changes from second quarter of 2025 compared to first quarter of 2025 on a continuing operations basis, unless otherwise noted.
| CEO Commentary | ||
“We delivered strong second-quarter results, driven by strategic loan growth and higher net interest income derived from continued strong production from our business. Our performance reflects the value of our client-centric business model and momentum in our strategy, as we see tangible results from investments we have made in talent and technology across our platforms.
We remain on track to achieve our annual expense growth target, which includes continued investments in talent and technology. Asset quality remained strong, and our strong capital position continues to support both our growth initiatives and our ability to return capital to shareholders.
As we stay on offense, our clear strategic focus, strong balance sheet, and unwavering commitment to our purpose—to inspire and build better lives and communities—position us well to continue driving improved performance in the evolving environment.”
— Bill Rogers, Truist Chairman & CEO
`
| Contact: | ||||||||
| Investors: | Brad Milsaps | [email protected] | ||||||
| Media: | Shelley Miller | [email protected] | ||||||
| Net Interest Income, Net Interest Margin, and Average Balances | |||||||||||||||||||||||||||||
| Quarter Ended | Change | ||||||||||||||||||||||||||||
| (Dollars in millions) | 2Q25 | 1Q25 | 2Q24 | Link | Like | ||||||||||||||||||||||||
| Interest income | $ | 6,154 | $ | 5,988 | $ | 6,351 | $ | 166 | 2.8 | % | $ | (197) | (3.1) | % | |||||||||||||||
| Plus: Taxable-equivalent adjustment | 48 | 48 | 53 | — | — | (5) | (9.4) | ||||||||||||||||||||||
Interest income - taxable equivalent(1) | 6,202 | 6,036 | 6,404 | 166 | 2.8 | (202) | (3.2) | ||||||||||||||||||||||
| Interest expense | 2,567 | 2,481 | 2,824 | 86 | 3.5 | (257) | (9.1) | ||||||||||||||||||||||
Net interest income - taxable equivalent(1) | $ | 3,635 | $ | 3,555 | $ | 3,580 | $ | 80 | 2.3 | $ | 55 | 1.5 | |||||||||||||||||
Net interest margin - taxable equivalent(1) | 3.02 | % | 3.01 | % | 3.02 | % | 1 bps | — bps | |||||||||||||||||||||
Average Balances(2) | |||||||||||||||||||||||||||||
| Total earning assets | $ | 480,983 | $ | 476,214 | $ | 474,144 | $ | 4,769 | 1.0 | % | $ | 6,839 | 1.4 | % | |||||||||||||||
| Total interest-bearing liabilities | 354,251 | 349,059 | 343,145 | 5,192 | 1.5 | 11,106 | 3.2 | ||||||||||||||||||||||
Yields / Rates(1) | |||||||||||||||||||||||||||||
| Total earning assets | 5.16 | % | 5.12 | % | 5.42 | % | 4 bps | (26) bps | |||||||||||||||||||||
| Total interest-bearing liabilities | 2.91 | 2.88 | 3.31 | 3 bps | (40) bps | ||||||||||||||||||||||||
(1)Amounts are on a taxable-equivalent basis, which represents a non-GAAP measure, utilizing the federal income tax rate of 21% for the periods presented. Interest income includes certain fees, deferred costs, and dividends.
(2)Represents daily average balances. Unrealized gains and losses on available-for-sale securities are included in nonearning assets. Active hedge basis adjustments for fair value hedges are included in nonearning assets and other liabilities.
Taxable-equivalent net interest income for the second quarter of 2025 was up $80 million, or 2.3%, compared to the first quarter of 2025. Net interest margin was 3.02%, up one basis point compared to the first quarter of 2025.
•Average earning assets increased $4.8 billion, or 1.0%, primarily due to an increase in average total loans of $6.3 billion, or 2.1%, partially offset by a decline in average securities of $2.2 billion, or 1.8%.
•The yield on the average total loan portfolio was 6.01%, up four basis points.
•Average deposits increased $8.3 billion, or 2.1% primarily due to higher short-term client deposits, average short-term borrowings decreased $4.1 billion, or 13%, and average long-term debt increased $1.8 billion, or 5.5%.
•The average cost of total deposits was 1.85%, up six basis points. The average cost of short-term borrowings was 4.47%, down two basis points reflecting lower market rates. The average cost of long-term debt was 5.02%, down three basis points.
Taxable-equivalent net interest income for the second quarter of 2025 was up $55 million, or 1.5%, compared to the second quarter of 2024. Net interest margin was 3.02%, flat compared to the second quarter of 2024.
•Average earning assets increased $6.8 billion, or 1.4%, primarily due to an increase in average total loans of $6.3 billion, or 2.0%.
•The yield on the average total loan portfolio was 6.01%, down 43 basis points due to the impact of variable rate loans repricing. The yield on the average securities portfolio was 3.16%, up 40 basis points, reflecting the balance sheet repositioning in the second quarter of 2024 and reinvesting cash flows into higher yielding securities.
•Average deposits increased $12.4 billion, or 3.2%, and average long-term debt decreased $2.5 billion, or 6.8%.
•The average cost of total deposits was 1.85%, down 24 basis points. The average cost of short-term borrowings was 4.47%, down 111 basis points. The average cost of long-term debt was 5.02%, up 15 basis points.
- 2 -
| Noninterest Income | |||||||||||||||||||||||||||||
| Quarter Ended | Change | ||||||||||||||||||||||||||||
| (Dollars in millions) | 2Q25 | 1Q25 | 2Q24 | Link | Like | ||||||||||||||||||||||||
| Wealth management income | $ | 348 | $ | 344 | $ | 361 | $ | 4 | 1.2 | % | $ | (13) | (3.6) | % | |||||||||||||||
| Investment banking and trading income | 205 | 273 | 286 | (68) | (24.9) | (81) | (28.3) | ||||||||||||||||||||||
| Card and payment related fees | 232 | 220 | 230 | 12 | 5.5 | 2 | 0.9 | ||||||||||||||||||||||
| Service charges on deposits | 227 | 230 | 232 | (3) | (1.3) | (5) | (2.2) | ||||||||||||||||||||||
| Mortgage banking income | 107 | 108 | 112 | (1) | (0.9) | (5) | (4.5) | ||||||||||||||||||||||
| Lending related fees | 99 | 95 | 89 | 4 | 4.2 | 10 | 11.2 | ||||||||||||||||||||||
| Operating lease income | 47 | 53 | 50 | (6) | (11.3) | (3) | (6.0) | ||||||||||||||||||||||
| Securities gains (losses) | (18) | (1) | (6,650) | (17) | NM | 6,632 | (99.7) | ||||||||||||||||||||||
| Other income | 153 | 70 | 78 | 83 | 118.6 | 75 | 96.2 | ||||||||||||||||||||||
| Total noninterest income | $ | 1,400 | $ | 1,392 | $ | (5,212) | $ | 8 | 0.6 | $ | 6,612 | NM | |||||||||||||||||
Noninterest income was up $8 million, or 0.6%, compared to the first quarter of 2025 primarily due to higher other income, offset by lower investment banking and trading income. Excluding securities losses, noninterest income was up $25 million, or 1.8%, compared to the first quarter of 2025.
•Other income increased due to higher income from investments held for certain post-retirement benefits (which is primarily offset by higher personnel expense) and higher income from certain solar equity investments and other investments.
•Investment banking and trading income decreased due to lower capital markets activity, trading income, and merger and acquisition fees.
Noninterest income was up $6.6 billion compared to the second quarter of 2024 primarily due to securities losses resulting from the balance sheet repositioning in 2024 and higher other income, partially offset by lower investment banking and trading income. Excluding securities losses, noninterest income was down $20 million, or 1.4%, compared to the second quarter of 2024.
•Other income increased due to higher income from certain solar investments and other investments.
•Investment banking and trading income decreased due to lower trading income and capital markets activity.
- 3 -
Noninterest Expense | |||||||||||||||||||||||||||||
| Quarter Ended | Change | ||||||||||||||||||||||||||||
| (Dollars in millions) | 2Q25 | 1Q25 | 2Q24 | Link | Like | ||||||||||||||||||||||||
| Personnel expense | $ | 1,653 | $ | 1,587 | $ | 1,661 | $ | 66 | 4.2 | % | $ | (8) | (0.5) | % | |||||||||||||||
| Professional fees and outside processing | 373 | 364 | 308 | 9 | 2.5 | 65 | 21.1 | ||||||||||||||||||||||
| Software expense | 231 | 230 | 218 | 1 | 0.4 | 13 | 6.0 | ||||||||||||||||||||||
| Net occupancy expense | 179 | 163 | 160 | 16 | 9.8 | 19 | 11.9 | ||||||||||||||||||||||
| Equipment expense | 89 | 82 | 89 | 7 | 8.5 | — | — | ||||||||||||||||||||||
| Amortization of intangibles | 73 | 75 | 89 | (2) | (2.7) | (16) | (18.0) | ||||||||||||||||||||||
| Marketing and customer development | 82 | 75 | 63 | 7 | 9.3 | 19 | 30.2 | ||||||||||||||||||||||
| Operating lease depreciation | 33 | 35 | 34 | (2) | (5.7) | (1) | (2.9) | ||||||||||||||||||||||
| Regulatory costs | 55 | 69 | 85 | (14) | (20.3) | (30) | (35.3) | ||||||||||||||||||||||
| Restructuring charges | 28 | 38 | 33 | (10) | (26.3) | (5) | (15.2) | ||||||||||||||||||||||
| Other expense | 190 | 188 | 354 | 2 | 1.1 | (164) | (46.3) | ||||||||||||||||||||||
| Total noninterest expense | $ | 2,986 | $ | 2,906 | $ | 3,094 | $ | 80 | 2.8 | $ | (108) | (3.5) | |||||||||||||||||
Noninterest expense was up $80 million, or 2.8%, compared to the first quarter of 2025 primarily due to higher personnel expense. Restructuring charges decreased $10 million. Adjusted noninterest expense, which excludes restructuring charges, increased $90 million, or 3.1%, compared to the prior quarter.
•Personnel expense increased due to higher salaries, other post-retirement benefit expense (which is primarily offset by higher other income), and incentives, partially offset by seasonally lower payroll taxes.
Noninterest expense was down $108 million, or 3.5%, compared to the second quarter of 2024 due to lower other expense and lower regulatory costs, partially offset by higher professional fees and outside processing expense. The second quarter of 2024 included a charitable contribution of $150 million (other expense) and a FDIC special assessment adjustment of $13 million (regulatory costs). Restructuring charges for both quarters include severance charges as well as costs associated with facilities optimization initiatives. Adjusted noninterest expense, which excludes the charitable contribution, the FDIC special assessment adjustment, and restructuring charges, increased $60 million, or 2.1%, compared to the earlier quarter.
•Professional fees and outside processing expense increased due to higher investments in technology and risk infrastructure.
- 4 -
| Provision for Income Taxes | |||||||||||||||||||||||||||||
| Quarter Ended | Change | ||||||||||||||||||||||||||||
| (Dollars in millions) | 2Q25 | 1Q25 | 2Q24 | Link | Like | ||||||||||||||||||||||||
| Provision (benefit) for income taxes | $ | 273 | $ | 274 | $ | (1,324) | $ | (1) | (0.4)% | $ | 1,597 | NM | |||||||||||||||||
| Effective tax rate | 18.0 | % | 17.9 | % | 25.3 | % | 10 bps | NM | |||||||||||||||||||||
The effective tax rate for the second quarter of 2025 was relatively flat compared to the first quarter of 2025.
The second quarter of 2025 reflects a provision for income taxes while the second quarter of 2024 reflects a benefit for income taxes driven by the discrete impact of the balance sheet repositioning of securities.
Average Loans and Leases | |||||||||||||||||||||||
| (Dollars in millions) | 2Q25 | 1Q25 | Change | % Change | |||||||||||||||||||
| Commercial: | |||||||||||||||||||||||
| Commercial and industrial | $ | 158,491 | $ | 155,214 | $ | 3,277 | 2.1 | % | |||||||||||||||
| CRE | 19,687 | 19,832 | (145) | (0.7) | |||||||||||||||||||
| Commercial construction | 8,613 | 8,734 | (121) | (1.4) | |||||||||||||||||||
| Total commercial | 186,791 | 183,780 | 3,011 | 1.6 | |||||||||||||||||||
| Consumer: | |||||||||||||||||||||||
| Residential mortgage | 56,789 | 55,658 | 1,131 | 2.0 | |||||||||||||||||||
| Home equity | 9,586 | 9,569 | 17 | 0.2 | |||||||||||||||||||
| Indirect auto | 24,158 | 23,248 | 910 | 3.9 | |||||||||||||||||||
| Other consumer | 30,387 | 29,291 | 1,096 | 3.7 | |||||||||||||||||||
| Total consumer | 120,920 | 117,766 | 3,154 | 2.7 | |||||||||||||||||||
| Credit card | 4,890 | 4,849 | 41 | 0.8 | |||||||||||||||||||
| Total loans and leases held for investment | $ | 312,601 | $ | 306,395 | $ | 6,206 | 2.0 | ||||||||||||||||
Average loans and leases HFI were $312.6 billion, an increase of $6.2 billion, or 2.0%, compared to the prior quarter.
•Average commercial loans increased 1.6% due to an increase in the commercial and industrial portfolio.
•Average consumer loans increased 2.7% due to growth in the residential mortgage, other consumer, and indirect auto portfolios.
End of period loans and leases HFI were $318.8 billion, up $10.2 billion, or 3.3%, primarily due to increases in the commercial and industrial, residential mortgage, and other consumer portfolios.
| Average Deposits | |||||||||||||||||||||||
| (Dollars in millions) | 2Q25 | 1Q25 | Change | % Change | |||||||||||||||||||
| Noninterest-bearing deposits | $ | 106,686 | $ | 105,895 | $ | 791 | 0.7 | % | |||||||||||||||
| Interest checking | 116,193 | 109,208 | 6,985 | 6.4 | |||||||||||||||||||
| Money market and savings | 135,607 | 136,897 | (1,290) | (0.9) | |||||||||||||||||||
| Time deposits | 41,997 | 40,204 | 1,793 | 4.5 | |||||||||||||||||||
| Total deposits | $ | 400,483 | $ | 392,204 | $ | 8,279 | 2.1 | ||||||||||||||||
Average deposits for the second quarter of 2025 were $400.5 billion, an increase of $8.3 billion, or 2.1%, compared to the prior quarter.
Average noninterest-bearing deposits increased 0.7% compared to the prior quarter and represented 26.6% of total deposits for the second quarter of 2025 compared to 27.0% for the first quarter of 2025. Average interest checking deposits increased 6.4% primarily due to short-term client deposits. Average money market and savings accounts decreased 0.9%. Average time deposits increased 4.5%.
- 5 -
Capital Ratios | |||||||||||||||||||||||||||||
| 2Q25 | 1Q25 | 4Q24 | 3Q24 | 2Q24 | |||||||||||||||||||||||||
| Risk-based: | (preliminary) | ||||||||||||||||||||||||||||
| CET1 | 11.0 | % | 11.3 | % | 11.5 | % | 11.6 | % | 11.6 | % | |||||||||||||||||||
| Tier 1 | 12.3 | 12.7 | 12.9 | 13.2 | 13.2 | ||||||||||||||||||||||||
| Total | 14.3 | 14.7 | 15.0 | 15.3 | 15.4 | ||||||||||||||||||||||||
| Leverage | 10.2 | 10.3 | 10.5 | 10.8 | 10.5 | ||||||||||||||||||||||||
| Supplementary leverage | 8.5 | 8.7 | 8.8 | 9.1 | 8.9 | ||||||||||||||||||||||||
Capital ratios remained strong compared to the regulatory requirements for well capitalized banks. Truist’s CET1 ratio was 11.0% as of June 30, 2025, down 30 basis points compared to March 31, 2025 due to capital returned to shareholders and an increase in risk-weighted assets, partially offset by current quarter earnings.
Truist declared common dividends of $0.52 per share during the second quarter of 2025 and repurchased $750 million of common stock. The dividend and total payout ratios for the second quarter of 2025 were 57% and 121%, respectively.
Truist completed the 2025 CCAR process and received the preliminary SCB requirement of 2.5% for the period October 1, 2025 to September 30, 2026. The Federal Reserve will provide Truist with its final SCB requirement by August 31, 2025.
Truist’s average consolidated LCR was 110% for the three months ended June 30, 2025, compared to the regulatory minimum of 100%.
- 6 -
| Asset Quality | |||||||||||||||||||||||||||||
| (Dollars in millions) | 2Q25 | 1Q25 | 4Q24 | 3Q24 | 2Q24 | ||||||||||||||||||||||||
| Total nonperforming assets | $ | 1,316 | $ | 1,618 | $ | 1,477 | $ | 1,528 | $ | 1,476 | |||||||||||||||||||
| Total loans 90 days past due and still accruing | 546 | 616 | 587 | 518 | 489 | ||||||||||||||||||||||||
| Total loans 30-89 days past due and still accruing | 1,811 | 1,619 | 1,949 | 1,769 | 1,791 | ||||||||||||||||||||||||
Nonperforming loans and leases as a percentage of loans and leases held for investment | 0.39 | % | 0.48 | % | 0.47 | % | 0.48 | % | 0.46 | % | |||||||||||||||||||
| Loans 30-89 days past due and still accruing as a percentage of loans and leases | 0.57 | 0.52 | 0.64 | 0.58 | 0.59 | ||||||||||||||||||||||||
| Loans 90 days or more past due and still accruing as a percentage of loans and leases | 0.17 | 0.20 | 0.19 | 0.17 | 0.16 | ||||||||||||||||||||||||
| Loans 90 days or more past due and still accruing as a percentage of loans and leases, excluding government guaranteed | 0.04 | 0.05 | 0.05 | 0.04 | 0.04 | ||||||||||||||||||||||||
Allowance for loan and lease losses as a percentage of loans and leases held for investment | 1.54 | 1.58 | 1.59 | 1.60 | 1.57 | ||||||||||||||||||||||||
Ratio of allowance for loan and lease losses to net charge-offs | 3.1x | 2.6x | 2.7x | 2.9x | 2.7x | ||||||||||||||||||||||||
Ratio of allowance for loan and lease losses to nonperforming loans and leases held for investment | 3.9x | 3.3x | 3.4x | 3.3x | 3.4x | ||||||||||||||||||||||||
Applicable ratios are annualized.
Nonperforming assets totaled $1.3 billion at June 30, 2025, down $302 million compared to March 31, 2025, due to decreases in the CRE, commercial and industrial, and LHFS portfolios. Nonperforming loans and leases were 0.39% of loans and leases held for investment at June 30, 2025, down nine basis points compared to March 31, 2025.
Loans 90 days or more past due and still accruing totaled $546 million at June 30, 2025, down three basis points as a percentage of loans and leases compared with the prior quarter. Excluding government guaranteed loans, the ratio of loans 90 days or more past due and still accruing as a percentage of loans and leases was 0.04% at June 30, 2025, down one basis point compared to March 31, 2025.
Loans 30-89 days past due and still accruing totaled $1.8 billion at June 30, 2025, up $192 million, or five basis points, as a percentage of loans and leases, compared to the prior quarter primarily due to an increase in the indirect auto, and residential mortgage portfolios.
The allowance for credit losses was $5.3 billion at June 30, 2025 and included $4.9 billion for the allowance for loan and lease losses and $354 million for the reserve for unfunded commitments. The ALLL ratio was 1.54%, down four basis points compared with March 31, 2025. The ALLL covered nonperforming loans and leases held for investment 3.9x, compared to 3.3x at March 31, 2025. At June 30, 2025, the ALLL was 3.1x annualized net charge-offs, compared to 2.6x at March 31, 2025.
Provision for Credit Losses | |||||||||||||||||||||||||||||
| Quarter Ended | Change | ||||||||||||||||||||||||||||
| (Dollars in millions) | 2Q25 | 1Q25 | 2Q24 | Link | Like | ||||||||||||||||||||||||
| Provision for credit losses | $ | 488 | $ | 458 | $ | 451 | $ | 30 | 6.6 | % | $ | 37 | 8.2 | % | |||||||||||||||
| Net charge-offs | 396 | 454 | 442 | (58) | (12.8) | (46) | (10.4) | ||||||||||||||||||||||
Net charge-offs as a percentage of average loans and leases | 0.51 | % | 0.60 | % | 0.58 | % | (9) bps | (7) bps | |||||||||||||||||||||
Applicable ratios are annualized.
The provision for credit losses was $488 million for the second quarter of 2025 compared to $458 million for the first quarter of 2025.
•The increase in the current quarter provision expense primarily reflects a higher allowance build.
•The net charge-off ratio for the current quarter was down compared to the first quarter of 2025 primarily driven by lower net charge-offs in the indirect auto and CRE portfolios.
The provision for credit losses was $488 million for the second quarter of 2025 compared to $451 million for the second quarter of 2024.
•The increase in the current quarter provision expense primarily reflects a higher allowance build.
•The net charge-off ratio for the current quarter was down compared to the second quarter of 2024 primarily driven by lower net charge-offs in the CRE portfolio, partially offset by the commercial and industrial portfolio.
- 7 -
Earnings Presentation and Quarterly Performance Summary | ||
Investors can access the live second quarter 2025 earnings call at 8 a.m. ET today by webcast or dial-in as follows:
Webcast: app.webinar.net/z5gqlB9OVNL
Dial-in: 1-877-883-0383, passcode 5911048
Additional details: The news release and presentation materials are available at ir.truist.com under “Events & Presentations.” A replay of the call will be available on the website for 30 days.
The presentation, including an appendix reconciling non-GAAP disclosures, and Truist’s Second Quarter 2025 Quarterly Performance Summary, which contains detailed financial schedules, are available at https://ir.truist.com/earnings.
About Truist | ||
Truist Financial Corporation is a purpose-driven financial services company committed to inspiring and building better lives and communities. Headquartered in Charlotte, North Carolina, Truist has leading market share in many of the high-growth markets in the U.S. and offers a wide range of products and services through wholesale and consumer businesses, including consumer and small business banking, commercial and corporate banking, investment banking and capital markets, wealth management, payments, and specialized lending businesses. Truist is a top-10 commercial bank with total assets of $544 billion as of June 30, 2025. Truist Bank, Member FDIC. Learn more at Truist.com.
#-#-#
| Glossary of Defined Terms | |||||
| Term | Definition | ||||
ALLL | Allowance for loan and lease losses | ||||
| BVPS | Book value (common equity) per share | ||||
| CCAR | Comprehensive Capital Analysis and Review | ||||
| CEO | Chief Executive Officer | ||||
CET1 | Common equity tier 1 | ||||
| CRE | Commercial real estate | ||||
| FDIC | Federal Deposit Insurance Corporation | ||||
| GAAP | Accounting principles generally accepted in the United States of America | ||||
| HFI | Held for investment | ||||
| LCR | Liquidity Coverage Ratio | ||||
| LHFS | Loans held for sale | ||||
| Like | Compared to second quarter of 2024 | ||||
| Link | Compared to first quarter of 2025 | ||||
NCO | Net charge-offs | ||||
| NIM | Net interest margin, computed on a TE basis | ||||
| NM | Not meaningful | ||||
| PPNR | Pre-provision net revenue | ||||
| ROCE | Return on average common equity | ||||
ROTCE | Return on average tangible common equity | ||||
| SCB | Stress Capital Buffer | ||||
TBVPS | Tangible book value per common share | ||||
| TE | Taxable-equivalent | ||||
- 8 -
| Non-GAAP Financial Information | ||
This news release contains financial information and performance measures determined by methods other than in accordance with GAAP. Truist’s management uses these “non-GAAP” measures in their analysis of Truist’s performance and the efficiency of its operations. Management believes these non-GAAP measures provide a greater understanding of ongoing operations, enhance comparability of results with prior periods and demonstrate the effects of significant items in the current period. Truist believes a meaningful analysis of its financial performance requires an understanding of the factors underlying that performance. These disclosures should not be viewed as a substitute for financial measures determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Below is a listing of the types of non-GAAP measures used in this news release:
•Adjusted net income available to common shareholders and adjusted diluted EPS - Adjusted net income available to common shareholders and adjusted diluted earnings per share are non-GAAP in that these measures exclude selected items, net of tax. Truist’s management uses these measures in their analysis of Truist’s performance. Truist’s management believes these measures provide a greater understanding of ongoing operations and enhance comparability of results with prior periods, as well as demonstrate the effects of significant gains and charges.
•Adjusted efficiency ratio, adjusted fee income ratio, and related measures - The adjusted efficiency ratio is non-GAAP in that it excludes securities gains and losses, amortization of intangible assets, restructuring charges, and other selected items. Adjusted revenue and adjusted noninterest expense are related measures used to calculate the adjusted efficiency ratio. Additionally, the adjusted fee income ratio is non-GAAP in that it excludes securities gains and losses and other selected items, and is calculated using adjusted revenue and adjusted noninterest income. Taxable equivalent revenue and taxable equivalent net interest income include a taxable equivalent adjustment utilizing the federal income tax rate of 21% for certain tax-exempt instruments. Adjusted revenue and adjusted noninterest income exclude securities gains and losses and other selected items. Adjusted noninterest expense excludes restructuring charges, and other selected items. Truist’s management calculated these measures based on Truist’s continuing operations. Truist’s management uses these measures in their analysis of Truist’s performance. Truist’s management believes these measures provide a greater understanding of ongoing operations and enhance comparability of results with prior periods, as well as demonstrate the effects of significant gains and charges.
•PPNR - Pre-provision net revenue is a non-GAAP measure that adjusts net income determined in accordance with GAAP to exclude the impact of the provision for credit losses and provision for income taxes. Adjusted pre-provision net revenue is a non-GAAP measure that additionally excludes securities gains (losses), restructuring charges, and other selected items. Truist’s management calculated these measures based on Truist’s continuing operations. Truist’s management believes these measures provide a greater understanding of ongoing operations and enhance comparability of results with prior periods.
•Tangible Common Equity and Related Measures - Tangible common equity and related measures, including ROTCE and TBVPS, are non-GAAP measures that exclude the impact of intangible assets, net of deferred taxes, and their related amortization. These measures are useful for evaluating the performance of a business consistently, whether acquired or developed internally. Truist’s management uses these measures to assess profitability, returns relative to balance sheet risk, and shareholder value.
A reconciliation of each of these non-GAAP measures to the most directly comparable GAAP measure is included in the appendix to Truist’s Second Quarter 2025 Earnings Presentation, which is available at https://ir.truist.com/earnings.
- 9 -
| Forward Looking Statements | ||
From time to time we have made, and in the future will make, forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements can be identified by the fact that they do not relate strictly to historical or current facts. Forward-looking statements often use words such as “believe,” “expect,” “anticipate,” “intend,” “pursue,” “seek,” “continue,” “estimate,” “project,” “outlook,” “forecast,” “potential,” “target,” “objective,” “trend,” “plan,” “goal,” “initiative,” “priorities,” or other words of comparable meaning or future-tense or conditional verbs such as “may,” “will,” “should,” “would,” or “could.” Forward-looking statements convey our expectations, intentions, or forecasts about future events, circumstances, or results.
This news release, including any information incorporated by reference herein, contains forward-looking statements. We also may make forward-looking statements in other documents that are filed or furnished with the SEC. In addition, we may make forward-looking statements orally or in writing to investors, analysts, members of the media, and others. All forward-looking statements, by their nature, are subject to assumptions, risks, and uncertainties, which may change over time and many of which are beyond our control. You should not rely on any forward-looking statement as a prediction or guarantee about the future. Actual future objectives, strategies, plans, prospects, performance, conditions, and results may differ materially from those set forth in any forward-looking statement. While no list of assumptions, risks, and uncertainties could be complete, some of the factors that may cause actual results or other future events or circumstances to differ from those in forward-looking statements include:
•evolving political, geopolitical, business, social, economic, and market conditions at local, regional, national, and international levels;
•monetary, fiscal, and trade laws or policies, including tariffs or responses to rates of inflation above target levels;
•the legal, regulatory, and supervisory environment, including changes in financial-services legislation, regulation, policies, or government officials or other personnel;
•our ability to address heightened scrutiny and expectations from supervisory or other governmental authorities and to timely and credibly remediate related concerns or deficiencies;
•judicial, regulatory, and administrative inquiries, examinations, investigations, proceedings, disputes, or rulings that create uncertainty for or are adverse to us or the financial-services industry;
•the outcomes of judicial, regulatory, and administrative inquiries, examinations, investigations, proceedings, disputes, or rulings to which we are or may be subject (either directly or indirectly through our ownership interests in other entities) and our ability to absorb and address any damages or other remedies that are sought or awarded and any collateral consequences;
•evolving accounting standards and policies;
•the adequacy of our corporate governance, risk-management framework, compliance programs, and internal controls over financial reporting, including our ability to control lapses or deficiencies in financial reporting, to make appropriate estimates, or to effectively mitigate or manage operational risk;
•any instability or breakdown in the financial system, including as a result of the actual or perceived soundness of another financial institution or another participant in the financial system;
•disruptions and shifts in investor sentiment or behavior in the securities, capital, or other financial markets, including financial or systemic shocks and volatility or changes in market liquidity, interest or currency rates, or valuations;
•our ability to cost-effectively fund our businesses and operations, including by accessing long- and short-term funding and liquidity and by retaining and growing client deposits;
•changes in any of our credit ratings;
•our ability to manage any unexpected outflows of uninsured deposits and avoid selling investment securities or other assets at an unfavorable time or at a loss;
•negative market perceptions of our investment portfolio or its value;
•adverse publicity or other reputational harm to us, our service providers, or our senior officers;
•business and consumer sentiment, preferences, or behavior, including spending, borrowing, or saving by businesses or households;
•our ability to execute on strategic and operational plans, including accelerating growth, improving profitability, investing in talent, technology, and risk infrastructure, maintaining expense, credit, and risk discipline, and returning capital to shareholders;
•changes in our corporate and business strategies, the composition of our assets, or the way in which we fund those assets;
•our ability to successfully make and integrate acquisitions and to effect divestitures;
•our ability to develop, maintain, and market our products or services or to absorb unanticipated costs or liabilities associated with those products or services;
•our ability to innovate, to anticipate the needs of current or future clients, to successfully compete, to increase or hold market share in changing competitive environments, or to deal with pricing or other competitive pressures;
•our ability to maintain secure and functional financial, accounting, technology, data processing, or other operating systems or infrastructure, including those that safeguard personal and other sensitive information;
•our ability to appropriately underwrite loans that we originate or purchase and to otherwise manage credit risk;
•our ability to satisfactorily and profitably perform loan servicing and similar obligations;
•the credit, liquidity, or other financial condition of our clients, counterparties, service providers, or competitors;
•our ability to effectively deal with economic, business, or market slowdowns or disruptions;
•the efficacy of our methods or models in assessing business strategies or opportunities or in valuing, measuring, estimating, monitoring, or managing positions or risk;
•our ability to keep pace with changes in technology that affect us or our clients, counterparties, service providers, or competitors or to maintain rights or interests in associated intellectual property;
•our ability to attract, hire, and retain key teammates and to engage in adequate succession planning;
•the performance and availability of third-party service providers on whom we rely in delivering products and services to our clients and otherwise in conducting our business and operations;
•our ability to detect, prevent, mitigate, and otherwise manage the risk of fraud or misconduct by internal or external parties;
•our ability to manage and mitigate physical-security and cybersecurity risks, including denial-of-service attacks, hacking, phishing, social-engineering attacks, malware intrusion, data-corruption attempts, system breaches, identity theft, ransomware attacks, environmental conditions, and intentional acts of destruction;
•natural or other disasters, calamities, and conflicts, including terrorist events, cyber-warfare, and pandemics;
•widespread outages of operational, communication, and other systems;
•our ability to maintain appropriate corporate responsibility practices, oversight, and disclosures;
•policies and other actions of governments to manage and mitigate climate and related environmental risks, and the effects of climate change or the transition to a lower-carbon economy on our business, operations, and reputation; and
•other assumptions, risks, or uncertainties described in the Risk Factors (Item 1A), Management’s Discussion and Analysis of Financial Condition and Results of Operations (Item 7), or the Notes to the Consolidated Financial Statements (Item 8) in our Annual Report on Form 10-K or described in any of the Company’s subsequent quarterly or current reports.
Any forward-looking statement made by us or on our behalf speaks only as of the date that it was made. We do not undertake to update any forward-looking statement to reflect the impact of events, circumstances, or results that arise after the date that the statement was made, except as required by applicable securities laws. You, however, should consult further disclosures (including disclosures of a forward-looking nature) that we may make in any subsequent Annual Report on Form 10-K, Quarterly Report on Form 10-Q, or Current Report on Form 8-K.
- 10 -
Quarterly Performance Summary
Truist Financial Corporation
Second Quarter 2025
| Table of Contents | ||||||||
| Quarterly Performance Summary | ||||||||
| Truist Financial Corporation | ||||||||
| Page | ||||||||
| Financial Highlights | ||||||||
| Consolidated Statements of Income | ||||||||
| Consolidated Ending Balance Sheets | ||||||||
| Average Balances and Rates | ||||||||
| Credit Quality | ||||||||
| Segment Financial Performance | ||||||||
| Capital Information | ||||||||
| Selected Mortgage Banking Information & Additional Information | ||||||||
| Selected Items | ||||||||
Financial Highlights
| Quarter Ended | Year-to-Date | ||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions, except per share data, shares in thousands) | June 30 | March 31 | Dec. 31 | Sept. 30 | June 30 | June 30 | June 30 | ||||||||||||||||||||||||||||||||||
| 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | |||||||||||||||||||||||||||||||||||
| Summary Income Statement | |||||||||||||||||||||||||||||||||||||||||
| Interest income | $ | 6,154 | $ | 5,988 | $ | 6,179 | $ | 6,352 | $ | 6,351 | $ | 12,142 | $ | 12,535 | |||||||||||||||||||||||||||
| Plus: Taxable-equivalent adjustment | 48 | 48 | 51 | 55 | 53 | 96 | 106 | ||||||||||||||||||||||||||||||||||
Interest income - taxable equivalent(1) | 6,202 | 6,036 | 6,230 | 6,407 | 6,404 | 12,238 | 12,641 | ||||||||||||||||||||||||||||||||||
| Interest expense | 2,567 | 2,481 | 2,589 | 2,750 | 2,824 | 5,048 | 5,636 | ||||||||||||||||||||||||||||||||||
| Net interest income | 3,587 | 3,507 | 3,590 | 3,602 | 3,527 | 7,094 | 6,899 | ||||||||||||||||||||||||||||||||||
Net interest income - taxable equivalent(1) | 3,635 | 3,555 | 3,641 | 3,657 | 3,580 | 7,190 | 7,005 | ||||||||||||||||||||||||||||||||||
| Provision for credit losses | 488 | 458 | 471 | 448 | 451 | 946 | 951 | ||||||||||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 3,099 | 3,049 | 3,119 | 3,154 | 3,076 | 6,148 | 5,948 | ||||||||||||||||||||||||||||||||||
| Noninterest income | 1,400 | 1,392 | 1,470 | 1,483 | (5,212) | 2,792 | (3,766) | ||||||||||||||||||||||||||||||||||
| Noninterest expense | 2,986 | 2,906 | 3,035 | 2,927 | 3,094 | 5,892 | 6,047 | ||||||||||||||||||||||||||||||||||
| Income (loss) before income taxes | 1,513 | 1,535 | 1,554 | 1,710 | (5,230) | 3,048 | (3,865) | ||||||||||||||||||||||||||||||||||
| Provision (benefit) for income taxes | 273 | 274 | 265 | 271 | (1,324) | 547 | (1,092) | ||||||||||||||||||||||||||||||||||
| Net income (loss) from continuing operations | 1,240 | 1,261 | 1,289 | 1,439 | (3,906) | 2,501 | (2,773) | ||||||||||||||||||||||||||||||||||
| Net income (loss) from discontinued operations | — | — | (13) | 3 | 4,828 | — | 4,895 | ||||||||||||||||||||||||||||||||||
| Net income | 1,240 | 1,261 | 1,276 | 1,442 | 922 | 2,501 | 2,122 | ||||||||||||||||||||||||||||||||||
| Noncontrolling interests from discontinued operations | — | — | — | — | 19 | — | 22 | ||||||||||||||||||||||||||||||||||
| Preferred stock dividends and other | 60 | 104 | 60 | 106 | 77 | 164 | 183 | ||||||||||||||||||||||||||||||||||
| Net Income available to common shareholders | 1,180 | 1,157 | 1,216 | 1,336 | 826 | 2,337 | 1,917 | ||||||||||||||||||||||||||||||||||
Net income available to common shareholders - adjusted(1) | 1,193 | 1,158 | 1,211 | 1,307 | 1,235 | 2,351 | 2,451 | ||||||||||||||||||||||||||||||||||
| Additional Income Statement Information | |||||||||||||||||||||||||||||||||||||||||
| Revenue | 4,987 | 4,899 | 5,060 | 5,085 | (1,685) | 9,886 | 3,133 | ||||||||||||||||||||||||||||||||||
Revenue - taxable equivalent(1) | 5,035 | 4,947 | 5,111 | 5,140 | (1,632) | 9,982 | 3,239 | ||||||||||||||||||||||||||||||||||
Pre-provision net revenue - unadjusted(1) | 2,049 | 2,041 | 2,076 | 2,213 | (4,726) | 4,090 | (2,808) | ||||||||||||||||||||||||||||||||||
Pre-provision net revenue - adjusted(1) | 2,095 | 2,080 | 2,080 | 2,222 | 2,120 | 4,175 | 4,164 | ||||||||||||||||||||||||||||||||||
| Key Metrics | |||||||||||||||||||||||||||||||||||||||||
| Earnings: | |||||||||||||||||||||||||||||||||||||||||
Earnings per share-basic from continuing operations(2) | $ | 0.91 | $ | 0.88 | $ | 0.93 | $ | 1.00 | $ | (2.98) | $ | 1.80 | $ | (2.21) | |||||||||||||||||||||||||||
| Earnings per share-basic | 0.91 | 0.88 | 0.92 | 1.00 | 0.62 | $ | 1.80 | $ | 1.43 | ||||||||||||||||||||||||||||||||
Earnings per share-diluted from continuing operations(2) | 0.90 | 0.87 | 0.92 | 0.99 | (2.98) | 1.78 | (2.21) | ||||||||||||||||||||||||||||||||||
| Earnings per share-diluted | 0.90 | 0.87 | 0.91 | 0.99 | 0.62 | 1.78 | 1.43 | ||||||||||||||||||||||||||||||||||
Earnings per share-adjusted diluted(1) | 0.91 | 0.87 | 0.91 | 0.97 | 0.91 | 1.79 | 1.82 | ||||||||||||||||||||||||||||||||||
| Cash dividends declared per share | 0.52 | 0.52 | 0.52 | 0.52 | 0.52 | 1.04 | 1.04 | ||||||||||||||||||||||||||||||||||
| Common shareholders’ equity per share | 45.70 | 44.85 | 43.90 | 44.46 | 42.71 | ||||||||||||||||||||||||||||||||||||
Tangible common shareholders’ equity per share(1) | 31.63 | 30.95 | 30.01 | 30.64 | 28.91 | ||||||||||||||||||||||||||||||||||||
| End of period shares outstanding | 1,289,435 | 1,309,539 | 1,315,936 | 1,327,521 | 1,338,223 | ||||||||||||||||||||||||||||||||||||
| Weighted average shares outstanding-basic | 1,292,292 | 1,307,457 | 1,317,017 | 1,334,212 | 1,338,149 | 1,299,833 | 1,336,620 | ||||||||||||||||||||||||||||||||||
| Weighted average shares outstanding-diluted | 1,305,005 | 1,324,339 | 1,333,701 | 1,349,129 | 1,338,149 | 1,314,779 | 1,336,620 | ||||||||||||||||||||||||||||||||||
| Return on average assets | 0.93 | % | 0.96 | % | 0.96 | % | 1.10 | % | 0.70 | % | 0.94 | % | 0.81 | % | |||||||||||||||||||||||||||
| Return on average common shareholders’ equity | 8.1 | 8.1 | 8.4 | 9.1 | 6.1 | 8.1 | 7.2 | ||||||||||||||||||||||||||||||||||
Return on average tangible common shareholders’ equity(1) | 12.3 | 12.3 | 12.9 | 13.8 | 10.4 | 12.3 | 12.5 | ||||||||||||||||||||||||||||||||||
Net interest margin - taxable equivalent(2) | 3.02 | 3.01 | 3.07 | 3.12 | 3.02 | 3.02 | 2.95 | ||||||||||||||||||||||||||||||||||
Efficiency ratio-unadjusted(2) | 59.9 | 59.3 | 60.0 | 57.5 | NM | 59.6 | NM | ||||||||||||||||||||||||||||||||||
Efficiency ratio-adjusted(1)(2) | 57.1 | 56.4 | 57.7 | 55.2 | 56.0 | 56.8 | 56.1 | ||||||||||||||||||||||||||||||||||
Fee income ratio-unadjusted(2) | 28.1 | 28.4 | 29.0 | 29.2 | NM | 28.2 | NM | ||||||||||||||||||||||||||||||||||
Fee income ratio-adjusted(1)(2) | 28.1 | 28.2 | 28.8 | 28.9 | 28.7 | 28.1 | 29.2 | ||||||||||||||||||||||||||||||||||
| Credit Quality | |||||||||||||||||||||||||||||||||||||||||
| Nonperforming loans and leases as a percentage of LHFI | 0.39 | % | 0.48 | % | 0.47 | % | 0.48 | % | 0.46 | % | |||||||||||||||||||||||||||||||
| Net charge-offs as a percentage of average LHFI | 0.51 | 0.60 | 0.59 | 0.55 | 0.58 | 0.55 | % | 0.61 | % | ||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses as a percentage of LHFI | 1.54 | 1.58 | 1.59 | 1.60 | 1.57 | ||||||||||||||||||||||||||||||||||||
| Ratio of allowance for loan and lease losses to nonperforming LHFI | 3.9x | 3.3x | 3.4x | 3.3x | 3.4x | ||||||||||||||||||||||||||||||||||||
| Average Balances | |||||||||||||||||||||||||||||||||||||||||
| Assets | $ | 537,069 | $ | 531,630 | $ | 527,013 | $ | 519,415 | $ | 526,894 | $ | 534,365 | $ | 528,948 | |||||||||||||||||||||||||||
Securities(3) | 121,829 | 124,061 | 124,871 | 117,172 | 121,796 | 122,939 | 126,726 | ||||||||||||||||||||||||||||||||||
| Loans and leases | 313,841 | 307,528 | 304,609 | 304,578 | 307,583 | 310,702 | 308,505 | ||||||||||||||||||||||||||||||||||
| Deposits | 400,483 | 392,204 | 390,042 | 384,344 | 388,042 | 396,366 | 388,550 | ||||||||||||||||||||||||||||||||||
| Common shareholders’ equity | 58,327 | 58,125 | 57,754 | 58,667 | 54,863 | 58,227 | 53,515 | ||||||||||||||||||||||||||||||||||
| Total shareholders’ equity | 64,235 | 64,033 | 64,295 | 65,341 | 61,677 | 64,135 | 60,344 | ||||||||||||||||||||||||||||||||||
| Period-End Balances | |||||||||||||||||||||||||||||||||||||||||
| Assets | $ | 543,833 | $ | 535,899 | $ | 531,176 | $ | 523,434 | $ | 519,853 | |||||||||||||||||||||||||||||||
Securities(3) | 115,363 | 117,888 | 118,104 | 115,606 | 108,416 | ||||||||||||||||||||||||||||||||||||
| Loans and leases | 319,999 | 309,752 | 307,771 | 304,362 | 307,149 | ||||||||||||||||||||||||||||||||||||
| Deposits | 406,122 | 403,736 | 390,524 | 387,778 | 385,411 | ||||||||||||||||||||||||||||||||||||
| Common shareholders’ equity | 58,933 | 58,728 | 57,772 | 59,023 | 57,154 | ||||||||||||||||||||||||||||||||||||
| Total shareholders’ equity | 64,840 | 64,635 | 63,679 | 65,696 | 63,827 | ||||||||||||||||||||||||||||||||||||
| Capital and Liquidity Ratios | (preliminary) | ||||||||||||||||||||||||||||||||||||||||
| Common equity tier 1 | 11.0 | % | 11.3 | % | 11.5 | % | 11.6 | % | 11.6 | % | |||||||||||||||||||||||||||||||
| Tier 1 | 12.3 | 12.7 | 12.9 | 13.2 | 13.2 | ||||||||||||||||||||||||||||||||||||
| Total | 14.3 | 14.7 | 15.0 | 15.3 | 15.4 | ||||||||||||||||||||||||||||||||||||
| Leverage | 10.2 | 10.3 | 10.5 | 10.8 | 10.5 | ||||||||||||||||||||||||||||||||||||
| Supplementary leverage | 8.5 | 8.7 | 8.8 | 9.1 | 8.9 | ||||||||||||||||||||||||||||||||||||
| Liquidity coverage ratio | 110 | 111 | 109 | 112 | 110 | ||||||||||||||||||||||||||||||||||||
Applicable ratios are annualized.
(1)Represents a non-GAAP measure. Reconciliations of these non-GAAP measures to the most directly comparable GAAP measures are included in this Quarterly Performance Summary or the appendix to Truist’s Second Quarter 2025 Earnings Presentation.
(2)This metric is calculated based on continuing operations.
(3)Includes AFS and HTM securities. Average balances reflect AFS and HTM securities at amortized cost. Period-end balances reflect AFS securities at fair value and HTM securities at amortized cost.
- 1 -
Consolidated Statements of Income
| Quarter Ended | Year-to-Date | ||||||||||||||||||||||||||||||||||||||||
| June 30 | March 31 | Dec. 31 | Sept. 30 | June 30 | June 30 | June 30 | |||||||||||||||||||||||||||||||||||
| (Dollars in millions, except per share data, shares in thousands) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||
| Interest Income | |||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans and leases | $ | 4,657 | $ | 4,493 | $ | 4,634 | $ | 4,852 | $ | 4,879 | $ | 9,150 | $ | 9,744 | |||||||||||||||||||||||||||
| Interest on securities | 961 | 975 | 994 | 869 | 838 | 1,936 | 1,643 | ||||||||||||||||||||||||||||||||||
| Interest on other earning assets | 536 | 520 | 551 | 631 | 634 | 1,056 | 1,148 | ||||||||||||||||||||||||||||||||||
| Total interest income | 6,154 | 5,988 | 6,179 | 6,352 | 6,351 | 12,142 | 12,535 | ||||||||||||||||||||||||||||||||||
| Interest Expense | |||||||||||||||||||||||||||||||||||||||||
| Interest on deposits | 1,844 | 1,736 | 1,855 | 2,014 | 2,016 | 3,580 | 3,980 | ||||||||||||||||||||||||||||||||||
| Interest on long-term debt | 431 | 409 | 431 | 454 | 446 | 840 | 928 | ||||||||||||||||||||||||||||||||||
| Interest on other borrowings | 292 | 336 | 303 | 282 | 362 | 628 | 728 | ||||||||||||||||||||||||||||||||||
| Total interest expense | 2,567 | 2,481 | 2,589 | 2,750 | 2,824 | 5,048 | 5,636 | ||||||||||||||||||||||||||||||||||
| Net Interest Income | 3,587 | 3,507 | 3,590 | 3,602 | 3,527 | 7,094 | 6,899 | ||||||||||||||||||||||||||||||||||
| Provision for credit losses | 488 | 458 | 471 | 448 | 451 | 946 | 951 | ||||||||||||||||||||||||||||||||||
| Net Interest Income After Provision for Credit Losses | 3,099 | 3,049 | 3,119 | 3,154 | 3,076 | 6,148 | 5,948 | ||||||||||||||||||||||||||||||||||
| Noninterest Income | |||||||||||||||||||||||||||||||||||||||||
| Wealth management income | 348 | 344 | 345 | 350 | 361 | 692 | 717 | ||||||||||||||||||||||||||||||||||
| Investment banking and trading income | 205 | 273 | 262 | 332 | 286 | 478 | 609 | ||||||||||||||||||||||||||||||||||
| Card and payment related fees | 232 | 220 | 231 | 222 | 230 | 452 | 454 | ||||||||||||||||||||||||||||||||||
| Service charges on deposits | 227 | 230 | 237 | 221 | 232 | 457 | 457 | ||||||||||||||||||||||||||||||||||
| Mortgage banking income | 107 | 108 | 117 | 106 | 112 | 215 | 209 | ||||||||||||||||||||||||||||||||||
| Lending related fees | 99 | 95 | 93 | 88 | 89 | 194 | 185 | ||||||||||||||||||||||||||||||||||
| Operating lease income | 47 | 53 | 47 | 49 | 50 | 100 | 109 | ||||||||||||||||||||||||||||||||||
| Securities gains (losses) | (18) | (1) | (1) | — | (6,650) | (19) | (6,650) | ||||||||||||||||||||||||||||||||||
| Other income | 153 | 70 | 139 | 115 | 78 | 223 | 144 | ||||||||||||||||||||||||||||||||||
| Total noninterest income | 1,400 | 1,392 | 1,470 | 1,483 | (5,212) | 2,792 | (3,766) | ||||||||||||||||||||||||||||||||||
| Noninterest Expense | |||||||||||||||||||||||||||||||||||||||||
| Personnel expense | 1,653 | 1,587 | 1,587 | 1,628 | 1,661 | 3,240 | 3,291 | ||||||||||||||||||||||||||||||||||
| Professional fees and outside processing | 373 | 364 | 415 | 336 | 308 | 737 | 586 | ||||||||||||||||||||||||||||||||||
| Software expense | 231 | 230 | 232 | 222 | 218 | 461 | 442 | ||||||||||||||||||||||||||||||||||
| Net occupancy expense | 179 | 163 | 179 | 157 | 160 | 342 | 320 | ||||||||||||||||||||||||||||||||||
| Equipment expense | 89 | 82 | 112 | 84 | 89 | 171 | 177 | ||||||||||||||||||||||||||||||||||
| Amortization of intangibles | 73 | 75 | 84 | 84 | 89 | 148 | 177 | ||||||||||||||||||||||||||||||||||
| Marketing and customer development | 82 | 75 | 74 | 75 | 63 | 157 | 119 | ||||||||||||||||||||||||||||||||||
| Operating lease depreciation | 33 | 35 | 36 | 34 | 34 | 68 | 74 | ||||||||||||||||||||||||||||||||||
| Regulatory costs | 55 | 69 | 56 | 51 | 85 | 124 | 237 | ||||||||||||||||||||||||||||||||||
| Restructuring charges | 28 | 38 | 11 | 25 | 33 | 66 | 84 | ||||||||||||||||||||||||||||||||||
| Other expense | 190 | 188 | 249 | 231 | 354 | 378 | 540 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | 2,986 | 2,906 | 3,035 | 2,927 | 3,094 | 5,892 | 6,047 | ||||||||||||||||||||||||||||||||||
| Earnings | |||||||||||||||||||||||||||||||||||||||||
| Income (loss) before income taxes | 1,513 | 1,535 | 1,554 | 1,710 | (5,230) | 3,048 | (3,865) | ||||||||||||||||||||||||||||||||||
| Provision (benefit) for income taxes | 273 | 274 | 265 | 271 | (1,324) | 547 | (1,092) | ||||||||||||||||||||||||||||||||||
| Net income (loss) from continuing operations | 1,240 | 1,261 | 1,289 | 1,439 | (3,906) | 2,501 | (2,773) | ||||||||||||||||||||||||||||||||||
| Net income from discontinued operations | — | — | (13) | 3 | 4,828 | — | 4,895 | ||||||||||||||||||||||||||||||||||
| Net income | 1,240 | 1,261 | 1,276 | 1,442 | 922 | 2,501 | 2,122 | ||||||||||||||||||||||||||||||||||
| Noncontrolling interests from discontinuing operations | — | — | — | — | 19 | — | 22 | ||||||||||||||||||||||||||||||||||
| Preferred stock dividends and other | 60 | 104 | 60 | 106 | 77 | 164 | 183 | ||||||||||||||||||||||||||||||||||
| Net income available to common shareholders | $ | 1,180 | $ | 1,157 | $ | 1,216 | $ | 1,336 | $ | 826 | $ | 2,337 | $ | 1,917 | |||||||||||||||||||||||||||
| Earnings Per Common Share | |||||||||||||||||||||||||||||||||||||||||
| Basic earnings from continuing operations | $ | 0.91 | $ | 0.88 | $ | 0.93 | $ | 1.00 | $ | (2.98) | $ | 1.80 | $ | (2.21) | |||||||||||||||||||||||||||
| Basic earnings | 0.91 | 0.88 | 0.92 | 1.00 | 0.62 | $ | 1.80 | 1.43 | |||||||||||||||||||||||||||||||||
| Diluted earnings from continuing operations | 0.90 | 0.87 | 0.92 | 0.99 | (2.98) | 1.78 | (2.21) | ||||||||||||||||||||||||||||||||||
| Diluted earnings | 0.90 | 0.87 | 0.91 | 0.99 | 0.62 | 1.78 | 1.43 | ||||||||||||||||||||||||||||||||||
| Weighted Average Shares Outstanding | |||||||||||||||||||||||||||||||||||||||||
| Basic | 1,292,292 | 1,307,457 | 1,317,017 | 1,334,212 | 1,338,149 | 1,299,833 | 1,336,620 | ||||||||||||||||||||||||||||||||||
| Diluted | 1,305,005 | 1,324,339 | 1,333,701 | 1,349,129 | 1,338,149 | 1,314,779 | 1,336,620 | ||||||||||||||||||||||||||||||||||
- 2 -
Consolidated Ending Balance Sheets - Five Quarter Trend
| June 30 | March 31 | Dec. 31 | Sept. 30 | June 30 | |||||||||||||||||||||||||
| (Dollars in millions) | 2025 | 2025 | 2024 | 2024 | 2024 | ||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||
| Cash and due from banks | $ | 5,157 | $ | 5,996 | $ | 5,793 | $ | 5,229 | $ | 5,204 | |||||||||||||||||||
| Interest-bearing deposits with banks | 36,294 | 36,175 | 33,975 | 34,411 | 35,675 | ||||||||||||||||||||||||
| Securities borrowed or purchased under resale agreements | 2,656 | 2,810 | 2,550 | 2,973 | 2,338 | ||||||||||||||||||||||||
| Trading assets at fair value | 5,963 | 5,838 | 5,100 | 5,209 | 5,558 | ||||||||||||||||||||||||
| Securities available for sale at fair value | 66,390 | 68,012 | 67,464 | 64,111 | 55,969 | ||||||||||||||||||||||||
| Securities held to maturity at amortized cost | 48,973 | 49,876 | 50,640 | 51,495 | 52,447 | ||||||||||||||||||||||||
| Loans and leases: | |||||||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||
| Commercial and industrial | 162,273 | 156,679 | 154,848 | 153,925 | 156,400 | ||||||||||||||||||||||||
| CRE | 20,270 | 19,578 | 20,363 | 20,912 | 21,730 | ||||||||||||||||||||||||
| Commercial construction | 8,277 | 8,766 | 8,520 | 7,980 | 7,787 | ||||||||||||||||||||||||
| Consumer: | |||||||||||||||||||||||||||||
| Residential mortgage | 57,828 | 56,099 | 55,599 | 53,963 | 54,344 | ||||||||||||||||||||||||
| Home equity | 9,591 | 9,523 | 9,642 | 9,680 | 9,772 | ||||||||||||||||||||||||
| Indirect auto | 24,558 | 23,628 | 23,089 | 22,508 | 21,994 | ||||||||||||||||||||||||
| Other consumer | 31,122 | 29,537 | 29,395 | 29,282 | 28,677 | ||||||||||||||||||||||||
| Credit card | 4,877 | 4,828 | 4,927 | 4,834 | 4,988 | ||||||||||||||||||||||||
| Total loans and leases held for investment | 318,796 | 308,638 | 306,383 | 303,084 | 305,692 | ||||||||||||||||||||||||
| Loans held for sale | 1,203 | 1,114 | 1,388 | 1,278 | 1,457 | ||||||||||||||||||||||||
| Total loans and leases | 319,999 | 309,752 | 307,771 | 304,362 | 307,149 | ||||||||||||||||||||||||
| Allowance for loan and lease losses | (4,899) | (4,870) | (4,857) | (4,842) | (4,808) | ||||||||||||||||||||||||
| Premises and equipment | 3,197 | 3,168 | 3,225 | 3,251 | 3,244 | ||||||||||||||||||||||||
| Goodwill | 17,125 | 17,125 | 17,125 | 17,125 | 17,157 | ||||||||||||||||||||||||
| Core deposit and other intangible assets | 1,399 | 1,473 | 1,550 | 1,635 | 1,729 | ||||||||||||||||||||||||
| Loan servicing rights at fair value | 3,612 | 3,628 | 3,708 | 3,499 | 3,410 | ||||||||||||||||||||||||
| Other assets | 37,967 | 36,916 | 37,132 | 34,976 | 34,781 | ||||||||||||||||||||||||
| Total assets | $ | 543,833 | $ | 535,899 | $ | 531,176 | $ | 523,434 | $ | 519,853 | |||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||
| Deposits: | |||||||||||||||||||||||||||||
| Noninterest-bearing deposits | $ | 106,442 | $ | 108,461 | $ | 107,451 | $ | 105,984 | $ | 107,310 | |||||||||||||||||||
| Interest checking | 118,122 | 118,043 | 109,042 | 109,493 | 102,654 | ||||||||||||||||||||||||
| Money market and savings | 133,891 | 136,777 | 137,307 | 134,349 | 136,989 | ||||||||||||||||||||||||
| Time deposits | 47,667 | 40,455 | 36,724 | 37,952 | 38,458 | ||||||||||||||||||||||||
| Total deposits | 406,122 | 403,736 | 390,524 | 387,778 | 385,411 | ||||||||||||||||||||||||
| Short-term borrowings | 16,631 | 23,730 | 29,205 | 20,859 | 22,816 | ||||||||||||||||||||||||
| Long-term debt | 44,427 | 32,030 | 34,956 | 36,770 | 34,616 | ||||||||||||||||||||||||
| Other liabilities | 11,813 | 11,768 | 12,812 | 12,331 | 13,183 | ||||||||||||||||||||||||
| Total liabilities | 478,993 | 471,264 | 467,497 | 457,738 | 456,026 | ||||||||||||||||||||||||
| Shareholders’ Equity: | |||||||||||||||||||||||||||||
| Preferred stock | 5,907 | 5,907 | 5,907 | 6,673 | 6,673 | ||||||||||||||||||||||||
| Common stock | 6,447 | 6,548 | 6,580 | 6,638 | 6,691 | ||||||||||||||||||||||||
| Additional paid-in capital | 34,620 | 35,178 | 35,628 | 36,020 | 36,364 | ||||||||||||||||||||||||
| Retained earnings | 24,759 | 24,252 | 23,777 | 23,248 | 22,603 | ||||||||||||||||||||||||
| Accumulated other comprehensive loss | (6,893) | (7,250) | (8,213) | (6,883) | (8,504) | ||||||||||||||||||||||||
| Total shareholders’ equity | 64,840 | 64,635 | 63,679 | 65,696 | 63,827 | ||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 543,833 | $ | 535,899 | $ | 531,176 | $ | 523,434 | $ | 519,853 | |||||||||||||||||||
- 3 -
Average Balances and Rates - Quarters
| Quarter Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| June 30, 2025 | March 31, 2025 | December 31, 2024 | September 30, 2024 | June 30, 2024 | |||||||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | Average Balances(1) | Income/ Expense(2) | Yields/ Rates(2) | Average Balances(1) | Income/ Expense(2) | Yields/ Rates(2) | Average Balances(1) | Income/ Expense(2) | Yields/ Rates(2) | Average Balances(1) | Income/ Expense(2) | Yields/ Rates(2) | Average Balances(1) | Income/ Expense(2) | Yields/ Rates(2) | ||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| AFS and HTM securities at amortized cost: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| U.S. Treasury | $ | 14,034 | $ | 181 | 5.20 | % | $ | 14,867 | $ | 191 | 5.19 | % | $ | 14,387 | $ | 196 | 5.40 | % | $ | 12,986 | $ | 151 | 4.65 | % | $ | 11,138 | $ | 101 | 3.66 | % | |||||||||||||||||||||||||||||
| U.S. government-sponsored entities (GSE) | 463 | 5 | 3.73 | 462 | 4 | 3.75 | 412 | 3 | 3.42 | 377 | 4 | 3.41 | 382 | 3 | 3.27 | ||||||||||||||||||||||||||||||||||||||||||||
| Mortgage-backed securities issued by GSE | 106,947 | 772 | 2.89 | 108,345 | 777 | 2.87 | 109,644 | 792 | 2.89 | 103,374 | 711 | 2.75 | 108,358 | 720 | 2.66 | ||||||||||||||||||||||||||||||||||||||||||||
| States and political subdivisions | 370 | 4 | 4.20 | 370 | 4 | 4.20 | 411 | 5 | 4.14 | 417 | 3 | 4.14 | 420 | 5 | 4.14 | ||||||||||||||||||||||||||||||||||||||||||||
| Non-agency mortgage-backed | — | — | — | — | — | — | — | — | — | — | — | — | 1,480 | 10 | 2.56 | ||||||||||||||||||||||||||||||||||||||||||||
| Other | 15 | — | 4.53 | 17 | — | 4.72 | 17 | — | 5.16 | 18 | 1 | 5.18 | 18 | — | 5.29 | ||||||||||||||||||||||||||||||||||||||||||||
| Total securities | 121,829 | 962 | 3.16 | 124,061 | 976 | 3.16 | 124,871 | 996 | 3.19 | 117,172 | 870 | 2.97 | 121,796 | 839 | 2.76 | ||||||||||||||||||||||||||||||||||||||||||||
| Loans and leases: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 158,491 | 2,262 | 5.72 | 155,214 | 2,184 | 5.70 | 153,209 | 2,293 | 5.95 | 154,102 | 2,482 | 6.41 | 157,043 | 2,550 | 6.53 | ||||||||||||||||||||||||||||||||||||||||||||
| CRE | 19,687 | 308 | 6.22 | 19,832 | 302 | 6.12 | 20,504 | 337 | 6.47 | 21,481 | 373 | 6.88 | 21,969 | 381 | 6.93 | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial construction | 8,613 | 144 | 6.85 | 8,734 | 145 | 6.84 | 8,261 | 147 | 7.26 | 7,870 | 152 | 7.79 | 7,645 | 147 | 7.85 | ||||||||||||||||||||||||||||||||||||||||||||
| Consumer: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | 56,789 | 579 | 4.08 | 55,658 | 562 | 4.04 | 54,390 | 536 | 3.94 | 53,999 | 525 | 3.89 | 54,490 | 525 | 3.86 | ||||||||||||||||||||||||||||||||||||||||||||
| Home equity | 9,586 | 178 | 7.47 | 9,569 | 177 | 7.48 | 9,675 | 189 | 7.78 | 9,703 | 196 | 8.04 | 9,805 | 195 | 8.02 | ||||||||||||||||||||||||||||||||||||||||||||
| Indirect auto | 24,158 | 441 | 7.32 | 23,248 | 412 | 7.19 | 22,790 | 411 | 7.19 | 22,121 | 399 | 7.18 | 22,016 | 381 | 6.95 | ||||||||||||||||||||||||||||||||||||||||||||
| Other consumer | 30,387 | 634 | 8.37 | 29,291 | 602 | 8.33 | 29,355 | 606 | 8.21 | 29,015 | 603 | 8.26 | 28,326 | 581 | 8.25 | ||||||||||||||||||||||||||||||||||||||||||||
| Credit card | 4,890 | 139 | 11.35 | 4,849 | 138 | 11.60 | 4,926 | 143 | 11.54 | 4,874 | 150 | 12.20 | 4,905 | 148 | 12.14 | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases held for investment | 312,601 | 4,685 | 6.01 | 306,395 | 4,522 | 5.97 | 303,110 | 4,662 | 6.12 | 303,165 | 4,880 | 6.41 | 306,199 | 4,908 | 6.44 | ||||||||||||||||||||||||||||||||||||||||||||
| Loans held for sale | 1,240 | 19 | 6.15 | 1,133 | 17 | 5.93 | 1,499 | 21 | 5.87 | 1,413 | 24 | 6.49 | 1,384 | 22 | 6.56 | ||||||||||||||||||||||||||||||||||||||||||||
| Total loans and leases | 313,841 | 4,704 | 6.01 | 307,528 | 4,539 | 5.97 | 304,609 | 4,683 | 6.12 | 304,578 | 4,904 | 6.41 | 307,583 | 4,930 | 6.44 | ||||||||||||||||||||||||||||||||||||||||||||
| Interest earning trading assets | 5,896 | 88 | 5.98 | 5,628 | 80 | 5.72 | 5,462 | 79 | 5.86 | 5,454 | 84 | 6.05 | 5,515 | 84 | 6.11 | ||||||||||||||||||||||||||||||||||||||||||||
Other earning assets(3) | 39,417 | 448 | 4.51 | 38,997 | 441 | 4.53 | 37,697 | 472 | 4.91 | 38,933 | 549 | 5.54 | 39,250 | 551 | 5.56 | ||||||||||||||||||||||||||||||||||||||||||||
| Total earning assets | 480,983 | 6,202 | 5.16 | 476,214 | 6,036 | 5.12 | 472,639 | 6,230 | 5.25 | 466,137 | 6,407 | 5.47 | 474,144 | 6,404 | 5.42 | ||||||||||||||||||||||||||||||||||||||||||||
| Nonearning assets | 56,086 | 55,416 | 54,374 | 53,278 | 50,109 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Assets of discontinued operations | — | — | — | — | 2,641 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 537,069 | $ | 531,630 | $ | 527,013 | $ | 519,415 | $ | 526,894 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities and Shareholders’ Equity | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits: | |||||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest checking | $ | 116,193 | 726 | 2.51 | $ | 109,208 | 640 | 2.37 | $ | 107,075 | 679 | 2.52 | $ | 103,899 | 732 | 2.80 | $ | 103,894 | 707 | 2.74 | |||||||||||||||||||||||||||||||||||||||
| Money market and savings | 135,607 | 751 | 2.22 | 136,897 | 743 | 2.20 | 138,242 | 838 | 2.41 | 136,639 | 914 | 2.66 | 135,264 | 873 | 2.60 | ||||||||||||||||||||||||||||||||||||||||||||
| Time deposits | 41,997 | 367 | 3.50 | 40,204 | 353 | 3.56 | 36,757 | 338 | 3.66 | 37,726 | 368 | 3.88 | 41,250 | 436 | 4.24 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 293,797 | 1,844 | 2.52 | 286,309 | 1,736 | 2.46 | 282,074 | 1,855 | 2.62 | 278,264 | 2,014 | 2.88 | 280,408 | 2,016 | 2.89 | ||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings | 26,241 | 292 | 4.47 | 30,332 | 336 | 4.49 | 25,006 | 303 | 4.81 | 20,781 | 282 | 5.41 | 26,016 | 362 | 5.58 | ||||||||||||||||||||||||||||||||||||||||||||
| Long-term debt | 34,213 | 431 | 5.02 | 32,418 | 409 | 5.05 | 34,133 | 431 | 5.06 | 35,318 | 454 | 5.13 | 36,721 | 446 | 4.87 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 354,251 | 2,567 | 2.91 | 349,059 | 2,481 | 2.88 | 341,213 | 2,589 | 3.02 | 334,363 | 2,750 | 3.27 | 343,145 | 2,824 | 3.31 | ||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 106,686 | 105,895 | 107,968 | 106,080 | 107,634 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 11,897 | 12,643 | 13,537 | 13,631 | 13,318 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities of discontinued operations | — | — | — | — | 1,120 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 64,235 | 64,033 | 64,295 | 65,341 | 61,677 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 537,069 | $ | 531,630 | $ | 527,013 | $ | 519,415 | $ | 526,894 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Average interest-rate spread | 2.25 | 2.24 | 2.23 | 2.20 | 2.11 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income/ net interest margin - taxable equivalent | $ | 3,635 | 3.02 | % | $ | 3,555 | 3.01 | % | $ | 3,641 | 3.07 | % | $ | 3,657 | 3.12 | % | $ | 3,580 | 3.02 | % | |||||||||||||||||||||||||||||||||||||||
| Taxable-equivalent adjustment | 48 | 48 | 51 | 55 | 53 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 3,587 | $ | 3,507 | $ | 3,590 | $ | 3,602 | $ | 3,527 | |||||||||||||||||||||||||||||||||||||||||||||||||
| Memo: Total deposits | $ | 400,483 | 1,844 | 1.85 | % | $ | 392,204 | 1,736 | 1.79 | % | $ | 390,042 | 1,855 | 1.89 | % | $ | 384,344 | 2,014 | 2.08 | % | $ | 388,042 | 2,016 | 2.09 | % | ||||||||||||||||||||||||||||||||||
(1)Represents daily average balances. Unrealized gains and losses on available-for-sale securities are included in nonearning assets. Active hedge basis adjustments for fair value hedges are included in nonearning assets and other liabilities.
(2)Amounts are on a taxable-equivalent basis, which represents a non-GAAP measure, utilizing the federal income tax rate of 21% for the periods presented. Interest income includes certain fees, deferred costs, and dividends.
(3)Includes cash equivalents, interest-bearing deposits with banks, FHLB stock, and other earning assets.
- 4 -
Average Balances and Rates - Year-To-Date
| Year-to-Date | ||||||||||||||||||||||||||||||||||||||
| June 30, 2025 | June 30, 2024 | |||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | Average Balances(1) | Income/Expense(2) | Yields/ Rates(2) | Average Balances(1) | Income/Expense(2) | Yields/ Rates(2) | ||||||||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||||||||
| AFS and HTM securities at amortized cost: | ||||||||||||||||||||||||||||||||||||||
| U.S. Treasury | $ | 14,448 | $ | 372 | 5.19 | % | $ | 10,496 | $ | 138 | 2.64 | % | ||||||||||||||||||||||||||
| U.S. government-sponsored entities (GSE) | 462 | 9 | 3.74 | 385 | 6 | 3.34 | ||||||||||||||||||||||||||||||||
| Mortgage-backed securities issued by GSE | 107,643 | 1,549 | 2.88 | 112,828 | 1,455 | 2.58 | ||||||||||||||||||||||||||||||||
| States and political subdivisions | 370 | 8 | 4.20 | 420 | 9 | 4.14 | ||||||||||||||||||||||||||||||||
| Non-agency mortgage-backed | — | — | — | 2,578 | 37 | 2.87 | ||||||||||||||||||||||||||||||||
| Other | 16 | — | 4.63 | 19 | — | 5.32 | ||||||||||||||||||||||||||||||||
| Total securities | 122,939 | 1,938 | 3.16 | 126,726 | 1,645 | 2.60 | ||||||||||||||||||||||||||||||||
| Loans and leases: | ||||||||||||||||||||||||||||||||||||||
| Commercial: | ||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 156,861 | 4,446 | 5.71 | 157,714 | 5,122 | 6.53 | ||||||||||||||||||||||||||||||||
| CRE | 19,759 | 610 | 6.17 | 22,185 | 770 | 6.94 | ||||||||||||||||||||||||||||||||
| Commercial construction | 8,673 | 289 | 6.84 | 7,389 | 284 | 7.84 | ||||||||||||||||||||||||||||||||
| Consumer: | ||||||||||||||||||||||||||||||||||||||
| Residential mortgage | 56,226 | 1,141 | 4.06 | 54,780 | 1,053 | 3.85 | ||||||||||||||||||||||||||||||||
| Home equity | 9,578 | 355 | 7.47 | 9,868 | 391 | 7.97 | ||||||||||||||||||||||||||||||||
| Indirect auto | 23,705 | 853 | 7.26 | 22,195 | 753 | 6.82 | ||||||||||||||||||||||||||||||||
| Other consumer | 29,843 | 1,236 | 8.35 | 28,306 | 1,142 | 8.12 | ||||||||||||||||||||||||||||||||
| Credit card | 4,870 | 277 | 11.47 | 4,913 | 294 | 12.05 | ||||||||||||||||||||||||||||||||
| Total loans and leases held for investment | 309,515 | 9,207 | 5.99 | 307,350 | 9,809 | 6.41 | ||||||||||||||||||||||||||||||||
| Loans held for sale | 1,187 | 36 | 6.04 | 1,155 | 37 | 6.49 | ||||||||||||||||||||||||||||||||
| Total loans and leases | 310,702 | 9,243 | 5.99 | 308,505 | 9,846 | 6.41 | ||||||||||||||||||||||||||||||||
| Interest earning trading assets | 5,763 | 168 | 5.85 | 5,180 | 163 | 6.29 | ||||||||||||||||||||||||||||||||
Other earning assets(3) | 39,208 | 889 | 4.52 | 34,909 | 987 | 5.60 | ||||||||||||||||||||||||||||||||
| Total earning assets | 478,612 | 12,238 | 5.14 | 475,320 | 12,641 | 5.33 | ||||||||||||||||||||||||||||||||
| Nonearning assets | 55,753 | 48,516 | ||||||||||||||||||||||||||||||||||||
| Assets of discontinued operations | — | 5,112 | ||||||||||||||||||||||||||||||||||||
| Total assets | $ | 534,365 | $ | 528,948 | ||||||||||||||||||||||||||||||||||
| Liabilities and Shareholders’ Equity | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits: | ||||||||||||||||||||||||||||||||||||||
| Interest checking | $ | 112,720 | 1,366 | 2.44 | $ | 103,716 | 1,391 | 2.70 | ||||||||||||||||||||||||||||||
| Money market and savings | 136,249 | 1,494 | 2.21 | 134,979 | 1,705 | 2.54 | ||||||||||||||||||||||||||||||||
| Time deposits | 41,104 | 720 | 3.53 | 41,594 | 884 | 4.27 | ||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 290,073 | 3,580 | 2.49 | 280,289 | 3,980 | 2.86 | ||||||||||||||||||||||||||||||||
| Short-term borrowings | 28,275 | 628 | 4.48 | 26,123 | 728 | 5.60 | ||||||||||||||||||||||||||||||||
| Long-term debt | 33,320 | 840 | 5.04 | 38,721 | 928 | 4.80 | ||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 351,668 | 5,048 | 2.89 | 345,133 | 5,636 | 3.28 | ||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 106,293 | 108,261 | ||||||||||||||||||||||||||||||||||||
| Other liabilities | 12,269 | 13,101 | ||||||||||||||||||||||||||||||||||||
| Liabilities of discontinued operations | — | 2,109 | ||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 64,135 | 60,344 | ||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 534,365 | $ | 528,948 | ||||||||||||||||||||||||||||||||||
| Average interest-rate spread | 2.25 | 2.05 | ||||||||||||||||||||||||||||||||||||
| Net interest income/ net interest margin - taxable equivalent | $ | 7,190 | 3.02 | % | $ | 7,005 | 2.95 | % | ||||||||||||||||||||||||||||||
| Taxable-equivalent adjustment | 96 | 106 | ||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 7,094 | $ | 6,899 | ||||||||||||||||||||||||||||||||||
| Memo: Total deposits | $ | 396,366 | 3,580 | 1.82 | % | $ | 388,550 | 3,980 | 2.06 | % | ||||||||||||||||||||||||||||
(1)Represents daily average balances. Unrealized gains and losses on available-for-sale securities are included in nonearning assets. Active hedge basis adjustments for fair value hedges are included in nonearning assets and other liabilities.
(2)Amounts are on a taxable-equivalent basis, which represents a non-GAAP measure, utilizing the federal income tax rate of 21% for the periods presented. Interest income includes certain fees, deferred costs, and dividends.
(3)Includes cash equivalents, interest-bearing deposits with banks, FHLB stock, and other earning assets.
- 5 -
Credit Quality
| June 30 | March 31 | Dec. 31 | Sept. 30 | June 30 | ||||||||||||||||||||||||||||
| (Dollars in millions) | 2025 | 2025 | 2024 | 2024 | 2024 | |||||||||||||||||||||||||||
| Nonperforming Assets | ||||||||||||||||||||||||||||||||
| Nonaccrual loans and leases: | ||||||||||||||||||||||||||||||||
| Commercial: | ||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 520 | $ | 586 | $ | 521 | $ | 575 | $ | 459 | ||||||||||||||||||||||
| CRE | 128 | 294 | 298 | 302 | 360 | |||||||||||||||||||||||||||
| Commercial construction | 1 | 2 | 3 | 1 | — | |||||||||||||||||||||||||||
| Consumer: | ||||||||||||||||||||||||||||||||
| Residential mortgage | 191 | 179 | 166 | 156 | 161 | |||||||||||||||||||||||||||
| Home equity | 107 | 114 | 116 | 118 | 123 | |||||||||||||||||||||||||||
| Indirect auto | 240 | 248 | 259 | 252 | 244 | |||||||||||||||||||||||||||
| Other consumer | 64 | 65 | 66 | 63 | 64 | |||||||||||||||||||||||||||
| Total nonaccrual loans and leases held for investment | 1,251 | 1,488 | 1,429 | 1,467 | 1,411 | |||||||||||||||||||||||||||
| Loans held for sale | 12 | 77 | — | 5 | 9 | |||||||||||||||||||||||||||
| Total nonaccrual loans and leases | 1,263 | 1,565 | 1,429 | 1,472 | 1,420 | |||||||||||||||||||||||||||
| Foreclosed real estate | 4 | 4 | 3 | 3 | 5 | |||||||||||||||||||||||||||
| Other foreclosed property | 49 | 49 | 45 | 53 | 51 | |||||||||||||||||||||||||||
| Total nonperforming assets | $ | 1,316 | $ | 1,618 | $ | 1,477 | $ | 1,528 | $ | 1,476 | ||||||||||||||||||||||
| Loans 90 Days or More Past Due and Still Accruing | ||||||||||||||||||||||||||||||||
| Commercial: | ||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 2 | $ | 5 | $ | 19 | $ | 5 | $ | 8 | ||||||||||||||||||||||
| CRE | — | — | 1 | — | — | |||||||||||||||||||||||||||
| Commercial construction | — | — | — | — | 1 | |||||||||||||||||||||||||||
| Consumer: | ||||||||||||||||||||||||||||||||
| Residential mortgage - government guaranteed | 424 | 468 | 430 | 394 | 375 | |||||||||||||||||||||||||||
| Residential mortgage - nonguaranteed | 41 | 62 | 51 | 39 | 27 | |||||||||||||||||||||||||||
| Home equity | 6 | 6 | 9 | 7 | 7 | |||||||||||||||||||||||||||
| Indirect auto | — | — | — | — | 1 | |||||||||||||||||||||||||||
| Other consumer | 24 | 23 | 23 | 22 | 19 | |||||||||||||||||||||||||||
| Credit card | 49 | 52 | 54 | 51 | 51 | |||||||||||||||||||||||||||
| Total loans 90 days past due and still accruing | $ | 546 | $ | 616 | $ | 587 | $ | 518 | $ | 489 | ||||||||||||||||||||||
| Loans 30-89 Days Past Due | ||||||||||||||||||||||||||||||||
| Commercial: | ||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 122 | $ | 118 | $ | 168 | $ | 116 | $ | 109 | ||||||||||||||||||||||
| CRE | 34 | 12 | 60 | 10 | 8 | |||||||||||||||||||||||||||
| Commercial construction | 15 | — | 3 | 4 | — | |||||||||||||||||||||||||||
| Consumer: | ||||||||||||||||||||||||||||||||
| Residential mortgage - government guaranteed | 330 | 284 | 318 | 305 | 340 | |||||||||||||||||||||||||||
| Residential mortgage - nonguaranteed | 365 | 347 | 401 | 366 | 392 | |||||||||||||||||||||||||||
| Home equity | 54 | 57 | 60 | 63 | 58 | |||||||||||||||||||||||||||
| Indirect auto | 582 | 484 | 622 | 596 | 592 | |||||||||||||||||||||||||||
| Other consumer | 239 | 246 | 236 | 233 | 214 | |||||||||||||||||||||||||||
| Credit card | 70 | 71 | 81 | 76 | 78 | |||||||||||||||||||||||||||
| Total loans 30-89 days past due | $ | 1,811 | $ | 1,619 | $ | 1,949 | $ | 1,769 | $ | 1,791 | ||||||||||||||||||||||
- 6 -
| As of/For the Quarter Ended | ||||||||||||||||||||||||||||||||
| June 30 | March 31 | Dec. 31 | Sept. 30 | June 30 | ||||||||||||||||||||||||||||
| 2025 | 2025 | 2024 | 2024 | 2024 | ||||||||||||||||||||||||||||
| Asset Quality Ratios | ||||||||||||||||||||||||||||||||
| Loans 30-89 days past due and still accruing as a percentage of loans and leases | 0.57 | % | 0.52 | % | 0.64 | % | 0.58 | % | 0.59 | % | ||||||||||||||||||||||
| Loans 90 days or more past due and still accruing as a percentage of loans and leases | 0.17 | 0.20 | 0.19 | 0.17 | 0.16 | |||||||||||||||||||||||||||
| Nonperforming loans and leases as a percentage of loans and leases | 0.39 | 0.48 | 0.47 | 0.48 | 0.46 | |||||||||||||||||||||||||||
Nonperforming loans and leases as a percentage of loans and leases(1) | 0.39 | 0.51 | 0.46 | 0.48 | 0.46 | |||||||||||||||||||||||||||
| Nonperforming assets as a percentage of: | ||||||||||||||||||||||||||||||||
Total assets(1) | 0.24 | 0.30 | 0.28 | 0.29 | 0.28 | |||||||||||||||||||||||||||
| Loans and leases plus foreclosed property | 0.41 | 0.50 | 0.48 | 0.50 | 0.48 | |||||||||||||||||||||||||||
| Net charge-offs as a percentage of average loans and leases | 0.51 | 0.60 | 0.59 | 0.55 | 0.58 | |||||||||||||||||||||||||||
| Allowance for loan and lease losses as a percentage of loans and leases | 1.54 | 1.58 | 1.59 | 1.60 | 1.57 | |||||||||||||||||||||||||||
| Ratio of allowance for loan and lease losses to: | ||||||||||||||||||||||||||||||||
| Net charge-offs | 3.1X | 2.6X | 2.7X | 2.9X | 2.7X | |||||||||||||||||||||||||||
| Nonperforming loans and leases | 3.9X | 3.3X | 3.4X | 3.3X | 3.4X | |||||||||||||||||||||||||||
| Asset Quality Ratios (Excluding Government Guaranteed) | ||||||||||||||||||||||||||||||||
| Loans 90 days or more past due and still accruing as a percentage of loans and leases | 0.04 | % | 0.05 | % | 0.05 | % | 0.04 | % | 0.04 | % | ||||||||||||||||||||||
| Applicable ratios are annualized. | ||||||||||||||||||||||||||||||||
(1)Includes loans held for sale. | ||||||||||||||||||||||||||||||||
| As of/For the Year-to-Date | ||||||||||||||||||||||||||||||||
| Period Ended June 30 | ||||||||||||||||||||||||||||||||
| 2025 | 2024 | |||||||||||||||||||||||||||||||
| Asset Quality Ratios | ||||||||||||||||||||||||||||||||
| Net charge-offs as a percentage of average loans and leases | 0.55 | % | 0.61 | % | ||||||||||||||||||||||||||||
| Ratio of allowance for loan and lease losses to net charge-offs | 2.9X | 2.6X | ||||||||||||||||||||||||||||||
| Applicable ratios are annualized. | ||||||||||||||||||||||||||||||||
- 7 -
| As of/For the Quarter Ended | As of/For the Year-to-Date | |||||||||||||||||||||||||||||||||||||||||||
| June 30 | March 31 | Dec. 31 | Sept. 30 | June 30 | Period Ended June 30 | |||||||||||||||||||||||||||||||||||||||
| (Dollars in millions) | 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | |||||||||||||||||||||||||||||||||||||
| Allowance for Credit Losses | ||||||||||||||||||||||||||||||||||||||||||||
| Beginning balance | $ | 5,166 | $ | 5,161 | $ | 5,140 | $ | 5,110 | $ | 5,100 | $ | 5,161 | $ | 5,093 | ||||||||||||||||||||||||||||||
| Provision for credit losses | 488 | 458 | 471 | 448 | 451 | 946 | 951 | |||||||||||||||||||||||||||||||||||||
| Charge-offs: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | (120) | (102) | (119) | (96) | (83) | (222) | (180) | |||||||||||||||||||||||||||||||||||||
| CRE | (38) | (70) | (51) | (65) | (97) | (108) | (200) | |||||||||||||||||||||||||||||||||||||
| Consumer: | ||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | (1) | (1) | (1) | — | (1) | (2) | (2) | |||||||||||||||||||||||||||||||||||||
| Home equity | (4) | (2) | (2) | (1) | (3) | (6) | (6) | |||||||||||||||||||||||||||||||||||||
| Indirect auto | (127) | (154) | (158) | (143) | (136) | (281) | (290) | |||||||||||||||||||||||||||||||||||||
| Other consumer | (146) | (154) | (148) | (152) | (141) | (300) | (306) | |||||||||||||||||||||||||||||||||||||
| Credit card | (70) | (74) | (74) | (71) | (74) | (144) | (151) | |||||||||||||||||||||||||||||||||||||
| Total charge-offs | (506) | (557) | (553) | (528) | (535) | (1,063) | (1,135) | |||||||||||||||||||||||||||||||||||||
| Recoveries: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 31 | 24 | 15 | 26 | 14 | 55 | 46 | |||||||||||||||||||||||||||||||||||||
| CRE | 3 | 7 | 17 | 5 | 5 | 10 | 12 | |||||||||||||||||||||||||||||||||||||
| Commercial construction | 1 | — | — | 1 | 1 | 1 | 1 | |||||||||||||||||||||||||||||||||||||
| Consumer: | ||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | — | 2 | 2 | 1 | 2 | 2 | 3 | |||||||||||||||||||||||||||||||||||||
| Home equity | 4 | 4 | 3 | 4 | 4 | 8 | 9 | |||||||||||||||||||||||||||||||||||||
| Indirect auto | 28 | 25 | 24 | 38 | 30 | 53 | 58 | |||||||||||||||||||||||||||||||||||||
| Other consumer | 31 | 30 | 28 | 26 | 28 | 61 | 56 | |||||||||||||||||||||||||||||||||||||
| Credit card | 12 | 11 | 11 | 9 | 9 | 23 | 18 | |||||||||||||||||||||||||||||||||||||
| Total recoveries | 110 | 103 | 100 | 110 | 93 | 213 | 203 | |||||||||||||||||||||||||||||||||||||
| Net charge-offs | (396) | (454) | (453) | (418) | (442) | (850) | (932) | |||||||||||||||||||||||||||||||||||||
| Other | (5) | 1 | 3 | — | 1 | (4) | (2) | |||||||||||||||||||||||||||||||||||||
| Ending balance | $ | 5,253 | $ | 5,166 | $ | 5,161 | $ | 5,140 | $ | 5,110 | $ | 5,253 | $ | 5,110 | ||||||||||||||||||||||||||||||
| Allowance for Credit Losses: | ||||||||||||||||||||||||||||||||||||||||||||
| Allowance for loan and lease losses | $ | 4,899 | $ | 4,870 | $ | 4,857 | $ | 4,842 | $ | 4,808 | ||||||||||||||||||||||||||||||||||
| Reserve for unfunded lending commitments (RUFC) | 354 | 296 | 304 | 298 | 302 | |||||||||||||||||||||||||||||||||||||||
| Allowance for credit losses | $ | 5,253 | $ | 5,166 | $ | 5,161 | $ | 5,140 | $ | 5,110 | ||||||||||||||||||||||||||||||||||
| Quarter Ended | As of/For the Year-to-Date | |||||||||||||||||||||||||||||||||||||||||||
| June 30 | March 31 | Dec. 31 | Sept. 30 | June 30 | Period Ended June 30 | |||||||||||||||||||||||||||||||||||||||
| 2025 | 2025 | 2024 | 2024 | 2024 | 2025 | 2024 | ||||||||||||||||||||||||||||||||||||||
| Net Charge-offs as a Percentage of Average Loans and Leases: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 0.22 | % | 0.20 | % | 0.27 | % | 0.18 | % | 0.18 | % | 0.21 | % | 0.17 | % | ||||||||||||||||||||||||||||||
| CRE | 0.71 | 1.29 | 0.66 | 1.12 | 1.67 | 1.00 | 1.70 | |||||||||||||||||||||||||||||||||||||
| Commercial construction | (0.02) | (0.02) | (0.02) | (0.01) | (0.05) | (0.02) | (0.04) | |||||||||||||||||||||||||||||||||||||
| Consumer: | ||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | — | — | (0.01) | (0.01) | (0.01) | — | — | |||||||||||||||||||||||||||||||||||||
| Home equity | (0.04) | (0.07) | (0.07) | (0.11) | (0.03) | (0.05) | (0.06) | |||||||||||||||||||||||||||||||||||||
| Indirect auto | 1.63 | 2.26 | 2.33 | 1.89 | 1.94 | 1.94 | 2.10 | |||||||||||||||||||||||||||||||||||||
| Other consumer | 1.54 | 1.71 | 1.63 | 1.73 | 1.60 | 1.62 | 1.78 | |||||||||||||||||||||||||||||||||||||
| Credit card | 4.84 | 5.21 | 5.10 | 5.04 | 5.33 | 5.02 | 5.44 | |||||||||||||||||||||||||||||||||||||
| Total loans and leases | 0.51 | 0.60 | 0.59 | 0.55 | 0.58 | 0.55 | 0.61 | |||||||||||||||||||||||||||||||||||||
| Applicable ratios are annualized. | ||||||||||||||||||||||||||||||||||||||||||||
- 8 -
Segment Financial Performance - Preliminary
| Quarter Ended | ||||||||||||||||||||||||||||||||
| June 30 | March 31 | Dec. 31 | Sept. 30 | June 30 | ||||||||||||||||||||||||||||
| (Dollars in millions) | 2025 | 2025 | 2024 | 2024 | 2024 | |||||||||||||||||||||||||||
| Consumer and Small Business Banking | ||||||||||||||||||||||||||||||||
| Net interest income (expense) | $ | 1,488 | $ | 1,427 | $ | 1,390 | $ | 1,346 | $ | 1,291 | ||||||||||||||||||||||
| Net intersegment interest income (expense) | 871 | 858 | 1,106 | 1,184 | 1,216 | |||||||||||||||||||||||||||
| Segment net interest income (expense) | 2,359 | 2,285 | 2,496 | 2,530 | 2,507 | |||||||||||||||||||||||||||
| Allocated provision for credit losses | 384 | 328 | 347 | 353 | 308 | |||||||||||||||||||||||||||
| Noninterest income | 519 | 503 | 535 | 506 | 504 | |||||||||||||||||||||||||||
| Personnel expense | 409 | 408 | 406 | 398 | 417 | |||||||||||||||||||||||||||
| Amortization of intangibles | 39 | 39 | 45 | 45 | 45 | |||||||||||||||||||||||||||
| Restructuring charges | 1 | — | 1 | 1 | 1 | |||||||||||||||||||||||||||
| Other direct noninterest expense | 281 | 275 | 308 | 298 | 265 | |||||||||||||||||||||||||||
| Direct noninterest expense | 730 | 722 | 760 | 742 | 728 | |||||||||||||||||||||||||||
| Expense allocations | 970 | 941 | 981 | 920 | 934 | |||||||||||||||||||||||||||
| Total noninterest expense | 1,700 | 1,663 | 1,741 | 1,662 | 1,662 | |||||||||||||||||||||||||||
| Income (loss) before income taxes | 794 | 797 | 943 | 1,021 | 1,041 | |||||||||||||||||||||||||||
| Provision (benefit) for income taxes | 193 | 194 | 226 | 245 | 250 | |||||||||||||||||||||||||||
| Segment net income (loss) | $ | 601 | $ | 603 | $ | 717 | $ | 776 | $ | 791 | ||||||||||||||||||||||
| Wholesale Banking | ||||||||||||||||||||||||||||||||
| Net interest income (expense) | $ | 1,880 | $ | 1,892 | $ | 1,976 | $ | 2,103 | $ | 2,182 | ||||||||||||||||||||||
| Net intersegment interest income (expense) | (219) | (299) | (376) | (516) | (559) | |||||||||||||||||||||||||||
| Segment net interest income (expense) | 1,661 | 1,593 | 1,600 | 1,587 | 1,623 | |||||||||||||||||||||||||||
| Allocated provision for credit losses | 104 | 131 | 123 | 96 | 142 | |||||||||||||||||||||||||||
| Noninterest income | 942 | 949 | 1,038 | 1,047 | 986 | |||||||||||||||||||||||||||
| Personnel expense | 559 | 548 | 553 | 569 | 586 | |||||||||||||||||||||||||||
| Amortization of intangibles | 35 | 36 | 39 | 39 | 41 | |||||||||||||||||||||||||||
| Restructuring charges | 7 | 1 | 4 | 9 | 8 | |||||||||||||||||||||||||||
| Other direct noninterest expense | 200 | 192 | 206 | 182 | 186 | |||||||||||||||||||||||||||
| Direct noninterest expense | 801 | 777 | 802 | 799 | 821 | |||||||||||||||||||||||||||
| Expense allocations | 526 | 525 | 497 | 437 | 447 | |||||||||||||||||||||||||||
| Total noninterest expense | 1,327 | 1,302 | 1,299 | 1,236 | 1,268 | |||||||||||||||||||||||||||
| Income (loss) before income taxes | 1,172 | 1,109 | 1,216 | 1,302 | 1,199 | |||||||||||||||||||||||||||
| Provision (benefit) for income taxes | 236 | 223 | 241 | 260 | 239 | |||||||||||||||||||||||||||
| Segment net income (loss) | $ | 936 | $ | 886 | $ | 975 | $ | 1,042 | $ | 960 | ||||||||||||||||||||||
Other, Treasury & Corporate(1) | ||||||||||||||||||||||||||||||||
| Net interest income (expense) | $ | 219 | $ | 188 | $ | 224 | $ | 153 | $ | 54 | ||||||||||||||||||||||
| Net intersegment interest income (expense) | (652) | (559) | (730) | (668) | (657) | |||||||||||||||||||||||||||
| Segment net interest income (expense) | (433) | (371) | (506) | (515) | (603) | |||||||||||||||||||||||||||
| Allocated provision for credit losses | — | (1) | 1 | (1) | 1 | |||||||||||||||||||||||||||
| Noninterest income | (61) | (60) | (103) | (70) | (6,702) | |||||||||||||||||||||||||||
| Personnel expense | 685 | 631 | 628 | 661 | 658 | |||||||||||||||||||||||||||
| Amortization of intangibles | (1) | — | — | — | 3 | |||||||||||||||||||||||||||
| Restructuring charges | 20 | 37 | 6 | 15 | 24 | |||||||||||||||||||||||||||
| Other direct noninterest expense | 751 | 739 | 839 | 710 | 860 | |||||||||||||||||||||||||||
| Direct Noninterest Expense | 1,455 | 1,407 | 1,473 | 1,386 | 1,545 | |||||||||||||||||||||||||||
| Expense Allocations | (1,496) | (1,466) | (1,478) | (1,357) | (1,381) | |||||||||||||||||||||||||||
| Total noninterest expense | (41) | (59) | (5) | 29 | 164 | |||||||||||||||||||||||||||
| Income (loss) before income taxes | (453) | (371) | (605) | (613) | (7,470) | |||||||||||||||||||||||||||
| Provision (benefit) for income taxes | (156) | (143) | (202) | (234) | (1,813) | |||||||||||||||||||||||||||
| Segment net income (loss) | $ | (297) | $ | (228) | $ | (403) | $ | (379) | $ | (5,657) | ||||||||||||||||||||||
| Total Truist Financial Corporation | ||||||||||||||||||||||||||||||||
| Net interest income (expense) | $ | 3,587 | $ | 3,507 | $ | 3,590 | $ | 3,602 | $ | 3,527 | ||||||||||||||||||||||
| Net intersegment interest income (expense) | — | — | — | — | — | |||||||||||||||||||||||||||
| Segment net interest income (expense) | 3,587 | 3,507 | 3,590 | 3,602 | 3,527 | |||||||||||||||||||||||||||
| Allocated provision for credit losses | 488 | 458 | 471 | 448 | 451 | |||||||||||||||||||||||||||
| Noninterest income | 1,400 | 1,392 | 1,470 | 1,483 | (5,212) | |||||||||||||||||||||||||||
| Personnel expense | 1,653 | 1,587 | 1,587 | 1,628 | 1,661 | |||||||||||||||||||||||||||
| Amortization of intangibles | 73 | 75 | 84 | 84 | 89 | |||||||||||||||||||||||||||
| Restructuring charges | 28 | 38 | 11 | 25 | 33 | |||||||||||||||||||||||||||
| Other direct noninterest expense | 1,232 | 1,206 | 1,353 | 1,190 | 1,311 | |||||||||||||||||||||||||||
| Direct Noninterest Expense | 2,986 | 2,906 | 3,035 | 2,927 | 3,094 | |||||||||||||||||||||||||||
| Expense Allocations | — | — | — | — | — | |||||||||||||||||||||||||||
| Total noninterest expense | 2,986 | 2,906 | 3,035 | 2,927 | 3,094 | |||||||||||||||||||||||||||
| Income (loss) before income taxes | 1,513 | 1,535 | 1,554 | 1,710 | (5,230) | |||||||||||||||||||||||||||
| Provision (benefit) for income taxes | 273 | 274 | 265 | 271 | (1,324) | |||||||||||||||||||||||||||
| Net income (loss) from continuing operations | $ | 1,240 | $ | 1,261 | $ | 1,289 | $ | 1,439 | $ | (3,906) | ||||||||||||||||||||||
(1)Includes financial data from subsidiaries below the quantitative and qualitative thresholds requiring disclosure.
- 9 -
Capital Information - Five Quarter Trend
| As of/For the Quarter Ended | ||||||||||||||||||||||||||||||||
| June 30 | March 31 | Dec. 31 | Sept. 30 | June 30 | ||||||||||||||||||||||||||||
| (Dollars in millions, except per share data, shares in thousands) | 2025 | 2025 | 2024 | 2024 | 2024 | |||||||||||||||||||||||||||
| Selected Capital Information | (preliminary) | |||||||||||||||||||||||||||||||
| Risk-based capital: | ||||||||||||||||||||||||||||||||
| Common equity tier 1 | $ | 47,678 | $ | 47,767 | $ | 48,225 | $ | 48,076 | $ | 47,706 | ||||||||||||||||||||||
| Tier 1 | 53,582 | 53,671 | 54,128 | 54,746 | 54,376 | |||||||||||||||||||||||||||
| Total | 62,119 | 62,349 | 62,583 | 63,349 | 63,345 | |||||||||||||||||||||||||||
| Risk-weighted assets | 434,892 | 424,059 | 418,337 | 414,828 | 412,607 | |||||||||||||||||||||||||||
| Average quarterly assets for leverage ratio | 525,566 | 519,981 | 515,830 | 508,280 | 519,467 | |||||||||||||||||||||||||||
| Average quarterly assets for supplementary leverage ratio | 628,266 | 619,992 | 612,764 | 600,000 | 608,627 | |||||||||||||||||||||||||||
| Risk-based capital ratios: | ||||||||||||||||||||||||||||||||
| Common equity tier 1 | 11.0 | % | 11.3 | % | 11.5 | % | 11.6 | % | 11.6 | % | ||||||||||||||||||||||
| Tier 1 | 12.3 | 12.7 | 12.9 | 13.2 | 13.2 | |||||||||||||||||||||||||||
| Total | 14.3 | 14.7 | 15.0 | 15.3 | 15.4 | |||||||||||||||||||||||||||
| Leverage capital ratio | 10.2 | 10.3 | 10.5 | 10.8 | 10.5 | |||||||||||||||||||||||||||
| Supplementary leverage | 8.5 | 8.7 | 8.8 | 9.1 | 8.9 | |||||||||||||||||||||||||||
| Common equity per common share | $ | 45.70 | $ | 44.85 | $ | 43.90 | $ | 44.46 | $ | 42.71 | ||||||||||||||||||||||
| June 30 | March 31 | Dec. 31 | Sept. 30 | June 30 | ||||||||||||||||||||||||||||
| (Dollars in millions, except per share data, shares in thousands) | 2025 | 2025 | 2024 | 2024 | 2024 | |||||||||||||||||||||||||||
Calculations of Tangible Common Equity and Related Measures:(1) | ||||||||||||||||||||||||||||||||
| Total shareholders’ equity | $ | 64,840 | $ | 64,635 | $ | 63,679 | $ | 65,696 | $ | 63,827 | ||||||||||||||||||||||
| Less: | ||||||||||||||||||||||||||||||||
| Preferred stock | 5,907 | 5,907 | 5,907 | 6,673 | 6,673 | |||||||||||||||||||||||||||
| Intangible assets, net of deferred taxes (including discontinued operations) | 18,143 | 18,203 | 18,274 | 18,350 | 18,471 | |||||||||||||||||||||||||||
| Tangible common equity | $ | 40,790 | $ | 40,525 | $ | 39,498 | $ | 40,673 | $ | 38,683 | ||||||||||||||||||||||
| Outstanding shares at end of period (in thousands) | 1,289,435 | 1,309,539 | 1,315,936 | 1,327,521 | 1,338,223 | |||||||||||||||||||||||||||
| Tangible common equity per common share | $ | 31.63 | $ | 30.95 | $ | 30.01 | $ | 30.64 | $ | 28.91 | ||||||||||||||||||||||
| Total assets | $ | 543,833 | $ | 535,899 | $ | 531,176 | $ | 523,434 | $ | 519,853 | ||||||||||||||||||||||
| Less: Intangible assets, net of deferred taxes (including discontinued operations prior to the sale of TIH) | 18,143 | 18,203 | 18,274 | 18,350 | 18,471 | |||||||||||||||||||||||||||
| Tangible assets | $ | 525,690 | $ | 517,696 | $ | 512,902 | $ | 505,084 | $ | 501,382 | ||||||||||||||||||||||
| Equity as a percentage of total assets | 11.9 | % | 12.1 | % | 12.0 | % | 12.6 | % | 12.3 | % | ||||||||||||||||||||||
| Tangible common equity as a percentage of tangible assets | 7.8 | 7.8 | 7.7 | 8.1 | 7.7 | |||||||||||||||||||||||||||
(1)Tangible common equity is a non-GAAP measure that excludes the impact of intangible assets, net of deferred taxes. This measure is useful for evaluating the performance of a business consistently, whether acquired or developed internally. Truist’s management uses this measure to assess balance sheet risk and shareholder value. These measures are not necessarily comparable to similar measures that may be presented by other companies.
- 10 -
Selected Mortgage Banking Information & Additional Information
| As of/For the Quarter Ended | ||||||||||||||||||||||||||||||||
| June 30 | March 31 | Dec. 31 | Sept. 30 | June 30 | ||||||||||||||||||||||||||||
| (Dollars in millions, except per share data) | 2025 | 2025 | 2024 | 2024 | 2024 | |||||||||||||||||||||||||||
| Mortgage Banking Income | ||||||||||||||||||||||||||||||||
| Residential mortgage income: | ||||||||||||||||||||||||||||||||
| Residential mortgage production revenue | $ | 25 | $ | 19 | $ | 25 | $ | 25 | $ | 24 | ||||||||||||||||||||||
| Residential mortgage servicing income: | ||||||||||||||||||||||||||||||||
| Residential mortgage servicing income before MSR valuation | 72 | 87 | 83 | 80 | 72 | |||||||||||||||||||||||||||
| Net MSRs valuation | 1 | (4) | (5) | (7) | (12) | |||||||||||||||||||||||||||
| Total residential mortgage servicing income | 73 | 83 | 78 | 73 | 60 | |||||||||||||||||||||||||||
| Total residential mortgage income | 98 | 102 | 103 | 98 | 84 | |||||||||||||||||||||||||||
| Commercial mortgage income: | ||||||||||||||||||||||||||||||||
| Commercial mortgage production revenue | 6 | 2 | 12 | 6 | 4 | |||||||||||||||||||||||||||
| Commercial mortgage servicing income: | ||||||||||||||||||||||||||||||||
| Commercial mortgage servicing income before MSR valuation | 3 | 4 | 4 | 3 | 7 | |||||||||||||||||||||||||||
| Net MSRs valuation | — | — | (2) | (1) | 17 | |||||||||||||||||||||||||||
| Total commercial mortgage servicing income | 3 | 4 | 2 | 2 | 24 | |||||||||||||||||||||||||||
| Total commercial mortgage income | 9 | 6 | 14 | 8 | 28 | |||||||||||||||||||||||||||
| Total mortgage banking income | $ | 107 | $ | 108 | $ | 117 | $ | 106 | $ | 112 | ||||||||||||||||||||||
Other Mortgage Banking Information | ||||||||||||||||||||||||||||||||
| Residential mortgage loan originations | $ | 5,855 | $ | 3,626 | $ | 4,745 | $ | 3,726 | $ | 3,881 | ||||||||||||||||||||||
Residential mortgage servicing portfolio:(1) | ||||||||||||||||||||||||||||||||
| Loans serviced for others | 213,002 | 216,148 | 218,475 | 221,143 | 208,270 | |||||||||||||||||||||||||||
| Bank-owned loans serviced | 57,748 | 55,120 | 54,937 | 54,281 | 54,903 | |||||||||||||||||||||||||||
| Total servicing portfolio | 270,750 | 271,268 | 273,412 | 275,424 | 263,173 | |||||||||||||||||||||||||||
| Weighted-average coupon rate on mortgage loans serviced for others | 3.70 | % | 3.68 | % | 3.65 | % | 3.62 | % | 3.63 | % | ||||||||||||||||||||||
| Weighted-average servicing fee on mortgage loans serviced for others | 0.28 | 0.28 | 0.28 | 0.28 | 0.28 | |||||||||||||||||||||||||||
| Additional Information | ||||||||||||||||||||||||||||||||
Brokered deposits(2) | $ | 30,008 | $ | 27,585 | $ | 28,085 | $ | 27,671 | $ | 27,384 | ||||||||||||||||||||||
NQDCP income (expense):(3) | ||||||||||||||||||||||||||||||||
| Interest income | $ | — | $ | — | $ | 4 | $ | 1 | $ | — | ||||||||||||||||||||||
| Other income | 21 | (6) | (2) | 12 | 4 | |||||||||||||||||||||||||||
| Personnel expense | (21) | 6 | (2) | (13) | (4) | |||||||||||||||||||||||||||
| Total NQDCP income (expense) | $ | — | $ | — | $ | — | $ | — | $ | — | ||||||||||||||||||||||
| Common stock prices: | ||||||||||||||||||||||||||||||||
| High | $ | 43.25 | $ | 48.53 | $ | 49.06 | $ | 45.31 | $ | 40.51 | ||||||||||||||||||||||
| Low | 33.56 | 39.41 | 41.08 | 37.85 | 35.09 | |||||||||||||||||||||||||||
| End of period | 42.99 | 41.15 | 43.38 | 42.77 | 38.85 | |||||||||||||||||||||||||||
| Banking offices | 1,927 | 1,928 | 1,928 | 1,930 | 1,930 | |||||||||||||||||||||||||||
| ATMs | 2,847 | 2,861 | 2,901 | 2,928 | 2,942 | |||||||||||||||||||||||||||
FTEs(4) | 37,996 | 37,529 | 37,661 | 37,867 | 41,368 | |||||||||||||||||||||||||||
FTEs - continuing operations(4) | 37,996 | 37,529 | 37,661 | 37,867 | 38,140 | |||||||||||||||||||||||||||
(1)Amounts reported are unpaid principal balance.
(2)Amounts represented in interest checking, money market and savings, and time deposits.
(3)Relates to plans where Truist holds assets in proportion to participant elections.
(4)FTEs represents an average for the quarter.
- 11 -
Selected Items(1)
| Favorable (Unfavorable) | |||||||||||||||||
| (Dollars in millions, except per share data) Description | Pre-Tax | After-Tax at Marginal Rate | Impact to Diluted EPS(2) | ||||||||||||||
| Selected Items | |||||||||||||||||
| Second Quarter 2025 | |||||||||||||||||
| Restructuring charges | $ | (28) | $ | (21) | $ | (0.02) | |||||||||||
| Loss on sale of securities (securities gains (losses)) | (18) | (13) | (0.01) | ||||||||||||||
| First Quarter 2025 | |||||||||||||||||
| Restructuring charges | $ | (38) | $ | (29) | $ | (0.02) | |||||||||||
| Fourth Quarter 2024 | |||||||||||||||||
| Restructuring charges | $ | (11) | $ | (9) | $ | (0.01) | |||||||||||
| FDIC special assessment (regulatory costs) | 8 | 6 | — | ||||||||||||||
| Third Quarter 2024 | |||||||||||||||||
| Gain on sale of TIH (net income from discontinued operations) | $ | 36 | $ | 16 | $ | 0.01 | |||||||||||
| Restructuring charges | (25) | (19) | (0.01) | ||||||||||||||
| FDIC special assessment (regulatory costs) | 16 | 13 | 0.01 | ||||||||||||||
| Second Quarter 2024 | |||||||||||||||||
| Gain on sale of TIH (net income from discontinued operations) | $ | 6,903 | $ | 4,814 | $ | 3.60 | |||||||||||
| Loss on sale of securities (securities gains (losses)) | (6,650) | (5,089) | (3.80) | ||||||||||||||
| Charitable contribution (other expense) | (150) | (115) | (0.09) | ||||||||||||||
| Restructuring charges ($33 million in restructuring charges and $63 million in net income from discontinued operations) | (96) | (73) | (0.05) | ||||||||||||||
| FDIC special assessment (regulatory costs) | (13) | (11) | (0.01) | ||||||||||||||
Accelerated recognition of TIH equity compensation expense (net income from discontinued operations) | (10) | (8) | (0.01) | ||||||||||||||
| First Quarter 2024 | |||||||||||||||||
Accelerated recognition of TIH equity compensation expense (net income from discontinued operations) | $ | (89) | $ | (68) | $ | (0.05) | |||||||||||
| FDIC special assessment (regulatory costs) | (75) | (57) | (0.04) | ||||||||||||||
| Restructuring charges ($51 million in restructuring charges and $19 million in net income from discontinued operations) | (70) | (53) | (0.04) | ||||||||||||||
(1)Includes certain selected items from the consolidated statements of income. A reconciliation of non-GAAP measures is included in the appendix to Truist’s Second Quarter 2025 Earnings Presentation.
(2)Diluted EPS impact for individual items may not foot to difference between GAAP diluted and adjusted EPS due to rounding.
- 12 -
Fourth Quarter 2024 Earnings Conference Call Bill Rogers – Chairman & CEO Mike Maguire – CFO July 18, 2025 Second Quarter 2025 Earnings Conference Call Bill Rog rs - Chairman & CEO Mike Maguire - CFO July 18, 2025
2 From time to time we have made, and in the future will make, forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements can be identified by the fact that they do not relate strictly to historical or current facts. Forward-looking statements often use words such as “believe,” “expect,” “anticipate,” “intend,” “pursue,” “seek,” “continue,” “estimate,” “project,” “outlook,” “forecast,” “potential,” “target,” “objective,” “trend,” “plan,” “goal,” “initiative,” “priorities,” or other words of comparable meaning or future-tense or conditional verbs such as “may,” “will,” “should,” “would,” or “could.” Forward-looking statements convey our expectations, intentions, or forecasts about future events, circumstances, or results. In particular, forward looking statements include statements we make about: (i) Truist’s ability to execute on strategic growth initiatives and meet expense targets; (ii) Truist’s ability to return capital to shareholders in future periods; (iii) estimates of earning asset growth and fixed asset repricing; (iv) Truist’s future capital levels and their ability to fund growth and capital returns; (v) guidance with respect to financial performance metrics in future periods, including future levels of adjusted revenue, net interest income, adjusted expenses, and net charge-off ratio; (vi) Truist’s effective tax rate in future periods; (vii) projections of preferred stock dividends and share repurchases; and (viii) Truist’s investment banking and trading outlook in the second half of 2025. This presentation, including any information incorporated by reference in this presentation, contains forward-looking statements. We also may make forward-looking statements in other documents that are filed or furnished with the SEC. In addition, we may make forward-looking statements orally or in writing to investors, analysts, members of the media, and others. All forward- looking statements, by their nature, are subject to assumptions, risks, and uncertainties, which may change over time and many of which are beyond our control. You should not rely on any forward-looking statement as a prediction or guarantee about the future. Actual future objectives, strategies, plans, prospects, performance, conditions, and results may differ materially from those set forth in any forward-looking statement. While no list of assumptions, risks, and uncertainties could be complete, some of the factors that may cause actual results or other future events or circumstances to differ from those in forward-looking statements include: • evolving political, geopolitical, business, social, economic, and market conditions at local, regional, national, and international levels; • monetary, fiscal, and trade laws or policies, including tariffs or responses to rates of inflation above target levels; • the legal, regulatory, and supervisory environment, including changes in financial-services legislation, regulation, policies, or government officials or other personnel; • our ability to address heightened scrutiny and expectations from supervisory or other governmental authorities and to timely and credibly remediate related concerns or deficiencies; • judicial, regulatory, and administrative inquiries, examinations, investigations, proceedings, disputes, or rulings that create uncertainty for or are adverse to us or the financial-services industry; • the outcomes of judicial, regulatory, and administrative inquiries, examinations, investigations, proceedings, disputes, or rulings to which we are or may be subject (either directly or indirectly through our ownership interests in other entities) and our ability to absorb and address any damages or other remedies that are sought or awarded and any collateral consequences; • evolving accounting standards and policies; • the adequacy of our corporate governance, risk-management framework, compliance programs, and internal controls over financial reporting, including our ability to control lapses or deficiencies in financial reporting, to make appropriate estimates, or to effectively mitigate or manage operational risk; • any instability or breakdown in the financial system, including as a result of the actual or perceived soundness of another financial institution or another participant in the financial system; • disruptions and shifts in investor sentiment or behavior in the securities, capital, or other financial markets, including financial or systemic shocks and volatility or changes in market liquidity, interest or currency rates, or valuations; • our ability to cost-effectively fund our businesses and operations, including by accessing long- and short-term funding and liquidity and by retaining and growing client deposits; • changes in any of our credit ratings; • our ability to manage any unexpected outflows of uninsured deposits and avoid selling investment securities or other assets at an unfavorable time or at a loss; • negative market perceptions of our investment portfolio or its value; • adverse publicity or other reputational harm to us, our service providers, or our senior officers; • business and consumer sentiment, preferences, or behavior, including spending, borrowing, or saving by businesses or households; • our ability to execute on strategic and operational plans, including accelerating growth, improving profitability, investing in talent, technology, and risk infrastructure, maintaining expense, credit, and risk discipline, and returning capital to shareholders; • changes in our corporate and business strategies, the composition of our assets, or the way in which we fund those assets; • our ability to successfully make and integrate acquisitions and to effect divestitures; • our ability to develop, maintain, and market our products or services or to absorb unanticipated costs or liabilities associated with those products or services; • our ability to innovate, to anticipate the needs of current or future clients, to successfully compete, to increase or hold market share in changing competitive environments, or to deal with pricing or other competitive pressures; • our ability to maintain secure and functional financial, accounting, technology, data processing, or other operating systems or infrastructure, including those that safeguard personal and other sensitive information; • our ability to appropriately underwrite loans that we originate or purchase and to otherwise manage credit risk; • our ability to satisfactorily and profitably perform loan servicing and similar obligations; • the credit, liquidity, or other financial condition of our clients, counterparties, service providers, or competitors; • our ability to effectively deal with economic, business, or market slowdowns or disruptions; • the efficacy of our methods or models in assessing business strategies or opportunities or in valuing, measuring, estimating, monitoring, or managing positions or risk; • our ability to keep pace with changes in technology that affect us or our clients, counterparties, service providers, or competitors or to maintain rights or interests in associated intellectual property; • our ability to attract, hire, and retain key teammates and to engage in adequate succession planning; • the performance and availability of third-party service providers on whom we rely in delivering products and services to our clients and otherwise in conducting our business and operations; • our ability to detect, prevent, mitigate, and otherwise manage the risk of fraud or misconduct by internal or external parties; • our ability to manage and mitigate physical-security and cybersecurity risks, including denial-of-service attacks, hacking, phishing, social-engineering attacks, malware intrusion, data-corruption attempts, system breaches, identity theft, ransomware attacks, environmental conditions, and intentional acts of destruction; • natural or other disasters, calamities, and conflicts, including terrorist events, cyber-warfare, and pandemics; • widespread outages of operational, communication, and other systems; • our ability to maintain appropriate corporate responsibility practices, oversight, and disclosures; • policies and other actions of governments to manage and mitigate climate and related environmental risks, and the effects of climate change or the transition to a lower-carbon economy on our business, operations, and reputation; and • other assumptions, risks, or uncertainties described in the Risk Factors (Item 1A), Management’s Discussion and Analysis of Financial Condition and Results of Operations (Item 7), or the Notes to the Consolidated Financial Statements (Item 8) in our Annual Report on Form 10-K or described in any of the Company’s subsequent quarterly or current reports. Any forward-looking statement made by us or on our behalf speaks only as of the date that it was made. We do not undertake to update any forward-looking statement to reflect the impact of events, circumstances, or results that arise after the date that the statement was made, except as required by applicable securities laws. You, however, should consult further disclosures (including disclosures of a forward-looking nature) that we may make in any subsequent Annual Report on Form 10-K, Quarterly Report on Form 10-Q, or Current Report on Form 8-K. Forward-Looking Statements
3 Non-GAAP Information This presentation contains financial information and performance measures determined by methods other than in accordance with accounting principles generally accepted in the United States of America ("GAAP"). Truist’s management uses these “non-GAAP” measures in their analysis of Truist’s performance and the efficiency of its operations. Management believes these non-GAAP measures are useful to investors because they provide a greater understanding of ongoing operations, enhance comparability of results with prior periods and demonstrate the effects of significant items in the current period. Truist believes a meaningful analysis of its financial performance requires an understanding of the factors underlying that performance. These disclosures should not be viewed as a substitute for financial measures determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Below is a listing of the types of non-GAAP measures used in this presentation: Adjusted Net income Available to Common Shareholders and Adjusted Diluted Earnings Per Share - Adjusted net income available to common shareholders and adjusted diluted earnings per share are non-GAAP in that these measures exclude selected items, net of tax. Truist’s management uses these measures in their analysis of Truist’s performance. Truist’s management believes these measures provide a greater understanding of ongoing operations and enhance comparability of results with prior periods, as well as demonstrate the effects of significant gains and charges. Adjusted Efficiency Ratio, Adjusted Fee Income, and Related Measures - The adjusted efficiency ratio is non-GAAP in that it excludes securities gains and losses, amortization of intangible assets, restructuring charges, and other selected items. Adjusted revenue and adjusted noninterest expense are related measures used to calculate the adjusted efficiency ratio. Additionally, the adjusted fee income ratio is non-GAAP in that it excludes securities gains and losses and other selected items, and is calculated using adjusted revenue and adjusted noninterest income. Taxable equivalent revenue and taxable equivalent net interest income include a taxable equivalent adjustment utilizing the federal income tax rate of 21% for certain tax-exempt instruments. Adjusted revenue and adjusted noninterest income exclude securities gains and losses and other selected items. Adjusted noninterest expense excludes restructuring charges, and other selected items. Truist’s management calculated these measures based on Truist’s continuing operations. Truist’s management uses these measures in their analysis of Truist’s performance. Truist’s management believes these measures provide a greater understanding of ongoing operations and enhance comparability of results with prior periods, as well as demonstrate the effects of significant gains and charges. Pre-Provision Net Revenue (PPNR) - Pre-provision net revenue is a non-GAAP measure that adjusts net income determined in accordance with GAAP to exclude the impact of the provision for credit losses and provision for income taxes. Adjusted pre-provision net revenue is a non-GAAP measure that additionally excludes securities gains (losses), restructuring charges, and other selected items. Truist’s management calculated these measures based on Truist’s continuing operations. Truist’s management believes these measures provide a greater understanding of ongoing operations and enhance comparability of results with prior periods. Tangible Common Equity and Related Measures - Tangible common equity and related measures, including ROTCE and TBVPS, are non-GAAP measures that exclude the impact of intangible assets, net of deferred taxes, and their related amortization. These measures are useful for evaluating the performance of a business consistently, whether acquired or developed internally. Truist’s management uses these measures to assess profitability, returns relative to balance sheet risk, and shareholder value. A copy of this presentation is available on the Truist Investor Relations website, ir.truist.com.
4 Purpose Inspire and build better lives and communities Mission Clients Provide distinctive, secure, and successful client experiences through touch and technology. Teammates Create an inclusive and energizing environment that empowers teammates to learn, grow, and have meaningful careers. Stakeholders Optimize long-term value for stakeholders through safe, sound, and ethical practices. Values Trustworthy We serve with integrity. Caring Everyone and every moment matters. One Team Together, we can accomplish anything. Success When our clients win, we all win. Happiness Positive energy changes lives.
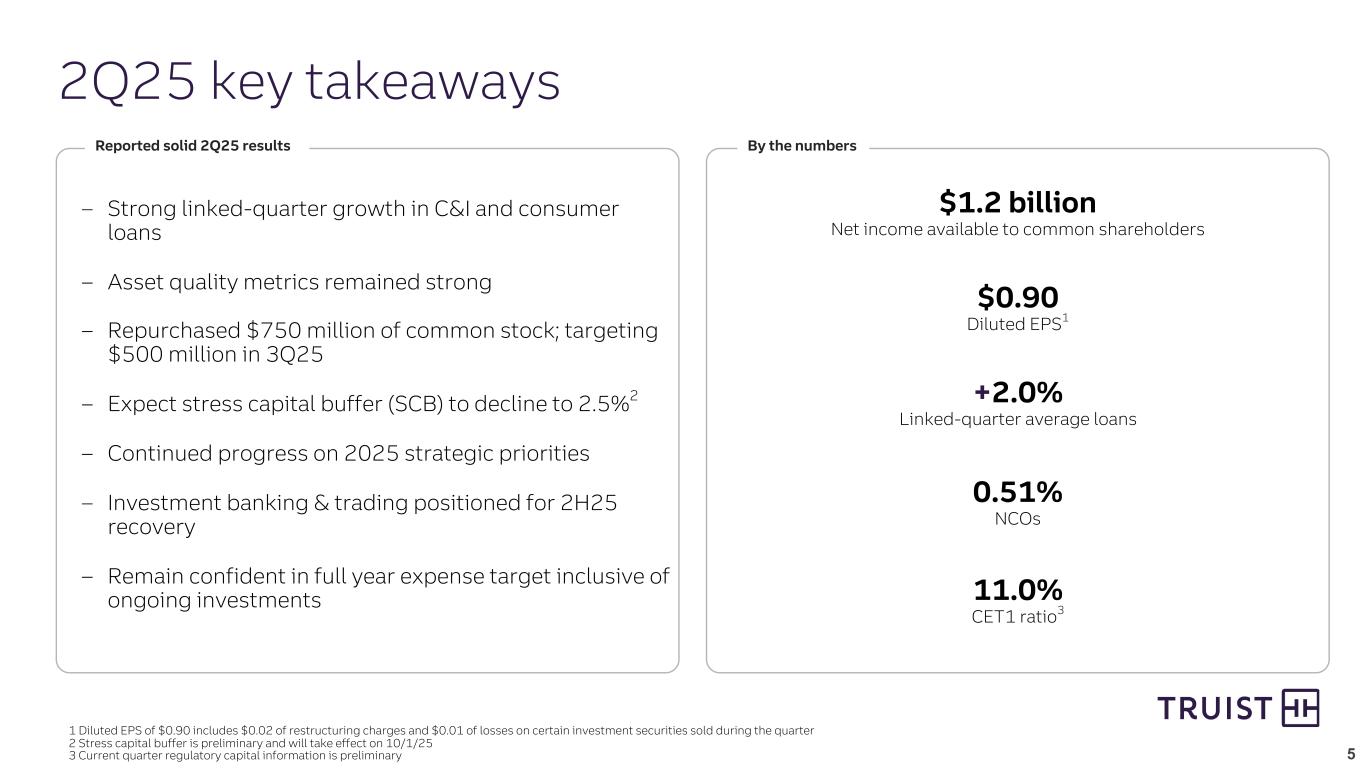
5 2Q25 key takeaways By the numbers 1 Diluted EPS of $0.90 includes $0.02 of restructuring charges and $0.01 of losses on certain investment securities sold during the quarter 2 Stress capital buffer is preliminary and will take effect on 10/1/25 3 Current quarter regulatory capital information is preliminary $1.2 billion Net income available to common shareholders $0.90 Diluted EPS1 +2.0% Linked-quarter average loans 0.51% NCOs 11.0% CET1 ratio3 – Strong linked-quarter growth in C&I and consumer loans – Asset quality metrics remained strong – Repurchased $750 million of common stock; targeting $500 million in 3Q25 – Expect stress capital buffer (SCB) to decline to 2.5%2 – Continued progress on 2025 strategic priorities – Investment banking & trading positioned for 2H25 recovery – Remain confident in full year expense target inclusive of ongoing investments Reported solid 2Q25 results
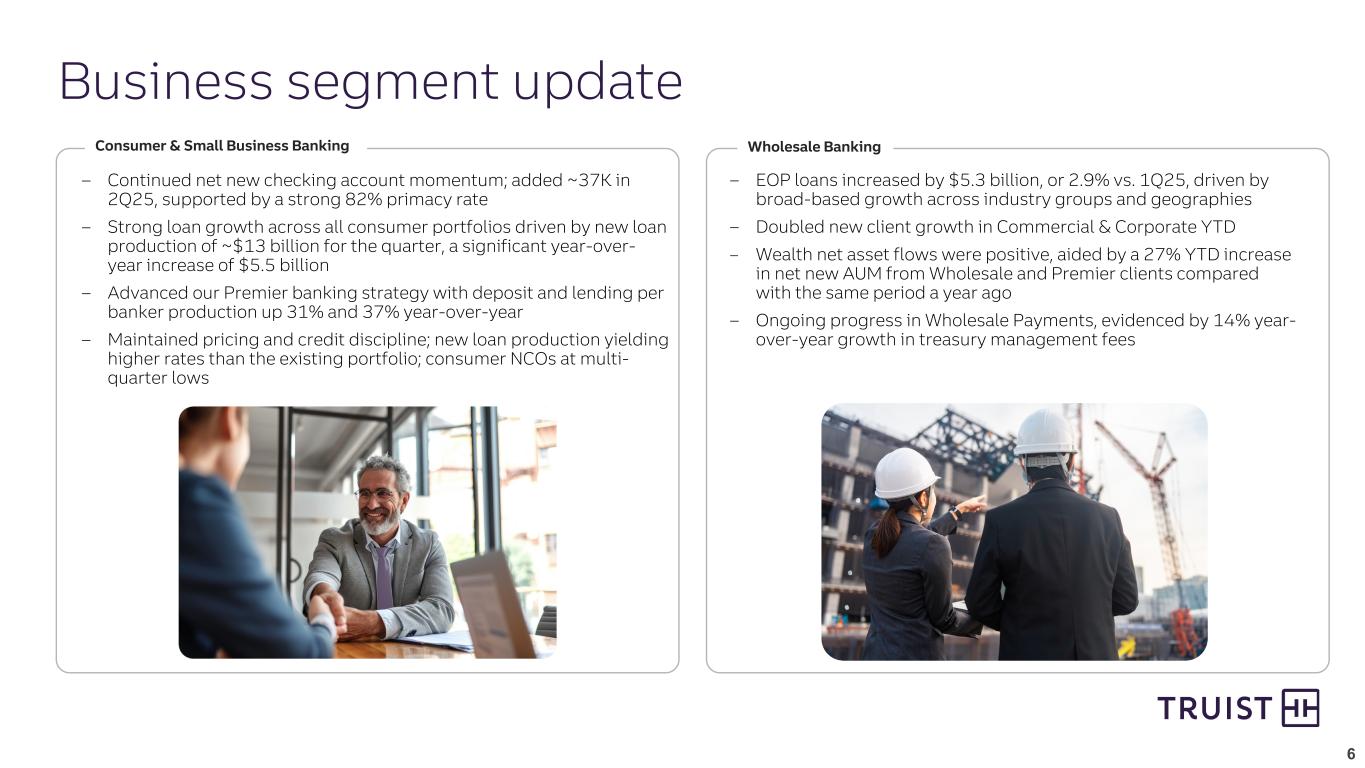
6 – Continued net new checking account momentum; added ~37K in 2Q25, supported by a strong 82% primacy rate – Strong loan growth across all consumer portfolios driven by new loan production of ~$13 billion for the quarter, a significant year-over- year increase of $5.5 billion – Advanced our Premier banking strategy with deposit and lending per banker production up 31% and 37% year-over-year – Maintained pricing and credit discipline; new loan production yielding higher rates than the existing portfolio; consumer NCOs at multi- quarter lows Business segment update Consumer & Small Business Banking – EOP loans increased by $5.3 billion, or 2.9% vs. 1Q25, driven by broad-based growth across industry groups and geographies – Doubled new client growth in Commercial & Corporate YTD – Wealth net asset flows were positive, aided by a 27% YTD increase in net new AUM from Wholesale and Premier clients compared with the same period a year ago – Ongoing progress in Wholesale Payments, evidenced by 14% year- over-year growth in treasury management fees Wholesale Banking
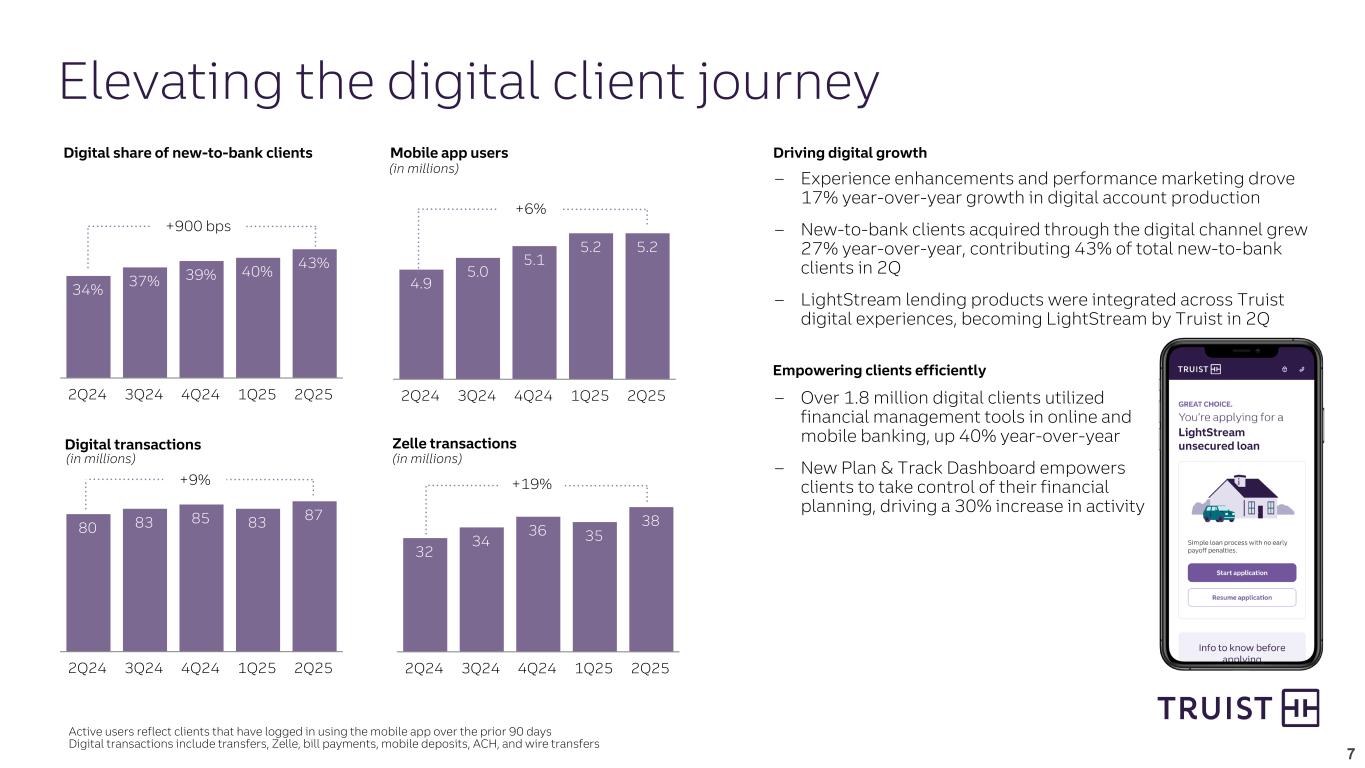
7 80 83 85 83 87 2Q24 3Q24 4Q24 1Q25 2Q25 34% 37% 39% 40% 43% 2Q24 3Q24 4Q24 1Q25 2Q25 32 34 36 35 38 2Q24 3Q24 4Q24 1Q25 2Q25 Digital share of new-to-bank clients Mobile app users Digital transactions Zelle transactions (in millions) 4.9 5.0 5.1 5.2 5.2 2Q24 3Q24 4Q24 1Q25 2Q25 (in millions) Elevating the digital client journey Driving digital growth – Experience enhancements and performance marketing drove 17% year-over-year growth in digital account production – New-to-bank clients acquired through the digital channel grew 27% year-over-year, contributing 43% of total new-to-bank clients in 2Q – LightStream lending products were integrated across Truist digital experiences, becoming LightStream by Truist in 2Q +900 bps +6% +9% +19% Empowering clients efficiently – Over 1.8 million digital clients utilized financial management tools in online and mobile banking, up 40% year-over-year – New Plan & Track Dashboard empowers clients to take control of their financial planning, driving a 30% increase in activity Active users reflect clients that have logged in using the mobile app over the prior 90 days Digital transactions include transfers, Zelle, bill payments, mobile deposits, ACH, and wire transfers (in millions)
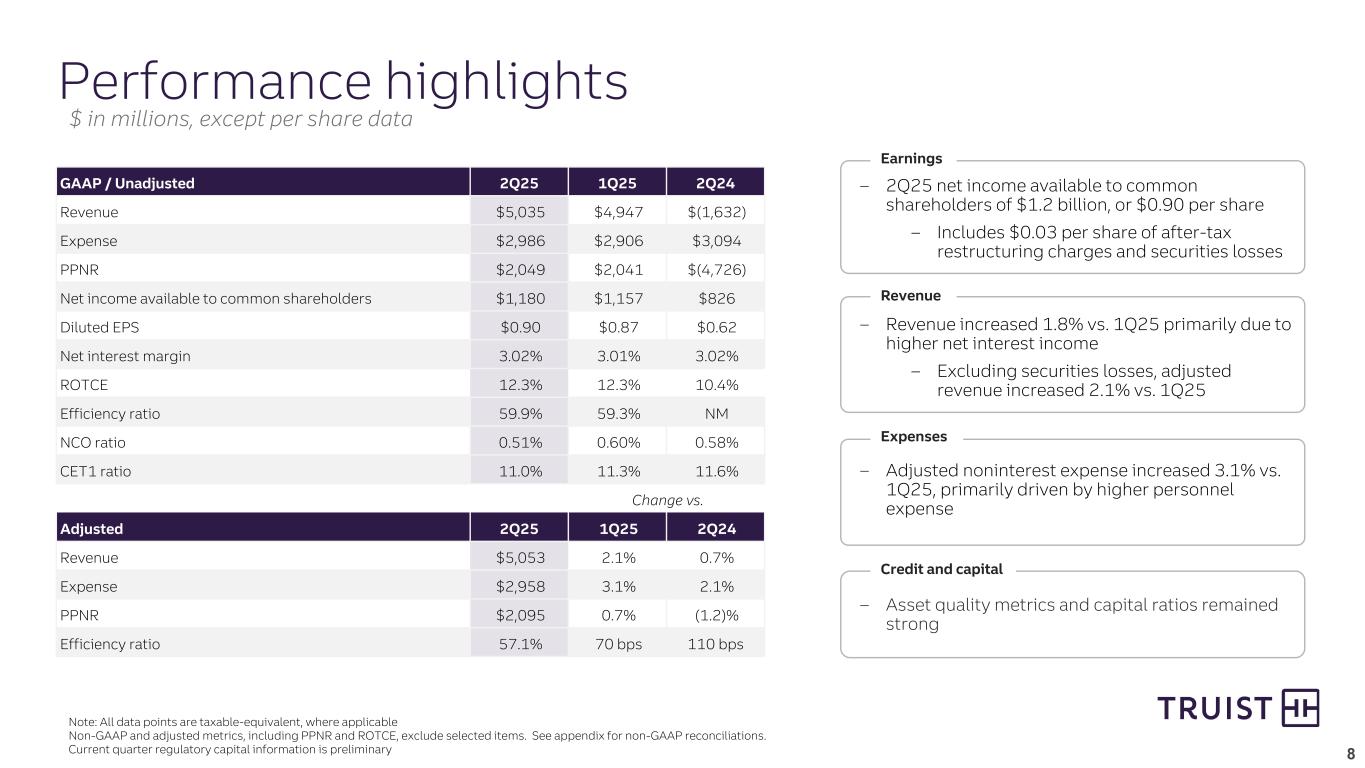
8 Note: All data points are taxable-equivalent, where applicable Non-GAAP and adjusted metrics, including PPNR and ROTCE, exclude selected items. See appendix for non-GAAP reconciliations. Current quarter regulatory capital information is preliminary $ in millions, except per share data GAAP / Unadjusted 2Q25 1Q25 2Q24 Revenue $5,035 $4,947 $(1,632) Expense $2,986 $2,906 $3,094 PPNR $2,049 $2,041 $(4,726) Net income available to common shareholders $1,180 $1,157 $826 Diluted EPS $0.90 $0.87 $0.62 Net interest margin 3.02% 3.01% 3.02% ROTCE 12.3% 12.3% 10.4% Efficiency ratio 59.9% 59.3% NM NCO ratio 0.51% 0.60% 0.58% CET1 ratio 11.0% 11.3% 11.6% Change vs. Adjusted 2Q25 1Q25 2Q24 Revenue $5,053 2.1% 0.7% Expense $2,958 3.1% 2.1% PPNR $2,095 0.7% (1.2)% Efficiency ratio 57.1% 70 bps 110 bps Performance highlights Earnings – 2Q25 net income available to common shareholders of $1.2 billion, or $0.90 per share – Includes $0.03 per share of after-tax restructuring charges and securities losses Revenue – Revenue increased 1.8% vs. 1Q25 primarily due to higher net interest income – Excluding securities losses, adjusted revenue increased 2.1% vs. 1Q25 Expenses Credit and capital – Asset quality metrics and capital ratios remained strong – Adjusted noninterest expense increased 3.1% vs. 1Q25, primarily driven by higher personnel expense
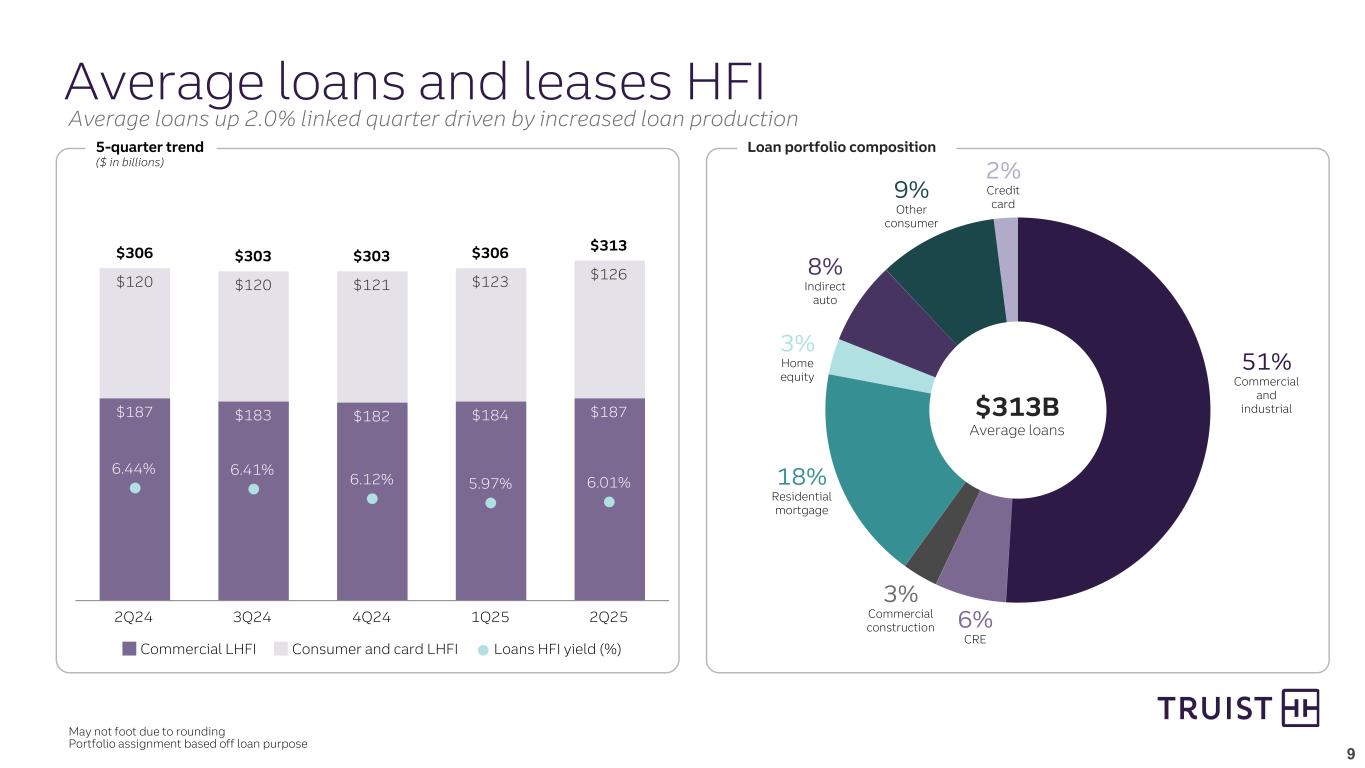
9 $306 $303 $303 $306 $313 $187 $183 $182 $184 $187 $120 $120 $121 $123 $126 6.44% 6.41% 6.12% 5.97% 6.01% Commercial LHFI Consumer and card LHFI Loans HFI yield (%) 2Q24 3Q24 4Q24 1Q25 2Q25 May not foot due to rounding Portfolio assignment based off loan purpose 5-quarter trend ($ in billions) Loan portfolio composition $313B Average loans 51% Commercial and industrial 6% CRE 3% Commercial construction 18% Residential mortgage 3% Home equity 8% Indirect auto 9% Other consumer 2% Credit card Average loans and leases HFI Average loans up 2.0% linked quarter driven by increased loan production
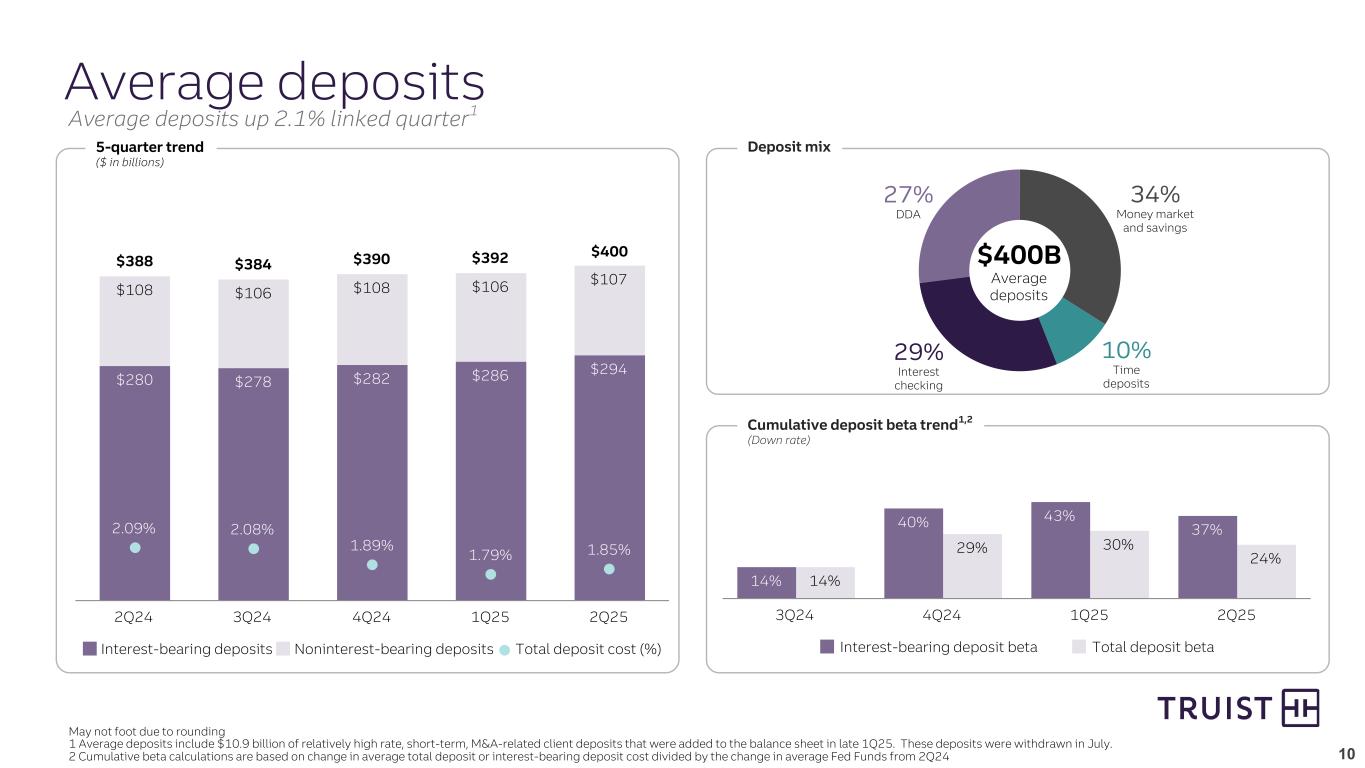
10 14% 40% 43% 37% 14% 29% 30% 24% Interest-bearing deposit beta Total deposit beta 3Q24 4Q24 1Q25 2Q25 Average deposits $388 $384 $390 $392 $280 $278 $282 $286 $294 $108 $106 $108 $106 $107 2.09% 2.08% 1.89% 1.79% 1.85% Interest-bearing deposits Noninterest-bearing deposits Total deposit cost (%) 2Q24 3Q24 4Q24 1Q25 2Q25 May not foot due to rounding 1 Average deposits include $10.9 billion of relatively high rate, short-term, M&A-related client deposits that were added to the balance sheet in late 1Q25. These deposits were withdrawn in July. 2 Cumulative beta calculations are based on change in average total deposit or interest-bearing deposit cost divided by the change in average Fed Funds from 2Q24 Deposit mix $400B Average deposits 34% Money market and savings 10% Time deposits 29% Interest checking 27% DDA Cumulative deposit beta trend1,2 (Down rate) 5-quarter trend ($ in billions) $400 Average deposits up 2.1% linked quarter1
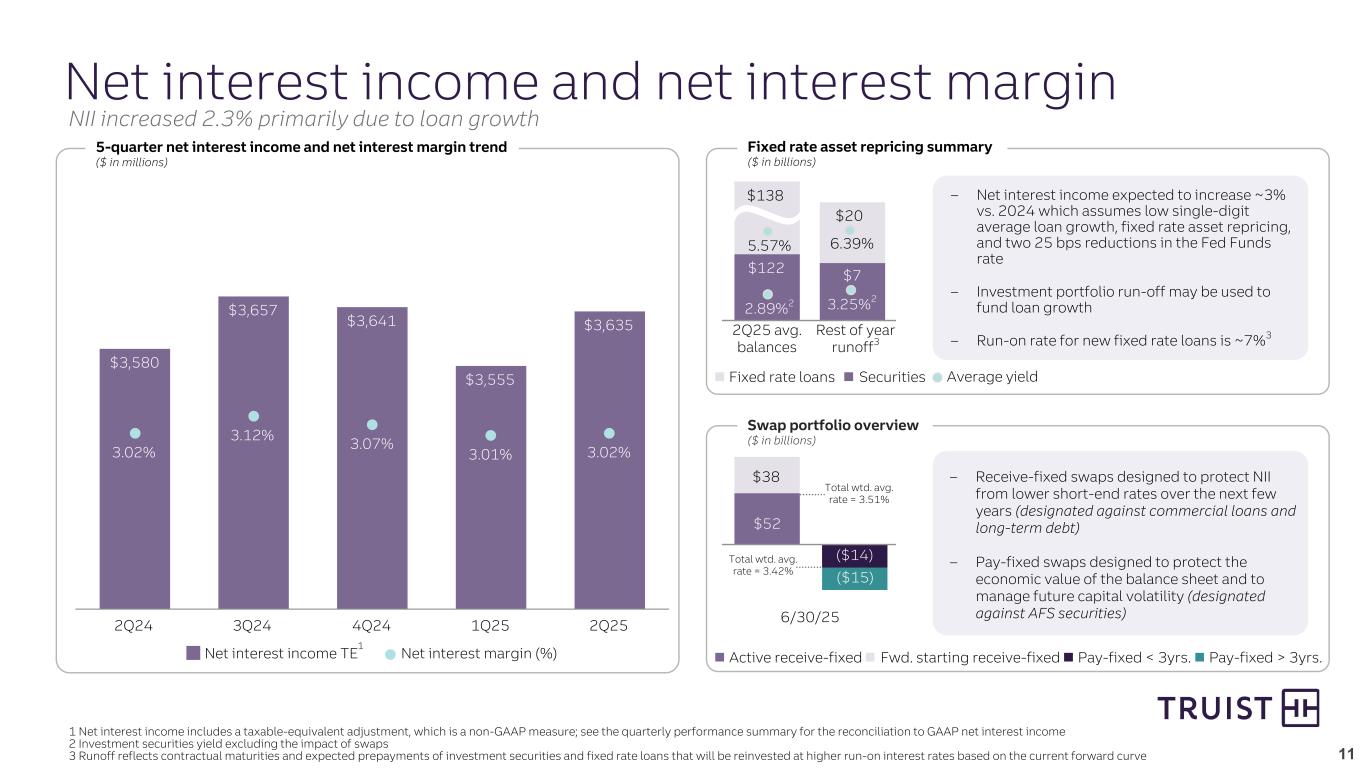
11 2Q25 avg. balances Fixed rate loans Securities Active receive-fixed $3,580 $3,657 $3,641 $3,555 $3,635 3.02% 3.12% 3.07% 3.01% 3.02% Net interest income TE Net interest margin (%) 2Q24 3Q24 4Q24 1Q25 2Q25 Fwd. starting receive-fixed Pay-fixed < 3yrs. – Receive-fixed swaps designed to protect NII from lower short-end rates over the next few years (designated against commercial loans and long-term debt) – Pay-fixed swaps designed to protect the economic value of the balance sheet and to manage future capital volatility (designated against AFS securities) Net interest income and net interest margin Fixed rate asset repricing summary ($ in billions) Swap portfolio overview ($ in billions) 1 Net interest income includes a taxable-equivalent adjustment, which is a non-GAAP measure; see the quarterly performance summary for the reconciliation to GAAP net interest income 2 Investment securities yield excluding the impact of swaps 3 Runoff reflects contractual maturities and expected prepayments of investment securities and fixed rate loans that will be reinvested at higher run-on interest rates based on the current forward curve 1 Average yield ($15) 6/30/25 $52 $38 Total wtd. avg. rate = 3.51% ($14)Total wtd. avg. rate = 3.42% Pay-fixed > 3yrs. 5-quarter net interest income and net interest margin trend ($ in millions) $122 $138 $7 $20 2.89%2 3.25%2 5.57% 6.39% – Net interest income expected to increase ~3% vs. 2024 which assumes low single-digit average loan growth, fixed rate asset repricing, and two 25 bps reductions in the Fed Funds rate – Investment portfolio run-off may be used to fund loan growth – Run-on rate for new fixed rate loans is ~7%3Rest of year runoff3 ~ 1 NII increased 2.3% primarily due to loan growth
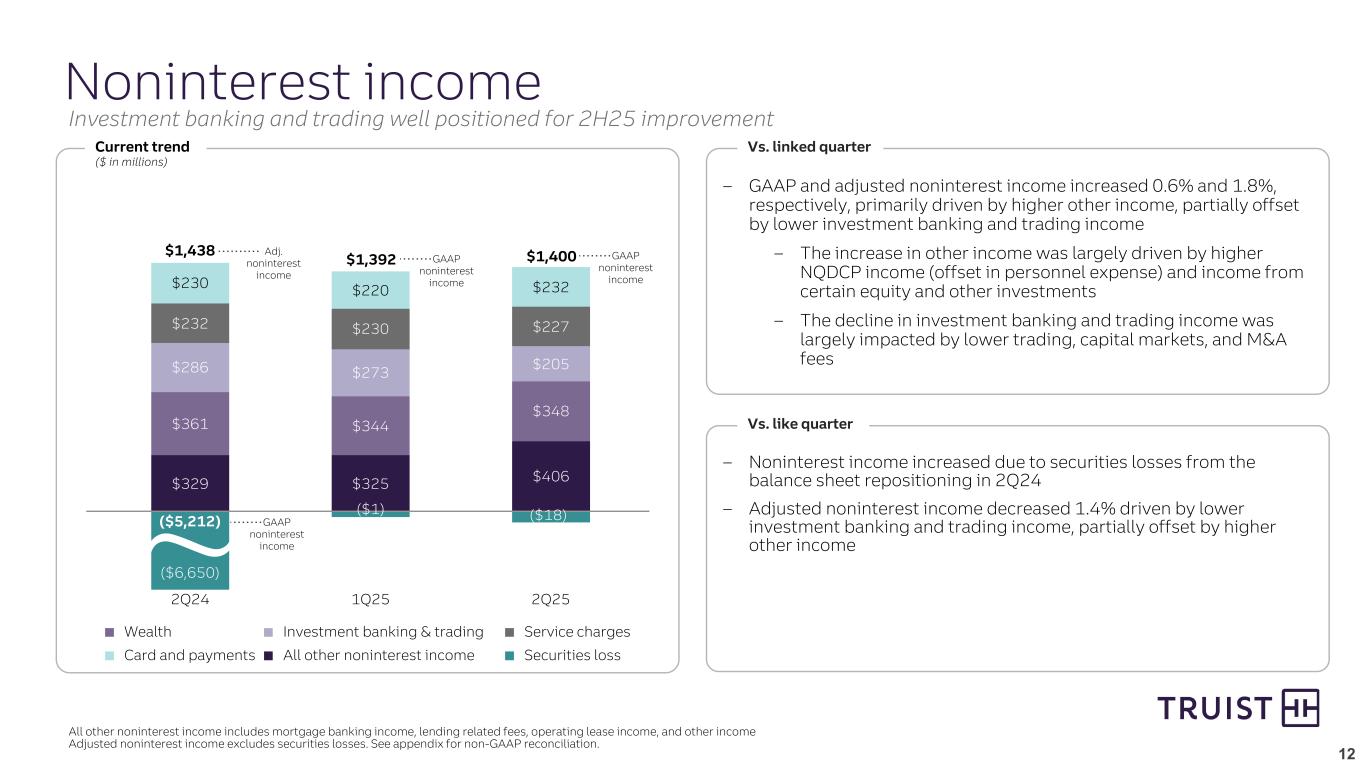
12 $329 $325 $406 $361 $344 $348 $286 $273 $205 $232 $230 $227 $230 $220 $232 Noninterest income Current trend ($ in millions) Wealth Investment banking & trading Service charges Card and payments All other noninterest income All other noninterest income includes mortgage banking income, lending related fees, operating lease income, and other income Adjusted noninterest income excludes securities losses. See appendix for non-GAAP reconciliation. Vs. linked quarter – GAAP and adjusted noninterest income increased 0.6% and 1.8%, respectively, primarily driven by higher other income, partially offset by lower investment banking and trading income – The increase in other income was largely driven by higher NQDCP income (offset in personnel expense) and income from certain equity and other investments – The decline in investment banking and trading income was largely impacted by lower trading, capital markets, and M&A fees Vs. like quarter – Noninterest income increased due to securities losses from the balance sheet repositioning in 2Q24 – Adjusted noninterest income decreased 1.4% driven by lower investment banking and trading income, partially offset by higher other income Securities loss ($1) 2Q24 1Q25 2Q25 $1,392 ~ GAAP noninterest income ($5,212) ($6,650) $1,400 ($18) Adj. noninterest income $1,438 GAAP noninterest income GAAP noninterest income Investment banking and trading well positioned for 2H25 improvement
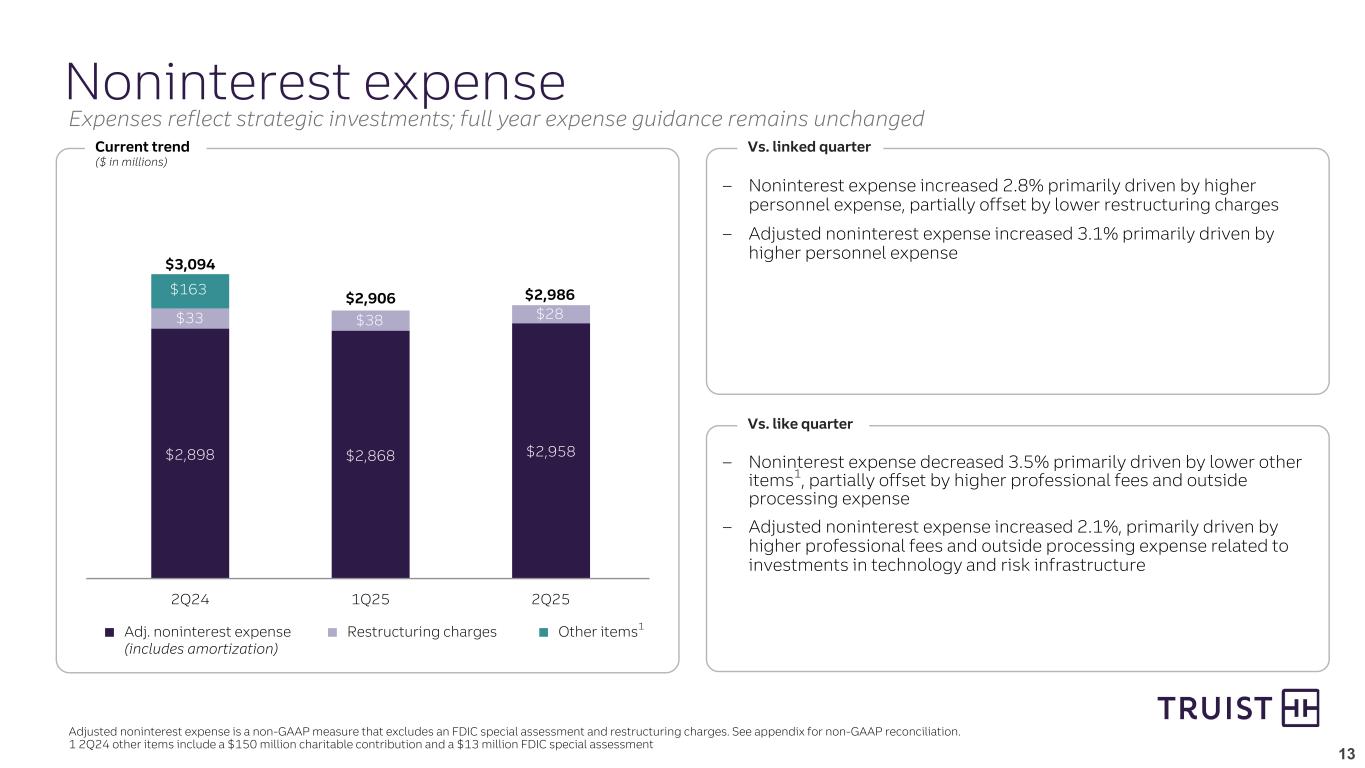
13 $2,898 $2,868 $2,958 Noninterest expense Adjusted noninterest expense is a non-GAAP measure that excludes an FDIC special assessment and restructuring charges. See appendix for non-GAAP reconciliation. 1 2Q24 other items include a $150 million charitable contribution and a $13 million FDIC special assessment Current trend ($ in millions) Adj. noninterest expense (includes amortization) Restructuring charges Vs. linked quarter Vs. like quarter $11 $38 – Noninterest expense increased 2.8% primarily driven by higher personnel expense, partially offset by lower restructuring charges – Adjusted noninterest expense increased 3.1% primarily driven by higher personnel expense – Noninterest expense decreased 3.5% primarily driven by lower other items1, partially offset by higher professional fees and outside processing expense – Adjusted noninterest expense increased 2.1%, primarily driven by higher professional fees and outside processing expense related to investments in technology and risk infrastructure Other items1 2Q24 1Q25 2Q25 $38$33 $163 $3,094 $2,906 $2,986 $28 Expenses reflect strategic investments; full year expense guidance remains unchanged
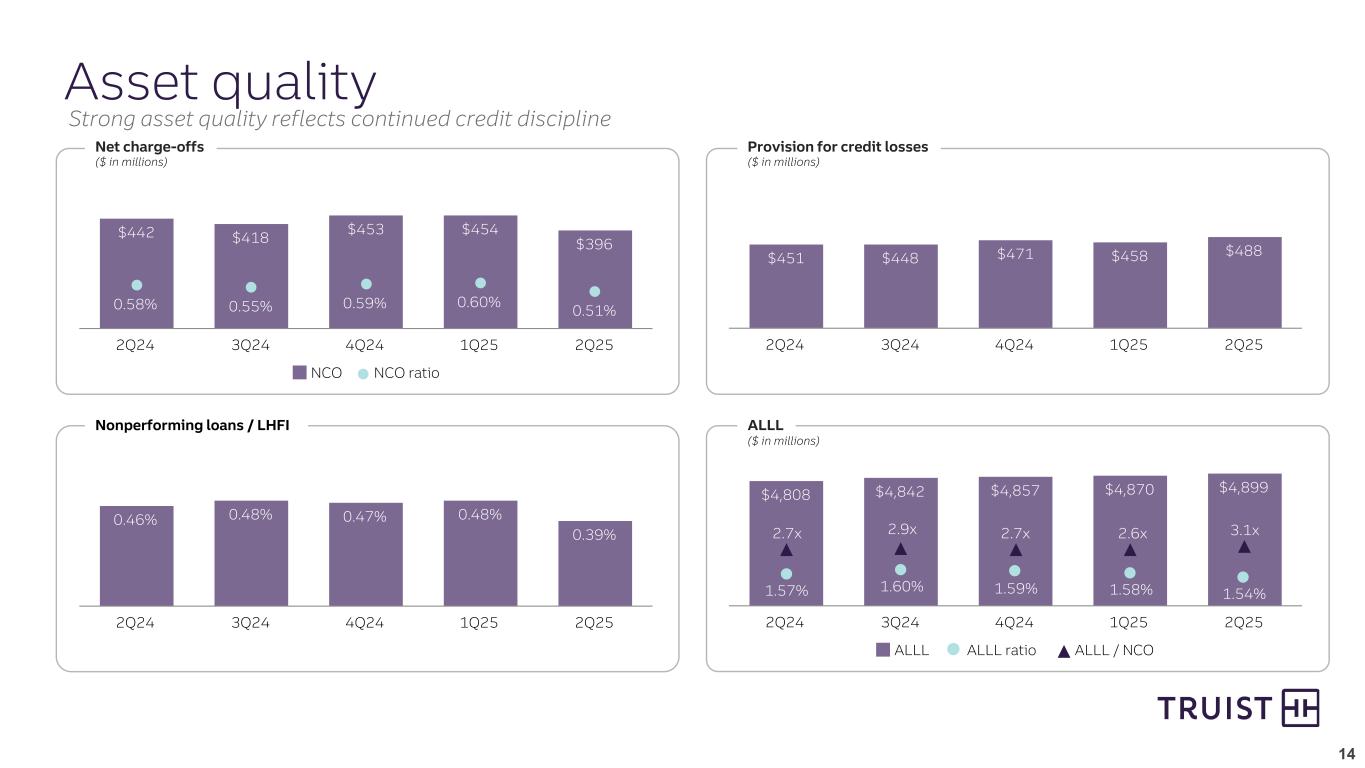
14 0.46% 0.48% 0.47% 0.48% 0.39% 2Q24 3Q24 4Q24 1Q25 2Q25 $451 $448 $471 $458 $488 2Q24 3Q24 4Q24 1Q25 2Q25 $442 $418 $453 $454 $396 0.58% 0.55% 0.59% 0.60% 0.51% NCO NCO ratio 2Q24 3Q24 4Q24 1Q25 2Q25 Asset quality Net charge-offs ($ in millions) Nonperforming loans / LHFI ALLL Provision for credit losses ($ in millions) Strong asset quality reflects continued credit discipline $4,808 $4,842 $4,857 $4,870 $4,899 ALLL ALLL ratio ALLL / NCO 2Q24 3Q24 4Q24 1Q25 2Q25 2.7x 1.57% 1.60% 2.9x 1.59% 2.7x 1.58% 2.6x 1.54% 3.1x ($ in millions)
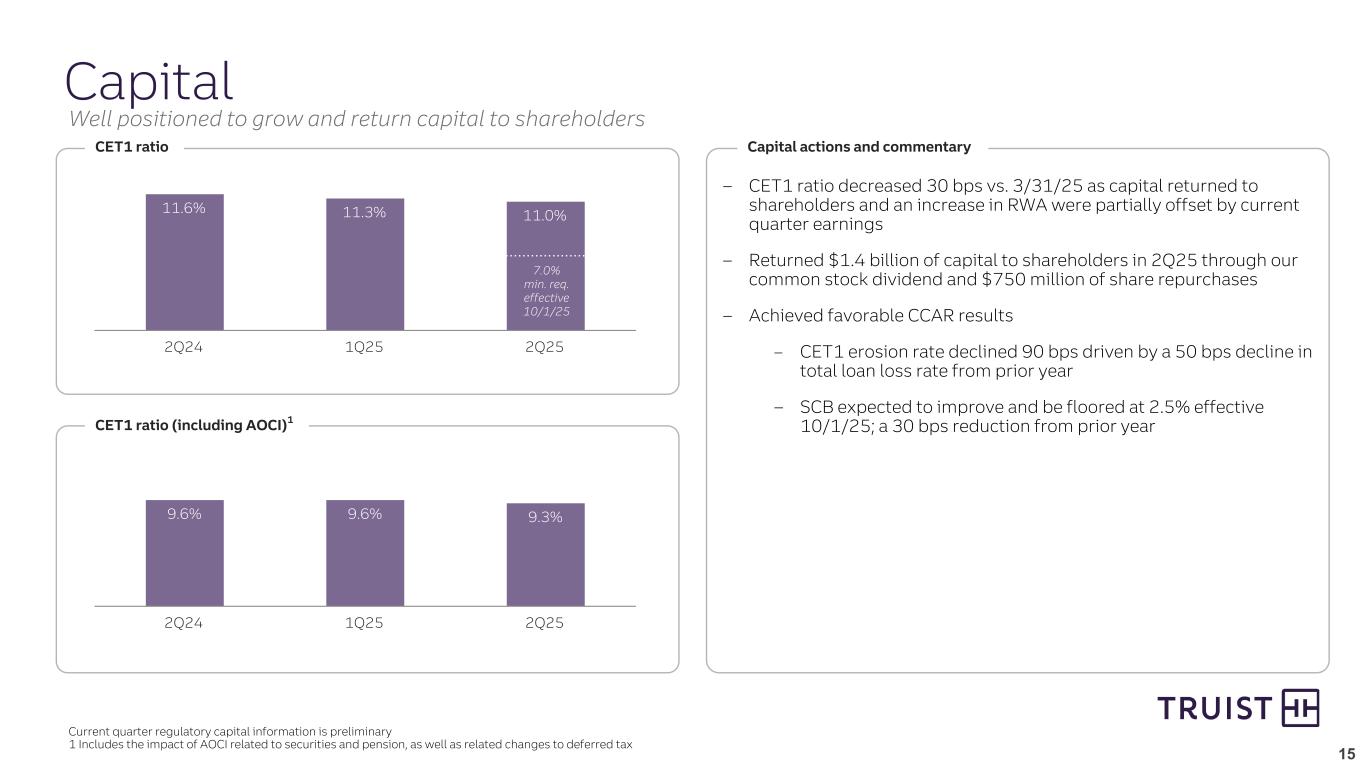
15 11.6% 11.3% 11.0% 2Q24 1Q25 2Q25 9.6% 9.6% 9.3% 2Q24 1Q25 2Q25 9.9% Capital Capital actions and commentary $0.6 $0.6 CET1 ratio CET1 ratio (including AOCI)1 Current quarter regulatory capital information is preliminary 1 Includes the impact of AOCI related to securities and pension, as well as related changes to deferred tax Well positioned to grow and return capital to shareholders 7.0% min. req. effective 10/1/25 – CET1 ratio decreased 30 bps vs. 3/31/25 as capital returned to shareholders and an increase in RWA were partially offset by current quarter earnings – Returned $1.4 billion of capital to shareholders in 2Q25 through our common stock dividend and $750 million of share repurchases – Achieved favorable CCAR results – CET1 erosion rate declined 90 bps driven by a 50 bps decline in total loan loss rate from prior year – SCB expected to improve and be floored at 2.5% effective 10/1/25; a 30 bps reduction from prior year
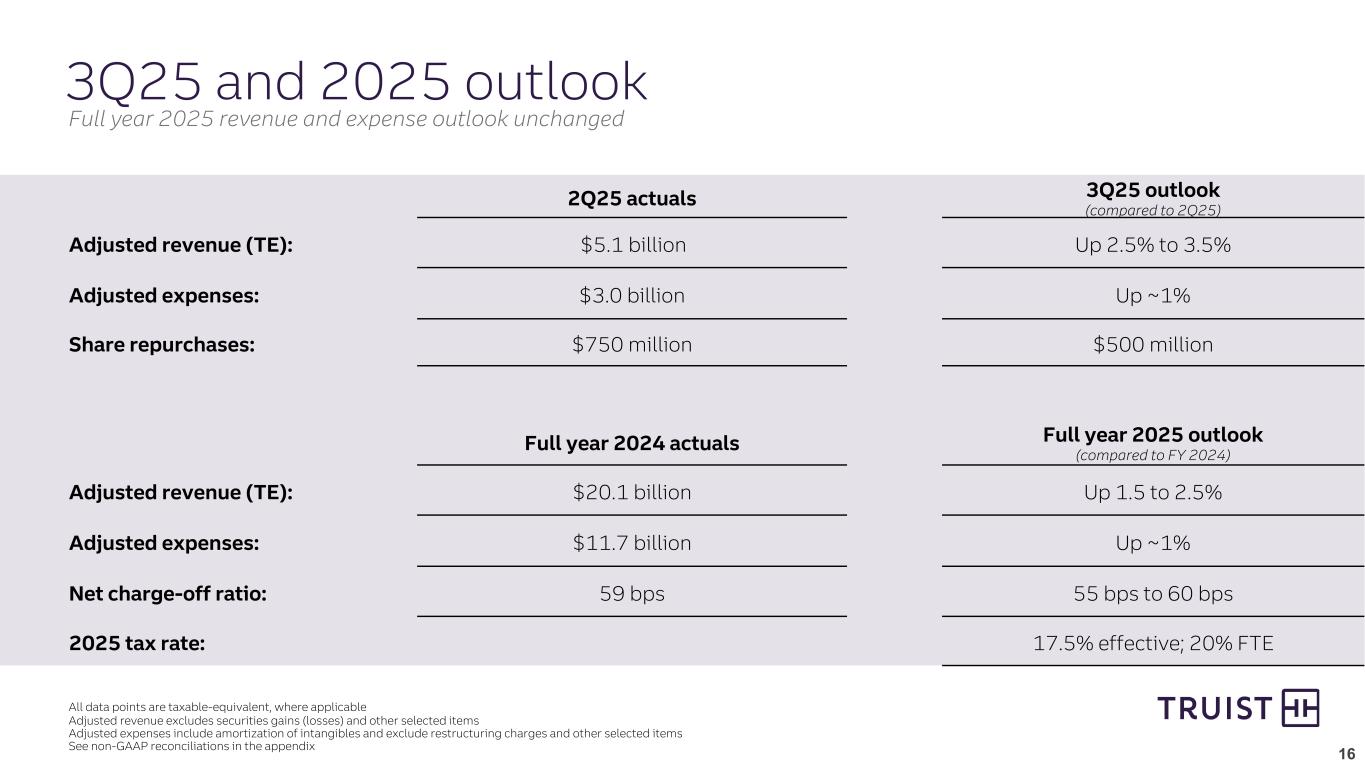
16 13.9% 3Q25 and 2025 outlook All data points are taxable-equivalent, where applicable Adjusted revenue excludes securities gains (losses) and other selected items Adjusted expenses include amortization of intangibles and exclude restructuring charges and other selected items See non-GAAP reconciliations in the appendix 2Q25 actuals 3Q25 outlook (compared to 2Q25) Adjusted revenue (TE): $5.1 billion Up 2.5% to 3.5% Adjusted expenses: $3.0 billion Up ~1% Share repurchases: $750 million $500 million Full year 2024 actuals Full year 2025 outlook (compared to FY 2024) Adjusted revenue (TE): $20.1 billion Up 1.5 to 2.5% Adjusted expenses: $11.7 billion Up ~1% Net charge-off ratio: 59 bps 55 bps to 60 bps 2025 tax rate: 17.5% effective; 20% FTE Full year 2025 revenue and expense outlook unchanged
17 Key takeaways Executing on strategic growth initiatives Driving positive operating leverage through revenue growth and expense discipline Investing in talent, technology, and risk infrastructure Maintaining credit and risk discipline Returning capital to shareholders 2025 strategic priorities
Appendix
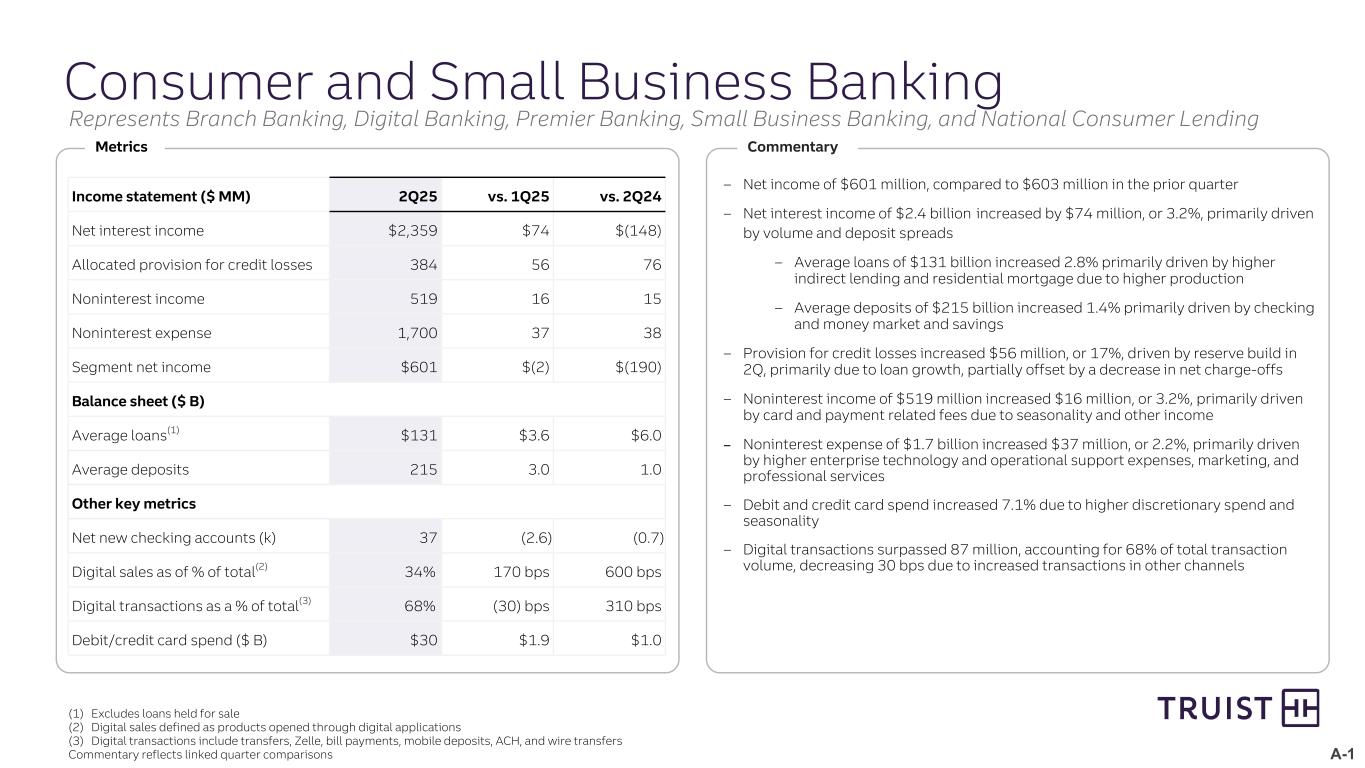
A-1 – Net income of $601 million, compared to $603 million in the prior quarter – Net interest income of $2.4 billion increased by $74 million, or 3.2%, primarily driven by volume and deposit spreads – Average loans of $131 billion increased 2.8% primarily driven by higher indirect lending and residential mortgage due to higher production – Average deposits of $215 billion increased 1.4% primarily driven by checking and money market and savings – Provision for credit losses increased $56 million, or 17%, driven by reserve build in 2Q, primarily due to loan growth, partially offset by a decrease in net charge-offs – Noninterest income of $519 million increased $16 million, or 3.2%, primarily driven by card and payment related fees due to seasonality and other income – Noninterest expense of $1.7 billion increased $37 million, or 2.2%, primarily driven by higher enterprise technology and operational support expenses, marketing, and professional services – Debit and credit card spend increased 7.1% due to higher discretionary spend and seasonality – Digital transactions surpassed 87 million, accounting for 68% of total transaction volume, decreasing 30 bps due to increased transactions in other channels Consumer and Small Business Banking (1) Excludes loans held for sale (2) Digital sales defined as products opened through digital applications (3) Digital transactions include transfers, Zelle, bill payments, mobile deposits, ACH, and wire transfers Commentary reflects linked quarter comparisons Metrics Commentary Income statement ($ MM) 2Q25 vs. 1Q25 vs. 2Q24 Net interest income $2,359 $74 $(148) Allocated provision for credit losses 384 56 76 Noninterest income 519 16 15 Noninterest expense 1,700 37 38 Segment net income $601 $(2) $(190) Balance sheet ($ B) Average loans(1) $131 $3.6 $6.0 Average deposits 215 3.0 1.0 Other key metrics Net new checking accounts (k) 37 (2.6) (0.7) Digital sales as of % of total(2) 34% 170 bps 600 bps Digital transactions as a % of total(3) 68% (30) bps 310 bps Debit/credit card spend ($ B) $30 $1.9 $1.0 Represents Branch Banking, Digital Banking, Premier Banking, Small Business Banking, and National Consumer Lending
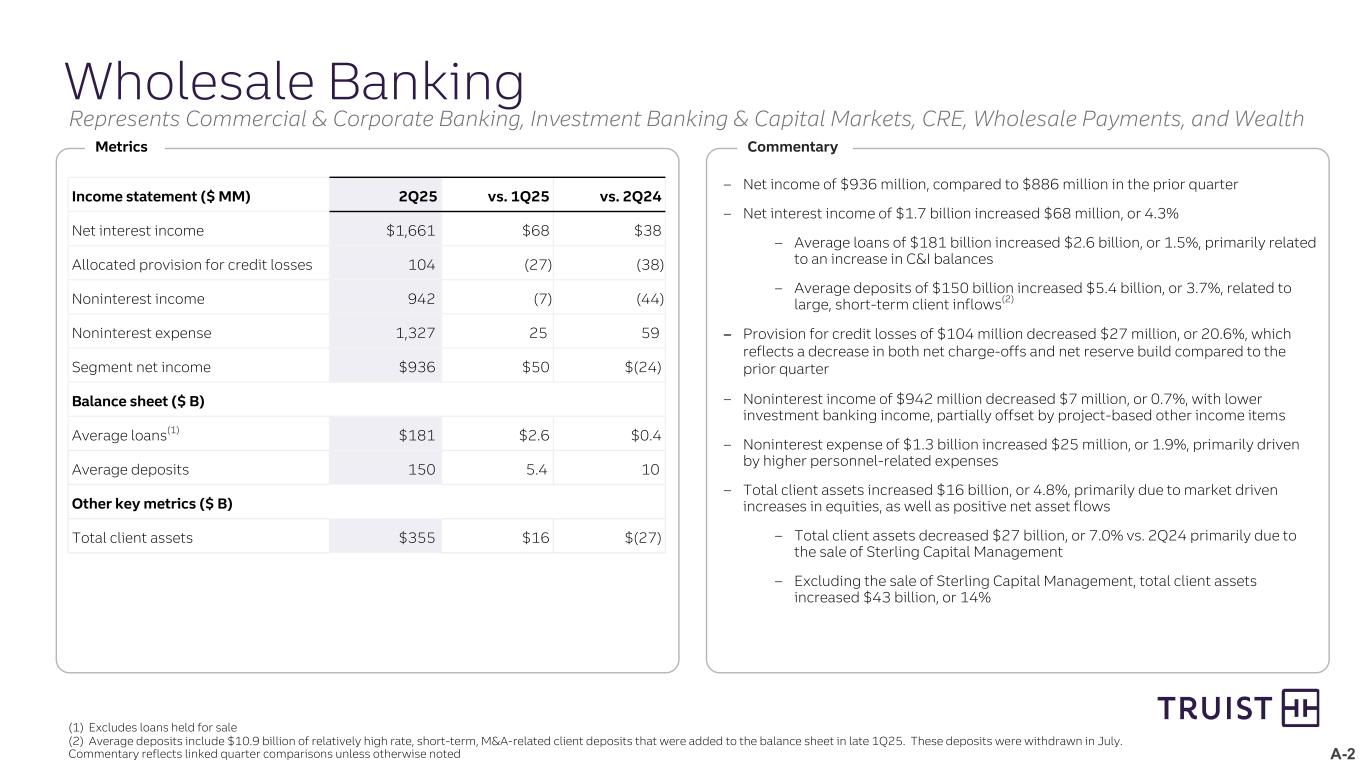
A-2 Wholesale Banking (1) Excludes loans held for sale (2) Average deposits include $10.9 billion of relatively high rate, short-term, M&A-related client deposits that were added to the balance sheet in late 1Q25. These deposits were withdrawn in July. Commentary reflects linked quarter comparisons unless otherwise noted – Net income of $936 million, compared to $886 million in the prior quarter – Net interest income of $1.7 billion increased $68 million, or 4.3% – Average loans of $181 billion increased $2.6 billion, or 1.5%, primarily related to an increase in C&I balances – Average deposits of $150 billion increased $5.4 billion, or 3.7%, related to large, short-term client inflows(2) – Provision for credit losses of $104 million decreased $27 million, or 20.6%, which reflects a decrease in both net charge-offs and net reserve build compared to the prior quarter – Noninterest income of $942 million decreased $7 million, or 0.7%, with lower investment banking income, partially offset by project-based other income items – Noninterest expense of $1.3 billion increased $25 million, or 1.9%, primarily driven by higher personnel-related expenses – Total client assets increased $16 billion, or 4.8%, primarily due to market driven increases in equities, as well as positive net asset flows – Total client assets decreased $27 billion, or 7.0% vs. 2Q24 primarily due to the sale of Sterling Capital Management – Excluding the sale of Sterling Capital Management, total client assets increased $43 billion, or 14% Metrics Commentary Income statement ($ MM) 2Q25 vs. 1Q25 vs. 2Q24 Net interest income $1,661 $68 $38 Allocated provision for credit losses 104 (27) (38) Noninterest income 942 (7) (44) Noninterest expense 1,327 25 59 Segment net income $936 $50 $(24) Balance sheet ($ B) Average loans(1) $181 $2.6 $0.4 Average deposits 150 5.4 10 Other key metrics ($ B) Total client assets $355 $16 $(27) Represents Commercial & Corporate Banking, Investment Banking & Capital Markets, CRE, Wholesale Payments, and Wealth
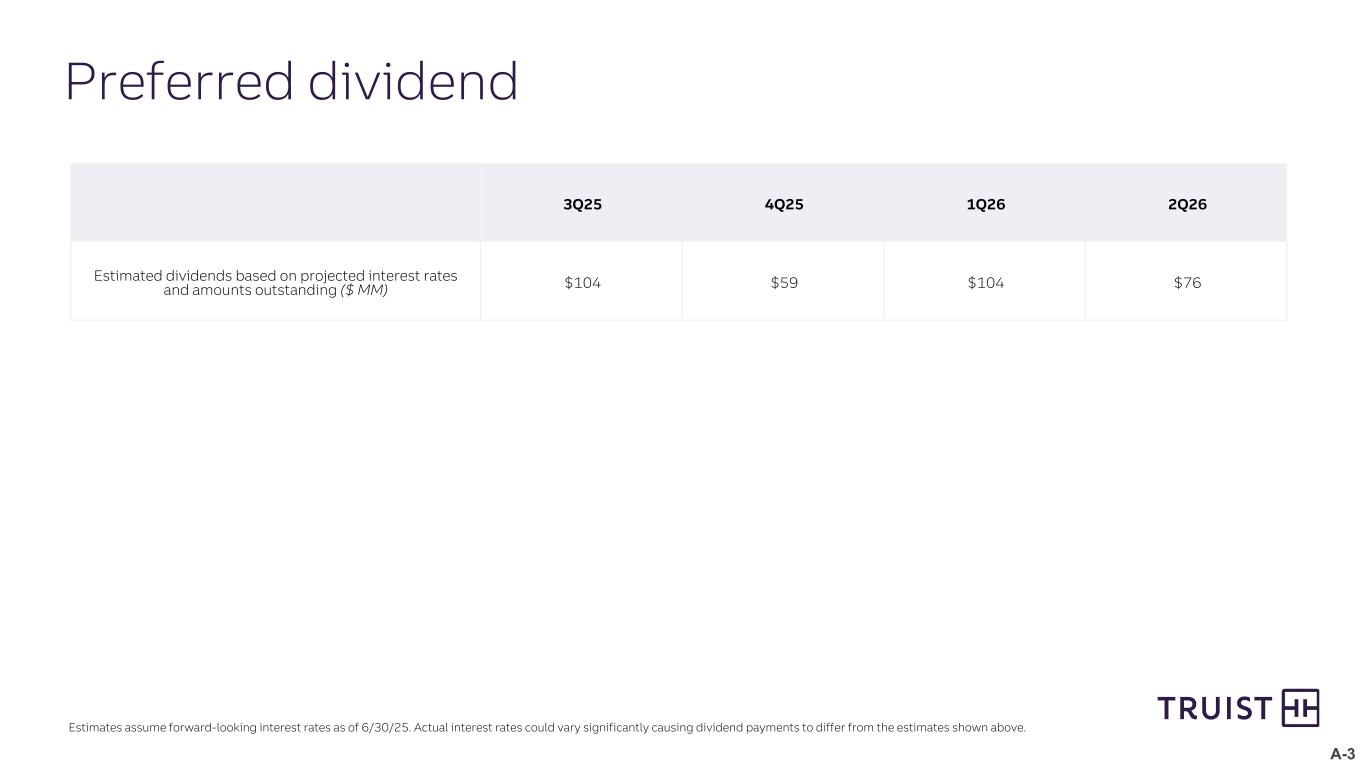
A-3 Preferred dividend 3Q25 4Q25 1Q26 2Q26 Estimated dividends based on projected interest rates and amounts outstanding ($ MM) $104 $59 $104 $76 Estimates assume forward-looking interest rates as of 6/30/25. Actual interest rates could vary significantly causing dividend payments to differ from the estimates shown above.
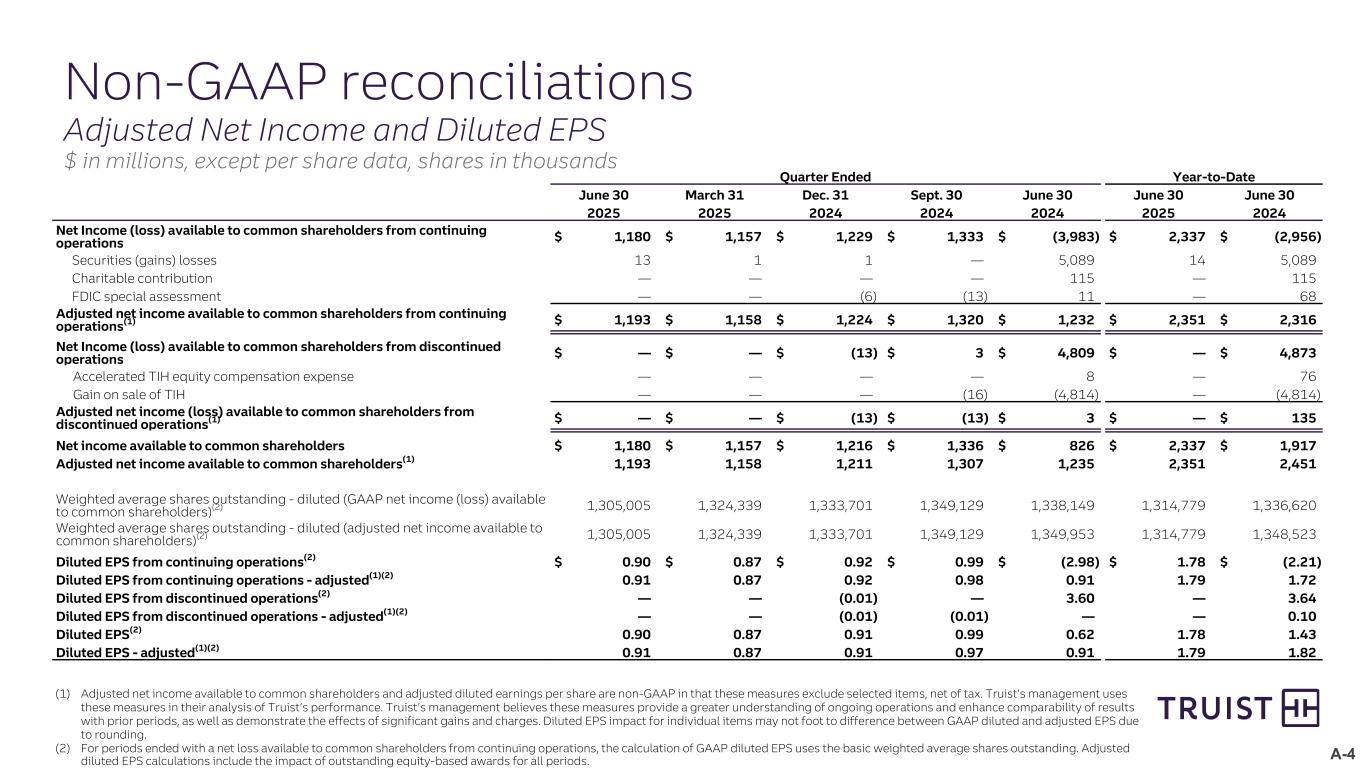
A-4 Quarter Ended Year-to-Date June 30 March 31 Dec. 31 Sept. 30 June 30 June 30 June 30 2025 2025 2024 2024 2024 2025 2024 Net Income (loss) available to common shareholders from continuing operations $ 1,180 $ 1,157 $ 1,229 $ 1,333 $ (3,983) $ 2,337 $ (2,956) Securities (gains) losses 13 1 1 — 5,089 14 5,089 Charitable contribution — — — — 115 — 115 FDIC special assessment — — (6) (13) 11 — 68 Adjusted net income available to common shareholders from continuing operations(1) $ 1,193 $ 1,158 $ 1,224 $ 1,320 $ 1,232 $ 2,351 $ 2,316 Net Income (loss) available to common shareholders from discontinued operations $ — $ — $ (13) $ 3 $ 4,809 $ — $ 4,873 Accelerated TIH equity compensation expense — — — — 8 — 76 Gain on sale of TIH — — — (16) (4,814) — (4,814) Adjusted net income (loss) available to common shareholders from discontinued operations(1) $ — $ — $ (13) $ (13) $ 3 $ — $ 135 Net income available to common shareholders $ 1,180 $ 1,157 $ 1,216 $ 1,336 $ 826 $ 2,337 $ 1,917 Adjusted net income available to common shareholders(1) 1,193 1,158 1,211 1,307 1,235 2,351 2,451 Weighted average shares outstanding - diluted (GAAP net income (loss) available to common shareholders)(2) 1,305,005 1,324,339 1,333,701 1,349,129 1,338,149 1,314,779 1,336,620 Weighted average shares outstanding - diluted (adjusted net income available to common shareholders)(2) 1,305,005 1,324,339 1,333,701 1,349,129 1,349,953 1,314,779 1,348,523 Diluted EPS from continuing operations(2) $ 0.90 $ 0.87 $ 0.92 $ 0.99 $ (2.98) $ 1.78 $ (2.21) Diluted EPS from continuing operations - adjusted(1)(2) 0.91 0.87 0.92 0.98 0.91 1.79 1.72 Diluted EPS from discontinued operations(2) — — (0.01) — 3.60 — 3.64 Diluted EPS from discontinued operations - adjusted(1)(2) — — (0.01) (0.01) — — 0.10 Diluted EPS(2) 0.90 0.87 0.91 0.99 0.62 1.78 1.43 Diluted EPS - adjusted(1)(2) 0.91 0.87 0.91 0.97 0.91 1.79 1.82 Non-GAAP reconciliations Adjusted Net Income and Diluted EPS $ in millions, except per share data, shares in thousands (1) Adjusted net income available to common shareholders and adjusted diluted earnings per share are non-GAAP in that these measures exclude selected items, net of tax. Truist’s management uses these measures in their analysis of Truist’s performance. Truist’s management believes these measures provide a greater understanding of ongoing operations and enhance comparability of results with prior periods, as well as demonstrate the effects of significant gains and charges. Diluted EPS impact for individual items may not foot to difference between GAAP diluted and adjusted EPS due to rounding. (2) For periods ended with a net loss available to common shareholders from continuing operations, the calculation of GAAP diluted EPS uses the basic weighted average shares outstanding. Adjusted diluted EPS calculations include the impact of outstanding equity-based awards for all periods.
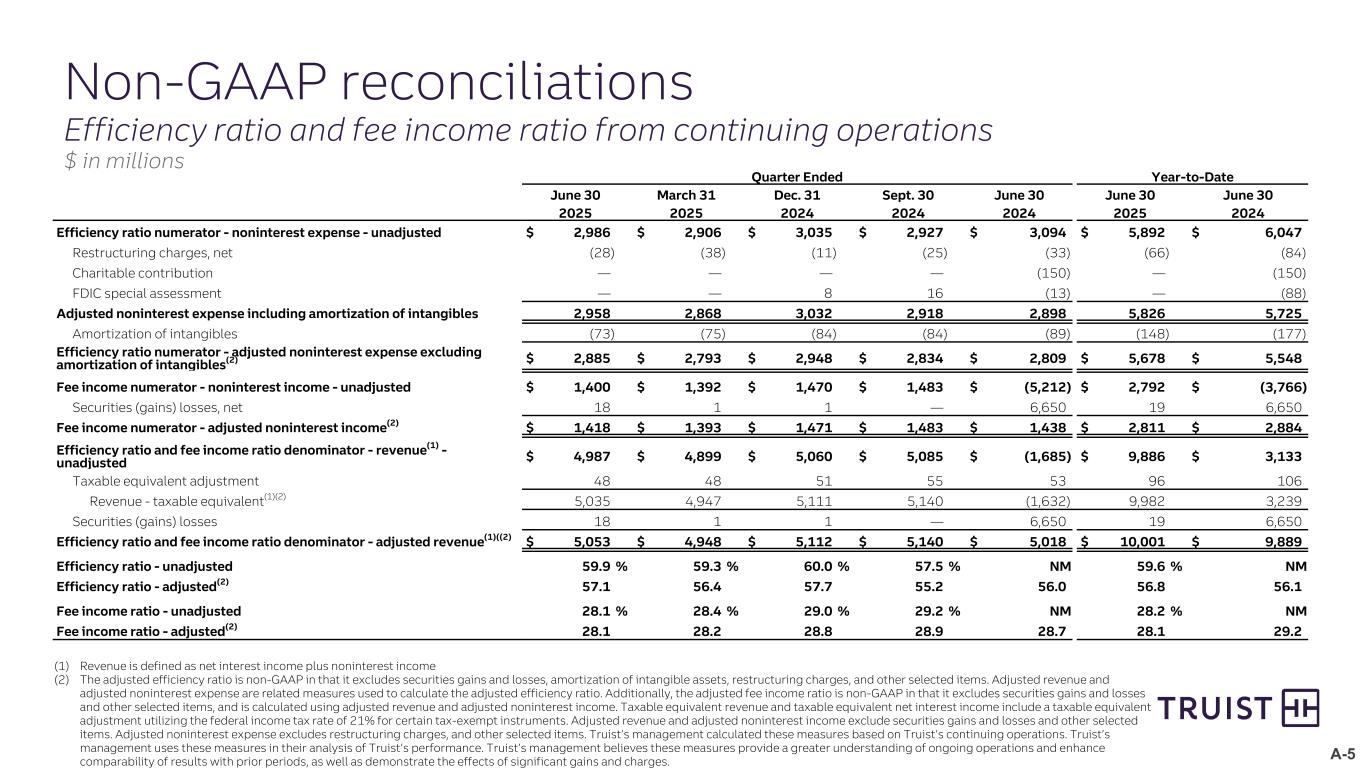
A-5 Non-GAAP reconciliations Efficiency ratio and fee income ratio from continuing operations $ in millions (1) Revenue is defined as net interest income plus noninterest income (2) The adjusted efficiency ratio is non-GAAP in that it excludes securities gains and losses, amortization of intangible assets, restructuring charges, and other selected items. Adjusted revenue and adjusted noninterest expense are related measures used to calculate the adjusted efficiency ratio. Additionally, the adjusted fee income ratio is non-GAAP in that it excludes securities gains and losses and other selected items, and is calculated using adjusted revenue and adjusted noninterest income. Taxable equivalent revenue and taxable equivalent net interest income include a taxable equivalent adjustment utilizing the federal income tax rate of 21% for certain tax-exempt instruments. Adjusted revenue and adjusted noninterest income exclude securities gains and losses and other selected items. Adjusted noninterest expense excludes restructuring charges, and other selected items. Truist’s management calculated these measures based on Truist’s continuing operations. Truist’s management uses these measures in their analysis of Truist’s performance. Truist’s management believes these measures provide a greater understanding of ongoing operations and enhance comparability of results with prior periods, as well as demonstrate the effects of significant gains and charges. Quarter Ended Year-to-Date June 30 March 31 Dec. 31 Sept. 30 June 30 June 30 June 30 2025 2025 2024 2024 2024 2025 2024 Efficiency ratio numerator - noninterest expense - unadjusted $ 2,986 $ 2,906 $ 3,035 $ 2,927 $ 3,094 $ 5,892 $ 6,047 Restructuring charges, net (28) (38) (11) (25) (33) (66) (84) Charitable contribution — — — — (150) — (150) FDIC special assessment — — 8 16 (13) — (88) Adjusted noninterest expense including amortization of intangibles 2,958 2,868 3,032 2,918 2,898 5,826 5,725 Amortization of intangibles (73) (75) (84) (84) (89) (148) (177) Efficiency ratio numerator - adjusted noninterest expense excluding amortization of intangibles(2) $ 2,885 $ 2,793 $ 2,948 $ 2,834 $ 2,809 $ 5,678 $ 5,548 Fee income numerator - noninterest income - unadjusted $ 1,400 $ 1,392 $ 1,470 $ 1,483 $ (5,212) $ 2,792 $ (3,766) Securities (gains) losses, net 18 1 1 — 6,650 19 6,650 Fee income numerator - adjusted noninterest income(2) $ 1,418 $ 1,393 $ 1,471 $ 1,483 $ 1,438 $ 2,811 $ 2,884 Efficiency ratio and fee income ratio denominator - revenue(1) - unadjusted $ 4,987 $ 4,899 $ 5,060 $ 5,085 $ (1,685) $ 9,886 $ 3,133 Taxable equivalent adjustment 48 48 51 55 53 96 106 Revenue - taxable equivalent(1)(2) 5,035 4,947 5,111 5,140 (1,632) 9,982 3,239 Securities (gains) losses 18 1 1 — 6,650 19 6,650 Efficiency ratio and fee income ratio denominator - adjusted revenue(1)((2) $ 5,053 $ 4,948 $ 5,112 $ 5,140 $ 5,018 $ 10,001 $ 9,889 Efficiency ratio - unadjusted 59.9 % 59.3 % 60.0 % 57.5 % NM 59.6 % NM Efficiency ratio - adjusted(2) 57.1 56.4 57.7 55.2 56.0 56.8 56.1 Fee income ratio - unadjusted 28.1 % 28.4 % 29.0 % 29.2 % NM 28.2 % NM Fee income ratio - adjusted(2) 28.1 28.2 28.8 28.9 28.7 28.1 29.2
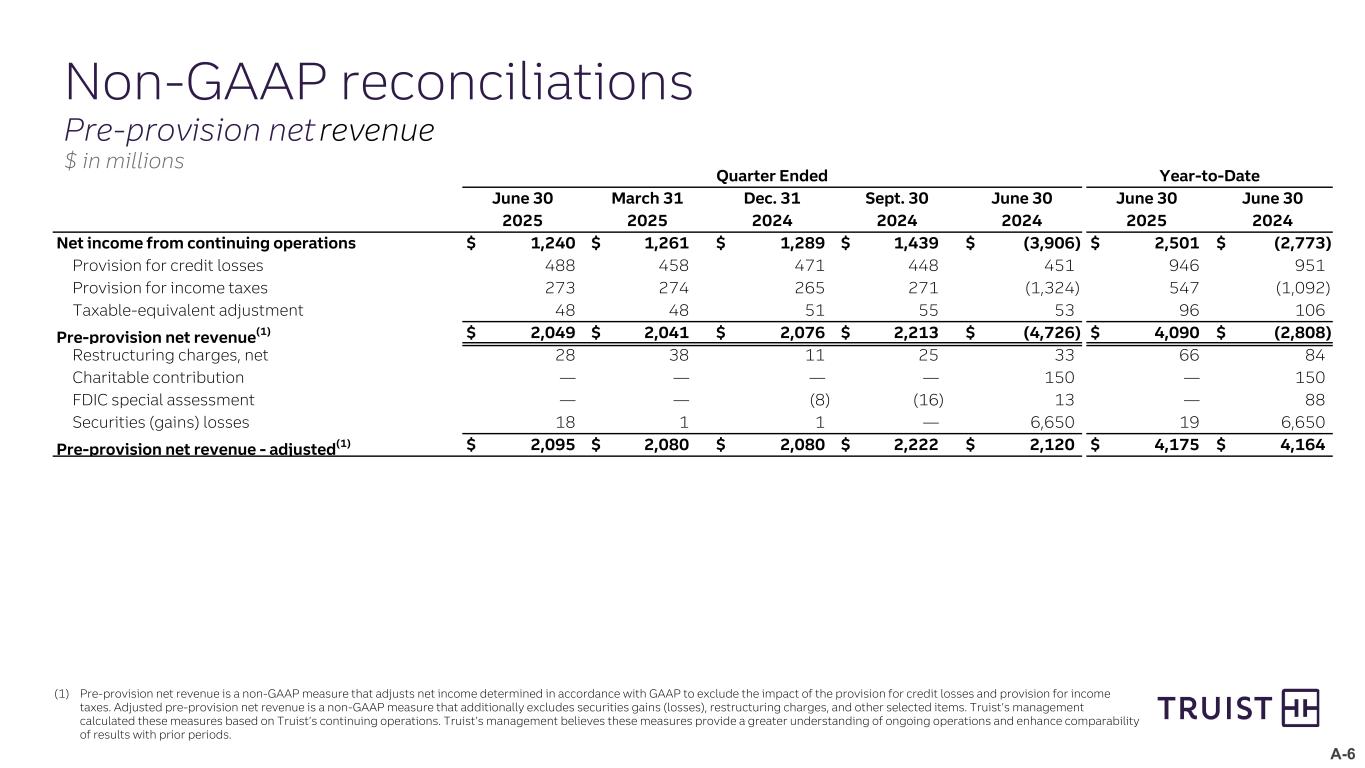
A-6 Non-GAAP reconciliations Pre-provision net revenue $ in millions (1) Pre-provision net revenue is a non-GAAP measure that adjusts net income determined in accordance with GAAP to exclude the impact of the provision for credit losses and provision for income taxes. Adjusted pre-provision net revenue is a non-GAAP measure that additionally excludes securities gains (losses), restructuring charges, and other selected items. Truist’s management calculated these measures based on Truist’s continuing operations. Truist’s management believes these measures provide a greater understanding of ongoing operations and enhance comparability of results with prior periods. Quarter Ended Year-to-Date June 30 March 31 Dec. 31 Sept. 30 June 30 June 30 June 30 2025 2025 2024 2024 2024 2025 2024 Net income from continuing operations $ 1,240 $ 1,261 $ 1,289 $ 1,439 $ (3,906) $ 2,501 $ (2,773) Provision for credit losses 488 458 471 448 451 946 951 Provision for income taxes 273 274 265 271 (1,324) 547 (1,092) Taxable-equivalent adjustment 48 48 51 55 53 96 106 Pre-provision net revenue(1) $ 2,049 $ 2,041 $ 2,076 $ 2,213 $ (4,726) $ 4,090 $ (2,808) Restructuring charges, net 28 38 11 25 33 66 84 Charitable contribution — — — — 150 — 150 FDIC special assessment — — (8) (16) 13 — 88 Securities (gains) losses 18 1 1 — 6,650 19 6,650 Pre-provision net revenue - adjusted(1) $ 2,095 $ 2,080 $ 2,080 $ 2,222 $ 2,120 $ 4,175 $ 4,164
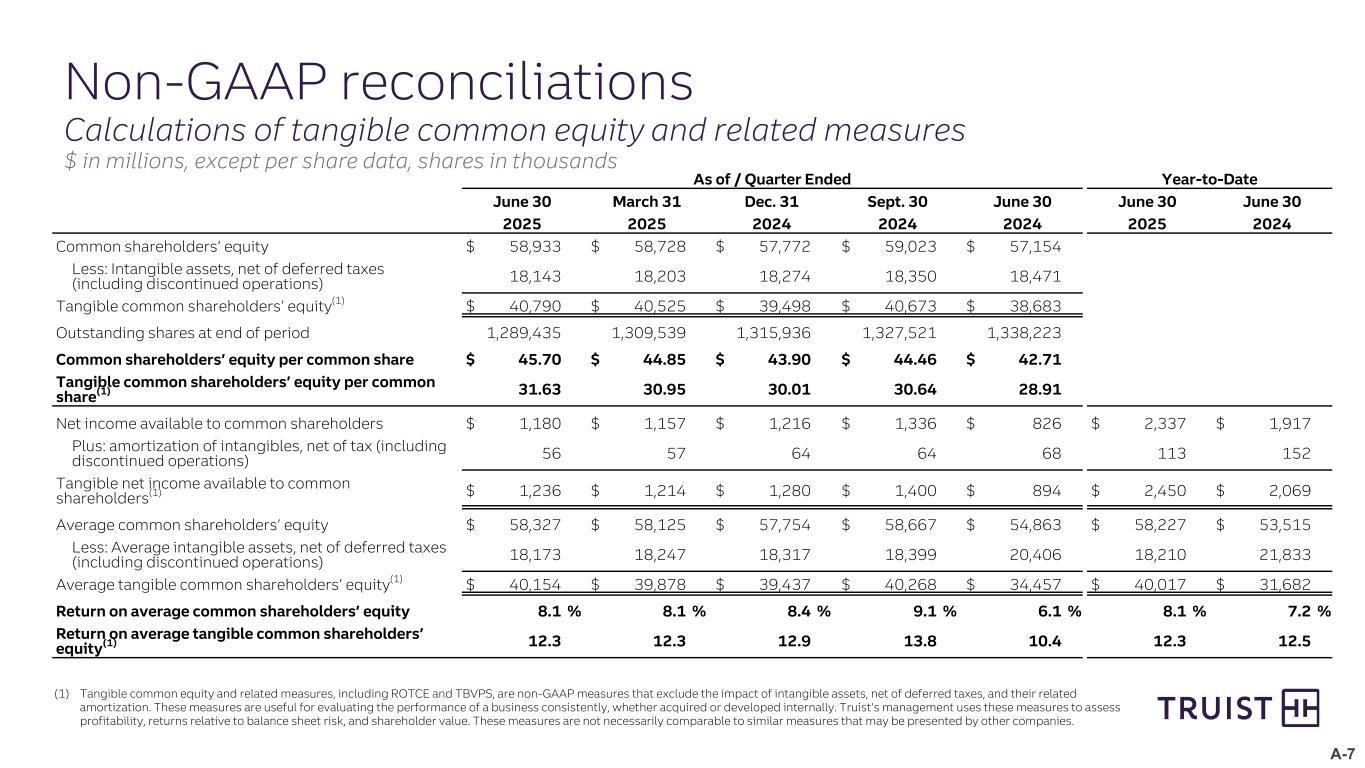
A-7 Non-GAAP reconciliations Calculations of tangible common equity and related measures $ in millions, except per share data, shares in thousands (1) Tangible common equity and related measures, including ROTCE and TBVPS, are non-GAAP measures that exclude the impact of intangible assets, net of deferred taxes, and their related amortization. These measures are useful for evaluating the performance of a business consistently, whether acquired or developed internally. Truist’s management uses these measures to assess profitability, returns relative to balance sheet risk, and shareholder value. These measures are not necessarily comparable to similar measures that may be presented by other companies. As of / Quarter Ended Year-to-Date June 30 March 31 Dec. 31 Sept. 30 June 30 June 30 June 30 2025 2025 2024 2024 2024 2025 2024 Common shareholders’ equity $ 58,933 $ 58,728 $ 57,772 $ 59,023 $ 57,154 Less: Intangible assets, net of deferred taxes (including discontinued operations) 18,143 18,203 18,274 18,350 18,471 Tangible common shareholders’ equity(1) $ 40,790 $ 40,525 $ 39,498 $ 40,673 $ 38,683 Outstanding shares at end of period 1,289,435 1,309,539 1,315,936 1,327,521 1,338,223 Common shareholders’ equity per common share $ 45.70 $ 44.85 $ 43.90 $ 44.46 $ 42.71 Tangible common shareholders’ equity per common share(1) 31.63 30.95 30.01 30.64 28.91 Net income available to common shareholders $ 1,180 $ 1,157 $ 1,216 $ 1,336 $ 826 $ 2,337 $ 1,917 Plus: amortization of intangibles, net of tax (including discontinued operations) 56 57 64 64 68 113 152 Tangible net income available to common shareholders(1) $ 1,236 $ 1,214 $ 1,280 $ 1,400 $ 894 $ 2,450 $ 2,069 Average common shareholders’ equity $ 58,327 $ 58,125 $ 57,754 $ 58,667 $ 54,863 $ 58,227 $ 53,515 Less: Average intangible assets, net of deferred taxes (including discontinued operations) 18,173 18,247 18,317 18,399 20,406 18,210 21,833 Average tangible common shareholders’ equity(1) $ 40,154 $ 39,878 $ 39,437 $ 40,268 $ 34,457 $ 40,017 $ 31,682 Return on average common shareholders’ equity 8.1 % 8.1 % 8.4 % 9.1 % 6.1 % 8.1 % 7.2 % Return on average tangible common shareholders’ equity(1) 12.3 12.3 12.9 13.8 10.4 12.3 12.5