
WTFC 8-K
Wintrust Financial Corp (WTFC)
8-K
2021-10-19
For: 2021-10-19
View Original
Added on
April 06, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
Current Report
Pursuant to Section 13 or 15(d) of The
Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): October 19, 2021
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of Incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) | ||||||||||||||||||
| (Address of principal executive offices) | (Zip Code) | |||||||||||||||||||
Registrant’s telephone number, including area code (847 ) 939-9000
Not Applicable
(Former name or former address, if changed since last year)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
| Title of Each Class | Ticker Symbol | Name of Each Exchange on Which Registered | ||||||
| | ||||||||
| Depositary Shares, Each Representing a 1/1,000th Interest in a Share of | ||||||||
| Preferred Stock, no par value | ||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition
The information in this Current Report is being furnished and shall not be deemed “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities of that Section. The information in this Current Report shall not be incorporated by reference into any registration statement or other document pursuant to the Securities Act of 1933, as amended.
On October 19, 2021 , Wintrust Financial Corporation (the “Company”) announced earnings for the third quarter of 2021 and posted on its website the Third Quarter 2021 Earnings Release Presentation. Copies of the press release relating to the Company’s earnings results and the related presentation are attached hereto as Exhibit 99.1 and Exhibit 99.2, respectively. Certain supplemental information relating to non-GAAP financial measures reported in the attached press release and presentation is included on pages 36 through 38 of Exhibit 99.1 and pages 23 through 24 of Exhibit 99.2.
Item 9.01. Financial Statements and Exhibits
(d) Exhibits
| Exhibit | |||||
2
Signature
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| WINTRUST FINANCIAL CORPORATION (Registrant) | ||||||||
| By: | /s/ David L. Stoehr | |||||||
| David L. Stoehr Executive Vice President and Chief Financial Officer | ||||||||
Date: October 19, 2021
3
INDEX TO EXHIBITS
| Exhibit | |||||
4
Exhibit 99.1
Wintrust Financial Corporation
9700 W. Higgins Road, Suite 800, Rosemont, Illinois 60018
News Release
| FOR IMMEDIATE RELEASE | October 19, 2021 | |||||||
FOR MORE INFORMATION CONTACT:
Edward J. Wehmer, Founder & Chief Executive Officer
David A. Dykstra, Vice Chairman & Chief Operating Officer
(847) 939-9000
Web site address: www.wintrust.com
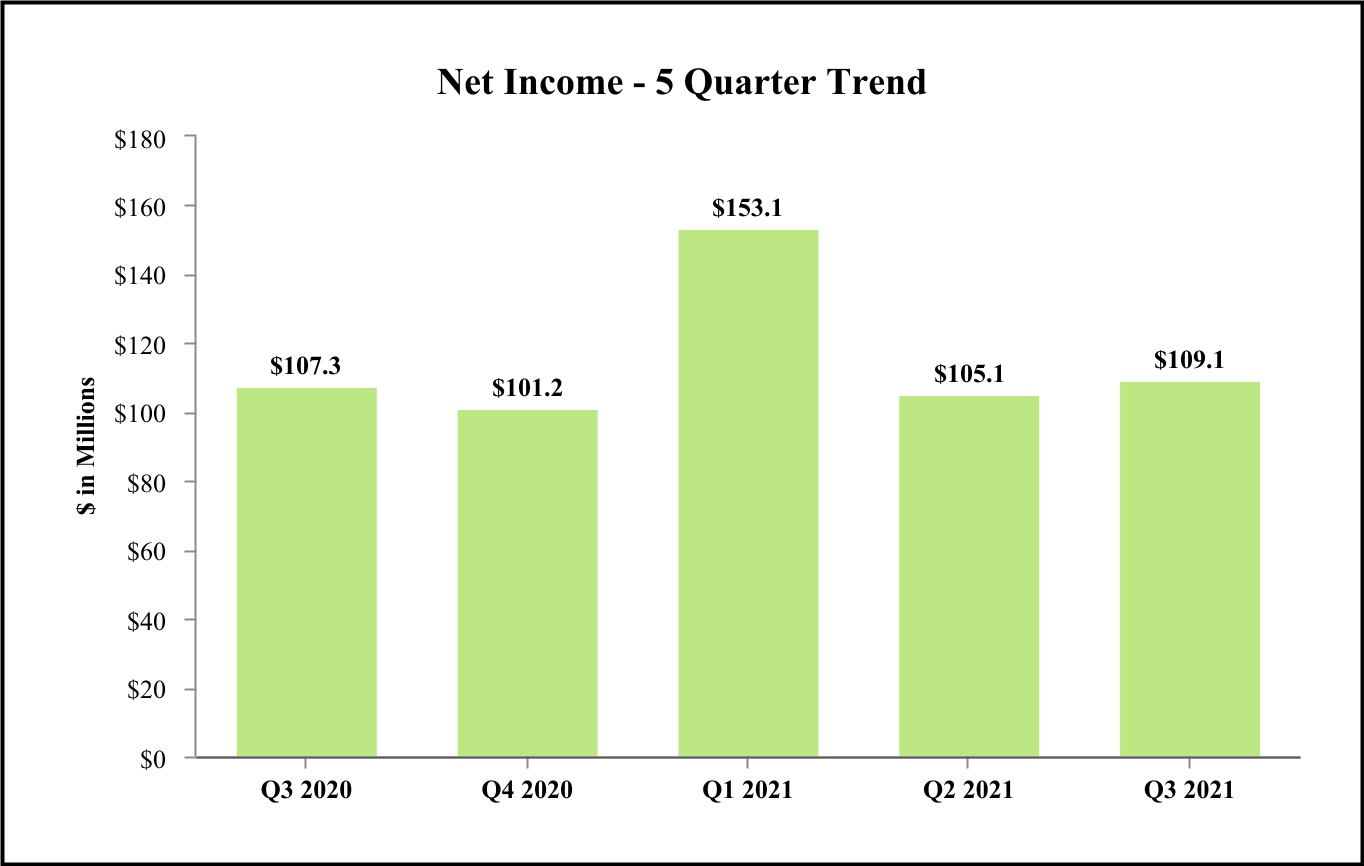
Wintrust Financial Corporation Reports Third Quarter 2021 Net Income of $109.1 million and Year-To-Date Net Income of $367.4 million
ROSEMONT, ILLINOIS – Wintrust Financial Corporation (“Wintrust”, “the Company”, "we" or "our") (Nasdaq: WTFC) announced net income of $109.1 million or $1.77 per diluted common share for the third quarter of 2021, an increase in diluted earnings per common share of 4% compared to the second quarter of 2021 and an increase of 6% compared to the third quarter of 2020. The Company recorded net income of $367.4 million or $6.00 per diluted common share for the first nine months of 2021 compared to net income of $191.8 million or $3.06 per diluted common share for the same period of 2020.
Highlights of the Third Quarter of 2021:
Comparative information to the second quarter of 2021
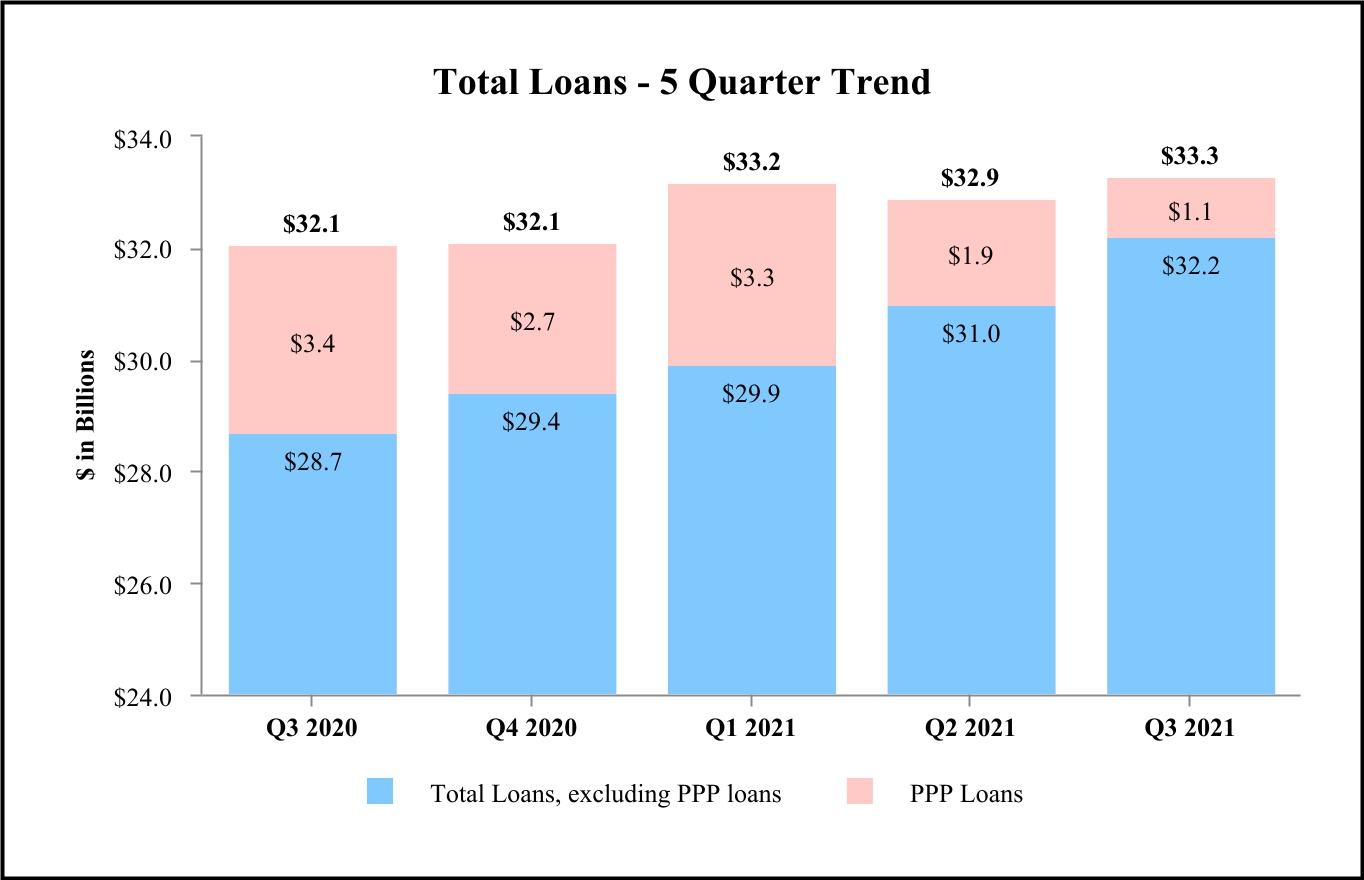
•Total loans, excluding Paycheck Protection Program ("PPP") loans, increased by $1.2 billion, or 15% on an annualized basis.
◦Core loans increased by $701 million and niche loans increased by $449 million. See Table 1 for more information.
•PPP loans declined by $797 million in the third quarter of 2021 primarily as a result of processing forgiveness payments.
•Total assets increased by $1.1 billion.
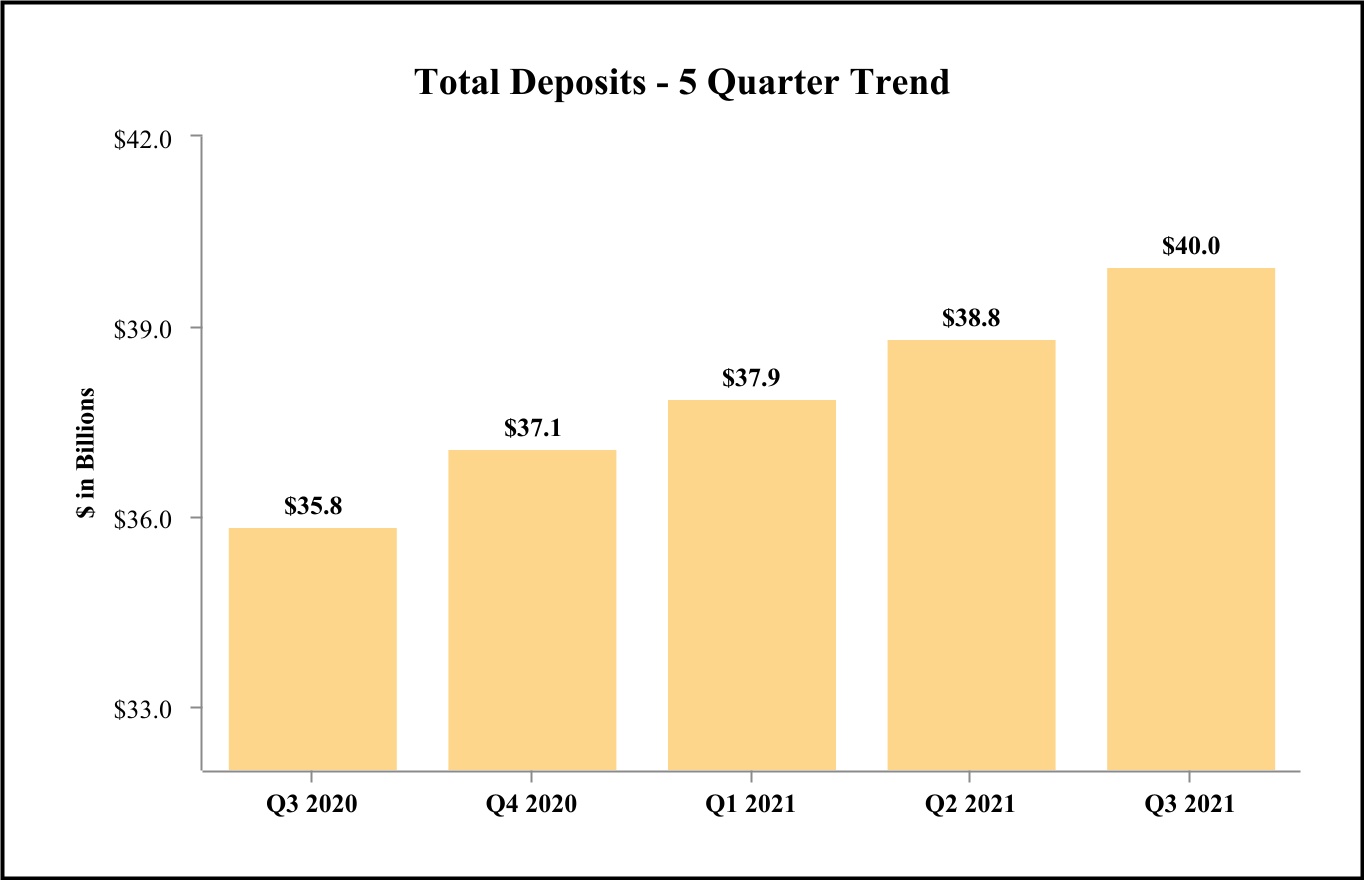
•Total deposits increased by $1.1 billion, including a $459 million increase in non-interest bearing deposits.
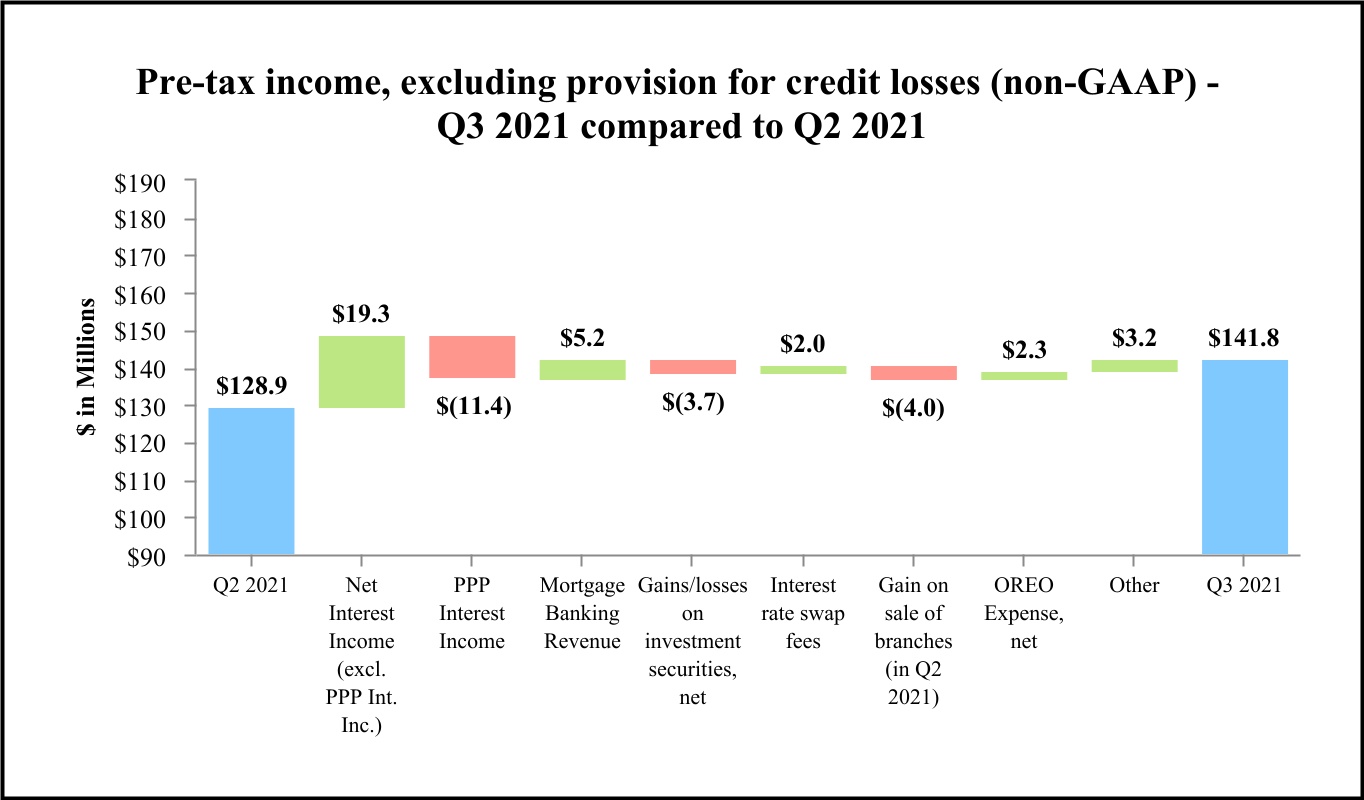
•Net interest income increased by $7.9 million as compared to the second quarter of 2021 as follows:
◦Increased $16.3 million primarily due to earning asset growth and a nine basis point decline in deposit costs.
◦Increased $3.0 million due to one additional day in the quarter.
◦Decreased by $11.4 million due to $3.6 million of less PPP interest income and $7.8 million of less PPP fee income.
•Net interest margin decreased by four basis points primarily due to increased liquidity.
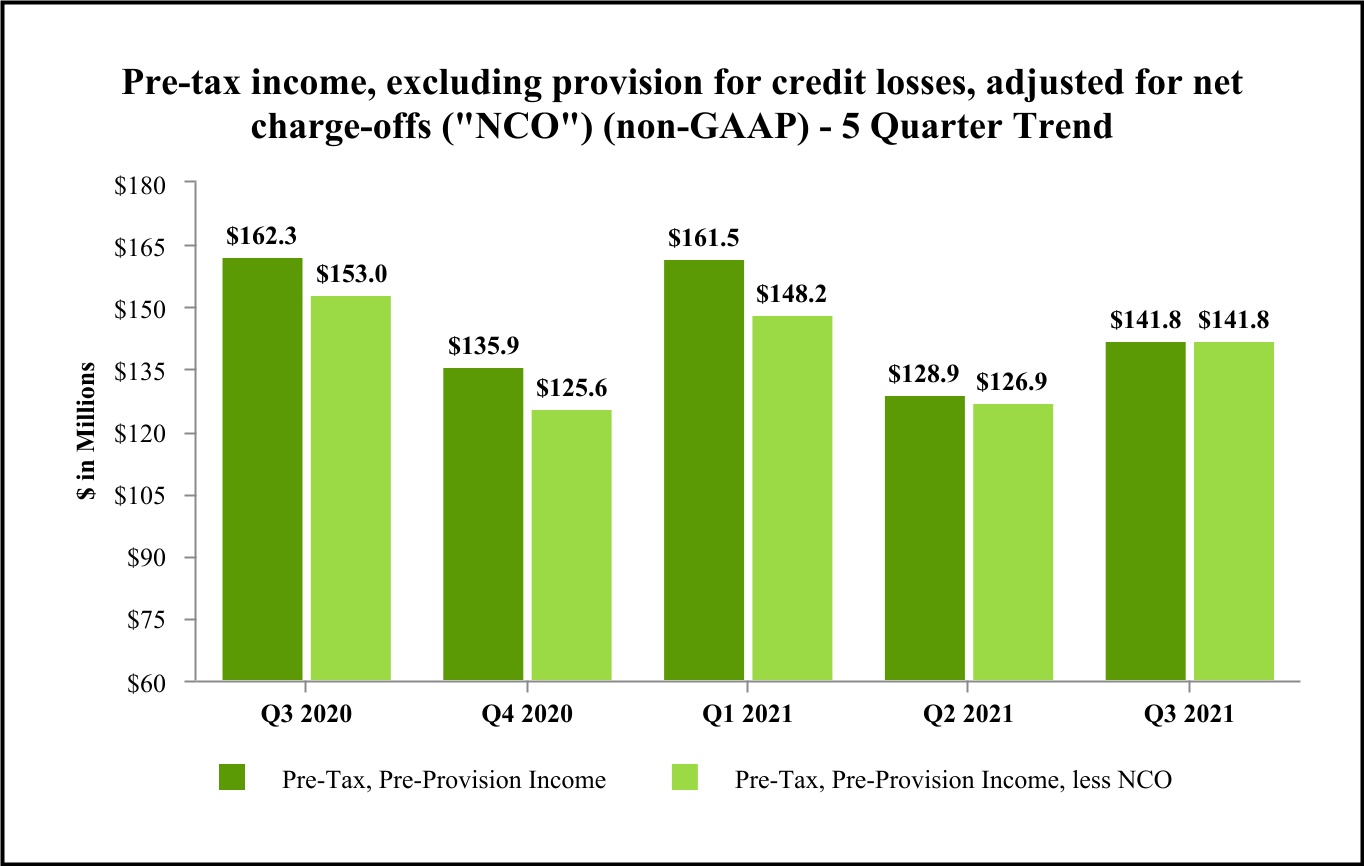
•Recorded no material net charge-offs in the third quarter of 2021 as compared to very minimal net charge-offs of $1.9 million in the second quarter of 2021.
•Recorded a negative provision for credit losses of $7.9 million in the third quarter of 2021 as compared to a negative provision for credit losses of $15.3 million in the second quarter of 2021.
•The allowance for credit losses on our core loan portfolio is approximately 1.38% of the outstanding balance as of September 30, 2021, down from 1.49% as of June 30, 2021. See Table 12 for more information.
•Non-performing loans remained low at 0.27% of total loans, as of September 30, 2021, unchanged from the second quarter of 2021.
•Mortgage banking revenue increased to $55.8 million for the third quarter of 2021 as compared to $50.6 million in the second quarter of 2021.
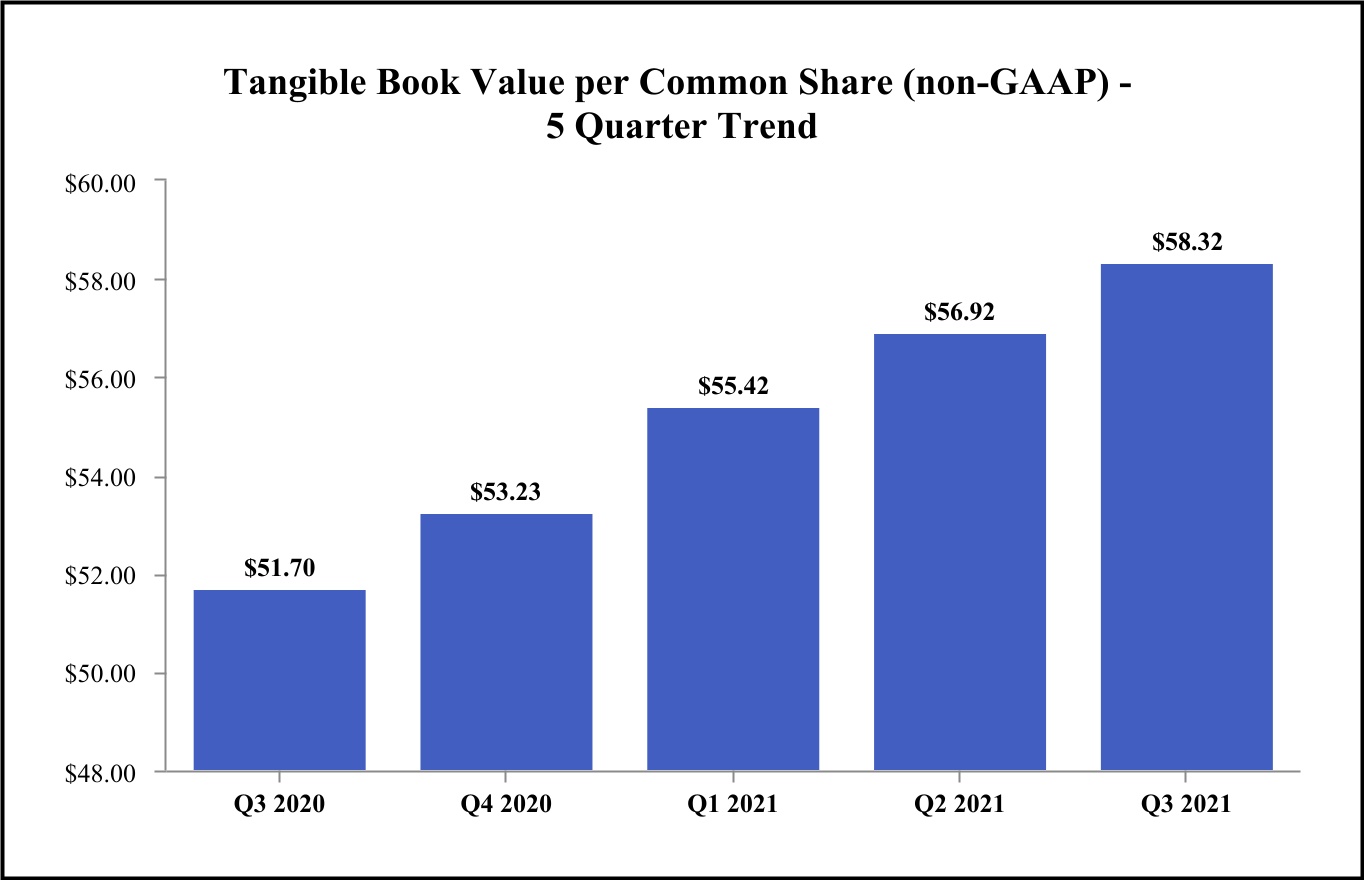
•Tangible book value per common share (non-GAAP) increased to $58.32 as compared to $56.92 as of June 30, 2021. See Table 18 for reconciliation of non-GAAP measures.
•Repurchased 134,062 shares of our common stock at a cost of $9.5 million, or an average price of $71.13 per share.
Edward J. Wehmer, Founder and Chief Executive Officer, commented, "The third quarter of 2021 was characterized by significant organic loan and deposit growth, increased net interest income, strong mortgage banking revenue, record wealth management revenue, tangible book value growth and very good credit quality metrics. Wintrust reported net income of $109.1
million for the third quarter of 2021, up from $105.1 million in the second quarter of 2021. On a year-to-date basis, net income totaled $367.4 million for the first nine months of 2021, up from $191.8 million in the first nine months of 2020, a 92% increase. The Company continues to grow as total assets of $47.8 billion as of September 30, 2021 increased by $1.1 billion as compared to June 30, 2021 and increased by $4.1 billion as compared to September 30, 2020."
Mr. Wehmer continued, "The Company experienced significant loan growth, excluding PPP loans, of $1.2 billion or 15%, on an annualized basis in the third quarter of 2021, including growth in its commercial, commercial real estate, residential real estate loans for investment, commercial insurance premium finance receivable and life insurance premium receivable portfolios. Growth was particularly strong in the commercial loan portfolio due to new customer relationships and a slight increase in line of credit utilization. We are still experiencing historically low commercial line of credit utilization and feel confident that we can continue to grow loans given our robust loan pipelines and diversified loan portfolio. Total deposits increased by $1.1 billion as compared to the second quarter of 2021 primarily in products with zero or near zero interest rates contributing to a decrease in our cost of funds. We continue to emphasize growing our franchise, including gathering low cost deposits, which we believe will drive value in the long term. Our loans to deposits ratio ended the quarter at 83.3% and we believe that we have sufficient liquidity to meet customer loan demand."
Mr. Wehmer commented, "Net interest income increased by $7.9 million in the third quarter of 2021 primarily due to earning asset growth and a decline in deposit costs. Even amid a challenging interest rate environment, the Company has managed to increase net interest income for four quarters in a row. Especially noteworthy this quarter was that net interest income increased considerably despite recording $11.4 million of less interest income on PPP loans. This demonstrates that our growth strategy has been able to replace PPP loans and sustain loan portfolio growth benefiting future quarters. Net interest margin decreased by four basis points in the third quarter of 2021 as compared to the second quarter of 2021 primarily due to increased liquidity. Excluding the unfavorable net interest margin impact from increased liquidity, the margin exhibited improvement as the rate on deposits declined nine basis points as compared to a two basis point decline in loan yields. We continue to monitor our excess liquidity position and the available market returns on investments. We believe that deploying liquidity could potentially increase our net interest margin and net interest income. Additionally, we remain in an asset sensitive interest rate position which should allow our net interest income and net interest margin to benefit from future increases in interest rates."
Mr. Wehmer noted, “We recorded mortgage banking revenue of $55.8 million in the third quarter of 2021 as compared to $50.6 million in the second quarter of 2021. Loan volumes originated for sale in the third quarter of 2021 were $1.6 billion, down from $1.7 billion in the second quarter of 2021. However, production margin improved in the third quarter of 2021 as compared to the second quarter of 2021. Additionally, the Company recorded an $888,000 decrease in the value of mortgage servicing rights related to changes in fair value model assumptions as compared to a $5.5 million decrease recognized in the second quarter of 2021. Based on current market conditions, we expect that mortgage originations will decline by 20-30% in the fourth quarter of 2021 as compared to the third quarter of 2021 due to the seasonal decline in home purchase activity and declining refinance volumes.
Commenting on credit quality, Mr. Wehmer stated, "The Company recorded no material net charge-offs in third quarter of 2021. This follows the second quarter of 2021 which also exhibited very low levels of net charge-offs totaling $1.9 million. The recent results demonstrate Wintrust’s conservative credit underwriting approach and our continued diligence in timely addressing problem credits. The Company recorded a negative provision for credit losses of $7.9 million in the third quarter of 2021 primarily related to improving credit quality in the loan portfolio. The level of non-performing loans remained historically low and unchanged at 0.27% of total loans as of both September 30, 2021 and June 30, 2021. The allowance for credit losses on our core loan portfolio as of September 30, 2021 is approximately 1.38% of the outstanding balance. We believe that the Company’s reserves remain appropriate and we remain diligent in our review of credit."
Mr. Wehmer concluded, "Our third quarter of 2021 results continued to demonstrate the multi-faceted nature of our business model which we believe uniquely positions us to be successful. We expect to leverage our differentiated, diversified loan portfolio to outperform peers with respect to loan growth which should allow us to continue to expand net interest income. We are focused on taking advantage of market opportunities to prudently deploy excess liquidity into earning assets including core and niche loans and investment securities while maintaining an interest rate sensitive asset portfolio. We are opportunistically evaluating the acquisition market which has been active for both banks and business lines of various sizes. Of course, we remain diligent in our consideration of acquisition targets and will be prudent in our decision-making, always seeking to minimize dilution."
2
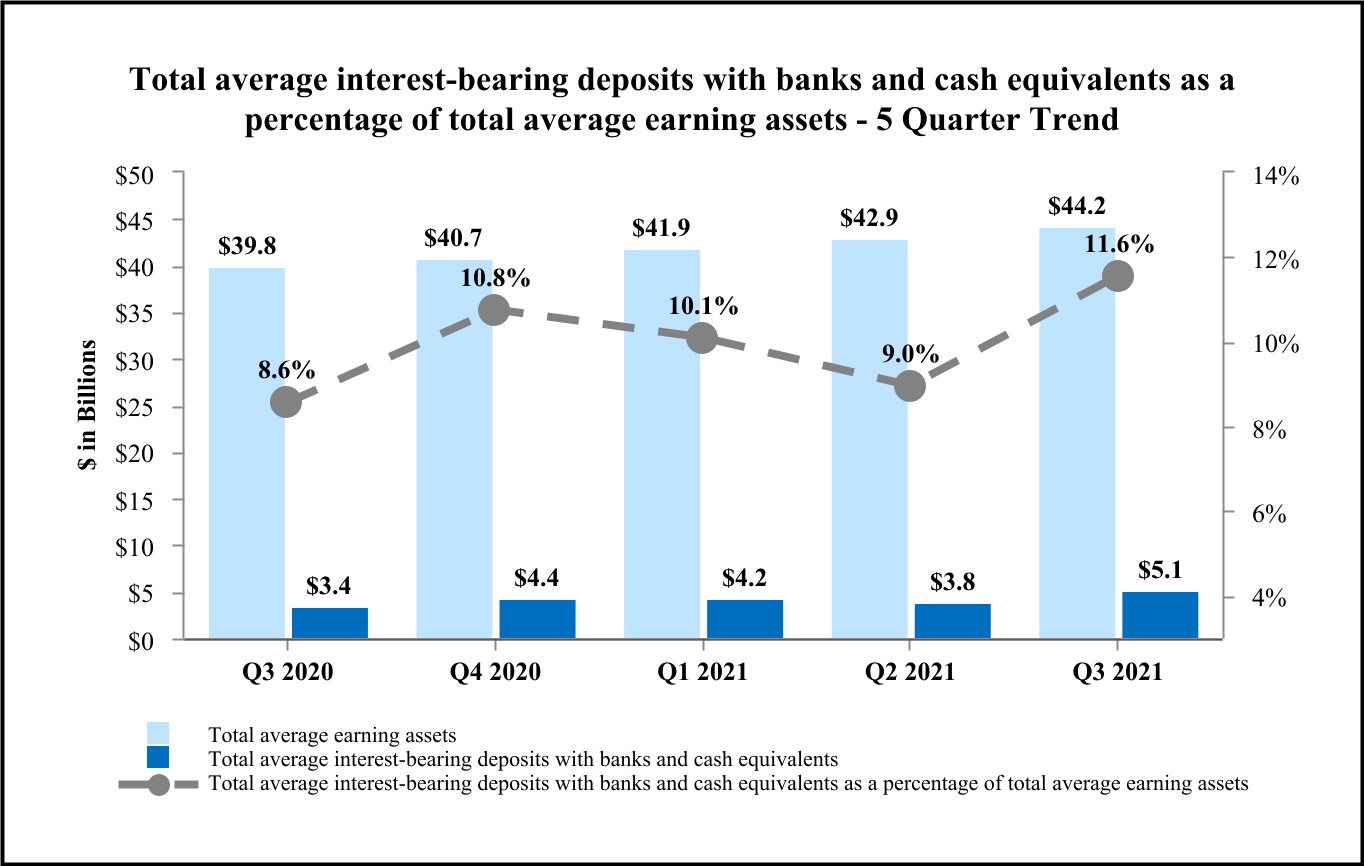
The graphs below illustrate certain financial highlights of the third quarter of 2021 as well as historical financial performance. See "Supplemental Non-GAAP Financial Measures/Ratios" at Table 18 for additional information with respect to non-GAAP financial measures/ratios, including the reconciliations to the corresponding GAAP financial measures/ratios.
3
4

5

6
7
8
SUMMARY OF RESULTS:
BALANCE SHEET
Total asset growth of $1.1 billion in the third quarter of 2021 was primarily comprised of a $525 million increase in interest bearing deposits with banks and a $1.2 billion increase in total loans, excluding PPP loans. These increases were partially offset by a $797 million decrease in PPP loans and a $59.7 million decrease in mortgage loans held-for-sale. As of September 30, 2021, approximately 95% of PPP loan balances originated in 2020 were forgiven with nearly all of the remaining loan balance in the forgiveness review or submission process. Whereas, as of September 30, 2021, approximately 32% of PPP loan balances originated in 2021 were forgiven, 16% are in the forgiveness review or submission process and 52% have yet to apply for forgiveness. Total loans, excluding PPP loans, increased by $1.2 billion primarily due to growth in the commercial, commercial real estate, residential real estate loans for investment, commercial insurance premium finance receivable and life insurance premium receivable portfolios. The Company believes that the $5.2 billion of interest-bearing deposits with banks held as of September 30, 2021 provides more than sufficient liquidity to operate its business plan with the ability to deploy excess liquidity into higher yielding investments when market returns improve.
Total liabilities increased $1.0 billion in the third quarter of 2021 resulting primarily from a $1.1 billion increase in total deposits. The increase in deposits was primarily due to a $914 million increase in money market deposits and a $459 million increase in non-interest bearing deposits. The Company's loans to deposits ratio ended the quarter at 83.3%. Management believes in substantially funding the Company's balance sheet with core deposits and utilizes brokered or wholesale funding sources as appropriate to manage its liquidity position as well as for interest rate risk management purposes.
For more information regarding changes in the Company’s balance sheet, see Consolidated Statements of Condition and Tables 1 through 3 in this report.
NET INTEREST INCOME
For the third quarter of 2021, net interest income totaled $287.5 million, an increase of $7.9 million as compared to the second quarter of 2021 and an increase of $31.6 million as compared to the third quarter of 2020. The $7.9 million increase in net interest income in the third quarter of 2021 compared to the second quarter of 2021 was primarily due to earning asset growth and a decline in deposit costs. Additionally, the net interest income growth occurred despite a decline of $11.4 million due to $3.6 million of less PPP interest income and $7.8 million of less PPP fee income. As of September 30, 2021, the Company had approximately $24.8 million of net PPP loan fees that have yet to be recognized in income.
Net interest margin was 2.58% (2.59% on a fully taxable-equivalent basis, non-GAAP) during the third quarter of 2021 compared to 2.62% (2.63% on a fully taxable-equivalent basis, non-GAAP) during the second quarter of 2021 and up from 2.56% (2.57% on a fully taxable-equivalent basis, non-GAAP) during the third quarter of 2020. The net interest margin decrease as compared to the prior quarter was primarily due to the 10 basis point decrease in yield on earning assets and two basis point decrease in the net free funds contribution partially offset by an eight basis point decrease in the rate paid on interest-bearing liabilities. The decrease in the rate paid on interest-bearing liabilities in the third quarter of 2021 as compared to the prior quarter is primarily due to a nine basis point decrease in the rate paid on interest-bearing deposits primarily due to lower repricing of time deposits. The 10 basis point decrease in the yield on earning assets in the third quarter of 2021 as compared to the second quarter of 2021 was primarily due to a shift in earning asset mix with increasing levels of low yielding liquidity management assets.
For more information regarding net interest income, see Tables 4 through 8 in this report.
ASSET QUALITY
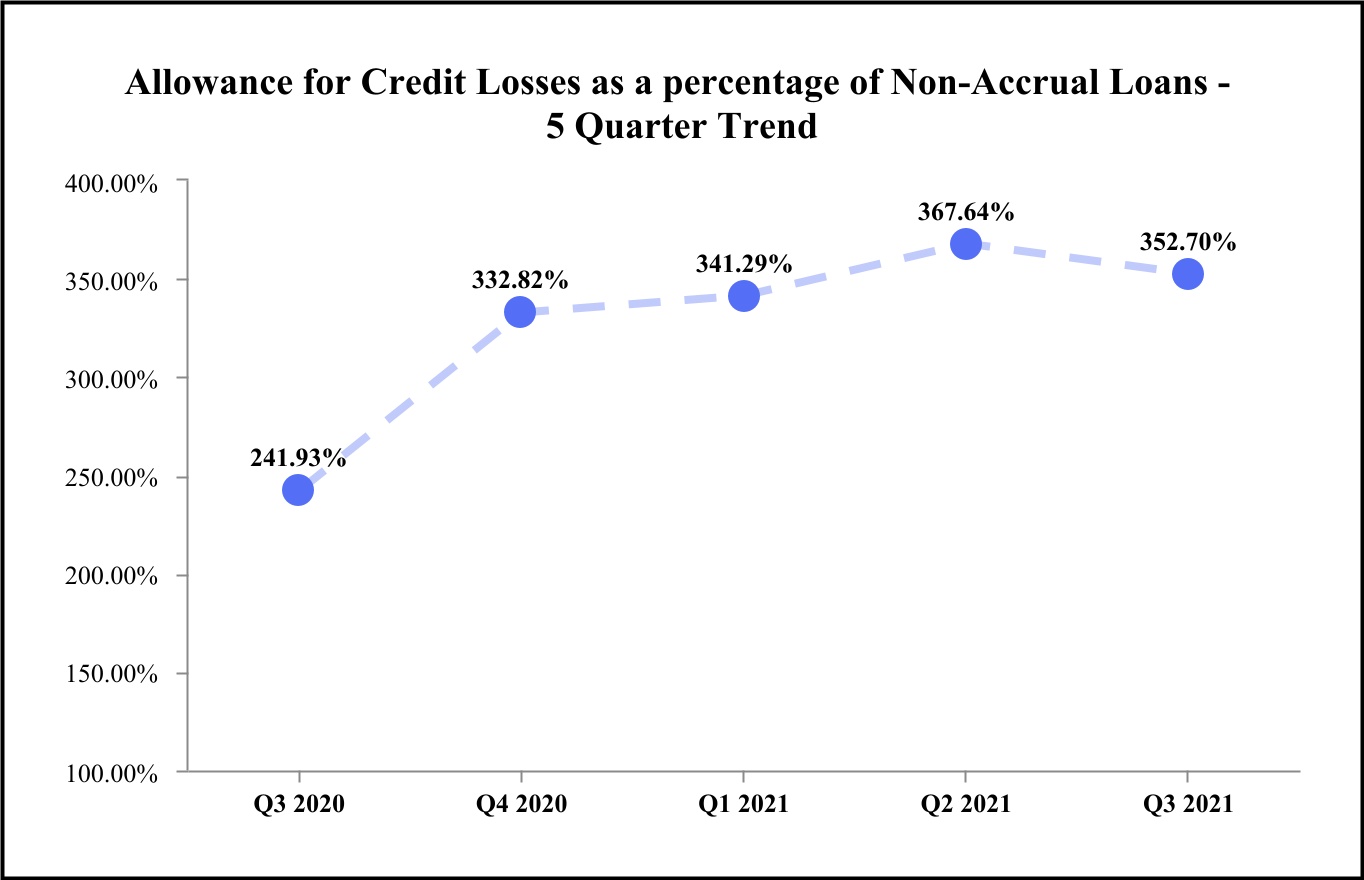
The allowance for credit losses totaled $296.1 million as of September 30, 2021, a decrease of $8.0 million as compared to $304.1 million as of June 30, 2021. The allowance for credit losses decreased primarily due to improving credit quality in the loan portfolio which was partially offset by uncertainty in the positive directionality of macroeconomic factors. A negative provision for credit losses totaling $7.9 million was recorded for the third quarter of 2021 compared to a negative provision of $15.3 million for the second quarter of 2021 and $25.0 million of expense for the third quarter of 2020. For more information regarding the provision for credit losses, see Table 11 in this report.
Management believes the allowance for credit losses is appropriate to account for expected credit losses. The Current Expected Credit Losses ("CECL") accounting standard requires the Company to estimate expected credit losses over the life of the Company’s financial assets as of the reporting date. There can be no assurances, however, that future losses will not
9
significantly exceed the amounts provided for, thereby affecting future results of operations. A summary of the allowance for credit losses calculated for the loan components in each portfolio as of September 30, 2021, June 30, 2021, and March 31, 2021 is shown on Table 12 of this report.
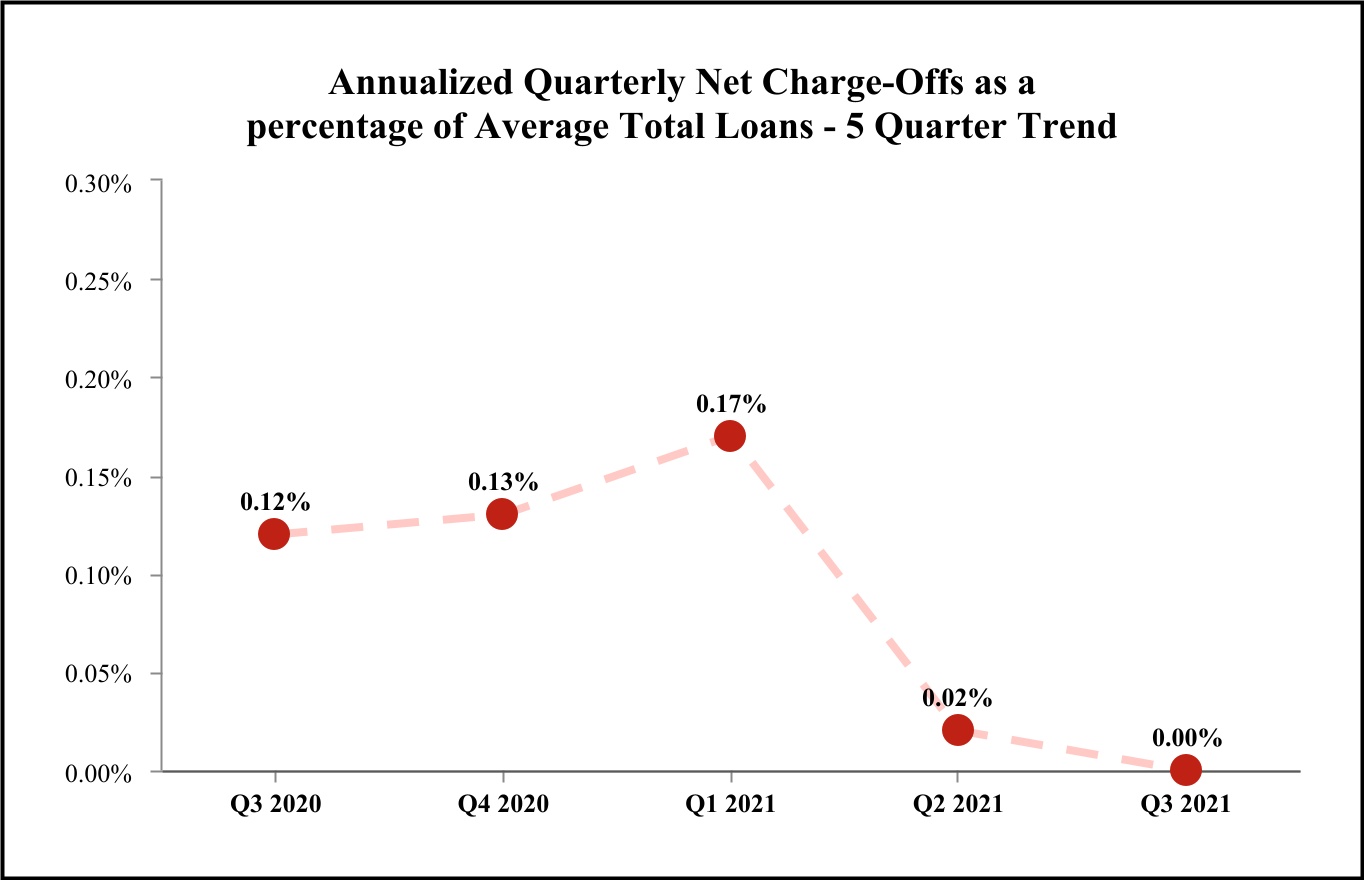
Net charge-offs totaled $2,000 in the third quarter of 2021, as compared to $1.9 million in the second quarter of 2021 and $9.3 million in the third quarter of 2020. Net charge-offs as a percentage of average total loans were reported as zero basis points in the third quarter of 2021 on an annualized basis compared to two basis points on an annualized basis in the second quarter of 2021 and 12 basis points on an annualized basis in the third quarter of 2020. For more information regarding net charge-offs, see Table 10 in this report.
As of September 30, 2021, $32.9 million of all loans, or 0.1%, were 60 to 89 days past due and $128.8 million, or 0.4%, were 30 to 59 days (or one payment) past due. As of June 30, 2021, $19.3 million of all loans, or 0.1%, were 60 to 89 days past due and $73.9 million, or 0.2%, were 30 to 59 days (or one payment) past due. Many of the commercial and commercial real-estate loans shown as 60 to 89 days and 30 to 59 days past due are included on the Company’s internal problem loan reporting system. Loans on this system are closely monitored by management on a monthly basis.
The Company’s home equity and residential real estate loan portfolios continue to exhibit low delinquency rates as of September 30, 2021. Home equity loans at September 30, 2021 that are current with regard to the contractual terms of the loan agreement represent 98.6% of the total home equity portfolio. Residential real estate loans at September 30, 2021 that are current with regards to the contractual terms of the loan agreements comprised 98.4% of total residential real estate loans outstanding. For more information regarding past due loans, see Table 13 in this report.
The outstanding balance of COVID-19 related modified loans totaled approximately $72 million or 0.2% of total loans, excluding PPP loans as of September 30, 2021 as compared to $146 million or 0.5% as of June 30, 2021. The most significant proportion of outstanding modifications changed terms to interest-only payments.
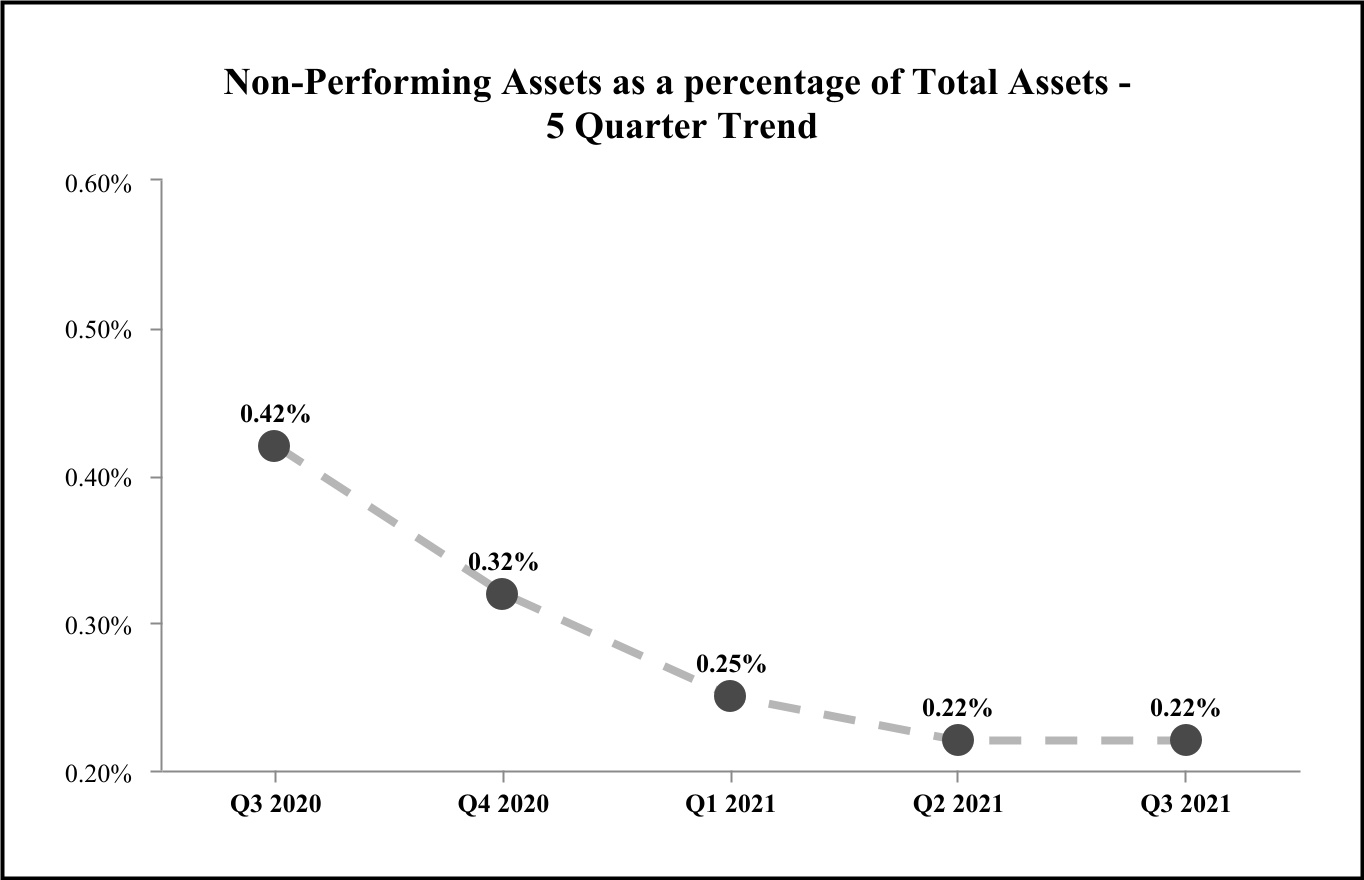
The ratio of non-performing assets to total assets was 0.22% as of September 30, 2021, compared to 0.22% at June 30, 2021, and 0.42% at September 30, 2020. Non-performing assets totaled $103.9 million at September 30, 2021, compared to $103.3 million at June 30, 2021 and $182.3 million at September 30, 2020. Non-performing loans totaled $90.0 million, or 0.27% of total loans, at September 30, 2021 compared to $87.7 million, or 0.27% of total loans, at June 30, 2021 and $173.1 million, or 0.54% of total loans, at September 30, 2020. Other real estate owned ("OREO") totaled $13.8 million at September 30, 2021, a decrease of $1.7 million compared to $15.6 million at June 30, 2021 and an increase of $4.6 million compared to $9.2 million at September 30, 2020. Management is pursuing the resolution of all non-performing assets. At this time, management believes OREO is appropriately valued at the lower of carrying value or fair value less estimated costs to sell. For more information regarding non-performing assets, see Table 14 in this report.
NON-INTEREST INCOME
Wealth management revenue increased by $841,000 during the third quarter of 2021 as compared to the second quarter of 2021 primarily due to increased trust and asset management fees. Wealth management revenue is comprised of the trust and asset management revenue of The Chicago Trust Company and Great Lakes Advisors, the brokerage commissions, managed money fees and insurance product commissions at Wintrust Investments and fees from tax-deferred like-kind exchange services provided by the Chicago Deferred Exchange Company.
Mortgage banking revenue increased by $5.2 million in the third quarter of 2021 as compared to the second quarter of 2021, primarily due to an $888,000 unfavorable mortgage servicing rights portfolio fair value adjustment as compared to a $5.5 million decrease recognized in the prior quarter related to changes in fair value model assumptions and a $1.7 million increase in production revenue. Loans originated for sale were $1.6 billion in the third quarter of 2021, a decrease of $165 million as compared to the second quarter of 2021. The percentage of origination volume from refinancing activities was 44% in the third quarter of 2021 as compared to 47% in the second quarter of 2021. Mortgage banking revenue includes revenue from activities related to originating, selling and servicing residential real estate loans for the secondary market.
During the third quarter of 2021, the fair value of the mortgage servicing rights portfolio increased primarily due to the capitalization of $15.5 million of servicing rights partially offset by a reduction in value of $8.6 million due to payoffs and paydowns of the existing portfolio and a fair value adjustment decrease of $888,000.
The Company recognized net losses on investment securities of $2.4 million in the third quarter of 2021 as compared to net gains of $1.3 million recognized in the second quarter of 2021.
10
Other non-interest income increased by $3.0 million in the third quarter of 2021 as compared to the second quarter of 2021 primarily due to a $2.0 million increase in interest rate swap fees and a $2.2 million increase in income on partnership investments. Other non-interest income during the second quarter of 2021 included a $4.0 million net gain recorded on the sale of three branches in southwestern Wisconsin.
For more information regarding non-interest income, see Tables 15 and 16 in this report.
NON-INTEREST EXPENSE
Salaries and employee benefits expense decreased by $1.9 million in the third quarter of 2021 as compared to the second quarter of 2021. The $1.9 million decline is primarily related to $6.3 million of lower compensation expense associated with the mortgage banking operation offset somewhat by higher incentive compensation expense for annual bonus and long-term incentive compensation plans during the third quarter relative to the second quarter.
Advertising and marketing expense totaled $13.4 million in the third quarter of 2021, an increase of $2.1 million as compared to the second quarter of 2021. The increase in the third quarter relates primarily to increased sponsorship activity for the summer months. Marketing costs are incurred to promote the Company's brand, commercial banking capabilities and various products, to attract loans and deposits and to announce new branch openings as well as the expansion of the Company's non-bank businesses. The level of marketing expenditures depends on the timing of sponsorship programs utilized which are determined based on the market area, targeted audience, competition and various other factors.
The Company recorded a net OREO gain of $1.5 million in the third quarter of 2021 as compared to a net expense of $769,000 in the second quarter of 2021. The net gain is primarily attributable to the sale of OREO properties during the third quarter of 2021.
Miscellaneous expense in the third quarter of 2021 increased by $2.2 million as compared to the second quarter of 2021. The increase was primarily impacted by approximately $1.7 million of more travel and entertainment expenses due to increased expenses associated with in-person client relationship meetings and conferences as well as some additional expense associated with an all-employee event to celebrate Wintrust’s 30th anniversary and to thank our employees for performing so well during the pandemic. Additionally, the third quarter of 2021 included a $271,000 reversal of contingent consideration expense related to the previous acquisition of mortgage operations as compared to a $1.4 million reversal of contingent consideration expense in the second quarter of 2021. The Company expects no additional material adjustments to the contingent consideration liability in future periods. Miscellaneous expense also includes ATM expenses, correspondent bank charges, directors fees, telephone, travel and entertainment, corporate insurance, dues and subscriptions, problem loan expenses and lending origination costs that are not deferred.
For more information regarding non-interest expense, see Table 17 in this report.
11
INCOME TAXES
The Company recorded income tax expense of $40.6 million in the third quarter of 2021 compared to $39.0 million in the second quarter of 2021 and $30.0 million in the third quarter of 2020. The effective tax rates were 27.12% in the third quarter of 2021 compared to 27.08% in the second quarter of 2021 and 21.83% in the third quarter of 2020. The lower effective tax rate in the third quarter of 2020 was a result of a $9.0 million state income tax benefit ($7.1 million after federal taxes) related to the settlement of an uncertain tax position in the quarter.
BUSINESS UNIT SUMMARY
Community Banking
Through its community banking unit, the Company provides banking and financial services primarily to individuals, small to mid-sized businesses, local governmental units and institutional clients residing primarily in the local areas the Company services. In the third quarter of 2021, this unit expanded its loan portfolio and its deposit portfolio. The segment’s net interest margin decreased in the third quarter of 2021 as compared to the second quarter of 2021 primarily due to increased liquidity.
Mortgage banking revenue was $55.8 million for the third quarter of 2021, an increase of $5.2 million as compared to the second quarter of 2021. Service charges on deposit accounts totaled $14.1 million in the third quarter of 2021, an increase of $900,000 as compared to the second quarter of 2021 primarily due to higher account analysis fees. The Company’s gross commercial and commercial real estate loan pipelines remained strong as of September 30, 2021. Before the impact of scheduled payments and prepayments, gross commercial and commercial real estate loan pipelines were estimated to be approximately $1.4 billion to $1.5 billion at September 30, 2021. When adjusted for the probability of closing, the pipelines were estimated to be approximately $900 million to $1.0 billion at September 30, 2021.
Specialty Finance
Through its specialty finance unit, the Company offers financing of insurance premiums for businesses and individuals, equipment financing through structured loans and lease products to customers in a variety of industries, accounts receivable financing and value-added, out-sourced administrative services and other services. Originations within the insurance premium financing receivables portfolio were $3.1 billion during the third quarter of 2021 and average balances increased by $735 million as compared to the second quarter of 2021. The increase in average balances in the insurance premium finance receivables portfolios primarily generated a $7.6 million increase in interest income. The Company’s leasing portfolio remained effectively unchanged from the second quarter of 2021 to the third quarter of 2021, with its portfolio of assets, including capital leases, loans and equipment on operating leases, at $2.3 billion at the end of the third quarter of 2021. Revenues from the Company’s out-sourced administrative services business were $1.4 million in the third quarter of 2021, up $131,000 from the second quarter of 2021.
Wealth Management
Through four separate subsidiaries within its wealth management unit, the Company offers a full range of wealth management services, including trust and investment services, tax-deferred like-kind exchange services, asset management, securities brokerage services and 401(k) and retirement plan services. Wealth management revenue totaled $31.5 million in the third quarter of 2021, an increase of $841,000 compared to the second quarter of 2021. Increases in asset management fees were primarily due to favorable equity market performance during the third quarter of 2021. At September 30, 2021, the Company’s wealth management subsidiaries had approximately $34.5 billion of assets under administration, which included $5.1 billion of assets owned by the Company and its subsidiary banks, representing a $326.3 million increase from the $34.2 billion of assets under administration at June 30, 2021.
12
WINTRUST FINANCIAL CORPORATION
Key Operating Measures
Wintrust’s key operating measures and growth rates for the third quarter of 2021, as compared to the second quarter of 2021 (sequential quarter) and third quarter of 2020 (linked quarter), are shown in the table below:
% or(1) basis point (bp) change from 2nd Quarter 2021 | % or basis point (bp) change from 3rd Quarter 2020 | ||||||||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | Sep 30, 2021 | Jun 30, 2021 | Sep 30, 2020 | ||||||||||||||||||||||||||||||||
| Net income | $ | 109,137 | $ | 105,109 | $ | 107,315 | 4 | % | 2 | % | |||||||||||||||||||||||||
Pre-tax income, excluding provision for credit losses (non-GAAP) (2) | 141,826 | 128,851 | 162,310 | 10 | (13) | ||||||||||||||||||||||||||||||
| Net income per common share – diluted | 1.77 | 1.70 | 1.67 | 4 | 6 | ||||||||||||||||||||||||||||||
Net revenue (3) | 423,970 | 408,963 | 426,529 | 4 | (1) | ||||||||||||||||||||||||||||||
| Net interest income | 287,496 | 279,590 | 255,936 | 3 | 12 | ||||||||||||||||||||||||||||||
| Net interest margin | 2.58 | % | 2.62 | % | 2.56 | % | (4) | bps | 2 | bps | |||||||||||||||||||||||||
Net interest margin – fully taxable-equivalent (non-GAAP) (2) | 2.59 | 2.63 | 2.57 | (4) | 2 | ||||||||||||||||||||||||||||||
Net overhead ratio (4) | 1.22 | 1.32 | 0.87 | (10) | 35 | ||||||||||||||||||||||||||||||
| Return on average assets | 0.92 | 0.92 | 0.99 | — | (7) | ||||||||||||||||||||||||||||||
| Return on average common equity | 10.31 | 10.24 | 10.66 | 7 | (35) | ||||||||||||||||||||||||||||||
Return on average tangible common equity (non-GAAP) (2) | 12.62 | 12.62 | 13.43 | — | (81) | ||||||||||||||||||||||||||||||
| At end of period | |||||||||||||||||||||||||||||||||||
| Total assets | $ | 47,832,271 | $ | 46,738,450 | $ | 43,731,718 | 9 | % | 9 | % | |||||||||||||||||||||||||
Total loans (5) | 33,264,043 | 32,911,187 | 32,135,555 | 4 | 4 | ||||||||||||||||||||||||||||||
| Total deposits | 39,952,558 | 38,804,616 | 35,844,422 | 12 | 11 | ||||||||||||||||||||||||||||||
| Total shareholders’ equity | 4,410,317 | 4,339,011 | 4,074,089 | 7 | 8 | ||||||||||||||||||||||||||||||
(1)Period-end balance sheet percentage changes are annualized.
(2)See "Supplemental Non-GAAP Financial Measures/Ratios" at Table 18 for additional information on this performance measure/ratio.
(3)Net revenue is net interest income plus non-interest income.
(4)The net overhead ratio is calculated by netting total non-interest expense and total non-interest income, annualizing this amount, and dividing by that period's average total assets. A lower ratio indicates a higher degree of efficiency.
(5)Excludes mortgage loans held-for-sale.
Certain returns, yields, performance ratios, or quarterly growth rates are “annualized” in this presentation to represent an annual time period. This is done for analytical purposes to better discern, for decision-making purposes, underlying performance trends when compared to full-year or year-over-year amounts. For example, a 5% growth rate for a quarter would represent an annualized 20% growth rate. Additional supplemental financial information showing quarterly trends can be found on the Company’s website at www.wintrust.com by choosing “Financial Reports” under the “Investor Relations” heading, and then choosing “Financial Highlights.”
13
WINTRUST FINANCIAL CORPORATION
Selected Financial Highlights
| Three Months Ended | Nine Months Ended | ||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | Sep 30, 2020 | Sep 30, 2021 | Sep 30, 2020 | ||||||||||||||||||||||||||||||||||
| Selected Financial Condition Data (at end of period): | |||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 47,832,271 | $ | 46,738,450 | $ | 45,682,202 | $ | 45,080,768 | $ | 43,731,718 | |||||||||||||||||||||||||||||||
Total loans (1) | 33,264,043 | 32,911,187 | 33,171,233 | 32,079,073 | 32,135,555 | ||||||||||||||||||||||||||||||||||||
| Total deposits | 39,952,558 | 38,804,616 | 37,872,652 | 37,092,651 | 35,844,422 | ||||||||||||||||||||||||||||||||||||
| Junior subordinated debentures | 253,566 | 253,566 | 253,566 | 253,566 | 253,566 | ||||||||||||||||||||||||||||||||||||
| Total shareholders’ equity | 4,410,317 | 4,339,011 | 4,252,511 | 4,115,995 | 4,074,089 | ||||||||||||||||||||||||||||||||||||
| Selected Statements of Income Data: | |||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 287,496 | $ | 279,590 | $ | 261,895 | $ | 259,397 | $ | 255,936 | $ | 828,981 | $ | 780,510 | |||||||||||||||||||||||||||
Net revenue (2) | 423,970 | 408,963 | 448,401 | 417,758 | 426,529 | 1,281,334 | 1,226,338 | ||||||||||||||||||||||||||||||||||
| Net income | 109,137 | 105,109 | 153,148 | 101,204 | 107,315 | 367,394 | 191,786 | ||||||||||||||||||||||||||||||||||
Pre-tax income, excluding provision for credit losses (non-GAAP) (3) | 141,826 | 128,851 | 161,512 | 135,891 | 162,310 | 432,189 | 468,110 | ||||||||||||||||||||||||||||||||||
| Net income per common share – Basic | 1.79 | 1.72 | 2.57 | 1.64 | 1.68 | 6.08 | 3.08 | ||||||||||||||||||||||||||||||||||
| Net income per common share – Diluted | 1.77 | 1.70 | 2.54 | 1.63 | 1.67 | 6.00 | 3.06 | ||||||||||||||||||||||||||||||||||
| Selected Financial Ratios and Other Data: | |||||||||||||||||||||||||||||||||||||||||
| Performance Ratios: | |||||||||||||||||||||||||||||||||||||||||
| Net interest margin | 2.58 | % | 2.62 | % | 2.53 | % | 2.53 | % | 2.56 | % | 2.58 | % | 2.79 | % | |||||||||||||||||||||||||||
Net interest margin – fully taxable-equivalent (non-GAAP) (3) | 2.59 | 2.63 | 2.54 | 2.54 | 2.57 | 2.59 | 2.80 | ||||||||||||||||||||||||||||||||||
| Non-interest income to average assets | 1.15 | 1.13 | 1.68 | 1.44 | 1.58 | 1.31 | 1.47 | ||||||||||||||||||||||||||||||||||
| Non-interest expense to average assets | 2.37 | 2.45 | 2.59 | 2.56 | 2.45 | 2.47 | 2.50 | ||||||||||||||||||||||||||||||||||
Net overhead ratio (4) | 1.22 | 1.32 | 0.90 | 1.12 | 0.87 | 1.15 | 1.03 | ||||||||||||||||||||||||||||||||||
| Return on average assets | 0.92 | 0.92 | 1.38 | 0.92 | 0.99 | 1.07 | 0.63 | ||||||||||||||||||||||||||||||||||
| Return on average common equity | 10.31 | 10.24 | 15.80 | 10.30 | 10.66 | 12.05 | 6.56 | ||||||||||||||||||||||||||||||||||
Return on average tangible common equity (non-GAAP) (3) | 12.62 | 12.62 | 19.49 | 12.95 | 13.43 | 14.82 | 8.38 | ||||||||||||||||||||||||||||||||||
| Average total assets | $ | 47,192,510 | $ | 45,946,751 | $ | 44,988,733 | $ | 43,810,005 | $ | 42,962,844 | $ | 46,050,737 | $ | 40,552,517 | |||||||||||||||||||||||||||
| Average total shareholders’ equity | 4,343,915 | 4,256,778 | 4,164,890 | 4,050,286 | 4,034,902 | 4,255,851 | 3,885,187 | ||||||||||||||||||||||||||||||||||
| Average loans to average deposits ratio | 83.8 | % | 86.7 | % | 87.1 | % | 87.9 | % | 89.6 | % | 85.8 | % | 89.1 | % | |||||||||||||||||||||||||||
| Period-end loans to deposits ratio | 83.3 | 84.8 | 87.6 | 86.5 | 89.7 | ||||||||||||||||||||||||||||||||||||
| Common Share Data at end of period: | |||||||||||||||||||||||||||||||||||||||||
| Market price per common share | $ | 80.37 | $ | 75.63 | $ | 75.80 | $ | 61.09 | $ | 40.05 | |||||||||||||||||||||||||||||||
| Book value per common share | 70.19 | 68.81 | 67.34 | 65.24 | 63.57 | ||||||||||||||||||||||||||||||||||||
Tangible book value per common share (non-GAAP) (3) | 58.32 | 56.92 | 55.42 | 53.23 | 51.70 | ||||||||||||||||||||||||||||||||||||
| Common shares outstanding | 56,956,026 | 57,066,677 | 57,023,273 | 56,769,625 | 57,601,991 | ||||||||||||||||||||||||||||||||||||
| Other Data at end of period: | |||||||||||||||||||||||||||||||||||||||||
Tier 1 leverage ratio (5) | 8.1 | % | 8.2 | % | 8.2 | % | 8.1 | % | 8.2 | % | |||||||||||||||||||||||||||||||
| Risk-based capital ratios: | |||||||||||||||||||||||||||||||||||||||||
Tier 1 capital ratio (5) | 9.9 | 10.1 | 10.2 | 10.0 | 10.2 | ||||||||||||||||||||||||||||||||||||
Common equity tier 1 capital ratio (5) | 8.8 | 9.0 | 9.0 | 8.8 | 9.0 | ||||||||||||||||||||||||||||||||||||
Total capital ratio (5) | 12.1 | 12.4 | 12.6 | 12.6 | 12.9 | ||||||||||||||||||||||||||||||||||||
Allowance for credit losses (6) | $ | 296,138 | $ | 304,121 | $ | 321,308 | $ | 379,969 | $ | 388,971 | |||||||||||||||||||||||||||||||
| Allowance for loan and unfunded lending-related commitment losses to total loans | 0.89 | % | 0.92 | % | 0.97 | % | 1.18 | % | 1.21 | % | |||||||||||||||||||||||||||||||
| Number of: | |||||||||||||||||||||||||||||||||||||||||
| Bank subsidiaries | 15 | 15 | 15 | 15 | 15 | ||||||||||||||||||||||||||||||||||||
| Banking offices | 172 | 172 | 182 | 181 | 182 | ||||||||||||||||||||||||||||||||||||
(1)Excludes mortgage loans held-for-sale.
(2)Net revenue is net interest income and non-interest income.
(3)See “Supplemental Non-GAAP Financial Measures/Ratios” at Table 18 for additional information on this performance measure/ratio.
(4)The net overhead ratio is calculated by netting total non-interest expense and total non-interest income, annualizing this amount, and dividing by that period’s total average assets. A lower ratio indicates a higher degree of efficiency.
(5)Capital ratios for current quarter-end are estimated.
(6)The allowance for credit losses includes the allowance for loan losses, the allowance for unfunded lending-related commitments and the allowance for held-to-maturity securities losses.
14
WINTRUST FINANCIAL CORPORATION AND SUBSIDIARIES
CONSOLIDATED STATEMENTS OF CONDITION
| (Unaudited) | (Unaudited) | (Unaudited) | (Unaudited) | |||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | ||||||||||||||||||||||||||||
| (In thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | |||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||
| Cash and due from banks | $ | 462,244 | $ | 434,957 | $ | 426,325 | $ | 322,415 | $ | 308,639 | ||||||||||||||||||||||
| Federal funds sold and securities purchased under resale agreements | 55 | 52 | 52 | 59 | 56 | |||||||||||||||||||||||||||
| Interest-bearing deposits with banks | 5,232,315 | 4,707,415 | 3,348,794 | 4,802,527 | 3,825,823 | |||||||||||||||||||||||||||
| Available-for-sale securities, at fair value | 2,373,478 | 2,188,608 | 2,430,749 | 3,055,839 | 2,946,459 | |||||||||||||||||||||||||||
| Held-to-maturity securities, at amortized cost | 2,736,722 | 2,498,232 | 2,166,419 | 579,138 | 560,267 | |||||||||||||||||||||||||||
| Trading account securities | 1,103 | 2,667 | 951 | 671 | 1,720 | |||||||||||||||||||||||||||
| Equity securities with readily determinable fair value | 88,193 | 86,316 | 90,338 | 90,862 | 54,398 | |||||||||||||||||||||||||||
| Federal Home Loan Bank and Federal Reserve Bank stock | 135,408 | 136,625 | 135,881 | 135,588 | 135,568 | |||||||||||||||||||||||||||
| Brokerage customer receivables | 26,378 | 23,093 | 19,056 | 17,436 | 16,818 | |||||||||||||||||||||||||||
| Mortgage loans held-for-sale | 925,312 | 984,994 | 1,260,193 | 1,272,090 | 959,671 | |||||||||||||||||||||||||||
| Loans, net of unearned income | 33,264,043 | 32,911,187 | 33,171,233 | 32,079,073 | 32,135,555 | |||||||||||||||||||||||||||
| Allowance for loan losses | (248,612) | (261,089) | (277,709) | (319,374) | (325,959) | |||||||||||||||||||||||||||
| Net loans | 33,015,431 | 32,650,098 | 32,893,524 | 31,759,699 | 31,809,596 | |||||||||||||||||||||||||||
| Premises, software and equipment, net | 748,872 | 752,375 | 760,522 | 768,808 | 774,288 | |||||||||||||||||||||||||||
| Lease investments, net | 243,933 | 219,023 | 238,984 | 242,434 | 230,373 | |||||||||||||||||||||||||||
| Accrued interest receivable and other assets | 1,166,917 | 1,185,811 | 1,230,362 | 1,351,455 | 1,424,728 | |||||||||||||||||||||||||||
| Trade date securities receivable | — | 189,851 | — | — | — | |||||||||||||||||||||||||||
| Goodwill | 645,792 | 646,336 | 646,017 | 645,707 | 644,644 | |||||||||||||||||||||||||||
| Other intangible assets | 30,118 | 31,997 | 34,035 | 36,040 | 38,670 | |||||||||||||||||||||||||||
| Total assets | $ | 47,832,271 | $ | 46,738,450 | $ | 45,682,202 | $ | 45,080,768 | $ | 43,731,718 | ||||||||||||||||||||||
| Liabilities and Shareholders’ Equity | ||||||||||||||||||||||||||||||||
| Deposits: | ||||||||||||||||||||||||||||||||
| Non-interest-bearing | $ | 13,255,417 | $ | 12,796,110 | $ | 12,297,337 | $ | 11,748,455 | $ | 10,409,747 | ||||||||||||||||||||||
| Interest-bearing | 26,697,141 | 26,008,506 | 25,575,315 | 25,344,196 | 25,434,675 | |||||||||||||||||||||||||||
| Total deposits | 39,952,558 | 38,804,616 | 37,872,652 | 37,092,651 | 35,844,422 | |||||||||||||||||||||||||||
| Federal Home Loan Bank advances | 1,241,071 | 1,241,071 | 1,228,436 | 1,228,429 | 1,228,422 | |||||||||||||||||||||||||||
| Other borrowings | 504,527 | 518,493 | 516,877 | 518,928 | 507,395 | |||||||||||||||||||||||||||
| Subordinated notes | 436,811 | 436,719 | 436,595 | 436,506 | 436,385 | |||||||||||||||||||||||||||
| Junior subordinated debentures | 253,566 | 253,566 | 253,566 | 253,566 | 253,566 | |||||||||||||||||||||||||||
| Trade date securities payable | 1,348 | — | 995 | 200,907 | — | |||||||||||||||||||||||||||
| Accrued interest payable and other liabilities | 1,032,073 | 1,144,974 | 1,120,570 | 1,233,786 | 1,387,439 | |||||||||||||||||||||||||||
| Total liabilities | 43,421,954 | 42,399,439 | 41,429,691 | 40,964,773 | 39,657,629 | |||||||||||||||||||||||||||
| Shareholders’ Equity: | ||||||||||||||||||||||||||||||||
| Preferred stock | 412,500 | 412,500 | 412,500 | 412,500 | 412,500 | |||||||||||||||||||||||||||
| Common stock | 58,794 | 58,770 | 58,727 | 58,473 | 58,323 | |||||||||||||||||||||||||||
| Surplus | 1,674,062 | 1,669,002 | 1,663,008 | 1,649,990 | 1,647,049 | |||||||||||||||||||||||||||
| Treasury stock | (109,903) | (100,363) | (100,363) | (100,363) | (44,891) | |||||||||||||||||||||||||||
| Retained earnings | 2,373,447 | 2,288,969 | 2,208,535 | 2,080,013 | 2,001,949 | |||||||||||||||||||||||||||
| Accumulated other comprehensive income (loss) | 1,417 | 10,133 | 10,104 | 15,382 | (841) | |||||||||||||||||||||||||||
| Total shareholders’ equity | 4,410,317 | 4,339,011 | 4,252,511 | 4,115,995 | 4,074,089 | |||||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 47,832,271 | $ | 46,738,450 | $ | 45,682,202 | $ | 45,080,768 | $ | 43,731,718 | ||||||||||||||||||||||
15
WINTRUST FINANCIAL CORPORATION AND SUBSIDIARIES
CONSOLIDATED STATEMENTS OF INCOME (UNAUDITED)
| Three Months Ended | Nine Months Ended | |||||||||||||||||||||||||||||||||||||
| (In thousands, except per share data) | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | Sep 30, 2020 | Sep 30, 2021 | Sep 30, 2020 | |||||||||||||||||||||||||||||||
| Interest income | ||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 285,587 | $ | 284,701 | $ | 274,100 | $ | 280,185 | $ | 280,479 | $ | 844,388 | $ | 877,064 | ||||||||||||||||||||||||
| Mortgage loans held-for-sale | 7,716 | 8,183 | 9,036 | 6,357 | 5,791 | 24,935 | 13,720 | |||||||||||||||||||||||||||||||
| Interest-bearing deposits with banks | 2,000 | 1,153 | 1,199 | 1,294 | 1,181 | 4,352 | 7,259 | |||||||||||||||||||||||||||||||
| Federal funds sold and securities purchased under resale agreements | — | — | — | — | — | — | 102 | |||||||||||||||||||||||||||||||
| Investment securities | 25,189 | 23,623 | 19,264 | 18,243 | 21,819 | 68,076 | 81,391 | |||||||||||||||||||||||||||||||
| Trading account securities | 3 | 1 | 2 | 11 | 6 | 6 | 26 | |||||||||||||||||||||||||||||||
| Federal Home Loan Bank and Federal Reserve Bank stock | 1,777 | 1,769 | 1,745 | 1,775 | 1,774 | 5,291 | 5,116 | |||||||||||||||||||||||||||||||
| Brokerage customer receivables | 185 | 149 | 123 | 116 | 106 | 457 | 361 | |||||||||||||||||||||||||||||||
| Total interest income | 322,457 | 319,579 | 305,469 | 307,981 | 311,156 | 947,505 | 985,039 | |||||||||||||||||||||||||||||||
| Interest expense | ||||||||||||||||||||||||||||||||||||||
| Interest on deposits | 19,305 | 24,298 | 27,944 | 32,602 | 39,084 | 71,547 | 156,576 | |||||||||||||||||||||||||||||||
| Interest on Federal Home Loan Bank advances | 4,931 | 4,887 | 4,840 | 4,952 | 4,947 | 14,658 | 13,241 | |||||||||||||||||||||||||||||||
| Interest on other borrowings | 2,501 | 2,568 | 2,609 | 2,779 | 3,012 | 7,678 | 9,994 | |||||||||||||||||||||||||||||||
| Interest on subordinated notes | 5,480 | 5,512 | 5,477 | 5,509 | 5,474 | 16,469 | 16,452 | |||||||||||||||||||||||||||||||
| Interest on junior subordinated debentures | 2,744 | 2,724 | 2,704 | 2,742 | 2,703 | 8,172 | 8,266 | |||||||||||||||||||||||||||||||
| Total interest expense | 34,961 | 39,989 | 43,574 | 48,584 | 55,220 | 118,524 | 204,529 | |||||||||||||||||||||||||||||||
| Net interest income | 287,496 | 279,590 | 261,895 | 259,397 | 255,936 | 828,981 | 780,510 | |||||||||||||||||||||||||||||||
| Provision for credit losses | (7,916) | (15,299) | (45,347) | 1,180 | 25,026 | (68,562) | 213,040 | |||||||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 295,412 | 294,889 | 307,242 | 258,217 | 230,910 | 897,543 | 567,470 | |||||||||||||||||||||||||||||||
| Non-interest income | ||||||||||||||||||||||||||||||||||||||
| Wealth management | 31,531 | 30,690 | 29,309 | 26,802 | 24,957 | 91,530 | 73,534 | |||||||||||||||||||||||||||||||
| Mortgage banking | 55,794 | 50,584 | 113,494 | 86,819 | 108,544 | 219,872 | 259,194 | |||||||||||||||||||||||||||||||
| Service charges on deposit accounts | 14,149 | 13,249 | 12,036 | 11,841 | 11,497 | 39,434 | 33,182 | |||||||||||||||||||||||||||||||
| (Losses) gains on investment securities, net | (2,431) | 1,285 | 1,154 | 1,214 | 411 | 8 | (3,140) | |||||||||||||||||||||||||||||||
| Fees from covered call options | 1,157 | 1,388 | — | — | — | 2,545 | 2,292 | |||||||||||||||||||||||||||||||
| Trading gains (losses), net | 58 | (438) | 419 | (102) | 183 | 39 | (902) | |||||||||||||||||||||||||||||||
| Operating lease income, net | 12,807 | 12,240 | 14,440 | 12,118 | 11,717 | 39,487 | 35,486 | |||||||||||||||||||||||||||||||
| Other | 23,409 | 20,375 | 15,654 | 19,669 | 13,284 | 59,438 | 46,182 | |||||||||||||||||||||||||||||||
| Total non-interest income | 136,474 | 129,373 | 186,506 | 158,361 | 170,593 | 452,353 | 445,828 | |||||||||||||||||||||||||||||||
| Non-interest expense | ||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 170,912 | 172,817 | 180,809 | 171,116 | 164,042 | 524,538 | 454,960 | |||||||||||||||||||||||||||||||
| Software and equipment | 22,029 | 20,866 | 20,912 | 20,565 | 17,251 | 63,807 | 47,931 | |||||||||||||||||||||||||||||||
| Operating lease equipment depreciation | 10,013 | 9,949 | 10,771 | 9,938 | 9,425 | 30,733 | 27,977 | |||||||||||||||||||||||||||||||
| Occupancy, net | 18,158 | 17,687 | 19,996 | 19,687 | 15,830 | 55,841 | 50,270 | |||||||||||||||||||||||||||||||
| Data processing | 7,104 | 6,920 | 6,048 | 5,728 | 5,689 | 20,072 | 24,468 | |||||||||||||||||||||||||||||||
| Advertising and marketing | 13,443 | 11,305 | 8,546 | 9,850 | 7,880 | 33,294 | 26,446 | |||||||||||||||||||||||||||||||
| Professional fees | 7,052 | 7,304 | 7,587 | 6,530 | 6,488 | 21,943 | 20,896 | |||||||||||||||||||||||||||||||
| Amortization of other intangible assets | 1,877 | 2,039 | 2,007 | 2,634 | 2,701 | 5,923 | 8,384 | |||||||||||||||||||||||||||||||
| FDIC insurance | 6,750 | 6,405 | 6,558 | 7,016 | 6,772 | 19,713 | 17,988 | |||||||||||||||||||||||||||||||
| OREO expense, net | (1,531) | 769 | (251) | (114) | (168) | (1,013) | (807) | |||||||||||||||||||||||||||||||
| Other | 26,337 | 24,051 | 23,906 | 28,917 | 28,309 | 74,294 | 79,715 | |||||||||||||||||||||||||||||||
| Total non-interest expense | 282,144 | 280,112 | 286,889 | 281,867 | 264,219 | 849,145 | 758,228 | |||||||||||||||||||||||||||||||
| Income before taxes | 149,742 | 144,150 | 206,859 | 134,711 | 137,284 | 500,751 | 255,070 | |||||||||||||||||||||||||||||||
| Income tax expense | 40,605 | 39,041 | 53,711 | 33,507 | 29,969 | 133,357 | 63,284 | |||||||||||||||||||||||||||||||
| Net income | $ | 109,137 | $ | 105,109 | $ | 153,148 | $ | 101,204 | $ | 107,315 | $ | 367,394 | $ | 191,786 | ||||||||||||||||||||||||
| Preferred stock dividends | 6,991 | 6,991 | 6,991 | 6,991 | 10,286 | 20,973 | 14,386 | |||||||||||||||||||||||||||||||
| Net income applicable to common shares | $ | 102,146 | $ | 98,118 | $ | 146,157 | $ | 94,213 | $ | 97,029 | $ | 346,421 | $ | 177,400 | ||||||||||||||||||||||||
| Net income per common share - Basic | $ | 1.79 | $ | 1.72 | $ | 2.57 | $ | 1.64 | $ | 1.68 | $ | 6.08 | $ | 3.08 | ||||||||||||||||||||||||
| Net income per common share - Diluted | $ | 1.77 | $ | 1.70 | $ | 2.54 | $ | 1.63 | $ | 1.67 | $ | 6.00 | $ | 3.06 | ||||||||||||||||||||||||
| Cash dividends declared per common share | $ | 0.31 | $ | 0.31 | $ | 0.31 | $ | 0.28 | $ | 0.28 | $ | 0.93 | $ | 0.84 | ||||||||||||||||||||||||
| Weighted average common shares outstanding | 57,000 | 57,049 | 56,904 | 57,309 | 57,597 | 56,985 | 57,595 | |||||||||||||||||||||||||||||||
| Dilutive potential common shares | 753 | 726 | 681 | 588 | 449 | 728 | 469 | |||||||||||||||||||||||||||||||
| Average common shares and dilutive common shares | 57,753 | 57,775 | 57,585 | 57,897 | 58,046 | 57,713 | 58,064 | |||||||||||||||||||||||||||||||
16
TABLE 1: LOAN PORTFOLIO MIX AND GROWTH RATES
% Growth From (2) | ||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | Sep 30, 2020 | Dec 31, 2020 (1) | Sep 30, 2020 | |||||||||||||||||||||||||||||||
| Balance: | ||||||||||||||||||||||||||||||||||||||
| Mortgage loans held-for-sale, excluding early buy-out exercised loans guaranteed by U.S. Government Agencies | $ | 570,663 | $ | 633,006 | $ | 890,749 | $ | 927,307 | $ | 862,924 | (51) | % | (34) | % | ||||||||||||||||||||||||
| Mortgage loans held-for-sale, early buy-out exercised loans guaranteed by U.S. Government Agencies | 354,649 | 351,988 | 369,444 | 344,783 | 96,747 | 4 | 267 | |||||||||||||||||||||||||||||||
| Total mortgage loans held-for-sale | $ | 925,312 | $ | 984,994 | $ | 1,260,193 | $ | 1,272,090 | $ | 959,671 | (36) | % | (4) | % | ||||||||||||||||||||||||
| Core loans: | ||||||||||||||||||||||||||||||||||||||
| Commercial | ||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 4,953,769 | $ | 4,650,607 | $ | 4,630,795 | $ | 4,675,594 | $ | 4,555,920 | 8 | % | 9 | % | ||||||||||||||||||||||||
| Asset-based lending | 1,066,376 | 892,109 | 720,772 | 721,666 | 707,365 | 64 | 51 | |||||||||||||||||||||||||||||||
| Municipal | 524,192 | 511,094 | 493,417 | 474,103 | 482,567 | 14 | 9 | |||||||||||||||||||||||||||||||
| Leases | 1,365,281 | 1,357,036 | 1,290,778 | 1,288,374 | 1,215,239 | 8 | 12 | |||||||||||||||||||||||||||||||
| Commercial real estate | ||||||||||||||||||||||||||||||||||||||
| Residential construction | 49,754 | 55,735 | 72,058 | 89,389 | 101,187 | (59) | (51) | |||||||||||||||||||||||||||||||
| Commercial construction | 1,038,034 | 1,090,447 | 1,040,631 | 1,041,729 | 1,005,708 | — | 3 | |||||||||||||||||||||||||||||||
| Land | 255,927 | 239,067 | 240,635 | 240,684 | 226,254 | 8 | 13 | |||||||||||||||||||||||||||||||
| Office | 1,169,466 | 1,098,386 | 1,131,472 | 1,136,844 | 1,163,790 | 4 | — | |||||||||||||||||||||||||||||||
| Industrial | 1,324,612 | 1,263,614 | 1,152,522 | 1,129,433 | 1,117,702 | 23 | 19 | |||||||||||||||||||||||||||||||
| Retail | 1,237,261 | 1,217,540 | 1,198,025 | 1,224,403 | 1,175,819 | 1 | 5 | |||||||||||||||||||||||||||||||
| Multi-family | 1,888,817 | 1,805,118 | 1,739,521 | 1,649,801 | 1,599,651 | 19 | 18 | |||||||||||||||||||||||||||||||
| Mixed use and other | 1,921,843 | 1,908,462 | 1,969,915 | 1,981,849 | 2,033,031 | (4) | (5) | |||||||||||||||||||||||||||||||
| Home equity | 347,662 | 369,806 | 390,253 | 425,263 | 446,274 | (24) | (22) | |||||||||||||||||||||||||||||||
| Residential real estate | ||||||||||||||||||||||||||||||||||||||
| Residential real estate loans for investment | 1,528,889 | 1,485,952 | 1,376,465 | 1,214,744 | 1,143,908 | 35 | 34 | |||||||||||||||||||||||||||||||
| Residential mortgage loans, early buy-out eligible loans guaranteed by U.S. Government Agencies | 18,847 | 44,333 | 45,508 | 44,854 | 240,902 | (78) | (92) | |||||||||||||||||||||||||||||||
| Total core loans | $ | 18,690,730 | $ | 17,989,306 | $ | 17,492,767 | $ | 17,338,730 | $ | 17,215,317 | 10 | % | 9 | % | ||||||||||||||||||||||||
| Niche loans: | ||||||||||||||||||||||||||||||||||||||
| Commercial | ||||||||||||||||||||||||||||||||||||||
| Franchise | $ | 1,176,569 | $ | 1,060,468 | $ | 1,128,493 | $ | 1,023,027 | $ | 964,150 | 20 | % | 22 | % | ||||||||||||||||||||||||
| Mortgage warehouse lines of credit | 468,162 | 529,867 | 587,868 | 567,389 | 503,371 | (23) | (7) | |||||||||||||||||||||||||||||||
| Community Advantage - homeowners association | 291,153 | 287,689 | 272,222 | 267,374 | 254,963 | 12 | 14 | |||||||||||||||||||||||||||||||
| Insurance agency lending | 260,482 | 273,999 | 290,880 | 222,519 | 214,411 | 23 | 21 | |||||||||||||||||||||||||||||||
| Premium Finance receivables | ||||||||||||||||||||||||||||||||||||||
| U.S. commercial insurance | 3,921,289 | 3,805,504 | 3,342,730 | 3,438,087 | 3,494,155 | 19 | 12 | |||||||||||||||||||||||||||||||
| Canada commercial insurance | 695,688 | 716,367 | 615,813 | 616,402 | 565,989 | 17 | 23 | |||||||||||||||||||||||||||||||
| Life insurance | 6,655,453 | 6,359,556 | 6,111,495 | 5,857,436 | 5,488,832 | 18 | 21 | |||||||||||||||||||||||||||||||
| Consumer and other | 22,529 | 9,024 | 35,983 | 32,188 | 55,354 | (40) | (59) | |||||||||||||||||||||||||||||||
| Total niche loans | $ | 13,491,325 | $ | 13,042,474 | $ | 12,385,484 | $ | 12,024,422 | $ | 11,541,225 | 16 | % | 17 | % | ||||||||||||||||||||||||
| Commercial PPP loans: | ||||||||||||||||||||||||||||||||||||||
| Originated in 2020 | $ | 172,849 | $ | 656,502 | $ | 2,049,342 | $ | 2,715,921 | $ | 3,379,013 | NM | (95) | % | |||||||||||||||||||||||||
| Originated in 2021 | 909,139 | 1,222,905 | 1,243,640 | — | — | 100 | 100 | |||||||||||||||||||||||||||||||
| Total commercial PPP loans | $ | 1,081,988 | $ | 1,879,407 | $ | 3,292,982 | $ | 2,715,921 | $ | 3,379,013 | (80) | % | (68) | % | ||||||||||||||||||||||||
| Total loans, net of unearned income | $ | 33,264,043 | $ | 32,911,187 | $ | 33,171,233 | $ | 32,079,073 | $ | 32,135,555 | 5 | % | 4 | % | ||||||||||||||||||||||||
(1)Annualized.
(2)NM - Not meaningful.
17
TABLE 2: DEPOSIT PORTFOLIO MIX AND GROWTH RATES
| % Growth From | ||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | Sep 30, 2020 | Dec 31, 2020 (1) | Sep 30, 2020 | |||||||||||||||||||||||||||||||
| Balance: | ||||||||||||||||||||||||||||||||||||||
| Non-interest-bearing | $ | 13,255,417 | $ | 12,796,110 | $ | 12,297,337 | $ | 11,748,455 | $ | 10,409,747 | 17 | % | 27 | % | ||||||||||||||||||||||||
| NOW and interest-bearing demand deposits | 3,769,825 | 3,625,538 | 3,562,312 | 3,349,021 | 3,294,071 | 17 | 14 | |||||||||||||||||||||||||||||||
Wealth management deposits (2) | 4,177,820 | 4,399,303 | 4,274,527 | 4,138,712 | 4,235,583 | 1 | (1) | |||||||||||||||||||||||||||||||
| Money market | 10,757,654 | 9,843,390 | 9,236,434 | 9,348,806 | 9,423,653 | 20 | 14 | |||||||||||||||||||||||||||||||
| Savings | 3,861,296 | 3,776,400 | 3,690,892 | 3,531,029 | 3,415,073 | 13 | 13 | |||||||||||||||||||||||||||||||
| Time certificates of deposit | 4,130,546 | 4,363,875 | 4,811,150 | 4,976,628 | 5,066,295 | (23) | (18) | |||||||||||||||||||||||||||||||
| Total deposits | $ | 39,952,558 | $ | 38,804,616 | $ | 37,872,652 | $ | 37,092,651 | $ | 35,844,422 | 10 | % | 11 | % | ||||||||||||||||||||||||
| Mix: | ||||||||||||||||||||||||||||||||||||||
| Non-interest-bearing | 33 | % | 33 | % | 32 | % | 32 | % | 29 | % | ||||||||||||||||||||||||||||
| NOW and interest-bearing demand deposits | 9 | 9 | 9 | 9 | 9 | |||||||||||||||||||||||||||||||||
Wealth management deposits (2) | 11 | 11 | 11 | 11 | 12 | |||||||||||||||||||||||||||||||||
| Money market | 27 | 25 | 25 | 25 | 26 | |||||||||||||||||||||||||||||||||
| Savings | 10 | 10 | 10 | 10 | 10 | |||||||||||||||||||||||||||||||||
| Time certificates of deposit | 10 | 12 | 13 | 13 | 14 | |||||||||||||||||||||||||||||||||
| Total deposits | 100 | % | 100 | % | 100 | % | 100 | % | 100 | % | ||||||||||||||||||||||||||||
(1)Annualized.
(2)Represents deposit balances of the Company’s subsidiary banks from brokerage customers of Wintrust Investments, Chicago Deferred Exchange Company, LLC ("CDEC"), trust and asset management customers of the Company and brokerage customers from unaffiliated companies which have been placed into deposit accounts.
TABLE 3: TIME CERTIFICATES OF DEPOSIT MATURITY/RE-PRICING ANALYSIS
As of September 30, 2021
| (Dollars in thousands) | Total Time Certificates of Deposit | Weighted-Average Rate of Maturing Time Certificates of Deposit (1) | ||||||||||||
| 1-3 months | $ | 918,517 | 0.99 | % | ||||||||||
| 4-6 months | 780,345 | 0.57 | ||||||||||||
| 7-9 months | 628,839 | 0.41 | ||||||||||||
| 10-12 months | 602,854 | 0.42 | ||||||||||||
| 13-18 months | 621,320 | 0.56 | ||||||||||||
| 19-24 months | 272,526 | 0.48 | ||||||||||||
| 24+ months | 306,145 | 0.55 | ||||||||||||
| Total | $ | 4,130,546 | 0.61 | % | ||||||||||
(1)Weighted-average rate excludes the impact of purchase accounting fair value adjustments.
18
TABLE 4: QUARTERLY AVERAGE BALANCES
| Average Balance for three months ended, | ||||||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | ||||||||||||||||||||||||||||
| (In thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | |||||||||||||||||||||||||||
Interest-bearing deposits with banks and cash equivalents (1) | $ | 5,112,720 | $ | 3,844,355 | $ | 4,230,886 | $ | 4,381,040 | $ | 3,411,164 | ||||||||||||||||||||||
Investment securities (2) | 5,065,593 | 4,771,403 | 3,944,676 | 3,534,594 | 3,789,422 | |||||||||||||||||||||||||||
| FHLB and FRB stock | 136,001 | 136,324 | 135,758 | 135,569 | 135,567 | |||||||||||||||||||||||||||
Liquidity management assets (3) | 10,314,314 | 8,752,082 | 8,311,320 | 8,051,203 | 7,336,153 | |||||||||||||||||||||||||||
Other earning assets (3)(4) | 28,238 | 23,354 | 20,370 | 18,716 | 16,656 | |||||||||||||||||||||||||||
| Mortgage loans held-for-sale | 871,824 | 991,011 | 1,151,848 | 893,395 | 822,908 | |||||||||||||||||||||||||||
Loans, net of unearned income (3)(5) | 32,985,445 | 33,085,174 | 32,442,927 | 31,783,279 | 31,634,608 | |||||||||||||||||||||||||||
Total earning assets (3) | 44,199,821 | 42,851,621 | 41,926,465 | 40,746,593 | 39,810,325 | |||||||||||||||||||||||||||
| Allowance for loan and investment security losses | (269,963) | (285,686) | (327,080) | (336,139) | (321,732) | |||||||||||||||||||||||||||
| Cash and due from banks | 425,000 | 470,566 | 366,413 | 344,536 | 345,438 | |||||||||||||||||||||||||||
| Other assets | 2,837,652 | 2,910,250 | 3,022,935 | 3,055,015 | 3,128,813 | |||||||||||||||||||||||||||
Total assets | $ | 47,192,510 | $ | 45,946,751 | $ | 44,988,733 | $ | 43,810,005 | $ | 42,962,844 | ||||||||||||||||||||||
| NOW and interest-bearing demand deposits | $ | 3,757,677 | $ | 3,626,424 | $ | 3,493,451 | $ | 3,320,527 | $ | 3,435,089 | ||||||||||||||||||||||
| Wealth management deposits | 4,672,402 | 4,369,998 | 4,156,398 | 4,066,948 | 4,239,300 | |||||||||||||||||||||||||||
| Money market accounts | 10,027,424 | 9,547,167 | 9,335,920 | 9,435,344 | 9,332,668 | |||||||||||||||||||||||||||
| Savings accounts | 3,851,523 | 3,728,271 | 3,587,566 | 3,413,388 | 3,419,586 | |||||||||||||||||||||||||||
| Time deposits | 4,236,317 | 4,632,796 | 4,875,392 | 5,043,558 | 4,900,839 | |||||||||||||||||||||||||||
| Interest-bearing deposits | 26,545,343 | 25,904,656 | 25,448,727 | 25,279,765 | 25,327,482 | |||||||||||||||||||||||||||
| Federal Home Loan Bank advances | 1,241,073 | 1,235,142 | 1,228,433 | 1,228,425 | 1,228,421 | |||||||||||||||||||||||||||
| Other borrowings | 512,785 | 525,924 | 518,188 | 510,725 | 512,787 | |||||||||||||||||||||||||||
| Subordinated notes | 436,746 | 436,644 | 436,532 | 436,433 | 436,323 | |||||||||||||||||||||||||||
| Junior subordinated debentures | 253,566 | 253,566 | 253,566 | 253,566 | 253,566 | |||||||||||||||||||||||||||
Total interest-bearing liabilities | 28,989,513 | 28,355,932 | 27,885,446 | 27,708,914 | 27,758,579 | |||||||||||||||||||||||||||
| Non-interest-bearing deposits | 12,834,084 | 12,246,274 | 11,811,194 | 10,874,912 | 9,988,769 | |||||||||||||||||||||||||||
| Other liabilities | 1,024,998 | 1,087,767 | 1,127,203 | 1,175,893 | 1,180,594 | |||||||||||||||||||||||||||
| Equity | 4,343,915 | 4,256,778 | 4,164,890 | 4,050,286 | 4,034,902 | |||||||||||||||||||||||||||
Total liabilities and shareholders’ equity | $ | 47,192,510 | $ | 45,946,751 | $ | 44,988,733 | $ | 43,810,005 | $ | 42,962,844 | ||||||||||||||||||||||
Net free funds/contribution (6) | $ | 15,210,308 | $ | 14,495,689 | $ | 14,041,019 | $ | 13,037,679 | $ | 12,051,746 | ||||||||||||||||||||||
(1)Includes interest-bearing deposits from banks, federal funds sold and securities purchased under resale agreements.
(2)Investment securities includes investment securities classified as available-for-sale and held-to-maturity, and equity securities with readily determinable fair values. Equity securities without readily determinable fair values are included within other assets.
(3)See "Supplemental Non-GAAP Financial Measures/Ratios" at Table 18 for additional information on this performance measure/ratio.
(4)Other earning assets include brokerage customer receivables and trading account securities.
(5)Loans, net of unearned income, include non-accrual loans.
(6)Net free funds are the difference between total average earning assets and total average interest-bearing liabilities. The estimated contribution to net interest margin from net free funds is calculated using the rate paid for total interest-bearing liabilities.
19
TABLE 5: QUARTERLY NET INTEREST INCOME
| Net Interest Income for three months ended, | ||||||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | ||||||||||||||||||||||||||||
| (In thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | |||||||||||||||||||||||||||
| Interest income: | ||||||||||||||||||||||||||||||||
| Interest-bearing deposits with banks and cash equivalents | $ | 2,000 | $ | 1,153 | $ | 1,199 | $ | 1,294 | $ | 1,181 | ||||||||||||||||||||||
| Investment securities | 25,681 | 24,117 | 19,764 | 18,773 | 22,365 | |||||||||||||||||||||||||||
| FHLB and FRB stock | 1,777 | 1,769 | 1,745 | 1,775 | 1,774 | |||||||||||||||||||||||||||
Liquidity management assets (1) | 29,458 | 27,039 | 22,708 | 21,842 | 25,320 | |||||||||||||||||||||||||||
Other earning assets (1) | 188 | 150 | 125 | 130 | 113 | |||||||||||||||||||||||||||
| Mortgage loans held-for-sale | 7,716 | 8,183 | 9,036 | 6,357 | 5,791 | |||||||||||||||||||||||||||
Loans, net of unearned income (1) | 285,998 | 285,116 | 274,484 | 280,509 | 280,960 | |||||||||||||||||||||||||||
| Total interest income | $ | 323,360 | $ | 320,488 | $ | 306,353 | $ | 308,838 | $ | 312,184 | ||||||||||||||||||||||
| Interest expense: | ||||||||||||||||||||||||||||||||
| NOW and interest-bearing demand deposits | $ | 767 | $ | 736 | $ | 901 | $ | 1,074 | $ | 1,342 | ||||||||||||||||||||||
| Wealth management deposits | 7,888 | 7,686 | 7,351 | 7,436 | 7,662 | |||||||||||||||||||||||||||
| Money market accounts | 2,342 | 2,795 | 2,865 | 3,740 | 7,245 | |||||||||||||||||||||||||||
| Savings accounts | 406 | 402 | 430 | 773 | 2,104 | |||||||||||||||||||||||||||
| Time deposits | 7,902 | 12,679 | 16,397 | 19,579 | 20,731 | |||||||||||||||||||||||||||
| Interest-bearing deposits | 19,305 | 24,298 | 27,944 | 32,602 | 39,084 | |||||||||||||||||||||||||||
| Federal Home Loan Bank advances | 4,931 | 4,887 | 4,840 | 4,952 | 4,947 | |||||||||||||||||||||||||||
| Other borrowings | 2,501 | 2,568 | 2,609 | 2,779 | 3,012 | |||||||||||||||||||||||||||
| Subordinated notes | 5,480 | 5,512 | 5,477 | 5,509 | 5,474 | |||||||||||||||||||||||||||
| Junior subordinated debentures | 2,744 | 2,724 | 2,704 | 2,742 | 2,703 | |||||||||||||||||||||||||||
| Total interest expense | $ | 34,961 | $ | 39,989 | $ | 43,574 | $ | 48,584 | $ | 55,220 | ||||||||||||||||||||||
| Less: Fully taxable-equivalent adjustment | (903) | (909) | (884) | (857) | (1,028) | |||||||||||||||||||||||||||
Net interest income (GAAP) (2) | 287,496 | 279,590 | 261,895 | 259,397 | 255,936 | |||||||||||||||||||||||||||
| Fully taxable-equivalent adjustment | 903 | 909 | 884 | 857 | 1,028 | |||||||||||||||||||||||||||
Net interest income, fully taxable-equivalent (non-GAAP) (2) | $ | 288,399 | $ | 280,499 | $ | 262,779 | $ | 260,254 | $ | 256,964 | ||||||||||||||||||||||
(1)Interest income on tax-advantaged loans, trading securities and investment securities reflects a taxable-equivalent adjustment based on the marginal federal corporate tax rate in effect as of the applicable period.
(2)See "Supplemental Non-GAAP Financial Measures/Ratios" at Table 18 for additional information on this performance measure/ratio.
20
TABLE 6: QUARTERLY NET INTEREST MARGIN
| Net Interest Margin for three months ended, | ||||||||||||||||||||||||||||||||
| Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | Sep 30, 2020 | ||||||||||||||||||||||||||||
| Yield earned on: | ||||||||||||||||||||||||||||||||
| Interest-bearing deposits with banks and cash equivalents | 0.16 | % | 0.12 | % | 0.11 | % | 0.12 | % | 0.14 | % | ||||||||||||||||||||||
| Investment securities | 2.01 | 2.03 | 2.03 | 2.11 | 2.35 | |||||||||||||||||||||||||||
| FHLB and FRB stock | 5.18 | 5.20 | 5.21 | 5.21 | 5.21 | |||||||||||||||||||||||||||
| Liquidity management assets | 1.13 | 1.24 | 1.11 | 1.08 | 1.37 | |||||||||||||||||||||||||||
| Other earning assets | 2.64 | 2.59 | 2.50 | 2.79 | 2.71 | |||||||||||||||||||||||||||
| Mortgage loans held-for-sale | 3.51 | 3.31 | 3.18 | 2.83 | 2.80 | |||||||||||||||||||||||||||
| Loans, net of unearned income | 3.44 | 3.46 | 3.43 | 3.51 | 3.53 | |||||||||||||||||||||||||||
| Total earning assets | 2.90 | % | 3.00 | % | 2.96 | % | 3.02 | % | 3.12 | % | ||||||||||||||||||||||
| Rate paid on: | ||||||||||||||||||||||||||||||||
| NOW and interest-bearing demand deposits | 0.08 | % | 0.08 | % | 0.10 | % | 0.13 | % | 0.16 | % | ||||||||||||||||||||||
| Wealth management deposits | 0.67 | 0.71 | 0.72 | 0.73 | 0.72 | |||||||||||||||||||||||||||
| Money market accounts | 0.09 | 0.12 | 0.12 | 0.16 | 0.31 | |||||||||||||||||||||||||||
| Savings accounts | 0.04 | 0.04 | 0.05 | 0.09 | 0.24 | |||||||||||||||||||||||||||
| Time deposits | 0.74 | 1.10 | 1.36 | 1.54 | 1.68 | |||||||||||||||||||||||||||
| Interest-bearing deposits | 0.29 | 0.38 | 0.45 | 0.51 | 0.61 | |||||||||||||||||||||||||||
| Federal Home Loan Bank advances | 1.58 | 1.59 | 1.60 | 1.60 | 1.60 | |||||||||||||||||||||||||||
| Other borrowings | 1.94 | 1.96 | 2.04 | 2.16 | 2.34 | |||||||||||||||||||||||||||
| Subordinated notes | 5.02 | 5.05 | 5.02 | 5.05 | 5.02 | |||||||||||||||||||||||||||
| Junior subordinated debentures | 4.23 | 4.25 | 4.27 | 4.23 | 4.17 | |||||||||||||||||||||||||||
| Total interest-bearing liabilities | 0.48 | % | 0.56 | % | 0.63 | % | 0.70 | % | 0.79 | % | ||||||||||||||||||||||
Interest rate spread (1)(2) | 2.42 | % | 2.44 | % | 2.33 | % | 2.32 | % | 2.33 | % | ||||||||||||||||||||||
| Less: Fully taxable-equivalent adjustment | (0.01) | (0.01) | (0.01) | (0.01) | (0.01) | |||||||||||||||||||||||||||
Net free funds/contribution (3) | 0.17 | 0.19 | 0.21 | 0.22 | 0.24 | |||||||||||||||||||||||||||
Net interest margin (GAAP) (2) | 2.58 | % | 2.62 | % | 2.53 | % | 2.53 | % | 2.56 | % | ||||||||||||||||||||||
| Fully taxable-equivalent adjustment | 0.01 | 0.01 | 0.01 | 0.01 | 0.01 | |||||||||||||||||||||||||||
Net interest margin, fully taxable-equivalent (non-GAAP) (2) | 2.59 | % | 2.63 | % | 2.54 | % | 2.54 | % | 2.57 | % | ||||||||||||||||||||||
(1)Interest rate spread is the difference between the yield earned on earning assets and the rate paid on interest-bearing liabilities.
(2)See "Supplemental Non-GAAP Financial Measures/Ratios" at Table 18 for additional information on this performance measure/ratio.
(3)Net free funds are the difference between total average earning assets and total average interest-bearing liabilities. The estimated contribution to net interest margin from net free funds is calculated using the rate paid for total interest-bearing liabilities.
21
TABLE 7: YEAR-TO-DATE AVERAGE BALANCES, AND NET INTEREST INCOME AND MARGIN
| Average Balance for nine months ended, | Interest for nine months ended, | Yield/Rate for nine months ended, | |||||||||||||||||||||||||||
| (Dollars in thousands) | Sep 30, 2021 | Sep 30, 2020 | Sep 30, 2021 | Sep 30, 2020 | Sep 30, 2021 | Sep 30, 2020 | |||||||||||||||||||||||
Interest-bearing deposits with banks and cash equivalents (1) | $ | 4,399,217 | $ | 2,692,678 | $ | 4,352 | $ | 7,361 | 0.13 | % | 0.37 | % | |||||||||||||||||
Investment securities (2) | 4,597,997 | 4,291,362 | 69,562 | 83,026 | 2.02 | 2.58 | |||||||||||||||||||||||
| FHLB and FRB stock | 136,028 | 128,611 | 5,291 | 5,116 | 5.20 | 5.31 | |||||||||||||||||||||||
Liquidity management assets (3)(4) | $ | 9,133,242 | $ | 7,112,651 | $ | 79,205 | $ | 95,503 | 1.16 | % | 1.79 | % | |||||||||||||||||
Other earning assets (3)(4)(5) | 24,016 | 17,576 | 463 | 393 | 2.59 | 2.99 | |||||||||||||||||||||||
| Mortgage loans held-for-sale | 1,003,868 | 644,611 | 24,935 | 13,720 | 3.32 | 2.84 | |||||||||||||||||||||||
Loans, net of unearned income (3)(4)(6) | 32,839,837 | 29,643,281 | 845,598 | 878,981 | 3.44 | 3.96 | |||||||||||||||||||||||
Total earning assets (4) | $ | 43,000,963 | $ | 37,418,119 | $ | 950,201 | $ | 988,597 | 2.95 | % | 3.53 | % | |||||||||||||||||
| Allowance for loan and investment security losses | (294,033) | (240,467) | |||||||||||||||||||||||||||
| Cash and due from banks | 420,874 | 339,968 | |||||||||||||||||||||||||||
| Other assets | 2,922,933 | 3,034,897 | |||||||||||||||||||||||||||
Total assets | $ | 46,050,737 | $ | 40,552,517 | |||||||||||||||||||||||||
| NOW and interest-bearing demand deposits | $ | 3,626,819 | $ | 3,291,176 | $ | 2,404 | $ | 6,569 | 0.09 | % | 0.27 | % | |||||||||||||||||
| Wealth management deposits | 4,401,489 | 3,821,203 | 22,925 | 21,840 | 0.70 | 0.76 | |||||||||||||||||||||||
| Money market accounts | 9,639,370 | 8,686,171 | 8,002 | 42,748 | 0.11 | 0.66 | |||||||||||||||||||||||
| Savings accounts | 3,723,420 | 3,334,944 | 1,238 | 11,736 | 0.04 | 0.47 | |||||||||||||||||||||||
| Time deposits | 4,579,161 | 5,176,307 | 36,978 | 73,683 | 1.08 | 1.90 | |||||||||||||||||||||||
| Interest-bearing deposits | $ | 25,970,259 | $ | 24,309,801 | $ | 71,547 | $ | 156,576 | 0.37 | % | 0.86 | % | |||||||||||||||||
| Federal Home Loan Bank advances | 1,234,929 | 1,131,823 | 14,658 | 13,241 | 1.59 | 1.56 | |||||||||||||||||||||||
| Other borrowings | 518,946 | 491,981 | 7,678 | 9,994 | 1.98 | 2.71 | |||||||||||||||||||||||
| Subordinated notes | 436,641 | 436,223 | 16,469 | 16,452 | 5.03 | 5.03 | |||||||||||||||||||||||
| Junior subordinated debentures | 253,566 | 253,566 | 8,172 | 8,266 | 4.25 | 4.28 | |||||||||||||||||||||||
Total interest-bearing liabilities | $ | 28,414,341 | $ | 26,623,394 | $ | 118,524 | $ | 204,529 | 0.56 | % | 1.03 | % | |||||||||||||||||
| Non-interest-bearing deposits | 12,300,931 | 8,947,639 | |||||||||||||||||||||||||||
| Other liabilities | 1,079,614 | 1,096,297 | |||||||||||||||||||||||||||
| Equity | 4,255,851 | 3,885,187 | |||||||||||||||||||||||||||
Total liabilities and shareholders’ equity | $ | 46,050,737 | $ | 40,552,517 | |||||||||||||||||||||||||
Interest rate spread (4)(7) | 2.39 | % | 2.50 | % | |||||||||||||||||||||||||
| Less: Fully taxable-equivalent adjustment | (2,696) | (3,558) | (0.01) | (0.01) | |||||||||||||||||||||||||
Net free funds/contribution (8) | $ | 14,586,622 | $ | 10,794,725 | 0.20 | 0.30 | |||||||||||||||||||||||
Net interest income/margin (GAAP) (4) | $ | 828,981 | $ | 780,510 | 2.58 | % | 2.79 | % | |||||||||||||||||||||
| Fully taxable-equivalent adjustment | 2,696 | 3,558 | 0.01 | 0.01 | |||||||||||||||||||||||||
Net interest income/margin, fully taxable-equivalent (non-GAAP) (4) | $ | 831,677 | $ | 784,068 | 2.59 | % | 2.80 | % | |||||||||||||||||||||
(1)Includes interest-bearing deposits from banks, federal funds sold and securities purchased under resale agreements.
(2)Investment securities includes investment securities classified as available-for-sale and held-to-maturity, and equity securities with readily determinable fair values. Equity securities without readily determinable fair values are included within other assets.
(3)Interest income on tax-advantaged loans, trading securities and investment securities reflects a taxable-equivalent adjustment based on a marginal federal corporate tax rate in effect as of the applicable period.
(4)See “Supplemental Non-GAAP Financial Measures/Ratios” at Table 18 for additional information on this performance ratio.
(5)Other earning assets include brokerage customer receivables and trading account securities.
(6)Loans, net of unearned income, include non-accrual loans.
(7)Interest rate spread is the difference between the yield earned on earning assets and the rate paid on interest-bearing liabilities.
(8)Net free funds are the difference between total average earning assets and total average interest-bearing liabilities. The estimated contribution to net interest margin from net free funds is calculated using the rate paid for total interest-bearing liabilities.
22
TABLE 8: INTEREST RATE SENSITIVITY
As an ongoing part of its financial strategy, the Company attempts to manage the impact of fluctuations in market interest rates on net interest income. Management measures its exposure to changes in interest rates by modeling many different interest rate scenarios.
The following interest rate scenarios display the percentage change in net interest income over a one-year time horizon assuming increases of 100 and 200 basis points and a decrease of 100 basis points. The Static Shock Scenario results incorporate actual cash flows and repricing characteristics for balance sheet instruments following an instantaneous, parallel change in market rates based upon a static (i.e. no growth or constant) balance sheet. Conversely, the Ramp Scenario results incorporate management’s projections of future volume and pricing of each of the product lines following a gradual, parallel change in market rates over twelve months. Actual results may differ from these simulated results due to timing, magnitude, and frequency of interest rate changes as well as changes in market conditions and management strategies. The interest rate sensitivity for both the Static Shock and Ramp Scenario is as follows:
| Static Shock Scenario | +200 Basis Points | +100 Basis Points | -100 Basis Points | |||||||||||||||||
| Sep 30, 2021 | 24.3 | % | 11.5 | % | (7.8) | % | ||||||||||||||
| Jun 30, 2021 | 24.6 | 11.7 | (6.9) | |||||||||||||||||
| Mar 31, 2021 | 22.0 | 10.2 | (7.2) | |||||||||||||||||
| Dec 31, 2020 | 25.0 | 11.6 | (7.9) | |||||||||||||||||
| Sep 30, 2020 | 23.4 | 10.9 | (8.1) | |||||||||||||||||
| Ramp Scenario | +200 Basis Points | +100 Basis Points | -100 Basis Points | ||||||||||||||
| Sep 30, 2021 | 10.8 | % | 5.4 | % | (3.8) | % | |||||||||||
| Jun 30, 2021 | 11.4 | 5.8 | (3.3) | ||||||||||||||
| Mar 31, 2021 | 10.7 | 5.4 | (3.6) | ||||||||||||||
| Dec 31, 2020 | 11.4 | 5.7 | (3.3) | ||||||||||||||
| Sep 30, 2020 | 10.7 | 5.2 | (3.5) | ||||||||||||||
23
TABLE 9: MATURITIES AND SENSITIVITIES TO CHANGES IN INTEREST RATES
| Loans repricing or maturity period | |||||||||||||||||||||||
| As of September 30, 2021 | One year or less | From one to five years | Over five years | ||||||||||||||||||||
| (In thousands) | Total | ||||||||||||||||||||||
| Commercial | |||||||||||||||||||||||
| Fixed rate | $ | 484,771 | $ | 2,015,188 | $ | 837,153 | $ | 3,337,112 | |||||||||||||||
| Fixed Rate - PPP | 141,394 | 940,594 | — | 1,081,988 | |||||||||||||||||||
| Variable rate | 6,765,489 | 3,323 | 60 | 6,768,872 | |||||||||||||||||||
| Total commercial | $ | 7,391,654 | $ | 2,959,105 | $ | 837,213 | $ | 11,187,972 | |||||||||||||||
| Commercial real estate | |||||||||||||||||||||||
| Fixed rate | 558,728 | 2,201,827 | 493,256 | 3,253,811 | |||||||||||||||||||
| Variable rate | 5,607,888 | 24,015 | — | 5,631,903 | |||||||||||||||||||
| Total commercial real estate | $ | 6,166,616 | $ | 2,225,842 | $ | 493,256 | $ | 8,885,714 | |||||||||||||||
| Home equity | |||||||||||||||||||||||
| Fixed rate | 14,818 | 4,618 | 45 | 19,481 | |||||||||||||||||||
| Variable rate | 328,181 | — | — | 328,181 | |||||||||||||||||||
| Total home equity | $ | 342,999 | $ | 4,618 | $ | 45 | $ | 347,662 | |||||||||||||||
| Residential real estate | |||||||||||||||||||||||
| Fixed rate | 19,165 | 6,415 | 819,685 | 845,265 | |||||||||||||||||||
| Variable rate | 58,698 | 258,143 | 385,630 | 702,471 | |||||||||||||||||||
| Total residential real estate | $ | 77,863 | $ | 264,558 | $ | 1,205,315 | $ | 1,547,736 | |||||||||||||||
| Premium finance receivables - commercial | |||||||||||||||||||||||
| Fixed rate | 4,479,551 | 137,426 | — | 4,616,977 | |||||||||||||||||||
| Variable rate | — | — | — | — | |||||||||||||||||||
| Total premium finance receivables - commercial | $ | 4,479,551 | $ | 137,426 | $ | — | $ | 4,616,977 | |||||||||||||||
| Premium finance receivables - life insurance | |||||||||||||||||||||||
| Fixed rate | 9,046 | 438,568 | 21,813 | 469,427 | |||||||||||||||||||
| Variable rate | 6,186,026 | — | — | 6,186,026 | |||||||||||||||||||
| Total premium finance receivables - life insurance | $ | 6,195,072 | $ | 438,568 | $ | 21,813 | $ | 6,655,453 | |||||||||||||||
| Consumer and other | |||||||||||||||||||||||
| Fixed rate | 4,366 | 4,852 | 906 | 10,124 | |||||||||||||||||||
| Variable rate | 12,405 | — | — | 12,405 | |||||||||||||||||||
| Total consumer and other | $ | 16,771 | $ | 4,852 | $ | 906 | $ | 22,529 | |||||||||||||||
| Total per category | |||||||||||||||||||||||
| Fixed rate | 5,570,445 | 4,808,894 | 2,172,858 | 12,552,197 | |||||||||||||||||||
| Fixed rate - PPP | 141,394 | 940,594 | — | 1,081,988 | |||||||||||||||||||
| Variable rate | 18,958,687 | 285,481 | 385,690 | 19,629,858 | |||||||||||||||||||
| Total loans, net of unearned income | $ | 24,670,526 | $ | 6,034,969 | $ | 2,558,548 | $ | 33,264,043 | |||||||||||||||
| Variable Rate Loan Pricing by Index: | |||||||||||||||||||||||
| Prime | $ | 2,989,860 | |||||||||||||||||||||
| One- month LIBOR | 9,177,387 | ||||||||||||||||||||||
| Three- month LIBOR | 374,045 | ||||||||||||||||||||||
| Twelve- month LIBOR | 6,499,434 | ||||||||||||||||||||||
| Thirty-day moving-average SOFR | 174,768 | ||||||||||||||||||||||
| Other | 414,364 | ||||||||||||||||||||||
| Total variable rate | $ | 19,629,858 | |||||||||||||||||||||
LIBOR - London Interbank Offered Rate.
SOFR - Secured Overnight Financing Rate.
24
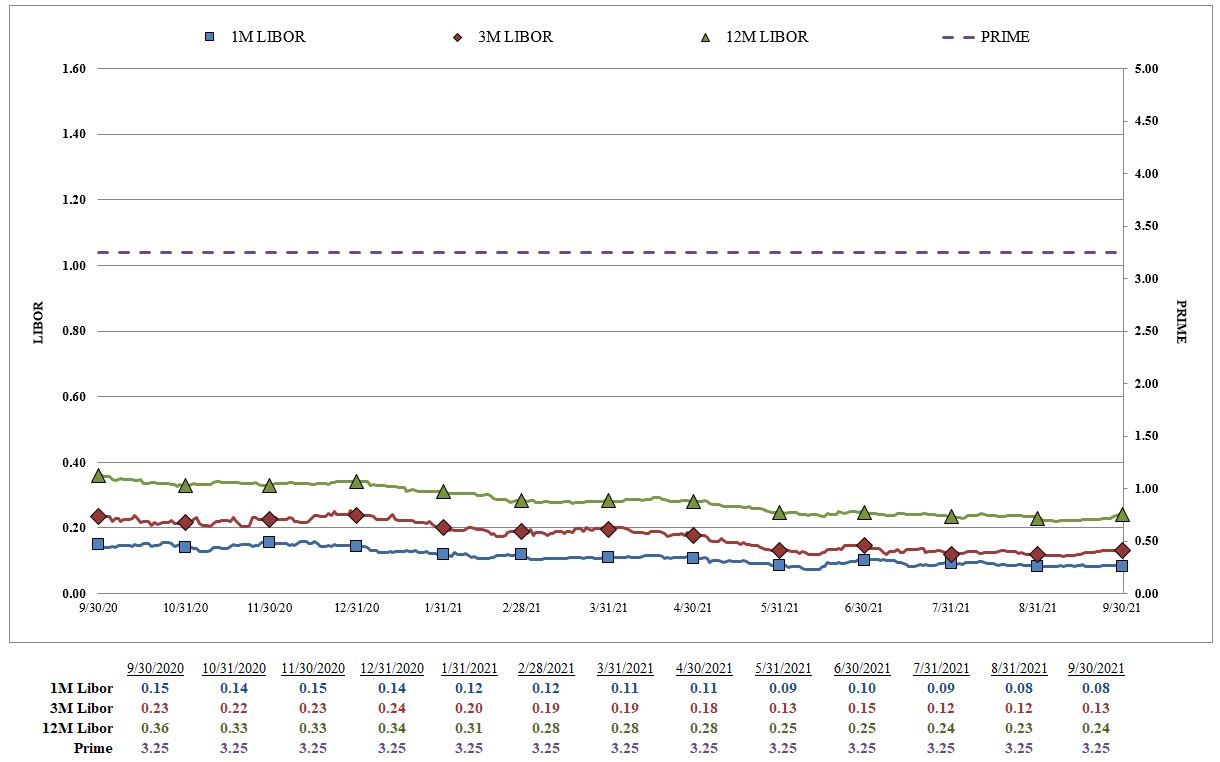 Source: Bloomberg
As noted in the table on the previous page, the majority of the Company’s portfolio is tied to LIBOR indices which, as shown in the table above, do not mirror the same changes as the Prime rate which has historically moved when the Federal Reserve raises or lowers interest rates. Specifically, the Company has $9.2 billion of variable rate loans tied to one-month LIBOR and $6.5 billion of variable rate loans tied to twelve-month LIBOR. The above chart shows:
| Basis Point (bp) Change in | |||||||||||||||||||||||
| Prime | 1-month LIBOR | 12-month LIBOR | |||||||||||||||||||||
| Third Quarter 2021 | 0 | bps | -2 | bps | -1 | bp | |||||||||||||||||
| Second Quarter 2021 | 0 | -1 | -3 | ||||||||||||||||||||
| First Quarter 2021 | 0 | -3 | -6 | ||||||||||||||||||||
| Fourth Quarter 2020 | 0 | -1 | -2 | ||||||||||||||||||||
| Third Quarter 2020 | 0 | -1 | -19 | ||||||||||||||||||||
25
TABLE 10: ALLOWANCE FOR CREDIT LOSSES
| Three Months Ended | Nine Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | Sep 30, | Sep 30, | |||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||
| Allowance for credit losses at beginning of period | $ | 304,121 | $ | 321,308 | $ | 379,969 | $ | 388,971 | $ | 373,174 | $ | 379,969 | $ | 158,461 | |||||||||||||||||||||||||||
| Cumulative effect adjustment from the adoption of ASU 2016-13 | — | — | — | — | — | — | 47,418 | ||||||||||||||||||||||||||||||||||
| Provision for credit losses | (7,916) | (15,299) | (45,347) | 1,180 | 25,026 | (68,562) | 213,040 | ||||||||||||||||||||||||||||||||||
| Other adjustments | (65) | 34 | 31 | 155 | 55 | — | 24 | ||||||||||||||||||||||||||||||||||
| Charge-offs: | |||||||||||||||||||||||||||||||||||||||||
| Commercial | 1,352 | 3,237 | 11,781 | 5,184 | 5,270 | 16,370 | 13,109 | ||||||||||||||||||||||||||||||||||
| Commercial real estate | 406 | 1,412 | 980 | 6,637 | 1,529 | 2,798 | 9,323 | ||||||||||||||||||||||||||||||||||
| Home equity | 59 | 142 | — | 683 | 138 | 201 | 1,378 | ||||||||||||||||||||||||||||||||||
| Residential real estate | 10 | 3 | 2 | 114 | 83 | 15 | 777 | ||||||||||||||||||||||||||||||||||
| Premium finance receivables | 1,390 | 2,077 | 3,239 | 4,214 | 4,640 | 6,706 | 11,258 | ||||||||||||||||||||||||||||||||||
| Consumer and other | 112 | 104 | 114 | 198 | 103 | 330 | 330 | ||||||||||||||||||||||||||||||||||
| Total charge-offs | 3,329 | 6,975 | 16,116 | 17,030 | 11,763 | 26,420 | 36,175 | ||||||||||||||||||||||||||||||||||
| Recoveries: | |||||||||||||||||||||||||||||||||||||||||
| Commercial | 816 | 902 | 452 | 4,168 | 428 | 2,170 | 924 | ||||||||||||||||||||||||||||||||||
| Commercial real estate | 373 | 514 | 200 | 904 | 175 | 1,087 | 931 | ||||||||||||||||||||||||||||||||||
| Home equity | 313 | 328 | 101 | 77 | 111 | 742 | 451 | ||||||||||||||||||||||||||||||||||
| Residential real estate | 5 | 36 | 204 | 69 | 25 | 245 | 115 | ||||||||||||||||||||||||||||||||||
| Premium finance receivables | 1,728 | 3,239 | 1,782 | 1,445 | 1,720 | 6,749 | 3,663 | ||||||||||||||||||||||||||||||||||
| Consumer and other | 92 | 34 | 32 | 30 | 20 | 158 | 119 | ||||||||||||||||||||||||||||||||||
| Total recoveries | 3,327 | 5,053 | 2,771 | 6,693 | 2,479 | 11,151 | 6,203 | ||||||||||||||||||||||||||||||||||
| Net charge-offs | (2) | (1,922) | (13,345) | (10,337) | (9,284) | (15,269) | (29,972) | ||||||||||||||||||||||||||||||||||
| Allowance for credit losses at period end | $ | 296,138 | $ | 304,121 | $ | 321,308 | $ | 379,969 | $ | 388,971 | $ | 296,138 | $ | 388,971 | |||||||||||||||||||||||||||
| Annualized net charge-offs (recoveries) by category as a percentage of its own respective category’s average: | |||||||||||||||||||||||||||||||||||||||||
| Commercial | 0.02 | % | 0.08 | % | 0.37 | % | 0.03 | % | 0.16 | % | 0.16 | % | 0.15 | % | |||||||||||||||||||||||||||
| Commercial real estate | 0.00 | 0.04 | 0.04 | 0.27 | 0.06 | 0.03 | 0.14 | ||||||||||||||||||||||||||||||||||
| Home equity | (0.28) | (0.20) | (0.10) | 0.55 | 0.02 | (0.19) | 0.26 | ||||||||||||||||||||||||||||||||||
| Residential real estate | 0.00 | (0.01) | (0.06) | 0.02 | 0.02 | (0.02) | 0.07 | ||||||||||||||||||||||||||||||||||
| Premium finance receivables | (0.01) | (0.04) | 0.06 | 0.11 | 0.12 | 0.00 | 0.11 | ||||||||||||||||||||||||||||||||||
| Consumer and other | 0.26 | 0.69 | 0.57 | 0.78 | 0.49 | 0.54 | 0.41 | ||||||||||||||||||||||||||||||||||
| Total loans, net of unearned income | 0.00 | % | 0.02 | % | 0.17 | % | 0.13 | % | 0.12 | % | 0.06 | % | 0.14 | % | |||||||||||||||||||||||||||
| Loans at period end | $ | 33,264,043 | $ | 32,911,187 | $ | 33,171,233 | $ | 32,079,073 | $ | 32,135,555 | |||||||||||||||||||||||||||||||
| Allowance for loan losses as a percentage of loans at period end | 0.75 | % | 0.79 | % | 0.84 | % | 1.00 | % | 1.01 | % | |||||||||||||||||||||||||||||||
| Allowance for loan and unfunded lending-related commitment losses as a percentage of loans at period end | 0.89 | 0.92 | 0.97 | 1.18 | 1.21 | ||||||||||||||||||||||||||||||||||||
| Allowance for loan and unfunded lending-related commitment losses as a percentage of loans at period end, excluding PPP loans | 0.92 | 0.98 | 1.08 | 1.29 | 1.35 | ||||||||||||||||||||||||||||||||||||
26
TABLE 11: ALLOWANCE AND PROVISION FOR CREDIT LOSSES BY COMPONENT
| Three Months Ended | Nine Months Ended | ||||||||||||||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | Sep 30, | Sep 30, | |||||||||||||||||||||||||||||||||||
| (In thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||||||||
| Provision for loan losses | $ | (12,410) | $ | (14,731) | $ | (28,351) | $ | 3,597 | $ | 21,678 | $ | (55,492) | $ | 184,896 | |||||||||||||||||||||||||||
| Provision for unfunded lending-related commitments losses | 4,501 | (558) | (17,035) | (2,413) | 3,350 | (13,092) | 28,155 | ||||||||||||||||||||||||||||||||||
| Provision for held-to-maturity securities losses | (7) | (10) | 39 | (4) | (2) | 22 | (11) | ||||||||||||||||||||||||||||||||||
| Provision for credit losses | $ | (7,916) | $ | (15,299) | $ | (45,347) | $ | 1,180 | $ | 25,026 | $ | (68,562) | $ | 213,040 | |||||||||||||||||||||||||||
| Allowance for loan losses | $ | 248,612 | $ | 261,089 | $ | 277,709 | $ | 319,374 | $ | 325,959 | |||||||||||||||||||||||||||||||
| Allowance for unfunded lending-related commitments losses | 47,443 | 42,942 | 43,500 | 60,536 | 62,949 | ||||||||||||||||||||||||||||||||||||
| Allowance for loan losses and unfunded lending-related commitments losses | 296,055 | 304,031 | 321,209 | 379,910 | 388,908 | ||||||||||||||||||||||||||||||||||||
| Allowance for held-to-maturity securities losses | 83 | 90 | 99 | 59 | 63 | ||||||||||||||||||||||||||||||||||||
| Allowance for credit losses | $ | 296,138 | $ | 304,121 | $ | 321,308 | $ | 379,969 | $ | 388,971 | |||||||||||||||||||||||||||||||
27
TABLE 12: ALLOWANCE BY LOAN PORTFOLIO
The table below summarizes the calculation of allowance for loan losses and allowance for unfunded lending-related commitments losses for the Company’s loan portfolios as well as core and niche portfolios, as of September 30, 2021, June 30, 2021, and March 31, 2021.
| As of Sep 30, 2021 | As of Jun 30, 2021 | As of Mar 31, 2021 | |||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Recorded Investment | Calculated Allowance | % of its category’s balance | Recorded Investment | Calculated Allowance | % of its category’s balance | Recorded Investment | Calculated Allowance | % of its category’s balance | ||||||||||||||||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||||||||||||||||||||
| Commercial, industrial and other, excluding PPP loans | $ | 10,105,984 | $ | 109,780 | 1.09 | % | $ | 9,562,869 | $ | 98,505 | 1.03 | % | $ | 9,415,225 | $ | 95,637 | 1.02 | % | |||||||||||||||||||||||||||||
| Commercial PPP loans | 1,081,988 | 2 | 0.00 | 1,879,407 | 2 | 0.00 | 3,292,982 | 3 | 0.00 | ||||||||||||||||||||||||||||||||||||||
| Commercial real estate: | |||||||||||||||||||||||||||||||||||||||||||||||
| Construction and development | 1,343,715 | 34,101 | 2.54 | 1,385,249 | 38,550 | 2.78 | 1,353,324 | 45,327 | 3.35 | ||||||||||||||||||||||||||||||||||||||
| Non-construction | 7,541,999 | 105,934 | 1.40 | 7,293,120 | 119,972 | 1.65 | 7,191,455 | 136,465 | 1.90 | ||||||||||||||||||||||||||||||||||||||
| Home equity | 347,662 | 10,939 | 3.15 | 369,806 | 11,207 | 3.03 | 390,253 | 11,382 | 2.92 | ||||||||||||||||||||||||||||||||||||||
| Residential real estate | 1,547,736 | 16,272 | 1.05 | 1,530,285 | 15,684 | 1.02 | 1,421,973 | 14,242 | 1.00 | ||||||||||||||||||||||||||||||||||||||
| Premium finance receivables | |||||||||||||||||||||||||||||||||||||||||||||||
| Commercial insurance loans | 4,616,977 | 17,996 | 0.39 | 4,521,871 | 19,346 | 0.43 | 3,958,543 | 16,945 | 0.43 | ||||||||||||||||||||||||||||||||||||||
| Life insurance loans | 6,655,453 | 579 | 0.01 | 6,359,556 | 553 | 0.01 | 6,111,495 | 532 | 0.01 | ||||||||||||||||||||||||||||||||||||||
| Consumer and other | 22,529 | 452 | 2.01 | 9,024 | 212 | 2.35 | 35,983 | 676 | 1.88 | ||||||||||||||||||||||||||||||||||||||
| Total loans, net of unearned income | $ | 33,264,043 | $ | 296,055 | 0.89 | % | $ | 32,911,187 | $ | 304,031 | 0.92 | % | $ | 33,171,233 | $ | 321,209 | 0.97 | % | |||||||||||||||||||||||||||||
| Total loans, net of unearned income, excluding PPP loans | $ | 32,182,055 | $ | 296,053 | 0.92 | % | $ | 31,031,780 | $ | 304,029 | 0.98 | % | $ | 29,878,251 | $ | 321,206 | 1.08 | % | |||||||||||||||||||||||||||||
Total core loans (1) | $ | 18,690,730 | $ | 257,788 | 1.38 | % | $ | 17,989,306 | $ | 267,999 | 1.49 | % | $ | 17,492,767 | $ | 283,505 | 1.62 | % | |||||||||||||||||||||||||||||
Total niche loans (1) | 13,491,325 | 38,265 | 0.28 | 13,042,474 | 36,030 | 0.28 | 12,385,484 | 37,701 | 0.30 | ||||||||||||||||||||||||||||||||||||||
| Total PPP loans | 1,081,988 | 2 | 0.00 | 1,879,407 | 2 | 0.00 | 3,292,982 | 3 | 0.00 | ||||||||||||||||||||||||||||||||||||||
(1)See Table 1 for additional detail on core and niche loans.
28
TABLE 13: LOAN PORTFOLIO AGING
| (Dollars in thousands) | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | Sep 30, 2020 | |||||||||||||||||||||||||||
| Loan Balances: | ||||||||||||||||||||||||||||||||
| Commercial | ||||||||||||||||||||||||||||||||
| Nonaccrual | $ | 26,468 | $ | 23,232 | $ | 22,459 | $ | 21,743 | $ | 42,036 | ||||||||||||||||||||||
| 90+ days and still accruing | — | 1,244 | — | 307 | — | |||||||||||||||||||||||||||
| 60-89 days past due | 9,768 | 5,204 | 13,292 | 6,900 | 2,168 | |||||||||||||||||||||||||||
| 30-59 days past due | 25,224 | 18,478 | 35,541 | 44,381 | 48,271 | |||||||||||||||||||||||||||
| Current | 11,126,512 | 11,394,118 | 12,636,915 | 11,882,636 | 12,184,524 | |||||||||||||||||||||||||||
| Total commercial | $ | 11,187,972 | $ | 11,442,276 | $ | 12,708,207 | $ | 11,955,967 | $ | 12,276,999 | ||||||||||||||||||||||
| Commercial real estate | ||||||||||||||||||||||||||||||||
| Nonaccrual | $ | 23,706 | $ | 26,035 | $ | 34,380 | $ | 46,107 | $ | 68,815 | ||||||||||||||||||||||
| 90+ days and still accruing | — | — | — | — | — | |||||||||||||||||||||||||||
| 60-89 days past due | 5,395 | 4,382 | 8,156 | 5,178 | 8,299 | |||||||||||||||||||||||||||
| 30-59 days past due | 79,818 | 19,698 | 70,168 | 32,116 | 53,462 | |||||||||||||||||||||||||||
| Current | 8,776,795 | 8,628,254 | 8,432,075 | 8,410,731 | 8,292,566 | |||||||||||||||||||||||||||
| Total commercial real estate | $ | 8,885,714 | $ | 8,678,369 | $ | 8,544,779 | $ | 8,494,132 | $ | 8,423,142 | ||||||||||||||||||||||
| Home equity | ||||||||||||||||||||||||||||||||
| Nonaccrual | $ | 3,449 | $ | 3,478 | $ | 5,536 | $ | 6,529 | $ | 6,329 | ||||||||||||||||||||||
| 90+ days and still accruing | 164 | — | — | — | — | |||||||||||||||||||||||||||
| 60-89 days past due | 340 | 301 | 492 | 47 | 70 | |||||||||||||||||||||||||||
| 30-59 days past due | 867 | 777 | 780 | 637 | 1,148 | |||||||||||||||||||||||||||
| Current | 342,842 | 365,250 | 383,445 | 418,050 | 438,727 | |||||||||||||||||||||||||||
| Total home equity | $ | 347,662 | $ | 369,806 | $ | 390,253 | $ | 425,263 | $ | 446,274 | ||||||||||||||||||||||
| Residential real estate | ||||||||||||||||||||||||||||||||
| Nonaccrual | $ | 22,633 | $ | 23,050 | $ | 21,553 | $ | 26,071 | $ | 22,069 | ||||||||||||||||||||||
| 90+ days and still accruing | — | — | — | — | — | |||||||||||||||||||||||||||
| 60-89 days past due | 1,540 | 1,584 | 944 | 1,635 | 814 | |||||||||||||||||||||||||||
| 30-59 days past due | 1,076 | 2,139 | 13,768 | 12,584 | 2,443 | |||||||||||||||||||||||||||
| Current | 1,522,487 | 1,503,512 | 1,385,708 | 1,219,308 | 1,359,484 | |||||||||||||||||||||||||||
| Total residential real estate | $ | 1,547,736 | $ | 1,530,285 | $ | 1,421,973 | $ | 1,259,598 | $ | 1,384,810 | ||||||||||||||||||||||
| Premium finance receivables | ||||||||||||||||||||||||||||||||
| Nonaccrual | $ | 7,300 | $ | 6,418 | $ | 9,690 | $ | 13,264 | $ | 21,080 | ||||||||||||||||||||||
| 90+ days and still accruing | 5,811 | 3,570 | 4,783 | 12,792 | 12,177 | |||||||||||||||||||||||||||
| 60-89 days past due | 15,804 | 7,759 | 5,113 | 27,801 | 38,286 | |||||||||||||||||||||||||||
| 30-59 days past due | 21,654 | 32,758 | 31,373 | 49,274 | 80,732 | |||||||||||||||||||||||||||
| Current | 11,221,861 | 10,830,922 | 10,019,079 | 9,808,794 | 9,396,701 | |||||||||||||||||||||||||||
| Total premium finance receivables | $ | 11,272,430 | $ | 10,881,427 | $ | 10,070,038 | $ | 9,911,925 | $ | 9,548,976 | ||||||||||||||||||||||
| Consumer and other | ||||||||||||||||||||||||||||||||
| Nonaccrual | $ | 384 | $ | 485 | $ | 497 | $ | 436 | $ | 422 | ||||||||||||||||||||||
| 90+ days and still accruing | 126 | 178 | 161 | 264 | 175 | |||||||||||||||||||||||||||
| 60-89 days past due | 16 | 22 | 8 | 24 | 273 | |||||||||||||||||||||||||||
| 30-59 days past due | 125 | 75 | 74 | 136 | 493 | |||||||||||||||||||||||||||
| Current | 21,878 | 8,264 | 35,243 | 31,328 | 53,991 | |||||||||||||||||||||||||||
| Total consumer and other | $ | 22,529 | $ | 9,024 | $ | 35,983 | $ | 32,188 | $ | 55,354 | ||||||||||||||||||||||
| Total loans, net of unearned income | ||||||||||||||||||||||||||||||||
| Nonaccrual | $ | 83,940 | $ | 82,698 | $ | 94,115 | $ | 114,150 | $ | 160,751 | ||||||||||||||||||||||
| 90+ days and still accruing | 6,101 | 4,992 | 4,944 | 13,363 | 12,352 | |||||||||||||||||||||||||||
| 60-89 days past due | 32,863 | 19,252 | 28,005 | 41,585 | 49,910 | |||||||||||||||||||||||||||
| 30-59 days past due | 128,764 | 73,925 | 151,704 | 139,128 | 186,549 | |||||||||||||||||||||||||||
| Current | 33,012,375 | 32,730,320 | 32,892,465 | 31,770,847 | 31,725,993 | |||||||||||||||||||||||||||
| Total loans, net of unearned income | $ | 33,264,043 | $ | 32,911,187 | $ | 33,171,233 | $ | 32,079,073 | $ | 32,135,555 | ||||||||||||||||||||||
29
TABLE 14: NON-PERFORMING ASSETS AND TROUBLED DEBT RESTRUCTURINGS ("TDRs")
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | |||||||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||
Loans past due greater than 90 days and still accruing (1): | |||||||||||||||||||||||||||||
| Commercial | $ | — | $ | 1,244 | $ | — | $ | 307 | $ | — | |||||||||||||||||||
| Commercial real estate | — | — | — | — | — | ||||||||||||||||||||||||
| Home equity | 164 | — | — | — | — | ||||||||||||||||||||||||
| Residential real estate | — | — | — | — | — | ||||||||||||||||||||||||
| Premium finance receivables | 5,811 | 3,570 | 4,783 | 12,792 | 12,177 | ||||||||||||||||||||||||
| Consumer and other | 126 | 178 | 161 | 264 | 175 | ||||||||||||||||||||||||
| Total loans past due greater than 90 days and still accruing | 6,101 | 4,992 | 4,944 | 13,363 | 12,352 | ||||||||||||||||||||||||
| Non-accrual loans: | |||||||||||||||||||||||||||||
| Commercial | 26,468 | 23,232 | 22,459 | 21,743 | 42,036 | ||||||||||||||||||||||||
| Commercial real estate | 23,706 | 26,035 | 34,380 | 46,107 | 68,815 | ||||||||||||||||||||||||
| Home equity | 3,449 | 3,478 | 5,536 | 6,529 | 6,329 | ||||||||||||||||||||||||
| Residential real estate | 22,633 | 23,050 | 21,553 | 26,071 | 22,069 | ||||||||||||||||||||||||
| Premium finance receivables | 7,300 | 6,418 | 9,690 | 13,264 | 21,080 | ||||||||||||||||||||||||
| Consumer and other | 384 | 485 | 497 | 436 | 422 | ||||||||||||||||||||||||
| Total non-accrual loans | 83,940 | 82,698 | 94,115 | 114,150 | 160,751 | ||||||||||||||||||||||||
| Total non-performing loans: | |||||||||||||||||||||||||||||
| Commercial | 26,468 | 24,476 | 22,459 | 22,050 | 42,036 | ||||||||||||||||||||||||
| Commercial real estate | 23,706 | 26,035 | 34,380 | 46,107 | 68,815 | ||||||||||||||||||||||||
| Home equity | 3,613 | 3,478 | 5,536 | 6,529 | 6,329 | ||||||||||||||||||||||||
| Residential real estate | 22,633 | 23,050 | 21,553 | 26,071 | 22,069 | ||||||||||||||||||||||||
| Premium finance receivables | 13,111 | 9,988 | 14,473 | 26,056 | 33,257 | ||||||||||||||||||||||||
| Consumer and other | 510 | 663 | 658 | 700 | 597 | ||||||||||||||||||||||||
| Total non-performing loans | $ | 90,041 | $ | 87,690 | $ | 99,059 | $ | 127,513 | $ | 173,103 | |||||||||||||||||||
| Other real estate owned | 9,934 | 10,510 | 8,679 | 9,711 | 2,891 | ||||||||||||||||||||||||
| Other real estate owned - from acquisitions | 3,911 | 5,062 | 7,134 | 6,847 | 6,326 | ||||||||||||||||||||||||
| Other repossessed assets | — | — | — | — | — | ||||||||||||||||||||||||
| Total non-performing assets | $ | 103,886 | $ | 103,262 | $ | 114,872 | $ | 144,071 | $ | 182,320 | |||||||||||||||||||
| Accruing TDRs not included within non-performing assets | $ | 38,468 | $ | 44,019 | $ | 46,151 | $ | 47,023 | $ | 46,410 | |||||||||||||||||||
| Total non-performing loans by category as a percent of its own respective category’s period-end balance: | |||||||||||||||||||||||||||||
| Commercial | 0.24 | % | 0.21 | % | 0.18 | % | 0.18 | % | 0.34 | % | |||||||||||||||||||
| Commercial real estate | 0.27 | 0.30 | 0.40 | 0.54 | 0.82 | ||||||||||||||||||||||||
| Home equity | 1.04 | 0.94 | 1.42 | 1.54 | 1.42 | ||||||||||||||||||||||||
| Residential real estate | 1.46 | 1.51 | 1.52 | 2.07 | 1.59 | ||||||||||||||||||||||||
| Premium finance receivables | 0.12 | 0.09 | 0.14 | 0.26 | 0.35 | ||||||||||||||||||||||||
| Consumer and other | 2.26 | 7.35 | 1.83 | 2.17 | 1.08 | ||||||||||||||||||||||||
| Total loans, net of unearned income | 0.27 | % | 0.27 | % | 0.30 | % | 0.40 | % | 0.54 | % | |||||||||||||||||||
| Total non-performing assets as a percentage of total assets | 0.22 | % | 0.22 | % | 0.25 | % | 0.32 | % | 0.42 | % | |||||||||||||||||||
| Allowance for loan losses and unfunded lending-related commitments losses as a percentage of non-accrual loans | 352.70 | % | 367.64 | % | 341.29 | % | 332.82 | % | 241.93 | % | |||||||||||||||||||
(1)As of September 30, 2021 and June 30, 2021, $445,000 and $320,000, respectively, of TDRs were past due greater than 90 days and still accruing interest. No TDRs as of March 31, 2021, December 31, 2020, and September 30, 2020 were past due greater than 90 days and still accruing interest.
30
Non-performing Loans Rollforward
| Three Months Ended | Nine Months Ended | |||||||||||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | Sep 30, | Sep 30, | ||||||||||||||||||||||||||||||||
| (In thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | 2021 | 2020 | |||||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 87,690 | $ | 99,059 | $ | 127,513 | $ | 173,103 | $ | 188,284 | $ | 127,513 | $ | 117,588 | ||||||||||||||||||||||||
| Additions from becoming non-performing in the respective period | 9,341 | 12,762 | 9,894 | 13,224 | 19,771 | 31,997 | 72,769 | |||||||||||||||||||||||||||||||
| Additions from the adoption of ASU 2016-13 | — | — | — | — | — | — | 37,285 | |||||||||||||||||||||||||||||||
| Return to performing status | (3,322) | — | (654) | (1,000) | (6,202) | (3,976) | (9,254) | |||||||||||||||||||||||||||||||
| Payments received | (5,568) | (12,312) | (22,731) | (30,146) | (3,733) | (40,611) | (22,883) | |||||||||||||||||||||||||||||||
| Transfer to OREO and other repossessed assets | (720) | (3,660) | (1,372) | (12,662) | (598) | (5,752) | (1,895) | |||||||||||||||||||||||||||||||
| Charge-offs, net | (548) | (4,684) | (2,952) | (7,817) | (6,583) | (8,184) | (22,018) | |||||||||||||||||||||||||||||||
Net change for niche loans (1) | 3,168 | (3,475) | (10,639) | (7,189) | (17,836) | (10,946) | 1,511 | |||||||||||||||||||||||||||||||
| Balance at end of period | $ | 90,041 | $ | 87,690 | $ | 99,059 | $ | 127,513 | $ | 173,103 | $ | 90,041 | $ | 173,103 | ||||||||||||||||||||||||
(1)This includes activity for premium finance receivables and indirect consumer loans.
TDRs
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | |||||||||||||||||||||||||
| (In thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||
| Accruing TDRs: | |||||||||||||||||||||||||||||
| Commercial | $ | 4,532 | $ | 6,911 | $ | 7,536 | $ | 7,699 | $ | 7,863 | |||||||||||||||||||
| Commercial real estate | 8,385 | 9,659 | 9,478 | 10,549 | 10,846 | ||||||||||||||||||||||||
| Residential real estate and other | 25,551 | 27,449 | 29,137 | 28,775 | 27,701 | ||||||||||||||||||||||||
| Total accrual | $ | 38,468 | $ | 44,019 | $ | 46,151 | $ | 47,023 | $ | 46,410 | |||||||||||||||||||
Non-accrual TDRs: (1) | |||||||||||||||||||||||||||||
| Commercial | $ | 3,079 | $ | 4,104 | $ | 5,583 | $ | 10,491 | $ | 13,132 | |||||||||||||||||||
| Commercial real estate | 3,239 | 3,434 | 1,309 | 6,177 | 13,601 | ||||||||||||||||||||||||
| Residential real estate and other | 3,685 | 4,190 | 3,540 | 4,501 | 5,392 | ||||||||||||||||||||||||
| Total non-accrual | $ | 10,003 | $ | 11,728 | $ | 10,432 | $ | 21,169 | $ | 32,125 | |||||||||||||||||||
| Total TDRs: | |||||||||||||||||||||||||||||
| Commercial | $ | 7,611 | $ | 11,015 | $ | 13,119 | $ | 18,190 | $ | 20,995 | |||||||||||||||||||
| Commercial real estate | 11,624 | 13,093 | 10,787 | 16,726 | 24,447 | ||||||||||||||||||||||||
| Residential real estate and other | 29,236 | 31,639 | 32,677 | 33,276 | 33,093 | ||||||||||||||||||||||||
| Total TDRs | $ | 48,471 | $ | 55,747 | $ | 56,583 | $ | 68,192 | $ | 78,535 | |||||||||||||||||||
(1)Included in total non-performing loans.
31
Other Real Estate Owned
| Three Months Ended | |||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | |||||||||||||||||||||||||
| (In thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||
| Balance at beginning of period | $ | 15,572 | $ | 15,813 | $ | 16,558 | $ | 9,217 | $ | 10,197 | |||||||||||||||||||
| Disposals/resolved | (1,949) | (3,152) | (2,162) | (3,839) | (1,532) | ||||||||||||||||||||||||
| Transfers in at fair value, less costs to sell | 315 | 3,660 | 1,587 | 11,508 | 777 | ||||||||||||||||||||||||
| Additions from acquisition | — | — | — | — | — | ||||||||||||||||||||||||
| Fair value adjustments | (93) | (749) | (170) | (328) | (225) | ||||||||||||||||||||||||
| Balance at end of period | $ | 13,845 | $ | 15,572 | $ | 15,813 | $ | 16,558 | $ | 9,217 | |||||||||||||||||||
| Period End | |||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | |||||||||||||||||||||||||
| Balance by Property Type: | 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||
| Residential real estate | $ | 1,592 | $ | 1,952 | $ | 2,713 | $ | 2,324 | $ | 1,839 | |||||||||||||||||||
| Residential real estate development | 934 | 1,030 | 1,287 | 1,691 | — | ||||||||||||||||||||||||
| Commercial real estate | 11,319 | 12,590 | 11,813 | 12,543 | 7,378 | ||||||||||||||||||||||||
| Total | $ | 13,845 | $ | 15,572 | $ | 15,813 | $ | 16,558 | $ | 9,217 | |||||||||||||||||||
32
TABLE 15: NON-INTEREST INCOME
| Three Months Ended | Q3 2021 compared to Q2 2021 | Q3 2021 compared to Q3 2020 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | |||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | $ Change | % Change | $ Change | % Change | ||||||||||||||||||||||||||||||||||||||||||||
| Brokerage | $ | 5,230 | $ | 5,148 | $ | 5,040 | $ | 4,740 | $ | 4,563 | $ | 82 | 2 | % | $ | 667 | 15 | % | |||||||||||||||||||||||||||||||||||
| Trust and asset management | 26,301 | 25,542 | 24,269 | 22,062 | 20,394 | 759 | 3 | 5,907 | 29 | ||||||||||||||||||||||||||||||||||||||||||||
| Total wealth management | 31,531 | 30,690 | 29,309 | 26,802 | 24,957 | 841 | 3 | 6,574 | 26 | ||||||||||||||||||||||||||||||||||||||||||||
| Mortgage banking | 55,794 | 50,584 | 113,494 | 86,819 | 108,544 | 5,210 | 10 | (52,750) | (49) | ||||||||||||||||||||||||||||||||||||||||||||
| Service charges on deposit accounts | 14,149 | 13,249 | 12,036 | 11,841 | 11,497 | 900 | 7 | 2,652 | 23 | ||||||||||||||||||||||||||||||||||||||||||||
| (Losses) gains on investment securities, net | (2,431) | 1,285 | 1,154 | 1,214 | 411 | (3,716) | NM | (2,842) | NM | ||||||||||||||||||||||||||||||||||||||||||||
| Fees from covered call options | 1,157 | 1,388 | — | — | — | (231) | (17) | 1,157 | NM | ||||||||||||||||||||||||||||||||||||||||||||
| Trading gains (losses), net | 58 | (438) | 419 | (102) | 183 | 496 | NM | (125) | (68) | ||||||||||||||||||||||||||||||||||||||||||||
| Operating lease income, net | 12,807 | 12,240 | 14,440 | 12,118 | 11,717 | 567 | 5 | 1,090 | 9 | ||||||||||||||||||||||||||||||||||||||||||||
| Other: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest rate swap fees | 4,868 | 2,820 | 2,488 | 4,930 | 4,029 | 2,048 | 73 | 839 | 21 | ||||||||||||||||||||||||||||||||||||||||||||
| BOLI | 2,154 | 1,342 | 1,124 | 2,846 | 1,218 | 812 | 61 | 936 | 77 | ||||||||||||||||||||||||||||||||||||||||||||
| Administrative services | 1,359 | 1,228 | 1,256 | 1,263 | 1,077 | 131 | 11 | 282 | 26 | ||||||||||||||||||||||||||||||||||||||||||||
| Foreign currency remeasurement gains (losses) | 77 | (782) | 99 | (208) | (54) | 859 | NM | 131 | NM | ||||||||||||||||||||||||||||||||||||||||||||
| Early pay-offs of capital leases | 209 | 195 | (52) | 118 | 165 | 14 | 7 | 44 | 27 | ||||||||||||||||||||||||||||||||||||||||||||
| Miscellaneous | 14,742 | 15,572 | 10,739 | 10,720 | 6,849 | (830) | (5) | 7,893 | NM | ||||||||||||||||||||||||||||||||||||||||||||
| Total Other | 23,409 | 20,375 | 15,654 | 19,669 | 13,284 | 3,034 | 15 | 10,125 | 76 | ||||||||||||||||||||||||||||||||||||||||||||
| Total Non-Interest Income | $ | 136,474 | $ | 129,373 | $ | 186,506 | $ | 158,361 | $ | 170,593 | $ | 7,101 | 5 | % | $ | (34,119) | (20) | % | |||||||||||||||||||||||||||||||||||
NM - Not meaningful.
| Nine Months Ended | |||||||||||||||||||||||
| Sep 30, | Sep 30, | $ | % | ||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Brokerage | $ | 15,418 | $ | 13,991 | $ | 1,427 | 10 | % | |||||||||||||||
| Trust and asset management | 76,112 | 59,543 | 16,569 | 28 | |||||||||||||||||||
| Total wealth management | 91,530 | 73,534 | 17,996 | 24 | |||||||||||||||||||
| Mortgage banking | 219,872 | 259,194 | (39,322) | (15) | |||||||||||||||||||
| Service charges on deposit accounts | 39,434 | 33,182 | 6,252 | 19 | |||||||||||||||||||
| Gains (losses) on investment securities, net | 8 | (3,140) | 3,148 | NM | |||||||||||||||||||
| Fees from covered call options | 2,545 | 2,292 | 253 | 11 | |||||||||||||||||||
| Trading gains (losses), net | 39 | (902) | 941 | NM | |||||||||||||||||||
| Operating lease income, net | 39,487 | 35,486 | 4,001 | 11 | |||||||||||||||||||
| Other: | |||||||||||||||||||||||
| Interest rate swap fees | 10,176 | 15,788 | (5,612) | (36) | |||||||||||||||||||
| BOLI | 4,620 | 1,884 | 2,736 | NM | |||||||||||||||||||
| Administrative services | 3,843 | 3,122 | 721 | 23 | |||||||||||||||||||
| Foreign currency remeasurement loss | (606) | (413) | (193) | 47 | |||||||||||||||||||
| Early pay-offs of leases | 352 | 514 | (162) | (32) | |||||||||||||||||||
| Miscellaneous | 41,053 | 25,287 | 15,766 | 62 | |||||||||||||||||||
| Total Other | 59,438 | 46,182 | 13,256 | 29 | |||||||||||||||||||
| Total Non-Interest Income | $ | 452,353 | $ | 445,828 | $ | 6,525 | 1 | % | |||||||||||||||
NM - Not meaningful.
33
TABLE 16: MORTGAGE BANKING
| Three Months Ended | Nine Months Ended | |||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Sep 30, 2021 | Jun 30, 2021 | Mar 31, 2021 | Dec 31, 2020 | Sep 30, 2020 | Sep 30, 2021 | Sep 30, 2020 | |||||||||||||||||||||||||||||||
| Originations: | ||||||||||||||||||||||||||||||||||||||
| Retail originations | $ | 1,153,265 | $ | 1,328,721 | $ | 1,641,664 | $ | 1,757,093 | $ | 1,590,699 | $ | 4,123,650 | $ | 3,952,775 | ||||||||||||||||||||||||
| Veterans First originations | 405,663 | 395,290 | 580,303 | 594,151 | 635,876 | 1,381,256 | 1,700,711 | |||||||||||||||||||||||||||||||
| Total originations for sale (A) | $ | 1,558,928 | $ | 1,724,011 | $ | 2,221,967 | $ | 2,351,244 | $ | 2,226,575 | $ | 5,504,906 | $ | 5,653,486 | ||||||||||||||||||||||||
| Originations for investment | 181,886 | 249,749 | 321,858 | 192,107 | 73,711 | 753,493 | 204,392 | |||||||||||||||||||||||||||||||
| Total originations | $ | 1,740,814 | $ | 1,973,760 | $ | 2,543,825 | $ | 2,543,351 | $ | 2,300,286 | $ | 6,258,399 | $ | 5,857,878 | ||||||||||||||||||||||||
| Retail originations as percentage of originations for sale | 74 | % | 77 | % | 74 | % | 75 | % | 71 | % | 75 | % | 70 | % | ||||||||||||||||||||||||
| Veterans First originations as a percentage of originations for sale | 26 | 23 | 26 | 25 | 29 | 25 | 30 | |||||||||||||||||||||||||||||||
| Purchases as a percentage of originations for sale | 56 | % | 53 | % | 27 | % | 35 | % | 41 | % | 43 | % | 36 | % | ||||||||||||||||||||||||
| Refinances as a percentage of originations for sale | 44 | 47 | 73 | 65 | 59 | 57 | 64 | |||||||||||||||||||||||||||||||
| Production Margin: | ||||||||||||||||||||||||||||||||||||||
Production revenue (B) (1) | $ | 39,247 | $ | 37,531 | $ | 71,282 | $ | 70,886 | $ | 94,148 | $ | 148,060 | $ | 236,908 | ||||||||||||||||||||||||
| Total originations for sale (A) | $ | 1,558,928 | $ | 1,724,011 | $ | 2,221,967 | $ | 2,351,244 | $ | 2,226,575 | $ | 5,504,906 | $ | 5,653,486 | ||||||||||||||||||||||||
Add: Current period end mandatory interest rate lock commitments to fund originations for sale (2) | 510,982 | 605,400 | 798,534 | 1,072,717 | 1,544,234 | 510,982 | 1,544,234 | |||||||||||||||||||||||||||||||
Less: Prior period end mandatory interest rate lock commitments to fund originations for sale (2) | 605,400 | 798,534 | 1,072,717 | 1,544,234 | 1,275,648 | 1,072,717 | 372,357 | |||||||||||||||||||||||||||||||
| Total mortgage production volume (C) | $ | 1,464,510 | $ | 1,530,877 | $ | 1,947,784 | $ | 1,879,727 | $ | 2,495,161 | $ | 4,943,171 | $ | 6,825,363 | ||||||||||||||||||||||||
| Production margin (B / C) | 2.68 | % | 2.45 | % | 3.66 | % | 3.77 | % | 3.77 | % | 3.00 | % | 3.47 | % | ||||||||||||||||||||||||
| Mortgage Servicing: | ||||||||||||||||||||||||||||||||||||||
| Loans serviced for others (D) | $ | 12,720,126 | $ | 12,307,337 | $ | 11,530,676 | $ | 10,833,135 | $ | 10,139,878 | ||||||||||||||||||||||||||||
| MSRs, at fair value (E) | 133,552 | 127,604 | 124,316 | 92,081 | 86,907 | |||||||||||||||||||||||||||||||||
| Percentage of MSRs to loans serviced for others (E / D) | 1.05 | % | 1.04 | % | 1.08 | % | 0.85 | % | 0.86 | % | ||||||||||||||||||||||||||||
| Servicing income | $ | 10,454 | $ | 9,830 | $ | 9,636 | $ | 9,829 | $ | 8,118 | $ | 29,920 | $ | 22,057 | ||||||||||||||||||||||||
| Components of MSR: | ||||||||||||||||||||||||||||||||||||||
| MSR - current period capitalization | $ | 15,546 | $ | 17,512 | $ | 24,616 | $ | 20,343 | $ | 20,936 | $ | 57,674 | $ | 50,734 | ||||||||||||||||||||||||
| MSR - collection of expected cash flows - paydowns | (1,036) | (991) | (728) | (688) | (590) | (2,755) | (1,556) | |||||||||||||||||||||||||||||||
| MSR - collection of expected cash flows - payoffs | (7,558) | (7,549) | (9,440) | (8,335) | (7,272) | (24,547) | (22,000) | |||||||||||||||||||||||||||||||
| Valuation: | ||||||||||||||||||||||||||||||||||||||
| MSR - changes in fair value model assumptions | (888) | (5,540) | 18,045 | (5,223) | (3,002) | 11,617 | (25,541) | |||||||||||||||||||||||||||||||
| Gain on derivative contract held as an economic hedge, net | — | — | — | — | — | — | 4,749 | |||||||||||||||||||||||||||||||
| MSR valuation adjustment, net of gain on derivative contract held as an economic hedge | $ | (888) | $ | (5,540) | $ | 18,045 | $ | (5,223) | $ | (3,002) | $ | 11,617 | $ | (20,792) | ||||||||||||||||||||||||
| Summary of Mortgage Banking Revenue: | ||||||||||||||||||||||||||||||||||||||
Production revenue (1) | $ | 39,247 | $ | 37,531 | $ | 71,282 | $ | 70,886 | $ | 94,148 | $ | 148,060 | $ | 236,908 | ||||||||||||||||||||||||
| Servicing income | 10,454 | 9,830 | 9,636 | 9,829 | 8,118 | 29,920 | 22,057 | |||||||||||||||||||||||||||||||
| MSR activity | 6,064 | 3,432 | 32,493 | 6,097 | 10,072 | 41,989 | 6,386 | |||||||||||||||||||||||||||||||
| Other | 29 | (209) | 83 | 7 | (3,794) | (97) | (6,157) | |||||||||||||||||||||||||||||||
| Total mortgage banking revenue | $ | 55,794 | $ | 50,584 | $ | 113,494 | $ | 86,819 | $ | 108,544 | $ | 219,872 | $ | 259,194 | ||||||||||||||||||||||||
(1)Production revenue represents revenue earned from the origination and subsequent sale of mortgages, including gains on loans sold and fees from originations, changes in other related financial instruments carried at fair value, processing and other related activities, and excludes servicing fees, changes in the fair value of servicing rights and changes to the mortgage recourse obligation and other non-production revenue.
(2)Certain volume adjusted for the estimated pull-through rate of the loan, which represents the Company’s best estimate of the likelihood that a committed loan will ultimately fund.
34
TABLE 17: NON-INTEREST EXPENSE
| Three Months Ended | Q3 2021 compared to Q2 2021 | Q3 2021 compared to Q3 2020 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | |||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | $ Change | % Change | $ Change | % Change | ||||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Salaries | $ | 88,161 | $ | 91,089 | $ | 91,053 | $ | 93,535 | $ | 89,849 | $ | (2,928) | (3) | % | $ | (1,688) | (2) | % | |||||||||||||||||||||||||||||||||||
| Commissions and incentive compensation | 57,026 | 53,751 | 61,367 | 52,383 | 48,475 | 3,275 | 6 | 8,551 | 18 | ||||||||||||||||||||||||||||||||||||||||||||
| Benefits | 25,725 | 27,977 | 28,389 | 25,198 | 25,718 | (2,252) | (8) | 7 | — | ||||||||||||||||||||||||||||||||||||||||||||
| Total salaries and employee benefits | 170,912 | 172,817 | 180,809 | 171,116 | 164,042 | (1,905) | (1) | 6,870 | 4 | ||||||||||||||||||||||||||||||||||||||||||||
| Software and equipment | 22,029 | 20,866 | 20,912 | 20,565 | 17,251 | 1,163 | 6 | 4,778 | 28 | ||||||||||||||||||||||||||||||||||||||||||||
| Operating lease equipment depreciation | 10,013 | 9,949 | 10,771 | 9,938 | 9,425 | 64 | 1 | 588 | 6 | ||||||||||||||||||||||||||||||||||||||||||||
| Occupancy, net | 18,158 | 17,687 | 19,996 | 19,687 | 15,830 | 471 | 3 | 2,328 | 15 | ||||||||||||||||||||||||||||||||||||||||||||
| Data processing | 7,104 | 6,920 | 6,048 | 5,728 | 5,689 | 184 | 3 | 1,415 | 25 | ||||||||||||||||||||||||||||||||||||||||||||
| Advertising and marketing | 13,443 | 11,305 | 8,546 | 9,850 | 7,880 | 2,138 | 19 | 5,563 | 71 | ||||||||||||||||||||||||||||||||||||||||||||
| Professional fees | 7,052 | 7,304 | 7,587 | 6,530 | 6,488 | (252) | (3) | 564 | 9 | ||||||||||||||||||||||||||||||||||||||||||||
| Amortization of other intangible assets | 1,877 | 2,039 | 2,007 | 2,634 | 2,701 | (162) | (8) | (824) | (31) | ||||||||||||||||||||||||||||||||||||||||||||
| FDIC insurance | 6,750 | 6,405 | 6,558 | 7,016 | 6,772 | 345 | 5 | (22) | — | ||||||||||||||||||||||||||||||||||||||||||||
| OREO expense, net | (1,531) | 769 | (251) | (114) | (168) | (2,300) | NM | (1,363) | NM | ||||||||||||||||||||||||||||||||||||||||||||
| Other: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commissions - 3rd party brokers | 884 | 889 | 846 | 764 | 778 | (5) | (1) | 106 | 14 | ||||||||||||||||||||||||||||||||||||||||||||
| Postage | 2,018 | 1,900 | 1,743 | 1,849 | 1,529 | 118 | 6 | 489 | 32 | ||||||||||||||||||||||||||||||||||||||||||||
| Miscellaneous | 23,435 | 21,262 | 21,317 | 26,304 | 26,002 | 2,173 | 10 | (2,567) | (10) | ||||||||||||||||||||||||||||||||||||||||||||
| Total other | 26,337 | 24,051 | 23,906 | 28,917 | 28,309 | 2,286 | 10 | (1,972) | (7) | ||||||||||||||||||||||||||||||||||||||||||||
| Total Non-Interest Expense | $ | 282,144 | $ | 280,112 | $ | 286,889 | $ | 281,867 | $ | 264,219 | $ | 2,032 | 1 | % | $ | 17,925 | 7 | % | |||||||||||||||||||||||||||||||||||
NM - Not meaningful.
| Nine Months Ended | |||||||||||||||||||||||
| Sep 30, | Sep 30, | $ | % | ||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2020 | Change | Change | |||||||||||||||||||
| Salaries and employee benefits: | |||||||||||||||||||||||
| Salaries | $ | 270,303 | $ | 258,240 | $ | 12,063 | 5 | % | |||||||||||||||
| Commissions and incentive compensation | 172,144 | 126,201 | 45,943 | 36 | |||||||||||||||||||
| Benefits | 82,091 | 70,519 | 11,572 | 16 | |||||||||||||||||||
| Total salaries and employee benefits | 524,538 | 454,960 | 69,578 | 15 | |||||||||||||||||||
| Software and equipment | 63,807 | 47,931 | 15,876 | 33 | |||||||||||||||||||
| Operating lease equipment depreciation | 30,733 | 27,977 | 2,756 | 10 | |||||||||||||||||||
| Occupancy, net | 55,841 | 50,270 | 5,571 | 11 | |||||||||||||||||||
| Data processing | 20,072 | 24,468 | (4,396) | (18) | |||||||||||||||||||
| Advertising and marketing | 33,294 | 26,446 | 6,848 | 26 | |||||||||||||||||||
| Professional fees | 21,943 | 20,896 | 1,047 | 5 | |||||||||||||||||||
| Amortization of other intangible assets | 5,923 | 8,384 | (2,461) | (29) | |||||||||||||||||||
| FDIC insurance | 19,713 | 17,988 | 1,725 | 10 | |||||||||||||||||||
| OREO expense, net | (1,013) | (807) | (206) | NM | |||||||||||||||||||
| Other: | |||||||||||||||||||||||
| Commissions - 3rd party brokers | 2,619 | 2,350 | 269 | 11 | |||||||||||||||||||
| Postage | 5,661 | 5,069 | 592 | 12 | |||||||||||||||||||
| Miscellaneous | 66,014 | 72,296 | (6,282) | (9) | |||||||||||||||||||
| Total other | 74,294 | 79,715 | (5,421) | (7) | |||||||||||||||||||
| Total Non-Interest Expense | $ | 849,145 | $ | 758,228 | $ | 90,917 | 12 | % | |||||||||||||||
NM - Not meaningful.
35
TABLE 18: SUPPLEMENTAL NON-GAAP FINANCIAL MEASURES/RATIOS
The accounting and reporting policies of Wintrust conform to generally accepted accounting principles (“GAAP”) in the United States and prevailing practices in the banking industry. However, certain non-GAAP performance measures and ratios are used by management to evaluate and measure the Company’s performance. These include taxable-equivalent net interest income (including its individual components), taxable-equivalent net interest margin (including its individual components), the taxable-equivalent efficiency ratio, tangible common equity ratio, tangible book value per common share, return on average tangible common equity, pre-tax income, excluding provision for credit losses, and pre-tax income, excluding provision for credit losses, adjusted for net charge-offs. Management believes that these measures and ratios provide users of the Company’s financial information a more meaningful view of the performance of the Company’s interest-earning assets and interest-bearing liabilities and of the Company’s operating efficiency. Other financial holding companies may define or calculate these measures and ratios differently.
Management reviews yields on certain asset categories and the net interest margin of the Company and its banking subsidiaries on a fully taxable-equivalent basis. In this non-GAAP presentation, net interest income is adjusted to reflect tax-exempt interest income on an equivalent before-tax basis using tax rates effective as of the end of the period. This measure ensures comparability of net interest income arising from both taxable and tax-exempt sources. Net interest income on a fully taxable-equivalent basis is also used in the calculation of the Company’s efficiency ratio. The efficiency ratio, which is calculated by dividing non-interest expense by total taxable-equivalent net revenue (less securities gains or losses), measures how much it costs to produce one dollar of revenue. Securities gains or losses are excluded from this calculation to better match revenue from daily operations to operational expenses. Management considers the tangible common equity ratio and tangible book value per common share as useful measurements of the Company’s equity. The Company references the return on average tangible common equity as a measurement of profitability. Management considers pre-tax income, excluding provision for credit losses, and pre-tax income, excluding provision for credit losses, adjusted for net charge-offs, as a useful measurement of the Company’s core net income.
36
| Three Months Ended | Nine Months Ended | |||||||||||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | Sep 30, | Sep 30, | ||||||||||||||||||||||||||||||||
| (Dollars and shares in thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | 2021 | 2020 | |||||||||||||||||||||||||||||||
| Reconciliation of Non-GAAP Net Interest Margin and Efficiency Ratio: | ||||||||||||||||||||||||||||||||||||||
| (A) Interest Income (GAAP) | $ | 322,457 | $ | 319,579 | $ | 305,469 | $ | 307,981 | $ | 311,156 | $ | 947,505 | $ | 985,039 | ||||||||||||||||||||||||
| Taxable-equivalent adjustment: | ||||||||||||||||||||||||||||||||||||||
- Loans | 411 | 415 | 384 | 324 | 481 | 1,210 | 1,917 | |||||||||||||||||||||||||||||||
| - Liquidity Management Assets | 492 | 494 | 500 | 530 | 546 | 1,486 | 1,635 | |||||||||||||||||||||||||||||||
| - Other Earning Assets | — | — | — | 3 | 1 | — | 6 | |||||||||||||||||||||||||||||||
| (B) Interest Income (non-GAAP) | $ | 323,360 | $ | 320,488 | $ | 306,353 | $ | 308,838 | $ | 312,184 | $ | 950,201 | $ | 988,597 | ||||||||||||||||||||||||
| (C) Interest Expense (GAAP) | 34,961 | 39,989 | 43,574 | 48,584 | 55,220 | 118,524 | 204,529 | |||||||||||||||||||||||||||||||
| (D) Net Interest Income (GAAP) (A minus C) | $ | 287,496 | $ | 279,590 | $ | 261,895 | $ | 259,397 | $ | 255,936 | $ | 828,981 | $ | 780,510 | ||||||||||||||||||||||||
| (E) Net Interest Income (non-GAAP) (B minus C) | $ | 288,399 | $ | 280,499 | $ | 262,779 | $ | 260,254 | $ | 256,964 | $ | 831,677 | $ | 784,068 | ||||||||||||||||||||||||
| Net interest margin (GAAP) | 2.58 | % | 2.62 | % | 2.53 | % | 2.53 | % | 2.56 | % | 2.58 | % | 2.79 | % | ||||||||||||||||||||||||
| Net interest margin, fully taxable-equivalent (non-GAAP) | 2.59 | 2.63 | 2.54 | 2.54 | 2.57 | 2.59 | 2.80 | |||||||||||||||||||||||||||||||
| (F) Non-interest income | $ | 136,474 | $ | 129,373 | $ | 186,506 | $ | 158,361 | $ | 170,593 | $ | 452,353 | $ | 445,828 | ||||||||||||||||||||||||
| (G) (Losses) gains on investment securities, net | (2,431) | 1,285 | 1,154 | 1,214 | 411 | 8 | (3,140) | |||||||||||||||||||||||||||||||
| (H) Non-interest expense | 282,144 | 280,112 | 286,889 | 281,867 | 264,219 | 849,145 | 758,228 | |||||||||||||||||||||||||||||||
| Efficiency ratio (H/(D+F-G)) | 66.17 | % | 68.71 | % | 64.15 | % | 67.67 | % | 62.01 | % | 66.27 | % | 61.67 | % | ||||||||||||||||||||||||
| Efficiency ratio (non-GAAP) (H/(E+F-G)) | 66.03 | 68.56 | 64.02 | 67.53 | 61.86 | 66.13 | 61.49 | |||||||||||||||||||||||||||||||
| Reconciliation of Non-GAAP Tangible Common Equity Ratio: | ||||||||||||||||||||||||||||||||||||||
| Total shareholders’ equity (GAAP) | $ | 4,410,317 | $ | 4,339,011 | $ | 4,252,511 | $ | 4,115,995 | $ | 4,074,089 | ||||||||||||||||||||||||||||
| Less: Non-convertible preferred stock (GAAP) | (412,500) | (412,500) | (412,500) | (412,500) | (412,500) | |||||||||||||||||||||||||||||||||
| Less: Intangible assets (GAAP) | (675,910) | (678,333) | (680,052) | (681,747) | (683,314) | |||||||||||||||||||||||||||||||||
| (I) Total tangible common shareholders’ equity (non-GAAP) | $ | 3,321,907 | $ | 3,248,178 | $ | 3,159,959 | $ | 3,021,748 | $ | 2,978,275 | ||||||||||||||||||||||||||||
| (J) Total assets (GAAP) | $ | 47,832,271 | $ | 46,738,450 | $ | 45,682,202 | $ | 45,080,768 | $ | 43,731,718 | ||||||||||||||||||||||||||||
| Less: Intangible assets (GAAP) | (675,910) | (678,333) | (680,052) | (681,747) | (683,314) | |||||||||||||||||||||||||||||||||
| (K) Total tangible assets (non-GAAP) | $ | 47,156,361 | $ | 46,060,117 | $ | 45,002,150 | $ | 44,399,021 | $ | 43,048,404 | ||||||||||||||||||||||||||||
| Common equity to assets ratio (GAAP) (L/J) | 8.4 | % | 8.4 | % | 8.4 | % | 8.2 | % | 8.4 | % | ||||||||||||||||||||||||||||
| Tangible common equity ratio (non-GAAP) (I/K) | 7.0 | 7.1 | 7.0 | 6.8 | 6.9 | |||||||||||||||||||||||||||||||||
37
| Three Months Ended | Nine Months Ended | |||||||||||||||||||||||||||||||||||||
| Sep 30, | Jun 30, | Mar 31, | Dec 31, | Sep 30, | Sep 30, | Sep 30, | ||||||||||||||||||||||||||||||||
| (Dollars and shares in thousands) | 2021 | 2021 | 2021 | 2020 | 2020 | 2021 | 2020 | |||||||||||||||||||||||||||||||
| Reconciliation of Non-GAAP Tangible Book Value per Common Share: | ||||||||||||||||||||||||||||||||||||||
| Total shareholders’ equity | $ | 4,410,317 | $ | 4,339,011 | $ | 4,252,511 | $ | 4,115,995 | $ | 4,074,089 | ||||||||||||||||||||||||||||
| Less: Preferred stock | (412,500) | (412,500) | (412,500) | (412,500) | (412,500) | |||||||||||||||||||||||||||||||||
| (L) Total common equity | $ | 3,997,817 | $ | 3,926,511 | $ | 3,840,011 | $ | 3,703,495 | $ | 3,661,589 | ||||||||||||||||||||||||||||
| (M) Actual common shares outstanding | 56,956 | 57,067 | 57,023 | 56,770 | 57,602 | |||||||||||||||||||||||||||||||||
| Book value per common share (L/M) | $ | 70.19 | $ | 68.81 | $ | 67.34 | $ | 65.24 | $ | 63.57 | ||||||||||||||||||||||||||||
| Tangible book value per common share (non-GAAP) (I/M) | 58.32 | 56.92 | 55.42 | 53.23 | 51.70 | |||||||||||||||||||||||||||||||||
| Reconciliation of Non-GAAP Return on Average Tangible Common Equity: | ||||||||||||||||||||||||||||||||||||||
| (N) Net income applicable to common shares | $ | 102,146 | $ | 98,118 | $ | 146,157 | $ | 94,213 | $ | 97,029 | $ | 346,421 | $ | 177,400 | ||||||||||||||||||||||||
| Add: Intangible asset amortization | 1,877 | 2,039 | 2,007 | 2,634 | 2,701 | 5,923 | 8,384 | |||||||||||||||||||||||||||||||
| Less: Tax effect of intangible asset amortization | (509) | (553) | (522) | (656) | (589) | (1,576) | (2,079) | |||||||||||||||||||||||||||||||
| After-tax intangible asset amortization | $ | 1,368 | $ | 1,486 | $ | 1,485 | $ | 1,978 | $ | 2,112 | $ | 4,347 | $ | 6,305 | ||||||||||||||||||||||||
| (O) Tangible net income applicable to common shares (non-GAAP) | $ | 103,514 | $ | 99,604 | $ | 147,642 | $ | 96,191 | $ | 99,141 | $ | 350,768 | $ | 183,705 | ||||||||||||||||||||||||
| Total average shareholders’ equity | $ | 4,343,915 | $ | 4,256,778 | $ | 4,164,890 | $ | 4,050,286 | $ | 4,034,902 | $ | 4,255,851 | $ | 3,885,187 | ||||||||||||||||||||||||
| Less: Average preferred stock | (412,500) | (412,500) | (412,500) | (412,500) | (412,500) | (412,500) | (270,849) | |||||||||||||||||||||||||||||||
| (P) Total average common shareholders’ equity | $ | 3,931,415 | $ | 3,844,278 | $ | 3,752,390 | $ | 3,637,786 | $ | 3,622,402 | $ | 3,843,351 | $ | 3,614,338 | ||||||||||||||||||||||||
| Less: Average intangible assets | (677,201) | (679,535) | (680,805) | (682,290) | (684,717) | (679,167) | (687,331) | |||||||||||||||||||||||||||||||
| (Q) Total average tangible common shareholders’ equity (non-GAAP) | $ | 3,254,214 | $ | 3,164,743 | $ | 3,071,585 | $ | 2,955,496 | $ | 2,937,685 | $ | 3,164,184 | $ | 2,927,007 | ||||||||||||||||||||||||
| Return on average common equity, annualized (N/P) | 10.31 | % | 10.24 | % | 15.80 | % | 10.30 | % | 10.66 | % | 12.05 | % | 6.56 | % | ||||||||||||||||||||||||
| Return on average tangible common equity, annualized (non-GAAP) (O/Q) | 12.62 | 12.62 | 19.49 | 12.95 | 13.43 | 14.82 | 8.38 | |||||||||||||||||||||||||||||||
| Reconciliation of Non-GAAP Pre-Tax, Pre-Provision Income, Adjusted for Net Charge-offs: | ||||||||||||||||||||||||||||||||||||||
| Income before taxes | $ | 149,742 | $ | 144,150 | $ | 206,859 | $ | 134,711 | $ | 137,284 | $ | 500,751 | $ | 255,070 | ||||||||||||||||||||||||
| Add: Provision for credit losses | (7,916) | (15,299) | (45,347) | 1,180 | 25,026 | (68,562) | 213,040 | |||||||||||||||||||||||||||||||
| Pre-tax income, excluding provision for credit losses (non-GAAP) | $ | 141,826 | $ | 128,851 | $ | 161,512 | $ | 135,891 | $ | 162,310 | $ | 432,189 | $ | 468,110 | ||||||||||||||||||||||||
| Less: Net charge-offs | (2) | (1,922) | (13,345) | (10,337) | (9,284) | (15,269) | (29,972) | |||||||||||||||||||||||||||||||
| Pre-tax income, excluding provision for credit losses, adjusted for net charge-offs (non-GAAP) | $ | 141,824 | $ | 126,929 | $ | 148,167 | $ | 125,554 | $ | 153,026 | $ | 416,920 | $ | 438,138 | ||||||||||||||||||||||||
38
WINTRUST SUBSIDIARIES AND LOCATIONS
Wintrust is a financial holding company whose common stock is traded on the Nasdaq Global Select Market (Nasdaq: WTFC). Its 15 community bank subsidiaries are: Lake Forest Bank & Trust Company, N.A., Hinsdale Bank & Trust Company, N.A., Wintrust Bank, N.A., in Chicago, Libertyville Bank & Trust Company, N.A., Barrington Bank & Trust Company, N.A., Crystal Lake Bank & Trust Company, N.A., Northbrook Bank & Trust Company, N.A., Schaumburg Bank & Trust Company, N.A., Village Bank & Trust, N.A., in Arlington Heights, Beverly Bank & Trust Company, N.A. in Chicago, Wheaton Bank & Trust Company, N.A., State Bank of The Lakes, N.A., in Antioch, Old Plank Trail Community Bank, N.A. in New Lenox, St. Charles Bank & Trust Company, N.A. and Town Bank, N.A., in Hartland, Wisconsin.
In addition to the locations noted above, the banks also operate facilities in Illinois in Addison, Algonquin, Aurora, Bloomingdale, Bolingbrook, Buffalo Grove, Burbank, Cary, Clarendon Hills, Crete, Countryside, Darien, Deerfield, Des Plaines, Downers Grove, Elgin, Elk Grove Village, Elmhurst, Evanston, Evergreen Park, Frankfort, Geneva, Glen Ellyn, Glencoe, Glenview, Gurnee, Grayslake, Hanover Park, Highland Park, Highwood, Hoffman Estates, Homer Glen, Itasca, Joliet, Lake Bluff, Lake Villa, Lansing, Lemont, Lindenhurst, Lynwood, Markham, Maywood, McHenry, Mokena, Mount Prospect, Mundelein, Naperville, Northfield, Norridge, Oak Lawn, Oak Park, Orland Park, Palatine, Park Ridge, Prospect Heights, Riverside, Rolling Meadows, Round Lake Beach, Shorewood, Skokie, South Holland, Spring Grove, Steger, Stone Park, Vernon Hills, Wauconda, Waukegan, Western Springs, Willowbrook, Wilmette, Winnetka and Wood Dale, and in Wisconsin in Burlington, Clinton, Delafield, Delavan, Elm Grove, Genoa City, Kenosha, Lake Geneva, Madison, Menomonee Falls, Milwaukee, Pewaukee, Racine, Wales, Walworth and Wind Lake, and in Dyer, Indiana and in Naples, Florida.
Additionally, the Company operates various non-bank business units:
•FIRST Insurance Funding and Wintrust Life Finance, each a division of Lake Forest Bank & Trust Company, N.A., serve commercial and life insurance loan customers, respectively, throughout the United States.
•First Insurance Funding of Canada serves commercial insurance loan customers throughout Canada.
•Tricom, Inc. of Milwaukee provides high-yielding, short-term accounts receivable financing and value-added out-sourced administrative services, such as data processing of payrolls, billing and cash management services, to temporary staffing service clients located throughout the United States.
•Wintrust Mortgage, a division of Barrington Bank & Trust Company, N.A., engages primarily in the origination and purchase of residential mortgages for sale into the secondary market through origination offices located throughout the United States. Loans are also originated nationwide through relationships with wholesale and correspondent offices.
•Wintrust Investments, LLC is a broker-dealer providing a full range of private client and brokerage services to clients and correspondent banks located primarily in the Midwest.
•Great Lakes Advisors LLC provides money management services and advisory services to individual accounts.
•The Chicago Trust Company, N.A., a trust subsidiary, allows Wintrust to service customers’ trust and investment needs at each banking location.
•Wintrust Asset Finance offers direct leasing opportunities.
•CDEC provides Qualified Intermediary services (as defined by U.S. Treasury regulations) for taxpayers seeking to structure tax-deferred like-kind exchanges under Internal Revenue Code Section 1031.
FORWARD-LOOKING STATEMENTS
This document contains forward-looking statements within the meaning of federal securities laws. Forward-looking information can be identified through the use of words such as “intend,” “plan,” “project,” “expect,” “anticipate,” “believe,” “estimate,” “contemplate,” “possible,” “will,” “may,” “should,” “would” and “could.” Forward-looking statements and information are not historical facts, are premised on many factors and assumptions, and represent only management’s expectations, estimates and projections regarding future events. Similarly, these statements are not guarantees of future performance and involve certain risks and uncertainties that are difficult to predict, such as the impacts of the COVID-19 pandemic (including the emergence of variant strains), and which may include, but are not limited to, those listed below and the Risk Factors discussed under Item 1A of the Company’s 2020 Annual Report on Form 10-K and in any of the Company’s subsequent SEC filings. The Company intends such forward-looking statements to be covered by the safe harbor provisions for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995, and is including this statement for purposes of invoking these safe harbor provisions. Such forward-looking statements may be deemed to include, among other things, statements relating to the Company’s future financial performance, the performance of its loan portfolio, the expected amount of future credit reserves and charge-offs, delinquency trends, growth plans, regulatory developments, securities that the Company may offer from time to time, and management’s long-term performance goals, as well as statements relating to the anticipated effects on financial condition and results of operations from expected developments or events, the Company’s business and growth strategies, including future acquisitions of banks, specialty finance or wealth management businesses, internal growth and plans to form
39
additional de novo banks or branch offices. Actual results could differ materially from those addressed in the forward-looking statements as a result of numerous factors, including the following:
•the severity, magnitude and duration of the COVID-19 pandemic, including the emergence of variant strains, and the direct and indirect impact of such pandemic, as well as responses to the pandemic by the government, businesses and consumers, on our operations and personnel, commercial activity and demand across our business and our customers’ businesses;
•the disruption of global, national, state and local economies associated with the COVID-19 pandemic, which could affect the Company’s liquidity and capital positions, impair the ability of our borrowers to repay outstanding loans, impair collateral values and further increase our allowance for credit losses;
•the impact of the COVID-19 pandemic on our financial results, including possible lost revenue and increased expenses (including the cost of capital), as well as possible goodwill impairment charges;
•economic conditions that affect the economy, housing prices, the job market and other factors that may adversely affect the Company’s liquidity and the performance of its loan portfolios, particularly in the markets in which it operates;
•negative effects suffered by us or our customers resulting from changes in U.S. trade policies;
•the extent of defaults and losses on the Company’s loan portfolio, which may require further increases in its allowance for credit losses;
•estimates of fair value of certain of the Company’s assets and liabilities, which could change in value significantly from period to period;
•the financial success and economic viability of the borrowers of our commercial loans;
•commercial real estate market conditions in the Chicago metropolitan area and southern Wisconsin;
•the extent of commercial and consumer delinquencies and declines in real estate values, which may require further increases in the Company’s allowance for credit losses;
•inaccurate assumptions in our analytical and forecasting models used to manage our loan portfolio;
•changes in the level and volatility of interest rates, the capital markets and other market indices (including developments and volatility arising from or related to the COVID-19 pandemic) that may affect, among other things, the Company’s liquidity and the value of its assets and liabilities;
•a prolonged period of near zero interest rates or potentially negative interest rates, either broadly or for some types of instruments, which may affect the Company’s net interest income and net interest margin, and which could materially adversely affect the Company’s profitability;
•competitive pressures in the financial services business which may affect the pricing of the Company’s loan and deposit products as well as its services (including wealth management services), which may result in loss of market share and reduced income from deposits, loans, advisory fees and income from other products;
•failure to identify and complete favorable acquisitions in the future or unexpected difficulties or developments related to the integration of the Company’s recent or future acquisitions;
•unexpected difficulties and losses related to FDIC-assisted acquisitions;
•harm to the Company’s reputation;
•any negative perception of the Company’s financial strength;
•ability of the Company to raise additional capital on acceptable terms when needed;
•disruption in capital markets, which may lower fair values for the Company’s investment portfolio;
•ability of the Company to use technology to provide products and services that will satisfy customer demands and create efficiencies in operations and to manage risks associated therewith;
•failure or breaches of our security systems or infrastructure, or those of third parties;
•security breaches, including denial of service attacks, hacking, social engineering attacks, malware intrusion or data corruption attempts and identity theft;
•adverse effects on our information technology systems resulting from failures, human error or cyberattacks (including ransomware);
•adverse effects of failures by our vendors to provide agreed upon services in the manner and at the cost agreed, particularly our information technology vendors;
•increased costs as a result of protecting our customers from the impact of stolen debit card information;
•accuracy and completeness of information the Company receives about customers and counterparties to make credit decisions;
•ability of the Company to attract and retain senior management experienced in the banking and financial services industries;
•environmental liability risk associated with lending activities;
•the impact of any claims or legal actions to which the Company is subject, including any effect on our reputation;
•losses incurred in connection with repurchases and indemnification payments related to mortgages and increases in reserves associated therewith;
•the loss of customers as a result of technological changes allowing consumers to complete their financial transactions
40
without the use of a bank;
•the soundness of other financial institutions;
•the expenses and delayed returns inherent in opening new branches and de novo banks;
•liabilities, potential customer loss or reputational harm related to closings of existing branches;
•examinations and challenges by tax authorities, and any unanticipated impact of the Tax Act;
•changes in accounting standards, rules and interpretations, and the impact on the Company’s financial statements;
•the ability of the Company to receive dividends from its subsidiaries;
•uncertainty about the discontinued use of LIBOR and transition to an alternative rate;
•a decrease in the Company’s capital ratios, including as a result of declines in the value of its loan portfolios, or otherwise;
•legislative or regulatory changes, particularly changes in regulation of financial services companies and/or the products and services offered by financial services companies, including those changes that are in response to the COVID-19 pandemic, including without limitation the Coronavirus Aid, Relief, and Economic Security Act (the “CARES Act”), the Economic Aid to Hard-Hit Small Businesses, Nonprofits and Venues Act, and the rules and regulations that may be promulgated thereunder;
•a lowering of our credit rating;
•changes in U.S. monetary policy and changes to the Federal Reserve’s balance sheet, including changes in response to the COVID-19 pandemic or otherwise;
•regulatory restrictions upon our ability to market our products to consumers and limitations on our ability to profitably operate our mortgage business;
•increased costs of compliance, heightened regulatory capital requirements and other risks associated with changes in regulation and the regulatory environment;
•the impact of heightened capital requirements;
•increases in the Company’s FDIC insurance premiums, or the collection of special assessments by the FDIC;
•delinquencies or fraud with respect to the Company’s premium finance business;
•credit downgrades among commercial and life insurance providers that could negatively affect the value of collateral securing the Company’s premium finance loans;
•the Company’s ability to comply with covenants under its credit facility; and
•fluctuations in the stock market, which may have an adverse impact on the Company’s wealth management business and brokerage operation.
Therefore, there can be no assurances that future actual results will correspond to these forward-looking statements. The reader is cautioned not to place undue reliance on any forward-looking statement made by the Company. Any such statement speaks only as of the date the statement was made or as of such date that may be referenced within the statement. The Company undertakes no obligation to update any forward-looking statement to reflect the impact of circumstances or events after the date of the press release. Persons are advised, however, to consult further disclosures management makes on related subjects in its reports filed with the Securities and Exchange Commission and in its press releases.
CONFERENCE CALL, WEBCAST AND REPLAY
The Company will hold a conference call on Wednesday, October 20, 2021 at 11:00 a.m. (Central Time) regarding third quarter and year-to-date 2021 results. Individuals interested in listening should call (877) 363-5049 and enter Conference ID #2695417. A simultaneous audio-only webcast and replay of the conference call as well as an accompanying slide presentation may be accessed via the Company’s website at https://www.wintrust.com, Investor Relations, Investor News and Events, Presentations & Conference Calls. The text of the third quarter and year-to-date 2021 earnings press release will be available on the home page of the Company’s website at https://www.wintrust.com and at the Investor Relations, Investor News and Events, Press Releases link on its website.
41
Earnings Release Presentation Q3 2021 Wintrust Financial Corporation
2 Our core fundamentals were strong, with robust loan and deposit growth, increased net interest income despite significant PPP loan reductions, record wealth management revenue, strong mortgage revenues, improved net overhead and efficiency ratios compared to the prior quarter, strong loan pipelines and very good credit quality metrics. Q3 2021 Summary
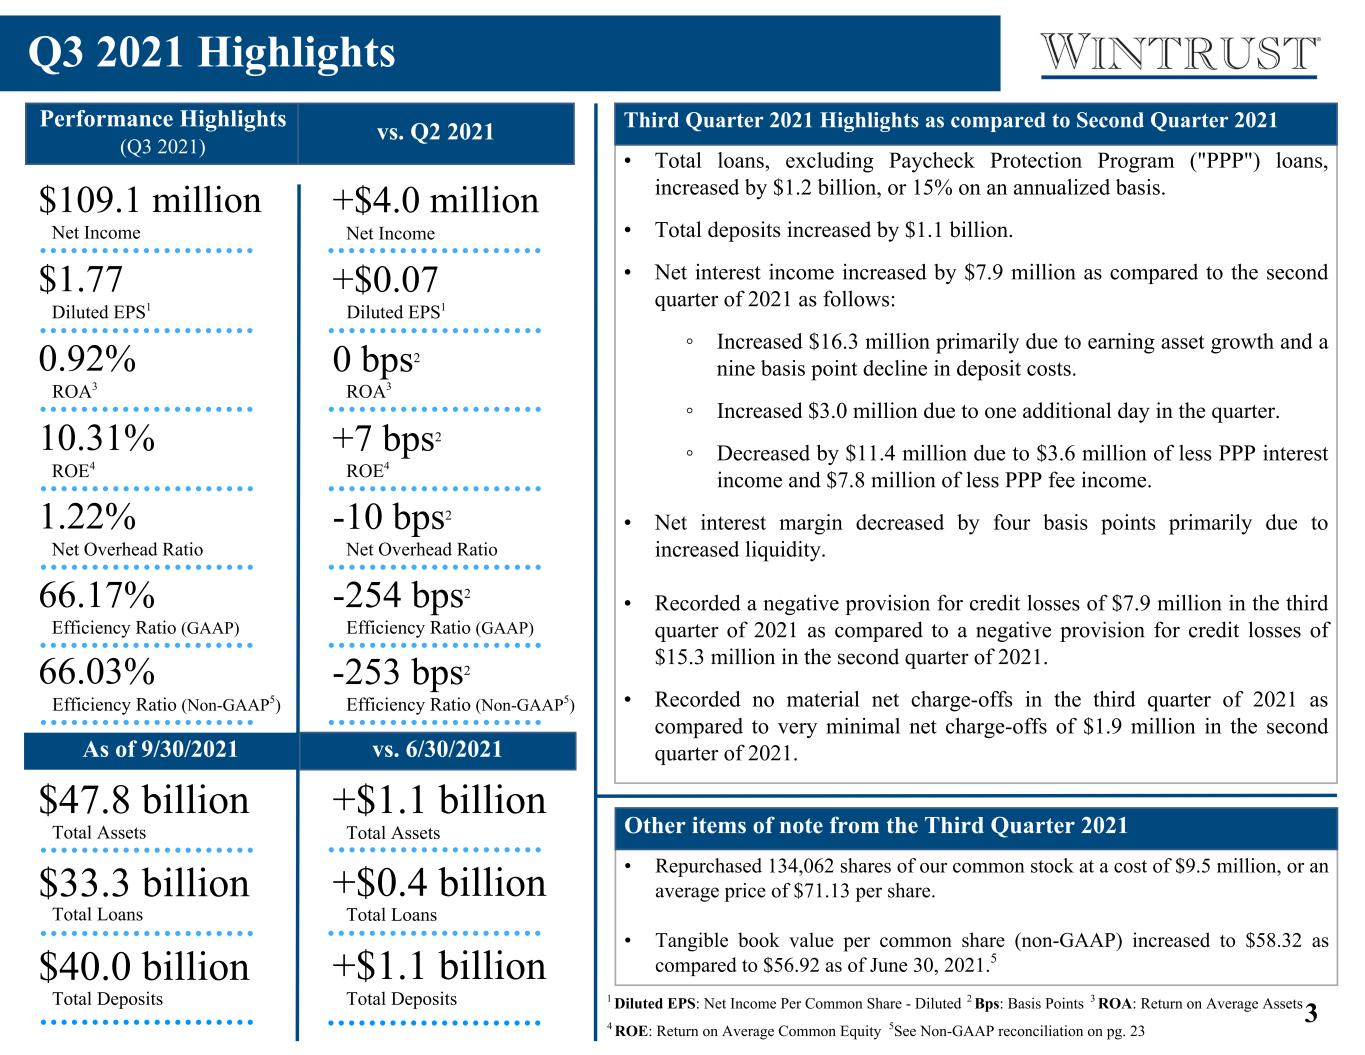
3 ROA3 • Total loans, excluding Paycheck Protection Program ("PPP") loans, increased by $1.2 billion, or 15% on an annualized basis. • Total deposits increased by $1.1 billion. • Net interest income increased by $7.9 million as compared to the second quarter of 2021 as follows: ◦ Increased $16.3 million primarily due to earning asset growth and a nine basis point decline in deposit costs. ◦ Increased $3.0 million due to one additional day in the quarter. ◦ Decreased by $11.4 million due to $3.6 million of less PPP interest income and $7.8 million of less PPP fee income. • Net interest margin decreased by four basis points primarily due to increased liquidity. • Recorded a negative provision for credit losses of $7.9 million in the third quarter of 2021 as compared to a negative provision for credit losses of $15.3 million in the second quarter of 2021. • Recorded no material net charge-offs in the third quarter of 2021 as compared to very minimal net charge-offs of $1.9 million in the second quarter of 2021. • Repurchased 134,062 shares of our common stock at a cost of $9.5 million, or an average price of $71.13 per share. • Tangible book value per common share (non-GAAP) increased to $58.32 as compared to $56.92 as of June 30, 2021.5 $33.3 billion $1.77 Q3 2021 Highlights Other items of note from the Third Quarter 2021 Performance Highlights (Q3 2021) $109.1 million Net Income Diluted EPS1 0.92% ROA3 10.31% ROE4 $47.8 billion Total Assets Total Loans $40.0 billion Total Deposits +$1.1 billion Total Assets +$0.4 billion +$1.1 billion Total Loans Total Deposits +$4.0 million Net Income +$0.07 Diluted EPS1 0 bps2 +7 bps2 ROE4 1.22% 66.03% Net Overhead Ratio Efficiency Ratio (Non-GAAP5) -253 bps2 Efficiency Ratio (Non-GAAP5) -10 bps2 Net Overhead Ratio Third Quarter 2021 Highlights as compared to Second Quarter 2021vs. Q2 2021 As of 9/30/2021 vs. 6/30/2021 66.17% Efficiency Ratio (GAAP) -254 bps2 Efficiency Ratio (GAAP) 4 ROE: Return on Average Common Equity 1 Diluted EPS: Net Income Per Common Share - Diluted 3 ROA: Return on Average Assets 5See Non-GAAP reconciliation on pg. 23 2 Bps: Basis Points
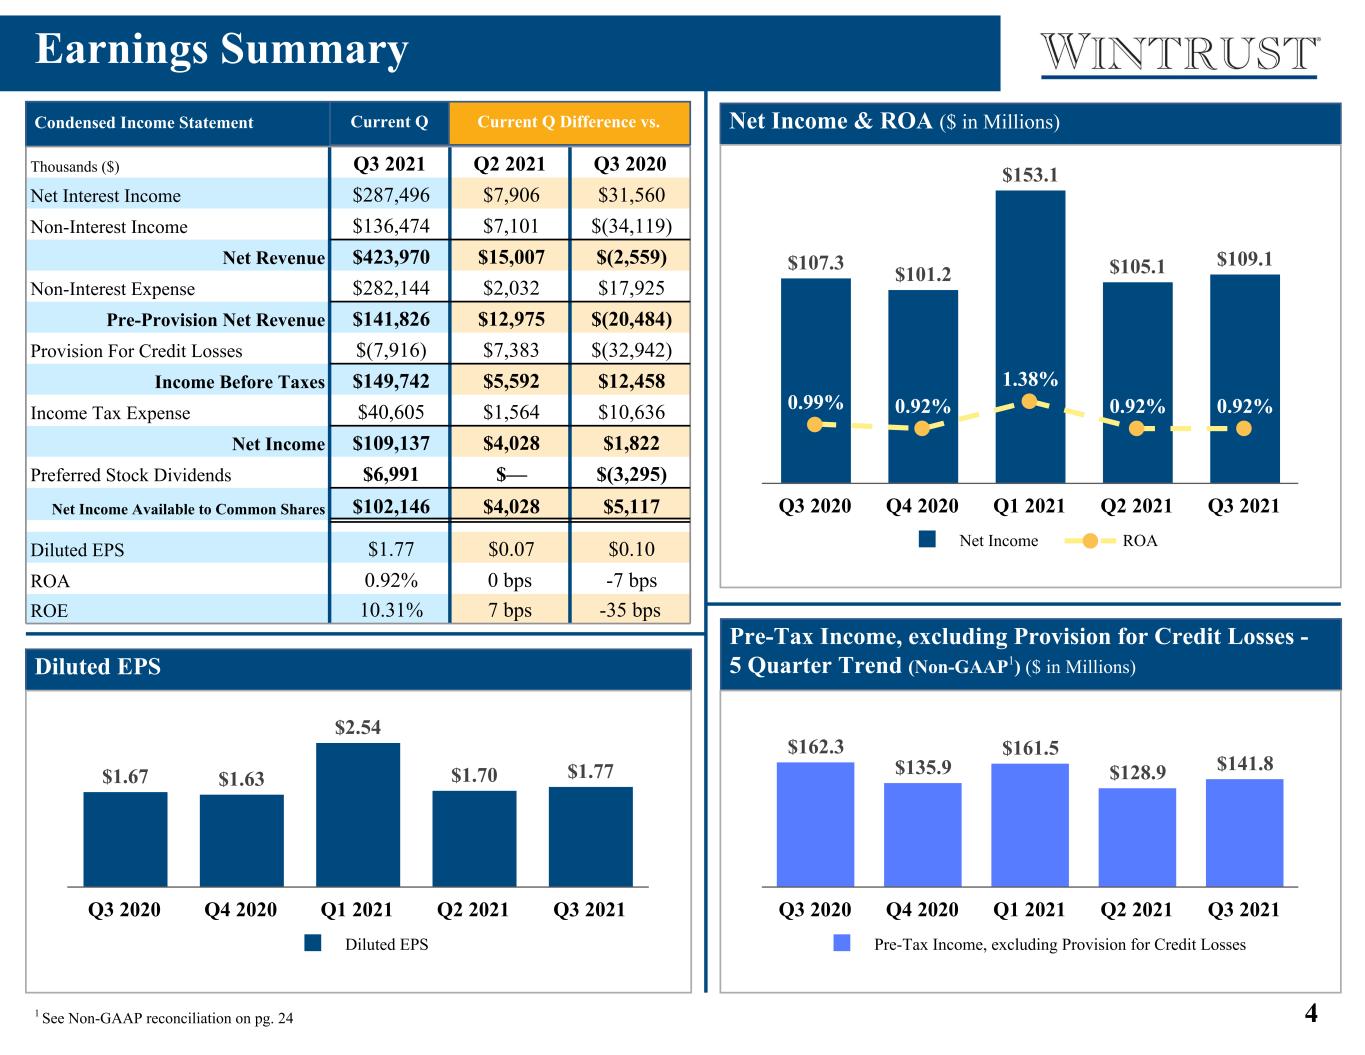
4 Earnings Summary Net Income & ROA ($ in Millions) Diluted EPS Key Observations Condensed Income Statement Current Q Difference vs.Current Q • Pre-Provision Net Revenue increased by $15.5 million compared to the prior quarter and $10.8 million as compared to Q3 2020 • $107.3 $101.2 $153.1 $105.1 $109.1 0.99% 0.92% 1.38% 0.92% 0.92% Net Income ROA Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 $1.67 $1.63 $2.54 $1.70 $1.77 Diluted EPS Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Pre-Tax Income, excluding Provision for Credit Losses - 5 Quarter Trend (Non-GAAP1) ($ in Millions) $162.3 $135.9 $161.5 $128.9 $141.8 Pre-Tax Income, excluding Provision for Credit Losses Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 1 See Non-GAAP reconciliation on pg. 24 Thousands ($) Q3 2021 Q2 2021 Q3 2020 Net Interest Income $287,496 $7,906 $31,560 Non-Interest Income $136,474 $7,101 $(34,119) Net Revenue $423,970 $15,007 $(2,559) Non-Interest Expense $282,144 $2,032 $17,925 Pre-Provision Net Revenue $141,826 $12,975 $(20,484) Provision For Credit Losses $(7,916) $7,383 $(32,942) Income Before Taxes $149,742 $5,592 $12,458 Income Tax Expense $40,605 $1,564 $10,636 Net Income $109,137 $4,028 $1,822 Preferred Stock Dividends $6,991 $— $(3,295) Net Income Available to Common Shares $102,146 $4,028 $5,117 Diluted EPS $1.77 $0.07 $0.10 ROA 0.92% 0 bps -7 bps ROE 10.31% 7 bps -35 bps 2 ### 1 Q3 2020 had a $9.0 million state income tax benefit.
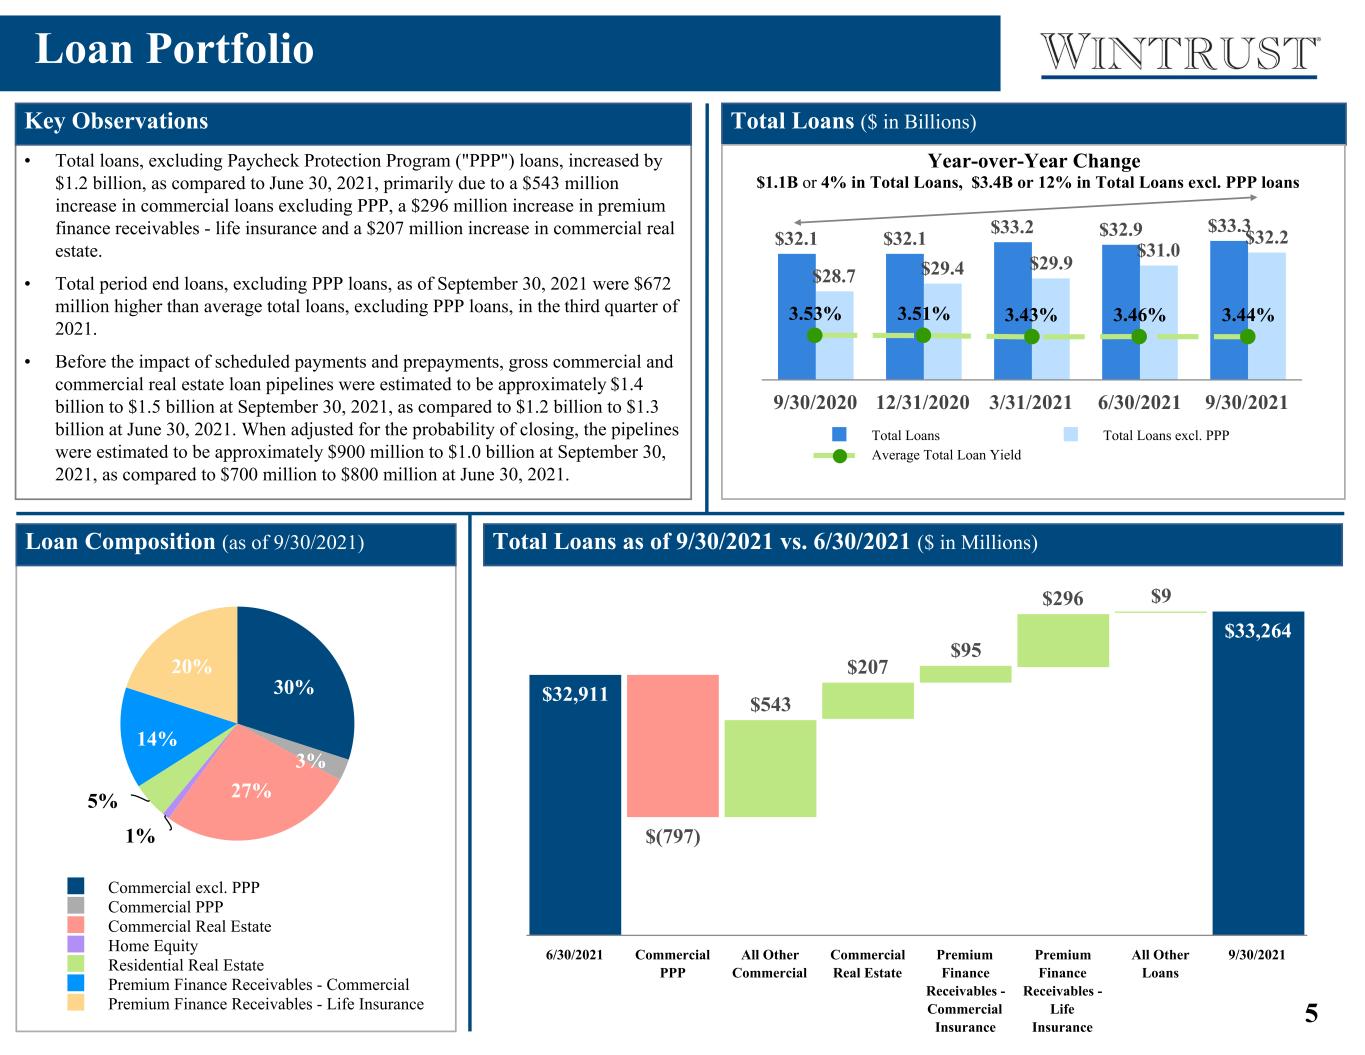
5 30% 3% 27% 1% 5% 14% 20% Commercial excl. PPP Commercial PPP Commercial Real Estate Home Equity Residential Real Estate Premium Finance Receivables - Commercial Premium Finance Receivables - Life Insurance • Total loans, excluding Paycheck Protection Program ("PPP") loans, increased by $1.2 billion, as compared to June 30, 2021, primarily due to a $543 million increase in commercial loans excluding PPP, a $296 million increase in premium finance receivables - life insurance and a $207 million increase in commercial real estate. • Total period end loans, excluding PPP loans, as of September 30, 2021 were $672 million higher than average total loans, excluding PPP loans, in the third quarter of 2021. • Before the impact of scheduled payments and prepayments, gross commercial and commercial real estate loan pipelines were estimated to be approximately $1.4 billion to $1.5 billion at September 30, 2021, as compared to $1.2 billion to $1.3 billion at June 30, 2021. When adjusted for the probability of closing, the pipelines were estimated to be approximately $900 million to $1.0 billion at September 30, 2021, as compared to $700 million to $800 million at June 30, 2021. $32,911 $(797) $543 $207 $95 $296 $9 $33,264 6/30/2021 Commercial PPP All Other Commercial Commercial Real Estate Premium Finance Receivables - Commercial Insurance Premium Finance Receivables - Life Insurance All Other Loans 9/30/2021 Loan Portfolio Total Loans ($ in Billions) Total Loans as of 9/30/2021 vs. 6/30/2021 ($ in Millions) Key Observations $32.1 $32.1 $33.2 $32.9 $33.3 $28.7 $29.4 $29.9 $31.0 $32.2 3.53% 3.51% 3.43% 3.46% 3.44% Total Loans Total Loans excl. PPP Average Total Loan Yield 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 Year-over-Year Change $1.1B or 4% in Total Loans, $3.4B or 12% in Total Loans excl. PPP loans Loan Composition (as of 9/30/2021)
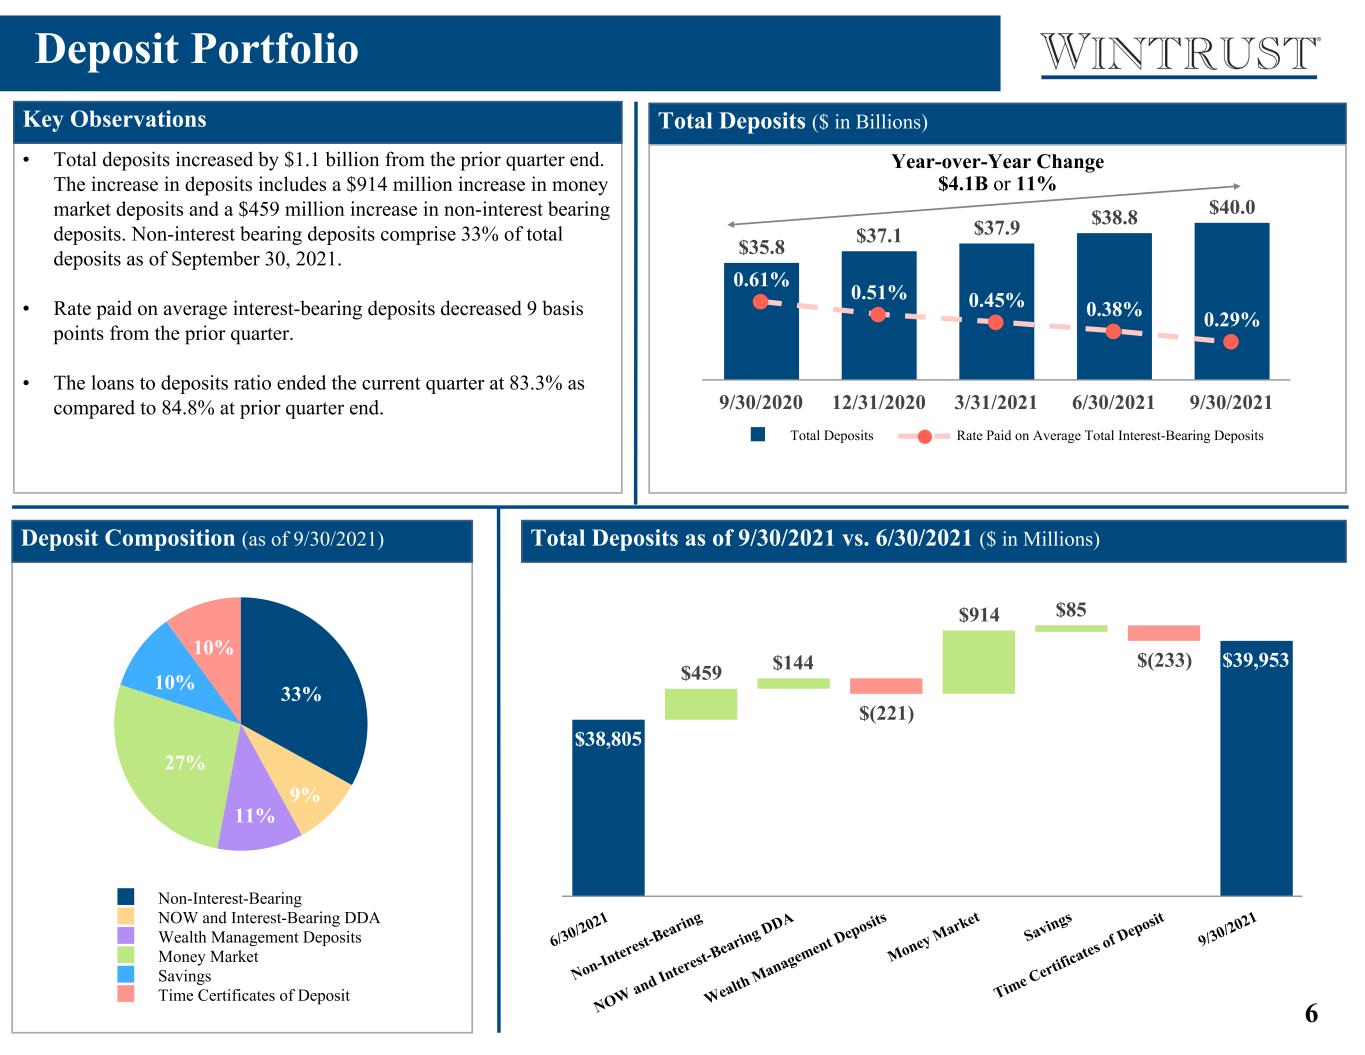
6 • Total deposits increased by $1.1 billion from the prior quarter end. The increase in deposits includes a $914 million increase in money market deposits and a $459 million increase in non-interest bearing deposits. Non-interest bearing deposits comprise 33% of total deposits as of September 30, 2021. • Rate paid on average interest-bearing deposits decreased 9 basis points from the prior quarter. • The loans to deposits ratio ended the current quarter at 83.3% as compared to 84.8% at prior quarter end. $38,805 $459 $144 $(221) $914 $85 $(233) $39,953 6/30/2021 Non-Interest-B earing NOW and Interest-B earing DDA Wealth Management Deposits Money Market Savings Time Certific ates of Deposit 9/30/2021 Deposit Portfolio Total Deposits ($ in Billions) Total Deposits as of 9/30/2021 vs. 6/30/2021 ($ in Millions)Deposit Composition (as of 9/30/2021) Key Observations $35.8 $37.1 $37.9 $38.8 $40.0 0.61% 0.51% 0.45% 0.38% 0.29% Total Deposits Rate Paid on Average Total Interest-Bearing Deposits 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 33% 9% 11% 27% 10% 10% Non-Interest-Bearing NOW and Interest-Bearing DDA Wealth Management Deposits Money Market Savings Time Certificates of Deposit Year-over-Year Change $4.1B or 11%
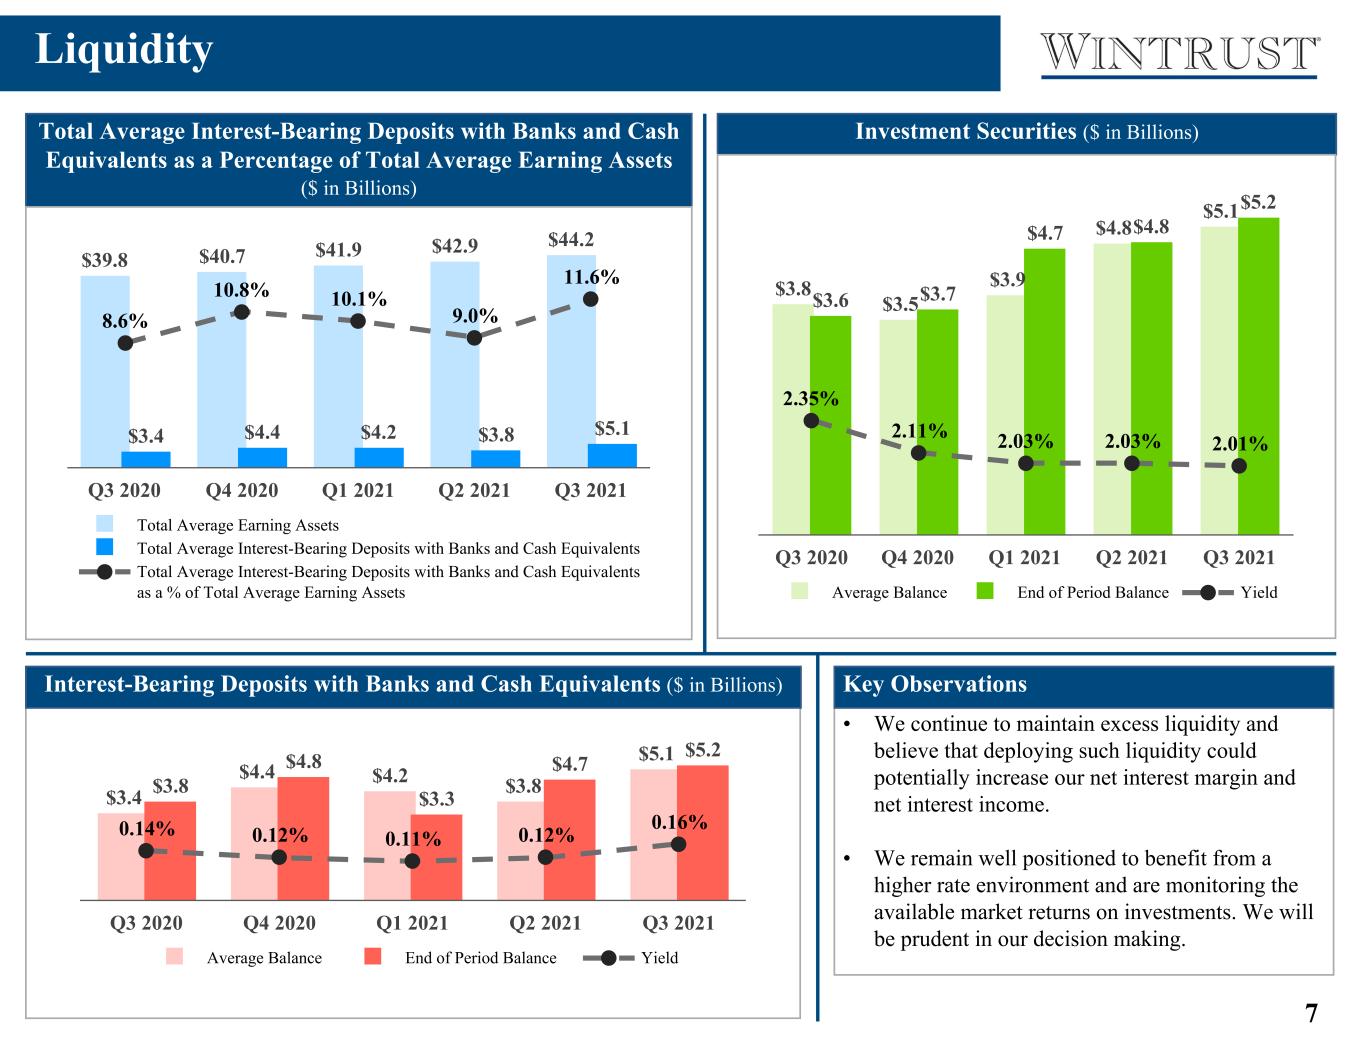
7 Liquidity • We continue to maintain excess liquidity and believe that deploying such liquidity could potentially increase our net interest margin and net interest income. • We remain well positioned to benefit from a higher rate environment and are monitoring the available market returns on investments. We will be prudent in our decision making. Key Observations Total Average Interest-Bearing Deposits with Banks and Cash Equivalents as a Percentage of Total Average Earning Assets ($ in Billions) $3.4 $4.4 $4.2 $3.8 $5.1 $3.8 $4.8 $3.3 $4.7 $5.2 0.14% 0.12% 0.11% 0.12% 0.16% Average Balance End of Period Balance Yield Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Interest-Bearing Deposits with Banks and Cash Equivalents ($ in Billions) $39.8 $40.7 $41.9 $42.9 $44.2 $3.4 $4.4 $4.2 $3.8 $5.1 8.6% 10.8% 10.1% 9.0% 11.6% Total Average Earning Assets Total Average Interest-Bearing Deposits with Banks and Cash Equivalents Total Average Interest-Bearing Deposits with Banks and Cash Equivalents as a % of Total Average Earning Assets Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Investment Securities ($ in Billions) $3.8 $3.5 $3.9 $4.8 $5.1 $3.6 $3.7 $4.7 $4.8 $5.2 2.35% 2.11% 2.03% 2.03% 2.01% Average Balance End of Period Balance Yield Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021
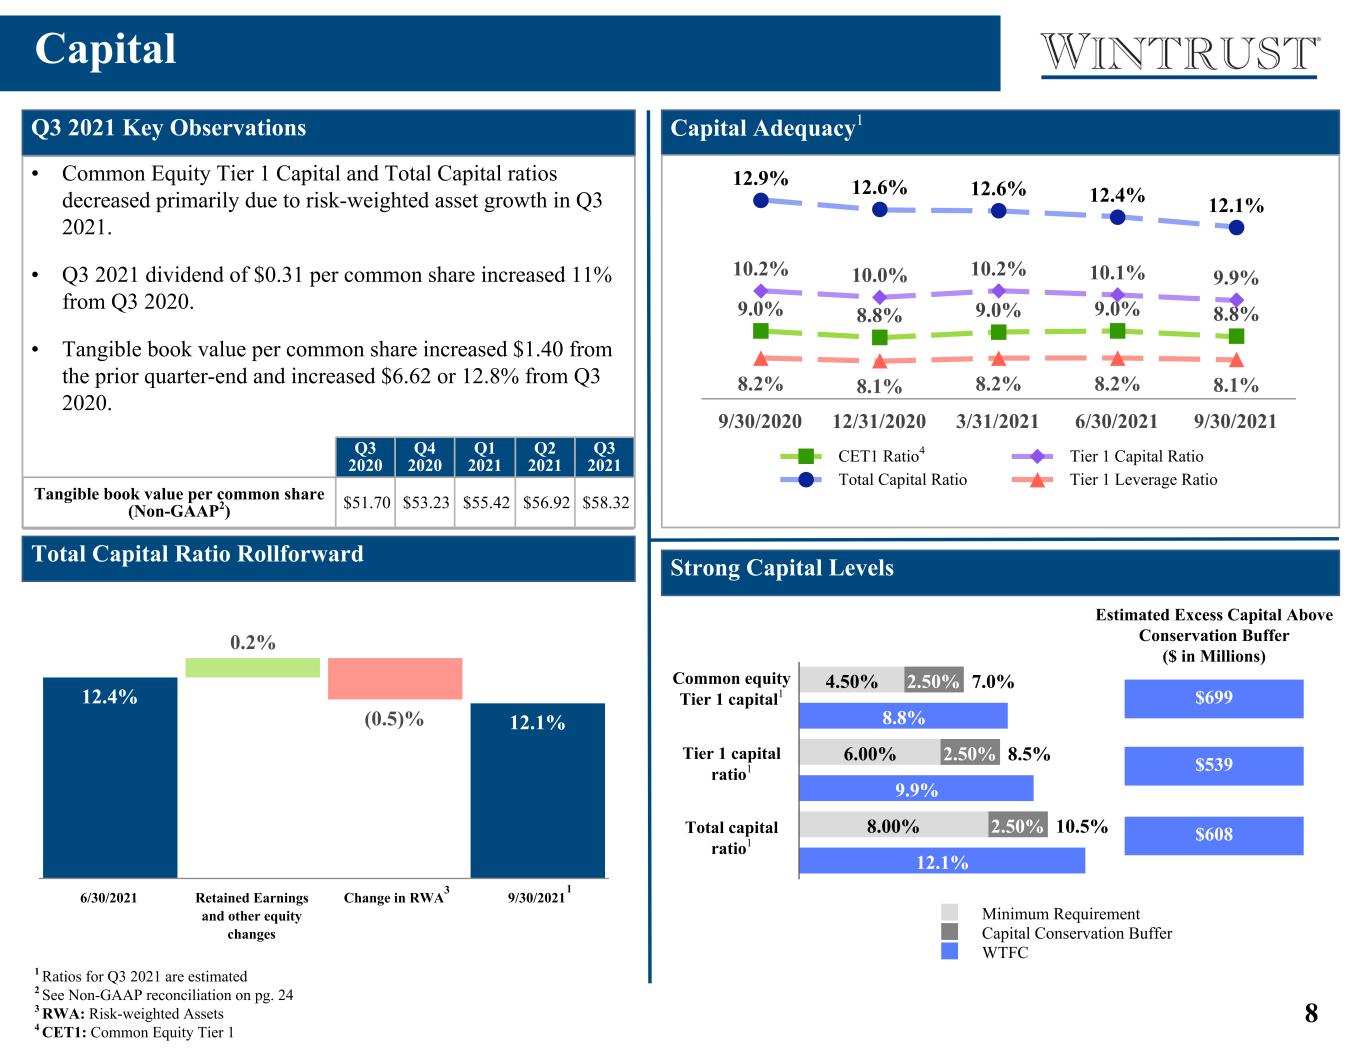
8 7.0% 8.5% 10.5% 4.50% 6.00% 8.00% 2.50% 2.50% 2.50% 8.8% 9.9% 12.1% Minimum Requirement Capital Conservation Buffer WTFC 12.4% 0.2% (0.5)% 12.1% 6/30/2021 Retained Earnings and other equity changes Change in RWA 9/30/2021 Capital Q3 2021 Key Observations Strong Capital Levels • Common Equity Tier 1 Capital and Total Capital ratios decreased primarily due to risk-weighted asset growth in Q3 2021. • Q3 2021 dividend of $0.31 per common share increased 11% from Q3 2020. • Tangible book value per common share increased $1.40 from the prior quarter-end and increased $6.62 or 12.8% from Q3 2020. Capital Adequacy1 Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Common equity tier 1 capital ratio1 9.0% 8.8% 9.0% 9.0% 8.8% Tier 1 capital ratio1 10.2% 10.0% 10.2% 10.1% 9.9% Total capital ratio1 12.9% 12.6% 12.6% 12.4% 12.1% Tier 1 leverage ratio1 8.2% 8.1% 8.2% 8.2% 8.1% Tangible book value per common share (Non-GAAP2) $51.70 $53.23 $55.42 $56.92 $58.32 Estimated Excess Capital Above Conservation Buffer ($ in Millions) Common equity Tier 1 capital1 Tier 1 capital ratio1 Total capital ratio1 $699 $539 $608 1 Ratios for Q3 2021 are estimated 2 See Non-GAAP reconciliation on pg. 24 3 RWA: Risk-weighted Assets 4 CET1: Common Equity Tier 1 9.0% 8.8% 9.0% 9.0% 8.8% 10.2% 10.0% 10.2% 10.1% 9.9% 12.9% 12.6% 12.6% 12.4% 12.1% 8.2% 8.1% 8.2% 8.2% 8.1% CET1 Ratio Tier 1 Capital Ratio Total Capital Ratio Tier 1 Leverage Ratio 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 Total Capital Ratio Rollforward Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Tangible book value per common share (Non-GAAP2) $51.70 $53.23 $55.42 $56.92 $58.32 1 4 3 5 5 Change in subordinated debt driven by a 20% annual phase out of subordinated debt from Tier 2 capital in compliance with Basel III requirements
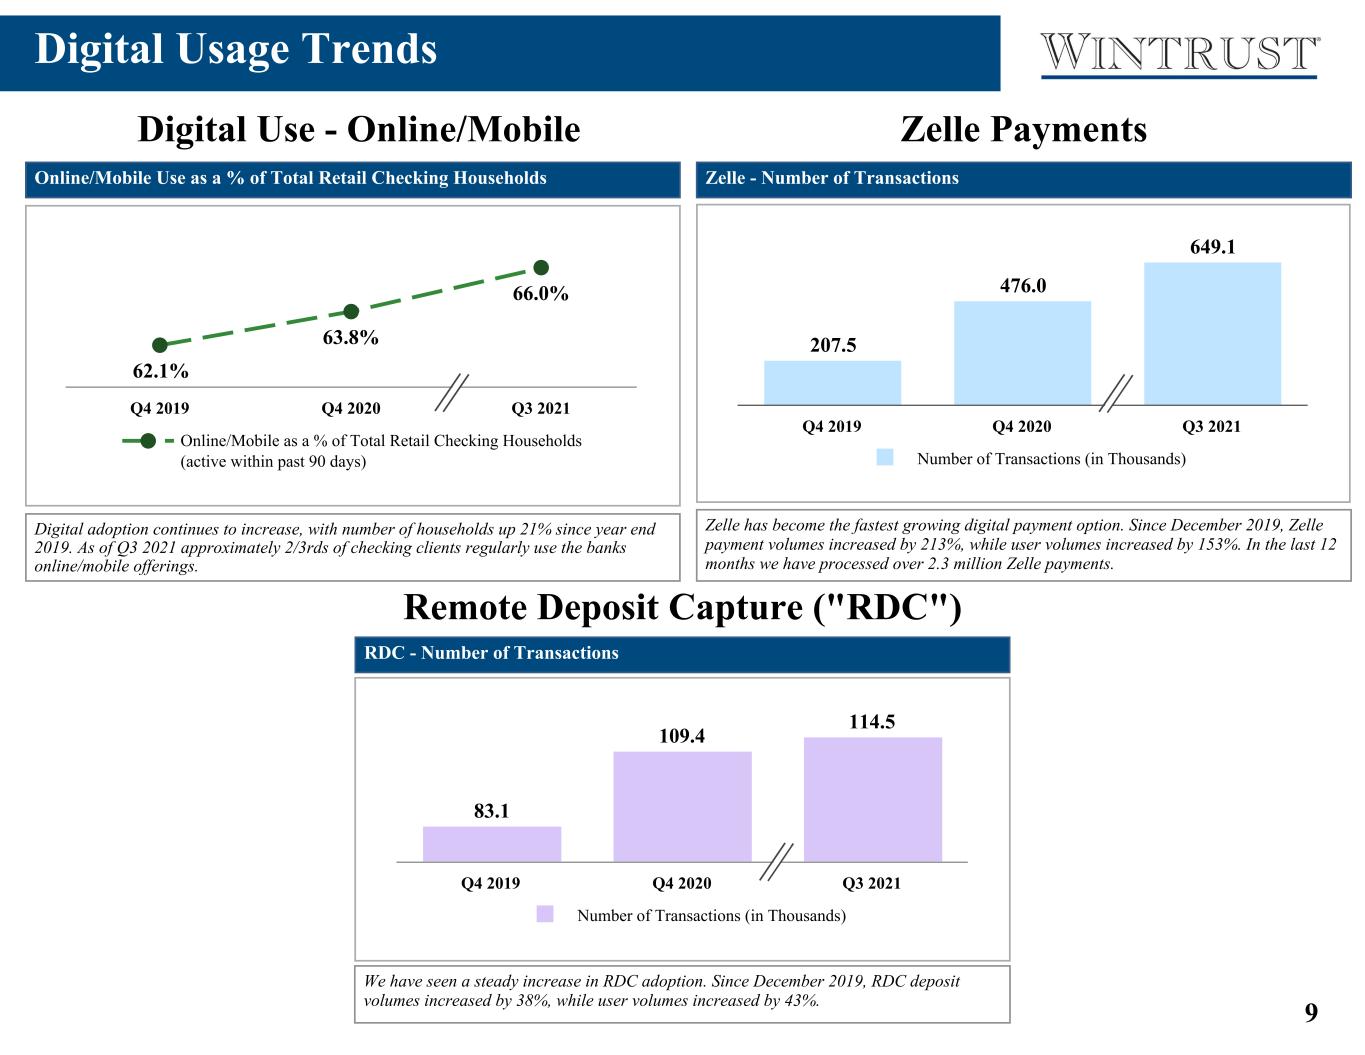
9 Zelle - Number of Transactions Digital Usage Trends • primarily due to increased trust and asset management fees and brokerage commissions Zelle Payments 83.1 109.4 114.5 Number of Transactions (in Thousands) Q4 2019 Q4 2020 Q3 2021 RDC - Number of Transactions 62.1% 63.8% 66.0% Online/Mobile as a % of Total Retail Checking Households (active within past 90 days) Q4 2019 Q4 2020 Q3 2021 Online/Mobile Use as a % of Total Retail Checking Households Digital Use - Online/Mobile Remote Deposit Capture ("RDC") Zelle has become the fastest growing digital payment option. Since December 2019, Zelle payment volumes increased by 213%, while user volumes increased by 153%. In the last 12 months we have processed over 2.3 million Zelle payments. We have seen a steady increase in RDC adoption. Since December 2019, RDC deposit volumes increased by 38%, while user volumes increased by 43%. Digital adoption continues to increase, with number of households up 21% since year end 2019. As of Q3 2021 approximately 2/3rds of checking clients regularly use the banks online/mobile offerings. 207.5 476.0 649.1 Number of Transactions (in Thousands) Q4 2019 Q4 2020 Q3 2021 544.2 561.1 578.8 590.5 605.5 52.5% 53.6% 54.7% 55.7% 56.5% Number of Retail Checking E-Statements E-Statements as a % of Retail Checking Statements Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Retail Checking E-Statements - Number of Transactions & Active Users (in Thousands) Retail Checking Electronic Statements ("E- Statements") With the recent deterioration in USPS service levels, e-statements adoption will likely increase as customers pivot to a more reliable delivery channel. Over the last year we have seen stable growth in E-statement adoption with year-over-year user volumes growth of: 11.3%.
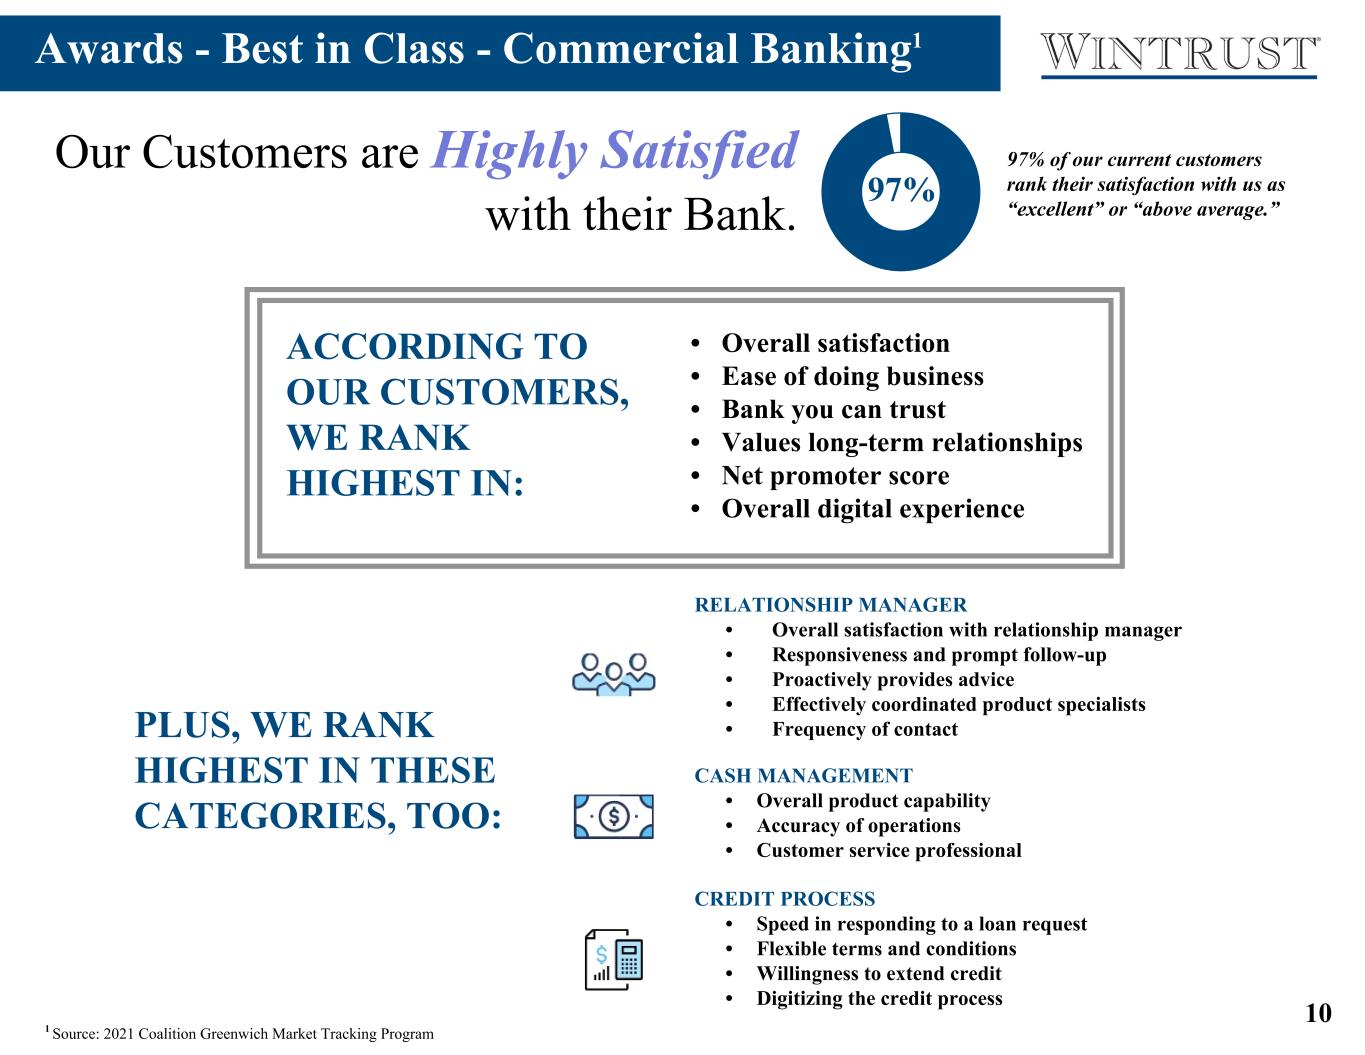
10 Awards - Best in Class - Commercial Banking1 • primarily due to increased trust and asset management fees and brokerage commissions 544.2 561.1 578.8 590.5 605.5 52.5% 53.6% 54.7% 55.7% 56.5% Number of Retail Checking E-Statements E-Statements as a % of Retail Checking Statements Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Retail Checking E-Statements - Number of Transactions & Active Users (in Thousands) Retail Checking Electronic Statements ("E- Statements") With the recent deterioration in USPS service levels, e-statements adoption will likely increase as customers pivot to a more reliable delivery channel. Over the last year we have seen stable growth in E-statement adoption with year-over-year user volumes growth of: 11.3%. 1 Source: 2021 Coalition Greenwich Market Tracking Program Our Customers are Highly Satisfied with their Bank. ACCORDING TO OUR CUSTOMERS, WE RANK HIGHEST IN: • Overall satisfaction • Ease of doing business • Bank you can trust • Values long-term relationships • Net promoter score • Overall digital experience PLUS, WE RANK HIGHEST IN THESE CATEGORIES, TOO: RELATIONSHIP MANAGER • Overall satisfaction with relationship manager • Responsiveness and prompt follow-up • Proactively provides advice • Effectively coordinated product specialists • Frequency of contact CASH MANAGEMENT • Overall product capability • Accuracy of operations • Customer service professional CREDIT PROCESS • Speed in responding to a loan request • Flexible terms and conditions • Willingness to extend credit • Digitizing the credit process 97% of our current customers rank their satisfaction with us as “excellent” or “above average.” 97%
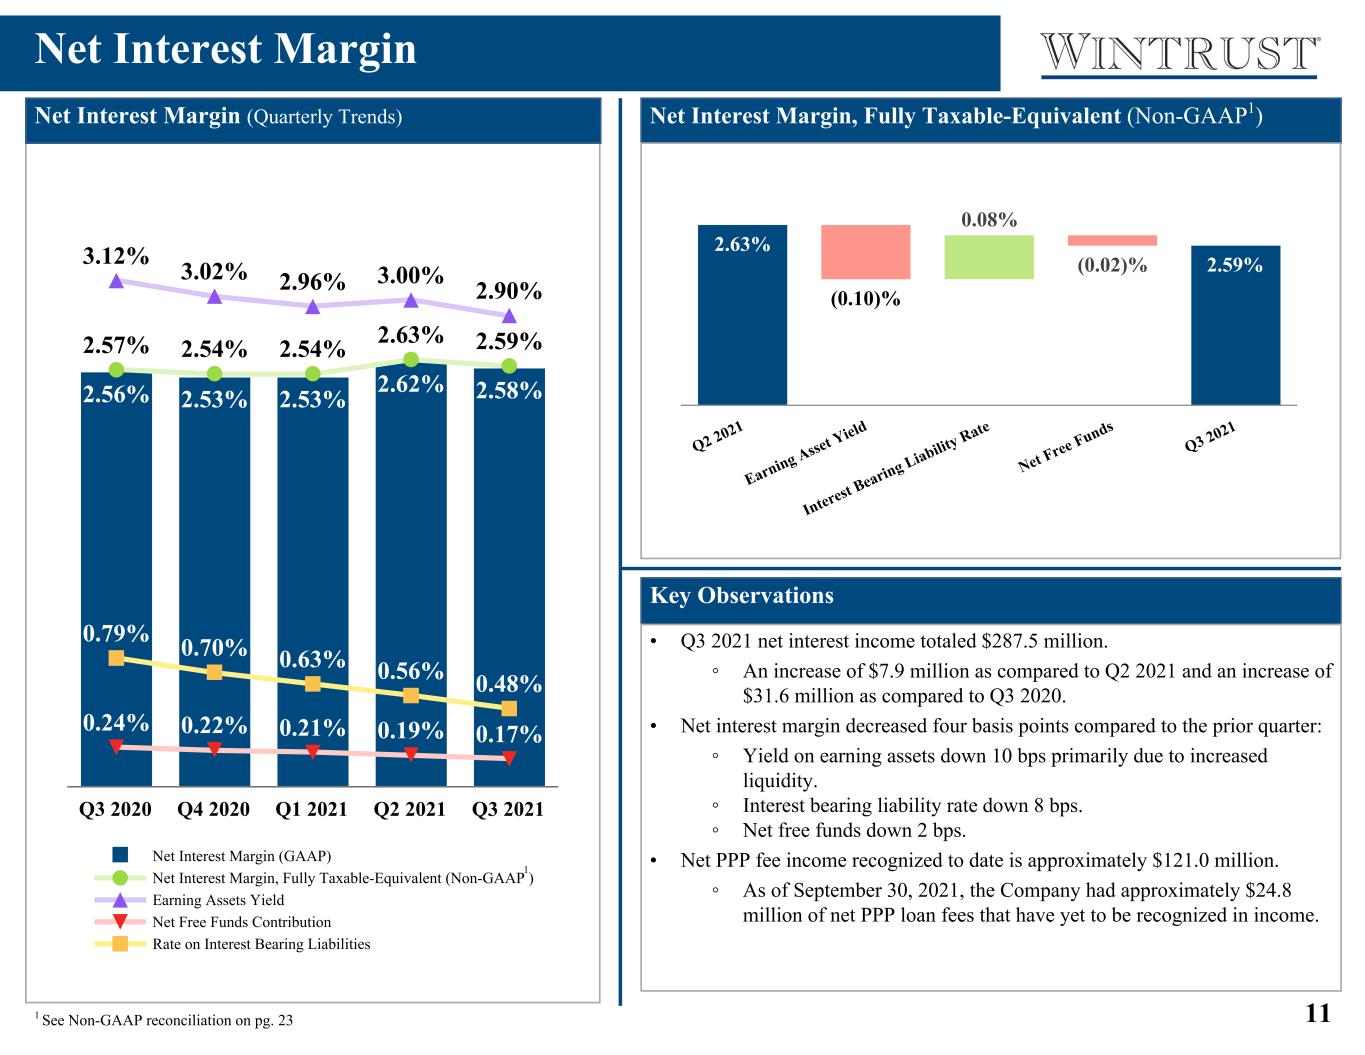
11 2.56% 2.53% 2.53% 2.62% 2.58% 2.57% 2.54% 2.54% 2.63% 2.59% 3.12% 3.02% 2.96% 3.00% 2.90% 0.24% 0.22% 0.21% 0.19% 0.17% 0.79% 0.70% 0.63% 0.56% 0.48% Net Interest Margin (GAAP) Net Interest Margin, Fully Taxable-Equivalent (Non-GAAP ) Earning Assets Yield Net Free Funds Contribution Rate on Interest Bearing Liabilities Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Net Interest Margin Net Interest Margin, Fully Taxable-Equivalent (Non-GAAP1) Key Observations Net Interest Margin (Quarterly Trends) 2.63% (0.1)% 0.08% (0.02)% 2.59% Q2 2021 Earning Asset Yield Interest B earing Liability Rate Net Free Funds Q3 2021 1 See Non-GAAP reconciliation on pg. 23 1 2.63% (0.10)% 0.08% (0.02)% 2.59% Q2 2021 Earning Asset Yield Interest B earing Liability Rate Net Free Funds Q3 2021 • Q3 2021 net interest income totaled $287.5 million. ◦ A decrease of $7.9 million as compared to Q2 2021 and a decrease of $31.6 million as compared to Q3 2020. • Net interest margin (Non-GAAP1) decreased by 4 bps from the prior quarter: ◦ Earning assets yield down 10 bps. ◦ Interest bearing liability rate down 8 bps. ◦ Net free funds down 2 bps. • Q3 2021 net interest income totaled $287.5 million. ◦ An increase of $7.9 million as compared to Q2 2021 and an increase of $31.6 million as compared to Q3 2020. • Net interest margin decreased four basis points compared to the prior quarter: ◦ Yield on earning assets down 10 bps primarily due to increased liquidity. ◦ Interest bearing liability rate down 8 bps. ◦ Net free funds down 2 bps. • Net PPP fee income recognized to date is approximately $121.0 million. ◦ As of September 30, 2021, the Company had approximately $24.8 million of net PPP loan fees that have yet to be recognized in income.
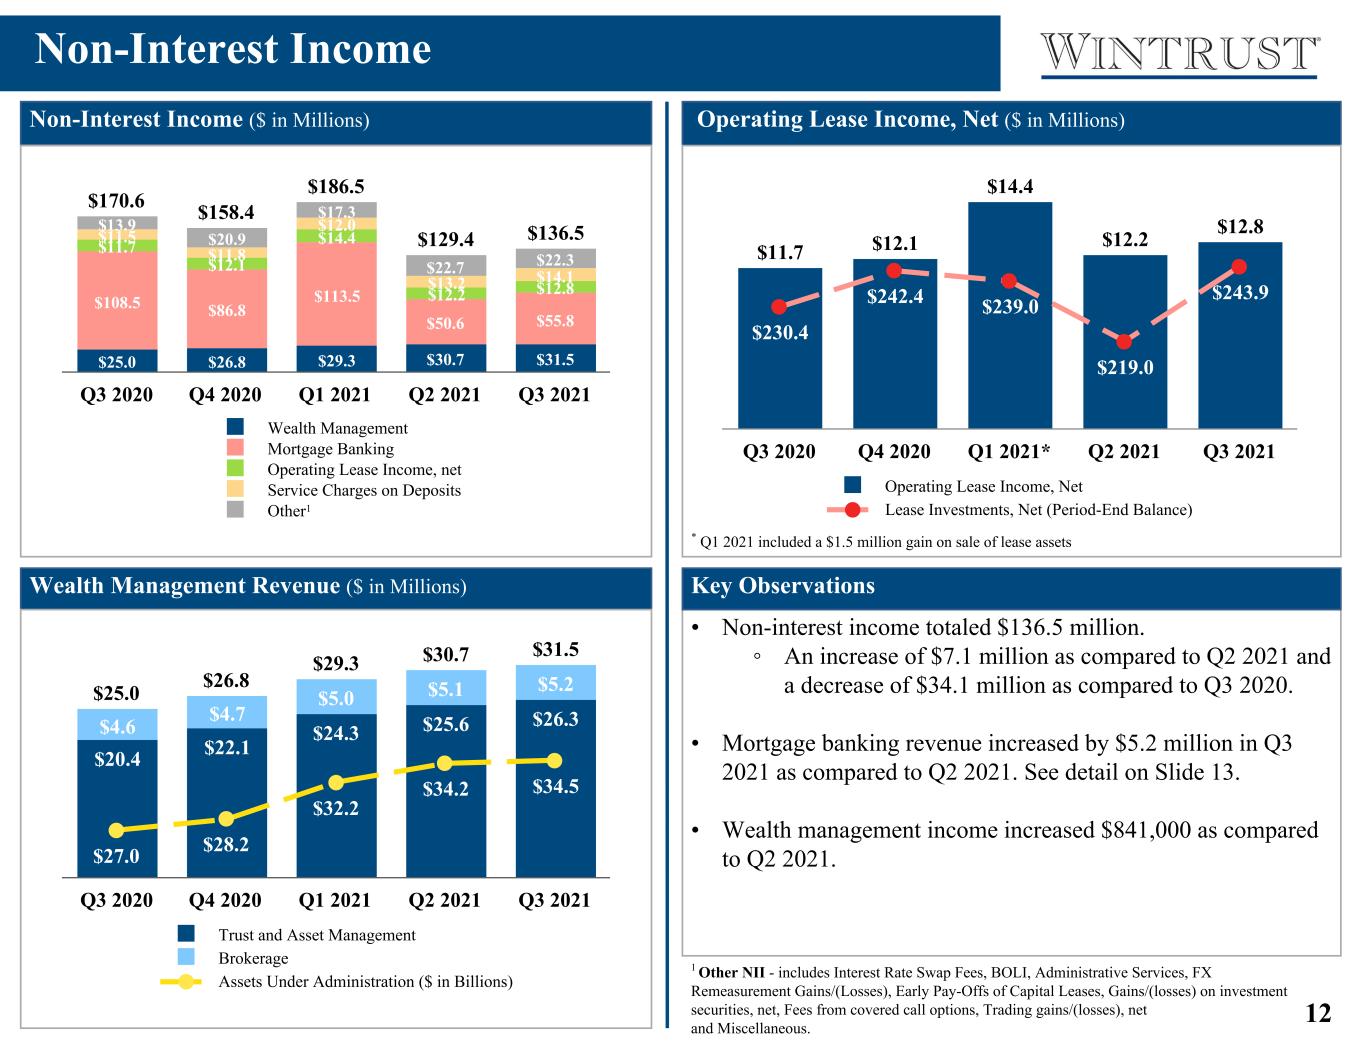
12 Non-Interest Income ($ in Millions) $170.6 $158.4 $186.5 $129.4 $136.5 $25.0 $26.8 $29.3 $30.7 $31.5 $108.5 $86.8 $113.5 $50.6 $55.8 $11.7 $12.1 $14.4 $12.2 $12.8 $11.5 $11.8 $12.0 $13.2 $14.1 $13.9 $20.9 $17.3 $22.7 $22.3 Wealth Management Mortgage Banking Operating Lease Income, net Service Charges on Deposits Other Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Non-Interest Income Wealth Management Revenue ($ in Millions) • Non-interest income totaled $136.5 million. ◦ An increase of $7.1 million as compared to Q2 2021 and a decrease of $34.1 million as compared to Q3 2020. • Mortgage banking revenue increased by $5.2 million in Q3 2021 as compared to Q2 2021. See detail on Slide 13. • Wealth management income increased $841,000 as compared to Q2 2021. Key Observations 1 Other NII - includes Interest Rate Swap Fees, BOLI, Administrative Services, FX Remeasurement Gains/(Losses), Early Pay-Offs of Capital Leases, Gains/(losses) on investment securities, net, Fees from covered call options, Trading gains/(losses), net and Miscellaneous. 1 $25.0 $26.8 $29.3 $30.7 $31.5 $20.4 $22.1 $24.3 $25.6 $26.3$4.6 $4.7 $5.0 $5.1 $5.2 $27.0 $28.2 $32.2 $34.2 $34.5 Trust and Asset Management Brokerage Assets Under Administration ($ in Billions) Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Operating Lease Income, Net ($ in Millions) $11.7 $12.1 $14.4 $12.2 $12.8 $230.4 $242.4 $239.0 $219.0 $243.9 Operating Lease Income, Net Lease Investments, Net (Period-End Balance) Q3 2020 Q4 2020 Q1 2021* Q2 2021 Q3 2021 • primarily due to increased trust and asset management fees and brokerage commissions * Q1 2021 included a $1.5 million gain on sale of lease assets
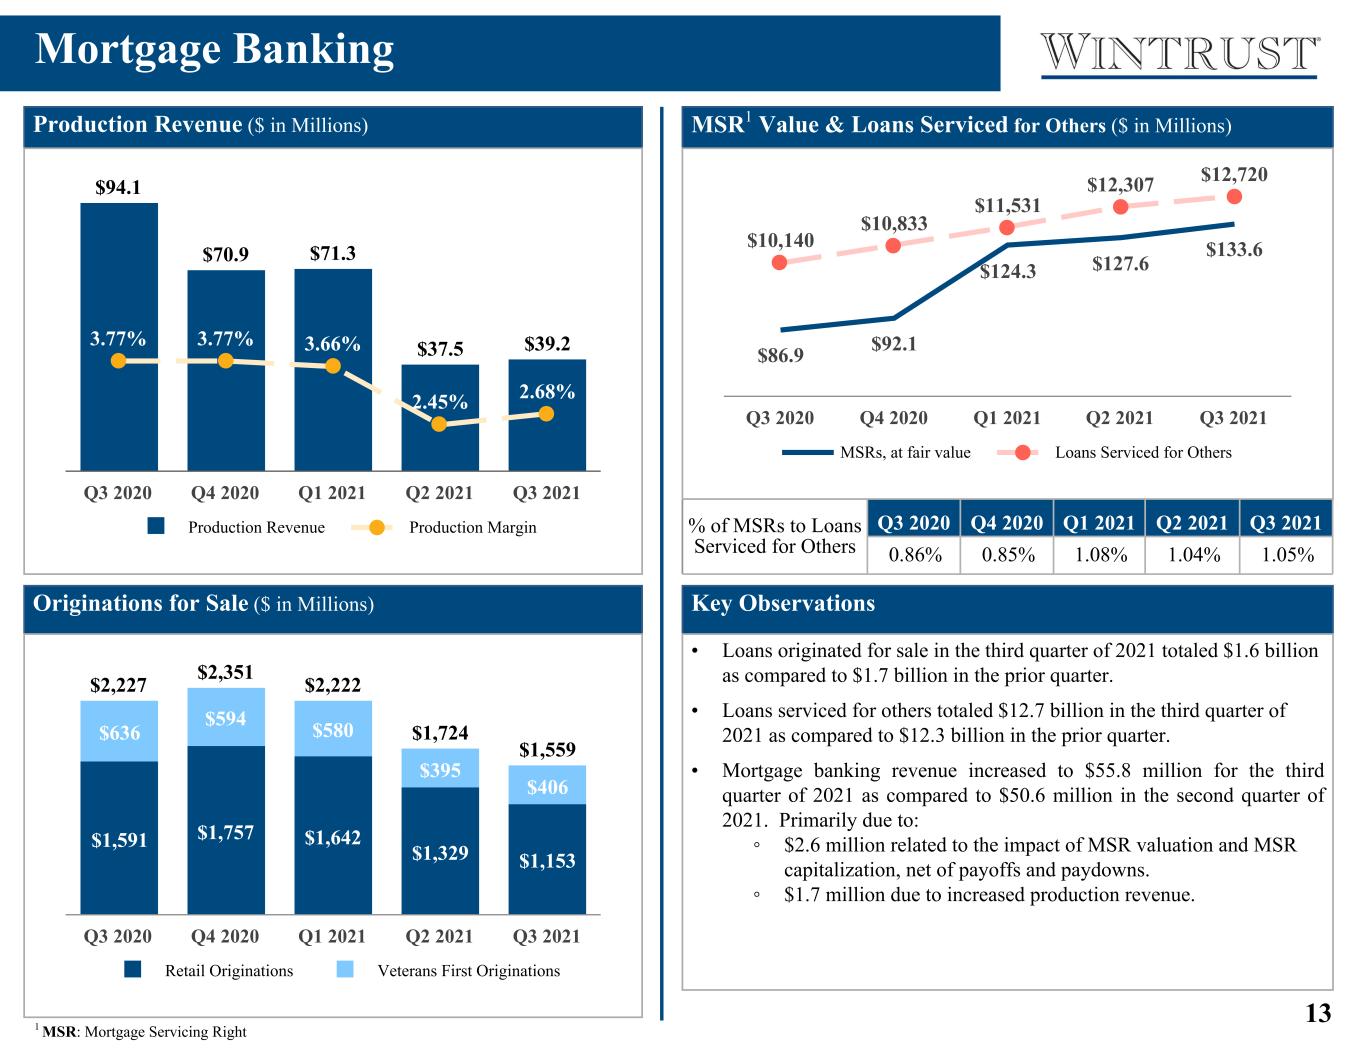
13 $47.996 $0.111 $(10.2)$(8.5)$(8.6) $(3.0)$(5.2) $18.0 $(5.5)$(0.9) $33.6 $70.9 $71.3 $37.5$39.2 $4.3 $(28.7)$(1.4)$(41.0)$(45.2) $20.9 $17.5$15.5 $— $— MSR - Payoffs/Paydowns MSR - Change in Fair Value Model Assumptions Production Revenue Servicing Income & Other MSR Capitalization MSR Hedging Gains (Losses) Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Mortgage Banking Production Revenue ($ in Millions) MSR1 Value & Loans Serviced for Others ($ in Millions) Originations for Sale ($ in Millions) Key Observations • Loans originated for sale in the third quarter of 2021 totaled $1.6 billion as compared to $1.7 billion in the prior quarter. • Loans serviced for others totaled $12.7 billion in the third quarter of 2021 as compared to $12.3 billion in the prior quarter. • Mortgage banking revenue increased to $55.8 million for the third quarter of 2021 as compared to $50.6 million in the second quarter of 2021. Primarily due to: ◦ $2.6 million related to the impact of MSR valuation and MSR capitalization, net of payoffs and paydowns. ◦ $1.7 million due to increased production revenue. % of MSRs to Loans Serviced for Others Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 0.86% 0.85% 1.08% 1.04% 1.05% 1 MSR: Mortgage Servicing Right LOGIC IN MORTGAGE BANKING REVENUE NEEDS TO BE MODIFIED Mortgage banking production revenue increased by $1.7 million as mortgage originations for sale totaled $1.6 billion in the third quarter of 2021 as compared to $1.7 billion in the second quarter of 2021. $94.1 $70.9 $71.3 $37.5 $39.23.77% 3.77% 3.66% 2.45% 2.68% Production Revenue Production Margin Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 $86.9 $92.1 $124.3 $127.6 $133.6$10,140 $10,833 $11,531 $12,307 $12,720 MSRs, at fair value Loans Serviced for Others Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 $2,227 $2,351 $2,222 $1,724 $1,559 $1,591 $1,757 $1,642 $1,329 $1,153 $636 $594 $580 $395 $406 Retail Originations Veterans First Originations Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021
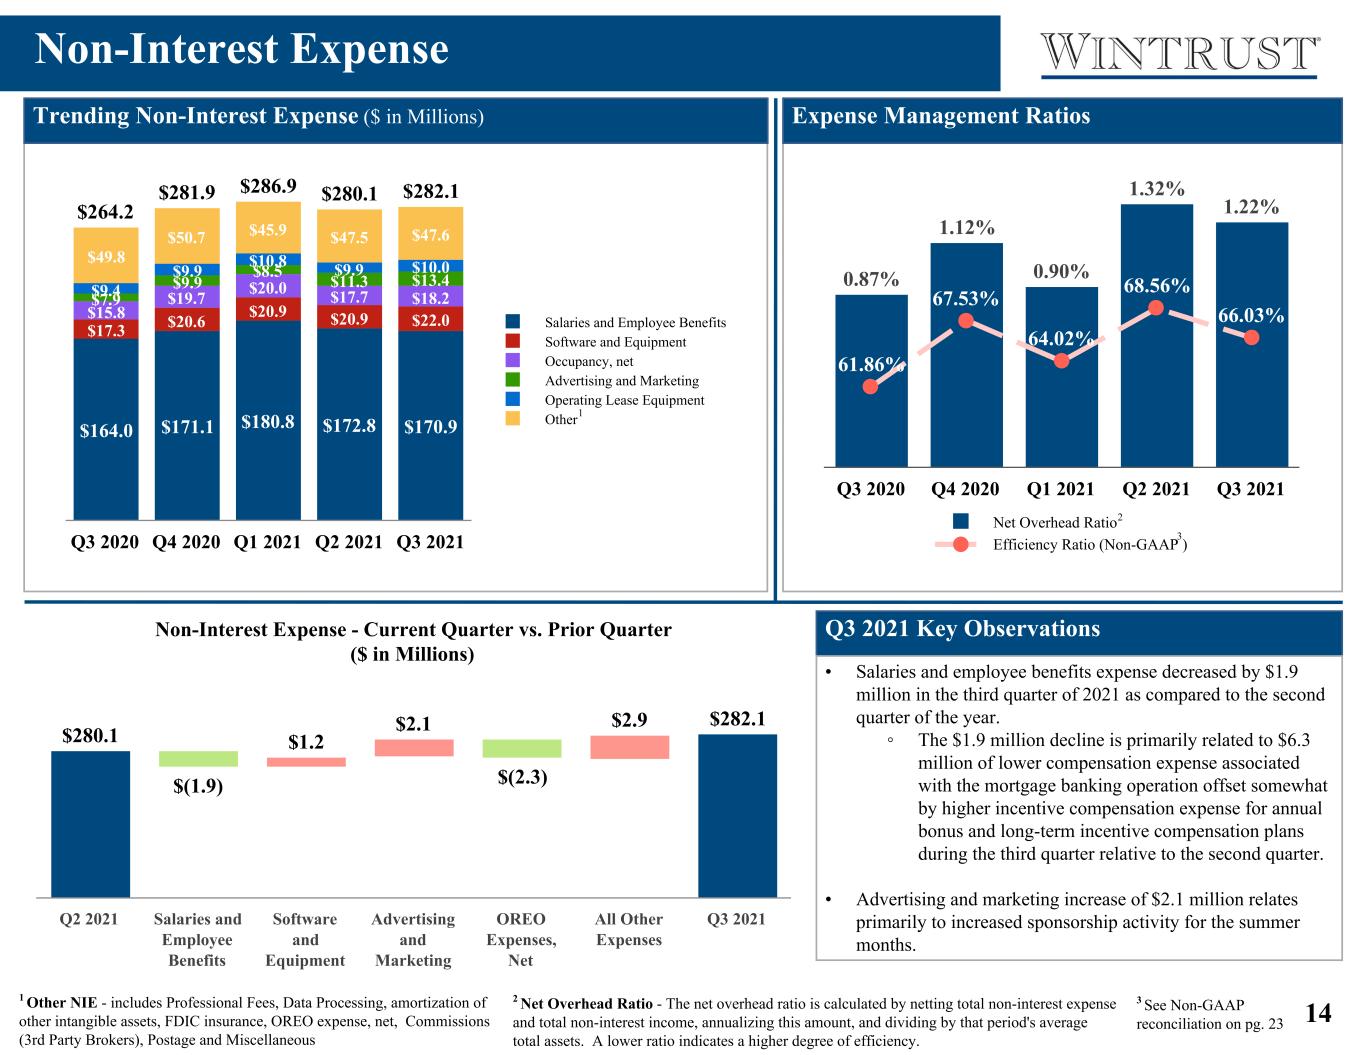
14 $264.2 $281.9 $286.9 $280.1 $282.1 $164.0 $171.1 $180.8 $172.8 $170.9 $17.3 $20.6 $20.9 $20.9 $22.0$15.8 $19.7 $20.0 $17.7 $18.2$7.9 $9.9 $8.5 $11.3 $13.4$9.4 $9.9 $10.8 $9.9 $10.0$49.8 $50.7 $45.9 $47.5 $47.6 Salaries and Employee Benefits Software and Equipment Occupancy, net Advertising and Marketing Operating Lease Equipment Other Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 0.87% 1.12% 0.90% 1.32% 1.22% 61.86% 67.53% 64.02% 68.56% 66.03% Net Overhead Ratio Efficiency Ratio (Non-GAAP ) Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Non-Interest Expense Trending Non-Interest Expense ($ in Millions) Q3 2021 Key Observations • Salaries and employee benefits expense decreased by $1.9 million in the third quarter of 2021 as compared to the second quarter of the year. ◦ The $1.9 million decline is primarily related to $6.3 million of lower compensation expense associated with the mortgage banking operation offset somewhat by higher incentive compensation expense for annual bonus and long-term incentive compensation plans during the third quarter relative to the second quarter. • Advertising and marketing increase of $2.1 million relates primarily to increased sponsorship activity for the summer months. 1 Other NIE - includes Professional Fees, Data Processing, amortization of other intangible assets, FDIC insurance, OREO expense, net, Commissions (3rd Party Brokers), Postage and Miscellaneous Non-Interest Expense - Current Quarter vs. Prior Quarter ($ in Millions) $280.1 $(1.9) $1.2 $2.1 $(2.3) $2.9 $282.1 Q2 2021 Salaries and Employee Benefits Software and Equipment Advertising and Marketing OREO Expenses, Net All Other Expenses Q3 2021 1 Expense Management Ratios 2 3 2 Net Overhead Ratio - The net overhead ratio is calculated by netting total non-interest expense and total non-interest income, annualizing this amount, and dividing by that period's average total assets. A lower ratio indicates a higher degree of efficiency. 3 See Non-GAAP reconciliation on pg. 23 Salaries and employee benefits expense decreased by $1.9 million in the third quarter of 2021 as compared to the second quarter of the year. The $1.9 million decline is primarily related to $6.3 million of lower compensation expense associated with the mortgage banking operation offset somewhat by higher incentive compensation expense for annual bonus and long-term incentive compensation plans during the third quarter relative to the second quarter. • Salaries and employee benefits decrease comprised of: ◦ $3.3 million increase in commissions and incentive compensation. ◦ $2.3 million decrease in employee benefits expense. ◦ $2.9 million decrease in salaries. • Advertising and marketing increase of $2.1 million relates primarily to increased sponsorship activity for the summer months.
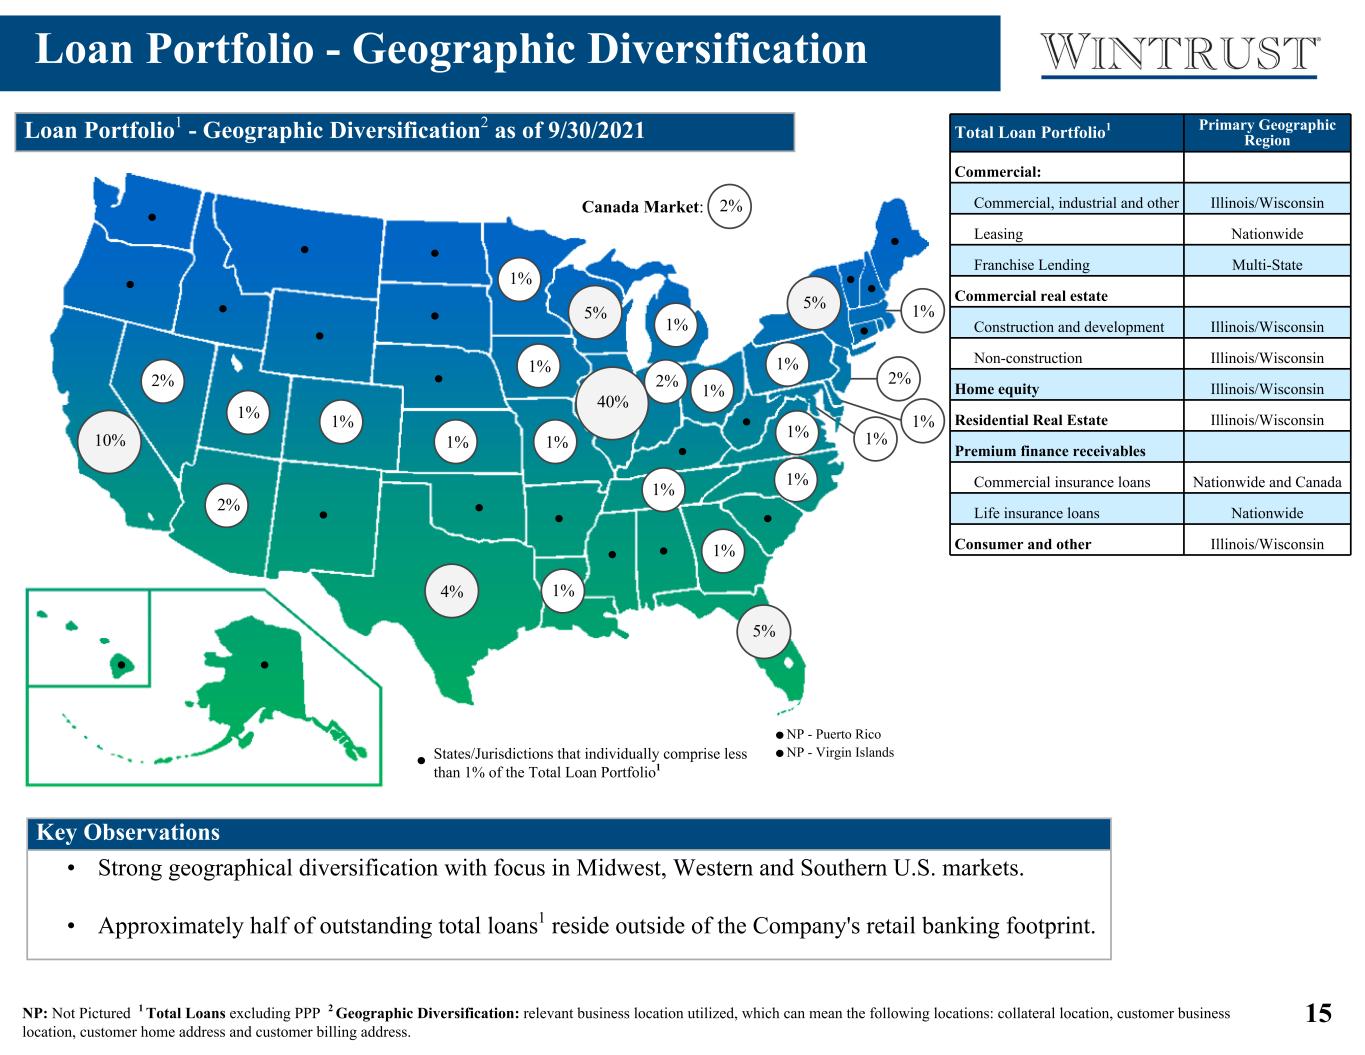
15 Loan Portfolio - Geographic Diversification Canada Market: Loan Portfolio1 - Geographic Diversification2 as of 9/30/2021 Total Loan Portfolio1 Primary Geographic Region Commercial: Commercial, industrial and other Illinois/Wisconsin Leasing Nationwide Franchise Lending Multi-State Commercial real estate Construction and development Illinois/Wisconsin Non-construction Illinois/Wisconsin Home equity Illinois/Wisconsin Residential Real Estate Illinois/Wisconsin Premium finance receivables Commercial insurance loans Nationwide and Canada Life insurance loans Nationwide Consumer and other Illinois/Wisconsin NP: Not Pictured 1 Total Loans excluding PPP 2 Geographic Diversification: relevant business location utilized, which can mean the following locations: collateral location, customer business location, customer home address and customer billing address. Key Observations • Strong geographical diversification with focus in Midwest, Western and Southern U.S. markets. • Approximately half of outstanding total loans1 reside outside of the Company's retail banking footprint. States/Jurisdictions that individually comprise less than 1% of the Total Loan Portfolio1 2% 10% 5% 40% 2% 2% 5% 1% 4% NP - Puerto Rico NP - Virgin Islands 1% 1% 1% 1% 2% 2% 5% 1% 1% 1% 1% 1% 1% 1% 1% 1% 1% 1% 1%
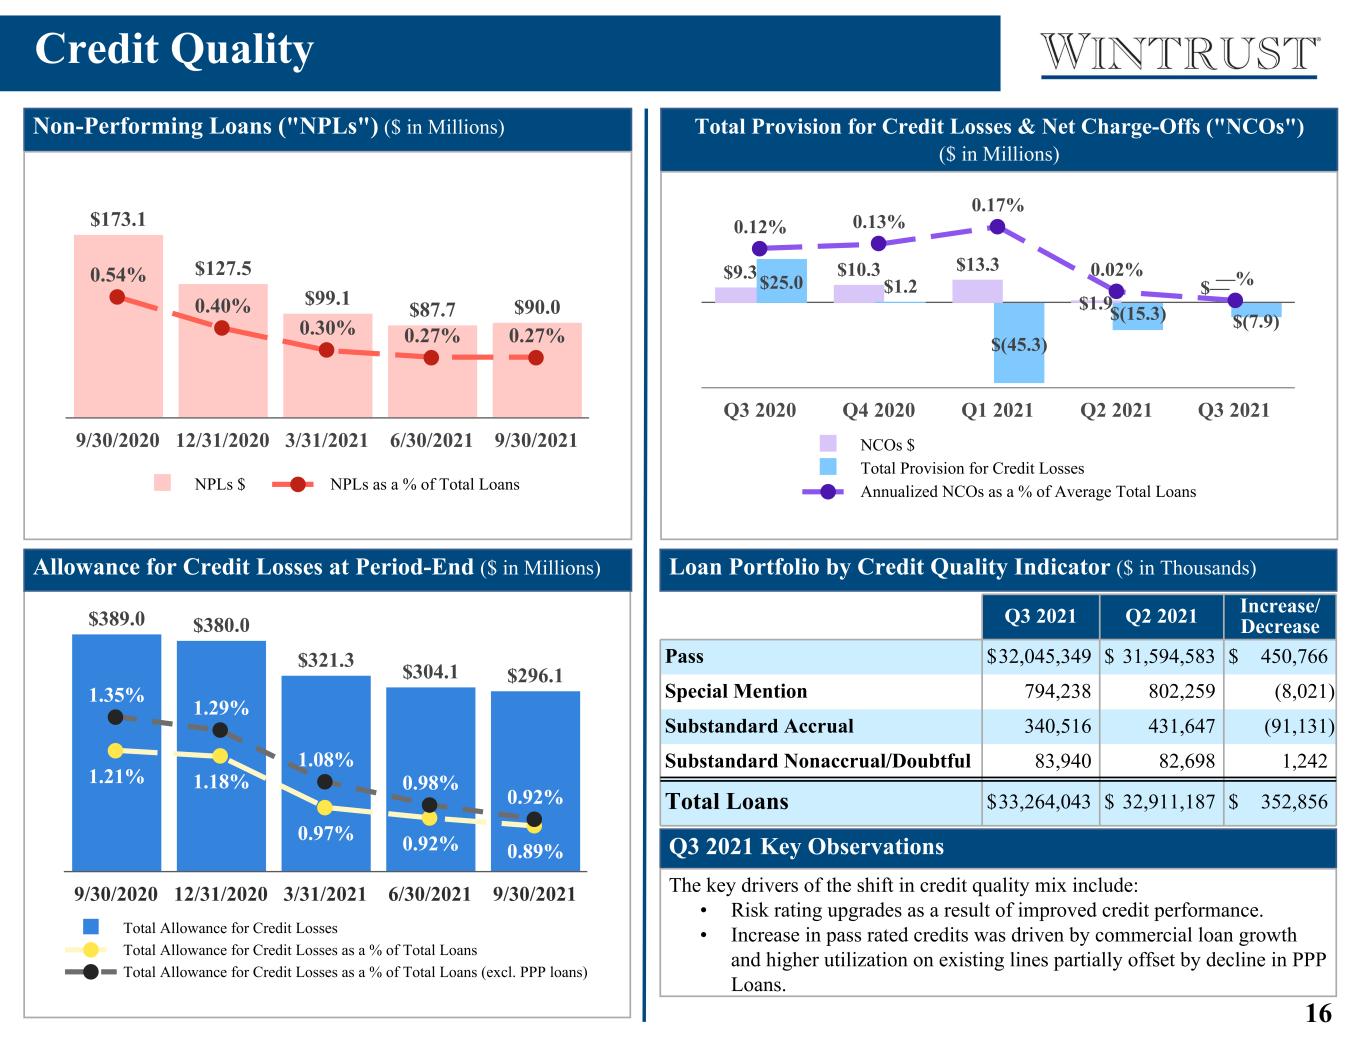
16 $389.0 $380.0 $321.3 $304.1 $296.1 1.21% 1.18% 0.97% 0.92% 0.89% 1.35% 1.29% 1.08% 0.98% 0.92% Total Allowance for Credit Losses Total Allowance for Credit Losses as a % of Total Loans Total Allowance for Credit Losses as a % of Total Loans (excl. PPP loans) 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 Credit Quality • The Company estimates an increase to the allowance for credit losses of approximately 30% to 50% at adoption related to its loan portfolios and related lending commitments. Approximately 80% of the estimated increase is related to: ◦ Additions to existing reserves for unfunded lending-related commitments due to the consideration under CECL of expected utilization by the Company's borrowers over the life of such commitments. ◦ Establishment of reserves for acquired loans which previously considered credit discounts. The Company estimates an insignificant impact at adoption of measuring an allowance for credit losses for other in-scope assets (e.g. held-to-maturity debt securities). Allowance for Credit Losses at Period-End ($ in Millions) Non-Performing Loans ("NPLs") ($ in Millions) Total Provision for Credit Losses & Net Charge-Offs ("NCOs") ($ in Millions) Loan Portfolio by Credit Quality Indicator ($ in Thousands) $173.1 $127.5 $99.1 $87.7 $90.0 0.54% 0.40% 0.30% 0.27% 0.27% NPLs $ NPLs as a % of Total Loans 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 $9.3 $10.3 $13.3 $1.9 $—$25.0 $1.2 $(45.3) $(15.3) $(7.9) 0.12% 0.13% 0.17% 0.02% —% NCOs $ Total Provision for Credit Losses Annualized NCOs as a % of Average Total Loans Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 $25.0 $1.2 $(45.3) $(15.3) $(7.9) 37.10% Total Provision for Credit Losses Net Charge-Offs as a % of the Provision for Credit Losses 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 $7.8 $53 $135.1 $0 $0 $— $— $— $— $—$7.8 $53.0 $135.1 37.1% 876.0% Provision for credit losses - PCD Provision for credit losses - non PCD Net charge-offs as a percentage of the provision for credit losses Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Incurred Loss Method CECL Incurred Loss Method CECL Q3 2021 Q2 2021 Increase/ Decrease Pass $ 32,045,349 $ 31,594,583 $ 450,766 Special Mention 794,238 802,259 (8,021) Substandard Accrual 340,516 431,647 (91,131) Substandard Nonaccrual/Doubtful 83,940 82,698 1,242 Total Loans $ 33,264,043 $ 32,911,187 $ 352,856 Q3 2021 Key Observations The key drivers of the shift in credit quality mix include: • Risk rating upgrades as a result of improved credit performance. • Increase in pass rated credits was driven by commercial loan growth and higher utilization on existing lines partially offset by decline in PPP Loans.
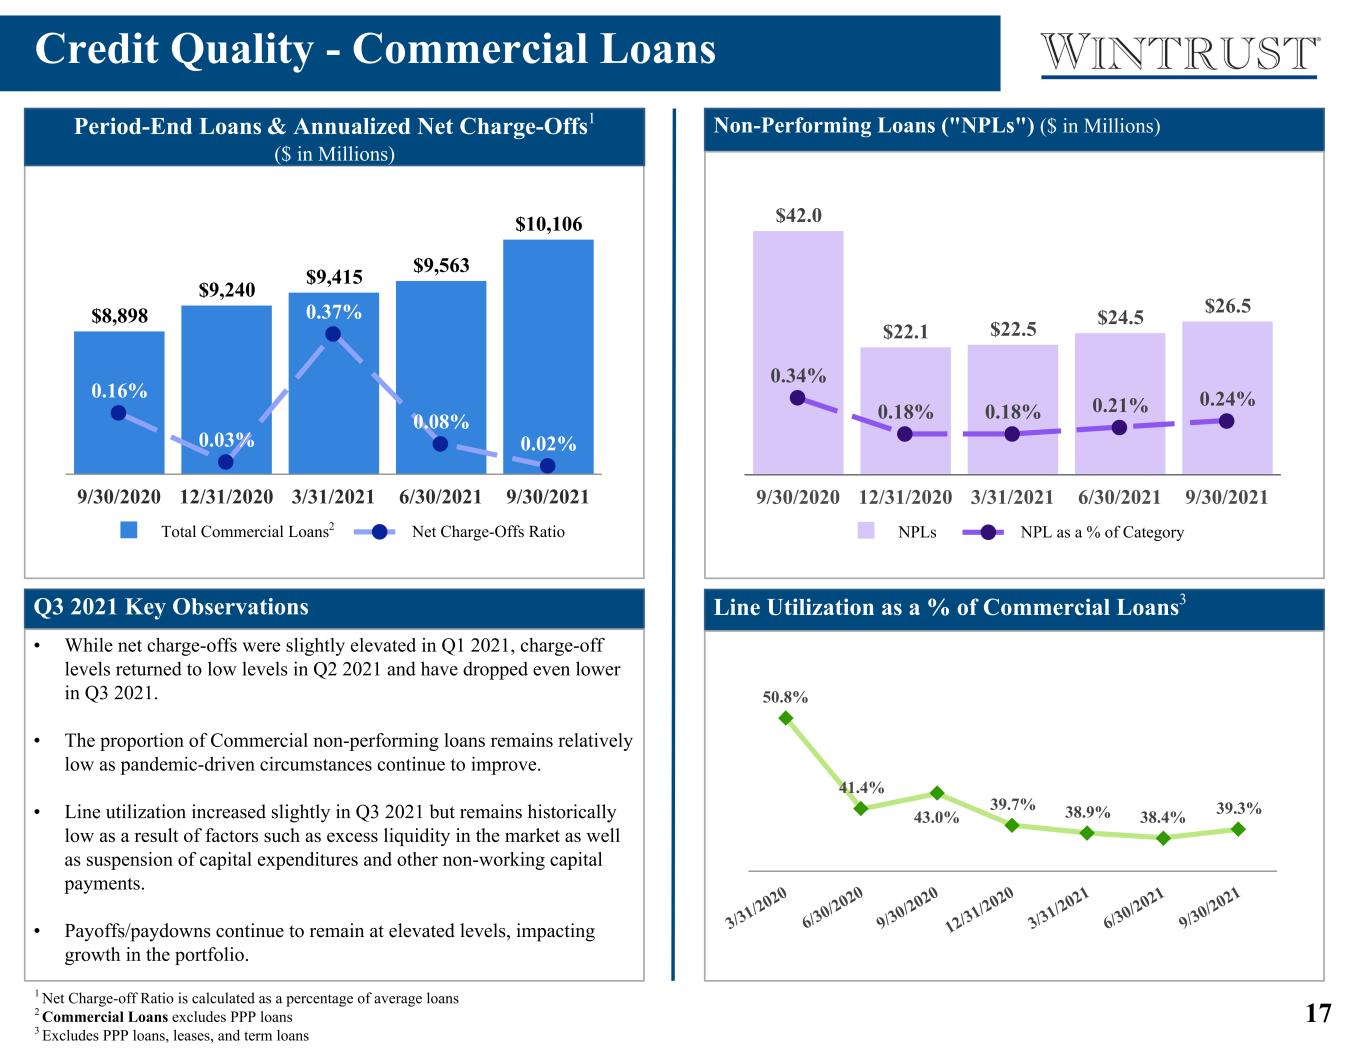
17 $8,898 $9,240 $9,415 $9,563 $10,106 0.16% 0.03% 0.37% 0.08% 0.02% Total Commercial Loans Net Charge-Offs Ratio 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 Credit Quality - Commercial Loans Line Utilization as a % of Commercial Loans3 Period-End Loans & Annualized Net Charge-Offs1 ($ in Millions) Non-Performing Loans ("NPLs") ($ in Millions) 50.8% 41.4% 43.0% 39.7% 38.9% 38.4% 39.3% 3/31/2020 6/30/2020 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 $42.0 $22.1 $22.5 $24.5 $26.5 0.34% 0.18% 0.18% 0.21% 0.24% NPLs NPL as a % of Category 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 Q3 2021 Key Observations • While net charge-offs were slightly elevated in Q1 2021, charge-off levels returned to low levels in Q2 2021 and have dropped even lower in Q3 2021. • The proportion of Commercial non-performing loans remains relatively low as pandemic-driven circumstances continue to improve. • Line utilization increased slightly in Q3 2021 but remains historically low as a result of factors such as excess liquidity in the market as well as suspension of capital expenditures and other non-working capital payments. • Payoffs/paydowns continue to remain at elevated levels, impacting growth in the portfolio. 1 Net Charge-off Ratio is calculated as a percentage of average loans 2 Commercial Loans excludes PPP loans 3 Excludes PPP loans, leases, and term loans 2 3 4
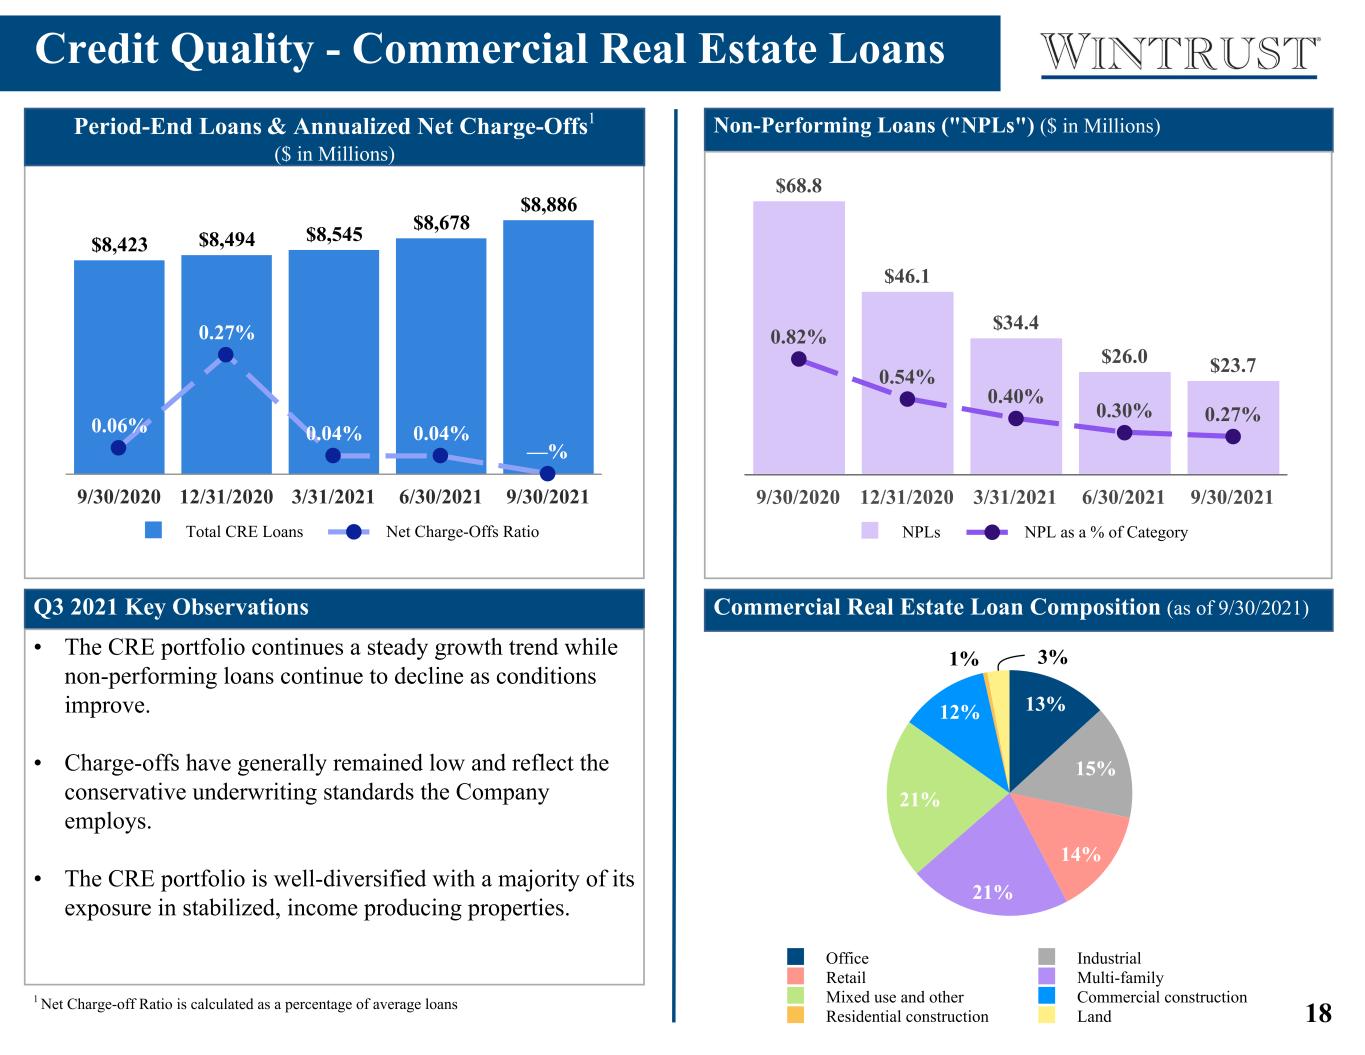
18 $8,423 $8,494 $8,545 $8,678 $8,886 0.06% 0.27% 0.04% 0.04% —% Total CRE Loans Net Charge-Offs Ratio 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 Credit Quality - Commercial Real Estate Loans Period-End Loans & Annualized Net Charge-Offs1 ($ in Millions) Non-Performing Loans ("NPLs") ($ in Millions) $68.8 $46.1 $34.4 $26.0 $23.7 0.82% 0.54% 0.40% 0.30% 0.27% NPLs NPL as a % of Category 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 Q3 2021 Key Observations • The CRE portfolio continues a steady growth trend while non-performing loans continue to decline as conditions improve. • Charge-offs have generally remained low and reflect the conservative underwriting standards the Company employs. • The CRE portfolio is well-diversified with a majority of its exposure in stabilized, income producing properties. 15% 17% 17%25% 26% Office Industrial Retail Multi-family Mixed use and other 79% 4% 17% Commercial construction Residential construction Land Commercial Real Estate Loan Composition (as of 9/30/2021) 1 Net Charge-off Ratio is calculated as a percentage of average loans 13% 15% 14% 21% 21% 12% 1% 3% Office Industrial Retail Multi-family Mixed use and other Commercial construction Residential construction Land
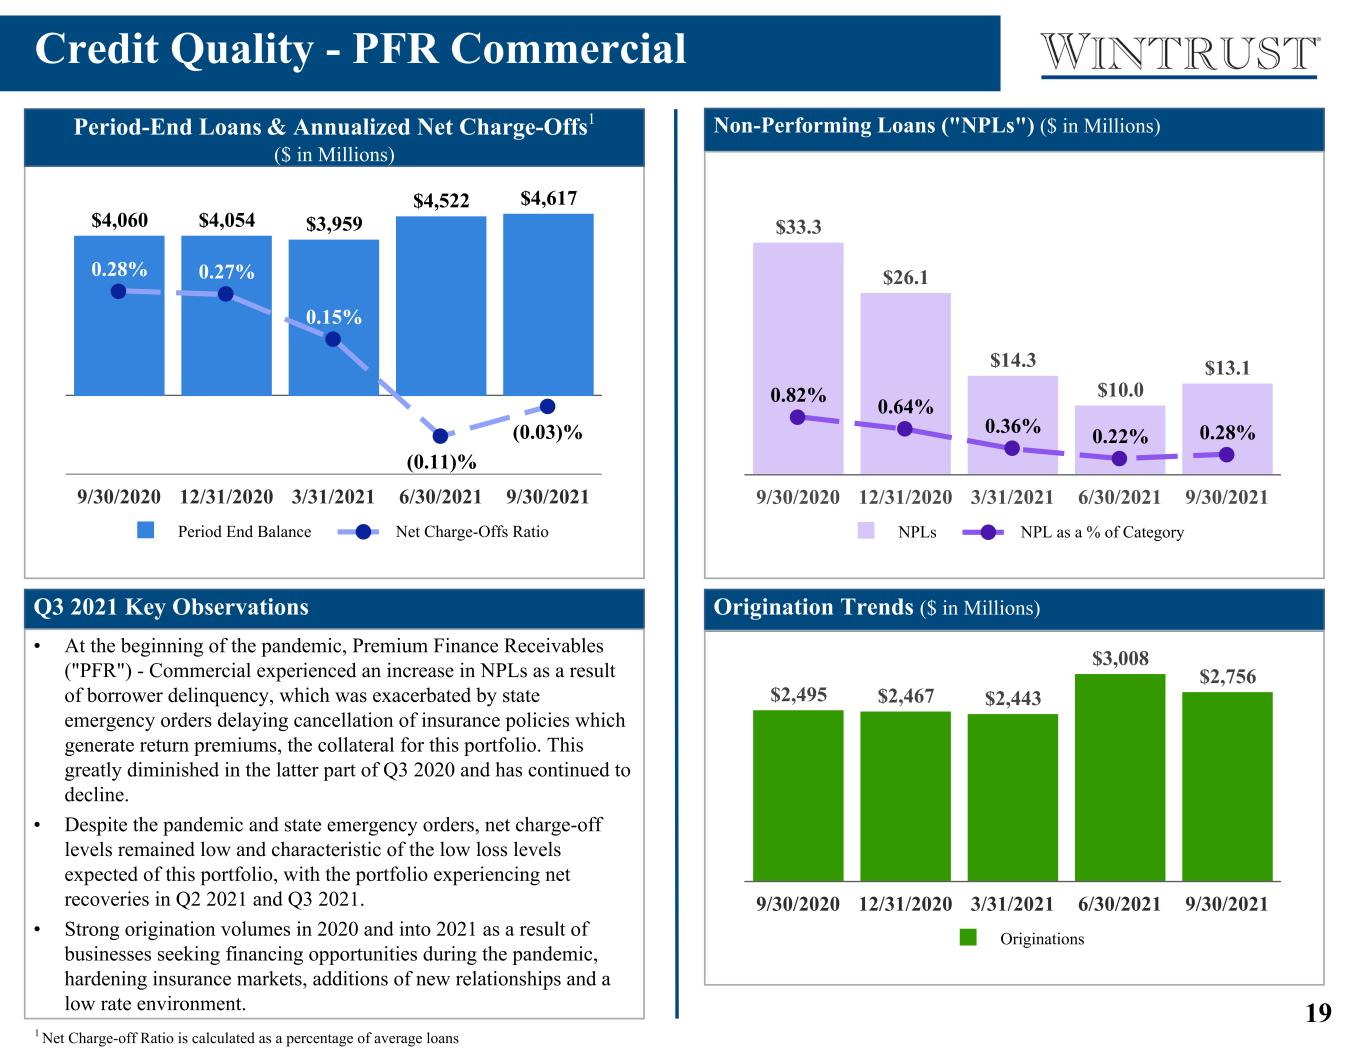
19 $4,060 $4,054 $3,959 $4,522 $4,617 0.28% 0.27% 0.15% (0.11)% (0.03)% Period End Balance Net Charge-Offs Ratio 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 Credit Quality - PFR Commercial Origination Trends ($ in Millions) Period-End Loans & Annualized Net Charge-Offs1 ($ in Millions) Average Balances & Quarterly Yields ($ in Millions) $3,724.6 $4,134.0 $4,010.5 $3,952.9 5.05% 4.60% 4.60% 4.42% Average Balance Yield Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Q3 2021 Key Observations • At the beginning of the pandemic, Premium Finance Receivables ("PFR") - Commercial experienced an increase in NPLs as a result of borrower delinquency, which was exacerbated by state emergency orders delaying cancellation of insurance policies which generate return premiums, the collateral for this portfolio. This greatly diminished in the latter part of Q3 2020 and has continued to decline. • Despite the pandemic and state emergency orders, net charge-off levels remained low and characteristic of the low loss levels expected of this portfolio, with the portfolio experiencing net recoveries in Q2 2021 and Q3 2021. • Strong origination volumes in 2020 and into 2021 as a result of businesses seeking financing opportunities during the pandemic, hardening insurance markets, additions of new relationships and a low rate environment. 1 Net Charge-off Ratio is calculated as a percentage of average loans $2,495 $2,467 $2,443 $3,008 $2,756 Originations 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 Non-Performing Loans ("NPLs") ($ in Millions) $33.3 $26.1 $14.3 $10.0 $13.1 0.82% 0.64% 0.36% 0.22% 0.28% NPLs NPL as a % of Category 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021
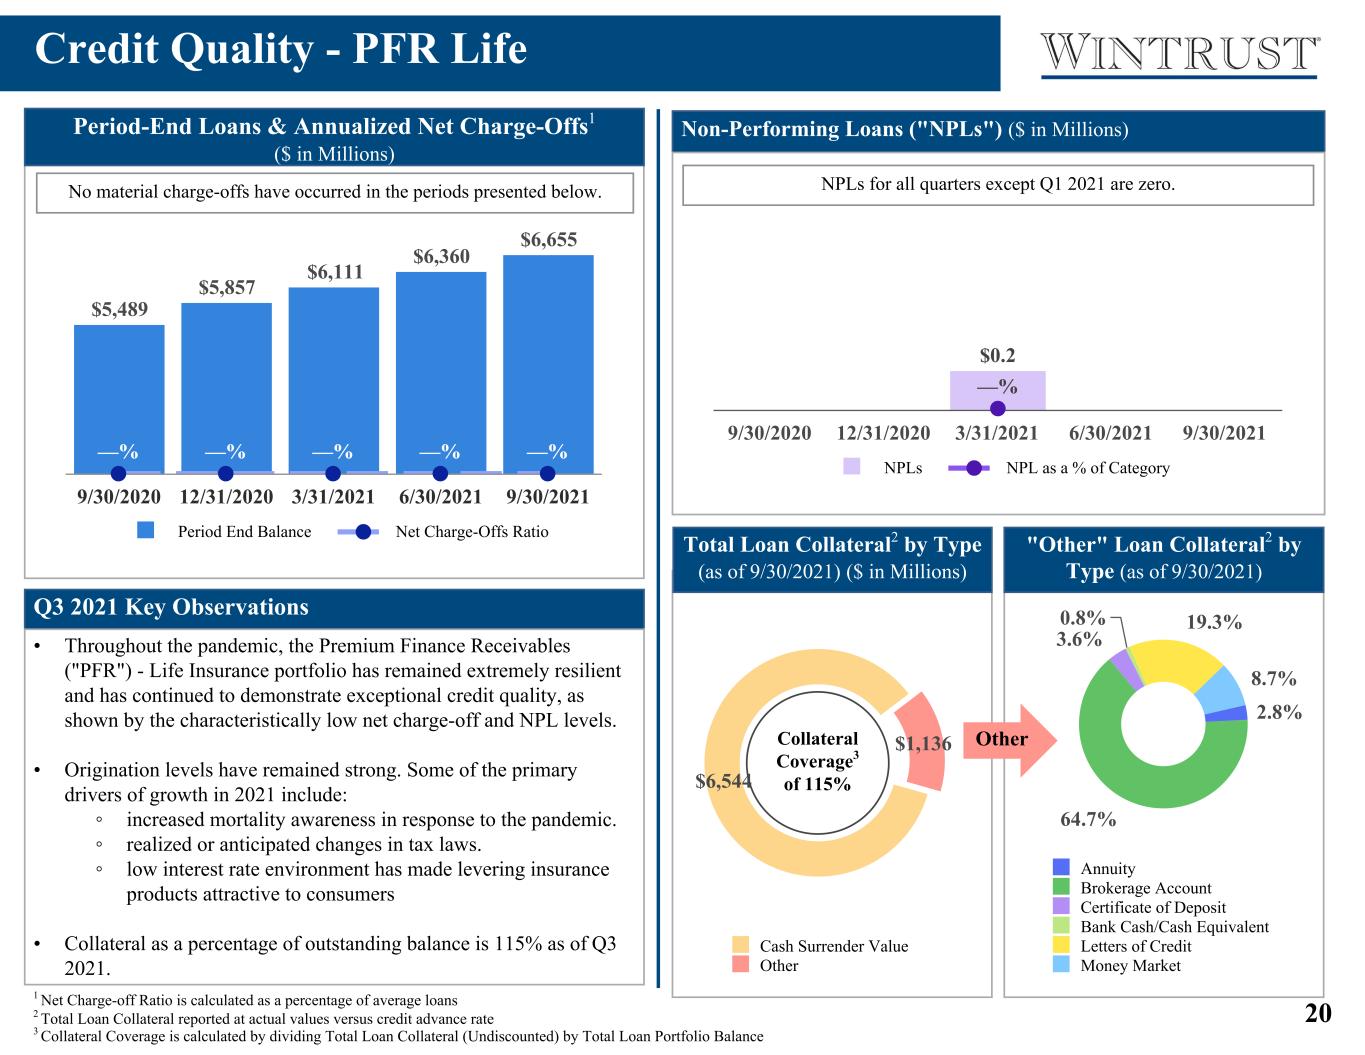
20 $5,489 $5,857 $6,111 $6,360 $6,655 —% —% —% —% —% Period End Balance Net Charge-Offs Ratio 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 Credit Quality - PFR Life Non-Performing Loans ("NPLs") ($ in Millions)Period-End Loans & Annualized Net Charge-Offs1 ($ in Millions) Average Balances & Quarterly Yields ($ in Millions) $5,290.1 $5,462.8 $5,636.3 $5,957.5 3.71% 3.38% 3.74% 2.89% Average Balance Yield Q3 2020 Q4 2020 Q1 2021 Q2 2021 Q3 2021 Q3 2021 Key Observations • Throughout the pandemic, the Premium Finance Receivables ("PFR") - Life Insurance portfolio has remained extremely resilient and has continued to demonstrate exceptional credit quality, as shown by the characteristically low net charge-off and NPL levels. • Origination levels have remained strong. Some of the primary drivers of growth in 2021 include: ◦ increased mortality awareness in response to the pandemic. ◦ realized or anticipated changes in tax laws. ◦ low interest rate environment has made levering insurance products attractive to consumers • Collateral as a percentage of outstanding balance is 115% as of Q3 2021. 1 Net Charge-off Ratio is calculated as a percentage of average loans 2 Total Loan Collateral reported at actual values versus credit advance rate 3 Collateral Coverage is calculated by dividing Total Loan Collateral (Undiscounted) by Total Loan Portfolio Balance $315.4 $442.7 $330.3 $360.0 $371.9 Originations 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 Total Loan Collateral2 by Type (as of 9/30/2021) ($ in Millions) No material charge-offs have occurred in the periods presented below. $0.2 —% NPLs NPL as a % of Category 9/30/2020 12/31/2020 3/31/2021 6/30/2021 9/30/2021 $6,544 $1,136 Cash Surrender Value Other 2.8% 64.7% 3.6% 0.8% 19.3% 8.7% Annuity Brokerage Account Certificate of Deposit Bank Cash/Cash Equivalent Letters of Credit Money Market "Other" Loan Collateral2 by Type (as of 9/30/2021) OtherCollateral Coverage3 of 115% NPLs for all quarters except Q1 2021 are zero.
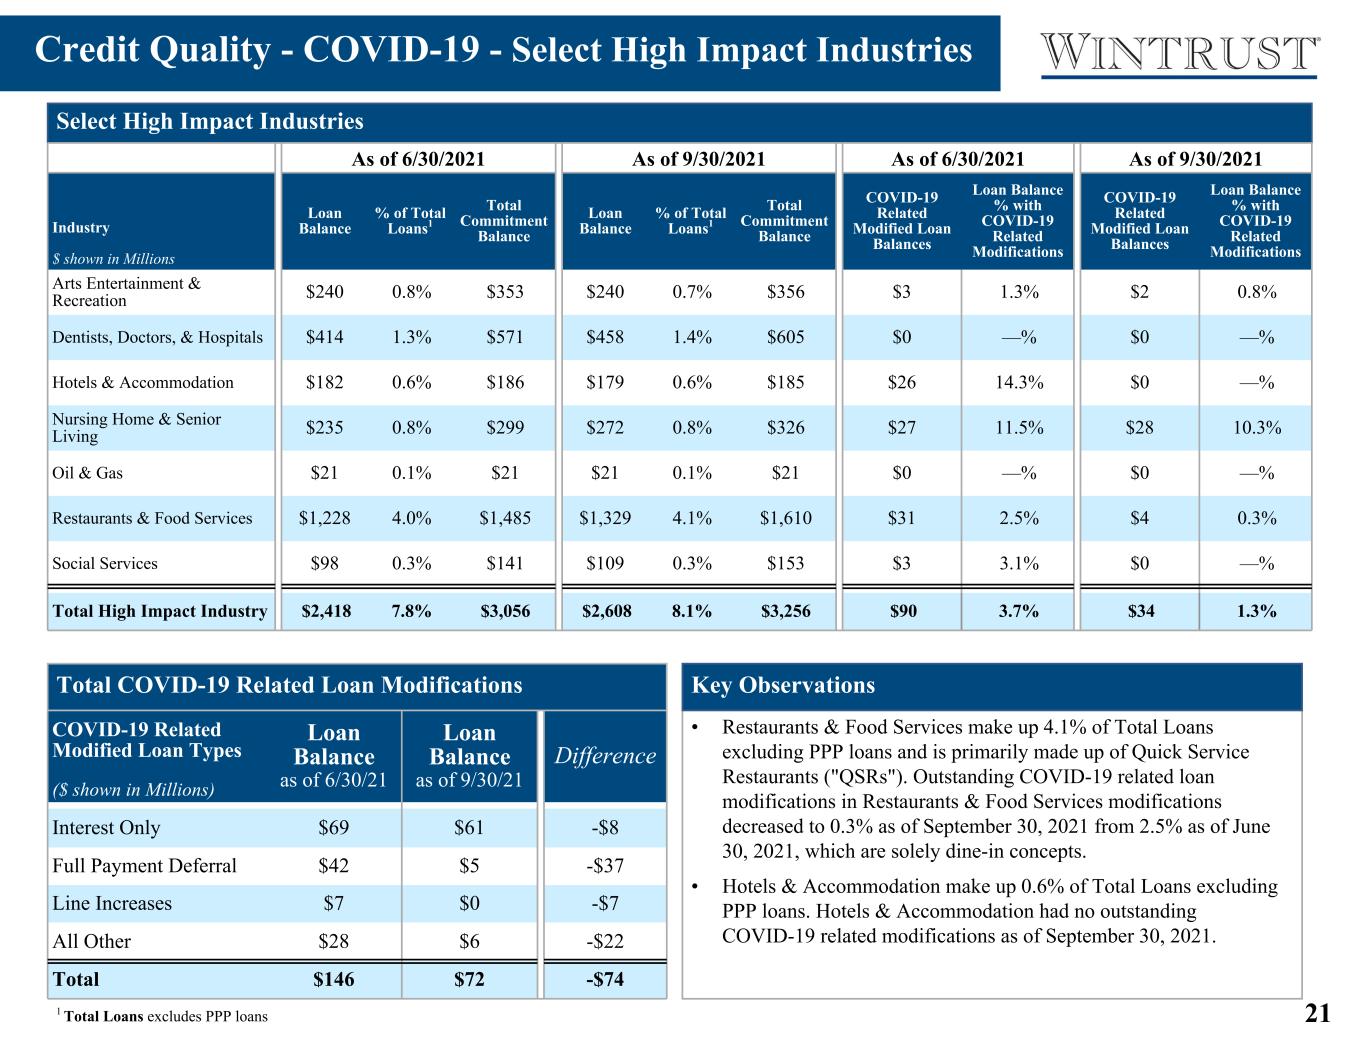
21 • Restaurants & Food Services make up 4.1% of Total Loans excluding PPP loans and is primarily made up of Quick Service Restaurants ("QSRs"). Outstanding COVID-19 related loan modifications in Restaurants & Food Services modifications decreased to 0.3% as of September 30, 2021 from 2.5% as of June 30, 2021, which are solely dine-in concepts. • Hotels & Accommodation make up 0.6% of Total Loans excluding PPP loans. Hotels & Accommodation had no outstanding COVID-19 related modifications as of September 30, 2021. Key Observations Select High Impact Industries 8.0% Credit Quality - COVID-19 - Select High Impact Industries Key Observations Other Loans 92.0% Total loans of $33.3 billion Total Loan Mix1 as of 9/30/2020: Select High Impact Industries Select High Impact Industries As of 6/30/2021 As of 9/30/2021 As of 6/30/2021 As of 9/30/2021 Industry $ shown in Millions Loan Balance % of Total Loans1 Total Commitment Balance Loan Balance % of Total Loans1 Total Commitment Balance COVID-19 Related Modified Loan Balances Loan Balance % with COVID-19 Related Modifications COVID-19 Related Modified Loan Balances Loan Balance % with COVID-19 Related Modifications Arts Entertainment & Recreation $240 0.8% $353 $240 0.7% $356 $3 1.3% $2 0.8% Dentists, Doctors, & Hospitals $414 1.3% $571 $458 1.4% $605 $0 —% $0 —% Hotels & Accommodation $182 0.6% $186 $179 0.6% $185 $26 14.3% $0 —% Nursing Home & Senior Living $235 0.8% $299 $272 0.8% $326 $27 11.5% $28 10.3% Oil & Gas $21 0.1% $21 $21 0.1% $21 $0 —% $0 —% Restaurants & Food Services $1,228 4.0% $1,485 $1,329 4.1% $1,610 $31 2.5% $4 0.3% Social Services $98 0.3% $141 $109 0.3% $153 $3 3.1% $0 —% Total High Impact Industry $2,418 7.8% $3,056 $2,608 8.1% $3,256 $90 3.7% $34 1.3% 1 Total Loans excludes PPP loans COVID-19 Related Modified Loan Types ($ shown in Millions) Loan Balance as of 6/30/21 Loan Balance as of 9/30/21 Difference Interest Only $69 $61 -$8 Full Payment Deferral $42 $5 -$37 Line Increases $7 $0 -$7 All Other $28 $6 -$22 Total $146 $72 -$74 Total COVID-19 Related Loan Modifications
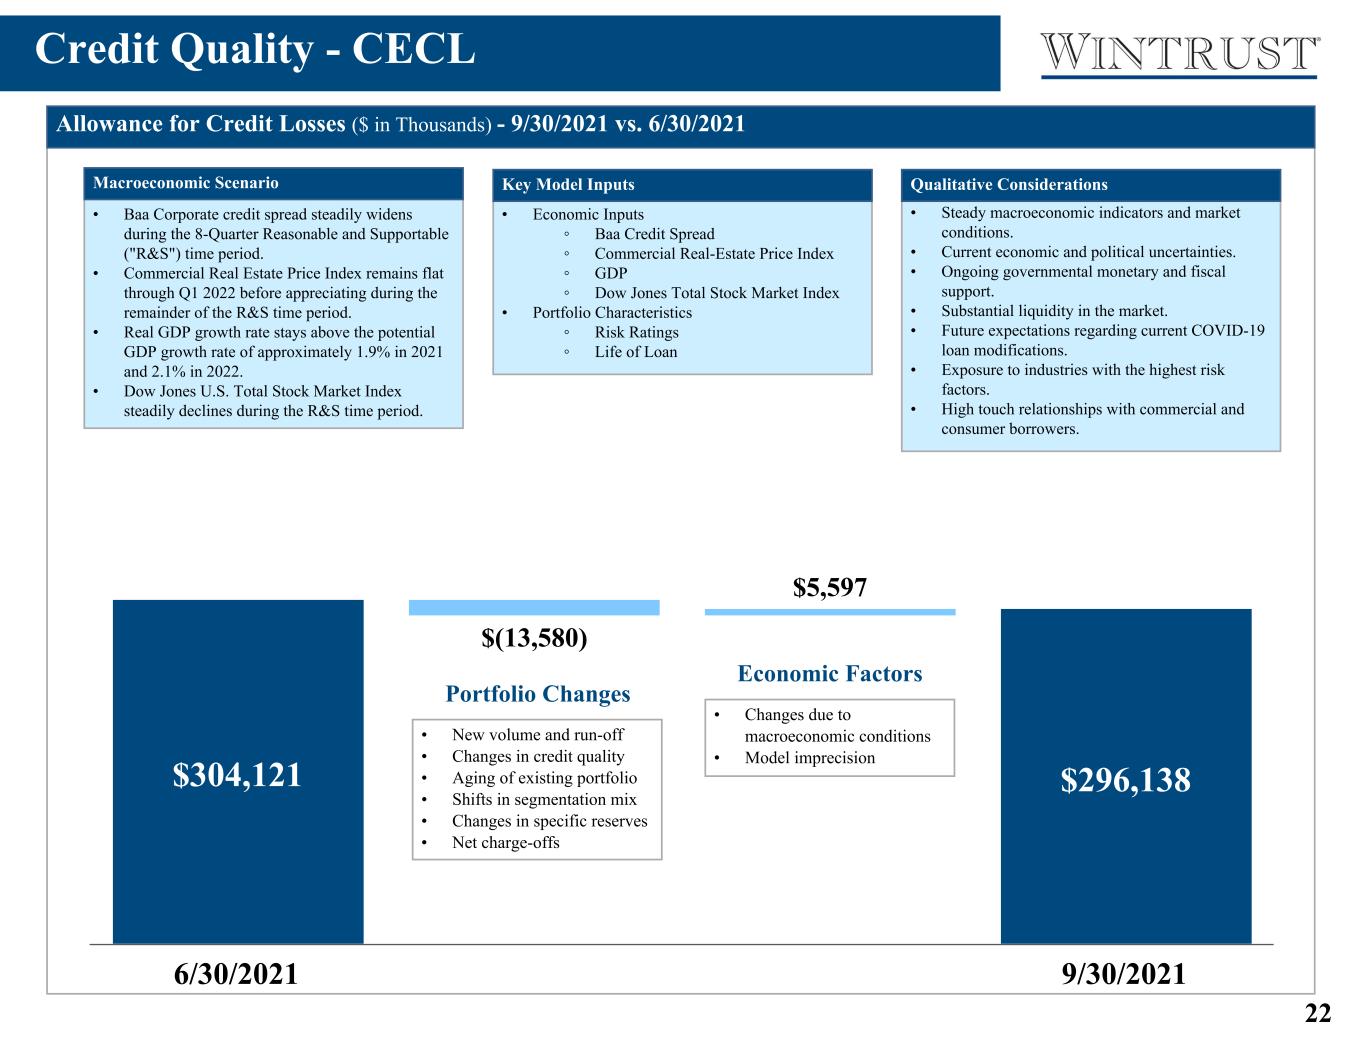
22 $304,121 $(13,580) $5,597 $296,138 6/30/2021 9/30/2021 • Steady macroeconomic indicators and market conditions. • Current economic and political uncertainties. • Ongoing governmental monetary and fiscal support. • Substantial liquidity in the market. • Future expectations regarding current COVID-19 loan modifications. • Exposure to industries with the highest risk factors. • High touch relationships with commercial and consumer borrowers. • Economic Inputs ◦ Baa Credit Spread ◦ Commercial Real-Estate Price Index ◦ GDP ◦ Dow Jones Total Stock Market Index • Portfolio Characteristics ◦ Risk Ratings ◦ Life of Loan Credit Quality - CECL Allowance for Credit Losses ($ in Thousands) - 9/30/2021 vs. 6/30/2021 Key Observations • CECL Day 1 transition adjustment • Includes ACL for loans and leases, off- balance sheet credit exposures and debt securities • New volume and run-off • Changes in credit quality • Aging of existing portfolio • Shifts in segmentation mix • Changes in specific reserves • Net charge-offs • Changes due to macroeconomic conditions • Model imprecision Day 1 Adjustment Portfolio Changes Economic Factors • Baa Corporate credit spread steadily widens during the 8-Quarter Reasonable and Supportable ("R&S") time period. • Commercial Real Estate Price Index remains flat through Q1 2022 before appreciating during the remainder of the R&S time period. • Real GDP growth rate stays above the potential GDP growth rate of approximately 1.9% in 2021 and 2.1% in 2022. • Dow Jones U.S. Total Stock Market Index steadily declines during the R&S time period. Macroeconomic Scenario Key Model Inputs Qualitative Considerations
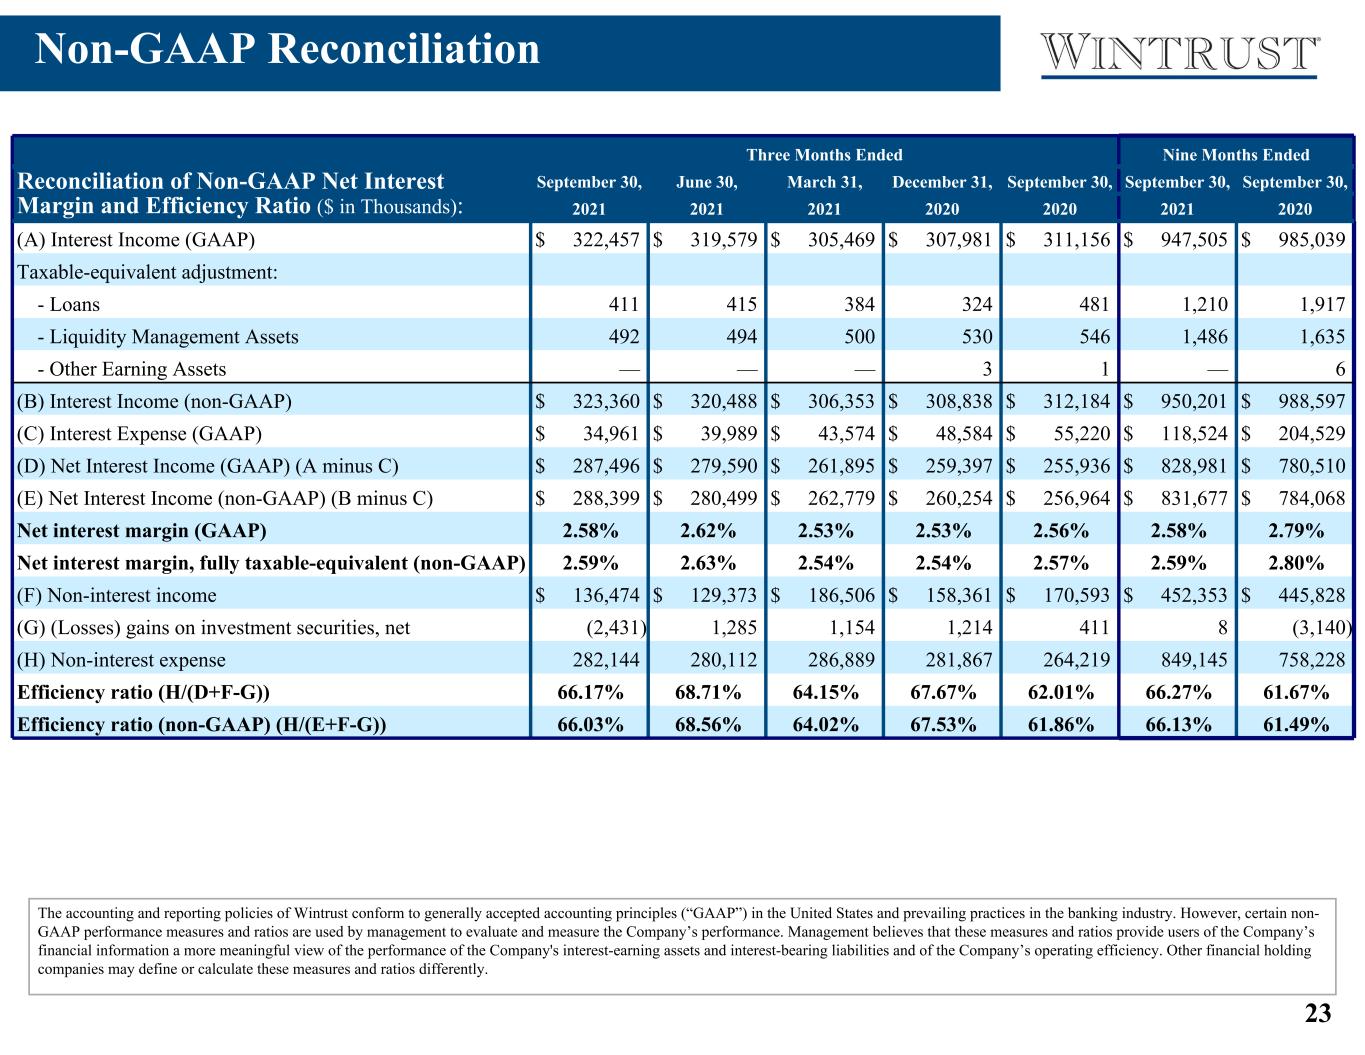
23 Three Months Ended Nine Months Ended Reconciliation of Non-GAAP Net Interest Margin and Efficiency Ratio ($ in Thousands): September 30, June 30, March 31, December 31, September 30, September 30, September 30, 2021 2021 2021 2020 2020 2021 2020 (A) Interest Income (GAAP) $ 322,457 $ 319,579 $ 305,469 $ 307,981 $ 311,156 $ 947,505 $ 985,039 Taxable-equivalent adjustment: - Loans 411 415 384 324 481 1,210 1,917 - Liquidity Management Assets 492 494 500 530 546 1,486 1,635 - Other Earning Assets — — — 3 1 — 6 (B) Interest Income (non-GAAP) $ 323,360 $ 320,488 $ 306,353 $ 308,838 $ 312,184 $ 950,201 $ 988,597 (C) Interest Expense (GAAP) $ 34,961 $ 39,989 $ 43,574 $ 48,584 $ 55,220 $ 118,524 $ 204,529 (D) Net Interest Income (GAAP) (A minus C) $ 287,496 $ 279,590 $ 261,895 $ 259,397 $ 255,936 $ 828,981 $ 780,510 (E) Net Interest Income (non-GAAP) (B minus C) $ 288,399 $ 280,499 $ 262,779 $ 260,254 $ 256,964 $ 831,677 $ 784,068 Net interest margin (GAAP) 2.58% 2.62% 2.53% 2.53% 2.56% 2.58% 2.79% Net interest margin, fully taxable-equivalent (non-GAAP) 2.59% 2.63% 2.54% 2.54% 2.57% 2.59% 2.80% (F) Non-interest income $ 136,474 $ 129,373 $ 186,506 $ 158,361 $ 170,593 $ 452,353 $ 445,828 (G) (Losses) gains on investment securities, net (2,431) 1,285 1,154 1,214 411 8 (3,140) (H) Non-interest expense 282,144 280,112 286,889 281,867 264,219 849,145 758,228 Efficiency ratio (H/(D+F-G)) 66.17% 68.71% 64.15% 67.67% 62.01% 66.27% 61.67% Efficiency ratio (non-GAAP) (H/(E+F-G)) 66.03% 68.56% 64.02% 67.53% 61.86% 66.13% 61.49% Non-GAAP Reconciliation The accounting and reporting policies of Wintrust conform to generally accepted accounting principles (“GAAP”) in the United States and prevailing practices in the banking industry. However, certain non- GAAP performance measures and ratios are used by management to evaluate and measure the Company’s performance. Management believes that these measures and ratios provide users of the Company’s financial information a more meaningful view of the performance of the Company's interest-earning assets and interest-bearing liabilities and of the Company’s operating efficiency. Other financial holding companies may define or calculate these measures and ratios differently.
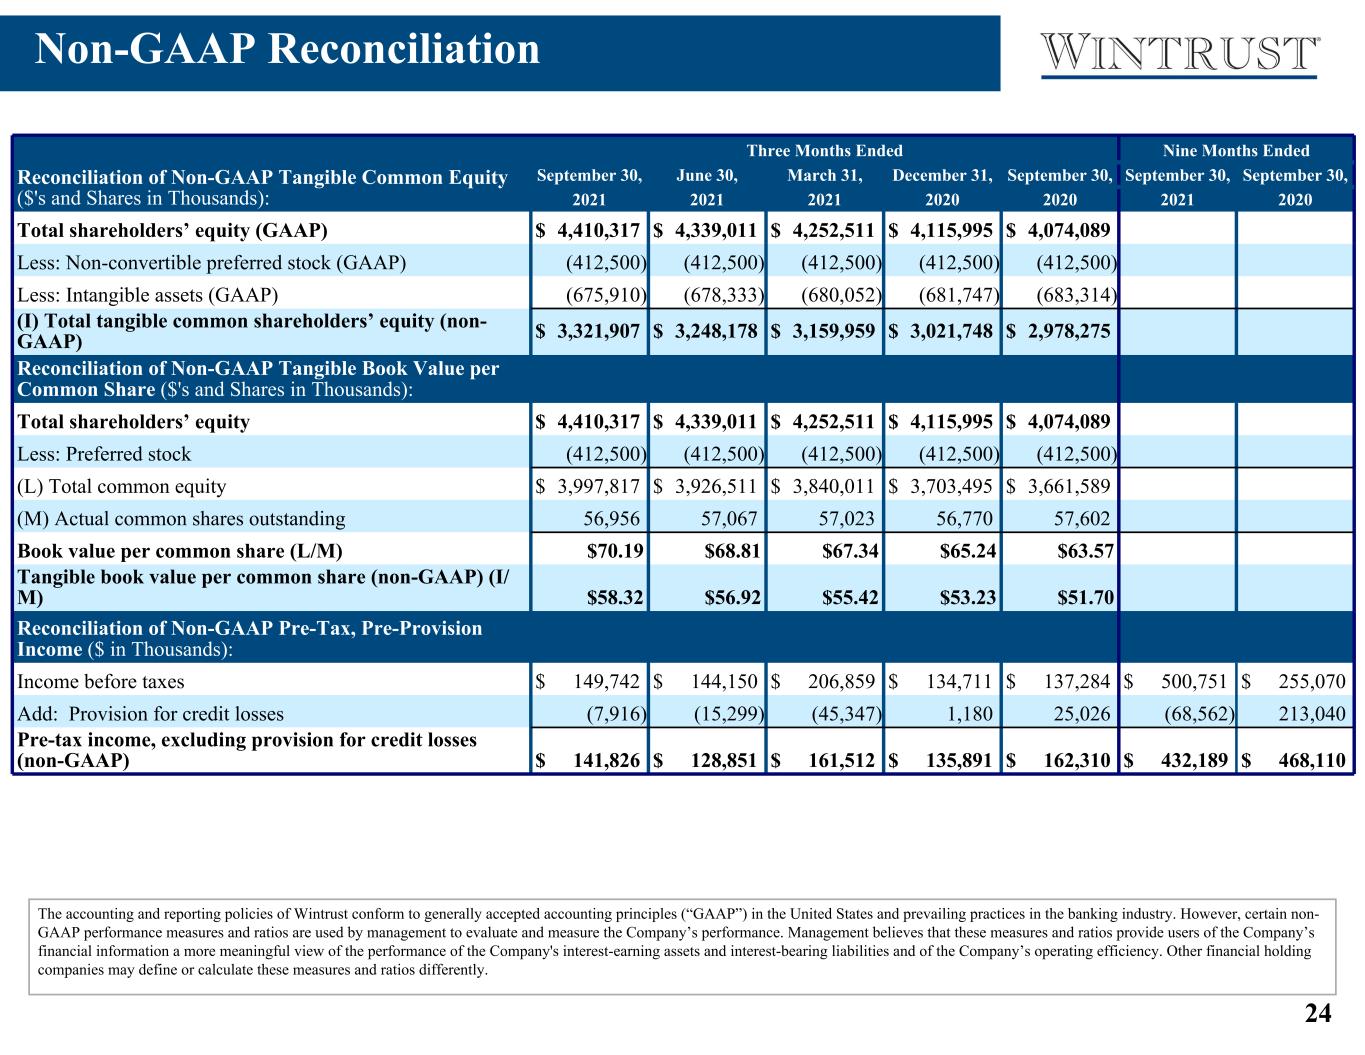
24 Three Months Ended Nine Months Ended Reconciliation of Non-GAAP Tangible Common Equity ($'s and Shares in Thousands): September 30, June 30, March 31, December 31, September 30, September 30, September 30, 2021 2021 2021 2020 2020 2021 2020 Total shareholders’ equity (GAAP) $ 4,410,317 $ 4,339,011 $ 4,252,511 $ 4,115,995 $ 4,074,089 Less: Non-convertible preferred stock (GAAP) (412,500) (412,500) (412,500) (412,500) (412,500) Less: Intangible assets (GAAP) (675,910) (678,333) (680,052) (681,747) (683,314) (I) Total tangible common shareholders’ equity (non- GAAP) $ 3,321,907 $ 3,248,178 $ 3,159,959 $ 3,021,748 $ 2,978,275 Reconciliation of Non-GAAP Tangible Book Value per Common Share ($'s and Shares in Thousands): Total shareholders’ equity $ 4,410,317 $ 4,339,011 $ 4,252,511 $ 4,115,995 $ 4,074,089 Less: Preferred stock (412,500) (412,500) (412,500) (412,500) (412,500) (L) Total common equity $ 3,997,817 $ 3,926,511 $ 3,840,011 $ 3,703,495 $ 3,661,589 (M) Actual common shares outstanding 56,956 57,067 57,023 56,770 57,602 Book value per common share (L/M) $70.19 $68.81 $67.34 $65.24 $63.57 Tangible book value per common share (non-GAAP) (I/ M) $58.32 $56.92 $55.42 $53.23 $51.70 Non-GAAP Reconciliation The accounting and reporting policies of Wintrust conform to generally accepted accounting principles (“GAAP”) in the United States and prevailing practices in the banking industry. However, certain non- GAAP performance measures and ratios are used by management to evaluate and measure the Company’s performance. Management believes that these measures and ratios provide users of the Company’s financial information a more meaningful view of the performance of the Company's interest-earning assets and interest-bearing liabilities and of the Company’s operating efficiency. Other financial holding companies may define or calculate these measures and ratios differently. Reconciliation of Non-GAAP Pre-Tax, Pre-Provision Income ($ in Thousands): Income before taxes $ 149,742 $ 144,150 $ 206,859 $ 134,711 $ 137,284 $ 500,751 $ 255,070 Add: Provision for credit losses (7,916) (15,299) (45,347) 1,180 25,026 (68,562) 213,040 Pre-tax income, excluding provision for credit losses (non-GAAP) $ 141,826 $ 128,851 $ 161,512 $ 135,891 $ 162,310 $ 432,189 $ 468,110
25 This document contains forward-looking statements within the meaning of federal securities laws. Forward-looking information can be identified through the use of words such as “intend,” “plan,” “project,” “expect,” “anticipate,” “believe,” “estimate,” “contemplate,” “possible,” “will,” “may,” “should,” “would” and “could.” Forward-looking statements and information are not historical facts, are premised on many factors and assumptions, and represent only management’s expectations, estimates and projections regarding future events. Similarly, these statements are not guarantees of future performance and involve certain risks and uncertainties that are difficult to predict, such as the impacts of the COVID-19 pandemic (including the emergence of variant strains), and which may include, but are not limited to, those listed below and the Risk Factors discussed under Item 1A of the Company’s 2020 Annual Report on Form 10-K and in any of the Company’s subsequent SEC filings. The Company intends such forward-looking statements to be covered by the safe harbor provisions for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995, and is including this statement for purposes of invoking these safe harbor provisions. Such forward-looking statements may be deemed to include, among other things, statements relating to the Company’s future financial performance, the performance of its loan portfolio, the expected amount of future credit reserves and charge-offs, delinquency trends, growth plans, regulatory developments, securities that the Company may offer from time to time, and management’s long-term performance goals, as well as statements relating to the anticipated effects on financial condition and results of operations from expected developments or events, the Company’s business and growth strategies, including future acquisitions of banks, specialty finance or wealth management businesses, internal growth and plans to form additional de novo banks or branch offices. Actual results could differ materially from those addressed in the forward-looking statements as a result of numerous factors, including the following: • the severity, magnitude and duration of the COVID-19 pandemic, including the emergence of variant strains, and the direct and indirect impact of such pandemic, as well as responses to the pandemic by the government, businesses and consumers, on our operations and personnel, commercial activity and demand across our business and our customers’ businesses; • the disruption of global, national, state and local economies associated with the COVID-19 pandemic, which could affect the Company’s liquidity and capital positions, impair the ability of our borrowers to repay outstanding loans, impair collateral values and further increase our allowance for credit losses; • the impact of the COVID-19 pandemic on our financial results, including possible lost revenue and increased expenses (including the cost of capital), as well as possible goodwill impairment charges; • economic conditions that affect the economy, housing prices, the job market and other factors that may adversely affect the Company’s liquidity and the performance of its loan portfolios, particularly in the markets in which it operates; • negative effects suffered by us or our customers resulting from changes in U.S. trade policies; • the extent of defaults and losses on the Company’s loan portfolio, which may require further increases in its allowance for credit losses; • estimates of fair value of certain of the Company’s assets and liabilities, which could change in value significantly from period to period; • the financial success and economic viability of the borrowers of our commercial loans; • commercial real estate market conditions in the Chicago metropolitan area and southern Wisconsin; • the extent of commercial and consumer delinquencies and declines in real estate values, which may require further increases in the Company’s allowance for credit losses; • inaccurate assumptions in our analytical and forecasting models used to manage our loan portfolio; • changes in the level and volatility of interest rates, the capital markets and other market indices (including developments and volatility arising from or related to the COVID-19 pandemic) that may affect, among other things, the Company’s liquidity and the value of its assets and liabilities; • a prolonged period of near zero interest rates or potentially negative interest rates, either broadly or for some types of instruments, which may affect the Company’s net interest income and net interest margin, and which could materially adversely affect the Company’s profitability; • competitive pressures in the financial services business which may affect the pricing of the Company’s loan and deposit products as well as its services (including wealth management services), which may result in loss of market share and reduced income from deposits, loans, advisory fees and income from other products; • failure to identify and complete favorable acquisitions in the future or unexpected difficulties or developments related to the integration of the Company’s recent or future acquisitions; • unexpected difficulties and losses related to FDIC-assisted acquisitions; • harm to the Company’s reputation; • any negative perception of the Company’s financial strength; • ability of the Company to raise additional capital on acceptable terms when needed; Forward-Looking Statements
26 • disruption in capital markets, which may lower fair values for the Company’s investment portfolio; • ability of the Company to use technology to provide products and services that will satisfy customer demands and create efficiencies in operations and to manage risks associated therewith; • failure or breaches of our security systems or infrastructure, or those of third parties; • security breaches, including denial of service attacks, hacking, social engineering attacks, malware intrusion or data corruption attempts and identity theft; • adverse effects on our information technology systems resulting from failures, human error or cyberattacks (including ransomware); • adverse effects of failures by our vendors to provide agreed upon services in the manner and at the cost agreed, particularly our information technology vendors; • increased costs as a result of protecting our customers from the impact of stolen debit card information; • accuracy and completeness of information the Company receives about customers and counterparties to make credit decisions; • ability of the Company to attract and retain senior management experienced in the banking and financial services industries; • environmental liability risk associated with lending activities; • the impact of any claims or legal actions to which the Company is subject, including any effect on our reputation; • losses incurred in connection with repurchases and indemnification payments related to mortgages and increases in reserves associated therewith; • the loss of customers as a result of technological changes allowing consumers to complete their financial transactions without the use of a bank; • the soundness of other financial institutions; • the expenses and delayed returns inherent in opening new branches and de novo banks; • liabilities, potential customer loss or reputational harm related to closings of existing branches; • examinations and challenges by tax authorities, and any unanticipated impact of the Tax Act; • changes in accounting standards, rules and interpretations, and the impact on the Company’s financial statements; • the ability of the Company to receive dividends from its subsidiaries; • uncertainty about the discontinued use of LIBOR and transition to an alternative rate; • a decrease in the Company’s capital ratios, including as a result of declines in the value of its loan portfolios, or otherwise; • legislative or regulatory changes, particularly changes in regulation of financial services companies and/or the products and services offered by financial services companies, including those changes that are in response to the COVID-19 pandemic, including without limitation the Coronavirus Aid, Relief, and Economic Security Act (the “CARES Act”), the Economic Aid to Hard-Hit Small Businesses, Nonprofits and Venues Act, and the rules and regulations that may be promulgated thereunder; • a lowering of our credit rating; • changes in U.S. monetary policy and changes to the Federal Reserve’s balance sheet, including changes in response to the COVID-19 pandemic or otherwise; • regulatory restrictions upon our ability to market our products to consumers and limitations on our ability to profitably operate our mortgage business; • increased costs of compliance, heightened regulatory capital requirements and other risks associated with changes in regulation and the regulatory environment; • the impact of heightened capital requirements; • increases in the Company’s FDIC insurance premiums, or the collection of special assessments by the FDIC; • delinquencies or fraud with respect to the Company’s premium finance business; • credit downgrades among commercial and life insurance providers that could negatively affect the value of collateral securing the Company’s premium finance loans; • the Company’s ability to comply with covenants under its credit facility; and • fluctuations in the stock market, which may have an adverse impact on the Company’s wealth management business and brokerage operation. • ability of the Company to use technology to provide products and services that will satisfy customer demands and create efficiencies in operations and to manage risks associated therewith; Therefore, there can be no assurances that future actual results will correspond to these forward-looking statements. The reader is cautioned not to place undue reliance on any forward- looking statement made by the Company. Any such statement speaks only as of the date the statement was made or as of such date that may be referenced within the statement. The Company undertakes no obligation to update any forward-looking statement to reflect the impact of circumstances or events after the date of the press release and this presentation. Persons are advised, however, to consult further disclosures management makes on related subjects in its reports filed with the Securities and Exchange Commission and in its press releases and presentations. Forward-Looking Statements