BWFG 8-K
Bankwell Financial Group, Inc. (BWFG)
8-K
2026-04-22
For: 2026-04-22
View Original
Added on
April 22, 2026
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF
THE SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported): April 22, 2026
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||
(203 ) 652-0166
(Address of Principal Executive Officers and Telephone Number)
N/A
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of Each Class | Trading Symbol(s) | Name of Each Exchange on Which Registered | ||||||
Common Stock, no par value per share | ||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (17 CFR 230.405) or Rule 12b-2 of the Securities Exchange Act of 1934 (17 CFR 240.12b-2).
| Emerging growth company | |||||
| If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. | ☐ | ||||
| Item 2.02 | Results of Operations and Financial Condition | ||||
On A copy of the press release is included as Exhibit 99.1 to this current report on Form 8-K and is incorporated herein by reference. | |||||
| The information furnished under this Item 2.02, including Exhibit 99.1, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or subject to the liabilities of that section. The information shall not be deemed incorporated by reference into any other filing with the Securities and Exchange Commission made by the Company, regardless of any general incorporation language in such filing. | |||||
| Item 7.01 | Regulation FD Disclosure | ||||
On A copy of the Presentation Material is included as Exhibit 99.2 to this current report on Form 8-K and is incorporated herein by reference. | |||||
| The information furnished under this Item 7.01, including Exhibit 99.2, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or subject to the liabilities of that section. The information shall not be deemed incorporated by reference into any other filing with the Securities and Exchange Commission made by the Company, regardless of any general incorporation language in such filing. | |||||
| Item 8.01 | Other Events | ||||
Quarterly Dividend Announcement On | |||||
| Item 9.01 | Financial Statements and Exhibits | ||||
| (a) | Not applicable. | ||||
| (b) | Not applicable. | ||||
| (c) | Not applicable. | ||||
| (d) | Exhibits. | ||||
| Exhibit Number | Description | ||||
| 99.1 | |||||
| 99.2 | |||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | ||||
| SIGNATURES | |||||
| Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized. | |||||
| BANKWELL FINANCIAL GROUP, INC. | |||||
| Registrant | |||||
By: /s/ Courtney E. Sacchetti | |||||
| Courtney E. Sacchetti | |||||
| Executive Vice President | |||||
| and Chief Financial Officer | |||||
BANKWELL FINANCIAL GROUP REPORTS OPERATING RESULTS FOR THE FIRST QUARTER, DECLARES SECOND QUARTER DIVIDEND
New Canaan, CT – April 22, 2026 – Bankwell Financial Group, Inc. (NASDAQ: BWFG) reported GAAP net income of $11.3 million, or $1.41 per share for the first quarter of 2026, versus $9.1 million, or $1.15 per share, for the fourth quarter of 2025. The Company's Board of Directors declared a $0.20 per share cash dividend, payable May 19, 2026 to shareholders of record on May 8, 2026.
Discussion of Outlook; Bankwell Financial Group Chief Executive Officer, Christopher R. Gruseke:
"We generated outstanding first quarter results while advancing our strategic priorities. Profitability increased during the quarter, reflected in a return on average assets of 1.35%, and the Company grew core deposits by $113 million sequentially. Our SBA division continues to execute measured, profitable growth, with originations this quarter of $34 million, and we have continued to improve our asset and liability mix as floating rate loans now comprise 42% of the loan portfolio.
Results for the quarter include a sequential increase to the Company’s non-interest expense of approximately $1.4 million. This increase reflects the timing of some expense recognition, and we believe current trends support our non-interest expense guidance previously provided of $64 to $65 million for the full year. We also affirm prior guidance regarding Net Interest Income and loan growth for 2026. Due to an improved outlook for SBA gains on sale and other commercial fees, however, we are increasing our guidance for Non-Interest Income to a range of $12 to $13 million.
As we enter the remainder of the year, we are confident in our credit quality and are well positioned to reduce NPAs in the quarters ahead."
1
Key Points for First Quarter and Bankwell’s Outlook
Core Deposit Growth Funds Loan Growth and Reduces Wholesale Reliance.
•Core deposit growth of $113 million during the quarter ended March 31, 2026, including $39.0 million growth in low‑cost deposits, when compared to December 31, 2025.
•Brokered deposits and FHLB borrowings declined by $44.5 million and $50.0 million, respectively, lowering the Wholesale Ratio to 18.1%(1) as of March 31, 2026.
•Since the peak brokered deposit balance of $1,026.6 million at December 31, 2022, the Company has successfully reduced brokered deposits by $512.4 million, or 49.9%, as of March 31, 2026.
•$27.1 million net loan growth during the quarter ended March 31, 2026, driven by $190 million of originations, including $34 million of SBA originations.
Funding Improvements Partially Offset Lower Portfolio Yields in Net Interest Margin.
•Reported Net Interest Margin was 3.28% for the first quarter of 2026, compared to 3.40% for the quarter ended December 31, 2025. Of the 12 basis-point decline versus the fourth quarter of 2025 Net Interest Margin, approximately 7 basis points relate to the previous quarter’s longer day count.
•Total deposit costs of 3.10% for the quarter ended March 31, 2026, represent a 5 basis point improvement compared to the quarter ended December 31, 2025. During the quarter, $270 million of time deposits repriced 44 basis points lower.
•Approximately $1,128 million of time deposits are scheduled to mature over the next 12 months at a weighted average rate of 3.99%; assuming repricing at current market levels and with no additional Fed action, these maturities represent an estimated annualized funding cost savings opportunity of approximately $1.6 million.
•Yield on new loan production averaged 7.53% for the quarter ended March 31, 2026; however, the overall portfolio yield declined 7 basis points from the previous quarter, to 6.56%.
Advancing Strategic Priorities.
•SBA loan sale gains increased to $2.4 million in the first quarter of 2025, compared to $2.2 million in the fourth quarter of 2025.
•On February 20, 2026, the Company opened its first full service branch in New York State, located in Bay Ridge, Brooklyn. This addition supports the Bank’s continued focus on serving closely held businesses, their owners, and professionals in key markets. The Brooklyn office is home to an experienced private client banking team and provides businesses and individuals with a dedicated single point of contact, along with tailored commercial banking, lending, and treasury management services.
(1) Wholesale Ratio is a Non-GAAP Financial Measure and is calculated as brokered deposits and FHLB borrowings divided by total assets. Refer to the "Non-GAAP Financial Measures" section of this document for additional detail.
2
First Quarter 2026 Financial Highlights and Key Performance Indicators (KPIs):
| March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
Return on average assets(1)(6) | 1.35 | % | 1.11 | % | 1.24 | % | 1.14 | % | 0.86 | % | |||||||||||||||||||
Pre-tax, pre-provision net revenue return on average assets(1)(6) | 1.60 | % | 1.80 | % | 1.70 | % | 1.43 | % | 1.18 | % | |||||||||||||||||||
Return on average shareholders' equity(1)(6) | 14.88 | % | 12.20 | % | 13.84 | % | 12.98 | % | 10.16 | % | |||||||||||||||||||
Return on average tangible shareholders' equity(1)(6) | 15.00 | % | 12.31 | % | 13.96 | % | 13.10 | % | 10.25 | % | |||||||||||||||||||
Net Interest Margin(1)(6)(7) | 3.28 | % | 3.40 | % | 3.34 | % | 3.10 | % | 2.81 | % | |||||||||||||||||||
Efficiency Ratio(1)(3) | 55.8 | % | 50.8 | % | 51.4 | % | 56.1 | % | 59.9 | % | |||||||||||||||||||
Noninterest expense to average assets(1)(6) | 2.03 | % | 1.87 | % | 1.80 | % | 1.83 | % | 1.76 | % | |||||||||||||||||||
Net loan (recoveries) charge-offs as a percentage of average loans(1)(6) | 0.01 | % | 0.00 | % | (0.01) | % | 0.00 | % | 0.00 | % | |||||||||||||||||||
Dividend payout(1)(4) | 14.18 | % | 17.39 | % | 15.75 | % | 17.39 | % | 22.99 | % | |||||||||||||||||||
Fully diluted tangible book value per common share(1)(2) | $ | 38.79 | $ | 37.84 | $ | 36.84 | $ | 35.65 | $ | 34.56 | |||||||||||||||||||
Total capital to risk-weighted assets(1)(5) | 12.99 | % | 12.94 | % | 13.48 | % | 13.28 | % | 13.22 | % | |||||||||||||||||||
Total common equity tier 1 capital to risk-weighted assets(1)(5) | 11.96 | % | 11.87 | % | 12.39 | % | 12.20 | % | 12.11 | % | |||||||||||||||||||
Tier I Capital to Average Assets(1)(5) | 10.31 | % | 10.55 | % | 10.71 | % | 10.57 | % | 10.13 | % | |||||||||||||||||||
Tangible common equity to tangible assets(1)(2) | 9.17 | % | 8.90 | % | 8.95 | % | 8.68 | % | 8.57 | % | |||||||||||||||||||
| Earnings per common share - diluted | $ | 1.41 | $ | 1.15 | $ | 1.27 | $ | 1.15 | $ | 0.87 | |||||||||||||||||||
| Common shares issued and outstanding | 7,973,180 | 7,899,943 | 7,877,443 | 7,873,387 | 7,888,013 | ||||||||||||||||||||||||
(1) Non-GAAP Financial Measure, refer to the "Non-GAAP Financial Measures" section of this document for additional detail.
(2) Refer to the "Reconciliation of GAAP to Non-GAAP Measures" section of this document for additional detail.
(3) Efficiency ratio is defined as noninterest expense, less other real estate owned expenses and amortization of intangible assets, divided by our operating revenue, which is equal to net interest income plus noninterest income excluding gains and losses on sales of securities and gains and losses on other real estate owned. In our judgment, the adjustments made to operating revenue allow investors and analysts to better assess our operating expenses in relation to our core operating revenue by removing the volatility that is associated with certain one-time items and other discrete items that are unrelated to our core business.
(4) The dividend payout ratio is calculated by dividing dividends per share by earnings per share.
(5) Represents Bank ratios. Current period capital ratios are preliminary subject to finalization of the FDIC Call Report.
(6) Return on average assets is calculated by dividing annualized net income by average assets. Pre-tax, pre-provision net revenue return on average is calculated by dividing PPNR (calculated as set forth in the "Pre-Tax, Pre-Provision Net Revenue (PPNR)" section of this document) by average assets. Return on average shareholders' equity is calculated by dividing annualized net income by average shareholders' equity. Return on average tangible shareholders' equity is calculated by dividing annualized net income by average shareholders' equity less average intangible assets. Net Interest Margin is calculated by dividing average annualized net interest income by average total earning assets. Noninterest expense to average assets is calculated by dividing annualized noninterest expense by average total assets. Net loan charge-offs as a percentage of average loans is calculated by dividing net loan (charge offs) recoveries by average total loans.
(7) Based on a fully tax equivalent basis.
3
Pre-Tax, Pre-Provision Net Revenue(1) ("PPNR")
PPNR for the fourth quarter ended March 31, 2026 was $13.3 million, a decrease of 10.2% from $14.9 million recognized for the fourth quarter ended December 31, 2025.
| For the Quarter Ended | ||||||||||||||||||||||||||||||||
| (Dollars in thousands) | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||||
| Net interest income | $ | 26,886 | $ | 26,946 | $ | 25,987 | $ | 23,936 | $ | 22,066 | ||||||||||||||||||||||
| Total noninterest income | 3,343 | 3,376 | 2,495 | 2,012 | 1,505 | |||||||||||||||||||||||||||
| Total revenues | 30,229 | 30,322 | 28,482 | 25,948 | 23,571 | |||||||||||||||||||||||||||
| Total noninterest expense | 16,889 | 15,470 | 14,631 | 14,546 | 14,141 | |||||||||||||||||||||||||||
| PPNR | $ | 13,340 | $ | 14,852 | $ | 13,851 | $ | 11,402 | $ | 9,430 | ||||||||||||||||||||||
(1) Non-GAAP Financial Measure, refer to the "Non-GAAP Financial Measures" section of this document for additional detail.
•Revenues (net interest income plus noninterest income) for the quarter ended March 31, 2026 were $30.2 million, compared with $30.3 million in the previous quarter.
•Noninterest expense for the quarter ended March 31, 2026 was $16.9 million, compared with $15.5 million in the previous quarter. The increase in noninterest expense was primarily due to an increase in salaries and employee benefits resulting from incremental new hires in support of strategic initiatives, as well as seasonal compensation-related costs recognized in the first quarter.
Allowance for Credit Losses - Loans ("ACL-Loans")
The ACL-Loans was $29.6 million as of March 31, 2026 compared to $30.7 million as of December 31, 2025. The ACL-Loans as a percentage of total loans was 1.03% as of March 31, 2026 compared to 1.08% as of December 31, 2025. The credit for credit losses - loans was $1.0 million for the quarter ended March 31, 2026.
Total nonperforming loans increased $2.7 million to $19.0 million as of March 31, 2026, when compared to the previous quarter. Nonperforming assets as a percentage of total assets increased to 0.56% at March 31, 2026, compared to the previous quarter's ratio of 0.49%. As of March 31, 2026, the ACL-Loans provided 155.39% coverage of total nonperforming loans.
4
BANKWELL FINANCIAL GROUP, INC.
ASSET QUALITY (unaudited)
(Dollars in thousands)
| For the Quarter Ended | |||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
| ACL-Loans: | |||||||||||||||||||||||||||||
| Balance at beginning of period | $ | 30,705 | $ | 29,984 | $ | 29,256 | $ | 29,485 | $ | 29,007 | |||||||||||||||||||
| Charge-offs: | |||||||||||||||||||||||||||||
| Residential real estate | — | — | — | — | — | ||||||||||||||||||||||||
| Commercial real estate | — | — | — | — | (67) | ||||||||||||||||||||||||
| Commercial business | (148) | — | (14) | (15) | — | ||||||||||||||||||||||||
| Consumer | (73) | — | (46) | (5) | (33) | ||||||||||||||||||||||||
| Construction | — | — | — | — | — | ||||||||||||||||||||||||
| Total charge-offs | (221) | — | (60) | (20) | (100) | ||||||||||||||||||||||||
| Recoveries: | |||||||||||||||||||||||||||||
| Residential real estate | — | — | — | — | — | ||||||||||||||||||||||||
| Commercial real estate | 5 | 7 | 272 | — | — | ||||||||||||||||||||||||
| Commercial business | 15 | 23 | 92 | 112 | 4 | ||||||||||||||||||||||||
| Consumer | 33 | 10 | 4 | 10 | 36 | ||||||||||||||||||||||||
| Construction | — | — | — | — | — | ||||||||||||||||||||||||
| Total recoveries | 53 | 40 | 368 | 122 | 40 | ||||||||||||||||||||||||
| Net loan recoveries (charge-offs) | (168) | 40 | 308 | 102 | (60) | ||||||||||||||||||||||||
| (Credit) provision for credit losses - loans | (957) | 681 | 420 | (331) | 538 | ||||||||||||||||||||||||
| Balance at end of period | $ | 29,580 | $ | 30,705 | $ | 29,984 | $ | 29,256 | $ | 29,485 | |||||||||||||||||||
| As of | |||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
| Asset quality: | |||||||||||||||||||||||||||||
| Nonaccrual loans | |||||||||||||||||||||||||||||
| Residential real estate | $ | 544 | $ | 557 | $ | 570 | $ | 617 | $ | 811 | |||||||||||||||||||
| Commercial real estate | 17,112 | 14,445 | 14,667 | 16,387 | 17,946 | ||||||||||||||||||||||||
| Commercial business | 1,380 | 1,302 | 1,729 | 6,871 | 7,626 | ||||||||||||||||||||||||
| Construction | — | — | — | — | — | ||||||||||||||||||||||||
| Consumer | — | — | — | — | — | ||||||||||||||||||||||||
| Total nonaccrual loans | 19,036 | 16,304 | 16,966 | 23,875 | 26,383 | ||||||||||||||||||||||||
| Other real estate owned | — | — | 1,284 | 1,284 | — | ||||||||||||||||||||||||
| Total nonperforming assets | $ | 19,036 | $ | 16,304 | $ | 18,250 | $ | 25,159 | $ | 26,383 | |||||||||||||||||||
| Nonperforming loans as a % of total loans | 0.66 | % | 0.57 | % | 0.62 | % | 0.89 | % | 1.00 | % | |||||||||||||||||||
| Nonperforming assets as a % of total assets | 0.56 | % | 0.49 | % | 0.56 | % | 0.78 | % | 0.83 | % | |||||||||||||||||||
| ACL-loans as a % of total loans | 1.03 | % | 1.08 | % | 1.10 | % | 1.10 | % | 1.11 | % | |||||||||||||||||||
| ACL-loans as a % of nonperforming loans | 155.39 | % | 188.33 | % | 176.73 | % | 122.54 | % | 111.76 | % | |||||||||||||||||||
| Total past due loans to total loans | 0.62 | % | 0.31 | % | 0.76 | % | 0.91 | % | 1.08 | % | |||||||||||||||||||
5
Financial Condition & Capital
Assets totaled $3.4 billion at March 31, 2026, an increase of $14.0 million, or 0.4% compared to December 31, 2025. Gross loans totaled $2.9 billion at March 31, 2026, an increase of $26.5 million, or 0.9% compared to December 31, 2025. Deposits totaled $2.9 billion at March 31, 2026, an increase of $55.8 million, or 2.0% compared to December 31, 2025. Brokered deposits have decreased $44.5 million or 8.0%, when compared to December 31, 2025.
| Period End Loan Composition | March 31, 2026 | December 31, 2025 | March 31, 2025 | Current QTD % Change | Year over Year % Change | ||||||||||||||||||||||||
| Residential Real Estate | $ | 30,128 | $ | 33,139 | $ | 40,089 | (9.1) | % | (24.8) | % | |||||||||||||||||||
Commercial Real Estate(1) | 1,896,565 | 1,930,979 | 1,810,923 | (1.8) | 4.7 | ||||||||||||||||||||||||
| Construction | 155,826 | 153,778 | 188,339 | 1.3 | (17.3) | ||||||||||||||||||||||||
| Total Real Estate Loans | 2,082,519 | 2,117,896 | 2,039,351 | (1.7) | 2.1 | ||||||||||||||||||||||||
| Commercial Business | 723,272 | 645,321 | 529,000 | 12.1 | 36.7 | ||||||||||||||||||||||||
| Consumer | 60,827 | 76,855 | 76,553 | (20.9) | (20.5) | ||||||||||||||||||||||||
| Total Loans | $ | 2,866,618 | $ | 2,840,072 | $ | 2,644,904 | 0.9 | % | 8.4 | % | |||||||||||||||||||
| (1) Includes owner occupied commercial real estate of $0.8 billion at March 31, 2026, $0.8 billion at December 31, 2025, and $0.7 billion at March 31, 2025, respectively. | |||||||||||||||||||||||||||||
| Period End Deposit Composition | March 31, 2026 | December 31, 2025 | March 31, 2025 | Current QTD % Change | Year over Year % Change | ||||||||||||||||||||||||
| Noninterest bearing demand | $ | 428,384 | $ | 403,652 | $ | 349,525 | 6.1 | % | 22.6 | % | |||||||||||||||||||
| NOW | 104,704 | 90,205 | 112,695 | 16.1 | (7.1) | ||||||||||||||||||||||||
| Money Market | 1,095,883 | 1,007,844 | 900,352 | 8.7 | 21.7 | ||||||||||||||||||||||||
| Savings | 99,008 | 97,418 | 91,378 | 1.6 | 8.3 | ||||||||||||||||||||||||
| Time | 1,157,270 | 1,230,362 | 1,296,495 | (5.9) | (10.7) | ||||||||||||||||||||||||
| Total Deposits | $ | 2,885,249 | $ | 2,829,481 | $ | 2,750,445 | 2.0 | % | 4.9 | % | |||||||||||||||||||
Shareholders’ equity totaled $311.9 million as of March 31, 2026, an increase of $10.4 million compared to December 31, 2025, primarily a result of year-to-date net income of $11.3 million. The increase was partially offset by dividends paid of $1.6 million.
As of March 31, 2026, the Bank's regulatory capital ratios were all above 'well capitalized' values, with total risk-based capital, common-equity tier 1 capital and leverage ratios at 12.99%, 11.96%, and 10.31%, respectively.
6
We recommend reading this earnings release in conjunction with the First Quarter 2026 Investor Presentation, located at https://investor.mybankwell.com/events-and-presentations/ and included as an exhibit to our April 22, 2026 Current Report on Form 8-K.
Conference Call
Bankwell will host a conference call to discuss the Company’s financial results and business outlook on April 23, 2026, at 9:00 a.m. E.T. The call will be accessible by telephone and webcast using https://investor.mybankwell.com/events-and-presentations/. A supplementary slide presentation will be posted to the website prior to the event, and a replay will be available for 12 months following the event.
About Bankwell Financial Group
Bankwell Financial Group, Inc. is the holding company for Bankwell Bank ("Bankwell"), a full-service commercial bank headquartered in New Canaan, CT. Bankwell provides businesses and professionals with a range of commercial financing solutions, including working capital lines of credit, SBA loans, acquisition financing, and commercial mortgages, along with treasury management and deposit services. Bankwell emphasizes accessibility, expertise, and responsiveness through experienced local banking teams serving its markets.
For more information about this press release, interested parties may contact Christopher R. Gruseke, Chief Executive Officer or Courtney E. Sacchetti, Executive Vice President and Chief Financial Officer of Bankwell Financial Group, Inc. at (203) 652-0166 or at [email protected].
For more information, visit www.mybankwell.com.
This press release may contain certain forward-looking statements about the Company. Forward-looking statements include statements regarding anticipated future events and can be identified by the fact that they do not relate strictly to historical or current facts. They often include words such as “believe,” “expect,” “anticipate,” “estimate,” and “intend” or future or conditional verbs such as “will,” “would,” “should,” “could,” or “may.” Forward-looking statements, by their nature, are subject to risks and uncertainties. Certain factors that could cause actual results to differ materially from expected results include increased competitive pressures, changes in the interest rate environment, general economic conditions or conditions within the banking industry or securities markets, and legislative and regulatory changes that could adversely affect the business in which the Company and its subsidiaries are engaged.
Non-GAAP Financial Measures
In addition to evaluating the Company's financial performance in accordance with U.S. generally accepted accounting principles ("GAAP"), management may evaluate certain non-GAAP financial measures, such as the efficiency ratio. A computation and reconciliation of certain non-GAAP financial measures used for these purposes is contained in the accompanying Reconciliation of GAAP to Non-GAAP Measures tables. We believe that providing certain non-GAAP financial measures provides investors with information useful in understanding our financial performance, our performance trends and financial position. For example, the Company believes that the efficiency ratio is useful in the assessment of financial performance, including noninterest expense control. The Company believes that tangible common equity, tangible assets, tangible common equity to tangible assets, tangible common shareholders' equity, fully diluted tangible book value per common share, efficiency ratio, noninterest expense to average assets, average tangible common equity, annualized return on average tangible shareholders' equity, return on average shareholders' equity, return on average tangible shareholders' equity, pre-tax, pre-provision net revenue, net interest margin, net loan charge-offs as a percentage of average loans, pre-tax, pre-provision net revenue on average assets, wholesale ratio, and the dividend payout ratio are useful to evaluate the relative strength of the Company's performance and capital position. We utilize these measures for internal planning and forecasting purposes. These non-GAAP financial measures should not be considered a substitute for GAAP basis measures and results, and we strongly encourage investors to review our consolidated financial statements in their entirety and not to rely on any single financial measure. See "Reconciliation of GAAP to Non-GAAP Measures (unaudited)".
7
BANKWELL FINANCIAL GROUP, INC.
CONSOLIDATED BALANCE SHEETS (unaudited)
(Dollars in thousands)
| March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
| ASSETS | |||||||||||||||||||||||||||||
| Cash and due from banks | $ | 208,904 | $ | 214,567 | $ | 289,628 | $ | 313,998 | $ | 292,006 | |||||||||||||||||||
| Federal funds sold | 8,997 | 10,354 | 5,732 | 8,466 | 12,922 | ||||||||||||||||||||||||
| Cash and cash equivalents | 217,901 | 224,921 | 295,360 | 322,464 | 304,928 | ||||||||||||||||||||||||
| Investment securities | |||||||||||||||||||||||||||||
| Marketable equity securities, at fair value | 2,254 | 2,248 | 2,223 | 2,188 | 2,164 | ||||||||||||||||||||||||
| Available for sale investment securities, at fair value | 155,934 | 160,409 | 96,473 | 103,930 | 97,321 | ||||||||||||||||||||||||
| Held to maturity investment securities, at amortized cost | 29,386 | 29,465 | 29,538 | 36,434 | 36,478 | ||||||||||||||||||||||||
| Total investment securities | 187,574 | 192,122 | 128,234 | 142,552 | 135,963 | ||||||||||||||||||||||||
| Loans receivable (net of ACL-Loans of $29,580, $30,705, $29,984, $29,256, and $29,485, at March 31, 2026, December 31, 2025, September 30, 2025, June 30, 2025, and March 31, 2025, respectively) | 2,832,678 | 2,804,441 | 2,684,016 | 2,635,742 | 2,611,495 | ||||||||||||||||||||||||
| Accrued interest receivable | 16,029 | 16,143 | 15,633 | 14,741 | 15,409 | ||||||||||||||||||||||||
| Federal Home Loan Bank stock, at cost | 4,207 | 6,207 | 4,951 | 5,051 | 3,583 | ||||||||||||||||||||||||
| Premises and equipment, net | 20,947 | 21,582 | 22,387 | 23,020 | 22,978 | ||||||||||||||||||||||||
| Bank-owned life insurance | 54,566 | 54,207 | 53,846 | 53,488 | 53,136 | ||||||||||||||||||||||||
| Goodwill | 2,589 | 2,589 | 2,589 | 2,589 | 2,589 | ||||||||||||||||||||||||
| Deferred income taxes, net | 11,436 | 11,356 | 9,027 | 9,684 | 9,551 | ||||||||||||||||||||||||
| Other real estate owned | — | — | 1,284 | 1,284 | — | ||||||||||||||||||||||||
| Other assets | 25,932 | 26,291 | 26,636 | 25,978 | 24,261 | ||||||||||||||||||||||||
| Total assets | $ | 3,373,859 | $ | 3,359,859 | $ | 3,243,963 | $ | 3,236,593 | $ | 3,183,893 | |||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS’ EQUITY | |||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||
| Deposits | |||||||||||||||||||||||||||||
| Noninterest bearing deposits | $ | 428,384 | $ | 403,652 | $ | 397,408 | $ | 397,195 | $ | 349,525 | |||||||||||||||||||
| Interest bearing deposits | 2,456,865 | 2,425,829 | 2,360,007 | 2,362,086 | 2,400,920 | ||||||||||||||||||||||||
| Total deposits | 2,885,249 | 2,829,481 | 2,757,415 | 2,759,281 | 2,750,445 | ||||||||||||||||||||||||
| Advances from the Federal Home Loan Bank | 60,000 | 110,000 | 75,000 | 75,000 | 40,000 | ||||||||||||||||||||||||
| Subordinated debentures | 69,759 | 69,697 | 69,636 | 69,574 | 69,513 | ||||||||||||||||||||||||
| Accrued expenses and other liabilities | 46,985 | 49,192 | 49,121 | 49,448 | 48,721 | ||||||||||||||||||||||||
| Total liabilities | 3,061,993 | 3,058,370 | 2,951,172 | 2,953,303 | 2,908,679 | ||||||||||||||||||||||||
| Shareholders’ equity | |||||||||||||||||||||||||||||
| Common stock, no par value | 121,060 | 120,118 | 119,353 | 118,698 | 118,439 | ||||||||||||||||||||||||
| Retained earnings | 191,281 | 181,587 | 174,008 | 165,495 | 157,971 | ||||||||||||||||||||||||
| Accumulated other comprehensive (loss) | (475) | (216) | (570) | (903) | (1,196) | ||||||||||||||||||||||||
| Total shareholders’ equity | 311,866 | 301,489 | 292,791 | 283,290 | 275,214 | ||||||||||||||||||||||||
| Total liabilities and shareholders’ equity | $ | 3,373,859 | $ | 3,359,859 | $ | 3,243,963 | $ | 3,236,593 | $ | 3,183,893 | |||||||||||||||||||
8
BANKWELL FINANCIAL GROUP, INC.
CONSOLIDATED STATEMENTS OF INCOME (unaudited)
(Dollars in thousands, except share data)
| For the Quarter Ended | |||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
| Interest and dividend income | |||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 46,787 | $ | 46,739 | $ | 46,328 | $ | 44,128 | $ | 43,475 | |||||||||||||||||||
| Interest and dividends on securities | 1,784 | 1,834 | 1,410 | 1,478 | 1,445 | ||||||||||||||||||||||||
| Interest on cash and cash equivalents | 1,965 | 2,037 | 2,853 | 3,043 | 3,557 | ||||||||||||||||||||||||
| Total interest and dividend income | 50,536 | 50,610 | 50,591 | 48,649 | 48,477 | ||||||||||||||||||||||||
| Interest expense | |||||||||||||||||||||||||||||
| Interest expense on deposits | 21,930 | 22,388 | 22,585 | 23,083 | 24,772 | ||||||||||||||||||||||||
| Interest expense on borrowings | 1,720 | 1,276 | 2,019 | 1,630 | 1,639 | ||||||||||||||||||||||||
| Total interest expense | 23,650 | 23,664 | 24,604 | 24,713 | 26,411 | ||||||||||||||||||||||||
| Net interest income | 26,886 | 26,946 | 25,987 | 23,936 | 22,066 | ||||||||||||||||||||||||
| (Credit) provision for credit losses | (1,029) | 616 | 372 | (411) | 463 | ||||||||||||||||||||||||
| Net interest income after (credit) provision for credit losses | 27,915 | 26,330 | 25,615 | 24,347 | 21,603 | ||||||||||||||||||||||||
| Noninterest income | |||||||||||||||||||||||||||||
| Bank owned life insurance | 358 | 361 | 359 | 352 | 344 | ||||||||||||||||||||||||
| Service charges and fees | 780 | 771 | 779 | 674 | 602 | ||||||||||||||||||||||||
| Gains and fees from sales of loans | 2,425 | 2,184 | 1,372 | 1,080 | 442 | ||||||||||||||||||||||||
| Other | (220) | 60 | (15) | (94) | 117 | ||||||||||||||||||||||||
| Total noninterest income | 3,343 | 3,376 | 2,495 | 2,012 | 1,505 | ||||||||||||||||||||||||
| Noninterest expense | |||||||||||||||||||||||||||||
| Salaries and employee benefits | 9,830 | 7,717 | 7,995 | 7,521 | 7,052 | ||||||||||||||||||||||||
| Occupancy and equipment | 2,705 | 2,575 | 2,469 | 2,505 | 2,575 | ||||||||||||||||||||||||
| Professional services | 1,393 | 1,415 | 1,412 | 1,632 | 1,529 | ||||||||||||||||||||||||
| Data processing | 716 | 877 | 633 | 712 | 885 | ||||||||||||||||||||||||
| Director fees | 363 | 337 | 333 | 333 | 348 | ||||||||||||||||||||||||
| FDIC insurance | 543 | 612 | 610 | 684 | 779 | ||||||||||||||||||||||||
| Marketing | 126 | 108 | 140 | 218 | 142 | ||||||||||||||||||||||||
| Other | 1,213 | 1,829 | 1,039 | 941 | 831 | ||||||||||||||||||||||||
| Total noninterest expense | 16,889 | 15,470 | 14,631 | 14,546 | 14,141 | ||||||||||||||||||||||||
| Income before income tax expense | 14,369 | 14,236 | 13,479 | 11,813 | 8,967 | ||||||||||||||||||||||||
| Income tax expense | 3,094 | 5,092 | 3,401 | 2,725 | 2,079 | ||||||||||||||||||||||||
| Net income | $ | 11,275 | $ | 9,144 | $ | 10,078 | $ | 9,088 | $ | 6,888 | |||||||||||||||||||
| Earnings Per Common Share: | |||||||||||||||||||||||||||||
| Basic | $ | 1.42 | $ | 1.16 | $ | 1.28 | $ | 1.16 | $ | 0.88 | |||||||||||||||||||
| Diluted | $ | 1.41 | $ | 1.15 | $ | 1.27 | $ | 1.15 | $ | 0.87 | |||||||||||||||||||
| Weighted Average Common Shares Outstanding: | |||||||||||||||||||||||||||||
| Basic | 7,724,253 | 7,776,740 | 7,774,887 | 7,777,469 | 7,670,224 | ||||||||||||||||||||||||
| Diluted | 7,800,935 | 7,858,047 | 7,844,785 | 7,819,829 | 7,740,521 | ||||||||||||||||||||||||
| Dividends per common share | $ | 0.20 | $ | 0.20 | $ | 0.20 | $ | 0.20 | $ | 0.20 | |||||||||||||||||||
9
BANKWELL FINANCIAL GROUP, INC.
RECONCILIATION OF GAAP TO NON-GAAP MEASURES (unaudited)
(Dollars in thousands, except share data)
| As of | |||||||||||||||||||||||||||||
| Computation of Tangible Common Equity to Tangible Assets | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | ||||||||||||||||||||||||
| Total Equity | $ | 311,866 | $ | 301,489 | $ | 292,791 | $ | 283,290 | $ | 275,214 | |||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||
| Goodwill | 2,589 | 2,589 | 2,589 | 2,589 | 2,589 | ||||||||||||||||||||||||
| Other intangibles | — | — | — | — | — | ||||||||||||||||||||||||
| Tangible Common Equity | $ | 309,277 | $ | 298,900 | $ | 290,202 | $ | 280,701 | $ | 272,625 | |||||||||||||||||||
| Total Assets | $ | 3,373,859 | $ | 3,359,859 | $ | 3,243,963 | $ | 3,236,593 | $ | 3,183,893 | |||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||
| Goodwill | 2,589 | 2,589 | 2,589 | 2,589 | 2,589 | ||||||||||||||||||||||||
| Other intangibles | — | — | — | — | — | ||||||||||||||||||||||||
| Tangible Assets | $ | 3,371,270 | $ | 3,357,270 | $ | 3,241,374 | $ | 3,234,004 | $ | 3,181,304 | |||||||||||||||||||
| Tangible Common Equity to Tangible Assets | 9.17 | % | 8.90 | % | 8.95 | % | 8.68 | % | 8.57 | % | |||||||||||||||||||
| As of | |||||||||||||||||||||||||||||
| Computation of Fully Diluted Tangible Book Value per Common Share | March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | ||||||||||||||||||||||||
| Total shareholders' equity | $ | 311,866 | $ | 301,489 | $ | 292,791 | $ | 283,290 | $ | 275,214 | |||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||
| Preferred stock | — | — | — | — | — | ||||||||||||||||||||||||
| Common shareholders' equity | $ | 311,866 | $ | 301,489 | $ | 292,791 | $ | 283,290 | $ | 275,214 | |||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||
| Goodwill | 2,589 | 2,589 | 2,589 | 2,589 | 2,589 | ||||||||||||||||||||||||
| Other intangibles | — | — | — | — | — | ||||||||||||||||||||||||
| Tangible common shareholders' equity | $ | 309,277 | $ | 298,900 | $ | 290,202 | $ | 280,701 | $ | 272,625 | |||||||||||||||||||
| Common shares issued and outstanding | 7,973,180 | 7,899,943 | 7,877,443 | 7,873,387 | 7,888,013 | ||||||||||||||||||||||||
| Fully Diluted Tangible Book Value per Common Share | $ | 38.79 | $ | 37.84 | $ | 36.84 | $ | 35.65 | $ | 34.56 | |||||||||||||||||||
10
BANKWELL FINANCIAL GROUP, INC.
EARNINGS PER SHARE ("EPS") (unaudited)
(Dollars in thousands, except share data)
For the Quarter Ended March 31, | |||||||||||
| 2026 | 2025 | ||||||||||
(In thousands, except per share data) | |||||||||||
Net income | $ | 11,275 | $ | 6,888 | |||||||
Dividends to participating securities(1) | (26) | (26) | |||||||||
Undistributed earnings allocated to participating securities(1) | (248) | (111) | |||||||||
Net income for earnings per share calculation | 11,001 | 6,751 | |||||||||
Weighted average shares outstanding, basic | 7,724,253 | 7,670,224 | |||||||||
Effect of dilutive equity-based awards(2) | 76,682 | 70,297 | |||||||||
Weighted average shares outstanding, diluted | 7,800,935 | 7,740,521 | |||||||||
Net earnings per common share: | |||||||||||
Basic earnings per common share | $ | 1.42 | $ | 0.88 | |||||||
Diluted earnings per common share | $ | 1.41 | $ | 0.87 | |||||||
(1) Represents dividends paid and undistributed earnings allocated to unvested stock-based awards that contain non-forfeitable rights to dividends.
(2) Represents the effect of the assumed exercise of stock options and the vesting of restricted shares, as applicable, utilizing the treasury stock method.
11
BANKWELL FINANCIAL GROUP, INC.
NET INTEREST MARGIN ANALYSIS ON A FULLY TAX EQUIVALENT BASIS - QTD (unaudited)
(Dollars in thousands)
| For the Quarter Ended | |||||||||||||||||||||||||||||||||||
| March 31, 2026 | March 31, 2025 | ||||||||||||||||||||||||||||||||||
| Average Balance | Interest | Yield/ Rate (4) | Average Balance | Interest | Yield/ Rate (4) | ||||||||||||||||||||||||||||||
| Assets: | |||||||||||||||||||||||||||||||||||
| Cash and Fed funds sold | $ | 244,216 | $ | 1,965 | 3.26 | % | $ | 349,235 | $ | 3,557 | 4.13 | % | |||||||||||||||||||||||
Securities(1) | 192,116 | 1,829 | 3.81 | 150,650 | 1,477 | 3.92 | |||||||||||||||||||||||||||||
| Loans: | |||||||||||||||||||||||||||||||||||
| Commercial real estate | 1,900,235 | 29,511 | 6.21 | 1,848,208 | 28,285 | 6.12 | |||||||||||||||||||||||||||||
| Residential real estate | 32,293 | 464 | 5.75 | 41,585 | 633 | 6.09 | |||||||||||||||||||||||||||||
| Construction | 163,728 | 2,939 | 7.18 | 178,878 | 3,468 | 7.76 | |||||||||||||||||||||||||||||
| Commercial business | 682,398 | 12,815 | 7.51 | 508,417 | 10,007 | 7.87 | |||||||||||||||||||||||||||||
| Consumer | 74,237 | 1,058 | 5.78 | 81,483 | 1,082 | 5.38 | |||||||||||||||||||||||||||||
| Total loans | 2,852,891 | 46,787 | 6.56 | 2,658,571 | 43,475 | 6.54 | |||||||||||||||||||||||||||||
| Federal Home Loan Bank stock | 5,789 | 64 | 4.49 | 4,596 | 110 | 9.71 | |||||||||||||||||||||||||||||
| Total earning assets | 3,295,012 | $ | 50,645 | 6.15 | % | 3,163,052 | $ | 48,619 | 6.15 | % | |||||||||||||||||||||||||
| Other assets | 86,396 | 89,743 | |||||||||||||||||||||||||||||||||
| Total assets | $ | 3,381,408 | $ | 3,252,795 | |||||||||||||||||||||||||||||||
| Liabilities and shareholders' equity: | |||||||||||||||||||||||||||||||||||
| Interest bearing liabilities: | |||||||||||||||||||||||||||||||||||
| NOW | $ | 98,330 | $ | 48 | 0.20 | % | $ | 99,487 | $ | 109 | 0.45 | % | |||||||||||||||||||||||
| Money market | 1,058,395 | 9,065 | 3.47 | 893,361 | 8,521 | 3.87 | |||||||||||||||||||||||||||||
| Savings | 97,719 | 672 | 2.79 | 88,167 | 658 | 3.03 | |||||||||||||||||||||||||||||
| Time | 1,218,184 | 12,145 | 4.04 | 1,378,468 | 15,484 | 4.56 | |||||||||||||||||||||||||||||
| Total interest bearing deposits | 2,472,628 | 21,930 | 3.60 | 2,459,483 | 24,772 | 4.10 | |||||||||||||||||||||||||||||
| Borrowed Money | 156,441 | 1,720 | 4.46 | 133,917 | 1,639 | 4.96 | |||||||||||||||||||||||||||||
| Total interest bearing liabilities | 2,629,069 | $ | 23,650 | 3.65 | % | 2,593,400 | $ | 26,411 | 4.13 | % | |||||||||||||||||||||||||
| Noninterest bearing deposits | 400,021 | 333,796 | |||||||||||||||||||||||||||||||||
| Other liabilities | 44,967 | 50,555 | |||||||||||||||||||||||||||||||||
| Total liabilities | 3,074,057 | 2,977,751 | |||||||||||||||||||||||||||||||||
| Shareholders' equity | 307,351 | 275,044 | |||||||||||||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 3,381,408 | $ | 3,252,795 | |||||||||||||||||||||||||||||||
Net interest income(2) | $ | 26,995 | $ | 22,208 | |||||||||||||||||||||||||||||||
| Interest rate spread | 2.50 | % | 2.02 | % | |||||||||||||||||||||||||||||||
Net Interest Margin(3) | 3.28 | % | 2.81 | % | |||||||||||||||||||||||||||||||
(1)Average balances and yields for securities are based on amortized cost.
(2)The adjustment for securities and loans taxable equivalency amounted to $109 thousand and $142 thousand for the quarters ended March 31, 2026 and 2025, respectively.
(3)Annualized net interest income as a percentage of earning assets.
(4)Yields are calculated using the contractual day count convention for each respective product type.
12
April 22, 2026 First Quarter 2026 BWFG Investor Presentation
Forward Looking Statement Important note regarding forward-looking statements: Statements made in this presentation which are not purely historical are forward-looking statements, as defined in the Private Securities Litigation Reform Act of 1995. This includes any statements regarding management’s plans, objectives, or goals for future operations, products or services, and forecasts of its revenues, earnings, or other measures of performance. Such forward-looking statements may be identified by the use of words such as “believe,” “expect,” “anticipate,” “plan,” “estimate,” “should,” “intend,” "target,” “outlook,” “project,” “guidance,” “forecast,” or similar expressions. Forward-looking statements are based on current management expectations and, by their nature, are subject to risks and uncertainties. Actual results may differ materially from those contained in the forward-looking statements. Factors which may cause actual results to differ materially from those contained in such forward-looking statements include those identified in the Company’s most recent Form 10-K and subsequent Form 10-Qs and other SEC filings, and such factors are incorporated herein by reference. Trademarks: All trademarks, service marks, and trade names referenced in this material are official trademarks and the property of their respective owners. Presentation: Within the charts and tables presented, certain segments, columns and rows may not sum to totals shown due to rounding. Non-GAAP Measures: This presentation includes certain non-GAAP financial measures. These non-GAAP measures are provided in addition to, and not as substitutes for, measures of our financial performance determined in accordance with GAAP. Our calculation of these non-GAAP measures may not be comparable to similarly titled measures of other companies due to potential differences between companies in the method of calculation. As a result, the use of these non-GAAP measures has limitations and should not be considered superior to, in isolation from, or as a substitute for, related GAAP measures. Reconciliations of these non-GAAP financial measures to the most directly comparable GAAP financial measures can be found at the end of this presentation. 2 2
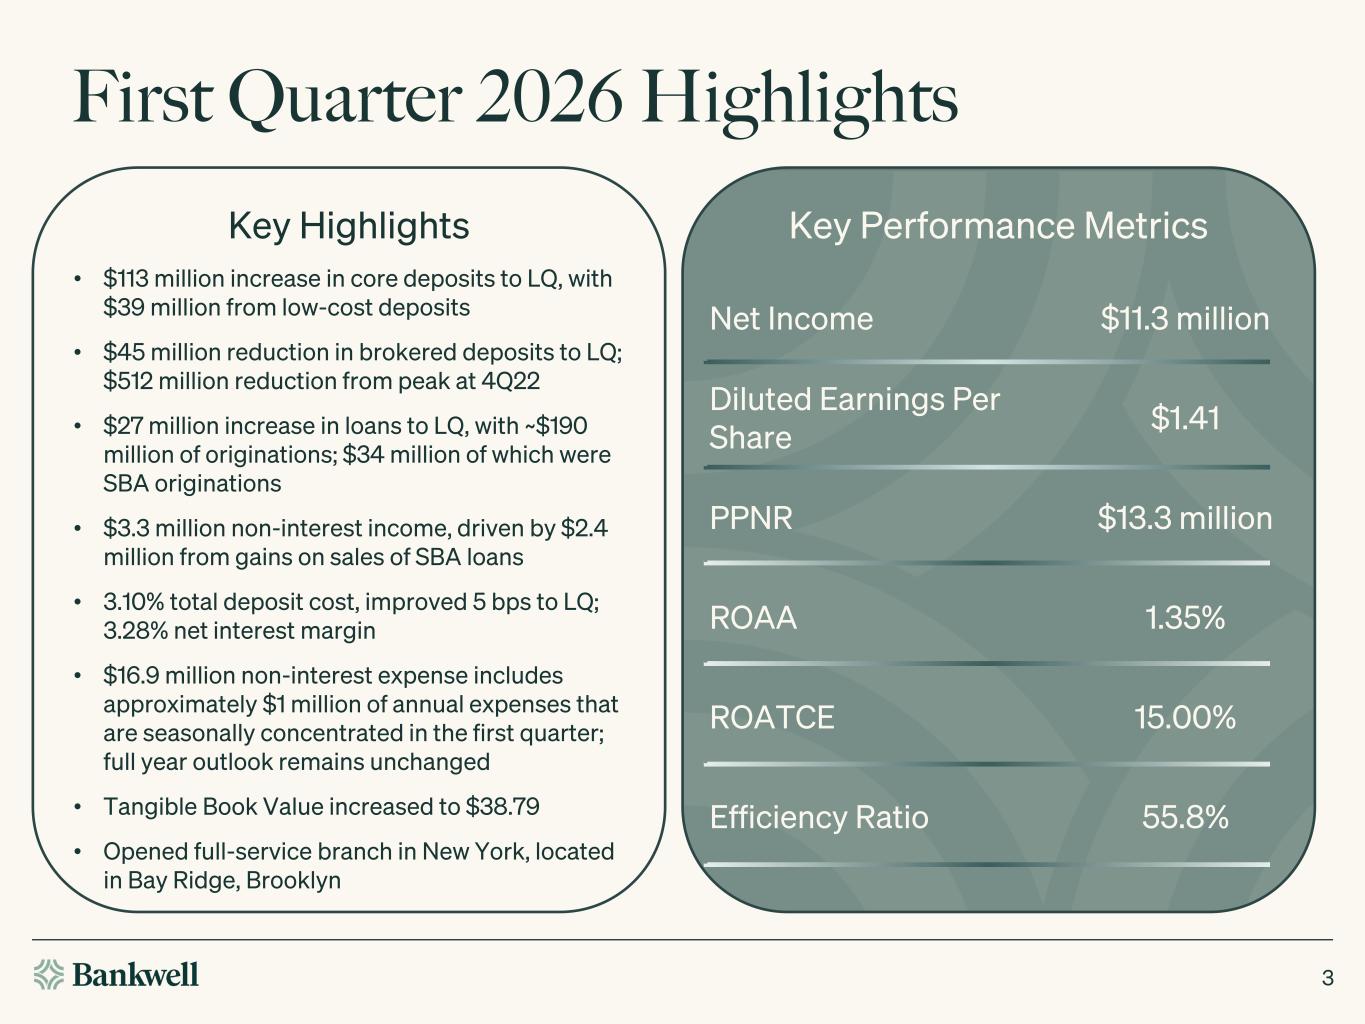
First Quarter 2026 Highlights Key Performance MetricsKey Highlights • $113 million increase in core deposits to LQ, with $39 million from low-cost deposits • $45 million reduction in brokered deposits to LQ; $512 million reduction from peak at 4Q22 • $27 million increase in loans to LQ, with ~$190 million of originations; $34 million of which were SBA originations • $3.3 million non-interest income, driven by $2.4 million from gains on sales of SBA loans • 3.10% total deposit cost, improved 5 bps to LQ; 3.28% net interest margin • $16.9 million non-interest expense includes approximately $1 million of annual expenses that are seasonally concentrated in the first quarter; full year outlook remains unchanged • Tangible Book Value increased to $38.79 • Opened full-service branch in New York, located in Bay Ridge, Brooklyn Net Income $11.3 million Diluted Earnings Per Share $1.41 PPNR $13.3 million ROAA 1.35% ROATCE 15.00% Efficiency Ratio 55.8% 3
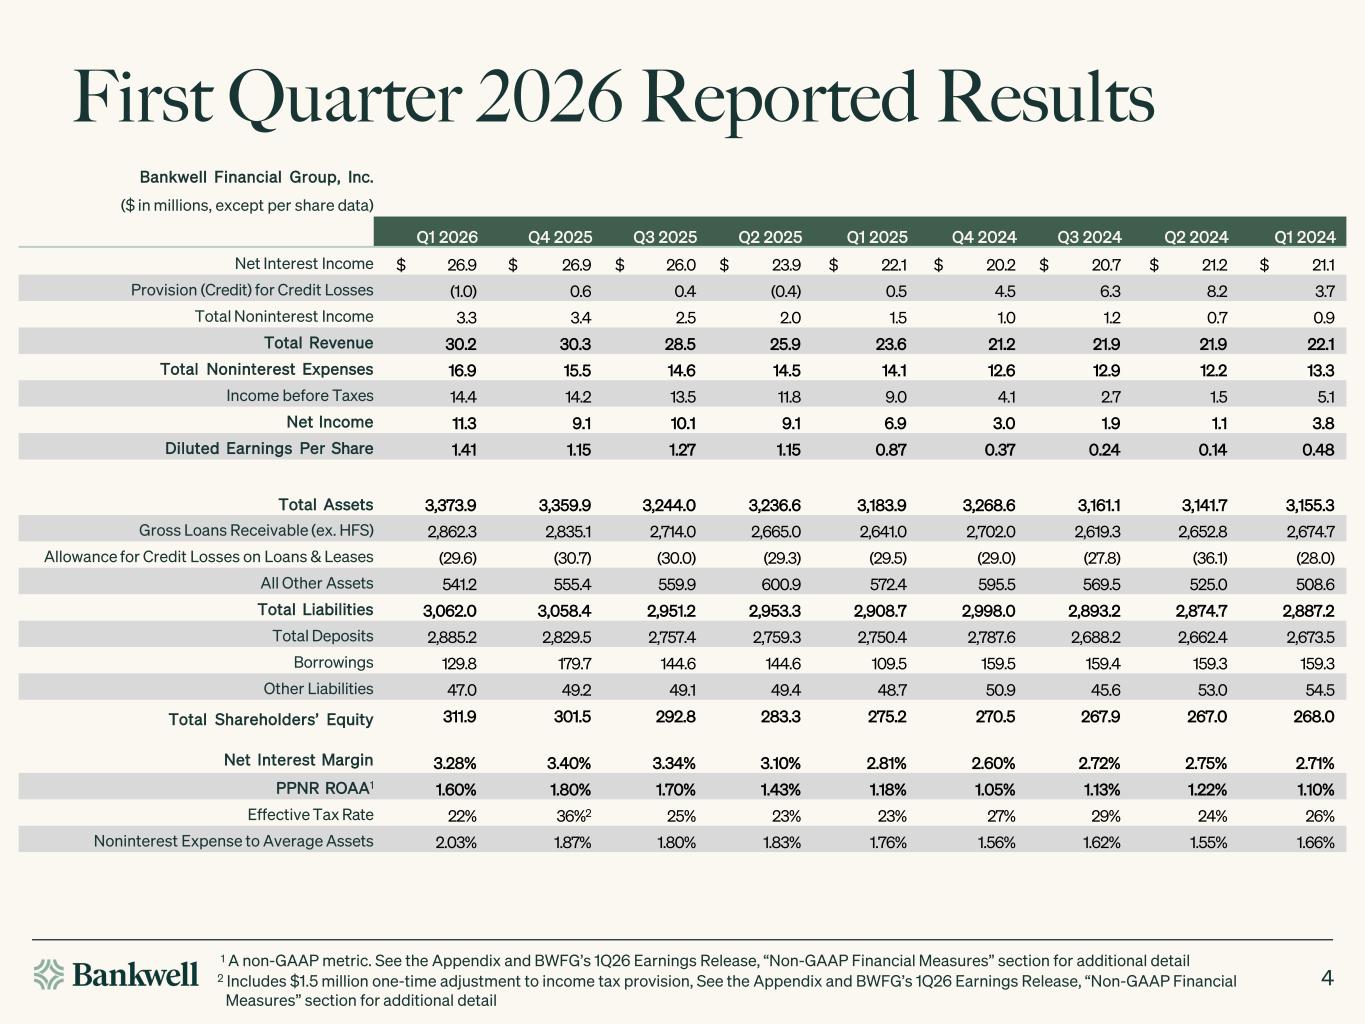
First Quarter 2026 Reported Results 4 Bankwell Financial Group, Inc. ($ in millions, except per share data) Q1 2026 Q4 2025 Q3 2025 Q2 2025 Q1 2025 Q4 2024 Q3 2024 Q2 2024 Q1 2024 Net Interest Income $ 26.9 $ 26.9 $ 26.0 $ 23.9 $ 22.1 $ 20.2 $ 20.7 $ 21.2 $ 21.1 Provision (Credit) for Credit Losses (1.0) 0.6 0.4 (0.4) 0.5 4.5 6.3 8.2 3.7 Total Noninterest Income 3.3 3.4 2.5 2.0 1.5 1.0 1.2 0.7 0.9 Total Revenue 30.2 30.3 28.5 25.9 23.6 21.2 21.9 21.9 22.1 Total Noninterest Expenses 16.9 15.5 14.6 14.5 14.1 12.6 12.9 12.2 13.3 Income before Taxes 14.4 14.2 13.5 11.8 9.0 4.1 2.7 1.5 5.1 Net Income 11.3 9.1 10.1 9.1 6.9 3.0 1.9 1.1 3.8 Diluted Earnings Per Share 1.41 1.15 1.27 1.15 0.87 0.37 0.24 0.14 0.48 Total Assets 3,373.9 3,359.9 3,244.0 3,236.6 3,183.9 3,268.6 3,161.1 3,141.7 3,155.3 Gross Loans Receivable (ex. HFS) 2,862.3 2,835.1 2,714.0 2,665.0 2,641.0 2,702.0 2,619.3 2,652.8 2,674.7 Allowance for Credit Losses on Loans & Leases (29.6) (30.7) (30.0) (29.3) (29.5) (29.0) (27.8) (36.1) (28.0) All Other Assets 541.2 555.4 559.9 600.9 572.4 595.5 569.5 525.0 508.6 Total Liabilities 3,062.0 3,058.4 2,951.2 2,953.3 2,908.7 2,998.0 2,893.2 2,874.7 2,887.2 Total Deposits 2,885.2 2,829.5 2,757.4 2,759.3 2,750.4 2,787.6 2,688.2 2,662.4 2,673.5 Borrowings 129.8 179.7 144.6 144.6 109.5 159.5 159.4 159.3 159.3 Other Liabilities 47.0 49.2 49.1 49.4 48.7 50.9 45.6 53.0 54.5 Total Shareholders’ Equity 311.9 301.5 292.8 283.3 275.2 270.5 267.9 267.0 268.0 Net Interest Margin 3.28% 3.40% 3.34% 3.10% 2.81% 2.60% 2.72% 2.75% 2.71% PPNR ROAA1 1.60% 1.80% 1.70% 1.43% 1.18% 1.05% 1.13% 1.22% 1.10% Effective Tax Rate 22% 36%2 25% 23% 23% 27% 29% 24% 26% Noninterest Expense to Average Assets 2.03% 1.87% 1.80% 1.83% 1.76% 1.56% 1.62% 1.55% 1.66% 1 A non-GAAP metric. See the Appendix and BWFG’s 1Q26 Earnings Release, “Non-GAAP Financial Measures” section for additional detail 2 Includes $1.5 million one-time adjustment to income tax provision, See the Appendix and BWFG’s 1Q26 Earnings Release, “Non-GAAP Financial Measures” section for additional detail
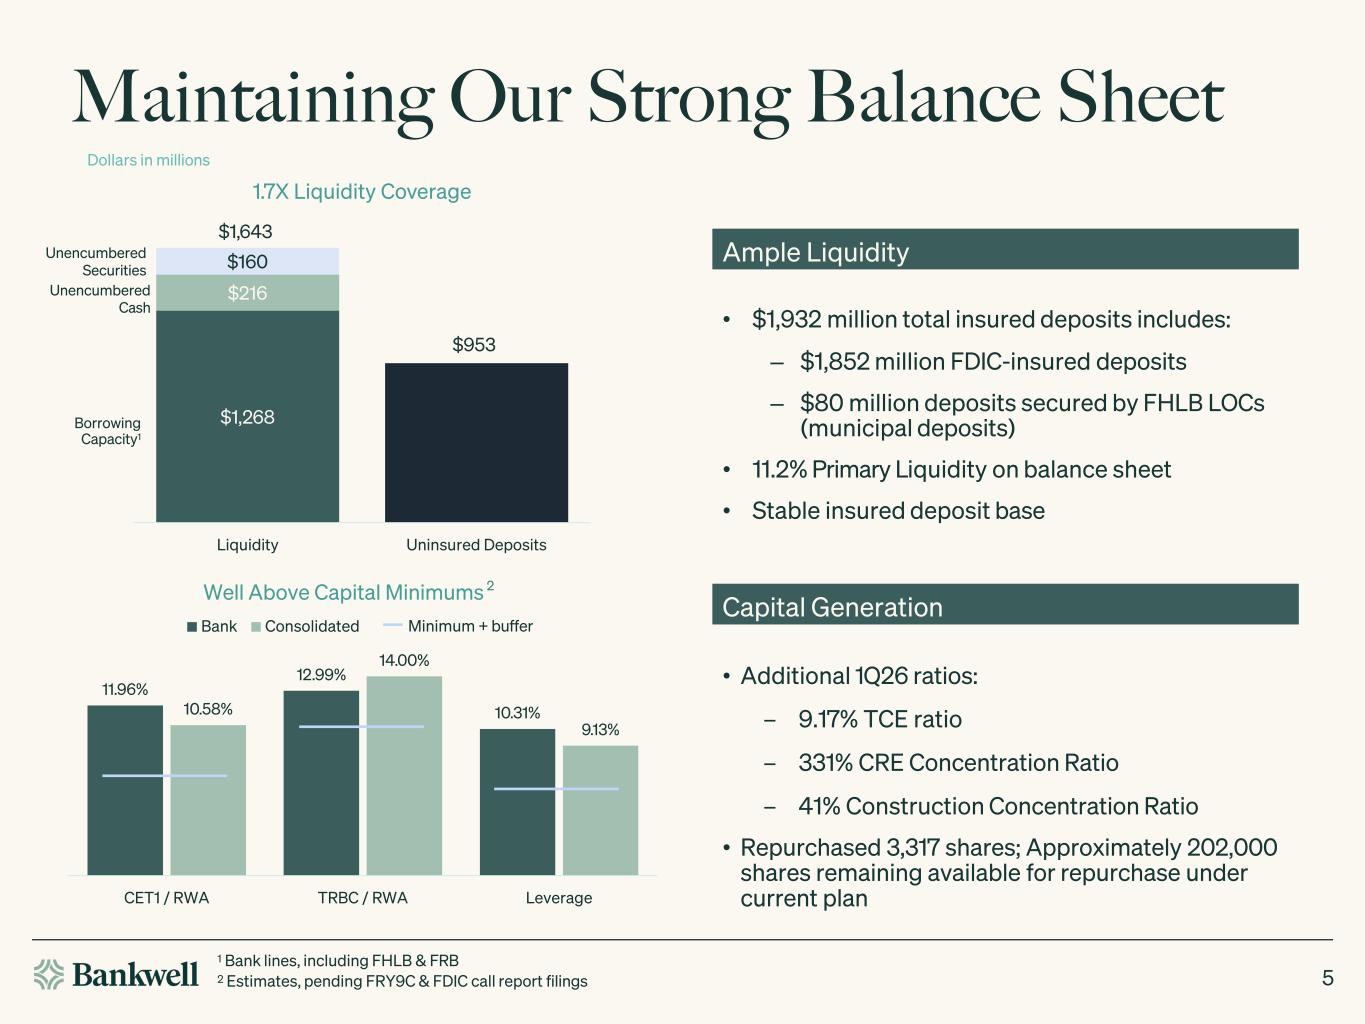
Maintaining Our Strong Balance Sheet 5 Unencumbered Securities Unencumbered Cash Borrowing Capacity1 1 Bank lines, including FHLB & FRB 2 Estimates, pending FRY9C & FDIC call report filings • $1,932 million total insured deposits includes: ‒ $1,852 million FDIC-insured deposits ‒ $80 million deposits secured by FHLB LOCs (municipal deposits) • 11.2% Primary Liquidity on balance sheet • Stable insured deposit base • Additional 1Q26 ratios: ‒ 9.17% TCE ratio ‒ 331% CRE Concentration Ratio ‒ 41% Construction Concentration Ratio • Repurchased 3,317 shares; Approximately 202,000 shares remaining available for repurchase under current plan Ample Liquidity Capital Generation Minimum + buffer Well Above Capital Minimums 2 Dollars in millions $1,268 $216 $160 $1,643 $953 Liquidity Uninsured Deposits 1.7X Liquidity Coverage 11.96% 12.99% 10.31%10.58% 14.00% 9.13% CET1 / RWA TRBC / RWA Leverage Bank Consolidated
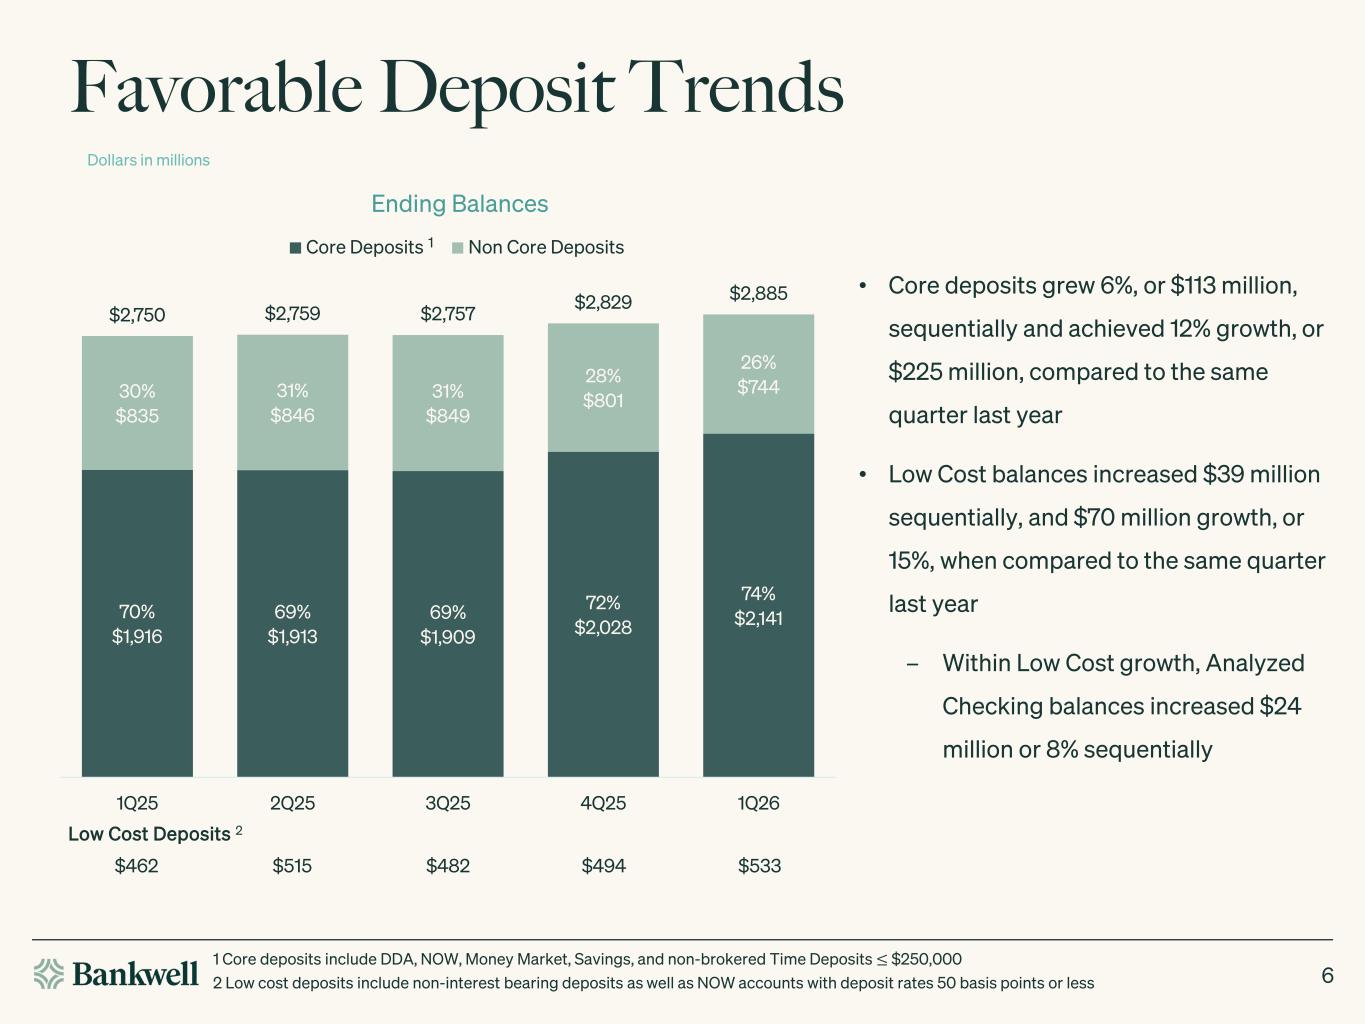
6 70% $1,916 69% $1,913 69% $1,909 72% $2,028 74% $2,141 30% $835 31% $846 31% $849 28% $801 26% $744 $2,750 $2,759 $2,757 $2,829 $2,885 1Q25 2Q25 3Q25 4Q25 1Q26 Ending Balances Core Deposits Non Core Deposits Favorable Deposit Trends Dollars in millions • Core deposits grew 6%, or $113 million, sequentially and achieved 12% growth, or $225 million, compared to the same quarter last year • Low Cost balances increased $39 million sequentially, and $70 million growth, or 15%, when compared to the same quarter last year ‒ Within Low Cost growth, Analyzed Checking balances increased $24 million or 8% sequentially 1 Core deposits include DDA, NOW, Money Market, Savings, and non-brokered Time Deposits ≤ $250,000 1 Low Cost Deposits 2 $462 $515 $482 $494 $533 2 Low cost deposits include non-interest bearing deposits as well as NOW accounts with deposit rates 50 basis points or less
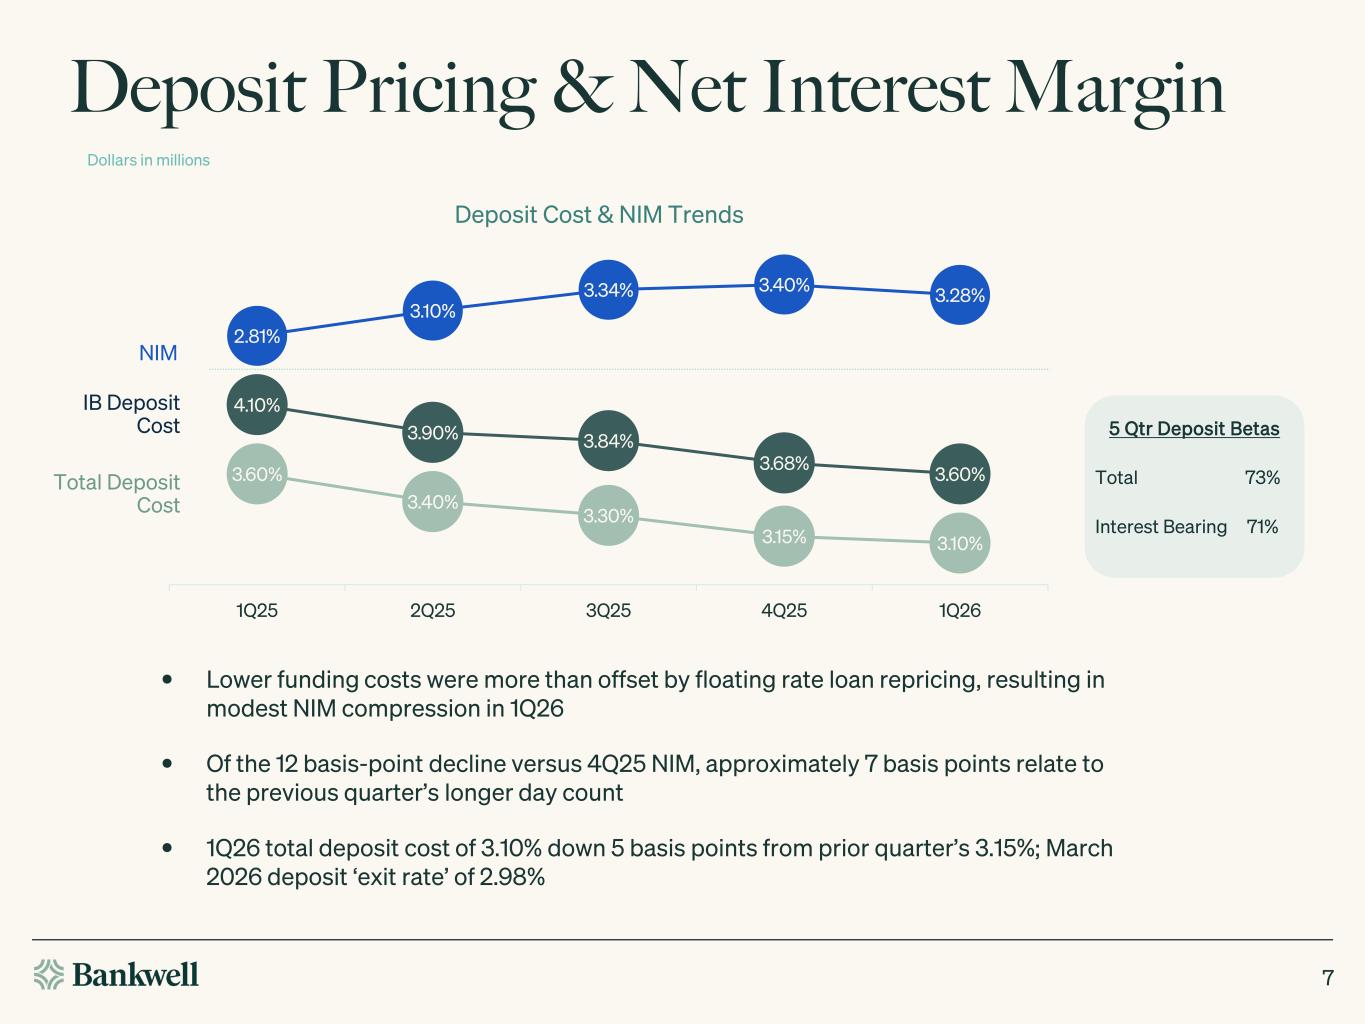
Deposit Pricing & Net Interest Margin NIM Total Deposit Cost IB Deposit Cost Deposit Cost & NIM Trends 4.10% 3.90% 3.84% 3.68% 3.60%3.60% 3.40% 3.30% 3.15% 3.10% 2.81% 3.10% 3.34% 3.40% 3.28% -0.05% 0.45% 0.95% 1.45% 1.95% 2.45% 2.95% 3.45% 1Q25 2Q25 3Q25 4Q25 1Q26 7 • Lower funding costs were more than offset by floating rate loan repricing, resulting in modest NIM compression in 1Q26 • Of the 12 basis-point decline versus 4Q25 NIM, approximately 7 basis points relate to the previous quarter’s longer day count • 1Q26 total deposit cost of 3.10% down 5 basis points from prior quarter’s 3.15%; March 2026 deposit ‘exit rate’ of 2.98% 5 Qtr Deposit Betas Total 73% Interest Bearing 71% Dollars in millions
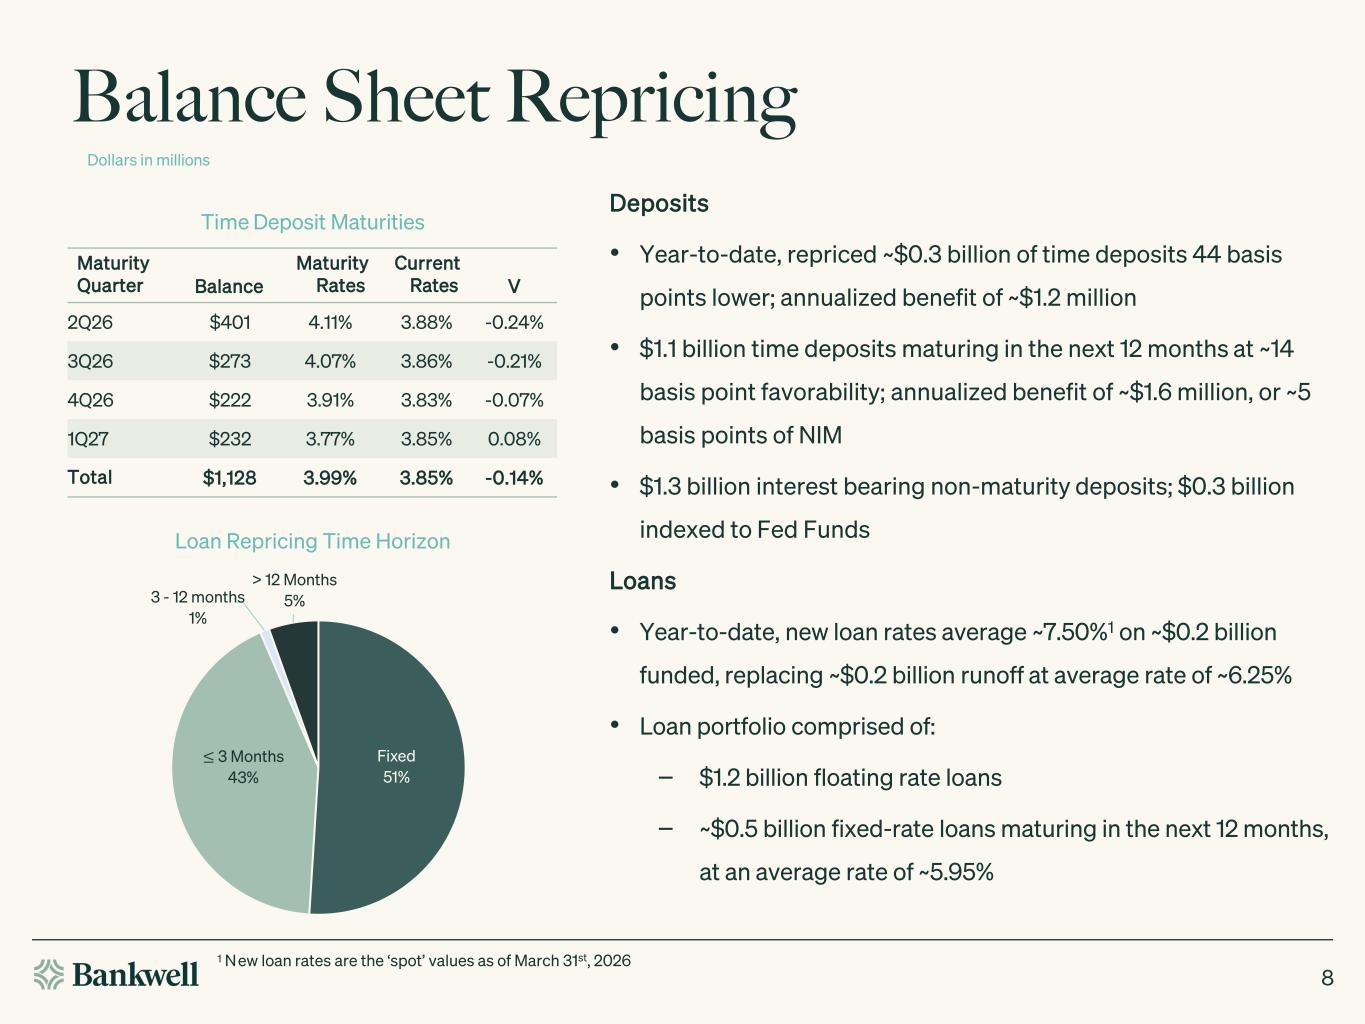
Balance Sheet Repricing 8 Maturity Quarter Balance Maturity Rates Current Rates V 2Q26 $401 4.11% 3.88% -0.24% 3Q26 $273 4.07% 3.86% -0.21% 4Q26 $222 3.91% 3.83% -0.07% 1Q27 $232 3.77% 3.85% 0.08% Total $1,128 3.99% 3.85% -0.14% Dollars in millions Time Deposit Maturities Deposits • Year-to-date, repriced ~$0.3 billion of time deposits 44 basis points lower; annualized benefit of ~$1.2 million • $1.1 billion time deposits maturing in the next 12 months at ~14 basis point favorability; annualized benefit of ~$1.6 million, or ~5 basis points of NIM • $1.3 billion interest bearing non-maturity deposits; $0.3 billion indexed to Fed Funds Loans • Year-to-date, new loan rates average ~7.50%1 on ~$0.2 billion funded, replacing ~$0.2 billion runoff at average rate of ~6.25% • Loan portfolio comprised of: ‒ $1.2 billion floating rate loans ‒ ~$0.5 billion fixed-rate loans maturing in the next 12 months, at an average rate of ~5.95% Loan Repricing Time Horizon 1 New loan rates are the ‘spot’ values as of March 31st, 2026 Fixed 51% ≤ 3 Months 43% 3 - 12 months 1% > 12 Months 5%
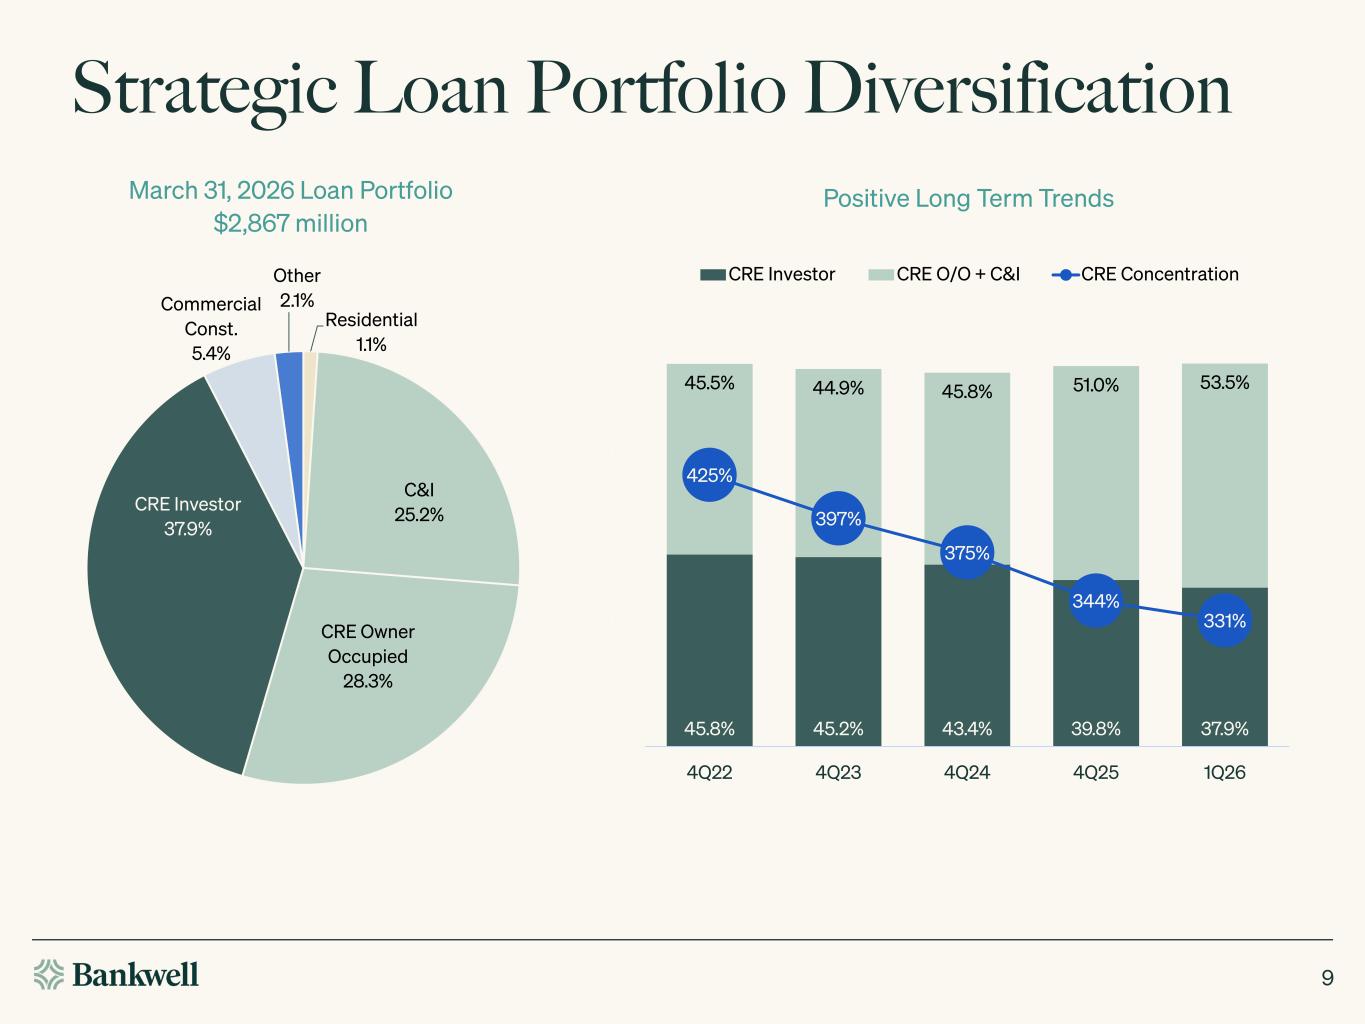
9 Strategic Loan Portfolio Diversification 45.8% 45.2% 43.4% 39.8% 37.9% 45.5% 44.9% 45.8% 51.0% 53.5% 425% 397% 375% 344% 331% 250% 300% 350% 400% 450% 500% 0% 10% 20% 30% 40% 50% 60% 70% 80% 90% 100% 4Q22 4Q23 4Q24 4Q25 1Q26 Positive Long Term Trends CRE Investor CRE O/O + C&I CRE Concentration Residential 1.1% C&I 25.2% CRE Owner Occupied 28.3% CRE Investor 37.9% Commercial Const. 5.4% Other 2.1% March 31, 2026 Loan Portfolio $2,867 million
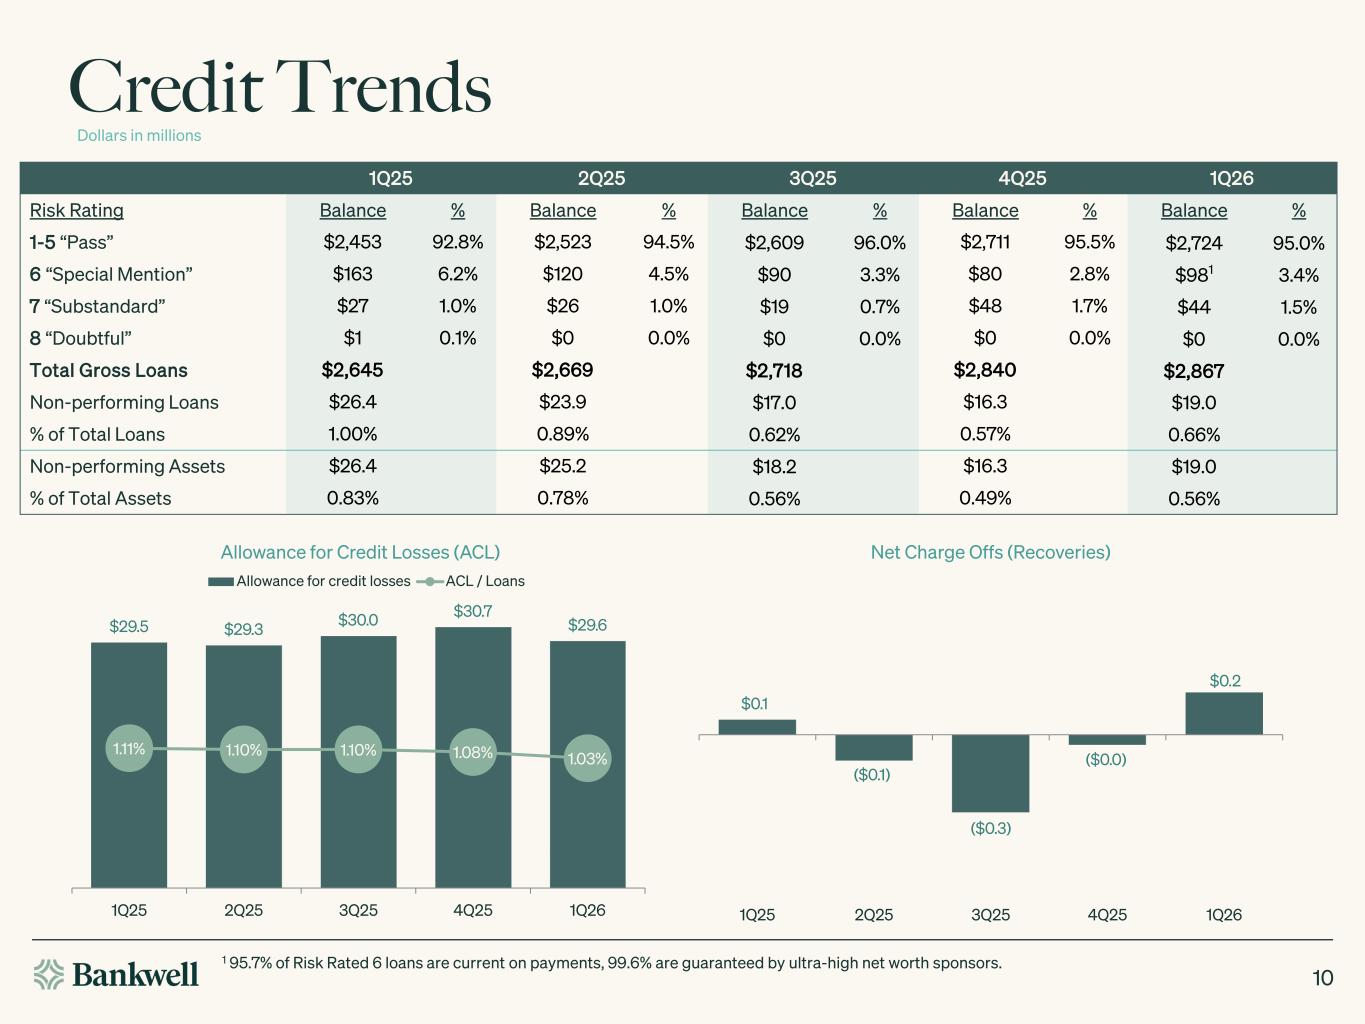
$29.5 $29.3 $30.0 $30.7 $29.6 1.11% 1.10% 1.10% 1.08% 1.03% 0.00% 0.50% 1.00% 1.50% 2.00% 2.50% $10 $15 $20 $25 $30 $35 1Q25 2Q25 3Q25 4Q25 1Q26 Allowance for Credit Losses (ACL) Allowance for credit losses ACL / Loans Dollars in millions $0.1 ($0.1) ($0.3) ($0.0) $0.2 1Q25 2Q25 3Q25 4Q25 1Q26 Net Charge Offs (Recoveries) 1Q25 2Q25 3Q25 4Q25 1Q26 Risk Rating Balance % Balance % Balance % Balance % Balance % 1-5 “Pass” $2,453 92.8% $2,523 94.5% $2,609 96.0% $2,711 95.5% $2,724 95.0% 6 “Special Mention” $163 6.2% $120 4.5% $90 3.3% $80 2.8% $981 3.4% 7 “Substandard” $27 1.0% $26 1.0% $19 0.7% $48 1.7% $44 1.5% 8 “Doubtful” $1 0.1% $0 0.0% $0 0.0% $0 0.0% $0 0.0% Total Gross Loans $2,645 $2,669 $2,718 $2,840 $2,867 Non-performing Loans $26.4 $23.9 $17.0 $16.3 $19.0 % of Total Loans 1.00% 0.89% 0.62% 0.57% 0.66% Non-performing Assets $26.4 $25.2 $18.2 $16.3 $19.0 % of Total Assets 0.83% 0.78% 0.56% 0.49% 0.56% 1 95.7% of Risk Rated 6 loans are current on payments, 99.6% are guaranteed by ultra-high net worth sponsors. 10 Credit Trends
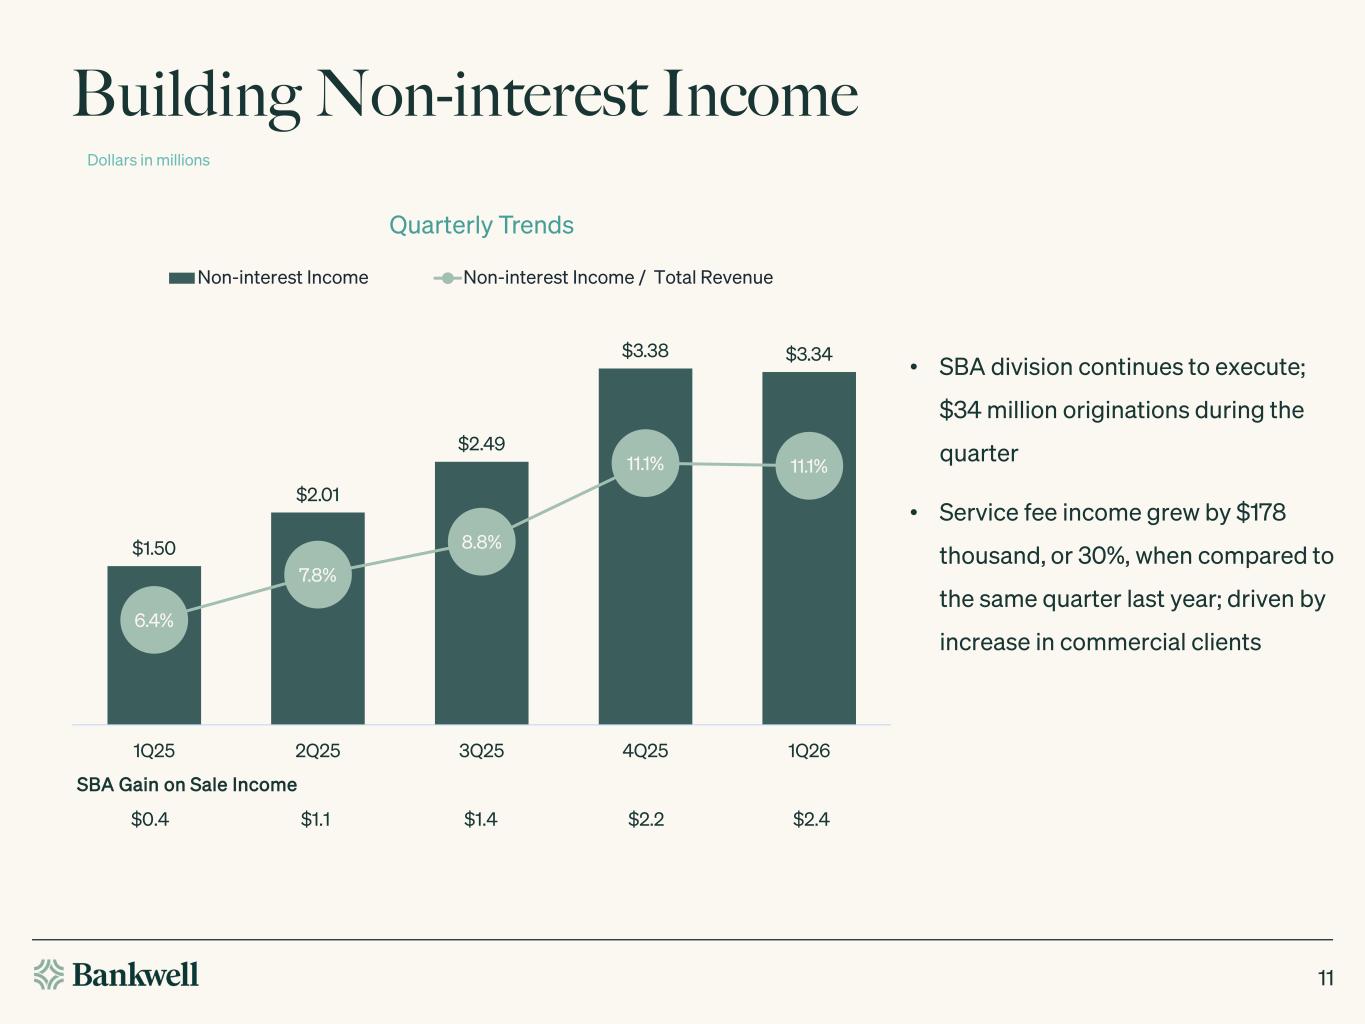
Building Non-interest Income 11 $1.50 $2.01 $2.49 $3.38 $3.34 6.4% 7.8% 8.8% 11.1% 11.1% 0.00% 2.00% 4.00% 6.00% 8.00% 10.00% 12.00% 14.00% 16.00% -$1.00 -$0.50 $0.00 $0.50 $1.00 $1.50 $2.00 $2.50 $3.00 $3.50 $4.00 1Q25 2Q25 3Q25 4Q25 1Q26 Quarterly Trends Non-interest Income Non-interest Income / Total Revenue • SBA division continues to execute; $34 million originations during the quarter • Service fee income grew by $178 thousand, or 30%, when compared to the same quarter last year; driven by increase in commercial clients Dollars in millions SBA Gain on Sale Income $0.4 $1.1 $1.4 $2.2 $2.4
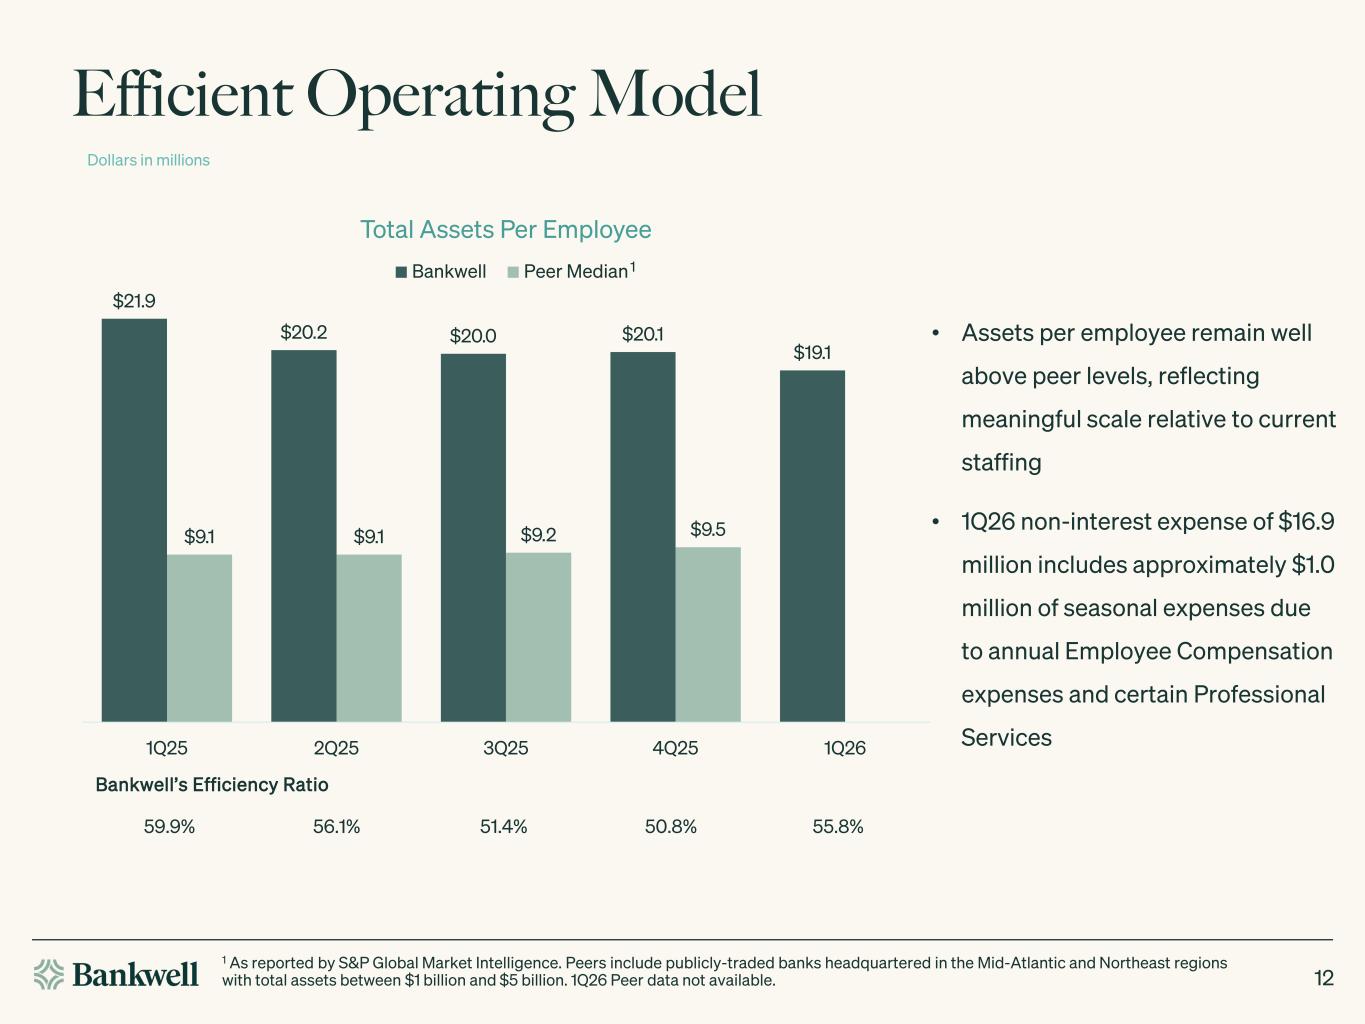
Efficient Operating Model 12 • Assets per employee remain well above peer levels, reflecting meaningful scale relative to current staffing • 1Q26 non-interest expense of $16.9 million includes approximately $1.0 million of seasonal expenses due to annual Employee Compensation expenses and certain Professional Services $21.9 $20.2 $20.0 $20.1 $19.1 $9.1 $9.1 $9.2 $9.5 1Q25 2Q25 3Q25 4Q25 1Q26 Total Assets Per Employee Bankwell Peer Median Dollars in millions 1 1 As reported by S&P Global Market Intelligence. Peers include publicly-traded banks headquartered in the Mid-Atlantic and Northeast regions with total assets between $1 billion and $5 billion. 1Q26 Peer data not available. Bankwell’s Efficiency Ratio 59.9% 56.1% 51.4% 50.8% 55.8%
Questions? 13
Appendix 14
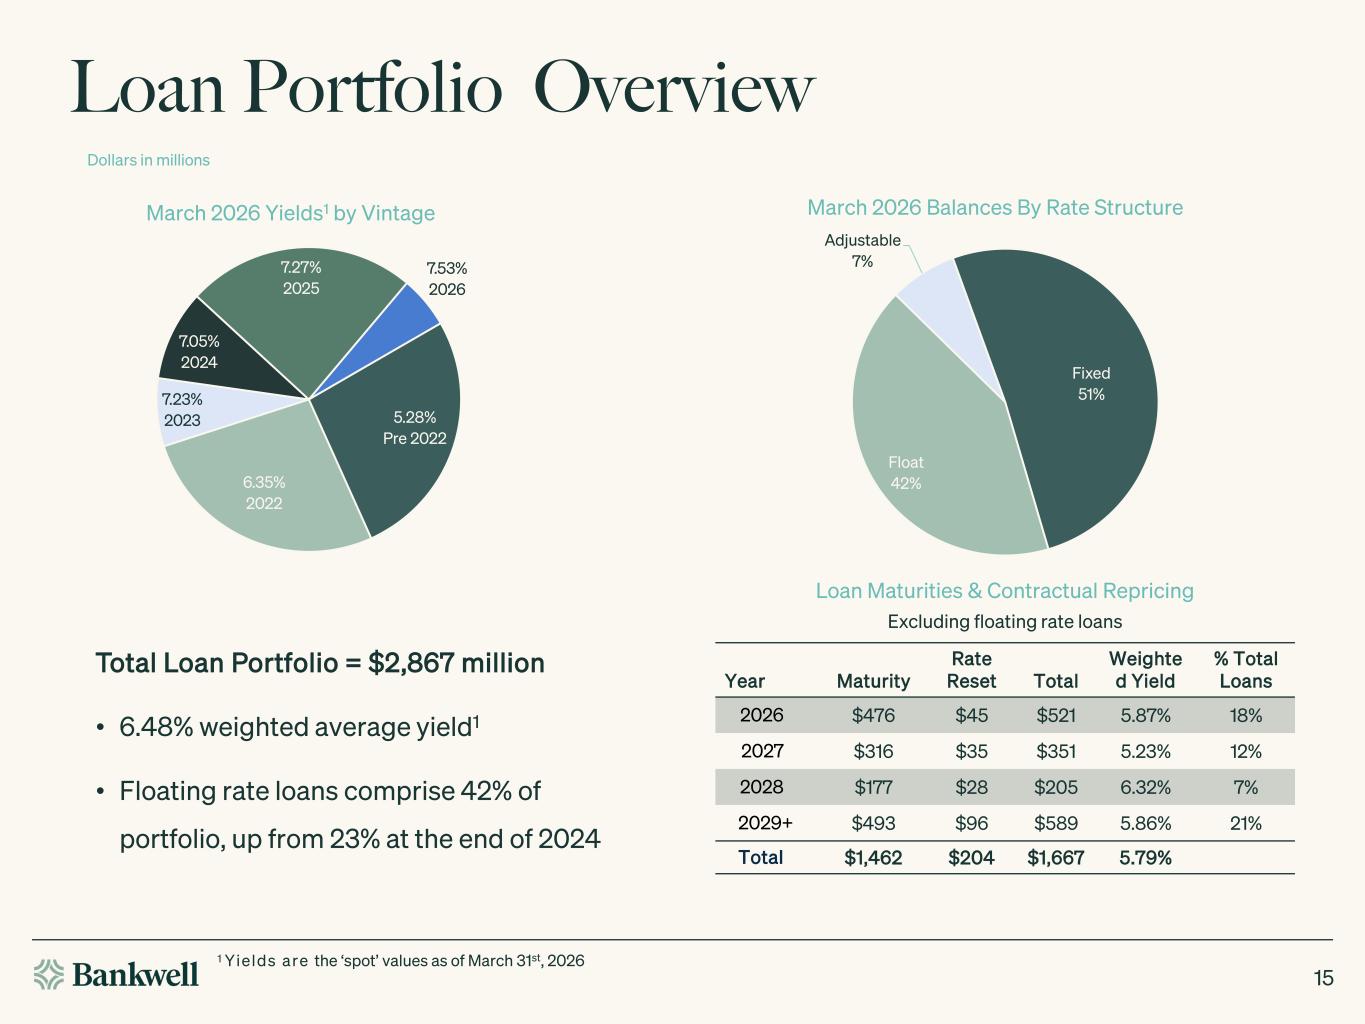
Fixed 51% Float 42% Adjustable 7% 15 Dollars in millions 1 Yields are the ‘spot’ values as of March 31st, 2026 March 2026 Yields1 by Vintage Year Maturity Rate Reset Total Weighte d Yield % Total Loans 2026 $476 $45 $521 5.87% 18% 2027 $316 $35 $351 5.23% 12% 2028 $177 $28 $205 6.32% 7% 2029+ $493 $96 $589 5.86% 21% Total $1,462 $204 $1,667 5.79% Loan Maturities & Contractual Repricing Excluding floating rate loans Loan Portfolio Overview March 2026 Balances By Rate Structure Total Loan Portfolio = $2,867 million • 6.48% weighted average yield1 • Floating rate loans comprise 42% of portfolio, up from 23% at the end of 2024 5.28% Pre 2022 6.35% 2022 7.23% 2023 7.05% 2024 7.27% 2025 7.53% 2026
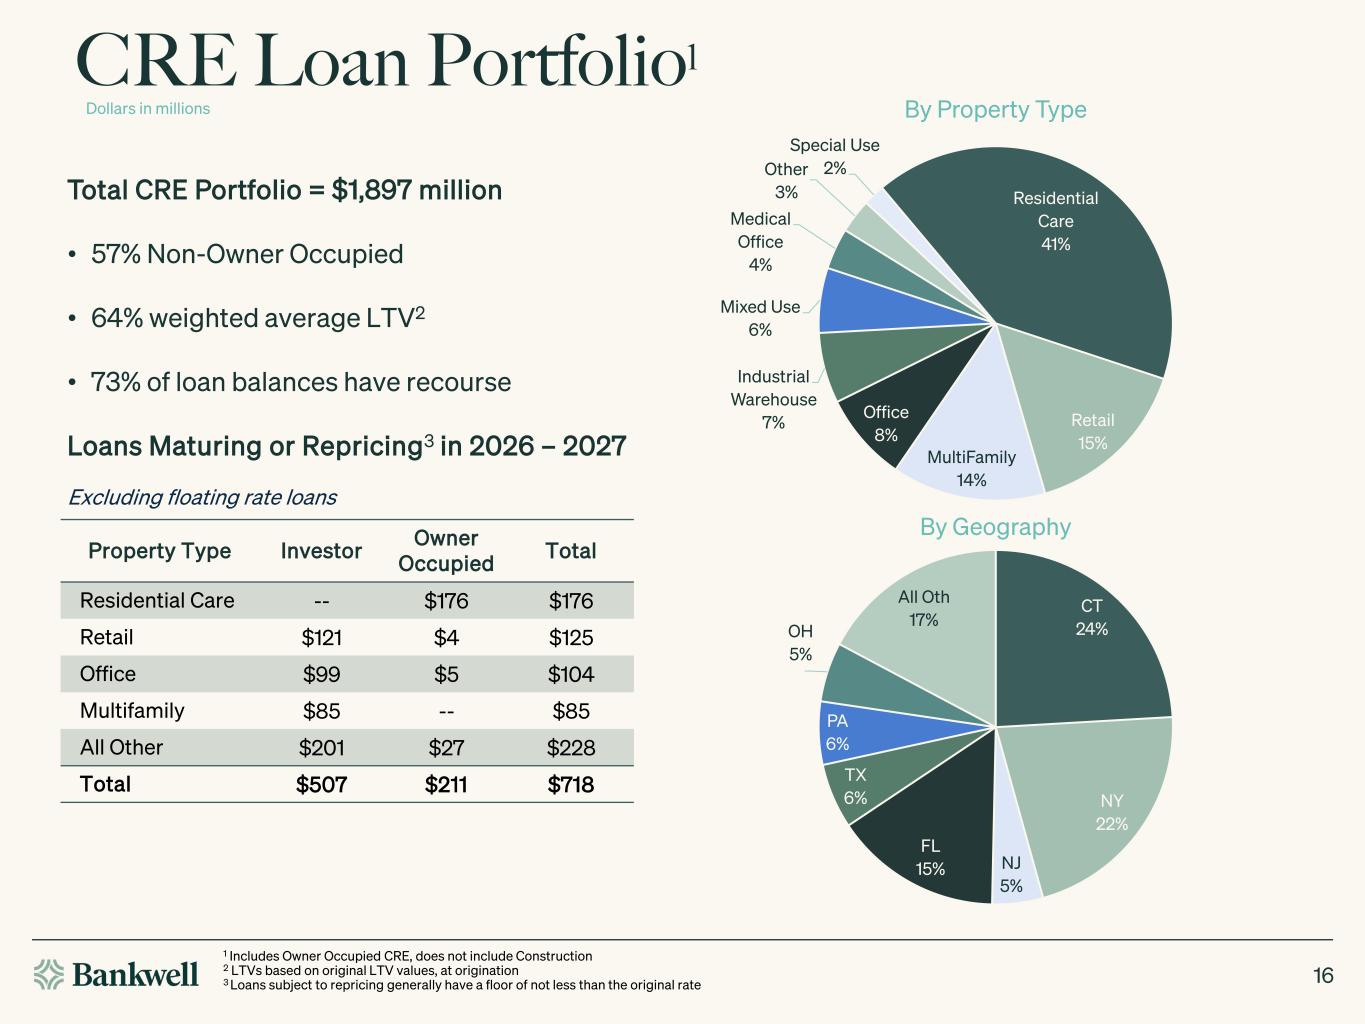
CT 24% NY 22% NJ 5% FL 15% TX 6% PA 6% OH 5% All Oth 17% Residential Care 41% Retail 15% MultiFamily 14% Office 8% Industrial Warehouse 7% Mixed Use 6% Medical Office 4% Other 3% Special Use 2% Total CRE Portfolio = $1,897 million • 57% Non-Owner Occupied • 64% weighted average LTV2 • 73% of loan balances have recourse Loans Maturing or Repricing3 in 2026 – 2027 Property Type Investor Owner Occupied Total Residential Care -- $176 $176 Retail $121 $4 $125 Office $99 $5 $104 Multifamily $85 -- $85 All Other $201 $27 $228 Total $507 $211 $718 Excluding floating rate loans By Property Type By Geography CRE Loan Portfolio1 Dollars in millions 16 1 Includes Owner Occupied CRE, does not include Construction 2 LTVs based on original LTV values, at origination 3 Loans subject to repricing generally have a floor of not less than the original rate
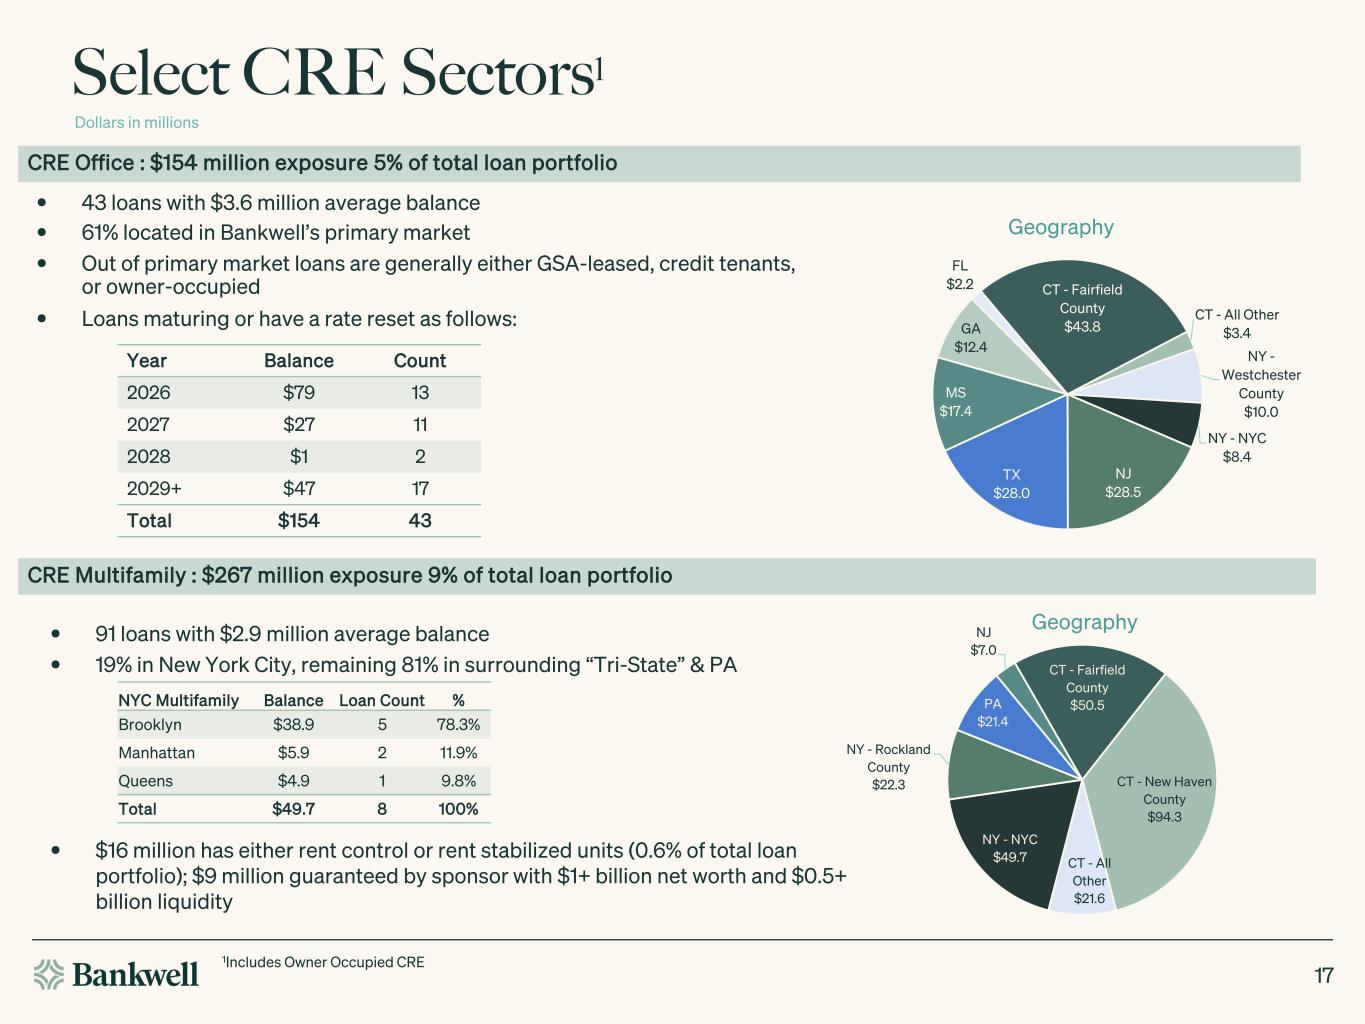
Select CRE Sectors1 1Includes Owner Occupied CRE CRE Office : $154 million exposure 5% of total loan portfolio Geography • 43 loans with $3.6 million average balance • 61% located in Bankwell’s primary market • Out of primary market loans are generally either GSA-leased, credit tenants, or owner-occupied • Loans maturing or have a rate reset as follows: Year Balance Count 2026 $79 13 2027 $27 11 2028 $1 2 2029+ $47 17 Total $154 43 Dollars in millions CRE Multifamily : $267 million exposure 9% of total loan portfolio • 91 loans with $2.9 million average balance • 19% in New York City, remaining 81% in surrounding “Tri-State” & PA • $16 million has either rent control or rent stabilized units (0.6% of total loan portfolio); $9 million guaranteed by sponsor with $1+ billion net worth and $0.5+ billion liquidity Geography NYC Multifamily Balance Loan Count % Brooklyn $38.9 5 78.3% Manhattan $5.9 2 11.9% Queens $4.9 1 9.8% Total $49.7 8 100% 17 CT - Fairfield County $43.8 CT - All Other $3.4 NY - Westchester County $10.0 NY - NYC $8.4 NJ $28.5 TX $28.0 MS $17.4 GA $12.4 FL $2.2 CT - Fairfield County $50.5 CT - New Haven County $94.3 CT - All Other $21.6 NY - NYC $49.7 NY - Rockland County $22.3 PA $21.4 NJ $7.0
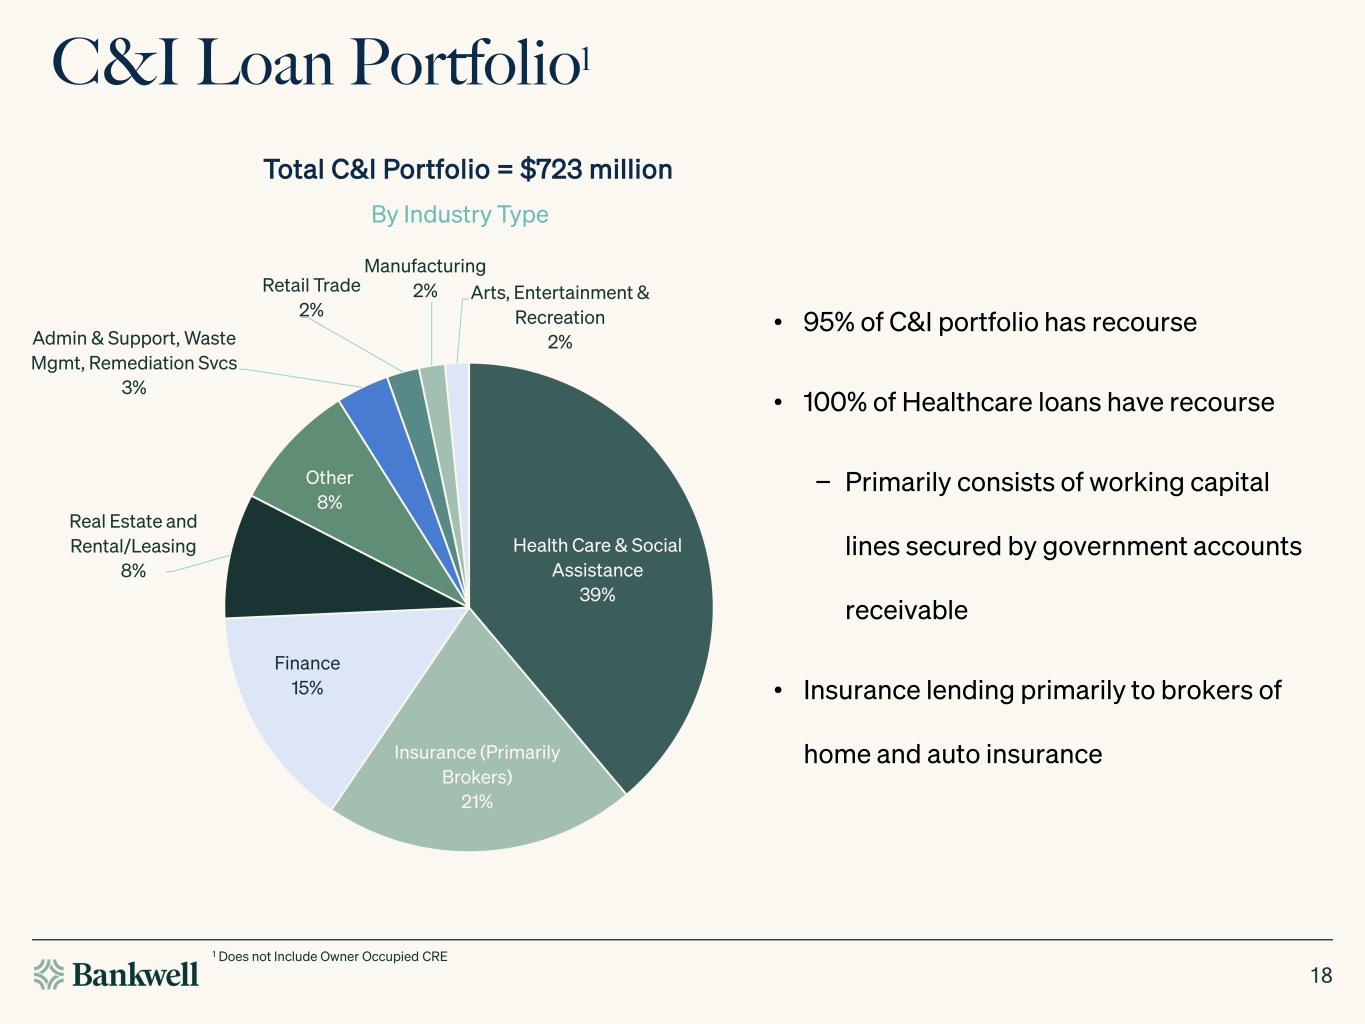
Health Care & Social Assistance 39% Insurance (Primarily Brokers) 21% Finance 15% Real Estate and Rental/Leasing 8% Other 8% Admin & Support, Waste Mgmt, Remediation Svcs 3% Retail Trade 2% Manufacturing 2% Arts, Entertainment & Recreation 2% 1 Does not Include Owner Occupied CRE C&I Loan Portfolio1 18 By Industry Type • 95% of C&I portfolio has recourse • 100% of Healthcare loans have recourse − Primarily consists of working capital lines secured by government accounts receivable • Insurance lending primarily to brokers of home and auto insurance Total C&I Portfolio = $723 million
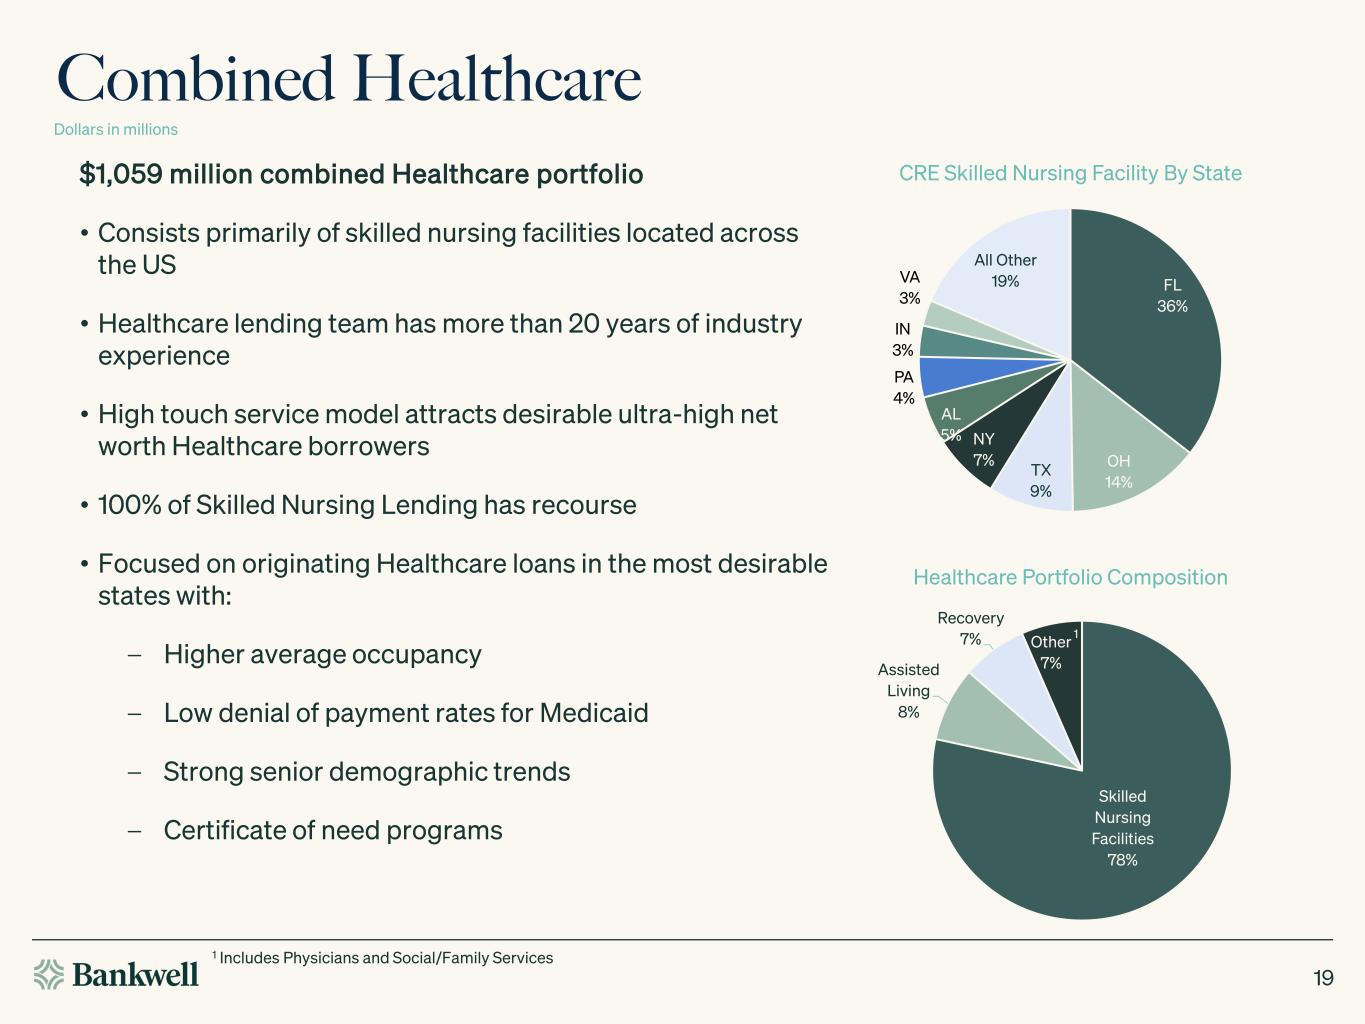
Skilled Nursing Facilities 78% Assisted Living 8% Recovery 7% Other 7% Healthcare Portfolio Composition CRE Skilled Nursing Facility By State 1 Includes Physicians and Social/Family Services 19 Combined Healthcare Dollars in millions $1,059 million combined Healthcare portfolio • Consists primarily of skilled nursing facilities located across the US • Healthcare lending team has more than 20 years of industry experience • High touch service model attracts desirable ultra-high net worth Healthcare borrowers • 100% of Skilled Nursing Lending has recourse • Focused on originating Healthcare loans in the most desirable states with: – Higher average occupancy – Low denial of payment rates for Medicaid – Strong senior demographic trends – Certificate of need programs 1 FL 36% OH 14% TX 9% NY 7% AL 5% PA 4% IN 3% VA 3% All Other 19%
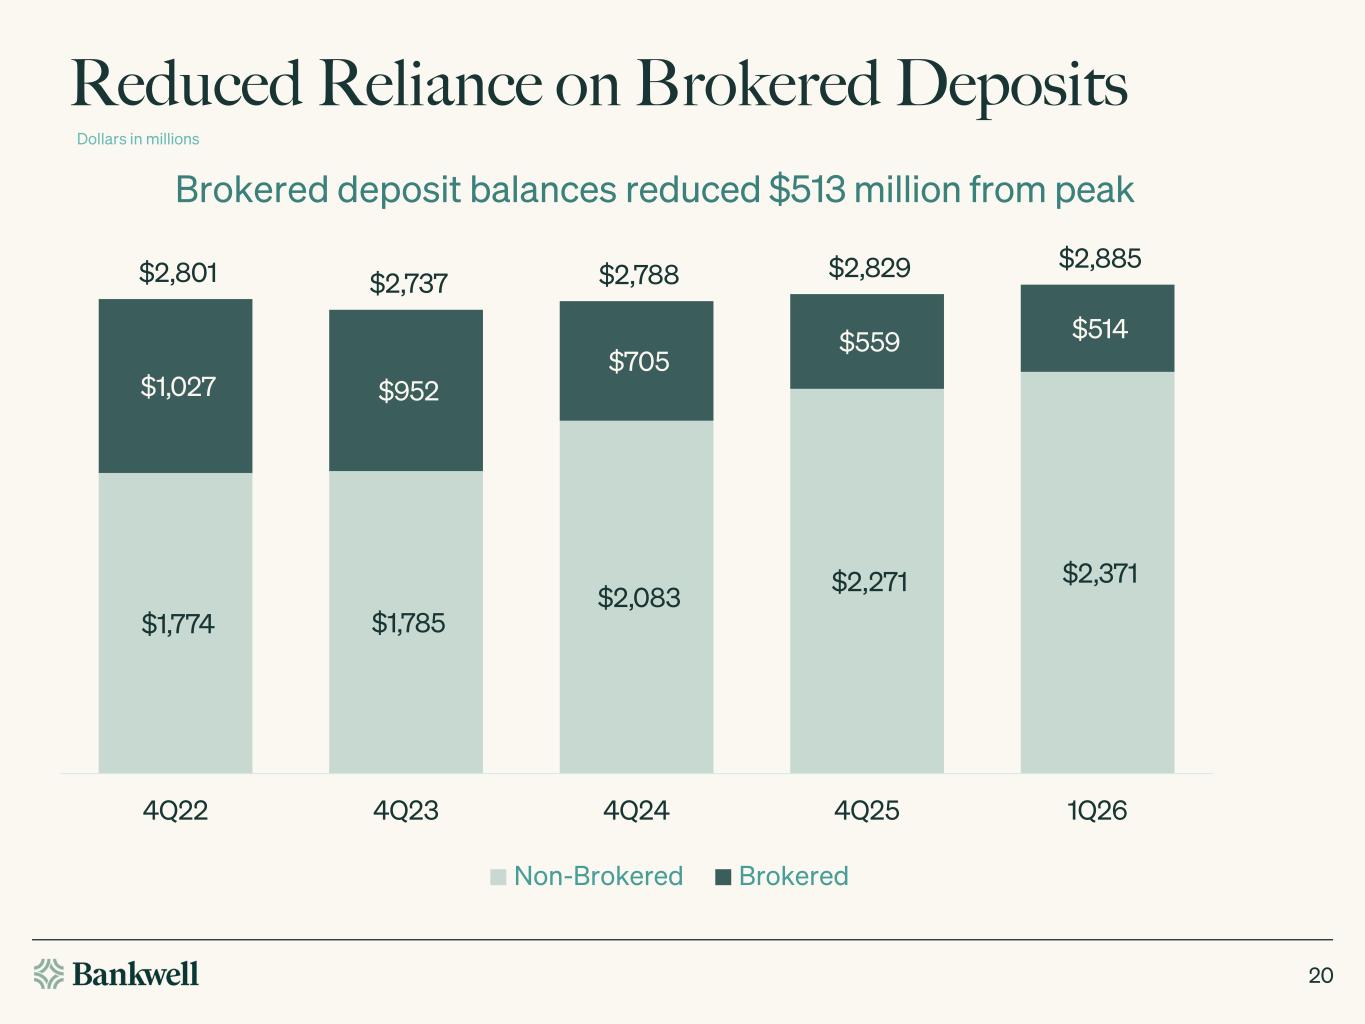
$1,774 $1,785 $2,083 $2,271 $2,371 $1,027 $952 $705 $559 $514 $2,801 $2,737 $2,788 $2,829 $2,885 - $500 $1,000 $1,500 $2,000 $2,500 $3,000 4Q22 4Q23 4Q24 4Q25 1Q26 Non-Brokered Brokered Reduced Reliance onReduced Reliance on Brokered Deposits Dollars in millions Brokered deposit balances reduced $513 million from peak 20
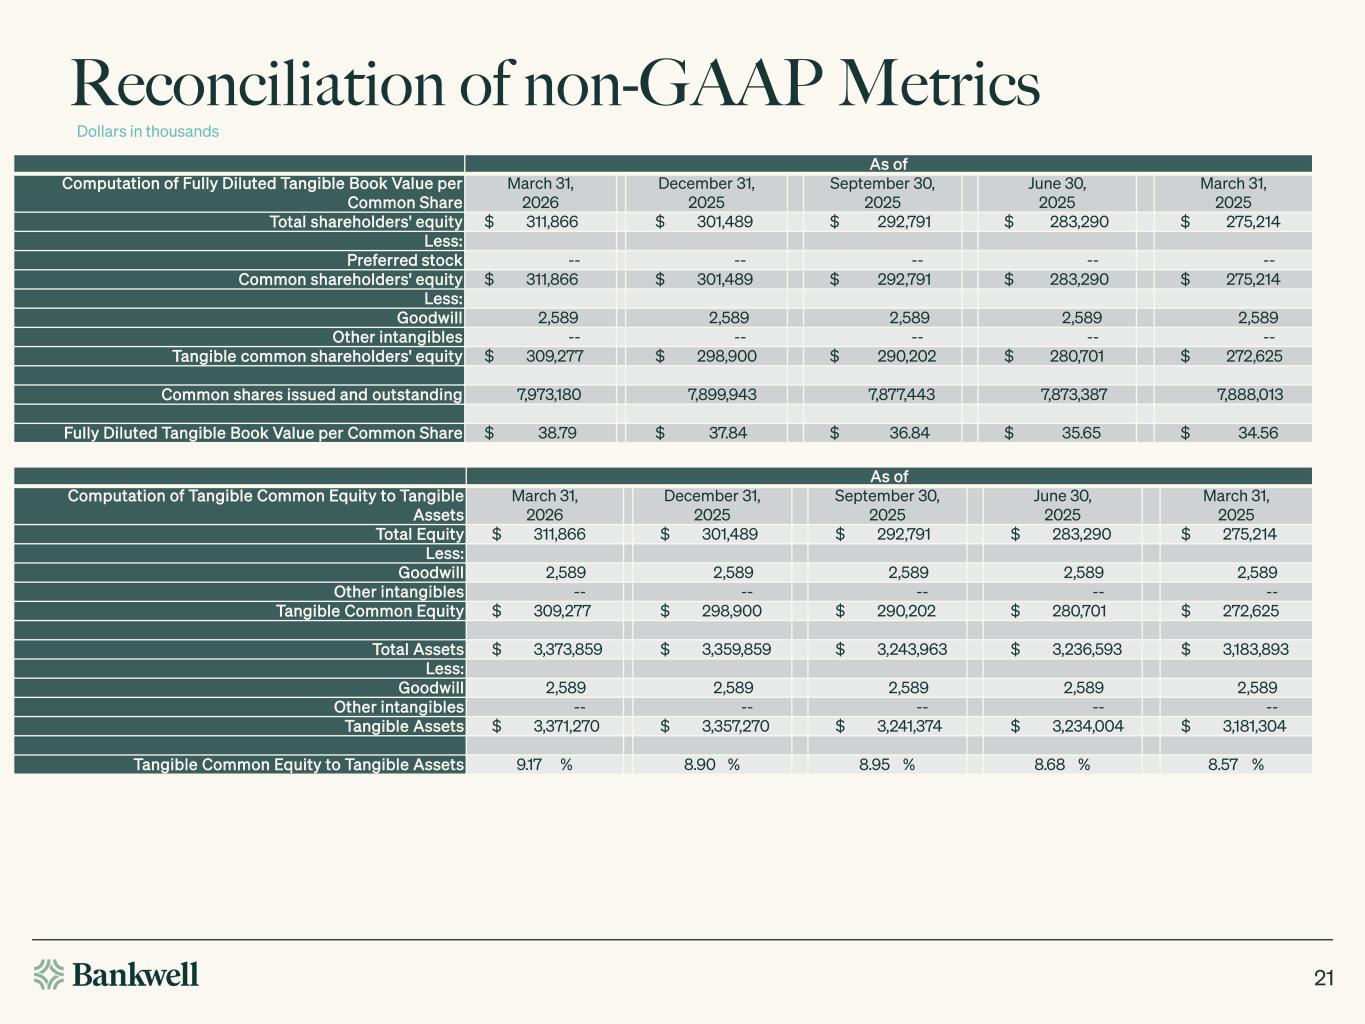
Reconciliation of non-GAAP Metrics As of Computation of Fully Diluted Tangible Book Value per Common Share March 31, 2026 December 31, 2025 September 30, 2025 June 30, 2025 March 31, 2025 Total shareholders' equity $ 311,866 $ 301,489 $ 292,791 $ 283,290 $ 275,214 Less: Preferred stock -- -- -- -- -- Common shareholders' equity $ 311,866 $ 301,489 $ 292,791 $ 283,290 $ 275,214 Less: Goodwill 2,589 2,589 2,589 2,589 2,589 Other intangibles -- -- -- -- -- Tangible common shareholders' equity $ 309,277 $ 298,900 $ 290,202 $ 280,701 $ 272,625 Common shares issued and outstanding 7,973,180 7,899,943 7,877,443 7,873,387 7,888,013 Fully Diluted Tangible Book Value per Common Share $ 38.79 $ 37.84 $ 36.84 $ 35.65 $ 34.56 Dollars in thousands 21 As of Computation of Tangible Common Equity to Tangible Assets March 31, 2026 December 31, 2025 September 30, 2025 June 30, 2025 March 31, 2025 Total Equity $ 311,866 $ 301,489 $ 292,791 $ 283,290 $ 275,214 Less: Goodwill 2,589 2,589 2,589 2,589 2,589 Other intangibles -- -- -- -- -- Tangible Common Equity $ 309,277 $ 298,900 $ 290,202 $ 280,701 $ 272,625 Total Assets $ 3,373,859 $ 3,359,859 $ 3,243,963 $ 3,236,593 $ 3,183,893 Less: Goodwill 2,589 2,589 2,589 2,589 2,589 Other intangibles -- -- -- -- -- Tangible Assets $ 3,371,270 $ 3,357,270 $ 3,241,374 $ 3,234,004 $ 3,181,304 Tangible Common Equity to Tangible Assets 9.17 % 8.90 % 8.95 % 8.68 % 8.57 %
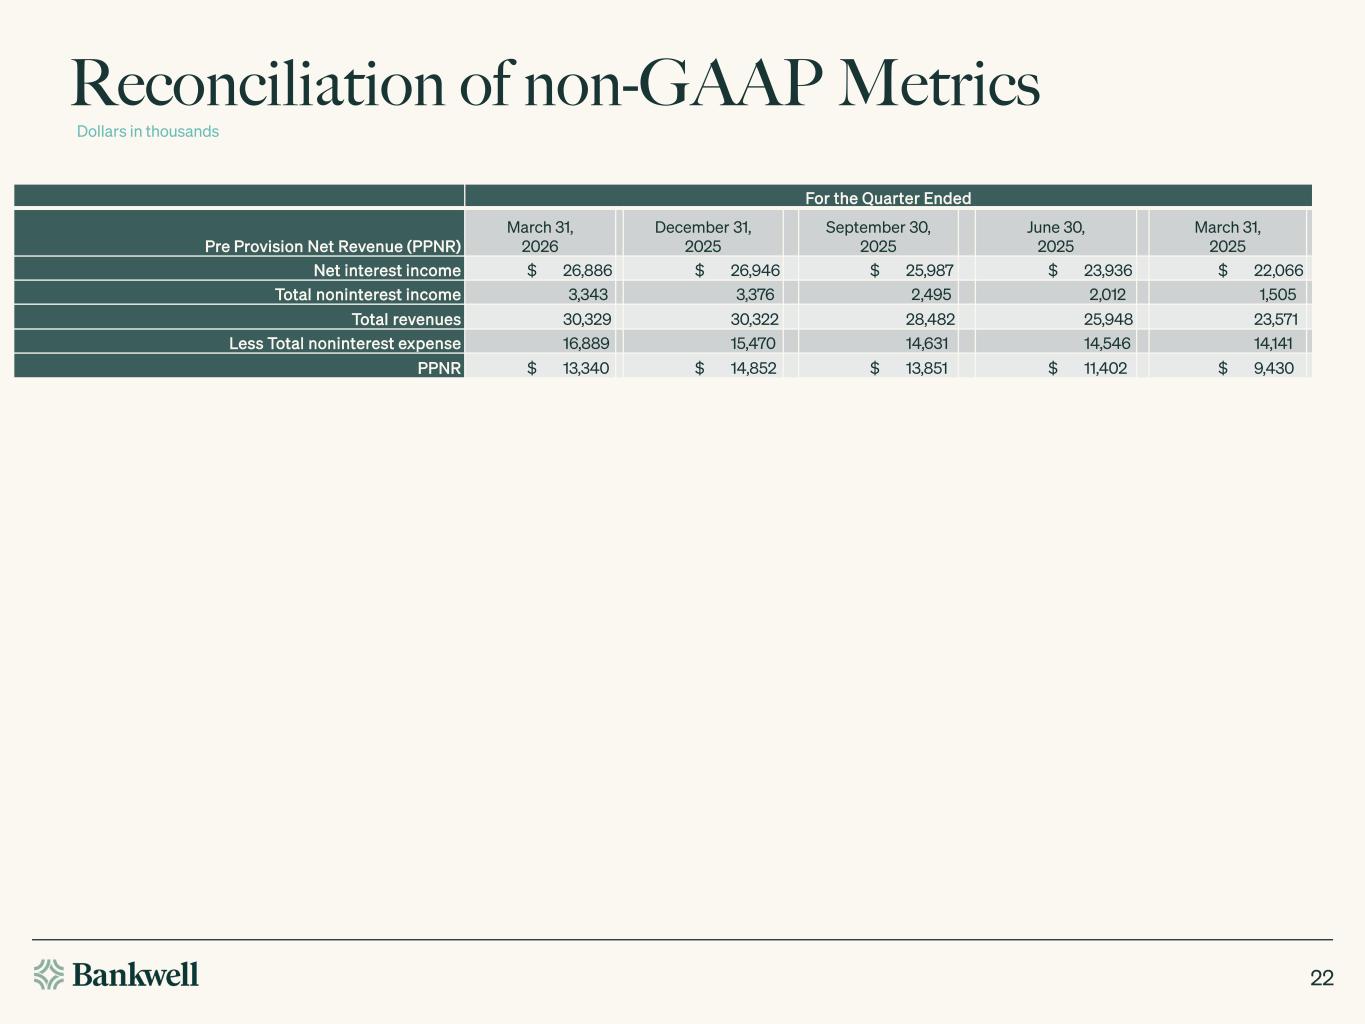
Reconciliation of non-GAAP Metrics For the Quarter Ended Pre Provision Net Revenue (PPNR) March 31, 2026 December 31, 2025 September 30, 2025 June 30, 2025 March 31, 2025 Net interest income $ 26,886 $ 26,946 $ 25,987 $ 23,936 $ 22,066 Total noninterest income 3,343 3,376 2,495 2,012 1,505 Total revenues 30,329 30,322 28,482 25,948 23,571 Less Total noninterest expense 16,889 15,470 14,631 14,546 14,141 PPNR $ 13,340 $ 14,852 $ 13,851 $ 11,402 $ 9,430 Dollars in thousands 22
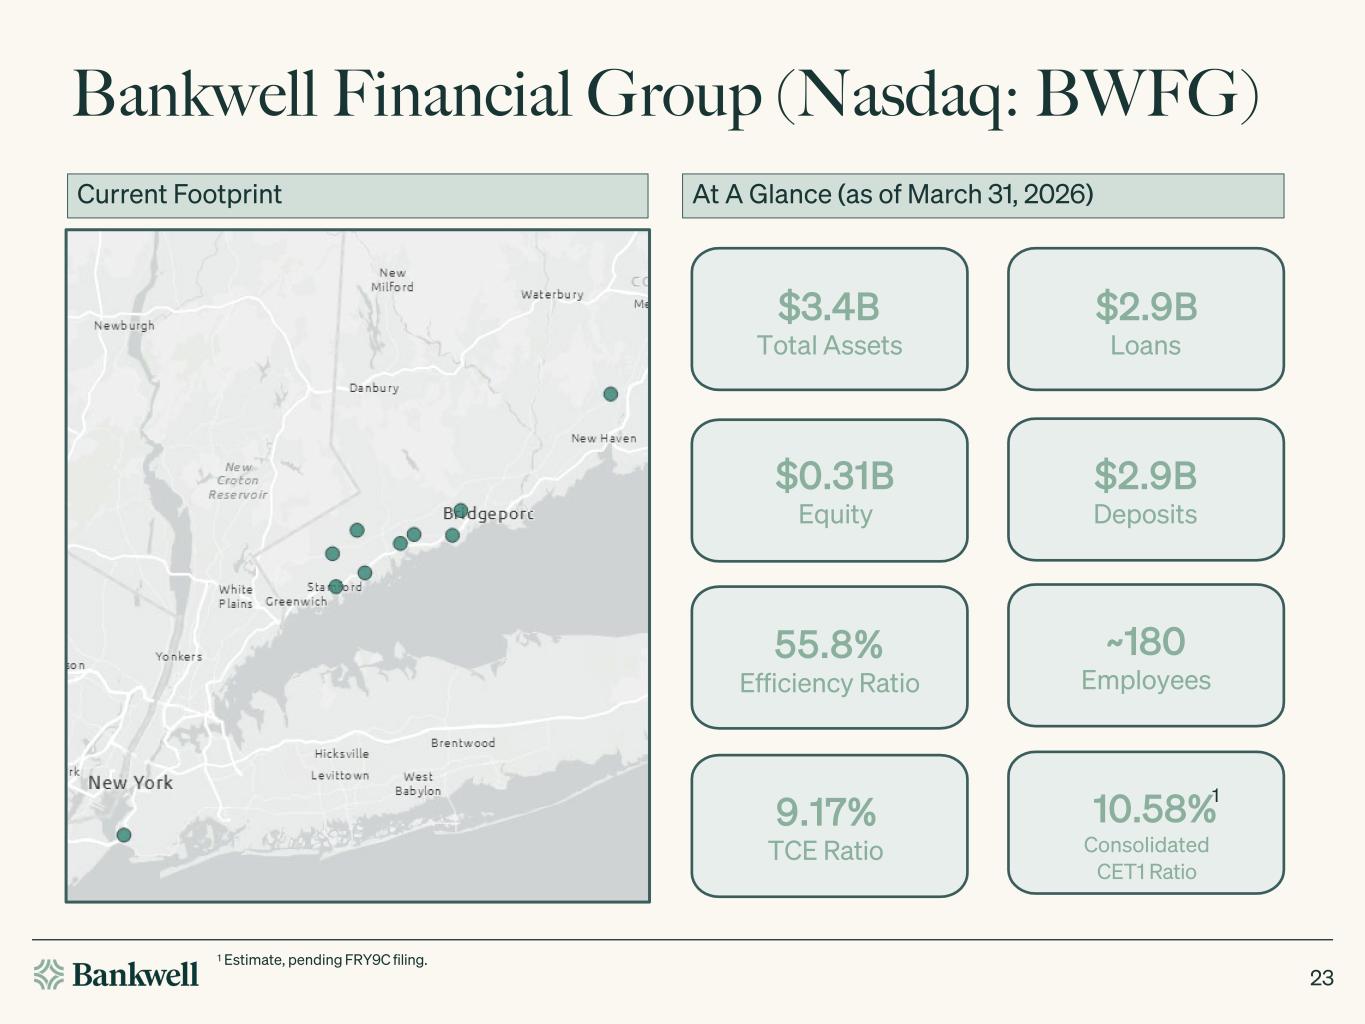
Bankwell Financial Group (Nasdaq: BWFG) 23 $3.4B Total Assets $2.9B Loans $0.31B Equity $2.9B Deposits 55.8% Efficiency Ratio ~180 Employees 9.17% TCE Ratio 10.58% Consolidated CET1 Ratio 1 Current Footprint At A Glance (as of March 31, 2026) 1 Estimate, pending FRY9C filing.