Operator
Hello, and welcome to Enterprise Financial Services Corp fourth quarter 2024 earnings conference call. Please note that this call is being recorded. After the speaker's prepared remarks, there will be a question and answer session. If you'd like to ask a question during that time, please press star followed by one on your telephone keypad. Thank you. I'd now like to hand the call over to Jim Lally, President and CEO. Please go ahead.
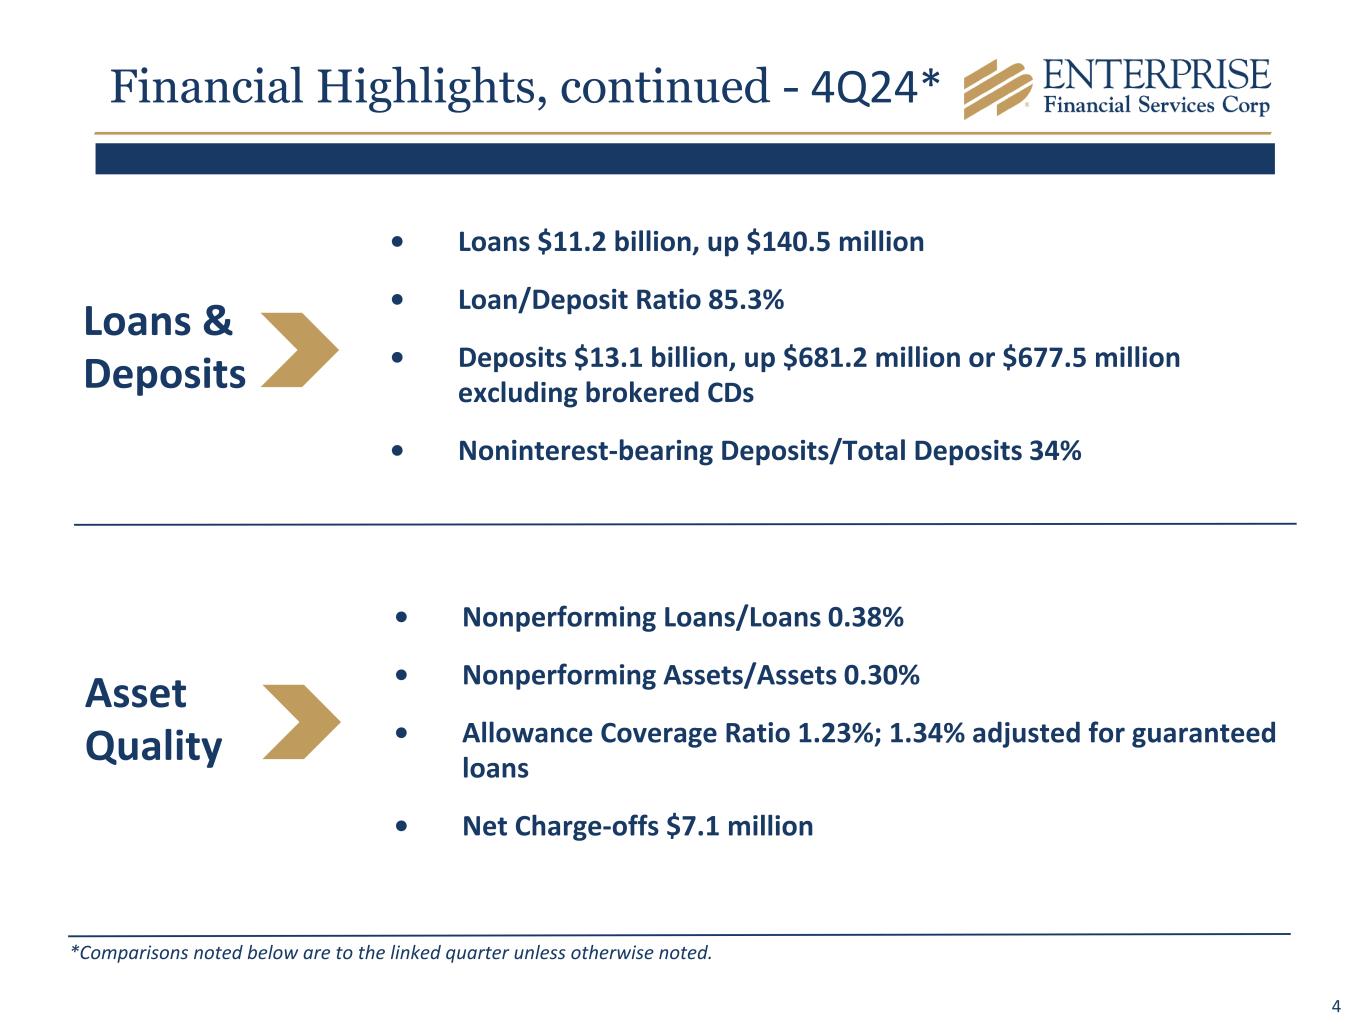
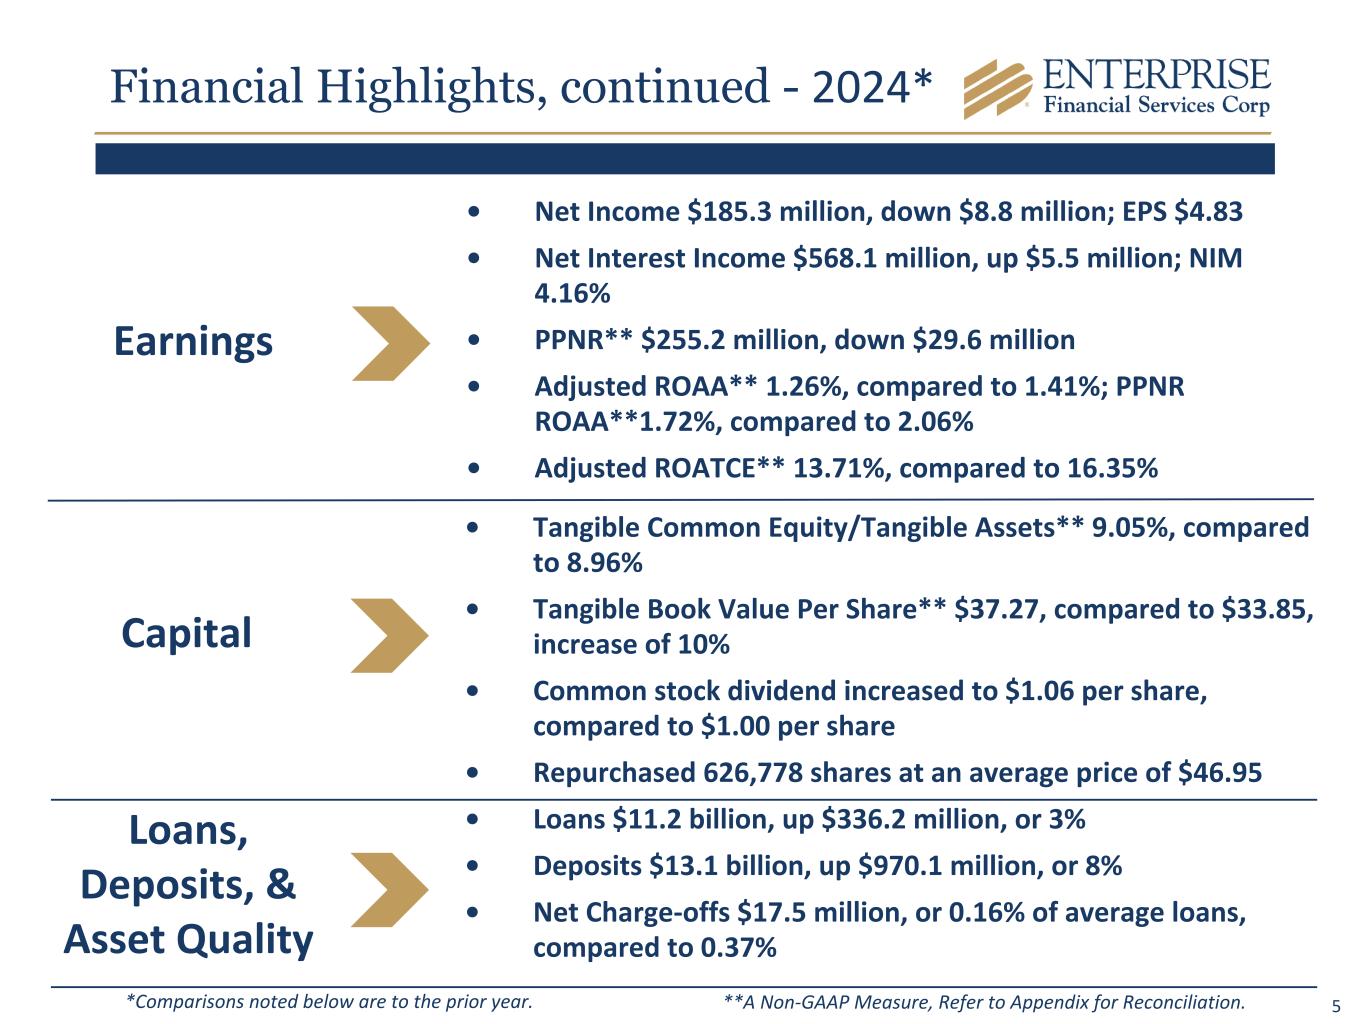
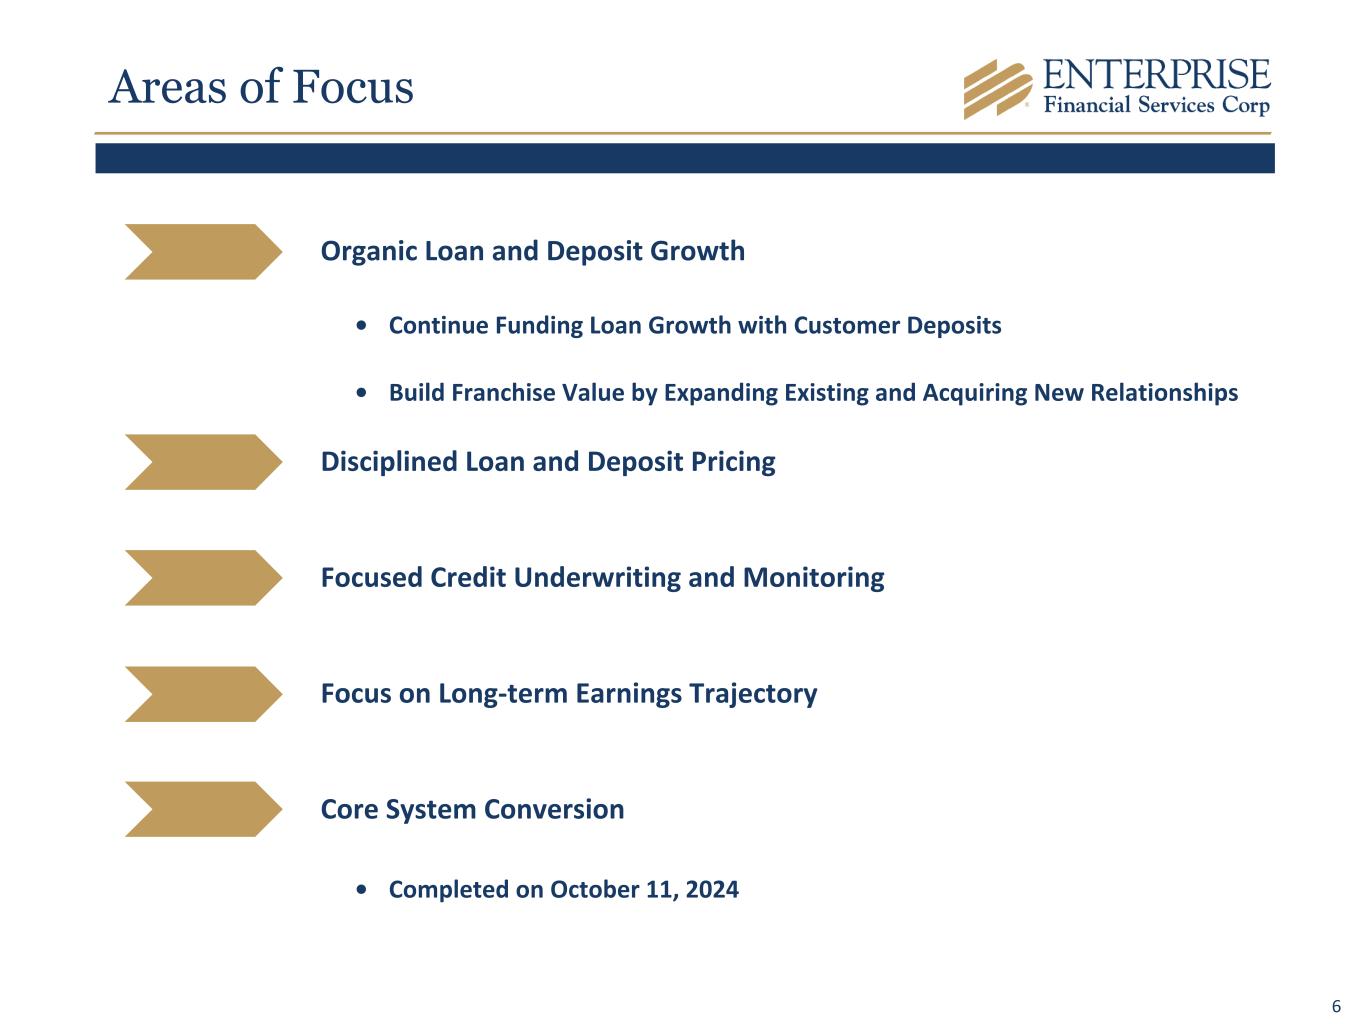
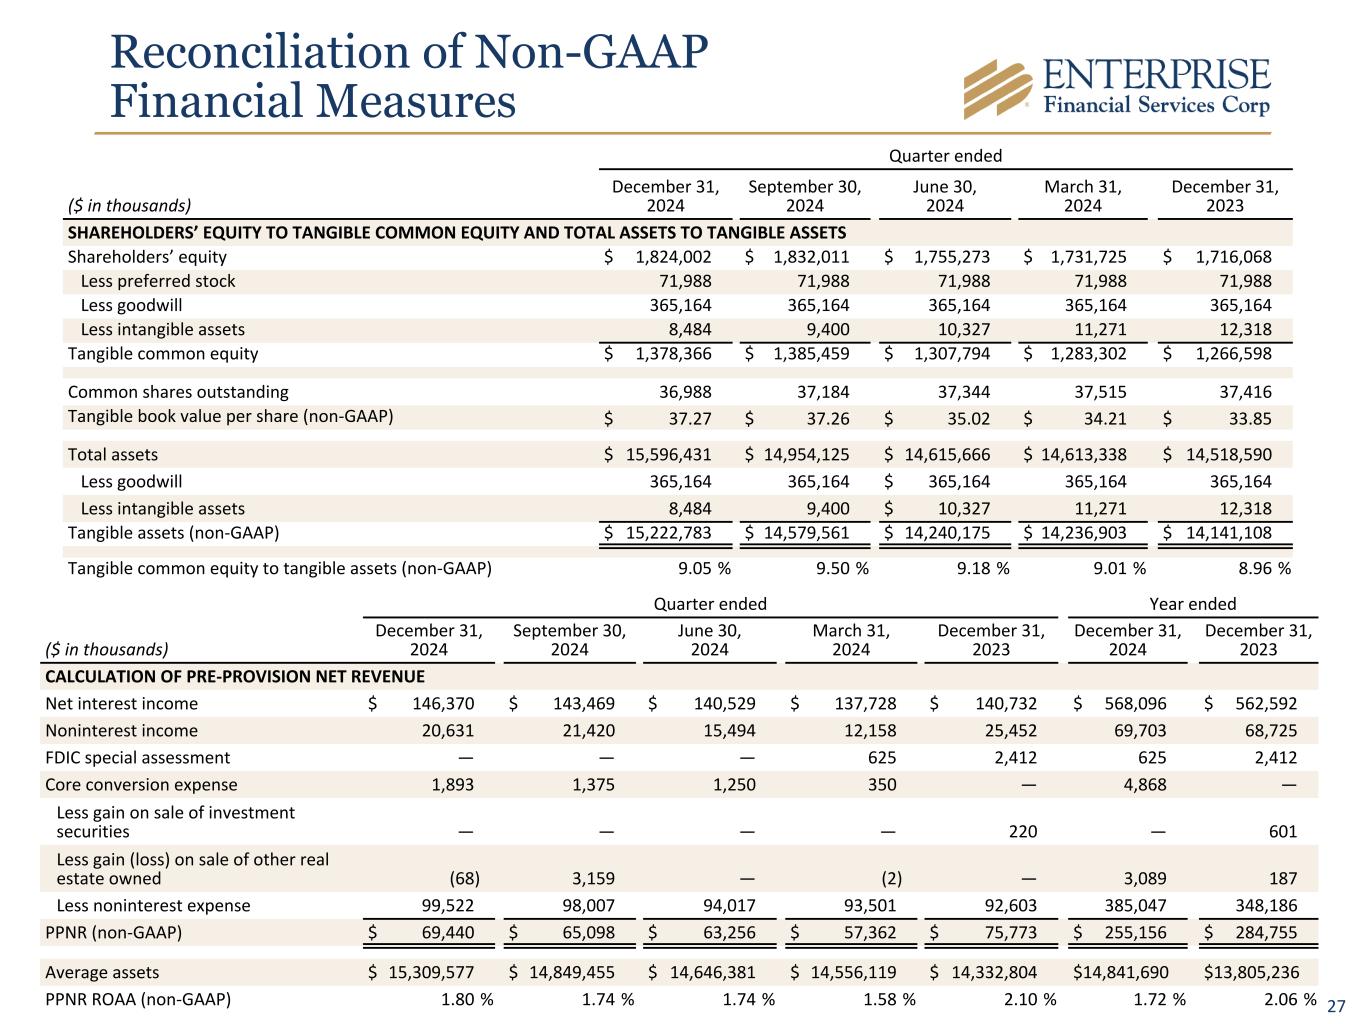
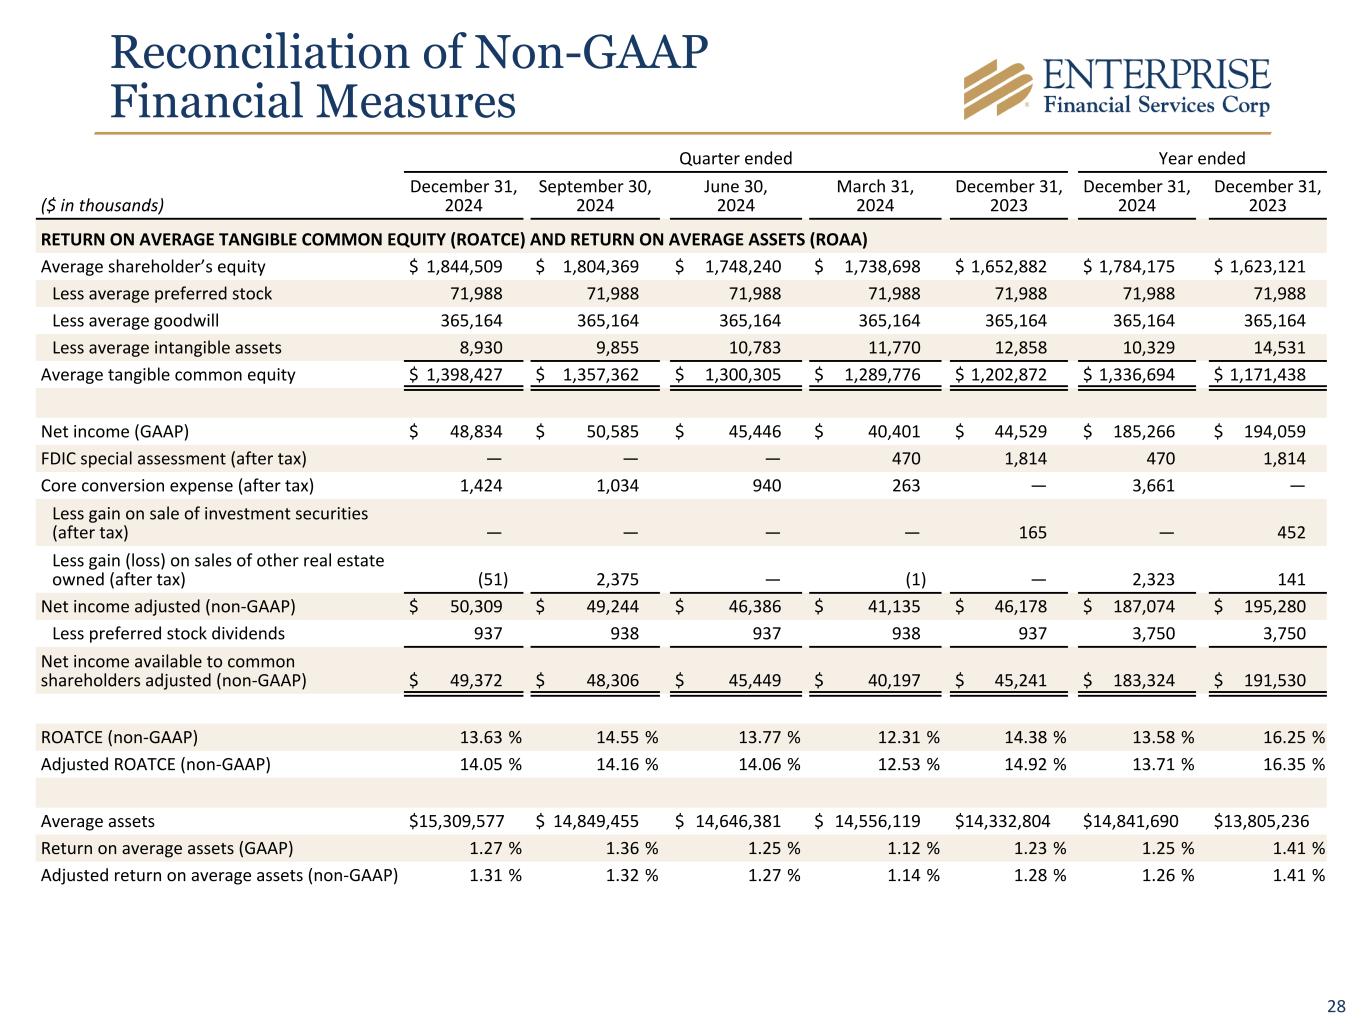
Well, thank you, Ellie, and good morning. Thank you all very much for joining us this morning, and welcome to our 2024 fourth quarter earnings call. Joining me this morning is Keane Turner, EFSC's Chief Financial Officer and Chief Operating Officer, Scott Goodman, President of Enterprise Bank and Trust, and Doug Bauke, Chief Credit Officer of Enterprise Bank and Trust. Before we begin, I would like to remind everybody on the call that a copy of the release and accompanying presentation can be found on our website. the presentation and earnings release for furnished on sec form 8k yesterday please refer to slide two of the presentation titled forward-looking statements for our most recent 10k and 10q for reasons why actual results may vary from any forward-looking statements that we make today our financial scorecard begins on slide three i'm very pleased with our results for the fourth quarter and for all of 2024. Our strong financial performance continued in the fourth quarter where we earned $1.28 per doula share, which compares to $1.32 in the length quarter and $1.16 in the fourth quarter of 2023. We produce an adjusted return on assets of 1.31% and a pre-provision return on assets of 1.80%. Our diversified business model drove an expansion in net interest income, while defending net interest margin, which was essentially flat when compared to the linked quarter, and remained above 4%. The talent investment in relationship managers that we made in late 2023 and throughout 2024 is beginning to pay off. These new associates have a pedigree in C&I banking and deposit generation. Their efforts contributed to the outstanding growth in client deposits that we experienced in the fourth quarter. Our ability to hold our margin at this level illustrates the quality of our deposit base and relationship-oriented loan portfolio. This reflects the strength of the franchise we have built, and we remain positioned to produce high-quality earnings that consistently improves shareholder value with a client-oriented model, focused on continuing a cadence of consistency that we had established a few years ago. We accomplished this in the fourth quarter and are positioned well for another strong year in 2025. I would like to remind you that our strategy is focused on diversification, and for us, this means growth and revenue from several different markets and businesses. We're not relying on any one market, business line, or economic trend for our success. We lean into our client-centric, team-oriented approach, focused on listening well and providing holistic solutions that guide our clients to their defined success. We will continue to refine and improve this strategy for quarters and years to come. In the last few quarters, I discussed the wait-and-see mindset of most of our client base with respect to significant financial moves. Since the presidential election, I can say that this mindset has changed, but has yet to translate into significant loan demand. Like we thought would happen, though, loan demand did tick up in the quarter, as evidenced by our growth of $140 million, or 5% on an annualized basis. This includes a $27 million decline in our agricultural portfolio that continues to wind down. I do think that we should see loan demand elevate slightly from here, but we will not force this by changing the credit and pricing disciplines that have long been a characteristic of our company. Deposit growth and the quality of the deposit base has become a significant differentiator for our company. In the quarter, we saw client deposits increase by $677 million, making this the fifth quarter in the last six that we saw client deposits grow. As impressive was the fact that we had just about equal contribution from our national deposit verticals in our geographic markets. The cost and composition of the deposit base improved and has significantly aided in the consistency of our earnings and profitability. The quarterly cost of deposits declined to 2% and our level of DDA to total deposits increased to over 34%. We have maintained our DDAs at over 31% of total deposits since the end of 2020. I remain confident that we will grow our balance sheet in 2025 at a mid to high single-digit pace. Our teams, both established and new, have done a good job building loan and deposit pipelines. The mix, too, is encouraging. With ample room to grow CRE, we are seeing really good opportunities here that complements our C&I bias. You will hear much more about our markets and businesses during Scott's comment. Another strength of our company is our well-positioned balance sheet, which provides for great flexibility with respect to capital planning. Capital levels at quarter end remain stable and strong with our tangible common equity to tangible assets ratio at 9.05%. As impressive was our 14.05% adjusted return on tangible common equity for the fourth quarter. Tangible book value for common share was $37.27. Given the strength of our earnings and our confidence in our continued execution, we increased the dividend by one cent per share for the first quarter of 2025 to 29 cents per share and we returned an additional 11 million dollars to shareholders during the quarter through common stock repurchases in 2024 the industry attempted to define what a normalized credit profile would look like for each institution i would characterize the credit quality and profile of our portfolio strong and stable npls to loans npas to total assets showed a slight increase compared to the third quarter but remained at very modest levels. We've been able to achieve this while maintaining a strong allowance for credit losses of 1.34% of unguaranteed total loans. Slide 5 provides a recap of our financial highlights for the full year 2024. $185.3 million in net income, or $4.83 of diluted earnings per common share. We invested heavily into the company in 2024 in in terms of both technology and talent while generating over 255 million in pre-provision net revenue. This resulted in a pre-provision ROA of 1.72% and an adjusted return on average tangible common equity of 37.71%. Keen will provide much more detail in these results in its comments along with our strategy to defend margin given the expected interest rate environment. Slide six shows we're focused for the foreseeable future. as we enter our 37th year in business our focus remains the same we will continue to focus our time on taking care of the great clients that we've accumulated while adding those family-owned businesses that cherish high touch consultative relationships doing this day in and day out will lead to several more quarters of really strong performance and the continued building of franchise value we will not alter our credit discipline to chase growth and will be cognizant of the current market pricing trends to make sure we continue to protect and grow our client base We will continue to take advantage of the disruption caused by M&A in just about all of our markets. As you know, over the past several quarters, we've been adding talent from these disruptive situations. While the pace of talent acquisitions will likely moderate, we are confident that these investments will add many new relationships and subsequent growth and profitability from just about every corner of our company. Before handing the call to Scott, I would like to provide a little perspective on how our clients are performing and provide a view of the overall economy from their vantage For the most part, our clients performed well in 2024. They have readied their balance sheets for anticipated opportunities that should manifest in 2025 and beyond. From large general and subcontractors to mid-market manufacturers and distributors, 2025 should continue the encouraging momentum that we've seen in the fourth quarter. Our teams continue to have many strategic conversations about expansion, succession, and acquisitions. we're also starting to see the positive impact of investments that companies are making for reshoring infrastructure development and power generation my expectation for sound CNI growth in 2025 should blend well with the continued success that we've experienced with our CRE clients our conservative approach towards CRE earlier this decade gives us plenty of capacity to grow this part of our business while our competitors remain restricted due to their 100 300 limitations overall I like the tempo that we are seeing in our business and feel good about our team's ability to consistently produce quality opportunities that will ultimately lead to consistent sound balance sheet growth we enjoy a great reputation and corresponding market share of middle market businesses and our mature geographies and specialized lending and deposit businesses as such I'm confident that we'll continue to get more than our fair share of corresponding opportunities our newer markets and higher growth areas will provide similar levels of opportunities while we continue to build our reputation in these markets. This blend is what gives me high confidence that we will continue to grow and earn at a predictable rate while continuing to compound tangible book value at a higher level than our peers over the foreseeable future. With that, I'd like to turn the call over to Scott Goodman.
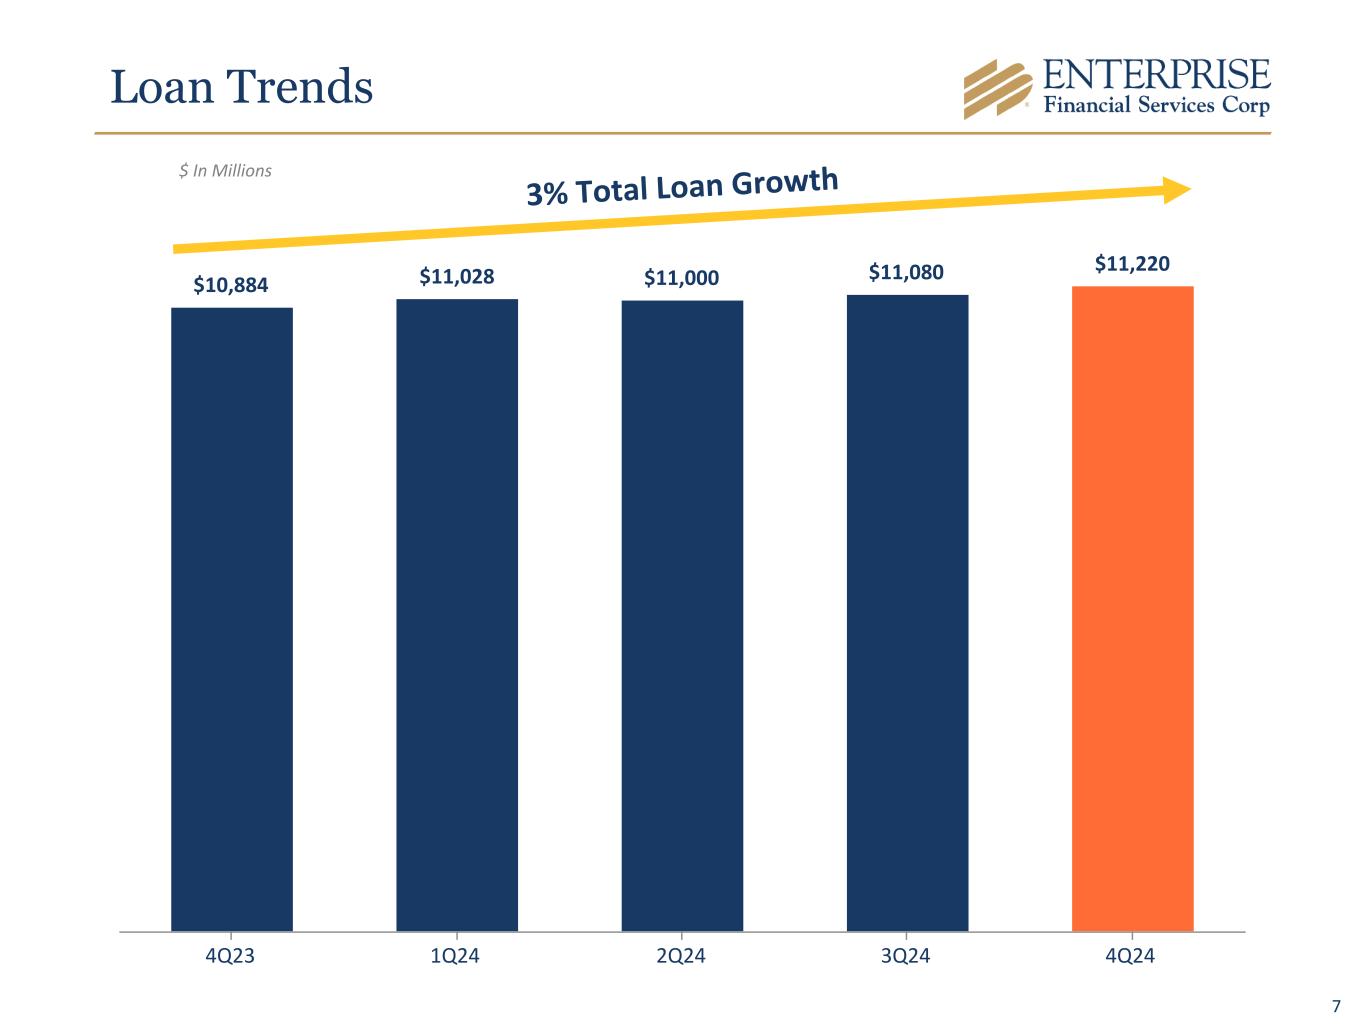
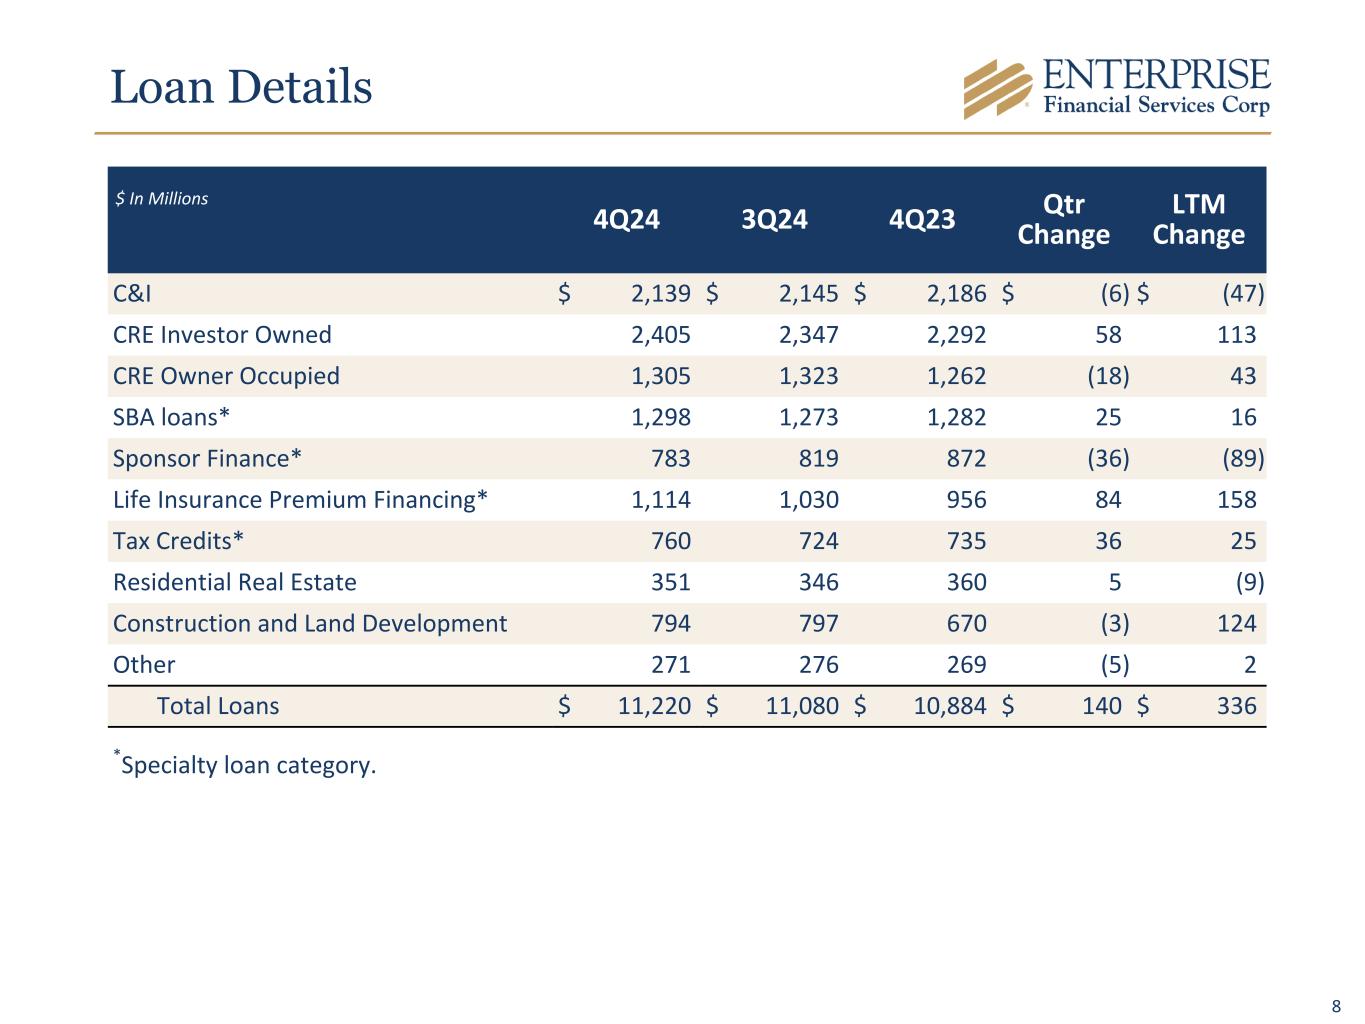
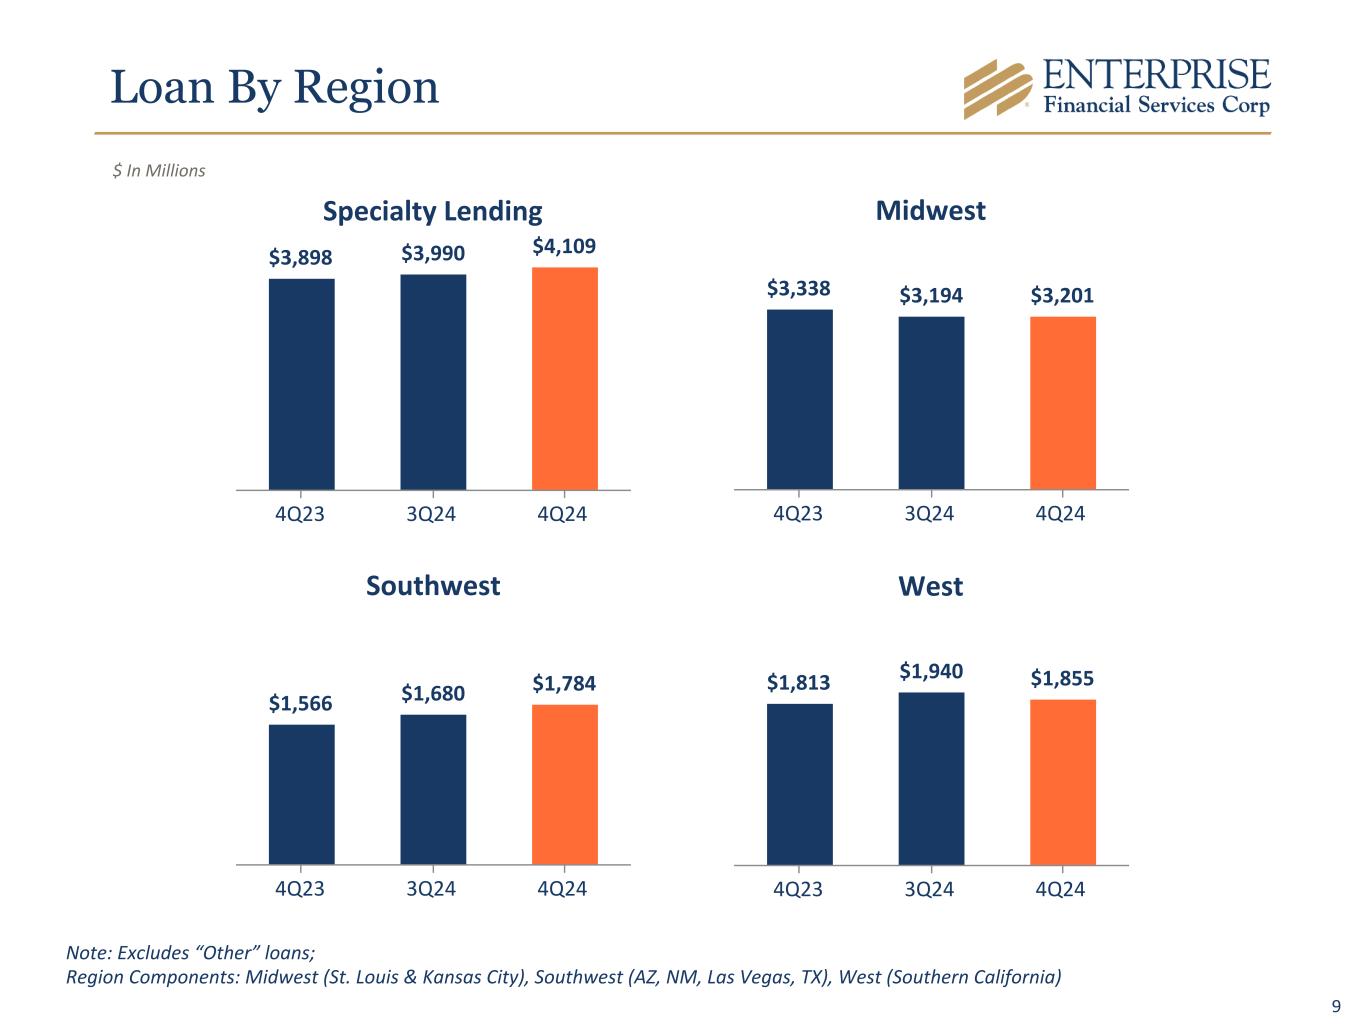
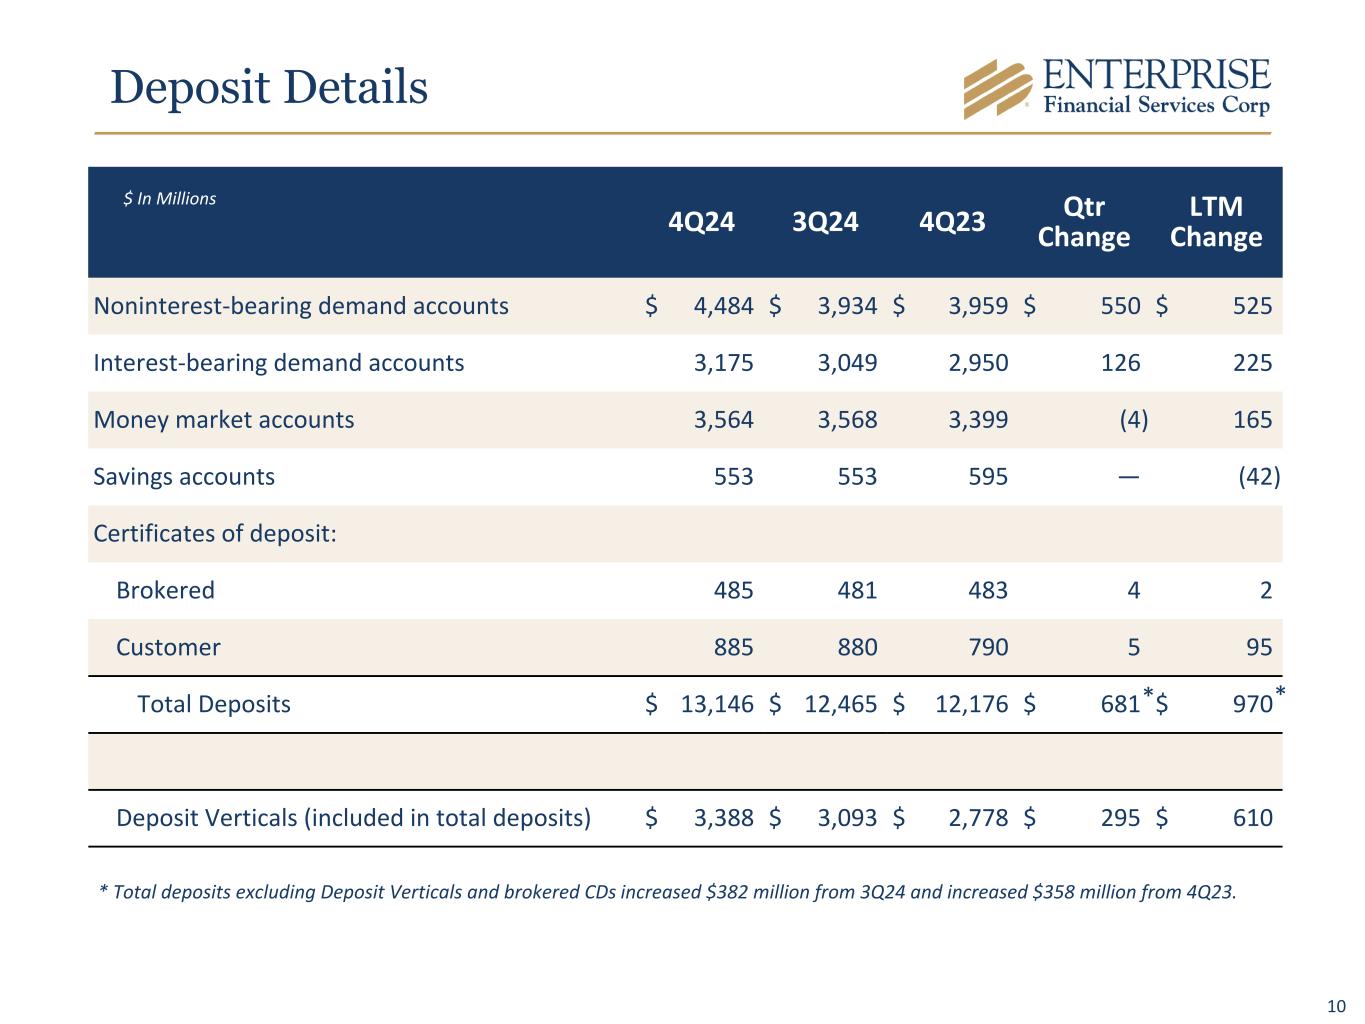
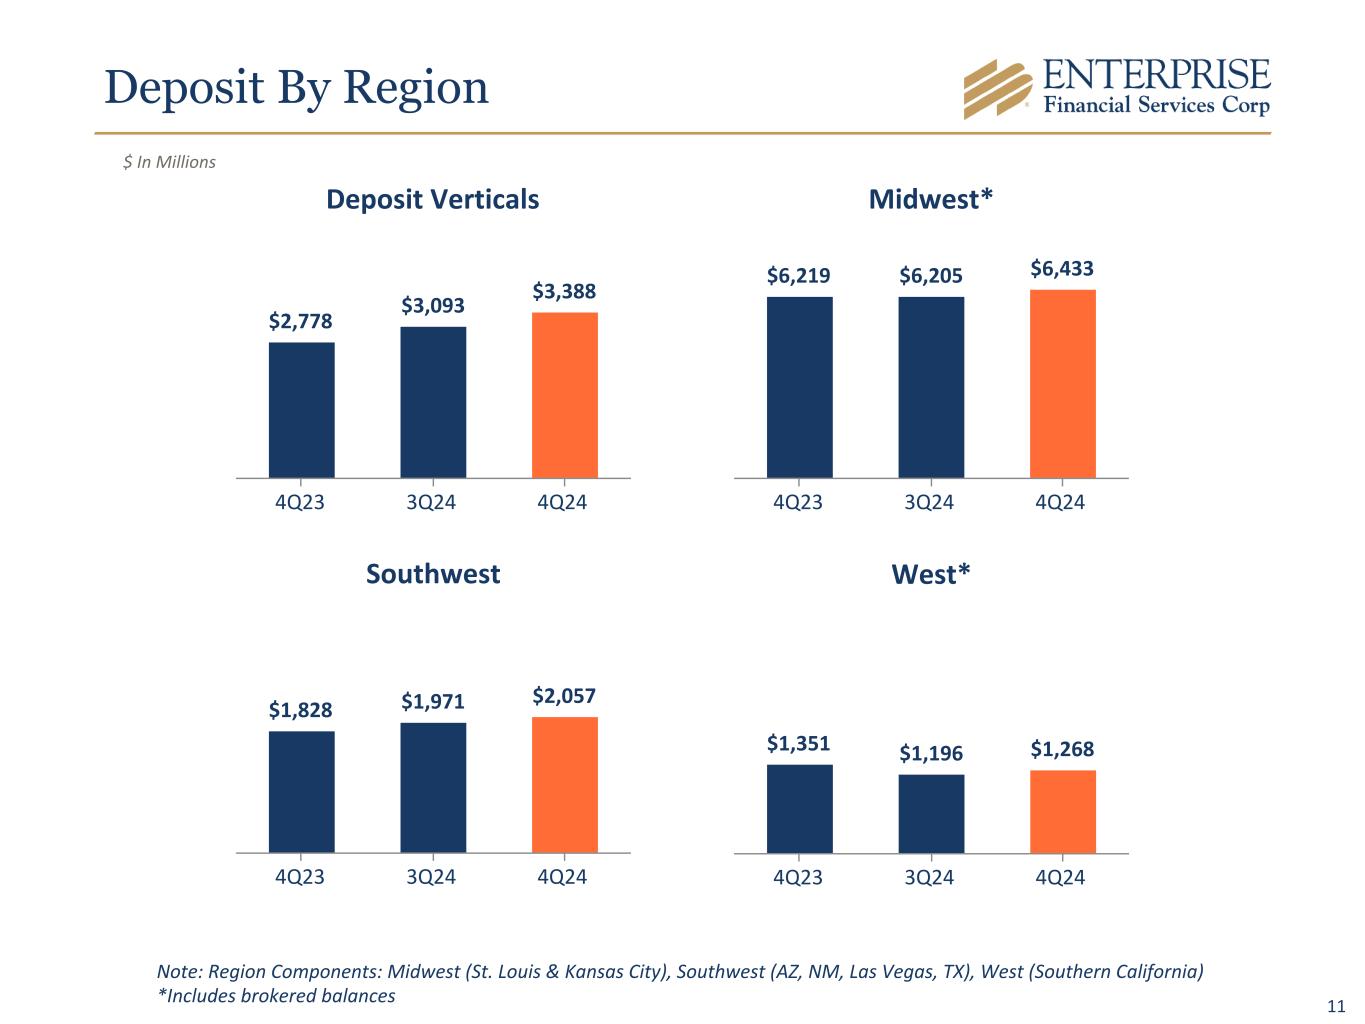
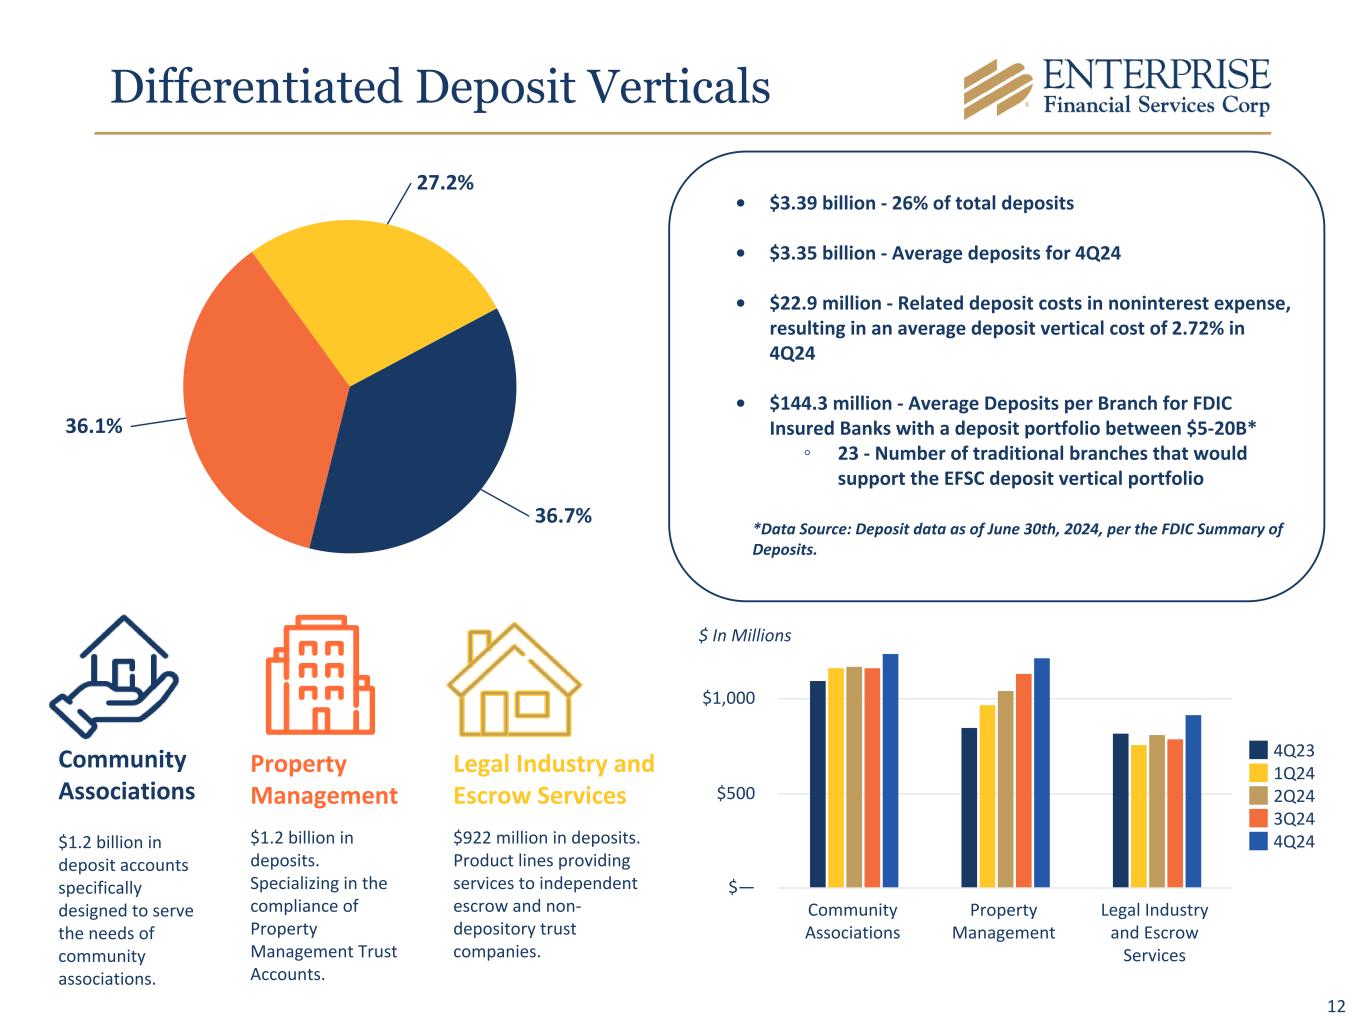
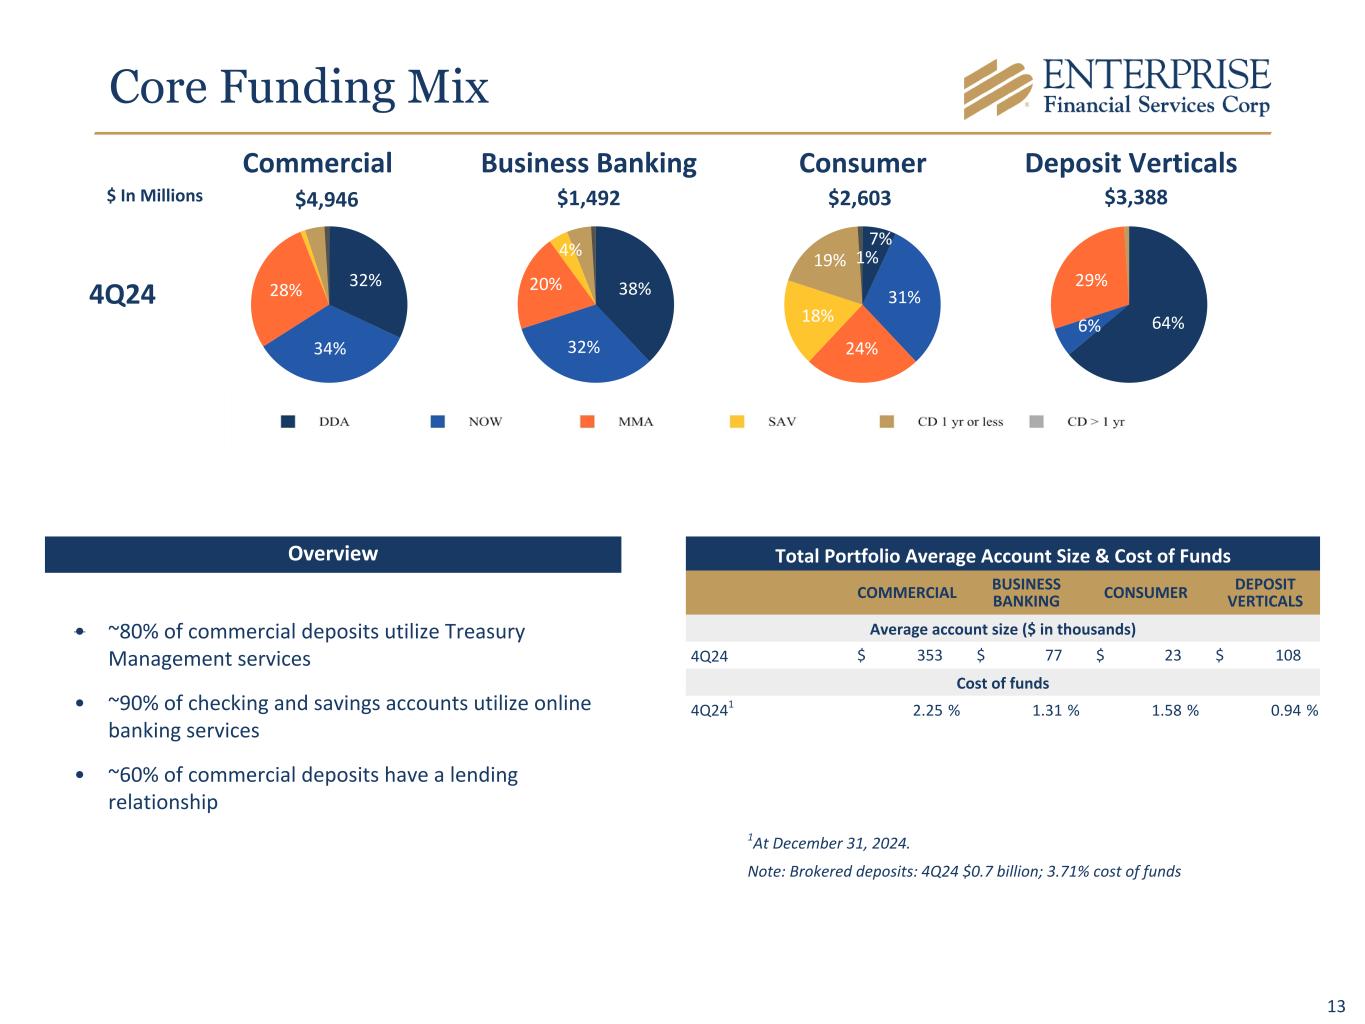
Thank you, Jim, and good morning, everyone. As you heard from Jim, and as we're showing on slides seven and eight, we ended the year with overall loan growth around three percent, including growth in Q4 of 140 million or five percent annualized. Production levels were solid with total originations trending up roughly 20 percent from the prior quarter. Increases were most prevalent in the general CNI construction and life insurance premium finance segments. However, net growth within the generalized CNI categories, while improved from the prior quarter, has been somewhat muted by operating businesses using lines of credit more sparingly and, in many cases, opting to use cash reserves to fund working capital means. Average usage on revolving lines declined about 2.5% in the quarter, with outstanding balances down $135 million from September 30th. Construction loan outstandings continue to fund on existing projects, with additional new project opportunities starting to come back online following a pause during the rising rate environment last year. Within the specialty lending verticals, life insurance premium finance and tax credit posted seasonally strong quarters, growing $84 million and $36 million, respectively. For the year, life insurance premium grew $158 million, or 16.5%, showing continued momentum from premium fundings on existing policies and bolstered by new opportunities from a growing base of referral partners. This business has proven over the years to be a steady and consistent source of growth with a certain level of immunity to overall economic headwinds while adding some balance and diversity to complement our other lines of business. SBA also posted a strong quarter growing 25 million or 7.9% annualized. Trends in this business are tracking well with production up materially in the quarter and payoffs continuing to moderate due to the lower interest rate environment. Overall, payoffs were down 26% in 2024 compared to 2023. For the sponsor finance business, 2024 was a year characterized by float origination and a bubble of payoff activity resulting in a net reduction in the loan portfolio of roughly 10%. Having been in this specialty now for nearly 20 years, we do understand it can be a more cyclical business, and we're prepared to exercise discipline in our origination process to protect the credit quality of our portfolio, as well as the reputation we've built with our sponsor Deal flow has picked up a bit in the latter part of the year, and the pipeline is active. Over time, the book has grown nicely and provided solid risk-adjusted returns with a three-year compounded growth rate of 15%. Moving on to the geographic regions on slide nine, the Midwest region of St. Louis and Kansas City grew modestly in Q4 to $3.2 billion, with the aforementioned revolving line paydown and sale of some commercial properties muting solid production of new CNI relationships. In St. Louis, we expanded relationships through equipment financing for a regional transportation client, as well as funded a new facility for a long-term client in the diversified energy services business. In Kansas City, we help several companies with acquisition and recapitalization credit facilities. As more and more companies face the issue of succession, we are seeing opportunities to assist with this process, and our team has developed a strong understanding of how to put these deals together to differentiate from other competitors and bring relevant advice and resources to the table for these clients. Growth was particularly strong in our southwestern markets of Arizona, Las Vegas, New Mexico, and Texas, with Q4 balances growing $104 million. For the full year of 2024, this region posted loan growth of $218 million, an increase of 13.9%. In addition to a strong base of funding on existing construction projects, we're seeing a higher level of new construction and commercial real estate opportunities in this region, particularly in the Arizona and Las Vegas markets. Larger deals this quarter included fundings for a large pre-leased industrial building, an equipment loan for a private tour operator, and several mixed-use investments by commercial real estate clients. In California, representing our West region, loan balances slipped $85 million during the quarter, mostly attributable to timing on some larger line paydowns and proactive management of several weaker credits out of the bank. These were legacy clients of the acquired portfolio tied to undersecured or non-cash-flowing commercial real estate collateral. With steady new production coming from our core team in this market and success in attracting new season talent to our platform, we feel confident in the near and long-term prospects for growth in California. We continue to target disruptive competitors in this market and move new banking relationships to enterprise, including this quarter clients in the professional medical, industrial, chemical, and digital media business line. Deposits are profiled beginning on slide 10. This shows strong growth of $681 million in Q4, and year-over-year growth of $970 million, or 8%. It is notable that this growth is almost entirely attributable to core client deposits, with no material change in brokered balances. The growth in Q4 was also heavily concentrated within non-interest-bearing categories, with contributions coming from both our commercial market and the national deposit verticals. With rates beginning to fall during the quarter, our teams also did a nice job of retaining relationship-based interest-pairing balances, while supporting an effective rate reduction plan, which effectively lowered our overall funding costs. Keen will have more on this in his comments. Within our geographic markets, commercial deposits were up $382 million in a seasonally strong fourth quarter, but also reflects our success in onboarding new relationships. As outlined on slide 11, deposit costs rose in all regions, I'm sorry, deposits rose in all regions during the quarter, as well as within our deposit verticals. The geographies contributed roughly 56% of the increase, with the largest increases coming from the heavier CNI markets of St. Louis and California. Midwest region balances are up 3.4% year-over-year, including $228 million or 14.6% annualized in the quarter. Growth within the Southwest markets continue at a steady pace, up 12.5% year-over-year. Balances in Q4 were up $86 million, including several new deposit-heavy commercial relationships with a large electrical contractor and an industrial warehousing company. West region balances also show strong seasonal growth in the quarter, as well as the benefits of new C&I relationships with construction, private lending, and dispersing companies. Balances there were up $72 million in the quarter, or 24% annualized. The deposit of verticals contributed $295 million of the increased balances for the quarters and continue a steady pace, providing year-over-year growth of $610 million or 22%. More detail is shown on slide 12, which illustrates the portfolio that is well-balanced between the three main verticals. Q4 produced increases in each business line at an average cost of 2.72% or a reduction of 20 basis points from the prior quarter. Growth in property management in Q4 and previous quarters follows a consistent pattern of continuing to onboard new relationships and expand account balances with existing clients. Community associations had a strong Q4, mainly attributable to new relationships which began funding during the quarter and which should add solid momentum to this business into the first part of 2025. legal and escrow also posted robust growth in key four and while this can be a bit lumpy quarter to quarter we have grown the balances and diversity in this channel year over year as we build our reputation in this space and extend this expertise into our existing geographic markets with our established clients and clis lastly core funding mix is outlined on slide 13 and shows an overall profile of the deposit portfolio by channel and mix within each. Generally speaking, our strategies have briefed the portfolio that is well-balanced, relationship-driven, and highly weighted in lower cost account types. I continue to be encouraged by our ability to lean into a value-added model to proactively manage the deposit costs down while retaining our relationship base and competing effectively for new clients across all of our major channels. Now, I'll hand the call over to Keane for the Financial College. Keane.
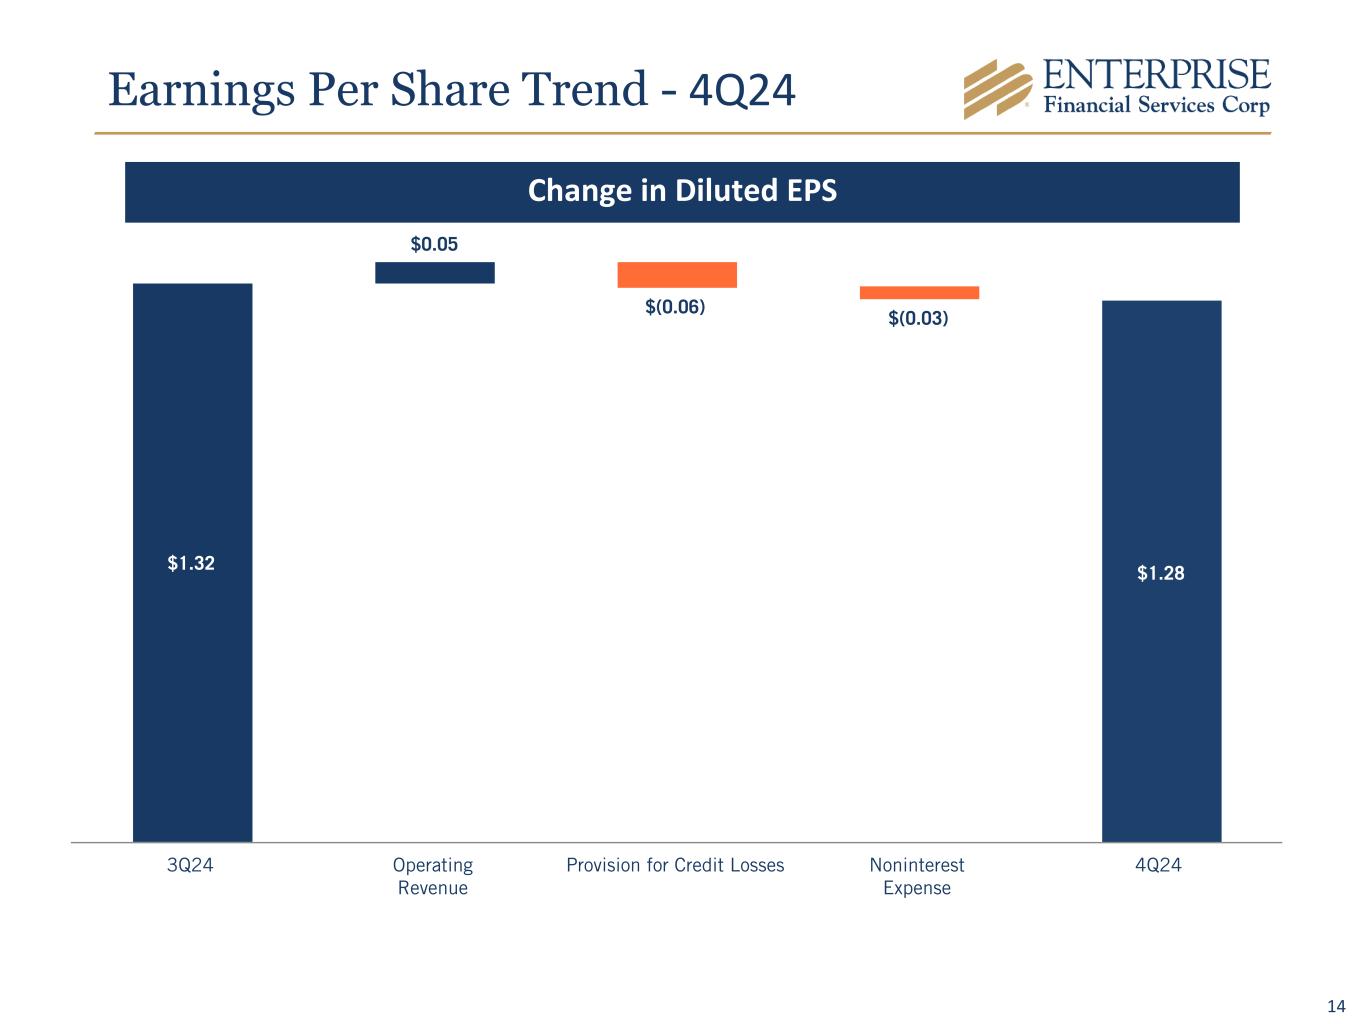
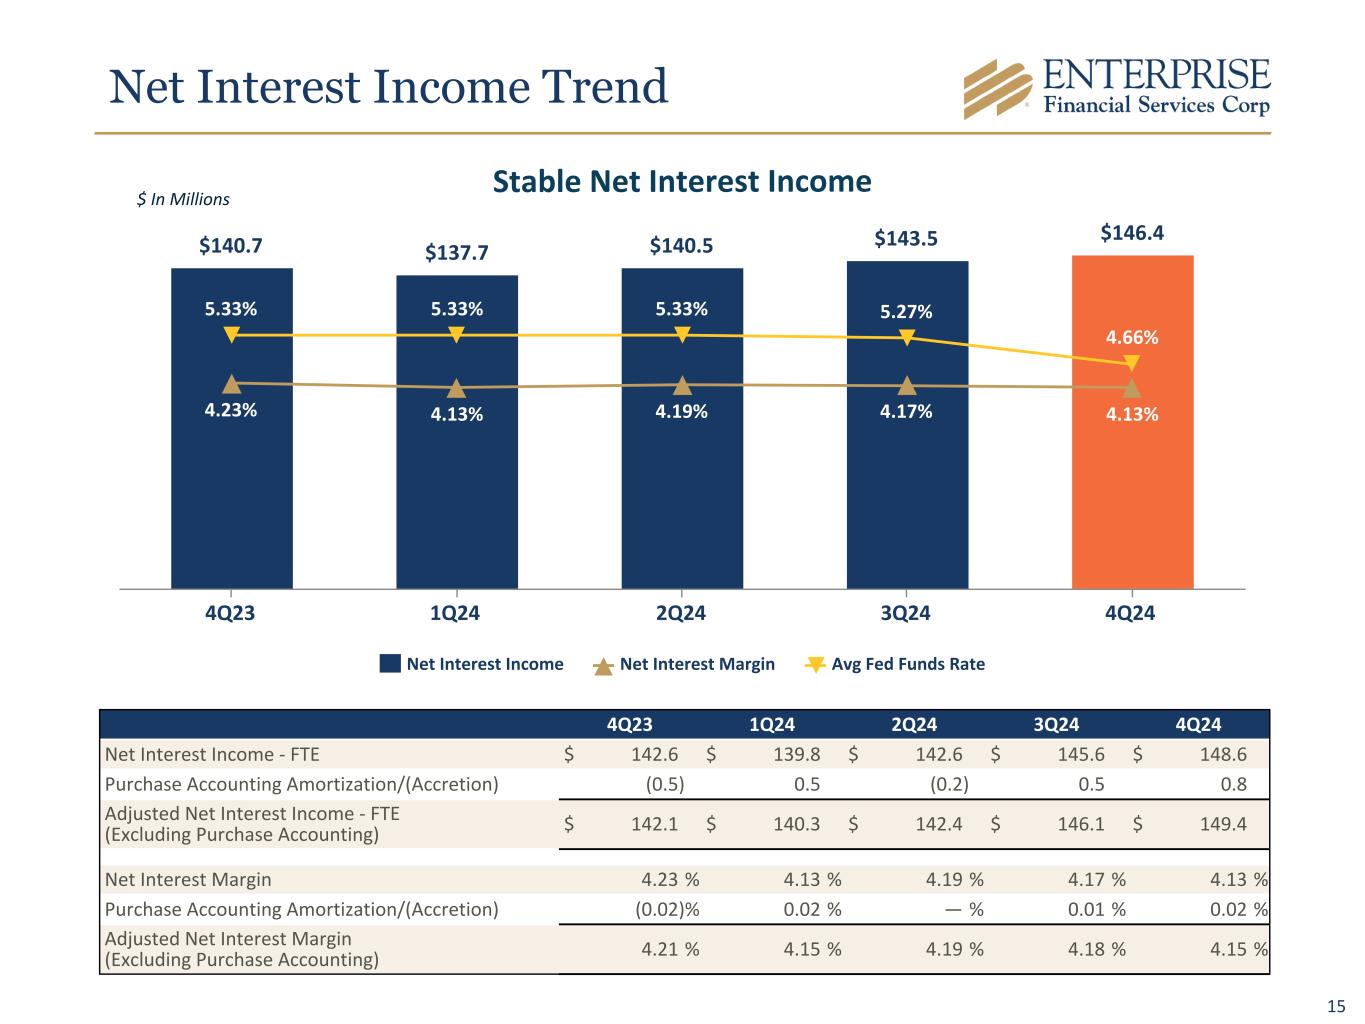
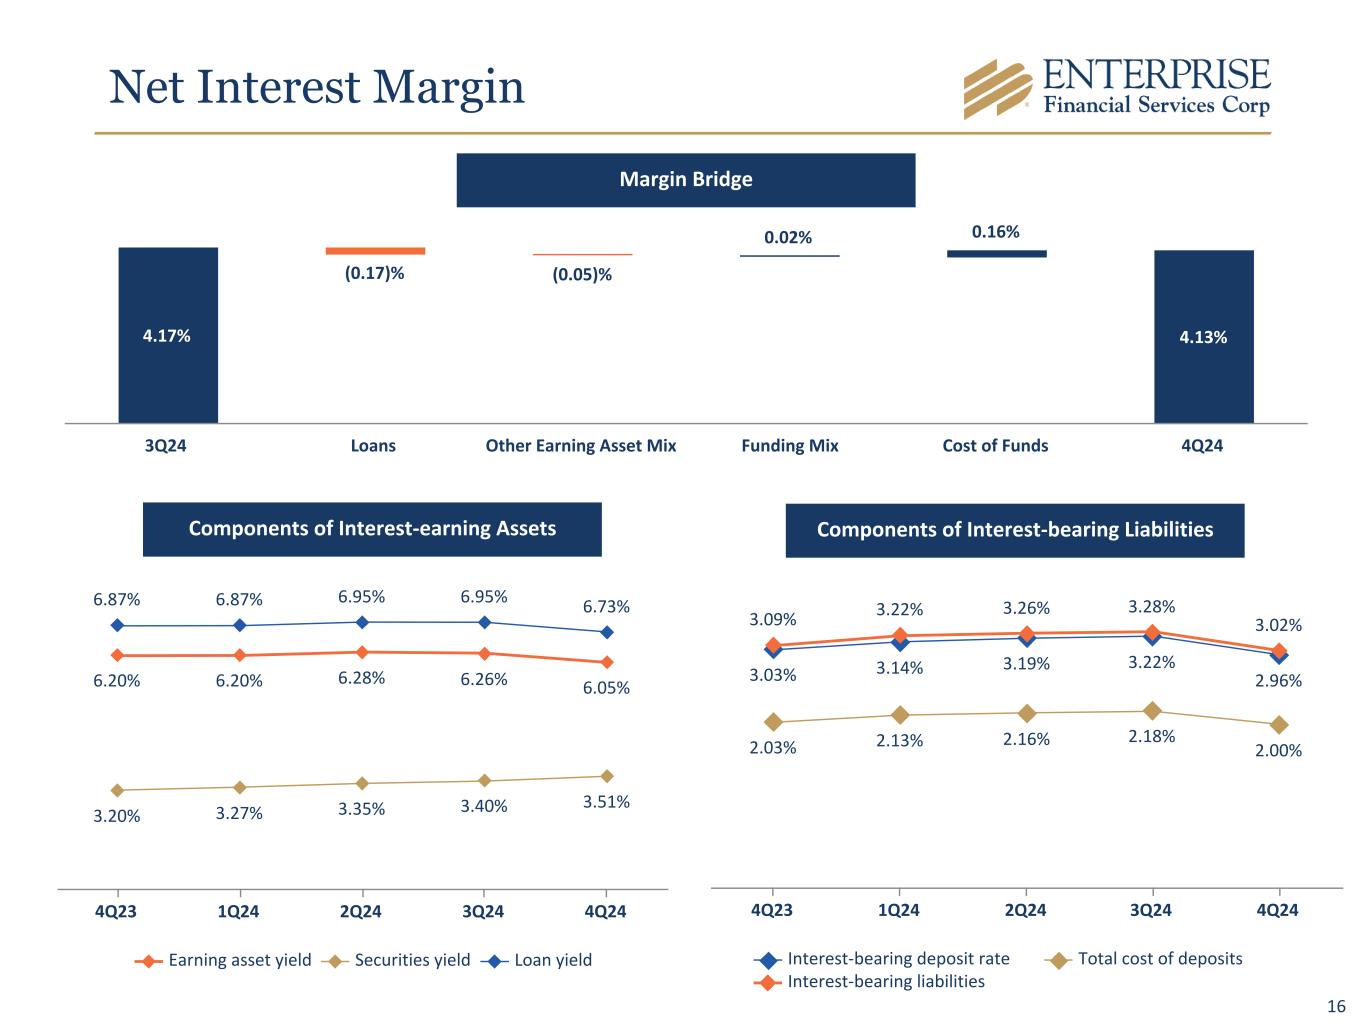
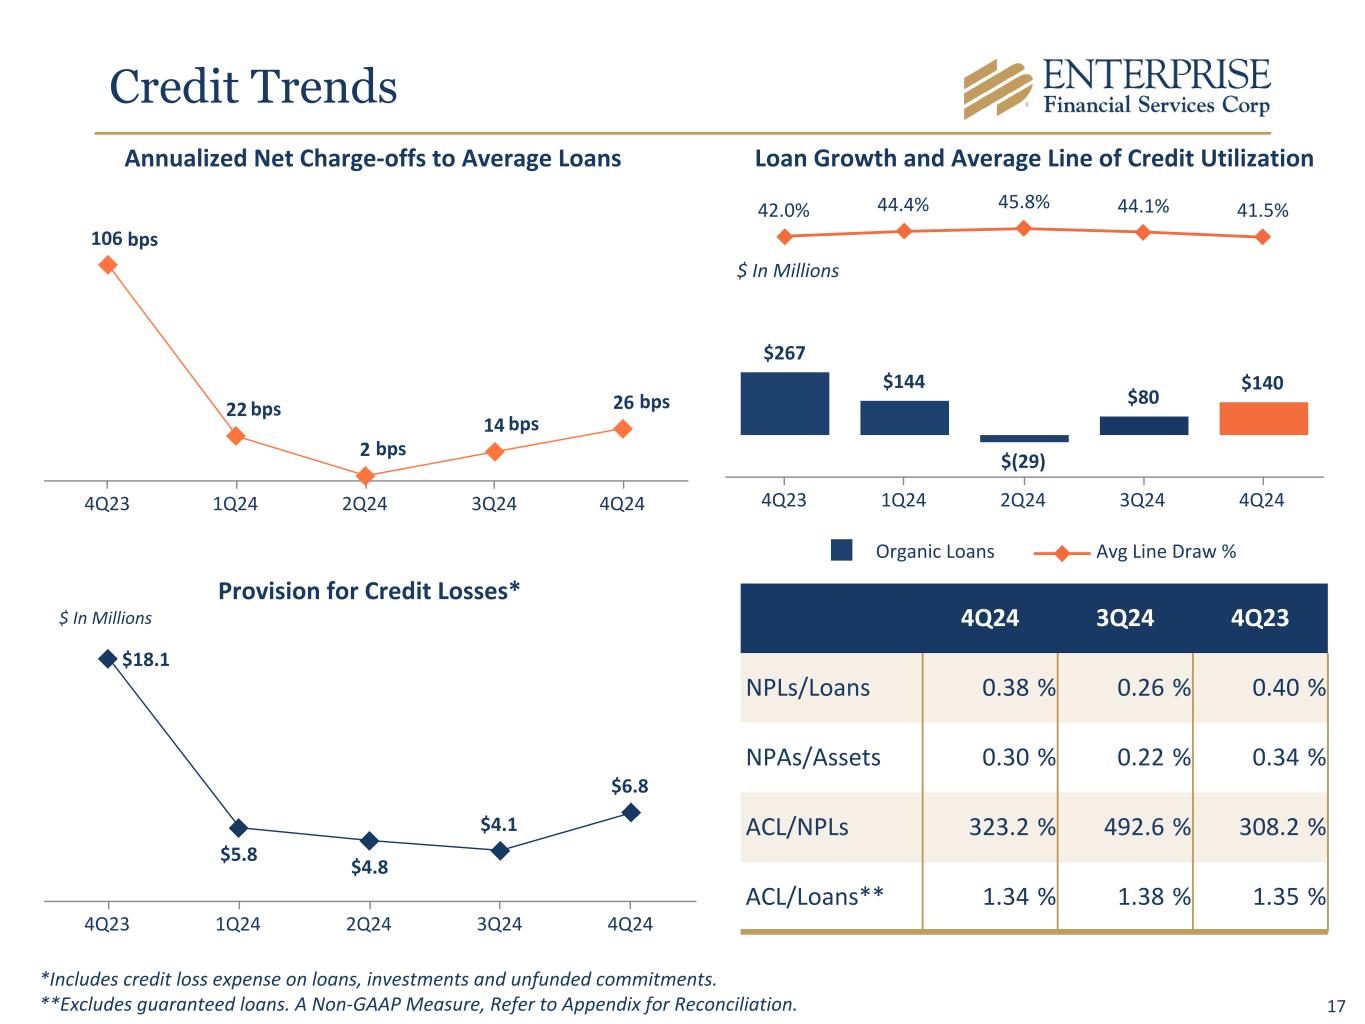
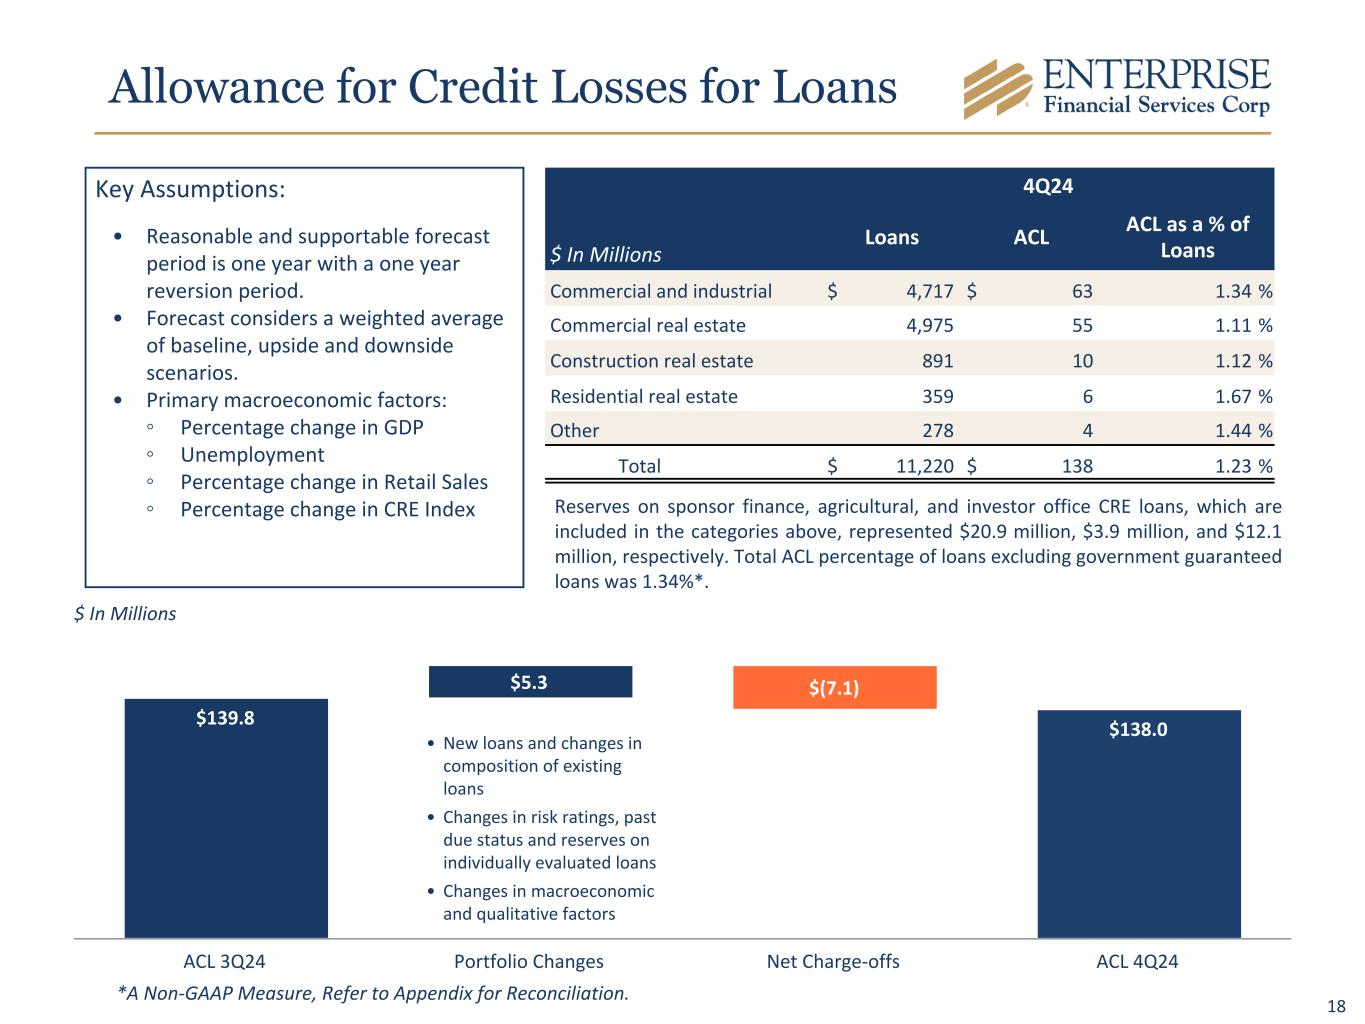
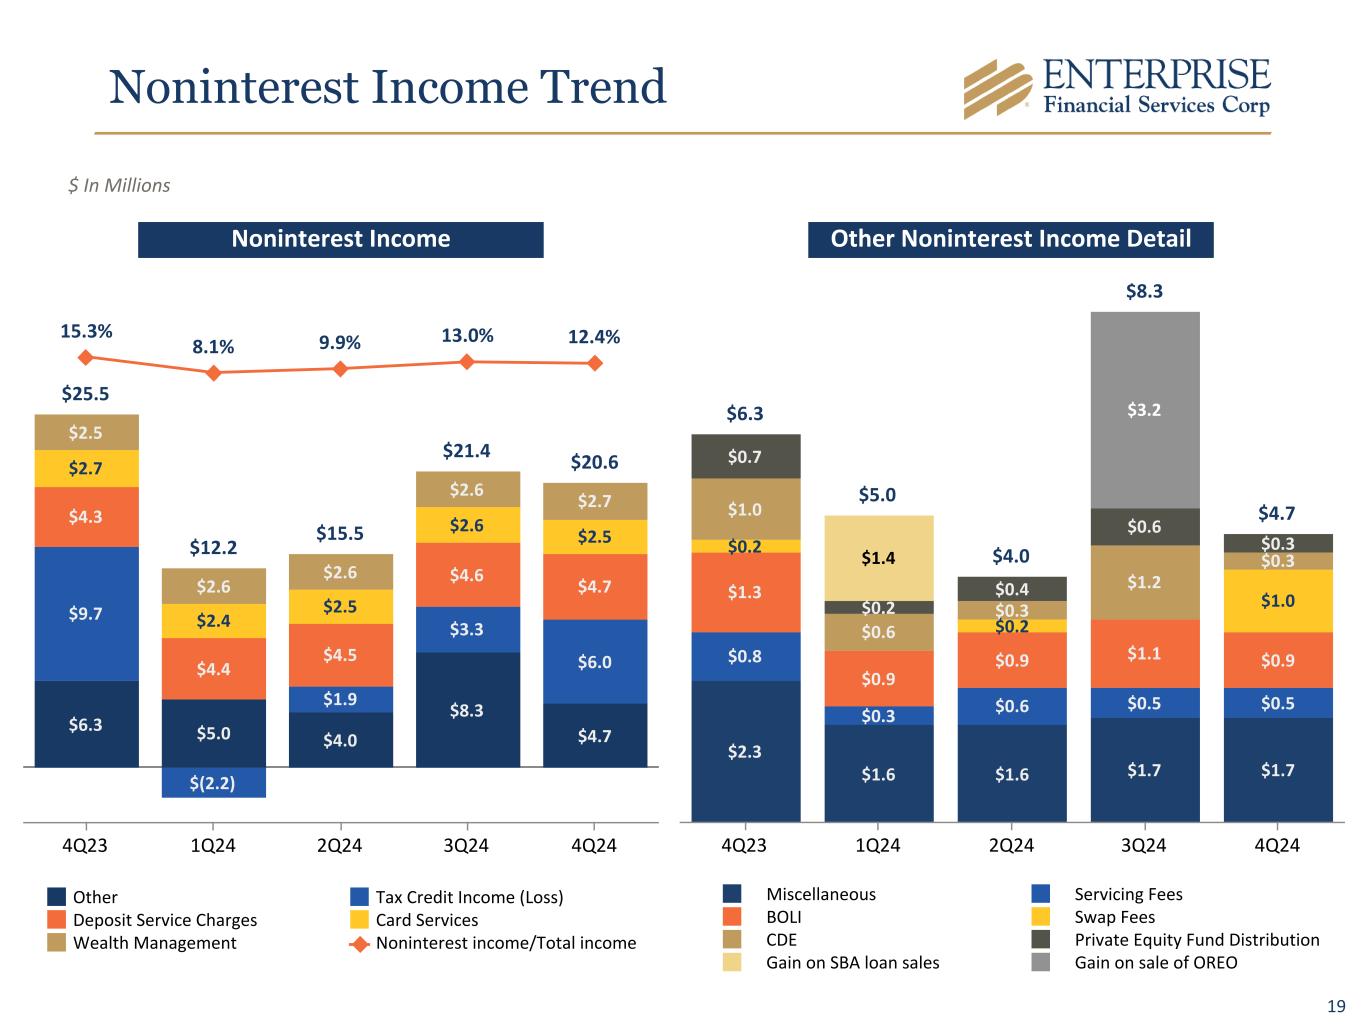
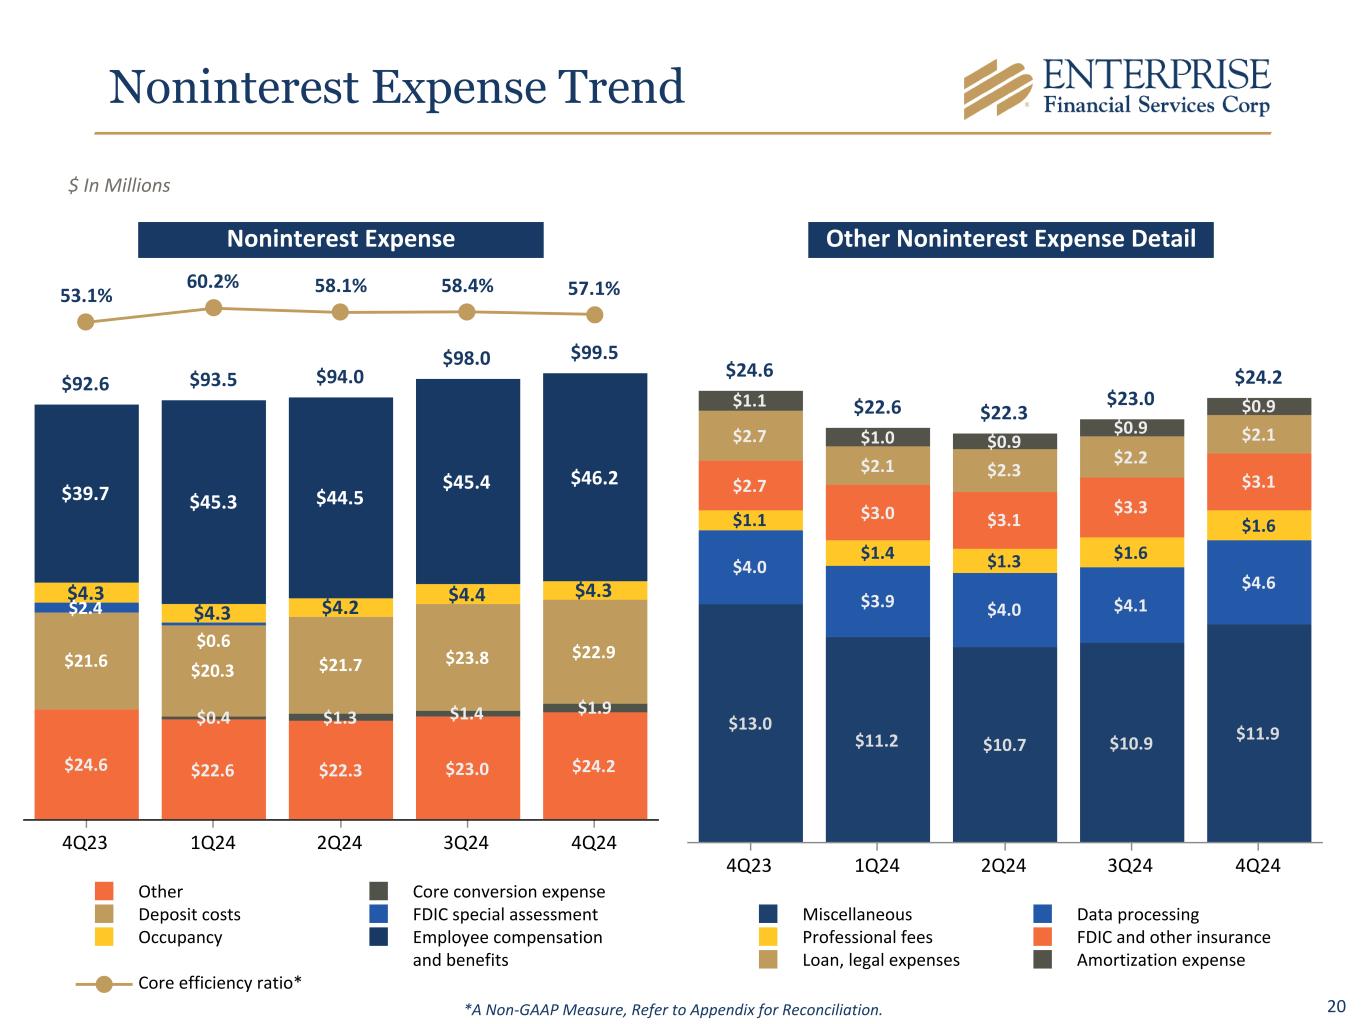
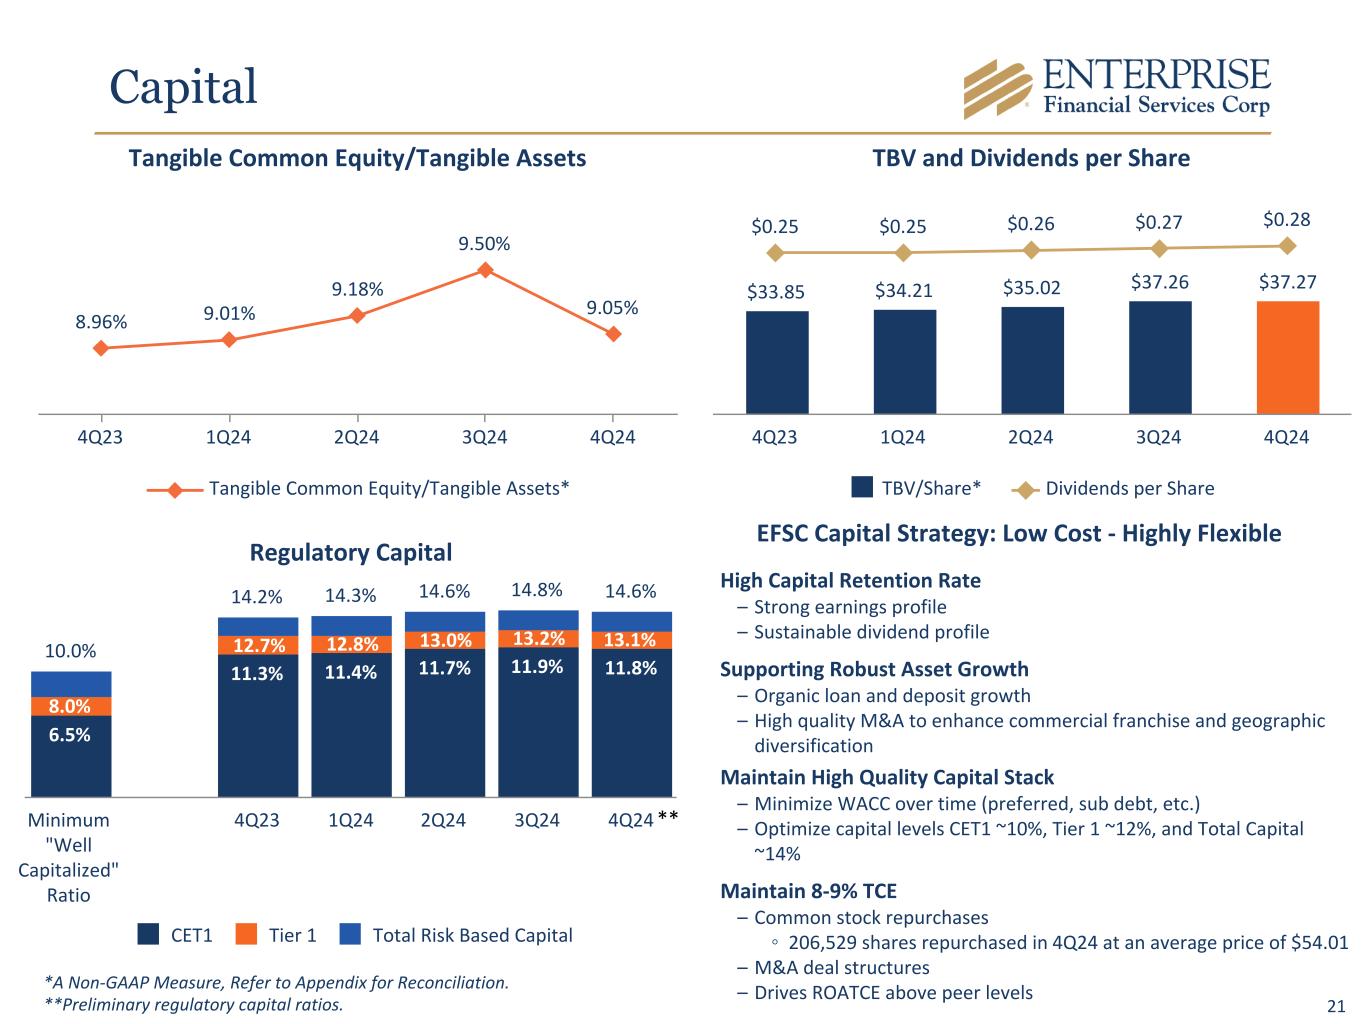
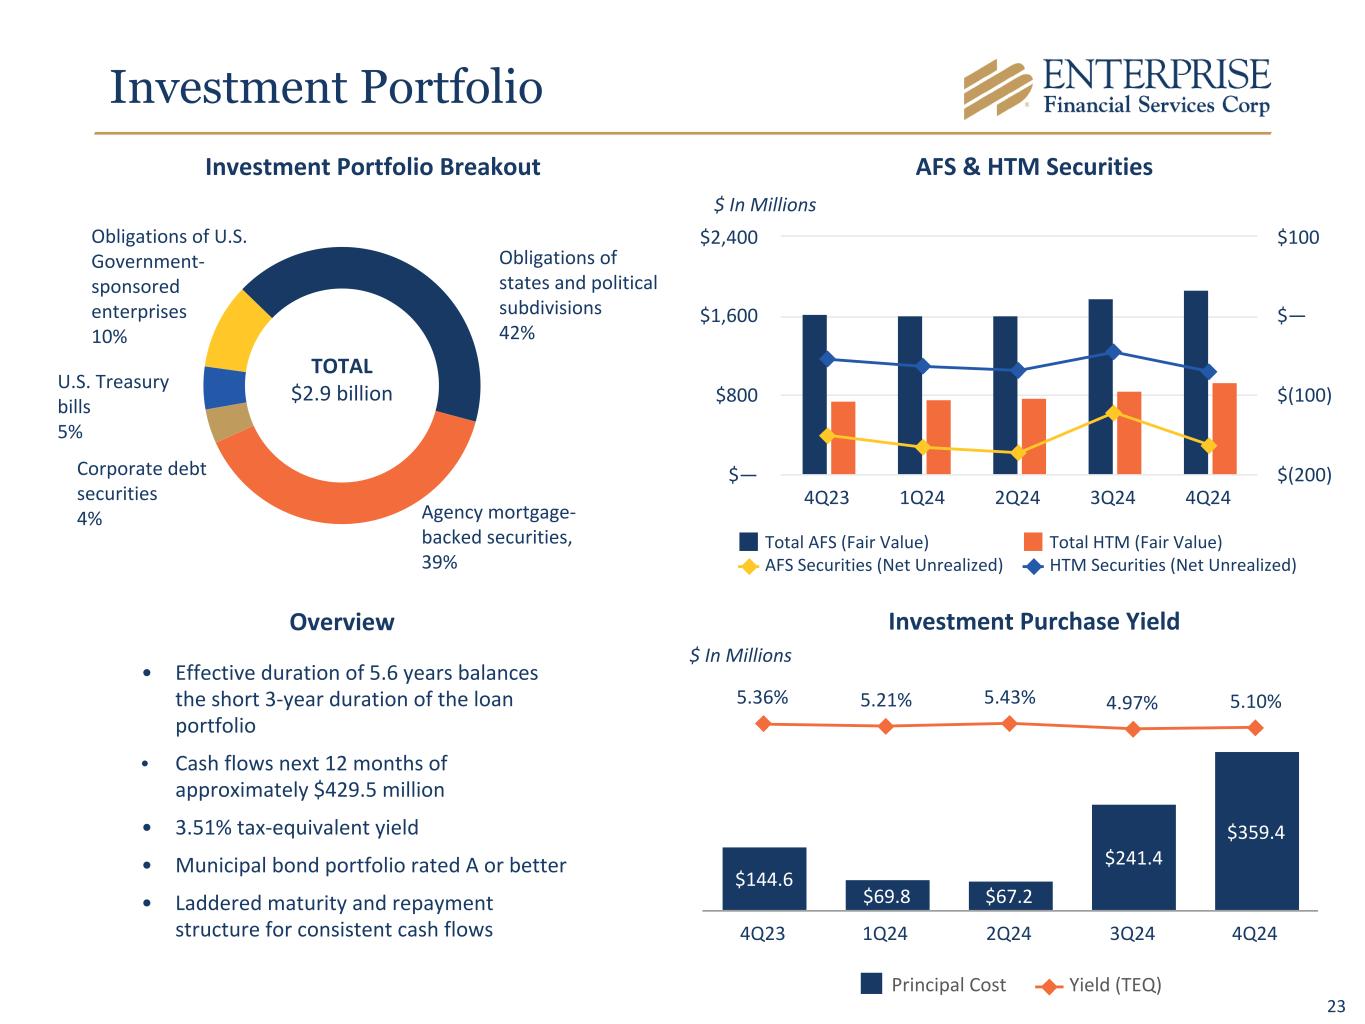
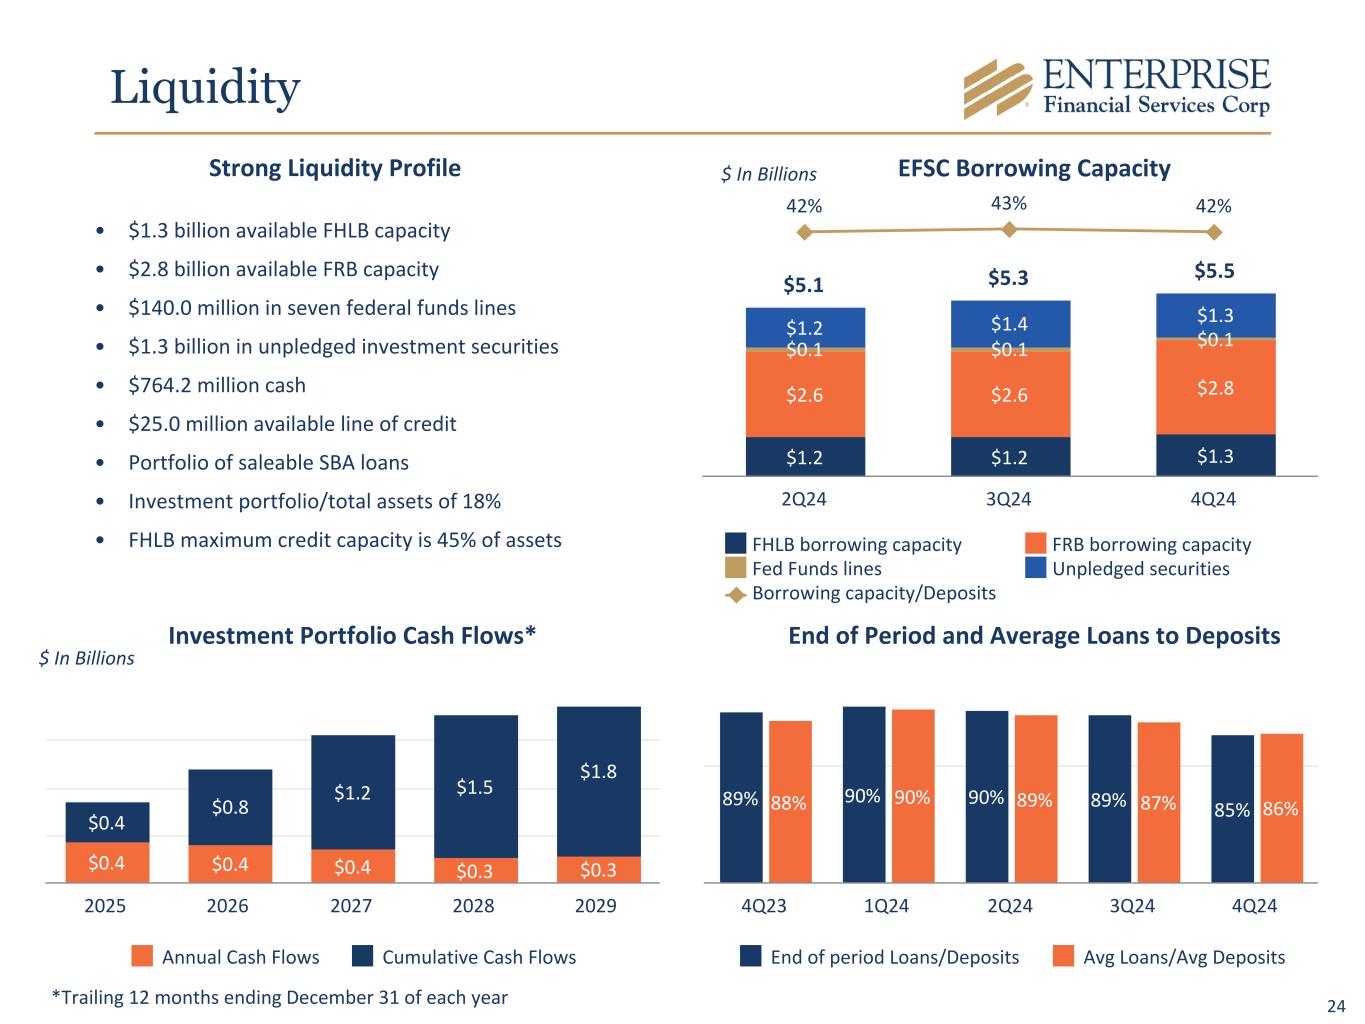
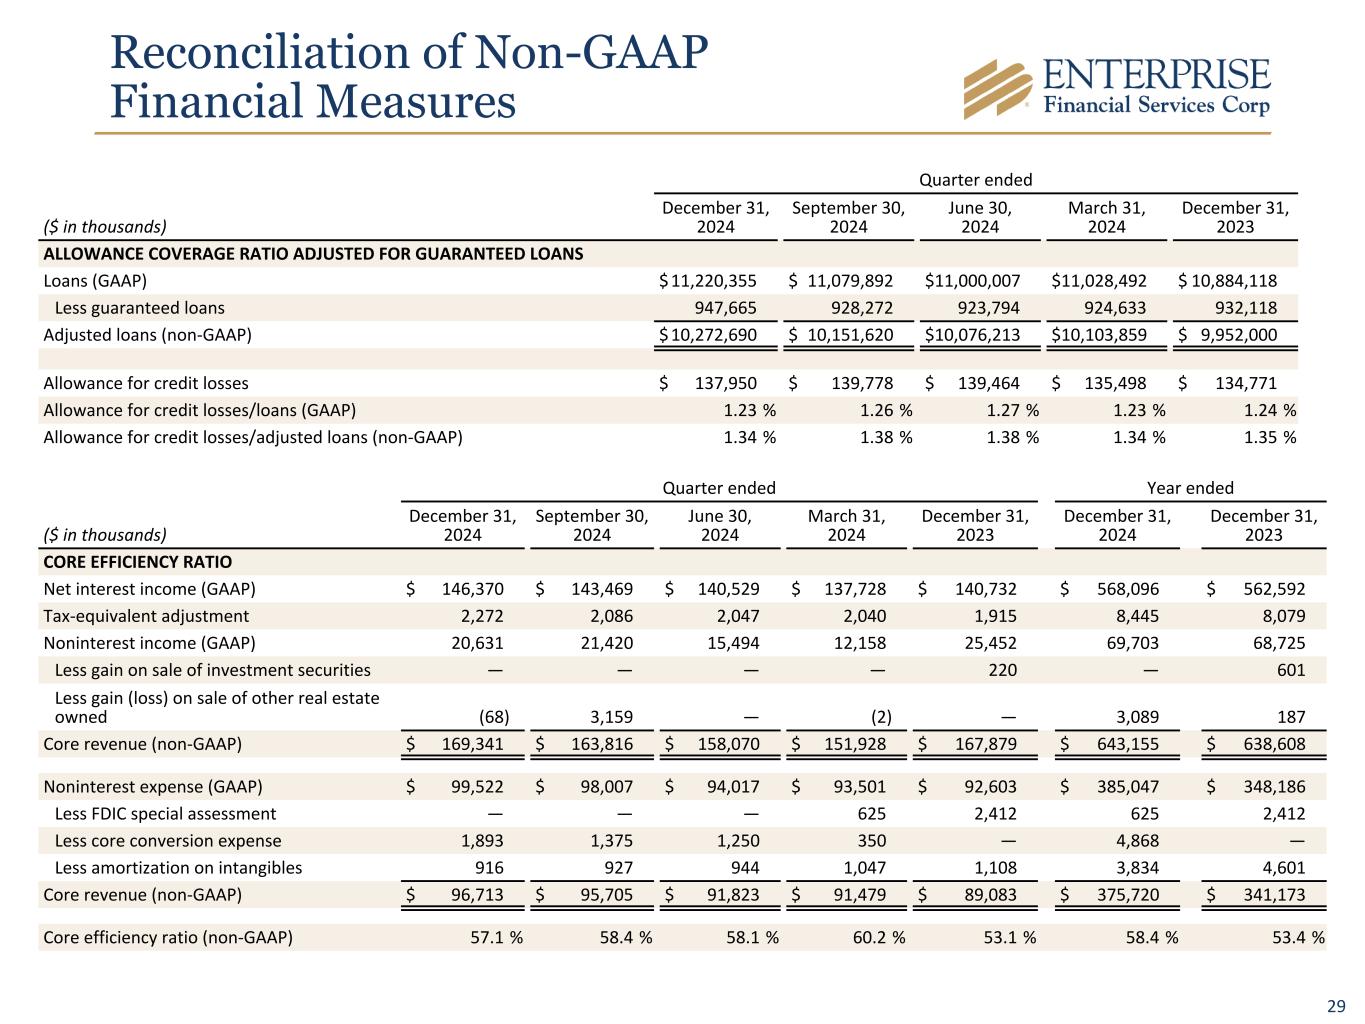
Thanks, Scott, and good morning. My comments begin on slide 14, where we reported earnings per share of $1.28 for the fourth quarter on net income of $49 million. On an adjusted basis, earnings per share was $1.32, a three-cent increase from adjusted EPS of $1.29 in the third quarter. Adjusted EPS excludes the impact of core conversion-related expenses, gains and losses on the sale of other real estate, and FDIC special assessment charges. Operating revenue contributed an increase to EPS again this period as net interest income expanded for the third consecutive quarter. Strong client deposit growth improved overall liquidity and drove an increase in the securities portfolio, cash balances, and related interest income. We proactively managed deposit rates with a decrease in the Fed Fund's target rate so that the decline in loan income was offset by a corresponding decrease in deposit interest expense. The provision for credit losses increased from the prior quarter as total loans expanded and net charge-offs increased. overall asset quality remained sound, and net charge-offs were 16 basis points for the full year. Non-interest expense increased in the quarter, primarily due to higher compensation for medical costs and variable incentives. The increase in compensation was partially offset by a decrease in variable deposit servicing costs due to a managed decline in the earnings credit rate turning to slide 15 net interest income was 146.4 million dollars in the fourth quarter an increase of 2.9 million dollars compared to the link quarter interest income decreased 0.9 million dollars during the quarter loan income declined 3.9 million from the linked period as lower fed funds prime and sofa rates drove a reduction in earnings on 5.5 billion dollars of variable rate loans. This was partially offset by growth in average balances. Earnings on investment securities grew $2.7 million from the linked quarter on higher average balances and higher portfolio yields. Strong deposit growth in the quarter allowed us to fund $200 million in new investment purchases in addition to the investment growth from the third quarter. Yields remain favorable for new purchases and reinvestment of cash flows with the treasury curve moving 70 to 80 basis points higher during the quarter. The average tax equivalent yield on purchases in the quarter was 5.10%. More details follow on slide 16. Interest expense declined by $3.8 million in the quarter, with nearly all of the reduction attributable to lower interest rate on deposit balances. Average interest-bearing deposits grew $236 million compared to the linked period, mainly in interest checking accounts. The average interest-bearing deposit rate declined 26 basis points, and interest on other borrowed funds declined in the quarter as well as a result of lower variable rates. The resulting net interest margin for the quarter was 4.13%, a decrease of only four basis points from the linked quarter. Earning asset yields declined by 22 basis points, driven mainly by lower yields on variable rate loans and interest earning cash balances. This was partially offset by improvement in investment yield and growth in earning asset balances. Our cost of liabilities decreased by 26 basis points compared to the length period, resulting from active rate reductions and growth that was skewed toward non-interest bearing and lower interest rate checking accounts. The total cost of deposits for the month of December was 1.91%, which is nine basis points lower than the 4Q average. While net interest margin did drift lower, the impact of rate changes was less than we'd anticipated in the quarter. We successfully managed our cost of deposits through recent Fed cuts, and deposit growth in the quarter outperformed in terms of both volume and composition. Our balance sheet remains modestly asset-sensitive overall, but sensitivity has declined. We have leveraged several quarters of strong deposit momentum to bolster the investment portfolio, adding durable earnings at favorable yields. The steepening of the yield curve compared to the end of the third quarter, with higher rates on terms two years and beyond, should result in improved pricing on fixed-rate loan originations and renewals. For some color, loans originated in the fourth quarter had an average interest rate of 7.10%, which is above the average portfolio rate. Our deposit mix continues to be a strength. Non-interest-bearing balances accounted for more than half of total deposit growth during 2024, and we remain focused on managing our deposit costs appropriately as rates change. Finally, interest rate swaps and collars provide protection against more severe downward movement and rates. That being said, we expect that further rate cuts will continue to put some pressure on net interest margin. Our modeling shows that each 25 basis point change in rates equates to approximately five basis points of margin, or 1.5 to 2 million, of net interest income per quarter based on the existing balance sheet. Consistent with the prior period, we expect deposit-related non-interest expense to move in the opposite direction, with each quarter point cut resulting an approximately $1 million of reduced non-interest expense. So all in, the total impact of each 25 basis points of Fed cuts is around $1 million or less of pre-tax income. To summarize all that, we look for net interest margin to be relatively stable once the balance sheet resets to start the year, somewhere around 4.10%. Net interest income dollars will face a headwind with lower day count the first quarter, but we believe our planned growth is sufficient to overcome those setbacks and will result in higher net interest income during the year. Slide 17 reflects our credit trends. Net charge-offs were $7.1 million for the quarter and $17 million for the year, or 16 basis points of average loans in 2024. This is an improvement from charge-offs of 37 basis points in 2023 and is a positive reversion toward our expected longer-term trend. Non-performing assets were 30 basis points of total assets compared to 22 basis points at the end of September. The eight basis point increase in non-performing asset ratio was primarily related to two relationships that are being actively managed and are adequately reserved. Our credit metrics have been relatively stable all year and reflect the underlying strength of our diversified loan portfolio. The increase in net charge-offs in loan growth resulted in a provision for credit losses of $6.8 million in the quarter, an increase of $2.7 million compared to the third quarter. Slide 18 presents the allowance for credit losses. The allowance for credit losses represents 1.23% of total loans, or 1.34% when adjusting for government-guaranteed loans. The weighted economic forecast used in the allowance calculation means more towards a downside scenario for the next 12 months. On slide 19, fourth quarter fee income of $21 million was essentially flat with the linked quarter as growth in tax credit income offset the gain on sale of other real estate that was recognized in the third quarter. Tax credit income was better than expected as sales activity outpaced fair value pressure from the increase in 10-year SOFR. Turning to slide 20, non-interest expense of $99.5 million was an increase of $1.5 million from the third quarter, driven primarily from compensation and benefits, seasonally higher charitable giving levels, and core conversion expenses, which were partially offset by lower deposit servicing expenses. Core conversion expenses were $1.9 million in the current quarter compared to $1.4 million in the prior quarter. Deposit servicing expenses were $0.9 million lower compared to the link quarter, despite average balance growth in the deposit verticals of roughly 12% annualized, as related earnings credit percentage were managed lower during the quarter following recent Fed funds interest rate reductions. The fourth quarter's core efficiency ratio improved 130 basis points to 57.1%, driven by higher operating revenue compared to 58% 0.4% for the linked quarter. Our capital metrics are shown on slide 21. We continue to manage our excess capital and repurchase 206,000 shares at an average price of $54.01 for approximately $11 million. We have approximately 1.4 million shares remaining under our repurchase plan. Our tangible common equity ratio was 9.05% at the end of the fourth quarter, down from 9.5% in the link quarter. The decrease was primarily due to strong balance sheet growth and a decline in the overall fair value of the available-for-sale securities portfolio. We will continue to monitor our capital levels and manage some of our access position with share repurchases. On a per share basis, tangible book value of $37.27 was stable with the link quarter and increased 10% for the full year. This is in line with our 10-year compound growth rate for tangible book value per share of just over 10%. For 2024, the common dividend per share was $1.06, a 6% increase from 2023. We also increased our dividend by $0.01 per share to $0.29 for the first quarter of 2025. In summary, our 2024 financial results reflect the strength of our diversified business and we closed the year demonstrating the high quality of our deposit base for the second consecutive year we significantly grew core deposits while expanding operating revenue supported by solid credit and managed expense levels we also invested in a new core system and recruited new talent in our higher growth markets in support of our expectation for continued growth we consistently posted strong profitability and returns throughout the year and we closed the year with a strong fourth-quarter performance. This is reflected in a 1.30% adjusted return on assets and a 14% return on tangible common equity. I appreciate your questions and attention today and we'll now open the line for analysts.
Operator
Thank you. We are now opening the floor for question and answer session. If you'd like to ask a question, please press star, followed by one on your telephone keypad. Your first question comes from Jeff Rolus, from DA Davidson. Your line is now open.
Thanks. Good morning. Morning, Jeff. I wanted to check in on the margin. Keen, thanks again for the kind of per-cut impact to the margin and the ECR cost. It seems like reality is a bit better than what you've previously framed up, as you mentioned, the steeper curve and good deposit success. So So the 410 expectation, does not include a rate cut in that expectation or does?
Yeah, Jeff, I would say 410 includes the reset predominantly of the SBA portfolio that didn't occur until January 1st. So there's a little bit of pressure to come. we're working to still mitigate that. But I think that's just a delayed impact because that resets quarterly. So that's 50 basis points on, you know, almost three quarters of a billion dollars. And then, you know, so there's no cut. And then I would also say it allows us a little bit of reversion on the mix of deposits. Deposits have held, you know, growth was strong in the fourth quarter and deposits have held well since then. But we do expect a little bit of remixing in the early part of the year is we typically get commercial DDA balances, some deployment with tax payments and bonuses on the underlying clients that experience some run up throughout the year. So those are a couple of things that we see that are sort of baked into that. And then I would say we maybe have a little bit of pessimism in there that the curve doesn't remain optimally upward sloping for that period of time. I mean, I think you can see with what happened in the fourth quarter, we managed to positive cost way better, and we're trying to continue to do that. But certainly, the shape of the curve helped, and we've got a little bit of estimation error built in there if the curve isn't quite as robust on the long end as it is right now.
Sure. Very, very helpful. And, okay, we'll just apply that math on margin with potential rate cuts, I guess, safe to say, I mean, odds have improved at a 4% plus, I don't want to put words in your mouth, but that has framed up firmer than expectations of a sub-4 being likely.
You think, I guess the core, the base around 4, even with cuts, is still potential to hold above that level yeah i i mean i think that unless we get a material degradation in the the slope of the curve or or something unexpected or we're not able to to manage deposit costs as well as we would anticipate or we really have mix going against us i don't expect any of those all three of those to occur at the same time i i do think that we can hold margin you know call it at four plus, even with a couple cuts here this year.
Thanks. My other question was on just expenses and post-conversion. I don't want to, if we, well, one, are there more core conversion costs expected going forward? And two, maybe just kind of reorient where we are on a core basis. And do we see just moderate expense growth from here or expectations on cost would be great? Sure thing, Jeff.
So, this is the last quarter. You should see core conversion-related expenses. If there's anything that trickles, we likely will just have it in the run rate. There's really no material change that we can see to run rate on data processing from that project. And I would say from a recurring expense basis, I think that the quarter is roughly $98 million if you strip that out. And I think that there were some seasonally high items in there that'll be replaced by some seasonal first quarter items. And with the growth offsetting some improvement in ECR, I think deposit-related expenses are roughly level. So I see expenses roughly level to modestly growing throughout 2025. And then I just, whatever you feel like is going to happen from a rate environment perspective, obviously we gave that sensitivity on the expense line item. But if we get, you know, two reductions with, you know, some of the seasonality working out, it's plausible that we'd have, you know, essentially flat, you know, roughly, you know, 97, 98, 99 million, a quarter of non-interest expense for the year.
Okay. Pretty clear. Thanks, Cain. Thanks, Jeff.
Operator
Your next question comes from David Long from Raymond James. Your line is now open.
The non-interest-bearing deposits, you talked a little bit about some of the moving parts there, but does it feel like that is temporary or permanent in the non-interest sparing side of the deposit growth david this is jim i would tell you that we saw we typically in our business what you see is a fourth quarter elevation and dda just based upon uh the growth of service-oriented businesses as keen mentioned in the last question that will dissipate somewhat in the first quarter but nonetheless our model is such that uh the cni model even the cre business we do demand full relationships relative to onboarding clients and what have you. So I think, you know, our ability to grow deposits I'm confident in and the mix being such that we'll still continue to have DDA in that low 30 percent range.
Got it. Thanks, Jim. And then switching to credit, you guys called out a couple of relationships that are being actively monitored. Do these represent any early warning signs in any specific segments or anything like that? in regard to your overall loan portfolio?
Yeah, thanks, David. It's Doug Bauke. Just to kind of level set, too, on where we end of the year, just keeping in mind net charge offs at 16 basis points and non-performers at 30 bps and classifieds, as Keane pointed out, just really remained level. We're at about 11% of capital. So credit quality has simply just kind of returned as we expected to our longer term historical norms. I'm pleased with the way the portfolio performs today. I think a couple of the material movements in the quarter really were one, it was a net charge off, largely related to a CNI chemical distribution company that invested heavily to vertically integrate into manufacturing and quite simply just failed to execute on the strategy so our exposure remaining book balance to that credit is less than a million dollars and then just relative to a couple of non-performers you know we saw non-performers just tick up in the fourth quarter really concentrated to two relationships one is a nine million dollar loan to a cni company that's a medical management and consulting firm the company is seeking refinance opportunity right now and we feel cautiously optimistic that there's a path to exiting the credit in its entirety here in the coming quarter and then smaller and less significant would be a two million dollar owner occupied real estate loan in our kansas city market so generally speaking no we feel really good about the performance of the portfolio and kind of back to historically normal levels.
Got it. Great. Appreciate the color, everyone. Thank you.
Operator
Your next question comes from Damon Del Monte from KBW. Your line is now open.
Hey, good morning, guys. Hope everybody's doing well today. Just wanted to start off with some commentary on loan growth. You know, Jim, it sounded like lots of opportunities for you guys to capitalize on market disruption and benefits from recent hiring efforts in recent quarters. But at the same time, I think somewhat cautious not to push for growth for the sake of getting growth. So just kind of wondering how you'd frame the kind of the full year outlook. Do you think kind of that mid single digit range is still achievable?
I do. I think the mid single digits is very achievable. And to the extent that some of the headwinds I referenced in my comments come to fruition, it might tick up slightly higher than that. But I do think those opportunities, Damon, allow us, to Keane's point about margin, is being selective nonetheless to make sure that we achieve the margin that we target. And again, it's full relationship-oriented and really not doing transaction lending. We feel good about just the tempo that we're seeing with our teams, and not just the ones that recently came on are established teams as well who have deep or deeply rooted in those communities um so i do feel that that mid single digits a very safe number okay and then i started curiosity you know with your operations on the west coast was the were there any impacts to any of the businesses um through the wildfires or you guys not really in those areas yeah david thank you for for bringing that forth first of all we're pleased to report that you know all of our associates are safe. And then with respect to our client base, we did not suffer any type of collateral issues based upon the loans we have out there. And then going forward, I think, you know, we'll just monitor the situation and certainly serve our communities well, serve our clients well in that regard. There's going to be a long rebuild in those communities and we'll be there to help.
Great. Okay. Good to hear on that front. And then I guess just lastly, kind of circling back to the credit, you know, we look at where the reserve level is now, you know, and it seemed like you had a little bit of normalization in credit or net charge off trends, you know, this last quarter or so. Do you think you kind of keep the reserve here in this, you know, call it almost mid-120 range, or do you think you need to kind of add to that?
Good. Damon, this is Keen. I would say, I think we feel good where we are. In my comments, I mentioned that we've got a fairly decent pessimistic view in the qualitative with some downside weighing, and it's about a third of the reserve. So I think there's sufficient pessimism there. And I think that, as Doug mentioned, to the extent that there's a creditor, too, that has a reserve against it with a favorable resolution, you know, that's a reserve release or a reduction in the reserve. So I feel like we're well positioned and I wouldn't expect coverage to move up or down dramatically. And, you know, we're 135 on, you know, unguaranteed loans. So that feels pretty robust, I think, at this point on, you know, pure commercial.
Got it. Okay, great. I appreciate all the caller, thank you.
Operator
Next question comes from Andrew Leash from Piper Sandler. Your line is now open.
Hey, guys. Thanks. You've covered nearly all my questions, but I just want to ask on capital. Regulatory ratios have been growing nicely. I mean, is there to remind us if there's a ratio that you specifically target over the long term?
Yeah, Andrew, you know, our capital targets are, you know, 10, 12, and 14 on CET1, tier one in total. You know, we're a little bit higher on CET1 right now, and we've been managing there. And, you know, I think the rest have sort of grown correspondingly. So, you know, we're trying to be steady with what we do on capital management. Obviously, we had a really great quarter from growth perspective, and we're still doesn't look like we're done yet in terms of having fair values move around so um you know we we try to be below nine percent tce um but it doesn't feel like it's it's hurting us or anyone in the market that that's a little bit higher so we'll continue to buy back you know smartly on the on the fringe and you know we're trying to just make sure that we're we're being prudent but we feel pretty pretty good about what we've done over the course of the year with both buybacks dividend policy growth, et cetera.
Got it. And Jim, you've mentioned many calls. Don't want to disrupt organic momentum with the deal, but any commentary you may have on any sort of M&A outreach or inbound interest you've been getting?
Yeah, thank you, Andrew. I'd say this. We are keenly focused on this executing the organic plan. And certainly, my day-to-day is such that we do talk to companies and iBankers and what have you. And to the extent that something that really allows us to accelerate what we're doing, not just to get bigger, but really accelerate what we're up to, we'll stop and take a look. But it's not a high priority in 2025.
Got it. Thanks so much. You've covered all my other questions.
Operator
If you'd like to ask a question, please press star followed by one on your telephone keypad. That's star followed by one on your telephone keypad. Your next question comes from Eric Grublich, private investor. Your line is now open.
Hi, good morning. Thanks for taking the call from me. It's just that question on the deposit side. You had pretty good growth in the regions and the deposit verticals. So I was just curious, on the deposit verticals, is there any geography that is driving that besides, I mean, you break it down by, you know, homeowners association, property management, you know, legal and escrow. But is there a geography where that's coming from, particularly on the community association and property management or not?
Hi, good morning, Eric. This is Scott. I can take that one. I think just by nature of some of those businesses, particularly HOAs, you find it a little heavier in the southwestern and western states. On the property management side, that's probably a little bit more well dispersed. There are some states in particular where you need to have a physical presence to actually have some of those accounts. And that's the branch that we opened in Florida that we talked about in the past. It was because of that. We have another one in Las Vegas because of that. But, you know, predominantly it's pretty well spread out when you talk about the property management accounts. And then the escrows are really national in scope and not really geographically focused at all.
And just one last thing, you know, most analysts want to know, gee, you have a loan relationship. where's the deposit relationship, right? But the other way around on these community associations and the property management, to what degree do those relationships have a loan tag with them as well? Is it pretty small? I mean, homeowners association, maybe not so much there, but maybe I'm wrong. What kind of color can you provide on that?
Yeah, we're focused on the deposit side. We don't really have a lending vertical focused on those things. We might have a small loan here and there, but it's not something we're focused on or not something that we really need to do in order to handle or grow that base.
I would just add on that, the hook there is the technology and the onboarding and the structuring. You know, it's specialized to those businesses, and I think that's where we're differentiated.
Oh, yeah. No, I – you know, my background, having been a board director at Metro Phoenix, that was a big business for the bank. No, I get it. That is super important for getting the customers in and keeping them on board. Yeah, no, I understand. Thanks very much, Keen.
Operator
I'd now like to hand the call back to Jim Lally. Thank you.
Thank you, Ellie. and thank you all for joining us this morning and thank you for your interest in our company. We look forward to speaking with you at the end of the first quarter, if not sooner. Have a great day.
Operator
Thank you for attending today's conference call. You may now disconnect. Have a wonderful day.