
HBT 8-K
HBT Financial, Inc. (HBT)
8-K
2026-04-27
For: 2026-04-27
View Original
Added on
April 27, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT PURSUANT TO
SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of report (Date of earliest event reported): April 27, 2026
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification Number) | ||||||
| (Address of principal executive offices) | (Zip Code) | |||||||
(309 ) 662-4444
(Registrant’s telephone number, including area code)
N/A
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02. Results of Operations and Financial Condition.
On April 27, 2026, HBT Financial, Inc. (the “Company”) issued a press release announcing its financial results for the first quarter ended March 31, 2026 (the “Earnings Release”). A copy of the Earnings Release is furnished as Exhibit 99.1 to this Current Report on Form 8-K (this “Report”) and is incorporated herein by reference.
The information contained in Item 2.02, including Exhibit 99.1 furnished herewith, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), or otherwise subject to the liabilities under that section, nor shall it be deemed incorporated by reference into any registration statement or other document pursuant to the Securities Act of 1933, as amended (the “Securities Act”), or into any filing or other document pursuant to the Exchange Act, except to the extent required by applicable law or regulation.
Item 7.01. Regulation FD Disclosure.
The Company has prepared a presentation of its results for the first quarter ended March 31, 2026 (the “Presentation”) to be used from time to time during meetings with members of the investment community. A copy of the Presentation is furnished as Exhibit 99.2 to this Report and is incorporated herein by reference. The Presentation will also be made available on the Company’s investor relations website at ir.hbtfinancial.com under the Presentations section.
The information contained in Item 7.01, including Exhibit 99.2 furnished herewith, shall not be deemed “filed” for purposes of Section 18 of the Exchange Act, or otherwise subject to the liabilities under that section, nor shall it be deemed incorporated by reference into any registration statement or other document pursuant to the Securities Act, or into any filing or other document pursuant to the Exchange Act, except to the extent required by applicable law or regulation.
Item 9.01. Financial Statements and Exhibits.
| Exhibit Number | Description of Exhibit | ||||
Earnings Release issued April 27, 2026 for the First Quarter Ended March 31, 2026. | |||||
Presentation of Results for the First Quarter Ended March 31, 2026. | |||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document). | ||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned thereunto duly authorized.
| HBT FINANCIAL, INC. | ||||||||
| By: | /s/ Peter R. Chapman | |||||||
| Name: Peter R. Chapman | ||||||||
| Title: Chief Financial Officer | ||||||||
Date: April 27, 2026 | ||||||||
EXHIBIT 99.1
HBT FINANCIAL, INC. ANNOUNCES
FIRST QUARTER 2026 FINANCIAL RESULTS
First Quarter Highlights
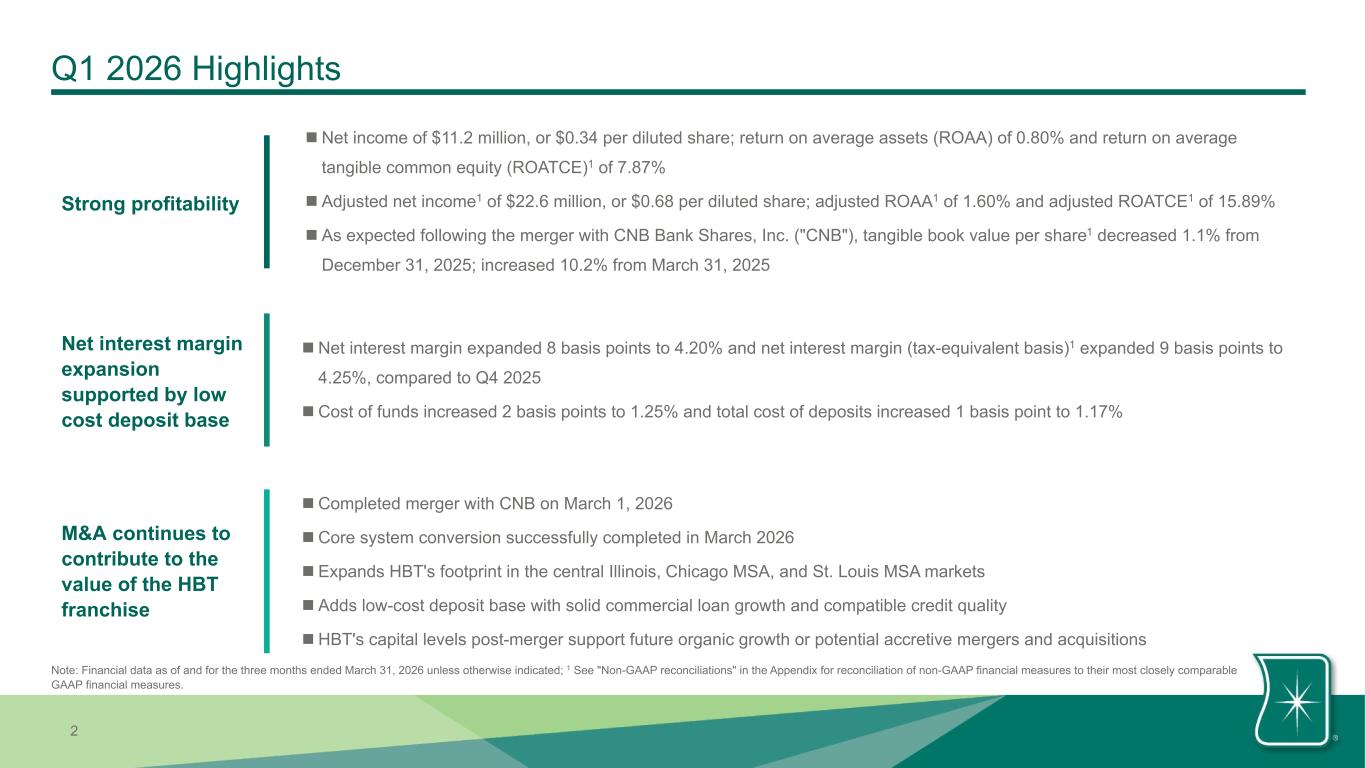
•Net income of $11.2 million, or $0.34 per diluted share; return on average assets (“ROAA”) of 0.80%; return on average stockholders' equity (“ROAE”) of 6.77%; and return on average tangible common equity (“ROATCE”)(1) of 7.87%
•Adjusted net income(1) of $22.6 million, or $0.68 per diluted share; adjusted ROAA(1) of 1.60%; adjusted ROAE(1) of 13.67%; and adjusted ROATCE(1) of 15.89%
•Completed merger with CNB Bank Shares, Inc. (“CNB”) on March 1, 2026 and core system conversion successfully completed in March 2026
•Asset quality remained strong with nonperforming assets to total assets of 0.21% and net charge-offs to average loans of 0.08%, on an annualized basis
•Net interest margin increased 8 basis points to 4.20% and net interest margin (tax-equivalent basis)(1) increased 9 basis points to 4.25%
Bloomington, IL, April 27, 2026 – HBT Financial, Inc. (NASDAQ: HBT) (the “Company”, “HBT Financial” or “HBT”), the holding company for Heartland Bank and Trust Company, today reported net income of $11.2 million, or $0.34 diluted earnings per share, for the first quarter of 2026. This compares to net income of $18.9 million, or $0.60 diluted earnings per share, for the fourth quarter of 2025, and net income of $19.1 million, or $0.60 diluted earnings per share, for the first quarter of 2025.
J. Lance Carter, President and Chief Executive Officer of HBT Financial, said, “We are off to a great start in 2026 with the closing of our acquisition of CNB and its wholly-owned subsidiary, CNB Bank & Trust, N.A. (“CNB Bank”), on March 1. We also successfully completed our systems conversions in March and have been busy welcoming our new customers and colleagues. We are excited for the opportunities that lie ahead.
“Results for the first quarter were strong and consistent with adjusted net income(1) of $22.6 million, or $0.68 per diluted share. Adjusted ROAA(1) was 1.60% and adjusted ROATCE(1) was 15.89% as we continue to report strong returns. Our net interest margin on a tax equivalent basis(1) increased by 9 basis points to 4.25% when compared to the fourth quarter of 2025. The increase was primarily driven by continued higher asset repricing for maturing fixed rate loans and securities. Our tangible book value per share(1) decreased by 1.1% for the quarter to $17.01 due to the CNB acquisition, elevated share repurchase activity, and a decrease in accumulated other comprehensive income (“AOCI”) due to higher market interest rates; however, our tangible book value per share(1) has nonetheless increased by 10.2% since the first quarter of 2025.
“Our balance sheet remains strong with good liquidity, solid capital ratios, and no significant credit issues. That gives us confidence that we are prepared for a variety of different economic environments. Our capital levels and operational structure support continued organic growth and attractive acquisition opportunities should the right opportunity arise.”
____________________________________
(1)See “Reconciliation of Non-GAAP Financial Measures” below for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures.
HBT Financial, Inc.
Page 2
Adjusted Net Income
In addition to reporting GAAP results, the Company believes non-GAAP measures such as adjusted net income and adjusted earnings per share, which adjust for acquisition expenses, branch closure expenses, net earnings (losses) on closed or sold operations, losses on extinguishment of debt, gains (losses) on closed branch premises, realized gains (losses) on sales of securities, mortgage servicing rights (“MSR”) fair value adjustments, and the tax effect of these pre-tax adjustments, provide investors with additional insight into its operational performance. The Company reported adjusted net income of $22.6 million, or $0.68 adjusted diluted earnings per share, for the first quarter of 2026. This compares to adjusted net income of $20.1 million, or $0.64 adjusted diluted earnings per share, for the fourth quarter of 2025, and adjusted net income of $19.3 million, or $0.61 adjusted diluted earnings per share, for the first quarter of 2025. See “Reconciliation of Non-GAAP Financial Measures” tables below for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures.
Acquisition of CNB Bank Shares, Inc.
On March 1, 2026, HBT Financial completed its previously announced acquisition of CNB and CNB Bank. The combined company will have increased density in the central Illinois, the Chicago MSA, and the St. Louis MSA markets. After considering business combination accounting adjustments, CNB added total assets of $1.8 billion, total loans held for investment of $1.3 billion, and total deposits of $1.5 billion.
Cash consideration of $33.8 million and stock consideration of 5.5 million shares of HBT Financial common stock resulted in aggregate consideration of $182.1 million, based upon the closing price of HBT Financial common stock of $26.96 on February 27, 2026. Goodwill of $23.7 million was recorded in the acquisition.
Acquisition-related expenses consisted of the following during the first quarter of 2026 and fourth quarter of 2025:
| Three Months Ended | |||||||||||
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | |||||||||
| Salaries | $ | 4,003 | $ | 43 | |||||||
| Occupancy of bank premises | 105 | — | |||||||||
| Furniture and equipment | 63 | — | |||||||||
| Data processing | 8,668 | 370 | |||||||||
| Marketing and customer relations | 69 | — | |||||||||
| Loan collection and servicing | 320 | — | |||||||||
| Professional fees and other noninterest expense | 2,438 | 586 | |||||||||
| Total acquisition-related expenses | $ | 15,666 | $ | 999 | |||||||
Net Interest Income and Net Interest Margin
Net interest income for the first quarter of 2026 was $56.4 million, an increase of 11.6% from $50.5 million for the fourth quarter of 2025. The increase was primarily attributable to higher average interest-earning asset balances following the CNB merger. A $0.5 million increase in loan fees and a $0.1 million increase in nonaccrual interest recoveries further contributed to the overall increase. Additionally, acquired loan discount accretion was $1.0 million during the first quarter of 2026 and $0.9 million during the fourth quarter of 2025.
Relative to the first quarter of 2025, net interest income increased 15.8% from $48.7 million. The increase was primarily attributable to higher average interest-earning asset balances following the CNB merger, improved yields on debt securities, and lower funding costs. Partially offsetting these improvements were a decrease in loan yields and a $0.4 million decrease in nonaccrual interest recoveries. Additionally, acquired loan discount accretion was $1.1 million during the first quarter of 2025.
Net interest margin for the first quarter of 2026 was 4.20%, compared to 4.12% for the fourth quarter of 2025, while net interest margin (tax-equivalent basis)(1) for the first quarter of 2026 was 4.25%, compared to 4.16% for
HBT Financial, Inc.
Page 3
the fourth quarter of 2025. These increases were primarily attributable to higher asset yields and the sale of the vast majority of the CNB securities portfolio, with the proceeds used to pay off higher cost sources of funding. Improvements in loan yields, which increased 6 basis points to 6.28%, and debt securities yields, which increased 20 basis points to 3.01%, were partially offset by higher funding costs, which increased 2 basis points to 1.25%.
Relative to the first quarter of 2025, net interest margin increased 8 basis points from 4.12% and net interest margin (tax-equivalent basis)(1) increased 9 basis points from 4.16%. These increases were primarily attributable to improved yields on debt securities and lower funding costs, which were partially offset by a decrease in loan yields.
____________________________________
(1)See “Reconciliation of Non-GAAP Financial Measures” below for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures.
Noninterest Income
Noninterest income for the first quarter of 2026 was $10.9 million, an increase from $9.9 million for the fourth quarter of 2025. A $0.4 million increase in wealth management fees, primarily driven by an increase in assets under management following the CNB merger, and the absence of $0.2 million in gains (losses) on foreclosed assets contributed to this improvement. Partially offsetting these improvements was a $0.2 million impairment on closed branch premises recognized during the first quarter of 2026. Additionally, a $0.2 million positive MSR fair value adjustment included in the first quarter of 2026 results compared to a $0.3 million negative MSR fair value adjustment included in the fourth quarter of 2025 results.
Relative to the first quarter of 2025, noninterest income increased 17.6% from $9.3 million. The increase was primarily attributable to a $0.9 million increase in wealth management fees, primarily driven by higher values of assets under management and the additional assets under management following the CNB merger, as well as changes in the MSR fair value adjustment, with a $0.2 million positive MSR fair value adjustment included in the first quarter of 2026 results compared to a $0.3 million negative MSR fair value adjustment included in the first quarter of 2025 results.
Noninterest Expense
Noninterest expense for the first quarter of 2026 was $52.4 million, a 58.6% increase from the fourth quarter of 2025. The increase was primarily attributable to $15.7 million of nonrecurring acquisition-related expenses included in the first quarter 2026 results. Excluding acquisition-related expenses, the $4.7 million increase in noninterest expense was primarily attributable to higher base costs following the CNB merger, including a $3.2 million increase in employee salaries and benefits expense, which were also impacted by annual merit increases and higher medical benefits costs, and a $0.9 million increase in other noninterest expense.
Relative to the first quarter of 2025, noninterest expense increased 64.2% from $31.9 million. Excluding acquisition-related expenses, the $4.8 million increase in noninterest expense was primarily attributable to higher base costs following the CNB merger, including a $2.6 million increase in employee salaries and benefits expense, which was also a result of merit increases and higher medical benefits costs, a $1.1 million increase in other noninterest expense, and a $0.4 million increase in data processing expense.
Loan Portfolio
Total loans outstanding, before allowance for credit losses, were $4.69 billion at March 31, 2026, compared with $3.46 billion at December 31, 2025, and $3.46 billion at March 31, 2025. The $1.23 billion increase from December 31, 2025 included $1.30 billion of loans held for investment acquired in the CNB merger. Excluding this impact, the $65.6 million decrease from December 31, 2025 was primarily attributable to several larger pay offs due to refinancings across the multi-family, commercial real estate – non-owner occupied, and the municipal, consumer, and other segments, as well as an $8.0 million reduction on two lines of credit that funded shortly before and paid off after December 31, 2025. These headwinds were partially offset by $26.3 million in seasonal draws on grain elevator lines, as well as new originations within the construction and land development and commercial and industrial segments.
HBT Financial, Inc.
Page 4
Deposits
Total deposits were $5.80 billion at March 31, 2026, compared with $4.36 billion at December 31, 2025, and $4.38 billion at March 31, 2025. The $1.44 billion increase from December 31, 2025 included $1.52 billion of deposits assumed in the CNB merger. Excluding the impact of the CNB merger, the $72.7 million decrease from December 31, 2025 was primarily attributable to an $88.9 million decrease in wealth management customer money market deposits, of which $85.0 million was moved off-balance sheet during the first quarter due to strong levels of on-balance sheet liquidity.
Asset Quality
Nonperforming assets totaled $14.4 million, or 0.21% of total assets, at March 31, 2026, compared with $8.7 million, or 0.17% of total assets, at December 31, 2025, and $5.6 million, or 0.11% of total assets, at March 31, 2025. The $5.7 million increase in nonperforming assets from December 31, 2025 was primarily attributable to the CNB merger, which added $6.1 million in nonperforming assets, primarily in the construction and land development segment. Additionally, of the $13.2 million of nonperforming loans held as of March 31, 2026, $2.3 million were either wholly or partially guaranteed by the U.S. government.
The Company recorded a negative provision for credit losses of $0.2 million for the first quarter of 2026. The negative provision for credit losses primarily reflects a $0.3 million decrease in specific reserves, partially offset by changes within the loan portfolio.
The Company had net charge-offs of $0.8 million, or 0.08% of average loans on an annualized basis, for the first quarter of 2026, compared to net charge-offs of $0.8 million, or 0.10% of average loans on an annualized basis, for the fourth quarter of 2025, and net charge-offs of $0.4 million, or 0.05% of average loans on an annualized basis, for the first quarter of 2025.
The Company’s allowance for credit losses was 1.29% of total loans and 457% of nonperforming loans at March 31, 2026, compared with 1.21% of total loans and 552% of nonperforming loans at December 31, 2025. In addition, the allowance for credit losses on unfunded lending-related commitments totaled $5.9 million as of March 31, 2026, compared with $4.1 million as of December 31, 2025.
Capital
As of March 31, 2026, the Company exceeded all regulatory capital requirements under Basel III as summarized in the following table:
| March 31, 2026 | For Capital Adequacy Purposes With Capital Conservation Buffer | |||||||||||||
| Total capital to risk-weighted assets | 15.99 | % | 10.50 | % | ||||||||||
| Tier 1 capital to risk-weighted assets | 13.38 | 8.50 | ||||||||||||
| Common equity tier 1 capital ratio | 12.42 | 7.00 | ||||||||||||
| Tier 1 leverage ratio | 12.63 | 4.00 | ||||||||||||
The ratio of tangible common equity to tangible assets(1) decreased to 9.31% as of March 31, 2026, from 10.82% as of December 31, 2025, and tangible book value per share(1) decreased by $0.19 to $17.01 as of March 31, 2026, when compared to December 31, 2025.
During the first quarter of 2026, the Company repurchased 602,855 shares of its common stock at a weighted average price of $25.84 under its stock repurchase program. The Company’s Board of Directors has authorized the repurchase of up to $30.0 million of HBT Financial common stock under its stock repurchase program, which is in effect until January 1, 2027. As of March 31, 2026, the Company had $14.4 million remaining under the stock repurchase program.
____________________________________
(1)See “Reconciliation of Non-GAAP Financial Measures” below for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures.
HBT Financial, Inc.
Page 5
Subordinated Note Issuance
To further enhance the Company’s strong capital and liquidity positions, HBT Financial successfully completed a private placement of $85.0 million of 5.75% Fixed-to-Floating Rate Subordinated Notes due 2036 during the quarter. The subordinated notes qualify as Tier 2 regulatory capital.
About HBT Financial, Inc.
HBT Financial, Inc., headquartered in Bloomington, Illinois, is the holding company for Heartland Bank and Trust Company, and has banking roots that can be traced back to 1920. HBT Financial provides a comprehensive suite of financial products and services to consumers, businesses, and municipal entities throughout Illinois, eastern Iowa, and suburban St. Louis through 83 full-service branches. As of March 31, 2026, HBT Financial had total assets of $6.8 billion, total loans of $4.7 billion, and total deposits of $5.8 billion.
Non-GAAP Financial Measures
Some of the financial measures included in this press release are not measures of financial performance recognized in accordance with GAAP. These non-GAAP financial measures include adjusted net income, adjusted earnings per share, adjusted ROAA, pre-provision net revenue, pre-provision net revenue less charge-offs (recoveries), adjusted pre-provision net revenue, adjusted pre-provision net revenue less charge-offs (recoveries), net interest income (tax-equivalent basis), net interest margin (tax-equivalent basis), efficiency ratio (tax-equivalent basis), adjusted efficiency ratio (tax-equivalent basis), the ratio of tangible common equity to tangible assets, tangible book value per share, adjusted ROAE, ROATCE, and adjusted ROATCE. Our management uses these non-GAAP financial measures, together with the related GAAP financial measures, in its analysis of our performance and in making business decisions. Management believes that it is a standard practice in the banking industry to present these non-GAAP financial measures, and accordingly believes that providing these measures may be useful for peer comparison purposes. These disclosures should not be viewed as substitutes for the results determined to be in accordance with GAAP; nor are they necessarily comparable to non-GAAP financial measures that may be presented by other companies. See our reconciliation of non-GAAP financial measures to their most directly comparable GAAP financial measures in the “Reconciliation of Non-GAAP Financial Measures” tables.
Forward-Looking Statements
Readers should note that in addition to the historical information contained herein, this press release contains, and future oral and written statements of the Company and its management may contain, “forward-looking statements” within the meanings of the Private Securities Litigation Reform Act of 1995, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements generally can be identified by the use of forward-looking terminology such as “will,” “propose,” “may,” “plan,” “seek,” “expect,” “intend,” “estimate,” “anticipate,” “believe,” “continue,” or “should,” or similar terminology and the negative forms of such words. Any forward-looking statements presented herein are made only as of the date of this press release, and the Company does not undertake any obligation to update or revise any forward-looking statements to reflect changes in assumptions, the occurrence of unanticipated events, or otherwise.
Factors that could cause actual results to differ materially from these forward-looking statements include, but are not limited to: (1) the strength of the local, state, national and international economies and financial markets (including effects of inflationary pressures, global energy market conditions, the threat or implementation of tariffs, immigration enforcement and changes in foreign policy); (2) policy changes in, and the interpretation and prioritization of, local, state and federal laws, regulations and governmental policies, including executive orders; (3) the economic impact of any future terrorist threats and attacks, widespread disease or pandemics, acts of war or other threats thereof (including the Russian invasion of Ukraine and the conflicts in the Middle East), or other adverse events that could cause economic deterioration or instability in credit markets, and the response of the local, state and national governments to any such adverse external events; (4) new and revised accounting policies and practices, as may be adopted by state and federal regulatory banking agencies, the Financial Accounting Standards Board or the Public Company Accounting Oversight Board; (5) the imposition of tariffs or other governmental policies impacting the value of products produced by the Company's commercial borrowers; (6) changes in interest rates and prepayment rates of the Company’s assets; (7) increased
HBT Financial, Inc.
Page 6
competition in the financial services sector, including from non-bank competitors such as credit unions, private credit firms, fintech companies, and digital asset service providers, and the inability to attract new customers; (8) technological changes implemented by us and other parties, including our third-party vendors, which may have unforeseen consequences to us and our customers, including the development and implementation of tools incorporating artificial intelligence; (9) unexpected results of acquisitions, which may include failure to realize the anticipated benefits of acquisitions and the possibility that transaction costs may be greater than anticipated, including the acquisition of CNB; (10) the loss of key executives and employees, talent shortages and employee turnover; (11) changes in consumer spending; (12) unexpected outcomes or costs of existing or new litigation or other legal proceedings and regulatory actions involving the Company; (13) the economic impact on the Company and its customers of climate change, natural disasters and of exceptional weather occurrences such as tornadoes, floods and blizzards; (14) fluctuations in the value of securities held in our securities portfolio, including as a result of changes in interest rates; (15) credit risks and risks from concentrations (by type of borrower, geographic area, collateral and industry) within our loan portfolio (including commercial real estate loans) and large loans to certain borrowers; (16) the overall health of the local and national real estate market; (17) the ability to maintain an adequate level of allowance for credit losses on loans; (18) the concentration of large deposits from certain clients who have balances above current FDIC insurance limits and who may withdraw deposits to diversify their exposure; (19) the ability to successfully manage liquidity risk, which may increase dependence on non-core funding sources such as brokered deposits, and may negatively impact the Company’s cost of funds; (20) the level of nonperforming assets on our balance sheet; (21) interruptions involving our information technology and communications systems or those of our third-party servicers; (22) the occurrence of fraudulent activity, breaches or failures of our third-party vendors’ information security controls or cybersecurity-related incidents, including as a result of sophisticated attacks using artificial intelligence and similar tools or as a result of insider fraud; (23) the effectiveness of the Company’s risk management framework; and (24) the ability of the Company to manage the risks associated with the foregoing as well as anticipated.
Readers should note that the forward-looking statements included in this press release are not a guarantee of future events, and that actual events may differ materially from those made in or suggested by the forward-looking statements. Additional information concerning the Company and its business, including additional factors that could materially affect the Company’s financial results, is included in the Company’s filings with the Securities and Exchange Commission.
CONTACT:
Peter Chapman
(309) 664-4556
HBT Financial, Inc.
Page 7
HBT Financial, Inc.
Unaudited Consolidated Financial Summary
| As of or for the Three Months Ended | ||||||||||||||||||||
| (dollars in thousands, except per share data) | March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||
| Interest and dividend income | $ | 71,839 | $ | 64,391 | $ | 63,138 | ||||||||||||||
| Interest expense | 15,452 | 13,848 | 14,430 | |||||||||||||||||
| Net interest income | 56,387 | 50,543 | 48,708 | |||||||||||||||||
| Provision for credit losses | (156) | 1,463 | 576 | |||||||||||||||||
| Net interest income after provision for credit losses | 56,543 | 49,080 | 48,132 | |||||||||||||||||
| Noninterest income | 10,944 | 9,895 | 9,306 | |||||||||||||||||
| Noninterest expense | 52,437 | 33,061 | 31,935 | |||||||||||||||||
| Income before income tax expense | 15,050 | 25,914 | 25,503 | |||||||||||||||||
| Income tax expense | 3,850 | 6,976 | 6,428 | |||||||||||||||||
| Net income | $ | 11,200 | $ | 18,938 | $ | 19,075 | ||||||||||||||
| Earnings per share - diluted | $ | 0.34 | $ | 0.60 | $ | 0.60 | ||||||||||||||
Adjusted net income (1) | $ | 22,610 | $ | 20,139 | $ | 19,253 | ||||||||||||||
Adjusted earnings per share - diluted (1) | 0.68 | 0.64 | 0.61 | |||||||||||||||||
| Book value per share | $ | 20.54 | $ | 19.58 | $ | 17.86 | ||||||||||||||
Tangible book value per share (1) | 17.01 | 17.20 | 15.43 | |||||||||||||||||
| Shares of common stock outstanding | 36,381,078 | 31,431,924 | 31,631,431 | |||||||||||||||||
| Weighted average shares of common stock outstanding, including all dilutive potential shares | 33,300,096 | 31,559,005 | 31,711,671 | |||||||||||||||||
| SUMMARY RATIOS | ||||||||||||||||||||
| Net interest margin * | 4.20 | % | 4.12 | % | 4.12 | % | ||||||||||||||
Net interest margin (tax-equivalent basis) * (1)(2) | 4.25 | 4.16 | 4.16 | |||||||||||||||||
| Efficiency ratio | 76.56 | % | 53.64 | % | 53.85 | % | ||||||||||||||
Efficiency ratio (tax-equivalent basis) (1)(2) | 75.83 | 53.15 | 53.35 | |||||||||||||||||
| Loan to deposit ratio | 80.76 | % | 79.28 | % | 78.95 | % | ||||||||||||||
| Return on average assets * | 0.80 | % | 1.47 | % | 1.54 | % | ||||||||||||||
| Return on average stockholders' equity * | 6.77 | 12.34 | 13.95 | |||||||||||||||||
Return on average tangible common equity * (1) | 7.87 | 14.08 | 16.20 | |||||||||||||||||
Adjusted return on average assets * (1) | 1.60 | % | 1.57 | % | 1.55 | % | ||||||||||||||
Adjusted return on average stockholders' equity * (1) | 13.67 | 13.12 | 14.08 | |||||||||||||||||
Adjusted return on average tangible common equity * (1) | 15.89 | 14.97 | 16.36 | |||||||||||||||||
| CAPITAL | ||||||||||||||||||||
| Total capital to risk-weighted assets | 15.99 | % | 16.82 | % | 16.85 | % | ||||||||||||||
| Tier 1 capital to risk-weighted assets | 13.38 | 15.72 | 14.77 | |||||||||||||||||
| Common equity tier 1 capital ratio | 12.42 | 14.42 | 13.48 | |||||||||||||||||
| Tier 1 leverage ratio | 12.63 | 12.26 | 11.64 | |||||||||||||||||
| Total stockholders' equity to total assets | 11.03 | 12.14 | 11.10 | |||||||||||||||||
Tangible common equity to tangible assets (1) | 9.31 | 10.82 | 9.73 | |||||||||||||||||
| ASSET QUALITY | ||||||||||||||||||||
| Net charge-offs (recoveries) to average loans * | 0.08 | % | 0.10 | % | 0.05 | % | ||||||||||||||
| Allowance for credit losses to loans, before allowance for credit losses | 1.29 | 1.21 | 1.22 | |||||||||||||||||
| Nonperforming loans to loans, before allowance for credit losses | 0.28 | 0.22 | 0.15 | |||||||||||||||||
| Nonperforming assets to total assets | 0.21 | 0.17 | 0.11 | |||||||||||||||||
____________________________________
*Annualized measure.
(1)See “Reconciliation of Non-GAAP Financial Measures” below for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures.
(2)On a tax-equivalent basis assuming a federal income tax rate of 21% and a state tax rate of 9.5%.
HBT Financial, Inc.
Page 8
HBT Financial, Inc.
Unaudited Consolidated Financial Summary
Consolidated Statements of Income
| Three Months Ended | |||||||||||||||||
| (dollars in thousands, except per share data) | March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||
| INTEREST AND DIVIDEND INCOME | |||||||||||||||||
| Loans, including fees: | |||||||||||||||||
| Taxable | $ | 58,881 | $ | 52,600 | $ | 53,369 | |||||||||||
| Federally tax exempt | 1,317 | 1,250 | 1,168 | ||||||||||||||
| Debt securities: | |||||||||||||||||
| Taxable | 9,544 | 8,385 | 6,936 | ||||||||||||||
| Federally tax exempt | 658 | 454 | 469 | ||||||||||||||
| Interest-bearing deposits in bank | 1,276 | 1,543 | 1,065 | ||||||||||||||
| Other interest and dividend income | 163 | 159 | 131 | ||||||||||||||
| Total interest and dividend income | 71,839 | 64,391 | 63,138 | ||||||||||||||
| INTEREST EXPENSE | |||||||||||||||||
| Deposits | 14,109 | 12,920 | 12,939 | ||||||||||||||
| Securities sold under agreements to repurchase | 16 | — | 22 | ||||||||||||||
| Borrowings | 209 | 33 | 109 | ||||||||||||||
| Subordinated notes | 278 | — | 470 | ||||||||||||||
| Junior subordinated debentures issued to capital trusts | 840 | 895 | 890 | ||||||||||||||
| Total interest expense | 15,452 | 13,848 | 14,430 | ||||||||||||||
| Net interest income | 56,387 | 50,543 | 48,708 | ||||||||||||||
| PROVISION FOR CREDIT LOSSES | (156) | 1,463 | 576 | ||||||||||||||
| Net interest income after provision for credit losses | 56,543 | 49,080 | 48,132 | ||||||||||||||
| NONINTEREST INCOME | |||||||||||||||||
| Card income | 2,751 | 2,708 | 2,548 | ||||||||||||||
| Wealth management fees | 3,764 | 3,358 | 2,841 | ||||||||||||||
| Service charges on deposit accounts | 2,160 | 2,088 | 1,944 | ||||||||||||||
| Mortgage servicing | 983 | 1,062 | 990 | ||||||||||||||
| Mortgage servicing rights fair value adjustment | 197 | (310) | (308) | ||||||||||||||
| Gains on sale of mortgage loans | 331 | 376 | 252 | ||||||||||||||
| Realized gains (losses) on sales of securities | — | (151) | — | ||||||||||||||
| Unrealized gains (losses) on equity securities | (112) | 43 | 8 | ||||||||||||||
| Gains (losses) on foreclosed assets | 40 | (171) | 13 | ||||||||||||||
| Gains (losses) on other assets | (210) | 3 | 54 | ||||||||||||||
| Income on bank owned life insurance | 188 | 171 | 164 | ||||||||||||||
| Other noninterest income | 852 | 718 | 800 | ||||||||||||||
| Total noninterest income | 10,944 | 9,895 | 9,306 | ||||||||||||||
| NONINTEREST EXPENSE | |||||||||||||||||
| Salaries | 23,061 | 16,486 | 17,053 | ||||||||||||||
| Employee benefits | 3,920 | 3,359 | 3,285 | ||||||||||||||
| Occupancy of bank premises | 3,124 | 2,791 | 2,625 | ||||||||||||||
| Furniture and equipment | 608 | 523 | 445 | ||||||||||||||
| Data processing | 11,794 | 3,571 | 2,717 | ||||||||||||||
| Marketing and customer relations | 1,144 | 984 | 1,144 | ||||||||||||||
| Amortization of intangible assets | 887 | 643 | 695 | ||||||||||||||
| FDIC insurance | 588 | 560 | 562 | ||||||||||||||
| Loan collection and servicing | 696 | 339 | 383 | ||||||||||||||
| Foreclosed assets | 60 | 35 | 5 | ||||||||||||||
| Other noninterest expense | 6,555 | 3,770 | 3,021 | ||||||||||||||
| Total noninterest expense | 52,437 | 33,061 | 31,935 | ||||||||||||||
| INCOME BEFORE INCOME TAX EXPENSE | 15,050 | 25,914 | 25,503 | ||||||||||||||
| INCOME TAX EXPENSE | 3,850 | 6,976 | 6,428 | ||||||||||||||
| NET INCOME | $ | 11,200 | $ | 18,938 | $ | 19,075 | |||||||||||
| EARNINGS PER SHARE - BASIC | $ | 0.34 | $ | 0.60 | $ | 0.60 | |||||||||||
| EARNINGS PER SHARE - DILUTED | $ | 0.34 | $ | 0.60 | $ | 0.60 | |||||||||||
| WEIGHTED AVERAGE SHARES OF COMMON STOCK OUTSTANDING | 33,180,009 | 31,434,409 | 31,584,989 | ||||||||||||||
HBT Financial, Inc.
Page 9
HBT Financial, Inc.
Unaudited Consolidated Financial Summary
Consolidated Balance Sheets
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||
| ASSETS | |||||||||||||||||
| Cash and due from banks | $ | 37,371 | $ | 24,423 | $ | 25,005 | |||||||||||
| Interest-bearing deposits with banks | 250,282 | 97,846 | 186,586 | ||||||||||||||
| Cash and cash equivalents | 287,653 | 122,269 | 211,591 | ||||||||||||||
| Interest-bearing time deposits with banks | 245 | — | — | ||||||||||||||
| Debt securities available-for-sale, at fair value | 1,025,992 | 813,101 | 706,135 | ||||||||||||||
| Debt securities held-to-maturity | 453,850 | 458,746 | 490,398 | ||||||||||||||
| Equity securities with readily determinable fair value | 3,355 | 3,322 | 3,323 | ||||||||||||||
| Equity securities with no readily determinable fair value | 6,395 | 2,612 | 2,629 | ||||||||||||||
| Restricted stock, at cost | 6,000 | 4,979 | 5,086 | ||||||||||||||
| Loans held for sale | 3,247 | 1,263 | 2,721 | ||||||||||||||
| Loans, before allowance for credit losses | 4,686,951 | 3,456,209 | 3,461,778 | ||||||||||||||
| Allowance for credit losses | (60,474) | (41,690) | (42,111) | ||||||||||||||
| Loans, net of allowance for credit losses | 4,626,477 | 3,414,519 | 3,419,667 | ||||||||||||||
| Bank owned life insurance | 37,677 | 24,660 | 24,153 | ||||||||||||||
| Bank premises and equipment, net | 90,973 | 73,642 | 67,272 | ||||||||||||||
| Bank premises held for sale | 337 | — | 190 | ||||||||||||||
| Foreclosed assets | 1,149 | 1,126 | 460 | ||||||||||||||
| Goodwill | 83,504 | 59,820 | 59,820 | ||||||||||||||
| Intangible assets, net | 44,313 | 15,117 | 17,148 | ||||||||||||||
| Intangible assets held for sale | 649 | — | — | ||||||||||||||
| Mortgage servicing rights, at fair value | 20,090 | 16,944 | 18,519 | ||||||||||||||
| Investments in unconsolidated subsidiaries | 1,614 | 1,614 | 1,614 | ||||||||||||||
| Accrued interest receivable | 35,313 | 23,779 | 22,735 | ||||||||||||||
| Other assets | 44,891 | 33,877 | 38,731 | ||||||||||||||
| Total assets | $ | 6,773,724 | $ | 5,071,390 | $ | 5,092,192 | |||||||||||
| LIABILITIES AND STOCKHOLDERS' EQUITY | |||||||||||||||||
| Liabilities | |||||||||||||||||
| Deposits: | |||||||||||||||||
| Noninterest-bearing | $ | 1,342,192 | $ | 1,049,043 | $ | 1,065,874 | |||||||||||
| Interest-bearing | 4,461,256 | 3,310,220 | 3,318,716 | ||||||||||||||
| Total deposits | 5,803,448 | 4,359,263 | 4,384,590 | ||||||||||||||
| Securities sold under agreements to repurchase | 5,046 | — | 2,698 | ||||||||||||||
| Federal Home Loan Bank advances | 12,332 | 12,301 | 7,209 | ||||||||||||||
| Subordinated notes | 84,003 | — | 39,573 | ||||||||||||||
| Junior subordinated debentures issued to capital trusts | 52,924 | 52,909 | 52,864 | ||||||||||||||
| Other liabilities | 68,566 | 31,419 | 40,201 | ||||||||||||||
| Total liabilities | 6,026,319 | 4,455,892 | 4,527,135 | ||||||||||||||
| Stockholders' Equity | |||||||||||||||||
| Common stock | 385 | 329 | 329 | ||||||||||||||
| Surplus | 446,555 | 298,548 | 297,024 | ||||||||||||||
| Retained earnings | 371,093 | 367,163 | 329,169 | ||||||||||||||
| Accumulated other comprehensive income (loss) | (27,371) | (23,018) | (38,446) | ||||||||||||||
| Treasury stock at cost | (43,257) | (27,524) | (23,019) | ||||||||||||||
| Total stockholders’ equity | 747,405 | 615,498 | 565,057 | ||||||||||||||
| Total liabilities and stockholders’ equity | $ | 6,773,724 | $ | 5,071,390 | $ | 5,092,192 | |||||||||||
| SHARES OF COMMON STOCK OUTSTANDING | 36,381,078 | 31,431,924 | 31,631,431 | ||||||||||||||
HBT Financial, Inc.
Page 10
HBT Financial, Inc.
Unaudited Consolidated Financial Summary
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||
| LOANS | |||||||||||||||||
| Commercial and industrial | $ | 528,301 | $ | 399,760 | $ | 441,261 | |||||||||||
| Commercial real estate - owner occupied | 519,847 | 320,434 | 321,990 | ||||||||||||||
| Commercial real estate - non-owner occupied | 1,099,784 | 937,094 | 891,022 | ||||||||||||||
| Construction and land development | 425,335 | 280,254 | 376,046 | ||||||||||||||
| Multi-family | 638,653 | 544,941 | 424,096 | ||||||||||||||
| One-to-four family residential | 614,563 | 445,463 | 455,376 | ||||||||||||||
| Agricultural and farmland | 596,294 | 275,251 | 292,240 | ||||||||||||||
| Municipal, consumer, and other | 264,174 | 253,012 | 259,747 | ||||||||||||||
| Total loans | $ | 4,686,951 | $ | 3,456,209 | $ | 3,461,778 | |||||||||||
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||
| DEPOSITS | |||||||||||||||||
| Noninterest-bearing deposits | $ | 1,342,192 | $ | 1,049,043 | $ | 1,065,874 | |||||||||||
| Interest-bearing deposits: | |||||||||||||||||
| Interest-bearing demand | 1,365,216 | 1,144,416 | 1,143,677 | ||||||||||||||
| Money market | 929,671 | 839,097 | 812,146 | ||||||||||||||
| Savings | 900,700 | 564,220 | 575,558 | ||||||||||||||
| Time | 1,265,669 | 762,487 | 787,335 | ||||||||||||||
| Total interest-bearing deposits | 4,461,256 | 3,310,220 | 3,318,716 | ||||||||||||||
| Total deposits | $ | 5,803,448 | $ | 4,359,263 | $ | 4,384,590 | |||||||||||
HBT Financial, Inc.
Page 11
HBT Financial, Inc.
Unaudited Consolidated Financial Summary
| Three Months Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands) | Average Balance | Interest | Yield/Cost * | Average Balance | Interest | Yield/Cost * | Average Balance | Interest | Yield/Cost * | ||||||||||||||||||||||||||||||||||||||||||||
| ASSETS | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Loans | $ | 3,890,388 | $ | 60,198 | 6.28 | % | $ | 3,432,308 | $ | 53,850 | 6.22 | % | $ | 3,460,906 | $ | 54,537 | 6.39 | % | |||||||||||||||||||||||||||||||||||
| Debt securities | 1,375,875 | 10,202 | 3.01 | 1,249,183 | 8,839 | 2.81 | 1,204,424 | 7,405 | 2.49 | ||||||||||||||||||||||||||||||||||||||||||||
| Deposits with banks | 163,761 | 1,276 | 3.16 | 177,348 | 1,543 | 3.45 | 120,014 | 1,065 | 3.60 | ||||||||||||||||||||||||||||||||||||||||||||
| Other | 14,389 | 163 | 4.60 | 12,481 | 159 | 5.05 | 12,677 | 131 | 4.19 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 5,444,413 | $ | 71,839 | 5.35 | % | 4,871,320 | $ | 64,391 | 5.24 | % | 4,798,021 | $ | 63,138 | 5.34 | % | ||||||||||||||||||||||||||||||||||||||
| Allowance for credit losses | (48,362) | (41,994) | (42,061) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-earning assets | 317,393 | 269,949 | 276,853 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 5,713,444 | $ | 5,099,275 | $ | 5,032,813 | |||||||||||||||||||||||||||||||||||||||||||||||
| LIABILITIES AND STOCKHOLDERS' EQUITY | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand | $ | 1,223,982 | $ | 1,931 | 0.64 | % | $ | 1,129,642 | $ | 1,800 | 0.63 | % | $ | 1,120,608 | $ | 1,453 | 0.53 | % | |||||||||||||||||||||||||||||||||||
| Money market | 906,663 | 4,448 | 1.99 | 866,762 | 4,614 | 2.11 | 807,728 | 4,397 | 2.21 | ||||||||||||||||||||||||||||||||||||||||||||
| Savings | 671,852 | 704 | 0.43 | 561,755 | 397 | 0.28 | 569,494 | 370 | 0.26 | ||||||||||||||||||||||||||||||||||||||||||||
| Time | 940,019 | 7,026 | 3.03 | 765,792 | 6,109 | 3.16 | 784,099 | 6,719 | 3.48 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 3,742,516 | 14,109 | 1.53 | 3,323,951 | 12,920 | 1.54 | 3,281,929 | 12,939 | 1.60 | ||||||||||||||||||||||||||||||||||||||||||||
| Securities sold under agreements to repurchase | 2,902 | 16 | 2.21 | — | — | — | 8,754 | 22 | 1.02 | ||||||||||||||||||||||||||||||||||||||||||||
| Borrowings | 28,886 | 209 | 2.94 | 7,819 | 33 | 1.68 | 12,890 | 109 | 3.41 | ||||||||||||||||||||||||||||||||||||||||||||
| Subordinated notes | 19,781 | 278 | 5.70 | — | — | — | 39,563 | 470 | 4.82 | ||||||||||||||||||||||||||||||||||||||||||||
| Junior subordinated debentures issued to capital trusts | 52,916 | 840 | 6.44 | 52,902 | 895 | 6.70 | 52,856 | 890 | 6.83 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 3,847,001 | $ | 15,452 | 1.63 | % | 3,384,672 | $ | 13,848 | 1.62 | % | 3,395,992 | $ | 14,430 | 1.72 | % | ||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 1,150,594 | 1,076,899 | 1,045,733 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing liabilities | 45,282 | 28,882 | 36,373 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities | 5,042,877 | 4,490,453 | 4,478,098 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Stockholders' Equity | 670,567 | 608,822 | 554,715 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 5,713,444 | $ | 5,099,275 | $ | 5,032,813 | |||||||||||||||||||||||||||||||||||||||||||||||
Net interest income/Net interest margin (1) | $ | 56,387 | 4.20 | % | $ | 50,543 | 4.12 | % | $ | 48,708 | 4.12 | % | |||||||||||||||||||||||||||||||||||||||||
Tax-equivalent adjustment (2) | 649 | 0.05 | 558 | 0.04 | 545 | 0.04 | |||||||||||||||||||||||||||||||||||||||||||||||
Net interest income (tax-equivalent basis)/ Net interest margin (tax-equivalent basis) (2) (3) | $ | 57,036 | 4.25 | % | $ | 51,101 | 4.16 | % | $ | 49,253 | 4.16 | % | |||||||||||||||||||||||||||||||||||||||||
Net interest rate spread (4) | 3.72 | % | 3.62 | % | 3.62 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Net interest-earning assets (5) | $ | 1,597,412 | $ | 1,486,648 | $ | 1,402,029 | |||||||||||||||||||||||||||||||||||||||||||||||
| Ratio of interest-earning assets to interest-bearing liabilities | 1.42 | 1.44 | 1.41 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Cost of total deposits | 1.17 | % | 1.16 | % | 1.21 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Cost of funds | 1.25 | 1.23 | 1.32 | ||||||||||||||||||||||||||||||||||||||||||||||||||
____________________________________
*Annualized measure.
(1)Net interest margin represents net interest income divided by average total interest-earning assets.
(2)On a tax-equivalent basis assuming a federal income tax rate of 21% and a state income tax rate of 9.5%.
(3)See “Reconciliation of Non-GAAP Financial Measures” below for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures.
(4)Net interest rate spread represents the difference between the yield on average interest-earning assets and the cost of average interest-bearing liabilities.
(5)Net interest-earning assets represents total interest-earning assets less total interest-bearing liabilities.
HBT Financial, Inc.
Page 12
HBT Financial, Inc.
Unaudited Consolidated Financial Summary
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||
| NONPERFORMING ASSETS | |||||||||||||||||
| Nonaccrual | $ | 13,229 | $ | 7,556 | $ | 5,102 | |||||||||||
| Past due 90 days or more, still accruing | — | — | 4 | ||||||||||||||
| Total nonperforming loans | 13,229 | 7,556 | 5,106 | ||||||||||||||
| Foreclosed assets | 1,149 | 1,126 | 460 | ||||||||||||||
| Total nonperforming assets | $ | 14,378 | $ | 8,682 | $ | 5,566 | |||||||||||
| Nonperforming loans that are wholly or partially guaranteed by the U.S. Government | $ | 2,291 | $ | 2,170 | $ | 1,350 | |||||||||||
| Allowance for credit losses | $ | 60,474 | $ | 41,690 | $ | 42,111 | |||||||||||
| Loans, before allowance for credit losses | 4,686,951 | 3,456,209 | 3,461,778 | ||||||||||||||
| CREDIT QUALITY RATIOS | |||||||||||||||||
| Allowance for credit losses to loans, before allowance for credit losses | 1.29 | % | 1.21 | % | 1.22 | % | |||||||||||
| Allowance for credit losses to nonaccrual loans | 457.13 | 551.75 | 825.38 | ||||||||||||||
| Allowance for credit losses to nonperforming loans | 457.13 | 551.75 | 824.74 | ||||||||||||||
| Nonaccrual loans to loans, before allowance for credit losses | 0.28 | 0.22 | 0.15 | ||||||||||||||
| Nonperforming loans to loans, before allowance for credit losses | 0.28 | 0.22 | 0.15 | ||||||||||||||
| Nonperforming assets to total assets | 0.21 | 0.17 | 0.11 | ||||||||||||||
| Nonperforming assets to loans, before allowance for credit losses, and foreclosed assets | 0.31 | 0.25 | 0.16 | ||||||||||||||
| Three Months Ended | |||||||||||||||||
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||
| ALLOWANCE FOR CREDIT LOSSES | |||||||||||||||||
| Beginning balance | $ | 41,690 | $ | 41,900 | $ | 42,044 | |||||||||||
| Allowance established in acquisition | 19,957 | — | — | ||||||||||||||
| Provision for credit losses | (415) | 638 | 496 | ||||||||||||||
| Charge-offs | (1,001) | (1,221) | (665) | ||||||||||||||
| Recoveries | 243 | 373 | 236 | ||||||||||||||
| Ending balance | $ | 60,474 | $ | 41,690 | $ | 42,111 | |||||||||||
| Net charge-offs | $ | 758 | $ | 848 | $ | 429 | |||||||||||
| Average loans | 3,890,388 | 3,432,308 | 3,460,906 | ||||||||||||||
| Net charge-offs to average loans * | 0.08 | % | 0.10 | % | 0.05 | % | |||||||||||
____________________________________
*Annualized measure.
| Three Months Ended | |||||||||||||||||
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||
| PROVISION FOR CREDIT LOSSES | |||||||||||||||||
| Loans | $ | (415) | $ | 638 | $ | 496 | |||||||||||
| Unfunded lending-related commitments | 259 | 825 | 80 | ||||||||||||||
| Total provision for credit losses | $ | (156) | $ | 1,463 | $ | 576 | |||||||||||
HBT Financial, Inc.
Page 13
Reconciliation of Non-GAAP Financial Measures –
Adjusted Net Income and Adjusted Return on Average Assets
| Three Months Ended | ||||||||||||||||||||
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||
| Net income | $ | 11,200 | $ | 18,938 | $ | 19,075 | ||||||||||||||
| Less: adjustments | ||||||||||||||||||||
| Acquisition expenses | (15,666) | (999) | — | |||||||||||||||||
| Net earnings (losses) on closed or sold operations | 4 | — | — | |||||||||||||||||
| Gains (losses) on closed branch premises | (210) | — | 59 | |||||||||||||||||
| Realized gains (losses) on sales of securities | — | (151) | — | |||||||||||||||||
| Mortgage servicing rights fair value adjustment | 197 | (310) | (308) | |||||||||||||||||
| Total adjustments | (15,675) | (1,460) | (249) | |||||||||||||||||
Tax effect of adjustments (1) | 4,265 | 259 | 71 | |||||||||||||||||
| Total adjustments after tax effect | (11,410) | (1,201) | (178) | |||||||||||||||||
| Adjusted net income | $ | 22,610 | $ | 20,139 | $ | 19,253 | ||||||||||||||
| Average assets | $ | 5,713,444 | $ | 5,099,275 | $ | 5,032,813 | ||||||||||||||
| Return on average assets * | 0.80 | % | 1.47 | % | 1.54 | % | ||||||||||||||
| Adjusted return on average assets * | 1.60 | 1.57 | 1.55 | |||||||||||||||||
____________________________________
*Annualized measure.
(1)Assumes a federal income tax rate of 21% and a state tax rate of 9.5%, and excludes non-deductible acquisition expenses.
Reconciliation of Non-GAAP Financial Measures –
Adjusted Earnings Per Share — Basic and Diluted
| Three Months Ended | ||||||||||||||||||||
| (dollars in thousands, except per share amounts) | March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||
| Numerator: | ||||||||||||||||||||
| Net income | $ | 11,200 | $ | 18,938 | $ | 19,075 | ||||||||||||||
| Adjusted net income | $ | 22,610 | $ | 20,139 | $ | 19,253 | ||||||||||||||
| Denominator: | ||||||||||||||||||||
| Weighted average common shares outstanding | 33,180,009 | 31,434,409 | 31,584,989 | |||||||||||||||||
| Dilutive effect of outstanding restricted stock units | 120,087 | 124,596 | 126,682 | |||||||||||||||||
| Weighted average common shares outstanding, including all dilutive potential shares | 33,300,096 | 31,559,005 | 31,711,671 | |||||||||||||||||
| Earnings per share - basic | $ | 0.34 | $ | 0.60 | $ | 0.60 | ||||||||||||||
| Earnings per share - diluted | $ | 0.34 | $ | 0.60 | $ | 0.60 | ||||||||||||||
| Adjusted earnings per share - basic | $ | 0.68 | $ | 0.64 | $ | 0.61 | ||||||||||||||
| Adjusted earnings per share - diluted | $ | 0.68 | $ | 0.64 | $ | 0.61 | ||||||||||||||
HBT Financial, Inc.
Page 14
Reconciliation of Non-GAAP Financial Measures –
Pre-Provision Net Revenue, Pre-Provision Net Revenue Less Net Charge-offs (Recoveries),
Adjusted Pre-Provision Net Revenue, and Adjusted Pre-Provision Net Revenue Less Net Charge-offs (Recoveries)
| Three Months Ended | ||||||||||||||||||||
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||
| Net interest income | $ | 56,387 | $ | 50,543 | $ | 48,708 | ||||||||||||||
| Noninterest income | 10,944 | 9,895 | 9,306 | |||||||||||||||||
| Noninterest expense | (52,437) | (33,061) | (31,935) | |||||||||||||||||
| Pre-provision net revenue | 14,894 | 27,377 | 26,079 | |||||||||||||||||
| Less: adjustments | ||||||||||||||||||||
| Acquisition expenses | (15,666) | (999) | — | |||||||||||||||||
| Net earnings (losses) on closed or sold operations | 4 | — | — | |||||||||||||||||
| Gains (losses) on closed branch premises | (210) | — | 59 | |||||||||||||||||
| Realized gains (losses) on sales of securities | — | (151) | — | |||||||||||||||||
| Mortgage servicing rights fair value adjustment | 197 | (310) | (308) | |||||||||||||||||
| Total adjustments | (15,675) | (1,460) | (249) | |||||||||||||||||
| Adjusted pre-provision net revenue | $ | 30,569 | $ | 28,837 | $ | 26,328 | ||||||||||||||
| Pre-provision net revenue | $ | 14,894 | $ | 27,377 | $ | 26,079 | ||||||||||||||
| Less: net charge-offs | 758 | 848 | 429 | |||||||||||||||||
| Pre-provision net revenue less net charge-offs | $ | 14,136 | $ | 26,529 | $ | 25,650 | ||||||||||||||
| Adjusted pre-provision net revenue | $ | 30,569 | $ | 28,837 | $ | 26,328 | ||||||||||||||
| Less: net charge-offs | 758 | 848 | 429 | |||||||||||||||||
| Adjusted pre-provision net revenue less net charge-offs | $ | 29,811 | $ | 27,989 | $ | 25,899 | ||||||||||||||
Reconciliation of Non-GAAP Financial Measures –
Net Interest Income (Tax-equivalent Basis) and Net Interest Margin (Tax-equivalent Basis)
| Three Months Ended | ||||||||||||||||||||
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||
| Net interest income (tax-equivalent basis) | ||||||||||||||||||||
| Net interest income | $ | 56,387 | $ | 50,543 | $ | 48,708 | ||||||||||||||
Tax-equivalent adjustment (1) | 649 | 558 | 545 | |||||||||||||||||
Net interest income (tax-equivalent basis) (1) | $ | 57,036 | $ | 51,101 | $ | 49,253 | ||||||||||||||
| Net interest margin (tax-equivalent basis) | ||||||||||||||||||||
| Net interest margin * | 4.20 | % | 4.12 | % | 4.12 | % | ||||||||||||||
Tax-equivalent adjustment * (1) | 0.05 | 0.04 | 0.04 | |||||||||||||||||
Net interest margin (tax-equivalent basis) * (1) | 4.25 | % | 4.16 | % | 4.16 | % | ||||||||||||||
| Average interest-earning assets | $ | 5,444,413 | $ | 4,871,320 | $ | 4,798,021 | ||||||||||||||
____________________________________
*Annualized measure.
(1)On a tax-equivalent basis assuming a federal income tax rate of 21% and a state tax rate of 9.5%.
HBT Financial, Inc.
Page 15
Reconciliation of Non-GAAP Financial Measures –
Efficiency Ratio (Tax-equivalent Basis) and Adjusted Efficiency Ratio (Tax-equivalent Basis)
| Three Months Ended | ||||||||||||||||||||
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||
| Total noninterest expense | $ | 52,437 | $ | 33,061 | $ | 31,935 | ||||||||||||||
| Less: amortization of intangible assets | 887 | 643 | 695 | |||||||||||||||||
| Noninterest expense excluding amortization of intangible assets | 51,550 | 32,418 | 31,240 | |||||||||||||||||
| Less: adjustments to noninterest expense | ||||||||||||||||||||
| Acquisition expenses | 15,666 | 999 | — | |||||||||||||||||
| Expenses from closed or sold operations | 149 | — | — | |||||||||||||||||
| Total adjustments to noninterest expense | 15,815 | 999 | — | |||||||||||||||||
| Adjusted noninterest expense | $ | 35,735 | $ | 31,419 | $ | 31,240 | ||||||||||||||
| Net interest income | $ | 56,387 | $ | 50,543 | $ | 48,708 | ||||||||||||||
| Total noninterest income | 10,944 | 9,895 | 9,306 | |||||||||||||||||
| Operating revenue | 67,331 | 60,438 | 58,014 | |||||||||||||||||
Tax-equivalent adjustment (1) | 649 | 558 | 545 | |||||||||||||||||
Operating revenue (tax-equivalent basis) (1) | 67,980 | 60,996 | 58,559 | |||||||||||||||||
| Less: adjustments to noninterest income | ||||||||||||||||||||
| Revenue from closed or sold operations | 153 | — | — | |||||||||||||||||
| Gains (losses) on closed branch premises | (210) | — | 59 | |||||||||||||||||
| Realized gains (losses) on sales of securities | — | (151) | — | |||||||||||||||||
| Mortgage servicing rights fair value adjustment | 197 | (310) | (308) | |||||||||||||||||
| Total adjustments to noninterest income | 140 | (461) | (249) | |||||||||||||||||
Adjusted operating revenue (tax-equivalent basis) (1) | $ | 67,840 | $ | 61,457 | $ | 58,808 | ||||||||||||||
| Efficiency ratio | 76.56 | % | 53.64 | % | 53.85 | % | ||||||||||||||
Efficiency ratio (tax-equivalent basis) (1) | 75.83 | 53.15 | 53.35 | |||||||||||||||||
Adjusted efficiency ratio (tax-equivalent basis) (1) | 52.68 | 51.12 | 53.12 | |||||||||||||||||
____________________________________
(1)On a tax-equivalent basis assuming a federal income tax rate of 21% and a state tax rate of 9.5%.
HBT Financial, Inc.
Page 16
Reconciliation of Non-GAAP Financial Measures –
Ratio of Tangible Common Equity to Tangible Assets and Tangible Book Value Per Share
| (dollars in thousands, except per share data) | March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||
| Tangible Common Equity | ||||||||||||||||||||
| Total stockholders' equity | $ | 747,405 | $ | 615,498 | $ | 565,057 | ||||||||||||||
| Less: Goodwill | 83,504 | 59,820 | 59,820 | |||||||||||||||||
| Less: Intangible assets | 44,962 | 15,117 | 17,148 | |||||||||||||||||
| Tangible common equity | $ | 618,939 | $ | 540,561 | $ | 488,089 | ||||||||||||||
| Tangible Assets | ||||||||||||||||||||
| Total assets | $ | 6,773,724 | $ | 5,071,390 | $ | 5,092,192 | ||||||||||||||
| Less: Goodwill | 83,504 | 59,820 | 59,820 | |||||||||||||||||
| Less: Intangible assets | 44,962 | 15,117 | 17,148 | |||||||||||||||||
| Tangible assets | $ | 6,645,258 | $ | 4,996,453 | $ | 5,015,224 | ||||||||||||||
| Total stockholders' equity to total assets | 11.03 | % | 12.14 | % | 11.10 | % | ||||||||||||||
| Tangible common equity to tangible assets | 9.31 | 10.82 | 9.73 | |||||||||||||||||
| Shares of common stock outstanding | 36,381,078 | 31,431,924 | 31,631,431 | |||||||||||||||||
| Book value per share | $ | 20.54 | $ | 19.58 | $ | 17.86 | ||||||||||||||
| Tangible book value per share | 17.01 | 17.20 | 15.43 | |||||||||||||||||
Reconciliation of Non-GAAP Financial Measures –
Return on Average Tangible Common Equity,
Adjusted Return on Average Stockholders' Equity and Adjusted Return on Average Tangible Common Equity
| Three Months Ended | ||||||||||||||||||||
| (dollars in thousands) | March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||
| Average Tangible Common Equity | ||||||||||||||||||||
| Total stockholders' equity | $ | 670,567 | $ | 608,822 | $ | 554,715 | ||||||||||||||
| Less: Goodwill | 67,977 | 59,820 | 59,820 | |||||||||||||||||
| Less: Intangible assets | 25,382 | 15,419 | 17,480 | |||||||||||||||||
| Average tangible common equity | $ | 577,208 | $ | 533,583 | $ | 477,415 | ||||||||||||||
| Net income | $ | 11,200 | $ | 18,938 | $ | 19,075 | ||||||||||||||
| Adjusted net income | 22,610 | 20,139 | 19,253 | |||||||||||||||||
| Return on average stockholders' equity * | 6.77 | % | 12.34 | % | 13.95 | % | ||||||||||||||
| Return on average tangible common equity * | 7.87 | 14.08 | 16.20 | |||||||||||||||||
| Adjusted return on average stockholders' equity * | 13.67 | % | 13.12 | % | 14.08 | % | ||||||||||||||
| Adjusted return on average tangible common equity * | 15.89 | 14.97 | 16.36 | |||||||||||||||||
____________________________________
*Annualized measure.
Q1 2026 Results Presentation April 27, 2026
1 Forward-Looking Statements Readers should note that in addition to the historical information contained herein, this presentation contains, and future oral and written statements of the Company and its management may contain, “forward-looking statements” within the meanings of the Private Securities Litigation Reform Act of 1995, Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Forward-looking statements generally can be identified by the use of forward-looking terminology such as “will,” “propose,” “may,” “plan,” “seek,” “expect,” “intend,” “estimate,” “anticipate,” “believe,” “continue,” or “should,” or similar terminology and the negative forms of such words. Any forward-looking statements presented herein are made only as of the date of this presentation, and the Company does not undertake any obligation to update or revise any forward-looking statements to reflect changes in assumptions, the occurrence of unanticipated events, or otherwise. Factors that could cause actual results to differ materially from these forward-looking statements include, but are not limited to: (1) the strength of the local, state, national and international economies and financial markets (including effects of inflationary pressures, global energy market conditions, the threat or implementation of tariffs, immigration enforcement and changes in foreign policy); (2) policy changes in, and the interpretation and prioritization of, local, state and federal laws, regulations and governmental policies, including executive orders; (3) the economic impact of any future terrorist threats and attacks, widespread disease or pandemics, acts of war or other threats thereof (including the Russian invasion of Ukraine and the conflicts in the Middle East), or other adverse events that could cause economic deterioration or instability in credit markets, and the response of the local, state and national governments to any such adverse external events; (4) new and revised accounting policies and practices, as may be adopted by state and federal regulatory banking agencies, the Financial Accounting Standards Board or the Public Company Accounting Oversight Board; (5) the imposition of tariffs or other governmental policies impacting the value of products produced by the Company's commercial borrowers; (6) changes in interest rates and prepayment rates of the Company’s assets; (7) increased competition in the financial services sector, including from non-bank competitors such as credit unions, private credit firms, fintech companies, and digital asset service providers, and the inability to attract new customers; (8) technological changes implemented by us and other parties, including our third-party vendors, which may have unforeseen consequences to us and our customers, including the development and implementation of tools incorporating artificial intelligence; (9) unexpected results of acquisitions, which may include failure to realize the anticipated benefits of acquisitions and the possibility that transaction costs may be greater than anticipated, including the acquisition of CNB; (10) the loss of key executives and employees, talent shortages and employee turnover; (11) changes in consumer spending; (12) unexpected outcomes or costs of existing or new litigation or other legal proceedings and regulatory actions involving the Company; (13) the economic impact on the Company and its customers of climate change, natural disasters and of exceptional weather occurrences such as tornadoes, floods and blizzards; (14) fluctuations in the value of securities held in our securities portfolio, including as a result of changes in interest rates; (15) credit risks and risks from concentrations (by type of borrower, geographic area, collateral and industry) within our loan portfolio (including commercial real estate loans) and large loans to certain borrowers; (16) the overall health of the local and national real estate market; (17) the ability to maintain an adequate level of allowance for credit losses on loans; (18) the concentration of large deposits from certain clients who have balances above current FDIC insurance limits and who may withdraw deposits to diversify their exposure; (19) the ability to successfully manage liquidity risk, which may increase dependence on non-core funding sources such as brokered deposits, and may negatively impact the Company’s cost of funds; (20) the level of nonperforming assets on our balance sheet; (21) interruptions involving our information technology and communications systems or those of our third-party servicers; (22) the occurrence of fraudulent activity, breaches or failures of our third-party vendors’ information security controls or cybersecurity-related incidents, including as a result of sophisticated attacks using artificial intelligence and similar tools or as a result of insider fraud; (23) the effectiveness of the Company’s risk management framework; and (24) the ability of the Company to manage the risks associated with the foregoing as well as anticipated. Readers should note that the forward-looking statements included in this press release are not a guarantee of future events, and that actual events may differ materially from those made in or suggested by the forward-looking statements. Additional information concerning the Company and its business, including additional factors that could materially affect the Company’s financial results, is included in the Company’s filings with the Securities and Exchange Commission. Non-GAAP Financial Measures This presentation includes certain non-GAAP financial measures. While the Company believes these are useful measures for investors, they are not presented in accordance with GAAP. You should not consider non- GAAP measures in isolation or as a substitute for the most directly comparable or other financial measures calculated in accordance with GAAP. Because not all companies use identical calculations, the presentation herein of non-GAAP financial measures may not be comparable to other similarly titled measures of other companies. Tax-equivalent adjustments assume a federal tax rate of 21% and state tax rate of 9.5%. For a reconciliation of the non-GAAP measures we use to the most closely comparable GAAP measures, see the Appendix to this presentation.
2 M&A continues to contribute to the value of the HBT franchise Strong profitability Net interest margin expansion supported by low cost deposit base n Completed merger with CNB on March 1, 2026 n Core system conversion successfully completed in March 2026 n Expands HBT's footprint in the central Illinois, Chicago MSA, and St. Louis MSA markets n Adds low-cost deposit base with solid commercial loan growth and compatible credit quality n HBT's capital levels post-merger support future organic growth or potential accretive mergers and acquisitions n Net income of $11.2 million, or $0.34 per diluted share; return on average assets (ROAA) of 0.80% and return on average tangible common equity (ROATCE)1 of 7.87% n Adjusted net income1 of $22.6 million, or $0.68 per diluted share; adjusted ROAA1 of 1.60% and adjusted ROATCE1 of 15.89% n As expected following the merger with CNB Bank Shares, Inc. ("CNB"), tangible book value per share1 decreased 1.1% from December 31, 2025; increased 10.2% from March 31, 2025 n Net interest margin expanded 8 basis points to 4.20% and net interest margin (tax-equivalent basis)1 expanded 9 basis points to 4.25%, compared to Q4 2025 n Cost of funds increased 2 basis points to 1.25% and total cost of deposits increased 1 basis point to 1.17% Q1 2026 Highlights Note: Financial data as of and for the three months ended March 31, 2026 unless otherwise indicated; 1 See "Non-GAAP reconciliations" in the Appendix for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures.
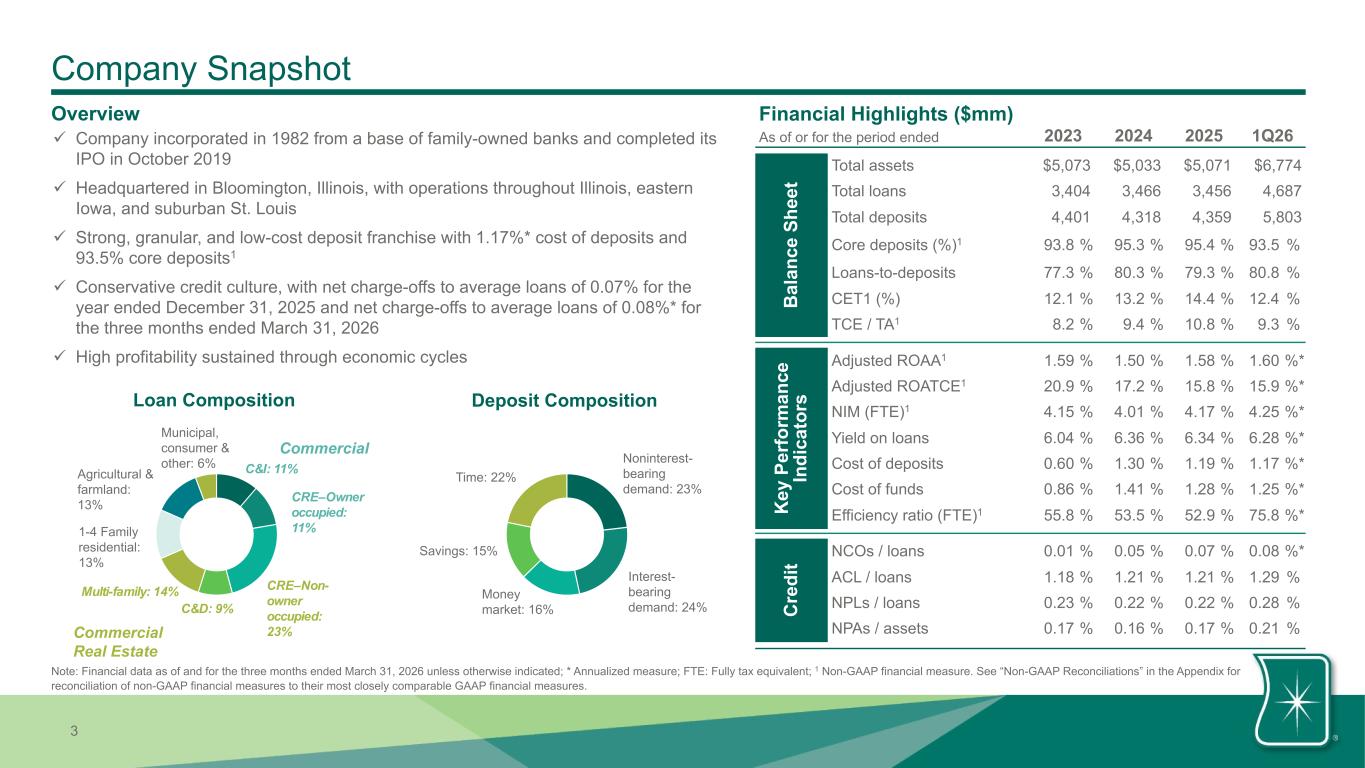
3 Company Snapshot Overview ü Company incorporated in 1982 from a base of family-owned banks and completed its IPO in October 2019 ü Headquartered in Bloomington, Illinois, with operations throughout Illinois, eastern Iowa, and suburban St. Louis ü Strong, granular, and low-cost deposit franchise with 1.17%* cost of deposits and 93.5% core deposits1 ü Conservative credit culture, with net charge-offs to average loans of 0.07% for the year ended December 31, 2025 and net charge-offs to average loans of 0.08%* for the three months ended March 31, 2026 ü High profitability sustained through economic cycles Loan Composition Deposit Composition Noninterest- bearing demand: 23% Interest- bearing demand: 24% Money market: 16% Savings: 15% Time: 22%C&I: 11% CRE–Owner occupied: 11% CRE–Non- owner occupied: 23% C&D: 9% Multi-family: 14% 1-4 Family residential: 13% Agricultural & farmland: 13% Municipal, consumer & other: 6% Commercial Real Estate Note: Financial data as of and for the three months ended March 31, 2026 unless otherwise indicated; * Annualized measure; FTE: Fully tax equivalent; 1 Non-GAAP financial measure. See “Non-GAAP Reconciliations” in the Appendix for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures. Commercial Financial Highlights ($mm) 2023 2024 2025 1Q26As of or for the period ended B al an ce S he et Total assets $5,073 $5,033 $5,071 $6,774 Total loans 3,404 3,466 3,456 4,687 Total deposits 4,401 4,318 4,359 5,803 Core deposits (%)1 93.8 % 95.3 % 95.4 % 93.5 % Loans-to-deposits 77.3 % 80.3 % 79.3 % 80.8 % CET1 (%) 12.1 % 13.2 % 14.4 % 12.4 % TCE / TA1 8.2 % 9.4 % 10.8 % 9.3 % K ey P er fo rm an ce In di ca to rs Adjusted ROAA1 1.59 % 1.50 % 1.58 % 1.60 %* Adjusted ROATCE1 20.9 % 17.2 % 15.8 % 15.9 %* NIM (FTE)1 4.15 % 4.01 % 4.17 % 4.25 %* Yield on loans 6.04 % 6.36 % 6.34 % 6.28 %* Cost of deposits 0.60 % 1.30 % 1.19 % 1.17 %* Cost of funds 0.86 % 1.41 % 1.28 % 1.25 %* Efficiency ratio (FTE)1 55.8 % 53.5 % 52.9 % 75.8 %* C re di t NCOs / loans 0.01 % 0.05 % 0.07 % 0.08 %* ACL / loans 1.18 % 1.21 % 1.21 % 1.29 % NPLs / loans 0.23 % 0.22 % 0.22 % 0.28 % NPAs / assets 0.17 % 0.16 % 0.17 % 0.21 %
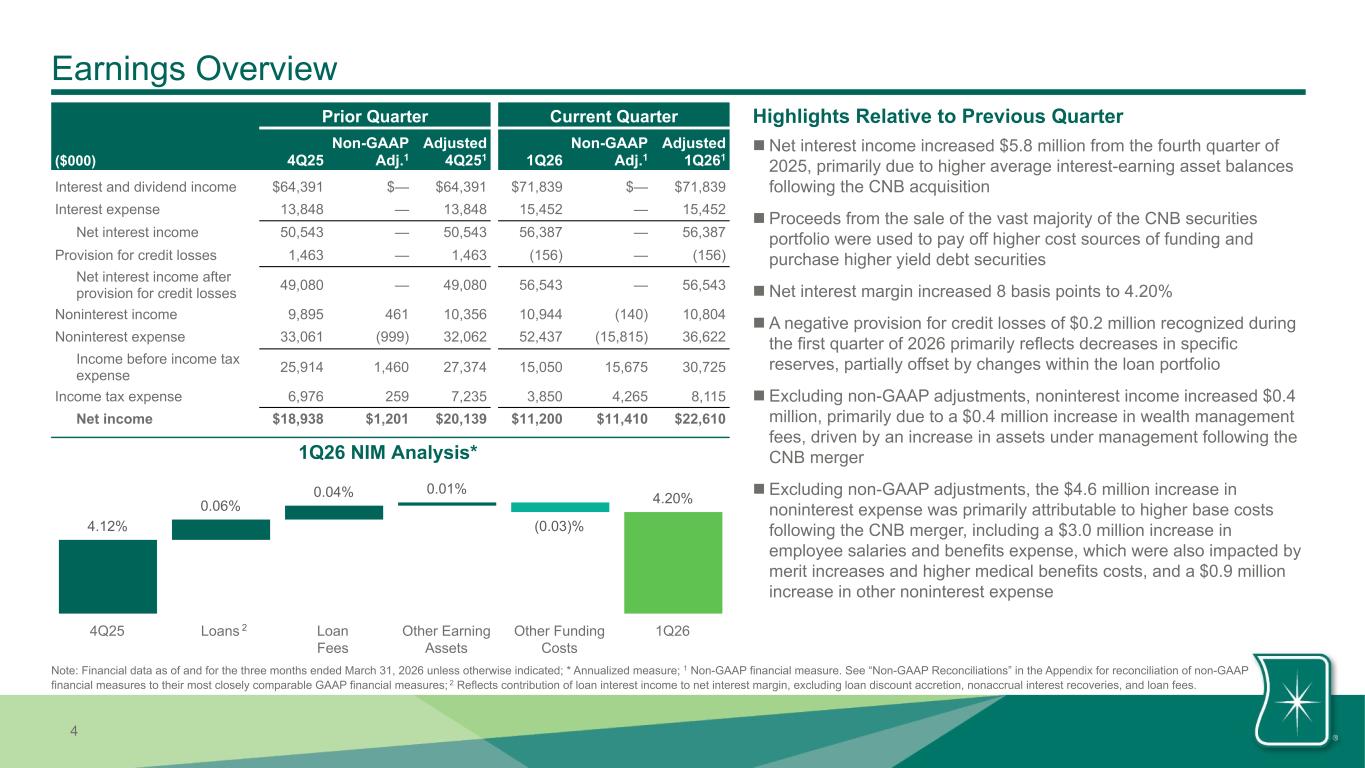
4 4.12% 0.06% 0.04% 0.01% (0.03)% 4.20% 4Q25 Loans Loan Fees Other Earning Assets Other Funding Costs 1Q26 Earnings Overview Prior Quarter Current Quarter ($000) 4Q25 Non-GAAP Adj.1 Adjusted 4Q251 1Q26 Non-GAAP Adj.1 Adjusted 1Q261 Interest and dividend income $64,391 $— $64,391 $71,839 $— $71,839 Interest expense 13,848 — 13,848 15,452 — 15,452 Net interest income 50,543 — 50,543 56,387 — 56,387 Provision for credit losses 1,463 — 1,463 (156) — (156) Net interest income after provision for credit losses 49,080 — 49,080 56,543 — 56,543 Noninterest income 9,895 461 10,356 10,944 (140) 10,804 Noninterest expense 33,061 (999) 32,062 52,437 (15,815) 36,622 Income before income tax expense 25,914 1,460 27,374 15,050 15,675 30,725 Income tax expense 6,976 259 7,235 3,850 4,265 8,115 Net income $18,938 $1,201 $20,139 $11,200 $11,410 $22,610 Highlights Relative to Previous Quarter 2 n Net interest income increased $5.8 million from the fourth quarter of 2025, primarily due to higher average interest-earning asset balances following the CNB acquisition n Proceeds from the sale of the vast majority of the CNB securities portfolio were used to pay off higher cost sources of funding and purchase higher yield debt securities n Net interest margin increased 8 basis points to 4.20% n A negative provision for credit losses of $0.2 million recognized during the first quarter of 2026 primarily reflects decreases in specific reserves, partially offset by changes within the loan portfolio n Excluding non-GAAP adjustments, noninterest income increased $0.4 million, primarily due to a $0.4 million increase in wealth management fees, driven by an increase in assets under management following the CNB merger n Excluding non-GAAP adjustments, the $4.6 million increase in noninterest expense was primarily attributable to higher base costs following the CNB merger, including a $3.0 million increase in employee salaries and benefits expense, which were also impacted by merit increases and higher medical benefits costs, and a $0.9 million increase in other noninterest expense 1Q26 NIM Analysis* Note: Financial data as of and for the three months ended March 31, 2026 unless otherwise indicated; * Annualized measure; 1 Non-GAAP financial measure. See “Non-GAAP Reconciliations” in the Appendix for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures; 2 Reflects contribution of loan interest income to net interest margin, excluding loan discount accretion, nonaccrual interest recoveries, and loan fees.
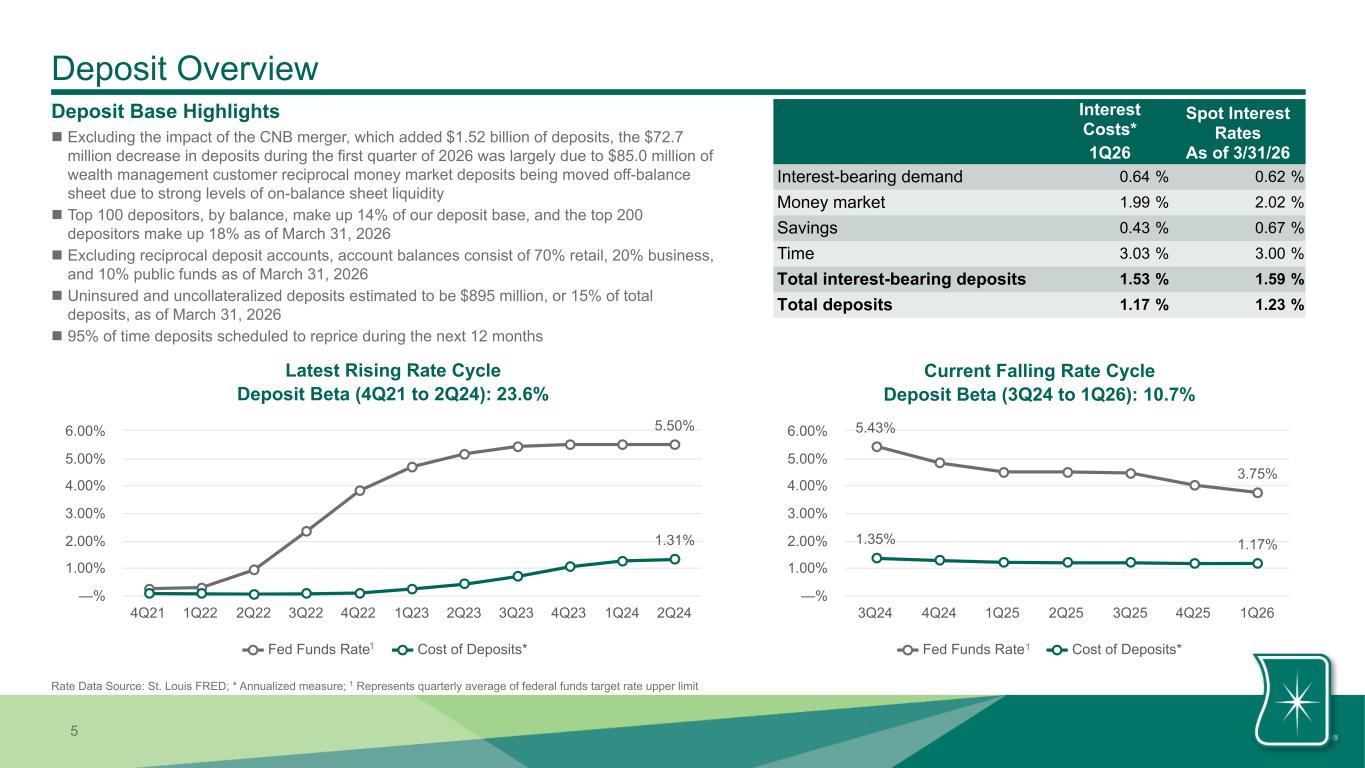
5 5.50% 1.31% Fed Funds Rate Cost of Deposits* 4Q21 1Q22 2Q22 3Q22 4Q22 1Q23 2Q23 3Q23 4Q23 1Q24 2Q24 —% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% Deposit Overview Deposit Base Highlights n Excluding the impact of the CNB merger, which added $1.52 billion of deposits, the $72.7 million decrease in deposits during the first quarter of 2026 was largely due to $85.0 million of wealth management customer reciprocal money market deposits being moved off-balance sheet due to strong levels of on-balance sheet liquidity n Top 100 depositors, by balance, make up 14% of our deposit base, and the top 200 depositors make up 18% as of March 31, 2026 n Excluding reciprocal deposit accounts, account balances consist of 70% retail, 20% business, and 10% public funds as of March 31, 2026 n Uninsured and uncollateralized deposits estimated to be $895 million, or 15% of total deposits, as of March 31, 2026 n 95% of time deposits scheduled to reprice during the next 12 months Interest Costs* 1Q26 Spot Interest Rates As of 3/31/26 Interest-bearing demand 0.64 % 0.62 % Money market 1.99 % 2.02 % Savings 0.43 % 0.67 % Time 3.03 % 3.00 % Total interest-bearing deposits 1.53 % 1.59 % Total deposits 1.17 % 1.23 % 1 Latest Rising Rate Cycle Deposit Beta (4Q21 to 2Q24): 23.6% 5.43% 3.75% 1.35% 1.17% Fed Funds Rate Cost of Deposits* 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 —% 1.00% 2.00% 3.00% 4.00% 5.00% 6.00% Current Falling Rate Cycle Deposit Beta (3Q24 to 1Q26): 10.7% 1 Rate Data Source: St. Louis FRED; * Annualized measure; 1 Represents quarterly average of federal funds target rate upper limit 1
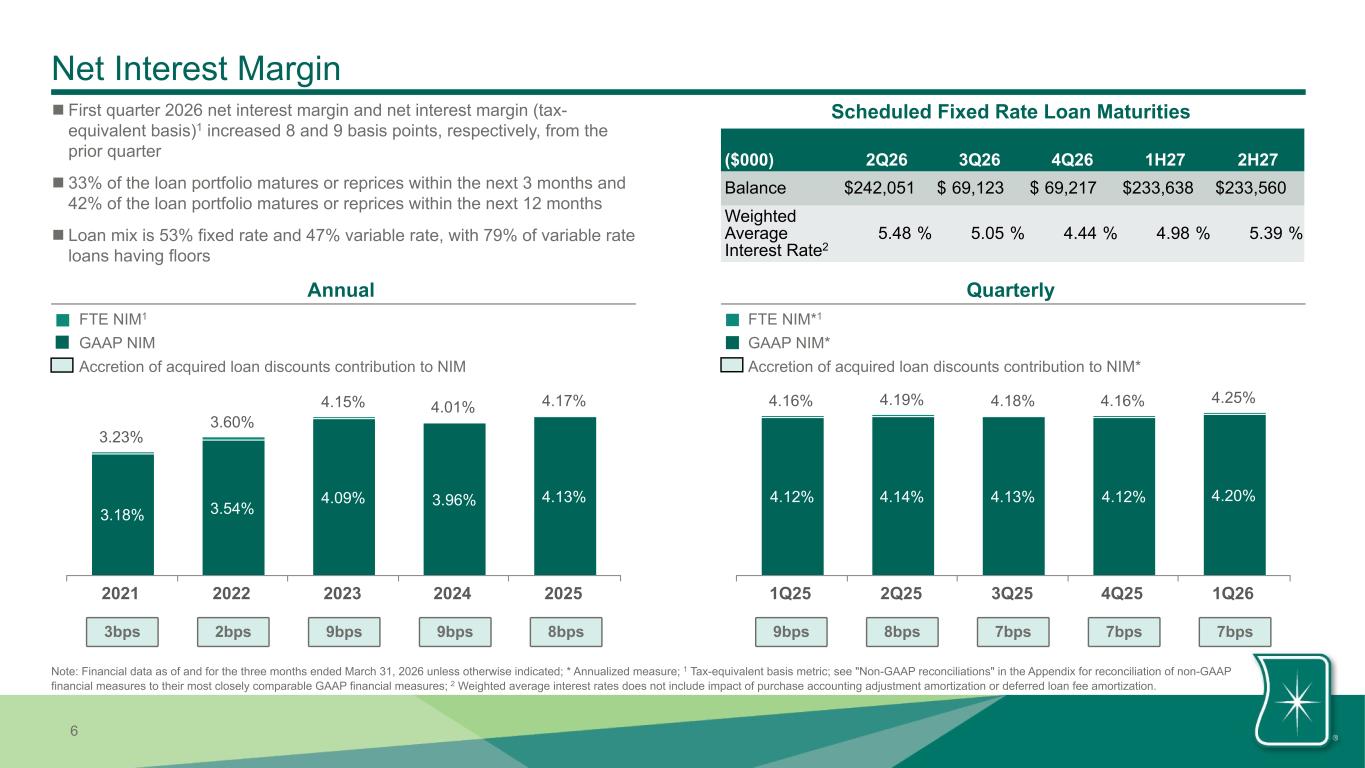
6 Net Interest Margin Annual Quarterly FTE NIM*1 GAAP NIM* Accretion of acquired loan discounts contribution to NIM* FTE NIM1 GAAP NIM Accretion of acquired loan discounts contribution to NIM 3.23% 3.60% 4.15% 4.01% 4.17% 3.18% 3.54% 4.09% 3.96% 4.13% 2021 2022 2023 2024 2025 4.16% 4.19% 4.18% 4.16% 4.25% 4.12% 4.14% 4.13% 4.12% 4.20% 1Q25 2Q25 3Q25 4Q25 1Q26 n First quarter 2026 net interest margin and net interest margin (tax- equivalent basis)1 increased 8 and 9 basis points, respectively, from the prior quarter n 33% of the loan portfolio matures or reprices within the next 3 months and 42% of the loan portfolio matures or reprices within the next 12 months n Loan mix is 53% fixed rate and 47% variable rate, with 79% of variable rate loans having floors Scheduled Fixed Rate Loan Maturities ($000) 2Q26 3Q26 4Q26 1H27 2H27 Balance $ 242,051 $ 69,123 $ 69,217 $ 233,638 $ 233,560 Weighted Average Interest Rate2 5.48 % 5.05 % 4.44 % 4.98 % 5.39 % Note: Financial data as of and for the three months ended March 31, 2026 unless otherwise indicated; * Annualized measure; 1 Tax-equivalent basis metric; see "Non-GAAP reconciliations" in the Appendix for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures; 2 Weighted average interest rates does not include impact of purchase accounting adjustment amortization or deferred loan fee amortization. 3bps 2bps 9bps 9bps 8bps 9bps 8bps 7bps 7bps 7bps
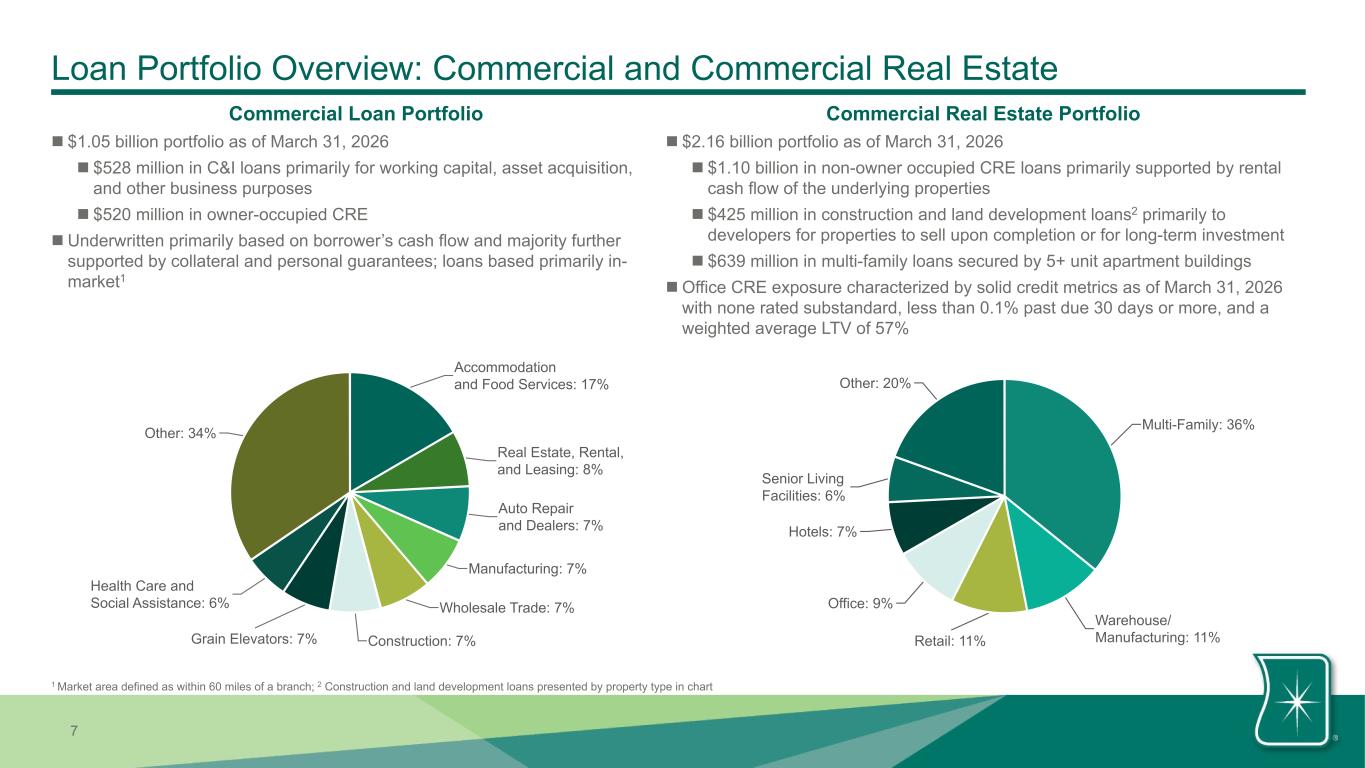
7 Loan Portfolio Overview: Commercial and Commercial Real Estate n $2.16 billion portfolio as of March 31, 2026 n $1.10 billion in non-owner occupied CRE loans primarily supported by rental cash flow of the underlying properties n $425 million in construction and land development loans2 primarily to developers for properties to sell upon completion or for long-term investment n $639 million in multi-family loans secured by 5+ unit apartment buildings n Office CRE exposure characterized by solid credit metrics as of March 31, 2026 with none rated substandard, less than 0.1% past due 30 days or more, and a weighted average LTV of 57% Commercial Real Estate PortfolioCommercial Loan Portfolio n $1.05 billion portfolio as of March 31, 2026 n $528 million in C&I loans primarily for working capital, asset acquisition, and other business purposes n $520 million in owner-occupied CRE n Underwritten primarily based on borrower’s cash flow and majority further supported by collateral and personal guarantees; loans based primarily in- market1 Accommodation and Food Services: 17% Real Estate, Rental, and Leasing: 8% Auto Repair and Dealers: 7% Manufacturing: 7% Wholesale Trade: 7% Construction: 7%Grain Elevators: 7% Health Care and Social Assistance: 6% Other: 34% Multi-Family: 36% Warehouse/ Manufacturing: 11%Retail: 11% Office: 9% Hotels: 7% Senior Living Facilities: 6% Other: 20% 1 Market area defined as within 60 miles of a branch; 2 Construction and land development loans presented by property type in chart
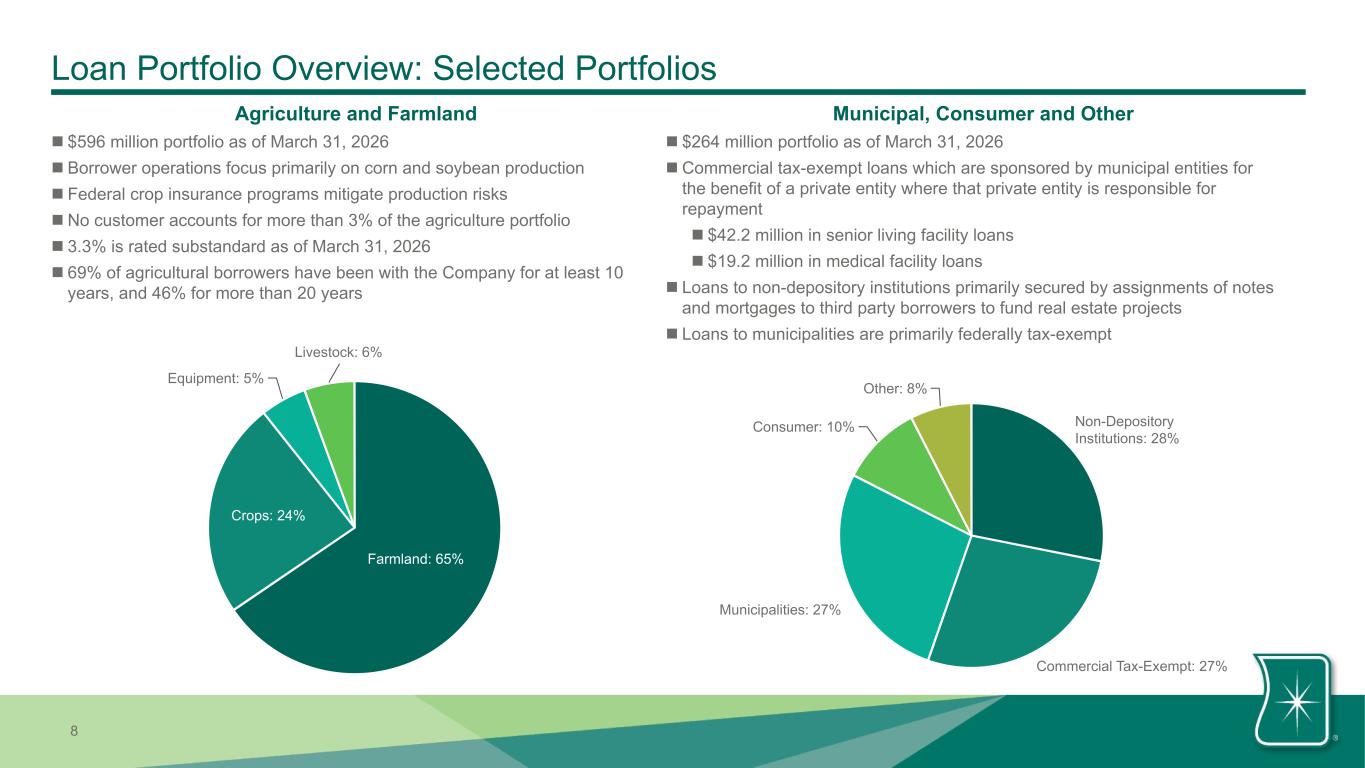
8 Loan Portfolio Overview: Selected Portfolios n $596 million portfolio as of March 31, 2026 n Borrower operations focus primarily on corn and soybean production n Federal crop insurance programs mitigate production risks n No customer accounts for more than 3% of the agriculture portfolio n 3.3% is rated substandard as of March 31, 2026 n 69% of agricultural borrowers have been with the Company for at least 10 years, and 46% for more than 20 years n $264 million portfolio as of March 31, 2026 n Commercial tax-exempt loans which are sponsored by municipal entities for the benefit of a private entity where that private entity is responsible for repayment n $42.2 million in senior living facility loans n $19.2 million in medical facility loans n Loans to non-depository institutions primarily secured by assignments of notes and mortgages to third party borrowers to fund real estate projects n Loans to municipalities are primarily federally tax-exempt Farmland: 65% Crops: 24% Equipment: 5% Livestock: 6% Non-Depository Institutions: 28% Commercial Tax-Exempt: 27% Municipalities: 27% Consumer: 10% Other: 8% Municipal, Consumer and OtherAgriculture and Farmland
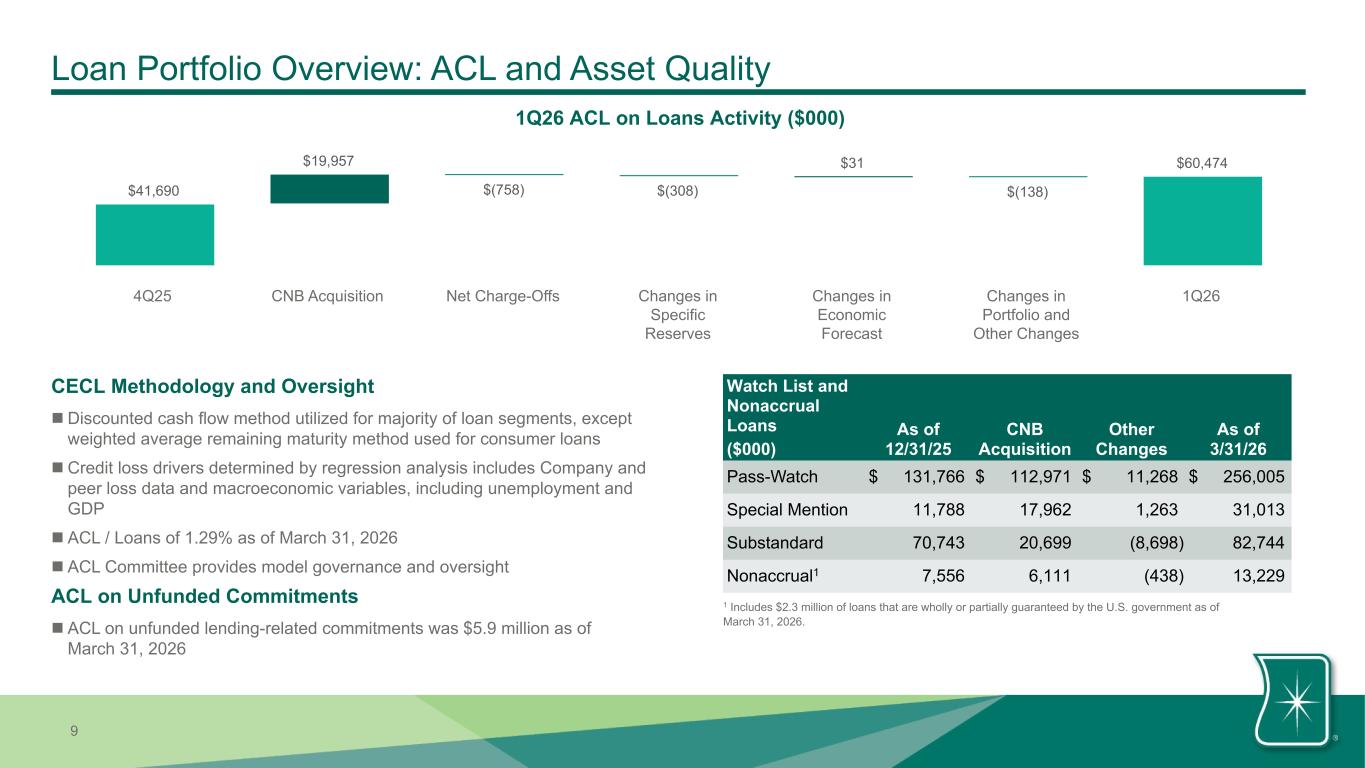
9 Loan Portfolio Overview: ACL and Asset Quality 1Q26 ACL on Loans Activity ($000) Watch List and Nonaccrual Loans ($000) As of 12/31/25 CNB Acquisition Other Changes As of 3/31/26 Pass-Watch $ 131,766 $ 112,971 $ 11,268 $ 256,005 Special Mention 11,788 17,962 1,263 31,013 Substandard 70,743 20,699 (8,698) 82,744 Nonaccrual1 7,556 6,111 (438) 13,229 CECL Methodology and Oversight n Discounted cash flow method utilized for majority of loan segments, except weighted average remaining maturity method used for consumer loans n Credit loss drivers determined by regression analysis includes Company and peer loss data and macroeconomic variables, including unemployment and GDP n ACL / Loans of 1.29% as of March 31, 2026 n ACL Committee provides model governance and oversight ACL on Unfunded Commitments n ACL on unfunded lending-related commitments was $5.9 million as of March 31, 2026 1 Includes $2.3 million of loans that are wholly or partially guaranteed by the U.S. government as of March 31, 2026. $41,690 $19,957 $(758) $(308) $31 $(138) $60,474 4Q25 CNB Acquisition Net Charge-Offs Changes in Specific Reserves Changes in Economic Forecast Changes in Portfolio and Other Changes 1Q26
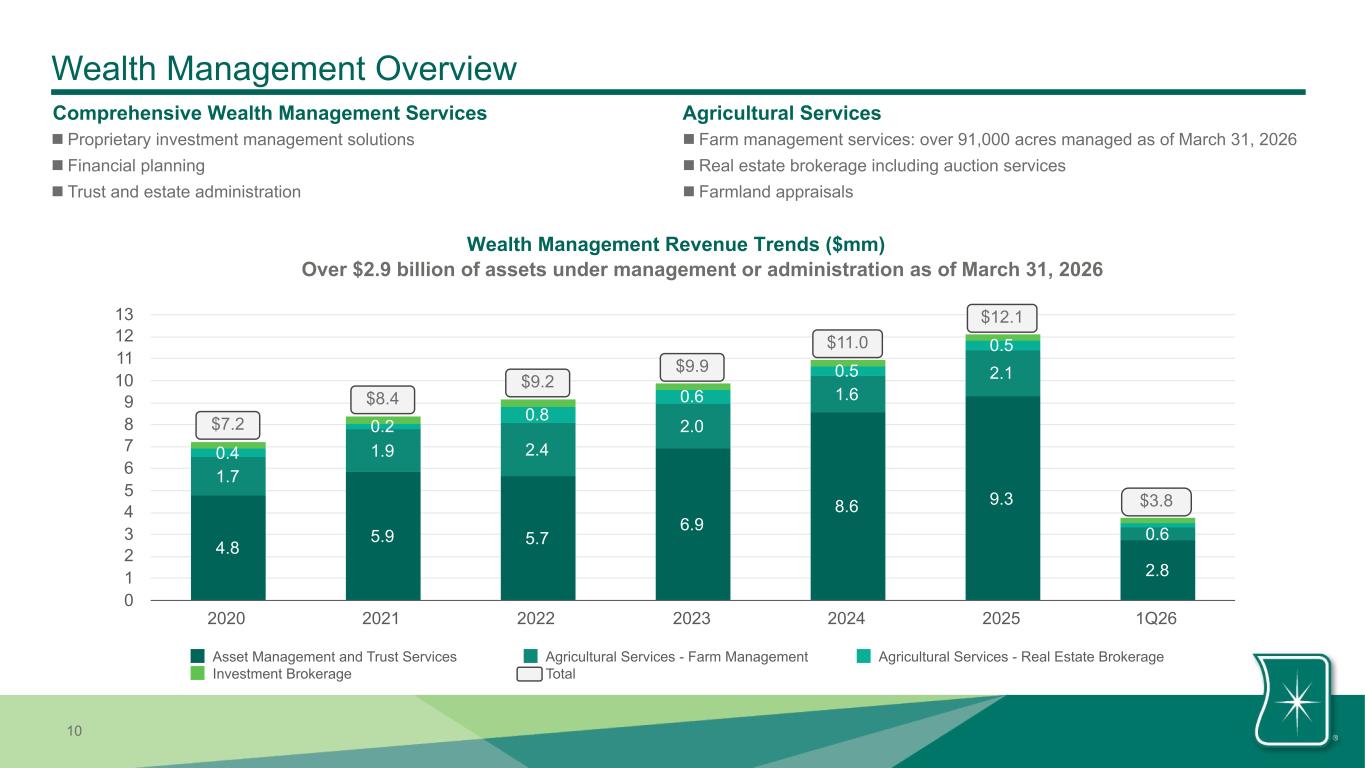
10 4.8 5.9 5.7 6.9 8.6 9.3 2.8 1.7 1.9 2.4 2.0 1.6 2.1 0.6 0.4 0.2 0.8 0.6 0.5 0.5 Asset Management and Trust Services Agricultural Services - Farm Management Agricultural Services - Real Estate Brokerage Investment Brokerage Total 2020 2021 2022 2023 2024 2025 1Q26 0 1 2 3 4 5 6 7 8 9 10 11 12 13 Wealth Management Overview Comprehensive Wealth Management Services n Proprietary investment management solutions n Financial planning n Trust and estate administration Wealth Management Revenue Trends ($mm) Agricultural Services n Farm management services: over 91,000 acres managed as of March 31, 2026 n Real estate brokerage including auction services n Farmland appraisals $12.1 $7.2 $8.4 $9.2 $9.9 Over $2.9 billion of assets under management or administration as of March 31, 2026 $11.0 $3.8
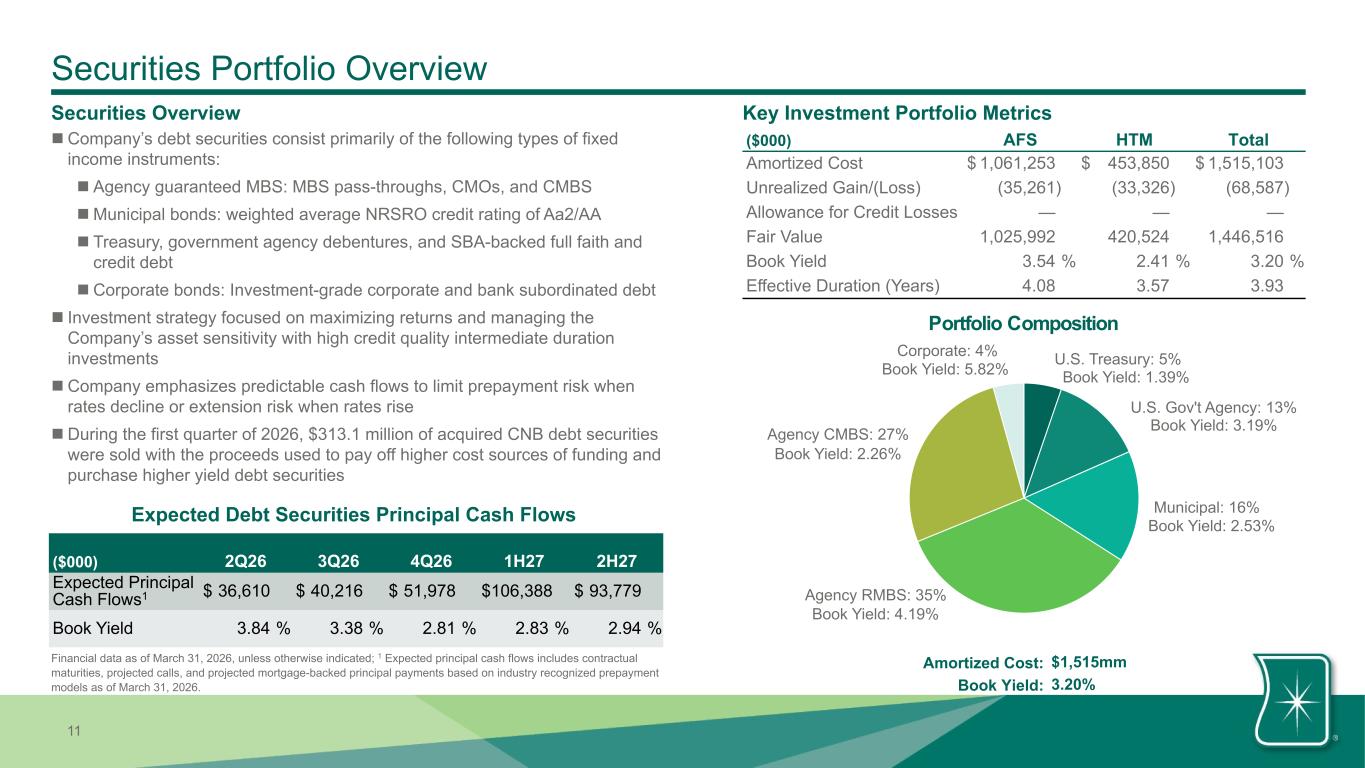
11 Securities Portfolio Overview Securities Overview Key Investment Portfolio Metrics ($000) AFS HTM Total Amortized Cost $ 1,061,253 $ 453,850 $ 1,515,103 Unrealized Gain/(Loss) (35,261) (33,326) (68,587) Allowance for Credit Losses — — — Fair Value 1,025,992 420,524 1,446,516 Book Yield 3.54 % 2.41 % 3.20 % Effective Duration (Years) 4.08 3.57 3.93 Portfolio Composition U.S. Treasury: 5% U.S. Gov't Agency: 13% Municipal: 16% Agency RMBS: 35% Agency CMBS: 27% Corporate: 4% Amortized Cost: $1,515mm Book Yield: 3.20% Book Yield: 3.19% Book Yield: 2.26% Book Yield: 1.39% Book Yield: 2.53% Book Yield: 4.19% Book Yield: 5.82% n Company’s debt securities consist primarily of the following types of fixed income instruments: n Agency guaranteed MBS: MBS pass-throughs, CMOs, and CMBS n Municipal bonds: weighted average NRSRO credit rating of Aa2/AA n Treasury, government agency debentures, and SBA-backed full faith and credit debt n Corporate bonds: Investment-grade corporate and bank subordinated debt n Investment strategy focused on maximizing returns and managing the Company’s asset sensitivity with high credit quality intermediate duration investments n Company emphasizes predictable cash flows to limit prepayment risk when rates decline or extension risk when rates rise n During the first quarter of 2026, $313.1 million of acquired CNB debt securities were sold with the proceeds used to pay off higher cost sources of funding and purchase higher yield debt securities Expected Debt Securities Principal Cash Flows ($000) 2Q26 3Q26 4Q26 1H27 2H27 Expected Principal Cash Flows1 $ 36,610 $ 40,216 $ 51,978 $ 106,388 $ 93,779 Book Yield 3.84 % 3.38 % 2.81 % 2.83 % 2.94 % Financial data as of March 31, 2026, unless otherwise indicated; 1 Expected principal cash flows includes contractual maturities, projected calls, and projected mortgage-backed principal payments based on industry recognized prepayment models as of March 31, 2026.
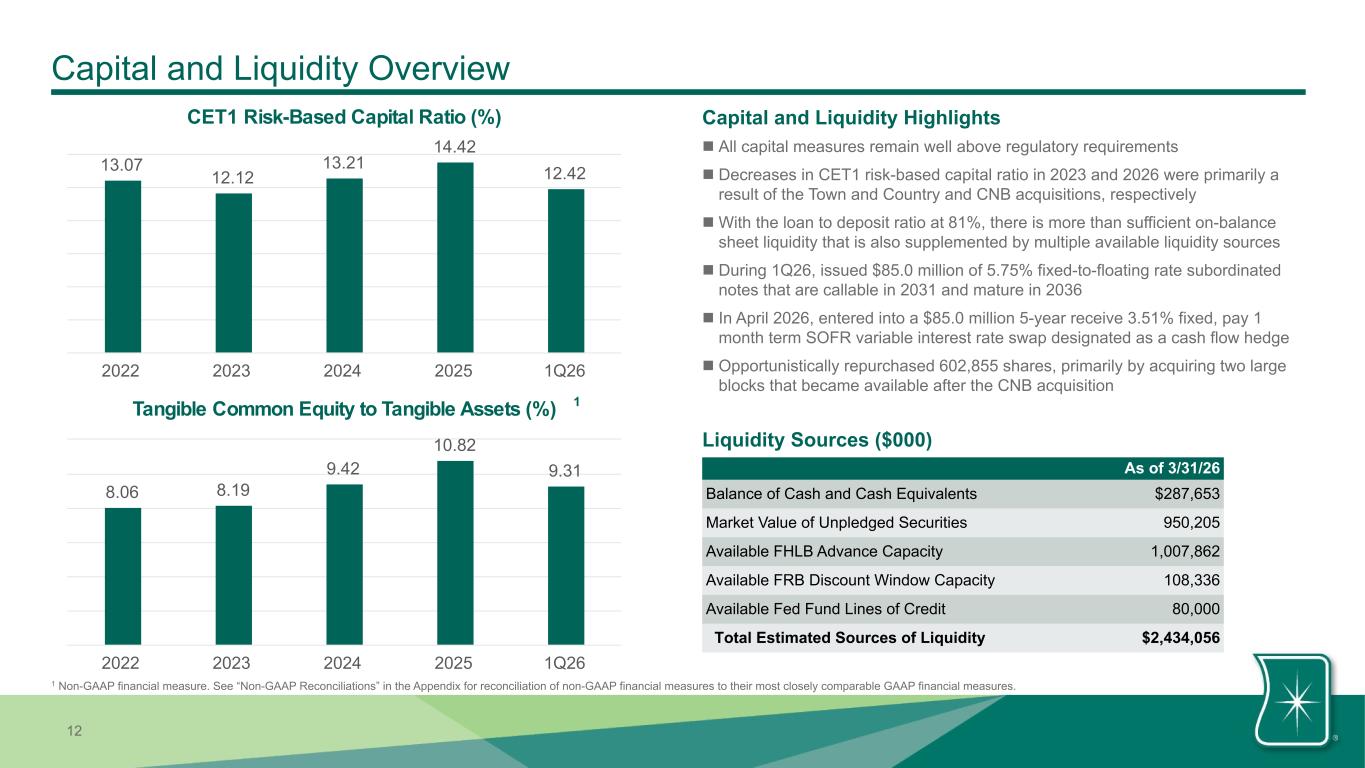
12 Capital and Liquidity Overview As of 3/31/26 Balance of Cash and Cash Equivalents $287,653 Market Value of Unpledged Securities 950,205 Available FHLB Advance Capacity 1,007,862 Available FRB Discount Window Capacity 108,336 Available Fed Fund Lines of Credit 80,000 Total Estimated Sources of Liquidity $2,434,056 Capital and Liquidity Highlights n All capital measures remain well above regulatory requirements n Decreases in CET1 risk-based capital ratio in 2023 and 2026 were primarily a result of the Town and Country and CNB acquisitions, respectively n With the loan to deposit ratio at 81%, there is more than sufficient on-balance sheet liquidity that is also supplemented by multiple available liquidity sources n During 1Q26, issued $85.0 million of 5.75% fixed-to-floating rate subordinated notes that are callable in 2031 and mature in 2036 n In April 2026, entered into a $85.0 million 5-year receive 3.51% fixed, pay 1 month term SOFR variable interest rate swap designated as a cash flow hedge n Opportunistically repurchased 602,855 shares, primarily by acquiring two large blocks that became available after the CNB acquisition CET1 Risk-Based Capital Ratio (%) 13.07 12.12 13.21 14.42 12.42 2022 2023 2024 2025 1Q26 Tangible Common Equity to Tangible Assets (%) 8.06 8.19 9.42 10.82 9.31 2022 2023 2024 2025 1Q26 1 1 Non-GAAP financial measure. See “Non-GAAP Reconciliations” in the Appendix for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures. Liquidity Sources ($000)
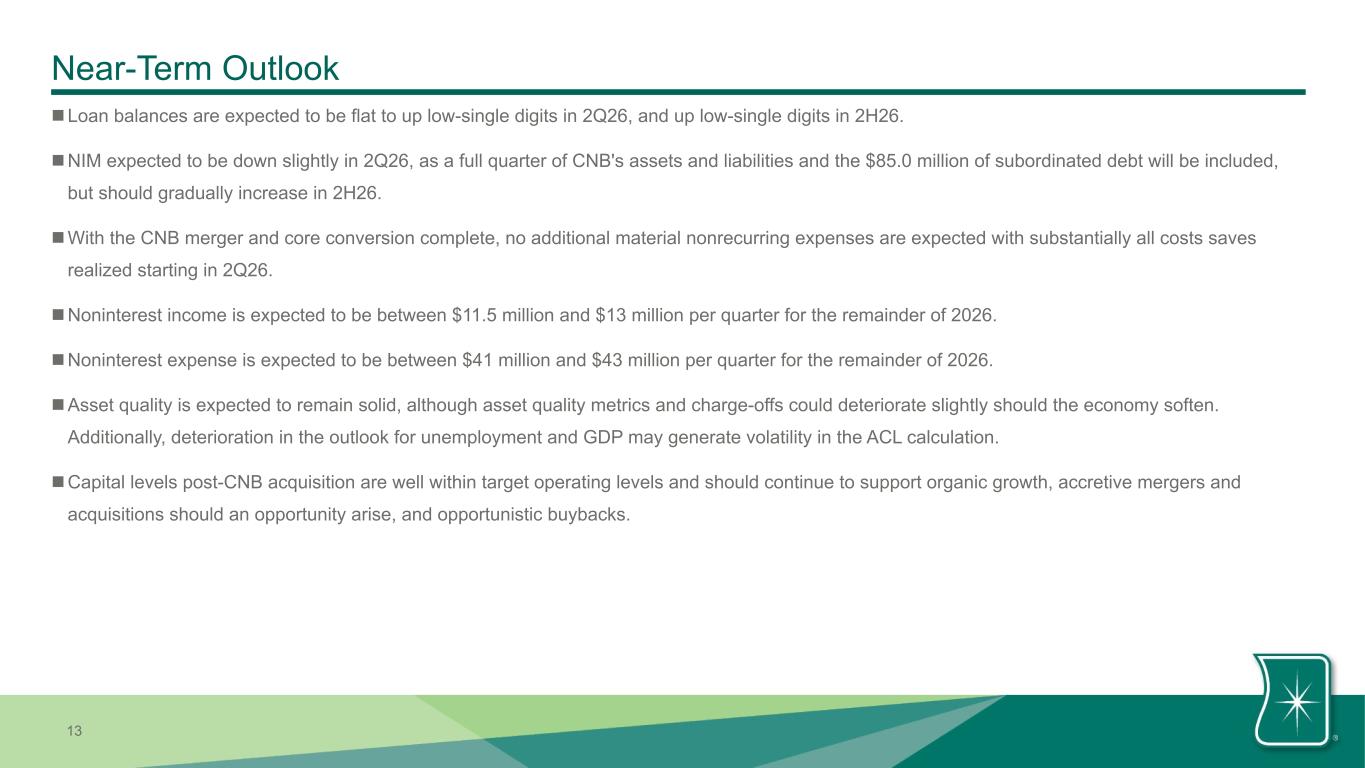
13 Near-Term Outlook nLoan balances are expected to be flat to up low-single digits in 2Q26, and up low-single digits in 2H26. nNIM expected to be down slightly in 2Q26, as a full quarter of CNB's assets and liabilities and the $85.0 million of subordinated debt will be included, but should gradually increase in 2H26. nWith the CNB merger and core conversion complete, no additional material nonrecurring expenses are expected with substantially all costs saves realized starting in 2Q26. nNoninterest income is expected to be between $11.5 million and $13 million per quarter for the remainder of 2026. nNoninterest expense is expected to be between $41 million and $43 million per quarter for the remainder of 2026. nAsset quality is expected to remain solid, although asset quality metrics and charge-offs could deteriorate slightly should the economy soften. Additionally, deterioration in the outlook for unemployment and GDP may generate volatility in the ACL calculation. nCapital levels post-CNB acquisition are well within target operating levels and should continue to support organic growth, accretive mergers and acquisitions should an opportunity arise, and opportunistic buybacks.
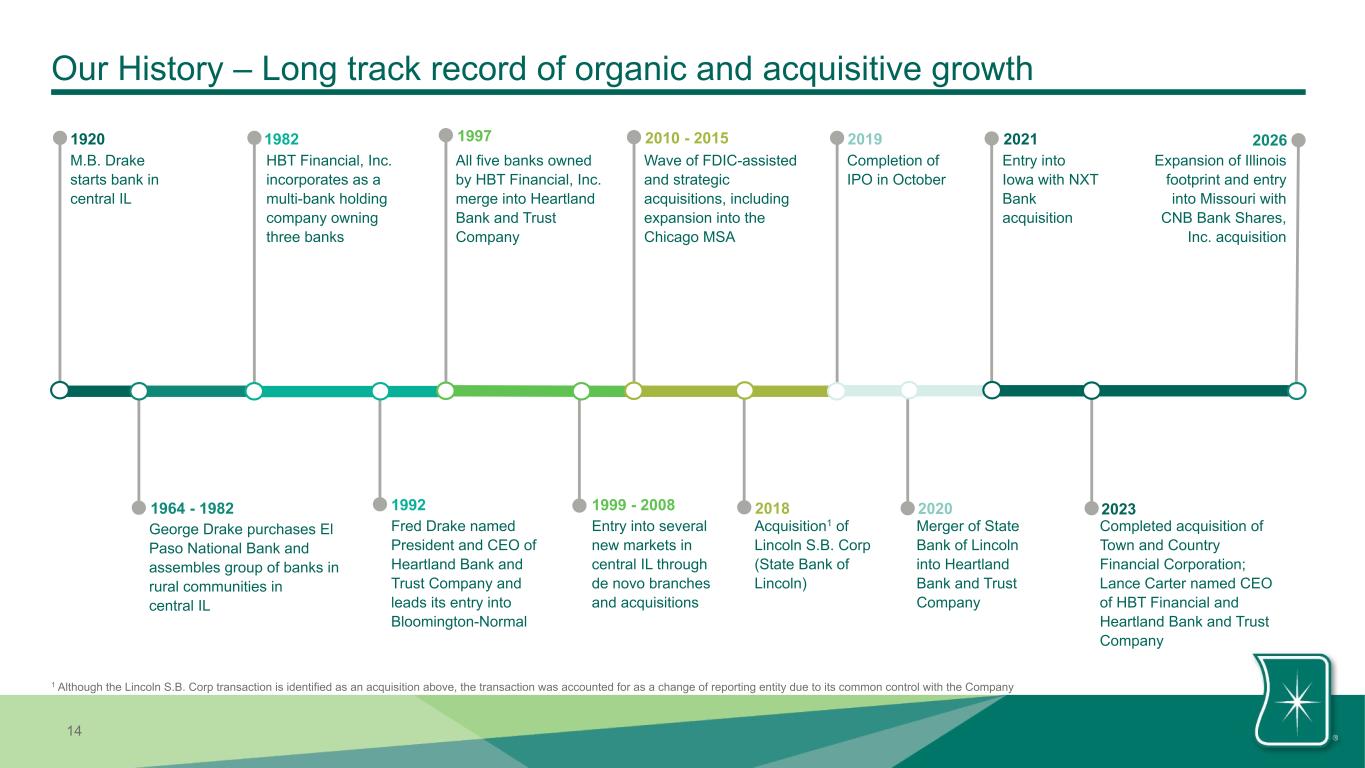
14 Our History – Long track record of organic and acquisitive growth All five banks owned by HBT Financial, Inc. merge into Heartland Bank and Trust Company 1997 1964 - 1982 George Drake purchases El Paso National Bank and assembles group of banks in rural communities in central IL M.B. Drake starts bank in central IL 1920 HBT Financial, Inc. incorporates as a multi-bank holding company owning three banks 1982 1992 Fred Drake named President and CEO of Heartland Bank and Trust Company and leads its entry into Bloomington-Normal Completion of IPO in October 2019 Acquisition1 of Lincoln S.B. Corp (State Bank of Lincoln) 2018 Entry into several new markets in central IL through de novo branches and acquisitions 1999 - 2008 2010 - 2015 Wave of FDIC-assisted and strategic acquisitions, including expansion into the Chicago MSA 2021 Entry into Iowa with NXT Bank acquisition 2020 Merger of State Bank of Lincoln into Heartland Bank and Trust Company 2026 Expansion of Illinois footprint and entry into Missouri with CNB Bank Shares, Inc. acquisition 1 Although the Lincoln S.B. Corp transaction is identified as an acquisition above, the transaction was accounted for as a change of reporting entity due to its common control with the Company Completed acquisition of Town and Country Financial Corporation; Lance Carter named CEO of HBT Financial and Heartland Bank and Trust Company 2023
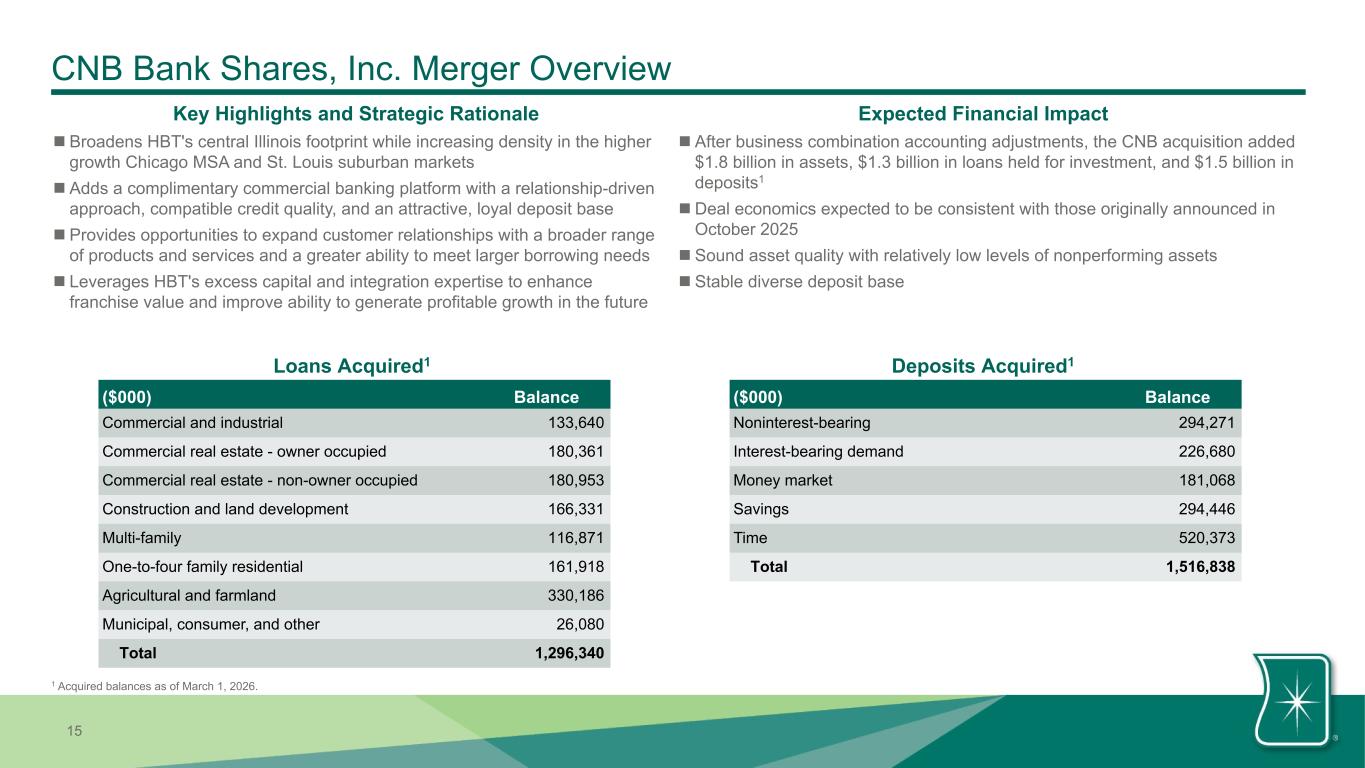
15 CNB Bank Shares, Inc. Merger Overview Expected Financial ImpactKey Highlights and Strategic Rationale n After business combination accounting adjustments, the CNB acquisition added $1.8 billion in assets, $1.3 billion in loans held for investment, and $1.5 billion in deposits1 n Deal economics expected to be consistent with those originally announced in October 2025 n Sound asset quality with relatively low levels of nonperforming assets n Stable diverse deposit base n Broadens HBT's central Illinois footprint while increasing density in the higher growth Chicago MSA and St. Louis suburban markets n Adds a complimentary commercial banking platform with a relationship-driven approach, compatible credit quality, and an attractive, loyal deposit base n Provides opportunities to expand customer relationships with a broader range of products and services and a greater ability to meet larger borrowing needs n Leverages HBT's excess capital and integration expertise to enhance franchise value and improve ability to generate profitable growth in the future ($000) Balance Commercial and industrial 133,640 Commercial real estate - owner occupied 180,361 Commercial real estate - non-owner occupied 180,953 Construction and land development 166,331 Multi-family 116,871 One-to-four family residential 161,918 Agricultural and farmland 330,186 Municipal, consumer, and other 26,080 Total 1,296,340 ($000) Balance Noninterest-bearing 294,271 Interest-bearing demand 226,680 Money market 181,068 Savings 294,446 Time 520,373 Total 1,516,838 Deposits Acquired1Loans Acquired1 1 Acquired balances as of March 1, 2026.
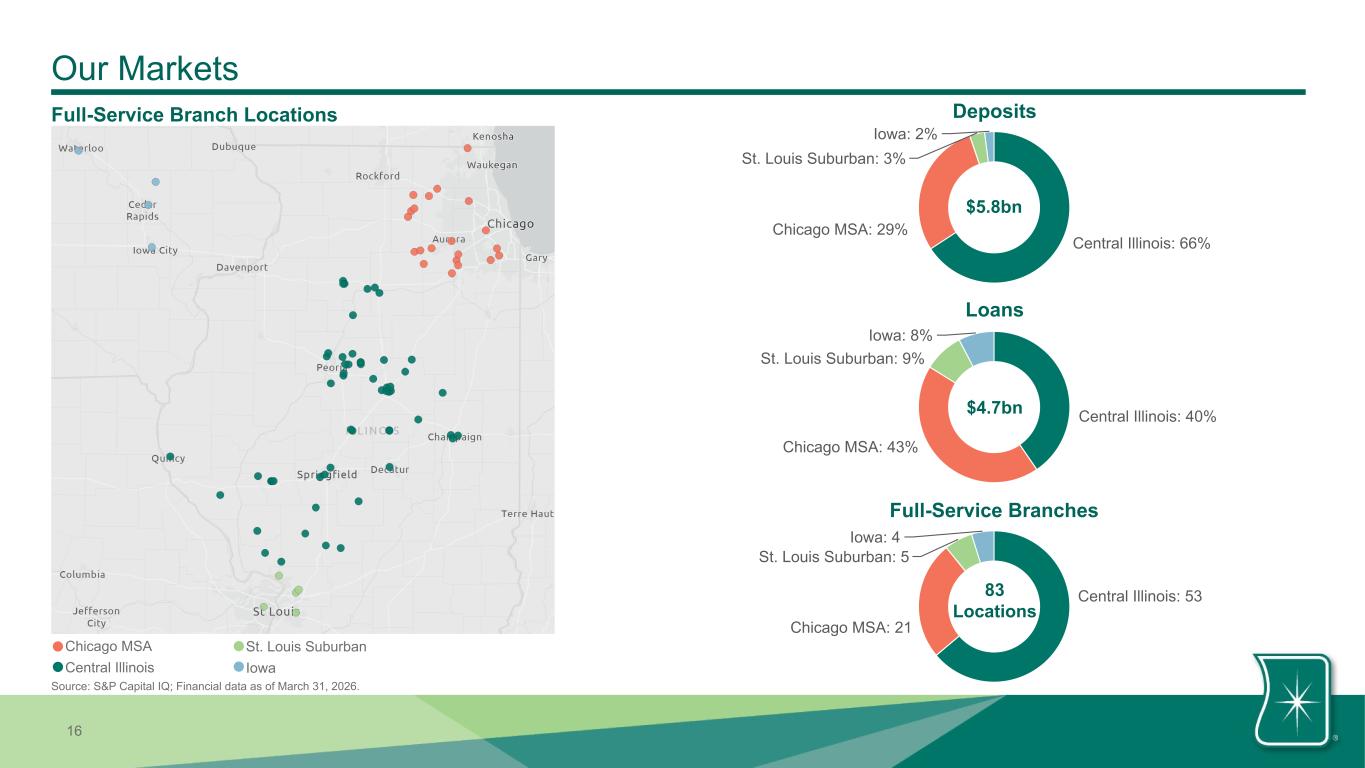
16 Central Illinois: 53 Chicago MSA: 21 St. Louis Suburban: 5 Iowa: 4 Our Markets Source: S&P Capital IQ; Financial data as of March 31, 2026. Full-Service Branch Locations Central Illinois: 66% Chicago MSA: 29% St. Louis Suburban: 3% Iowa: 2% $5.8bn Central Illinois: 40% Chicago MSA: 43% St. Louis Suburban: 9% Iowa: 8% $4.7bn 83 Locations Deposits Loans Full-Service Branches Chicago MSA Central Illinois St. Louis Suburban Iowa
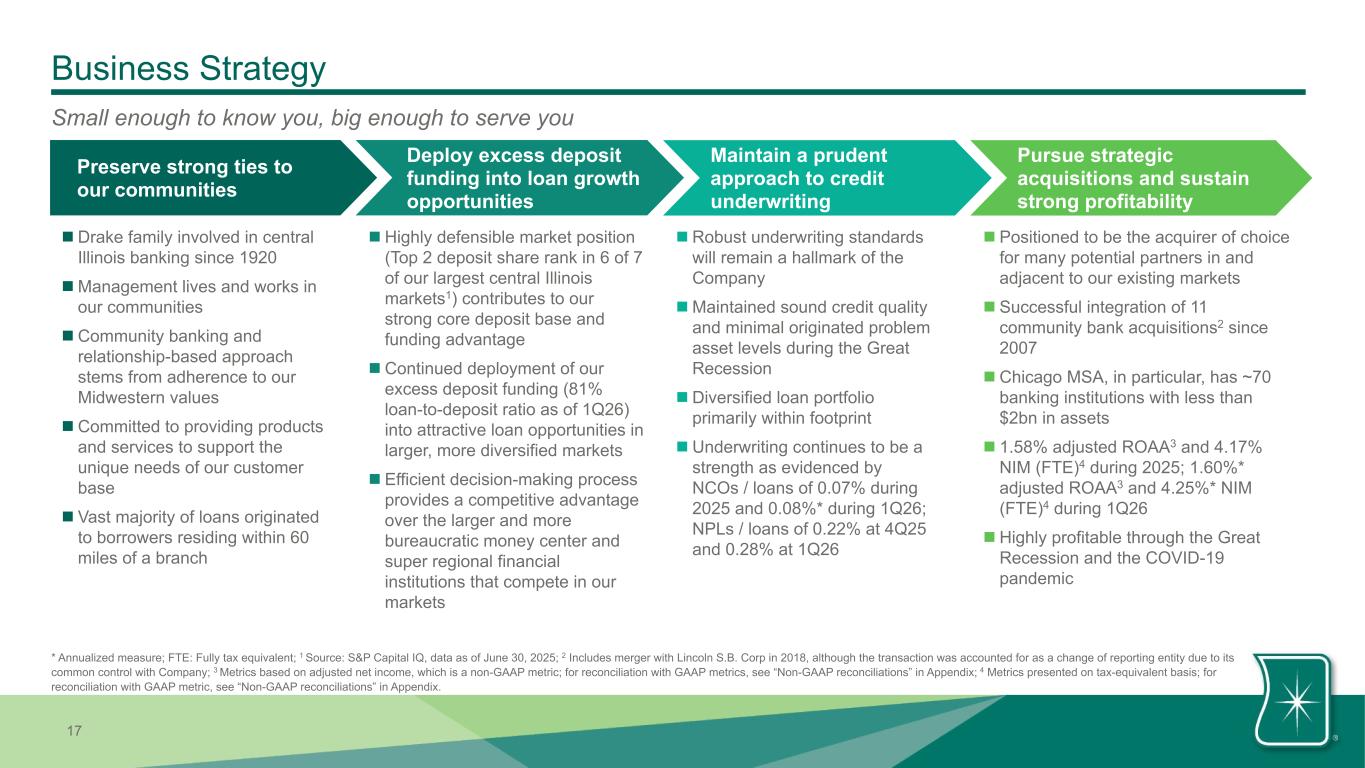
17 Business Strategy n Drake family involved in central Illinois banking since 1920 n Management lives and works in our communities n Community banking and relationship-based approach stems from adherence to our Midwestern values n Committed to providing products and services to support the unique needs of our customer base n Vast majority of loans originated to borrowers residing within 60 miles of a branch n Robust underwriting standards will remain a hallmark of the Company n Maintained sound credit quality and minimal originated problem asset levels during the Great Recession n Diversified loan portfolio primarily within footprint n Underwriting continues to be a strength as evidenced by NCOs / loans of 0.07% during 2025 and 0.08%* during 1Q26; NPLs / loans of 0.22% at 4Q25 and 0.28% at 1Q26 n Positioned to be the acquirer of choice for many potential partners in and adjacent to our existing markets n Successful integration of 11 community bank acquisitions2 since 2007 n Chicago MSA, in particular, has ~70 banking institutions with less than $2bn in assets n 1.58% adjusted ROAA3 and 4.17% NIM (FTE)4 during 2025; 1.60%* adjusted ROAA3 and 4.25%* NIM (FTE)4 during 1Q26 n Highly profitable through the Great Recession and the COVID-19 pandemic n Highly defensible market position (Top 2 deposit share rank in 6 of 7 of our largest central Illinois markets1) contributes to our strong core deposit base and funding advantage n Continued deployment of our excess deposit funding (81% loan-to-deposit ratio as of 1Q26) into attractive loan opportunities in larger, more diversified markets n Efficient decision-making process provides a competitive advantage over the larger and more bureaucratic money center and super regional financial institutions that compete in our markets Preserve strong ties to our communities Deploy excess deposit funding into loan growth opportunities Maintain a prudent approach to credit underwriting Pursue strategic acquisitions and sustain strong profitability Small enough to know you, big enough to serve you * Annualized measure; FTE: Fully tax equivalent; 1 Source: S&P Capital IQ, data as of June 30, 2025; 2 Includes merger with Lincoln S.B. Corp in 2018, although the transaction was accounted for as a change of reporting entity due to its common control with Company; 3 Metrics based on adjusted net income, which is a non-GAAP metric; for reconciliation with GAAP metrics, see “Non-GAAP reconciliations” in Appendix; 4 Metrics presented on tax-equivalent basis; for reconciliation with GAAP metric, see “Non-GAAP reconciliations” in Appendix.
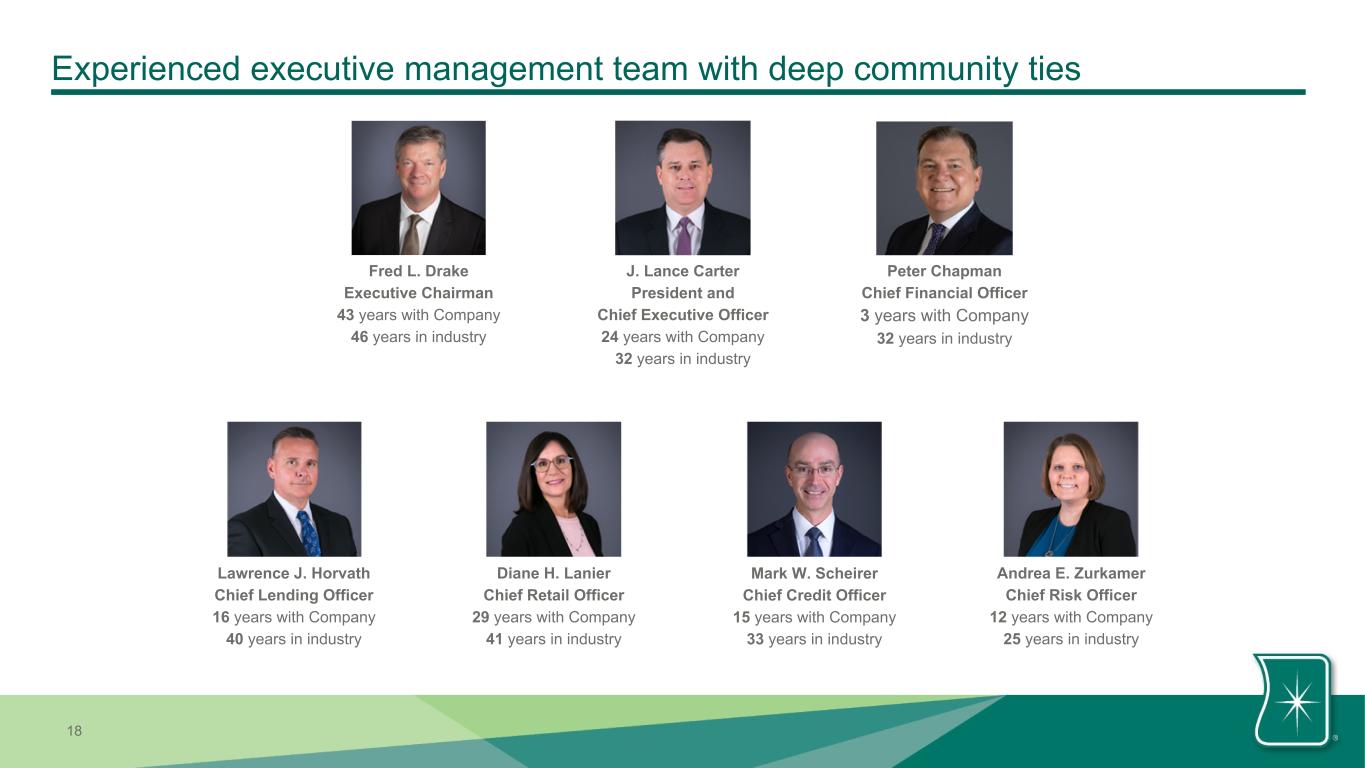
18 Experienced executive management team with deep community ties Fred L. Drake Executive Chairman 43 years with Company 46 years in industry J. Lance Carter President and Chief Executive Officer 24 years with Company 32 years in industry Lawrence J. Horvath Chief Lending Officer 16 years with Company 40 years in industry Mark W. Scheirer Chief Credit Officer 15 years with Company 33 years in industry Andrea E. Zurkamer Chief Risk Officer 12 years with Company 25 years in industry Diane H. Lanier Chief Retail Officer 29 years with Company 41 years in industry Peter Chapman Chief Financial Officer 3 years with Company 32 years in industry
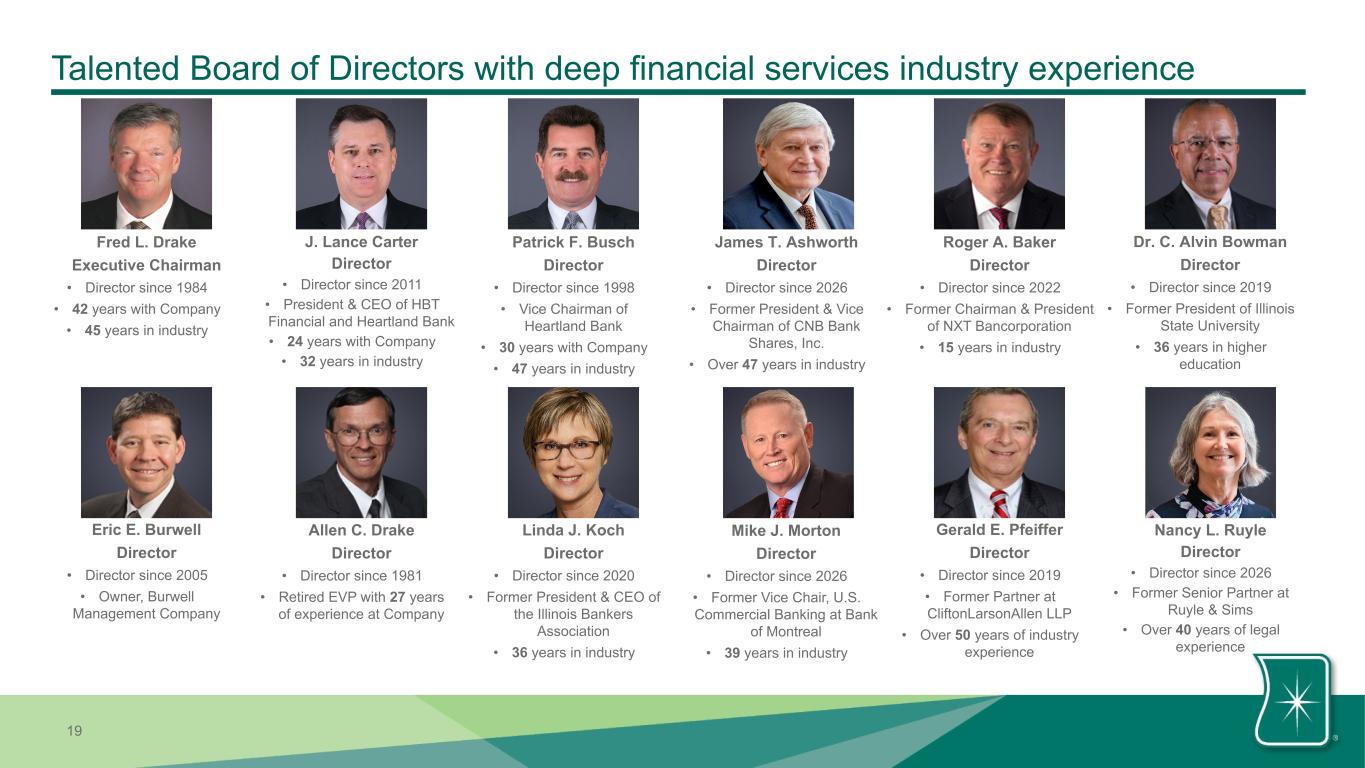
19 Talented Board of Directors with deep financial services industry experience Fred L. Drake Executive Chairman • Director since 1984 • 42 years with Company • 45 years in industry J. Lance Carter Director • Director since 2011 • President & CEO of HBT Financial and Heartland Bank • 24 years with Company • 32 years in industry Patrick F. Busch Director • Director since 1998 • Vice Chairman of Heartland Bank • 30 years with Company • 47 years in industry Eric E. Burwell Director • Director since 2005 • Owner, Burwell Management Company Linda J. Koch Director • Director since 2020 • Former President & CEO of the Illinois Bankers Association • 36 years in industry Gerald E. Pfeiffer Director • Director since 2019 • Former Partner at CliftonLarsonAllen LLP • Over 50 years of industry experience Allen C. Drake Director • Director since 1981 • Retired EVP with 27 years of experience at Company Dr. C. Alvin Bowman Director • Director since 2019 • Former President of Illinois State University • 36 years in higher education Roger A. Baker Director • Director since 2022 • Former Chairman & President of NXT Bancorporation • 15 years in industry James T. Ashworth Director • Director since 2026 • Former President & Vice Chairman of CNB Bank Shares, Inc. • Over 47 years in industry Nancy L. Ruyle Director • Director since 2026 • Former Senior Partner at Ruyle & Sims • Over 40 years of legal experience Mike J. Morton Director • Director since 2026 • Former Vice Chair, U.S. Commercial Banking at Bank of Montreal • 39 years in industry
20 Investment Highlights 3 1 2 4 Track record of successfully integrating acquisitions Consistent performance through economic cycles and consistent out-performance of peers drives long-term shareholder value Strong, granular, low-cost deposit base provides funding for diversified loan portfolio and loan growth opportunities Prudent risk management
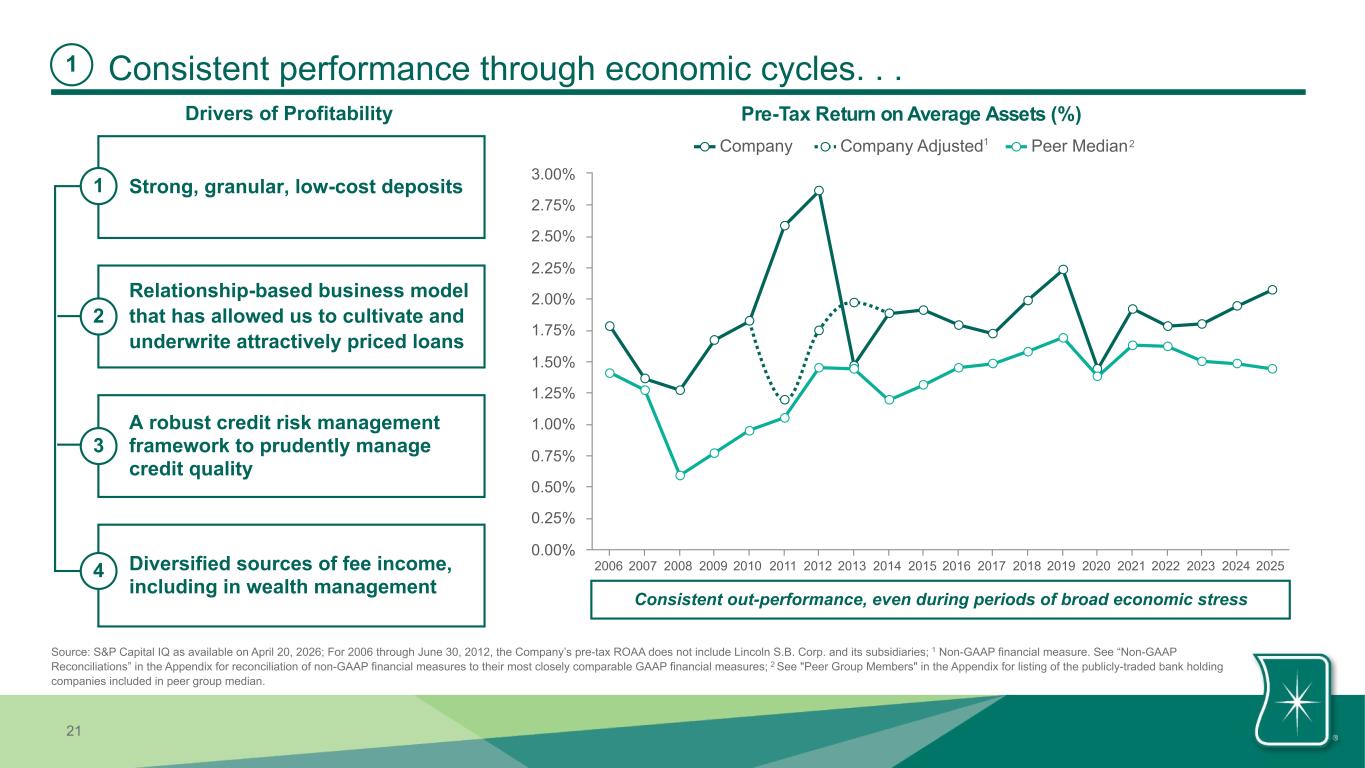
21 Consistent performance through economic cycles. . . Drivers of Profitability Strong, granular, low-cost deposits1 Relationship-based business model that has allowed us to cultivate and underwrite attractively priced loans A robust credit risk management framework to prudently manage credit quality Diversified sources of fee income, including in wealth management 4 Consistent out-performance, even during periods of broad economic stress 1 2 3 Pre-Tax Return on Average Assets (%) Company Company Adjusted Peer Median 2006 2007 2008 2009 2010 2011 2012 2013 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 0.00% 0.25% 0.50% 0.75% 1.00% 1.25% 1.50% 1.75% 2.00% 2.25% 2.50% 2.75% 3.00% 1 Source: S&P Capital IQ as available on April 20, 2026; For 2006 through June 30, 2012, the Company’s pre-tax ROAA does not include Lincoln S.B. Corp. and its subsidiaries; 1 Non-GAAP financial measure. See “Non-GAAP Reconciliations” in the Appendix for reconciliation of non-GAAP financial measures to their most closely comparable GAAP financial measures; 2 See "Peer Group Members" in the Appendix for listing of the publicly-traded bank holding companies included in peer group median. 2
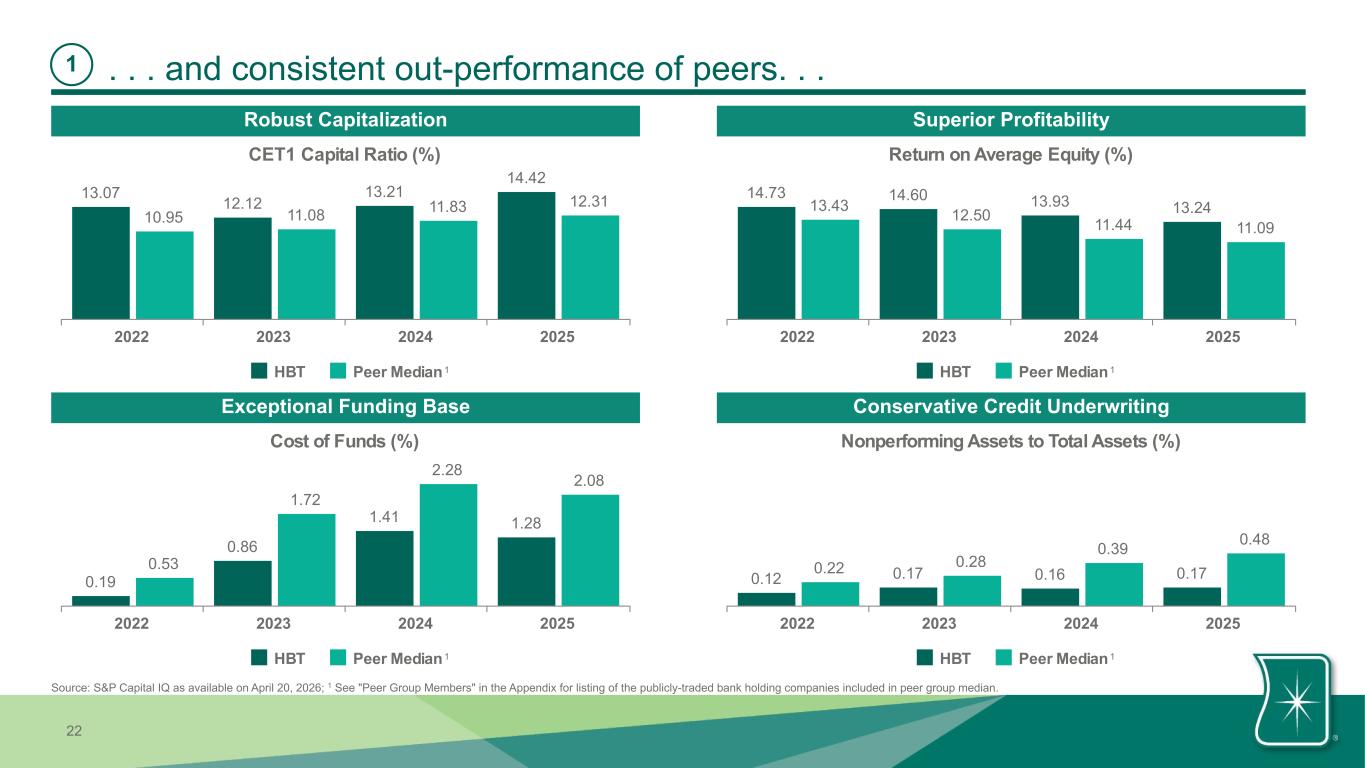
22 . . . and consistent out-performance of peers. . .1 CET1 Capital Ratio (%) 13.07 12.12 13.21 14.42 10.95 11.08 11.83 12.31 HBT Peer Median 2022 2023 2024 2025 Return on Average Equity (%) 14.73 14.60 13.93 13.2413.43 12.50 11.44 11.09 HBT Peer Median 2022 2023 2024 2025 Cost of Funds (%) 0.19 0.86 1.41 1.28 0.53 1.72 2.28 2.08 HBT Peer Median 2022 2023 2024 2025 Nonperforming Assets to Total Assets (%) 0.12 0.17 0.16 0.170.22 0.28 0.39 0.48 HBT Peer Median 2022 2023 2024 2025 Robust Capitalization Superior Profitability Exceptional Funding Base Conservative Credit Underwriting 1 11 1 Source: S&P Capital IQ as available on April 20, 2026; 1 See "Peer Group Members" in the Appendix for listing of the publicly-traded bank holding companies included in peer group median.
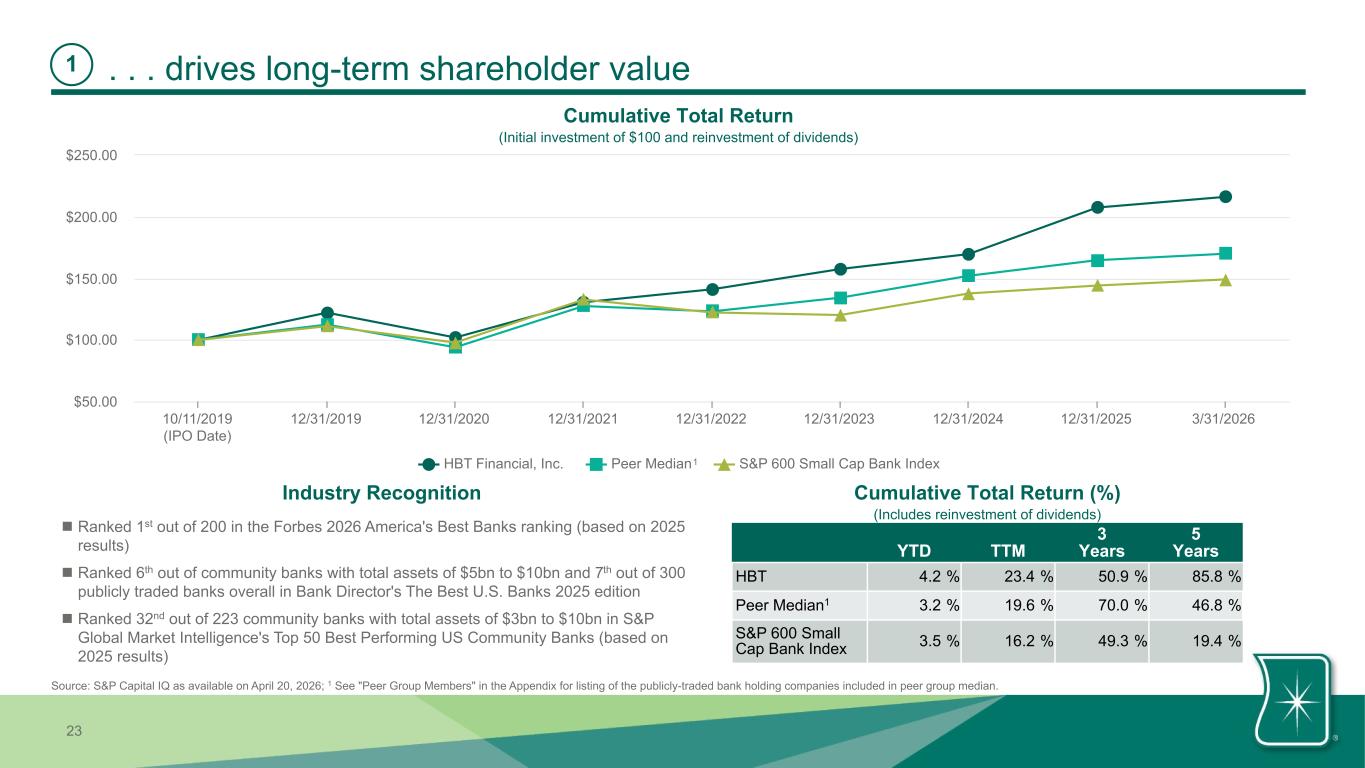
23 . . . drives long-term shareholder value1 HBT Financial, Inc. Peer Median S&P 600 Small Cap Bank Index 10/11/2019 (IPO Date) 12/31/2019 12/31/2020 12/31/2021 12/31/2022 12/31/2023 12/31/2024 12/31/2025 3/31/2026 $50.00 $100.00 $150.00 $200.00 $250.00 Cumulative Total Return (Initial investment of $100 and reinvestment of dividends) 1 Source: S&P Capital IQ as available on April 20, 2026; 1 See "Peer Group Members" in the Appendix for listing of the publicly-traded bank holding companies included in peer group median. YTD TTM 3 Years 5 Years HBT 4.2 % 23.4 % 50.9 % 85.8 % Peer Median1 3.2 % 19.6 % 70.0 % 46.8 % S&P 600 Small Cap Bank Index 3.5 % 16.2 % 49.3 % 19.4 % Cumulative Total Return (%) (Includes reinvestment of dividends) Industry Recognition n Ranked 1st out of 200 in the Forbes 2026 America's Best Banks ranking (based on 2025 results) n Ranked 6th out of community banks with total assets of $5bn to $10bn and 7th out of 300 publicly traded banks overall in Bank Director's The Best U.S. Banks 2025 edition n Ranked 32nd out of 223 community banks with total assets of $3bn to $10bn in S&P Global Market Intelligence's Top 50 Best Performing US Community Banks (based on 2025 results)
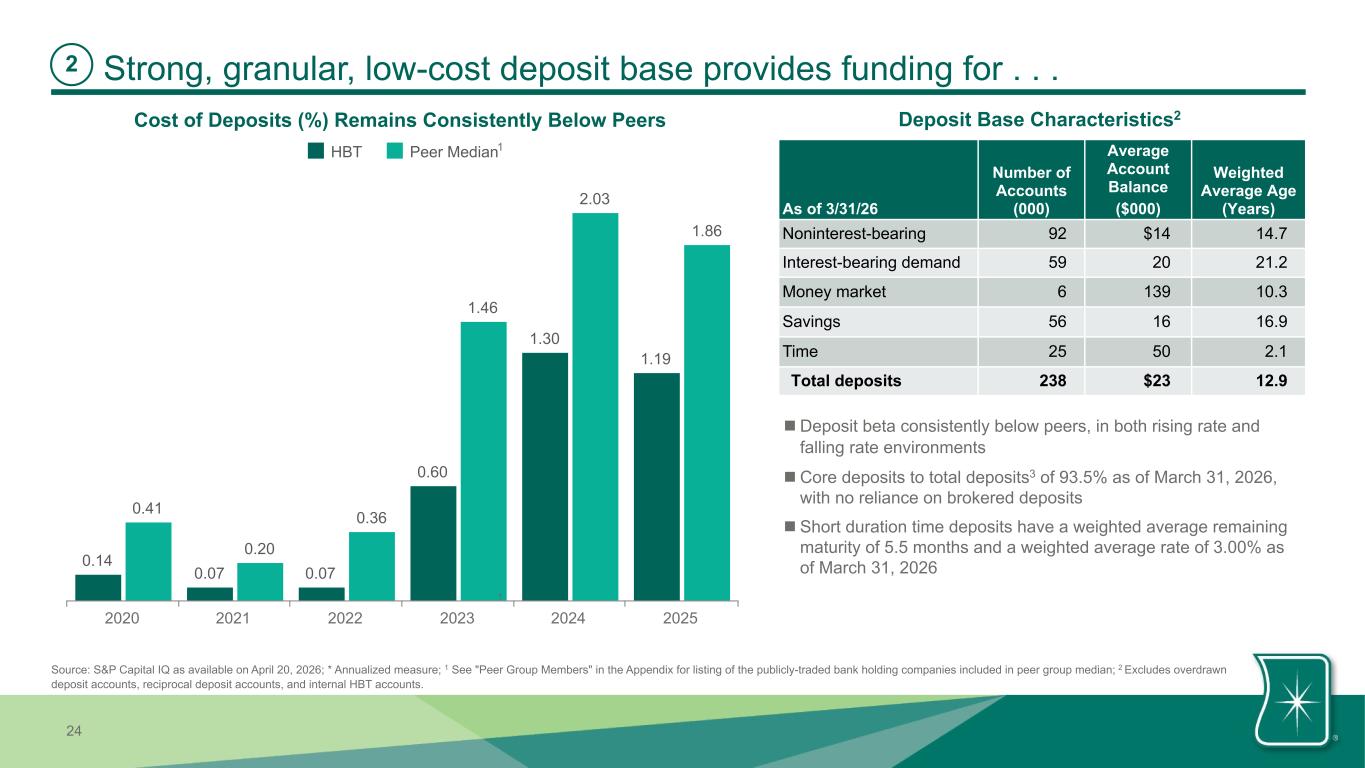
24 0.14 0.07 0.07 0.60 1.30 1.19 0.41 0.20 0.36 1.46 2.03 1.86 HBT Peer Median 2020 2021 2022 2023 2024 2025 Strong, granular, low-cost deposit base provides funding for . . . Cost of Deposits (%) Remains Consistently Below Peers 1 2 As of 3/31/26 Number of Accounts (000) Average Account Balance ($000) Weighted Average Age (Years) Noninterest-bearing 92 $14 14.7 Interest-bearing demand 59 20 21.2 Money market 6 139 10.3 Savings 56 16 16.9 Time 25 50 2.1 Total deposits 238 $23 12.9 Deposit Base Characteristics2 1 Source: S&P Capital IQ as available on April 20, 2026; * Annualized measure; 1 See "Peer Group Members" in the Appendix for listing of the publicly-traded bank holding companies included in peer group median; 2 Excludes overdrawn deposit accounts, reciprocal deposit accounts, and internal HBT accounts. n Deposit beta consistently below peers, in both rising rate and falling rate environments n Core deposits to total deposits3 of 93.5% as of March 31, 2026, with no reliance on brokered deposits n Short duration time deposits have a weighted average remaining maturity of 5.5 months and a weighted average rate of 3.00% as of March 31, 2026 1
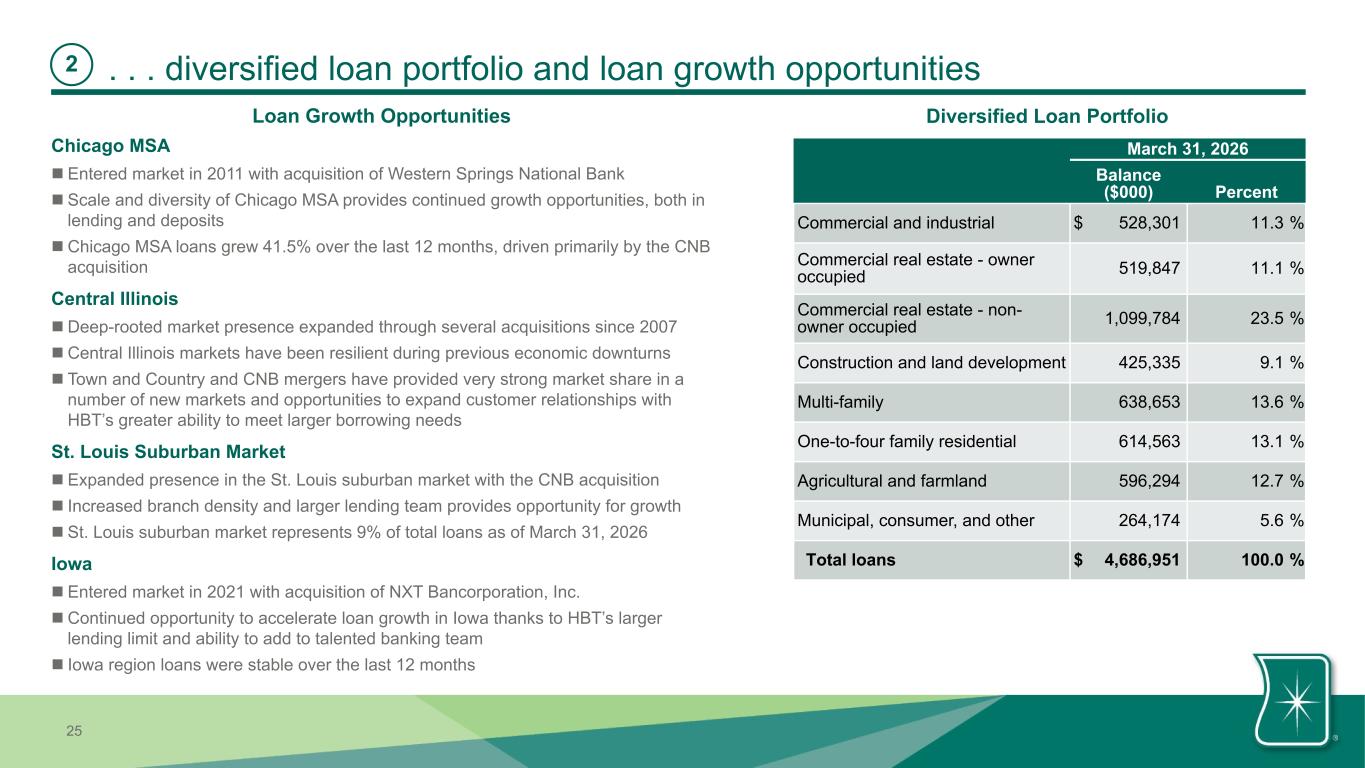
25 . . . diversified loan portfolio and loan growth opportunities2 March 31, 2026 Balance ($000) Percent Commercial and industrial $ 528,301 11.3 % Commercial real estate - owner occupied 519,847 11.1 % Commercial real estate - non- owner occupied 1,099,784 23.5 % Construction and land development 425,335 9.1 % Multi-family 638,653 13.6 % One-to-four family residential 614,563 13.1 % Agricultural and farmland 596,294 12.7 % Municipal, consumer, and other 264,174 5.6 % Total loans $ 4,686,951 100.0 % Diversified Loan Portfolio Chicago MSA n Entered market in 2011 with acquisition of Western Springs National Bank n Scale and diversity of Chicago MSA provides continued growth opportunities, both in lending and deposits n Chicago MSA loans grew 41.5% over the last 12 months, driven primarily by the CNB acquisition Central Illinois n Deep-rooted market presence expanded through several acquisitions since 2007 n Central Illinois markets have been resilient during previous economic downturns n Town and Country and CNB mergers have provided very strong market share in a number of new markets and opportunities to expand customer relationships with HBT’s greater ability to meet larger borrowing needs St. Louis Suburban Market n Expanded presence in the St. Louis suburban market with the CNB acquisition n Increased branch density and larger lending team provides opportunity for growth n St. Louis suburban market represents 9% of total loans as of March 31, 2026 Iowa n Entered market in 2021 with acquisition of NXT Bancorporation, Inc. n Continued opportunity to accelerate loan growth in Iowa thanks to HBT’s larger lending limit and ability to add to talented banking team n Iowa region loans were stable over the last 12 months Loan Growth Opportunities
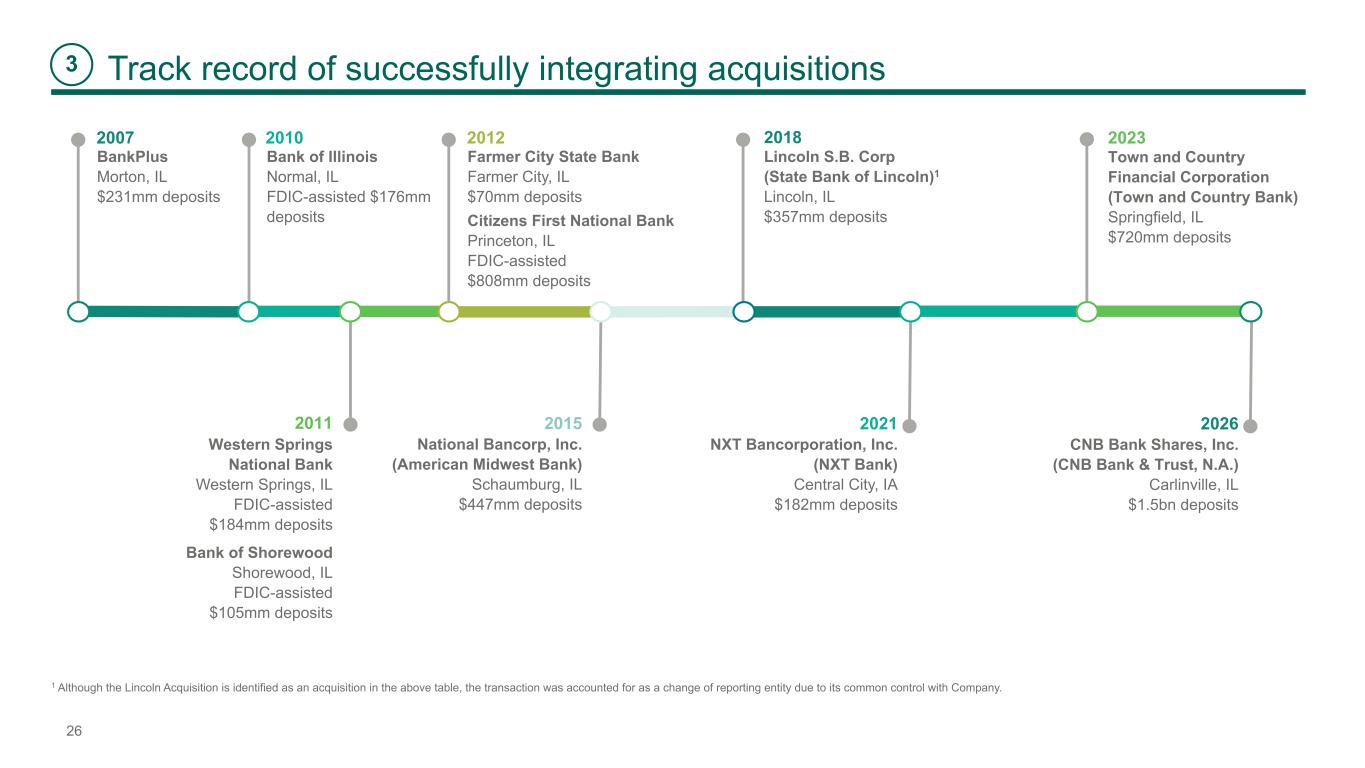
26 2026 CNB Bank Shares, Inc. (CNB Bank & Trust, N.A.) Carlinville, IL $1.5bn deposits Track record of successfully integrating acquisitions BankPlus Morton, IL $231mm deposits 2007 2012 Bank of Illinois Normal, IL FDIC-assisted $176mm deposits Western Springs National Bank Western Springs, IL FDIC-assisted $184mm deposits 2011 Citizens First National Bank Princeton, IL FDIC-assisted $808mm deposits Farmer City State Bank Farmer City, IL $70mm deposits 20182010 Bank of Shorewood Shorewood, IL FDIC-assisted $105mm deposits Lincoln S.B. Corp (State Bank of Lincoln)1 Lincoln, IL $357mm deposits 2021 NXT Bancorporation, Inc. (NXT Bank) Central City, IA $182mm deposits 2015 National Bancorp, Inc. (American Midwest Bank) Schaumburg, IL $447mm deposits 2023 Town and Country Financial Corporation (Town and Country Bank) Springfield, IL $720mm deposits 3 1 Although the Lincoln Acquisition is identified as an acquisition in the above table, the transaction was accounted for as a change of reporting entity due to its common control with Company.
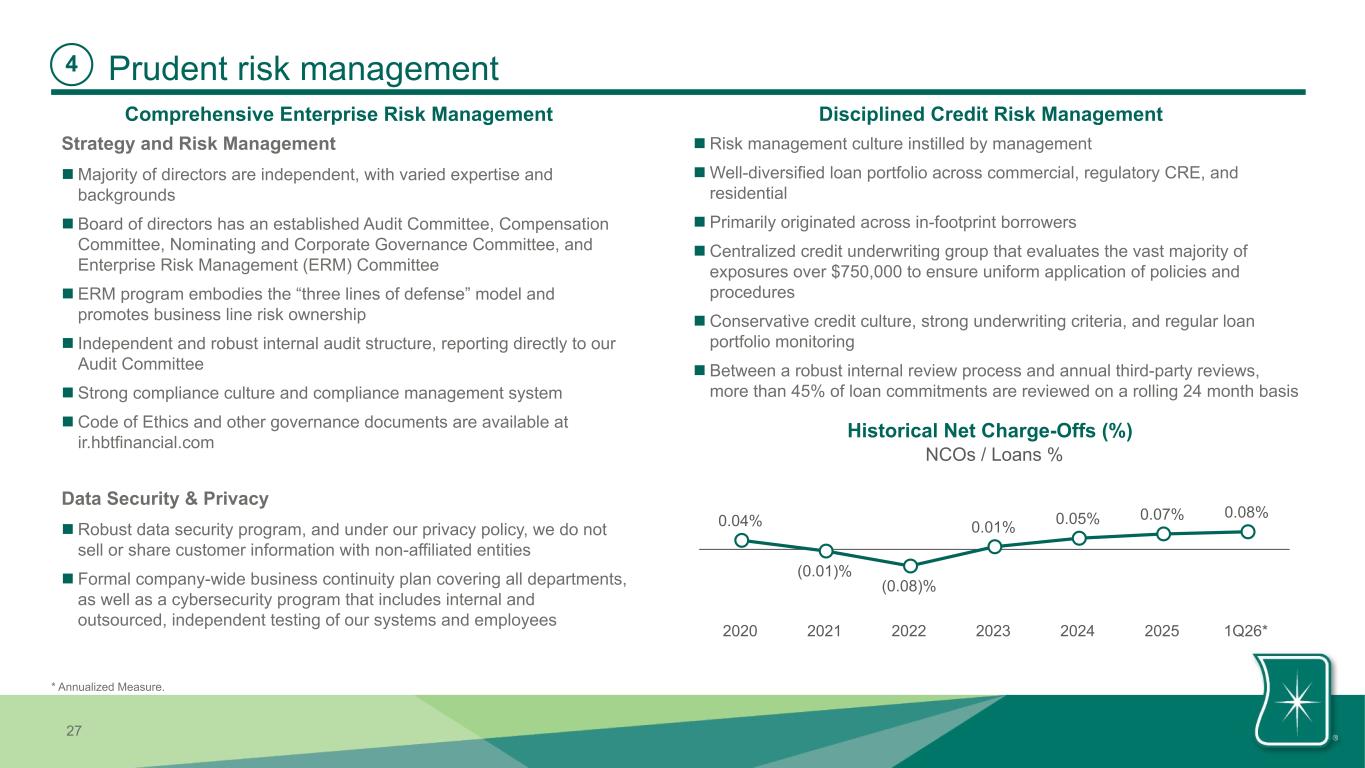
27 Prudent risk management n Risk management culture instilled by management n Well-diversified loan portfolio across commercial, regulatory CRE, and residential n Primarily originated across in-footprint borrowers n Centralized credit underwriting group that evaluates the vast majority of exposures over $750,000 to ensure uniform application of policies and procedures n Conservative credit culture, strong underwriting criteria, and regular loan portfolio monitoring n Between a robust internal review process and annual third-party reviews, more than 45% of loan commitments are reviewed on a rolling 24 month basis Strategy and Risk Management n Majority of directors are independent, with varied expertise and backgrounds n Board of directors has an established Audit Committee, Compensation Committee, Nominating and Corporate Governance Committee, and Enterprise Risk Management (ERM) Committee n ERM program embodies the “three lines of defense” model and promotes business line risk ownership n Independent and robust internal audit structure, reporting directly to our Audit Committee n Strong compliance culture and compliance management system n Code of Ethics and other governance documents are available at ir.hbtfinancial.com Data Security & Privacy n Robust data security program, and under our privacy policy, we do not sell or share customer information with non-affiliated entities n Formal company-wide business continuity plan covering all departments, as well as a cybersecurity program that includes internal and outsourced, independent testing of our systems and employees Comprehensive Enterprise Risk Management Disciplined Credit Risk Management Historical Net Charge-Offs (%) 4 NCOs / Loans % 0.04% (0.01)% (0.08)% 0.01% 0.05% 0.07% 0.08% 2020 2021 2022 2023 2024 2025 1Q26* * Annualized Measure.
28 Appendix
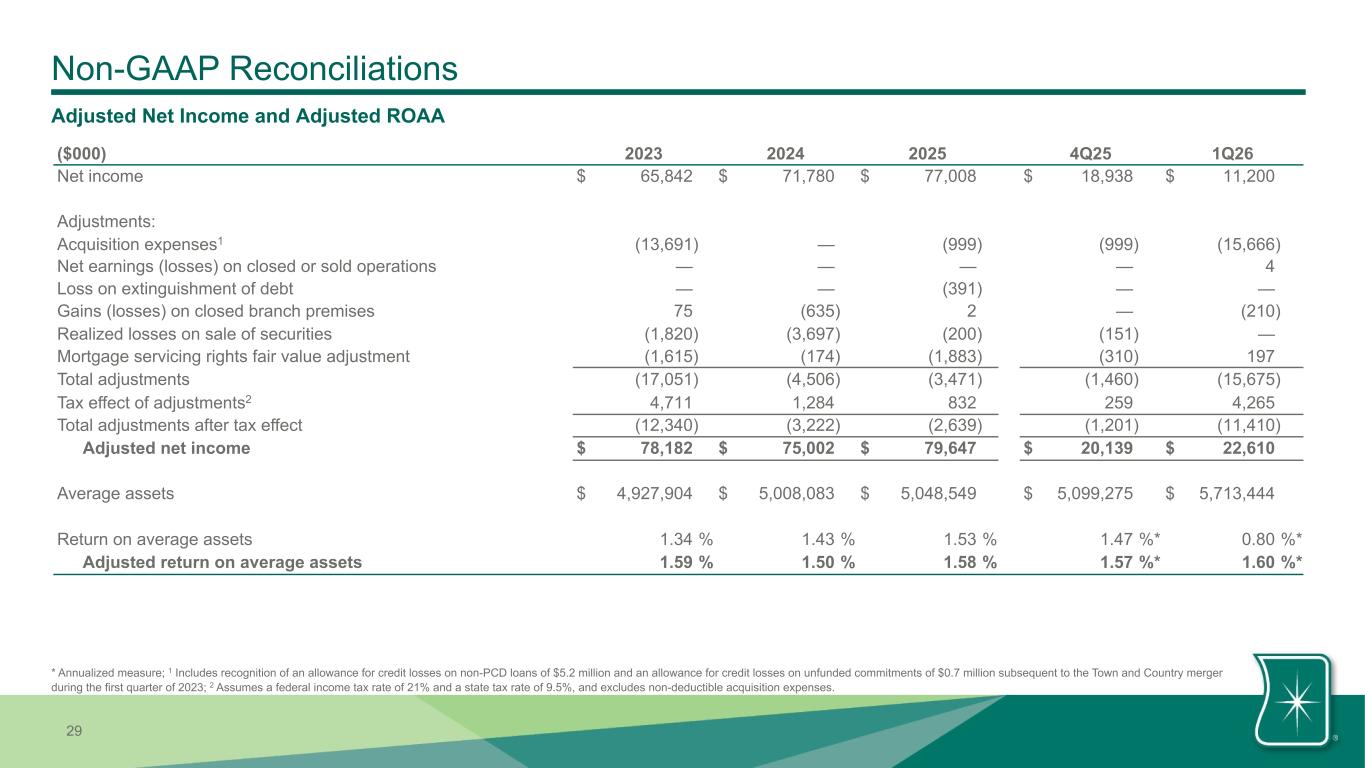
29 Non-GAAP Reconciliations Adjusted Net Income and Adjusted ROAA ($000) 2023 2024 2025 4Q25 1Q26 Net income $ 65,842 $ 71,780 $ 77,008 $ 18,938 $ 11,200 Adjustments: Acquisition expenses1 (13,691) — (999) (999) (15,666) Net earnings (losses) on closed or sold operations — — — — 4 Loss on extinguishment of debt — — (391) — — Gains (losses) on closed branch premises 75 (635) 2 — (210) Realized losses on sale of securities (1,820) (3,697) (200) (151) — Mortgage servicing rights fair value adjustment (1,615) (174) (1,883) (310) 197 Total adjustments (17,051) (4,506) (3,471) (1,460) (15,675) Tax effect of adjustments2 4,711 1,284 832 259 4,265 Total adjustments after tax effect (12,340) (3,222) (2,639) (1,201) (11,410) Adjusted net income $ 78,182 $ 75,002 $ 79,647 $ 20,139 $ 22,610 Average assets $ 4,927,904 $ 5,008,083 $ 5,048,549 $ 5,099,275 $ 5,713,444 Return on average assets 1.34 % 1.43 % 1.53 % 1.47 %* 0.80 %* Adjusted return on average assets 1.59 % 1.50 % 1.58 % 1.57 %* 1.60 %* * Annualized measure; 1 Includes recognition of an allowance for credit losses on non-PCD loans of $5.2 million and an allowance for credit losses on unfunded commitments of $0.7 million subsequent to the Town and Country merger during the first quarter of 2023; 2 Assumes a federal income tax rate of 21% and a state tax rate of 9.5%, and excludes non-deductible acquisition expenses.
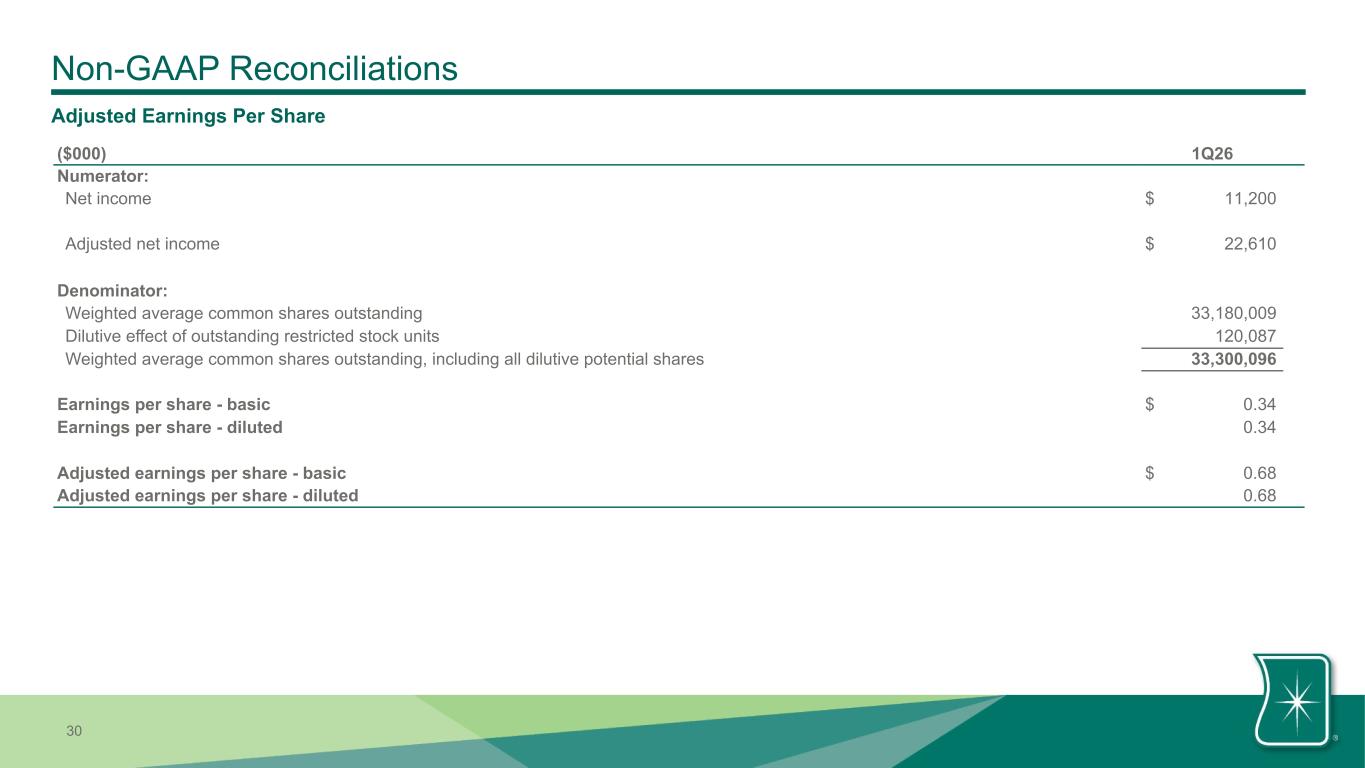
30 Non-GAAP Reconciliations Adjusted Earnings Per Share ($000) 1Q26 Numerator: Net income $ 11,200 Adjusted net income $ 22,610 Denominator: Weighted average common shares outstanding 33,180,009 Dilutive effect of outstanding restricted stock units 120,087 Weighted average common shares outstanding, including all dilutive potential shares 33,300,096 Earnings per share - basic $ 0.34 Earnings per share - diluted 0.34 Adjusted earnings per share - basic $ 0.68 Adjusted earnings per share - diluted 0.68
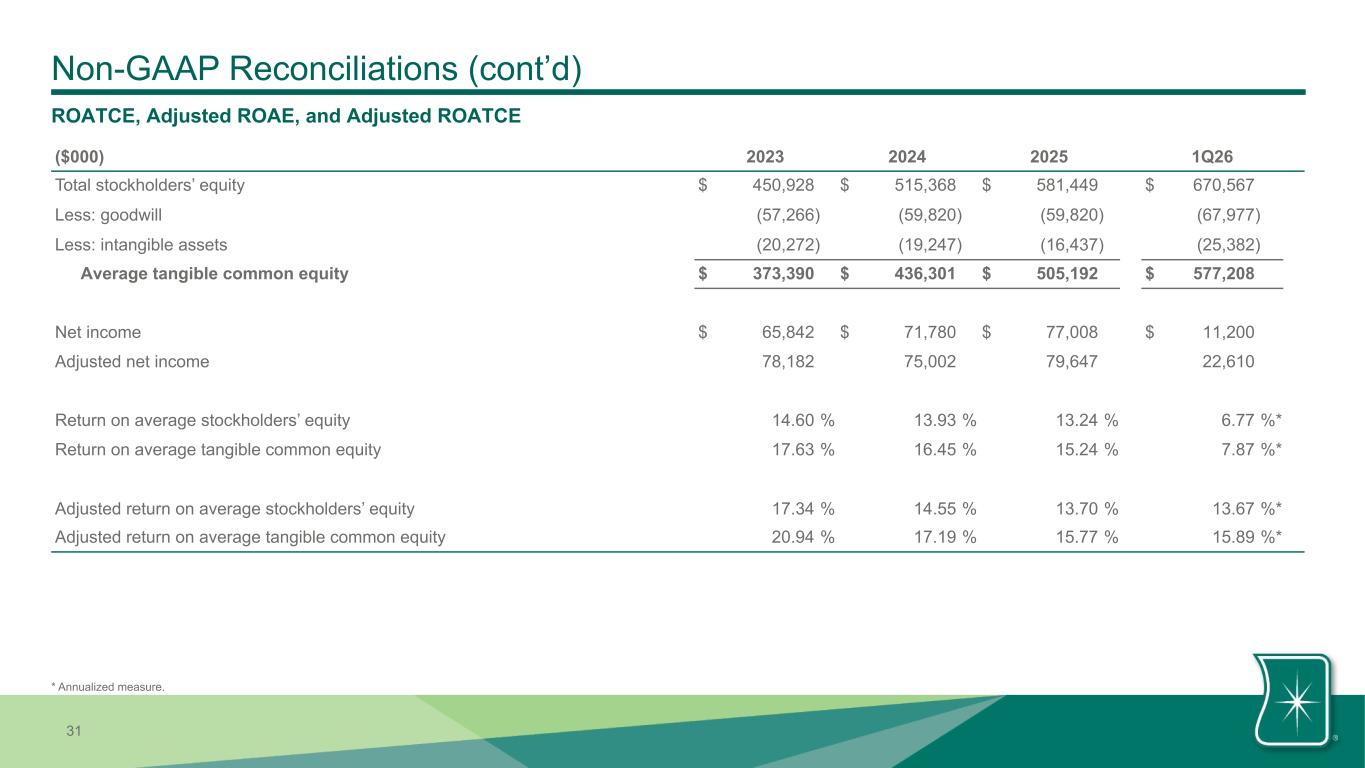
31 Non-GAAP Reconciliations (cont’d) ROATCE, Adjusted ROAE, and Adjusted ROATCE ($000) 2023 2024 2025 1Q26 Total stockholders’ equity $ 450,928 $ 515,368 $ 581,449 $ 670,567 Less: goodwill (57,266) (59,820) (59,820) (67,977) Less: intangible assets (20,272) (19,247) (16,437) (25,382) Average tangible common equity $ 373,390 $ 436,301 $ 505,192 $ 577,208 Net income $ 65,842 $ 71,780 $ 77,008 $ 11,200 Adjusted net income 78,182 75,002 79,647 22,610 Return on average stockholders’ equity 14.60 % 13.93 % 13.24 % 6.77 %* Return on average tangible common equity 17.63 % 16.45 % 15.24 % 7.87 %* Adjusted return on average stockholders’ equity 17.34 % 14.55 % 13.70 % 13.67 %* Adjusted return on average tangible common equity 20.94 % 17.19 % 15.77 % 15.89 %* * Annualized measure.
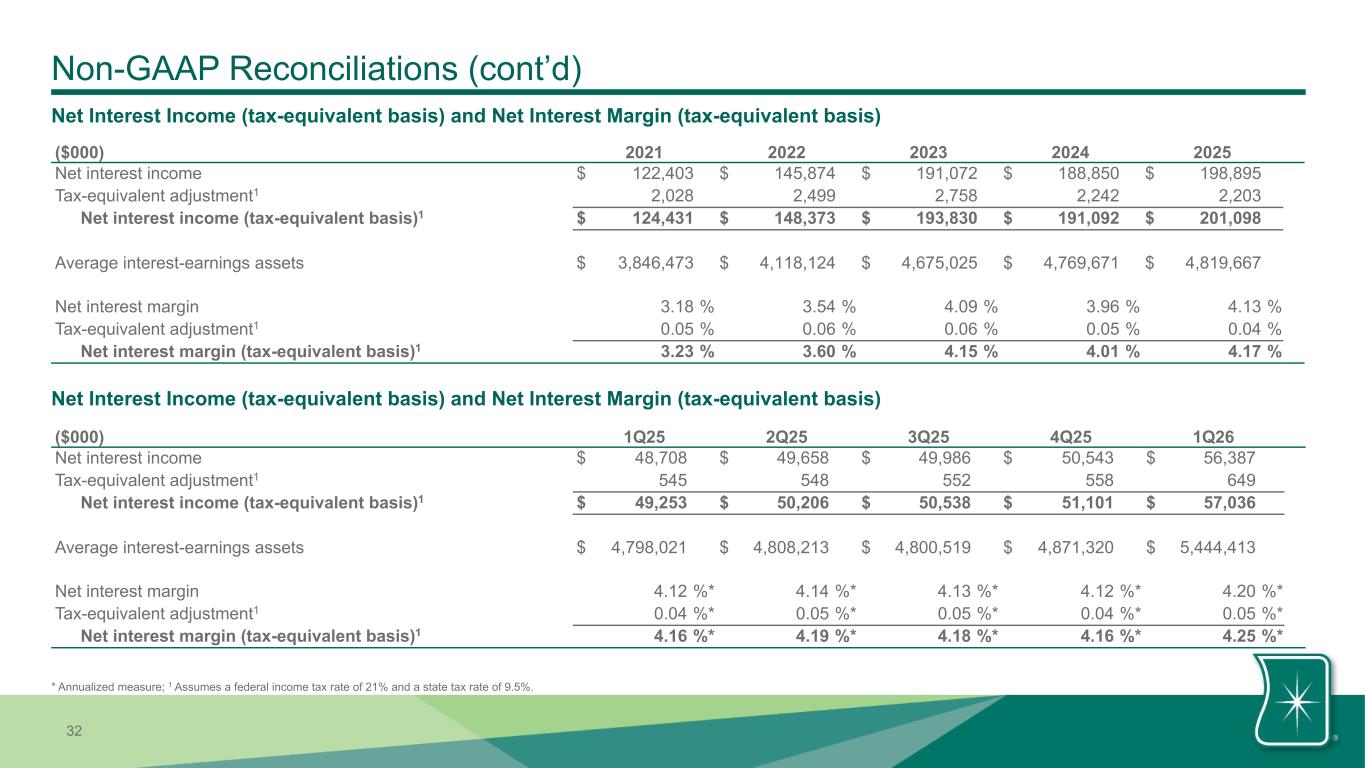
32 Non-GAAP Reconciliations (cont’d) ($000) 2021 2022 2023 2024 2025 Net interest income $ 122,403 $ 145,874 $ 191,072 $ 188,850 $ 198,895 Tax-equivalent adjustment1 2,028 2,499 2,758 2,242 2,203 Net interest income (tax-equivalent basis)1 $ 124,431 $ 148,373 $ 193,830 $ 191,092 $ 201,098 Average interest-earnings assets $ 3,846,473 $ 4,118,124 $ 4,675,025 $ 4,769,671 $ 4,819,667 Net interest margin 3.18 % 3.54 % 4.09 % 3.96 % 4.13 % Tax-equivalent adjustment1 0.05 % 0.06 % 0.06 % 0.05 % 0.04 % Net interest margin (tax-equivalent basis)1 3.23 % 3.60 % 4.15 % 4.01 % 4.17 % Net Interest Income (tax-equivalent basis) and Net Interest Margin (tax-equivalent basis) Net Interest Income (tax-equivalent basis) and Net Interest Margin (tax-equivalent basis) ($000) 1Q25 2Q25 3Q25 4Q25 1Q26 Net interest income $ 48,708 $ 49,658 $ 49,986 $ 50,543 $ 56,387 Tax-equivalent adjustment1 545 548 552 558 649 Net interest income (tax-equivalent basis)1 $ 49,253 $ 50,206 $ 50,538 $ 51,101 $ 57,036 Average interest-earnings assets $ 4,798,021 $ 4,808,213 $ 4,800,519 $ 4,871,320 $ 5,444,413 Net interest margin 4.12 %* 4.14 %* 4.13 %* 4.12 %* 4.20 %* Tax-equivalent adjustment1 0.04 %* 0.05 %* 0.05 %* 0.04 %* 0.05 %* Net interest margin (tax-equivalent basis)1 4.16 %* 4.19 %* 4.18 %* 4.16 %* 4.25 %* * Annualized measure; 1 Assumes a federal income tax rate of 21% and a state tax rate of 9.5%.
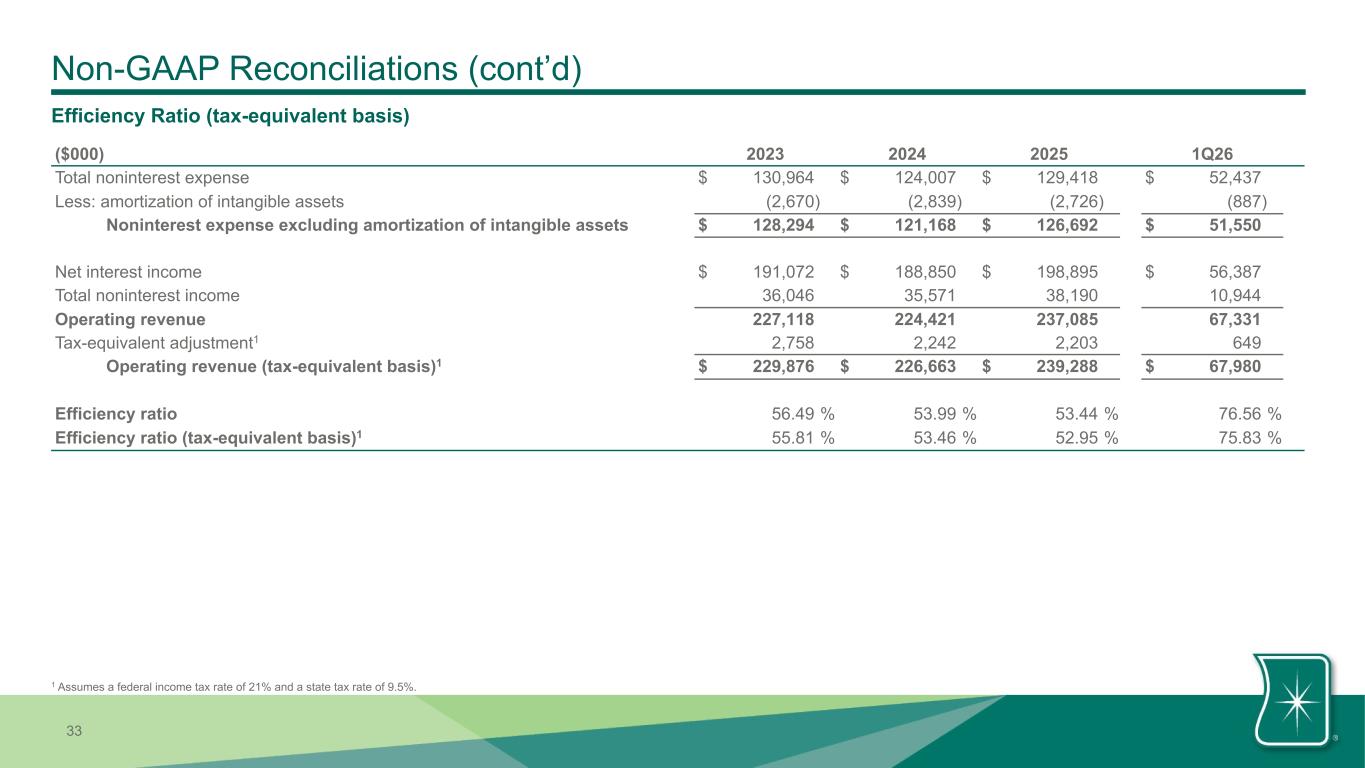
33 Non-GAAP Reconciliations (cont’d) Efficiency Ratio (tax-equivalent basis) ($000) 2023 2024 2025 1Q26 Total noninterest expense $ 130,964 $ 124,007 $ 129,418 $ 52,437 Less: amortization of intangible assets (2,670) (2,839) (2,726) (887) Noninterest expense excluding amortization of intangible assets $ 128,294 $ 121,168 $ 126,692 $ 51,550 Net interest income $ 191,072 $ 188,850 $ 198,895 $ 56,387 Total noninterest income 36,046 35,571 38,190 10,944 Operating revenue 227,118 224,421 237,085 67,331 Tax-equivalent adjustment1 2,758 2,242 2,203 649 Operating revenue (tax-equivalent basis)1 $ 229,876 $ 226,663 $ 239,288 $ 67,980 Efficiency ratio 56.49 % 53.99 % 53.44 % 76.56 % Efficiency ratio (tax-equivalent basis)1 55.81 % 53.46 % 52.95 % 75.83 % 1 Assumes a federal income tax rate of 21% and a state tax rate of 9.5%.
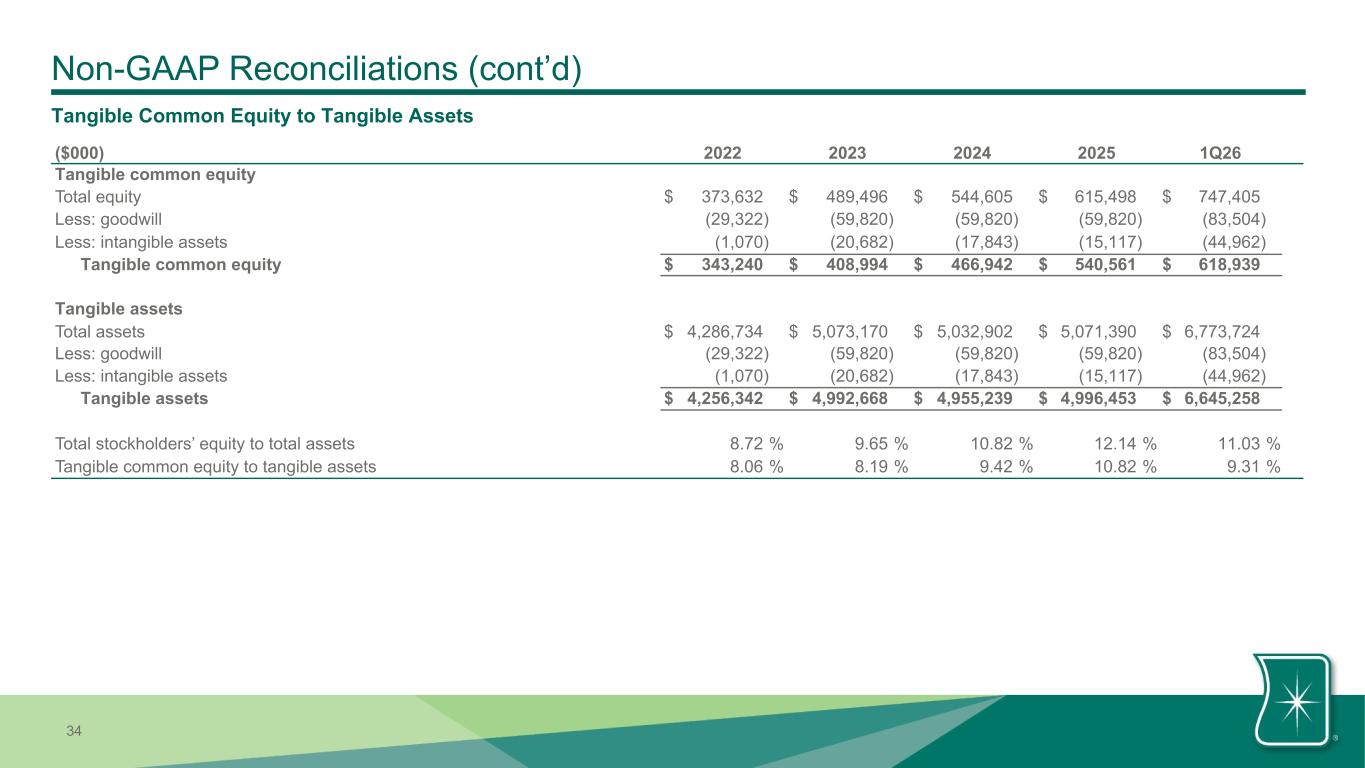
34 Non-GAAP Reconciliations (cont’d) ($000) 2022 2023 2024 2025 1Q26 Tangible common equity Total equity $ 373,632 $ 489,496 $ 544,605 $ 615,498 $ 747,405 Less: goodwill (29,322) (59,820) (59,820) (59,820) (83,504) Less: intangible assets (1,070) (20,682) (17,843) (15,117) (44,962) Tangible common equity $ 343,240 $ 408,994 $ 466,942 $ 540,561 $ 618,939 Tangible assets Total assets $ 4,286,734 $ 5,073,170 $ 5,032,902 $ 5,071,390 $ 6,773,724 Less: goodwill (29,322) (59,820) (59,820) (59,820) (83,504) Less: intangible assets (1,070) (20,682) (17,843) (15,117) (44,962) Tangible assets $ 4,256,342 $ 4,992,668 $ 4,955,239 $ 4,996,453 $ 6,645,258 Total stockholders’ equity to total assets 8.72 % 9.65 % 10.82 % 12.14 % 11.03 % Tangible common equity to tangible assets 8.06 % 8.19 % 9.42 % 10.82 % 9.31 % Tangible Common Equity to Tangible Assets
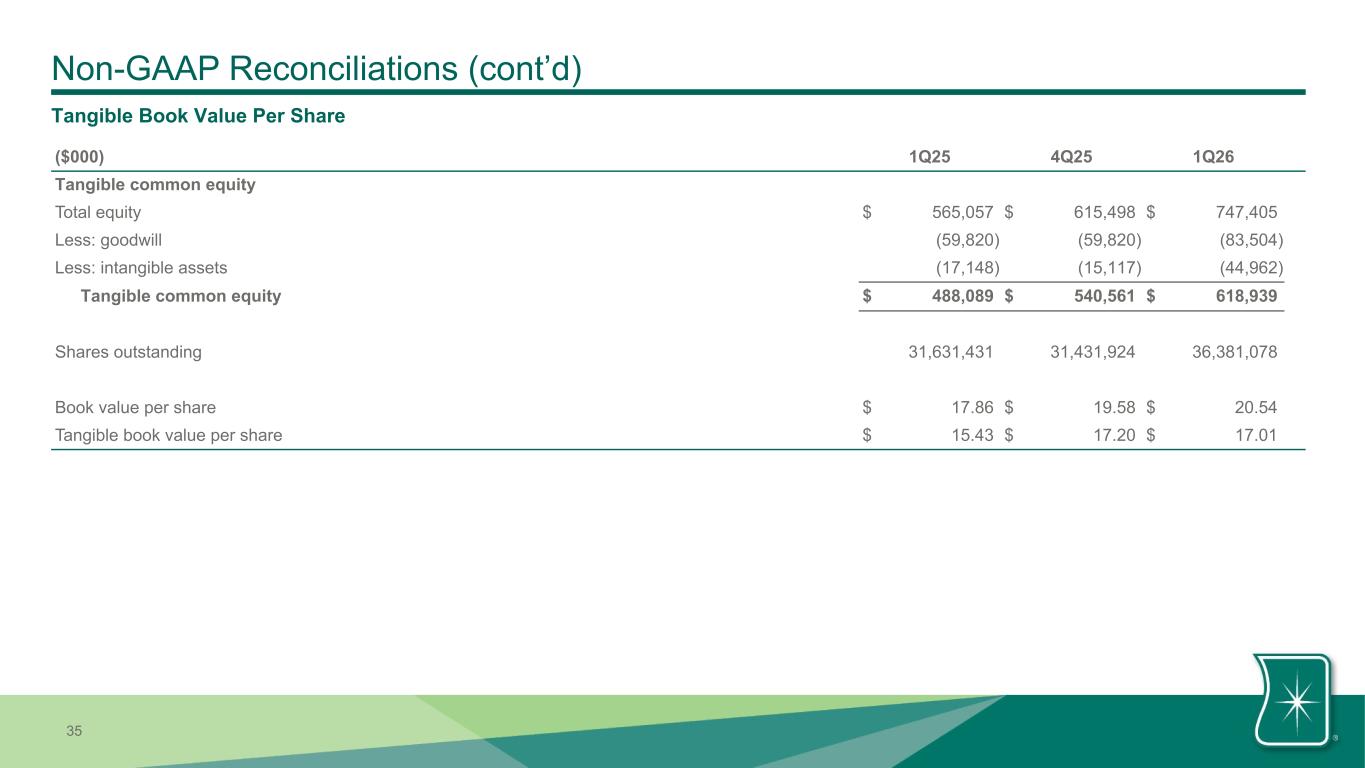
35 Non-GAAP Reconciliations (cont’d) ($000) 1Q25 4Q25 1Q26 Tangible common equity Total equity $ 565,057 $ 615,498 $ 747,405 Less: goodwill (59,820) (59,820) (83,504) Less: intangible assets (17,148) (15,117) (44,962) Tangible common equity $ 488,089 $ 540,561 $ 618,939 Shares outstanding 31,631,431 31,431,924 36,381,078 Book value per share $ 17.86 $ 19.58 $ 20.54 Tangible book value per share $ 15.43 $ 17.20 $ 17.01 Tangible Book Value Per Share
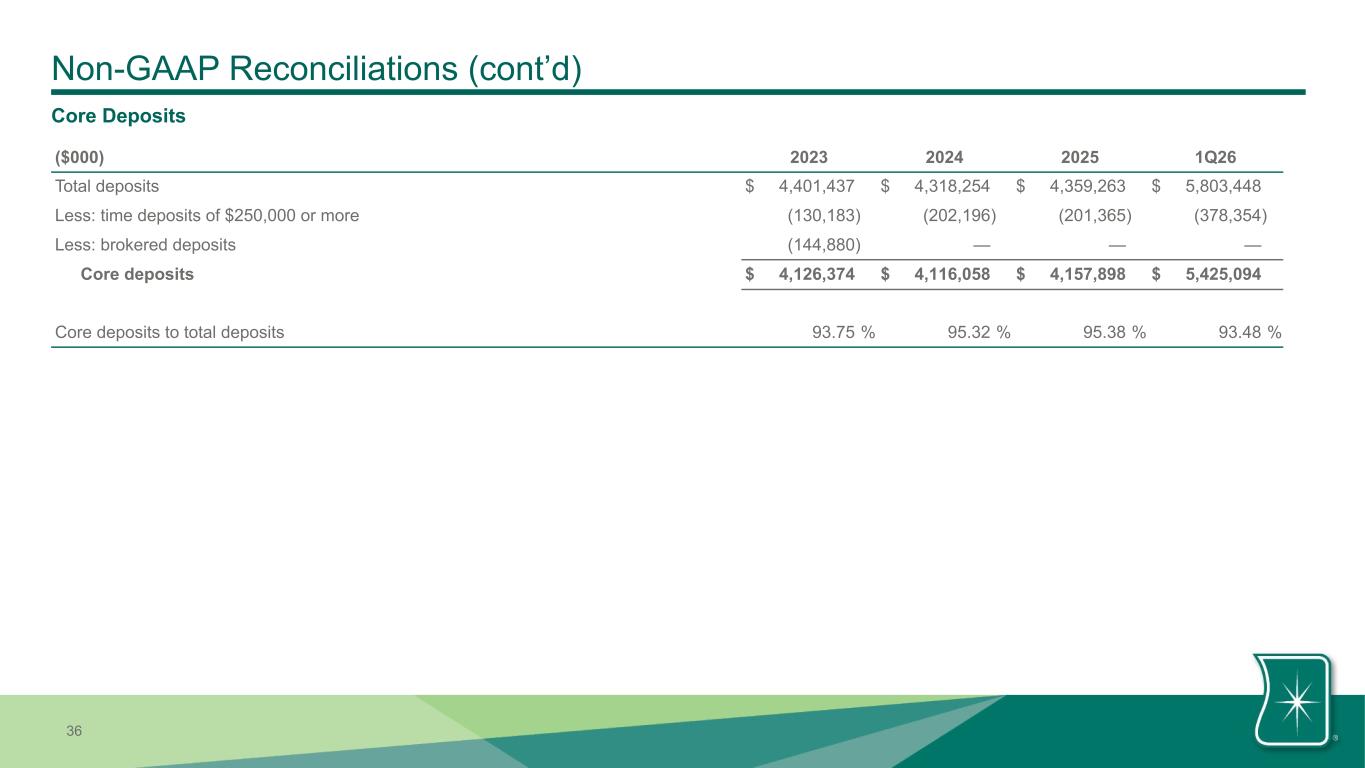
36 Non-GAAP Reconciliations (cont’d) ($000) 2023 2024 2025 1Q26 Total deposits $ 4,401,437 $ 4,318,254 $ 4,359,263 $ 5,803,448 Less: time deposits of $250,000 or more (130,183) (202,196) (201,365) (378,354) Less: brokered deposits (144,880) — — — Core deposits $ 4,126,374 $ 4,116,058 $ 4,157,898 $ 5,425,094 Core deposits to total deposits 93.75 % 95.32 % 95.38 % 93.48 % Core Deposits
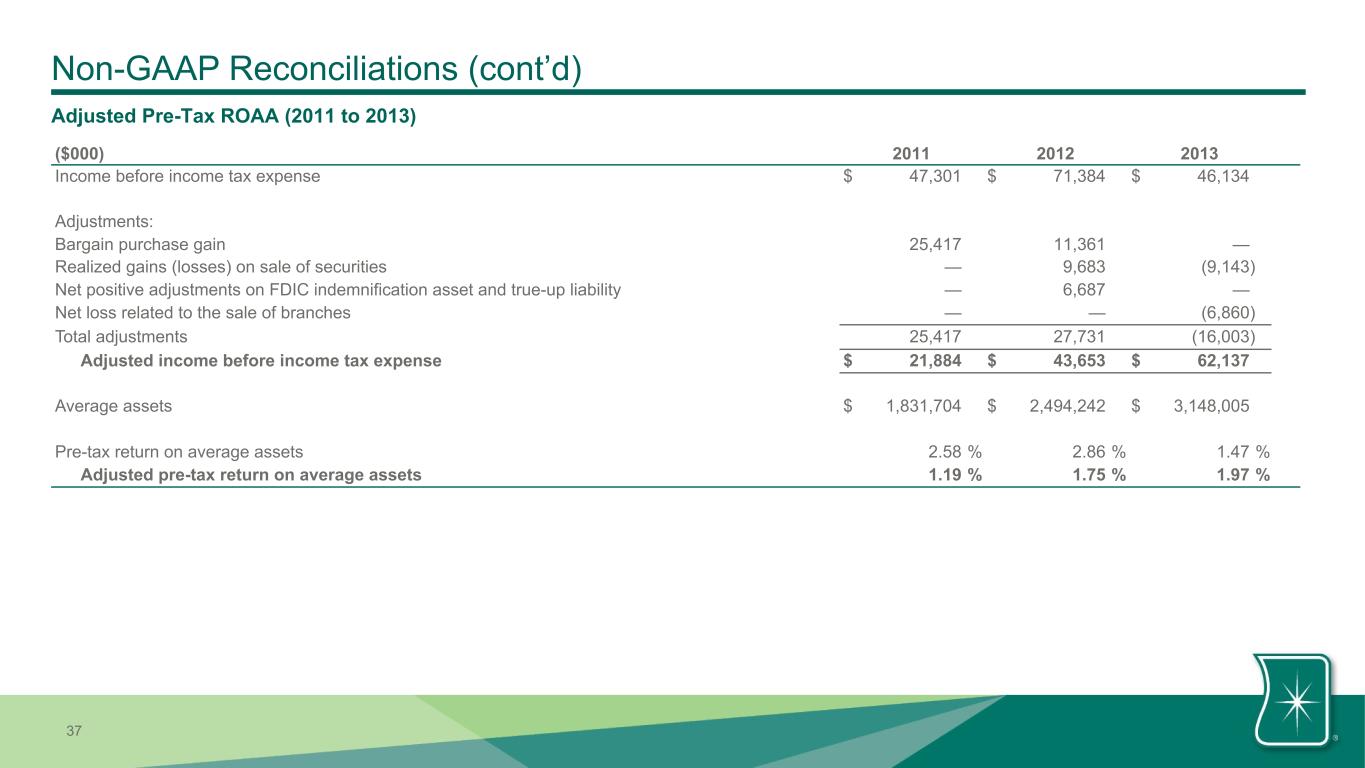
37 Non-GAAP Reconciliations (cont’d) ($000) 2011 2012 2013 Income before income tax expense $ 47,301 $ 71,384 $ 46,134 Adjustments: Bargain purchase gain 25,417 11,361 — Realized gains (losses) on sale of securities — 9,683 (9,143) Net positive adjustments on FDIC indemnification asset and true-up liability — 6,687 — Net loss related to the sale of branches — — (6,860) Total adjustments 25,417 27,731 (16,003) Adjusted income before income tax expense $ 21,884 $ 43,653 $ 62,137 Average assets $ 1,831,704 $ 2,494,242 $ 3,148,005 Pre-tax return on average assets 2.58 % 2.86 % 1.47 % Adjusted pre-tax return on average assets 1.19 % 1.75 % 1.97 % Adjusted Pre-Tax ROAA (2011 to 2013)
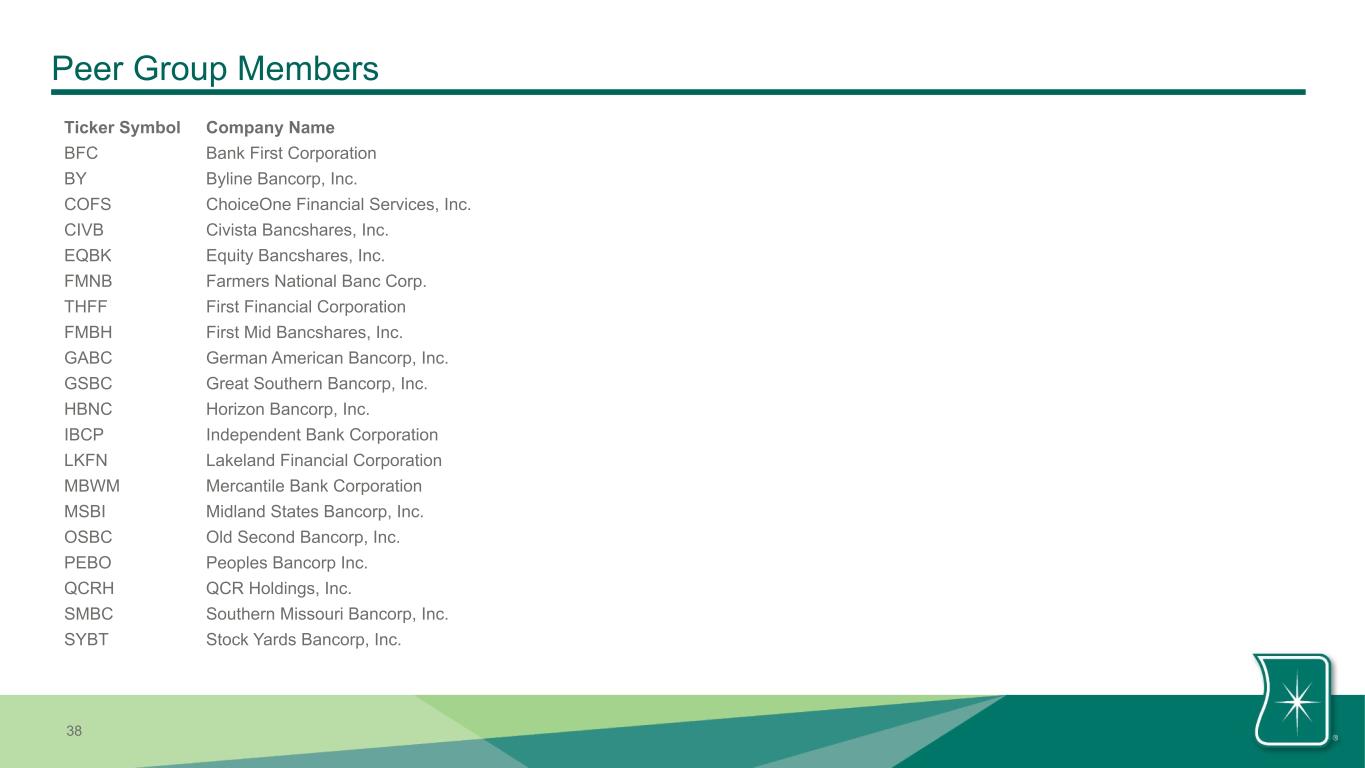
38 Peer Group Members Ticker Symbol Company Name BFC Bank First Corporation BY Byline Bancorp, Inc. COFS ChoiceOne Financial Services, Inc. CIVB Civista Bancshares, Inc. EQBK Equity Bancshares, Inc. FMNB Farmers National Banc Corp. THFF First Financial Corporation FMBH First Mid Bancshares, Inc. GABC German American Bancorp, Inc. GSBC Great Southern Bancorp, Inc. HBNC Horizon Bancorp, Inc. IBCP Independent Bank Corporation LKFN Lakeland Financial Corporation MBWM Mercantile Bank Corporation MSBI Midland States Bancorp, Inc. OSBC Old Second Bancorp, Inc. PEBO Peoples Bancorp Inc. QCRH QCR Holdings, Inc. SMBC Southern Missouri Bancorp, Inc. SYBT Stock Yards Bancorp, Inc.
0 118 104 0 118 104 0 118 104 165 211 142 165 211 142 245 230 168 245 230 168 255 255 255