
HFWA 8-K
Heritage Financial Corp /Wa/ (HFWA)
8-K
2026-04-23
For: 2026-04-23
View Original
Added on
April 23, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d)
of the Securities and Exchange Act of 1934
Date of Report (Dated of earliest event reported): April 23, 2026
(Exact name of registrant as specified in its charter)
Commission File Number 000-29480
| (State or other jurisdiction of incorporation or organization) | (I.R.S. Employer Identification No.) | |||||||||||||
| (Address of principal executive offices) | (Zip Code) | |||||||||||||
(Registrant’s telephone number, including area code)
Not applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12 (b) of the Act:
| Title of each class | Trading symbol | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1934 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging Growth Company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition
On April 23, 2026, Heritage Financial Corporation (“Heritage”) issued a press release announcing its first quarter 2026 results.
A copy of the release is attached hereto as Exhibit 99.1 to this Current Report on Form 8-K and is incorporated herein by reference. The information furnished pursuant to this Item and the related exhibit is being “furnished” and will not, except to the extent required by applicable law or regulation, be deemed “filed” by Heritage for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), or incorporated by reference in any filing under the Securities Act of 1933, as amended, or the Exchange Act, except as may be expressly set forth by specific reference in such filing.
Item 7.01 Regulation FD Disclosure
Heritage is filing an investor presentation that it reviewed in conjunction with its earnings release conference call on April 23, 2026.
A copy of the presentation materials is attached hereto as Exhibit 99.2 to this Current Report on Form 8-K and is incorporated herein by reference. The information furnished pursuant to this Item and the related exhibit is being “furnished” and will not, except to the extent required by applicable law or regulation, be deemed “filed” by Heritage for purposes of Section 18 of the Exchange Act, or incorporated by reference in any filing under the Securities Act of 1933, as amended, or the Exchange Act, except as may be expressly set forth by specific reference in such filing.
Item 8.01 Other Events
On April 23, 2026, Heritage issued a press release announcing a regular quarterly cash dividend of $0.24 per common share. The dividend will be paid on May 20, 2026 to shareholders of record at the close of business on May 6, 2026.
A copy of the release is attached hereto as Exhibit 99.1 to this Current Report on Form 8-K and is incorporated herein by reference.
Item 9.01 Financial Statements and Exhibits
(d) Exhibits
| Exhibit 99.1 | ||||||||
| Exhibit 99.2 | ||||||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | |||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| HERITAGE FINANCIAL CORPORATION | ||||||||
| Date: | ||||||||
| April 23, 2026 | /S/ BRYAN MCDONALD | |||||||
| Bryan McDonald | ||||||||
| President and Chief Executive Officer | ||||||||
| (Duly Authorized Officer) | ||||||||
FOR IMMEDIATE RELEASE
DATE: April 23, 2026
Heritage Financial Announces First Quarter 2026 Results and Declares Regular Cash Dividend of $0.24 Per Share
First Quarter 2026 Highlights
•Net income was $18.9 million, or $0.48 per diluted share, compared to $22.2 million, or $0.65 per diluted share for the fourth quarter of 2025.
•Excluding merger-related costs, net income was $0.59 per adjusted diluted share(1), compared to $0.66 per adjusted diluted share(1) in the fourth quarter of 2025.
•Net interest margin increased to 3.96%, an increase of 24 basis points from 3.72% for the fourth quarter of 2025.
•Yield on loans increased to 5.73%, an increase of 19 basis points from 5.54% for the fourth quarter of 2025.
•Cost of interest bearing deposits decreased to 1.71%, from 1.83% for the fourth quarter of 2025.
•Declared a regular cash dividend of $0.24 per share on April 22, 2026.
•Completed the acquisition of Olympic Bancorp, Inc. ("Olympic") on January 31, 2026.
Olympia, WA - Heritage Financial Corporation (Nasdaq GS: HFWA) (the “Company," ”we," or "us"), the parent company of Heritage Bank (the "Bank"), today reported net income of $18.9 million for the first quarter of 2026, compared to $22.2 million for the fourth quarter of 2025 and $13.9 million for the first quarter of 2025. Diluted earnings per share were $0.48 for the first quarter of 2026, compared to $0.65 for the fourth quarter of 2025 and $0.40 for the first quarter of 2025. Adjusted diluted earnings per share(1) were $0.59 for the first quarter of 2026, compared to $0.66 for the fourth quarter of 2025 and $0.49 for the first quarter of 2025.
Bryan McDonald, President and Chief Executive Officer of the Company, commented, "We successfully closed our strategic acquisition of Olympic Bancorp during the first quarter. This acquisition provides us with a stronger market position in the Puget Sound region, and has contributed to our improved profitability and net interest margin in the quarter. We are on track to complete the system conversion by the end of the third quarter 2026 at which time we will begin to recognize further cost savings, which aligns with our original timeline.”
“We are pleased with our operating results for the first quarter and remain focused on maintaining our strong banking organization with sustainable growth and prudent risk management which allows us to generate strong capital returns for our shareholders.”
(1) Represents a non-GAAP financial measure. See “Non-GAAP Financial Measures” section for a reconciliation to the comparable GAAP financial measure.
1
Financial Highlights
The following table provides financial highlights as of the dates and for the periods indicated:
| As of or for the Quarter Ended | |||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||
| (Dollars in thousands, except per share amounts) | |||||||||||||||||
| Net income | $ | 18,947 | $ | 22,237 | $ | 13,911 | |||||||||||
| Diluted earnings per share | 0.48 | 0.65 | 0.40 | ||||||||||||||
Adjusted diluted earnings per share(1) | 0.59 | 0.66 | 0.49 | ||||||||||||||
Return on average assets(2) | 0.97 | % | 1.27 | % | 0.79 | % | |||||||||||
Return on average common equity(2) | 7.32 | 9.68 | 6.51 | ||||||||||||||
Return on average tangible common equity(1)(2) | 11.14 | 13.33 | 9.22 | ||||||||||||||
Adjusted return on average tangible common equity(1)(2) | 13.36 | 13.51 | 11.21 | ||||||||||||||
Net interest margin(2) | 3.96 | 3.72 | 3.44 | ||||||||||||||
Cost of total deposits(2) | 1.25 | 1.32 | 1.38 | ||||||||||||||
| Efficiency ratio | 72.6 | 62.5 | 71.9 | ||||||||||||||
Adjusted efficiency ratio(1) | 63.3 | 61.5 | 66.8 | ||||||||||||||
Noninterest expense to average total assets(2) | 2.89 | 2.37 | 2.36 | ||||||||||||||
Adjusted noninterest expense to average total assets(1)(2) | 2.52 | 2.33 | 2.35 | ||||||||||||||
| Total assets | $ | 8,498,404 | $ | 6,967,350 | $ | 7,129,862 | |||||||||||
Loans receivable | 5,722,238 | 4,783,266 | 4,764,848 | ||||||||||||||
| Total deposits | 7,248,537 | 5,920,199 | 5,845,335 | ||||||||||||||
Loan to deposit ratio(3) | 78.9 | % | 80.8 | % | 81.5 | % | |||||||||||
| Book value per share | $ | 27.05 | $ | 27.13 | $ | 25.85 | |||||||||||
Tangible book value per share(1) | 19.07 | 19.98 | 18.70 | ||||||||||||||
(1) Represents a non-GAAP financial measure. See “Non-GAAP Financial Measures” section for a reconciliation to the comparable GAAP financial measure.
(2) Annualized.
(3) Loans receivable divided by total deposits.
Acquisition of Olympic Bancorp, Inc. (the "Merger")
On January 31, 2026, the Company completed the acquisition of Olympic, the holding company for Kitsap Bank. As of the acquisition date, Olympic was merged with and into Heritage and Kitsap Bank was merged with and into Heritage Bank.
Pursuant to the Agreement and Plan of Merger, each issued and outstanding share of Olympic capital stock was exchanged for 45.0 shares of Heritage common stock, with cash paid in lieu of fractional shares. After the Merger was completed, based on the number of issued and outstanding shares of Olympic capital stock on January 30, 2026 (the trading day immediately preceding the completion of the Merger), 7,167,600 shares of Heritage common stock were issued as Merger consideration. Based on the closing price of Heritage common stock on Nasdaq as of January 30, 2026 of $25.81, the Merger consideration that an Olympic shareholder was entitled to receive for each share of Olympic capital stock owned had a value of $1,161.45 with an aggregate transaction value of approximately $185.0 million.
Acquisition Accounting
The Merger was accounted for using the acquisition method. Accordingly, Heritage’s cost to acquire Olympic was allocated to the assets (including identifiable intangible assets) and the liabilities at their respective estimated fair values as of the acquisition date. The excess of the purchase price over the fair value of the net assets acquired was allocated to goodwill.
Heritage adopted Financial Accounting Standards Board Accounting Standards Update 2025-08 as of January 1, 2026. Under the updated guidance, the acquired financial assets were classified as either Purchased Credit Deteriorated ("PCD"), loans that have experienced more than insignificant credit deterioration since origination, or Purchased Seasoned Loans ("PSLs"). Per ASC 326-20-30-16, all loans that are acquired as part of a business combination accounted for using the acquisition method in accordance with Subtopic 805-20 that do not meet the definition of a PCD loan are determined to be PSLs. Under both classifications, the gross-up approach is applied whereby the estimated allowance for credit loss as of the acquisition date is added back to the fair value to determine the gross amortized cost basis.
Fair values on the acquisition date are preliminary and represent management’s best estimates based on available information and facts and circumstances in existence on the acquisition date. Fair values are subject to refinement for up to one year after the closing date of the acquisition as additional information regarding the closing date fair values becomes available.
2
The following table provides the estimated fair value of the assets acquired and liabilities assumed at the Merger date of January 31, 2026:
| (dollars in thousands) | ||||||||
| Total Merger consideration | $ | 184,996 | ||||||
| Assets | ||||||||
| Cash and cash equivalents | 155,167 | |||||||
| Investment securities | 311,979 | |||||||
| Loans receivable | 954,300 | |||||||
| Allowance for credit losses on loans | (9,339) | |||||||
| Loans receivable, net | 944,961 | |||||||
| Premises and equipment, net | 27,437 | |||||||
| Federal Home Loan Bank stock, at cost | 999 | |||||||
| Bank owned life insurance | 37,734 | |||||||
| Accrued interest receivable | 4,253 | |||||||
| Prepaid expenses and other assets | 19,634 | |||||||
| Other intangible assets, net | 50,305 | |||||||
| Total assets | 1,552,469 | |||||||
| Liabilities | ||||||||
| Deposits | 1,388,996 | |||||||
| Accrued expenses and other liabilities | 16,567 | |||||||
| Total liabilities | 1,405,563 | |||||||
| Fair value of net assets acquired | 146,906 | |||||||
| Goodwill acquired | 38,090 | |||||||
Total Assets
The Company’s total assets increased $1.53 billion, or 22.0%, to $8.50 billion at March 31, 2026 from $6.97 billion at December 31, 2025 primarily as a result of the Merger. Assets acquired, including goodwill, from the Merger totaled $1.59 billion at the closing date of January 31, 2026.
Investment Securities
Total investment securities increased $387.8 million, or 30.3%, to $1.67 billion at March 31, 2026, from $1.28 billion at December 31, 2025. The increase was primarily due to the Merger, with acquired balances of $312.0 million. The Company repositioned a portion of the portfolio acquired in the Merger during the first quarter of 2026, with sales of $193.5 million and purchases of $315.9 million. Purchases exceeded sales in the repositioning due to the investment of excess cash acquired in the Merger, which was a result of the sale of securities by Olympic during the month preceding the Merger. Investment maturities and repayments totaled $44.5 million during the first quarter of 2026.
The following table summarizes the composition of the Company's investment securities portfolio at the dates indicated:
| March 31, 2026 | December 31, 2025 | Change | |||||||||||||||||||||||||||||||||
| Balance | % of Total | Balance | % of Total | $ | % | ||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Investment securities available for sale, at fair value: | |||||||||||||||||||||||||||||||||||
| U.S. government and agency securities | $ | 11,861 | 0.7 | % | $ | 11,702 | 0.9 | % | $ | 159 | 1.4 | % | |||||||||||||||||||||||
| Municipal securities | 63,972 | 3.8 | 51,423 | 4.0 | 12,549 | 24.4 | |||||||||||||||||||||||||||||
Residential CMO and MBS(1) | 497,228 | 29.8 | 275,268 | 21.5 | 221,960 | 80.6 | |||||||||||||||||||||||||||||
Commercial CMO and MBS(1) | 396,816 | 23.7 | 252,164 | 19.7 | 144,652 | 57.4 | |||||||||||||||||||||||||||||
| Corporate obligations | 11,580 | 0.7 | 10,532 | 0.8 | 1,048 | 10.0 | |||||||||||||||||||||||||||||
| Other asset-backed securities | 19,691 | 1.2 | 6,433 | 0.5 | 13,258 | 206.1 | |||||||||||||||||||||||||||||
| Total | $ | 1,001,148 | 59.9 | % | $ | 607,522 | 47.4 | % | $ | 393,626 | 64.8 | % | |||||||||||||||||||||||
3
| March 31, 2026 | December 31, 2025 | Change | |||||||||||||||||||||||||||||||||
| Balance | % of Total | Balance | % of Total | $ | % | ||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Investment securities held to maturity, at amortized cost: | |||||||||||||||||||||||||||||||||||
| U.S. government and agency securities | $ | 151,341 | 9.1 | % | $ | 151,319 | 11.8 | % | $ | 22 | — | % | |||||||||||||||||||||||
Residential CMO and MBS(1) | 213,096 | 12.8 | 217,707 | 17.0 | (4,611) | (2.1) | |||||||||||||||||||||||||||||
Commercial CMO and MBS(1) | 303,826 | 18.2 | 305,081 | 23.8 | (1,255) | (0.4) | |||||||||||||||||||||||||||||
| Total | $ | 668,263 | 40.1 | % | $ | 674,107 | 52.6 | % | $ | (5,844) | (0.9) | % | |||||||||||||||||||||||
| Total investment securities | $ | 1,669,411 | 100.0 | % | $ | 1,281,629 | 100.0 | % | $ | 387,782 | 30.3 | % | |||||||||||||||||||||||
Loans Receivable
Loans receivable increased $939.0 million, or 19.6%, during the first quarter of 2026 due primarily to loans acquired in the Merger. New loans funded during the first quarter of 2026 were $97.0 million, which was lower than new loans funded during the fourth quarter of 2025 of $173.1 million and in line with new loans funded during the first quarter of 2025 of $95.8 million. Loan prepayments were similar to the prior quarter at $72.5 million, compared to $77.2 million during the fourth quarter of 2025. Loan payoffs decreased to $46.5 million, compared to $74.5 million in the prior quarter.
The following table summarizes the composition of acquired loans at the Merger date of January 31, 2026:
January 31, 2026 | |||||||||||
| Balance | % of Total | ||||||||||
Merger - Loan Composition | (Dollars in thousands) | ||||||||||
| Commercial business: | |||||||||||
| Commercial and industrial | $ | 251,819 | 26.4 | % | |||||||
Owner-occupied CRE | 172,141 | 18.0 | % | ||||||||
| Non-owner occupied CRE | 414,899 | 43.5 | % | ||||||||
| Total commercial business | 838,859 | 87.9 | % | ||||||||
Residential real estate | 11,703 | 1.2 | % | ||||||||
| Real estate construction and land development: | |||||||||||
Residential | 26,765 | 2.8 | % | ||||||||
Commercial and multifamily | 35,894 | 3.8 | % | ||||||||
| Total real estate construction and land development | 62,659 | 6.6 | % | ||||||||
| Consumer | 41,079 | 4.3 | % | ||||||||
| Loans receivable | 954,300 | 100.0 | % | ||||||||
The following table summarizes the Company's loans receivable at the dates indicated:
| March 31, 2026 | December 31, 2025 | Change | |||||||||||||||||||||||||||||||||
| Balance | % of Total | Balance | % of Total | $ | % | ||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Commercial business: | |||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 1,059,457 | 18.5 | % | $ | 818,000 | 17.1 | % | $ | 241,457 | 29.5 | % | |||||||||||||||||||||||
Owner-occupied CRE | 1,213,585 | 21.2 | 1,034,829 | 21.6 | 178,756 | 17.3 | |||||||||||||||||||||||||||||
| Non-owner occupied CRE | 2,466,417 | 43.1 | 2,057,844 | 43.0 | 408,573 | 19.9 | |||||||||||||||||||||||||||||
| Total commercial business | 4,739,459 | 82.8 | 3,910,673 | 81.7 | 828,786 | 21.2 | |||||||||||||||||||||||||||||
Residential real estate | 361,384 | 6.3 | 358,834 | 7.5 | 2,550 | 0.7 | |||||||||||||||||||||||||||||
4
| March 31, 2026 | December 31, 2025 | Change | |||||||||||||||||||||||||||||||||
| Balance | % of Total | Balance | % of Total | $ | % | ||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Real estate construction and land development: | |||||||||||||||||||||||||||||||||||
Residential | 123,409 | 2.2 | 95,350 | 2.0 | 28,059 | 29.4 | |||||||||||||||||||||||||||||
Commercial and multifamily | 288,493 | 5.0 | 247,975 | 5.2 | 40,518 | 16.3 | |||||||||||||||||||||||||||||
| Total real estate construction and land development | 411,902 | 7.2 | 343,325 | 7.2 | 68,577 | 20.0 | |||||||||||||||||||||||||||||
| Consumer | 209,493 | 3.7 | 170,434 | 3.6 | 39,059 | 22.9 | |||||||||||||||||||||||||||||
| Loans receivable | $ | 5,722,238 | 100.0 | % | $ | 4,783,266 | 100.0 | % | $ | 938,972 | 19.6 | ||||||||||||||||||||||||
Deposits
Total deposits increased $1.33 billion, or 22.4%, to $7.25 billion at March 31, 2026 from $5.92 billion at December 31, 2025 due primarily to deposits acquired in the Merger.
The following table summarizes the composition of acquired deposits at the Merger date of January 31, 2026:
| January 31, 2026 | |||||||||||
Balance | % of Total | ||||||||||
Merger - Deposit Composition | (Dollars in thousands) | ||||||||||
| Noninterest demand deposits | $ | 410,394 | 29.5 | % | |||||||
| Interest bearing demand deposits | 336,742 | 24.2 | % | ||||||||
| Money market accounts | 217,685 | 15.7 | % | ||||||||
| Savings accounts | 175,032 | 12.6 | % | ||||||||
| Total non-maturity deposits | 1,139,853 | 82.1 | % | ||||||||
| Certificates of deposit | 249,143 | 17.9 | % | ||||||||
| Total deposits | $ | 1,388,996 | 100.0 | % | |||||||
Total deposits, excluding the $1.39 billion of deposits acquired in the Merger, decreased $60.7 million during the first quarter of 2026 due primarily to the maturity of brokered certificates of deposit of $29 million.
The following table summarizes the Company's total deposits at the dates indicated:
| March 31, 2026 | December 31, 2025 | Change | |||||||||||||||||||||||||||||||||
Balance | % of Total | Balance | % of Total | $ | % | ||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||
| Noninterest demand deposits | $ | 2,066,383 | 28.5 | % | $ | 1,597,650 | 27.0 | % | $ | 468,733 | 29.3 | % | |||||||||||||||||||||||
| Interest bearing demand deposits | 1,860,679 | 25.7 | 1,627,259 | 27.5 | 233,420 | 14.3 | |||||||||||||||||||||||||||||
| Money market accounts | 1,588,678 | 21.9 | 1,334,904 | 22.5 | 253,774 | 19.0 | |||||||||||||||||||||||||||||
| Savings accounts | 606,119 | 8.4 | 422,523 | 7.1 | 183,596 | 43.5 | |||||||||||||||||||||||||||||
| Total non-maturity deposits | 6,121,859 | 84.5 | 4,982,336 | 84.1 | 1,139,523 | 22.9 | |||||||||||||||||||||||||||||
| Certificates of deposit | 1,126,678 | 15.5 | 937,863 | 15.9 | 188,815 | 20.1 | |||||||||||||||||||||||||||||
| Total deposits | $ | 7,248,537 | 100.0 | % | $ | 5,920,199 | 100.0 | % | $ | 1,328,338 | 22.4 | % | |||||||||||||||||||||||
5
Borrowings
Total borrowings were $20.0 million at March 31, 2026 and December 31, 2025. All outstanding borrowings at March 31, 2026 were with the Federal Home Loan Bank ("FHLB") and mature within one year.
Stockholders' Equity
Total stockholders' equity increased $194.2 million, or 21.1%, to $1.12 billion at March 31, 2026, compared to $921.5 million at December 31, 2025. The increase was due primarily to the common stock issued for the Merger.
The following table summarizes changes in stockholders' equity for the Company for the period indicated:
| Quarter Ended | |||||
| March 31, 2026 | |||||
| (In thousands) | |||||
| Balance, beginning of period | $ | 921,504 | |||
Common stock issued in the Merger | 184,996 | ||||
| Net income | 18,947 | ||||
| Cash dividends declared on common stock | (8,311) | ||||
Other comprehensive loss | (1,781) | ||||
| Other | 336 | ||||
| Balance, end of period | $ | 1,115,691 | |||
The Company and Bank continued to maintain capital levels in excess of the applicable regulatory requirements to be categorized as “well-capitalized” at March 31, 2026.
The following table summarizes the capital ratios for the Company at the dates indicated:
| March 31, 2026 | December 31, 2025 | ||||||||||
| Stockholders' equity to total assets | 13.1% | 13.2% | |||||||||
Tangible common equity to tangible assets (1) | 9.6 | 10.1 | |||||||||
Common equity tier 1 capital ratio (2) | 12.2 | 12.7 | |||||||||
Leverage ratio (2) | 10.3 | 10.8 | |||||||||
Tier 1 capital ratio (2) | 12.5 | 13.1 | |||||||||
Total capital ratio (2) | 13.5 | 14.1 | |||||||||
(1) Represents a non-GAAP financial measure. See “Non-GAAP Financial Measures” section for a reconciliation to the comparable GAAP financial measure.
(2) Current quarter ratios are estimates pending completion and filing of the Company’s regulatory reports.
Allowance for Credit Losses and Provision for Credit Losses
The allowance for credit losses ("ACL") on loans as a percentage of loans receivable was 1.06% at March 31, 2026 compared to 1.10% at December 31, 2025. The decrease in the ACL as a percentage of loans was due primarily to the addition of the loan portfolio acquired in the Merger, which had a lower weighted average life of loans contributing to a lower ACL. On January 31, 2026, the Company recorded an initial ACL of $9.3 million for the PSL and PCD loans under ASU 2025-08 as part of the acquisition of Olympic. The ACL on loans as a percentage of loans receivable for the acquired portfolio as of the acquisition date was 0.98%.
During the first quarter of 2026, the Company recorded a $0.8 million reversal of provision for credit losses on loans, compared to a $0.9 million reversal of provision during the fourth quarter of 2025. During the first quarter of 2026, the Company recorded a $210,000 reversal provision for credit losses on unfunded commitments compared to a $95,000 provision during the fourth quarter of 2025. The reversal of provision for credit losses on unfunded commitments during the first quarter of 2026 was due primarily to an increase in utilization rates.
6
The following table provides detail on the changes in the ACL on loans and the ACL on unfunded commitments ("ACL on Unfunded"), and the related (reversal of) provision for credit losses for the periods indicated:
| As of or for the Quarter Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| ACL on Loans | ACL on Unfunded | Total | ACL on Loans | ACL on Unfunded | Total | ACL on Loans | ACL on Unfunded | Total | |||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Balance, beginning of period | $ | 52,584 | $ | 1,047 | $ | 53,631 | $ | 53,974 | $ | 952 | $ | 54,926 | $ | 52,468 | $ | 587 | $ | 53,055 | |||||||||||||||||||||||||||||||||||
Initial ACL recorded for the Merger | 9,339 | 348 | $ | 9,687 | — | — | $ | — | — | — | $ | — | |||||||||||||||||||||||||||||||||||||||||
| (Reversal of) provision for credit losses | (820) | (210) | (1,030) | (909) | 95 | (814) | (9) | 60 | 51 | ||||||||||||||||||||||||||||||||||||||||||||
| (Net charge-offs) / recoveries | (552) | — | (552) | (481) | — | (481) | (299) | — | (299) | ||||||||||||||||||||||||||||||||||||||||||||
| Balance, end of period | $ | 60,551 | $ | 1,185 | $ | 61,736 | $ | 52,584 | $ | 1,047 | $ | 53,631 | $ | 52,160 | $ | 647 | $ | 52,807 | |||||||||||||||||||||||||||||||||||
Credit Quality
Classified loans (loans rated substandard or worse) increased $4.5 million from the prior quarter and was due primarily to the addition of classified loans acquired from Olympic of $11.4 million, offset by loan payoffs. The percentage of classified loans to loans receivable decreased to 2.1% at March 31, 2026, compared to 2.4% at December 31, 2025 due to an increase in total loans as a result of the Merger during the first quarter of 2026.
The following table illustrates total loans by risk rating and their respective percentage of total loans at the dates indicated:
| March 31, 2026 | December 31, 2025 | ||||||||||||||||||||||
| Balance | % of Total | Balance | % of Total | ||||||||||||||||||||
| (Dollars in thousands) | |||||||||||||||||||||||
| Risk Rating: | |||||||||||||||||||||||
| Pass | $ | 5,497,208 | 96.1 | % | $ | 4,595,321 | 96.1 | % | |||||||||||||||
| Special Mention | 103,699 | 1.8 | 71,122 | 1.5 | |||||||||||||||||||
| Substandard | 121,331 | 2.1 | 116,823 | 2.4 | |||||||||||||||||||
| Total | $ | 5,722,238 | 100.0 | % | $ | 4,783,266 | 100.0 | % | |||||||||||||||
Nonaccrual loans decreased by $6.0 million during the first quarter of 2026 due primarily to principal payoffs of one $5.8 million residential construction loan, one $1.5 million CRE non-owner occupied loan, and one $0.5 million CRE owner-occupied loan, offset partially by the migration of three commercial and industrial loans totaling $2.6 million, one $0.5 million CRE owner-occupied loan, and one $0.2 million residential construction loan. Olympic did not have any nonaccrual loans as of the acquisition date of January 31, 2026.
The following table illustrates changes in nonaccrual loans during the periods indicated:
| Quarter Ended | |||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||
(Dollars in thousands) | |||||||||||||||||
| Balance, beginning of period | $ | 20,976 | $ | 17,612 | $ | 4,079 | |||||||||||
| Additions | 3,388 | 4,446 | 832 | ||||||||||||||
Net principal payments | (261) | (1,082) | (214) | ||||||||||||||
| Payoffs | (7,800) | — | (38) | ||||||||||||||
| Charge-offs | (463) | — | (221) | ||||||||||||||
| Transfer to OREO | (741) | — | — | ||||||||||||||
| Return to accrual | (141) | — | — | ||||||||||||||
| Balance, end of period | $ | 14,958 | $ | 20,976 | $ | 4,438 | |||||||||||
| Nonaccrual loans to loans receivable | 0.26 | % | 0.44 | % | 0.09 | % | |||||||||||
7
Liquidity
Total liquidity sources available at March 31, 2026 were $3.20 billion. This included on- and off-balance sheet liquidity. The Company has access to FHLB advances and the Federal Reserve Bank ("FRB") Discount Window. The Company's available liquidity sources at March 31, 2026 represented a coverage ratio of 44.2% of total deposits and 113.0% of estimated uninsured deposits.
The following table summarizes the Company's available liquidity as of the dates indicated:
| Quarter Ended | |||||||||||
| March 31, 2026 | December 31, 2025 | ||||||||||
| (Dollars in thousands) | |||||||||||
On-balance sheet liquidity | |||||||||||
| Cash and cash equivalents | $ | 268,143 | $ | 233,089 | |||||||
Unencumbered investment securities available for sale (1) | 978,332 | 606,968 | |||||||||
Total on-balance sheet liquidity | $ | 1,246,475 | $ | 840,057 | |||||||
Off-balance sheet liquidity | |||||||||||
| FRB borrowing availability | $ | 341,449 | $ | 346,307 | |||||||
FHLB borrowing availability (2) | 1,469,277 | 1,285,640 | |||||||||
| Fed funds line borrowing availability with correspondent banks | 145,000 | 145,000 | |||||||||
Total off-balance sheet liquidity | $ | 1,955,726 | $ | 1,776,947 | |||||||
| Total available liquidity | $ | 3,202,201 | $ | 2,617,004 | |||||||
(1) Investment securities available for sale at fair value.
(2) Includes FHLB total borrowing availability of $1.49 billion at March 31, 2026 based on pledged assets, however, maximum credit capacity was 45% of the Bank's total assets one quarter in arrears or $3.13 billion.
Net Interest Income and Net Interest Margin
Net interest income increased $10.9 million, or 18.6%, during the first quarter of 2026 compared to the fourth quarter of 2025 due to an $11.8 million increase in total interest income, offset partially by an increase in interest expense of $1.0 million. The increase in net interest income was primarily due to an increase in average interest earning assets, which grew substantially as a result of the Merger.
Net interest margin increased 24 basis points to 3.96% during the first quarter of 2026, from 3.72% during the fourth quarter of 2025. The increase in net interest margin was due primarily to the increase in net interest income as discussed above with the primary contributor being increases in both the average loan balance and loan yield as a result of the Merger.
The yield on interest earning assets increased 16 basis points to 5.19% for the first quarter of 2026, compared to 5.03% for the fourth quarter of 2025. The yield on loans receivable increased 19 basis points to 5.73% during the first quarter of 2026, compared to 5.54% during the fourth quarter of 2025. The increase was due primarily to the incremental accretion on purchased loans which contributed 12 basis points to loan yield and interest income recognized on nonaccrual loans which contributed six basis points to loan yield. The incremental accretion and the impact to loan yield will change during any period based on the volume of prepayments, but is expected to decrease over time as the balance of the purchased loans decreases.
The cost of interest bearing deposits decreased 12 basis points to 1.71% for the first quarter of 2026, from 1.83% for the fourth quarter of 2025. This decrease was primarily due to the deposits acquired from Olympic, which had a lower cost of deposits.
Net interest margin increased 52 basis points to 3.96% during the first quarter of 2026, compared to 3.44% for the same period in the prior year. Net interest income increased $15.5 million, or 28.9%, during the first quarter of 2026 compared to the same period in the prior year. The increase was due primarily to an increase in average interest earning assets, which increased substantially as a result of the Merger.
The following table provides net interest income information for the periods indicated:
| Quarter Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Balance | Interest Earned/ Paid | Average Yield/ Rate (1) | Average Balance | Interest Earned/ Paid | Average Yield/ Rate (1) | Average Balance | Interest Earned/ Paid | Average Yield/ Rate (1) | |||||||||||||||||||||||||||||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest Earning Assets: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Loans receivable (2)(3) | $ | 5,412,943 | $ | 76,445 | 5.73 | % | $ | 4,770,300 | $ | 66,669 | 5.54 | % | $ | 4,793,917 | $ | 64,436 | 5.45 | % | |||||||||||||||||||||||||||||||||||
| Taxable securities | 1,486,343 | 12,570 | 3.43 | 1,285,948 | 10,546 | 3.25 | 1,427,976 | 11,739 | 3.33 | ||||||||||||||||||||||||||||||||||||||||||||
Nontaxable securities (3) | 15,662 | 129 | 3.34 | 15,578 | 135 | 3.44 | 15,686 | 139 | 3.59 | ||||||||||||||||||||||||||||||||||||||||||||
| Interest earning deposits | 172,723 | 1,531 | 3.59 | 151,477 | 1,512 | 3.96 | 96,118 | 1,052 | 4.44 | ||||||||||||||||||||||||||||||||||||||||||||
8
| Quarter Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Balance | Interest Earned/ Paid | Average Yield/ Rate (1) | Average Balance | Interest Earned/ Paid | Average Yield/ Rate (1) | Average Balance | Interest Earned/ Paid | Average Yield/ Rate (1) | |||||||||||||||||||||||||||||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total interest earning assets | 7,087,671 | 90,675 | 5.19 | % | 6,223,303 | 78,862 | 5.03 | % | 6,333,697 | 77,366 | 4.95 | % | |||||||||||||||||||||||||||||||||||||||||
| Noninterest earning assets | 847,331 | 730,807 | 769,530 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 7,935,002 | $ | 6,954,110 | $ | 7,103,227 | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest Bearing Liabilities: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Certificates of deposit | $ | 1,064,676 | $ | 8,814 | 3.36 | % | $ | 950,097 | $ | 8,425 | 3.52 | % | $ | 980,336 | $ | 9,670 | 4.00 | % | |||||||||||||||||||||||||||||||||||
| Savings accounts | 540,403 | 315 | 0.24 | 424,214 | 277 | 0.26 | 426,321 | 293 | 0.28 | ||||||||||||||||||||||||||||||||||||||||||||
| Interest bearing demand and money market accounts | 3,303,007 | 11,618 | 1.43 | 2,876,278 | 10,874 | 1.50 | 2,705,686 | 9,526 | 1.43 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest bearing deposits | 4,908,086 | 20,747 | 1.71 | 4,250,589 | 19,576 | 1.83 | 4,112,343 | 19,489 | 1.92 | ||||||||||||||||||||||||||||||||||||||||||||
| Junior subordinated debentures | 22,382 | 430 | 7.79 | 22,312 | 455 | 8.09 | 22,086 | 471 | 8.65 | ||||||||||||||||||||||||||||||||||||||||||||
| Securities sold under agreement to repurchase | — | — | — | — | — | — | — | — | — | ||||||||||||||||||||||||||||||||||||||||||||
| Borrowings | 27,372 | 279 | 4.13 | 43,228 | 470 | 4.31 | 320,286 | 3,716 | 4.71 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest bearing liabilities | 4,957,840 | 21,456 | 1.76 | % | 4,316,129 | 20,501 | 1.88 | % | 4,454,715 | 23,676 | 2.16 | % | |||||||||||||||||||||||||||||||||||||||||
| Noninterest demand deposits | 1,833,284 | 1,635,539 | 1,631,268 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Other noninterest bearing liabilities | 94,834 | 90,988 | 150,615 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Stockholders’ equity | 1,049,044 | 911,454 | 866,629 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 7,935,002 | $ | 6,954,110 | $ | 7,103,227 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income and spread | $ | 69,219 | 3.43 | % | $ | 58,361 | 3.15 | % | $ | 53,690 | 2.79 | % | |||||||||||||||||||||||||||||||||||||||||
| Net interest margin | 3.96 | % | 3.72 | % | 3.44 | % | |||||||||||||||||||||||||||||||||||||||||||||||
(1) Annualized; average balances are calculated using daily balances.
(2) Average loans receivable includes loans classified as nonaccrual, which carry a zero yield. Interest earned on loans receivable includes the amortization of net deferred loan fees of $0.8 million, $1.0 million and $0.8 million for the first quarter of 2026, fourth quarter of 2025 and first quarter of 2025, respectively and the incremental accretion on purchased loans of $1.6 million, $49,000, and $153,000 for the first quarter of 2026, fourth quarter of 2025 and first quarter of 2025, respectively.
(3) Yields on tax-exempt loans and securities have not been stated on a tax-equivalent basis.
The following table presents the net interest margin and loan yield and the effect of the incremental accretion on purchased loans on these ratios for the periods indicated:
| Quarter Ended | |||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||
Net Interest Margin, excluding incremental accretion on purchased loans, annualized: | |||||||||||||||||
Net interest margin | 3.96 | % | 3.72 | % | 3.44 | % | |||||||||||
Exclude impact from incremental accretion on purchased loans(2) | (0.09) | % | — | % | (0.01) | % | |||||||||||
Net interest margin, excluding incremental accretion on purchased loans(1) | 3.87 | % | 3.72 | % | 3.43 | % | |||||||||||
Loan yield, excluding incremental accretion on purchased loans, annualized: | |||||||||||||||||
Loan yield | 5.73 | % | 5.54 | % | 5.45 | % | |||||||||||
Exclude impact from incremental accretion on purchased loans(2) | (0.12) | — | (0.01) | ||||||||||||||
Loan yield, excluding incremental accretion on purchased loans(1) | 5.61 | % | 5.54 | % | 5.44 | % | |||||||||||
Incremental accretion on purchased loans(1) | $ | 1,623 | $ | 49 | $ | 153 | |||||||||||
(1) Represents a non-GAAP financial measure. See “Non-GAAP Financial Measures” section for a reconciliation to the comparable GAAP financial measure.
(2)Represents the amount of interest income recorded on purchased loans in excess of the contractual stated interest rate in the individual loan notes due to incremental accretion of purchased discount or premium. Purchased discount or premium is the difference between the contractual loan balance and the fair value of acquired loans at the acquisition date. The purchased discount is accreted into income over the remaining life of the loan. The impact of incremental accretion on loan yield will change during any period based on the volume of prepayments, but it is expected to decrease over time as the balance of the purchased loans decreases.
9
Noninterest Income
Noninterest income increased $712,000 to $8.7 million during the first quarter of 2026 from $8.0 million during the fourth quarter of 2025. The increase was due primarily to increases in service charges and other fees, card revenue and other income due to income from the acquired deposit portfolio, offset partially by a decrease in interest rate swap fees due to decreased swap activity.
Noninterest income increased $4.8 million during the first quarter of 2026 from the same period in 2025 due primarily to a $3.9 million loss recognized in the first quarter of 2025 resulting from the sale of investment securities as part of the strategic repositioning of the Company's balance sheet, and due to increases in service charges and other fees, card revenue, and BOLI income due to income from the acquired deposit portfolio and acquired BOLI.
The following table presents the key components of noninterest income and the change for the periods indicated:
| Quarter Ended | Quarter Over Quarter Change | Prior Year Quarter Change | |||||||||||||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | $ | % | $ | % | |||||||||||||||||||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||
| Service charges and other fees | $ | 3,367 | $ | 3,052 | $ | 2,975 | $ | 315 | 10.3 | % | $ | 392 | 13.2 | % | |||||||||||||||||||||||||||
| Card revenue | 2,103 | 1,792 | 1,733 | 311 | 17.4 | 370 | 21.4 | ||||||||||||||||||||||||||||||||||
| Loss on sale of investment securities | — | — | (3,887) | — | — | 3,887 | 100.0 | ||||||||||||||||||||||||||||||||||
| Interest rate swap fees | — | 381 | — | (381) | (100.0) | — | — | ||||||||||||||||||||||||||||||||||
BOLI income | 1,119 | 1,172 | 918 | (53) | (4.5) | 201 | 21.9 | ||||||||||||||||||||||||||||||||||
| Gain on sale of other assets, net | — | — | 3 | — | — | (3) | (100.0) | ||||||||||||||||||||||||||||||||||
| Other income | 2,110 | 1,590 | 2,161 | 520 | 32.7 | (51) | (2.4) | ||||||||||||||||||||||||||||||||||
Total noninterest income (loss) | $ | 8,699 | $ | 7,987 | $ | 3,903 | $ | 712 | 8.9 | % | $ | 4,796 | 122.9 | % | |||||||||||||||||||||||||||
Noninterest Expense
Noninterest expense increased $15.1 million, or 36.3%, to $56.6 million during the first quarter of 2026, compared to $41.5 million in the fourth quarter of 2025. The increases were primarily due to expenses from the Merger, including increases related to compensation and employee benefits due to increased headcount, severance expense, occupancy and equipment expense primarily due to additional rent expense, and additional data processing expense due to an increase in transactional accounts and balances. Noninterest expense also increased due to an increase in the amortization of intangible assets of $1.8 million, relating to the Merger. Professional fees increased due primarily to Merger-related costs recognized in the first quarter of 2026. Total Merger-related costs, which consisted of severance expense, professional fees, core conversion costs, and contract termination costs incurred in the first quarter of 2026 were $5.2 million compared to $385,000 in the fourth quarter of 2025.
Noninterest expense increased $15.2 million, or 36.7%, during the first quarter of 2026 compared to the same period in 2025 due primarily to an increase in expenses related to the Merger.
The following table presents the key components of noninterest expense and the change for the periods indicated:
| Quarter Ended | Quarter Over Quarter Change | Prior Year Quarter Change | |||||||||||||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | $ | % | $ | % | |||||||||||||||||||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||
| Compensation and employee benefits | $ | 33,972 | $ | 26,675 | $ | 25,799 | $ | 7,297 | 27.4 | % | $ | 8,173 | 31.7 | % | |||||||||||||||||||||||||||
| Occupancy and equipment | 5,330 | 4,450 | 4,926 | 880 | 19.8 | 404 | 8.2 | ||||||||||||||||||||||||||||||||||
| Data processing | 5,093 | 3,681 | 3,897 | 1,412 | 38.4 | 1,196 | 30.7 | ||||||||||||||||||||||||||||||||||
| Marketing | 383 | 296 | 335 | 87 | 29.4 | 48 | 14.3 | ||||||||||||||||||||||||||||||||||
| Professional services | 2,842 | 1,070 | 734 | 1,772 | 165.6 | 2,108 | 287.2 | ||||||||||||||||||||||||||||||||||
State/municipal business and use taxes | 1,674 | 1,247 | 1,220 | 427 | 34.2 | 454 | 37.2 | ||||||||||||||||||||||||||||||||||
| Federal deposit insurance premium | 1,037 | 789 | 812 | 248 | 31.4 | 225 | 27.7 | ||||||||||||||||||||||||||||||||||
| Other real estate owned, net | 4 | — | — | 4 | — | 4 | — | ||||||||||||||||||||||||||||||||||
10
| Quarter Ended | Quarter Over Quarter Change | Prior Year Quarter Change | |||||||||||||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | $ | % | $ | % | |||||||||||||||||||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||||||||||||||||||||||||
| Amortization of intangible assets | 2,058 | 285 | 303 | 1,773 | 622.1 | 1,755 | 579.2 | ||||||||||||||||||||||||||||||||||
| Other expense | 4,158 | 2,990 | 3,357 | 1,168 | 39.1 | 801 | 23.9 | ||||||||||||||||||||||||||||||||||
| Total noninterest expense | $ | 56,551 | $ | 41,483 | $ | 41,383 | $ | 15,068 | 36.3 | % | $ | 15,168 | 36.7 | % | |||||||||||||||||||||||||||
Income Tax Expense
The effective income tax rate increased due to lower impact of favorable permanent tax items such as tax-exempt investments, investments in bank owned life insurance and tax credits.
Income tax expense and the effective income tax rate increased in the first quarter of 2026, compared to same period in 2025 due primarily to higher pre-tax income during the first quarter of 2026 and lower impact of favorable permanent tax items such as tax-exempt investments, investments in bank owned life insurance and tax credits.
The following table presents the income tax expense and related metrics and the change for the periods indicated:
| Quarter Ended | Change | ||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | Quarter Over Quarter | Prior Year Quarter | |||||||||||||||||||||||||
(Dollars in thousands) | |||||||||||||||||||||||||||||
| Income before income taxes | $ | 22,397 | $ | 25,679 | $ | 16,159 | $ | (3,282) | $ | 6,238 | |||||||||||||||||||
| Income tax expense | $ | 3,450 | $ | 3,442 | $ | 2,248 | $ | 8 | $ | 1,202 | |||||||||||||||||||
| Effective income tax rate | 15.4 | % | 13.4 | % | 13.9 | % | 2.0 | % | 1.5 | % | |||||||||||||||||||
Dividends
On April 22, 2026, the Company’s Board of Directors declared a quarterly cash dividend of $0.24 per share. The dividend is payable on May 20, 2026 to shareholders of record as of the close of business on May 6, 2026.
Earnings Conference Call
The Company will hold a telephone conference call to discuss first quarter of 2026 earnings on Thursday, April 23, 2026 at 10:00 a.m. Pacific time. To access the call, please dial (800) 715-9871 -- access code 74100 a few minutes prior to 10:00 a.m. Pacific time. The call will be available for replay through May 7, 2026 by dialing (609) 800-9909 -- access code 74100#.
About Heritage Financial Corporation
Heritage Financial Corporation (the “Company”) is an Olympia, Washington-based bank holding company for Heritage Bank, a full-service commercial bank and its sole wholly-owned banking subsidiary. Heritage Bank has a network of branches and loan production offices in Washington, Oregon and Idaho. Heritage Bank does business under the Whidbey Island Bank name on Whidbey Island, Washington and the Kitsap Bank name at certain branches acquired through the Merger. The Company's stock is traded on the Nasdaq Global Select Market under the symbol “HFWA.” More information about the Company can be found on its website at www.hf-wa.com and more information about Heritage Bank can be found on its website at www.heritagebanknw.com.
Contact
Bryan McDonald, President and Chief Executive Officer, (360) 943-1500
Don Hinson, Executive Vice President and Chief Financial Officer, (360) 943-1500
Forward-Looking Statements
This press release includes "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. The Company intends such forward-looking statements to be covered by the safe harbor provisions for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. Such statements often include words such as "believes," "expects," "anticipates," "estimates," “forecasts,” "intends," “plans,” “targets,” “potentially,” “probably,” “projects,” “outlook” or similar expressions or future or conditional verbs such as “may,” "will," “should,” "would," and "could," as well as the negative of such words. Forward-looking statements are not historical facts but instead represent management's current expectations and forecasts regarding future events, many of which are inherently uncertain and outside of our control. Actual results may differ, possibly materially, from those currently expected or projected in these forward-looking statements. These forward-looking statements are subject to known and unknown risks, uncertainties and other factors that could cause actual results to differ materially from the results anticipated or implied by forward-looking statements. Factors that could cause our actual results to differ materially from those
11
described in the forward-looking statements include, but are not limited to, the following: potential adverse impacts to economic conditions nationally or in our local market areas, other markets where we have lending relationships, or other aspects of our business operations or financial markets, including, without limitation, as a result of credit quality deterioration, pronounced and sustained reductions in real estate market values, employment levels, labor shortages and a potential recession or slowed economic growth; changes in the interest rate environment, which could adversely affect our revenues and expenses, the value of assets and obligations, and the availability and cost of capital and liquidity; the level and impact of inflation and the current and future monetary policies of the Board of Governors of the Federal Reserve System and executive orders in response thereto; previous and potential future disruptions, security breaches, insider fraud, cybersecurity incidents or other adverse events, failures or interruptions in, or attacks on, our information technology systems or on the third-party vendors who perform critical processing functions for our business, including sophisticated attacks using artificial intelligence and similar tools; legislative or regulatory changes that adversely affect our business, including changes in banking, securities, and tax laws, in regulatory policies and principles, or the interpretation and prioritization of such rules and regulations; effects on the U.S. economy resulting from actions taken by the federal government, including the threat or implementation of tariffs, immigration enforcement and changes in foreign policy; the effects of acts of war or terrorism, foreign relations, military conflicts, including the wars in Iran and Ukraine and the military conflict between Israel and Hamas in the Middle East, and other external events on our business and the businesses of our clients; credit and interest rate risks associated with our business, including our customers’ borrowing, repayment, and deposit practices; fluctuations in deposits and the concentration of large deposits from certain customers, who have deposit balances above current FDIC insurance limits; liquidity issues, including our ability to borrow funds or raise additional capital, if necessary; fluctuations in the value of our investment securities; credit risks and risks from concentrations (including by type of geographic area, collateral and industry) within our loan portfolio; the effectiveness of our risk management framework; rapid technological changes implemented by us and other parties, including third-party vendors, which may be more difficult to implement or more expensive than anticipated or which may have unforeseen consequences to us and our customers, including the development and implementation of tools incorporating artificial intelligence; increased competition in the financial services industry from non-banks such as credit unions and financial technology companies, including digital asset service providers; our ability to adapt successfully to technological changes to compete effectively in the marketplace, including as a result of competition from other commercial banks, mortgage banking firms, credit unions, securities brokerage firms, insurance companies, and financial technology companies; our ability to implement our organic and acquisition growth strategies, including the recent acquisition of Olympic, and our ability to successfully integrate Olympic's customers and operations following the acquisition; effects of critical accounting policies and judgments, including the use of estimates in determining fair value of certain of our assets, which estimates may prove to be incorrect and result in significant declines in valuation; the commencement, costs, effects and outcome of litigation and other legal proceedings and regulatory actions against us or to which we may become subject, including in connection with prior acquisitions; potential impairment to the goodwill we recorded in connection with our past acquisitions, including as a result of the recent acquisition of Olympic; loss of, or inability to attract, key personnel; our ability to successfully integrate any assets, liabilities, customers, systems, and management personnel we may acquire, including as a result of the recent acquisition of Olympic, into our operations and our ability to realize related revenue synergies and cost savings within expected time frames or at all, and any goodwill charges related thereto and costs or difficulties relating to integration matters, including but not limited to customer and employee retention, which might be greater than expected; the effects of climate change, severe weather events, natural disasters, pandemics, epidemics and other public health crises; the impact of bank failures or adverse developments at other banks and related negative publicity about the banking industry in general on investor and depositor sentiment regarding the stability and liquidity of banks; our success at managing and responding to the risks involved in the foregoing items; and other factors described in our latest Annual Report on Form 10-K and Quarterly Reports on Form 10-Q and other documents filed with or furnished to the Securities and Exchange Commission (the “SEC”) which are available on our website at www.hf-wa.com and on the SEC's website at www.sec.gov. We caution readers not to place undue reliance on any forward-looking statements. Moreover, any of the forward-looking statements that we make in this press release or the documents we file with or furnish to the SEC are based only on information then actually known to us and upon management's beliefs and assumptions at the time they are made which may turn out to be wrong because of inaccurate assumptions we might make, because of the factors described above or because of other factors that we cannot foresee. Forward-looking statements speak only as of the date they are made, and we do not undertake and specifically disclaim any obligation to revise any forward-looking statements to reflect the occurrence of anticipated or unanticipated events or circumstances after the date of such statements.
12
HERITAGE FINANCIAL CORPORATION
CONDENSED CONSOLIDATED STATEMENTS OF FINANCIAL CONDITION (Unaudited)
(Dollars in thousands, except shares)
| March 31, 2026 | December 31, 2025 | ||||||||||
| Assets | |||||||||||
| Cash on hand and in banks | $ | 98,263 | $ | 52,587 | |||||||
| Interest earning deposits | 169,880 | 180,502 | |||||||||
| Cash and cash equivalents | 268,143 | 233,089 | |||||||||
Investment securities available for sale, at fair value (amortized cost of $1,043,442 and $647,505, respectively) | 1,001,148 | 607,522 | |||||||||
Investment securities held to maturity, at amortized cost (fair value of $617,490 and $625,287, respectively) | 668,263 | 674,107 | |||||||||
| Total investment securities | 1,669,411 | 1,281,629 | |||||||||
| Loans receivable | 5,722,238 | 4,783,266 | |||||||||
| Allowance for credit losses on loans | (60,551) | (52,584) | |||||||||
| Loans receivable, net | 5,661,687 | 4,730,682 | |||||||||
| Other real estate owned | 755 | — | |||||||||
| Premises and equipment, net | 100,509 | 74,690 | |||||||||
| Federal Home Loan Bank stock, at cost | 6,072 | 5,163 | |||||||||
| Bank owned life insurance | 144,865 | 105,974 | |||||||||
| Accrued interest receivable | 24,278 | 19,280 | |||||||||
| Prepaid expenses and other assets | 293,429 | 273,925 | |||||||||
| Other intangible assets, net | 50,226 | 1,979 | |||||||||
| Goodwill | 279,029 | 240,939 | |||||||||
| Total assets | $ | 8,498,404 | $ | 6,967,350 | |||||||
| Liabilities and Stockholders' Equity | |||||||||||
Non-interest bearing deposits | 2,066,383 | 1,597,650 | |||||||||
Interest bearing deposits | 5,182,154 | 4,322,549 | |||||||||
Total deposits | 7,248,537 | 5,920,199 | |||||||||
| Borrowings | 20,000 | 20,000 | |||||||||
| Junior subordinated debentures | 22,424 | 22,350 | |||||||||
| Accrued expenses and other liabilities | 91,752 | 83,297 | |||||||||
| Total liabilities | 7,382,713 | 6,045,846 | |||||||||
| Common stock | 716,432 | 531,100 | |||||||||
| Retained earnings | 432,255 | 421,619 | |||||||||
| Accumulated other comprehensive loss, net | (32,996) | (31,215) | |||||||||
| Total stockholders' equity | 1,115,691 | 921,504 | |||||||||
| Total liabilities and stockholders' equity | $ | 8,498,404 | $ | 6,967,350 | |||||||
| Shares outstanding | 41,249,873 | 33,963,500 | |||||||||
13
HERITAGE FINANCIAL CORPORATION
CONDENSED CONSOLIDATED STATEMENTS OF INCOME (Unaudited)
(Dollars in thousands, except per share amounts)
| Quarter Ended | |||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||
| Interest Income | |||||||||||||||||
| Interest and fees on loans | $ | 76,445 | $ | 66,669 | $ | 64,436 | |||||||||||
| Taxable interest on investment securities | 12,570 | 10,546 | 11,739 | ||||||||||||||
| Nontaxable interest on investment securities | 129 | 135 | 139 | ||||||||||||||
| Interest on interest earning deposits | 1,531 | 1,512 | 1,052 | ||||||||||||||
| Total interest income | 90,675 | 78,862 | 77,366 | ||||||||||||||
| Interest Expense | |||||||||||||||||
| Deposits | 20,747 | 19,576 | 19,489 | ||||||||||||||
| Junior subordinated debentures | 430 | 455 | 471 | ||||||||||||||
| Borrowings | 279 | 470 | 3,716 | ||||||||||||||
| Total interest expense | 21,456 | 20,501 | 23,676 | ||||||||||||||
| Net interest income | 69,219 | 58,361 | 53,690 | ||||||||||||||
| (Reversal of) provision for credit losses | (1,030) | (814) | 51 | ||||||||||||||
| Net interest income after (reversal of) provision for credit losses | 70,249 | 59,175 | 53,639 | ||||||||||||||
| Noninterest Income | |||||||||||||||||
| Service charges and other fees | 3,367 | 3,052 | 2,975 | ||||||||||||||
| Card revenue | 2,103 | 1,792 | 1,733 | ||||||||||||||
| Loss on sale of investment securities, net | — | — | (3,887) | ||||||||||||||
| Interest rate swap fees | — | 381 | — | ||||||||||||||
| Bank owned life insurance income | 1,119 | 1,172 | 918 | ||||||||||||||
| Gain on sale of other assets, net | — | — | 3 | ||||||||||||||
| Other income | 2,110 | 1,590 | 2,161 | ||||||||||||||
| Total noninterest income (loss) | 8,699 | 7,987 | 3,903 | ||||||||||||||
| Noninterest Expense | |||||||||||||||||
| Compensation and employee benefits | 33,972 | 26,675 | 25,799 | ||||||||||||||
| Occupancy and equipment | 5,330 | 4,450 | 4,926 | ||||||||||||||
| Data processing | 5,093 | 3,681 | 3,897 | ||||||||||||||
| Marketing | 383 | 296 | 335 | ||||||||||||||
| Professional services | 2,842 | 1,070 | 734 | ||||||||||||||
| State/municipal business and use taxes | 1,674 | 1,247 | 1,220 | ||||||||||||||
| Federal deposit insurance premium | 1,037 | 789 | 812 | ||||||||||||||
| Other real estate owned, net | 4 | — | — | ||||||||||||||
| Amortization of intangible assets | 2,058 | 285 | 303 | ||||||||||||||
| Other expense | 4,158 | 2,990 | 3,357 | ||||||||||||||
| Total noninterest expense | 56,551 | 41,483 | 41,383 | ||||||||||||||
| Income before income taxes | 22,397 | 25,679 | 16,159 | ||||||||||||||
| Income tax expense | 3,450 | 3,442 | 2,248 | ||||||||||||||
| Net income | $ | 18,947 | $ | 22,237 | $ | 13,911 | |||||||||||
| Basic earnings per share | $ | 0.49 | $ | 0.66 | $ | 0.41 | |||||||||||
| Diluted earnings per share | $ | 0.48 | $ | 0.65 | $ | 0.40 | |||||||||||
| Dividends declared per share | $ | 0.24 | $ | 0.24 | $ | 0.24 | |||||||||||
| Average shares outstanding - basic | 38,683,375 | 33,957,987 | 34,012,490 | ||||||||||||||
| Average shares outstanding - diluted | 39,104,569 | 34,405,793 | 34,506,238 | ||||||||||||||
14
HERITAGE FINANCIAL CORPORATION
FINANCIAL STATISTICS (Unaudited)
(Dollars in thousands)
Nonperforming Assets and Credit Quality Metrics:
| Quarter Ended | |||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||
| Allowance for Credit Losses on Loans: | |||||||||||||||||
| Balance, beginning of period | $ | 52,584 | $ | 53,974 | $ | 52,468 | |||||||||||
| Initial ACL recorded for PSL and PCD loans acquired during the period | 9,339 | — | — | ||||||||||||||
(Reversal of) provision for credit losses on loans | (820) | (909) | (9) | ||||||||||||||
| Charge-offs: | |||||||||||||||||
| Commercial business | (400) | (565) | (222) | ||||||||||||||
Residential real estate | (64) | — | — | ||||||||||||||
| Real estate construction and land development | — | — | — | ||||||||||||||
| Consumer | (119) | (75) | (154) | ||||||||||||||
| Total charge-offs | (583) | (640) | (376) | ||||||||||||||
| Recoveries: | |||||||||||||||||
| Commercial business | 4 | 140 | 26 | ||||||||||||||
Residential real estate | — | — | — | ||||||||||||||
| Real estate construction and land development | — | — | — | ||||||||||||||
| Consumer | 27 | 19 | 51 | ||||||||||||||
| Total recoveries | 31 | 159 | 77 | ||||||||||||||
| Net (charge-offs) recoveries | (552) | (481) | (299) | ||||||||||||||
| Balance, end of period | $ | 60,551 | $ | 52,584 | $ | 52,160 | |||||||||||
Net charge-offs on loans to average loans receivable (1) | 0.04 | % | 0.04 | % | 0.03 | % | |||||||||||
(1) Annualized.
| March 31, 2026 | December 31, 2025 | ||||||||||
| Nonperforming Assets: | |||||||||||
| Nonaccrual loans: | |||||||||||
| Commercial business | $ | 7,454 | $ | 6,886 | |||||||
Residential real estate | 583 | 1,196 | |||||||||
| Real estate construction and land development | 6,514 | 12,408 | |||||||||
| Consumer | 407 | 486 | |||||||||
| Total nonaccrual loans | 14,958 | 20,976 | |||||||||
Accruing loans past due 90 days or more | 67 | 194 | |||||||||
Total nonperforming loans | 15,025 | 21,170 | |||||||||
| Other real estate owned | 755 | — | |||||||||
| Nonperforming assets | $ | 15,780 | $ | 21,170 | |||||||
| ACL on loans to: | |||||||||||
| Loans receivable | 1.06 | % | 1.10 | % | |||||||
| Nonaccrual loans | 404.81 | 250.69 | |||||||||
Nonaccrual loans to loans receivable | 0.26 | 0.44 | |||||||||
Nonperforming loans to loans receivable | 0.26 | 0.44 | |||||||||
| Nonperforming assets to total assets | 0.19 | 0.30 | |||||||||
15
HERITAGE FINANCIAL CORPORATION
QUARTERLY FINANCIAL STATISTICS (Unaudited)
(Dollars in thousands, except per share amounts)
| Quarter Ended | |||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
| Earnings: | |||||||||||||||||||||||||||||
| Net interest income | $ | 69,219 | $ | 58,361 | $ | 57,371 | $ | 54,983 | $ | 53,690 | |||||||||||||||||||
| (Reversal of) provision for credit losses | (1,030) | (814) | 1,775 | 956 | 51 | ||||||||||||||||||||||||
| Noninterest income | 8,699 | 7,987 | 8,325 | 1,517 | 3,903 | ||||||||||||||||||||||||
| Noninterest expense | 56,551 | 41,483 | 41,615 | 41,085 | 41,383 | ||||||||||||||||||||||||
| Net income | 18,947 | 22,237 | 19,169 | 12,215 | 13,911 | ||||||||||||||||||||||||
| Basic earnings per share | $ | 0.49 | $ | 0.66 | $ | 0.56 | $ | 0.36 | $ | 0.41 | |||||||||||||||||||
| Diluted earnings per share | $ | 0.48 | $ | 0.65 | $ | 0.55 | $ | 0.36 | $ | 0.40 | |||||||||||||||||||
Adjusted diluted earnings per share (1) | $ | 0.59 | $ | 0.66 | $ | 0.56 | $ | 0.53 | $ | 0.49 | |||||||||||||||||||
| Average Balances: | |||||||||||||||||||||||||||||
Loans receivable | $ | 5,412,943 | $ | 4,770,300 | $ | 4,762,648 | $ | 4,768,558 | $ | 4,793,917 | |||||||||||||||||||
| Total investment securities | 1,502,005 | 1,301,526 | 1,329,616 | 1,390,064 | 1,443,662 | ||||||||||||||||||||||||
| Total interest earning assets | 7,087,671 | 6,223,303 | 6,258,446 | 6,286,309 | 6,333,697 | ||||||||||||||||||||||||
| Total assets | 7,935,002 | 6,954,110 | 7,006,140 | 7,046,943 | 7,103,227 | ||||||||||||||||||||||||
| Total interest bearing deposits | 4,908,086 | 4,250,589 | 4,217,041 | 4,176,052 | 4,112,343 | ||||||||||||||||||||||||
| Total noninterest demand deposits | 1,833,284 | 1,635,539 | 1,625,945 | 1,602,987 | 1,631,268 | ||||||||||||||||||||||||
| Stockholders' equity | 1,049,044 | 911,454 | 892,280 | 879,808 | 866,629 | ||||||||||||||||||||||||
| Financial Ratios: | |||||||||||||||||||||||||||||
Return on average assets (2) | 0.97 | % | 1.27 | % | 1.09 | % | 0.70 | % | 0.79 | % | |||||||||||||||||||
Return on average common equity (2) | 7.32 | 9.68 | 8.52 | 5.57 | 6.51 | ||||||||||||||||||||||||
Return on average tangible common equity (1)(2) | 11.14 | 13.33 | 11.86 | 7.85 | 9.22 | ||||||||||||||||||||||||
Adjusted return on average tangible common equity (1)(2) | 13.36 | 13.51 | 12.16 | 11.59 | 11.21 | ||||||||||||||||||||||||
| Efficiency ratio | 72.6 | 62.5 | 63.3 | 72.7 | 71.9 | ||||||||||||||||||||||||
Adjusted efficiency ratio (1) | 63.3 | 61.5 | 61.9 | 64.4 | 66.8 | ||||||||||||||||||||||||
Noninterest expense to average total assets (2) | 2.89 | 2.37 | 2.36 | 2.34 | 2.36 | ||||||||||||||||||||||||
Adjusted noninterest expense to average total assets(1)(2) | 2.52 | 2.33 | 2.30 | 2.32 | 2.35 | ||||||||||||||||||||||||
Net interest spread (2) | 3.43 | 3.15 | 3.03 | 2.89 | 2.79 | ||||||||||||||||||||||||
Net interest margin (2) | 3.96 | 3.72 | 3.64 | 3.51 | 3.44 | ||||||||||||||||||||||||
(1) Represents a non-GAAP financial measure. See “Non-GAAP Financial Measures” section for a reconciliation to the comparable GAAP financial measure.
(2) Annualized.
16
HERITAGE FINANCIAL CORPORATION
QUARTERLY FINANCIAL STATISTICS (Unaudited)
(Dollars in thousands, except per share amounts)
| As of or for the Quarter Ended | |||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
| Select Balance Sheet: | |||||||||||||||||||||||||||||
| Total assets | $ | 8,498,404 | $ | 6,967,350 | $ | 7,011,879 | $ | 7,070,641 | $ | 7,129,862 | |||||||||||||||||||
Loans receivable | 5,722,238 | 4,783,266 | 4,769,160 | 4,774,855 | 4,764,848 | ||||||||||||||||||||||||
| Total investment securities | 1,669,411 | 1,281,629 | 1,312,857 | 1,346,274 | 1,413,903 | ||||||||||||||||||||||||
| Total deposits | 7,248,537 | 5,920,199 | 5,857,464 | 5,784,413 | 5,845,335 | ||||||||||||||||||||||||
| Noninterest demand deposits | 2,066,383 | 1,597,650 | 1,617,909 | 1,584,231 | 1,621,890 | ||||||||||||||||||||||||
| Stockholders' equity | 1,115,691 | 921,504 | 904,064 | 888,212 | 881,515 | ||||||||||||||||||||||||
| Financial Measures: | |||||||||||||||||||||||||||||
| Book value per share | $ | 27.05 | $ | 27.13 | $ | 26.62 | $ | 26.16 | $ | 25.85 | |||||||||||||||||||
Tangible book value per share (1) | 19.07 | 19.98 | 19.46 | 18.99 | 18.70 | ||||||||||||||||||||||||
| Stockholders' equity to total assets | 13.1 | % | 13.2 | % | 12.9 | % | 12.6 | % | 12.4 | % | |||||||||||||||||||
Tangible common equity to tangible assets (1) | 9.6 | 10.1 | 9.8 | 9.4 | 9.3 | ||||||||||||||||||||||||
| Loans to deposits ratio | 78.9 | 80.8 | 81.4 | 82.5 | 81.5 | ||||||||||||||||||||||||
Regulatory Capital Ratios:(2) | |||||||||||||||||||||||||||||
Common equity tier 1 capital ratio | 12.2 | % | 12.7 | % | 12.4 | % | 12.2 | % | 12.2 | % | |||||||||||||||||||
Leverage ratio | 10.3 | 10.8 | 10.5 | 10.3 | 10.2 | ||||||||||||||||||||||||
Tier 1 capital ratio | 12.5 | 13.1 | 12.8 | 12.6 | 12.6 | ||||||||||||||||||||||||
Total capital ratio | 13.5 | 14.1 | 13.8 | 13.6 | 13.6 | ||||||||||||||||||||||||
| Credit Quality Metrics: | |||||||||||||||||||||||||||||
ACL on loans to: | |||||||||||||||||||||||||||||
| Loans receivable | 1.06 | % | 1.10 | % | 1.13 | % | 1.10 | % | 1.09 | % | |||||||||||||||||||
Nonaccrual loans | 404.8 | 250.7 | 306.5 | 532.5 | 1,175.3 | ||||||||||||||||||||||||
Nonaccrual loans to loans receivable | 0.26 | 0.44 | 0.37 | 0.21 | 0.09 | ||||||||||||||||||||||||
| Nonperforming loans to loans receivable | 0.26 | 0.44 | 0.44 | 0.39 | 0.09 | ||||||||||||||||||||||||
| Nonperforming assets to total assets | 0.19 | 0.30 | 0.30 | 0.26 | 0.06 | ||||||||||||||||||||||||
Net charge-offs on loans to average loans receivable (3) | 0.04 | 0.04 | 0.01 | 0.04 | 0.03 | ||||||||||||||||||||||||
| Criticized Loans by Credit Quality Rating: | |||||||||||||||||||||||||||||
| Special mention | $ | 103,699 | $ | 71,122 | $ | 100,160 | $ | 114,146 | $ | 113,704 | |||||||||||||||||||
| Substandard | 121,331 | 116,823 | 94,377 | 99,715 | 64,387 | ||||||||||||||||||||||||
| Other Metrics: | |||||||||||||||||||||||||||||
| Number of branches | 65 | 50 | 50 | 50 | 50 | ||||||||||||||||||||||||
| Deposits per branch | $ | 111,516 | $ | 118,404 | $ | 117,149 | $ | 115,688 | $ | 116,907 | |||||||||||||||||||
| Average number of full-time equivalent employees | 905 | 742 | 749 | 745 | 757 | ||||||||||||||||||||||||
| Average assets per full-time equivalent employee | 8,768 | 9,372 | 9,354 | 9,459 | 9,383 | ||||||||||||||||||||||||
(1) See Non-GAAP Financial Measures section herein.
(2) Current quarter ratios are estimates pending completion and filing of the Company’s regulatory reports.
(3) Annualized.
17
HERITAGE FINANCIAL CORPORATION
NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share amounts)
This earnings release contains certain financial measures not presented in accordance with U.S. Generally Accepted Accounting Principles ("GAAP") in addition to financial measures presented in accordance with GAAP. The Company has presented these non-GAAP financial measures in this earnings release because it believes that they provide useful and comparative information to assess trends in the Company’s capital, performance and asset quality reflected in the current quarter and comparable period results and to facilitate comparison of its performance with the performance of its peers. These non-GAAP financial measures have inherent limitations, are not required to be uniformly applied and are not audited. They should not be considered in isolation or as a substitute for financial measures presented in accordance with GAAP. These non-GAAP financial measures may not be comparable to similarly titled measures reported by other companies. Reconciliations of the non-GAAP financial measures used in this earnings release to the comparable GAAP financial measures are presented below.
The Company believes that presenting the adjusted diluted earnings per share provides useful and comparative information to assess trends in the Company's core operations reflected in the current quarter’s results and facilitate the comparison of our performance with the performance of our peers.
| March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
Diluted Earnings per Share and Adjusted Diluted Earnings per Share: | |||||||||||||||||||||||||||||
| Net income (GAAP) | $ | 18,947 | $ | 22,237 | $ | 19,169 | $ | 12,215 | $ | 13,911 | |||||||||||||||||||
Exclude loss on sale of investment securities, net | — | — | — | 6,854 | 3,887 | ||||||||||||||||||||||||
| Exclude merger related costs | 5,178 | 385 | 635 | — | — | ||||||||||||||||||||||||
| Exclude gain on sale of premises and equipment | — | — | — | (5) | (3) | ||||||||||||||||||||||||
| Exclude tax effect of adjustment | (1,087) | (81) | (133) | (1,438) | (816) | ||||||||||||||||||||||||
| Exclude tax expense related to BOLI restructuring | — | — | — | 515 | — | ||||||||||||||||||||||||
Adjusted net income (non-GAAP) | $ | 23,038 | $ | 22,541 | $ | 19,671 | $ | 18,141 | $ | 16,979 | |||||||||||||||||||
| Average number of diluted shares outstanding | 39,104,569 | 34,405,793 | 34,413,386 | 34,446,710 | 34,506,238 | ||||||||||||||||||||||||
| Diluted earnings per share (GAAP) | $ | 0.48 | $ | 0.65 | $ | 0.55 | $ | 0.36 | $ | 0.40 | |||||||||||||||||||
| Adjusted diluted earnings per share (non-GAAP) | $ | 0.59 | $ | 0.66 | $ | 0.56 | $ | 0.53 | $ | 0.49 | |||||||||||||||||||
18
HERITAGE FINANCIAL CORPORATION
NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share amounts)
The Company considers the tangible common equity to tangible assets ratio and tangible book value per share to be useful measurements of the adequacy of the Company’s capital levels.
| March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
| Tangible Common Equity to Tangible Assets and Tangible Book Value Per Share: | |||||||||||||||||||||||||||||
| Total stockholders' equity (GAAP) | $ | 1,115,691 | $ | 921,504 | $ | 904,064 | $ | 888,212 | $ | 881,515 | |||||||||||||||||||
| Exclude intangible assets | (329,255) | (242,918) | (243,203) | (243,487) | (243,789) | ||||||||||||||||||||||||
| Tangible common equity (non-GAAP) | $ | 786,436 | $ | 678,586 | $ | 660,861 | $ | 644,725 | $ | 637,726 | |||||||||||||||||||
| Total assets (GAAP) | $ | 8,498,404 | $ | 6,967,350 | $ | 7,011,879 | $ | 7,070,641 | $ | 7,129,862 | |||||||||||||||||||
| Exclude intangible assets | (329,255) | (242,918) | (243,203) | (243,487) | (243,789) | ||||||||||||||||||||||||
| Tangible assets (non-GAAP) | $ | 8,169,149 | $ | 6,724,432 | $ | 6,768,676 | $ | 6,827,154 | $ | 6,886,073 | |||||||||||||||||||
| Stockholders' equity to total assets (GAAP) | 13.1 | % | 13.2 | % | 12.9 | % | 12.6 | % | 12.4 | % | |||||||||||||||||||
Tangible common equity to tangible assets (non-GAAP) | 9.6 | % | 10.1 | % | 9.8 | % | 9.4 | % | 9.3 | % | |||||||||||||||||||
| Shares outstanding | 41,249,873 | 33,963,500 | 33,956,738 | 33,953,194 | 34,105,516 | ||||||||||||||||||||||||
| Book value per share (GAAP) | $ | 27.05 | $ | 27.13 | $ | 26.62 | $ | 26.16 | $ | 25.85 | |||||||||||||||||||
| Tangible book value per share (non-GAAP) | $ | 19.07 | $ | 19.98 | $ | 19.46 | $ | 18.99 | $ | 18.70 | |||||||||||||||||||
19
HERITAGE FINANCIAL CORPORATION
NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share amounts)
The Company considers the return on average tangible common equity ratio to be a useful measurement of the Company’s ability to generate returns for its common shareholders. By removing the impact of intangible assets and their related amortization and tax effects, the performance of the Company's ongoing business operations can be evaluated. The Company believes that presenting an adjusted return on tangible common equity ratio provides useful and comparative information to assess trends in the Company's core operations reflected in the current quarter’s results and facilitate the comparison of our performance with the performance of our peers.
| Quarter Ended | |||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
| Return on Average Tangible Common Equity, annualized: | |||||||||||||||||||||||||||||
| Net income (GAAP) | $ | 18,947 | $ | 22,237 | $ | 19,169 | $ | 12,215 | $ | 13,911 | |||||||||||||||||||
| Add amortization of intangible assets | 2,058 | 285 | 284 | 302 | 303 | ||||||||||||||||||||||||
| Exclude tax effect of adjustment | (432) | (60) | (60) | (63) | (64) | ||||||||||||||||||||||||
| Tangible net income (non-GAAP) | $ | 20,573 | $ | 22,462 | $ | 19,393 | $ | 12,454 | $ | 14,150 | |||||||||||||||||||
| Tangible net income (non-GAAP) | $ | 20,573 | $ | 22,462 | $ | 19,393 | $ | 12,454 | $ | 14,150 | |||||||||||||||||||
Exclude loss on sale of investment securities, net | — | — | — | 6,854 | 3,887 | ||||||||||||||||||||||||
| Exclude merger related costs | 5,178 | 385 | 635 | — | — | ||||||||||||||||||||||||
| Exclude gain on sale of premises and equipment | — | — | — | (5) | (3) | ||||||||||||||||||||||||
| Exclude tax effect of adjustment | (1,087) | (81) | (133) | (1,438) | (816) | ||||||||||||||||||||||||
| Exclude tax expense related to BOLI restructuring | — | — | — | 515 | — | ||||||||||||||||||||||||
| Adjusted tangible net income (non-GAAP) | $ | 24,664 | $ | 22,766 | $ | 19,895 | $ | 18,380 | $ | 17,218 | |||||||||||||||||||
| Average stockholders' equity (GAAP) | $ | 1,049,044 | $ | 911,454 | $ | 892,280 | $ | 879,808 | $ | 866,629 | |||||||||||||||||||
| Exclude average intangible assets | (300,391) | (243,069) | (243,350) | (243,651) | (243,945) | ||||||||||||||||||||||||
| Average tangible common stockholders' equity (non-GAAP) | $ | 748,653 | $ | 668,385 | $ | 648,930 | $ | 636,157 | $ | 622,684 | |||||||||||||||||||
| Return on average common equity, annualized (GAAP) | 7.32 | % | 9.68 | % | 8.52 | % | 5.57 | % | 6.51 | % | |||||||||||||||||||
| Return on average tangible common equity, annualized (non-GAAP) | 11.14 | % | 13.33 | % | 11.86 | % | 7.85 | % | 9.22 | % | |||||||||||||||||||
| Adjusted return on average tangible common equity, annualized (non-GAAP) | 13.36 | % | 13.51 | % | 12.16 | % | 11.59 | % | 11.21 | % | |||||||||||||||||||
20
HERITAGE FINANCIAL CORPORATION
NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share amounts)
The Company believes that presenting an adjusted efficiency ratio and adjusted noninterest expense to average assets ratio provides useful and comparative information to assess trends in the Company's core operations reflected in the current quarter’s results and facilitate the comparison of our performance with the performance of our peers.
| Quarter Ended | |||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | September 30, 2025 | June 30, 2025 | March 31, 2025 | |||||||||||||||||||||||||
Adjusted Efficiency Ratio and Adjusted Noninterest Expense to Average Assets Ratio: | |||||||||||||||||||||||||||||
| Total noninterest expense (GAAP) | $ | 56,551 | $ | 41,483 | $ | 41,615 | $ | 41,085 | $ | 41,383 | |||||||||||||||||||
Exclude Merger-related costs | 5,178 | 385 | 635 | — | — | ||||||||||||||||||||||||
| Exclude amortization of intangible assets | 2,058 | 285 | 284 | 302 | 303 | ||||||||||||||||||||||||
| Adjusted noninterest expense (non-GAAP) | $ | 49,315 | $ | 40,813 | $ | 40,696 | $ | 40,783 | $ | 41,080 | |||||||||||||||||||
| Net interest income (GAAP) | $ | 69,219 | $ | 58,361 | $ | 57,371 | $ | 54,983 | $ | 53,690 | |||||||||||||||||||
| Total noninterest income (GAAP) | $ | 8,699 | $ | 7,987 | $ | 8,325 | $ | 1,517 | $ | 3,903 | |||||||||||||||||||
Exclude loss on sale of investment securities, net | — | — | — | 6,854 | 3,887 | ||||||||||||||||||||||||
Exclude gain on sale of premises and equipment | — | — | — | (5) | (3) | ||||||||||||||||||||||||
| Adjusted total noninterest income (non-GAAP) | $ | 8,699 | $ | 7,987 | $ | 8,325 | $ | 8,366 | $ | 7,787 | |||||||||||||||||||
| Efficiency ratio (GAAP) | 72.6 | % | 62.5 | % | 63.3 | % | 72.7 | % | 71.9 | % | |||||||||||||||||||
| Adjusted efficiency ratio (non-GAAP) | 63.3 | % | 61.5 | % | 61.9 | % | 64.4 | % | 66.8 | % | |||||||||||||||||||
| Average Total assets | $ | 7,935,002 | $ | 6,954,110 | $ | 7,006,140 | $ | 7,046,943 | $ | 7,103,227 | |||||||||||||||||||
| Noninterest expense to average assets (GAAP) | 2.89 | % | 2.37 | % | 2.36 | % | 2.34 | % | 2.36 | % | |||||||||||||||||||
| Adjusted noninterest expense to average assets (non-GAAP) | 2.52 | % | 2.33 | % | 2.30 | % | 2.32 | % | 2.35 | % | |||||||||||||||||||
21
HERITAGE FINANCIAL CORPORATION
NON-GAAP FINANCIAL MEASURES (Unaudited)
(Dollars in thousands, except per share amounts)
The Company believes presenting loan yield and net interest margin excluding the effect of discount accretion on purchased loans is useful in assessing the impact of acquisition accounting on loan yield as the effect of loan discount accretion is expected to decrease as the acquired loans mature or roll off our balance sheet.
| Three Months Ended | |||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||
| (Dollar amounts in thousands) | |||||||||||||||||
| Loan yield, excluding incremental accretion on purchased loans, annualized: | |||||||||||||||||
| Interest and fees on loans (GAAP) | $ | 76,445 | $ | 66,669 | $ | 64,436 | |||||||||||
| Exclude incremental accretion on purchased loans | 1,623 | 49 | 153 | ||||||||||||||
| Adjusted interest and fees on loans (non-GAAP) | $ | 74,822 | $ | 66,620 | $ | 64,283 | |||||||||||
| Average loans receivable, net (GAAP) | $ | 5,412,943 | $ | 4,770,300 | $ | 4,793,917 | |||||||||||
| Loan yield, annualized (GAAP) | 5.73 | % | 5.54 | % | 5.45 | % | |||||||||||
Loan yield, excluding incremental accretion on purchased loans, annualized (non-GAAP) | 5.61 | % | 5.54 | % | 5.44 | % | |||||||||||
| Net Interest Margin, excluding incremental accretion on purchased loans, annualized: | |||||||||||||||||
| Net interest income before provision (GAAP) | $ | 69,219 | $ | 58,361 | $ | 53,690 | |||||||||||
| Exclude incremental accretion on purchased loans | 1,623 | 49 | 153 | ||||||||||||||
| Adjusted net interest income before provision (non-GAAP) | $ | 67,596 | $ | 58,312 | $ | 53,537 | |||||||||||
| Average Interest earning assets (GAAP) | $ | 7,087,671 | $ | 6,223,303 | $ | 6,333,697 | |||||||||||
| Net interest margin (GAAP) | 3.96 | % | 3.72 | % | 3.44 | % | |||||||||||
| Net interest margin, excluding incremental accretion on purchased loans (non-GAAP) | 3.87 | % | 3.72 | % | 3.43 | % | |||||||||||
22
INVESTOR PRESENTATION Q1 2026
2 FORWARD LOOKING STATEMENTS This press release includes "forward-looking statements" within the meaning of Section 27A of the Securities Act of 1933, as amended, and Section 21E of the Securities Exchange Act of 1934, as amended. Heritage Financial Corporation (the" Company") intends such forward-looking statements to be covered by the safe harbor provisions for forward-looking statements contained in the Private Securities Litigation Reform Act of 1995. Such statements often include words such as "believes," "expects," "anticipates," "estimates," “forecasts,” "intends," “plans,” “targets,” “potentially,” “probably,” “projects,” “outlook” or similar expressions or future or conditional verbs such as “may,” "will," “should,” "would," and "could," as well as the negative of such words. Forward-looking statements are not historical facts but instead represent management's current expectations and forecasts regarding future events, many of which are inherently uncertain and outside of our control. Actual results may differ, possibly materially, from those currently expected or projected in these forward-looking statements. These forward-looking statements are subject to known and unknown risks, uncertainties and other factors that could cause actual results to differ materially from the results anticipated or implied by forward-looking statements. Factors that could cause our actual results to differ materially from those described in the forward-looking statements include, but are not limited to, the following: • potential adverse impacts to economic conditions nationally or in our local market areas, other markets where we have lending relationships, or other aspects of our business operations or financial markets, including, without limitation, as a result of credit quality deterioration, pronounced and sustained reductions in real estate market values, employment levels, labor shortages and a potential recession or slowed economic growth; • changes in the interest rate environment, which could adversely affect our revenues and expenses, the value of assets and obligations, and the availability and cost of capital and liquidity; • the level and impact of inflation and the current and future monetary policies of the Board of Governors of the Federal Reserve System and executive orders in response thereto; • previous and potential future disruptions, security breaches, insider fraud, cybersecurity incidents or other adverse events, failures or interruptions in, or attacks on, our information technology systems or on the third-party vendors who perform critical processing functions for our business, including sophisticated attacks using artificial intelligence and similar tools; • legislative or regulatory changes that adversely affect our business, including changes in banking, securities, and tax laws, in regulatory policies and principles, or the interpretation and prioritization of such rules and regulations; • effects on the U.S. economy resulting from actions taken by the federal government, including the threat or implementation of tariffs, immigration enforcement and changes in foreign policy; • the effects of acts of war or terrorism, foreign relations, military conflicts, including the wars in Iran and Ukraine and the military conflict between Israel and Hamas in the Middle East, and other external events on our business and the businesses of our clients; • credit and interest rate risks associated with our business, including our customers’ borrowing, repayment, and deposit practices; • fluctuations in deposits and the concentration of large deposits from certain customers, who have deposit balances above current FDIC insurance limits; • liquidity issues, including our ability to borrow funds or raise additional capital, if necessary; • fluctuations in the value of our investment securities; • credit risks and risks from concentrations (including by type of geographic area, collateral and industry) within our loan portfolio; • the effectiveness of our risk management framework; • rapid technological changes implemented by us and other parties, including third-party vendors, which may be more difficult to implement or more expensive than anticipated or which may have unforeseen consequences to us and our customers, including the development and implementation of tools incorporating artificial intelligence; • increased competition in the financial services industry from non-banks such as credit unions and financial technology companies, including digital asset service providers; • our ability to adapt successfully to technological changes to compete effectively in the marketplace, including as a result of competition from other commercial banks, mortgage banking firms, credit unions, securities brokerage firms, insurance companies, and financial technology companies; • our ability to implement our organic and acquisition growth strategies, including the recent acquisition of Olympic Bancorp, Inc. ("Olympic"), and our ability to successfully integrate Olympic's customers and operations following the acquisition; • effects of critical accounting policies and judgments, including the use of estimates in determining fair value of certain of our assets, which estimates may prove to be incorrect and result in significant declines in valuation; • the commencement, costs, effects and outcome of litigation and other legal proceedings and regulatory actions against us or to which we may become subject, including in connection with prior acquisitions; • potential impairment to the goodwill we recorded in connection with our past acquisitions, including as a result of the recent acquisition of Olympic; • loss of, or inability to attract, key personnel; • our ability to successfully integrate any assets, liabilities, customers, systems, and management personnel we may acquire, including as a result of the recent acquisition of Olympic, into our operations and our ability to realize related revenue synergies and cost savings within expected time frames or at all, and any goodwill charges related thereto and costs or difficulties relating to integration matters, including but not limited to customer and employee retention, which might be greater than expected; • the effects of climate change, severe weather events, natural disasters, pandemics, epidemics and other public health crises; • the impact of bank failures or adverse developments at other banks and related negative publicity about the banking industry in general on investor and depositor sentiment regarding the stability and liquidity of banks; and • our success at managing and responding to the risks involved in the foregoing items. You should also consider the risks, assumptions and uncertainties set forth in the “Risk Factors” section in our Annual Report on Form 10-K for the year ended December 31, 2025, as well as those set forth in other reports we file with or furnish to the Securities and Exchange Commission (the “SEC”) which are available on our website at www.hf-wa.com and on the SEC's website at www.sec.gov. These risks, assumptions and uncertainties should be considered in evaluating any forward-looking statements, and undue reliance should not be placed on such statements. Any forward-looking statement speaks only as of the date on which it is made, and the Company undertakes no obligation to update any forward-looking statement, whether to reflect events or circumstances after the date on which the statement is made, to reflect new information or the occurrence of unanticipated events, or otherwise. Except as otherwise indicated, this presentation speaks as of March 31, 2026. The delivery of this presentation shall not, under any circumstances, create any implication that there has been no change in the affairs of the Company after such date. Certain of the information contained herein may be derived from information provided by industry sources. We believe that such information is accurate and that the sources from which it has been obtained are reliable. We cannot guarantee the accuracy of such information, however, and we have not independently verified such information. Non-GAAP Financial Information The Company reports its results in accordance with United States generally accepted accounting principles (“GAAP”). However, management believes that certain non-GAAP performance measures used in managing the business may provide meaningful information about underlying trends in its business. Non-GAAP financial measures should be viewed in addition to, and not as an alternative for, the Company’s reported results prepared in accordance with GAAP. Slides containing a discussion and reconciliation of non-GAAP financial measures are contained in the Appendix - Reconciliation of Non-GAAP Financial Measures and Quarterly Financial Statistics hereto. All dollars amounts presented throughout the entire presentation are in millions unless otherwise noted, except per share amounts. Percentages presented may not total 100% due to rounding. All tables and charts are as of March 31, 2026, unless otherwise indicated.
HERITAGE FINANCIAL CORPORATION OVERVIEW
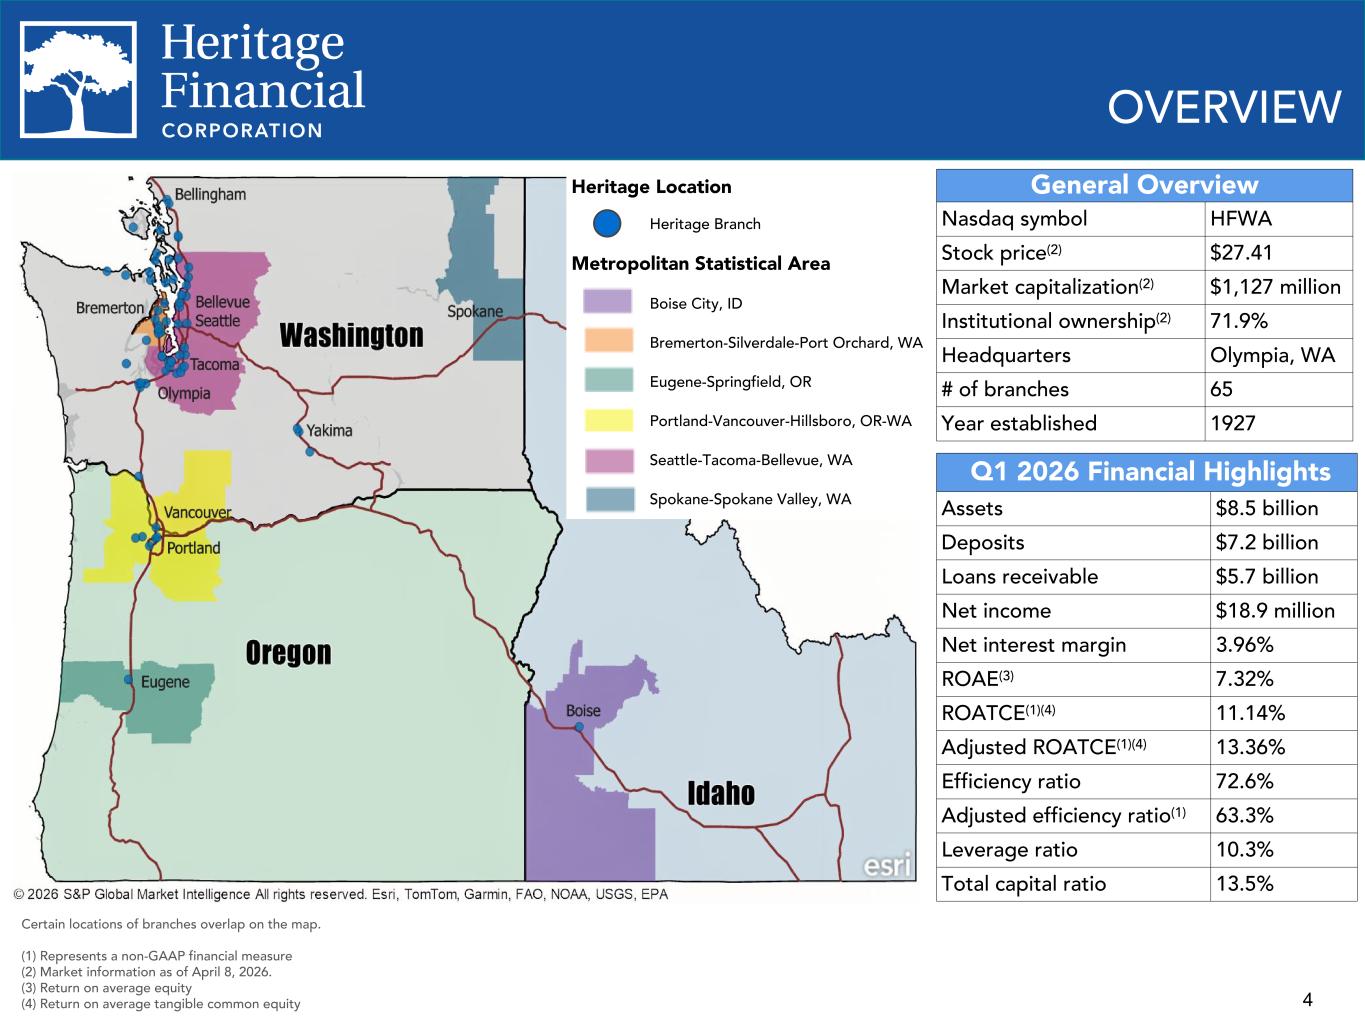
4 OVERVIEW General Overview Nasdaq symbol HFWA Stock price(2) $27.41 Market capitalization(2) $1,127 million Institutional ownership(2) 71.9% Headquarters Olympia, WA # of branches 65 Year established 1927 Q1 2026 Financial Highlights Assets $8.5 billion Deposits $7.2 billion Loans receivable $5.7 billion Net income $18.9 million Net interest margin 3.96% ROAE(3) 7.32% ROATCE(1)(4) 11.14% Adjusted ROATCE(1)(4) 13.36% Efficiency ratio 72.6% Adjusted efficiency ratio(1) 63.3% Leverage ratio 10.3% Total capital ratio 13.5% Certain locations of branches overlap on the map. (1) Represents a non-GAAP financial measure (2) Market information as of April 8, 2026. (3) Return on average equity (4) Return on average tangible common equity Metropolitan Statistical Areas Seattle-Tacoma-Bellevue, WA Portland-Vancouver-Hillsboro, OR-WA Eugene-Springfield, OR Boise–Nampa, ID Heritage Location Heritage Location Heritage Branch Metropolitan Statistical Area Boise City, ID Bremerton-Silverdale-Port Orchard, WA Eugene-Springfield, OR Portland-Vancouver-Hillsboro, OR-WA Seattle-Tacoma-Bellevue, WA Spokane-Spokane Valley, WA
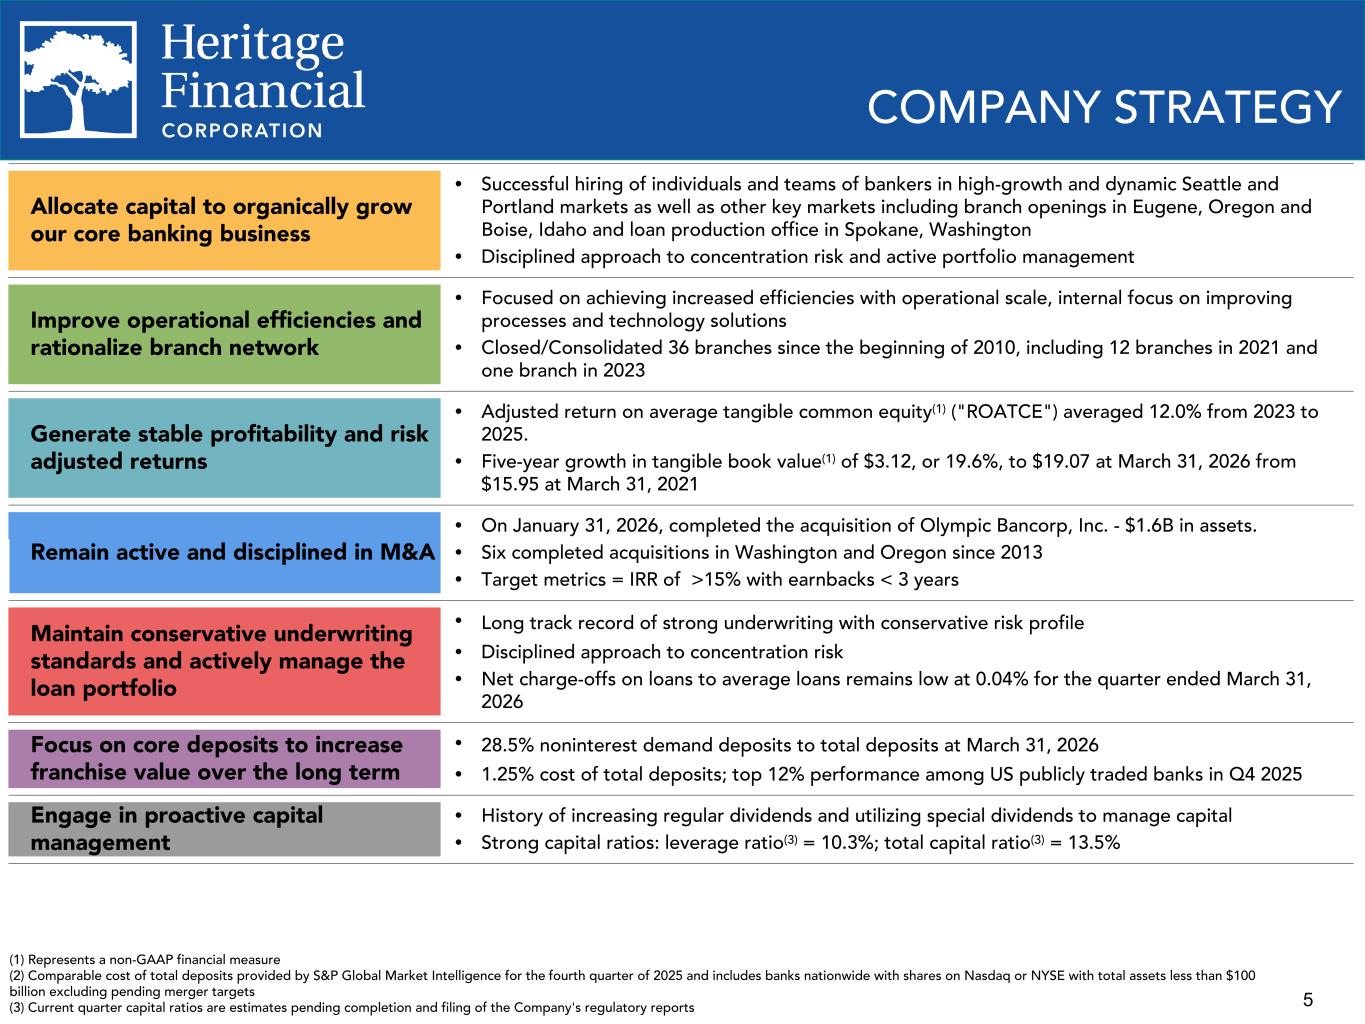
5 COMPANY STRATEGY Allocate capital to organically grow our core banking business Ÿ Successful hiring of individuals and teams of bankers in high-growth and dynamic Seattle and Portland markets as well as other key markets including branch openings in Eugene, Oregon and Boise, Idaho and loan production office in Spokane, Washington Ÿ Disciplined approach to concentration risk and active portfolio management Improve operational efficiencies and rationalize branch network Ÿ Focused on achieving increased efficiencies with operational scale, internal focus on improving processes and technology solutions Ÿ Closed/Consolidated 36 branches since the beginning of 2010, including 12 branches in 2021 and one branch in 2023 Generate stable profitability and risk adjusted returns Ÿ Adjusted return on average tangible common equity(1) ("ROATCE") averaged 12.0% from 2023 to 2025. Ÿ Five-year growth in tangible book value(1) of $3.12, or 19.6%, to $19.07 at March 31, 2026 from $15.95 at March 31, 2021 Remain active and disciplined in M&A Ÿ On January 31, 2026, completed the acquisition of Olympic Bancorp, Inc. - $1.6B in assets. Ÿ Six completed acquisitions in Washington and Oregon since 2013 Ÿ Target metrics = IRR of >15% with earnbacks < 3 years Maintain conservative underwriting standards and actively manage the loan portfolio Ÿ Long track record of strong underwriting with conservative risk profile Ÿ Disciplined approach to concentration risk Ÿ Net charge-offs on loans to average loans remains low at 0.04% for the quarter ended March 31, 2026 Focus on core deposits to increase franchise value over the long term Ÿ 28.5% noninterest demand deposits to total deposits at March 31, 2026 Ÿ 1.25% cost of total deposits; top 12% performance among US publicly traded banks in Q4 2025 Engage in proactive capital management Ÿ History of increasing regular dividends and utilizing special dividends to manage capital Ÿ Strong capital ratios: leverage ratio(3) = 10.3%; total capital ratio(3) = 13.5% (1) Represents a non-GAAP financial measure (2) Comparable cost of total deposits provided by S&P Global Market Intelligence for the fourth quarter of 2025 and includes banks nationwide with shares on Nasdaq or NYSE with total assets less than $100 billion excluding pending merger targets (3) Current quarter capital ratios are estimates pending completion and filing of the Company's regulatory reports
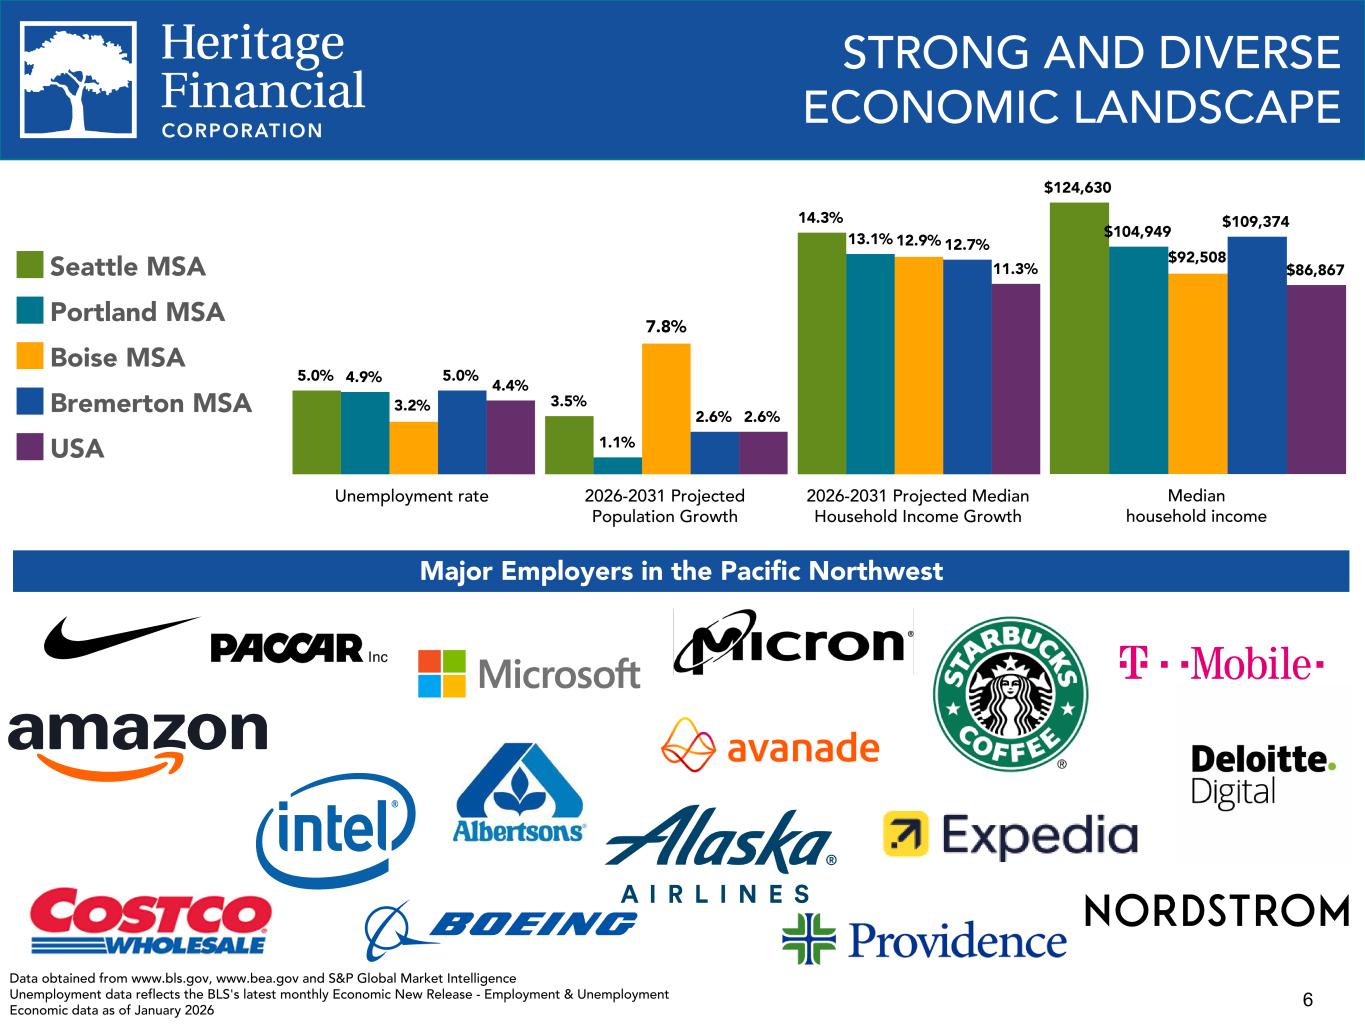
6 $124,630 $104,949 $92,508 $109,374 $86,867 Median household income 5.0% 3.5% 14.3% 4.9% 1.1% 13.1% 3.2% 7.8% 12.9% 5.0% 2.6% 12.7% 4.4% 2.6% 11.3%Seattle MSA Portland MSA Boise MSA Bremerton MSA USA Unemployment rate 2026-2031 Projected Population Growth 2026-2031 Projected Median Household Income Growth STRONG AND DIVERSE ECONOMIC LANDSCAPE Major Employers in the Pacific Northwest Data obtained from www.bls.gov, www.bea.gov and S&P Global Market Intelligence Unemployment data reflects the BLS's latest monthly Economic New Release - Employment & Unemployment Economic data as of January 2026 MSA Tie-out of websites used: https://www.bls.gov/web/metro/laulrgma.htm https://www.bls.gov/web/laus/laumstcm.htm https://data.bls.gov/timeseries/LNS14000000 https://www.zippia.com/advice/largest-companies-in-washington/https://www.zippia.com/advice/largest-companies-in-oregon/
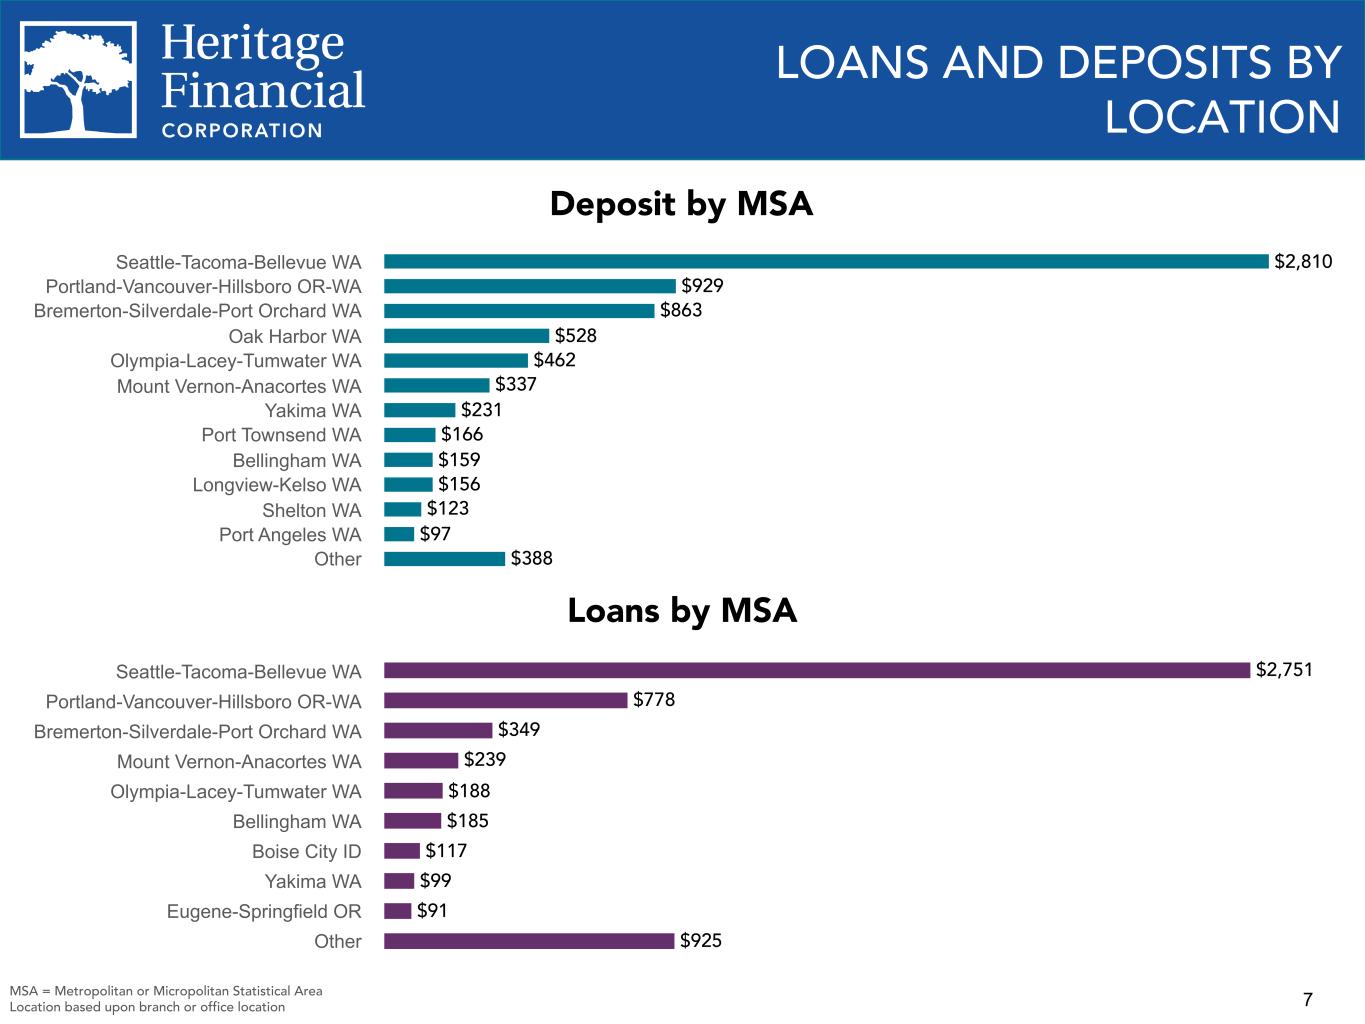
7 LOANS AND DEPOSITS BY LOCATION MSA = Metropolitan or Micropolitan Statistical Area Location based upon branch or office location Deposit by MSA $2,810 $929 $863 $528 $462 $337 $231 $166 $159 $156 $123 $97 $388 Seattle-Tacoma-Bellevue WA Portland-Vancouver-Hillsboro OR-WA Bremerton-Silverdale-Port Orchard WA Oak Harbor WA Olympia-Lacey-Tumwater WA Mount Vernon-Anacortes WA Yakima WA Port Townsend WA Bellingham WA Longview-Kelso WA Shelton WA Port Angeles WA Other Loans by MSA $2,751 $778 $349 $239 $188 $185 $117 $99 $91 $925 Seattle-Tacoma-Bellevue WA Portland-Vancouver-Hillsboro OR-WA Bremerton-Silverdale-Port Orchard WA Mount Vernon-Anacortes WA Olympia-Lacey-Tumwater WA Bellingham WA Boise City ID Yakima WA Eugene-Springfield OR Other
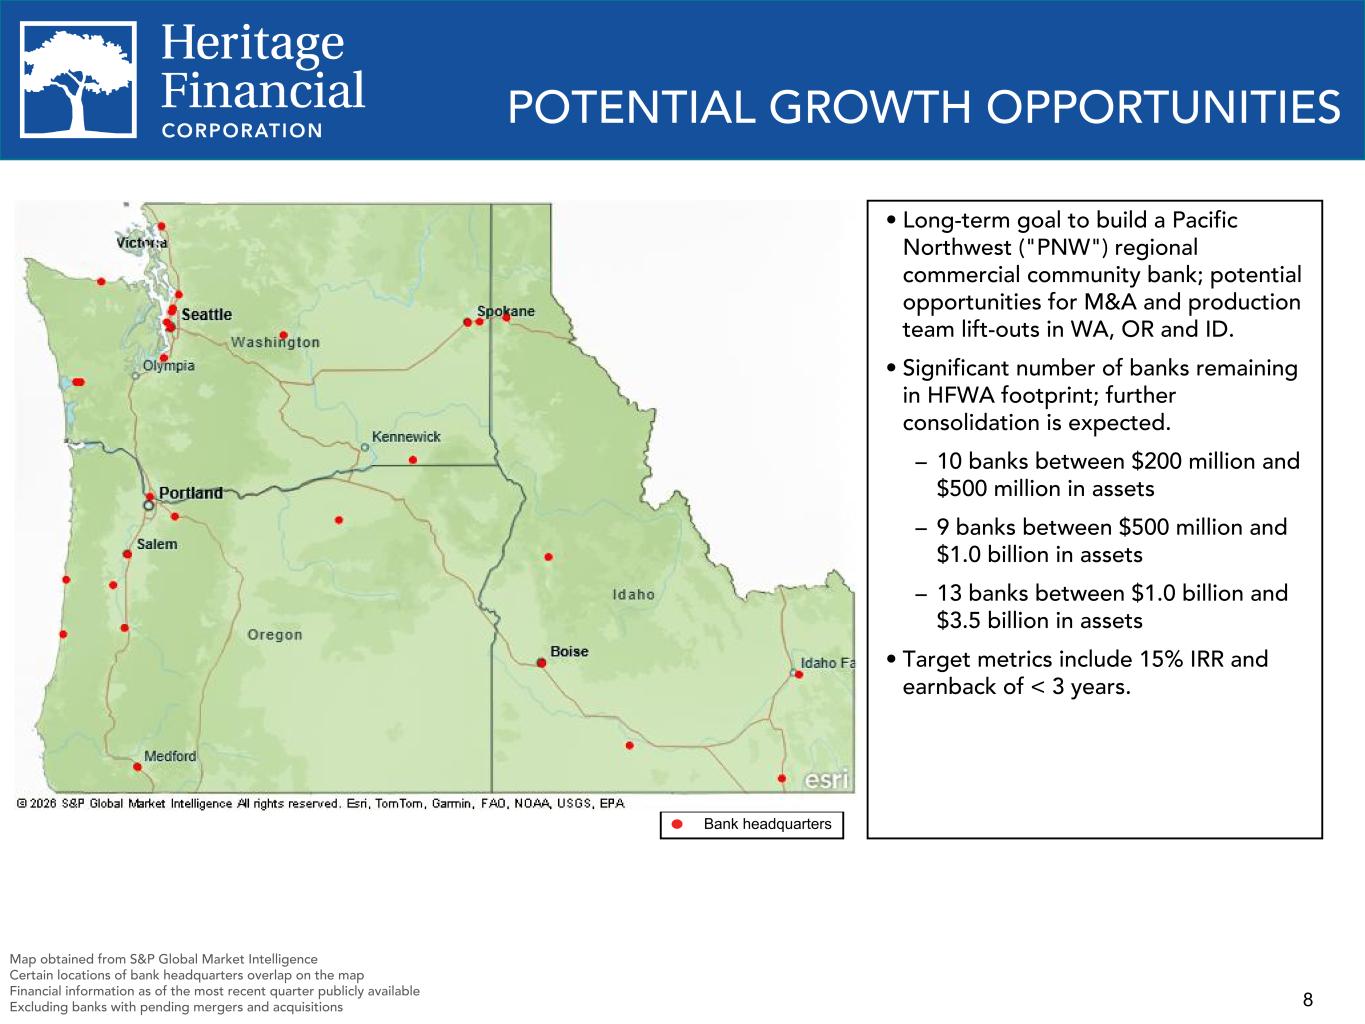
8 POTENTIAL GROWTH OPPORTUNITIES Map obtained from S&P Global Market Intelligence Certain locations of bank headquarters overlap on the map Financial information as of the most recent quarter publicly available Excluding banks with pending mergers and acquisitions • Long-term goal to build a Pacific Northwest ("PNW") regional commercial community bank; potential opportunities for M&A and production team lift-outs in WA, OR and ID. • Significant number of banks remaining in HFWA footprint; further consolidation is expected. – 10 banks between $200 million and $500 million in assets – 9 banks between $500 million and $1.0 billion in assets – 13 banks between $1.0 billion and $3.5 billion in assets • Target metrics include 15% IRR and earnback of < 3 years. Bank headquarters
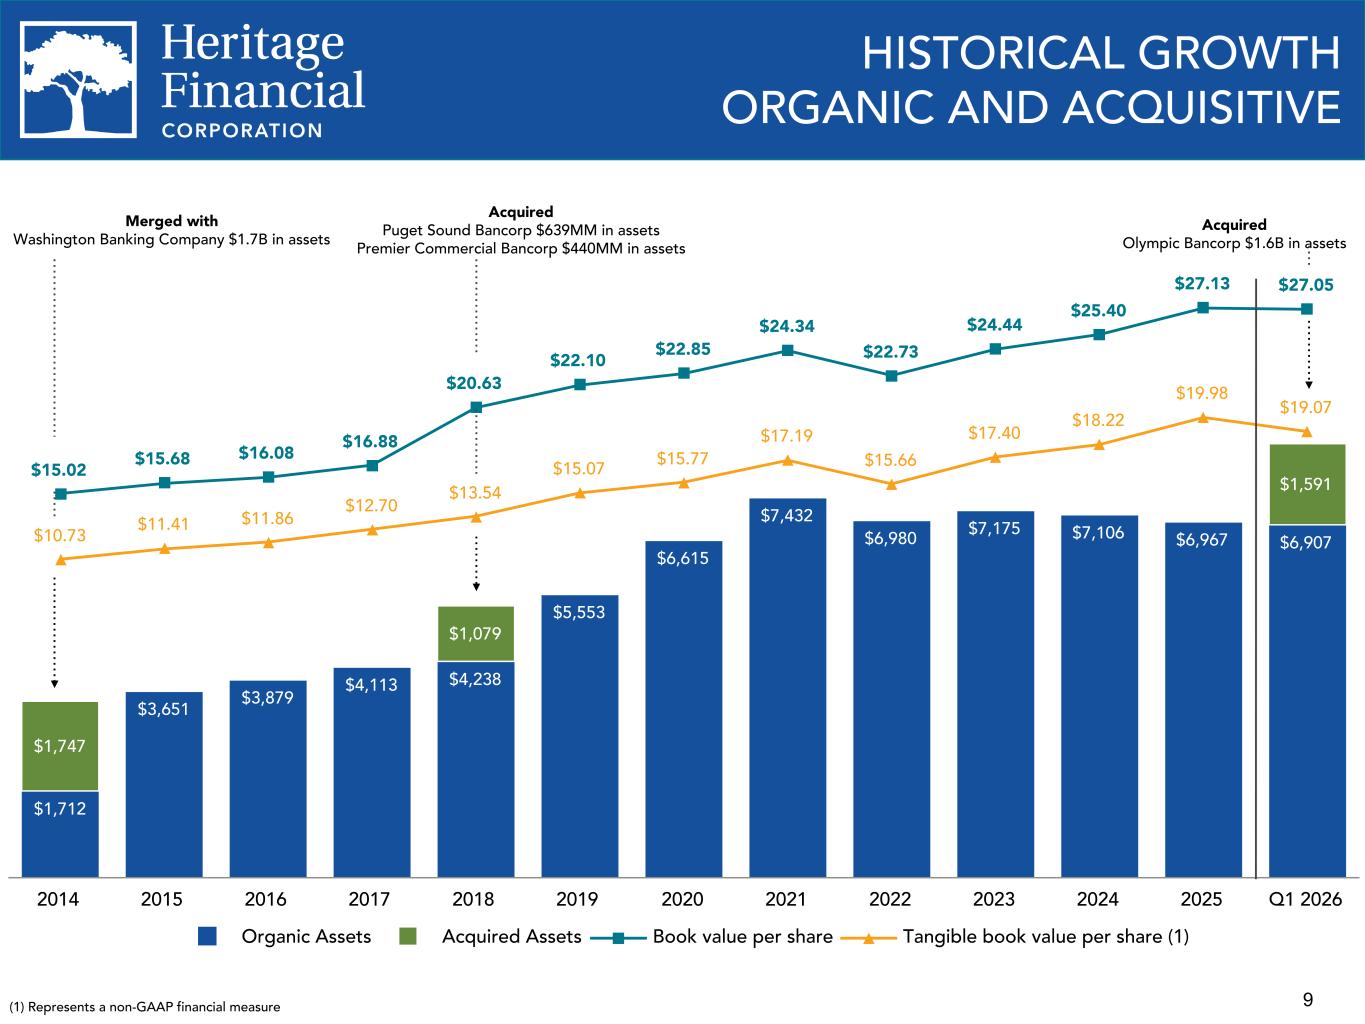
9 $1,712 $3,651 $3,879 $4,113 $4,238 $5,553 $6,615 $7,432 $6,980 $7,175 $7,106 $6,967 $6,907 $1,747 $1,079 $1,591 $15.02 $15.68 $16.08 $16.88 $20.63 $22.10 $22.85 $24.34 $22.73 $24.44 $25.40 $27.13 $27.05 $10.73 $11.41 $11.86 $12.70 $13.54 $15.07 $15.77 $17.19 $15.66 $17.40 $18.22 $19.98 $19.07 Organic Assets Acquired Assets Book value per share Tangible book value per share (1) 2014 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 2025 Q1 2026 Acquired Puget Sound Bancorp $639MM in assets Premier Commercial Bancorp $440MM in assets HISTORICAL GROWTH ORGANIC AND ACQUISITIVE Merged with Washington Banking Company $1.7B in assets (1) Represents a non-GAAP financial measure Acquired Olympic Bancorp $1.6B in assets
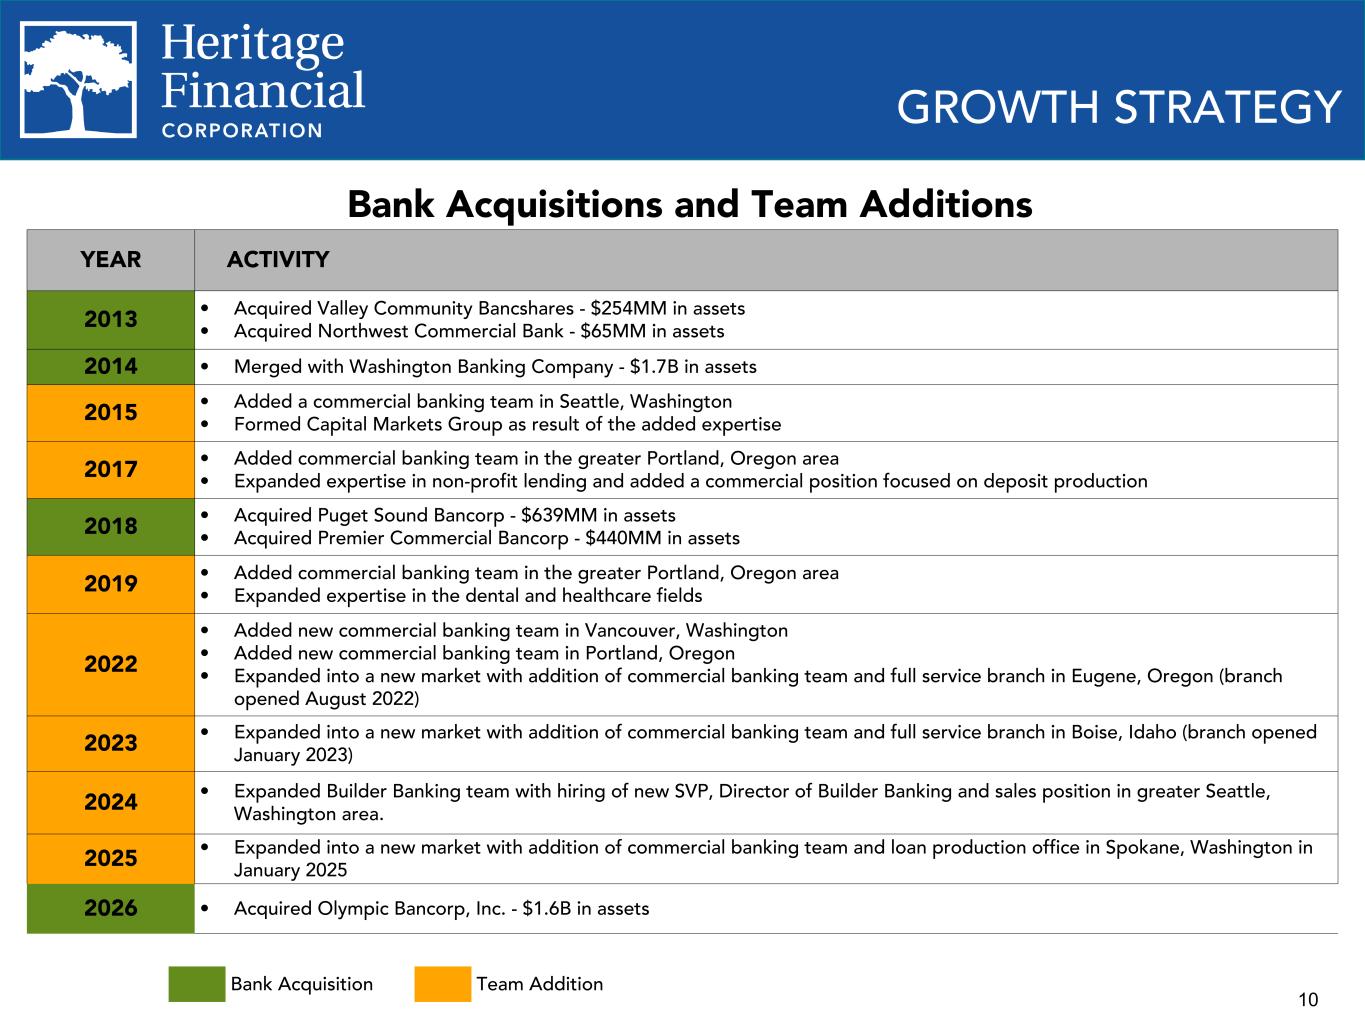
10 GROWTH STRATEGY YEAR ACTIVITY 2013 • Acquired Valley Community Bancshares - $254MM in assets • Acquired Northwest Commercial Bank - $65MM in assets 2014 • Merged with Washington Banking Company - $1.7B in assets 2015 • Added a commercial banking team in Seattle, Washington • Formed Capital Markets Group as result of the added expertise 2017 • Added commercial banking team in the greater Portland, Oregon area • Expanded expertise in non-profit lending and added a commercial position focused on deposit production 2018 • Acquired Puget Sound Bancorp - $639MM in assets • Acquired Premier Commercial Bancorp - $440MM in assets 2019 • Added commercial banking team in the greater Portland, Oregon area • Expanded expertise in the dental and healthcare fields 2022 • Added new commercial banking team in Vancouver, Washington • Added new commercial banking team in Portland, Oregon • Expanded into a new market with addition of commercial banking team and full service branch in Eugene, Oregon (branch opened August 2022) 2023 • Expanded into a new market with addition of commercial banking team and full service branch in Boise, Idaho (branch opened January 2023) 2024 • Expanded Builder Banking team with hiring of new SVP, Director of Builder Banking and sales position in greater Seattle, Washington area. 2025 • Expanded into a new market with addition of commercial banking team and loan production office in Spokane, Washington in January 2025 2026 • Acquired Olympic Bancorp, Inc. - $1.6B in assets Bank Acquisitions and Team Additions Bank Acquisition Team Addition
FINANCIAL UPDATE
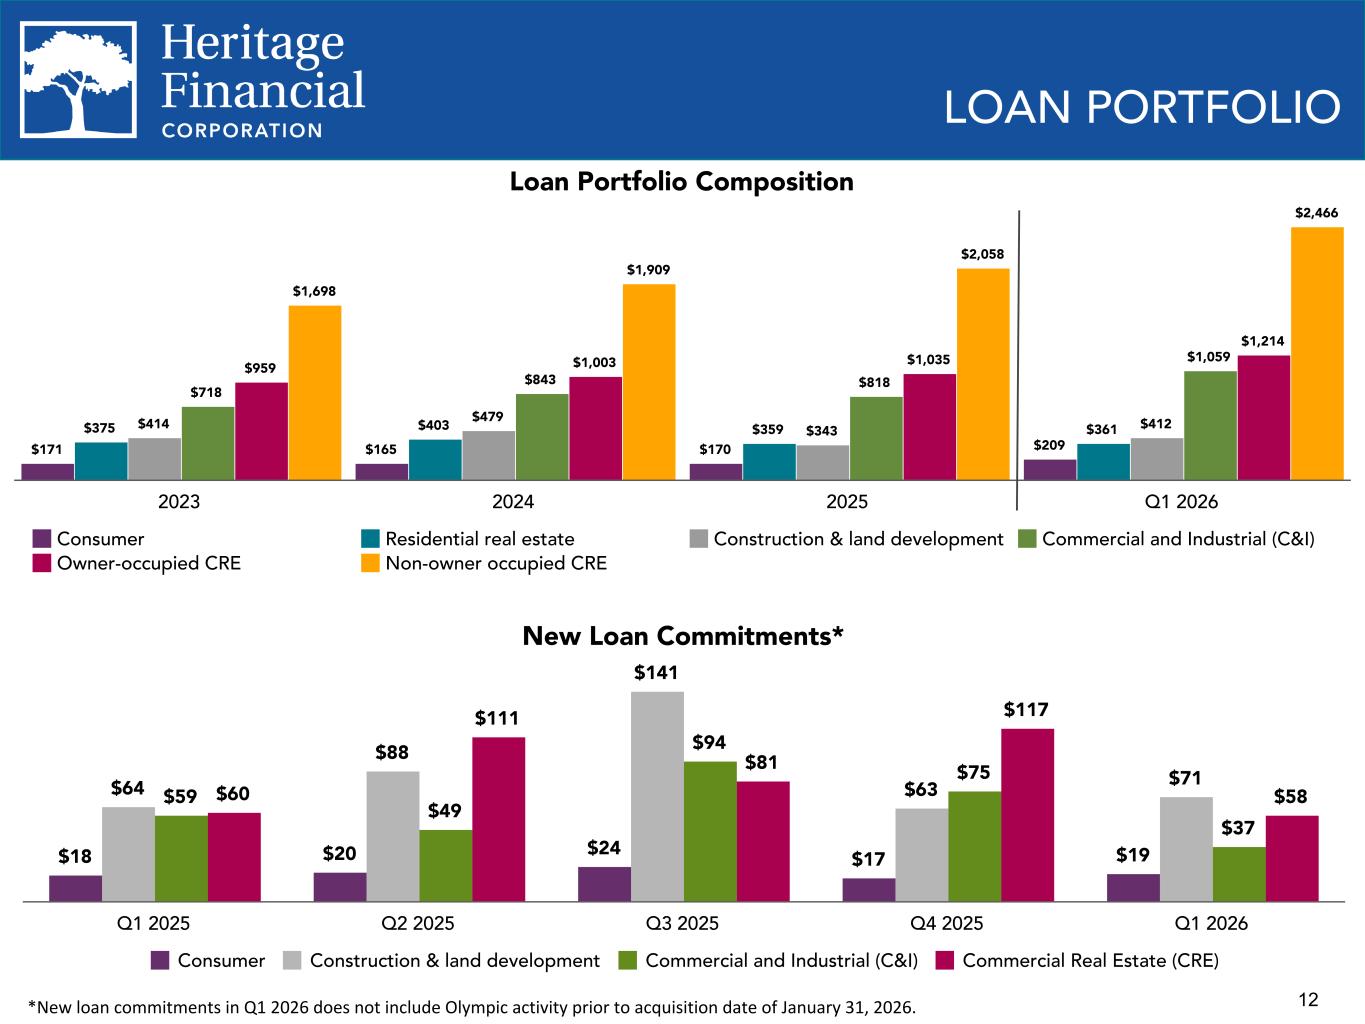
12 LOAN PORTFOLIO Loan Portfolio Composition $171 $165 $170 $209 $375 $403 $359 $361$414 $479 $343 $412 $718 $843 $818 $1,059 $959 $1,003 $1,035 $1,214 $1,698 $1,909 $2,058 $2,466 Consumer Residential real estate Construction & land development Commercial and Industrial (C&I) Owner-occupied CRE Non-owner occupied CRE 2023 2024 2025 Q1 2026 New Loan Commitments* $18 $20 $24 $17 $19 $64 $88 $141 $63 $71 $59 $49 $94 $75 $37 $60 $111 $81 $117 $58 Consumer Construction & land development Commercial and Industrial (C&I) Commercial Real Estate (CRE) Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 *New loan commitments in Q1 2026 does not include Olympic activity prior to acquisition date of January 31, 2026.
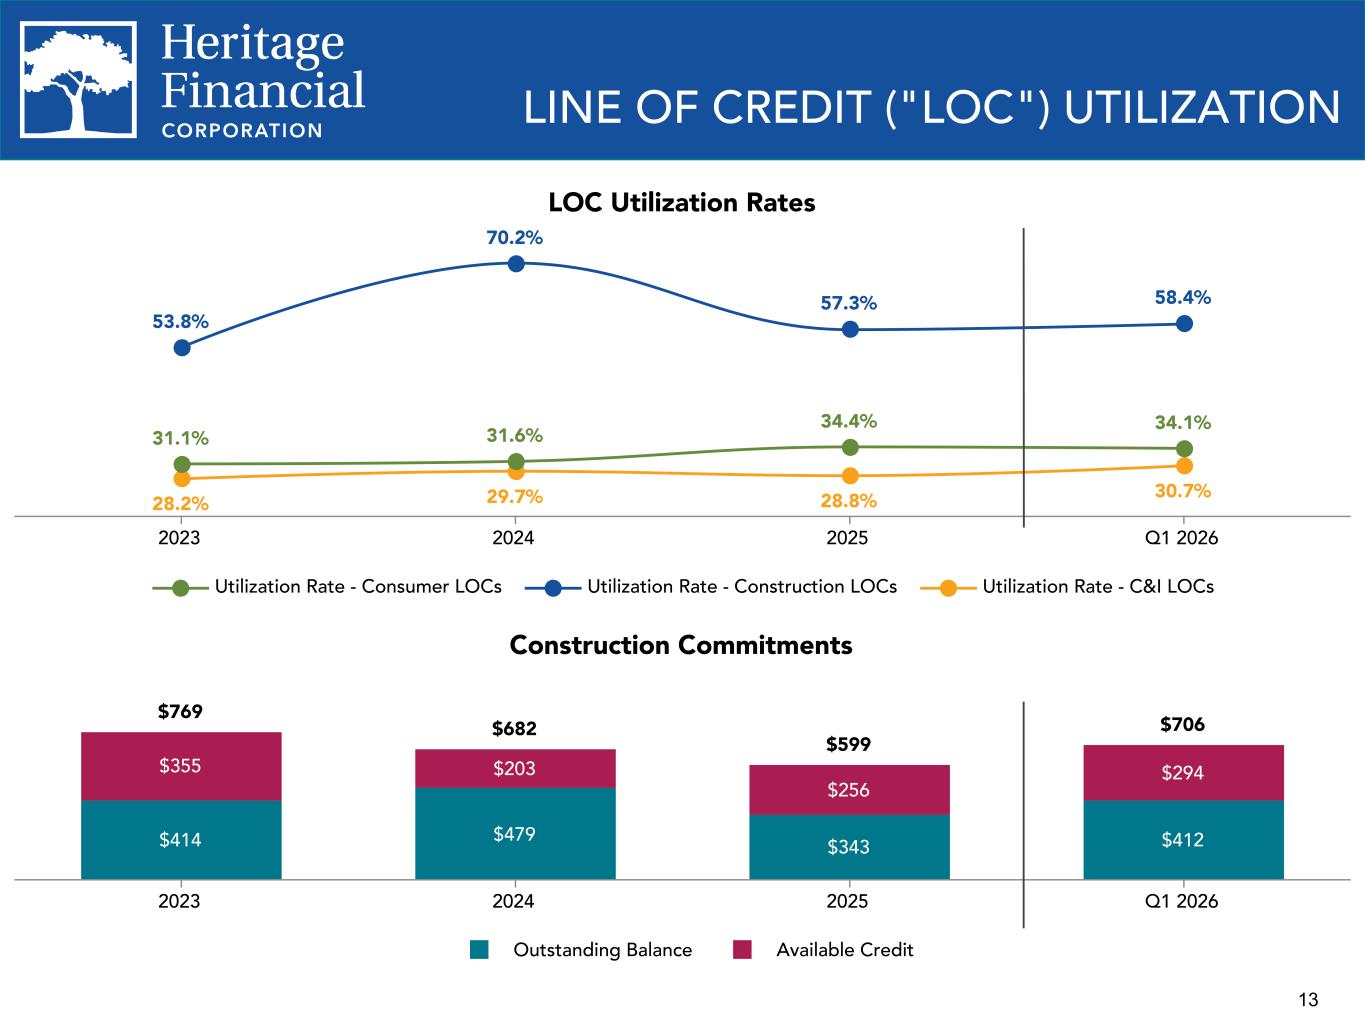
13 LOC Utilization Rates 28.2% 29.7% 28.8% 30.7% 53.8% 70.2% 57.3% 58.4% 31.1% 31.6% 34.4% 34.1% Utilization Rate - Consumer LOCs Utilization Rate - Construction LOCs Utilization Rate - C&I LOCs 2023 2024 2025 Q1 2026 Construction Commitments $769 $682 $599 $706 $414 $479 $343 $412 $355 $203 $256 $294 Outstanding Balance Available Credit 2023 2024 2025 Q1 2026 LINE OF CREDIT ("LOC") UTILIZATION
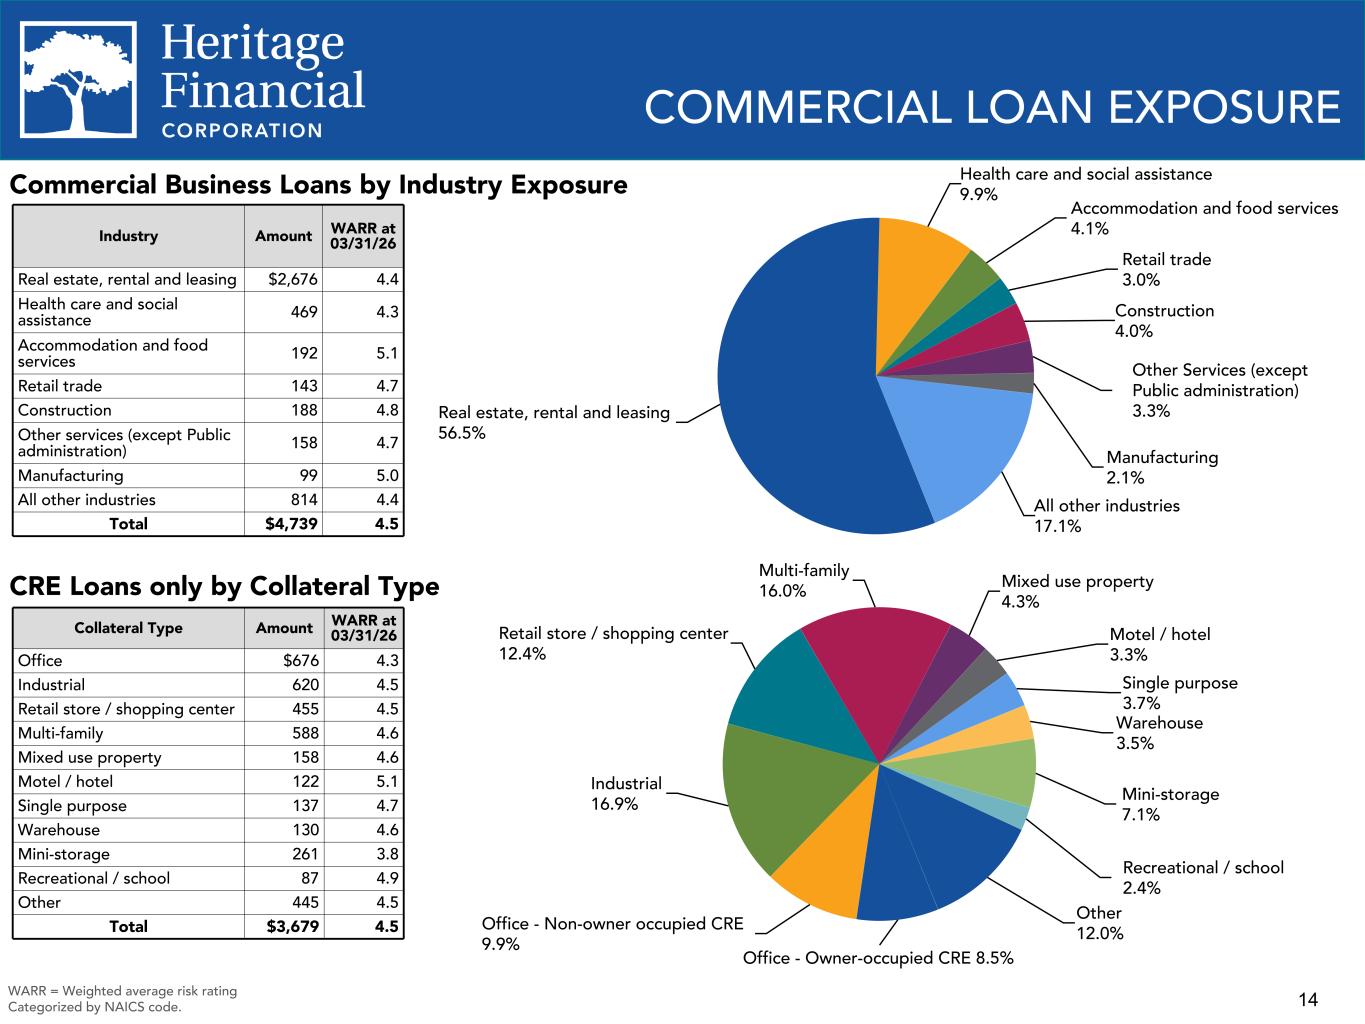
14 COMMERCIAL LOAN EXPOSURE Commercial Business Loans by Industry Exposure Industry Amount WARR at 03/31/26 Real estate, rental and leasing $2,676 4.4 Health care and social assistance 469 4.3 Accommodation and food services 192 5.1 Retail trade 143 4.7 Construction 188 4.8 Other services (except Public administration) 158 4.7 Manufacturing 99 5.0 All other industries 814 4.4 Total $4,739 4.5 CRE Loans only by Collateral Type Collateral Type Amount WARR at 03/31/26 Office $676 4.3 Industrial 620 4.5 Retail store / shopping center 455 4.5 Multi-family 588 4.6 Mixed use property 158 4.6 Motel / hotel 122 5.1 Single purpose 137 4.7 Warehouse 130 4.6 Mini-storage 261 3.8 Recreational / school 87 4.9 Other 445 4.5 Total $3,679 4.5 WARR = Weighted average risk rating Categorized by NAICS code. Office - Owner-occupied CRE 8.5% Office - Non-owner occupied CRE 9.9% Industrial 16.9% Retail store / shopping center 12.4% Multi-family 16.0% Mixed use property 4.3% Motel / hotel 3.3% Single purpose 3.7% Warehouse 3.5% Mini-storage 7.1% Recreational / school 2.4% Other 12.0% Real estate, rental and leasing 56.5% Health care and social assistance 9.9% Accommodation and food services 4.1% Retail trade 3.0% Construction 4.0% Other Services (except Public administration) 3.3% Manufacturing 2.1% All other industries 17.1%
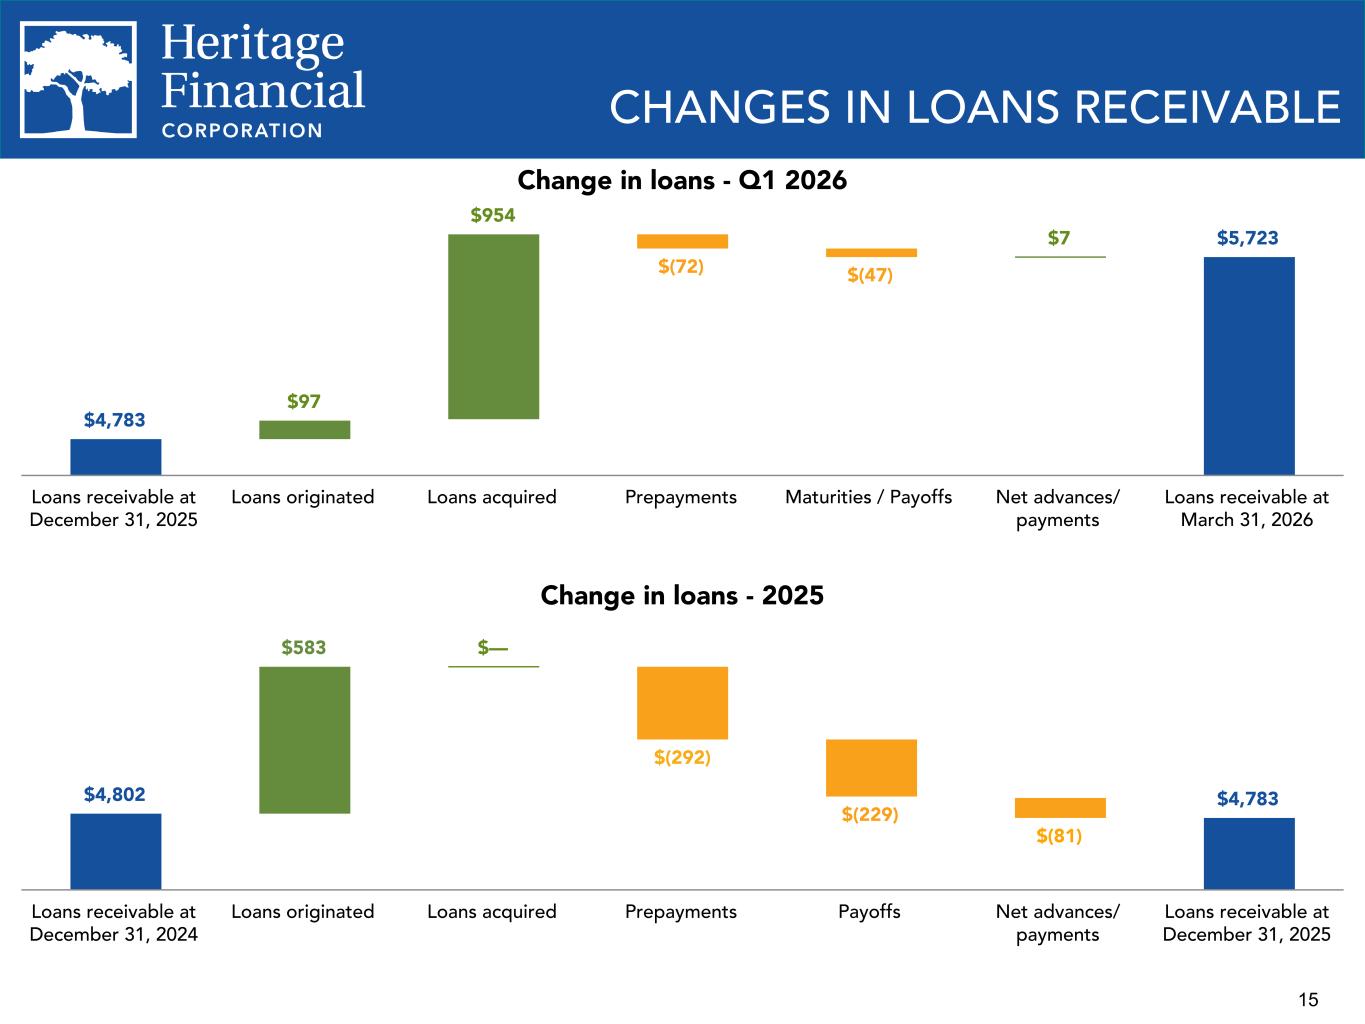
15 CHANGES IN LOANS RECEIVABLE $4,783 $97 $954 $(72) $(47) $7 $5,723 Loans receivable at December 31, 2025 Loans originated Loans acquired Prepayments Maturities / Payoffs Net advances/ payments Loans receivable at March 31, 2026 $4,802 $583 $— $(292) $(229) $(81) $4,783 Loans receivable at December 31, 2024 Loans originated Loans acquired Prepayments Payoffs Net advances/ payments Loans receivable at December 31, 2025 Change in loans - Q1 2026 Change in loans - 2025
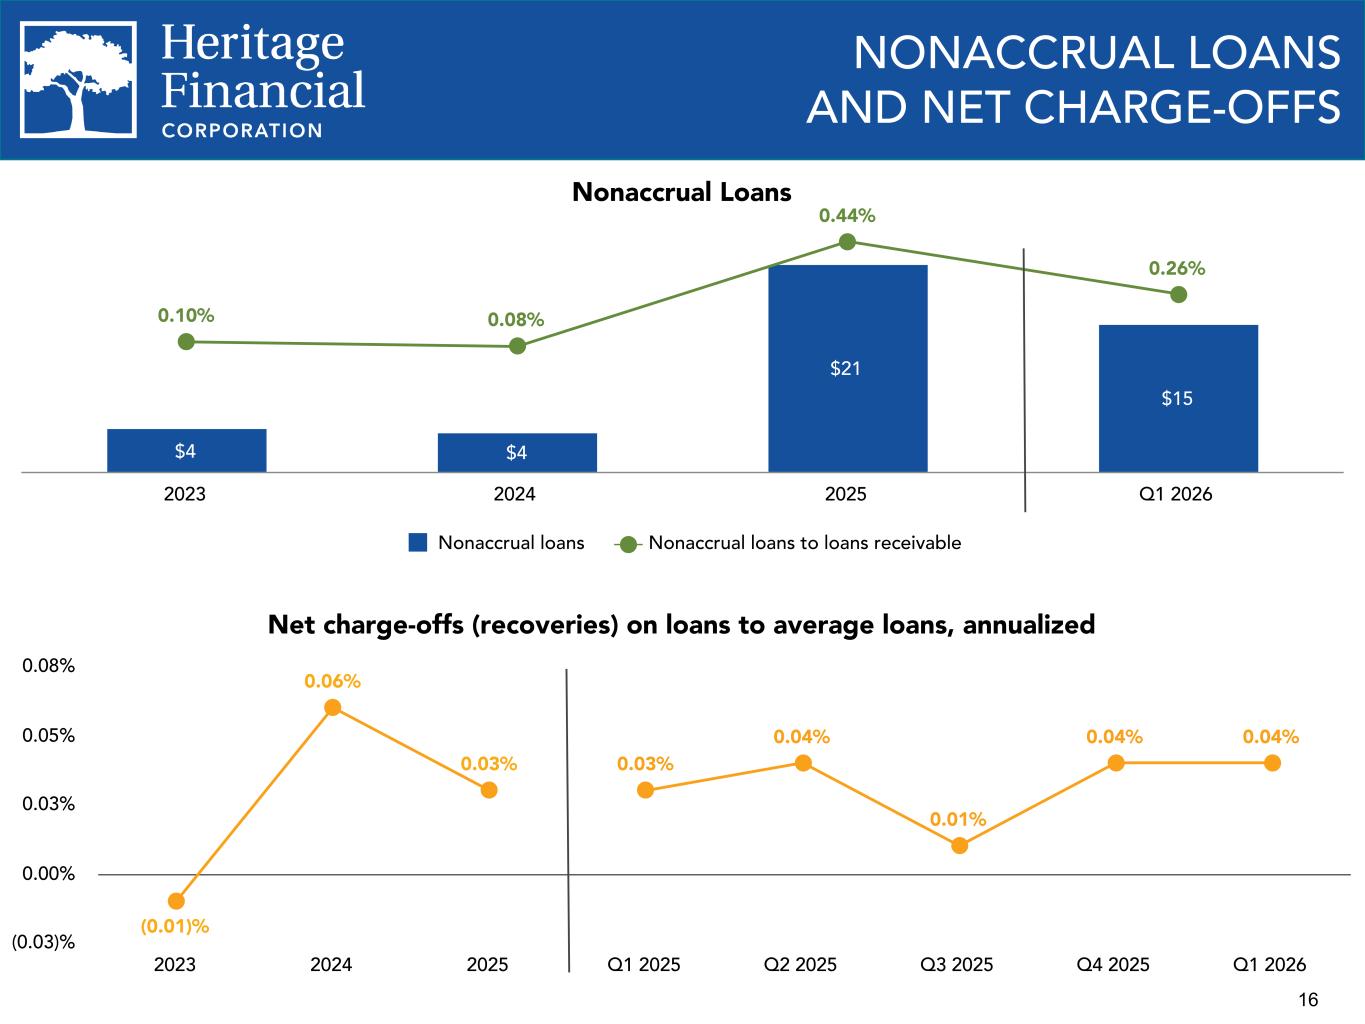
16 Net charge-offs (recoveries) on loans to average loans, annualized (0.01)% 0.06% 0.03% 0.03% 0.04% 0.01% 0.04% 0.04% 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 (0.03)% 0.00% 0.03% 0.05% 0.08% Nonaccrual Loans $4 $4 $21 $15 Nonaccrual loans Nonaccrual loans to loans receivable 2023 2024 2025 Q1 2026 0.10% 0.08% 0.44% 0.26% NONACCRUAL LOANS AND NET CHARGE-OFFS
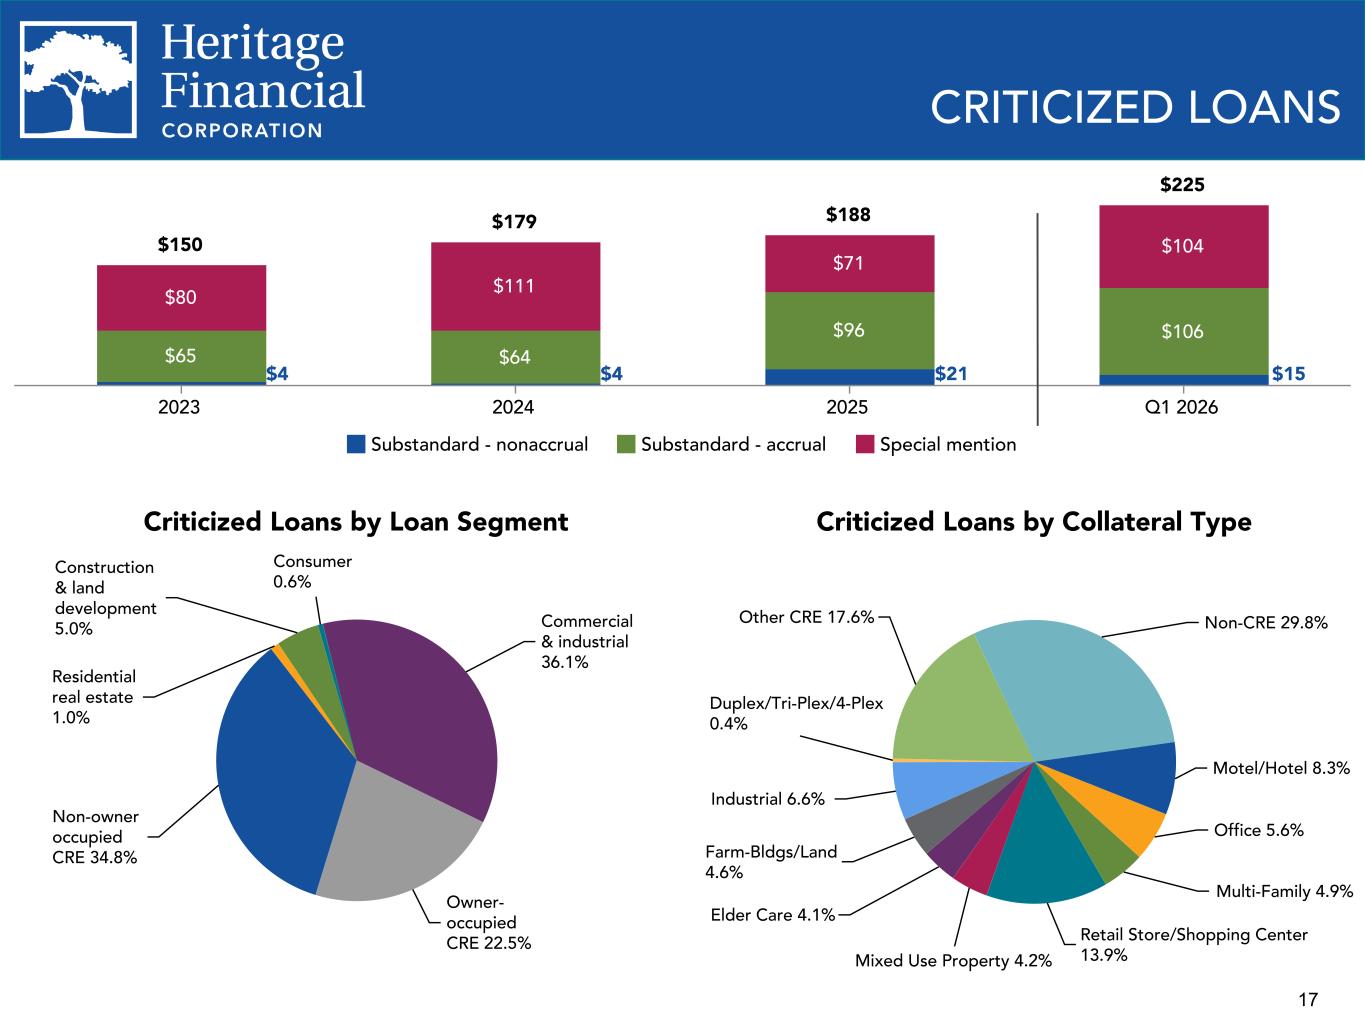
17 CRITICIZED LOANS $150 $179 $188 $225 $65 $64 $96 $106 $80 $111 $71 $104 Substandard - nonaccrual Substandard - accrual Special mention 2023 2024 2025 Q1 2026 Criticized Loans by Loan Segment Commercial & industrial 36.1% Owner- occupied CRE 22.5% Non-owner occupied CRE 34.8% Residential real estate 1.0% Construction & land development 5.0% Consumer 0.6% Criticized Loans by Collateral Type Motel/Hotel 8.3% Office 5.6% Multi-Family 4.9% Retail Store/Shopping Center 13.9%Mixed Use Property 4.2% Elder Care 4.1% Farm-Bldgs/Land 4.6% Industrial 6.6% Duplex/Tri-Plex/4-Plex 0.4% Other CRE 17.6% Non-CRE 29.8% $4 $4 $21 $15
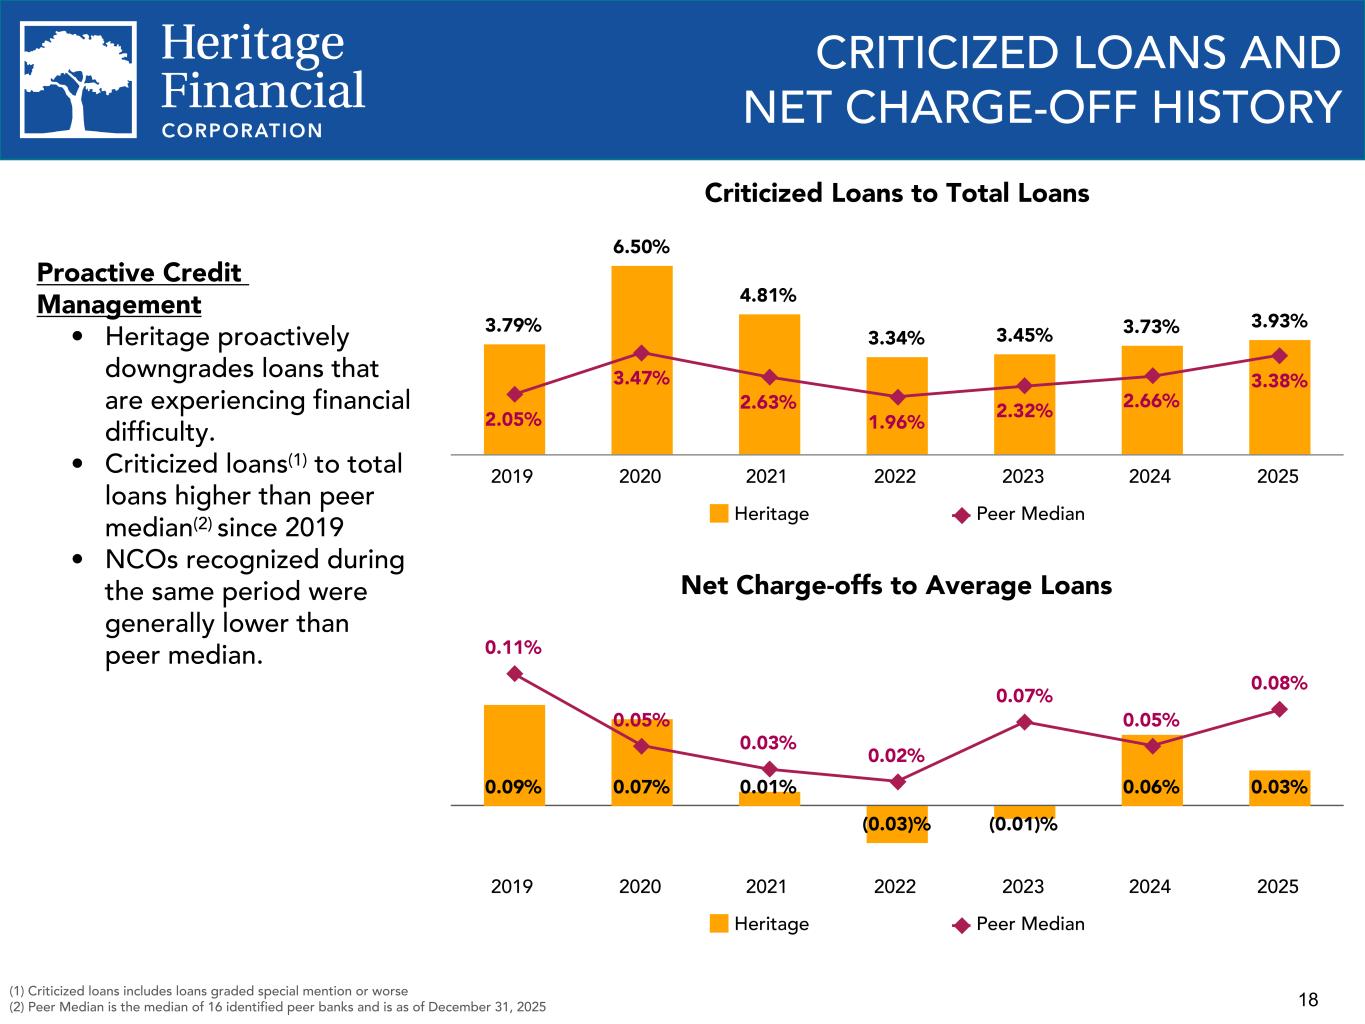
18 CRITICIZED LOANS AND NET CHARGE-OFF HISTORY Criticized Loans to Total Loans 3.79% 6.50% 4.81% 3.34% 3.45% 3.73% 3.93% 2.05% 3.47% 2.63% 1.96% 2.32% 2.66% 3.38% Heritage Peer Median 2019 2020 2021 2022 2023 2024 2025 Net Charge-offs to Average Loans 0.09% 0.07% 0.01% (0.03)% (0.01)% 0.06% 0.03% 0.11% 0.05% 0.03% 0.02% 0.07% 0.05% 0.08% Heritage Peer Median 2019 2020 2021 2022 2023 2024 2025 (1) Criticized loans includes loans graded special mention or worse (2) Peer Median is the median of 16 identified peer banks and is as of December 31, 2025 Proactive Credit Management • Heritage proactively downgrades loans that are experiencing financial difficulty. • Criticized loans(1) to total loans higher than peer median(2) since 2019 • NCOs recognized during the same period were generally lower than peer median.
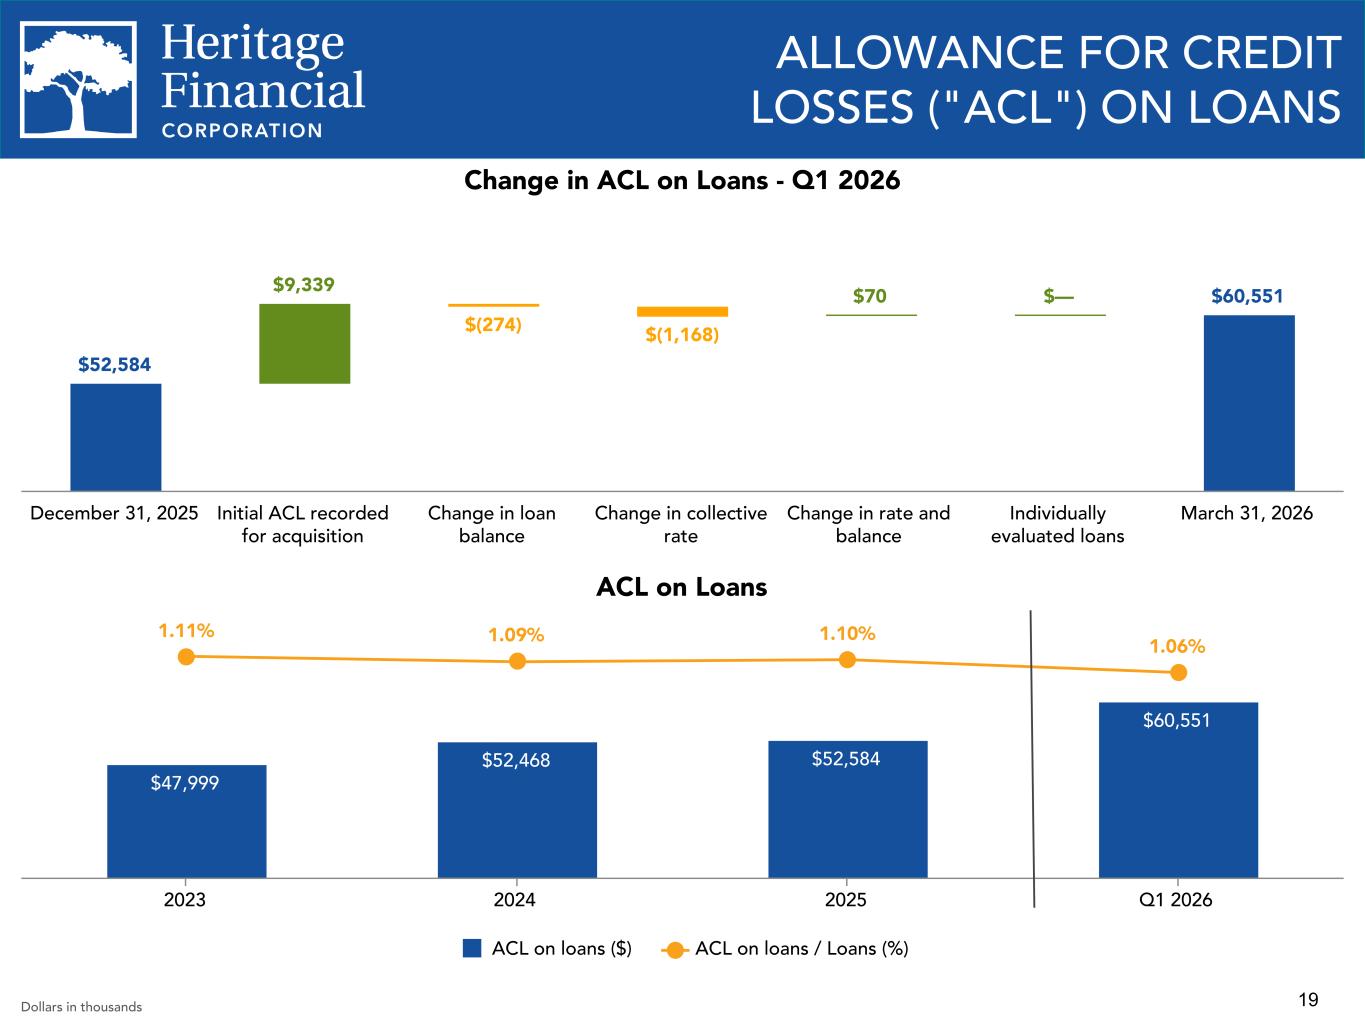
19 ACL on Loans $47,999 $52,468 $52,584 $60,551 1.11% 1.09% 1.10% 1.06% ACL on loans ($) ACL on loans / Loans (%) 2023 2024 2025 Q1 2026 ALLOWANCE FOR CREDIT LOSSES ("ACL") ON LOANS $52,584 $9,339 $(274) $(1,168) $70 $— $60,551 December 31, 2025 Initial ACL recorded for acquisition Change in loan balance Change in collective rate Change in rate and balance Individually evaluated loans March 31, 2026 Change in ACL on Loans - Q1 2026 Dollars in thousands
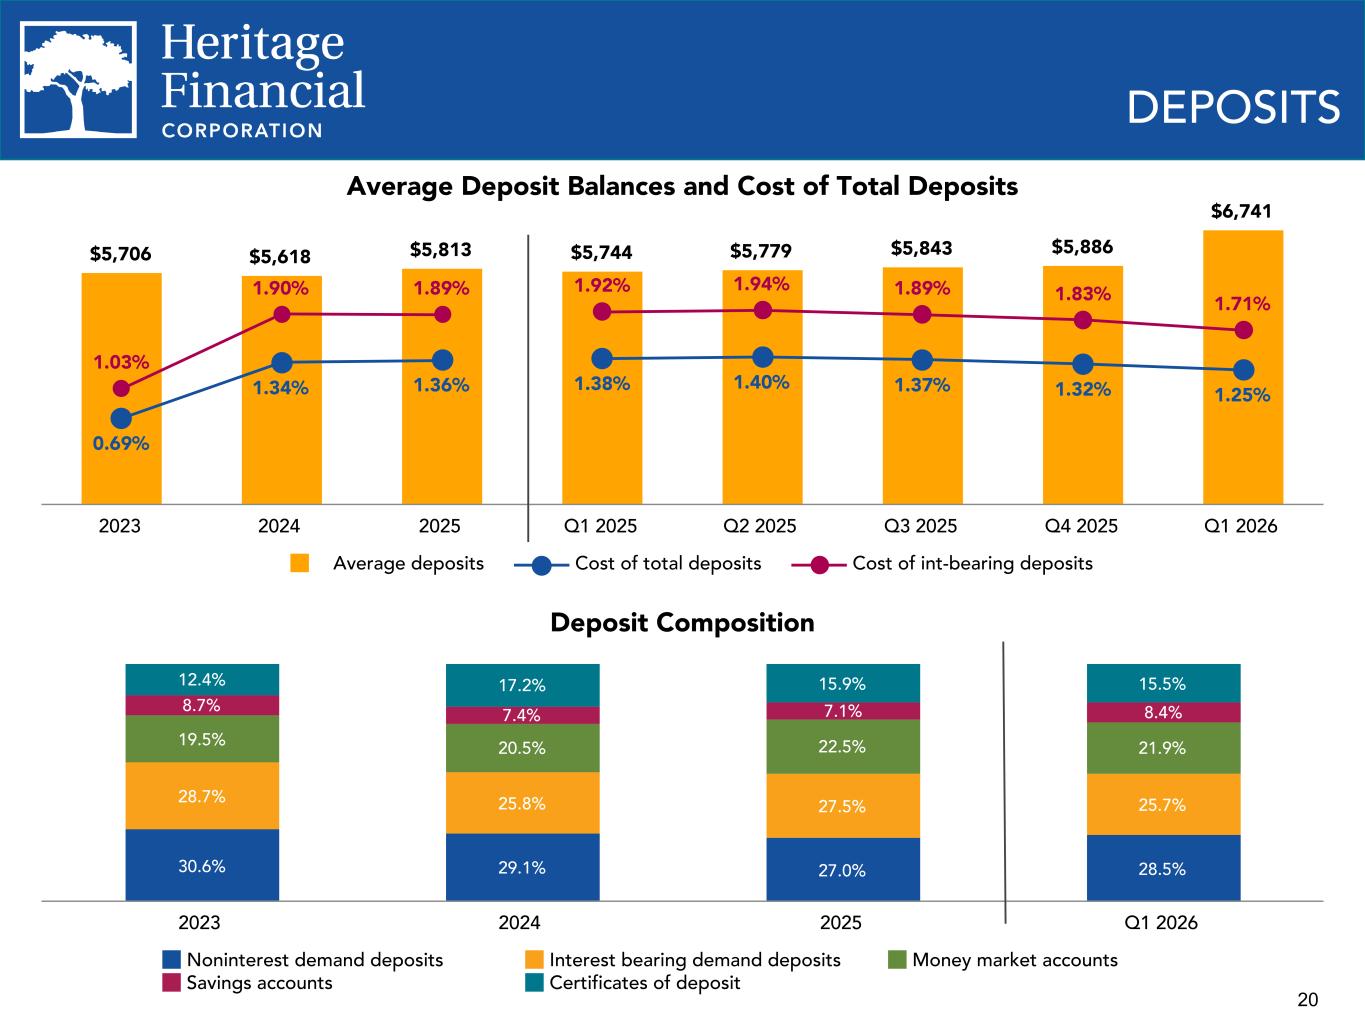
20 Average Deposit Balances and Cost of Total Deposits $5,706 $5,618 $5,813 $5,744 $5,779 $5,843 $5,886 $6,741 0.69% 1.34% 1.36% 1.38% 1.40% 1.37% 1.32% 1.25% 1.92% 1.94% 1.89% 1.83% 1.71% 1.03% 1.90% 1.89% Average deposits Cost of total deposits Cost of int-bearing deposits 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 DEPOSITS Deposit Composition 30.6% 29.1% 27.0% 28.5% 28.7% 25.8% 27.5% 25.7% 19.5% 20.5% 22.5% 21.9% 8.7% 7.4% 7.1% 8.4% 12.4% 17.2% 15.9% 15.5% Noninterest demand deposits Interest bearing demand deposits Money market accounts Savings accounts Certificates of deposit 2023 2024 2025 Q1 2026
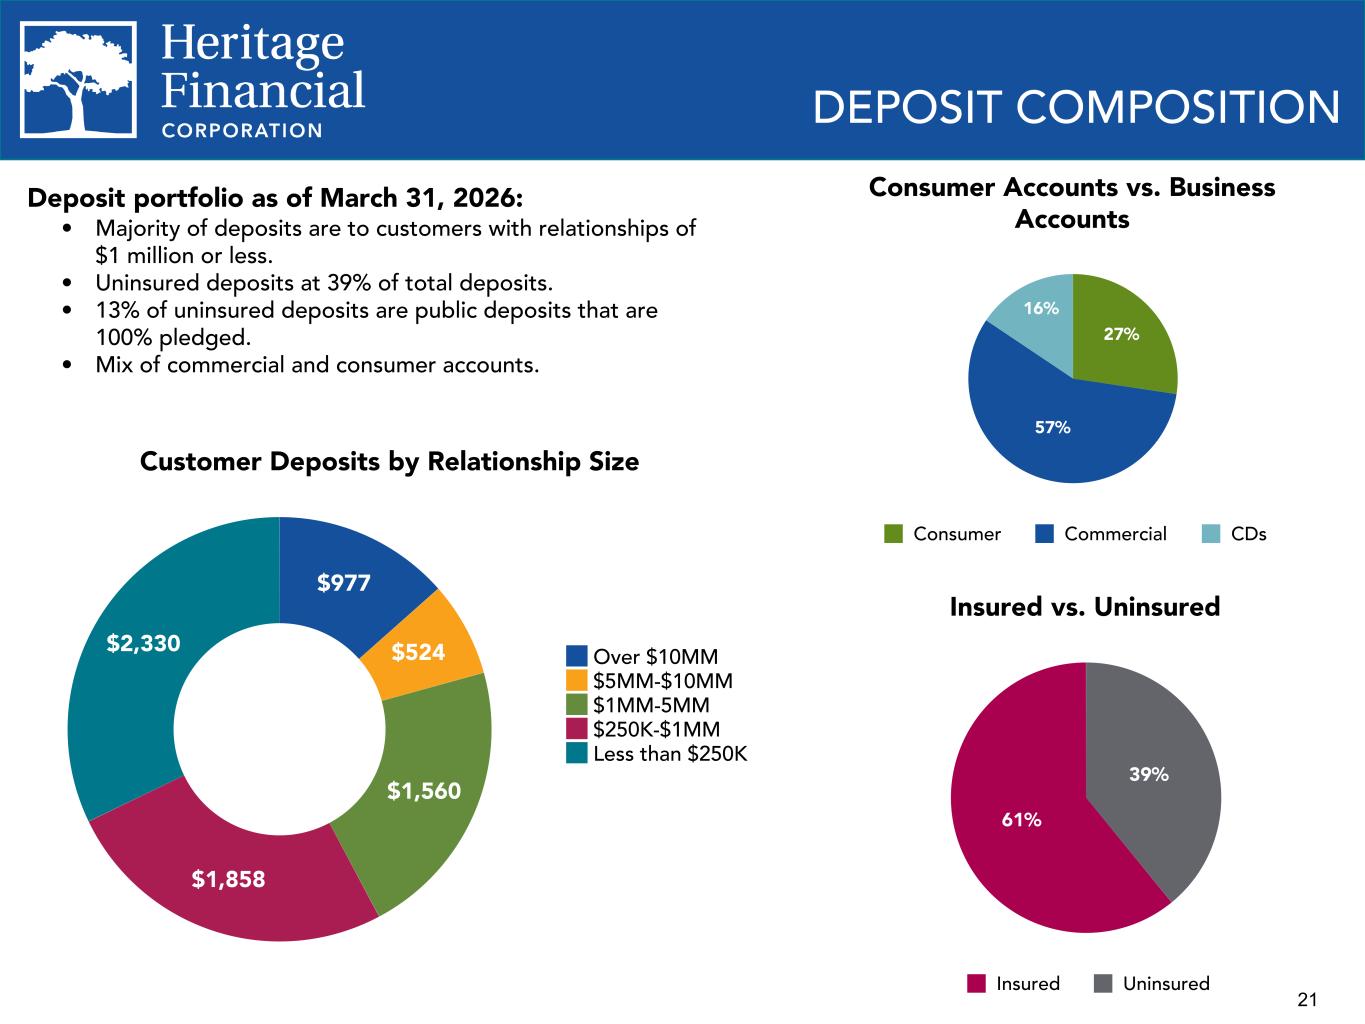
21 DEPOSIT COMPOSITION Customer Deposits by Relationship Size $977 $524 $1,560 $1,858 $2,330 Over $10MM $5MM-$10MM $1MM-5MM $250K-$1MM Less than $250K Consumer Accounts vs. Business Accounts 27% 57% 16% Consumer Commercial CDs Insured vs. Uninsured 39% 61% Insured Uninsured Deposit portfolio as of March 31, 2026: • Majority of deposits are to customers with relationships of $1 million or less. • Uninsured deposits at 39% of total deposits. • 13% of uninsured deposits are public deposits that are 100% pledged. • Mix of commercial and consumer accounts.
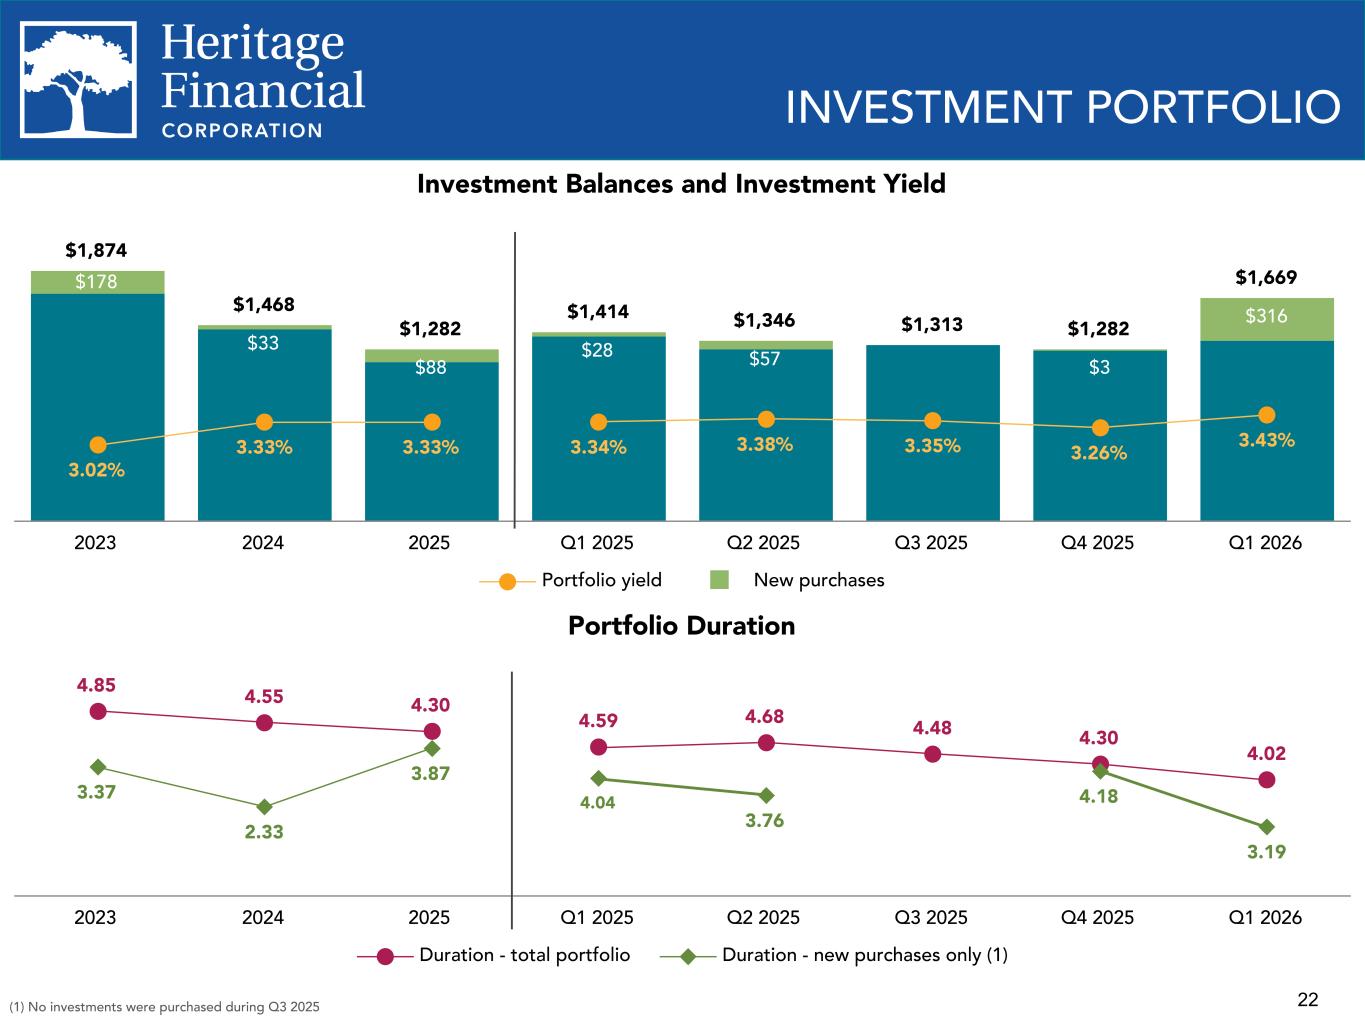
22 Investment Balances and Investment Yield $1,874 $1,468 $1,282 $1,414 $1,346 $1,313 $1,282 $1,669$178 $33 $88 $28 $57 $3 $316 3.02% 3.33% 3.33% 3.34% 3.38% 3.35% 3.26% 3.43% Portfolio yield New purchases 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 INVESTMENT PORTFOLIO Portfolio Duration 4.85 4.55 4.30 3.37 2.33 3.87 4.59 4.68 4.48 4.30 4.02 4.04 3.76 4.18 3.19 Duration - total portfolio Duration - new purchases only (1) 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 (1) No investments were purchased during Q3 2025
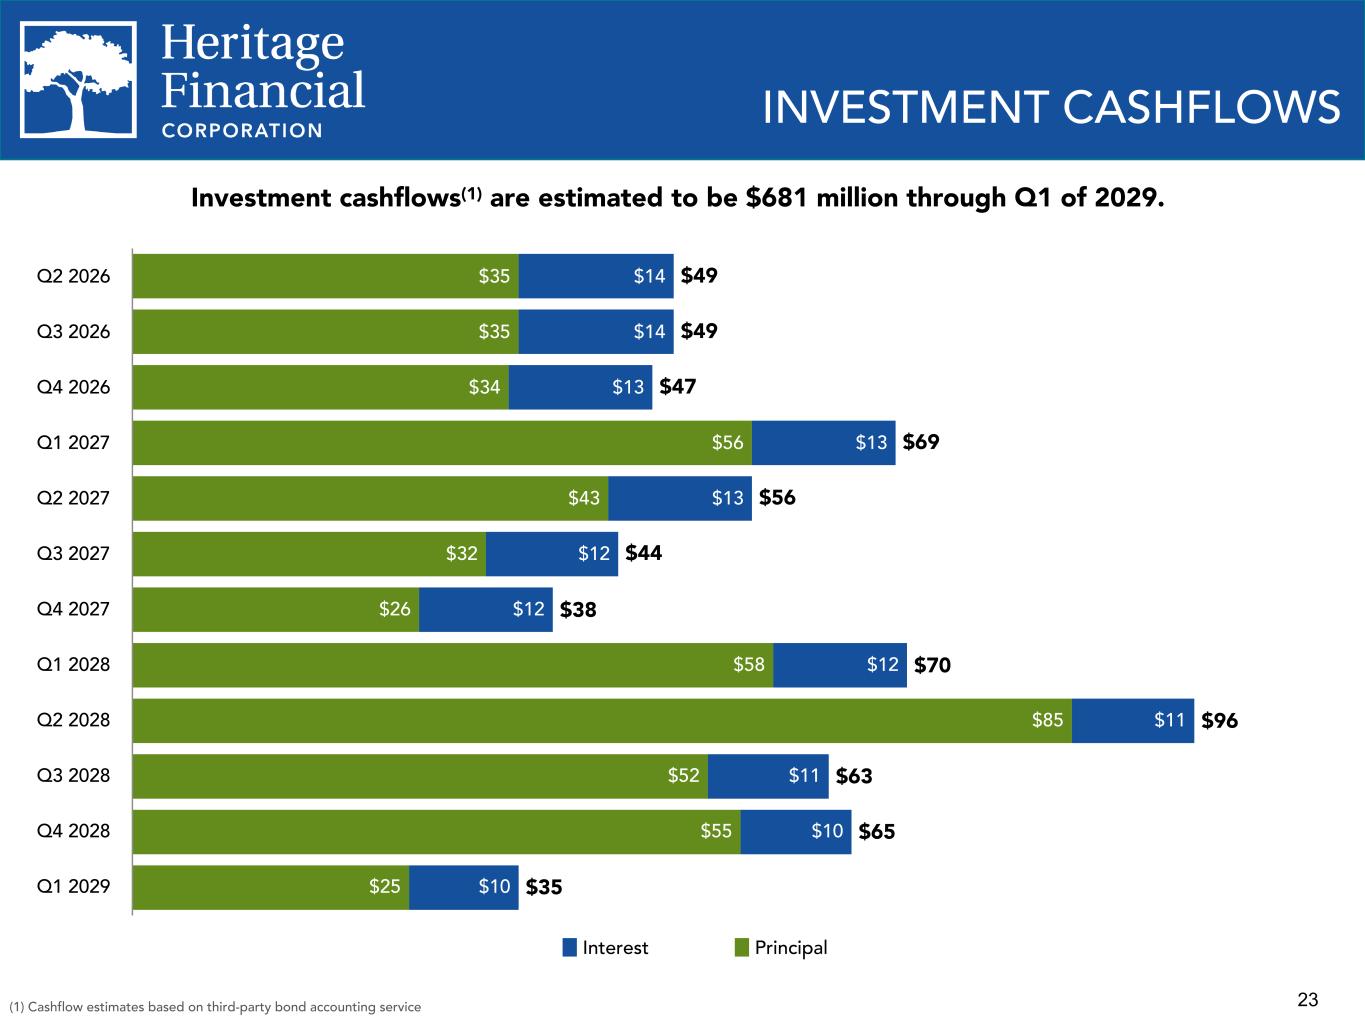
23 $49 $49 $47 $69 $56 $44 $38 $70 $96 $63 $65 $35 $35 $35 $34 $56 $43 $32 $26 $58 $85 $52 $55 $25 $14 $14 $13 $13 $13 $12 $12 $12 $11 $11 $10 $10 Interest Principal Q2 2026 Q3 2026 Q4 2026 Q1 2027 Q2 2027 Q3 2027 Q4 2027 Q1 2028 Q2 2028 Q3 2028 Q4 2028 Q1 2029 INVESTMENT CASHFLOWS Investment cashflows(1) are estimated to be $681 million through Q1 of 2029. (1) Cashflow estimates based on third-party bond accounting service
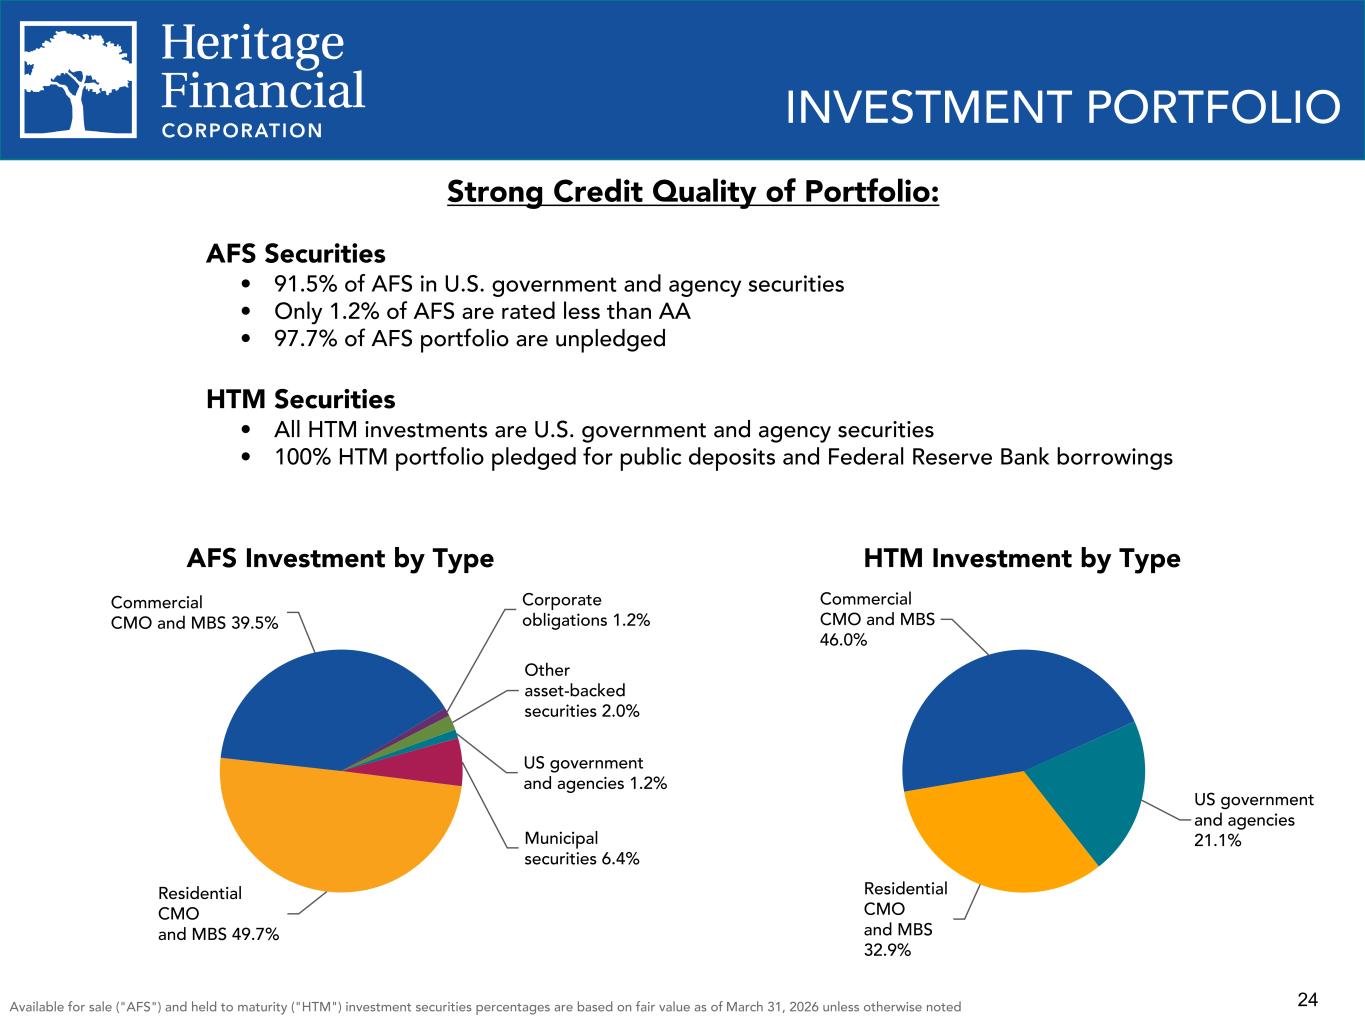
24 INVESTMENT PORTFOLIO HTM Investment by Type US government and agencies 21.1% Residential CMO and MBS 32.9% Commercial CMO and MBS 46.0% Available for sale ("AFS") and held to maturity ("HTM") investment securities percentages are based on fair value as of March 31, 2026 unless otherwise noted Strong Credit Quality of Portfolio: AFS Securities • 91.5% of AFS in U.S. government and agency securities • Only 1.2% of AFS are rated less than AA • 97.7% of AFS portfolio are unpledged HTM Securities • All HTM investments are U.S. government and agency securities • 100% HTM portfolio pledged for public deposits and Federal Reserve Bank borrowings AFS Investment by Type US government and agencies 1.2% Municipal securities 6.4% Residential CMO and MBS 49.7% Commercial CMO and MBS 39.5% Corporate obligations 1.2% Other asset-backed securities 2.0%
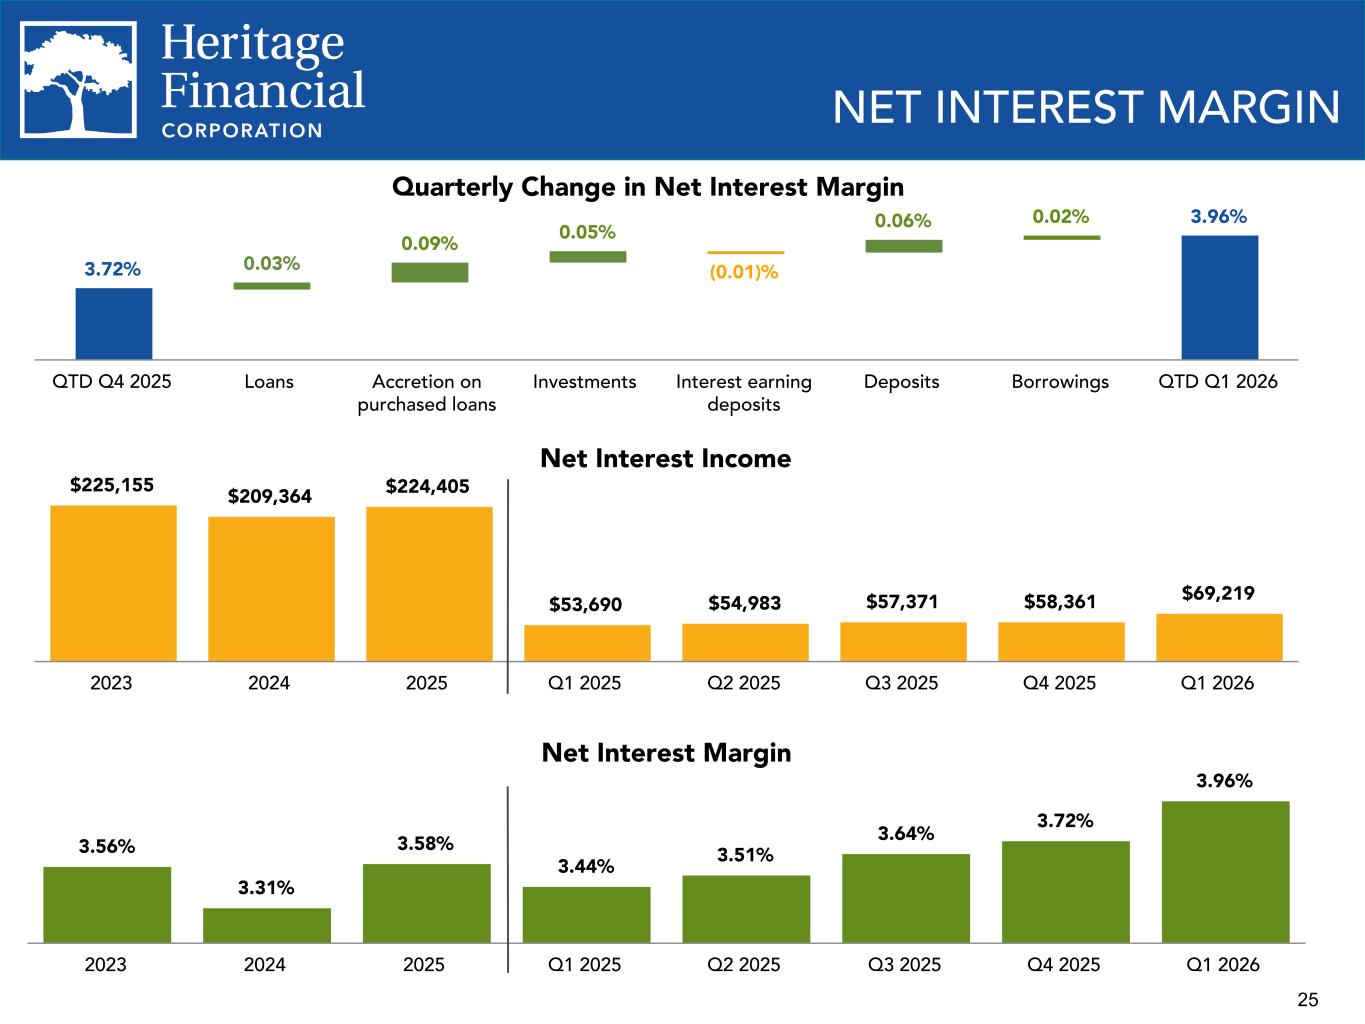
25 Net Interest Margin 3.56% 3.31% 3.58% 3.44% 3.51% 3.64% 3.72% 3.96% 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 NET INTEREST MARGIN Quarterly Change in Net Interest Margin 3.72% 0.03% 0.09% 0.05% (0.01)% 0.06% 0.02% 3.96% QTD Q4 2025 Loans Accretion on purchased loans Investments Interest earning deposits Deposits Borrowings QTD Q1 2026 Net Interest Income $225,155 $209,364 $224,405 $53,690 $54,983 $57,371 $58,361 $69,219 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026
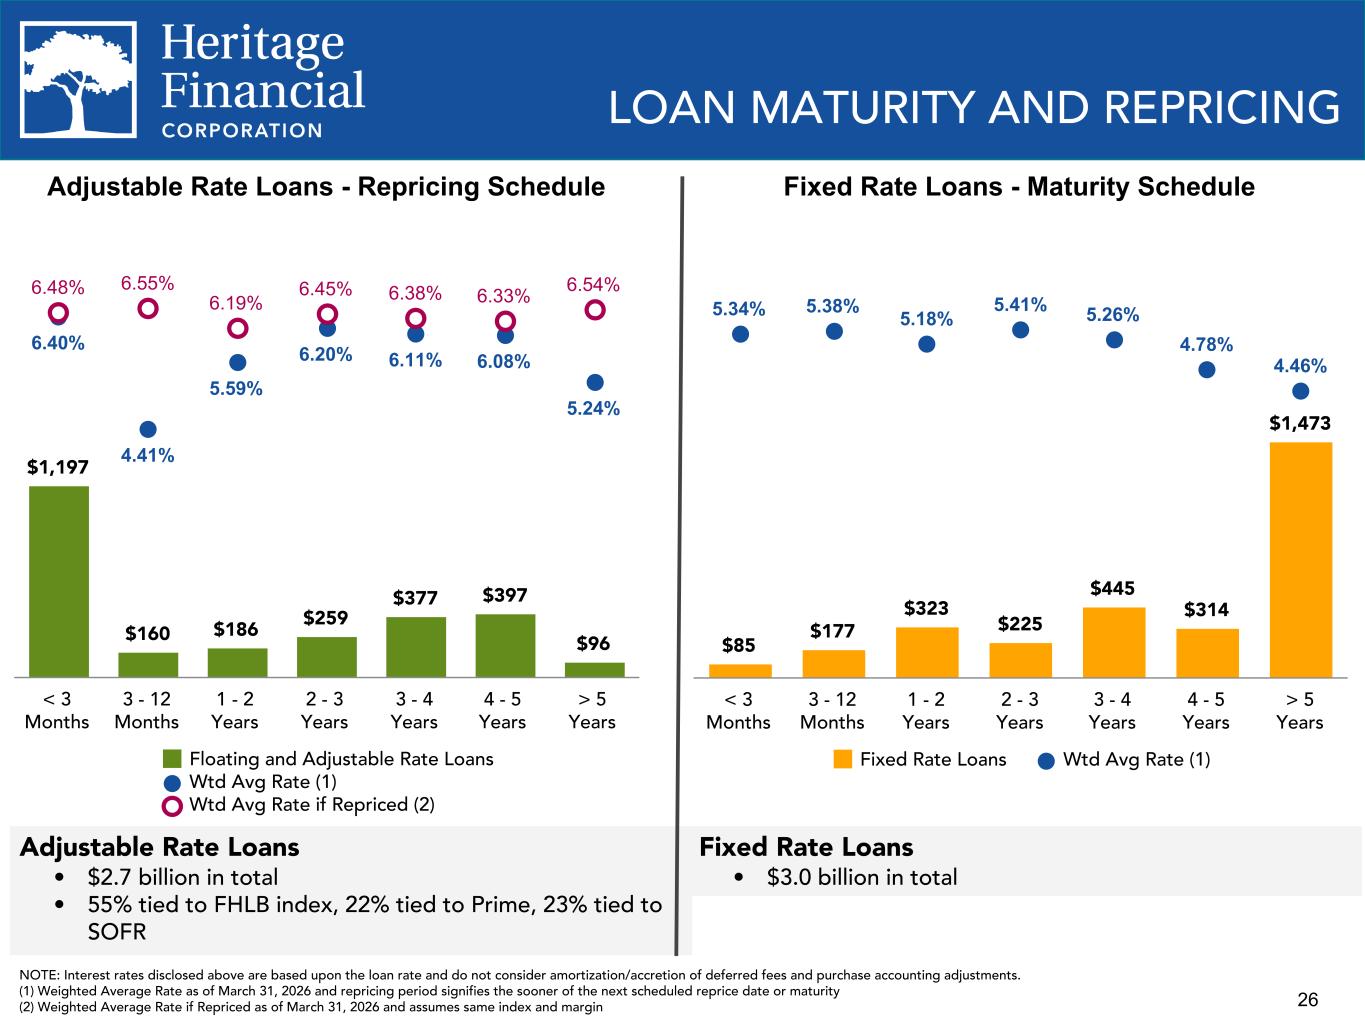
26 Adjustable Rate Loans - Repricing Schedule $1,197 $160 $186 $259 $377 $397 $96 6.40% 4.41% 5.59% 6.20% 6.11% 6.08% 5.24% 6.48% 6.55% 6.19% 6.45% 6.38% 6.33% 6.54% Floating and Adjustable Rate Loans Wtd Avg Rate (1) Wtd Avg Rate if Repriced (2) < 3 Months 3 - 12 Months 1 - 2 Years 2 - 3 Years 3 - 4 Years 4 - 5 Years > 5 Years LOAN MATURITY AND REPRICING NOTE: Interest rates disclosed above are based upon the loan rate and do not consider amortization/accretion of deferred fees and purchase accounting adjustments. (1) Weighted Average Rate as of March 31, 2026 and repricing period signifies the sooner of the next scheduled reprice date or maturity (2) Weighted Average Rate if Repriced as of March 31, 2026 and assumes same index and margin Adjustable Rate Loans • $2.7 billion in total • 55% tied to FHLB index, 22% tied to Prime, 23% tied to SOFR Fixed Rate Loans - Maturity Schedule $85 $177 $323 $225 $445 $314 $1,473 5.34% 5.38% 5.18% 5.41% 5.26% 4.78% 4.46% Fixed Rate Loans Wtd Avg Rate (1) < 3 Months 3 - 12 Months 1 - 2 Years 2 - 3 Years 3 - 4 Years 4 - 5 Years > 5 Years Fixed Rate Loans • $3.0 billion in total
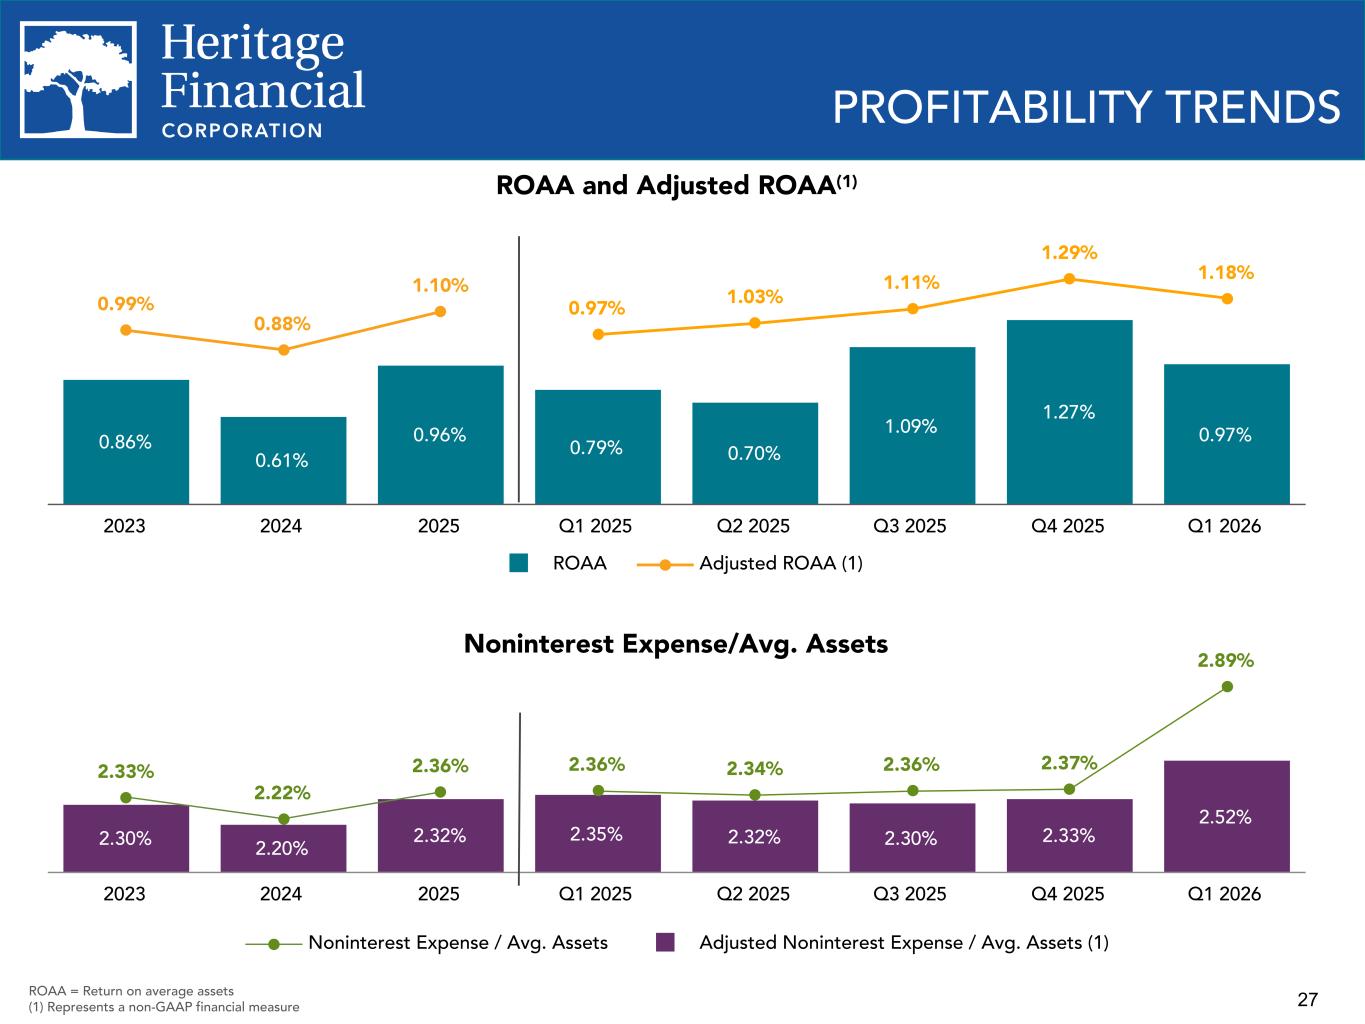
27 PROFITABILITY TRENDS ROAA and Adjusted ROAA(1) 0.86% 0.61% 0.96% 0.79% 0.70% 1.09% 1.27% 0.97% 0.99% 0.88% 1.10% 0.97% 1.03% 1.11% 1.29% 1.18% ROAA Adjusted ROAA (1) 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Noninterest Expense/Avg. Assets 2.30% 2.20% 2.32% 2.35% 2.32% 2.30% 2.33% 2.52% 2.33% 2.22% 2.36% 2.36% 2.34% 2.36% 2.37% 2.89% Noninterest Expense / Avg. Assets Adjusted Noninterest Expense / Avg. Assets (1) 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 ROAA = Return on average assets (1) Represents a non-GAAP financial measure
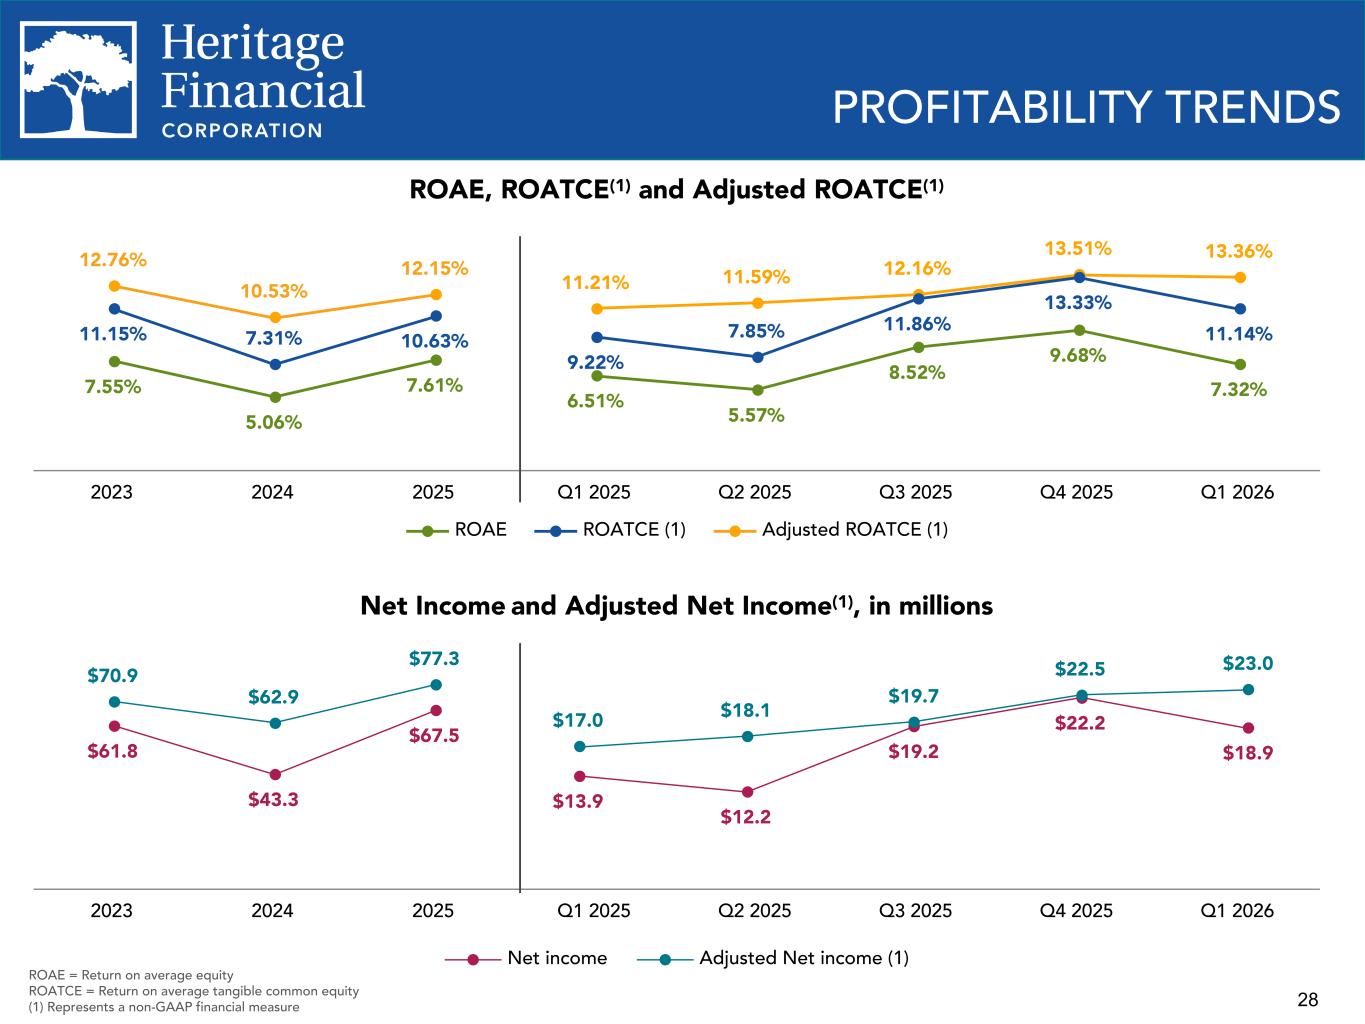
28 $61.8 $43.3 $67.5 $70.9 $62.9 $77.3 Net income Adjusted Net income (1) 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 $13.9 $12.2 $19.2 $22.2 $18.9 $17.0 $18.1 $19.7 $22.5 $23.0 PROFITABILITY TRENDS ROAE, ROATCE(1) and Adjusted ROATCE(1) Net Income and Adjusted Net Income(1), in millions 12.76% 10.53% 12.15% 11.21% 11.59% 12.16% 13.51% 13.36% 11.15% 7.31% 10.63% 9.22% 7.85% 11.86% 13.33% 11.14% 7.55% 5.06% 7.61% 6.51% 5.57% 8.52% 9.68% 7.32% ROAE ROATCE (1) Adjusted ROATCE (1) 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 ROAE = Return on average equity ROATCE = Return on average tangible common equity (1) Represents a non-GAAP financial measure
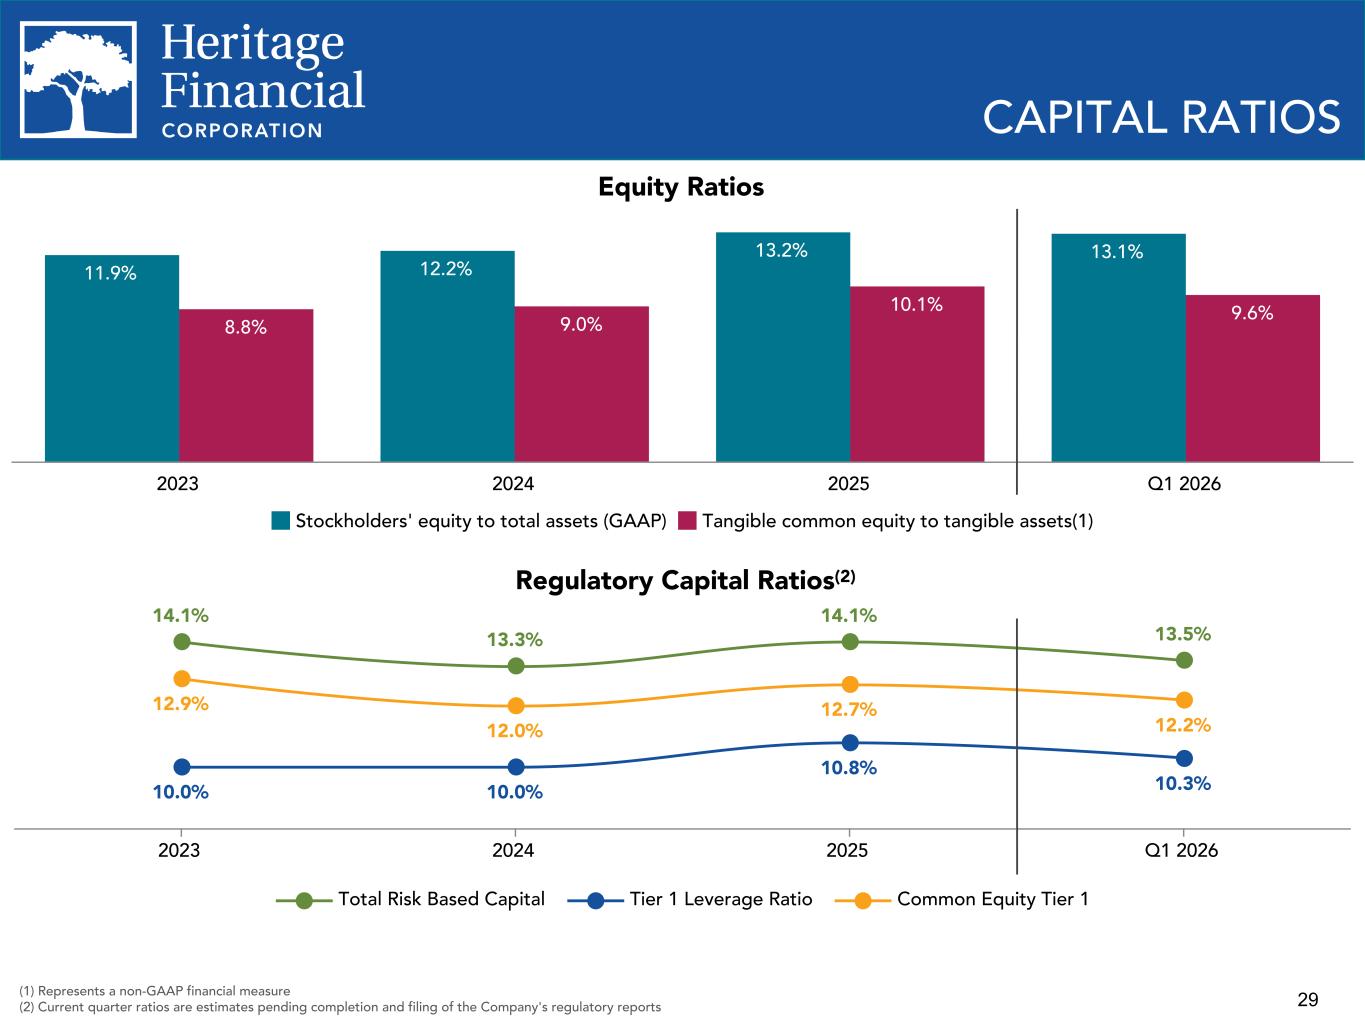
29(1) Represents a non-GAAP financial measure (2) Current quarter ratios are estimates pending completion and filing of the Company's regulatory reports CAPITAL RATIOS Equity Ratios 11.9% 12.2% 13.2% 13.1% 8.8% 9.0% 10.1% 9.6% Stockholders' equity to total assets (GAAP) Tangible common equity to tangible assets(1) 2023 2024 2025 Q1 2026 12.9% 12.0% 12.7% 12.2% 10.0% 10.0% 10.8% 10.3% 14.1% 13.3% 14.1% 13.5% Total Risk Based Capital Tier 1 Leverage Ratio Common Equity Tier 1 2023 2024 2025 Q1 2026 Regulatory Capital Ratios(2)
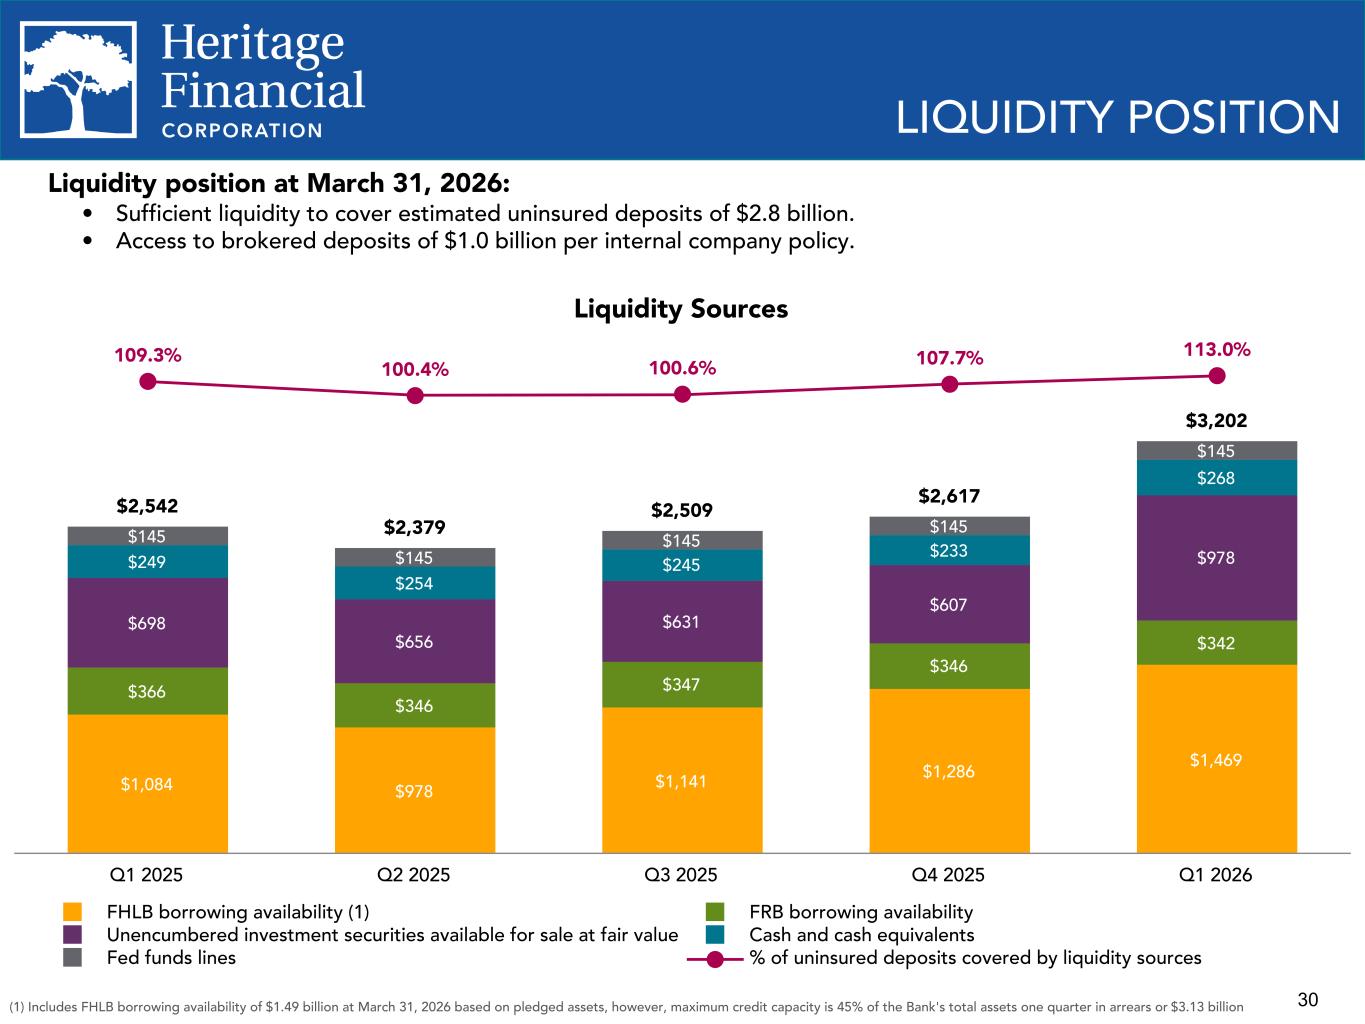
30 LIQUIDITY POSITION (1) Includes FHLB borrowing availability of $1.49 billion at March 31, 2026 based on pledged assets, however, maximum credit capacity is 45% of the Bank's total assets one quarter in arrears or $3.13 billion Liquidity position at March 31, 2026: • Sufficient liquidity to cover estimated uninsured deposits of $2.8 billion. • Access to brokered deposits of $1.0 billion per internal company policy. Liquidity Sources $2,542 $2,379 $2,509 $2,617 $3,202 $1,084 $978 $1,141 $1,286 $1,469 $366 $346 $347 $346 $342 $698 $656 $631 $607 $978$249 $254 $245 $233 $268 $145 $145 $145 $145 $145 109.3% 100.4% 100.6% 107.7% 113.0% FHLB borrowing availability (1) FRB borrowing availability Unencumbered investment securities available for sale at fair value Cash and cash equivalents Fed funds lines % of uninsured deposits covered by liquidity sources Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026
SHAREHOLDER RETURN
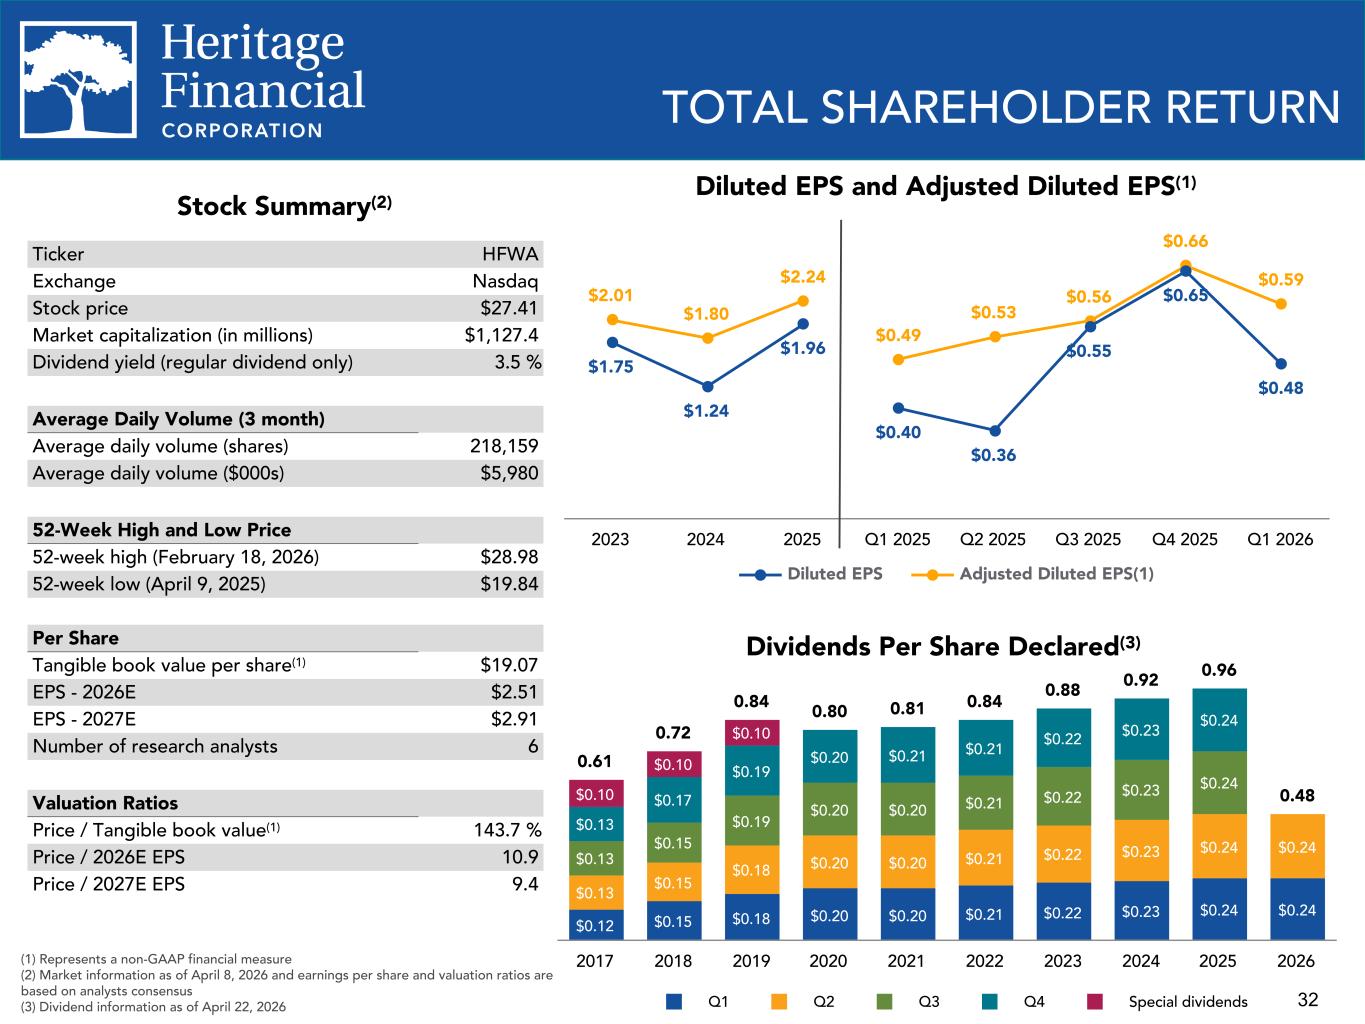
32 TOTAL SHAREHOLDER RETURN Stock Summary(2) Ticker HFWA Exchange Nasdaq Stock price $27.41 Market capitalization (in millions) $1,127.4 Dividend yield (regular dividend only) 3.5 % Average Daily Volume (3 month) Average daily volume (shares) 218,159 Average daily volume ($000s) $5,980 52-Week High and Low Price 52-week high (February 18, 2026) $28.98 52-week low (April 9, 2025) $19.84 Per Share Tangible book value per share(1) $19.07 EPS - 2026E $2.51 EPS - 2027E $2.91 Number of research analysts 6 Valuation Ratios Price / Tangible book value(1) 143.7 % Price / 2026E EPS 10.9 Price / 2027E EPS 9.4 Dividends Per Share Declared(3) 0.61 0.72 0.84 0.80 0.81 0.84 0.88 0.92 0.96 0.48 $0.12 $0.15 $0.18 $0.20 $0.20 $0.21 $0.22 $0.23 $0.24 $0.24 $0.13 $0.15 $0.18 $0.20 $0.20 $0.21 $0.22 $0.23 $0.24 $0.24 $0.13 $0.15 $0.19 $0.20 $0.20 $0.21 $0.22 $0.23 $0.24 $0.13 $0.17 $0.19 $0.20 $0.21 $0.21 $0.22 $0.23 $0.24 $0.10 $0.10 $0.10 Q1 Q2 Q3 Q4 Special dividends 2017 2018 2019 2020 2021 2022 2023 2024 2025 2026(1) Represents a non-GAAP financial measure (2) Market information as of April 8, 2026 and earnings per share and valuation ratios are based on analysts consensus (3) Dividend information as of April 22, 2026 $2.01 $1.80 $2.24 $1.75 $1.24 $1.96 $0.49 $0.53 $0.56 $0.66 $0.59 $0.40 $0.36 $0.55 $0.65 $0.48 Diluted EPS Adjusted Diluted EPS(1) 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Diluted EPS and Adjusted Diluted EPS(1)
APPENDIX - RECONCILIATION OF NON-GAAP FINANCIAL MEASURES AND QUARTERLY FINANCIAL STATISTICS
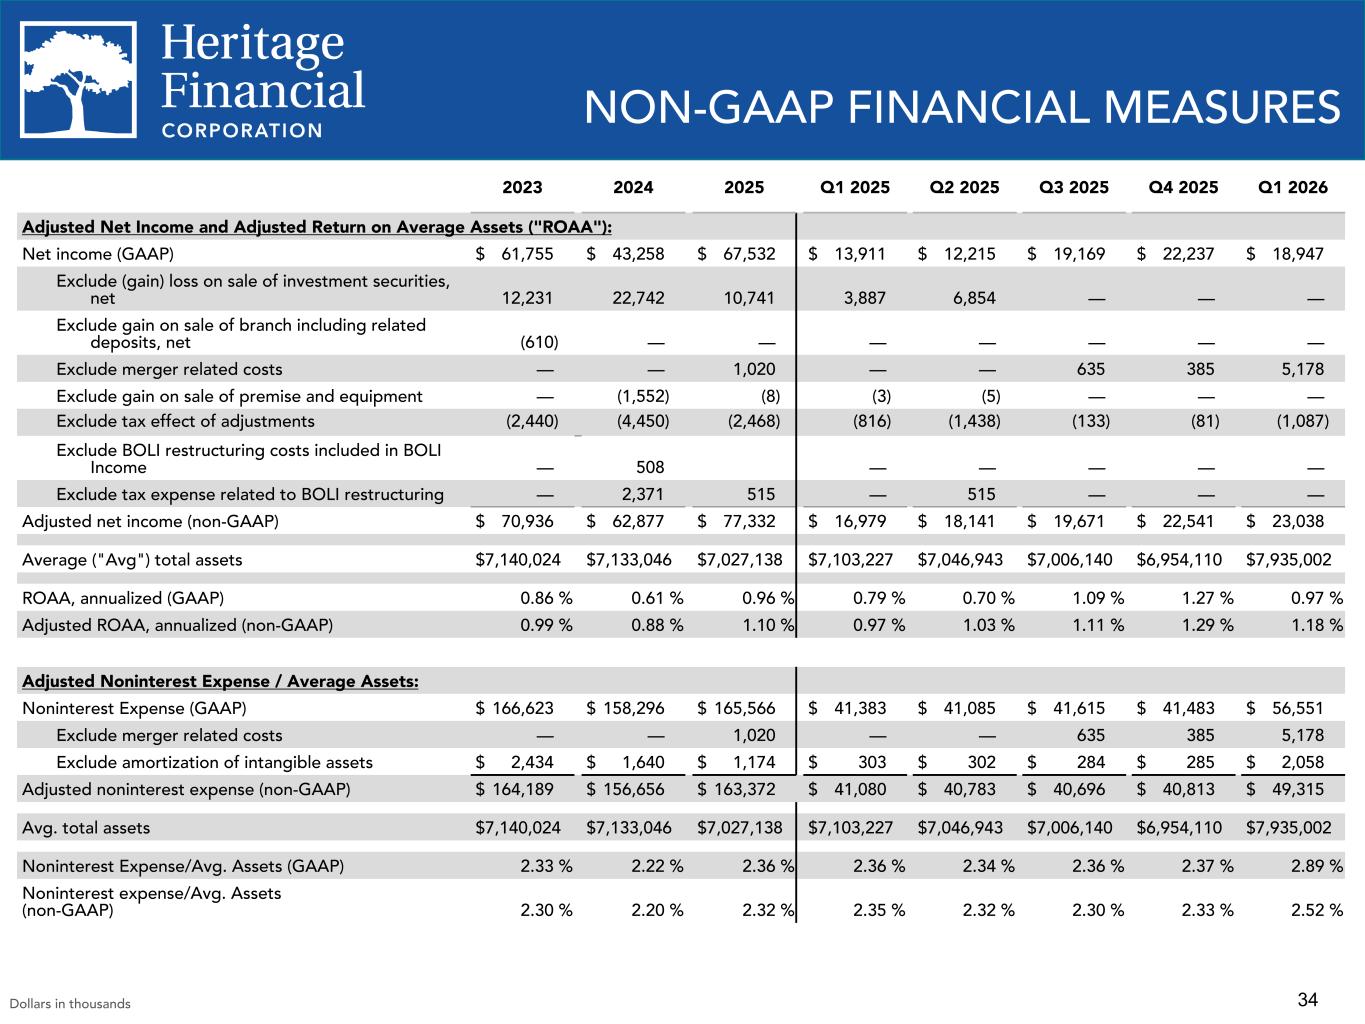
34 NON-GAAP FINANCIAL MEASURES Dollars in thousands 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Adjusted Net Income and Adjusted Return on Average Assets ("ROAA"): Net income (GAAP) $ 61,755 $ 43,258 $ 67,532 $ 13,911 $ 12,215 $ 19,169 $ 22,237 $ 18,947 Exclude (gain) loss on sale of investment securities, net 12,231 22,742 10,741 3,887 6,854 — — — Exclude gain on sale of branch including related deposits, net (610) — — — — — — — Exclude merger related costs — — 1,020 — — 635 385 5,178 Exclude gain on sale of premise and equipment — (1,552) (8) (3) (5) — — — Exclude tax effect of adjustments (2,440) (4,450) (2,468) (816) (1,438) (133) (81) (1,087) Exclude BOLI restructuring costs included in BOLI Income — 508 — — — — — Exclude tax expense related to BOLI restructuring — 2,371 515 — 515 — — — Adjusted net income (non-GAAP) $ 70,936 $ 62,877 $ 77,332 $ 16,979 $ 18,141 $ 19,671 $ 22,541 $ 23,038 Average ("Avg") total assets $ 7,140,024 $ 7,133,046 $ 7,027,138 $7,103,227 $7,046,943 $7,006,140 $6,954,110 $7,935,002 ROAA, annualized (GAAP) 0.86 % 0.61 % 0.96 % 0.79 % 0.70 % 1.09 % 1.27 % 0.97 % Adjusted ROAA, annualized (non-GAAP) 0.99 % 0.88 % 1.10 % 0.97 % 1.03 % 1.11 % 1.29 % 1.18 % Adjusted Noninterest Expense / Average Assets: Noninterest Expense (GAAP) $ 166,623 $ 158,296 $ 165,566 $ 41,383 $ 41,085 $ 41,615 $ 41,483 $ 56,551 Exclude merger related costs — — 1,020 — — 635 385 5,178 Exclude amortization of intangible assets $ 2,434 $ 1,640 $ 1,174 $ 303 $ 302 $ 284 $ 285 $ 2,058 Adjusted noninterest expense (non-GAAP) $ 164,189 $ 156,656 $ 163,372 $ 41,080 $ 40,783 $ 40,696 $ 40,813 $ 49,315 Avg. total assets $ 7,140,024 $ 7,133,046 $ 7,027,138 $7,103,227 $7,046,943 $7,006,140 $6,954,110 $7,935,002 Noninterest Expense/Avg. Assets (GAAP) 2.33 % 2.22 % 2.36 % 2.36 % 2.34 % 2.36 % 2.37 % 2.89 % Noninterest expense/Avg. Assets (non-GAAP) 2.30 % 2.20 % 2.32 % 2.35 % 2.32 % 2.30 % 2.33 % 2.52 %
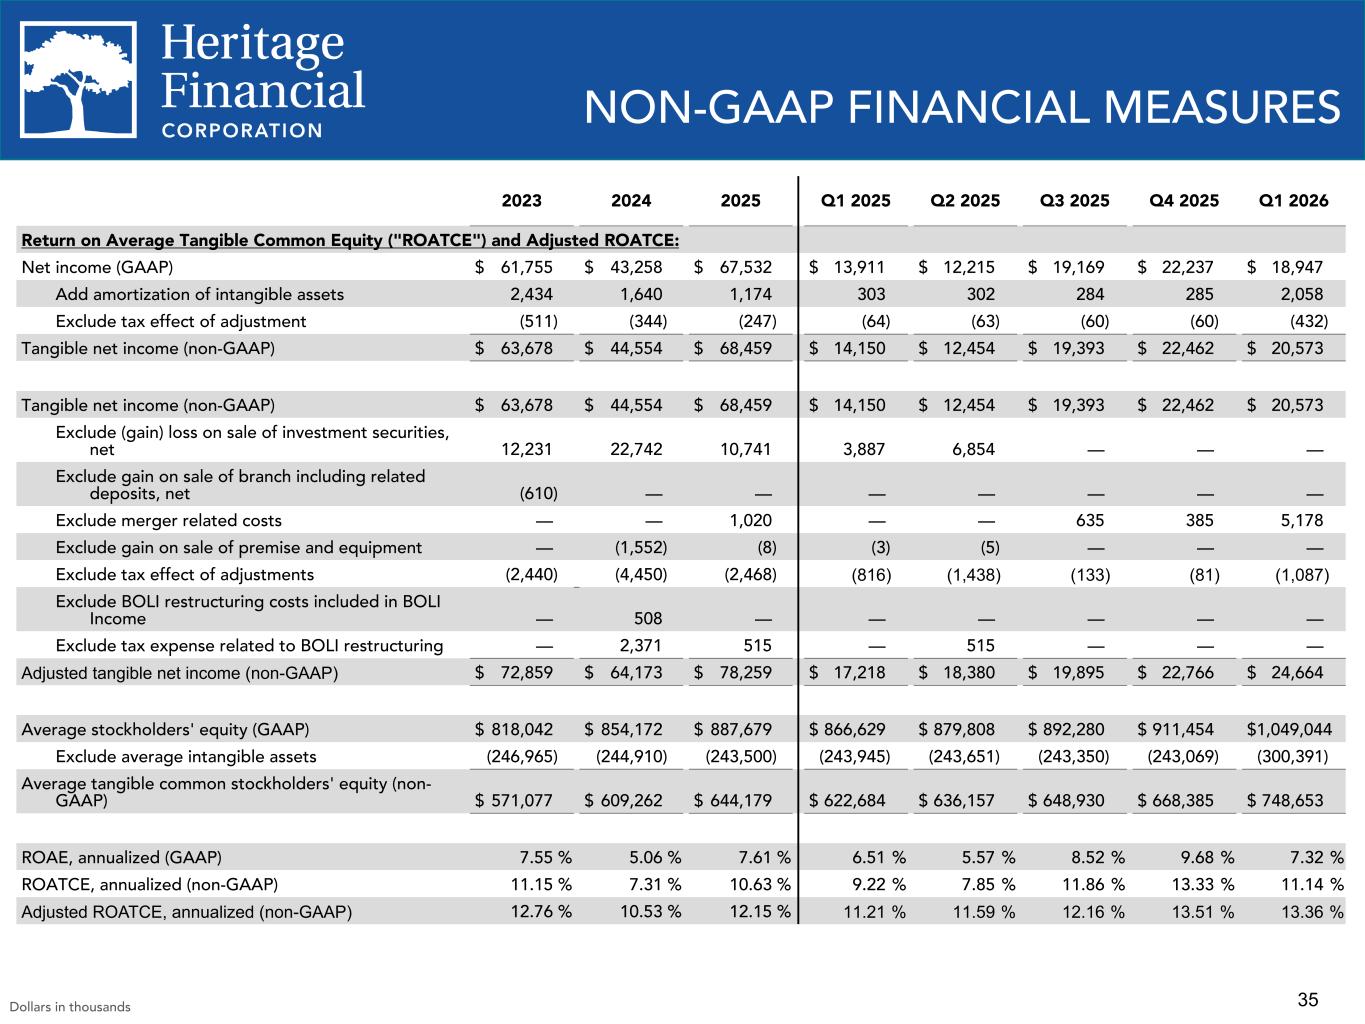
35 NON-GAAP FINANCIAL MEASURES 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Return on Average Tangible Common Equity ("ROATCE") and Adjusted ROATCE: Net income (GAAP) $ 61,755 $ 43,258 $ 67,532 $ 13,911 $ 12,215 $ 19,169 $ 22,237 $ 18,947 Add amortization of intangible assets 2,434 1,640 1,174 303 302 284 285 2,058 Exclude tax effect of adjustment (511) (344) (247) (64) (63) (60) (60) (432) Tangible net income (non-GAAP) $ 63,678 $ 44,554 $ 68,459 $ 14,150 $ 12,454 $ 19,393 $ 22,462 $ 20,573 Tangible net income (non-GAAP) $ 63,678 $ 44,554 $ 68,459 $ 14,150 $ 12,454 $ 19,393 $ 22,462 $ 20,573 Exclude (gain) loss on sale of investment securities, net 12,231 22,742 10,741 3,887 6,854 — — — Exclude gain on sale of branch including related deposits, net (610) — — — — — — — Exclude merger related costs — — 1,020 — — 635 385 5,178 Exclude gain on sale of premise and equipment — (1,552) (8) (3) (5) — — — Exclude tax effect of adjustments (2,440) (4,450) (2,468) (816) (1,438) (133) (81) (1,087) Exclude BOLI restructuring costs included in BOLI Income — 508 — — — — — — Exclude tax expense related to BOLI restructuring — 2,371 515 — 515 — — — Adjusted tangible net income (non-GAAP) $ 72,859 $ 64,173 $ 78,259 $ 17,218 $ 18,380 $ 19,895 $ 22,766 $ 24,664 Average stockholders' equity (GAAP) $ 818,042 $ 854,172 $ 887,679 $ 866,629 $ 879,808 $ 892,280 $ 911,454 $ 1,049,044 Exclude average intangible assets (246,965) (244,910) (243,500) (243,945) (243,651) (243,350) (243,069) (300,391) Average tangible common stockholders' equity (non- GAAP) $ 571,077 $ 609,262 $ 644,179 $ 622,684 $ 636,157 $ 648,930 $ 668,385 $ 748,653 ROAE, annualized (GAAP) 7.55 % 5.06 % 7.61 % 6.51 % 5.57 % 8.52 % 9.68 % 7.32 % ROATCE, annualized (non-GAAP) 11.15 % 7.31 % 10.63 % 9.22 % 7.85 % 11.86 % 13.33 % 11.14 % Adjusted ROATCE, annualized (non-GAAP) 12.76 % 10.53 % 12.15 % 11.21 % 11.59 % 12.16 % 13.51 % 13.36 % Dollars in thousands
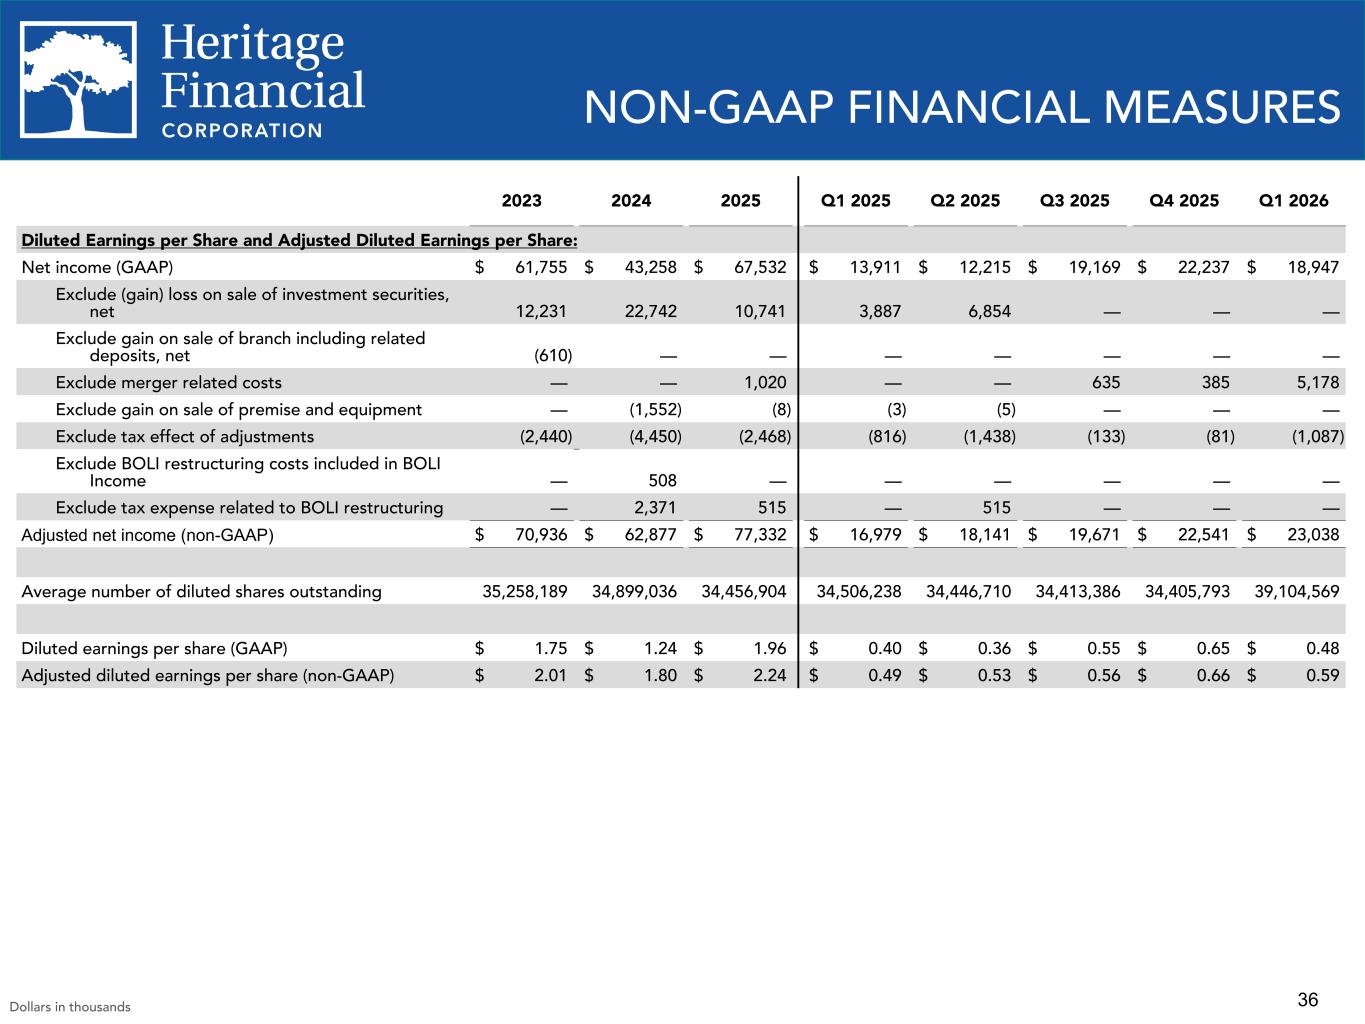
36 NON-GAAP FINANCIAL MEASURES 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Diluted Earnings per Share and Adjusted Diluted Earnings per Share: Net income (GAAP) $ 61,755 $ 43,258 $ 67,532 $ 13,911 $ 12,215 $ 19,169 $ 22,237 $ 18,947 Exclude (gain) loss on sale of investment securities, net 12,231 22,742 10,741 3,887 6,854 — — — Exclude gain on sale of branch including related deposits, net (610) — — — — — — — Exclude merger related costs — — 1,020 — — 635 385 5,178 Exclude gain on sale of premise and equipment — (1,552) (8) (3) (5) — — — Exclude tax effect of adjustments (2,440) (4,450) (2,468) (816) (1,438) (133) (81) (1,087) Exclude BOLI restructuring costs included in BOLI Income — 508 — — — — — — Exclude tax expense related to BOLI restructuring — 2,371 515 — 515 — — — Adjusted net income (non-GAAP) $ 70,936 $ 62,877 $ 77,332 $ 16,979 $ 18,141 $ 19,671 $ 22,541 $ 23,038 Average number of diluted shares outstanding 35,258,189 34,899,036 34,456,904 34,506,238 34,446,710 34,413,386 34,405,793 39,104,569 Diluted earnings per share (GAAP) $ 1.75 $ 1.24 $ 1.96 $ 0.40 $ 0.36 $ 0.55 $ 0.65 $ 0.48 Adjusted diluted earnings per share (non-GAAP) $ 2.01 $ 1.80 $ 2.24 $ 0.49 $ 0.53 $ 0.56 $ 0.66 $ 0.59 Dollars in thousands
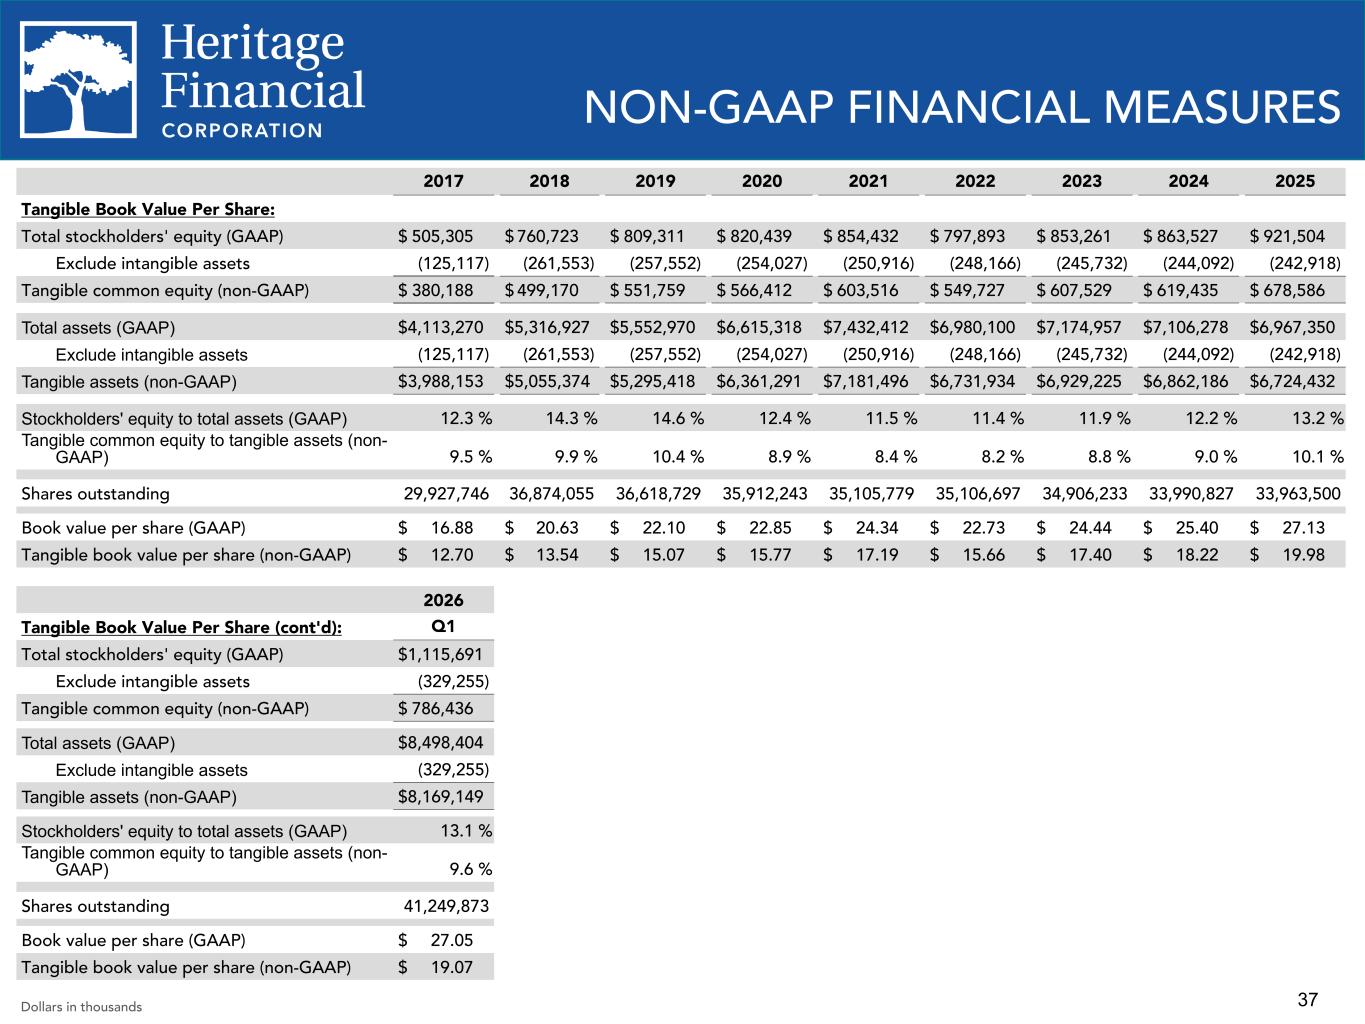
37 2017 2018 2019 2020 2021 2022 2023 2024 2025 Tangible Book Value Per Share: Total stockholders' equity (GAAP) $ 505,305 $ 760,723 $ 809,311 $ 820,439 $ 854,432 $ 797,893 $ 853,261 $ 863,527 $ 921,504 Exclude intangible assets (125,117) (261,553) (257,552) (254,027) (250,916) (248,166) (245,732) (244,092) (242,918) Tangible common equity (non-GAAP) $ 380,188 $ 499,170 $ 551,759 $ 566,412 $ 603,516 $ 549,727 $ 607,529 $ 619,435 $ 678,586 Total assets (GAAP) $ 4,113,270 $ 5,316,927 $ 5,552,970 $ 6,615,318 $ 7,432,412 $ 6,980,100 $ 7,174,957 $ 7,106,278 $ 6,967,350 Exclude intangible assets (125,117) (261,553) (257,552) (254,027) (250,916) (248,166) (245,732) (244,092) (242,918) Tangible assets (non-GAAP) $ 3,988,153 $ 5,055,374 $ 5,295,418 $ 6,361,291 $ 7,181,496 $ 6,731,934 $ 6,929,225 $ 6,862,186 $ 6,724,432 Stockholders' equity to total assets (GAAP) 12.3 % 14.3 % 14.6 % 12.4 % 11.5 % 11.4 % 11.9 % 12.2 % 13.2 % Tangible common equity to tangible assets (non- GAAP) 9.5 % 9.9 % 10.4 % 8.9 % 8.4 % 8.2 % 8.8 % 9.0 % 10.1 % Shares outstanding 29,927,746 36,874,055 36,618,729 35,912,243 35,105,779 35,106,697 34,906,233 33,990,827 33,963,500 Book value per share (GAAP) $ 16.88 $ 20.63 $ 22.10 $ 22.85 $ 24.34 $ 22.73 $ 24.44 $ 25.40 $ 27.13 Tangible book value per share (non-GAAP) $ 12.70 $ 13.54 $ 15.07 $ 15.77 $ 17.19 $ 15.66 $ 17.40 $ 18.22 $ 19.98 Moved to 2nd slide 2026 Tangible Book Value Per Share (cont'd): Q1 Total stockholders' equity (GAAP) $ 1,115,691 Exclude intangible assets (329,255) Tangible common equity (non-GAAP) $ 786,436 Total assets (GAAP) $ 8,498,404 Exclude intangible assets (329,255) Tangible assets (non-GAAP) $ 8,169,149 Stockholders' equity to total assets (GAAP) 13.1 % Tangible common equity to tangible assets (non- GAAP) 9.6 % Shares outstanding 41,249,873 Book value per share (GAAP) $ 27.05 Tangible book value per share (non-GAAP) $ 19.07 NON-GAAP FINANCIAL MEASURES Dollars in thousands
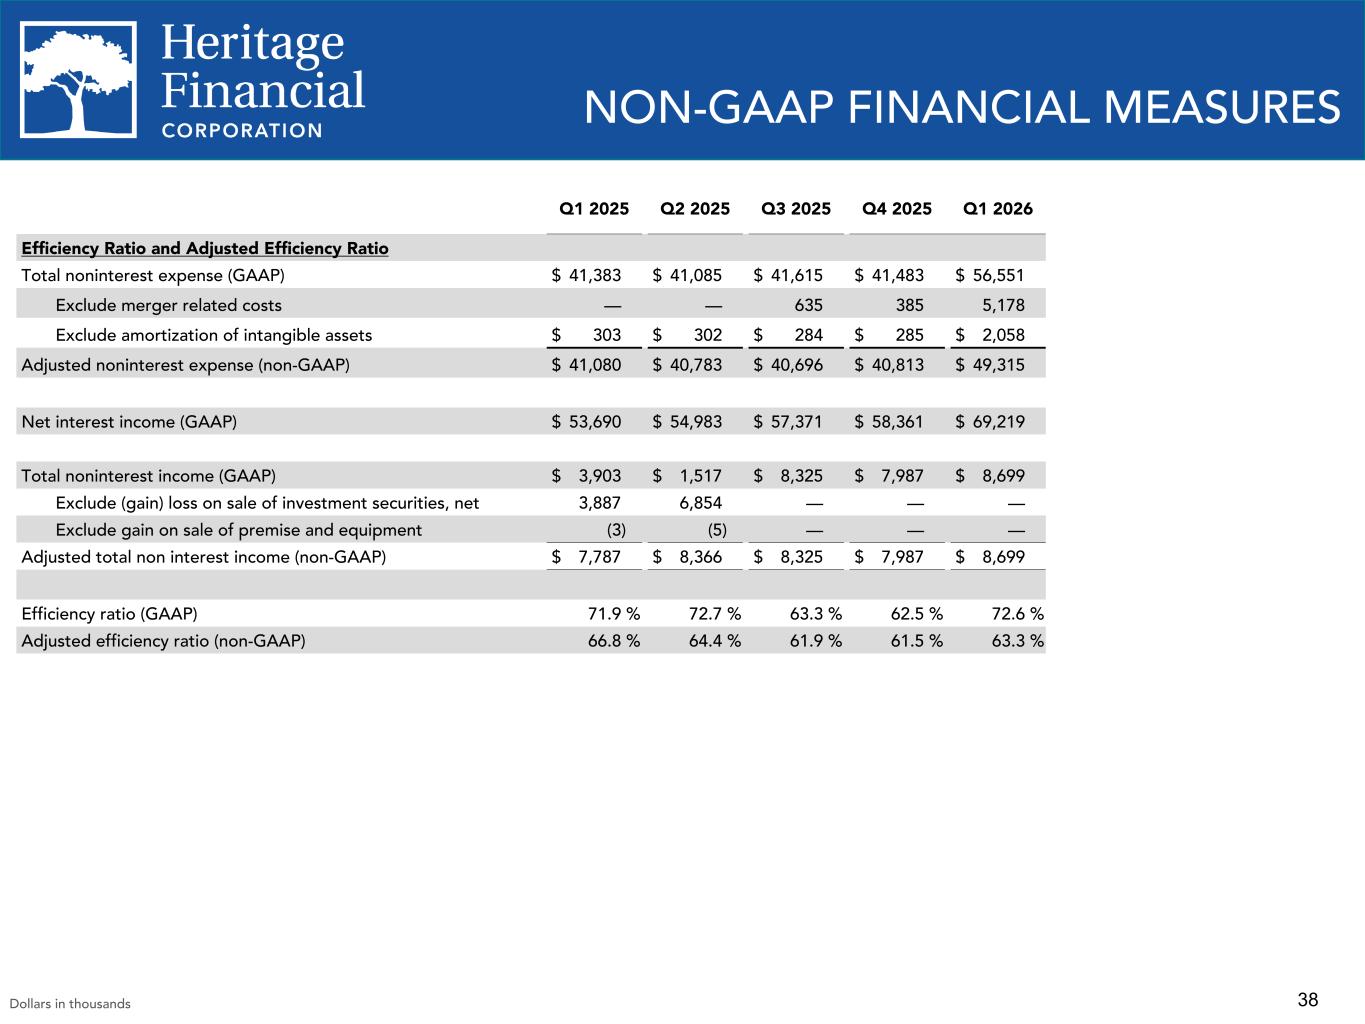
38 NON-GAAP FINANCIAL MEASURES Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Efficiency Ratio and Adjusted Efficiency Ratio Total noninterest expense (GAAP) $ 41,383 $ 41,085 $ 41,615 $ 41,483 $ 56,551 Exclude merger related costs — — 635 385 5,178 Exclude amortization of intangible assets $ 303 $ 302 $ 284 $ 285 $ 2,058 Adjusted noninterest expense (non-GAAP) $ 41,080 $ 40,783 $ 40,696 $ 40,813 $ 49,315 Net interest income (GAAP) $ 53,690 $ 54,983 $ 57,371 $ 58,361 $ 69,219 Total noninterest income (GAAP) $ 3,903 $ 1,517 $ 8,325 $ 7,987 $ 8,699 Exclude (gain) loss on sale of investment securities, net 3,887 6,854 — — — Exclude gain on sale of premise and equipment (3) (5) — — — Adjusted total non interest income (non-GAAP) $ 7,787 $ 8,366 $ 8,325 $ 7,987 $ 8,699 Efficiency ratio (GAAP) 71.9 % 72.7 % 63.3 % 62.5 % 72.6 % Adjusted efficiency ratio (non-GAAP) 66.8 % 64.4 % 61.9 % 61.5 % 63.3 % Dollars in thousands
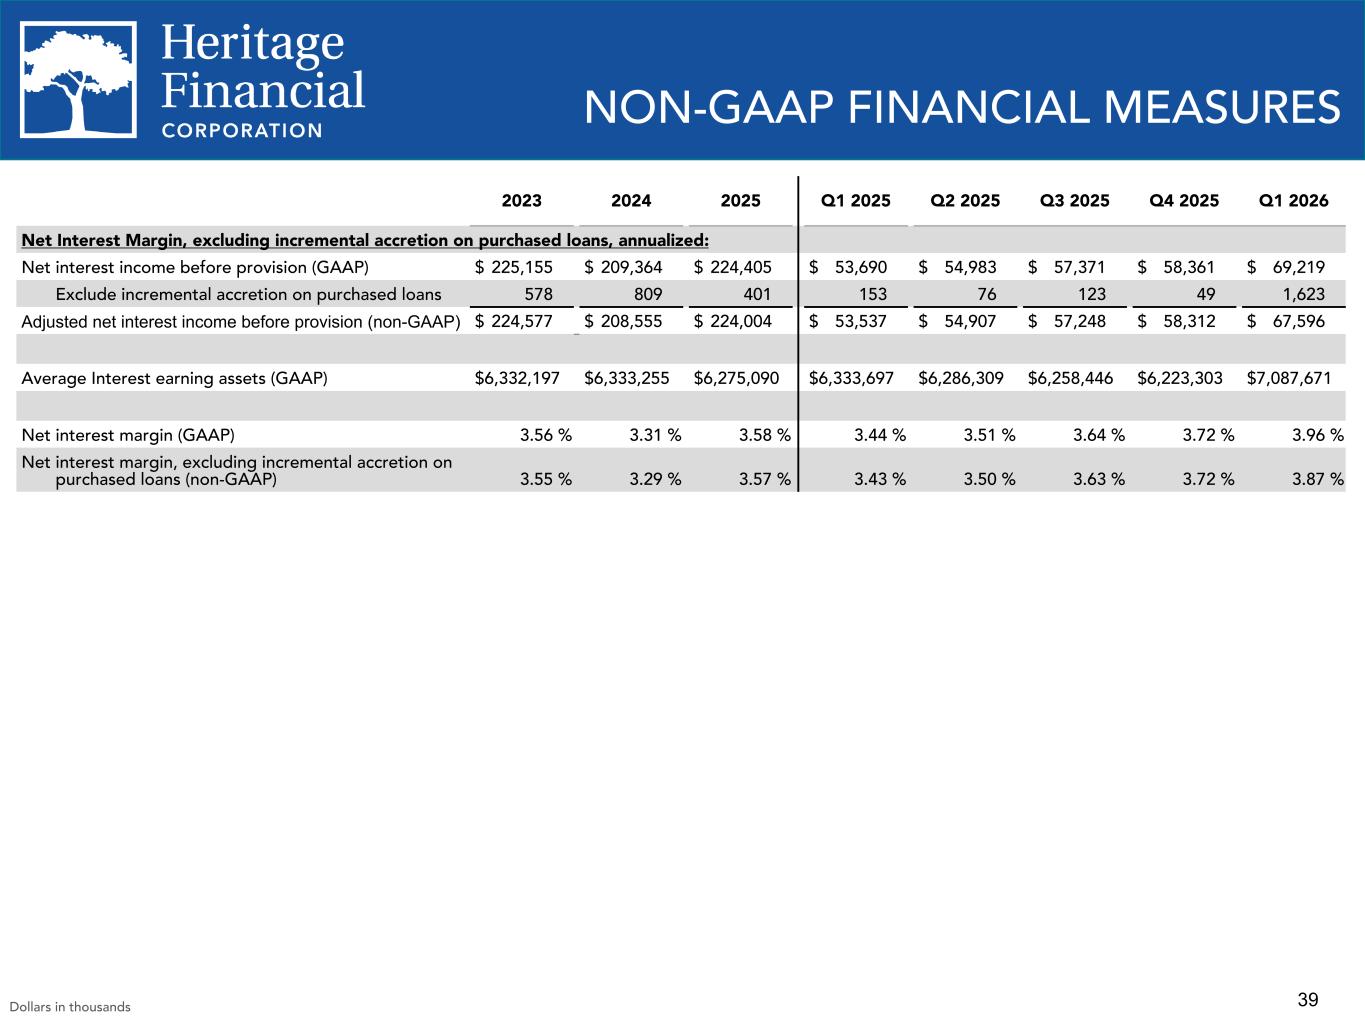
39 NON-GAAP FINANCIAL MEASURES 2023 2024 2025 Q1 2025 Q2 2025 Q3 2025 Q4 2025 Q1 2026 Net Interest Margin, excluding incremental accretion on purchased loans, annualized: Net interest income before provision (GAAP) $ 225,155 $ 209,364 $ 224,405 $ 53,690 $ 54,983 $ 57,371 $ 58,361 $ 69,219 Exclude incremental accretion on purchased loans 578 809 401 153 76 123 49 1,623 Adjusted net interest income before provision (non-GAAP) $ 224,577 $ 208,555 $ 224,004 $ 53,537 $ 54,907 $ 57,248 $ 58,312 $ 67,596 Average Interest earning assets (GAAP) $ 6,332,197 $ 6,333,255 $ 6,275,090 $ 6,333,697 $ 6,286,309 $ 6,258,446 $ 6,223,303 $ 7,087,671 Net interest margin (GAAP) 3.56 % 3.31 % 3.58 % 3.44 % 3.51 % 3.64 % 3.72 % 3.96 % Net interest margin, excluding incremental accretion on purchased loans (non-GAAP) 3.55 % 3.29 % 3.57 % 3.43 % 3.50 % 3.63 % 3.72 % 3.87 % Dollars in thousands
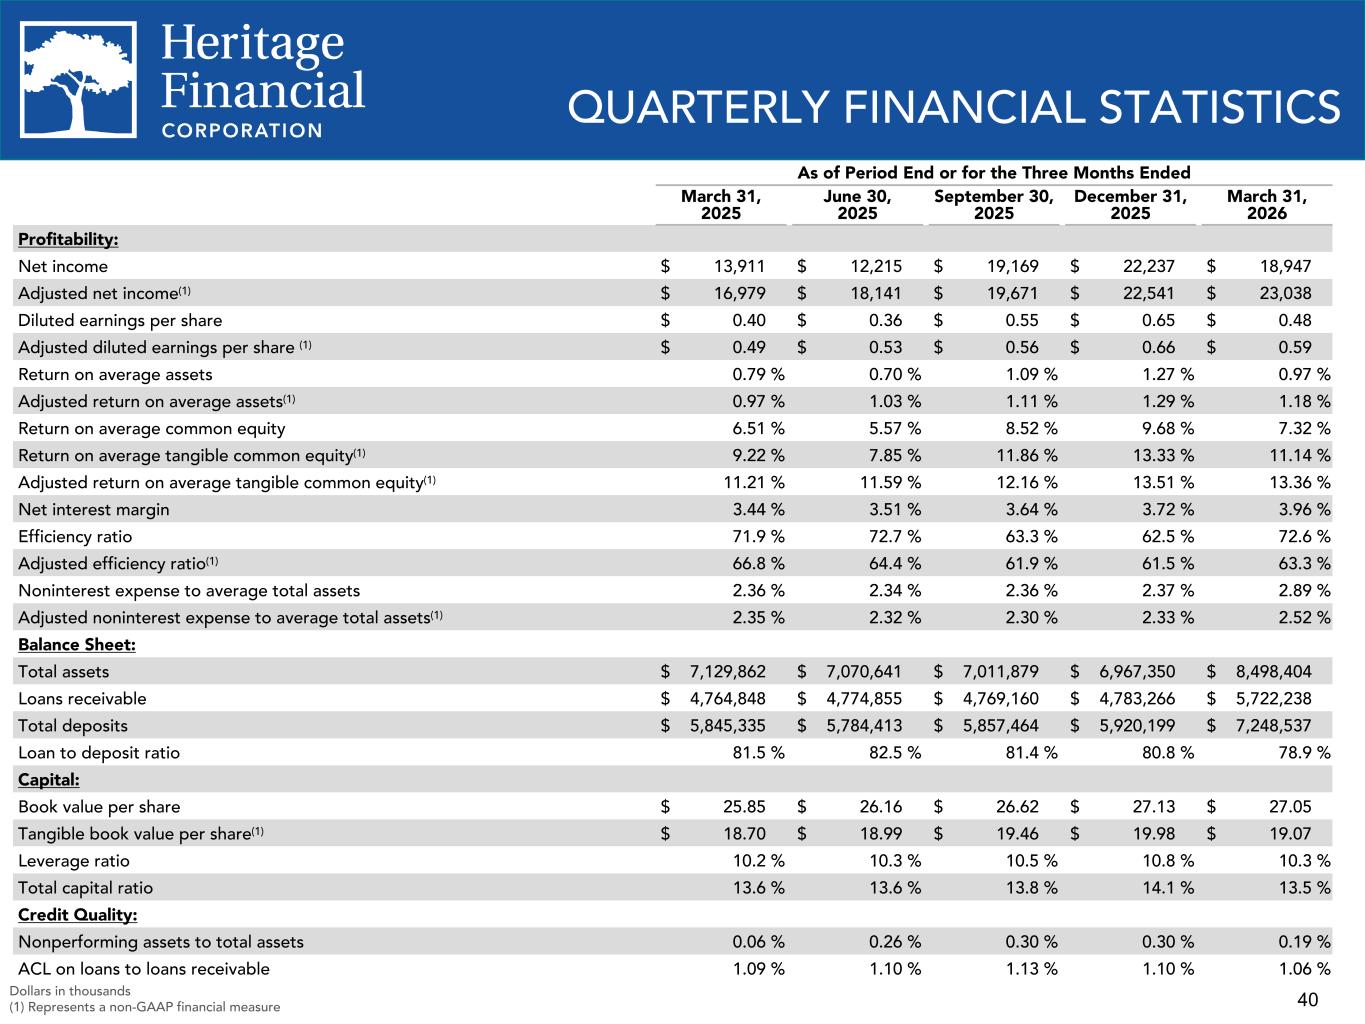
40 As of Period End or for the Three Months Ended March 31, 2025 June 30, 2025 September 30, 2025 December 31, 2025 March 31, 2026 Profitability: Net income $ 13,911 $ 12,215 $ 19,169 $ 22,237 $ 18,947 Adjusted net income(1) $ 16,979 $ 18,141 $ 19,671 $ 22,541 $ 23,038 Diluted earnings per share $ 0.40 $ 0.36 $ 0.55 $ 0.65 $ 0.48 Adjusted diluted earnings per share (1) $ 0.49 $ 0.53 $ 0.56 $ 0.66 $ 0.59 Return on average assets 0.79 % 0.70 % 1.09 % 1.27 % 0.97 % Adjusted return on average assets(1) 0.97 % 1.03 % 1.11 % 1.29 % 1.18 % Return on average common equity 6.51 % 5.57 % 8.52 % 9.68 % 7.32 % Return on average tangible common equity(1) 9.22 % 7.85 % 11.86 % 13.33 % 11.14 % Adjusted return on average tangible common equity(1) 11.21 % 11.59 % 12.16 % 13.51 % 13.36 % Net interest margin 3.44 % 3.51 % 3.64 % 3.72 % 3.96 % Efficiency ratio 71.9 % 72.7 % 63.3 % 62.5 % 72.6 % Adjusted efficiency ratio(1) 66.8 % 64.4 % 61.9 % 61.5 % 63.3 % Noninterest expense to average total assets 2.36 % 2.34 % 2.36 % 2.37 % 2.89 % Adjusted noninterest expense to average total assets(1) 2.35 % 2.32 % 2.30 % 2.33 % 2.52 % Balance Sheet: Total assets $ 7,129,862 $ 7,070,641 $ 7,011,879 $ 6,967,350 $ 8,498,404 Loans receivable $ 4,764,848 $ 4,774,855 $ 4,769,160 $ 4,783,266 $ 5,722,238 Total deposits $ 5,845,335 $ 5,784,413 $ 5,857,464 $ 5,920,199 $ 7,248,537 Loan to deposit ratio 81.5 % 82.5 % 81.4 % 80.8 % 78.9 % Capital: Book value per share $ 25.85 $ 26.16 $ 26.62 $ 27.13 $ 27.05 Tangible book value per share(1) $ 18.70 $ 18.99 $ 19.46 $ 19.98 $ 19.07 Leverage ratio 10.2 % 10.3 % 10.5 % 10.8 % 10.3 % Total capital ratio 13.6 % 13.6 % 13.8 % 14.1 % 13.5 % Credit Quality: Nonperforming assets to total assets 0.06 % 0.26 % 0.30 % 0.30 % 0.19 % ACL on loans to loans receivable 1.09 % 1.10 % 1.13 % 1.10 % 1.06 % Dollars in thousands (1) Represents a non-GAAP financial measure QUARTERLY FINANCIAL STATISTICS