
OCFC 8-K
Oceanfirst Financial Corp (OCFC)
8-K
2021-10-29
For: 2021-10-28
View Original
Added on
April 08, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, DC
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d)
of the Securities Exchange Act of 1934
Date of report (Date of earliest event reported): October 28, 2021
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation or organization) | (Commission File No.) | (IRS Employer Identification No.) | ||||||||||||
(Address of principal executive offices, including zip code)
(732 )240-4500
(Registrant’s telephone number, including area code)
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading symbol | Name of each exchange in which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (17 CFR 230.405) or Rule 12b-2 of the Securities Exchange Act of 1934 (17 CFR 240.12b-2).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
ITEM 2.02RESULTS OF OPERATIONS AND FINANCIAL CONDITION
On October 28, 2021, OceanFirst Financial Corp. (the “Company”) issued a press release announcing its financial results for the quarter ended September 30, 2021. That press release is attached to this Report as Exhibit 99.1.
ITEM 7.01 REGULATION FD DISCLOSURE
The Company is scheduled to make presentations to current and prospective investors after October 28, 2021. Attached as Exhibit 99.2 of this Form 8-K is a copy of the presentation which OceanFirst Financial Corp. will make available at these presentations and will post on its website at www.oceanfirst.com. This report is being furnished to the SEC and shall not be deemed “filed” for any purpose.
ITEM 8.01OTHER EVENTS
In the press release described in Item 2.02, the Company announced that the Board of Directors declared a regular quarterly cash dividend on the Company’s outstanding common stock. The cash dividend will be in the amount of $0.17 per share and will be payable on November 19, 2021 to the stockholders of record at the close of business on November 8, 2021.
ITEM 9.01FINANCIAL STATEMENTS AND EXHIBITS
| (d) | EXHIBITS | |||||||
| Press Release dated | October 28, 2021 | |||||||
Text of written presentation which OceanFirst Financial Corp. intends to provide to current and prospective investors after October 28, 2021. | ||||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| OCEANFIRST FINANCIAL CORP. | ||||||||
| Dated: | October 28, 2021 | /s/ Michael J. Fitzpatrick | ||||||
| Michael J. Fitzpatrick | ||||||||
| Executive Vice President and Chief Financial Officer | ||||||||
 | Press Release | |||||||
Exhibit 99.1
Company Contact:
Michael J. Fitzpatrick
Chief Financial Officer
OceanFirst Financial Corp.
Tel: (732) 240-4500, ext. 7506
Email: [email protected]
FOR IMMEDIATE RELEASE
OCEANFIRST FINANCIAL CORP.
ANNOUNCES THIRD QUARTER
FINANCIAL RESULTS
RED BANK, NEW JERSEY, October 28, 2021 - OceanFirst Financial Corp. (NASDAQ:“OCFC”), (the “Company”), the holding company for OceanFirst Bank N.A. (the “Bank”), announced net income available to common stockholders of $23.2 million, or $0.39 per diluted share, for the three months ended September 30, 2021 as compared to net loss available to common stockholders of $6.0 million, or $0.10 per diluted share, for the corresponding prior year period. For the nine months ended September 30, 2021, the Company reported net income available to common stockholders of $84.4 million, or $1.41 per diluted share, as compared to $29.2 million, or $0.49 per diluted share, for the corresponding prior year period. Selected performance metrics are as follows (refer to “Selected Quarterly Financial Data” for additional information regarding the metrics):
| For the Three Months Ended, | For the Nine Months Ended, | ||||||||||||||||||||||||||||
| Performance Ratios (Annualized): | September 30, | June 30, | September 30, | September 30, | September 30, | ||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2021 | 2020 | |||||||||||||||||||||||||
| Return on average assets | 0.78 | % | 1.03 | % | (0.21) | % | 0.98 | % | 0.35 | % | |||||||||||||||||||
| Return on average stockholders’ equity | 6.05 | 7.88 | (1.61) | 7.49 | 2.68 | ||||||||||||||||||||||||
Return on average tangible stockholders’ equity (a) | 9.20 | 12.07 | (2.51) | 11.46 | 4.22 | ||||||||||||||||||||||||
| Efficiency ratio | 67.43 | 60.21 | 66.83 | 60.62 | 65.39 | ||||||||||||||||||||||||
| Net interest margin | 2.93 | 2.89 | 2.97 | 2.91 | 3.23 | ||||||||||||||||||||||||
(a) Return on average tangible stockholders’ equity, a non-GAAP (“generally accepted accounting principles”) measure, excludes the impact of intangible assets and goodwill from both assets and stockholders’ equity. Refer to “Explanation of Non-GAAP Financial Measures” and the “Non-GAAP Reconciliation” tables for additional information regarding our non-GAAP measures and impact per period.
Core earnings1 for the three and nine months ended September 30, 2021 amounted to $26.7 million and $82.7 million, respectively, or $0.45 and $1.38 per diluted share, respectively. Non-core operations had an adverse impact, net of tax, of $3.6 million for the three months ended September 30, 2021 and a favorable impact, net of tax, of $1.7 million for the nine months ended September 30, 2021, respectively.
| For the Three Months Ended, | For the Nine Months Ended, | ||||||||||||||||||||||||||||
| September 30, | June 30, | September 30, | September 30, | September 30, | |||||||||||||||||||||||||
Core Ratios1 (Annualized): | 2021 | 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||
| Return on average assets | 0.90 | % | 1.02 | % | (0.01) | % | 0.95 | % | 0.59 | % | |||||||||||||||||||
| Return on average tangible stockholders’ equity | 10.62 | 12.04 | (0.11) | 11.23 | 7.10 | ||||||||||||||||||||||||
| Efficiency ratio | 62.22 | 60.06 | 59.63 | 60.23 | 57.95 | ||||||||||||||||||||||||
Key developments for the recent quarter are described below:
•Loan Growth: Total loan growth for the quarter was $361.0 million. Total loan growth, excluding the impact of Paycheck Protection Program (“PPP”) loans of $30.5 million, was $391.5 million for the quarter, reflecting quarterly loan originations of $771.8 million and the purchase of a residential loan pool of $219.7 million. Along with record loan production during the quarter, the committed loan pipeline remains strong at $651.4 million.
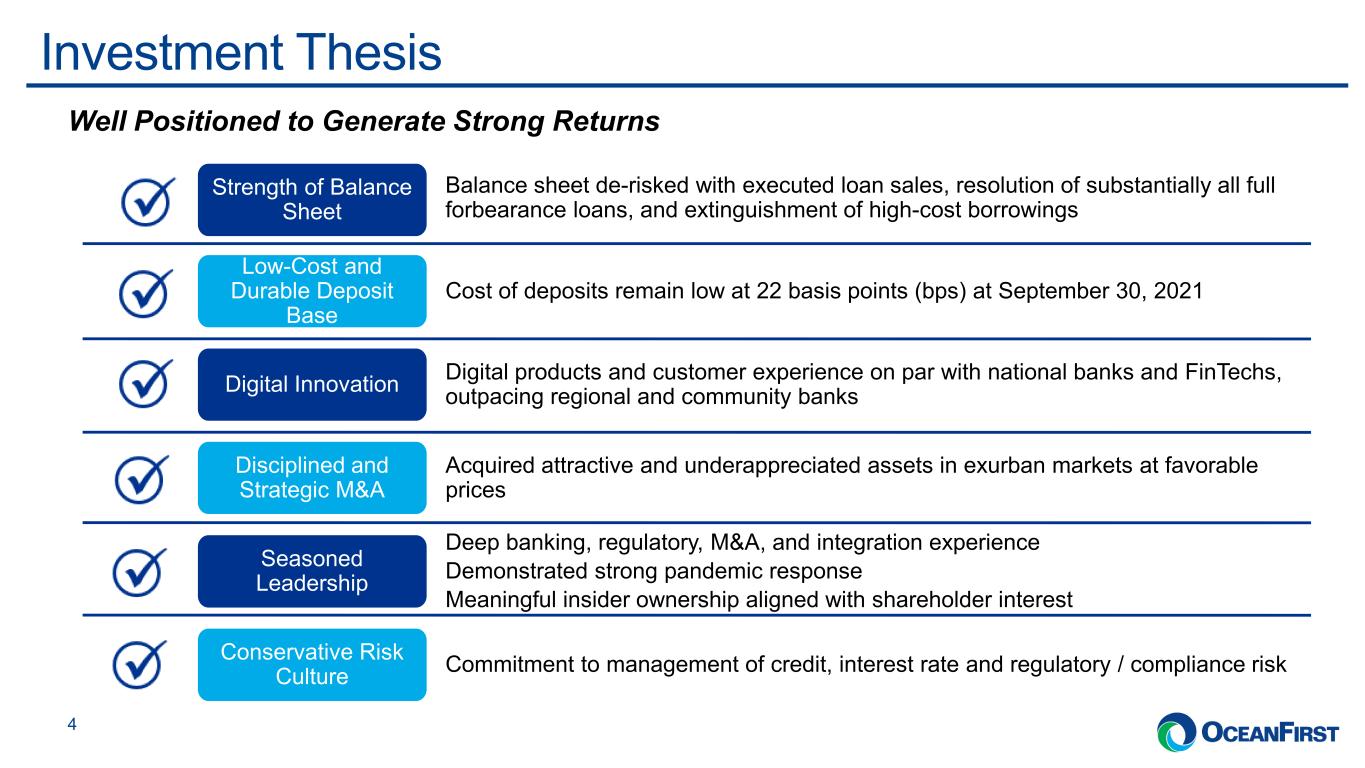
•Deposit Growth: Deposits increased $358.8 million during the third quarter, while cost of deposits decreased 5 basis points to 0.22% from 0.27% in the prior linked quarter, reflecting a trend in improving deposit quality.
1 Core earnings, a non-GAAP measure, and ratios derived from core earnings, for the periods presented, excludes merger related expenses, branch consolidation expenses, net loss (gain) on equity investments, Federal Home Loan Bank (“FHLB”) advance prepayment fees, gain on sale of PPP loans, the opening credit loss expense under the Current Expected Credit Loss (“CECL”) model related to the acquisitions of Two River Bancorp (“Two River”) and Country Bank Holding Company, Inc. (“Country Bank”) and the income tax effect of these items, (collectively referred to as “non-core” operations). Refer to “Explanation of Non-GAAP Financial Measures” and the “Non-GAAP Reconciliation” tables for additional information regarding our non-GAAP measures and impact per period.
2
•Net Interest Income and Margin: Net interest income increased by $3.1 million to $77.1 million from $74.0 million in the prior linked quarter. Net interest margin increased to 2.93%, compared to 2.89% in the prior linked quarter, largely driven by the Bank’s disciplined deposit pricing practices.
Chairman and Chief Executive Officer, Christopher D. Maher, commented on the Company’s results, “We are pleased to report strong loan originations of $771.8 million along with a record loan pipeline of $651.4 million, reflecting the momentum from our expanding commercial banking team.” Mr. Maher added, “During the quarter, the system integration of our New York Region was completed, which included the customers acquired from Country Bank last year. With this latest system conversion, all OceanFirst customers are able to take advantage of our accounts and services across all channels providing seamless and fully integrated operations.”
The Company’s Board of Directors declared its ninety-ninth consecutive quarterly cash dividend on common stock. The quarterly cash dividend on common stock of $0.17 per share, will be paid on November 19, 2021 to common stockholders of record on November 8, 2021. The Board previously declared a quarterly cash dividend on preferred stock of $0.4375 per depositary share, representing 1/40th interest in the Series A Preferred Stock. This dividend will be paid on November 15, 2021 to preferred stockholders of record on October 29, 2021.
As previously announced on August 4, 2021, the Bank entered into a definitive agreement to sell two New Jersey branch locations to First Bank, including the owned premises and equipment, all deposits associated with the branches, which totaled approximately $124 million as of June 30, 2021, as well as selected performing loans totaling approximately $14 million as of June 30, 2021. The Bank has received the required regulatory approval and the closing of the sale and customer conversion is expected to take place in early December.
3
Results of Operations
Net income for the three months ended September 30, 2021 and net loss for the three months ended September 30, 2020 were adversely impacted by non-core operations of $3.6 million, net of tax, and $5.8 million, net of tax, respectively. Net income was favorably impacted by $1.7 million, net of tax, and adversely impacted by $19.9 million, net of tax, of non-core operations for the nine months ended September 30, 2021 and 2020, respectively. Core earnings for the three months ended September 30, 2021 were $26.7 million, or $0.45 per diluted share, an increase from core losses of $266,000, or $0.00 per diluted share, for the corresponding prior year period. Core earnings for the nine months ended September 30, 2021 were $82.7 million, or $1.38 per diluted share, an increase from core earnings of $49.0 million, or $0.82 per diluted share, for the corresponding prior year period. Net income was favorably impacted by $78,000, net of tax, of non-core operations for the prior linked quarter. Core earnings for the three months ended September 30, 2021 decreased from $29.5 million, or $0.49 per diluted share, for the prior linked quarter.
Net Interest Income and Margin
Net interest income for the three months ended September 30, 2021, increased to $77.1 million, as compared to $76.8 million for the corresponding prior year period. Net interest income for the nine months ended September 30, 2021 decreased to $224.8 million as compared to $235.1 million for the corresponding prior year period, as a result of the lower interest rate environment. Average interest-earning assets increased by $192.3 million and $590.4 million for the three and nine months ended September 30, 2021, respectively, as compared to the same prior year periods, primarily concentrated in excess balance sheet liquidity. Average loans receivable, net of allowance for loan credit losses, decreased by $486.1 million and $371.4 million for the three and nine months ended September 30, 2021, respectively, as compared to the same prior year periods, primarily due to reductions in PPP loans. Net interest margin for the three and nine months ended September 30, 2021 decreased to 2.93% and 2.91%, respectively, from 2.97% and 3.23%, respectively, for the same prior year periods. The net
4
interest margin compression was primarily due to the excess balance sheet liquidity and the lower interest rate environment. For the three and nine months ended September 30, 2021, the cost of average interest-bearing liabilities decreased to 0.44% and 0.52%, respectively, from 0.83% and 0.93%, respectively, for the corresponding prior year periods. The total cost of deposits (including non-interest bearing deposits) was 0.22% and 0.28% for the three and nine months ended September 30, 2021, respectively, as compared to 0.49% and 0.58%, respectively, for the same prior year periods.
Net interest income for the three months ended September 30, 2021 increased by $3.1 million, as compared to the prior linked quarter, and net interest margin increased to 2.93%, compared to 2.89% for the prior linked quarter. Excluding the impact of purchase accounting accretion and prepayment fees, of 0.18% and 0.16% for the three months ended September 30, 2021 and June 30, 2021, respectively, net interest margin increased to 2.75% from 2.73%. The yield on average interest-earning assets decreased marginally to 3.24% from 3.25% in the prior linked quarter. The total cost of average interest-bearing liabilities was 0.44% for the three months ended September 30, 2021, as compared to 0.50% in the prior linked quarter, due to repricing of deposit costs and maturities of higher-yielding time deposits.
Benefit/Provision for Credit Losses
For the three and nine months ended September 30, 2021, the credit loss benefit was $3.2 million and $10.3 million, respectively, as compared to credit loss expense of $35.7 million and $55.3 million, respectively, for the corresponding prior year periods, and a credit loss benefit of $6.5 million in the prior linked quarter. The credit loss benefit for the three and nine months ended September 30, 2021 was significantly influenced by positive trends in the Bank’s asset quality combined with stabilizing trends in economic forecasts, including strong employment levels and GDP growth, partly offset by the economic uncertainty related to supply chain and labor market constraints.
5
Net loan recoveries were $386,000 and $442,000 for the three and nine months ended September 30, 2021, respectively, as compared to net loan charge-offs of $15.0 million and $15.9 million for the corresponding prior year periods, respectively, and net loan charge-offs of $224,000 in the prior linked quarter. The three months ended September 30, 2020 included $14.2 million in charge-offs related to the transfer of higher-risk commercial loans to held-for-sale, which were ultimately sold in the fourth quarter of 2020. Non-performing loans held-for-investment totaled $23.3 million at September 30, 2021, as compared to $31.7 million at June 30, 2021 and $29.9 million at September 30, 2020.
Non-interest Income
For the three and nine months ended September 30, 2021, other income increased to $9.9 million and $42.5 million, respectively, as compared to $8.2 million and $33.3 million, respectively, for the corresponding prior year periods. Other income for the three and nine months ended September 30, 2021 included non-core operations of $466,000 related to net losses on equity investments and $8.4 million related to net gains on equity investments, respectively. Other income for both the three and nine months ended September 30, 2020 included $3.6 million of net losses on equity investments. Excluding non-core operations, the decrease in other income for the three months ended September 30, 2021, as compared to the corresponding prior year period, was primarily due to decreases in gain on sale of loans of $1.0 million and fees and service charges of $759,000.
Excluding non-core operations, the decrease in other income for the nine months ended September 30, 2021, as compared to the corresponding prior year period, was primarily due to decreases in commercial loan swap income of $5.2 million, as a result of lower activity, and lower fees and service charges of $1.3 million, partially offset by increases in bankcard services of $1.7 million, due to lower card activity in the prior year period as a result of the pandemic, gain on sale of loans of $1.3 million, and PPP loan referral fees of $800,000.
6
Excluding non-core operations, other income for the three months ended September 30, 2021 decreased $878,000, as compared to the prior linked quarter, primarily due to decreases in gain on sale of loans of $1.3 million and lower fees and service charges of $836,000, partially offset by an increase in commercial loan swap income of $1.5 million, as a result of higher activity.
Non-interest Expense
Operating expenses increased to $58.7 million and decreased to $162.0 million for the three and nine months ended September 30, 2021, respectively, as compared to $56.8 million and $175.5 million, respectively, in the same prior year periods. Operating expenses for the three and nine months ended September 30, 2021 included $4.2 million and $6.1 million, respectively, of net expenses related to non-core operations. Operating expenses for the three and nine months ended September 30, 2020 included $4.0 million and $20.0 million, respectively, of net expenses related to non-core operations. Excluding non-core operations, the $1.6 million increase in operating expenses for the three months ended September 30, 2021, as compared to the corresponding prior year period, was primarily due to increases in compensation and benefits expense of $1.7 million and data processing expense of $846,000, partly offset by a decrease in equipment expense of $782,000.
Excluding non-core operations, the $372,000 increase in operating expenses for the nine months ended September 30, 2021, as compared to the corresponding prior year period, was primarily due to increases in compensation and benefits expense of $2.2 million, primarily related to higher benefit costs, federal deposit insurance and regulatory assessments of $1.4 million, and data processing expense of $953,000, partly offset by decreases in equipment expense of $1.8 million, marketing expense of $930,000, other operating expense of $469,000, and occupancy expense of $434,000.
Excluding non-core operations, operating expenses for the quarter ended September 30, 2021, increased $3.2 million, as compared to the prior linked quarter. The change was due to increases in data processing expense of $961,000, compensation and benefits expense of $818,000, professional fees of $698,000, and federal deposit insurance and regulatory assessments of $360,000.
7
Income Tax Expense/Benefit
The provision for income taxes was $7.4 million and $28.1 million for the three and nine months ended September 30, 2021, respectively, as compared to a benefit for income taxes of $2.6 million and provision for income taxes of $7.3 million for the same prior year periods, respectively, and provision for income taxes of $10.1 million for the prior linked quarter. The effective tax rate was 23.3% and 24.3% for the three and nine months ended September 30, 2021, respectively, as compared to 34.6% and 19.5% for the same prior year periods, respectively, and 24.8% for the prior linked quarter. The higher effective tax rate for the three months ended September 30, 2020 was primarily attributable to the net loss recognized during the quarter. The higher effective tax rate for the nine months ended September 30, 2021, as compared to the prior year period, was primarily due to the impact of a New Jersey tax code change and a higher allocation of taxable income to New York.
Financial Condition
Total assets increased by $381.4 million to $11.83 billion at September 30, 2021, from $11.45 billion at December 31, 2020. Cash and due from banks decreased $291.0 million, to $981.1 million at September 30, 2021, from $1.27 billion at December 31, 2020 as excess liquidity was primarily used to purchase securities and fund loan growth. Total debt securities increased by $319.4 million at September 30, 2021, as compared to December 31, 2020. Total loans, excluding PPP loans of $52.5 million and $95.4 million at September 30, 2021 and December 31, 2020, respectively, increased by $468.6 million, to $8.13 billion at September 30, 2021, from $7.66 billion at December 31, 2020.
Deposits increased by $346.5 million to $9.77 billion at September 30, 2021, from $9.43 billion at December 31, 2020. Excluding time deposits of $855.4 million at September 30, 2021 and $1.37 billion at December 31, 2020, total deposits increased by $863.8 million to $8.92 billion at September 30, 2021 from $8.05 billion at December 31, 2020. The loans-to-deposit ratio at September 30, 2021 was 83.7%, as compared to 82.3% at December 31, 2020.
8
Stockholders’ equity increased to $1.51 billion at September 30, 2021, as compared to $1.48 billion at December 31, 2020. On June 25, 2021, the Company announced the authorization of the Board of Directors of the 2021 Stock Repurchase Program to repurchase up to an additional 3.0 million shares, which is approximately 5% of the Company’s outstanding common stock. For the nine months ended September 30, 2021, the Company repurchased 1,460,009 shares under its stock repurchase program at a weighted average cost of $20.98, and there were 3,559,136 shares available for repurchase at September 30, 2021 under the existing repurchase programs. Stockholders’ equity per common share increased to $25.47 at September 30, 2021, as compared to $24.57 at December 31, 2020. Tangible common equity per common share increased to $15.78 at September 30, 2021, as compared to $14.98 at December 31, 2020.
Asset Quality
The Company’s non-performing loans decreased to $23.3 million at September 30, 2021, as compared to $36.4 million at December 31, 2020. Non-performing loans at September 30, 2021 do not include $41.4 million of purchased with credit deterioration (“PCD”) loans from prior bank acquisitions. The allowance for loan credit losses as a percentage of non-performing loans was 214.8% at September 30, 2021, as compared to 166.8% at December 31, 2020. The Company’s level of 30 to 89 days delinquent loans, excluding non-performing and PCD loans, improved to $6.6 million at September 30, 2021, from $34.7 million at December 31, 2020.
The Company’s allowance for loan credit losses was 0.61% of total loans at September 30, 2021, as compared to 0.78% at December 31, 2020. The allowance for loan credit losses plus the unamortized credit and PCD marks amounted to $71.5 million, or 0.87% of total loans, at September 30, 2021.
9
Explanation of Non-GAAP Financial Measures
Reported amounts are presented in accordance with GAAP. The Company’s management believes that the supplemental non-GAAP information, which consists of reported net income excluding non-core operations and reporting equity and asset amounts excluding intangible assets and goodwill, which can vary from period to period, provides a better comparison of period to period operating performance. Additionally, the Company believes this information is utilized by regulators and market analysts to evaluate a company’s financial condition and, therefore, such information is useful to investors. These disclosures should not be viewed as a substitute for financial results in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures which may be presented by other companies. Refer to the Non-GAAP Reconciliation table at the end of this document for details on the earnings impact of these items.
Conference Call
As previously announced, the Company will host an earnings conference call on Friday, October 29, 2021 at 11:00 a.m. Eastern Time. The direct dial number for the call is (844) 200-6205, using the access code 946108. For those unable to participate in the conference call, a replay will be available. To access the replay, dial (866) 813-9403, access code 327620, from one hour after the end of the call until January 27, 2022. The conference call, as well as the replay, are also available (listen-only) by internet webcast at www.oceanfirst.com in the Investor Relations section.
* * *
10
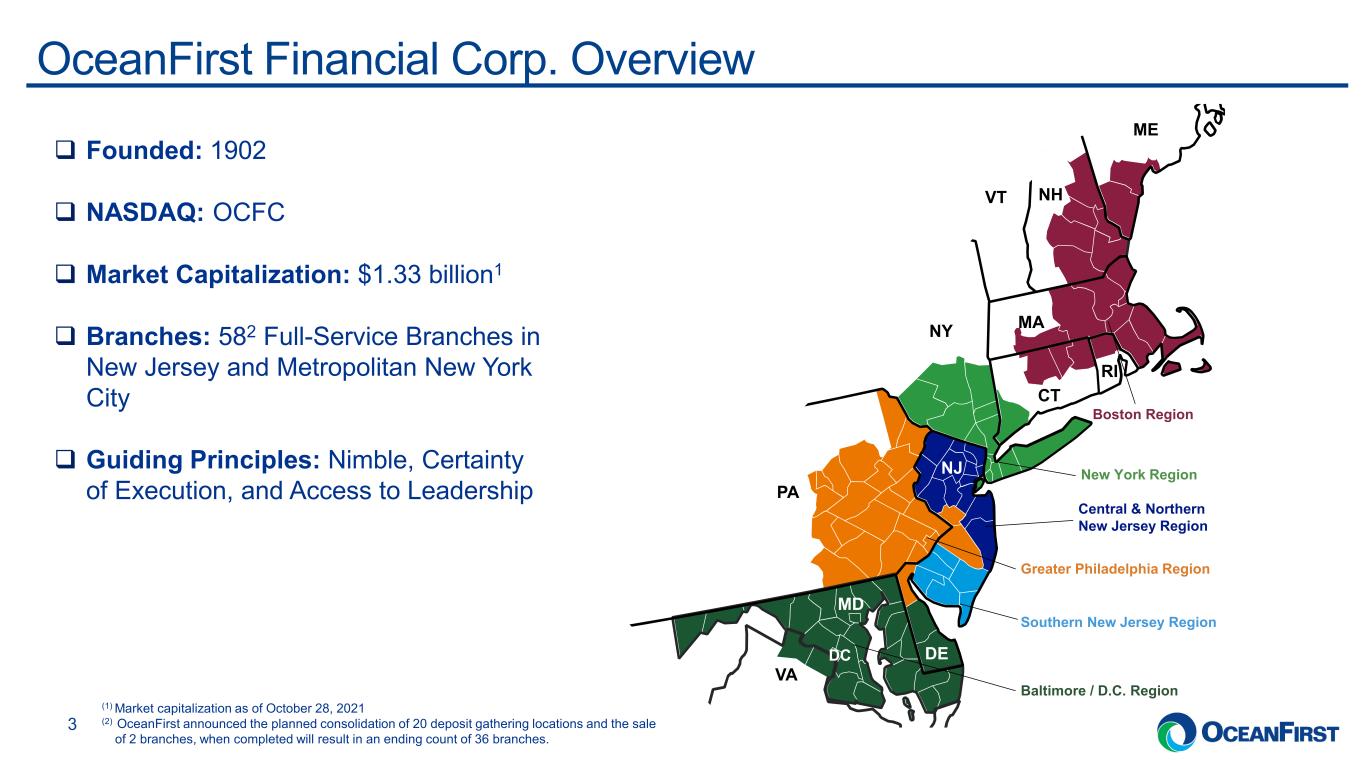
OceanFirst Financial Corp.’s subsidiary, OceanFirst Bank N.A., founded in 1902, is a $11.8 billion regional bank providing financial services throughout New Jersey and in the major metropolitan markets of Philadelphia, New York, Baltimore, Washington D.C. and Boston. OceanFirst Bank delivers commercial and residential financing, treasury management, trust and asset management, and deposit services and is one of the largest and oldest community-based financial institutions headquartered in New Jersey. To learn more about OceanFirst, go to www.oceanfirst.com.
Forward-Looking Statements
In addition to historical information, this news release contains certain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995, which are based on certain assumptions and describe future plans, strategies and expectations of the Company. These forward-looking statements are generally identified by use of the words “believe,” “expect,” “intend,” “anticipate,” “estimate,” “project,” “will,” “should,” “may,” “view,” “opportunity,” “potential,” or similar expressions or expressions of confidence. The Company’s ability to predict results or the actual effect of future plans or strategies is inherently uncertain. Factors which could have a material adverse effect on the operations of the Company and its subsidiaries include, but are not limited to: the impact of the COVID-19 or any other pandemic on our operations and financial results and those of our customers, changes in interest rates, general economic conditions, levels of unemployment in the Bank’s lending area, real estate market values in the Bank’s lending area, future natural disasters and increases to flood insurance premiums, the level of prepayments on loans and mortgage-backed securities, legislative/regulatory changes, monetary and fiscal policies of the U.S. Government including policies of the U.S. Treasury and the Board of Governors of the Federal Reserve System, the quality or composition of the loan or investment portfolios, demand for loan products, deposit flows, competition, demand for financial services in the Company’s market area, accounting principles and guidelines and the Bank’s ability to successfully integrate acquired operations. These risks and uncertainties are further discussed in the Company’s Annual Report on Form 10-K for the year ended December 31, 2020, under Item 1A - Risk Factors and elsewhere, and subsequent securities filings and should be considered in evaluating forward-looking statements and undue reliance should not be placed on such statements. The Company does not undertake, and specifically disclaims any obligation, to publicly release the result of any revisions which may be made to any forward-looking statements to reflect events or circumstances after the date of such statements or to reflect the occurrence of anticipated or unanticipated events.
11
OceanFirst Financial Corp.
CONSOLIDATED STATEMENTS OF FINANCIAL CONDITION
(dollars in thousands, except per share amounts)
| September 30, | June 30, | December 31, | September 30, | |||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2020 | |||||||||||||||||||||||
| (Unaudited) | (Unaudited) | (Unaudited) | ||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||
| Cash and due from banks | $ | 981,126 | $ | 1,084,029 | $ | 1,272,134 | $ | 980,870 | ||||||||||||||||||
| Debt securities available-for-sale, at estimated fair value | 314,620 | 249,330 | 183,302 | 169,634 | ||||||||||||||||||||||
Debt securities held-to-maturity, net of allowance for securities credit losses of $1,503 at September 30, 2021, $1,609 at June 30, 2021, $1,715 at December 31, 2020 and $2,393 at September 30, 2020 (estimated fair value of $1,143,381 at September 30, 2021, $1,169,123 at June 30, 2021, $968,466 at December 31, 2020 and $902,418 at September 30, 2020) | 1,125,382 | 1,146,735 | 937,253 | 871,688 | ||||||||||||||||||||||
| Equity investments | 101,314 | 90,917 | 107,079 | 63,846 | ||||||||||||||||||||||
| Restricted equity investments, at cost | 53,017 | 52,519 | 51,705 | 67,505 | ||||||||||||||||||||||
Loans receivable, net of allowance for loan credit losses of $50,153 at September 30, 2021, $53,876 at June 30, 2021, $60,735 at December 31, 2020 and $56,350 at September 30, 2020 | 8,139,961 | 7,774,351 | 7,704,857 | 7,943,390 | ||||||||||||||||||||||
| Loans held-for-sale | 13,428 | 1,493 | 45,524 | 388,763 | ||||||||||||||||||||||
| Interest and dividends receivable | 32,512 | 28,014 | 35,269 | 40,671 | ||||||||||||||||||||||
| Other real estate owned | 106 | 106 | 106 | 106 | ||||||||||||||||||||||
| Premises and equipment, net | 123,669 | 117,509 | 107,094 | 103,249 | ||||||||||||||||||||||
| Bank owned life insurance | 260,072 | 259,608 | 265,253 | 264,167 | ||||||||||||||||||||||
| Assets held for sale | 4,613 | 4,032 | 5,782 | 6,717 | ||||||||||||||||||||||
| Goodwill | 500,319 | 500,319 | 500,319 | 500,849 | ||||||||||||||||||||||
| Core deposit intangible | 19,558 | 20,912 | 23,668 | 25,194 | ||||||||||||||||||||||
| Other assets | 159,991 | 154,027 | 208,968 | 224,648 | ||||||||||||||||||||||
| Total assets | $ | 11,829,688 | $ | 11,483,901 | $ | 11,448,313 | $ | 11,651,297 | ||||||||||||||||||
| Liabilities and Stockholders’ Equity | ||||||||||||||||||||||||||
| Deposits | $ | 9,774,097 | $ | 9,415,286 | $ | 9,427,616 | $ | 9,283,288 | ||||||||||||||||||
| Federal Home Loan Bank advances | — | — | — | 343,452 | ||||||||||||||||||||||
Securities sold under agreements to repurchase with retail customers | 143,292 | 141,475 | 128,454 | 142,823 | ||||||||||||||||||||||
| Other borrowings | 228,887 | 228,564 | 235,471 | 246,941 | ||||||||||||||||||||||
| Advances by borrowers for taxes and insurance | 22,214 | 21,281 | 17,296 | 20,104 | ||||||||||||||||||||||
| Other liabilities | 147,949 | 168,506 | 155,346 | 152,975 | ||||||||||||||||||||||
| Total liabilities | 10,316,439 | 9,975,112 | 9,964,183 | 10,189,583 | ||||||||||||||||||||||
| Total stockholders’ equity | 1,513,249 | 1,508,789 | 1,484,130 | 1,461,714 | ||||||||||||||||||||||
| Total liabilities and stockholders’ equity | $ | 11,829,688 | $ | 11,483,901 | $ | 11,448,313 | $ | 11,651,297 | ||||||||||||||||||
12
OceanFirst Financial Corp.
CONSOLIDATED STATEMENTS OF INCOME
(in thousands, except per share amounts)
| For the Three Months Ended, | For the Nine Months Ended, | |||||||||||||||||||||||||||||||
| September 30, | June 30, | September 30, | September 30, | September 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | 2021 | 2020 | ||||||||||||||||||||||||||||
| |---------------------- (Unaudited) ----------------------| | |---------- (Unaudited) -----------| | |||||||||||||||||||||||||||||||
| Interest income: | ||||||||||||||||||||||||||||||||
| Loans | $ | 78,889 | $ | 77,048 | $ | 85,933 | $ | 233,845 | $ | 264,224 | ||||||||||||||||||||||
| Debt securities | 5,040 | 5,984 | 5,596 | 16,379 | 18,577 | |||||||||||||||||||||||||||
| Equity investments and other | 1,491 | 309 | 1,433 | 3,411 | 4,245 | |||||||||||||||||||||||||||
| Total interest income | 85,420 | 83,341 | 92,962 | 253,635 | 287,046 | |||||||||||||||||||||||||||
| Interest expense: | ||||||||||||||||||||||||||||||||
| Deposits | 5,379 | 6,325 | 11,370 | 20,200 | 37,611 | |||||||||||||||||||||||||||
| Borrowed funds | 2,909 | 3,000 | 4,804 | 8,683 | 14,335 | |||||||||||||||||||||||||||
| Total interest expense | 8,288 | 9,325 | 16,174 | 28,883 | 51,946 | |||||||||||||||||||||||||||
| Net interest income | 77,132 | 74,016 | 76,788 | 224,752 | 235,100 | |||||||||||||||||||||||||||
| Credit loss (benefit) expense | (3,179) | (6,460) | 35,714 | (10,259) | 55,332 | |||||||||||||||||||||||||||
| Net interest income after credit loss (benefit) expense | 80,311 | 80,476 | 41,074 | 235,011 | 179,768 | |||||||||||||||||||||||||||
| Other income: | ||||||||||||||||||||||||||||||||
| Bankcard services revenue | 3,409 | 3,591 | 3,097 | 10,052 | 8,319 | |||||||||||||||||||||||||||
| Trust and asset management revenue | 584 | 591 | 490 | 1,774 | 1,560 | |||||||||||||||||||||||||||
| Fees and service charges | 2,973 | 3,809 | 3,732 | 10,519 | 11,858 | |||||||||||||||||||||||||||
| Net (loss) gain on sales of loans | (15) | 1,279 | 1,001 | 3,180 | 1,930 | |||||||||||||||||||||||||||
| Net (loss) gain on equity investments | (466) | 576 | (3,576) | 8,397 | (3,273) | |||||||||||||||||||||||||||
| Net (loss) gain from other real estate operations | (3) | (1) | 214 | (12) | 12 | |||||||||||||||||||||||||||
| Income from bank owned life insurance | 1,640 | 1,716 | 1,530 | 4,771 | 4,626 | |||||||||||||||||||||||||||
| Commercial loan swap income | 1,588 | 73 | 1,425 | 2,772 | 7,964 | |||||||||||||||||||||||||||
| Other | 173 | 169 | 266 | 1,068 | 310 | |||||||||||||||||||||||||||
| Total other income | 9,883 | 11,803 | 8,179 | 42,521 | 33,306 | |||||||||||||||||||||||||||
| Operating expenses: | ||||||||||||||||||||||||||||||||
| Compensation and employee benefits | 30,730 | 29,912 | 29,012 | 89,008 | 86,832 | |||||||||||||||||||||||||||
| Occupancy | 5,005 | 5,314 | 5,270 | 15,380 | 15,814 | |||||||||||||||||||||||||||
| Equipment | 1,124 | 1,306 | 1,906 | 4,008 | 5,831 | |||||||||||||||||||||||||||
| Marketing | 496 | 625 | 963 | 1,555 | 2,485 | |||||||||||||||||||||||||||
| Federal deposit insurance and regulatory assessments | 1,459 | 1,099 | 1,212 | 4,422 | 3,012 | |||||||||||||||||||||||||||
| Data processing | 5,363 | 4,402 | 4,517 | 13,796 | 12,843 | |||||||||||||||||||||||||||
| Check card processing | 1,337 | 1,303 | 1,385 | 4,012 | 3,951 | |||||||||||||||||||||||||||
| Professional fees | 3,089 | 2,391 | 3,354 | 8,317 | 8,339 | |||||||||||||||||||||||||||
| Other operating expense | 4,477 | 3,485 | 3,644 | 11,315 | 11,784 | |||||||||||||||||||||||||||
| FHLB advance prepayment fees | — | — | — | — | 924 | |||||||||||||||||||||||||||
| Amortization of core deposit intangible | 1,354 | 1,361 | 1,538 | 4,110 | 4,660 | |||||||||||||||||||||||||||
| Branch consolidation expense | 4,014 | 26 | 830 | 5,051 | 4,287 | |||||||||||||||||||||||||||
| Merger related expenses | 225 | 446 | 3,156 | 1,052 | 14,753 | |||||||||||||||||||||||||||
| Total operating expenses | 58,673 | 51,670 | 56,787 | 162,026 | 175,515 | |||||||||||||||||||||||||||
| Income (loss) before provision (benefit) for income taxes | 31,521 | 40,609 | (7,534) | 115,506 | 37,559 | |||||||||||||||||||||||||||
| Provision (benefit) for income taxes | 7,354 | 10,054 | (2,608) | 28,087 | 7,314 | |||||||||||||||||||||||||||
| Net income (loss) | 24,167 | 30,555 | (4,926) | 87,419 | 30,245 | |||||||||||||||||||||||||||
| Dividends on preferred shares | 1,004 | 1,004 | 1,093 | 3,012 | 1,093 | |||||||||||||||||||||||||||
| Net income (loss) available to common stockholders | $ | 23,163 | $ | 29,551 | $ | (6,019) | $ | 84,407 | $ | 29,152 | ||||||||||||||||||||||
| Basic earnings (loss) per share | $ | 0.40 | $ | 0.49 | $ | (0.10) | $ | 1.42 | $ | 0.49 | ||||||||||||||||||||||
| Diluted earnings (loss) per share | $ | 0.39 | $ | 0.49 | $ | (0.10) | $ | 1.41 | $ | 0.49 | ||||||||||||||||||||||
| Average basic shares outstanding | 59,311 | 59,701 | 59,935 | 59,619 | 59,901 | |||||||||||||||||||||||||||
| Average diluted shares outstanding | 59,515 | 59,966 | 59,935 | 59,862 | 60,076 | |||||||||||||||||||||||||||
13
OceanFirst Financial Corp.
SELECTED LOAN AND DEPOSIT DATA
(dollars in thousands)
| LOANS RECEIVABLE | At | ||||||||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | |||||||||||||||||||||||||||||||
| 2021 | 2021 | 2021 | 2020 | 2020 | |||||||||||||||||||||||||||||||
| Commercial: | |||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 457,674 | $ | 474,919 | $ | 498,245 | $ | 470,656 | $ | 599,188 | |||||||||||||||||||||||||
| Commercial real estate - owner-occupied | 1,123,973 | 1,045,514 | 1,066,351 | 1,145,065 | 1,176,529 | ||||||||||||||||||||||||||||||
| Commercial real estate - investor | 3,922,983 | 3,836,230 | 3,804,351 | 3,491,464 | 3,453,276 | ||||||||||||||||||||||||||||||
| Total commercial | 5,504,630 | 5,356,663 | 5,368,947 | 5,107,185 | 5,228,993 | ||||||||||||||||||||||||||||||
| Consumer: | |||||||||||||||||||||||||||||||||||
| Residential real estate | 2,401,240 | 2,168,545 | 2,189,348 | 2,309,459 | 2,407,178 | ||||||||||||||||||||||||||||||
| Home equity loans and lines and other consumer | 275,962 | 295,582 | 314,242 | 339,462 | 364,807 | ||||||||||||||||||||||||||||||
| Total consumer | 2,677,202 | 2,464,127 | 2,503,590 | 2,648,921 | 2,771,985 | ||||||||||||||||||||||||||||||
| Total loans | 8,181,832 | 7,820,790 | 7,872,537 | 7,756,106 | 8,000,978 | ||||||||||||||||||||||||||||||
| Deferred origination costs (fees), net | 8,282 | 7,437 | 8,029 | 9,486 | (1,238) | ||||||||||||||||||||||||||||||
| Allowance for loan credit losses | (50,153) | (53,876) | (59,976) | (60,735) | (56,350) | ||||||||||||||||||||||||||||||
| Loans receivable, net | $ | 8,139,961 | $ | 7,774,351 | $ | 7,820,590 | $ | 7,704,857 | $ | 7,943,390 | |||||||||||||||||||||||||
| Mortgage loans serviced for others | $ | 64,840 | $ | 68,778 | $ | 74,037 | $ | 95,789 | $ | 88,210 | |||||||||||||||||||||||||
| At September 30, 2021 Average Yield | |||||||||||||||||||||||||||||||||||
Loan pipeline (1): | |||||||||||||||||||||||||||||||||||
| Commercial | 3.69 | % | $ | 482,942 | $ | 463,388 | $ | 154,946 | $ | 210,024 | $ | 154,700 | |||||||||||||||||||||||
| Residential real estate | 3.08 | 160,070 | 153,798 | 178,352 | 151,152 | 212,107 | |||||||||||||||||||||||||||||
| Home equity loans and lines | 4.13 | 8,420 | 11,369 | 11,031 | 6,630 | 10,301 | |||||||||||||||||||||||||||||
| Total | 3.55 | % | $ | 651,432 | $ | 628,555 | $ | 344,329 | $ | 367,806 | $ | 377,108 | |||||||||||||||||||||||
| For the Three Months Ended | ||||||||||||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||||||||||||||
| 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||||||||||||
| Average Yield | ||||||||||||||||||||||||||||||||||||||
| Loan originations: | ||||||||||||||||||||||||||||||||||||||
| Commercial | 3.12 | % | $ | 585,667 | $ | 259,163 | (2) | $ | 547,591 | (2) | $ | 173,715 | $ | 187,747 | ||||||||||||||||||||||||
| Residential real estate | 3.04 | 174,365 | (3) | 173,354 | 189,942 | 222,780 | 219,325 | |||||||||||||||||||||||||||||||
| Home equity loans and lines | 4.13 | 11,782 | 14,870 | 10,278 | 13,435 | 10,966 | ||||||||||||||||||||||||||||||||
| Total | 3.12 | % | $ | 771,814 | $ | 447,387 | $ | 747,811 | $ | 409,930 | $ | 418,038 | ||||||||||||||||||||||||||
| Loans sold | $ | 1,756 | $ | 29,556 | $ | 67,500 | $ | 56,126 | (4) | $ | 56,722 | |||||||||||||||||||||||||||
(1)Loan pipeline includes loans approved but not funded.
(2)Excludes loans originated through the PPP of $13 million and $60 million for the three months ended June 30, 2021 and March 31, 2021, respectively.
(3)Excludes a residential real estate loan pool purchase of $219.7 million for the three months ended September 30, 2021.
(4)Excludes the sale of PPP loans of $298.1 million, higher risk commercial loans of $64.8 million, net of charge-offs and under-performing residential and home equity loans and lines of $10.5 million, net of charge-offs, for the three months ended December 31, 2020.
| DEPOSITS | At | ||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | |||||||||||||||||||||||||
| 2021 | 2021 | 2021 | 2020 | 2020 | |||||||||||||||||||||||||
| Type of Account | |||||||||||||||||||||||||||||
| Non-interest-bearing | $ | 2,467,952 | $ | 2,505,355 | $ | 2,417,935 | $ | 2,133,195 | $ | 2,240,799 | |||||||||||||||||||
| Interest-bearing checking | 4,013,565 | 3,628,741 | 3,623,132 | 3,646,866 | 3,317,296 | ||||||||||||||||||||||||
| Money market deposit | 816,691 | 734,320 | 782,459 | 783,521 | 691,872 | ||||||||||||||||||||||||
| Savings | 1,620,447 | 1,590,441 | 1,568,528 | 1,491,251 | 1,471,554 | ||||||||||||||||||||||||
| Time deposits | 855,442 | 956,429 | 1,110,758 | 1,372,783 | 1,561,767 | ||||||||||||||||||||||||
| Total Deposits | $ | 9,774,097 | $ | 9,415,286 | $ | 9,502,812 | $ | 9,427,616 | $ | 9,283,288 | |||||||||||||||||||
14
OceanFirst Financial Corp.
ASSET QUALITY
(dollars in thousands)
| ASSET QUALITY | September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||||
| 2021 | 2021 | 2021 | 2020 | 2020 | |||||||||||||||||||||||||
| Non-performing loans held-for-investment: | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 354 | $ | 1,566 | $ | 1,616 | $ | 1,551 | $ | 586 | |||||||||||||||||||
| Commercial real estate - owner-occupied | 8,997 | 11,527 | 11,676 | 13,054 | 11,365 | ||||||||||||||||||||||||
| Commercial real estate - investor | 6,904 | 10,549 | 12,366 | 10,660 | 2,978 | ||||||||||||||||||||||||
| Residential real estate | 5,484 | 6,114 | 6,398 | 8,642 | 11,518 | ||||||||||||||||||||||||
| Home equity loans and lines and other consumer | 1,605 | 1,924 | 2,072 | 2,503 | 3,448 | ||||||||||||||||||||||||
| Total non-performing loans held-for-investment | 23,344 | 31,680 | 34,128 | 36,410 | 29,895 | ||||||||||||||||||||||||
| Non-performing loans held-for-sale | — | — | — | — | 67,489 | ||||||||||||||||||||||||
| Other real estate owned | 106 | 106 | 106 | 106 | 106 | ||||||||||||||||||||||||
| Total non-performing assets | $ | 23,450 | $ | 31,786 | $ | 34,234 | $ | 36,516 | $ | 97,490 | |||||||||||||||||||
PCD loans (1) | $ | 41,372 | $ | 40,064 | $ | 44,421 | $ | 48,488 | $ | 56,422 | |||||||||||||||||||
| Delinquent loans 30 to 89 days | $ | 6,647 | $ | 5,313 | $ | 16,477 | $ | 34,683 | $ | 13,753 | |||||||||||||||||||
| Troubled debt restructurings: | |||||||||||||||||||||||||||||
| Non-performing (included in total non-performing loans above) | $ | 9,617 | $ | 9,803 | $ | 4,785 | $ | 5,158 | $ | 9,866 | |||||||||||||||||||
| Performing | 9,661 | 10,311 | 11,466 | 12,009 | 12,777 | ||||||||||||||||||||||||
| Total troubled debt restructurings | $ | 19,278 | $ | 20,114 | $ | 16,251 | $ | 17,167 | $ | 22,643 | |||||||||||||||||||
| Allowance for loan credit losses | $ | 50,153 | $ | 53,876 | $ | 59,976 | $ | 60,735 | $ | 56,350 | |||||||||||||||||||
Allowance for loan credit losses as a percent of total loans held-for-investment (2) | 0.61 | % | 0.69 | % | 0.76 | % | 0.78 | % | 0.70 | % | |||||||||||||||||||
Allowance for loan credit losses as a percent of total non-performing loans held-for-investment (2) | 214.84 | 170.06 | 175.74 | 166.81 | 188.49 | ||||||||||||||||||||||||
| Non-performing loans held-for-investment as a percent of total loans held-for-investment | 0.29 | 0.41 | 0.43 | 0.47 | 0.37 | ||||||||||||||||||||||||
| Non-performing assets as a percent of total assets | 0.20 | 0.28 | 0.30 | 0.32 | 0.84 | ||||||||||||||||||||||||
(1)PCD loans are not included in non-performing loans held-for-investment, troubled debt restructurings or delinquent loans totals.
(2)Loans acquired from prior bank acquisitions were recorded at fair value. The net unamortized credit and PCD marks on these loans, not reflected in the allowance for loan credit losses, was $21.3 million, $23.6 million, $25.7 million, $28.0 million and $31.6 million at September 30, 2021, June 30, 2021, March 31, 2021, December 31, 2020 and September 30, 2020, respectively.
| NET RECOVERIES (CHARGE-OFFS) | For the Three Months Ended | |||||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Net recoveries (charge-offs): | ||||||||||||||||||||||||||||||||
| Loan charge-offs | $ | (163) | $ | (420) | $ | (356) | $ | (3,220) | $ | (15,411) | ||||||||||||||||||||||
| Recoveries on loans | 549 | 196 | 636 | 278 | 416 | |||||||||||||||||||||||||||
| Net loan recoveries (charge-offs) | $ | 386 | $ | (224) | $ | 280 | $ | (2,942) | (1) | $ | (14,995) | (2) | ||||||||||||||||||||
| Net loan recoveries (charge-offs) to average total loans (annualized) | NM* | 0.01 | % | NM* | 0.15 | % | 0.71 | % | ||||||||||||||||||||||||
| Net loan recoveries (charge-offs) detail: | ||||||||||||||||||||||||||||||||
| Commercial | $ | (33) | $ | (304) | $ | 126 | $ | (775) | $ | (14,801) | ||||||||||||||||||||||
| Residential real estate | 280 | — | (203) | (1,731) | 314 | |||||||||||||||||||||||||||
| Home equity loans and lines and other consumer | 139 | 80 | 357 | (436) | (508) | |||||||||||||||||||||||||||
| Net loan recoveries (charge-offs) | $ | 386 | $ | (224) | $ | 280 | $ | (2,942) | (1) | $ | (14,995) | (2) | ||||||||||||||||||||
(1)Included in net loan charge-offs for the three months ended December 31, 2020 was $2.3 million related to under-performing residential and consumer loans sold.
(2)Included in net loan charge-offs for the three months ended September 30, 2020 was $14.2 million related to loans transferred to held-for-sale.
* Not meaningful
15
OceanFirst Financial Corp.
ANALYSIS OF NET INTEREST INCOME
| For the Three Months Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| September 30, | June 30, | September 30, | |||||||||||||||||||||||||||||||||||||||||||||||||||
| 2021 | 2021 | 2020 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (dollars in thousands) | Average Balance | Interest | Average Yield/ Cost | Average Balance | Interest | Average Yield/ Cost | Average Balance | Interest | Average Yield/ Cost | ||||||||||||||||||||||||||||||||||||||||||||
| Assets: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning deposits and short-term investments | $ | 1,053,797 | $ | 441 | 0.17 | % | $ | 992,485 | $ | 241 | 0.10 | % | $ | 805,863 | $ | 236 | 0.12 | % | |||||||||||||||||||||||||||||||||||
Securities (1) | 1,542,630 | 6,090 | 1.57 | 1,501,484 | 6,052 | 1.62 | 1,112,174 | 6,793 | 2.43 | ||||||||||||||||||||||||||||||||||||||||||||
Loans receivable, net (2) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Commercial | 5,361,472 | 55,387 | 4.10 | 5,318,436 | 54,258 | 4.09 | 5,554,897 | 58,639 | 4.20 | ||||||||||||||||||||||||||||||||||||||||||||
| Residential real estate | 2,260,673 | 20,076 | 3.55 | 2,219,425 | 19,097 | 3.44 | 2,462,513 | 23,091 | 3.75 | ||||||||||||||||||||||||||||||||||||||||||||
| Home equity loans and lines and other consumer | 289,011 | 3,426 | 4.70 | 304,541 | 3,693 | 4.86 | 379,299 | 4,203 | 4.41 | ||||||||||||||||||||||||||||||||||||||||||||
| Allowance for loan credit losses, net of deferred loan costs and fees | (46,436) | — | — | (53,483) | — | — | (45,912) | — | — | ||||||||||||||||||||||||||||||||||||||||||||
| Loans receivable, net | 7,864,720 | 78,889 | 3.98 | 7,788,919 | 77,048 | 3.97 | 8,350,797 | 85,933 | 4.09 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 10,461,147 | 85,420 | 3.24 | 10,282,888 | 83,341 | 3.25 | 10,268,834 | 92,962 | 3.60 | ||||||||||||||||||||||||||||||||||||||||||||
| Non-interest-earning assets | 1,276,890 | 1,256,844 | 1,353,135 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 11,738,037 | $ | 11,539,732 | $ | 11,621,969 | |||||||||||||||||||||||||||||||||||||||||||||||
Liabilities and Stockholders’ Equity: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing checking | $ | 3,841,475 | 2,854 | 0.29 | % | $ | 3,701,496 | 3,385 | 0.37 | % | $ | 3,289,319 | 4,627 | 0.56 | % | ||||||||||||||||||||||||||||||||||||||
| Money market | 767,854 | 245 | 0.13 | 760,323 | 212 | 0.11 | 675,841 | 571 | 0.34 | ||||||||||||||||||||||||||||||||||||||||||||
| Savings | 1,609,197 | 146 | 0.04 | 1,581,284 | 166 | 0.04 | 1,460,232 | 296 | 0.08 | ||||||||||||||||||||||||||||||||||||||||||||
| Time deposits | 904,384 | 2,134 | 0.94 | 1,002,086 | 2,562 | 1.03 | 1,606,632 | 5,876 | 1.45 | ||||||||||||||||||||||||||||||||||||||||||||
| Total | 7,122,910 | 5,379 | 0.30 | 7,045,189 | 6,325 | 0.36 | 7,032,024 | 11,370 | 0.64 | ||||||||||||||||||||||||||||||||||||||||||||
| FHLB Advances | — | — | — | — | — | — | 343,412 | 1,470 | 1.70 | ||||||||||||||||||||||||||||||||||||||||||||
| Securities sold under agreements to repurchase | 142,494 | 51 | 0.14 | 135,181 | 56 | 0.17 | 144,720 | 174 | 0.48 | ||||||||||||||||||||||||||||||||||||||||||||
| Other borrowings | 228,695 | 2,858 | 4.96 | 228,350 | 2,944 | 5.17 | 246,903 | 3,160 | 5.09 | ||||||||||||||||||||||||||||||||||||||||||||
| Total borrowings | 371,189 | 2,909 | 3.11 | 363,531 | 3,000 | 3.31 | 735,035 | 4,804 | 2.60 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 7,494,099 | 8,288 | 0.44 | 7,408,720 | 9,325 | 0.50 | 7,767,059 | 16,174 | 0.83 | ||||||||||||||||||||||||||||||||||||||||||||
| Non-interest-bearing deposits | 2,576,123 | 2,462,203 | 2,209,241 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-interest-bearing liabilities | 148,327 | 164,774 | 162,987 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities | 10,218,549 | 10,035,697 | 10,139,287 | ||||||||||||||||||||||||||||||||||||||||||||||||||
Stockholders’ equity | 1,519,488 | 1,504,035 | 1,482,682 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 11,738,037 | $ | 11,539,732 | $ | 11,621,969 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 77,132 | $ | 74,016 | $ | 76,788 | |||||||||||||||||||||||||||||||||||||||||||||||
Net interest rate spread (3) | 2.80 | % | 2.75 | % | 2.77 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Net interest margin (4) | 2.93 | % | 2.89 | % | 2.97 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Total cost of deposits (including non-interest-bearing deposits) | 0.22 | % | 0.27 | % | 0.49 | % | |||||||||||||||||||||||||||||||||||||||||||||||
(continued)
16
| For the Nine Months Ended September 30, | |||||||||||||||||||||||||||||||||||
| 2021 | 2020 | ||||||||||||||||||||||||||||||||||
| (dollars in thousands) | Average Balance | Interest | Average Yield/ Cost | Average Balance | Interest | Average Yield/ Cost | |||||||||||||||||||||||||||||
| Assets: | |||||||||||||||||||||||||||||||||||
| Interest-earning assets: | |||||||||||||||||||||||||||||||||||
| Interest-earning deposits and short-term investments | $ | 1,061,419 | $ | 958 | 0.12 | % | $ | 409,321 | $ | 693 | 0.23 | % | |||||||||||||||||||||||
Securities (1) | 1,452,778 | 18,832 | 1.73 | 1,143,049 | 22,129 | 2.59 | |||||||||||||||||||||||||||||
Loans receivable, net (2) | |||||||||||||||||||||||||||||||||||
| Commercial | 5,270,138 | 163,315 | 4.14 | 5,309,275 | 177,973 | 4.48 | |||||||||||||||||||||||||||||
| Residential real estate | 2,269,066 | 59,242 | 3.48 | 2,480,932 | 71,590 | 3.85 | |||||||||||||||||||||||||||||
| Home equity loans and lines and other consumer | 306,681 | 11,288 | 4.92 | 403,348 | 14,661 | 4.86 | |||||||||||||||||||||||||||||
| Allowance for loan credit losses, net of deferred loan costs and fees | (50,912) | — | — | (27,186) | — | — | |||||||||||||||||||||||||||||
| Loans receivable, net | 7,794,973 | 233,845 | 4.01 | 8,166,369 | 264,224 | 4.32 | |||||||||||||||||||||||||||||
| Total interest-earning assets | 10,309,170 | 253,635 | 3.29 | 9,718,739 | 287,046 | 3.95 | |||||||||||||||||||||||||||||
| Non-interest-earning assets | 1,264,347 | 1,306,568 | |||||||||||||||||||||||||||||||||
| Total assets | $ | 11,573,517 | $ | 11,025,307 | |||||||||||||||||||||||||||||||
| Liabilities and Stockholders’ Equity: | |||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | |||||||||||||||||||||||||||||||||||
| Interest-bearing checking | $ | 3,753,457 | 10,549 | 0.38 | % | $ | 3,023,093 | 14,559 | 0.64 | % | |||||||||||||||||||||||||
| Money market | 761,975 | 823 | 0.14 | 647,566 | 2,316 | 0.48 | |||||||||||||||||||||||||||||
| Savings | 1,571,345 | 490 | 0.04 | 1,436,594 | 2,266 | 0.21 | |||||||||||||||||||||||||||||
| Time deposits | 1,041,371 | 8,338 | 1.07 | 1,563,449 | 18,470 | 1.58 | |||||||||||||||||||||||||||||
| Total | 7,128,148 | 20,200 | 0.38 | 6,670,702 | 37,611 | 0.75 | |||||||||||||||||||||||||||||
| FHLB Advances | — | — | — | 483,267 | 6,239 | 1.72 | |||||||||||||||||||||||||||||
| Securities sold under agreements to repurchase | 135,754 | 203 | 0.20 | 119,495 | 408 | 0.46 | |||||||||||||||||||||||||||||
| Other borrowings | 228,472 | 8,480 | 4.96 | 195,754 | 7,688 | 5.25 | |||||||||||||||||||||||||||||
| Total borrowings | 364,226 | 8,683 | 3.19 | 798,516 | 14,335 | 2.40 | |||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 7,492,374 | 28,883 | 0.52 | 7,469,218 | 51,946 | 0.93 | |||||||||||||||||||||||||||||
| Non-interest-bearing deposits | 2,416,866 | 1,971,622 | |||||||||||||||||||||||||||||||||
| Non-interest-bearing liabilities | 157,821 | 133,928 | |||||||||||||||||||||||||||||||||
| Total liabilities | 10,067,061 | 9,574,768 | |||||||||||||||||||||||||||||||||
| Stockholders’ equity | 1,506,456 | 1,450,539 | |||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 11,573,517 | $ | 11,025,307 | |||||||||||||||||||||||||||||||
| Net interest income | $ | 224,752 | $ | 235,100 | |||||||||||||||||||||||||||||||
Net interest rate spread (3) | 2.77 | % | 3.02 | % | |||||||||||||||||||||||||||||||
Net interest margin (4) | 2.91 | % | 3.23 | % | |||||||||||||||||||||||||||||||
Total cost of deposits (including non-interest-bearing deposits) | 0.28 | % | 0.58 | % | |||||||||||||||||||||||||||||||
(1) Amounts represent debt and equity securities, including FHLB and Federal Reserve Bank stock, and are recorded at average amortized cost, net of allowance for securities credit losses.
(2) Amount is net of deferred loan costs and fees, undisbursed loan funds, discounts and premiums and allowance for loan credit losses, and includes loans held for sale and non-performing loans.
(3) Net interest rate spread represents the difference between the yield on interest-earning assets and the cost of interest-bearing liabilities.
(4) Net interest margin represents net interest income divided by average interest-earning assets.
17
OceanFirst Financial Corp.
SELECTED QUARTERLY FINANCIAL DATA
(in thousands, except per share amounts)
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Selected Financial Condition Data: | ||||||||||||||||||||||||||||||||
| Total assets | $ | 11,829,688 | $ | 11,483,901 | $ | 11,577,472 | $ | 11,448,313 | $ | 11,651,297 | ||||||||||||||||||||||
Debt securities available-for-sale, at estimated fair value | 314,620 | 249,330 | 268,511 | 183,302 | 169,634 | |||||||||||||||||||||||||||
| Debt securities held-to-maturity, net of allowance for securities credit losses | 1,125,382 | 1,146,735 | 1,082,326 | 937,253 | 871,688 | |||||||||||||||||||||||||||
| Equity investments | 101,314 | 90,917 | 50,159 | 107,079 | 63,846 | |||||||||||||||||||||||||||
| Restricted equity investments, at cost | 53,017 | 52,519 | 52,199 | 51,705 | 67,505 | |||||||||||||||||||||||||||
| Loans receivable, net of allowance for loan credit losses | 8,139,961 | 7,774,351 | 7,820,590 | 7,704,857 | 7,943,390 | |||||||||||||||||||||||||||
| Deposits | 9,774,097 | 9,415,286 | 9,502,812 | 9,427,616 | 9,283,288 | |||||||||||||||||||||||||||
| Federal Home Loan Bank advances | — | — | — | — | 343,452 | |||||||||||||||||||||||||||
| Securities sold under agreements to repurchase and other borrowings | 372,179 | 370,039 | 362,641 | 363,925 | 389,764 | |||||||||||||||||||||||||||
Stockholders’ equity | 1,513,249 | 1,508,789 | 1,498,719 | 1,484,130 | 1,461,714 | |||||||||||||||||||||||||||
| For the Three Months Ended, | ||||||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Selected Operating Data: | ||||||||||||||||||||||||||||||||
| Interest income | $ | 85,420 | $ | 83,341 | $ | 84,874 | $ | 92,562 | $ | 92,962 | ||||||||||||||||||||||
| Interest expense | 8,288 | 9,325 | 11,270 | 14,711 | 16,174 | |||||||||||||||||||||||||||
| Net interest income | 77,132 | 74,016 | 73,604 | 77,851 | 76,788 | |||||||||||||||||||||||||||
| Credit loss (benefit) expense | (3,179) | (6,460) | (620) | 4,072 | 35,714 | |||||||||||||||||||||||||||
| Net interest income after credit loss (benefit) expense | 80,311 | 80,476 | 74,224 | 73,779 | 41,074 | |||||||||||||||||||||||||||
| Other income (excluding net (loss) gain on equity investments and gain on sale of PPP loans) | 10,349 | 11,227 | 12,548 | 11,032 | 11,755 | |||||||||||||||||||||||||||
| Net (loss) gain on equity investments | (466) | 576 | 8,287 | 24,487 | (3,576) | |||||||||||||||||||||||||||
| Gain on sale of PPP loans | — | — | — | 5,101 | — | |||||||||||||||||||||||||||
| Operating expenses (excluding FHLB advance prepayment fees, branch consolidation and merger related expenses) | 54,434 | 51,198 | 50,291 | 53,053 | 52,801 | |||||||||||||||||||||||||||
| FHLB advance prepayment fees | — | — | — | 13,333 | — | |||||||||||||||||||||||||||
| Branch consolidation expense | 4,014 | 26 | 1,011 | 3,336 | 830 | |||||||||||||||||||||||||||
| Merger related expenses | 225 | 446 | 381 | 1,194 | 3,156 | |||||||||||||||||||||||||||
| Income (loss) before provision (benefit) for income taxes | 31,521 | 40,609 | 43,376 | 43,483 | (7,534) | |||||||||||||||||||||||||||
| Provision (benefit) for income taxes | 7,354 | 10,054 | 10,679 | 10,419 | (2,608) | |||||||||||||||||||||||||||
| Net income (loss) | $ | 24,167 | $ | 30,555 | $ | 32,697 | $ | 33,064 | $ | (4,926) | ||||||||||||||||||||||
| Net income (loss) available to common stockholders | $ | 23,163 | $ | 29,551 | $ | 31,693 | $ | 32,060 | $ | (6,019) | ||||||||||||||||||||||
| Diluted earnings (loss) per share | $ | 0.39 | $ | 0.49 | $ | 0.53 | $ | 0.54 | $ | (0.10) | ||||||||||||||||||||||
| Net accretion/amortization of purchase accounting adjustments included in net interest income | $ | 3,644 | $ | 2,835 | $ | 3,650 | $ | 6,186 | $ | 4,364 | ||||||||||||||||||||||
18
(continued)
| At or For the Three Months Ended | ||||||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||||||
Selected Financial Ratios and Other Data(1): | ||||||||||||||||||||||||||||||||
| Performance Ratios (Annualized): | ||||||||||||||||||||||||||||||||
Return on average assets (2) | 0.78 | % | 1.03 | % | 1.12 | % | 1.09 | % | (0.21) | % | ||||||||||||||||||||||
Return on average tangible assets (2) (3) | 0.82 | 1.08 | 1.18 | 1.14 | (0.22) | |||||||||||||||||||||||||||
Return on average stockholders’ equity (2) | 6.05 | 7.88 | 8.59 | 8.65 | (1.61) | |||||||||||||||||||||||||||
Return on average tangible stockholders’ equity (2) (3) | 9.20 | 12.07 | 13.22 | 13.43 | (2.51) | |||||||||||||||||||||||||||
| Stockholders’ equity to total assets | 12.79 | 13.14 | 12.95 | 12.96 | 12.55 | |||||||||||||||||||||||||||
Tangible stockholders’ equity to tangible assets (3) | 8.78 | 9.01 | 8.83 | 8.79 | 8.41 | |||||||||||||||||||||||||||
Tangible common equity to tangible assets (3) | 8.29 | 8.50 | 8.33 | 8.28 | 7.91 | |||||||||||||||||||||||||||
| Net interest rate spread | 2.80 | 2.75 | 2.78 | 2.79 | 2.77 | |||||||||||||||||||||||||||
| Net interest margin | 2.93 | 2.89 | 2.93 | 2.97 | 2.97 | |||||||||||||||||||||||||||
Operating expenses to average assets (2) | 1.98 | 1.80 | 1.83 | 2.40 | 1.94 | |||||||||||||||||||||||||||
Efficiency ratio (2) (4) | 67.43 | 60.21 | 54.73 | 59.86 | 66.83 | |||||||||||||||||||||||||||
| Loans to deposits | 83.71 | 83.06 | 82.84 | 82.27 | 86.19 | |||||||||||||||||||||||||||
| For the Nine Months Ended September 30, | ||||||||||||||
| 2021 | 2020 | |||||||||||||
| Performance Ratios (Annualized): | ||||||||||||||
Return on average assets (2) | 0.98 | % | 0.35 | % | ||||||||||
Return on average tangible assets (2) (3) | 1.02 | 0.37 | ||||||||||||
Return on average stockholders’ equity (2) | 7.49 | 2.68 | ||||||||||||
Return on average tangible stockholders’ equity (2) (3) | 11.46 | 4.22 | ||||||||||||
| Net interest rate spread | 2.77 | 3.02 | ||||||||||||
| Net interest margin | 2.91 | 3.23 | ||||||||||||
Operating expenses to average assets (2) | 1.87 | 2.13 | ||||||||||||
Efficiency ratio (2) (4) | 60.62 | 65.39 | ||||||||||||
19
(continued)
| At or For the Three Months Ended | ||||||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Trust and Asset Management: | ||||||||||||||||||||||||||||||||
| Wealth assets under administration and management | $ | 274,807 | $ | 278,785 | $ | 274,172 | $ | 245,175 | $ | 232,292 | ||||||||||||||||||||||
| Nest Egg | 138,087 | 129,674 | 101,701 | 93,237 | 80,472 | |||||||||||||||||||||||||||
| Per Share Data: | ||||||||||||||||||||||||||||||||
| Cash dividends per common share | $ | 0.17 | $ | 0.17 | $ | 0.17 | $ | 0.17 | $ | 0.17 | ||||||||||||||||||||||
| Stockholders' equity per common share at end of period | 25.47 | 25.22 | 24.84 | 24.57 | 24.21 | |||||||||||||||||||||||||||
Tangible common equity per common share at end of period (3) | 15.78 | 15.58 | 15.26 | 14.98 | 14.58 | |||||||||||||||||||||||||||
| Common shares outstanding at end of period | 59,417,266 | 59,834,018 | 60,329,504 | 60,392,043 | 60,378,120 | |||||||||||||||||||||||||||
| Preferred shares outstanding at end of period | 57,370 | 57,370 | 57,370 | 57,370 | 57,370 | |||||||||||||||||||||||||||
| Number of full-service customer facilities: | 58 | 58 | 62 | 62 | 62 | |||||||||||||||||||||||||||
| Quarterly Average Balances | ||||||||||||||||||||||||||||||||
| Total securities | $ | 1,542,630 | $ | 1,501,484 | $ | 1,311,683 | $ | 1,209,543 | $ | 1,112,174 | ||||||||||||||||||||||
| Loans receivable, net | 7,864,720 | 7,788,919 | 7,729,798 | 7,992,365 | 8,350,797 | |||||||||||||||||||||||||||
| Total interest-earning assets | 10,461,147 | 10,282,888 | 10,180,392 | 10,425,380 | 10,268,834 | |||||||||||||||||||||||||||
| Total goodwill and core deposit intangible | 520,765 | 522,122 | 523,499 | 525,511 | 527,679 | |||||||||||||||||||||||||||
| Total assets | 11,738,037 | 11,539,732 | 11,439,501 | 11,747,439 | 11,621,969 | |||||||||||||||||||||||||||
| Time deposits | 904,384 | 1,002,086 | 1,221,123 | 1,437,770 | 1,606,632 | |||||||||||||||||||||||||||
| Total deposits (including non-interest-bearing deposits) | 9,699,033 | 9,507,392 | 9,425,609 | 9,505,835 | 9,241,265 | |||||||||||||||||||||||||||
| Total borrowed funds | 371,189 | 363,531 | 357,812 | 590,295 | 735,035 | |||||||||||||||||||||||||||
| Total interest-bearing liabilities | 7,494,099 | 7,408,720 | 7,571,148 | 7,886,598 | 7,767,059 | |||||||||||||||||||||||||||
| Non-interest bearing deposits | 2,576,123 | 2,462,203 | 2,212,273 | 2,209,532 | 2,209,241 | |||||||||||||||||||||||||||
| Stockholders' equity | 1,519,488 | 1,504,035 | 1,495,580 | 1,475,088 | 1,482,682 | |||||||||||||||||||||||||||
| Quarterly Yields | ||||||||||||||||||||||||||||||||
| Total securities | 1.57 | % | 1.62 | % | 2.07 | % | 2.38 | % | 2.43 | % | ||||||||||||||||||||||
| Loans receivable, net | 3.98 | 3.97 | 4.09 | 4.23 | 4.09 | |||||||||||||||||||||||||||
| Total interest-earning assets | 3.24 | 3.25 | 3.38 | 3.53 | 3.60 | |||||||||||||||||||||||||||
| Time deposits | 0.94 | 1.03 | 1.21 | 1.39 | 1.45 | |||||||||||||||||||||||||||
| Total cost of deposits (including non-interest-bearing deposits) | 0.22 | 0.27 | 0.37 | 0.45 | 0.49 | |||||||||||||||||||||||||||
| Total borrowed funds | 3.11 | 3.31 | 3.14 | 2.72 | 2.60 | |||||||||||||||||||||||||||
| Total interest-bearing liabilities | 0.44 | 0.50 | 0.60 | 0.74 | 0.83 | |||||||||||||||||||||||||||
| Net interest spread | 2.80 | 2.75 | 2.78 | 2.79 | 2.77 | |||||||||||||||||||||||||||
| Net interest margin | 2.93 | 2.89 | 2.93 | 2.97 | 2.97 | |||||||||||||||||||||||||||
(1) With the exception of end of quarter ratios, all ratios are based on average daily balances.
(2) Performance ratios for each period are presented on a GAAP basis and include non-core operations. Refer to “Non-GAAP Reconciliation.”
(3) Tangible stockholders’ equity and tangible assets exclude intangible assets related to goodwill and core deposit intangible. Tangible common equity excludes goodwill, core deposit intangible and preferred equity.
(4) Efficiency ratio represents the ratio of operating expenses to the aggregate of other income and net interest income.
20
OceanFirst Financial Corp.
SUPPLEMENTAL INFORMATION
(dollars in thousands, except per share amounts)
NON-GAAP RECONCILIATION
| For the Three Months Ended | ||||||||||||||||||||||||||||||||
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Core Earnings: | ||||||||||||||||||||||||||||||||
Net income (loss) available to common stockholders (GAAP) | $ | 23,163 | $ | 29,551 | $ | 31,693 | $ | 32,060 | $ | (6,019) | ||||||||||||||||||||||
| Add (less) non-recurring and non-core items: | ||||||||||||||||||||||||||||||||
| Merger related expenses | 225 | 446 | 381 | 1,194 | 3,156 | |||||||||||||||||||||||||||
| Branch consolidation expenses | 4,014 | 26 | 1,011 | 3,336 | 830 | |||||||||||||||||||||||||||
| Net loss (gain) on equity investments | 466 | (576) | (8,287) | (24,487) | 3,576 | |||||||||||||||||||||||||||
| FHLB advance prepayment fees | — | — | — | 13,333 | — | |||||||||||||||||||||||||||
| Gain on sale of PPP loans | — | — | — | (5,101) | — | |||||||||||||||||||||||||||
| Income tax (benefit) expense on items | (1,138) | 26 | 1,666 | 2,832 | (1,809) | |||||||||||||||||||||||||||
Core earnings (loss) (Non-GAAP) | $ | 26,730 | $ | 29,473 | $ | 26,464 | $ | 23,167 | $ | (266) | ||||||||||||||||||||||
| Core diluted earnings (loss) per share | $ | 0.45 | $ | 0.49 | $ | 0.44 | $ | 0.39 | $ | — | ||||||||||||||||||||||
| Core Ratios (Annualized): | ||||||||||||||||||||||||||||||||
| Return on average assets | 0.90 | % | 1.02 | % | 0.94 | % | 0.78 | % | (0.01) | % | ||||||||||||||||||||||
| Return on average tangible assets | 0.95 | 1.07 | 0.98 | 0.82 | (0.01) | |||||||||||||||||||||||||||
| Return on average tangible stockholders’ equity | 10.62 | 12.04 | 11.04 | 9.71 | (0.11) | |||||||||||||||||||||||||||
| Efficiency ratio | 62.22 | 60.06 | 58.37 | 59.69 | 59.63 | |||||||||||||||||||||||||||
| For the Nine Months Ended September 30, | ||||||||||||||
| 2021 | 2020 | |||||||||||||
| Core Earnings: | ||||||||||||||
Net income available to common stockholders (GAAP) | $ | 84,407 | $ | 29,152 | ||||||||||
| Add (less) non-recurring and non-core items: | ||||||||||||||
| Merger related expenses | 1,052 | 14,753 | ||||||||||||
| Branch consolidation expenses | 5,051 | 4,287 | ||||||||||||
| Net (gain) loss on equity investments | (8,397) | 3,576 | ||||||||||||
| Two River and Country Bank opening credit loss expense under the CECL model | — | 2,447 | ||||||||||||
| FHLB advance prepayment fees | — | 924 | ||||||||||||
| Income tax expense (benefit) on items | 554 | (6,120) | ||||||||||||
Core earnings (Non-GAAP) | $ | 82,667 | $ | 49,019 | ||||||||||
| Core diluted earnings per share | $ | 1.38 | $ | 0.82 | ||||||||||
| Core Ratios (Annualized): | ||||||||||||||
| Return on average assets | 0.95 | % | 0.59 | % | ||||||||||
| Return on average tangible assets | 1.00 | 0.62 | ||||||||||||
| Return on average tangible stockholders’ equity | 11.23 | 7.10 | ||||||||||||
| Efficiency ratio | 60.23 | 57.95 | ||||||||||||
21
(continued)
| September 30, | June 30, | March 31, | December 31, | September 30, | ||||||||||||||||||||||||||||
| 2021 | 2021 | 2021 | 2020 | 2020 | ||||||||||||||||||||||||||||
| Tangible Equity: | ||||||||||||||||||||||||||||||||
| Total stockholders' equity | $ | 1,513,249 | $ | 1,508,789 | $ | 1,498,719 | $ | 1,484,130 | $ | 1,461,714 | ||||||||||||||||||||||
| Less: | ||||||||||||||||||||||||||||||||
| Goodwill | 500,319 | 500,319 | 500,319 | 500,319 | 500,849 | |||||||||||||||||||||||||||
| Core deposit intangible | 19,558 | 20,912 | 22,273 | 23,668 | 25,194 | |||||||||||||||||||||||||||
| Tangible stockholders' equity | 993,372 | 987,558 | 976,127 | 960,143 | 935,671 | |||||||||||||||||||||||||||
| Less: | ||||||||||||||||||||||||||||||||
| Preferred Stock | 55,527 | 55,527 | 55,527 | 55,527 | 55,544 | |||||||||||||||||||||||||||
| Tangible common equity | $ | 937,845 | $ | 932,031 | $ | 920,600 | $ | 904,616 | $ | 880,127 | ||||||||||||||||||||||
| Tangible Assets: | ||||||||||||||||||||||||||||||||
| Total assets | $ | 11,829,688 | $ | 11,483,901 | $ | 11,577,472 | $ | 11,448,313 | $ | 11,651,297 | ||||||||||||||||||||||
| Less: | ||||||||||||||||||||||||||||||||
| Goodwill | 500,319 | 500,319 | 500,319 | 500,319 | 500,849 | |||||||||||||||||||||||||||
| Core deposit intangible | 19,558 | 20,912 | 22,273 | 23,668 | 25,194 | |||||||||||||||||||||||||||
| Tangible assets | $ | 11,309,811 | $ | 10,962,670 | $ | 11,054,880 | $ | 10,924,326 | $ | 11,125,254 | ||||||||||||||||||||||
| Tangible stockholders' equity to tangible assets | 8.78 | % | 9.01 | % | 8.83 | % | 8.79 | % | 8.41 | % | ||||||||||||||||||||||
| Tangible common equity to tangible assets | 8.29 | % | 8.50 | % | 8.33 | % | 8.28 | % | 7.91 | % | ||||||||||||||||||||||
22
. . . 1 The 3Q 2021 Investor Presentation is for the purpose and use in conjunction with the Earnings Release furnished as Exhibit 99.1 to Form 8-K on October 28, 2021. Exhibit 99.2 OceanFirst Financial Corp. 3Q 2021 Investor Presentation1 October 2021
. . .Legal Disclaimer FORWARD LOOKING STATEMENTS. In addition to historical information, this news release contains certain forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 which are based on certain assumptions and describe future plans, strategies and expectations of OceanFirst Financial Corp. (the Company) and its wholly-owned subsidiary, OceanFirst Bank N.A. (the Bank). These forward-looking statements are generally identified by use of the words “believe,” “expect,” “intend,” “anticipate,” “estimate,” “project,” “will,” “should,” “may,” “view,” “opportunity,” “potential,” or similar expressions or expressions of confidence. The Company’s ability to predict results or the actual effect of future plans or strategies is inherently uncertain. Factors which could have a material adverse effect on the operations of the Company and its subsidiaries include, but are not limited to: the impact of the COVID-19 pandemic on our operations and financial results and those of our customers, changes in interest rates, general economic conditions, levels of unemployment in the Bank’s lending area, real estate market values in the Bank’s lending area, future natural disasters and increases to flood insurance premiums, the level of prepayments on loans and mortgage-backed securities, legislative/regulatory changes, monetary and fiscal policies of the U.S. Government including policies of the U.S. Treasury and the Board of Governors of the Federal Reserve System, the quality or composition of the loan or investment portfolios, demand for loan products, deposit flows, competition, demand for financial services in the Company’s market area, accounting principles and guidelines and the Bank’s ability to successfully integrate acquired operations. These risks and uncertainties are further discussed in the Company’s Annual Report on Form 10-K for the year ended December 31, 2020, under Item 1A - Risk Factors and elsewhere, and subsequent securities filings and should be considered in evaluating forward-looking statements and undue reliance should not be placed on such statements. The Company does not undertake, and specifically disclaims any obligation, to publicly release the result of any revisions which may be made to any forward-looking statements to reflect events or circumstances after the date of such statements or to reflect the occurrence of anticipated or unanticipated events. NON-GAAP FINANCIAL INFORMATION. This presentation contains certain non-GAAP (generally accepted accounting principles) measures. These non-GAAP measures, as calculated by the Company, are not necessarily comparable to similarly titled measures reported by other companies. Additionally, these non-GAAP measures are not measures of financial performance or liquidity under GAAP and should not be considered alternatives to the Company's other financial information determined under GAAP. See reconciliations of certain non-GAAP measures included at the end of this presentation. MARKET AND INDUSTRY DATA. This presentation references certain market, industry and demographic data, forecasts and other statistical information. We have obtained this data, forecasts and information from various independent, third-party industry sources and publications. Nothing in the data, forecasts or information used or derived from third party sources should be construed as advice. Some data and other information are also based on our good faith estimates, which are derived from our review of industry publications and surveys and independent sources. We believe that these sources and estimates are reliable but have not independently verified them. Statements as to our market position are based on market data currently available to us. These estimates involve inherent risks and uncertainties and are based on assumptions that are subject to change. 2
. . .OceanFirst Financial Corp. Overview 3 Founded: 1902 NASDAQ: OCFC Market Capitalization: $1.33 billion1 Branches: 582 Full-Service Branches in New Jersey and Metropolitan New York City Guiding Principles: Nimble, Certainty of Execution, and Access to Leadership (1) Market capitalization as of October 28, 2021 (2) OceanFirst announced the planned consolidation of 20 deposit gathering locations and the sale of 2 branches, when completed will result in an ending count of 36 branches. VA PA NY MA CT RI MD DC DE NJ NH ME VT Central & Northern New Jersey Region Southern New Jersey Region Greater Philadelphia Region New York Region Boston Region Baltimore / D.C. Region
. . .Investment Thesis 4 Balance sheet de-risked with executed loan sales, resolution of substantially all full forbearance loans, and extinguishment of high-cost borrowings Strength of Balance Sheet Cost of deposits remain low at 22 basis points (bps) at September 30, 2021 Low-Cost and Durable Deposit Base Digital products and customer experience on par with national banks and FinTechs, outpacing regional and community banksDigital Innovation Acquired attractive and underappreciated assets in exurban markets at favorable prices Disciplined and Strategic M&A Deep banking, regulatory, M&A, and integration experience Demonstrated strong pandemic response Meaningful insider ownership aligned with shareholder interest Seasoned Leadership Commitment to management of credit, interest rate and regulatory / compliance riskConservative Risk Culture Well Positioned to Generate Strong Returns
. . . I N V E S T O R P R E S E N T A T I O N 5 Quarterly Update
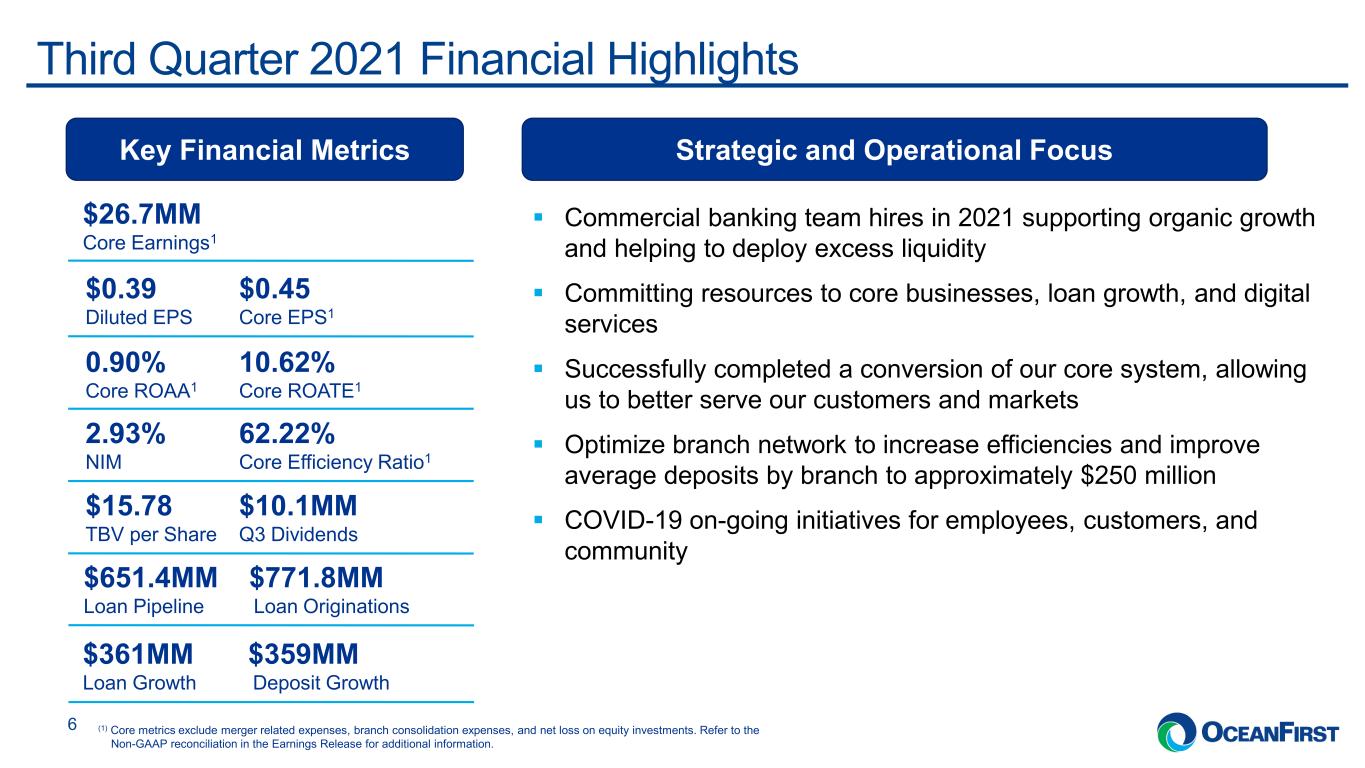
. . . $651.4MM $771.8MM Loan Pipeline Loan Originations Third Quarter 2021 Financial Highlights 6 Key Financial Metrics Strategic and Operational Focus $26.7MM Core Earnings1 $0.39 $0.45 Diluted EPS Core EPS1 0.90% 10.62% Core ROAA1 Core ROATE1 2.93% 62.22% NIM Core Efficiency Ratio1 $15.78 $10.1MM TBV per Share Q3 Dividends Commercial banking team hires in 2021 supporting organic growth and helping to deploy excess liquidity Committing resources to core businesses, loan growth, and digital services Successfully completed a conversion of our core system, allowing us to better serve our customers and markets Optimize branch network to increase efficiencies and improve average deposits by branch to approximately $250 million COVID-19 on-going initiatives for employees, customers, and community $361MM $359MM Loan Growth Deposit Growth (1) Core metrics exclude merger related expenses, branch consolidation expenses, and net loss on equity investments. Refer to the Non-GAAP reconciliation in the Earnings Release for additional information.
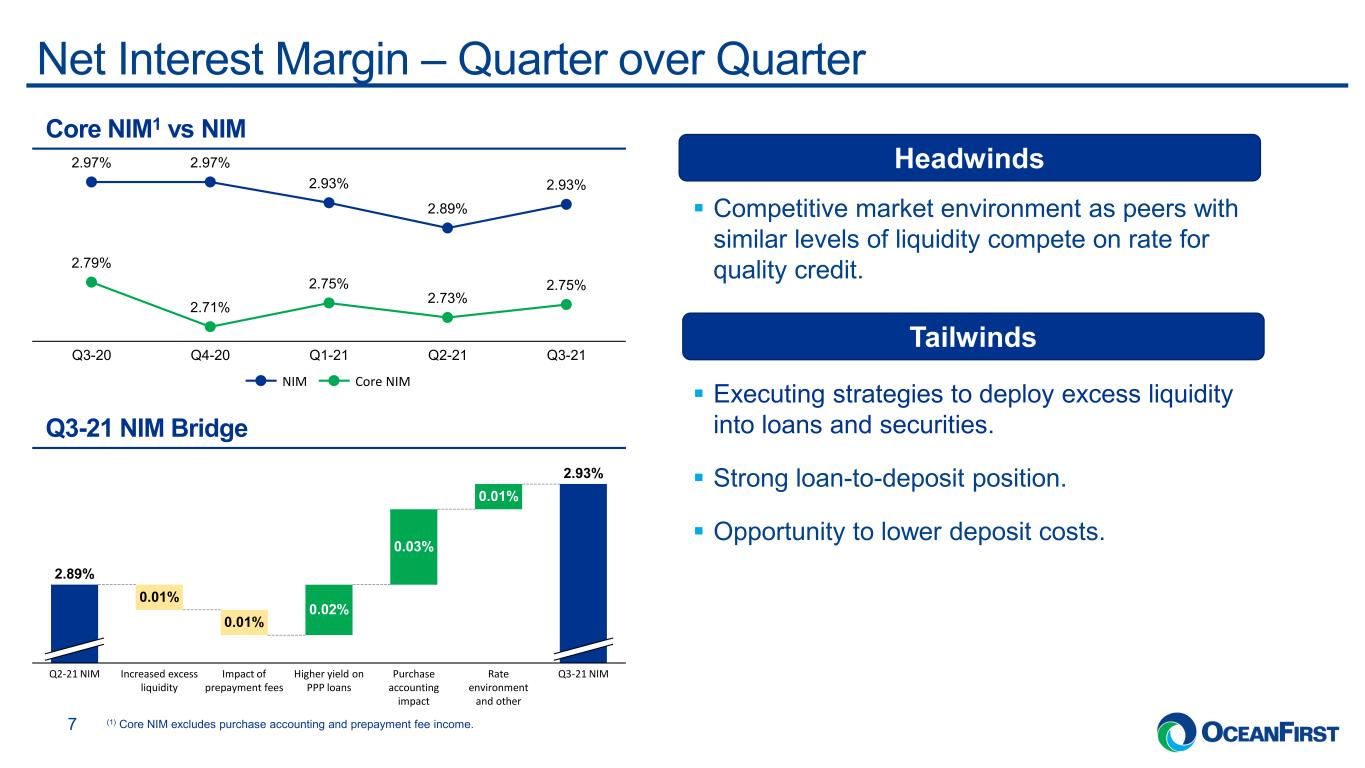
. . .Net Interest Margin – Quarter over Quarter 7 Competitive market environment as peers with similar levels of liquidity compete on rate for quality credit. Executing strategies to deploy excess liquidity into loans and securities. Strong loan-to-deposit position. Opportunity to lower deposit costs. (1) Core NIM excludes purchase accounting and prepayment fee income. Core NIM1 vs NIM Q3-21 NIM Bridge Headwinds Tailwinds Higher yield on PPP loans 2.89% Impact of prepayment fees 2.93% 0.01% Q3-21 NIM 0.01% Q2-21 NIM Rate environment and other Increased excess liquidity 0.02% 0.03% Purchase accounting impact 0.01% Q3-20 2.97% 2.79% 2.75% 2.97% 2.71% Q4-20 2.93% 2.75% Q1-21 2.89% 2.73% 2.93% Q2-21 Q3-21 NIM Core NIM
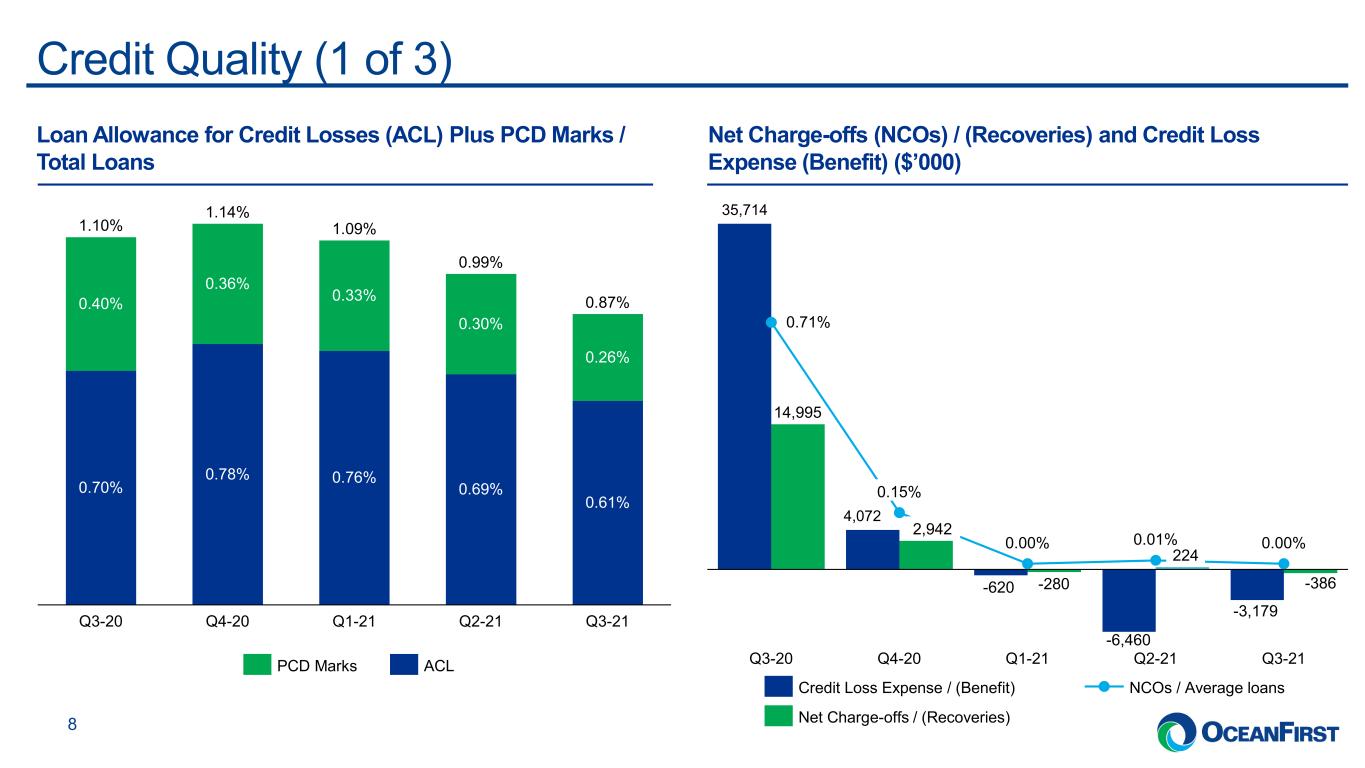
. . .Credit Quality (1 of 3) 8 Loan Allowance for Credit Losses (ACL) Plus PCD Marks / Total Loans Net Charge-offs (NCOs) / (Recoveries) and Credit Loss Expense (Benefit) ($’000) Q3-20 1.09% 0.40% 0.36% 0.70% 0.78% Q4-20 0.76% 0.33% Q1-21 0.30% 0.69% Q2-21 0.26% 0.61% Q3-21 1.10% 1.14% 0.99% 0.87% PCD Marks ACL 35,714 4,072 -386 Q4-20 0.71% 0.01% Q3-20 -280 0.15% Q3-21 -620 0.00% Q1-21 -6,460 224 Q2-21 2,942 -3,179 0.00% 14,995 Credit Loss Expense / (Benefit) Net Charge-offs / (Recoveries) NCOs / Average loans
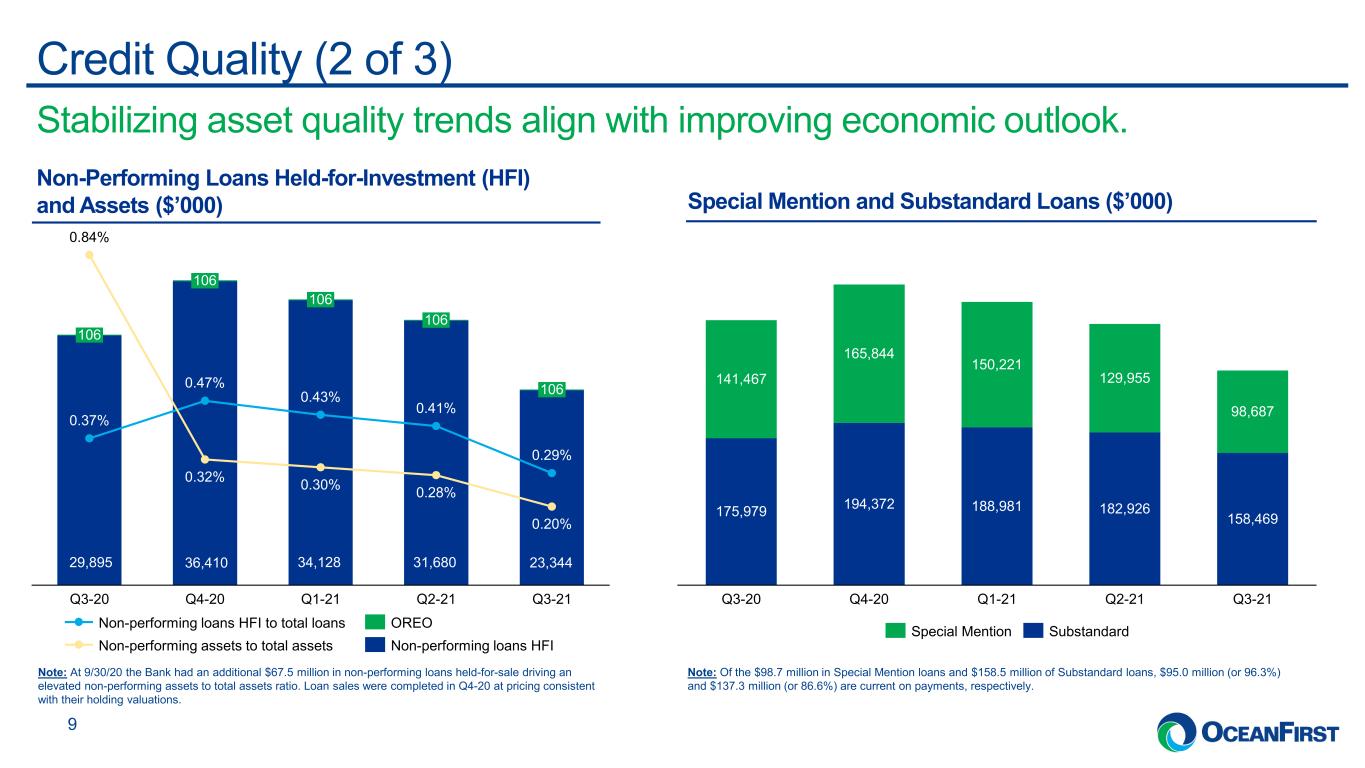
. . . Stabilizing asset quality trends align with improving economic outlook. Credit Quality (2 of 3) 9 Non-Performing Loans Held-for-Investment (HFI) and Assets ($’000) Special Mention and Substandard Loans ($’000) Note: At 9/30/20 the Bank had an additional $67.5 million in non-performing loans held-for-sale driving an elevated non-performing assets to total assets ratio. Loan sales were completed in Q4-20 at pricing consistent with their holding valuations. Note: Of the $98.7 million in Special Mention loans and $158.5 million of Substandard loans, $95.0 million (or 96.3%) and $137.3 million (or 86.6%) are current on payments, respectively. 106 0.37% 0.84% 106 0.32% Q3-20 0.47% 106 Q4-20 0.29% 0.43% 106 0.30% Q3-21 0.28% Q1-21 Q2-21 0.41% 106 0.20% Non-performing loans HFI to total loans Non-performing loans HFI OREO Non-performing assets to total assets 29,895 36,410 34,128 31,680 23,344 175,979 194,372 188,981 182,926 158,469 141,467 165,844 150,221 129,955 98,687 Q3-20 Q2-21Q4-20 Q1-21 Q3-21 Special Mention Substandard
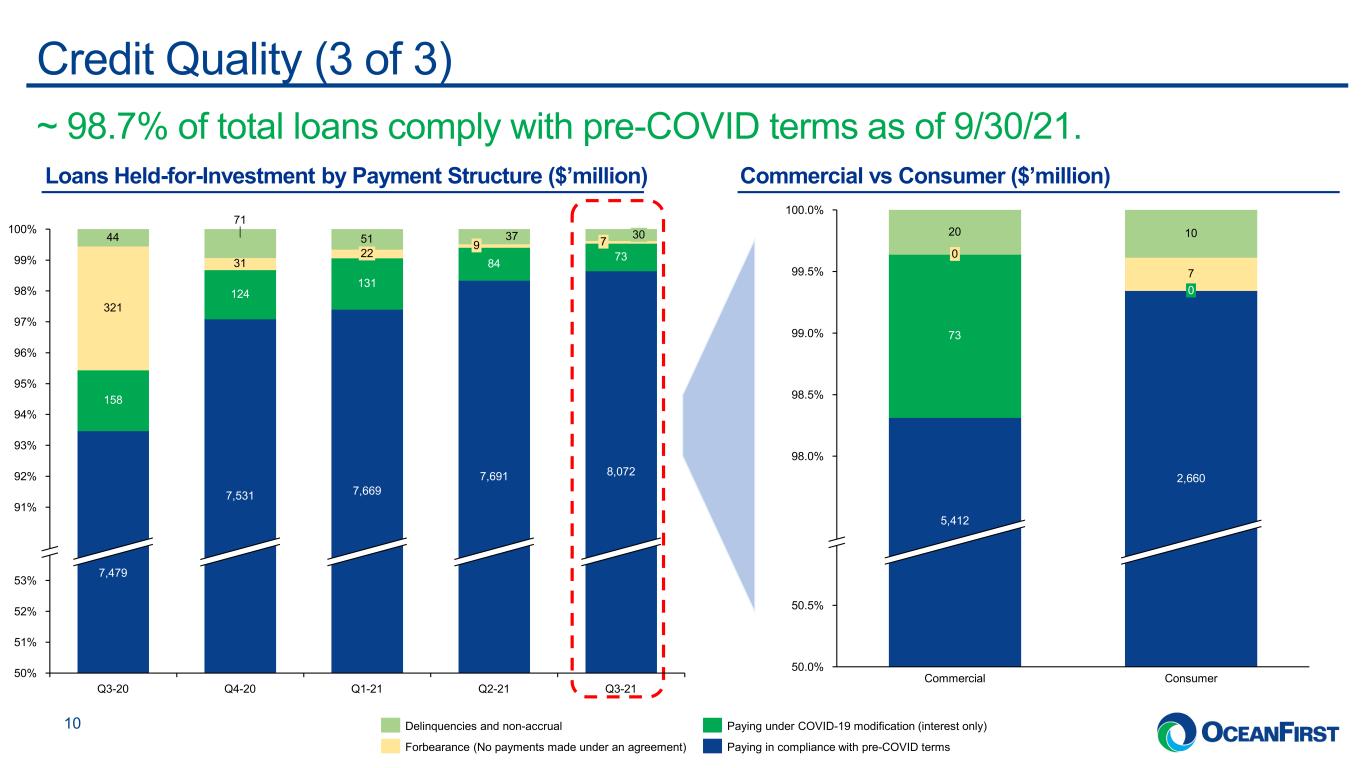
. . .Credit Quality (3 of 3) 10 Commercial vs Consumer ($’million)Loans Held-for-Investment by Payment Structure ($’million) ~ 98.7% of total loans comply with pre-COVID terms as of 9/30/21. 91% 52% 96% 98% 95% 51% 92% 100% 94% 97% 53% 99% 93% 50% 37 951 7,691 Q4-20 Q2-21 31 22 7,531 131 44 71 Q3-20 7,479 124 84 321 8,072 73 158 30 Q3-21Q1-21 7,669 7 Delinquencies and non-accrual Forbearance (No payments made under an agreement) Paying under COVID-19 modification (interest only) Paying in compliance with pre-COVID terms 99.5% 98.0% 100.0% 98.5% 99.0% 50.0% 50.5% Commercial 10 7 Consumer 73 2,660 20 0 5,412 0
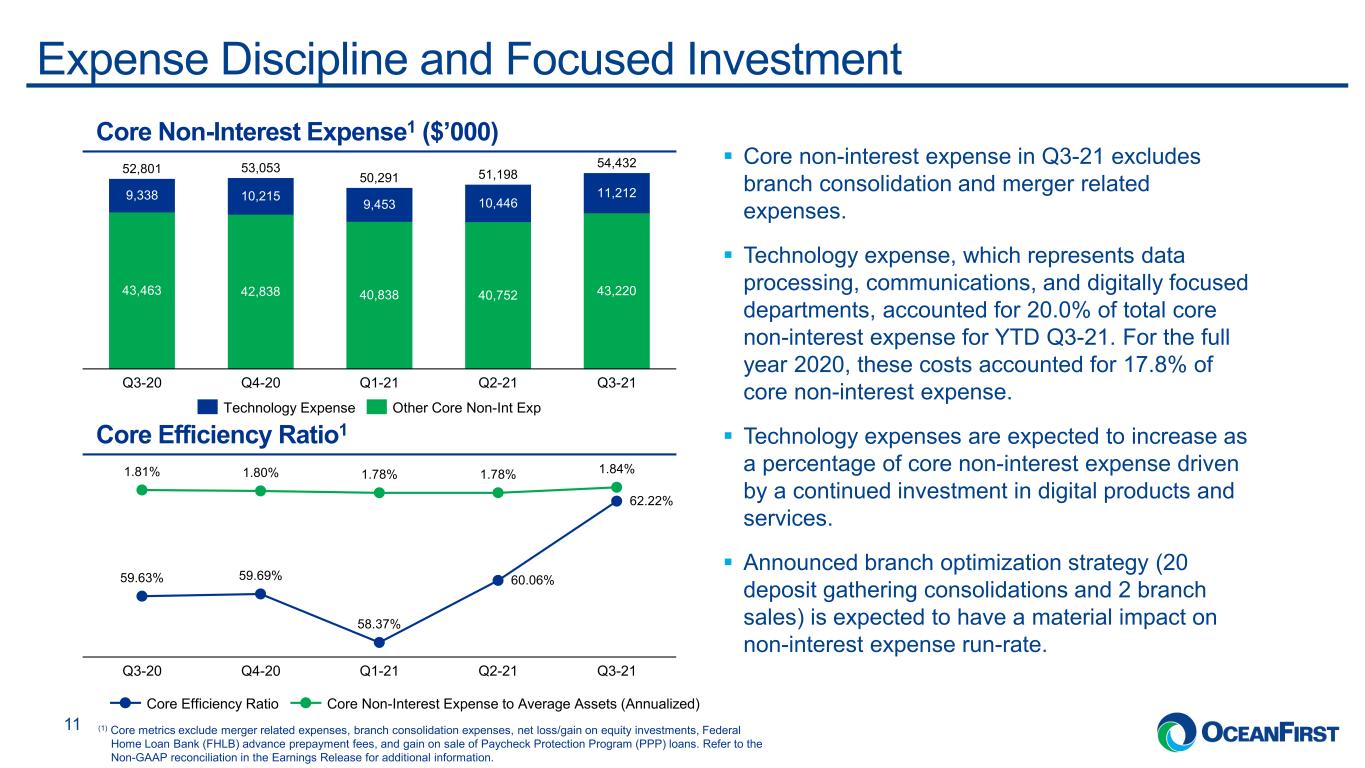
. . . Core Efficiency Ratio1 Expense Discipline and Focused Investment 11 Core non-interest expense in Q3-21 excludes branch consolidation and merger related expenses. Technology expense, which represents data processing, communications, and digitally focused departments, accounted for 20.0% of total core non-interest expense for YTD Q3-21. For the full year 2020, these costs accounted for 17.8% of core non-interest expense. Technology expenses are expected to increase as a percentage of core non-interest expense driven by a continued investment in digital products and services. Announced branch optimization strategy (20 deposit gathering consolidations and 2 branch sales) is expected to have a material impact on non-interest expense run-rate. Core Non-Interest Expense1 ($’000) 43,463 42,838 40,838 40,752 43,220 9,338 10,215 9,453 10,446 11,212 50,291 54,432 Q2-21Q3-20 52,801 Q3-21Q4-20 Q1-21 53,053 51,198 Other Core Non-Int ExpTechnology Expense Q3-21 1.78% 59.69% Q1-21 59.63% 1.81% Q3-20 1.80% Q4-20 58.37% 60.06% 1.78% Q2-21 62.22% 1.84% Core Efficiency Ratio Core Non-Interest Expense to Average Assets (Annualized) (1) Core metrics exclude merger related expenses, branch consolidation expenses, net loss/gain on equity investments, Federal Home Loan Bank (FHLB) advance prepayment fees, and gain on sale of Paycheck Protection Program (PPP) loans. Refer to the Non-GAAP reconciliation in the Earnings Release for additional information.
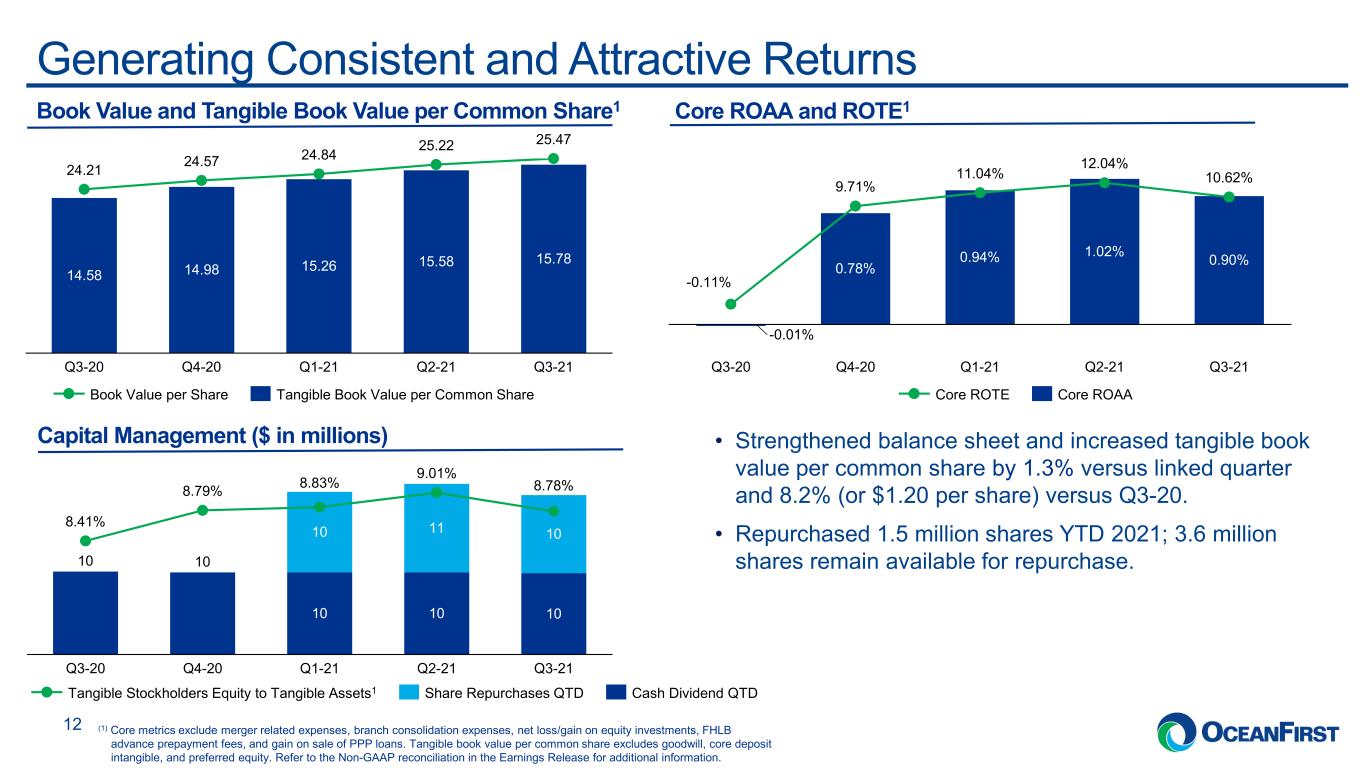
. . .Generating Consistent and Attractive Returns 12 Book Value and Tangible Book Value per Common Share1 Core ROAA and ROTE1 • Strengthened balance sheet and increased tangible book value per common share by 1.3% versus linked quarter and 8.2% (or $1.20 per share) versus Q3-20. • Repurchased 1.5 million shares YTD 2021; 3.6 million shares remain available for repurchase. Capital Management ($ in millions) 14.58 14.98 15.26 15.58 15.78 24.21 24.57 24.84 25.22 25.47 Q2-21Q3-20 Q1-21Q4-20 Q3-21 Book Value per Share Tangible Book Value per Common Share Q4-20 -0.11% -0.01% 11.04% 0.90%0.78% Q1-21Q3-20 9.71% 0.94% Q3-21 12.04% 1.02% Q2-21 10.62% Core ROTE Core ROAA 10 10 10 10 10 10 11 10 Q4-20Q3-20 Q1-21 Q2-21 Q3-21 8.41% 8.79% 8.83% 9.01% 8.78% Tangible Stockholders Equity to Tangible Assets1 Cash Dividend QTDShare Repurchases QTD (1) Core metrics exclude merger related expenses, branch consolidation expenses, net loss/gain on equity investments, FHLB advance prepayment fees, and gain on sale of PPP loans. Tangible book value per common share excludes goodwill, core deposit intangible, and preferred equity. Refer to the Non-GAAP reconciliation in the Earnings Release for additional information.
. . . I N V E S T O R P R E S E N T A T I O N 13 Investor Presentation
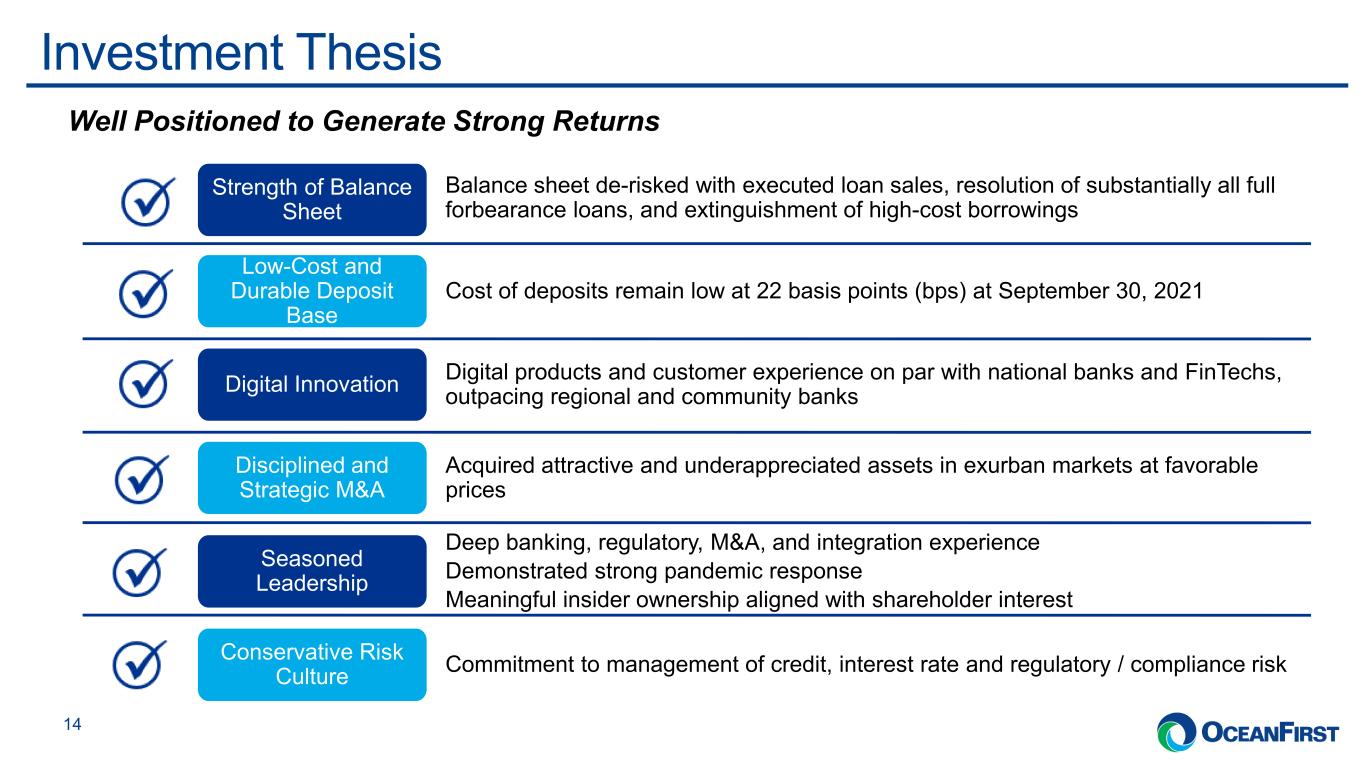
. . .Investment Thesis 14 Balance sheet de-risked with executed loan sales, resolution of substantially all full forbearance loans, and extinguishment of high-cost borrowings Strength of Balance Sheet Cost of deposits remain low at 22 basis points (bps) at September 30, 2021 Low-Cost and Durable Deposit Base Digital products and customer experience on par with national banks and FinTechs, outpacing regional and community banksDigital Innovation Acquired attractive and underappreciated assets in exurban markets at favorable prices Disciplined and Strategic M&A Deep banking, regulatory, M&A, and integration experience Demonstrated strong pandemic response Meaningful insider ownership aligned with shareholder interest Seasoned Leadership Commitment to management of credit, interest rate and regulatory / compliance riskConservative Risk Culture Well Positioned to Generate Strong Returns
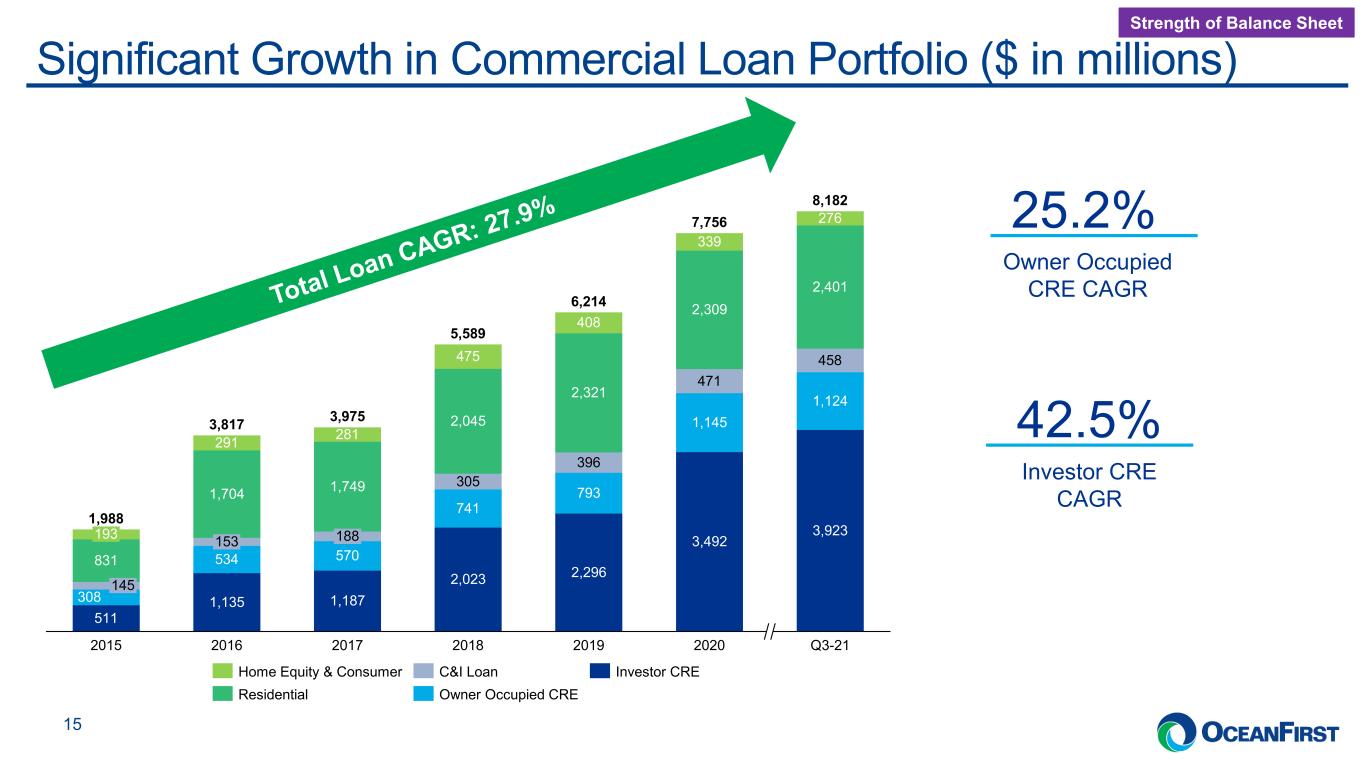
. . .Significant Growth in Commercial Loan Portfolio ($ in millions) 15 Investor CRE CAGR 42.5% Owner Occupied CRE CAGR 25.2% Strength of Balance Sheet 511 1,135 1,187 2,023 2,296 3,492 3,923 308 534 570 741 793 1,145 1,124 305 396 471 458 831 1,704 1,749 2,045 2,321 2,309 2,401 291 281 475 408 339 276 153193 2015 145 2016 188 2017 2018 2019 2020 Q3-21 1,988 3,817 3,975 5,589 6,214 7,756 8,182 Investor CREHome Equity & Consumer Residential Owner Occupied CRE C&I Loan
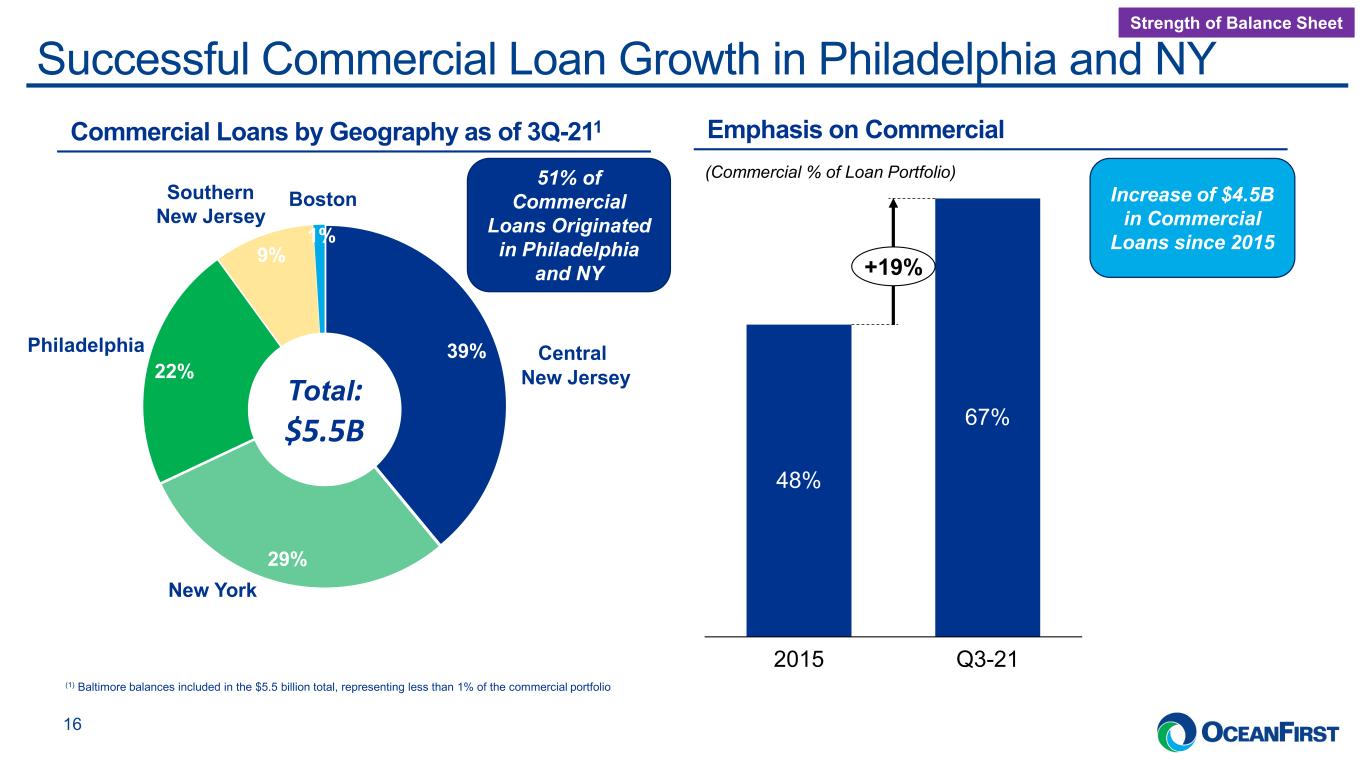
. . .Successful Commercial Loan Growth in Philadelphia and NY 16 48% 2015 67% Q3-21 +19% (Commercial % of Loan Portfolio) 39% 29% 22% 9% 1% Central New Jersey Southern New Jersey New York Philadelphia Boston Commercial Loans by Geography as of 3Q-211 Total: $5.5B 51% of Commercial Loans Originated in Philadelphia and NY Emphasis on Commercial Increase of $4.5B in Commercial Loans since 2015 Strength of Balance Sheet (1) Baltimore balances included in the $5.5 billion total, representing less than 1% of the commercial portfolio
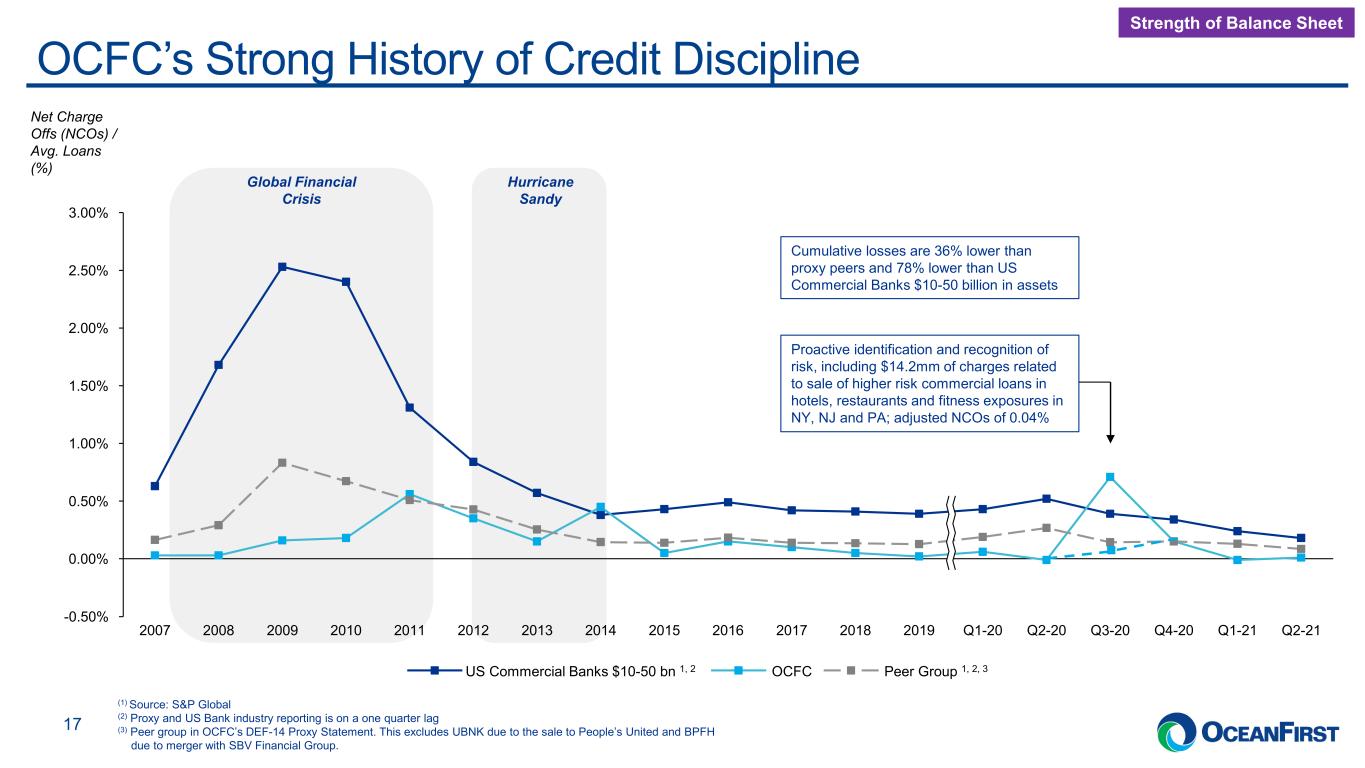
. . .OCFC’s Strong History of Credit Discipline 17 Global Financial Crisis Net Charge Offs (NCOs) / Avg. Loans (%) Hurricane Sandy (1) Source: S&P Global (2) Proxy and US Bank industry reporting is on a one quarter lag (3) Peer group in OCFC’s DEF-14 Proxy Statement. This excludes UBNK due to the sale to People’s United and BPFH due to merger with SBV Financial Group. Strength of Balance Sheet -0.50% 0.00% 0.50% 3.00% 2.00% 1.00% 1.50% 2.50% 2010 Q1-2120132007 20152008 Q4-202009 Q1-2020122011 2014 20172016 2018 2019 Q2-20 Q3-20 Q2-21 US Commercial Banks $10-50 bn 1, 2 OCFC Peer Group 1, 2, 3 Proactive identification and recognition of risk, including $14.2mm of charges related to sale of higher risk commercial loans in hotels, restaurants and fitness exposures in NY, NJ and PA; adjusted NCOs of 0.04% Cumulative losses are 36% lower than proxy peers and 78% lower than US Commercial Banks $10-50 billion in assets
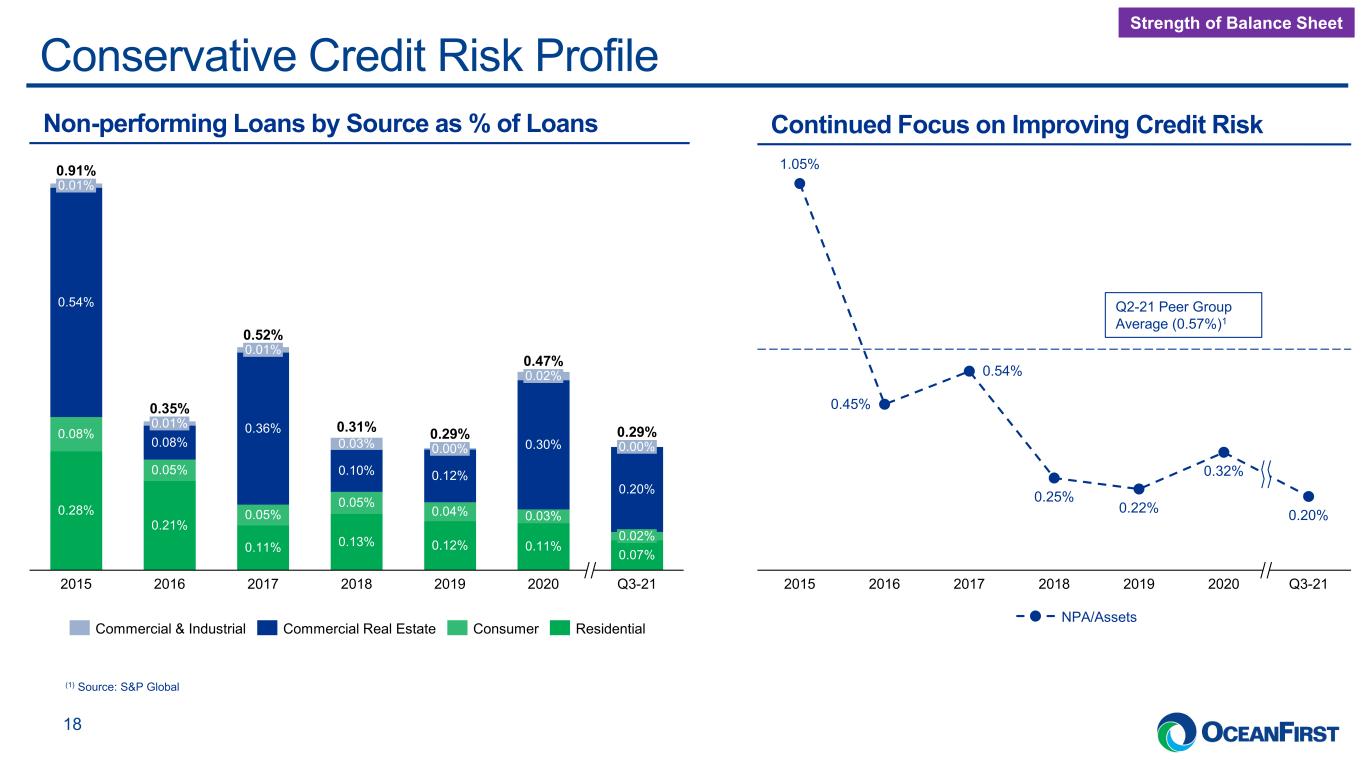
. . .Conservative Credit Risk Profile 18 0.01% 0.01% 0.08% 0.47% 0.03% 0.54% 2015 0.05% 0.35% 2018 0.21% 0.29% 2016 0.01% 0.36% 0.05% 2017 0.11% 0.03% 0.10% 0.05% 0.13% 0.02% 0.12% 0.04% 0.00% 0.12% 2019 0.31% 0.30% 0.11% 0.28% 0.02% 0.07% Q3-21 0.91% 0.20% 0.29% 2020 0.00%0.08% 0.52% Commercial & Industrial ConsumerCommercial Real Estate Residential (1) Source: S&P Global 1.05% 2015 2018 0.54% 0.45% 2016 2017 0.25% 0.22% 2019 0.32% 2020 0.20% Q3-21 Q2-21 Peer Group Average (0.57%)1 NPA/Assets Strength of Balance Sheet Continued Focus on Improving Credit RiskNon-performing Loans by Source as % of Loans
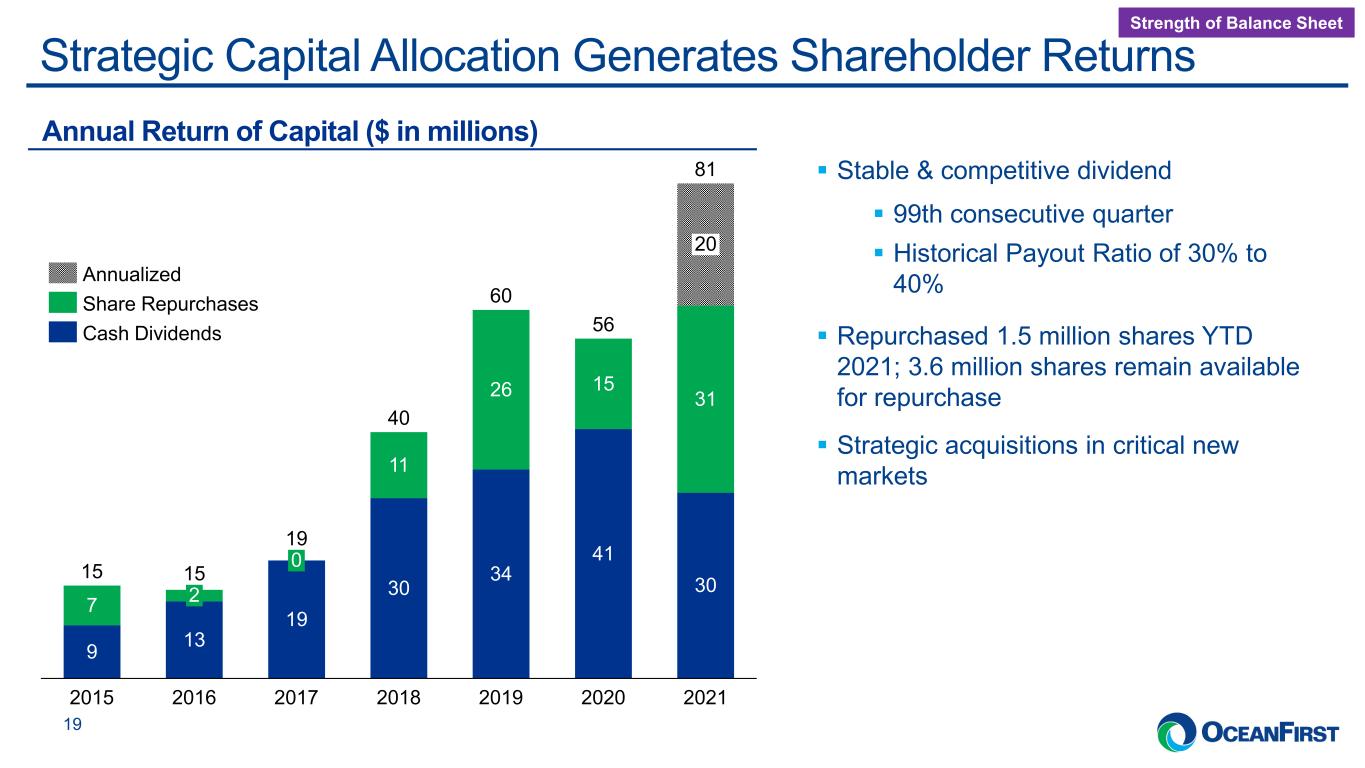
. . .Strategic Capital Allocation Generates Shareholder Returns 19 Strength of Balance Sheet Stable & competitive dividend 99th consecutive quarter Historical Payout Ratio of 30% to 40% Repurchased 1.5 million shares YTD 2021; 3.6 million shares remain available for repurchase Strategic acquisitions in critical new markets 9 13 19 30 34 41 30 7 11 26 15 31 2 20192016 2018 0 20 2017 2020 20212015 15 19 40 60 56 81 15 Annualized Share Repurchases Cash Dividends Annual Return of Capital ($ in millions)
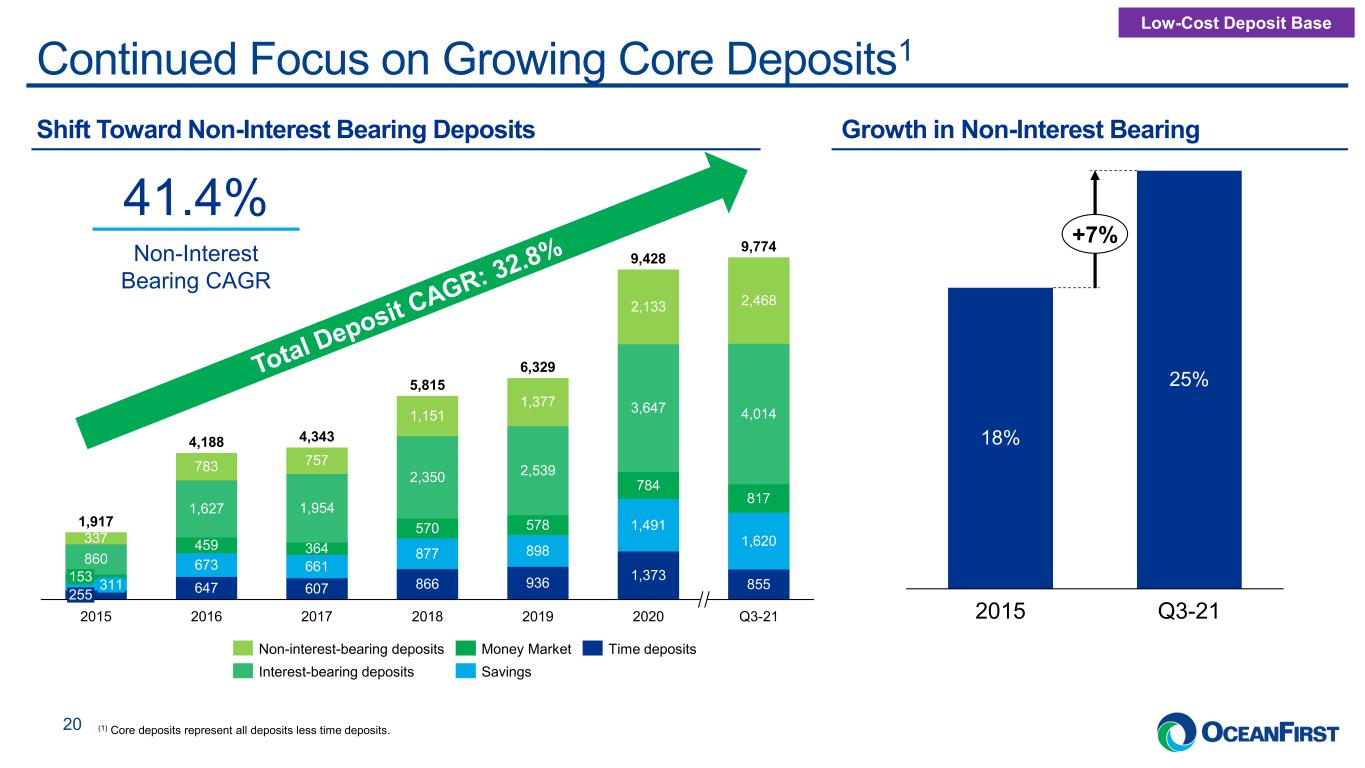
. . .Continued Focus on Growing Core Deposits1 20 25% 18% 2015 Q3-21 +7% Growth in Non-Interest BearingShift Toward Non-Interest Bearing Deposits Non-Interest Bearing CAGR 41.4% Low-Cost Deposit Base 647 607 866 936 1,373 855 673 661 877 898 1,491 1,620459 364 570 578 784 817 860 1,627 1,954 2,350 2,539 3,647 4,014 337 783 757 1,151 1,377 2,133 2,468 2015 9,774 153 2019 311 255 2016 Q3-212017 2018 2020 1,917 4,188 6,329 4,343 5,815 9,428 Non-interest-bearing deposits Time deposits SavingsInterest-bearing deposits Money Market (1) Core deposits represent all deposits less time deposits.
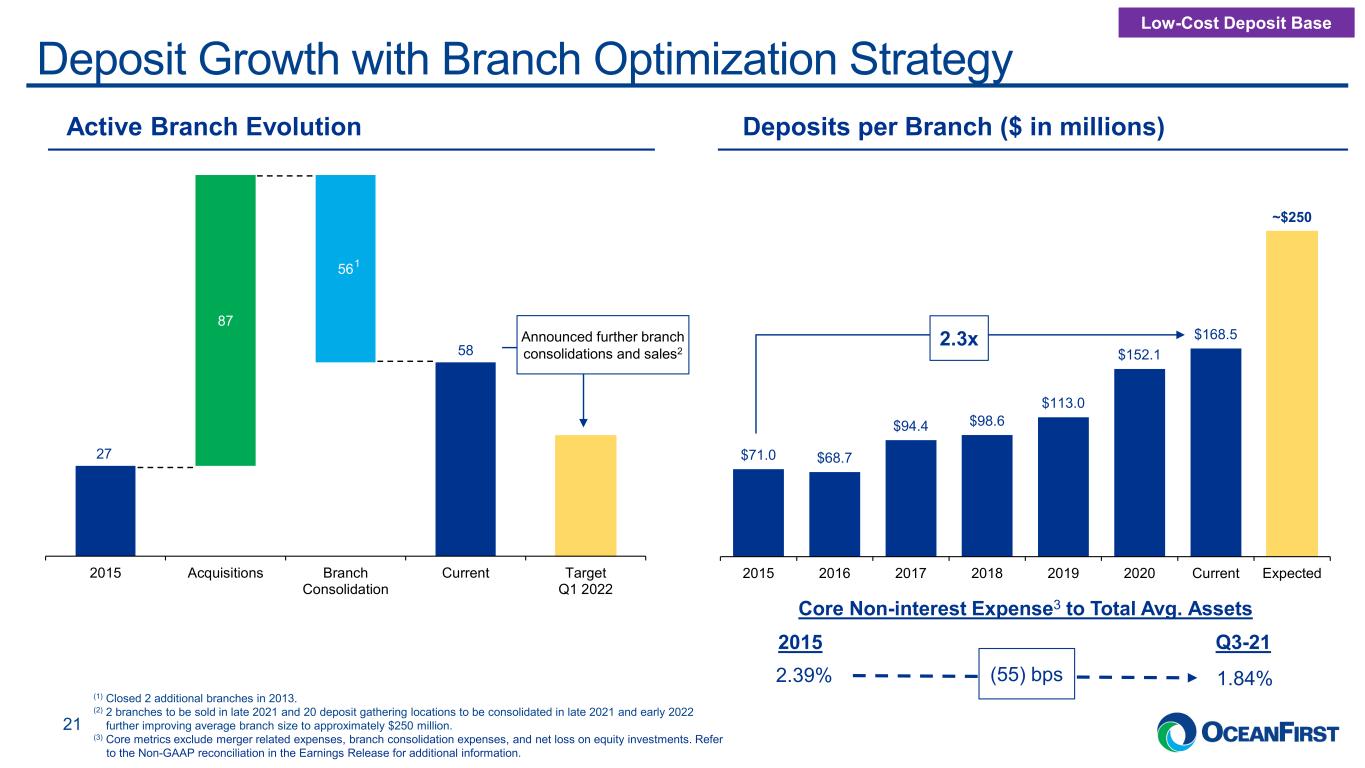
. . . 27 58 87 56 2015 Acquisitions Branch Consolidation Current Target Q1 2022 Deposit Growth with Branch Optimization Strategy 21 Announced further branch consolidations and sales2 1 (1) Closed 2 additional branches in 2013. (2) 2 branches to be sold in late 2021 and 20 deposit gathering locations to be consolidated in late 2021 and early 2022 further improving average branch size to approximately $250 million. (3) Core metrics exclude merger related expenses, branch consolidation expenses, and net loss on equity investments. Refer to the Non-GAAP reconciliation in the Earnings Release for additional information. $71.0 $68.7 $94.4 $98.6 $113.0 $152.1 $168.5 ~$250 2015 2016 2017 2018 2019 2020 Current Expected 2.3x Low-Cost Deposit Base Active Branch Evolution Deposits per Branch ($ in millions) (55) bps2.39% 1.84% 2015 Q3-21 Core Non-interest Expense3 to Total Avg. Assets
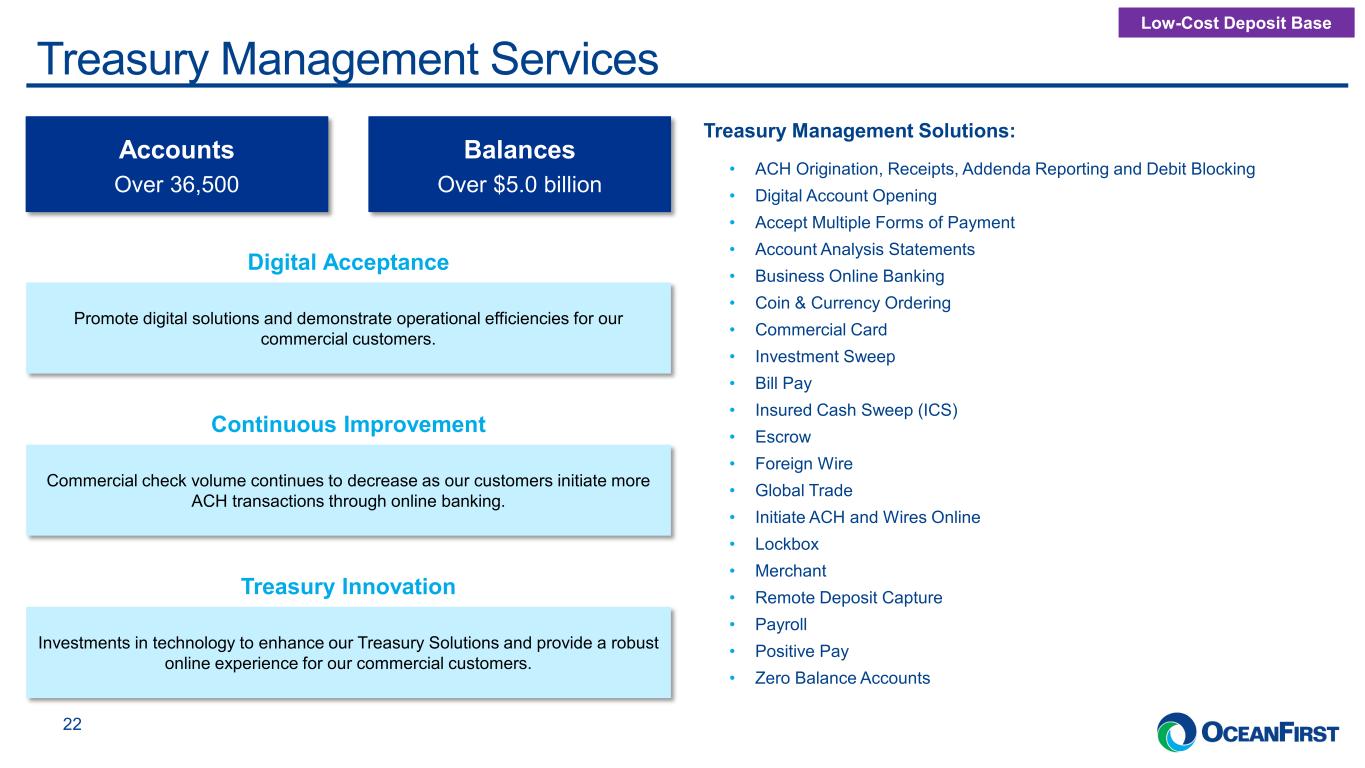
. . .Treasury Management Services 22 Treasury Management Solutions: • ACH Origination, Receipts, Addenda Reporting and Debit Blocking • Digital Account Opening • Accept Multiple Forms of Payment • Account Analysis Statements • Business Online Banking • Coin & Currency Ordering • Commercial Card • Investment Sweep • Bill Pay • Insured Cash Sweep (ICS) • Escrow • Foreign Wire • Global Trade • Initiate ACH and Wires Online • Lockbox • Merchant • Remote Deposit Capture • Payroll • Positive Pay • Zero Balance Accounts Balances Over $5.0 billion Accounts Over 36,500 Digital Acceptance Promote digital solutions and demonstrate operational efficiencies for our commercial customers. Continuous Improvement Commercial check volume continues to decrease as our customers initiate more ACH transactions through online banking. Treasury Innovation Investments in technology to enhance our Treasury Solutions and provide a robust online experience for our commercial customers. Low-Cost Deposit Base
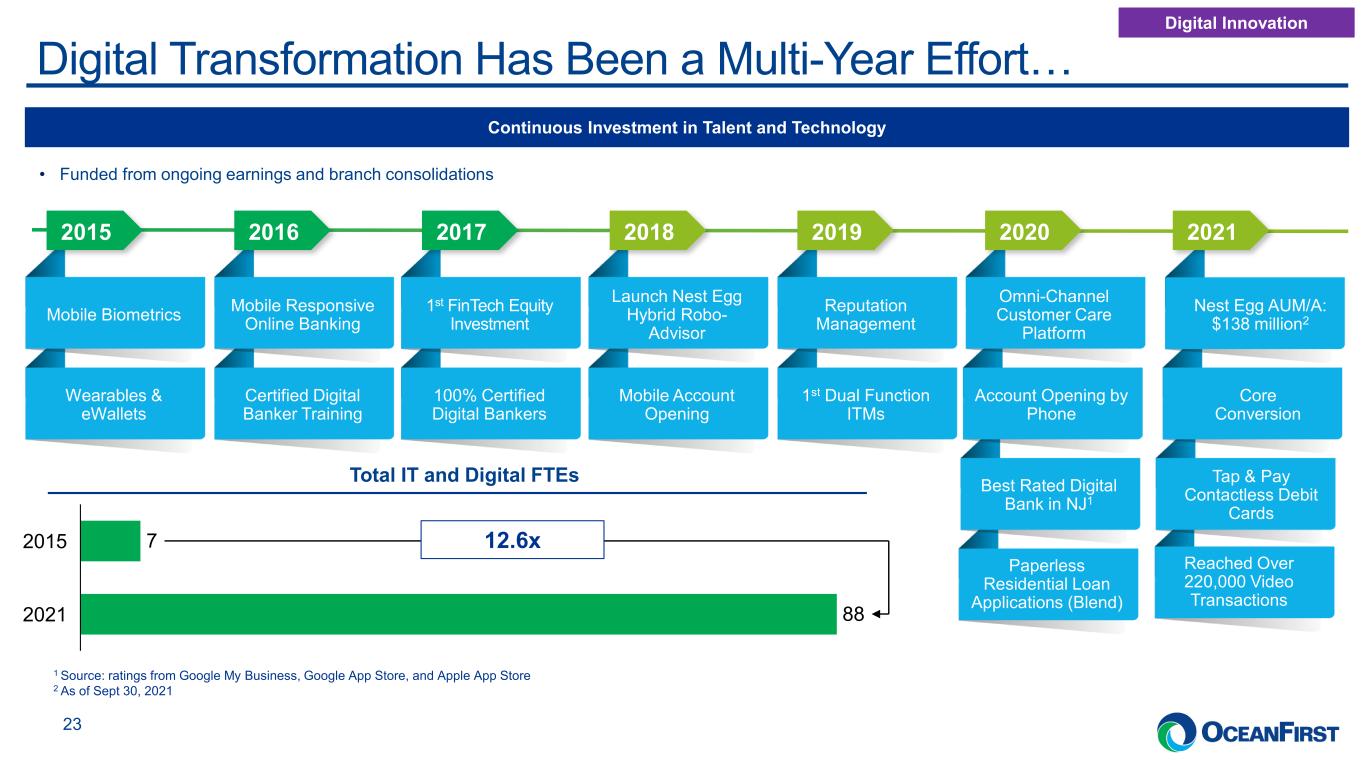
. . . Tap & Pay Contactless Debit Cards Core Conversion Digital Transformation Has Been a Multi-Year Effort… 23 Continuous Investment in Talent and Technology • Funded from ongoing earnings and branch consolidations Nest Egg AUM/A: $138 million2 Paperless Residential Loan Applications (Blend) Best Rated Digital Bank in NJ1 Account Opening by Phone 1st Dual Function ITMs Wearables & eWallets Mobile Account Opening Reputation Management 100% Certified Digital Bankers Certified Digital Banker Training Launch Nest Egg Hybrid Robo- Advisor 1st FinTech Equity Investment Mobile Responsive Online BankingMobile Biometrics Omni-Channel Customer Care Platform 2015 2016 2017 2018 2019 2020 2021 Digital Innovation Reached Over 220,000 Video Transactions 1 Source: ratings from Google My Business, Google App Store, and Apple App Store 2 As of Sept 30, 2021 Total IT and Digital FTEs 7 88 2015 2021 12.6x
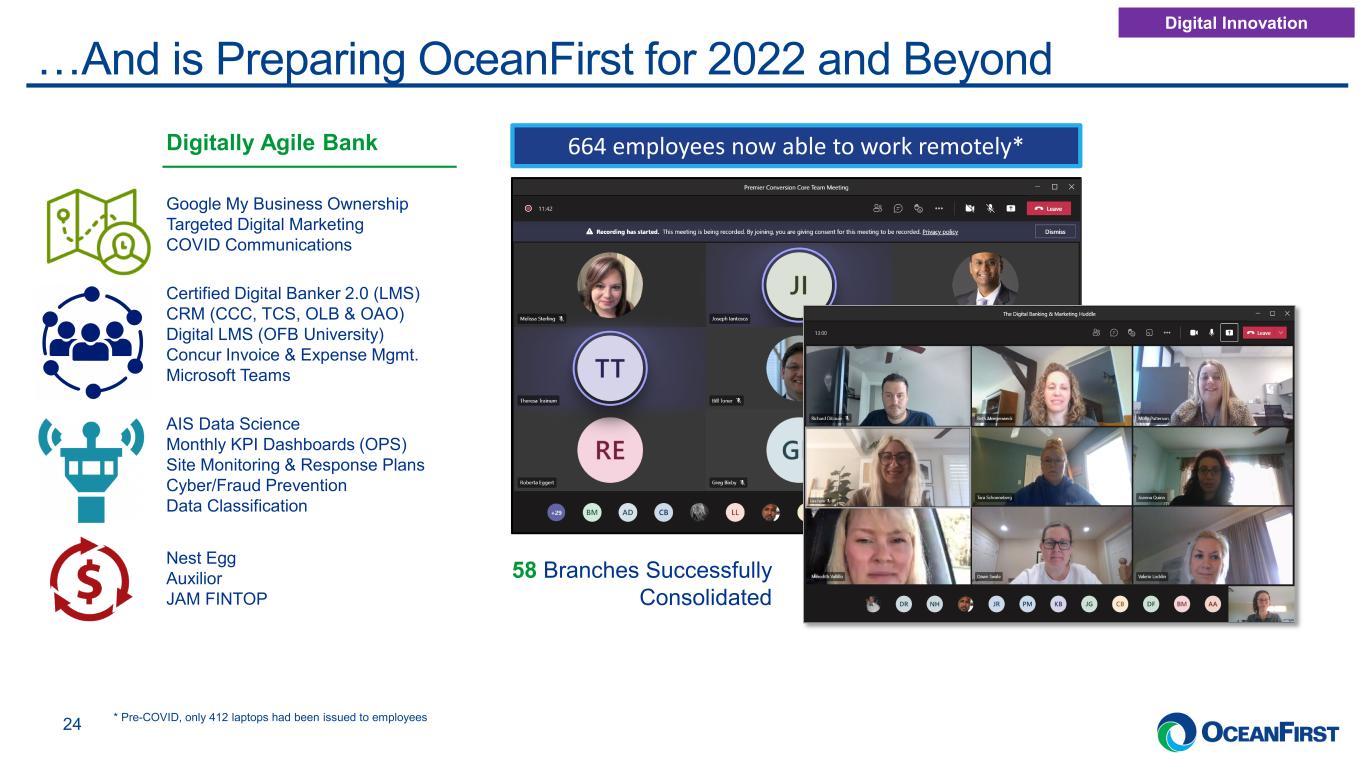
. . .…And is Preparing OceanFirst for 2022 and Beyond 24 Digitally Agile Bank Google My Business Ownership Targeted Digital Marketing COVID Communications Certified Digital Banker 2.0 (LMS) CRM (CCC, TCS, OLB & OAO) Digital LMS (OFB University) Concur Invoice & Expense Mgmt. Microsoft Teams AIS Data Science Monthly KPI Dashboards (OPS) Site Monitoring & Response Plans Cyber/Fraud Prevention Data Classification 58 Branches Successfully Consolidated 664 employees now able to work remotely* Nest Egg Auxilior JAM FINTOP * Pre-COVID, only 412 laptops had been issued to employees Digital Innovation
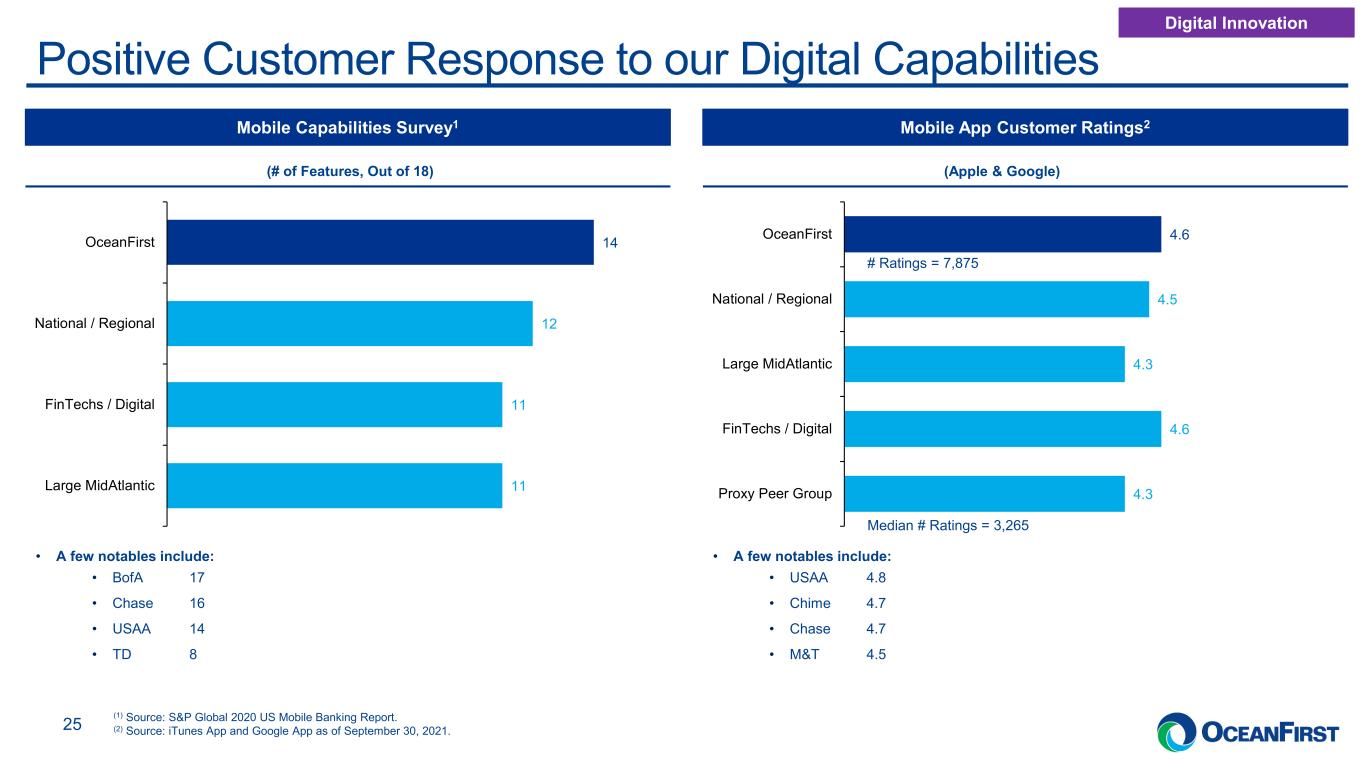
. . .Positive Customer Response to our Digital Capabilities 25 Mobile Capabilities Survey1 Mobile App Customer Ratings2 11 11 12 14 Large MidAtlantic FinTechs / Digital National / Regional OceanFirst • A few notables include: • BofA 17 • Chase 16 • USAA 14 • TD 8 (# of Features, Out of 18) (Apple & Google) 4.3 4.6 4.3 4.5 4.6 Proxy Peer Group FinTechs / Digital Large MidAtlantic National / Regional OceanFirst • A few notables include: • USAA 4.8 • Chime 4.7 • Chase 4.7 • M&T 4.5 # Ratings = 7,875 Median # Ratings = 3,265 (1) Source: S&P Global 2020 US Mobile Banking Report. (2) Source: iTunes App and Google App as of September 30, 2021. Digital Innovation
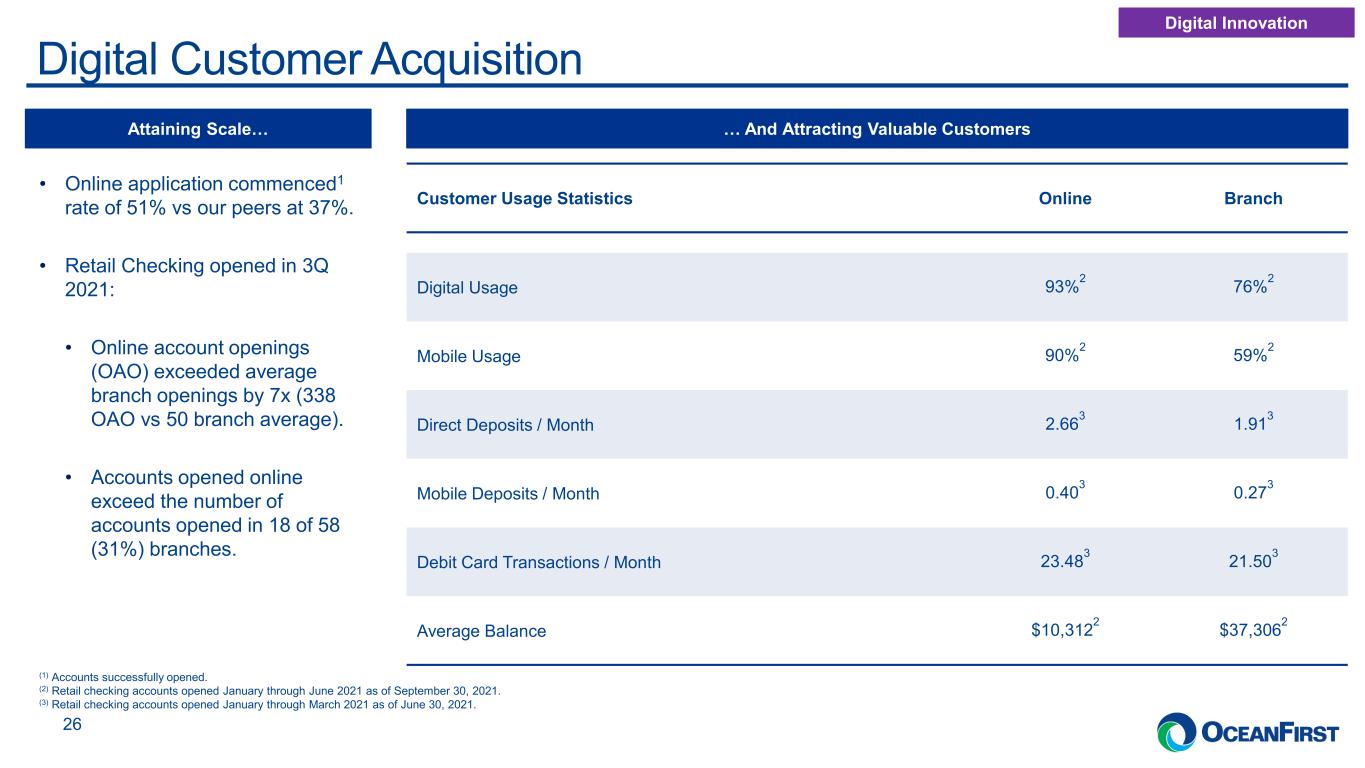
. . .Digital Customer Acquisition 26 Attaining Scale… … And Attracting Valuable Customers • Online application commenced1 rate of 51% vs our peers at 37%. • Retail Checking opened in 3Q 2021: • Online account openings (OAO) exceeded average branch openings by 7x (338 OAO vs 50 branch average). • Accounts opened online exceed the number of accounts opened in 18 of 58 (31%) branches. Customer Usage Statistics Online Branch Digital Usage 93%2 76%2 Mobile Usage 90%2 59%2 Direct Deposits / Month 2.663 1.913 Mobile Deposits / Month 0.403 0.273 Debit Card Transactions / Month 23.483 21.503 Average Balance $10,3122 $37,3062 (1) Accounts successfully opened. (2) Retail checking accounts opened January through June 2021 as of September 30, 2021. (3) Retail checking accounts opened January through March 2021 as of June 30, 2021. Digital Innovation
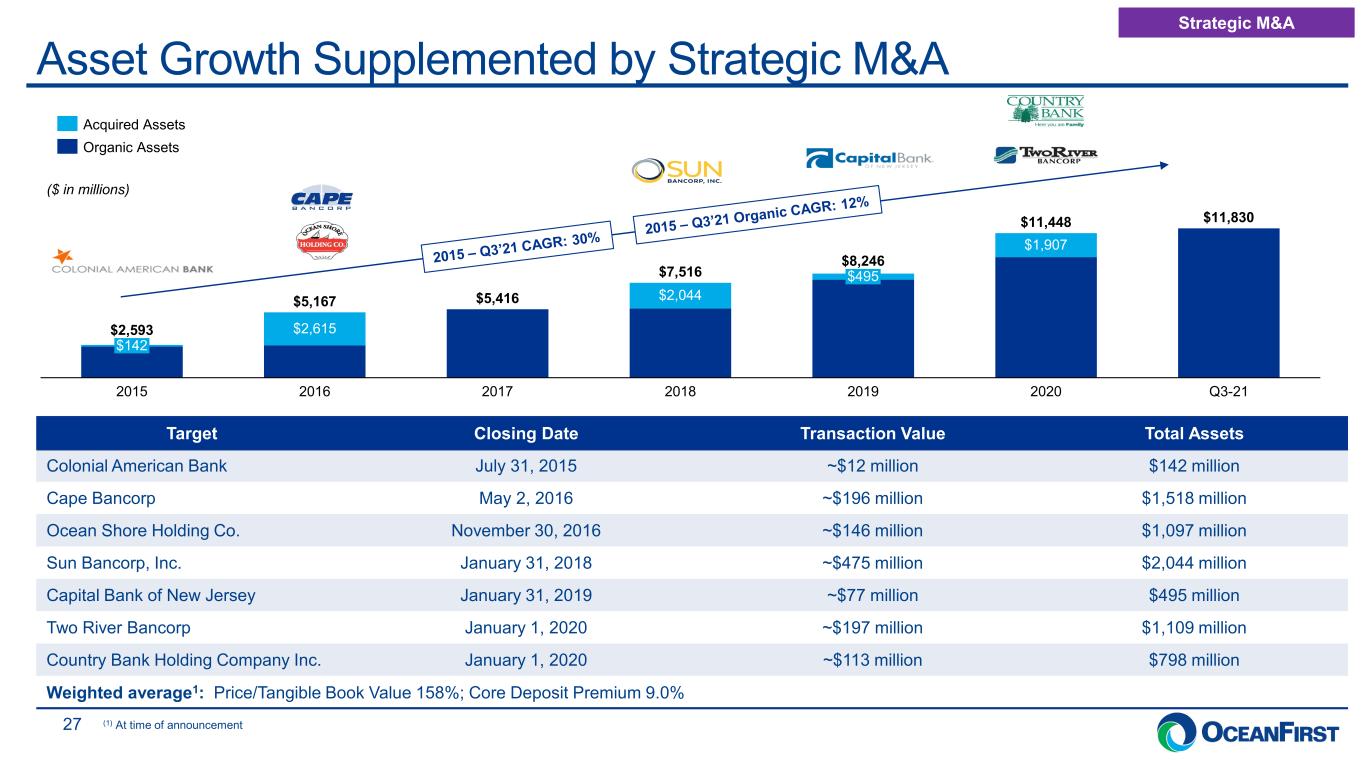
. . .Asset Growth Supplemented by Strategic M&A 27 ($ in millions) Strategic M&A Target Closing Date Transaction Value Total Assets Colonial American Bank July 31, 2015 ~$12 million $142 million Cape Bancorp May 2, 2016 ~$196 million $1,518 million Ocean Shore Holding Co. November 30, 2016 ~$146 million $1,097 million Sun Bancorp, Inc. January 31, 2018 ~$475 million $2,044 million Capital Bank of New Jersey January 31, 2019 ~$77 million $495 million Two River Bancorp January 1, 2020 ~$197 million $1,109 million Country Bank Holding Company Inc. January 1, 2020 ~$113 million $798 million Weighted average1: Price/Tangible Book Value 158%; Core Deposit Premium 9.0% $495 20172016 $142 20192015 2018 2020 Q3-21 $2,593 $2,044$5,167 $5,416 $7,516 $8,246 $11,448 $11,830 $1,907 $2,615 Acquired Assets Organic Assets (1) At time of announcement
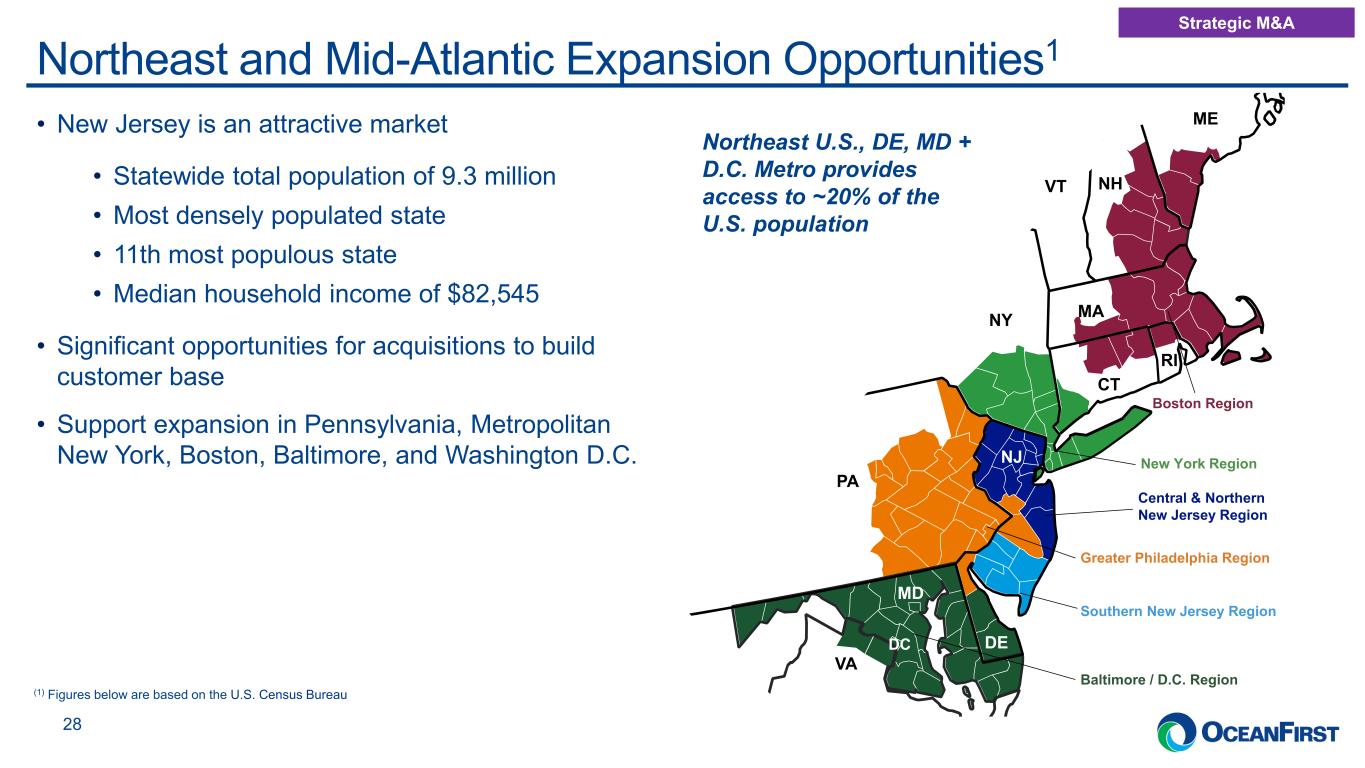
. . .Northeast and Mid-Atlantic Expansion Opportunities1 28 Strategic M&A • New Jersey is an attractive market • Statewide total population of 9.3 million • Most densely populated state • 11th most populous state • Median household income of $82,545 • Significant opportunities for acquisitions to build customer base • Support expansion in Pennsylvania, Metropolitan New York, Boston, Baltimore, and Washington D.C. VA PA NY MA CT RI MD DC DE NJ NH ME VT Central & Northern New Jersey Region Southern New Jersey Region Greater Philadelphia Region New York Region Boston Region Baltimore / D.C. Region Northeast U.S., DE, MD + D.C. Metro provides access to ~20% of the U.S. population (1) Figures below are based on the U.S. Census Bureau
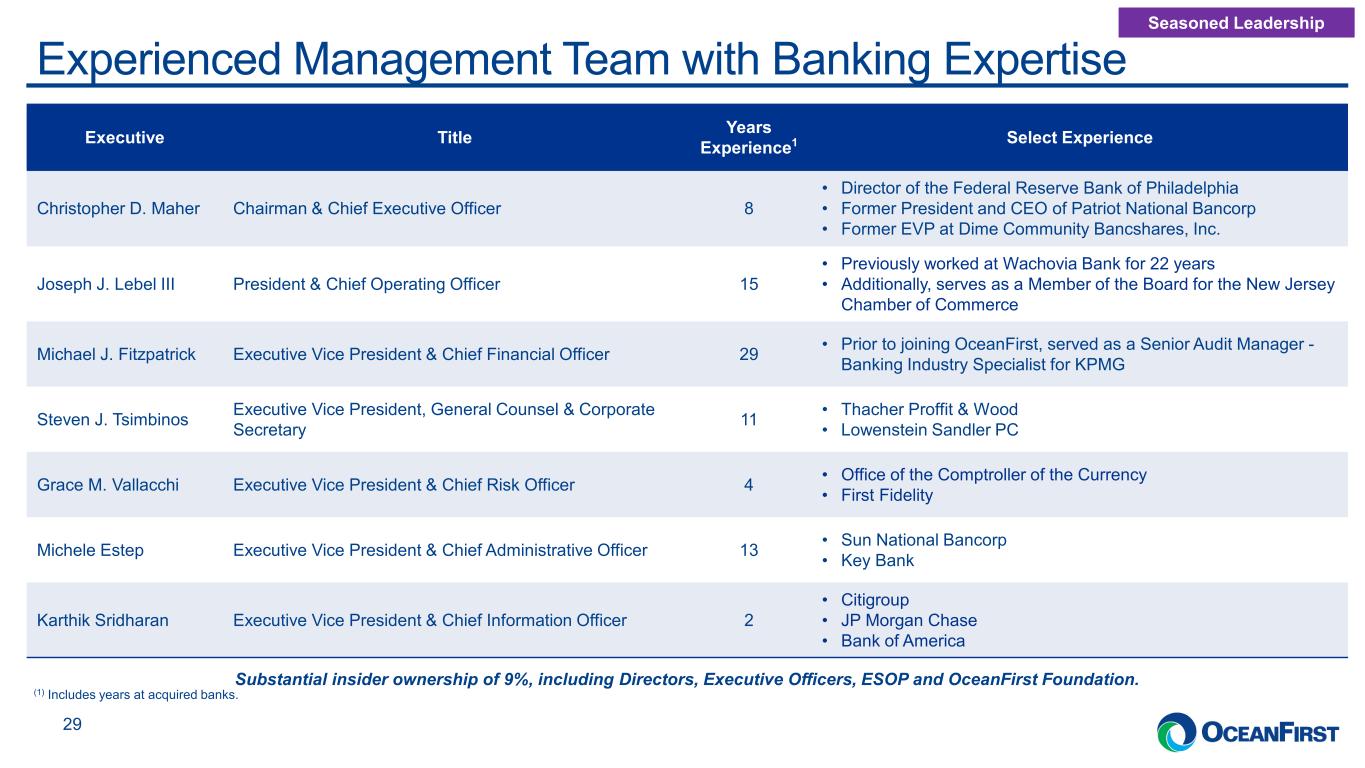
. . .Experienced Management Team with Banking Expertise 29 Seasoned Leadership Substantial insider ownership of 9%, including Directors, Executive Officers, ESOP and OceanFirst Foundation. Executive Title Years Experience1 Select Experience Christopher D. Maher Chairman & Chief Executive Officer 8 • Director of the Federal Reserve Bank of Philadelphia • Former President and CEO of Patriot National Bancorp • Former EVP at Dime Community Bancshares, Inc. Joseph J. Lebel III President & Chief Operating Officer 15 • Previously worked at Wachovia Bank for 22 years • Additionally, serves as a Member of the Board for the New Jersey Chamber of Commerce Michael J. Fitzpatrick Executive Vice President & Chief Financial Officer 29 • Prior to joining OceanFirst, served as a Senior Audit Manager - Banking Industry Specialist for KPMG Steven J. Tsimbinos Executive Vice President, General Counsel & Corporate Secretary 11 • Thacher Proffit & Wood • Lowenstein Sandler PC Grace M. Vallacchi Executive Vice President & Chief Risk Officer 4 • Office of the Comptroller of the Currency • First Fidelity Michele Estep Executive Vice President & Chief Administrative Officer 13 • Sun National Bancorp • Key Bank Karthik Sridharan Executive Vice President & Chief Information Officer 2 • Citigroup • JP Morgan Chase • Bank of America (1) Includes years at acquired banks.
. . . I N V E S T O R P R E S E N T A T I O N 30 Appendix
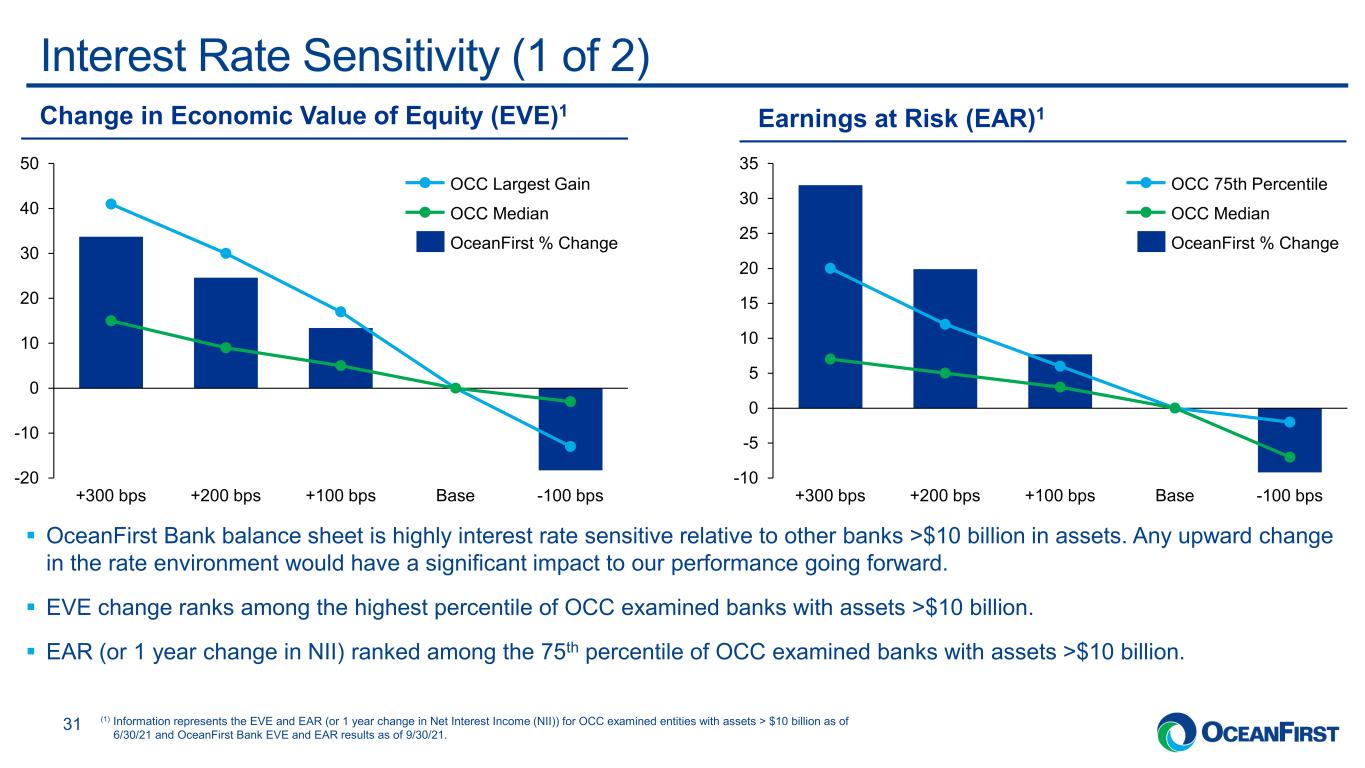
. . .Interest Rate Sensitivity (1 of 2) 31 (1) Information represents the EVE and EAR (or 1 year change in Net Interest Income (NII)) for OCC examined entities with assets > $10 billion as of 6/30/21 and OceanFirst Bank EVE and EAR results as of 9/30/21. OceanFirst Bank balance sheet is highly interest rate sensitive relative to other banks >$10 billion in assets. Any upward change in the rate environment would have a significant impact to our performance going forward. EVE change ranks among the highest percentile of OCC examined banks with assets >$10 billion. EAR (or 1 year change in NII) ranked among the 75th percentile of OCC examined banks with assets >$10 billion. Change in Economic Value of Equity (EVE)1 Earnings at Risk (EAR)1 -20 -10 0 10 20 30 40 50 +300 bps Base+100 bps+200 bps -100 bps OCC Largest Gain OCC Median OceanFirst % Change -10 -5 0 5 10 15 20 25 30 35 +300 bps -100 bps+100 bps+200 bps Base OCC 75th Percentile OceanFirst % Change OCC Median
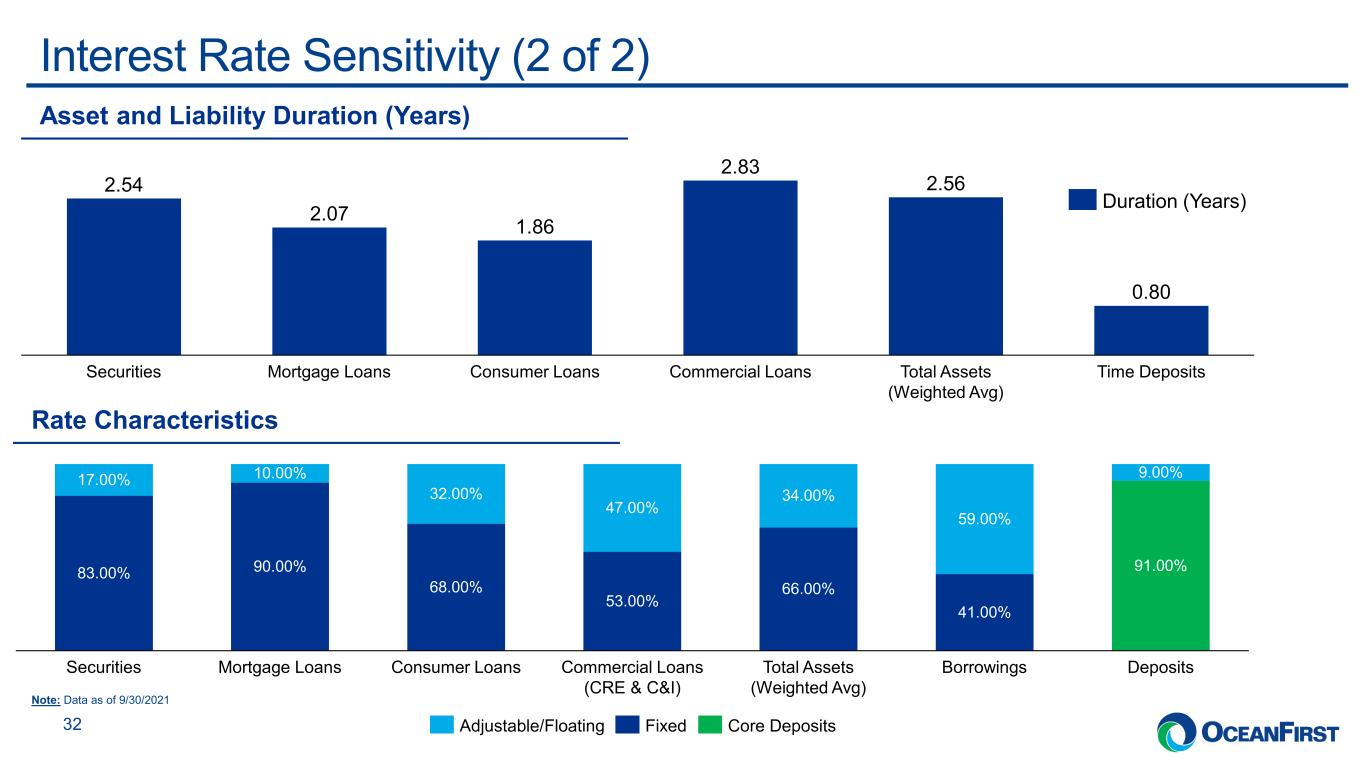
. . .Interest Rate Sensitivity (2 of 2) 32 2.54 2.07 1.86 2.83 2.56 0.80 Securities Total Assets (Weighted Avg) Mortgage Loans Consumer Loans Time DepositsCommercial Loans Duration (Years) Asset and Liability Duration (Years) Rate Characteristics 83.00% 90.00% 68.00% 53.00% 66.00% 41.00% 91.00% 17.00% 10.00% 32.00% 47.00% 34.00% 59.00% 9.00% Securities Mortgage Loans Commercial Loans (CRE & C&I) Consumer Loans Total Assets (Weighted Avg) DepositsBorrowings Adjustable/Floating Fixed Core Deposits Note: Data as of 9/30/2021
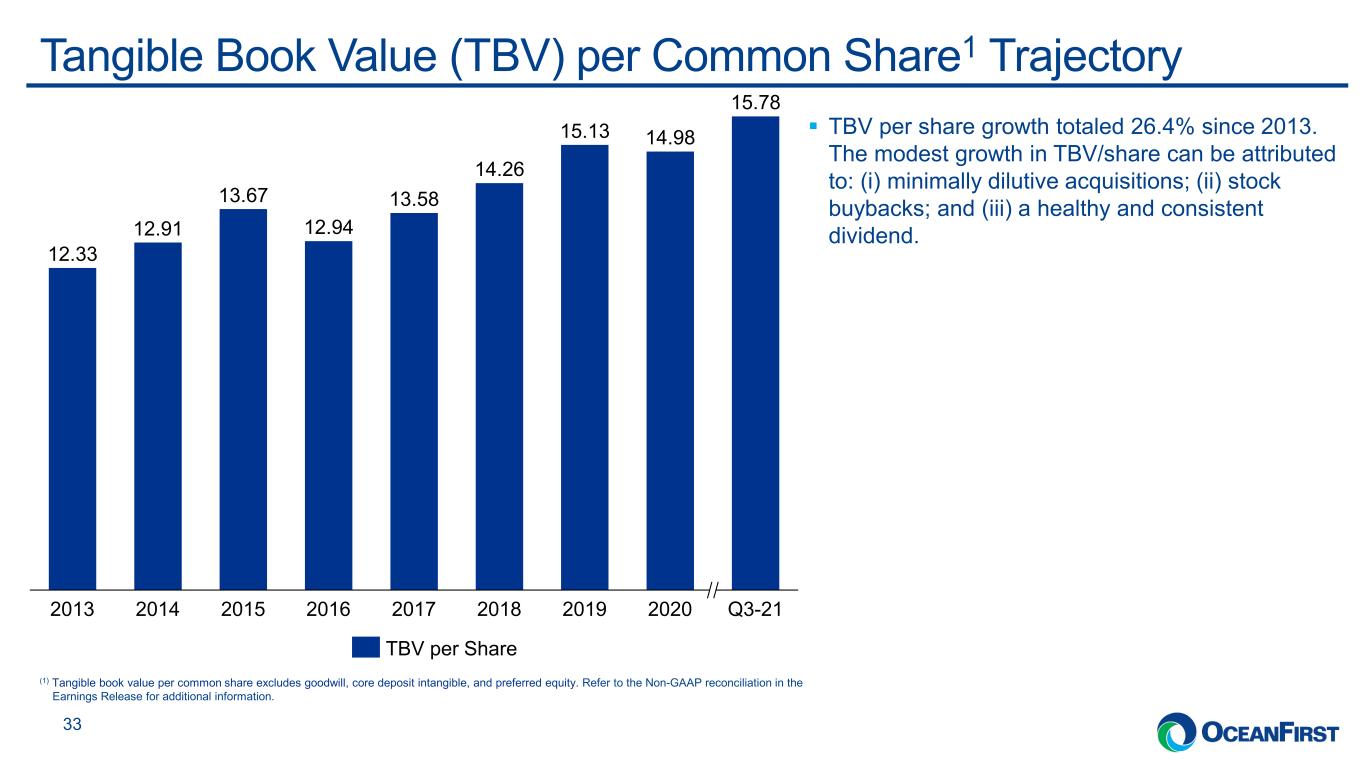
. . .Tangible Book Value (TBV) per Common Share1 Trajectory 33 12.33 12.91 13.67 12.94 13.58 14.26 15.13 14.98 15.78 20192013 2014 202020172015 2016 2018 Q3-21 TBV per Share TBV per share growth totaled 26.4% since 2013. The modest growth in TBV/share can be attributed to: (i) minimally dilutive acquisitions; (ii) stock buybacks; and (iii) a healthy and consistent dividend. (1) Tangible book value per common share excludes goodwill, core deposit intangible, and preferred equity. Refer to the Non-GAAP reconciliation in the Earnings Release for additional information.
. . .Quarterly Non-GAAP / Adjusted to GAAP Disclosure Reported amounts are presented in accordance with generally accepted accounting principles in the United States (“GAAP”). The Company’s management believes that the supplemental Non-GAAP information, which consists of reported net income excluding non-core operations, which can vary from period to period, provides a better comparison of period to period operating performance. Additionally, the Company believes this information is utilized by regulators and market analysts to evaluate a company’s financial condition and therefore, such information is useful to investors. These disclosures should not be viewed as a substitute for financial results in accordance with GAAP, nor are they necessarily comparable to Non-GAAP performance measures which may be presented by other companies. 34
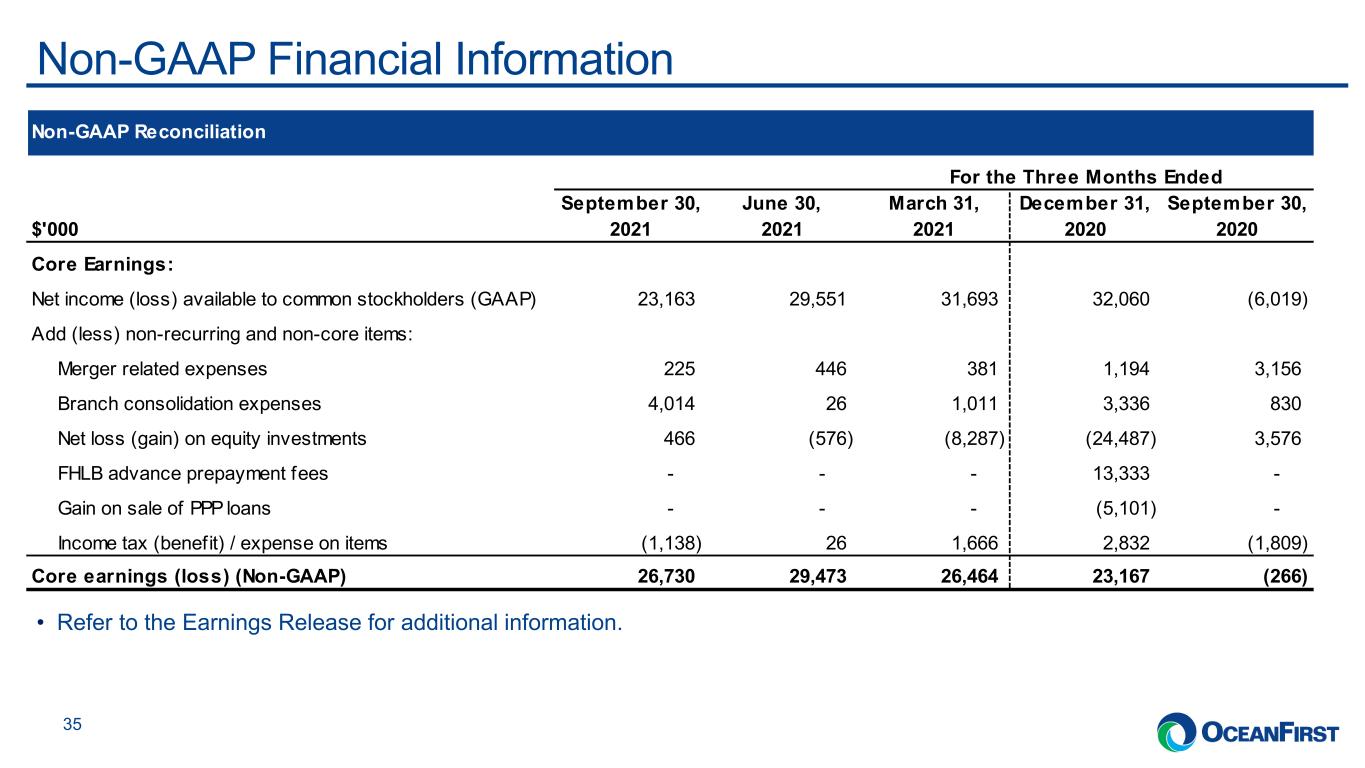
. . .Non-GAAP Financial Information 35 • Refer to the Earnings Release for additional information. Non-GAAP Reconciliation For the Three Months Ended $'000 September 30, 2021 June 30, 2021 March 31, 2021 December 31, 2020 September 30, 2020 Core Earnings: Net income (loss) available to common stockholders (GAAP) 23,163 29,551 31,693 32,060 (6,019) Add (less) non-recurring and non-core items: Merger related expenses 225 446 381 1,194 3,156 Branch consolidation expenses 4,014 26 1,011 3,336 830 Net loss (gain) on equity investments 466 (576) (8,287) (24,487) 3,576 FHLB advance prepayment fees - - - 13,333 - Gain on sale of PPP loans - - - (5,101) - Income tax (benefit) / expense on items (1,138) 26 1,666 2,832 (1,809) Core earnings (loss) (Non-GAAP) 26,730 29,473 26,464 23,167 (266)