
WAL 8-K
Western Alliance Bancorporation (WAL)
8-K
2026-01-27
For: 2026-01-26
View Original
Added on
April 09, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the
Securities Exchange Act of 1934
Date of Report (Date of earliest event reported): January 26, 2026
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||||||||
(Address of principal executive offices) (Zip Code)
(602 ) 389-3500
(Registrant's telephone number, including area code)
Not Applicable
(Former name or former address, if changed since last report)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
Depositary Shares, Each Representing a 1/400th Interest in a Share of 4.250% Fixed-Rate Reset Non-Cumulative Perpetual Preferred Stock, Series A | ||||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
ITEM 2.02. RESULTS OF OPERATIONS AND FINANCIAL CONDITION.
On January 26, 2026, Western Alliance Bancorporation (the “Company”) issued a press release reporting results for the fiscal quarter ended December 31, 2025 and posted on its website its fourth quarter 2025 Earnings Conference Call Presentation, which contains certain additional historical and forward-looking information relating to the Company. Copies of the press release and presentation slides are attached hereto as Exhibits 99.1 and 99.2, respectively.
The information in this report (including Exhibits 99.1 and 99.2 hereto) is being “furnished” and shall not be deemed “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended, is not subject to the liabilities of that section and is not deemed incorporated by reference in any filing under the Securities Act of 1933, as amended, or the Securities Exchange Act of 1934, as amended, except as shall be expressly set forth by specific reference in such filing.
ITEM 9.01. FINANCIAL STATEMENTS AND EXHIBITS.
(d) Exhibits.
| 99.1 | ||||||||
| 99.2 | ||||||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document) | |||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| WESTERN ALLIANCE BANCORPORATION | ||||||||
| (Registrant) | ||||||||
| /s/ Dale Gibbons | ||||||||
| Dale Gibbons | ||||||||
| Vice Chairman and | ||||||||
| Chief Banking Officer, Deposit Initiatives and Innovation (Principle Financial Officer) | ||||||||
| Date: | January 26, 2026 | |||||||
| Western Alliance Bancorporation |  | |||||||
| One East Washington Street | ||||||||
| Phoenix, AZ 85004 | ||||||||
| www.westernalliancebancorporation.com | ||||||||
PHOENIX--(BUSINESS WIRE)--January 26, 2026
FOURTH QUARTER AND FULL YEAR 2025 FINANCIAL RESULTS
| Quarter Highlights: | ||||||||||||||||||||||||||||||||
| Net income | Earnings per share | PPNR1 | Net interest margin | Efficiency ratio1 | Book value per common share | |||||||||||||||||||||||||||
| $293.2 million | $2.59 | $428.7 million | 3.51% | 55.7% | $67.20 | |||||||||||||||||||||||||||
46.5%1, adjusted for deposit costs | $61.291, excluding goodwill and intangibles | |||||||||||||||||||||||||||||||
| CEO COMMENTARY: | ||||||||||||||||||||||||||
“Western Alliance delivered exceptional results to close out 2025, highlighted by record net interest income, revenues, and PPNR¹. Outstanding loan and deposit growth, gathering strength in commercial banking non-interest income, improved efficiency, and a steady net interest margin were key factors behind our solid operating leverage and strong financial performance. These results position us to sustain a strong earnings trajectory in 2026," said Kenneth A. Vecchione, President and Chief Executive Officer. "Impressive quarterly loan growth of $2.0 billion boosted total assets to approximately $93 billion and PPNR¹ by 35.4% annualized to $429 million. Asset quality remained steady as total criticized assets declined $8 million quarterly. Overall, we achieved earnings per share of $2.59 for the quarter, 32.8% higher than Q4 2024, which resulted in a return on assets of 1.23%, a return on tangible common equity1 of 16.9%, while tangible book value per share1 rose 17.3% year-over-year to $61.29." "Our full year results directly reflect the success of our credit and deposit platforms, while maintaining our commitment to sound asset quality management. Net charge-offs to average loans were 0.24% for the year, with a nonperforming assets to total assets ratio of 0.69%. Our net revenue growth drove a substantial increase in earnings as PPNR1 climbed 25.9% over the prior year to $1.4 billion, with net income of $991 million and earnings per share up 23.1% to $8.73.” | ||||||||||||||||||||||||||
| LINKED-QUARTER BASIS | FULL YEAR | ||||
| FINANCIAL HIGHLIGHTS: | |||||
▪Net income of $293.2 million and earnings per share of $2.59, up 12.6% and 13.6%, from $260.5 million and $2.28, respectively
▪Net revenue of $980.9 million, an increase of 4.6%, or $42.7 million, compared to an increase in non-interest expenses of 1.4%, or $7.8 million
▪Pre-provision net revenue1 of $428.7 million, up $34.9 million from $393.8 million
▪Effective tax rate of 17.6%, compared to 17.0%
▪Net income of $990.6 million and earnings per share of $8.73, up 25.8% and 23.1%, from $787.7 million and $7.09, respectively
▪Net revenue of $3.5 billion, an increase of 12.0%, or $380.9 million, compared to an increase in non-interest expenses of 4.3%, or $86.7 million
▪Pre-provision net revenue1 of $1.4 billion, up $294.2 million from $1.1 billion
▪Effective tax rate of 17.9%, compared to 20.5%
| FINANCIAL POSITION RESULTS: | ||
▪HFI loans of $58.7 billion, up $2.0 billion, or 3.6%
▪Total deposits of $77.2 billion, down $88 million due to seasonality
▪HFI loan-to-deposit ratio of 76.0%, up from 73.3%
▪Total equity of $7.9 billion, up $256 million, or 3.3%
▪Increase in HFI loans of $5.0 billion, or 9.3%
▪Increase in total deposits of $10.8 billion, or 16.3%
▪HFI loan-to-deposit ratio of 76.0%, down from 80.9%
▪Increase in total equity of $1.2 billion, or 18.5%
| LOANS AND ASSET QUALITY: | ||
▪Nonperforming (nonaccrual) loans to funded HFI loans of 0.85%, decreased from 0.92%
▪Criticized loans of $1.3 billion, down $15 million
▪Repossessed assets of $137 million, up $7 million from $130 million
▪Annualized net loan charge-offs to average loans outstanding of 0.31%, compared to 0.22%
▪Nonperforming (nonaccrual) loans to funded HFI loans of 0.85% decreased from 0.89%
▪Criticized loans of $1.3 billion, down $73 million
▪Repossessed assets of $137 million, up $85 million from $52 million
▪Net loan charge-offs to average loans outstanding of 0.24%, compared to 0.18%
| KEY PERFORMANCE METRICS: | ||
▪Net interest margin of 3.51%, decreased from 3.53%
▪Return on average assets and on tangible common equity1 of 1.23% and 16.9%, compared to 1.13% and 15.6%, respectively
▪Tangible common equity ratio1 of 7.3%, increased from 7.1%
▪CET 1 ratio of 11.0%, compared to 11.3%
▪Tangible book value per share1, net of tax, of $61.29, an increase of 4.7% from $58.56
▪Efficiency ratio1 of 55.7% and adjusted efficiency ratio1 of 46.5%, compared to 57.4% and 47.8%, respectively
▪Share repurchases of $57.5 million, or 0.7 million shares at $79.55 per share
▪Net interest margin of 3.51%, decreased from 3.58%
▪Return on average assets and on tangible common equity1 of 1.12% and 15.3%, compared to 0.99% and 14.0%, respectively
▪Tangible common equity ratio1 of 7.3%, increased from 7.2%
▪CET 1 ratio of 11.0%, compared to 11.3%
▪Tangible book value per share1, net of tax, of $61.29, an increase of 17.3% from $52.27
▪Efficiency ratio1 of 58.9% and adjusted efficiency ratio1 of 50.2%, compared to 63.2% and 53.1%, respectively
▪Share repurchases of $68.1 million, or 0.8 million shares at $80.82 per share
1 See Reconciliation of Non-GAAP Financial Measures starting on page 16.
Income Statement
Net interest income totaled $766.2 million in the fourth quarter 2025, an increase of $15.8 million, or 2.1%, from $750.4 million in the third quarter 2025, and an increase of $99.7 million, or 15.0%, compared to the fourth quarter 2024. The increase in net interest income from the third quarter 2025 was largely due to higher average interest earning asset balances. The increase in net interest income from the fourth quarter 2024 was driven by an increase in average interest earning asset balances and lower rates on interest bearing liabilities, partially offset by decreased yields on interest earning assets.
The Company recorded a provision for credit losses of $73.0 million in the fourth quarter 2025, a decrease of $7.0 million from $80.0 million in the third quarter 2025, and an increase of $13.0 million from $60.0 million in the fourth quarter 2024. The provision for credit losses during the fourth quarter 2025 was primarily driven by higher net charge-offs of $44.6 million and loan growth.
The Company’s net interest margin was 3.51% in the fourth quarter 2025, a decrease from 3.53% in the third quarter 2025, and an increase from 3.48% in the fourth quarter 2024. Net interest margin decreased from the third quarter 2025 due to lower yields on interest earning assets, partially offset by lower rates on deposits and short-term borrowings. The decrease in net interest margin from the fourth quarter 2024 was primarily driven by the impact of a lower rate environment on interest earning asset yields, partially offset by lower rates on interest bearing liabilities.
Non-interest income was $214.7 million for the fourth quarter 2025, compared to $187.8 million for the third quarter 2025, and $171.9 million for the fourth quarter 2024. The increase in non-interest income of $26.9 million from the third quarter 2025 was primarily due to increases in service charges and fees of $33.1 million and net gain on mortgage loan origination and sale activities of $15.6 million. These increases were partially offset by a decrease in net loan servicing (loss) revenue of $20.5 million. The increase in non-interest income of $42.8 million from the fourth quarter 2024 was primarily driven by increases in service charges and fees, net gain on mortgage loan origination and sale activities, and other non-interest income, primarily due to an increase in rental income from OREO properties. These increases were partially offset by a decrease in net loan servicing (loss) revenue.
Net revenue totaled $980.9 million for the fourth quarter 2025, an increase of $42.7 million, or 4.6%, compared to $938.2 million for the third quarter 2025, and an increase of $142.5 million, or 17.0%, compared to $838.4 million for the fourth quarter 2024.
Non-interest expense was $552.2 million for the fourth quarter 2025, compared to $544.4 million for the third quarter 2025, and $519.0 million for the fourth quarter 2024. The increase in non-interest expense of $7.8 million from the third quarter 2025 was primarily due to increases of $8.2 million in salaries and employee benefits and $5.5 million in both legal, professional, and directors' fees and business development and marketing expenses, partially offset by decreases of $7.7 million in other non-interest expense, primarily related to OREO properties, and $6.8 million in insurance costs. The increase in non-interest expense of $33.2 million from the fourth quarter 2024 was primarily attributable to increased salaries and employee benefits of $36.3 million and data processing costs of $9.6 million, partially offset by decreased insurance costs of $19.0 million. The Company’s efficiency ratio, adjusted for deposit costs1, was 46.5% for the fourth quarter 2025, compared to 47.8% in the third quarter 2025, and 51.1% for the fourth quarter 2024.
Income tax expense was $62.5 million for the fourth quarter 2025, compared to $53.3 million for the third quarter 2025, and $42.5 million for the fourth quarter 2024. The increase in income tax expense from the third quarter 2025 and the fourth quarter 2024 was primarily driven by increased pre-tax income.
Net income was $293.2 million for the fourth quarter 2025, an increase of $32.7 million from $260.5 million for the third quarter 2025, and an increase of $76.3 million from $216.9 million for the fourth quarter 2024. Earnings per share totaled $2.59 for the fourth quarter 2025, compared to $2.28 for the third quarter 2025, and $1.95 for the fourth quarter 2024.
The Company believes its pre-provision net revenue1 ("PPNR") is a key metric for assessing the Company’s earnings power, which it defines as net revenue less non-interest expense. For the fourth quarter 2025, the Company’s PPNR1 was $428.7 million, up $34.9 million from $393.8 million in the third quarter 2025, and up $109.3 million from $319.4 million in the fourth quarter 2024.
The Company had 3,769 full-time equivalent employees and 57 offices at December 31, 2025, compared to 3,701 full-time equivalent employees and 57 offices at September 30, 2025, and 3,524 full-time equivalent employees and 56 offices at December 31, 2024.
1 See Reconciliation of Non-GAAP Financial Measures starting on page 16.
2
Balance Sheet
HFI loans, net of deferred fees, totaled $58.7 billion at December 31, 2025, compared to $56.6 billion at September 30, 2025, and $53.7 billion at December 31, 2024. The increase in HFI loans of $2.0 billion from the prior quarter was primarily driven by an increase of $2.2 billion in commercial and industrial loans, partially offset by a decrease in commercial real estate non-owner occupied loans of $147 million. The increase in HFI loans of $5.0 billion from December 31, 2024 was primarily driven by increases of $4.8 billion, $472 million, and $326 million in commercial and industrial, commercial real estate non-owner occupied, and residential real estate loans, respectively, partially offset by decreases of $424 million and $142 million in construction and land development and commercial real estate owner occupied loans, respectively. HFS loans totaled $3.5 billion at December 31, 2025 and September 30, 2025, and $2.3 billion at December 31, 2024. The increase in HFS loans of $1.2 billion from December 31, 2024 was primarily driven by increases of $793 million, $204 million, and $132 million in government-insured or guaranteed, agency-conforming, and non-agency mortgage loans, respectively.
The Company's allowance for credit losses on HFI loans consists of an allowance for funded HFI loans and an allowance for unfunded loan commitments. The allowance for loan losses to funded HFI loans ratio was 0.78%, 0.78%, and 0.70% at December 31, 2025, September 30, 2025, and December 31, 2024, respectively. The allowance for credit losses, which includes the allowance for unfunded loan commitments, to funded HFI loans ratio was 0.87% at December 31, 2025, 0.85% at September 30, 2025, and 0.77% at December 31, 2024. The Company is a party to credit linked note transactions which effectively transfer a portion of the risk of losses on reference pools of loans to the purchasers of the notes. The Company is protected from first credit losses on reference pools of loans totaling $8.1 billion, $8.2 billion, and $8.6 billion as of December 31, 2025, September 30, 2025, and December 31, 2024, respectively, under these transactions. However, as these note transactions are considered to be free standing credit enhancements, the allowance for credit losses cannot be reduced by the expected credit losses that may be mitigated by these notes. Accordingly, the allowance for loan and credit losses ratios include an allowance related to these pools of loans of $11.8 million as of December 31, 2025 and September 30, 2025, and $11.4 million as of December 31, 2024. The allowance for credit losses to funded HFI loans ratio, adjusted to reduce the HFI loan balance by the amount of loans in covered reference pools, was 1.01% at December 31, 2025, 1.00% at September 30, 2025, and 0.92% at December 31, 2024.
Deposits totaled $77.2 billion at December 31, 2025, a decrease of $88 million from September 30, 2025, and an increase of $10.8 billion from $66.3 billion at December 31, 2024. By deposit type, the decrease from the prior quarter is primarily attributable to a decrease of $2.3 billion from non-interest bearing deposits, partially offset by increases of $2.0 billion and $234 million in interest-bearing demand deposits and certificates of deposit, respectively. The modest $88 million decrease reflects not only changes in customer deposit mix, but also the fourth-quarter seasonal runoff in mortgage related balances, which accounted for a $3.1 billion decrease. From December 31, 2024, non-interest bearing, savings and money market, and interest-bearing demand deposits increased $5.5 billion, $3.4 billion, and $2.5 billion, respectively, partially offset by a decrease in certificates of deposit of $605 million. Non-interest bearing deposits totaled $24.4 billion at December 31, 2025, compared to $26.6 billion at September 30, 2025, and $18.8 billion at December 31, 2024.
The table below shows the Company's deposit types as a percentage of total deposits:
| Dec 31, 2025 | Sep 30, 2025 | Dec 31, 2024 | ||||||||||||||||||
| Non-interest bearing | 31.5 | % | 34.5 | % | 28.4 | % | ||||||||||||||
| Interest-bearing demand | 23.9 | 21.3 | 23.9 | |||||||||||||||||
| Savings and money market | 31.9 | 31.9 | 32.0 | |||||||||||||||||
| Certificates of deposit | 12.7 | 12.4 | 15.7 | |||||||||||||||||
The Company’s ratio of HFI loans to deposits was 76.0% at December 31, 2025, compared to 73.3% at September 30, 2025, and 80.9% at December 31, 2024.
Borrowings totaled $5.2 billion at December 31, 2025, $3.9 billion at September 30, 2025, and $5.6 billion at December 31, 2024. Borrowings increased $1.4 billion from September 30, 2025 driven by a $2.9 billion increase in short-term borrowings, partially offset by a $1.5 billion decrease in long-term borrowings. Borrowings decreased $333 million from December 31, 2024, reflecting a $1.0 billion decrease in long-term borrowings, partially offset by an increase in short-term borrowings of $696 million.
Qualifying debt totaled $1.1 billion at December 31, 2025, compared to $681 million and $899 million at September 30, 2025 and December 31, 2024, respectively. The increase in qualifying debt from September 30, 2025 was primarily due to the issuance of $400 million of subordinated debt during the quarter ended December 31, 2025. The increase in qualifying debt from December 31, 2024 was primarily due to the issuance of $400 million of subordinated debt, partially offset by the repayment of $225 million of subordinated debt during the quarter ended June 30, 2025.
Total equity was $7.9 billion at December 31, 2025, compared to $7.7 billion at September 30, 2025, and $6.7 billion at December 31, 2024. The increase in total equity from the prior quarter was primarily due to net income of $293.2 million and net AOCI gains of $65 million, partially offset by cash dividends paid during the fourth quarter, comprised of $46.1 million or $0.42 per common share, $3.2 million or $0.27 per depositary share, and $7.1 million on preferred stock of the Company's REIT subsidiary. In addition, the Company repurchased 0.7 million shares for $57.5 million during the fourth quarter of 2025 under the Company's $300 million share repurchase program. The increase in equity from December 31, 2024 was primarily driven by net income and the issuance of preferred stock from the Company's REIT subsidiary, partially offset by dividends to stockholders and share repurchases.
The Company's common equity tier 1 capital ratio was 11.0% at December 31, 2025, compared to 11.3% at September 30, 2025 and December 31, 2024. At December 31, 2025, tangible common equity, net of tax1, was 7.3% of tangible assets1 and total capital was 14.5% of risk-weighted assets. The Company’s tangible book value per share1 was $61.29 at December 31, 2025, an increase of 4.7% from $58.56 at September 30, 2025, and an increase of 17.3% from $52.27 at December 31, 2024. The increase in tangible book value per share from September 30, 2025 and December 31, 2024 was primarily attributable to net income.
3
Total assets increased $1.8 billion, or 2.0%, to $92.8 billion at December 31, 2025 from $91.0 billion at September 30, 2025, and increased 14.6% from $80.9 billion at December 31, 2024. The increase in total assets from September 30, 2025 was primarily driven by increased HFI loans and investment securities, partially offset by a decrease in cash. The increase in total assets from December 31, 2024 was primarily driven by increases in HFI and HFS loans and investment securities.
Asset Quality
Provision for credit losses totaled $73.0 million for the fourth quarter 2025, compared to $80.0 million for the third quarter 2025, and $60.0 million for the fourth quarter 2024. Net loan charge-offs in the fourth quarter 2025 totaled $44.6 million, or 0.31% of average loans (annualized), compared to $31.1 million, or 0.22%, in the third quarter 2025, and $34.1 million, or 0.25%, in the fourth quarter 2024.
Nonaccrual loans decreased $22 million to $500 million during the quarter and increased $24 million from December 31, 2024. Loans past due 90 days and still accruing interest totaled $66 million at December 31, 2025, $49 million at September 30, 2025, and zero at December 31, 2024 (excluding government guaranteed loans of $290 million, $282 million, and $326 million, respectively). Loans past due 30-89 days and still accruing interest totaled $108 million at December 31, 2025, a decrease from $196 million at September 30, 2025, and an increase from $92 million at December 31, 2024 (excluding government guaranteed loans of $145 million, $149 million, and $183 million, respectively). Criticized loans of $1.3 billion decreased $15 million during the quarter and decreased $73 million from December 31, 2024.
Repossessed assets totaled $137 million at December 31, 2025, compared to $130 million at September 30, 2025, and $52 million at December 31, 2024. Classified assets of $1.1 billion at December 31, 2025 decreased $41 million from September 30, 2025, and increased $79 million from December 31, 2024.
The ratio of classified assets to Tier 1 capital plus the allowance for credit losses2, a common regulatory measure of asset quality, was 13.3% at December 31, 2025, compared to 14.3% at September 30, 2025, and 14.2% at December 31, 2024.
1 See Reconciliation of Non-GAAP Financial Measures starting on page 16.
2 The allowance for credit losses used in this ratio is calculated in accordance with regulatory capital rules.
4
Conference Call and Webcast
Western Alliance Bancorporation will host a conference call and live webcast to discuss its fourth quarter and full year 2025 financial results at 12:00 p.m. ET on Tuesday, January 27, 2026. Participants may access the call by dialing 1-833-470-1428 and using access code 336835 or via live audio webcast using the website link https://events.q4inc.com/attendee/372994694. The webcast is also available via the Company’s website at www.westernalliancebancorporation.com. Participants should log in at least 15 minutes early to receive instructions. The call will be recorded and made available for replay after 3:00 p.m. ET January 27th through 1:00 p.m. ET February 3rd by dialing 1-866-813-9403, using access code 931710.
Reclassifications
Certain amounts in the Consolidated Income Statements for the prior periods have been reclassified to conform to the current presentation. The reclassifications have no effect on net income or stockholders’ equity as previously reported.
Use of Non-GAAP Financial Information
This press release contains both financial measures based on GAAP and non-GAAP based financial measures, which are used where management believes them to be helpful in understanding the Company’s results of operations or financial position. Where non-GAAP financial measures are used, the comparable GAAP financial measure, as well as the reconciliation to the comparable GAAP financial measure, can be found in this press release. These disclosures should not be viewed as a substitute for operating results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies.
Cautionary Note Regarding Forward-Looking Statements
This release contains forward-looking statements that relate to expectations, beliefs, projections, future plans and strategies, anticipated events or trends and similar expressions concerning matters that are not historical facts. Examples of forward-looking statements include, among others, statements we make regarding our expectations with regard to our business, financial and operating results, including our deposits, liquidity and funding, changes in economic conditions and related impacts on the Company's business, future economic performance and dividends. The forward-looking statements contained herein reflect our current views about future events and financial performance and are subject to risks, uncertainties, assumptions and changes in circumstances that may cause our actual results to differ significantly from historical results and those expressed in any forward-looking statement. Some factors that could cause actual results to differ materially from historical or expected results include, among others: the risk factors discussed in the Company’s Annual Report on Form 10-K for the year ended December 31, 2024 and the Company's subsequent Quarterly Reports on Form 10-Q, each as filed with the Securities and Exchange Commission; adverse developments in the financial services industry generally and any related impact on depositor behavior; risks related to the sufficiency of liquidity; changes in international trade policies, tariffs and treaties affecting imports and exports, trade disputes, barriers to trade or the emergence of other trade restrictions, and their related impacts on macroeconomic conditions and customer behavior; the potential adverse effects of unusual and infrequently occurring events and any governmental or societal responses thereto; changes in general economic conditions, either nationally or locally in the areas in which we conduct or will conduct our business; the impact on financial markets from geopolitical conflicts such as the wars in Ukraine and the Middle East; inflation, interest rate, market and monetary fluctuations; increases in competitive pressures among financial institutions and businesses offering similar products and services; higher defaults on our loan portfolio than we expect; increased foreclosures and ownership of real property; changes in management’s estimate of the adequacy of the allowance for credit losses; legislative or regulatory changes or changes in accounting principles, policies or guidelines; supervisory actions by regulatory agencies which may limit our ability to pursue certain growth opportunities, including expansion through acquisitions; additional regulatory requirements resulting from our continued growth; management’s estimates and projections of interest rates and interest rate policy; the execution of our business plan; any adverse determination by a court regarding the Cantor Group V loan and any adverse economic or other events impacting the collateral, borrower or guarantors with respect to such loan; and other factors affecting the financial services industry generally or the banking industry in particular.
Any forward-looking statement made by us in this release is based only on information currently available to us and speaks only as of the date on which it is made. We do not intend and disclaim any duty or obligation to update or revise any industry information or forward-looking statements, whether written or oral, that may be made from time to time, set forth in this press release to reflect new information, future events or otherwise, except to the extent required by applicable law. In light of these risks, uncertainties and assumptions, the forward-looking events discussed in this press release might not occur, and you should not put undue reliance on any forward-looking statements.
About Western Alliance Bancorporation
Western Alliance Bancorporation (NYSE:WAL) is one of the country’s top-performing banking companies. Its primary subsidiary, Western Alliance Bank, Member FDIC, is a leading national bank for business that puts customers first, delivering tailored business banking solutions and consumer products backed by outstanding, personalized service and specific expertise in more than 30 industries and sectors. With $90 billion in assets and offices nationwide, Western Alliance has ranked as a top U.S. bank by American Banker and Bank Director since 2016. In 2025, Western Alliance Bancorporation was #2 for Best CEO, Best CFO and Best Company Board of Directors on Extel’s All-America Executive Team Midcap Banks list. For more information on offerings, subsidiaries and affiliates, visit www.westernalliancebank.com or follow Western Alliance Bank on LinkedIn.
Contacts
Investors: Miles Pondelik, 602-346-7462
Email: [email protected]
Media: Stephanie Whitlow, 480-998-6547
Email: [email protected]
5
| Western Alliance Bancorporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||
| Summary Consolidated Financial Data | ||||||||||||||||||||||||||||||||||||||
| Unaudited | ||||||||||||||||||||||||||||||||||||||
| Selected Balance Sheet Data: | ||||||||||||||||||||||||||||||||||||||
| As of December 31, | ||||||||||||||||||||||||||||||||||||||
| 2025 | 2024 | Change % | ||||||||||||||||||||||||||||||||||||
| (in millions) | ||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 92,774 | $ | 80,934 | 14.6 | % | ||||||||||||||||||||||||||||||||
| Loans held for sale | 3,498 | 2,286 | 53.0 | |||||||||||||||||||||||||||||||||||
| HFI loans, net of deferred fees | 58,677 | 53,676 | 9.3 | |||||||||||||||||||||||||||||||||||
| Investment securities | 20,438 | 15,095 | 35.4 | |||||||||||||||||||||||||||||||||||
| Total deposits | 77,159 | 66,341 | 16.3 | |||||||||||||||||||||||||||||||||||
| Borrowings | 5,240 | 5,573 | (6.0) | |||||||||||||||||||||||||||||||||||
| Qualifying debt | 1,076 | 899 | 19.7 | |||||||||||||||||||||||||||||||||||
| Total equity | 7,946 | 6,707 | 18.5 | |||||||||||||||||||||||||||||||||||
| Tangible common equity, net of tax (1) | 6,711 | 5,755 | 16.6 | |||||||||||||||||||||||||||||||||||
| Common equity Tier 1 capital | 7,002 | 6,311 | 10.9 | |||||||||||||||||||||||||||||||||||
| Selected Income Statement Data: | ||||||||||||||||||||||||||||||||||||||
| For the Three Months Ended December 31, | For the Year Ended December 31, | |||||||||||||||||||||||||||||||||||||
| 2025 | 2024 | Change % | 2025 | 2024 | Change % | |||||||||||||||||||||||||||||||||
| (in millions, except per share data) | (in millions, except per share data) | |||||||||||||||||||||||||||||||||||||
| Interest income | $ | 1,217.4 | $ | 1,138.6 | 6.9 | % | $ | 4,692.9 | $ | 4,541.1 | 3.3 | % | ||||||||||||||||||||||||||
| Interest expense | 451.2 | 472.1 | (4.4) | 1,828.1 | 1,922.2 | (4.9) | ||||||||||||||||||||||||||||||||
| Net interest income | 766.2 | 666.5 | 15.0 | 2,864.8 | 2,618.9 | 9.4 | ||||||||||||||||||||||||||||||||
| Provision for credit losses | 73.0 | 60.0 | 21.7 | 224.1 | 145.9 | 53.6 | ||||||||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 693.2 | 606.5 | 14.3 | 2,640.7 | 2,473.0 | 6.8 | ||||||||||||||||||||||||||||||||
| Non-interest income | 214.7 | 171.9 | 24.9 | 678.2 | 543.2 | 24.9 | ||||||||||||||||||||||||||||||||
| Non-interest expense | 552.2 | 519.0 | 6.4 | 2,111.7 | 2,025.0 | 4.3 | ||||||||||||||||||||||||||||||||
| Income before income taxes | 355.7 | 259.4 | 37.1 | 1,207.2 | 991.2 | 21.8 | ||||||||||||||||||||||||||||||||
| Income tax expense | 62.5 | 42.5 | 47.1 | 216.6 | 203.5 | 6.4 | ||||||||||||||||||||||||||||||||
| Net income | 293.2 | 216.9 | 35.2 | 990.6 | 787.7 | 25.8 | ||||||||||||||||||||||||||||||||
| Net income attributable to noncontrolling interest | 7.1 | — | NM | 21.6 | — | NM | ||||||||||||||||||||||||||||||||
| Net income attributable to Western Alliance | 286.1 | 216.9 | 31.9 | 969.0 | 787.7 | 23.0 | ||||||||||||||||||||||||||||||||
| Dividends on preferred stock | 3.2 | 3.2 | — | 12.8 | 12.8 | — | ||||||||||||||||||||||||||||||||
| Net income available to common stockholders | $ | 282.9 | $ | 213.7 | 32.4 | $ | 956.2 | $ | 774.9 | 23.4 | ||||||||||||||||||||||||||||
| Diluted earnings per common share | $ | 2.59 | $ | 1.95 | 32.8 | $ | 8.73 | $ | 7.09 | 23.1 | ||||||||||||||||||||||||||||
(1) See Reconciliation of Non-GAAP Financial Measures.
NM Changes +/- 100% are not meaningful.
6
| Western Alliance Bancorporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||
| Summary Consolidated Financial Data | ||||||||||||||||||||||||||||||||||||||
| Unaudited | ||||||||||||||||||||||||||||||||||||||
| Common Share Data: | ||||||||||||||||||||||||||||||||||||||
| At or For the Three Months Ended December 31, | For the Year Ended December 31, | |||||||||||||||||||||||||||||||||||||
| 2025 | 2024 | Change % | 2025 | 2024 | Change % | |||||||||||||||||||||||||||||||||
| Diluted earnings per common share | $ | 2.59 | $ | 1.95 | 32.8 | % | $ | 8.73 | $ | 7.09 | 23.1 | % | ||||||||||||||||||||||||||
| Book value per common share | 67.20 | 58.24 | 15.4 | |||||||||||||||||||||||||||||||||||
| Tangible book value per common share, net of tax (1) | 61.29 | 52.27 | 17.3 | |||||||||||||||||||||||||||||||||||
| Average common shares outstanding (in millions): | ||||||||||||||||||||||||||||||||||||||
| Basic | 108.4 | 108.7 | (0.3) | 108.8 | 108.6 | 0.2 | ||||||||||||||||||||||||||||||||
| Diluted | 109.3 | 109.6 | (0.3) | 109.5 | 109.3 | 0.2 | ||||||||||||||||||||||||||||||||
| Common shares outstanding | 109.5 | 110.1 | (0.5) | |||||||||||||||||||||||||||||||||||
| Selected Performance Ratios: | ||||||||||||||||||||||||||||||||||||||
| Return on average assets (2) | 1.23 | % | 1.04 | % | 18.3 | % | 1.12 | % | 0.99 | % | 13.1 | % | ||||||||||||||||||||||||||
| Return on average tangible common equity (1, 2) | 16.9 | 14.6 | 15.8 | 15.3 | 14.0 | 9.3 | ||||||||||||||||||||||||||||||||
| Net interest margin (2) | 3.51 | 3.48 | 0.9 | 3.51 | 3.58 | (2.0) | ||||||||||||||||||||||||||||||||
| Efficiency ratio (1) | 55.7 | 61.2 | (9.0) | 58.9 | 63.2 | (6.8) | ||||||||||||||||||||||||||||||||
| Efficiency ratio, adjusted for deposit costs (1) | 46.5 | 51.1 | (9.0) | 50.2 | 53.1 | (5.5) | ||||||||||||||||||||||||||||||||
| HFI loan to deposit ratio | 76.0 | 80.9 | (6.1) | |||||||||||||||||||||||||||||||||||
| Asset Quality Ratios: | ||||||||||||||||||||||||||||||||||||||
| Net charge-offs to average loans outstanding (2) | 0.31 | % | 0.25 | % | 24.0 | % | 0.24 | % | 0.18 | % | 33.3 | % | ||||||||||||||||||||||||||
| Nonaccrual loans to funded HFI loans | 0.85 | 0.89 | (4.5) | |||||||||||||||||||||||||||||||||||
| Nonaccrual loans and repossessed assets to total assets | 0.69 | 0.65 | 6.2 | |||||||||||||||||||||||||||||||||||
| Allowance for loan losses to funded HFI loans | 0.78 | 0.70 | 11.4 | |||||||||||||||||||||||||||||||||||
| Allowance for loan losses to nonaccrual HFI loans | 92 | 79 | 16.5 | |||||||||||||||||||||||||||||||||||
| Allowance for credit losses to nonaccrual HFI loans | 102 | 87 | 17.2 | |||||||||||||||||||||||||||||||||||
| Capital Ratios: | ||||||||||||||||||||
| Dec 31, 2025 | Sep 30, 2025 | Dec 31, 2024 | ||||||||||||||||||
| Tangible common equity (1) | 7.3 | % | 7.1 | % | 7.2 | % | ||||||||||||||
| Common Equity Tier 1 (3) | 11.0 | 11.3 | 11.3 | |||||||||||||||||
| Tier 1 Leverage ratio (3) | 8.2 | 8.1 | 8.1 | |||||||||||||||||
| Tier 1 Capital (3) | 12.1 | 12.4 | 11.9 | |||||||||||||||||
| Total Capital (3) | 14.5 | 14.2 | 14.1 | |||||||||||||||||
(1) See Reconciliation of Non-GAAP Financial Measures.
(2) Annualized on an actual/actual basis for periods less than 12 months.
(3) Capital ratios for December 31, 2025 are preliminary.
NM Changes +/- 100% are not meaningful.
7
| Western Alliance Bancorporation and Subsidiaries | ||||||||||||||||||||||||||
| Condensed Consolidated Income Statements | ||||||||||||||||||||||||||
| Unaudited | ||||||||||||||||||||||||||
| Three Months Ended December 31, | Year Ended December 31, | |||||||||||||||||||||||||
| 2025 | 2024 | 2025 | 2024 | |||||||||||||||||||||||
| (in millions, except per share data) | ||||||||||||||||||||||||||
| Interest income: | ||||||||||||||||||||||||||
| Loans | $ | 936.2 | $ | 915.2 | $ | 3,679.8 | $ | 3,629.1 | ||||||||||||||||||
| Investment securities | 221.6 | 179.4 | 822.8 | 711.0 | ||||||||||||||||||||||
| Other | 59.6 | 44.0 | 190.3 | 201.0 | ||||||||||||||||||||||
| Total interest income | 1,217.4 | 1,138.6 | 4,692.9 | 4,541.1 | ||||||||||||||||||||||
| Interest expense: | ||||||||||||||||||||||||||
| Deposits | 383.5 | 387.2 | 1,537.8 | 1,600.2 | ||||||||||||||||||||||
| Qualifying debt | 9.0 | 9.4 | 32.8 | 38.0 | ||||||||||||||||||||||
| Borrowings | 58.7 | 75.5 | 257.5 | 284.0 | ||||||||||||||||||||||
| Total interest expense | 451.2 | 472.1 | 1,828.1 | 1,922.2 | ||||||||||||||||||||||
| Net interest income | 766.2 | 666.5 | 2,864.8 | 2,618.9 | ||||||||||||||||||||||
| Provision for credit losses | 73.0 | 60.0 | 224.1 | 145.9 | ||||||||||||||||||||||
| Net interest income after provision for credit losses | 693.2 | 606.5 | 2,640.7 | 2,473.0 | ||||||||||||||||||||||
| Non-interest income: | ||||||||||||||||||||||||||
| Service charges and fees | 73.6 | 39.7 | 194.3 | 109.6 | ||||||||||||||||||||||
| Net gain on mortgage loan origination and sale activities | 91.1 | 67.9 | 255.5 | 206.3 | ||||||||||||||||||||||
Net loan servicing (loss) revenue | (1.4) | 24.7 | 77.8 | 121.5 | ||||||||||||||||||||||
| Income from bank owned life insurance | 11.8 | 12.1 | 46.0 | 27.8 | ||||||||||||||||||||||
| Gain on sales of investment securities | 7.4 | 7.2 | 29.4 | 17.4 | ||||||||||||||||||||||
| Fair value gain adjustments, net | 3.5 | 2.4 | 12.9 | 7.5 | ||||||||||||||||||||||
| Income (loss) from equity investments | 12.2 | 11.1 | 18.1 | 38.2 | ||||||||||||||||||||||
| Other | 16.5 | 6.8 | 44.2 | 14.9 | ||||||||||||||||||||||
| Total non-interest income | 214.7 | 171.9 | 678.2 | 543.2 | ||||||||||||||||||||||
| Non-interest expenses: | ||||||||||||||||||||||||||
| Salaries and employee benefits | 201.7 | 165.4 | 757.5 | 631.1 | ||||||||||||||||||||||
| Deposit costs | 171.2 | 174.5 | 630.5 | 693.2 | ||||||||||||||||||||||
| Data processing | 48.9 | 39.3 | 187.2 | 149.7 | ||||||||||||||||||||||
| Legal, professional, and directors' fees | 33.6 | 28.7 | 115.9 | 109.4 | ||||||||||||||||||||||
| Insurance | 17.7 | 36.7 | 117.5 | 164.8 | ||||||||||||||||||||||
| Occupancy | 19.7 | 19.6 | 70.6 | 73.1 | ||||||||||||||||||||||
| Loan servicing expenses | 17.7 | 17.8 | 69.2 | 68.1 | ||||||||||||||||||||||
| Loan acquisition and origination expenses | 7.9 | 5.7 | 26.2 | 21.5 | ||||||||||||||||||||||
| Business development and marketing | 11.1 | 11.1 | 28.7 | 32.7 | ||||||||||||||||||||||
| Other | 22.7 | 20.2 | 108.4 | 81.4 | ||||||||||||||||||||||
| Total non-interest expense | 552.2 | 519.0 | 2,111.7 | 2,025.0 | ||||||||||||||||||||||
| Income before income taxes | 355.7 | 259.4 | 1,207.2 | 991.2 | ||||||||||||||||||||||
| Income tax expense | 62.5 | 42.5 | 216.6 | 203.5 | ||||||||||||||||||||||
| Net income | 293.2 | 216.9 | 990.6 | 787.7 | ||||||||||||||||||||||
| Net income attributable to noncontrolling interest | 7.1 | — | 21.6 | — | ||||||||||||||||||||||
| Net income attributable to Western Alliance | 286.1 | 216.9 | 969.0 | 787.7 | ||||||||||||||||||||||
| Dividends on preferred stock | 3.2 | 3.2 | 12.8 | 12.8 | ||||||||||||||||||||||
| Net income available to common stockholders | $ | 282.9 | $ | 213.7 | $ | 956.2 | $ | 774.9 | ||||||||||||||||||
| Earnings per common share: | ||||||||||||||||||||||||||
| Diluted shares | 109.3 | 109.6 | 109.5 | 109.3 | ||||||||||||||||||||||
| Diluted earnings per share | $ | 2.59 | $ | 1.95 | $ | 8.73 | $ | 7.09 | ||||||||||||||||||
8
| Western Alliance Bancorporation and Subsidiaries | ||||||||||||||||||||||||||||||||
| Five Quarter Condensed Consolidated Income Statements | ||||||||||||||||||||||||||||||||
| Unaudited | ||||||||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||||||||
| Dec 31, 2025 | Sep 30, 2025 | Jun 30, 2025 | Mar 31, 2025 | Dec 31, 2024 | ||||||||||||||||||||||||||||
| (in millions, except per share data) | ||||||||||||||||||||||||||||||||
| Interest income: | ||||||||||||||||||||||||||||||||
| Loans | $ | 936.2 | $ | 948.3 | $ | 914.3 | $ | 881.0 | $ | 915.2 | ||||||||||||||||||||||
| Investment securities | 221.6 | 231.7 | 201.5 | 168.0 | 179.4 | |||||||||||||||||||||||||||
| Other | 59.6 | 45.5 | 38.6 | 46.6 | 44.0 | |||||||||||||||||||||||||||
| Total interest income | 1,217.4 | 1,225.5 | 1,154.4 | 1,095.6 | 1,138.6 | |||||||||||||||||||||||||||
| Interest expense: | ||||||||||||||||||||||||||||||||
| Deposits | 383.5 | 398.2 | 377.8 | 378.3 | 387.2 | |||||||||||||||||||||||||||
| Qualifying debt | 9.0 | 6.3 | 8.2 | 9.3 | 9.4 | |||||||||||||||||||||||||||
| Borrowings | 58.7 | 70.6 | 70.8 | 57.4 | 75.5 | |||||||||||||||||||||||||||
| Total interest expense | 451.2 | 475.1 | 456.8 | 445.0 | 472.1 | |||||||||||||||||||||||||||
| Net interest income | 766.2 | 750.4 | 697.6 | 650.6 | 666.5 | |||||||||||||||||||||||||||
| Provision for credit losses | 73.0 | 80.0 | 39.9 | 31.2 | 60.0 | |||||||||||||||||||||||||||
| Net interest income after provision for credit losses | 693.2 | 670.4 | 657.7 | 619.4 | 606.5 | |||||||||||||||||||||||||||
| Non-interest income: | ||||||||||||||||||||||||||||||||
| Service charges and fees | 73.6 | 40.5 | 39.7 | 40.5 | 39.7 | |||||||||||||||||||||||||||
| Net gain on mortgage loan origination and sale activities | 91.1 | 75.5 | 39.4 | 49.5 | 67.9 | |||||||||||||||||||||||||||
Net loan servicing (loss) revenue | (1.4) | 19.1 | 38.3 | 21.8 | 24.7 | |||||||||||||||||||||||||||
| Income from bank owned life insurance | 11.8 | 11.8 | 11.0 | 11.4 | 12.1 | |||||||||||||||||||||||||||
| Gain on sales of investment securities | 7.4 | 8.5 | 11.4 | 2.1 | 7.2 | |||||||||||||||||||||||||||
| Fair value gain adjustments, net | 3.5 | 8.3 | 0.1 | 1.0 | 2.4 | |||||||||||||||||||||||||||
| Income (loss) from equity investments | 12.2 | 7.8 | 2.9 | (4.8) | 11.1 | |||||||||||||||||||||||||||
| Other | 16.5 | 16.3 | 5.5 | 5.9 | 6.8 | |||||||||||||||||||||||||||
| Total non-interest income | 214.7 | 187.8 | 148.3 | 127.4 | 171.9 | |||||||||||||||||||||||||||
| Non-interest expenses: | ||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 201.7 | 193.5 | 179.9 | 182.4 | 165.4 | |||||||||||||||||||||||||||
| Deposit costs | 171.2 | 175.1 | 147.4 | 136.8 | 174.5 | |||||||||||||||||||||||||||
| Data processing | 48.9 | 48.1 | 45.0 | 45.2 | 39.3 | |||||||||||||||||||||||||||
| Legal, professional, and directors' fees | 33.6 | 28.1 | 25.3 | 28.9 | 28.7 | |||||||||||||||||||||||||||
| Insurance | 17.7 | 24.5 | 37.4 | 37.9 | 36.7 | |||||||||||||||||||||||||||
| Occupancy | 19.7 | 16.8 | 16.9 | 17.2 | 19.6 | |||||||||||||||||||||||||||
| Loan servicing expenses | 17.7 | 15.0 | 20.1 | 16.4 | 17.8 | |||||||||||||||||||||||||||
| Loan acquisition and origination expenses | 7.9 | 7.3 | 5.8 | 5.2 | 5.7 | |||||||||||||||||||||||||||
| Business development and marketing | 11.1 | 5.6 | 6.1 | 5.9 | 11.1 | |||||||||||||||||||||||||||
| Other | 22.7 | 30.4 | 30.8 | 24.5 | 20.2 | |||||||||||||||||||||||||||
| Total non-interest expense | 552.2 | 544.4 | 514.7 | 500.4 | 519.0 | |||||||||||||||||||||||||||
| Income before income taxes | 355.7 | 313.8 | 291.3 | 246.4 | 259.4 | |||||||||||||||||||||||||||
| Income tax expense | 62.5 | 53.3 | 53.5 | 47.3 | 42.5 | |||||||||||||||||||||||||||
| Net income | 293.2 | 260.5 | 237.8 | 199.1 | 216.9 | |||||||||||||||||||||||||||
| Net income attributable to noncontrolling interest | 7.1 | 7.1 | 7.4 | — | — | |||||||||||||||||||||||||||
| Net income attributable to Western Alliance | 286.1 | 253.4 | 230.4 | 199.1 | 216.9 | |||||||||||||||||||||||||||
| Dividends on preferred stock | 3.2 | 3.2 | 3.2 | 3.2 | 3.2 | |||||||||||||||||||||||||||
| Net income available to common stockholders | $ | 282.9 | $ | 250.2 | $ | 227.2 | $ | 195.9 | $ | 213.7 | ||||||||||||||||||||||
| Earnings per common share: | ||||||||||||||||||||||||||||||||
| Diluted shares | 109.3 | 109.8 | 109.6 | 109.6 | 109.6 | |||||||||||||||||||||||||||
| Diluted earnings per share | $ | 2.59 | $ | 2.28 | $ | 2.07 | $ | 1.79 | $ | 1.95 | ||||||||||||||||||||||
9
| Western Alliance Bancorporation and Subsidiaries | ||||||||||||||||||||||||||||||||
| Five Quarter Condensed Consolidated Balance Sheets | ||||||||||||||||||||||||||||||||
| Unaudited | ||||||||||||||||||||||||||||||||
| Dec 31, 2025 | Sep 30, 2025 | Jun 30, 2025 | Mar 31, 2025 | Dec 31, 2024 | ||||||||||||||||||||||||||||
| (in millions) | ||||||||||||||||||||||||||||||||
| Assets: | ||||||||||||||||||||||||||||||||
| Cash and due from banks | $ | 3,596 | $ | 5,756 | $ | 2,767 | $ | 3,279 | $ | 4,096 | ||||||||||||||||||||||
| Investment securities | 20,438 | 18,841 | 18,601 | 15,868 | 15,095 | |||||||||||||||||||||||||||
| Loans held for sale | 3,498 | 3,502 | 3,022 | 3,238 | 2,286 | |||||||||||||||||||||||||||
| Loans held for investment: | ||||||||||||||||||||||||||||||||
| Commercial and industrial | 27,928 | 25,734 | 24,920 | 24,117 | 23,128 | |||||||||||||||||||||||||||
| Commercial real estate - non-owner occupied | 10,340 | 10,487 | 10,255 | 10,040 | 9,868 | |||||||||||||||||||||||||||
| Commercial real estate - owner occupied | 1,683 | 1,682 | 1,749 | 1,787 | 1,825 | |||||||||||||||||||||||||||
| Construction and land development | 4,055 | 4,065 | 4,526 | 4,504 | 4,479 | |||||||||||||||||||||||||||
| Residential real estate | 14,652 | 14,651 | 14,465 | 14,275 | 14,326 | |||||||||||||||||||||||||||
| Consumer | 19 | 27 | 24 | 38 | 50 | |||||||||||||||||||||||||||
| Loans HFI, net of deferred fees | 58,677 | 56,646 | 55,939 | 54,761 | 53,676 | |||||||||||||||||||||||||||
| Allowance for loan losses | (461) | (440) | (395) | (389) | (374) | |||||||||||||||||||||||||||
| Loans HFI, net of deferred fees and allowance | 58,216 | 56,206 | 55,544 | 54,372 | 53,302 | |||||||||||||||||||||||||||
| Mortgage servicing rights | 1,494 | 1,213 | 1,044 | 1,241 | 1,127 | |||||||||||||||||||||||||||
| Premises and equipment, net | 442 | 416 | 365 | 361 | 361 | |||||||||||||||||||||||||||
| Operating lease right-of-use asset | 131 | 134 | 130 | 125 | 128 | |||||||||||||||||||||||||||
| Other assets acquired through foreclosure, net | 137 | 130 | 218 | 51 | 52 | |||||||||||||||||||||||||||
| Bank owned life insurance | 1,057 | 1,045 | 1,033 | 1,022 | 1,011 | |||||||||||||||||||||||||||
| Goodwill and other intangibles, net | 649 | 651 | 653 | 656 | 659 | |||||||||||||||||||||||||||
| Other assets | 3,116 | 3,076 | 3,348 | 2,830 | 2,817 | |||||||||||||||||||||||||||
| Total assets | $ | 92,774 | $ | 90,970 | $ | 86,725 | $ | 83,043 | $ | 80,934 | ||||||||||||||||||||||
| Liabilities and stockholders' equity: | ||||||||||||||||||||||||||||||||
| Liabilities: | ||||||||||||||||||||||||||||||||
| Deposits | ||||||||||||||||||||||||||||||||
| Non-interest bearing deposits | $ | 24,353 | $ | 26,628 | $ | 22,997 | $ | 22,009 | $ | 18,846 | ||||||||||||||||||||||
| Interest bearing: | ||||||||||||||||||||||||||||||||
| Demand | 18,416 | 16,422 | 15,674 | 15,507 | 15,878 | |||||||||||||||||||||||||||
| Savings and money market | 24,586 | 24,627 | 22,231 | 21,728 | 21,208 | |||||||||||||||||||||||||||
| Certificates of deposit | 9,804 | 9,570 | 10,205 | 10,078 | 10,409 | |||||||||||||||||||||||||||
| Total deposits | 77,159 | 77,247 | 71,107 | 69,322 | 66,341 | |||||||||||||||||||||||||||
| Borrowings | 5,240 | 3,862 | 6,052 | 4,151 | 5,573 | |||||||||||||||||||||||||||
| Qualifying debt | 1,076 | 681 | 678 | 898 | 899 | |||||||||||||||||||||||||||
| Operating lease liability | 160 | 164 | 160 | 154 | 159 | |||||||||||||||||||||||||||
| Accrued interest payable and other liabilities | 1,193 | 1,326 | 1,321 | 1,303 | 1,255 | |||||||||||||||||||||||||||
| Total liabilities | 84,828 | 83,280 | 79,318 | 75,828 | 74,227 | |||||||||||||||||||||||||||
| Equity: | ||||||||||||||||||||||||||||||||
| Preferred stock | 295 | 295 | 295 | 295 | 295 | |||||||||||||||||||||||||||
| Common stock and additional paid-in capital | 2,095 | 2,140 | 2,136 | 2,125 | 2,120 | |||||||||||||||||||||||||||
| Retained earnings | 5,607 | 5,371 | 5,165 | 4,980 | 4,826 | |||||||||||||||||||||||||||
| Accumulated other comprehensive loss | (344) | (409) | (482) | (478) | (534) | |||||||||||||||||||||||||||
| Total Western Alliance stockholders' equity | 7,653 | 7,397 | 7,114 | 6,922 | 6,707 | |||||||||||||||||||||||||||
| Noncontrolling interest in subsidiary | 293 | 293 | 293 | 293 | — | |||||||||||||||||||||||||||
| Total equity | 7,946 | 7,690 | 7,407 | 7,215 | 6,707 | |||||||||||||||||||||||||||
| Total liabilities and equity | $ | 92,774 | $ | 90,970 | $ | 86,725 | $ | 83,043 | $ | 80,934 | ||||||||||||||||||||||
10
| Western Alliance Bancorporation and Subsidiaries | ||||||||||||||||||||||||||||||||
| Changes in the Allowance For Credit Losses on Loans | ||||||||||||||||||||||||||||||||
| Unaudited | ||||||||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||||||||
| Dec 31, 2025 | Sep 30, 2025 | Jun 30, 2025 | Mar 31, 2025 | Dec 31, 2024 | ||||||||||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||||||||||||||
| Allowance for loan losses | ||||||||||||||||||||||||||||||||
| Balance, beginning of period | $ | 440.4 | $ | 394.7 | $ | 388.6 | $ | 373.8 | $ | 356.6 | ||||||||||||||||||||||
| Provision for credit losses (1) | 64.8 | 76.8 | 35.7 | 40.6 | 51.3 | |||||||||||||||||||||||||||
| Recoveries of loans previously charged-off: | ||||||||||||||||||||||||||||||||
| Commercial and industrial | 1.7 | 0.7 | 0.6 | 1.0 | 0.1 | |||||||||||||||||||||||||||
| Commercial real estate - non-owner occupied | — | — | 5.1 | 0.6 | — | |||||||||||||||||||||||||||
| Commercial real estate - owner occupied | 0.4 | — | — | 0.1 | 0.2 | |||||||||||||||||||||||||||
| Construction and land development | 1.5 | — | — | — | — | |||||||||||||||||||||||||||
| Residential real estate | — | — | — | — | — | |||||||||||||||||||||||||||
| Consumer | 0.1 | — | — | — | — | |||||||||||||||||||||||||||
| Total recoveries | 3.7 | 0.7 | 5.7 | 1.7 | 0.3 | |||||||||||||||||||||||||||
| Loans charged-off: | ||||||||||||||||||||||||||||||||
| Commercial and industrial | 28.9 | 12.4 | 17.0 | 13.0 | 24.8 | |||||||||||||||||||||||||||
| Commercial real estate - non-owner occupied | 10.7 | 12.9 | 17.4 | 14.5 | 9.6 | |||||||||||||||||||||||||||
| Commercial real estate - owner occupied | — | — | 0.2 | — | — | |||||||||||||||||||||||||||
| Construction and land development | 8.6 | 6.3 | 0.6 | — | — | |||||||||||||||||||||||||||
| Residential real estate | — | — | 0.1 | — | — | |||||||||||||||||||||||||||
| Consumer | 0.1 | 0.2 | — | — | — | |||||||||||||||||||||||||||
| Total loans charged-off | 48.3 | 31.8 | 35.3 | 27.5 | 34.4 | |||||||||||||||||||||||||||
| Net loan charge-offs | 44.6 | 31.1 | 29.6 | 25.8 | 34.1 | |||||||||||||||||||||||||||
| Balance, end of period | $ | 460.6 | $ | 440.4 | $ | 394.7 | $ | 388.6 | $ | 373.8 | ||||||||||||||||||||||
| Allowance for unfunded loan commitments | ||||||||||||||||||||||||||||||||
| Balance, beginning of period | $ | 42.3 | $ | 39.2 | $ | 35.1 | $ | 39.5 | $ | 37.6 | ||||||||||||||||||||||
| Provision for (recovery of) credit losses (1) | 7.3 | 3.1 | 4.1 | (4.4) | 1.9 | |||||||||||||||||||||||||||
| Balance, end of period (2) | $ | 49.6 | $ | 42.3 | $ | 39.2 | $ | 35.1 | $ | 39.5 | ||||||||||||||||||||||
| Components of the allowance for credit losses on loans | ||||||||||||||||||||||||||||||||
| Allowance for loan losses | $ | 460.6 | $ | 440.4 | $ | 394.7 | $ | 388.6 | $ | 373.8 | ||||||||||||||||||||||
| Allowance for unfunded loan commitments | 49.6 | 42.3 | 39.2 | 35.1 | 39.5 | |||||||||||||||||||||||||||
| Total allowance for credit losses on loans | $ | 510.2 | $ | 482.7 | $ | 433.9 | $ | 423.7 | $ | 413.3 | ||||||||||||||||||||||
| Net charge-offs to average loans - annualized | 0.31 | % | 0.22 | % | 0.22 | % | 0.20 | % | 0.25 | % | ||||||||||||||||||||||
| Allowance ratios | ||||||||||||||||||||||||||||||||
| Allowance for loan losses to funded HFI loans (3) | 0.78 | % | 0.78 | % | 0.71 | % | 0.71 | % | 0.70 | % | ||||||||||||||||||||||
| Allowance for credit losses to funded HFI loans (3) | 0.87 | 0.85 | 0.78 | 0.77 | 0.77 | |||||||||||||||||||||||||||
| Allowance for loan losses to nonaccrual HFI loans | 92 | 84 | 92 | 86 | 79 | |||||||||||||||||||||||||||
| Allowance for credit losses to nonaccrual HFI loans | 102 | 92 | 102 | 94 | 87 | |||||||||||||||||||||||||||
(1) The above tables reflect the provision for credit losses on funded and unfunded loans. For the three months ended December 31, 2025, provision for credit losses for HTM investment securities totaled $0.9 million. The allowance for credit losses on HTM investment securities totaled $12.9 million as of December 31, 2025.
(2) The allowance for unfunded loan commitments is included as part of accrued interest payable and other liabilities on the balance sheet.
(3) Ratio includes an allowance for credit losses of $11.8 million as of December 31, 2025 related to a pool of loans covered under three separate credit linked note transactions.
11
| Western Alliance Bancorporation and Subsidiaries | ||||||||||||||||||||||||||||||||
| Asset Quality Metrics | ||||||||||||||||||||||||||||||||
| Unaudited | ||||||||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||||||||
| Dec 31, 2025 | Sep 30, 2025 | Jun 30, 2025 | Mar 31, 2025 | Dec 31, 2024 | ||||||||||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||||||||||||||
| Nonaccrual loans and repossessed assets | ||||||||||||||||||||||||||||||||
| Nonaccrual loans | $ | 500 | $ | 522 | $ | 427 | $ | 451 | $ | 476 | ||||||||||||||||||||||
| Nonaccrual loans to funded HFI loans | 0.85 | % | 0.92 | % | 0.76 | % | 0.82 | % | 0.89 | % | ||||||||||||||||||||||
| Repossessed assets | $ | 137 | $ | 130 | $ | 218 | $ | 51 | $ | 52 | ||||||||||||||||||||||
| Nonaccrual loans and repossessed assets to total assets | 0.69 | % | 0.72 | % | 0.74 | % | 0.60 | % | 0.65 | % | ||||||||||||||||||||||
| Loans Past Due | ||||||||||||||||||||||||||||||||
| Loans past due 90 days, still accruing (1) | $ | 66 | $ | 49 | $ | 51 | $ | 44 | $ | — | ||||||||||||||||||||||
| Loans past due 90 days, still accruing to funded HFI loans | 0.11 | % | 0.09 | % | 0.09 | % | 0.08 | % | — | % | ||||||||||||||||||||||
| Loans past due 30 to 89 days, still accruing (2) | $ | 108 | $ | 196 | $ | 175 | $ | 182 | $ | 92 | ||||||||||||||||||||||
| Loans past due 30 to 89 days, still accruing to funded HFI loans | 0.18 | % | 0.35 | % | 0.31 | % | 0.33 | % | 0.17 | % | ||||||||||||||||||||||
| Other credit quality metrics | ||||||||||||||||||||||||||||||||
| Special mention loans | $ | 325 | $ | 292 | $ | 444 | $ | 460 | $ | 392 | ||||||||||||||||||||||
| Special mention loans to funded HFI loans | 0.55 | % | 0.52 | % | 0.79 | % | 0.84 | % | 0.73 | % | ||||||||||||||||||||||
| Classified loans on accrual | $ | 450 | $ | 476 | $ | 615 | $ | 693 | $ | 480 | ||||||||||||||||||||||
| Classified loans on accrual to funded HFI loans | 0.77 | % | 0.84 | % | 1.10 | % | 1.27 | % | 0.89 | % | ||||||||||||||||||||||
| Classified assets | $ | 1,088 | $ | 1,129 | $ | 1,261 | $ | 1,195 | $ | 1,009 | ||||||||||||||||||||||
| Classified assets to total assets | 1.17 | % | 1.24 | % | 1.45 | % | 1.44 | % | 1.25 | % | ||||||||||||||||||||||
(1) Excludes government guaranteed residential mortgage loans of $290 million, $282 million, $326 million, $275 million, and $326 million as of each respective date in the table above.
(2) Excludes government guaranteed residential mortgage loans of $145 million, $149 million, $168 million, $161 million, and $183 million as of each respective date in the table above.
12
| Western Alliance Bancorporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||
| Analysis of Average Balances, Yields and Rates | ||||||||||||||||||||||||||||||||||||||
| Unaudited | ||||||||||||||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||||||||||||||
| December 31, 2025 | September 30, 2025 | |||||||||||||||||||||||||||||||||||||
| Average Balance | Interest | Average Yield / Cost | Average Balance | Interest | Average Yield / Cost | |||||||||||||||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||||||||||||||||||||
| Interest earning assets | ||||||||||||||||||||||||||||||||||||||
| Loans HFS | $ | 5,195 | $ | 75.2 | 5.74 | % | $ | 5,009 | $ | 77.1 | 6.11 | % | ||||||||||||||||||||||||||
| Loans HFI: | ||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 26,246 | 415.1 | 6.32 | 25,216 | 410.9 | 6.51 | ||||||||||||||||||||||||||||||||
| CRE - non-owner occupied | 10,454 | 182.5 | 6.93 | 10,473 | 190.8 | 7.23 | ||||||||||||||||||||||||||||||||
| CRE - owner occupied | 1,695 | 24.0 | 5.74 | 1,688 | 25.2 | 6.05 | ||||||||||||||||||||||||||||||||
| Construction and land development | 4,003 | 82.5 | 8.17 | 4,233 | 88.8 | 8.32 | ||||||||||||||||||||||||||||||||
| Residential real estate | 14,690 | 156.6 | 4.23 | 14,557 | 155.1 | 4.23 | ||||||||||||||||||||||||||||||||
| Consumer | 21 | 0.3 | 5.34 | 24 | 0.4 | 7.43 | ||||||||||||||||||||||||||||||||
| Total HFI loans (1), (2), (3), (4) | 57,109 | 861.0 | 6.01 | 56,191 | 871.2 | 6.18 | ||||||||||||||||||||||||||||||||
| Investment securities: | ||||||||||||||||||||||||||||||||||||||
| Taxable | 17,690 | 197.8 | 4.44 | 17,794 | 208.2 | 4.64 | ||||||||||||||||||||||||||||||||
| Tax-exempt | 2,212 | 23.8 | 5.39 | 2,193 | 23.5 | 5.32 | ||||||||||||||||||||||||||||||||
| Total investment securities (1) | 19,902 | 221.6 | 4.54 | 19,987 | 231.7 | 4.72 | ||||||||||||||||||||||||||||||||
| Cash and other | 5,633 | 59.6 | 4.20 | 4,147 | 45.5 | 4.35 | ||||||||||||||||||||||||||||||||
| Total interest earning assets | 87,839 | 1,217.4 | 5.54 | 85,334 | 1,225.5 | 5.74 | ||||||||||||||||||||||||||||||||
| Non-interest earning assets | ||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 462 | 397 | ||||||||||||||||||||||||||||||||||||
| Allowance for credit losses | (459) | (414) | ||||||||||||||||||||||||||||||||||||
| Bank owned life insurance | 1,049 | 1,038 | ||||||||||||||||||||||||||||||||||||
| Other assets | 5,310 | 4,957 | ||||||||||||||||||||||||||||||||||||
| Total assets | $ | 94,201 | $ | 91,312 | ||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits: | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand accounts | $ | 17,374 | $ | 102.2 | 2.33 | % | $ | 16,071 | $ | 101.4 | 2.50 | % | ||||||||||||||||||||||||||
| Savings and money market | 24,113 | 180.9 | 2.98 | 23,373 | 189.4 | 3.21 | ||||||||||||||||||||||||||||||||
| Certificates of deposit | 9,834 | 100.4 | 4.05 | 10,124 | 107.4 | 4.21 | ||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 51,321 | 383.5 | 2.96 | 49,568 | 398.2 | 3.19 | ||||||||||||||||||||||||||||||||
| Short-term borrowings | 3,243 | 33.7 | 4.13 | 2,577 | 30.2 | 4.66 | ||||||||||||||||||||||||||||||||
| Long-term debt | 1,723 | 25.0 | 5.75 | 2,905 | 40.4 | 5.52 | ||||||||||||||||||||||||||||||||
| Qualifying debt | 845 | 9.0 | 4.27 | 678 | 6.3 | 3.63 | ||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 57,132 | 451.2 | 3.13 | 55,728 | 475.1 | 3.38 | ||||||||||||||||||||||||||||||||
| Interest cost of funding earning assets | 2.04 | 2.21 | ||||||||||||||||||||||||||||||||||||
| Non-interest-bearing liabilities | ||||||||||||||||||||||||||||||||||||||
| Non-interest-bearing deposits | 27,524 | 26,438 | ||||||||||||||||||||||||||||||||||||
| Other liabilities | 1,681 | 1,539 | ||||||||||||||||||||||||||||||||||||
| Equity | 7,864 | 7,607 | ||||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 94,201 | $ | 91,312 | ||||||||||||||||||||||||||||||||||
| Net interest income and margin (5) | $ | 766.2 | 3.51 | % | $ | 750.4 | 3.53 | % | ||||||||||||||||||||||||||||||
(1) Yields on loans and securities have been adjusted to a tax equivalent basis. The tax equivalent adjustment was $9.9 million and $9.7 million for the three months ended December 31, 2025 and September 30, 2025, respectively.
(2) Included in the yield computation are net loan fees of $25.0 million and $28.1 million for the three months ended December 31, 2025 and September 30, 2025, respectively
(3) Interest income includes a reduction for earnings credits totaling $56.6 million and $64.9 million for the three months ended December 31, 2025 and September 30, 2025, respectively.
(4) Includes non-accrual loans.
(5) Net interest margin is computed by dividing net interest income by total average earning assets, annualized on an actual/actual basis.
13
| Western Alliance Bancorporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||
| Analysis of Average Balances, Yields and Rates | ||||||||||||||||||||||||||||||||||||||
| Unaudited | ||||||||||||||||||||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||||||||||||||||||||
| December 31, 2025 | December 31, 2024 | |||||||||||||||||||||||||||||||||||||
| Average Balance | Interest | Average Yield / Cost | Average Balance | Interest | Average Yield / Cost | |||||||||||||||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||||||||||||||||||||
| Interest earning assets | ||||||||||||||||||||||||||||||||||||||
| Loans HFS | $ | 5,195 | $ | 75.2 | 5.74 | % | $ | 4,542 | $ | 67.3 | 5.90 | % | ||||||||||||||||||||||||||
| Loans HFI: | ||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 26,246 | 415.1 | 6.32 | 22,708 | 382.8 | 6.76 | ||||||||||||||||||||||||||||||||
| CRE - non-owner occupied | 10,454 | 182.5 | 6.93 | 9,883 | 184.1 | 7.42 | ||||||||||||||||||||||||||||||||
| CRE - owner occupied | 1,695 | 24.0 | 5.74 | 1,826 | 27.7 | 6.14 | ||||||||||||||||||||||||||||||||
| Construction and land development | 4,003 | 82.5 | 8.17 | 4,571 | 100.1 | 8.72 | ||||||||||||||||||||||||||||||||
| Residential real estate | 14,690 | 156.6 | 4.23 | 14,424 | 152.3 | 4.20 | ||||||||||||||||||||||||||||||||
| Consumer | 21 | 0.3 | 5.34 | 52 | 0.9 | 6.57 | ||||||||||||||||||||||||||||||||
| Total loans HFI (1), (2), (3), (4) | 57,109 | 861.0 | 6.01 | 53,464 | 847.9 | 6.34 | ||||||||||||||||||||||||||||||||
| Investment securities: | ||||||||||||||||||||||||||||||||||||||
| Taxable | 17,690 | 197.8 | 4.44 | 13,550 | 155.0 | 4.55 | ||||||||||||||||||||||||||||||||
| Tax-exempt | 2,212 | 23.8 | 5.39 | 2,269 | 24.4 | 5.36 | ||||||||||||||||||||||||||||||||
| Total investment securities (1) | 19,902 | 221.6 | 4.54 | 15,819 | 179.4 | 4.67 | ||||||||||||||||||||||||||||||||
| Cash and other | 5,633 | 59.6 | 4.20 | 3,481 | 44.0 | 5.03 | ||||||||||||||||||||||||||||||||
| Total interest earning assets | 87,839 | 1,217.4 | 5.54 | 77,306 | 1,138.6 | 5.91 | ||||||||||||||||||||||||||||||||
| Non-interest earning assets | ||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 462 | 316 | ||||||||||||||||||||||||||||||||||||
| Allowance for credit losses | (459) | (364) | ||||||||||||||||||||||||||||||||||||
| Bank owned life insurance | 1,049 | 1,003 | ||||||||||||||||||||||||||||||||||||
| Other assets | 5,310 | 4,427 | ||||||||||||||||||||||||||||||||||||
| Total assets | $ | 94,201 | $ | 82,688 | ||||||||||||||||||||||||||||||||||
| Interest bearing liabilities | ||||||||||||||||||||||||||||||||||||||
| Interest bearing deposits: | ||||||||||||||||||||||||||||||||||||||
| Interest bearing demand accounts | $ | 17,374 | $ | 102.2 | 2.33 | % | $ | 14,555 | $ | 101.3 | 2.77 | % | ||||||||||||||||||||||||||
| Savings and money market accounts | 24,113 | 180.9 | 2.98 | 19,895 | 167.8 | 3.36 | ||||||||||||||||||||||||||||||||
| Certificates of deposit | 9,834 | 100.4 | 4.05 | 9,654 | 118.1 | 4.87 | ||||||||||||||||||||||||||||||||
| Total interest bearing deposits | 51,321 | 383.5 | 2.96 | 44,104 | 387.2 | 3.49 | ||||||||||||||||||||||||||||||||
| Short-term borrowings | 3,243 | 33.7 | 4.13 | 3,480 | 45.8 | 5.24 | ||||||||||||||||||||||||||||||||
| Long-term debt | 1,723 | 25.0 | 5.75 | 1,861 | 29.7 | 6.34 | ||||||||||||||||||||||||||||||||
| Qualifying debt | 845 | 9.0 | 4.27 | 898 | 9.4 | 4.19 | ||||||||||||||||||||||||||||||||
| Total interest bearing liabilities | 57,132 | 451.2 | 3.13 | 50,343 | 472.1 | 3.73 | ||||||||||||||||||||||||||||||||
| Interest cost of funding earning assets | 2.04 | 2.43 | ||||||||||||||||||||||||||||||||||||
| Non-interest bearing liabilities | ||||||||||||||||||||||||||||||||||||||
| Non-interest bearing deposits | 27,524 | 24,200 | ||||||||||||||||||||||||||||||||||||
| Other liabilities | 1,681 | 1,380 | ||||||||||||||||||||||||||||||||||||
| Equity | 7,864 | 6,765 | ||||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 94,201 | $ | 82,688 | ||||||||||||||||||||||||||||||||||
| Net interest income and margin (5) | $ | 766.2 | 3.51 | % | $ | 666.5 | 3.48 | % | ||||||||||||||||||||||||||||||
(1) Yields on loans and securities have been adjusted to a tax equivalent basis. The tax equivalent adjustment was $9.9 million and $10.0 million for the three months ended December 31, 2025 and 2024, respectively.
(2) Included in the yield computation are net loan fees of $25.0 million and $22.1 million for the three months ended December 31, 2025 and 2024, respectively.
(3) Interest income includes a reduction for earnings credits totaling of $56.6 million and $61.4 million for the three months ended December 31, 2025 and 2024, respectively.
(4) Includes non-accrual loans.
(5) Net interest margin is computed by dividing net interest income by total average earning assets, annualized on an actual/actual basis.
14
| Western Alliance Bancorporation and Subsidiaries | ||||||||||||||||||||||||||||||||||||||
| Analysis of Average Balances, Yields and Rates | ||||||||||||||||||||||||||||||||||||||
| Unaudited | ||||||||||||||||||||||||||||||||||||||
| Year Ended | ||||||||||||||||||||||||||||||||||||||
| December 31, 2025 | December 31, 2024 | |||||||||||||||||||||||||||||||||||||
| Average Balance | Interest | Average Yield / Cost | Average Balance | Interest | Average Yield / Cost | |||||||||||||||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||||||||||||||||||||
| Interest earning assets | ||||||||||||||||||||||||||||||||||||||
| Loans HFS | $ | 4,844 | $ | 292.9 | 6.05 | % | $ | 3,531 | $ | 216.4 | 6.13 | % | ||||||||||||||||||||||||||
| Loans HFI: | ||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | 24,608 | 1,583.9 | 6.49 | 20,845 | 1,490.6 | 7.21 | ||||||||||||||||||||||||||||||||
| CRE - non-owner occupied | 10,299 | 730.3 | 7.10 | 9,681 | 744.7 | 7.70 | ||||||||||||||||||||||||||||||||
| CRE - owner occupied | 1,762 | 104.7 | 6.05 | 1,833 | 111.2 | 6.17 | ||||||||||||||||||||||||||||||||
| Construction and land development | 4,232 | 351.7 | 8.31 | 4,747 | 440.1 | 9.28 | ||||||||||||||||||||||||||||||||
| Residential real estate | 14,499 | 614.2 | 4.24 | 14,529 | 622.3 | 4.28 | ||||||||||||||||||||||||||||||||
| Consumer | 31 | 2.1 | 6.70 | 54 | 3.8 | 7.00 | ||||||||||||||||||||||||||||||||
| Total loans HFI (1), (2), (3), (4) | 55,431 | 3,386.9 | 6.14 | 51,689 | 3,412.7 | 6.63 | ||||||||||||||||||||||||||||||||
| Investment securities: | ||||||||||||||||||||||||||||||||||||||
| Taxable | 15,919 | 726.9 | 4.57 | 13,159 | 616.0 | 4.68 | ||||||||||||||||||||||||||||||||
| Tax-exempt | 2,218 | 95.9 | 5.42 | 2,230 | 95.0 | 5.34 | ||||||||||||||||||||||||||||||||
| Total investment securities (1) | 18,137 | 822.8 | 4.67 | 15,389 | 711.0 | 4.78 | ||||||||||||||||||||||||||||||||
| Cash and other | 4,344 | 190.3 | 4.38 | 3,656 | 201.0 | 5.50 | ||||||||||||||||||||||||||||||||
| Total interest earning assets | 82,756 | 4,692.9 | 5.72 | 74,265 | 4,541.1 | 6.17 | ||||||||||||||||||||||||||||||||
| Non-interest earning assets | ||||||||||||||||||||||||||||||||||||||
| Cash and due from banks | 384 | 293 | ||||||||||||||||||||||||||||||||||||
| Allowance for credit losses | (418) | (357) | ||||||||||||||||||||||||||||||||||||
| Bank owned life insurance | 1,032 | 589 | ||||||||||||||||||||||||||||||||||||
| Other assets | 4,974 | 4,483 | ||||||||||||||||||||||||||||||||||||
| Total assets | $ | 88,728 | $ | 79,273 | ||||||||||||||||||||||||||||||||||
| Interest bearing liabilities | ||||||||||||||||||||||||||||||||||||||
| Interest bearing deposits: | ||||||||||||||||||||||||||||||||||||||
| Interest bearing demand accounts | $ | 16,259 | $ | 400.7 | 2.46 | % | $ | 16,155 | $ | 480.7 | 2.98 | % | ||||||||||||||||||||||||||
| Savings and money market accounts | 22,617 | 705.6 | 3.12 | 17,462 | 610.2 | 3.49 | ||||||||||||||||||||||||||||||||
| Certificates of deposit | 10,015 | 431.5 | 4.31 | 10,085 | 509.3 | 5.05 | ||||||||||||||||||||||||||||||||
| Total interest bearing deposits | 48,891 | 1,537.8 | 3.15 | 43,702 | 1,600.2 | 3.66 | ||||||||||||||||||||||||||||||||
| Short-term borrowings | 2,651 | 120.4 | 4.54 | 3,893 | 216.3 | 5.56 | ||||||||||||||||||||||||||||||||
| Long-term debt | 2,444 | 137.1 | 5.61 | 830 | 67.7 | 8.16 | ||||||||||||||||||||||||||||||||
| Qualifying debt | 811 | 32.8 | 4.05 | 896 | 38.0 | 4.25 | ||||||||||||||||||||||||||||||||
| Total interest bearing liabilities | 54,797 | 1,828.1 | 3.34 | 49,321 | 1,922.2 | 3.90 | ||||||||||||||||||||||||||||||||
| Interest cost of funding earning assets | 2.21 | 2.59 | ||||||||||||||||||||||||||||||||||||
| Non-interest bearing liabilities | ||||||||||||||||||||||||||||||||||||||
| Non-interest bearing deposits | 24,926 | 22,017 | ||||||||||||||||||||||||||||||||||||
| Other liabilities | 1,571 | 1,455 | ||||||||||||||||||||||||||||||||||||
| Equity | 7,434 | 6,480 | ||||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 88,728 | $ | 79,273 | ||||||||||||||||||||||||||||||||||
| Net interest income and margin (5) | $ | 2,864.8 | 3.51 | % | $ | 2,618.9 | 3.58 | % | ||||||||||||||||||||||||||||||
(1) Yields on loans and securities have been adjusted to a tax equivalent basis. The tax equivalent adjustment was $40.0 million and $39.5 million for the years ended December 31, 2025 and 2024, respectively.
(2) Included in the yield computation are net loan fees of $102.4 million and $109.0 million for the years ended December 31, 2025 and 2024, respectively.
(3) Interest income includes a reduction for earnings credits totaling $240.9 million and $239.8 million for the years ended December 31, 2025 and 2024, respectively.
(4) Includes non-accrual loans.
(5) Net interest margin is computed by dividing net interest income by total average earning assets, annualized on an actual/actual basis.
15
| Western Alliance Bancorporation and Subsidiaries | ||
Income Statement Classification of Earnings Credits | ||
| Unaudited | ||
The tables below show the income statement classification for earnings credit amounts earned on non-interest bearing DDA:
| Three Months Ended | |||||||||||||||||||||||||||||
| 12/31/2025 | 9/30/2025 | 6/30/2025 | 3/31/2025 | 12/31/2024 | |||||||||||||||||||||||||
| Income statement line item | (in millions) | ||||||||||||||||||||||||||||
| Interest income | $ | 56.6 | $ | 64.9 | $ | 61.3 | $ | 58.1 | $ | 61.4 | |||||||||||||||||||
| Service charges and fees | 7.2 | 5.4 | 4.4 | 4.2 | 6.3 | ||||||||||||||||||||||||
| Deposit costs (1) | 123.6 | 126.3 | 101.7 | 90.9 | 133.3 | ||||||||||||||||||||||||
| Total ECR costs | $ | 187.4 | $ | 196.6 | $ | 167.4 | $ | 153.2 | $ | 201.0 | |||||||||||||||||||
| Year Ended December 31, | |||||||||||||||||||||||||||||
| 2025 | 2024 | ||||||||||||||||||||||||||||
| Income statement line item | (in millions) | ||||||||||||||||||||||||||||
| Interest income | $ | 240.9 | $ | 239.8 | |||||||||||||||||||||||||
| Service charges and fees | 21.2 | 26.1 | |||||||||||||||||||||||||||
| Deposit costs (1) | 442.5 | 489.2 | |||||||||||||||||||||||||||
| Total ECR costs | $ | 704.6 | $ | 755.1 | |||||||||||||||||||||||||
(1) Earnings credits are a subset of total Deposit costs, which also include referral, reciprocal deposit and other costs.
| Western Alliance Bancorporation and Subsidiaries | ||
| Reconciliation of Non-GAAP Financial Measures | ||
| Unaudited | ||
| Pre-Provision Net Revenue by Quarter: | |||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||
| Dec 31, 2025 | Sep 30, 2025 | Jun 30, 2025 | Mar 31, 2025 | Dec 31, 2024 | |||||||||||||||||||||||||
| (in millions) | |||||||||||||||||||||||||||||
| Net interest income | $ | 766.2 | $ | 750.4 | $ | 697.6 | $ | 650.6 | $ | 666.5 | |||||||||||||||||||
| Total non-interest income | 214.7 | 187.8 | 148.3 | 127.4 | 171.9 | ||||||||||||||||||||||||
| Net revenue | $ | 980.9 | $ | 938.2 | $ | 845.9 | $ | 778.0 | $ | 838.4 | |||||||||||||||||||
| Total non-interest expense | 552.2 | 544.4 | 514.7 | 500.4 | 519.0 | ||||||||||||||||||||||||
| Pre-provision net revenue (1) | $ | 428.7 | $ | 393.8 | $ | 331.2 | $ | 277.6 | $ | 319.4 | |||||||||||||||||||
| Adjusted for: | |||||||||||||||||||||||||||||
| Provision for credit losses | 73.0 | 80.0 | 39.9 | 31.2 | 60.0 | ||||||||||||||||||||||||
| Income tax expense | 62.5 | 53.3 | 53.5 | 47.3 | 42.5 | ||||||||||||||||||||||||
| Net income | $ | 293.2 | $ | 260.5 | $ | 237.8 | $ | 199.1 | $ | 216.9 | |||||||||||||||||||
16
| Western Alliance Bancorporation and Subsidiaries | ||
| Reconciliation of Non-GAAP Financial Measures | ||
| Unaudited | ||
| Efficiency Ratio (Tax Equivalent Basis) by Quarter: | |||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||
| Dec 31, 2025 | Sep 30, 2025 | Jun 30, 2025 | Mar 31, 2025 | Dec 31, 2024 | |||||||||||||||||||||||||
| (dollars in millions) | |||||||||||||||||||||||||||||
| Total non-interest expense | $ | 552.2 | $ | 544.4 | $ | 514.7 | $ | 500.4 | $ | 519.0 | |||||||||||||||||||
| Less: Deposit costs | 171.2 | 175.1 | 147.4 | 136.8 | 174.5 | ||||||||||||||||||||||||
| Total non-interest expense, excluding deposit costs | 381.0 | 369.3 | 367.3 | 363.6 | 344.5 | ||||||||||||||||||||||||
| Divided by: | |||||||||||||||||||||||||||||
| Total net interest income | 766.2 | 750.4 | 697.6 | 650.6 | 666.5 | ||||||||||||||||||||||||
| Plus: | |||||||||||||||||||||||||||||
| Tax equivalent interest adjustment | 9.9 | 9.7 | 10.2 | 10.2 | 10.0 | ||||||||||||||||||||||||
| Total non-interest income | 214.7 | 187.8 | 148.3 | 127.4 | 171.9 | ||||||||||||||||||||||||
| Less: Deposit costs | 171.2 | 175.1 | 147.4 | 136.8 | 174.5 | ||||||||||||||||||||||||
| $ | 819.6 | $ | 772.8 | $ | 708.7 | $ | 651.4 | $ | 673.9 | ||||||||||||||||||||
| Efficiency ratio (2) | 55.7 | % | 57.4 | % | 60.1 | % | 63.5 | % | 61.2 | % | |||||||||||||||||||
| Efficiency ratio, adjusted for deposit costs (2) | 46.5 | % | 47.8 | % | 51.8 | % | 55.8 | % | 51.1 | % | |||||||||||||||||||
| Tangible Common Equity: | |||||||||||||||||||||||||||||
| Dec 31, 2025 | Sep 30, 2025 | Jun 30, 2025 | Mar 31, 2025 | Dec 31, 2024 | |||||||||||||||||||||||||
| (dollars and shares in millions, except per share data) | |||||||||||||||||||||||||||||
| Total equity | $ | 7,946 | $ | 7,690 | $ | 7,407 | $ | 7,215 | $ | 6,707 | |||||||||||||||||||
| Less: | |||||||||||||||||||||||||||||
| Goodwill and intangible assets, net | 649 | 651 | 653 | 656 | 659 | ||||||||||||||||||||||||
| Preferred stock | 295 | 295 | 295 | 295 | 295 | ||||||||||||||||||||||||
| Noncontrolling interest in subsidiary | 293 | 293 | 293 | 293 | — | ||||||||||||||||||||||||
| Total tangible common equity | 6,709 | 6,451 | 6,166 | 5,971 | 5,753 | ||||||||||||||||||||||||
| Plus: deferred tax - attributed to intangible assets | 2 | 2 | 2 | 2 | 2 | ||||||||||||||||||||||||
| Total tangible common equity, net of tax | $ | 6,711 | $ | 6,453 | $ | 6,168 | $ | 5,973 | $ | 5,755 | |||||||||||||||||||
| Total assets | $ | 92,774 | $ | 90,970 | $ | 86,725 | $ | 83,043 | $ | 80,934 | |||||||||||||||||||
| Less: goodwill and intangible assets, net | 649 | 651 | 653 | 656 | 659 | ||||||||||||||||||||||||
| Tangible assets | 92,125 | 90,319 | 86,072 | 82,387 | 80,275 | ||||||||||||||||||||||||
| Plus: deferred tax - attributed to intangible assets | 2 | 2 | 2 | 2 | 2 | ||||||||||||||||||||||||
| Total tangible assets, net of tax | $ | 92,127 | $ | 90,321 | $ | 86,074 | $ | 82,389 | $ | 80,277 | |||||||||||||||||||
| Tangible common equity ratio (3) | 7.3 | % | 7.1 | % | 7.2 | % | 7.2 | % | 7.2 | % | |||||||||||||||||||
| Common shares outstanding | 109.5 | 110.2 | 110.4 | 110.4 | 110.1 | ||||||||||||||||||||||||
| Tangible book value per share, net of tax (3) | $ | 61.29 | $ | 58.56 | $ | 55.87 | $ | 54.10 | $ | 52.27 | |||||||||||||||||||
| Non-GAAP Financial Measures Footnotes | ||||||||||||||||||||||||||
| (1) | We believe this non-GAAP measurement is a key indicator of the earnings power of the Company. | |||||||||||||||||||||||||
| (2) | We believe this non-GAAP ratio provides a useful metric to measure the efficiency of the Company. | |||||||||||||||||||||||||
| (3) | We believe this non-GAAP metric provides an important metric with which to analyze and evaluate the financial condition and capital strength of the Company. | |||||||||||||||||||||||||
17
EARNINGS CALL 4th Quarter 2025 January 27, 2026
2 This presentation contains forward-looking statements that relate to expectations, beliefs, projections, future plans and strategies, anticipated events or trends and similar expressions concerning matters that are not historical facts. Examples of forward-looking statements include, among others, statements we make regarding our expectations with regard to our business, financial and operating results, including our deposits, liquidity and funding, changes in economic conditions and related impacts on the Company's business, future economic performance and dividends, including our statements on the slide entitled "Management Outlook." The forward-looking statements contained herein reflect our current views about future events and financial performance and are subject to risks, uncertainties, assumptions and changes in circumstances that may cause our actual results to differ significantly from historical results and those expressed in any forward- looking statement. Some factors that could cause actual results to differ materially from historical or expected results include, among others: the risk factors discussed in the Company’s Annual Report on Form 10-K for the year ended December 31, 2024, and the Company's subsequent Quarterly Reports on Form 10-Q, each as filed with the Securities and Exchange Commission; adverse developments in the financial services industry generally and any related impact on depositor behavior; risks related to the sufficiency of liquidity; changes in international trade policies, tariffs and treaties affecting imports and exports, trade disputes, barriers to trade or the emergence of other trade restrictions, and their related impacts on macroeconomic conditions and customer behavior; the potential adverse effects of unusual and infrequently occurring events and any governmental or societal responses thereto; changes in general economic conditions, either nationally or locally in the areas in which we conduct or will conduct our business; the impact on financial markets from geopolitical conflicts such as the wars in Ukraine and the Middle East; inflation, interest rate, market and monetary fluctuations; increases in competitive pressures among financial institutions and businesses offering similar products and services; higher defaults on our loan portfolio than we expect; increased foreclosures and ownership of real property; changes in management’s estimate of the adequacy of the allowance for credit losses; legislative or regulatory changes or changes in accounting principles, policies or guidelines; supervisory actions by regulatory agencies which may limit our ability to pursue certain growth opportunities, including expansion through acquisitions; additional regulatory requirements resulting from our continued growth; management’s estimates and projections of interest rates and interest rate policy; the execution of our business plan; any adverse determination by a court regarding the Cantor Group V loan and any adverse economic or other events impacting the collateral, borrower or guarantors with respect to such loan; and other factors affecting the financial services industry generally or the banking industry in particular. Any forward-looking statement made by us in this presentation is based only on information currently available to us and speaks only as of the date on which it is made. We do not intend and disclaim any duty or obligation to update or revise any industry information or forward-looking statements, whether written or oral, that may be made from time to time, set forth in this presentation to reflect new information, future events or otherwise, except to the extent required by applicable law. In light of these risks, uncertainties and assumptions, the forward-looking events in this presentation might not occur, and you should not put undue reliance on any forward-looking statements. Non-GAAP Financial Measures This presentation contains both financial measures based on GAAP and non-GAAP based financial measures, which are used where management believes them to be helpful in understanding the Company’s results of operations or financial position. Where non-GAAP financial measures are used, the comparable GAAP financial measure, as well as the reconciliation to the comparable GAAP financial measure, can be found in the Company’s press release as of and for the quarter ended December 31, 2025. These disclosures should not be viewed as a substitute for operating results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Forward-Looking Statements
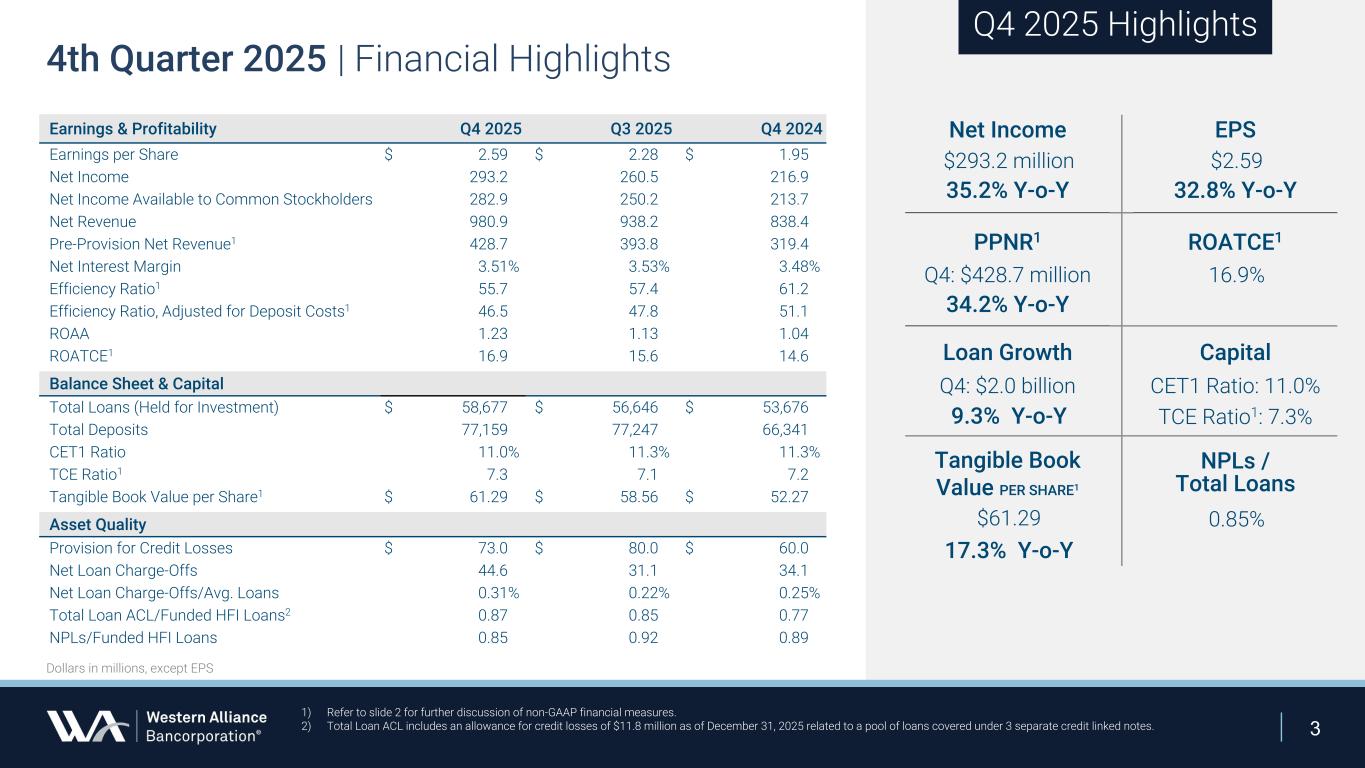
3 4th Quarter 2025 | Financial Highlights Earnings & Profitability Q4 2025 Q3 2025 Q4 2024 Earnings per Share $ 2.59 $ 2.28 $ 1.95 Net Income 293.2 260.5 216.9 Net Income Available to Common Stockholders 282.9 250.2 213.7 Net Revenue 980.9 938.2 838.4 Pre-Provision Net Revenue1 428.7 393.8 319.4 Net Interest Margin 3.51% 3.53% 3.48% Efficiency Ratio1 55.7 57.4 61.2 Efficiency Ratio, Adjusted for Deposit Costs1 46.5 47.8 51.1 ROAA 1.23 1.13 1.04 ROATCE1 16.9 15.6 14.6 Balance Sheet & Capital Total Loans (Held for Investment) $ 58,677 $ 56,646 $ 53,676 Total Deposits 77,159 77,247 66,341 CET1 Ratio 11.0% 11.3% 11.3% TCE Ratio1 7.3 7.1 7.2 Tangible Book Value per Share1 $ 61.29 $ 58.56 $ 52.27 Asset Quality Provision for Credit Losses $ 73.0 $ 80.0 $ 60.0 Net Loan Charge-Offs 44.6 31.1 34.1 Net Loan Charge-Offs/Avg. Loans 0.31% 0.22% 0.25% Total Loan ACL/Funded HFI Loans2 0.87 0.85 0.77 NPLs/Funded HFI Loans 0.85 0.92 0.89 Dollars in millions, except EPS 1) Refer to slide 2 for further discussion of non-GAAP financial measures. 2) Total Loan ACL includes an allowance for credit losses of $11.8 million as of December 31, 2025 related to a pool of loans covered under 3 separate credit linked notes. Q4 2025 Highlights Net Income EPS $293.2 million $2.59 35.2% Y-o-Y 32.8% Y-o-Y PPNR1 ROATCE1 Q4: $428.7 million 16.9% 34.2% Y-o-Y Loan Growth Capital Q4: $2.0 billion CET1 Ratio: 11.0% 9.3% Y-o-Y TCE Ratio1: 7.3% Tangible Book Value PER SHARE1 NPLs / Total Loans $61.29 0.85% 17.3% Y-o-Y
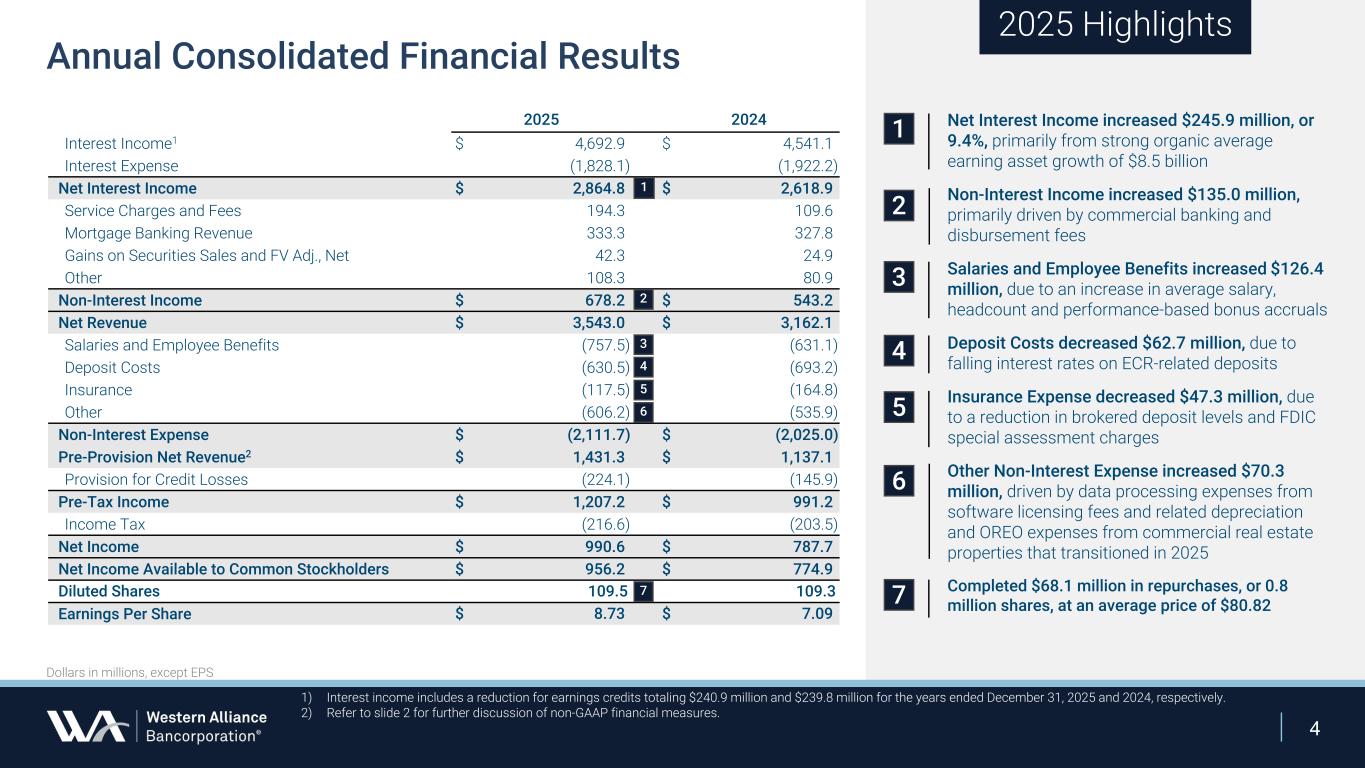
4 Annual Consolidated Financial Results 2025 Highlights 2025 2024 Interest Income1 $ 4,692.9 $ 4,541.1 Interest Expense (1,828.1) (1,922.2) Net Interest Income $ 2,864.8 $ 2,618.9 Service Charges and Fees 194.3 109.6 Mortgage Banking Revenue 333.3 327.8 Gains on Securities Sales and FV Adj., Net 42.3 24.9 Other 108.3 80.9 Non-Interest Income $ 678.2 $ 543.2 Net Revenue $ 3,543.0 $ 3,162.1 Salaries and Employee Benefits (757.5) (631.1) Deposit Costs (630.5) (693.2) Insurance (117.5) (164.8) Other (606.2) (535.9) Non-Interest Expense $ (2,111.7) $ (2,025.0) Pre-Provision Net Revenue2 $ 1,431.3 $ 1,137.1 Provision for Credit Losses (224.1) (145.9) Pre-Tax Income $ 1,207.2 $ 991.2 Income Tax (216.6) (203.5) Net Income $ 990.6 $ 787.7 Net Income Available to Common Stockholders $ 956.2 $ 774.9 Diluted Shares 109.5 109.3 Earnings Per Share $ 8.73 $ 7.09 1 2 4 5 Net Interest Income increased $245.9 million, or 9.4%, primarily from strong organic average earning asset growth of $8.5 billion Non-Interest Income increased $135.0 million, primarily driven by commercial banking and disbursement fees Salaries and Employee Benefits increased $126.4 million, due to an increase in average salary, headcount and performance-based bonus accruals Deposit Costs decreased $62.7 million, due to falling interest rates on ECR-related deposits Insurance Expense decreased $47.3 million, due to a reduction in brokered deposit levels and FDIC special assessment charges Other Non-Interest Expense increased $70.3 million, driven by data processing expenses from software licensing fees and related depreciation and OREO expenses from commercial real estate properties that transitioned in 2025 Completed $68.1 million in repurchases, or 0.8 million shares, at an average price of $80.82 1) Interest income includes a reduction for earnings credits totaling $240.9 million and $239.8 million for the years ended December 31, 2025 and 2024, respectively. 2) Refer to slide 2 for further discussion of non-GAAP financial measures. 1 2 4 5 Dollars in millions, except EPS 6 6 3 3 7 7
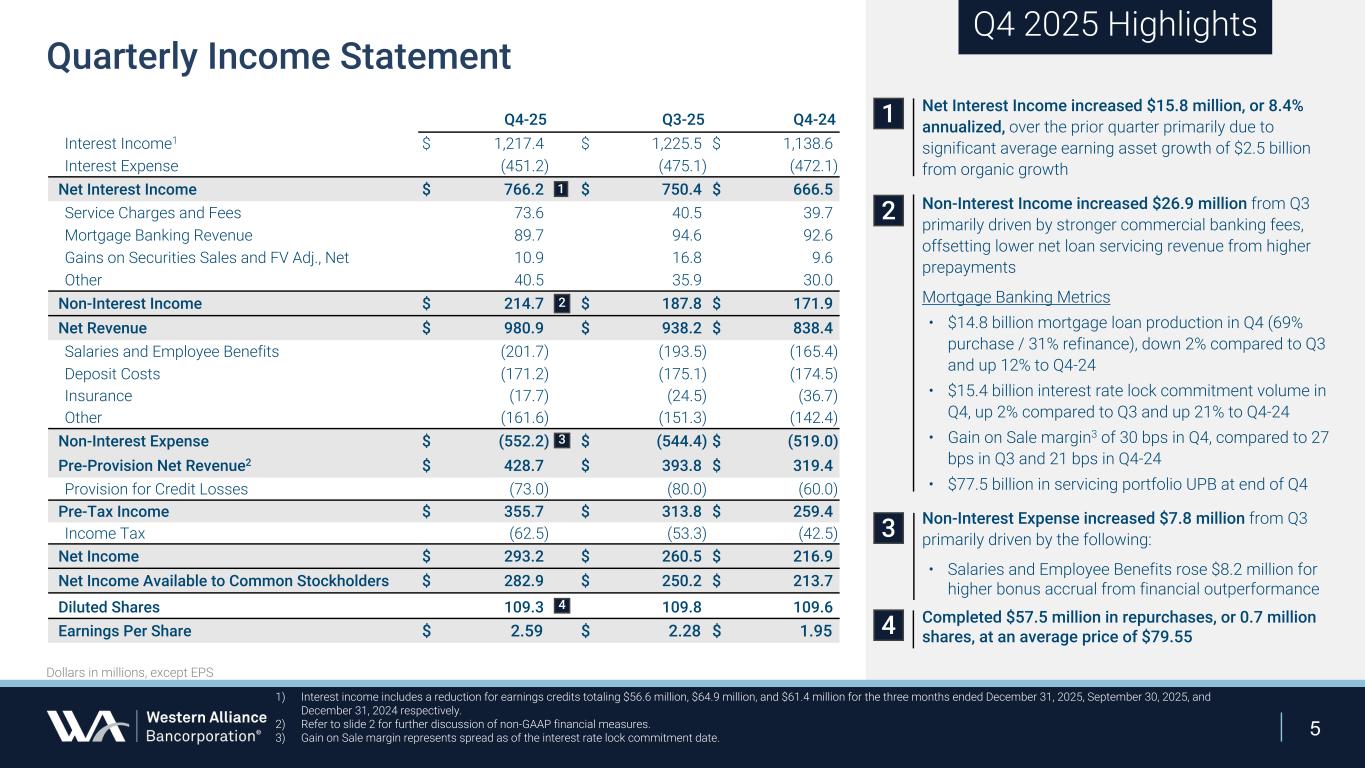
5 Q4-25 Q3-25 Q4-24 Interest Income1 $ 1,217.4 $ 1,225.5 $ 1,138.6 Interest Expense (451.2) (475.1) (472.1) Net Interest Income $ 766.2 $ 750.4 $ 666.5 Service Charges and Fees 73.6 40.5 39.7 Mortgage Banking Revenue 89.7 94.6 92.6 Gains on Securities Sales and FV Adj., Net 10.9 16.8 9.6 Other 40.5 35.9 30.0 Non-Interest Income $ 214.7 $ 187.8 $ 171.9 Net Revenue $ 980.9 $ 938.2 $ 838.4 Salaries and Employee Benefits (201.7) (193.5) (165.4) Deposit Costs (171.2) (175.1) (174.5) Insurance (17.7) (24.5) (36.7) Other (161.6) (151.3) (142.4) Non-Interest Expense $ (552.2) $ (544.4) $ (519.0) Pre-Provision Net Revenue2 $ 428.7 $ 393.8 $ 319.4 Provision for Credit Losses (73.0) (80.0) (60.0) Pre-Tax Income $ 355.7 $ 313.8 $ 259.4 Income Tax (62.5) (53.3) (42.5) Net Income $ 293.2 $ 260.5 $ 216.9 Net Income Available to Common Stockholders $ 282.9 $ 250.2 $ 213.7 Diluted Shares 109.3 109.8 109.6 Earnings Per Share $ 2.59 $ 2.28 $ 1.95 Net Interest Income increased $15.8 million, or 8.4% annualized, over the prior quarter primarily due to significant average earning asset growth of $2.5 billion from organic growth Non-Interest Income increased $26.9 million from Q3 primarily driven by stronger commercial banking fees, offsetting lower net loan servicing revenue from higher prepayments Mortgage Banking Metrics • $14.8 billion mortgage loan production in Q4 (69% purchase / 31% refinance), down 2% compared to Q3 and up 12% to Q4-24 • $15.4 billion interest rate lock commitment volume in Q4, up 2% compared to Q3 and up 21% to Q4-24 • Gain on Sale margin3 of 30 bps in Q4, compared to 27 bps in Q3 and 21 bps in Q4-24 • $77.5 billion in servicing portfolio UPB at end of Q4 Non-Interest Expense increased $7.8 million from Q3 primarily driven by the following: • Salaries and Employee Benefits rose $8.2 million for higher bonus accrual from financial outperformance Completed $57.5 million in repurchases, or 0.7 million shares, at an average price of $79.55 1) Interest income includes a reduction for earnings credits totaling $56.6 million, $64.9 million, and $61.4 million for the three months ended December 31, 2025, September 30, 2025, and December 31, 2024 respectively. 2) Refer to slide 2 for further discussion of non-GAAP financial measures. 3) Gain on Sale margin represents spread as of the interest rate lock commitment date. Quarterly Income Statement Q4 2025 Highlights 1 2 3 1 2 4 Dollars in millions, except EPS 3 4
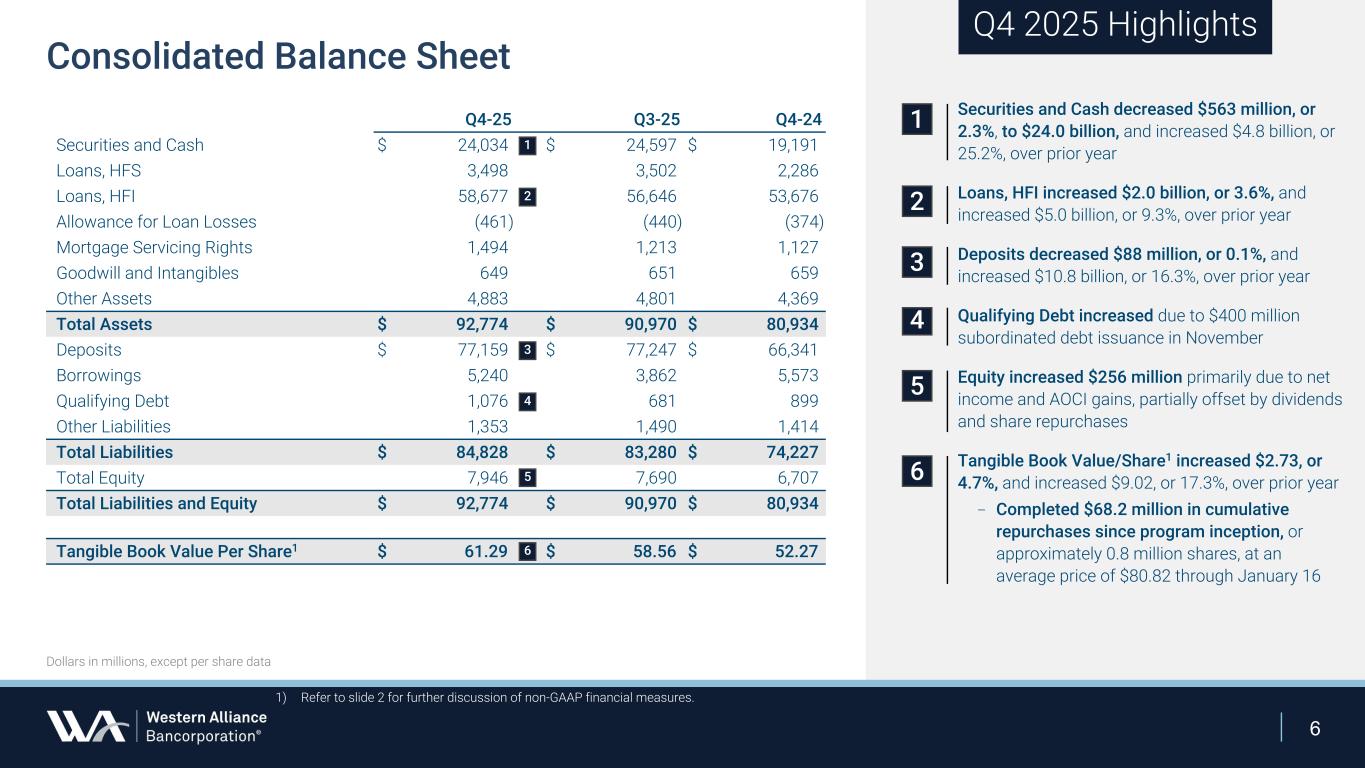
6 Q4-25 Q3-25 Q4-24 Securities and Cash $ 24,034 $ 24,597 $ 19,191 Loans, HFS 3,498 3,502 2,286 Loans, HFI 58,677 56,646 53,676 Allowance for Loan Losses (461) (440) (374) Mortgage Servicing Rights 1,494 1,213 1,127 Goodwill and Intangibles 649 651 659 Other Assets 4,883 4,801 4,369 Total Assets $ 92,774 $ 90,970 $ 80,934 Deposits $ 77,159 $ 77,247 $ 66,341 Borrowings 5,240 3,862 5,573 Qualifying Debt 1,076 681 899 Other Liabilities 1,353 1,490 1,414 Total Liabilities $ 84,828 $ 83,280 $ 74,227 Total Equity 7,946 7,690 6,707 Total Liabilities and Equity $ 92,774 $ 90,970 $ 80,934 Tangible Book Value Per Share1 $ 61.29 $ 58.56 $ 52.27 Dollars in millions, except per share data Consolidated Balance Sheet Q4 2025 Highlights 1 2 3 4 Securities and Cash decreased $563 million, or 2.3%, to $24.0 billion, and increased $4.8 billion, or 25.2%, over prior year Loans, HFI increased $2.0 billion, or 3.6%, and increased $5.0 billion, or 9.3%, over prior year Deposits decreased $88 million, or 0.1%, and increased $10.8 billion, or 16.3%, over prior year Qualifying Debt increased due to $400 million subordinated debt issuance in November Equity increased $256 million primarily due to net income and AOCI gains, partially offset by dividends and share repurchases Tangible Book Value/Share1 increased $2.73, or 4.7%, and increased $9.02, or 17.3%, over prior year – Completed $68.2 million in cumulative repurchases since program inception, or approximately 0.8 million shares, at an average price of $80.82 through January 16 1) Refer to slide 2 for further discussion of non-GAAP financial measures. 5 1 2 3 5 6 4 6
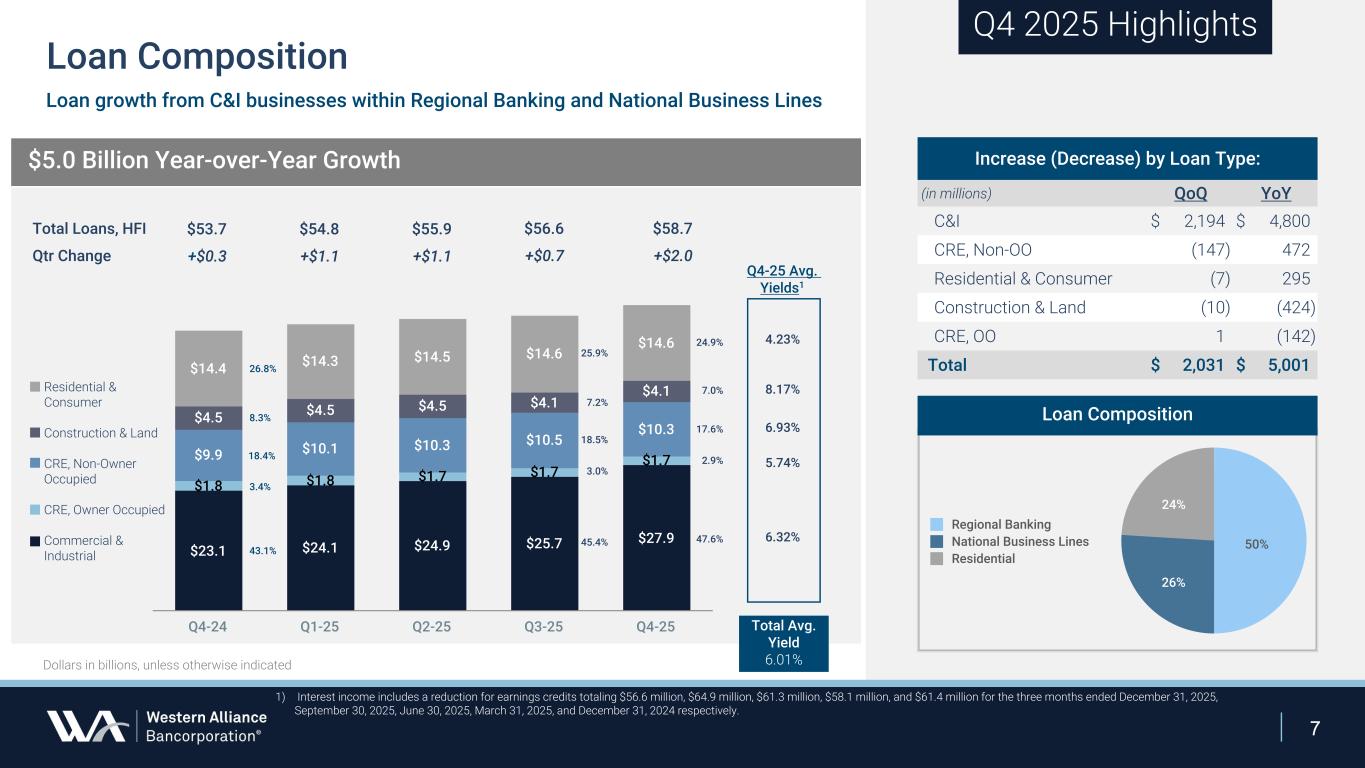
7 $5.0 Billion Year-over-Year Growth $23.1 $24.1 $24.9 $25.7 $27.9 $1.8 $1.8 $1.7 $1.7 $1.7$9.9 $10.1 $10.3 $10.5 $10.3 $4.5 $4.5 $4.5 $4.1 $4.1 $14.4 $14.3 $14.5 $14.6 $14.6 Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 26.8% 3.4% 18.4% 43.1% 8.3% 24.9% 2.9% 17.6% 47.6% 7.0% Residential & Consumer Construction & Land CRE, Non-Owner Occupied CRE, Owner Occupied Commercial & Industrial $53.7 +$0.3 $54.8 +$1.1 $55.9 +$1.1 $56.6 +$0.7 $58.7 +$2.0 Dollars in billions, unless otherwise indicated Total Loans, HFI Qtr Change Loan Composition Q4 2025 Highlights Increase (Decrease) by Loan Type: (in millions) QoQ YoY C&I $ 2,194 $ 4,800 CRE, Non-OO (147) 472 Residential & Consumer (7) 295 Construction & Land (10) (424) CRE, OO 1 (142) Total $ 2,031 $ 5,001 25.9% 3.0% 18.5% 45.4% 7.2% 4.23% 5.74% 6.93% 6.32% 8.17% Q4-25 Avg. Yields1 Total Avg. Yield 6.01% 1) Interest income includes a reduction for earnings credits totaling $56.6 million, $64.9 million, $61.3 million, $58.1 million, and $61.4 million for the three months ended December 31, 2025, September 30, 2025, June 30, 2025, March 31, 2025, and December 31, 2024 respectively. Loan growth from C&I businesses within Regional Banking and National Business Lines 50% 26% 24% Regional Banking National Business Lines Residential Loan Composition
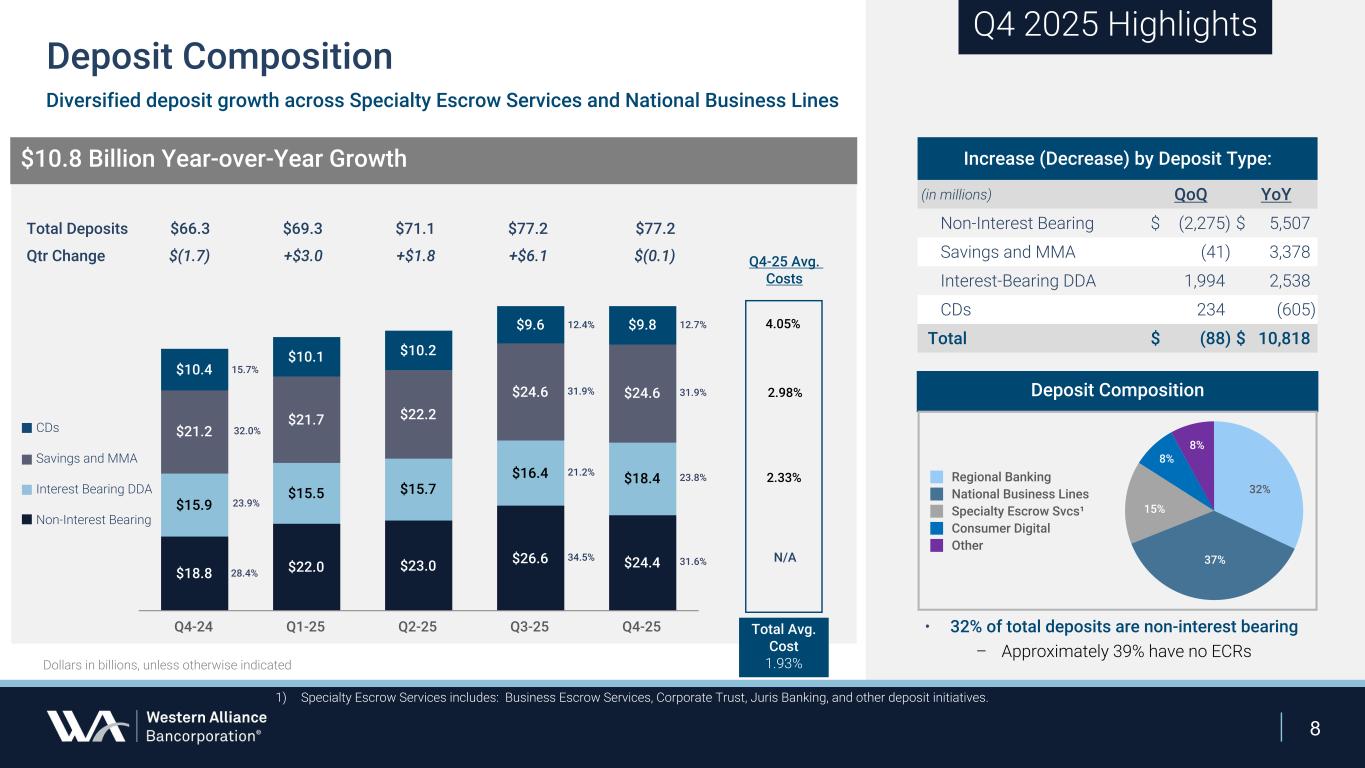
8 Diversified deposit growth across Specialty Escrow Services and National Business Lines Q4 2025 Highlights $18.8 $22.0 $23.0 $26.6 $24.4 $15.9 $15.5 $15.7 $16.4 $18.4 $21.2 $21.7 $22.2 $24.6 $24.6 $10.4 $10.1 $10.2 $9.6 $9.8 Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 23.9% 15.7% 28.4% 32.0% 23.8% 12.7% 31.6% 31.9% $10.8 Billion Year-over-Year Growth CDs Savings and MMA Interest Bearing DDA Non-Interest Bearing $69.3 +$3.0 $66.3 $(1.7) $77.2 +$6.1 $77.2 $(0.1) Increase (Decrease) by Deposit Type: (in millions) QoQ YoY Non-Interest Bearing $ (2,275) $ 5,507 Savings and MMA (41) 3,378 Interest-Bearing DDA 1,994 2,538 CDs 234 (605) Total $ (88) $ 10,818 $71.1 +$1.8 Total Deposits Qtr Change Deposit Composition Q4-25 Avg. Costs Total Avg. Cost 1.93%Dollars in billions, unless otherwise indicated 4.05% 2.33% N/A 2.98% 21.2% 12.4% 34.5% 31.9% Deposit Composition • 32% of total deposits are non-interest bearing – Approximately 39% have no ECRs 32% 37% 15% 8% 8% Regional Banking National Business Lines Specialty Escrow Svcs¹ Consumer Digital Other 1) Specialty Escrow Services includes: Business Escrow Services, Corporate Trust, Juris Banking, and other deposit initiatives.
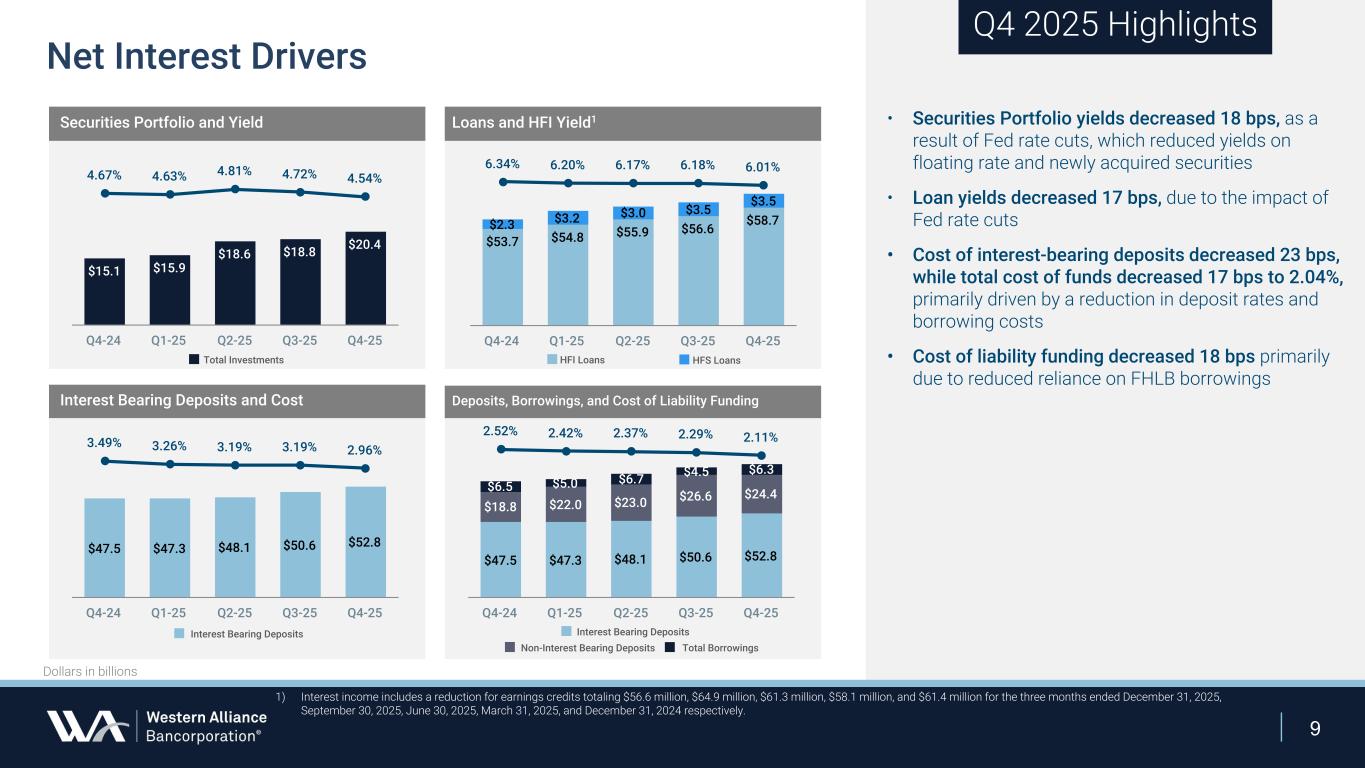
9 • Securities Portfolio yields decreased 18 bps, as a result of Fed rate cuts, which reduced yields on floating rate and newly acquired securities • Loan yields decreased 17 bps, due to the impact of Fed rate cuts • Cost of interest-bearing deposits decreased 23 bps, while total cost of funds decreased 17 bps to 2.04%, primarily driven by a reduction in deposit rates and borrowing costs • Cost of liability funding decreased 18 bps primarily due to reduced reliance on FHLB borrowings Interest Bearing Deposits and Cost Loans and HFI Yield1 Deposits, Borrowings, and Cost of Liability Funding Securities Portfolio and Yield $15.1 $15.9 $18.6 $18.8 $20.4 4.67% 4.63% 4.81% 4.72% 4.54% Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 $53.7 $54.8 $55.9 $56.6 $58.7$2.3 $3.2 $3.0 $3.5 $3.5 6.34% 6.20% 6.17% 6.18% 6.01% Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 $47.5 $47.3 $48.1 $50.6 $52.8 3.49% 3.26% 3.19% 3.19% 2.96% Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 $47.5 $47.3 $48.1 $50.6 $52.8 $18.8 $22.0 $23.0 $26.6 $24.4$6.5 $5.0 $6.7 $4.5 $6.3 2.52% 2.42% 2.37% 2.29% 2.11% Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 Non-Interest Bearing Deposits Total Borrowings Q4 2025 Highlights Net Interest Drivers Dollars in billions Interest Bearing DepositsInterest Bearing Deposits Total Investments HFI Loans HFS Loans 1) Interest income includes a reduction for earnings credits totaling $56.6 million, $64.9 million, $61.3 million, $58.1 million, and $61.4 million for the three months ended December 31, 2025, September 30, 2025, June 30, 2025, March 31, 2025, and December 31, 2024 respectively.
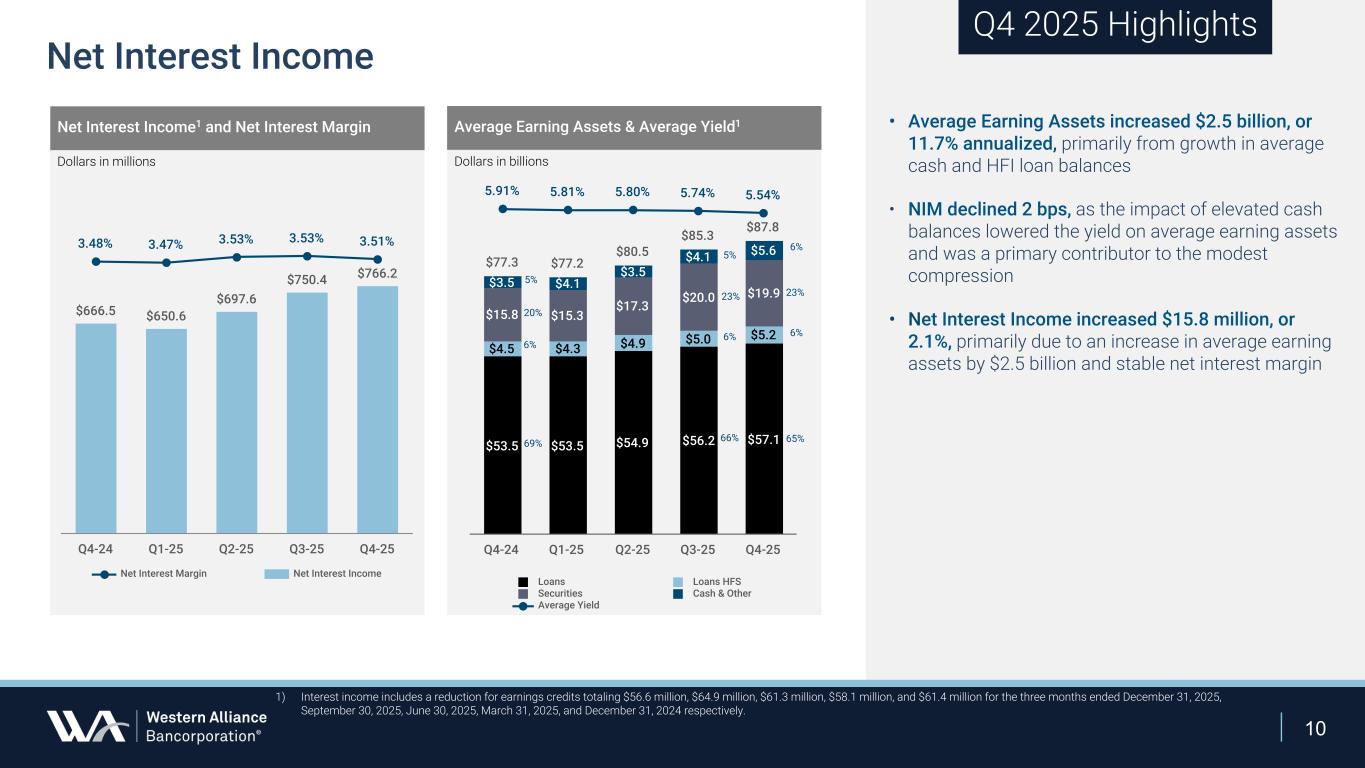
10 • Average Earning Assets increased $2.5 billion, or 11.7% annualized, primarily from growth in average cash and HFI loan balances • NIM declined 2 bps, as the impact of elevated cash balances lowered the yield on average earning assets and was a primary contributor to the modest compression • Net Interest Income increased $15.8 million, or 2.1%, primarily due to an increase in average earning assets by $2.5 billion and stable net interest margin Net Interest Income1 and Net Interest Margin $666.5 $650.6 $697.6 $750.4 $766.2 3.48% 3.47% 3.53% 3.53% 3.51% Net Interest Margin Net Interest Income Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 $77.3 $77.2 $80.5 $85.3 $87.8 $53.5 $53.5 $54.9 $56.2 $57.1 $4.5 $4.3 $4.9 $5.0 $5.2 $15.8 $15.3 $17.3 $20.0 $19.9 $3.5 $4.1 $3.5 $4.1 $5.6 5.91% 5.81% 5.80% 5.74% 5.54% Loans Loans HFS Securities Cash & Other Average Yield Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 Average Earning Assets & Average Yield1 Dollars in millions Dollars in billions Net Interest Income Q4 2025 Highlights 5% 20% 6% 5% 23% 6% 6% 23% 6% 69% 66% 65% 1) Interest income includes a reduction for earnings credits totaling $56.6 million, $64.9 million, $61.3 million, $58.1 million, and $61.4 million for the three months ended December 31, 2025, September 30, 2025, June 30, 2025, March 31, 2025, and December 31, 2024 respectively.
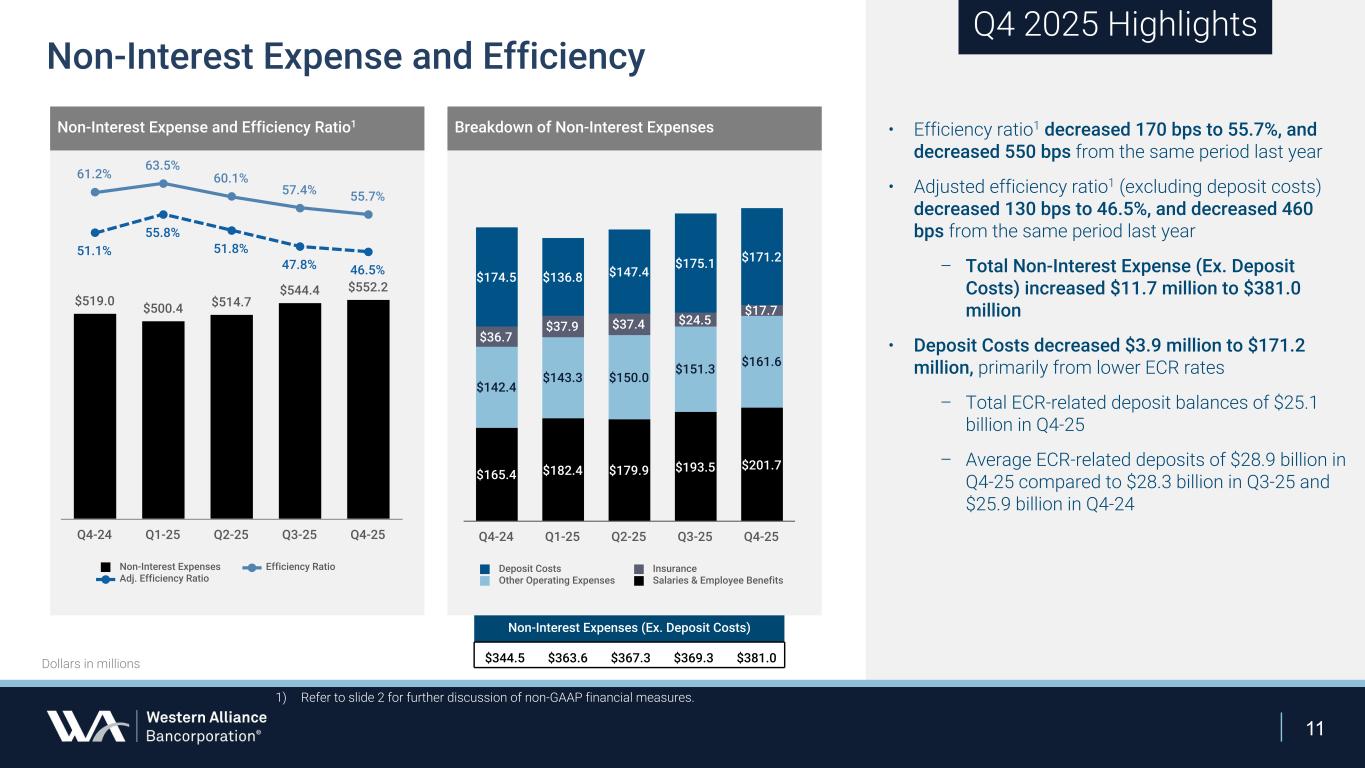
11 • Efficiency ratio1 decreased 170 bps to 55.7%, and decreased 550 bps from the same period last year • Adjusted efficiency ratio1 (excluding deposit costs) decreased 130 bps to 46.5%, and decreased 460 bps from the same period last year – Total Non-Interest Expense (Ex. Deposit Costs) increased $11.7 million to $381.0 million • Deposit Costs decreased $3.9 million to $171.2 million, primarily from lower ECR rates – Total ECR-related deposit balances of $25.1 billion in Q4-25 – Average ECR-related deposits of $28.9 billion in Q4-25 compared to $28.3 billion in Q3-25 and $25.9 billion in Q4-24 $519.0 $500.4 $514.7 $544.4 $552.2 61.2% 63.5% 60.1% 57.4% 55.7% 51.1% 55.8% 51.8% 47.8% 46.5% Non-Interest Expenses Efficiency Ratio Adj. Efficiency Ratio Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 Dollars in millions Non-Interest Expense and Efficiency $165.4 $182.4 $179.9 $193.5 $201.7 $142.4 $143.3 $150.0 $151.3 $161.6 $36.7 $37.9 $37.4 $24.5 $17.7 $174.5 $136.8 $147.4 $175.1 $171.2 Deposit Costs Insurance Other Operating Expenses Salaries & Employee Benefits Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 Q4 2025 Highlights Non-Interest Expense and Efficiency Ratio1 1) Refer to slide 2 for further discussion of non-GAAP financial measures. Breakdown of Non-Interest Expenses Non-Interest Expenses (Ex. Deposit Costs) $344.5 $363.6 $367.3 $369.3 $381.0
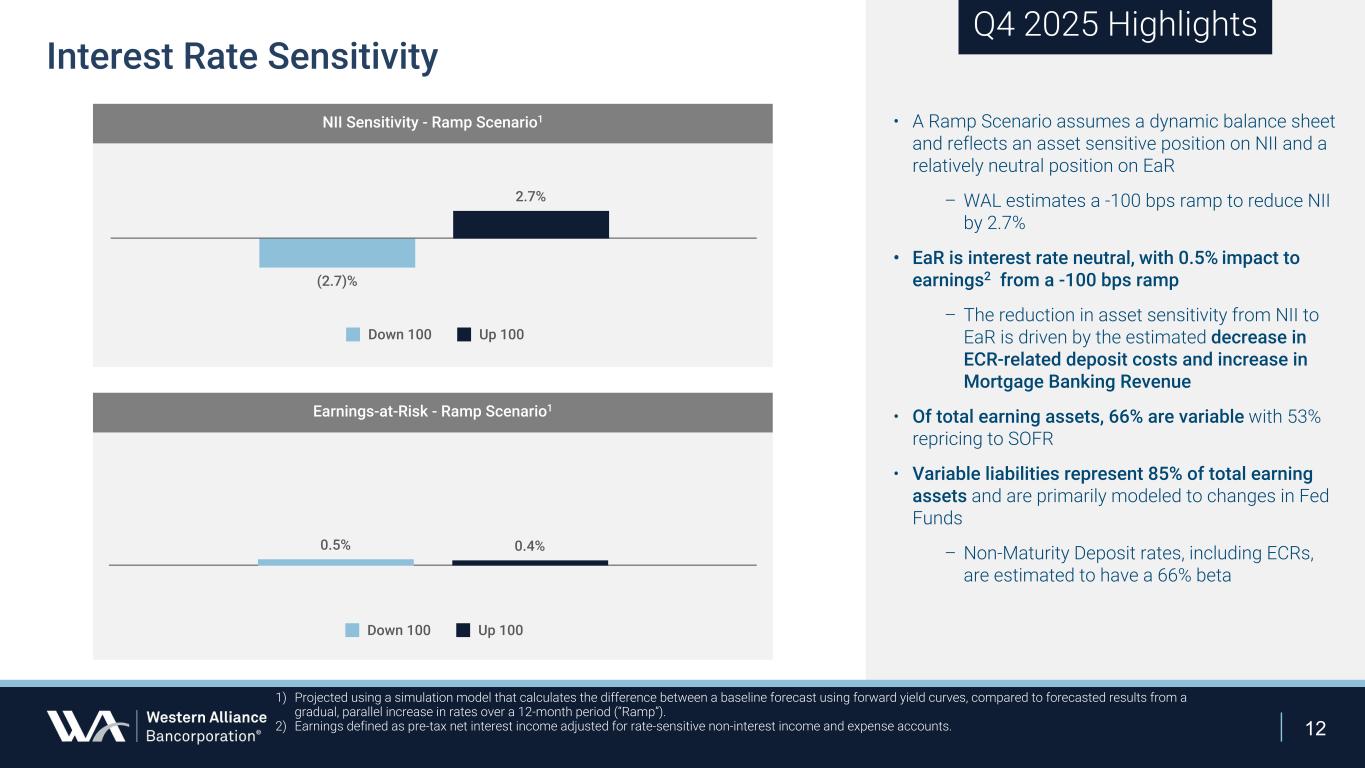
12 Interest Rate Sensitivity Q4 2025 Highlights • A Ramp Scenario assumes a dynamic balance sheet and reflects an asset sensitive position on NII and a relatively neutral position on EaR – WAL estimates a -100 bps ramp to reduce NII by 2.7% • EaR is interest rate neutral, with 0.5% impact to earnings2 from a -100 bps ramp – The reduction in asset sensitivity from NII to EaR is driven by the estimated decrease in ECR-related deposit costs and increase in Mortgage Banking Revenue • Of total earning assets, 66% are variable with 53% repricing to SOFR • Variable liabilities represent 85% of total earning assets and are primarily modeled to changes in Fed Funds – Non-Maturity Deposit rates, including ECRs, are estimated to have a 66% beta (2.7)% 2.7% Down 100 Up 100 0.5% 0.4% Down 100 Up 100 1) Projected using a simulation model that calculates the difference between a baseline forecast using forward yield curves, compared to forecasted results from a gradual, parallel increase in rates over a 12-month period (“Ramp”). 2) Earnings defined as pre-tax net interest income adjusted for rate-sensitive non-interest income and expense accounts. NII Sensitivity - Ramp Scenario1 Earnings-at-Risk - Ramp Scenario1
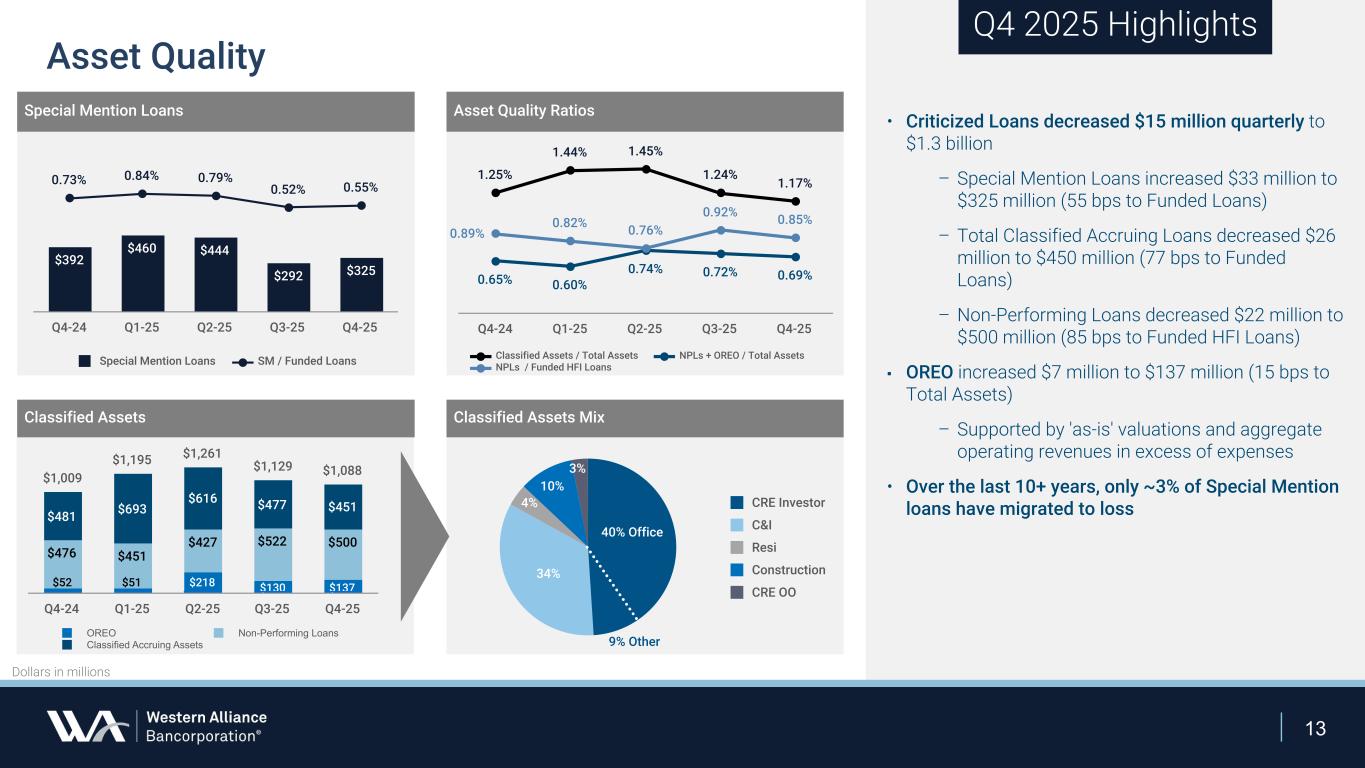
13 1.25% 1.44% 1.45% 1.24% 1.17% 0.65% 0.60% 0.74% 0.72% 0.69% 0.89% 0.82% 0.76% 0.92% 0.85% Classified Assets / Total Assets NPLs + OREO / Total Assets NPLs / Funded HFI Loans Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 $1,009 $1,195 $1,261 $1,129 $1,088 $52 $51 $218 $130 $137 $476 $451 $427 $522 $500 $481 $693 $616 $477 $451 OREO Non-Performing Loans Classified Accruing Assets Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 Dollars in millions Asset Quality RatiosSpecial Mention Loans • Criticized Loans decreased $15 million quarterly to $1.3 billion – Special Mention Loans increased $33 million to $325 million (55 bps to Funded Loans) – Total Classified Accruing Loans decreased $26 million to $450 million (77 bps to Funded Loans) – Non-Performing Loans decreased $22 million to $500 million (85 bps to Funded HFI Loans) ▪ OREO increased $7 million to $137 million (15 bps to Total Assets) – Supported by 'as-is' valuations and aggregate operating revenues in excess of expenses • Over the last 10+ years, only ~3% of Special Mention loans have migrated to loss Classified Assets $392 $460 $444 $292 $325 0.73% 0.84% 0.79% 0.52% 0.55% Special Mention Loans SM / Funded Loans Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 Q4 2025 Highlights Classified Assets Mix 34% 4% 10% 3% CRE Investor C&I Resi Construction CRE OO 9% Other 40% Office Asset Quality
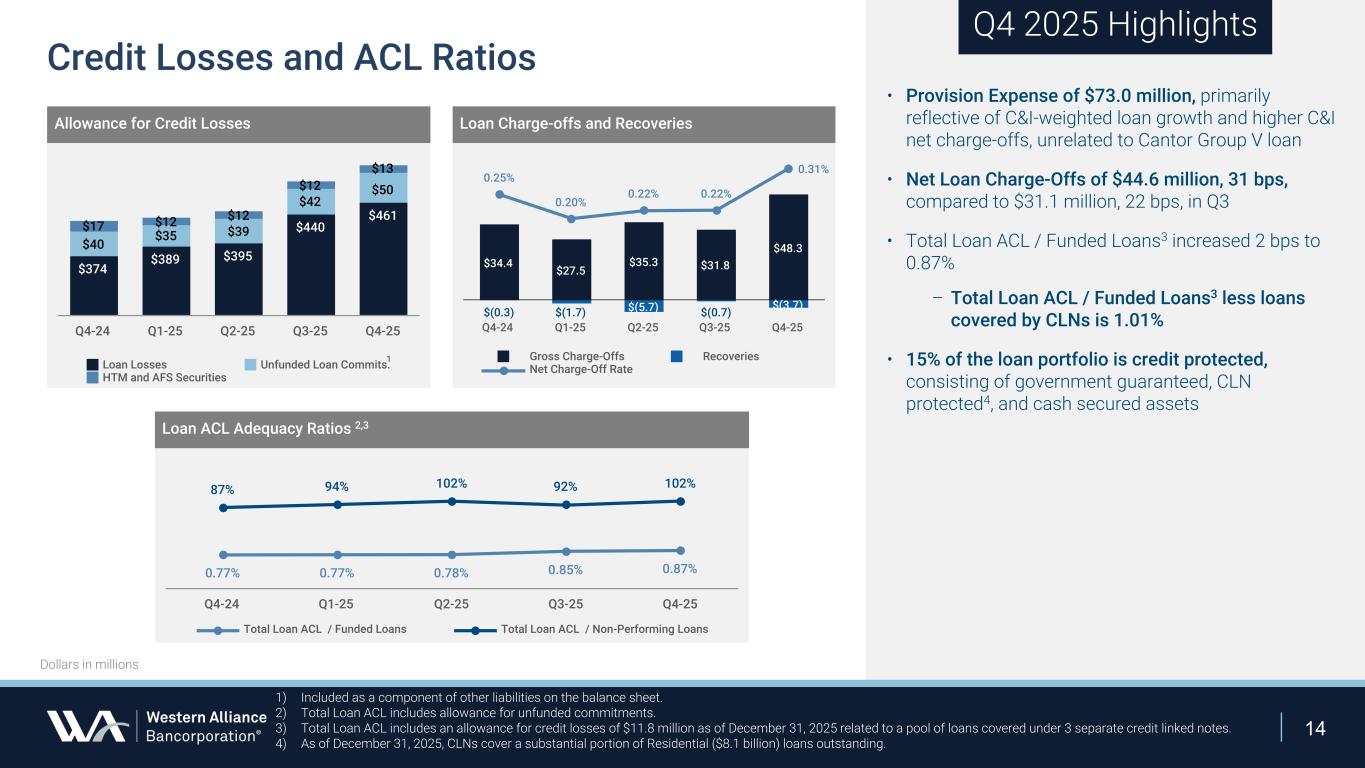
14 $34.4 $27.5 $35.3 $31.8 $48.3 $(0.3) $(1.7) $(5.7) $(0.7) $(3.7) 0.25% 0.20% 0.22% 0.22% 0.31% Gross Charge-Offs Recoveries Net Charge-Off Rate Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 $374 $389 $395 $440 $461 $40 $35 $39 $42 $50 $17 $12 $12 $12 $13 Loan Losses Unfunded Loan Commits. HTM and AFS Securities Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 0.77% 0.77% 0.78% 0.85% 0.87% 87% 94% 102% 92% 102% Total Loan ACL / Funded Loans Total Loan ACL / Non-Performing Loans Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 Dollars in millions • Provision Expense of $73.0 million, primarily reflective of C&I-weighted loan growth and higher C&I net charge-offs, unrelated to Cantor Group V loan • Net Loan Charge-Offs of $44.6 million, 31 bps, compared to $31.1 million, 22 bps, in Q3 • Total Loan ACL / Funded Loans3 increased 2 bps to 0.87% – Total Loan ACL / Funded Loans3 less loans covered by CLNs is 1.01% • 15% of the loan portfolio is credit protected, consisting of government guaranteed, CLN protected4, and cash secured assets Credit Losses and ACL Ratios Q4 2025 Highlights Loan Charge-offs and RecoveriesAllowance for Credit Losses Loan ACL Adequacy Ratios 2,3 1) Included as a component of other liabilities on the balance sheet. 2) Total Loan ACL includes allowance for unfunded commitments. 3) Total Loan ACL includes an allowance for credit losses of $11.8 million as of December 31, 2025 related to a pool of loans covered under 3 separate credit linked notes. 4) As of December 31, 2025, CLNs cover a substantial portion of Residential ($8.1 billion) loans outstanding. 1
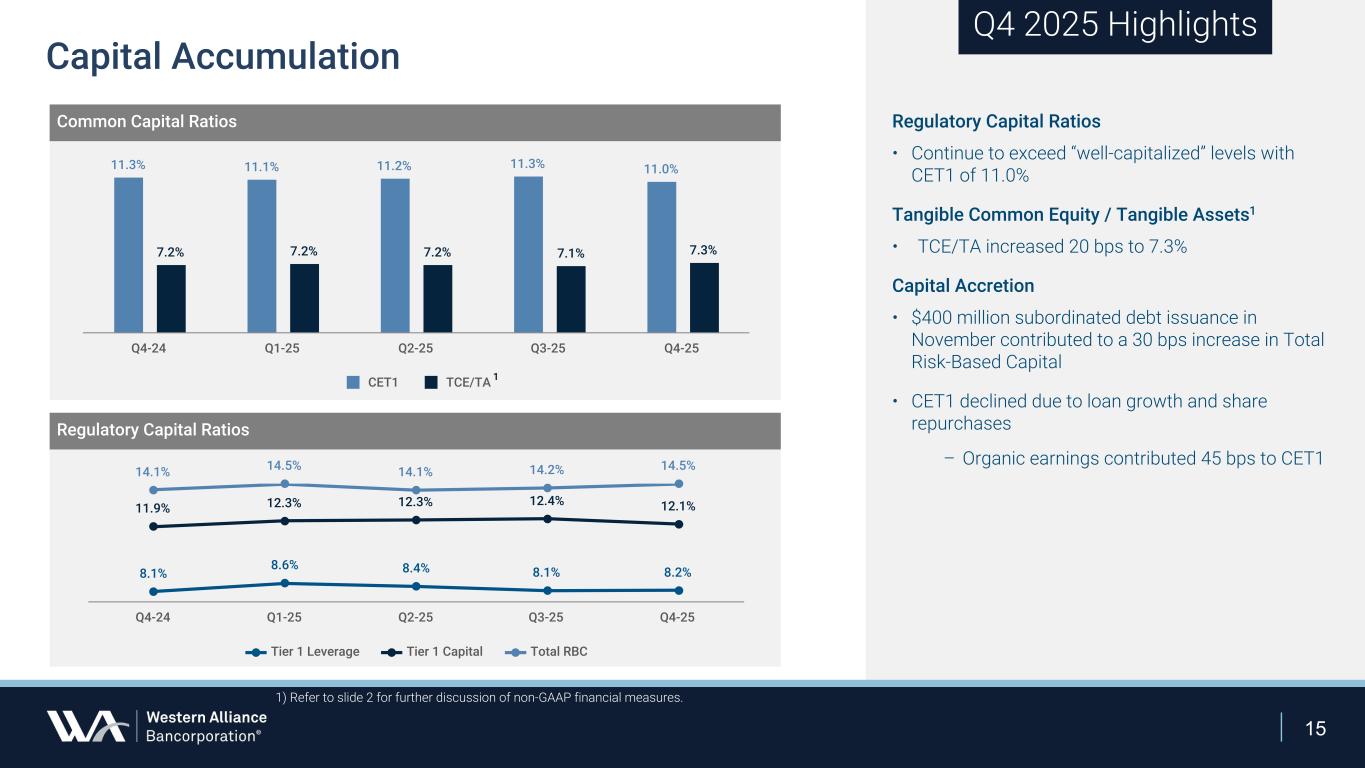
15 Regulatory Capital Ratios • Continue to exceed “well-capitalized” levels with CET1 of 11.0% Tangible Common Equity / Tangible Assets1 • TCE/TA increased 20 bps to 7.3% Capital Accretion • $400 million subordinated debt issuance in November contributed to a 30 bps increase in Total Risk-Based Capital • CET1 declined due to loan growth and share repurchases – Organic earnings contributed 45 bps to CET1 11.3% 11.1% 11.2% 11.3% 11.0% 7.2% 7.2% 7.2% 7.1% 7.3% CET1 TCE/TA Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 1) Refer to slide 2 for further discussion of non-GAAP financial measures. 14.1% 14.5% 14.1% 14.2% 14.5% 11.9% 12.3% 12.3% 12.4% 12.1% 8.1% 8.6% 8.4% 8.1% 8.2% Tier 1 Leverage Tier 1 Capital Total RBC Q4-24 Q1-25 Q2-25 Q3-25 Q4-25 Q4 2025 Highlights Common Capital Ratios Capital Accumulation Regulatory Capital Ratios 1
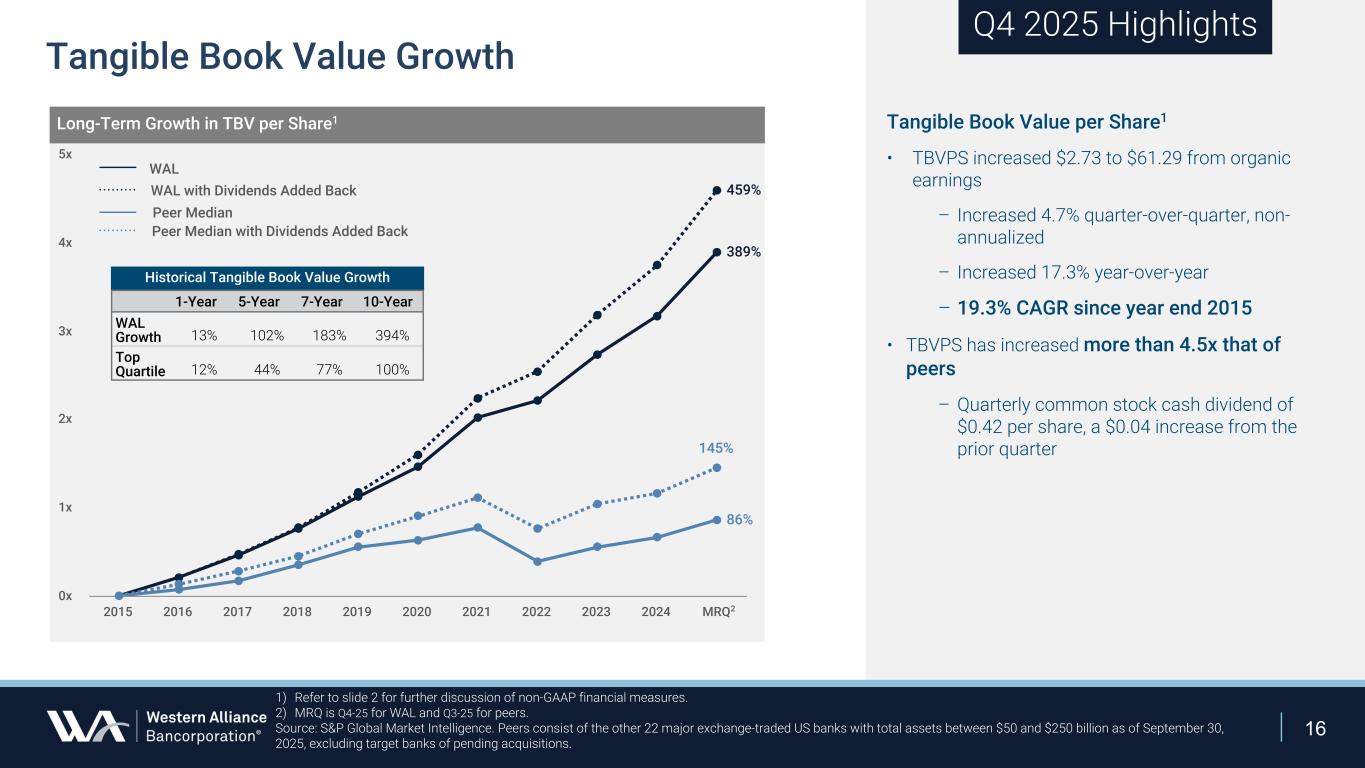
16 389% 459% 86% 145% 2015 2016 2017 2018 2019 2020 2021 2022 2023 2024 MRQ 0x 1x 2x 3x 4x 5x Tangible Book Value per Share1 • TBVPS increased $2.73 to $61.29 from organic earnings – Increased 4.7% quarter-over-quarter, non- annualized – Increased 17.3% year-over-year – 19.3% CAGR since year end 2015 • TBVPS has increased more than 4.5x that of peers – Quarterly common stock cash dividend of $0.42 per share, a $0.04 increase from the prior quarter 1) Refer to slide 2 for further discussion of non-GAAP financial measures. 2) MRQ is Q4-25 for WAL and Q3-25 for peers. Source: S&P Global Market Intelligence. Peers consist of the other 22 major exchange-traded US banks with total assets between $50 and $250 billion as of September 30, 2025, excluding target banks of pending acquisitions. Q4 2025 Highlights Tangible Book Value Growth Long-Term Growth in TBV per Share1 WAL Peer Median with Dividends Added Back Peer Median WAL with Dividends Added Back 2 Historical Tangible Book Value Growth 1-Year 5-Year 7-Year 10-Year WAL Growth 13% 102% 183% 394% Top Quartile 12% 44% 77% 100%
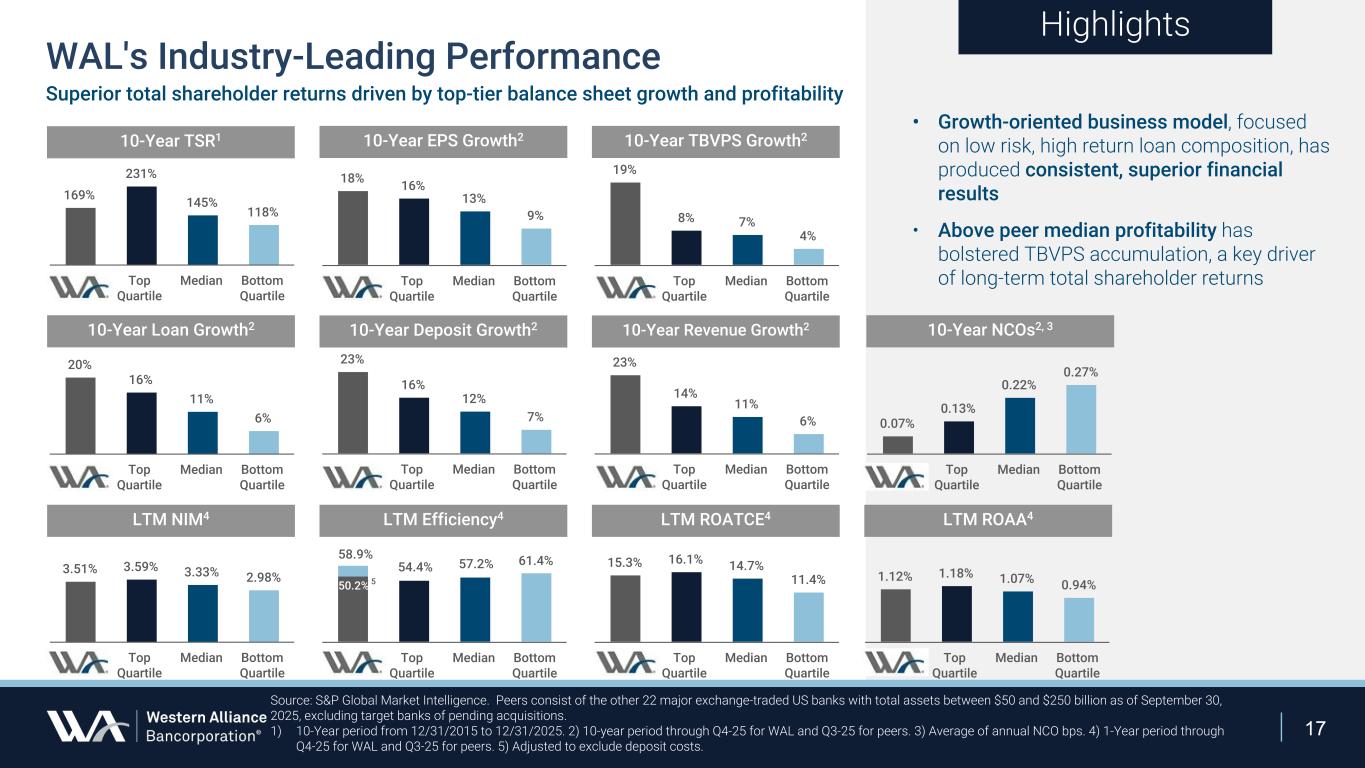
17 • Growth-oriented business model, focused on low risk, high return loan composition, has produced consistent, superior financial results • Above peer median profitability has bolstered TBVPS accumulation, a key driver of long-term total shareholder returns Highlights Source: S&P Global Market Intelligence. Peers consist of the other 22 major exchange-traded US banks with total assets between $50 and $250 billion as of September 30, 2025, excluding target banks of pending acquisitions. 1) 10-Year period from 12/31/2015 to 12/31/2025. 2) 10-year period through Q4-25 for WAL and Q3-25 for peers. 3) Average of annual NCO bps. 4) 1-Year period through Q4-25 for WAL and Q3-25 for peers. 5) Adjusted to exclude deposit costs. WAL's Industry-Leading Performance Superior total shareholder returns driven by top-tier balance sheet growth and profitability 10-Year TSR1 10-Year EPS Growth2 10-Year TBVPS Growth2 169% 231% 145% 118% WAL Top Quartile Median Bottom Quartile 18% 16% 13% 9% WAL Top Quartile Median Bottom Quartile 19% 8% 7% 4% WAL Top Quartile Median Bottom Quartile 20% 16% 11% 6% WAL Top Quartile Median Bottom Quartile 23% 16% 12% 7% WAL Top Quartile Median Bottom Quartile 23% 14% 11% 6% WAL Top Quartile Median Bottom Quartile 15.3% 16.1% 14.7% 11.4% WAL Top Quartile Median Bottom Quartile WAL Top Quartile Median Bottom Quartile 3.51% 3.59% 3.33% 2.98% WAL Top Quartile Median Bottom Quartile 10-Year Loan Growth2 10-Year Deposit Growth2 10-Year Revenue Growth2 LTM NIM4 LTM Efficiency4 LTM ROATCE4 LTM ROAA4 1.12% 1.18% 1.07% 0.94% WAL Top Quartile Median Bottom Quartile 10-Year NCOs2, 3 0.07% 0.13% 0.22% 0.27% WAL Top Quartile Median Bottom Quartile 54.4% 57.2% 61.4%58.9% 50.2% 5
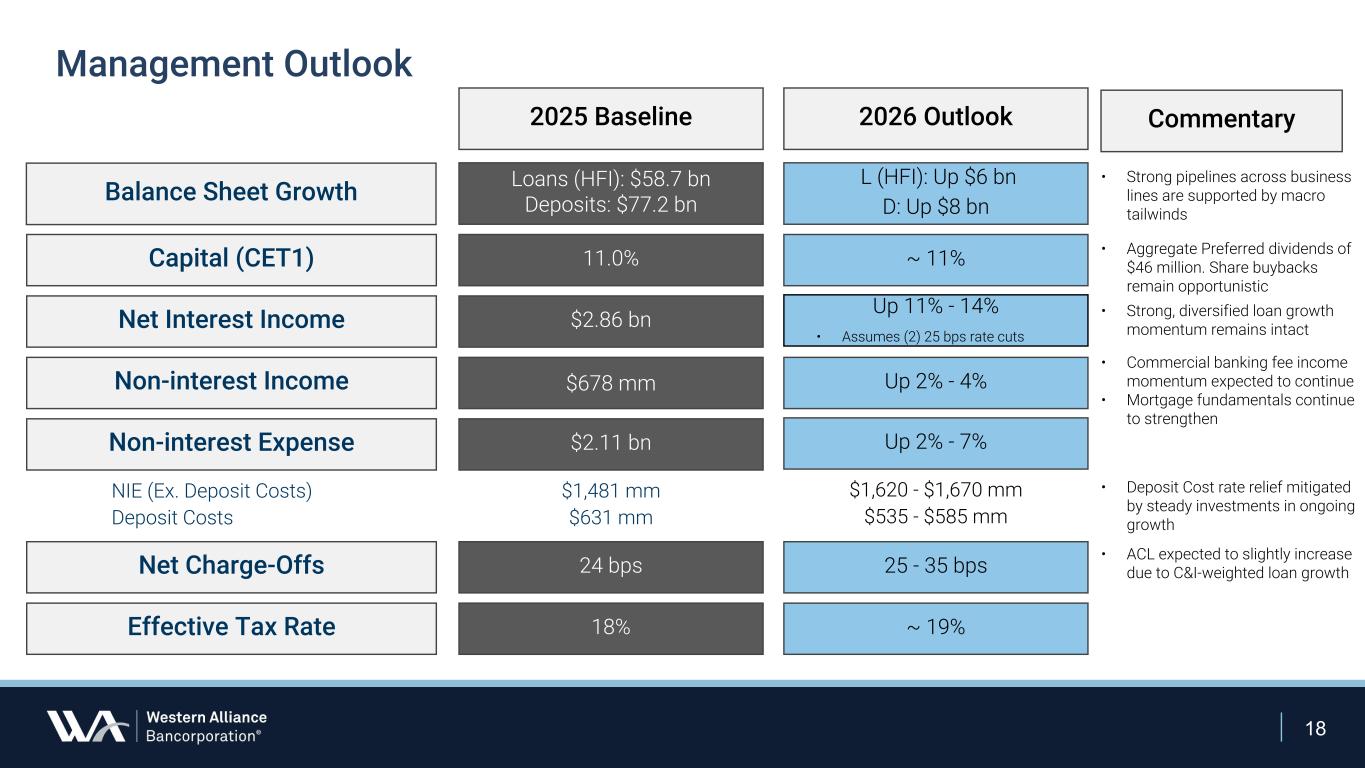
18 • Commercial banking fee income momentum expected to continue • Mortgage fundamentals continue to strengthen • ACL expected to slightly increase due to C&I-weighted loan growth • Strong pipelines across business lines are supported by macro tailwinds Balance Sheet Growth Capital (CET1) Net Interest Income Non-interest Income Non-interest Expense Net Charge-Offs Effective Tax Rate 2025 Baseline 2026 Outlook Loans (HFI): $58.7 bn Deposits: $77.2 bn L (HFI): Up $6 bn D: Up $8 bn 11.0% ~ 11% $2.86 bn Up 11% - 14% $678 mm Up 2% - 4% $2.11 bn 24 bps Up 2% - 7% 25 - 35 bps 18% ~ 19% NIE (Ex. Deposit Costs) Deposit Costs $1,620 - $1,670 mm $535 - $585 mm $1,481 mm $631 mm Management Outlook Commentary • Aggregate Preferred dividends of $46 million. Share buybacks remain opportunistic • Assumes (2) 25 bps rate cuts • Deposit Cost rate relief mitigated by steady investments in ongoing growth • Strong, diversified loan growth momentum remains intact
Questions & Answers
Appendix
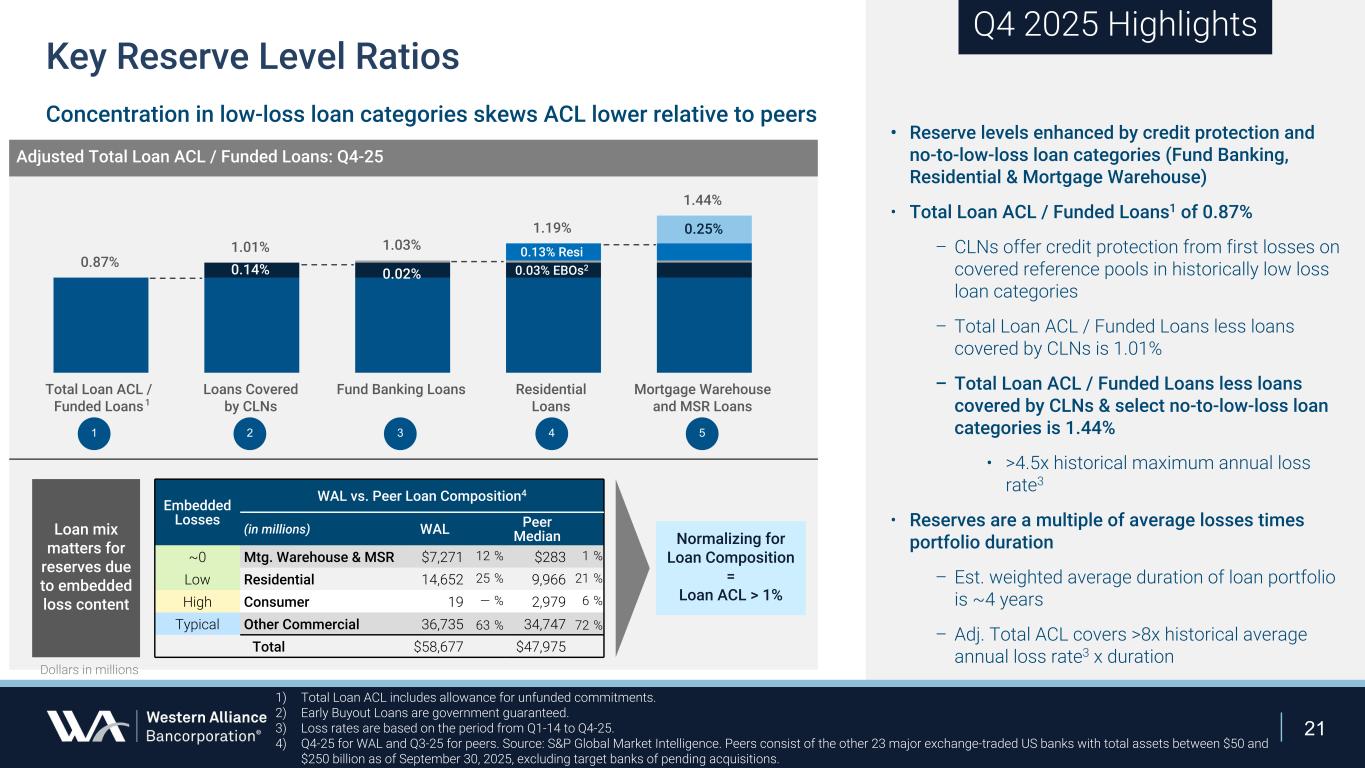
21 • Reserve levels enhanced by credit protection and no-to-low-loss loan categories (Fund Banking, Residential & Mortgage Warehouse) • Total Loan ACL / Funded Loans1 of 0.87% – CLNs offer credit protection from first losses on covered reference pools in historically low loss loan categories – Total Loan ACL / Funded Loans less loans covered by CLNs is 1.01% – Total Loan ACL / Funded Loans less loans covered by CLNs & select no-to-low-loss loan categories is 1.44% • >4.5x historical maximum annual loss rate3 • Reserves are a multiple of average losses times portfolio duration – Est. weighted average duration of loan portfolio is ~4 years – Adj. Total ACL covers >8x historical average annual loss rate3 x duration Q4 2025 Highlights Adjusted Total Loan ACL / Funded Loans: Q4-25 1) Total Loan ACL includes allowance for unfunded commitments. 2) Early Buyout Loans are government guaranteed. 3) Loss rates are based on the period from Q1-14 to Q4-25. 4) Q4-25 for WAL and Q3-25 for peers. Source: S&P Global Market Intelligence. Peers consist of the other 23 major exchange-traded US banks with total assets between $50 and $250 billion as of September 30, 2025, excluding target banks of pending acquisitions. Key Reserve Level Ratios Concentration in low-loss loan categories skews ACL lower relative to peers 0.87% 1.01% 1.03% 1.19% 1.44% 0.14% 0.02% 0.25% Total Loan ACL / Funded Loans Loans Covered by CLNs Fund Banking Loans Residential Loans Mortgage Warehouse and MSR Loans 1 2 3 4 5 0.13% Resi 1 Embedded Losses WAL vs. Peer Loan Composition4 (in millions) WAL Peer Median ~0 Mtg. Warehouse & MSR $7,271 12 % $283 1 % Low Residential 14,652 25 % 9,966 21 % High Consumer 19 — % 2,979 6 % Typical Other Commercial 36,735 63 % 34,747 72 % Total $58,677 $47,975 Loan mix matters for reserves due to embedded loss content Normalizing for Loan Composition = Loan ACL > 1% 0.03% EBOs2 Dollars in millions
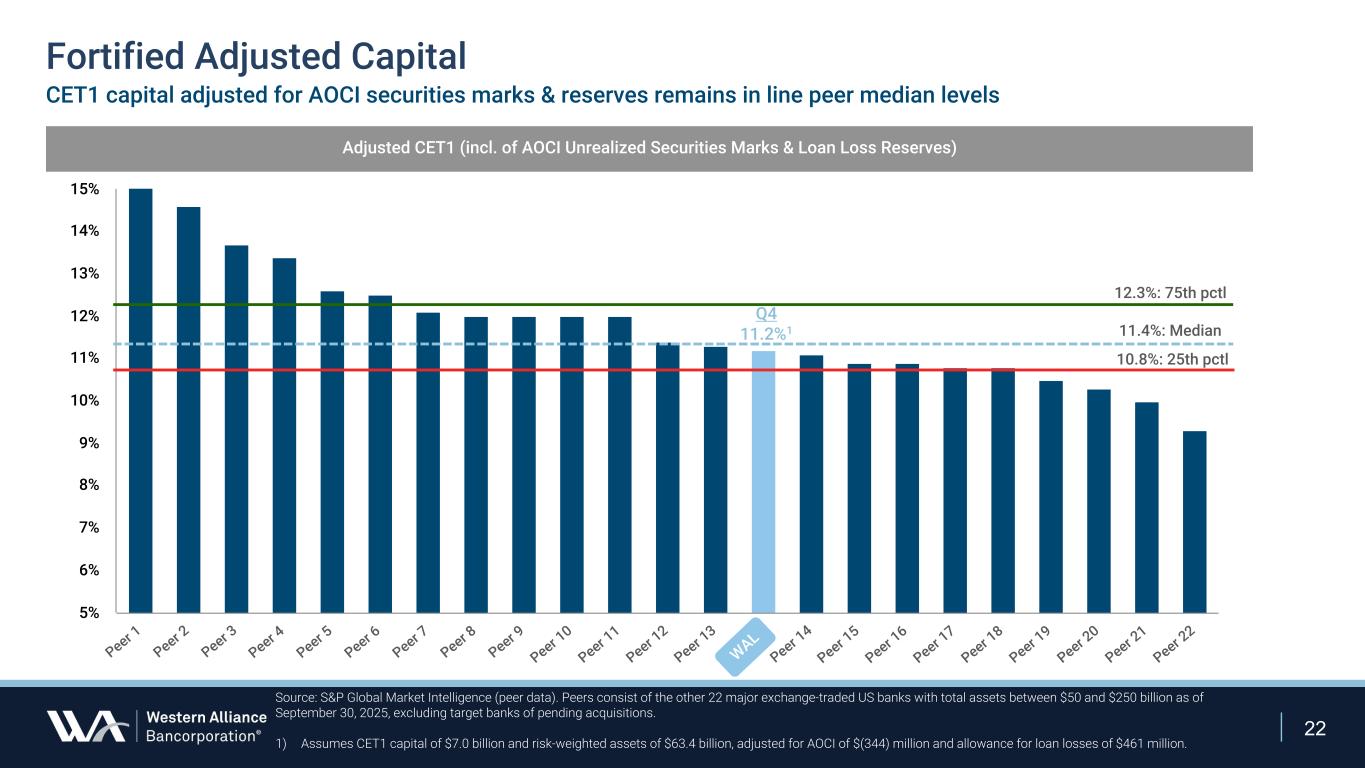
22 Peer 1 Peer 2 Peer 3 Peer 4 Peer 5 Peer 6 Peer 7 Peer 8 Peer 9 Peer 1 0 Peer 1 1 Peer 1 2 Peer 1 3 WAL Peer 1 4 Peer 1 5 Peer 1 6 Peer 1 7 Peer 1 8 Peer 1 9 Peer 2 0 Peer 2 1 Peer 2 2 5% 6% 7% 8% 9% 10% 11% 12% 13% 14% 15% Source: S&P Global Market Intelligence (peer data). Peers consist of the other 22 major exchange-traded US banks with total assets between $50 and $250 billion as of September 30, 2025, excluding target banks of pending acquisitions. 1) Assumes CET1 capital of $7.0 billion and risk-weighted assets of $63.4 billion, adjusted for AOCI of $(344) million and allowance for loan losses of $461 million. 11.4%: Median 12.3%: 75th pctl 10.8%: 25th pctl Adjusted CET1 (incl. of AOCI Unrealized Securities Marks & Loan Loss Reserves) Fortified Adjusted Capital CET1 capital adjusted for AOCI securities marks & reserves remains in line peer median levels Q4 11.2%1 WAL
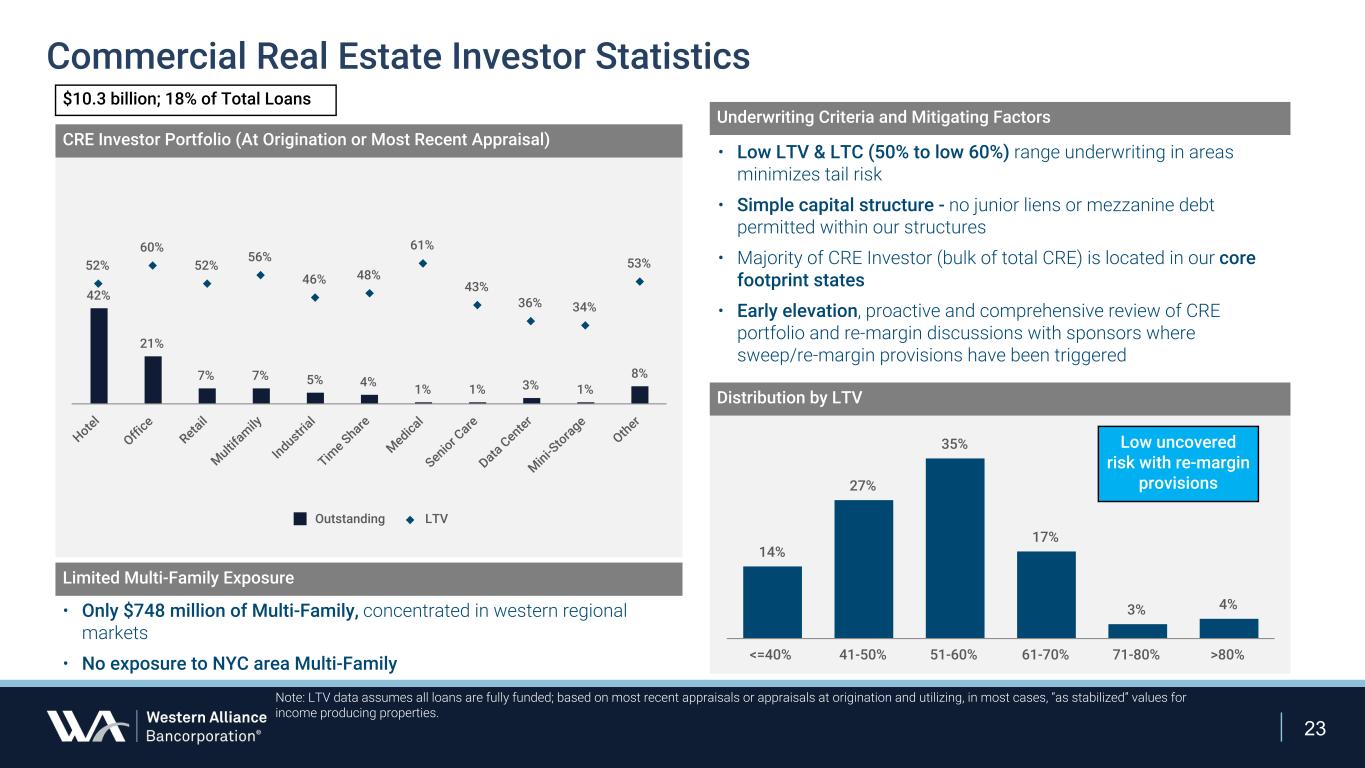
23 Commercial Real Estate Investor Statistics CRE Investor Portfolio (At Origination or Most Recent Appraisal) Note: LTV data assumes all loans are fully funded; based on most recent appraisals or appraisals at origination and utilizing, in most cases, “as stabilized” values for income producing properties. Underwriting Criteria and Mitigating Factors Distribution by LTV • Low LTV & LTC (50% to low 60%) range underwriting in areas minimizes tail risk • Simple capital structure - no junior liens or mezzanine debt permitted within our structures • Majority of CRE Investor (bulk of total CRE) is located in our core footprint states • Early elevation, proactive and comprehensive review of CRE portfolio and re-margin discussions with sponsors where sweep/re-margin provisions have been triggered 14% 27% 35% 17% 3% 4% <=40% 41-50% 51-60% 61-70% 71-80% >80% 42% 21% 7% 7% 5% 4% 1% 1% 3% 1% 8% 52% 60% 52% 56% 46% 48% 61% 43% 36% 34% 53% Outstanding LTV Hotel Offi ce Retail Multif amily Industr ial Tim e Share Medical Senior C are Data Center Mini-S torage Other Low uncovered risk with re-margin provisions • Only $748 million of Multi-Family, concentrated in western regional markets • No exposure to NYC area Multi-Family Limited Multi-Family Exposure $10.3 billion; 18% of Total Loans
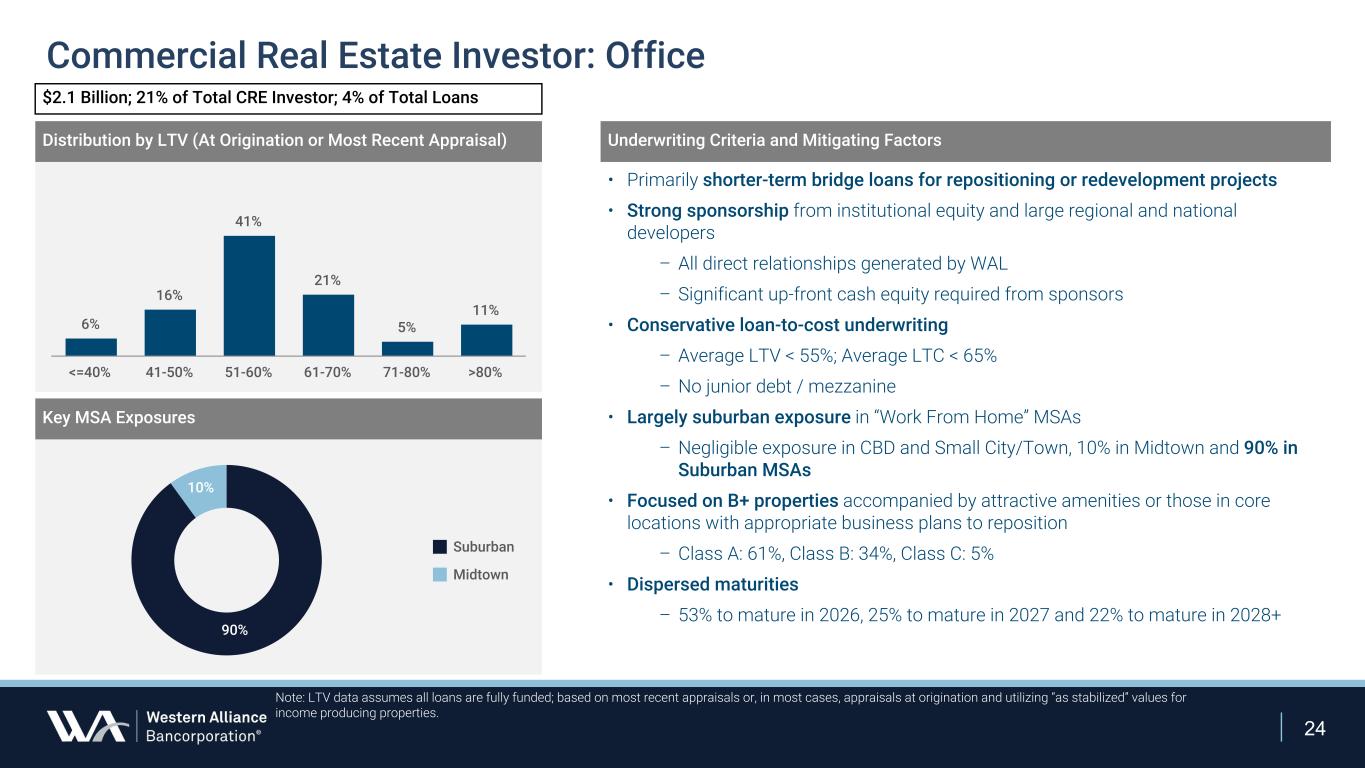
24 Commercial Real Estate Investor: Office Distribution by LTV (At Origination or Most Recent Appraisal) 6% 16% 41% 21% 5% 11% <=40% 41-50% 51-60% 61-70% 71-80% >80% Key MSA Exposures $2.1 Billion; 21% of Total CRE Investor; 4% of Total Loans Underwriting Criteria and Mitigating Factors • Primarily shorter-term bridge loans for repositioning or redevelopment projects • Strong sponsorship from institutional equity and large regional and national developers – All direct relationships generated by WAL – Significant up-front cash equity required from sponsors • Conservative loan-to-cost underwriting – Average LTV < 55%; Average LTC < 65% – No junior debt / mezzanine • Largely suburban exposure in “Work From Home” MSAs – Negligible exposure in CBD and Small City/Town, 10% in Midtown and 90% in Suburban MSAs • Focused on B+ properties accompanied by attractive amenities or those in core locations with appropriate business plans to reposition – Class A: 61%, Class B: 34%, Class C: 5% • Dispersed maturities – 53% to mature in 2026, 25% to mature in 2027 and 22% to mature in 2028+ 90% 10% Suburban Midtown Note: LTV data assumes all loans are fully funded; based on most recent appraisals or, in most cases, appraisals at origination and utilizing “as stabilized” values for income producing properties.
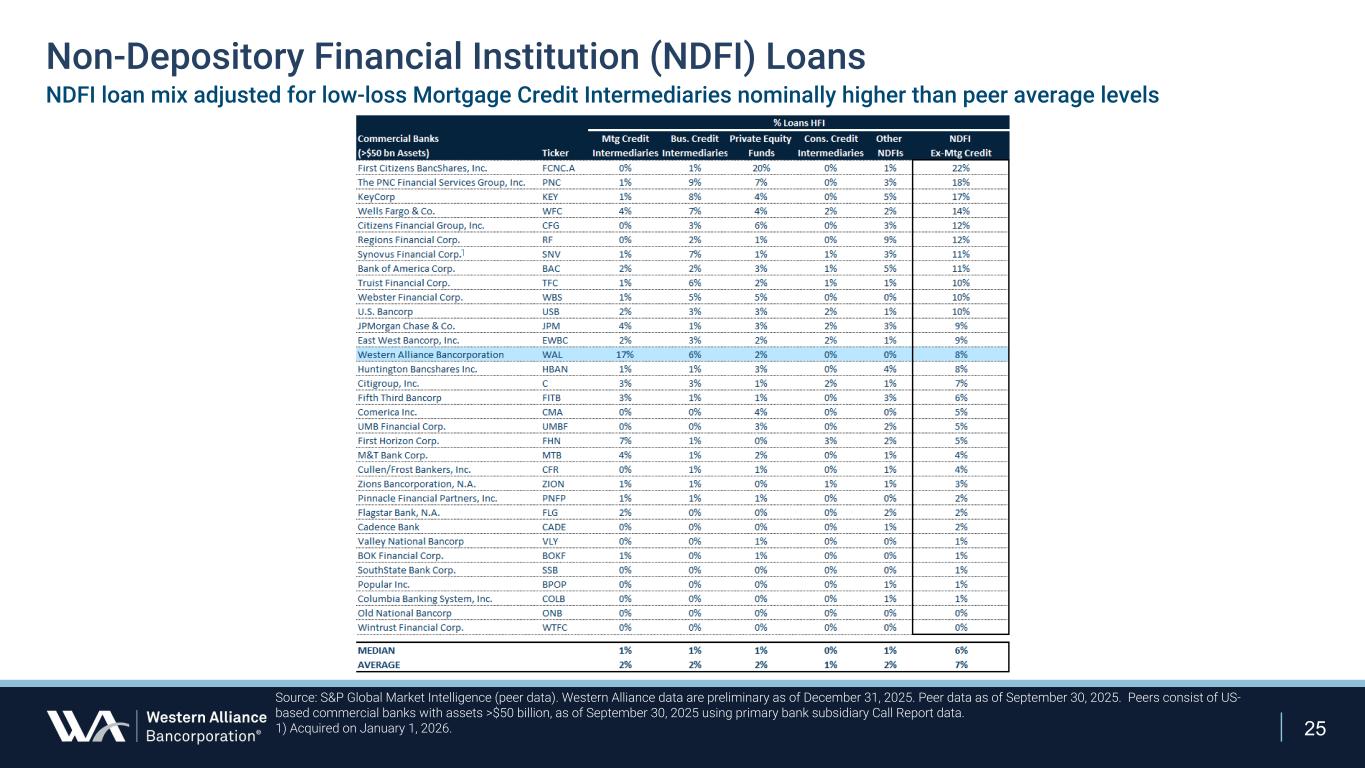
25 Source: S&P Global Market Intelligence (peer data). Western Alliance data are preliminary as of December 31, 2025. Peer data as of September 30, 2025. Peers consist of US- based commercial banks with assets >$50 billion, as of September 30, 2025 using primary bank subsidiary Call Report data. 1) Acquired on January 1, 2026. Non-Depository Financial Institution (NDFI) Loans NDFI loan mix adjusted for low-loss Mortgage Credit Intermediaries nominally higher than peer average levels 1