CBSH 8-K
Commerce Bancshares Inc /Mo/ (CBSH)
8-K
2025-10-16
For: 2025-10-16
View Original
Added on
April 11, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
__________________________
Form 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of Report (Date of earliest event reported): October 16, 2025
(Exact name of registrant as specified in its charter)
| (State of Incorporation) | (Commission File Number) | (IRS Employer Identification No.) | ||||||||||||
| (Address of principal executive offices) | (Zip Code) | ||||||||||
(816 ) 234-2000
(Registrant’s telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
| Securities registered pursuant to Section 12(b) of the Act: | ||||||||
| Title of class | Trading symbol(s) | Name of exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 or Rule 12b-2 of the Securities Exchange Act of 1934.
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition
A copy of the press release issued October 16, 2025 by Commerce Bancshares, Inc. announcing Third Quarter 2025 earnings is furnished under Item 2.02 of this Current Report on Form 8-K as Exhibit 99.1. Additionally, a slide presentation for investors and analysts is being furnished as Exhibit 99.2 to this Current Report on Form 8-K.
The information in this Current Report on Form 8-K, including the exhibits, is furnished pursuant to Item 2.02 and shall not be deemed “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended, or otherwise subject to the liabilities under that Section. Furthermore, the information in this Current Report on Form 8-K, including the exhibits, shall not be deemed to be incorporated by reference into the filings of Commerce Bancshares, Inc. under the Securities Act of 1933, as amended.
All information included in this Current Report on Form 8-K is available on the Company’s website at https://investor.commercebank.com/news-info/financial-news-releases/default.aspx.
Item 9.01 Financial Statements and Exhibits
Exhibits
104 The XBRL tags on the cover page of this Form 8-K are embedded within the Inline XBRL document.
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the Registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| COMMERCE BANCSHARES, INC. | |||||||||||
| By: | /s/ Paul A. Steiner | ||||||||||
| Paul A. Steiner | |||||||||||
Controller (Chief Accounting Officer) | |||||||||||
Date: October 16, 2025
Exhibit 99.1
Exhibit 99.1
 | CBSH | ||||
1000 Walnut Street / Suite 700 / Kansas City, Missouri 64106 / 816.234.2000 | |||||
FOR IMMEDIATE RELEASE:
Thursday, October 16, 2025
COMMERCE BANCSHARES, INC. REPORTS
THIRD QUARTER EARNINGS PER SHARE OF $1.06
Commerce Bancshares, Inc. announced earnings of $1.06 per share for the three months ended September 30, 2025, compared to $1.01 per share in the same quarter last year and $1.14 per share in the second quarter of 2025. Net income for the third quarter of 2025 amounted to $141.5 million, compared to $138.0 million in the third quarter of 2024 and $152.5 million in the prior quarter.
For the nine months ended September 30, 2025, earnings per share totaled $3.18, compared to $2.86 for the first nine months of 2024. Net income amounted to $425.6 million for the nine months ended September 30, 2025, compared to $390.2 million in the comparable period last year. For the year to date, the return on average assets was 1.81%, and the return on average equity was 16.15%.
In making this announcement, John Kemper, Chief Executive Officer, said, “Commerce delivered another strong quarter, underscoring the resilience of our diversified operating model and the dedication of our talented team. Our third quarter results reflect steady loan balances, robust fee income, and disciplined expense management, all of which contributed to another period of high profitability.
“Our return on average assets remained solid at 1.78%, and our return on average equity was 15.26%. We maintained excellent credit quality, with non-accrual loans at just .09% of total loans, and added a modest reserve to the allowance for credit losses. Our capital and liquidity positions remain strong, supporting our ability to serve customers and invest in future growth.
“Net interest income was $279.5 million, reflecting the continued benefits of our strong balance sheet, even as the interest rate environment remains dynamic. Non-interest income was $161.5 million, led by growth in trust and deposit fees, and comprised 36.6% of total revenue.”
Mr. Kemper continued, “We look forward to welcoming FineMark's team, clients, and shareholders to Commerce on January 1, 2026, our expected close date, which will mark a strategic milestone after years of relationship building and months of integration planning by our dedicated teams.
“As we continue to build on our momentum, our franchise is well-positioned to execute on our long-term strategies, deliver value to our shareholders, and support our customers and communities.”
Third Quarter 2025 Financial Highlights:
•Net interest income was $279.5 million, a $690 thousand decrease compared to the prior quarter. The net yield on interest earning assets decreased six basis points to 3.64%.
1
Exhibit 99.1
•Non-interest income totaled $161.5 million, an increase of $2.5 million, or 1.6%, over the same quarter last year.
•Trust fees grew $3.7 million, or 6.8%, compared to the same period last year, mostly due to higher private client fees.
•Non-interest expense totaled $244.0 million, an increase of $6.4 million, or 2.7%, over the same quarter last year.
•Average loan balances totaled $17.5 billion, flat compared to the prior quarter.
•Total average available for sale debt securities decreased $214.5 million compared to the prior quarter to $8.9 billion, at fair value.
•Total average deposits decreased $140.1 million, or .6%, compared to the prior quarter. The average rate paid on interest bearing deposits increased four basis points to 1.71%, compared to the prior quarter.
•The ratio of annualized net loan charge-offs to average loans was .23% in the current quarter compared to .22% in the prior quarter.
•The allowance for credit losses on loans increased $10.4 million during the third quarter of 2025 to $175.7 million, and the ratio of the allowance for credit losses on loans to total loans was .99% at September 30, 2025, compared to .94% at June 30, 2025.
•Total assets on September 30, 2025 were $32.3 billion, flat compared to the prior quarter.
•For the quarter, the return on average assets was 1.78%, the return on average equity was 15.26%, and the efficiency ratio was 55.3%.
Commerce Bancshares, Inc. is a regional bank holding company offering a full line of banking services through its subsidiaries, including payment solutions, investment management and securities brokerage. One of its subsidiaries, Commerce Bank, leverages 160 years of proven strength and experience to help individuals and businesses solve financial challenges. In addition to offering payment solutions across the U.S., Commerce Bank currently operates full-service banking facilities across the Midwest including the St. Louis and Kansas City metropolitan areas, Springfield, Central Missouri, Central Illinois, Wichita, Tulsa, Oklahoma City, and Denver. Beyond the Midwest, Commerce also maintains commercial offices in Dallas, Houston, Cincinnati, Nashville, Des Moines, Indianapolis, and Grand Rapids and wealth offices in Dallas, Houston, and Naples. Commerce delivers high-touch service and sophisticated financial solutions at regional branches, commercial and wealth offices, ATMs, online, mobile and through a 24/7 customer service line.
This financial news release and the supplementary Earnings Highlights presentation are available on the Company’s website at https://investor.commercebank.com/news-info/financial-news-releases/default.aspx.
* * * * * * * * * * * * * * *
For additional information, contact
Matt Burkemper, Investor Relations
(314) 746-7485
www.commercebank.com
2
Exhibit 99.1
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
FINANCIAL HIGHLIGHTS
| For the Three Months Ended | For the Nine Months Ended | |||||||||||||||||||
| (Unaudited) (Dollars in thousands, except per share data) | Sep. 30, 2025 | Jun. 30, 2025 | Sep. 30, 2024 | Sep. 30, 2025 | Sep. 30, 2024 | |||||||||||||||
| FINANCIAL SUMMARY | ||||||||||||||||||||
| Net interest income | $279,457 | $280,147 | $262,351 | $828,706 | $773,599 | |||||||||||||||
| Non-interest income | 161,511 | 165,613 | 159,025 | 486,073 | 460,117 | |||||||||||||||
| Total revenue | 440,968 | 445,760 | 421,376 | 1,314,779 | 1,233,716 | |||||||||||||||
| Investment securities gains (losses) | 7,885 | 437 | 3,872 | 731 | 6,846 | |||||||||||||||
| Provision for credit losses | 20,061 | 5,597 | 9,140 | 40,145 | 19,395 | |||||||||||||||
| Non-interest expense | 244,018 | 244,437 | 237,600 | 726,831 | 715,511 | |||||||||||||||
| Income before taxes | 184,774 | 196,163 | 178,508 | 548,534 | 505,656 | |||||||||||||||
| Income taxes | 41,152 | 42,400 | 38,245 | 120,516 | 108,499 | |||||||||||||||
| Non-controlling interest expense (income) | 2,104 | 1,284 | 2,256 | 2,429 | 6,934 | |||||||||||||||
| Net income attributable to Commerce Bancshares, Inc. | $141,518 | $152,479 | $138,007 | $425,589 | $390,223 | |||||||||||||||
| Earnings per common share: | ||||||||||||||||||||
| Net income — basic | $1.06 | $1.14 | $1.02 | $3.18 | $2.87 | |||||||||||||||
| Net income — diluted | $1.06 | $1.14 | $1.01 | $3.18 | $2.86 | |||||||||||||||
| Effective tax rate | 22.53 | % | 21.76 | % | 21.70 | % | 22.07 | % | 21.76 | % | ||||||||||
| Fully-taxable equivalent net interest income | $281,770 | $282,428 | $264,638 | $835,614 | $780,528 | |||||||||||||||
Average total interest earning assets (1) | $30,732,665 | $30,629,715 | $30,051,845 | $30,753,879 | $30,144,221 | |||||||||||||||
| Diluted wtd. average shares outstanding | 132,463,271 | 132,582,673 | 134,394,825 | 132,703,659 | 135,024,776 | |||||||||||||||
| RATIOS | ||||||||||||||||||||
Average loans to deposits (2) | 70.61 | % | 70.22 | % | 69.93 | % | 70.08 | % | 70.17 | % | ||||||||||
| Return on total average assets | 1.78 | 1.95 | 1.80 | 1.81 | 1.71 | |||||||||||||||
Return on average equity (3) | 15.26 | 17.40 | 16.81 | 16.15 | 16.92 | |||||||||||||||
| Non-interest income to total revenue | 36.63 | 37.15 | 37.74 | 36.97 | 37.30 | |||||||||||||||
Efficiency ratio (4) | 55.26 | 54.77 | 56.31 | 55.21 | 57.92 | |||||||||||||||
| Net yield on interest earning assets | 3.64 | 3.70 | 3.50 | 3.63 | 3.46 | |||||||||||||||
| EQUITY SUMMARY | ||||||||||||||||||||
| Cash dividends per share | $.275 | $.275 | $.257 | $.825 | $.771 | |||||||||||||||
| Cash dividends on common stock | $36,733 | $36,761 | $34,794 | $110,360 | $104,894 | |||||||||||||||
Book value per share (5) | $28.51 | $27.43 | $25.62 | |||||||||||||||||
Market value per share (5) | $59.76 | $62.17 | $56.57 | |||||||||||||||||
| High market value per share | $66.34 | $66.14 | $62.72 | |||||||||||||||||
| Low market value per share | $57.92 | $52.69 | $52.27 | |||||||||||||||||
Common shares outstanding (5) | 133,021,127 | 133,419,701 | 134,797,835 | |||||||||||||||||
Tangible common equity to tangible assets (6) | 11.27 | % | 10.86 | % | 10.47 | % | ||||||||||||||
| Tier I leverage ratio | 12.95 | % | 12.75 | % | 12.31 | % | ||||||||||||||
| OTHER QTD INFORMATION | ||||||||||||||||||||
| Number of bank/ATM locations | 239 | 239 | 244 | |||||||||||||||||
| Full-time equivalent employees | 4,666 | 4,658 | 4,711 | |||||||||||||||||
(1) Excludes allowance for credit losses on loans and unrealized gains/(losses) on available for sale debt securities.
(2) Includes loans held for sale.
(3) Annualized net income attributable to Commerce Bancshares, Inc. divided by average total equity.
(4) The efficiency ratio is calculated as non-interest expense (excluding intangibles amortization) as a percent of total revenue.
(5) As of period end.
(6) The tangible common equity ratio is a non-gaap ratio and is calculated as stockholders’ equity reduced by goodwill and other intangible assets (excluding mortgage servicing rights) divided by total assets reduced by goodwill and other intangible assets (excluding mortgage servicing rights).
All share and per share amounts have been restated to reflect the 5% stock dividend distributed in December 2024.
3
Exhibit 99.1
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
CONSOLIDATED STATEMENTS OF INCOME
| (Unaudited) (In thousands, except per share data) | For the Three Months Ended | For the Nine Months Ended | ||||||||||||||||||||||||
| Sep. 30, 2025 | Jun. 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | Sep. 30, 2025 | Sep. 30, 2024 | ||||||||||||||||||||
| Interest income | $374,105 | $371,636 | $364,365 | $369,405 | $372,068 | $1,110,106 | $1,100,152 | |||||||||||||||||||
| Interest expense | 94,648 | 91,489 | 95,263 | 102,758 | 109,717 | 281,400 | 326,553 | |||||||||||||||||||
| Net interest income | 279,457 | 280,147 | 269,102 | 266,647 | 262,351 | 828,706 | 773,599 | |||||||||||||||||||
| Provision for credit losses | 20,061 | 5,597 | 14,487 | 13,508 | 9,140 | 40,145 | 19,395 | |||||||||||||||||||
| Net interest income after credit losses | 259,396 | 274,550 | 254,615 | 253,139 | 253,211 | 788,561 | 754,204 | |||||||||||||||||||
| NON-INTEREST INCOME | ||||||||||||||||||||||||||
| Trust fees | 58,412 | 55,571 | 56,592 | 56,345 | 54,689 | 170,575 | 158,085 | |||||||||||||||||||
| Bank card transaction fees | 45,551 | 46,362 | 45,593 | 47,807 | 47,570 | 137,506 | 141,977 | |||||||||||||||||||
| Deposit account charges and other fees | 27,427 | 26,248 | 26,622 | 25,480 | 25,380 | 80,297 | 74,856 | |||||||||||||||||||
| Capital market fees | 5,138 | 6,175 | 5,112 | 5,129 | 5,995 | 16,425 | 14,647 | |||||||||||||||||||
| Consumer brokerage services | 6,698 | 5,383 | 4,785 | 4,636 | 4,619 | 16,866 | 13,505 | |||||||||||||||||||
| Loan fees and sales | 3,465 | 3,419 | 3,404 | 2,874 | 3,444 | 10,288 | 10,016 | |||||||||||||||||||
| Other | 14,820 | 22,455 | 16,841 | 13,165 | 17,328 | 54,116 | 47,031 | |||||||||||||||||||
| Total non-interest income | 161,511 | 165,613 | 158,949 | 155,436 | 159,025 | 486,073 | 460,117 | |||||||||||||||||||
| INVESTMENT SECURITIES GAINS (LOSSES), NET | 7,885 | 437 | (7,591) | 977 | 3,872 | 731 | 6,846 | |||||||||||||||||||
| NON-INTEREST EXPENSE | ||||||||||||||||||||||||||
| Salaries and employee benefits | 157,461 | 155,025 | 153,078 | 153,819 | 153,122 | 465,564 | 454,043 | |||||||||||||||||||
| Data processing and software | 33,555 | 32,904 | 32,238 | 32,514 | 32,194 | 98,697 | 94,876 | |||||||||||||||||||
| Net occupancy | 13,474 | 13,654 | 14,020 | 13,694 | 13,411 | 41,148 | 39,529 | |||||||||||||||||||
| Professional and other services | 11,284 | 12,973 | 10,026 | 8,982 | 8,830 | 34,283 | 26,095 | |||||||||||||||||||
| Marketing | 6,670 | 5,974 | 5,843 | 5,683 | 7,278 | 18,487 | 16,670 | |||||||||||||||||||
| Equipment | 5,421 | 5,157 | 5,248 | 5,232 | 5,286 | 15,826 | 15,387 | |||||||||||||||||||
| Supplies and communication | 4,837 | 4,962 | 5,046 | 4,948 | 4,963 | 14,845 | 14,343 | |||||||||||||||||||
| Deposit Insurance | 3,074 | 3,312 | 3,744 | 3,181 | 2,930 | 10,130 | 13,301 | |||||||||||||||||||
| Other | 8,242 | 10,476 | 9,133 | 7,665 | 9,586 | 27,851 | 41,267 | |||||||||||||||||||
| Total non-interest expense | 244,018 | 244,437 | 238,376 | 235,718 | 237,600 | 726,831 | 715,511 | |||||||||||||||||||
| Income before income taxes | 184,774 | 196,163 | 167,597 | 173,834 | 178,508 | 548,534 | 505,656 | |||||||||||||||||||
| Less income taxes | 41,152 | 42,400 | 36,964 | 36,590 | 38,245 | 120,516 | 108,499 | |||||||||||||||||||
| Net income | 143,622 | 153,763 | 130,633 | 137,244 | 140,263 | 428,018 | 397,157 | |||||||||||||||||||
| Less non-controlling interest expense (income) | 2,104 | 1,284 | (959) | 1,136 | 2,256 | 2,429 | 6,934 | |||||||||||||||||||
| Net income attributable to Commerce Bancshares, Inc. | $141,518 | $152,479 | $131,592 | $136,108 | $138,007 | $425,589 | $390,223 | |||||||||||||||||||
| Net income per common share — basic | $1.06 | $1.14 | $0.98 | $1.01 | $1.02 | $3.18 | $2.87 | |||||||||||||||||||
| Net income per common share — diluted | $1.06 | $1.14 | $0.98 | $1.01 | $1.01 | $3.18 | $2.86 | |||||||||||||||||||
| OTHER INFORMATION | ||||||||||||||||||||||||||
| Return on total average assets | 1.78 | % | 1.95 | % | 1.69 | % | 1.73 | % | 1.80 | % | 1.81 | % | 1.71 | % | ||||||||||||
Return on average equity (1) | 15.26 | 17.40 | 15.82 | 15.97 | 16.81 | 16.15 | 16.92 | |||||||||||||||||||
Efficiency ratio (2) | 55.26 | 54.77 | 55.61 | 55.77 | 56.31 | 55.21 | 57.92 | |||||||||||||||||||
| Effective tax rate | 22.53 | 21.76 | 21.93 | 21.19 | 21.70 | 22.07 | 21.76 | |||||||||||||||||||
| Net yield on interest earning assets | 3.64 | 3.70 | 3.56 | 3.49 | 3.50 | 3.63 | 3.46 | |||||||||||||||||||
| Fully-taxable equivalent net interest income | $281,770 | $282,428 | $271,416 | $268,935 | $264,638 | $835,614 | $780,528 | |||||||||||||||||||
(1) Annualized net income attributable to Commerce Bancshares, Inc. divided by average total equity.
(2) The efficiency ratio is calculated as non-interest expense (excluding intangibles amortization) as a percent of total revenue.
4
Exhibit 99.1
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
CONSOLIDATED BALANCE SHEETS - PERIOD END
| (Unaudited) (In thousands) | Sep. 30, 2025 | Jun. 30, 2025 | Sep. 30, 2024 | |||||||||||
| ASSETS | ||||||||||||||
| Loans | ||||||||||||||
| Business | $6,414,792 | $6,328,684 | $6,048,328 | |||||||||||
| Real estate — construction and land | 1,433,652 | 1,405,398 | 1,381,607 | |||||||||||
| Real estate — business | 3,745,000 | 3,757,778 | 3,586,999 | |||||||||||
| Real estate — personal | 3,070,980 | 3,058,845 | 3,043,391 | |||||||||||
| Consumer | 2,171,599 | 2,157,867 | 2,108,281 | |||||||||||
| Revolving home equity | 364,241 | 364,429 | 342,376 | |||||||||||
| Consumer credit card | 575,317 | 576,151 | 574,746 | |||||||||||
| Overdrafts | 11,186 | 16,316 | 4,272 | |||||||||||
| Total loans | 17,786,767 | 17,665,468 | 17,090,000 | |||||||||||
| Allowance for credit losses on loans | (175,671) | (165,260) | (160,839) | |||||||||||
| Net loans | 17,611,096 | 17,500,208 | 16,929,161 | |||||||||||
| Loans held for sale | 2,538 | 3,592 | 1,707 | |||||||||||
| Investment securities: | ||||||||||||||
| Available for sale debt securities | 8,998,586 | 8,915,779 | 9,167,681 | |||||||||||
| Trading debt securities | 56,282 | 46,630 | 42,645 | |||||||||||
| Equity securities | 53,193 | 54,511 | 57,115 | |||||||||||
| Other securities | 227,430 | 219,906 | 216,543 | |||||||||||
| Total investment securities | 9,335,491 | 9,236,826 | 9,483,984 | |||||||||||
| Federal funds sold | — | — | 10 | |||||||||||
| Securities purchased under agreements to resell | 850,000 | 850,000 | 475,000 | |||||||||||
| Interest earning deposits with banks | 2,477,668 | 2,624,264 | 2,642,048 | |||||||||||
| Cash and due from banks | 476,441 | 522,049 | 507,941 | |||||||||||
| Premises and equipment — net | 483,000 | 477,401 | 469,986 | |||||||||||
| Goodwill | 146,539 | 146,539 | 146,539 | |||||||||||
| Other intangible assets — net | 13,329 | 13,333 | 13,722 | |||||||||||
| Other assets | 892,586 | 910,035 | 823,494 | |||||||||||
| Total assets | $32,288,688 | $32,284,247 | $31,493,592 | |||||||||||
| LIABILITIES AND STOCKHOLDERS’ EQUITY | ||||||||||||||
| Deposits: | ||||||||||||||
| Non-interest bearing | $7,489,645 | $7,393,559 | $7,396,153 | |||||||||||
| Savings, interest checking and money market | 15,551,799 | 15,727,549 | 15,216,557 | |||||||||||
| Certificates of deposit of less than $100,000 | 1,002,640 | 986,014 | 1,113,962 | |||||||||||
| Certificates of deposit of $100,000 and over | 1,413,965 | 1,386,906 | 1,511,120 | |||||||||||
| Total deposits | 25,458,049 | 25,494,028 | 25,237,792 | |||||||||||
| Federal funds purchased and securities sold under agreements to repurchase | 2,473,065 | 2,596,461 | 2,182,229 | |||||||||||
| Other borrowings | 9,270 | 15,049 | 10,201 | |||||||||||
| Other liabilities | 555,257 | 518,595 | 609,831 | |||||||||||
| Total liabilities | 28,495,641 | 28,624,133 | 28,040,053 | |||||||||||
| Stockholders’ equity: | ||||||||||||||
| Common stock | 676,054 | 676,054 | 655,322 | |||||||||||
| Capital surplus | 3,390,526 | 3,386,218 | 3,154,300 | |||||||||||
| Retained earnings | 360,723 | 255,938 | 338,512 | |||||||||||
| Treasury stock | (121,972) | (96,589) | (139,149) | |||||||||||
| Accumulated other comprehensive income (loss) | (533,666) | (581,049) | (576,904) | |||||||||||
| Total stockholders’ equity | 3,771,665 | 3,640,572 | 3,432,081 | |||||||||||
| Non-controlling interest | 21,382 | 19,542 | 21,458 | |||||||||||
| Total equity | 3,793,047 | 3,660,114 | 3,453,539 | |||||||||||
| Total liabilities and equity | $32,288,688 | $32,284,247 | $31,493,592 | |||||||||||
5
Exhibit 99.1
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
AVERAGE BALANCE SHEETS
| (Unaudited) (In thousands) | For the Three Months Ended | ||||||||||||||||
| Sep. 30, 2025 | Jun. 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | |||||||||||||
| ASSETS: | |||||||||||||||||
| Loans: | |||||||||||||||||
| Business | $6,230,019 | $6,247,252 | $6,106,185 | $5,963,217 | $5,966,797 | ||||||||||||
| Real estate — construction and land | 1,396,977 | 1,430,758 | 1,415,349 | 1,411,437 | 1,400,563 | ||||||||||||
| Real estate — business | 3,715,597 | 3,692,405 | 3,667,833 | 3,636,026 | 3,580,772 | ||||||||||||
| Real estate — personal | 3,059,913 | 3,048,895 | 3,045,876 | 3,047,494 | 3,047,563 | ||||||||||||
| Consumer | 2,160,637 | 2,148,666 | 2,082,360 | 2,087,237 | 2,129,483 | ||||||||||||
| Revolving home equity | 360,820 | 362,312 | 358,684 | 350,541 | 335,817 | ||||||||||||
| Consumer credit card | 563,351 | 559,858 | 560,534 | 568,138 | 559,410 | ||||||||||||
| Overdrafts | 7,037 | 5,663 | 5,860 | 5,628 | 5,460 | ||||||||||||
Total loans | 17,494,351 | 17,495,809 | 17,242,681 | 17,069,718 | 17,025,865 | ||||||||||||
| Allowance for credit losses on loans | (164,623) | (166,391) | (162,186) | (160,286) | (158,003) | ||||||||||||
| Net loans | 17,329,728 | 17,329,418 | 17,080,495 | 16,909,432 | 16,867,862 | ||||||||||||
| Loans held for sale | 2,369 | 1,741 | 1,584 | 2,080 | 2,448 | ||||||||||||
| Investment securities: | |||||||||||||||||
| U.S. government and federal agency obligations | 2,693,327 | 2,623,896 | 2,586,944 | 2,459,485 | 1,888,985 | ||||||||||||
| Government-sponsored enterprise obligations | 55,014 | 55,038 | 55,330 | 55,428 | 55,583 | ||||||||||||
| State and municipal obligations | 756,137 | 780,063 | 804,363 | 831,695 | 856,620 | ||||||||||||
| Mortgage-backed securities | 4,461,056 | 4,641,295 | 4,788,102 | 4,905,187 | 5,082,091 | ||||||||||||
| Asset-backed securities | 1,466,770 | 1,585,364 | 1,655,701 | 1,570,878 | 1,525,593 | ||||||||||||
Other debt securities | 204,281 | 237,385 | 258,136 | 221,076 | 224,528 | ||||||||||||
| Unrealized gain (loss) on debt securities | (766,025) | (838,028) | (935,054) | (896,346) | (961,695) | ||||||||||||
| Total available for sale debt securities | 8,870,560 | 9,085,013 | 9,213,522 | 9,147,403 | 8,671,705 | ||||||||||||
Trading debt securities | 56,032 | 51,131 | 38,298 | 56,440 | 47,440 | ||||||||||||
| Equity securities | 50,823 | 54,472 | 57,028 | 56,758 | 85,118 | ||||||||||||
| Other securities | 220,041 | 216,560 | 233,461 | 222,529 | 217,377 | ||||||||||||
| Total investment securities | 9,197,456 | 9,407,176 | 9,542,309 | 9,483,130 | 9,021,640 | ||||||||||||
| Federal funds sold | 23 | 158 | 2,089 | 826 | 12 | ||||||||||||
| Securities purchased under agreements to resell | 850,000 | 850,000 | 788,889 | 566,307 | 474,997 | ||||||||||||
| Interest earning deposits with banks | 2,422,441 | 2,036,803 | 2,388,504 | 2,610,315 | 2,565,188 | ||||||||||||
| Other assets | 1,709,247 | 1,671,763 | 1,698,296 | 1,701,822 | 1,648,321 | ||||||||||||
| Total assets | $31,511,264 | $31,297,059 | $31,502,166 | $31,273,912 | $30,580,468 | ||||||||||||
| LIABILITIES AND EQUITY: | |||||||||||||||||
| Non-interest bearing deposits | $7,345,156 | $7,356,882 | $7,298,686 | $7,464,255 | $7,284,834 | ||||||||||||
| Savings | 1,283,671 | 1,303,391 | 1,294,174 | 1,281,291 | 1,303,675 | ||||||||||||
| Interest checking and money market | 13,740,770 | 13,901,634 | 13,906,827 | 13,679,666 | 13,242,398 | ||||||||||||
| Certificates of deposit of less than $100,000 | 991,877 | 984,845 | 991,826 | 1,061,783 | 1,055,683 | ||||||||||||
| Certificates of deposit of $100,000 and over | 1,416,572 | 1,371,428 | 1,363,655 | 1,451,851 | 1,464,143 | ||||||||||||
| Total deposits | 24,778,046 | 24,918,180 | 24,855,168 | 24,938,846 | 24,350,733 | ||||||||||||
| Borrowings: | |||||||||||||||||
| Federal funds purchased | 130,622 | 129,891 | 128,340 | 121,781 | 206,644 | ||||||||||||
| Securities sold under agreements to repurchase | 2,519,660 | 2,371,031 | 2,723,227 | 2,445,956 | 2,351,870 | ||||||||||||
| Other borrowings | 1,860 | 2,748 | 616 | 1,067 | 496 | ||||||||||||
| Total borrowings | 2,652,142 | 2,503,670 | 2,852,183 | 2,568,804 | 2,559,010 | ||||||||||||
| Other liabilities | 402,265 | 360,204 | 421,370 | 375,463 | 405,490 | ||||||||||||
| Total liabilities | 27,832,453 | 27,782,054 | 28,128,721 | 27,883,113 | 27,315,233 | ||||||||||||
| Equity | 3,678,811 | 3,515,005 | 3,373,445 | 3,390,799 | 3,265,235 | ||||||||||||
| Total liabilities and equity | $31,511,264 | $31,297,059 | $31,502,166 | $31,273,912 | $30,580,468 | ||||||||||||
6
Exhibit 99.1
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
AVERAGE RATES
| (Unaudited) | For the Three Months Ended | ||||||||||||||||
| Sep. 30, 2025 | Jun. 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | |||||||||||||
| ASSETS: | |||||||||||||||||
| Loans: | |||||||||||||||||
Business (1) | 5.72 | % | 5.72 | % | 5.75 | % | 5.86 | % | 6.17 | % | |||||||
| Real estate — construction and land | 7.37 | 7.39 | 7.30 | 7.75 | 8.44 | ||||||||||||
| Real estate — business | 5.92 | 5.92 | 5.88 | 6.01 | 6.28 | ||||||||||||
| Real estate — personal | 4.34 | 4.30 | 4.28 | 4.17 | 4.10 | ||||||||||||
| Consumer | 6.42 | 6.43 | 6.52 | 6.52 | 6.64 | ||||||||||||
| Revolving home equity | 7.94 | 7.41 | 7.26 | 7.28 | 7.69 | ||||||||||||
| Consumer credit card | 13.21 | 13.18 | 13.49 | 13.60 | 14.01 | ||||||||||||
| Overdrafts | — | — | — | — | — | ||||||||||||
| Total loans | 6.02 | 6.01 | 6.02 | 6.11 | 6.35 | ||||||||||||
| Loans held for sale | 6.03 | 9.22 | 5.89 | 7.65 | 6.34 | ||||||||||||
| Investment securities: | |||||||||||||||||
| U.S. government and federal agency obligations | 4.06 | 4.28 | 4.09 | 3.86 | 3.68 | ||||||||||||
| Government-sponsored enterprise obligations | 2.35 | 2.38 | 2.40 | 2.36 | 2.37 | ||||||||||||
State and municipal obligations (1) | 2.05 | 2.05 | 2.05 | 2.01 | 2.00 | ||||||||||||
| Mortgage-backed securities | 2.01 | 2.08 | 2.08 | 2.17 | 1.95 | ||||||||||||
| Asset-backed securities | 3.69 | 3.73 | 3.46 | 2.99 | 2.66 | ||||||||||||
| Other debt securities | 2.97 | 2.94 | 2.69 | 2.11 | 2.07 | ||||||||||||
| Total available for sale debt securities | 2.86 | 2.95 | 2.83 | 2.70 | 2.41 | ||||||||||||
Trading debt securities (1) | 4.67 | 4.63 | 4.97 | 4.26 | 4.52 | ||||||||||||
Equity securities (1) | 6.09 | 6.26 | 8.02 | 6.58 | 4.44 | ||||||||||||
Other securities (1) | 7.29 | 11.63 | 7.85 | 5.75 | 6.09 | ||||||||||||
| Total investment securities | 2.99 | 3.16 | 2.98 | 2.80 | 2.52 | ||||||||||||
| Federal funds sold | — | 5.08 | 5.63 | 5.78 | — | ||||||||||||
| Securities purchased under agreements to resell | 4.00 | 4.02 | 3.81 | 3.57 | 3.53 | ||||||||||||
| Interest earning deposits with banks | 4.45 | 4.46 | 4.46 | 4.78 | 5.43 | ||||||||||||
| Total interest earning assets | 4.86 | 4.90 | 4.81 | 4.83 | 4.96 | ||||||||||||
| LIABILITIES AND EQUITY: | |||||||||||||||||
| Interest bearing deposits: | |||||||||||||||||
| Savings | .05 | .05 | .05 | .05 | .07 | ||||||||||||
| Interest checking and money market | 1.54 | 1.49 | 1.52 | 1.63 | 1.74 | ||||||||||||
| Certificates of deposit of less than $100,000 | 3.33 | 3.44 | 3.65 | 3.91 | 4.17 | ||||||||||||
| Certificates of deposit of $100,000 and over | 3.71 | 3.78 | 3.96 | 4.24 | 4.51 | ||||||||||||
| Total interest bearing deposits | 1.71 | 1.67 | 1.72 | 1.87 | 2.00 | ||||||||||||
| Borrowings: | |||||||||||||||||
| Federal funds purchased | 4.34 | 4.37 | 4.37 | 4.71 | 5.38 | ||||||||||||
| Securities sold under agreements to repurchase | 2.88 | 2.85 | 2.86 | 3.11 | 3.56 | ||||||||||||
| Other borrowings | 1.71 | 3.79 | .66 | 3.36 | 4.81 | ||||||||||||
| Total borrowings | 2.95 | 2.93 | 2.93 | 3.18 | 3.71 | ||||||||||||
| Total interest bearing liabilities | 1.87 | % | 1.83 | % | 1.89 | % | 2.04 | % | 2.22 | % | |||||||
| Net yield on interest earning assets | 3.64 | % | 3.70 | % | 3.56 | % | 3.49 | % | 3.50 | % | |||||||
(1) Stated on a fully taxable-equivalent basis using a federal income tax rate of 21%.
7
Exhibit 99.1
COMMERCE BANCSHARES, INC. and SUBSIDIARIES
CREDIT QUALITY
| For the Three Months Ended | For the Nine Months Ended | |||||||||||||||||||||||||
| (Unaudited) (In thousands, except ratios) | Sep. 30, 2025 | Jun. 30, 2025 | Mar. 31, 2025 | Dec. 31, 2024 | Sep. 30, 2024 | Sep. 30, 2025 | Sep. 30, 2024 | |||||||||||||||||||
| ALLOWANCE FOR CREDIT LOSSES ON LOANS | ||||||||||||||||||||||||||
| Balance at beginning of period | $165,260 | $167,031 | $162,742 | $160,839 | $158,557 | $162,742 | $162,395 | |||||||||||||||||||
| Provision for credit losses on loans | 20,739 | 7,919 | 15,095 | 12,557 | 11,861 | 43,753 | 26,657 | |||||||||||||||||||
| Net charge-offs (recoveries): | ||||||||||||||||||||||||||
| Commercial portfolio: | ||||||||||||||||||||||||||
| Business | 826 | 432 | 46 | 335 | 114 | 1,304 | 759 | |||||||||||||||||||
| Real estate — construction and land | — | 24 | — | — | — | 24 | — | |||||||||||||||||||
| Real estate — business | (23) | (425) | 377 | 50 | (7) | (71) | (156) | |||||||||||||||||||
| 803 | 31 | 423 | 385 | 107 | 1,257 | 603 | ||||||||||||||||||||
| Personal banking portfolio: | ||||||||||||||||||||||||||
| Consumer credit card | 6,515 | 7,085 | 6,967 | 6,557 | 6,273 | 20,567 | 19,454 | |||||||||||||||||||
| Consumer | 2,310 | 2,168 | 2,852 | 3,237 | 2,759 | 7,330 | 6,546 | |||||||||||||||||||
| Overdraft | 432 | 360 | 495 | 470 | 464 | 1,287 | 1,542 | |||||||||||||||||||
| Real estate — personal | 269 | 35 | 72 | 8 | 128 | 376 | 231 | |||||||||||||||||||
| Revolving home equity | (1) | 11 | (3) | (3) | (152) | 7 | (163) | |||||||||||||||||||
| 9,525 | 9,659 | 10,383 | 10,269 | 9,472 | 29,567 | 27,610 | ||||||||||||||||||||
| Total net loan charge-offs | 10,328 | 9,690 | 10,806 | 10,654 | 9,579 | 30,824 | 28,213 | |||||||||||||||||||
| Balance at end of period | $175,671 | $165,260 | $167,031 | $162,742 | $160,839 | $175,671 | $160,839 | |||||||||||||||||||
| LIABILITY FOR UNFUNDED LENDING COMMITMENTS | $15,327 | $16,005 | $18,327 | $18,935 | $17,984 | |||||||||||||||||||||
NET CHARGE-OFF RATIOS (1) | ||||||||||||||||||||||||||
| Commercial portfolio: | ||||||||||||||||||||||||||
| Business | .05 | % | .03 | % | — | % | .02 | % | .01 | % | .03 | % | .02 | % | ||||||||||||
| Real estate — construction and land | — | .01 | — | — | — | — | — | |||||||||||||||||||
| Real estate — business | — | (.05) | .04 | .01 | — | — | (.01) | |||||||||||||||||||
| .03 | — | .02 | .01 | — | .01 | .01 | ||||||||||||||||||||
| Personal banking portfolio: | ||||||||||||||||||||||||||
| Consumer credit card | 4.59 | 5.08 | 5.04 | 4.59 | 4.46 | 4.90 | 4.65 | |||||||||||||||||||
| Consumer | .42 | .40 | .56 | .62 | .52 | .46 | .41 | |||||||||||||||||||
| Overdraft | 24.36 | 25.50 | 34.26 | 33.22 | 33.81 | 27.79 | 34.32 | |||||||||||||||||||
| Real estate — personal | .03 | — | .01 | — | .02 | .02 | .01 | |||||||||||||||||||
| Revolving home equity | — | .01 | — | — | (.18) | — | (.07) | |||||||||||||||||||
| .61 | .63 | .70 | .67 | .62 | .65 | .61 | ||||||||||||||||||||
| Total | .23 | % | .22 | % | .25 | % | .25 | % | .22 | % | .24 | % | .22 | % | ||||||||||||
| CREDIT QUALITY RATIOS | ||||||||||||||||||||||||||
| Non-accrual loans to total loans | .09 | % | .11 | % | .13 | % | .11 | % | .11 | % | ||||||||||||||||
| Allowance for credit losses on loans to total loans | .99 | .94 | .96 | .95 | .94 | |||||||||||||||||||||
| NON-ACCRUAL AND PAST DUE LOANS | ||||||||||||||||||||||||||
| Non-accrual loans: | ||||||||||||||||||||||||||
| Business | $255 | $410 | $1,112 | $101 | $354 | |||||||||||||||||||||
| Real estate — construction and land | 191 | 426 | 220 | 220 | — | |||||||||||||||||||||
| Real estate — business | 14,940 | 15,109 | 18,305 | 14,954 | 14,944 | |||||||||||||||||||||
| Real estate — personal | 867 | 948 | 989 | 1,026 | 1,144 | |||||||||||||||||||||
| Revolving home equity | — | 1,977 | 1,977 | 1,977 | 1,977 | |||||||||||||||||||||
| Total | 16,253 | 18,870 | 22,603 | 18,278 | 18,419 | |||||||||||||||||||||
| Loans past due 90 days and still accruing interest | $21,536 | $25,303 | $19,417 | $24,516 | $21,986 | |||||||||||||||||||||
8
Exhibit 99.1
COMMERCE BANCSHARES, INC.
Management Discussion of Third Quarter Results
September 30, 2025
For the quarter ended September 30, 2025, net income amounted to $141.5 million, compared to $152.5 million in the previous quarter and $138.0 million in the same quarter last year. The decrease in net income compared to the previous quarter was primarily the result of an increase in the provision for credit losses and lower non-interest income, partly offset by higher gains on investment securities. The net yield on interest earning assets decreased six basis points from the previous quarter. Average loans were flat, while average available for sale investment securities, at fair value, and deposits decreased $214.5 million and $140.1 million, respectively, compared to the prior quarter. For the quarter, the return on average assets was 1.78%, the return on average equity was 15.26%, and the efficiency ratio was 55.3%.
Balance Sheet Review
During the 3rd quarter of 2025, average loans totaled $17.5 billion, flat compared to the prior quarter, and an increase of $468.5 million over the same quarter last year. Compared to the previous quarter, average balances of business real estate loans grew $23.2 million, while construction and business loans declined $33.8 million and $17.2 million, respectively. During the current quarter, the Company sold certain fixed rate personal real estate loans totaling $30.6 million, compared to $19.7 million in the prior quarter.
Total average available for sale debt securities decreased $214.5 million compared to the previous quarter to $8.9 billion, at fair value. The decrease in available for sale debt securities was mainly the result of lower average balances of mortgage-backed and asset-backed securities. During the 3rd quarter of 2025, the unrealized loss on available for sale debt securities decreased $75.9 million to $688.5 million, at period end. Also, during the 3rd quarter of 2025, purchases of available for sale debt securities totaled $459.3 million with a weighted average yield of approximately 4.15%, and maturities and pay downs of available for sale debt securities were $456.7 million. On September 30, 2025, the duration of the available for sale investment portfolio was 4.4 years, and maturities and pay downs of approximately $1.3 billion are expected to occur during the next 12 months.
Total average deposits decreased $140.1 million this quarter compared to the previous quarter. The decrease in deposits mostly resulted from lower average interest checking and money market balances of $160.9 million. Compared to the previous quarter, total average wealth and consumer deposits declined $132.4 million and $111.1 million, respectively, while average commercial deposits grew $118.1 million. The average loans to deposits ratio was 70.6% in the current quarter and 70.2% in the prior quarter. The Company’s average borrowings, which included average customer repurchase agreements of $2.5 billion, increased $148.5 million to $2.7 billion in the 3rd quarter of 2025.
Net Interest Income
Net interest income in the 3rd quarter of 2025 amounted to $279.5 million, a decrease of $690 thousand compared to the previous quarter. On a fully taxable-equivalent (FTE) basis, net interest income for the current quarter decreased $658 thousand compared to the previous quarter to $281.8 million. The decrease in net interest income was mostly due to lower interest income on investment securities and higher interest expense on borrowings and deposits, partly offset by higher interest income on loans and deposits with banks. The net yield (FTE) on earning assets decreased to 3.64%, from 3.70% in the prior quarter.
Compared to the previous quarter, interest income on loans (FTE) increased $3.5 million, mostly due to an additional day of interest earned in the 3rd quarter, partly offset by lower average balances of construction loans. The average yield (FTE) on the loan portfolio increased one basis point to 6.02% this quarter.
Interest income on investment securities (FTE) decreased $5.6 million compared to the prior quarter, mostly due to lower average balances of asset-backed and mortgage-backed securities and lower rates on U.S. government and federal agency securities and other securities, partially offset by higher average balances of U.S. government and federal agency securities. Interest income earned on U.S. government and federal agency securities included the impact of a $1.1 million decline in inflation income from Treasury inflation-protected securities compared to previous quarter. Interest on other securities included $1.3 million of non-accrual interest income related to a private equity investment but was lower than the $1.8 million of dividend and non-accrual interest recorded in the prior quarter. Additionally, the Company recorded a $314 thousand adjustment to premium amortization on September 30, 2025, which increased interest income to reflect slower forward prepayment speed estimates on mortgage-backed securities. This increase was lower than the $1.0 million adjustment that increased interest income in the prior quarter. The average yield (FTE) on total investment securities was 2.99% in the current quarter, compared to 3.16% in the previous quarter.
Compared to the previous quarter, interest income on deposits with banks increased $4.5 million, due to higher average balances.
Interest expense increased $3.2 million compared to the previous quarter, mainly due to higher average rates paid on deposits and higher average balances of borrowings. Interest expense on borrowings increased $1.4 million mostly due to an increase of $148.6 million in average securities sold under repurchase agreement balances. Interest expense on deposits increased $1.8 million mostly due to higher average rates. The average rate paid on interest bearing deposits totaled 1.71% in the current quarter compared to 1.67% in the prior quarter. The overall rate paid on interest bearing liabilities was
9
Exhibit 99.1
COMMERCE BANCSHARES, INC.
Management Discussion of Third Quarter Results
September 30, 2025
1.87% in the current quarter and 1.83% in the prior quarter.
Non-Interest Income
In the 3rd quarter of 2025, total non-interest income amounted to $161.5 million, an increase of $2.5 million, or 1.6%, over the same period last year and a decrease of $4.1 million compared to the prior quarter. The increase in non-interest income compared to the same period last year was mainly due to higher trust fees, deposit account fees and brokerage fees, partly offset by lower bank card fees and lower gains on sales of assets. The decrease in non-interest income compared to the prior quarter was mainly due to lower gains on sales of assets of $6.5 million, partly offset by higher trust fees.
Total net bank card fees in the current quarter decreased $2.0 million, or 4.2%, compared to the same period last year, and decreased $811 thousand compared to the prior quarter. Net corporate card fees decreased $1.7 million compared to the same quarter of last year mainly due to higher rewards expense, partly offset by higher interchange fees. Net merchant fees increased $89 thousand, or 1.6%, while net debit card fees decreased $107 thousand, or .9%. Net credit card fees decreased $336 thousand, or 8.5%, mostly due to higher rewards expense. Total net bank card fees this quarter were comprised of fees on corporate card ($25.1 million), debit card ($11.3 million), merchant ($5.6 million) and credit card ($3.6 million) transactions.
In the current quarter, trust fees increased $3.7 million, or 6.8%, over the same period last year, mostly resulting from higher private client fees. Compared to the same period last year, deposit account fees increased $2.0 million, or 8.1%, mostly due to higher corporate cash management fees, while consumer brokerage fees increased $2.1 million.
Other non-interest income decreased compared to the same period last year primarily due to lower gains on sales of assets of $4.7 million. For the 3rd quarter of 2025, non-interest income comprised 36.6% of the Company’s total revenue.
Investment Securities Gains and Losses
The Company recorded net securities gains of $7.9 million in the current quarter, compared to $437 thousand in the prior quarter and $3.9 million in the 3rd quarter of 2024. Net securities gains in the current quarter mostly resulted from net fair value adjustments of $8.0 million on the Company’s portfolio of private equity investments.
Non-Interest Expense
Non-interest expense for the current quarter amounted to $244.0 million, compared to $237.6 million in the same period last year and $244.4 million in the prior quarter. The increase in non-interest expense over the same period last year was mainly due to higher salaries and benefits expense, data processing and software, and professional and other services expense.
Compared to the 3rd quarter of 2024, salaries and employee benefits expense increased $4.3 million, or 2.8%, mostly due to higher full-time salaries of $3.0 million and higher incentive compensation of $1.4 million, partly offset by lower healthcare expense of $805 thousand. Full-time equivalent employees totaled 4,666 and 4,711 on September 30, 2025 and 2024, respectively.
Compared to the same period last year, data processing and software expense increased $1.4 million due to higher costs for service providers and software. Professional and other services, which increased $2.5 million compared to the 3rd quarter of 2024, included $1.1 million of acquisition related legal and professional services expense. Other non-interest expense decreased mainly due to a $1.5 million reimbursement during the 3rd quarter of 2025 related to a litigation settlement.
Income Taxes
The effective tax rate for the Company was 22.5% in the current quarter, 21.8% in the prior quarter, and 21.7% in the 3rd quarter of 2024. The increase in the effective tax rate compared to the prior quarter was mostly due to tax law changes enacted in the prior quarter that decreased the effective tax rate. The increase in the effective tax rate compared to the 3rd quarter of 2024 was mostly due to higher state and local income taxes.
Credit Quality
Net loan charge-offs in the 3rd quarter of 2025 amounted to $10.3 million, compared to $9.7 million in the prior quarter, and $9.6 million in the same period last year. The ratio of annualized net loan charge-offs to total average loans was .23% in the current quarter, .22% in the previous quarter, and .22% in the same quarter of last year. Compared to the prior quarter, net loan charge-offs on business real estate, business and personal real estate loans increased $402 thousand, $394 thousand and $234 thousand, respectively, while net charge-offs on consumer credit card loans decreased $570 thousand.
In the 3rd quarter of 2025, annualized net loan charge-offs on average consumer credit card loans were 4.59%, compared to 5.08% in the previous quarter and 4.46% in the same quarter last year. Consumer loan net charge-offs were .42% of average consumer loans in the current quarter, .40% in the prior quarter, and .52% in the same quarter last year.
On September 30, 2025, the allowance for credit losses on loans totaled $175.7 million, or .99% of total loans, and increased $10.4 million compared to the prior quarter. The increase in the allowance for credit losses on loans was primarily due to weakness in soft commodity prices impacting certain industries. Additionally, the liability for unfunded lending commitments on September 30, 2025 was $15.3 million, a decrease of $678 thousand compared to the liability on June 30, 2025.
On September 30, 2025, total non-accrual loans amounted to $16.3 million, a decrease of $2.6 million
10
Exhibit 99.1
COMMERCE BANCSHARES, INC.
Management Discussion of Third Quarter Results
September 30, 2025
compared to the previous quarter. On September 30, 2025, the balance of non-accrual loans, which represented .09% of loans outstanding, included business real estate loans of $14.9 million, personal real estate loans of $867 thousand, business loans of $255 thousand and construction loans of $191 thousand. Loans more than 90 days past due and still accruing interest totaled $21.5 million on September 30, 2025.
Other
During the 3rd quarter of 2025, the Company paid a cash dividend of $.275 per common share, representing a 7.0% increase over the same period last year. The Company purchased 418,131 shares of treasury stock during the current quarter at an average price of $60.32.
On June 16, 2025, the Company announced that it has entered into a definitive merger agreement to acquire FineMark Holdings, Inc. (OTCQX:FNBT) (“FineMark”), Ft. Meyers, Florida, with 13 banking locations in Florida, Arizona, and South Carolina. As of June 30, 2025, FineMark had loans and deposits of $2.7 billion and $3.1 billion, respectively, and $8.3 billion of assets under administration. The Company has received all regulatory approvals to complete its proposed merger. The transaction has been approved by the Federal Reserve Bank of Kansas City, the Missouri Division of Finance, and FineMark shareholders. The transaction remains subject to customary closing conditions and is anticipated to close on January 1, 2026.
Forward Looking Information
This information contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements include future financial and operating results, expectations, intentions, and other statements that are not historical facts. Such statements are based on current beliefs and expectations of the Company’s management and are subject to significant risks and uncertainties. Actual results may differ materially from those set forth in the forward-looking statements. Additional information about risks and uncertainties is included in the “Risk Factors” and “Management’s Discussion and Analysis of Financial Condition and Results of Operations” sections within the Company's Annual Report on Form 10-K.
11
COMMERCE BANCSHARES, INC. EARNINGS HIGHLIGHTS 3rd Quarter 2025
DISCLOSURES 2 CAUTIONARY NOTE REGARDING FORWARD-LOOKING STATEMENTS This presentation may contain forward-looking statements, including, but not limited to, certain plans, expectations, goals, projections, and statements about the benefits of the proposed business combination transaction between Commerce Bancshares, Inc. (“Commerce”) and FineMark Holdings, Inc. (“FineMark”) (the “Proposed Transaction”), the plans, objectives, expectations and intentions of Commerce and FineMark, the expected timing of completion of the Proposed Transaction, and other statements that are not historical facts. All statements other than statements of historical fact, including statements about beliefs and expectations, are forward-looking statements. Forward-looking statements may be identified by words such as “may,” “will,” “should,” “could,” “would,” “plan,” “potential,” “estimate,” “project,” “believe,” “intend,” “anticipate,” “expect,” “target” and similar expressions. Forward-looking statements, by their nature, are subject to risks and uncertainties. There are many factors that could cause actual results to differ materially from expected results described in the forward-looking statements. The forward-looking statements are intended to be subject to the safe harbor provided by Section 27A of the Securities Act of 1933, as amended, Section 21E of the Securities Exchange Act of 1934, as amended, and the Private Securities Litigation Reform Act of 1995. Factors relating to the Proposed Transaction that could cause or contribute to actual results differing materially from those contained or implied in forward-looking statements or historical performance include, in addition to those factors identified elsewhere in this presentation the occurrence of any event, change or other circumstances that could give rise to the right of Commerce or FineMark to terminate the definitive merger agreement governing the terms and conditions of the Proposed Transaction; the outcome of any legal proceedings that may be instituted against Commerce or FineMark; the possibility that revenue or expense synergies or the other expected benefits of the Proposed Transaction may not fully materialize or may take longer to realize than expected, or may be more costly to achieve than anticipated, including as a result of the impact of, or problems arising from, the integration of the two companies, the strength of the economy and competitive factors in the areas where Commerce and FineMark do business, or other unexpected factors or events; the possibility that the Proposed Transaction may not be completed when expected or at all because conditions to closing are not satisfied on a timely basis or at all; the risk that Commerce is unable to successfully and promptly implement its integration strategies; reputational risks and potential adverse reactions from or changes to the relationships with the companies’ customers, employees or other business partners, including resulting from the announcement or the completion of the Proposed Transaction; the dilution caused by Commerce’s issuance of common stock in connection with the Proposed Transaction; diversion of management’s attention and time from ongoing business operations and other opportunities on matters relating to the Proposed Transaction; and other factors that may affect the future results of Commerce and FineMark, including continued pressures and uncertainties within the banking industry and Commerce’s and FineMark’s markets, including changes in interest rates and deposit amounts and composition, adverse developments in the level and direction of loan delinquencies, charge-offs, and estimates of the adequacy of the allowance for loan losses, increased competitive pressures, asset and credit quality deterioration, the impact of proposed or imposed tariffs by the U.S. government or retaliatory tariffs proposed or imposed by U.S. trading partners that could have an adverse impact on customers or any recession or slowdown in economic growth particularly in the markets in which Commerce or FineMark operate, and legislative, regulatory, and fiscal policy changes and related compliance costs. These factors are not necessarily all of the factors that could cause Commerce’s or FineMark’s actual results, performance, or achievements to differ materially from those expressed in or implied by any of the forward-looking statements. Other unknown or unpredictable factors also could harm Commerce’s or FineMark’s results. Further information regarding Commerce and factors that could affect the forward-looking statements contained herein can be found in Commerce’s Annual Report on Form 10-K for the year ended December 31, 2024, which is accessible on the Securities and Exchange Commission’s (the “SEC”) website at www.sec.gov and at Investor.Commercebank.com, and in other documents Commerce files with the SEC. Information on these websites is not part of this document. All forward-looking statements attributable to Commerce or FineMark, or persons acting on Commerce’s or FineMark’s behalf, are expressly qualified in their entirety by the cautionary statements set forth above. Forward-looking statements speak only as of the date they are made and Commerce and FineMark do not undertake or assume any obligation to update publicly any of these statements to reflect actual results, new information or future events, changes in assumptions, or changes in other factors affecting forward-looking statements, except to the extent required by applicable law. If Commerce or FineMark update one or more forward-looking statements, no inference should be drawn that Commerce or FineMark will make additional updates with respect to those or other forward-looking statements.
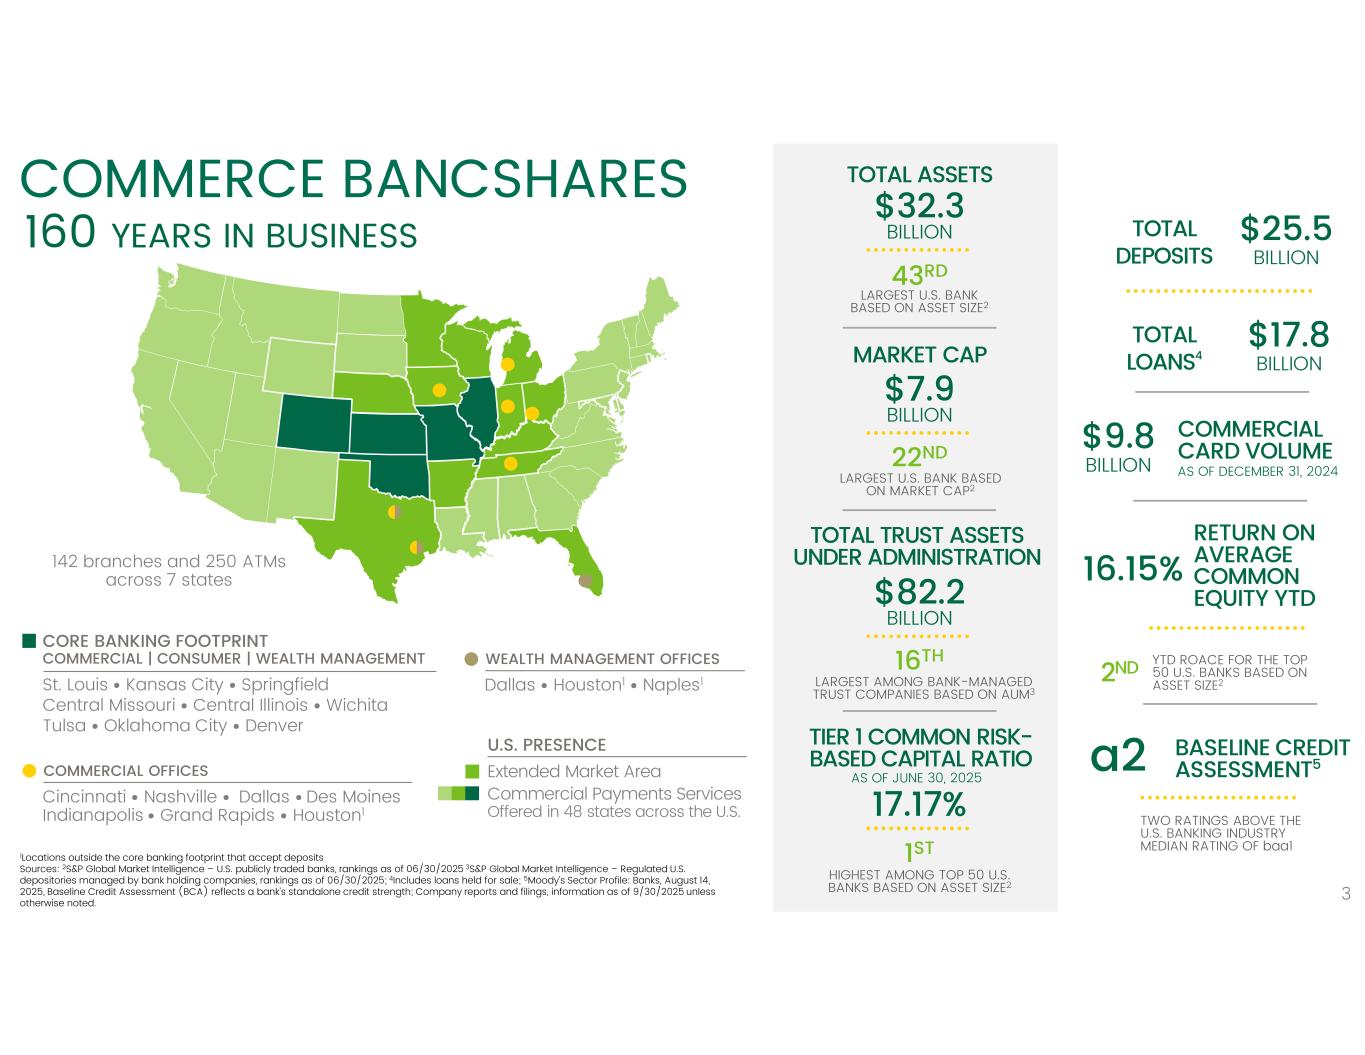
COMMERCE BANCSHARES 160 YEARS IN BUSINESS 142 branches and 250 ATMs across 7 states CORE BANKING FOOTPRINT COMMERCIAL | CONSUMER | WEALTH MANAGEMENT St. Louis • Kansas City • Springfield Central Missouri • Central Illinois • Wichita Tulsa • Oklahoma City • Denver COMMERCIAL OFFICES Cincinnati • Nashville • Dallas • Des Moines Indianapolis • Grand Rapids • Houston1 WEALTH MANAGEMENT OFFICES Dallas • Houston1 • Naples1 U.S. PRESENCE Extended Market Area Commercial Payments Services Offered in 48 states across the U.S. $32.3 BILLION TOTAL ASSETS 43RD LARGEST U.S. BANK BASED ON ASSET SIZE2 $7.9 BILLION MARKET CAP 22ND LARGEST U.S. BANK BASED ON MARKET CAP2 $82.2 BILLION TOTAL TRUST ASSETS UNDER ADMINISTRATION 16TH LARGEST AMONG BANK-MANAGED TRUST COMPANIES BASED ON AUM3 17.17% TIER 1 COMMON RISK- BASED CAPITAL RATIO 1ST HIGHEST AMONG TOP 50 U.S. BANKS BASED ON ASSET SIZE2 AS OF JUNE 30, 2025 $25.5 BILLION TOTAL DEPOSITS $17.8 BILLION TOTAL LOANS4 $9.8 BILLION COMMERCIAL CARD VOLUME AS OF DECEMBER 31, 2024 16.15% RETURN ON AVERAGE COMMON EQUITY YTD 2ND YTD ROACE FOR THE TOP 50 U.S. BANKS BASED ON ASSET SIZE2 a2 BASELINE CREDIT ASSESSMENT5 TWO RATINGS ABOVE THE U.S. BANKING INDUSTRY MEDIAN RATING OF baa1 3 1Locations outside the core banking footprint that accept deposits Sources: 2S&P Global Market Intelligence – U.S. publicly traded banks, rankings as of 06/30/2025 3S&P Global Market Intelligence – Regulated U.S. depositories managed by bank holding companies, rankings as of 06/30/2025; 4Includes loans held for sale; 5Moody’s Sector Profile: Banks, August 14, 2025, Baseline Credit Assessment (BCA) reflects a bank’s standalone credit strength; Company reports and filings, information as of 9/30/2025 unless otherwise noted.
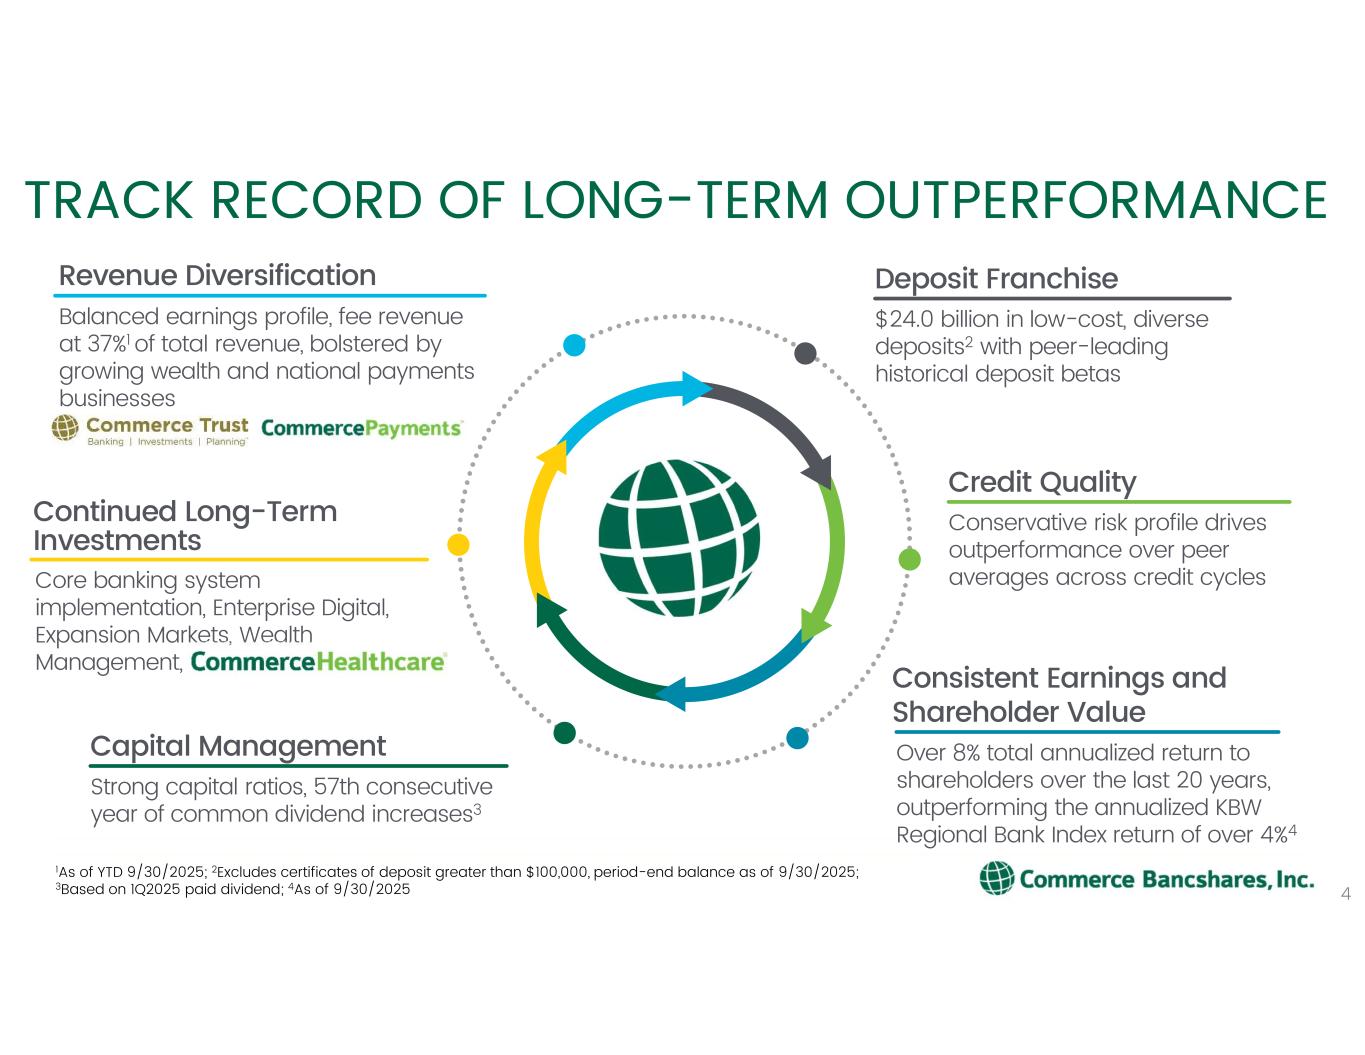
TRACK RECORD OF LONG-TERM OUTPERFORMANCE Revenue Diversification Balanced earnings profile, fee revenue at 37%1 of total revenue, bolstered by growing wealth and national payments businesses Deposit Franchise $24.0 billion in low-cost, diverse deposits2 with peer-leading historical deposit betas Credit Quality Conservative risk profile drives outperformance over peer averages across credit cycles Consistent Earnings and Shareholder Value Over 8% total annualized return to shareholders over the last 20 years, outperforming the annualized KBW Regional Bank Index return of over 4%4 Capital Management Strong capital ratios, 57th consecutive year of common dividend increases3 Continued Long-Term Investments Core banking system implementation, Enterprise Digital, Expansion Markets, Wealth Management, 1As of YTD 9/30/2025; 2Excludes certificates of deposit greater than $100,000, period-end balance as of 9/30/2025; 3Based on 1Q2025 paid dividend; 4As of 9/30/2025 4
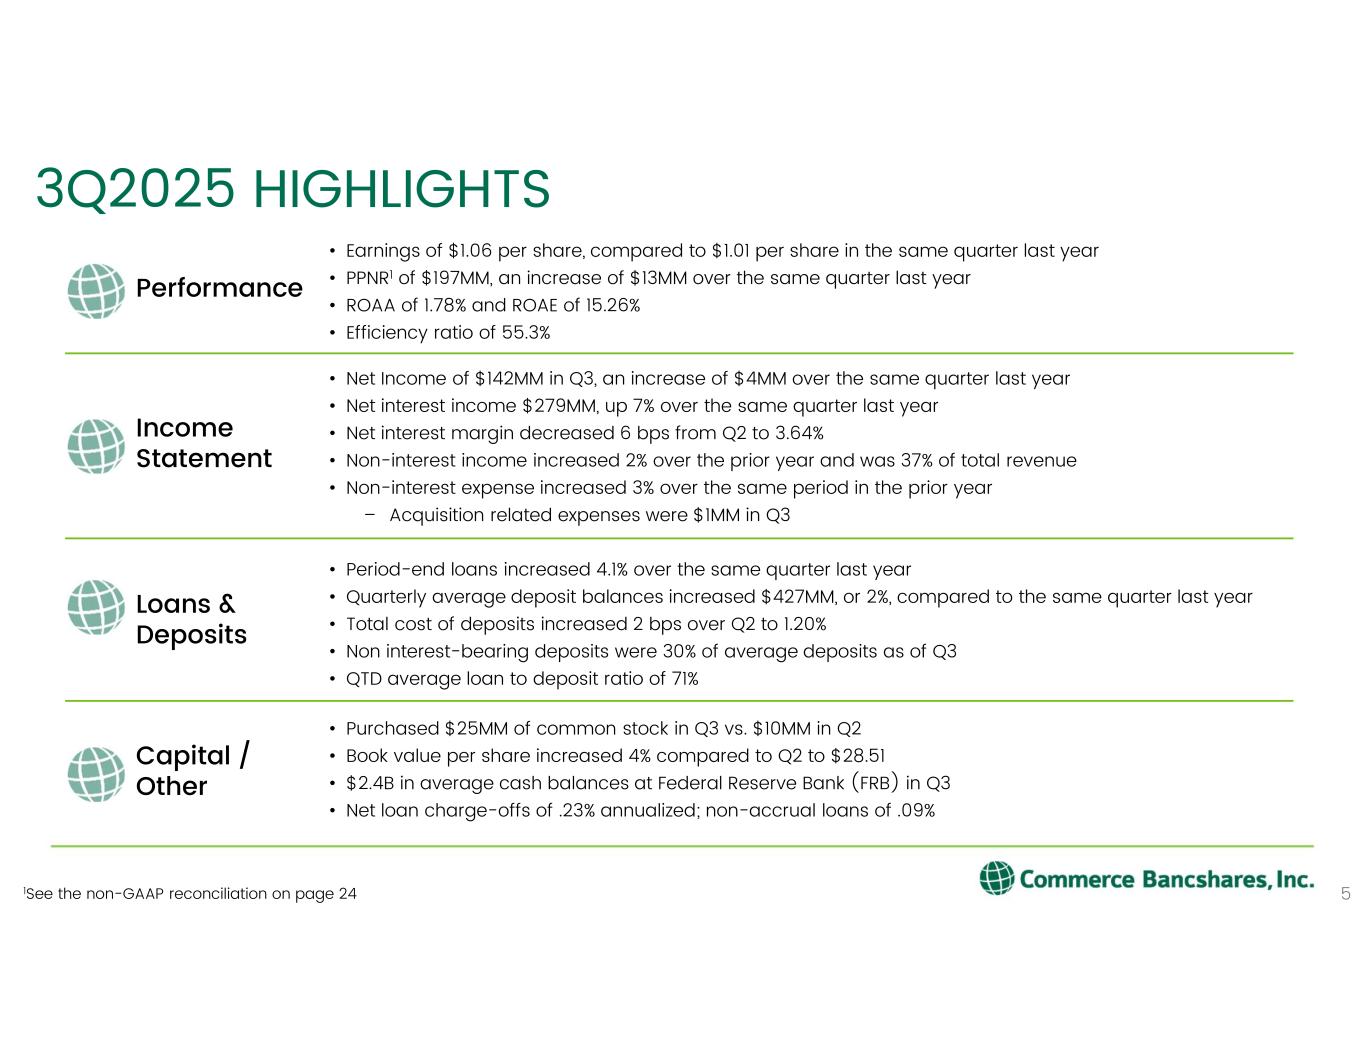
3Q2025 HIGHLIGHTS • Earnings of $1.06 per share, compared to $1.01 per share in the same quarter last year • PPNR1 of $197MM, an increase of $13MM over the same quarter last year • ROAA of 1.78% and ROAE of 15.26% • Efficiency ratio of 55.3% • Net Income of $142MM in Q3, an increase of $4MM over the same quarter last year • Net interest income $279MM, up 7% over the same quarter last year • Net interest margin decreased 6 bps from Q2 to 3.64% • Non-interest income increased 2% over the prior year and was 37% of total revenue • Non-interest expense increased 3% over the same period in the prior year – Acquisition related expenses were $1MM in Q3 • Period-end loans increased 4.1% over the same quarter last year • Quarterly average deposit balances increased $427MM, or 2%, compared to the same quarter last year • Total cost of deposits increased 2 bps over Q2 to 1.20% • Non interest-bearing deposits were 30% of average deposits as of Q3 • QTD average loan to deposit ratio of 71% • Purchased $25MM of common stock in Q3 vs. $10MM in Q2 • Book value per share increased 4% compared to Q2 to $28.51 • $2.4B in average cash balances at Federal Reserve Bank (FRB) in Q3 • Net loan charge-offs of .23% annualized; non-accrual loans of .09% 51See the non-GAAP reconciliation on page 24 Performance Income Statement Loans & Deposits Capital / Other
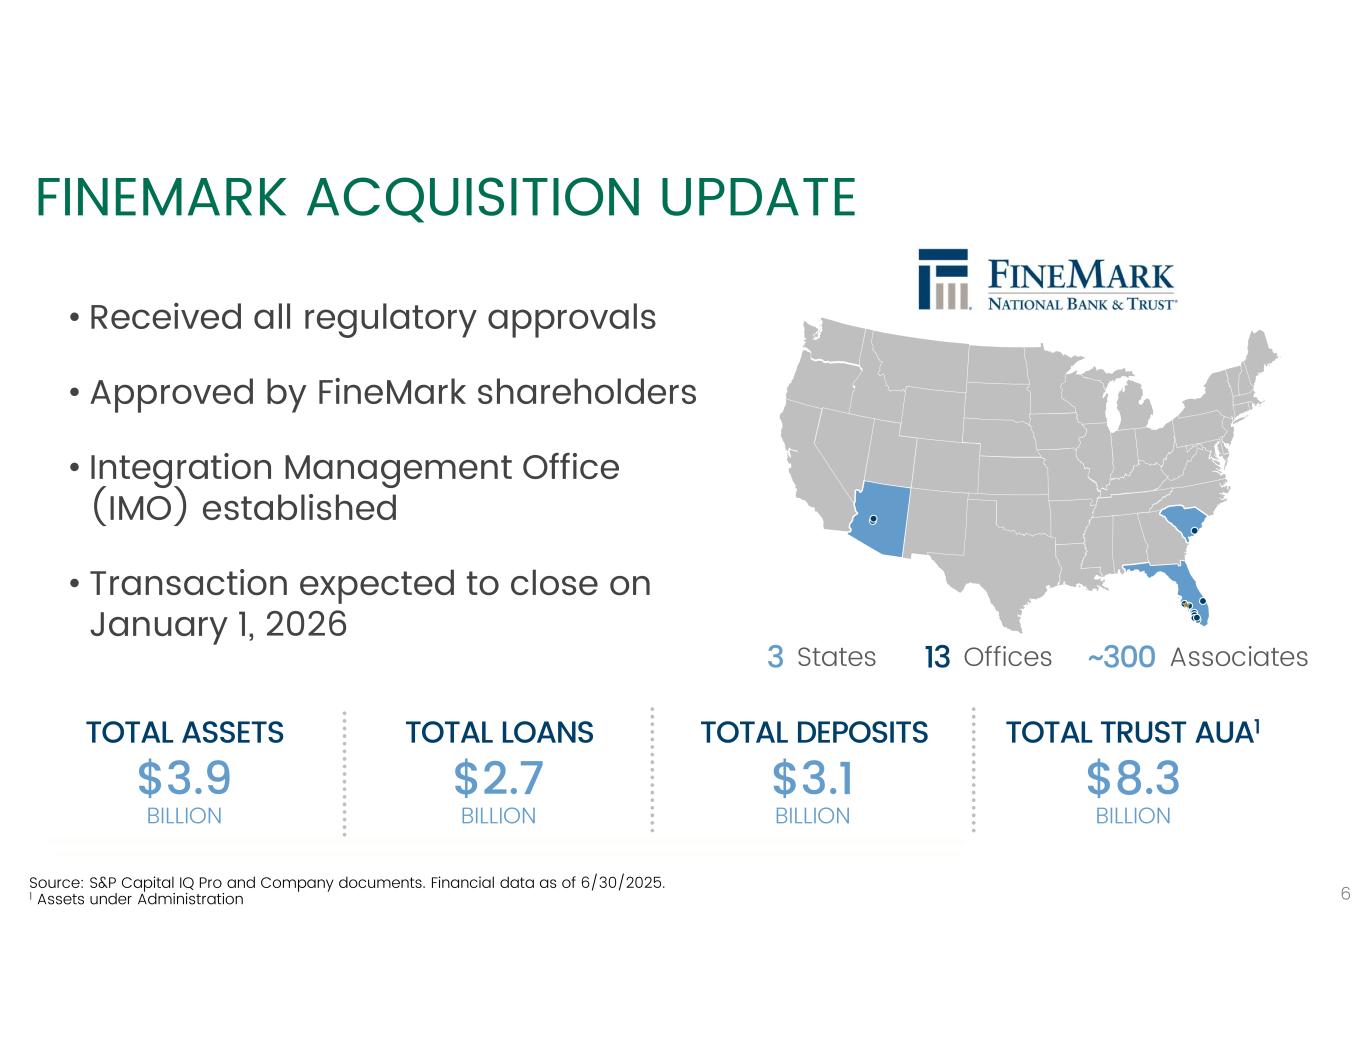
FINEMARK ACQUISITION UPDATE • Received all regulatory approvals • Approved by FineMark shareholders • Integration Management Office (IMO) established • Transaction expected to close on January 1, 2026 3 States 13 Offices ~300 Associates 6Source: S&P Capital IQ Pro and Company documents. Financial data as of 6/30/2025. 1 Assets under Administration TOTAL ASSETS TOTAL TRUST AUA1 $3.1 BILLION TOTAL DEPOSITS $3.9 BILLION TOTAL LOANS $2.7 BILLION $8.3 BILLION
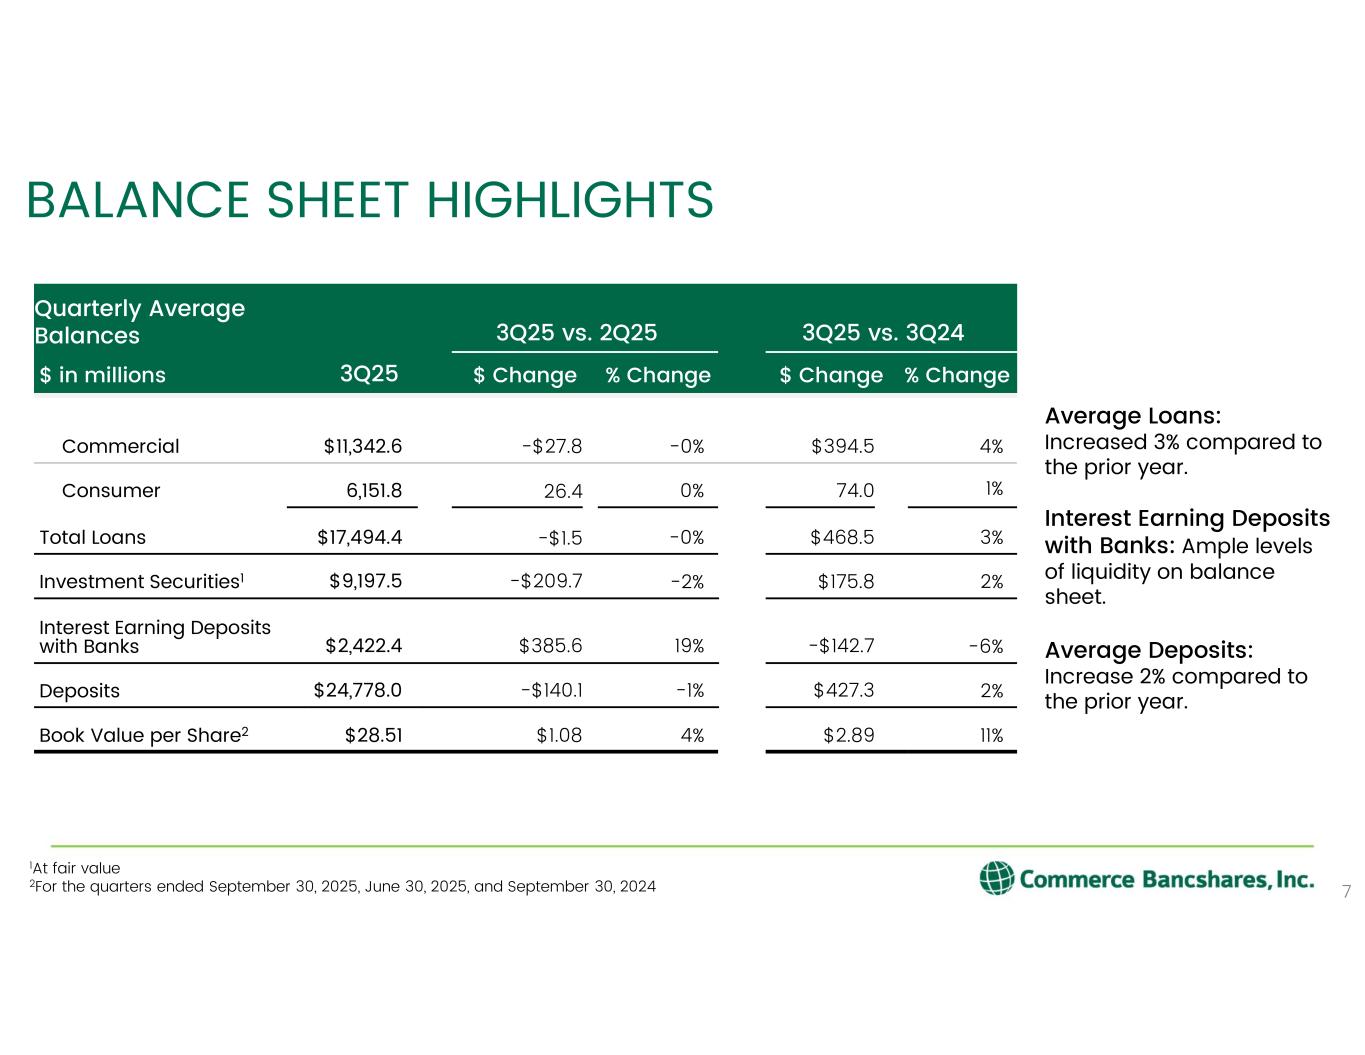
BALANCE SHEET HIGHLIGHTS 3Q25 vs. 3Q24 3Q25 vs. 2Q25 Quarterly Average Balances % Change$ Change% Change$ Change3Q25$ in millions 4%$394.5-0%-$27.8$11,342.6Commercial 1%74.00%26.46,151.8Consumer 3%$468.5-0%-$1.5$17,494.4Total Loans 2%$175.8-2%-$209.7$9,197.5Investment Securities1 -6%-$142.719%$385.6$2,422.4 Interest Earning Deposits with Banks 2%$427.3-1%-$140.1$24,778.0Deposits 11%$2.894%$1.08$28.51Book Value per Share2 Average Loans: Increased 3% compared to the prior year. Interest Earning Deposits with Banks: Ample levels of liquidity on balance sheet. Average Deposits: Increase 2% compared to the prior year. 1At fair value 2For the quarters ended September 30, 2025, June 30, 2025, and September 30, 2024 7
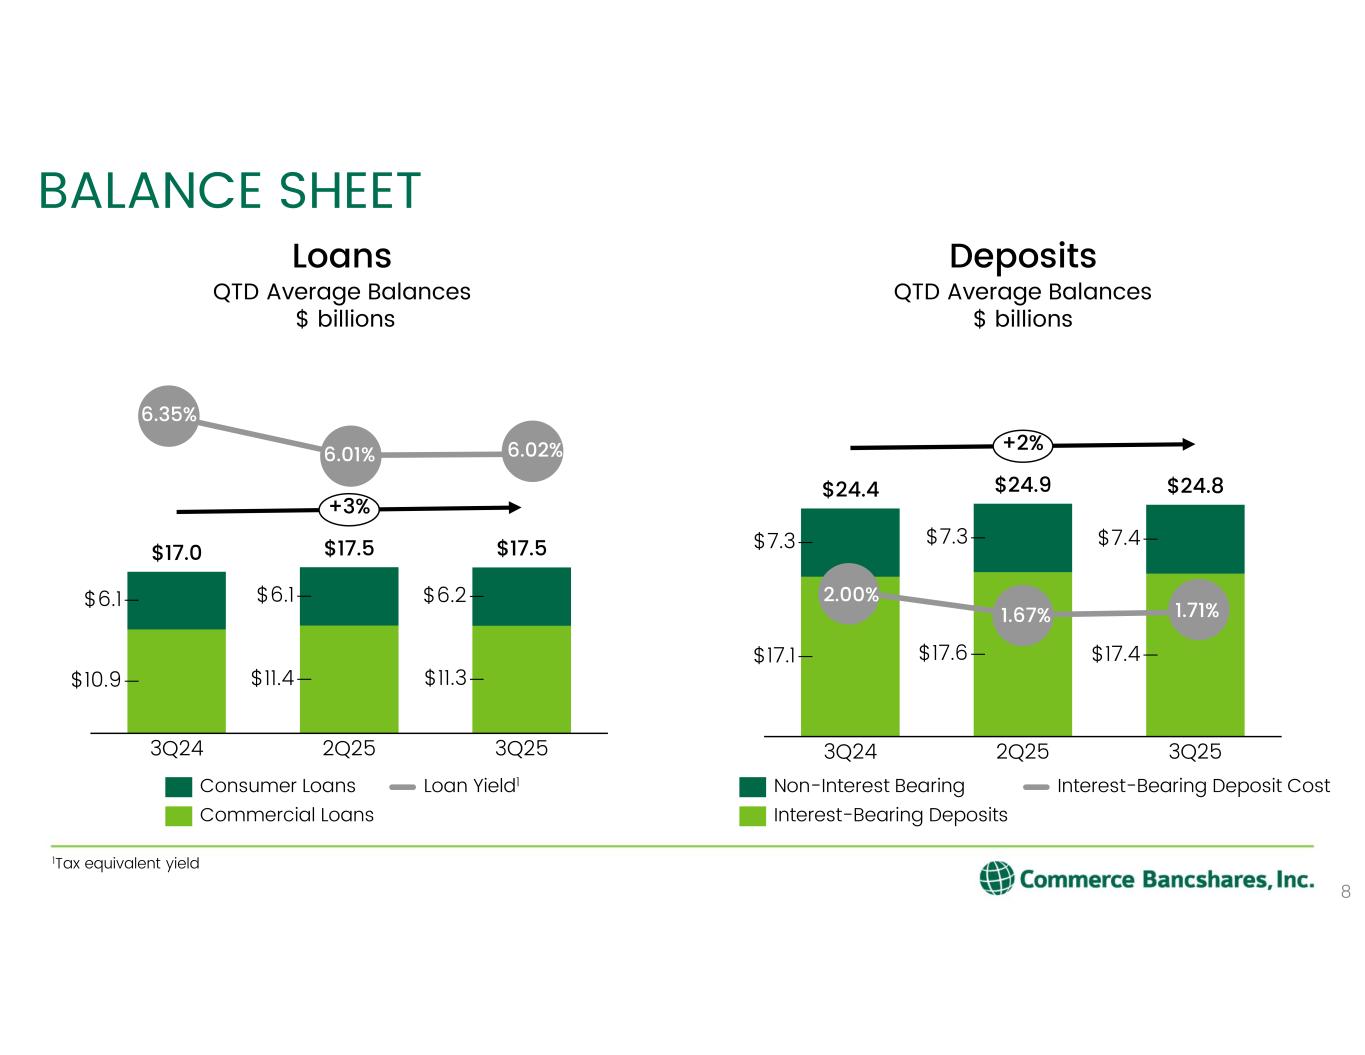
$17.1 $17.6 $17.4 $7.3 $7.3 $7.4 3Q24 2Q25 3Q25 $24.4 $24.9 $24.8 +2% $10.9 $11.4 $11.3 $6.1 $6.1 $6.2 3Q24 2Q25 3Q25 $17.0 $17.5 $17.5 +3% BALANCE SHEET 8 Loans Consumer Loans Commercial Loans Loan Yield1 Deposits QTD Average Balances $ billions Non-Interest Bearing Interest-Bearing Deposits Interest-Bearing Deposit Cost QTD Average Balances $ billions 6.35% 6.01% 6.02% 2.00% 1.67% 1.71% 1Tax equivalent yield
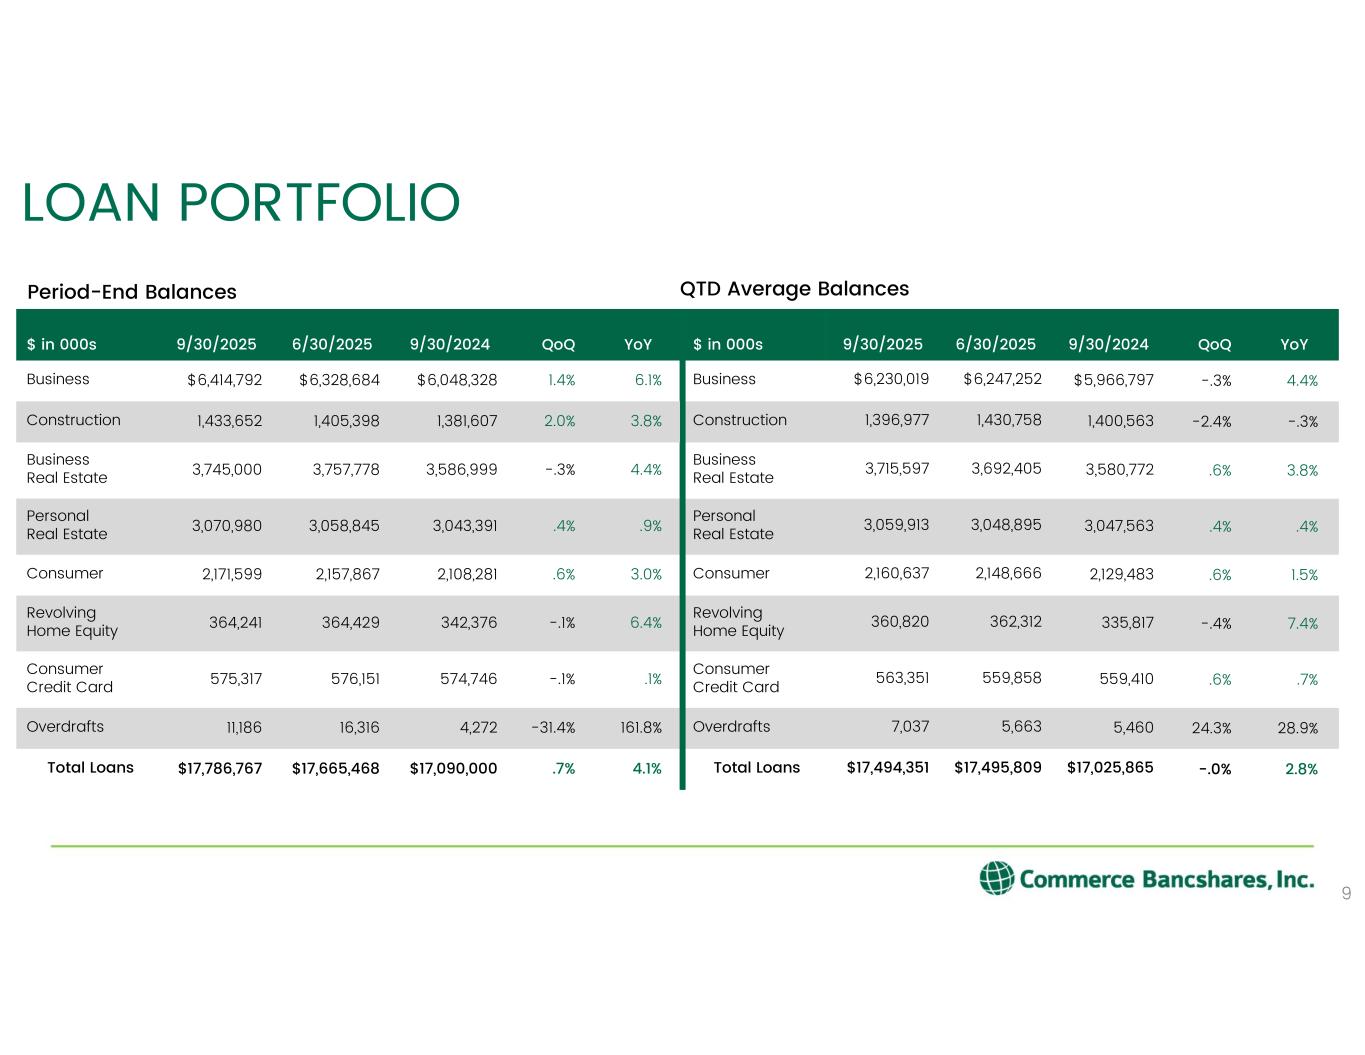
LOAN PORTFOLIO 9 YoYQoQ9/30/20246/30/20259/30/2025$ in 000s 6.1%1.4%$6,048,328 $6,328,684$6,414,792Business 3.8%2.0%1,381,6071,405,3981,433,652Construction 4.4%-.3%3,586,9993,757,7783,745,000Business Real Estate .9%.4%3,043,3913,058,8453,070,980Personal Real Estate 3.0%.6%2,108,2812,157,8672,171,599Consumer 6.4%-.1%342,376364,429364,241Revolving Home Equity .1%-.1%574,746576,151575,317Consumer Credit Card 161.8%-31.4%4,27216,31611,186Overdrafts 4.1%.7%$17,090,000$17,665,468$17,786,767Total Loans Period-End Balances YoYQoQ9/30/20246/30/20259/30/2025$ in 000s 4.4%-.3%$5,966,797$6,247,252$6,230,019 Business -.3%-2.4%1,400,5631,430,7581,396,977Construction 3.8%.6%3,580,7723,692,4053,715,597Business Real Estate .4%.4%3,047,5633,048,8953,059,913Personal Real Estate 1.5%.6%2,129,4832,148,6662,160,637Consumer 7.4%-.4%335,817362,312360,820Revolving Home Equity .7%.6%559,410559,858563,351Consumer Credit Card 28.9%24.3%5,4605,6637,037Overdrafts 2.8%-.0%$17,025,865$17,495,809$17,494,351Total Loans QTD Average Balances
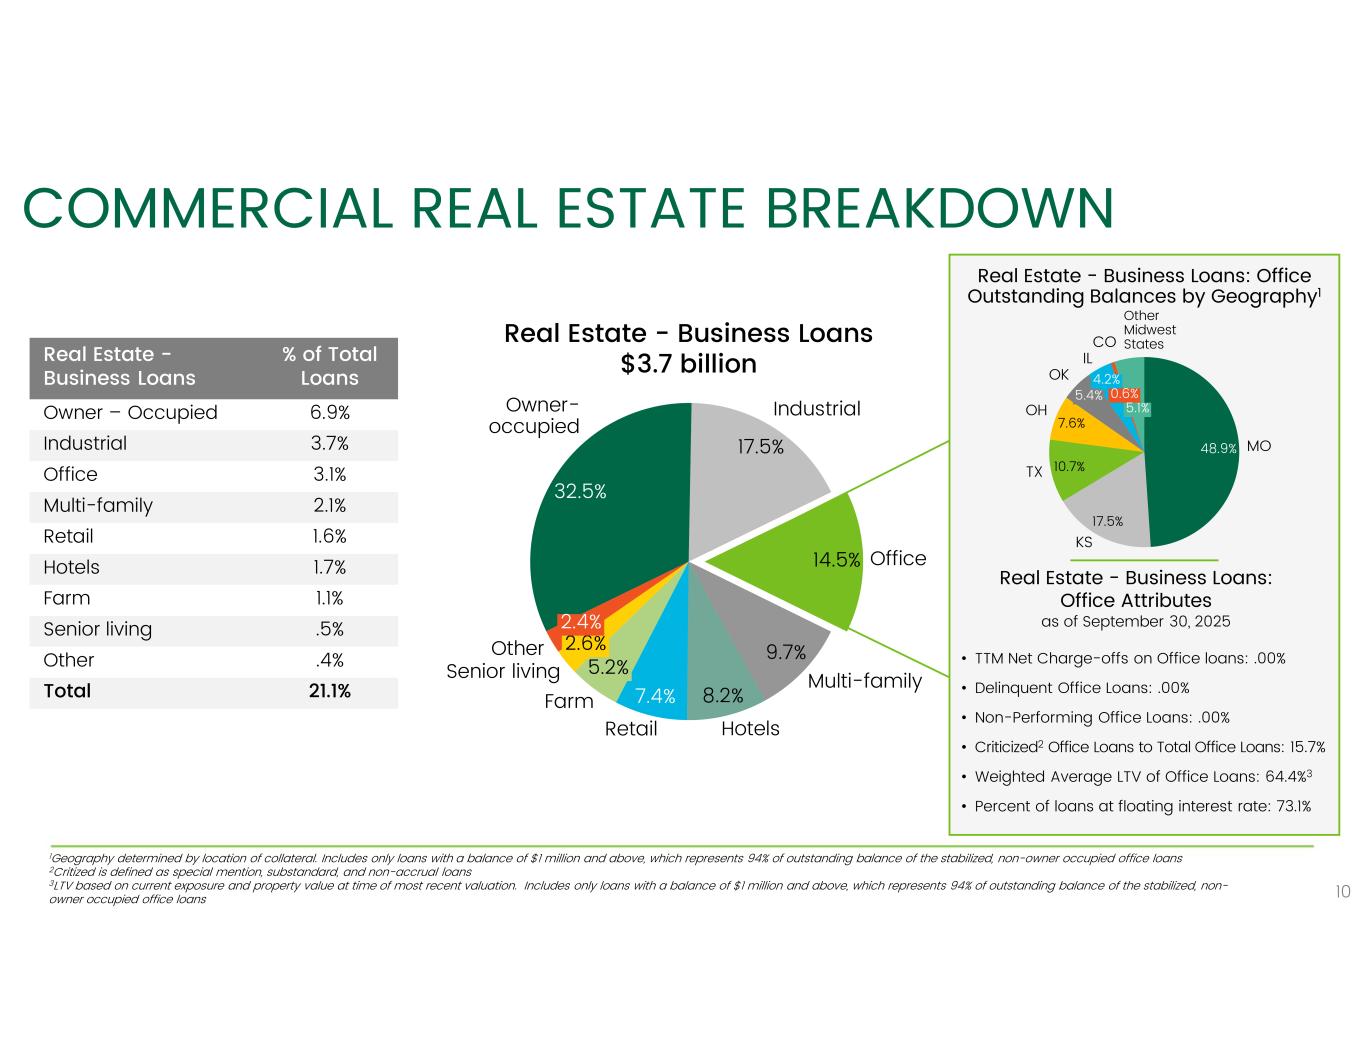
32.5% 17.5% 14.5% 9.7% 8.2%7.4% Owner- occupied Industrial Office Multi-family Retail Hotels Farm 2.6% Senior living 2.4% Other 5.2% Real Estate - Business Loans: Office Outstanding Balances by Geography1 % of Total Loans Real Estate - Business Loans 6.9%Owner – Occupied 3.7%Industrial 3.1%Office 2.1%Multi-family 1.6%Retail 1.7%Hotels 1.1%Farm .5%Senior living .4%Other 21.1%Total COMMERCIAL REAL ESTATE BREAKDOWN 10 Real Estate - Business Loans $3.7 billion 1Geography determined by location of collateral. Includes only loans with a balance of $1 million and above, which represents 94% of outstanding balance of the stabilized, non-owner occupied office loans 2Critized is defined as special mention, substandard, and non-accrual loans 3LTV based on current exposure and property value at time of most recent valuation. Includes only loans with a balance of $1 million and above, which represents 94% of outstanding balance of the stabilized, non- owner occupied office loans Real Estate - Business Loans: Office Attributes as of September 30, 2025 48.9% 17.5% 10.7% 7.6% MO KS TX OH 5.4% OK 4.2% IL 0.6% CO 5.1% Other Midwest States • TTM Net Charge-offs on Office loans: .00% • Delinquent Office Loans: .00% • Non-Performing Office Loans: .00% • Criticized2 Office Loans to Total Office Loans: 15.7% • Weighted Average LTV of Office Loans: 64.4%3 • Percent of loans at floating interest rate: 73.1%
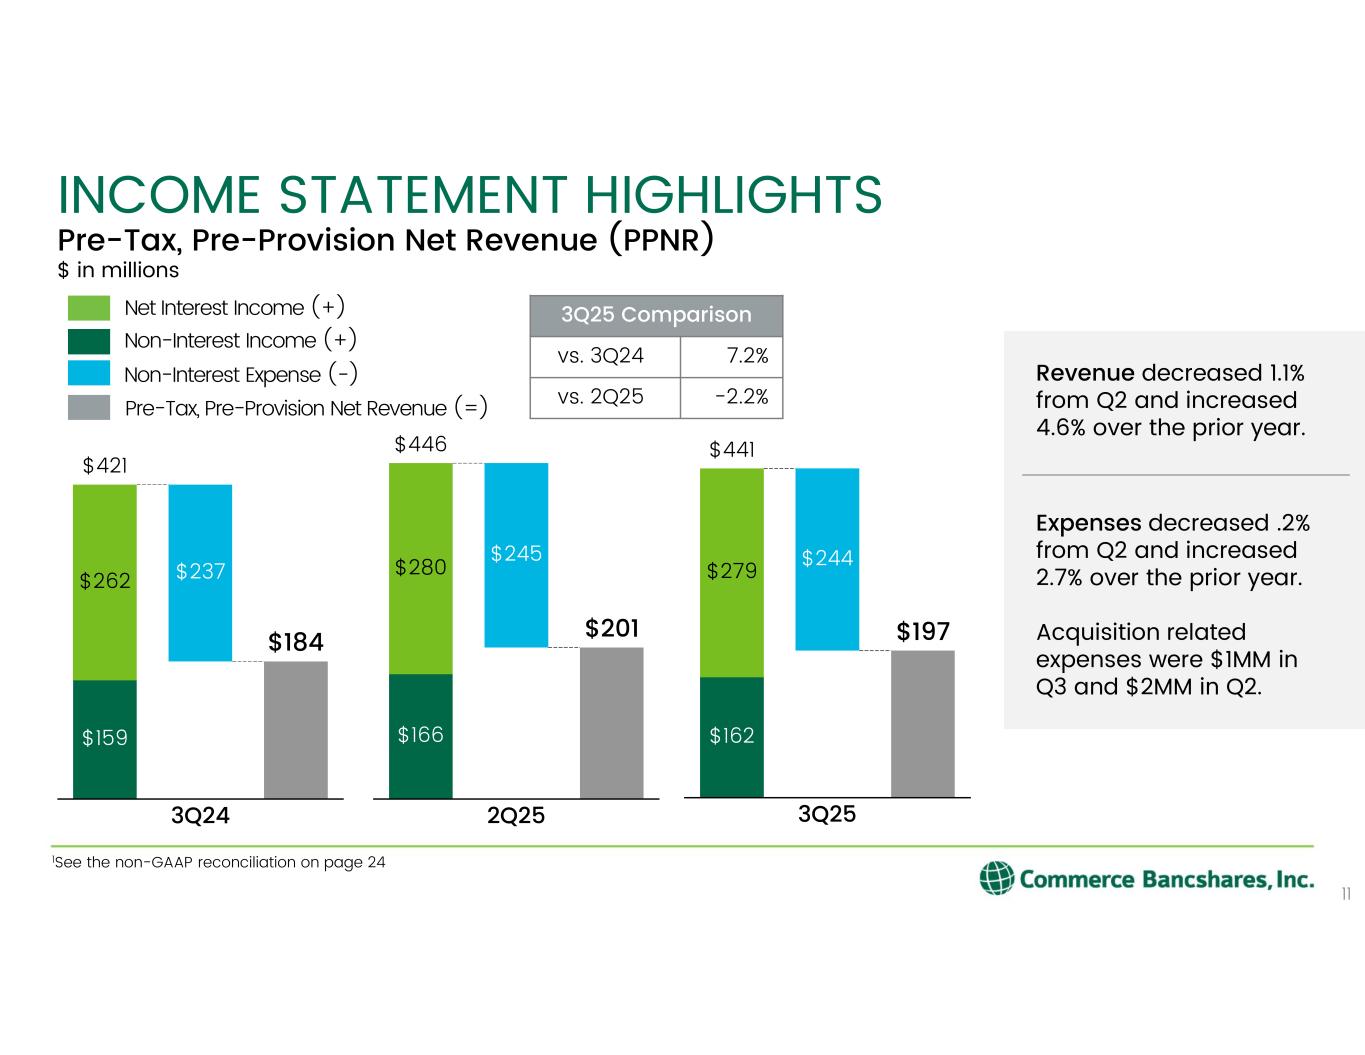
$166 $201 $280 $245 2Q25 $446 11 INCOME STATEMENT HIGHLIGHTS $159 $184 $262 $237 3Q24 $421 $162 $197 $279 $244 3Q25 $441 Non-Interest Income (+) Net Interest Income (+) Non-Interest Expense (-) Pre-Tax, Pre-Provision Net Revenue (=) 3Q25 Comparison 7.2%vs. 3Q24 -2.2%vs. 2Q25 Pre-Tax, Pre-Provision Net Revenue (PPNR) $ in millions Expenses decreased .2% from Q2 and increased 2.7% over the prior year. Acquisition related expenses were $1MM in Q3 and $2MM in Q2. Revenue decreased 1.1% from Q2 and increased 4.6% over the prior year. 1See the non-GAAP reconciliation on page 24
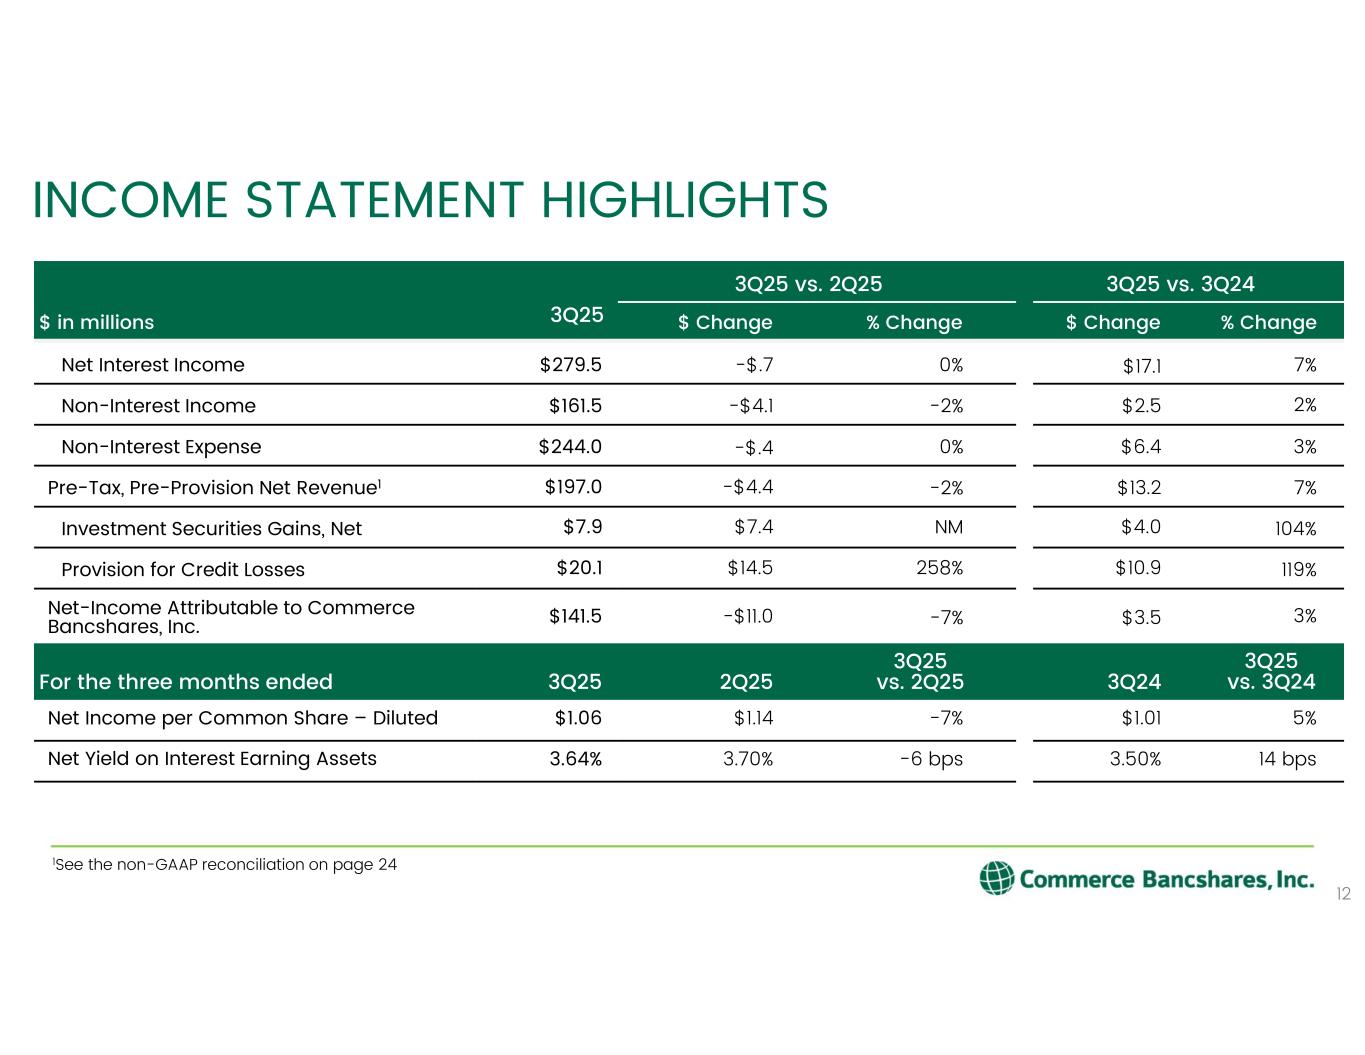
3Q25 vs. 3Q24 3Q25 vs. 2Q25 % Change$ Change% Change$ Change3Q25$ in millions 7%$17.10%-$.7$279.5Net Interest Income 2%$2.5-2%-$4.1$161.5Non-Interest Income 3%$6.40%-$.4$244.0Non-Interest Expense 7%$13.2-2%-$4.4$197.0Pre-Tax, Pre-Provision Net Revenue1 104%$4.0NM$7.4$7.9Investment Securities Gains, Net 119%$10.9258%$14.5$20.1Provision for Credit Losses 3%$3.5-7%-$11.0$141.5Net-Income Attributable to Commerce Bancshares, Inc. 3Q25 vs. 3Q243Q24 3Q25 vs. 2Q252Q253Q25For the three months ended 5%$1.01-7%$1.14$1.06Net Income per Common Share – Diluted 14 bps3.50%-6 bps3.70%3.64%Net Yield on Interest Earning Assets INCOME STATEMENT HIGHLIGHTS 1See the non-GAAP reconciliation on page 24 12
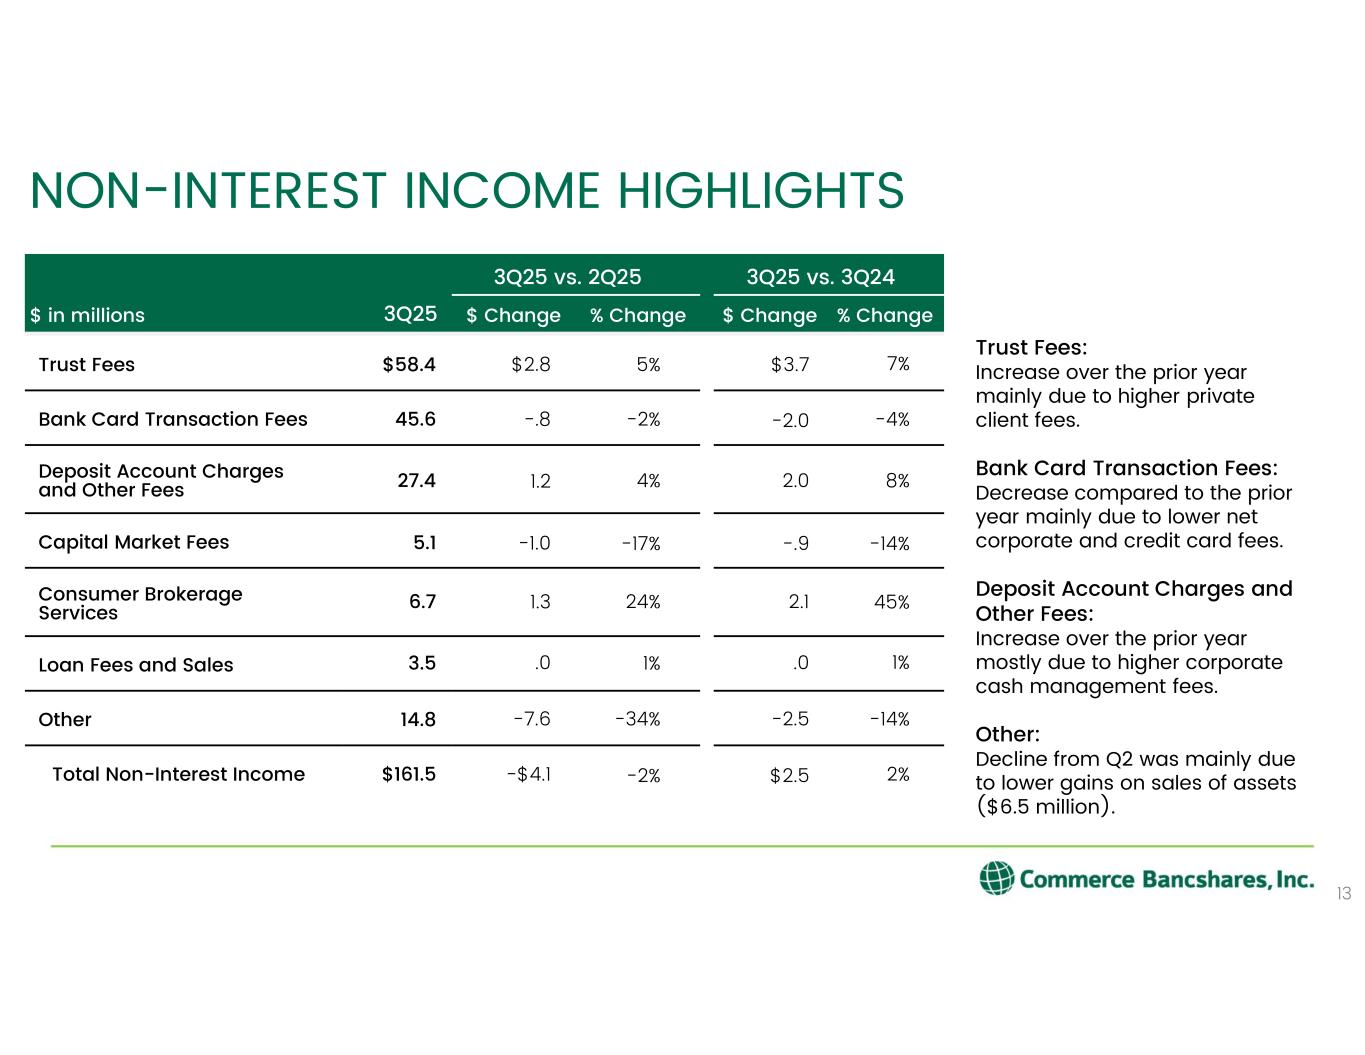
NON-INTEREST INCOME HIGHLIGHTS 13 3Q25 vs. 3Q24 3Q25 vs. 2Q25 % Change$ Change% Change$ Change3Q25$ in millions 7%$3.75%$2.8$58.4Trust Fees -4%-2.0-2%-.845.6Bank Card Transaction Fees 8%2.04%1.227.4Deposit Account Charges and Other Fees -14%-.9-17%-1.05.1Capital Market Fees 45%2.124%1.36.7Consumer Brokerage Services 1%.01%.03.5Loan Fees and Sales -14%-2.5-34%-7.614.8Other 2%$2.5-2%-$4.1$161.5Total Non-Interest Income Trust Fees: Increase over the prior year mainly due to higher private client fees. Bank Card Transaction Fees: Decrease compared to the prior year mainly due to lower net corporate and credit card fees. Deposit Account Charges and Other Fees: Increase over the prior year mostly due to higher corporate cash management fees. Other: Decline from Q2 was mainly due to lower gains on sales of assets ($6.5 million).
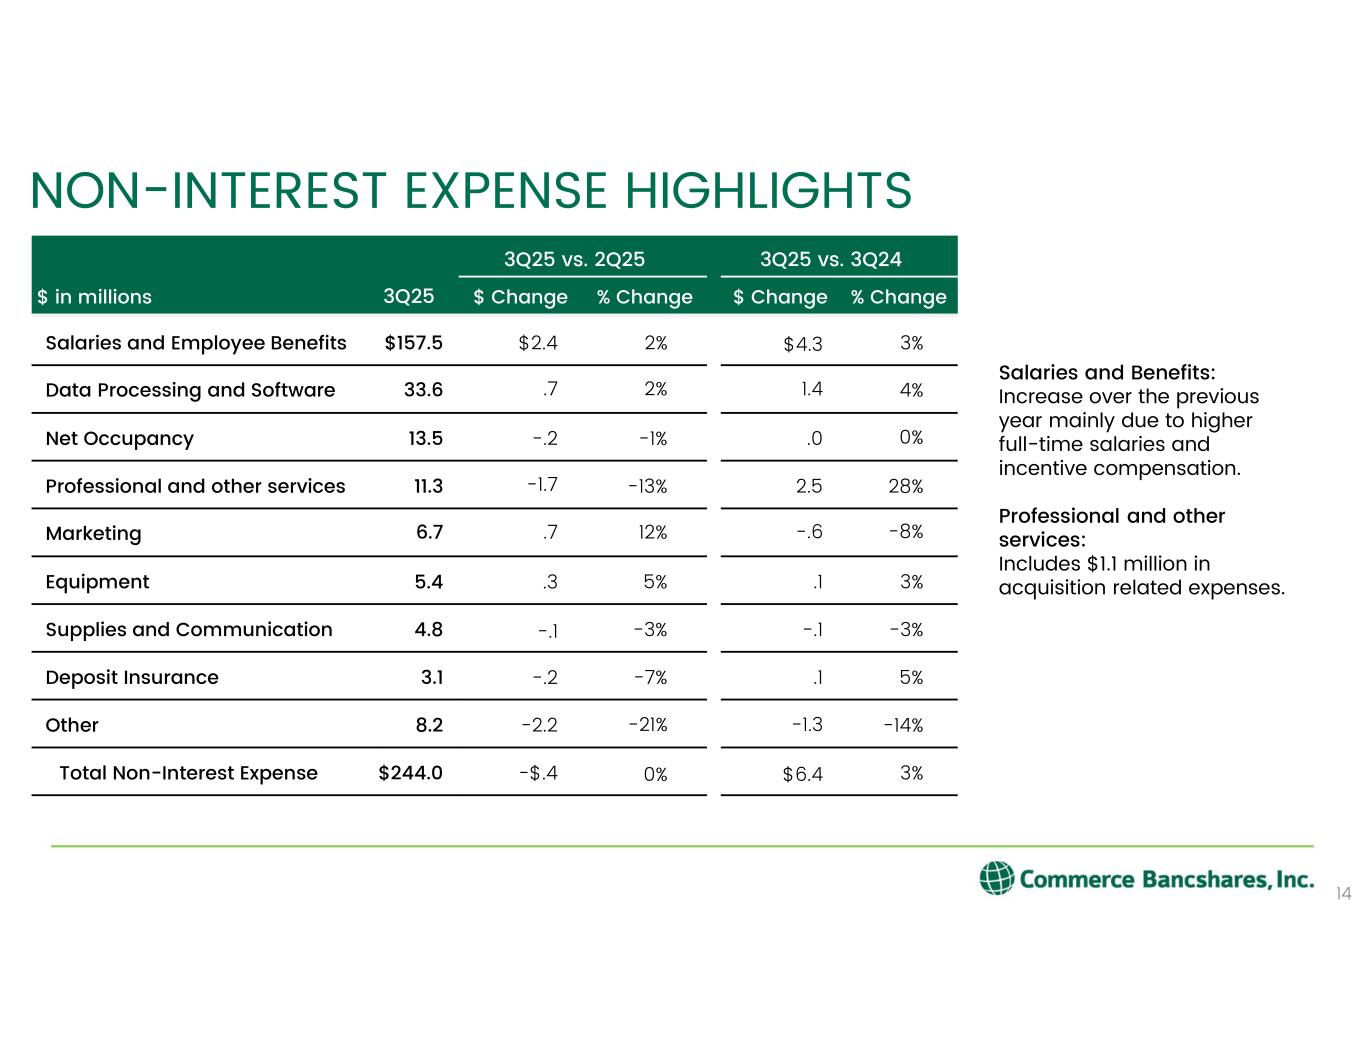
NON-INTEREST EXPENSE HIGHLIGHTS 14 3Q25 vs. 3Q24 3Q25 vs. 2Q25 % Change$ Change% Change$ Change3Q25$ in millions 3%$4.32%$2.4$157.5Salaries and Employee Benefits 4%1.42%.733.6Data Processing and Software 0%.0-1%-.213.5Net Occupancy 28%2.5-13%-1.711.3Professional and other services -8%-.612%.76.7Marketing 3%.15%.35.4Equipment -3%-.1-3%-.14.8Supplies and Communication 5%.1-7%-.23.1Deposit Insurance -14%-1.3-21%-2.28.2Other 3%$6.40%-$.4$244.0Total Non-Interest Expense Salaries and Benefits: Increase over the previous year mainly due to higher full-time salaries and incentive compensation. Professional and other services: Includes $1.1 million in acquisition related expenses.
15 LIQUIDITY AND CAPITAL
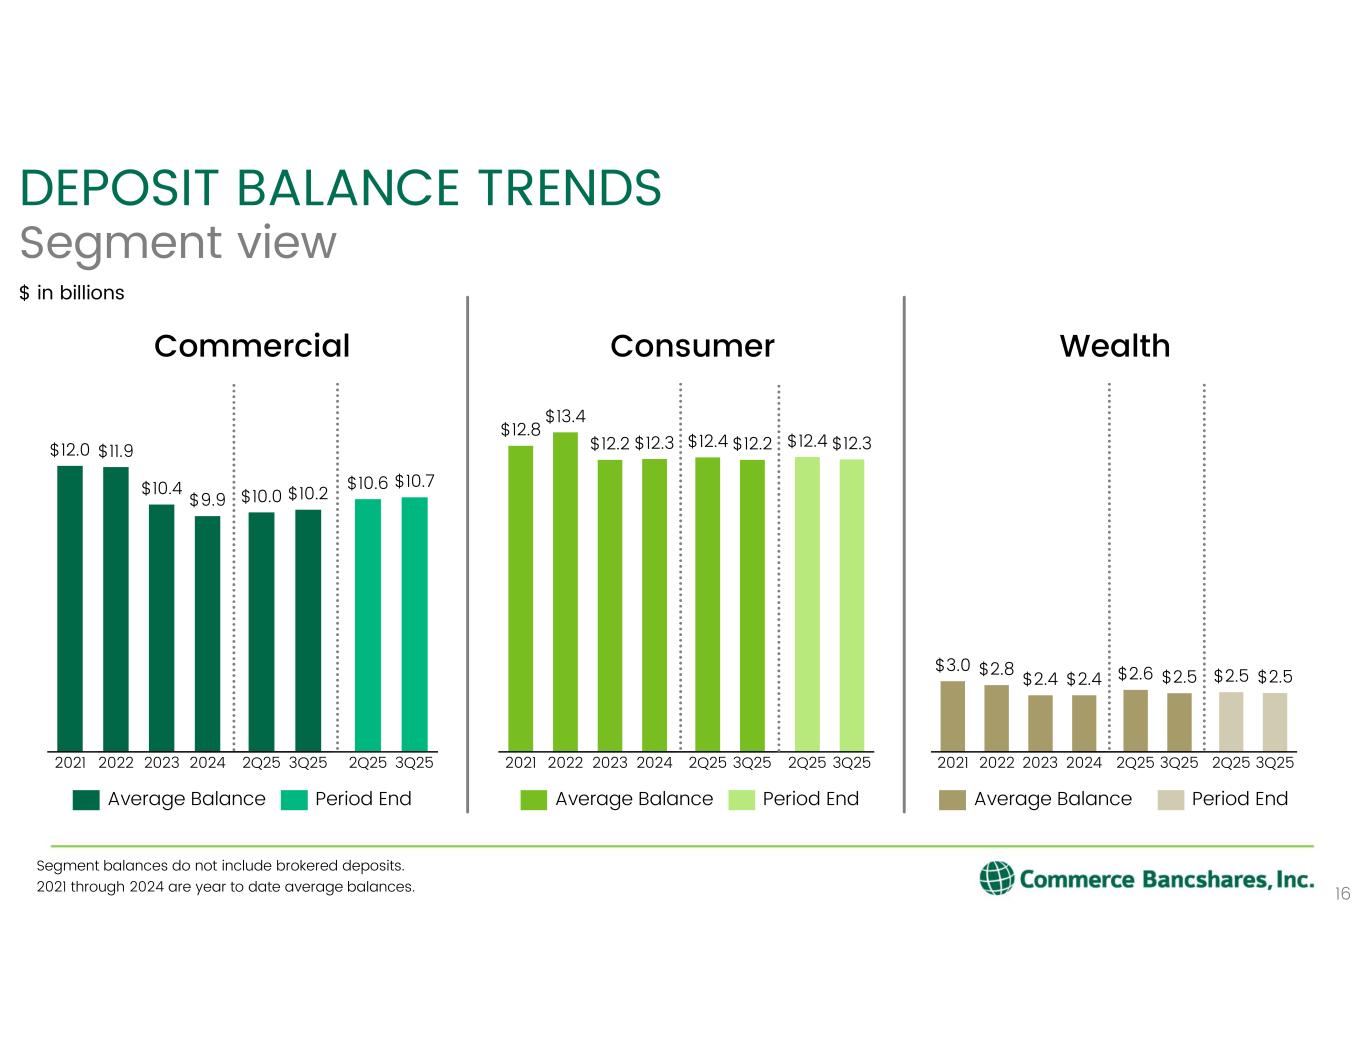
2021 2022 2023 2024 $3.0 $2.8 $2.4 $2.4 DEPOSIT BALANCE TRENDS Segment view $ in billions 16 2021 2022 2023 2024 $12.0 $11.9 $10.4 $9.9 2021 2022 2023 2024 $12.8 $13.4 $12.2 $12.3 Commercial Consumer Wealth Average Balance 2Q25 3Q25 $12.4 $12.3 Period EndAverage Balance Average Balance Segment balances do not include brokered deposits. 2021 through 2024 are year to date average balances. 2Q25 3Q25 $10.6 $10.7 Period End 2Q25 3Q25 $2.5 $2.5 Period End 2Q25 3Q25 $10.0 $10.2 2Q25 3Q25 $12.4 $12.2 2Q25 3Q25 $2.6 $2.5
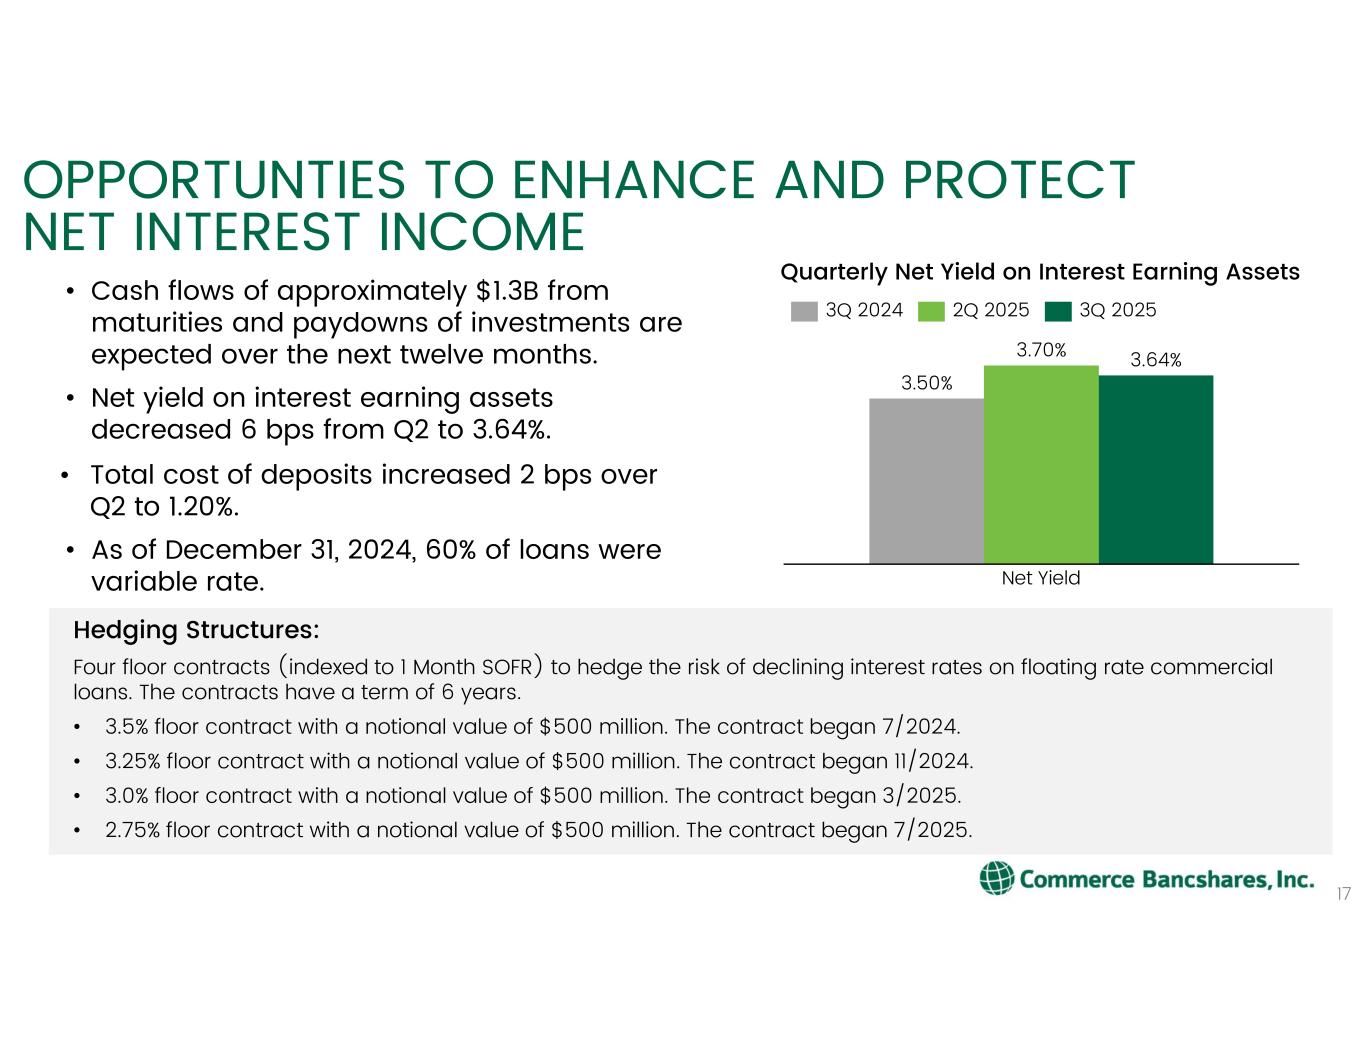
3.50% 3.70% 3.64% Net Yield Hedging Structures: Four floor contracts (indexed to 1 Month SOFR) to hedge the risk of declining interest rates on floating rate commercial loans. The contracts have a term of 6 years. • 3.5% floor contract with a notional value of $500 million. The contract began 7/2024. • 3.25% floor contract with a notional value of $500 million. The contract began 11/2024. • 3.0% floor contract with a notional value of $500 million. The contract began 3/2025. • 2.75% floor contract with a notional value of $500 million. The contract began 7/2025. OPPORTUNTIES TO ENHANCE AND PROTECT NET INTEREST INCOME • Cash flows of approximately $1.3B from maturities and paydowns of investments are expected over the next twelve months. • Net yield on interest earning assets decreased 6 bps from Q2 to 3.64%. • Total cost of deposits increased 2 bps over Q2 to 1.20%. • As of December 31, 2024, 60% of loans were variable rate. 17 3Q 2024 2Q 2025 3Q 2025 Quarterly Net Yield on Interest Earning Assets
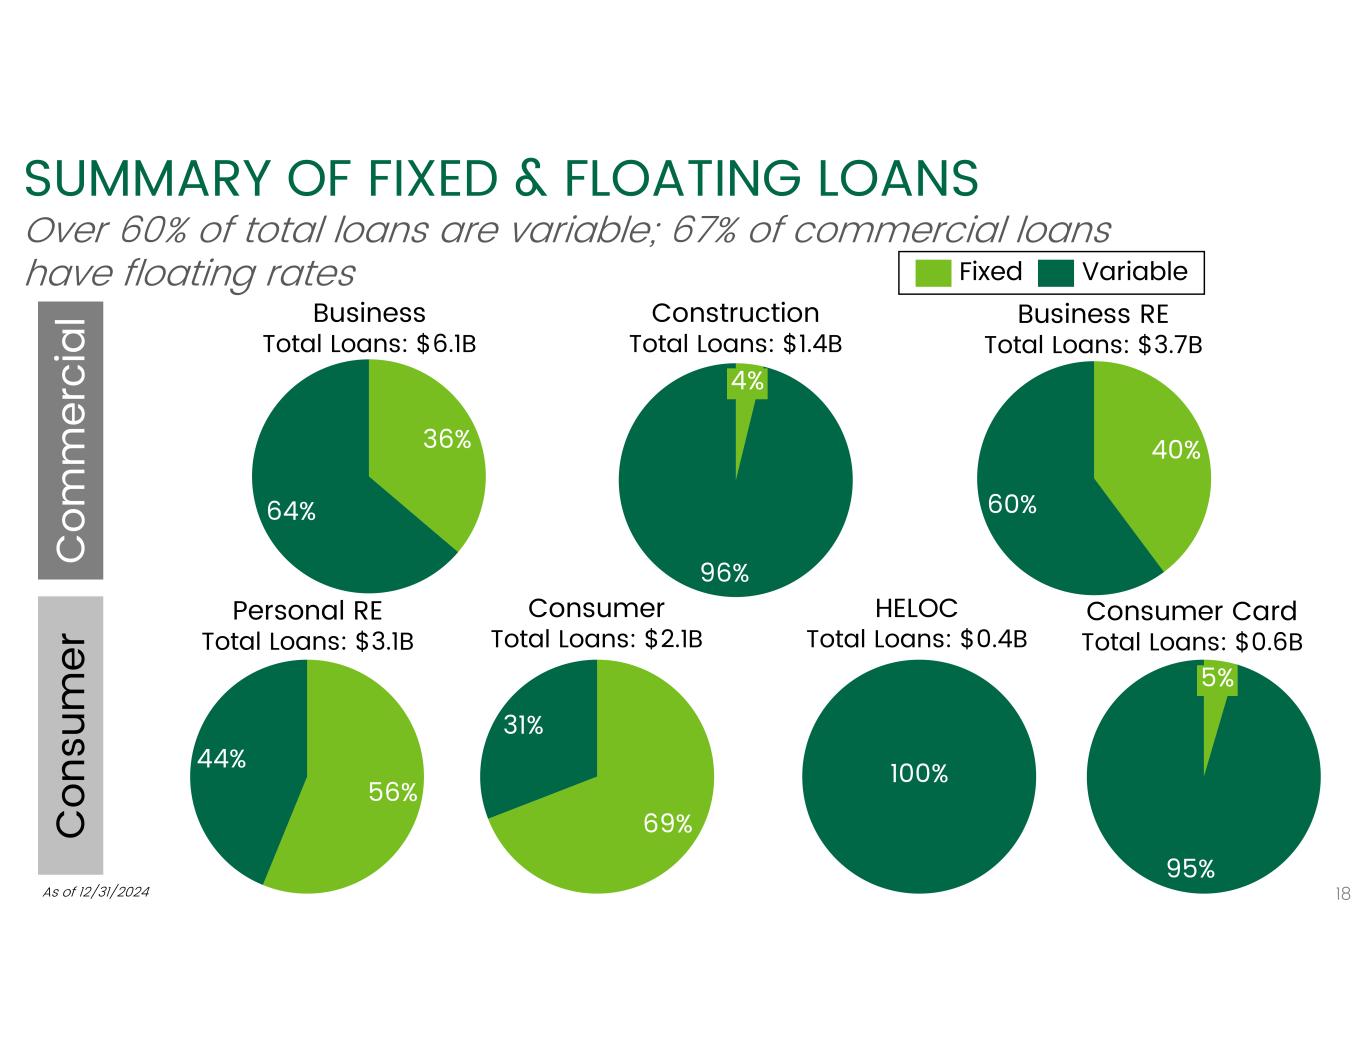
Over 60% of total loans are variable; 67% of commercial loans have floating rates SUMMARY OF FIXED & FLOATING LOANS 36% 64% Business Total Loans: $6.1B Fixed Variable C om m er ci al 56% 44% Personal RE Total Loans: $3.1B C on su m er 100% 40% 60% Business RE Total Loans: $3.7B 95% 5% Consumer Card Total Loans: $0.6B 69% 31% Consumer Total Loans: $2.1B 18 96% 4% Construction Total Loans: $1.4B As of 12/31/2024 HELOC Total Loans: $0.4B
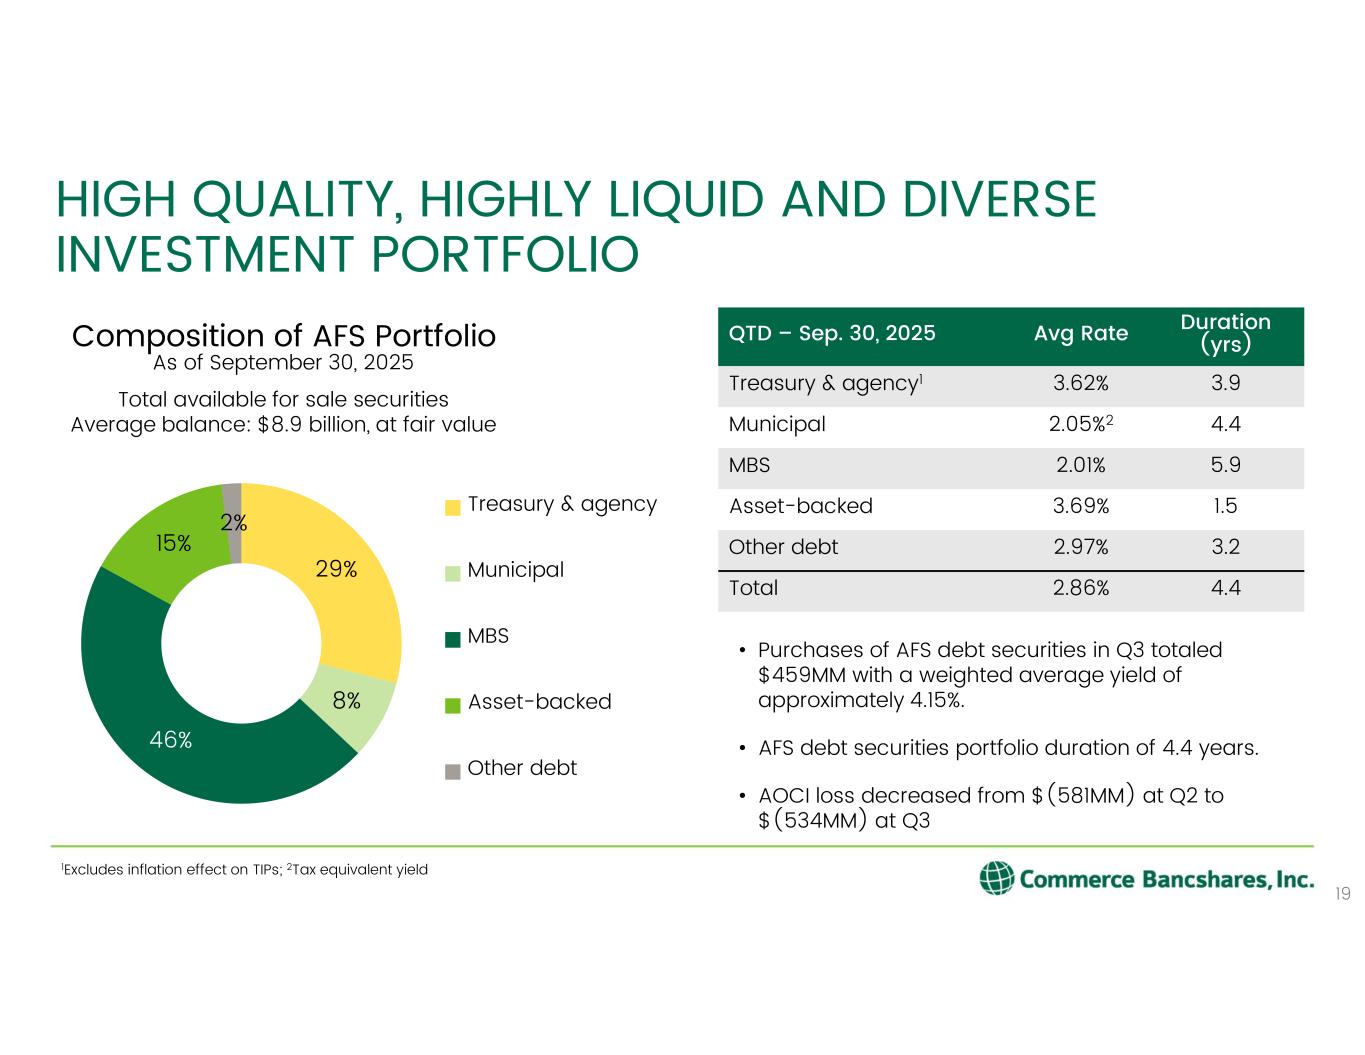
29% 8% 46% 15% 2% Composition of AFS Portfolio Treasury & agency Municipal MBS Asset-backed Other debt HIGH QUALITY, HIGHLY LIQUID AND DIVERSE INVESTMENT PORTFOLIO 1Excludes inflation effect on TIPs; 2Tax equivalent yield Duration (yrs)Avg RateQTD – Sep. 30, 2025 3.93.62%Treasury & agency1 4.42.05%2Municipal 5.92.01%MBS 1.53.69%Asset-backed 3.22.97%Other debt 4.42.86%Total 19 Total available for sale securities Average balance: $8.9 billion, at fair value As of September 30, 2025 • Purchases of AFS debt securities in Q3 totaled $459MM with a weighted average yield of approximately 4.15%. • AFS debt securities portfolio duration of 4.4 years. • AOCI loss decreased from $(581MM) at Q2 to $(534MM) at Q3
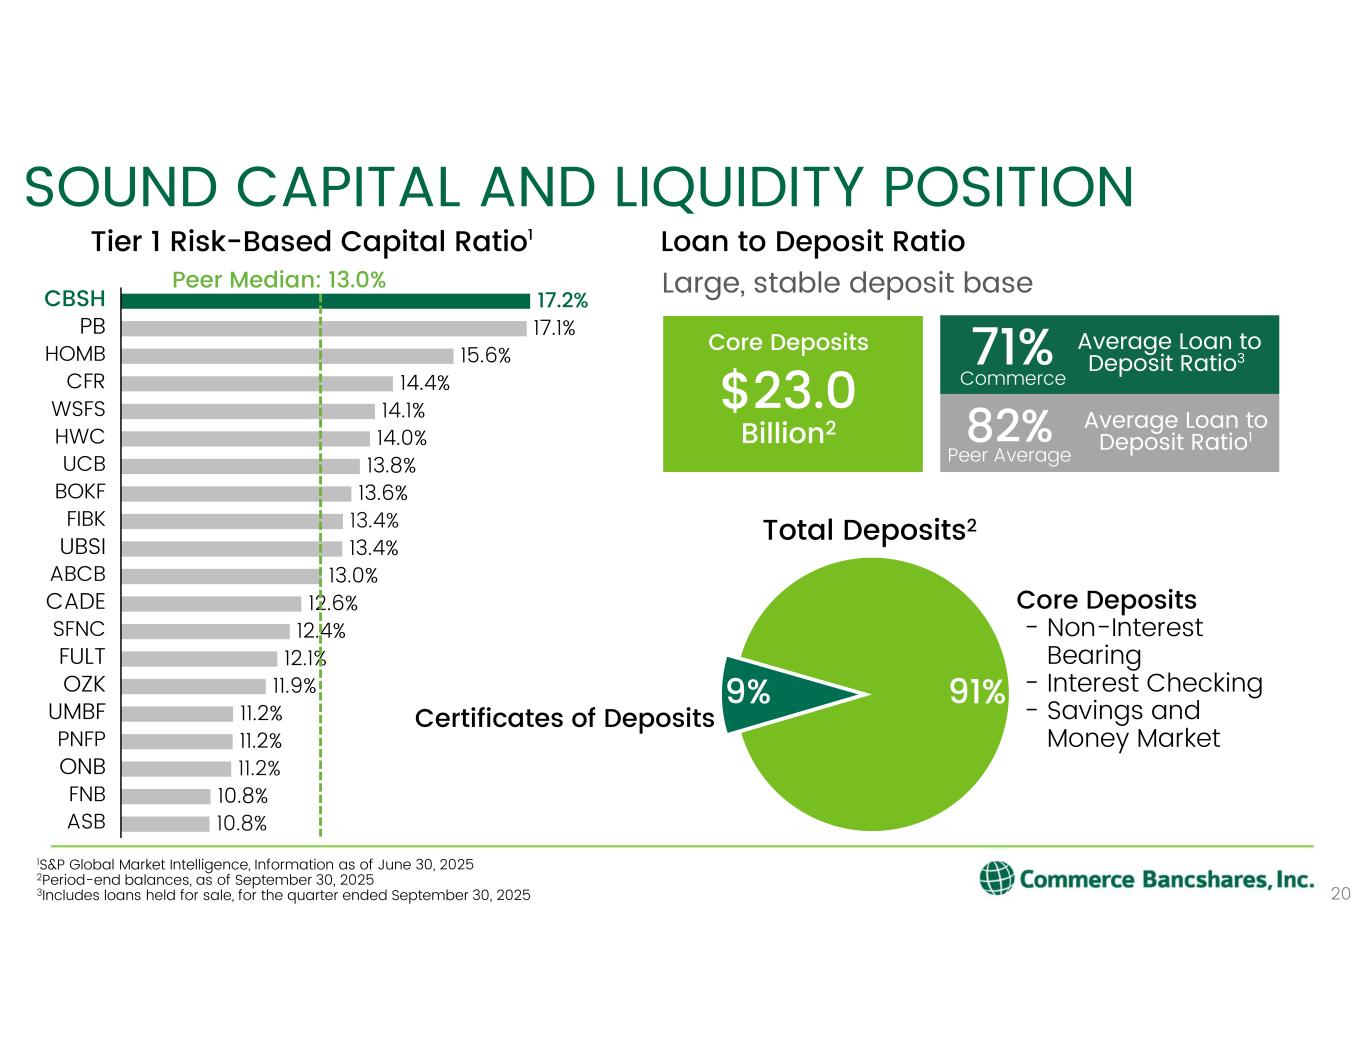
91%9% Core Deposits - Non-Interest Bearing - Interest Checking - Savings and Money Market Certificates of Deposits Average Loan to Deposit Ratio3 SOUND CAPITAL AND LIQUIDITY POSITION 20 Tier 1 Risk-Based Capital Ratio1 1S&P Global Market Intelligence, Information as of June 30, 2025 2Period-end balances, as of September 30, 2025 3Includes loans held for sale, for the quarter ended September 30, 2025 17.2% 17.1% 15.6% 14.4% 14.1% 14.0% 13.8% 13.6% 13.4% 13.4% 13.0% 12.6% 12.4% 12.1% 11.9% 11.2% 11.2% 11.2% 10.8% 10.8% PB CBSH HOMB HWC CFR WSFS UCB BOKF UBSI CADE ABCB FIBK SFNC ONB OZK FULT PNFP FNB ASB UMBF Peer Median: 13.0% Core Deposits $23.0 Billion2 Large, stable deposit base Loan to Deposit Ratio Total Deposits2 71% Average Loan to Deposit Ratio182% Commerce Peer Average
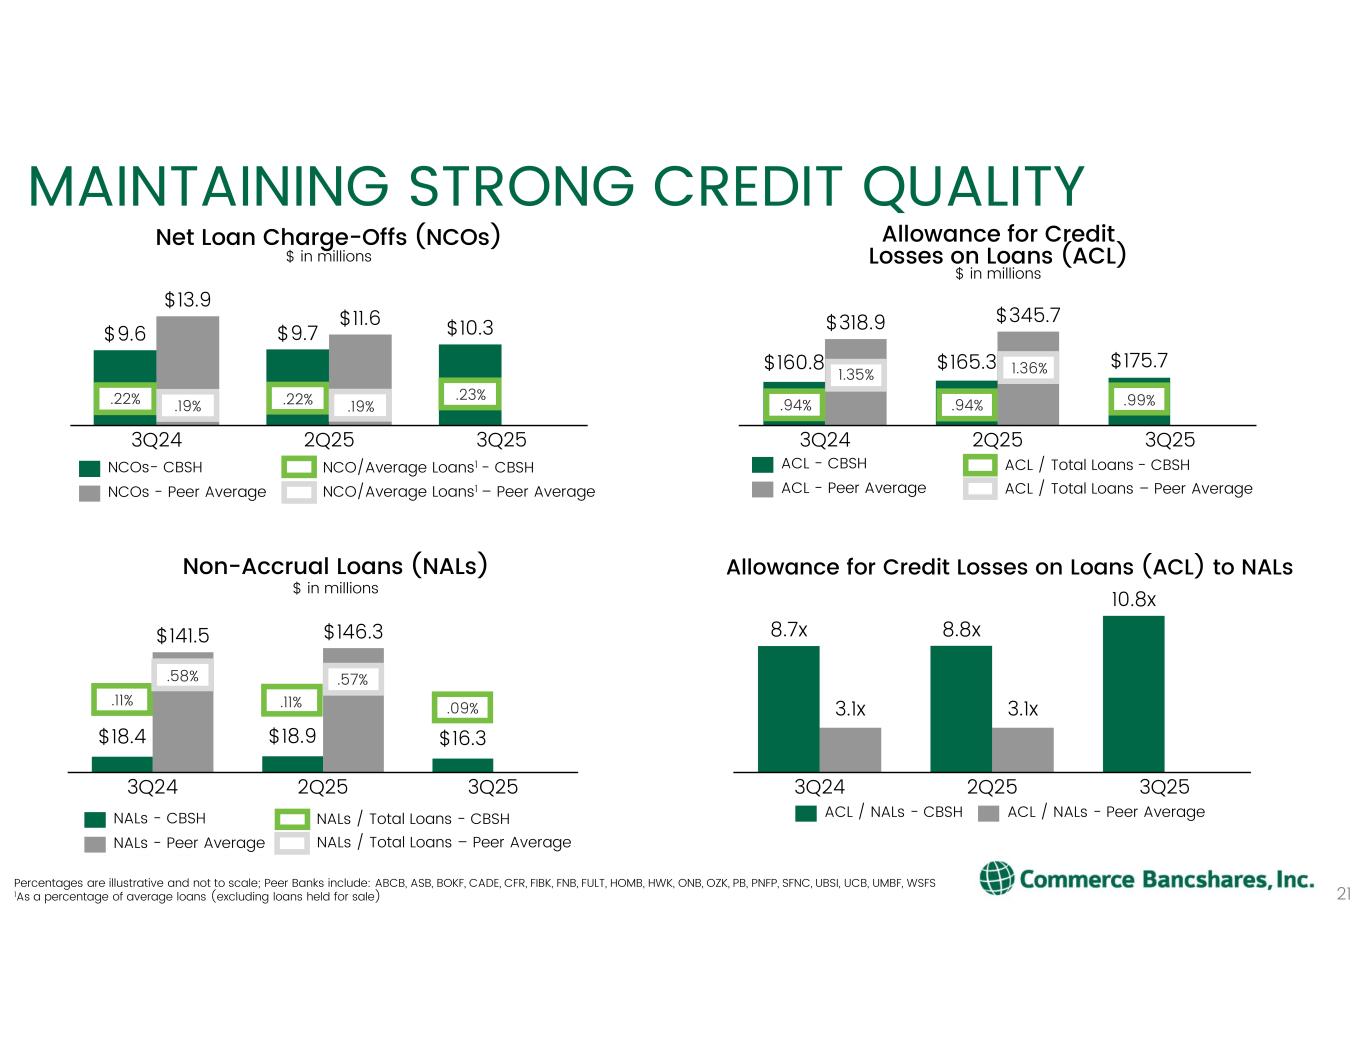
$18.4 $18.9 $16.3 $141.5 $146.3 3Q24 2Q25 3Q25 $9.6 $9.7 $10.3 $13.9 $11.6 3Q24 2Q25 3Q25 MAINTAINING STRONG CREDIT QUALITY Net Loan Charge-Offs (NCOs) $ in millions NCOs- CBSH NCOs - Peer Average NCO/Average Loans1 - CBSH $160.8 $165.3 $175.7 $318.9 $345.7 3Q24 2Q25 3Q25 Allowance for Credit Losses on Loans (ACL) $ in millions ACL - CBSH ACL - Peer Average ACL / Total Loans - CBSH Non-Accrual Loans (NALs) $ in millions NALs - CBSH NALs - Peer Average 8.7x 8.8x 10.8x 3.1x 3.1x 3Q24 2Q25 3Q25 Allowance for Credit Losses on Loans (ACL) to NALs ACL / NALs - CBSH ACL / NALs - Peer AverageNALs / Total Loans - CBSH NCO/Average Loans1 – Peer Average .11% NALs / Total Loans – Peer Average .11% .09% .58% .57% ACL / Total Loans – Peer Average .94% .94% .99% 1.35% 1.36% .22% .22% .23% .19% .19% Percentages are illustrative and not to scale; Peer Banks include: ABCB, ASB, BOKF, CADE, CFR, FIBK, FNB, FULT, HOMB, HWK, ONB, OZK, PB, PNFP, SFNC, UBSI, UCB, UMBF, WSFS 1As a percentage of average loans (excluding loans held for sale) 21
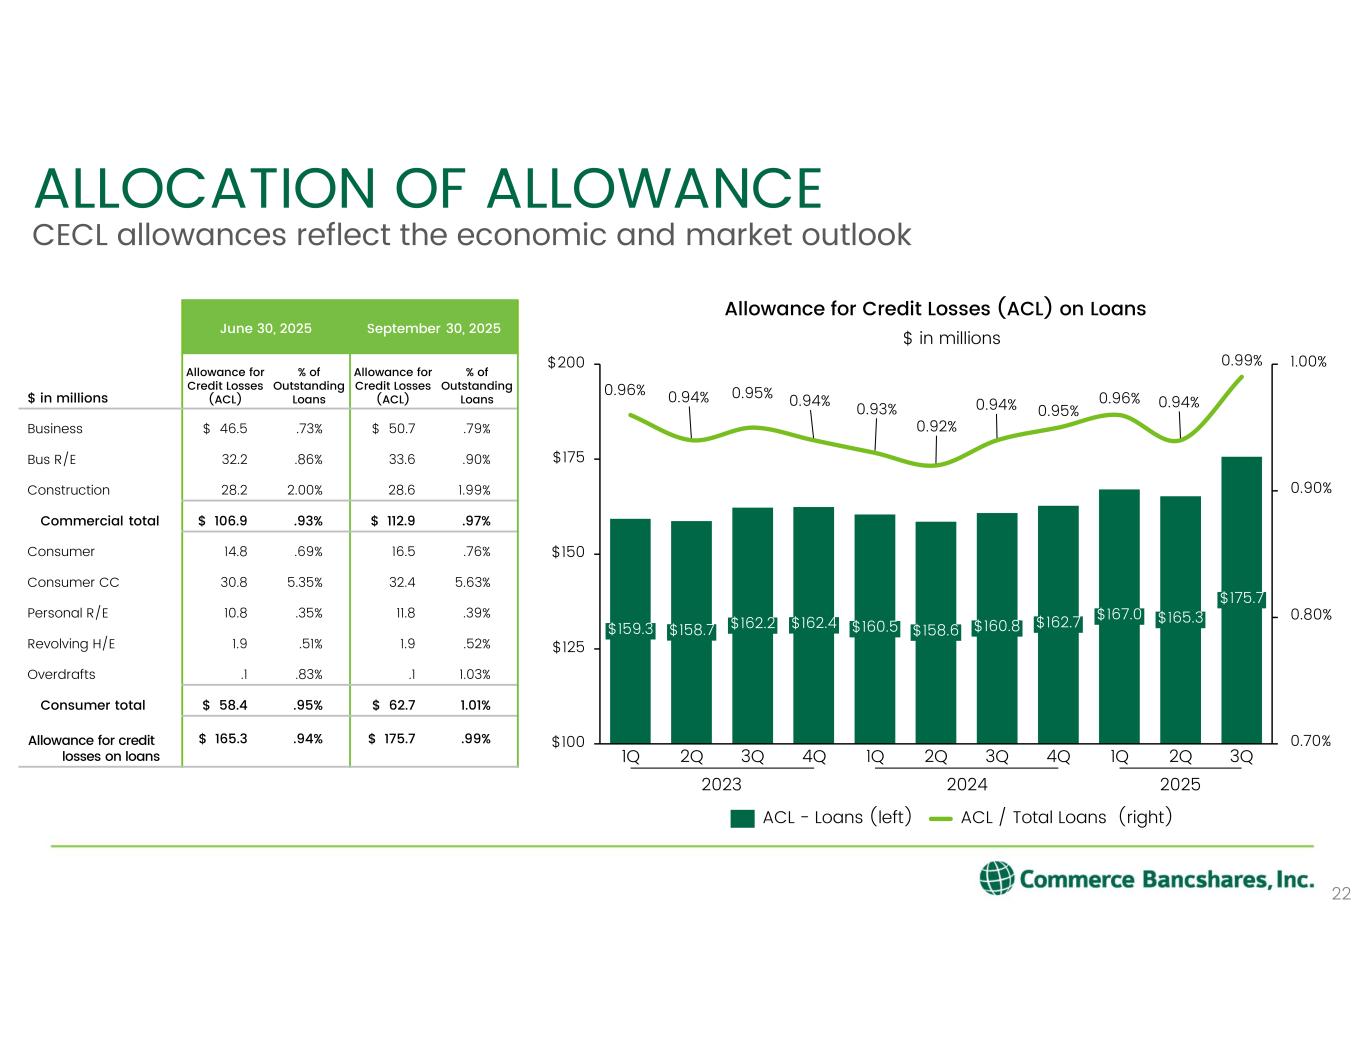
ALLOCATION OF ALLOWANCE 22 CECL allowances reflect the economic and market outlook September 30, 2025June 30, 2025 % of Outstanding Loans Allowance for Credit Losses (ACL) % of Outstanding Loans Allowance for Credit Losses (ACL)$ in millions .79%$ 50.7.73%$ 46.5Business .90%33.6 .86%32.2 Bus R/E 1.99%28.62.00%28.2Construction .97%$ 112.9.93%$ 106.9Commercial total .76%16.5 .69%14.8 Consumer 5.63%32.45.35%30.8Consumer CC .39%11.8.35%10.8Personal R/E .52%1.9.51%1.9Revolving H/E 1.03%.1 .83%.1 Overdrafts 1.01%$ 62.7.95%$ 58.4Consumer total .99%$ 175.7.94%$ 165.3Allowance for credit losses on loans 0.96% 0.94% 0.95% 0.94% 0.93% 0.92% 0.94% 0.95% 0.96% 0.94% 0.99% 0.70% 0.80% 0.90% 1.00% $125 $150 $175 $200 $100 $159.3 1Q $158.7 2Q $162.2 3Q $162.4 4Q $160.5 $158.6 2Q $160.8 3Q $162.7 4Q $167.0 1Q $165.3 2Q $175.7 3Q1Q Allowance for Credit Losses (ACL) on Loans ACL - Loans (left) ACL / Total Loans (right) $ in millions 2023 2024 2025
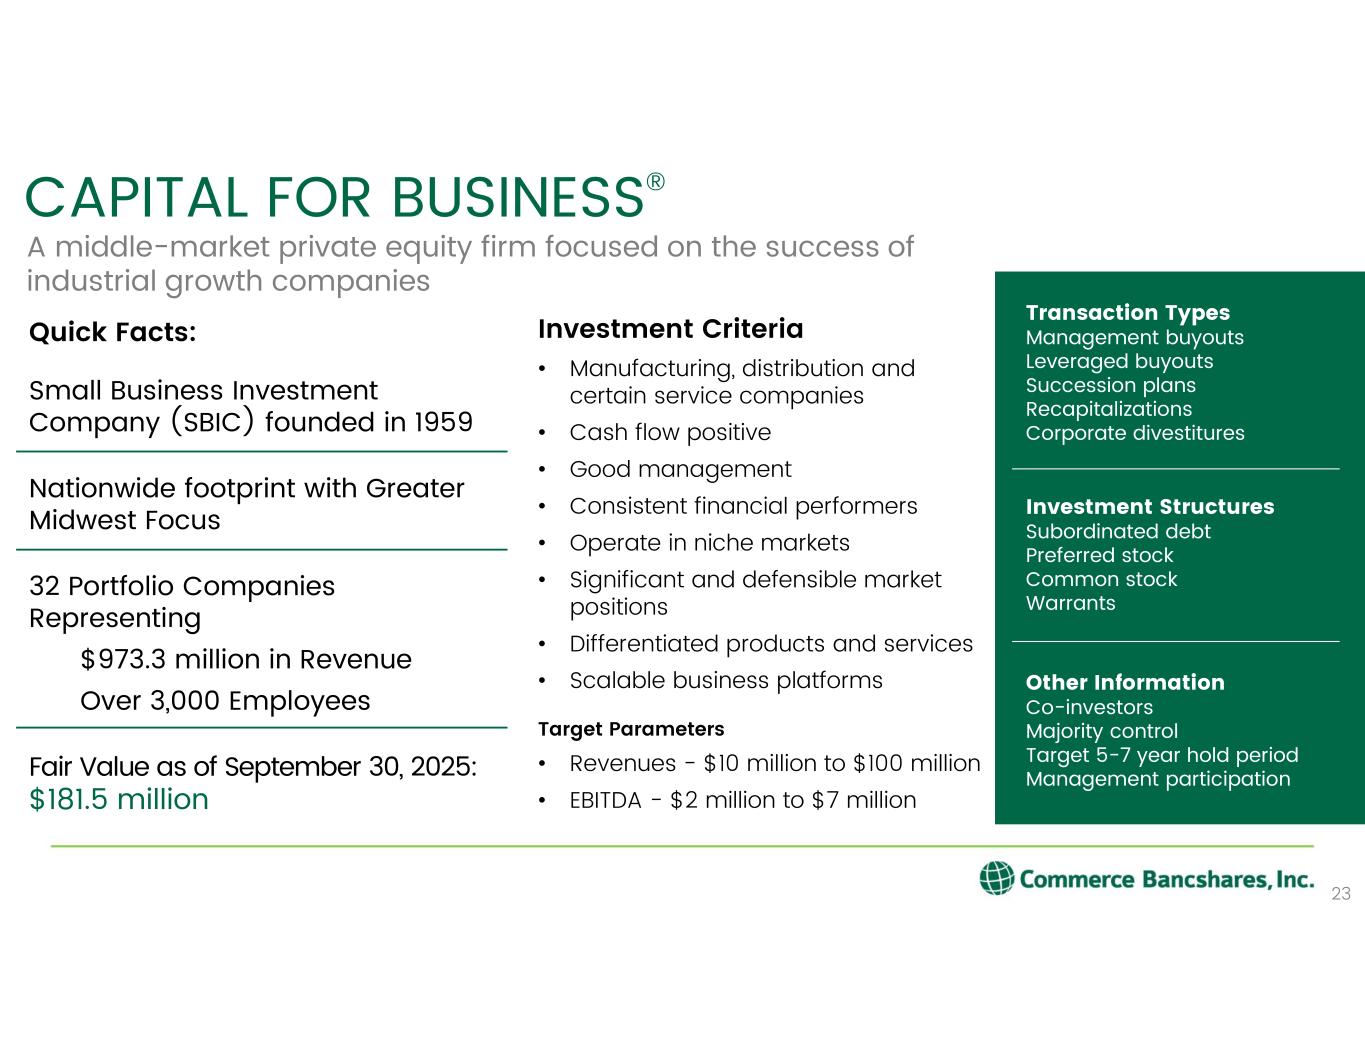
Quick Facts: Small Business Investment Company (SBIC) founded in 1959 Nationwide footprint with Greater Midwest Focus 32 Portfolio Companies Representing $973.3 million in Revenue Over 3,000 Employees Fair Value as of September 30, 2025: $181.5 million Investment Criteria • Manufacturing, distribution and certain service companies • Cash flow positive • Good management • Consistent financial performers • Operate in niche markets • Significant and defensible market positions • Differentiated products and services • Scalable business platforms Target Parameters • Revenues - $10 million to $100 million • EBITDA - $2 million to $7 million CAPITAL FOR BUSINESS® A middle-market private equity firm focused on the success of industrial growth companies Transaction Types Management buyouts Leveraged buyouts Succession plans Recapitalizations Corporate divestitures Investment Structures Subordinated debt Preferred stock Common stock Warrants Other Information Co-investors Majority control Target 5-7 year hold period Management participation 23
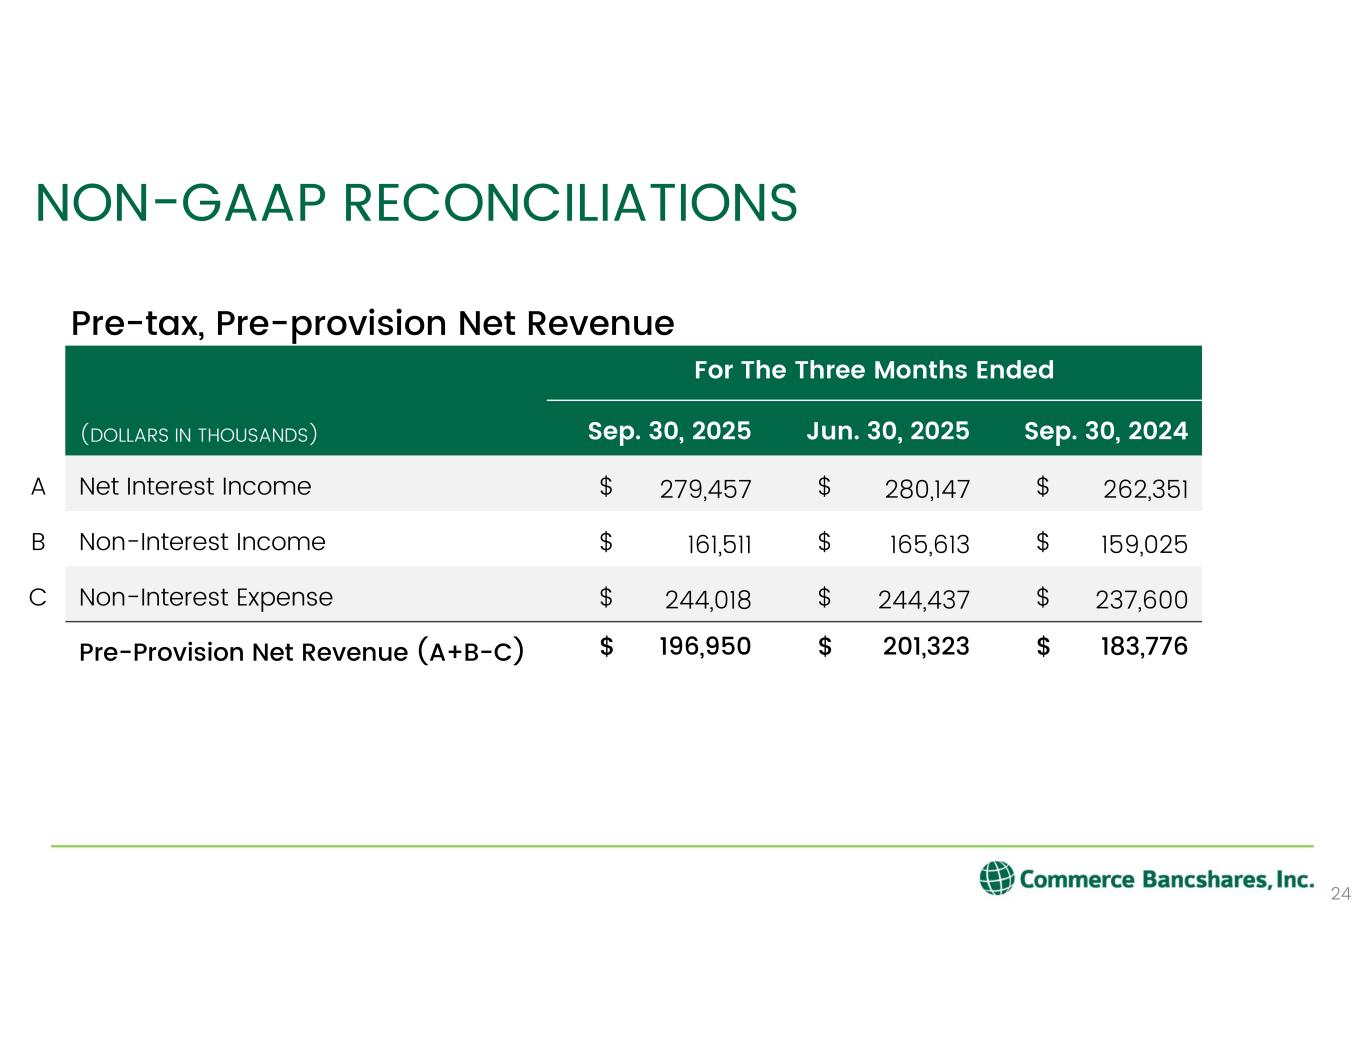
NON-GAAP RECONCILIATIONS 24 For The Three Months Ended Sep. 30, 2024Jun. 30, 2025Sep. 30, 2025(DOLLARS IN THOUSANDS) 262,351$280,147$279,457$Net Interest IncomeA 159,025$165,613$161,511$Non-Interest IncomeB 237,600$244,437$244,018$Non-Interest ExpenseC 183,776$201,323$196,950$Pre-Provision Net Revenue (A+B-C) Pre-tax, Pre-provision Net Revenue
Contact Information: Matt Burkemper Senior Vice President, Commerce Bank Corporate Development and Investor Relations 314.746.7485 [email protected] Commerce Bancshares, Inc. Investor Relations website: http://investor.commercebank.com/ 25