
CPF 8-K
Central Pacific Financial Corp (CPF)
8-K
2022-01-26
For: 2022-01-26
View Original
Added on
April 07, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of report (Date of earliest event reported):
(Exact name of registrant as specified in its charter)
| (State or other jurisdiction of incorporation) | (Commission File Number) | (I.R.S. Employer Identification No.) | ||||||||||||
(Address of principal executive offices)
(Zip Code)
(808 ) 544-0500
(Registrant’s telephone number, including area code)
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions:
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
ITEM 2.02. RESULTS OF OPERATIONS AND FINANCIAL CONDITION
On January 26, 2022, Central Pacific Financial Corp. (the "Company") issued a press release regarding its results of operations and financial condition for the quarter ended December 31, 2021. A copy of the press release is furnished herewith as Exhibit 99.1 and incorporated herein by reference. In addition, the Company has furnished hereto as Exhibit 99.2 an Earnings Supplement providing additional financial information which the Company has made available on its website and which exhibit is incorporated herein by reference.
ITEM 7.01. REGULATION FD DISCLOSURE
On January 26, 2022, Central Pacific Financial Corp. will hold an investor conference call and webcast to discuss financial results for the quarter ended December 31, 2021, including the attached press release and other matters relating to the Company.
The Company has also made available on its website two slide presentations containing certain additional information about the Company's financial results for the quarter ended December 31, 2021 (the "Earnings Supplement") and its Banking-as-a-Service ("BaaS") initiative (the "BaaS Launch Supplement"). The Earnings Supplement is furnished herewith as Exhibit 99.2 and the BaaS Launch Supplement is furnished herewith as Exhibit 99.3 and are incorporated herein by reference. All information in Exhibits 99.2 and 99.3 is presented as of the particular date or dates referenced therein, and the Company does not undertake any obligation to, and disclaims any duty to, update any of the information provided except as required by law.
The Earnings Supplement and the BaaS Launch Supplement contain forward-looking statements within the meaning of Section 27A of the Securities Act and Section 21E of the Exchange Act and, as such, may involve known and unknown risks, uncertainties and assumptions. These forward-looking statements relate to the Company’s current expectations and are subject to the limitations and qualifications set forth in the attached presentation as well as in the Company’s other documents filed with the Securities and Exchange Commission, including, without limitation, that actual events and/or results may differ materially from those projected in such forward-looking statements.
The information provided in Items 2.02 and 7.01 of this Current Report, including Exhibits 99.1, 99.2 and 99.3, shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended, nor shall the information in Exhibits 99.1, 99.2, and 99.3 be deemed incorporated by reference in any filings under the Securities Act of 1933, as amended.
ITEM 9.01. FINANCIAL STATEMENTS AND EXHIBITS
| (d) | Exhibits | |||||||||||||
| 99.1 | ||||||||||||||
| 99.2 | ||||||||||||||
| 99.3 | ||||||||||||||
| 104 | Cover Page Interactive Data File (embedded in the cover page formatted in Inline XBRL) | |||||||||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, as amended, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Central Pacific Financial Corp. | ||||||||
| (Registrant) | ||||||||
| Date: | January 26, 2022 | /s/ David S. Morimoto | ||||||
| David S. Morimoto | ||||||||
| Senior Executive Vice President and Chief Financial Officer | ||||||||
Exhibit 99.1
| FOR IMMEDIATE RELEASE | |||||||||||
| Investor Contact: | Ian Tanaka | Media Contact: | Brandt Farias | ||||||||
| SVP, Treasurer | EVP, Chief Marketing Officer | ||||||||||
| (808) 544-3646 | (808) 544-3687 | ||||||||||
| [email protected] | [email protected] | ||||||||||
NEWS RELEASE
CENTRAL PACIFIC FINANCIAL ANNOUNCES RECORD EARNINGS AND LAUNCHES NEW BANKING-AS-A-SERVICE INITIATIVE TO DRIVE MAINLAND EXPANSION
•Net income of $22.3 million, or $0.80 per diluted share for the quarter. Net income of $79.9 million, or $2.83 per diluted share for the year.
•ROA of 1.22% and ROE of 16.05% for the quarter. ROA of 1.13% and ROE of 14.38% for the year.
•Board of Directors increased quarterly cash dividend by 4.0% to $0.26 per share.
•Board of Directors approved new $30 million share repurchase program. Repurchased 305,594 shares of the Company's common stock, at a total cost of $8.4 million in the fourth quarter.
•Core loans increased by $183.2 million, or 3.8%, in the fourth quarter, while PPP loans decreased by $127.3 million for a net increase in total loans of $55.9 million, or 1.1%, from the third quarter of 2021.
•Core deposits of $6.16 billion increased by $66.0 million, or 1.1%, from the third quarter of 2021. Total deposits of $6.64 billion increased by $123.3 million, or 1.9%, from the third quarter of 2021.
•Cost of average total deposits was 0.06% in the fourth quarter.
HONOLULU, HI, January 26, 2022 – Central Pacific Financial Corp. (NYSE: CPF) (the "Company"), parent company of Central Pacific Bank (the "Bank"), today reported record net income for the fourth quarter and the 2021 year. Net income for the quarter was $22.3 million, or fully diluted earnings per share ("EPS") of $0.80, compared to net income in the fourth quarter of 2020 of $12.2 million, or EPS of $0.43, and net income in the third quarter of 2021 of $20.8 million, or EPS of $0.74. For the year, net income was $79.9 million, or EPS of $2.83, compared to net income of $37.3 million, or EPS of $1.32 for all of 2020. Pre-tax net income was $29.9 million and $105.7 million for the fourth quarter and the 2021 year, which represents the best pre-tax quarter and full year results since 2007.
The Company is also announcing the launch of a new Banking-as-a-Service ("BaaS") initiative with the goal of expanding the Company both in and beyond Hawaii by investing in or collaborating with leading fintech companies. The BaaS initiative is being developed based on the successful product development and launch strategies used in the Company's new Shaka digital product. Shaka, Hawaii’s first all-digital checking account, was launched with a VIP waitlist campaign and the largest social media influencer campaign in Hawaii’s history. Since the product launch on November 8, 2021, over 3,300 Shaka accounts have been opened.
Central Pacific Financial Announces Record Earnings and Launches New Banking-as-a-Service Initiative to Drive Mainland Expansion
Page 2
Beginning in the first quarter of 2022, the Company will continue its BaaS initiatives with an equity investment in Swell, a new fintech company. Swell plans to launch a consumer banking app that combines checking, credit and more into one integrated account, and Central Pacific Bank will serve as the bank sponsor. There will also be a collaboration between the Company, Swell and Elevate Credit (NYSE:ELVT), a leading provider of digital lending solutions. Swell is scheduled to launch its first product in mid-2022.
“We are very pleased with our record earnings and an extremely successful 2021,” said Paul Yonamine, Chairman and Chief Executive Officer. “We will maintain our commitment to be a top community bank in Hawaii, combining the latest in digital convenience with our strong tradition of customer service. Today’s announcement of our BaaS initiatives, represents an exciting new chapter of our Company as we expand beyond the Hawaii market which we believe will drive revenue growth and create even more shareholder value.”
On January 25, 2022, the Company's Board of Directors declared a quarterly cash dividend of $0.26 per share on its outstanding common shares. This represents a 4.0% increase from the dividend paid of $0.25 per share in the fourth quarter of 2021. The dividend will be payable on March 15, 2022 to shareholders of record at the close of business on February 28, 2022.
On January 25, 2022, the Company's Board of Directors authorized the repurchase of up to $30 million of its common stock from time to time in the open market or in privately negotiated transactions, pursuant to a newly authorized share repurchase program (the "Repurchase Plan"). The Repurchase Plan replaces and supersedes in its entirety the share repurchase program previously approved by the Company's Board of Directors, which had $6.3 million in remaining repurchase authority as of December 31, 2021. During the fourth quarter of 2021, the Company repurchased 305,594 shares of common stock, at a total cost of $8.4 million, or an average cost per share of $27.64. During the year ended December 31, 2021, the Company returned $45.6 million in capital to its shareholders through cash dividends and share repurchases.
Earnings Highlights
Net interest income for the fourth quarter of 2021 was $53.1 million, compared to $51.5 million in the year-ago quarter and $56.1 million in the previous quarter. Net interest margin for the fourth quarter of 2021 was 3.08%, compared to 3.32% in the year-ago quarter and 3.31% in the previous quarter. The sequential quarter decrease in net interest income and net interest margin is primarily due to lower net interest income and loan fees on PPP loans, and lower yields on core loans, partially offset by higher average loan and investment security balances. Net interest income for the fourth quarter of 2021 included $4.7 million in net interest income and loan fees on PPP loans, compared to $8.6 million in the previous quarter. Net deferred fees on PPP loans totaled $3.5 million at December 31, 2021, compared to $7.9 million at September 30, 2021, respectively. Additional information on average balances, interest income and expenses and yields and rates is presented in Tables 4 and 5.
In the fourth quarter of 2021, the Company recorded a credit to the provision for credit losses of $7.7 million, compared to a provision of $4.9 million in the year-ago quarter and a credit to the provision of $2.6 million in the previous quarter. The credit to the provision for credit losses in the fourth quarter of 2021 was driven by continued improvements in the economic forecast, net recoveries during the current quarter and strong asset quality as the State of Hawaii continues to recover from the COVID-19 pandemic.
Other operating income for the fourth quarter of 2021 totaled $11.6 million, compared to $14.1 million in the year-ago quarter and $10.3 million in the previous quarter. The decrease from the year-ago quarter was primarily due to lower mortgage banking income of $3.5 million, partially offset by higher other service charges and fees of $1.3 million. The increase from the previous quarter was primarily due to higher mortgage banking income and bank-owned life insurance of $0.6 million and $0.4 million, respectively. Additional information on other operating income is presented in Table 3.
Other operating expense for the fourth quarter of 2021 totaled $42.4 million, compared to $44.7 million in the year-ago quarter and $41.3 million in the previous quarter. Other operating expense in the current quarter included $1.1 million in severance expense and $0.4 million in costs related to the consolidation of our Kapalama Branch on Oahu. The Company plans to consolidate three additional branches in 2022. The decrease in other operating expense from the year-ago quarter was primarily due to $3.9 million in nonrecurring expenses (included in other) in the year-ago quarter, which included: branch consolidation costs of $1.3 million, litigation settlements of $0.8 million, Federal Home Loan Bank advance prepayment fee of $0.7 million, loss on disposal of fixed assets of $0.6 million and other nonrecurring expenses totaling $0.5 million. The increase in other operating expense from the previous quarter is primarily due to branch consolidation costs, higher deferred compensation plan expenses and higher promotions expense of $0.4 million each. Additional information on other operating expense is presented in Table 3.
The efficiency ratio for the fourth quarter of 2021 was 65.61%, compared to 68.20% in the year-ago quarter and 62.32% in the previous quarter.
Central Pacific Financial Announces Record Earnings and Launches New Banking-as-a-Service Initiative to Drive Mainland Expansion
Page 3
The effective tax rate for the fourth quarter of 2021 was 25.4%, compared to 23.7% in the year-ago quarter and 24.7% in the previous quarter.
Balance Sheet Highlights
Total assets at December 31, 2021 of $7.42 billion increased from $6.59 billion at December 31, 2020, and increased from $7.30 billion at September 30, 2021.
Total loans, net of deferred fees and costs, at December 31, 2021 of $5.10 billion increased from $4.96 billion at December 31, 2020, and increased from $5.05 billion at September 30, 2021. The sequential quarter increase in total loans included a net increase in core loans (or non-PPP loans) of $183.2 million led by residential mortgage loan growth of $127.3 million, offset by a decline in PPP loans of $127.3 million due to SBA forgiveness and payments. Loans on forbearance or deferral totaled $0.4 million, or less than 1% of total loans at December 31, 2021. Loans by geographic distribution are summarized in Table 6.
Total deposits at December 31, 2021 of $6.64 billion increased from $5.80 billion at December 31, 2020, and increased from $6.52 billion at September 30, 2021. Core deposits, which include demand deposits, savings and money market deposits and time deposits up to $250,000, totaled $6.16 billion at December 31, 2021, and increased by $66.0 million from September 30, 2021. Non-core deposits increased by $57.3 million from September 30, 2021. The Company's loan-to-deposit ratio was 76.8% at December 31, 2021, compared to 77.4% at September 30, 2021. Core deposit and total deposit balances are summarized in Table 7.
Asset Quality
Nonperforming assets at December 31, 2021 totaled $5.9 million, or 0.08% of total assets, compared to $6.2 million, or 0.09% of total assets at December 31, 2020, and $7.2 million, or 0.10% of total assets at September 30, 2021. Additional information on nonperforming assets, past due and restructured loans is presented in Table 8.
Net recoveries in the fourth quarter of 2021 totaled $0.9 million, compared to net charge-offs of $1.8 million in the year-ago quarter, and net charge-offs of $0.2 million in the previous quarter.
The allowance for credit losses, as a percentage of total loans at December 31, 2021 was 1.33%, compared to 1.68% at December 31, 2020 and 1.48% at September 30, 2021. Excluding PPP loans, the allowance for credit losses, as a percentage of core loans at December 31, 2021 was 1.36%, compared to 1.55% at September 30, 2021. Additional information on net charge-offs and recoveries and the allowance for credit losses is presented in Tables 9 and 10.
Capital
Total shareholders' equity was $558.2 million at December 31, 2021, compared to $546.7 million and $555.4 million at December 31, 2020 and September 30, 2021, respectively.
The Company maintained its strong capital position and its capital ratios continue to exceed the levels required to be considered a "well-capitalized" institution for regulatory purposes under Basel III. At December 31, 2021, the Company's leverage capital, tier 1 risk-based capital, total risk-based capital, and common equity tier 1 ratios were 8.5%, 12.2%, 14.5%, and 11.2%, respectively, compared to 8.5%, 12.2%, 14.6%, and 11.2%, respectively, at September 30, 2021.
Non-GAAP Financial Measures
This press release contains certain references to financial measures that have been adjusted to exclude certain expenses and other specified items. These financial measures differ from comparable measures calculated and presented in accordance with accounting principles generally accepted in the United States of America ("GAAP") in that they exclude unusual or non-recurring charges, losses, credits or gains. This press release identifies the specific items excluded from the comparable GAAP financial measure in the calculation of each non-GAAP financial measure. Management believes that financial presentations excluding the impact of these items provide useful supplemental information that is important to a proper understanding of the Company's core business results by investors. These presentations should not be viewed as a substitute for results determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP financial measures presented by other companies.
Conference Call
The Company's management will host a conference call today at 1:00 p.m. Eastern Time (8:00 a.m. Hawaii Time) to discuss the quarterly results. Individuals are encouraged to listen to the live webcast of the presentation by visiting the investor relations page of the Company's website at http://ir.cpb.bank. Alternatively, investors may participate in the live call by dialing 1-844-200-6205 (access code: 319900). A playback of the call will be available through February 25, 2022 by dialing 1-866-813-9403 (access code: 961340) and on the Company's website. Information which may be discussed in the conference call is provided in an earnings supplement presentation on the Company's website at http://ir.cpb.bank.
Central Pacific Financial Announces Record Earnings and Launches New Banking-as-a-Service Initiative to Drive Mainland Expansion
Page 4
About Central Pacific Financial Corp.
Central Pacific Financial Corp. is a Hawaii-based bank holding company with approximately $7.4 billion in assets as of December 31, 2021. Central Pacific Bank, its primary subsidiary, operates 30 branches and 69 ATMs in the state of Hawaii. For additional information, please visit the Company's website at http://www.cpb.bank.
**********
Central Pacific Financial Announces Record Earnings and Launches New Banking-as-a-Service Initiative to Drive Mainland Expansion
Page 5
Forward-Looking Statements
This document may contain forward-looking statements concerning: projections of revenues, expenses, income or loss, earnings or loss per share, capital expenditures, the payment or nonpayment of dividends, capital position, credit losses, net interest margin or other financial items; statements of plans, objectives and expectations of Central Pacific Financial Corp. or its management or Board of Directors, including those relating to business plans, use of capital resources, products or services and regulatory developments and regulatory actions; statements of future economic performance including anticipated performance results from our business initiatives; or any statements of the assumptions underlying or relating to any of the foregoing. Words such as "believes," "plans," "anticipates," "expects," "intends," "forecasts," "hopes," "targeting," "continue," "remain," "will," "should," "estimates," "may" and other similar expressions are intended to identify forward-looking statements but are not the exclusive means of identifying such statements.
While we believe that our forward-looking statements and the assumptions underlying them are reasonably based, such statements and assumptions are by their nature subject to risks and uncertainties, and thus could later prove to be inaccurate or incorrect. Accordingly, actual results could differ materially from those statements or projections for a variety of reasons, including, but not limited to: the adverse effects of the COVID-19 pandemic virus on local, national and international economies, including, but not limited to, the adverse impact on tourism and construction in the State of Hawaii, our borrowers, customers, third-party contractors, vendors and employees as well as the effects of government programs and initiatives in response to COVID-19; the impact of our participation in the Paycheck Protection Program ("PPP") and fulfillment of government guarantees on our PPP loans; our ability to successfully implement our Banking-as-a-Service initiatives, including adoption of the initiatives by customers and risks faced by any of our bank collaborations including reputational and regulatory risk; the increase in inventory or adverse conditions in the real estate market and deterioration in the construction industry; adverse changes in the financial performance and/or condition of our borrowers and, as a result, increased loan delinquency rates, deterioration in asset quality, and losses in our loan portfolio; our ability to successfully implement our business initiatives; the impact of local, national, and international economies and events (including natural disasters such as wildfires, volcanic eruptions, hurricanes, tsunamis, storms, earthquakes and pandemic viruses and diseases, including COVID-19) on the Company's business and operations and on tourism, the military, and other major industries operating within the Hawaii market and any other markets in which the Company does business; deterioration or malaise in domestic economic conditions, including any destabilization in the financial industry and deterioration of the real estate market, as well as the impact of declining levels of consumer and business confidence in the state of the economy in general and in financial institutions in particular; changes in estimates of future reserve requirements based upon the periodic review thereof under relevant regulatory and accounting requirements; the impact of the Dodd-Frank Wall Street Reform and Consumer Protection Act (the "Dodd-Frank Act"), changes in capital standards, other regulatory reform and federal and state legislation, including but not limited to regulations promulgated by the Consumer Financial Protection Bureau (the "CFPB"), government-sponsored enterprise reform, and any related rules and regulations which affect our business operations and competitiveness; the costs and effects of legal and regulatory developments, including legal proceedings or regulatory or other governmental inquiries and proceedings and the resolution thereof, the results of regulatory examinations or reviews and the effect of, and our ability to comply with, any regulatory orders or actions we are or may become subject to; ability to successfully implement our initiatives to lower our efficiency ratio; the effects of and changes in trade, monetary and fiscal policies and laws, including the interest rate policies of the Board of Governors of the Federal Reserve System (the "FRB" or the "Federal Reserve"); inflation, interest rate, securities market and monetary fluctuations, including the anticipated replacement of the London Interbank Offered Rate ("LIBOR") Index and the impact on our loans and debt which are tied to that index; negative trends in our market capitalization and adverse changes in the price of the Company's common stock; political instability; acts of war or terrorism; pandemic virus and disease, including COVID-19; changes in consumer spending, borrowings and savings habits; failure to maintain effective internal control over financial reporting or disclosure controls and procedures; cybersecurity and data privacy breaches and the consequence therefrom; the ability to address deficiencies in our internal controls over financial reporting or disclosure controls and procedures; technological changes and developments; changes in the competitive environment among financial holding companies and other financial service providers; the effect of changes in accounting policies and practices, as may be adopted by the regulatory agencies, as well as the Public Company Accounting Oversight Board, the Financial Accounting Standards Board ("FASB") and other accounting standard setters and the cost and resources required to implement such changes; our ability to attract and retain key personnel; changes in our personnel, organization, compensation and benefit plans; and our success at managing the risks involved in the foregoing items.
For further information with respect to factors that could cause actual results to materially differ from the expectations or projections stated in the forward-looking statements, please see the Company's publicly available Securities and Exchange Commission filings, including the Company's Form 10-K for the last fiscal year and, in particular, the discussion of "Risk Factors" set forth therein. We urge investors to consider all of these factors carefully in evaluating the forward-looking statements contained in this Form 8-K. Forward-looking statements speak only as of the date on which such statements are made. We undertake no obligation to update any forward-looking statements to reflect events or circumstances after the date on which such statements are made, or to reflect the occurrence of unanticipated events except as required by law.
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Financial Highlights | |||||
| (Unaudited) | TABLE 1 | ||||
| Three Months Ended | Year Ended | |||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, | Dec 31, | Sep 30, | Jun 30, | Mar 31, | Dec 31, | Dec 31, | ||||||||||||||||||||||||||||||||||||||
| except for per share amounts) | 2021 | 2021 | 2021 | 2021 | 2020 | 2021 | 2020 | |||||||||||||||||||||||||||||||||||||
| CONDENSED INCOME STATEMENT | ||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 53,096 | $ | 56,086 | $ | 52,061 | $ | 49,804 | $ | 51,474 | $ | 211,047 | $ | 197,683 | ||||||||||||||||||||||||||||||
| (Credit) provision for credit losses [1] | (7,692) | (2,635) | (3,443) | (821) | 4,898 | (14,591) | 42,111 | |||||||||||||||||||||||||||||||||||||
| Total other operating income | 11,566 | 10,253 | 10,530 | 10,711 | 14,057 | 43,060 | 45,198 | |||||||||||||||||||||||||||||||||||||
| Total other operating expense [1] | 42,422 | 41,345 | 41,433 | 37,846 | 44,690 | 163,046 | 151,737 | |||||||||||||||||||||||||||||||||||||
| Income tax expense | 7,605 | 6,814 | 5,887 | 5,452 | 3,772 | 25,758 | 11,760 | |||||||||||||||||||||||||||||||||||||
| Net income | 22,327 | 20,815 | 18,714 | 18,038 | 12,171 | 79,894 | 37,273 | |||||||||||||||||||||||||||||||||||||
| Basic earnings per common share | $ | 0.80 | $ | 0.74 | $ | 0.66 | $ | 0.64 | $ | 0.43 | $ | 2.85 | $ | 1.33 | ||||||||||||||||||||||||||||||
| Diluted earnings per common share | 0.80 | 0.74 | 0.66 | 0.64 | 0.43 | 2.83 | 1.32 | |||||||||||||||||||||||||||||||||||||
| Dividends declared per common share | 0.25 | 0.24 | 0.24 | 0.23 | 0.23 | 0.96 | 0.92 | |||||||||||||||||||||||||||||||||||||
| PERFORMANCE RATIOS | ||||||||||||||||||||||||||||||||||||||||||||
| Return on average assets (ROA) [2] | 1.22 | % | 1.15 | % | 1.06 | % | 1.07 | % | 0.74 | % | 1.13 | % | 0.58 | % | ||||||||||||||||||||||||||||||
| Return on average shareholders’ equity (ROE) [2] | 16.05 | 14.82 | 13.56 | 13.07 | 8.87 | 14.38 | 6.85 | |||||||||||||||||||||||||||||||||||||
| Average shareholders’ equity to average assets | 7.61 | 7.79 | 7.84 | 8.19 | 8.29 | 7.85 | 8.47 | |||||||||||||||||||||||||||||||||||||
| Efficiency ratio [3] | 65.61 | 62.32 | 66.20 | 62.54 | 68.20 | 64.16 | 62.47 | |||||||||||||||||||||||||||||||||||||
| Net interest margin (NIM) [2] | 3.08 | 3.31 | 3.16 | 3.19 | 3.32 | 3.18 | 3.30 | |||||||||||||||||||||||||||||||||||||
| Dividend payout ratio [4] | 31.25 | 32.43 | 36.36 | 35.94 | 53.49 | 33.92 | 69.70 | |||||||||||||||||||||||||||||||||||||
| SELECTED AVERAGE BALANCES | ||||||||||||||||||||||||||||||||||||||||||||
| Average loans, including loans held for sale | $ | 5,073,069 | $ | 5,022,909 | $ | 5,110,820 | $ | 5,079,874 | $ | 5,034,717 | $ | 5,071,516 | $ | 4,855,169 | ||||||||||||||||||||||||||||||
| Average interest-earning assets | 6,890,829 | 6,761,643 | 6,606,779 | 6,305,786 | 6,202,228 | 6,643,193 | 6,015,166 | |||||||||||||||||||||||||||||||||||||
| Average assets | 7,315,325 | 7,210,210 | 7,039,928 | 6,738,825 | 6,621,127 | 7,078,025 | 6,418,661 | |||||||||||||||||||||||||||||||||||||
| Average deposits | 6,536,826 | 6,424,768 | 6,269,516 | 5,958,742 | 5,755,257 | 6,299,369 | 5,555,877 | |||||||||||||||||||||||||||||||||||||
| Average interest-bearing liabilities | 4,407,612 | 4,221,073 | 4,253,382 | 4,161,453 | 4,163,396 | 4,288,041 | 4,070,923 | |||||||||||||||||||||||||||||||||||||
| Average shareholders’ equity | 556,462 | 561,606 | 552,102 | 551,976 | 548,663 | 555,600 | 543,919 | |||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Financial Highlights | |||||
| (Unaudited) | TABLE 1 (CONTINUED) | ||||
| Dec 31, | Sep 30, | Jun 30, | Mar 31, | Dec 31, | ||||||||||||||||||||||||||||
| (dollars in thousands) | 2021 | 2021 | 2021 | 2021 | 2020 | |||||||||||||||||||||||||||
| REGULATORY CAPITAL RATIOS | ||||||||||||||||||||||||||||||||
| Central Pacific Financial Corp. | ||||||||||||||||||||||||||||||||
| Leverage capital ratio | 8.5 | % | 8.5 | % | 8.6 | % | 8.9 | % | 8.8 | % | ||||||||||||||||||||||
| Tier 1 risk-based capital ratio | 12.2 | 12.2 | 12.7 | 13.1 | 12.9 | |||||||||||||||||||||||||||
| Total risk-based capital ratio | 14.5 | 14.6 | 14.9 | 15.4 | 15.2 | |||||||||||||||||||||||||||
| Common equity tier 1 capital ratio | 11.2 | 11.2 | 11.6 | 12.0 | 11.8 | |||||||||||||||||||||||||||
| Central Pacific Bank | ||||||||||||||||||||||||||||||||
| Leverage capital ratio | 8.9 | 9.0 | 9.1 | 9.4 | 9.4 | |||||||||||||||||||||||||||
| Tier 1 risk-based capital ratio | 12.8 | 13.0 | 13.5 | 13.9 | 13.7 | |||||||||||||||||||||||||||
| Total risk-based capital ratio | 14.0 | 14.3 | 14.6 | 15.0 | 14.9 | |||||||||||||||||||||||||||
| Common equity tier 1 capital ratio | 12.8 | 13.0 | 13.5 | 13.9 | 13.7 | |||||||||||||||||||||||||||
| Dec 31, | Sep 30, | Jun 30, | Mar 31, | Dec 31, | ||||||||||||||||||||||||||||
| (dollars in thousands, except for per share amounts) | 2021 | 2021 | 2021 | 2021 | 2020 | |||||||||||||||||||||||||||
| BALANCE SHEET | ||||||||||||||||||||||||||||||||
| Total loans, net of deferred fees and costs | $ | 5,101,649 | $ | 5,045,797 | $ | 5,077,318 | $ | 5,137,849 | $ | 4,964,113 | ||||||||||||||||||||||
| Total assets | 7,419,089 | 7,298,231 | 7,178,481 | 6,979,265 | 6,594,583 | |||||||||||||||||||||||||||
| Total deposits | 6,639,158 | 6,515,863 | 6,397,159 | 6,208,950 | 5,796,118 | |||||||||||||||||||||||||||
| Long-term debt | 105,616 | 105,556 | 105,495 | 105,436 | 105,385 | |||||||||||||||||||||||||||
| Total shareholders’ equity | 558,219 | 555,419 | 552,793 | 542,865 | 546,685 | |||||||||||||||||||||||||||
| Total shareholders’ equity to total assets | 7.52 | % | 7.61 | % | 7.70 | % | 7.78 | % | 8.29 | % | ||||||||||||||||||||||
| ASSET QUALITY | ||||||||||||||||||||||||||||||||
| Allowance for credit losses (ACL) [1] | $ | 68,097 | $ | 74,587 | $ | 77,781 | $ | 81,553 | $ | 83,269 | ||||||||||||||||||||||
| Non-performing assets (NPA) | 5,881 | 7,237 | 6,745 | 7,194 | 6,192 | |||||||||||||||||||||||||||
| ACL to total loans [1] | 1.33 | % | 1.48 | % | 1.53 | % | 1.59 | % | 1.68 | % | ||||||||||||||||||||||
| ACL to core loans (refer to Table 10) [1] | 1.36 | % | 1.55 | % | 1.68 | % | 1.80 | % | 1.83 | % | ||||||||||||||||||||||
| ACL to non-performing assets [1] | 1,157.92 | % | 1,030.63 | % | 1,153.17 | % | 1,133.63 | % | 1,344.78 | % | ||||||||||||||||||||||
| NPA to total assets | 0.08 | % | 0.10 | % | 0.09 | % | 0.10 | % | 0.09 | % | ||||||||||||||||||||||
| PER SHARE OF COMMON STOCK OUTSTANDING | ||||||||||||||||||||||||||||||||
| Book value per common share | $ | 20.14 | $ | 19.84 | $ | 19.59 | $ | 19.19 | $ | 19.40 | ||||||||||||||||||||||
| Closing market price per common share | 28.17 | 25.68 | 26.06 | 26.68 | 19.01 | |||||||||||||||||||||||||||
| [1] As of January 1, 2021, the provision for credit losses on off-balance sheet credit exposures (previously included in other operating expense) is included in the provision for credit losses line on the consolidated statements of income. Prior period amounts have been reclassified to conform to the current period presentation. The allowance for off-balance sheet credit exposures continues to be included in other liabilities. | ||||||||||||||||||||||||||||||||
| [2] ROA, ROE and ROTE are annualized based on a 30/360 day convention. Annualized net interest income and expense in the NIM calculation are based on the day count interest payment conventions at the interest-earning asset or interest-bearing liability level (i.e. 30/360, actual/actual). | ||||||||||||||||||||||||||||||||
| [3] Efficiency ratio is defined as total operating expense divided by total revenue (net interest income and total other operating income). | ||||||||||||||||||||||||||||||||
| [4] Dividend payout ratio is defined as dividends declared per share divided by diluted earnings per share. | ||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Consolidated Balance Sheets | |||||
| (Unaudited) | TABLE 2 | ||||
| Dec 31, | Sep 30, | Jun 30, | Mar 31, | Dec 31, | ||||||||||||||||||||||||||||
| (Dollars in thousands, except share data) | 2021 | 2021 | 2021 | 2021 | 2020 | |||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||
| Cash and due from financial institutions | $ | 81,506 | $ | 108,669 | $ | 116,009 | $ | 93,358 | $ | 97,546 | ||||||||||||||||||||||
| Interest-bearing deposits in other financial institutions | 247,401 | 240,173 | 224,469 | 166,533 | 6,521 | |||||||||||||||||||||||||||
| Investment securities: | ||||||||||||||||||||||||||||||||
| Available-for-sale debt securities, at fair value | 1,631,699 | 1,535,450 | 1,407,340 | 1,216,341 | 1,182,609 | |||||||||||||||||||||||||||
| Equity securities, at fair value | — | 1,593 | 1,578 | 1,435 | 1,351 | |||||||||||||||||||||||||||
| Total investment securities | 1,631,699 | 1,537,043 | 1,408,918 | 1,217,776 | 1,183,960 | |||||||||||||||||||||||||||
| Loans held for sale | 3,531 | 5,290 | 5,361 | 5,234 | 16,687 | |||||||||||||||||||||||||||
| Loans, net of deferred fees and costs | 5,101,649 | 5,045,797 | 5,077,318 | 5,137,849 | 4,964,113 | |||||||||||||||||||||||||||
| Less allowance for credit losses | 68,097 | 74,587 | 77,781 | 81,553 | 83,269 | |||||||||||||||||||||||||||
| Loans, net of allowance for credit losses | 5,033,552 | 4,971,210 | 4,999,537 | 5,056,296 | 4,880,844 | |||||||||||||||||||||||||||
| Premises and equipment, net | 80,354 | 80,190 | 76,740 | 72,599 | 65,278 | |||||||||||||||||||||||||||
| Accrued interest receivable | 16,709 | 17,110 | 19,014 | 19,440 | 20,224 | |||||||||||||||||||||||||||
| Investment in unconsolidated entities | 29,679 | 30,397 | 31,052 | 31,487 | 29,968 | |||||||||||||||||||||||||||
| Other real estate owned | — | — | — | — | — | |||||||||||||||||||||||||||
| Mortgage servicing rights | 9,738 | 9,976 | 10,500 | 11,094 | 11,865 | |||||||||||||||||||||||||||
| Bank-owned life insurance | 169,148 | 167,961 | 167,289 | 167,110 | 163,161 | |||||||||||||||||||||||||||
| Federal Home Loan Bank ("FHLB") stock | 7,964 | 7,952 | 8,149 | 8,155 | 8,237 | |||||||||||||||||||||||||||
| Right of use lease asset | 39,441 | 40,757 | 41,890 | 44,727 | 45,857 | |||||||||||||||||||||||||||
| Other assets | 68,367 | 81,503 | 69,553 | 85,456 | 64,435 | |||||||||||||||||||||||||||
| Total assets | $ | 7,419,089 | $ | 7,298,231 | $ | 7,178,481 | $ | 6,979,265 | $ | 6,594,583 | ||||||||||||||||||||||
| LIABILITIES AND SHAREHOLDERS' EQUITY | ||||||||||||||||||||||||||||||||
| Deposits: | ||||||||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 2,291,246 | $ | 2,195,404 | $ | 2,203,806 | $ | 2,070,428 | $ | 1,790,269 | ||||||||||||||||||||||
| Interest-bearing demand | 1,415,277 | 1,372,626 | 1,341,280 | 1,237,574 | 1,174,888 | |||||||||||||||||||||||||||
| Savings and money market | 2,225,903 | 2,296,968 | 2,048,945 | 2,004,368 | 1,932,043 | |||||||||||||||||||||||||||
| Time | 706,732 | 650,865 | 803,128 | 896,580 | 898,918 | |||||||||||||||||||||||||||
| Total deposits | 6,639,158 | 6,515,863 | 6,397,159 | 6,208,950 | 5,796,118 | |||||||||||||||||||||||||||
| FHLB advances and other short-term borrowings | — | — | — | — | 22,000 | |||||||||||||||||||||||||||
| Long-term debt | 105,616 | 105,556 | 105,495 | 105,436 | 105,385 | |||||||||||||||||||||||||||
| Lease liability | 40,731 | 41,933 | 43,112 | 46,033 | 47,191 | |||||||||||||||||||||||||||
| Other liabilities | 75,317 | 79,412 | 79,874 | 75,933 | 77,156 | |||||||||||||||||||||||||||
| Total liabilities | 6,860,822 | 6,742,764 | 6,625,640 | 6,436,352 | 6,047,850 | |||||||||||||||||||||||||||
| Shareholders' equity: | ||||||||||||||||||||||||||||||||
| Preferred stock, no par value, authorized 1,000,000 shares; issued and outstanding: none at December 31, 2021, September 30, 2021, June 30, 2021, March 31, 2021, and December 31, 2020 | — | — | — | — | — | |||||||||||||||||||||||||||
| Common stock, no par value, authorized 185,000,000 shares; issued and outstanding: 27,714,071 at December 31, 2021, 27,999,588 at September 30, 2021, 28,218,860 at June 30, 2021, 28,282,530 at March 31, 2021, and 28,183,340 at December 31, 2020 | 433,263 | 436,957 | 440,854 | 443,505 | 442,635 | |||||||||||||||||||||||||||
| Additional paid-in capital | 98,073 | 97,279 | 96,182 | 95,721 | 94,842 | |||||||||||||||||||||||||||
| Retained earnings (accumulated deficit) | 34,843 | 22,916 | 10,831 | 628 | (10,920) | |||||||||||||||||||||||||||
| Accumulated other comprehensive (loss) income | (7,960) | (1,733) | 4,926 | 3,011 | 20,128 | |||||||||||||||||||||||||||
| Total shareholders' equity | 558,219 | 555,419 | 552,793 | 542,865 | 546,685 | |||||||||||||||||||||||||||
| Non-controlling interest | 48 | 48 | 48 | 48 | 48 | |||||||||||||||||||||||||||
| Total equity | 558,267 | 555,467 | 552,841 | 542,913 | 546,733 | |||||||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 7,419,089 | $ | 7,298,231 | $ | 7,178,481 | $ | 6,979,265 | $ | 6,594,583 | ||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Consolidated Statements of Income | |||||
| (Unaudited) | TABLE 3 | ||||
| Three Months Ended | Year Ended | |||||||||||||||||||||||||||||||||||||||||||
| December 31, | September 30, | June 30, | March 31, | December 31, | December 31, | |||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands, except per share data) | 2021 | 2021 | 2021 | 2021 | 2020 | 2021 | 2020 | |||||||||||||||||||||||||||||||||||||
| Interest income: | ||||||||||||||||||||||||||||||||||||||||||||
| Interest and fees on loans | $ | 47,576 | $ | 51,104 | $ | 49,024 | $ | 46,074 | $ | 48,259 | $ | 193,778 | $ | 186,129 | ||||||||||||||||||||||||||||||
| Interest and dividends on investment securities: | ||||||||||||||||||||||||||||||||||||||||||||
| Taxable investment securities | 6,667 | 6,210 | 4,447 | 5,106 | 5,002 | 22,430 | 23,302 | |||||||||||||||||||||||||||||||||||||
| Tax-exempt investment securities | 642 | 470 | 346 | 514 | 504 | 1,972 | 2,392 | |||||||||||||||||||||||||||||||||||||
| Dividend income on investment securities | 21 | 18 | 18 | 18 | 18 | 75 | 69 | |||||||||||||||||||||||||||||||||||||
| Interest on deposits in other financial institutions | 86 | 105 | 61 | 10 | 4 | 262 | 46 | |||||||||||||||||||||||||||||||||||||
| Dividend income on FHLB stock | 61 | 62 | 63 | 59 | 114 | 245 | 480 | |||||||||||||||||||||||||||||||||||||
| Total interest income | 55,053 | 57,969 | 53,959 | 51,781 | 53,901 | 218,762 | 212,418 | |||||||||||||||||||||||||||||||||||||
| Interest expense: | ||||||||||||||||||||||||||||||||||||||||||||
| Interest on deposits: | ||||||||||||||||||||||||||||||||||||||||||||
| Demand | 104 | 101 | 93 | 86 | 105 | 384 | 510 | |||||||||||||||||||||||||||||||||||||
| Savings and money market | 352 | 332 | 282 | 274 | 314 | 1,240 | 2,416 | |||||||||||||||||||||||||||||||||||||
| Time | 478 | 428 | 498 | 588 | 813 | 1,992 | 7,489 | |||||||||||||||||||||||||||||||||||||
| Interest on short-term borrowings | — | — | — | 2 | 65 | 2 | 718 | |||||||||||||||||||||||||||||||||||||
| Interest on long-term debt | 1,023 | 1,022 | 1,025 | 1,027 | 1,130 | 4,097 | 3,602 | |||||||||||||||||||||||||||||||||||||
| Total interest expense | 1,957 | 1,883 | 1,898 | 1,977 | 2,427 | 7,715 | 14,735 | |||||||||||||||||||||||||||||||||||||
| Net interest income | 53,096 | 56,086 | 52,061 | 49,804 | 51,474 | 211,047 | 197,683 | |||||||||||||||||||||||||||||||||||||
| (Credit) provision for credit losses | (7,692) | (2,635) | (3,443) | (821) | 4,898 | (14,591) | 42,111 | |||||||||||||||||||||||||||||||||||||
| Net interest income after (credit) provision for credit losses | 60,788 | 58,721 | 55,504 | 50,625 | 46,576 | 225,638 | 155,572 | |||||||||||||||||||||||||||||||||||||
| Other operating income: | ||||||||||||||||||||||||||||||||||||||||||||
| Mortgage banking income | 1,902 | 1,327 | 1,533 | 2,970 | 5,434 | 7,732 | 13,682 | |||||||||||||||||||||||||||||||||||||
| Service charges on deposit accounts | 1,800 | 1,637 | 1,443 | 1,478 | 1,560 | 6,358 | 6,234 | |||||||||||||||||||||||||||||||||||||
| Other service charges and fees | 5,016 | 4,942 | 4,619 | 3,790 | 3,709 | 18,367 | 14,867 | |||||||||||||||||||||||||||||||||||||
| Income from fiduciary activities | 1,283 | 1,292 | 1,269 | 1,231 | 1,113 | 5,075 | 4,829 | |||||||||||||||||||||||||||||||||||||
| Net gain (loss) on sales of investment securities | — | 100 | 50 | — | 151 | 150 | (201) | |||||||||||||||||||||||||||||||||||||
| Income from bank-owned life insurance | 946 | 540 | 1,210 | 797 | 1,219 | 3,493 | 3,803 | |||||||||||||||||||||||||||||||||||||
| Other | 619 | 415 | 406 | 445 | 871 | 1,885 | 1,984 | |||||||||||||||||||||||||||||||||||||
| Total other operating income | 11,566 | 10,253 | 10,530 | 10,711 | 14,057 | 43,060 | 45,198 | |||||||||||||||||||||||||||||||||||||
| Other operating expense: | ||||||||||||||||||||||||||||||||||||||||||||
| Salaries and employee benefits | 23,030 | 23,566 | 23,790 | 19,827 | 23,090 | 90,213 | 83,848 | |||||||||||||||||||||||||||||||||||||
| Net occupancy | 4,129 | 4,185 | 4,055 | 3,764 | 4,011 | 16,133 | 15,162 | |||||||||||||||||||||||||||||||||||||
| Equipment | 1,207 | 1,089 | 1,048 | 1,000 | 1,157 | 4,344 | 4,531 | |||||||||||||||||||||||||||||||||||||
| Communication expense | 922 | 824 | 756 | 769 | 758 | 3,271 | 3,225 | |||||||||||||||||||||||||||||||||||||
| Legal and professional services | 2,928 | 2,575 | 2,572 | 2,377 | 2,507 | 10,452 | 9,035 | |||||||||||||||||||||||||||||||||||||
| Computer software expense | 3,125 | 2,998 | 3,398 | 3,783 | 3,625 | 13,304 | 12,717 | |||||||||||||||||||||||||||||||||||||
| Advertising expense | 1,179 | 1,329 | 1,329 | 1,658 | 756 | 5,495 | 3,791 | |||||||||||||||||||||||||||||||||||||
| Other | 5,902 | 4,779 | 4,485 | 4,668 | 8,786 | 19,834 | 19,428 | |||||||||||||||||||||||||||||||||||||
| Total other operating expense | 42,422 | 41,345 | 41,433 | 37,846 | 44,690 | 163,046 | 151,737 | |||||||||||||||||||||||||||||||||||||
| Income before income taxes | 29,932 | 27,629 | 24,601 | 23,490 | 15,943 | 105,652 | 49,033 | |||||||||||||||||||||||||||||||||||||
| Income tax expense | 7,605 | 6,814 | 5,887 | 5,452 | 3,772 | 25,758 | 11,760 | |||||||||||||||||||||||||||||||||||||
| Net income | $ | 22,327 | $ | 20,815 | $ | 18,714 | $ | 18,038 | $ | 12,171 | $ | 79,894 | $ | 37,273 | ||||||||||||||||||||||||||||||
| Per common share data: | ||||||||||||||||||||||||||||||||||||||||||||
| Basic earnings per share | $ | 0.80 | $ | 0.74 | $ | 0.66 | $ | 0.64 | $ | 0.43 | $ | 2.85 | $ | 1.33 | ||||||||||||||||||||||||||||||
| Diluted earnings per share | 0.80 | 0.74 | 0.66 | 0.64 | 0.43 | 2.83 | 1.32 | |||||||||||||||||||||||||||||||||||||
| Cash dividends declared | 0.25 | 0.24 | 0.24 | 0.23 | 0.23 | 0.96 | 0.92 | |||||||||||||||||||||||||||||||||||||
| Basic weighted average shares outstanding | 27,769,651 | 27,967,089 | 28,173,710 | 28,108,648 | 28,071,151 | 28,003,744 | 28,074,543 | |||||||||||||||||||||||||||||||||||||
| Diluted weighted average shares outstanding | 28,045,826 | 28,175,953 | 28,456,624 | 28,313,014 | 28,177,366 | 28,257,323 | 28,180,576 | |||||||||||||||||||||||||||||||||||||
| Note: Certain amounts in the prior period financial statements have been reclassified to conform to the presentation of the current period. | ||||||||||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Average Balances, Interest Income & Expense, Yields and Rates (Taxable Equivalent) | |||||
| (Unaudited) | TABLE 4 | ||||
| Three Months Ended | Three Months Ended | Three Months Ended | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| December 31, 2021 | September 30, 2021 | December 31, 2020 | ||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | Average | Average | |||||||||||||||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Balance | Yield/Rate | Interest | Balance | Yield/Rate | Interest | Balance | Yield/Rate | Interest | |||||||||||||||||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in other financial institutions | $ | 225,560 | 0.15 | % | $ | 86 | $ | 273,039 | 0.15 | % | $ | 105 | $ | 16,786 | 0.10 | % | $ | 4 | ||||||||||||||||||||||||||||||||||||||
| Investment securities, excluding valuation allowance: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Taxable | 1,469,711 | 1.82 | 6,688 | 1,351,272 | 1.84 | 6,228 | 1,048,665 | 1.91 | 5,020 | |||||||||||||||||||||||||||||||||||||||||||||||
| Tax-exempt | 114,529 | 2.84 | 813 | 106,333 | 2.24 | 595 | 90,452 | 2.83 | 638 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total investment securities | 1,584,240 | 1.89 | 7,501 | 1,457,605 | 1.87 | 6,823 | 1,139,117 | 1.99 | 5,658 | |||||||||||||||||||||||||||||||||||||||||||||||
| Loans, including loans held for sale | 5,073,069 | 3.73 | 47,576 | 5,022,909 | 4.05 | 51,104 | 5,034,717 | 3.82 | 48,259 | |||||||||||||||||||||||||||||||||||||||||||||||
| Federal Home Loan Bank stock | 7,960 | 3.05 | 61 | 8,090 | 3.09 | 62 | 11,608 | 3.91 | 114 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 6,890,829 | 3.19 | 55,224 | 6,761,643 | 3.42 | 58,094 | 6,202,228 | 3.48 | 54,035 | |||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-earning assets | 424,496 | 448,567 | 418,899 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 7,315,325 | $ | 7,210,210 | $ | 6,621,127 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| LIABILITIES AND EQUITY | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand deposits | $ | 1,383,696 | 0.03 | % | $ | 104 | $ | 1,356,967 | 0.03 | % | $ | 101 | $ | 1,149,759 | 0.04 | % | $ | 105 | ||||||||||||||||||||||||||||||||||||||
| Savings and money market deposits | 2,224,592 | 0.06 | 352 | 2,168,055 | 0.06 | 332 | 1,902,876 | 0.07 | 314 | |||||||||||||||||||||||||||||||||||||||||||||||
| Time deposits up to $250,000 | 225,451 | 0.31 | 176 | 228,762 | 0.31 | 181 | 246,573 | 0.57 | 351 | |||||||||||||||||||||||||||||||||||||||||||||||
| Time deposits over $250,000 | 468,292 | 0.26 | 302 | 467,289 | 0.21 | 247 | 662,390 | 0.28 | 462 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 4,302,031 | 0.09 | 934 | 4,221,073 | 0.08 | 861 | 3,961,598 | 0.12 | 1,232 | |||||||||||||||||||||||||||||||||||||||||||||||
| Federal Home Loan Bank advances and other short-term borrowings | — | — | — | — | — | — | 76,968 | 0.33 | 65 | |||||||||||||||||||||||||||||||||||||||||||||||
| Long-term debt | 105,581 | 3.85 | 1,023 | 105,516 | 3.84 | 1,022 | 124,830 | 3.60 | 1,130 | |||||||||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 4,407,612 | 0.18 | 1,957 | 4,326,589 | 0.17 | 1,883 | 4,163,396 | 0.23 | 2,427 | |||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 2,234,795 | 2,203,695 | 1,793,659 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 116,408 | 118,272 | 115,407 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities | 6,758,815 | 6,648,556 | 6,072,462 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 556,462 | 561,606 | 548,663 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Non-controlling interest | 48 | 48 | 2 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total equity | 556,510 | 561,654 | 548,665 | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 7,315,325 | $ | 7,210,210 | $ | 6,621,127 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 53,267 | $ | 56,211 | $ | 51,608 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest rate spread | 3.01 | % | 3.25 | % | 3.25 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin | 3.08 | % | 3.31 | % | 3.32 | % | ||||||||||||||||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Average Balances, Interest Income & Expense, Yields and Rates (Taxable Equivalent) | |||||
| (Unaudited) | TABLE 5 | ||||
| Year Ended | Year Ended | |||||||||||||||||||||||||||||||||||||
| December 31, 2021 | December 31, 2020 | |||||||||||||||||||||||||||||||||||||
| Average | Average | Average | Average | |||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | Balance | Yield/Rate | Interest | Balance | Yield/Rate | Interest | ||||||||||||||||||||||||||||||||
| ASSETS | ||||||||||||||||||||||||||||||||||||||
| Interest-earning assets: | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing deposits in other financial institutions | $ | 191,967 | 0.14 | % | $ | 262 | $ | 13,980 | 0.33 | % | $ | 46 | ||||||||||||||||||||||||||
| Investment securities, excluding valuation allowance: | ||||||||||||||||||||||||||||||||||||||
| Taxable | 1,269,900 | 1.77 | 22,505 | 1,037,209 | 2.25 | 23,371 | ||||||||||||||||||||||||||||||||
| Tax-exempt | 101,877 | 2.45 | 2,496 | 96,217 | 3.15 | 3,028 | ||||||||||||||||||||||||||||||||
| Total investment securities | 1,371,777 | 1.82 | 25,001 | 1,133,426 | 2.33 | 26,399 | ||||||||||||||||||||||||||||||||
| Loans, including loans held for sale | 5,071,516 | 3.82 | 193,778 | 4,855,169 | 3.83 | 186,129 | ||||||||||||||||||||||||||||||||
| Federal Home Loan Bank stock | 7,933 | 3.09 | 245 | 12,591 | 3.81 | 480 | ||||||||||||||||||||||||||||||||
| Total interest-earning assets | 6,643,193 | 3.30 | 219,286 | 6,015,166 | 3.54 | 213,054 | ||||||||||||||||||||||||||||||||
| Noninterest-earning assets | 434,832 | 403,495 | ||||||||||||||||||||||||||||||||||||
| Total assets | $ | 7,078,025 | $ | 6,418,661 | ||||||||||||||||||||||||||||||||||
| LIABILITIES AND EQUITY | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities: | ||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand deposits | $ | 1,300,022 | 0.03 | % | $ | 384 | $ | 1,078,589 | 0.05 | % | $ | 510 | ||||||||||||||||||||||||||
| Savings and money market deposits | 2,099,388 | 0.06 | 1,240 | 1,830,972 | 0.13 | 2,416 | ||||||||||||||||||||||||||||||||
| Time deposits up to $250,000 | 230,705 | 0.34 | 795 | 257,708 | 0.75 | 1,921 | ||||||||||||||||||||||||||||||||
| Time deposits over $250,000 | 551,831 | 0.22 | 1,197 | 696,650 | 0.80 | 5,568 | ||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 4,181,946 | 0.09 | 3,616 | 3,863,919 | 0.27 | 10,415 | ||||||||||||||||||||||||||||||||
| Federal Home Loan Bank advances and other short-term borrowings | 607 | 0.30 | 2 | 89,904 | 0.80 | 718 | ||||||||||||||||||||||||||||||||
| Long-term debt | 105,488 | 3.88 | 4,097 | 117,100 | 3.08 | 3,602 | ||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 4,288,041 | 0.18 | 7,715 | 4,070,923 | 0.36 | 14,735 | ||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 2,117,423 | 1,691,958 | ||||||||||||||||||||||||||||||||||||
| Other liabilities | 116,936 | 111,859 | ||||||||||||||||||||||||||||||||||||
| Total liabilities | 6,522,400 | 5,874,740 | ||||||||||||||||||||||||||||||||||||
| Shareholders’ equity | 555,600 | 543,919 | ||||||||||||||||||||||||||||||||||||
| Non-controlling interest | 25 | 2 | ||||||||||||||||||||||||||||||||||||
| Total equity | 555,625 | 543,921 | ||||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 7,078,025 | $ | 6,418,661 | ||||||||||||||||||||||||||||||||||
| Net interest income | $ | 211,571 | $ | 198,319 | ||||||||||||||||||||||||||||||||||
| Interest rate spread | 3.12 | % | 3.18 | % | ||||||||||||||||||||||||||||||||||
| Net interest margin | 3.18 | % | 3.30 | % | ||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Loans by Geographic Distribution | |||||
| (Unaudited) | TABLE 6 | ||||
| December 31, | September 30, | June 30, | March 31, | December 31, | ||||||||||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2021 | 2021 | 2021 | 2020 | |||||||||||||||||||||||||||
| HAWAII: | ||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural: | ||||||||||||||||||||||||||||||||
| SBA Paycheck Protection Program | $ | 87,459 | $ | 198,315 | $ | 395,352 | $ | 548,880 | $ | 375,879 | ||||||||||||||||||||||
| Other | 422,388 | 404,751 | 389,341 | 399,154 | 426,670 | |||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Construction | 122,867 | 128,908 | 133,457 | 137,976 | 125,407 | |||||||||||||||||||||||||||
| Residential mortgage | 1,875,980 | 1,748,729 | 1,711,801 | 1,687,513 | 1,690,212 | |||||||||||||||||||||||||||
| Home equity | 637,249 | 618,951 | 583,430 | 559,514 | 551,266 | |||||||||||||||||||||||||||
| Commercial mortgage | 922,146 | 915,746 | 926,006 | 911,216 | 898,055 | |||||||||||||||||||||||||||
| Consumer | 333,843 | 331,987 | 328,332 | 319,032 | 332,430 | |||||||||||||||||||||||||||
| Total loans, net of deferred fees and costs | 4,401,932 | 4,347,387 | 4,467,719 | 4,563,285 | 4,399,919 | |||||||||||||||||||||||||||
| Allowance for credit losses | (55,808) | (62,126) | (67,773) | (70,961) | (73,152) | |||||||||||||||||||||||||||
| Loans, net of allowance for credit losses | $ | 4,346,124 | $ | 4,285,261 | $ | 4,399,946 | $ | 4,492,324 | $ | 4,326,767 | ||||||||||||||||||||||
| U.S. MAINLAND: [1] | ||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural: | ||||||||||||||||||||||||||||||||
| SBA Paycheck Protection Program | $ | 3,868 | $ | 20,356 | $ | 39,258 | $ | 48,939 | $ | 40,496 | ||||||||||||||||||||||
| Other | 107,733 | 114,122 | 96,884 | 115,035 | 118,421 | |||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Commercial mortgage | 298,058 | 292,671 | 260,424 | 253,122 | 258,273 | |||||||||||||||||||||||||||
| Consumer | 290,058 | 271,261 | 213,033 | 157,468 | 147,004 | |||||||||||||||||||||||||||
| Total loans, net of deferred fees and costs | 699,717 | 698,410 | 609,599 | 574,564 | 564,194 | |||||||||||||||||||||||||||
| Allowance for credit losses | (12,289) | (12,461) | (10,008) | (10,592) | (10,117) | |||||||||||||||||||||||||||
| Loans, net of allowance for credit losses | $ | 687,428 | $ | 685,949 | $ | 599,591 | $ | 563,972 | $ | 554,077 | ||||||||||||||||||||||
| TOTAL: | ||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural: | ||||||||||||||||||||||||||||||||
| SBA Paycheck Protection Program | $ | 91,327 | $ | 218,671 | $ | 434,610 | $ | 597,819 | $ | 416,375 | ||||||||||||||||||||||
| Other | 530,121 | 518,873 | 486,225 | 514,189 | 545,091 | |||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Construction | 122,867 | 128,908 | 133,457 | 137,976 | 125,407 | |||||||||||||||||||||||||||
| Residential mortgage | 1,875,980 | 1,748,729 | 1,711,801 | 1,687,513 | 1,690,212 | |||||||||||||||||||||||||||
| Home equity | 637,249 | 618,951 | 583,430 | 559,514 | 551,266 | |||||||||||||||||||||||||||
| Commercial mortgage | 1,220,204 | 1,208,417 | 1,186,430 | 1,164,338 | 1,156,328 | |||||||||||||||||||||||||||
| Consumer | 623,901 | 603,248 | 541,365 | 476,500 | 479,434 | |||||||||||||||||||||||||||
| Total loans, net of deferred fees and costs | 5,101,649 | 5,045,797 | 5,077,318 | 5,137,849 | 4,964,113 | |||||||||||||||||||||||||||
| Allowance for credit losses | (68,097) | (74,587) | (77,781) | (81,553) | (83,269) | |||||||||||||||||||||||||||
| Loans, net of allowance for credit losses | $ | 5,033,552 | $ | 4,971,210 | $ | 4,999,537 | $ | 5,056,296 | $ | 4,880,844 | ||||||||||||||||||||||
| [1] U.S. Mainland includes territories of the United States. | ||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Deposits | |||||
| (Unaudited) | TABLE 7 | ||||
| December 31, | September 30, | June 30, | March 31, | December 31, | ||||||||||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2021 | 2021 | 2021 | 2020 | |||||||||||||||||||||||||||
| Noninterest-bearing demand | $ | 2,291,246 | $ | 2,195,404 | $ | 2,203,806 | $ | 2,070,428 | $ | 1,790,269 | ||||||||||||||||||||||
| Interest-bearing demand | 1,415,277 | 1,372,626 | 1,341,280 | 1,237,574 | 1,174,888 | |||||||||||||||||||||||||||
| Savings and money market | 2,225,903 | 2,296,968 | 2,048,945 | 2,004,368 | 1,932,043 | |||||||||||||||||||||||||||
| Time deposits less than $100,000 | 136,584 | 139,358 | 141,498 | 145,497 | 149,063 | |||||||||||||||||||||||||||
| Other time deposits $100,000 to $250,000 [1] | 88,873 | 87,491 | 89,710 | 88,814 | 90,149 | |||||||||||||||||||||||||||
| Core deposits | 6,157,883 | 6,091,847 | 5,825,239 | 5,546,681 | 5,136,412 | |||||||||||||||||||||||||||
| Government time deposits | 214,950 | 238,950 | 403,755 | 500,194 | 500,344 | |||||||||||||||||||||||||||
| Other time deposits greater than $250,000 | 266,325 | 185,066 | 168,165 | 162,075 | 159,362 | |||||||||||||||||||||||||||
| Total time deposits greater than $250,000 | 481,275 | 424,016 | 571,920 | 662,269 | 659,706 | |||||||||||||||||||||||||||
| Total deposits | $ | 6,639,158 | $ | 6,515,863 | $ | 6,397,159 | $ | 6,208,950 | $ | 5,796,118 | ||||||||||||||||||||||
| [1] As of January 1, 2021, other time deposits $100,000 to $250,000 have been included in core deposits. Prior period amounts have been reclassified to conform to current period presentation. | ||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Nonperforming Assets, Past Due and Restructured Loans | |||||
| (Unaudited) | TABLE 8 | ||||
| December 31, | September 30, | June 30, | March 31, | December 31, | ||||||||||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2021 | 2021 | 2021 | 2020 | |||||||||||||||||||||||||||
| Nonaccrual loans: [1] | ||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural - Other | $ | 183 | $ | 689 | $ | 699 | $ | 1,412 | $ | 1,461 | ||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Residential mortgage | 4,623 | 5,351 | 5,280 | 4,553 | 4,115 | |||||||||||||||||||||||||||
| Home equity | 786 | 880 | 434 | 439 | 524 | |||||||||||||||||||||||||||
| Commercial mortgage | — | — | — | — | — | |||||||||||||||||||||||||||
| Consumer | 289 | 317 | 332 | 790 | 92 | |||||||||||||||||||||||||||
| Total nonaccrual loans | 5,881 | 7,237 | 6,745 | 7,194 | 6,192 | |||||||||||||||||||||||||||
| Other real estate owned ("OREO"): | ||||||||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Residential mortgage | — | — | — | — | — | |||||||||||||||||||||||||||
| Total OREO | — | — | — | — | — | |||||||||||||||||||||||||||
| Total nonperforming assets ("NPAs") | 5,881 | 7,237 | 6,745 | 7,194 | 6,192 | |||||||||||||||||||||||||||
| Loans delinquent for 90 days or more still accruing interest: [1] | ||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural - Other | 945 | — | 29 | — | — | |||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Residential mortgage | — | 444 | 1,438 | 4,522 | 567 | |||||||||||||||||||||||||||
| Home equity | 44 | — | — | — | — | |||||||||||||||||||||||||||
| Consumer | 374 | 166 | 100 | 262 | 240 | |||||||||||||||||||||||||||
| Total loans delinquent for 90 days or more still accruing interest | 1,363 | 610 | 1,567 | 4,784 | 807 | |||||||||||||||||||||||||||
| Restructured loans still accruing interest: [1] | ||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural - Other | — | 12 | 26 | 63 | 100 | |||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||
| Residential mortgage | 3,768 | 4,458 | 4,258 | 5,473 | 5,718 | |||||||||||||||||||||||||||
| Commercial mortgage | 1,043 | 1,577 | 1,636 | 1,698 | 1,761 | |||||||||||||||||||||||||||
| Consumer | 92 | 99 | 132 | 198 | 207 | |||||||||||||||||||||||||||
| Total restructured loans still accruing interest | 4,903 | 6,146 | 6,052 | 7,432 | 7,786 | |||||||||||||||||||||||||||
| Total NPAs and loans delinquent for 90 days or more and restructured loans still accruing interest | $ | 12,147 | $ | 13,993 | $ | 14,364 | $ | 19,410 | $ | 14,785 | ||||||||||||||||||||||
| Total nonaccrual loans as a percentage of total loans | 0.12 | % | 0.14 | % | 0.13 | % | 0.14 | % | 0.12 | % | ||||||||||||||||||||||
| Total NPAs as a percentage of total loans and OREO | 0.12 | % | 0.14 | % | 0.13 | % | 0.14 | % | 0.12 | % | ||||||||||||||||||||||
| Total NPAs and loans delinquent for 90 days or more still accruing interest as a percentage of total loans and OREO | 0.14 | % | 0.16 | % | 0.16 | % | 0.23 | % | 0.14 | % | ||||||||||||||||||||||
| Total NPAs, loans delinquent for 90 days or more and restructured loans still accruing interest as a percentage of total loans and OREO | 0.24 | % | 0.28 | % | 0.28 | % | 0.38 | % | 0.30 | % | ||||||||||||||||||||||
| Quarter-to-quarter changes in NPAs: | ||||||||||||||||||||||||||||||||
| Balance at beginning of quarter | $ | 7,237 | $ | 6,745 | $ | 7,194 | $ | 6,192 | $ | 13,187 | ||||||||||||||||||||||
| Additions | 1,375 | 1,951 | 1,879 | 2,257 | 1,370 | |||||||||||||||||||||||||||
| Reductions: | ||||||||||||||||||||||||||||||||
| Payments | (933) | (767) | (1,120) | (292) | (3,186) | |||||||||||||||||||||||||||
| Return to accrual status | (1,034) | (141) | (84) | (99) | (548) | |||||||||||||||||||||||||||
| Sales of NPAs | — | — | — | — | (4,353) | |||||||||||||||||||||||||||
| Charge-offs, valuation and other adjustments | (764) | (551) | (1,124) | (864) | (278) | |||||||||||||||||||||||||||
| Total reductions | (2,731) | (1,459) | (2,328) | (1,255) | (8,365) | |||||||||||||||||||||||||||
| Balance at end of quarter | $ | 5,881 | $ | 7,237 | $ | 6,745 | $ | 7,194 | $ | 6,192 | ||||||||||||||||||||||
| [1] Section 4013 of the CARES Act and the revised Interagency Statement are being applied to loan modifications related to the COVID-19 pandemic as eligible and applicable. These loan modifications are not included in the delinquent or restructured loan balances presented above. | ||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Allowance for Credit Losses on Loans | |||||
| (Unaudited) | TABLE 9 | ||||
| Three Months Ended | Year Ended | |||||||||||||||||||||||||||||||||||||||||||
| Dec 31, | Sep 30, | Jun 30, | Mar 31, | Dec 31, | December 31, | |||||||||||||||||||||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2021 | 2021 | 2021 | 2020 | 2021 | 2020 | |||||||||||||||||||||||||||||||||||||
| Allowance for credit losses ("ACL"): | ||||||||||||||||||||||||||||||||||||||||||||
| ACL at beginning of period | $ | 74,587 | $ | 77,781 | $ | 81,553 | $ | 83,269 | $ | 80,542 | $ | 83,269 | $ | 47,971 | ||||||||||||||||||||||||||||||
| Adoption of ASU 2016-13 | — | — | — | — | — | — | 3,566 | |||||||||||||||||||||||||||||||||||||
| Adjusted ACL at beginning of period | 74,587 | 77,781 | 81,553 | 83,269 | 80,542 | 83,269 | 51,537 | |||||||||||||||||||||||||||||||||||||
| (Credit) provision for credit losses on loans [1] [2] | (7,417) | (2,969) | (2,963) | (974) | 4,496 | (14,323) | 38,930 | |||||||||||||||||||||||||||||||||||||
| Charge-offs: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural - Other | 379 | 334 | 401 | 609 | 676 | 1,723 | 3,026 | |||||||||||||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||||||||||||||
| Residential mortgage | — | — | — | — | — | — | 63 | |||||||||||||||||||||||||||||||||||||
| Commercial mortgage | — | — | — | — | — | — | 75 | |||||||||||||||||||||||||||||||||||||
| Consumer | 952 | 829 | 1,523 | 1,098 | 1,856 | 4,402 | 8,191 | |||||||||||||||||||||||||||||||||||||
| Total charge-offs | 1,331 | 1,163 | 1,924 | 1,707 | 2,532 | 6,125 | 11,355 | |||||||||||||||||||||||||||||||||||||
| Recoveries: | ||||||||||||||||||||||||||||||||||||||||||||
| Commercial, financial and agricultural - Other | 358 | 281 | 276 | 89 | 189 | 1,004 | 1,157 | |||||||||||||||||||||||||||||||||||||
| Real estate: | ||||||||||||||||||||||||||||||||||||||||||||
| Construction | 1,159 | — | — | — | — | 1,159 | 131 | |||||||||||||||||||||||||||||||||||||
| Residential mortgage | 13 | 53 | 186 | 106 | 15 | 358 | 229 | |||||||||||||||||||||||||||||||||||||
| Home equity | — | — | — | 9 | 2 | 9 | 33 | |||||||||||||||||||||||||||||||||||||
| Commercial mortgage | — | — | 65 | 8 | 1 | 73 | 16 | |||||||||||||||||||||||||||||||||||||
| Consumer | 728 | 604 | 588 | 753 | 556 | 2,673 | 2,591 | |||||||||||||||||||||||||||||||||||||
| Total recoveries | 2,258 | 938 | 1,115 | 965 | 763 | 5,276 | 4,157 | |||||||||||||||||||||||||||||||||||||
Net (recoveries) charge-offs | (927) | 225 | 809 | 742 | 1,769 | 849 | 7,198 | |||||||||||||||||||||||||||||||||||||
| ACL at end of period | $ | 68,097 | $ | 74,587 | $ | 77,781 | $ | 81,553 | $ | 83,269 | $ | 68,097 | $ | 83,269 | ||||||||||||||||||||||||||||||
| Average loans, net of deferred fees and costs | $ | 5,073,069 | $ | 5,022,909 | $ | 5,110,820 | $ | 5,079,874 | $ | 5,034,717 | $ | 5,071,516 | $ | 4,855,169 | ||||||||||||||||||||||||||||||
| Annualized ratio of net charge-offs to average loans | (0.07) | % | 0.02 | % | 0.06 | % | 0.06 | % | 0.14 | % | 0.02 | % | 0.15 | % | ||||||||||||||||||||||||||||||
| [1] In 2020, the Company recorded a reserve on accrued interest receivable ("AIR") of $0.2 million for loans on payment forbearance or deferral, which were granted to borrowers impacted by the COVID-19 pandemic. This reserve was recorded as a contra-asset against AIR with the offset to the provision for credit losses. During the second quarter of 2021, the Company reversed the entire reserve on AIR. The provision for credit losses presented in this table excludes the provision for credit losses on AIR. | ||||||||||||||||||||||||||||||||||||||||||||
| [2] As of January 1, 2021, the provision for credit losses on off-balance sheet credit exposures (previously included in other operating expense) is included in the provision for credit losses line on the consolidated statements of income. The allowance for off-balance sheet credit exposures continues to be included in other liabilities. For roll-forward purposes, in this table we exclude the provision for credit losses on off-balance sheet credit exposures. | ||||||||||||||||||||||||||||||||||||||||||||
| CENTRAL PACIFIC FINANCIAL CORP. AND SUBSIDIARIES | |||||
| Reconciliation of Non-GAAP Financial Measures | |||||
| (Unaudited) | TABLE 10 | ||||
The following table sets forth a reconciliation of our core loans and the ratios of our allowance for credit losses ("ACL") to total loans and ACL to core loans (or total loans, excluding SBA Paycheck Protection Program ("PPP") loans), for each of the periods indicated:
| Dec 31, | Sep 30, | Jun 30, | Mar 31, | Dec 31, | ||||||||||||||||||||||||||||
| (Dollars in thousands) | 2021 | 2021 | 2021 | 2021 | 2020 | |||||||||||||||||||||||||||
| ACL | $ | 68,097 | $ | 74,587 | $ | 77,781 | $ | 81,553 | $ | 83,269 | ||||||||||||||||||||||
| Total loans | $ | 5,101,649 | $ | 5,045,797 | $ | 5,077,318 | $ | 5,137,849 | $ | 4,964,113 | ||||||||||||||||||||||
| Less: PPP loans | 91,327 | 218,671 | 434,610 | 597,819 | 416,375 | |||||||||||||||||||||||||||
| Core loans (or total loans, excluding PPP loans) | $ | 5,010,322 | $ | 4,827,126 | 4,642,708 | 4,540,030 | $ | 4,547,738 | ||||||||||||||||||||||||
| Ratio of ACL to total loans | 1.33 | % | 1.48 | % | 1.53 | % | 1.59 | % | 1.68 | % | ||||||||||||||||||||||
| Ratio of ACL to core loans | 1.36 | % | 1.55 | % | 1.68 | % | 1.80 | % | 1.83 | % | ||||||||||||||||||||||
4th Quarter 2021 Earnings Supplement January 26, 2022
2Central Pacific Financial Corp. Forward-Looking Statements This document may contain forward-looking statements concerning: projections of revenues, expenses, income or loss, earnings or loss per share, capital expenditures, the payment or nonpayment of dividends, capital position, credit losses, net interest margin or other financial items; statements of plans, objectives and expectations of Central Pacific Financial Corp. or its management or Board of Directors, including those relating to business plans, use of capital resources, products or services and regulatory developments and regulatory actions; statements of future economic performance including anticipated performance results from our various business initiatives; or any statements of the assumptions underlying or relating to any of the foregoing. Words such as "believes," "plans," "anticipates," "expects," "intends," "forecasts," "hopes," "targeting," "continue," "remain," "will," "should," "estimates," "may" and other similar expressions are intended to identify forward-looking statements but are not the exclusive means of identifying such statements. While we believe that our forward-looking statements and the assumptions underlying them are reasonably based, such statements and assumptions are by their nature subject to risks and uncertainties, and thus could later prove to be inaccurate or incorrect. Accordingly, actual results could differ materially from those statements or projections for a variety of reasons, including, but not limited to: the adverse effects of the COVID-19 pandemic virus on local, national and international economies, including, but not limited to, the adverse impact on tourism and construction in the State of Hawaii, our borrowers, customers, third-party contractors, vendors and employees as well as the effects of government programs and initiatives in response to COVID-19; the impact of our participation in the Paycheck Protection Program (“PPP”) and fulfillment of government guarantees on our PPP loans; our ability to successfully implement our Banking-as-a-Service initiatives, including adoption of the initiatives by customers and risks faced by any of our bank partnerships including reputational and regulatory risk; the increase in inventory or adverse conditions in the real estate market and deterioration in the construction industry; adverse changes in the financial performance and/or condition of our borrowers and, as a result, increased loan delinquency rates, deterioration in asset quality, and losses in our loan portfolio; our ability to successfully implement our business initiatives; the impact of local, national, and international economies and events (including natural disasters such as wildfires, volcanic eruptions, hurricanes, tsunamis, storms, earthquakes and pandemic virus and disease, including COVID-19) on the Company's business and operations and on tourism, the military, and other major industries operating within the Hawaii market and any other markets in which the Company does business; deterioration or malaise in domestic economic conditions, including any destabilization in the financial industry and deterioration of the real estate market, as well as the impact of declining levels of consumer and business confidence in the state of the economy in general and in financial institutions in particular; changes in estimates of future reserve requirements based upon the periodic review thereof under relevant regulatory and accounting requirements; the impact of the Dodd- Frank Wall Street Reform and Consumer Protection Act (the "Dodd-Frank Act"), changes in capital standards, other regulatory reform and federal and state legislation, including but not limited to regulations promulgated by the Consumer Financial Protection Bureau (the "CFPB"), government-sponsored enterprise reform, and any related rules and regulations which affect our business operations and competitiveness; the costs and effects of legal and regulatory developments, including legal proceedings or regulatory or other governmental inquiries and proceedings and the resolution thereof, the results of regulatory examinations or reviews and the effect of, and our ability to comply with, any regulations or regulatory orders or actions we are or may become subject to; ability to successfully implement our initiatives to lower our efficiency ratio; the effects of and changes in trade, monetary and fiscal policies and laws, including the interest rate policies of the Board of Governors of the Federal Reserve System (the "FRB" or the "Federal Reserve"); inflation, interest rate, securities market and monetary fluctuations, including the anticipated replacement of the London Interbank Offered Rate ("LIBOR") Index and the impact on our loans and debt which are tied to that index; negative trends in our market capitalization and adverse changes in the price of the Company's common stock; political instability; acts of war or terrorism; pandemic virus and disease, including COVID- 19; changes in consumer spending, borrowing and savings habits; failure to maintain effective internal control over financial reporting or disclosure controls and procedures; cybersecurity and data privacy breaches and the consequence therefrom; the ability to address deficiencies in our internal controls over financial reporting or disclosure controls and procedures; technological changes and developments; changes in the competitive environment among financial holding companies and other financial service providers; the effect of changes in accounting policies and practices, as may be adopted by the regulatory agencies, as well as the Public Company Accounting Oversight Board, the Financial Accounting Standards Board ("FASB") and other accounting standard setters and the cost and resources required to implement such changes; our ability to attract and retain key personnel; changes in our personnel, organization, compensation and benefit plans; and our success at managing the risks involved in the foregoing items. For further information with respect to factors that could cause actual results to materially differ from the expectations or projections stated in the forward-looking statements, please see the Company's publicly available Securities and Exchange Commission filings, including the Company's Form 10-K for the last fiscal year and, in particular, the discussion of "Risk Factors" set forth therein. We urge investors to consider all of these factors carefully in evaluating the forward-looking statements contained in this Form 8-K. Forward-looking statements speak only as of the date on which such statements are made. We undertake no obligation to update any forward-looking statements to reflect events or circumstances after the date on which such statements are made, or to reflect the occurrence of unanticipated events except as required by law.
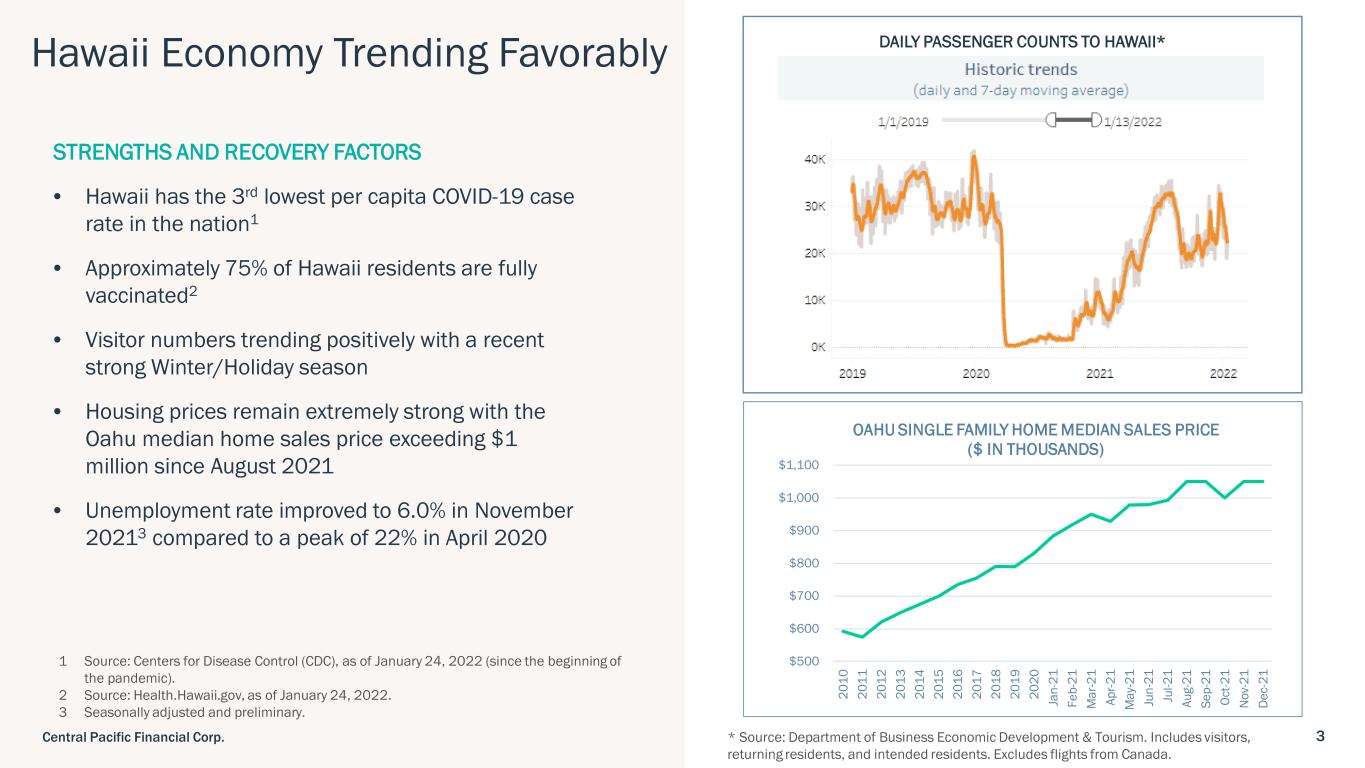
3Central Pacific Financial Corp. Hawaii Economy Trending Favorably STRENGTHS AND RECOVERY FACTORS • Hawaii has the 3rd lowest per capita COVID-19 case rate in the nation1 • Approximately 75% of Hawaii residents are fully vaccinated2 • Visitor numbers trending positively with a recent strong Winter/Holiday season • Housing prices remain extremely strong with the Oahu median home sales price exceeding $1 million since August 2021 • Unemployment rate improved to 6.0% in November 20213 compared to a peak of 22% in April 2020 * Source: Department of Business Economic Development & Tourism. Includes visitors, returning residents, and intended residents. Excludes flights from Canada. DAILY PASSENGER COUNTS TO HAWAII* 1 Source: Centers for Disease Control (CDC), as of January 24, 2022 (since the beginning of the pandemic). 2 Source: Health.Hawaii.gov, as of January 24, 2022. 3 Seasonally adjusted and preliminary. $500 $600 $700 $800 $900 $1,000 $1,100 20 10 20 11 20 12 20 13 20 14 20 15 20 16 20 17 20 18 20 19 20 20 Ja n- 21 Fe b- 21 M ar -2 1 Ap r-2 1 M ay -2 1 Ju n- 21 Ju l-2 1 Au g- 21 Se p- 21 Oc t-2 1 N ov -2 1 De c- 21 OAHU SINGLE FAMILY HOME MEDIAN SALES PRICE ($ IN THOUSANDS)
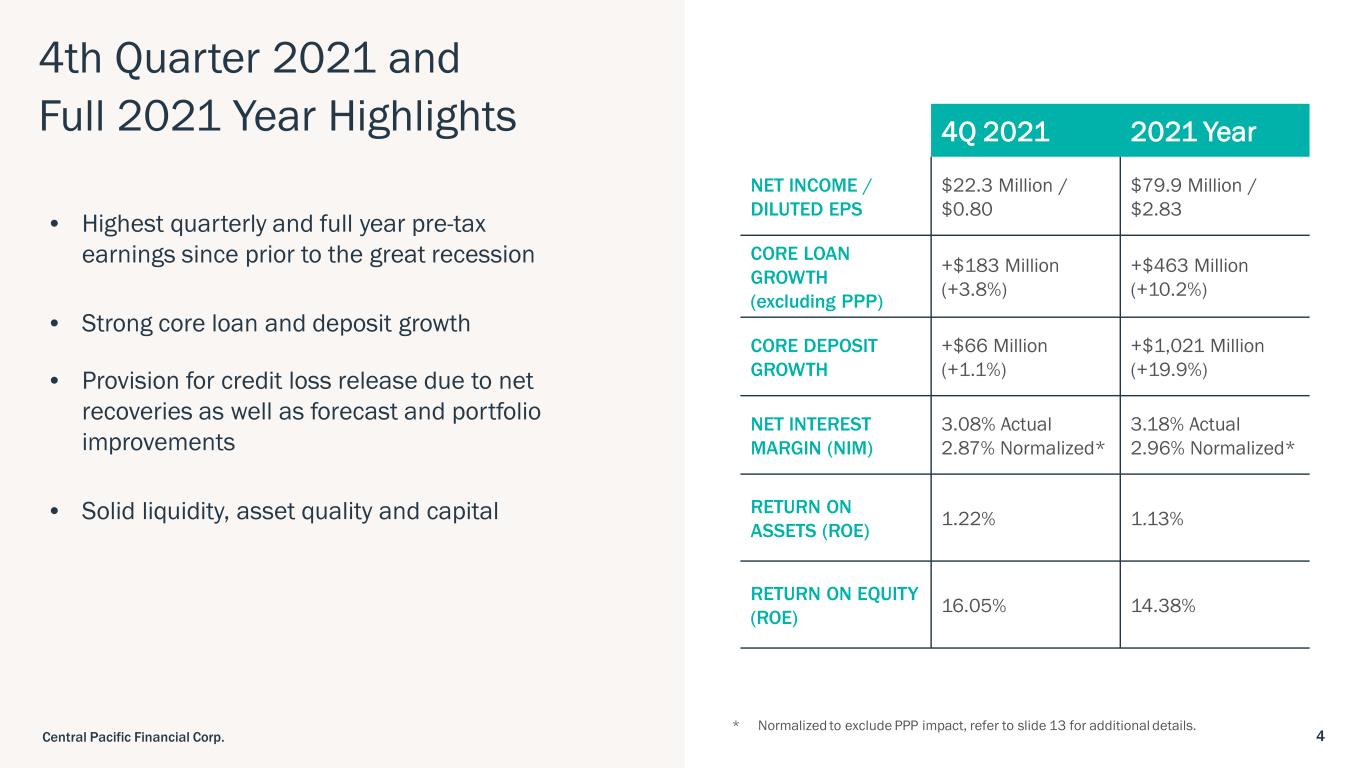
4Central Pacific Financial Corp. 4th Quarter 2021 and Full 2021 Year Highlights • Highest quarterly and full year pre-tax earnings since prior to the great recession • Strong core loan and deposit growth • Provision for credit loss release due to net recoveries as well as forecast and portfolio improvements • Solid liquidity, asset quality and capital 4Q 2021 2021 Year NET INCOME / DILUTED EPS $22.3 Million / $0.80 $79.9 Million / $2.83 CORE LOAN GROWTH (excluding PPP) +$183 Million (+3.8%) +$463 Million (+10.2%) CORE DEPOSIT GROWTH +$66 Million (+1.1%) +$1,021 Million (+19.9%) NET INTEREST MARGIN (NIM) 3.08% Actual 2.87% Normalized* 3.18% Actual 2.96% Normalized* RETURN ON ASSETS (ROE) 1.22% 1.13% RETURN ON EQUITY (ROE) 16.05% 14.38% * Normalized to exclude PPP impact, refer to slide 13 for additional details.
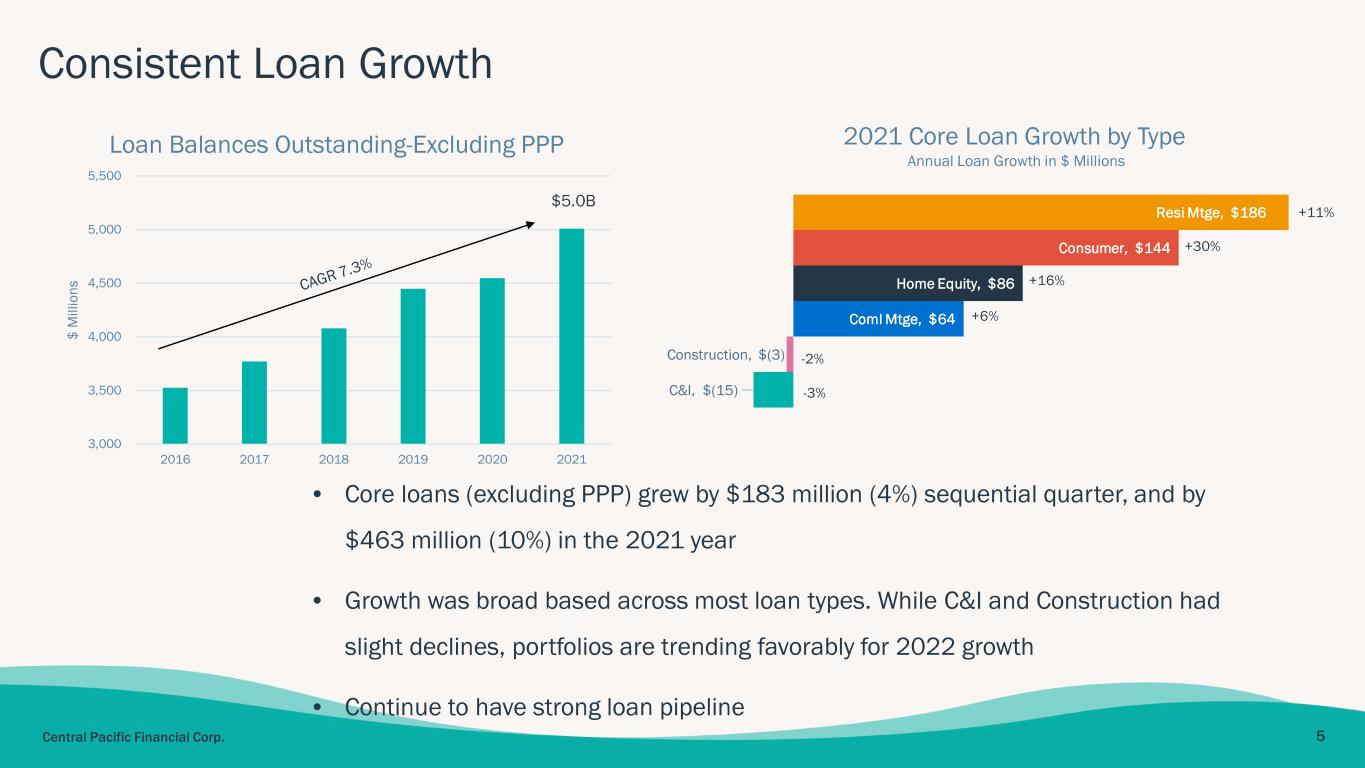
5Central Pacific Financial Corp. Consistent Loan Growth • Core loans (excluding PPP) grew by $183 million (4%) sequential quarter, and by $463 million (10%) in the 2021 year • Growth was broad based across most loan types. While C&I and Construction had slight declines, portfolios are trending favorably for 2022 growth • Continue to have strong loan pipeline $5.0B 3,000 3,500 4,000 4,500 5,000 5,500 2016 2017 2018 2019 2020 2021 $ M ill io ns Loan Balances Outstanding-Excluding PPP C&I, $(15) Construction, $(3) Coml Mtge, $64 Home Equity, $86 Consumer, $144 Resi Mtge, $186 Annual Loan Growth in $ Millions 2021 Core Loan Growth by Type +30% +16% +6% -2% -3% +11%
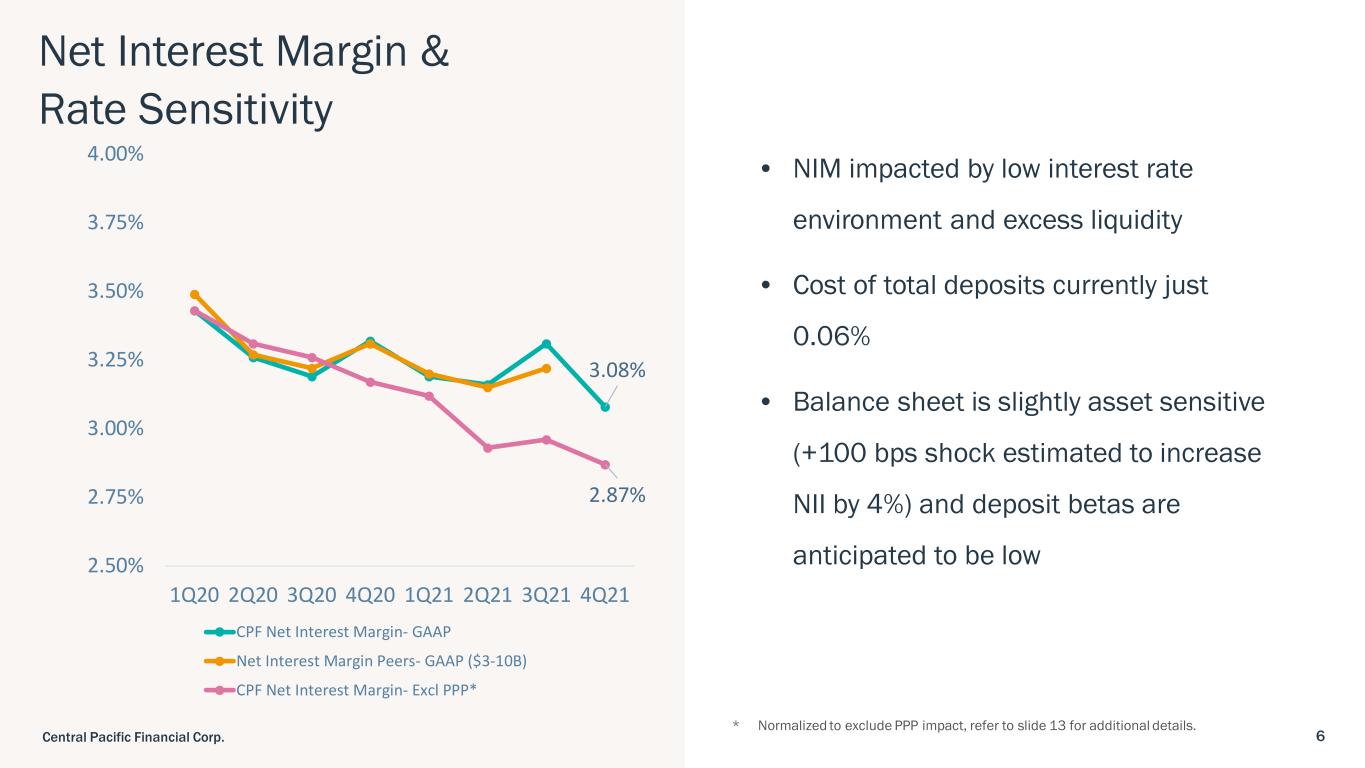
6Central Pacific Financial Corp. Net Interest Margin & Rate Sensitivity * Normalized to exclude PPP impact, refer to slide 13 for additional details. 3.08% 2.87% 2.50% 2.75% 3.00% 3.25% 3.50% 3.75% 4.00% 1Q20 2Q20 3Q20 4Q20 1Q21 2Q21 3Q21 4Q21 CPF Net Interest Margin- GAAP Net Interest Margin Peers- GAAP ($3-10B) CPF Net Interest Margin- Excl PPP* • NIM impacted by low interest rate environment and excess liquidity • Cost of total deposits currently just 0.06% • Balance sheet is slightly asset sensitive (+100 bps shock estimated to increase NII by 4%) and deposit betas are anticipated to be low
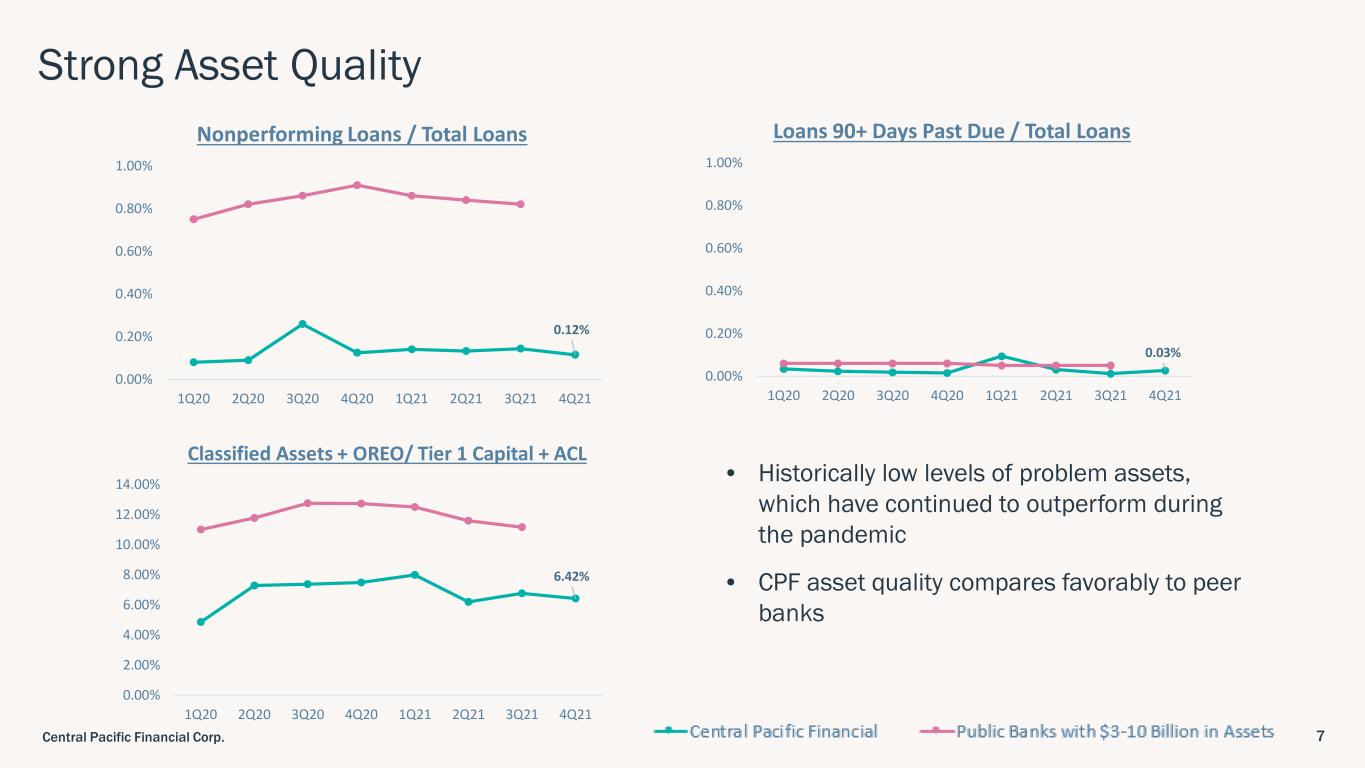
7Central Pacific Financial Corp. Strong Asset Quality 0.03% 0.00% 0.20% 0.40% 0.60% 0.80% 1.00% 1Q20 2Q20 3Q20 4Q20 1Q21 2Q21 3Q21 4Q21 Loans 90+ Days Past Due / Total Loans 0.12% 0.00% 0.20% 0.40% 0.60% 0.80% 1.00% 1Q20 2Q20 3Q20 4Q20 1Q21 2Q21 3Q21 4Q21 Nonperforming Loans / Total Loans 6.42% 0.00% 2.00% 4.00% 6.00% 8.00% 10.00% 12.00% 14.00% 1Q20 2Q20 3Q20 4Q20 1Q21 2Q21 3Q21 4Q21 Classified Assets + OREO/ Tier 1 Capital + ACL • Historically low levels of problem assets, which have continued to outperform during the pandemic • CPF asset quality compares favorably to peer banks
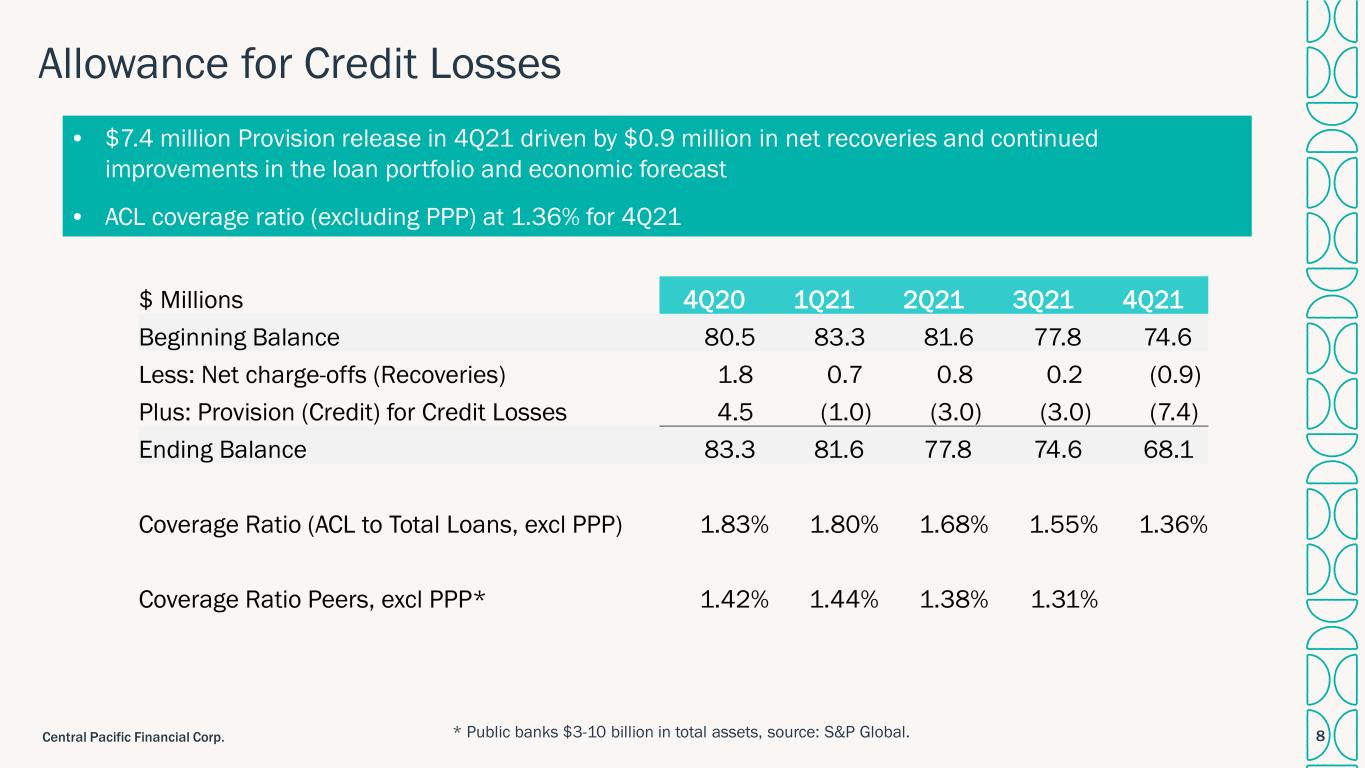
8Central Pacific Financial Corp. Allowance for Credit Losses $ Millions 4Q20 1Q21 2Q21 3Q21 4Q21 Beginning Balance 80.5 83.3 81.6 77.8 74.6 Less: Net charge-offs (Recoveries) 1.8 0.7 0.8 0.2 (0.9) Plus: Provision (Credit) for Credit Losses 4.5 (1.0) (3.0) (3.0) (7.4) Ending Balance 83.3 81.6 77.8 74.6 68.1 Coverage Ratio (ACL to Total Loans, excl PPP) 1.83% 1.80% 1.68% 1.55% 1.36% Coverage Ratio Peers, excl PPP* 1.42% 1.44% 1.38% 1.31% • $7.4 million Provision release in 4Q21 driven by $0.9 million in net recoveries and continued improvements in the loan portfolio and economic forecast • ACL coverage ratio (excluding PPP) at 1.36% for 4Q21 * Public banks $3-10 billion in total assets, source: S&P Global.
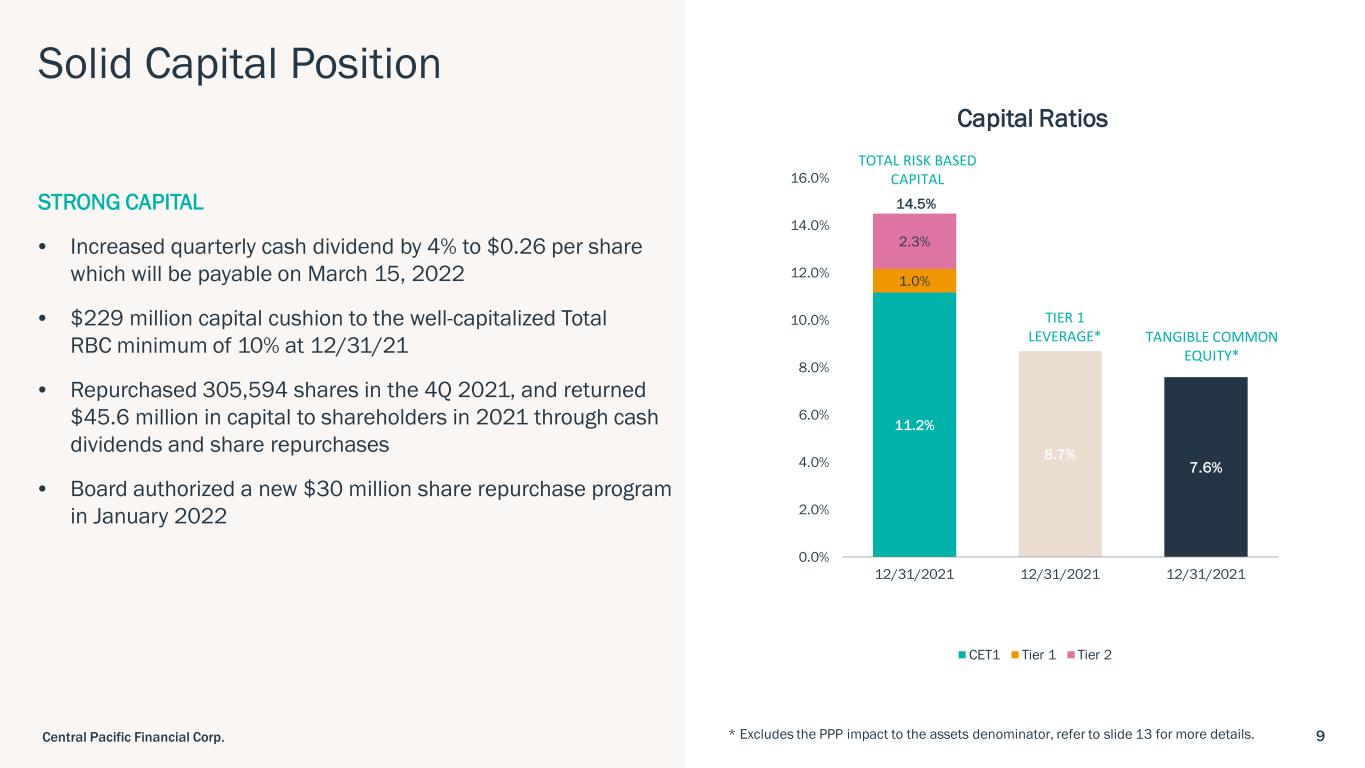
9Central Pacific Financial Corp. Solid Capital Position STRONG CAPITAL • Increased quarterly cash dividend by 4% to $0.26 per share which will be payable on March 15, 2022 • $229 million capital cushion to the well-capitalized Total RBC minimum of 10% at 12/31/21 • Repurchased 305,594 shares in the 4Q 2021, and returned $45.6 million in capital to shareholders in 2021 through cash dividends and share repurchases • Board authorized a new $30 million share repurchase program in January 2022 * Excludes the PPP impact to the assets denominator, refer to slide 13 for more details. 11.2% 1.0% 2.3% 8.7% 7.6% 0.0% 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 14.0% 16.0% 12/31/2021 12/31/2021 12/31/2021 Capital Ratios CET1 Tier 1 Tier 2 TOTAL RISK BASED CAPITAL TIER 1 LEVERAGE* TANGIBLE COMMON EQUITY* 14.5%
Mahalo
11Central Pacific Financial Corp. Appendix
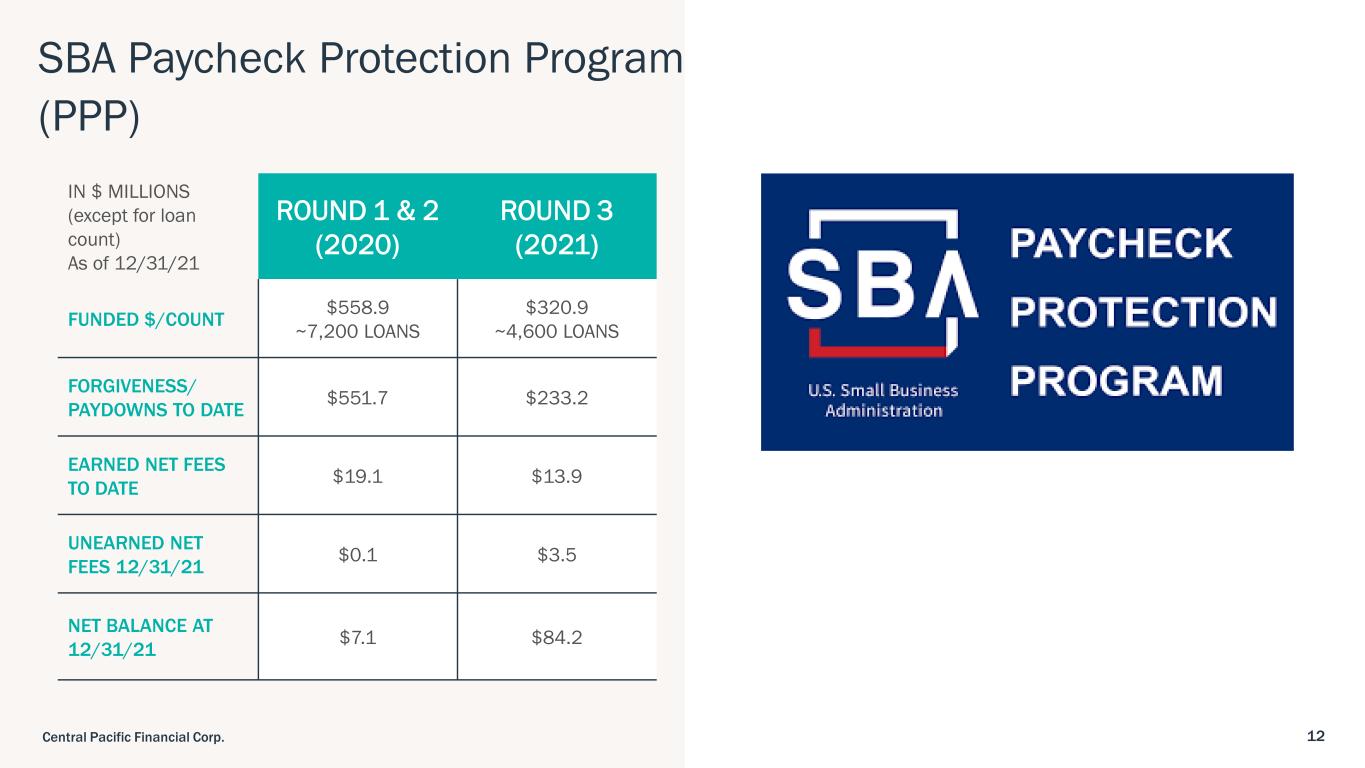
12Central Pacific Financial Corp. SBA Paycheck Protection Program (PPP) IN $ MILLIONS (except for loan count) As of 12/31/21 ROUND 1 & 2 (2020) ROUND 3 (2021) FUNDED $/COUNT $558.9 ~7,200 LOANS $320.9 ~4,600 LOANS FORGIVENESS/ PAYDOWNS TO DATE $551.7 $233.2 EARNED NET FEES TO DATE $19.1 $13.9 UNEARNED NET FEES 12/31/21 $0.1 $3.5 NET BALANCE AT 12/31/21 $7.1 $84.2
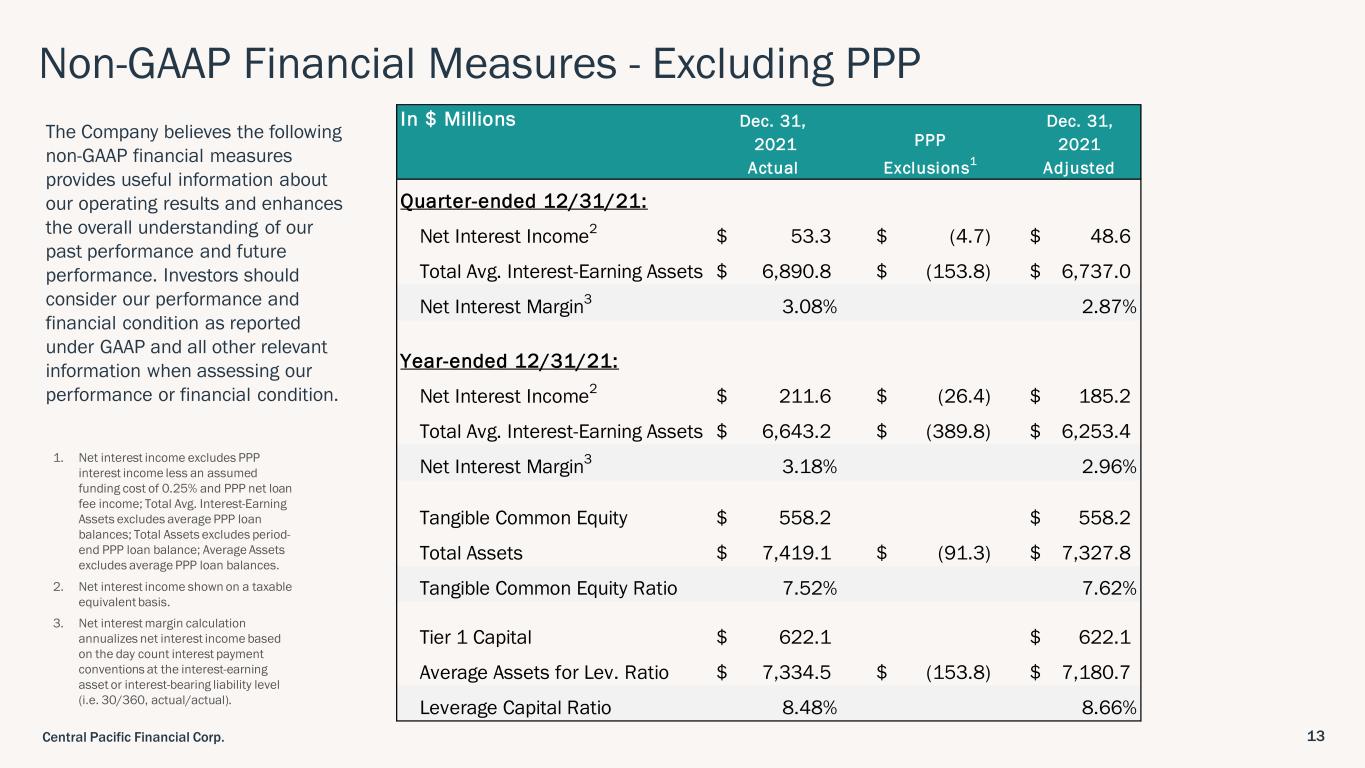
13Central Pacific Financial Corp. Non-GAAP Financial Measures - Excluding PPP 1. Net interest income excludes PPP interest income less an assumed funding cost of 0.25% and PPP net loan fee income; Total Avg. Interest-Earning Assets excludes average PPP loan balances; Total Assets excludes period- end PPP loan balance; Average Assets excludes average PPP loan balances. 2. Net interest income shown on a taxable equivalent basis. 3. Net interest margin calculation annualizes net interest income based on the day count interest payment conventions at the interest-earning asset or interest-bearing liability level (i.e. 30/360, actual/actual). The Company believes the following non-GAAP financial measures provides useful information about our operating results and enhances the overall understanding of our past performance and future performance. Investors should consider our performance and financial condition as reported under GAAP and all other relevant information when assessing our performance or financial condition. In $ Millions Dec. 31, 2021 Actual PPP Exclusions1 Dec. 31, 2021 Adjusted Quarter-ended 12/31/21: Net Interest Income2 53.3$ (4.7)$ 48.6$ Total Avg. Interest-Earning Assets 6,890.8$ (153.8)$ 6,737.0$ Net Interest Margin3 3.08% 2.87% Year-ended 12/31/21: Net Interest Income2 211.6$ (26.4)$ 185.2$ Total Avg. Interest-Earning Assets 6,643.2$ (389.8)$ 6,253.4$ Net Interest Margin3 3.18% 2.96% Tangible Common Equity 558.2$ 558.2$ Total Assets 7,419.1$ (91.3)$ 7,327.8$ Tangible Common Equity Ratio 7.52% 7.62% Tier 1 Capital 622.1$ 622.1$ Average Assets for Lev. Ratio 7,334.5$ (153.8)$ 7,180.7$ Leverage Capital Ratio 8.48% 8.66%
Banking-as-a-Service (BaaS) Launch Supplement January 26, 2022
2Central Pacific Financial Corp. Forward-Looking Statements This document may contain forward-looking statements concerning: projections of revenues, expenses, income or loss, earnings or loss per share, capital expenditures, the payment or nonpayment of dividends, capital position, credit losses, net interest margin or other financial items; statements of plans, objectives and expectations of Central Pacific Financial Corp. or its management or Board of Directors, including those relating to business plans, use of capital resources, products or services and regulatory developments and regulatory actions; statements of future economic performance including anticipated performance results from our various business initiatives; or any statements of the assumptions underlying or relating to any of the foregoing. Words such as "believes," "plans," "anticipates," "expects," "intends," "forecasts," "hopes," "targeting," "continue," "remain," "will," "should," "estimates," "may" and other similar expressions are intended to identify forward-looking statements but are not the exclusive means of identifying such statements. While we believe that our forward-looking statements and the assumptions underlying them are reasonably based, such statements and assumptions are by their nature subject to risks and uncertainties, and thus could later prove to be inaccurate or incorrect. Accordingly, actual results could differ materially from those statements or projections for a variety of reasons, including, but not limited to: the adverse effects of the COVID-19 pandemic virus on local, national and international economies, including, but not limited to, the adverse impact on tourism and construction in the State of Hawaii, our borrowers, customers, third-party contractors, vendors and employees as well as the effects of government programs and initiatives in response to COVID-19; the impact of our participation in the Paycheck Protection Program (“PPP”) and fulfillment of government guarantees on our PPP loans; our ability to successfully implement our Banking-as-a-Service initiatives, including adoption of the initiatives by customers and risks faced by any of our bank partnerships including reputational and regulatory risk; the increase in inventory or adverse conditions in the real estate market and deterioration in the construction industry; adverse changes in the financial performance and/or condition of our borrowers and, as a result, increased loan delinquency rates, deterioration in asset quality, and losses in our loan portfolio; our ability to successfully implement our business initiatives; the impact of local, national, and international economies and events (including natural disasters such as wildfires, volcanic eruptions, hurricanes, tsunamis, storms, earthquakes and pandemic virus and disease, including COVID-19) on the Company's business and operations and on tourism, the military, and other major industries operating within the Hawaii market and any other markets in which the Company does business; deterioration or malaise in domestic economic conditions, including any destabilization in the financial industry and deterioration of the real estate market, as well as the impact of declining levels of consumer and business confidence in the state of the economy in general and in financial institutions in particular; changes in estimates of future reserve requirements based upon the periodic review thereof under relevant regulatory and accounting requirements; the impact of the Dodd-Frank Wall Street Reform and Consumer Protection Act (the "Dodd-Frank Act"), changes in capital standards, other regulatory reform and federal and state legislation, including but not limited to regulations promulgated by the Consumer Financial Protection Bureau (the "CFPB"), government-sponsored enterprise reform, and any related rules and regulations which affect our business operations and competitiveness; the costs and effects of legal and regulatory developments, including legal proceedings or regulatory or other governmental inquiries and proceedings and the resolution thereof, the results of regulatory examinations or reviews and the effect of, and our ability to comply with, any regulations or regulatory orders or actions we are or may become subject to; ability to successfully implement our initiatives to lower our efficiency ratio; the effects of and changes in trade, monetary and fiscal policies and laws, including the interest rate policies of the Board of Governors of the Federal Reserve System (the "FRB" or the "Federal Reserve"); inflation, interest rate, securities market and monetary fluctuations, including the anticipated replacement of the London Interbank Offered Rate ("LIBOR") Index and the impact on our loans and debt which are tied to that index; negative trends in our market capitalization and adverse changes in the price of the Company's common stock; political instability; acts of war or terrorism; pandemic virus and disease, including COVID-19; changes in consumer spending, borrowing and savings habits; failure to maintain effective internal control over financial reporting or disclosure controls and procedures; cybersecurity and data privacy breaches and the consequence therefrom; the ability to address deficiencies in our internal controls over financial reporting or disclosure controls and procedures; technological changes and developments; changes in the competitive environment among financial holding companies and other financial service providers; the effect of changes in accounting policies and practices, as may be adopted by the regulatory agencies, as well as the Public Company Accounting Oversight Board, the Financial Accounting Standards Board ("FASB") and other accounting standard setters and the cost and resources required to implement such changes; our ability to attract and retain key personnel; changes in our personnel, organization, compensation and benefit plans; and our success at managing the risks involved in the foregoing items. For further information with respect to factors that could cause actual results to materially differ from the expectations or projections stated in the forward-looking statements, please see the Company's publicly available Securities and Exchange Commission filings, including the Company's Form 10-K for the last fiscal year and, in particular, the discussion of "Risk Factors" set forth therein. We urge investors to consider all of these factors carefully in evaluating the forward-looking statements contained in this Form 8-K. Forward-looking statements speak only as of the date on which such statements are made. We undertake no obligation to update any forward-looking statements to reflect events or circumstances after the date on which such statements are made, or to reflect the occurrence of unanticipated events except as required by law.
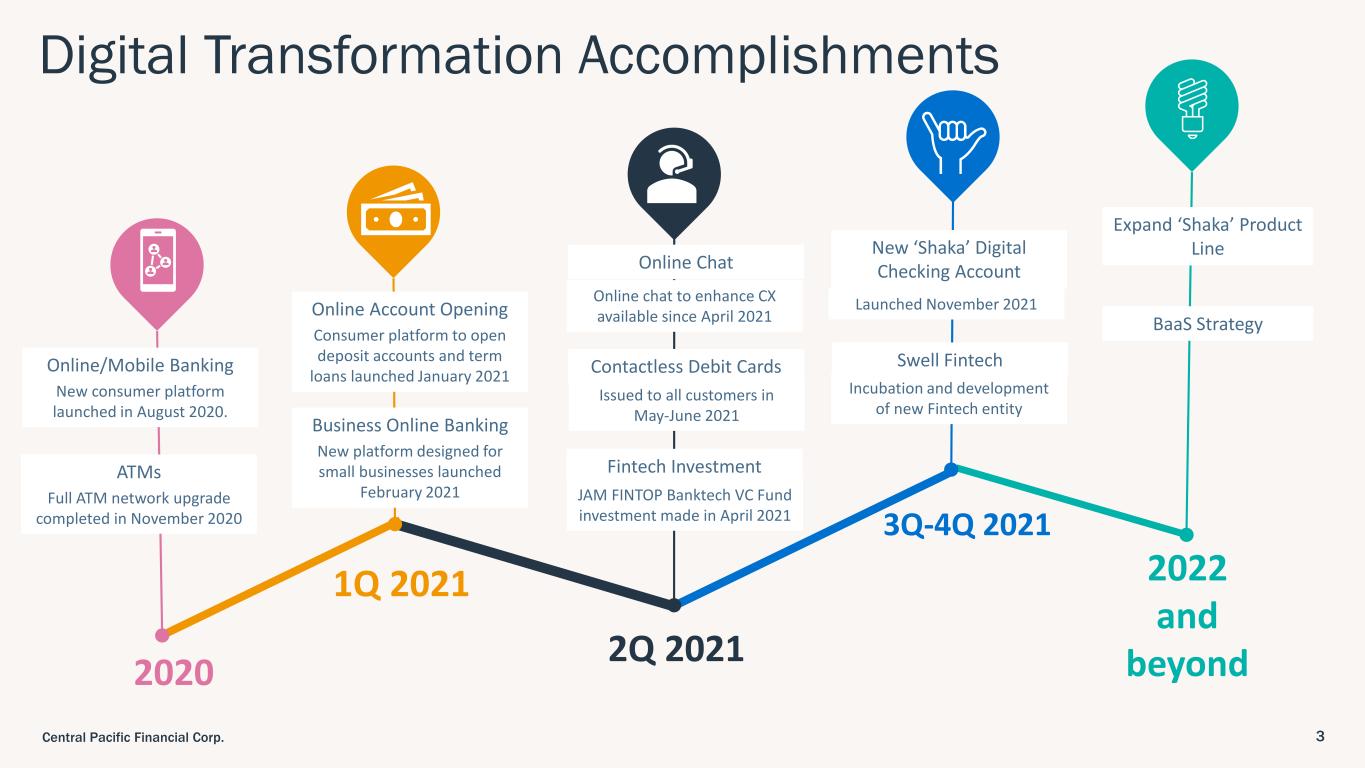
3Central Pacific Financial Corp. 2Q 2021 3Q-4Q 2021 1Q 2021 2020 2022 and beyond Online Account Opening Consumer platform to open deposit accounts and term loans launched January 2021 Business Online Banking New platform designed for small businesses launched February 2021 Online/Mobile Banking New consumer platform launched in August 2020. Expand ‘Shaka’ Product Line BaaS Strategy Digital Transformation Accomplishments ATMs Full ATM network upgrade completed in November 2020 Contactless Debit Cards Issued to all customers in May-June 2021 Online Chat Online chat to enhance CX available since April 2021 New ‘Shaka’ Digital Checking Account Launched November 2021 Fintech Investment JAM FINTOP Banktech VC Fund investment made in April 2021 Swell Fintech Incubation and development of new Fintech entity
Central Pacific Financial Corp. 4 Our Blueprint Forward • Our new BaaS program under development since 2019 • BaaS program will leverage successful product development and launch strategies used in Shaka • Current partners for BaaS mainland expansion: Swell (new Fintech) and Elevate (NYSE: ELVT) a leading provider of digital lending solutions • Future BaaS opportunities on the horizon
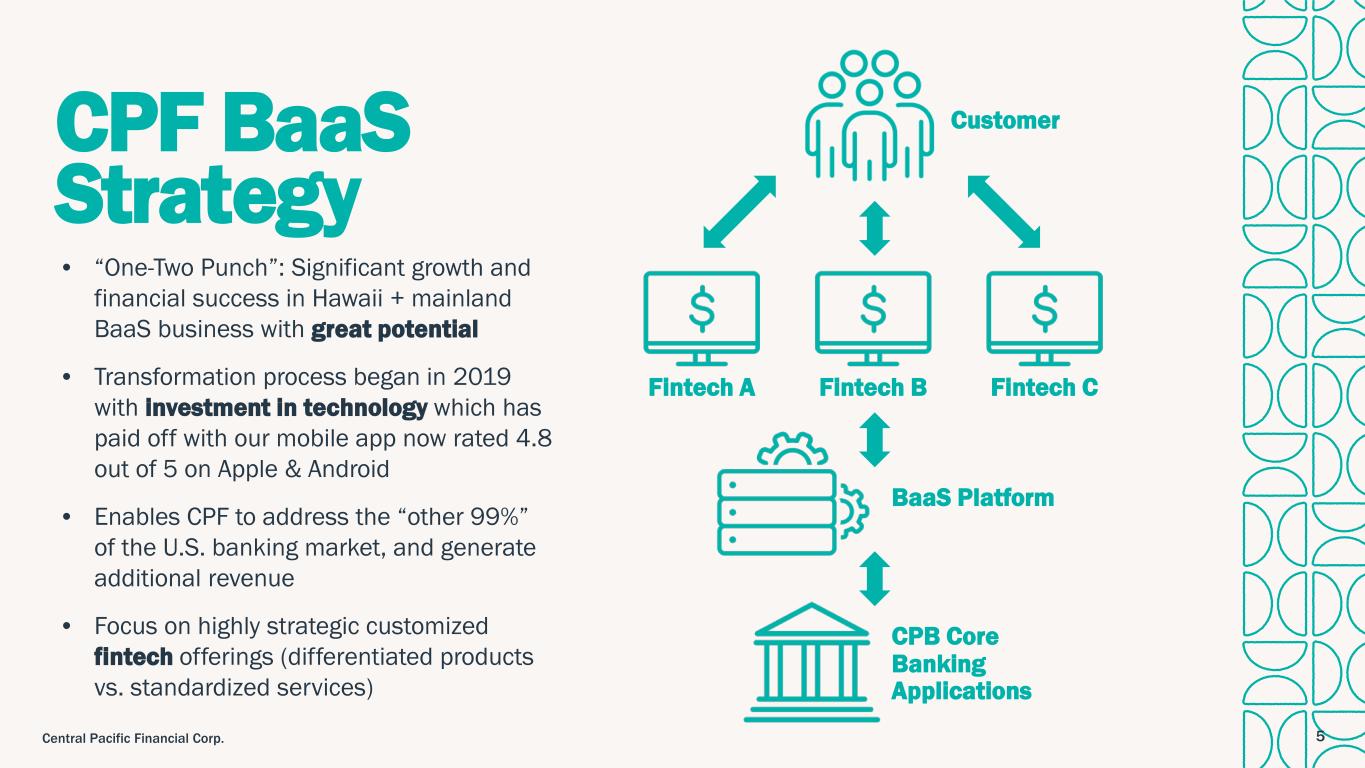
5Central Pacific Financial Corp. CPF BaaS Strategy • “One-Two Punch”: Significant growth and financial success in Hawaii + mainland BaaS business with great potential • Transformation process began in 2019 with investment in technology which has paid off with our mobile app now rated 4.8 out of 5 on Apple & Android • Enables CPF to address the “other 99%” of the U.S. banking market, and generate additional revenue • Focus on highly strategic customized fintech offerings (differentiated products vs. standardized services) CPB Core Banking Applications BaaS Platform Fintech A Fintech B Fintech C Customer
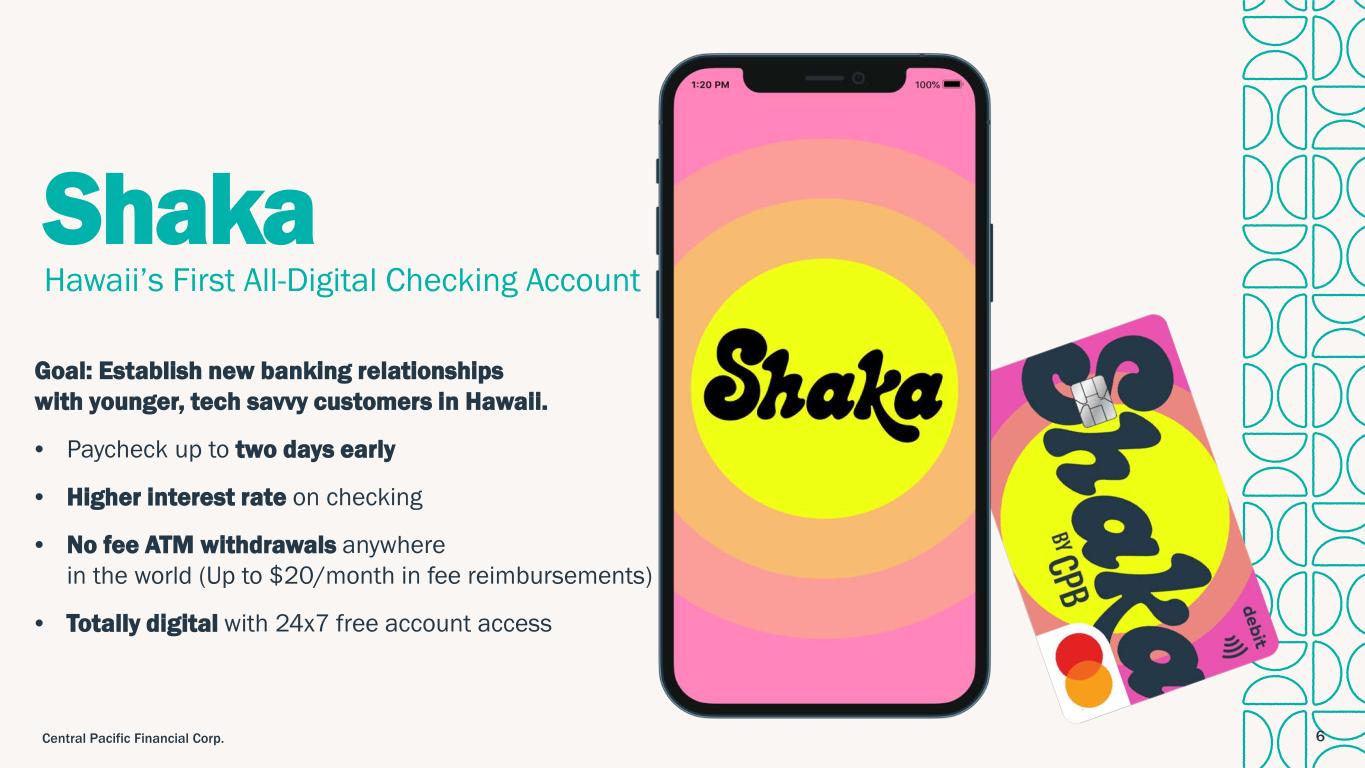
6Central Pacific Financial Corp. Shaka Hawaii’s First All-Digital Checking Account Goal: Establish new banking relationships with younger, tech savvy customers in Hawaii. • Paycheck up to two days early • Higher interest rate on checking • No fee ATM withdrawals anywhere in the world (Up to $20/month in fee reimbursements) • Totally digital with 24x7 free account access
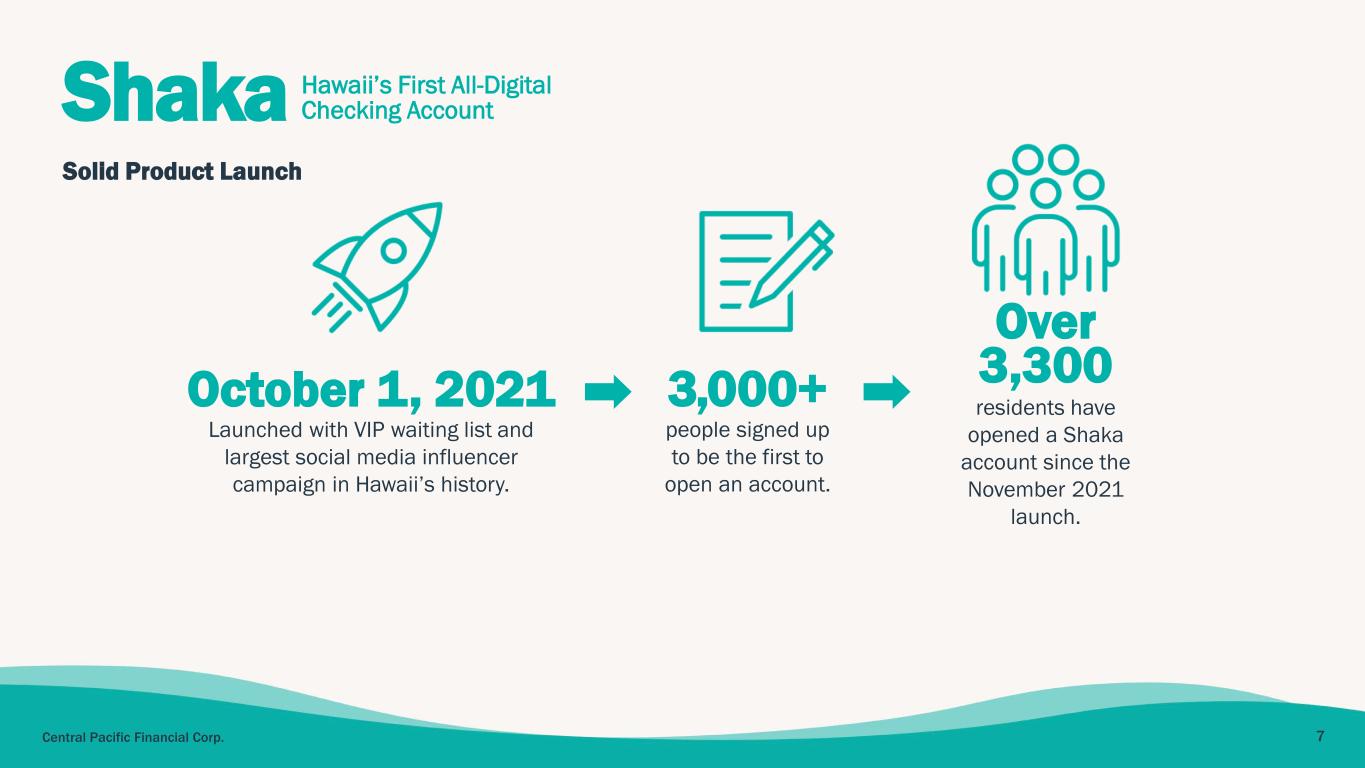
7Central Pacific Financial Corp. Shaka Hawaii’s First All-Digital Checking Account Solid Product Launch October 1, 2021 Launched with VIP waiting list and largest social media influencer campaign in Hawaii’s history. 3,000+ people signed up to be the first to open an account. Over 3,300 residents have opened a Shaka account since the November 2021 launch.
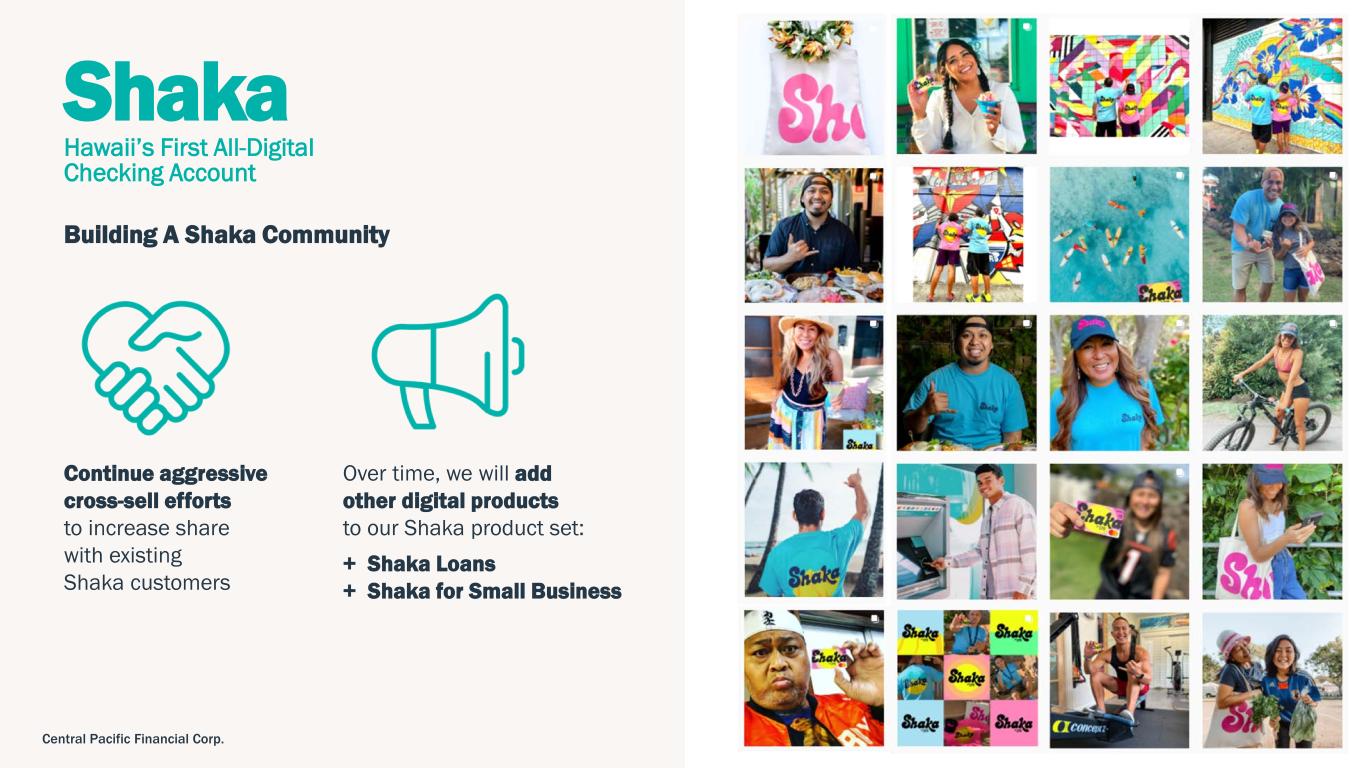
8Central Pacific Financial Corp. Shaka Hawaii’s First All-Digital Checking Account Building A Shaka Community Continue aggressive cross-sell efforts to increase share with existing Shaka customers Over time, we will add other digital products to our Shaka product set: + Shaka Loans + Shaka for Small Business
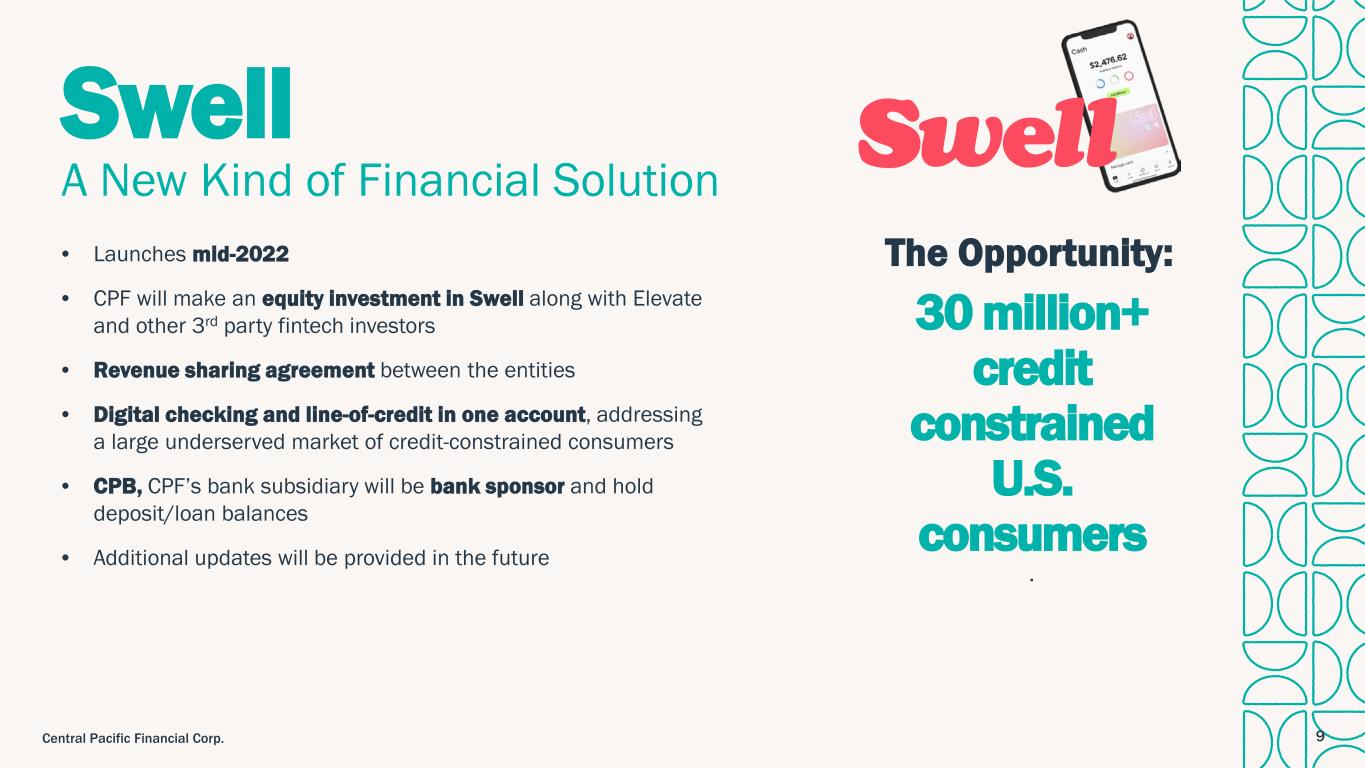
9Central Pacific Financial Corp. Swell A New Kind of Financial Solution • Launches mid-2022 • CPF will make an equity investment in Swell along with Elevate and other 3rd party fintech investors • Revenue sharing agreement between the entities • Digital checking and line-of-credit in one account, addressing a large underserved market of credit-constrained consumers • CPB, CPF’s bank subsidiary will be bank sponsor and hold deposit/loan balances • Additional updates will be provided in the future 30 million+ credit constrained U.S. consumers . The Opportunity:
Thank you.