
INBK 8-K
First Internet Bancorp (INBK)
8-K
2026-04-30
For: 2026-04-30
View Original
Added on
April 30, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, DC 20549
FORM 8-K
CURRENT REPORT PURSUANT
TO SECTION 13 OR 15(D) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of report (Date of earliest event reported): April 30, 2026
| (Exact Name of Registrant as Specified in Its Charter) | ||||||||||||||
| (State or Other Jurisdiction of Incorporation) | ||||||||||||||
| (Commission File Number) | (IRS Employer Identification No.) | |||||||||||||
| (Address of Principal Executive Offices) | (Zip Code) | |||||||||||||
( | ||||||||||||||
| (Registrant's Telephone Number, Including Area Code) | ||||||||||||||
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbols | Name of each exchange on which registered | ||||||||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ¨
Item 2.02 Results of Operations and Financial Condition
On April 30, 2026 First Internet Bancorp (the “Company”) issued a press release announcing its financial results for the quarter ended March 31, 2026. A copy of the press release is furnished as Exhibit 99.1 to this report and is incorporated by reference herein.
On April 30, 2026 at 5:00 p.m. (Eastern Time), the Company will host a conference call and webcast to discuss its financial results for the quarter ended March 31, 2026. The electronic presentation slides, which will accompany the call and webcast, are furnished as Exhibit 99.2 and are incorporated by reference herein.
The information contained in this Item 2.02, including Exhibits 99.1 and 99.2, is being furnished and shall not be deemed to be “filed” for the purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”) or otherwise subject to the liabilities of that section, and shall not be deemed to be incorporated by reference into any filing made by us under the Exchange Act or Securities Act of 1933, as amended, regardless of any general incorporation language in any such filing, except as shall be expressly set forth by specific reference in such filing.
Item 9.01 Financial Statements and Exhibits
(d) Exhibits
| Number | Description | Method of filing | ||||||||||||
| Furnished electronically | ||||||||||||||
| Furnished electronically | ||||||||||||||
| 104 | Cover Page Interactive Data File (embedded in the cover page formatted in inline XBRL) | |||||||||||||
SIGNATURES
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
| Dated: | April 30, 2026 | |||||||||||||
| FIRST INTERNET BANCORP | ||||||||||||||
| By: | /s/ Kenneth J. Lovik | |||||||||||||
| Kenneth J. Lovik, Executive Vice President & Chief Financial Officer | ||||||||||||||
First Internet Bancorp Reports First Quarter 2026 Results
-Net income of $2.5 million, up 166% year-over-year -
- Diluted earnings per share of $0.29, up 164% year-over-year -
- Company to hold earnings call today at 5pm ET -
Fishers, Indiana, April 30, 2026 – First Internet Bancorp (the “Company”) (Nasdaq: INBK), the parent company of First Internet Bank (the “Bank”), announced today financial and operational results for the first quarter ended March 31, 2026.
Key Business Updates
•Revenue Momentum: Growth in net interest income (up 26%) and fully-taxable equivalent (“FTE”) net interest margin (now 2.45%) drove quarterly revenue up 21% year-over-year to $43.1 million. When combined with well-managed expenses, pre-provision net revenue grew 51% year-over-year.
•Credit Trends: Provision for credit losses for the first quarter of 2026 of $16.3 million. The provision reflects our quarterly CECL re-measurement of expected lifetime losses for the portfolio, based on observed credit performance and updates to current conditions. During the first quarter, ongoing proactive credit actions continued to drive progress in resolving problem credits. Notably, nonaccrual unguaranteed SBA and franchise finance balances declined from the fourth quarter of 2025.
•Strong Loan Production: Commercial loan production remained strong during the first quarter led by construction and single tenant lease financing. Additionally, loan pipelines at the end of the quarter were solid, setting the stage for continued loan growth as we move through 2026.
First Quarter 2026 Financial Performance
•Net income of $2.5 million and diluted earnings per share of $0.29, up 166% and 164%, respectively, from the prior year period
•Total revenue of $43.1 million, which increased 21% from the prior year period
•Net interest income of $31.6 million and FTE net interest income of $32.8 million1, increased 26% and 25%, respectively, over the prior year period
•Net interest margin of 2.36% and FTE net interest margin of 2.45%1, both increased 54 basis points (“bps”) from the prior year period
•Noninterest income of $11.5 million, which increased 10% from the prior year period
1 This information represents a non-GAAP financial measure. For a discussion of non-GAAP financial measures, see the section below entitled "Non-GAAP Financial Measures."
•Pre-provision net revenue (“PPNR”) of $18.1 million1, which increased 51% from the prior year period
•Total loan balances of $3.8 billion, up $29.1 million, or 1%, from the fourth quarter of 2025
•The yield on the loan portfolio increased 37 bps from the prior year period to 6.36%
•Strong loan production partially offset by elevated payoffs and maturities
•Total deposits of $5.0 billion, up $141.8 million, or 3%, from the fourth quarter of 2025
•Continued growth in fintech deposits, allowing higher-cost CDs and brokered deposits to mature
•The cost of interest-bearing deposits declined 56 bps from the prior year period to 3.45%
•Approximately $1.5 billion of fintech deposits moved off-balance sheet into a deposit network, providing flexibility to manage the size of the balance sheet
•Loans to deposits ratio of 75.8%
•Provision for credit losses of $16.3 million, up $4.3 million, or 36.1%, from the fourth quarter of 2025
•Net charge-offs to average loans of 1.65%, slightly improved from 1.68% in the fourth quarter of 2025
•Nonperforming loans (“NPLs”) to total loans of 1.63%; allowance for credit losses - loans (“ACL”) to total loans of 1.50%
•Increase in NPLs consisted primarily of fully-guaranteed SBA 7(a) balances and accruing loans past due 90 days or more, partially offset by lower nonaccrual franchise finance loans
•NPLs / total loans of 1.22%1 excluding fully-guaranteed balances
•ACL to NPLs of 92%; or 122%1 excluding fully-guaranteed balances
•Tangible common equity to tangible assets of 6.24%1, and 6.99%1 ex-AOCI and adjusted for normalized cash balances; CET1 ratio of 8.97%2; total capital ratio of 12.50%2
•Tangible book value per share of $40.871, consistent with the fourth quarter of 2025
“We kicked off the new year with strong first quarter results, demonstrating the resilience of our diversified business model and the solid foundation we've built to navigate an uncertain macroeconomic environment from a position of strength”, said David Becker, Chairman and CEO of First Internet Bancorp. “We generated 21% revenue growth, 51% growth in pre-provision net revenue, and expanded our net interest margin 54 basis points year-over-year to 2.45%, reflecting years of disciplined balance sheet repositioning and proactive liability management. We're also seeing tangible evidence that our enhanced underwriting standards and risk management initiatives are yielding favorable results, particularly in our SBA portfolio where unguaranteed nonperforming loans and delinquencies have improved both sequentially and year-over-year.”
“Beyond the strong quarterly financial results, we continued to make strategic investments in AI and digital capabilities that are already delivering measurable results - our virtual customer service agents resolve 45% of inquiries, our fraud detection agents enhance security, and our Net Promoter Scores are well above industry averages. Additionally, our Banking-as-a-Service partnerships continue to grow and provide valuable deposit funding flexibility, while our commercial lending pipelines remain robust across multiple verticals. With improving credit trends, strong margin momentum, and disciplined cost management, we are well-positioned to deliver improving profitability through 2026 and accelerating performance into 2027."
1 This information represents a non-GAAP financial measure. For a discussion of non-GAAP financial measures, see the section below entitled "Non-GAAP Financial Measures."
2 Regulatory capital ratios are preliminary pending filing of the Company’s regulatory reports
Full Year 2026 Outlook
The Company is broadly maintaining its 2026 guidance. However, management acknowledges the heightened macroeconomic uncertainty, including volatile energy prices and other geopolitical developments, which could have negative impacts. Regarding loan growth specifically, while commercial pipelines remain robust, the Company recognizes that the full-year target of 15-17% may prove ambitious due to higher-than-expected loan payoffs and potential further tightening of underwriting standards due to macro uncertainties.
Conference Call and Webcast
The Company will host a conference call and webcast at 5:00 p.m. Eastern Time today, April 30, 2026, to discuss its quarterly financial results. The call can be accessed via telephone at (800) 715-9871; access code: 9553116. A recorded replay can be accessed through May 7, 2026, by dialing (800) 770-2030; access code: 9553116.
Additionally, interested parties can listen to a live webcast of the call on the Company's website at www.firstinternetbancorp.com. An archived version of the webcast will be available in the same location shortly after the live call has ended.
About First Internet Bancorp
First Internet Bancorp is a bank holding company with assets of $5.7 billion as of March 31, 2026. The Company’s subsidiary, First Internet Bank, opened for business in 1999 as an industry pioneer in the branchless delivery of banking services. First Internet Bank provides consumer and small business deposit, commercial real estate and construction financing, SBA financing, public finance, consumer loans, and specialty finance services nationally, as well as commercial and industrial loans and treasury management services on a regional basis. First Internet Bancorp’s common stock trades on the Nasdaq Global Select Market under the symbol “INBK” and is a component of the Russell 2000® Index. Additional information about the Company is available at www.firstinternetbancorp.com and additional information about First Internet Bank, including its products and services, is available at www.firstib.com.
Forward-Looking Statements
This press release contains forward-looking statements within the meaning of the safe harbor provisions of the Private Securities Litigation Reform Act of 1995, including statements with respect to the financial condition, results of operations, trends in lending policies and loan programs, plans and prospective business partnerships, objectives, future performance and business of the Company. Forward-looking statements are generally identifiable by the use of words such as “anticipate,” “believe,” “better than,” “continue,” “could,” “drive,” “enhance,” “estimate,” “expand,” “expect,” “future,” “going forward,” “growth,” ”improve,” “increase,” “looking ahead,” “maintain,” “may,” “ongoing,” “opportunities,” “pending,” “plan,” “position,” “preliminary,” “progress,” “remain,” “setting the stage,” “should,” “stable,” “thereafter,” “well-positioned,” “will,” or other similar expressions. Forward-looking statements are not a guarantee of future performance or results, are based on information available at the time the statements are made and involve known and unknown risks, uncertainties and other factors that could cause actual results to differ materially from the information in the forward-looking statements. Such statements are subject to certain risks and uncertainties including: our business and operations and the business and operations of our vendors and customers; general economic conditions, whether national or regional, and conditions in the lending markets in which we participate that may have an adverse effect on the demand for our loans and other products; our credit quality and related levels of nonperforming assets and loan losses, and the value and salability of the real estate that is the collateral for our loans. Other factors that may cause such differences include: failures or breaches of or interruptions in the communications and information systems on which we rely to conduct our business; failure of our plans to grow our commercial and industrial, construction, and SBA loan portfolios; competition with national, regional and community financial institutions; the loss of key members of senior management; the anticipated impacts of inflation and rising interest rates on the general economy; risks relating to the regulation of financial institutions; and other factors identified in reports we file with the U.S. Securities and Exchange Commission. All statements in this press release, including forward-looking statements, speak only as of the date they are made, and the Company undertakes no obligation to update any statement in light of new information or future events.
Non-GAAP Financial Measures
This press release contains financial information determined by methods other than in accordance with U.S. generally accepted accounting principles (“GAAP”). Non-GAAP financial measures, specifically tangible common equity, tangible assets, tangible book value per common share, tangible common equity
to tangible assets, average tangible common equity, return on average tangible common equity, total interest income – FTE, net interest income – FTE, net interest margin – FTE, adjusted total revenue, pre-provision net revenue, adjusted pre-provision net revenue, adjusted noninterest income, adjusted income before income taxes, adjusted income tax (benefit) provision, adjusted net income, adjusted diluted earnings per share, adjusted return on average assets, adjusted return on average shareholders’ equity, adjusted return on average tangible common equity, adjusted tangible common equity, adjusted tangible assets, adjusted tangible common equity to adjusted tangible assets, adjusted nonperforming loans to total loans and adjusted allowance for credit losses – loans to nonperforming loans are used by the Company’s management to measure the strength of its capital and analyze profitability, including its ability to generate earnings on tangible capital invested by its shareholders. Although management believes these non-GAAP measures are useful to investors by providing a greater understanding of its business, they should not be considered a substitute for financial measures determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Reconciliations of these non-GAAP financial measures to the most directly comparable GAAP financial measures are included in the table at the end of this release under the caption “Reconciliation of Non-GAAP Financial Measures.”
| Contact Information: | |||||||||||
| Investors/Analysts | |||||||||||
| Paula Deemer | |||||||||||
| Director of Corporate Administration | |||||||||||
| (317) 428-4628 | |||||||||||
| [email protected] | |||||||||||
| Media | |||||||||||
| PANBlast | |||||||||||
| Zach Weismiller | |||||||||||
| [email protected] | |||||||||||
| First Internet Bancorp | ||||||||||||||||||||
| Summary Financial Information (unaudited) | ||||||||||||||||||||
| Dollar amounts in thousands, except per share data | ||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||
| Net income | $ | 2,509 | $ | 5,289 | $ | 943 | ||||||||||||||
| Per share and share information | ||||||||||||||||||||
| Earnings per share - basic | $ | 0.29 | $ | 0.61 | $ | 0.11 | ||||||||||||||
| Earnings per share - diluted | 0.29 | 0.60 | 0.11 | |||||||||||||||||
| Dividends declared per share | 0.06 | 0.06 | 0.06 | |||||||||||||||||
| Book value per common share | 41.41 | 41.41 | 44.58 | |||||||||||||||||
Tangible book value per common share 1 | 40.87 | 40.87 | 44.04 | |||||||||||||||||
| Common shares outstanding | 8,716,662 | 8,686,994 | 8,697,085 | |||||||||||||||||
| Average common shares outstanding: | ||||||||||||||||||||
| Basic | 8,734,383 | 8,728,342 | 8,715,655 | |||||||||||||||||
| Diluted | 8,774,111 | 8,769,456 | 8,784,970 | |||||||||||||||||
| Performance ratios | ||||||||||||||||||||
| Return on average assets | 0.18 | % | 0.37 | % | 0.07 | % | ||||||||||||||
| Return on average shareholders' equity | 2.72 | % | 5.79 | % | 0.98 | % | ||||||||||||||
Return on average tangible common equity 1 | 2.75 | % | 5.87 | % | 0.99 | % | ||||||||||||||
| Net interest margin | 2.36 | % | 2.22 | % | 1.82 | % | ||||||||||||||
Net interest margin - FTE 1,2 | 2.45 | % | 2.30 | % | 1.91 | % | ||||||||||||||
Capital ratios 3 | ||||||||||||||||||||
| Total shareholders' equity to assets | 6.32 | % | 6.46 | % | 6.63 | % | ||||||||||||||
Tangible common equity to tangible assets 1 | 6.24 | % | 6.38 | % | 6.55 | % | ||||||||||||||
| Tier 1 leverage ratio | 6.23 | % | 6.24 | % | 6.87 | % | ||||||||||||||
| Common equity tier 1 capital ratio | 8.97 | % | 8.97 | % | 9.15 | % | ||||||||||||||
| Tier 1 capital ratio | 8.97 | % | 8.97 | % | 9.15 | % | ||||||||||||||
| Total risk-based capital ratio | 12.50 | % | 12.50 | % | 12.52 | % | ||||||||||||||
| Asset quality | ||||||||||||||||||||
| Nonperforming loans | $ | 61,596 | $ | 58,538 | $ | 34,243 | ||||||||||||||
| Nonperforming assets | 63,691 | 61,355 | 35,921 | |||||||||||||||||
| Nonperforming loans to loans | 1.63 | % | 1.56 | % | 0.80 | % | ||||||||||||||
| Nonperforming assets to total assets | 1.12 | % | 1.10 | % | 0.61 | % | ||||||||||||||
| Allowance for credit losses - loans to: | ||||||||||||||||||||
| Loans | 1.50 | % | 1.49 | % | 1.11 | % | ||||||||||||||
| Nonperforming loans | 91.7 | % | 95.1 | % | 138.0 | % | ||||||||||||||
| Net charge-offs to average loans | 1.65 | % | 1.68 | % | 0.92 | % | ||||||||||||||
| Average balance sheet information | ||||||||||||||||||||
| Loans | $ | 3,874,174 | $ | 3,798,831 | $ | 4,237,300 | ||||||||||||||
| Total securities | 1,022,872 | 943,418 | 901,918 | |||||||||||||||||
| Other earning assets | 521,697 | 665,022 | 445,280 | |||||||||||||||||
| Total interest-earning assets | 5,424,700 | 5,426,126 | 5,590,131 | |||||||||||||||||
| Total assets | 5,635,646 | 5,618,089 | 5,770,380 | |||||||||||||||||
| Noninterest-bearing deposits | 143,305 | 155,030 | 135,878 | |||||||||||||||||
| Interest-bearing deposits | 4,744,189 | 4,723,879 | 4,815,978 | |||||||||||||||||
| Total deposits | 4,887,494 | 4,878,909 | 4,951,856 | |||||||||||||||||
| Shareholders' equity | 374,276 | 362,183 | 392,035 | |||||||||||||||||
1 Refer to "Non-GAAP Financial Measures" section above and "Reconciliation of Non-GAAP Financial Measures" below
2 On a fully-taxable equivalent (“FTE”) basis assuming a 21% tax rate
3 Regulatory capital ratios are preliminary pending filing of the Company's regulatory reports
| First Internet Bancorp | ||||||||||||||||||||
| Condensed Consolidated Balance Sheets (unaudited) | ||||||||||||||||||||
| Dollar amounts in thousands | ||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||
| Assets | ||||||||||||||||||||
| Cash and due from banks | $ | 10,528 | $ | 6,145 | $ | 6,344 | ||||||||||||||
| Interest-bearing deposits | 591,277 | 450,632 | 388,110 | |||||||||||||||||
| Securities available-for-sale, at fair value | 772,035 | 778,687 | 681,785 | |||||||||||||||||
| Securities held-to-maturity, at amortized cost, net of allowance for credit losses | 276,042 | 250,609 | 276,542 | |||||||||||||||||
| Loans held-for-sale | 55,240 | 108,608 | 31,738 | |||||||||||||||||
| Loans | 3,775,870 | 3,746,728 | 4,254,412 | |||||||||||||||||
| Allowance for credit losses - loans | (56,496) | (55,686) | (47,238) | |||||||||||||||||
| Net loans | 3,719,374 | 3,691,042 | 4,207,174 | |||||||||||||||||
| Accrued interest receivable | 28,182 | 27,909 | 29,022 | |||||||||||||||||
| Federal Home Loan Bank of Indianapolis stock | 28,350 | 28,350 | 28,350 | |||||||||||||||||
| Cash surrender value of bank-owned life insurance | 42,864 | 42,559 | 41,675 | |||||||||||||||||
| Premises and equipment, net | 67,006 | 67,934 | 70,461 | |||||||||||||||||
| Goodwill | 4,687 | 4,687 | 4,687 | |||||||||||||||||
| Servicing asset | 23,614 | 22,793 | 17,445 | |||||||||||||||||
| Other real estate owned | 1,945 | 2,631 | 1,518 | |||||||||||||||||
| Accrued income and other assets | 90,544 | 89,061 | 66,757 | |||||||||||||||||
| Total assets | $ | 5,711,688 | $ | 5,571,647 | $ | 5,851,608 | ||||||||||||||
| Liabilities | ||||||||||||||||||||
| Noninterest-bearing deposits | $ | 149,505 | $ | 146,879 | $ | 151,815 | ||||||||||||||
| Interest-bearing deposits | 4,832,145 | 4,692,934 | 4,793,810 | |||||||||||||||||
| Total deposits | 4,981,650 | 4,839,813 | 4,945,625 | |||||||||||||||||
| Advances from Federal Home Loan Bank | 239,500 | 249,500 | 395,000 | |||||||||||||||||
| Subordinated debt | 105,546 | 105,465 | 105,228 | |||||||||||||||||
| Accrued interest payable | 1,232 | 1,744 | 1,645 | |||||||||||||||||
| Accrued expenses and other liabilities | 22,806 | 15,358 | 16,363 | |||||||||||||||||
| Total liabilities | 5,350,734 | 5,211,880 | 5,463,861 | |||||||||||||||||
| Shareholders' equity | ||||||||||||||||||||
| Voting common stock | 186,967 | 186,577 | 185,873 | |||||||||||||||||
| Retained earnings | 195,292 | 193,320 | 231,031 | |||||||||||||||||
| Accumulated other comprehensive loss | (21,305) | (20,130) | (29,157) | |||||||||||||||||
| Total shareholders' equity | 360,954 | 359,767 | 387,747 | |||||||||||||||||
| Total liabilities and shareholders' equity | $ | 5,711,688 | $ | 5,571,647 | $ | 5,851,608 | ||||||||||||||
| First Internet Bancorp | |||||||||||||||||
| Condensed Consolidated Statements of Income (unaudited) | |||||||||||||||||
| Dollar amounts in thousands, except per share data | |||||||||||||||||
| Three Months Ended | |||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||
| Interest income | |||||||||||||||||
| Loans | $ | 60,839 | $ | 61,535 | $ | 62,662 | |||||||||||
| Securities - taxable | 9,496 | 8,811 | 8,463 | ||||||||||||||
| Securities - non-taxable | 654 | 651 | 661 | ||||||||||||||
| Other earning assets | 4,821 | 7,057 | 5,043 | ||||||||||||||
| Total interest income | 75,810 | 78,054 | 76,829 | ||||||||||||||
| Interest expense | |||||||||||||||||
| Deposits | 40,359 | 43,836 | 47,626 | ||||||||||||||
| Other borrowed funds | 3,853 | 3,896 | 4,107 | ||||||||||||||
| Total interest expense | 44,212 | 47,732 | 51,733 | ||||||||||||||
| Net interest income | 31,598 | 30,322 | 25,096 | ||||||||||||||
| Provision for credit losses | 16,305 | 11,984 | 11,933 | ||||||||||||||
| Net interest income after provision for credit losses | 15,293 | 18,338 | 13,163 | ||||||||||||||
| Noninterest income | |||||||||||||||||
| Service charges and fees | 844 | 454 | 265 | ||||||||||||||
| Loan servicing revenue | 2,856 | 2,713 | 1,983 | ||||||||||||||
| Loan servicing asset revaluation | (1,060) | (1,800) | (1,181) | ||||||||||||||
| Gain on sale of loans | 7,377 | 8,470 | 8,647 | ||||||||||||||
| Other | 1,501 | 1,538 | 713 | ||||||||||||||
| Total noninterest income | 11,518 | 11,375 | 10,427 | ||||||||||||||
| Noninterest expense | |||||||||||||||||
| Salaries and employee benefits | 13,236 | 12,668 | 13,107 | ||||||||||||||
| Marketing, advertising and promotion | 615 | 644 | 647 | ||||||||||||||
| Consulting and professional fees | 1,080 | 1,184 | 1,228 | ||||||||||||||
| Data processing | 775 | 712 | 635 | ||||||||||||||
| Loan expenses | 2,179 | 1,813 | 1,531 | ||||||||||||||
| Premises and equipment | 3,676 | 3,705 | 3,115 | ||||||||||||||
| Deposit insurance premium | 1,487 | 1,563 | 1,398 | ||||||||||||||
| Other | 1,979 | 1,922 | 1,895 | ||||||||||||||
| Total noninterest expense | 25,027 | 24,211 | 23,556 | ||||||||||||||
| Income before income taxes | 1,784 | 5,502 | 34 | ||||||||||||||
| Income tax (benefit) provision | (725) | 213 | (909) | ||||||||||||||
| Net income | $ | 2,509 | $ | 5,289 | $ | 943 | |||||||||||
| Per common share data | |||||||||||||||||
| Earnings per share - basic | $ | 0.29 | $ | 0.61 | $ | 0.11 | |||||||||||
| Earnings per share - diluted | $ | 0.29 | $ | 0.60 | $ | 0.11 | |||||||||||
| Dividends declared per share | $ | 0.06 | $ | 0.06 | $ | 0.06 | |||||||||||
| First Internet Bancorp | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Balances and Rates (unaudited) | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Dollar amounts in thousands | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Three Months Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Average Balance | Interest / Dividends | Yield / Cost | Average Balance | Interest / Dividends | Yield / Cost | Average Balance | Interest / Dividends | Yield / Cost | |||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-earning assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Loans, including loans held-for-sale 1 | $ | 3,880,131 | $ | 60,839 | 6.36 | % | $ | 3,817,686 | $ | 61,535 | 6.39 | % | $ | 4,242,933 | $ | 62,662 | 5.99 | % | |||||||||||||||||||||||||||||||||||
| Securities - taxable | 943,079 | 9,496 | 4.08 | % | 863,071 | 8,811 | 4.05 | % | 820,175 | 8,463 | 4.18 | % | |||||||||||||||||||||||||||||||||||||||||
| Securities - non-taxable | 79,793 | 654 | 3.32 | % | 80,347 | 651 | 3.21 | % | 81,743 | 661 | 3.28 | % | |||||||||||||||||||||||||||||||||||||||||
| Other earning assets | 521,697 | 4,821 | 3.75 | % | 665,022 | 7,057 | 4.21 | % | 445,280 | 5,043 | 4.59 | % | |||||||||||||||||||||||||||||||||||||||||
| Total interest-earning assets | 5,424,700 | 75,810 | 5.67 | % | 5,426,126 | 78,054 | 5.71 | % | 5,590,131 | 76,829 | 5.57 | % | |||||||||||||||||||||||||||||||||||||||||
| Allowance for credit losses - loans | (56,106) | (61,378) | (45,664) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Noninterest-earning assets | 267,052 | 253,341 | 225,913 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 5,635,646 | $ | 5,618,089 | $ | 5,770,380 | |||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing liabilities | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest-bearing demand deposits | $ | 1,243,549 | $ | 8,168 | 2.66 | % | $ | 1,023,305 | $ | 7,524 | 2.92 | % | $ | 956,322 | $ | 6,974 | 2.96 | % | |||||||||||||||||||||||||||||||||||
| Savings accounts | 19,542 | 41 | 0.85 | % | 18,575 | 40 | 0.85 | % | 20,568 | 43 | 0.85 | % | |||||||||||||||||||||||||||||||||||||||||
| Money market accounts | 1,292,126 | 10,103 | 3.17 | % | 1,312,201 | 11,238 | 3.40 | % | 1,221,795 | 11,361 | 3.77 | % | |||||||||||||||||||||||||||||||||||||||||
| Certificates and brokered deposits | 2,188,972 | 22,047 | 4.08 | % | 2,369,798 | 25,034 | 4.19 | % | 2,617,293 | 29,248 | 4.53 | % | |||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing deposits | 4,744,189 | 40,359 | 3.45 | % | 4,723,879 | 43,836 | 3.68 | % | 4,815,978 | 47,626 | 4.01 | % | |||||||||||||||||||||||||||||||||||||||||
| Other borrowed funds | 352,117 | 3,853 | 4.44 | % | 354,926 | 3,896 | 4.35 | % | 401,300 | 4,107 | 4.15 | % | |||||||||||||||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 5,096,306 | 44,212 | 3.52 | % | 5,078,805 | 47,732 | 3.73 | % | 5,217,278 | 51,733 | 4.02 | % | |||||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 143,305 | 155,030 | 135,878 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Other noninterest-bearing liabilities | 21,759 | 22,071 | 25,189 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities | 5,261,370 | 5,255,906 | 5,378,345 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity | 374,276 | 362,183 | 392,035 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 5,635,646 | $ | 5,618,089 | $ | 5,770,380 | |||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income | $ | 31,598 | $ | 30,322 | $ | 25,096 | |||||||||||||||||||||||||||||||||||||||||||||||
| Interest rate spread | 2.15 | % | 1.98 | % | 1.55 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Net interest margin | 2.36 | % | 2.22 | % | 1.82 | % | |||||||||||||||||||||||||||||||||||||||||||||||
Net interest margin - FTE 2,3 | 2.45 | % | 2.30 | % | 1.91 | % | |||||||||||||||||||||||||||||||||||||||||||||||
1 Includes nonaccrual loans
2 On a fully-taxable equivalent (“FTE”) basis assuming a 21% tax rate
3 Refer to "Non-GAAP Financial Measures" section above and "Reconciliation of Non-GAAP Financial Measures" below
| First Internet Bancorp | ||||||||||||||||||||||||||||||||||||||
| Loans and Deposits (unaudited) | ||||||||||||||||||||||||||||||||||||||
| Dollar amounts in thousands | ||||||||||||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||||||||||||||||||||
| Amount | Percent | Amount | Percent | Amount | Percent | |||||||||||||||||||||||||||||||||
| Commercial loans | ||||||||||||||||||||||||||||||||||||||
| Commercial and industrial | $ | 225,425 | 6.0 | % | $ | 221,714 | 5.9 | % | $ | 140,239 | 3.3 | % | ||||||||||||||||||||||||||
| Owner-occupied commercial real estate | 48,136 | 1.3 | % | 48,575 | 1.3 | % | 49,954 | 1.2 | % | |||||||||||||||||||||||||||||
| Investor commercial real estate | 598,933 | 15.9 | % | 647,394 | 17.3 | % | 297,874 | 7.0 | % | |||||||||||||||||||||||||||||
| Construction | 449,888 | 11.9 | % | 372,668 | 9.9 | % | 471,082 | 11.1 | % | |||||||||||||||||||||||||||||
| Single tenant lease financing | 254,044 | 6.7 | % | 222,925 | 5.9 | % | 950,814 | 22.4 | % | |||||||||||||||||||||||||||||
| Public finance | 441,734 | 11.7 | % | 442,234 | 11.8 | % | 482,558 | 11.3 | % | |||||||||||||||||||||||||||||
| Healthcare finance | 131,161 | 3.5 | % | 139,469 | 3.7 | % | 171,430 | 4.0 | % | |||||||||||||||||||||||||||||
| Small business lending | 433,964 | 11.5 | % | 430,024 | 11.5 | % | 353,408 | 8.3 | % | |||||||||||||||||||||||||||||
| Franchise finance | 389,249 | 10.3 | % | 417,045 | 11.1 | % | 514,700 | 12.1 | % | |||||||||||||||||||||||||||||
| Total commercial loans | 2,972,534 | 78.8 | % | 2,942,048 | 78.4 | % | 3,432,059 | 80.7 | % | |||||||||||||||||||||||||||||
| Consumer loans | ||||||||||||||||||||||||||||||||||||||
| Residential mortgage | 338,058 | 9.0 | % | 343,110 | 9.2 | % | 367,722 | 8.6 | % | |||||||||||||||||||||||||||||
| Home equity | 14,219 | 0.4 | % | 14,725 | 0.4 | % | 17,421 | 0.4 | % | |||||||||||||||||||||||||||||
| Trailers | 242,022 | 6.4 | % | 235,876 | 6.3 | % | 220,012 | 5.2 | % | |||||||||||||||||||||||||||||
| Recreational vehicles | 142,442 | 3.8 | % | 141,952 | 3.8 | % | 145,690 | 3.4 | % | |||||||||||||||||||||||||||||
| Other consumer loans | 46,874 | 1.2 | % | 47,630 | 1.3 | % | 46,851 | 1.1 | % | |||||||||||||||||||||||||||||
| Total consumer loans | 783,615 | 20.8 | % | 783,293 | 21.0 | % | 797,696 | 18.7 | % | |||||||||||||||||||||||||||||
Net deferred loan fees, premiums, discounts and other 1 | 19,721 | 0.4 | % | 21,387 | 0.6 | % | 24,657 | 0.6 | % | |||||||||||||||||||||||||||||
| Total loans | $ | 3,775,870 | 100.0 | % | $ | 3,746,728 | 100.0 | % | $ | 4,254,412 | 100.0 | % | ||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||||||||||||||||||||
| Amount | Percent | Amount | Percent | Amount | Percent | |||||||||||||||||||||||||||||||||
| Deposits | ||||||||||||||||||||||||||||||||||||||
| Noninterest-bearing deposits | $ | 149,505 | 3.0 | % | $ | 146,880 | 3.0 | % | $ | 151,815 | 3.1 | % | ||||||||||||||||||||||||||
| Interest-bearing demand deposits | 1,358,028 | 27.3 | % | 1,120,850 | 23.2 | % | 1,103,540 | 22.3 | % | |||||||||||||||||||||||||||||
| Savings accounts | 20,344 | 0.4 | % | 18,990 | 0.4 | % | 21,632 | 0.4 | % | |||||||||||||||||||||||||||||
| Money market accounts | 1,325,382 | 26.6 | % | 1,272,845 | 26.3 | % | 1,292,235 | 26.2 | % | |||||||||||||||||||||||||||||
| Certificates of deposits | 1,869,181 | 37.5 | % | 2,004,909 | 41.4 | % | 2,029,801 | 41.0 | % | |||||||||||||||||||||||||||||
| Brokered deposits | 259,210 | 5.2 | % | 275,339 | 5.7 | % | 346,602 | 7.0 | % | |||||||||||||||||||||||||||||
| Total deposits | $ | 4,981,650 | 100.0 | % | $ | 4,839,813 | 100.0 | % | $ | 4,945,625 | 100.0 | % | ||||||||||||||||||||||||||
1 Includes carrying value adjustments of $18.1 million, $19.1 million and $22.1 million related to terminated interest rate swaps associated with public finance loans as of March 31, 2026, December 31, 2025 and March 31, 2025, respectively.
| First Internet Bancorp | ||||||||||||||||||||
| Reconciliation of Non-GAAP Financial Measures | ||||||||||||||||||||
| Dollar amounts in thousands, except per share data | ||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||
| Total equity - GAAP | $ | 360,954 | $ | 359,767 | $ | 387,747 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Goodwill | (4,687) | (4,687) | (4,687) | |||||||||||||||||
| Tangible common equity | $ | 356,267 | $ | 355,080 | $ | 383,060 | ||||||||||||||
| Total assets - GAAP | $ | 5,711,688 | $ | 5,571,647 | $ | 5,851,608 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Goodwill | (4,687) | (4,687) | (4,687) | |||||||||||||||||
| Tangible assets | $ | 5,707,001 | $ | 5,566,960 | $ | 5,846,921 | ||||||||||||||
| Common shares outstanding | 8,716,662 | 8,686,994 | 8,697,085 | |||||||||||||||||
| Book value per common share | $ | 41.41 | $ | 41.41 | $ | 44.58 | ||||||||||||||
| Effect of goodwill | (0.54) | (0.54) | (0.54) | |||||||||||||||||
| Tangible book value per common share | $ | 40.87 | $ | 40.87 | $ | 44.04 | ||||||||||||||
| Total shareholders' equity to assets | 6.32 | % | 6.46 | % | 6.63 | % | ||||||||||||||
| Effect of goodwill | (0.08 | %) | (0.08 | %) | (0.08 | %) | ||||||||||||||
| Tangible common equity to tangible assets | 6.24 | % | 6.38 | % | 6.55 | % | ||||||||||||||
| Total average equity - GAAP | $ | 374,276 | $ | 362,183 | $ | 392,035 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Average goodwill | (4,687) | (4,687) | (4,687) | |||||||||||||||||
| Average tangible common equity | $ | 369,589 | $ | 357,496 | $ | 387,348 | ||||||||||||||
| Return on average shareholders' equity | 2.72 | % | 5.79 | % | 0.98 | % | ||||||||||||||
| Effect of goodwill | 0.03 | % | 0.08 | % | 0.01 | % | ||||||||||||||
| Return on average tangible common equity | 2.75 | % | 5.87 | % | 0.99 | % | ||||||||||||||
| Total interest income | $ | 75,810 | $ | 78,054 | $ | 76,829 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
Fully-taxable equivalent adjustments 1 | 1,160 | 1,161 | 1,169 | |||||||||||||||||
| Total interest income - FTE | $ | 76,970 | $ | 79,215 | $ | 77,998 | ||||||||||||||
| Net interest income | $ | 31,598 | $ | 30,322 | $ | 25,096 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
Fully-taxable equivalent adjustments 1 | 1,160 | 1,161 | 1,169 | |||||||||||||||||
| Net interest income - FTE | $ | 32,758 | $ | 31,483 | $ | 26,265 | ||||||||||||||
| Net interest margin | 2.36 | % | 2.22 | % | 1.82 | % | ||||||||||||||
Effect of fully-taxable equivalent adjustments 1 | 0.09 | % | 0.08 | % | 0.09 | % | ||||||||||||||
| Net interest margin - FTE | 2.45 | % | 2.30 | % | 1.91 | % | ||||||||||||||
1Assuming a 21% tax rate
| First Internet Bancorp | ||||||||||||||||||||
| Reconciliation of Non-GAAP Financial Measures | ||||||||||||||||||||
| Dollar amounts in thousands, except per share data | ||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||
| Total revenue - GAAP | $ | 43,116 | $ | 41,697 | $ | 35,523 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Loss on sale of loans | — | 411 | — | |||||||||||||||||
| Adjusted total revenue | $ | 43,116 | $ | 42,108 | $ | 35,523 | ||||||||||||||
| Net income - GAAP | $ | 2,509 | $ | 5,289 | $ | 943 | ||||||||||||||
Adjustments:1 | ||||||||||||||||||||
| Provision for credit losses | 16,305 | 11,984 | 11,933 | |||||||||||||||||
| Income tax (benefit) provision | (725) | 213 | (909) | |||||||||||||||||
| Pre-provision net revenue | $ | 18,089 | $ | 17,486 | $ | 11,967 | ||||||||||||||
| Pre-provision net revenue | $ | 18,089 | $ | 17,486 | $ | 11,967 | ||||||||||||||
Adjustments:1 | ||||||||||||||||||||
| Loss on sale of loans | — | 411 | — | |||||||||||||||||
| Adjusted pre-provision net revenue | $ | 18,089 | $ | 17,897 | $ | 11,967 | ||||||||||||||
| Noninterest income - GAAP | $ | 11,518 | $ | 11,375 | $ | 10,427 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Loss on sale of loans | — | 411 | — | |||||||||||||||||
| Adjusted noninterest income | $ | 11,518 | $ | 11,786 | $ | 10,427 | ||||||||||||||
| Income before income taxes - GAAP | $ | 1,784 | $ | 5,502 | $ | 34 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Loss on sale of loans | — | 411 | — | |||||||||||||||||
| Adjusted income before income taxes | $ | 1,784 | $ | 5,913 | $ | 34 | ||||||||||||||
| Income tax (benefit) provision - GAAP | $ | (725) | $ | 213 | $ | (909) | ||||||||||||||
Adjustments:1 | ||||||||||||||||||||
| Loss on sale of loans | — | 86 | — | |||||||||||||||||
| Adjusted income tax (benefit) provision | $ | (725) | $ | 299 | $ | (909) | ||||||||||||||
| Net income - GAAP | $ | 2,509 | $ | 5,289 | $ | 943 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Loss on sale of loans | — | 325 | — | |||||||||||||||||
| Adjusted net income | $ | 2,509 | $ | 5,614 | $ | 943 | ||||||||||||||
| Diluted average common shares outstanding | 8,774,111 | 8,769,456 | 8,784,970 | |||||||||||||||||
| Diluted earnings per share - GAAP | $ | 0.29 | $ | 0.60 | $ | 0.11 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Effect of loss on sale of loans | — | 0.04 | — | |||||||||||||||||
| Adjusted diluted earnings per share | $ | 0.29 | $ | 0.64 | $ | 0.11 | ||||||||||||||
| Return on average assets | 0.18 | % | 0.37 | % | 0.07 | % | ||||||||||||||
| Effect of loss on sale of loans | 0.00 | % | 0.02 | % | 0.00 | % | ||||||||||||||
| Adjusted return on average assets | 0.18 | % | 0.39 | % | 0.07 | % | ||||||||||||||
| Return on average shareholders' equity | 2.72 | % | 5.79 | % | 0.98 | % | ||||||||||||||
| Effect of loss on sale of loans | 0.00 | % | 0.36 | % | 0.00 | % | ||||||||||||||
| Adjusted return on average shareholders' equity | 2.72 | % | 6.15 | % | 0.98 | % | ||||||||||||||
| Return on average tangible common equity | 2.75 | % | 5.87 | % | 0.99 | % | ||||||||||||||
| Effect of loss on sale of loans | 0.00 | % | 0.36 | % | 0.00 | % | ||||||||||||||
| Adjusted return on average tangible common equity | 2.75 | % | 6.23 | % | 0.99 | % | ||||||||||||||
1Assuming a 21% tax rate | ||||||||||||||||||||
| First Internet Bancorp | ||||||||||||||||||||
| Reconciliation of Non-GAAP Financial Measures | ||||||||||||||||||||
| Dollar amounts in thousands, except per share data | ||||||||||||||||||||
| Three Months Ended | ||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||
| Tangible common equity | $ | 356,267 | $ | 355,080 | $ | 383,060 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Accumulated other comprehensive loss | 21,305 | 20,130 | 29,157 | |||||||||||||||||
| Adjusted tangible common equity | $ | 377,572 | $ | 375,210 | $ | 412,217 | ||||||||||||||
| Tangible assets | $ | 5,707,001 | $ | 5,566,960 | $ | 5,846,921 | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Cash in excess of $300 million | (301,805) | (156,777) | (94,454) | |||||||||||||||||
| Adjusted tangible assets | $ | 5,405,196 | $ | 5,410,183 | $ | 5,752,467 | ||||||||||||||
| Adjusted tangible common equity | $ | 377,572 | $ | 375,210 | $ | 412,217 | ||||||||||||||
| Adjusted tangible assets | 5,405,196 | 5,410,183 | 5,752,467 | |||||||||||||||||
| Adjusted tangible common equity to adjusted tangible assets | 6.99 | % | 6.94 | % | 7.17 | % | ||||||||||||||
| Nonperforming loans to total loans | 1.63 | % | 1.56 | % | 0.80 | % | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Fully guaranteed balances | (0.41 | %) | (0.36 | %) | (0.12 | %) | ||||||||||||||
| Adjusted nonperforming loans to total loans | 1.22 | % | 1.20 | % | 0.68 | % | ||||||||||||||
| Allowance for credit losses - loans to nonperforming loans | 91.72 | % | 95.13 | % | 137.95 | % | ||||||||||||||
| Adjustments: | ||||||||||||||||||||
| Fully guaranteed balances | 30.73 | % | 28.84 | % | 24.87 | % | ||||||||||||||
| Adjusted allowance for credit losses - loans to nonperforming loans | 122.45 | % | 123.97 | % | 162.82 | % | ||||||||||||||
April 2026 Investor Presentation NASDAQ: INBK Exhibit 99.2
2 Forward-Looking Statements & Non-GAAP Financial Measures This presentation contains forward-looking statements within the meaning of the safe harbor provisions of the Private Securities Litigation Reform Act of 1995, including statements with respect to the financial condition, results of operations, trends in lending policies and loan programs, plans and prospective business partnerships, objectives, future performance and business of the Company. Forward-looking statements are generally identifiable by the use of words such as “believe,” “continue,” “could,” “decline,” “drive,” “enhance,” “estimate,” “expanding,” “expect,” “grow,” “growth,” “improve,” “increase,” “looking ahead,” “may,” “pending,” “plan,” “position,” “preliminary,” “remain,” “rising,” “should,” “slow,” “stable,” “strategy,” “well-positioned,” or other similar expressions. Forward-looking statements are not a guarantee of future performance or results, are based on information available at the time the statements are made and involve known and unknown risks, uncertainties and other factors that could cause actual results to differ materially from the information in the forward- looking statements. Such statements are subject to certain risks and uncertainties including: our business and operations and the business and operations of our vendors and customers; general economic conditions, whether national or regional, and conditions in the lending markets in which we participate may have an adverse effect on the demand for our loans and other products; our credit quality and related levels of nonperforming assets and loan losses, and the value and salability of the real estate that is the collateral for our loans. Other factors that may cause such differences include: failures or breaches of or interruptions in the communications and information systems on which we rely to conduct our business; failure of our plans to grow our commercial and industrial, construction and SBA loan portfolios; competition with national, regional and community financial institutions; the loss of any key members of senior management; the impacts of inflation and rising interest rates on the general economy; risks relating to the regulation of financial institutions; and other factors identified in reports we file with the U.S. Securities and Exchange Commission. All statements in this presentation, including forward-looking statements, speak only as of the date they are made, and the Company undertakes no obligation to update any statement in light of new information or future events. This presentation contains financial information determined by methods other than in accordance with U.S. generally accepted accounting principles (“GAAP”). Non-GAAP financial measures, specifically tangible common equity, tangible assets, tangible book value per common share, tangible common equity to tangible assets, total interest income – FTE, net interest income – FTE, net interest margin – FTE, adjusted total revenue, pre-provision net revenue (loss), adjusted pre-provision net revenue, adjusted noninterest income, adjusted income (loss) before income taxes, adjusted income tax provision (benefit), adjusted net income (loss), adjusted diluted earnings per share, adjusted return on average assets, adjusted return on average shareholders’ equity, adjusted return on average tangible common equity, adjusted tangible common equity, adjusted tangible assets and adjusted tangible common equity to adjusted tangible assets, adjusted nonperforming loans to total loans and adjusted allowance for credit losses - loans to nonperforming loans are used by the Company’s management to measure the strength of its capital and analyze profitability, including its ability to generate earnings on tangible capital invested by its shareholders. Although management believes these non-GAAP measures are useful to investors by providing a greater understanding of its business, they should not be considered a substitute for financial measures determined in accordance with GAAP, nor are they necessarily comparable to non-GAAP performance measures that may be presented by other companies. Reconciliations of these non-GAAP financial measures to the most directly comparable GAAP financial measures are included in the table at the end of this presentation under the caption “Reconciliation of Non-GAAP Financial Measures.”
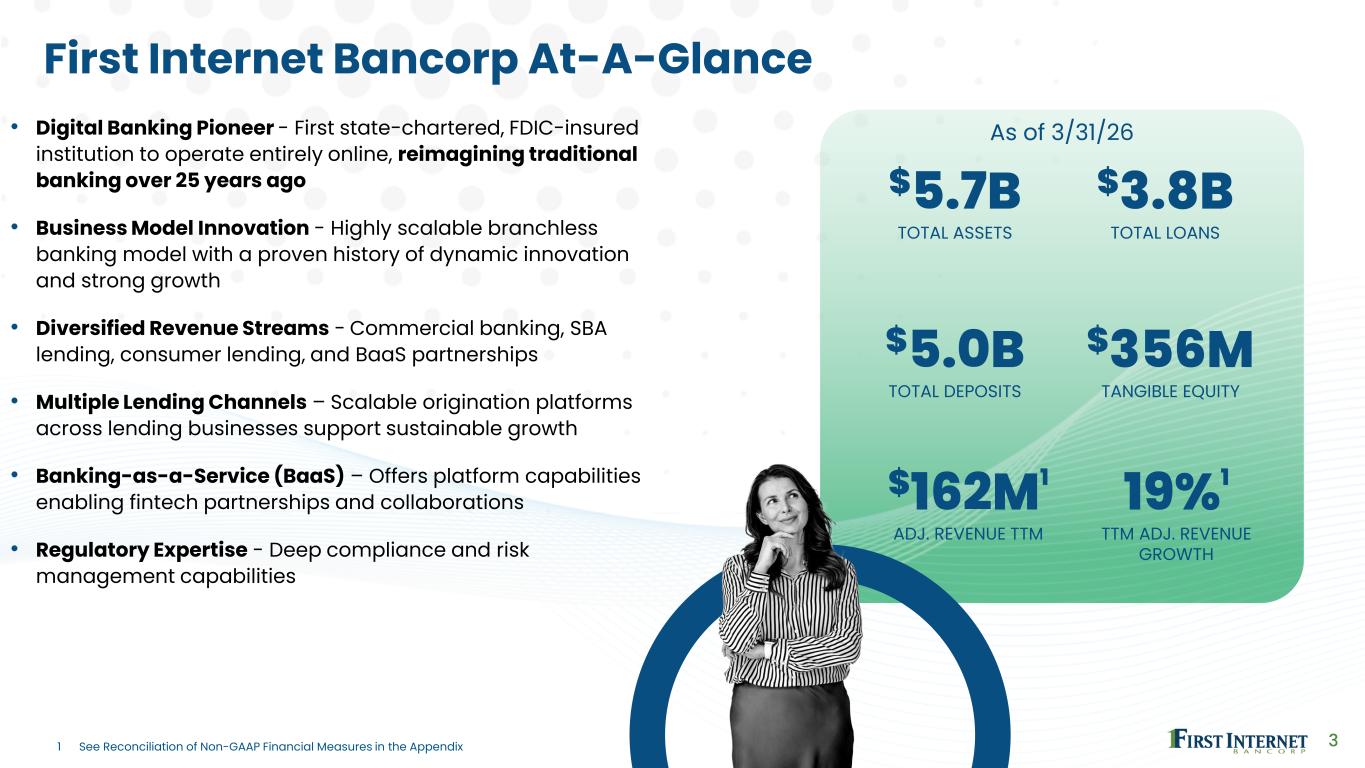
3 First Internet Bancorp At-A-Glance • Digital Banking Pioneer - First state-chartered, FDIC-insured institution to operate entirely online, reimagining traditional banking over 25 years ago • Business Model Innovation - Highly scalable branchless banking model with a proven history of dynamic innovation and strong growth • Diversified Revenue Streams - Commercial banking, SBA lending, consumer lending, and BaaS partnerships • Multiple Lending Channels – Scalable origination platforms across lending businesses support sustainable growth • Banking-as-a-Service (BaaS) – Offers platform capabilities enabling fintech partnerships and collaborations • Regulatory Expertise - Deep compliance and risk management capabilities $5.7B TOTAL ASSETS 19%1 TTM ADJ. REVENUE GROWTH $162M1 ADJ. REVENUE TTM $3.8B TOTAL LOANS $5.0B TOTAL DEPOSITS $356M TANGIBLE EQUITY As of 3/31/26 1 See Reconciliation of Non-GAAP Financial Measures in the Appendix
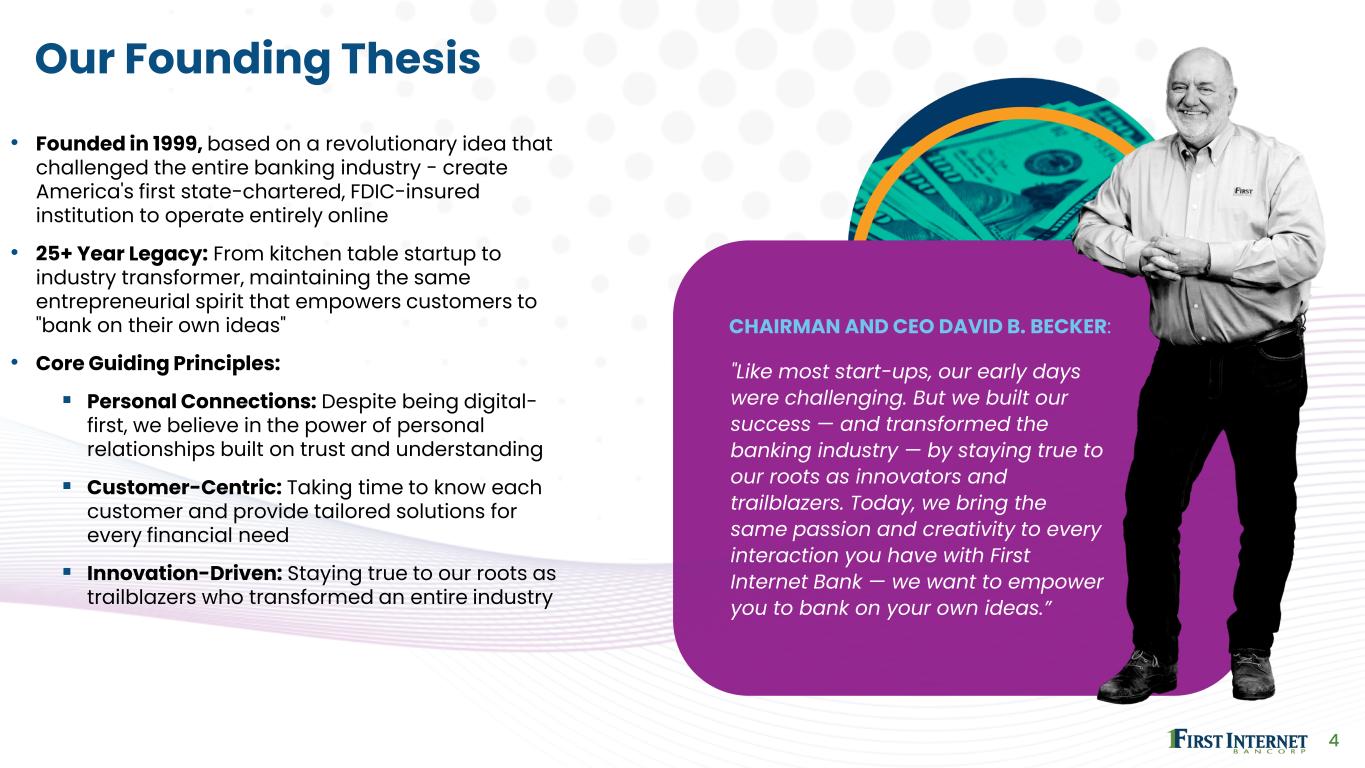
4 Our Founding Thesis • Founded in 1999, based on a revolutionary idea that challenged the entire banking industry - create America's first state-chartered, FDIC-insured institution to operate entirely online • 25+ Year Legacy: From kitchen table startup to industry transformer, maintaining the same entrepreneurial spirit that empowers customers to "bank on their own ideas" • Core Guiding Principles: Personal Connections: Despite being digital- first, we believe in the power of personal relationships built on trust and understanding Customer-Centric: Taking time to know each customer and provide tailored solutions for every financial need Innovation-Driven: Staying true to our roots as trailblazers who transformed an entire industry "Like most start-ups, our early days were challenging. But we built our success — and transformed the banking industry — by staying true to our roots as innovators and trailblazers. Today, we bring the same passion and creativity to every interaction you have with First Internet Bank — we want to empower you to bank on your own ideas.” CHAIRMAN AND CEO DAVID B. BECKER:
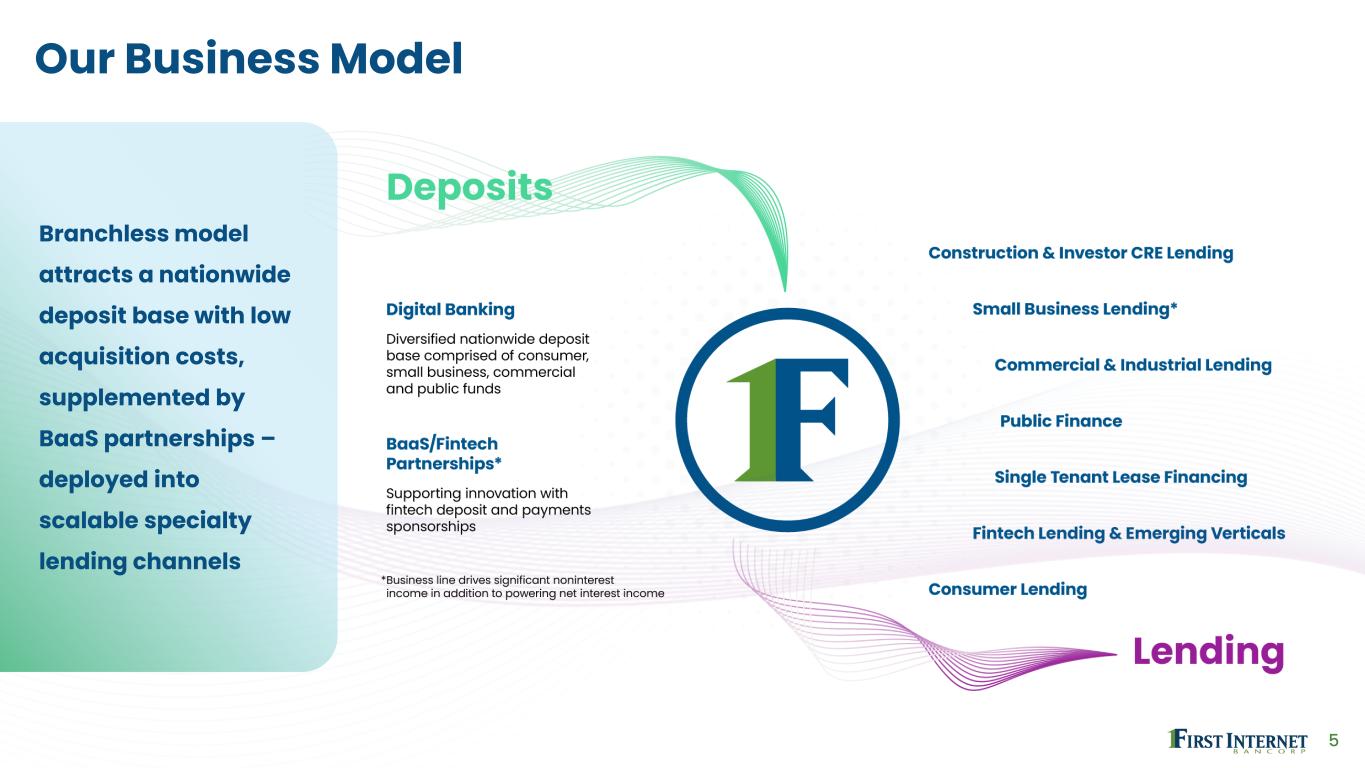
5 Our Business Model Branchless model attracts a nationwide deposit base with low acquisition costs, supplemented by BaaS partnerships – deployed into scalable specialty lending channels
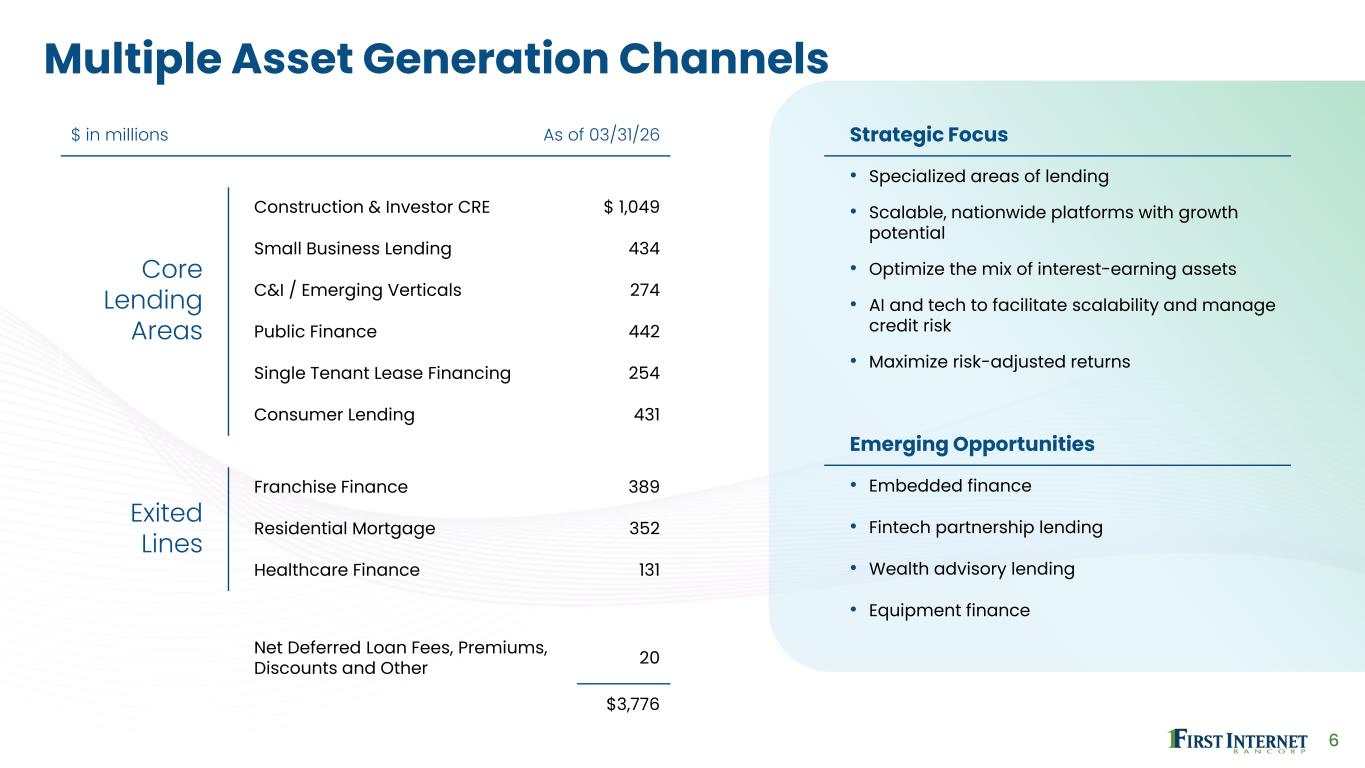
6 Multiple Asset Generation Channels $ in millions As of 03/31/26 Core Lending Areas Construction & Investor CRE $ 1,049 Small Business Lending 434 C&I / Emerging Verticals 274 Public Finance 442 Single Tenant Lease Financing 254 Consumer Lending 431 Exited Lines Franchise Finance 389 Residential Mortgage 352 Healthcare Finance 131 Net Deferred Loan Fees, Premiums, Discounts and Other 20 $3,776 Strategic Focus • Specialized areas of lending • Scalable, nationwide platforms with growth potential • Optimize the mix of interest-earning assets • AI and tech to facilitate scalability and manage credit risk • Maximize risk-adjusted returns Emerging Opportunities • Embedded finance • Fintech partnership lending • Wealth advisory lending • Equipment finance
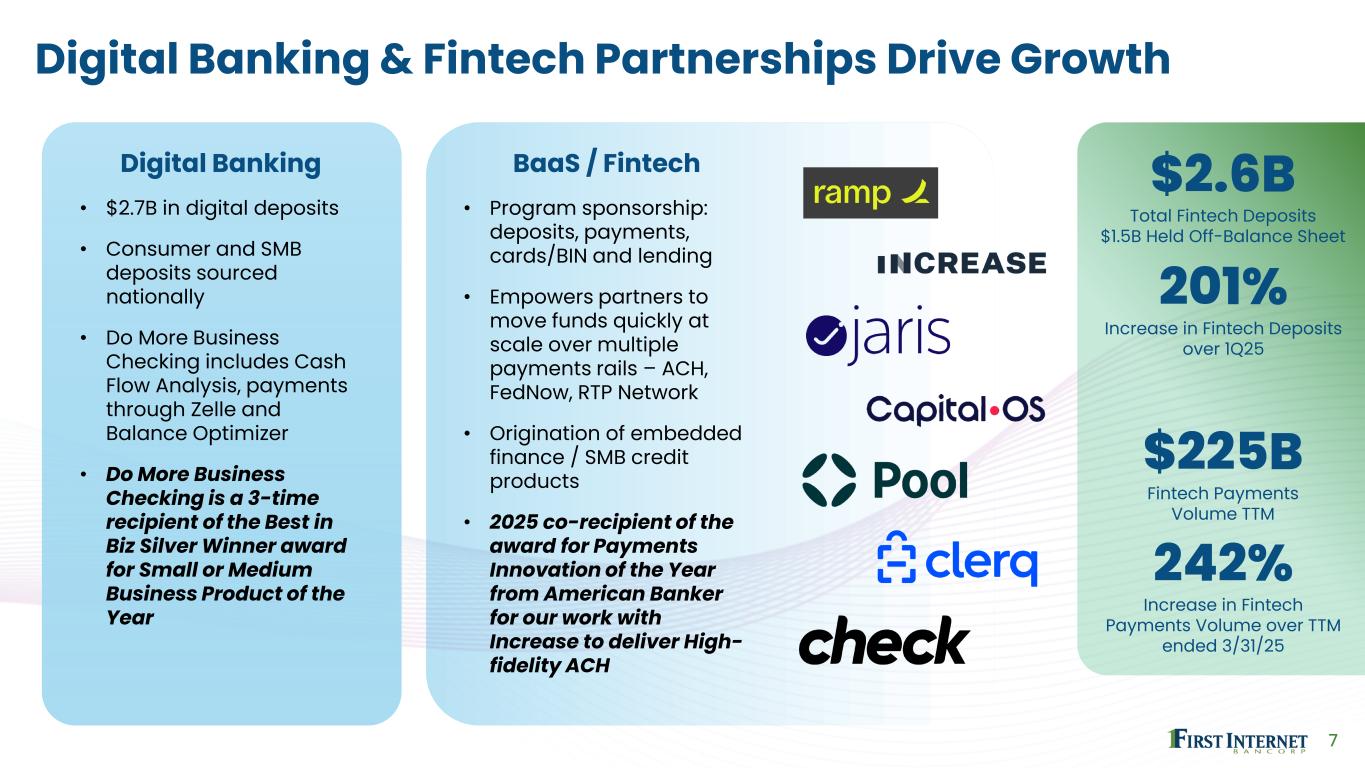
7 Digital Banking & Fintech Partnerships Drive Growth Digital Banking • $2.7B in digital deposits • Consumer and SMB deposits sourced nationally • Do More Business Checking includes Cash Flow Analysis, payments through Zelle and Balance Optimizer • Do More Business Checking is a 3-time recipient of the Best in Biz Silver Winner award for Small or Medium Business Product of the Year BaaS / Fintech • Program sponsorship: deposits, payments, cards/BIN and lending • Empowers partners to move funds quickly at scale over multiple payments rails – ACH, FedNow, RTP Network • Origination of embedded finance / SMB credit products • 2025 co-recipient of the award for Payments Innovation of the Year from American Banker for our work with Increase to deliver High- fidelity ACH $2.6B Total Fintech Deposits $1.5B Held Off-Balance Sheet 201% Increase in Fintech Deposits over 1Q25 $225B Fintech Payments Volume TTM 242% Increase in Fintech Payments Volume over TTM ended 3/31/25
8 Key Investment Highlights • Digital Banking - America's first online bank with a 25+ year branchless model delivering superior cost structure and geographic reach • Technology Moat & Fintech Edge - Quarter-century digital head start creates competitive barriers and compelling partnership platform • Balance Sheet Restructuring - Accelerated optimization of the asset mix to drive increased earnings and improve interest rate risk • Disciplined credit underwriting – Historically strong credit quality through prudent underwriting and proactive portfolio management • Strong Financial Momentum - Continuous growth in net interest income with expanding net interest margin and strong loan originations • Pathway to Improved Profitability - Revenue growth is driving increased pre-provision, net revenue and positive operating leverage • BaaS-Powered Balance Sheet - Fintech partnerships fuel robust deposit growth creating strong liquidity and expansion capacity • Compelling Deep Value - Trading at significant discount to peers and tangible book value despite superior growth model Founder-led organization focused on building long-term shareholder value, with an attractive value-oriented entry point
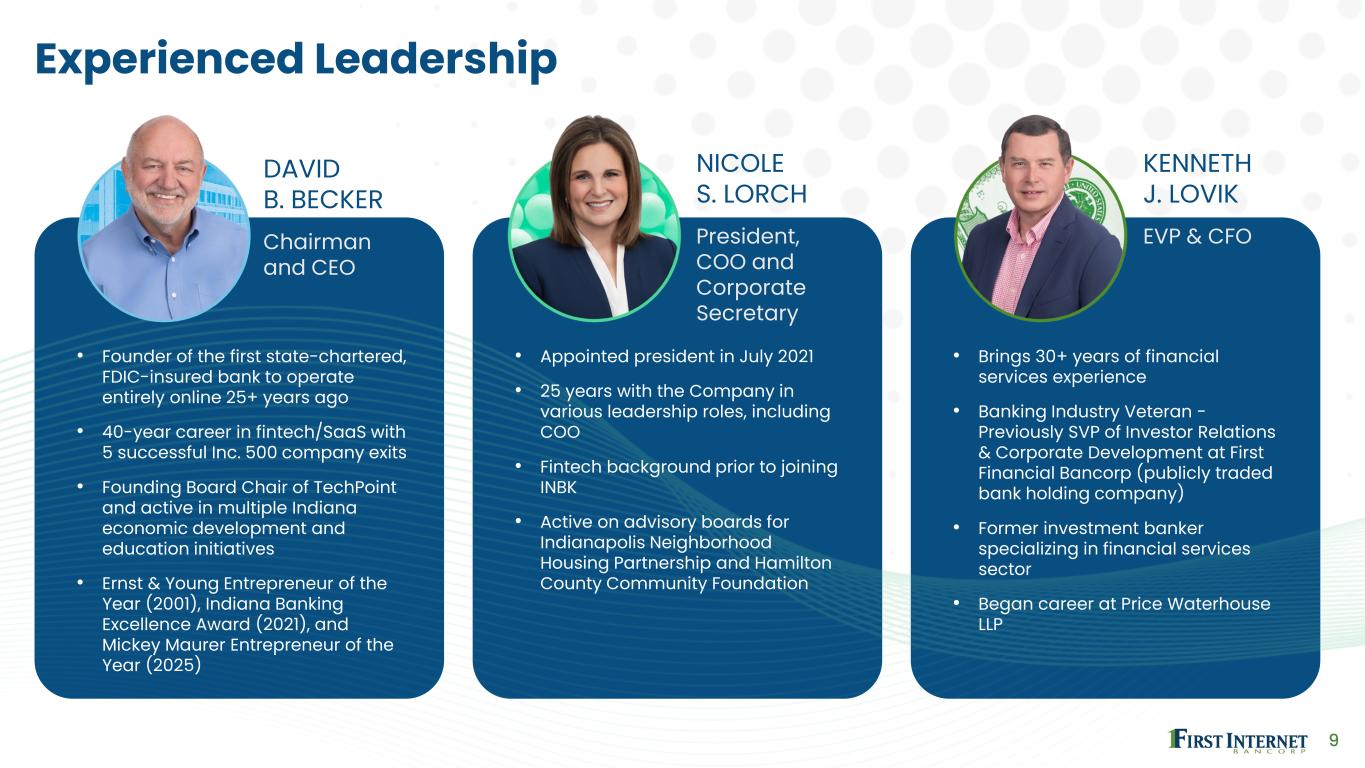
9 Experienced Leadership • Founder of the first state-chartered, FDIC-insured bank to operate entirely online 25+ years ago • 40-year career in fintech/SaaS with 5 successful Inc. 500 company exits • Founding Board Chair of TechPoint and active in multiple Indiana economic development and education initiatives • Ernst & Young Entrepreneur of the Year (2001), Indiana Banking Excellence Award (2021), and Mickey Maurer Entrepreneur of the Year (2025) • Appointed president in July 2021 • 25 years with the Company in various leadership roles, including COO • Fintech background prior to joining INBK • Active on advisory boards for Indianapolis Neighborhood Housing Partnership and Hamilton County Community Foundation • Brings 30+ years of financial services experience • Banking Industry Veteran - Previously SVP of Investor Relations & Corporate Development at First Financial Bancorp (publicly traded bank holding company) • Former investment banker specializing in financial services sector • Began career at Price Waterhouse LLP DAVID B. BECKER Chairman and CEO NICOLE S. LORCH President, COO and Corporate Secretary KENNETH J. LOVIK EVP & CFO
Financial Review
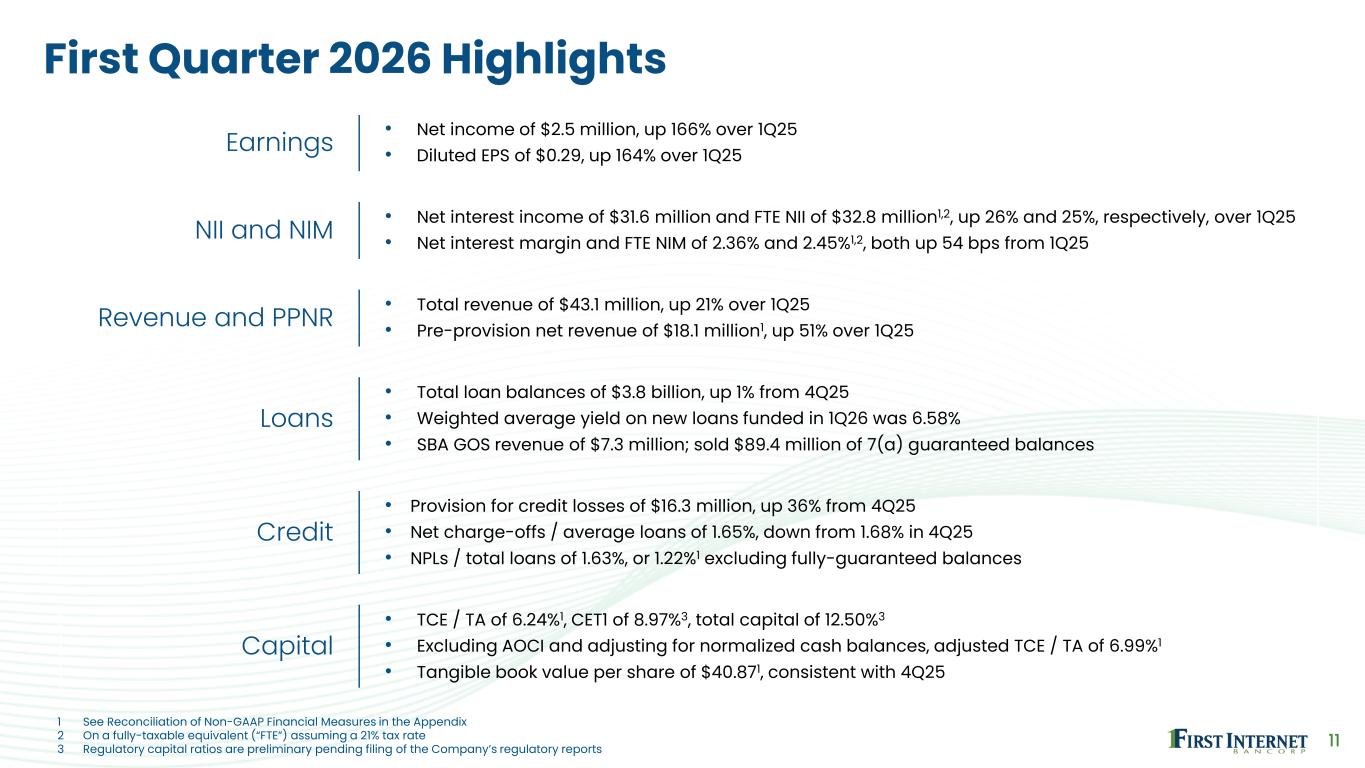
11 First Quarter 2026 Highlights Earnings • Net income of $2.5 million, up 166% over 1Q25 • Diluted EPS of $0.29, up 164% over 1Q25 NII and NIM • Net interest income of $31.6 million and FTE NII of $32.8 million1,2, up 26% and 25%, respectively, over 1Q25 • Net interest margin and FTE NIM of 2.36% and 2.45%1,2, both up 54 bps from 1Q25 Revenue and PPNR • Total revenue of $43.1 million, up 21% over 1Q25 • Pre-provision net revenue of $18.1 million1, up 51% over 1Q25 Loans • Total loan balances of $3.8 billion, up 1% from 4Q25 • Weighted average yield on new loans funded in 1Q26 was 6.58% • SBA GOS revenue of $7.3 million; sold $89.4 million of 7(a) guaranteed balances Credit • Provision for credit losses of $16.3 million, up 36% from 4Q25 • Net charge-offs / average loans of 1.65%, down from 1.68% in 4Q25 • NPLs / total loans of 1.63%, or 1.22%1 excluding fully-guaranteed balances Capital • TCE / TA of 6.24%1, CET1 of 8.97%3, total capital of 12.50%3 • Excluding AOCI and adjusting for normalized cash balances, adjusted TCE / TA of 6.99%1 • Tangible book value per share of $40.871, consistent with 4Q25 1 See Reconciliation of Non-GAAP Financial Measures in the Appendix 2 On a fully-taxable equivalent (“FTE”) assuming a 21% tax rate 3 Regulatory capital ratios are preliminary pending filing of the Company’s regulatory reports
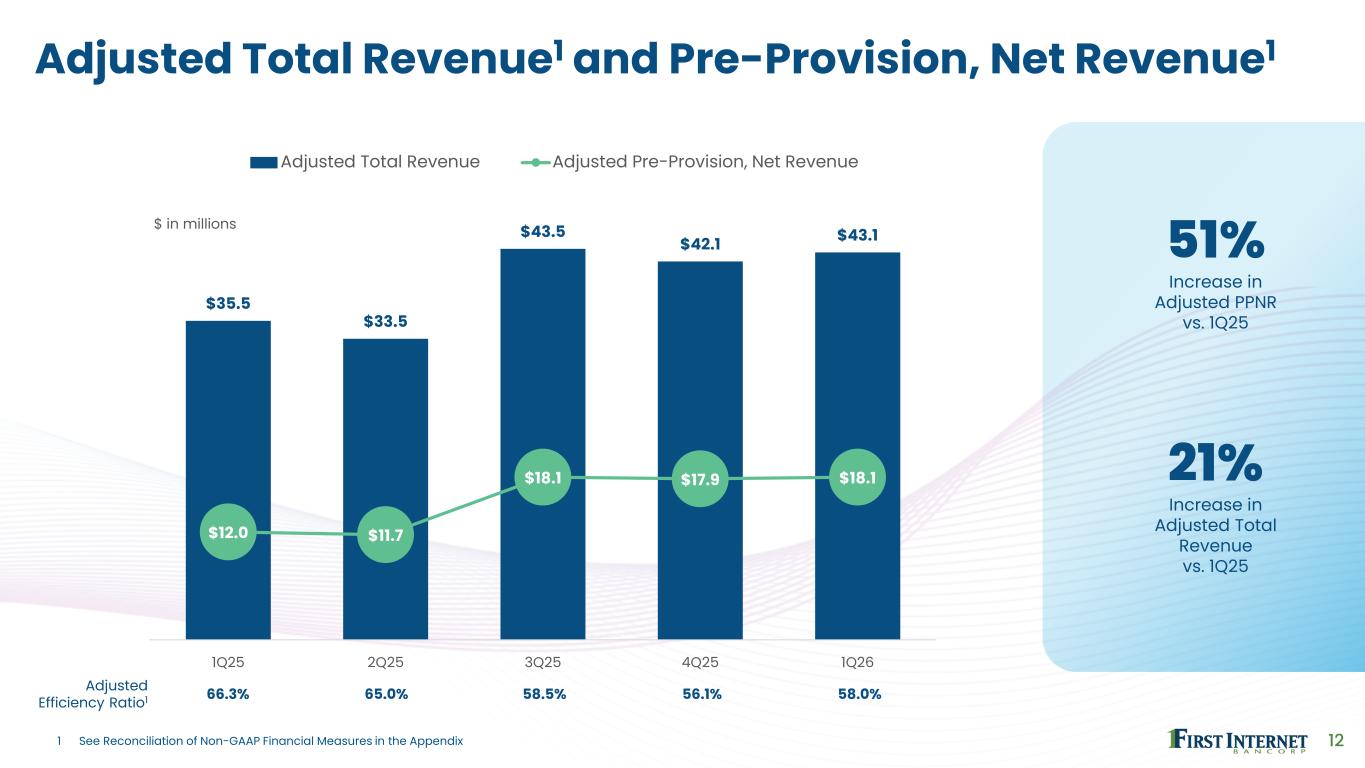
12 Adjusted Total Revenue1 and Pre-Provision, Net Revenue1 $35.5 $33.5 $43.5 $42.1 $43.1 $12.0 $11.7 $18.1 $17.9 $18.1 1Q25 2Q25 3Q25 4Q25 1Q26 Adjusted Total Revenue Adjusted Pre-Provision, Net Revenue Adjusted Efficiency Ratio1 66.3% 65.0% 58.5% 56.1% 58.0% 51% Increase in Adjusted PPNR vs. 1Q25 21% Increase in Adjusted Total Revenue vs. 1Q25 $ in millions 1 See Reconciliation of Non-GAAP Financial Measures in the Appendix
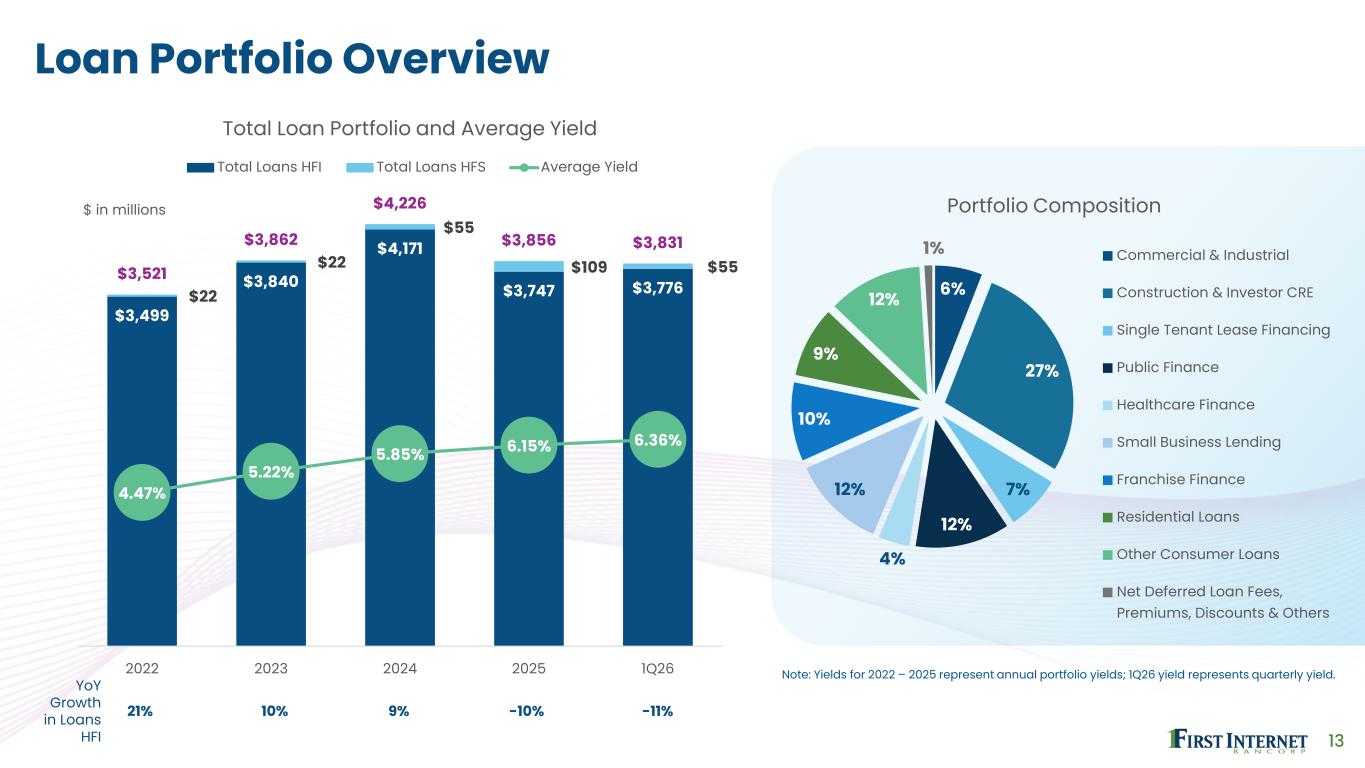
13 Loan Portfolio Overview $3,499 $3,840 $4,171 $3,747 $3,776 $22 $22 $55 $109 $55 $3,521 $3,862 $4,226 $3,856 $3,831 4.47% 5.22% 5.85% 6.15% 6.36% 2022 2023 2024 2025 1Q26 Total Loan Portfolio and Average Yield Total Loans HFI Total Loans HFS Average Yield 6% 27% 7% 12% 4% 12% 10% 9% 12% 1% Portfolio Composition Commercial & Industrial Construction & Investor CRE Single Tenant Lease Financing Public Finance Healthcare Finance Small Business Lending Franchise Finance Residential Loans Other Consumer Loans Net Deferred Loan Fees, Premiums, Discounts & Others YoY Growth in Loans HFI 21% 10% 9% -10% -11% $ in millions Note: Yields for 2022 – 2025 represent annual portfolio yields; 1Q26 yield represents quarterly yield.
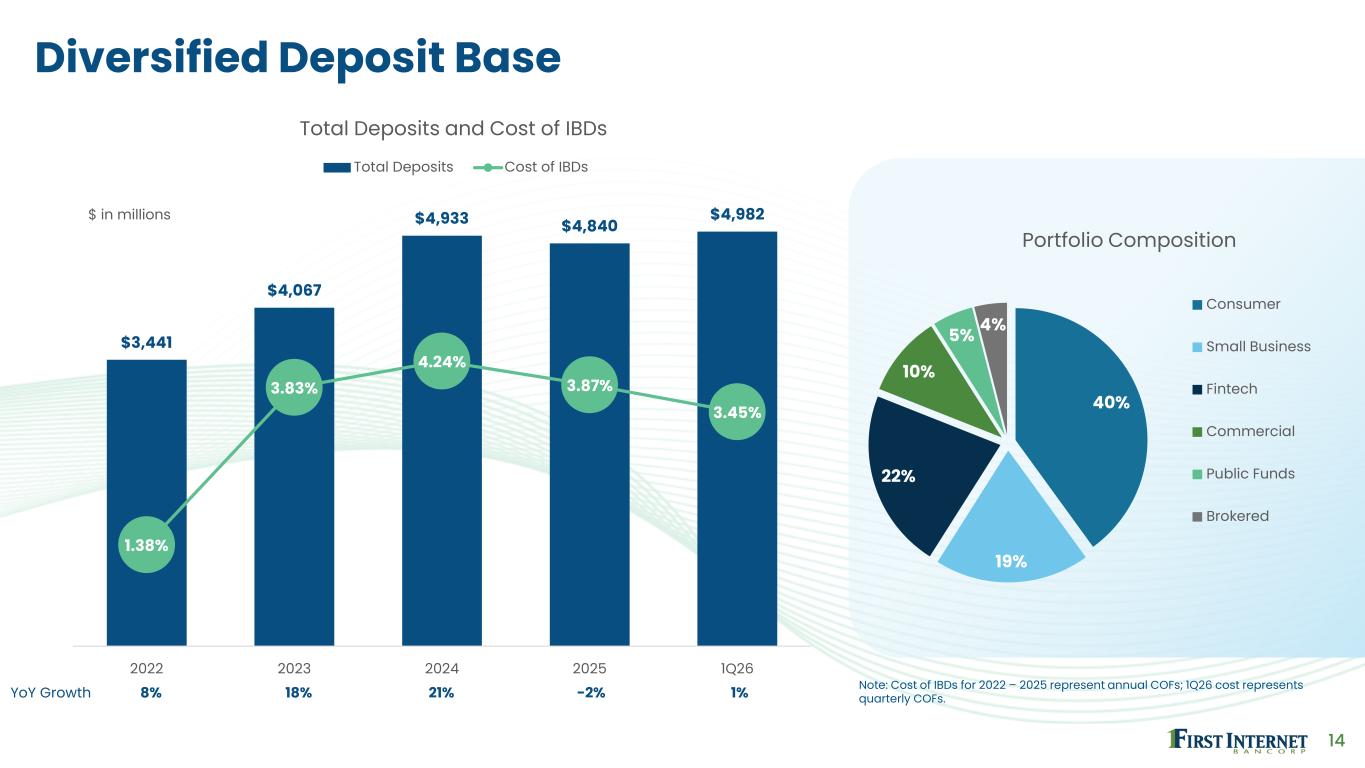
14 Diversified Deposit Base $3,441 $4,067 $4,933 $4,840 $4,982 1.38% 3.83% 4.24% 3.87% 3.45% 2022 2023 2024 2025 1Q26 Total Deposits and Cost of IBDs Total Deposits Cost of IBDs $ in millions 40% 19% 22% 10% 5% 4% Portfolio Composition Consumer Small Business Fintech Commercial Public Funds Brokered YoY Growth 8% 18% 21% -2% 1% Note: Cost of IBDs for 2022 – 2025 represent annual COFs; 1Q26 cost represents quarterly COFs.
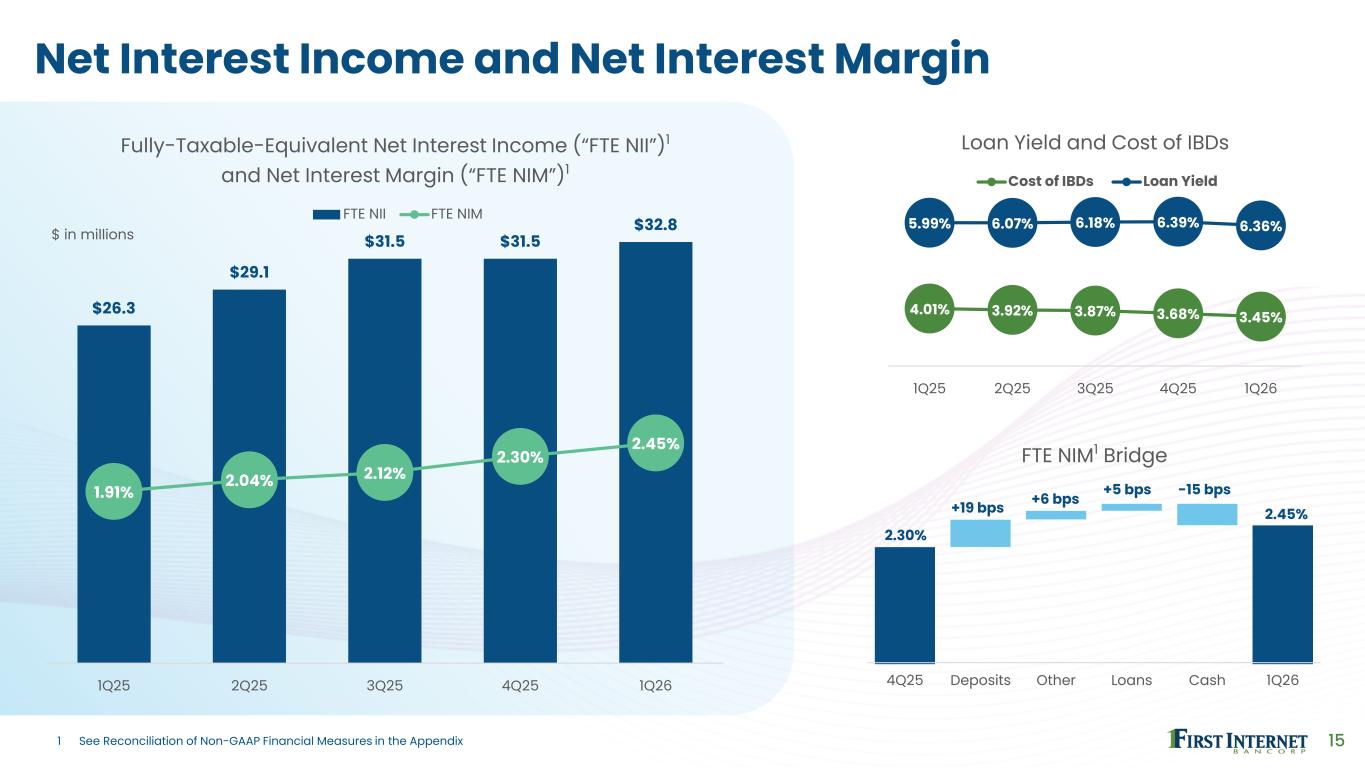
15 $26.3 $29.1 $31.5 $31.5 $32.8 1.91% 2.04% 2.12% 2.30% 2.45% 1Q25 2Q25 3Q25 4Q25 1Q26 Fully-Taxable-Equivalent Net Interest Income (“FTE NII”)1 and Net Interest Margin (“FTE NIM”)1 FTE NII FTE NIM 4.01% 3.92% 3.87% 3.68% 3.45% 5.99% 6.07% 6.18% 6.39% 6.36% 1Q25 2Q25 3Q25 4Q25 1Q26 Loan Yield and Cost of IBDs Cost of IBDs Loan Yield 4Q25 Deposits Other Loans Cash 1Q26 Net Interest Income and Net Interest Margin 2.30% -15 bps+6 bps +5 bps 2.45%+19 bps FTE NIM1 Bridge $ in millions 1 See Reconciliation of Non-GAAP Financial Measures in the Appendix
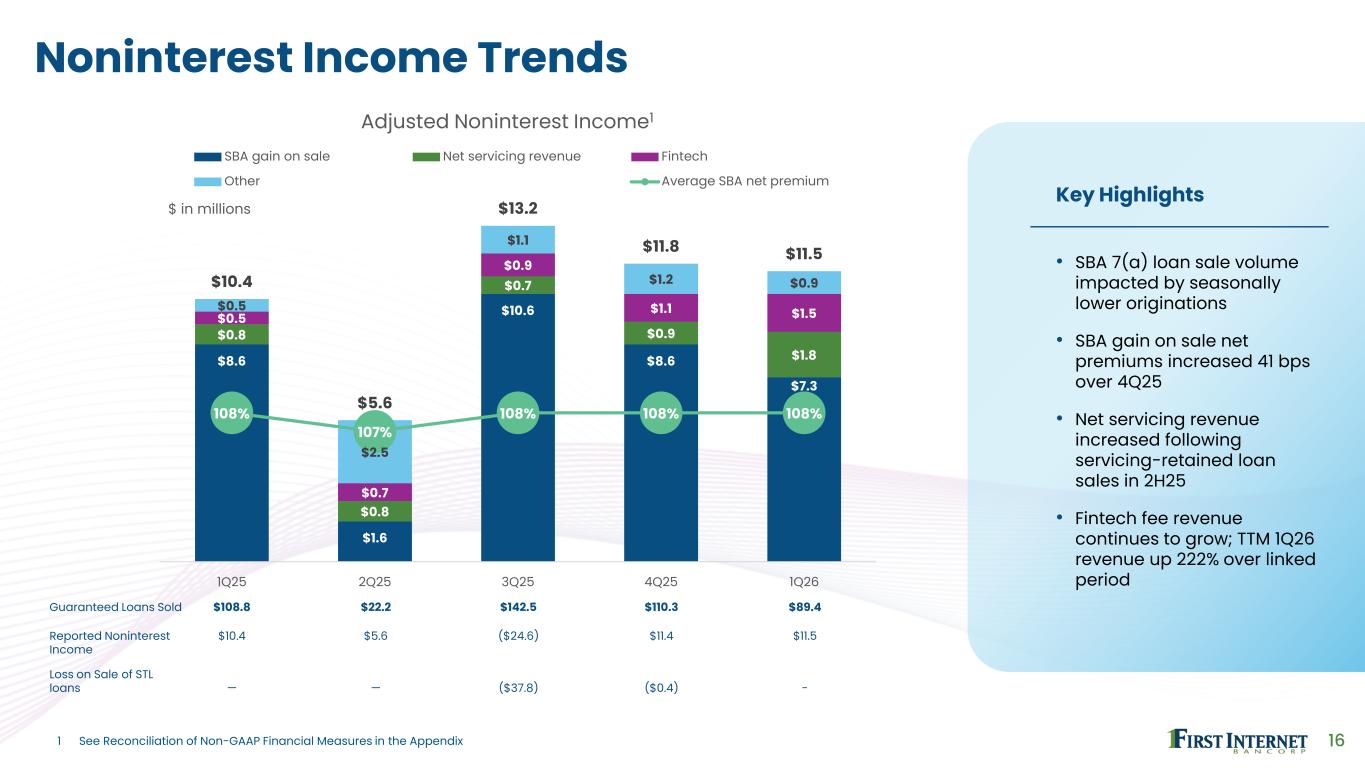
16 Noninterest Income Trends 1 See Reconciliation of Non-GAAP Financial Measures in the Appendix $ in millions Key Highlights • SBA 7(a) loan sale volume impacted by seasonally lower originations • SBA gain on sale net premiums increased 41 bps over 4Q25 • Net servicing revenue increased following servicing-retained loan sales in 2H25 • Fintech fee revenue continues to grow; TTM 1Q26 revenue up 222% over linked period Guaranteed Loans Sold $108.8 $22.2 $142.5 $110.3 $89.4 Reported Noninterest Income $10.4 $5.6 ($24.6) $11.4 $11.5 Loss on Sale of STL loans — — ($37.8) ($0.4) - $8.6 $1.6 $10.6 $8.6 $7.3 $0.8 $0.8 $0.7 $0.9 $1.8 $0.5 $0.7 $0.9 $1.1 $1.5$0.5 $2.5 $1.1 $1.2 $0.9$10.4 $5.6 $13.2 $11.8 $11.5 108% 107% 108% 108% 108% 1Q25 2Q25 3Q25 4Q25 1Q26 Adjusted Noninterest Income1 SBA gain on sale Net servicing revenue Fintech Other Average SBA net premium
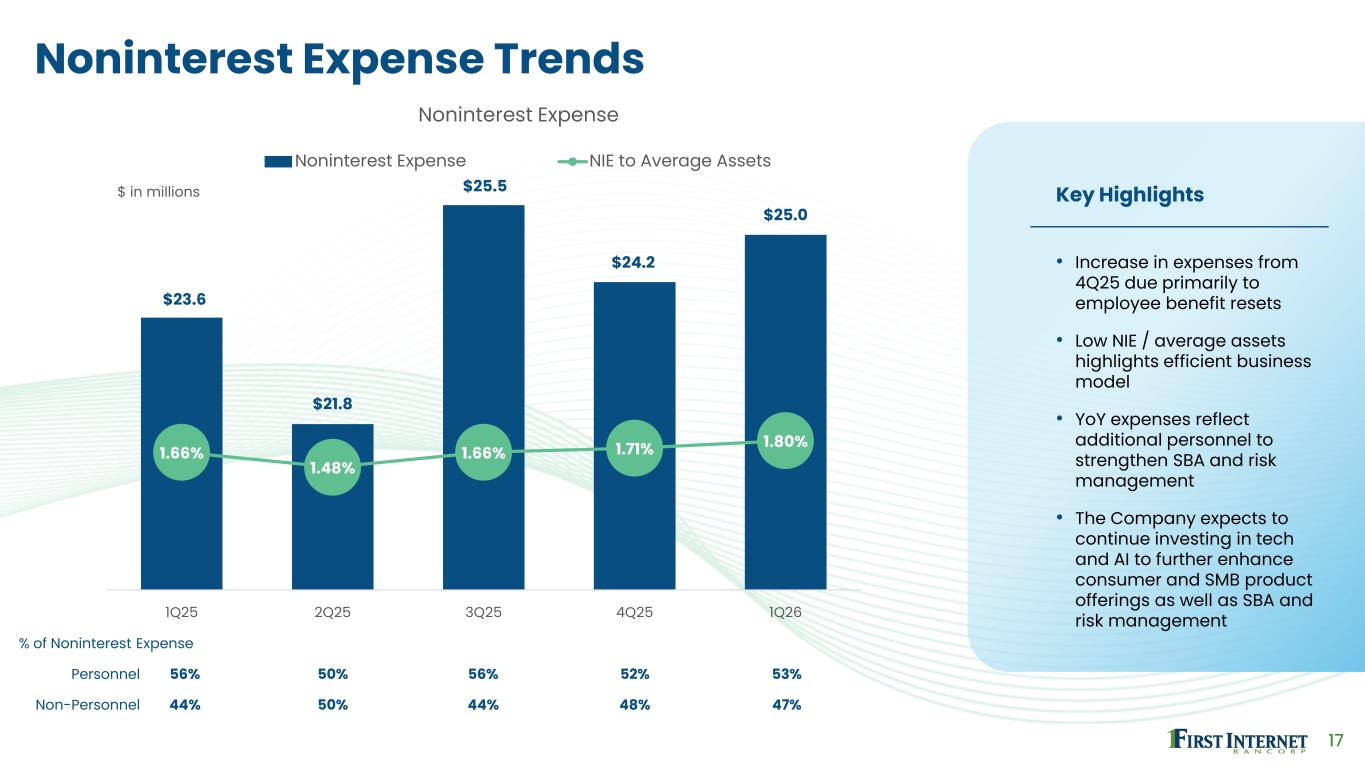
17 Noninterest Expense Trends $23.6 $21.8 $25.5 $24.2 $25.0 1.66% 1.48% 1.66% 1.71% 1.80% 1Q25 2Q25 3Q25 4Q25 1Q26 Noninterest Expense Noninterest Expense NIE to Average Assets $ in millions Key Highlights • Increase in expenses from 4Q25 due primarily to employee benefit resets • Low NIE / average assets highlights efficient business model • YoY expenses reflect additional personnel to strengthen SBA and risk management • The Company expects to continue investing in tech and AI to further enhance consumer and SMB product offerings as well as SBA and risk management % of Noninterest Expense Personnel 56% 50% 56% 52% 53% Non-Personnel 44% 50% 44% 48% 47%
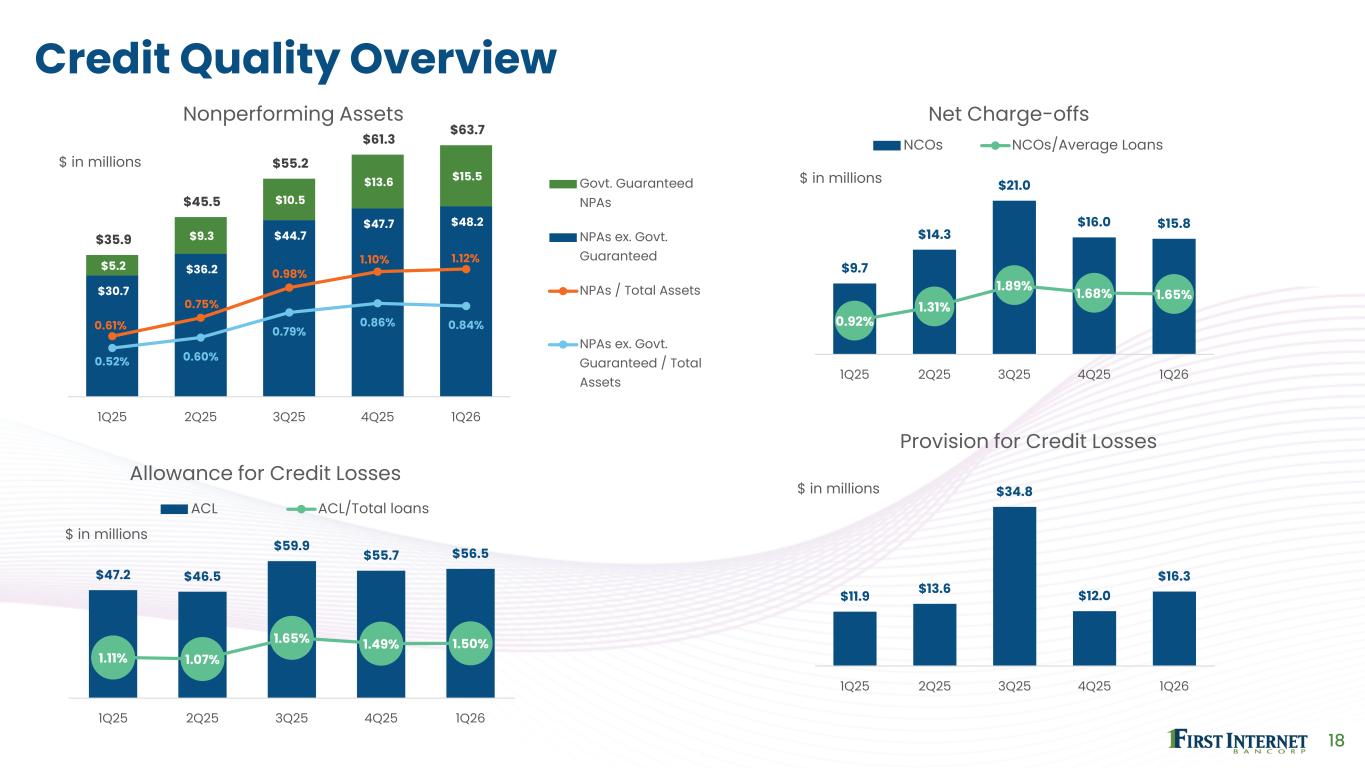
18 Credit Quality Overview $47.2 $46.5 $59.9 $55.7 $56.5 1.11% 1.07% 1.65% 1.49% 1.50% 1Q25 2Q25 3Q25 4Q25 1Q26 Allowance for Credit Losses ACL ACL/Total loans $ in millions $9.7 $14.3 $21.0 $16.0 $15.8 0.92% 1.31% 1.89% 1.68% 1.65% 1Q25 2Q25 3Q25 4Q25 1Q26 Net Charge-offs NCOs NCOs/Average Loans $ in millions $11.9 $13.6 $34.8 $12.0 $16.3 1Q25 2Q25 3Q25 4Q25 1Q26 Provision for Credit Losses $ in millions $ in millions $30.7 $36.2 $44.7 $47.7 $48.2 $5.2 $9.3 $10.5 $13.6 $15.5 $35.9 $45.5 $55.2 $61.3 $63.7 0.61% 0.75% 0.98% 1.10% 1.12% 0.52% 0.60% 0.79% 0.86% 0.84% 1Q25 2Q25 3Q25 4Q25 1Q26 Nonperforming Assets Govt. Guaranteed NPAs NPAs ex. Govt. Guaranteed NPAs / Total Assets NPAs ex. Govt. Guaranteed / Total Assets
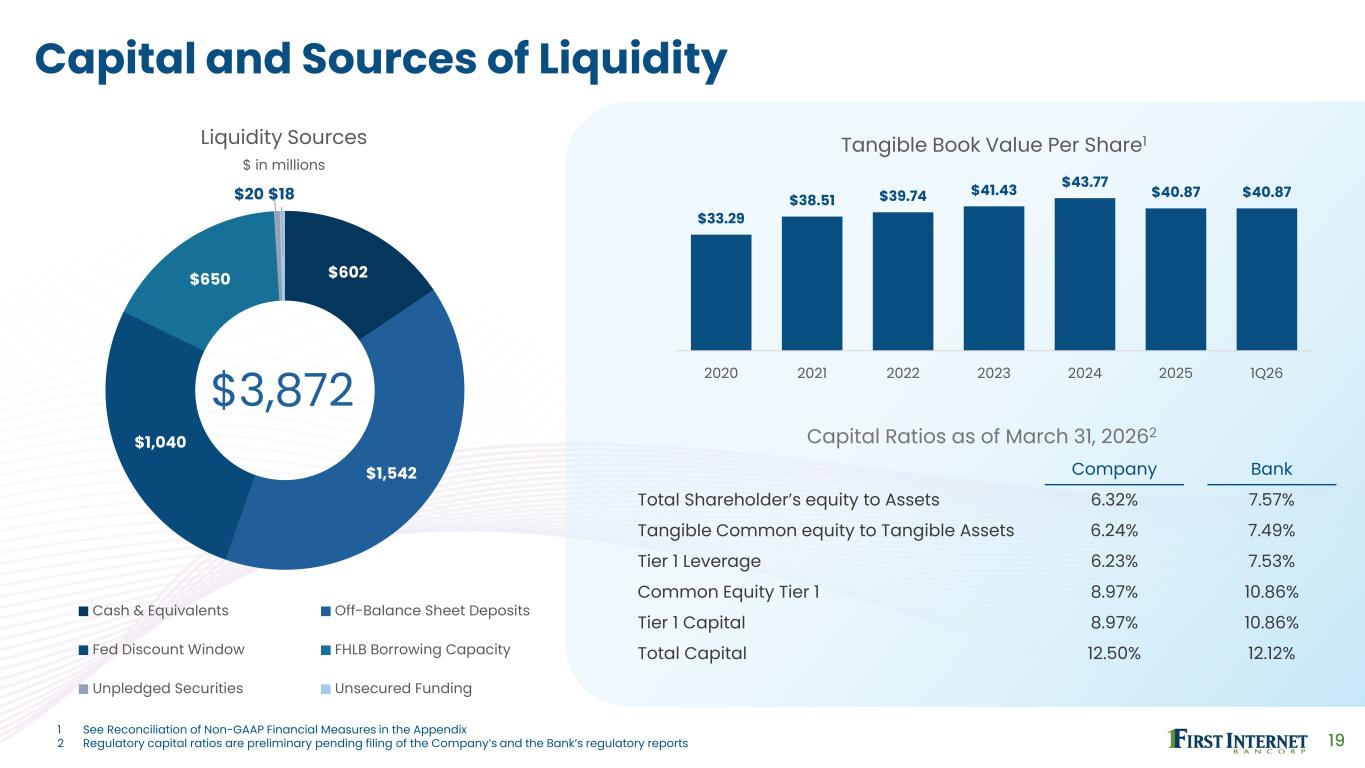
19 Capital and Sources of Liquidity $33.29 $38.51 $39.74 $41.43 $43.77 $40.87 $40.87 2020 2021 2022 2023 2024 2025 1Q26 Tangible Book Value Per Share1 Capital Ratios as of March 31, 20262 Company Bank Total Shareholder’s equity to Assets 6.32% 7.57% Tangible Common equity to Tangible Assets 6.24% 7.49% Tier 1 Leverage 6.23% 7.53% Common Equity Tier 1 8.97% 10.86% Tier 1 Capital 8.97% 10.86% Total Capital 12.50% 12.12% $602 $1,542 $1,040 $650 $20 $18 Liquidity Sources $ in millions Cash & Equivalents Off-Balance Sheet Deposits Fed Discount Window FHLB Borrowing Capacity Unpledged Securities Unsecured Funding $3,872 1 See Reconciliation of Non-GAAP Financial Measures in the Appendix 2 Regulatory capital ratios are preliminary pending filing of the Company’s and the Bank’s regulatory reports
20 2026 Outlook • The Company is broadly maintaining its 2026 guidance. However, management acknowledges the heightened macroeconomic uncertainty, including volatile energy prices and other geopolitical developments, which could have negative impacts. • Regarding loan growth specifically, while commercial pipelines remain robust, the Company recognizes that the full-year target of 15-17% may prove ambitious due to higher-than-expected loan payoffs and potential further tightening of underwriting standards due to macro uncertainties.
Appendix
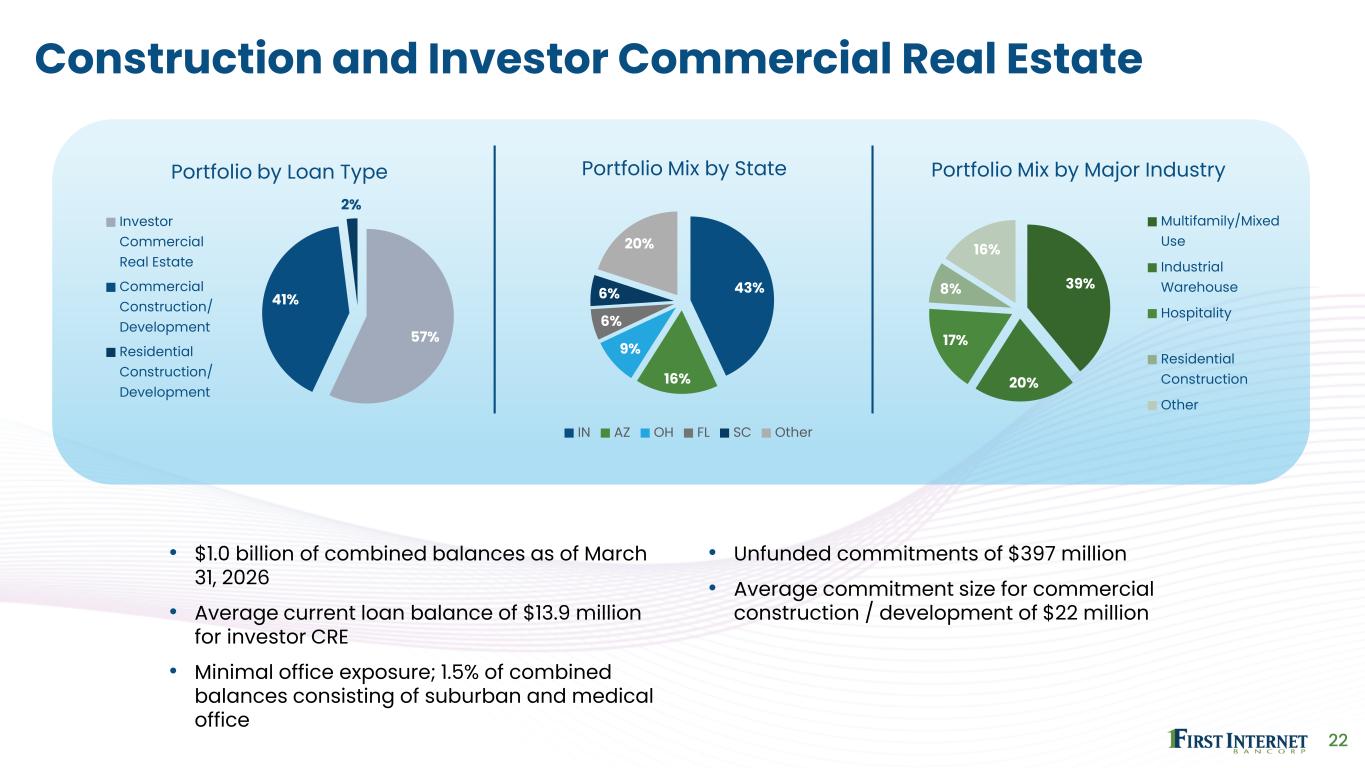
22 Construction and Investor Commercial Real Estate 43% 16% 9% 6% 6% 20% Portfolio Mix by State IN AZ OH FL SC Other 57% 41% 2% Portfolio by Loan Type Investor Commercial Real Estate Commercial Construction/ Development Residential Construction/ Development 39% 20% 17% 8% 16% Portfolio Mix by Major Industry Multifamily/Mixed Use Industrial Warehouse Hospitality Residential Construction Other • $1.0 billion of combined balances as of March 31, 2026 • Average current loan balance of $13.9 million for investor CRE • Minimal office exposure; 1.5% of combined balances consisting of suburban and medical office • Unfunded commitments of $397 million • Average commitment size for commercial construction / development of $22 million
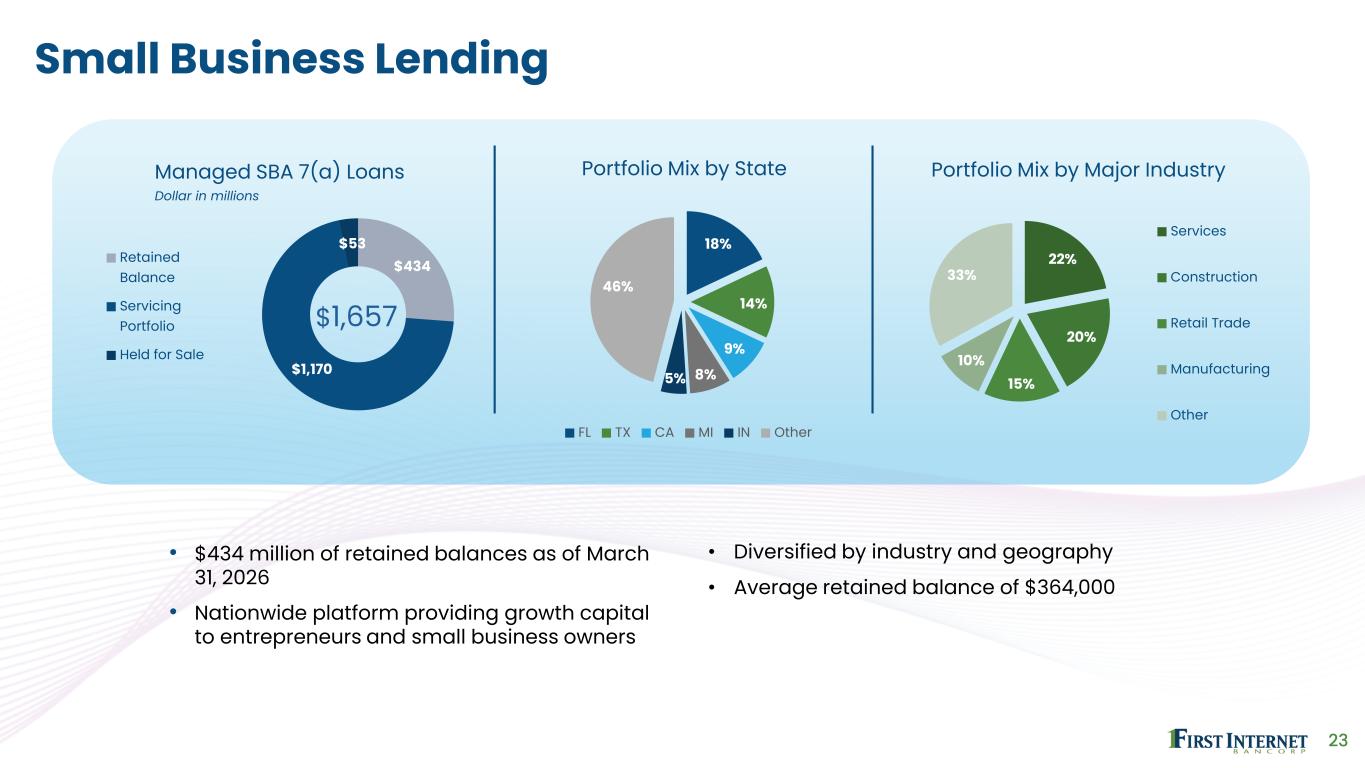
23 Small Business Lending 22% 20% 15% 10% 33% Portfolio Mix by Major Industry Services Construction Retail Trade Manufacturing Other $434 $1,170 $53 Managed SBA 7(a) Loans Dollar in millions Retained Balance Servicing Portfolio Held for Sale $1,657 18% 14% 9% 8%5% 46% Portfolio Mix by State FL TX CA MI IN Other • $434 million of retained balances as of March 31, 2026 • Nationwide platform providing growth capital to entrepreneurs and small business owners • Diversified by industry and geography • Average retained balance of $364,000
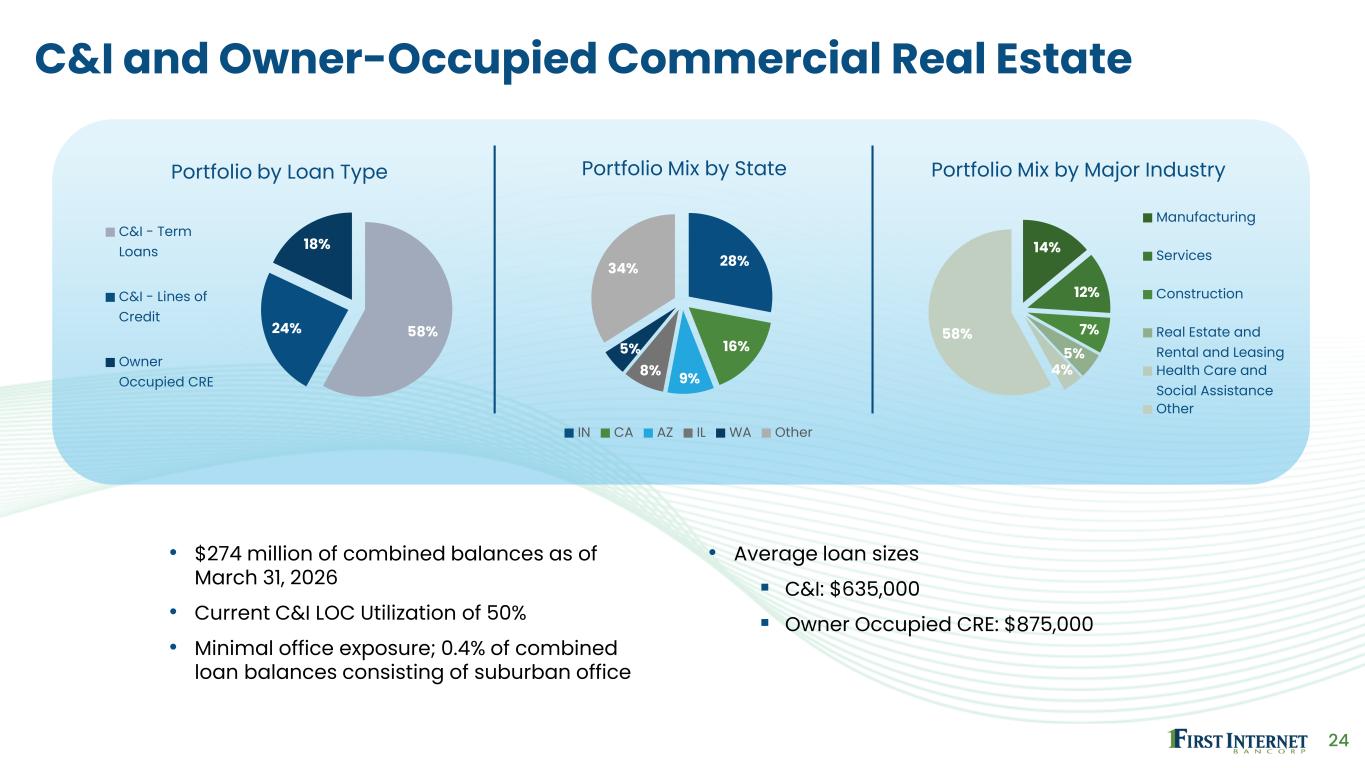
24 C&I and Owner-Occupied Commercial Real Estate • $274 million of combined balances as of March 31, 2026 • Current C&I LOC Utilization of 50% • Minimal office exposure; 0.4% of combined loan balances consisting of suburban office • Average loan sizes C&I: $635,000 Owner Occupied CRE: $875,000 58%24% 18% Portfolio by Loan Type C&I - Term Loans C&I - Lines of Credit Owner Occupied CRE 28% 16% 9%8% 5% 34% Portfolio Mix by State IN CA AZ IL WA Other 14% 12% 7% 5% 4% 58% Portfolio Mix by Major Industry Manufacturing Services Construction Real Estate and Rental and Leasing Health Care and Social Assistance Other
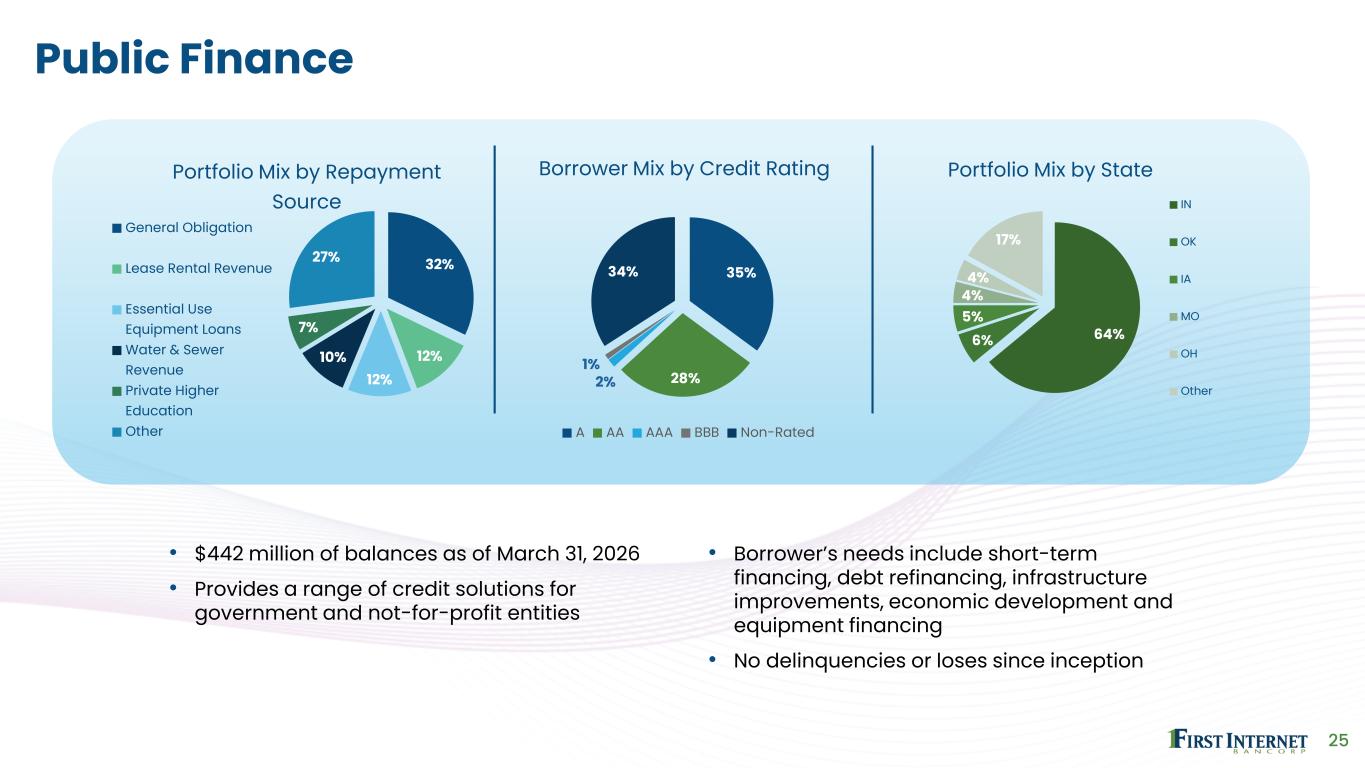
25 Public Finance • $442 million of balances as of March 31, 2026 • Provides a range of credit solutions for government and not-for-profit entities • Borrower’s needs include short-term financing, debt refinancing, infrastructure improvements, economic development and equipment financing • No delinquencies or loses since inception 32% 12% 12% 10% 7% 27% Portfolio Mix by Repayment Source General Obligation Lease Rental Revenue Essential Use Equipment Loans Water & Sewer Revenue Private Higher Education Other 35% 28%2% 1% 34% Borrower Mix by Credit Rating A AA AAA BBB Non-Rated 64%6% 5% 4% 4% 17% Portfolio Mix by State IN OK IA MO OH Other
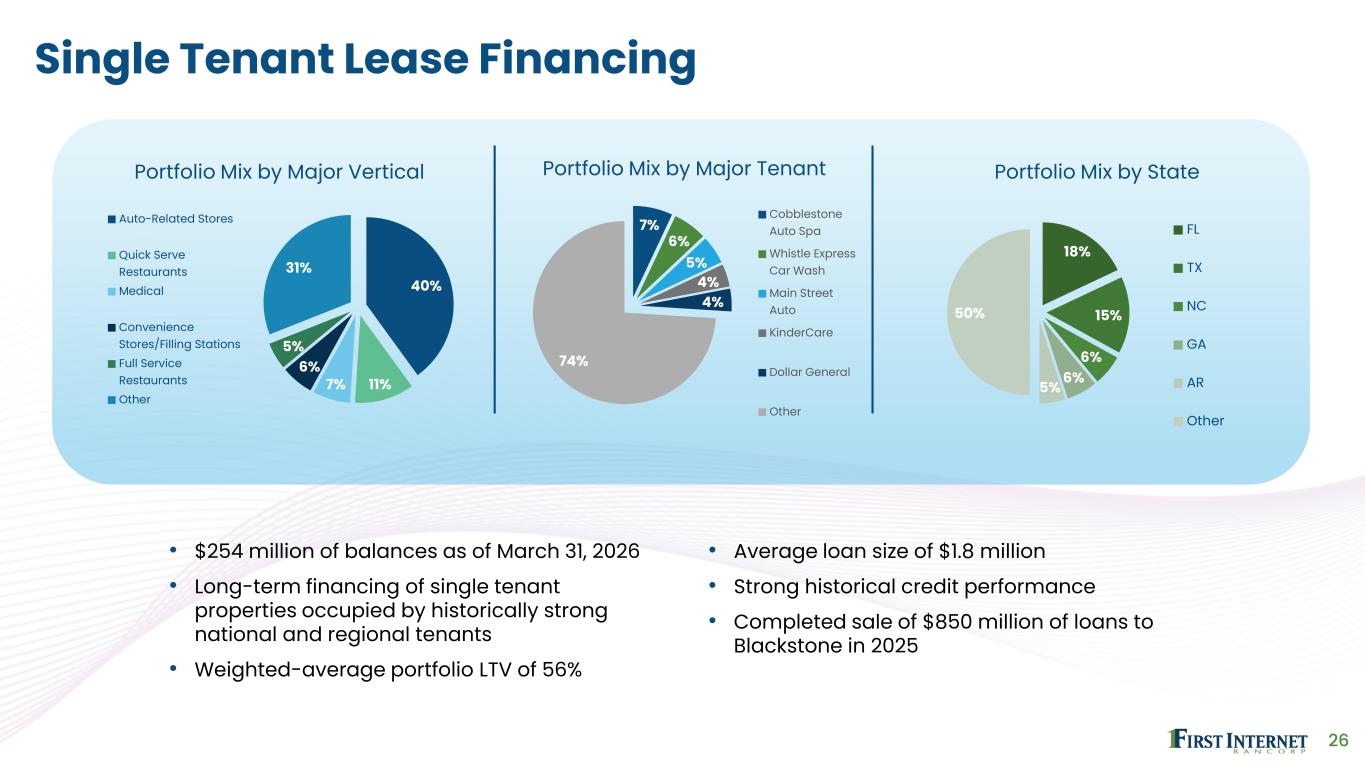
26 Single Tenant Lease Financing • $254 million of balances as of March 31, 2026 • Long-term financing of single tenant properties occupied by historically strong national and regional tenants • Weighted-average portfolio LTV of 56% • Average loan size of $1.8 million • Strong historical credit performance • Completed sale of $850 million of loans to Blackstone in 2025 40% 11%7% 6% 5% 31% Portfolio Mix by Major Vertical Auto-Related Stores Quick Serve Restaurants Medical Convenience Stores/Filling Stations Full Service Restaurants Other 7% 6% 5% 4% 4% 74% Portfolio Mix by Major Tenant Cobblestone Auto Spa Whistle Express Car Wash Main Street Auto KinderCare Dollar General Other 18% 15% 6% 6%5% 50% Portfolio Mix by State FL TX NC GA AR Other
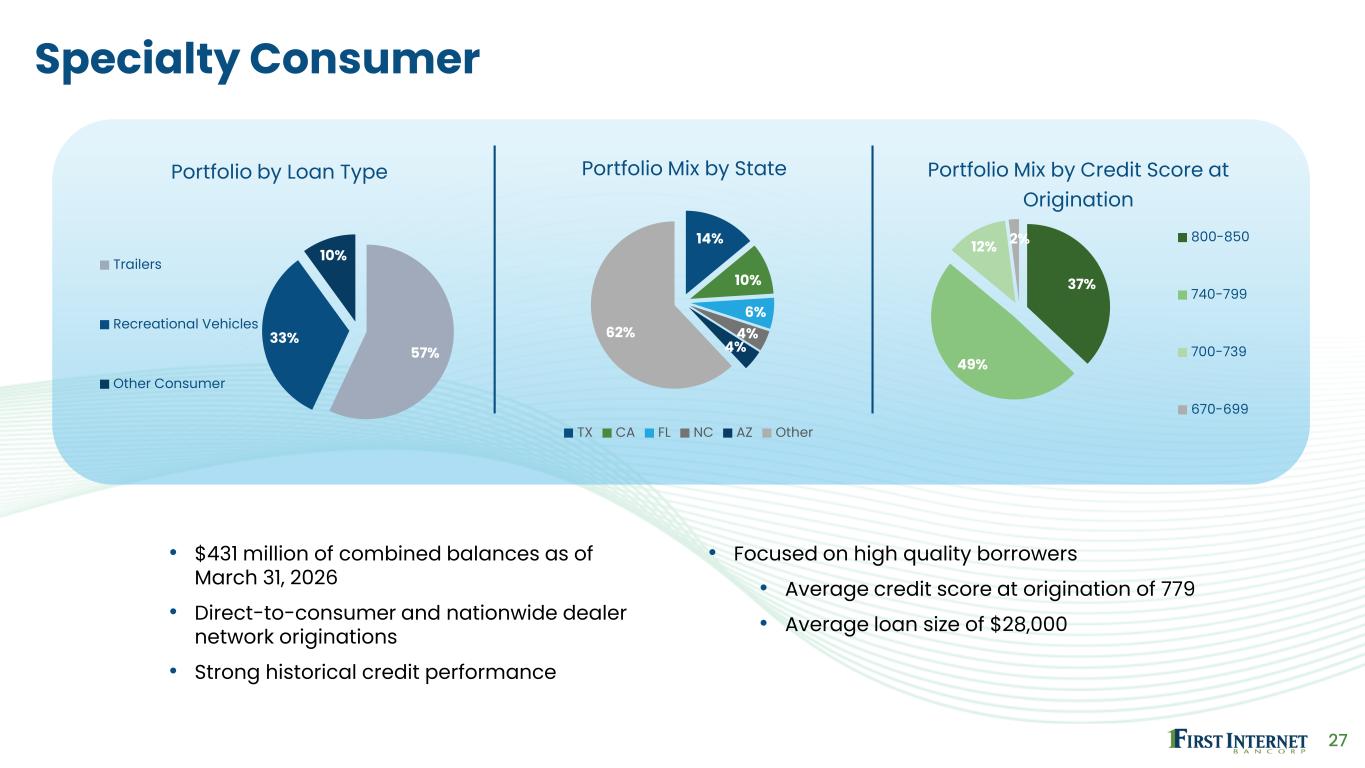
27 Specialty Consumer • $431 million of combined balances as of March 31, 2026 • Direct-to-consumer and nationwide dealer network originations • Strong historical credit performance • Focused on high quality borrowers • Average credit score at origination of 779 • Average loan size of $28,000 57% 33% 10% Portfolio by Loan Type Trailers Recreational Vehicles Other Consumer 14% 10% 6% 4% 4% 62% Portfolio Mix by State TX CA FL NC AZ Other 37% 49% 12% 2% Portfolio Mix by Credit Score at Origination 800-850 740-799 700-739 670-699
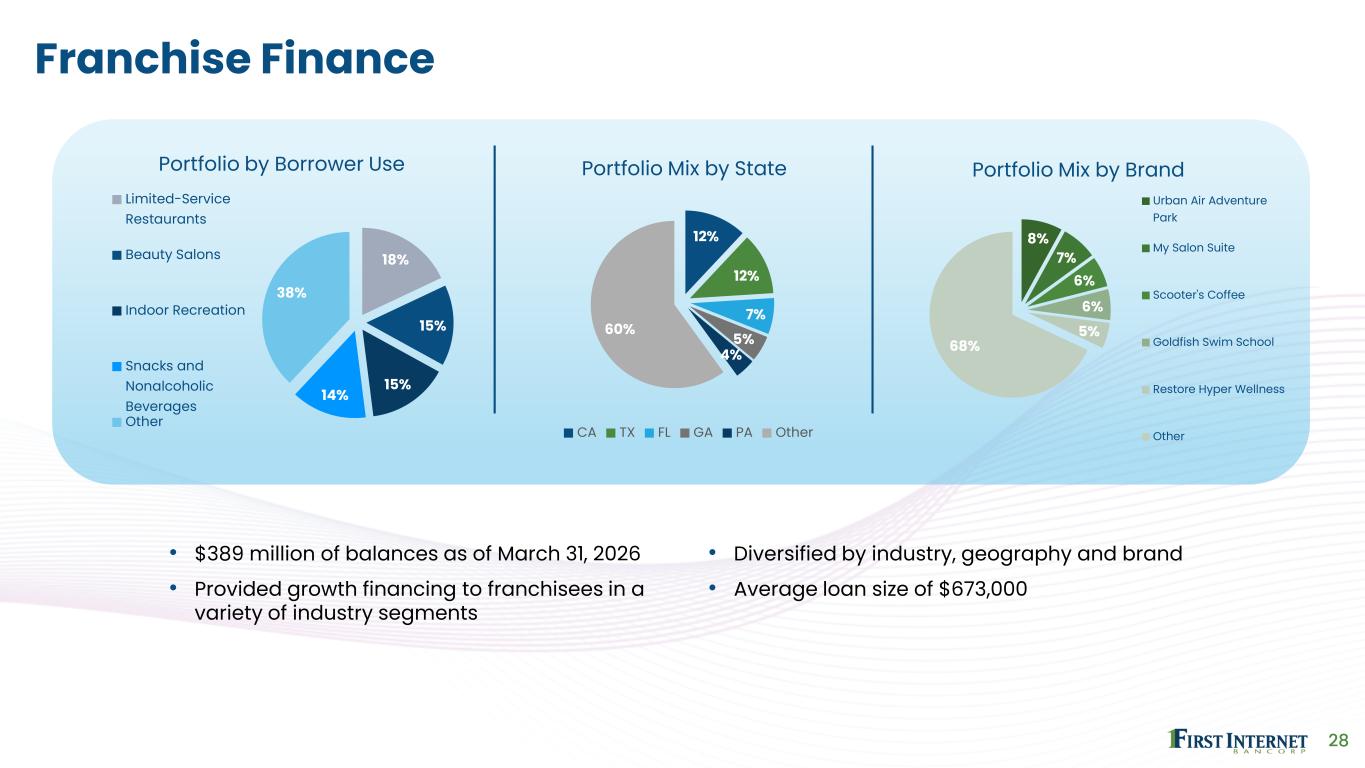
28 Franchise Finance • $389 million of balances as of March 31, 2026 • Provided growth financing to franchisees in a variety of industry segments • Diversified by industry, geography and brand • Average loan size of $673,000 18% 15% 15% 14% 38% Portfolio by Borrower Use Limited-Service Restaurants Beauty Salons Indoor Recreation Snacks and Nonalcoholic Beverages Other 12% 12% 7% 5% 4% 60% Portfolio Mix by State CA TX FL GA PA Other 8% 7% 6% 6% 5% 68% Portfolio Mix by Brand Urban Air Adventure Park My Salon Suite Scooter's Coffee Goldfish Swim School Restore Hyper Wellness Other
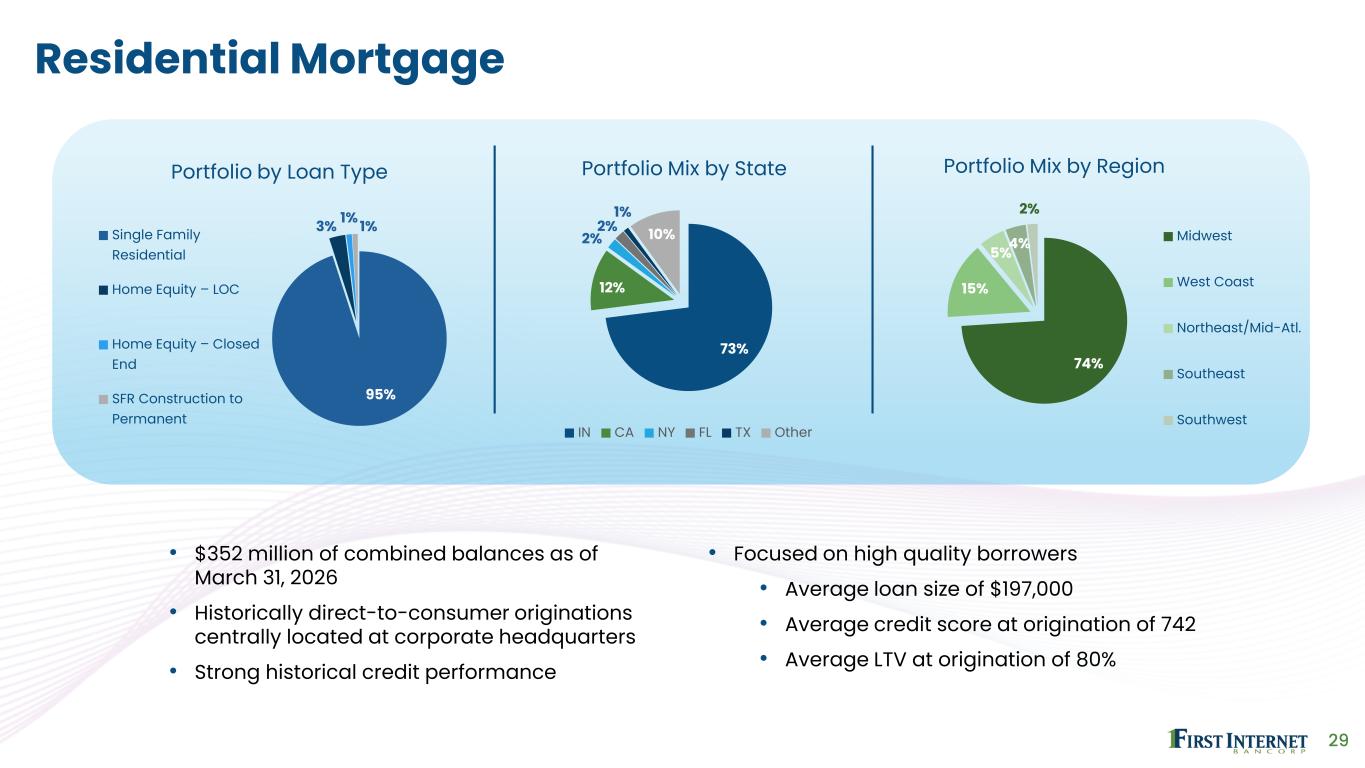
29 Residential Mortgage • $352 million of combined balances as of March 31, 2026 • Historically direct-to-consumer originations centrally located at corporate headquarters • Strong historical credit performance • Focused on high quality borrowers • Average loan size of $197,000 • Average credit score at origination of 742 • Average LTV at origination of 80% 95% 3% 1% 1% Portfolio by Loan Type Single Family Residential Home Equity – LOC Home Equity – Closed End SFR Construction to Permanent 73% 12% 2% 2% 1% 10% Portfolio Mix by State IN CA NY FL TX Other 74% 15% 5%4% 2% Portfolio Mix by Region Midwest West Coast Northeast/Mid-Atl. Southeast Southwest
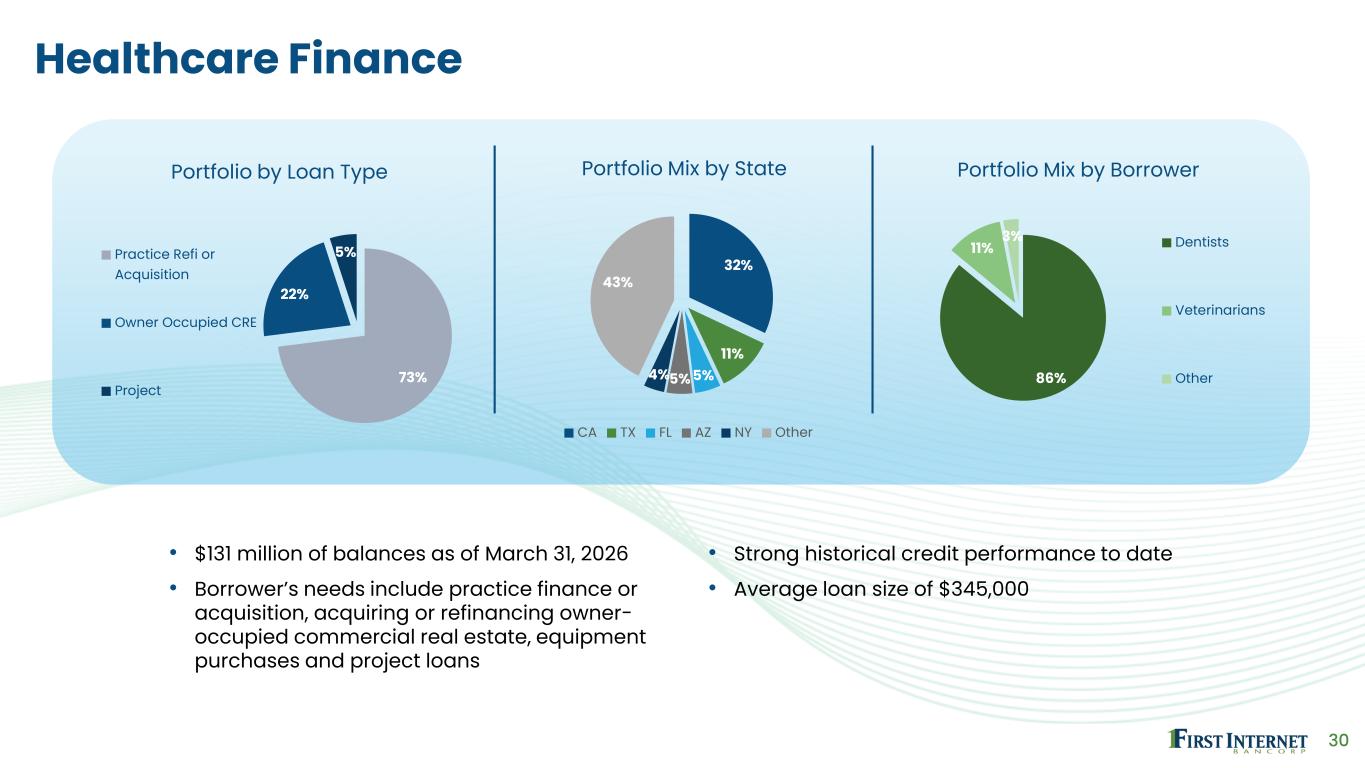
30 Healthcare Finance • $131 million of balances as of March 31, 2026 • Borrower’s needs include practice finance or acquisition, acquiring or refinancing owner- occupied commercial real estate, equipment purchases and project loans • Strong historical credit performance to date • Average loan size of $345,000 73% 22% 5% Portfolio by Loan Type Practice Refi or Acquisition Owner Occupied CRE Project 32% 11% 5%5%4% 43% Portfolio Mix by State CA TX FL AZ NY Other 86% 11% 3% Portfolio Mix by Borrower Dentists Veterinarians Other
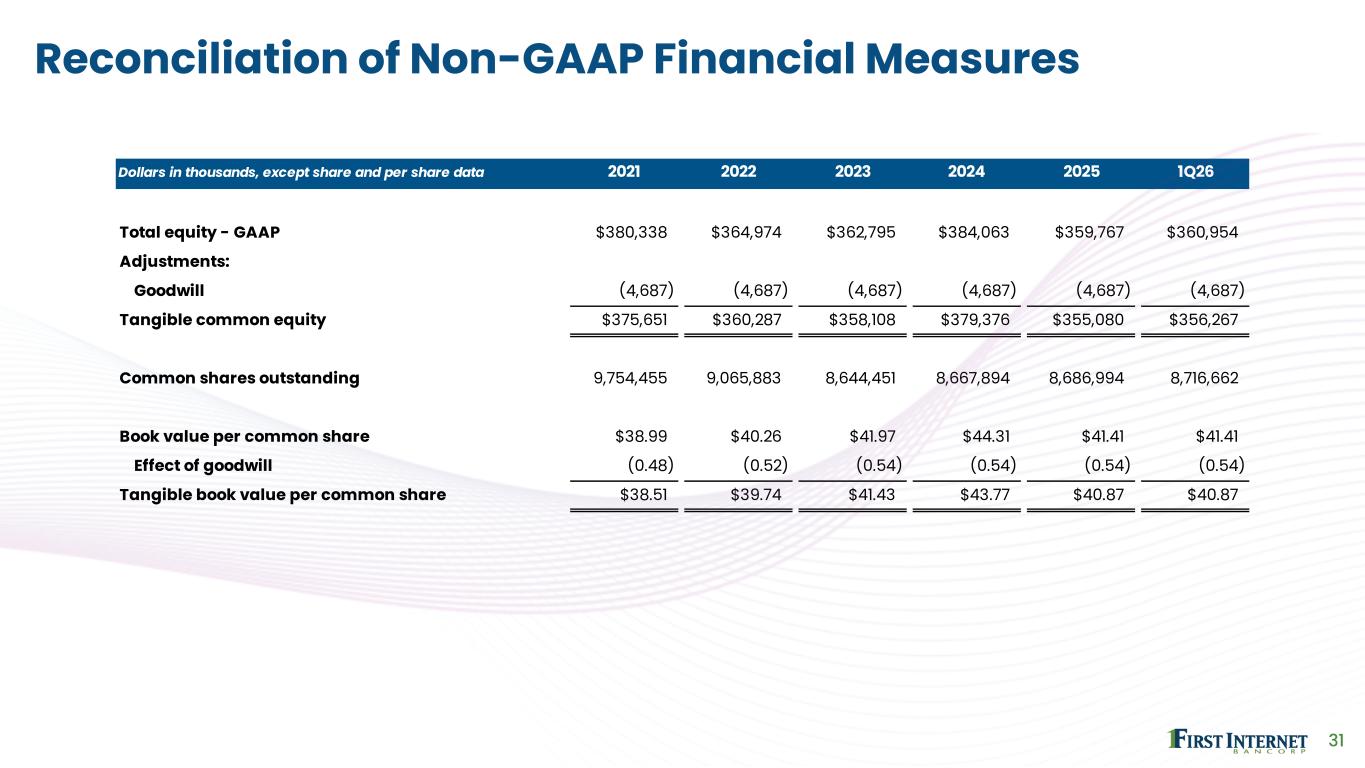
Dollars in thousands, except share and per share data 2021 2022 2023 2024 2025 1Q26 Total equity - GAAP $380,338 $364,974 $362,795 $384,063 $359,767 $360,954 Adjustments: Goodwill (4,687) (4,687) (4,687) (4,687) (4,687) (4,687) Tangible common equity $375,651 $360,287 $358,108 $379,376 $355,080 $356,267 Common shares outstanding 9,754,455 9,065,883 8,644,451 8,667,894 8,686,994 8,716,662 Book value per common share $38.99 $40.26 $41.97 $44.31 $41.41 $41.41 Effect of goodwill (0.48) (0.52) (0.54) (0.54) (0.54) (0.54) Tangible book value per common share $38.51 $39.74 $41.43 $43.77 $40.87 $40.87 31 Reconciliation of Non-GAAP Financial Measures
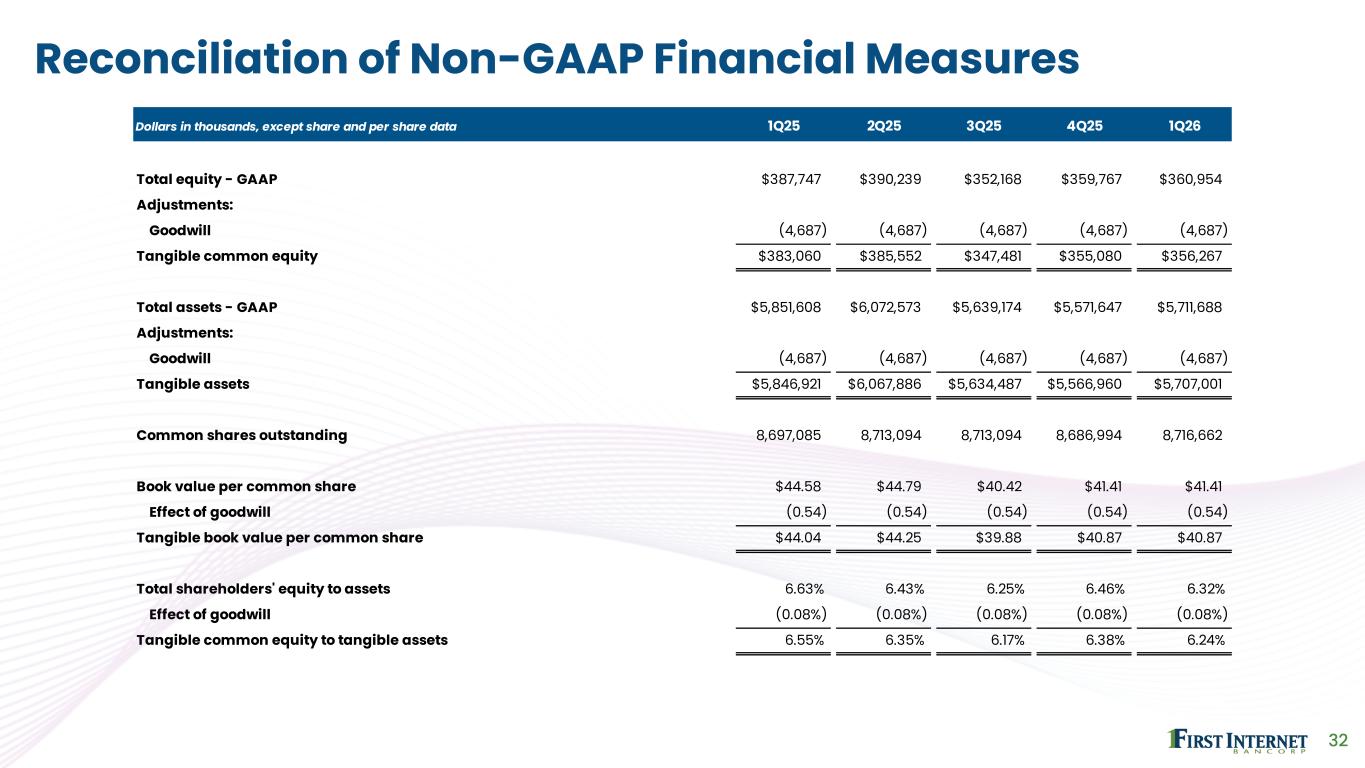
Dollars in thousands, except share and per share data 1Q25 2Q25 3Q25 4Q25 1Q26 Total equity - GAAP $387,747 $390,239 $352,168 $359,767 $360,954 Adjustments: Goodwill (4,687) (4,687) (4,687) (4,687) (4,687) Tangible common equity $383,060 $385,552 $347,481 $355,080 $356,267 Total assets - GAAP $5,851,608 $6,072,573 $5,639,174 $5,571,647 $5,711,688 Adjustments: Goodwill (4,687) (4,687) (4,687) (4,687) (4,687) Tangible assets $5,846,921 $6,067,886 $5,634,487 $5,566,960 $5,707,001 Common shares outstanding 8,697,085 8,713,094 8,713,094 8,686,994 8,716,662 Book value per common share $44.58 $44.79 $40.42 $41.41 $41.41 Effect of goodwill (0.54) (0.54) (0.54) (0.54) (0.54) Tangible book value per common share $44.04 $44.25 $39.88 $40.87 $40.87 Total shareholders' equity to assets 6.63% 6.43% 6.25% 6.46% 6.32% Effect of goodwill (0.08%) (0.08%) (0.08%) (0.08%) (0.08%) Tangible common equity to tangible assets 6.55% 6.35% 6.17% 6.38% 6.24% 32 Reconciliation of Non-GAAP Financial Measures
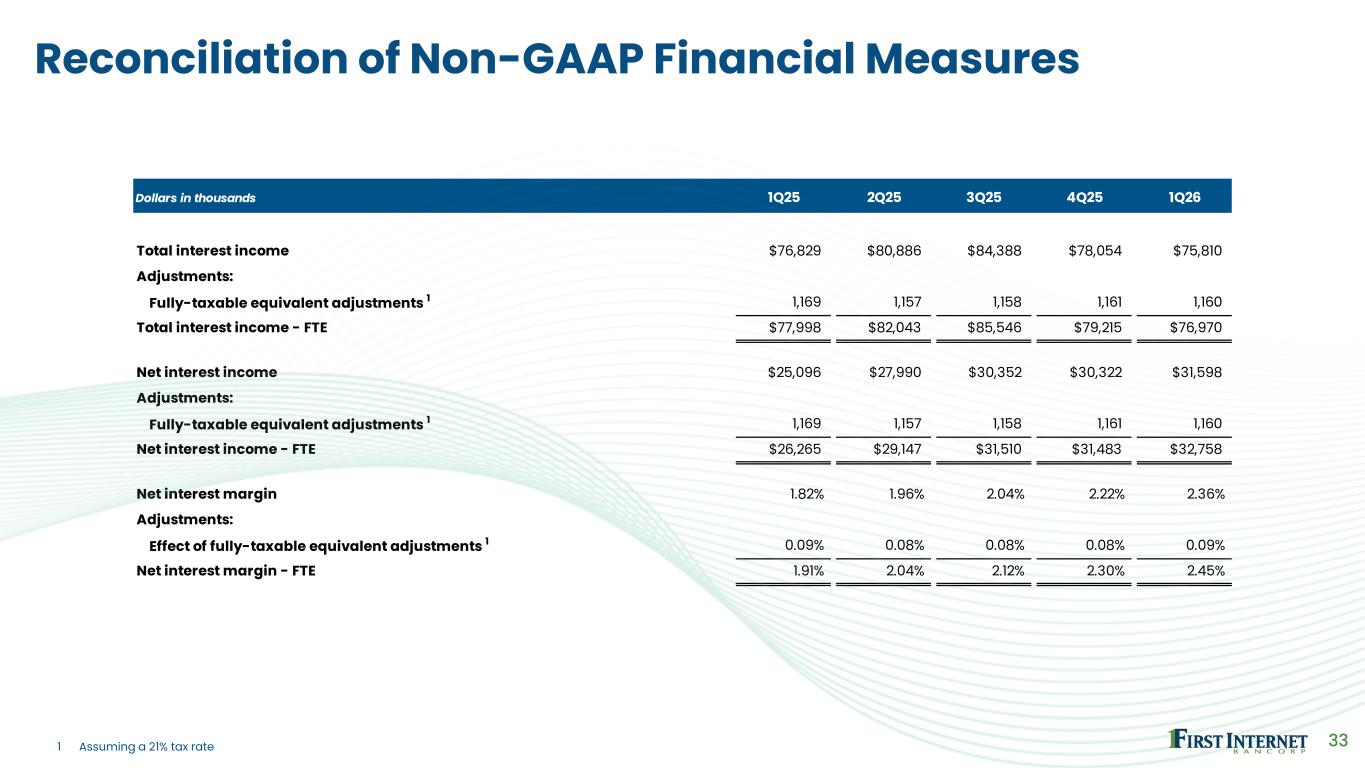
Dollars in thousands 1Q25 2Q25 3Q25 4Q25 1Q26 Total interest income $76,829 $80,886 $84,388 $78,054 $75,810 Adjustments: Fully-taxable equivalent adjustments 1 1,169 1,157 1,158 1,161 1,160 Total interest income - FTE $77,998 $82,043 $85,546 $79,215 $76,970 Net interest income $25,096 $27,990 $30,352 $30,322 $31,598 Adjustments: Fully-taxable equivalent adjustments 1 1,169 1,157 1,158 1,161 1,160 Net interest income - FTE $26,265 $29,147 $31,510 $31,483 $32,758 Net interest margin 1.82% 1.96% 2.04% 2.22% 2.36% Adjustments: Effect of fully-taxable equivalent adjustments 1 0.09% 0.08% 0.08% 0.08% 0.09% Net interest margin - FTE 1.91% 2.04% 2.12% 2.30% 2.45% 33 Reconciliation of Non-GAAP Financial Measures 1 Assuming a 21% tax rate
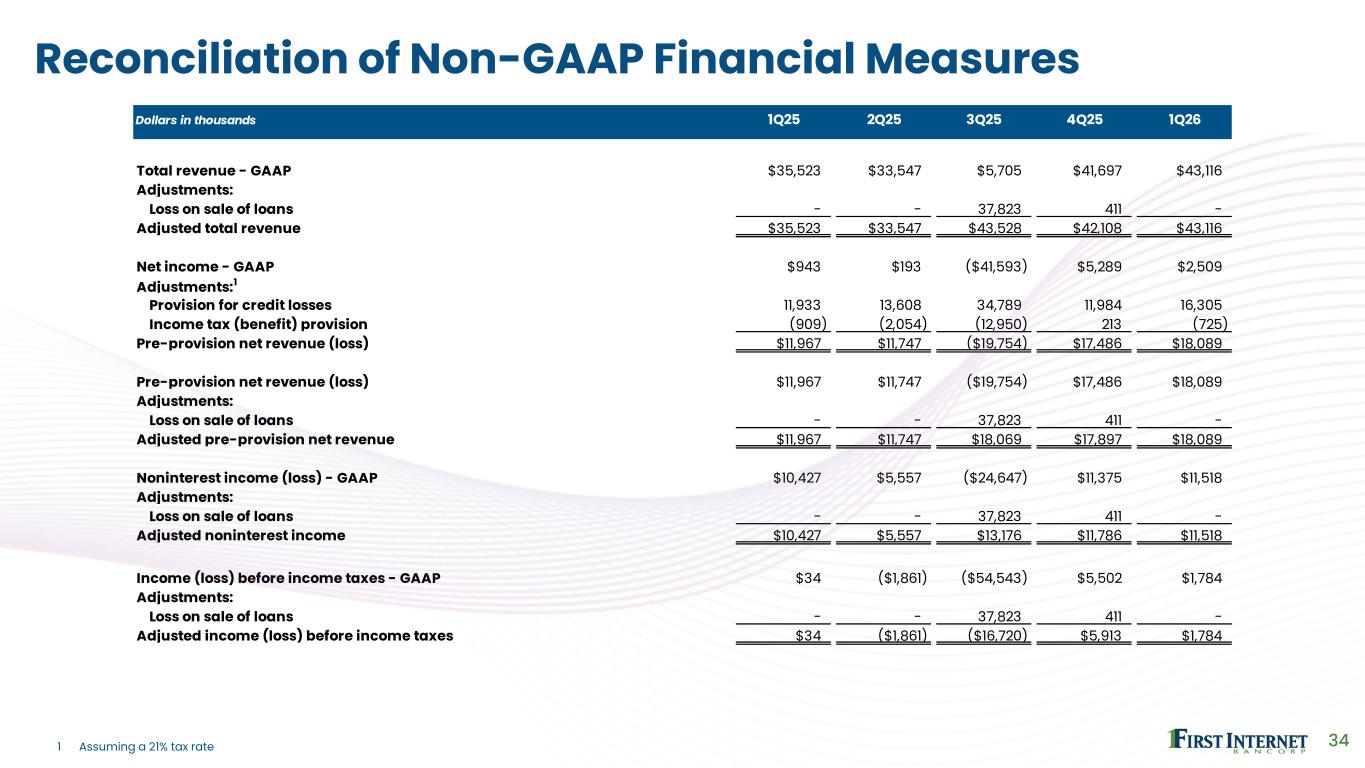
Dollars in thousands 1Q25 2Q25 3Q25 4Q25 1Q26 Total revenue - GAAP $35,523 $33,547 $5,705 $41,697 $43,116 Adjustments: Loss on sale of loans - - 37,823 411 - Adjusted total revenue $35,523 $33,547 $43,528 $42,108 $43,116 Net income - GAAP $943 $193 ($41,593) $5,289 $2,509 Adjustments:1 Provision for credit losses 11,933 13,608 34,789 11,984 16,305 Income tax (benefit) provision (909) (2,054) (12,950) 213 (725) Pre-provision net revenue (loss) $11,967 $11,747 ($19,754) $17,486 $18,089 Pre-provision net revenue (loss) $11,967 $11,747 ($19,754) $17,486 $18,089 Adjustments: Loss on sale of loans - - 37,823 411 - Adjusted pre-provision net revenue $11,967 $11,747 $18,069 $17,897 $18,089 Noninterest income (loss) - GAAP $10,427 $5,557 ($24,647) $11,375 $11,518 Adjustments: Loss on sale of loans - - 37,823 411 - Adjusted noninterest income $10,427 $5,557 $13,176 $11,786 $11,518 Income (loss) before income taxes - GAAP $34 ($1,861) ($54,543) $5,502 $1,784 Adjustments: Loss on sale of loans - - 37,823 411 - Adjusted income (loss) before income taxes $34 ($1,861) ($16,720) $5,913 $1,784 34 Reconciliation of Non-GAAP Financial Measures 1 Assuming a 21% tax rate
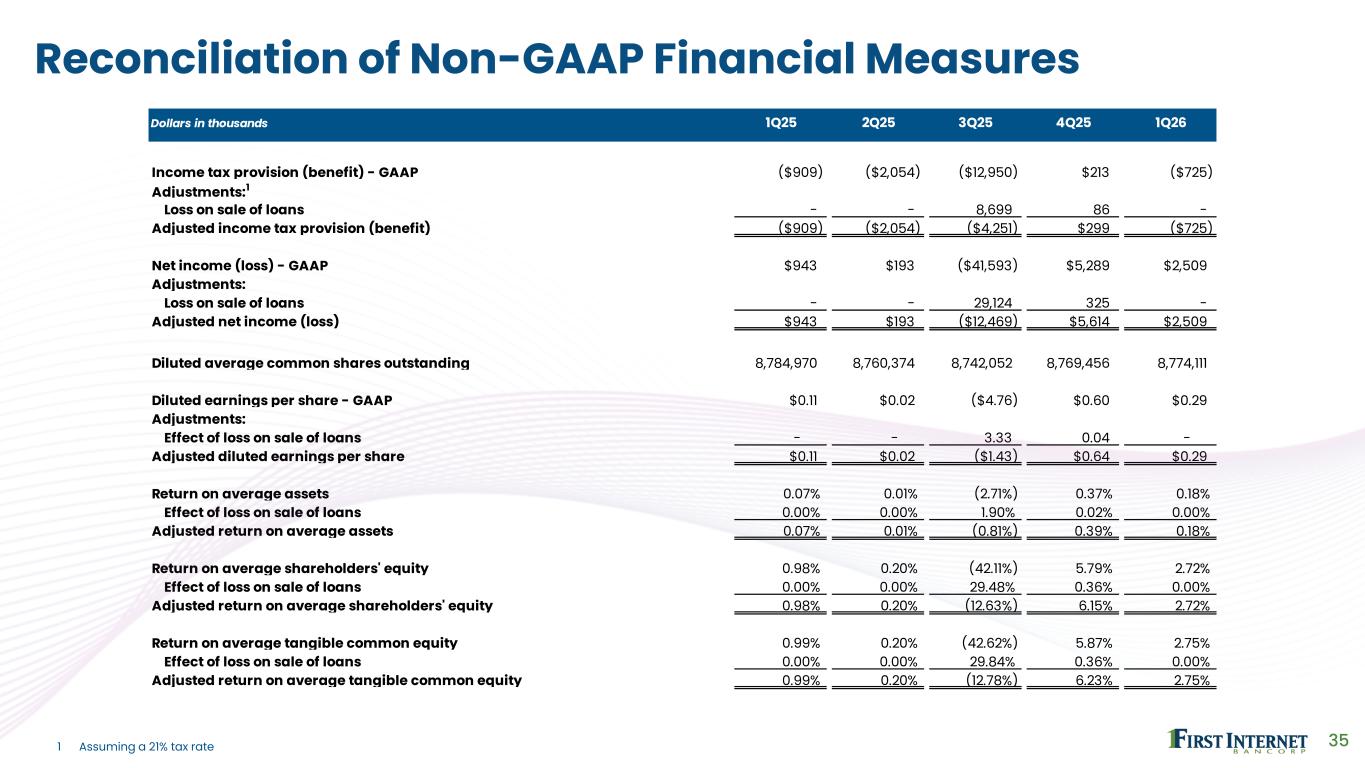
Dollars in thousands 1Q25 2Q25 3Q25 4Q25 1Q26 Income tax provision (benefit) - GAAP ($909) ($2,054) ($12,950) $213 ($725) Adjustments:1 Loss on sale of loans - - 8,699 86 - Adjusted income tax provision (benefit) ($909) ($2,054) ($4,251) $299 ($725) Net income (loss) - GAAP $943 $193 ($41,593) $5,289 $2,509 Adjustments: Loss on sale of loans - - 29,124 325 - Adjusted net income (loss) $943 $193 ($12,469) $5,614 $2,509 Diluted average common shares outstanding 8,784,970 8,760,374 8,742,052 8,769,456 8,774,111 Diluted earnings per share - GAAP $0.11 $0.02 ($4.76) $0.60 $0.29 Adjustments: Effect of loss on sale of loans - - 3.33 0.04 - Adjusted diluted earnings per share $0.11 $0.02 ($1.43) $0.64 $0.29 Return on average assets 0.07% 0.01% (2.71%) 0.37% 0.18% Effect of loss on sale of loans 0.00% 0.00% 1.90% 0.02% 0.00% Adjusted return on average assets 0.07% 0.01% (0.81%) 0.39% 0.18% Return on average shareholders' equity 0.98% 0.20% (42.11%) 5.79% 2.72% Effect of loss on sale of loans 0.00% 0.00% 29.48% 0.36% 0.00% Adjusted return on average shareholders' equity 0.98% 0.20% (12.63%) 6.15% 2.72% Return on average tangible common equity 0.99% 0.20% (42.62%) 5.87% 2.75% Effect of loss on sale of loans 0.00% 0.00% 29.84% 0.36% 0.00% Adjusted return on average tangible common equity 0.99% 0.20% (12.78%) 6.23% 2.75% 35 Reconciliation of Non-GAAP Financial Measures 1 Assuming a 21% tax rate
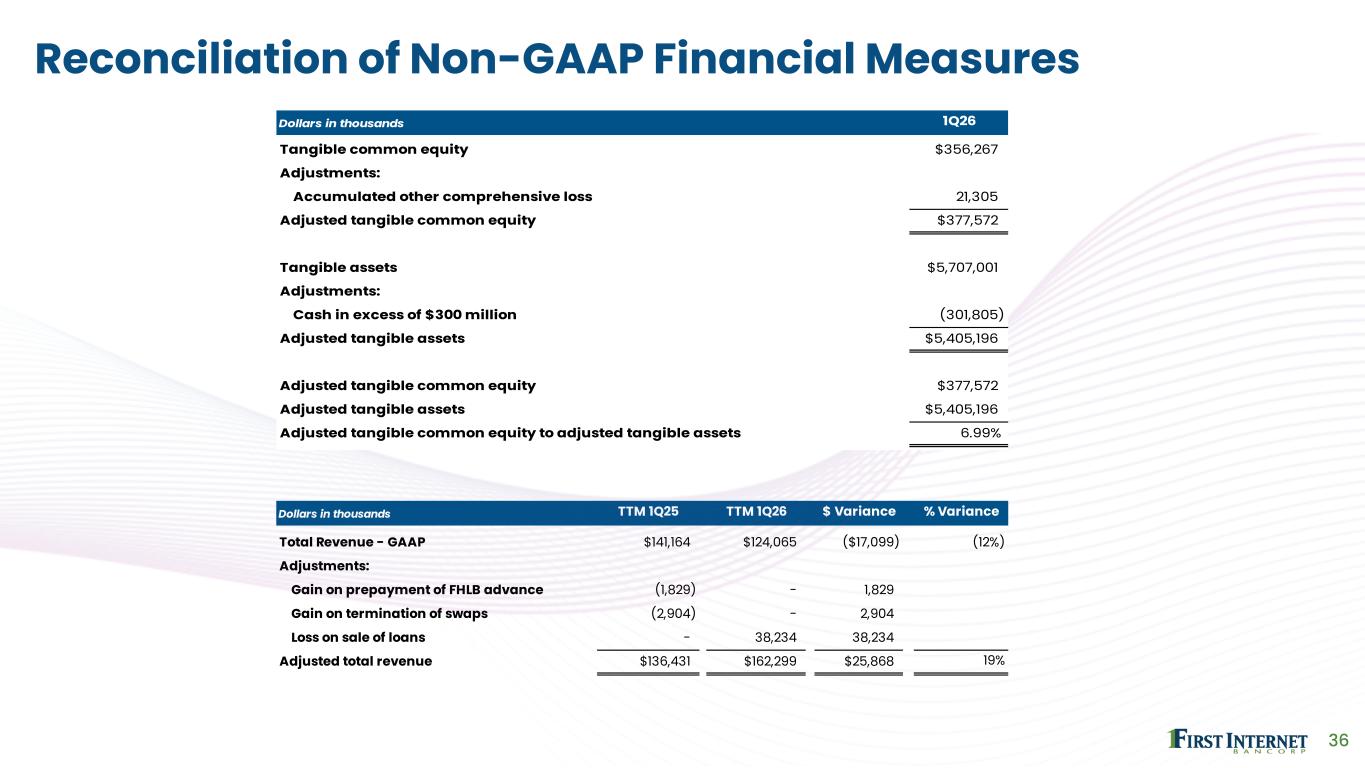
Dollars in thousands TTM 1Q25 TTM 1Q26 $ Variance % Variance Total Revenue - GAAP $141,164 $124,065 ($17,099) (12%) Adjustments: Gain on prepayment of FHLB advance (1,829) - 1,829 Gain on termination of swaps (2,904) - 2,904 Loss on sale of loans - 38,234 38,234 Adjusted total revenue $136,431 $162,299 $25,868 19% Dollars in thousands 1Q26 Tangible common equity $356,267 Adjustments: Accumulated other comprehensive loss 21,305 Adjusted tangible common equity $377,572 Tangible assets $5,707,001 Adjustments: Cash in excess of $300 million (301,805) Adjusted tangible assets $5,405,196 Adjusted tangible common equity $377,572 Adjusted tangible assets $5,405,196 Adjusted tangible common equity to adjusted tangible assets 6.99% 36 Reconciliation of Non-GAAP Financial Measures
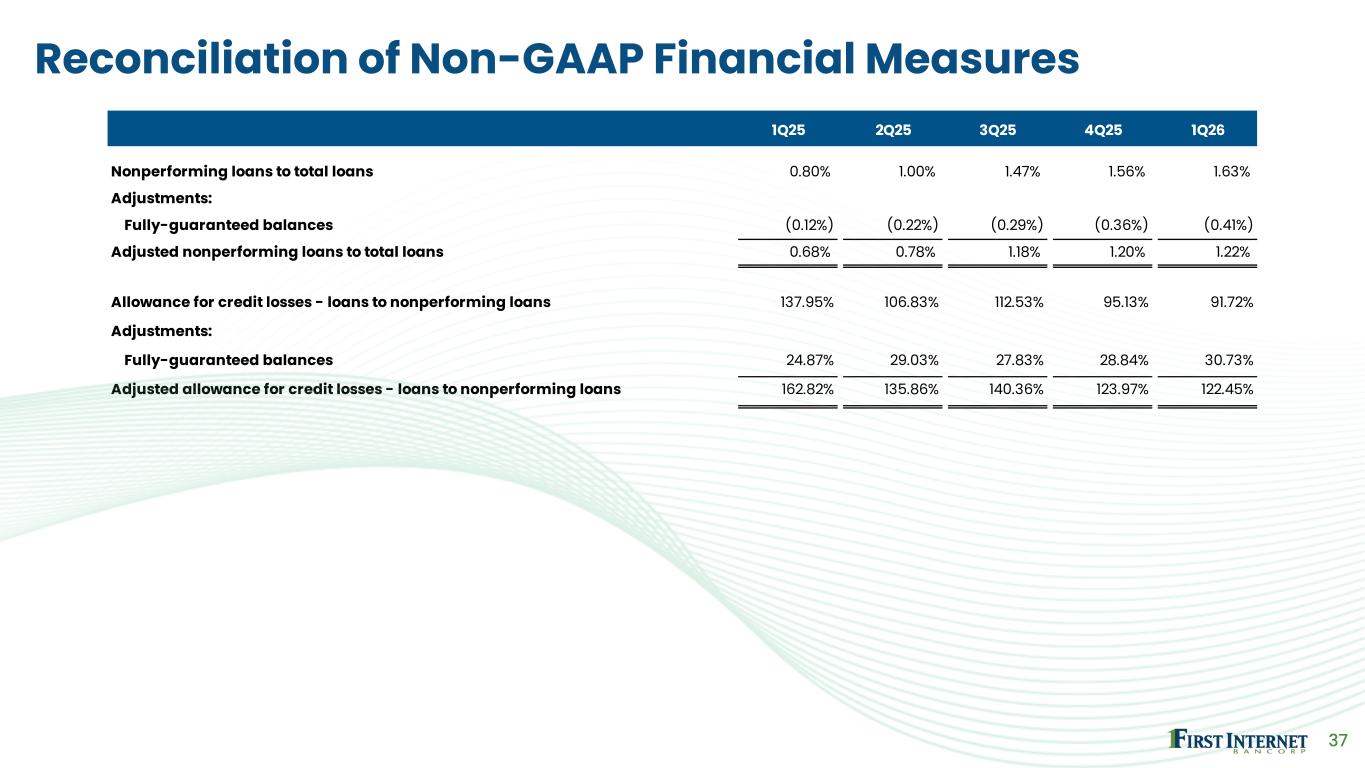
1Q25 2Q25 3Q25 4Q25 1Q26 Nonperforming loans to total loans 0.80% 1.00% 1.47% 1.56% 1.63% Adjustments: Fully-guaranteed balances (0.12%) (0.22%) (0.29%) (0.36%) (0.41%) Adjusted nonperforming loans to total loans 0.68% 0.78% 1.18% 1.20% 1.22% Allowance for credit losses - loans to nonperforming loans 137.95% 106.83% 112.53% 95.13% 91.72% Adjustments: Fully-guaranteed balances 24.87% 29.03% 27.83% 28.84% 30.73% Adjusted allowance for credit losses - loans to nonperforming loans 162.82% 135.86% 140.36% 123.97% 122.45% 37 Reconciliation of Non-GAAP Financial Measures