
KEY 8-K
Keycorp /New/ (KEY)
8-K
2021-01-21
For: 2021-01-21
View Original
Added on
April 10, 2026
UNITED STATES SECURITIES AND EXCHANGE COMMISSION
Washington, D.C. 20549
FORM 8-K
CURRENT REPORT
Pursuant to Section 13 or 15(d) of the Securities Exchange Act of 1934 | ||
Date of Report (Date of earliest event reported): January 21, 2021
(Exact name of registrant as specified in its charter)
| State or other jurisdiction of incorporation or organization: | Commission File Number | I.R.S. Employer Identification Number: | ||||||||||||
| Address of principal executive offices: | Zip Code: | |||||||||||||
(216 ) 689-3000
Registrant’s telephone number, including area code:
| Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below): | |||||
| Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
| Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
| Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
| Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities Registered Pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbol(s) | Name of each exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933 (§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
Item 2.02 Results of Operations and Financial Condition.
On January 21, 2021, KeyCorp issued a press release announcing its financial results for the three- and twelve-month period ended December 31, 2020 (the “Press Release”), and posted on its website its fourth quarter 2020 Supplemental Information Package (the “Supplemental Information Package”). The Press Release and Supplemental Information Package are being furnished as Exhibit 99.1 and Exhibit 99.2, respectively.
The information in the preceding paragraph, as well as Exhibit 99.1 and Exhibit 99.2 referenced therein, shall not be deemed “filed” for purposes of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), nor shall it be incorporated by reference in any filing under the Securities Act of 1933, as amended (the “Securities Act”).
KeyCorp’s Consolidated Balance Sheets and Consolidated Statements of Income (collectively, the “Financial Statements”), included as part of the Press Release, are filed as Exhibit 99.3 to this report. Exhibit 99.3 is deemed “filed” for purposes of Section 18 of the Exchange Act and, therefore, may be incorporated by reference in filings under the Securities Act.
Item 9.01 Financial Statements and Exhibits.
(d) Exhibits
The following exhibits are furnished, or filed in the case of Exhibit 99.3, herewith:
104 Cover Page Interactive Data File (embedded within the Inline XBRL document).
| SIGNATURE | ||||||||
| Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized. | ||||||||
| KEYCORP | ||||||||
| (Registrant) | ||||||||
| Date: January 21, 2021 | /s/ Douglas M. Schosser | |||||||
| By: Douglas M. Schosser | ||||||||
| Chief Accounting Officer | ||||||||
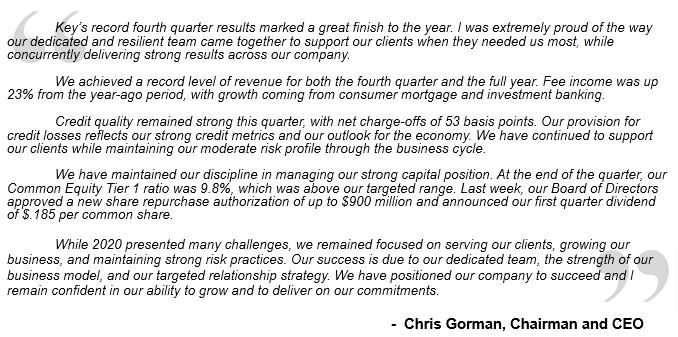
KEYCORP REPORTS RECORD FOURTH QUARTER 2020 NET INCOME OF $549 MILLION,
OR $.56 PER DILUTED COMMON SHARE
Record revenue for the fourth quarter and full year 2020
All-time high level of investment banking and debt placement fees for the fourth quarter and full year
Strong credit quality: net charge-offs to average loans of 53 basis points
Return on average tangible common equity of 16.6%, up 440 basis points from the prior quarter
Strong capital position with Common Equity Tier 1 Capital of 9.8%, above targeted range
Announced new common share repurchase authorization of up to $900 million
CLEVELAND, January 21, 2021 - KeyCorp (NYSE: KEY) today announced net income from continuing operations attributable to Key common shareholders of $549 million, or $.56 per diluted common share for the fourth quarter of 2020. This compared to $397 million, or $.41 per diluted common share, for the third quarter of 2020 and $439 million, or $.45 per diluted common share, for the fourth quarter of 2019.
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 2
| Selected Financial Highlights | |||||||||||||||||||||||
| dollars in millions, except per share data | Change 4Q20 vs. | ||||||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | |||||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | 549 | $ | 397 | $ | 439 | 38.3 | % | 25.1 | % | |||||||||||||
Income (loss) from continuing operations attributable to Key common shareholders per common share — assuming dilution | .56 | .41 | .45 | 36.6 | 24.4 | ||||||||||||||||||
Return on average tangible common equity from continuing operations (a) | 16.61 | % | 12.19 | % | 14.09 | % | N/A | N/A | |||||||||||||||
| Return on average total assets from continuing operations | 1.35 | 1.00 | 1.27 | N/A | N/A | ||||||||||||||||||
Common Equity Tier 1 ratio (b) | 9.8 | 9.5 | 9.4 | N/A | N/A | ||||||||||||||||||
| Book value at period end | $ | 16.53 | $ | 16.25 | $ | 15.54 | 1.7 | % | 6.4 | % | |||||||||||||
| Net interest margin (TE) from continuing operations | 2.70 | % | 2.62 | % | 2.98 | % | N/A | N/A | |||||||||||||||
(a)The table entitled “GAAP to Non-GAAP Reconciliations” in the attached financial supplement presents the computations of certain financial measures related to “Return on average tangible common equity from continuing operations.” The table reconciles the GAAP performance measures to the corresponding non-GAAP measures, which provides a basis for period-to-period comparisons.
(b)12/31/20 ratio is estimated.
TE = Taxable Equivalent, N/A = Not Applicable
| INCOME STATEMENT HIGHLIGHTS | ||||||||||||||||||||
| Revenue | ||||||||||||||||||||
| dollars in millions | Change 4Q20 vs. | |||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | ||||||||||||||||
| Net interest income (TE) | $ | 1,043 | $ | 1,006 | $ | 987 | 3.7 | % | 5.7 | % | ||||||||||
| Noninterest income | 802 | 681 | 651 | 17.8 | 23.2 | |||||||||||||||
| Total revenue | $ | 1,845 | $ | 1,687 | $ | 1,638 | 9.4 | % | 12.6 | % | ||||||||||
TE = Taxable Equivalent
Taxable-equivalent net interest income was $1.043 billion for the fourth quarter of 2020, compared to taxable-equivalent net interest income of $987 million for the fourth quarter of 2019. The increase in net interest income reflects higher earning asset balances and loan fees, partially offset by a lower net interest margin. The net interest margin was impacted by lower interest rates and a change in balance sheet mix, including elevated levels of liquidity and Key's participation in the Paycheck Protection Program ("PPP").
Compared to the third quarter of 2020, taxable-equivalent net interest income increased by $37 million and the net interest margin increased by 8 basis points. The increase in both net interest income and the net interest margin reflects lower interest-bearing deposit costs and higher loan fees related to PPP, partly offset by elevated levels of liquidity.
| Noninterest Income | ||||||||||||||||||||
| dollars in millions | Change 4Q20 vs. | |||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | ||||||||||||||||
| Trust and investment services income | $ | 123 | $ | 128 | $ | 120 | (3.9) | % | 2.5 | % | ||||||||||
| Investment banking and debt placement fees | 243 | 146 | 181 | 66.4 | 34.3 | |||||||||||||||
| Service charges on deposit accounts | 82 | 77 | 86 | 6.5 | (4.7) | |||||||||||||||
| Operating lease income and other leasing gains | 39 | 38 | 39 | 2.6 | — | |||||||||||||||
| Corporate services income | 63 | 51 | 65 | 23.5 | (3.1) | |||||||||||||||
| Cards and payments income | 97 | 114 | 67 | (14.9) | 44.8 | |||||||||||||||
| Corporate-owned life insurance income | 38 | 30 | 39 | 26.7 | (2.6) | |||||||||||||||
| Consumer mortgage income | 43 | 51 | 21 | (15.7) | 104.8 | |||||||||||||||
| Commercial mortgage servicing fees | 32 | 18 | 19 | 77.8 | 68.4 | |||||||||||||||
| Other income | 42 | 28 | 14 | 50.0 | 200.0 | |||||||||||||||
| Total noninterest income | $ | 802 | $ | 681 | $ | 651 | 17.8 | % | 23.2 | % | ||||||||||
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 3
Compared to the fourth quarter of 2019, noninterest income increased by $151 million, primarily driven by a $62 million increase in investment banking and debt placement fees. The record fourth quarter of 2020 for investment banking and debt placement fees was largely related to strong M&A activity. Cards and payments income increased $30 million from the year-ago period, driven by higher prepaid card activity. Additionally, investments made in Key's mortgage business continue to drive consumer mortgage income and commercial mortgage servicing fees, which increased $22 million and $13 million, respectively, from the year-ago quarter.
Compared to the third quarter of 2020, noninterest income increased by $121 million. The largest driver of the quarter-over-quarter increase was a $97 million increase in investment banking and debt placement fees, largely driven by strong M&A activity and higher loan syndication. Commercial mortgage servicing fees were also strong, up $14 million compared to prior quarter and corporate services income increased $12 million, primarily driven by higher derivatives income. Partially offsetting these increases were a $17 million decrease in cards and payments income related to lower prepaid card activity and a $8 million decrease in consumer mortgage income.
| Noninterest Expense | ||||||||||||||||||||
| dollars in millions | Change 4Q20 vs. | |||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | ||||||||||||||||
| Personnel expense | $ | 661 | $ | 588 | $ | 551 | 12.4 | % | 20.0 | % | ||||||||||
| Nonpersonnel expense | 467 | 449 | 429 | 4.0 | 8.9 | |||||||||||||||
| Total noninterest expense | $ | 1,128 | $ | 1,037 | $ | 980 | 8.8 | % | 15.1 | % | ||||||||||
Key’s noninterest expense was $1.128 billion for the fourth quarter of 2020, an increase of $148 million from the year-ago period. The increase is primarily related to higher personnel costs of $110 million, reflecting higher production-related incentives and higher salaries due to merit increases. Other drivers for the year-over-year increases include payments-related expenses from prepaid card activity incurred in the current period, as well as COVID-19-related costs related to steps that Key has taken to ensure the health and safety of teammates.
Compared to the third quarter of 2020, noninterest expense increased $91 million. The increase was largely due to incentive-related costs following a strong quarter for investment banking revenue, higher severance, as well as higher related stock-based compensation which drove the increase in personnel costs quarter-over-quarter.
| BALANCE SHEET HIGHLIGHTS | ||||||||||||||||||||
| Average Loans | ||||||||||||||||||||
| dollars in millions | Change 4Q20 vs. | |||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | ||||||||||||||||
Commercial and industrial (a) | $ | 53,562 | $ | 57,067 | $ | 48,345 | (6.1) | % | 10.8 | % | ||||||||||
| Other commercial loans | 19,174 | 19,677 | 19,312 | (2.6) | (.7) | |||||||||||||||
| Total consumer loans | 28,974 | 28,175 | 25,950 | 2.8 | 11.7 | |||||||||||||||
| Total loans | $ | 101,710 | $ | 104,919 | $ | 93,607 | (3.1) | % | 8.7 | % | ||||||||||
(a)Commercial and industrial average loan balances include $129 million, $129 million, and $146 million of assets from commercial credit cards at December 31, 2020, September 30, 2020, and December 31, 2019, respectively.
Average loans were $101.7 billion for the fourth quarter of 2020, an increase of $8.1 billion compared to the fourth quarter of 2019. Commercial loans increased $5.1 billion, reflecting Key’s participation in the PPP, partially offset by decreased utilization versus the year-ago period. Consumer loans increased $3.0 billion, driven by strength from Laurel Road and Key's consumer mortgage business.
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 4
Compared to the third quarter of 2020, average loans decreased by $3.2 billion. Commercial loans declined as clients paid down elevated line draws from earlier in the year. Consumer loans continue to reflect strength from Laurel Road, as well as Key's consumer mortgage business.
| Average Deposits | ||||||||||||||||||||
| dollars in millions | Change 4Q20 vs. | |||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | ||||||||||||||||
| Non-time deposits | $ | 129,529 | $ | 127,347 | $ | 100,518 | 1.7 | % | 28.9 | % | ||||||||||
| Certificates of deposit ($100,000 or more) | 2,983 | 3,862 | 6,899 | (22.8) | (56.8) | |||||||||||||||
| Other time deposits | 3,209 | 3,735 | 5,187 | (14.1) | (38.1) | |||||||||||||||
| Total deposits | $ | 135,721 | $ | 134,944 | $ | 112,604 | .6 | % | 20.5 | % | ||||||||||
| Cost of total deposits | .08 | % | .16 | % | .71 | % | N/A | N/A | ||||||||||||
N/A = Not Applicable
Average deposits totaled $135.7 billion for the fourth quarter of 2020, an increase of $23.1 billion compared to the year-ago quarter, reflecting growth from consumer and commercial relationships, partially offset by a decline in time deposits as a result of lower interest rates.
Compared to the third quarter of 2020, average deposits increased by $777 million, primarily driven by broad-based commercial growth and higher consumer balances. This growth was offset by a continued decline in time deposits.
| ASSET QUALITY | ||||||||||||||||||||
| dollars in millions | Change 4Q20 vs. | |||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | ||||||||||||||||
| Net loan charge-offs | $ | 135 | $ | 128 | $ | 99 | 5.5 | % | 36.4 | % | ||||||||||
| Net loan charge-offs to average total loans | .53 | % | .49 | % | .42 | % | N/A | N/A | ||||||||||||
| Nonperforming loans at period end | $ | 785 | $ | 834 | $ | 577 | (5.9) | 36.0 | ||||||||||||
| Nonperforming assets at period end | 937 | 1,003 | 715 | (6.6) | 31.0 | |||||||||||||||
| Allowance for loan and lease losses | 1,626 | 1,730 | 900 | (6.0) | 80.7 | |||||||||||||||
| Allowance for credit losses | 1,823 | 1,938 | 968 | (5.9) | 88.3 | |||||||||||||||
| Allowance for loan and lease losses to nonperforming loans | 207.1 | % | 207.4 | % | 156.0 | % | N/A | N/A | ||||||||||||
| Allowance for credit losses to nonperforming loans | 232.2 | 232.4 | 167.8 | N/A | N/A | |||||||||||||||
| Provision for credit losses | $ | 20 | $ | 160 | $ | 109 | (87.5) | % | (81.7) | % | ||||||||||
N/A = Not Applicable
Key’s provision for credit losses was $20 million for the fourth quarter of 2020, compared to $109 million for the fourth quarter of 2019 and $160 million for the third quarter of 2020. The provision for credit losses reflects the adoption of the accounting standard, often referred to as Current Expected Credit Losses ("CECL"), beginning in the first quarter of 2020. This framework requires that management estimate credit losses over the full remaining expected life and consider expected future changes in macroeconomic conditions.
Net loan charge-offs for the fourth quarter of 2020 totaled $135 million, or .53% of average total loans. These results compare to $99 million, or .42%, for the fourth quarter of 2019 and $128 million, or .49%, for the third quarter of 2020. Key’s allowance for credit losses was $1.8 billion, or 1.80% of total period-end loans at December 31, 2020, compared to 1.02% at December 31, 2019, and 1.88% at September 30, 2020.
At December 31, 2020, Key’s nonperforming loans totaled $785 million, which represented .78% of period-end portfolio loans. These results compare to .61% at December 31, 2019, and .81% at September 30, 2020. Nonperforming assets at December 31, 2020, totaled $937 million, and represented .92% of period-end
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 5
portfolio loans and OREO and other nonperforming assets. These results compare to .75% at December 31, 2019, and .97% at September 30, 2020.
CAPITAL
Key’s estimated risk-based capital ratios included in the following table continued to exceed all “well-capitalized” regulatory benchmarks at December 31, 2020.
| Capital Ratios | |||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | |||||||||
Common Equity Tier 1 (a) | 9.8 | % | 9.5 | % | 9.4 | % | |||||
Tier 1 risk-based capital (a) | 11.1 | 10.9 | 10.9 | ||||||||
Total risk based capital (a) | 13.4 | 13.3 | 12.8 | ||||||||
Tangible common equity to tangible assets (b) | 7.9 | 7.8 | 8.6 | ||||||||
Leverage (a) | 8.9 | 8.7 | 9.9 | ||||||||
(a)12/31/2020 ratio is estimated and reflects Key's election to adopt the CECL optional transition provision.
(b)The table entitled “GAAP to Non-GAAP Reconciliations” in the attached financial supplement presents the computations of certain financial measures related to “tangible common equity.” The table reconciles the GAAP performance measures to the corresponding non-GAAP measures, which provides a basis for period-to-period comparisons.
Key's capital position remained strong in the fourth quarter of 2020. As shown in the preceding table, at December 31, 2020, Key’s estimated Common Equity Tier 1 and Tier 1 risk-based capital ratios stood at 9.8% and 11.1%, respectively. Key's tangible common equity ratio was 7.9% at December 31, 2020.
Key has elected the CECL phase-in option provided by regulatory guidance which delays for two years the estimated impact of CECL on regulatory capital and phases it in over three years beginning in 2022. On a fully phased-in basis, Key's Common Equity Tier 1 ratio would be reduced by 29 basis points.
| Summary of Changes in Common Shares Outstanding | |||||||||||||||||||||||
| in thousands | Change 4Q20 vs. | ||||||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | |||||||||||||||||||
| Shares outstanding at beginning of period | 976,205 | 975,947 | 988,538 | — | (1.2) | % | |||||||||||||||||
Open market repurchases and return of shares under employee compensation plans | (1,092) | (1) | (12,968) | N/M | (91.6) | ||||||||||||||||||
| Shares issued under employee compensation plans (net of cancellations) | 660 | 259 | 1,619 | 154.8 | % | (59.2) | |||||||||||||||||
| Shares outstanding at end of period | 975,773 | 976,205 | 977,189 | — | (.1) | % | |||||||||||||||||
N/M = Not Meaningful
Consistent with Key's 2020 Capital Plan, during the fourth quarter of 2020, Key declared a dividend of $.185 per common share. Key announced a new share repurchase authorization program of up to $900 million, applicable through September 30, 2021.
LINE OF BUSINESS RESULTS
The following table shows the contribution made by each major business segment to Key’s taxable-equivalent revenue from continuing operations and income (loss) from continuing operations attributable to Key for the periods presented. For more detailed financial information pertaining to each business segment, see the tables at the end of this release.
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 6
| Major Business Segments | |||||||||||||||||||||||
| dollars in millions | Change 4Q20 vs. | ||||||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | |||||||||||||||||||
| Revenue from continuing operations (TE) | |||||||||||||||||||||||
| Consumer Bank | $ | 905 | $ | 871 | $ | 825 | 3.9 | % | 9.7 | % | |||||||||||||
| Commercial Bank | 913 | 804 | 771 | 13.6 | 18.4 | ||||||||||||||||||
Other (a) | 27 | 12 | 42 | 125.0 | (35.7) | ||||||||||||||||||
| Total | $ | 1,845 | $ | 1,687 | $ | 1,638 | 9.4 | % | 12.6 | % | |||||||||||||
| Income (loss) from continuing operations attributable to Key | |||||||||||||||||||||||
| Consumer Bank | $ | 228 | $ | 241 | $ | 168 | (5.4) | % | 35.7 | % | |||||||||||||
| Commercial Bank | 308 | 160 | 311 | 92.5 | (1.0) | ||||||||||||||||||
Other (a) | 39 | 23 | (13) | 69.6 | N/M | ||||||||||||||||||
| Total | $ | 575 | $ | 424 | $ | 466 | 35.6 | % | 23.4 | % | |||||||||||||
(a)Other includes other segments that consists of corporate treasury, our principal investing unit, and various exit portfolios as well as reconciling items which primarily represents the unallocated portion of nonearning assets of corporate support functions. Charges related to the funding of these assets are part of net interest income and are allocated to the business segments through noninterest expense. Reconciling items also includes intercompany eliminations and certain items that are not allocated to the business segments because they do not reflect their normal operations.
TE = Taxable Equivalent, N/M = Not Meaningful
| Consumer Bank | ||||||||||||||||||||
| dollars in millions | Change 4Q20 vs. | |||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | ||||||||||||||||
| Summary of operations | ||||||||||||||||||||
| Net interest income (TE) | $ | 645 | $ | 604 | $ | 587 | 6.8 | % | 9.9 | % | ||||||||||
| Noninterest income | 260 | 267 | 238 | (2.6) | 9.2 | |||||||||||||||
| Total revenue (TE) | 905 | 871 | 825 | 3.9 | 9.7 | |||||||||||||||
| Provision for credit losses | (4) | (16) | 55 | (75.0) | (129.1) | |||||||||||||||
| Noninterest expense | 611 | 571 | 550 | 7.0 | 11.1 | |||||||||||||||
| Income (loss) before income taxes (TE) | 298 | 316 | 220 | (5.7) | 35.5 | |||||||||||||||
| Allocated income taxes (benefit) and TE adjustments | 70 | 75 | 52 | (6.7) | 34.6 | |||||||||||||||
| Net income (loss) attributable to Key | $ | 228 | $ | 241 | $ | 168 | (5.4) | % | 35.7 | % | ||||||||||
| Average balances | ||||||||||||||||||||
| Loans and leases | $ | 41,137 | $ | 41,471 | $ | 34,148 | (.8) | % | 20.5 | % | ||||||||||
| Total assets | 44,357 | 44,888 | 37,709 | (1.2) | 17.6 | |||||||||||||||
| Deposits | 83,171 | 83,175 | 73,561 | — | 13.1 | |||||||||||||||
| Assets under management at period end | $ | 44,140 | $ | 41,312 | $ | 40,833 | 6.8 | % | 8.1 | % | ||||||||||
TE = Taxable Equivalent
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 7
| Additional Consumer Bank Data | ||||||||||||||||||||
| dollars in millions | Change 4Q20 vs. | |||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | ||||||||||||||||
| Noninterest income | ||||||||||||||||||||
| Trust and investment services income | $ | 95 | $ | 100 | $ | 91 | (5.0) | % | 4.4 | % | ||||||||||
| Service charges on deposit accounts | 50 | 44 | 58 | 13.6 | (13.8) | |||||||||||||||
| Cards and payments income | 54 | 55 | 53 | (1.8) | 1.9 | |||||||||||||||
| Consumer mortgage income | 43 | 51 | 20 | (15.7) | 115.0 | |||||||||||||||
| Other noninterest income | 18 | 17 | 16 | 5.9 | 12.5 | |||||||||||||||
| Total noninterest income | $ | 260 | $ | 267 | $ | 238 | (2.6) | % | 9.2 | % | ||||||||||
| Average deposit balances | ||||||||||||||||||||
| NOW and money market deposit accounts | $ | 53,055 | $ | 52,550 | $ | 44,765 | 1.0 | % | 18.5 | % | ||||||||||
| Savings deposits | 5,408 | 5,169 | 4,332 | 4.6 | 24.8 | |||||||||||||||
| Certificates of deposit ($100,000 or more) | 2,801 | 3,550 | 6,065 | (21.1) | (53.8) | |||||||||||||||
| Other time deposits | 3,187 | 3,701 | 5,164 | (13.9) | (38.3) | |||||||||||||||
| Noninterest-bearing deposits | 18,720 | 18,205 | 13,235 | 2.8 | 41.4 | |||||||||||||||
| Total deposits | $ | 83,171 | $ | 83,175 | $ | 73,561 | — | 13.1 | % | |||||||||||
| Home equity loans | ||||||||||||||||||||
| Average balance | $ | 9,360 | $ | 9,528 | $ | 10,295 | ||||||||||||||
| Combined weighted-average loan-to-value ratio (at date of origination) | 69 | % | 70 | % | 70 | % | ||||||||||||||
| Percent first lien positions | 66 | 64 | 61 | |||||||||||||||||
| Other data | ||||||||||||||||||||
| Branches | 1,073 | 1,077 | 1,098 | |||||||||||||||||
| Automated teller machines | 1,386 | 1,388 | 1,420 | |||||||||||||||||
Consumer Bank Summary of Operations (4Q20 vs. 4Q19)
•Net income attributable to Key of $228 million for the fourth quarter of 2020, compared to $168 million for the year-ago quarter
•Taxable-equivalent net interest income increased by $58 million, or 9.9%, compared to the fourth quarter of 2019, driven by strong balance sheet growth and fees related to PPP loans, partially offset by the lower interest rate environment
•Average loans and leases increased $7.0 billion, or 20.5%, driven by benefit from the PPP, as well as growth from Laurel Road and consumer mortgage
•Average deposits increased $9.6 billion, or 13.1%, from the fourth quarter of 2019. This was driven by consumer stimulus payments, lower spend activity, and relationship growth
•Provision for credit losses decreased $59 million compared to the fourth quarter of 2019. The decrease in provision for credit losses is attributable to lower net charge-offs and a reduced allowance from the third quarter of 2020, driven by continued strength in client credit quality
•Noninterest income increased $22 million, or 9.2%, from the year ago quarter, driven by strength in consumer mortgage income and higher trust and investment services income
•Noninterest expense increased $61 million, or 11.1%, from the year ago quarter driven by higher variable compensation from strong revenue growth and higher variable expenses related to higher loan volumes
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 8
| Commercial Bank | ||||||||||||||||||||
| dollars in millions | Change 4Q20 vs. | |||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | ||||||||||||||||
| Summary of operations | ||||||||||||||||||||
| Net interest income (TE) | $ | 413 | $ | 421 | $ | 416 | (1.9) | % | (.7) | % | ||||||||||
| Noninterest income | 500 | 383 | 355 | 30.5 | 40.8 | |||||||||||||||
| Total revenue (TE) | 913 | 804 | 771 | 13.6 | 18.4 | |||||||||||||||
| Provision for credit losses | 42 | 163 | 38 | (74.2) | 10.5 | |||||||||||||||
| Noninterest expense | 494 | 443 | 393 | 11.5 | 25.7 | |||||||||||||||
| Income (loss) before income taxes (TE) | 377 | 198 | 340 | 90.4 | 10.9 | |||||||||||||||
| Allocated income taxes and TE adjustments | 69 | 38 | 29 | 81.6 | 137.9 | |||||||||||||||
| Net income (loss) attributable to Key | $ | 308 | $ | 160 | $ | 311 | 92.5 | % | (1.0) | % | ||||||||||
| Average balances | ||||||||||||||||||||
| Loans and leases | $ | 59,992 | $ | 62,925 | $ | 58,535 | (4.7) | % | 2.5 | % | ||||||||||
| Loans held for sale | 1,285 | 1,383 | 1,465 | (7.1) | (12.3) | |||||||||||||||
| Total assets | 69,277 | 72,613 | 67,135 | (4.6) | 3.2 | |||||||||||||||
| Deposits | 52,163 | 51,238 | 38,224 | 1.8 | % | 36.5 | % | |||||||||||||
TE = Taxable Equivalent, N/M = Not Meaningful
| Additional Commercial Bank Data | ||||||||||||||||||||
| dollars in millions | Change 4Q20 vs. | |||||||||||||||||||
| 4Q20 | 3Q20 | 4Q19 | 3Q20 | 4Q19 | ||||||||||||||||
| Noninterest income | ||||||||||||||||||||
| Trust and investment services income | $ | 28 | $ | 27 | $ | 29 | 3.7 | % | (3.4) | |||||||||||
| Investment banking and debt placement fees | 243 | 146 | 179 | 66.4 | 35.8 | % | ||||||||||||||
| Operating lease income and other leasing gains | 39 | 38 | 39 | 2.6 | — | |||||||||||||||
| Corporate services income | 55 | 44 | 58 | 25.0 | (5.2) | |||||||||||||||
| Service charges on deposit accounts | 31 | 32 | 27 | (3.1) | 14.8 | |||||||||||||||
| Cards and payments income | 43 | 60 | 15 | (28.3) | 186.7 | |||||||||||||||
| Payments and services income | 129 | 136 | 100 | (5.1) | 29.0 | |||||||||||||||
| Commercial mortgage servicing fees | 32 | 18 | 19 | 77.8 | 68.4 | |||||||||||||||
| Other noninterest income | 29 | 18 | (11) | 61.1 | N/M | |||||||||||||||
| Total noninterest income | $ | 500 | $ | 383 | $ | 355 | 30.5 | % | 40.8 | % | ||||||||||
N/M = Not Meaningful
Commercial Bank Summary of Operations (4Q20 vs. 4Q19)
•Net income attributable to Key of $308 million for the fourth quarter of 2020, compared to $311 million for the year-ago quarter
•Taxable-equivalent net interest income decreased by $3.0 million, compared to the fourth quarter of 2019, as the lower interest rate environment offset balance sheet growth and fees related to PPP loans
•Average loan and lease balances increased $1.5 billion, or 2.5%, compared to the fourth quarter of 2019 as PPP loans offset lower utilization
•Average deposit balances increased $14 billion, or 36.5%, compared to the fourth quarter of 2019, driven by growth in targeted relationships and the impact of government programs
•Provision for credit losses increased $4.0 million compared to the fourth quarter of 2019
•Noninterest income increased $145 million, from the fourth quarter of 2019, driven by a record quarter in investment banking income, benefit from market-related adjustments to customer derivatives, and higher cards and payments income related to prepaid card revenue
•Noninterest expense increased by $101 million, or 25.7%, from the fourth quarter of 2019, driven by elevated variable expenses related to prepaid card and higher variable compensation from strong revenue growth
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 9
*******************************************
KeyCorp's roots trace back 190 years to Albany, New York. Headquartered in Cleveland, Ohio, Key is one of the nation’s largest bank-based financial services companies, with assets of approximately $170.3 billion at December 31, 2020.
Key provides deposit, lending, cash management, and investment services to individuals and businesses in 15 states under the name KeyBank National Association through a network of more than 1,000 branches and approximately 1,400 ATMs. Key also provides a broad range of sophisticated corporate and investment banking products, such as merger and acquisition advice, public and private debt and equity, syndications and derivatives to middle market companies in selected industries throughout the United States under the KeyBanc Capital Markets trade name. For more information, visit https://www.key.com/. KeyBank is Member FDIC.
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 10
| CONTACTS: | |||||
| ANALYSTS | MEDIA | ||||
| Vernon L. Patterson | Susan Donlan | ||||
| 216.689.0520 | 216.471.3133 | ||||
| [email protected] | [email protected] | ||||
| Melanie S. Kaiser | Tracy Pesho | ||||
| 216.689.4545 | 216.471.2825 | ||||
| [email protected] | [email protected] | ||||
| Halle A. Nichols | Twitter: @keybank | ||||
| 216.471.2184 | |||||
| [email protected] | |||||
| INVESTOR RELATIONS: | KEY MEDIA NEWSROOM: | ||||
| www.key.com/ir | www.key.com/newsroom | ||||
| This earnings release contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. These statements do not relate strictly to historical or current facts. Forward-looking statements usually can be identified by the use of words such as “goal,” “objective,” “plan,” “expect,” “assume,” “anticipate,” “intend,” “project,” “believe,” “estimate,” or other words of similar meaning. Forward-looking statements provide our current expectations or forecasts of future events, circumstances, results, or aspirations. Forward-looking statements, by their nature, are subject to assumptions, risks and uncertainties, many of which are outside of our control. Our actual results may differ materially from those set forth in our forward-looking statements. There is no assurance that any list of risks and uncertainties or risk factors is complete. Factors that could cause Key’s actual results to differ from those described in the forward-looking statements can be found in KeyCorp’s Form 10-K for the year ended December 31, 2019, as well as in KeyCorp’s subsequent SEC filings, all of which have been or will be filed with the Securities and Exchange Commission (the “SEC”) and are or will be available on Key’s website (www.key.com/ir) and on the SEC’s website (www.sec.gov). These factors may include, among others: deterioration of commercial real estate market fundamentals, adverse changes in credit quality trends, declining asset prices, a reversal of the U.S. economic recovery due to financial, political, or other shocks, and the extensive regulation of the U.S. financial services industry. In addition to the aforementioned factors, the COVID–19 global pandemic is adversely affecting us, our clients, and third–party service providers, among others, and its impact may adversely affect our business and results of operations over a period of time. Any forward-looking statements made by us or on our behalf speak only as of the date they are made and we do not undertake any obligation to update any forward-looking statement to reflect the impact of subsequent events or circumstances. | ||
Notes to Editors:
A live Internet broadcast of KeyCorp’s conference call to discuss quarterly results and currently anticipated earnings trends and to answer analysts’ questions can be accessed through the Investor Relations section at https://www.key.com/ir at 10:00 a.m. ET, on Thursday, January 21, 2021. A replay of the call will be available through January 30, 2021.
For up-to-date company information, media contacts, and facts and figures about Key’s lines of business, visit our Media Newsroom at https://www.key.com/newsroom.
*****
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 11
KeyCorp
Fourth Quarter 2020
Financial Supplement
| Page | |||||
| Financial Highlights | |||||
| GAAP to Non-GAAP Reconciliation | |||||
| Consolidated Balance Sheets | |||||
| Consolidated Statements of Income | |||||
| Consolidated Average Balance Sheets, and Net Interest Income and Yields/Rates From Continuing Operations | |||||
| Noninterest Expense | |||||
| Personnel Expense | |||||
| Loan Composition | |||||
| Loans Held for Sale Composition | |||||
| Summary of Changes in Loans Held for Sale | |||||
| Summary of Loan and Lease Loss Experience From Continuing Operations | |||||
| Asset Quality Statistics From Continuing Operations | |||||
| Summary of Nonperforming Assets and Past Due Loans From Continuing Operations | |||||
| Summary of Changes in Nonperforming Loans From Continuing Operations | |||||
| Line of Business Results | |||||
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 12
| Financial Highlights | |||||||||||||||||
| (dollars in millions, except per share amounts) | |||||||||||||||||
| Three months ended | |||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | |||||||||||||||
| Summary of operations | |||||||||||||||||
| Net interest income (TE) | $ | 1,043 | $ | 1,006 | $ | 987 | |||||||||||
| Noninterest income | 802 | 681 | 651 | ||||||||||||||
Total revenue (TE) | 1,845 | 1,687 | 1,638 | ||||||||||||||
| Provision for credit losses | 20 | 160 | 109 | ||||||||||||||
| Noninterest expense | 1,128 | 1,037 | 980 | ||||||||||||||
| Income (loss) from continuing operations attributable to Key | 575 | 424 | 466 | ||||||||||||||
| Income (loss) from discontinued operations, net of taxes | 7 | 4 | 3 | ||||||||||||||
| Net income (loss) attributable to Key | 582 | 428 | 469 | ||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | 549 | 397 | 439 | ||||||||||||||
| Income (loss) from discontinued operations, net of taxes | 7 | 4 | 3 | ||||||||||||||
| Net income (loss) attributable to Key common shareholders | 556 | 401 | 442 | ||||||||||||||
| Per common share | |||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | .57 | $ | .41 | $ | .45 | |||||||||||
| Income (loss) from discontinued operations, net of taxes | .01 | — | — | ||||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .57 | .41 | .45 | ||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders — assuming dilution | .56 | .41 | .45 | ||||||||||||||
| Income (loss) from discontinued operations, net of taxes — assuming dilution | .01 | — | — | ||||||||||||||
Net income (loss) attributable to Key common shareholders — assuming dilution (a) | .57 | .41 | .45 | ||||||||||||||
| Cash dividends declared | .185 | .185 | .185 | ||||||||||||||
| Book value at period end | 16.53 | 16.25 | 15.54 | ||||||||||||||
| Tangible book value at period end | 13.61 | 13.32 | 12.56 | ||||||||||||||
| Market price at period end | 16.41 | 11.93 | 20.24 | ||||||||||||||
| Performance ratios | |||||||||||||||||
| From continuing operations: | |||||||||||||||||
| Return on average total assets | 1.35 | % | 1.00 | % | 1.27 | % | |||||||||||
| Return on average common equity | 13.65 | 9.98 | 11.40 | ||||||||||||||
Return on average tangible common equity (b) | 16.61 | 12.19 | 14.09 | ||||||||||||||
| Net interest margin (TE) | 2.70 | 2.62 | 2.98 | ||||||||||||||
Cash efficiency ratio (b) | 60.3 | 60.6 | 58.7 | ||||||||||||||
| From consolidated operations: | |||||||||||||||||
| Return on average total assets | 1.36 | % | 1.00 | % | 1.27 | % | |||||||||||
| Return on average common equity | 13.82 | 10.08 | 11.48 | ||||||||||||||
Return on average tangible common equity (b) | 16.82 | 12.31 | 14.19 | ||||||||||||||
| Net interest margin (TE) | 2.69 | 2.62 | 2.97 | ||||||||||||||
Loan to deposit (c) | 76.5 | 77.2 | 86.6 | ||||||||||||||
| Capital ratios at period end | |||||||||||||||||
| Key shareholders’ equity to assets | 10.6 | % | 10.4 | % | 11.8 | % | |||||||||||
| Key common shareholders’ equity to assets | 9.5 | 9.3 | 10.5 | ||||||||||||||
Tangible common equity to tangible assets (b) | 7.9 | 7.8 | 8.6 | ||||||||||||||
Common Equity Tier 1 (d) | 9.8 | 9.5 | 9.4 | ||||||||||||||
Tier 1 risk-based capital (d) | 11.1 | 10.9 | 10.9 | ||||||||||||||
Total risk-based capital (d) | 13.4 | 13.3 | 12.8 | ||||||||||||||
Leverage (d) | 8.9 | 8.7 | 9.9 | ||||||||||||||
Asset quality — from continuing operations | |||||||||||||||||
Net loan charge-offs | $ | 135 | $ | 128 | $ | 99 | |||||||||||
Net loan charge-offs to average loans | .53 | % | .49 | % | .42 | % | |||||||||||
Allowance for loan and lease losses | $ | 1,626 | $ | 1,730 | $ | 900 | |||||||||||
Allowance for credit losses | 1,823 | 1,938 | 968 | ||||||||||||||
Allowance for loan and lease losses to period-end loans | 1.61 | % | 1.68 | % | .95 | % | |||||||||||
Allowance for credit losses to period-end loans | 1.80 | 1.88 | 1.02 | ||||||||||||||
Allowance for loan and lease losses to nonperforming loans (e) | 207.1 | 207.4 | 156.0 | ||||||||||||||
Allowance for credit losses to nonperforming loans (e) | 232.2 | 232.4 | 167.8 | ||||||||||||||
Nonperforming loans at period-end (e) | $ | 785 | $ | 834 | $ | 577 | |||||||||||
Nonperforming assets at period-end (e) | 937 | 1,003 | 715 | ||||||||||||||
Nonperforming loans to period-end portfolio loans (e) | .78 | % | .81 | % | .61 | % | |||||||||||
Nonperforming assets to period-end portfolio loans plus OREO and other nonperforming assets (e) | .92 | .97 | .75 | ||||||||||||||
Trust assets | |||||||||||||||||
Assets under management | $ | 44,140 | $ | 41,312 | $ | 40,833 | |||||||||||
Other data | |||||||||||||||||
Average full-time equivalent employees | 17,029 | 17,097 | 16,537 | ||||||||||||||
Branches | 1,073 | 1,077 | 1,098 | ||||||||||||||
Taxable-equivalent adjustment | $ | 8 | $ | 6 | $ | 8 | |||||||||||
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 13
| Financial Highlights (continued) | |||||||||||
| (dollars in millions, except per share amounts) | |||||||||||
| Twelve months ended | |||||||||||
| 12/31/2020 | 12/31/2019 | ||||||||||
| Summary of operations | |||||||||||
| Net interest income (TE) | $ | 4,063 | $ | 3,941 | |||||||
| Noninterest income | 2,652 | 2,459 | |||||||||
| Total revenue (TE) | 6,715 | 6,400 | |||||||||
| Provision for credit losses | 1,021 | 445 | |||||||||
| Noninterest expense | 4,109 | 3,901 | |||||||||
| Income (loss) from continuing operations attributable to Key | 1,329 | 1,708 | |||||||||
| Income (loss) from discontinued operations, net of taxes | 14 | 9 | |||||||||
| Net income (loss) attributable to Key | 1,343 | 1,717 | |||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | 1,223 | $ | 1,611 | |||||||
| Income (loss) from discontinued operations, net of taxes | 14 | 9 | |||||||||
| Net income (loss) attributable to Key common shareholders | 1,237 | 1,620 | |||||||||
| Per common share | |||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | 1.26 | $ | 1.62 | |||||||
| Income (loss) from discontinued operations, net of taxes | .01 | .01 | |||||||||
Net income (loss) attributable to Key common shareholders (a) | 1.28 | 1.63 | |||||||||
| Income (loss) from continuing operations attributable to Key common shareholders — assuming dilution | 1.26 | 1.61 | |||||||||
| Income (loss) from discontinued operations, net of taxes — assuming dilution | .01 | .01 | |||||||||
Net income (loss) attributable to Key common shareholders — assuming dilution (a) | 1.27 | 1.62 | |||||||||
| Cash dividends paid | .74 | .71 | |||||||||
| Performance ratios | |||||||||||
| From continuing operations: | |||||||||||
| Return on average total assets | .82 | % | 1.19 | % | |||||||
| Return on average common equity | 7.77 | 10.83 | |||||||||
Return on average tangible common equity (b) | 9.51 | 13.46 | |||||||||
| Net interest margin (TE) | 2.77 | 3.04 | |||||||||
Cash efficiency ratio (b) | 60.2 | 59.6 | |||||||||
| From consolidated operations: | |||||||||||
| Return on average total assets | .82 | % | 1.19 | % | |||||||
| Return on average common equity | 7.86 | 10.89 | |||||||||
Return on average tangible common equity (b) | 9.62 | 13.53 | |||||||||
| Net interest margin (TE) | 2.76 | 3.03 | |||||||||
| Asset quality — from continuing operations | |||||||||||
| Net loan charge-offs | $ | 443 | $ | 424 | |||||||
| Net loan charge-offs to average total loans | .43 | % | .46 | % | |||||||
| Other data | |||||||||||
| Average full-time equivalent employees | 16,826 | 17,045 | |||||||||
| Taxable-equivalent adjustment | 29 | 32 | |||||||||
(a)Earnings per share may not foot due to rounding.
(b)The following table entitled “GAAP to Non-GAAP Reconciliations” presents the computations of certain financial measures related to “tangible common equity” and “cash efficiency.” The table reconciles the GAAP performance measures to the corresponding non-GAAP measures, which provides a basis for period-to-period comparisons.
(c)Represents period-end consolidated total loans and loans held for sale divided by period-end consolidated total deposits.
(d)December 31, 2020, ratio is estimated and reflects Key's election to adopt the CECL optional transition provision.
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 14
GAAP to Non-GAAP Reconciliations
(dollars in millions)
The table below presents certain non-GAAP financial measures related to “tangible common equity,” “return on average tangible common equity,” “pre-provision net revenue," and “cash efficiency ratio" and certain ratios excluding notable items.
Notable items include certain revenue or expense items that may occur in a reporting period which management does not consider indicative of ongoing financial performance. Management believes it is useful to consider certain financial metrics with and without notable items, in order to enable a better understanding of company results, increase comparability of period-to-period results, and to evaluate and forecast those results.
The tangible common equity ratio and the return on average tangible common equity ratio have been a focus for some investors, and management believes these ratios may assist investors in analyzing Key’s capital position without regard to the effects of intangible assets and preferred stock.
The table also shows the computation for pre-provision net revenue, which is not formally defined by GAAP. Management believes that eliminating the effects of the provision for credit losses makes it easier to analyze the results by presenting them on a more comparable basis.
The cash efficiency ratio is a ratio of two non-GAAP performance measures. As such, there is no directly comparable GAAP performance measure. The cash efficiency ratio performance measure removes the impact of Key’s intangible asset amortization from the calculation. Management believes this ratio provide greater consistency and comparability between Key’s results and those of its peer banks. Additionally, this ratio is used by analysts and investors as they develop earnings forecasts and peer bank analysis.
Non-GAAP financial measures have inherent limitations, are not required to be uniformly applied, and are not audited. Although these non-GAAP financial measures are frequently used by investors to evaluate a company, they have limitations as analytical tools, and should not be considered in isolation, or as a substitute for analyses of results as reported under GAAP.
| Three months ended | Twelve months ended | |||||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | 12/31/2020 | 12/31/2019 | ||||||||||||||||
| Tangible common equity to tangible assets at period-end | ||||||||||||||||||||
| Key shareholders’ equity (GAAP) | $ | 17,981 | $ | 17,722 | $ | 17,038 | ||||||||||||||
Less: Intangible assets (a) | 2,848 | 2,862 | 2,910 | |||||||||||||||||
Preferred Stock (b) | 1,856 | 1,856 | 1,856 | |||||||||||||||||
| Tangible common equity (non-GAAP) | $ | 13,277 | $ | 13,004 | $ | 12,272 | ||||||||||||||
| Total assets (GAAP) | $ | 170,336 | $ | 170,540 | $ | 144,988 | ||||||||||||||
Less: Intangible assets (a) | 2,848 | 2,862 | 2,910 | |||||||||||||||||
| Tangible assets (non-GAAP) | $ | 167,488 | $ | 167,678 | $ | 142,078 | ||||||||||||||
| Tangible common equity to tangible assets ratio (non-GAAP) | 7.9 | % | 7.8 | % | 8.6 | % | ||||||||||||||
| Pre-provision net revenue | ||||||||||||||||||||
| Net interest income (GAAP) | $ | 1,035 | $ | 1,000 | $ | 979 | $ | 4,034 | $ | 3,909 | ||||||||||
| Plus: Taxable-equivalent adjustment | 8 | 6 | 8 | 29 | 32 | |||||||||||||||
| Noninterest income | 802 | 681 | 651 | 2,652 | 2,459 | |||||||||||||||
| Less: Noninterest expense | 1,128 | 1,037 | 980 | 4,109 | 3,901 | |||||||||||||||
| Pre-provision net revenue from continuing operations (non-GAAP) | $ | 717 | $ | 650 | $ | 658 | $ | 2,606 | $ | 2,499 | ||||||||||
| Average tangible common equity | ||||||||||||||||||||
| Average Key shareholders' equity (GAAP) | $ | 17,905 | $ | 17,730 | $ | 17,178 | $ | 17,636 | $ | 16,636 | ||||||||||
Less: Intangible assets (average) (c) | 2,855 | 2,870 | 2,919 | 2,878 | 2,909 | |||||||||||||||
| Preferred stock (average) | 1,900 | 1,900 | 1,900 | 1,900 | 1,755 | |||||||||||||||
| Average tangible common equity (non-GAAP) | $ | 13,150 | $ | 12,960 | $ | 12,359 | $ | 12,858 | $ | 11,972 | ||||||||||
| Return on average tangible common equity from continuing operations | ||||||||||||||||||||
Net income (loss) from continuing operations attributable to Key common shareholders (GAAP) | $ | 549 | $ | 397 | $ | 439 | $ | 1,223 | $ | 1,611 | ||||||||||
Plus: Notable items, after tax (d) | — | — | 29 | — | 183 | |||||||||||||||
Net income (loss) from continuing operations attributable to Key common shareholders excluding notable items (non-GAAP) | $ | 549 | $ | 397 | $ | 468 | $ | 1,223 | $ | 1,794 | ||||||||||
| Average tangible common equity (non-GAAP) | 13,150 | 12,960 | 12,359 | 12,858 | 11,972 | |||||||||||||||
Return on average tangible common equity from continuing operations (non-GAAP) | 16.61 | % | 12.19 | % | 14.09 | % | 9.51 | % | 13.46 | % | ||||||||||
Return on average tangible common equity from continuing operations excluding notable items (non-GAAP) | 16.61 | % | 12.19 | % | 15.02 | % | 9.51 | % | 14.98 | % | ||||||||||
| Return on average tangible common equity consolidated | ||||||||||||||||||||
| Net income (loss) attributable to Key common shareholders (GAAP) | $ | 556 | $ | 401 | $ | 442 | $ | 1,237 | $ | 1,620 | ||||||||||
| Average tangible common equity (non-GAAP) | 13,150 | 12,960 | 12,359 | 12,858 | 11,972 | |||||||||||||||
| Return on average tangible common equity consolidated (non-GAAP) | 16.82 | % | 12.31 | % | 14.19 | % | 9.62 | % | 13.53 | % | ||||||||||
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 15
| GAAP to Non-GAAP Reconciliations (continued) | ||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||
| Three months ended | Twelve months ended | |||||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | 12/31/2020 | 12/31/2019 | ||||||||||||||||
| Cash efficiency ratio | ||||||||||||||||||||
| Noninterest expense (GAAP) | $ | 1,128 | $ | 1,037 | $ | 980 | $ | 4,109 | $ | 3,901 | ||||||||||
| Less: Intangible asset amortization | 15 | 15 | 19 | 65 | 89 | |||||||||||||||
| Adjusted noninterest expense (non-GAAP) | $ | 1,113 | $ | 1,022 | $ | 961 | $ | 4,044 | $ | 3,812 | ||||||||||
Less: Notable items (d) | — | — | 22 | — | 100 | |||||||||||||||
| Adjusted noninterest expense excluding notable items (non-GAAP) | $ | 1,113 | $ | 1,022 | $ | 939 | $ | 4,044 | $ | 3,712 | ||||||||||
| Net interest income (GAAP) | $ | 1,035 | $ | 1,000 | $ | 979 | $ | 4,034 | $ | 3,909 | ||||||||||
| Plus: Taxable-equivalent adjustment | 8 | 6 | 8 | 29 | 32 | |||||||||||||||
| Noninterest income | 802 | 681 | 651 | 2,652 | 2,459 | |||||||||||||||
| Total taxable-equivalent revenue (non-GAAP) | $ | 1,845 | $ | 1,687 | $ | 1,638 | $ | 6,715 | $ | 6,400 | ||||||||||
| Cash efficiency ratio (non-GAAP) | 60.3 | % | 60.6 | % | 58.7 | % | 60.2 | % | 59.6 | % | ||||||||||
| Cash efficiency ratio excluding notable items (non-GAAP) | 60.3 | % | 60.6 | % | 57.3 | % | 60.2 | % | 58.0 | % | ||||||||||
(a)For the three months ended December 31, 2020, September 30, 2020, and December 31, 2019, intangible assets exclude $4 million, $5 million, and $7 million, respectively, of period-end purchased credit card receivables.
(b)Net of capital surplus.
(c)For the three months ended December 31, 2020, September 30, 2020, and December 31, 2019, average intangible assets exclude $5 million, $5 million, and $8 million, respectively, of average purchased credit card receivables. For the twelve months ended December 31, 2020, and December 31, 2019, average intangible assets exclude $6 million and $10 million, respectively, of average purchase credit card receivables.
(d)Additional detail provided in Notable Items table on page 24 of this release.
GAAP = U.S. generally accepted accounting principles
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 16
| Consolidated Balance Sheets | |||||||||||||||||
| (dollars in millions) | |||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | |||||||||||||||
| Assets | |||||||||||||||||
| Loans | $ | 101,185 | $ | 103,081 | $ | 94,646 | |||||||||||
| Loans held for sale | 1,583 | 1,724 | 1,334 | ||||||||||||||
| Securities available for sale | 27,556 | 26,895 | 21,843 | ||||||||||||||
| Held-to-maturity securities | 7,595 | 8,384 | 10,067 | ||||||||||||||
| Trading account assets | 735 | 733 | 1,040 | ||||||||||||||
| Short-term investments | 16,194 | 14,148 | 1,272 | ||||||||||||||
| Other investments | 621 | 620 | 605 | ||||||||||||||
| Total earning assets | 155,469 | 155,585 | 130,807 | ||||||||||||||
| Allowance for loan and lease losses | (1,626) | (1,730) | (900) | ||||||||||||||
| Cash and due from banks | 1,091 | 956 | 732 | ||||||||||||||
| Premises and equipment | 753 | 765 | 814 | ||||||||||||||
| Goodwill | 2,664 | 2,664 | 2,664 | ||||||||||||||
| Other intangible assets | 188 | 203 | 253 | ||||||||||||||
| Corporate-owned life insurance | 4,286 | 4,274 | 4,233 | ||||||||||||||
| Accrued income and other assets | 6,812 | 7,084 | 5,494 | ||||||||||||||
| Discontinued assets | 699 | 739 | 891 | ||||||||||||||
| Total assets | $ | 170,336 | 170,540 | 144,988 | |||||||||||||
| Liabilities | |||||||||||||||||
| Deposits in domestic offices: | |||||||||||||||||
| NOW and money market deposit accounts | $ | 80,427 | $ | 80,791 | $ | 66,714 | |||||||||||
| Savings deposits | 5,913 | 5,585 | 4,651 | ||||||||||||||
| Certificates of deposit ($100,000 or more) | 2,733 | 3,345 | 6,598 | ||||||||||||||
| Other time deposits | 3,010 | 3,450 | 5,054 | ||||||||||||||
| Total interest-bearing deposits | 92,083 | 93,171 | 83,017 | ||||||||||||||
| Noninterest-bearing deposits | 43,199 | 43,575 | 28,853 | ||||||||||||||
| Total deposits | 135,282 | 136,746 | 111,870 | ||||||||||||||
| Federal funds purchased and securities sold under repurchase agreements | 220 | 213 | 387 | ||||||||||||||
| Bank notes and other short-term borrowings | 759 | 818 | 705 | ||||||||||||||
| Accrued expense and other liabilities | 2,385 | 2,356 | 2,540 | ||||||||||||||
| Long-term debt | 13,709 | 12,685 | 12,448 | ||||||||||||||
| Total liabilities | 152,355 | 152,818 | 127,950 | ||||||||||||||
| Equity | |||||||||||||||||
| Preferred stock | 1,900 | 1,900 | 1,900 | ||||||||||||||
| Common shares | 1,257 | 1,257 | 1,257 | ||||||||||||||
| Capital surplus | 6,281 | 6,263 | 6,295 | ||||||||||||||
| Retained earnings | 12,751 | 12,375 | 12,469 | ||||||||||||||
| Treasury stock, at cost | (4,946) | (4,940) | (4,909) | ||||||||||||||
| Accumulated other comprehensive income (loss) | 738 | 867 | 26 | ||||||||||||||
| Key shareholders’ equity | 17,981 | 17,722 | 17,038 | ||||||||||||||
| Noncontrolling interests | — | — | — | ||||||||||||||
| Total equity | 17,981 | 17,722 | 17,038 | ||||||||||||||
| Total liabilities and equity | $ | 170,336 | $ | 170,540 | $ | 144,988 | |||||||||||
| Common shares outstanding (000) | 975,773 | 976,205 | 977,189 | ||||||||||||||
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 17
| Consolidated Statements of Income | ||||||||||||||||||||||||||
| (dollars in millions, except per share amounts) | ||||||||||||||||||||||||||
Three months ended | Twelve months ended | |||||||||||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | 12/31/2020 | 12/31/2019 | ||||||||||||||||||||||
| Interest income | ||||||||||||||||||||||||||
| Loans | $ | 933 | $ | 927 | $ | 1,046 | $ | 3,866 | $ | 4,267 | ||||||||||||||||
| Loans held for sale | 11 | 18 | 17 | 69 | 63 | |||||||||||||||||||||
| Securities available for sale | 119 | 115 | 137 | 484 | 537 | |||||||||||||||||||||
| Held-to-maturity securities | 51 | 53 | 63 | 222 | 262 | |||||||||||||||||||||
| Trading account assets | 4 | 3 | 8 | 20 | 32 | |||||||||||||||||||||
| Short-term investments | 4 | 1 | 12 | 18 | 61 | |||||||||||||||||||||
| Other investments | 3 | 2 | 2 | 6 | 13 | |||||||||||||||||||||
| Total interest income | 1,125 | 1,119 | 1,285 | 4,685 | 5,235 | |||||||||||||||||||||
| Interest expense | ||||||||||||||||||||||||||
| Deposits | 28 | 54 | 201 | 347 | 853 | |||||||||||||||||||||
| Federal funds purchased and securities sold under repurchase agreements | — | — | 1 | 6 | 2 | |||||||||||||||||||||
| Bank notes and other short-term borrowings | 1 | 1 | 4 | 12 | 17 | |||||||||||||||||||||
| Long-term debt | 61 | 64 | 100 | 286 | 454 | |||||||||||||||||||||
| Total interest expense | 90 | 119 | 306 | 651 | 1326 | |||||||||||||||||||||
| Net interest income | 1,035 | 1,000 | 979 | 4,034 | 3,909 | |||||||||||||||||||||
| Provision for credit losses | 20 | 160 | 109 | 1,021 | 445 | |||||||||||||||||||||
| Net interest income after provision for credit losses | 1015 | 840 | 870 | 3,013 | 3,464 | |||||||||||||||||||||
| Noninterest income | ||||||||||||||||||||||||||
| Trust and investment services income | 123 | 128 | 120 | 507 | 475 | |||||||||||||||||||||
| Investment banking and debt placement fees | 243 | 146 | 181 | 661 | 630 | |||||||||||||||||||||
| Service charges on deposit accounts | 82 | 77 | 86 | 311 | 337 | |||||||||||||||||||||
| Operating lease income and other leasing gains | 39 | 38 | 39 | 167 | 162 | |||||||||||||||||||||
| Corporate services income | 63 | 51 | 65 | 228 | 236 | |||||||||||||||||||||
| Cards and payments income | 97 | 114 | 67 | 368 | 275 | |||||||||||||||||||||
| Corporate-owned life insurance income | 38 | 30 | 39 | 139 | 136 | |||||||||||||||||||||
| Consumer mortgage income | 43 | 51 | 21 | 176 | 63 | |||||||||||||||||||||
| Commercial mortgage servicing fees | 32 | 18 | 19 | 80 | 77 | |||||||||||||||||||||
| Other income | 42 | 28 | 14 | 15 | 68 | |||||||||||||||||||||
| Total noninterest income | 802 | 681 | 651 | 2,652 | 2,459 | |||||||||||||||||||||
| Noninterest expense | ||||||||||||||||||||||||||
| Personnel | 661 | 588 | 551 | 2,336 | 2,250 | |||||||||||||||||||||
| Net occupancy | 75 | 76 | 76 | 298 | 293 | |||||||||||||||||||||
| Computer processing | 62 | 59 | 51 | 232 | 214 | |||||||||||||||||||||
| Business services and professional fees | 54 | 49 | 54 | 196 | 186 | |||||||||||||||||||||
| Equipment | 26 | 25 | 25 | 100 | 100 | |||||||||||||||||||||
| Operating lease expense | 35 | 33 | 32 | 138 | 123 | |||||||||||||||||||||
| Marketing | 30 | 22 | 27 | 97 | 96 | |||||||||||||||||||||
| FDIC assessment | 9 | 6 | 8 | 32 | 31 | |||||||||||||||||||||
| Intangible asset amortization | 15 | 15 | 19 | 65 | 89 | |||||||||||||||||||||
| OREO expense, net | — | (1) | 3 | 8 | 13 | |||||||||||||||||||||
| Other expense | 161 | 165 | 134 | 607 | 506 | |||||||||||||||||||||
| Total noninterest expense | 1,128 | 1,037 | 980 | 4,109 | 3,901 | |||||||||||||||||||||
| Income (loss) from continuing operations before income taxes | 689 | 484 | 541 | 1,556 | 2,022 | |||||||||||||||||||||
| Income taxes | 114 | 60 | 75 | 227 | 314 | |||||||||||||||||||||
| Income (loss) from continuing operations | 575 | 424 | 466 | 1,329 | 1,708 | |||||||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | 7 | 4 | 3 | 14 | 9 | |||||||||||||||||||||
| Net income (loss) | 582 | 428 | 469 | 1,343 | 1,717 | |||||||||||||||||||||
| Less: Net income (loss) attributable to noncontrolling interests | — | — | — | — | — | |||||||||||||||||||||
| Net income (loss) attributable to Key | $ | 582 | $ | 428 | $ | 469 | $ | 1,343 | $ | 1,717 | ||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | 549 | $ | 397 | $ | 439 | $ | 1,223 | $ | 1,611 | ||||||||||||||||
| Net income (loss) attributable to Key common shareholders | 556 | 401 | 442 | 1,237 | 1,620 | |||||||||||||||||||||
| Per common share | ||||||||||||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | .57 | $ | .41 | $ | .45 | $ | 1.26 | $ | 1.62 | ||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | 0.01 | — | — | .01 | .01 | |||||||||||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .57 | .41 | .45 | 1.28 | 1.63 | |||||||||||||||||||||
| Per common share — assuming dilution | ||||||||||||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | .56 | $ | .41 | $ | .45 | $ | 1.26 | $ | 1.61 | ||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | 0.01 | — | — | .01 | .01 | |||||||||||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .57 | .41 | .45 | 1.27 | 1.62 | |||||||||||||||||||||
| Cash dividends declared per common share | $ | .185 | $ | .185 | $ | .185 | $ | .740 | $ | .710 | ||||||||||||||||
| Weighted-average common shares outstanding (000) | 967,987 | 967,804 | 973,450 | 967,783 | 992,091 | |||||||||||||||||||||
| Effect of common share options and other stock awards | 8,473 | 6,184 | 10,911 | 7,024 | 10,163 | |||||||||||||||||||||
Weighted-average common shares and potential common shares outstanding (000) (b) | 976,460 | 973,988 | 984,361 | 974,807 | 1,002,254 | |||||||||||||||||||||
(a)Earnings per share may not foot due to rounding.
(b)Assumes conversion of common share options and other stock awards, as applicable.
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 18
| Consolidated Average Balance Sheets, and Net Interest Income and Yields/Rates From Continuing Operations | ||||||||||||||||||||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||||||||||||||||||||
| Fourth Quarter 2020 | Third Quarter 2020 | Fourth Quarter 2019 | ||||||||||||||||||||||||||||||||||||
| Average | Yield/ | Average | Yield/ | Average | Yield/ | |||||||||||||||||||||||||||||||||
| Balance | Interest (a) | Rate (a) | Balance | Interest (a) | Rate (a) | Balance | Interest (a) | Rate (a) | ||||||||||||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||||||||||||||
Loans: (b), (c) | ||||||||||||||||||||||||||||||||||||||
Commercial and industrial (d) | $ | 53,562 | $ | 477 | 3.54 | % | $ | 57,067 | $ | 474 | 3.31 | % | $ | 48,345 | $ | 522 | 4.28 | % | ||||||||||||||||||||
| Real estate — commercial mortgage | 12,862 | 121 | 3.74 | 13,202 | 117 | 3.54 | 13,335 | 159 | 4.71 | |||||||||||||||||||||||||||||
| Real estate — construction | 1,959 | 19 | 3.79 | 1,987 | 18 | 3.57 | 1,495 | 18 | 4.87 | |||||||||||||||||||||||||||||
| Commercial lease financing | 4,353 | 32 | 2.92 | 4,488 | 35 | 3.10 | 4,482 | 39 | 3.52 | |||||||||||||||||||||||||||||
| Total commercial loans | 72,736 | 649 | 3.55 | 76,744 | 644 | 3.34 | 67,657 | 738 | 4.33 | |||||||||||||||||||||||||||||
| Real estate — residential mortgage | 8,968 | 74 | 3.29 | 8,398 | 73 | 3.46 | 6,777 | 65 | 3.83 | |||||||||||||||||||||||||||||
| Home equity loans | 9,410 | 91 | 3.81 | 9,580 | 91 | 3.82 | 10,362 | 122 | 4.69 | |||||||||||||||||||||||||||||
| Consumer direct loans | 4,583 | 56 | 4.93 | 4,403 | 56 | 5.07 | 3,125 | 51 | 6.45 | |||||||||||||||||||||||||||||
| Credit cards | 973 | 26 | 10.57 | 967 | 25 | 10.24 | 1,103 | 32 | 11.38 | |||||||||||||||||||||||||||||
| Consumer indirect loans | 5,040 | 45 | 3.56 | 4,827 | 44 | 3.66 | 4,583 | 46 | 3.99 | |||||||||||||||||||||||||||||
| Total consumer loans | 28,974 | 292 | 4.01 | 28,175 | 289 | 4.10 | 25,950 | 316 | 4.84 | |||||||||||||||||||||||||||||
| Total loans | 101,710 | 941 | 3.68 | 104,919 | 933 | 3.55 | 93,607 | 1,054 | 4.47 | |||||||||||||||||||||||||||||
| Loans held for sale | 1,621 | 11 | 2.76 | 1,924 | 17 | 3.61 | 1,653 | 17 | 4.11 | |||||||||||||||||||||||||||||
Securities available for sale (b), (e) | 28,046 | 119 | 1.75 | 24,941 | 115 | 1.90 | 22,262 | 137 | 2.49 | |||||||||||||||||||||||||||||
Held-to-maturity securities (b) | 7,939 | 51 | 2.56 | 8,677 | 53 | 2.44 | 10,264 | 63 | 2.43 | |||||||||||||||||||||||||||||
| Trading account assets | 744 | 4 | 2.21 | 686 | 4 | 2.08 | 1,103 | 8 | 3.08 | |||||||||||||||||||||||||||||
| Short-term investments | 14,111 | 4 | .14 | 12,525 | 1 | 0.04 | 2,716 | 12 | 1.73 | |||||||||||||||||||||||||||||
Other investments (e) | 615 | 3 | 1.31 | 640 | 2 | 1.49 | 603 | 2 | 1.82 | |||||||||||||||||||||||||||||
| Total earning assets | 154,786 | 1,133 | 2.93 | 154,312 | 1,125 | 2.93 | 132,208 | 1,293 | 3.90 | |||||||||||||||||||||||||||||
| Allowance for loan and lease losses | (1,715) | (1,696) | (882) | |||||||||||||||||||||||||||||||||||
| Accrued income and other assets | 15,861 | 16,195 | 14,402 | |||||||||||||||||||||||||||||||||||
| Discontinued assets | 717 | 752 | 908 | |||||||||||||||||||||||||||||||||||
| Total assets | $ | 169,649 | $ | 169,563 | $ | 146,636 | ||||||||||||||||||||||||||||||||
| Liabilities | ||||||||||||||||||||||||||||||||||||||
| NOW and money market deposit accounts | $ | 80,636 | 12 | .06 | $ | 80,175 | 26 | .13 | $ | 66,412 | 135 | .81 | ||||||||||||||||||||||||||
| Savings deposits | 5,737 | — | .03 | 5,478 | 1 | .04 | 4,660 | 1 | .07 | |||||||||||||||||||||||||||||
| Certificates of deposit ($100,000 or more) | 2,983 | 9 | 1.20 | 3,862 | 16 | 1.60 | 6,899 | 40 | 2.31 | |||||||||||||||||||||||||||||
| Other time deposits | 3,209 | 7 | .80 | 3,735 | 11 | 1.17 | 5,187 | 25 | 1.92 | |||||||||||||||||||||||||||||
| Total interest-bearing deposits | 92,565 | 28 | .12 | 93,250 | 54 | .23 | 83,158 | 201 | .96 | |||||||||||||||||||||||||||||
Federal funds purchased and securities sold under repurchase agreements | 220 | — | .04 | 225 | — | .05 | 267 | 1 | .75 | |||||||||||||||||||||||||||||
| Bank notes and other short-term borrowings | 791 | 1 | .73 | 761 | 1 | .68 | 801 | 4 | 2.02 | |||||||||||||||||||||||||||||
Long-term debt (f), (g) | 12,118 | 61 | 2.05 | 12,801 | 64 | 2.12 | 12,531 | 100 | 3.22 | |||||||||||||||||||||||||||||
| Total interest-bearing liabilities | 105,694 | 90 | .34 | 107,037 | 119 | .45 | 96,757 | 306 | 1.25 | |||||||||||||||||||||||||||||
| Noninterest-bearing deposits | 43,156 | 41,694 | 29,446 | |||||||||||||||||||||||||||||||||||
| Accrued expense and other liabilities | 2,177 | 2,350 | 2,347 | |||||||||||||||||||||||||||||||||||
Discontinued liabilities (g) | 717 | 752 | 908 | |||||||||||||||||||||||||||||||||||
| Total liabilities | 151,744 | 151,833 | 129,458 | |||||||||||||||||||||||||||||||||||
| Equity | ||||||||||||||||||||||||||||||||||||||
| Key shareholders’ equity | 17,905 | 17,730 | 17,178 | |||||||||||||||||||||||||||||||||||
| Noncontrolling interests | — | — | — | |||||||||||||||||||||||||||||||||||
| Total equity | 17,905 | 17,730 | 17,178 | |||||||||||||||||||||||||||||||||||
| Total liabilities and equity | $ | 169,649 | $ | 169,563 | $ | 146,636 | ||||||||||||||||||||||||||||||||
| Interest rate spread (TE) | 2.59 | % | 2.48 | % | 2.65 | % | ||||||||||||||||||||||||||||||||
Net interest income (TE) and net interest margin (TE) | 1,043 | 2.70 | % | 1,006 | 2.62 | % | 987 | 2.98 | % | |||||||||||||||||||||||||||||
TE adjustment (b) | 8 | 6 | 8 | |||||||||||||||||||||||||||||||||||
| Net interest income, GAAP basis | $ | 1,035 | $ | 1,000 | $ | 979 | ||||||||||||||||||||||||||||||||
(a)Results are from continuing operations. Interest excludes the interest associated with the liabilities referred to in (g) below, calculated using a matched funds transfer pricing methodology.
(b)Interest income on tax-exempt securities and loans has been adjusted to a taxable-equivalent basis using the statutory federal income tax rate of 21% for the three months ended December 31, 2020, September 30, 2020, and December 31, 2019.
(c)For purposes of these computations, nonaccrual loans are included in average loan balances.
(d)Commercial and industrial average balances include $129 million, $129 million, and $146 million of assets from commercial credit cards for the three months ended December 31, 2020, September 30, 2020, and December 31, 2019, respectively.
(e)Yield is calculated on the basis of amortized cost.
(f)Rate calculation excludes basis adjustments related to fair value hedges.
(g)A portion of long-term debt and the related interest expense is allocated to discontinued liabilities as a result of applying Key’s matched funds transfer pricing methodology to discontinued operations.
TE = Taxable Equivalent, GAAP = U.S. generally accepted accounting principles
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 19
| Consolidated Average Balance Sheets, and Net Interest Income and Yields/Rates From Continuing Operations | ||||||||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||||||||
| Twelve months ended December 31, 2020 | Twelve months ended December 31, 2019 | |||||||||||||||||||||||||
| Average | Yield/ | Average | Yield/ | |||||||||||||||||||||||
| Balance | Interest (a) | Rate (a) | Balance | Interest (a) | Rate (a) | |||||||||||||||||||||
| Assets | ||||||||||||||||||||||||||
Loans: (b), (c) | ||||||||||||||||||||||||||
Commercial and industrial (d) | $ | 55,145 | $ | 1,977 | 3.59 | % | $ | 47,482 | $ | 2,144 | 4.51 | % | ||||||||||||||
| Real estate — commercial mortgage | 13,279 | 521 | 3.92 | 13,641 | 676 | 4.95 | ||||||||||||||||||||
| Real estate — construction | 1,843 | 74 | 3.99 | 1,485 | 78 | 5.24 | ||||||||||||||||||||
| Commercial lease financing | 4,497 | 139 | 3.09 | 4,488 | 163 | 3.63 | ||||||||||||||||||||
| Total commercial loans | 74,764 | 2,711 | 3.63 | 67,096 | 3,061 | 4.56 | ||||||||||||||||||||
| Real estate — residential mortgage | 8,094 | 284 | 3.50 | 6,095 | 241 | 3.95 | ||||||||||||||||||||
| Home equity loans | 9,772 | 392 | 4.01 | 10,634 | 526 | 4.95 | ||||||||||||||||||||
| Consumer direct loans | 4,213 | 221 | 5.26 | 2,475 | 176 | 7.11 | ||||||||||||||||||||
| Credit cards | 1,001 | 107 | 10.65 | 1,100 | 127 | 11.51 | ||||||||||||||||||||
| Consumer indirect loans | 4,845 | 180 | 3.72 | 4,111 | 168 | 4.09 | ||||||||||||||||||||
| Total consumer loans | 27,925 | 1,184 | 4.24 | 24,415 | 1,238 | 5.07 | ||||||||||||||||||||
| Total loans | 102,689 | 3,895 | 3.79 | 91,511 | 4,299 | 4.70 | ||||||||||||||||||||
| Loans held for sale | 1,972 | 69 | 3.49 | 1,411 | 63 | 4.48 | ||||||||||||||||||||
Securities available for sale (b), (e) | 23,742 | 484 | 2.10 | 21,362 | 537 | 2.51 | ||||||||||||||||||||
Held-to-maturity securities (b) | 8,938 | 222 | 2.49 | 10,841 | 262 | 2.41 | ||||||||||||||||||||
| Trading account assets | 814 | 20 | 2.47 | 1017 | 32 | 3.18 | ||||||||||||||||||||
| Short-term investments | 9,096 | 18 | .20 | 2,876 | 61 | 2.11 | ||||||||||||||||||||
Other investments (e) | 635 | 6 | .87 | 630 | 13 | 2.09 | ||||||||||||||||||||
| Total earning assets | 147,886 | 4,714 | 3.20 | 129,648 | 5,267 | 4.06 | ||||||||||||||||||||
| Allowance for loan and lease losses | (1481) | (880) | ||||||||||||||||||||||||
| Accrued income and other assets | 15,650 | 14,411 | ||||||||||||||||||||||||
| Discontinued assets | 775 | 984 | ||||||||||||||||||||||||
| Total assets | $ | 162,830 | $ | 144,163 | ||||||||||||||||||||||
| Liabilities | ||||||||||||||||||||||||||
| NOW and money market deposit accounts | $ | 75,733 | 206 | .27 | $ | 63,731 | 566 | .89 | ||||||||||||||||||
| Savings deposits | 5,252 | 2 | .04 | 4,740 | 4 | .09 | ||||||||||||||||||||
| Certificates of deposit ($100,000 or more) | 4,520 | 83 | 1.83 | 7,757 | 180 | 2.32 | ||||||||||||||||||||
| Other time deposits | 4,041 | 56 | 1.38 | 5,426 | 103 | 1.90 | ||||||||||||||||||||
| Total interest-bearing deposits | 89,546 | 347 | .39 | 81,654 | 853 | 1.04 | ||||||||||||||||||||
| Federal funds purchased and securities sold under repurchase agreements | 670 | 6 | .88 | 264 | 2 | .66 | ||||||||||||||||||||
| Bank notes and other short-term borrowings | 1,452 | 12 | .85 | 730 | 17 | 2.31 | ||||||||||||||||||||
Long-term debt (f), (g) | 12,578 | 286 | 2.36 | 13,062 | 454 | 3.52 | ||||||||||||||||||||
| Total interest-bearing liabilities | 104,246 | 651 | .63 | 95,710 | 1326 | 1.39 | ||||||||||||||||||||
| Noninterest-bearing deposits | 37,740 | 28,376 | ||||||||||||||||||||||||
| Accrued expense and other liabilities | 2,433 | 2,456 | ||||||||||||||||||||||||
Discontinued liabilities (g) | 775 | 984 | ||||||||||||||||||||||||
| Total liabilities | 145,194 | 127,526 | ||||||||||||||||||||||||
| Equity | ||||||||||||||||||||||||||
| Key shareholders’ equity | 17,636 | 16,636 | ||||||||||||||||||||||||
| Noncontrolling interests | — | 1 | ||||||||||||||||||||||||
| Total equity | 17,636 | 16,637 | ||||||||||||||||||||||||
| Total liabilities and equity | $ | 162,830 | $ | 144,163 | ||||||||||||||||||||||
| Interest rate spread (TE) | 2.57 | % | 2.67 | % | ||||||||||||||||||||||
| Net interest income (TE) and net interest margin (TE) | 4,063 | 2.77 | % | 3,941 | 3.04 | % | ||||||||||||||||||||
TE adjustment (b) | 29 | 32 | ||||||||||||||||||||||||
| Net interest income, GAAP basis | $ | 4,034 | $ | 3,909 | ||||||||||||||||||||||
(a)Results are from continuing operations. Interest excludes the interest associated with the liabilities referred to in (g) below, calculated using a matched funds transfer pricing methodology.
(b)Interest income on tax-exempt securities and loans has been adjusted to a taxable-equivalent basis using the statutory federal income tax rate of 21% for the twelve months ended December 31, 2020, and December 31, 2019, respectively.
(c)For purposes of these computations, nonaccrual loans are included in average loan balances.
(d)Commercial and industrial average balances include $135 million and $141 million of assets from commercial credit cards for the twelve months ended December 31, 2020, and December 31, 2019, respectively.
(e)Yield is calculated on the basis of amortized cost.
(f)Rate calculation excludes basis adjustments related to fair value hedges.
(g)A portion of long-term debt and the related interest expense is allocated to discontinued liabilities as a result of applying Key’s matched funds transfer pricing methodology to discontinued operations.
TE = Taxable Equivalent, GAAP = U.S. generally accepted accounting principles
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 20
| Noninterest Expense | ||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||
| Three months ended | Twelve months ended | |||||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | 12/31/2020 | 12/31/2019 | ||||||||||||||||
Personnel (a) | $ | 661 | $ | 588 | $ | 551 | $ | 2,336 | $ | 2,250 | ||||||||||
| Net occupancy | 75 | 76 | 76 | 298 | 293 | |||||||||||||||
| Computer processing | 62 | 59 | 51 | 232 | 214 | |||||||||||||||
| Business services and professional fees | 54 | 49 | 54 | 196 | 186 | |||||||||||||||
| Equipment | 26 | 25 | 25 | 100 | 100 | |||||||||||||||
| Operating lease expense | 35 | 33 | 32 | 138 | 123 | |||||||||||||||
| Marketing | 30 | 22 | 27 | 97 | 96 | |||||||||||||||
| FDIC assessment | 9 | 6 | 8 | 32 | 31 | |||||||||||||||
| Intangible asset amortization | 15 | 15 | 19 | 65 | 89 | |||||||||||||||
| OREO expense, net | — | (1) | 3 | 8 | 13 | |||||||||||||||
| Other expense | 161 | 165 | 134 | 607 | 506 | |||||||||||||||
| Total noninterest expense | $ | 1,128 | $ | 1,037 | $ | 980 | $ | 4,109 | $ | 3,901 | ||||||||||
Average full-time equivalent employees (b) | 17,029 | 17,097 | 16,537 | 16,826 | 17,045 | |||||||||||||||
(a)Additional detail provided in Personnel Expense table below.
(b)The number of average full-time equivalent employees has not been adjusted for discontinued operations.
| Personnel Expense | ||||||||||||||||||||
| (in millions) | ||||||||||||||||||||
| Three months ended | Twelve months ended | |||||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | 12/31/2020 | 12/31/2019 | ||||||||||||||||
| Salaries and contract labor | $ | 342 | $ | 339 | $ | 312 | $ | 1,329 | $ | 1,268 | ||||||||||
| Incentive and stock-based compensation | 208 | 155 | 154 | 627 | 584 | |||||||||||||||
| Employee benefits | 89 | 93 | 85 | 350 | 348 | |||||||||||||||
| Severance | 22 | 1 | — | 30 | 50 | |||||||||||||||
| Total personnel expense | $ | 661 | $ | 588 | $ | 551 | $ | 2,336 | $ | 2,250 | ||||||||||
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 21
| Loan Composition | ||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||
| Percent change 12/31/2020 vs | ||||||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | 9/30/2020 | 12/31/2019 | ||||||||||||||||
Commercial and industrial (a) | $ | 52,907 | $ | 55,025 | $ | 48,295 | (3.8) | % | 9.5 | % | ||||||||||
| Commercial real estate: | ||||||||||||||||||||
| Commercial mortgage | 12,687 | 13,059 | 13,491 | (2.8) | (6.0) | |||||||||||||||
| Construction | 1,987 | 1,947 | 1,558 | 2.1 | 27.5 | |||||||||||||||
| Total commercial real estate loans | 14,674 | 15,006 | 15,049 | (2.2) | (2.5) | |||||||||||||||
Commercial lease financing (b) | 4,399 | 4,450 | 4,688 | (1.1) | (6.2) | |||||||||||||||
| Total commercial loans | 71,980 | 74,481 | 68,032 | (3.4) | 5.8 | |||||||||||||||
| Residential — prime loans: | ||||||||||||||||||||
| Real estate — residential mortgage | 9,298 | 8,715 | 7,023 | 6.7 | 32.4 | |||||||||||||||
| Home equity loans | 9,360 | 9,488 | 10,274 | (1.3) | (8.9) | |||||||||||||||
| Total residential — prime loans | 18,658 | 18,203 | 17,297 | 2.5 | 7.9 | |||||||||||||||
| Consumer direct loans | 4,714 | 4,395 | 3,513 | 7.3 | 34.2 | |||||||||||||||
| Credit cards | 989 | 970 | 1,130 | 2.0 | (12.5) | |||||||||||||||
| Consumer indirect loans | 4,844 | 5,032 | 4,674 | (3.7) | 3.6 | |||||||||||||||
| Total consumer loans | 29,205 | 28,600 | 26,614 | 2.1 | 9.7 | |||||||||||||||
Total loans (c), (d) | $ | 101,185 | $ | 103,081 | $ | 94,646 | (1.8) | % | 6.9 | % | ||||||||||
(a)Loan balances include $127 million, $128 million, and $144 million of commercial credit card balances at December 31, 2020, September 30, 2020, and December 31, 2019, respectively.
(b)Commercial lease financing includes receivables held as collateral for a secured borrowing of $23 million, $18 million, and $15 million at December 31, 2020, September 30, 2020, and December 31, 2019, respectively. Principal reductions are based on the cash payments received from these related receivables.
(c)Total loans exclude loans of $710 million at December 31, 2020, $743 million at September 30, 2020, and $865 million at December 31, 2019, related to the discontinued operations of the education lending business.
(d)Accrued interest of $241 million, $235 million, and $244 million at December 31, 2020, September 30, 2020, and December 31, 2019, respectively, presented in "other assets" on the Consolidated Balance Sheets is excluded from the amortized cost basis disclosed in this table.
| Loans Held for Sale Composition | ||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||
| Percent change 12/31/2020 vs | ||||||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | 9/30/2020 | 12/31/2019 | ||||||||||||||||
| Commercial and industrial | $ | 249 | $ | 336 | $ | 367 | (25.9) | % | (32.2) | % | ||||||||||
| Real estate — commercial mortgage | 1,014 | 1,031 | 772 | (1.6) | 31.3 | |||||||||||||||
| Commercial lease financing | — | 1 | 2 | N/M | N/M | |||||||||||||||
| Real estate — residential mortgage | 264 | 288 | 140 | (8.3) | 88.6 | |||||||||||||||
| Consumer direct loans | 56 | 68 | 53 | (17.6) | 5.7 | |||||||||||||||
Total loans held for sale (a) | $ | 1,583 | $ | 1,724 | $ | 1,334 | (8.2) | % | 18.7 | % | ||||||||||
(a)Total loans held for sale include Real estate — residential mortgage loans held for sale at fair value of $264 million at December 31, 2020, $288 million at September 30, 2020, and $140 million at December 31, 2019.
| Summary of Changes in Loans Held for Sale | |||||||||||||||||
| (in millions) | |||||||||||||||||
| 4Q20 | 3Q20 | 2Q20 | 1Q20 | 4Q19 | |||||||||||||
| Balance at beginning of period | $ | 1,724 | $ | 2,007 | $ | 2,143 | $ | 1,334 | $ | 1,598 | |||||||
| New originations | 3,835 | 3,282 | 3,621 | 3,333 | 3,659 | ||||||||||||
| Transfers from (to) held to maturity, net | (24) | 75 | (15) | 200 | 26 | ||||||||||||
| Loan sales | (3,932) | (3,583) | (3,679) | (2,649) | (3,933) | ||||||||||||
| Loan draws (payments), net | (19) | (57) | (61) | (77) | (18) | ||||||||||||
| Valuation adjustments | — | — | (2) | 2 | 2 | ||||||||||||
Balance at end of period (a) | $ | 1,583 | $ | 1,724 | $ | 2,007 | $ | 2,143 | $ | 1,334 | |||||||
(a)Total loans held for sale include Real estate — residential mortgage loans held for sale at fair value of $264 million at December 31, 2020, $288 million at September 30, 2020, $250 million at June 30, 2020, $152 million at March 31, 2020, and $140 million at December 31, 2019.
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 22
| Summary of Loan and Lease Loss Experience From Continuing Operations | ||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||
| Three months ended | Twelve months ended | |||||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | 12/31/2020 | 12/31/2019 | ||||||||||||||||
| Average loans outstanding | $ | 101,710 | $ | 104,919 | $ | 93,607 | $ | 102,689 | $ | 91,511 | ||||||||||
| Allowance for loan and lease losses at the end of the prior period | $ | 1,730 | $ | 1708 | $ | 893 | $ | 900 | $ | 883 | ||||||||||
Cumulative effect from change in accounting principle (a) | — | — | — | 204 | — | |||||||||||||||
| Allowance for loan and lease losses at the beginning of the period | 1,730 | 1,708 | 893 | 1,104 | 883 | |||||||||||||||
| Loans charged off: | ||||||||||||||||||||
| Commercial and industrial | 119 | 101 | 77 | 351 | 319 | |||||||||||||||
| Real estate — commercial mortgage | 1 | 13 | 2 | 19 | 8 | |||||||||||||||
| Real estate — construction | — | — | 1 | — | 5 | |||||||||||||||
| Total commercial real estate loans | 1 | 13 | 3 | 19 | 13 | |||||||||||||||
| Commercial lease financing | 19 | 10 | 1 | 35 | 26 | |||||||||||||||
| Total commercial loans | 139 | 124 | 81 | 405 | 358 | |||||||||||||||
| Real estate — residential mortgage | — | — | — | 2 | 3 | |||||||||||||||
| Home equity loans | 1 | 4 | 3 | 11 | 19 | |||||||||||||||
| Consumer direct loans | 7 | 8 | 11 | 37 | 41 | |||||||||||||||
| Credit cards | 7 | 9 | 10 | 39 | 44 | |||||||||||||||
| Consumer indirect loans | 6 | 6 | 10 | 28 | 34 | |||||||||||||||
| Total consumer loans | 21 | 27 | 34 | 117 | 141 | |||||||||||||||
| Total loans charged off | 160 | 151 | 115 | 522 | 499 | |||||||||||||||
| Recoveries: | ||||||||||||||||||||
| Commercial and industrial | 15 | 9 | 5 | 34 | 27 | |||||||||||||||
| Real estate — commercial mortgage | — | 2 | — | 3 | 2 | |||||||||||||||
| Total commercial real estate loans | — | 2 | — | 3 | 2 | |||||||||||||||
| Commercial lease financing | — | — | 1 | 1 | 5 | |||||||||||||||
| Total commercial loans | 15 | 11 | 6 | 38 | 34 | |||||||||||||||
| Real estate — residential mortgage | — | 1 | 1 | 1 | 2 | |||||||||||||||
| Home equity loans | 1 | 3 | 2 | 7 | 8 | |||||||||||||||
| Consumer direct loans | 1 | 2 | 2 | 7 | 7 | |||||||||||||||
| Credit cards | 2 | 2 | 1 | 8 | 7 | |||||||||||||||
| Consumer indirect loans | 6 | 4 | 4 | 18 | 17 | |||||||||||||||
| Total consumer loans | 10 | 12 | 10 | 41 | 41 | |||||||||||||||
| Total recoveries | 25 | 23 | 16 | 79 | 75 | |||||||||||||||
| Net loan charge-offs | (135) | (128) | (99) | (443) | (424) | |||||||||||||||
| Provision (credit) for loan and lease losses | 31 | 150 | 106 | 965 | 441 | |||||||||||||||
| Allowance for loan and lease losses at end of period | $ | 1,626 | $ | 1,730 | $ | 900 | $ | 1,626 | $ | 900 | ||||||||||
Liability for credit losses on lending-related commitments at the end of the prior period | $ | 208 | $ | 198 | $ | 65 | $ | 68 | $ | 64 | ||||||||||
| Liability for credit losses on contingent guarantees at the end of the prior period | — | — | — | 7 | — | |||||||||||||||
Cumulative effect from change in accounting principle (a), (b) | — | — | — | 66 | — | |||||||||||||||
| Liability for credit losses on lending-related commitments at beginning of period | 208 | 198 | 65 | 141 | 64 | |||||||||||||||
| Provision (credit) for losses on lending-related commitments | (11) | 10 | 3 | 56 | 4 | |||||||||||||||
Liability for credit losses on lending-related commitments at end of period (c) | $ | 197 | $ | 208 | $ | 68 | $ | 197 | $ | 68 | ||||||||||
| Total allowance for credit losses at end of period | $ | 1,823 | $ | 1,938 | $ | 968 | $ | 1,823 | $ | 968 | ||||||||||
| Net loan charge-offs to average total loans | .53 | % | .49 | % | .42 | % | .43 | % | .46 | % | ||||||||||
| Allowance for loan and lease losses to period-end loans | 1.61 | 1.68 | .95 | 1.61 | .95 | |||||||||||||||
| Allowance for credit losses to period-end loans | 1.80 | 1.88 | 1.02 | 1.80 | 1.02 | |||||||||||||||
| Allowance for loan and lease losses to nonperforming loans | 207.1 | 207.4 | 156.0 | 207.1 | 156.0 | |||||||||||||||
| Allowance for credit losses to nonperforming loans | 232.2 | 232.4 | 167.8 | 232.2 | 167.8 | |||||||||||||||
| Discontinued operations — education lending business: | ||||||||||||||||||||
| Loans charged off | $ | 1 | — | $ | 3 | $ | 5 | $ | 12 | |||||||||||
| Recoveries | 2 | — | 2 | 5 | 5 | |||||||||||||||
| Net loan charge-offs | $ | 1 | — | $ | (1) | — | $ | (7) | ||||||||||||
(a)The cumulative effect from change in accounting principle relates to the January 1, 2020, adoption of ASU 2016-13.
(b)The twelve months ended December 30, 2020, amount excludes $4 million related to the provision for other financial assets as a result of the change in accounting principle.
(c)Included in "Accrued expense and other liabilities" on the balance sheet.
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 23
| Asset Quality Statistics From Continuing Operations | |||||||||||||||||
| (dollars in millions) | |||||||||||||||||
| 4Q20 | 3Q20 | 2Q20 | 1Q20 | 4Q19 | |||||||||||||
| Net loan charge-offs | $ | 135 | $ | 128 | $ | 96 | $ | 84 | $ | 99 | |||||||
| Net loan charge-offs to average total loans | .53 | % | .49 | % | .36 | % | .35 | % | .42 | % | |||||||
| Allowance for loan and lease losses | $ | 1,626 | $ | 1,730 | $ | 1,708 | $ | 1,359 | $ | 900 | |||||||
Allowance for credit losses (a) | 1,823 | 1,938 | 1,906 | 1,520 | 968 | ||||||||||||
| Allowance for loan and lease losses to period-end loans | 1.61 | % | 1.68 | % | 1.61 | % | 1.32 | % | .95 | % | |||||||
| Allowance for credit losses to period-end loans | 1.80 | 1.88 | 1.80 | 1.47 | 1.02 | ||||||||||||
| Allowance for loan and lease losses to nonperforming loans | 207.1 | 207.4 | 224.7 | 215.0 | 156.0 | ||||||||||||
| Allowance for credit losses to nonperforming loans | 232.2 | 232.4 | 250.8 | 240.5 | 167.8 | ||||||||||||
| Nonperforming loans at period end | $ | 785 | $ | 834 | $ | 760 | $ | 632 | $ | 577 | |||||||
| Nonperforming assets at period end | 937 | 1,003 | 951 | 844 | 715 | ||||||||||||
| Nonperforming loans to period-end portfolio loans | .78 | % | .81 | % | .72 | % | .61 | % | .61 | % | |||||||
Nonperforming assets to period-end portfolio loans plus OREO and other nonperforming assets | .92 | .97 | .89 | .82 | .75 | ||||||||||||
(a)Includes the allowance for loan and lease losses plus the liability for credit losses on lending-related commitments.
| Summary of Nonperforming Assets and Past Due Loans From Continuing Operations | |||||||||||||||||
| (dollars in millions) | |||||||||||||||||
| 12/31/2020 | 9/30/2020 | 6/30/2020 | 3/31/2020 | 12/31/2019 | |||||||||||||
| Commercial and industrial | $ | 385 | $ | 459 | $ | 404 | $ | 277 | $ | 264 | |||||||
| Real estate — commercial mortgage | 104 | 104 | 91 | 87 | 83 | ||||||||||||
| Real estate — construction | — | 1 | 1 | 2 | 2 | ||||||||||||
| Total commercial real estate loans | 104 | 105 | 92 | 89 | 85 | ||||||||||||
| Commercial lease financing | 8 | 6 | 9 | 5 | 6 | ||||||||||||
| Total commercial loans | 497 | 570 | 505 | 371 | 355 | ||||||||||||
| Real estate — residential mortgage | 110 | 96 | 89 | 89 | 48 | ||||||||||||
| Home equity loans | 154 | 146 | 141 | 143 | 145 | ||||||||||||
| Consumer direct loans | 5 | 3 | 3 | 4 | 4 | ||||||||||||
| Credit cards | 2 | 2 | 2 | 3 | 3 | ||||||||||||
| Consumer indirect loans | 17 | 17 | 20 | 22 | 22 | ||||||||||||
| Total consumer loans | 288 | 264 | 255 | 261 | 222 | ||||||||||||
| Total nonperforming loans | 785 | 834 | 760 | 632 | 577 | ||||||||||||
| OREO | 100 | 105 | 112 | 119 | 35 | ||||||||||||
| Nonperforming loans held for sale | 49 | 61 | 75 | 89 | 94 | ||||||||||||
| Other nonperforming assets | 3 | 3 | 4 | 4 | 9 | ||||||||||||
| Total nonperforming assets | $ | 937 | $ | 1,003 | $ | 951 | $ | 844 | $ | 715 | |||||||
| Accruing loans past due 90 days or more | 86 | 73 | 87 | 128 | 97 | ||||||||||||
| Accruing loans past due 30 through 89 days | 241 | 336 | 419 | 393 | 329 | ||||||||||||
Restructured loans — accruing and nonaccruing (a) | 363 | 306 | 310 | 340 | 347 | ||||||||||||
Restructured loans included in nonperforming loans (a) | 229 | 168 | 166 | 172 | 183 | ||||||||||||
| Nonperforming assets from discontinued operations — education lending business | 5 | 6 | 7 | 7 | 7 | ||||||||||||
| Nonperforming loans to period-end portfolio loans | .78 | % | .81 | % | .72 | % | .61 | % | .61 | % | |||||||
Nonperforming assets to period-end portfolio loans plus OREO and other nonperforming assets | .92 | .97 | .89 | .82 | .75 | ||||||||||||
(a)Restructured loans (i.e., troubled debt restructuring) are those for which Key, for reasons related to a borrower’s financial difficulties, grants a concession to the borrower that it would not otherwise consider. These concessions are made to improve the collectability of the loan and generally take the form of a reduction of the interest rate, extension of the maturity date or reduction in the principal balance.
| Summary of Changes in Nonperforming Loans From Continuing Operations | |||||||||||||||||
| (in millions) | |||||||||||||||||
| 4Q20 | 3Q20 | 2Q20 | 1Q20 | 4Q19 | |||||||||||||
| Balance at beginning of period | $ | 834 | $ | 760 | $ | 632 | $ | 577 | $ | 585 | |||||||
Loans placed on nonaccrual status (a) | 300 | 387 | 293 | 219 | 268 | ||||||||||||
| Charge-offs | (160) | (150) | (111) | (100) | (114) | ||||||||||||
| Loans sold | (9) | (6) | (5) | (4) | (1) | ||||||||||||
| Payments | (83) | (83) | (29) | (31) | (59) | ||||||||||||
| Transfers to OREO | (3) | — | — | (3) | (3) | ||||||||||||
| Transfers to nonperforming loans held for sale | — | — | — | — | (47) | ||||||||||||
| Loans returned to accrual status | (94) | (74) | (20) | (26) | (52) | ||||||||||||
| Balance at end of period | $ | 785 | $ | 834 | $ | 760 | $ | 632 | $ | 577 | |||||||
(a)Purchase credit impaired (PCI) loans meeting nonperforming criteria were historically excluded from Key's nonperforming disclosures. As a result of CECL implementation on January 1, 2020, PCI loans became purchased credit deteriorated (PCD) loans. PCD loans that met the definition of nonperforming are now included in nonperforming disclosures, resulting in a $45 million increase in nonperforming loans in the first quarter of 2020.
KeyCorp Reports Fourth Quarter 2020 Profit
January 21, 2021
Page 24
| Line of Business Results | ||||||||||||||||||||||||||
| (dollars in millions) | ||||||||||||||||||||||||||
| Percentage change 4Q20 vs. | ||||||||||||||||||||||||||
| 4Q20 | 3Q20 | 2Q20 | 1Q20 | 4Q19 | 3Q20 | 4Q19 | ||||||||||||||||||||
| Consumer Bank | ||||||||||||||||||||||||||
| Summary of operations | ||||||||||||||||||||||||||
| Total revenue (TE) | $ | 905 | $ | 871 | $ | 841 | $ | 820 | $ | 825 | 3.9 | % | 9.7 | % | ||||||||||||
| Provision for credit losses | (4) | (16) | 167 | 140 | 55 | N/M | N/M | |||||||||||||||||||
| Noninterest expense | 611 | 571 | 555 | 542 | 550 | 7.0 | 11.1 | |||||||||||||||||||
| Net income (loss) attributable to Key | 228 | 241 | 91 | 105 | 168 | (5.4) | 35.7 | |||||||||||||||||||
| Average loans and leases | 41,137 | 41,471 | 39,197 | 35,197 | 34,148 | (.8) | 20.5 | |||||||||||||||||||
| Average deposits | 83,171 | 83,175 | 79,502 | 73,320 | 73,561 | — | 13.1 | |||||||||||||||||||
| Net loan charge-offs | 28 | 23 | 39 | 43 | 43 | 21.7 | (34.9) | |||||||||||||||||||
| Net loan charge-offs to average total loans | .27 | % | .22 | % | .40 | % | .49 | % | .50 | % | N/A | N/A | ||||||||||||||
| Nonperforming assets at period end | $ | 374 | $ | 353 | $ | 332 | $ | 342 | $ | 306 | 5.9 | 22.2 | ||||||||||||||
| Return on average allocated equity | 25.45 | % | 27.03 | % | 10.45 | % | 12.26 | % | 19.64 | % | N/A | N/A | ||||||||||||||
| Commercial Bank | ||||||||||||||||||||||||||
| Summary of operations | ||||||||||||||||||||||||||
| Total revenue (TE) | $ | 913 | $ | 804 | $ | 857 | $ | 630 | $ | 771 | 13.6 | % | 18.4 | % | ||||||||||||
| Provision for credit losses | 42 | 163 | 314 | 218 | 38 | (74.2) | 10.5 | |||||||||||||||||||
| Noninterest expense | 494 | 443 | 438 | 358 | 393 | 11.5 | 25.7 | |||||||||||||||||||
| Net income (loss) attributable to Key | 308 | 160 | 101 | 63 | 311 | 92.5 | (1.0) | |||||||||||||||||||
| Average loans and leases | 59,992 | 62,925 | 68,038 | 60,082 | 58,535 | (4.7) | 2.5 | |||||||||||||||||||
| Average loans held for sale | 1,285 | 1,383 | 2,012 | 1,607 | 1,465 | (7.1) | (12.3) | |||||||||||||||||||
| Average deposits | 52,163 | 51,238 | 47,685 | 36,256 | 38,224 | 1.8 | 36.5 | |||||||||||||||||||
| Net loan charge-offs | 108 | 104 | 57 | 40 | 39 | 3.8 | 176.9 | |||||||||||||||||||
| Net loan charge-offs to average total loans | .72 | % | .66 | % | .34 | % | .27 | % | .26 | % | N/A | N/A | ||||||||||||||
| Nonperforming assets at period end | $ | 558 | $ | 645 | $ | 616 | $ | 407 | $ | 402 | (13.5) | 38.8 | ||||||||||||||
| Return on average allocated equity | 24.04 | % | 12.57 | % | 8.41 | % | 5.40 | % | 26.40 | % | N/A | N/A | ||||||||||||||
TE = Taxable Equivalent, N/A = Not Applicable, N/M = Not Meaningful
| Notable Items | ||||||||||||||||||||
| (in millions) | ||||||||||||||||||||
| Three months ended | Twelve months ended | |||||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | 12/31/2020 | 12/31/2019 | ||||||||||||||||
| Provision for credit losses | — | — | $ | (16) | — | $ | (139) | |||||||||||||
| Professional fees related to fraud loss | — | — | (4) | — | (4) | |||||||||||||||
| Efficiency initiative expenses | — | — | — | — | (76) | |||||||||||||||
| Laurel Road acquisition expenses | — | — | — | — | (2) | |||||||||||||||
| Pension settlement charge | — | — | (18) | — | (18) | |||||||||||||||
| Total notable items | — | — | (38) | — | (239) | |||||||||||||||
| Income taxes | — | — | (9) | — | (56) | |||||||||||||||
| Total notable items, after tax | — | — | $ | (29) | — | $ | (183) | |||||||||||||
KeyCorp Fourth Quarter 2020 Earnings Review January 21, 2021 Chris Gorman Chairman and Chief Executive Officer Don Kimble Vice Chairman and Chief Financial Officer
FORWARD-LOOKING STATEMENTS AND ADDITIONAL INFORMATION This communication contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995 including, but not limited to, KeyCorp’s expectations or predictions of future financial or business performance or conditions. Forward-looking statements are typically identified by words such as “believe,” “seek,” “expect,” “anticipate,” “intend,” “target,” “estimate,” “continue,” “positions,” “plan,” “predict,” “project,” “forecast,” “guidance,” “goal,” “objective,” “prospects,” “possible,” “potential,” “strategy,” “opportunities,” or “trends,” by future conditional verbs such as “assume,” “will,” “would,” “should,” “could” or “may”, or by variations of such words or by similar expressions. These forward-looking statements are based on assumptions that involve risks and uncertainties, which are subject to change based on various important factors (some of which are beyond KeyCorp’s control.) Actual results may differ materially from current projections. Actual outcomes may differ materially from those expressed or implied as a result of the factors described under “Forward-looking Statements” and “Risk Factors” in KeyCorp’s Annual Report on Form 10-K for the year ended December 31, 2019 and in other filings of KeyCorp with the Securities and Exchange Commission (the “SEC”). In addition to the aforementioned factors, the COVID-19 global pandemic is adversely affecting us, our clients, and our third-party service providers, among others, and its impact may adversely affect our business and results of operations over a period of time. Risks related to and stemming from COVID-19 are more fully described under “Risk Factors” in KeyCorp’s Quarterly Report on Form 10-Q for the quarters ended March 31, 2020 and September 30, 2020. Such forward-looking statements speak only as of the date they are made, and we undertake no obligation to update any forward-looking statement to reflect events or circumstances after that date or to reflect the occurrence of unanticipated events. For additional information regarding KeyCorp, please refer to our SEC filings available at www.key.com/ir. Annualized, pro forma, projected and estimated numbers are used for illustrative purpose only, are not forecasts and may not reflect actual results. This presentation also includes certain non-GAAP financial measures related to “tangible common equity,” “cash efficiency ratio,” “pre-provision net revenue,” and certain financial measures excluding notable items. Notable items include certain revenue or expense items that may occur in a reporting period in which management does not consider indicative of ongoing financial performance. Management believes it is useful for the investment community to consider financial metrics with and without notable items in order to enable a better understanding of company results, facilitate comparability of period-to-period financial results, and to evaluate and forecast those results. Although Key has procedures in place to ensure that these measures are calculated using the appropriate GAAP or regulatory components, they have limitations as analytical tools and should not be considered in isolation, or as a substitute for analysis of results under GAAP. For more information on these calculations and to view the reconciliations to the most comparable GAAP measures, please refer to the appendix of this presentation, or page 48 of our Form 10-Q dated September 30, 2020. GAAP: Generally Accepted Accounting Principles 2
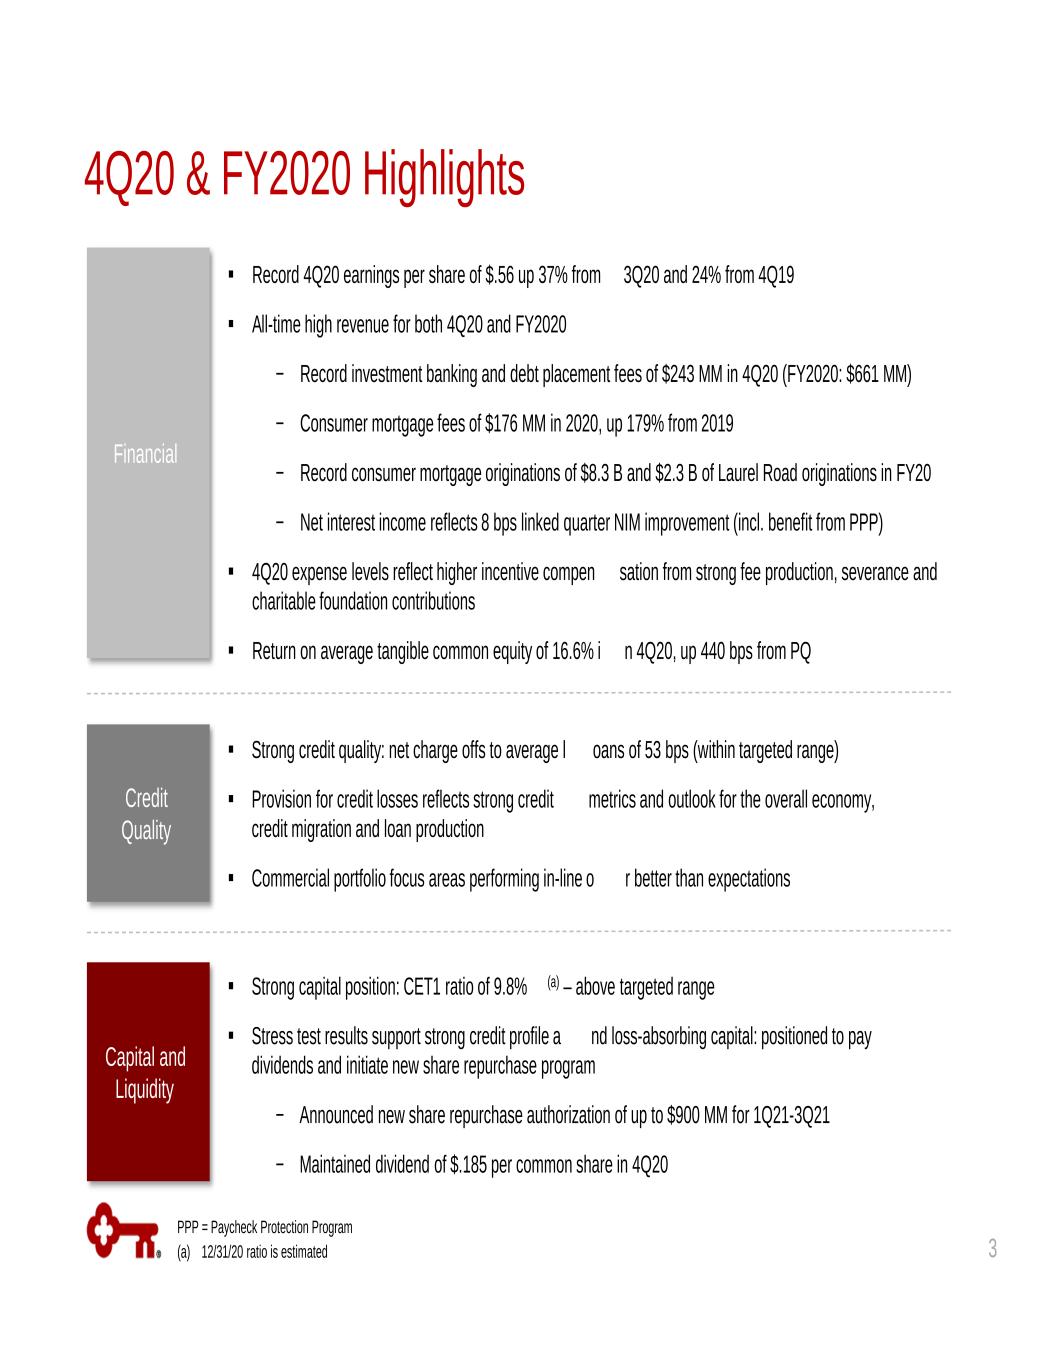
3 4Q20 & FY2020 Highlights Capital and Liquidity Strong capital position: CET1 ratio of 9.8% (a) – above targeted range Stress test results support strong credit profile a nd loss-absorbing capital: positioned to pay dividends and initiate new share repurchase program − Announced new share repurchase authorization of up to $900 MM for 1Q21-3Q21 − Maintained dividend of $.185 per common share in 4Q20 Financial Credit Quality Strong credit quality: net charge offs to average l oans of 53 bps (within targeted range) Provision for credit losses reflects strong credit metrics and outlook for the overall economy, credit migration and loan production Commercial portfolio focus areas performing in-line o r better than expectations Record 4Q20 earnings per share of $.56 up 37% from 3Q20 and 24% from 4Q19 All-time high revenue for both 4Q20 and FY2020 − Record investment banking and debt placement fees of $243 MM in 4Q20 (FY2020: $661 MM) − Consumer mortgage fees of $176 MM in 2020, up 179% from 2019 − Record consumer mortgage originations of $8.3 B and $2.3 B of Laurel Road originations in FY20 − Net interest income reflects 8 bps linked quarter NIM improvement (incl. benefit from PPP) 4Q20 expense levels reflect higher incentive compen sation from strong fee production, severance and charitable foundation contributions Return on average tangible common equity of 16.6% i n 4Q20, up 440 bps from PQ PPP = Paycheck Protection Program (a) 12/31/20 ratio is estimated
Financial Review 4
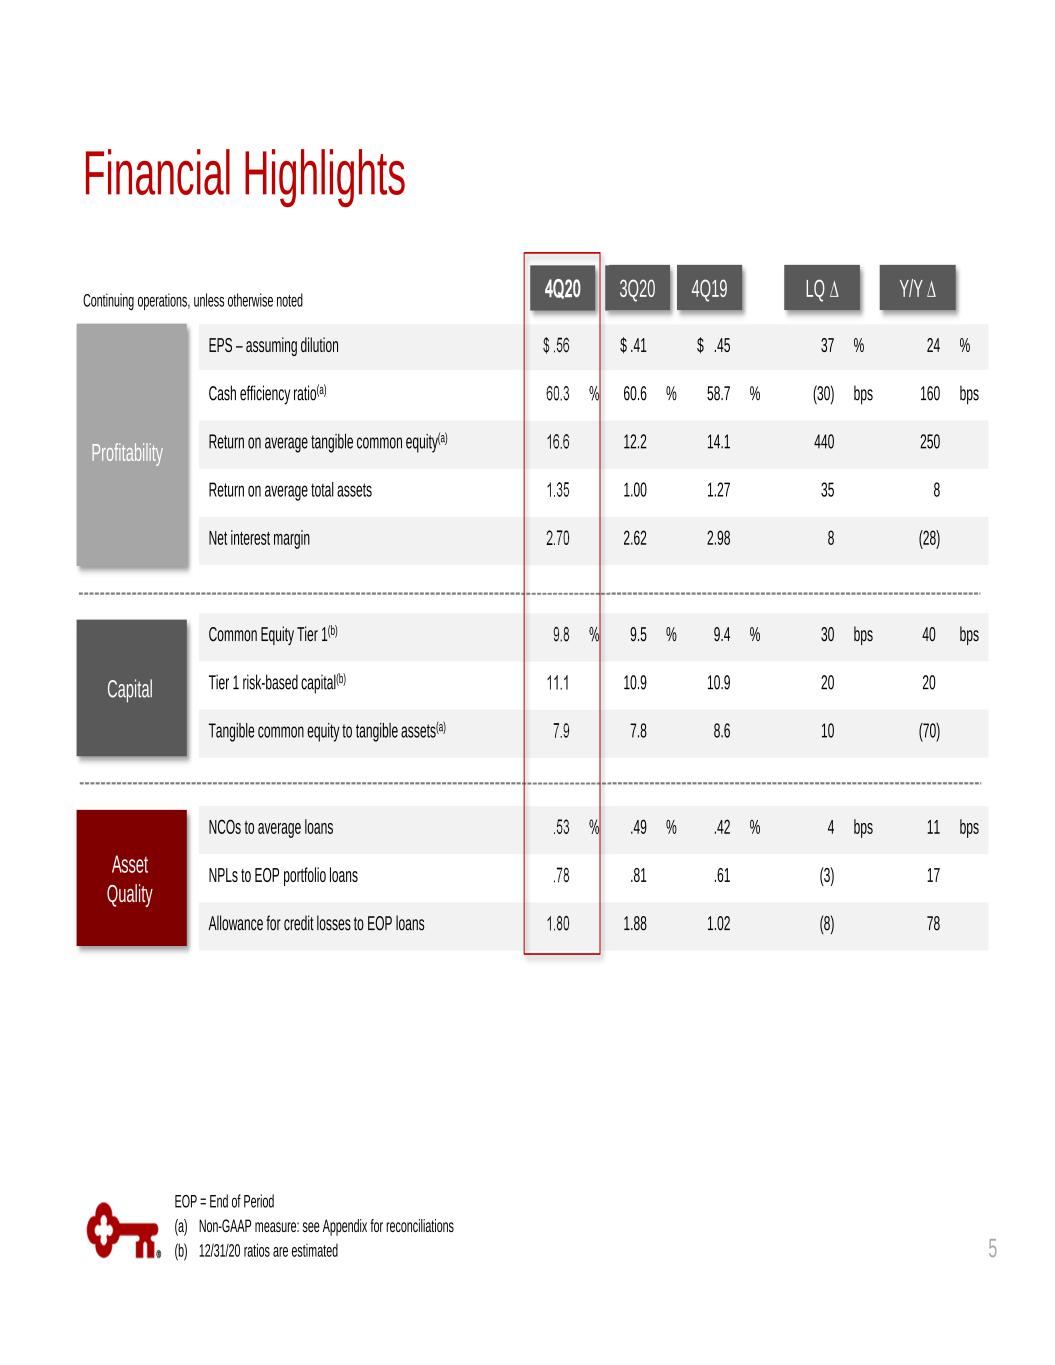
Financial Highlights EOP = End of Period (a) Non-GAAP measure: see Appendix for reconciliations (b) 12/31/20 ratios are estimated EPS – assuming dilution $ .56 $ .41 $ .45 37 % 24 % Cash efficiency ratio(a) 60.3 % 60.6 % 58.7 % (30) bps 160 bps Return on average tangible common equity(a) 16.6 12.2 14.1 440 250 Return on average total assets 1.35 1.00 1.27 35 8 Net interest margin 2.70 2.62 2.98 8 (28) Common Equity Tier 1(b) 9.8 % 9.5 % 9.4 % 30 bps 40 bps Tier 1 risk-based capital(b) 11.1 10.9 10.9 20 20 Tangible common equity to tangible assets(a) 7.9 7.8 8.6 10 (70) NCOs to average loans .53 % .49 % .42 % 4 bps 11 bps NPLs to EOP portfolio loans .78 .81 .61 (3) 17 Allowance for credit losses to EOP loans 1.80 1.88 1.02 (8) 78 Asset Quality Profitability Continuing operations, unless otherwise noted 4Q20 3Q20 4Q19 LQ ∆ Y/Y ∆ Capital 5
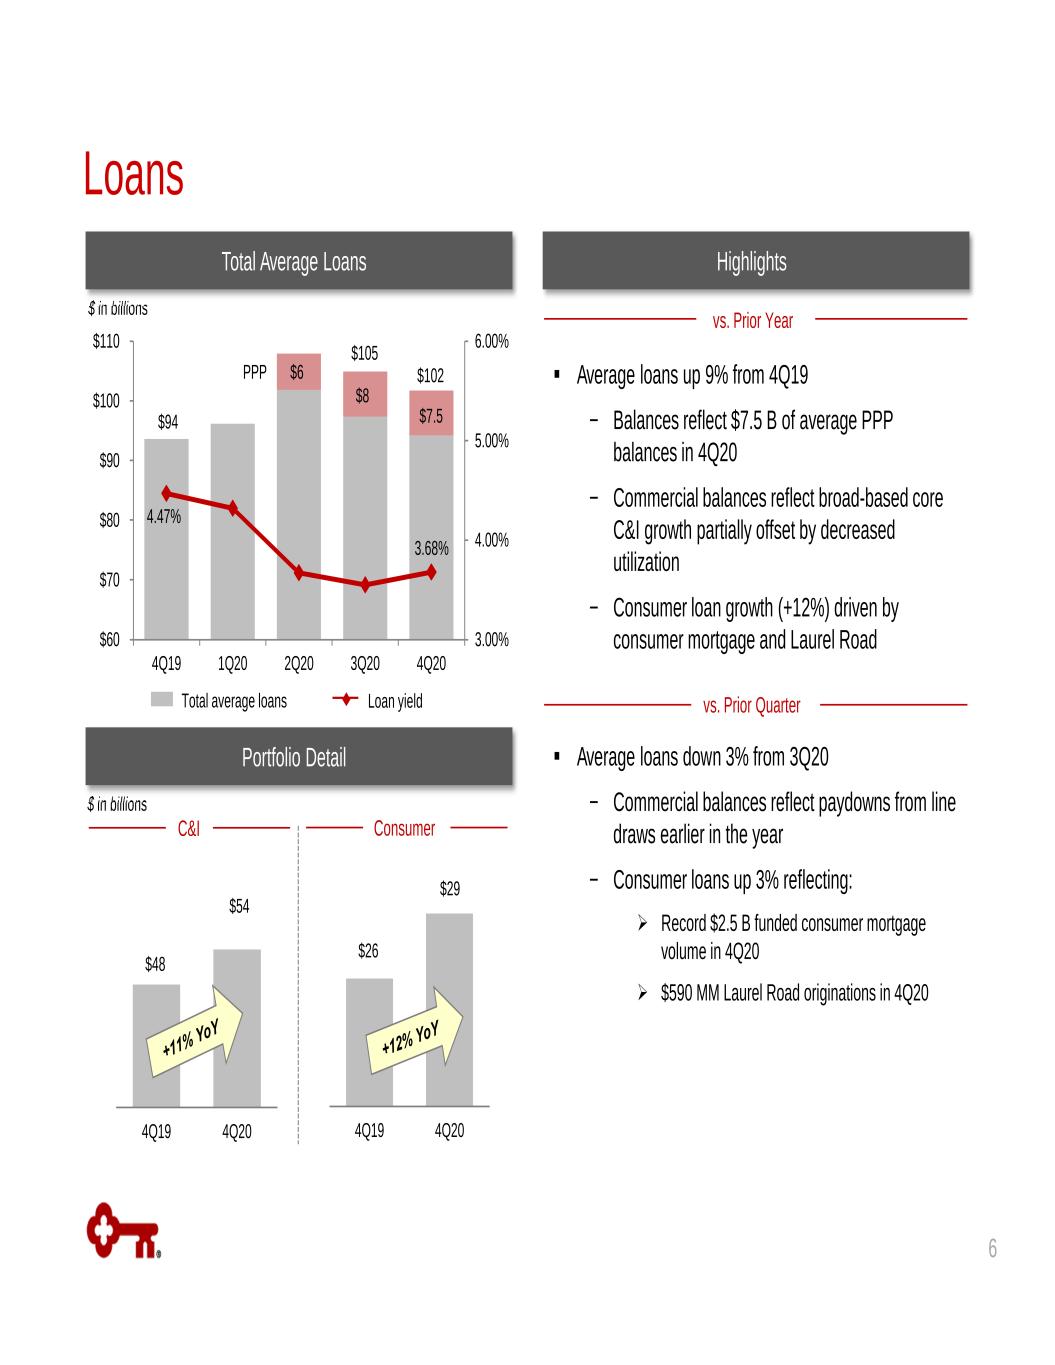
Loans $ in billions vs. Prior Year Total Average Loans Highlights Average loans up 9% from 4Q19 − Balances reflect $7.5 B of average PPP balances in 4Q20 − Commercial balances reflect broad-based core C&I growth partially offset by decreased utilization − Consumer loan growth (+12%) driven by consumer mortgage and Laurel Road vs. Prior Quarter Average loans down 3% from 3Q20 − Commercial balances reflect paydowns from line draws earlier in the year − Consumer loans up 3% reflecting: Record $2.5 B funded consumer mortgage volume in 4Q20 $590 MM Laurel Road originations in 4Q20 $ in billions Portfolio Detail $94 4.47% 3.68% 3.00% 4.00% 5.00% 6.00% $60 $70 $80 $90 $100 $110 4Q19 1Q20 2Q20 3Q20 4Q20 Loan yieldTotal average loans $48 $54 4Q19 4Q20 ConsumerC&I $26 $29 4Q19 4Q20 PPP $6 $105 $8 6 $102 $7.5
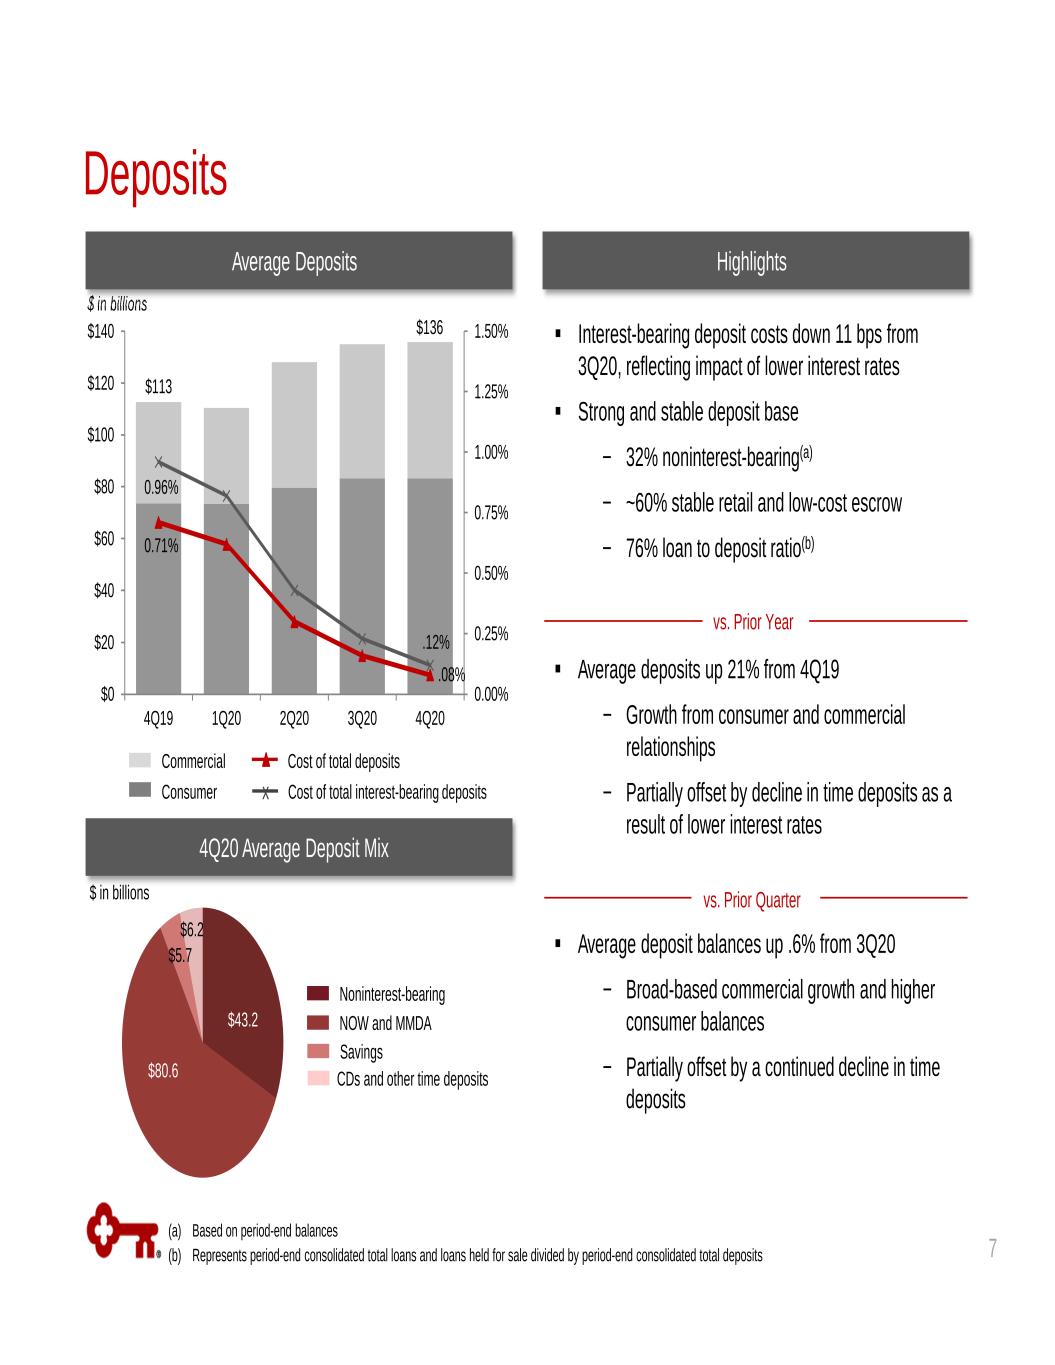
$43.2 $80.6 $5.7 $6.2 0.71% 0.96% 0.00% 0.25% 0.50% 0.75% 1.00% 1.25% 1.50% $0 $20 $40 $60 $80 $100 $120 $140 4Q19 1Q20 2Q20 3Q20 4Q20 Cost of total interest-bearing deposits Average deposit balances up .6% from 3Q20 − Broad-based commercial growth and higher consumer balances − Partially offset by a continued decline in time deposits 4Q20 Average Deposit Mix Average deposits up 21% from 4Q19 − Growth from consumer and commercial relationships − Partially offset by decline in time deposits as a result of lower interest rates Cost of total deposits CDs and other time deposits Savings Noninterest-bearing NOW and MMDA $ in billions $ in billions vs. Prior Year vs. Prior Quarter Consumer Commercial $113 .12% Average Deposits Highlights $136 .08% Interest-bearing deposit costs down 11 bps from 3Q20, reflecting impact of lower interest rates Strong and stable deposit base − 32% noninterest-bearing(a) − ~60% stable retail and low-cost escrow − 76% loan to deposit ratio(b) (a) Based on period-end balances (b) Represents period-end consolidated total loans and loans held for sale divided by period-end consolidated total deposits x 7 Deposits
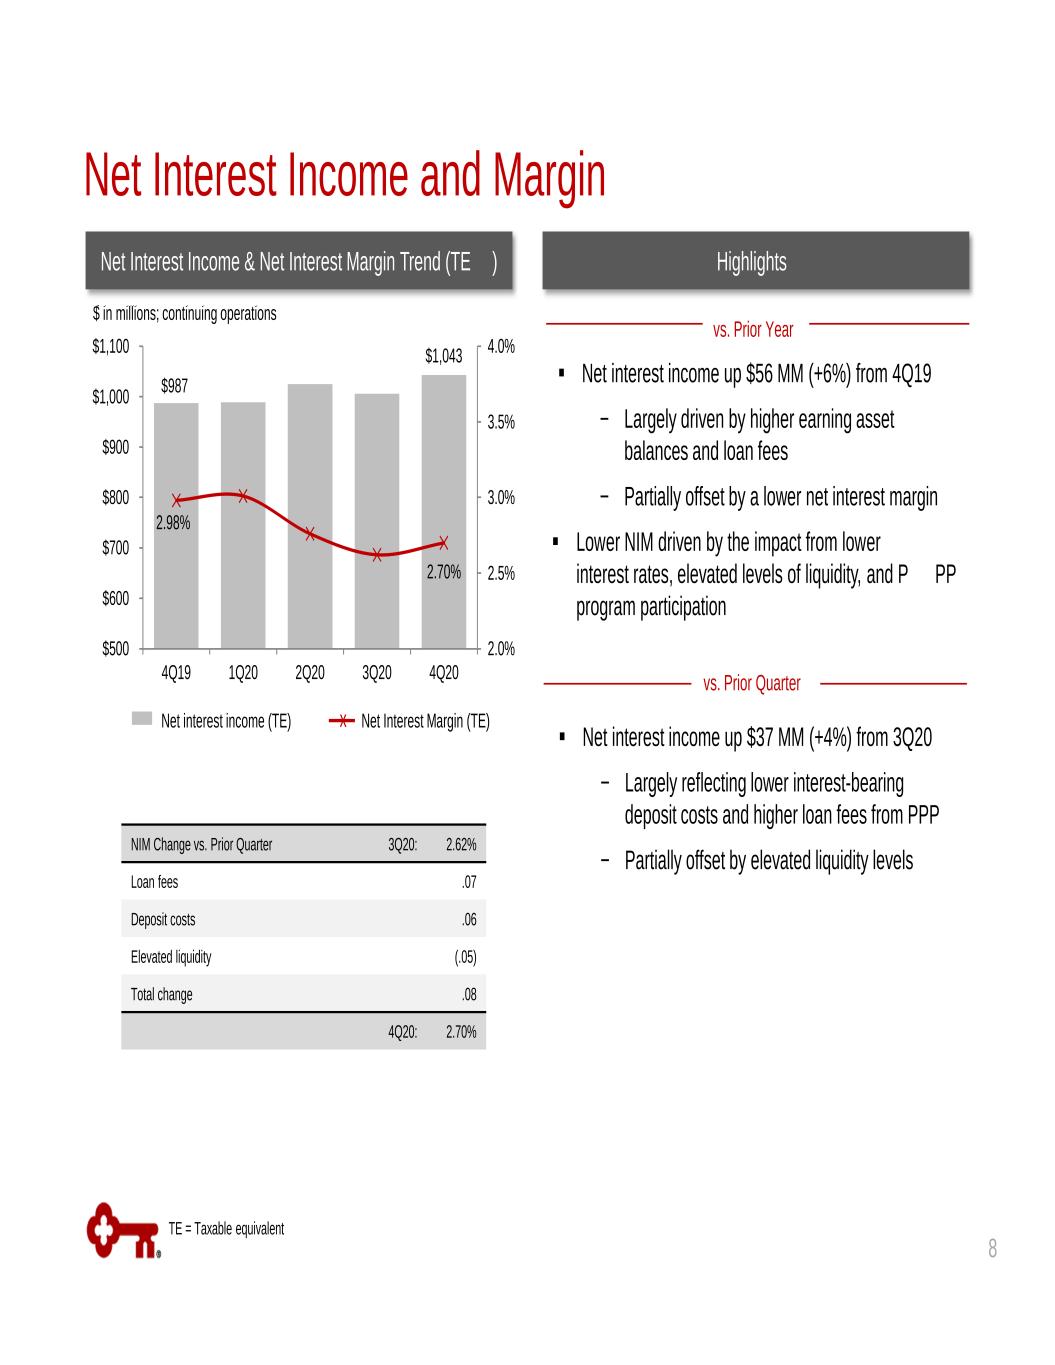
2.98% 2.70% 2.0% 2.5% 3.0% 3.5% 4.0% $500 $600 $700 $800 $900 $1,000 $1,100 4Q19 1Q20 2Q20 3Q20 4Q20 Net interest income up $37 MM (+4%) from 3Q20 − Largely reflecting lower interest-bearing deposit costs and higher loan fees from PPP − Partially offset by elevated liquidity levels TE = Taxable equivalent Net interest income (TE) Net Interest Margin (TE) Net Interest Income and Margin $ in millions; continuing operations vs. Prior Year vs. Prior Quarter $987 $1,043 Net Interest Income & Net Interest Margin Trend (TE ) Highlights x NIM Change vs. Prior Quarter 3Q20: 2.62% Loan fees .07 Deposit costs .06 Elevated liquidity (.05) Total change .08 4Q20: 2.70% Net interest income up $56 MM (+6%) from 4Q19 − Largely driven by higher earning asset balances and loan fees − Partially offset by a lower net interest margin Lower NIM driven by the impact from lower interest rates, elevated levels of liquidity, and P PP program participation 8
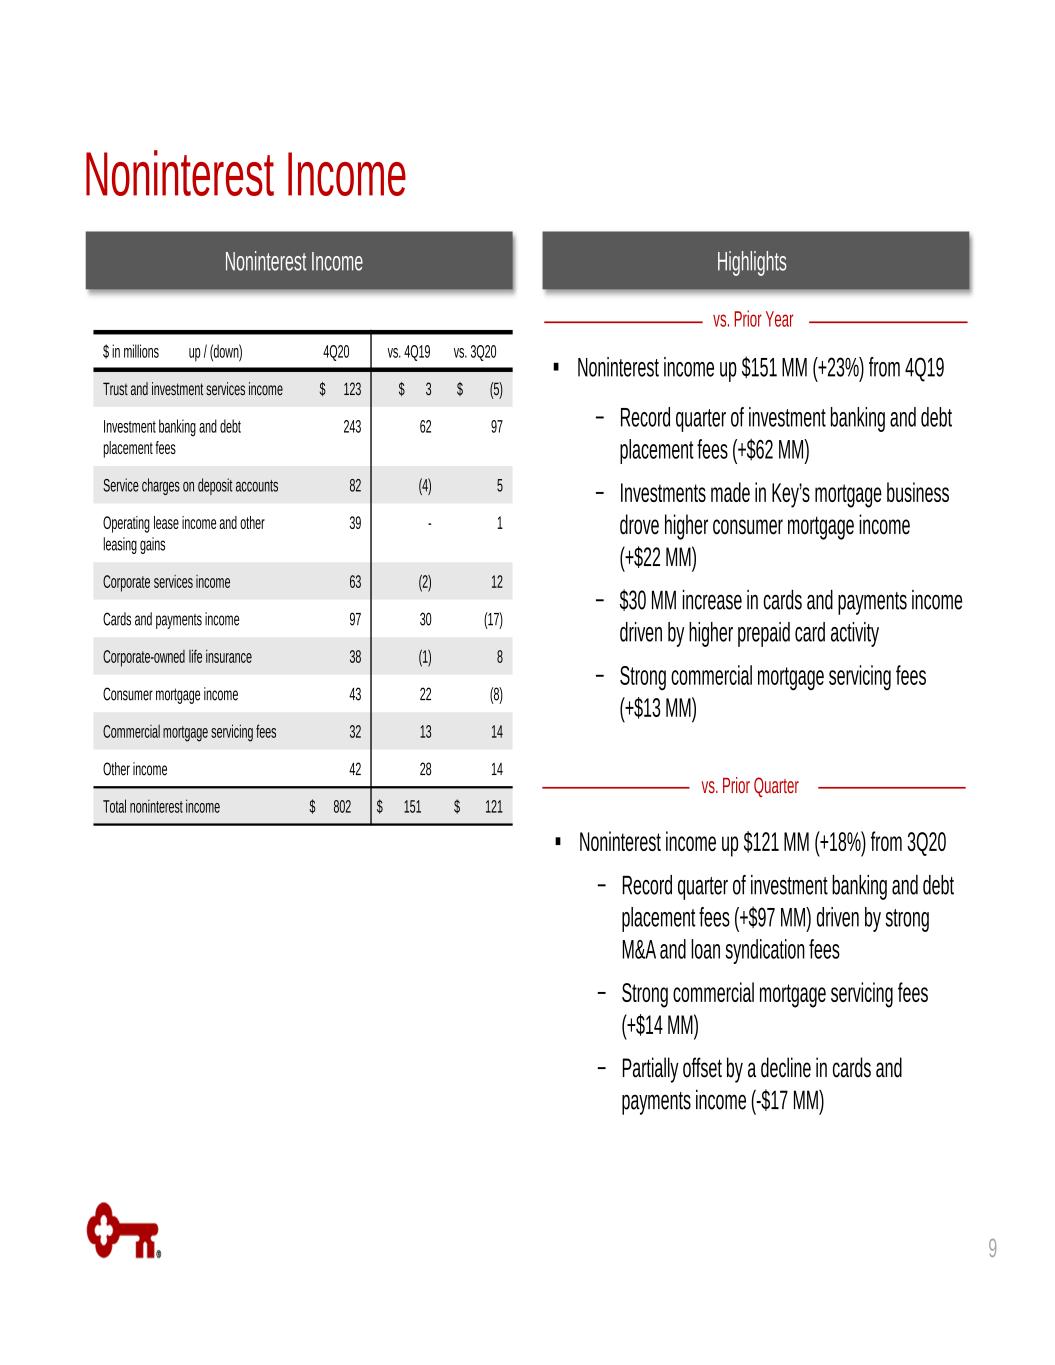
Noninterest income up $151 MM (+23%) from 4Q19 − Record quarter of investment banking and debt placement fees (+$62 MM) − Investments made in Key’s mortgage business drove higher consumer mortgage income (+$22 MM) − $30 MM increase in cards and payments income driven by higher prepaid card activity − Strong commercial mortgage servicing fees (+$13 MM) Noninterest Income Noninterest Income Noninterest income up $121 MM (+18%) from 3Q20 − Record quarter of investment banking and debt placement fees (+$97 MM) driven by strong M&A and loan syndication fees − Strong commercial mortgage servicing fees (+$14 MM) − Partially offset by a decline in cards and payments income (-$17 MM) vs. Prior Year vs. Prior Quarter Highlights $ in millions up / (down) 4Q20 vs. 4Q19 vs. 3Q20 Trust and investment services income $ 123 $ 3 $ (5) Investment banking and debt placement fees 243 62 97 Service charges on deposit accounts 82 (4) 5 Operating lease income and other leasing gains 39 - 1 Corporate services income 63 (2) 12 Cards and payments income 97 30 (17) Corporate-owned life insurance 38 (1) 8 Consumer mortgage income 43 22 (8) Commercial mortgage servicing fees 32 13 14 Other income 42 28 14 Total noninterest income $ 802 $ 151 $ 121 9
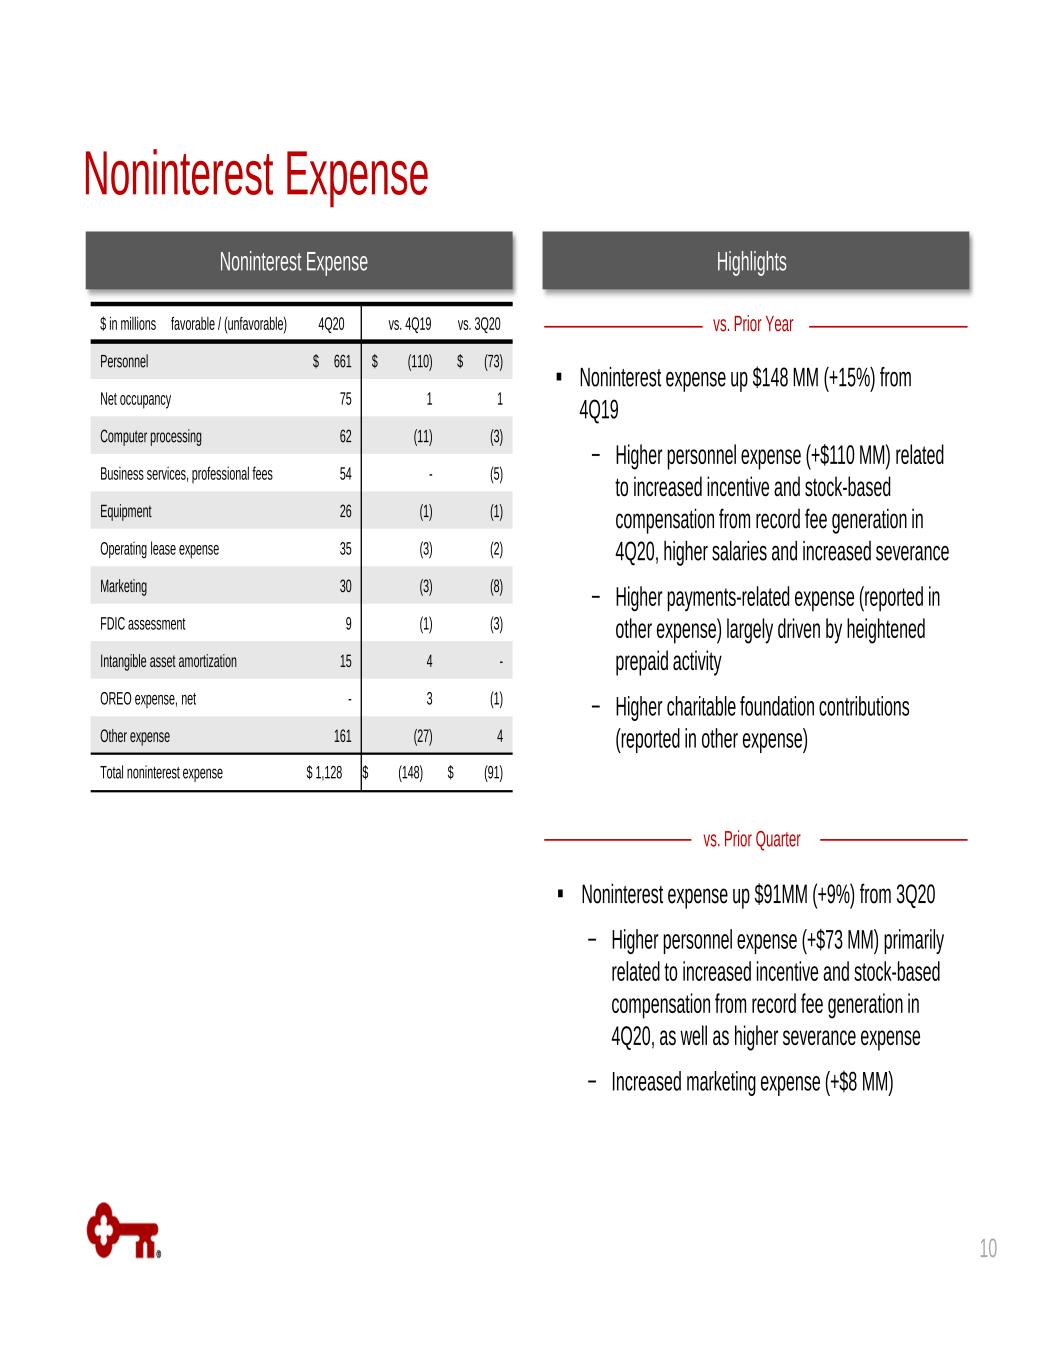
Noninterest Expense vs. Prior Year vs. Prior Quarter Noninterest Expense Highlights $ in millions favorable / (unfavorable) 4Q20 vs. 4Q19 vs. 3Q20 Personnel $ 661 $ (110) $ (73) Net occupancy 75 1 1 Computer processing 62 (11) (3) Business services, professional fees 54 - (5) Equipment 26 (1) (1) Operating lease expense 35 (3) (2) Marketing 30 (3) (8) FDIC assessment 9 (1) (3) Intangible asset amortization 15 4 - OREO expense, net - 3 (1) Other expense 161 (27) 4 Total noninterest expense $ 1,128 $ (148) $ (91) Noninterest expense up $148 MM (+15%) from 4Q19 − Higher personnel expense (+$110 MM) related to increased incentive and stock-based compensation from record fee generation in 4Q20, higher salaries and increased severance − Higher payments-related expense (reported in other expense) largely driven by heightened prepaid activity − Higher charitable foundation contributions (reported in other expense) Noninterest expense up $91MM (+9%) from 3Q20 − Higher personnel expense (+$73 MM) primarily related to increased incentive and stock-based compensation from record fee generation in 4Q20, as well as higher severance expense − Increased marketing expense (+$8 MM) 10
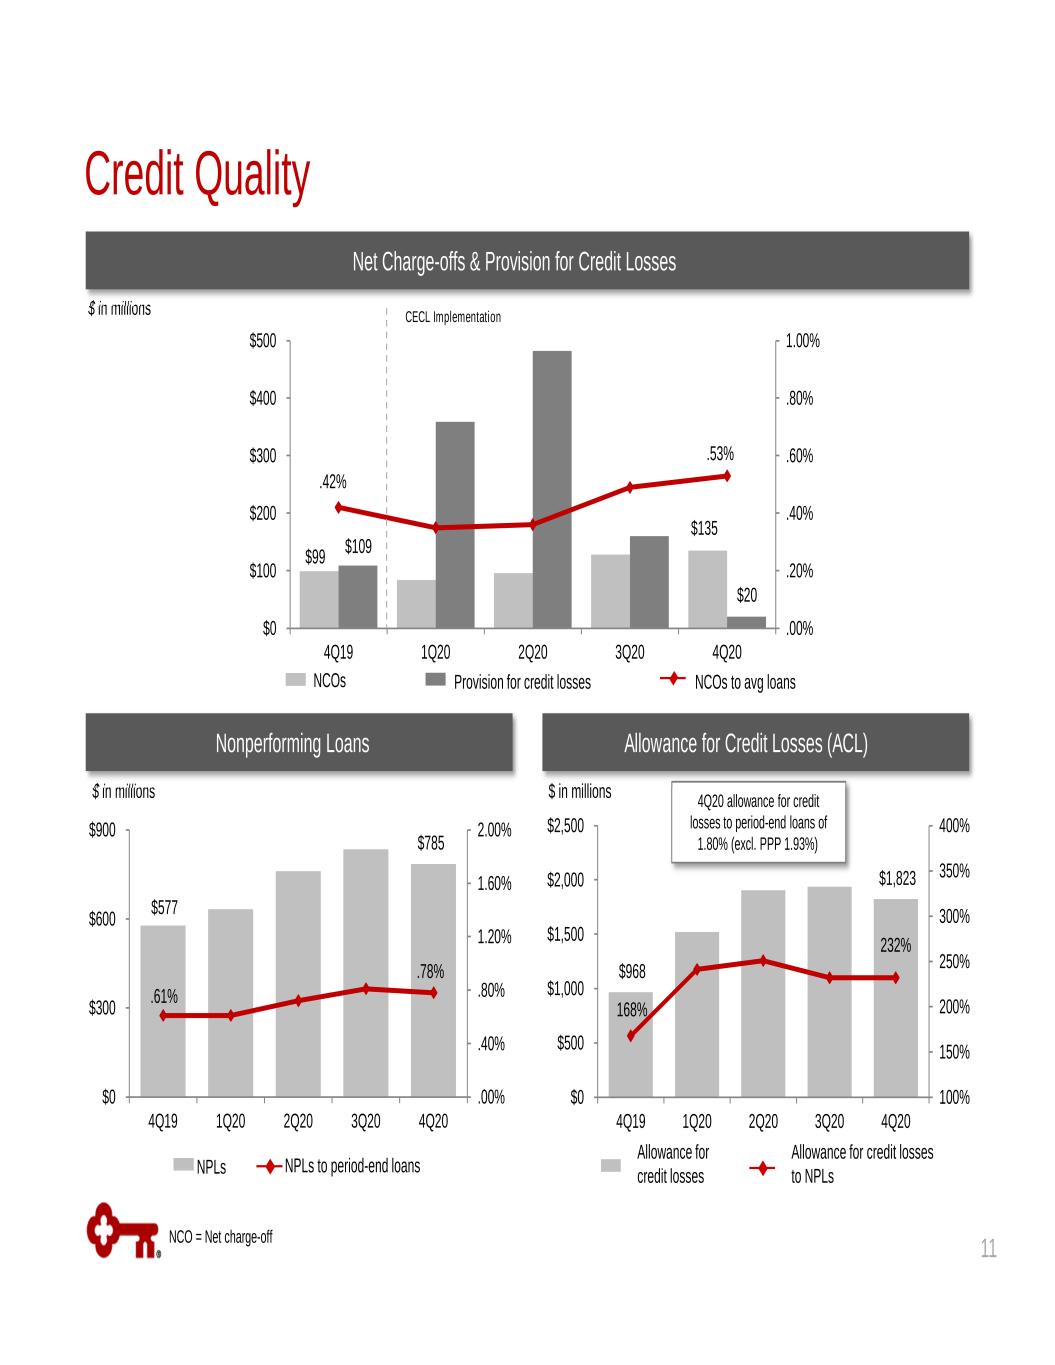
.42% .00% .20% .40% .60% .80% 1.00% $0 $100 $200 $300 $400 $500 4Q19 1Q20 2Q20 3Q20 4Q20 $ in millions Credit Quality $ in millions NCOs Provision for credit losses NCOs to avg loans $577 $785 .61% .78% .00% .40% .80% 1.20% 1.60% 2.00% $0 $300 $600 $900 4Q19 1Q20 2Q20 3Q20 4Q20 NPLs NPLs to period-end loans NCO = Net charge-off $968 $1,823 168% 232% 100% 150% 200% 250% 300% 350% 400% $0 $500 $1,000 $1,500 $2,000 $2,500 4Q19 1Q20 2Q20 3Q20 4Q20 Allowance for credit losses to NPLs Allowance for credit losses Nonperforming Loans 4Q20 allowance for credit losses to period-end loans of 1.80% (excl. PPP 1.93%) Allowance for Credit Losses (ACL) Net Charge-offs & Provision for Credit Losses $ in millions .53% CECL Implementation $109 $20 $135 11 $99
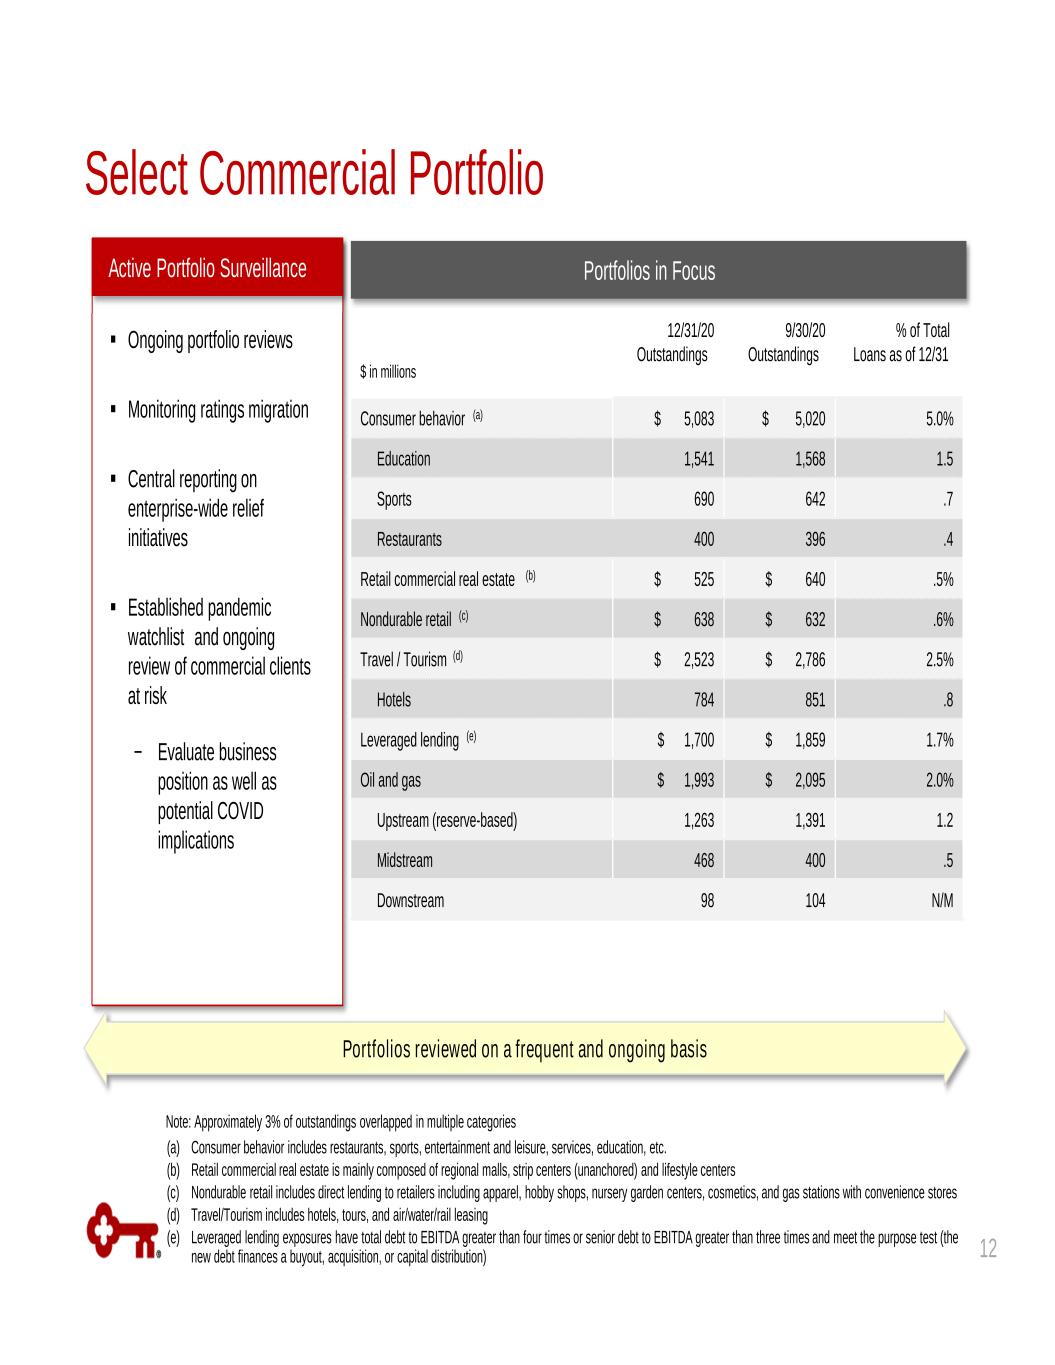
Portfolios in Focus Ongoing portfolio reviews Monitoring ratings migration Central reporting on enterprise-wide relief initiatives Established pandemic watchlist and ongoing review of commercial clients at risk − Evaluate business position as well as potential COVID implications Active Portfolio Surveillance Portfolios reviewed on a frequent and ongoing basis $ in millions 12/31/20 Outstandings 9/30/20 Outstandings % of Total Loans as of 12/31 Consumer behavior (a) $ 5,083 $ 5,020 5.0% Education 1,541 1,568 1.5 Sports 690 642 .7 Restaurants 400 396 .4 Retail commercial real estate (b) $ 525 $ 640 .5% Nondurable retail (c) $ 638 $ 632 .6% Travel / Tourism (d) $ 2,523 $ 2,786 2.5% Hotels 784 851 .8 Leveraged lending (e) $ 1,700 $ 1,859 1.7% Oil and gas $ 1,993 $ 2,095 2.0% Upstream (reserve-based) 1,263 1,391 1.2 Midstream 468 400 .5 Downstream 98 104 N/M (a) Consumer behavior includes restaurants, sports, entertainment and leisure, services, education, etc. (b) Retail commercial real estate is mainly composed of regional malls, strip centers (unanchored) and lifestyle centers (c) Nondurable retail includes direct lending to retailers including apparel, hobby shops, nursery garden centers, cosmetics, and gas stations with convenience stores (d) Travel/Tourism includes hotels, tours, and air/water/rail leasing (e) Leveraged lending exposures have total debt to EBITDA greater than four times or senior debt to EBITDA greater than three times and meet the purpose test (the new debt finances a buyout, acquisition, or capital distribution) Note: Approximately 3% of outstandings overlapped in multiple categories 12 Select Commercial Portfolio
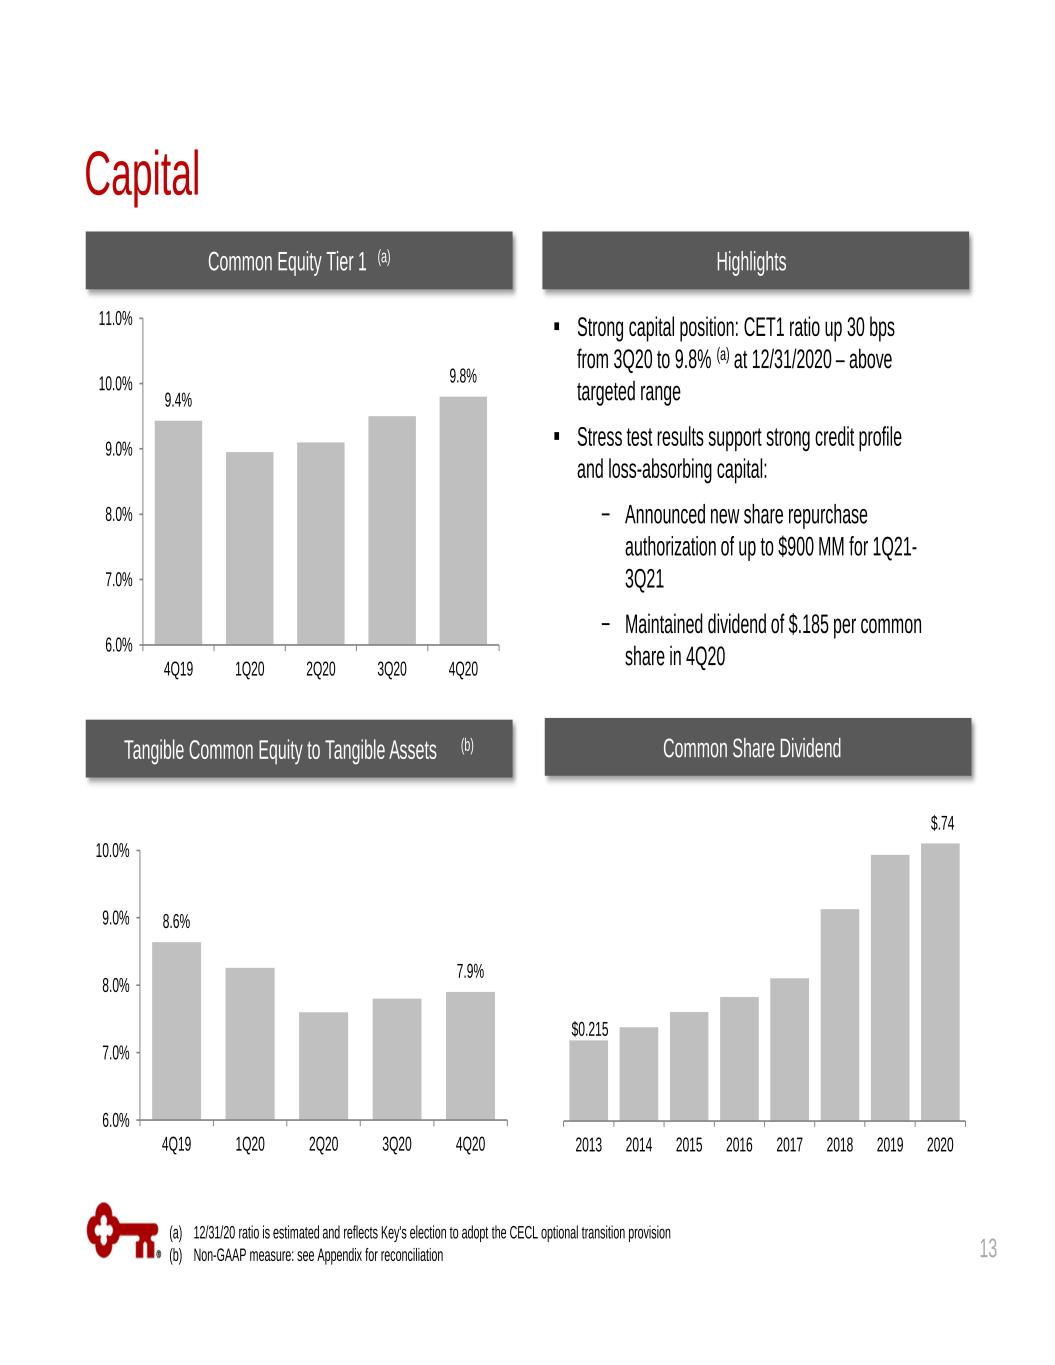
Common Equity Tier 1 (a) Strong capital position: CET1 ratio up 30 bps from 3Q20 to 9.8% (a) at 12/31/2020 – above targeted range Stress test results support strong credit profile and loss-absorbing capital: − Announced new share repurchase authorization of up to $900 MM for 1Q21- 3Q21 − Maintained dividend of $.185 per common share in 4Q20 Tangible Common Equity to Tangible Assets (b) (a) 12/31/20 ratio is estimated and reflects Key's election to adopt the CECL optional transition provision (b) Non-GAAP measure: see Appendix for reconciliation 9.4% 9.8% 6.0% 7.0% 8.0% 9.0% 10.0% 11.0% 4Q19 1Q20 2Q20 3Q20 4Q20 8.6% 7.9% 6.0% 7.0% 8.0% 9.0% 10.0% 4Q19 1Q20 2Q20 3Q20 4Q20 Capital Highlights Common Share Dividend $0.215 2013 2014 2015 2016 2017 2018 2019 2020 $.74 13
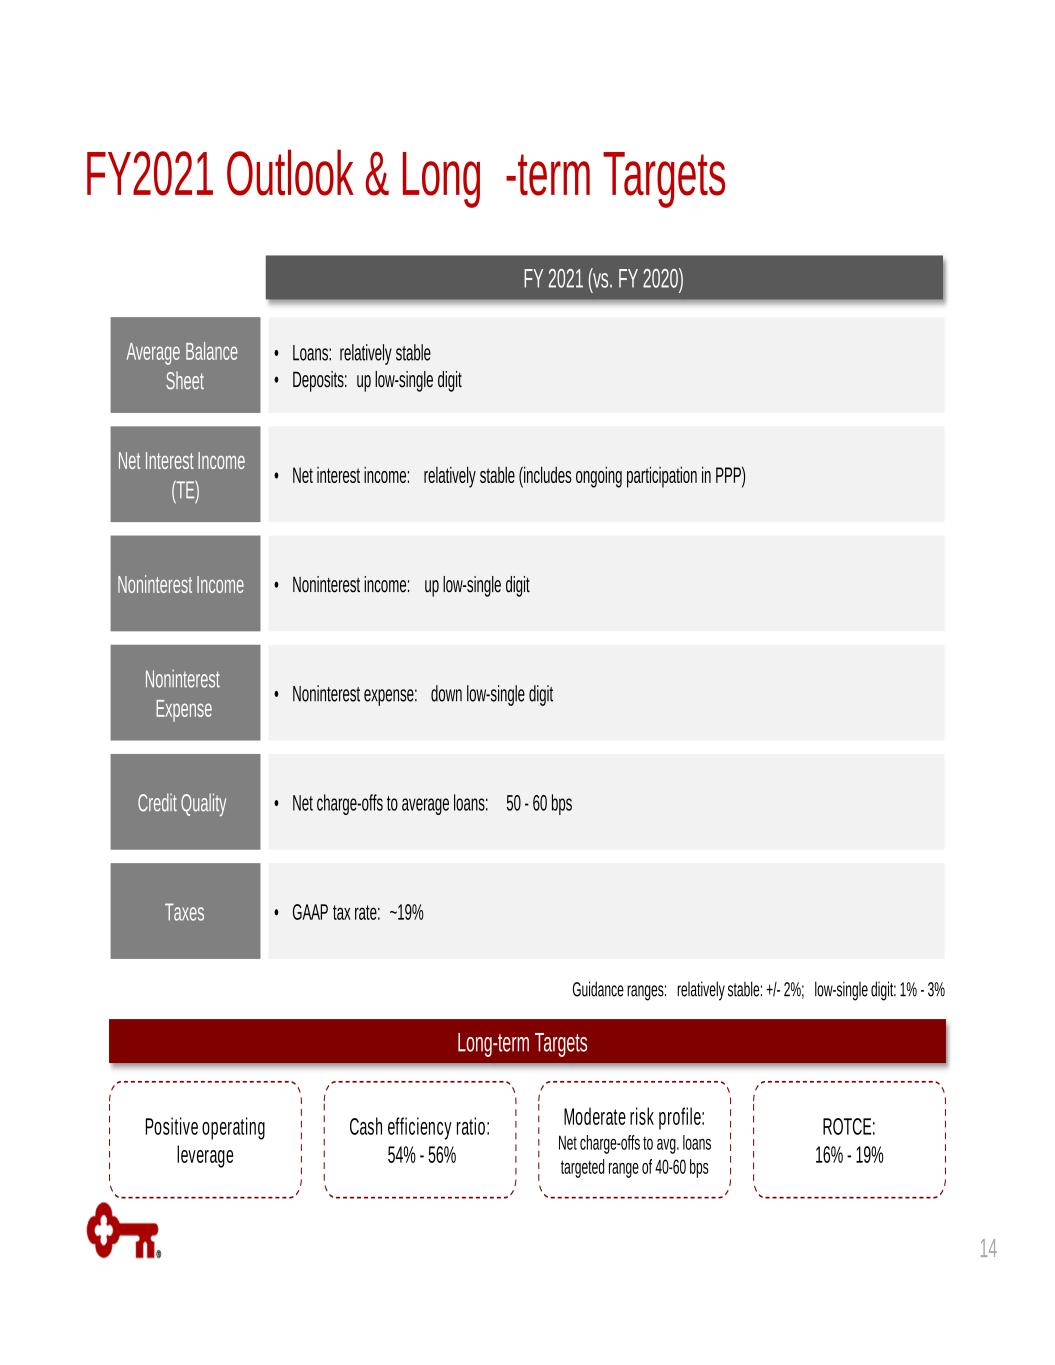
FY2021 Outlook & Long -term Targets Average Balance Sheet • Loans: relatively stable • Deposits: up low-single digit Net Interest Income (TE) • Net interest income: relatively stable (includes ongoing participation in PPP) Noninterest Income • Noninterest income: up low-single digit Noninterest Expense • Noninterest expense: down low-single digit Credit Quality • Net charge-offs to average loans: 50 - 60 bps Taxes • GAAP tax rate: ~19% FY 2021 (vs. FY 2020) Long-term Targets Positive operating leverage Cash efficiency ratio: 54% - 56% Moderate risk profile: Net charge-offs to avg. loans targeted range of 40-60 bps ROTCE: 16% - 19% Guidance ranges: relatively stable: +/- 2%; low-single digit: 1% - 3% 14
Appendix 15
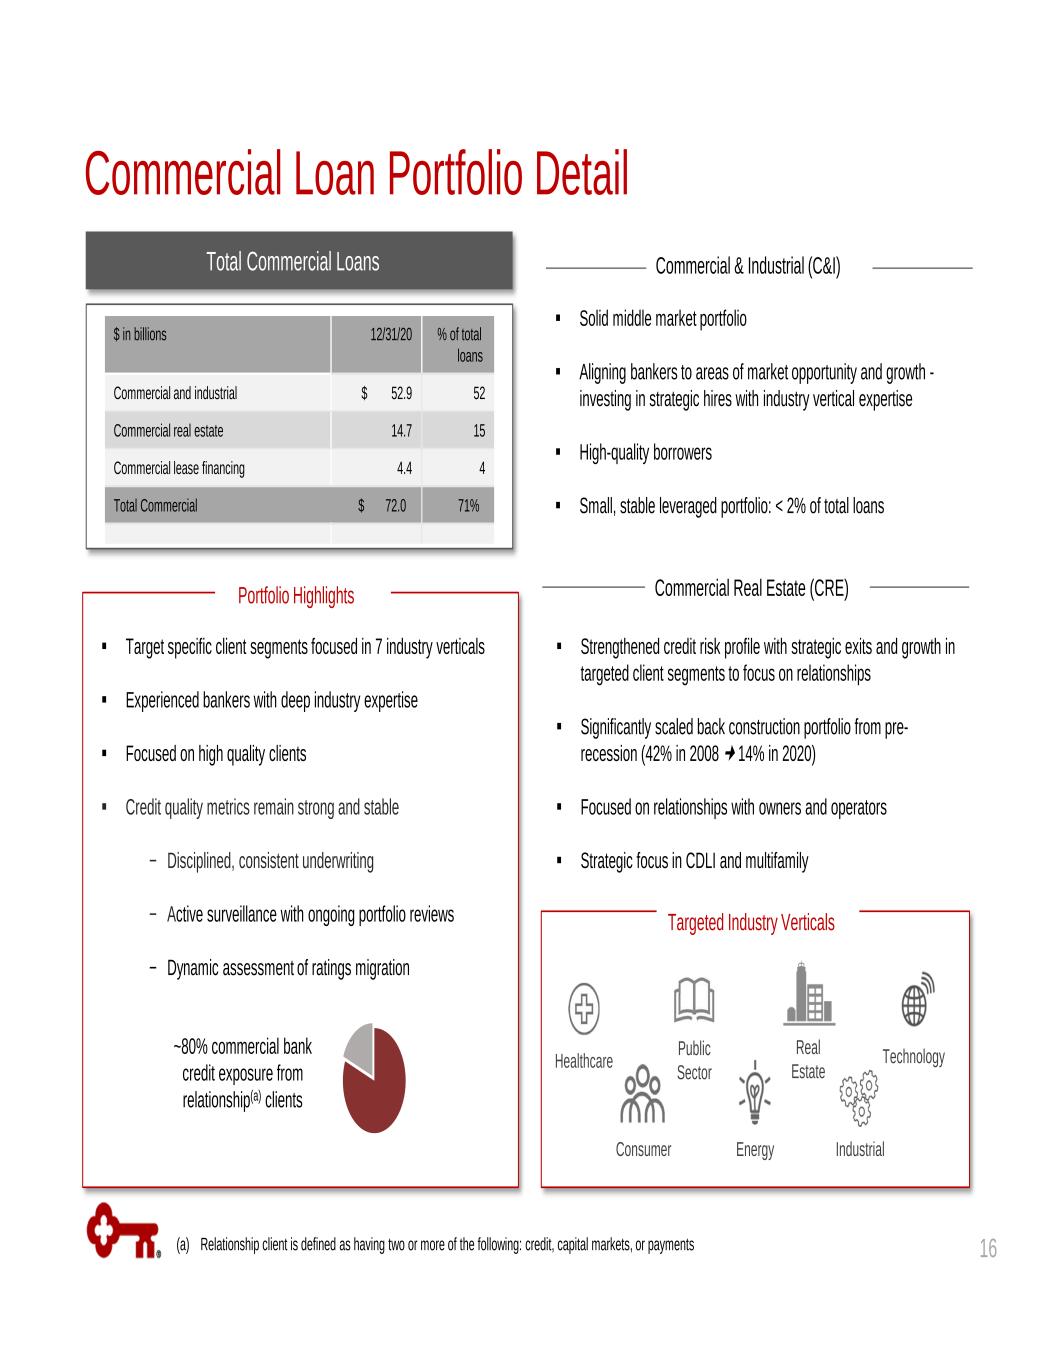
Total Commercial Loans C&I $40 CRE $18 $ in billions 12/31/20 % of total loans Commercial and industrial $ 52.9 52 Commercial real estate 14.7 15 Commercial lease financing 4.4 4 Total Commercial $ 72.0 71% Commercial Loan Portfolio Detail Solid middle market portfolio Aligning bankers to areas of market opportunity and growth - investing in strategic hires with industry vertical expertise High-quality borrowers Small, stable leveraged portfolio: < 2% of total loans Portfolio Highlights Target specific client segments focused in 7 industry verticals Experienced bankers with deep industry expertise Focused on high quality clients Credit quality metrics remain strong and stable − Disciplined, consistent underwriting − Active surveillance with ongoing portfolio reviews − Dynamic assessment of ratings migration Strengthened credit risk profile with strategic exits and growth in targeted client segments to focus on relationships Significantly scaled back construction portfolio from pre- recession (42% in 2008 14% in 2020) Focused on relationships with owners and operators Strategic focus in CDLI and multifamily Commercial Real Estate (CRE) Commercial & Industrial (C&I) Consumer Energy Healthcare Industrial Public Sector Real Estate Technology Targeted Industry Verticals ~80% commercial bank credit exposure from relationship(a) clients (a) Relationship client is defined as having two or more of the following: credit, capital markets, or payments 16
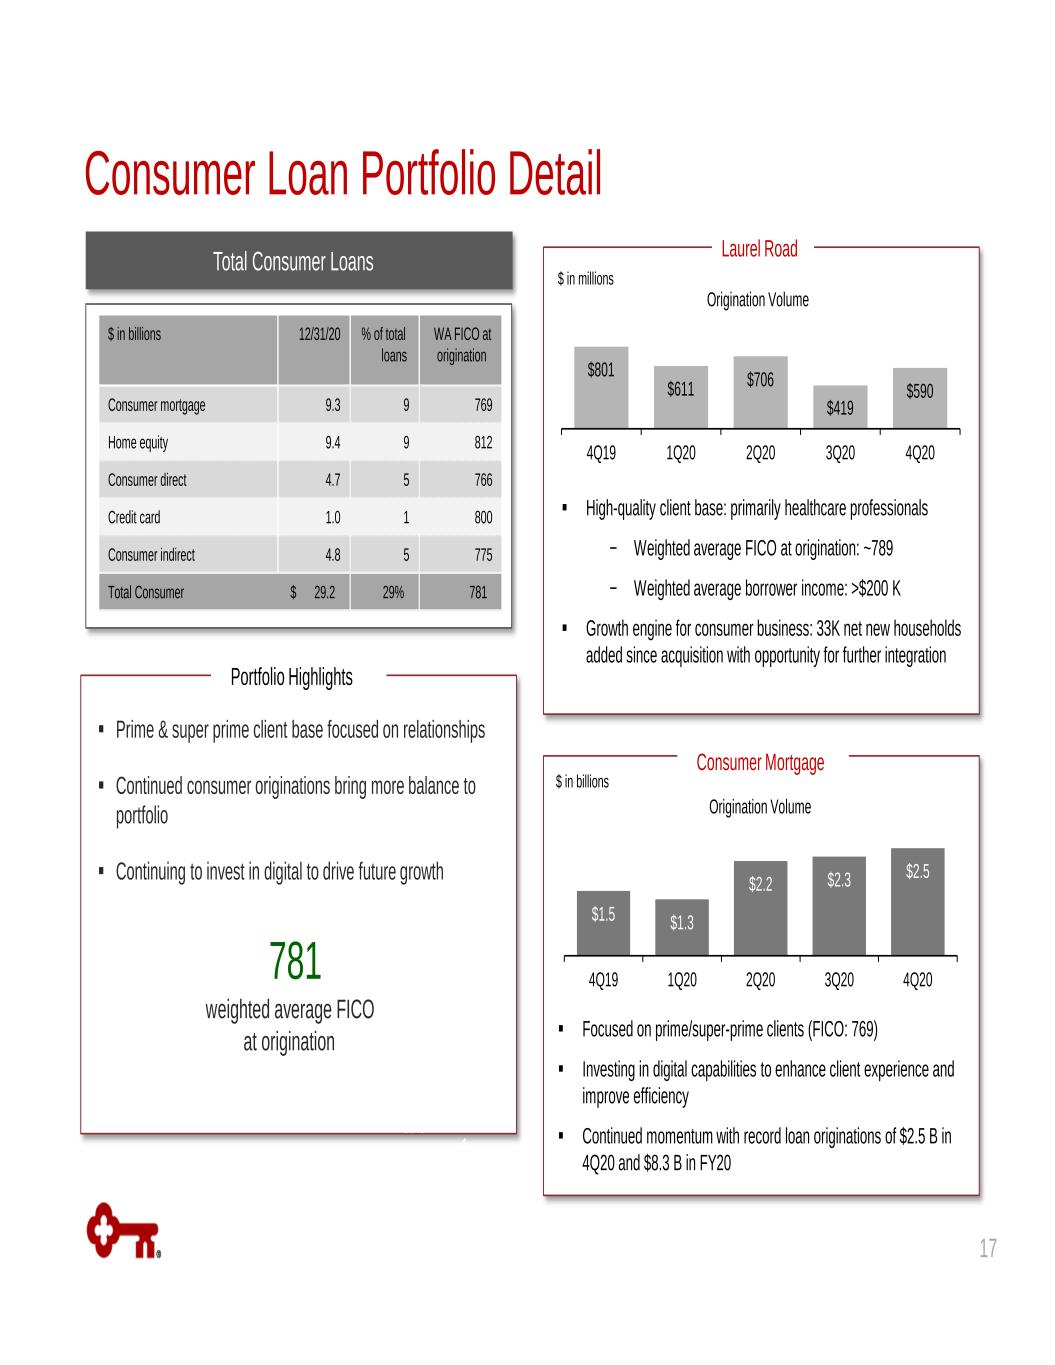
$1.5 $1.3 $2.2 $2.3 $2.5 4Q19 1Q20 2Q20 3Q20 4Q20 Origination Volume $801 $611 $706 $419 $590 4Q19 1Q20 2Q20 3Q20 4Q20 Origination Volume Portfolio Highlights Prime & super prime client base focused on relationships Continued consumer originations bring more balance to portfolio Continuing to invest in digital to drive future growth weighted average FICO at origination Total Consumer Loans Consumer Loan Portfolio Detail C&I $40 CRE $18 $ in billions 12/31/20 % of total loans WA FICO at origination Consumer mortgage 9.3 9 769 Home equity 9.4 9 812 Consumer direct 4.7 5 766 Credit card 1.0 1 800 Consumer indirect 4.8 5 775 Total Consumer $ 29.2 29% 781 $ in millions East Other $ in billions High-quality client base: primarily healthcare professionals − Weighted average FICO at origination: ~789 − Weighted average borrower income: >$200 K Growth engine for consumer business: 33K net new households added since acquisition with opportunity for further integration Focused on prime/super-prime clients (FICO: 769) Investing in digital capabilities to enhance client experience and improve efficiency Continued momentum with record loan originations of $2.5 B in 4Q20 and $8.3 B in FY20 Laurel Road Consumer Mortgage Other East Other 781 17
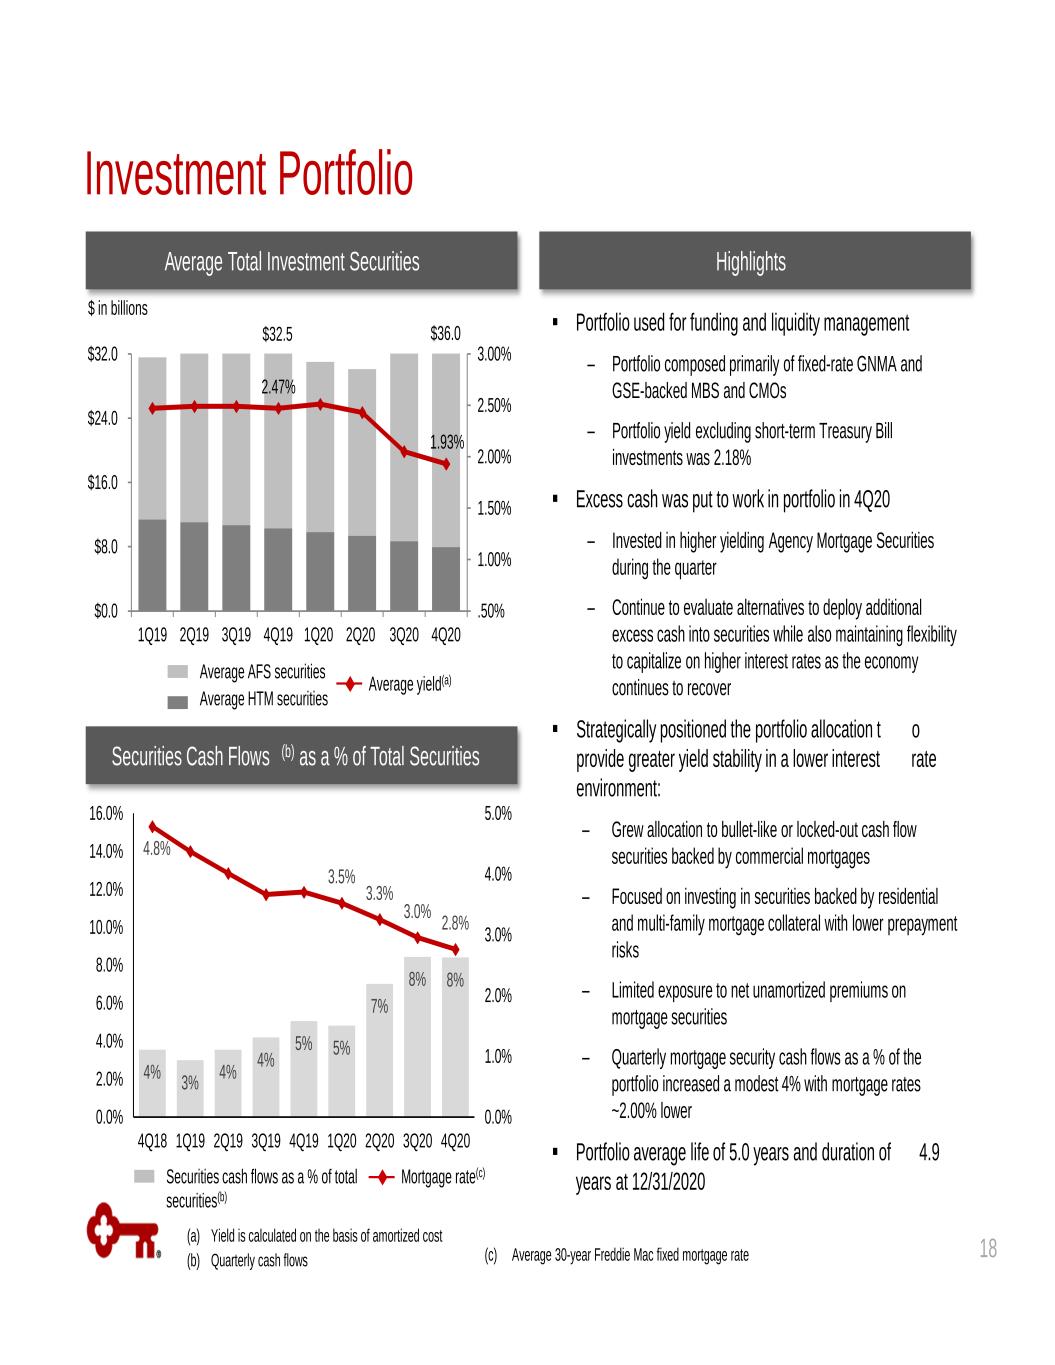
Average Total Investment Securities Average AFS securities Investment Portfolio Average yield(a) Average HTM securities $ in billions Highlights 2.47% .50% 1.00% 1.50% 2.00% 2.50% 3.00% $0.0 $8.0 $16.0 $24.0 $32.0 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 3Q20 4Q20 $32.5 $36.0 1.93% Securities Cash Flows (b) as a % of Total Securities Securities cash flows as a % of total securities(b) Mortgage rate(c) (a) Yield is calculated on the basis of amortized cost (b) Quarterly cash flows (c) Average 30-year Freddie Mac fixed mortgage rate Portfolio used for funding and liquidity management ‒ Portfolio composed primarily of fixed-rate GNMA and GSE-backed MBS and CMOs ‒ Portfolio yield excluding short-term Treasury Bill investments was 2.18% Excess cash was put to work in portfolio in 4Q20 ‒ Invested in higher yielding Agency Mortgage Securities during the quarter ‒ Continue to evaluate alternatives to deploy additional excess cash into securities while also maintaining flexibility to capitalize on higher interest rates as the economy continues to recover Strategically positioned the portfolio allocation t o provide greater yield stability in a lower interest rate environment: ‒ Grew allocation to bullet-like or locked-out cash flow securities backed by commercial mortgages ‒ Focused on investing in securities backed by residential and multi-family mortgage collateral with lower prepayment risks ‒ Limited exposure to net unamortized premiums on mortgage securities ‒ Quarterly mortgage security cash flows as a % of the portfolio increased a modest 4% with mortgage rates ~2.00% lower Portfolio average life of 5.0 years and duration of 4.9 years at 12/31/2020 18 4% 3% 4% 4% 5% 5% 7% 8% 8% 4.8% 3.5% 3.3% 3.0% 2.8% 0.0% 1.0% 2.0% 3.0% 4.0% 5.0% 0.0% 2.0% 4.0% 6.0% 8.0% 10.0% 12.0% 14.0% 16.0% 4Q18 1Q19 2Q19 3Q19 4Q19 1Q20 2Q20 3Q20 4Q20
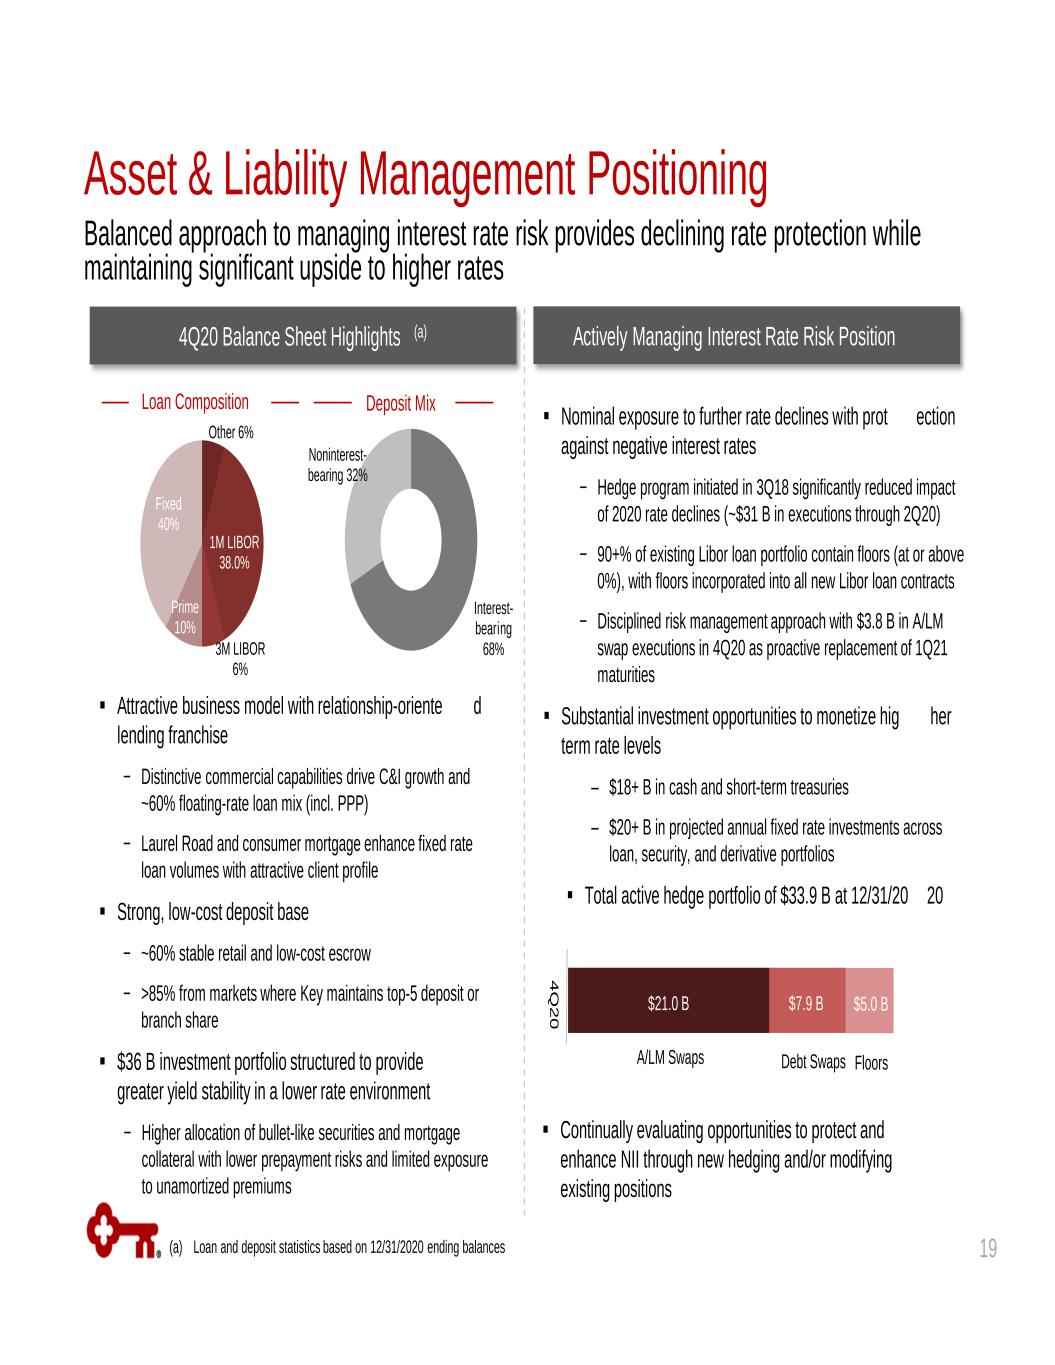
Prime 10% 1M LIBOR 38.0% 3M LIBOR 6% Other 6% Fixed 40% Balanced approach to managing interest rate risk provides declining rate protection while maintaining significant upside to higher rates 4Q20 Balance Sheet Highlights (a) Loan Composition Deposit Mix Attractive business model with relationship-oriente d lending franchise − Distinctive commercial capabilities drive C&I growth and ~60% floating-rate loan mix (incl. PPP) − Laurel Road and consumer mortgage enhance fixed rate loan volumes with attractive client profile Strong, low-cost deposit base − ~60% stable retail and low-cost escrow − >85% from markets where Key maintains top-5 deposit or branch share $36 B investment portfolio structured to provide greater yield stability in a lower rate environment − Higher allocation of bullet-like securities and mortgage collateral with lower prepayment risks and limited exposure to unamortized premiums Actively Managing Interest Rate Risk Position Nominal exposure to further rate declines with prot ection against negative interest rates − Hedge program initiated in 3Q18 significantly reduced impact of 2020 rate declines (~$31 B in executions through 2Q20) − 90+% of existing Libor loan portfolio contain floors (at or above 0%), with floors incorporated into all new Libor loan contracts − Disciplined risk management approach with $3.8 B in A/LM swap executions in 4Q20 as proactive replacement of 1Q21 maturities Substantial investment opportunities to monetize hig her term rate levels ‒ $18+ B in cash and short-term treasuries ‒ $20+ B in projected annual fixed rate investments across loan, security, and derivative portfolios Total active hedge portfolio of $33.9 B at 12/31/20 20 (a) Loan and deposit statistics based on 12/31/2020 ending balances Continually evaluating opportunities to protect and enhance NII through new hedging and/or modifying existing positions FloorsA/LM Swaps Debt Swaps 4 Q 2 0 $21.0 B $7.9 B $5.0 B Interest- bearing 68% Noninterest- bearing 32% 19 Asset & Liability Management Positioning
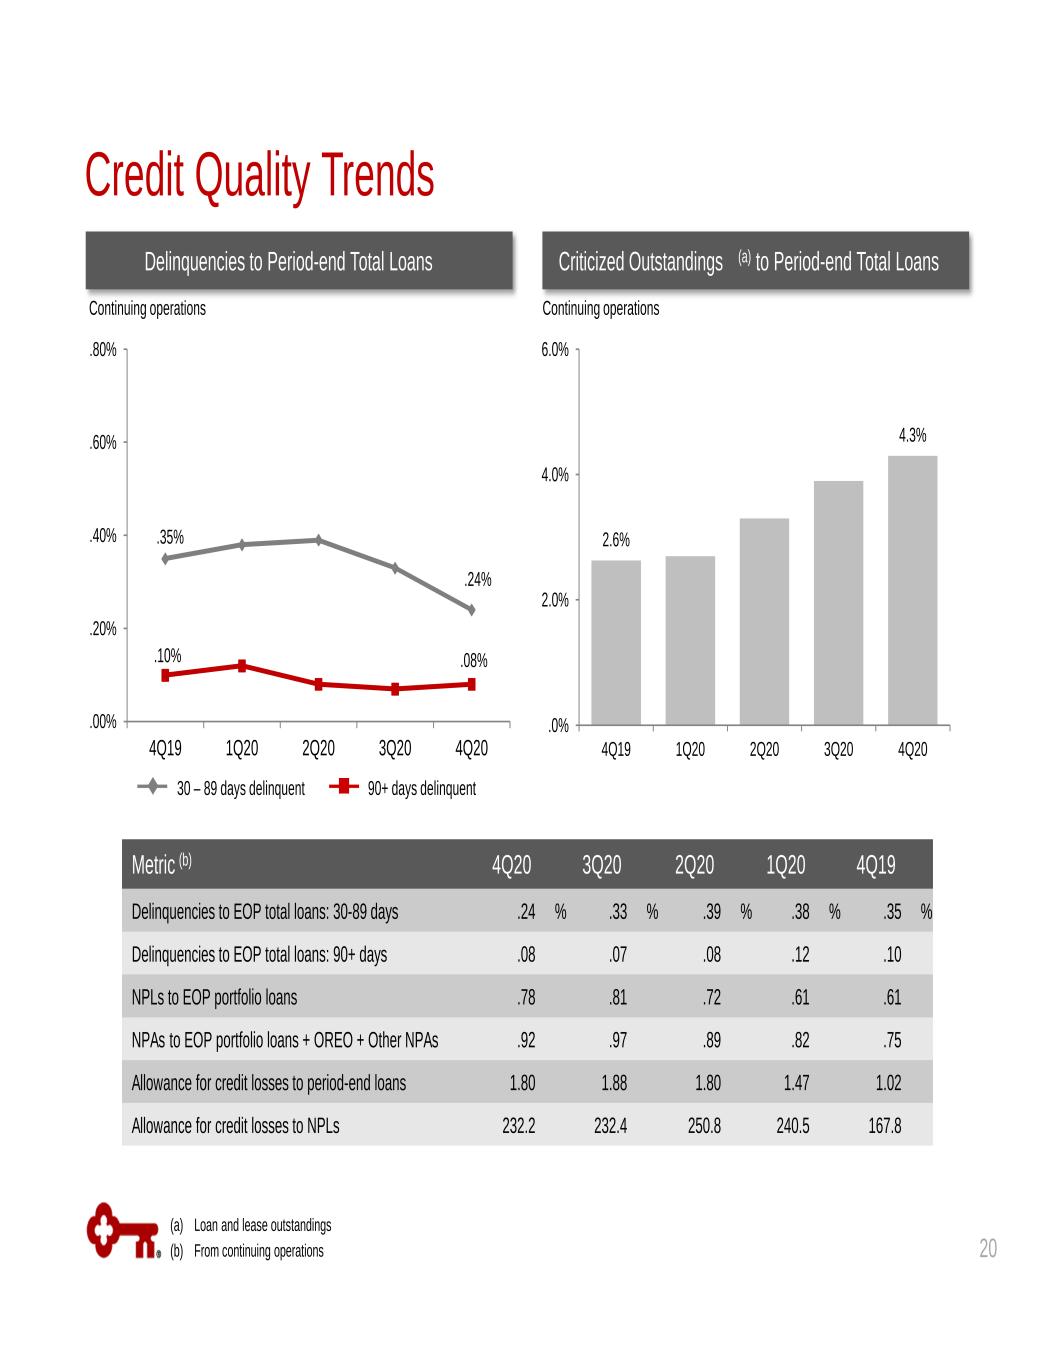
Criticized Outstandings (a) to Period-end Total LoansDelinquencies to Period-end Total Loans Credit Quality Trends (a) Loan and lease outstandings (b) From continuing operations 30 – 89 days delinquent 90+ days delinquent .35% .24% .10% .08% .00% .20% .40% .60% .80% 4Q19 1Q20 2Q20 3Q20 4Q20 2.6% 4.3% .0% 2.0% 4.0% 6.0% 4Q19 1Q20 2Q20 3Q20 4Q20 Metric (b) 4Q20 3Q20 2Q20 1Q20 4Q19 Delinquencies to EOP total loans: 30-89 days .24 % .33 % .39 % .38 % .35 % Delinquencies to EOP total loans: 90+ days .08 .07 .08 .12 .10 NPLs to EOP portfolio loans .78 .81 .72 .61 .61 NPAs to EOP portfolio loans + OREO + Other NPAs .92 .97 .89 .82 .75 Allowance for credit losses to period-end loans 1.80 1.88 1.80 1.47 1.02 Allowance for credit losses to NPLs 232.2 232.4 250.8 240.5 167.8 Continuing operations Continuing operations 20
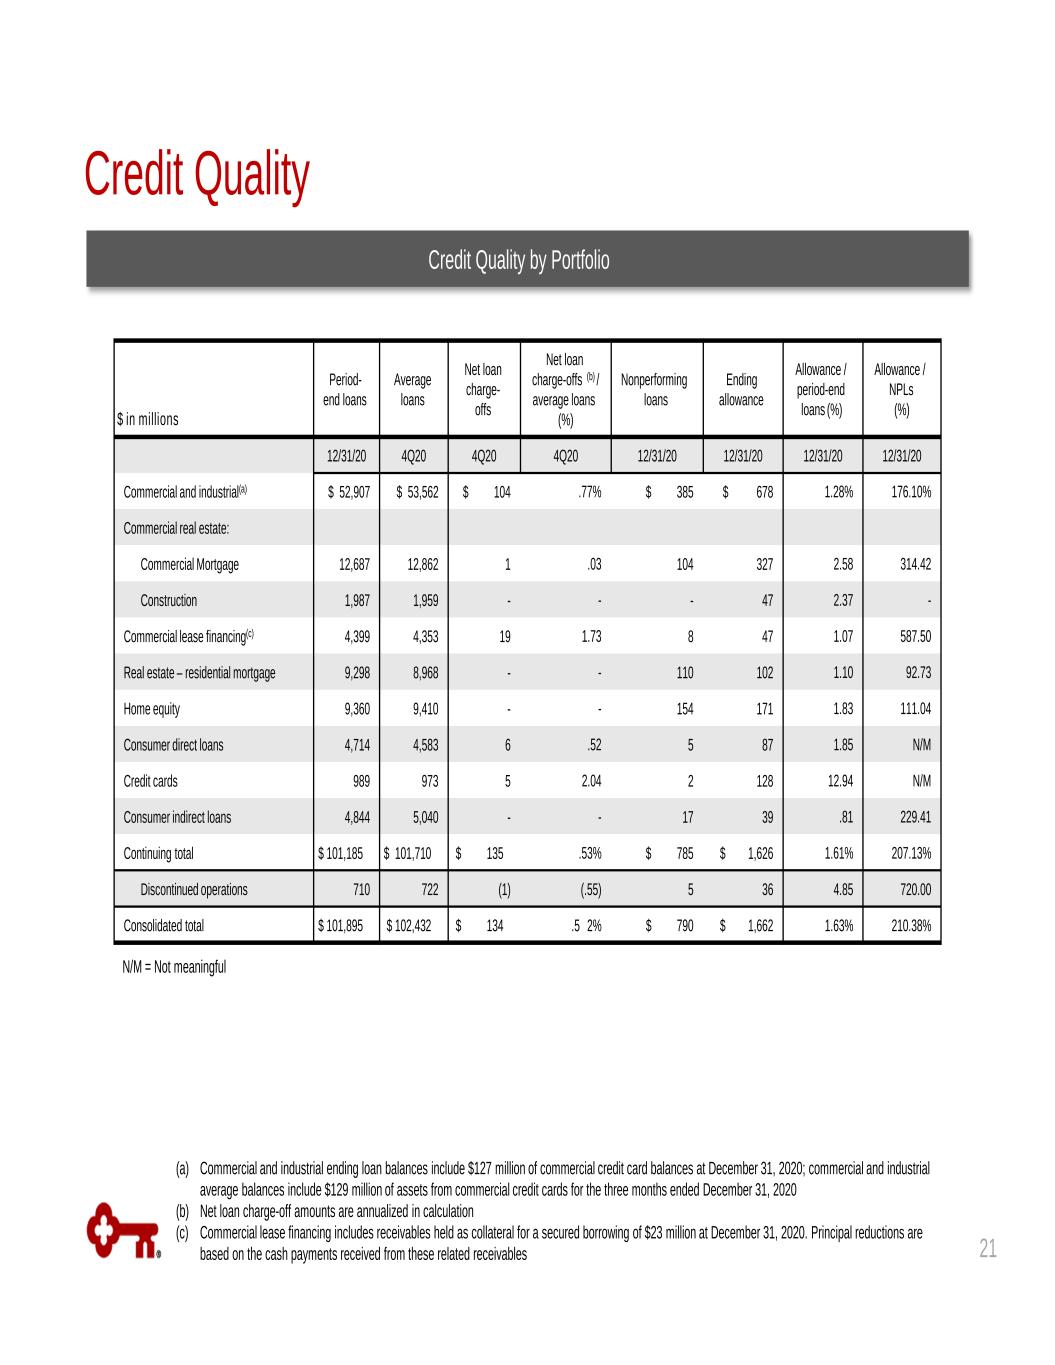
Period- end loans Average loans Net loan charge- offs Net loan charge-offs (b) / average loans (%) Nonperforming loans Ending allowance Allowance / period-end loans (%) Allowance / NPLs (%) 12/31/20 4Q20 4Q20 4Q20 12/31/20 12/31/20 12/31/20 12/31/20 Commercial and industrial(a) $ 52,907 $ 53,562 $ 104 .77% $ 385 $ 678 1.28% 176.10% Commercial real estate: Commercial Mortgage 12,687 12,862 1 .03 104 327 2.58 314.42 Construction 1,987 1,959 - - - 47 2.37 - Commercial lease financing(c) 4,399 4,353 19 1.73 8 47 1.07 587.50 Real estate – residential mortgage 9,298 8,968 - - 110 102 1.10 92.73 Home equity 9,360 9,410 - - 154 171 1.83 111.04 Consumer direct loans 4,714 4,583 6 .52 5 87 1.85 N/M Credit cards 989 973 5 2.04 2 128 12.94 N/M Consumer indirect loans 4,844 5,040 - - 17 39 .81 229.41 Continuing total $ 101,185 $ 101,710 $ 135 .53% $ 785 $ 1,626 1.61% 207.13% Discontinued operations 710 722 (1) (.55) 5 36 4.85 720.00 Consolidated total $ 101,895 $ 102,432 $ 134 .5 2% $ 790 $ 1,662 1.63% 210.38% Credit Quality by Portfolio Credit Quality $ in millions N/M = Not meaningful (a) Commercial and industrial ending loan balances include $127 million of commercial credit card balances at December 31, 2020; commercial and industrial average balances include $129 million of assets from commercial credit cards for the three months ended December 31, 2020 (b) Net loan charge-off amounts are annualized in calculation (c) Commercial lease financing includes receivables held as collateral for a secured borrowing of $23 million at December 31, 2020. Principal reductions are based on the cash payments received from these related receivables 21
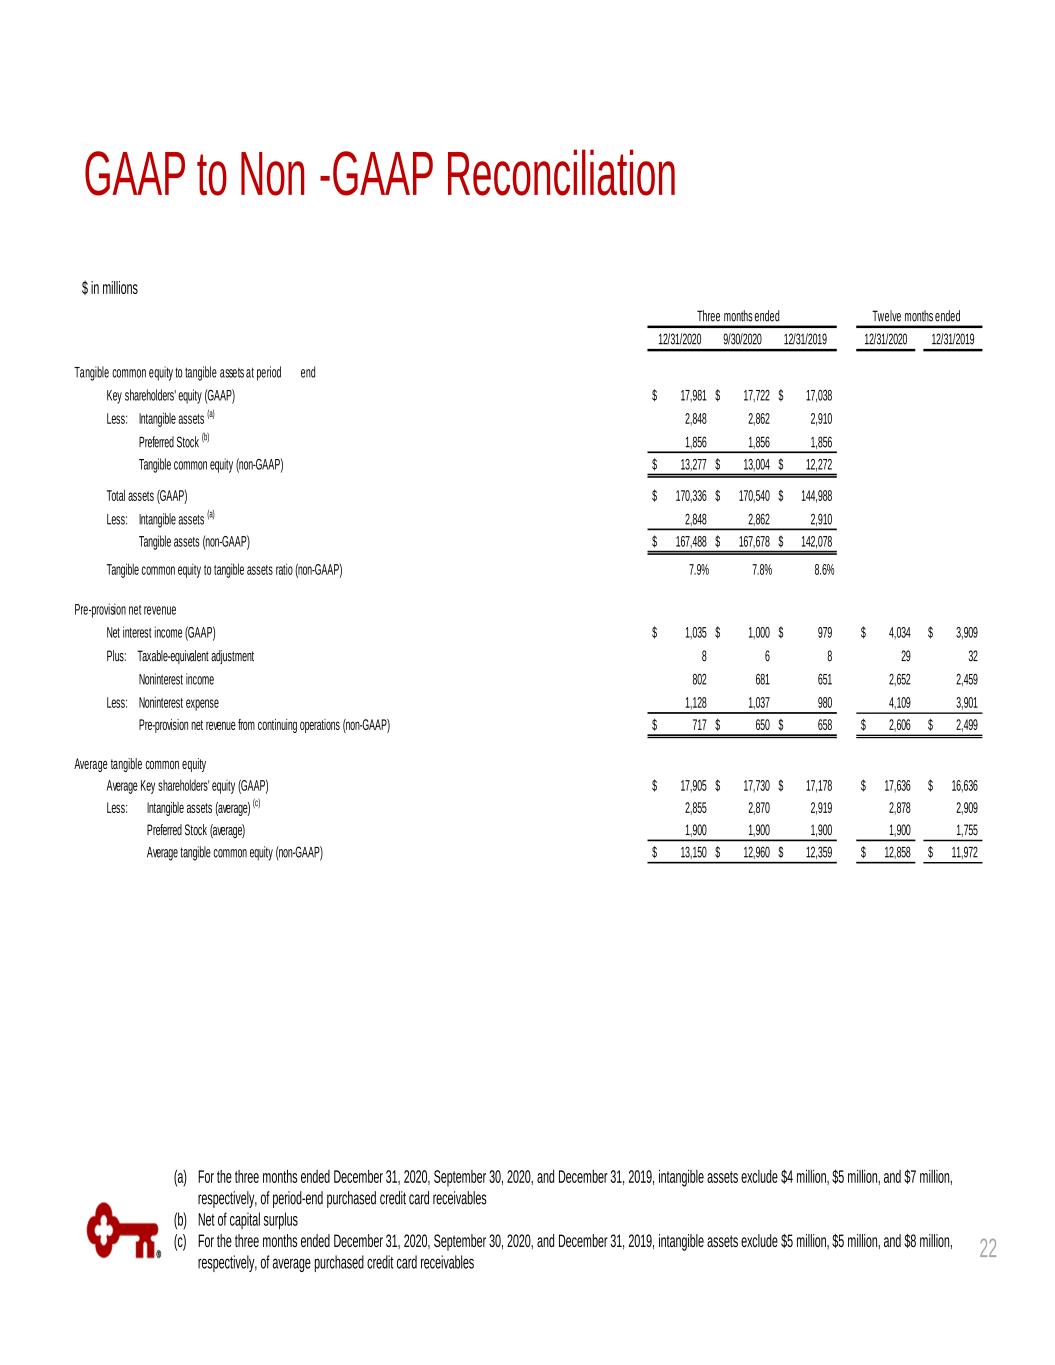
GAAP to Non -GAAP Reconciliation (a) For the three months ended December 31, 2020, September 30, 2020, and December 31, 2019, intangible assets exclude $4 million, $5 million, and $7 million, respectively, of period-end purchased credit card receivables (b) Net of capital surplus (c) For the three months ended December 31, 2020, September 30, 2020, and December 31, 2019, intangible assets exclude $5 million, $5 million, and $8 million, respectively, of average purchased credit card receivables $ in millions 12/31/2020 9/30/2020 12/31/2019 12/31/2020 12/31/2019 Tangible common equity to tangible assets at period end Key shareholders' equity (GAAP) 17,981$ 17,722$ 17,038$ Less: Intangible assets (a) 2,848 2,862 2,910 Preferred Stock (b) 1,856 1,856 1,856 Tangible common equity (non-GAAP) 13,277$ 13,004$ 12,272$ Total assets (GAAP) 170,336$ 170,540$ 144,988$ Less: Intangible assets (a) 2,848 2,862 2,910 Tangible assets (non-GAAP) 167,488$ 167,678$ 142,078$ Tangible common equity to tangible assets ratio (non-GAAP) 7.9% 7.8% 8.6% Pre-provision net revenue Net interest income (GAAP) 1,035$ 1,000$ 979$ 4,034$ 3,909$ Plus: Taxable-equivalent adjustment 8 6 8 29 32 Noninterest income 802 681 651 2,652 2,459 Less: Noninterest expense 1,128 1,037 980 4,109 3,901 Pre-provision net revenue from continuing operations (non-GAAP) 717$ 650$ 658$ 2,606$ 2,499$ Average tangible common equity Average Key shareholders' equity (GAAP) 17,905$ 17,730$ 17,178$ 17,636$ 16,636$ Less: Intangible assets (average) (c) 2,855 2,870 2,919 2,878 2,909 Preferred Stock (average) 1,900 1,900 1,900 1,900 1,755 Average tangible common equity (non-GAAP) 13,150$ 12,960$ 12,359$ 12,858$ 11,972$ Twelve months endedThree months ended 22
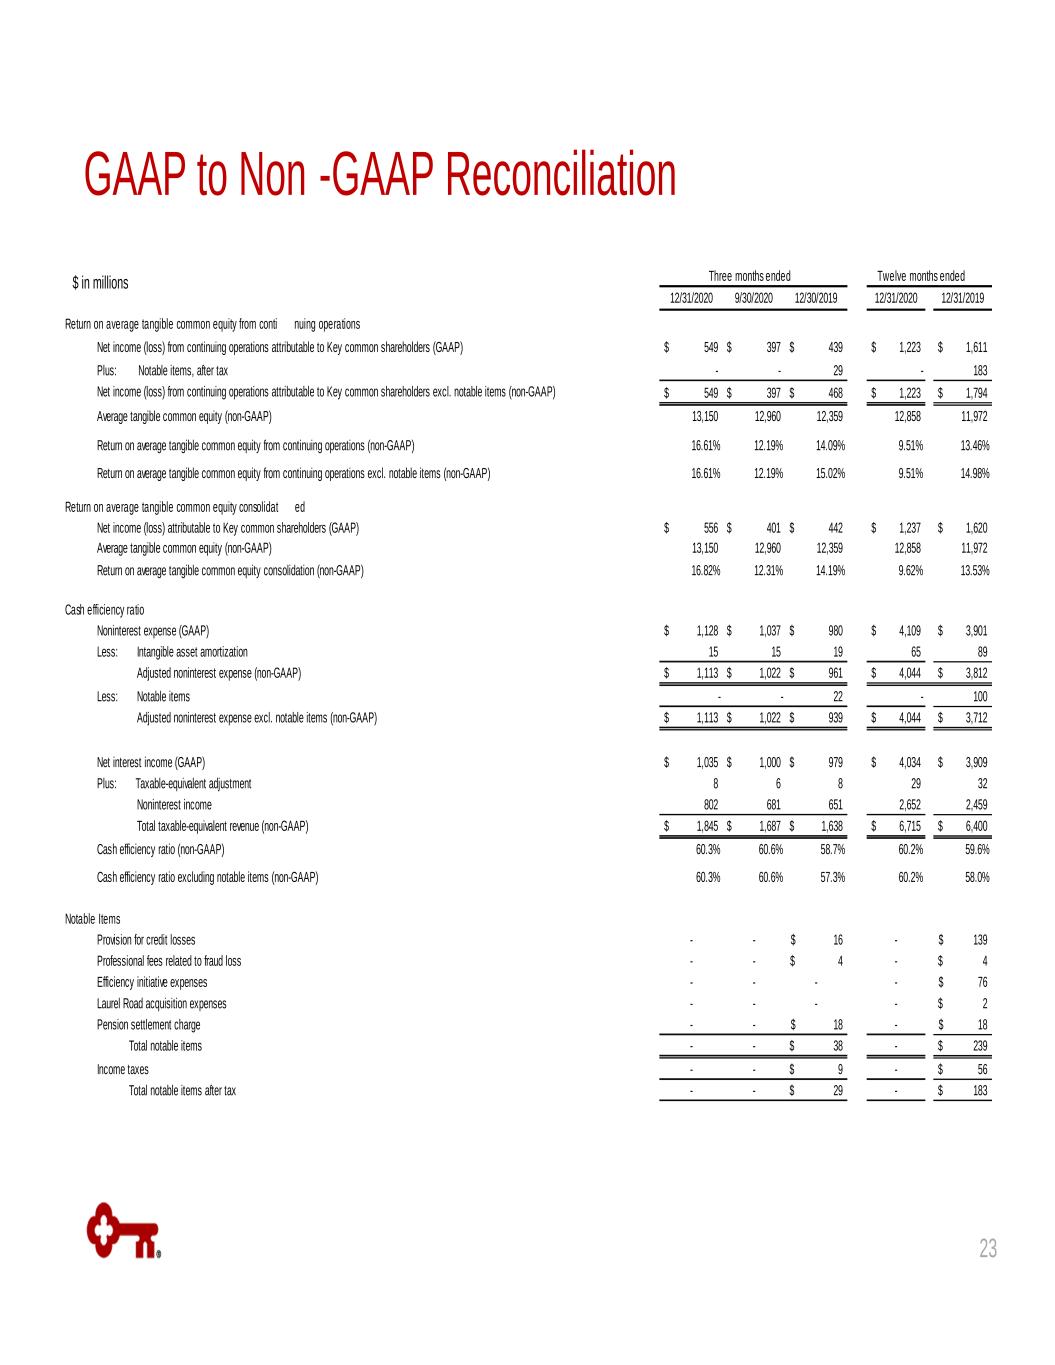
12/31/2020 9/30/2020 12/30/2019 12/31/2020 12/31/2019 Return on average tangible common equity from conti nuing operations Net income (loss) from continuing operations attributable to Key common shareholders (GAAP) 549$ 397$ 439$ 1,223$ 1,611$ Plus: Notable items, after tax - - 29 - 183 Net income (loss) from continuing operations attributable to Key common shareholders excl. notable items (non-GAAP) 549$ 397$ 468$ 1,223$ 1,794$ Average tangible common equity (non-GAAP) 13,150 12,960 12,359 12,858 11,972 Return on average tangible common equity from continuing operations (non-GAAP) 16.61% 12.19% 14.09% 9.51% 13.46% Return on average tangible common equity from continuing operations excl. notable items (non-GAAP) 16.61% 12.19% 15.02% 9.51% 14.98% Return on average tangible common equity consolidat ed Net income (loss) attributable to Key common shareholders (GAAP) 556$ 401$ 442$ 1,237$ 1,620$ Average tangible common equity (non-GAAP) 13,150 12,960 12,359 12,858 11,972 Return on average tangible common equity consolidation (non-GAAP) 16.82% 12.31% 14.19% 9.62% 13.53% Cash efficiency ratio Noninterest expense (GAAP) 1,128$ 1,037$ 980$ 4,109$ 3,901$ Less: Intangible asset amortization 15 15 19 65 89 Adjusted noninterest expense (non-GAAP) 1,113$ 1,022$ 961$ 4,044$ 3,812$ Less: Notable items - - 22 - 100 Adjusted noninterest expense excl. notable items (non-GAAP) 1,113$ 1,022$ 939$ 4,044$ 3,712$ Net interest income (GAAP) 1,035$ 1,000$ 979$ 4,034$ 3,909$ Plus: Taxable-equivalent adjustment 8 6 8 29 32 Noninterest income 802 681 651 2,652 2,459 Total taxable-equivalent revenue (non-GAAP) 1,845$ 1,687$ 1,638$ 6,715$ 6,400$ Cash efficiency ratio (non-GAAP) 60.3% 60.6% 58.7% 60.2% 59.6%0.602 0.602 Cash efficiency ratio excluding notable items (non-GAAP) 60.3% 60.6% 57.3% 60.2% 58.0% Notable Items Provision for credit losses - - 16$ - 139$ Professional fees related to fraud loss - - 4$ - 4$ Efficiency initiative expenses - - - - 76$ Laurel Road acquisition expenses - - - - 2$ Pension settlement charge - - 18$ - 18$ Total notable items - - 38$ - 239$ Income taxes - - 9$ - 56$ Total notable items after tax - - 29$ - 183$ Three months ended Twelve months ended GAAP to Non -GAAP Reconciliation $ in millions 23
Exhibit 99.3
| Consolidated Balance Sheets | |||||||||||||||||
| (dollars in millions) | |||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | |||||||||||||||
| Assets | |||||||||||||||||
| Loans | $ | 101,185 | $ | 103,081 | $ | 94,646 | |||||||||||
| Loans held for sale | 1,583 | 1,724 | 1,334 | ||||||||||||||
| Securities available for sale | 27,556 | 26,895 | 21,843 | ||||||||||||||
| Held-to-maturity securities | 7,595 | 8,384 | 10,067 | ||||||||||||||
| Trading account assets | 735 | 733 | 1,040 | ||||||||||||||
| Short-term investments | 16,194 | 14,148 | 1,272 | ||||||||||||||
| Other investments | 621 | 620 | 605 | ||||||||||||||
| Total earning assets | 155,469 | 155,585 | 130,807 | ||||||||||||||
| Allowance for loan and lease losses | (1,626) | (1,730) | (900) | ||||||||||||||
| Cash and due from banks | 1,091 | 956 | 732 | ||||||||||||||
| Premises and equipment | 753 | 765 | 814 | ||||||||||||||
| Goodwill | 2,664 | 2,664 | 2,664 | ||||||||||||||
| Other intangible assets | 188 | 203 | 253 | ||||||||||||||
| Corporate-owned life insurance | 4,286 | 4,274 | 4,233 | ||||||||||||||
| Accrued income and other assets | 6,812 | 7,084 | 5,494 | ||||||||||||||
| Discontinued assets | 699 | 739 | 891 | ||||||||||||||
| Total assets | $ | 170,336 | $ | 170,540 | $ | 144,988 | |||||||||||
| Liabilities | |||||||||||||||||
| Deposits in domestic offices: | |||||||||||||||||
| NOW and money market deposit accounts | $ | 80,427 | $ | 80,791 | $ | 66,714 | |||||||||||
| Savings deposits | 5,913 | 5,585 | 4,651 | ||||||||||||||
| Certificates of deposit ($100,000 or more) | 2,733 | 3,345 | 6,598 | ||||||||||||||
| Other time deposits | 3,010 | 3,450 | 5,054 | ||||||||||||||
| Total interest-bearing deposits | 92,083 | 93,171 | 83,017 | ||||||||||||||
| Noninterest-bearing deposits | 43,199 | 43,575 | 28,853 | ||||||||||||||
| Total deposits | 135,282 | 136,746 | 111,870 | ||||||||||||||
| Federal funds purchased and securities sold under repurchase agreements | 220 | 213 | 387 | ||||||||||||||
| Bank notes and other short-term borrowings | 759 | 818 | 705 | ||||||||||||||
| Accrued expense and other liabilities | 2,385 | 2,356 | 2,540 | ||||||||||||||
| Long-term debt | 13,709 | 12,685 | 12,448 | ||||||||||||||
| Total liabilities | 152,355 | 152,818 | 127,950 | ||||||||||||||
| Equity | |||||||||||||||||
| Preferred stock | 1,900 | 1,900 | 1,900 | ||||||||||||||
| Common shares | 1,257 | 1,257 | 1,257 | ||||||||||||||
| Capital surplus | 6,281 | 6,263 | 6,295 | ||||||||||||||
| Retained earnings | 12,751 | 12,375 | 12,469 | ||||||||||||||
| Treasury stock, at cost | (4,946) | (4,940) | (4,909) | ||||||||||||||
| Accumulated other comprehensive income (loss) | 738 | 867 | 26 | ||||||||||||||
| Key shareholders’ equity | 17,981 | 17,722 | 17,038 | ||||||||||||||
| Noncontrolling interests | — | — | — | ||||||||||||||
| Total equity | 17,981 | 17,722 | 17,038 | ||||||||||||||
| Total liabilities and equity | $ | 170,336 | $ | 170,540 | $ | 144,988 | |||||||||||
| Common shares outstanding (000) | 975,773 | 976,205 | 977,189 | ||||||||||||||
| Consolidated Statements of Income | ||||||||||||||||||||||||||
| (dollars in millions, except per share amounts) | ||||||||||||||||||||||||||
| Three months ended | Twelve months ended | |||||||||||||||||||||||||
| 12/31/2020 | 9/30/2020 | 12/31/2019 | 12/31/2020 | 12/31/2019 | ||||||||||||||||||||||
| Interest income | ||||||||||||||||||||||||||
| Loans | $ | 933 | $ | 927 | $ | 1,046 | $ | 3,866 | $ | 4,267 | ||||||||||||||||
| Loans held for sale | 11 | 18 | 17 | 69 | 63 | |||||||||||||||||||||
| Securities available for sale | 119 | 115 | 137 | 484 | 537 | |||||||||||||||||||||
| Held-to-maturity securities | 51 | 53 | 63 | 222 | 262 | |||||||||||||||||||||
| Trading account assets | 4 | 3 | 8 | 20 | 32 | |||||||||||||||||||||
| Short-term investments | 4 | 1 | 12 | 18 | 61 | |||||||||||||||||||||
| Other investments | 3 | 2 | 2 | 6 | 13 | |||||||||||||||||||||
| Total interest income | 1,125 | 1,119 | 1,285 | 4,685 | 5,235 | |||||||||||||||||||||
| Interest expense | ||||||||||||||||||||||||||
| Deposits | 28 | 54 | 201 | 347 | 853 | |||||||||||||||||||||
| Federal funds purchased and securities sold under repurchase agreements | — | — | 1 | 6 | 2 | |||||||||||||||||||||
| Bank notes and other short-term borrowings | 1 | 1 | 4 | 12 | 17 | |||||||||||||||||||||
| Long-term debt | 61 | 64 | 100 | 286 | 454 | |||||||||||||||||||||
| Total interest expense | 90 | 119 | 306 | 651 | 1,326 | |||||||||||||||||||||
| Net interest income | 1,035 | 1,000 | 979 | 4,034 | 3,909 | |||||||||||||||||||||
| Provision for credit losses | 20 | 160 | 109 | 1,021 | 445 | |||||||||||||||||||||
| Net interest income after provision for credit losses | 1,015 | 840 | 870 | 3,013 | 3,464 | |||||||||||||||||||||
| Noninterest income | ||||||||||||||||||||||||||
| Trust and investment services income | 123 | 128 | 120 | 507 | 475 | |||||||||||||||||||||
| Investment banking and debt placement fees | 243 | 146 | 181 | 661 | 630 | |||||||||||||||||||||
| Service charges on deposit accounts | 82 | 77 | 86 | 311 | 337 | |||||||||||||||||||||
| Operating lease income and other leasing gains | 39 | 38 | 39 | 167 | 162 | |||||||||||||||||||||
| Corporate services income | 63 | 51 | 65 | 228 | 236 | |||||||||||||||||||||
| Cards and payments income | 97 | 114 | 67 | 368 | 275 | |||||||||||||||||||||
| Corporate-owned life insurance income | 38 | 30 | 39 | 139 | 136 | |||||||||||||||||||||
| Consumer mortgage income | 43 | 51 | 21 | 176 | 63 | |||||||||||||||||||||
| Commercial mortgage servicing fees | 32 | 18 | 19 | 80 | 77 | |||||||||||||||||||||
| Other income | 42 | 28 | 14 | 15 | 68 | |||||||||||||||||||||
| Total noninterest income | 802 | 681 | 651 | 2,652 | 2,459 | |||||||||||||||||||||
| Noninterest expense | ||||||||||||||||||||||||||
| Personnel | 661 | 588 | 551 | 2,336 | 2,250 | |||||||||||||||||||||
| Net occupancy | 75 | 76 | 76 | 298 | 293 | |||||||||||||||||||||
| Computer processing | 62 | 59 | 51 | 232 | 214 | |||||||||||||||||||||
| Business services and professional fees | 54 | 49 | 54 | 196 | 186 | |||||||||||||||||||||
| Equipment | 26 | 25 | 25 | 100 | 100 | |||||||||||||||||||||
| Operating lease expense | 35 | 33 | 32 | 138 | 123 | |||||||||||||||||||||
| Marketing | 30 | 22 | 27 | 97 | 96 | |||||||||||||||||||||
| FDIC assessment | 9 | 6 | 8 | 32 | 31 | |||||||||||||||||||||
| Intangible asset amortization | 15 | 15 | 19 | 65 | 89 | |||||||||||||||||||||
| OREO expense, net | — | (1) | 3 | 8 | 13 | |||||||||||||||||||||
| Other expense | 161 | 165 | 134 | 607 | 506 | |||||||||||||||||||||
| Total noninterest expense | 1,128 | 1,037 | 980 | 4,109 | 3,901 | |||||||||||||||||||||
| Income (loss) from continuing operations before income taxes | 689 | 484 | 541 | 1,556 | 2,022 | |||||||||||||||||||||
| Income taxes | 114 | 60 | 75 | 227 | 314 | |||||||||||||||||||||
| Income (loss) from continuing operations | 575 | 424 | 466 | 1,329 | 1,708 | |||||||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | 7 | 4 | 3 | 14 | 9 | |||||||||||||||||||||
| Net income (loss) | 582 | 428 | 469 | 1,343 | 1,717 | |||||||||||||||||||||
| Less: Net income (loss) attributable to noncontrolling interests | — | — | — | — | — | |||||||||||||||||||||
| Net income (loss) attributable to Key | $ | 582 | $ | 428 | $ | 469 | $ | 1,343 | $ | 1,717 | ||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | 549 | $ | 397 | $ | 439 | $ | 1,223 | $ | 1,611 | ||||||||||||||||
| Net income (loss) attributable to Key common shareholders | 556 | 401 | 442 | 1,237 | 1,620 | |||||||||||||||||||||
| Per common share | ||||||||||||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | .57 | $ | .41 | $ | .45 | $ | 1.26 | $ | 1.62 | ||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | .01 | — | — | .01 | .01 | |||||||||||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .57 | .41 | .45 | 1.28 | 1.63 | |||||||||||||||||||||
| Per common share — assuming dilution | ||||||||||||||||||||||||||
| Income (loss) from continuing operations attributable to Key common shareholders | $ | .56 | $ | .41 | $ | .45 | $ | 1.26 | $ | 1.61 | ||||||||||||||||
| Income (loss) from discontinued operations, net of taxes | .01 | — | — | .01 | .01 | |||||||||||||||||||||
Net income (loss) attributable to Key common shareholders (a) | .57 | .41 | $ | .45 | 1.27 | 1.62 | ||||||||||||||||||||
| Cash dividends declared per common share | $ | .185 | $ | .185 | $ | .185 | $ | .74 | $ | .71 | ||||||||||||||||
| Weighted-average common shares outstanding (000) | 967,987 | 967,804 | 973,450 | 967,783 | 992,091 | |||||||||||||||||||||
| Effect of common share options and other stock awards | 8,473 | 6,184 | 10,911 | 7,024 | 10,163 | |||||||||||||||||||||
Weighted-average common shares and potential common shares outstanding (000) (b) | 976,460 | 973,988 | 984,361 | 974,807 | 1,002,254 | |||||||||||||||||||||
(a)Earnings per share may not foot due to rounding.
(b)Assumes conversion of common share options and other stock awards and/or convertible preferred stock, as applicable.