
VLY 8-K
Valley National Bancorp (VLY)
8-K
2026-04-23
For: 2026-04-23
View Original
Added on
April 23, 2026
UNITED STATES
SECURITIES AND EXCHANGE COMMISSION
WASHINGTON, D.C. 20549
FORM 8-K
CURRENT REPORT
PURSUANT TO SECTION 13 OR 15(d) OF THE
SECURITIES EXCHANGE ACT OF 1934
Date of report (Date of earliest event reported): April 23, 2026
(Exact Name of Registrant as Specified in Charter)
(State or Other Jurisdiction of Incorporation) | (Commission File Number) | (I.R.S. Employer Identification Number) | ||||||||||||
(Address of Principal Executive Offices) | (Zip Code) | |||||||||||||
Registrant’s telephone number, including area code (973 ) 305-8800
Check the appropriate box below if the Form 8-K filing is intended to simultaneously satisfy the filing obligation of the registrant under any of the following provisions (see General Instruction A.2. below):
Written communications pursuant to Rule 425 under the Securities Act (17 CFR 230.425) | |||||
Soliciting material pursuant to Rule 14a-12 under the Exchange Act (17 CFR 240.14a-12) | |||||
Pre-commencement communications pursuant to Rule 14d-2(b) under the Exchange Act (17 CFR 240.14d-2(b)) | |||||
Pre-commencement communications pursuant to Rule 13e-4(c) under the Exchange Act (17 CFR 240.13e-4(c)) | |||||
Securities registered pursuant to Section 12(b) of the Act:
| Title of each class | Trading Symbols | Name of exchange on which registered | ||||||
Indicate by check mark whether the registrant is an emerging growth company as defined in Rule 405 of the Securities Act of 1933(§230.405 of this chapter) or Rule 12b-2 of the Securities Exchange Act of 1934 (§240.12b-2 of this chapter).
Emerging growth company ☐
If an emerging growth company, indicate by check mark if the registrant has elected not to use the extended transition period for complying with any new or revised financial accounting standards provided pursuant to Section 13(a) of the Exchange Act. ☐
| Item 2.02 | Results of Operations and Financial Condition. | ||||
On April 23, 2026 , Valley National Bancorp (“Valley”) issued a press release announcing Valley’s financial results for the first quarter 2026. A copy of the press release is furnished herewith as Exhibit 99.1.
The information in this Item 2.02, including Exhibit 99.1 attached hereto, is being furnished and shall not be deemed “filed” for purposes of Section 18 of the Securities Exchange Act of 1934, as amended (the “Exchange Act”), or otherwise subject to the liabilities of that section, nor shall it be incorporated by reference into a filing under the Securities Act of 1933, as amended (the "Securities Act"), except as shall be expressly set forth by specific reference in such a filing.
| Item 7.01 | Regulation FD Disclosure. | ||||
Valley is furnishing presentation materials attached hereto as Exhibit 99.2 pursuant to Item 7.01 of Form 8-K. Valley is not undertaking to update these presentation materials. The information in this Item 7.01, including Exhibit 99.2, is being furnished and shall not be deemed “filed” for purposes of Section 18 of the Exchange Act, or otherwise subject to the liabilities of that section, nor shall it be incorporated by reference into a filing under the Securities Act, except as shall be expressly set forth by specific reference in such a filing. This report will not be deemed an admission as to the materiality of any information herein (including Exhibit 99.2).
| Item 9.01 | Financial Statements and Exhibits. | ||||||||||
| (d) | Exhibits. | ||||||||||
| Exhibit No. | Description | ||||||||||
| 99.1 | |||||||||||
| 99.2 | |||||||||||
| 104 | Cover Page Interactive Data File (embedded within the Inline XBRL document). | ||||||||||
SIGNATURE
Pursuant to the requirements of the Securities Exchange Act of 1934, the registrant has duly caused this report to be signed on its behalf by the undersigned hereunto duly authorized.
Dated: April 23, 2026 | VALLEY NATIONAL BANCORP | ||||||||||
By: | /s/ Travis Lan | ||||||||||
| Travis Lan | |||||||||||
Senior Executive Vice President and | |||||||||||
Chief Financial Officer (Principal Financial Officer) | |||||||||||
Exhibit 99.1
 | News Release | |||||||
| FOR IMMEDIATE RELEASE | Contact: | Travis Lan | |||||||||
| Senior Executive Vice President and | |||||||||||
| Chief Financial Officer | |||||||||||
| 973-686-5007 | |||||||||||
VALLEY NATIONAL BANCORP ANNOUNCES FIRST QUARTER 2026 RESULTS
NEW YORK, NY – April 23, 2026 -- Valley National Bancorp (NASDAQ:VLY), the holding company for Valley National Bank, today reported net income for the first quarter 2026 of $163.9 million, or $0.28 per diluted common share, as compared to the fourth quarter 2025 net income of $195.4 million, or $0.33 per diluted common share, and net income of $106.1 million, or $0.18 per diluted common share, for the first quarter 2025. Excluding all non-core income and charges, our adjusted net income (a non-GAAP measure) was $168.9 million, or $0.29 per diluted common share, for the first quarter 2026, $180.2 million, or $0.31 per diluted common share, for the fourth quarter 2025, and $106.1 million, or $0.18 per diluted common share, for the first quarter 2025. See further details below, including a reconciliation of our non-GAAP adjusted net income, in the "Consolidated Financial Highlights" tables.
Ira Robbins, CEO, commented, "We continue to execute on our strategic priorities by growing low-cost core deposits and further diversifying our loan portfolio. These efforts have strengthened our balance sheet metrics and enhanced the sustainability of our earnings and profitability. Through targeted hiring efforts of strategically focused bankers, we are positioned to build on the momentum that we have established in recent years."
Mr. Robbins continued, "We simultaneously acknowledge that the banking landscape is evolving rapidly as artificial intelligence adoption accelerates. I believe that Valley is well-positioned to differentiate itself as a beneficiary from these changes. We invested early in AI talent, and continue to devote resources and focus to solutions that can augment the capabilities of our associates. Client relationships sit at the heart of our mission, and we firmly believe that AI can enhance the client experience and the efficiency of our delivery efforts."
Key financial highlights for the first quarter 2026:
•Net Interest Margin and Income: Our net interest margin on a tax equivalent basis of 3.17 percent for the first quarter 2026 remained unchanged from the fourth quarter 2025 and increased 21 basis points compared to the first quarter 2025. Net interest income on a tax equivalent basis of $472.8 million for the first quarter 2026 increased $6.7 million and $51.4 million compared to the fourth quarter 2025 and first quarter 2025, respectively. The increase in net interest income from the fourth quarter 2025 was mainly driven by an 18 basis point decline in our cost of total average deposits due to our disciplined deposit pricing and continued runoff of higher-cost indirect customer deposits. See additional details in the "Net Interest Income and Margin" section below.
Valley National Bancorp (NASDAQ: VLY)
First Quarter 2026 Earnings
April 23, 2026
•Deposits: Total deposit balances increased $676.5 million to $52.9 billion at March 31, 2026 as compared to $52.2 billion at December 31, 2025. During the quarter, our direct customer deposits increased $955.0 million which enabled us to reduce total indirect (brokered) customer deposits by $278.5 million at March 31, 2026. Direct customer deposit growth was driven by strength in the savings, NOW and money market deposit category primarily as a result of new commercial and online customer deposits. Non-Interest bearing deposits also increased $95.5 million reflecting inflows from both commercial and retail customers during the first quarter 2026. See the "Deposits" section below for more details.
•Loan Portfolio: Total loans increased $692.1 million, or 5.5 percent on an annualized basis, to $50.8 billion at March 31, 2026 from December 31, 2025 mostly due to increases of $466.0 million and $142.6 million in total commercial real estate (CRE) loans and commercial and industrial (C&I) loans, respectively. New owner occupied loans continued to drive a disproportionate amount of growth within the CRE loan portfolio during the first quarter 2026 while loan originations from a range of relationship-driven small to midsize clients contributed to the increase in C&I loans at March 31, 2026. Our CRE loan concentration ratio (defined as total CRE loans held for investment and held for sale, excluding owner occupied loans, as a percentage of total risk-based capital) continued to modestly decline to approximately 329 percent at March 31, 2026 from 333 percent at December 31, 2025. See the "Loans" section below for more details.
•Allowance and Provision for Credit Losses for Loans: The allowance for credit losses for loans totaled $599.8 million and $596.1 million at March 31, 2026 and December 31, 2025, respectively, representing 1.18 percent and 1.19 percent of total loans at each respective date. During the first quarter 2026, we recorded a provision for credit losses for loans of $21.2 million as compared to $20.0 million and $62.7 million for the fourth quarter 2025 and first quarter 2025, respectively. See the "Credit Quality" section below for more details.
•Credit Quality: Net loan charge-offs totaled $17.5 million for the first quarter 2026 as compared to $22.6 million and $41.9 million for the fourth quarter 2025 and first quarter 2025, respectively. Total accruing past due loans (i.e., loans past due 30 days or more and still accruing interest) decreased $13.4 million to $127.9 million, or 0.25 percent of total loans, at March 31, 2026 as compared to $141.3 million, or 0.28 percent of total loans, at December 31, 2025. Non-accrual loans totaled $432.6 million, or 0.85 percent of total loans, at March 31, 2026 as compared to $433.9 million, or 0.87 percent of total loans, at December 31, 2025. See the "Credit Quality" section below for more details.
•Non-Interest Income: Non-interest income decreased $7.5 million to $68.8 million for the first quarter 2026 as compared to the fourth quarter 2025 mainly driven by expected decreases of $5.1 million, $3.2 million and $2.2 million in capital markets, other income, and wealth management and trust fees, respectively. The decreases were mostly due to a lower volume of capital markets transactions, a decline in net gains related to the valuation of certain fintech investments and lower transaction-related tax credit advisory fees during the first quarter 2026. These decreases were partially offset by increases in both service charges on deposit accounts and net gains on sales of loans as compared to the fourth quarter 2025.
2
Valley National Bancorp (NASDAQ: VLY)
First Quarter 2026 Earnings
April 23, 2026
•Non-Interest Expense: Non-interest expense increased $10.5 million to $309.9 million for the first quarter 2026 as compared to the fourth quarter 2025 largely due to an increase of $11.1 million in salary and employee benefits expense. The increase in salary and employee benefits expense was mainly driven by normal seasonal increases in both salary and payroll taxes during the first quarter 2026, as well as a $5.1 million increase in severance charges during the first quarter 2026. The FDIC insurance assessment expense also increased $4.8 million during the first quarter 2026 as compared to the fourth quarter 2025. The FDIC assessment expense for the fourth quarter 2025 was net of a $5.7 million decrease in our estimated special assessment losses at December 31, 2025. These increases were partially offset by a decline of $4.4 million in other non-interest expense largely caused by elevated fourth quarter 2025 variable expenses within the category, including those related to charitable contributions, seasonal travel and events and other real estate owned expenses. Additionally, professional and legal fees also decreased $1.7 million mostly due to a moderate decline in consulting fees related to our operational transformation efforts.
•Efficiency Ratio: Our efficiency ratio was 53.10 percent for the first quarter 2026 as compared to 53.49 percent and 55.87 percent for the fourth quarter 2025 and first quarter 2025, respectively. See the "Consolidated Financial Highlights" tables below for additional information regarding our non-GAAP measures.
•Performance Ratios: Annualized return on average assets (ROA), shareholders’ equity (ROE) and tangible common shareholders' equity (ROTCE) were 1.02 percent, 8.35 percent and 11.56 percent for the first quarter 2026, respectively. Annualized ROA, ROE, and ROTCE, adjusted for non-core income and charges, were 1.05 percent, 8.60 percent and 11.92 percent for the first quarter 2026, respectively. See the "Consolidated Financial Highlights" tables below for additional information regarding our non-GAAP measures.
Net Interest Income and Margin
Net interest income on a tax equivalent basis of $472.8 million for the first quarter 2026 increased $6.7 million and $51.4 million compared to the fourth quarter 2025 and the first quarter 2025, respectively, largely resulting from a decline in the cost of average deposits and, to a lesser extent, lower average long-term borrowings and additional interest income from higher average overnight interest bearing cash balances. Interest income on a tax equivalent basis decreased $13.0 million to $804.0 million for the first quarter 2026 as compared to the fourth quarter 2025. The decrease was mostly the result of two fewer days in the first quarter 2026 and downward repricing of adjustable rate loans, partially offset by the additional interest income from interest bearing cash balances in the first quarter 2026. Total interest expense decreased $19.7 million to $331.2 million for the first quarter 2026 as compared to the fourth quarter 2025. The decrease was mainly the result of lower costs on most interest bearing deposit products and the maturity and repayment of higher-cost time deposits as well as certain long-term borrowings during the first quarter 2026. See the "Deposits" and "Other Borrowings" sections below for more details.
Net interest margin on a tax equivalent basis of 3.17 percent for the first quarter 2026 remained unchanged as compared to the fourth quarter 2025 and increased 21 basis points from 2.96 percent for the first quarter 2025. The yield on average interest earning assets decreased by 17 basis points to 5.39 percent on a linked quarter basis largely due to downward repricing of our adjustable rate loans
3
Valley National Bancorp (NASDAQ: VLY)
First Quarter 2026 Earnings
April 23, 2026
and the lower yield on overnight interest bearing cash balances, partially offset by the higher level of yields on new loans and investment securities during the first quarter 2026. The overall cost of average interest bearing liabilities decreased by 24 basis points to 3.06 percent for the first quarter 2026 as compared to the fourth quarter 2025 largely due to disciplined management of our deposit pricing in the current market environment. Our cost of total average deposits was 2.27 percent for the first quarter 2026 as compared to 2.45 percent and 2.65 percent for the fourth quarter 2025 and first quarter 2025, respectively.
Loans, Deposits and Other Borrowings
Loans. Total loans increased $692.1 million, or 5.5 percent on an annualized basis, to $50.8 billion at March 31, 2026 from December 31, 2025. C&I loans increased by $142.6 million, or 5.2 percent on an annualized basis, to $11.1 billion at March 31, 2026 from December 31, 2025 largely driven by new originations from a range of relationship-driven small to midsize clients as a result of our continued focus on expansion of new loan production within this category. Total CRE (including construction) loans increased $466.0 million to $29.7 billion at March 31, 2026 from December 31, 2025 mostly due to solid customer demand and loan originations within the owner occupied category. Non-owner occupied loans decreased $67.3 million from December 31, 2025 mainly due to our continued targeted runoff of transactional/non-relationship loans in the first quarter 2026. Residential mortgage and total consumer loans increased $42.9 million and $40.7 million, respectively, at March 31, 2026 from December 31, 2025 due to modest broad-based growth in these products.
Loans held for sale decreased $15.0 million to $11.2 million at March 31, 2026 from December 31, 2025 due, in part, to the sale of a non-performing CRE loan relationship totaling $9.1 million to an unrelated party during the first quarter 2026. The non-performing loan sale resulted in a net gain of $767 thousand recognized within net gains on sales of loans for the first quarter 2026.
Deposits. Actual ending balances for deposits increased $676.5 million to $52.9 billion at March 31, 2026 from December 31, 2025 mainly due to additional commercial and online customer deposit balances within the savings, NOW and money market deposit category. The non-interest bearing deposits increased $95.5 million to $12.3 billion at March 31, 2026 as compared to December 31, 2025 largely driven by deposit inflows from a blend of commercial and retail customers during the first quarter 2026. Total indirect customer deposits (consisting of brokered time and money market deposits) totaled $5.1 billion and $5.4 billion at March 31, 2026 and December 31, 2025, respectively. The decrease in indirect customer deposits from December 31, 2025 was mainly related to lower brokered money market deposit balances at March 31, 2026. Non-interest bearing deposits; savings, NOW and money market deposits; and time deposits represented approximately 23 percent, 55 percent and 22 percent of total deposits at both March 31, 2026 and December 31, 2025.
Other Borrowings. Short-term borrowings, consisting of securities sold under repurchase agreements, decreased $27.6 million to $63.9 million at March 31, 2026 from December 31, 2025. Long-term borrowings totaled $2.6 billion at March 31, 2026 and decreased $347.7 million as compared to December 31, 2025 due to the maturity and repayment of certain FHLB advances.
4
Valley National Bancorp (NASDAQ: VLY)
First Quarter 2026 Earnings
April 23, 2026
Credit Quality
Non-Performing Assets (NPAs). NPAs, consisting of non-accrual loans, other real estate owned (OREO) and other repossessed assets, totaled $439.6 million at March 31, 2026 and remained relatively unchanged as compared to December 31, 2025. Non-accrual loans decreased $1.3 million to $432.6 million, or 0.85 percent of total loans at March 31, 2026 as compared to $433.9 million, or 0.87 percent of total loans, at December 31, 2025. The decrease was primarily driven by a decline in non-accrual CRE loans, partially offset by higher non-accrual C&I and, to a lesser extent, residential mortgage loans. Non-accrual CRE loans decreased $10.8 million at March 31, 2026 from December 31, 2025 mainly due to the sale of the $9.1 million non-performing loan relationship that was classified as held for sale at December 31, 2025.
Accruing Past Due Loans. Total accruing past due loans (i.e., loans past due 30 days or more and still accruing interest) decreased $13.4 million to $127.9 million, or 0.25 percent of total loans, at March 31, 2026 as compared to $141.3 million, or 0.28 percent of total loans, at December 31, 2025.
Loans 30 to 59 days past due decreased $11.6 million to $108.4 million at March 31, 2026 as compared to December 31, 2025 largely due to lower delinquencies across all loan categories and a C&I loan relationship totaling $3.5 million that migrated from this past due category at December 31, 2025 to loans 90 days or more past due and still accruing at March 31, 2026. Loans 60 to 89 days past due decreased $7.9 million to $8.8 million at March 31, 2026 as compared to December 31, 2025 primarily due to lower residential mortgage and consumer loan delinquencies. Loans 90 days or more past due and still accruing interest increased $6.1 million to $10.7 million at March 31, 2026 as compared to December 31, 2025 largely due to higher residential mortgage loans delinquencies and the migration of the aforementioned C&I loan relationship from the 30 to 59 days past due delinquency category during the first quarter of 2026. All loans 90 days or more past due and still accruing interest are well-secured and in the process of collection.
5
Valley National Bancorp (NASDAQ: VLY)
First Quarter 2026 Earnings
April 23, 2026
Allowance for Credit Losses for Loans and Unfunded Commitments. The following table summarizes the allocation of the allowance for credit losses to loan categories and the allocation as a percentage of each loan category at March 31, 2026, December 31, 2025, and March 31, 2025:
| March 31, 2026 | December 31, 2025 | March 31, 2025 | ||||||||||||||||||||||||||||||||||||
| Allocation | Allocation | Allocation | ||||||||||||||||||||||||||||||||||||
| as a % of | as a % of | as a % of | ||||||||||||||||||||||||||||||||||||
| Allowance | Loan | Allowance | Loan | Allowance | Loan | |||||||||||||||||||||||||||||||||
| Allocation | Category | Allocation | Category | Allocation | Category | |||||||||||||||||||||||||||||||||
| ($ in thousands) | ||||||||||||||||||||||||||||||||||||||
| Loan Category: | ||||||||||||||||||||||||||||||||||||||
| Commercial and industrial loans | $ | 186,143 | 1.68 | % | $ | 180,865 | 1.65 | % | $ | 184,700 | 1.82 | % | ||||||||||||||||||||||||||
| Commercial real estate loans: | ||||||||||||||||||||||||||||||||||||||
| Commercial real estate | 269,847 | 0.99 | 271,890 | 1.02 | 266,938 | 1.02 | ||||||||||||||||||||||||||||||||
| Construction | 54,946 | 2.21 | 55,536 | 2.25 | 54,724 | 1.81 | ||||||||||||||||||||||||||||||||
| Total commercial real estate loans | 324,793 | 1.09 | 327,426 | 1.12 | 321,662 | 1.10 | ||||||||||||||||||||||||||||||||
| Residential mortgage loans | 51,700 | 0.88 | 53,529 | 0.92 | 48,906 | 0.87 | ||||||||||||||||||||||||||||||||
| Consumer loans: | ||||||||||||||||||||||||||||||||||||||
| Home equity | 4,120 | 0.59 | 3,878 | 0.56 | 3,401 | 0.56 | ||||||||||||||||||||||||||||||||
| Auto and other consumer | 17,744 | 0.52 | 17,702 | 0.52 | 19,531 | 0.62 | ||||||||||||||||||||||||||||||||
| Total consumer loans | 21,864 | 0.53 | 21,580 | 0.53 | 22,932 | 0.61 | ||||||||||||||||||||||||||||||||
| Allowance for loan losses | 584,500 | 1.15 | 583,400 | 1.16 | 578,200 | 1.19 | ||||||||||||||||||||||||||||||||
| Allowance for unfunded credit commitments | 15,300 | 12,700 | 15,854 | |||||||||||||||||||||||||||||||||||
| Total allowance for credit losses for loans | $ | 599,800 | $ | 596,100 | $ | 594,054 | ||||||||||||||||||||||||||||||||
| Allowance for credit losses for loans as a % of total loans | 1.18 | % | 1.19 | % | 1.22 | % | ||||||||||||||||||||||||||||||||
Our loan portfolio, totaling $50.8 billion at March 31, 2026, had net loan charge-offs totaling $17.5 million for the first quarter 2026 as compared to $22.6 million and $41.9 million for the fourth quarter 2025 and the first quarter 2025, respectively. Gross loan charge-offs totaled $19.8 million for the first quarter 2026 and were mostly driven by the partial charge-offs of non-performing loan relationships within the CRE loan category.
The allowance for credit losses for loans, comprised of our allowance for loan losses and unfunded credit commitments, as a percentage of total loans was 1.18 percent at March 31, 2026, 1.19 percent at December 31, 2025, and 1.22 percent at March 31, 2025. For the first quarter 2026, the provision for credit losses for loans totaled $21.2 million as compared to $20.0 million and $62.7 million for the fourth quarter 2025 and first quarter 2025, respectively. The first quarter 2026 provision was mainly impacted by (i) increases in the economic forecast and non-economic qualitative components of our reserve and (ii) commercial loan growth, partially offset by (iii) lower quantitative reserves in certain loan categories at March 31, 2026.
6
Valley National Bancorp (NASDAQ: VLY)
First Quarter 2026 Earnings
April 23, 2026
Capital Adequacy
Valley's total risk-based capital, Tier 1 capital, common equity tier 1 capital, and Tier 1 leverage capital ratios were 13.66 percent, 11.60 percent, 10.91 percent and 9.56 percent, respectively, at March 31, 2026 as compared to 13.77 percent, 11.69 percent, 10.99 percent and 9.63 percent, respectively, at December 31, 2025. During the first quarter 2026, we repurchased 4.0 million shares of our common stock at an average price of $12.95 under our current stock repurchase plan.
Investor Conference Call
Valley’s CEO, Ira Robbins, will host a conference call with investors and the financial community at 8:30 AM (ET) today to discuss Valley's first quarter 2026 earnings and related matters. Interested parties should preregister using this link: https://register.vevent.com/register to receive the dial-in number and a personal PIN, which are required to access the conference call. The teleconference will also be webcast live: https://edge.media-server.com and archived on Valley’s website through Monday, May 25, 2026. Investor presentation materials will be made available prior to the conference call at www.valley.com.
About Valley
As the principal subsidiary of Valley National Bancorp (NASDAQ: VLY), Valley National Bank is a regional financial institution with over $64 billion in assets. Founded in 1927, Valley has more than 200 offices nationwide and serves clients across New Jersey, New York, Florida, Alabama, California, Illinois, Pennsylvania and Arizona. Valley delivers a full range of consumer, commercial, and wealth management solutions designed to support everything from homeownership and business growth to long-term financial planning. Big enough to support complex financial needs and small enough to stay deeply connected, Valley is grounded in a relationship-led approach focused on understanding people first. That same relationship-led approach guides Valley’s commitment to community investment and responsible corporate citizenship. To learn more, visit www.valley.com or call the Valley Customer Care Center at 800-522-4100.
Forward-Looking Statements
The foregoing contains forward-looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements are not historical facts and include expressions about management’s confidence and strategies and management’s expectations about our business, new and existing programs and products, acquisitions, relationships, opportunities, taxation, technology, market conditions and economic expectations. These statements may be identified by forward-looking terminology such as “intend,” “should,” “expect,” “believe,” "position", “view,” “opportunity,” “allow,” “continues,” “reflects,” “would,” “could,” “typically,” “usually,” “anticipate,” “may,” “estimate,” “outlook,” “project” or similar statements or variations of such terms. Such forward-looking statements involve certain risks and uncertainties. Actual results may differ materially from such forward-looking statements. Factors that may cause actual results to differ materially from those contemplated in these forward-looking statements include, but are not limited to:
7
Valley National Bancorp (NASDAQ: VLY)
First Quarter 2026 Earnings
April 23, 2026
•the impact of market interest rates and monetary and fiscal policies of the U.S. federal government and its agencies in connection with prolonged inflationary pressures, which could have a material adverse effect on our clients, our business, our employees, and our ability to provide services to our customers;
•the impact of unfavorable macroeconomic conditions or downturns, including instability or volatility in financial markets resulting from the impact of tariffs/import fees and other trade policies and practices, any retaliatory actions, related market uncertainty, or other factors; U.S. government debt default or rating downgrade; unanticipated loan delinquencies; loss of collateral; decreased service revenues; increased business disruptions or failures; reductions in employment; and other potential negative effects on our business, employees or clients caused by factors outside of our control, such as new legislation and policy changes under the current U.S. presidential administration, any shutdown of the U.S federal government, geopolitical instabilities or events, including ongoing conflicts in the Middle East, natural and other disasters, including severe weather events and other climate-related risks, health emergencies, acts of terrorism, or other external events;
•the impact of any potential instability within the U.S. financial sector or future bank failures, including the possibility of a run on deposits by a coordinated deposit base, and the impact of any actual or perceived concerns regarding the soundness, or creditworthiness, of other financial institutions, including any resulting disruption within the financial markets, increased expenses, including FDIC insurance assessments, or adverse impact on our stock price, deposits or our ability to borrow or raise capital;
•the impact of negative public opinion regarding Valley or banks in general that damages our reputation and adversely impacts business and revenues;
•changes in the statutes, regulations, policies, enforcement priorities, or composition of the federal bank regulatory agencies;
•the loss of or decrease in lower-cost funding sources within our deposit base;
•investigations, damage verdicts, settlements or restrictions related to existing or potential class action litigation or individual litigation arising from claims of violations of laws or regulations, contractual claims, breach of fiduciary responsibility, negligence, fraud, environmental laws, patent, trademark or other intellectual property infringement, misappropriation or other violation, employment-related claims, and other matters;
•a prolonged downturn and contraction in the economy, as well as any decline in commercial real estate values collateralizing a significant portion of our loan portfolio;
•higher or lower than expected income tax expense or tax rates, including increases or decreases resulting from changes in uncertain tax position liabilities, tax laws, regulations, and case law;
•the inability to grow customer deposits to keep pace with the level of loan growth;
•a material change in our allowance for credit losses due to forecasted economic conditions and/or unexpected credit deterioration in our loan and investment portfolios;
•the need to supplement debt or equity capital to maintain or exceed internal capital thresholds;
•changes in our business, strategy, market conditions or other factors that may negatively impact the estimated fair value of our goodwill and other intangible assets and result in future impairment charges;
8
Valley National Bancorp (NASDAQ: VLY)
First Quarter 2026 Earnings
April 23, 2026
•greater than expected technology-related costs due to, among other factors, prolonged or failed implementations, additional project staffing and obsolescence caused by continuous and rapid market innovations;
•increased competitive challenges and competitive pressure on pricing of our products and services;
•our ability to stay current with rapid technological changes and evolving legal and regulatory requirements in the financial services industry, including developments relating to the use of artificial intelligence, blockchain, and related regulatory developments, as well as our ability to effectively assess and monitor the effects of, and risks associated with, the implementation and use of such technology;
•cyberattacks, ransomware attacks, computer viruses, malware or other cybersecurity incidents that may breach the security of our or our third-party service providers’ websites or other systems or networks to obtain unauthorized access to personal, confidential, proprietary or sensitive information, destroy data, disable or degrade service, or sabotage our systems or networks, and the increasing sophistication of such attacks and use of targeted tactics against the financial services industry;
•any disruption of our systems and network, or those of our third-party service providers, resulting from events that are wholly or partially beyond our control, including, for example, electrical, telecommunications, or other major service outages, or actions by employees, which may give rise to financial loss or liability;
•results of examinations by the Office of the Comptroller of the Currency (OCC), the Federal Reserve Bank, the Consumer Financial Protection Bureau and other regulatory authorities, including the possibility that any such regulatory authority may, among other things, require us to increase our allowance for credit losses, write-down assets, reimburse customers, change the way we do business, or limit or eliminate certain other banking activities;
•application of heightened regulatory standards for certain large insured national banks, and the expenses we will incur to develop policies, programs, and systems that comply with the enhanced standards applicable to us;
•our inability or determination not to pay dividends at current levels, or at all, because of inadequate earnings, regulatory restrictions or limitations, changes in our capital requirements, or a decision to increase capital by retaining more earnings;
•unanticipated loan delinquencies, loss of collateral, decreased service revenues, and other potential negative effects on our business caused by severe weather and other climate-related risks, pandemics or other public health crises, acts of terrorism or other external events;
•our ability to successfully execute our business plan and strategic initiatives; and
•unexpected significant declines in the loan portfolio due to the lack of economic expansion, increased competition, large prepayments, risk mitigation strategies, changes in regulatory lending guidance or other factors.
A detailed discussion of factors that could affect our results is included in our SEC filings, including Item 1A. "Risk Factors" of our Annual Report on Form 10-K for the year ended December 31, 2025.
9
Valley National Bancorp (NASDAQ: VLY)
First Quarter 2026 Earnings
April 23, 2026
We undertake no duty to update any forward-looking statement to conform the statement to actual results or changes in our expectations, except as required by law. Although we believe that the expectations reflected in the forward-looking statements are reasonable, we cannot guarantee future results, levels of activity, performance or achievements.
# # #
-Tables to Follow-
10
VALLEY NATIONAL BANCORP
CONSOLIDATED FINANCIAL HIGHLIGHTS
SELECTED FINANCIAL DATA
| Three Months Ended | |||||||||||||||||
| March 31, | December 31, | March 31, | |||||||||||||||
| ($ in thousands, except for share data and stock price) | 2026 | 2025 | 2025 | ||||||||||||||
| FINANCIAL DATA: | |||||||||||||||||
Net interest income - FTE (1) | $ | 472,801 | $ | 466,143 | $ | 421,378 | |||||||||||
| Net interest income | $ | 471,525 | $ | 464,907 | $ | 420,105 | |||||||||||
| Non-interest income | 68,836 | 76,341 | 58,294 | ||||||||||||||
| Total revenue | 540,361 | 541,248 | 478,399 | ||||||||||||||
| Non-interest expense | 309,926 | 299,401 | 276,618 | ||||||||||||||
| Pre-provision net revenue | 230,435 | 241,847 | 201,781 | ||||||||||||||
| Provision for credit losses | 21,256 | 20,143 | 62,661 | ||||||||||||||
| Income tax expense | 45,266 | 26,301 | 33,062 | ||||||||||||||
| Net income | 163,913 | 195,403 | 106,058 | ||||||||||||||
| Dividends on preferred stock | 7,217 | 7,434 | 6,955 | ||||||||||||||
| Net income available to common shareholders | $ | 156,696 | $ | 187,969 | $ | 99,103 | |||||||||||
| Weighted average number of common shares outstanding: | |||||||||||||||||
| Basic | 555,777,748 | 558,104,197 | 559,613,272 | ||||||||||||||
| Diluted | 559,254,972 | 562,214,037 | 563,305,525 | ||||||||||||||
| Per common share data: | |||||||||||||||||
| Basic earnings | $ | 0.28 | $ | 0.34 | $ | 0.18 | |||||||||||
| Diluted earnings | 0.28 | 0.33 | 0.18 | ||||||||||||||
| Cash dividends declared | 0.11 | 0.11 | 0.11 | ||||||||||||||
| Closing stock price - high | 13.71 | 12.08 | 10.42 | ||||||||||||||
| Closing stock price - low | 11.66 | 9.72 | 8.56 | ||||||||||||||
| FINANCIAL RATIOS: | |||||||||||||||||
| Net interest margin | 3.16 | % | 3.17 | % | 2.95 | % | |||||||||||
Net interest margin - FTE (1) | 3.17 | 3.17 | 2.96 | ||||||||||||||
| Annualized return on average assets | 1.02 | 1.24 | 0.69 | ||||||||||||||
| Annualized return on average shareholders' equity | 8.35 | 10.12 | 5.69 | ||||||||||||||
NON-GAAP FINANCIAL DATA AND RATIOS: (2) | |||||||||||||||||
| Basic earnings per share, as adjusted | $ | 0.29 | $ | 0.31 | $ | 0.18 | |||||||||||
| Diluted earnings per share, as adjusted | 0.29 | 0.31 | 0.18 | ||||||||||||||
| Annualized return on average assets, as adjusted | 1.05 | % | 1.14 | % | 0.69 | % | |||||||||||
| Annualized return on average shareholders' equity, as adjusted | 8.60 | 9.33 | 5.69 | ||||||||||||||
| Annualized return on average tangible common shareholders' equity | 11.56 | 14.17 | 8.11 | ||||||||||||||
| Annualized return on average tangible common shareholders' equity, as adjusted | 11.92 | 13.06 | 8.11 | ||||||||||||||
| Efficiency ratio | 53.10 | 53.49 | 55.87 | ||||||||||||||
| AVERAGE BALANCE SHEET ITEMS: | |||||||||||||||||
| Assets | $ | 64,190,084 | $ | 63,255,554 | $ | 61,502,768 | |||||||||||
| Interest earning assets | 59,718,887 | 58,755,395 | 56,891,691 | ||||||||||||||
| Loans | 50,265,383 | 49,614,838 | 48,654,921 | ||||||||||||||
| Interest bearing liabilities | 43,352,140 | 42,503,586 | 41,230,709 | ||||||||||||||
| Deposits | 52,373,174 | 51,361,780 | 49,139,303 | ||||||||||||||
| Shareholders' equity | 7,855,550 | 7,722,962 | 7,458,177 | ||||||||||||||
11
VALLEY NATIONAL BANCORP
CONSOLIDATED FINANCIAL HIGHLIGHTS
| As of | |||||||||||||||||||||||||||||
| BALANCE SHEET ITEMS: | March 31, | December 31, | September 30, | June 30, | March 31, | ||||||||||||||||||||||||
| (In thousands) | 2026 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||
| Assets | $ | 64,466,585 | $ | 64,132,725 | $ | 63,018,614 | $ | 62,705,358 | $ | 61,865,655 | |||||||||||||||||||
| Total loans | 50,828,820 | 50,136,728 | 49,272,823 | 49,391,420 | 48,657,128 | ||||||||||||||||||||||||
| Deposits | 52,859,621 | 52,183,093 | 51,175,758 | 50,725,284 | 49,965,844 | ||||||||||||||||||||||||
| Shareholders' equity | 7,828,443 | 7,807,698 | 7,695,374 | 7,575,421 | 7,499,897 | ||||||||||||||||||||||||
| LOANS: | |||||||||||||||||||||||||||||
| (In thousands) | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 11,104,079 | $ | 10,961,519 | $ | 10,757,857 | $ | 10,870,036 | $ | 10,150,205 | |||||||||||||||||||
| Commercial real estate: | |||||||||||||||||||||||||||||
| Non-owner occupied | 11,503,874 | 11,571,127 | 11,674,103 | 11,747,491 | 11,945,222 | ||||||||||||||||||||||||
| Multifamily | 8,588,462 | 8,571,713 | 8,394,694 | 8,434,173 | 8,420,385 | ||||||||||||||||||||||||
| Owner occupied | 7,132,254 | 6,629,909 | 6,097,319 | 5,789,397 | 5,722,014 | ||||||||||||||||||||||||
| Construction | 2,485,387 | 2,471,233 | 2,517,258 | 2,854,859 | 3,026,935 | ||||||||||||||||||||||||
| Total commercial real estate | 29,709,977 | 29,243,982 | 28,683,374 | 28,825,920 | 29,114,556 | ||||||||||||||||||||||||
| Residential mortgage | 5,869,070 | 5,826,192 | 5,795,395 | 5,709,971 | 5,636,407 | ||||||||||||||||||||||||
| Consumer: | |||||||||||||||||||||||||||||
| Home equity | 701,136 | 687,680 | 655,872 | 634,553 | 602,161 | ||||||||||||||||||||||||
| Automobile | 2,198,102 | 2,184,600 | 2,191,976 | 2,178,841 | 2,041,227 | ||||||||||||||||||||||||
| Other consumer | 1,246,456 | 1,232,755 | 1,188,349 | 1,172,099 | 1,112,572 | ||||||||||||||||||||||||
| Total consumer loans | 4,145,694 | 4,105,035 | 4,036,197 | 3,985,493 | 3,755,960 | ||||||||||||||||||||||||
| Total loans | $ | 50,828,820 | $ | 50,136,728 | $ | 49,272,823 | $ | 49,391,420 | $ | 48,657,128 | |||||||||||||||||||
| CAPITAL RATIOS: | |||||||||||||||||||||||||||||
| Book value per common share | $ | 13.48 | $ | 13.39 | $ | 13.09 | $ | 12.89 | $ | 12.76 | |||||||||||||||||||
Tangible book value per common share (2) | 9.94 | 9.85 | 9.57 | 9.35 | 9.21 | ||||||||||||||||||||||||
Tangible common equity to tangible assets (2) | 8.82 | % | 8.82 | % | 8.79 | % | 8.63 | % | 8.61 | % | |||||||||||||||||||
| Tier 1 leverage capital | 9.56 | 9.63 | 9.52 | 9.49 | 9.41 | ||||||||||||||||||||||||
| Common equity tier 1 capital | 10.91 | 10.99 | 11.00 | 10.85 | 10.80 | ||||||||||||||||||||||||
| Tier 1 risk-based capital | 11.60 | 11.69 | 11.72 | 11.57 | 11.53 | ||||||||||||||||||||||||
| Total risk-based capital | 13.66 | 13.77 | 13.83 | 13.67 | 13.91 | ||||||||||||||||||||||||
12
VALLEY NATIONAL BANCORP
CONSOLIDATED FINANCIAL HIGHLIGHTS
| Three Months Ended | |||||||||||||||||
ALLOWANCE FOR CREDIT LOSSES: | March 31, | December 31, | March 31, | ||||||||||||||
| ($ in thousands) | 2026 | 2025 | 2025 | ||||||||||||||
| Allowance for credit losses for loans | |||||||||||||||||
| Beginning balance - Allowance for credit losses for loans | $ | 596,100 | $ | 598,604 | $ | 573,328 | |||||||||||
| Loans charged-off: | |||||||||||||||||
| Commercial and industrial | (2,782) | (5,958) | (28,456) | ||||||||||||||
| Commercial real estate | (13,756) | (16,034) | (12,260) | ||||||||||||||
| Construction | — | — | (1,163) | ||||||||||||||
| Total consumer | (3,263) | (3,060) | (2,140) | ||||||||||||||
| Total loans charged-off | (19,801) | (25,052) | (44,019) | ||||||||||||||
| Charged-off loans recovered: | |||||||||||||||||
| Commercial and industrial | 1,398 | 636 | 810 | ||||||||||||||
| Commercial real estate | 347 | 1,096 | 249 | ||||||||||||||
| Construction | — | 193 | — | ||||||||||||||
| Residential mortgage | 83 | 180 | 168 | ||||||||||||||
| Total consumer | 429 | 397 | 843 | ||||||||||||||
| Total loans recovered | 2,257 | 2,502 | 2,070 | ||||||||||||||
| Total net charge-offs | (17,544) | (22,550) | (41,949) | ||||||||||||||
| Provision for credit losses for loans | 21,244 | 20,046 | 62,675 | ||||||||||||||
| Ending balance | $ | 599,800 | $ | 596,100 | $ | 594,054 | |||||||||||
| Components of allowance for credit losses for loans: | |||||||||||||||||
| Allowance for loan losses | $ | 584,500 | $ | 583,400 | $ | 578,200 | |||||||||||
| Allowance for unfunded credit commitments | 15,300 | 12,700 | 15,854 | ||||||||||||||
| Allowance for credit losses for loans | $ | 599,800 | $ | 596,100 | $ | 594,054 | |||||||||||
| Components of provision for credit losses for loans: | |||||||||||||||||
| Provision for credit losses for loans | $ | 18,644 | $ | 20,950 | $ | 61,299 | |||||||||||
| Provision (credit) for unfunded credit commitments | 2,600 | (904) | 1,376 | ||||||||||||||
| Total provision for credit losses for loans | $ | 21,244 | $ | 20,046 | $ | 62,675 | |||||||||||
| Annualized ratio of total net charge-offs to total average loans | 0.14 | % | 0.18 | % | 0.34 | % | |||||||||||
| Allowance for credit losses for loans as a % of total loans | 1.18 | % | 1.19 | % | 1.22 | % | |||||||||||
13
VALLEY NATIONAL BANCORP
CONSOLIDATED FINANCIAL HIGHLIGHTS
| As of | |||||||||||||||||||||||||||||
| ASSET QUALITY: | March 31, | December 31, | September 30, | June 30, | March 31, | ||||||||||||||||||||||||
| ($ in thousands) | 2026 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||
| Accruing past due loans: | |||||||||||||||||||||||||||||
| 30 to 59 days past due: | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 5,285 | $ | 11,177 | $ | 912 | $ | 10,451 | $ | 3,609 | |||||||||||||||||||
| Commercial real estate | 69,494 | 72,810 | 26,371 | 42,884 | 170 | ||||||||||||||||||||||||
| Construction | — | — | — | 35,000 | — | ||||||||||||||||||||||||
| Residential mortgage | 20,534 | 21,615 | 23,556 | 21,744 | 16,747 | ||||||||||||||||||||||||
| Total consumer | 13,112 | 14,420 | 12,728 | 12,878 | 12,887 | ||||||||||||||||||||||||
| Total 30 to 59 days past due | 108,425 | 120,022 | 63,567 | 122,957 | 33,413 | ||||||||||||||||||||||||
| 60 to 89 days past due: | |||||||||||||||||||||||||||||
| Commercial and industrial | 1,015 | 1,274 | 1,061 | 1,095 | 420 | ||||||||||||||||||||||||
| Commercial real estate | — | — | 6,033 | 60,601 | — | ||||||||||||||||||||||||
| Residential mortgage | 4,285 | 10,181 | 5,040 | 7,627 | 7,700 | ||||||||||||||||||||||||
| Total consumer | 3,506 | 5,269 | 4,023 | 4,001 | 2,408 | ||||||||||||||||||||||||
| Total 60 to 89 days past due | 8,806 | 16,724 | 16,157 | 73,324 | 10,528 | ||||||||||||||||||||||||
| 90 or more days past due: | |||||||||||||||||||||||||||||
| Commercial and industrial | 3,499 | — | — | — | — | ||||||||||||||||||||||||
| Commercial real estate | — | 212 | — | — | — | ||||||||||||||||||||||||
| Residential mortgage | 5,894 | 3,300 | 3,911 | 2,062 | 6,892 | ||||||||||||||||||||||||
| Total consumer | 1,309 | 1,070 | 1,125 | 859 | 864 | ||||||||||||||||||||||||
| Total 90 or more days past due | 10,702 | 4,582 | 5,036 | 2,921 | 7,756 | ||||||||||||||||||||||||
| Total accruing past due loans | $ | 127,933 | $ | 141,328 | $ | 84,760 | $ | 199,202 | $ | 51,697 | |||||||||||||||||||
| Non-accrual loans: | |||||||||||||||||||||||||||||
| Commercial and industrial | $ | 145,804 | $ | 138,321 | $ | 92,214 | $ | 90,973 | $ | 110,146 | |||||||||||||||||||
| Commercial real estate | 225,417 | 236,221 | 235,754 | 193,604 | 172,011 | ||||||||||||||||||||||||
| Construction | 9,148 | 9,140 | 48,248 | 24,068 | 24,275 | ||||||||||||||||||||||||
| Residential mortgage | 45,988 | 44,424 | 38,949 | 41,099 | 35,393 | ||||||||||||||||||||||||
| Total consumer | 6,289 | 5,832 | 6,324 | 4,615 | 4,626 | ||||||||||||||||||||||||
| Total non-accrual loans | 432,646 | 433,938 | 421,489 | 354,359 | 346,451 | ||||||||||||||||||||||||
| Other real estate owned (OREO) | 5,161 | 4,531 | 4,783 | 4,783 | 7,714 | ||||||||||||||||||||||||
| Other repossessed assets | 1,758 | 1,286 | 1,065 | 1,642 | 2,054 | ||||||||||||||||||||||||
| Total non-performing assets | $ | 439,565 | $ | 439,755 | $ | 427,337 | $ | 360,784 | $ | 356,219 | |||||||||||||||||||
| Total non-accrual loans as a % of loans | 0.85 | % | 0.87 | % | 0.86 | % | 0.72 | % | 0.71 | % | |||||||||||||||||||
Total accruing past due and non-accrual loans as a % of loans | 1.10 | % | 1.15 | % | 1.03 | % | 1.12 | % | 0.82 | % | |||||||||||||||||||
Allowance for losses on loans as a % of non-accrual loans | 135.10 | % | 134.44 | % | 138.79 | % | 163.53 | % | 166.89 | % | |||||||||||||||||||
14
VALLEY NATIONAL BANCORP
CONSOLIDATED FINANCIAL HIGHLIGHTS
NOTES TO SELECTED FINANCIAL DATA
(1) | Net interest income and net interest margin are presented on a tax equivalent basis using a 21 percent federal tax rate. Valley believes that this presentation provides comparability of net interest income and net interest margin arising from both taxable and tax-exempt sources and is consistent with industry practice and SEC rules. | ||||
| (2) | Non-GAAP Reconciliations. This press release contains certain supplemental financial information, described in the Notes below, which has been determined by methods other than U.S. Generally Accepted Accounting Principles ("GAAP") that management uses in its analysis of Valley's performance. The Company believes that the non-GAAP financial measures provide useful supplemental information to both management and investors in understanding Valley’s underlying operational performance, business and performance trends, and may facilitate comparisons of our current and prior performance with the performance of others in the financial services industry. Management utilizes these measures for internal planning, forecasting and analysis purposes. Management believes that Valley’s presentation and discussion of this supplemental information, together with the accompanying reconciliations to the GAAP financial measures, also allows investors to view performance in a manner similar to management. These non-GAAP financial measures should not be considered in isolation or as a substitute for or superior to financial measures calculated in accordance with U.S. GAAP. These non-GAAP financial measures may also be calculated differently from similar measures disclosed by other companies. | ||||
Non-GAAP Reconciliations to GAAP Financial Measures
| Three Months Ended | |||||||||||||||||
| March 31, | December 31, | March 31, | |||||||||||||||
| ($ in thousands, except for share data) | 2026 | 2025 | 2025 | ||||||||||||||
| Adjusted net income available to common shareholders (non-GAAP): | |||||||||||||||||
| Net income, as reported (GAAP) | $ | 163,913 | $ | 195,403 | $ | 106,058 | |||||||||||
Add: Restructuring charge (a) | 5,689 | 630 | — | ||||||||||||||
Add: Litigation reserve (b) | 1,262 | (239) | — | ||||||||||||||
Add: Losses on available for sale and held to maturity debt securities, net (c) | 10 | — | 11 | ||||||||||||||
Less: FDIC special assessment (d) | — | (5,672) | — | ||||||||||||||
Less: Income tax benefit (e) | — | (11,417) | — | ||||||||||||||
| Total non-GAAP adjustments to net income | 6,961 | (16,698) | 11 | ||||||||||||||
Income tax adjustments related to non-GAAP adjustments (f) | (1,984) | 1,505 | (3) | ||||||||||||||
| Net income, as adjusted (non-GAAP) | $ | 168,890 | $ | 180,210 | $ | 106,066 | |||||||||||
| Dividends on preferred stock | 7,217 | 7,434 | 6,955 | ||||||||||||||
| Net income available to common shareholders, as adjusted (non-GAAP) | $ | 161,673 | $ | 172,776 | $ | 99,111 | |||||||||||
| __________ | |||||||||||||||||
| (a) Represents severance expense related to workforce reductions within salary and employee benefits expense. | |||||||||||||||||
| (b) Represents the change in legal reserves and settlement charges included in professional and legal fees. | |||||||||||||||||
| (c) Included in gains on securities transactions, net. | |||||||||||||||||
| (d) Represents the change in estimated special assessment losses included in the FDIC insurance assessment expense. | |||||||||||||||||
| (e) Represents tax benefits from discrete tax events included in income tax expense. | |||||||||||||||||
| (f) Calculated using the appropriate blended statutory tax rate for the applicable period. | |||||||||||||||||
| Adjusted per common share data (non-GAAP): | |||||||||||||||||
| Net income available to common shareholders, as adjusted (non-GAAP) | $ | 161,673 | $ | 172,776 | $ | 99,111 | |||||||||||
| Weighted average number of shares outstanding | 555,777,748 | 558,104,197 | 559,613,272 | ||||||||||||||
| Basic earnings, as adjusted (non-GAAP) | $ | 0.29 | $ | 0.31 | $ | 0.18 | |||||||||||
| Weighted average number of diluted shares outstanding | 559,254,972 | 562,214,037 | 563,305,525 | ||||||||||||||
| Diluted earnings, as adjusted (non-GAAP) | $ | 0.29 | $ | 0.31 | $ | 0.18 | |||||||||||
| Adjusted annualized return on average tangible common shareholder's equity (non-GAAP): | |||||||||||||||||
| Net income available to common shareholders, as adjusted (non-GAAP) | $ | 161,673 | $ | 172,776 | $ | 99,111 | |||||||||||
| Add: Amortization of other intangible assets (net of tax), other than loan servicing rights | 4,746 | 5,027 | 5,619 | ||||||||||||||
| Net income available to common shareholders excluding intangible amortization, as adjusted (non-GAAP) | 166,419 | 177,803 | 104,730 | ||||||||||||||
| Average shareholders' equity | 7,855,550 | 7,722,962 | 7,458,177 | ||||||||||||||
| Less: Average preferred shareholders equity | 354,345 | 354,345 | 354,345 | ||||||||||||||
| Less: Average goodwill (net of deferred tax liability) | 1,858,851 | 1,858,851 | 1,859,614 | ||||||||||||||
| Less: Average intangible assets (net of deferred tax liability), other than loan servicing rights | 57,080 | 63,235 | 76,167 | ||||||||||||||
| Average tangible common shareholders' equity | $ | 5,585,274 | $ | 5,446,531 | $ | 5,168,051 | |||||||||||
| Annualized return on average tangible common shareholders' equity, as adjusted (non-GAAP) | 11.92 | % | 13.06 | % | 8.11 | % | |||||||||||
15
VALLEY NATIONAL BANCORP
CONSOLIDATED FINANCIAL HIGHLIGHTS
Non-GAAP Reconciliations to GAAP Financial Measures (Continued)
| Three Months Ended | |||||||||||||||||
| March 31, | December 31, | March 31, | |||||||||||||||
| ($ in thousands, except for share data) | 2026 | 2025 | 2025 | ||||||||||||||
| Adjusted annualized return on average assets (non-GAAP): | |||||||||||||||||
| Net income, as adjusted (non-GAAP) | $ | 168,890 | $ | 180,210 | $ | 106,066 | |||||||||||
| Average assets | $ | 64,190,084 | $ | 63,255,554 | $ | 61,502,768 | |||||||||||
| Annualized return on average assets, as adjusted (non-GAAP) | 1.05 | % | 1.14 | % | 0.69 | % | |||||||||||
| Adjusted annualized return on average shareholders' equity (non-GAAP): | |||||||||||||||||
| Net income, as adjusted (non-GAAP) | $ | 168,890 | $ | 180,210 | $ | 106,066 | |||||||||||
| Average shareholders' equity | $ | 7,855,550 | $ | 7,722,962 | $ | 7,458,177 | |||||||||||
| Annualized return on average shareholders' equity, as adjusted (non-GAAP) | 8.60 | % | 9.33 | % | 5.69 | % | |||||||||||
| Annualized return on average tangible common shareholders' equity (non-GAAP): | |||||||||||||||||
| Net income available to common shareholders | $ | 156,696 | $ | 187,969 | $ | 99,103 | |||||||||||
| Add: Amortization of other intangible assets (net of tax), other than loan servicing rights | 4,746 | 5,027 | 5,619 | ||||||||||||||
| Net income available to common shareholders excluding intangible amortization (non-GAAP) | 161,442 | 192,996 | 104,722 | ||||||||||||||
| Average tangible common shareholders' equity (non- GAAP) | $ | 5,585,274 | $ | 5,446,531 | $ | 5,168,051 | |||||||||||
| Annualized return on average tangible common shareholders' equity (non-GAAP) | 11.56 | % | 14.17 | % | 8.11 | % | |||||||||||
| Efficiency ratio (non-GAAP): | |||||||||||||||||
| Non-interest expense, as reported (GAAP) | $ | 309,926 | $ | 299,401 | $ | 276,618 | |||||||||||
| Less: Restructuring charge (pre-tax) | 5,689 | 630 | — | ||||||||||||||
| Less: Amortization of tax credit investments (pre-tax) | 16,014 | 15,191 | 9,320 | ||||||||||||||
| Less: Litigation reserve (pre-tax) | 1,262 | (239) | — | ||||||||||||||
| Add: FDIC special assessment (pre-tax) | — | (5,672) | — | ||||||||||||||
| Non-interest expense, as adjusted (non-GAAP) | $ | 286,961 | $ | 289,491 | $ | 267,298 | |||||||||||
| Net interest income, as reported (GAAP) | 471,525 | 464,907 | 420,105 | ||||||||||||||
| Non-interest income, as reported (GAAP) | 68,836 | 76,341 | 58,294 | ||||||||||||||
| Add: Losses on available for sale and held to maturity securities transactions, net (pre-tax) | 10 | — | 11 | ||||||||||||||
| Gross operating income, as adjusted (non-GAAP) | $ | 540,371 | $ | 541,248 | $ | 478,410 | |||||||||||
| Efficiency ratio (non-GAAP) | 53.10 | % | 53.49 | % | 55.87 | % | |||||||||||
| As of | |||||||||||||||||||||||||||||
| March 31, | December 31, | September 30, | June 30, | March 31, | |||||||||||||||||||||||||
| ($ in thousands, except for share data) | 2026 | 2025 | 2025 | 2025 | 2025 | ||||||||||||||||||||||||
| Tangible book value per common share (non-GAAP): | |||||||||||||||||||||||||||||
| Common shares outstanding | 554,316,876 | 556,618,021 | 560,784,352 | 560,281,821 | 560,028,101 | ||||||||||||||||||||||||
| Shareholders' equity (GAAP) | $ | 7,828,443 | $ | 7,807,698 | $ | 7,695,374 | $ | 7,575,421 | $ | 7,499,897 | |||||||||||||||||||
| Less: Preferred stock | 354,345 | 354,345 | 354,345 | 354,345 | 354,345 | ||||||||||||||||||||||||
| Less: Goodwill and other intangible assets | 1,963,706 | 1,969,811 | 1,976,594 | 1,983,515 | 1,990,276 | ||||||||||||||||||||||||
| Tangible common shareholders' equity (non-GAAP) | $ | 5,510,392 | $ | 5,483,542 | $ | 5,364,435 | $ | 5,237,561 | $ | 5,155,276 | |||||||||||||||||||
| Tangible book value per common share (non-GAAP) | $ | 9.94 | $ | 9.85 | $ | 9.57 | $ | 9.35 | $ | 9.21 | |||||||||||||||||||
| Tangible common equity to tangible assets (non-GAAP): | |||||||||||||||||||||||||||||
| Tangible common shareholders' equity (non-GAAP) | $ | 5,510,392 | $ | 5,483,542 | $ | 5,364,435 | $ | 5,237,561 | $ | 5,155,276 | |||||||||||||||||||
| Total assets (GAAP) | 64,466,585 | 64,132,725 | 63,018,614 | 62,705,358 | 61,865,655 | ||||||||||||||||||||||||
| Less: Goodwill and other intangible assets | 1,963,706 | 1,969,811 | 1,976,594 | 1,983,515 | 1,990,276 | ||||||||||||||||||||||||
| Tangible assets (non-GAAP) | $ | 62,502,879 | $ | 62,162,914 | $ | 61,042,020 | $ | 60,721,843 | $ | 59,875,379 | |||||||||||||||||||
| Tangible common equity to tangible assets (non-GAAP) | 8.82 | % | 8.82 | % | 8.79 | % | 8.63 | % | 8.61 | % | |||||||||||||||||||
16
VALLEY NATIONAL BANCORP
CONSOLIDATED STATEMENTS OF FINANCIAL CONDITION
(in thousands, except for share data)
| March 31, | December 31, | ||||||||||
| 2026 | 2025 | ||||||||||
| (Unaudited) | |||||||||||
| Assets | |||||||||||
| Cash and due from banks | $ | 362,073 | $ | 315,166 | |||||||
| Interest bearing deposits with banks | 797,357 | 1,268,399 | |||||||||
| Investment securities: | |||||||||||
| Equity securities | 83,866 | 82,774 | |||||||||
| Available for sale debt securities | 4,157,034 | 4,202,218 | |||||||||
Held to maturity debt securities (net of allowance for credit losses of $746 at March 31, 2026 and $734 at December 31, 2025) | 3,619,808 | 3,495,837 | |||||||||
| Total investment securities | 7,860,708 | 7,780,829 | |||||||||
Loans held for sale (includes fair value of $2,477 at March 31, 2026 and $8,212 at December 31, 2025 for loans originated for sale) | 11,227 | 26,236 | |||||||||
| Loans | 50,828,820 | 50,136,728 | |||||||||
| Less: Allowance for loan losses | (584,500) | (583,400) | |||||||||
| Net loans | 50,244,320 | 49,553,328 | |||||||||
| Premises and equipment, net | 321,739 | 330,757 | |||||||||
| Lease right of use assets | 306,271 | 313,891 | |||||||||
| Bank owned life insurance | 740,411 | 738,090 | |||||||||
| Accrued interest receivable | 244,275 | 243,897 | |||||||||
| Goodwill | 1,868,936 | 1,868,936 | |||||||||
| Other intangible assets, net | 94,770 | 100,875 | |||||||||
| Other assets | 1,614,498 | 1,592,321 | |||||||||
| Total Assets | $ | 64,466,585 | $ | 64,132,725 | |||||||
| Liabilities | |||||||||||
| Deposits: | |||||||||||
| Non-interest bearing | $ | 12,250,974 | $ | 12,155,500 | |||||||
| Interest bearing: | |||||||||||
| Savings, NOW and money market | 29,172,499 | 28,603,470 | |||||||||
| Time | 11,436,148 | 11,424,123 | |||||||||
| Total deposits | 52,859,621 | 52,183,093 | |||||||||
| Short-term borrowings | 63,877 | 91,475 | |||||||||
| Long-term borrowings | 2,560,887 | 2,908,579 | |||||||||
| Junior subordinated debentures issued to capital trusts | 57,890 | 57,803 | |||||||||
| Lease liabilities | 363,990 | 372,448 | |||||||||
| Accrued expenses and other liabilities | 731,877 | 711,629 | |||||||||
| Total Liabilities | 56,638,142 | 56,325,027 | |||||||||
| Shareholders’ Equity | |||||||||||
| Preferred stock, no par value; 50,000,000 authorized shares: | |||||||||||
Series A (4,600,000 shares issued at March 31, 2026 and December 31, 2025) | 111,590 | 111,590 | |||||||||
Series B (4,000,000 shares issued at March 31, 2026 and December 31, 2025) | 98,101 | 98,101 | |||||||||
Series C (6,000,000 shares issued at March 31, 2026 and December 31, 2025) | 144,654 | 144,654 | |||||||||
| Common stock (no par value, authorized 650,000,000 shares; issued 560,878,750 shares at March 31, 2026 and December 31, 2025) | 196,730 | 196,730 | |||||||||
| Surplus | 5,451,735 | 5,464,845 | |||||||||
| Retained earnings | 2,003,048 | 1,912,933 | |||||||||
| Accumulated other comprehensive loss | (97,603) | (74,379) | |||||||||
Treasury stock, at cost (6,561,874 common shares at March 31, 2026 and 4,260,729 common shares at December 31, 2025) | (79,812) | (46,776) | |||||||||
| Total Shareholders’ Equity | 7,828,443 | 7,807,698 | |||||||||
| Total Liabilities and Shareholders’ Equity | $ | 64,466,585 | $ | 64,132,725 | |||||||
17
VALLEY NATIONAL BANCORP
CONSOLIDATED STATEMENTS OF INCOME (Unaudited)
(in thousands, except for share data)
| Three Months Ended | |||||||||||||||||
| March 31, | December 31, | March 31, | |||||||||||||||
| 2026 | 2025 | 2025 | |||||||||||||||
| Interest Income | |||||||||||||||||
| Interest and fees on loans | $ | 708,640 | $ | 724,208 | $ | 703,609 | |||||||||||
| Interest and dividends on investment securities: | |||||||||||||||||
| Taxable | 73,808 | 73,111 | 63,898 | ||||||||||||||
| Tax-exempt | 4,718 | 4,564 | 4,702 | ||||||||||||||
| Dividends | 4,800 | 5,322 | 5,664 | ||||||||||||||
| Interest on federal funds sold and other short-term investments | 10,758 | 8,592 | 6,879 | ||||||||||||||
| Total interest income | 802,724 | 815,797 | 784,752 | ||||||||||||||
| Interest Expense | |||||||||||||||||
| Interest on deposits: | |||||||||||||||||
| Savings, NOW and money market | 190,785 | 197,892 | 200,221 | ||||||||||||||
| Time | 106,678 | 116,657 | 125,069 | ||||||||||||||
| Interest on short-term borrowings | 236 | 502 | 2,946 | ||||||||||||||
| Interest on long-term borrowings and junior subordinated debentures | 33,500 | 35,839 | 36,411 | ||||||||||||||
| Total interest expense | 331,199 | 350,890 | 364,647 | ||||||||||||||
| Net Interest Income | 471,525 | 464,907 | 420,105 | ||||||||||||||
| Provision (credit) for credit losses for available for sale and held to maturity securities | 12 | 97 | (14) | ||||||||||||||
| Provision for credit losses for loans | 21,244 | 20,046 | 62,675 | ||||||||||||||
| Net Interest Income After Provision for Credit Losses | 450,269 | 444,764 | 357,444 | ||||||||||||||
| Non-Interest Income | |||||||||||||||||
| Wealth management and trust fees | 16,006 | 18,215 | 15,031 | ||||||||||||||
| Insurance commissions | 2,867 | 3,628 | 3,402 | ||||||||||||||
| Capital markets | 10,381 | 15,498 | 6,940 | ||||||||||||||
| Service charges on deposit accounts | 18,204 | 17,032 | 12,726 | ||||||||||||||
| Gains on securities transactions, net | 21 | 1 | 46 | ||||||||||||||
| Fees from loan servicing | 3,218 | 3,061 | 3,215 | ||||||||||||||
| Gains on sales of loans, net | 3,090 | 1,944 | 2,197 | ||||||||||||||
| Bank owned life insurance | 5,835 | 4,595 | 4,777 | ||||||||||||||
| Other | 9,214 | 12,367 | 9,960 | ||||||||||||||
| Total non-interest income | 68,836 | 76,341 | 58,294 | ||||||||||||||
| Non-Interest Expense | |||||||||||||||||
| Salary and employee benefits expense | 155,715 | 144,660 | 142,618 | ||||||||||||||
| Net occupancy expense | 27,182 | 26,058 | 25,888 | ||||||||||||||
| Technology, furniture and equipment expense | 31,878 | 32,605 | 29,896 | ||||||||||||||
| FDIC insurance assessment | 10,476 | 5,643 | 12,867 | ||||||||||||||
| Amortization of other intangible assets | 6,919 | 7,438 | 8,019 | ||||||||||||||
| Professional and legal fees | 25,142 | 26,846 | 15,670 | ||||||||||||||
| Amortization of tax credit investments | 16,014 | 15,191 | 9,320 | ||||||||||||||
| Other | 36,600 | 40,960 | 32,340 | ||||||||||||||
| Total non-interest expense | 309,926 | 299,401 | 276,618 | ||||||||||||||
| Income Before Income Taxes | 209,179 | 221,704 | 139,120 | ||||||||||||||
| Income tax expense | 45,266 | 26,301 | 33,062 | ||||||||||||||
| Net Income | 163,913 | 195,403 | 106,058 | ||||||||||||||
| Dividends on preferred stock | 7,217 | 7,434 | 6,955 | ||||||||||||||
| Net Income Available to Common Shareholders | $ | 156,696 | $ | 187,969 | $ | 99,103 | |||||||||||
18
VALLEY NATIONAL BANCORP
Quarterly Analysis of Average Assets, Liabilities and Shareholders' Equity and
Net Interest Income on a Tax Equivalent Basis
| Three Months Ended | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| March 31, 2026 | December 31, 2025 | March 31, 2025 | |||||||||||||||||||||||||||||||||||||||||||||||||||
| Average | Avg. | Average | Avg. | Average | Avg. | ||||||||||||||||||||||||||||||||||||||||||||||||
| ($ in thousands) | Balance | Interest | Rate | Balance | Interest | Rate | Balance | Interest | Rate | ||||||||||||||||||||||||||||||||||||||||||||
| Assets | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest earning assets: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Loans (1)(2) | $ | 50,265,383 | $ | 708,662 | 5.64 | % | $ | 49,614,838 | $ | 724,231 | 5.84 | % | $ | 48,654,921 | $ | 703,632 | 5.78 | % | |||||||||||||||||||||||||||||||||||
Taxable investments (3) | 7,732,330 | 78,608 | 4.07 | 7,737,669 | 78,433 | 4.05 | 7,100,958 | 69,562 | 3.92 | ||||||||||||||||||||||||||||||||||||||||||||
Tax-exempt investments (1)(3) | 542,177 | 5,972 | 4.41 | 533,578 | 5,777 | 4.33 | 552,291 | 5,952 | 4.31 | ||||||||||||||||||||||||||||||||||||||||||||
| Interest bearing deposits with banks | 1,178,997 | 10,758 | 3.65 | 869,310 | 8,592 | 3.95 | 583,521 | 6,879 | 4.72 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest earning assets | 59,718,887 | 804,000 | 5.39 | 58,755,395 | 817,033 | 5.56 | 56,891,691 | 786,025 | 5.53 | ||||||||||||||||||||||||||||||||||||||||||||
| Other assets | 4,471,197 | 4,500,159 | 4,611,077 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total assets | $ | 64,190,084 | $ | 63,255,554 | $ | 61,502,768 | |||||||||||||||||||||||||||||||||||||||||||||||
| Liabilities and shareholders' equity | |||||||||||||||||||||||||||||||||||||||||||||||||||||
| Interest bearing liabilities: | |||||||||||||||||||||||||||||||||||||||||||||||||||||
Savings, NOW and money market deposits | $ | 29,203,978 | $ | 190,785 | 2.61 | % | $ | 27,891,256 | $ | 197,892 | 2.84 | % | $ | 26,345,983 | $ | 200,221 | 3.04 | % | |||||||||||||||||||||||||||||||||||
| Time deposits | 11,226,874 | 106,678 | 3.80 | 11,553,390 | 116,657 | 4.04 | 11,570,758 | 125,069 | 4.32 | ||||||||||||||||||||||||||||||||||||||||||||
| Short-term borrowings | 71,809 | 236 | 1.31 | 94,353 | 502 | 2.13 | 307,637 | 2,946 | 3.83 | ||||||||||||||||||||||||||||||||||||||||||||
Long-term borrowings (4) | 2,849,479 | 33,500 | 4.70 | 2,964,587 | 35,839 | 4.84 | 3,006,331 | 36,411 | 4.84 | ||||||||||||||||||||||||||||||||||||||||||||
| Total interest bearing liabilities | 43,352,140 | 331,199 | 3.06 | 42,503,586 | 350,890 | 3.30 | 41,230,709 | 364,647 | 3.54 | ||||||||||||||||||||||||||||||||||||||||||||
| Non-interest bearing deposits | 11,942,322 | 11,917,134 | 11,222,562 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Other liabilities | 1,040,072 | 1,111,872 | 1,591,320 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Shareholders' equity | 7,855,550 | 7,722,962 | 7,458,177 | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Total liabilities and shareholders' equity | $ | 64,190,084 | $ | 63,255,554 | $ | 61,502,768 | |||||||||||||||||||||||||||||||||||||||||||||||
Net interest income/interest rate spread (5) | $ | 472,801 | 2.33 | % | $ | 466,143 | 2.26 | % | $ | 421,378 | 1.99 | % | |||||||||||||||||||||||||||||||||||||||||
| Tax equivalent adjustment | (1,276) | (1,236) | (1,273) | ||||||||||||||||||||||||||||||||||||||||||||||||||
| Net interest income, as reported | $ | 471,525 | $ | 464,907 | $ | 420,105 | |||||||||||||||||||||||||||||||||||||||||||||||
Net interest margin (6) | 3.16 | % | 3.17 | % | 2.95 | % | |||||||||||||||||||||||||||||||||||||||||||||||
| Tax equivalent effect | 0.01 | 0.00 | 0.01 | ||||||||||||||||||||||||||||||||||||||||||||||||||
Net interest margin on a fully tax equivalent basis (6) | 3.17 | % | 3.17 | % | 2.96 | % | |||||||||||||||||||||||||||||||||||||||||||||||
(1) Interest income is presented on a tax equivalent basis using a 21 percent federal tax rate.
(2) Loans are stated net of unearned income and include non-accrual loans.
(3) The yield for securities that are classified as available for sale is based on the average historical amortized cost.
(4) Includes junior subordinated debentures issued to capital trusts which are presented separately on the consolidated statements of financial condition.
(5) Interest rate spread represents the difference between the average yield on interest earning assets and the average cost of interest bearing liabilities and is presented on a fully tax equivalent basis.
(6) Net interest income as a percentage of total average interest earning assets.
INVESTOR RELATIONS Requests for copies of reports and/or other inquiries should be directed to Andrew Jianette, Investor Relations, Valley National Bancorp, 70 Speedwell Avenue, Morristown, New Jersey, 07960 by e-mail at [email protected]. | ||
19
1Q26 Earnings Presentation April 23, 2026 Exhibit 99.2
2 Forward Looking Statements The foregoing contains forward -looking statements within the meaning of the Private Securities Litigation Reform Act of 1995. Such statements are not historical facts and include expressions about management’s confidence and strategies and management’s expectations about our business, new and existing programs and products, acquisitions, relationships, opportunities, taxation, technology, market conditions and economic expectations . These statements may be identified by forward -looking terminology such as “intend,” “should,” “expect,” “believe,” "position", “view,” “opportunity,” “allow,” “continues,” “reflects,” “would,” “could,” “typically,” “usually,” “anticipate,” “may,” “estimate,” “outlook,” “project,” “focus,” “roadmap,” or similar statements or variations of such terms . Such forward -looking statements involve certain risks and uncertainties . Actual results may differ materially from such forward -looking statements . Factors that may cause actual results to differ materially from those contemplated by such forward -looking statements include, but are not limited to : the impact of market interest rates and monetary and fiscal policies of the U.S . federal government and its agencies in connection with prolonged inflationary pressures, which could have a material adverse effect on our clients, our business, our employees, and our ability to provide services to our customers ; the impact of unfavorable macroeconomic conditions or downturns, including instability or volatility in financial markets resulting from the impact of tariffs/import fees and other trade policies and practices, any retaliatory actions, related market uncertainty, or other factors ; U.S . government debt default or rating downgrade ; unanticipated loan delinquencies ; loss of collateral ; decreased service revenues ; increased business disruptions or failures ; reductions in employment ; and other potential negative effects on our business, employees or clients caused by factors outside of our control, such as new legislation and policy changes under the current U.S . presidential administration, any shutdown of the U.S federal government, geopolitical instabilities or events, including ongoing conflicts in the Middle East, natural and other disasters, including severe weather events and other climate -related risks, health emergencies, acts of terrorism, or other external events ; the impact of any potential instability within the U.S . financial sector or future bank failures, including the possibility of a run on deposits by a coordinated deposit base, and the impact of any actual or perceived concerns regarding the soundness, or creditworthiness, of other financial institutions, including any resulting disruption within the financial markets, increased expenses, including FDIC insurance assessments, or adverse impact on our stock price, deposits or our ability to borrow or raise capital ; the impact of negative public opinion regarding Valley or banks in general that damages our reputation and adversely impacts business and revenues ; changes in the statutes, regulations, policies, enforcement priorities, or composition of the federal bank regulatory agencies ; the loss of or decrease in lower -cost funding sources within our deposit base ; investigations, damage verdicts, settlements or restrictions related to existing or potential class action litigation or individual litigation arising from claims of violations of laws or regulations, contractual claims, breach of fiduciary responsibility, negligence, fraud, environmental laws, patent, trademark or other intellectual property infringement, misappropriation or other violation, employment -related claims, and other matters ; a prolonged downturn and contraction in the economy, as well as any decline in commercial real estate values collateralizing a significant portion of our loan portfolio ; higher or lower than expected income tax expense or tax rates, including increases or decreases resulting from changes in uncertain tax position liabilities, tax laws, regulations, and case law; the inability to grow customer deposits to keep pace with the level of loan growth ; a material change in our allowance for credit losses due to forecasted economic conditions and/or unexpected credit deterioration in our loan and investment portfolios ; the need to supplement debt or equity capital to maintain or exceed internal capital thresholds ; changes in our business, strategy, market conditions or other factors that may negatively impact the estimated fair value of our goodwill and other intangible assets and result in future impairment charges ; greater than expected technology -related costs due to, among other factors, prolonged or failed implementations, additional project staffing and obsolescence caused by continuous and rapid market innovations ; increased competitive challenges and competitive pressure on pricing of our products and services ; our ability to stay current with rapid technological changes and evolving legal and regulatory requirements in the financial services industry, including developments relating to the use of artificial intelligence, blockchain, and related regulatory developments, as well as our ability to effectively assess and monitor the effects of, and risks associated with, the implementation and use of such technology ; cyberattacks, ransomware attacks, computer viruses, malware or other cybersecurity incidents that may breach the security of our or our third -party service providers’ websites or other systems or networks to obtain unauthorized access to personal, confidential, proprietary or sensitive information, destroy data, disable or degrade service, or sabotage our systems or networks, and the increasing sophistication of such attacks and use of targeted tactics against the financial services industry ; any disruption of our systems and network, or those of our third - party service providers, resulting from events that are wholly or partially beyond our control, including, for example, electrical, telecommunications, or other major service outages, or actions by employees, which may give rise to financial loss or liability ; results of examinations by the Office of the Comptroller of the Currency (OCC), the Federal Reserve Bank, the Consumer Financial Protection Bureau and other regulatory authorities, including the possibility that any such regulatory authority may, among other things, require us to increase our allowance for credit losses, write -down assets, reimburse customers, change the way we do business, or limit or eliminate certain other banking activities ; application of heightened regulatory standards for certain large insured national banks, and the expenses we will incur to develop policies, programs, and systems that comply with the enhanced standards applicable to us ; our inability or determination not to pay dividends at current levels, or at all, because of inadequate earnings, regulatory restrictions or limitations, changes in our capital requirements, or a decision to increase capital by retaining more earnings ; unanticipated loan delinquencies, loss of collateral, decreased service revenues, and other potential negative effects on our business caused by severe weather and other climate -related risks, pandemics or other public health crises, acts of terrorism or other external events ; our ability to successfully execute our business plan and strategic initiatives ; and unexpected significant declines in the loan portfolio due to the lack of economic expansion, increased competition, large prepayments, risk mitigation strategies, changes in regulatory lending guidance or other factors . A detailed discussion of factors that could affect our results is included in our SEC filings, including Item 1A. "Risk Factors" of our Annual Report on Form 10-K for the year ended December 31, 2025 . We undertake no duty to update any forward -looking statement to conform the statement to actual results or changes in our expectations, except as required by law. Although we believe that the expectations reflected in the forward -looking statements are reasonable, we cannot guarantee future results, levels of activity, performance or achievements .
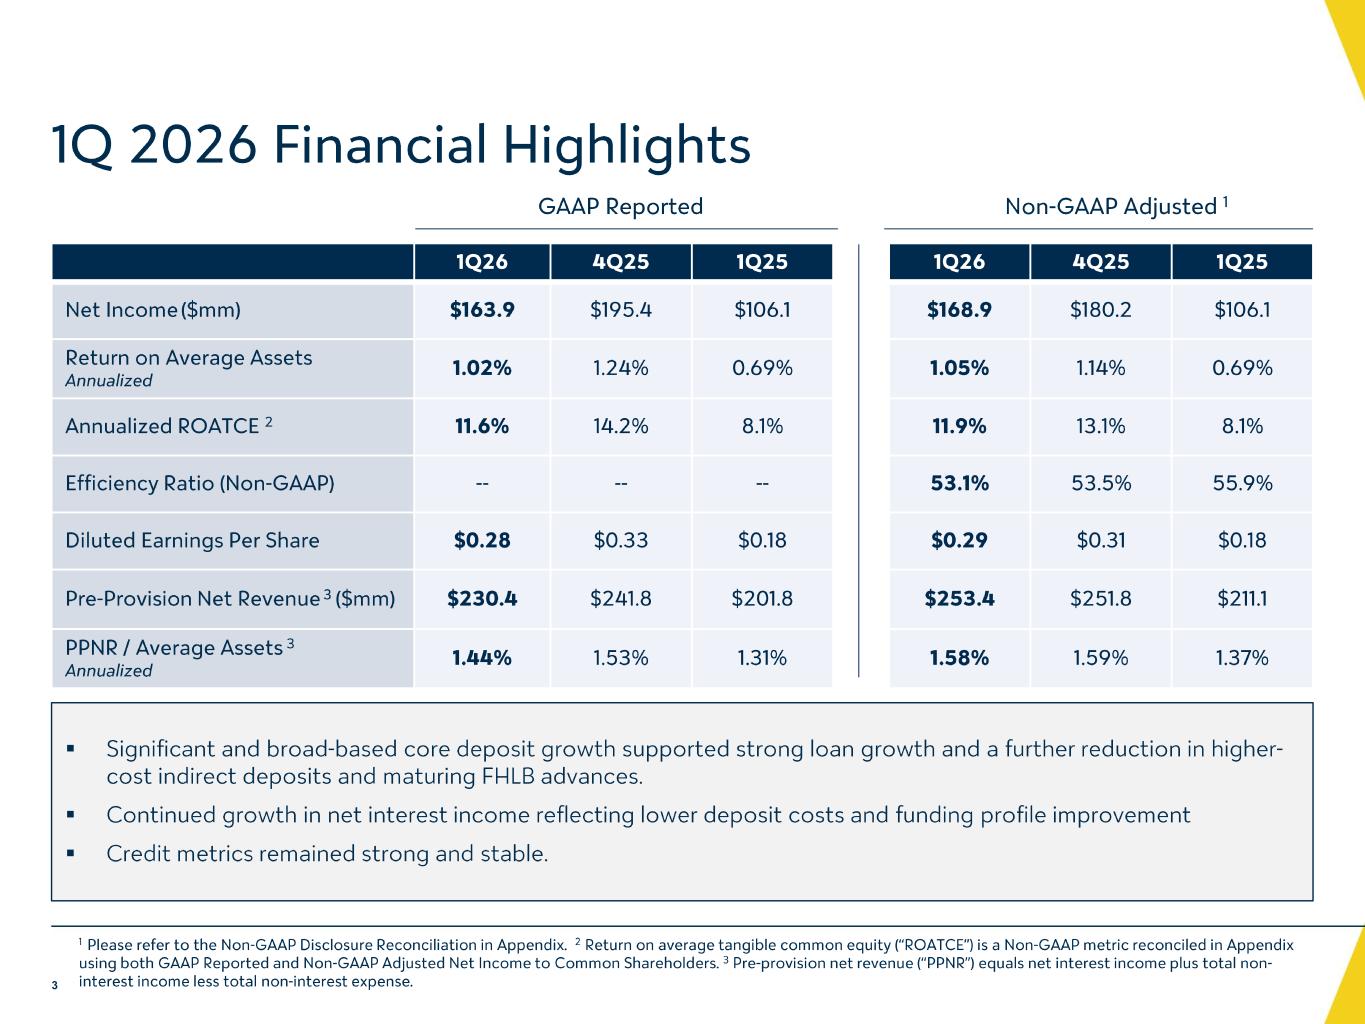
1Q 2026 Financial Highlights 1Q26 4Q25 1Q25 1Q26 4Q25 1Q25 Net Income ($mm) $163.9 $195.4 $106.1 $168.9 $180.2 $106.1 Return on Average Assets Annualized 1.02% 1.24% 0.69% 1.05% 1.14% 0.69% Annualized ROATCE 2 11.6% 14.2% 8.1% 11.9% 13.1% 8.1% Efficiency Ratio (Non -GAAP) -- -- -- 53.1% 53.5% 55.9% Diluted Earnings Per Share $0.28 $0.33 $0.18 $0.29 $0.31 $0.18 Pre -Provision Net Revenue 3 ($mm) $230.4 $241.8 $201.8 $253.4 $251.8 $211.1 PPNR / Average Assets 3 Annualized 1.44% 1.53% 1.31% 1.58% 1.59% 1.37% GAAP Reported Non -GAAP Adjusted 1 1 Please refer to the Non -GAAP Disclosure Reconciliation in Appendix. 2 Return on average tangible common equity (“ROATCE”) is a Non -GAAP metric reconciled in Appendix using both GAAP Reported and Non -GAAP Adjusted Net Income to Common Shareholders. 3 Pre -provision net revenue (“PPNR”) equals net interest income plus total non - interest income less total non -interest expense. ▪ Significant and broad -based core deposit growth supported strong loan growth and a further reduction in higher - cost indirect deposits and maturing FHLB advances. ▪ Continued growth in net interest income reflecting lower deposit costs and funding profile improvement ▪ Credit metrics remained strong and stable. 3 Source- Earnings Release in Workiva
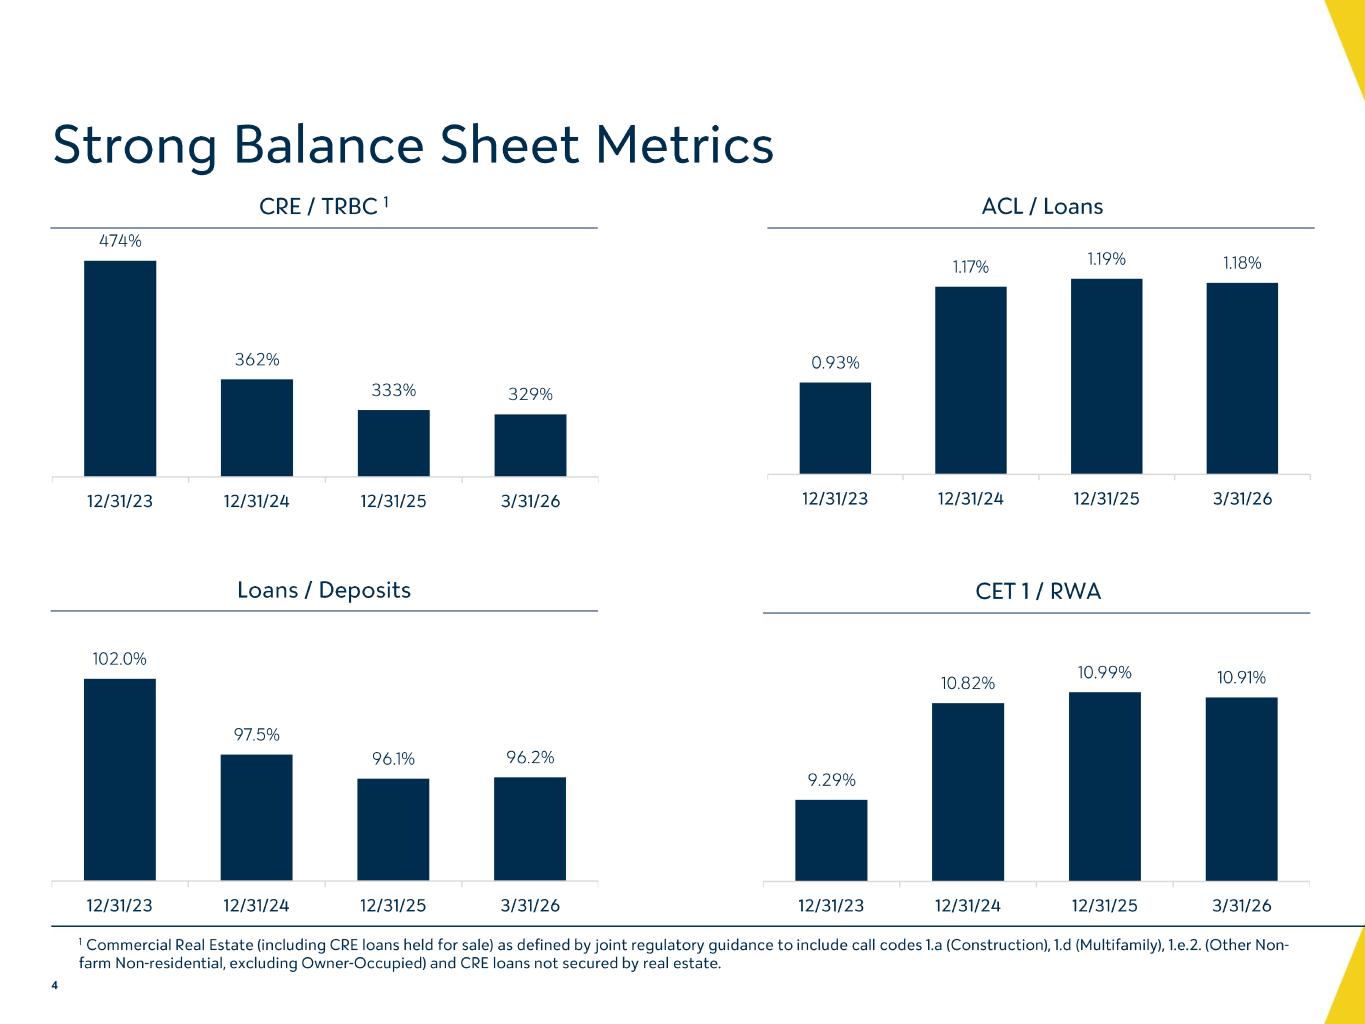
9.29% 10.82% 10.99% 10.91% 12/31/23 12/31/24 12/31/25 3/31/26 Strong Balance Sheet Metrics 4 ACL / Loans 0.93% 1.17% 1.19% 1.18% 12/31/23 12/31/24 12/31/25 3/31/26 Loans / Deposits 102.0% 97.5% 96.1% 96.2% 12/31/23 12/31/24 12/31/25 3/31/26 CET 1 / RWA 1 Commercial Real Estate (including CRE loans held for sale) as defined by joint regulatory guidance to include call codes 1.a (C onstruction), 1.d (Multifamily), 1.e.2. (Other Non - farm Non -residential, excluding Owner -Occupied) and CRE loans not secured by real estate . CRE / TRBC 1 474% 362% 333% 329% 12/31/23 12/31/24 12/31/25 3/31/26 CRE Concentration - 5 Quarter Trend_2Q25_FINAL Source- Earnings Release in Workiva Source- Earnings Release in Workiva Source- Earnings Release in Workiva
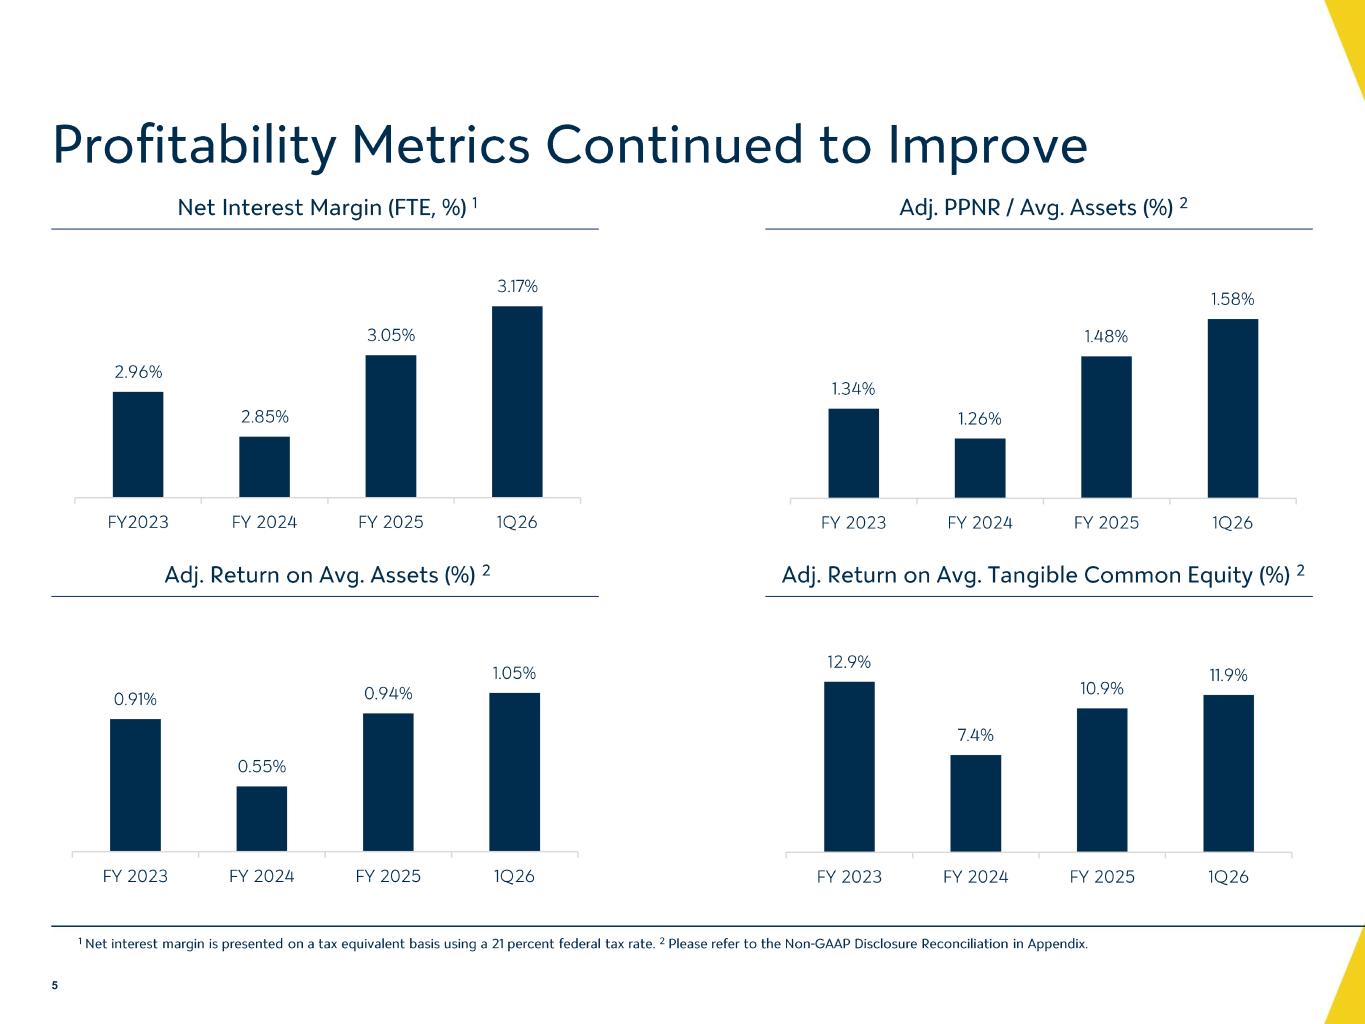
Profitability Metrics Continued to Improve 5 Net Interest Margin (FTE, %) 1 Adj. PPNR / Avg. Assets (%) 2 Adj. Return on Avg. Assets (%) 2 Adj. Return on Avg. Tangible Common Equity (%) 2 2.96% 2.85% 3.05% 3.17% FY2023 FY 2024 FY 2025 1Q26 1.34% 1.26% 1.48% 1.58% FY 2023 FY 2024 FY 2025 1Q26 0.91% 0.55% 0.94% 1.05% FY 2023 FY 2024 FY 2025 1Q26 12.9% 7.4% 10.9% 11.9% FY 2023 FY 2024 FY 2025 1Q26 Source- Earnings Release in Workiva Source- Earnings Release in Workiva Source- Earnings Release in Workiva Source- Earnings Release in Workiva 1 Net interest margin is presented on a tax equivalent basis using a 21 percent federal tax rate. 2 Please refer to the Non -GAAP Disclosure Reconciliation in Appendix.
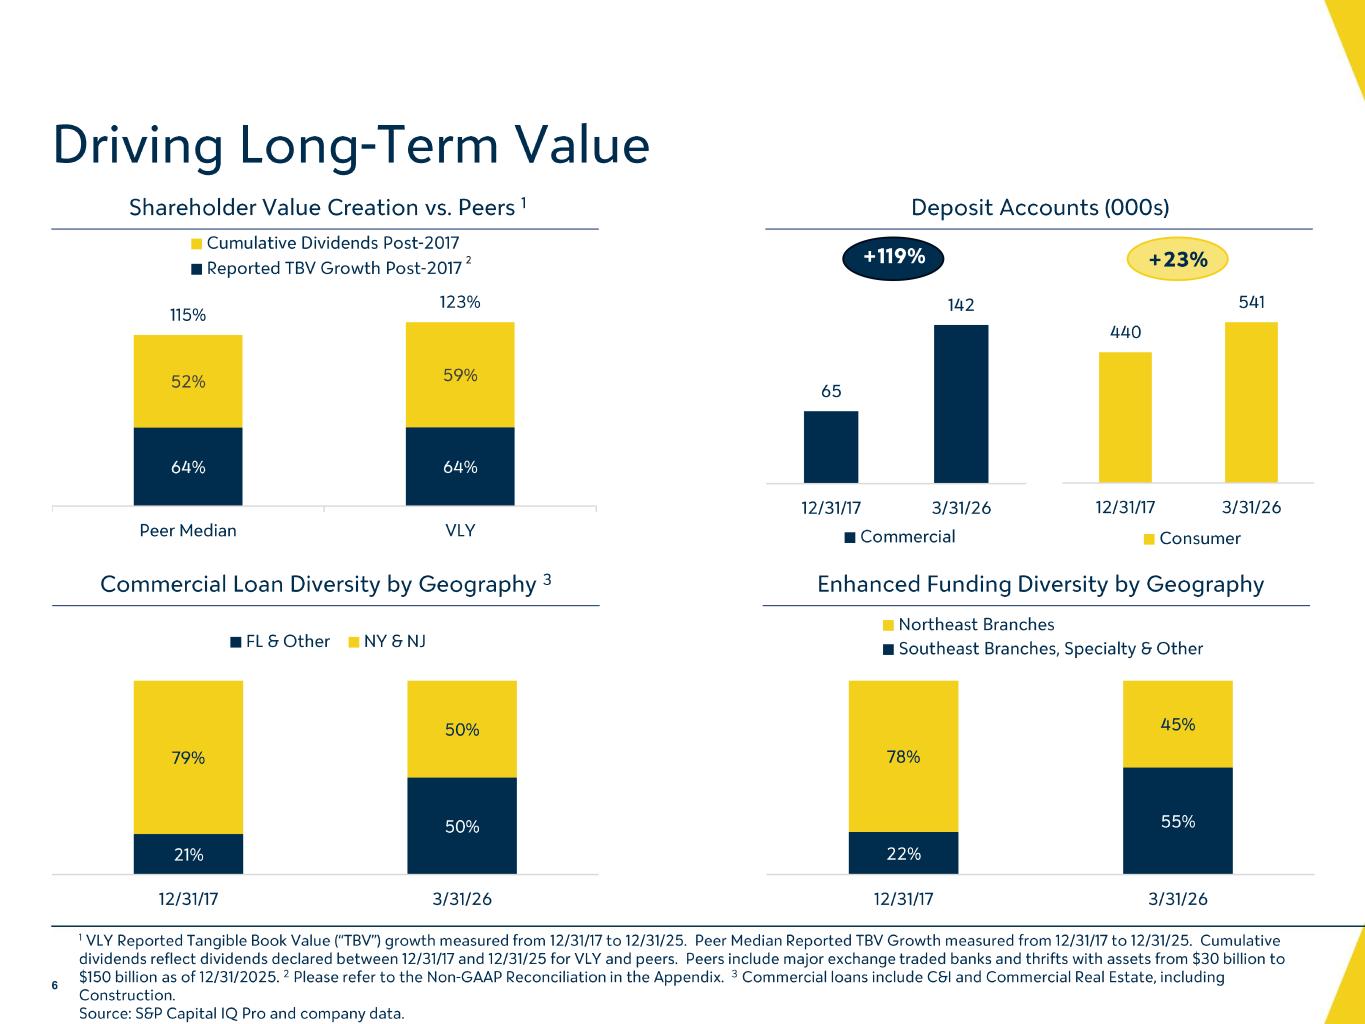
65 142 12/31/17 3/31/26 Commercial 64%64% 59%52% 123% 115% VLYPeer Median Cumulative Dividends Post-2017 Reported TBV Growth Post-2017 +119% Shareholder Value Creation vs. Peers 1 Deposit Accounts (000s) Commercial Loan Diversity by Geography 3 Enhanced Funding Diversity by Geography 21% 50% 79% 50% 12/31/17 3/31/26 FL & Other NY & NJ 22% 55% 78% 45% 12/31/17 3/31/26 Northeast Branches Southeast Branches, Specialty & Other 440 541 12/31/17 3/31/26 Consumer +23% Driving Long -Term Value 1 VLY Reported Tangible Book Value (“TBV”) growth measured from 12/31/17 to 12 /31/25. Peer Median Reported TBV Growth measured from 12/31/17 to 12/31/25. Cumulative dividends reflect dividends declared between 12/31/17 and 12/31/25 for VLY and peers. Peers include major exchange traded ba nks and thrifts with assets from $30 billion to $150 billion as of 12/31/2025. 2 Please refer to the Non -GAAP Reconciliation in the Appendix. 3 Commercial loans include C&I and Commercial Real Estate, including Construction. Source: S&P Capital IQ Pro and company data. 6 Source- “TBV Support 1Q26” Source- SAC Source- SAC Source- “Existing Accounts 03-2026” 2
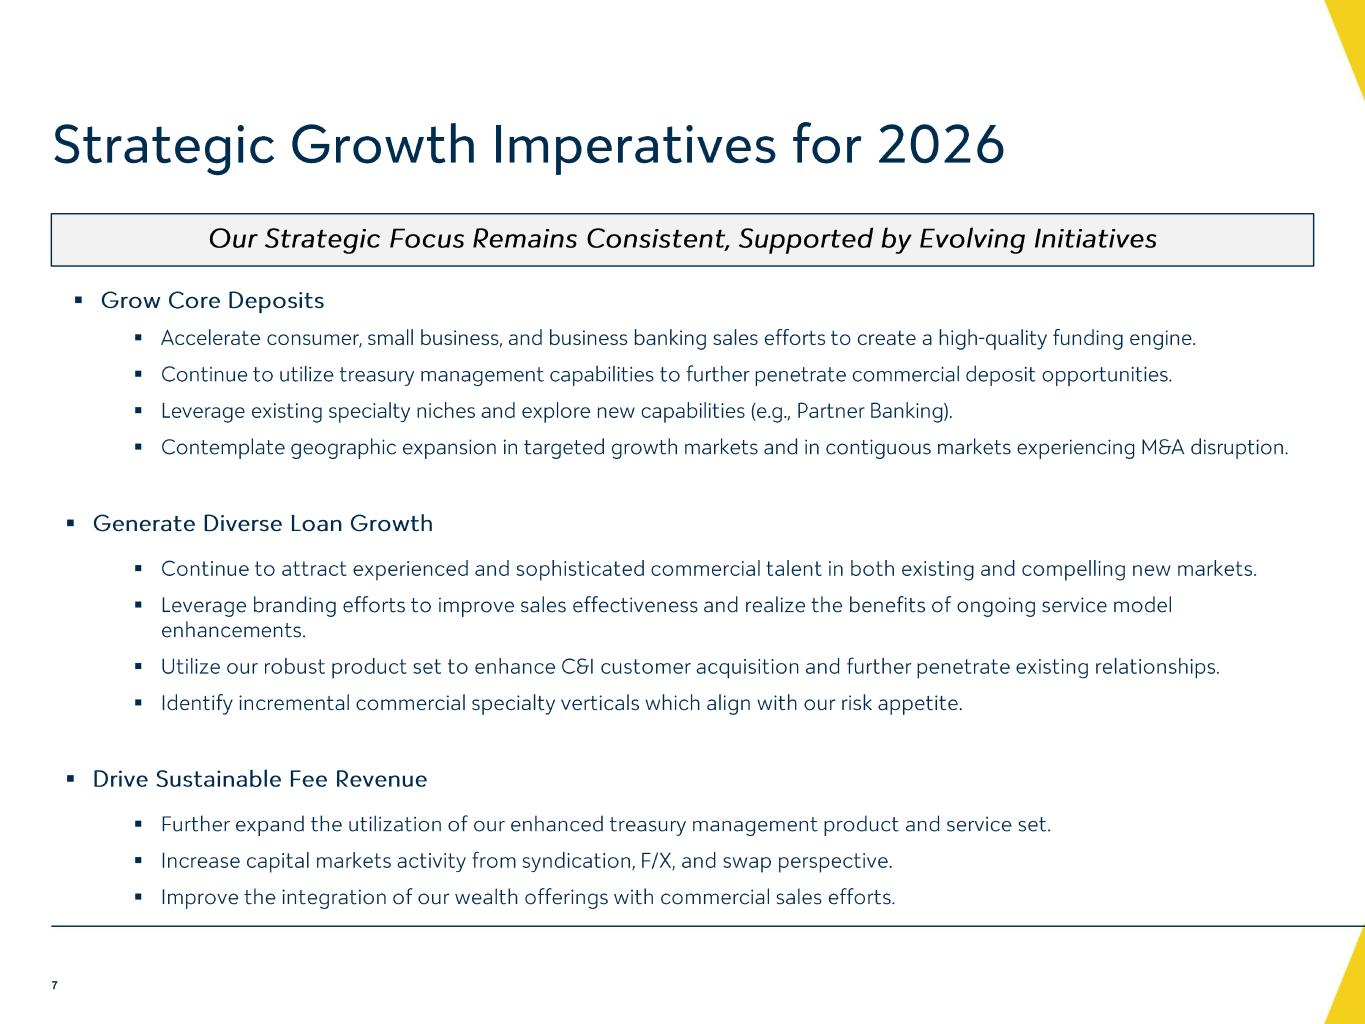
▪ Grow Core Deposits ▪ Accelerate consumer, small business, and business banking sales efforts to create a high -quality funding engine. ▪ Continue to utilize treasury management capabilities to further penetrate commercial deposit opportunities. ▪ Leverage existing specialty niches and explore new capabilities (e.g., Partner Banking). ▪ Contemplate geographic expansion in targeted growth markets and in contiguous markets experiencing M&A disruption. ▪ Generate Diverse Loan Growth ▪ Continue to attract experienced and sophisticated commercial talent in both existing and compelling new markets. ▪ Leverage branding efforts to improve sales effectiveness and realize the benefits of ongoing service model enhancements. ▪ Utilize our robust product set to enhance C&I customer acquisition and further penetrate existing relationships. ▪ Identify incremental commercial specialty verticals which align with our risk appetite. ▪ Drive Sustainable Fee Revenue ▪ Further expand the utilization of our enhanced treasury management product and service set. ▪ Increase capital markets activity from syndication, F/X, and swap perspective. ▪ Improve the integration of our wealth offerings with commercial sales efforts. Our Strategic Focus Remains Consistent, Supported by Evolving Initiatives Strategic Growth Imperatives for 2026 7
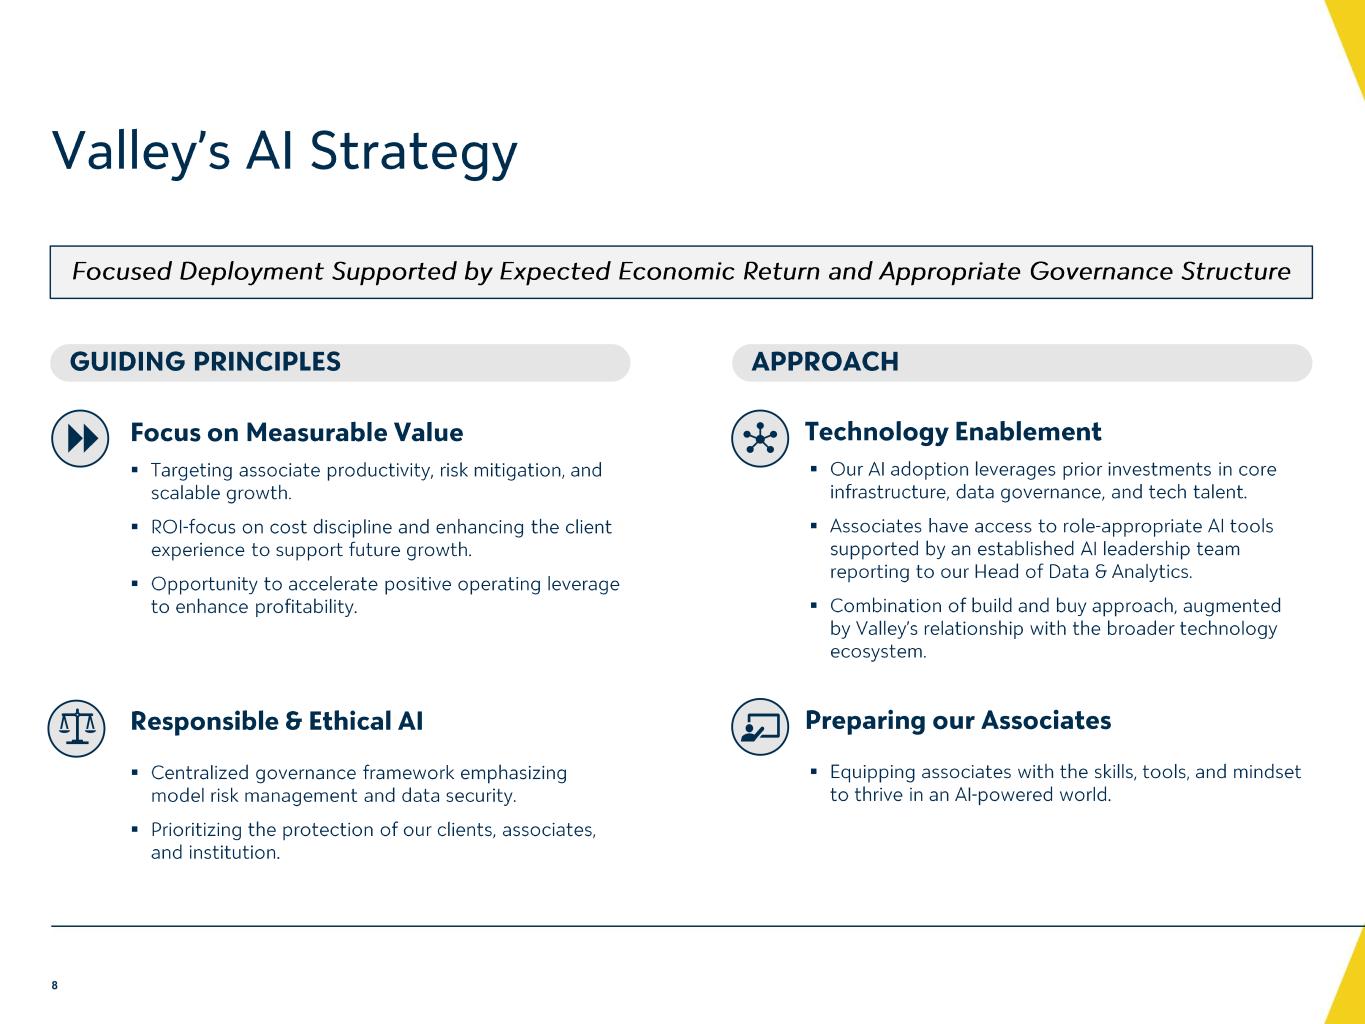
Valley’s AI Strategy Focused Deployment Supported by Expected Economic Return and Appropriate Governance Structure GUIDING PRINCIPLES Focus on Measurable Value Responsible & Ethical AI ▪ Targeting associate productivity, risk mitigation, and scalable growth. ▪ ROI -focus on cost discipline and enhancing the client experience to support future growth. ▪ Opportunity to accelerate positive operating leverage to enhance profitability. ▪ Centralized governance framework emphasizing model risk management and data security. ▪ Prioritizing the protection of our clients, associates, and institution. APPROACH Technology Enablement Preparing our Associates ▪ Our AI adoption leverages prior investments in core infrastructure, data governance, and tech talent. ▪ Associates have access to role -appropriate AI tools supported by an established AI leadership team reporting to our Head of Data & Analytics. ▪ Combination of build and buy approach, augmented by Valley’s relationship with the broader technology ecosystem. ▪ Equipping associates with the skills, tools, and mindset to thrive in an AI -powered world. 8
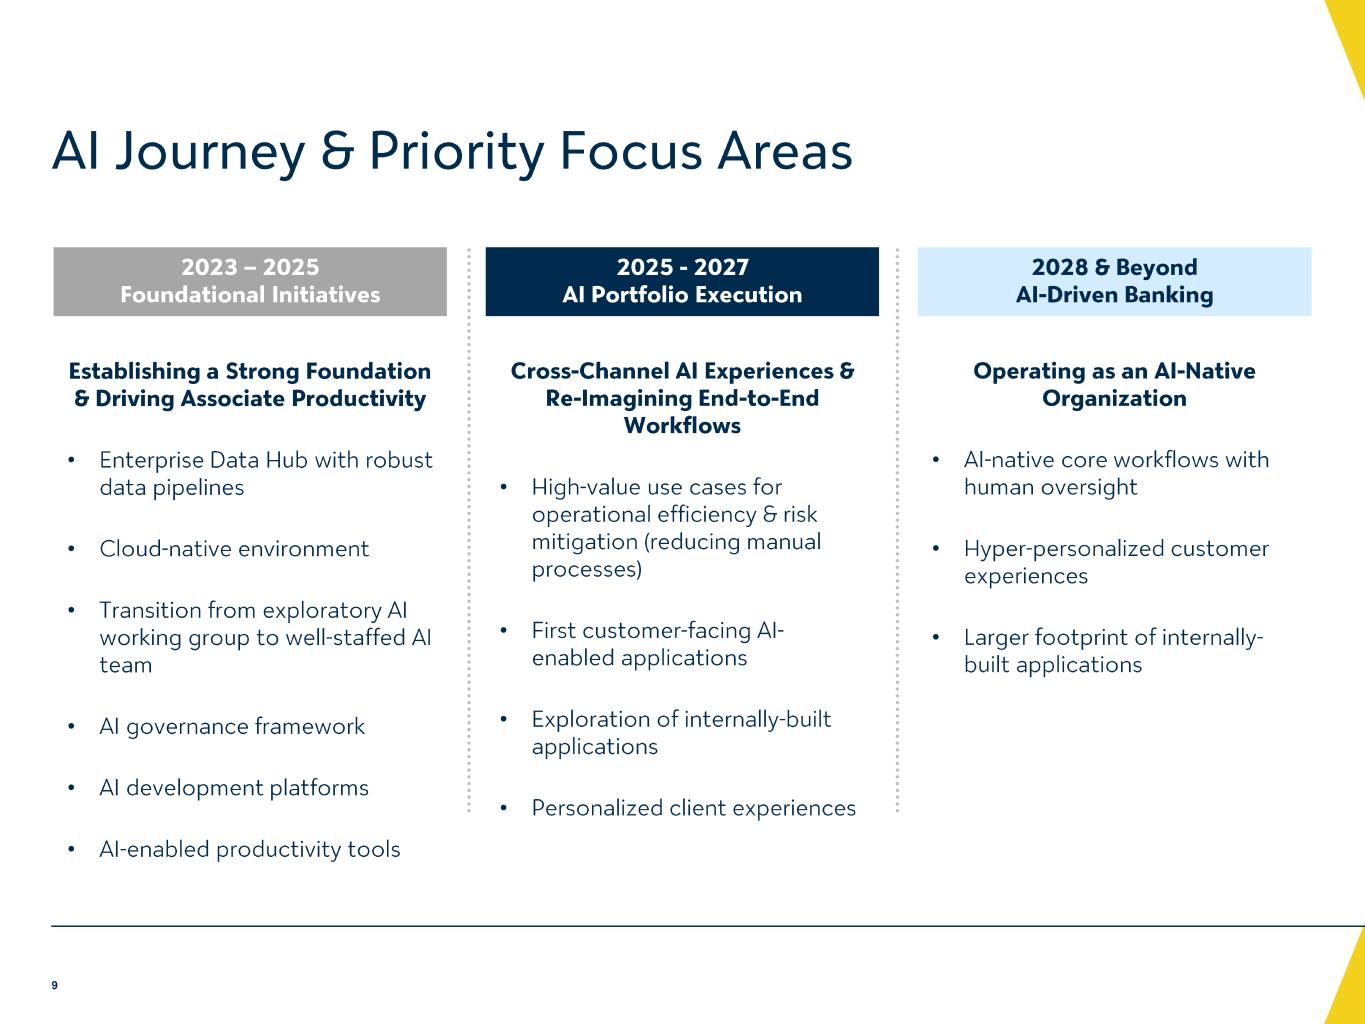
AI Journey & Priority Focus Areas 2023 – 2025 Foundational Initiatives 2025 - 2027 AI Portfolio Execution 2028 & Beyond AI -Driven Banking Establishing a Strong Foundation & Driving Associate Productivity • Enterprise Data Hub with robust data pipelines • Cloud -native environment • Transition from exploratory AI working group to well -staffed AI team • AI governance framework • AI development platforms • AI-enabled productivity tools Cross -Channel AI Experiences & Re -Imagining End -to -End Workflows • High -value use cases for operational efficiency & risk mitigation (reducing manual processes) • First customer -facing AI - enabled applications • Exploration of internally -built applications • Personalized client experiences Operating as an AI -Native Organization • AI-native core workflows with human oversight • Hyper -personalized customer experiences • Larger footprint of internally - built applications 9
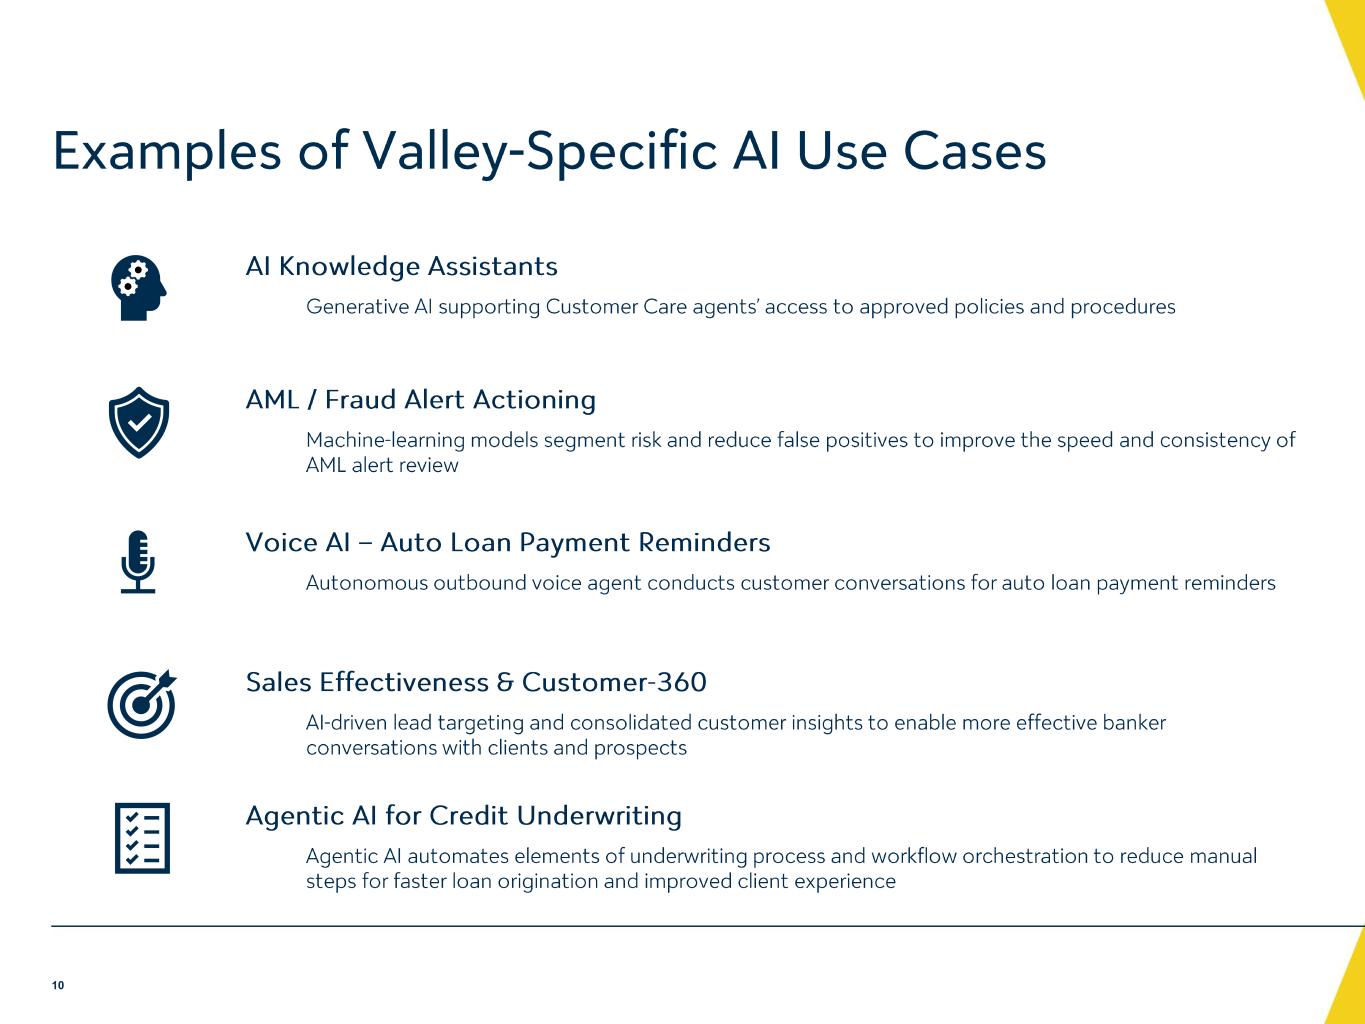
Examples of Valley -Specific AI Use Cases 10 AI Knowledge Assistants Generative AI supporting Customer Care agents’ access to approved policies and procedures AML / Fraud Alert Actioning Machine -learning models segment risk and reduce false positives to improve the speed and consistency of AML alert review Voice AI – Auto Loan Payment Reminders Autonomous outbound voice agent conducts customer conversations for auto loan payment reminders Sales Effectiveness & Customer -360 AI-driven lead targeting and consolidated customer insights to enable more effective banker conversations with clients and prospects Agentic AI for Credit Underwriting Agentic AI automates elements of underwriting process and workflow orchestration to reduce manual steps for faster loan origination and improved client experience
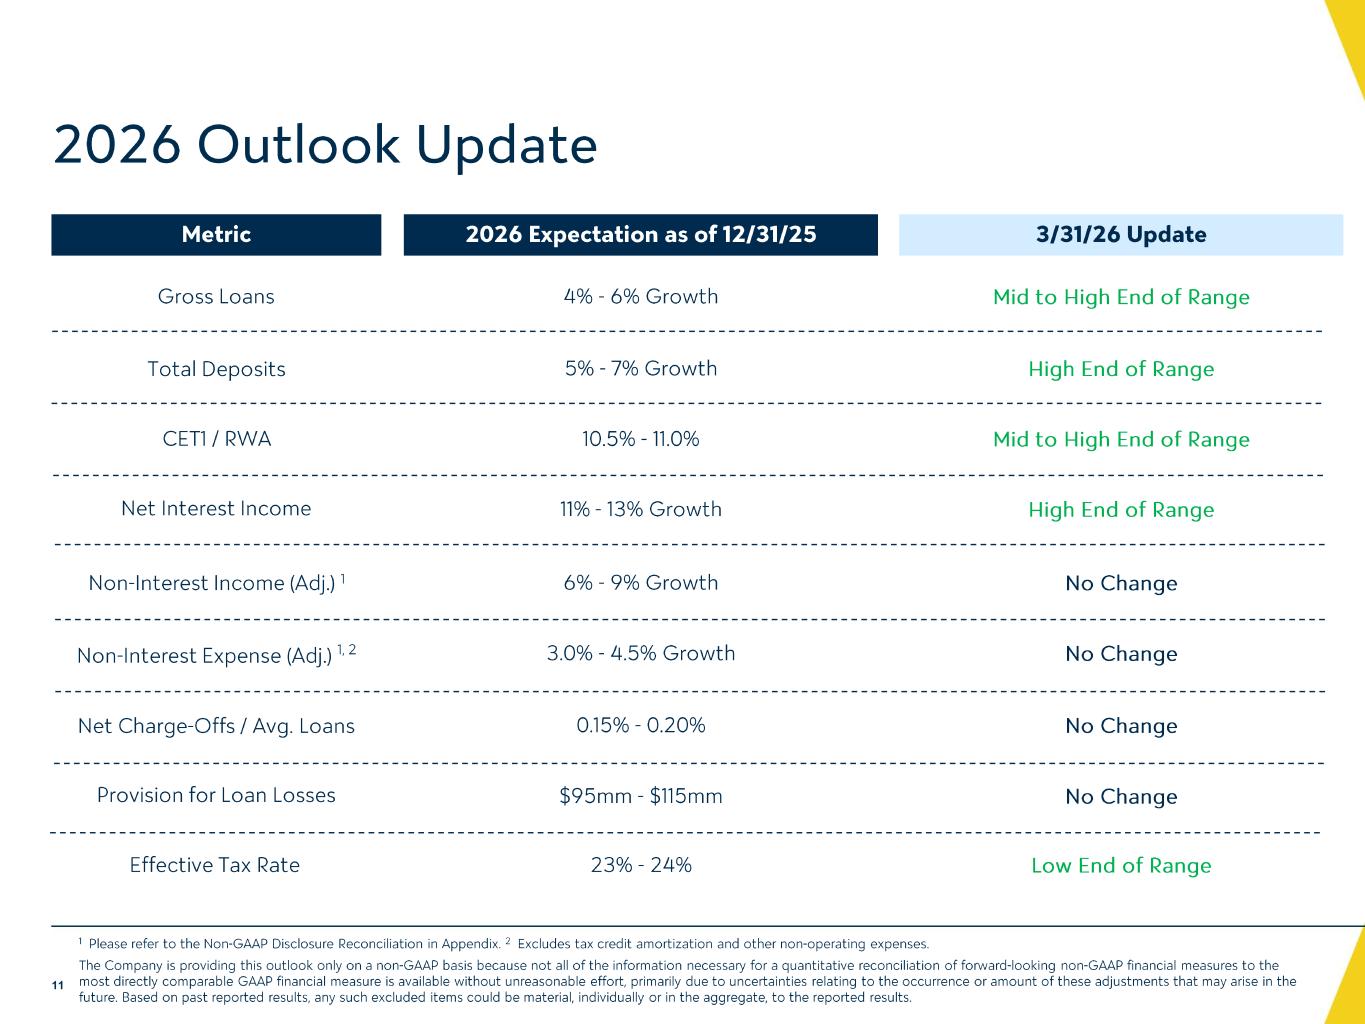
Metric Gross Loans 2026 Outlook Update 1 Please refer to the Non -GAAP Disclosure Reconciliation in Appendix. 2 Excludes tax credit amortization and other non -operating expenses. The Company is providing this outlook only on a non -GAAP basis because not all of the information necessary for a quantitative reconciliation of forward -looking non -GAAP financial measures to the most directly comparable GAAP financial measure is available without unreasonable effort, primarily due to uncertainties rela ting to the occurrence or amount of these adjustments that may arise in the future. Based on past reported results, any such excluded items could be material, individually or in the aggregate, to the r epo rted results. 11 Total Deposits CET1 / RWA Net Interest Income Non -Interest Income (Adj.) 1 Non -Interest Expense (Adj.) 1, 2 Net Charge -Offs / Avg. Loans Provision for Loan Losses Effective Tax Rate 2026 Expectation as of 12/31/25 4% - 6% Growth 5% - 7% Growth 10.5% - 11.0% 11% - 13% Growth 6% - 9% Growth 3.0% - 4.5% Growth 0.15% - 0.20% $95mm - $115mm 23% - 24% 3/31/26 Update Mid to High End of Range High End of Range Mid to High End of Range High End of Range No Change No Change No Change No Change Low End of Range
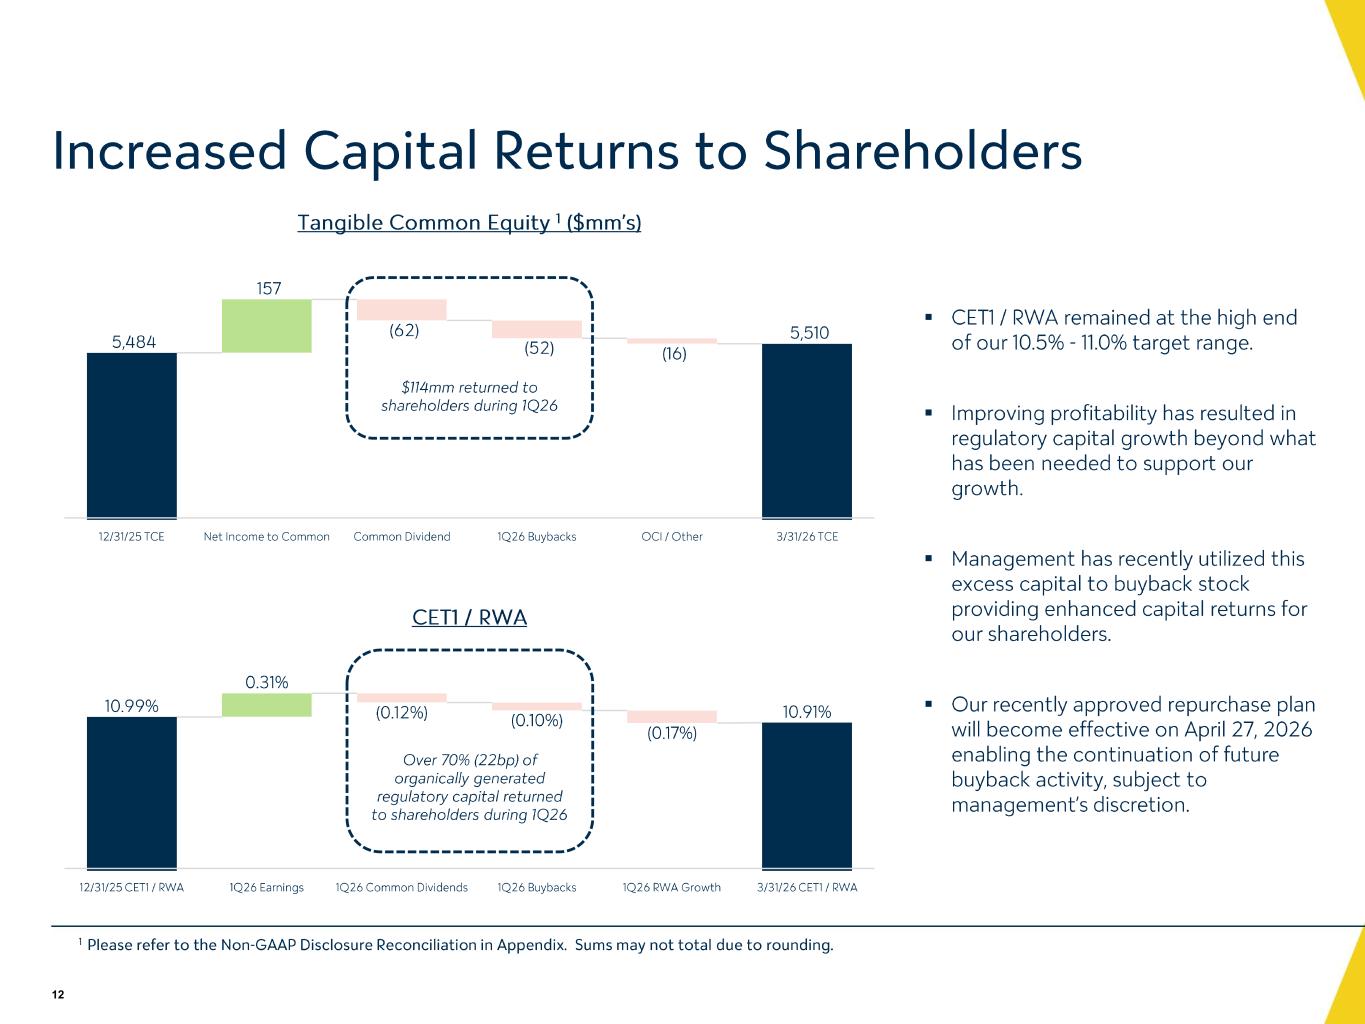
10.99% 0.31% (0.12%) (0.10%) (0.17%) 10.91% 12/31/25 CET1 / RWA 1Q26 Earnings 1Q26 Common Dividends 1Q26 Buybacks 1Q26 RWA Growth 3/31/26 CET1 / RWA CET1 / RWA 5,484 157 (62) (52) (16) 5,510 12/31/25 TCE Net Income to Common Common Dividend 1Q26 Buybacks OCI / Other 3/31/26 TCE Tangible Common Equity 1 ($mm’s) 12 Increased Capital Returns to Shareholders $114mm returned to shareholders during 1Q26 Over 70% (22bp) of organically generated regulatory capital returned to shareholders during 1Q26 ▪ CET1 / RWA remained at the high end of our 10.5% - 11.0% target range. ▪ Improving profitability has resulted in regulatory capital growth beyond what has been needed to support our growth. ▪ Management has recently utilized this excess capital to buyback stock providing enhanced capital returns for our shareholders. ▪ Our recently approved repurchase plan will become effective on April 27, 2026 enabling the continuation of future buyback activity, subject to management’s discretion. 1 Please refer to the Non -GAAP Disclosure Reconciliation in Appendix. Sums may not total due to rounding. Support- 1Q26 TCE Waterfall Support- 1Q26 CET1 Waterfall Support
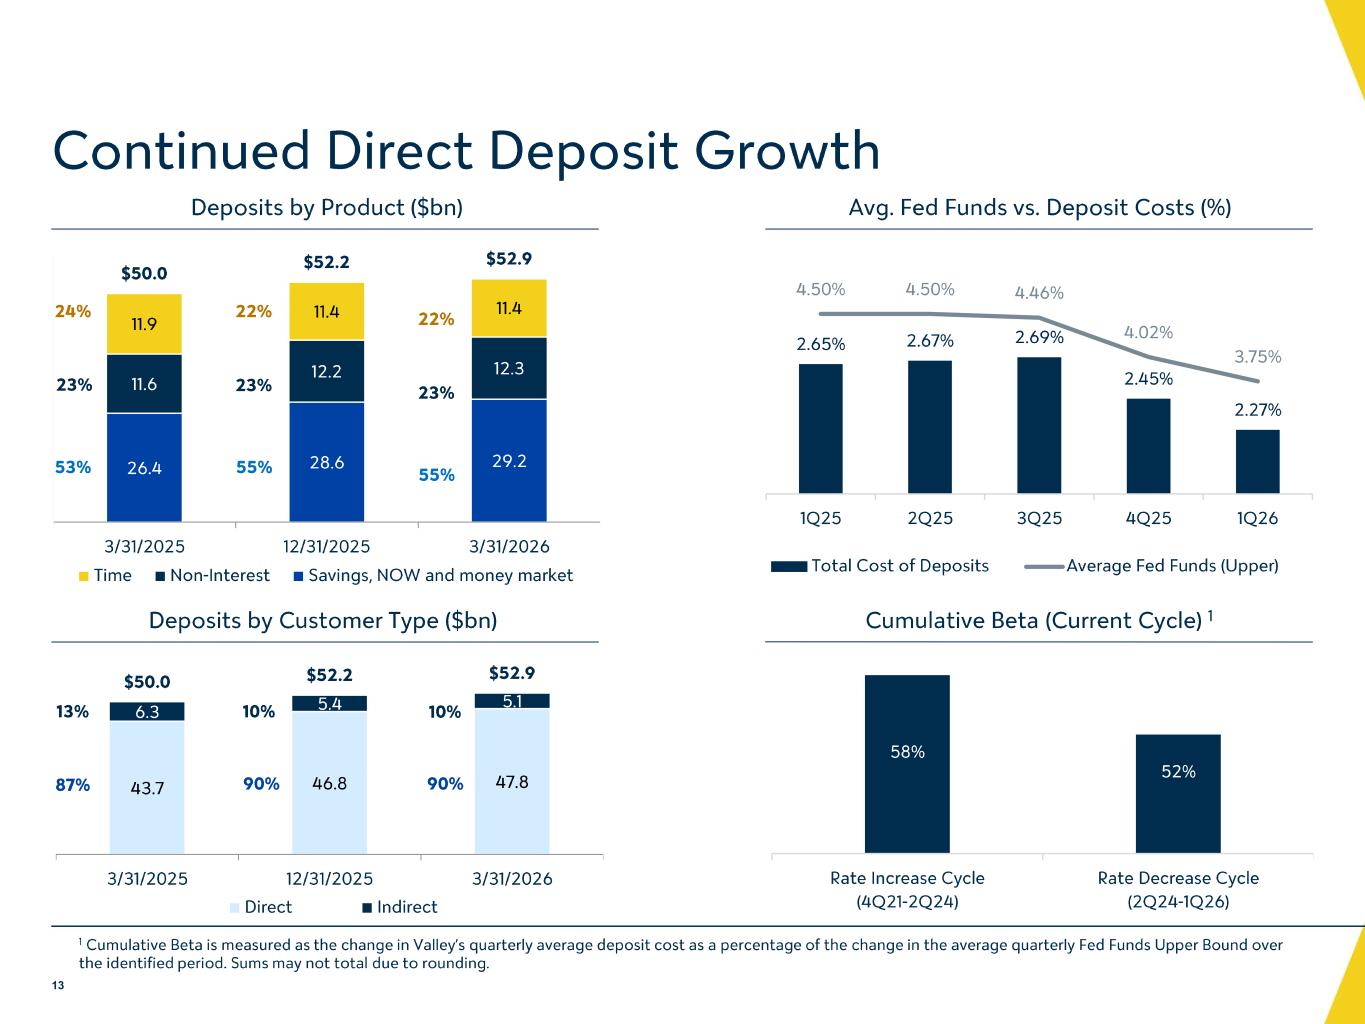
Continued Direct Deposit Growth 26.4 28.6 29.2 11.6 12.2 12.3 11.9 11.4 11.4 $50.0 $52.2 $52.9 3/31/2025 12/31/2025 3/31/2026 Time Non-Interest Savings, NOW and money market 22% 23% 55% 23% 53% 23% 24% 2.65% 2.67% 2.69% 2.45% 2.27% 4.50% 4.50% 4.46% 4.02% 3.75% 1Q25 2Q25 3Q25 4Q25 1Q26 Total Cost of Deposits Average Fed Funds (Upper) Deposits by Product ($bn) 22% 55% Avg. Fed Funds vs. Deposit Costs (%) Cumulative Beta (Current Cycle) 1Deposits by Customer Type ($bn) 1 Cumulative Beta is measured as the change in Valley’s quarterly average deposit cost as a percentage of the change in the ave rage quarterly Fed Funds Upper Bound over the identified period. Sums may not total due to rounding. 13 58% 52% Rate Increase Cycle (4Q21-2Q24) Rate Decrease Cycle (2Q24-1Q26) Source- Earnings Release in Workiva Source- Earnings Release in Workiva Brokered Deposits_1Q26 1Q26 Beta Support Calculation made using data from Workiva Calculation also shown in 1Q26 Beta Support 43.7 46.8 47.8 6.3 5.4 5.1 $50.0 $52.2 $52.9 3/31/2025 12/31/2025 3/31/2026 Direct Indirect 87% 90% 10%13% 90% 10%
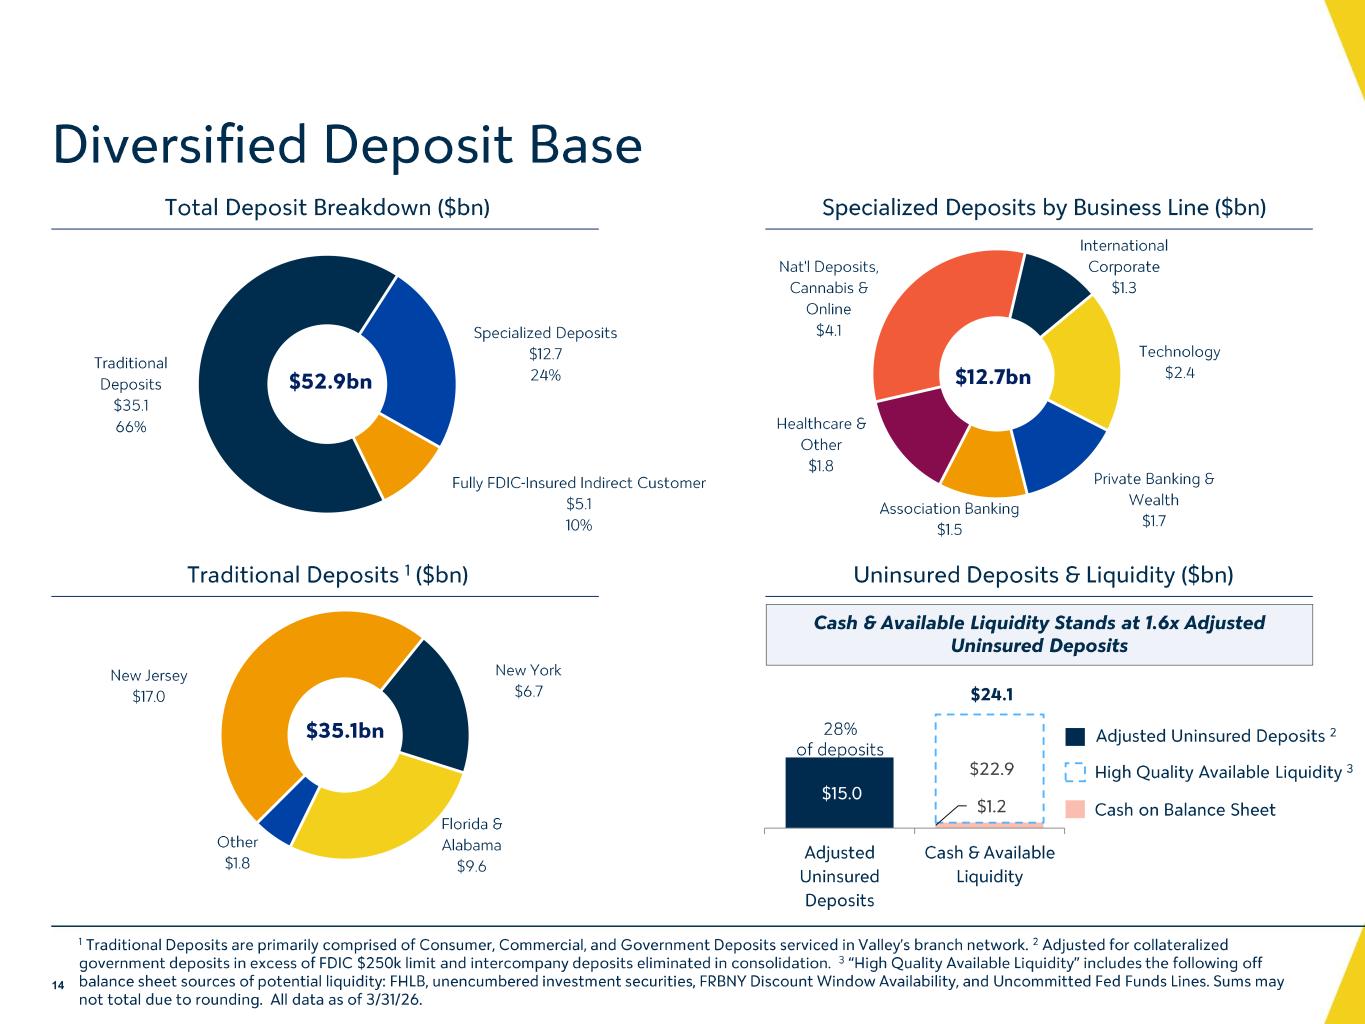
Traditional Deposits $35.1 66% Specialized Deposits $12.7 24% Fully FDIC -Insured Indirect Customer $5.1 10% $52.9bn New Jersey $17.0 New York $6.7 Florida & Alabama $9.6 Other $1.8 $3 5.1bn Total Deposit Breakdown ($bn) Traditional Deposits 1 ($bn) Uninsured Deposits & Liquidity ($bn) $15.0 $1.2 $22.9 $24.1 Adjusted Uninsured Deposits Cash & Available Liquidity Cash on Balance Sheet High Quality Available Liquidity 3 Cash & Available Liquidity Stands at 1.6x Adjusted Uninsured Deposits Adjusted Uninsured Deposits 228% of deposits Nat'l Deposits, Cannabis & Online $4.1 International Corporate $1.3 Technology $2.4 Private Banking & Wealth $1.7 Association Banking $1.5 Healthcare & Other $1.8 $12.7bn Specialized Deposits by Business Line ($bn) 1 Traditional Deposits are primarily comprised of Consumer, Commercial, and Government Deposits serviced in Valley’s branch net wor k. 2 Adjusted for collateralized government deposits in excess of FDIC $250k limit and intercompany deposits eliminated in consolidation . 3 “High Quality Available Liquidity” includes the following off balance sheet sources of potential liquidity: FHLB, unencumbered investment securities, FRBNY Discount Window Availability, a nd Uncommitted Fed Funds Lines. Sums may not total due to rounding. All data as of 3/31/26. 14 Diversified Deposit Base Uninsured data comes from managed funding report, and cash on balance sheet comes from Workiva ER Source- Deposit charts come from SAC
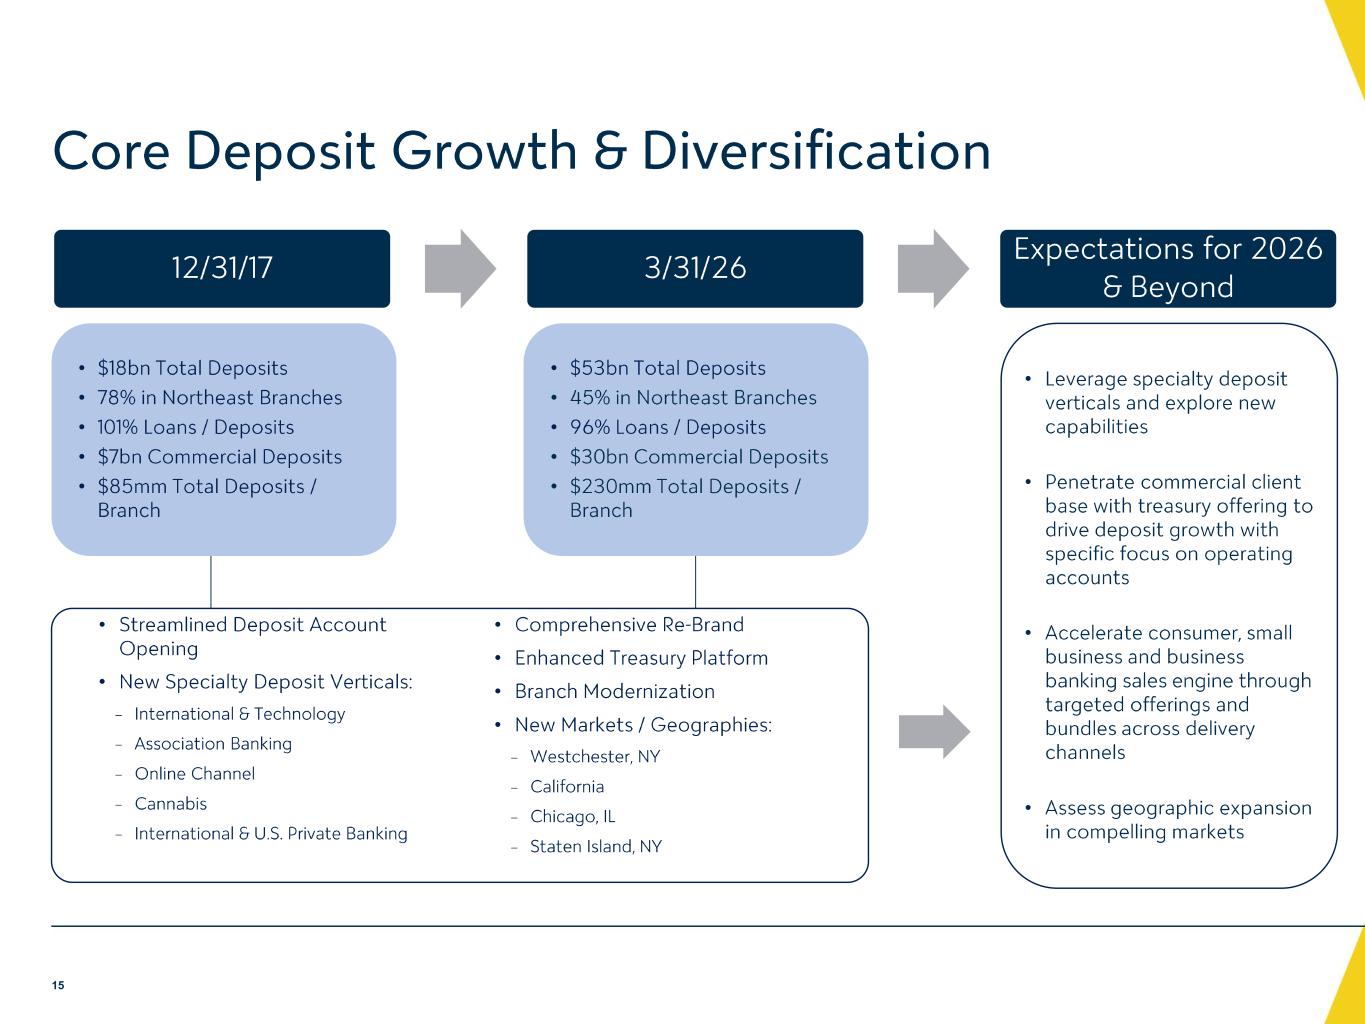
Core Deposit Growth & Diversification 12/31/17 3/31/26 Expectations for 2026 & Beyond • $18bn Total Deposits • 78% in Northeast Branches • 101% Loans / Deposits • $7bn Commercial Deposits • $85mm Total Deposits / Branch • $53bn Total Deposits • 45% in Northeast Branches • 96% Loans / Deposits • $30bn Commercial Deposits • $230mm Total Deposits / Branch • Streamlined Deposit Account Opening • New Specialty Deposit Verticals: − International & Technology − Association Banking − Online Channel − Cannabis − International & U.S. Private Banking • Comprehensive Re -Brand • Enhanced Treasury Platform • Branch Modernization • New Markets / Geographies: − Westchester, NY − California − Chicago, IL − Staten Island, NY • Leverage specialty deposit verticals and explore new capabilities • Penetrate commercial client base with treasury offering to drive deposit growth with specific focus on operating accounts • Accelerate consumer, small business and business banking sales engine through targeted offerings and bundles across delivery channels • Assess geographic expansion in compelling markets 15
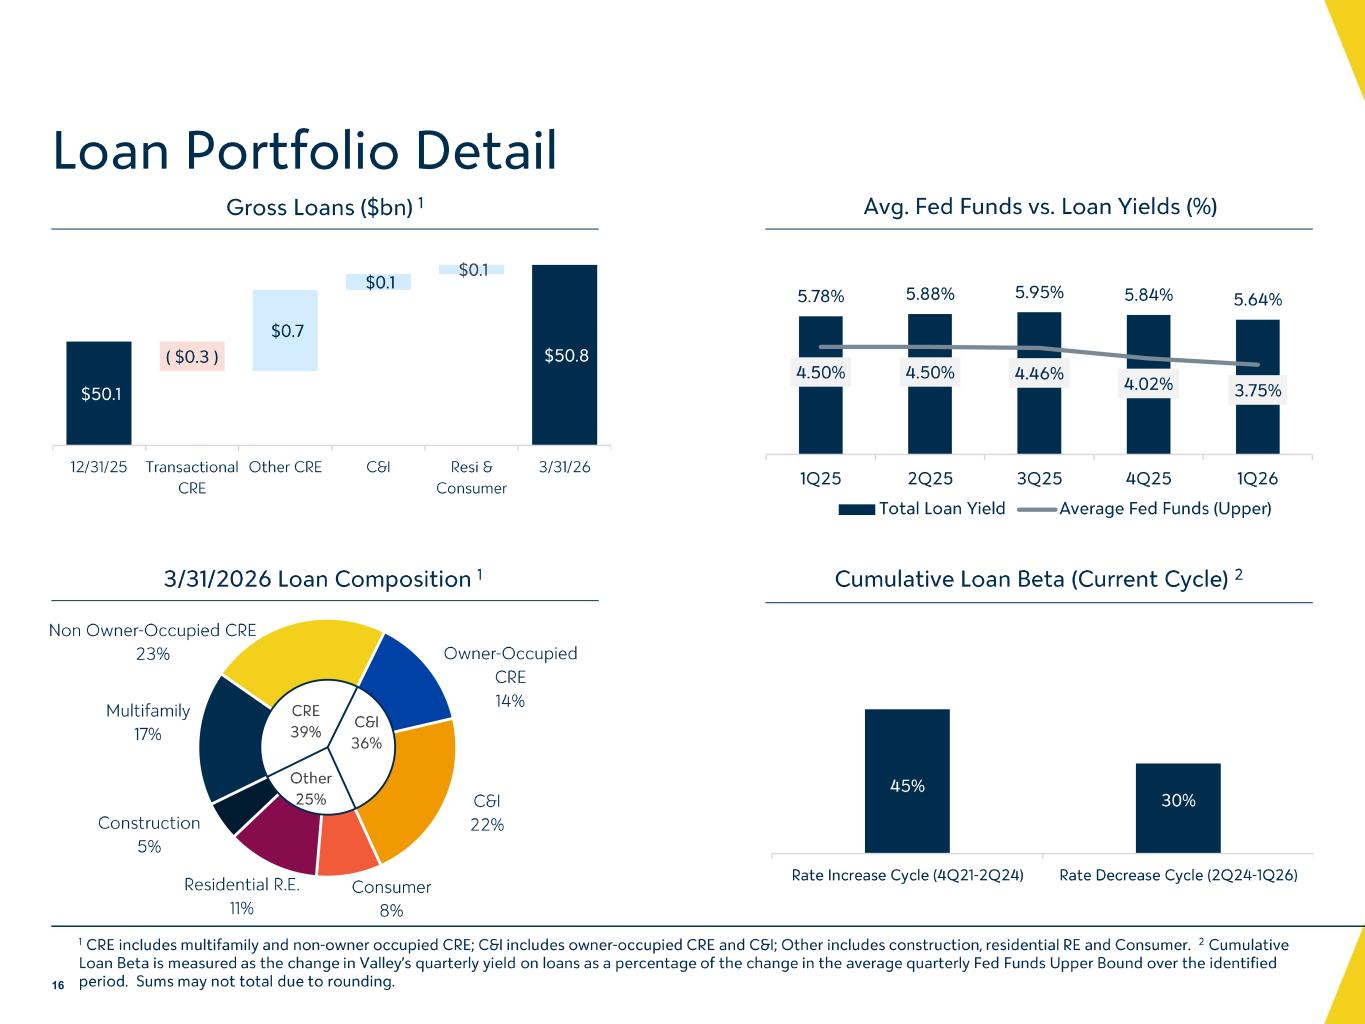
Multifamily 17% Non Owner -Occupied CRE 23% Owner -Occupied CRE 14% C&I 22% Consumer 8% Residential R.E. 11% Construction 5% CRE 39% C&I 36% Other 25% 3/31/2026 Loan Composition 1 Loan Portfolio Detail Gross Loans ($bn) 1 Avg. Fed Funds vs. Loan Yields (%) Cumulative Loan Beta (Current Cycle) 2 Avg. Fed Funds (Upper) Avg. Loan Yield Cumulative Beta 4Q21 0.25% 3.83% -- 4Q22 3.82% 5.20% 38% 4Q23 5.50% 6.10% 43% 1Q24 5.50% 6.14% 44% 2Q24 5.50% 6.17% 45% 3Q24 5.43% 6.28% 47% 4Q24 1 CRE includes multifamily and non -owner occupied CRE; C&I includes owner -occupied CRE and C&I; Other includes construction, resi dential RE and Consumer. 2 Cumulative Loan Beta is measured as the change in Valley’s quarterly yield on loans as a percentage of the change in the average quarter ly Fed Funds Upper Bound over the identified period . Sums may not total due to rounding.16 $50.1 $50.8 ( $0.3 ) $0.7 $0.1 $0.1 12/31/25 Transactional CRE Other CRE C&I Resi & Consumer 3/31/26 Source- “Loan Balances- 5 Quarter Trend_1Q26_FINAL” 45% 30% Rate Increase Cycle (4Q21-2Q24) Rate Decrease Cycle (2Q24-1Q26) Source- “Loan Balances – 5 Quarter Trend_1Q26_FINAL” Transactional CRE comes from SAC under CenCRE, netted with the increase in CRE as a whole to get to “Other CRE” 5.78% 5.88% 5.95% 5.84% 5.64% 4.50% 4.50% 4.46% 4.02% 3.75% 1Q25 2Q25 3Q25 4Q25 1Q26 Total Loan Yield Average Fed Funds (Upper) Workiva- loan yield Calculation for avg fed funds upper 1Q26 Beta Support
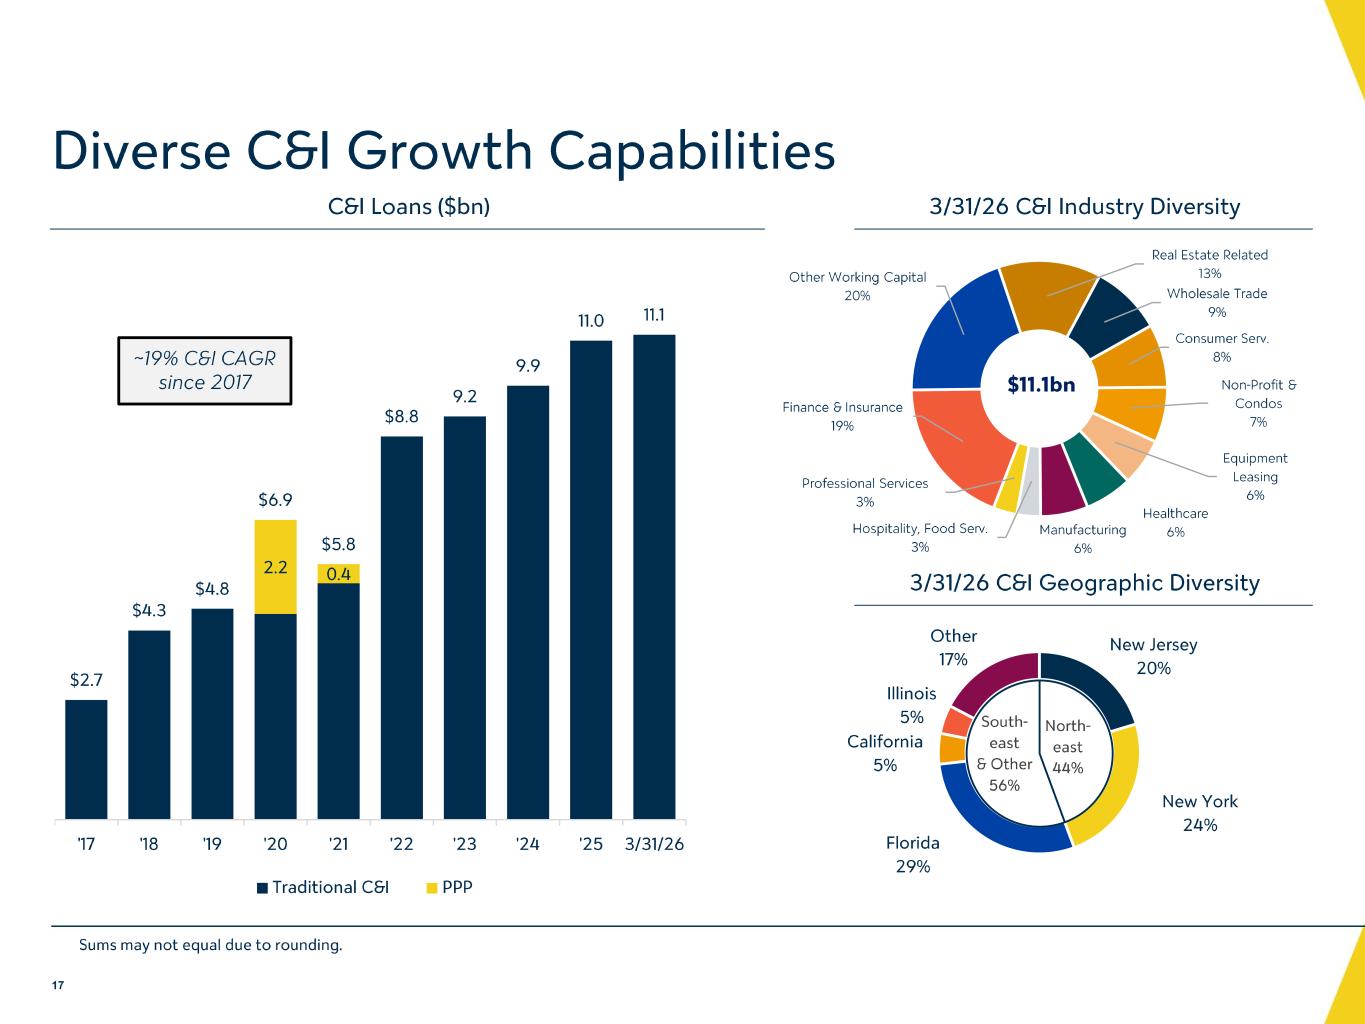
New Jersey 20% New York 24% Florida 29% California 5% Illinois 5% Other 17% North - east 44% South - east & Other 56% Diverse C&I Growth Capabilities 2.2 0.4 $2.7 $4.3 $4.8 $6.9 $5.8 $8.8 9.2 9.9 11.0 11.1 '17 '18 '19 '20 '21 '22 '23 '24 '25 3/31/26 Traditional C&I PPP ~19% C&I CAGR since 2017 Source- “Loan Balances- 5 Quarter Trend_1Q26_FINAL” Source- “Summary_HC” 17 3/31/26 C&I Industry Diversity 3/31/26 C&I Geographic Diversity C&I Loans ($bn) Finance & Insurance 19% Other Working Capital 20% Real Estate Related 13% Wholesale Trade 9% Consumer Serv. 8% Non -Profit & Condos 7% Equipment Leasing 6% Healthcare 6%Manufacturing 6% Hospitality, Food Serv. 3% Professional Services 3% $11.1bn Source- “Commercial Portfolio by Industry- 3.31.26” Sums may not equal due to rounding.
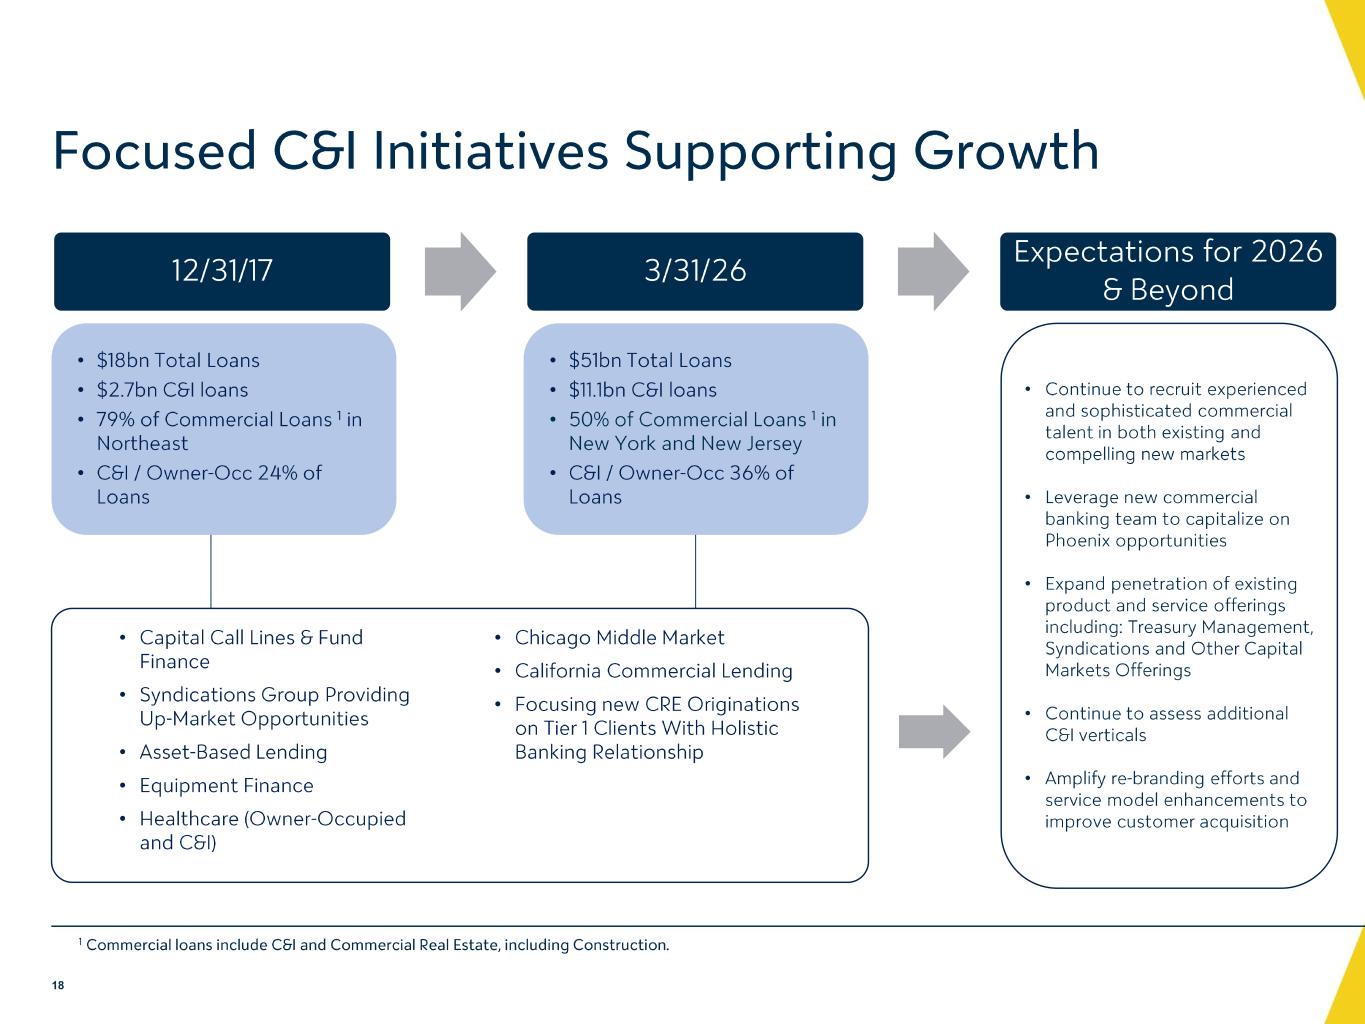
• $18bn Total Loans • $2.7bn C&I loans • 79% of Commercial Loans 1 in Northeast • C&I / Owner -Occ 24% of Loans • $51bn Total Loans • $11.1bn C&I loans • 50% of Commercial Loans 1 in New York and New Jersey • C&I / Owner -Occ 36% of Loans Focused C&I Initiatives Supporting Growth • Capital Call Lines & Fund Finance • Syndications Group Providing Up -Market Opportunities • Asset -Based Lending • Equipment Finance • Healthcare (Owner -Occupied and C&I) • Chicago Middle Market • California Commercial Lending • Focusing new CRE Originations on Tier 1 Clients With Holistic Banking Relationship 12/31/17 3/31/26 Expectations for 2026 & Beyond • Continue to recruit experienced and sophisticated commercial talent in both existing and compelling new markets • Leverage new commercial banking team to capitalize on Phoenix opportunities • Expand penetration of existing product and service offerings including: Treasury Management, Syndications and Other Capital Markets Offerings • Continue to assess additional C&I verticals • Amplify re -branding efforts and service model enhancements to improve customer acquisition 18 1 Commercial loans include C&I and Commercial Real Estate, including Construction.
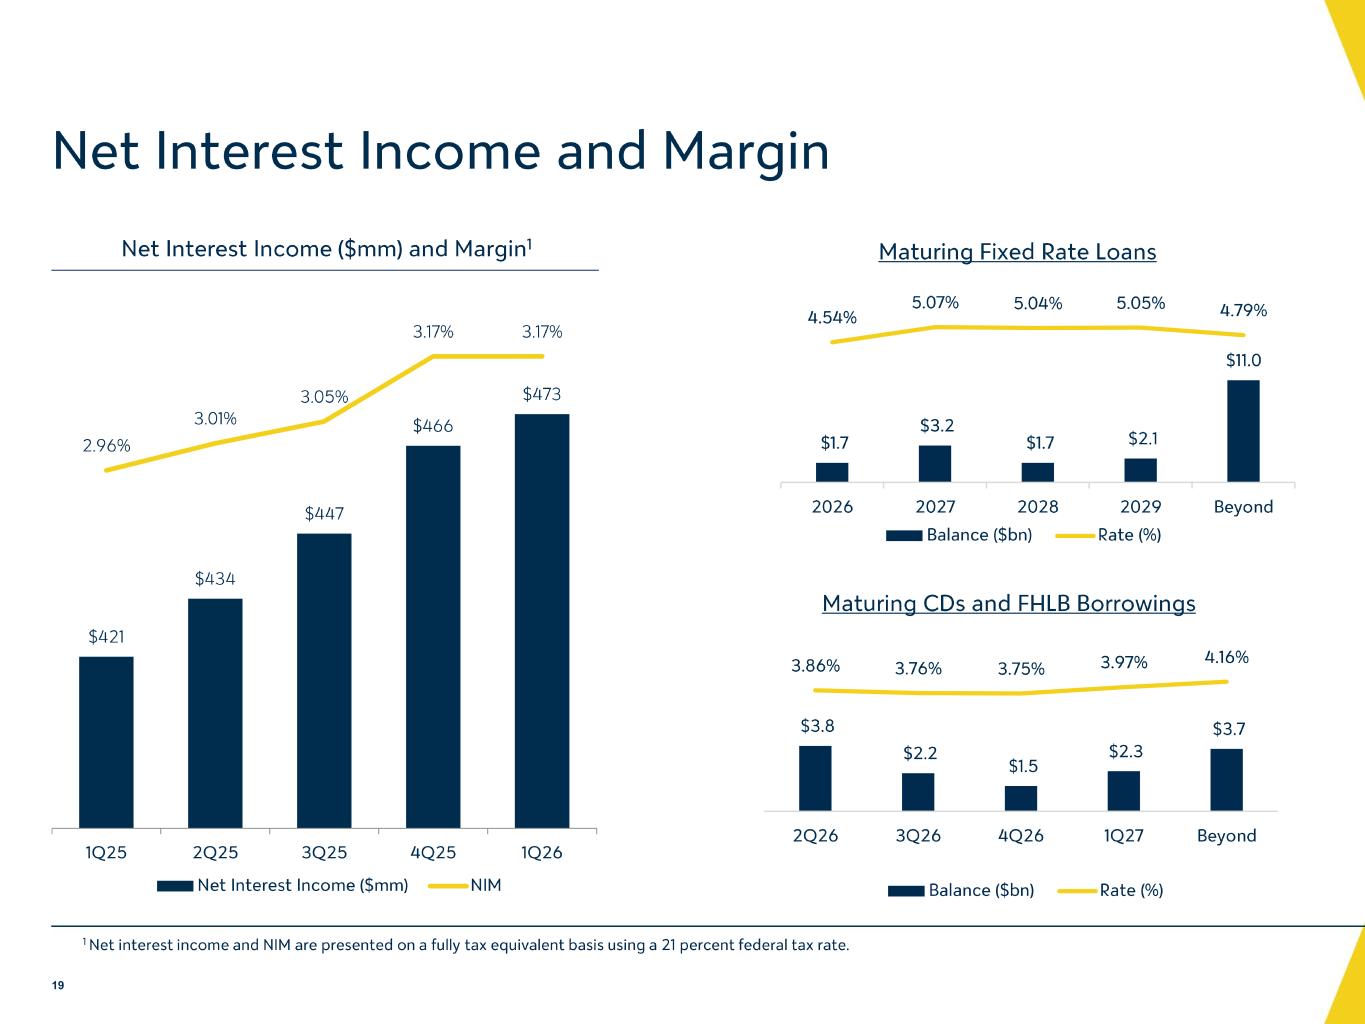
Net Interest Income ($mm) and Margin 1 $421 $434 $447 $466 $473 2.96% 3.01% 3.05% 3.17% 3.17% 1Q25 2Q25 3Q25 4Q25 1Q26 Net Interest Income ($mm) NIM $3.8 $2.2 $1.5 $2.3 $3.7 3.86% 3.76% 3.75% 3.97% 4.16% 2Q26 3Q26 4Q26 1Q27 Beyond Maturing CDs and FHLB Borrowings Balance ($bn) Rate (%) Net Interest Income and Margin 1 Net interest income and NIM are presented on a fully tax equivalent basis using a 21 percent federal tax rate. 19 Workiva Source- “ALCO Report Packet_0331_EMP_CDs Runoff” $1.7 $3.2 $1.7 $2.1 $11.0 4.54% 5.07% 5.04% 5.05% 4.79% 2026 2027 2028 2029 Beyond Maturing Fixed Rate Loans Balance ($bn) Rate (%) Note – “Beyond” $11.0bn is accurate. The supporting excel has a lower number to make the chart more reasonable.
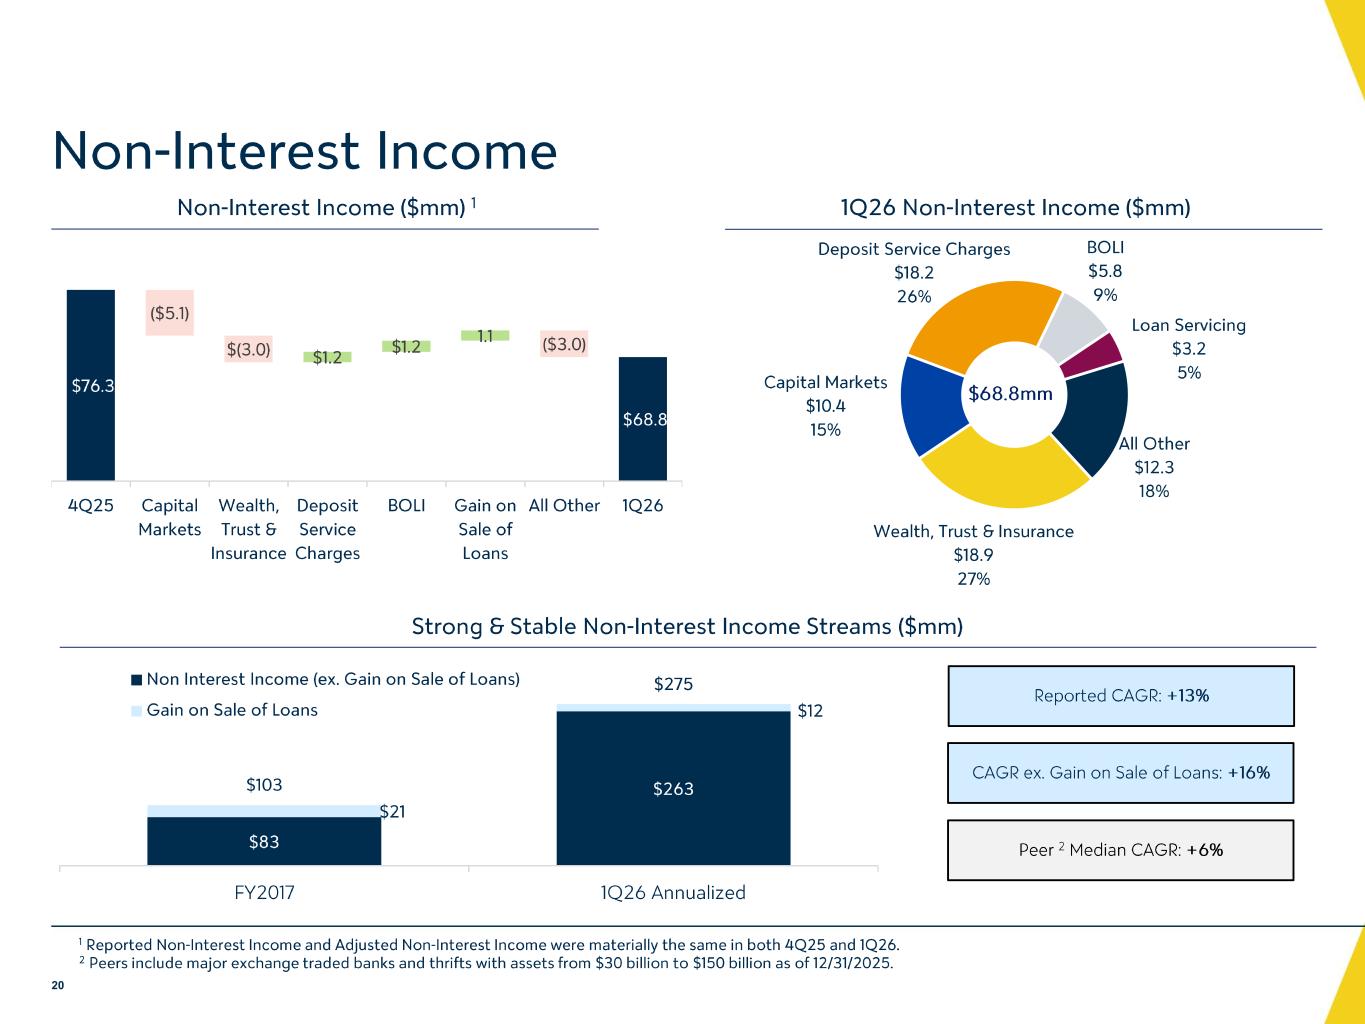
All Other $12.3 18% Wealth, Trust & Insurance $18.9 27% Capital Markets $10.4 15% Deposit Service Charges $18.2 26% BOLI $5.8 9% Loan Servicing $3.2 5% $68.8 mm Non -Interest Income 20 Strong & Stable Non -Interest Income Streams ($mm) $76.3 $68.8 ($5.1) $(3.0 ) $1.2 $1.2 1.1 ($3.0 ) 4Q25 Capital Markets Wealth, Trust & Insurance Deposit Service Charges BOLI Gain on Sale of Loans All Other 1Q26 Workiva Workiva 1Q26 Non -Interest Income ($mm) $83 $263 $21 $12 $103 $275 FY2017 1Q26 Annualized Non Interest Income (ex. Gain on Sale of Loans) Gain on Sale of Loans CAGR ex. Gain on Sale of Loans: +16% 1 Reported Non -Interest Income and Adjusted Non -Interest Income were materially the same in both 4Q25 and 1Q26. 2 Peers include major exchange traded banks and thrifts with assets from $30 billion to $150 billion as of 12/31/2025. “Fee Income CAGR Support” Reported CAGR: +13% Peer 2 Median CAGR: +6% Non -Interest Income ($mm) 1 Non -Interest Income ($ mm) 1
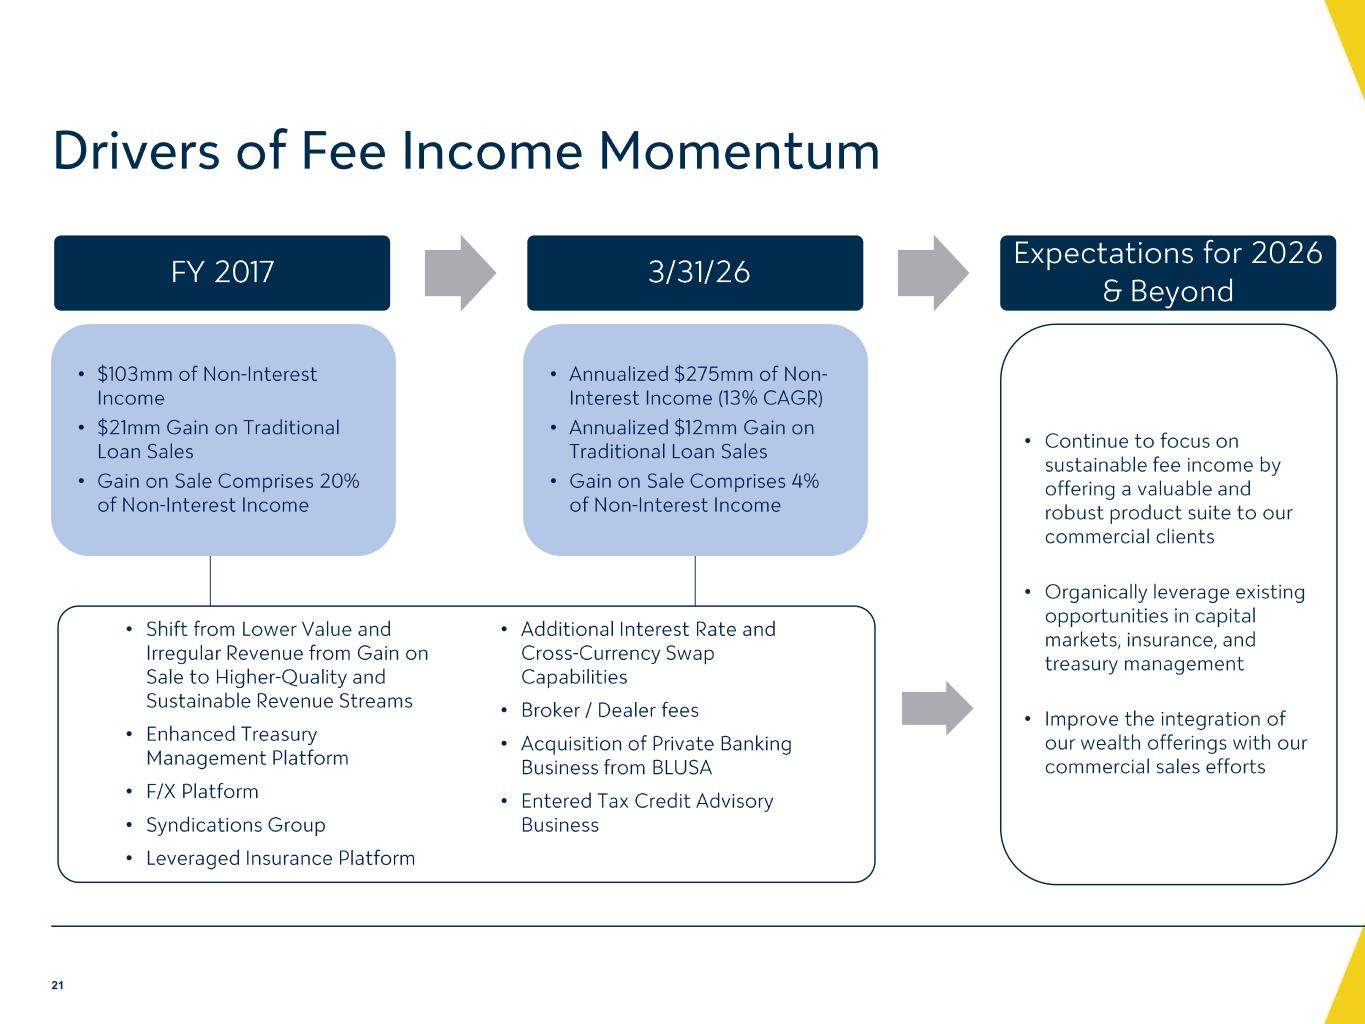
Drivers of Fee Income Momentum 21 Workiva Workiva • Continue to focus on sustainable fee income by offering a valuable and robust product suite to our commercial clients • Organically leverage existing opportunities in capital markets, insurance, and treasury management • Improve the integration of our wealth offerings with our commercial sales efforts FY 2017 3/31/26 Expectations for 2026 & Beyond • Shift from Lower Value and Irregular Revenue from Gain on Sale to Higher -Quality and Sustainable Revenue Streams • Enhanced Treasury Management Platform • F/X Platform • Syndications Group • Leveraged Insurance Platform • Additional Interest Rate and Cross -Currency Swap Capabilities • Broker / Dealer fees • Acquisition of Private Banking Business from BLUSA • Entered Tax Credit Advisory Business • Annualized $275mm of Non - Interest Income (13% CAGR) • Annualized $12mm Gain on Traditional Loan Sales • Gain on Sale Comprises 4% of Non -Interest Income • $103mm of Non -Interest Income • $21mm Gain on Traditional Loan Sales • Gain on Sale Comprises 20% of Non -Interest Income
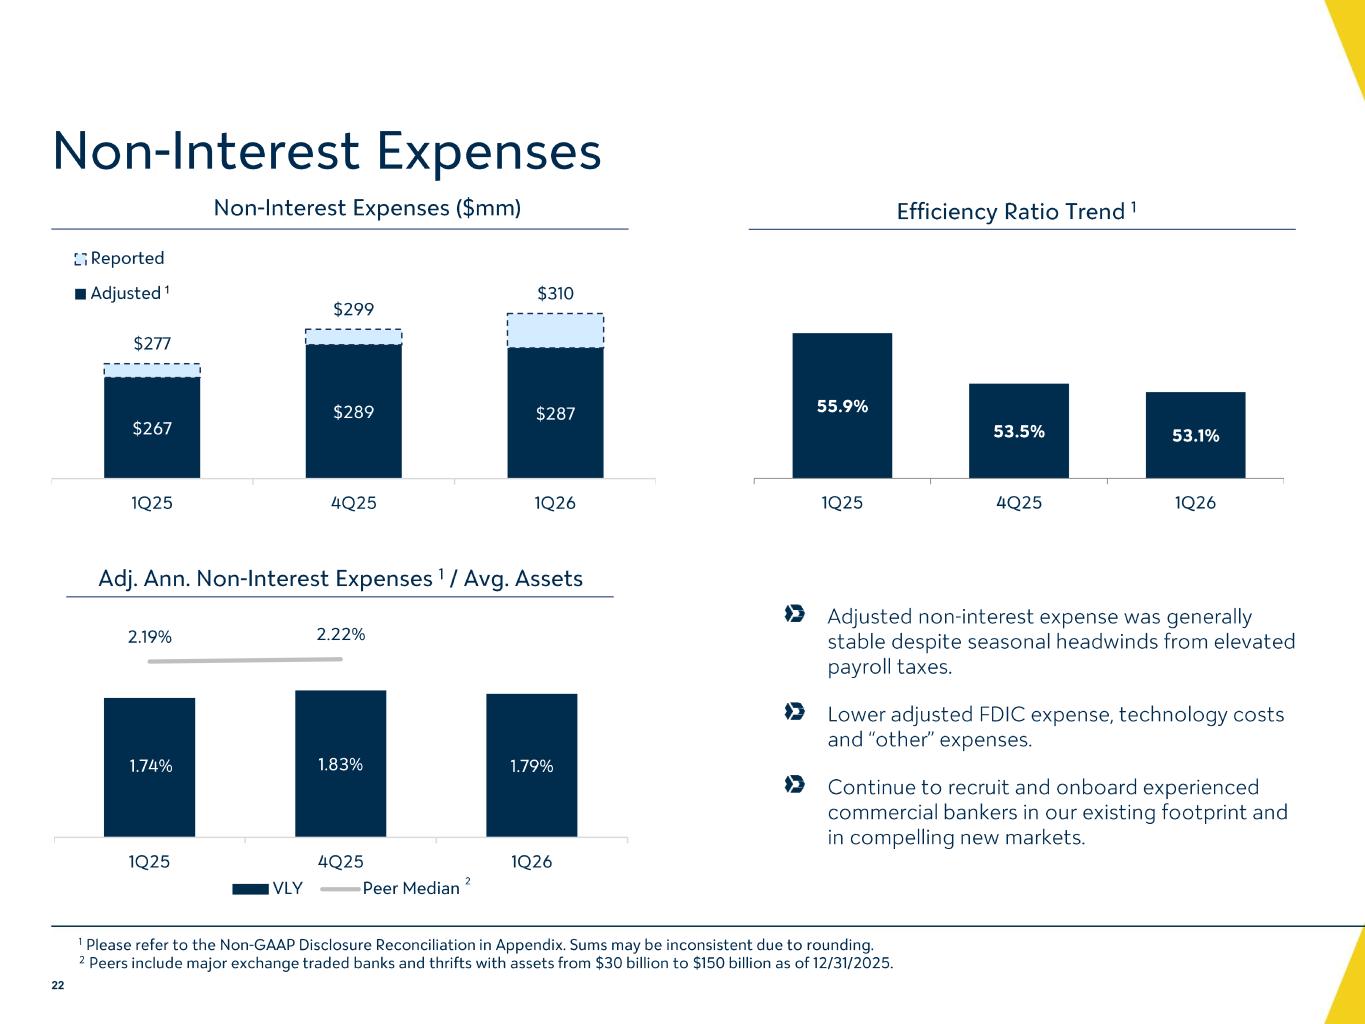
$267 $289 $287 $277 $299 $310 1Q25 4Q25 1Q26 Reported Adjusted Non -Interest Expenses ($mm) Adjusted non -interest expense was generally stable despite seasonal headwinds from elevated payroll taxes. Lower adjusted FDIC expense, technology costs and “other” expenses. Continue to recruit and onboard experienced commercial bankers in our existing footprint and in compelling new markets. Non -Interest Expenses 1 Please refer to the Non -GAAP Disclosure Reconciliation in Appendix. Sums may be inconsistent due to rounding. 2 Peers include major exchange traded banks and thrifts with assets from $30 billion to $150 billion as of 12/31/2025. 22 Workiva Workiva Workiva 1 1.74% 1.83% 1.79% 2.19% 2.22% 1Q25 4Q25 1Q26 VLY Peer Median Adj. Ann. Non -Interest Expenses 1 / Avg. Assets Efficiency Ratio Trend 1 55.9% 53.5% 53.1% 1Q25 4Q25 1Q26 2
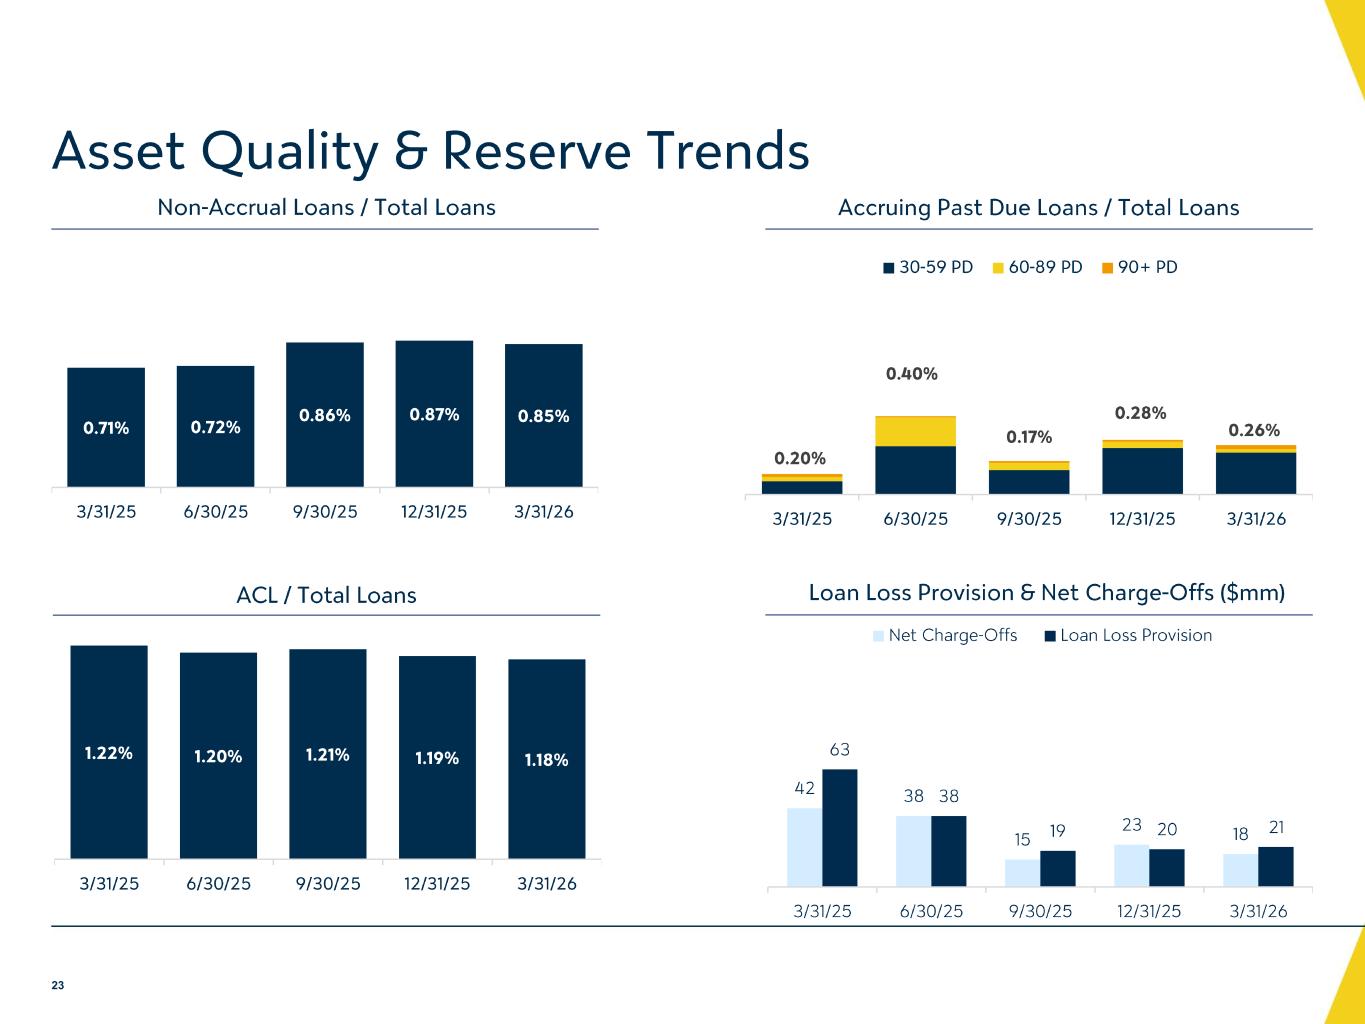
Non -Accrual Loans / Total Loans 0.99 % 1.03 % Accruing Past Due Loans / Total Loans Asset Quality & Reserve Trends 23 ACL / Total Loans 0.71% 0.72% 0.86% 0.87% 0.85% 3/31/25 6/30/25 9/30/25 12/31/25 3/31/26 0.20% 0.40% 0.17% 0.28% 0.26% 3/31/25 6/30/25 9/30/25 12/31/25 3/31/26 30-59 PD 60-89 PD 90+ PD 1.22% 1.20% 1.21% 1.19% 1.18% 3/31/25 6/30/25 9/30/25 12/31/25 3/31/26 42 38 15 23 18 63 38 19 20 21 3/31/25 6/30/25 9/30/25 12/31/25 3/31/26 Net Charge-Offs Loan Loss Provision Loan Loss Provision & Net Charge -Offs ($mm) Workiva Workiva Workiva / KEITH Chargeoff's and Recoveries - 5 Quarter Trend_Draft_1Q26_Final Workiva / KEITH 5-Quarter Trend (1Q26)_Final
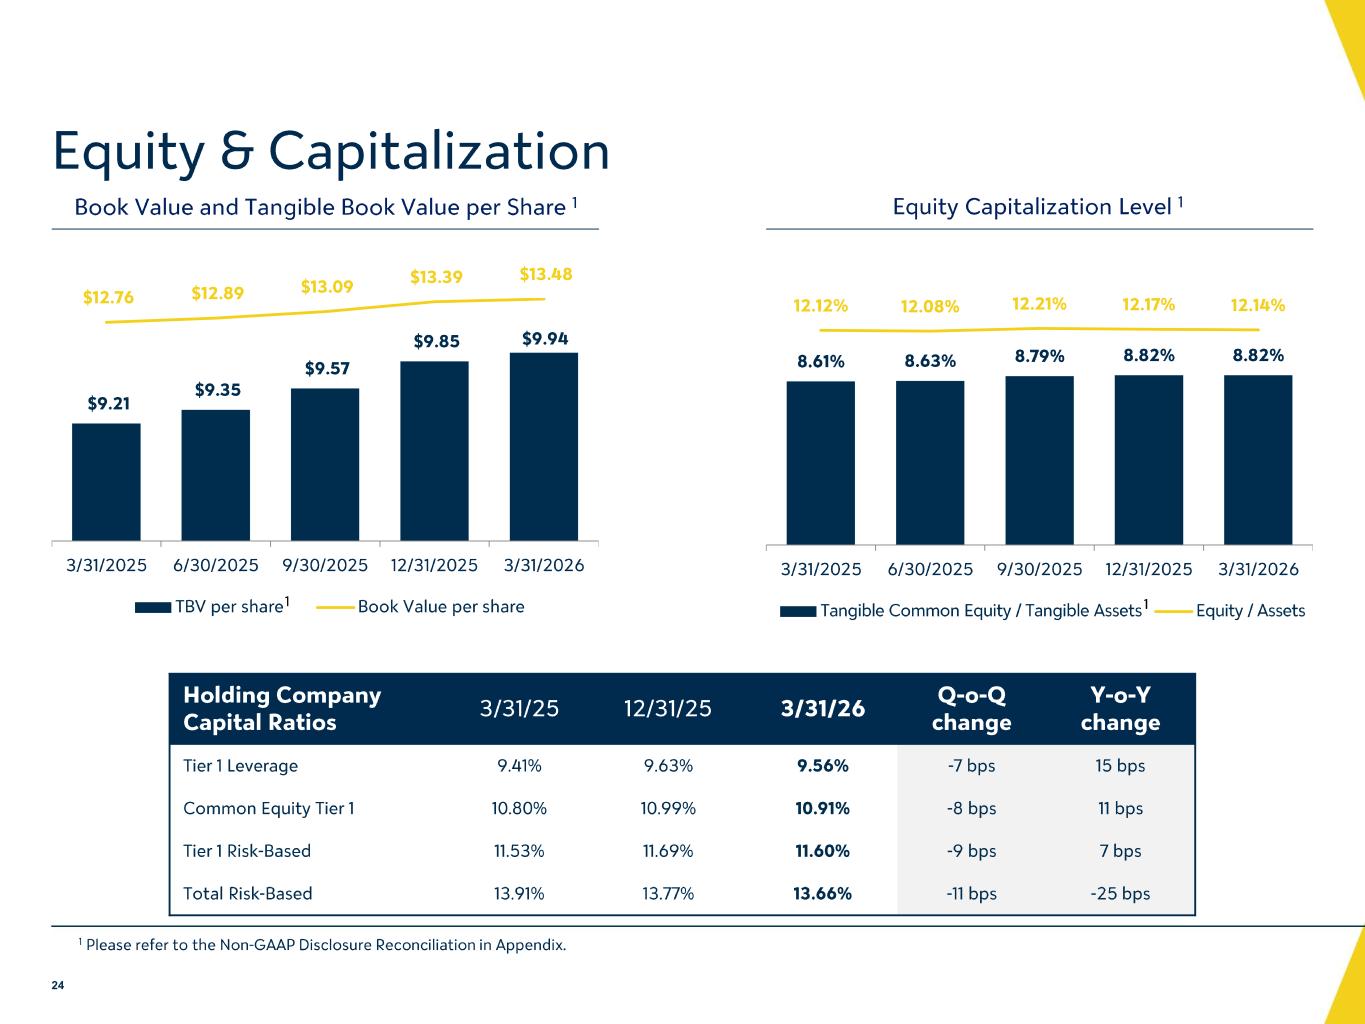
$9.21 $9.35 $9.57 $9.85 $9.94 $12.76 $12.89 $13.09 $13.39 $13.48 3/31/2025 6/30/2025 9/30/2025 12/31/2025 3/31/2026 TBV per share Book Value per share Book Value and Tangible Book Value per Share 1 Equity Capitalization Level 1 8.61% 8.63% 8.79% 8.82% 8.82% 12.12% 12.08% 12.21% 12.17% 12.14% 3/31/2025 6/30/2025 9/30/2025 12/31/2025 3/31/2026 Tangible Common Equity / Tangible Assets Equity / Assets Holding Company Capital Ratios 3/31/25 12/31/25 3/31/26 Q -o-Q change Y -o-Y change Tier 1 Leverage 9.41% 9.63% 9.56% -7 bps 15 bps Common Equity Tier 1 10.80% 10.99% 10.91% -8 bps 11 bps Tier 1 Risk -Based 11.53% 11.69% 11.60% -9 bps 7 bps Total Risk -Based 13.91% 13.77% 13.66% -11 bps -25 bps 1 Equity & Capitalization 1 Please refer to the Non -GAAP Disclosure Reconciliation in Appendix. 24 Workiva Workiva Workiva 1
APPENDIX
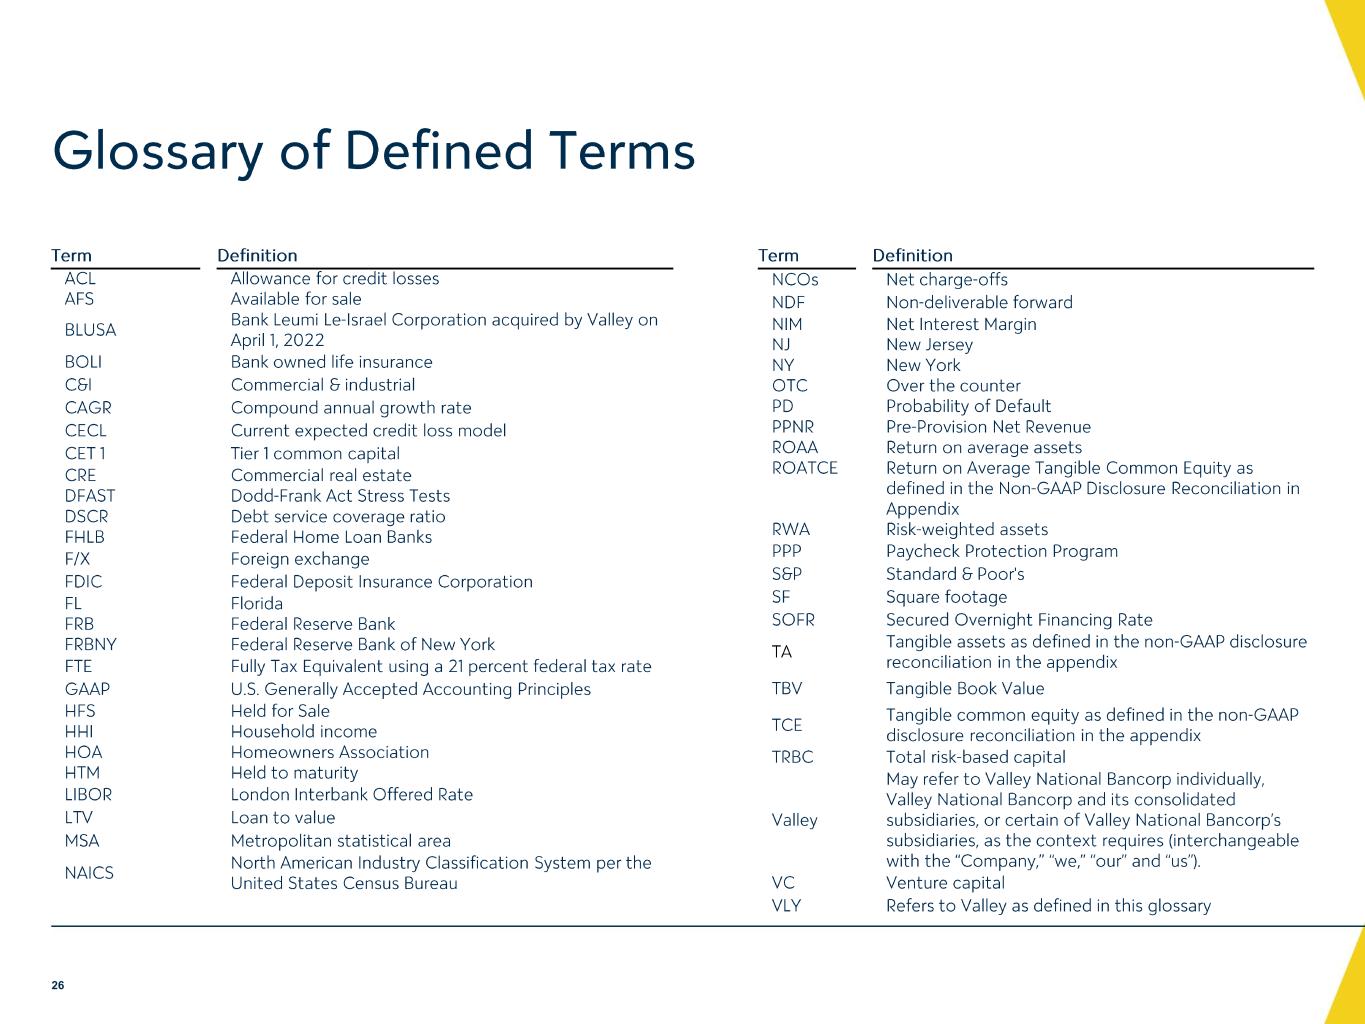
Term Definition ACL AFS Allowance for credit losses Available for sale BLUSA Bank Leumi Le -Israel Corporation acquired by Valley on April 1, 2022 BOLI Bank owned life insurance C&I Commercial & industrial CAGR Compound annual growth rate CECL Current expected credit loss model CET 1 Tier 1 common capital CRE DFAST Commercial real estate Dodd -Frank Act Stress Tests DSCR FHLB Debt service coverage ratio Federal Home Loan Banks F/X Foreign exchange FDIC Federal Deposit Insurance Corporation FL FRB FRBNY Florida Federal Reserve Bank Federal Reserve Bank of New York FTE Fully Tax Equivalent using a 21 percent federal tax rate GAAP U.S. Generally Accepted Accounting Principles HFS HHI Held for Sale Household income HOA HTM Homeowners Association Held to maturity LIBOR London Interbank Offered Rate LTV Loan to value MSA Metropolitan statistical area NAICS North American Industry Classification System per the United States Census Bureau Term Definition NCOs Net charge -offs NDF Non -deliverable forward NIM NJ NY OTC PD Net Interest Margin New Jersey New York Over the counter Probability of Default PPNR ROAA ROATCE RWA Pre -Provision Net Revenue Return on average assets Return on Average Tangible Common Equity as defined in the Non -GAAP Disclosure Reconciliation in Appendix Risk -weighted assets PPP Paycheck Protection Program S&P Standard & Poor's SF Square footage SOFR Secured Overnight Financing Rate TA Tangible assets as defined in the non -GAAP disclosure reconciliation in the appendix TBV Tangible Book Value TCE Tangible common equity as defined in the non -GAAP disclosure reconciliation in the appendix TRBC Total risk -based capital Valley May refer to Valley National Bancorp individually, Valley National Bancorp and its consolidated subsidiaries, or certain of Valley National Bancorp’s subsidiaries, as the context requires (interchangeable with the “Company,” “we,” “our” and “us”). VC Venture capital VLY Refers to Valley as defined in this glossary Glossary of Defined Terms 26
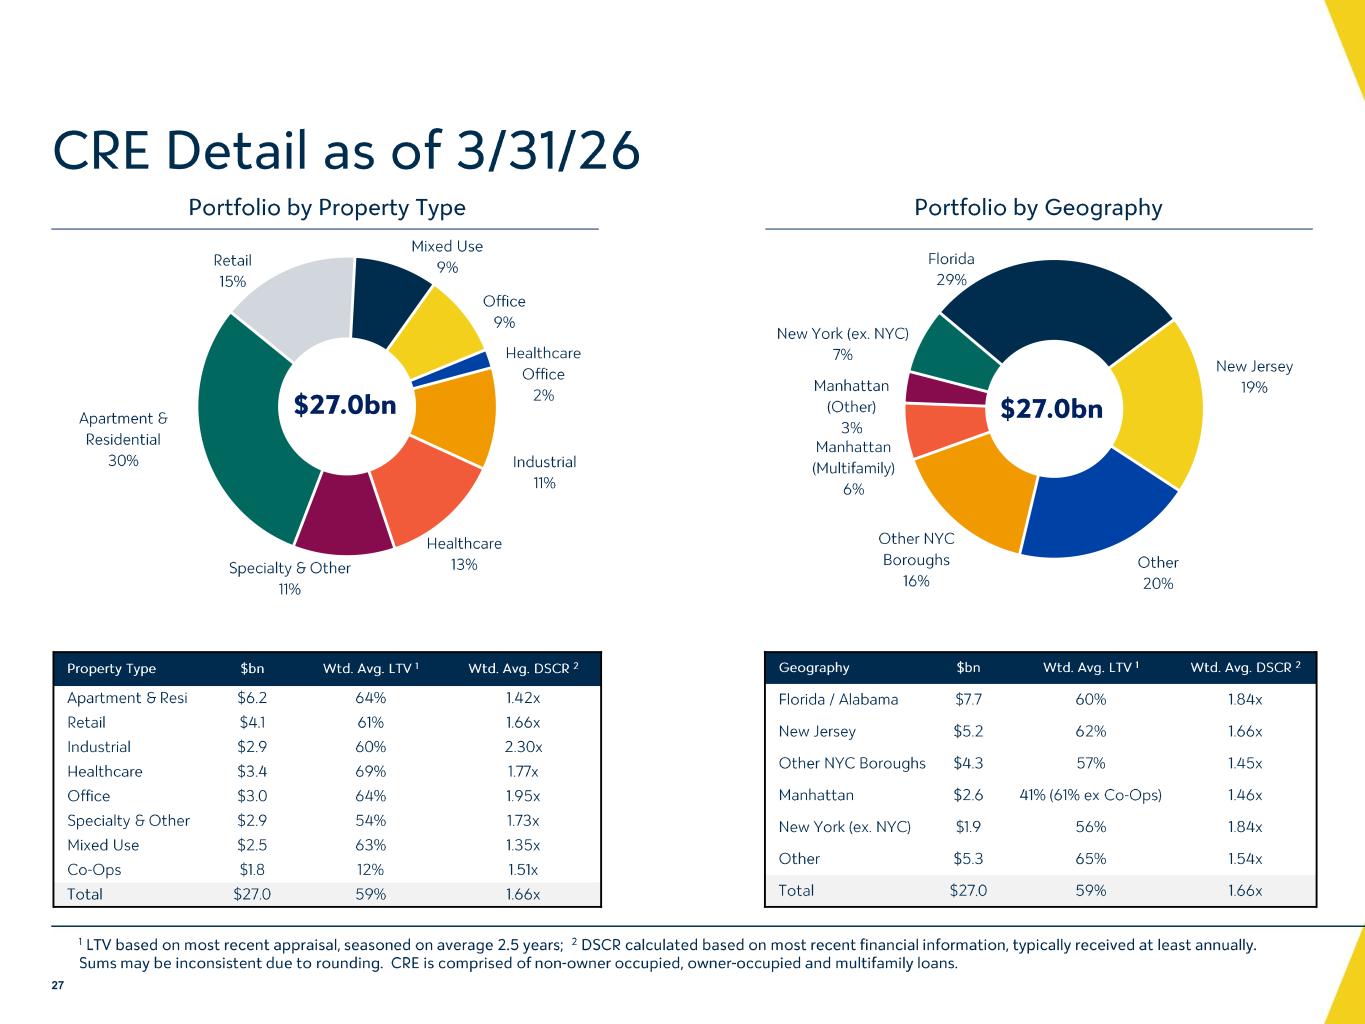
Apartment & Residential 30% Retail 15% Mixed Use 9% Office 9% Healthcare Office 2% Industrial 11% Healthcare 13%Specialty & Other 11% CRE Detail as of 3/31/26 Portfolio by Property Type Portfolio by Geography Florida 29% New Jersey 19% Other 20% Other NYC Boroughs 16% Manhattan (Multifamily) 6% Manhattan (Other) 3% New York (ex. NYC) 7% Geography $bn Wtd . Avg. LTV 1 Wtd . Avg. DSCR 2 Florida / Alabama $7.7 60% 1.84x New Jersey $5.2 62% 1.66x Other NYC Boroughs $4.3 57% 1.45x Manhattan $2.6 41% (61% ex Co -Ops) 1.46x New York (ex. NYC) $1.9 56% 1.84x Other $5.3 65% 1.54x Total $27.0 59% 1.66x $27.0bn $27.0bn 1 LTV based on most recent appraisal, seasoned on average 2.5 years; 2 DSCR calculated based on most recent financial information, typically received at least annually. Sums may be inconsistent due to rounding. CRE is comprised of non -owner occupied, owner -occupied and multifamily loans. 27 Property Type $bn Wtd . Avg. LTV 1 Wtd . Avg. DSCR 2 Apartment & Resi $6.2 64% 1.42x Retail $4.1 61% 1.66x Industrial $2.9 60% 2.30x Healthcare $3.4 69% 1.77x Office $3.0 64% 1.95x Specialty & Other $2.9 54% 1.73x Mixed Use $2.5 63% 1.35x Co -Ops $1.8 12% 1.51x Total $27.0 59% 1.66x Source- “CRE Portfolio Review 3.31.2026” Co-op info comes directly from Joel Souza via email
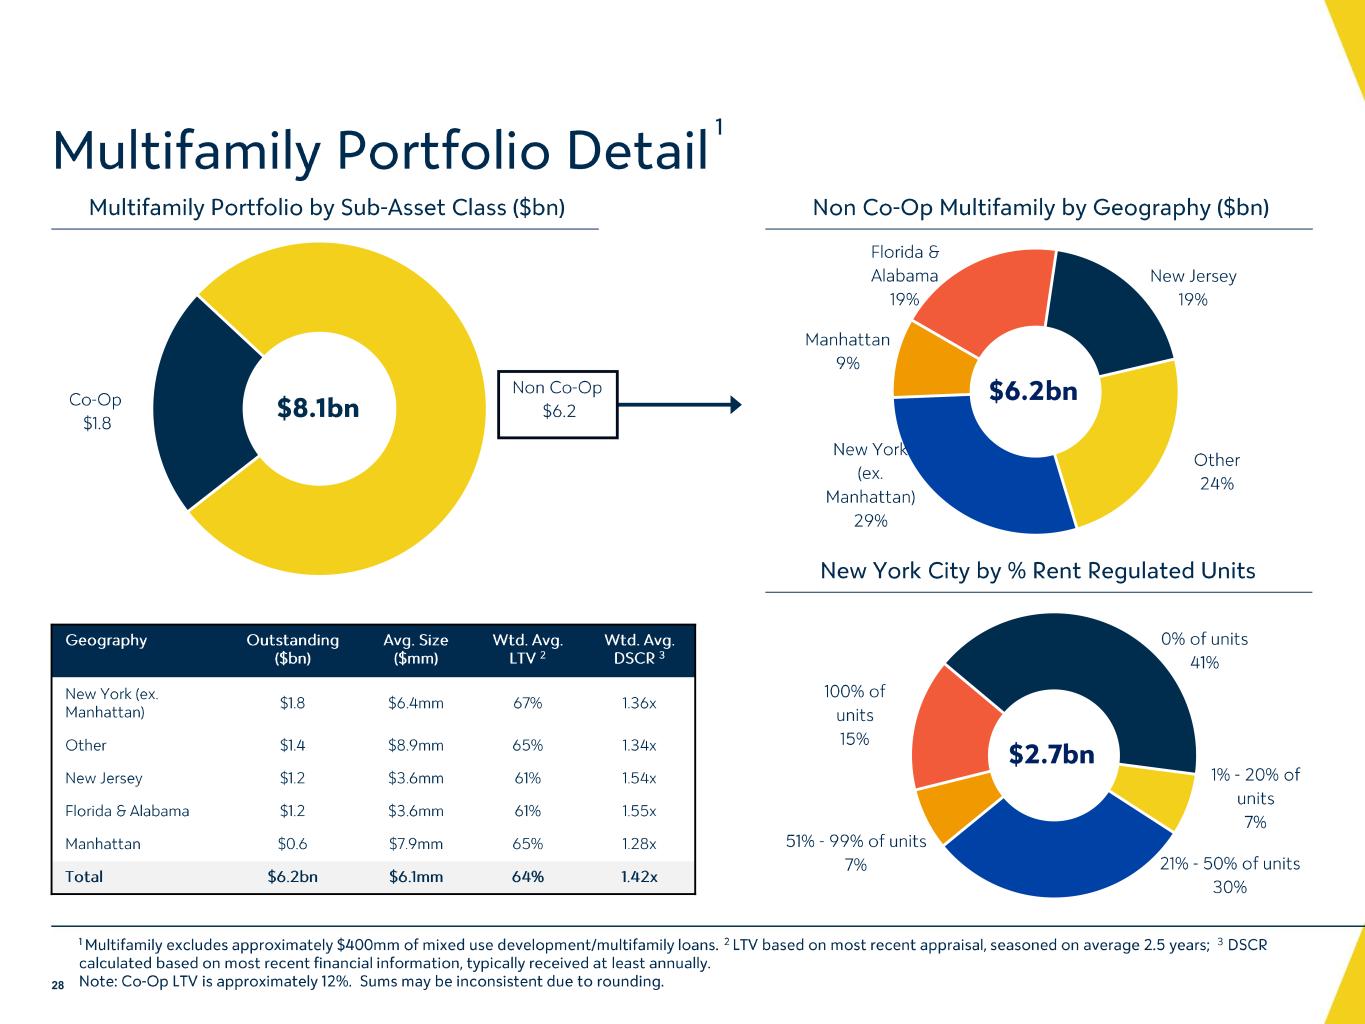
0% of units 41% 1% - 20% of units 7% 21% - 50% of units 30% 51% - 99% of units 7% 100% of units 15% Co -Op $1.8 Non Co -Op $6.2 Multifamily Portfolio by Sub -Asset Class ($bn) Non Co -Op Multifamily by Geography ($bn) $8.1bn Geography Outstanding ($bn) Avg. Size ($mm) Wtd . Avg. LTV 2 Wtd . Avg. DSCR 3 New York (ex. Manhattan) $1.8 $6.4mm 67% 1.36x Other $1.4 $8.9mm 65% 1.34x New Jersey $1.2 $3.6mm 61% 1.54x Florida & Alabama $1.2 $3.6mm 61% 1.55x Manhattan $0.6 $7.9mm 65% 1.28x Total $6.2bn $6.1mm 64% 1.42x Florida & Alabama 19% New Jersey 19% Other 24% New York (ex. Manhattan) 29% Manhattan 9% $6.2bn New York City by % Rent Regulated Units $2.7bn Multifamily Portfolio Detail 1 Multifamily excludes approximately $400mm of mixed use development/multifamily loans. 2 LTV based on most recent appraisal, seasoned on average 2.5 years; 3 DSCR calculated based on most recent financial information, typically received at least annually. Note: Co -Op LTV is approximately 12%. Sums may be inconsistent due to rounding.28 Source- “CRE Portfolio Review 3.31.2026” 1
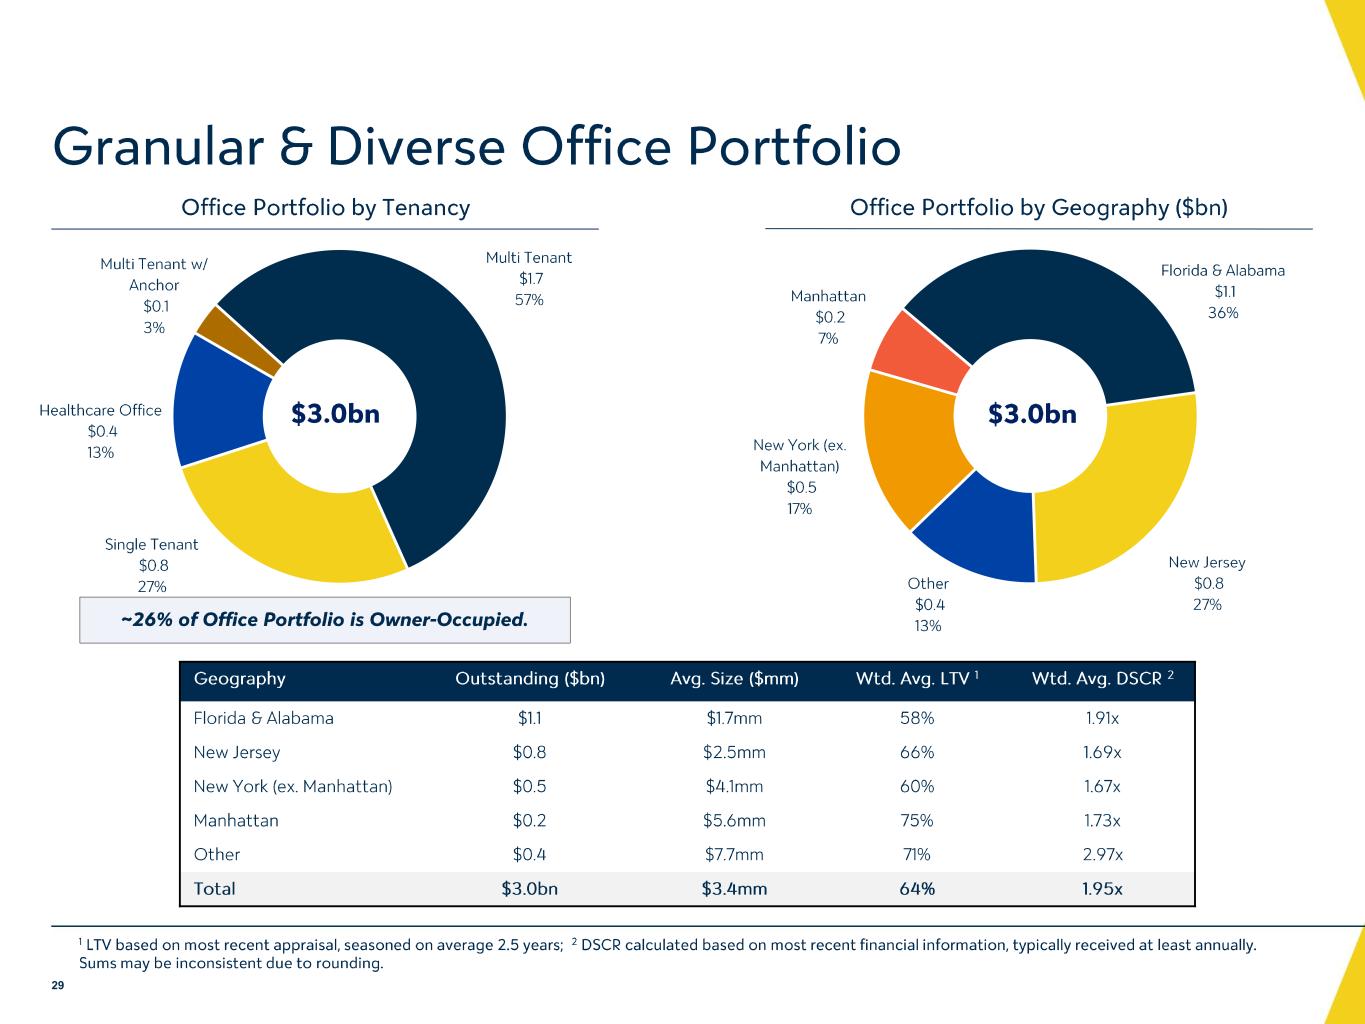
Granular & Diverse Office Portfolio Multi Tenant w/ Anchor $0.1 3% Multi Tenant $1.7 57% Single Tenant $0.8 27% Healthcare Office $0.4 13% Office Portfolio by Tenancy $3.0bn Office Portfolio by Geography ($bn) Geography Outstanding ($bn) Avg. Size ($mm) Wtd . Avg. LTV 1 Wtd . Avg. DSCR 2 Florida & Alabama $1.1 $1.7mm 58% 1.91x New Jersey $0.8 $2.5mm 66% 1.69x New York (ex. Manhattan) $0.5 $4.1mm 60% 1.67x Manhattan $0.2 $5.6mm 75% 1.73x Other $0.4 $7.7mm 71% 2.97x Total $3.0bn $3.4mm 64% 1.95x ~26% of Office Portfolio is Owner -Occupied. Florida & Alabama $1.1 36% New Jersey $0.8 27% Other $0.4 13% New York (ex. Manhattan) $0.5 17% Manhattan $0.2 7% 1 LTV based on most recent appraisal, seasoned on average 2.5 years; 2 DSCR calculated based on most recent financial information, typically received at least annually. Sums may be inconsistent due to rounding. 29 $3.0bn Source- “CRE Portfolio Review 3.31.2026”
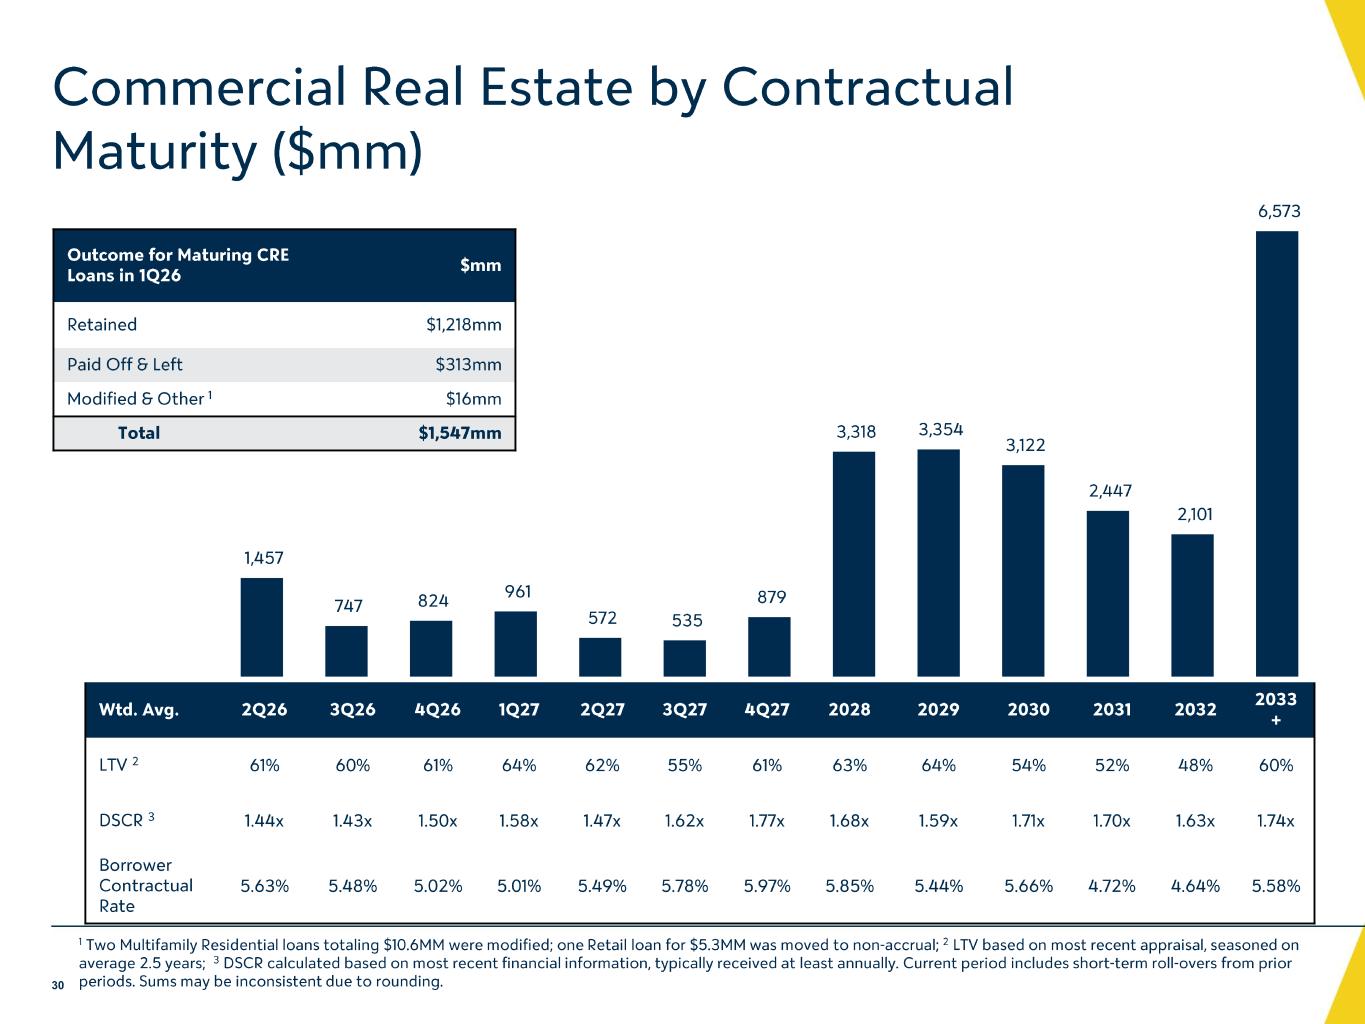
Commercial Real Estate by Contractual Maturity ($mm) 1,457 747 824 961 572 535 879 3,318 3,354 3,122 2,447 2,101 6,573 2Q26 3Q26 4Q26 1Q27 2Q27 3Q27 4Q27 2028 2029 2030 2031 2032 2033 + Wtd . Avg. 2Q26 3Q26 4Q26 1Q27 2Q27 3Q27 4Q27 2028 2029 2030 2031 2032 20 + LTV 2 61% 60% 61% 64% 62% 55% 61% 63% 64% 54% 52% 48% 60% DSCR 3 1.44x 1.43x 1.50x 1.58x 1.47x 1.62x 1.77x 1.68x 1.59x 1.71x 1.70x 1.63x 1.74x Borrower Contractual Rate 5.63% 5.48% 5.02% 5.01% 5.49% 5.78% 5.97% 5.85% 5.44% 5.66% 4.72% 4.64% 5.58% 1 Two Multifamily Residential loans totaling $10.6MM were modified; one Retail loan for $5.3MM was moved to non -accrual; 2 LTV based on most recent appraisal, seasoned on average 2.5 years; 3 DSCR calculated based on most recent financial information, typically received at least annually. Current period includes sho rt-term roll -overs from prior periods. Sums may be inconsistent due to rounding.30 Outcome for Maturing CRE Loans in 1Q26 $mm Retained $1,218mm Paid Off & Left $313mm Modified & Other 1 $16mm Total $1,547mm CRE Maturity Details 12.31.25
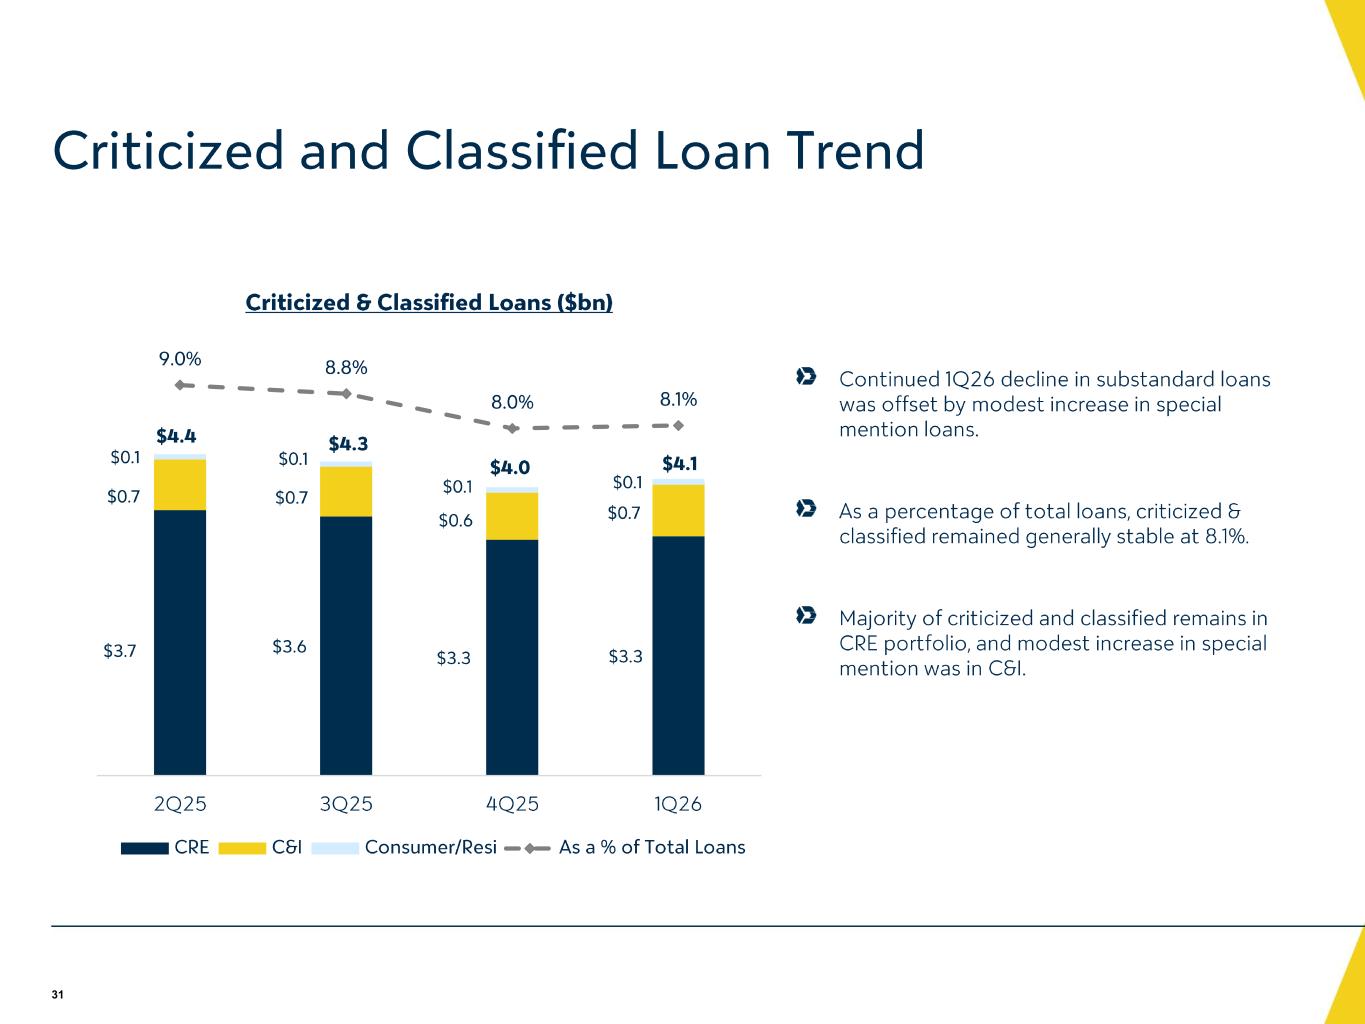
31 Criticized and Classified Loan Trend Continued 1Q26 decline in substandard loans was offset by modest increase in special mention loans. As a percentage of total loans, criticized & classified remained generally stable at 8.1%. Majority of criticized and classified remains in CRE portfolio, and modest increase in special mention was in C&I. $3.7 $3.6 $3.3 $3.3 $0.7 $0.7 $0.6 $0.7 $0.1 $0.1 $0.1 $0.1 9.0% 8.8% 8.0% 8.1% 2Q25 3Q25 4Q25 1Q26 Criticized & Classified Loans ($bn) CRE C&I Consumer/Resi As a % of Total Loans $4.1$4.0 $4.3$4.4
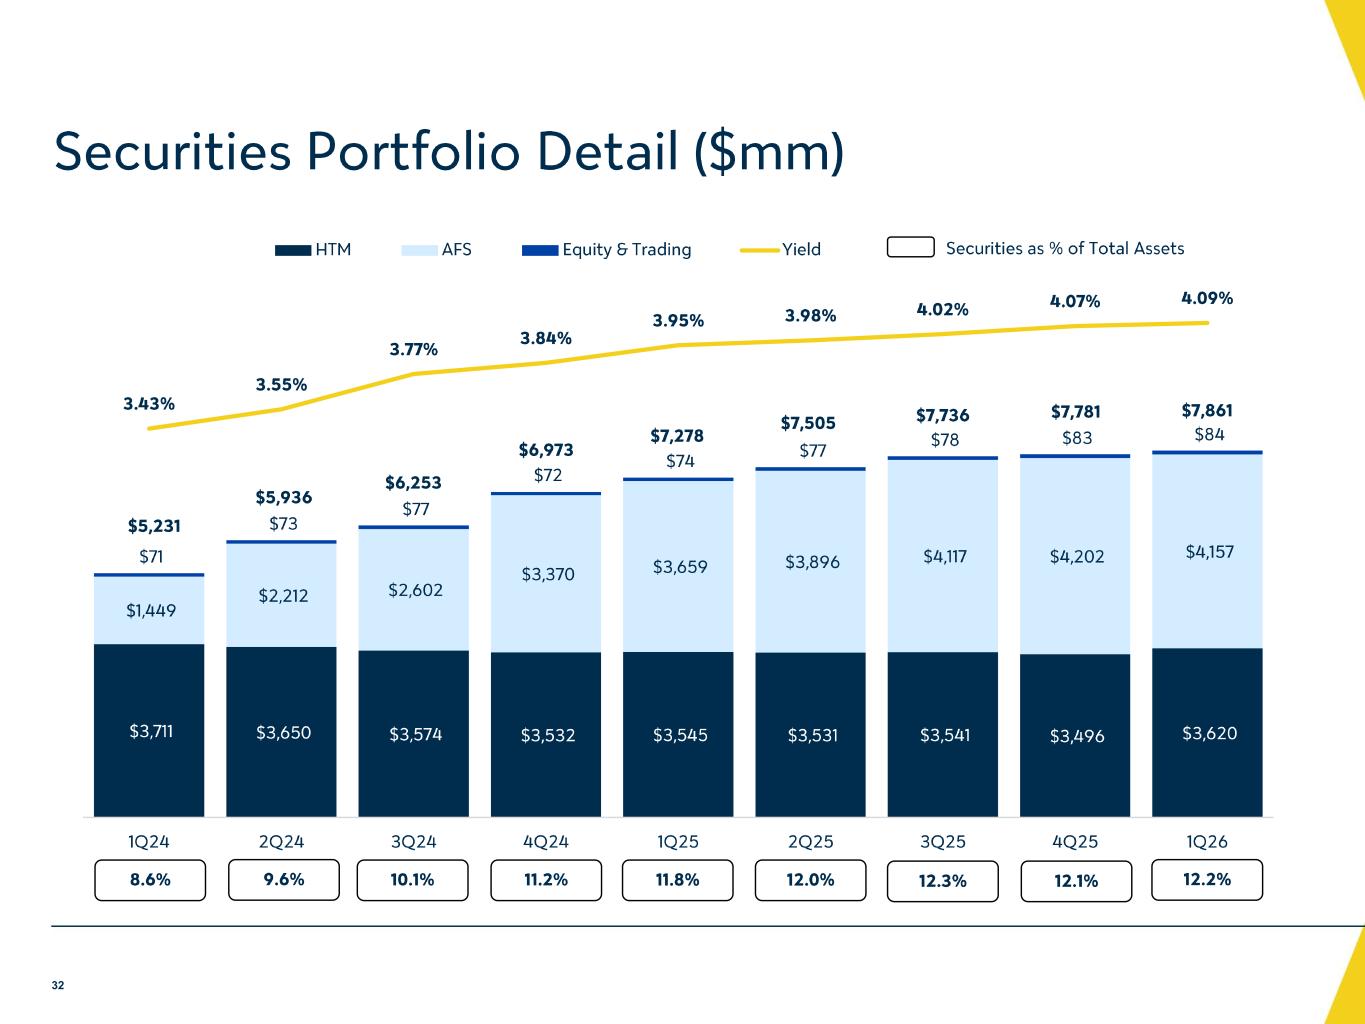
$3,711 $3,650 $3,574 $3,532 $3,545 $3,531 $3,541 $3,496 $3,620 $1,449 $2,212 $2,602 $3,370 $3,659 $3,896 $4,117 $4,202 $4,157 $71 $73 $77 $72 $74 $77 $78 $83 $84 3.43% 3.55% 3.77% 3.84% 3.95% 3.98% 4.02% 4.07% 4.09% 1Q24 2Q24 3Q24 4Q24 1Q25 2Q25 3Q25 4Q25 1Q26 HTM AFS Equity & Trading Yield 12.1% $7,736 $7,781 12.2% Securities Portfolio Detail ($mm) Securities as % of Total Assets Historical data from S&P Capital IQ, Current data from Workiva $5,231 $5,936 $6,253 $6,973 $7,278 $7,505 8.6% 9.6% 10.1% 11.2% 11.8% 12.0% 12.3% 32 $7,861
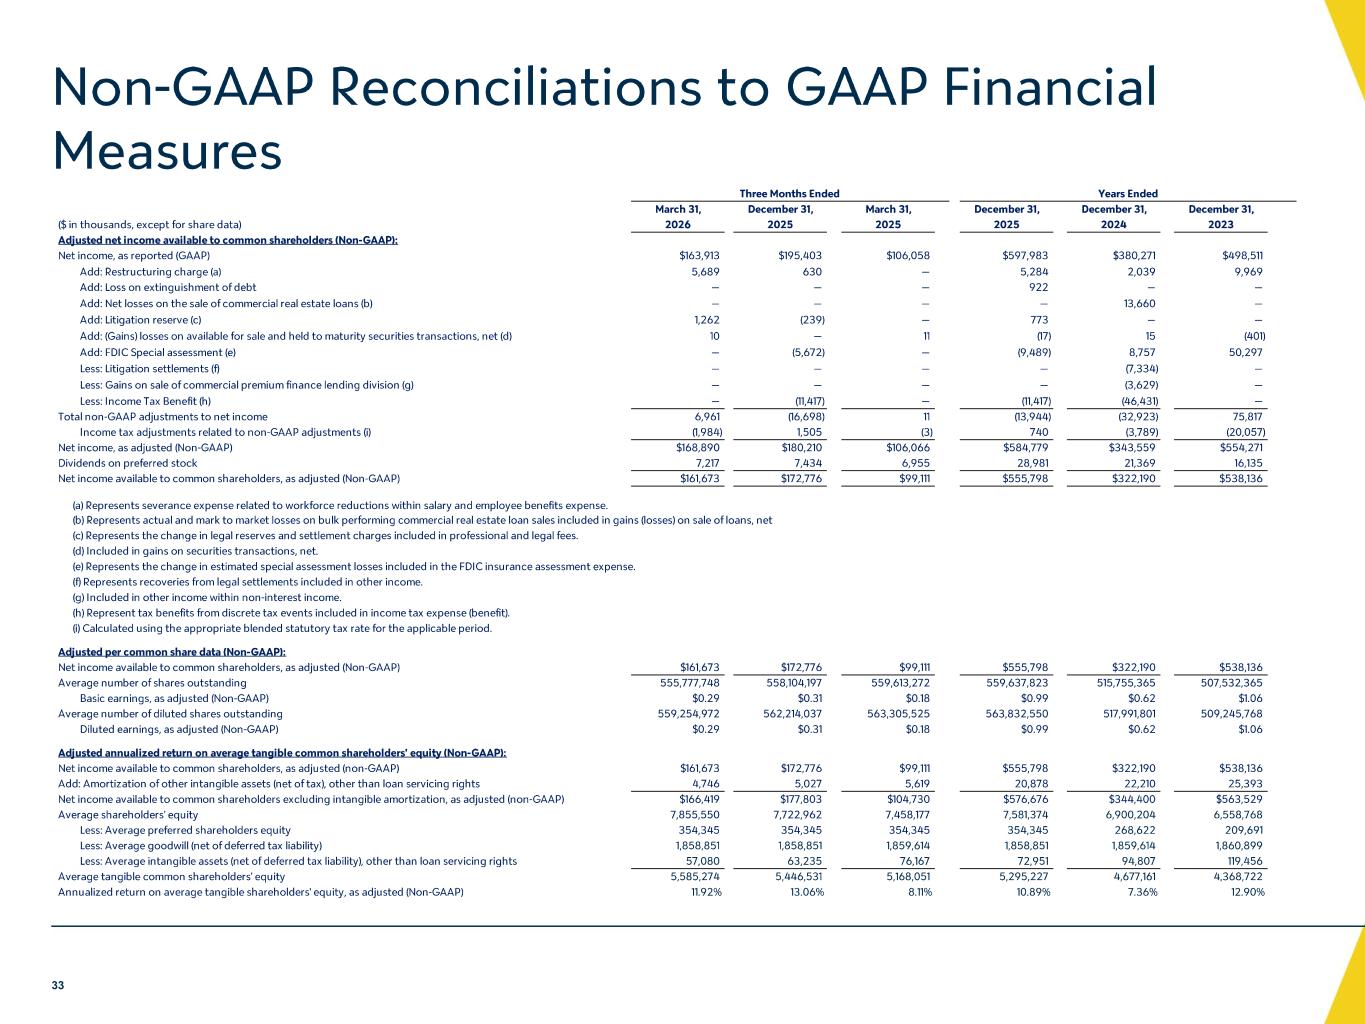
Non -GAAP Reconciliations to GAAP Financial Measures 33 March 31, December 31, March 31, December 31, December 31, December 31, ($ in thousands, except for share data) 2026 2025 2025 2025 2024 2023 Adjusted net income available to common shareholders (Non-GAAP): Net income, as reported (GAAP) $163,913 $195,403 $106,058 $597,983 $380,271 $498,511 Add: Restructuring charge (a) 5,689 630 — 5,284 2,039 9,969 Add: Loss on extinguishment of debt — — — 922 — — Add: Net losses on the sale of commercial real estate loans (b) — — — — 13,660 — Add: Litigation reserve (c) 1,262 (239) — 773 — — Add: (Gains) losses on available for sale and held to maturity securities transactions, net (d) 10 — 11 (17) 15 (401) Add: FDIC Special assessment (e) — (5,672) — (9,489) 8,757 50,297 Less: Litigation settlements (f) — — — — (7,334) — Less: Gains on sale of commercial premium finance lending division (g) — — — — (3,629) — Less: Income Tax Benefit (h) — (11,417) — (11,417) (46,431) — Total non-GAAP adjustments to net income 6,961 (16,698) 11 (13,944) (32,923) 75,817 Income tax adjustments related to non-GAAP adjustments (i) (1,984) 1,505 (3) 740 (3,789) (20,057) Net income, as adjusted (Non-GAAP) $168,890 $180,210 $106,066 $584,779 $343,559 $554,271 Dividends on preferred stock 7,217 7,434 6,955 28,981 21,369 16,135 Net income available to common shareholders, as adjusted (Non-GAAP) $161,673 $172,776 $99,111 $555,798 $322,190 $538,136 (a) Represents severance expense related to workforce reductions within salary and employee benefits expense. (b) Represents actual and mark to market losses on bulk performing commercial real estate loan sales included in gains (losses) on sale of loans, net (c) Represents the change in legal reserves and settlement charges included in professional and legal fees. (d) Included in gains on securities transactions, net. (e) Represents the change in estimated special assessment losses included in the FDIC insurance assessment expense. (f) Represents recoveries from legal settlements included in other income. (g) Included in other income within non-interest income. (h) Represent tax benefits from discrete tax events included in income tax expense (benefit). (i) Calculated using the appropriate blended statutory tax rate for the applicable period. Adjusted per common share data (Non-GAAP): Net income available to common shareholders, as adjusted (Non-GAAP) $161,673 $172,776 $99,111 $555,798 $322,190 $538,136 Average number of shares outstanding 555,777,748 558,104,197 559,613,272 559,637,823 515,755,365 507,532,365 Basic earnings, as adjusted (Non-GAAP) $0.29 $0.31 $0.18 $0.99 $0.62 $1.06 Average number of diluted shares outstanding 559,254,972 562,214,037 563,305,525 563,832,550 517,991,801 509,245,768 Diluted earnings, as adjusted (Non-GAAP) $0.29 $0.31 $0.18 $0.99 $0.62 $1.06 Adjusted annualized return on average tangible common shareholders' equity (Non-GAAP): Net income available to common shareholders, as adjusted (non-GAAP) $161,673 $172,776 $99,111 $555,798 $322,190 $538,136 Add: Amortization of other intangible assets (net of tax), other than loan servicing rights 4,746 5,027 5,619 20,878 22,210 25,393 Net income available to common shareholders excluding intangible amortization, as adjusted (non-GAAP) $166,419 $177,803 $104,730 $576,676 $344,400 $563,529 Average shareholders' equity 7,855,550 7,722,962 7,458,177 7,581,374 6,900,204 6,558,768 Less: Average preferred shareholders equity 354,345 354,345 354,345 354,345 268,622 209,691 Less: Average goodwill (net of deferred tax liability) 1,858,851 1,858,851 1,859,614 1,858,851 1,859,614 1,860,899 Less: Average intangible assets (net of deferred tax liability), other than loan servicing rights 57,080 63,235 76,167 72,951 94,807 119,456 Average tangible common shareholders' equity 5,585,274 5,446,531 5,168,051 5,295,227 4,677,161 4,368,722 Annualized return on average tangible shareholders' equity, as adjusted (Non-GAAP) 11.92% 13.06% 8.11% 10.89% 7.36% 12.90% Years EndedThree Months Ended
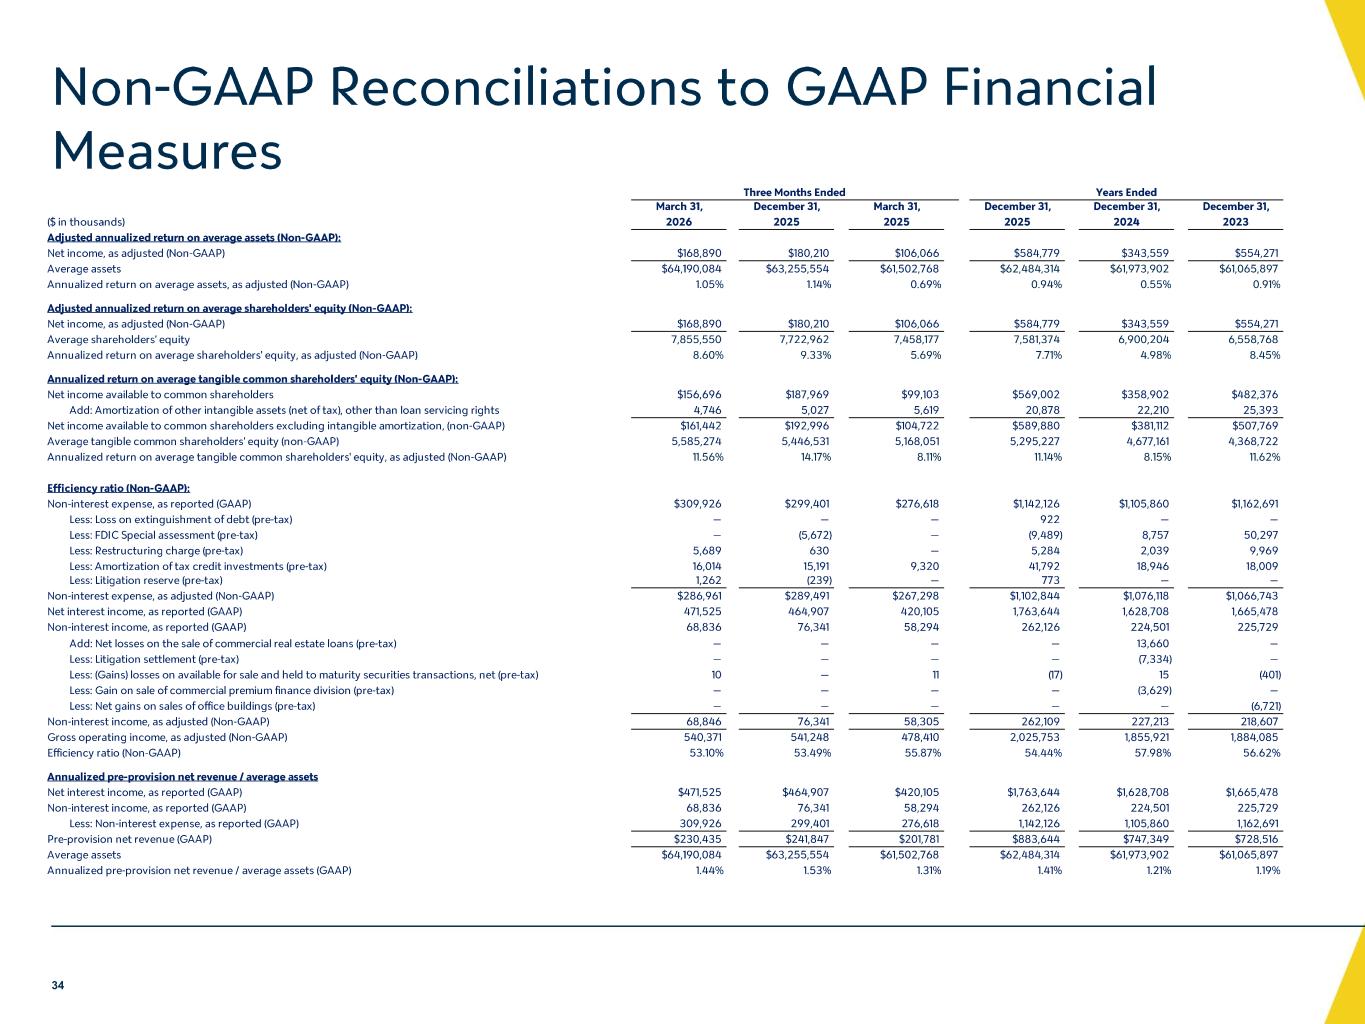
Non -GAAP Reconciliations to GAAP Financial Measures 34 March 31, December 31, March 31, December 31, December 31, December 31, ($ in thousands) 2026 2025 2025 2025 2024 2023 Adjusted annualized return on average assets (Non-GAAP): Net income, as adjusted (Non-GAAP) $168,890 $180,210 $106,066 $584,779 $343,559 $554,271 Average assets $64,190,084 $63,255,554 $61,502,768 $62,484,314 $61,973,902 $61,065,897 Annualized return on average assets, as adjusted (Non-GAAP) 1.05% 1.14% 0.69% 0.94% 0.55% 0.91% Adjusted annualized return on average shareholders' equity (Non-GAAP): Net income, as adjusted (Non-GAAP) $168,890 $180,210 $106,066 $584,779 $343,559 $554,271 Average shareholders' equity 7,855,550 7,722,962 7,458,177 7,581,374 6,900,204 6,558,768 Annualized return on average shareholders' equity, as adjusted (Non-GAAP) 8.60% 9.33% 5.69% 7.71% 4.98% 8.45% Annualized return on average tangible common shareholders' equity (Non-GAAP): Net income available to common shareholders $156,696 $187,969 $99,103 $569,002 $358,902 $482,376 Add: Amortization of other intangible assets (net of tax), other than loan servicing rights 4,746 5,027 5,619 20,878 22,210 25,393 Net income available to common shareholders excluding intangible amortization, (non-GAAP) $161,442 $192,996 $104,722 $589,880 $381,112 $507,769 Average tangible common shareholders' equity (non-GAAP) 5,585,274 5,446,531 5,168,051 5,295,227 4,677,161 4,368,722 Annualized return on average tangible common shareholders' equity, as adjusted (Non-GAAP) 11.56% 14.17% 8.11% 11.14% 8.15% 11.62% Efficiency ratio (Non-GAAP): Non-interest expense, as reported (GAAP) $309,926 $299,401 $276,618 $1,142,126 $1,105,860 $1,162,691 Less: Loss on extinguishment of debt (pre-tax) — — — 922 — — Less: FDIC Special assessment (pre-tax) — (5,672) — (9,489) 8,757 50,297 Less: Restructuring charge (pre-tax) 5,689 630 — 5,284 2,039 9,969 Less: Amortization of tax credit investments (pre-tax) 16,014 15,191 9,320 41,792 18,946 18,009 Less: Litigation reserve (pre-tax) 1,262 (239) — 773 — — Non-interest expense, as adjusted (Non-GAAP) $286,961 $289,491 $267,298 $1,102,844 $1,076,118 $1,066,743 Net interest income, as reported (GAAP) 471,525 464,907 420,105 1,763,644 1,628,708 1,665,478 Non-interest income, as reported (GAAP) 68,836 76,341 58,294 262,126 224,501 225,729 Add: Net losses on the sale of commercial real estate loans (pre-tax) — — — — 13,660 — Less: Litigation settlement (pre-tax) — — — — (7,334) — Less: (Gains) losses on available for sale and held to maturity securities transactions, net (pre-tax) 10 — 11 (17) 15 (401) Less: Gain on sale of commercial premium finance division (pre-tax) — — — — (3,629) — Less: Net gains on sales of office buildings (pre-tax) — — — — — (6,721) Non-interest income, as adjusted (Non-GAAP) 68,846 76,341 58,305 262,109 227,213 218,607 Gross operating income, as adjusted (Non-GAAP) 540,371 541,248 478,410 2,025,753 1,855,921 1,884,085 Efficiency ratio (Non-GAAP) 53.10% 53.49% 55.87% 54.44% 57.98% 56.62% Annualized pre-provision net revenue / average assets Net interest income, as reported (GAAP) $471,525 $464,907 $420,105 $1,763,644 $1,628,708 $1,665,478 Non-interest income, as reported (GAAP) 68,836 76,341 58,294 262,126 224,501 225,729 Less: Non-interest expense, as reported (GAAP) 309,926 299,401 276,618 1,142,126 1,105,860 1,162,691 Pre-provision net revenue (GAAP) $230,435 $241,847 $201,781 $883,644 $747,349 $728,516 Average assets $64,190,084 $63,255,554 $61,502,768 $62,484,314 $61,973,902 $61,065,897 Annualized pre-provision net revenue / average assets (GAAP) 1.44% 1.53% 1.31% 1.41% 1.21% 1.19% Years EndedThree Months Ended
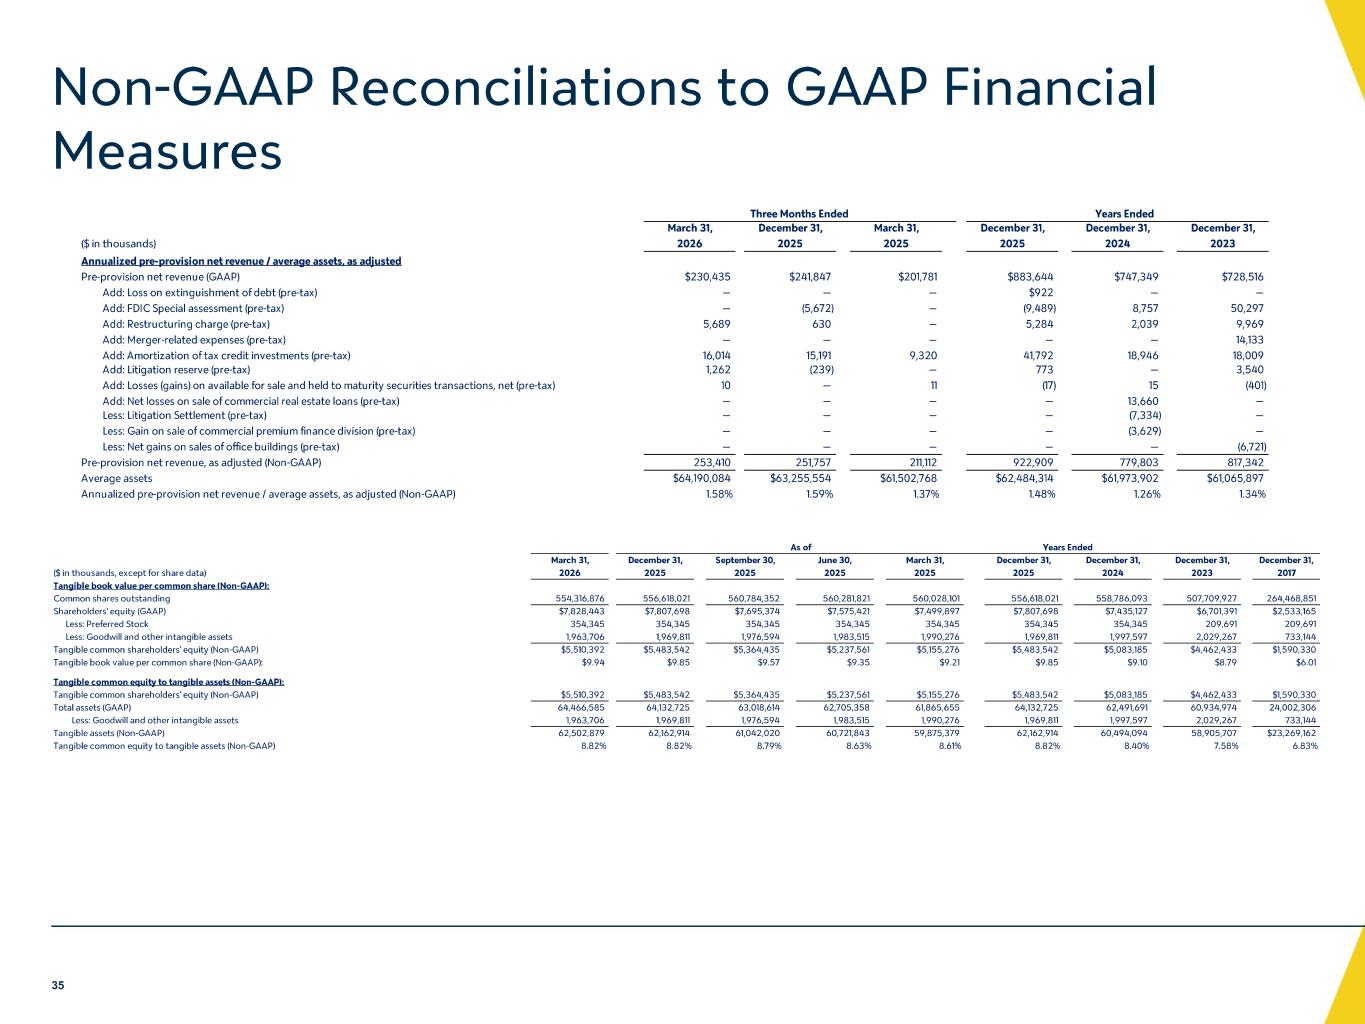
Non -GAAP Reconciliations to GAAP Financial Measures 35 March 31, December 31, March 31, December 31, December 31, December 31, ($ in thousands) 2026 2025 2025 2025 2024 2023 Annualized pre-provision net revenue / average assets, as adjusted Pre-provision net revenue (GAAP) $230,435 $241,847 $201,781 $883,644 $747,349 $728,516 Add: Loss on extinguishment of debt (pre-tax) — — — $922 — — Add: FDIC Special assessment (pre-tax) — (5,672) — (9,489) 8,757 50,297 Add: Restructuring charge (pre-tax) 5,689 630 — 5,284 2,039 9,969 Add: Merger-related expenses (pre-tax) — — — — — 14,133 Add: Amortization of tax credit investments (pre-tax) 16,014 15,191 9,320 41,792 18,946 18,009 Add: Litigation reserve (pre-tax) 1,262 (239) — 773 — 3,540 Add: Losses (gains) on available for sale and held to maturity securities transactions, net (pre-tax) 10 — 11 (17) 15 (401) Add: Net losses on sale of commercial real estate loans (pre-tax) — — — — 13,660 — Less: Litigation Settlement (pre-tax) — — — — (7,334) — Less: Gain on sale of commercial premium finance division (pre-tax) — — — — (3,629) — Less: Net gains on sales of office buildings (pre-tax) — — — — — (6,721) Pre-provision net revenue, as adjusted (Non-GAAP) 253,410 251,757 211,112 922,909 779,803 817,342 Average assets $64,190,084 $63,255,554 $61,502,768 $62,484,314 $61,973,902 $61,065,897 Annualized pre-provision net revenue / average assets, as adjusted (Non-GAAP) 1.58% 1.59% 1.37% 1.48% 1.26% 1.34% Years EndedThree Months Ended March 31, December 31, September 30, June 30, March 31, December 31, December 31, December 31, December 31, ($ in thousands, except for share data) 2026 2025 2025 2025 2025 2025 2024 2023 2017 Tangible book value per common share (Non-GAAP): Common shares outstanding 554,316,876 556,618,021 560,784,352 560,281,821 560,028,101 556,618,021 558,786,093 507,709,927 264,468,851 Shareholders' equity (GAAP) $7,828,443 $7,807,698 $7,695,374 $7,575,421 $7,499,897 $7,807,698 $7,435,127 $6,701,391 $2,533,165 Less: Preferred Stock 354,345 354,345 354,345 354,345 354,345 354,345 354,345 209,691 209,691 Less: Goodwill and other intangible assets 1,963,706 1,969,811 1,976,594 1,983,515 1,990,276 1,969,811 1,997,597 2,029,267 733,144 Tangible common shareholders' equity (Non-GAAP) $5,510,392 $5,483,542 $5,364,435 $5,237,561 $5,155,276 $5,483,542 $5,083,185 $4,462,433 $1,590,330 Tangible book value per common share (Non-GAAP): $9.94 $9.85 $9.57 $9.35 $9.21 $9.85 $9.10 $8.79 $6.01 Tangible common equity to tangible assets (Non-GAAP): Tangible common shareholders' equity (Non-GAAP) $5,510,392 $5,483,542 $5,364,435 $5,237,561 $5,155,276 $5,483,542 $5,083,185 $4,462,433 $1,590,330 Total assets (GAAP) 64,466,585 64,132,725 63,018,614 62,705,358 61,865,655 64,132,725 62,491,691 60,934,974 24,002,306 Less: Goodwill and other intangible assets 1,963,706 1,969,811 1,976,594 1,983,515 1,990,276 1,969,811 1,997,597 2,029,267 733,144 Tangible assets (Non-GAAP) 62,502,879 62,162,914 61,042,020 60,721,843 59,875,379 62,162,914 60,494,094 58,905,707 $23,269,162 Tangible common equity to tangible assets (Non-GAAP) 8.82% 8.82% 8.79% 8.63% 8.61% 8.82% 8.40% 7.58% 6.83% Years EndedAs of
© 2025 Valley Bank. All rights reserved. Please see www.valley.com for further details. For More Information ▪ Go to our website: www.valley.com ▪ Email requests to: [email protected] ▪ Call Andrew Jianette in Investor Relations at: (551) 288 -3182 ▪ Go to our website above or www.sec.gov to obtain free copies of documents filed by Valley with the SEC